Questions as text
Q1 · The following figures are given for a factory’s overheads and machine hours worked 9706/11 May/June 2006
28 The following figures are given for a factory’s overheads and machine hours worked. overhead machine hours total overhead costs absorption rate budgeted 122 000 $268 400 $2.20 actual 116 000 $261 000 $2.25 What was the under- or over-absorption of overhead for the quarter? A $5800 under-absorbed B $5800 over-absorbed C $7400 under-absorbed D $7400 over-absorbed
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q2 · A company manufactures a single product with a selling price of $75 per unit 9706/11 May/June 2006
29 A company manufactures a single product with a selling price of $75 per unit. The table shows the costs, based on sales and production volume of 8000 units. $ 000 prime costs 158 variable manufacturing overheads 74 fixed manufacturing overheads 80 variable selling overheads 20 fixed administration overheads 100 If absorption costing is applied, what is the gross profit on each unit sold? A $21.00 B $36.00 C $43.50 D $46.00
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q3 · A company has two departments X and Y 9706/11 May/June 2006
30 A company has two departments X and Y. Management provides the following information. department X department Y total power used 7 500 kwh 17 500 kwh 25 000 kwh area 30 000 square metres 20 000 square metres 50 000 square metres The power bill for the year is $20 000 and the rent is $100 000. What is the total amount for rent and heating to be attributed to department X? A $54 000 B $62 000 C $66 000 D $72 000
1 marks
Answer: C
This question in 9706/11 May/June 2006
Q4 · Existing fixed overheads are $100 000, unit selling price is $10 and unit variable costs… 9706/11 Oct/Nov 2006
28 Existing fixed overheads are $100 000, unit selling price is $10 and unit variable costs are $5. Fixed overheads are expected to increase by $20 000. What is the new break-even sales volume? A 10 000 units B 12 000 units C 20 000 units D 24 000 units
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2006
Q5 · A business manufactures 175 units of a product a month 9706/11 Oct/Nov 2006
29 A business manufactures 175 units of a product a month. The following total information is available for the month: $ sales income 580 variable costs 230 fixed overheads 90 What is the break-even point in units? A 45 units B 49 units C 61 units D 88 units
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2006
Q6 · A department makes radios 9706/11 Oct/Nov 2006
30 A department makes radios. The production at the end of the month was 1000 units, of which 600 units were completed and 400 units were 50 % complete. production costs for the month $ materials 60 000 labour 30 000 departmental overheads 10 000 What is the cost per unit? A $100 B $112 C $125 D $150
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2006
Q7 · The break-even chart for a product is shown 9706/11 May/June 2007
25 The break-even chart for a product is shown. sales revenue total costs costs and break-even revenues point $000 X Y sales volume What does XY represent? A fixed costs B gross profit C net loss D variable costs
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q8 · What will cause under-absorption of fixed production overheads? 9706/11 May/June 2007
26 What will cause under-absorption of fixed production overheads? A absorption of overheads is based on actual expenditure and actual activity B actual expenditure of overheads is below budget expenditure C actual activity is above budgeted activity D actual activity is below budgeted activity and actual expenditure is as budgeted
1 marks
Answer: D
This question in 9706/11 May/June 2007
Q9 · A company makes two products 9706/11 May/June 2007
28 A company makes two products. product X Y $ $ selling price 10 12 variable costs per unit 4 8 maximum sales (units) 4 000 14 000 Fixed costs are $48 000. 4000 units of X are sold. How many units of Y must be sold to break even? A 2000 B 3000 C 6000 D 12 000
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q10 · A hospital budgets for overheads totalling $11 500 000 for a financial year 9706/11 May/June 2007
29 A hospital budgets for overheads totalling $11 500 000 for a financial year. It expects to treat 25 000 patients in the year. Each patient stays an average of 10 days and the hospital absorbs overheads on a patient/day basis. Its direct costs for the year are budgeted at $25 000 000. What is its overhead absorption rate? A $46 per patient day B $100 per patient day C $146 per patient day D $460 per patient day
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q11 · A video cassette has a selling price of $10 9706/11 May/June 2007
30 A video cassette has a selling price of $10. cost per video cassette $ direct materials 1.20 direct labour 0.80 factory overhead (fixed) 1.40 royalty payment 1.00 administration overhead (fixed) 0.60 What is the contribution per video cassette? A $5.00 B $6.00 C $7.00 D $8.00
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q12 · When valuing stocks of finished goods on an absorption cost basis, which costs should be… 9706/11 May/June 2008
11 When valuing stocks of finished goods on an absorption cost basis, which costs should be included? A production B production and administration C production, marketing and distribution D production, marketing, administration and distribution
1 marks
Answer: A
This question in 9706/11 May/June 2008
Q13 · A manufacturing company has the following information for the year ended 31 December 9706/11 May/June 2008
13 A manufacturing company has the following information for the year ended 31 December. $ purchase of raw materials 58 000 wages of machine operators 97 000 depreciation on factory plant 15 000 opening stock raw materials 10 000 closing stock raw materials 8 000 wages of factory supervisor 18 000 factory light and heating costs 22 000 What is the prime cost for the year? A $153 000 B $157 000 C $175 000 D $212 000
1 marks
Answer: B
This question in 9706/11 May/June 2008
Q14 · A company uses a predetermined direct labour rate of $5.40 per hour to absorb production… 9706/11 May/June 2008
27 A company uses a predetermined direct labour rate of $5.40 per hour to absorb production overhead. Each unit of product manufactured requires four direct labour hours. The following information is available for a period. actual production overhead $518 400 under-absorbed production overhead $32 400 What was the actual output of the product in the period? A 22 500 units B 24 000 units C 25 500 units D 30 000 units
1 marks
Answer: A
This question in 9706/11 May/June 2008
Q15 · A company sells two products, X and Y 9706/11 May/June 2008
30 A company sells two products, X and Y. X Y sales (units) 1000 2000 $ $ selling price per unit 22 12 contribution per unit 12 4 Which would increase the company’s profit by $10 000? A a 30 % increase in the sales of X B a 50 % increase in the sales of both products C an increase in the selling price of X by $1 and Y by $6 D a reduction in the variable costs of both products by $5
1 marks
Answer: B
This question in 9706/11 May/June 2008
Q16 · The graph shows a break-even chart 9706/11 Oct/Nov 2008
26 The graph shows a break-even chart. sales revenue 50 total costs 40 30 $000 20 10 0 0 1000 2000 3000 4000 units of sales What are the fixed costs? A $0 B $10 000 C $20 000 D $30 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2008
Q17 · What is a benefit of using absorption costing? 9706/11 Oct/Nov 2008
27 What is a benefit of using absorption costing? A It allows a business to calculate the break-even point for production. B It allows a business to calculate the total cost of goods produced. C It allows a business to calculate the profit to be made on a product. D It allows decision-making on utilising spare capacity by increasing production.
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2008
Q18 · A business provides the following data for the year 9706/11 Oct/Nov 2008
28 A business provides the following data for the year. budgeted output (units) 10 000 actual output (units) 8 000 $ budgeted fixed production costs 1 200 000 budgeted variable production costs 800 000 budgeted fixed selling overhead 600 000 What is the absorption cost per unit used for stocktaking? A $200 B $250 C $260 D $325
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2008
Q19 · The following data applies to a business 9706/11 Oct/Nov 2008
29 The following data applies to a business. budgeted labour hours 10 000 actual labour hours 9 500 budgeted overheads $150 000 actual overheads $160 000 What is the amount of overhead under-absorbed? A $7500 B $8000 C $10 000 D $17 500
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2008
Q20 · A company manufactures one product 9706/11 Oct/Nov 2008
30 A company manufactures one product. Variable costs are $600 000. Fixed costs are $300 000. If it bought the product from another supplier, it could use existing machinery to make a total contribution of $400 000. Fixed costs would not change. What is the maximum price it should pay to obtain the product from another supplier? A $600 000 B $700 000 C $900 000 D $1 000 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2008
Q21 · A company manufactured 3000 widgets and transferred them out of its factory at cost plus… 9706/11 May/June 2009
14 A company manufactured 3000 widgets and transferred them out of its factory at cost plus 20 %. per widget $ selling price 25 direct materials 6 direct labour 5 fixed overheads 4 What is the factory cost of goods manufactured as it would appear in the trading account? A $36 000 B $39 600 C $45 000 D $54 000
1 marks
Answer: D
This question in 9706/11 May/June 2009
Q22 · The following figures are given for a factory’s overheads and machine hours worked 9706/11 May/June 2009
30 The following figures are given for a factory’s overheads and machine hours worked. overhead machine hours total overhead costs absorption rate budgeted 122 000 $268 400 $2.20 actual 116 000 $261 000 $2.25 What was the under- or over-absorption of overhead for the quarter? A $5800 over-absorbed B $5800 under-absorbed C $7400 over-absorbed D $7400 under-absorbed
1 marks
Answer: B
This question in 9706/11 May/June 2009
Q23 · When are the reported profits under marginal costing and absorption costing principles… 9706/11 Oct/Nov 2009
24 When are the reported profits under marginal costing and absorption costing principles the same amount? A when sales revenue exceeds cost of sales B when units produced equals sales in units C when units produced exceeds sales in units D when unit sales exceeds production in units
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2009
Q24 · A business uses job costing to calculate the cost of vehicle repair jobs 9706/11 Oct/Nov 2009
27 A business uses job costing to calculate the cost of vehicle repair jobs. Overheads are allocated on an absorption costing basis. What is the effect of this method of allocation? A overheads will include both fixed and variable overhead costs B overheads will include direct costs only C overheads will include fixed overhead costs only D overheads will include variable overhead costs only
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2009
Q25 · A company has a product which sells for $1 per unit 9706/11 Oct/Nov 2009
28 A company has a product which sells for $1 per unit. The variable costs are $0.60 per unit, and production of 200 000 units is planned. Fixed costs are $0.20 per unit at the budgeted production level. What is the break-even level? A 40 000 units B 66 667 units C 100 000 units D 160 000 units
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2009
Q26 · How is total contribution calculated? 9706/11 Oct/Nov 2009
29 How is total contribution calculated? A actual sales revenue less break-even sales revenue B sales revenue less fixed costs C sales revenue less total costs D sales revenue less variable costs
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2009
Q27 · In January, a business had opening stocks of 25 200 units and closing stocks of 28 200… 9706/11 Oct/Nov 2009
30 In January, a business had opening stocks of 25 200 units and closing stocks of 28 200 units. The profit calculated on marginal costing principles was $100 800 and that calculated on absorption costing principles was $120 300. What was the fixed overhead absorption rate per unit? A $4.00 B $4.27 C $6.17 D $6.50
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2009
Q28 · An extract from the accounts of a manufacturing company shows the following 9706/12 Oct/Nov 2009
14 An extract from the accounts of a manufacturing company shows the following. $ depreciation of factory machinery 16 700 direct factory labour 476 200 factory cleaning costs 18 300 factory heat, light and power 22 600 factory supervisor’s salary 18 200 indirect factory labour 52 470 purchases of raw materials 184 300 stock of raw materials - opening stock 21 500 - closing stock 17 900 What is the prime cost of production? A $660 500 B $664 100 C $680 800 D $716 570
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q29 · When are the reported profits under marginal costing and absorption costing principles… 9706/12 Oct/Nov 2009
23 When are the reported profits under marginal costing and absorption costing principles the same amount? A when sales revenue exceeds cost of sales B when units produced equals sales in units C when units produced exceeds sales in units D when unit sales exceeds production in units
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q30 · A business uses job costing to calculate the cost of vehicle repair jobs 9706/12 Oct/Nov 2009
26 A business uses job costing to calculate the cost of vehicle repair jobs. Overheads are allocated on an absorption costing basis. What is the effect of this method of allocation? A overheads will include both fixed and variable overhead costs B overheads will include direct costs only C overheads will include fixed overhead costs only D overheads will include variable overhead costs only
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2009
Q31 · A company has a product which sells for $1 per unit 9706/12 Oct/Nov 2009
27 A company has a product which sells for $1 per unit. The variable costs are $0.60 per unit, and production of 200 000 units is planned. Fixed costs are $0.20 per unit at the budgeted production level. What is the break-even level? A 40 000 units B 66 667 units C 100 000 units D 160 000 units
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q32 · How is total contribution calculated? 9706/12 Oct/Nov 2009
28 How is total contribution calculated? A actual sales revenue less break-even sales revenue B sales revenue less fixed costs C sales revenue less total costs D sales revenue less variable costs
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2009
Q33 · In January, a business had opening stocks of 25 200 units and closing stocks of 28 200… 9706/12 Oct/Nov 2009
29 In January, a business had opening stocks of 25 200 units and closing stocks of 28 200 units. The profit calculated on marginal costing principles was $100 800 and that calculated on absorption costing principles was $120 300. What was the fixed overhead absorption rate per unit? A $4.00 B $4.27 C $6.17 D $6.50
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2009
Q34 · The following information is given about four products 9706/11 May/June 2010
24 The following information is given about four products. Which product makes the most gross profit? inventory (stock) average inventory mark up on cost turnover (per annum) (stock) in units % A 8 times 1000 15 B 6 times 1000 30 C 7 times 1000 25 D 10 times 1000 20
1 marks
Answer: D
This question in 9706/11 May/June 2010
Q35 · A soup manufacturer uses batch costing 9706/11 May/June 2010
25 A soup manufacturer uses batch costing. It produces a batch of 10 000 tins of soup with a direct materials cost of $2500. Direct labour involved 200 hours at a cost of $2000, and overheads are absorbed at the rate of $15 per direct labour hour. What is the cost of a tin of soup? A $0.25 B $0.45 C $0.55 D $0.75
1 marks
Answer: D
This question in 9706/11 May/June 2010
Q36 · A customer places an order for 20 000 bricks 9706/11 May/June 2010
27 A customer places an order for 20 000 bricks. Which costing method will the supplier use to price the order? A batch B job C marginal D unit
1 marks
Answer: A
This question in 9706/11 May/June 2010
Q37 · A business makes wedding dresses 9706/11 May/June 2010
29 A business makes wedding dresses. Each machinist is paid $30 a day and each supervisor $40 a day. Each supervisor can work with up to 10 machinists and each machinist can produce one wedding dress a day. If 95 wedding dresses a day are produced, what is the daily labour cost? A $2850 B $3210 C $3230 D $3250
1 marks
Answer: D
This question in 9706/11 May/June 2010
Q38 · The graphs show projected sales and cost information for products X and Y 9706/11 May/June 2010
30 The graphs show projected sales and cost information for products X and Y. product X product Y $ $ sales 50 50 sales 40 total 40 cost total cost 30 30 fixed 20 cost 20 10 10 fixed cost 0 0 0 10 20 30 40 0 10 20 30 40 quantity quantity Which statement most accurately interprets the graphs? A Product X breaks even at a higher number of units sold than product Y. B Product X has lower fixed costs than product Y. C Product X has a lower selling price per unit than product Y. D Product X has a lower variable cost per unit than product Y.
1 marks
Answer: D
This question in 9706/11 May/June 2010
Q39 · The following information is given about four products 9706/12 May/June 2010
23 The following information is given about four products. Which product makes the most gross profit? inventory (stock) average inventory mark up on cost turnover (per annum) (stock) in units % A 8 times 1000 15 B 6 times 1000 30 C 7 times 1000 25 D 10 times 1000 20
1 marks
Answer: D
This question in 9706/12 May/June 2010
Q40 · A soup manufacturer uses batch costing 9706/12 May/June 2010
24 A soup manufacturer uses batch costing. It produces a batch of 10 000 tins of soup with a direct materials cost of $2500. Direct labour involved 200 hours at a cost of $2000, and overheads are absorbed at the rate of $15 per direct labour hour. What is the cost of a tin of soup? A $0.25 B $0.45 C $0.55 D $0.75
1 marks
Answer: D
This question in 9706/12 May/June 2010
Q41 · A customer places an order for 20 000 bricks 9706/12 May/June 2010
26 A customer places an order for 20 000 bricks. Which costing method will the supplier use to price the order? A batch B job C marginal D unit
1 marks
Answer: A
This question in 9706/12 May/June 2010
Q42 · A company has total production costs of $6000 to make 10 000 units, and $13 000 to make… 9706/12 May/June 2010
27 A company has total production costs of $6000 to make 10 000 units, and $13 000 to make 24 000 units. What is its total cost to make 20 000 units? A $1000 B $10 000 C $11 000 D $12 000
1 marks
Answer: C
This question in 9706/12 May/June 2010
Q43 · The graphs show projected sales and cost information for products X and Y 9706/12 May/June 2010
29 The graphs show projected sales and cost information for products X and Y. product X product Y $ $ sales 50 50 sales 40 total 40 cost total cost 30 30 fixed 20 cost 20 10 10 fixed cost 0 0 0 10 20 30 40 0 10 20 30 40 quantity quantity Which statement most accurately interprets the graphs? A Product X breaks even at a higher number of units sold than product Y. B Product X has lower fixed costs than product Y. C Product X has a lower selling price per unit than product Y. D Product X has a lower variable cost per unit than product Y.
1 marks
Answer: D
This question in 9706/12 May/June 2010
Q44 · A company calculates factory profit at a mark-up of 20 % on the cost of production 9706/13 May/June 2010
12 A company calculates factory profit at a mark-up of 20 % on the cost of production. The following information is available. $ inventory (stock) of finished goods at cost at 31 December 2007 40 000 cost of goods produced for the year to 31 December 2008 240 000 closing inventory (stock) of finished goods at cost plus factory profit at 54 000 31 December 2008 How much will be shown as factory profit in the accounts for the year ended 31 December 2008? A $39 000 B $40 000 C $47 000 D $48 000
1 marks
Answer: C
This question in 9706/13 May/June 2010
Q45 · A soup manufacturer uses batch costing 9706/13 May/June 2010
23 A soup manufacturer uses batch costing. It produces a batch of 10 000 tins of soup with a direct materials cost of $2500. Direct labour involved 200 hours at a cost of $2000, and overheads are absorbed at the rate of $15 per direct labour hour. What is the cost of a tin of soup? A $0.25 B $0.45 C $0.55 D $0.75
1 marks
Answer: D
This question in 9706/13 May/June 2010
Q46 · A customer places an order for 20 000 bricks 9706/13 May/June 2010
25 A customer places an order for 20 000 bricks. Which costing method will the supplier use to price the order? A batch B job C marginal D unit
1 marks
Answer: A
This question in 9706/13 May/June 2010
Q47 · A company has total production costs of $6000 to make 10 000 units, and $13 000 to make… 9706/13 May/June 2010
26 A company has total production costs of $6000 to make 10 000 units, and $13 000 to make 24 000 units. What is its total cost to make 20 000 units? A $1000 B $10 000 C $11 000 D $12 000
1 marks
Answer: C
This question in 9706/13 May/June 2010
Q48 · A business makes wedding dresses 9706/13 May/June 2010
27 A business makes wedding dresses. Each machinist is paid $30 a day and each supervisor $40 a day. Each supervisor can work with up to 10 machinists and each machinist can produce one wedding dress a day. If 95 wedding dresses a day are produced, what is the daily labour cost? A $2850 B $3210 C $3230 D $3250
1 marks
Answer: D
This question in 9706/13 May/June 2010
Q49 · The graphs show projected sales and cost information for products X and Y 9706/13 May/June 2010
28 The graphs show projected sales and cost information for products X and Y. product X product Y $ $ sales 50 50 sales 40 total 40 cost total cost 30 30 fixed 20 cost 20 10 10 fixed cost 0 0 0 10 20 30 40 0 10 20 30 40 quantity quantity Which statement most accurately interprets the graphs? A Product X breaks even at a higher number of units sold than product Y. B Product X has lower fixed costs than product Y. C Product X has a lower selling price per unit than product Y. D Product X has a lower variable cost per unit than product Y.
1 marks
Answer: D
This question in 9706/13 May/June 2010
Q50 · In a job costing system, what is the correct entry to record the return of unused direct… 9706/11 Oct/Nov 2010
25 In a job costing system, what is the correct entry to record the return of unused direct materials from production to stores? debit credit A cost of sales work in progress B stores control finished goods C stores control work in progress D work in progress stores control
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2010
Q51 · A company manufactures two products 9706/11 Oct/Nov 2010
26 A company manufactures two products. product X product Y $ $ selling price 20 30 direct labour (per unit) 10 20 direct materials (per unit) 4 2 Total fixed costs are $48 000. Only 3000 units of Y can be made and sold. How many units of product X must be made and sold to break even? A 1800 B 3000 C 4000 D 8000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2010
Q52 · A job cost sheet showed the following estimates 9706/11 Oct/Nov 2010
29 A job cost sheet showed the following estimates. $ materials 680 labour at $20 per hour 200 overheads at $10 per labour hour 100 profit 280 price of job 1 260 The job actually took 25 % more labour hours than were estimated. What was the profit? A $205 B $230 C $330 D $355
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2010
Q53 · In a job costing system, what is the correct entry to record the return of unused direct… 9706/12 Oct/Nov 2010
25 In a job costing system, what is the correct entry to record the return of unused direct materials from production to stores? debit credit A cost of sales work in progress B stores control finished goods C stores control work in progress D work in progress stores control
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2010
Q54 · A company manufactures two products 9706/12 Oct/Nov 2010
26 A company manufactures two products. product X product Y $ $ selling price 20 30 direct labour (per unit) 10 20 direct materials (per unit) 4 2 Total fixed costs are $48 000. Only 3000 units of Y can be made and sold. How many units of product X must be made and sold to break even? A 1800 B 3000 C 4000 D 8000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2010
Q55 · A manufacturer has 700 units of finished goods in stock on 1 March 9706/12 Oct/Nov 2010
28 A manufacturer has 700 units of finished goods in stock on 1 March. On 31 March the total number of units in stock is 770. At present, stock is valued using the total costing method. What would be the effect on the operating profit if the marginal costing method is used for stock valuation? A increase operating profit B no change in operating profit C no change in operating profit but a 10 % increase in gross profit D reduce operating profit
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2010
Q56 · A job cost sheet showed the following estimates 9706/12 Oct/Nov 2010
29 A job cost sheet showed the following estimates. $ materials 680 labour at $20 per hour 200 overheads at $10 per labour hour 100 profit 280 price of job 1 260 The job actually took 25 % more labour hours than were estimated. What was the profit? A $205 B $230 C $330 D $355
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2010
Q57 · A business has two departments, men’s clothing and ladies’ clothing 9706/13 Oct/Nov 2010
16 A business has two departments, men’s clothing and ladies’ clothing. The following information is available. men’s department ladies’ department sales assistants 7 9 floor space 160 m2 200 m2 value of non current (fixed) assets $59 000 $61 000 annual sales $450 000 $750 000 The cost of heating and lighting is $17 692. What is the cost of heating and lighting for the men’s department? A $6634.50 B $7740.25 C $7863.11 D $8698.57
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q58 · In a job costing system, what is the correct entry to record the return of unused direct… 9706/13 Oct/Nov 2010
24 In a job costing system, what is the correct entry to record the return of unused direct materials from production to stores? debit credit A cost of sales work in progress B stores control finished goods C stores control work in progress D work in progress stores control
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q59 · A company manufactures two products 9706/13 Oct/Nov 2010
25 A company manufactures two products. product X product Y $ $ selling price 20 30 direct labour (per unit) 10 20 direct materials (per unit) 4 2 Total fixed costs are $48 000. Only 3000 units of Y can be made and sold. How many units of product X must be made and sold to break even? A 1800 B 3000 C 4000 D 8000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q60 · A manufacturer has 700 units of finished goods in stock on 1 March 9706/13 Oct/Nov 2010
27 A manufacturer has 700 units of finished goods in stock on 1 March. On 31 March the total number of units in stock is 770. At present, stock is valued using the total costing method. What would be the effect on the operating profit if the marginal costing method is used for stock valuation? A increase operating profit B no change in operating profit C no change in operating profit but a 10 % increase in gross profit D reduce operating profit
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2010
Q61 · A job cost sheet showed the following estimates 9706/13 Oct/Nov 2010
28 A job cost sheet showed the following estimates. $ materials 680 labour at $20 per hour 200 overheads at $10 per labour hour 100 profit 280 price of job 1 260 The job actually took 25 % more labour hours than were estimated. What was the profit? A $205 B $230 C $330 D $355
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2010
Q62 · A manufacturing company has the following balances at its year end 9706/11 May/June 2011
10 A manufacturing company has the following balances at its year end. $ closing inventory of raw materials 24 500 direct manufacturing wages 162 800 purchases of raw materials 85 200 supervisors’ wages 44 000 opening inventory of raw materials 27 800 What is the prime cost for the year? A $244 700 B $248 000 C $251 300 D $295 300
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q63 · A business sells its product for $50 a unit and has variable costs of $30 per unit 9706/11 May/June 2011
25 A business sells its product for $50 a unit and has variable costs of $30 per unit. Its fixed costs for this year were $200 000. Next year, fixed costs are expected to be $260 000. How many more units will have to be sold next year to make the same profit as this year? A 3000 B 5200 C 10 000 D 13 000
1 marks
Answer: A
This question in 9706/11 May/June 2011
Q64 · A business has sales of $250 000, fixed costs of $50 000 and a contribution / sales ratio… 9706/11 May/June 2011
26 A business has sales of $250 000, fixed costs of $50 000 and a contribution / sales ratio of 30 %. What is the profit? A $25 000 B $60 000 C $75 000 D $200 000
1 marks
Answer: A
This question in 9706/11 May/June 2011
Q65 · A business provides the following information for a month 9706/11 May/June 2011
27 A business provides the following information for a month. actual direct labour hours worked 8000 actual overhead expenditure $88 000 budgeted direct labour hours 7500 budgeted overhead expenditure $90 000 What is the amount of the overhead over / under recovery? A $2000 over-recovered B $2000 under-recovered C $8000 over-recovered D $8000 under-recovered
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q66 · The following information is provided by a company for a month 9706/11 May/June 2011
28 The following information is provided by a company for a month. actual direct labour hours worked 4500 budgeted direct labour hours 5000 budgeted overhead expenditure $80 000 overheads under-recovered $12 000 What is the amount of the actual overhead expenditure? A $60 000 B $68 000 C $72 000 D $84 000
1 marks
Answer: D
This question in 9706/11 May/June 2011
Q67 · What do the break-even charts show regarding the profitability of and risk attaching to… 9706/11 May/June 2011
29 What do the break-even charts show regarding the profitability of and risk attaching to products 1 and 2? product 1 product 2 revenue revenue $1m $1m total cost total cost 0 0 1000 1000 units units profitability risk A 1 is greater 1 is greater B 1 is greater 1 is less C 2 is greater 2 is greater D 2 is greater 2 is less
1 marks
Answer: B
This question in 9706/11 May/June 2011
Q68 · A manufacturing company has the following balances at its year end 9706/12 May/June 2011
15 A manufacturing company has the following balances at its year end. $ closing inventory of raw materials 24 500 direct manufacturing wages 162 800 purchases of raw materials 85 200 supervisors’ wages 44 000 opening inventory of raw materials 27 800 What is the prime cost for the year? A $244 700 B $248 000 C $251 300 D $295 300
1 marks
Answer: C
This question in 9706/12 May/June 2011
Q69 · A business sells its product for $50 a unit and has variable costs of $30 per unit 9706/12 May/June 2011
23 A business sells its product for $50 a unit and has variable costs of $30 per unit. Its fixed costs for this year were $200 000. Next year, fixed costs are expected to be $260 000. How many more units will have to be sold next year to make the same profit as this year? A 3000 B 5200 C 10 000 D 13 000
1 marks
Answer: A
This question in 9706/12 May/June 2011
Q70 · A business has sales of $250 000, fixed costs of $50 000 and a contribution / sales ratio… 9706/12 May/June 2011
24 A business has sales of $250 000, fixed costs of $50 000 and a contribution / sales ratio of 30 %. What is the profit? A $25 000 B $60 000 C $75 000 D $200 000
1 marks
Answer: A
This question in 9706/12 May/June 2011
Q71 · A business provides the following information for a month 9706/12 May/June 2011
25 A business provides the following information for a month. actual direct labour hours worked 8000 actual overhead expenditure $88 000 budgeted direct labour hours 7500 budgeted overhead expenditure $90 000 What is the amount of the overhead over / under recovery? A $2000 over-recovered B $2000 under-recovered C $8000 over-recovered D $8000 under-recovered
1 marks
Answer: C
This question in 9706/12 May/June 2011
Q72 · The following information is provided by a company for a month 9706/12 May/June 2011
26 The following information is provided by a company for a month. actual direct labour hours worked 4500 budgeted direct labour hours 5000 budgeted overhead expenditure $80 000 overheads under-recovered $12 000 What is the amount of the actual overhead expenditure? A $60 000 B $68 000 C $72 000 D $84 000
1 marks
Answer: D
This question in 9706/12 May/June 2011
Q73 · What do the break-even charts show regarding the profitability of and risk attaching to… 9706/12 May/June 2011
27 What do the break-even charts show regarding the profitability of and risk attaching to products 1 and 2? product 1 product 2 revenue revenue $1m $1m total cost total cost 0 0 1000 1000 units units profitability risk A 1 is greater 1 is greater B 1 is greater 1 is less C 2 is greater 2 is greater D 2 is greater 2 is less
1 marks
Answer: B
This question in 9706/12 May/June 2011
Q74 · A manufacturing company has the following balances at its year end 9706/13 May/June 2011
11 A manufacturing company has the following balances at its year end. $ closing inventory of raw materials 24 500 direct manufacturing wages 162 800 purchases of raw materials 85 200 supervisors’ wages 44 000 opening inventory of raw materials 27 800 What is the prime cost for the year? A $244 700 B $248 000 C $251 300 D $295 300
1 marks
Answer: C
This question in 9706/13 May/June 2011
Q75 · A business has sales of $250 000, fixed costs of $50 000 and a contribution / sales ratio… 9706/13 May/June 2011
25 A business has sales of $250 000, fixed costs of $50 000 and a contribution / sales ratio of 30 %. What is the profit? A $25 000 B $60 000 C $75 000 D $200 000
1 marks
Answer: A
This question in 9706/13 May/June 2011
Q76 · A business sells its product for $50 a unit and has variable costs of $30 per unit 9706/13 May/June 2011
26 A business sells its product for $50 a unit and has variable costs of $30 per unit. Its fixed costs for this year were $200 000. Next year, fixed costs are expected to be $260 000. How many more units will have to be sold next year to make the same profit as this year? A 3000 B 5200 C 10 000 D 13 000
1 marks
Answer: A
This question in 9706/13 May/June 2011
Q77 · The following information is provided by a company for a month 9706/13 May/June 2011
27 The following information is provided by a company for a month. actual direct labour hours worked 4500 budgeted direct labour hours 5000 budgeted overhead expenditure $80 000 overheads under-recovered $12 000 What is the amount of the actual overhead expenditure? A $60 000 B $68 000 C $72 000 D $84 000
1 marks
Answer: D
This question in 9706/13 May/June 2011
Q78 · A business provides the following information for a month 9706/13 May/June 2011
28 A business provides the following information for a month. actual direct labour hours worked 8000 actual overhead expenditure $88 000 budgeted direct labour hours 7500 budgeted overhead expenditure $90 000 What is the amount of the overhead over / under recovery? A $2000 over-recovered B $2000 under-recovered C $8000 over-recovered D $8000 under-recovered
1 marks
Answer: C
This question in 9706/13 May/June 2011
Q79 · What do the break-even charts show regarding the profitability of and risk attaching to… 9706/13 May/June 2011
30 What do the break-even charts show regarding the profitability of and risk attaching to products 1 and 2? product 1 product 2 revenue revenue $1m $1m total cost total cost 0 0 1000 1000 units units profitability risk A 1 is greater 1 is greater B 1 is greater 1 is less C 2 is greater 2 is greater D 2 is greater 2 is less
1 marks
Answer: B
This question in 9706/13 May/June 2011
Q80 · Which statements about marginal costing are correct? 9706/11 Oct/Nov 2011
25 Which statements about marginal costing are correct? 1 The marginal cost of a product includes an allowance for fixed overheads. 2 The marginal cost of a product represents the additional cost of making one extra unit. 3 If inventory decreases during a period, the profits under absorption costing will be lower than under marginal costing. A 1 only B 1, 2 and 3 C 2 only D 2 and 3 only
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2011
Q81 · A company absorbs overheads on machine hours which are budgeted at 11 250 9706/11 Oct/Nov 2011
26 A company absorbs overheads on machine hours which are budgeted at 11 250. The budgeted overhead is $281 250. Results show actual hours of 10 980 and overhead of $276 652. What is the under/over-absorption? A overhead over-absorbed by $2152 B overhead over-absorbed by $4598 C overhead under-absorbed by $2152 D overhead under-absorbed by $4598
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2011
Q82 · A company uses absorption costing and makes and sells one product 9706/11 Oct/Nov 2011
27 A company uses absorption costing and makes and sells one product. In the last month budgeted overheads totalled $60 000. Budgeted production was 15 000 units and budgeted sales were 14 000 units. The company now decides to apply marginal costing principles for the last month. Which effect will this have on profits? A $3500 decrease B $4000 decrease C $4000 increase D no effect
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2011
Q83 · A DVD has a selling price of $10 9706/11 Oct/Nov 2011
29 A DVD has a selling price of $10. cost per DVD $ direct materials 1.20 direct labour 0.80 factory overhead (fixed) 1.50 royalty payment 1.00 administration overhead (fixed) 0.60 What is the contribution per DVD? A $4.90 B $5.90 C $7.00 D $8.00
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2011
Q84 · A business has the following budgeted and actual results for a period 9706/11 Oct/Nov 2011
30 A business has the following budgeted and actual results for a period. $ budgeted fixed overheads 354 000 actual fixed overheads 360 000 under absorption of overheads 3 000 The fixed overheads are absorbed per unit. The budgeted number of units was 118 000. What is the actual level of activity in units? A 118 000 B 119 000 C 120 000 D 121 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2011
Q85 · A manufacturing company incurred the following costs 9706/12 Oct/Nov 2011
10 A manufacturing company incurred the following costs. $ manufacturing labour 350 000 raw materials purchased 230 000 opening inventory of raw materials 40 000 closing inventory of raw materials 50 000 factory overheads 400 000 What was the prime cost of production? A $570 000 B $580 000 C $970 000 D $980 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2011
Q86 · A company has two departments X and Y 9706/12 Oct/Nov 2011
11 A company has two departments X and Y. Management provides the following information. department X department Y total power used 7 500 kwh 17 500 kwh 25 000 kwh area 30 000 square metres 20 000 square metres 50 000 square metres The power bill for the year is $20 000 and the rent is $100 000. What is the total amount for rent and heating to be attributed to department X? A $54 000 B $62 000 C $66 000 D $72 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2011
Q87 · A company makes and sells one product that has a variable cost of $21 and a contribution… 9706/12 Oct/Nov 2011
26 A company makes and sells one product that has a variable cost of $21 and a contribution to sales ratio of 30 %. Total fixed costs per month are $112 500. How many units need to be sold each month to break-even? A 3750 units B 5357 units C 12 500 units D 16 071 units
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2011
Q88 · A product has a contribution per unit of $20 9706/12 Oct/Nov 2011
27 A product has a contribution per unit of $20. Which action would increase the total contribution by the greatest amount? A a 10 % increase in selling price B a 10 % increase in the volume of sales C a 10 % reduction in variable costs D a 20 % reduction in fixed costs
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2011
Q89 · What is a benefit of using absorption costing? 9706/12 Oct/Nov 2011
28 What is a benefit of using absorption costing? A It allows a business to calculate the break-even point for production. B It allows a business to calculate the total cost of goods produced. C It allows a business to show a lower value for year end inventory. D It allows decision-making on utilising spare capacity by increasing production.
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2011
Q90 · What will cause under-absorption of fixed production overheads? 9706/12 Oct/Nov 2011
29 What will cause under-absorption of fixed production overheads? A absorption of overheads is based on actual expenditure and actual activity B actual expenditure on overheads is below budget expenditure C actual activity is above budgeted activity D actual activity is below budgeted activity and actual expenditure is as budgeted
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2011
Q91 · A business provides the following data for the year 9706/12 Oct/Nov 2011
30 A business provides the following data for the year. budgeted output (units) 10 000 actual output (units) 8 000 $ budgeted fixed production costs 1 200 000 budgeted variable production costs 800 000 budgeted fixed selling overhead 600 000 What is the absorption cost per unit used for inventory valuation? A $200 B $250 C $260 D $325
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2011
Q92 · Which statements about marginal costing are correct? 9706/13 Oct/Nov 2011
24 Which statements about marginal costing are correct? 1 The marginal cost of a product includes an allowance for fixed overheads. 2 The marginal cost of a product represents the additional cost of making one extra unit. 3 If inventory decreases during a period, the profits under absorption costing will be lower than under marginal costing. A 1 only B 1, 2 and 3 C 2 only D 2 and 3 only
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2011
Q93 · A company absorbs overheads on machine hours which are budgeted at 11 250 9706/13 Oct/Nov 2011
25 A company absorbs overheads on machine hours which are budgeted at 11 250. The budgeted overhead is $281 250. Results show actual hours of 10 980 and overhead of $276 652. What is the under/over-absorption? A overhead over-absorbed by $2152 B overhead over-absorbed by $4598 C overhead under-absorbed by $2152 D overhead under-absorbed by $4598
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2011
Q94 · A company uses absorption costing and makes and sells one product 9706/13 Oct/Nov 2011
26 A company uses absorption costing and makes and sells one product. In the last month budgeted overheads totalled $60 000. Budgeted production was 15 000 units and budgeted sales were 14 000 units. The company now decides to apply marginal costing principles for the last month. Which effect will this have on profits? A $3500 decrease B $4000 decrease C $4000 increase D no effect
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2011
Q95 · A DVD has a selling price of $10 9706/13 Oct/Nov 2011
28 A DVD has a selling price of $10. cost per DVD $ direct materials 1.20 direct labour 0.80 factory overhead (fixed) 1.50 royalty payment 1.00 administration overhead (fixed) 0.60 What is the contribution per DVD? A $4.90 B $5.90 C $7.00 D $8.00
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2011
Q96 · A business has the following budgeted and actual results for a period 9706/13 Oct/Nov 2011
29 A business has the following budgeted and actual results for a period. $ budgeted fixed overheads 354 000 actual fixed overheads 360 000 under absorption of overheads 3 000 The fixed overheads are absorbed per unit. The budgeted number of units was 118 000. What is the actual level of activity in units? A 118 000 B 119 000 C 120 000 D 121 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2011
Q97 · Ehsen Nadeen manufactures one product, the miji 9706/11 May/June 2012
25 Ehsen Nadeen manufactures one product, the miji. Each miji has a selling price of $10 and variable costs of $8 and annual fixed costs total $12 000. Ehsen wishes to make a profit of $14 000 a year. How many mijis should Ehsen make each year? A 2600 B 6000 C 7000 D 13 000
1 marks
Answer: D
This question in 9706/11 May/June 2012
Q98 · Which costing method is most suitable for fixing a selling price and which for deciding… 9706/11 May/June 2012
26 Which costing method is most suitable for fixing a selling price and which for deciding whether to make or buy in a product? decision to make or fixing of selling price buy in a product A absorption costing absorption costing B absorption costing marginal costing C marginal costing absorption costing D marginal costing marginal costing
1 marks
Answer: B
This question in 9706/11 May/June 2012
Q99 · A business provides the following data 9706/11 May/June 2012
27 A business provides the following data. output level 1 2 direct labour hours 8 500 9 250 total overheads $123 250 $124 563 The variable overhead cost is $1.75 per direct labour hour. What is the fixed overheads cost when 8500 labour hours are used? A $1313 B $14 875 C $108 375 D $123 250
1 marks
Answer: C
This question in 9706/11 May/June 2012
Q100 · The following information is forecast for May 9706/11 May/June 2012
28 The following information is forecast for May. units opening inventory 25 200 closing inventory 28 200 $ marginal cost profit 100 800 absorption cost profit 120 300 What is the overhead absorption rate? A $3.57 B $4.27 C $4.77 D $6.50
1 marks
Answer: D
This question in 9706/11 May/June 2012
Q101 · The manufacture of which product is best suited to job costing? 9706/11 May/June 2012
29 The manufacture of which product is best suited to job costing? A aeroplanes B medicines C newspapers D paint
1 marks
Answer: A
This question in 9706/11 May/June 2012
Q102 · What is the purpose of a job cost sheet? 9706/11 May/June 2012
30 What is the purpose of a job cost sheet? A to enable the business to recover its overheads B to ensure the customer knows the split between materials and labour C to inform the customer of the profit margin D to let the business find the price for a quotation
1 marks
Answer: D
This question in 9706/11 May/June 2012
Q103 · Which costs are classified as manufacturing overheads for a car assembly plant? 9706/12 May/June 2012
26 Which costs are classified as manufacturing overheads for a car assembly plant? 1 assembly line employees’ wages 2 cost of components assembled 3 depreciation of assembly line equipment 4 production managers’ salaries A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: D
This question in 9706/12 May/June 2012
Q104 · A business has the following budget for April 9706/12 May/June 2012
27 A business has the following budget for April. $ sales revenue 1 000 000 contribution 550 000 fixed production costs 275 000 fixed selling costs 55 000 What is the break-even sales revenue for April? A $450 000 B $500 000 C $600 000 D $670 000
1 marks
Answer: C
This question in 9706/12 May/June 2012
Q105 · Which costing method is best suited to valuing inventory and which for deciding whether… 9706/12 May/June 2012
28 Which costing method is best suited to valuing inventory and which for deciding whether to accept an order below normal selling price? decision on accepting order valuation of inventory below normal selling price A absorption costing absorption costing B absorption costing marginal costing C marginal costing absorption costing D marginal costing marginal costing
1 marks
Answer: B
This question in 9706/12 May/June 2012
Q106 · The following information is forecast for May 9706/12 May/June 2012
29 The following information is forecast for May. units opening inventory 25 200 closing inventory 28 200 $ marginal cost profit 100 800 absorption cost profit 120 300 What is the overhead absorption rate? A $3.57 B $4.27 C $4.77 D $6.50
1 marks
Answer: D
This question in 9706/12 May/June 2012
Q107 · What is the purpose of a job cost sheet? 9706/12 May/June 2012
30 What is the purpose of a job cost sheet? A to enable the business to recover its overheads B to ensure the customer knows the split between materials and labour C to inform the customer of the profit margin D to let the business find the price for a quotation
1 marks
Answer: D
This question in 9706/12 May/June 2012
Q108 · Information about a business is given 9706/13 May/June 2012
9 Information about a business is given. $ production overheads 23 000 opening inventory of raw materials 3 000 purchases of raw materials 35 000 closing inventory of raw materials 2 000 production wages 33 000 production supervisor’s salary 2 000 What is the prime cost? A $69 000 B $71 000 C $92 000 D $94 000
1 marks
Answer: A
This question in 9706/13 May/June 2012
Q109 · What usually makes up the total cost of a manufactured product for inventory valuation… 9706/13 May/June 2012
24 What usually makes up the total cost of a manufactured product for inventory valuation purposes? A cost of production and selling and distribution overhead B direct materials and direct labour C direct materials and manufacturing overhead D prime cost and manufacturing overhead
1 marks
Answer: D
This question in 9706/13 May/June 2012
Q110 · Ehsen Nadeen manufactures one product, the miji 9706/13 May/June 2012
26 Ehsen Nadeen manufactures one product, the miji. Each miji has a selling price of $10 and variable costs of $8 and annual fixed costs total $12 000. Ehsen wishes to make a profit of $14 000 a year. How many mijis should Ehsen make each year? A 2600 B 6000 C 7000 D 13 000
1 marks
Answer: D
This question in 9706/13 May/June 2012
Q111 · Which costing method is most suitable for fixing a selling price and which for deciding… 9706/13 May/June 2012
27 Which costing method is most suitable for fixing a selling price and which for deciding whether to make or buy in a product? decision to make or fixing of selling price buy in a product A absorption costing absorption costing B absorption costing marginal costing C marginal costing absorption costing D marginal costing marginal costing
1 marks
Answer: B
This question in 9706/13 May/June 2012
Q112 · A business provides the following data 9706/13 May/June 2012
28 A business provides the following data. output level 1 2 direct labour hours 8 500 9 250 total overheads $123 250 $124 563 The variable overhead cost is $1.75 per direct labour hour. What is the fixed overheads cost when 8500 labour hours are used? A $1313 B $14 875 C $108 375 D $123 250
1 marks
Answer: C
This question in 9706/13 May/June 2012
Q113 · A business uses absorption costing 9706/13 May/June 2012
29 A business uses absorption costing. Which cost is used to value finished inventory? A full cost B prime cost C variable cost of production D variable cost of sales
1 marks
Answer: A
This question in 9706/13 May/June 2012
Q114 · The manufacture of which product is best suited to job costing? 9706/13 May/June 2012
30 The manufacture of which product is best suited to job costing? A aeroplanes B medicines C newspapers D paint
1 marks
Answer: A
This question in 9706/13 May/June 2012
Q115 · A business has fixed costs for a month of $150 000 9706/11 Oct/Nov 2012
27 A business has fixed costs for a month of $150 000. It sells its single product for $20 per unit and has a contribution/sales ratio of 0.75. It wishes to make a profit of $300 000 for the month. How many units does the business need to sell? A 10 000 B 20 000 C 22 500 D 30 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2012
Q116 · When valuing inventory of finished goods on an absorption cost basis, which costs should… 9706/11 Oct/Nov 2012
28 When valuing inventory of finished goods on an absorption cost basis, which costs should be included? A production B production and administration C production, marketing and distribution D production, marketing, administration and distribution
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2012
Q117 · A hospital budgets for overheads totalling $11 500 000 for a financial year 9706/11 Oct/Nov 2012
29 A hospital budgets for overheads totalling $11 500 000 for a financial year. It expects to treat 25 000 patients in the year. Each patient stays an average of 10 days and the hospital absorbs overheads on a patient /day basis. Its direct costs for the year are budgeted at $25 000 000. What is its overhead absorption rate per patient day? A $46 B $100 C $146 D $460
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2012
Q118 · The following data applies to a business 9706/11 Oct/Nov 2012
30 The following data applies to a business. budgeted labour hours 10 000 actual labour hours 9 500 budgeted overheads $150 000 actual overheads $160 000 What is the amount of overhead under-absorbed? A $7500 B $8000 C $10 000 D $17 500
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2012
Q119 · A company operates three departments and apportions heat and light on the most… 9706/12 Oct/Nov 2012
12 A company operates three departments and apportions heat and light on the most appropriate basis. The table shows information for a year. department department department total X Y Z revenue $950 000 $710 000 $690 000 $2 350 000 floor area (square metres) 500 800 680 1980 number of employees 85 60 58 203 heat and light $90 000 Which cost for heat and light is apportioned to department X? $ A 22 727 B 30 000 C 36 383 D 37 685
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2012
Q120 · The total cost of making product X is shown on the graph 9706/12 Oct/Nov 2012
26 The total cost of making product X is shown on the graph. 2500 2000 1500 cost $ 1000 500 0 0 1000 2000 3000 number of units What is the variable cost per unit? A $0.50 B $0.83 C $1.00 D $1.50
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2012
Q121 · The diagram shows a break-even chart 9706/12 Oct/Nov 2012
27 The diagram shows a break-even chart. $ X sales revenue total cost revenue and costs Y fixed cost O budgeted level of activity level of activity What does line XY represent? A the break-even point revenue B the margin of safety in terms of revenue C the profit at break-even point D the total contribution at break-even point
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2012
Q122 · The budget for a product is shown 9706/12 Oct/Nov 2012
28 The budget for a product is shown. unit sales 620 000 $ selling price per unit 31 variable cost per unit 16 contribution per unit 15 fixed costs $7 500 000 If the fixed costs rise to $7 800 000, the selling price is reduced to $29 per unit, and the variable cost remains unchanged at $16 per unit, the sales are likely to reach 660 000 units. By what percentage will the break-even point increase? A 4.0 % B 11.2 % C 16.7 % D 20.0 %
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2012
Q123 · When are the reported profits under marginal costing and absorption costing principles… 9706/12 Oct/Nov 2012
29 When are the reported profits under marginal costing and absorption costing principles the same amount? A when sales revenue exceeds cost of sales B when units produced equals sales in units C when units produced exceeds sales in units D when unit sales exceeds production in units
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2012
Q124 · A business provides the following information 9706/12 Oct/Nov 2012
30 A business provides the following information. number of overheads month labour hours $ May 68 000 986 000 June 134 000 1 316 000 The variable overhead rate per labour hour was $5. What was the monthly fixed overhead cost? A $330 000 B $340 000 C $646 000 D $670 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2012
Q125 · In whose accounts will the term ‘prime cost’ appear? 9706/13 Oct/Nov 2012
11 In whose accounts will the term ‘prime cost’ appear? A a limited company running a retail business B a partnership of accountants C a sole trader manufacturing car components D a sports and athletics club
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2012
Q126 · A clothing retailer provides the following information for its three departments 9706/13 Oct/Nov 2012
12 A clothing retailer provides the following information for its three departments. Gentlemen Ladies Children gross profit $35 000 $42 500 $22 500 number of employees 3 3 2 The total overheads incurred by the retailer are $76 000 and these are apportioned to the departments on the basis of number of employees. What is the net profit or loss made by the children’s department? A $3500 loss B $3500 profit C $6000 loss D $13 000 profit
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2012
Q127 · ‘Contribution’ is an important feature of marginal costing 9706/13 Oct/Nov 2012
27 ‘Contribution’ is an important feature of marginal costing. How can the total contribution from a given activity be calculated? A total direct costs minus total profit B total fixed costs plus total profit C total sales minus total fixed costs D total sales minus total profit
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2012
Q128 · A business forecasts its margin of safety for the next month as 20 % of budgeted sales 9706/13 Oct/Nov 2012
28 A business forecasts its margin of safety for the next month as 20 % of budgeted sales. It expects to sell 10 000 units in the month. The selling price per unit is $5 and the marginal cost is $3.50. What is the forecast fixed cost? A $12 000 B $12 500 C $15 000 D $18 000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2012
Q129 · What is the reason for overhead absorption in a manufacturing business? 9706/13 Oct/Nov 2012
29 What is the reason for overhead absorption in a manufacturing business? A to control overhead expenditure B to determine the net realisable value of inventory C to enable overheads to be apportioned to cost centres D to establish costs per unit of product
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2012
Q130 · A business reports a profit using marginal costing of $75 000 for a month 9706/13 Oct/Nov 2012
30 A business reports a profit using marginal costing of $75 000 for a month. Opening inventory was 10 000 units and closing inventory 15 000 units. The fixed production overhead absorption rate is $5 per unit. What is the profit using absorption costing? A $25 000 B $50 000 C $100 000 D $125 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2012
Q131 · A business finds that its profit for 2012 is the same whether marginal costing or… 9706/11 May/June 2013
27 A business finds that its profit for 2012 is the same whether marginal costing or absorption costing is used. What does this mean? A Inventories have been written down to zero value in the period. B Inventories have decreased during the period. C Inventories have increased during the period. D Inventories have stayed the same during the period.
1 marks
Answer: D
This question in 9706/11 May/June 2013
Q132 · A baker receives one order for 350 loaves of bread 9706/11 May/June 2013
28 A baker receives one order for 350 loaves of bread. Which costing method will the baker use? A absorption costing B batch costing C job costing D unit costing
1 marks
Answer: B
This question in 9706/11 May/June 2013
Q133 · A company manufactures and sells chairs 9706/11 May/June 2013
29 A company manufactures and sells chairs. The following financial information is available. per unit $ selling price 25 direct material and labour 12 other variable production costs 3 variable selling costs 2 fixed costs 4 The company has the option of buying in the chairs for resale instead of making them. At which purchase price would the company’s profit be unchanged? A $15 B $17 C $19 D $21
1 marks
Answer: A
This question in 9706/11 May/June 2013
Q134 · A company has ordered a new machine, to be delivered in six months 9706/12 May/June 2013
24 A company has ordered a new machine, to be delivered in six months. In the short term, the machine hours will be a limiting factor. It has made the following calculations. product X product Y product Z contribution per unit made $24 $12 $20 machine hours used per unit 6 1 2 What will be the most profitable ranking order for production? A X → Y → Z B X → Z → Y C Y → Z → X D Z → Y → X
1 marks
Answer: C
This question in 9706/12 May/June 2013
Q135 · The following data is available for the production department of a manufacturing company 9706/12 May/June 2013
25 The following data is available for the production department of a manufacturing company. Overheads are absorbed on a direct labour hour basis. total direct overhead costs labour hours $ budgeted 96 000 242 880 actual 97 600 253 760 What is the over or under absorption of overheads for the period? A $6832 over absorbed B $6832 under absorbed C $10 880 over absorbed D $10 880 under absorbed
1 marks
Answer: B
This question in 9706/12 May/June 2013
Q136 · The following information applies to a business 9706/12 May/June 2013
26 The following information applies to a business. output sales profits (units) $ $ 375 750 000 100 000 500 1 000 000 250 000 What is the contribution to sales ratio? A 25% B 40% C 50% D 60%
1 marks
Answer: D
This question in 9706/12 May/June 2013
Q137 · A business produces one product 9706/12 May/June 2013
27 A business produces one product. The following details are available for the budgeted production of 150 000 units. $ selling price per unit 1.20 variable cost per unit 0.70 fixed cost per unit 0.20 What is the break-even point in sales value? A $30 000 B $60 000 C $72 000 D $180 000
1 marks
Answer: C
This question in 9706/12 May/June 2013
Q138 · Which business would use a job costing system of accounting? 9706/12 May/June 2013
29 Which business would use a job costing system of accounting? A a chocolate factory B a dairy milk farmer C a house builder D an oil refinery
1 marks
Answer: C
This question in 9706/12 May/June 2013
Q139 · A business allocates the following expenses to departments on the basis either of sales… 9706/13 May/June 2013
12 A business allocates the following expenses to departments on the basis either of sales or floor area. 1 advertising 2 carriage out 3 heating 4 rent Which expenses are allocated on the basis of floor area? A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: D
This question in 9706/13 May/June 2013
Q140 · The manufacturing account of a business includes the following 9706/13 May/June 2013
15 The manufacturing account of a business includes the following. $ prime costs 143 260 production overheads 92 170 opening work-in-progress 5 720 closing work-in-progress 6 840 opening inventory of finished goods 29 480 closing inventory of finished goods 25 990 What was the cost of production? A $234 310 B $235 430 C $236 550 D $237 800
1 marks
Answer: A
This question in 9706/13 May/June 2013
Q141 · A company produces two different products which use the same material 9706/13 May/June 2013
27 A company produces two different products which use the same material. One month there is a shortage of material and the company needs to reduce production of one product. Of which product should the company reduce production first? A the one with the higher contribution per kilo of material B the one with the higher contribution per unit C the one with the lower contribution per kilo of material D the one with the lower contribution per unit
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q142 · A factory has forecast total production overhead of $400 000 and forecast activity of 80… 9706/13 May/June 2013
28 A factory has forecast total production overhead of $400 000 and forecast activity of 80 000 machine hours. In April actual overheads are $385 000 and actual activity is 70 000 hours. What is the level of under or over absorption in April? A $35 000 over B $35 000 under C $40 000 over D $40 000 under
1 marks
Answer: B
This question in 9706/13 May/June 2013
Q143 · Which type of organisation would use process costing? 9706/13 May/June 2013
29 Which type of organisation would use process costing? A charity B college C oil refinery D supermarket
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q144 · Which statements about absorption costing are correct? 9706/11 Oct/Nov 2013
27 Which statements about absorption costing are correct? 1 It apportions overheads between production and service departments. 2 It enables a company to know its break-even level of production. 3 It leads to higher inventory valuations than marginal costing. 4 It is used by management for make or buy decisions. A 1, 2 and 3 B 1 and 3 only C 2 and 4 only D 3 and 4 only
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2013
Q145 · An accountant prepared the following break-even chart 9706/11 Oct/Nov 2013
28 An accountant prepared the following break-even chart. 10 sales revenue budget 8 total costs costs 6 and revenues ($m) 4 2 fixed costs 0 0 1 2 3 4 5 sales volume (millions of units) The budgeted sales volume is 4.5 million units. Which profit can be anticipated at this level? A $2.5 million B $4.5 million C $7 million D $9 million
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2013
Q146 · Which statement best describes job costing? 9706/11 Oct/Nov 2013
29 Which statement best describes job costing? A a costing method that calculates the cost of meeting a specific customer order B a costing method that calculates the cost of producing a number of identical units for a customer C a costing method that enables overheads to be absorbed into the cost of the product D a costing method that separates fixed costs from variable costs
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2013
Q147 · A company makes three products 9706/12 Oct/Nov 2013
25 A company makes three products. contribution contribution per unit $ per hour $ product 1 14 2.1 product 2 13 2.6 product 3 8 2.4 Total available labour hours are insufficient to make enough of each product to meet demand. In what order should the products be produced to maximise profit? A 1, 2, 3 B 1, 3, 2 C 2, 3, 1 D 3, 2, 1
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2013
Q148 · A business sells its product for $10 per unit and has variable costs of $6 per unit 9706/12 Oct/Nov 2013
27 A business sells its product for $10 per unit and has variable costs of $6 per unit. The table shows the fixed costs for the year. $ factory rent 30 000 other fixed costs 70 000 What is the break-even point? A 10 000 units B 16 667 units C 17 500 units D 25 000 units
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2013
Q149 · A company’s financial information is as follows 9706/12 Oct/Nov 2013
28 A company’s financial information is as follows. $ selling price per unit 55 variable costs per unit 15 total fixed costs 33 000 If the selling price is reduced to $40, how many extra units need to be sold to break-even? A 495 B 825 C 1320 D 2200
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2013
Q150 · A company is asked to make a new machine for a customer 9706/12 Oct/Nov 2013
29 A company is asked to make a new machine for a customer. It provides the following estimates. materials will cost $1100 labour will be 30 hours at a cost of $14 per hour The company charges overheads at $10 per labour hour and has a mark up of 30% on total cost. What is the price on the job cost sheet? A $1520 B $1820 C $1976 D $2366
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2013
Q151 · Which group of items are included in the prime cost? 9706/13 Oct/Nov 2013
15 Which group of items are included in the prime cost? A inventories of finished goods, purchases of raw materials, direct wages B inventories of raw materials, purchases of raw materials, direct wages C inventories of raw materials, purchases of raw materials, indirect wages D inventories of work in progress, purchases of raw materials, indirect wages
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2013
Q152 · A business provides the following information for the year 9706/13 Oct/Nov 2013
16 A business provides the following information for the year. $ prime cost 165 000 factory overheads 43 000 opening work in progress 6 000 closing work in progress 15 000 What is the cost of goods transferred to the trading account of the income statement? A $113 000 B $199 000 C $208 000 D $217 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2013
Q153 · A company makes and sells one product incurring the following costs 9706/13 Oct/Nov 2013
26 A company makes and sells one product incurring the following costs. 12 kilos of material at $3 per kilo 4.5 labour hours at $12 per hour production overheads $6 per unit selling overheads $5 per unit What is the total direct cost per unit? A $36 B $42 C $90 D $101
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2013
Q154 · A company receives an order for 10 000 units 9706/13 Oct/Nov 2013
27 A company receives an order for 10 000 units. The following information is available. units produced per machine hour 500 labour costs per machine hour $25 raw material cost per unit $2 overheads recovered per machine hour $40 What is the cost of production? A $11 300 B $21 300 C $33 500 D $52 500
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2013
Q155 · The costs of a company that annually sells 10 000 units are as follows 9706/13 Oct/Nov 2013
28 The costs of a company that annually sells 10 000 units are as follows. $ direct material 50 000 assembly labour 100 000 factory overheads 70 000 The normal selling price of each unit is $50. If it was reduced to $35, how many more units need to be sold to break-even? A 1500 units B 2000 units C 3500 units D 5000 units
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2013
Q156 · A company manufactures four products 9706/13 Oct/Nov 2013
29 A company manufactures four products. Gamma Rho Theta Zeta contribution per unit ($) 10 12 14 16 material required (litres) 5 4 6 7 If there is only enough material to make three of the products, which product should be discontinued? A Gamma B Rho C Theta D Zeta
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2013
Q157 · The following information is available about a customer order 9706/11 May/June 2014
25 The following information is available about a customer order. $ direct material cost 75.00 direct labour cost 42.00 cost per labour hour 7.00 fixed overhead absorption rate per direct labour hour 6.50 The order has a mark-up calculated at 20% of total cost. What is the selling price? A $117.00 B $140.40 C $156.00 D $187.20
1 marks
Answer: D
This question in 9706/11 May/June 2014
Q158 · What can be used to apportion production overheads to cost centres? 9706/11 May/June 2014
26 What can be used to apportion production overheads to cost centres? A cost of machinery B direct labour hours C indirect material cost D sales department labour hours
1 marks
Answer: A
This question in 9706/11 May/June 2014
Q159 · The following information relates to two production departments of a manufacturing… 9706/11 May/June 2014
27 The following information relates to two production departments of a manufacturing business. assembly polishing prime cost ($000) 880 1100 indirect overheads ($000) 996 1363 machine hours (000) 100 150 labour hours (000) 75 220 What are the overhead absorption rates? assembly polishing $ $ A 9.96 6.20 B 13.28 9.09 C 18.76 11.20 D 25.01 16.42
1 marks
Answer: A
This question in 9706/11 May/June 2014
Q160 · A manufacturer has a total production cost of $50 000 to make 20 000 units 9706/11 May/June 2014
28 A manufacturer has a total production cost of $50 000 to make 20 000 units. This increases to $60 000 if production is increased to 25 000 units. What is the total cost of 35 000 units? A $70 000 B $80 000 C $84 000 D $87 500
1 marks
Answer: B
This question in 9706/11 May/June 2014
Q161 · A company provides the following information about its product 9706/11 May/June 2014
29 A company provides the following information about its product. selling price $100 variable cost per unit $40 fixed costs $21 600 break even point 360 units If the business changes its production method, contribution will increase by 10% and fixed costs will increase by 5%. What would be the effect on the break even point? A decrease by 16 units B decrease by 36 units C increase by 6 units D increase by 18 units
1 marks
Answer: A
This question in 9706/11 May/June 2014
Q162 · A sole trader runs a retail store 9706/12 May/June 2014
13 A sole trader runs a retail store. Which department is most likely to close? A the one with a negative contribution B the one with a negative profit C the one with a positive contribution D the one with a positive profit
1 marks
Answer: A
This question in 9706/12 May/June 2014
Q163 · Simon provides the following information about his costs for the year 9706/12 May/June 2014
18 Simon provides the following information about his costs for the year. $ raw materials 16 100 factory depreciation 2 400 production labour 18 000 factory supervisor 8 500 factory heating 1 100 carriage in 1 500 rent 12 000 administration costs 11 500 Half of the rent relates to the factory and half to the offices. What is the total of indirect manufacturing costs? A $18 000 B $19 500 C $35 500 D $35 600
1 marks
Answer: A
This question in 9706/12 May/June 2014
Q164 · A company uses absorption costing and makes and sells one product 9706/12 May/June 2014
27 A company uses absorption costing and makes and sells one product. In the last month budgeted overheads totalled $60 000. Budgeted production was 15 000 units and budgeted sales were 14 000 units. The company now decides to apply marginal costing principles for last month. Which effect will this have on profits? A $3500 decrease B $3500 increase C $4000 decrease D $4000 increase
1 marks
Answer: C
This question in 9706/12 May/June 2014
Q165 · The data relates to the production of three products 9706/12 May/June 2014
29 The data relates to the production of three products. product X product Y product Z $ $ $ contribution per unit 160 175 190 fixed overhead per unit 125 130 160 labour hours per unit 1 1.25 0.75 The company is experiencing a shortage of labour. In which order should the products be ranked to maximise profit? 1 2 3 A X Y Z B Y X Z C Z X Y D Z Y X
1 marks
Answer: C
This question in 9706/12 May/June 2014
Q166 · The direct material cost of 20 000 units is $8000 9706/13 May/June 2014
25 The direct material cost of 20 000 units is $8000. 400 direct labour hours are required at a cost of $6000. Overheads are absorbed at 150% of the cost of direct labour. What is the cost per unit? A $0.40 B $0.70 C $0.85 D $1.15
1 marks
Answer: D
This question in 9706/13 May/June 2014
Q167 · The following information is available 9706/13 May/June 2014
26 The following information is available. $ break even sales revenue 15 000 unit sales price 10 fixed costs 6 000 What is the variable cost per unit? A $2.00 B $2.50 C $4.00 D $6.00
1 marks
Answer: D
This question in 9706/13 May/June 2014
Q168 · A business absorbs overheads at a rate of $10.50 per labour hour 9706/13 May/June 2014
27 A business absorbs overheads at a rate of $10.50 per labour hour. The following information is available. budgeted overheads $68 250 actual overheads $66 175 actual labour hours 5976 What is the value of under or over absorbed overheads? A $2075 over B $2075 under C $3427 over D $3427 under
1 marks
Answer: D
This question in 9706/13 May/June 2014
Q169 · A company uses a direct labour rate of $5.40 per hour to absorb production overhead 9706/13 May/June 2014
28 A company uses a direct labour rate of $5.40 per hour to absorb production overhead. Each unit of product manufactured requires four direct labour hours. The following information is available for a period. $ actual production overhead 518 400 under absorbed production overhead 32 400 What was the actual output of the product in the period? A 22 500 units B 24 000 units C 25 500 units D 90 000 units
1 marks
Answer: A
This question in 9706/13 May/June 2014
Q170 · A company sells a product for $12 per batch 9706/13 May/June 2014
29 A company sells a product for $12 per batch. The variable cost is $4 per batch. Fixed costs are absorbed based on a normal activity level of 100 batches at $3 per batch. What is the profit under marginal costing if the company makes and sells 125 batches? A $500 B $625 C $700 D $1000
1 marks
Answer: C
This question in 9706/13 May/June 2014
Q171 · In departmental accounts, which overhead might be apportioned according to floor space? 9706/11 Oct/Nov 2014
13 In departmental accounts, which overhead might be apportioned according to floor space? A advertising B depreciation of machinery C office wages D rent
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2014
Q172 · A manufacturer provides the following information 9706/11 Oct/Nov 2014
14 A manufacturer provides the following information. $ total rent 50 000 factory heat and light 8 000 carriage inwards 2 000 carriage outwards 3 000 indirect labour 60 000 total factory overheads 98 000 Which proportion of rent relates to the factory? A 50% B 54% C 56% D 60%
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2014
Q173 · What does the line between points X and Y on the break-even chart represent? 9706/11 Oct/Nov 2014
25 What does the line between points X and Y on the break-even chart represent? X Y $ revenues and costs 0 units A total costs B total gross profit C total profit for the year D total variable costs
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2014
Q174 · Extracts from the costing records of a builder who has completed two houses are shown 9706/11 Oct/Nov 2014
26 Extracts from the costing records of a builder who has completed two houses are shown. $ building inspection fees 2 000 land (four plots) 100 000 labour 160 000 materials used 40 000 What is the cost of completing one house? A $125 000 B $126 000 C $127 000 D $151 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2014
Q175 · Which item needs to be increased to make a break-even point fall? 9706/11 Oct/Nov 2014
27 Which item needs to be increased to make a break-even point fall? A budgeted sales B fixed costs C marginal costs D selling prices
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2014
Q176 · A business provides the following information about a product 9706/11 Oct/Nov 2014
28 A business provides the following information about a product. $ variable cost per unit 16 selling price per unit 30 total fixed costs 35 000 budgeted profit 95 000 How many units should it produce to achieve the budgeted profit? A 4286 B 4334 C 6786 D 9286
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2014
Q177 · The following information is available for a manufacturing company for June 2014 9706/11 Oct/Nov 2014
29 The following information is available for a manufacturing company for June 2014. budgeted overheads $108 000 actual overheads $112 000 budgeted labour hours 24 000 actual labour hours 23 000 What is the over or under absorption of overheads for June 2014? A $4000 over absorbed B $4000 under absorbed C $8500 over absorbed D $8500 under absorbed
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2014
Q178 · What will cause under-absorption of fixed production overheads? 9706/12 Oct/Nov 2014
25 What will cause under-absorption of fixed production overheads? A absorption of overheads is based on actual expenditure and actual activity B actual activity is above budgeted activity C actual activity is below budgeted activity and actual expenditure is as budgeted D actual expenditure on overheads is below budget expenditure
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2014
Q179 · A business has fixed costs of $100 000 9706/12 Oct/Nov 2014
26 A business has fixed costs of $100 000. It sells a single product for $25 per unit, and its contribution to sales ratio is 40%. What is the break-even point in units? A 6667 B 10 000 C 40 000 D 250 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2014
Q180 · A business provides the following financial information 9706/12 Oct/Nov 2014
28 A business provides the following financial information. $ per unit selling price 41 direct materials 5 direct labour 8 variable overhead 3 fixed overhead 4 profit 21 What is the marginal cost per unit? A $13 B $16 C $20 D $25
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2014
Q181 · A business hires machinery at a cost of $700 per machine per month 9706/12 Oct/Nov 2014
29 A business hires machinery at a cost of $700 per machine per month. Each machine can produce 1000 units a month. A maximum of 10 machines can fit into the factory. The factory rent is $4900 per month. Other costs amount to $2 per unit. What is the unit cost if 8500 units are produced in a month? A $3.19 B $3.23 C $3.28 D $3.32
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2014
Q182 · A company has been asked to prepare a quotation to print 100 leaflets for a customer 9706/13 Oct/Nov 2014
26 A company has been asked to prepare a quotation to print 100 leaflets for a customer. The total cost of direct materials, direct labour and a share of overheads is $820 and a profit of 25% on cost has been added. This is an example of which costing method? A absorption costing B job costing C marginal costing D unit costing
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2014
Q183 · A company manufactures one product 9706/13 Oct/Nov 2014
27 A company manufactures one product. During the year it produced 1000 units. Total costs were as follows. $ raw materials ? production labour 18 000 factory supervisor 8 000 depreciation of equipment 3 000 rent 7 000 carriage inwards 1 000 Variable cost per unit was $51. What was the total cost of raw materials? A $21 000 B $25 000 C $32 000 D $33 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q184 · A product has a variable cost of $50 and a selling price of $80 9706/13 Oct/Nov 2014
28 A product has a variable cost of $50 and a selling price of $80. Fixed costs are $90 000. Budgeted sales are 8000 units. What is the margin of safety? A 1800 units B 3000 units C 5000 units D 6200 units
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q185 · A business has sales of $250 000, fixed costs of $50 000 and a contribution / sales ratio… 9706/13 Oct/Nov 2014
29 A business has sales of $250 000, fixed costs of $50 000 and a contribution / sales ratio of 30%. What is the profit? A $25 000 B $60 000 C $75 000 D $200 000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2014
Q186 · A manufacturing business has the following costs 1 carriage inwards 2 depreciation of… 9706/11 May/June 2015
22 A manufacturing business has the following costs 1 carriage inwards 2 depreciation of factory machinery 3 insurance of machinery 4 machine operators’ wages 5 raw material costs Which items make up factory overhead? A 1 and 2 B 2 and 3 C 2 and 4 D 3 and 5
1 marks
Answer: B
This question in 9706/11 May/June 2015
Q187 · A business has an activity level below budget and fixed overhead expenditure below budget 9706/11 May/June 2015
25 A business has an activity level below budget and fixed overhead expenditure below budget. Do these result in an under absorption of fixed overhead? activity below expenditure below budget budget A no no B no yes C yes no D yes yes
1 marks
Answer: C
This question in 9706/11 May/June 2015
Q188 · A company has been asked to quote a price for a specific job 9706/11 May/June 2015
27 A company has been asked to quote a price for a specific job. Estimated costs are as follows. $ direct materials 2000 direct labour 3300 Overheads are charged at 50% of labour cost. Profit is 20% of the total job cost. What is the total of the quotation for the job? A $5300 B $6360 C $6950 D $8340
1 marks
Answer: D
This question in 9706/11 May/June 2015
Q189 · A company has the following budget 9706/11 May/June 2015
29 A company has the following budget. $ revenue 1 000 000 contribution 550 000 fixed production costs 275 000 fixed non-production costs 55 000 What is its budgeted break-even revenue? A $220 000 B $275 000 C $500 000 D $600 000
1 marks
Answer: D
This question in 9706/11 May/June 2015
Q190 · The following figures are given for a factory’s overheads and machine hours worked 9706/12 May/June 2015
24 The following figures are given for a factory’s overheads and machine hours worked. overhead machine hours total overhead costs absorption rate budgeted 122 000 $268 400 $2.20 actual 116 000 $261 000 $2.25 What was the under or over absorption of overhead for the quarter? A $5800 over absorbed B $5800 under absorbed C $7400 over absorbed D $7400 under absorbed
1 marks
Answer: B
This question in 9706/12 May/June 2015
Q191 · Which costing method is used to calculate a break-even point? 9706/12 May/June 2015
25 Which costing method is used to calculate a break-even point? A absorption B batch C marginal D unit
1 marks
Answer: C
This question in 9706/12 May/June 2015
Q192 · Which is not a characteristic of job costing? 9706/12 May/June 2015
26 Which is not a characteristic of job costing? A Each cost unit is separately identifiable. B Production involves repetitive operations. C Production is based on specific customer orders. D Production is usually of short duration.
1 marks
Answer: B
This question in 9706/12 May/June 2015
Q193 · A business manufactures three products which all use the same material 9706/12 May/June 2015
28 A business manufactures three products which all use the same material. The following information is available. X Y Z $000 $000 $000 selling price 160 190 240 direct material 56 68 90 direct labour 35 32 50 variable overhead 28 34 45 contribution 41 56 55 Direct material is in short supply. In which order should the products be manufactured to maximise profits? A X → Y → Z B Y → X → Z C Y → Z → X D Z → Y → X
1 marks
Answer: B
This question in 9706/12 May/June 2015
Q194 · A company is forecasting its profits at two levels of activity 9706/12 May/June 2015
29 A company is forecasting its profits at two levels of activity. sales units 5000 8000 $ $ total fixed and variable costs 20 000 26 000 profit 15 000 30 000 sales revenue 35 000 56 000 Fixed costs and selling prices are unchanged within the above activity range. What is the forecast profit if sales were 7000 units? A $21 000 B $25 000 C $26 000 D $26 250
1 marks
Answer: B
This question in 9706/12 May/June 2015
Q195 · The break-even chart for a product is shown 9706/13 May/June 2015
22 The break-even chart for a product is shown. sales revenue total costs break-even costs and point revenues $000 X Y sales volume What does XY represent? A fixed costs B gross profit C profit for the period D variable costs
1 marks
Answer: A
This question in 9706/13 May/June 2015
Q196 · Which business would use a job costing system? 9706/13 May/June 2015
23 Which business would use a job costing system? A a chemical plant B a retailer of food C a ship builder’s yard D a wholesaler of car parts
1 marks
Answer: C
This question in 9706/13 May/June 2015
Q197 · Which cost relating to a manufacturing business is apportioned between its cost centres? 9706/13 May/June 2015
24 Which cost relating to a manufacturing business is apportioned between its cost centres? A depreciation of delivery vehicles B factory power C finance costs D raw materials
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q198 · A company absorbs overheads on the basis of machine hours, which are budgeted at 11 250 9706/13 May/June 2015
25 A company absorbs overheads on the basis of machine hours, which are budgeted at 11 250. The budgeted overhead is $281 250. Results show actual hours of 10 980 and overhead of $276 652. What is the under or over absorption? A $2152 over absorbed B $2152 under absorbed C $4598 over absorbed D $4598 under absorbed
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q199 · A manufacturing company produces 10 000 units and sells 8000 units in a year 9706/13 May/June 2015
27 A manufacturing company produces 10 000 units and sells 8000 units in a year. The selling price per unit is $30. Total costs incurred during that year were as follows. $ direct materials 50 000 direct labour 80 000 prime cost 130 000 factory overhead 50 000 production cost 180 000 administration cost 65 000 total costs 245 000 The company uses absorption costing. What is the value of closing inventory? A $26 000 B $36 000 C $49 000 D $60 000
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q200 · The following information is available for a manufacturing company 9706/13 May/June 2015
28 The following information is available for a manufacturing company. budgeted direct labour hours 26 200 actual direct labour hours 28 000 budgeted overhead costs $166 500 actual overhead costs $172 600 What is the overhead absorption rate? A $5.95 B $6.16 C $6.35 D $6.59
1 marks
Answer: C
This question in 9706/13 May/June 2015
Q201 · The following information is available 9706/13 May/June 2015
29 The following information is available. $ $ sales 250 000 variable production costs 150 000 fixed production costs 30 000 180 000 gross profit 70 000 fixed administrative costs 50 000 profit for the year 20 000 What is the break-even point? A $100 000 B $170 000 C $200 000 D $230 000
1 marks
Answer: C
This question in 9706/13 May/June 2015
Q202 · A manufacturing business incurs the following costs 9706/11 Oct/Nov 2015
18 A manufacturing business incurs the following costs. 1 carriage inwards 2 depreciation of plant 3 wages Which item(s) can be shown as either a direct cost or an indirect cost in the manufacturing account? A 1 only B 1 and 2 C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2015
Q203 · A company makes one product with a selling price of $384 per unit 9706/11 Oct/Nov 2015
27 A company makes one product with a selling price of $384 per unit. Costs are as follows. per unit direct materials 4 kilos at $8 per kilo direct labour 8 hours at $12 per hour selling and distribution $40 The mark up is 50%. What is the factory overhead absorption rate per labour hour? A $3 B $5 C $11 D $22
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2015
Q204 · A company’s profit for a period using marginal costing was $70 000 9706/11 Oct/Nov 2015
29 A company’s profit for a period using marginal costing was $70 000. Opening inventory was 2000 units and closing inventory 2500 units. The fixed production overhead absorption rate is $10 per unit. What was the profit under absorption costing? A $50 000 B $65 000 C $75 000 D $90 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2015
Q205 · A trader runs a manufacturing business 9706/12 Oct/Nov 2015
19 A trader runs a manufacturing business. Which department should it close? A department 1 where contribution exceeds fixed costs B department 2 where contribution is less than fixed costs C department 3 where revenue exceeds marginal costs D department 4 where revenue is less than marginal costs
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2015
Q206 · A customer places an order for 20 000 bricks 9706/12 Oct/Nov 2015
24 A customer places an order for 20 000 bricks. Which costing method will the supplier use to price the order? A batch B job C marginal D unit
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2015
Q207 · A business sells its product for $50 a unit and has variable costs of $30 per unit 9706/12 Oct/Nov 2015
26 A business sells its product for $50 a unit and has variable costs of $30 per unit. Its fixed costs for this year were $200 000. Next year, fixed costs are expected to be $260 000. How many more units will have to be sold next year to make the same profit as this year? A 3000 B 5200 C 10 000 D 13 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2015
Q208 · A manufacturer produces 100 000 tins of paint with a total direct materials cost of $300… 9706/12 Oct/Nov 2015
27 A manufacturer produces 100 000 tins of paint with a total direct materials cost of $300 000. Direct labour is 2000 hours at a cost of $400 000, and overheads are absorbed at the rate of $100 per direct labour hour. What is the cost of a tin of paint? A $3 B $5 C $7 D $9
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2015
Q209 · A business provides the following information 9706/12 Oct/Nov 2015
28 A business provides the following information. number of total overheads month machine hours $ August 72 000 842 000 September 84 000 938 000 The variable overhead rate per machine hour was $8. What was the monthly fixed cost? A $96 000 B $266 000 C $576 000 D $672 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2015
Q210 · A business produces a single product 9706/12 Oct/Nov 2015
29 A business produces a single product. number of units opening inventory 5 000 production 15 000 closing inventory 2 000 The variable production cost per unit is $10 and the fixed production cost is $60 000. The sales revenue is $360 000. Profit is $108 000 based on full absorption costing. What is the profit based on marginal costing? A $8000 higher B $8000 lower C $12 000 higher D $12 000 lower
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2015
Q211 · A business provides the following information for a cost centre 9706/12 Oct/Nov 2015
30 A business provides the following information for a cost centre. apportioned overhead costs $160 000 re-apportioned service department costs $60 000 total labour hours 25 000 total machine hours 40 000 What is the overhead absorption rate for the cost centre? A $4.00 per hour B $5.50 per hour C $6.40 per hour D $8.80 per hour
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2015
Q212 · A business has two departments 9706/13 Oct/Nov 2015
18 A business has two departments. profit revenue number of floor space for the year for the year staff occupied / $ $ $ square metres department X 25 000 84 000 2 1500 department Y 65 000 204 000 4 2500 90 000 288 000 6 4000 Total rent expense in the income statement is $72 000. What is the rent cost apportioned to each department? department X department Y $ $ A 20 000 52 000 B 21 000 51 000 C 24 000 48 000 D 27 000 45 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2015
Q213 · The following information relates to a product 9706/13 Oct/Nov 2015
23 The following information relates to a product. $ fixed costs 72 000 required profit 30 000 selling price per unit 10 variable cost per unit 4 How many units must be produced and sold to cover fixed costs and make the required profit? A 12 000 B 17 000 C 18 000 D 25 500
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q214 · A company has sales of $192 000, fixed costs of $40 000 and a contribution / sales ratio… 9706/13 Oct/Nov 2015
24 A company has sales of $192 000, fixed costs of $40 000 and a contribution / sales ratio of one-third. What are its profits? A $24 000 B $50 667 C $64 000 D $88 000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2015
Q215 · A company sells a single product for $24 per batch 9706/13 Oct/Nov 2015
25 A company sells a single product for $24 per batch. The variable cost is $8 per batch. Fixed costs have been absorbed based on a normal activity level of 1000 batches at $6 per batch. What is the profit under marginal costing if the company makes and sells 1250 batches? A $10 000 B $12 500 C $14 000 D $20 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2015
Q216 · The following information is forecast for next period 9706/13 Oct/Nov 2015
26 The following information is forecast for next period. opening inventory 20 300 units closing inventory 22 500 units marginal cost profit $90 600 absorption cost profit $100 400 What is the overhead absorption rate per unit? A $4.03 B $4.45 C $4.46 D $4.95
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q217 · A company has total fixed costs of $100 000 and a break-even point of 4000 units 9706/13 Oct/Nov 2015
28 A company has total fixed costs of $100 000 and a break-even point of 4000 units. Variable costs per unit are $40. It produced and sold 10 000 units. How much is revenue per unit? A $25 B $35 C $65 D $75
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2015
Q218 · A trader received an order for 1000 shirts, 500 units printed in red and 500 units in blue 9706/13 Oct/Nov 2015
29 A trader received an order for 1000 shirts, 500 units printed in red and 500 units in blue. The printing machine had to be set up two times. The relevant cost information is shown. variable costs per unit $20 factory overhead 200% of unit variable cost machine setup per batch $1000 What is the unit cost of this order? A $60 B $61 C $62 D $66
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2015
Q219 · A production centre uses 20 000 machine hours and 17 000 labour hours each month 9706/12 Feb/March 2016
23 A production centre uses 20 000 machine hours and 17 000 labour hours each month. Which formula is used to calculate the overhead absorption rate? A total machine hours total overhead cost B total overhead cost total labour hours total overhead cost C total (labour hours + machine hours) ÷ 2 total overhead cost D total machine hours
1 marks
Answer: D
This question in 9706/12 Feb/March 2016
Q220 · The following information is available 9706/12 Feb/March 2016
24 The following information is available. budget actual overheads $60 000 $66 000 direct labour 30 000 hours 35 000 hours The overhead absorption rate is based on direct labour hours. What is the amount of overhead over-absorbed or under-absorbed? A $4000 over B $4000 under C $6000 over D $6000 under
1 marks
Answer: A
This question in 9706/12 Feb/March 2016
Q221 · A business produces and sells watches 9706/12 Feb/March 2016
26 A business produces and sells watches. In 2015, 4000 watches were produced and 3600 watches were sold. Other information for the year included the following: $ per unit direct materials 60 direct labour 80 variable selling expenses 15 fixed manufacturing overheads 45 fixed administrative costs 50 What is the cost of goods sold for 2015 if the business uses absorption costing? A $558 000 B $666 000 C $720 000 D $740 000
1 marks
Answer: B
This question in 9706/12 Feb/March 2016
Q222 · Which items are included in the marginal cost of a unit of production? 9706/12 Feb/March 2016
27 Which items are included in the marginal cost of a unit of production? A direct labour, direct materials, fixed production costs and variable production overheads B direct labour, direct materials, fixed costs and variable production overheads C direct labour, direct materials and variable production overheads only D direct labour and direct materials only
1 marks
Answer: C
This question in 9706/12 Feb/March 2016
Q223 · Which statements about cost-volume-profit analysis are correct? 9706/12 Feb/March 2016
28 Which statements about cost-volume-profit analysis are correct? 1 Profits are calculated on an absorption costing basis. 2 Profits are calculated on a marginal costing basis. 3 It only applies where there is a constant sales mix. 4 It only applies where there is a changing sales mix. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/12 Feb/March 2016
Q224 · A business has the following budgeted and actual results for a period 9706/12 Feb/March 2016
29 A business has the following budgeted and actual results for a period. $ budgeted fixed overheads 354 000 actual fixed overheads 360 000 under-absorption of overheads 3 000 The fixed overheads are absorbed per unit. The budgeted number of units were 118 000. What is the actual level of activity in units? A 118 000 B 119 000 C 120 000 D 121 000
1 marks
Answer: B
This question in 9706/12 Feb/March 2016
Q225 · A business incurs the following costs 9706/11 May/June 2016
26 A business incurs the following costs. 1 direct material and direct labour costs 2 indirect factory production overheads 3 administrative expenses 4 distribution costs Which costs are included in the cost per unit using absorption costing? A 1, 2, 3 and 4 B 1 and 2 only C 1 only D 2, 3 and 4 only
1 marks
Answer: B
This question in 9706/11 May/June 2016
Q226 · A company absorbs overheads using machine hours 9706/11 May/June 2016
27 A company absorbs overheads using machine hours. The following information is available. overheads machine hours budgeted $200 000 40 000 hours actual $240 000 60 000 hours What was the over or under absorption of overheads? A $40 000 over B $40 000 under C $60 000 over D $60 000 under
1 marks
Answer: C
This question in 9706/11 May/June 2016
Q227 · How is margin of safety calculated? 9706/11 May/June 2016
28 How is margin of safety calculated? A actual sales minus break-even sales B actual sales minus budgeted sales C actual sales minus cost of sales D budgeted sales minus cost of sales
1 marks
Answer: A
This question in 9706/11 May/June 2016
Q228 · A company incurs total costs of $2200 for producing 100 units and $4600 for 300 units 9706/11 May/June 2016
29 A company incurs total costs of $2200 for producing 100 units and $4600 for 300 units. The selling price per unit is $20. What is the total profit or loss at a production level of 200 units? A $400 loss B $600 profit C $933 profit D $1600 profit
1 marks
Answer: B
This question in 9706/11 May/June 2016
Q229 · An employee works a standard 40-hour week 9706/12 May/June 2016
22 An employee works a standard 40-hour week. In that time he is expected to make 200 complete units. He is paid a bonus of $10 for every hour saved in production. For week 25 he worked 44 hours and produced 250 units. How much was his bonus payment for week 25? A $30 B $40 C $50 D $60
1 marks
Answer: D
This question in 9706/12 May/June 2016
Q230 · A business was started on 1 January 9706/12 May/June 2016
23 A business was started on 1 January. The purchases and sales of inventory for January were as follows. date purchases sales 4 January 3 at $200 each – 13 January – 2 at $400 each 26 January 3 at $250 each – 28 January – 2 at $400 each The business used the first in first out (FIFO) method of inventory valuation. What was the gross profit for January? A $250 B $650 C $700 D $750
1 marks
Answer: D
This question in 9706/12 May/June 2016
Q231 · A manager is preparing a quotation for Job 88 9706/12 May/June 2016
24 A manager is preparing a quotation for Job 88. A specialised technician is hired to work for this job only. He will use machinery that the company already owns. Which statement is correct about expenses for Job 88? A Both machinery depreciation and technician wage are direct. B Both machinery depreciation and technician wage are indirect. C Machinery depreciation is direct and technician wage is indirect. D Machinery depreciation is indirect and technician wage is direct.
1 marks
Answer: D
This question in 9706/12 May/June 2016
Q232 · Budgeted overhead expenditure was $180 000 and budgeted labour hours were 12 000 9706/12 May/June 2016
25 Budgeted overhead expenditure was $180 000 and budgeted labour hours were 12 000. Actual overheads amounted to $196 000 and actual labour hours were 12 200. What was the under or over absorption of overheads? A $3000 over B $3000 under C $13 000 over D $13 000 under
1 marks
Answer: D
This question in 9706/12 May/June 2016
Q233 · Why might a business use marginal costing? 9706/12 May/June 2016
26 Why might a business use marginal costing? 1 to calculate break-even units 2 to decide on the most profitable use of limited resources 3 to decide whether to make a product or buy it A 1 and 2 only B 1, 2 and 3 C 2 only D 3 only
1 marks
Answer: B
This question in 9706/12 May/June 2016
Q234 · A business provided the following information for the past two months 9706/12 May/June 2016
27 A business provided the following information for the past two months. number of total overheads month labour hours $ February 64 000 918 000 March 76 000 1 062 000 What was the monthly fixed overhead cost? A $144 000 B $150 000 C $768 000 D $912 000
1 marks
Answer: B
This question in 9706/12 May/June 2016
Q235 · A company uses marginal costing 9706/12 May/June 2016
28 A company uses marginal costing. Which costs are included in its inventory valuation? A variable manufacturing cost, fixed manufacturing overhead and variable selling expenses B variable manufacturing cost and fixed manufacturing overhead only C variable manufacturing cost and variable selling expenses only D variable manufacturing cost only
1 marks
Answer: D
This question in 9706/12 May/June 2016
Q236 · The break-even sales of a company are 1000 units when the variable costs are $30 000 and… 9706/12 May/June 2016
29 The break-even sales of a company are 1000 units when the variable costs are $30 000 and fixed costs are $20 000. What is the profit if 70 units above the break-even point are sold? A $700 B $1400 C $2100 D $3500
1 marks
Answer: B
This question in 9706/12 May/June 2016
Q237 · A business incurs the following costs 9706/13 May/June 2016
26 A business incurs the following costs. 1 direct material and direct labour costs 2 indirect factory production overheads 3 administrative expenses 4 distribution costs Which costs are included in the cost per unit using absorption costing? A 1, 2, 3 and 4 B 1 and 2 only C 1 only D 2, 3 and 4 only
1 marks
Answer: B
This question in 9706/13 May/June 2016
Q238 · A company absorbs overheads using machine hours 9706/13 May/June 2016
27 A company absorbs overheads using machine hours. The following information is available. overheads machine hours budgeted $200 000 40 000 hours actual $240 000 60 000 hours What was the over or under absorption of overheads? A $40 000 over B $40 000 under C $60 000 over D $60 000 under
1 marks
Answer: C
This question in 9706/13 May/June 2016
Q239 · How is margin of safety calculated? 9706/13 May/June 2016
28 How is margin of safety calculated? A actual sales minus break-even sales B actual sales minus budgeted sales C actual sales minus cost of sales D budgeted sales minus cost of sales
1 marks
Answer: A
This question in 9706/13 May/June 2016
Q240 · A manufacturer operates a bonus system 9706/11 Oct/Nov 2016
23 A manufacturer operates a bonus system. He provides the following information. output required from each worker 175 units time allowed to complete output 10.5 hours actual time worked by Fred 7 hours A bonus is paid of 25% of the labour costs for time saved, in addition to the hourly rate of $8.75. What did Fred earn for his output of 175 units? A $68.91 B $76.56 C $91.88 D $99.53
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q241 · A potential investor looks at the financial statements of four companies 9706/11 Oct/Nov 2016
24 A potential investor looks at the financial statements of four companies. Their income statements all show the same level of revenue and profit from operations. The cost of purchasing inventory is increasing. company 1 uses AVCO to value inventory company 2 uses FIFO to value inventory company 3 uses absorption costing company 4 uses marginal costing The investor wishes to invest in companies with the best underlying profitability. Which companies should he select? A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2016
Q242 · When does under absorption of overheads occur? 9706/11 Oct/Nov 2016
26 When does under absorption of overheads occur? 1 Actual expenditure is less than budgeted. 2 Actual expenditure is more than budgeted. 3 Production is lower than planned. 4 Production is higher than planned. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2016
Q243 · The following information is available in respect of department 1 9706/11 Oct/Nov 2016
27 The following information is available in respect of department 1. actual forecast direct labour hours 45 000 40 000 machine hours 12 000 10 000 overheads to be apportioned to department 1 $90 000 The company has been asked to quote for an order. The expected time taken in department 1 will be four direct labour hours and seven machine hours. How much overhead should be charged to the order as it passes through department 1? A $8.00 B $9.00 C $52.50 D $63.00
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2016
Q244 · A business manufactures a single product 9706/11 Oct/Nov 2016
28 A business manufactures a single product. The following information is available. estimated this year next year $ $ selling price per unit 25 25 variable cost per unit 15 17 total fixed costs 80 000 84 000 profit for the year 20 000 How many units must be sold to achieve the same profit next year? A 10 000 B 10 500 C 12 500 D 13 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2016
Q245 · A company wants to sell 50 000 units and achieve a profit of $600 000 9706/11 Oct/Nov 2016
29 A company wants to sell 50 000 units and achieve a profit of $600 000. It has variable costs of $60 per unit and total fixed overheads of $400 000. What is the selling price per unit it needs to charge? A $64 B $68 C $72 D $80
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2016
Q246 · A business manufactures several products 9706/11 Oct/Nov 2016
30 A business manufactures several products. There is a shortage of direct materials. Which product will it manufacture first? A the one with the highest contribution per unit of limiting factor B the one with the highest demand C the one with the lowest quantity of total direct materials used D the one with the lowest variable costs
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q247 · In a manufacturing business the following could occur 9706/12 Oct/Nov 2016
25 In a manufacturing business the following could occur. 1 Actual overheads paid are less than budgeted overheads. 2 Actual overheads paid are more than budgeted overheads. 3 Actual units produced are less than budgeted units. 4 Actual units produced are more than budgeted units. Which situations would result in an under absorption of overhead expenditure? A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2016
Q248 · A company makes and sells a single product for $12 per batch 9706/12 Oct/Nov 2016
26 A company makes and sells a single product for $12 per batch. The variable cost is $4 per batch. Fixed costs have been absorbed based on a normal activity level of 1000 batches at $3 per batch. What is the profit under marginal costing if the company makes and sells 1500 batches? A $6000 B $7500 C $9000 D $12 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2016
Q249 · The following information was provided about a product 9706/12 Oct/Nov 2016
27 The following information was provided about a product. selling price per unit $50 variable cost per unit $26 total fixed costs $10 000 demand 1800 units If the selling price increases only demand changes. When the selling price increased by $4 profit fell by $1200. What was the decrease in demand? A 214 units B 300 units C 571 units D 657 units
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2016
Q250 · A company makes a product for which the following information is given 9706/12 Oct/Nov 2016
29 A company makes a product for which the following information is given. per unit $ selling price 100 direct materials 40 direct labour 30 Total fixed costs are $40 000. Planned production is 1000 units. Which action should the company take to break-even? A decrease direct labour cost by 30% B decrease direct material cost by 25% C increase direct labour cost by 30% D increase direct materials cost by 25%
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2016
Q251 · A business provided the following information 9706/13 Oct/Nov 2016
22 A business provided the following information. budgeted overheads $20 000 budgeted direct labour hours 2000 direct labour rate $20 per hour A job used materials costing $45 and 6 hours of direct labour. Overheads are charged on the basis of direct labour hours used. What was the cost of the job before adding any profit? A $165 B $175 C $180 D $225
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2016
Q252 · What is a reason for overhead absorption in a manufacturing business? 9706/13 Oct/Nov 2016
23 What is a reason for overhead absorption in a manufacturing business? A to control overhead expenditure B to determine the net realisable value of inventory C to enable overheads to be apportioned to cost centres D to establish costs per unit of product
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2016
Q253 · The following inventory transactions are available for a business 9706/13 Oct/Nov 2016
24 The following inventory transactions are available for a business. opening inventory on 1 January 16 items at $525 each receipts on 3 January 24 items at $675 each issues on 5 January 28 items The business uses the AVCO method to value inventory. What was the value of closing inventory on 7 January? A $6300 B $7200 C $7380 D $8100
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2016
Q254 · A business absorbs overheads on the basis of direct labour hours 9706/13 Oct/Nov 2016
26 A business absorbs overheads on the basis of direct labour hours. The following information is available. budgeted labour hours 6600 hours actual labour hours 7100 hours budgeted overheads $75 900 actual overheads $74 250 What is the value of overheads over or under absorbed? A $5625 over B $5625 under C $7400 over D $7400 under
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2016
Q255 · A manufacturing business has two production departments: assembly and painting 9706/13 Oct/Nov 2016
27 A manufacturing business has two production departments: assembly and painting. The following information is available. assembly painting machinery at net book value ($) 150 000 100 000 machinery repair costs ($) 14 000 6 000 machine operating hours 60 000 15 000 number of machines 30 10 The total machinery insurance cost for the year was $5000. How much insurance should be apportioned to the assembly department? A $3000 B $3500 C $3750 D $4000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2016
Q256 · The table shows figures for a week’s production 9706/13 Oct/Nov 2016
29 The table shows figures for a week’s production. expected production 10 000 units expected production overheads $50 000 actual production overheads $60 000 under absorption of overheads $5 000 What is the actual amount of production in the week? A 9000 units B 9167 units C 11 000 units D 13 000 units
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2016
Q257 · A business makes a single product 9706/13 Oct/Nov 2016
30 A business makes a single product. The following information is available. total cost production $ 600 units 4200 800 units 5200 What is the fixed cost per unit? for 600 units for 800 units $ $ A 2.00 1.50 B 2.00 2.00 C 5.00 5.00 D 7.00 6.50
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2016
Q258 · How is the issue of inventory from stores valued when using FIFO? 9706/12 Feb/March 2017
22 How is the issue of inventory from stores valued when using FIFO? A It is calculated using the average purchase price of goods. B It is calculated using the price paid for the earliest delivery of goods. C It is the same as the current replacement cost. D It is the same as the most recent price paid for the goods.
1 marks
Answer: B
This question in 9706/12 Feb/March 2017
Q259 · A business absorbs overheads based on machine hours 9706/12 Feb/March 2017
23 A business absorbs overheads based on machine hours. During the last quarter it had the following budgeted and actual results. actual overheads $118 505 actual machine hours 6 230 budgeted overheads $126 725 budgeted machine hours 6 850 By how much were overheads over or under absorbed? A over absorbed by $3250 B over absorbed by $8220 C under absorbed by $3250 D under absorbed by $8220
1 marks
Answer: C
This question in 9706/12 Feb/March 2017
Q260 · Actual output exceeds budgeted output 9706/12 Feb/March 2017
24 Actual output exceeds budgeted output. Which cost is higher than budgeted? A fixed costs per unit B total fixed costs C total variable costs D variable costs per unit
1 marks
Answer: C
This question in 9706/12 Feb/March 2017
Q261 · A company manufactures three products 9706/12 Feb/March 2017
25 A company manufactures three products. The following information is obtained in respect of next month’s budgeted production. product X product Y product Z contribution per unit $7 $6 $8 contribution per kilo $3 $4 $6 kilos of material required 400 600 1000 for production The company has been advised that only 1800 kilos of material will be available for production next month. What is the maximum contribution the company can earn? A $9000 B $9600 C $13 000 D $13 200
1 marks
Answer: A
This question in 9706/12 Feb/March 2017
Q262 · The following information is available 9706/12 Feb/March 2017
26 The following information is available. $ direct materials 20 000 direct labour 45 000 direct expenses 6 000 variable overheads 11 000 fixed overheads 38 000 sales 240 000 What is the contribution to sales ratio? A 50% B 54.58% C 65.83% D 70.42%
1 marks
Answer: C
This question in 9706/12 Feb/March 2017
Q263 · A company provides the following information 9706/12 Feb/March 2017
27 A company provides the following information. budgeted overheads $136 000 budgeted labour hours 10 568 actual overheads $146 000 actual labour hours 10 110 What is the overhead absorption rate per labour hour? A $12.87 B $13.45 C $13.82 D $14.44
1 marks
Answer: A
This question in 9706/12 Feb/March 2017
Q264 · The following information is for a business 9706/12 Feb/March 2017
28 The following information is for a business. $ budgeted fixed costs per month 2000 target profit per month 3000 budget variable cost per unit 15 selling price per unit 40 Fixed costs are expected to increase by $500 per month and variable costs increase by $5 per unit. Which value of revenue will be required to achieve the target profit? A $8000 B $8800 C $10 000 D $11 000
1 marks
Answer: D
This question in 9706/12 Feb/March 2017
Q265 · The costs of a company that annually sells 10 000 units are as follows 9706/12 Feb/March 2017
29 The costs of a company that annually sells 10 000 units are as follows. $ direct material 50 000 assembly labour 100 000 factory overheads 70 000 The normal selling price of each unit is $50. How many more units need to be sold to break even if the selling price is reduced to $35? A 1500 units B 2000 units C 3500 units D 5000 units
1 marks
Answer: A
This question in 9706/12 Feb/March 2017
Q266 · Which statements identify a disadvantage of break-even analysis? 9706/12 Feb/March 2017
30 Which statements identify a disadvantage of break-even analysis? 1 It does not show the effect of changes in output on the break-even point. 2 It is assumed that all costs can be split between fixed and variable. 3 It makes it difficult to decide the profitability of a product at different levels of activity. A 1 and 2 B 2 and 3 C 2 only D 3 only
1 marks
Answer: C
This question in 9706/12 Feb/March 2017
Q267 · A business has the following information available 9706/11 May/June 2017
23 A business has the following information available. selling price per unit $35 direct labour per unit $9 direct material per unit $6 budgeted sales 8000 units margin of safety 2000 units What is the value of fixed costs? A $40 000 B $120 000 C $160 000 D $200 000
1 marks
Answer: B
This question in 9706/11 May/June 2017
Q268 · A company has allocated its costs between different departments as shown 9706/11 May/June 2017
24 A company has allocated its costs between different departments as shown. production production maintenance details department 1 department 2 department allocated costs $80 000 $60 000 $10 000 split of maintenance department costs 60% 40% direct labour hours 20 000 8 000 What is the overhead absorption rate per labour hour for production department 1? A $3.70 B $4.00 C $4.20 D $4.30
1 marks
Answer: D
This question in 9706/11 May/June 2017
Q269 · Vikram is paid $10 an hour for a 40-hour week and at time and a half for overtime 9706/11 May/June 2017
25 Vikram is paid $10 an hour for a 40-hour week and at time and a half for overtime. He is expected to produce four units an hour. If he produces more than this, a bonus of $2 per extra unit is paid. Last week Vikram worked 41 hours and produced 161 units. How much was Vikram paid? A $410 B $412 C $415 D $417
1 marks
Answer: C
This question in 9706/11 May/June 2017
Q270 · A business operated a staff canteen at a cost of $12 000 9706/11 May/June 2017
26 A business operated a staff canteen at a cost of $12 000. What is the most appropriate basis of apportioning this overhead cost? A book value of canteen equipment B direct labour hours C floor area D number of employees
1 marks
Answer: D
This question in 9706/11 May/June 2017
Q271 · A business apportions some of its overhead expenses across its production departments 9706/11 May/June 2017
27 A business apportions some of its overhead expenses across its production departments. Why might building maintenance costs not be included with the other overheads being apportioned? A Building maintenance costs are fixed. B Building maintenance is not necessary for production to take place. C No suitable basis for apportionment can be found. D They can be identified with specific cost centres.
1 marks
Answer: D
This question in 9706/11 May/June 2017
Q272 · The following information is available for a business 9706/11 May/June 2017
28 The following information is available for a business. budgeted manufacturing overhead $234 000 budgeted direct labour hours 45 000 actual manufacturing overhead $243 600 actual direct labour hours 42 000 How much overhead was under or over absorbed? A $25 200 over absorbed B $25 200 under absorbed C $27 000 over absorbed D $27 000 under absorbed
1 marks
Answer: B
This question in 9706/11 May/June 2017
Q273 · A company manufactures and sells 10 000 units 9706/11 May/June 2017
29 A company manufactures and sells 10 000 units. Details of the revenues and costs are as follows. total $ sales revenue 200 000 variable costs 80 000 fixed costs 90 000 profit 30 000 What is the break-even point in units? A 2500 B 4500 C 7500 D 10 000
1 marks
Answer: C
This question in 9706/11 May/June 2017
Q274 · The data in the table relates to a business 9706/11 May/June 2017
30 The data in the table relates to a business. $ sales 6000 variable costs 4500 fixed costs 900 profit for the year 600 What is the contribution to sales ratio? A 10% B 25% C 33.33% D 75%
1 marks
Answer: B
This question in 9706/11 May/June 2017
Q275 · Jamal uses the AVCO system to value his inventory 9706/12 May/June 2017
22 Jamal uses the AVCO system to value his inventory. He provides the following information: March 1 no opening inventory 6 60 units were purchased at $120 per unit 17 100 units were purchased at $116 per unit 23 110 units were sold for $150 per unit What was the cost of sales for March? A $5875 B $12 925 C $13 000 D $18 800
1 marks
Answer: B
This question in 9706/12 May/June 2017
Q276 · A business makes wedding dresses 9706/12 May/June 2017
23 A business makes wedding dresses. Each machinist is paid $30 a day and each supervisor $40 a day. Each supervisor can work with up to 10 machinists and each machinist can produce one wedding dress a day. If 95 wedding dresses a day are produced, what is the daily labour cost? A $2850 B $3210 C $3230 D $3250
1 marks
Answer: D
This question in 9706/12 May/June 2017
Q277 · A company manufactures and sells chairs 9706/12 May/June 2017
25 A company manufactures and sells chairs. The following per unit information is available. $ selling price 25 direct material and labour 12 other variable production costs 3 variable selling costs 2 fixed costs 4 The company has the option of buying in the chairs for resale instead of making them. At which purchase price would the company’s profit be unchanged? A $15 B $17 C $19 D $21
1 marks
Answer: A
This question in 9706/12 May/June 2017
Q278 · The budgeted income statement of J Limited shows the following 9706/12 May/June 2017
26 The budgeted income statement of J Limited shows the following. $ sales 400 000 variable costs 240 000 fixed costs 132 000 profit for the year 28 000 What is the margin of safety in dollars? A $70 000 B $160 000 C $268 000 D $330 000
1 marks
Answer: A
This question in 9706/12 May/June 2017
Q279 · The following details are supplied by a company for the month of August 9706/12 May/June 2017
27 The following details are supplied by a company for the month of August. budgeted machine hours 36 000 budgeted overheads $162 000 actual machine hours 36 500 actual overheads $155 000 What is the under or over absorption of the overheads? A $2250 over absorbed B $2250 under absorbed C $9250 over absorbed D $9250 under absorbed
1 marks
Answer: C
This question in 9706/12 May/June 2017
Q280 · A company has fixed costs of $40 000 per month 9706/12 May/June 2017
28 A company has fixed costs of $40 000 per month. It provided the following information. March units April units production 30 000 15 000 Total production costs for March were $90 000. What were the total production costs for April? A $45 000 B $65 000 C $70 000 D $110 000
1 marks
Answer: B
This question in 9706/12 May/June 2017
Q281 · A company’s profits using marginal costing and absorption costing principles were… 9706/12 May/June 2017
29 A company’s profits using marginal costing and absorption costing principles were identical. Which statement is true about the company’s production units? A they were greater than break-even units B they were greater than the sales units C they were the same as the break-even units D they were the same as the sales units
1 marks
Answer: D
This question in 9706/12 May/June 2017
Q282 · The labour costs of a company are based on hours worked plus a bonus scheme 9706/13 May/June 2017
22 The labour costs of a company are based on hours worked plus a bonus scheme. The production workers all earn the same rate and bonus. The daily rate is $6 per hour for an 8-hour day, 5 days per week. The bonus is based on the number of units produced above 2000 units in a week at a rate of $2 per 100 units. In one week each worker produces 2600 units. All workers work the full number of hours. What will be the week’s gross wage for one worker? A $240 B $252 C $292 D $304
1 marks
Answer: B
This question in 9706/13 May/June 2017
Q283 · The following information is available for a business 9706/13 May/June 2017
24 The following information is available for a business. budgeted sales per month 500 units selling price per unit $30 variable cost per unit $24 budgeted monthly fixed costs $600 The business plans to rent a machine which will increase monthly fixed costs to $2400 and reduce variable costs to $18 per unit. What will be the effect on the margin of safety of the business? A increase by 100 units B increase by 150 units C reduce by 100 units D reduce by 150 units
1 marks
Answer: C
This question in 9706/13 May/June 2017
Q284 · The following information concerning a product is available 9706/13 May/June 2017
25 The following information concerning a product is available. $ per unit selling price 10.00 variable labour costs 3.50 production material costs 2.50 break-even point 2500 units What is the total fixed cost? A $10 000 B $15 000 C $16 250 D $18 750
1 marks
Answer: A
This question in 9706/13 May/June 2017
Q285 · The data shows the budget of a small manufacturing company 9706/13 May/June 2017
26 The data shows the budget of a small manufacturing company. sales in units 6 000 12 000 $ $ direct materials 18 000 36 000 direct labour 6 000 12 000 production overheads 33 000 45 000 administrative overheads 27 000 27 000 The units are sold for $16 each. What is the break-even point in units? A 2700 B 3000 C 4000 D 4800
1 marks
Answer: D
This question in 9706/13 May/June 2017
Q286 · A company uses direct labour hours to calculate the overhead absorption rate 9706/13 May/June 2017
27 A company uses direct labour hours to calculate the overhead absorption rate. What results in over-absorption? 1 actual overheads exceed budgeted overheads 2 actual overheads are less than budgeted overheads 3 budgeted production is greater than actual production 4 budgeted production is less than actual production A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: D
This question in 9706/13 May/June 2017
Q287 · A company’s limiting factor is production materials 9706/13 May/June 2017
28 A company’s limiting factor is production materials. It manufactures three different products. Which product should it manufacture first in order to maximise profits? A the product making the highest contribution per kilo of materials B the product making the highest number of unit sales C the product making the most contribution per unit D the product using the least materials per unit
1 marks
Answer: A
This question in 9706/13 May/June 2017
Q288 · The following information has been provided for the year 9706/13 May/June 2017
29 The following information has been provided for the year. $ sales 400 000 variable costs 240 000 total contribution 160 000 fixed administrative expenses 90 000 fixed selling expenses 50 000 profit for the year 20 000 The company plans to increase the selling price by 10%. By how much will profit for the year increase? A 10% B 55% C 80% D 200%
1 marks
Answer: D
This question in 9706/13 May/June 2017
Q289 · A business manufactures a single product 9706/11 Oct/Nov 2017
22 A business manufactures a single product. Which cost can be allocated to its production departments? A administrative expenses B direct materials C factory light and heat D factory rent
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2017
Q290 · A business absorbs overheads based on machine hours 9706/11 Oct/Nov 2017
25 A business absorbs overheads based on machine hours. During the last quarter it had the following budgeted and actual results. actual overheads $127 346 actual machine hours 5 490 budgeted overheads $129 375 budgeted machine hours 5 625 By how much were overheads under or over absorbed? A over absorbed by $1076 B over absorbed by $2029 C under absorbed by $1076 D under absorbed by $2029
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2017
Q291 · Which statements about marginal costing are correct? 9706/11 Oct/Nov 2017
26 Which statements about marginal costing are correct? 1 It only uses fixed and variable costs in calculations. 2 It only uses variable costs in calculations. 3 It should only be used for long-term planning decisions. 4 It should only be used for short-term planning decisions. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2017
Q292 · A business has the following budget for April 9706/11 Oct/Nov 2017
27 A business has the following budget for April. $ sales revenue 1 000 000 contribution 550 000 fixed production costs 275 000 fixed selling costs 55 000 What is the break-even sales revenue for April? A $450 000 B $500 000 C $600 000 D $670 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2017
Q293 · A company has fixed costs during a quarter of $300 000 9706/11 Oct/Nov 2017
28 A company has fixed costs during a quarter of $300 000. It sells its single product for $25 per unit and has a contribution to sales ratio of 40%. How many units of product does it need to sell to make a profit of $100 000? A 10 000 B 16 000 C 30 000 D 40 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2017
Q294 · The following information is available about two products 9706/11 Oct/Nov 2017
29 The following information is available about two products. product 1 product 2 per unit per unit material X 2 kilos 4 kilos material Y 3 kilos 1 kilo direct labour 3 hours 6 hours Production is planned to be 100 units of each product. 700 kilos of material X and 400 kilos of material Y are available. A total of 800 direct labour hours can be worked. What is / are the limiting factor(s)? A direct labour B material X C material Y D all three inputs
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2017
Q295 · The following information is forecast for next period 9706/12 Oct/Nov 2017
24 The following information is forecast for next period. units opening inventory 54 275 closing inventory 60 120 $ profit using marginal costing 300 600 profit using absorption costing 390 780 What is the overhead absorption rate per unit? A $5.00 B $6.50 C $7.20 D $15.43
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2017
Q296 · A business has total fixed costs of $240 000 9706/12 Oct/Nov 2017
25 A business has total fixed costs of $240 000. Products have a unit selling price of $25 and a unit variable cost of $15. How many units need to be sold to break even? A 6000 B 9600 C 16 000 D 24 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2017
Q297 · The table contains information provided by a company 9706/12 Oct/Nov 2017
26 The table contains information provided by a company. budgeted direct labour hours 8000 actual direct labour hours worked 7500 budgeted overhead expenditure $104 000 actual overhead expenditure $112 500 What is the over or under recovery of overheads? A $8500 over recovered B $8500 under recovered C $15 000 over recovered D $15 000 under recovered
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2017
Q298 · Which statements about the limitations of marginal costing are correct? 9706/12 Oct/Nov 2017
28 Which statements about the limitations of marginal costing are correct? 1 Finance costs are not included in the manufacturing overheads. 2 Variable cost per unit changes at different levels of activity. 3 Some costs may be semi-variable costs. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2017
Q299 · A product has a variable cost of $31.32 per unit 9706/12 Oct/Nov 2017
29 A product has a variable cost of $31.32 per unit. Total fixed costs are $93 600. When production is 13 000 units the margin of safety is 5000 units. What is the selling price per unit? A $36.52 B $38.52 C $43.02 D $50.04
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2017
Q300 · Which will result in a high valuation of closing inventory? 9706/13 Oct/Nov 2017
23 Which will result in a high valuation of closing inventory? A AVCO in periods of rising cost prices B AVCO in periods of rising selling prices C FIFO in periods of rising cost prices D FIFO in periods of rising selling prices
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2017
Q301 · A manufacturing business has the following data 9706/13 Oct/Nov 2017
24 A manufacturing business has the following data. budgeted factory overheads $144 000 budgeted machine hours 40 000 actual factory overheads $147 600 actual machine hours 36 000 What is the overhead absorption rate per machine hour? A $3.60 B $3.69 C $4.00 D $4.10
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2017
Q302 · Which values can be calculated when absorption costing is used? 9706/13 Oct/Nov 2017
25 Which values can be calculated when absorption costing is used? 1 an inventory value which includes all production costs 2 the margin of safety at the current level of production 3 the selling price of the product A 1 and 2 B 1 and 3 C 1 only D 2 and 3
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2017
Q303 · How is margin of safety calculated? 9706/13 Oct/Nov 2017
28 How is margin of safety calculated? A actual total contribution – break-even contribution B actual total contribution – budgeted total contribution C budgeted total sales units – actual total sales units D budgeted total sales units – break-even sales units
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2017
Q304 · A business has fixed costs for a month of $150 000 9706/13 Oct/Nov 2017
29 A business has fixed costs for a month of $150 000. It sells its single product for $20 per unit and has a contribution to sales ratio of 75%. It wishes to make a profit of $300 000 for the month. How many units does the business need to sell? A 10 000 B 20 000 C 22 500 D 30 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2017
Q305 · The following information is available for a product 9706/13 Oct/Nov 2017
30 The following information is available for a product. The budgeted selling price per unit is $250. Break-even quantity is 800 units. Contribution to sales ratio is 60%. What are the values for both fixed and variable costs? variable costs total fixed costs per unit $ $ A 80 000 100 B 80 000 150 C 120 000 100 D 120 000 150
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2017
Q306 · Which business would use a job costing system of accounting? 9706/12 Feb/March 2018
18 Which business would use a job costing system of accounting? A a beauty parlour B a chocolate factory C a dairy milk farmer D an oil refinery
1 marks
Answer: A
This question in 9706/12 Feb/March 2018
Q307 · Which statements about absorption costing are correct? 9706/12 Feb/March 2018
22 Which statements about absorption costing are correct? 1 It can be used as a basis for calculating the selling price of a product. 2 It ensures that all the costs of the business are charged to the production. 3 It ensures that only variable costs are charged to production. 4 It is used to calculate the factory cost for a unit of production. A 1 and 2 B 1 and 4 C 2 and 4 D 3 and 4
1 marks
Answer: B
This question in 9706/12 Feb/March 2018
Q308 · How is the margin of safety calculated? 9706/12 Feb/March 2018
23 How is the margin of safety calculated? A actual contribution less budgeted contribution B actual profit less budgeted profit C budgeted contribution less break-even point D budgeted sales less break-even point
1 marks
Answer: D
This question in 9706/12 Feb/March 2018
Q309 · A business provides the following information about a product 9706/12 Feb/March 2018
24 A business provides the following information about a product. $ variable cost per unit 16 selling price per unit 30 total fixed costs 35 000 budgeted profit 95 000 How many units should it produce to achieve the budgeted profit? A 4286 B 4334 C 6786 D 9286
1 marks
Answer: D
This question in 9706/12 Feb/March 2018
Q310 · A company manufactures two products 9706/12 Feb/March 2018
27 A company manufactures two products. product X product Y per unit $ $ selling price 20 30 direct labour 10 20 direct materials 4 2 Total fixed costs are $54 000. Only 3000 units of Y can be made and sold. How many units of product X must be made and sold to break even? A 4000 B 4500 C 5000 D 9000
1 marks
Answer: C
This question in 9706/12 Feb/March 2018
Q311 · A company uses absorption costing and makes and sells one product 9706/12 Feb/March 2018
28 A company uses absorption costing and makes and sells one product. In the last month budgeted overheads totalled $60 000. Budgeted production was 15 000 units and budgeted sales were 14 000 units. The company now decides to apply marginal costing principles for last month. What effect will this have on profits? A $3500 decrease B $3500 increase C $4000 decrease D $4000 increase
1 marks
Answer: C
This question in 9706/12 Feb/March 2018
Q312 · A business had the following transactions relating to inventory 9706/11 May/June 2018
23 A business had the following transactions relating to inventory. March 1 opening inventory 20 items at $7.50 each 3 sales of inventory 12 items at $9 each 6 purchases of inventory 18 items at $8.20 each What was the cost per unit of closing inventory on 7 March using the AVCO (perpetual) method? A $7.29 B $7.85 C $7.98 D $8.23
1 marks
Answer: C
This question in 9706/11 May/June 2018
Q313 · Which statements about marginal costing are correct? 9706/11 May/June 2018
24 Which statements about marginal costing are correct? 1 The marginal cost of a product includes an allowance for fixed overheads. 2 The marginal cost of a product represents the additional cost of making one extra unit. 3 If inventory decreases during a period, the profits under absorption costing will be lower than under marginal costing. A 1, 2 and 3 B 1 only C 2 and 3 only D 2 only
1 marks
Answer: C
This question in 9706/11 May/June 2018
Q314 · How is an overhead absorption rate per machine hour calculated? 9706/11 May/June 2018
25 How is an overhead absorption rate per machine hour calculated? A by dividing actual overheads with actual machine hours B by dividing actual overheads with budgeted machine hours C by dividing budgeted overheads with actual machine hours D by dividing budgeted overheads with budgeted machine hours
1 marks
Answer: D
This question in 9706/11 May/June 2018
Q315 · A baker receives one order for 350 loaves of bread 9706/12 May/June 2018
20 A baker receives one order for 350 loaves of bread. Which costing method will the baker use? A absorption costing B batch costing C job costing D unit costing
1 marks
Answer: B
This question in 9706/12 May/June 2018
Q316 · A business values their inventory using the AVCO method 9706/12 May/June 2018
24 A business values their inventory using the AVCO method. The inventory on 1 June 2017 was 100 units valued at $2.40 each. The following took place. June 5 purchased 40 units at $2.50 per unit 7 sold 60 units at $3.50 per unit What was the value of the inventory on 8 June 2017 to the nearest dollar? A $194 B $196 C $200 D $224
1 marks
Answer: A
This question in 9706/12 May/June 2018
Q317 · The following budgeted information is available for a hotel for the next financial year 9706/12 May/June 2018
25 The following budgeted information is available for a hotel for the next financial year. fixed overheads $192 000 direct costs $240 000 number of guests 2400 average guest stay 4 nights What is the overhead absorption rate per guest night? A $20 B $45 C $80 D $180
1 marks
Answer: A
This question in 9706/12 May/June 2018
Q318 · The direct material cost of 20 000 units is $8000 9706/12 May/June 2018
29 The direct material cost of 20 000 units is $8000. 400 direct labour hours are required at a cost of $6000. Overheads are absorbed at 150% of the cost of direct labour. What is the cost per unit? A $0.40 B $0.70 C $0.85 D $1.15
1 marks
Answer: D
This question in 9706/12 May/June 2018
Q319 · A business apportions some of its overhead expenses across its production departments 9706/13 May/June 2018
20 A business apportions some of its overhead expenses across its production departments. Why might building maintenance costs not be included with the other overheads being apportioned? A Building maintenance costs are fixed. B Building maintenance is not necessary for production to take place. C No suitable basis for apportionment can be found. D They can be identified with specific cost centres.
1 marks
Answer: D
This question in 9706/13 May/June 2018
Q320 · The following information is available for a manufacturing business 9706/13 May/June 2018
22 The following information is available for a manufacturing business. What could cause an under-absorption of overheads? actual budget A machine hours 2 000 1 000 B overhead expenditure ($) 8 000 10 000 C production units 3 000 5 000 D sales units 6 000 5 000
1 marks
Answer: C
This question in 9706/13 May/June 2018
Q321 · A business produces two products for the month of January 9706/13 May/June 2018
23 A business produces two products for the month of January. Overheads are absorbed using the direct labour hour rate. The production details are as follows. product P Q units manufactured and sold 5000 2000 direct labour hours per unit 1.5 1 Direct costs for the month were $23 750. The fixed overheads were $6500. What was the overhead absorption rate? A $0.68 per hour B $2.50 per hour C $3.18 per hour D $3.39 per hour
1 marks
Answer: A
This question in 9706/13 May/June 2018
Q322 · A chemical plant produces a batch of 50 000 units 9706/13 May/June 2018
26 A chemical plant produces a batch of 50 000 units. Direct materials cost $400 000. Direct labour is 1000 hours at a cost of $60 000, and overheads are absorbed at the rate of $60 per direct labour hour. What is the cost of one unit? A $8.00 B $9.20 C $10.40 D $14.00
1 marks
Answer: C
This question in 9706/13 May/June 2018
Q323 · A company uses a direct labour rate of $5.40 per hour to absorb production overhead 9706/13 May/June 2018
29 A company uses a direct labour rate of $5.40 per hour to absorb production overhead. Each unit of product manufactured requires four direct labour hours. The following information is available for a period. $ actual production overhead 518 400 under absorbed production overhead 32 400 What was the actual output for the period? A 22 500 units B 24 000 units C 25 500 units D 90 000 units
1 marks
Answer: A
This question in 9706/13 May/June 2018
Q324 · A business absorbs overheads based on machine hours 9706/11 Oct/Nov 2018
25 A business absorbs overheads based on machine hours. During last month it had the following results. actual overheads $158 200 actual machine hours 7310 budgeted overheads $168 200 budgeted machine hours 8410 Which statement is correct? A Overheads were over-absorbed by $10 000. B Overheads were over-absorbed by $12 000. C Overheads were under-absorbed by $10 000. D Overheads were under-absorbed by $12 000.
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2018
Q325 · The diagram shows a break-even chart 9706/11 Oct/Nov 2018
26 The diagram shows a break-even chart. 100 sales revenue 90 total costs 80 70 60 $000 50 40 30 20 10 0 0 1000 2000 3000 4000 5000 number of units sold What is the margin of safety? A $10 000 B $15 000 C $40 000 D $60 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2018
Q326 · The following information applies to a business 9706/11 Oct/Nov 2018
27 The following information applies to a business. output sales profits (units) $ $ 375 750 000 100 000 500 1 000 000 250 000 What is the contribution to sales ratio? A 25% B 50% C 60% D 83%
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2018
Q327 · A business makes and sells three products: X, Y and Z 9706/11 Oct/Nov 2018
29 A business makes and sells three products: X, Y and Z. There will be a maximum of 3000 hours of labour time available in January. The following information for the three products is available: X Y Z contribution per unit $50 $60 $70 maximum demand per month (units) 1000 500 800 labour time per unit 1 hour 1.5 hours 2 hours What will be the optimal sales mix of products in January? X Y Z A 825 500 800 B 1000 325 800 C 1000 500 625 D 1000 500 800
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2018
Q328 · A retailer uses the FIFO method for inventory valuation 9706/12 Oct/Nov 2018
23 A retailer uses the FIFO method for inventory valuation. The following information is available. June $ 1 opening inventory 300 units at $12 per unit 3 600 10 purchased 1000 units at $12.50 per unit 12 500 21 sold 1200 units for $16 each 19 200 28 purchased 700 units at $13 per unit 9 100 What was the value of the inventory at 30 June? A $6000 B $9850 C $10 080 D $10 350
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2018
Q329 · A business manufactures 175 units of a product each month 9706/12 Oct/Nov 2018
24 A business manufactures 175 units of a product each month. The following information is available for the month. Per unit $ revenue 580 variable costs 230 fixed overheads 90 What is the break-even point in units? A 45 units B 61 units C 88 units D 160 units
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2018
Q330 · When is marginal costing less useful than absorption costing? 9706/12 Oct/Nov 2018
25 When is marginal costing less useful than absorption costing? A when choosing to make or buy a product B when dealing with a limiting factor C when producing a special order D when valuing closing inventory
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2018
Q331 · A company manufactures a single product with a selling price of $75 per unit 9706/12 Oct/Nov 2018
26 A company manufactures a single product with a selling price of $75 per unit. The table shows the costs based on sales and production volume of 8000 units. $ direct costs 158 000 variable manufacturing overheads 74 000 fixed manufacturing overheads 80 000 variable selling overheads 20 000 fixed administration overheads 100 000 If absorption costing is applied, what is the gross profit on each unit sold? A $21.00 B $36.00 C $43.50 D $46.00
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2018
Q332 · A company has the following revenue information for a month 9706/12 Oct/Nov 2018
27 A company has the following revenue information for a month. $ actual revenue 510 000 break-even revenue 555 000 budgeted revenue 570 000 What was its margin of safety during the month? A –$60 000 B –$45 000 C +$45 000 D +$60 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2018
Q333 · A business provides the following information 9706/12 Oct/Nov 2018
28 A business provides the following information. budgeted overhead costs $280 000 budgeted labour hours 25 000 budgeted machine hours 20 000 actual overhead cost $336 000 actual labour hours 35 000 actual machine hours 30 000 What is the over-absorption or under-absorption of overheads? A $56 000 over absorbed B $56 000 under absorbed C $84 000 over absorbed D $84 000 under absorbed
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2018
Q334 · A business provides the following budgeted information 9706/12 Oct/Nov 2018
29 A business provides the following budgeted information. contribution to sales ratio 60% budgeted sales $240 000 budgeted production units 40 000 What is the contribution per unit? A $3.60 B $3.75 C $9.60 D $10.00
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2018
Q335 · The inventory records of a business show the following information for product X 9706/13 Oct/Nov 2018
22 The inventory records of a business show the following information for product X. cost per unit units $ 1 January opening balance 100 3 3 January receipts into inventory 50 4 8 January inventory issued 120 – What is the value of the inventory issued on 8 January using the FIFO method? A $360 B $380 C $410 D $420
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2018
Q336 · A company has the following budgeted information 9706/13 Oct/Nov 2018
23 A company has the following budgeted information. units opening inventory 60 900 closing inventory 67 500 $ profit using marginal costing 271 350 profit using absorption costing 300 126 What is the value of overheads absorbed by each unit? A $4.02 B $4.36 C $4.45 D $4.93
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2018
Q337 · A business provided the following information 9706/12 Feb/March 2019
21 A business provided the following information. budgeted overheads $127 000 budgeted machine hours 10 450 actual overheads $149 000 actual machine hours 9 300 What was the absorption rate per machine hour? A $12.15 B $13.66 C $14.26 D $16.02
1 marks
Answer: A
This question in 9706/12 Feb/March 2019
Q338 · A company uses machine hours to absorb its overheads 9706/12 Feb/March 2019
24 A company uses machine hours to absorb its overheads. The following information is provided for a month. actual budgeted overheads $237 010 $253 450 machine hours 12 460 13 700 Which statement regarding overheads is correct? A $6500 over-absorbed B $6500 under-absorbed C $16 440 over-absorbed D $16 440 under-absorbed
1 marks
Answer: B
This question in 9706/12 Feb/March 2019
Q339 · The following information is available in respect of a product 9706/12 Feb/March 2019
26 The following information is available in respect of a product. per unit $ selling price 25 variable costs 15 contribution 10 Production is 50 000 units. The fixed costs are $300 000. The margin of safety is 20 000 units. The directors propose to increase the unit selling price by 10%. What will be the percentage increase in the margin of safety? A 13.6% B 20% C 30% D 36.4%
1 marks
Answer: C
This question in 9706/12 Feb/March 2019
Q340 · A company makes a single product and sells it for $12 per batch 9706/12 Feb/March 2019
27 A company makes a single product and sells it for $12 per batch. The variable cost is $4 per batch. Fixed costs have been absorbed based on a normal activity level of 1000 batches at $3 per batch. What is the profit under marginal costing if the company makes and sells 1500 batches? A $6000 B $7500 C $9000 D $12 000
1 marks
Answer: C
This question in 9706/12 Feb/March 2019
Q341 · The following information relates to one unit of a product 9706/12 Feb/March 2019
28 The following information relates to one unit of a product. per unit $ selling price 20 marginal cost 8 fixed costs 5 What is its contribution to sales ratio? A 35% B 40% C 60% D 65%
1 marks
Answer: C
This question in 9706/12 Feb/March 2019
Q342 · A company uses the weighted average cost (AVCO) method to value its inventory 9706/11 May/June 2019
22 A company uses the weighted average cost (AVCO) method to value its inventory. The following information is available for an item of inventory. February 1 Balance 20 units at $4 each 14 Purchased 40 units at $5 each April 1 Purchased 40 units at $8 each May 22 Issued 55 units What was the total cost of the units issued? A $255 B $270 C $330 D $345
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q343 · A factory employs a large number of staff who pack different products for different… 9706/11 May/June 2019
23 A factory employs a large number of staff who pack different products for different customers. What would be the most suitable basis to absorb the packing department overheads? A customer B labour hours C machine hours D product
1 marks
Answer: B
This question in 9706/11 May/June 2019
Q344 · The following information is available 9706/11 May/June 2019
24 The following information is available. budget actual overhead cost $ 60 000 66 000 direct labour hours 30 000 35 000 Overheads are absorbed on the basis of direct labour hours. What was the amount of over absorption or under absorption of overheads? A $4000 over B $4000 under C $6000 over D $6000 under
1 marks
Answer: A
This question in 9706/11 May/June 2019
Q345 · A company makes two products 9706/11 May/June 2019
26 A company makes two products. product X Y selling price $10 $12 variable costs per unit $4 $8 maximum sales (units) 4000 14 000 Total fixed costs are $44 700. 4000 units of X are sold. How many units of Y must be sold to break even? A 3450 B 3725 C 5175 D 11 175
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q346 · A business changed from using absorption costing to marginal costing 9706/11 May/June 2019
29 A business changed from using absorption costing to marginal costing. This had no effect on profit for the month. What had happened in the month? A Production was stopped during the period. B Units produced and sold were equal. C Units produced were greater than units sold. D Units produced were less than units sold.
1 marks
Answer: B
This question in 9706/11 May/June 2019
Q347 · A business uses the First In First Out (FIFO) method to value its inventory 9706/12 May/June 2019
21 A business uses the First In First Out (FIFO) method to value its inventory. The following inventory transactions took place during a month. There was no opening balance. receipts issues date units $ per unit units 1 July 100 15.50 6 July 100 15.60 10 July 80 20 July 50 15.80 25 July 100 What was the value of inventory at the end of the month? A $1085 B $1092 C $1102 D $1106
1 marks
Answer: C
This question in 9706/12 May/June 2019
Q348 · A business has two production departments: assembly and machinery 9706/12 May/June 2019
22 A business has two production departments: assembly and machinery. The following budgeted information is available. assembly machinery labour hours 5600 1350 machine hours 1200 6900 overheads $75 000 $80 000 What is the overhead absorption rate for the assembly department? A $13.39 per labour hour B $19.14 per machine hour C $22.30 per labour hour D $62.50 per machine hour
1 marks
Answer: A
This question in 9706/12 May/June 2019
Q349 · A company produces less than it sells in a particular period 9706/12 May/June 2019
25 A company produces less than it sells in a particular period. Which statement is correct? A Reported profit is the same whether absorption or marginal costing is used. B Reported profit is the difference between absorption and marginal costing closing inventories. C Reported profit is lower using absorption costing. D Reported profit is lower using marginal costing.
1 marks
Answer: C
This question in 9706/12 May/June 2019
Q350 · Which statements are true about the preparation of a break-even chart? 9706/12 May/June 2019
26 Which statements are true about the preparation of a break-even chart? 1 Costs are easily classified into fixed and variable. 2 Fixed costs always change as output changes. 3 The break-even point is clearly seen. A 1 and 2 only B 1, 2 and 3 C 2 and 3 only D 3 only
1 marks
Answer: D
This question in 9706/12 May/June 2019
Q351 · When a company had sales revenue of $600 000, its variable costs were $300 000 9706/12 May/June 2019
27 When a company had sales revenue of $600 000, its variable costs were $300 000. At the break-even point, its sales were $400 000. How much profit did it make when sales were $600 000? A $100 000 B $200 000 C $300 000 D $400 000
1 marks
Answer: A
This question in 9706/12 May/June 2019
Q352 · A company provided the following information 9706/12 May/June 2019
28 A company provided the following information. total sales $400 000 production and sales (units) 10 000 total costs $250 000 total fixed costs $60 000 What was the contribution to sales ratio? A 37.5% B 47.5% C 52.5% D 62.5%
1 marks
Answer: C
This question in 9706/12 May/June 2019
Q353 · Last year a company sold 2000 units and made a contribution of $50 per unit 9706/12 May/June 2019
29 Last year a company sold 2000 units and made a contribution of $50 per unit. Profit, after deducting total fixed costs, was $60 000. This year: sales volume increased by 10% contribution per unit decreased by 5% total fixed costs increased by 25%. What was the company’s profit this year? A $45 000 B $54 500 C $60 000 D $64 500
1 marks
Answer: B
This question in 9706/12 May/June 2019
Q354 · The following information relates to one accounting period 9706/13 May/June 2019
22 The following information relates to one accounting period. opening inventory 40 000 units closing inventory 44 000 units absorption cost profit $284 000 marginal cost profit $250 000 What was the overhead absorption rate per unit during the accounting period? A $6.25 B $6.45 C $7.10 D $8.50
1 marks
Answer: D
This question in 9706/13 May/June 2019
Q355 · A business uses the weighted average cost (AVCO) method of inventory valuation 9706/13 May/June 2019
23 A business uses the weighted average cost (AVCO) method of inventory valuation. date units $ per unit 1 September purchased 50 4.00 10 September purchased 30 4.80 21 September sold 15 What was the cost of each unit sold? A $4.00 B $4.30 C $4.40 D $4.80
1 marks
Answer: B
This question in 9706/13 May/June 2019
Q356 · What may cause the under absorption of overheads? 9706/13 May/June 2019
24 What may cause the under absorption of overheads? 1 Overheads have been lower than budgeted. 2 Overheads have been higher than budgeted. 3 Production volumes have been lower than budgeted. 4 Production volumes have been higher than budgeted. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/13 May/June 2019
Q357 · A company’s reported profit for the year is the same whether it uses marginal costing or… 9706/11 Oct/Nov 2019
23 A company’s reported profit for the year is the same whether it uses marginal costing or absorption costing. Which statement is correct? A Selling costs have increased. B Selling costs have not changed. C The inventory has increased. D The inventory has not changed.
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2019
Q358 · A business uses an overhead absorption rate based on direct labour hours 9706/11 Oct/Nov 2019
24 A business uses an overhead absorption rate based on direct labour hours. The following information is provided for its last year. actual budgeted overheads $120 000 $100 000 direct labour hours 10 000 8000 indirect labour hours 2000 4500 Which statement regarding overheads is correct? A They were over absorbed by $5000. B They were under absorbed by $5000. C They were over absorbed by $24 000. D They were under absorbed by $24 000.
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2019
Q359 · The following information relates to the inventory of a business 9706/12 Oct/Nov 2019
22 The following information relates to the inventory of a business. date purchases unit cost sales unit selling price 2 June 1000 units $12 12 June 1000 units $13 18 June 800 units $18 28 June 1000 units $14 Estimated unit selling price at 30 June is $20. There was no opening inventory. What was the value of closing inventory at 30 June using FIFO? A $24 600 B $28 600 C $29 400 D $44 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2019
Q360 · Inventory cost prices are rising for a business 9706/12 Oct/Nov 2019
23 Inventory cost prices are rising for a business. The company uses AVCO rather than FIFO to value its inventory. What is the effect on inventory valuation and profit of using AVCO rather than FIFO? inventory profit valuation A higher higher B higher lower C lower higher D lower lower
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2019
Q361 · A company calculates its profit using marginal costing as $90 000 for a month 9706/12 Oct/Nov 2019
24 A company calculates its profit using marginal costing as $90 000 for a month. Opening inventory was 4000 units and closing inventory 6000 units. The fixed production overhead absorption rate is $20 per unit. What is the profit under absorption costing? A $10 000 B $50 000 C $130 000 D $170 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2019
Q362 · A manufacturing business has provided the following information 9706/12 Oct/Nov 2019
25 A manufacturing business has provided the following information. budgeted labour hours 12 000 budgeted overhead absorption rate $7.50 per labour hour actual overhead cost $101 250 actual labour hours 15 000 What is the over or under absorption of overheads? A $11 250 under absorbed B $11 250 over absorbed C $20 250 under absorbed D $20 250 over absorbed
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2019
Q363 · The inventory movements of a business in a three-month period are shown 9706/13 Oct/Nov 2019
22 The inventory movements of a business in a three-month period are shown. receipts issues date units per unit units January 200 $10 January 400 $12 February 100 March 400 The business uses the AVCO method of inventory valuation. What was the value of inventory at the end of March? A $1000 B $1100 C $1133 D $1200
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2019
Q364 · A manufacturer has an inventory at the end of the first year of operation 9706/13 Oct/Nov 2019
23 A manufacturer has an inventory at the end of the first year of operation. What is the impact on profit if the manufacturer is considering using either marginal costing or absorption costing? A The profit is the same if using either marginal costing or absorption costing. B The profit using absorption costing is higher because the inventory includes fixed overheads. C The profit using absorption costing is lower because all the fixed overheads are deducted. D The profit using absorption costing is lower because fixed overheads are under absorbed.
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2019
Q365 · A business has provided the following costing information for its production departments 9706/13 Oct/Nov 2019
24 A business has provided the following costing information for its production departments. machining assembly total production overheads $180 000 $260 000 machine hours 65 000 38 000 labour hours 42 000 76 000 What would be a suitable overhead absorption rate for each department? machining assembly $ $ A 2.77 3.42 B 2.77 6.84 C 4.29 3.42 D 4.29 6.84
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2019
Q366 · A company uses a machine hour basis to absorb its overheads 9706/13 Oct/Nov 2019
25 A company uses a machine hour basis to absorb its overheads. The following information is provided for its last period. actual budgeted overheads $299 000 $350 000 machine hours 46 000 50 000 Which statement regarding overheads is correct? A They were over absorbed by $23 000. B They were under absorbed by $23 000. C They were over absorbed by $51 000. D They were under absorbed by $51 000.
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2019
Q367 · A manufacturer uses the weighted average cost (AVCO) method of inventory valuation 9706/12 Feb/March 2020
22 A manufacturer uses the weighted average cost (AVCO) method of inventory valuation. Opening inventory was 10 units at $50 each. During the month: 30 units were purchased costing $70 each. 20 units were sold at $80 each. What was the value of the inventory at the end of the month? A $1200 B $1300 C $1400 D $1600
1 marks
Answer: B
This question in 9706/12 Feb/March 2020
Q368 · Why might absorption costing be used? 9706/12 Feb/March 2020
24 Why might absorption costing be used? 1 to calculate contribution 2 to decide whether or not to accept a special order 3 to make long-term decisions 4 to set the selling price of a product A 1 and 3 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: D
This question in 9706/12 Feb/March 2020
Q369 · The following information is available for a business 9706/12 Feb/March 2020
25 The following information is available for a business. fixed overheads hours $ budget 180 000 10 000 actual 190 000 11 000 What was the over-absorption or under-absorption of fixed overheads? A $8000 over B $8000 under C $10 000 over D $10 000 under
1 marks
Answer: A
This question in 9706/12 Feb/March 2020
Q370 · A company has been asked to prepare a quotation to print 100 leaflets for a customer 9706/11 May/June 2020
21 A company has been asked to prepare a quotation to print 100 leaflets for a customer. The total cost of direct materials, direct labour and a share of overheads is $820 and a profit of 25% on cost has been added. Which costing method is this an example of? A absorption costing B job costing C marginal costing D unit costing
1 marks
Answer: B
This question in 9706/11 May/June 2020
Q371 · The inventory movements of a business in a three-month period are shown 9706/11 May/June 2020
23 The inventory movements of a business in a three-month period are shown. receipts issues date units per unit units January 100 $5 January 200 $6 February 50 March 200 The business uses the first in first out (FIFO) method of inventory valuation. What was the value of inventory at the end of March? A $250 B $275 C $283 D $300
1 marks
Answer: D
This question in 9706/11 May/June 2020
Q372 · A company uses absorption costing based on predetermined absorption rates 9706/11 May/June 2020
24 A company uses absorption costing based on predetermined absorption rates. Which statement about absorption rates is correct? A They will be based on budgeted costs and outputs. B They will be calculated only when actual costs and outputs are known. C They will be changed each time outputs and costs change. D They will be set for a period of more than one year.
1 marks
Answer: A
This question in 9706/11 May/June 2020
Q373 · A business absorbs fixed overheads using direct labour hours 9706/11 May/June 2020
25 A business absorbs fixed overheads using direct labour hours. The following information is provided. actual budgeted overheads $525 000 $525 000 direct labour hours 16 300 15 000 indirect labour hours 2700 2500 Which statement is correct? A Overheads were over absorbed by $45 000. B Overheads were under absorbed by $45 000. C Overheads were over absorbed by $45 500. D Overheads were under absorbed by $45 500.
1 marks
Answer: C
This question in 9706/11 May/June 2020
Q374 · The data relate to the production of three products 9706/11 May/June 2020
26 The data relate to the production of three products. product X product Y product Z $ $ $ contribution per unit 160 175 190 fixed overhead per unit 125 130 160 labour hours per unit 1 1.25 0.75 The company is experiencing a shortage of labour. In which order should the products be ranked to maximise profit? 1 2 3 A X Y Z B Y X Z C Z X Y D Z Y X
1 marks
Answer: C
This question in 9706/11 May/June 2020
Q375 · A business provided the following information 9706/12 May/June 2020
21 A business provided the following information. budgeted overheads $20 000 budgeted direct labour hours 2000 direct labour rate $20 per hour A job used materials costing $45 and 6 hours of direct labour. Overheads are charged on the basis of direct labour hours used. What was the cost of the job before adding any profit? A $105 B $165 C $180 D $225
1 marks
Answer: D
This question in 9706/12 May/June 2020
Q376 · Why are service centre costs apportioned to production departments? 9706/12 May/June 2020
23 Why are service centre costs apportioned to production departments? A to act as a check on service centre managers B to ascertain whether service centres are cost effective C to ensure the service centre costs are included in selling prices D to minimise the total costs of service centres
1 marks
Answer: C
This question in 9706/12 May/June 2020
Q377 · The following data were available for a department for July 9706/12 May/June 2020
24 The following data were available for a department for July. budget actual direct labour hours 40 000 41 950 machine hours 60 000 60 900 overheads $480 000 $499 200 What was the over or under absorption of overheads for July? A $4200 over absorbed B $4200 under absorbed C $12 000 over absorbed D $12 000 under absorbed
1 marks
Answer: D
This question in 9706/12 May/June 2020
Q378 · Which statements about marginal costing are correct? 9706/12 May/June 2020
25 Which statements about marginal costing are correct? 1 It cannot be used as a basis to calculate contribution. 2 It is useful for decision-making. 3 It recognises the importance of fixed costs. A 1 and 2 B 2 and 3 C 2 only D 3 only
1 marks
Answer: C
This question in 9706/12 May/June 2020
Q379 · A company with fixed costs of $50 000 and a contribution to sales ratio of 40% makes a… 9706/12 May/June 2020
26 A company with fixed costs of $50 000 and a contribution to sales ratio of 40% makes a profit of $30 000. What are the total costs? A $130 000 B $170 000 C $175 000 D $200 000
1 marks
Answer: B
This question in 9706/12 May/June 2020
Q380 · What is not an assumption made in cost–volume–profit analysis? 9706/12 May/June 2020
27 What is not an assumption made in cost–volume–profit analysis? A Unit fixed cost is constant. B Unit selling price is constant. C Unit variable cost is constant. D Units produced are all sold.
1 marks
Answer: A
This question in 9706/12 May/June 2020
Q381 · A manufacturer produces a single product 9706/12 May/June 2020
29 A manufacturer produces a single product. The following information is available. $ selling price per unit 14 variable costs per unit 8 fixed costs per annum 96 000 There are plans to reduce the selling price by $3 per unit and to reduce variable costs by $1 per unit. Fixed costs will remain unchanged. What will be the new break-even point? A 9600 units B 12 000 units C 24 000 units D 48 000 units
1 marks
Answer: C
This question in 9706/12 May/June 2020
Q382 · A company has been asked to prepare a quotation to print 100 leaflets for a customer 9706/13 May/June 2020
21 A company has been asked to prepare a quotation to print 100 leaflets for a customer. The total cost of direct materials, direct labour and a share of overheads is $820 and a profit of 25% on cost has been added. Which costing method is this an example of? A absorption costing B job costing C marginal costing D unit costing
1 marks
Answer: B
This question in 9706/13 May/June 2020
Q383 · The inventory movements of a business in a three-month period are shown 9706/13 May/June 2020
23 The inventory movements of a business in a three-month period are shown. receipts issues date units per unit units January 100 $5 January 200 $6 February 50 March 200 The business uses the first in first out (FIFO) method of inventory valuation. What was the value of inventory at the end of March? A $250 B $275 C $283 D $300
1 marks
Answer: D
This question in 9706/13 May/June 2020
Q384 · A company uses absorption costing based on predetermined absorption rates 9706/13 May/June 2020
24 A company uses absorption costing based on predetermined absorption rates. Which statement about absorption rates is correct? A They will be based on budgeted costs and outputs. B They will be calculated only when actual costs and outputs are known. C They will be changed each time outputs and costs change. D They will be set for a period of more than one year.
1 marks
Answer: A
This question in 9706/13 May/June 2020
Q385 · A business absorbs fixed overheads using direct labour hours 9706/13 May/June 2020
25 A business absorbs fixed overheads using direct labour hours. The following information is provided. actual budgeted overheads $525 000 $525 000 direct labour hours 16 300 15 000 indirect labour hours 2700 2500 Which statement is correct? A Overheads were over absorbed by $45 000. B Overheads were under absorbed by $45 000. C Overheads were over absorbed by $45 500. D Overheads were under absorbed by $45 500.
1 marks
Answer: C
This question in 9706/13 May/June 2020
Q386 · The data relate to the production of three products 9706/13 May/June 2020
26 The data relate to the production of three products. product X product Y product Z $ $ $ contribution per unit 160 175 190 fixed overhead per unit 125 130 160 labour hours per unit 1 1.25 0.75 The company is experiencing a shortage of labour. In which order should the products be ranked to maximise profit? 1 2 3 A X Y Z B Y X Z C Z X Y D Z Y X
1 marks
Answer: C
This question in 9706/13 May/June 2020
Q387 · Details of inventory movements for an item are shown 9706/11 Oct/Nov 2020
23 Details of inventory movements for an item are shown. quantity unit value date transaction (units) $ 1 January opening balance 400 10.00 2 February bought 200 11.00 3 June sold 100 12.50 4 August bought 200 12.00 4 December sold 300 13.00 31 December closing inventory 400 ? What is the value of closing inventory if the first in first out (FIFO) method of inventory valuation is used? A $4000 B $4600 C $5000 D $5200
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2020
Q388 · What are advantages of absorption costing? 9706/11 Oct/Nov 2020
24 What are advantages of absorption costing? 1 conforms to the matching concept 2 is a recognised method of inventory valuation 3 is suitable for determining selling price A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2020
Q389 · A business calculates its overhead absorption rates on the basis of direct labour hours 9706/11 Oct/Nov 2020
25 A business calculates its overhead absorption rates on the basis of direct labour hours. For the month of October the following information is available. $ budgeted overhead expenditure 15 000 budgeted direct labour hours 5 000 actual overhead expenditure 15 800 actual direct labour hours worked 4 000 What was the under or over absorption of overheads for October? A $3000 over B $3000 under C $3800 over D $3800 under
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2020
Q390 · A business uses the weighted average (AVCO) method to value its inventory 9706/12 Oct/Nov 2020
23 A business uses the weighted average (AVCO) method to value its inventory. It purchased the following units of inventory. cost per unit total cost units $ $ 100 36 3600 120 48 5760 80 54 4320 After these receipts it issued 250 units to production. What was the value of the issue? A $10 980 B $11 400 C $11 500 D $11 880
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2020
Q391 · A business absorbs its fixed overheads using direct labour hours 9706/12 Oct/Nov 2020
25 A business absorbs its fixed overheads using direct labour hours. The following information is provided. actual budgeted overheads $600 000 $508 000 labour hours 14 300 12 700 Which statement is correct? A Overheads were over absorbed by $28 000. B Overheads were under absorbed by $28 000. C Overheads were over absorbed by $92 000. D Overheads were under absorbed by $92 000.
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2020
Q392 · A company sells a single product for $24 per unit 9706/12 Oct/Nov 2020
26 A company sells a single product for $24 per unit. The variable cost is $8 per unit. Fixed costs have been absorbed based on a normal activity level of 1000 units at $6 per unit. What is the profit under marginal costing if the company makes and sells 1250 units? A $10 000 B $12 500 C $14 000 D $20 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2020
Q393 · A product has the following revenue and costs per unit 9706/12 Oct/Nov 2020
27 A product has the following revenue and costs per unit. $ selling price 40 marginal cost 22 fixed manufacturing overhead 6 non-manufacturing overhead 2 What is the contribution to sales ratio? A 25% B 30% C 45% D 55%
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2020
Q394 · Which statements about cost–volume–profit analysis are correct? 9706/12 Oct/Nov 2020
28 Which statements about cost–volume–profit analysis are correct? 1 It applies over any time period. 2 It is suitable for any range of output. 3 Profits are calculated using marginal costing. A 1 and 3 B 1 only C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2020
Q395 · A business uses the first in first out (FIFO) inventory system 9706/13 Oct/Nov 2020
22 A business uses the first in first out (FIFO) inventory system. The following information is available. per unit value date details units $ 1 March opening inventory 1 200 10.00 12 March purchases 2 000 10.20 22 March sales 3 000 15.00 26 March purchases 800 10.50 The inventory at 31 March could be sold for $10 800. What is the value of inventory to be included in the statement of financial position at 31 March? A $10 000 B $10 425 C $10 440 D $10 800
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2020
Q396 · The following data is available for the production department of a manufacturing company… 9706/13 Oct/Nov 2020
23 The following data is available for the production department of a manufacturing company for a period. Overheads are absorbed on a direct labour hour basis. total direct overhead costs labour hours $ budgeted 96 000 242 880 actual 97 600 253 760 What is the over or under absorption of overheads for the period? A $6832 over absorbed B $6832 under absorbed C $10 880 over absorbed D $10 880 under absorbed
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2020
Q397 · The records of a company showed the following 9706/13 Oct/Nov 2020
24 The records of a company showed the following. machining assembly total fixed overheads $150 000 $60 000 machine hours 3000 employee hours worked 2000 What is the hourly fixed overhead absorption rate for the machining department? A $30 B $42 C $50 D $70
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2020
Q398 · Which costs are included in inventory valuation under absorption costing? 9706/13 Oct/Nov 2020
25 Which costs are included in inventory valuation under absorption costing? 1 fixed manufacturing overhead 2 variable manufacturing overhead 3 variable selling expenses A 1 and 2 only B 1 and 3 only C 2 and 3 only D 1, 2 and 3
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2020
Q399 · A company makes and sells a single product for $50 per unit 9706/13 Oct/Nov 2020
27 A company makes and sells a single product for $50 per unit. The variable cost is $16 per unit. Fixed costs have been absorbed based on a normal activity level of 1000 units at $4 per unit. What is the profit under marginal costing if the company makes and sells 2000 units? A $32 000 B $60 000 C $64 000 D $68 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2020
Q400 · A company receives the following units of raw material into inventory 9706/12 Feb/March 2021
22 A company receives the following units of raw material into inventory. per unit total units $ $ 120 38 4560 100 40 4000 60 44 2640 It then issued 240 units. Inventory is valued using the weighted average (AVCO) method. What was the closing value of inventory? A $1440 B $1520 C $1600 D $1760
1 marks
Answer: C
This question in 9706/12 Feb/March 2021
Q401 · In March, a company’s overhead absorption rate was $2 per machine hour 9706/12 Feb/March 2021
24 In March, a company’s overhead absorption rate was $2 per machine hour. In April this rate increased. What had increased in April causing the change in the overhead absorption rate? A cost of insurance for the factory B hourly pay rate of production workers C number of actual machine hours worked D number of budgeted machine hours
1 marks
Answer: A
This question in 9706/12 Feb/March 2021
Q402 · A business absorbs its overheads on the basis of machine hours 9706/12 Feb/March 2021
25 A business absorbs its overheads on the basis of machine hours. The following information is provided. actual budgeted overheads $564 000 $560 000 machine hours 6700 7000 By how much are overheads under or over-absorbed? A over-absorbed by $4000 B under-absorbed by $4000 C over-absorbed by $28 000 D under-absorbed by $28 000
1 marks
Answer: D
This question in 9706/12 Feb/March 2021
Q403 · The following budgeted information is available for 10 000 units 9706/12 Feb/March 2021
27 The following budgeted information is available for 10 000 units. per unit $ selling price 53 direct materials and wages 22 variable manufacturing overhead 2 fixed manufacturing overhead 21 variable selling expenses 1 fixed selling expenses 5 What is the budgeted break-even point in units? A 7242 B 7500 C 8966 D 9286
1 marks
Answer: D
This question in 9706/12 Feb/March 2021
Q404 · The budgeted income statement of J Limited shows the following 9706/12 Feb/March 2021
28 The budgeted income statement of J Limited shows the following. $ sales 400 000 variable costs 240 000 fixed costs 132 000 profit for the year 28 000 What is the margin of safety in dollars? A $70 000 B $160 000 C $268 000 D $330 000
1 marks
Answer: A
This question in 9706/12 Feb/March 2021
Q405 · Which business would use a batch costing system? 9706/11 May/June 2021
22 Which business would use a batch costing system? A a clothing retailer B a footwear manufacturer C a stationery wholesaler D an oil refinery
1 marks
Answer: B
This question in 9706/11 May/June 2021
Q406 · Details of a company’s fixed overhead in a period were as follows 9706/11 May/June 2021
23 Details of a company’s fixed overhead in a period were as follows. budgeted actual direct labour hours 5000 5500 Total budgeted fixed overhead was $50 000. Overheads over-absorbed for the period were $4000. What was the actual fixed overhead incurred in the period? A $51 000 B $54 000 C $55 000 D $59 000
1 marks
Answer: A
This question in 9706/11 May/June 2021
Q407 · How might an under-absorption of overheads arise? 9706/11 May/June 2021
24 How might an under-absorption of overheads arise? 1 Overheads have been over-budgeted. 2 Overheads have been under-budgeted. 3 Production was less than budgeted. 4 Production was more than budgeted. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/11 May/June 2021
Q408 · A business uses absorption costing 9706/12 May/June 2021
22 A business uses absorption costing. What will be included in cost of sales? A variable manufacturing costs, variable selling costs and fixed manufacturing costs B variable manufacturing costs and fixed manufacturing costs only C variable manufacturing costs and variable selling costs only D variable manufacturing costs only
1 marks
Answer: B
This question in 9706/12 May/June 2021
Q409 · A business absorbs its overheads on the basis of machine hours 9706/12 May/June 2021
23 A business absorbs its overheads on the basis of machine hours. The following information is provided. actual budgeted overheads $960 000 $900 000 machine hours 6200 6000 By how much were overheads under-absorbed or over-absorbed? A over-absorbed by $30 000 B under-absorbed by $30 000 C over-absorbed by $60 000 D under-absorbed by $60 000
1 marks
Answer: B
This question in 9706/12 May/June 2021
Q410 · The following information is provided about one unit of a product 9706/12 May/June 2021
24 The following information is provided about one unit of a product. $ selling price 100 contribution 40 profit 10 The selling price is expected to increase by $10. Costs are expected to remain unchanged. What will be the change in the contribution to sales ratio? A 3.64% decrease B 3.64% increase C 5.45% decrease D 5.45% increase
1 marks
Answer: D
This question in 9706/12 May/June 2021
Q411 · The following information is available 9706/12 May/June 2021
25 The following information is available. $ unit selling price 36 direct cost per unit 18 selling commission per unit 2 total fixed costs 180 000 total units manufactured and sold 18 000 What was the margin of safety? A 37.50% B 44.44% C 55.56% D 62.50%
1 marks
Answer: A
This question in 9706/12 May/June 2021
Q412 · How is break-even revenue calculated? 9706/12 May/June 2021
26 How is break-even revenue calculated? A (total fixed costs + total variable costs) divided by contribution per unit B (total fixed costs + total variable costs) divided by contribution to sales ratio C total fixed costs divided by contribution per unit D total fixed costs divided by contribution to sales ratio
1 marks
Answer: D
This question in 9706/12 May/June 2021
Q413 · A business manufactures three products 9706/12 May/June 2021
27 A business manufactures three products. The following information was provided. X Y Z per unit $ $ $ selling price 450 350 400 direct material 160 100 150 direct labour 115 95 190 contribution 175 155 60 fixed overheads 135 110 10 profit 40 45 50 Direct labour is in short supply. All direct labour is paid at the same hourly rate. Which order of production should be used to maximise the profit? A X Z Y B X Y Z C Y X Z D Z Y X
1 marks
Answer: C
This question in 9706/12 May/June 2021
Q414 · The following information is available for a month 9706/12 May/June 2021
28 The following information is available for a month. per unit $ selling price 100 contribution 30 Total fixed costs were $100 000 and budgeted sales were 5000 units. The directors think that if they reduce the unit selling price to $95, sales will increase to 6500 units a month. What would be the increase in profit as a result of this? A $12 500 B $32 500 C $45 000 D $77 500
1 marks
Answer: A
This question in 9706/12 May/June 2021
Q415 · A business makes and sells a single product 9706/12 May/June 2021
29 A business makes and sells a single product. It has a selling price of $100 and a contribution per unit of $40. When output is 500 units, the business makes a profit of $2000. The direct material price is expected to rise by $4 per unit. How many units will need to be made and sold for the profit to be unchanged? A 450 B 455 C 550 D 556
1 marks
Answer: D
This question in 9706/12 May/June 2021
Q416 · Which costs are included when calculating the cost of sales using absorption costing? 9706/13 May/June 2021
23 Which costs are included when calculating the cost of sales using absorption costing? 1 factory overhead costs 2 fixed selling and distribution costs 3 finance costs 4 direct costs A 1 and 3 B 1 and 4 C 2, 3 and 4 D 4 only
1 marks
Answer: B
This question in 9706/13 May/June 2021
Q417 · A company has budgeted the following factory overheads for the next financial year 9706/13 May/June 2021
24 A company has budgeted the following factory overheads for the next financial year. machining assembly stores total overheads $80 000 $50 000 $10 000 $140 000 Machining and assembly are production departments and stores is the service department. The two production departments issued requisitions to stores as follows. machining 120 assembly 80 total 200 What was the budgeted overhead absorption rate for the machining department based on 4300 budgeted machine hours? A $18.60 B $20.00 C $30.23 D $32.56
1 marks
Answer: B
This question in 9706/13 May/June 2021
Q418 · Which values per unit are not sufficient to enable the calculation of the contribution to… 9706/13 May/June 2021
25 Which values per unit are not sufficient to enable the calculation of the contribution to sales ratio? A contribution, fixed cost B selling price, fixed cost, profit C selling price, variable cost D variable cost, fixed cost, profit
1 marks
Answer: A
This question in 9706/13 May/June 2021
Q419 · Which statement concerning the break-even point is correct? 9706/13 May/June 2021
26 Which statement concerning the break-even point is correct? A At the break-even point a company makes a profit. B Contribution equals fixed costs at the break-even point. C Fixed costs are equal to sales revenue at the break-even point. D Variable costs equal fixed costs at the break-even point.
1 marks
Answer: B
This question in 9706/13 May/June 2021
Q420 · Which assumptions about cost–volume–profit analysis are correct? 9706/13 May/June 2021
27 Which assumptions about cost–volume–profit analysis are correct? 1 Many different factors cause costs and revenues to change. 2 Selling price and variable cost per unit are usually constant. 3 Selling price and variable cost per unit change. 4 The only factor causing costs and revenues to change is volume. A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: C
This question in 9706/13 May/June 2021
Q421 · For the month of April a business manufactured 4000 units and sold 3600 units 9706/13 May/June 2021
28 For the month of April a business manufactured 4000 units and sold 3600 units. The following total costs have been incurred. $ direct materials 80 000 direct labour 120 000 variable production overheads 36 000 variable selling commission 18 000 fixed production overheads 144 000 There was no opening inventory. The business values inventory using marginal costing. What is the value of the closing inventory? A $20 000 B $23 600 C $25 400 D $39 800
1 marks
Answer: B
This question in 9706/13 May/June 2021
Q422 · A manufacturer has fixed costs of $300 000 9706/13 May/June 2021
29 A manufacturer has fixed costs of $300 000. It manufactures and sells a single product for $80 per unit. The contribution to sales ratio is 60%. How many units does it need to sell to make a profit of $600 000? A 6250 B 6750 C 12 500 D 18 750
1 marks
Answer: D
This question in 9706/13 May/June 2021
Q423 · A business absorbs its overheads on the basis of direct labour hours 9706/11 Oct/Nov 2021
23 A business absorbs its overheads on the basis of direct labour hours. The following information is provided. actual budgeted overheads $560 000 $546 000 direct labour hours 19 300 18 200 By how much are overheads under or over absorbed? A over absorbed by $14 000 B under absorbed by $14 000 C over absorbed by $19 000 D under absorbed by $19 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2021
Q424 · Which would be a suitable basis to apportion depreciation to production departments? 9706/11 Oct/Nov 2021
24 Which would be a suitable basis to apportion depreciation to production departments? 1 machine hours 2 net book value of machinery 3 number of machines 4 original cost of machinery A 1 and 2 only B 1, 2 and 4 C 2, 3 and 4 D 3 and 4 only
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2021
Q425 · The following information is available 9706/11 Oct/Nov 2021
25 The following information is available. per unit $ selling price 10 variable costs 4 Budgeted break-even sales volume is 15 000 units. Budgeted sales volume is 20 000 units. What were the fixed costs? A $20 000 B $30 000 C $60 000 D $90 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2021
Q426 · A business increased its profits by changing from marginal costing to absorption costing 9706/11 Oct/Nov 2021
26 A business increased its profits by changing from marginal costing to absorption costing. Which statement is correct? A Production and sales were equal. B Production stopped in the period. C Production was greater than sales. D Production was less than sales.
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2021
Q427 · A company makes and sells a single product 9706/11 Oct/Nov 2021
27 A company makes and sells a single product. The following budgeted information is available for one month. selling price per unit $750 variable costs per unit $550 total monthly sales 600 units total fixed costs $80 000 The directors are able to reduce the variable costs to $500 per unit. By how many units can budgeted sales reduce to achieve the same monthly profit? A 120 B 320 C 400 D 480
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2021
Q428 · Which assumption of cost–volume–profit analysis is not correct? 9706/11 Oct/Nov 2021
28 Which assumption of cost–volume–profit analysis is not correct? A Costs can easily be divided into variable and fixed. B Total fixed costs remain the same within the relevant range. C Units produced and sold are equal. D Unit selling price is constant.
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2021
Q429 · A business manufactures four products: A, B, C and D 9706/11 Oct/Nov 2021
29 A business manufactures four products: A, B, C and D. Information relating to these products is shown. In the coming month, labour hours available for production are limited and only one product can be produced. Which product should be produced in order to maximise the profit? unit selling contribution overhead absorption labour hours price per unit rate per labour hour per unit $ $ $ A 45 18 9 2.5 B 50 16 4 3.2 C 40 9 1.5 1.2 D 36 15 2 1.8
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2021
Q430 · A business uses absorption costing to set its selling prices 9706/12 Oct/Nov 2021
23 A business uses absorption costing to set its selling prices. Which overheads are accounted for by the use of the overhead absorption rate? A total production, administrative and selling B total production only C variable production, administrative and selling D variable production only
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2021
Q431 · A business uses absorption costing and applies a mark-up of 50% when setting selling… 9706/12 Oct/Nov 2021
24 A business uses absorption costing and applies a mark-up of 50% when setting selling prices. Each unit of product X has a direct cost of $60 and a selling price of $150 and requires two hours of machine time. What is the overhead absorption rate per machine hour? A $7.50 B $15.00 C $20.00 D $40.00
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2021
Q432 · A business had no opening inventory 9706/12 Oct/Nov 2021
25 A business had no opening inventory. In one month it produced 4000 units and sold 3500 units. The following information is available. per unit $ selling price 70 variable cost 30 fixed cost 15 How would inventory value and profit vary between using absorption costing and marginal costing? inventory value profit A absorption costing higher by $7500 absorption costing higher by $7500 B absorption costing higher by $7500 absorption costing lower by $7500 C marginal costing higher by $7500 marginal costing higher by $7500 D marginal costing higher by $7500 marginal costing lower by $7500
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2021
Q433 · A company provided the following information 9706/12 Oct/Nov 2021
27 A company provided the following information. $ variable costs 540 000 contribution 360 000 fixed production costs 100 000 fixed selling and distribution costs 320 000 What is its budgeted break-even sales revenue? A $420 000 B $460 000 C $700 000 D $1 050 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2021
Q434 · Details for two products made by a company were as follows 9706/12 Oct/Nov 2021
28 Details for two products made by a company were as follows. product X product Y $ $ selling price per unit 13 8 variable cost per unit 11 4 The company could sell a maximum of 11 000 units of X and 9000 units of Y. However, the company cannot produce more than 10 000 units of X and Y together due to production constraints. Which production mix will maximise profits? units of X units of Y A 10 000 0 B 1 000 9000 C 9 000 1000 D 5 000 5000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2021
Q435 · A company’s fixed overheads details were as shown 9706/13 Oct/Nov 2021
24 A company’s fixed overheads details were as shown. fixed hours overheads $ budget 10 000 150 000 actual 11 000 170 000 What was the over or under absorption of fixed overheads? A $5000 over absorbed B $5000 under absorbed C $15 000 over absorbed D $15 000 under absorbed
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2021
Q436 · The following budgeted data is available for July 2021 9706/13 Oct/Nov 2021
25 The following budgeted data is available for July 2021. $ direct labour ($20 per hour) 80 000 indirect labour 12 000 factory expenses 36 000 depreciation on machinery 30 000 depreciation on office equipment 18 000 administrative expenses 44 000 What is the budgeted overhead absorption rate per direct labour hour? A $19.50 B $24 C $35 D $39.50
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2021
Q437 · The following budgeted information is available for a business 9706/13 Oct/Nov 2021
26 The following budgeted information is available for a business. $ revenue 650 000 variable costs 390 000 fixed non-production cost 150 000 fixed selling and distribution costs 90 000 What is its budgeted break-even sales revenue? A $250 000 B $375 000 C $400 000 D $600 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2021
Q438 · Which statements relating to marginal costing are correct? 9706/13 Oct/Nov 2021
27 Which statements relating to marginal costing are correct? 1 Fixed production costs are included in inventory valuations. 2 Fixed production costs are fully written off as an expense. 3 Variable production costs are included in inventory valuations. 4 Variable production costs are fully written off as an expense. A 1 and 3 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2021
Q439 · A business makes and sells four products A, B, C and D 9706/13 Oct/Nov 2021
28 A business makes and sells four products A, B, C and D. Which product should be produced first when labour hours are not sufficient to produce all four products? selling price variable costs labour hours $ $ $ A 10 15 1 B 35 10 5 C 50 30 2 D 75 57 3
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2021
Q440 · When does cost–volume–profit analysis inform users about cost behaviour? 9706/13 Oct/Nov 2021
29 When does cost–volume–profit analysis inform users about cost behaviour? A when different time periods are involved and when absorption costing is used B when different time periods are involved and when marginal costing is used C when the level of output changes and when absorption costing is used D when the level of output changes and when marginal costing is used
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2021
Q441 · A retailer made the following purchases of inventory in October 9706/12 Feb/March 2022
24 A retailer made the following purchases of inventory in October. quantity unit price total cost purchase (units) $ $ 5 Oct 50 500 25 000 12 Oct 50 500 25 000 23 Oct 150 525 78 750 128 750 There was no opening inventory for October. The business uses the first-in first-out (FIFO) method to value its inventory. In October, 200 units were sold for $900 each. What was the gross profit for October? A $76 667 B $77 000 C $77 500 D $96 250
1 marks
Answer: C
This question in 9706/12 Feb/March 2022
Q442 · A company has two departments in its factory 9706/12 Feb/March 2022
25 A company has two departments in its factory. The details are shown. budgeted fixed budgeted department overheads hours $ machining 180 000 6 000 assembly 90 000 10 000 total 270 000 16 000 What is the fixed overhead absorption rate per hour in the machining department? A $11.25 B $16.875 C $30 D $45
1 marks
Answer: C
This question in 9706/12 Feb/March 2022
Q443 · What would cause overheads to be over-absorbed? 9706/12 Feb/March 2022
26 What would cause overheads to be over-absorbed? A Overhead absorbed is greater than overhead budgeted. B Overhead absorbed is less than overhead budgeted. C Overhead incurred is greater than overhead absorbed. D Overhead incurred is less than overhead absorbed.
1 marks
Answer: D
This question in 9706/12 Feb/March 2022
Q444 · A company has the following information for producing 2000 units of a product 9706/12 Feb/March 2022
27 A company has the following information for producing 2000 units of a product. $ sales revenue 85 000 direct materials 30 000 direct labour 14 000 direct expenses 2 500 other variable overheads 10 200 fixed overheads 8 000 What is the contribution to sales ratio? A 23.88% B 33.29% C 45.29% D 54.71%
1 marks
Answer: B
This question in 9706/12 Feb/March 2022
Q445 · The following information is available about two products 9706/12 Feb/March 2022
28 The following information is available about two products. product 1 product 2 per unit per unit material X 2 kilos 4 kilos material Y 3 kilos 1 kilo direct labour 3 hours 6 hours Production is planned to be 100 units of each product. 700 kilos of material X and 400 kilos of material Y are available. A total of 800 direct labour hours can be worked. What are the limiting factors? A direct labour only B material X only C material Y only D all three inputs
1 marks
Answer: A
This question in 9706/12 Feb/March 2022
Q446 · A company provides the following information about its product 9706/12 Feb/March 2022
29 A company provides the following information about its product. selling price $100 variable cost per unit $40 fixed costs $21 600 break-even point 360 units If the business changes its production method, contribution will increase by 10% and fixed costs will increase by 5%. What would be the effect on the break-even point? A decrease by 16 units B decrease by 18 units C increase by 16 units D increase by 18 units
1 marks
Answer: A
This question in 9706/12 Feb/March 2022
Q447 · A manufacturing business uses direct labour hours to calculate its overhead absorption… 9706/11 May/June 2022
24 A manufacturing business uses direct labour hours to calculate its overhead absorption rate. What are the causes for over-absorption of overhead? 1 More labour hours have been used than budgeted. 2 More products have been produced than budgeted. 3 More products have been sold than budgeted. A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: B
This question in 9706/11 May/June 2022
Q448 · The following information is provided by a company for a month 9706/11 May/June 2022
25 The following information is provided by a company for a month. actual direct labour hours worked 4500 budgeted direct labour hours 5000 budgeted overhead expenditure $80 000 overheads under-absorbed $12 000 What is the amount of the actual overhead expenditure? A $60 000 B $68 000 C $72 000 D $84 000
1 marks
Answer: D
This question in 9706/11 May/June 2022
Q449 · What is the contribution to sales ratio used to calculate? 9706/11 May/June 2022
26 What is the contribution to sales ratio used to calculate? A break-even point B overhead absorption rate C profit for the period D value of inventory
1 marks
Answer: A
This question in 9706/11 May/June 2022
Q450 · The following information relates to the first year of operation of a business 9706/11 May/June 2022
27 The following information relates to the first year of operation of a business. production (units) 5000 sales (units) 4000 unit selling price $10 variable production costs per unit $4 selling expense per unit $1 total fixed manufacturing overhead $13 000 What is the value of gross profit if the business uses absorption costing to value its inventory? A $7000 B $11 000 C $13 600 D $20 000
1 marks
Answer: C
This question in 9706/11 May/June 2022
Q451 · A company makes and sells a single product type which has a selling price of $20 per unit 9706/11 May/June 2022
28 A company makes and sells a single product type which has a selling price of $20 per unit. Variable costs are $8 per unit. Total fixed costs are $7000. The company wishes to achieve a target profit of $20 000. How many units should be produced and sold to achieve the target profit? A 1000 B 1350 C 1667 D 2250
1 marks
Answer: D
This question in 9706/11 May/June 2022
Q452 · Last year a company sold 2000 units and made a contribution of $50 per unit 9706/11 May/June 2022
29 Last year a company sold 2000 units and made a contribution of $50 per unit. After deducting total fixed costs, profit was $60 000. This year: sales volume increased by 10% contribution per unit decreased by 5% total fixed costs increased by 25%. What was the company’s profit this year? A $45 000 B $54 500 C $60 000 D $64 500
1 marks
Answer: B
This question in 9706/11 May/June 2022
Q453 · What is a limitation of absorption costing? 9706/12 May/June 2022
24 What is a limitation of absorption costing? A It does not comply with accounting principles. B It does not take into account all costs of production. C It is not accepted for preparing published financial statements. D It is not useful for improving the organisation’s performance.
1 marks
Answer: D
This question in 9706/12 May/June 2022
Q454 · The following information relates to one accounting period 9706/12 May/June 2022
25 The following information relates to one accounting period. opening inventory 40 000 units closing inventory 44 000 units absorption cost profit $284 000 marginal cost profit $250 000 What was the overhead absorption rate per unit during the accounting period? A $6.25 B $6.45 C $7.10 D $8.50
1 marks
Answer: D
This question in 9706/12 May/June 2022
Q455 · A company makes and sells a single product type 9706/12 May/June 2022
27 A company makes and sells a single product type. The product is sold for $50 per unit and variable costs are $30 per unit. Total fixed costs are $500 000. How many units of the product does the company need to sell to make a profit of $300 000? A 6400 B 15 000 C 25 000 D 40 000
1 marks
Answer: D
This question in 9706/12 May/June 2022
Q456 · A business makes and sells three different product types, M, N and O 9706/12 May/June 2022
28 A business makes and sells three different product types, M, N and O. The following information is available. product M N O per unit $ $ $ selling price 240 280 250 direct material 110 120 90 direct labour 65 90 100 variable overheads 20 30 25 fixed overheads 50 30 18 profit / (loss) (5) 10 17 Each product uses the same direct material, which is in short supply. In which order of priority should the products be produced to maximise the profit? A M N O B M O N C N O M D O N M
1 marks
Answer: B
This question in 9706/12 May/June 2022
Q457 · A business has the following information 9706/12 May/June 2022
29 A business has the following information. break-even point 5000 units variable costs per unit $27 contribution to sales ratio 40% What is the total fixed cost? A $54 000 B $81 000 C $90 000 D $135 000
1 marks
Answer: C
This question in 9706/12 May/June 2022
Q458 · A company has a financial year end of 30 November 9706/13 May/June 2022
23 A company has a financial year end of 30 November. It has no opening inventory at the beginning of the financial year. During the year, the following amounts of inventory are purchased. unit cost date quantity $ 30 March 330 40 1 November 288 50 Sales for the period are 500 units at $100 each. Inventory is valued using the average cost (AVCO) method. What is the value of inventory, to the nearest dollar, at the end of the year? A $4720 B $5270 C $5900 D $11 800
1 marks
Answer: B
This question in 9706/13 May/June 2022
Q459 · A business has the following budgeted data for a production of 50 000 units 9706/13 May/June 2022
24 A business has the following budgeted data for a production of 50 000 units. $ direct production cost 300 000 indirect labour 20 000 factory supervisor salaries 60 000 sales staff salaries 70 000 depreciation on machinery for production 80 000 depreciation on motor vehicles for delivery 50 000 administrative expenses 360 000 total costs 940 000 To determine the selling price, the business adds 40% on the cost of production. What would be the total selling price of 500 units? A $4200 B $5600 C $6440 D $7140
1 marks
Answer: C
This question in 9706/13 May/June 2022
Q460 · When might a business calculate its contribution to sales ratio rather than contribution… 9706/13 May/June 2022
26 When might a business calculate its contribution to sales ratio rather than contribution per unit? A when the break-even point needs to be expressed in units B when the business produces and sells several different products C when the value of fixed costs is uncertain D when there are limiting factors affecting production
1 marks
Answer: B
This question in 9706/13 May/June 2022
Q461 · The following information is available 9706/13 May/June 2022
27 The following information is available. $ selling price per unit 50 variable manufacturing expense per unit 26 variable selling expense per unit 4 total manufacturing overhead 360 000 total administrative overhead 120 000 What is the break-even point in units? A 15 000 B 18 000 C 20 000 D 24 000
1 marks
Answer: D
This question in 9706/13 May/June 2022
Q462 · K Limited manufactures and sells a single type of product 9706/13 May/June 2022
28 K Limited manufactures and sells a single type of product. The following budgeted information is available in respect of it. selling price $80 per unit variable costs $28 per unit total fixed costs $70 000 production and sales 3500 units How many extra units would the company need to produce and sell to increase the budgeted profit by $26 000? A 325 B 362 C 500 D 813
1 marks
Answer: C
This question in 9706/13 May/June 2022
Q463 · M Limited manufactures and sells two different colours of paint 9706/13 May/June 2022
29 M Limited manufactures and sells two different colours of paint. The following actual information is available for last year. red paint blue paint total $ $ $ revenue 350 000 150 000 500 000 direct materials and labour 180 000 65 000 245 000 allocated fixed overheads 110 000 88 000 198 000 profit / (loss) 60 000 (3 000) 57 000 The company is considering closing the blue paint department and using the extra space to increase revenue in red paint by 20%. Variable costs will increase in the same proportion as the increase in revenue. What would be the change in the total profit if this action is taken? A $3000 increase B $29 000 increase C $51 000 decrease D $85 000 decrease
1 marks
Answer: C
This question in 9706/13 May/June 2022
Q464 · What would result in the under-absorption of overheads? 9706/11 Oct/Nov 2022
24 What would result in the under-absorption of overheads? expenditure units produced A actual is less than budgeted actual is less than budgeted B actual is less than budgeted actual is more than budgeted C actual is more than budgeted actual is less than budgeted D actual is more than budgeted actual is more than budgeted
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2022
Q465 · A company has received an order to supply 3000 pairs of safety glasses 9706/11 Oct/Nov 2022
25 A company has received an order to supply 3000 pairs of safety glasses. The costs of production are shown. $ raw materials 975 packaging for 50 pairs 4.20 direct labour at $8.00 per direct labour hour 800 order setting up costs 100 overhead absorption rate per direct labour hour 6.25 What is the cost of manufacturing this order? A $2552 B $2652 C $2710 D $2752
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2022
Q466 · How is break-even point in units calculated? 9706/11 Oct/Nov 2022
26 How is break-even point in units calculated? A fixed costs ÷ contribution per unit B fixed costs ÷ selling price per unit C fixed costs ÷ variable cost per unit D (sales – fixed costs) ÷ contribution per unit
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2022
Q467 · The fixed costs of a business increase 9706/11 Oct/Nov 2022
28 The fixed costs of a business increase. All other revenues and costs remain unchanged. What happens if output is unchanged? contribution break-even margin of per unit point per unit safety per unit A decreases decreases decreases B increases no change increases C no change increases decreases D no change increases increases
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2022
Q468 · A business manufactures three types of products which all use the same material 9706/11 Oct/Nov 2022
29 A business manufactures three types of products which all use the same material. The following information is available. X Y Z $ $ $ selling price 160 190 240 direct material 56 68 90 direct labour 35 32 50 variable overhead 28 34 45 contribution 41 56 55 Direct material is in short supply. In which order should the products be manufactured to maximise profits? A X → Y → Z B Y → X → Z C Y → Z → X D Z → Y → X
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2022
Q469 · Which statements are correct about the first in first out (FIFO) method for inventory… 9706/12 Oct/Nov 2022
23 Which statements are correct about the first in first out (FIFO) method for inventory valuation? 1 issues to production are valued at the most recent purchase prices 2 issues to production are valued at the oldest purchase prices 3 provides a higher profit during periods of inflation 4 provides a lower profit during periods of inflation A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2022
Q470 · A manufacturing business has two production departments: assembly and painting 9706/12 Oct/Nov 2022
24 A manufacturing business has two production departments: assembly and painting. The following information is available. assembly painting machinery at net book value ($) 150 000 100 000 machinery repair costs ($) 14 000 6 000 machine operating hours 60 000 15 000 number of machines 30 10 The total machinery insurance cost for the year was $5000. How much insurance should be apportioned to the assembly department? A $3000 B $3500 C $3750 D $4000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2022
Q471 · Which statement about absorption costing is correct? 9706/12 Oct/Nov 2022
25 Which statement about absorption costing is correct? A It allocates fixed costs to a product when it is sold. B It allocates fixed costs to a product whether it is sold or not. C It increases the costs charged to the income statement. D It reduces the cost of the closing inventory.
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2022
Q472 · A business manufactures and sells a single product 9706/12 Oct/Nov 2022
27 A business manufactures and sells a single product. It is sold for $10 per batch. The variable cost is $4 per batch. Fixed costs are absorbed based on a normal activity level of 5000 batches at $1 per batch. What is the profit, using marginal costing, if the company makes and sells 6000 batches? A $24 000 B $30 000 C $31 000 D $36 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2022
Q473 · Why are service department costs transferred to production departments? 9706/13 Oct/Nov 2022
24 Why are service department costs transferred to production departments? 1 so that both direct and indirect costs can be covered by revenue 2 so that overhead absorption rates can be calculated and applied 3 so that the break-even point can be calculated A 1 and 2 B 1 and 3 C 2 and 3 D 3 only
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2022
Q474 · A company’s profit was $100 000 using marginal costing 9706/13 Oct/Nov 2022
25 A company’s profit was $100 000 using marginal costing. Its opening inventory was 2000 units and closing inventory was 3000 units. The fixed production overhead absorption rate is $30 per unit. What was the profit using absorption costing? A $40 000 B $70 000 C $130 000 D $190 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2022
Q475 · A business prepares its income statement using marginal costing 9706/13 Oct/Nov 2022
26 A business prepares its income statement using marginal costing. The profit is reduced by changing from marginal costing to absorption costing. Which statement is correct? A All units produced in the period were sold. B Units sold were greater than units produced. C Units sold were fewer than units produced. D There were no units produced in the period.
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2022
Q476 · A manufacturer operates a bonus system 9706/12 Feb/March 2023
23 A manufacturer operates a bonus system. He provides the following information. output required from each worker 175 units time allowed to complete output 10.5 hours actual time worked by Fred 7 hours A bonus is paid of 25% of the labour costs for time saved, in addition to the hourly rate of $8.75. What did Fred earn for his output of 175 units? A $68.91 B $76.56 C $91.88 D $99.53
1 marks
Answer: A
This question in 9706/12 Feb/March 2023
Q477 · A job cost sheet showed the following estimates 9706/12 Feb/March 2023
24 A job cost sheet showed the following estimates. $ materials 680 labour at $20 per hour 200 overheads at $10 per labour hour 100 profit 280 price of job 1260 The job actually took 25% more labour hours than were estimated. What was the actual profit? A $205 B $230 C $330 D $355
1 marks
Answer: A
This question in 9706/12 Feb/March 2023
Q478 · What is the most suitable basis to apportion power costs between two production centres? 9706/12 Feb/March 2023
25 What is the most suitable basis to apportion power costs between two production centres? A capital cost of machinery B maintenance cost of machinery C number of employees D number of units produced
1 marks
Answer: D
This question in 9706/12 Feb/March 2023
Q479 · A manufacturing business makes a single type of product 9706/12 Feb/March 2023
26 A manufacturing business makes a single type of product. It has two production departments, machining and assembly. A maintenance department provides services to the production departments. Budgeted figures for these departments are shown. machining assembly maintenance overheads $800 000 $400 000 $300 000 production units 200 000 50 000 The business uses a cost per unit rate to absorb overheads. Maintenance department overheads are transferred to production departments in proportion to output. Which figures are correct for the machining department? overheads cost per unit $ $ A 950 000 4.75 B 1 000 000 5.00 C 1 040 000 4.16 D 1 040 000 5.20
1 marks
Answer: D
This question in 9706/12 Feb/March 2023
Q480 · The following data applies to the budget for a job 9706/12 Feb/March 2023
27 The following data applies to the budget for a job. direct materials $4800 direct labour $2200 machine hours 240 Direct labour is employed at an hourly rate of $11. Production overheads are charged at $25 per direct labour hour and an amount for selling and distribution overhead is calculated at 20% of factory cost. What is the total cost of the job? A $8400 B $12 000 C $14 400 D $15 600
1 marks
Answer: C
This question in 9706/12 Feb/March 2023
Q481 · A company has two production departments, manufacturing and assembly, and a stores… 9706/12 Feb/March 2023
28 A company has two production departments, manufacturing and assembly, and a stores service department. The overheads are apportioned to each department using the appropriate costing information supplied. manufacturing assembly stores direct labour hours 8 400 33 600 machine hours 20 160 6 720 total cost of the stores department $32 800 number of store requisitions 3 000 2 000 What are the overhead absorption rates for the two production departments in respect of the stores? manufacturing department assembly department A $0.39 direct labour hour $0.98 machine hour B $0.58 direct labour hour $0.65 machine hour C $0.65 machine hour $0.58 direct labour hour D $0.98 machine hour $0.39 direct labour hour
1 marks
Answer: D
This question in 9706/12 Feb/March 2023
Q482 · Justine is an accountant and charges her clients a fee at an hourly rate plus overheads 9706/11 May/June 2023
25 Justine is an accountant and charges her clients a fee at an hourly rate plus overheads. She adds a mark-up of 20%. The following budgeted information is available. annual hours worked 1610 annual overhead expenditure $56 350 direct labour rate per hour $45 extra charge if job is greater than 15 hours $200 overheads are charged on a direct labour hour basis How much will Justine charge a client for a job which takes 20 hours to complete? A $1920 B $2000 C $2160 D $2250
1 marks
Answer: C
This question in 9706/11 May/June 2023
Q483 · Which statement describes the purpose of overhead apportionment? 9706/11 May/June 2023
26 Which statement describes the purpose of overhead apportionment? A to assign specific costs to production departments B to assign specific costs to service departments C to share common costs to production departments D to share common costs to service departments
1 marks
Answer: C
This question in 9706/11 May/June 2023
Q484 · A business has two production departments: machining and assembly 9706/11 May/June 2023
27 A business has two production departments: machining and assembly. The budgeted direct labour hours for each department are: machining 4000 assembly 16 000. The business has calculated overhead absorption rates as: machining $12 per direct machining hour assembly $7.70 per direct labour hour. Insurance of $4800 relating to the assembly department was incorrectly omitted when making the calculations. What is the correct overhead absorption rate for the assembly department? A $6.40 B $7.94 C $8.00 D $8.80
1 marks
Answer: C
This question in 9706/11 May/June 2023
Q485 · Which costs are charged to individual jobs in a job costing system? 9706/12 May/June 2023
24 Which costs are charged to individual jobs in a job costing system? A direct labour plus direct materials B direct labour plus direct materials plus production overhead C direct labour plus production overhead D direct materials plus production overhead
1 marks
Answer: B
This question in 9706/12 May/June 2023
Q486 · A business absorbs its overheads on the basis of direct labour hours 9706/12 May/June 2023
25 A business absorbs its overheads on the basis of direct labour hours. The following information is provided for its last period. actual budgeted overheads $640 000 $620 000 labour hours 13 100 12 400 By how much were overheads over-absorbed or under-absorbed? A over-absorbed by $15 000 B under-absorbed by $15 000 C over-absorbed by $20 000 D under-absorbed by $20 000
1 marks
Answer: A
This question in 9706/12 May/June 2023
Q487 · Why might a business use absorption costing? 9706/12 May/June 2023
26 Why might a business use absorption costing? 1 to calculate inventory valuation for financial statements 2 to calculate selling price by adding profit to total cost 3 to include all production costs for the units produced A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: A
This question in 9706/12 May/June 2023
Q488 · Which type of business is most likely to use a job costing system? 9706/13 May/June 2023
25 Which type of business is most likely to use a job costing system? A an aircraft manufacturer B a paint manufacturer C a pet food manufacturer D a stationery manufacturer
1 marks
Answer: A
This question in 9706/13 May/June 2023
Q489 · Which statement describes a cost centre rather than a cost unit? 9706/13 May/June 2023
26 Which statement describes a cost centre rather than a cost unit? A a location where only variable costs are incurred B a measurable part of a product or service C a part of a product or service for which costs are calculated D any location where costs are incurred
1 marks
Answer: D
This question in 9706/13 May/June 2023
Q490 · A business marks up all of its products by 20% on total cost to calculate a selling price 9706/13 May/June 2023
27 A business marks up all of its products by 20% on total cost to calculate a selling price. Each unit of product uses 4 hours of direct labour and 2 kilos of direct material. The correct overhead absorption rate to be used is $8 per direct labour hour. In error the book-keeper used a rate of $13 per direct labour hour. What was the effect of this error on the selling price of one unit of the product? A $5 B $12 C $20 D $24
1 marks
Answer: D
This question in 9706/13 May/June 2023
Q491 · Which type of business is most likely to use a batch costing system? 9706/11 Oct/Nov 2023
25 Which type of business is most likely to use a batch costing system? A an aircraft manufacturer B a car component manufacturer C a ship construction yard D a wedding cake maker
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2023
Q492 · A company is asked to make a new machine for a customer 9706/11 Oct/Nov 2023
26 A company is asked to make a new machine for a customer. It provides the following estimates. Materials will cost $1100. Labour will be 30 hours at a cost of $14 per hour. The company charges overheads at $10 per labour hour and has a mark-up of 30% on total cost. What is the price on the job cost sheet? A $1520 B $1820 C $1976 D $2366
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2023
Q493 · Which formula would be used to calculate an overhead absorption rate for a… 9706/11 Oct/Nov 2023
27 Which formula would be used to calculate an overhead absorption rate for a capital-intensive production process? A labour hours overhead costs B machine hours overhead costs C overhead costs labour hours D overhead costs machine hours
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2023
Q494 · A company provides the following information 9706/11 Oct/Nov 2023
28 A company provides the following information. department X department Y budgeted overheads $150 000 $210 000 budgeted direct labour hours 2000 10 000 budgeted machine hours 8000 1000 What is the most appropriate overhead absorption rate for each department? department X department Y A $18.75 per machine hour $21 per direct labour hour B $75 per direct labour hour $210 per machine hour C $18.75 per machine hour $210 per machine hour D $75 per direct labour hour $21 per direct labour hour
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2023
Q495 · A company has been asked to quote a price for a specific job 9706/12 Oct/Nov 2023
24 A company has been asked to quote a price for a specific job. Estimated costs are as follows: $ direct materials 2000 direct labour 3300 Overheads are charged at 50% of labour cost. Profit is 20% of the total job cost. What is the total of the quotation for the job? A $5300 B $6360 C $6950 D $8340
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2023
Q496 · A manufacturing business has a service department, X, and production departments, Y and Z 9706/12 Oct/Nov 2023
25 A manufacturing business has a service department, X, and production departments, Y and Z. Department Z is labour intensive. How is the overhead absorption rate set for department Z? first task second task third task A apportion total overheads reapportion X’s overheads divide Z’s overheads by across X, Y and Z to Y and Z budgeted labour hours B apportion total overheads reapportion X’s overheads divide Z’s overheads by across X, Y and Z to Y and Z actual labour hours C subtract X’s overheads from apportion remaining divide Z’s overheads by total overheads overheads across Y and Z budgeted labour hours D subtract X’s overheads from apportion remaining divide Z’s overheads by total overheads overheads across Y and Z actual labour hours
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2023
Q497 · What would cause overheads to be under absorbed? 9706/12 Oct/Nov 2023
26 What would cause overheads to be under absorbed? A Overhead absorbed is greater than overhead budgeted. B Overhead absorbed is less than overhead budgeted. C Overhead incurred is greater than overhead absorbed. D Overhead incurred is less than overhead absorbed.
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2023
Q498 · A business produces two types of product, P and Q, for the month of January 9706/12 Oct/Nov 2023
27 A business produces two types of product, P and Q, for the month of January. Overheads are absorbed using direct labour hours. The production details are as follows: P Q units manufactured and sold 5000 2000 direct labour hours per unit 1.5 1 Direct costs for the month were $23 750. The fixed overheads were $6500. What was the overhead absorption rate per hour? A $0.68 B $2.50 C $3.18 D $3.39
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2023
Q499 · A company makes a single type of product and sells it for $12 per batch 9706/13 Oct/Nov 2023
25 A company makes a single type of product and sells it for $12 per batch. The variable cost is $4 per batch. Fixed costs have been absorbed based on a normal activity level of 1000 batches at $3 per batch. What is the profit under marginal costing if the company makes and sells 1500 batches? A $6000 B $7500 C $9000 D $12 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2023
Q500 · A business operates a system of absorption costing 9706/13 Oct/Nov 2023
26 A business operates a system of absorption costing. Which statements are correct? 1 Overheads would be over absorbed if the actual activity level was below the budgeted level. 2 Overheads would be under absorbed if the actual activity level was below the budgeted level. 3 Overheads would be over absorbed if the actual overhead exceeded the budgeted overhead. 4 Overheads would be under absorbed if the actual overhead exceeded the budgeted overhead. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2023
Q501 · A business uses an overhead absorption rate of $20 per direct labour hour 9706/13 Oct/Nov 2023
27 A business uses an overhead absorption rate of $20 per direct labour hour. In April budgeted direct labour hours were 6000 and actual direct labour hours were 6100. Overheads for the month were under absorbed by $3000. What were the actual overheads in April? A $117 000 B $119 000 C $123 000 D $125 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2023
Q502 · Which statement is an argument for using marginal costing? 9706/13 Oct/Nov 2023
28 Which statement is an argument for using marginal costing? A International accounting standards require use of marginal costing. B Marginal costing data enables the use of decision-making techniques. C Setting selling prices is made easier under marginal costing because all costs are considered. D The distinction between fixed and variable overheads under marginal costing is no longer relevant.
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2023
Q503 · The following information is available for a business 9706/13 Oct/Nov 2023
29 The following information is available for a business. total fixed costs $15 000 variable cost $12 per unit selling price $20 per unit break-even point 1875 units The business wants to reduce the break-even point to 1500 units. Which strategy will not achieve the target break-even level? A increasing the selling price to $22 per unit B reducing fixed costs to $12 750 and reducing variable cost to $11.50 per unit C reducing fixed costs to $12 800 D reducing variable costs to $10 per unit
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2023
Q504 · Which assumption does not apply for cost–volume–profit (CVP) analysis? 9706/13 Oct/Nov 2023
30 Which assumption does not apply for cost–volume–profit (CVP) analysis? A All units produced are sold. B Only a single type of product is produced and sold. C Total fixed costs change over a period. D Variable cost changes in direct proportion with sales volume.
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2023
Q505 · The direct materials cost of a batch of soft drinks is $10 000 for 50 000 cans 9706/12 Feb/March 2024
24 The direct materials cost of a batch of soft drinks is $10 000 for 50 000 cans. 60 direct labour hours are required at a cost of $40 per labour hour. Overheads are absorbed at 250% of the cost of direct labour. What is the cost per soft drink can to the nearest dollar? A $0.20 B $0.37 C $0.44 D $1.04
1 marks
Answer: B
This question in 9706/12 Feb/March 2024
Q506 · What is an advantage of absorption costing? 9706/12 Feb/March 2024
25 What is an advantage of absorption costing? A It helps to determine a product‘s selling price. B It is used to improve operational efficiency. C It makes it easy to analyse costs at different production levels. D It takes into account only variable costs.
1 marks
Answer: A
This question in 9706/12 Feb/March 2024
Q507 · The following information is forecast for the next month 9706/12 Feb/March 2024
26 The following information is forecast for the next month. opening inventory 20 300 units closing inventory 22 500 units marginal cost profit $90 600 absorption cost profit $100 400 What is the overhead absorption rate per unit? A $4.03 B $4.45 C $4.46 D $4.95
1 marks
Answer: B
This question in 9706/12 Feb/March 2024
Q508 · X Limited has budgeted monthly overheads of $125 000 9706/12 Feb/March 2024
27 X Limited has budgeted monthly overheads of $125 000. Its overhead absorption rate is $5 per machine hour. In July there was an under-absorption of overheads of $1000. Which changes from budgeted data caused this to happen? overheads machine hours A $500 higher 100 hours less B $500 lower 100 hours more C $750 higher 50 hours more D $750 lower 50 hours less
1 marks
Answer: A
This question in 9706/12 Feb/March 2024
Q509 · P Limited makes wooden chairs at a unit cost of $70 each 9706/11 May/June 2024
24 P Limited makes wooden chairs at a unit cost of $70 each. It has received an order to produce a batch of 1000 wooden chairs with padded seats. This requires $6000 of additional materials, an extra 500 labour hours at $15 per hour and a $2000 increase in overheads. What is the cost of the batch? A $13 500 B $15 500 C $83 500 D $85 500
1 marks
Answer: D
This question in 9706/11 May/June 2024
Q510 · Why would overheads be over absorbed? 9706/11 May/June 2024
25 Why would overheads be over absorbed? A Overheads absorbed is less than overheads budgeted. B Overheads absorbed is more than overheads budgeted. C Overheads incurred is less than overheads absorbed. D Overheads incurred is more than overheads absorbed.
1 marks
Answer: C
This question in 9706/11 May/June 2024
Q511 · A company makes one product with a selling price of $384 per unit 9706/11 May/June 2024
26 A company makes one product with a selling price of $384 per unit. The costs are as follows: per unit direct materials 4 kilos at $8 per kilo direct labour 8 hours at $12 per hour selling and distribution $40 The mark-up is 50%. What is the factory overhead absorption rate per labour hour? A $3 B $5 C $11 D $22
1 marks
Answer: C
This question in 9706/11 May/June 2024
Q512 · Which statements about marginal costing are correct? 9706/11 May/June 2024
27 Which statements about marginal costing are correct? 1 It enables a business to make the best use of its resources when there is a limiting factor. 2 It ensures that decisions taken are based upon the total cost of producing a product. 3 It takes into account apportionment of service costs to production cost centres. 4 It usually leads to a lower inventory valuation than absorption costing. A 1 and 4 only B 1, 2 and 4 C 2 and 3 D 3 and 4 only
1 marks
Answer: A
This question in 9706/11 May/June 2024
Q513 · A company makes and sells a single type of product 9706/11 May/June 2024
28 A company makes and sells a single type of product. The budgeted information for 6000 units is as follows: $ variable manufacturing costs 90 000 variable selling expenses 6 000 fixed manufacturing overheads 54 000 fixed administrative overheads 21 000 The unit selling price is $40. How many units must the company produce and sell to achieve a target profit of $45 000? A 3960 B 4125 C 4800 D 5000
1 marks
Answer: D
This question in 9706/11 May/June 2024
Q514 · The diagram shows a break-even chart 9706/11 May/June 2024
29 The diagram shows a break-even chart. X sales revenue revenue total cost and costs $ Y fixed cost 0 budgeted level of activity level of activity What does line XY represent? A the break-even point revenue B the margin of safety in terms of revenue C the profit at break-even point D the total contribution at break-even point
1 marks
Answer: B
This question in 9706/11 May/June 2024
Q515 · What is not an assumption in cost–volume–profit analysis? 9706/11 May/June 2024
30 What is not an assumption in cost–volume–profit analysis? A The unit fixed cost is constant. B The unit selling price is constant. C The unit variable cost is constant. D The units produced are all sold.
1 marks
Answer: A
This question in 9706/11 May/June 2024
Q516 · There was no opening inventory in July 9706/13 May/June 2024
24 There was no opening inventory in July. The business purchased direct materials during July as follows: quantity cost per kg July kg $ 3 purchases 2000 25 15 purchases 3000 28 Each unit required 4 kg of direct materials. The labour cost for each unit was $42. The fixed overhead for July was $85 000. In July 1000 units were produced and 800 units were sold. What is the average direct cost for each unit? A $148 B $176 C $185 D $233
1 marks
Answer: A
This question in 9706/13 May/June 2024
Q517 · A business provides accounting services to its clients 9706/13 May/June 2024
25 A business provides accounting services to its clients. One of its employees takes 30 hours to complete a job. The employee’s hourly rate is $25. The business absorbs its overheads at a rate of $10 per labour hour. It adds 20% profit to the total cost of the job. What is the total price of the job charged to the client? A $900 B $1050 C $1200 D $1260 A business operates a staff cafeteria at a cost of $12 000.
1 marks
Answer: D
This question in 9706/13 May/June 2024
Q518 · What is the most appropriate basis for apportioning this overhead cost? 9706/13 May/June 2024
26 What is the most appropriate basis for apportioning this overhead cost? A carrying value of cafeteria equipment B direct labour hours C floor area D number of employees
1 marks
Answer: D
This question in 9706/13 May/June 2024
Q519 · A business has the following budgeted and actual results for a month 9706/13 May/June 2024
27 A business has the following budgeted and actual results for a month. $ budgeted fixed overheads 354 000 actual fixed overheads 360 000 under-absorption of overheads 3 000 The fixed overheads are absorbed per unit. The budgeted number of units is 118 000. What is the actual level of activity in units? A 118 000 B 119 000 C 120 000 D 121 000
1 marks
Answer: B
This question in 9706/13 May/June 2024
Q520 · Ammu provided the following information about a specific job to make jewellery for a… 9706/11 Oct/Nov 2024
25 Ammu provided the following information about a specific job to make jewellery for a wedding. 1 Cost of materials required is $10000. 2 Ammu needs 10 hours at $125 per hour to design the jewellery. 3 Her assistant needs 100 hours at $70 per hour to make the jewellery. 4 Fixed overheads are absorbed at $50 per labour hour. 5 A mark-up of 20% is to be applied. What will be the price quoted for the job to make the jewellery for the wedding? A $21900 B $23750 C $26400 D $28500
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2024
Q521 · Which statement about absorption costing is correct? 9706/11 Oct/Nov 2024
26 Which statement about absorption costing is correct? A It aids the preparation of budgets. B It follows the matching/accruals concept. C It is the best costing method for managerial decision making. D It produces the same unit cost in the long run whatever the output.
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2024
Q522 · The canteen costs of a business have been apportioned to production departments 1 and 2 9706/11 Oct/Nov 2024
27 The canteen costs of a business have been apportioned to production departments 1 and 2. Total canteen costs apportioned to production department 1 were $40200. Of these, $3900 could be attributed to a special function by production department 1. The remainder were apportioned on the basis of employee numbers, which were 15 for production department 1 and 10 for production department 2. What were the total canteen costs for the whole business? A $63100 B $64400 C $67000 D $70900
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2024
Q523 · The inventory movements of a business in a three-month period are shown 9706/12 Oct/Nov 2024
24 The inventory movements of a business in a three-month period are shown. receipts issues month cost per units units unit January 100 $5 January 200 $6 February 50 March 200 The business uses the first in first out (FIFO) method of inventory valuation. What was the value of inventory at the end of March? A $250 B $275 C $283 D $300
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2024
Q524 · A customer places an order for 20000 bricks 9706/12 Oct/Nov 2024
25 A customer places an order for 20000 bricks. Which costing method will the supplier use to price the order? A batch B job C marginal D unit
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2024
Q525 · The following budgeted and actual information is available 9706/12 Oct/Nov 2024
26 The following budgeted and actual information is available. budgeted actual overheads $460000 $420000 labour hours 28750 21000 machine hours 9200 7000 What would be the company’s most suitable overheads absorption rate? A $16 per labour hour B $20 per labour hour C $50 per machine hour D $60 per machine hour
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2024
Q526 · The following information is available from the costing records 9706/12 Oct/Nov 2024
27 The following information is available from the costing records. budgeted overheads cost $32000 budgeted direct labour hours 4000 actual overheads cost incurred $34 000 actual direct labour hours worked 3900 By how much are the overheads over-absorbed or under-absorbed? A $2000 under-absorbed B $2000 over-absorbed C $2800 under-absorbed D $2800 over-absorbed
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2024
Q527 · Which statements about a job costing system are correct? 9706/13 Oct/Nov 2024
25 Which statements about a job costing system are correct? 1 Costs of production are averaged across all jobs. 2 Costs are charged individually to each job. 3 Jobs are not produced to customers’ own specifications. 4 Jobs are produced to customers’ own specifications. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2024
Q528 · A bakery produces 1000 muffins a day 9706/13 Oct/Nov 2024
26 A bakery produces 1000 muffins a day. The total direct costs for these are shown. $ direct materials 1800 direct wages 600 An oven must be set up for each batch of 50 muffins. The cost for each oven set-up is $40. Production overheads are 20% of direct wages. The bakery requires a profit margin of 25%. What is the selling price of one muffin? A $3.41 B $4.15 C $4.43 D $6.03
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2024
Q529 · A business provided the following budgeted information 9706/13 Oct/Nov 2024
27 A business provided the following budgeted information. Production and sales were forecast to be 5000 units. $ selling price per unit 80 variable cost per unit direct materials (2kg) 10 direct labour (5 hours) 35 Fixed overheads of $75000 are to be absorbed on the basis of direct labour hours. What is the budgeted profit per unit? A $20.00 B $28.00 C $32.00 D $35.00
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2024
Q530 · A company sells a product for $12 per batch 9706/11 May/June 2025
24 A company sells a product for $12 per batch. The variable cost is $4 per batch. Fixed costs are absorbed based on a normal activity level of 100 batches at $3 per batch. What is the profit under marginal costing if the company makes and sells 125 batches? A $500 B $625 C $700 D $1000
1 marks
Answer: C
This question in 9706/11 May/June 2025
Q531 · Which statements correctly compare the benefits of absorption and marginal costing? 9706/11 May/June 2025
25 Which statements correctly compare the benefits of absorption and marginal costing? absorption costing marginal costing A avoids the need to separate useful when there is a fixed costs and variable costs limiting factor affecting production B is a recognised method of ensures fixed costs are valuing inventory attributed to cost centres C useful for determining is a recognised method of selling price valuing inventory D useful for short-term useful for determining decision-making selling price
1 marks
Answer: A
This question in 9706/11 May/June 2025
Q532 · The following table shows details of production for a week 9706/11 May/June 2025
26 The following table shows details of production for a week. budgeted production overheads $100000 actual production overheads $80000 expected production 5000 units over-absorption of overheads $10000 How many units were produced during the week? A 3500 B 4375 C 4500 D 5625
1 marks
Answer: C
This question in 9706/11 May/June 2025
Q533 · A business has produced the following budget 9706/11 May/June 2025
27 A business has produced the following budget. $ revenue 700000 contribution 560000 fixed production costs 350000 fixed non-production costs 20000 What is its budgeted break-even sales revenue? A $280000 B $296000 C $437500 D $462500
1 marks
Answer: D
This question in 9706/11 May/June 2025
Q534 · How is a margin of safety calculated? 9706/11 May/June 2025
28 How is a margin of safety calculated? A actual total contribution minus break-even contribution B actual total contribution minus budgeted total contribution C budgeted total sales units minus actual total sales units D budgeted total sales units minus break-even sales units
1 marks
Answer: D
This question in 9706/11 May/June 2025
Q535 · A business had a contribution to sales ratio of 40% 9706/11 May/June 2025
29 A business had a contribution to sales ratio of 40%. The following information is available. $ sales revenue 100000 fixed costs 30000 profit 10000 It is predicted that the sales revenue will increase by 20% next year. Total fixed costs will remain unchanged. What will be the increase in the profit? A $8000 B $18000 C $38000 D $48000
1 marks
Answer: A
This question in 9706/11 May/June 2025
Q536 · P Limited uses an overhead absorption rate of $15 per machine hour, based on budgeted… 9706/12 May/June 2025
25 P Limited uses an overhead absorption rate of $15 per machine hour, based on budgeted machine hours of 8000 per month. In July, production required 8500 machine hours, and the under-absorption of overheads amounted to $16 500. What were the actual overheads in July? A $103500 B $111000 C $136500 D $144000
1 marks
Answer: D
This question in 9706/12 May/June 2025
Q537 · Which statement describes the purpose of overhead allocation? 9706/12 May/June 2025
26 Which statement describes the purpose of overhead allocation? A assignment of specific costs to production departments B assignment of specific costs to service departments C sharing out common costs between production departments D sharing out common costs between service departments
1 marks
Answer: A
This question in 9706/12 May/June 2025
Q538 · A manufacturing business provides the following budgeted annual information 9706/12 May/June 2025
27 A manufacturing business provides the following budgeted annual information. $ direct wages ($12 per labour hour) 600000 fixed overheads 160000 Fixed overheads are absorbed on the basis of direct labour hours. A job requires direct materials costing $480 and needs 30 labour hours. The business wishes to make a profit margin of 25% for this job. What is the price to be quoted for this job? A $1170 B $1248 C $1270 D $1404
1 marks
Answer: B
This question in 9706/12 May/June 2025
Q539 · A company sells a product for $12 per batch 9706/13 May/June 2025
24 A company sells a product for $12 per batch. The variable cost is $4 per batch. Fixed costs are absorbed based on a normal activity level of 100 batches at $3 per batch. What is the profit under marginal costing if the company makes and sells 125 batches? A $500 B $625 C $700 D $1000
1 marks
Answer: C
This question in 9706/13 May/June 2025
Q540 · Which statements correctly compare the benefits of absorption and marginal costing? 9706/13 May/June 2025
25 Which statements correctly compare the benefits of absorption and marginal costing? absorption costing marginal costing A avoids the need to separate useful when there is a fixed costs and variable costs limiting factor affecting production B is a recognised method of ensures fixed costs are valuing inventory attributed to cost centres C useful for determining is a recognised method of selling price valuing inventory D useful for short-term useful for determining decision-making selling price
1 marks
Answer: A
This question in 9706/13 May/June 2025
Q541 · The following table shows details of production for a week 9706/13 May/June 2025
26 The following table shows details of production for a week. budgeted production overheads $100000 actual production overheads $80000 expected production 5000 units over-absorption of overheads $10000 How many units were produced during the week? A 3500 B 4375 C 4500 D 5625
1 marks
Answer: C
This question in 9706/13 May/June 2025
Q542 · A business has produced the following budget 9706/13 May/June 2025
27 A business has produced the following budget. $ revenue 700000 contribution 560000 fixed production costs 350000 fixed non-production costs 20000 What is its budgeted break-even sales revenue? A $280000 B $296000 C $437500 D $462500
1 marks
Answer: D
This question in 9706/13 May/June 2025
Q543 · How is a margin of safety calculated? 9706/13 May/June 2025
28 How is a margin of safety calculated? A actual total contribution minus break-even contribution B actual total contribution minus budgeted total contribution C budgeted total sales units minus actual total sales units D budgeted total sales units minus break-even sales units
1 marks
Answer: D
This question in 9706/13 May/June 2025
Q544 · A business had a contribution to sales ratio of 40% 9706/13 May/June 2025
29 A business had a contribution to sales ratio of 40%. The following information is available. $ sales revenue 100000 fixed costs 30000 profit 10000 It is predicted that the sales revenue will increase by 20% next year. Total fixed costs will remain unchanged. What will be the increase in the profit? A $8000 B $18000 C $38000 D $48000
1 marks
Answer: A
This question in 9706/13 May/June 2025
Q545 · In which circumstances are unit costing and job costing used? 9706/11 Oct/Nov 2025
24 In which circumstances are unit costing and job costing used? unit costing job costing A in continuous when a quantity of operations identical items is made B in continuous when each product operations is different C when a quantity of when each product identical items is made is different D when each product in continuous is different operations
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2025
Q546 · What is the most appropriate way to apportion the rent of a factory to each department? 9706/11 Oct/Nov 2025
25 What is the most appropriate way to apportion the rent of a factory to each department? A floor space B number of employees C production output D value of machinery
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2025
Q547 · The table shows figures for a factory’s production in one week 9706/11 Oct/Nov 2025
26 The table shows figures for a factory’s production in one week. budgeted production 10000 units budgeted production overheads $50 000 actual production overheads $60 000 under-absorption of overheads $5 000 What is the actual amount of production in the week? A 9000 units B 9167 units C 11000 units D 13000 units
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2025
Q548 · W Limited is unsure whether to use marginal costing or absorption costing 9706/12 Oct/Nov 2025
23 W Limited is unsure whether to use marginal costing or absorption costing. Which row is correct? charges overheads to gives higher profits expenses rather than when inventory levels to products are increasing A absorption absorption B absorption marginal C marginal absorption D marginal marginal
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2025
Q549 · J Limited makes individual pieces of furniture in customers’ homes 9706/12 Oct/Nov 2025
24 J Limited makes individual pieces of furniture in customers’ homes. The business adds a mark-up of 40% when quoting for jobs. It received an enquiry from a prospective customer who lived 10 kilometres away. The materials would cost $400 and the labour $240. The business charges $2 per kilometre for each part of the journey. What price will the company quote for the job? A $916 B $924 C $936 D $952
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2025
Q550 · A manufacturing company uses absorption costing 9706/12 Oct/Nov 2025
25 A manufacturing company uses absorption costing. The following information for one month is available for the cutting department. budget actual overheads $40000 $44000 machine hours 2800 2700 labour hours 2600 2900 What overhead absorption rate would have been used? A $14.29 per machine hour B $15.17 per labour hour C $15.38 per labour hour D $16.30 per machine hour
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2025
Q551 · A business provides the following information 9706/12 Oct/Nov 2025
26 A business provides the following information. number of units produced and sold 48000 $ direct materials ($3 per kg) 298000 direct labour ($4 per labour hour) 240000 fixed selling costs 150000 variable selling costs 24000 Fixed production overheads are absorbed at $10 per labour hour. What is the total absorption cost per unit? A $14.83 B $23.71 C $26.83 D $27.33
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2025
Q552 · A new manufacturing business has just completed its first year of operation 9706/13 Oct/Nov 2025
23 A new manufacturing business has just completed its first year of operation. The following details relate to its inventory of direct materials. date units $ 2 January 700 20 2 July 300 26 The following items were taken from inventory for production. items 4 January 250 5 July 450 What would be the value of inventory at the end of the year using the AVCO (periodic) method? A $6540 B $6720 C $6900 D $7800
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2025
Q553 · What is the purpose of a job cost sheet? 9706/13 Oct/Nov 2025
24 What is the purpose of a job cost sheet? A to enable the business to recover its overheads B to ensure the customer knows the split between materials and labour C to inform the customer of the profit margin D to let the business find the price for a quotation
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2025
Q554 · The following information is available 9706/13 Oct/Nov 2025
25 The following information is available. budgeted labour hours 10000 budgeted production overheads $80000 actual labour hours 11000 actual production overheads $82000 By how much are production overheads under-absorbed or over-absorbed? A $6000 over-absorbed B $6000 under-absorbed C $8000 over-absorbed D $8000 under-absorbed
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2025
Q555 · Which basis should be used to apportion stores overheads to production departments? 9706/13 Oct/Nov 2025
26 Which basis should be used to apportion stores overheads to production departments? A number of employees in each production department B number of machines in each production department C number of requisitions made by each production department D number of units produced in each production department
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2025
Q556 · The following information relates to a company’s previous accounting period 9706/13 Oct/Nov 2025
27 The following information relates to a company’s previous accounting period. opening inventory 10000 units closing inventory 20000 units absorption cost profit $180000 marginal cost profit $100000 What was the overhead absorption rate per unit during the accounting period? A $4 B $8 C $9 D $18
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2025
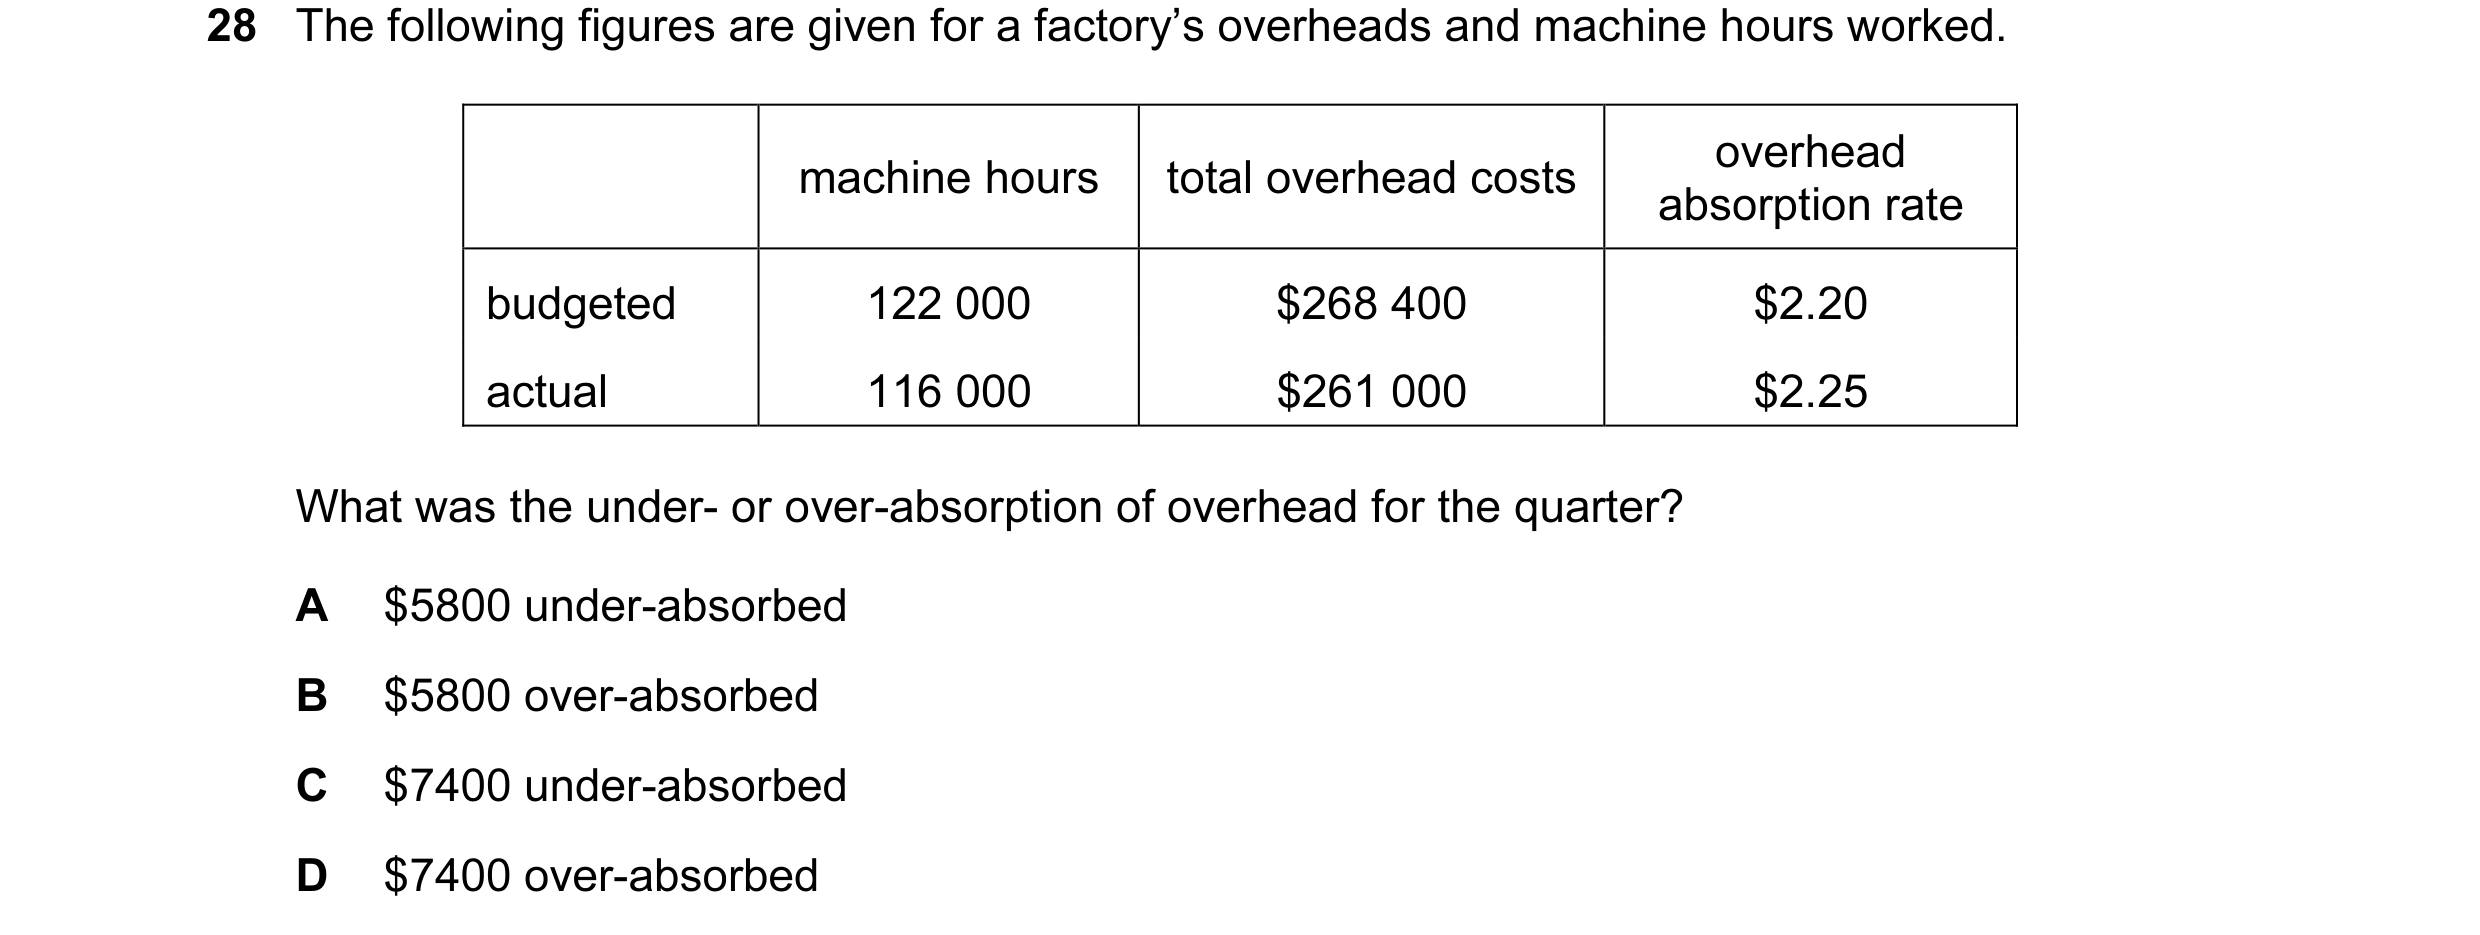
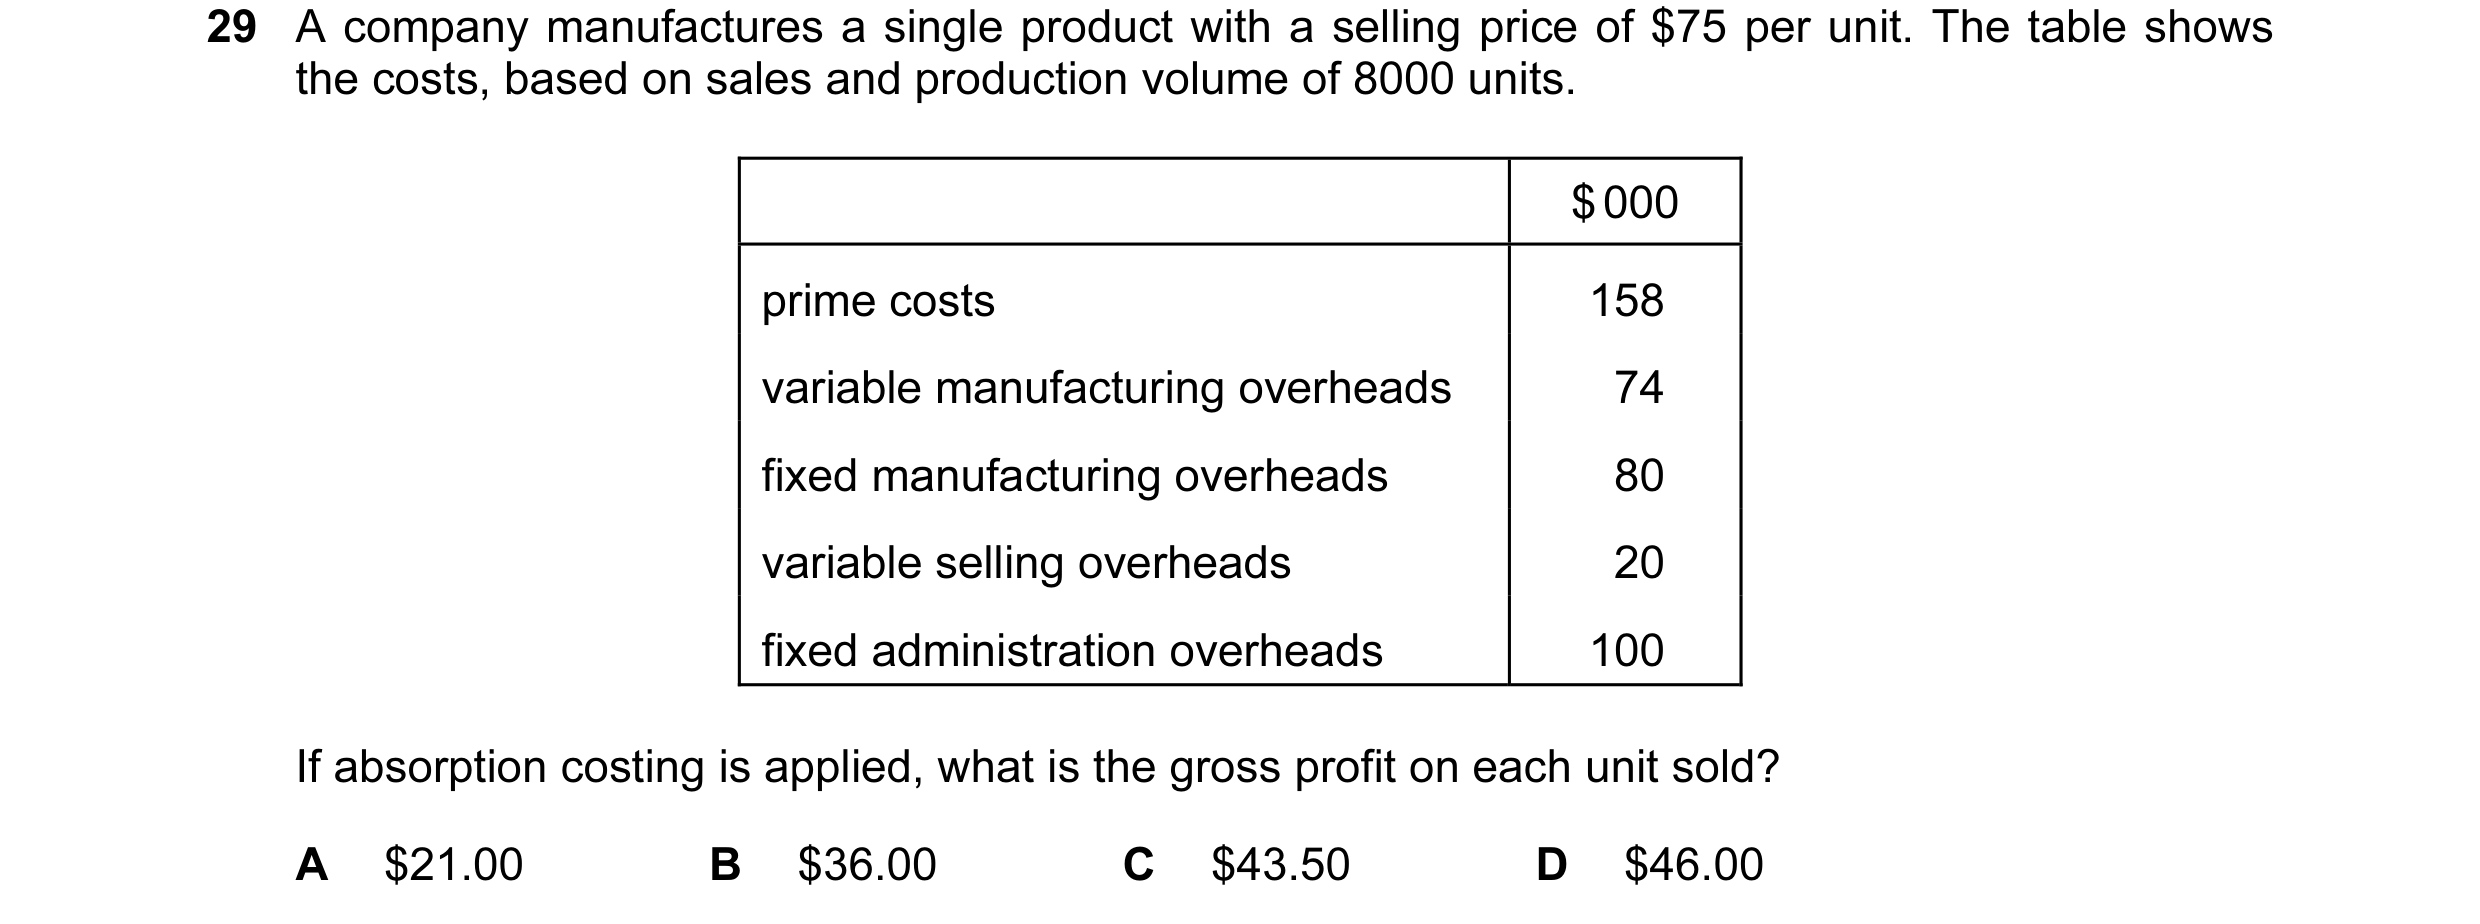
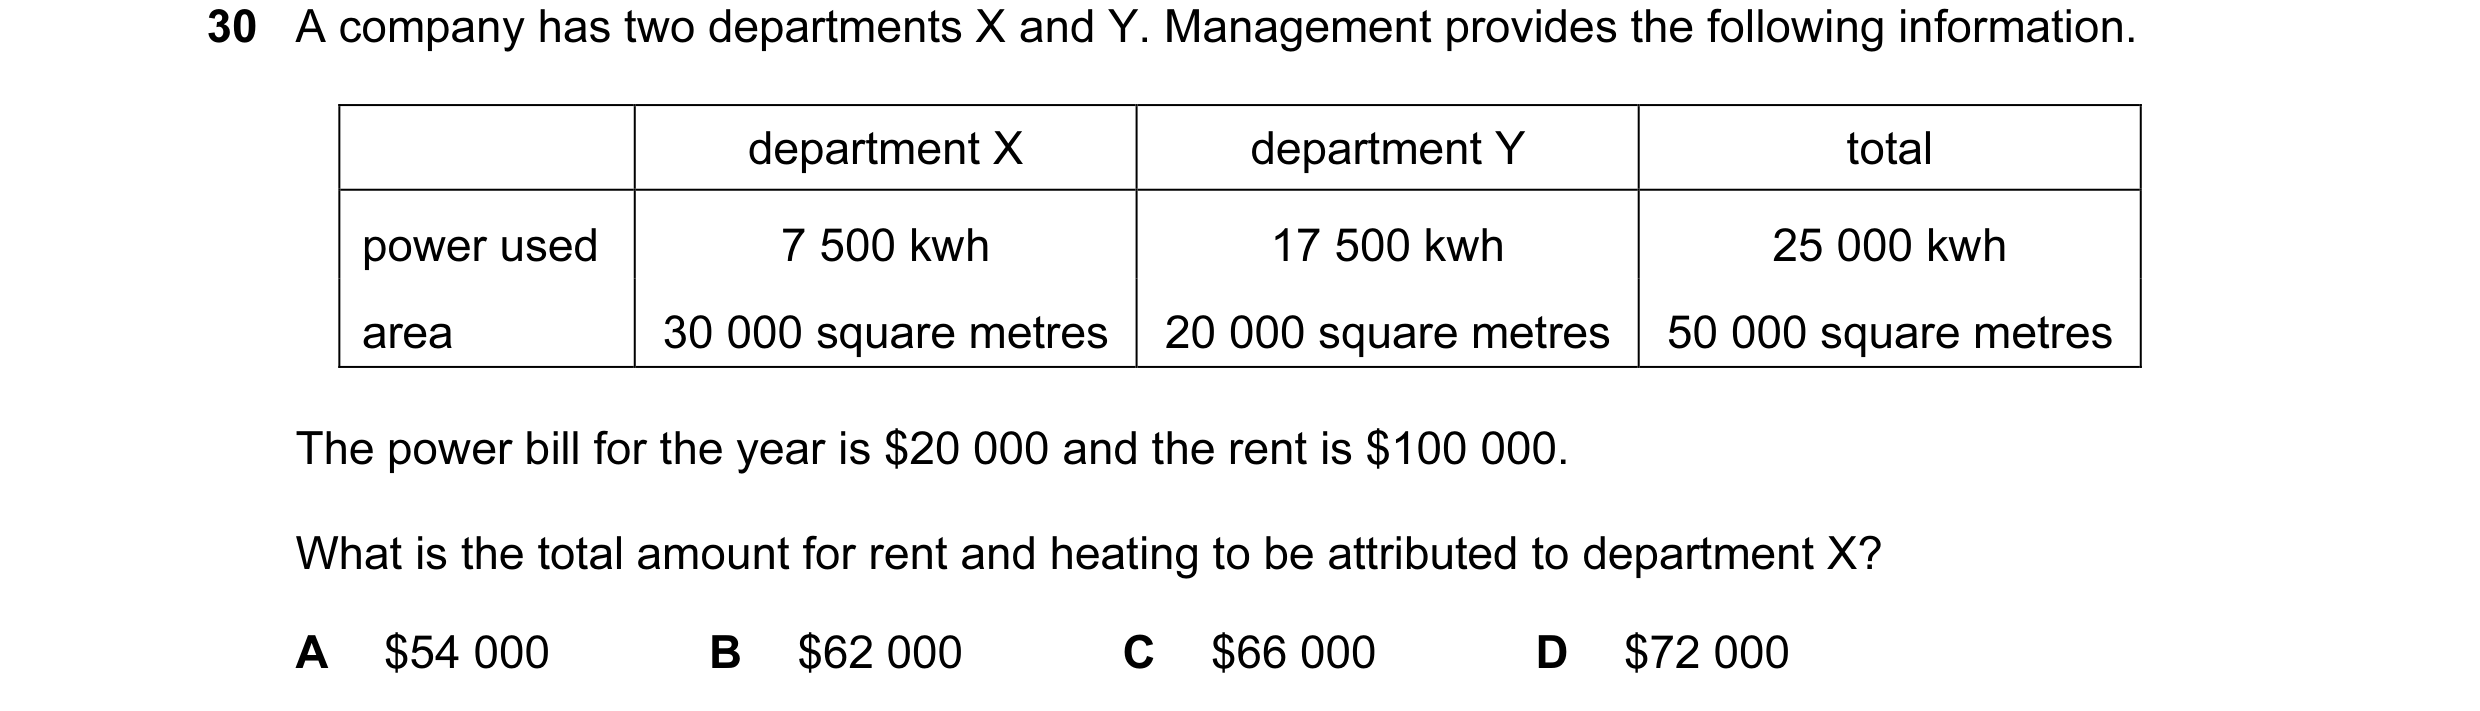
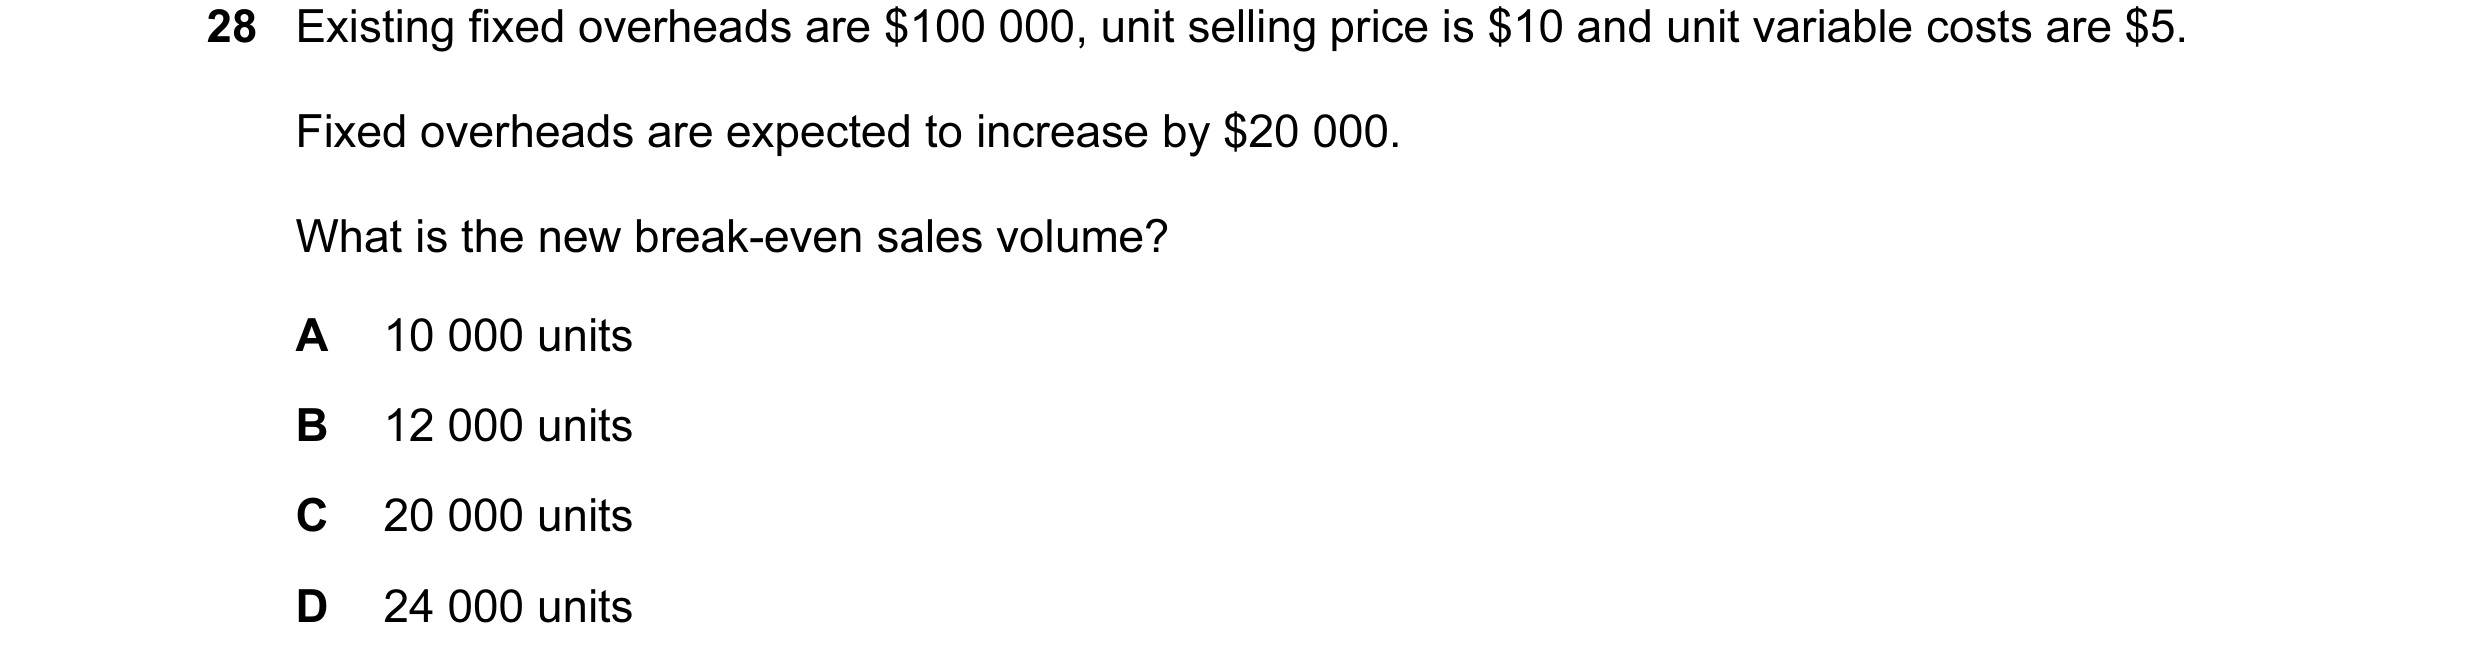 1 / 143
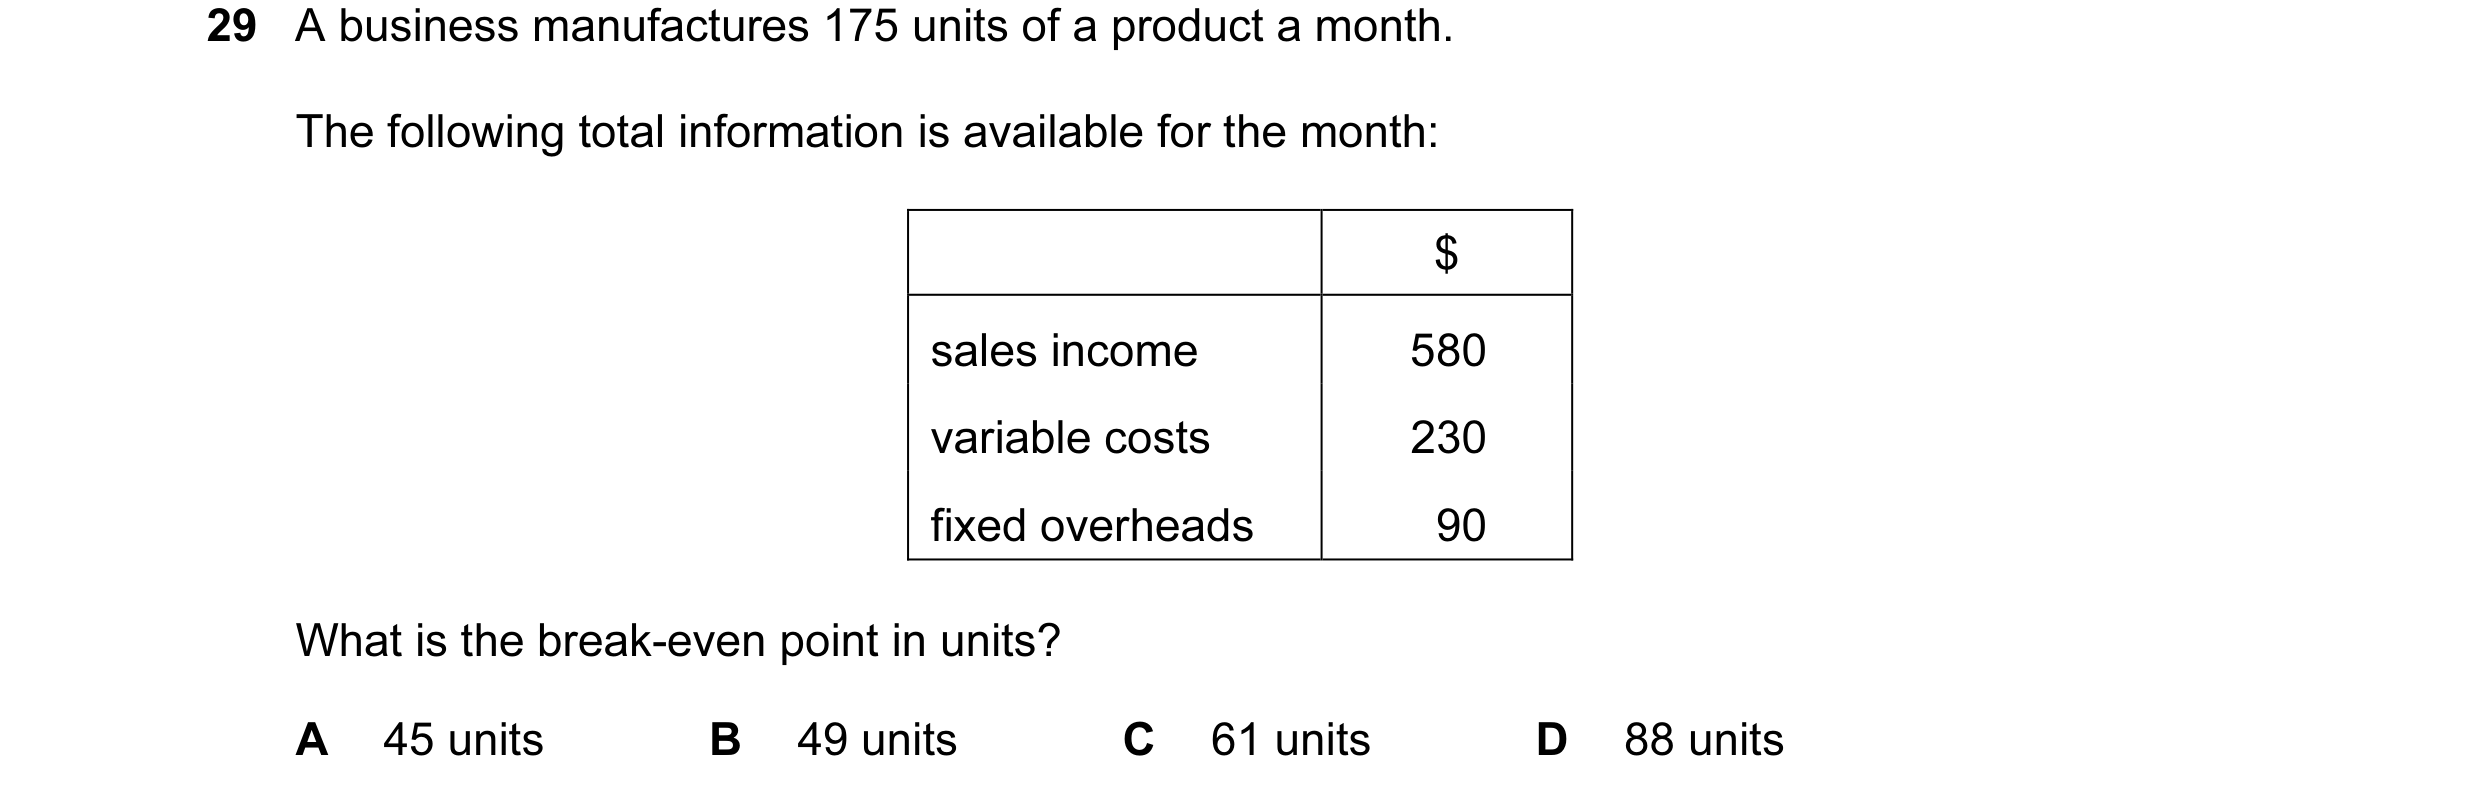
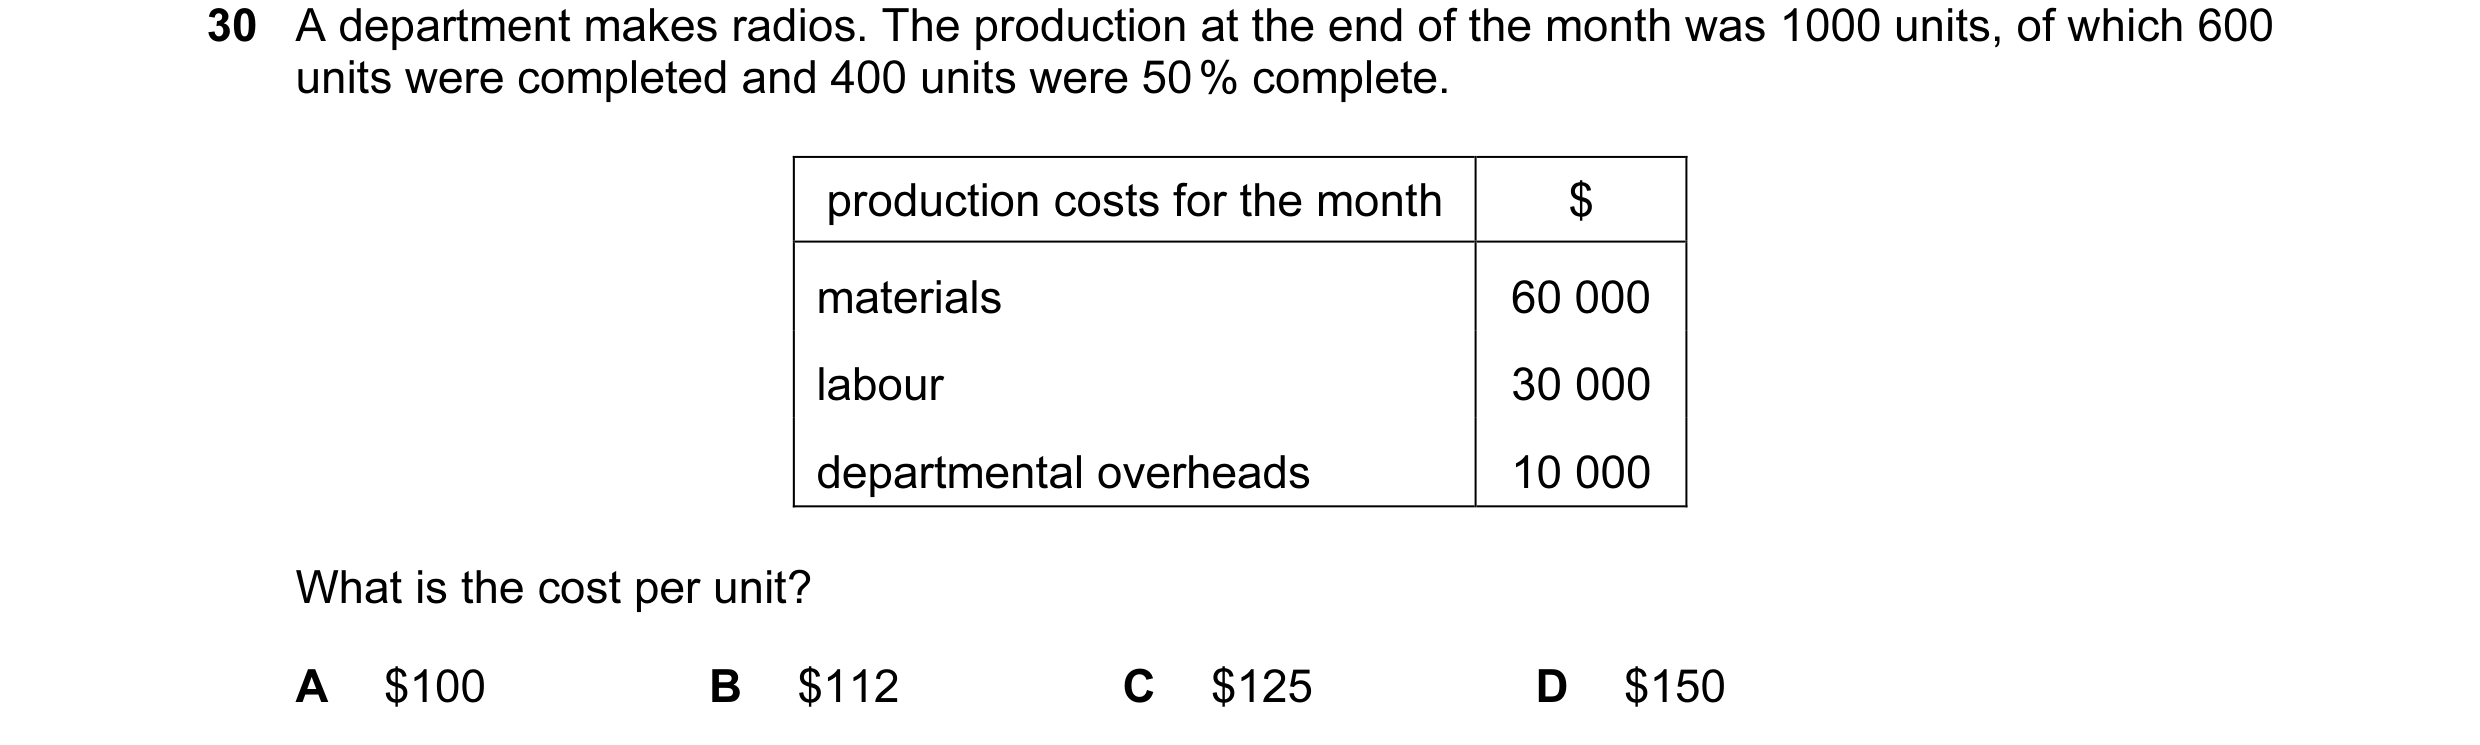
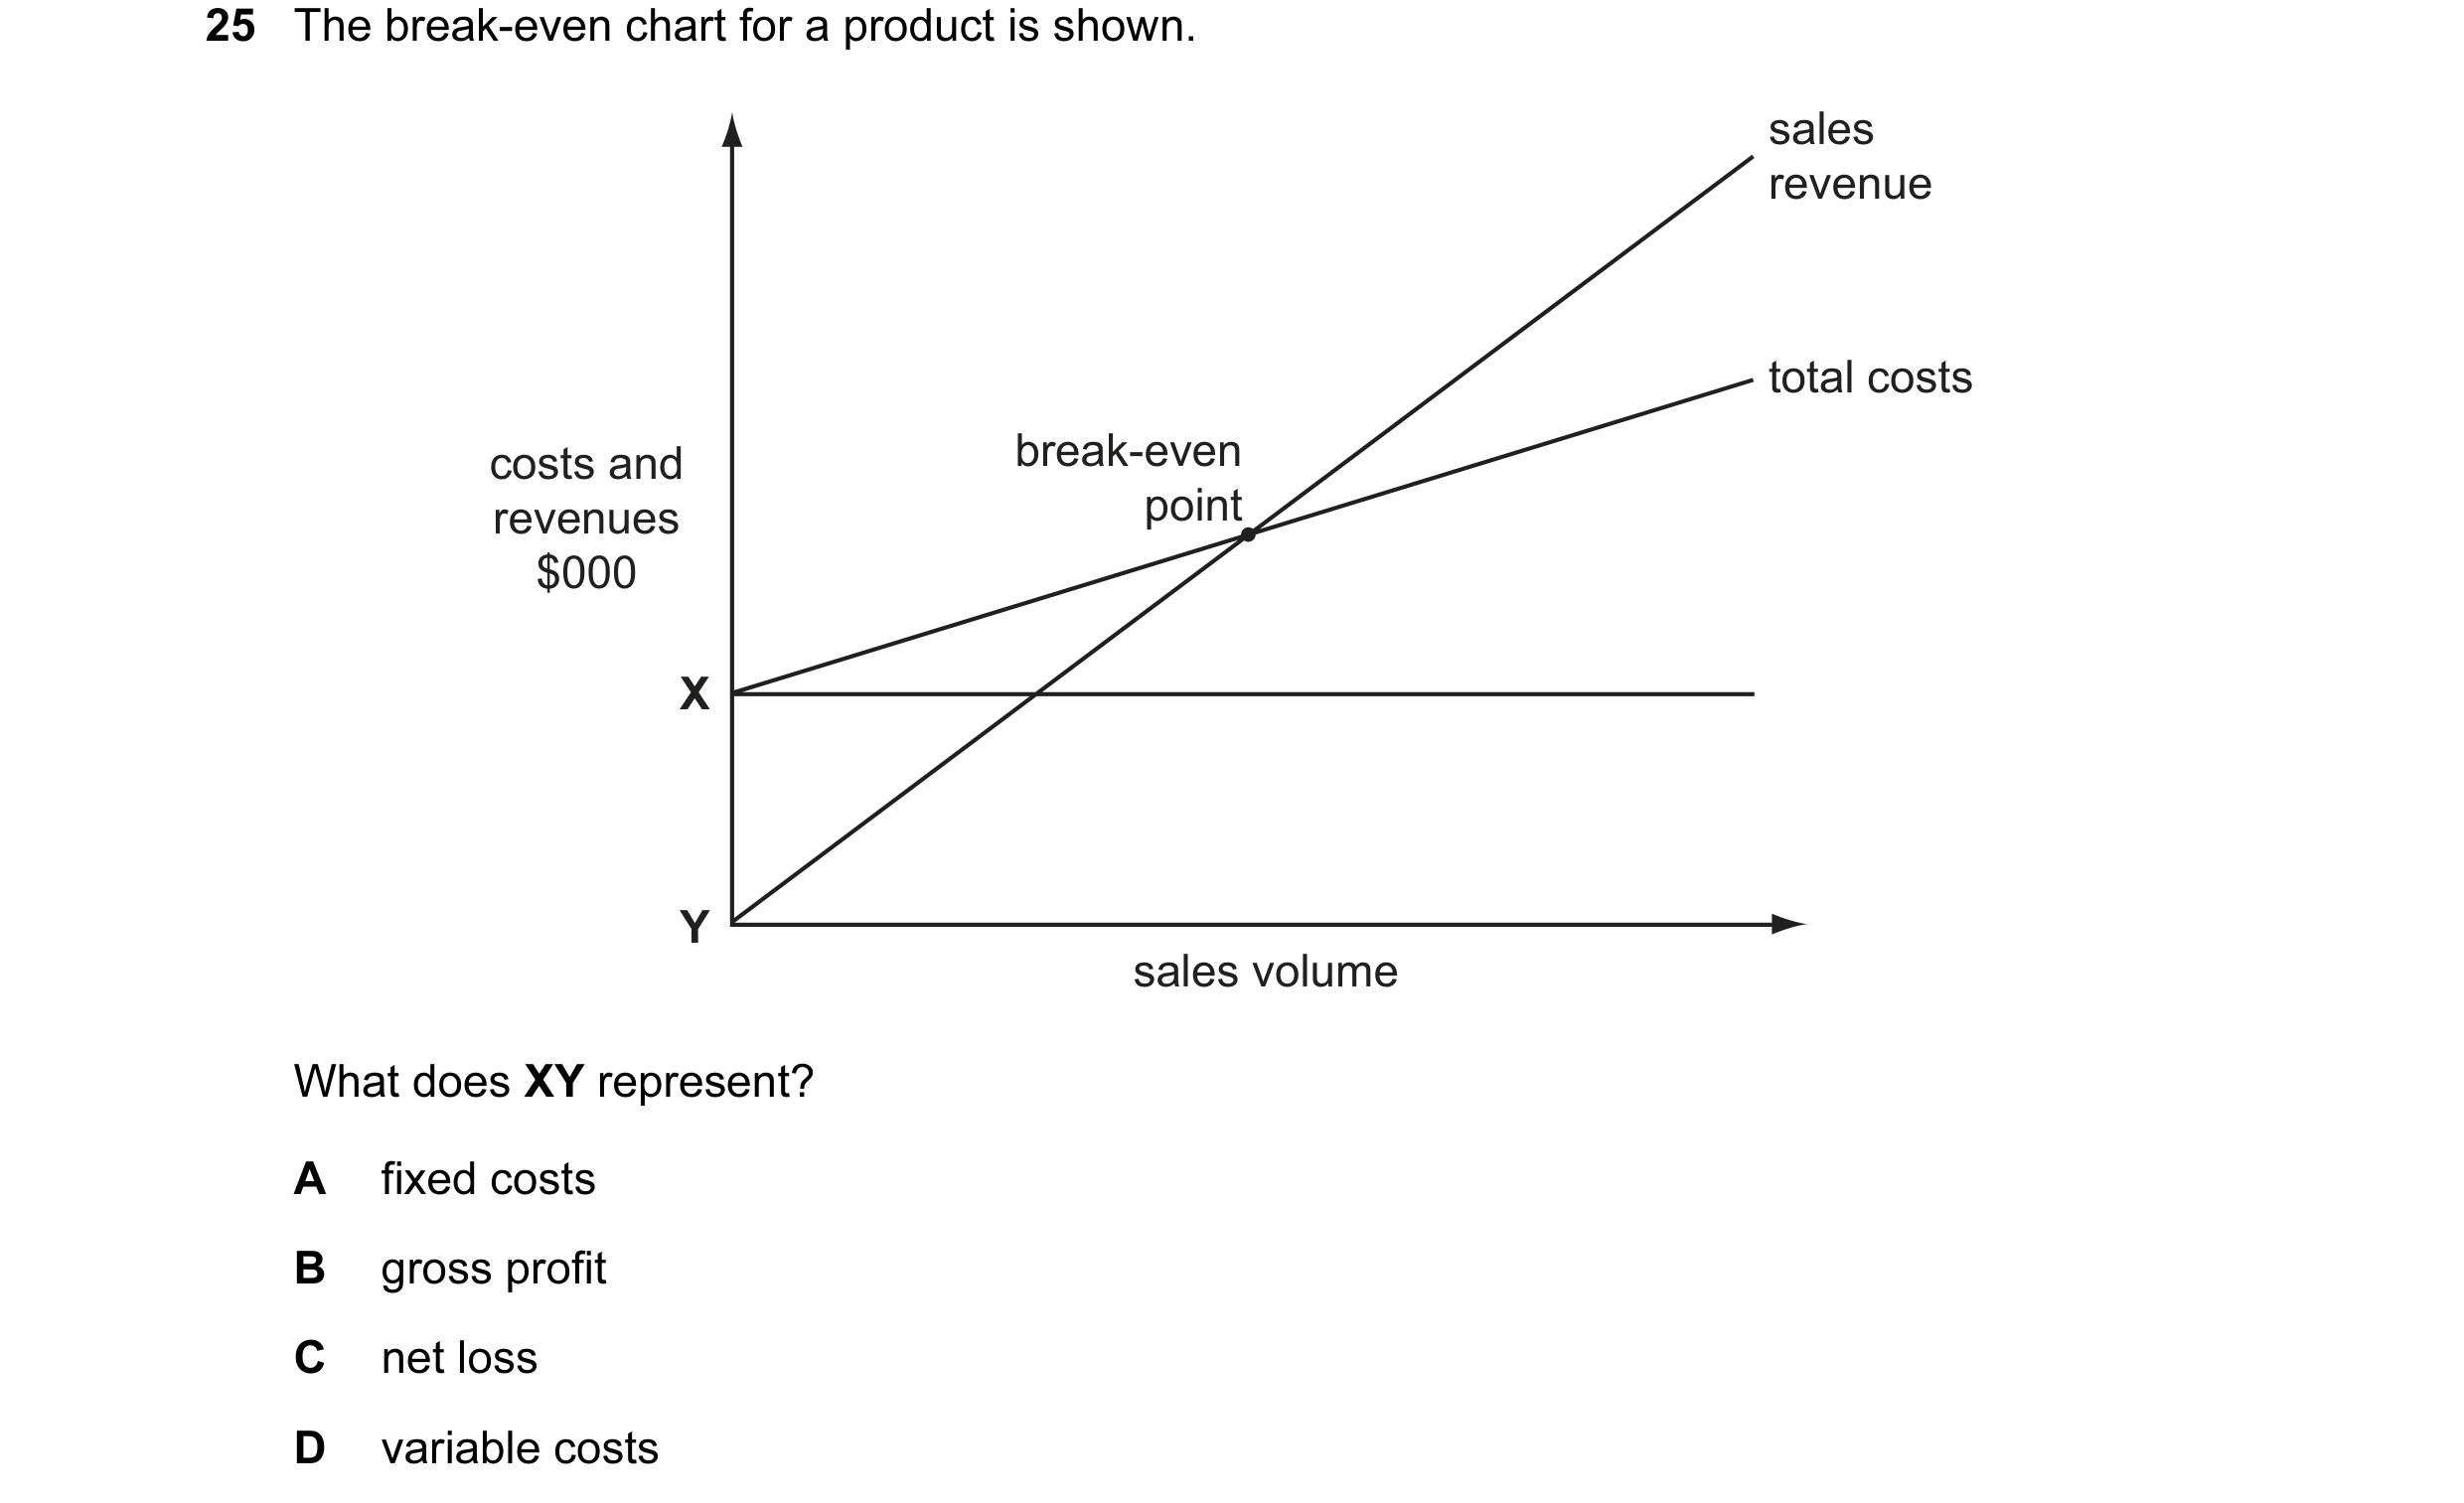 2 / 143
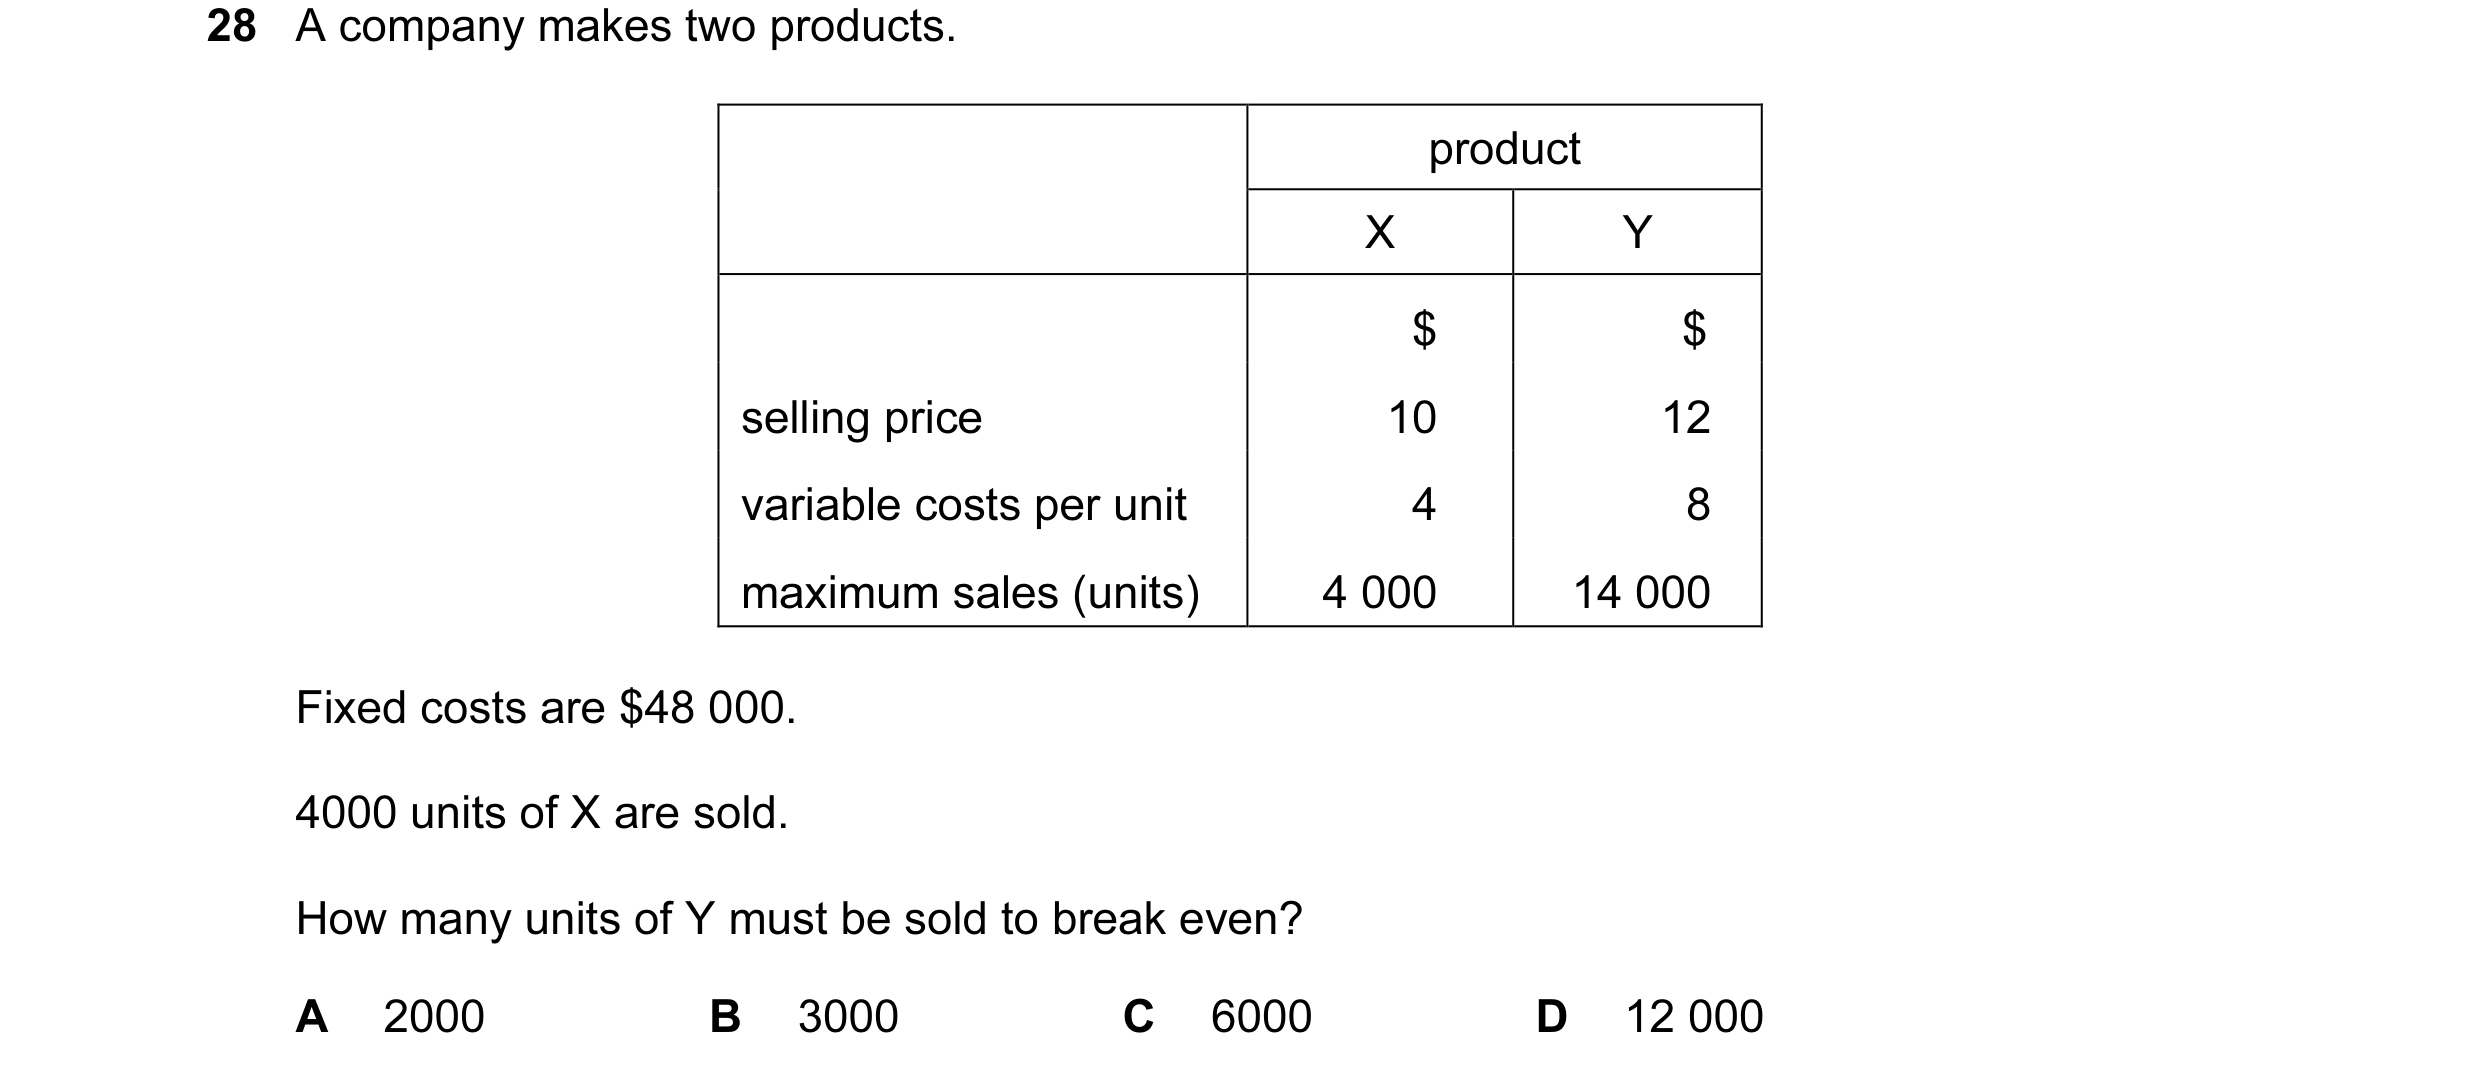
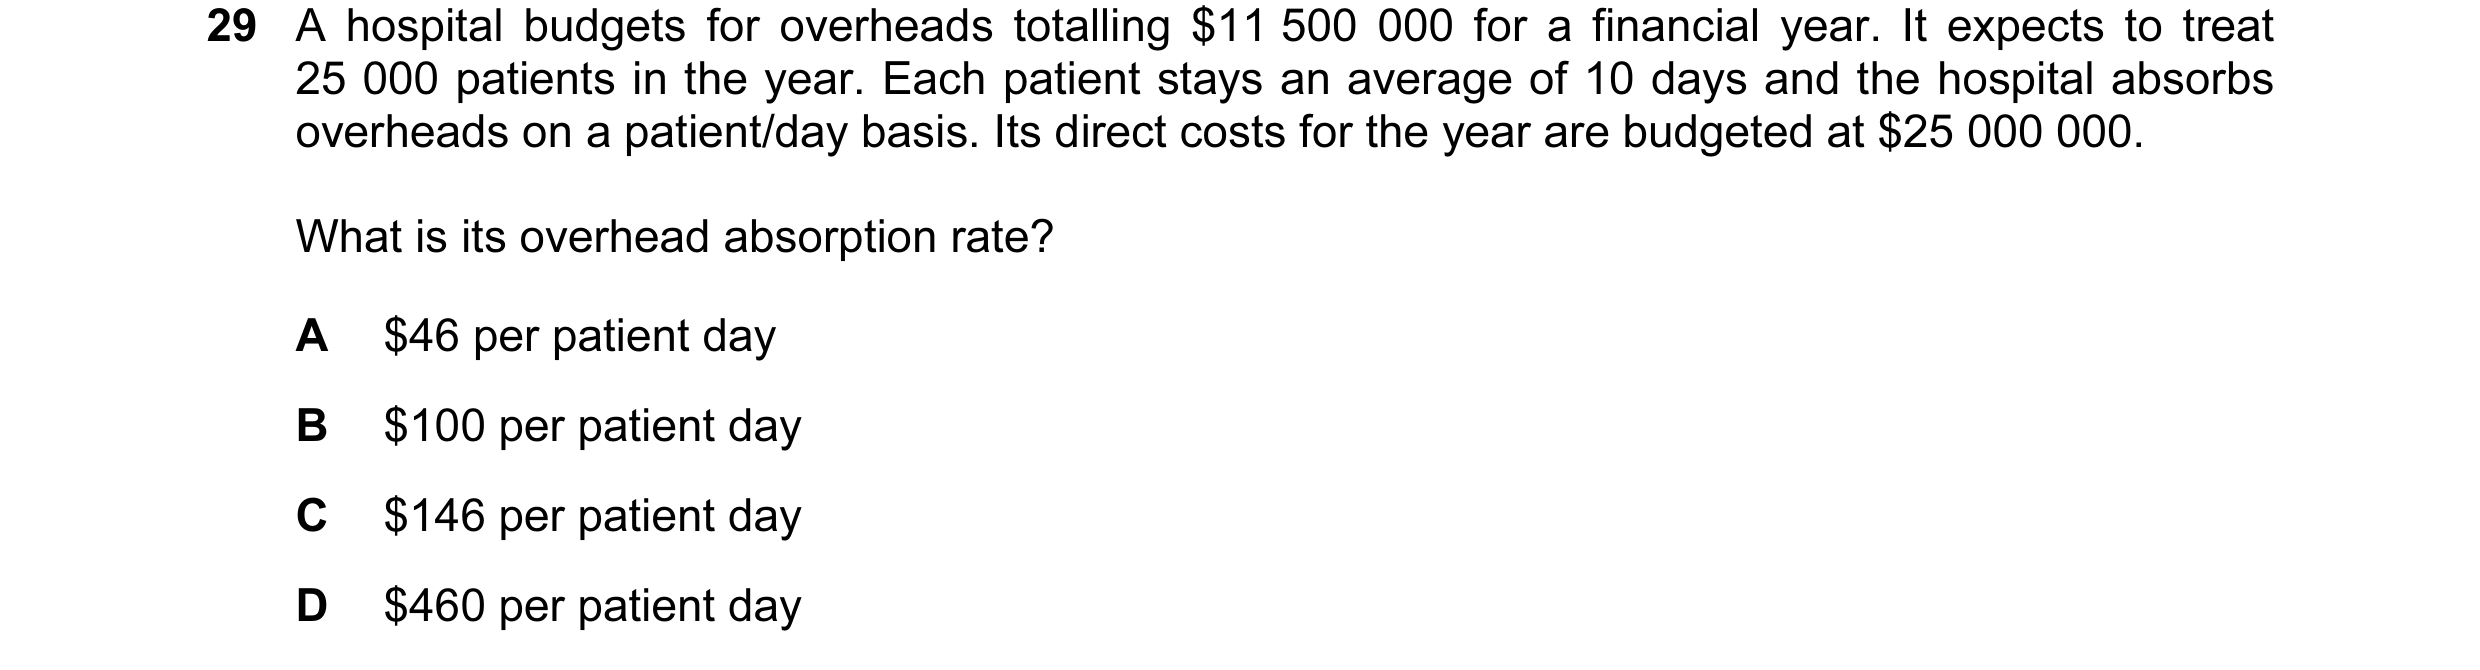
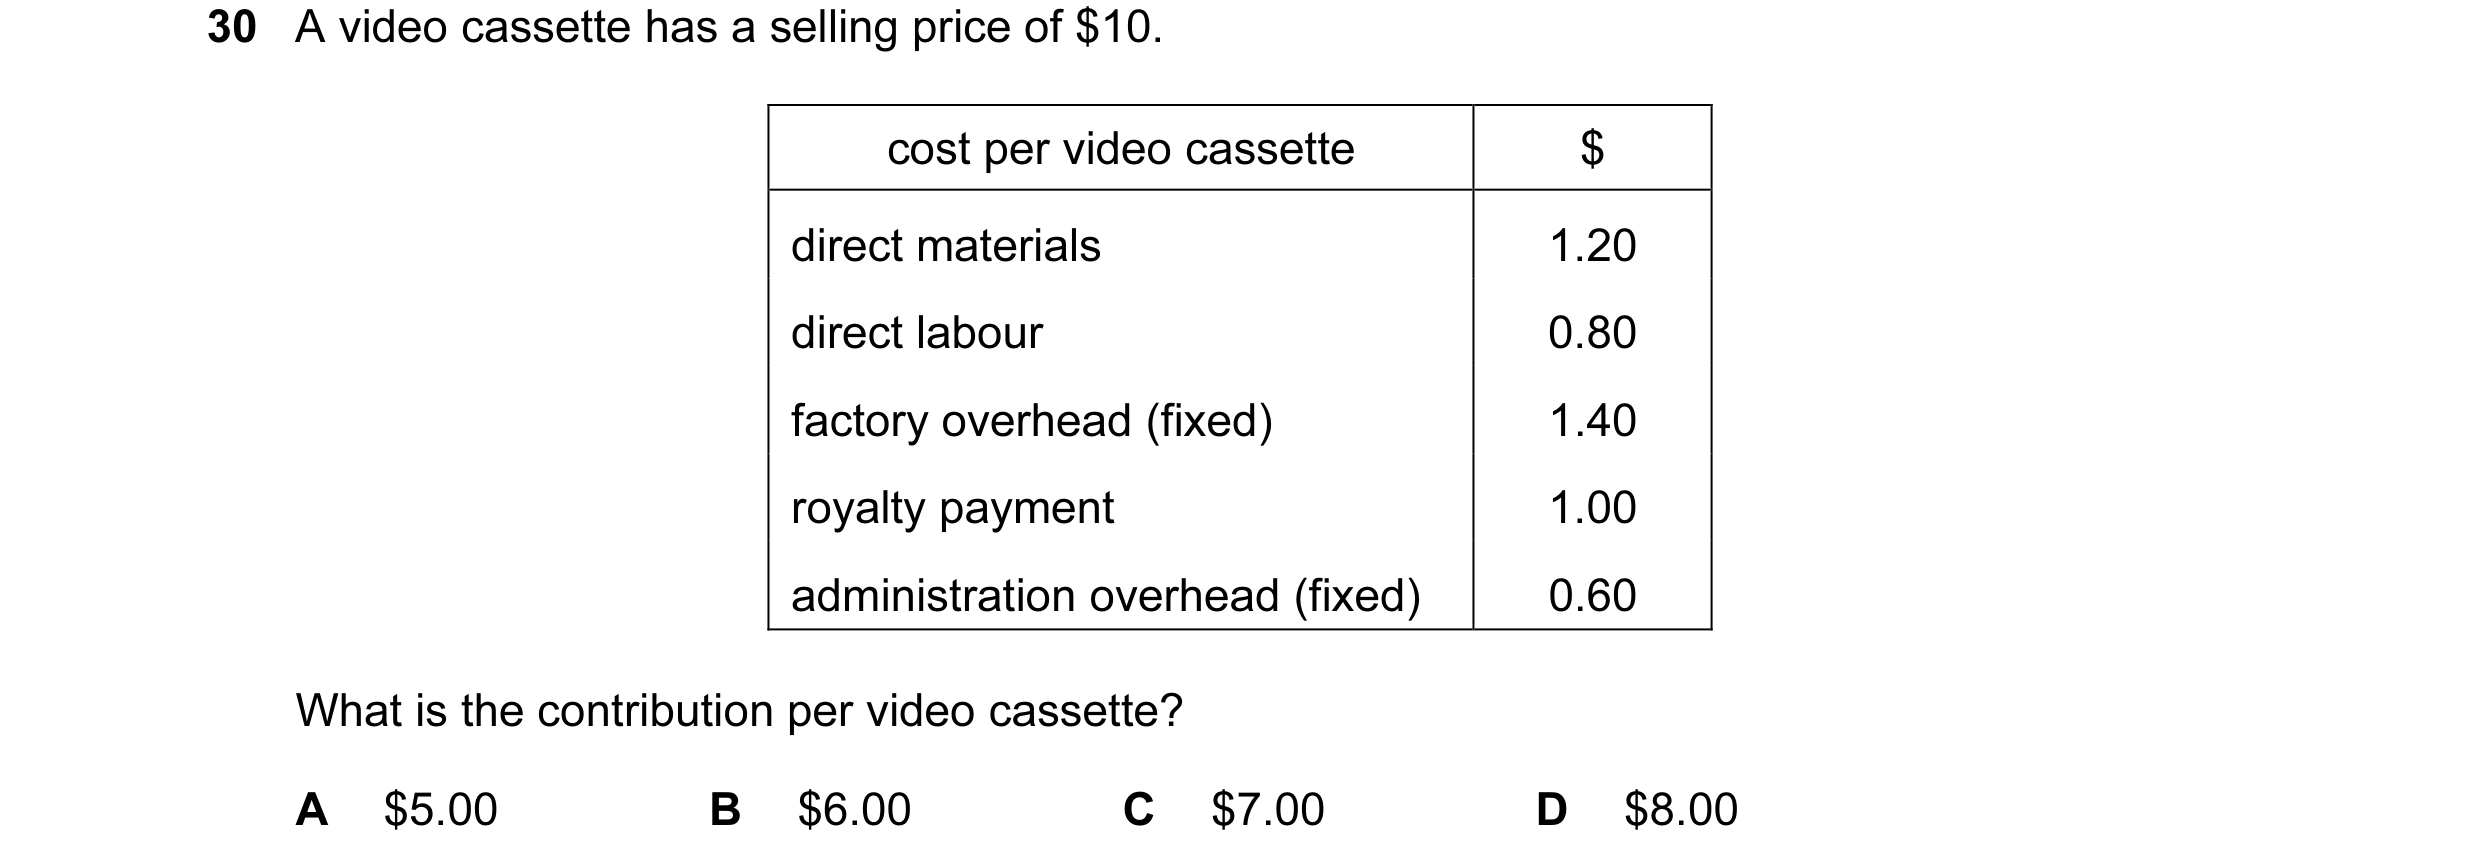 3 / 143
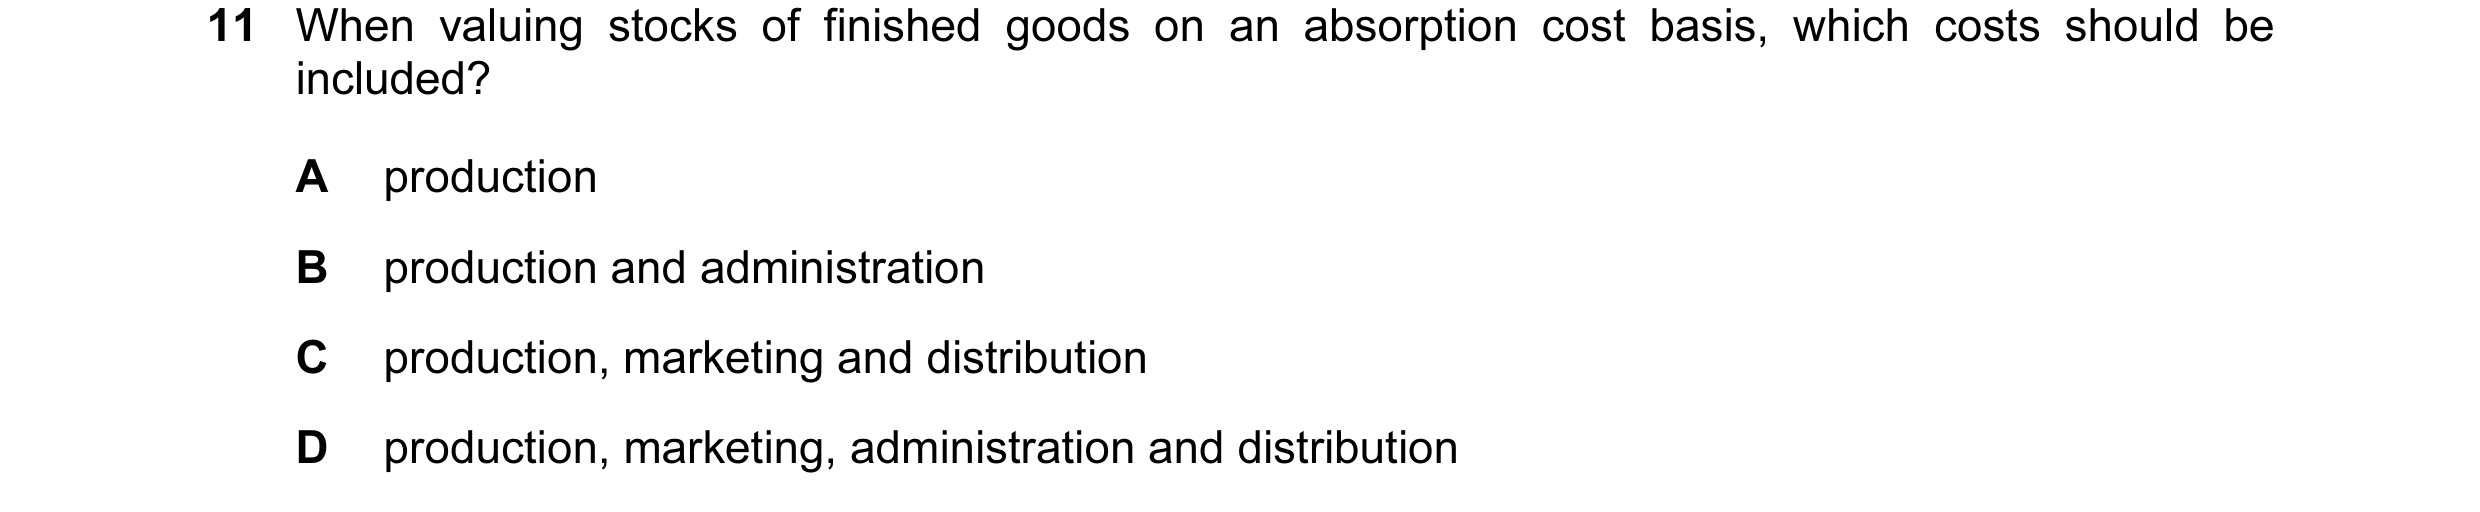
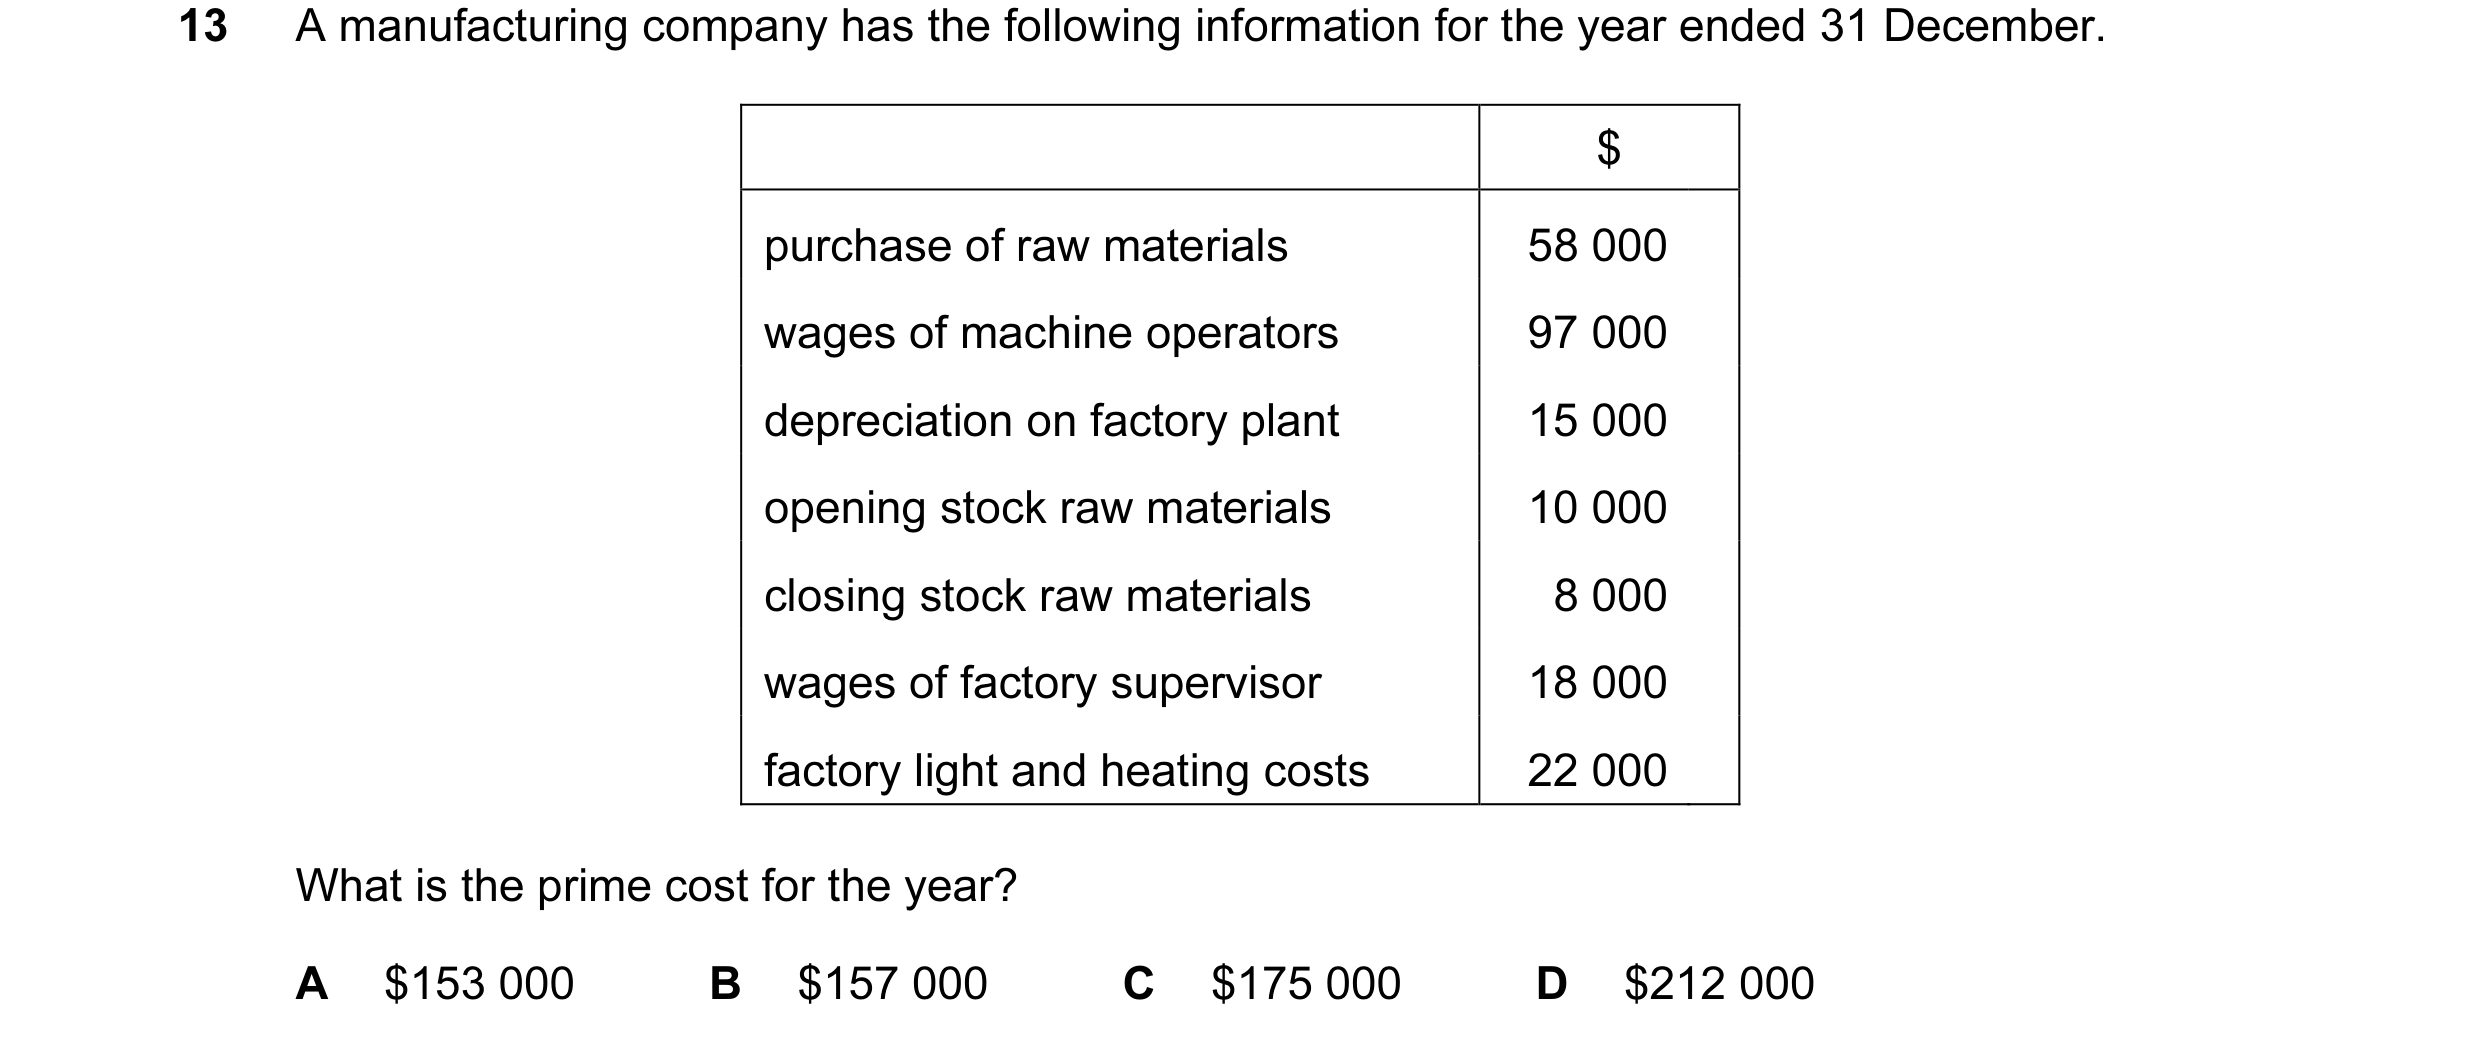
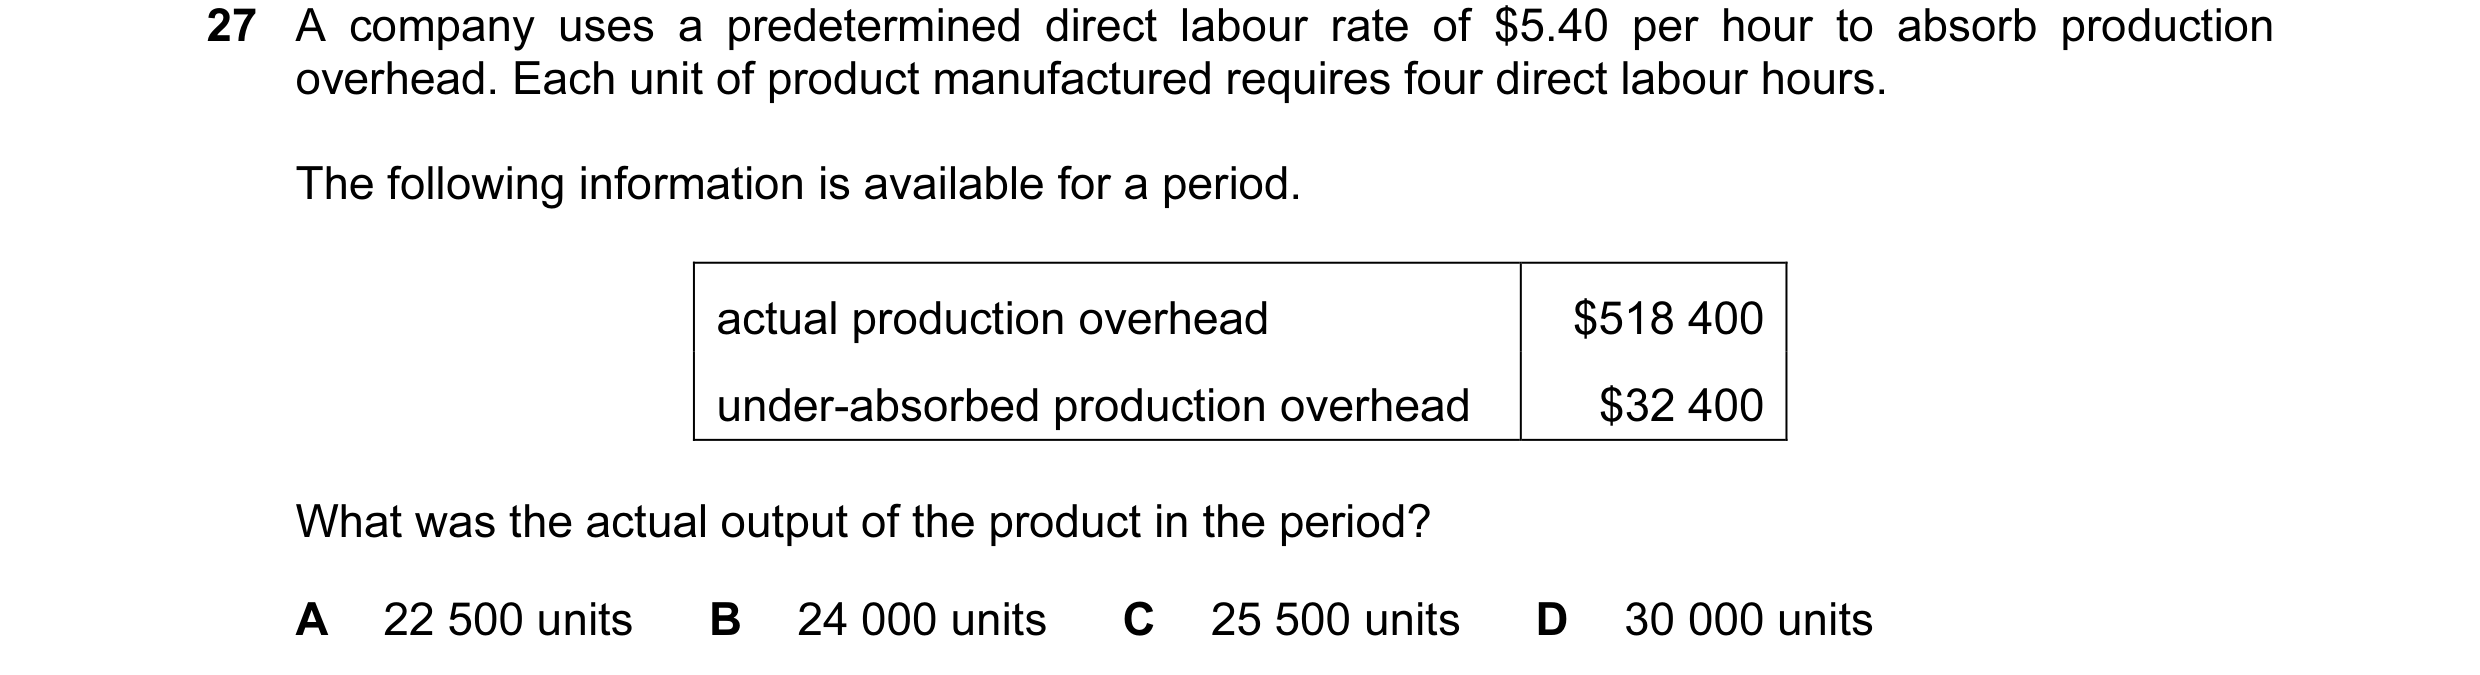
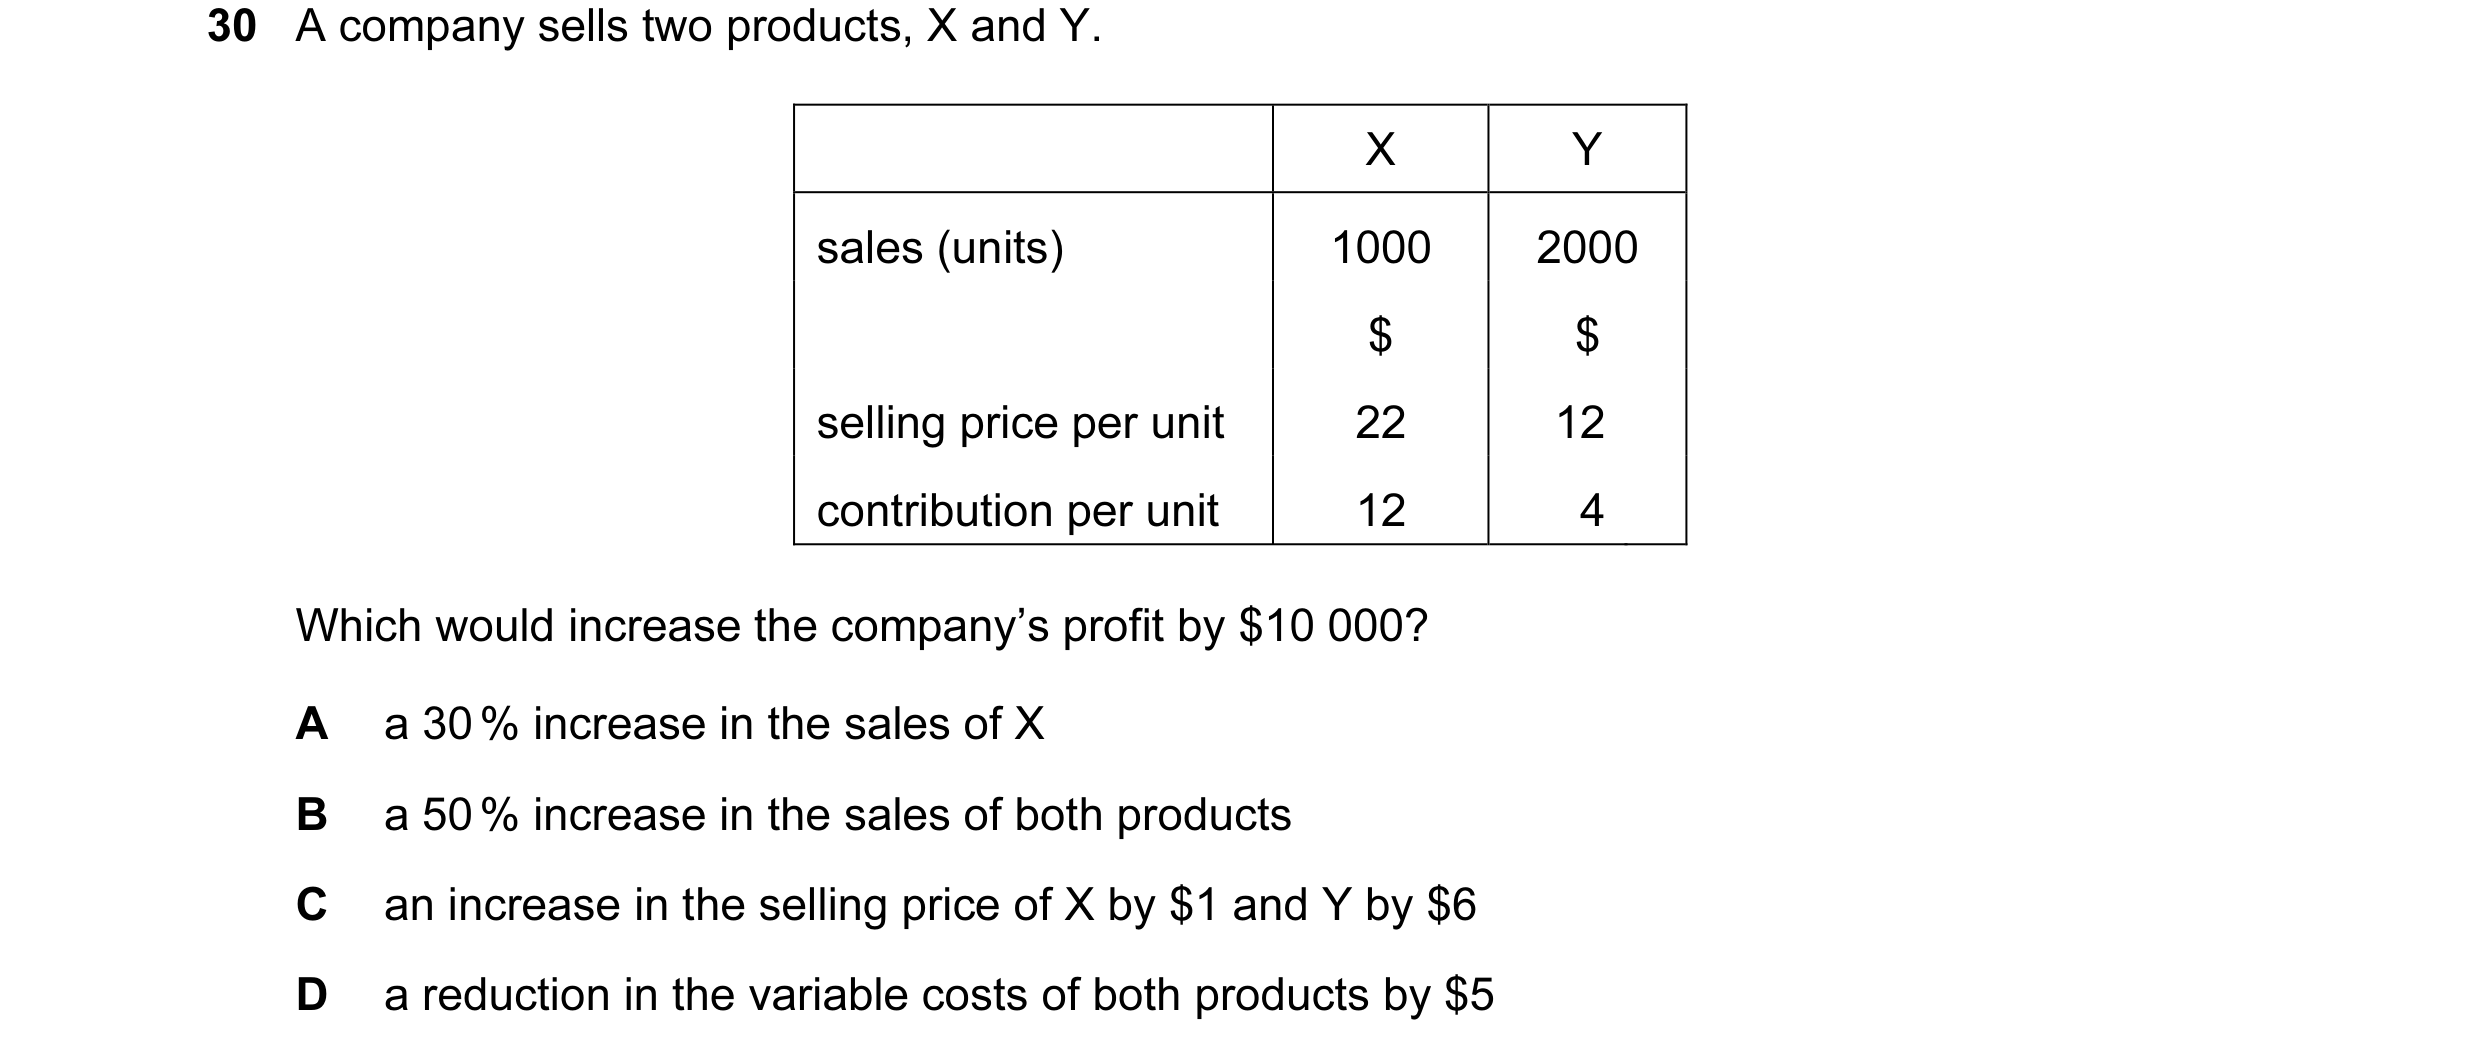 4 / 143
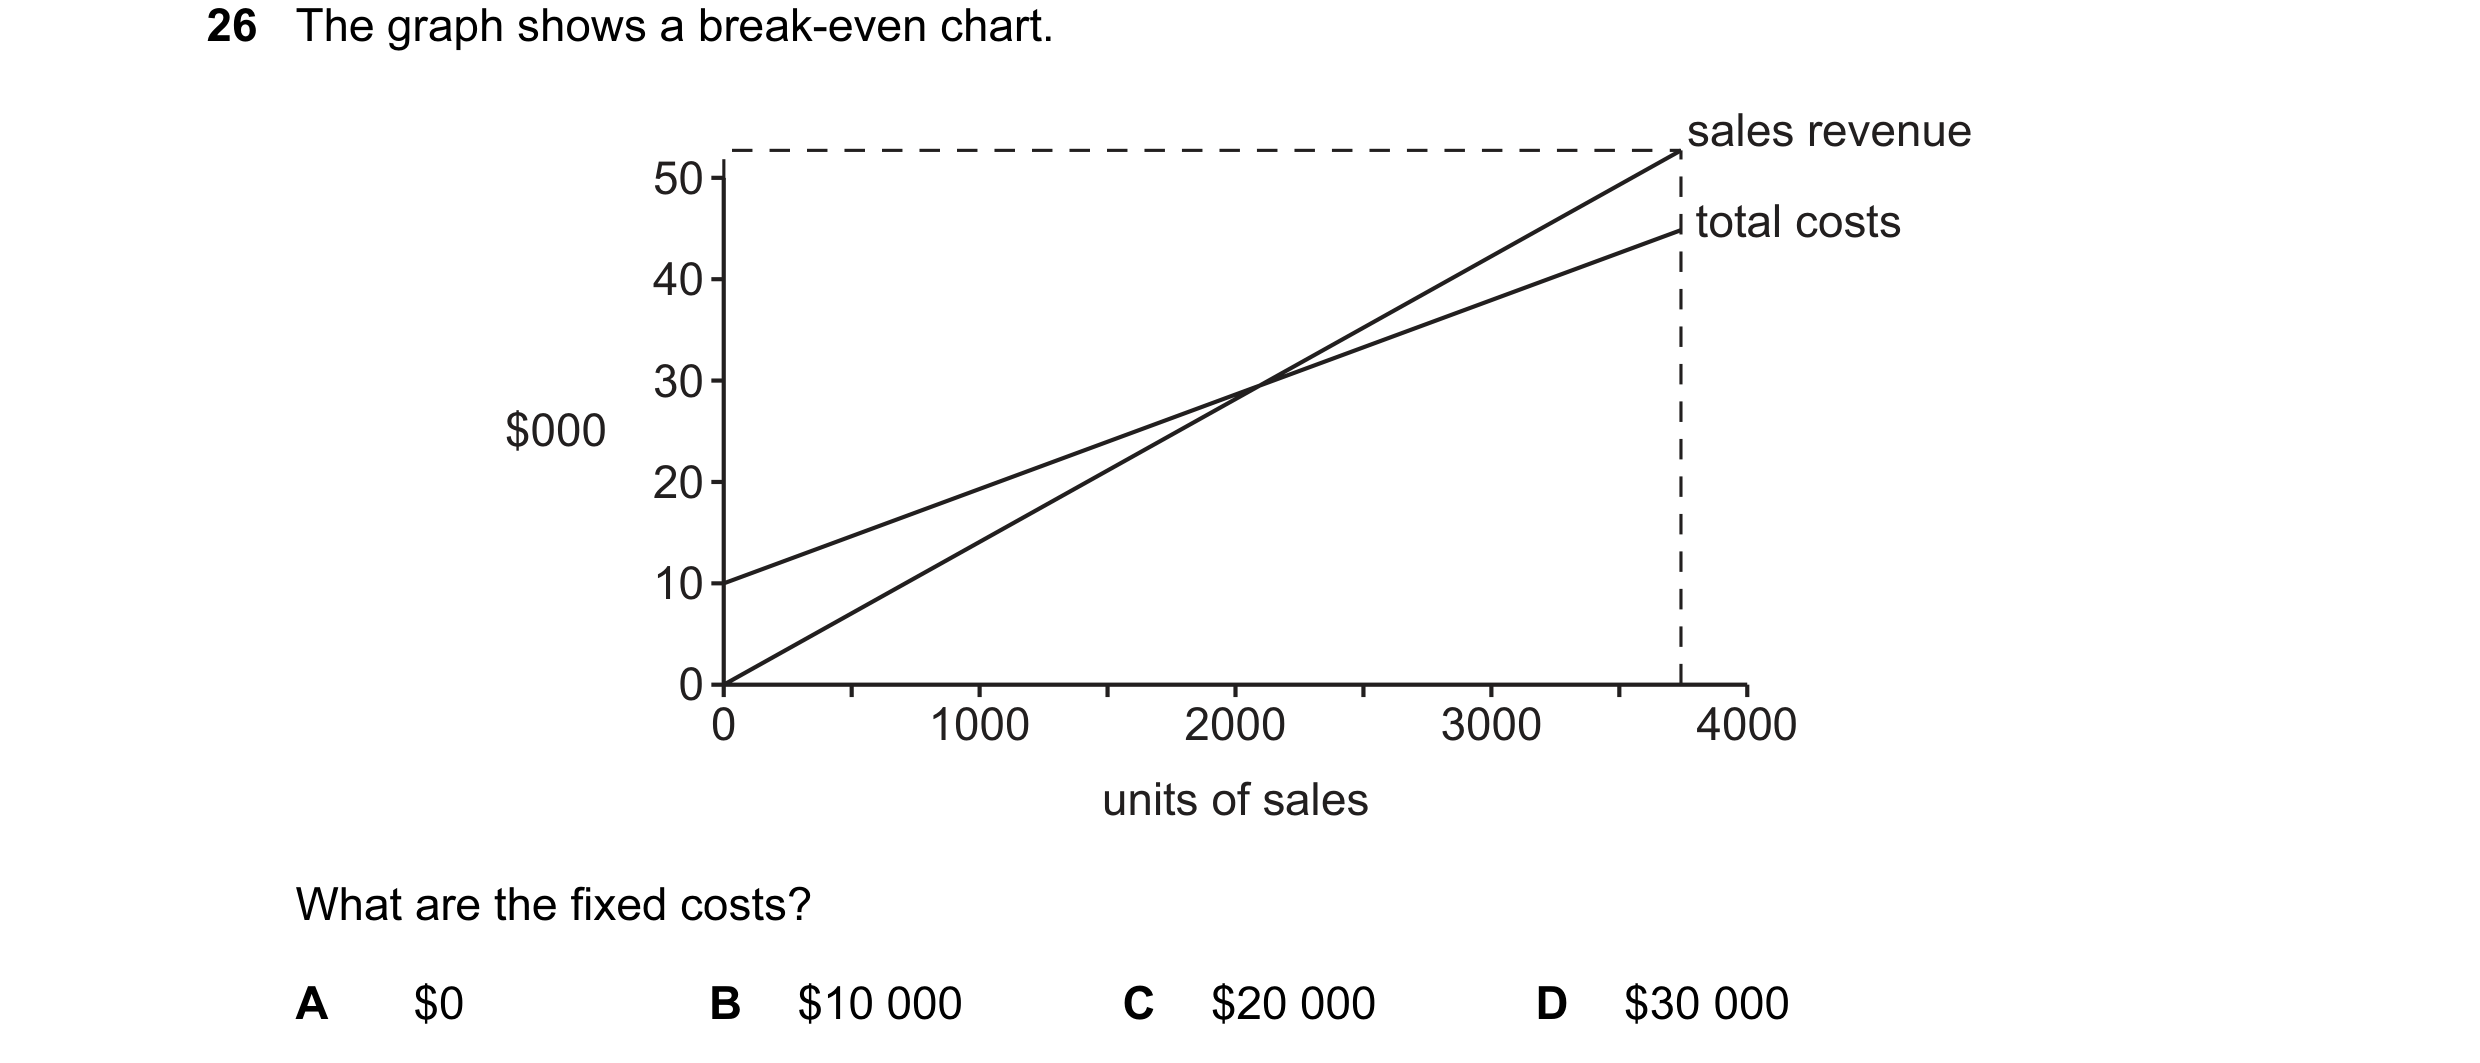
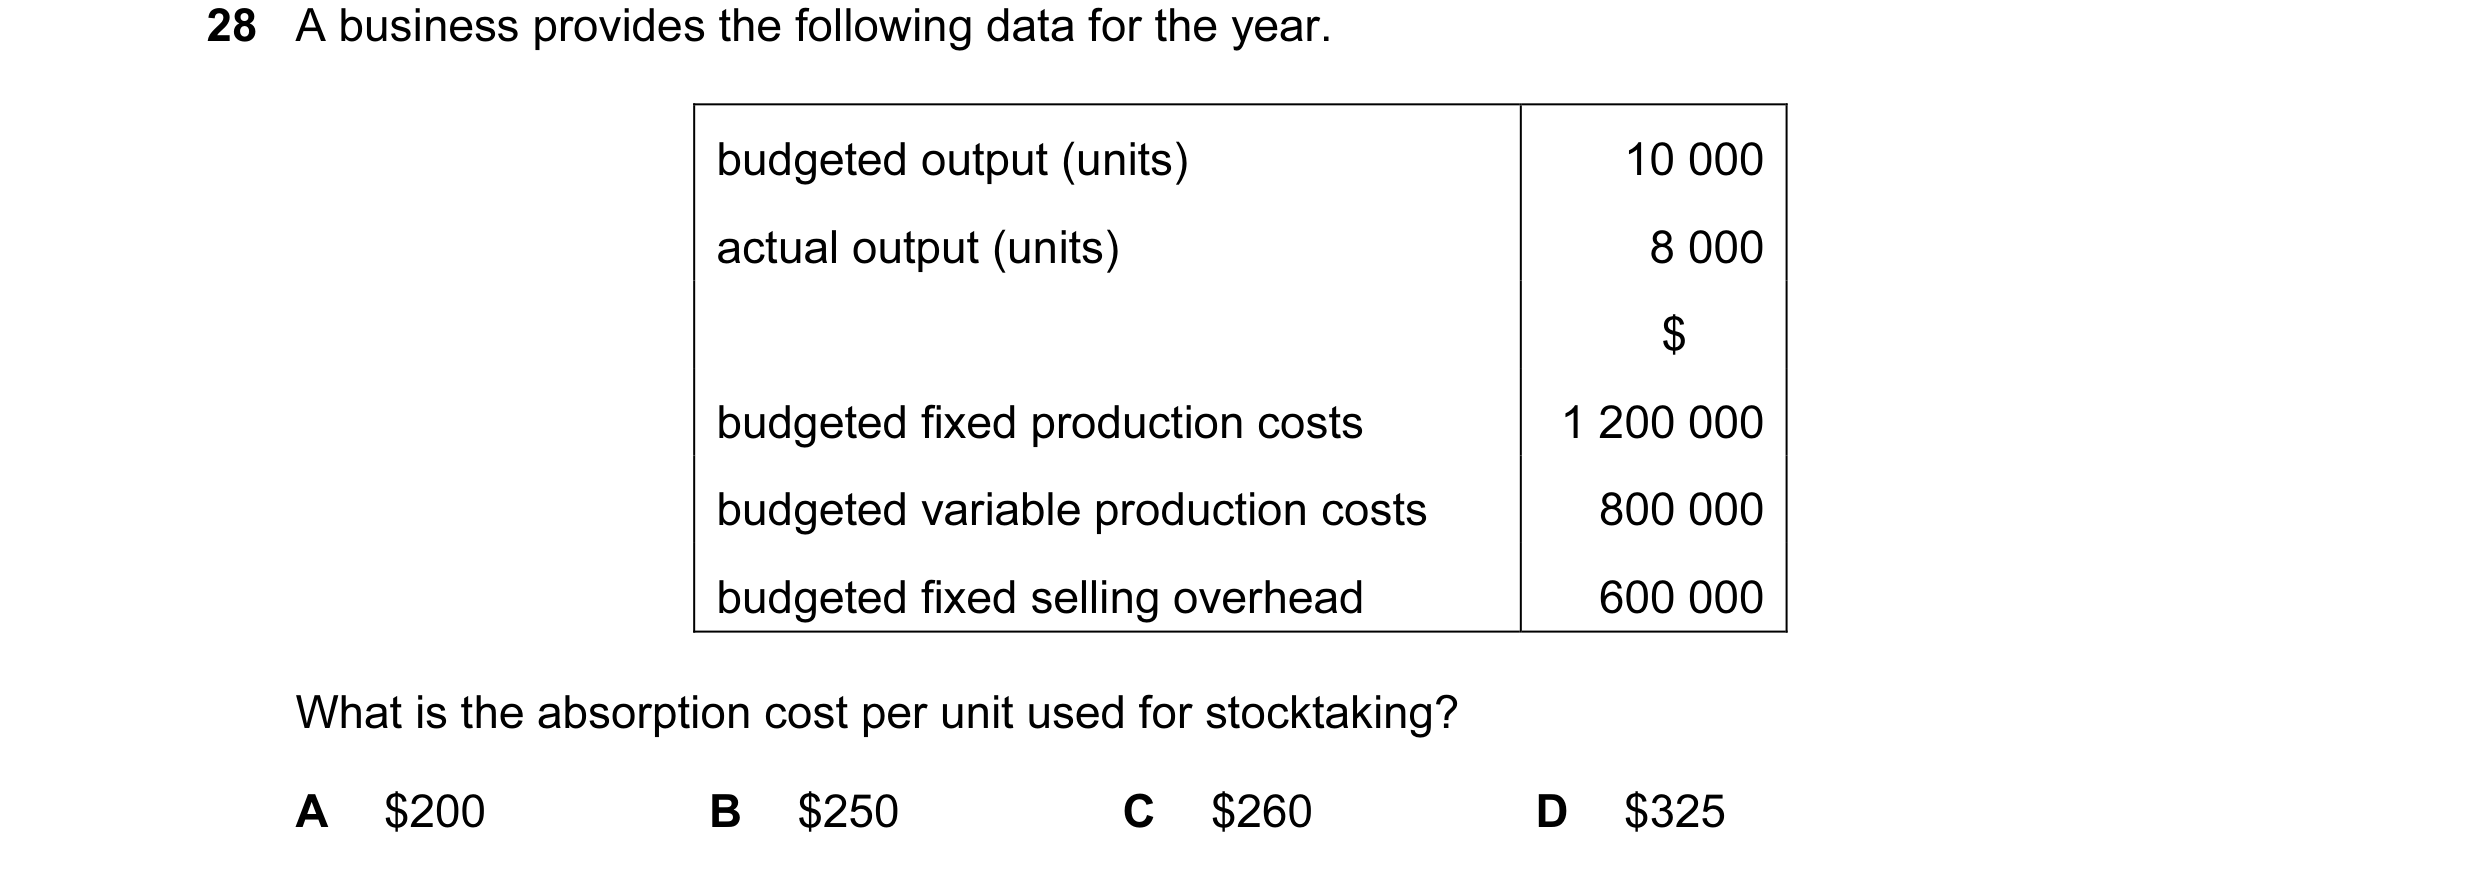
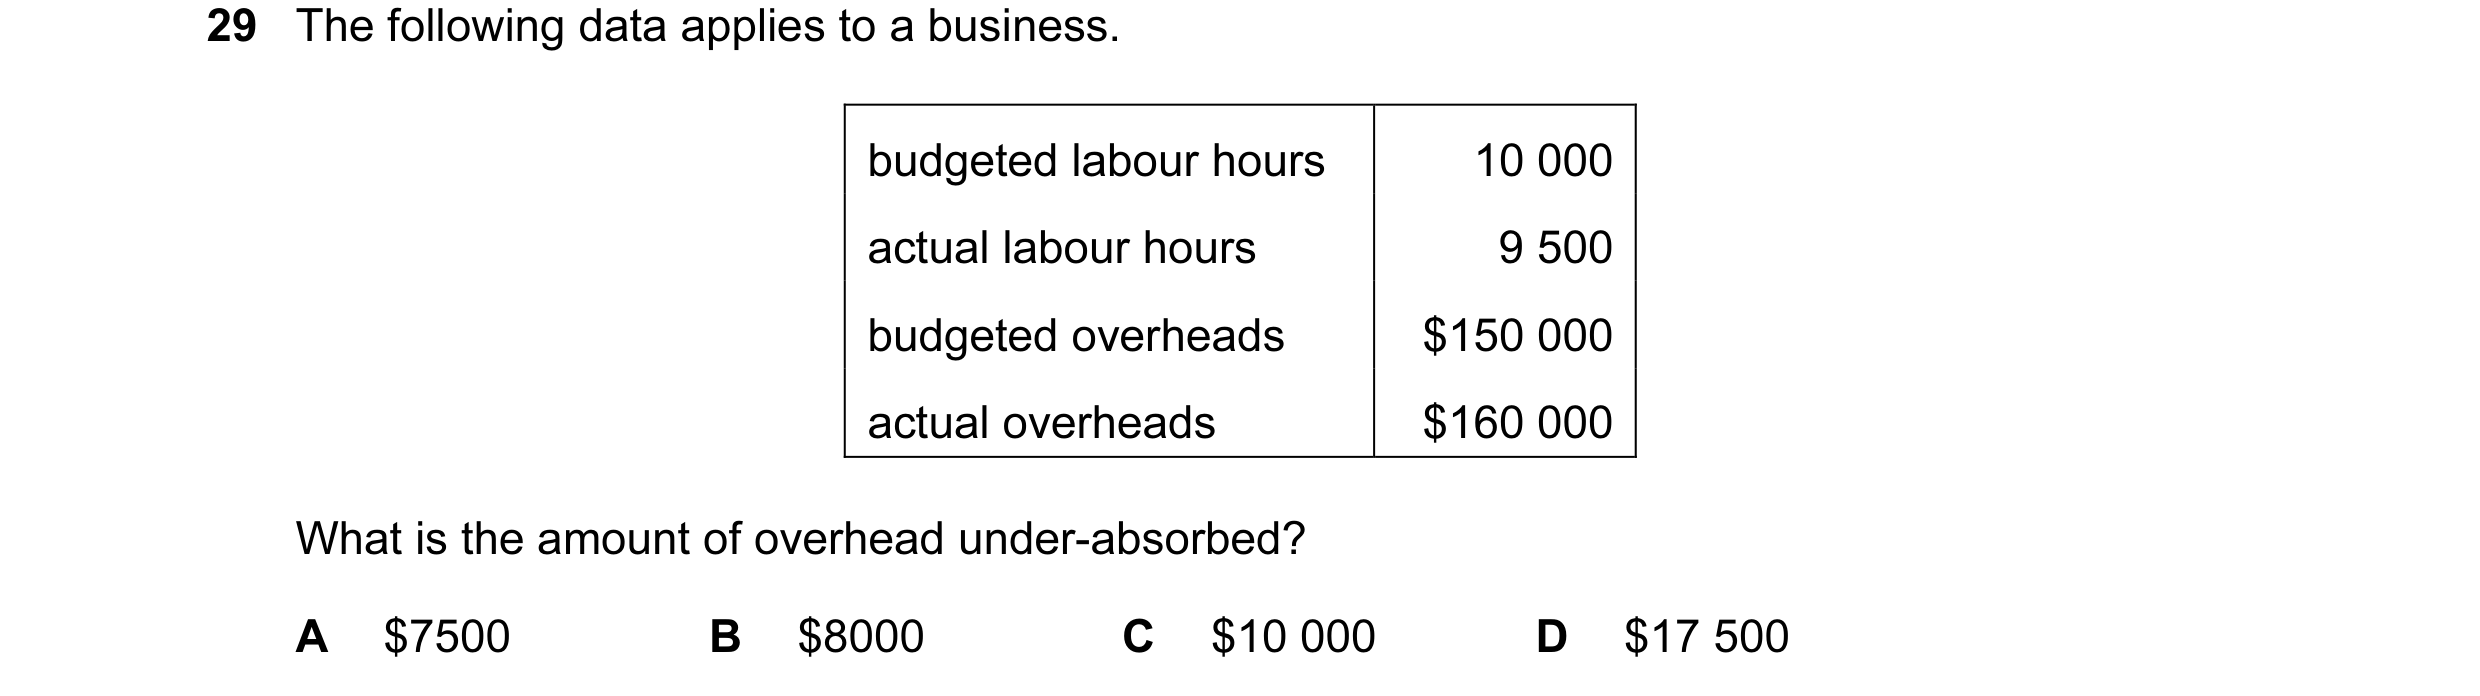 5 / 143
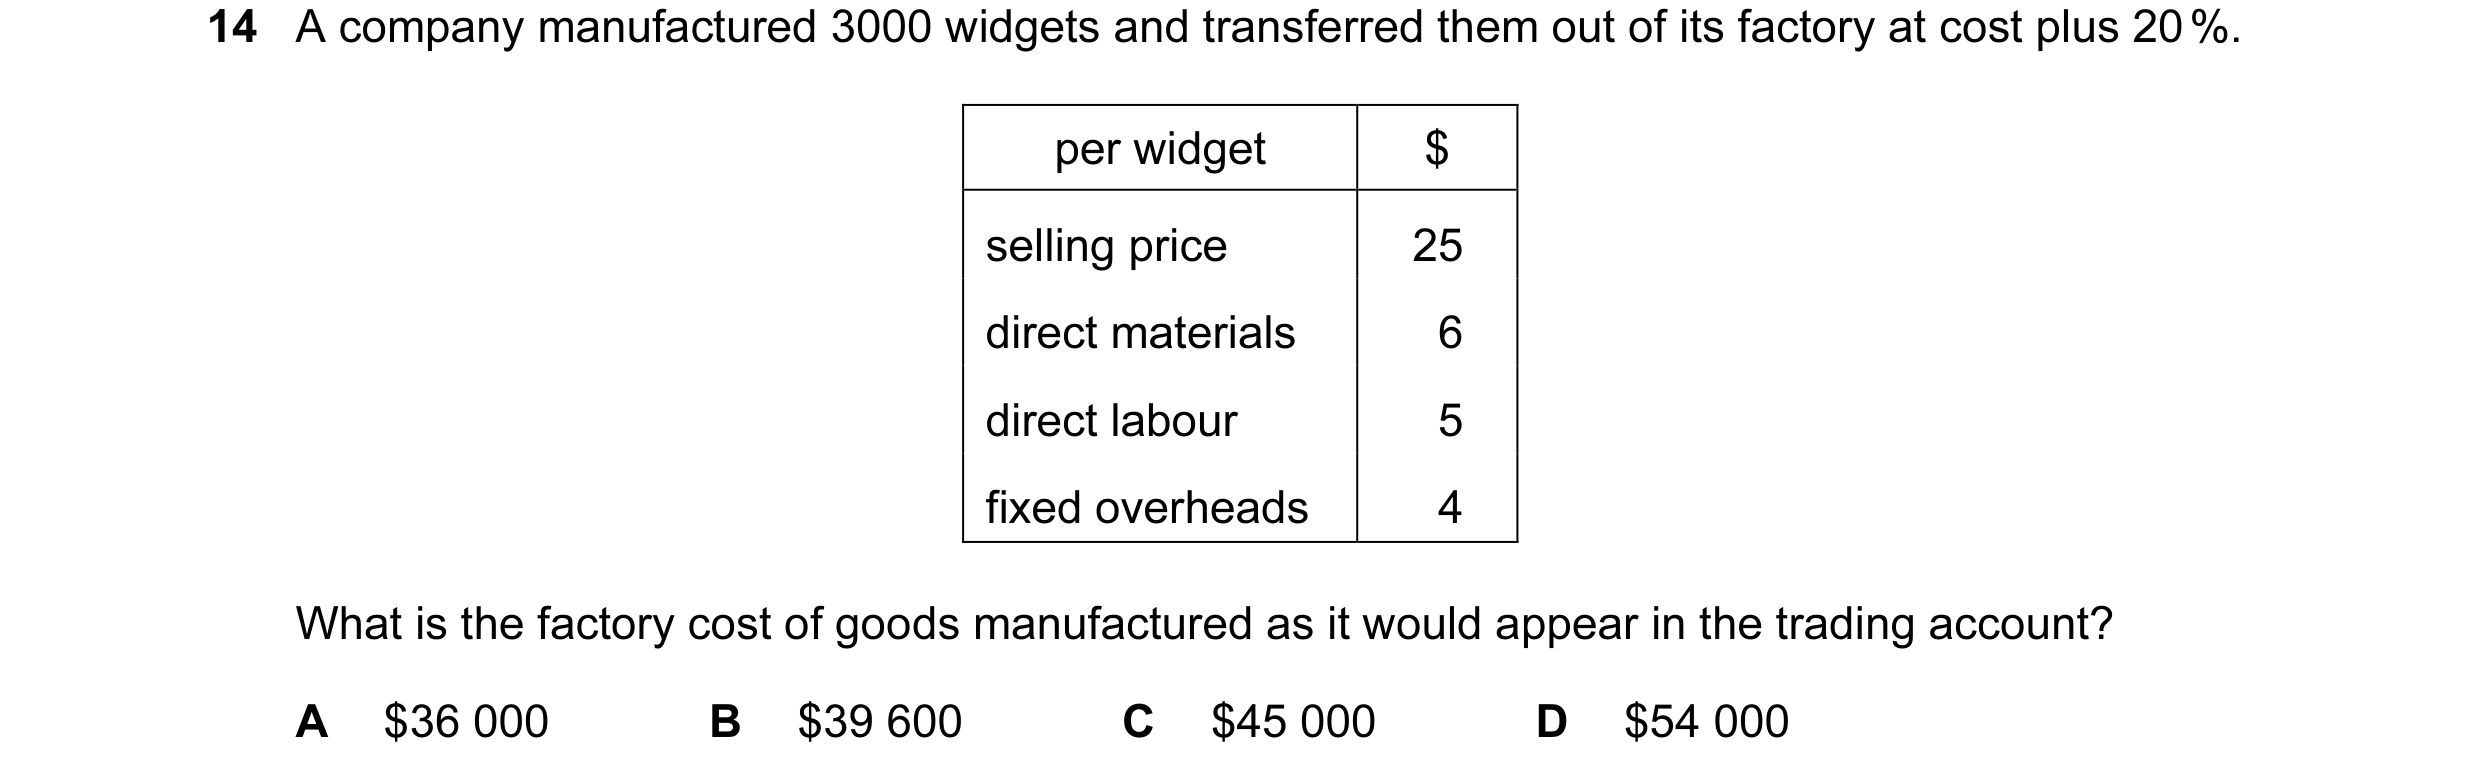
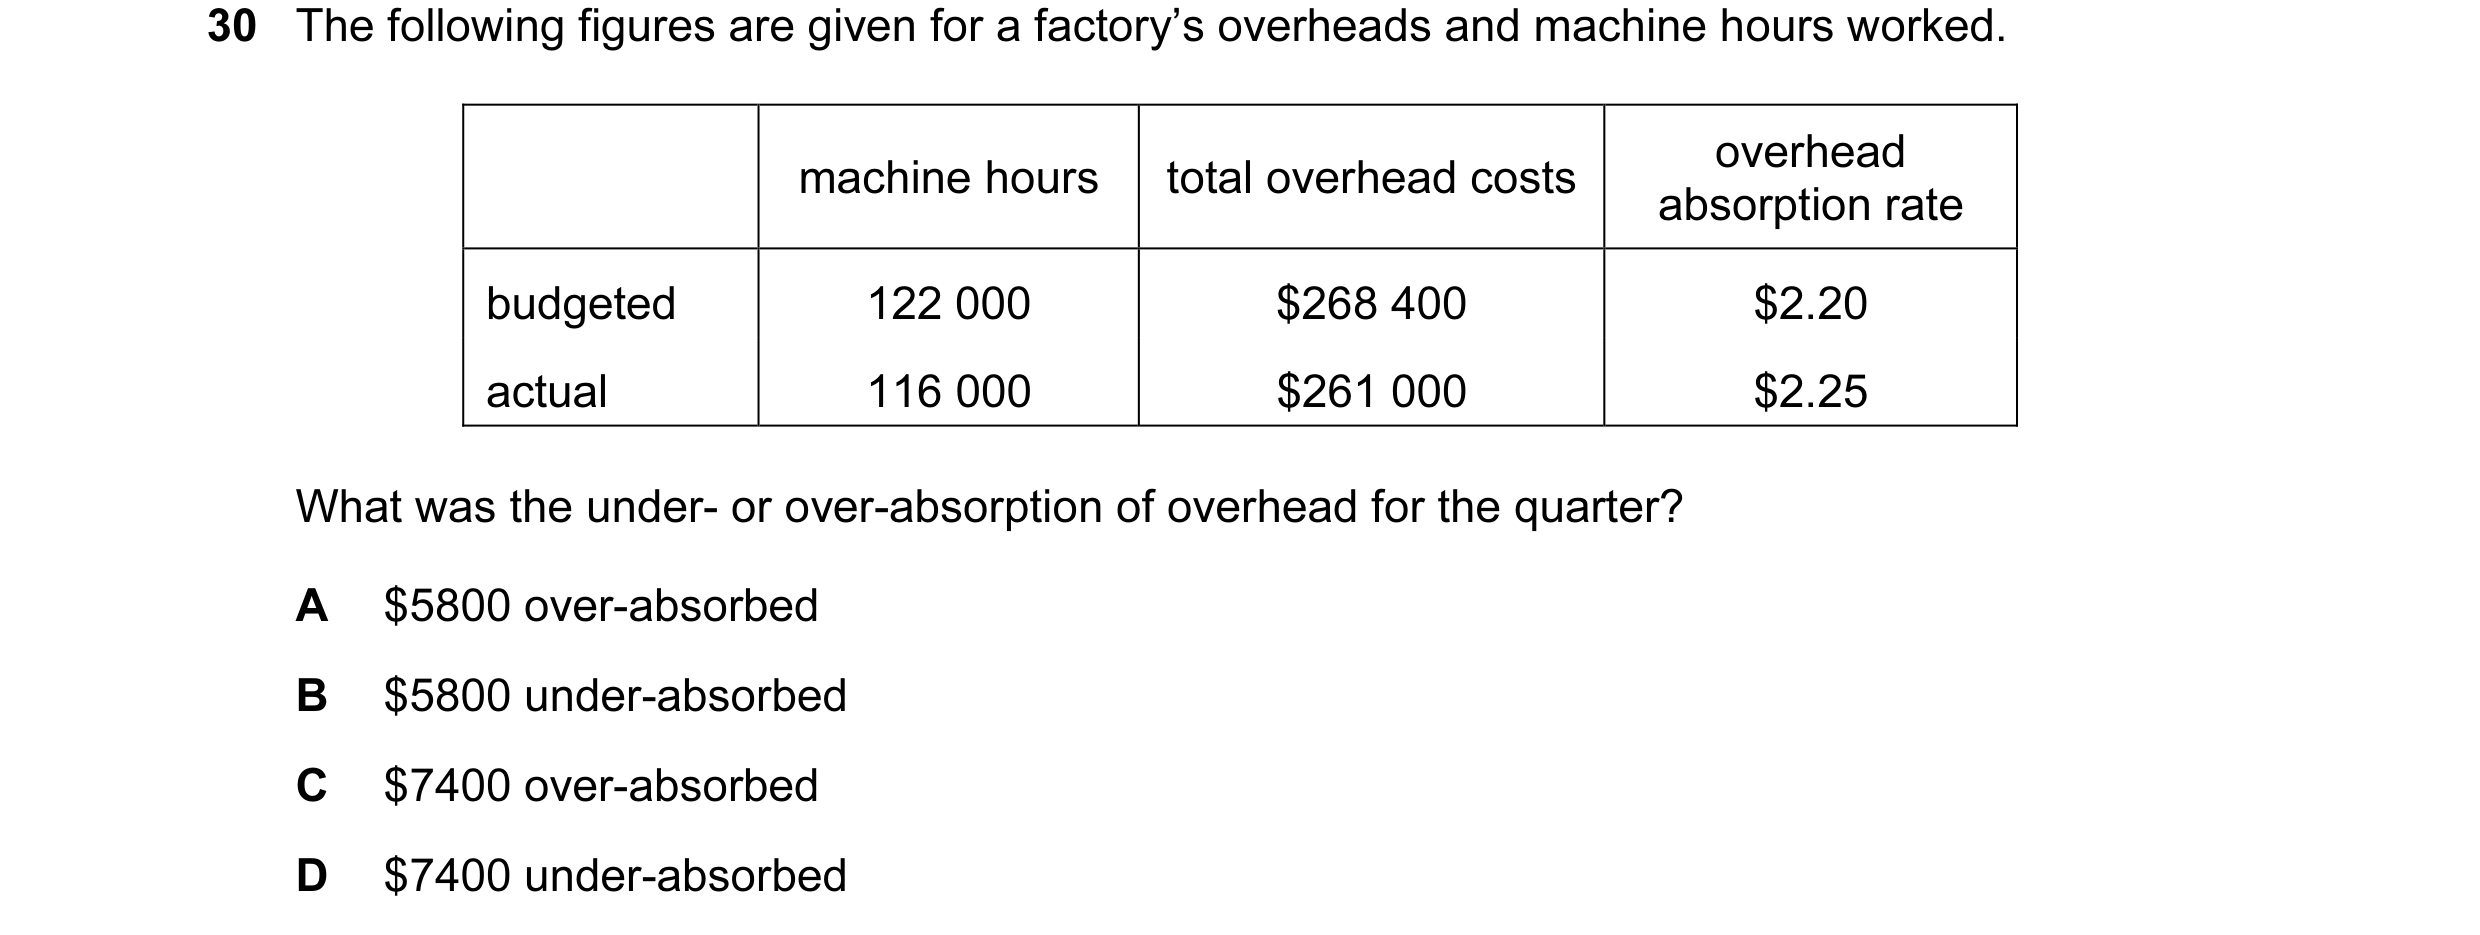
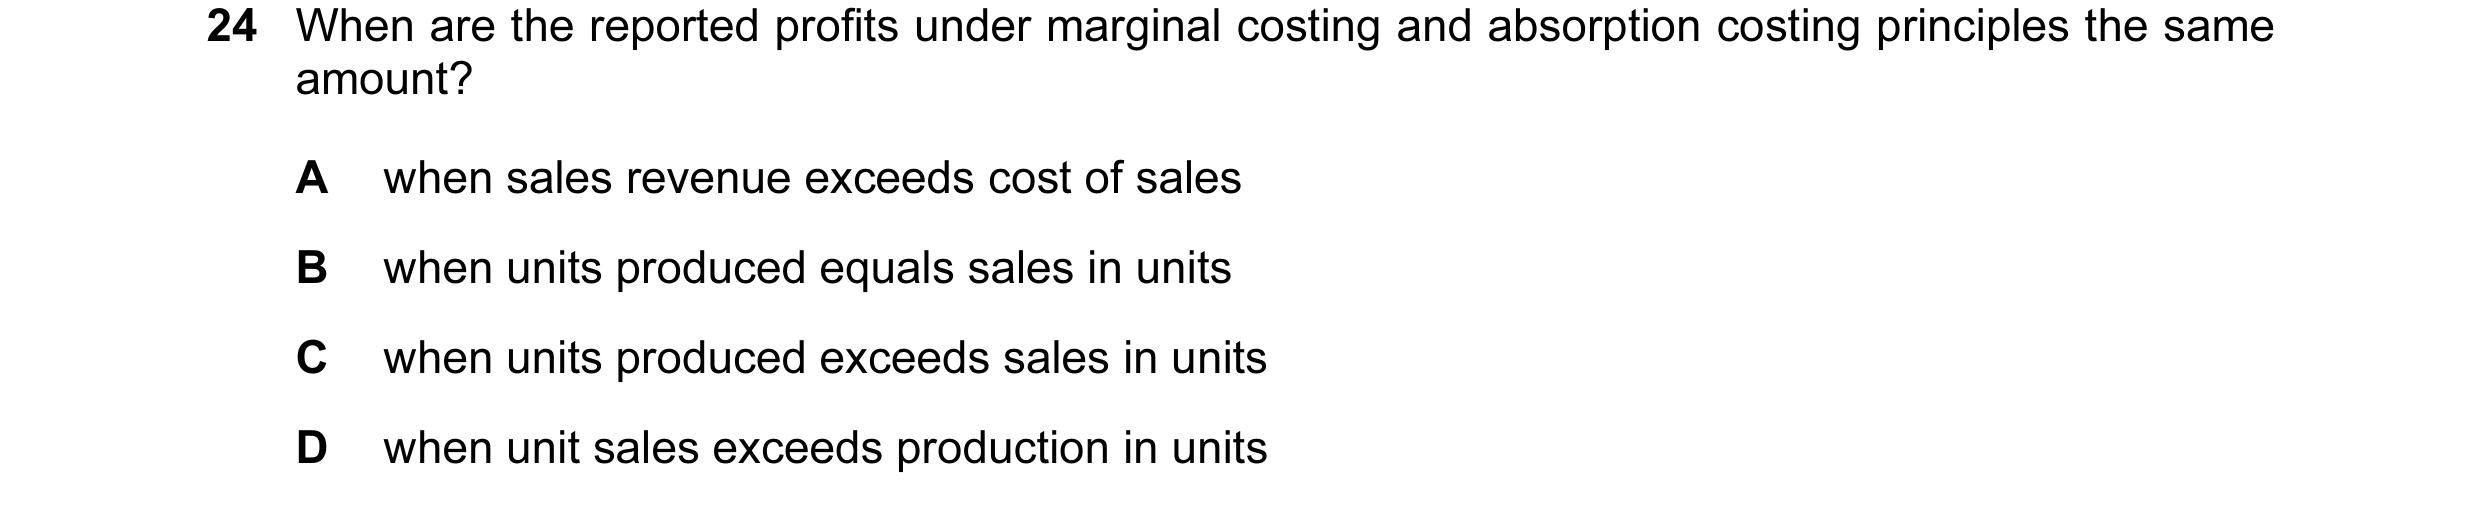 6 / 143
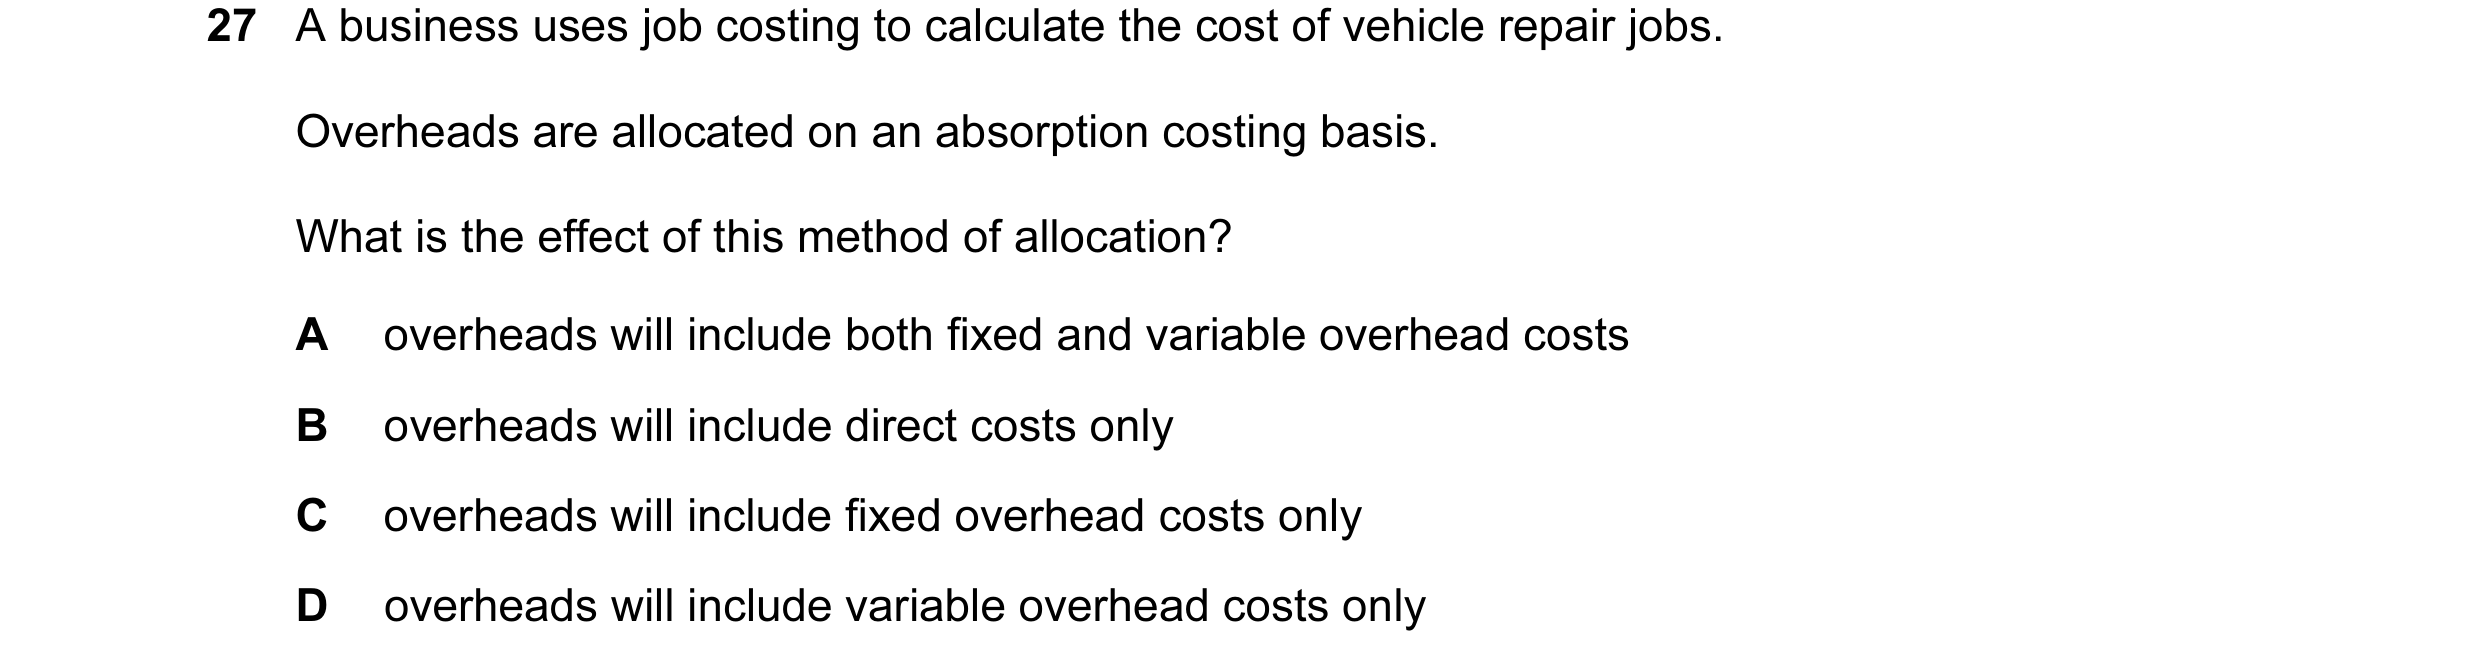
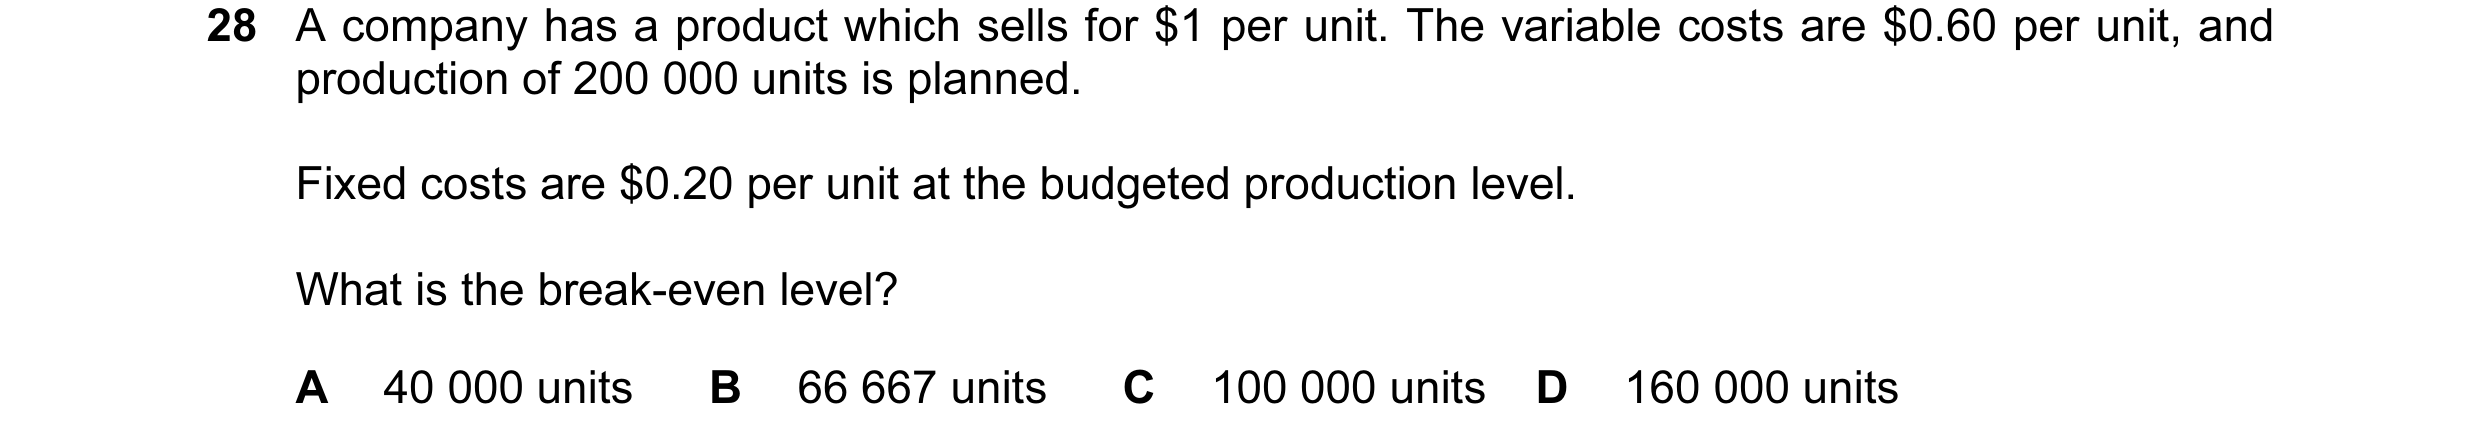
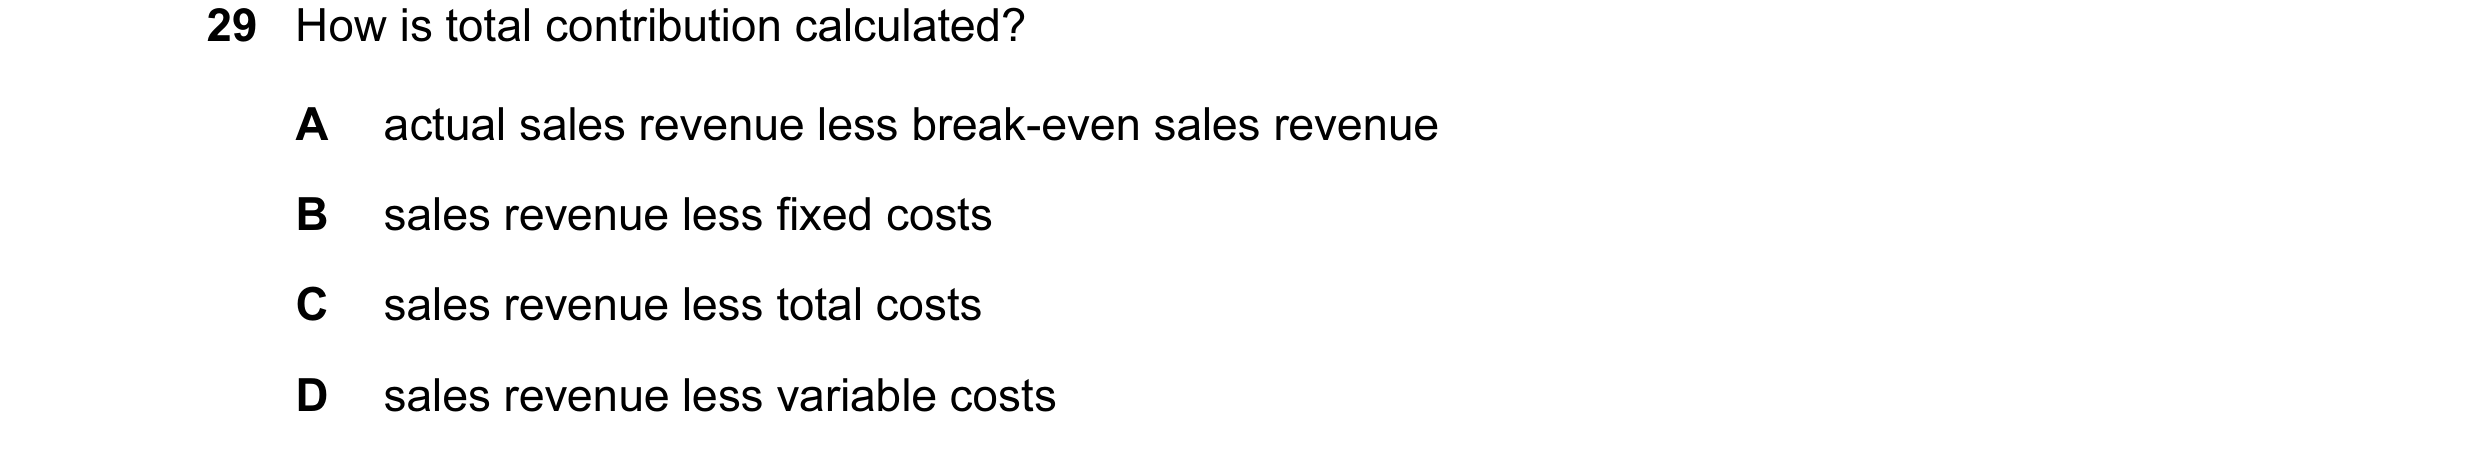
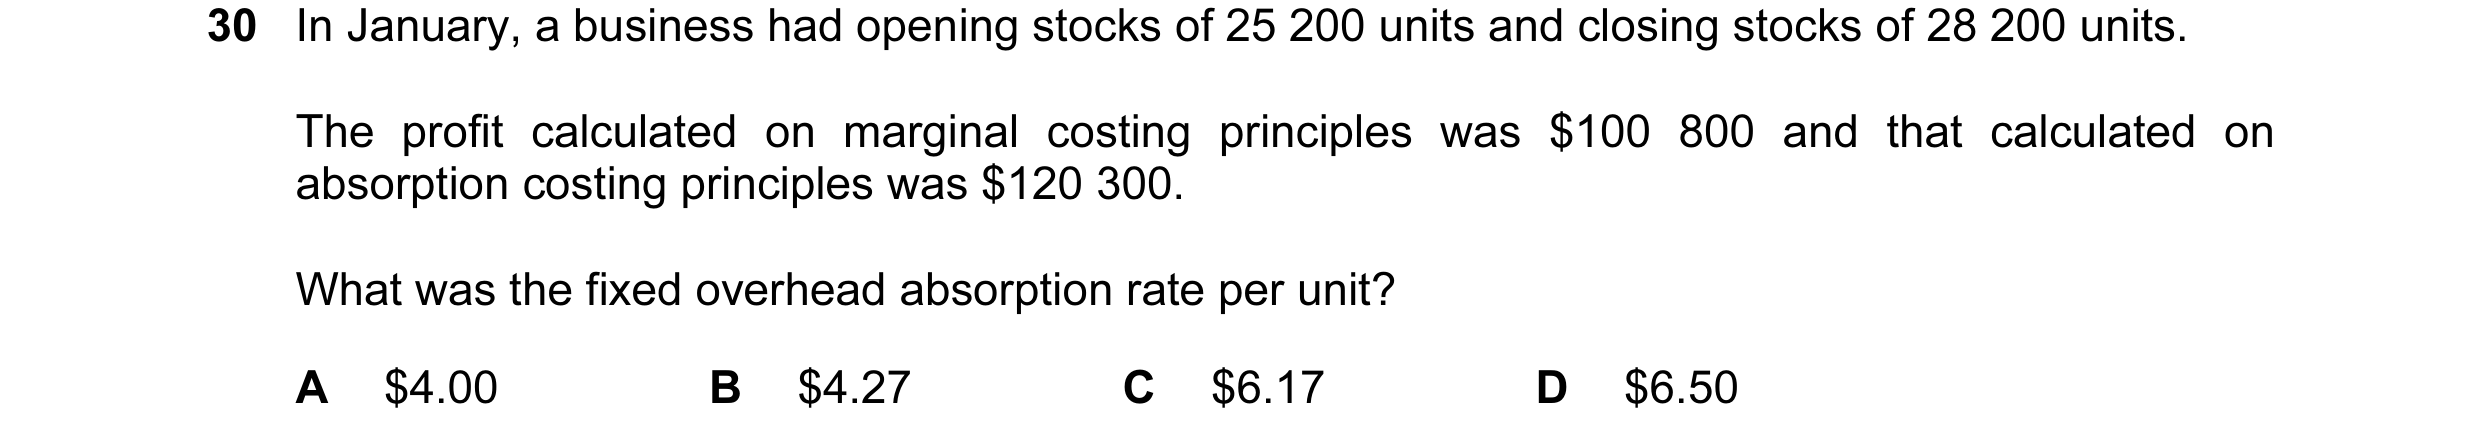 7 / 143
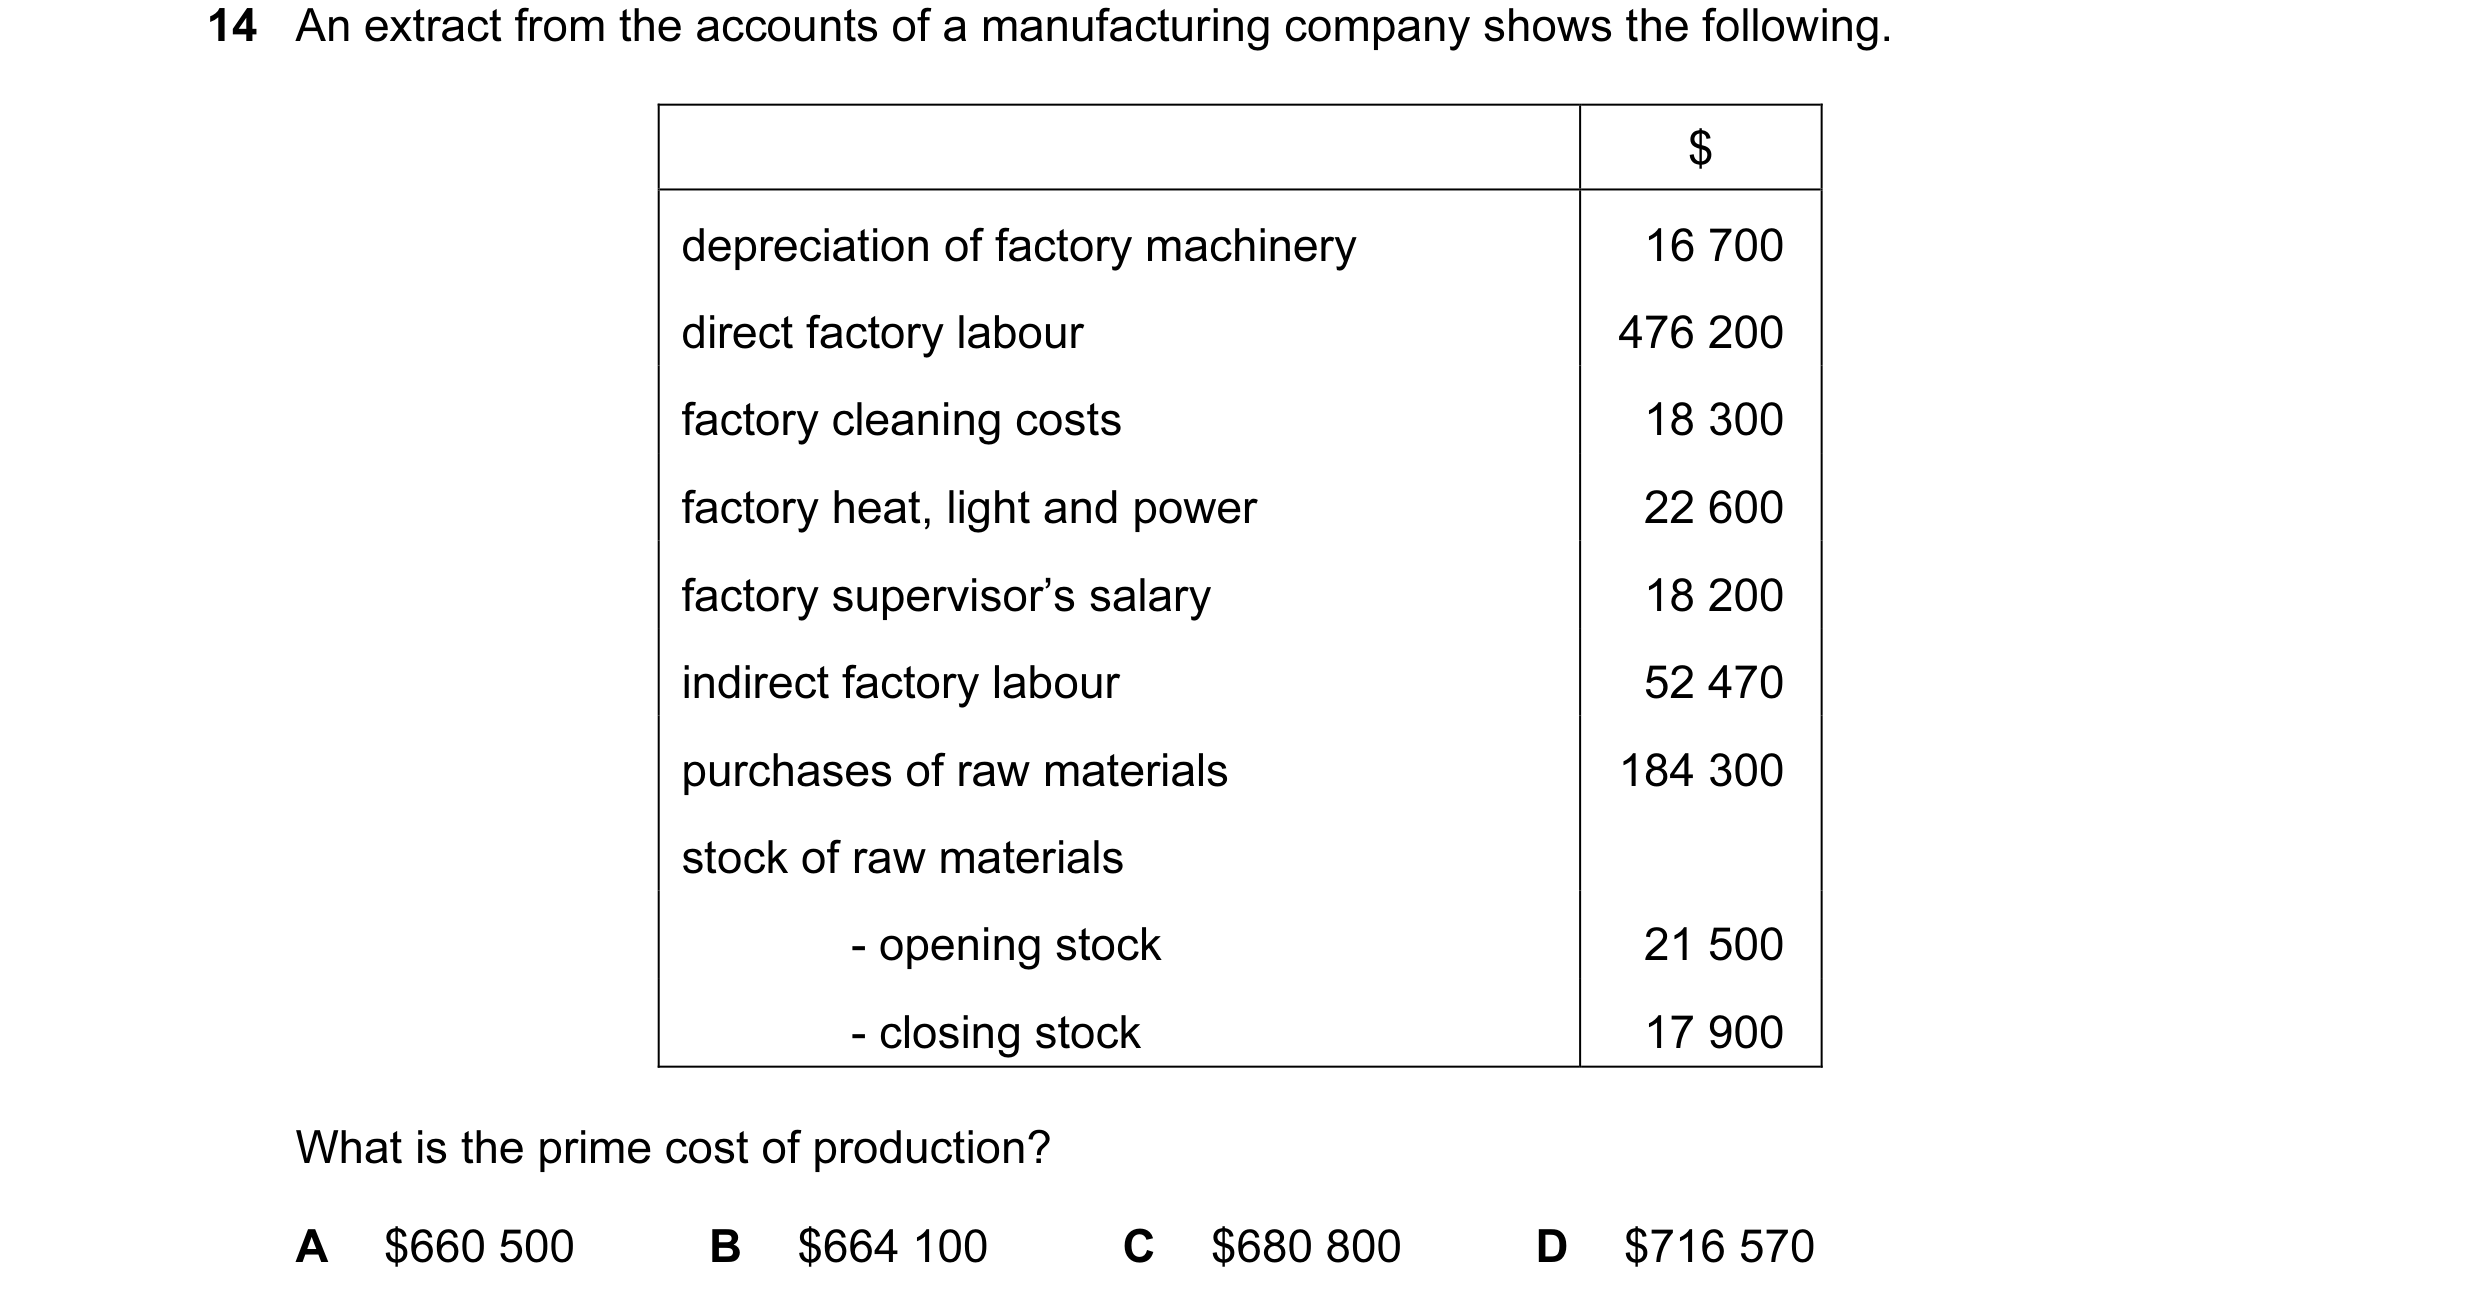
 8 / 143
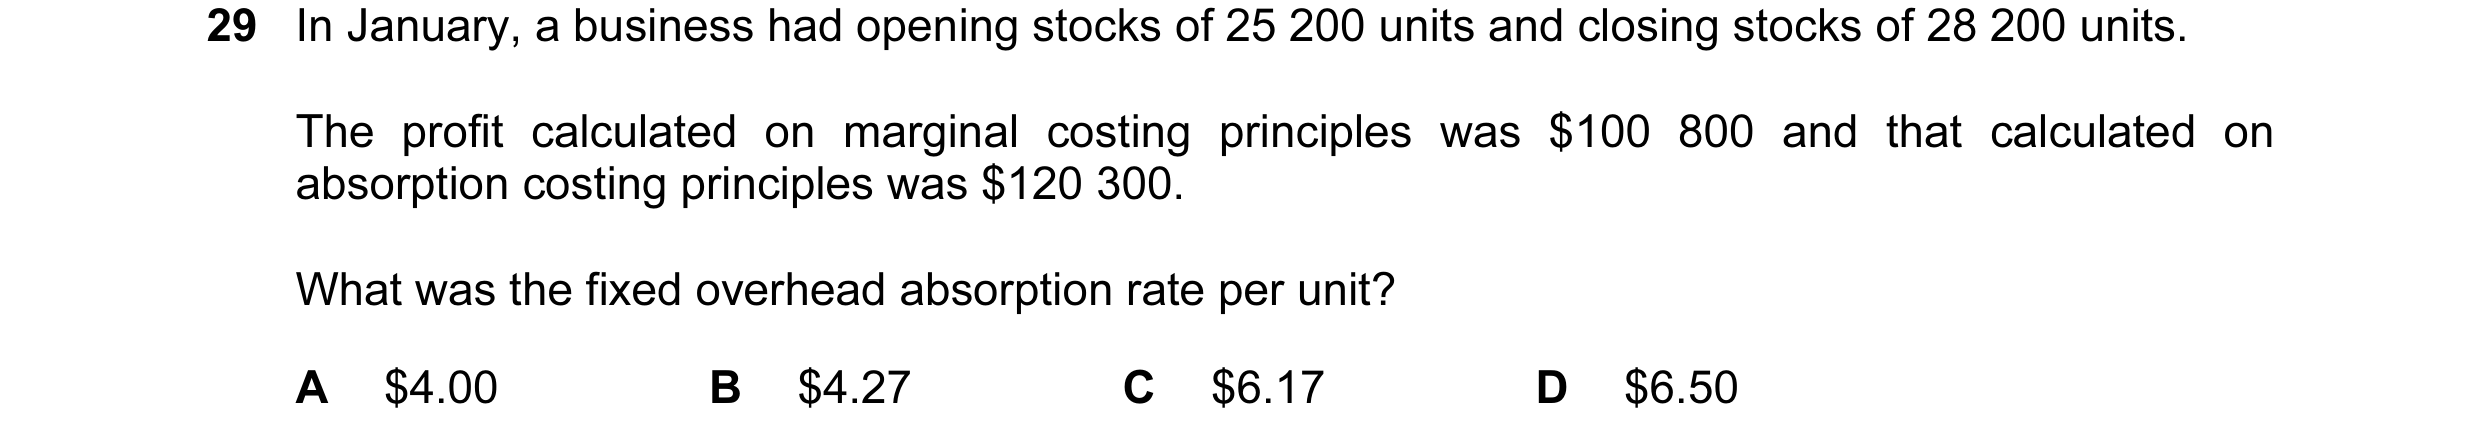
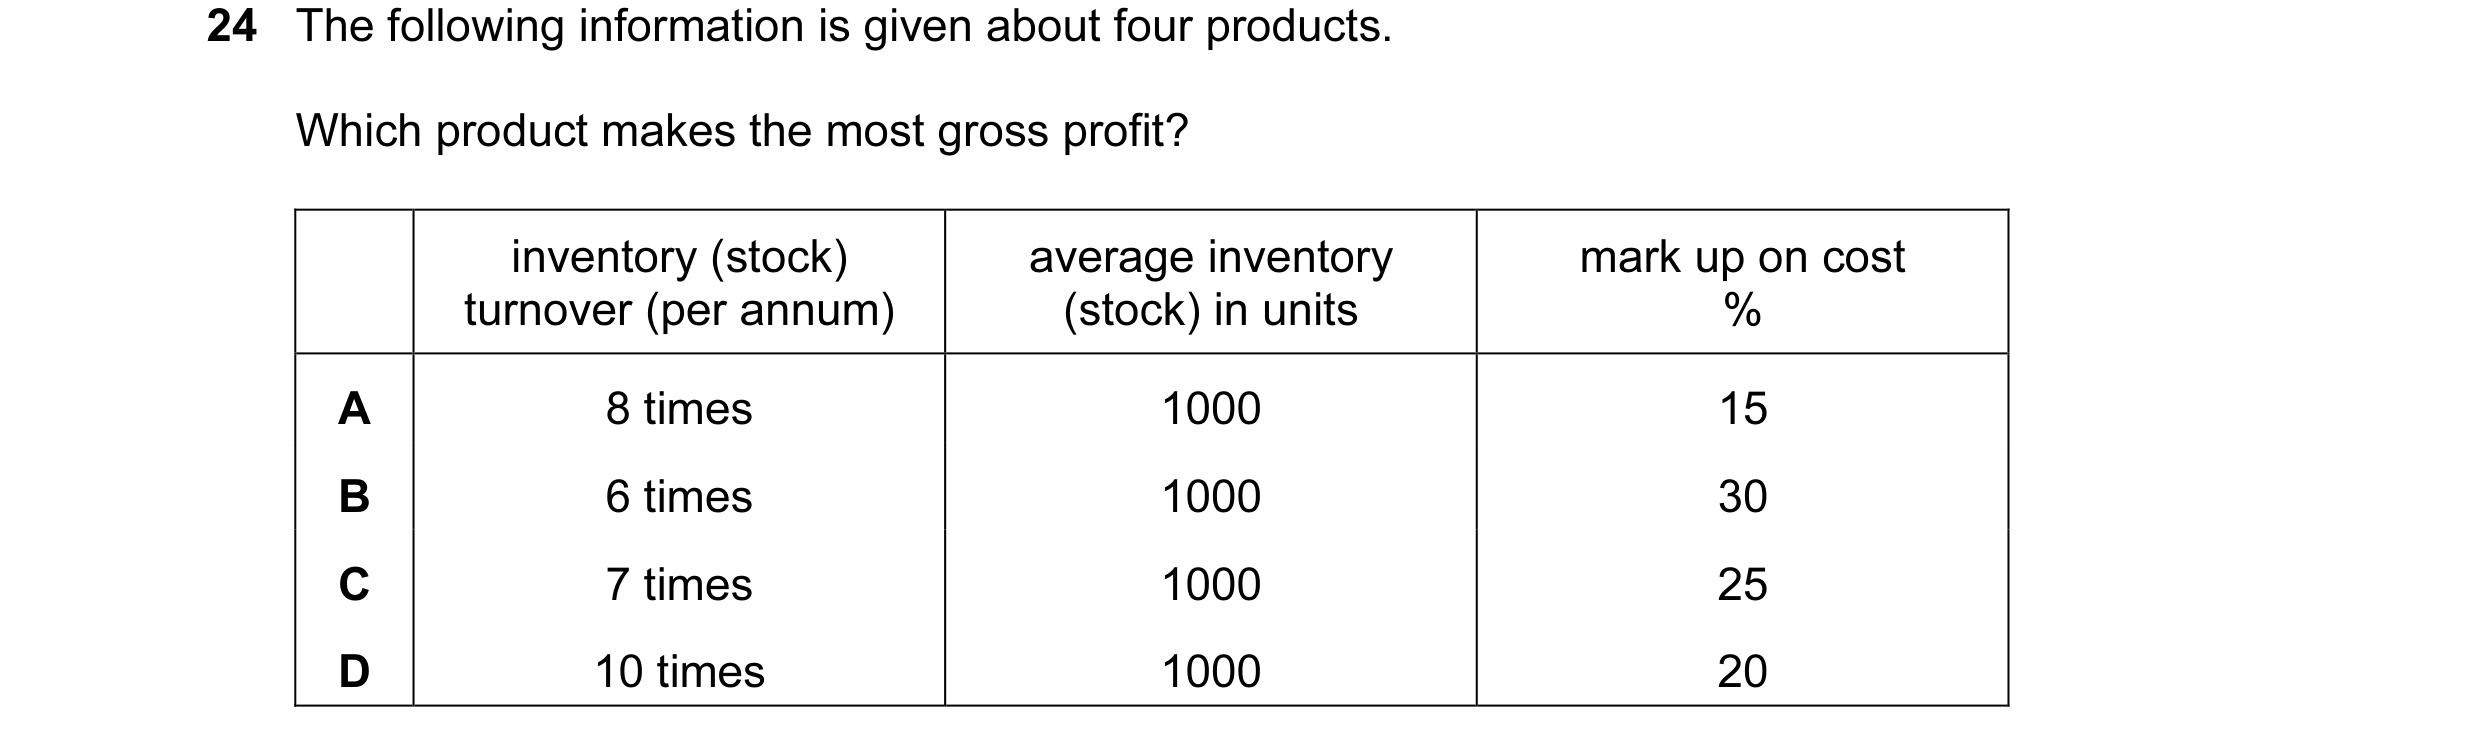
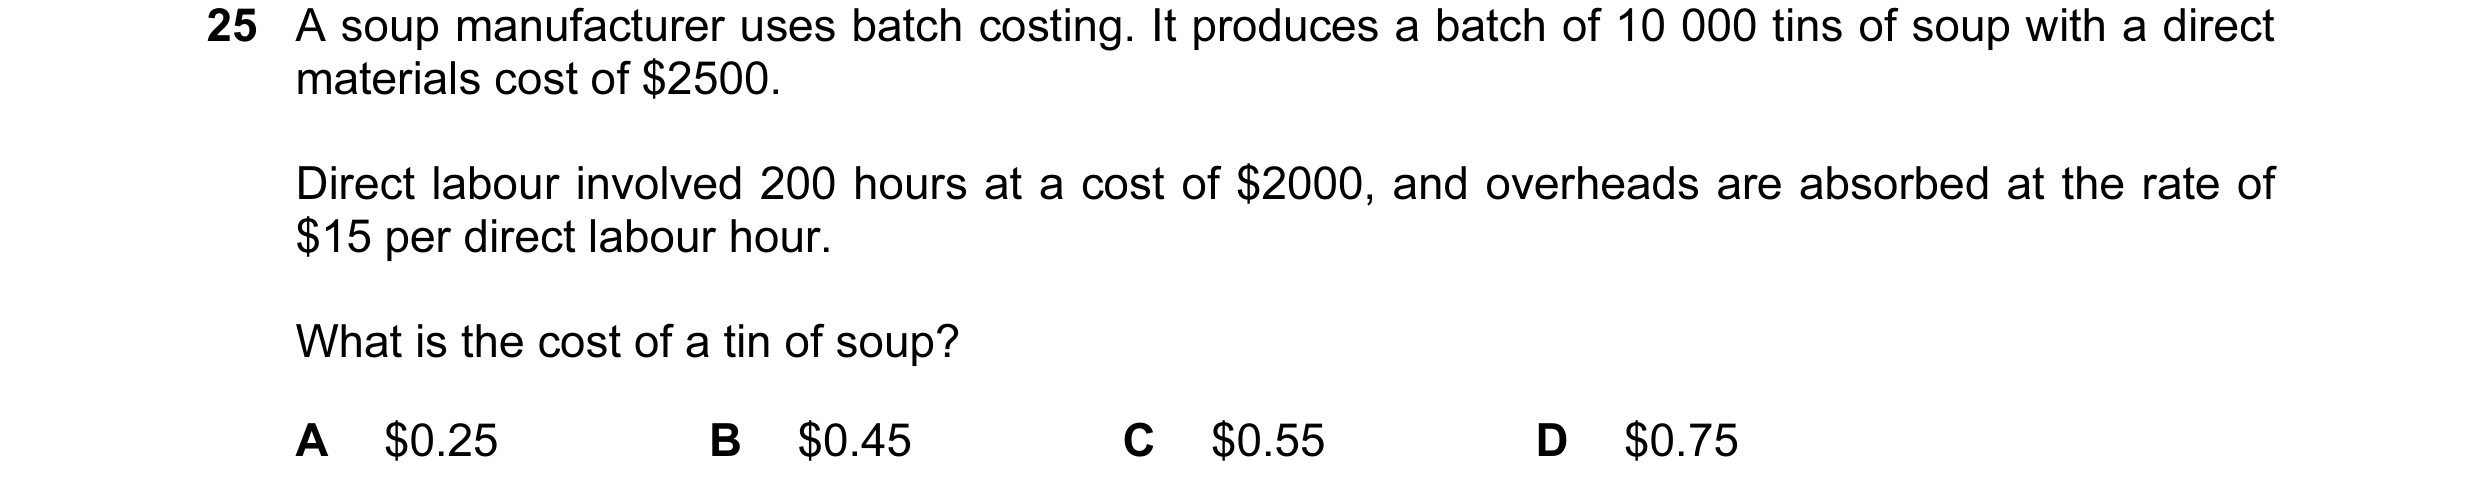
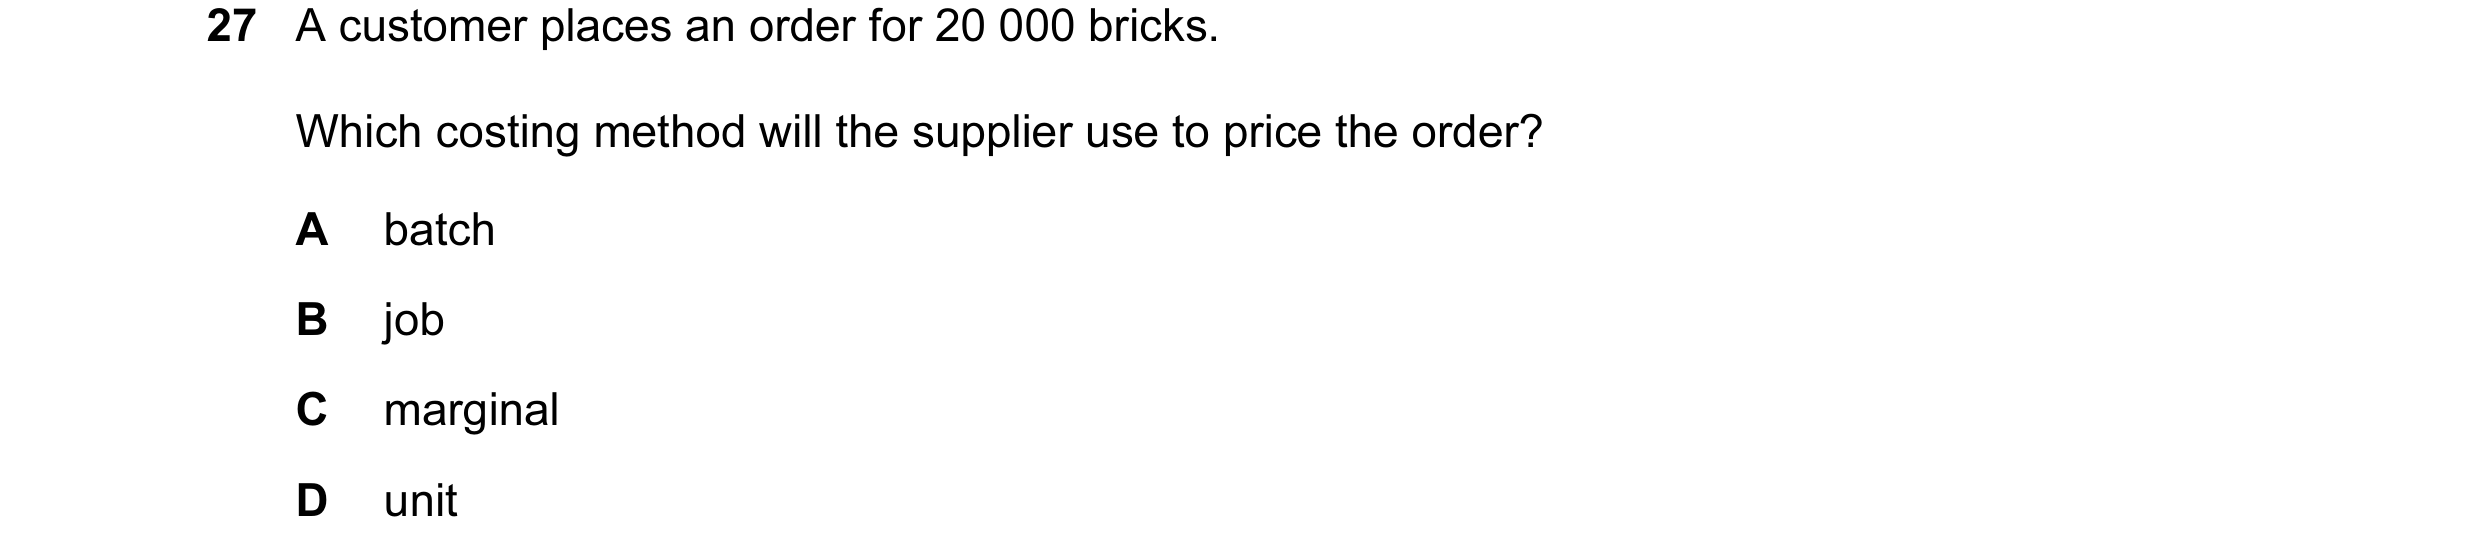
 9 / 143
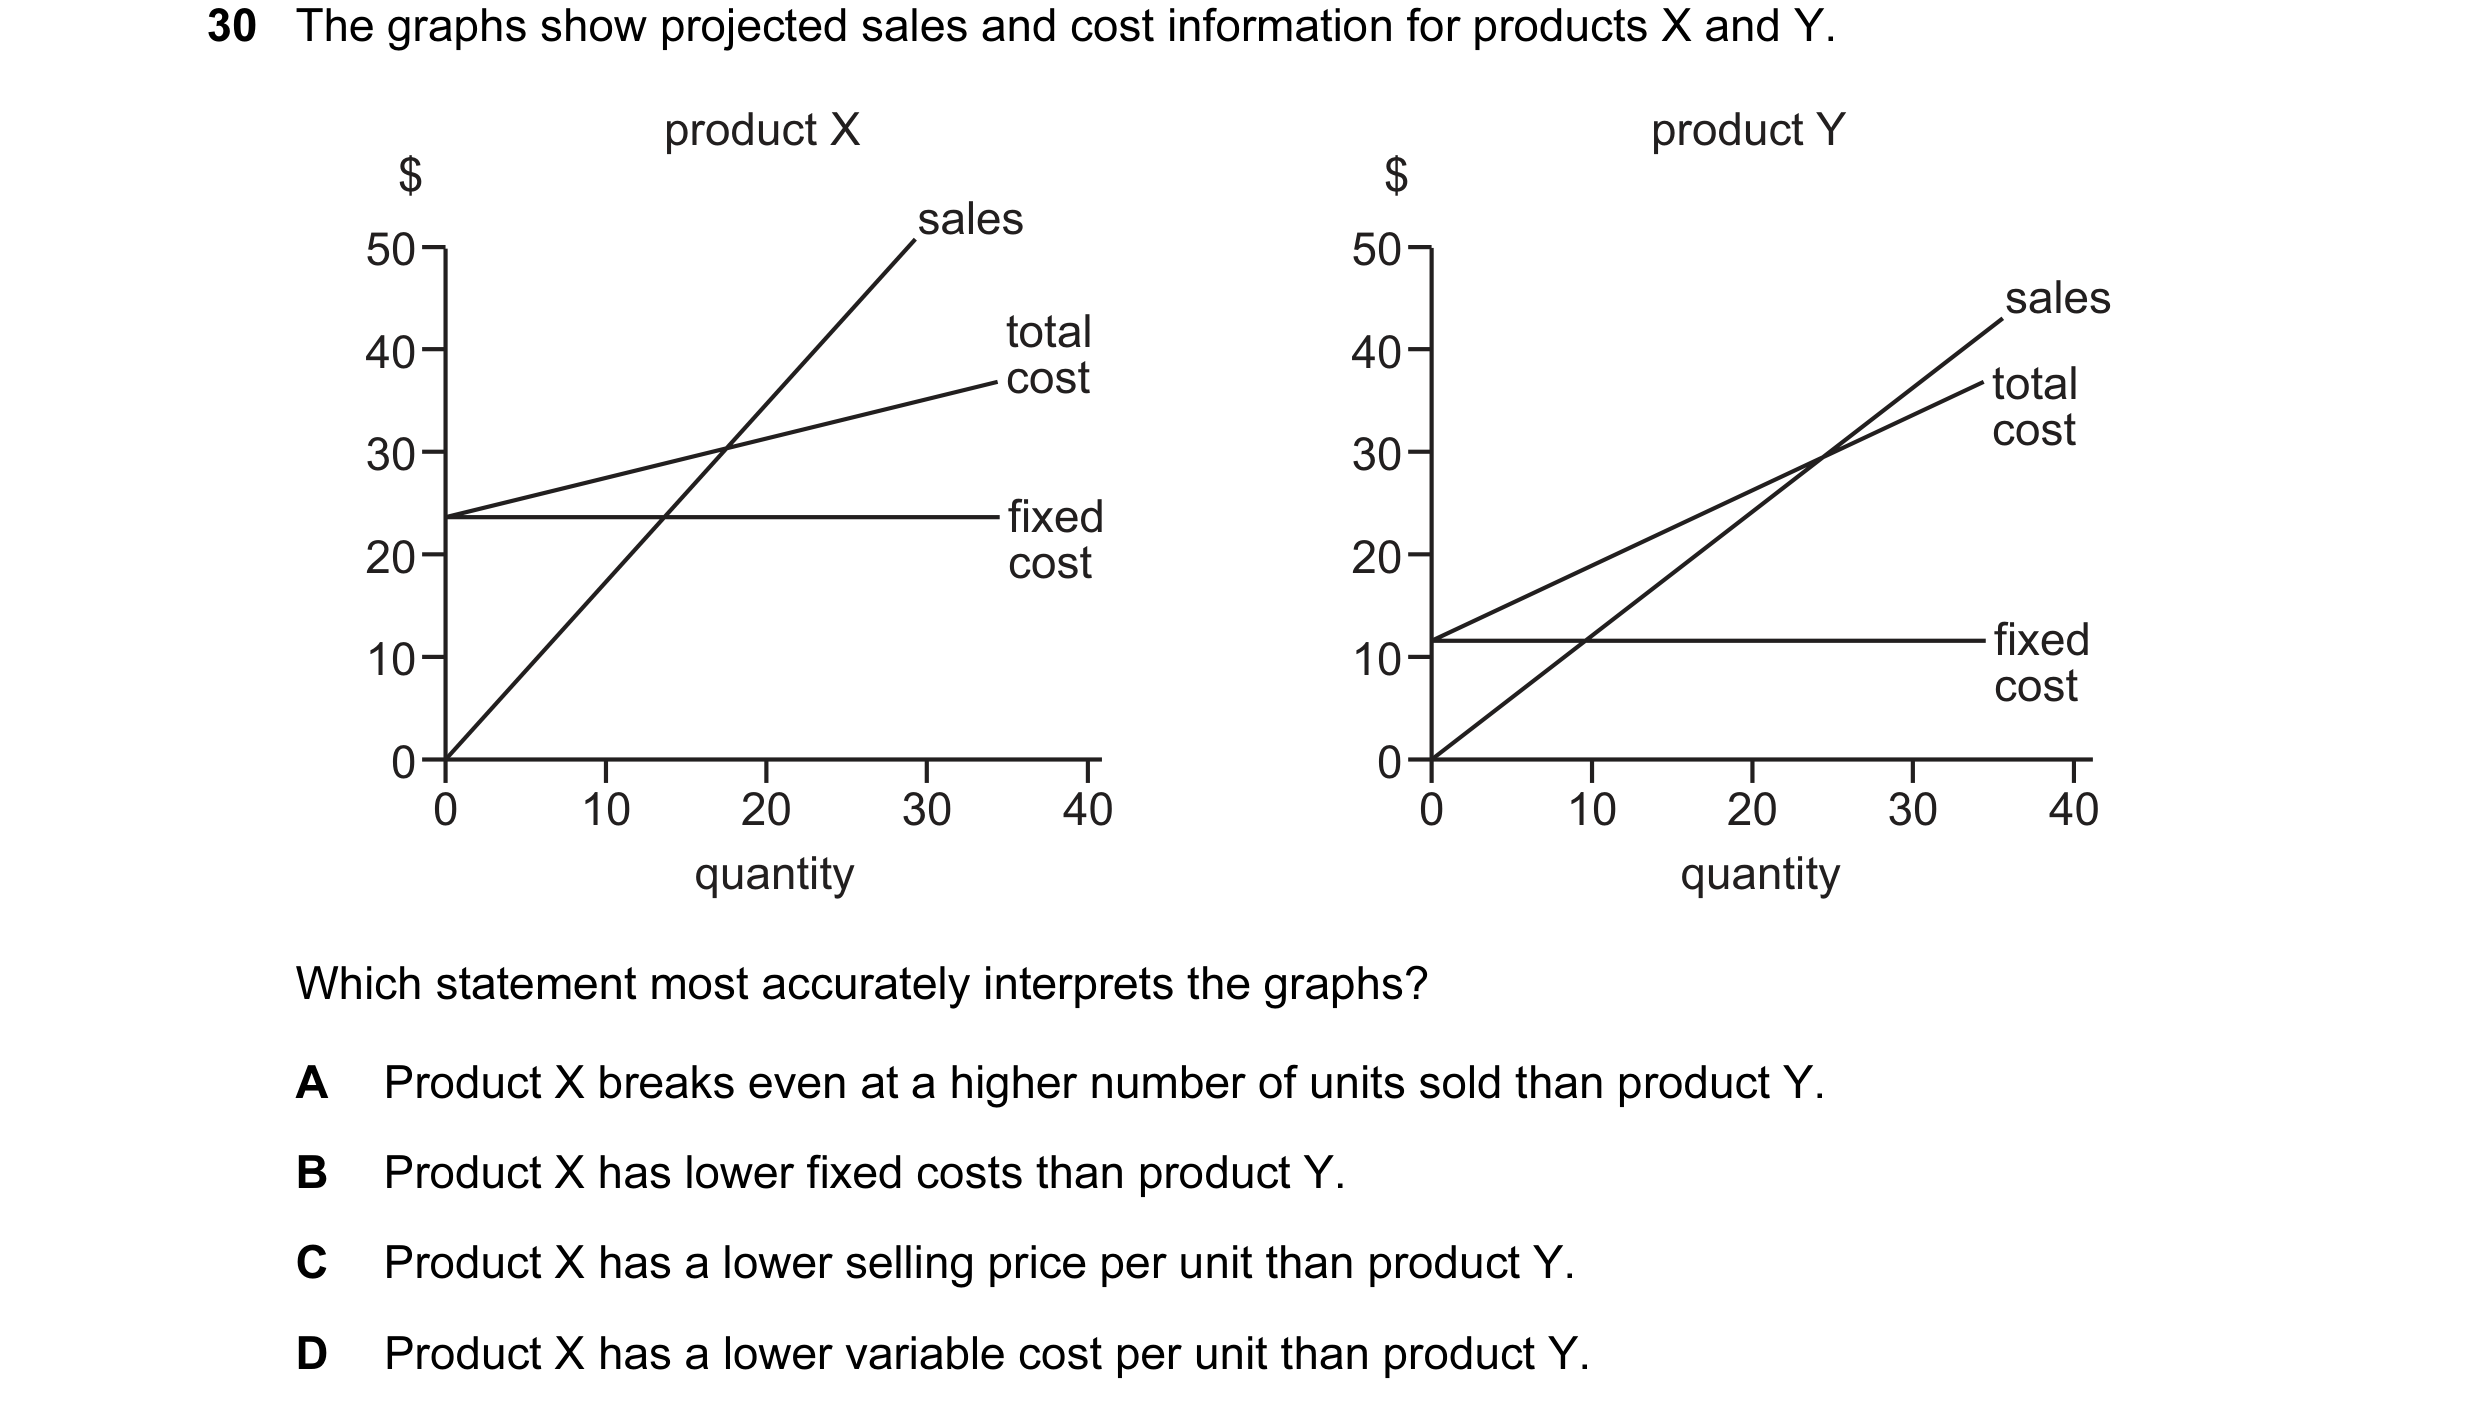
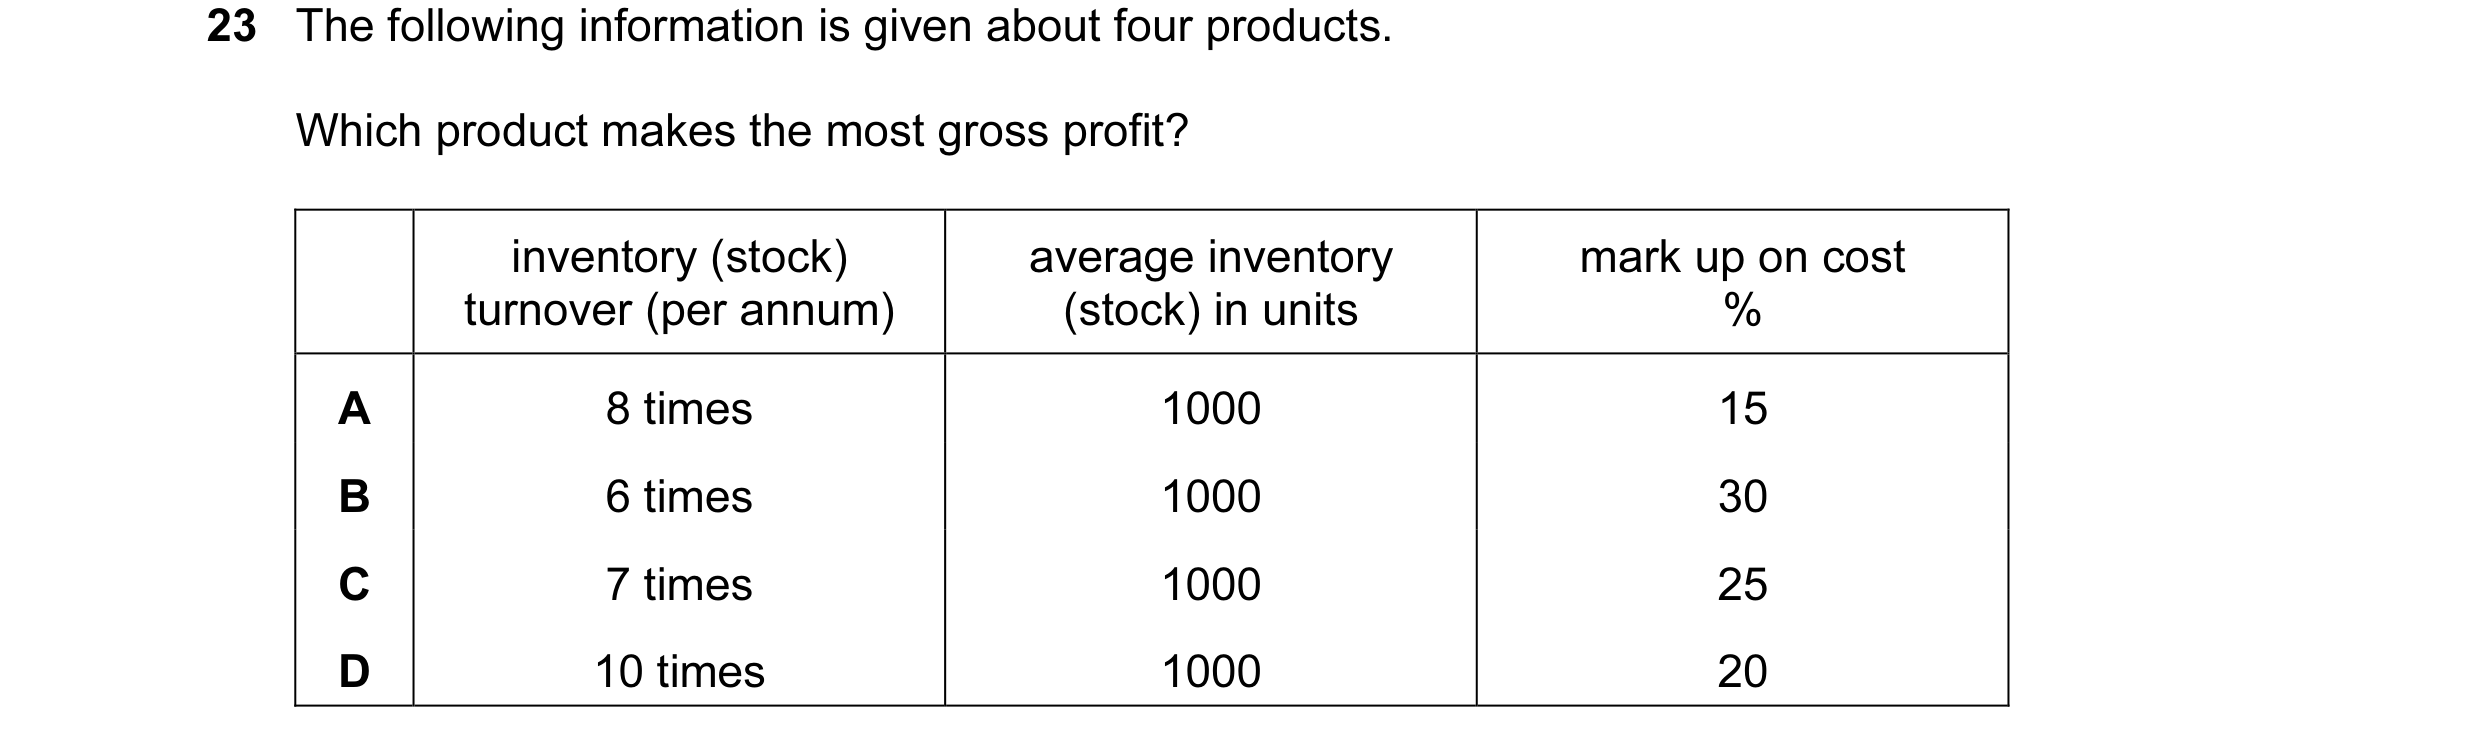
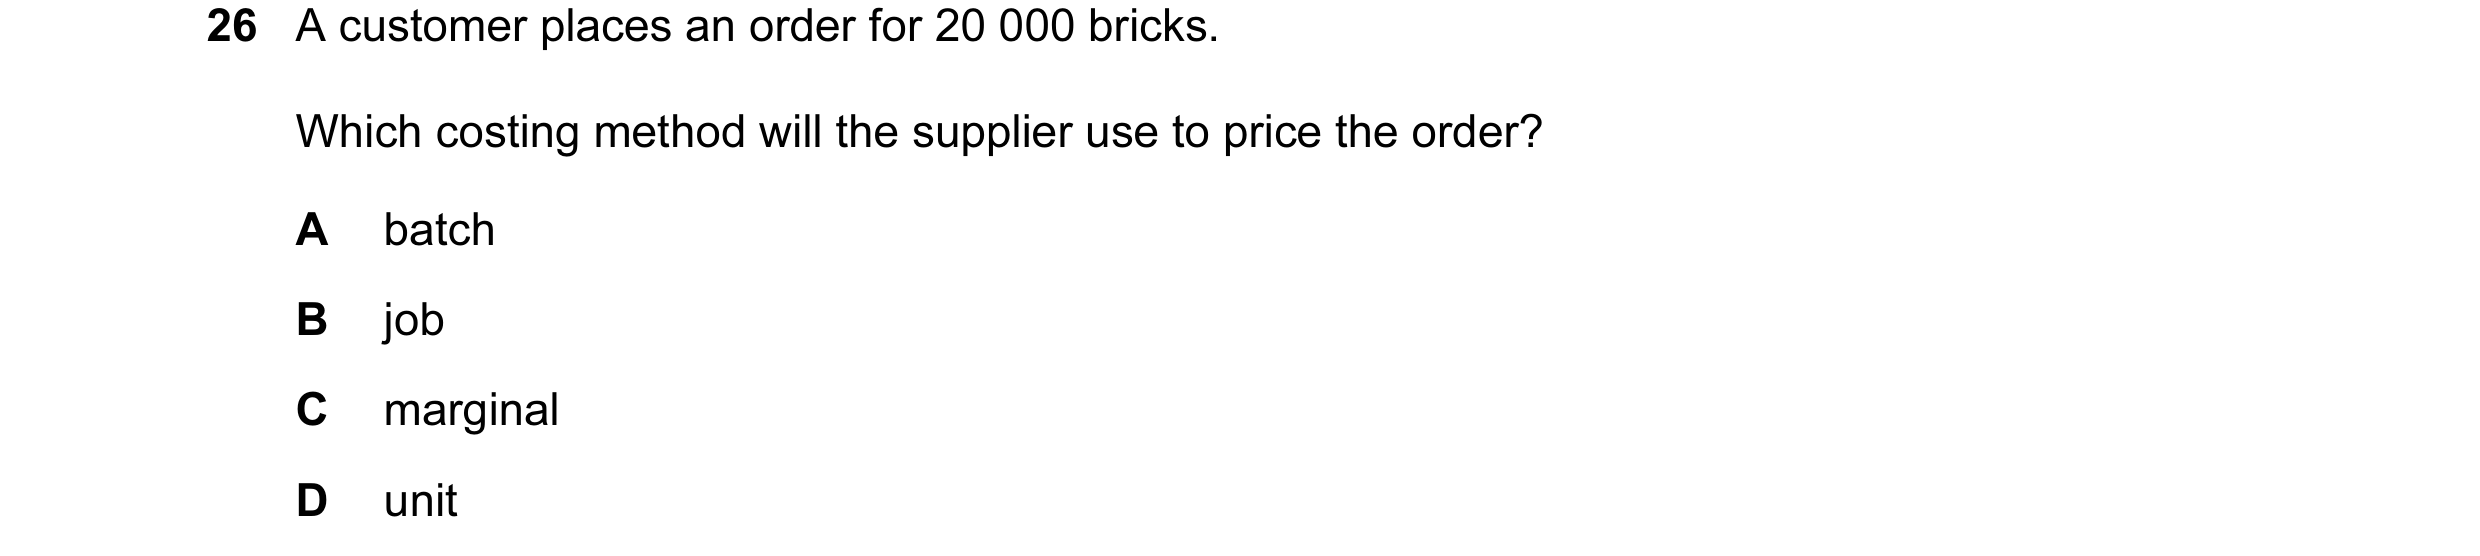 10 / 143
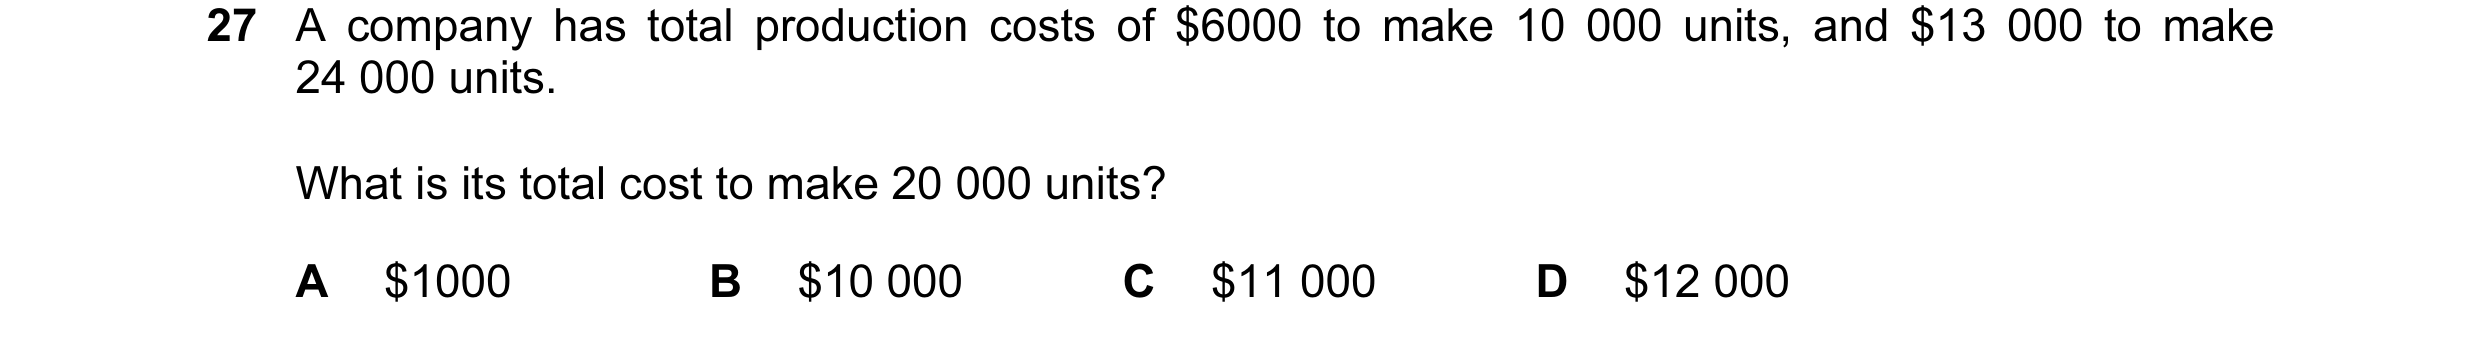
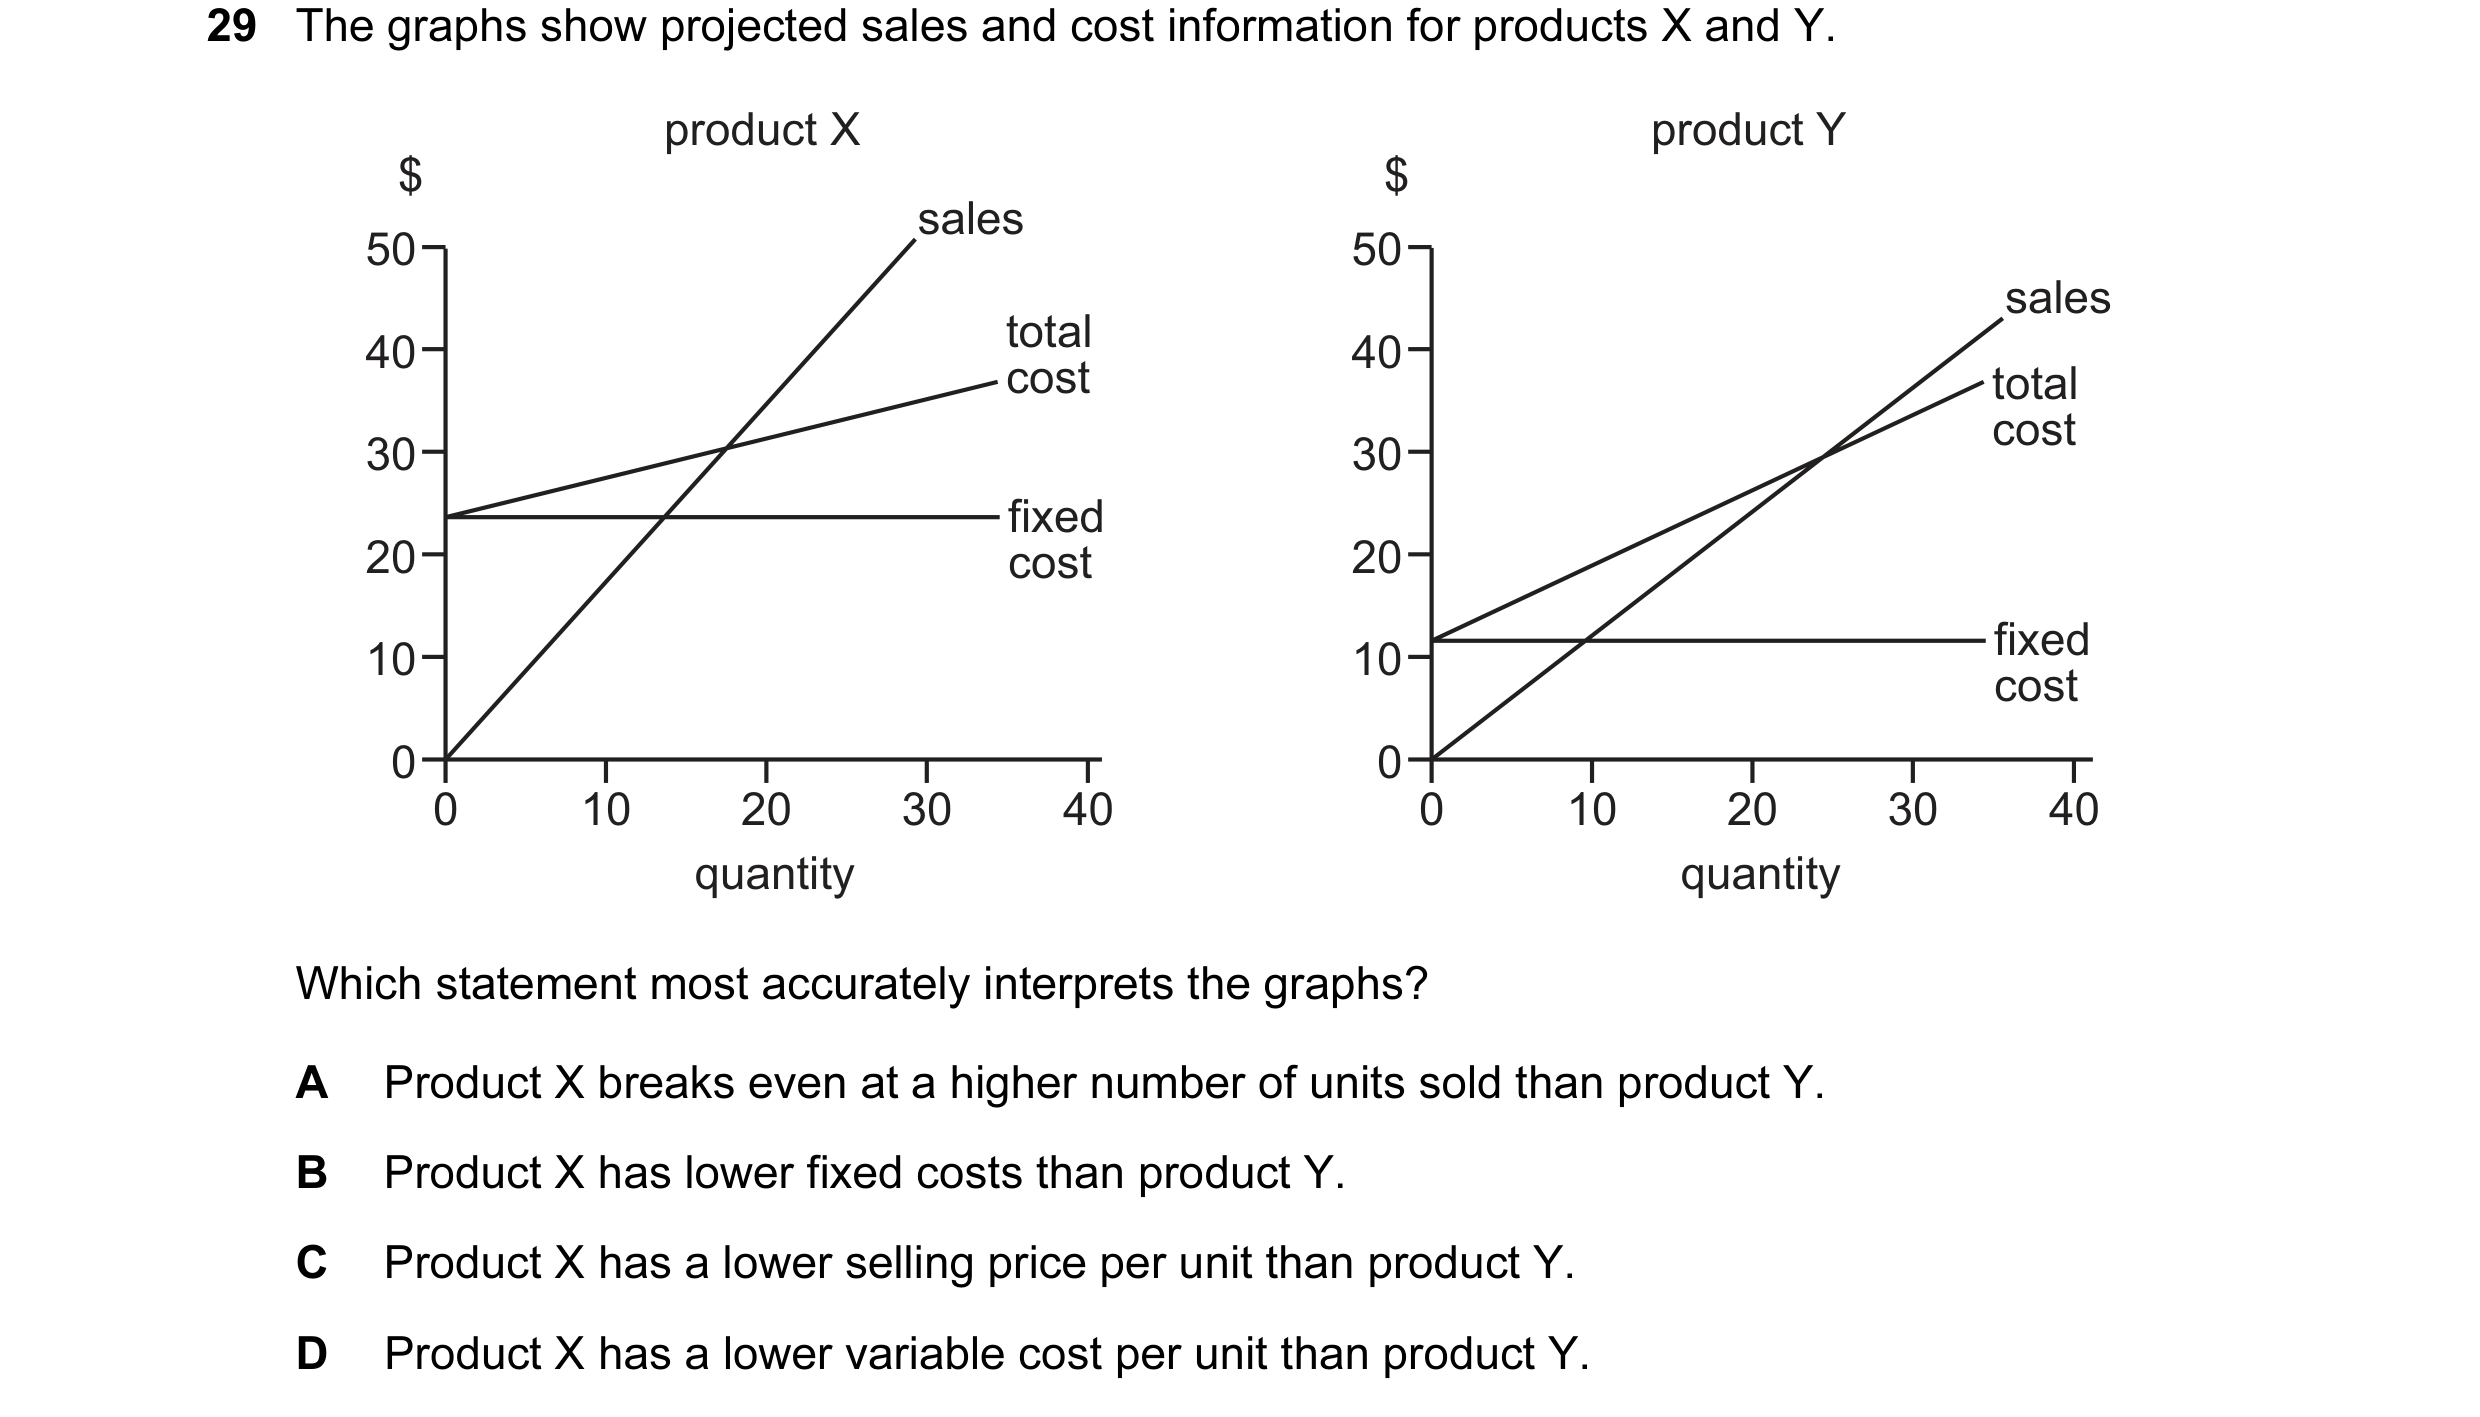
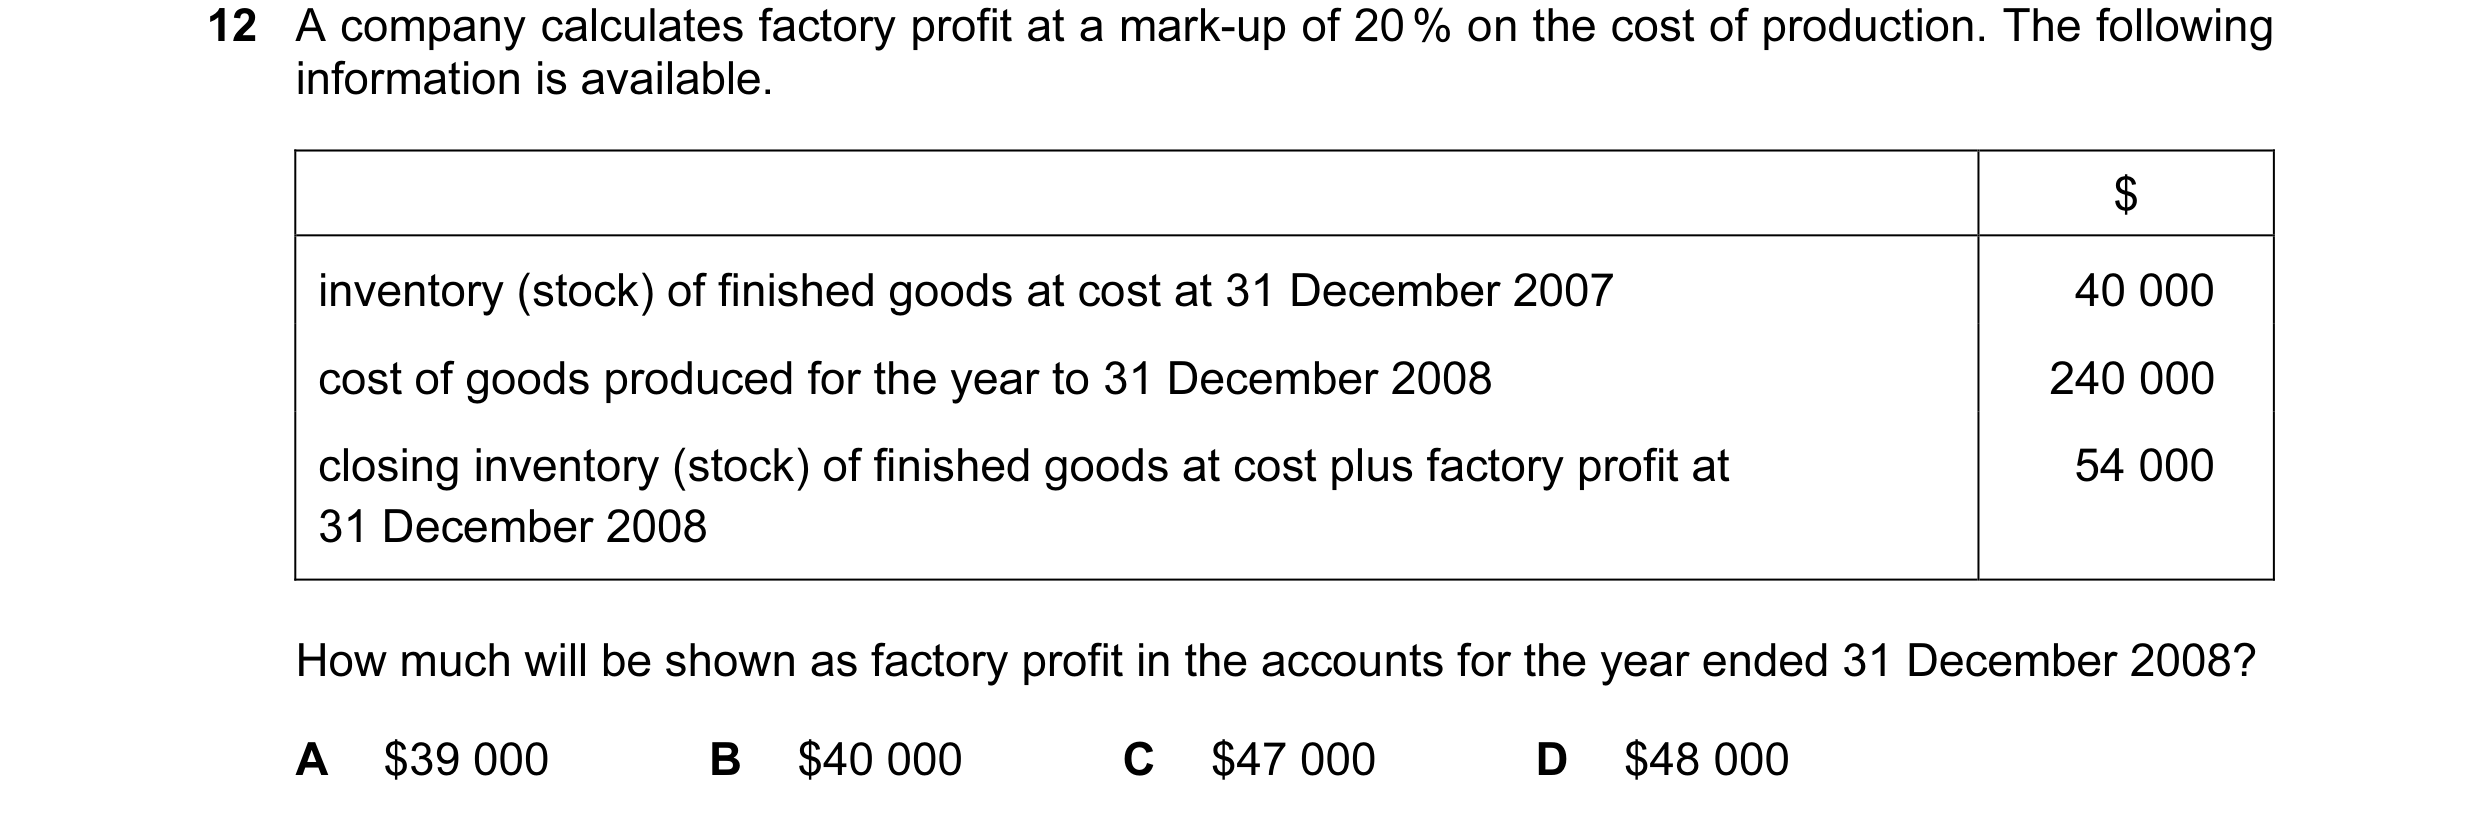
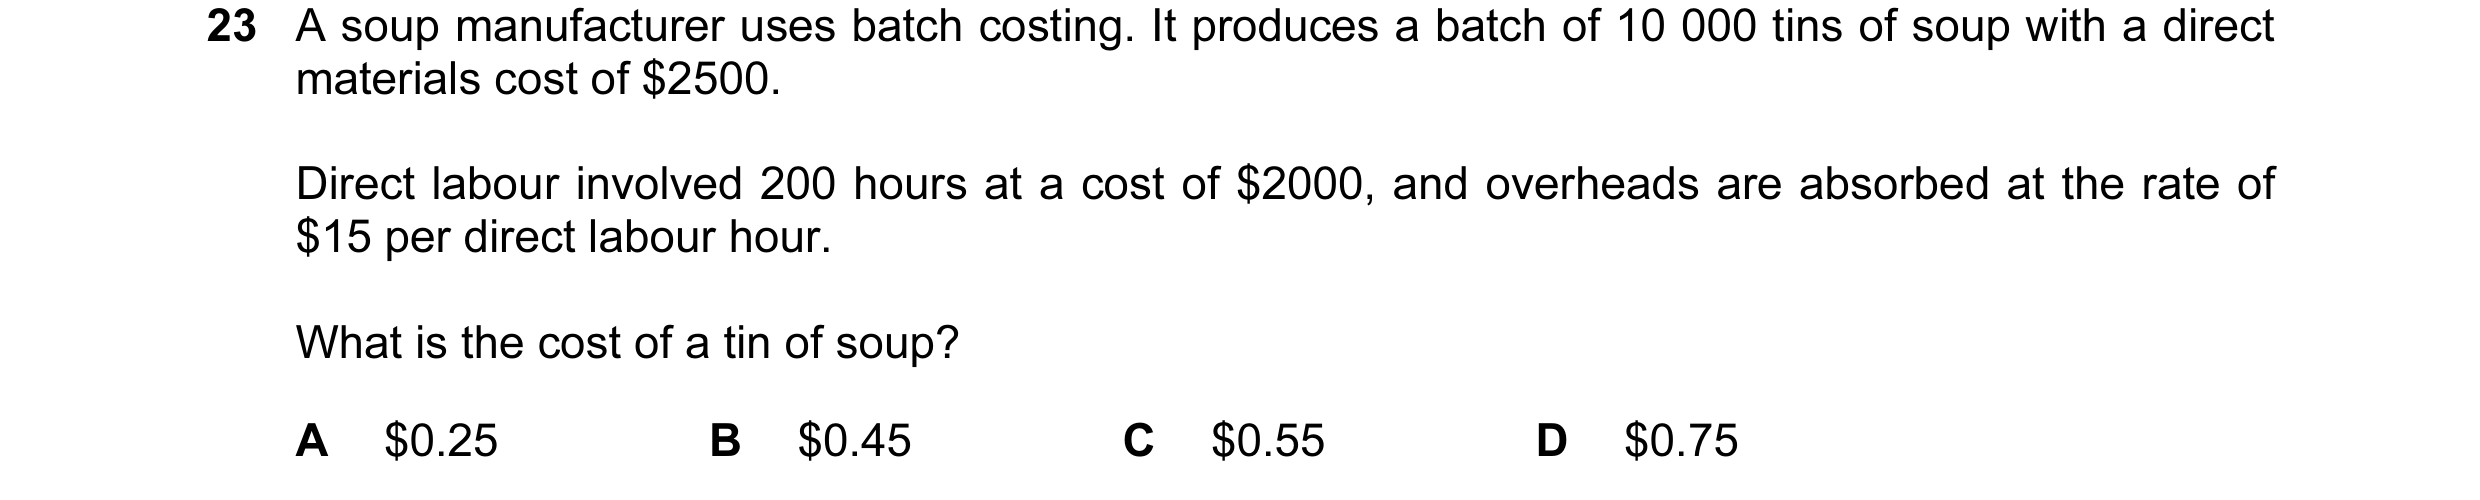 11 / 143
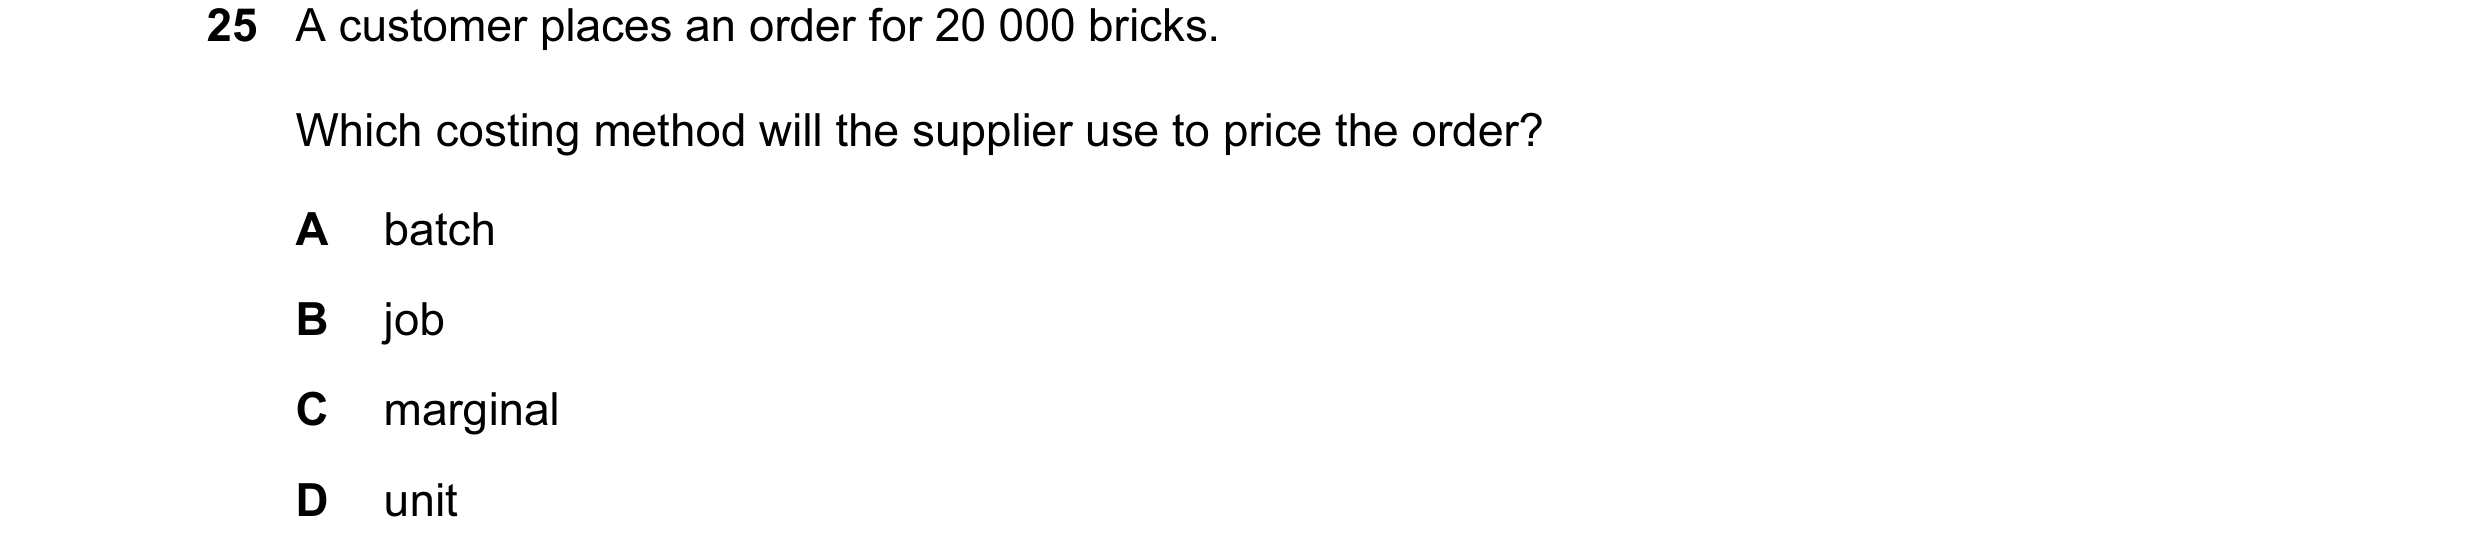
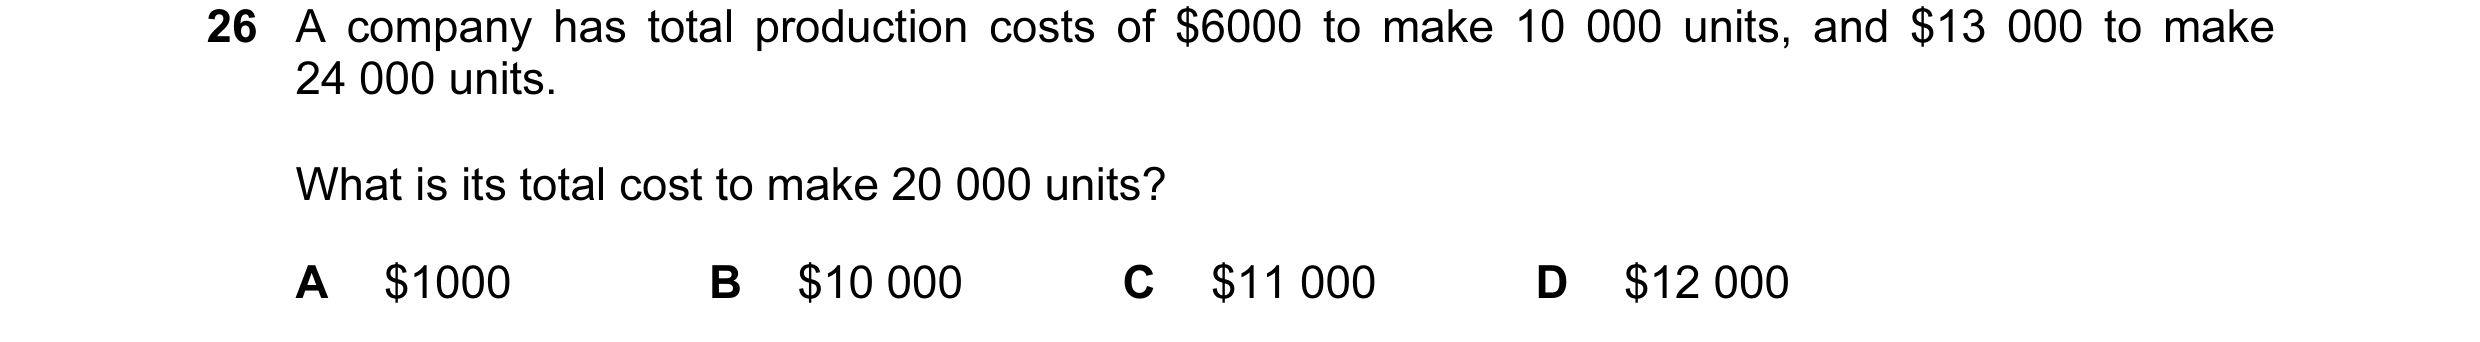
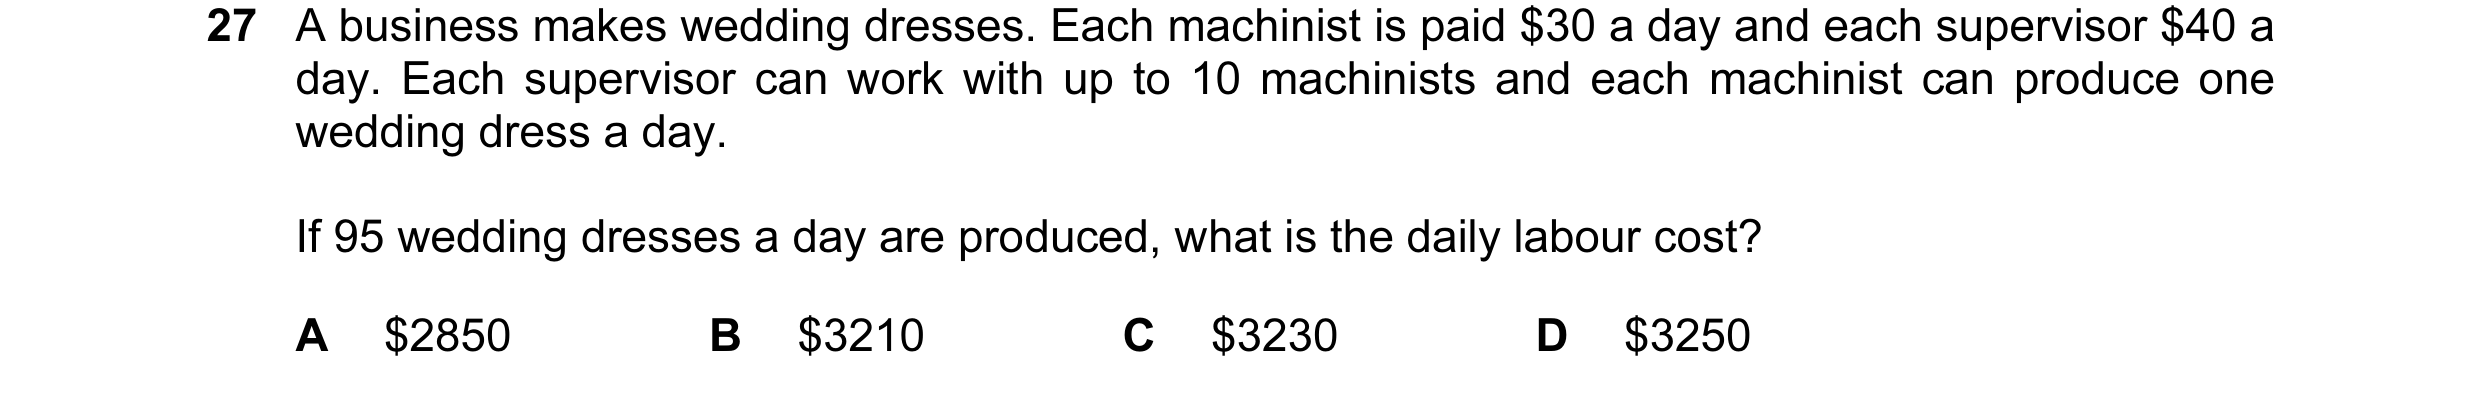
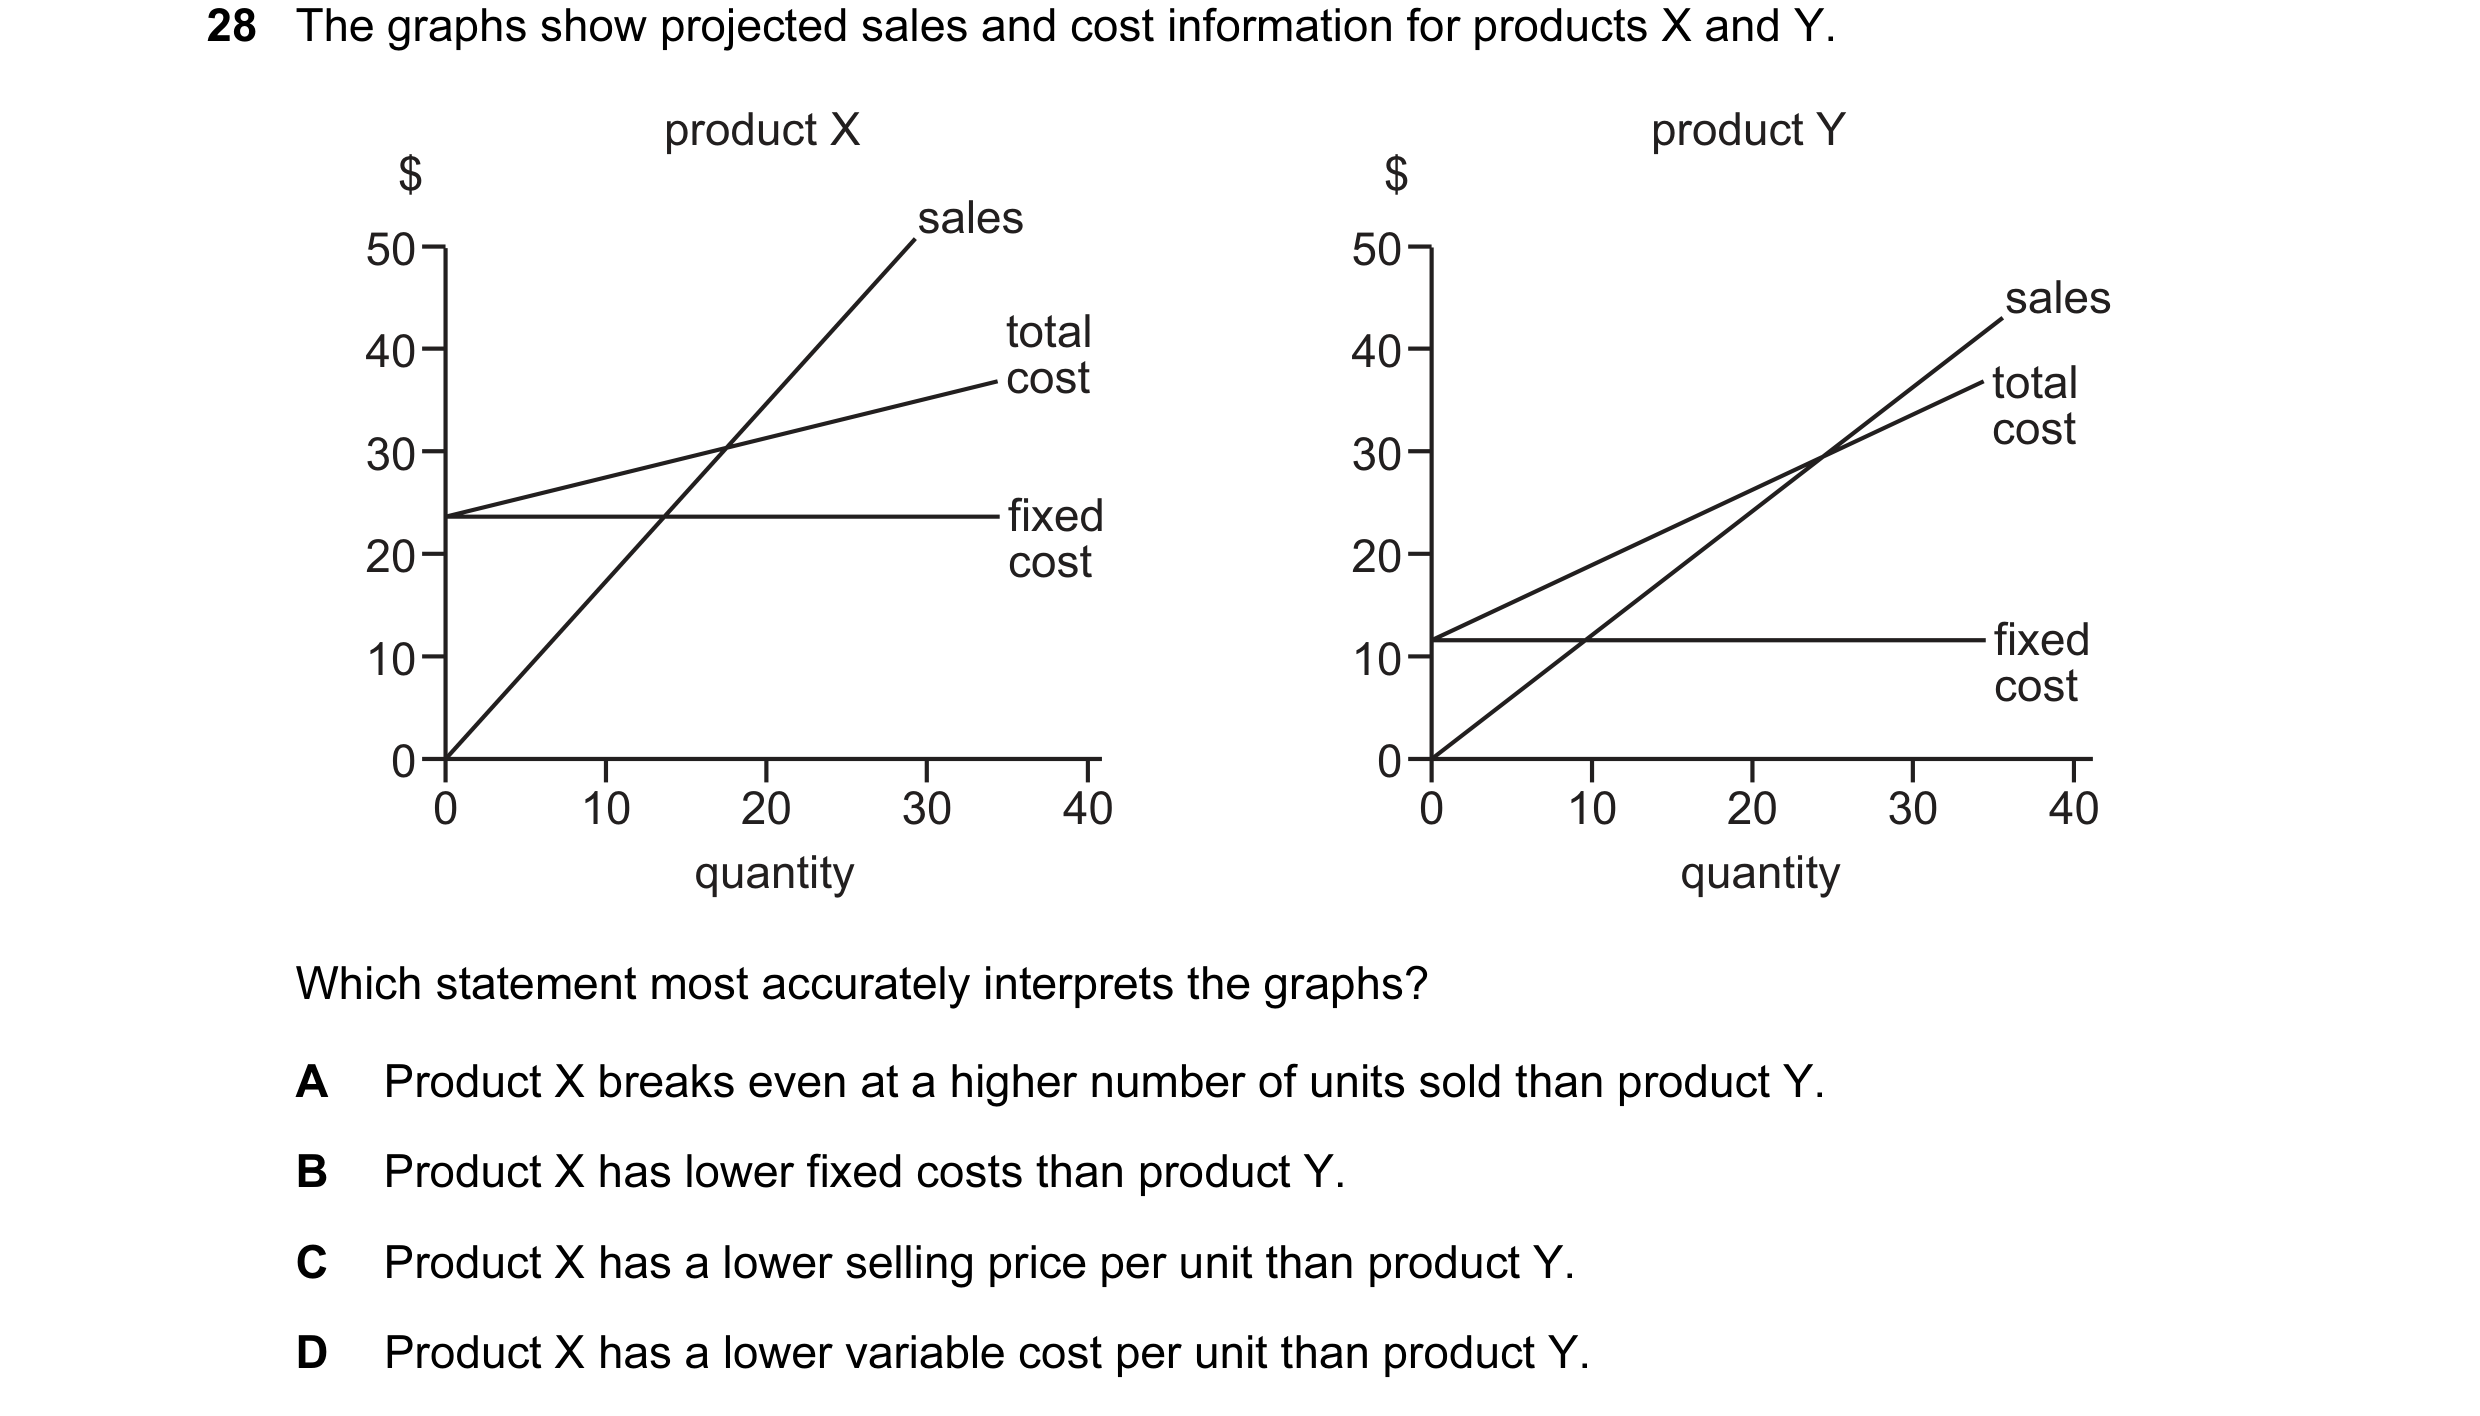 12 / 143
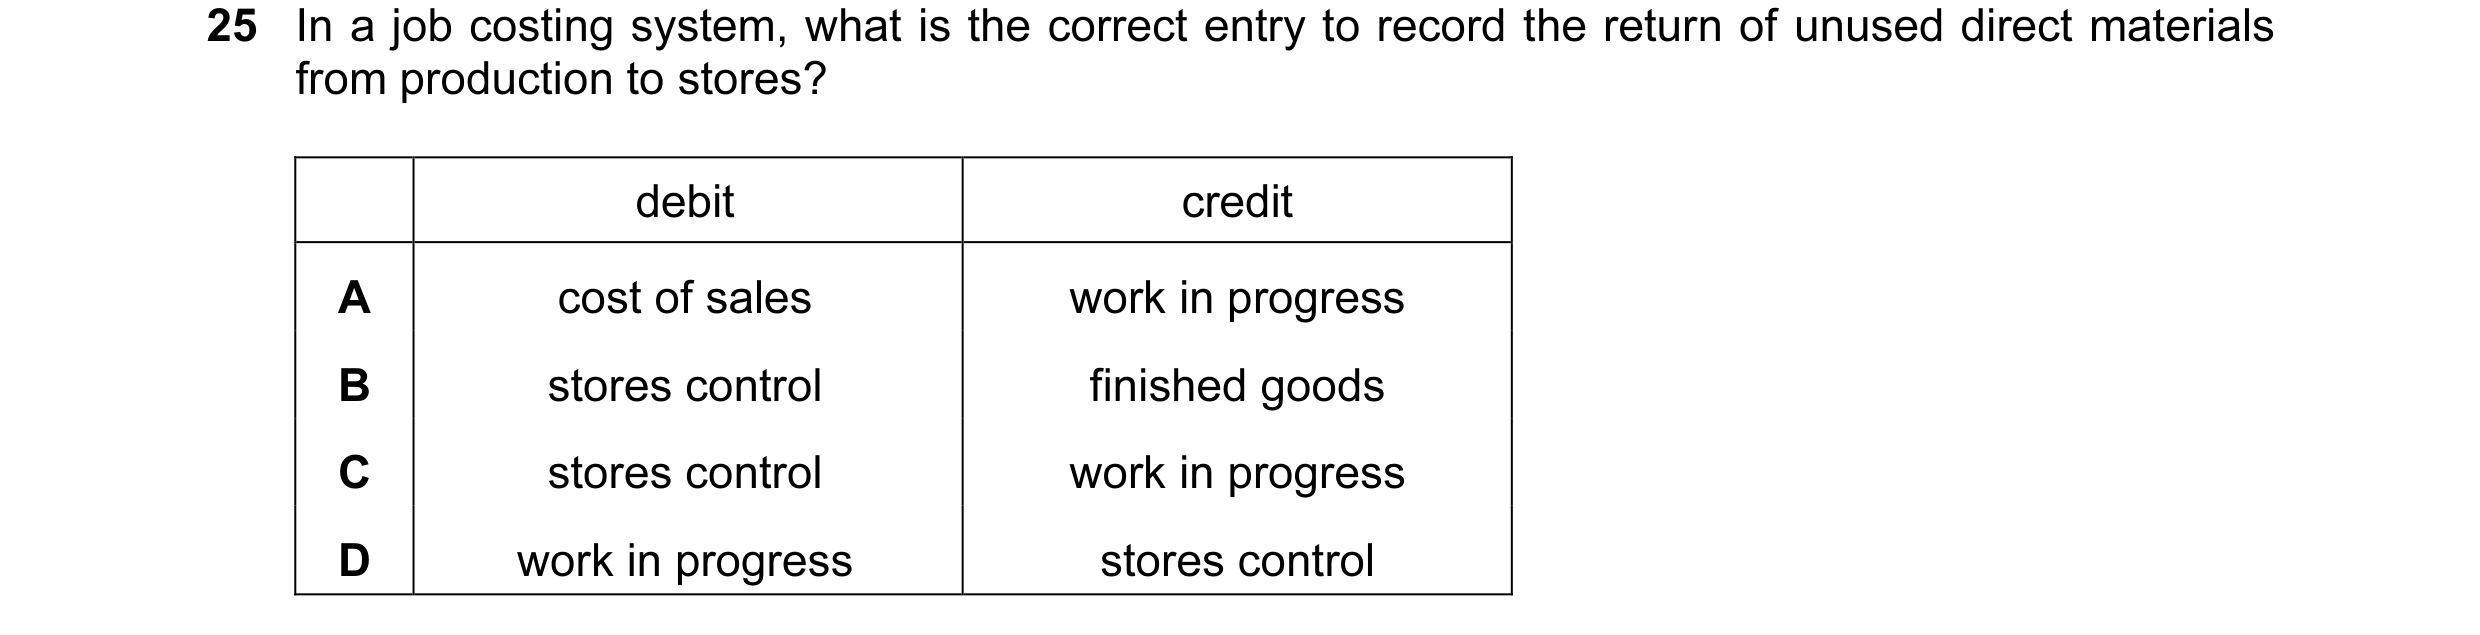
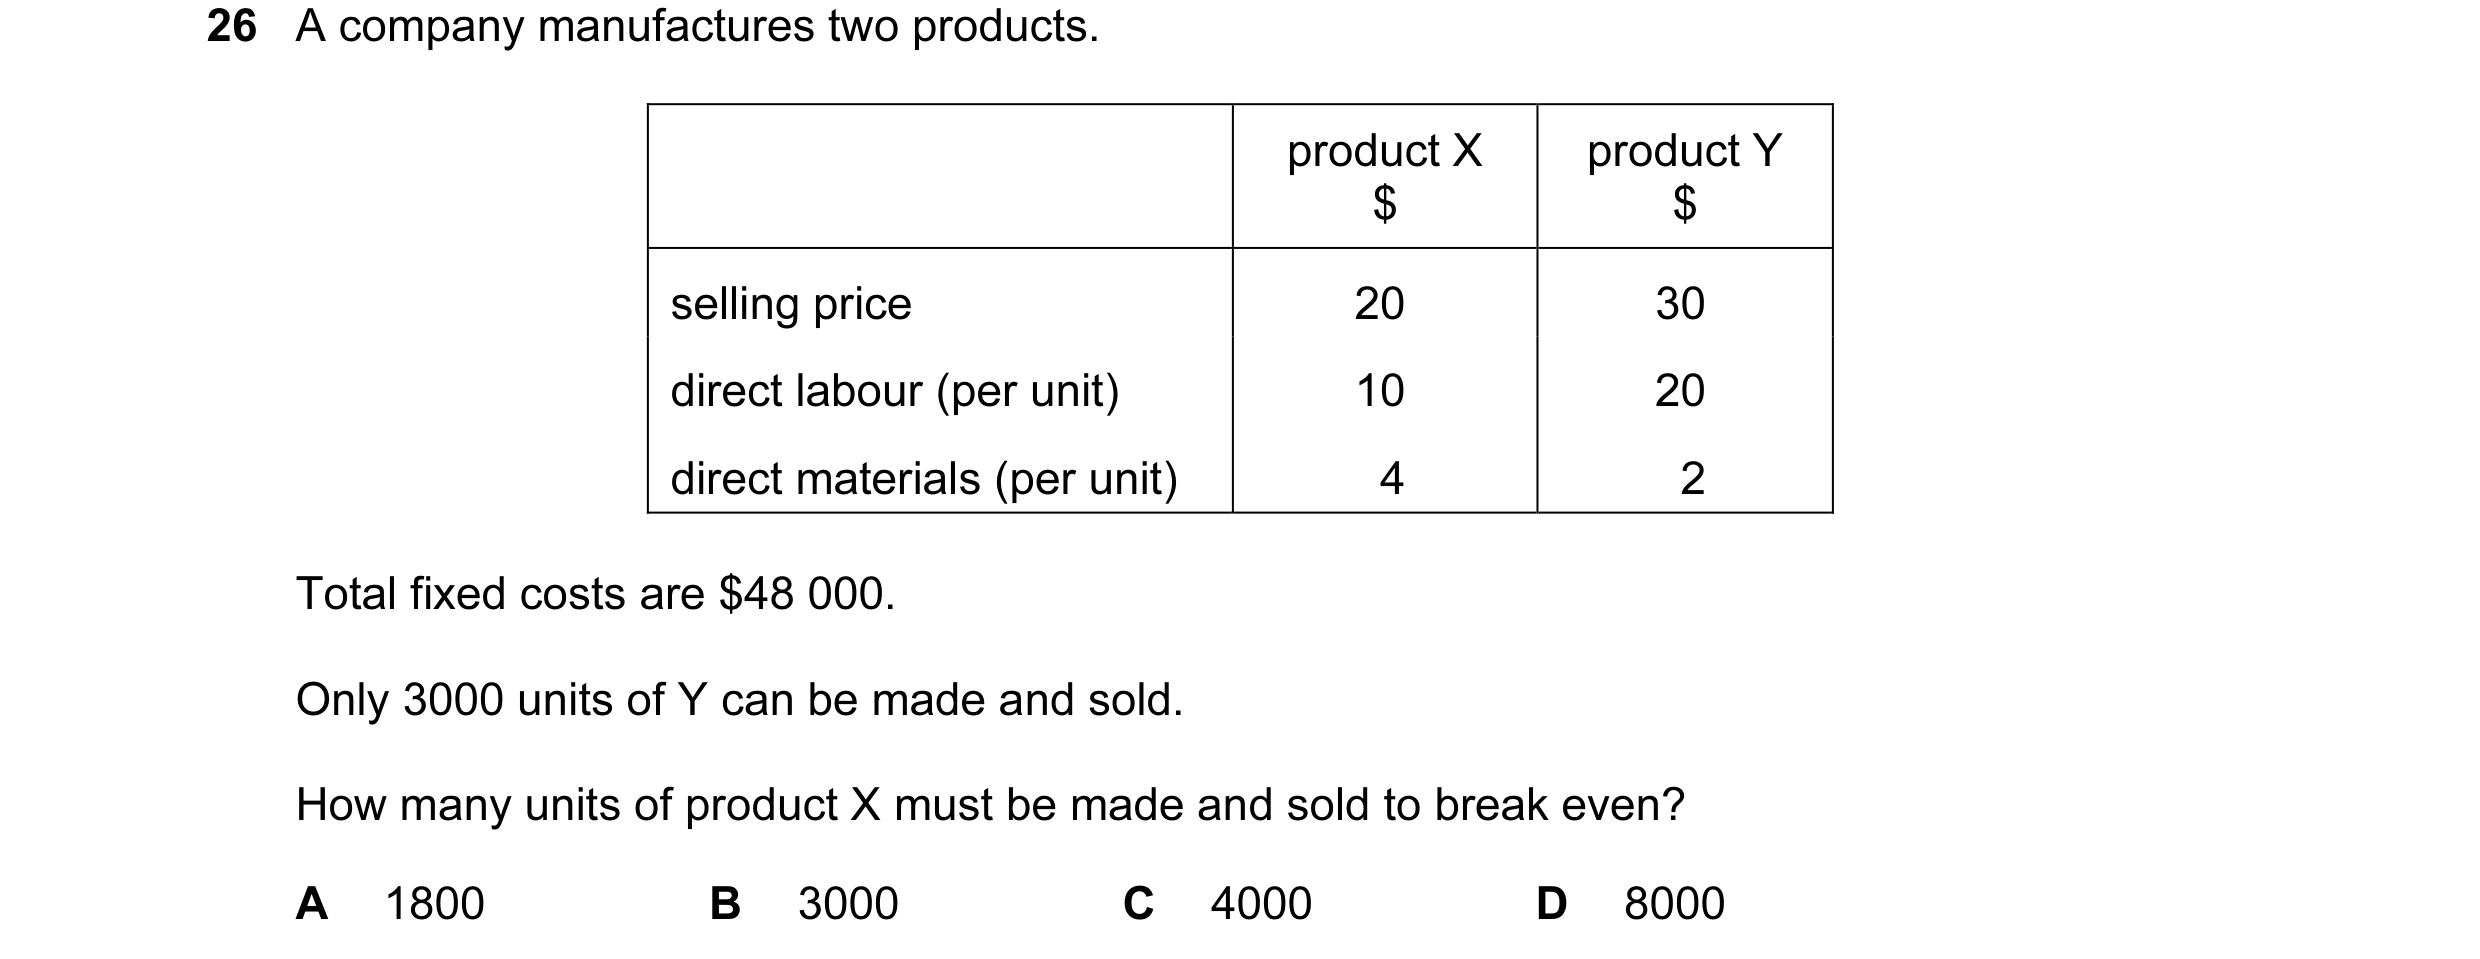
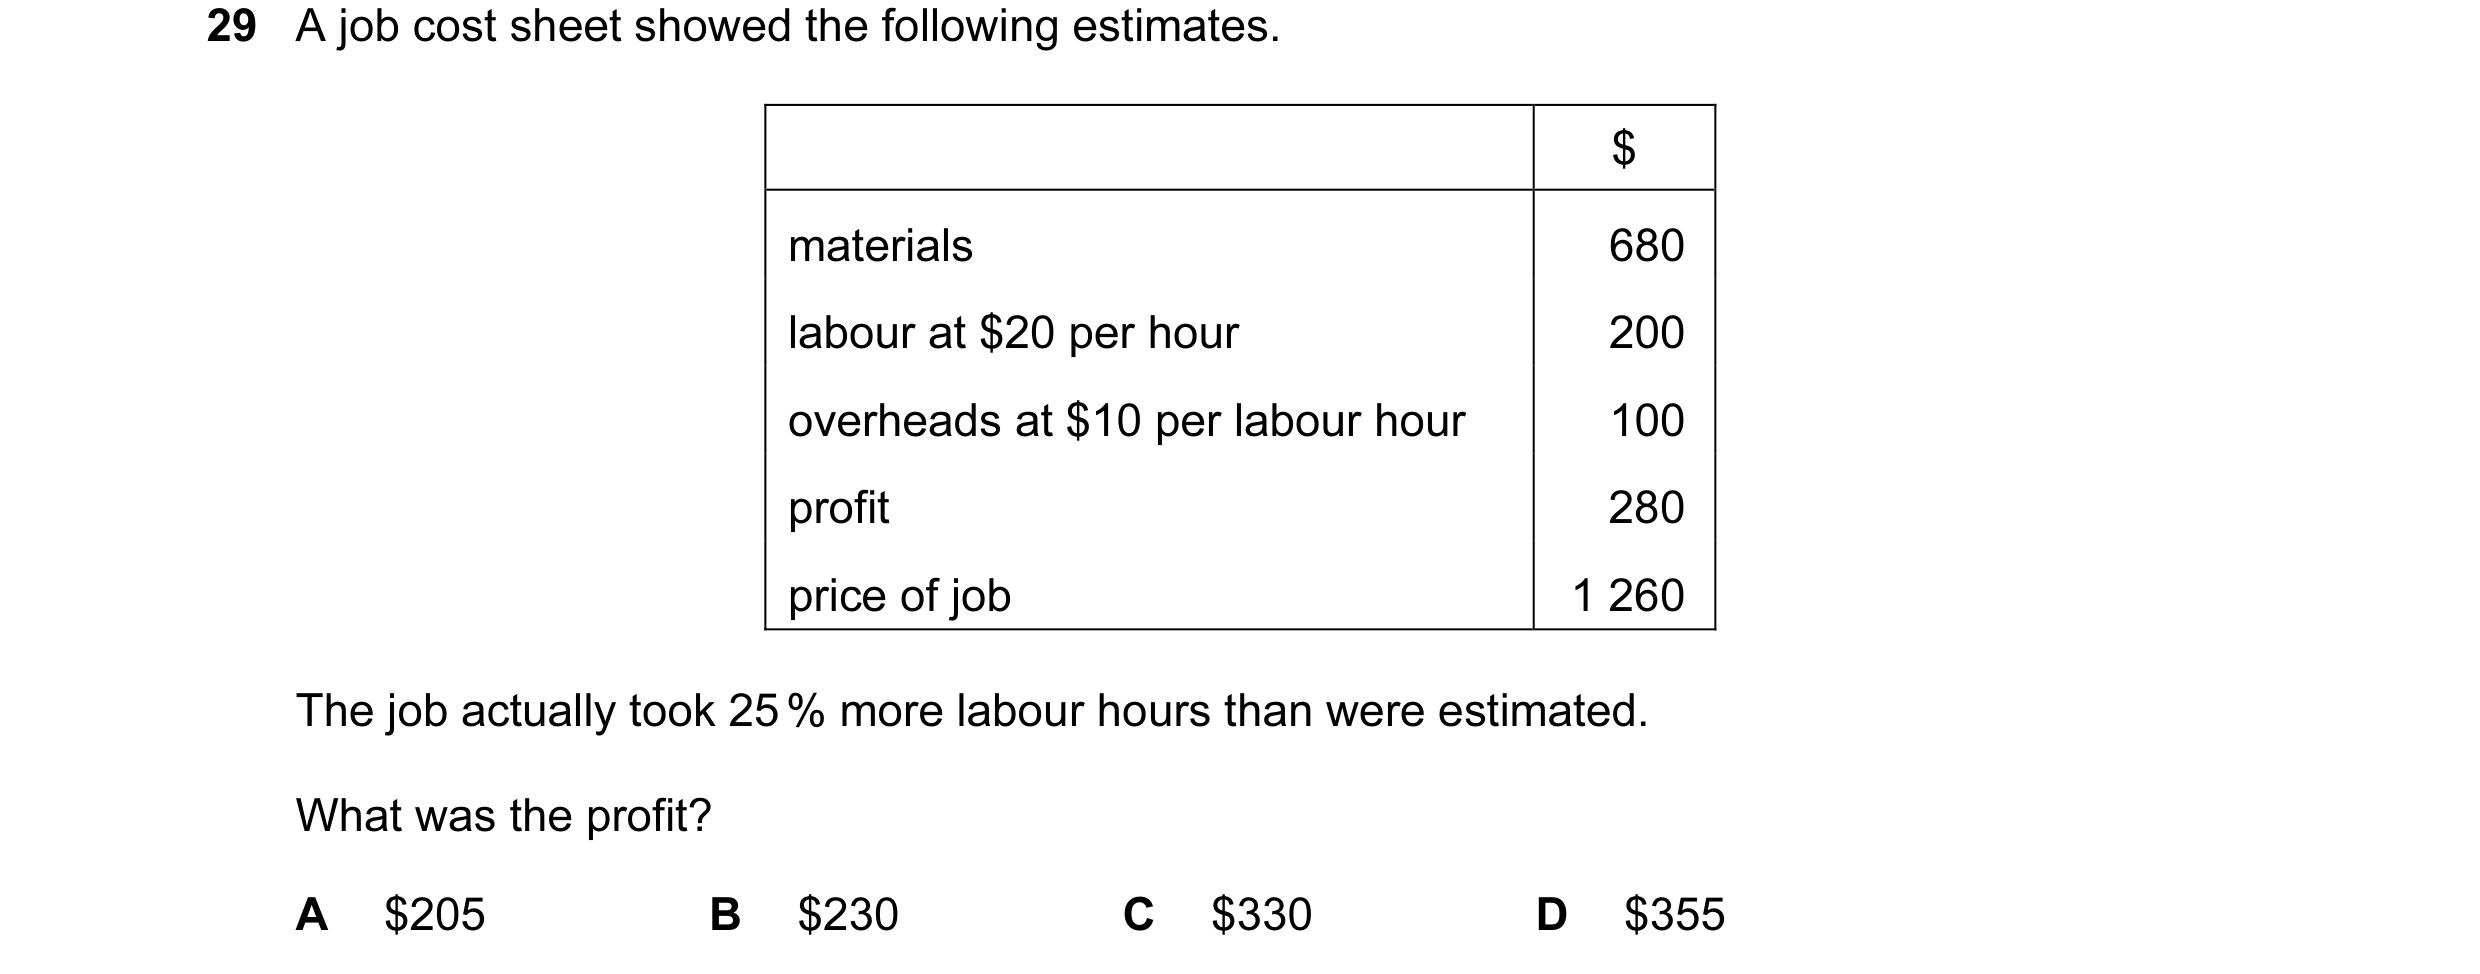
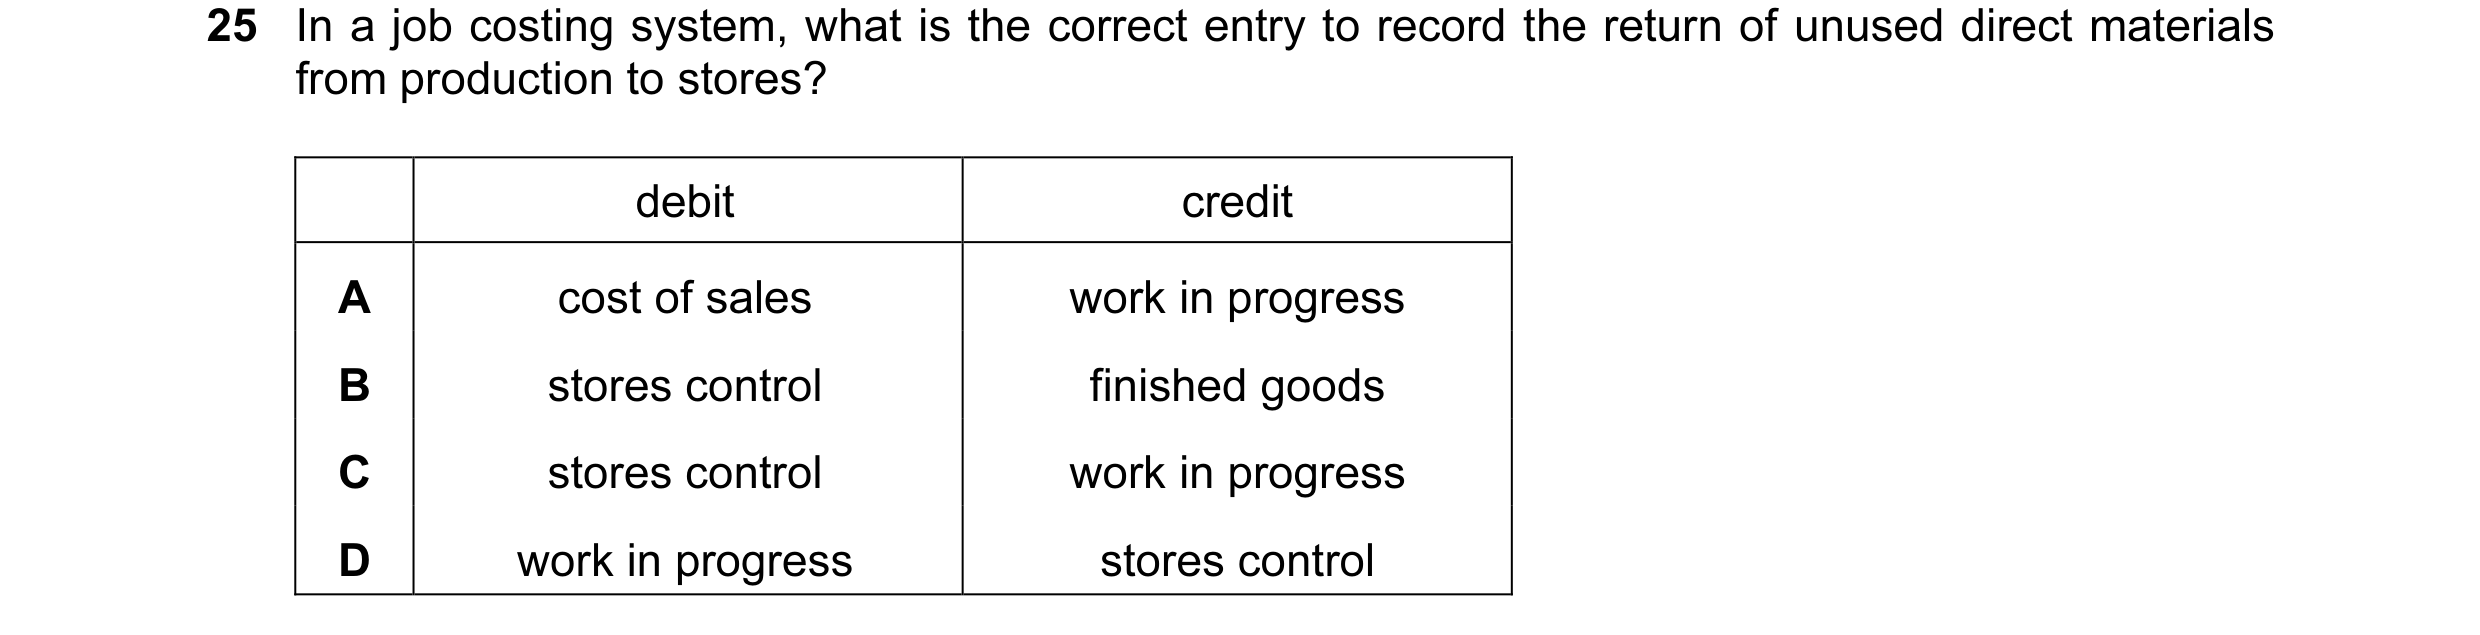 13 / 143
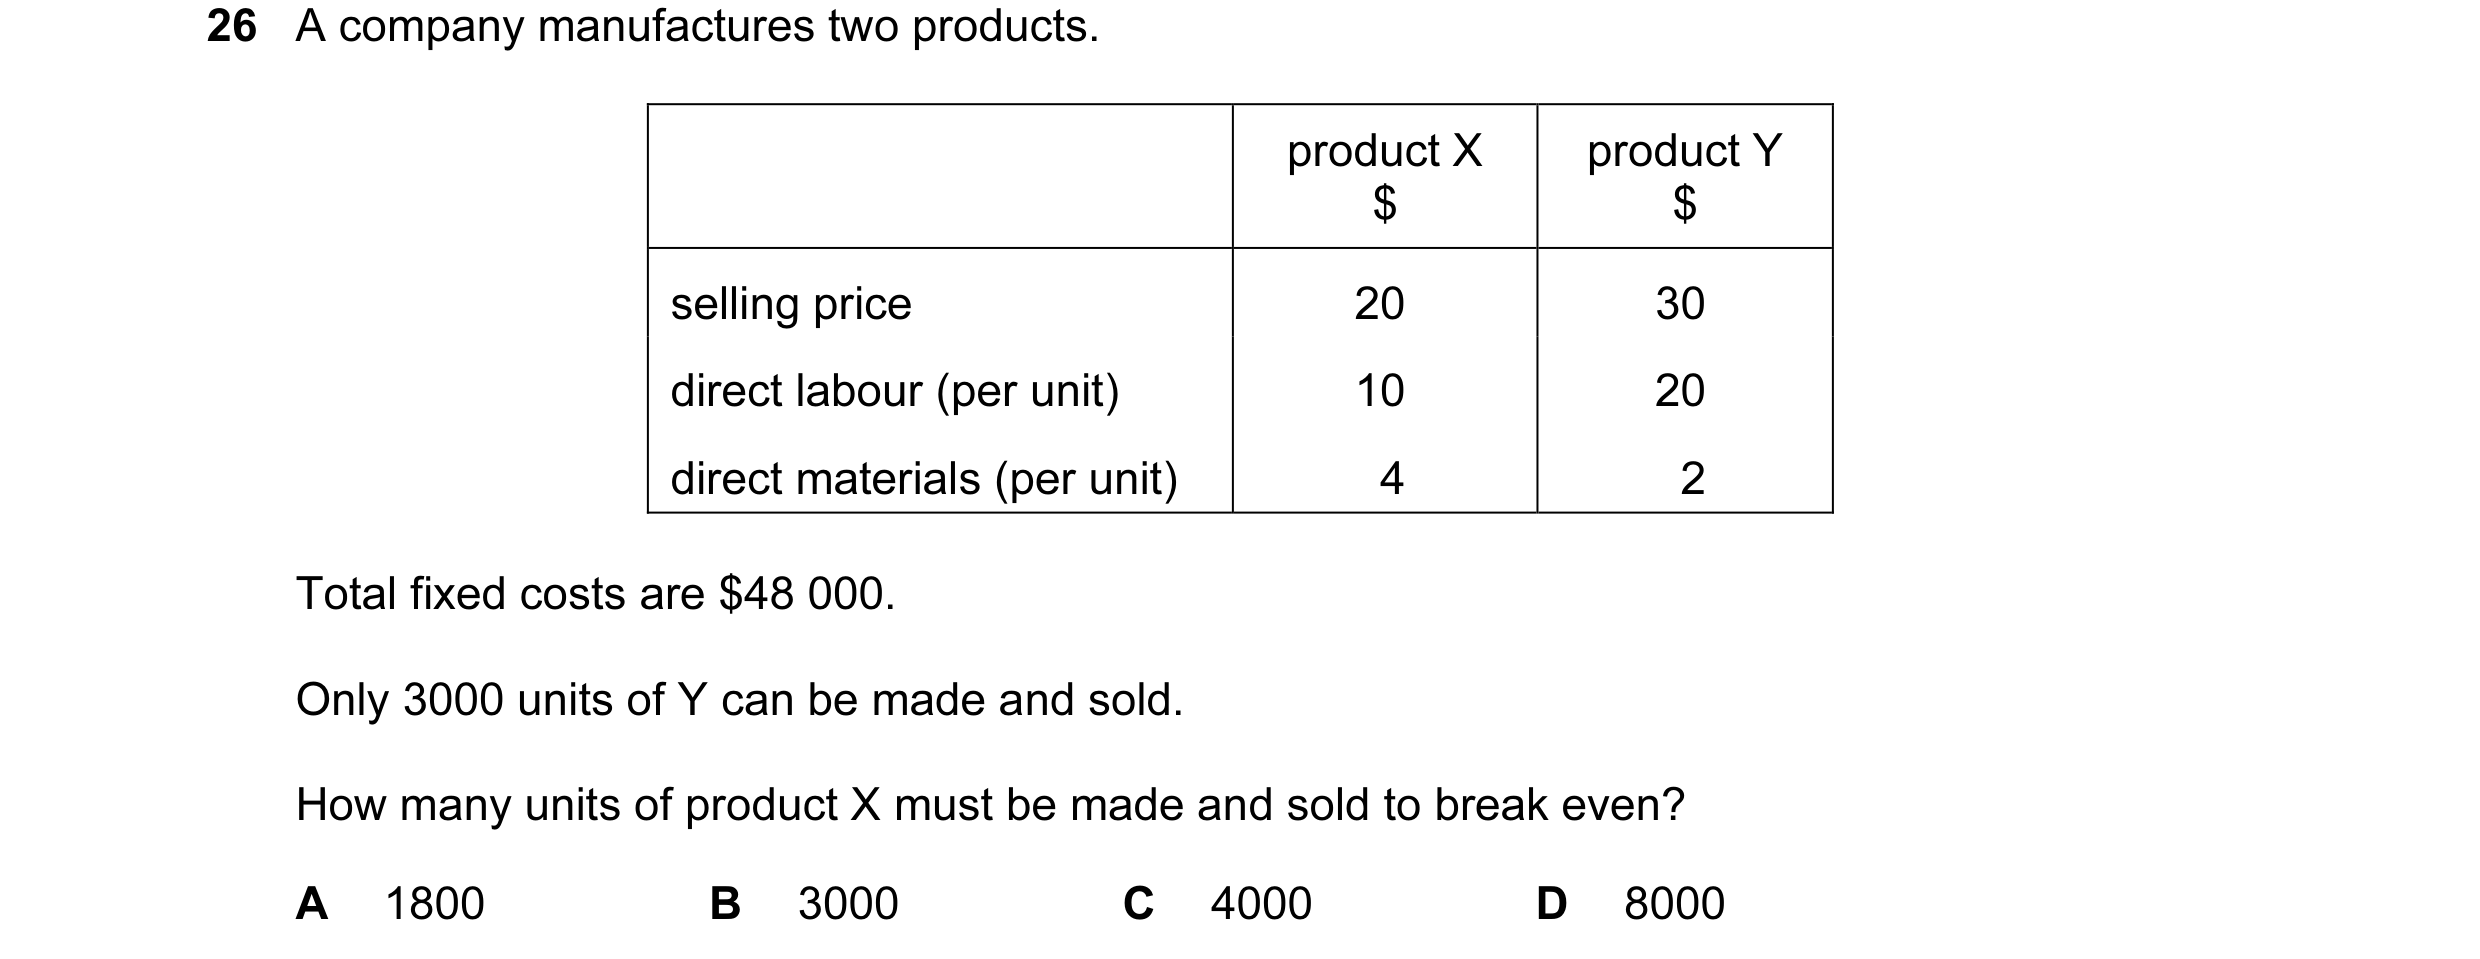
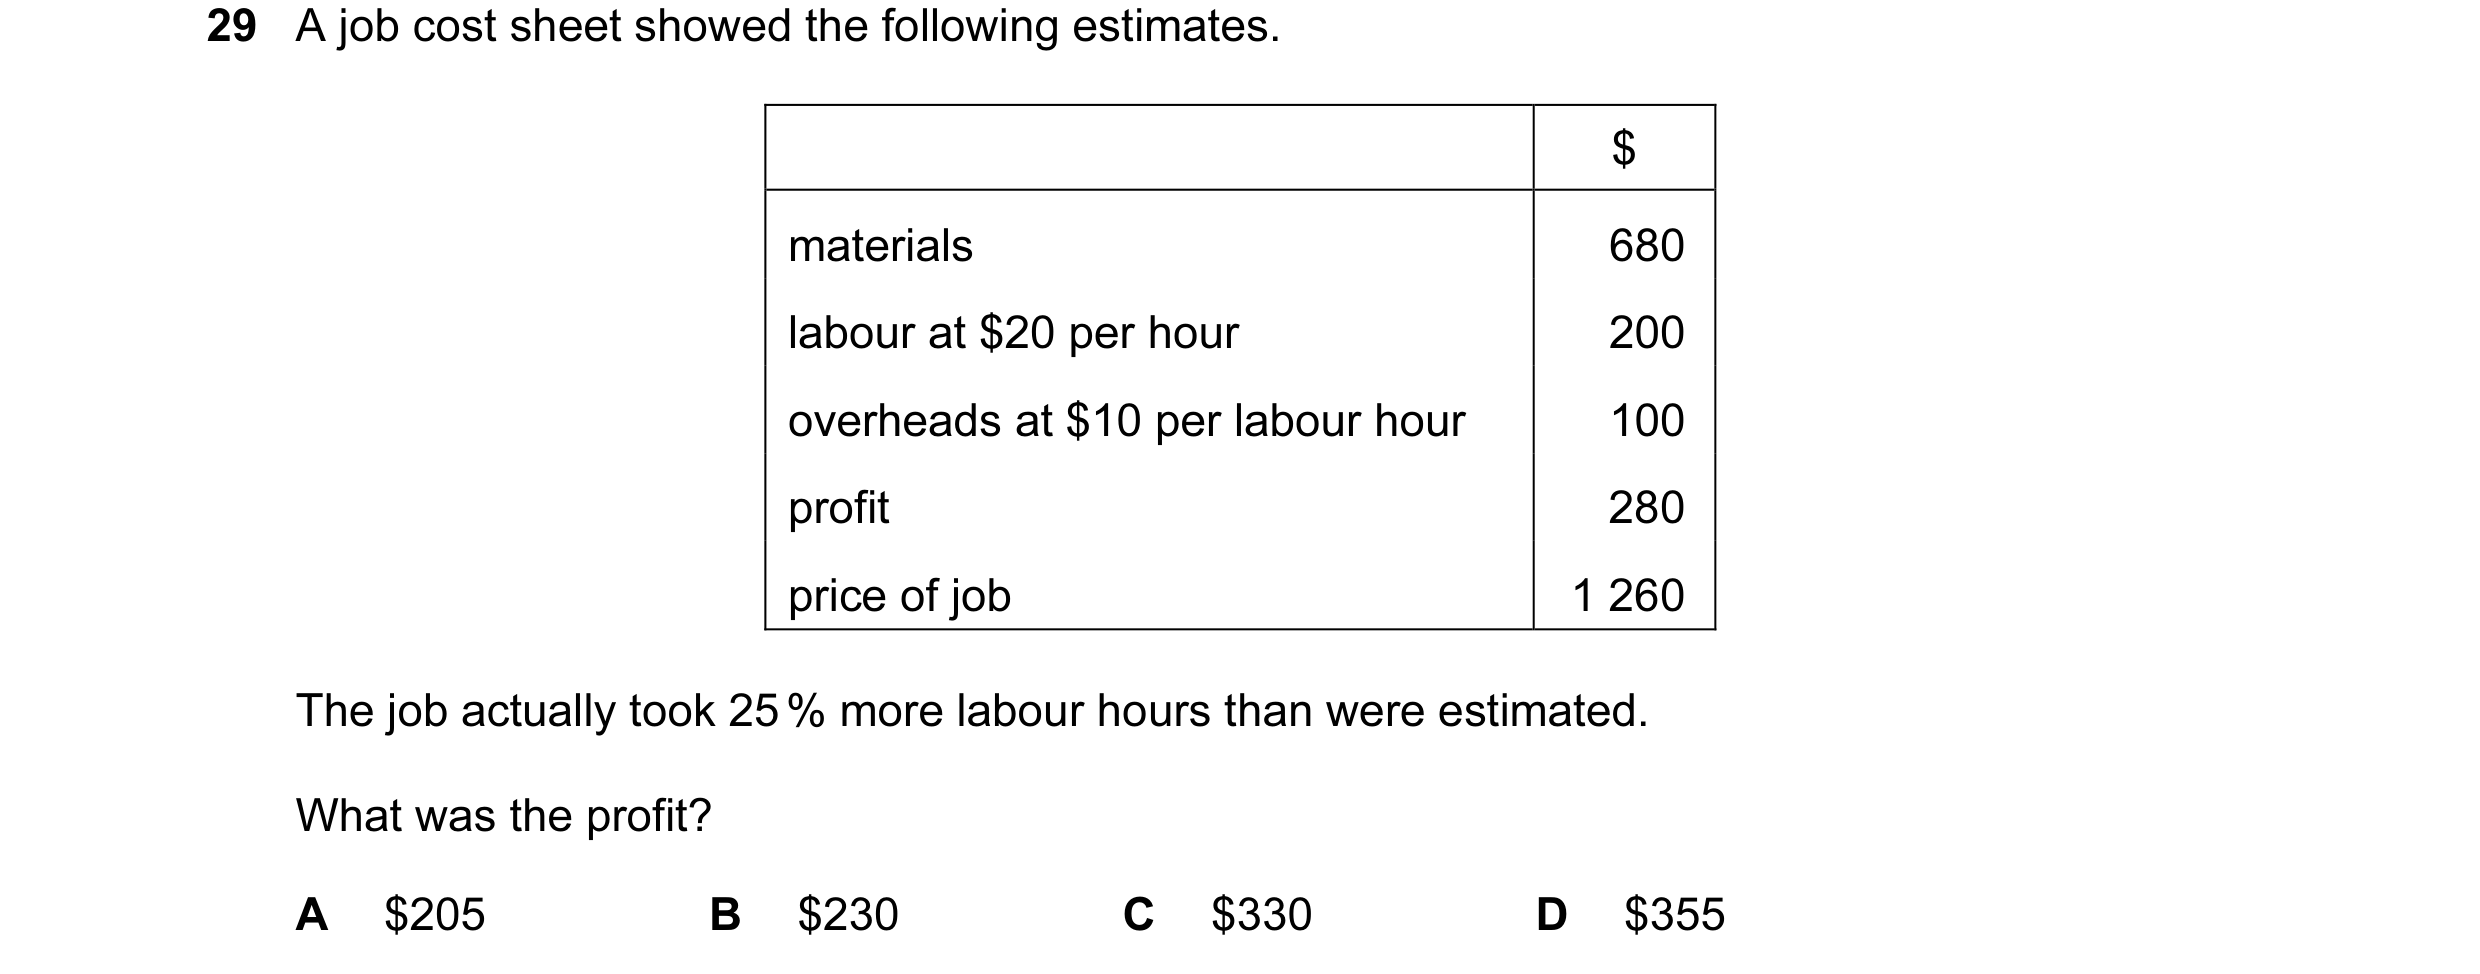 14 / 143
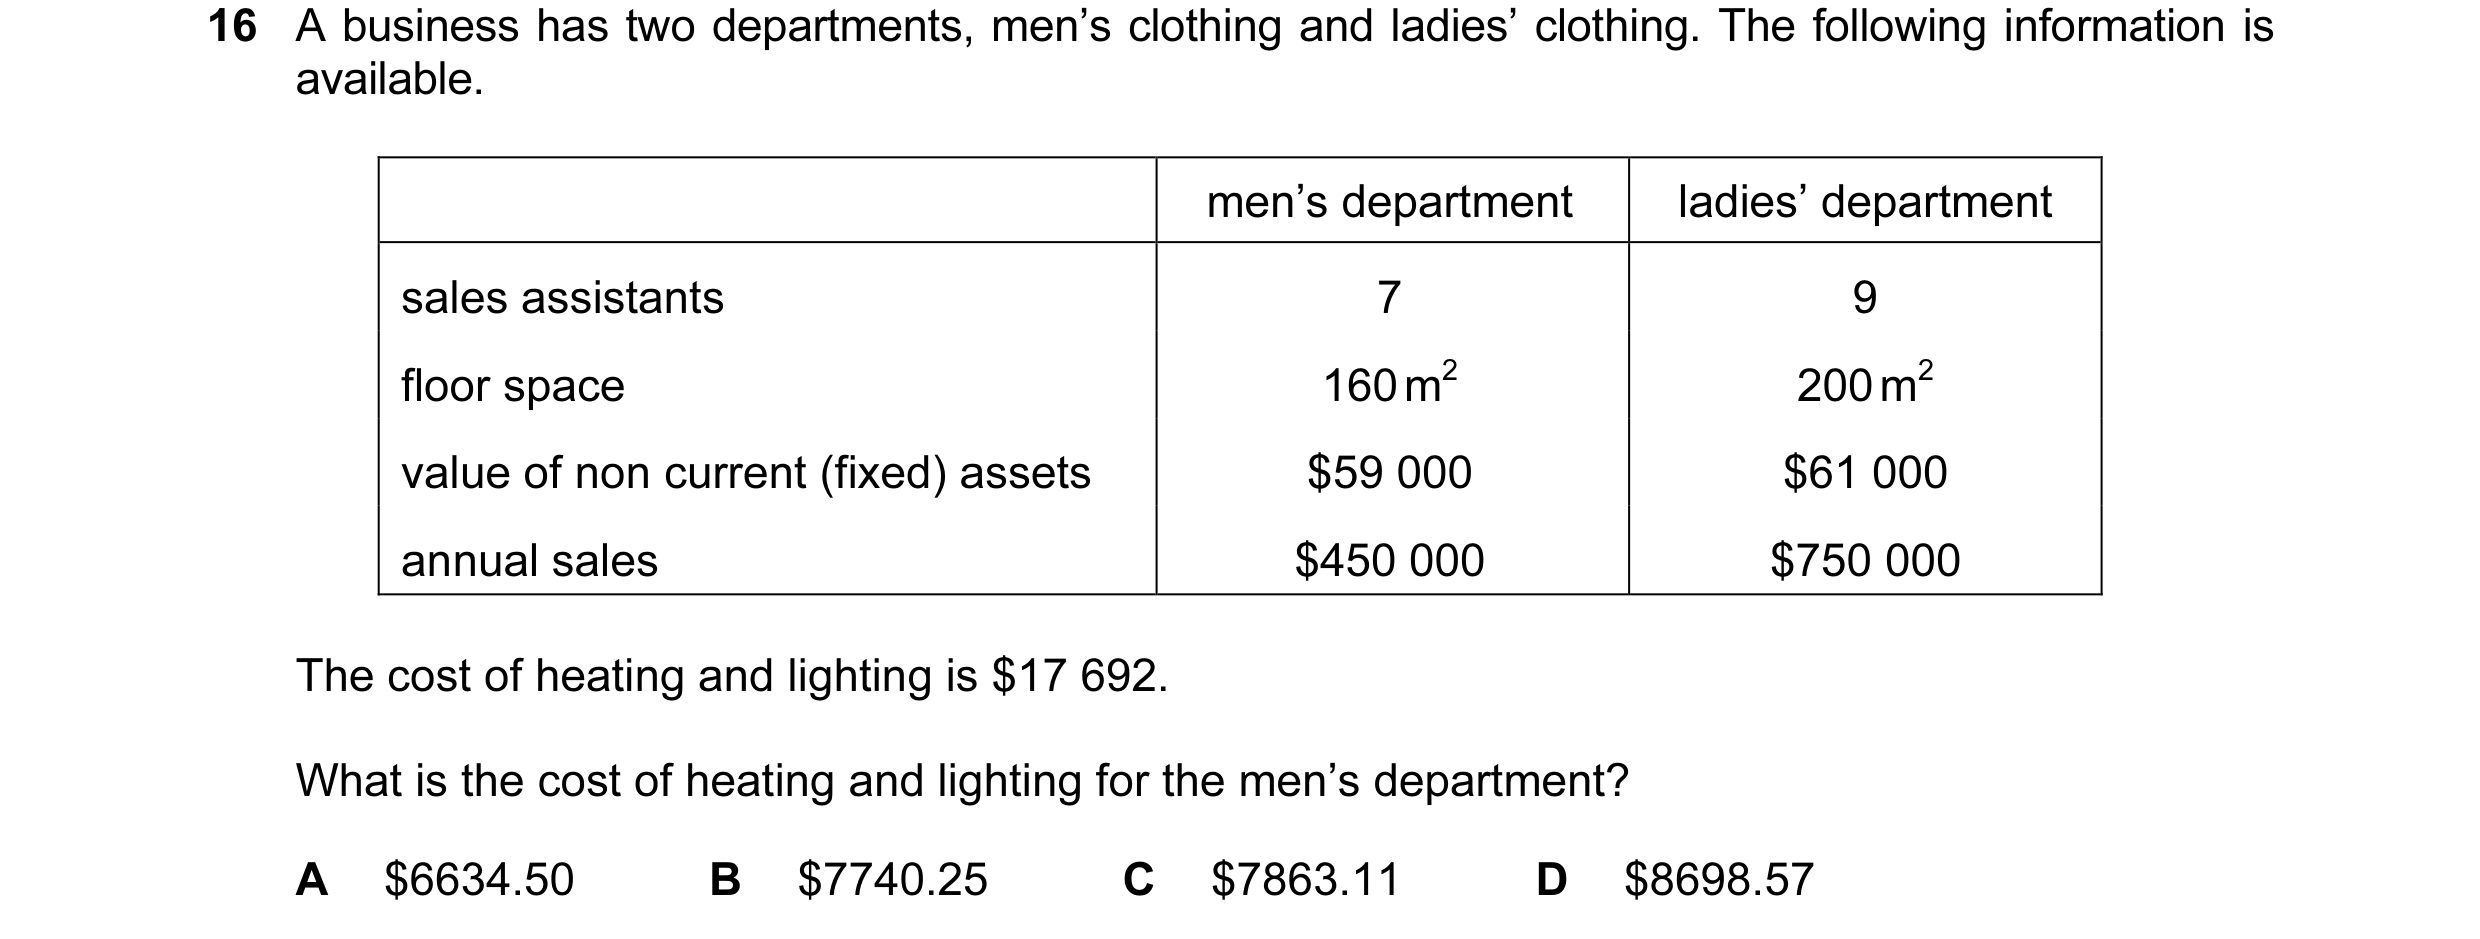
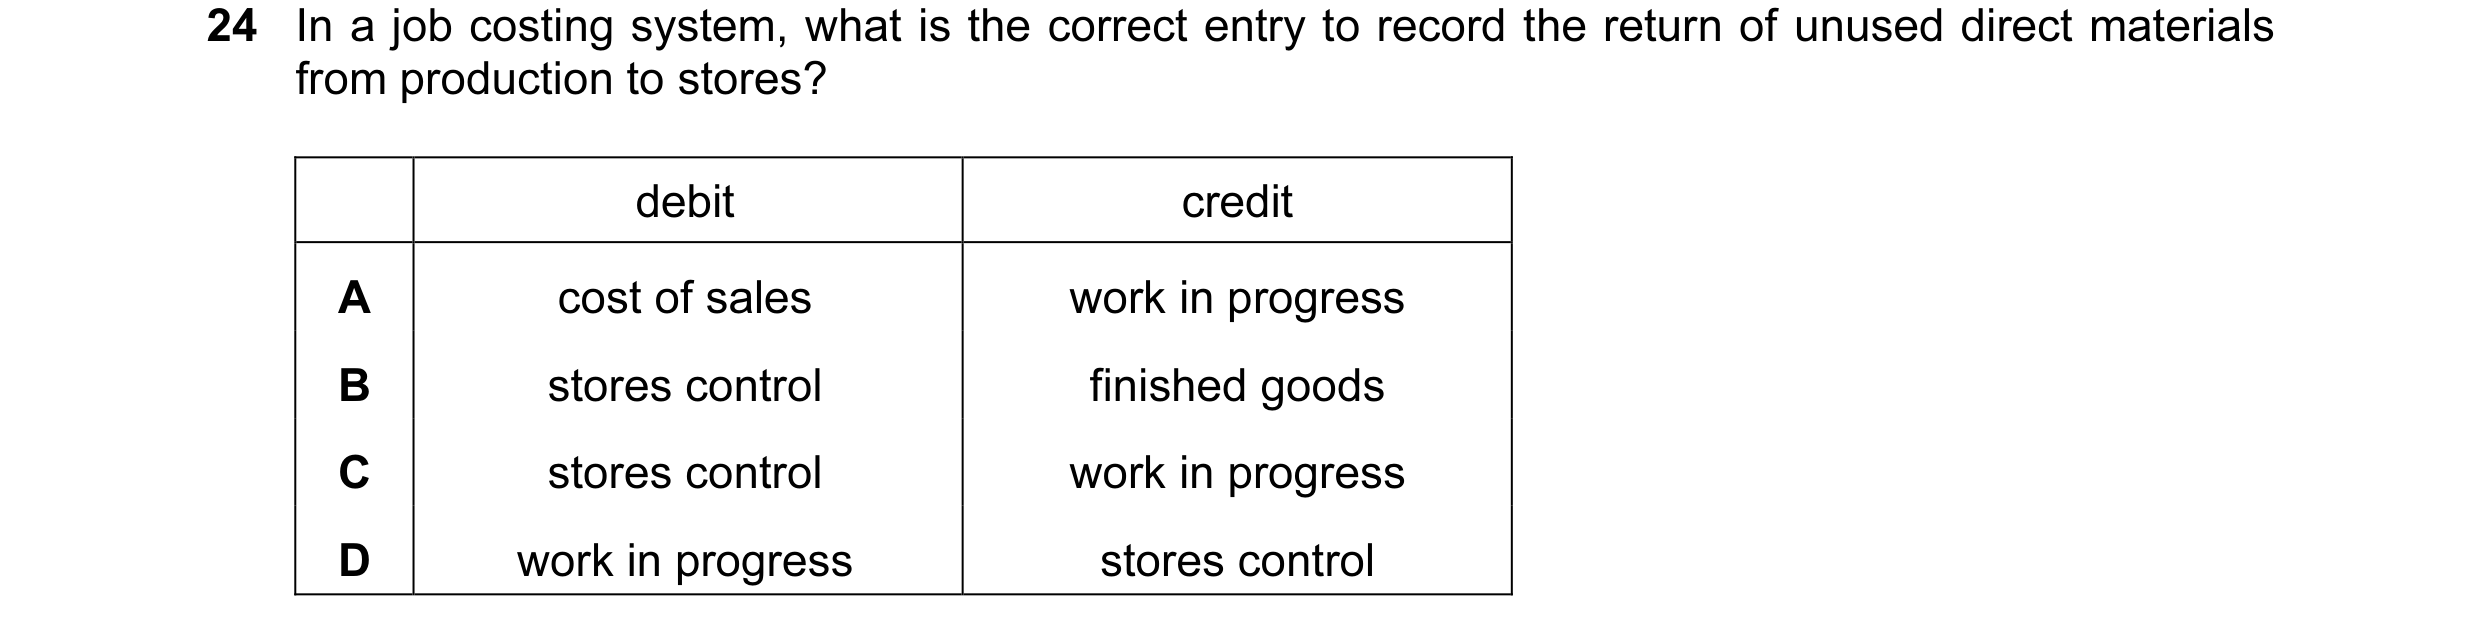
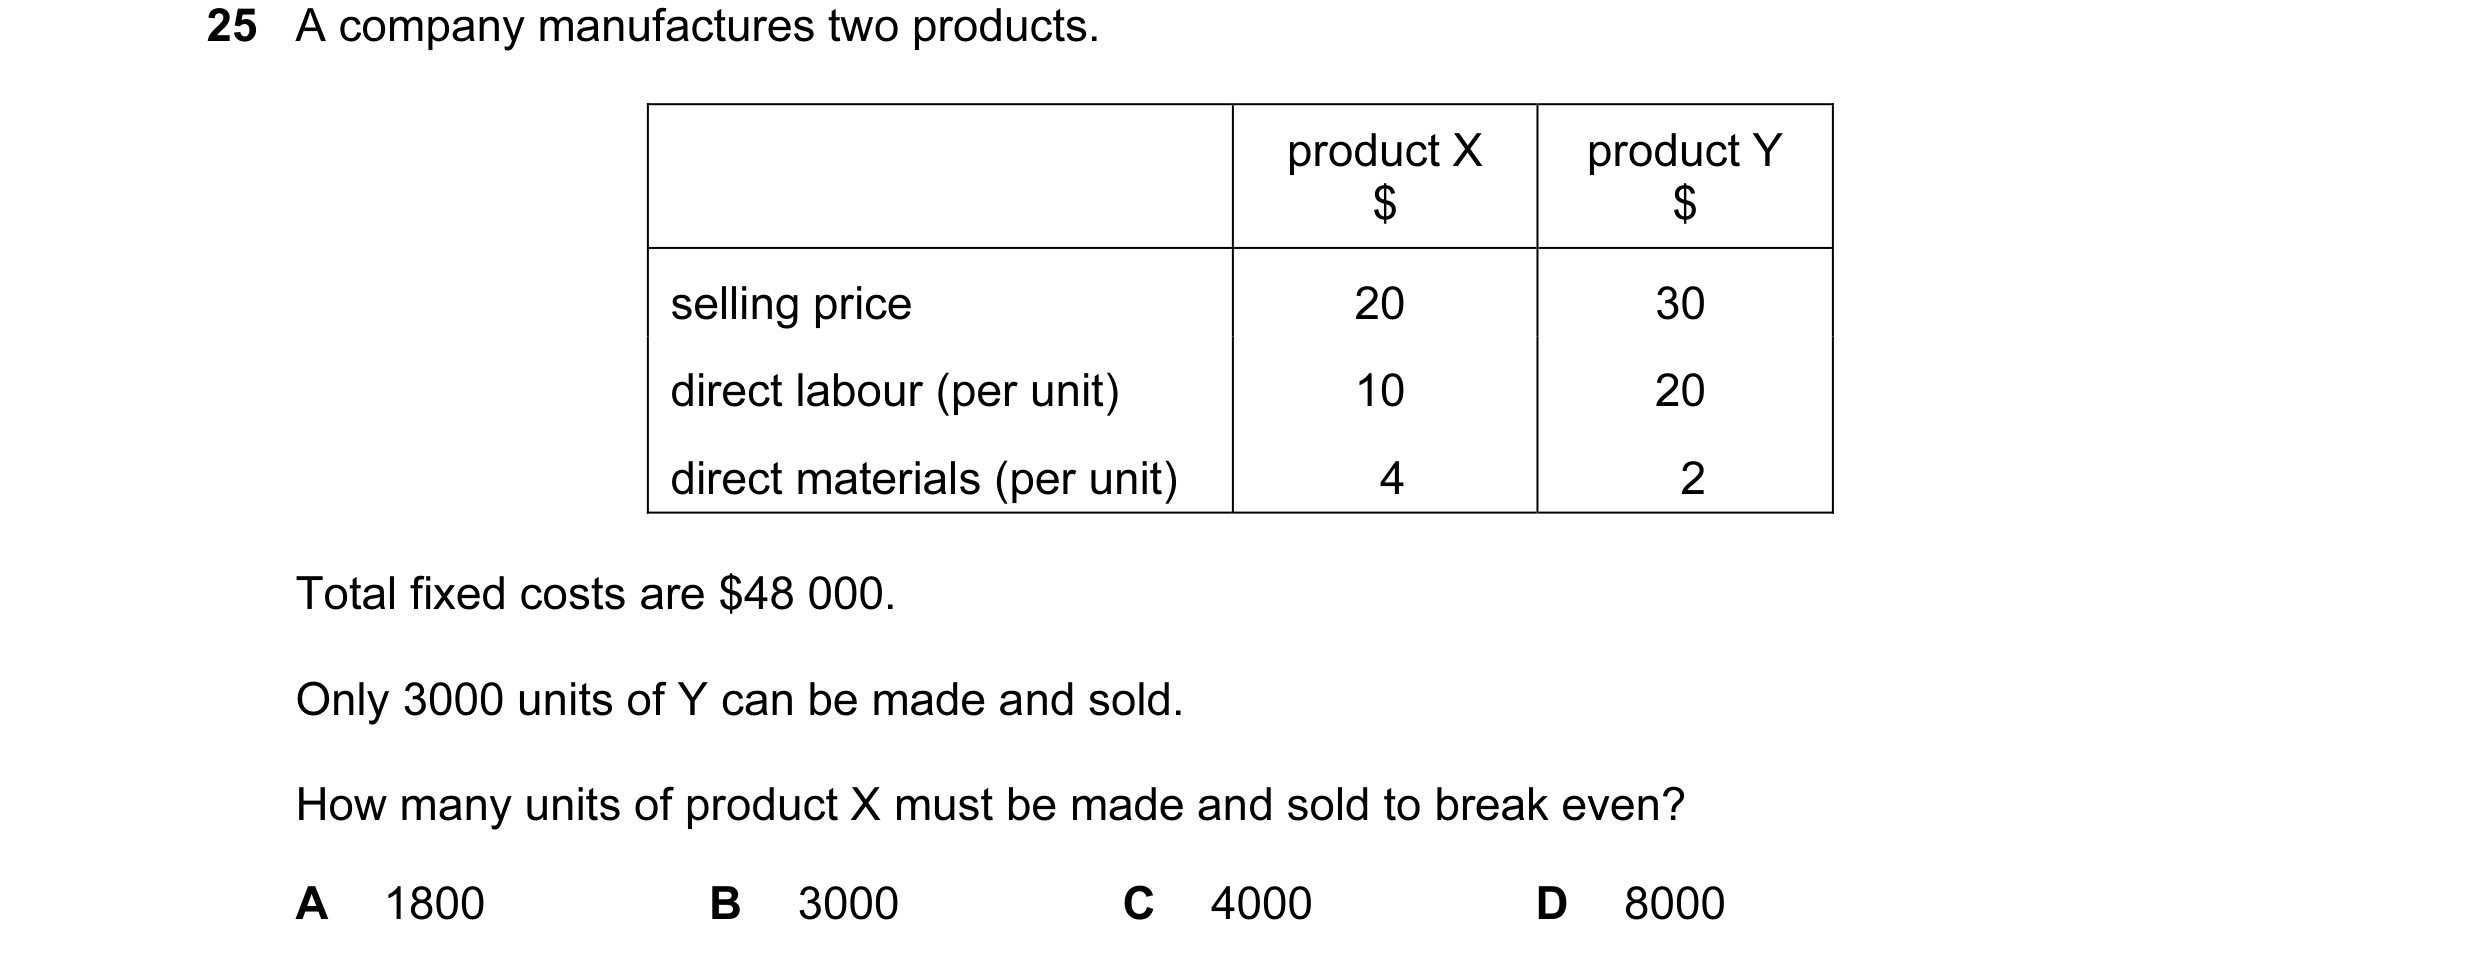 15 / 143
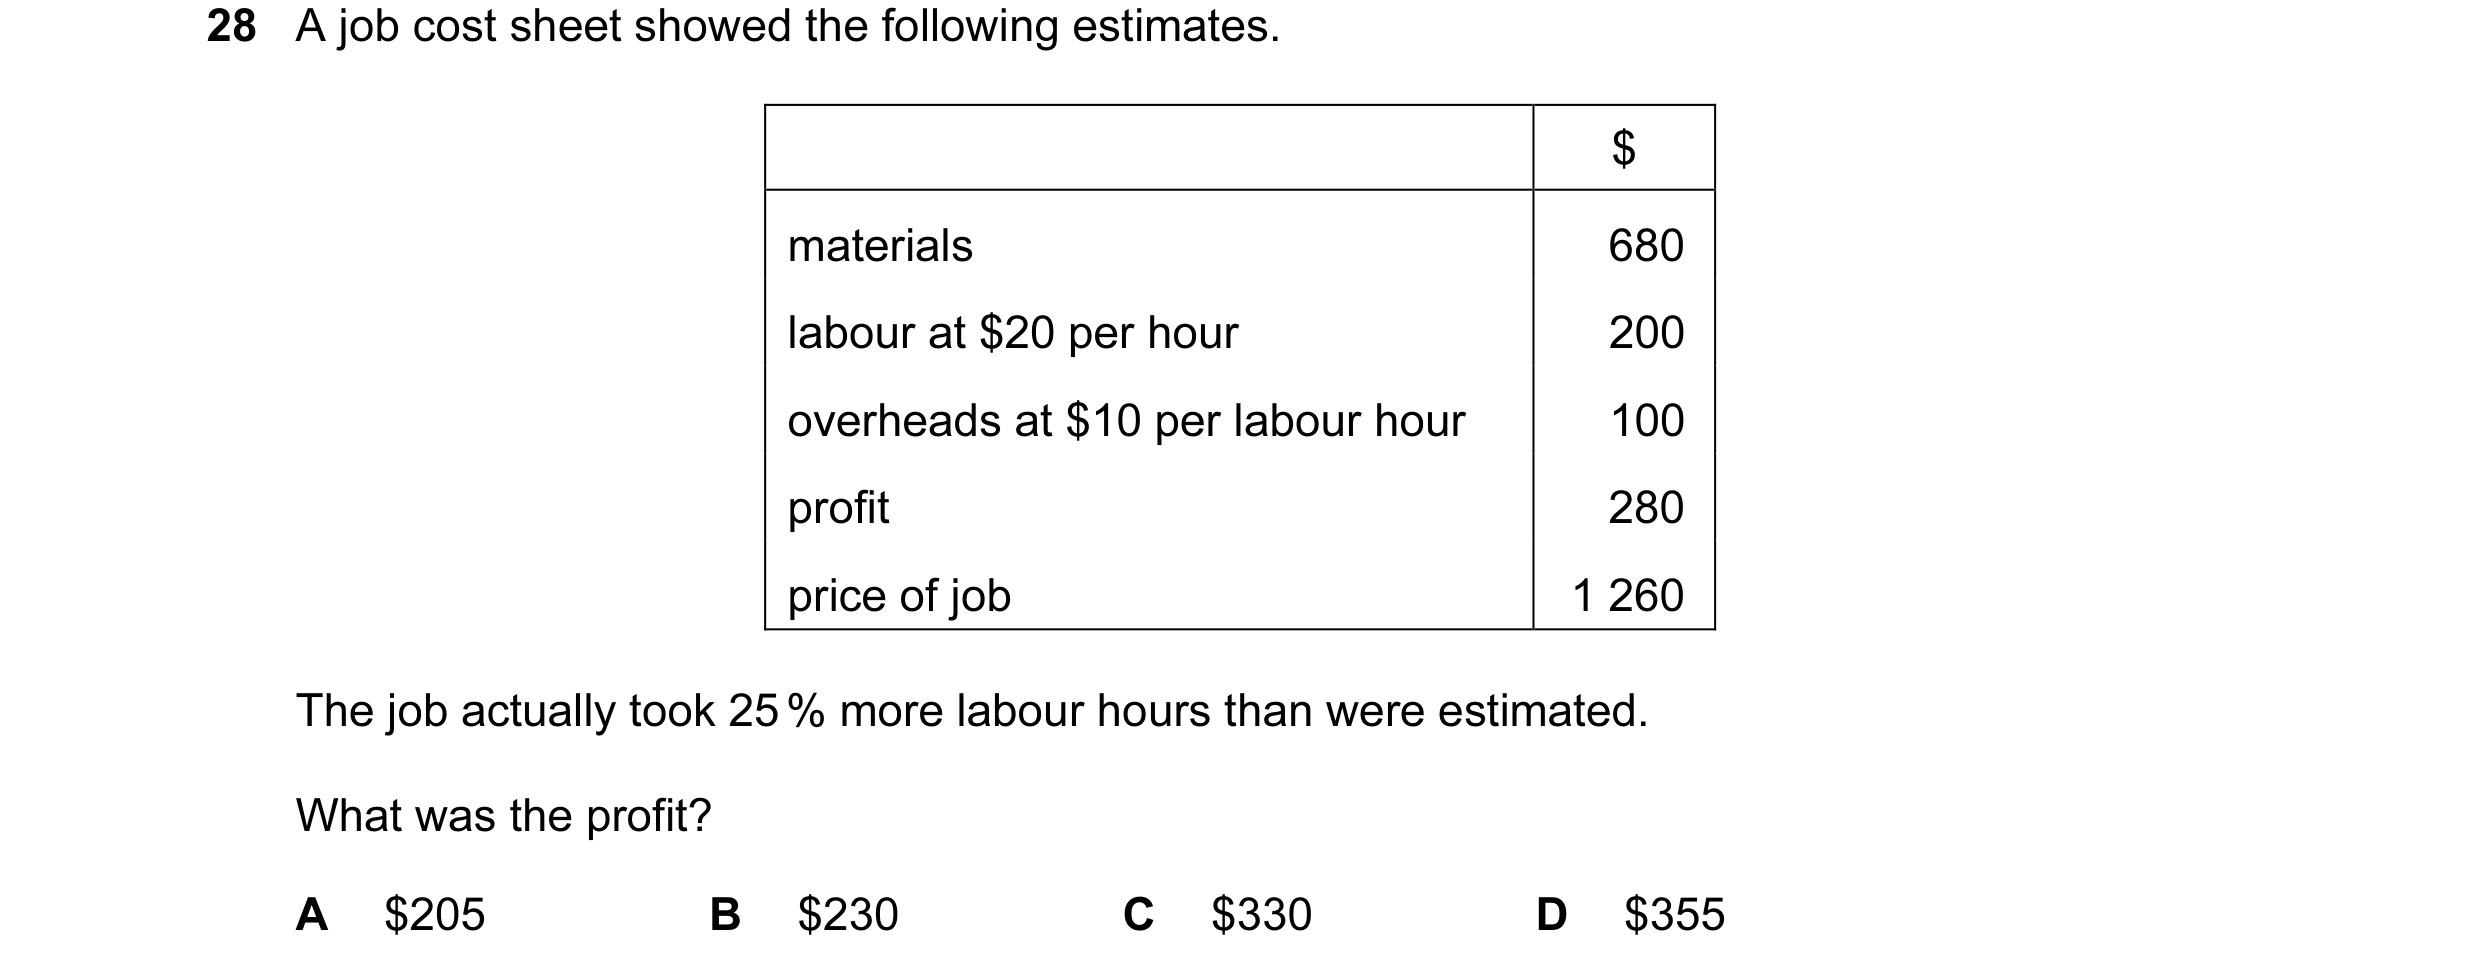
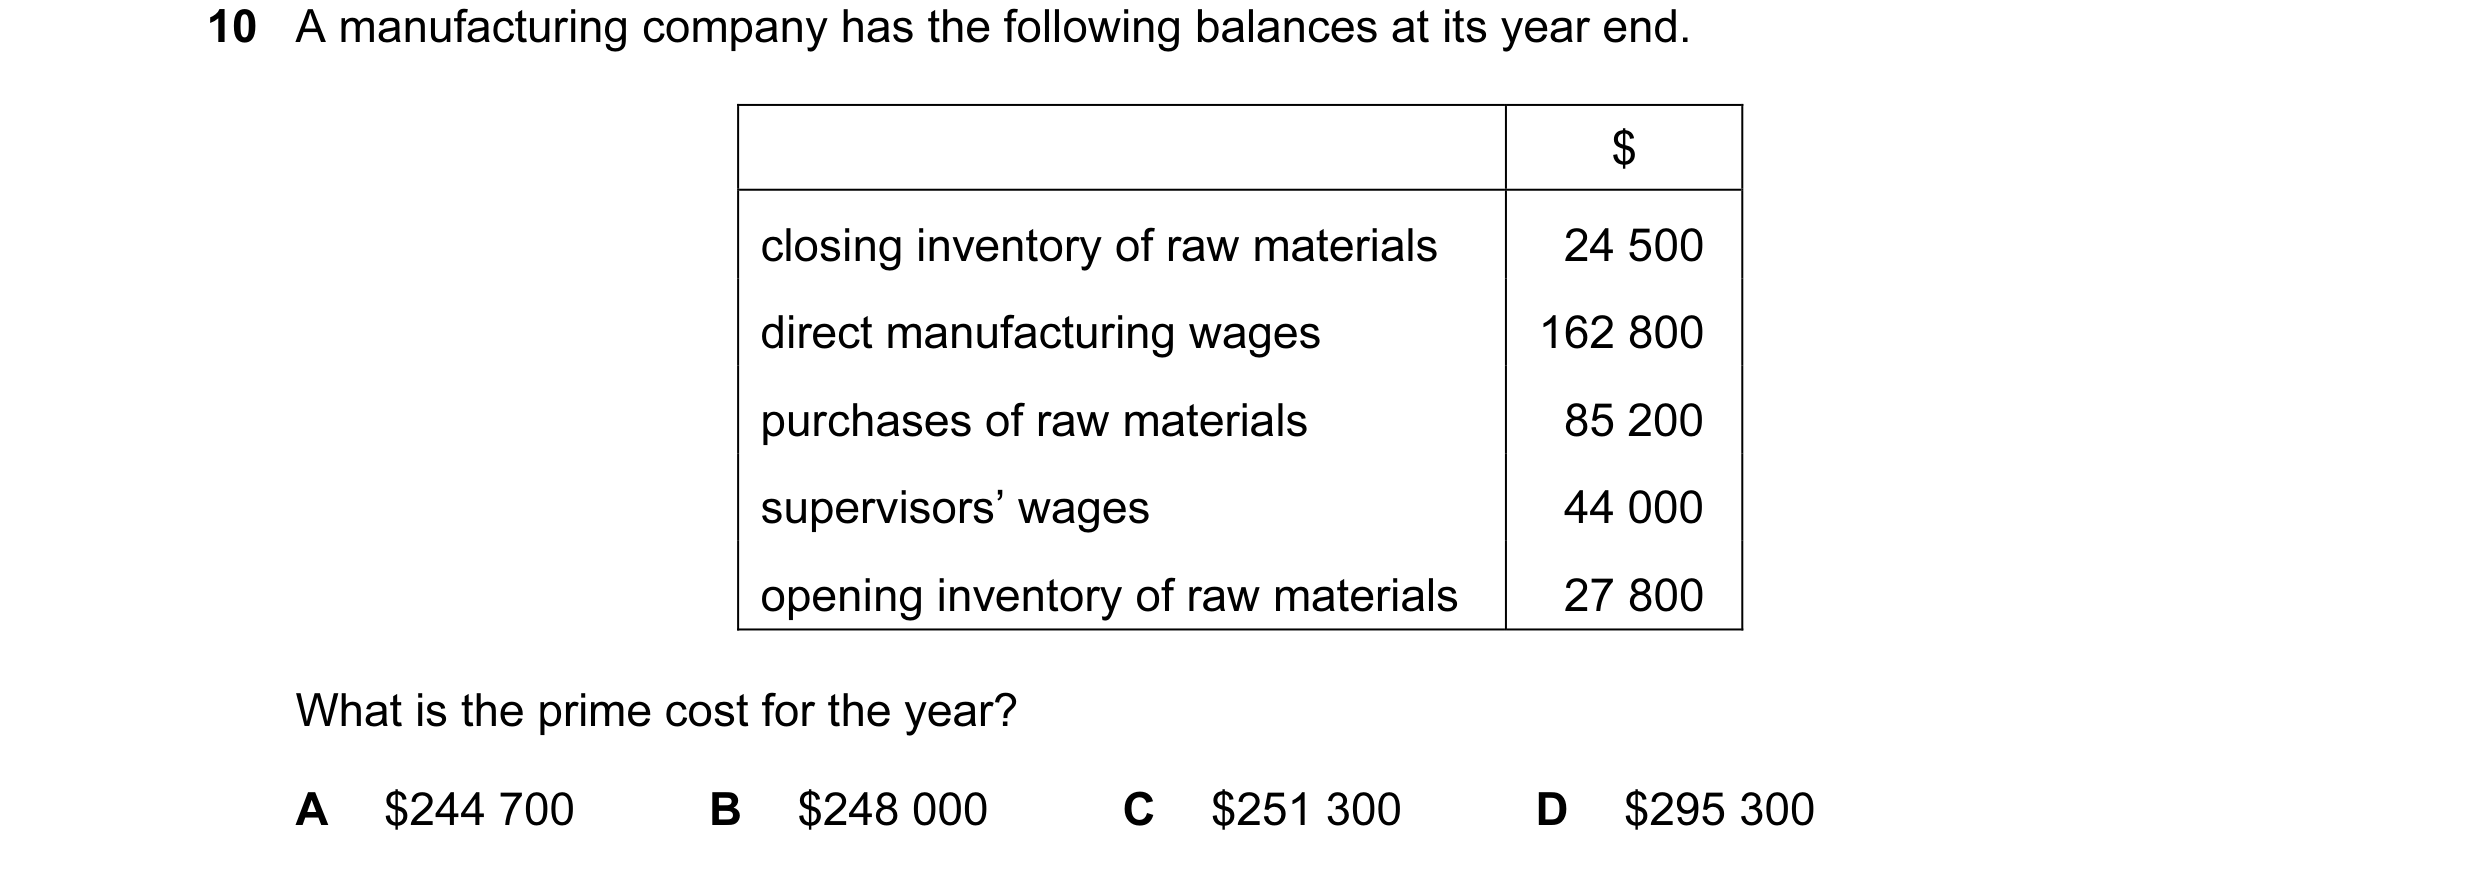
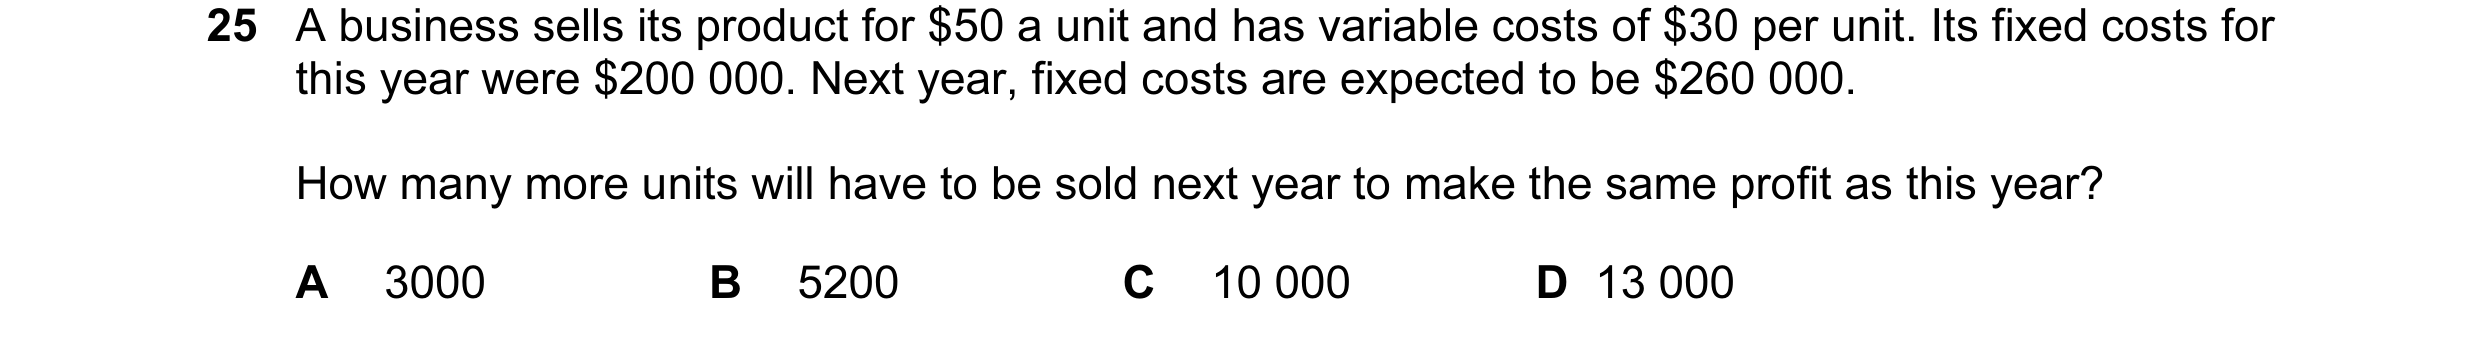 16 / 143
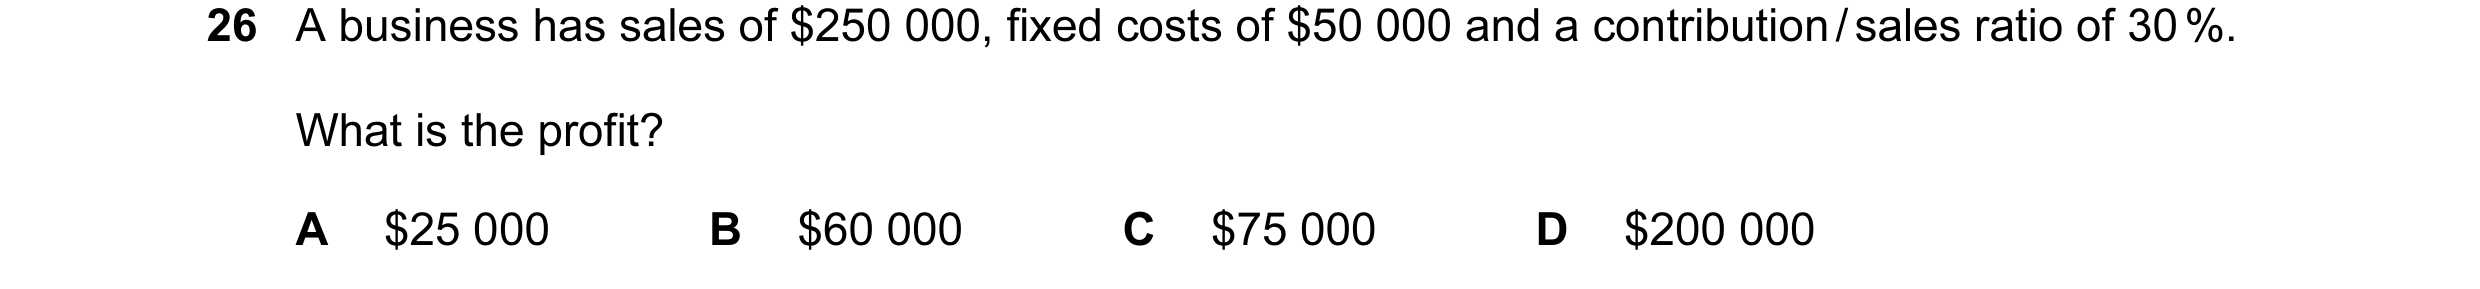
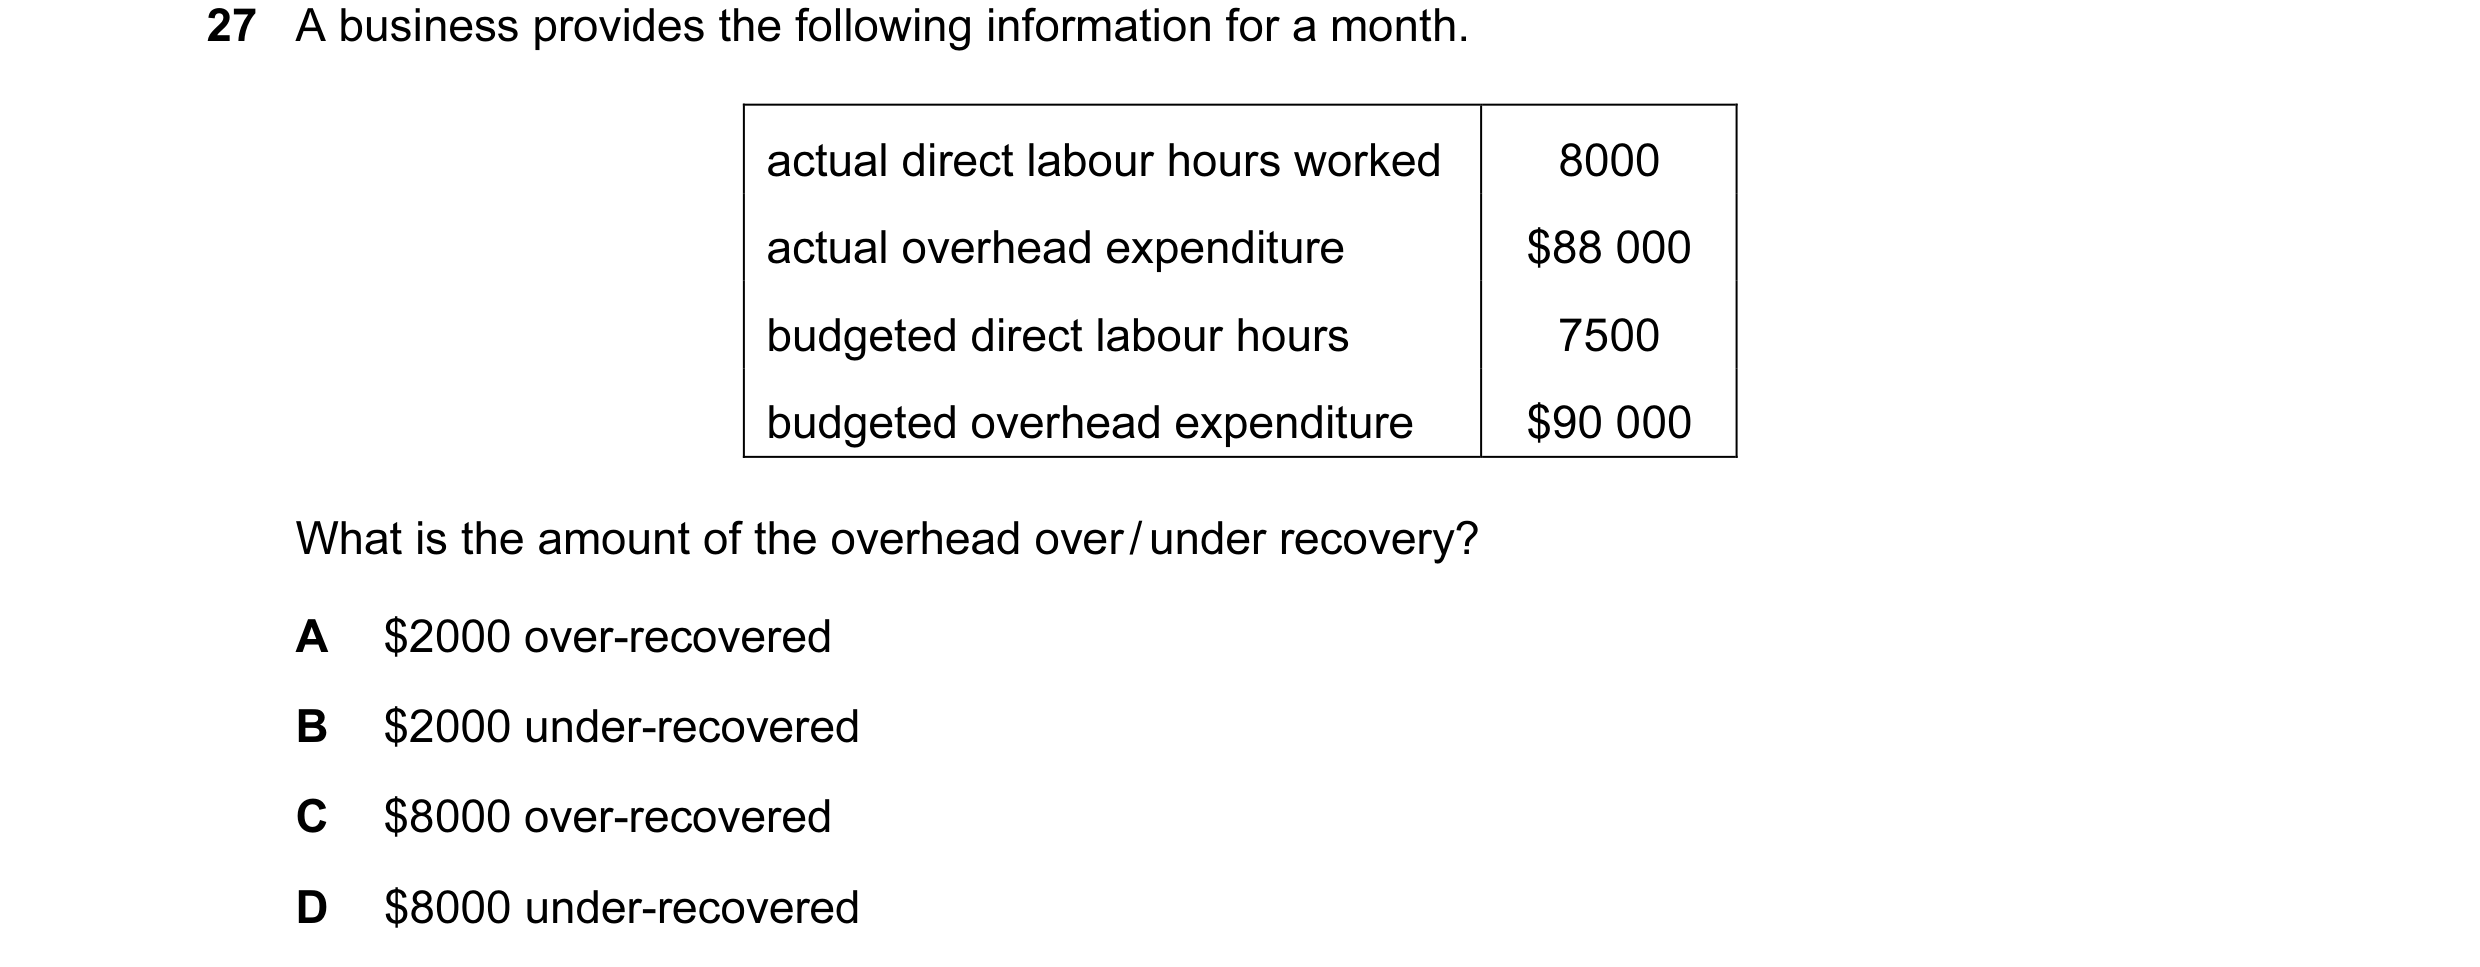
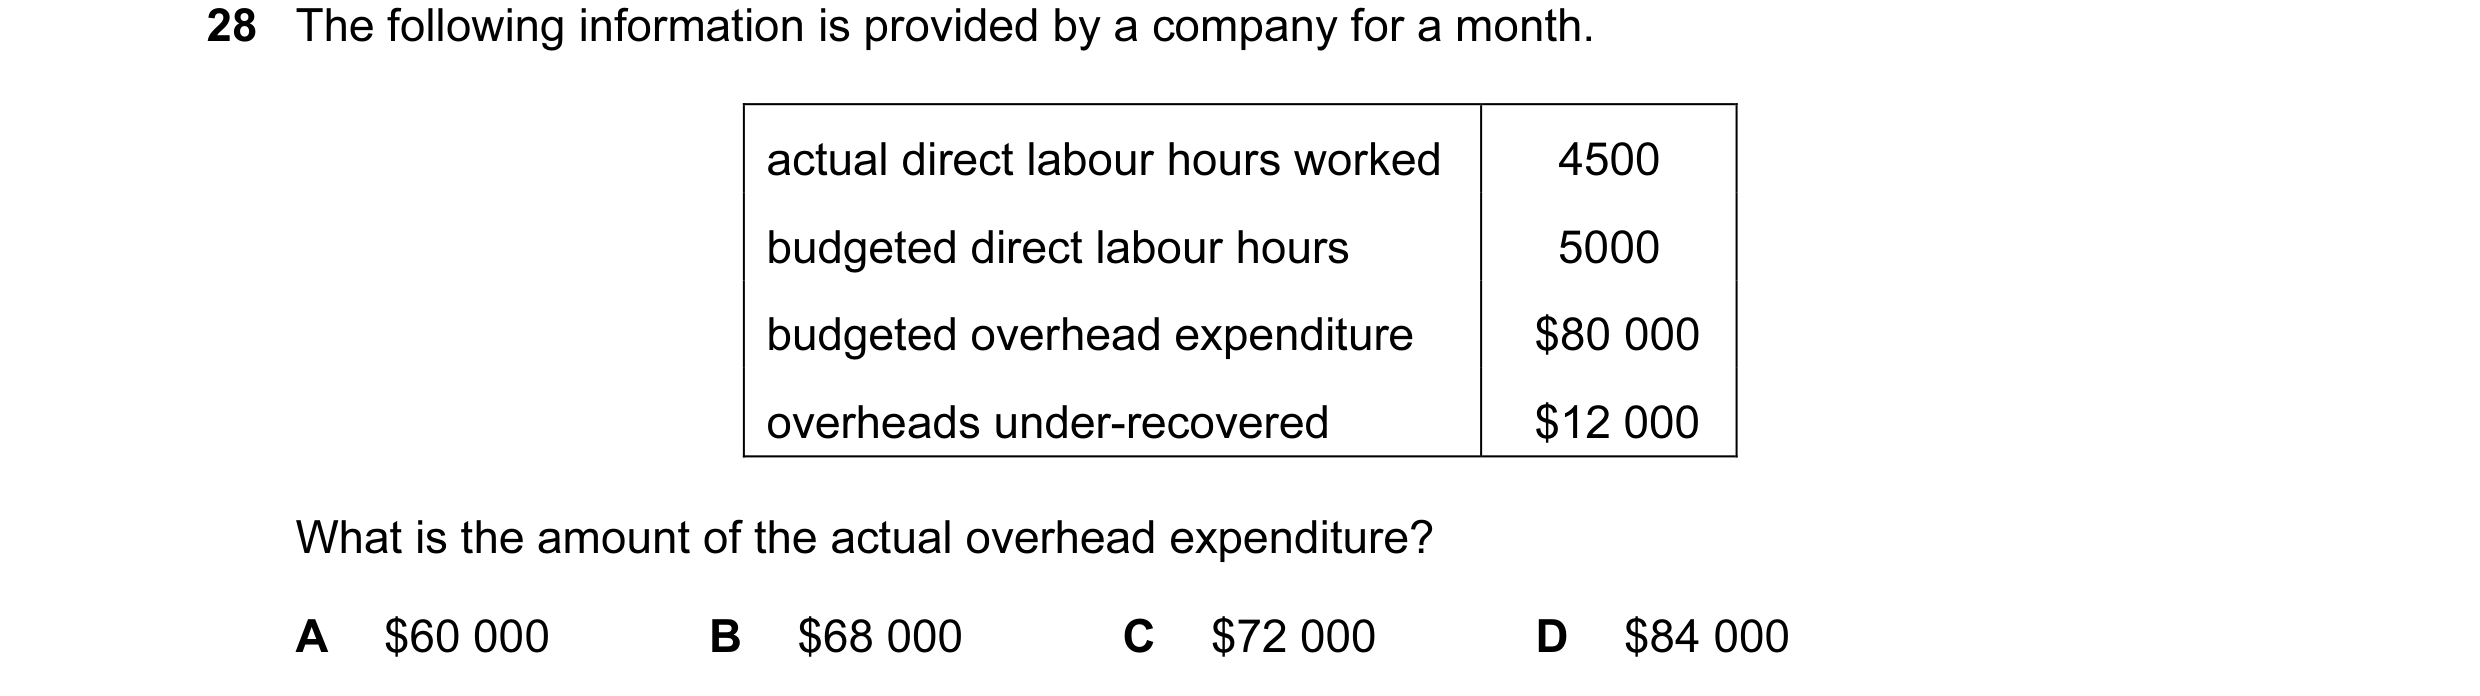 17 / 143
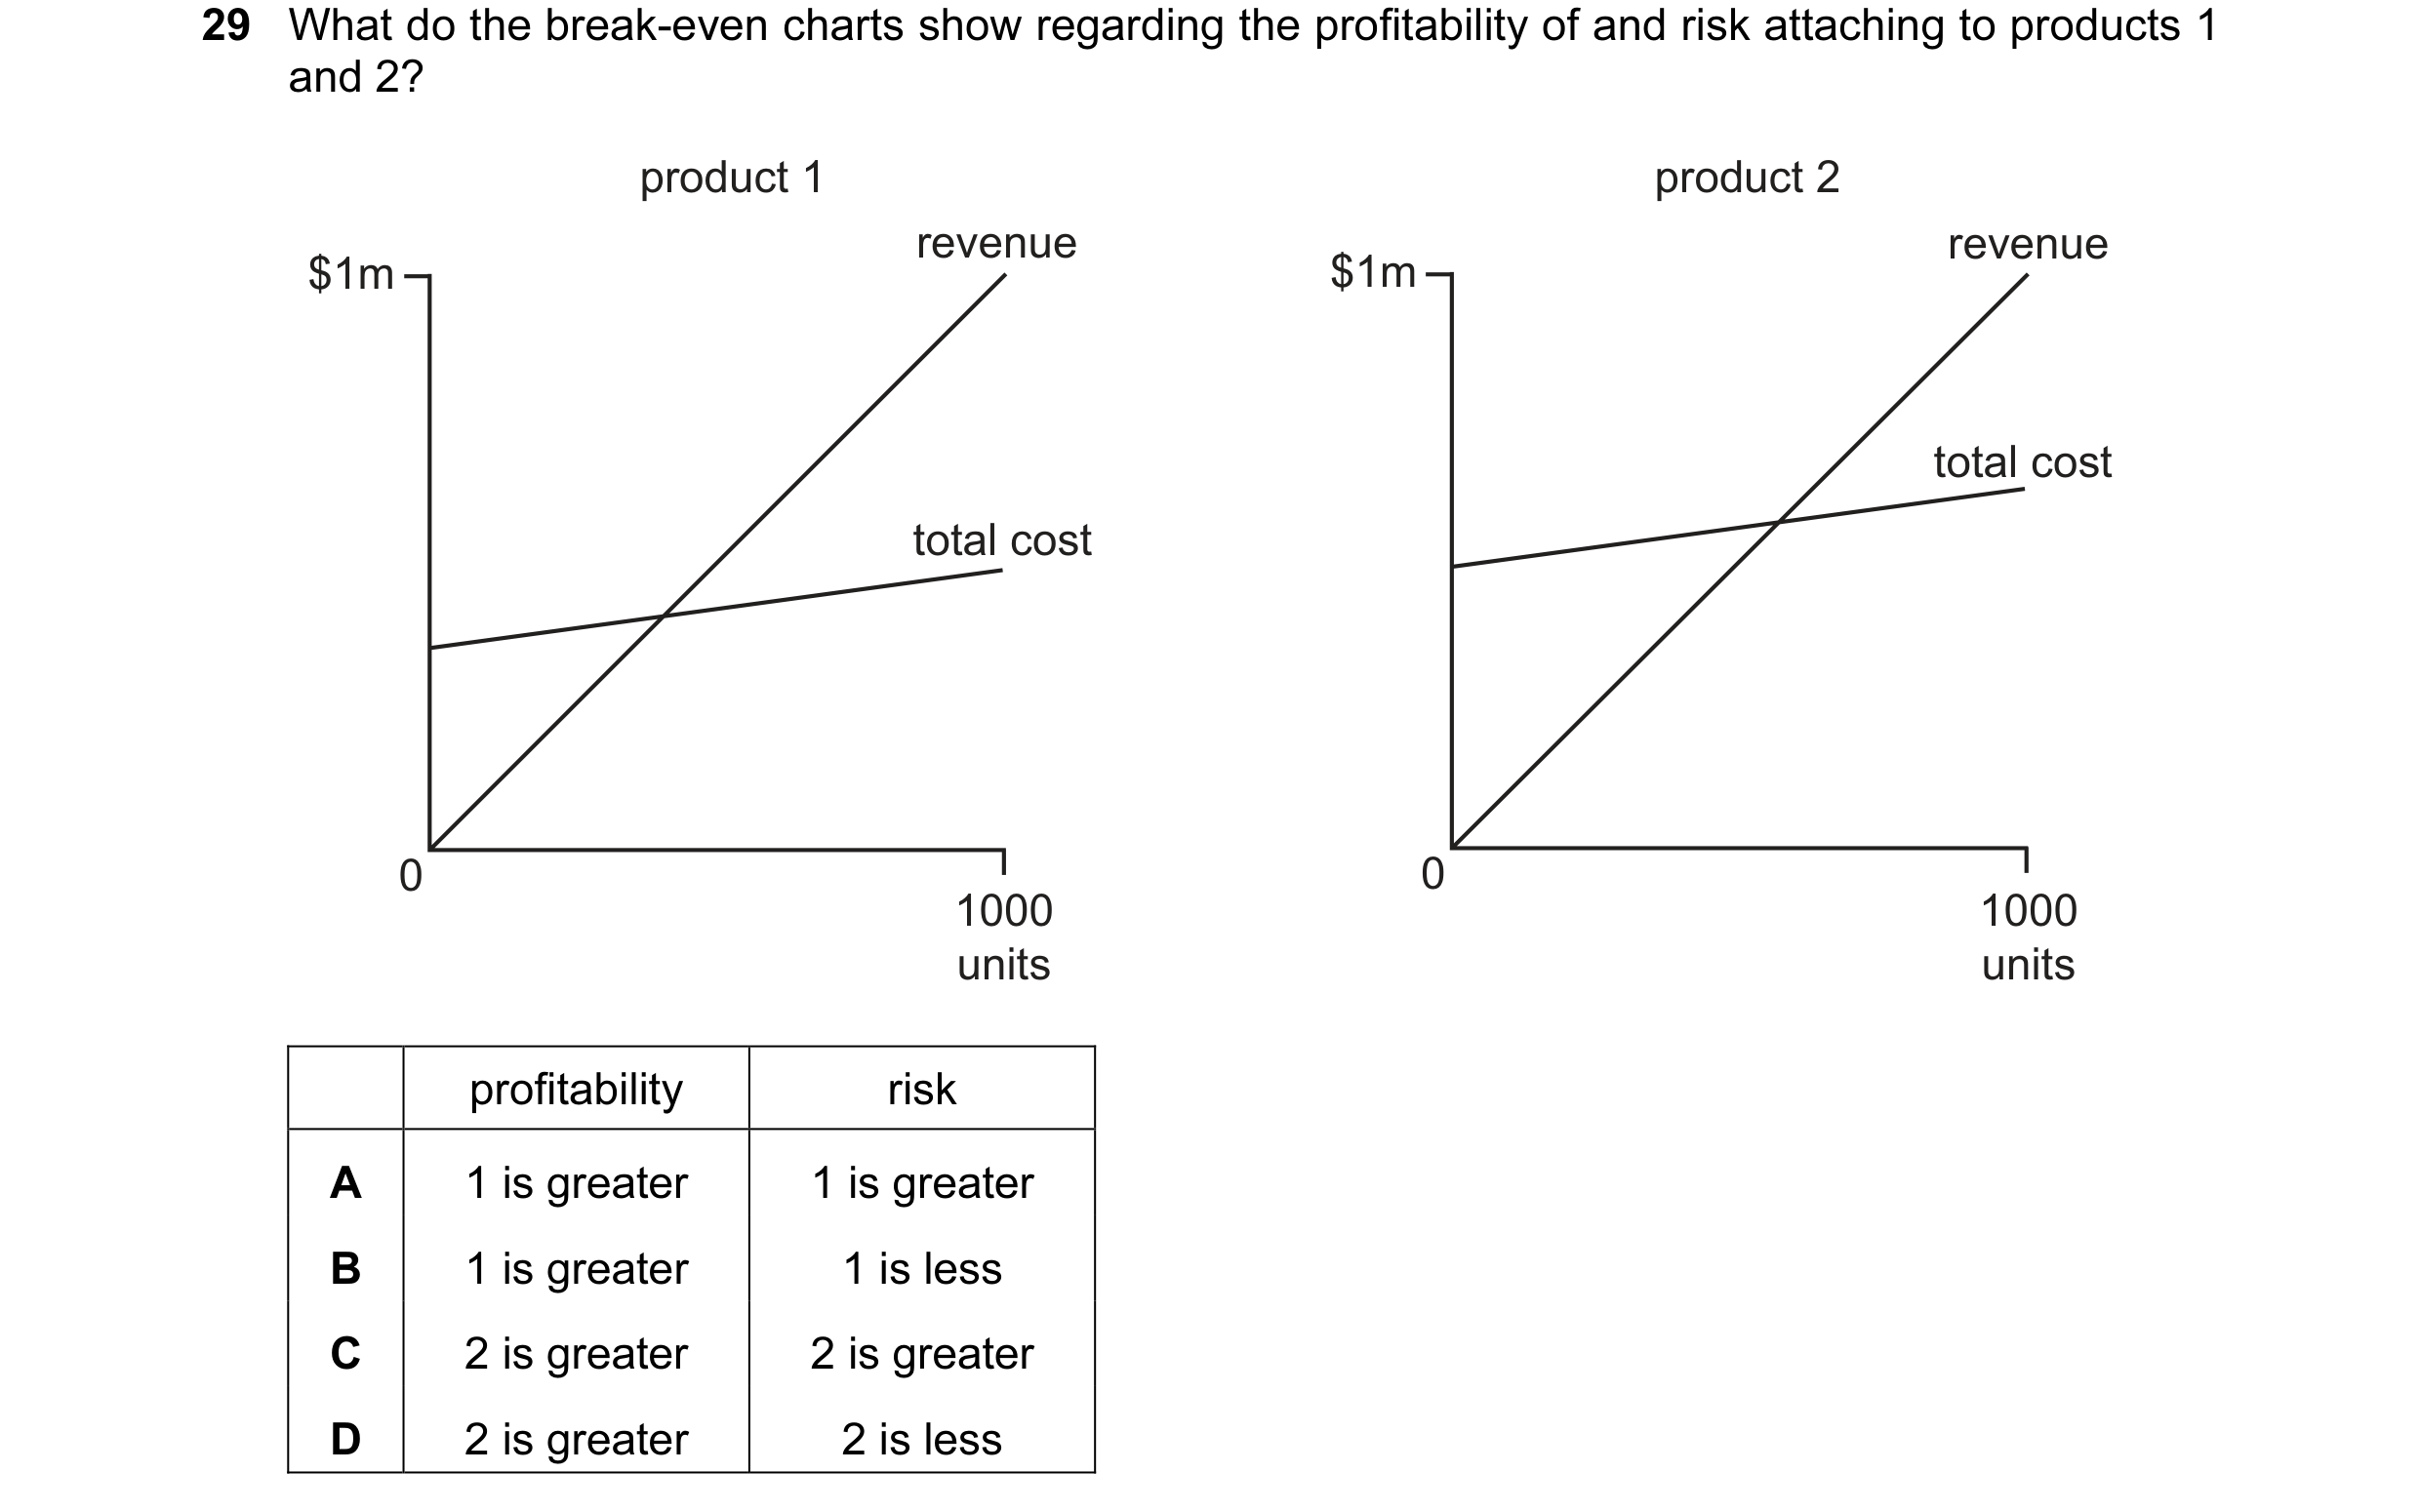
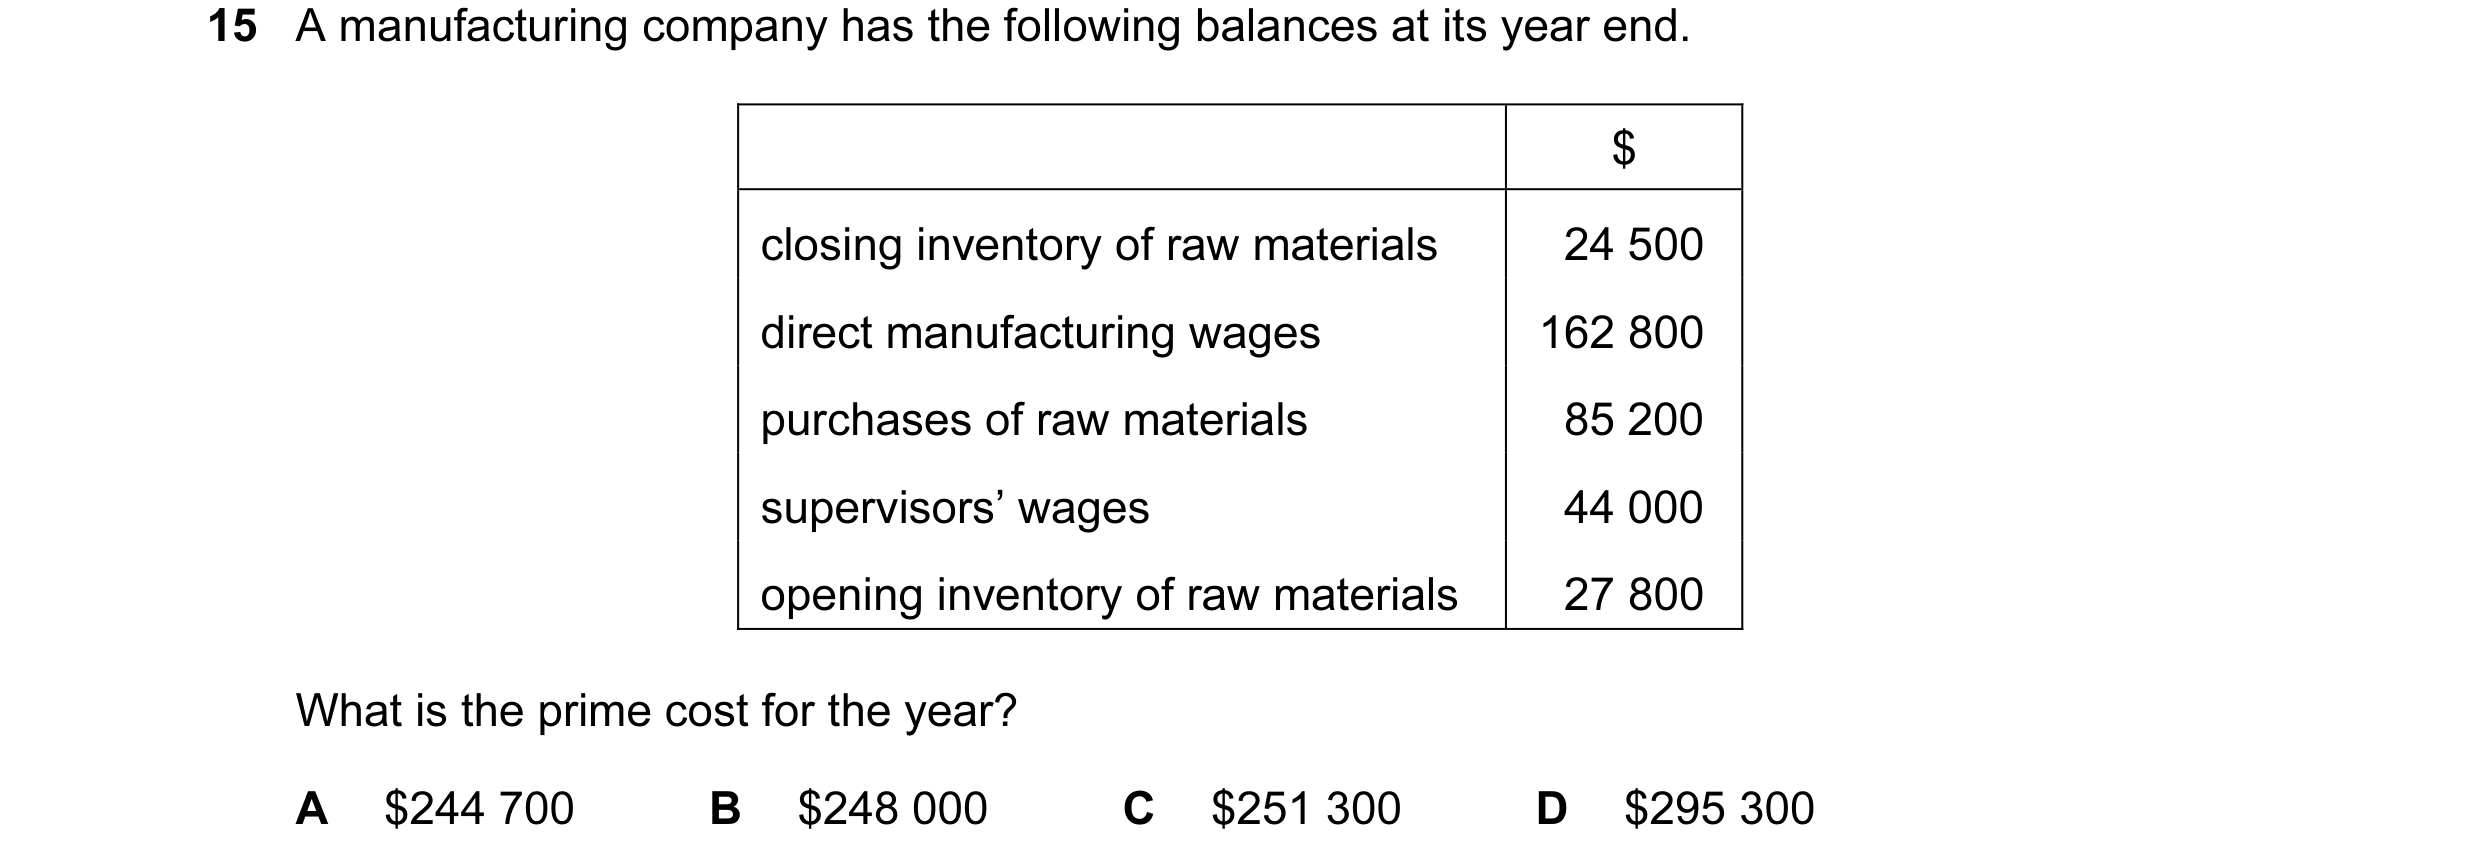
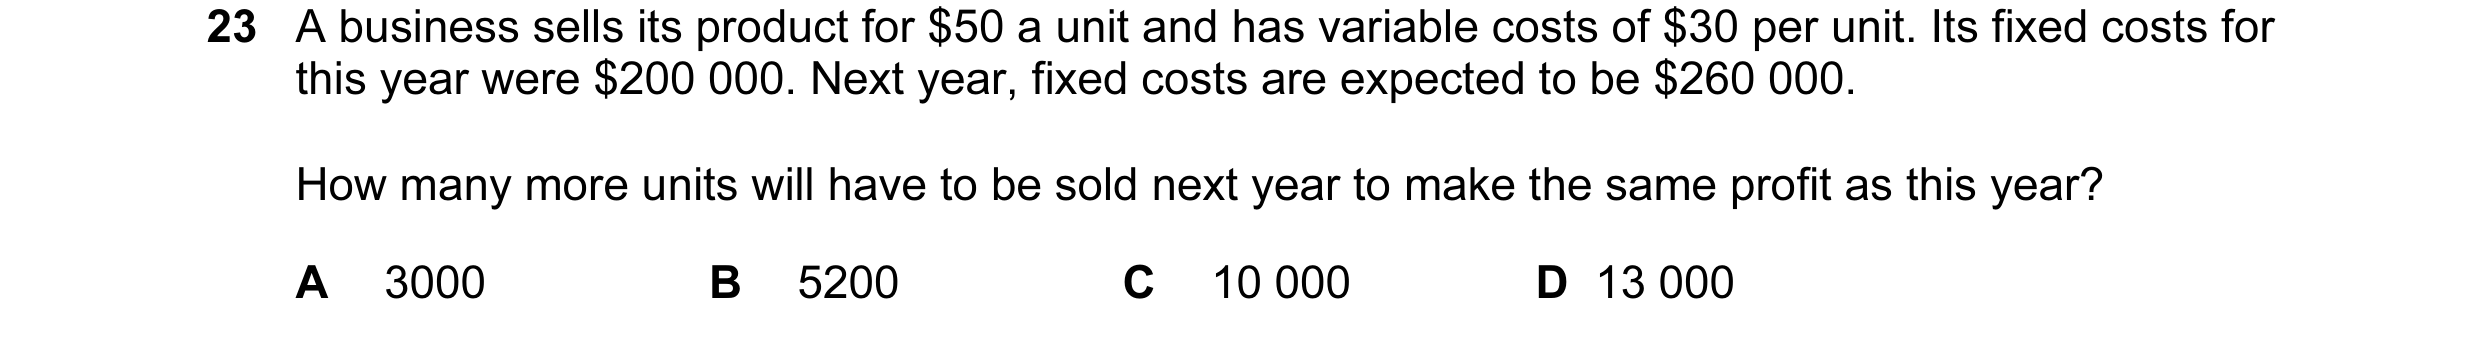
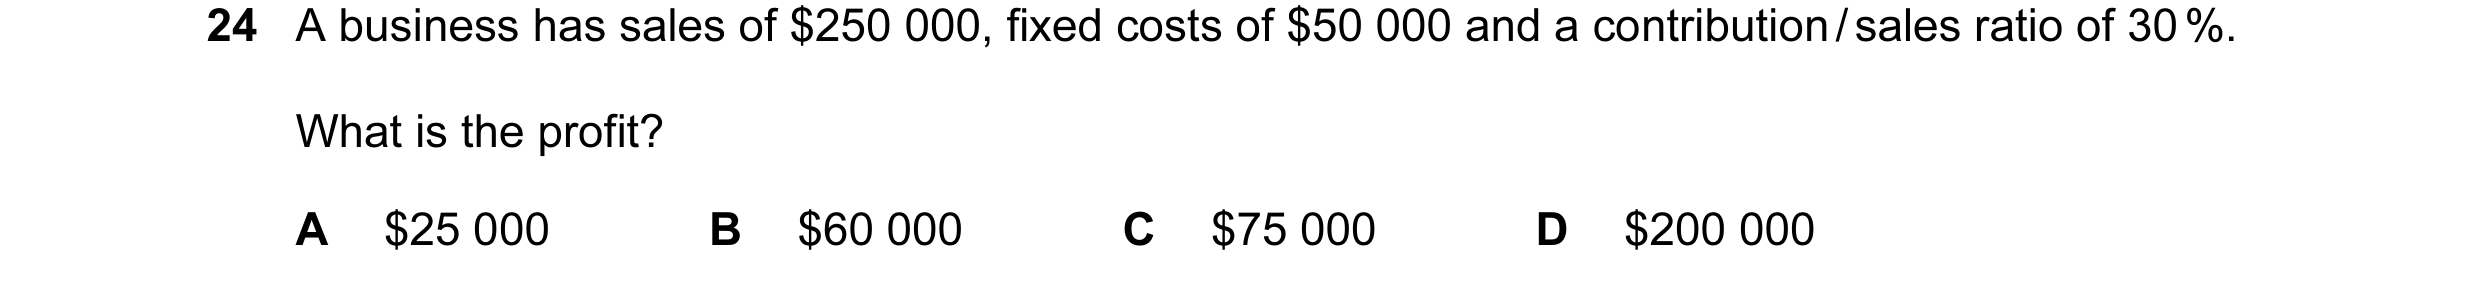 18 / 143
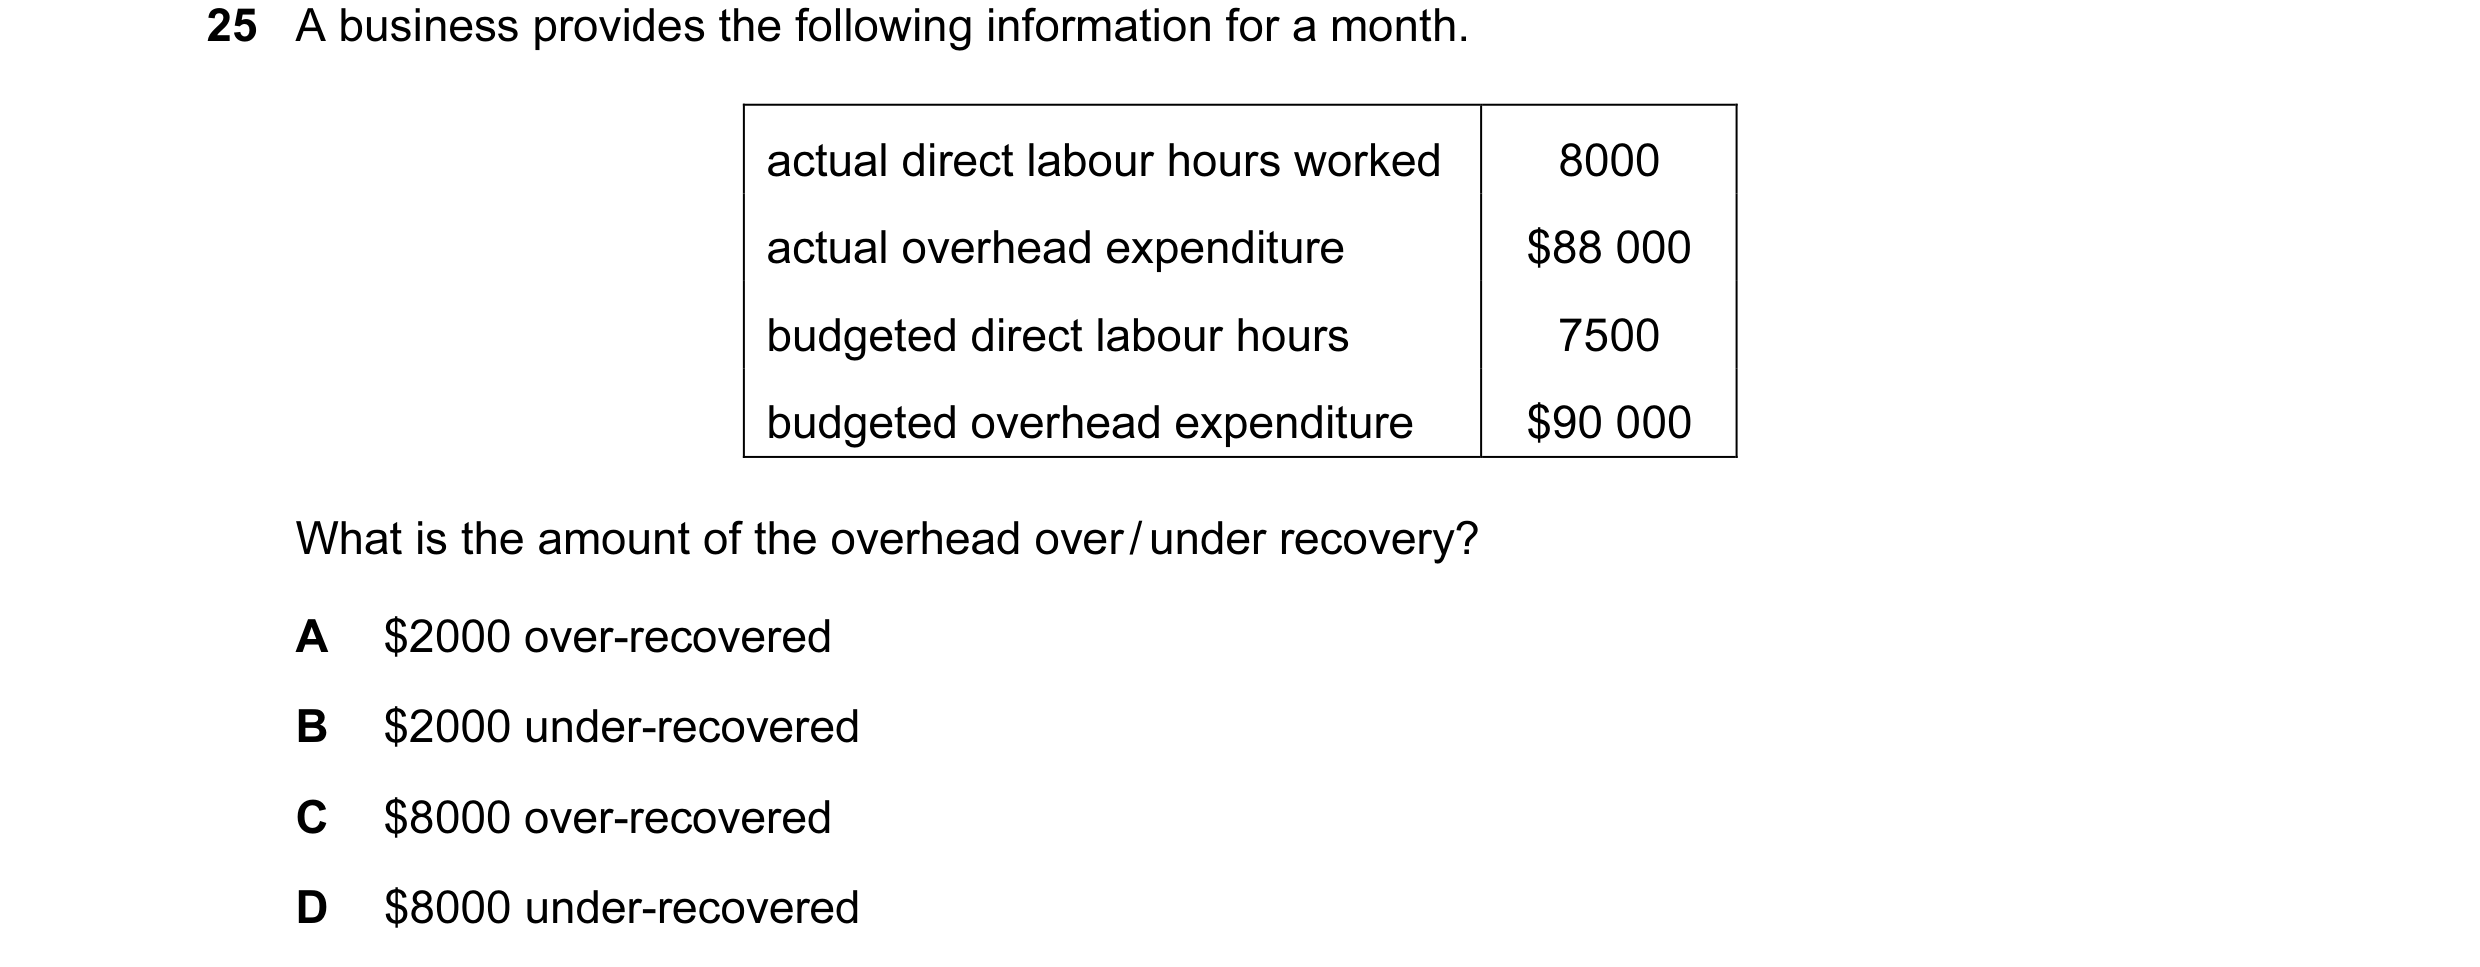
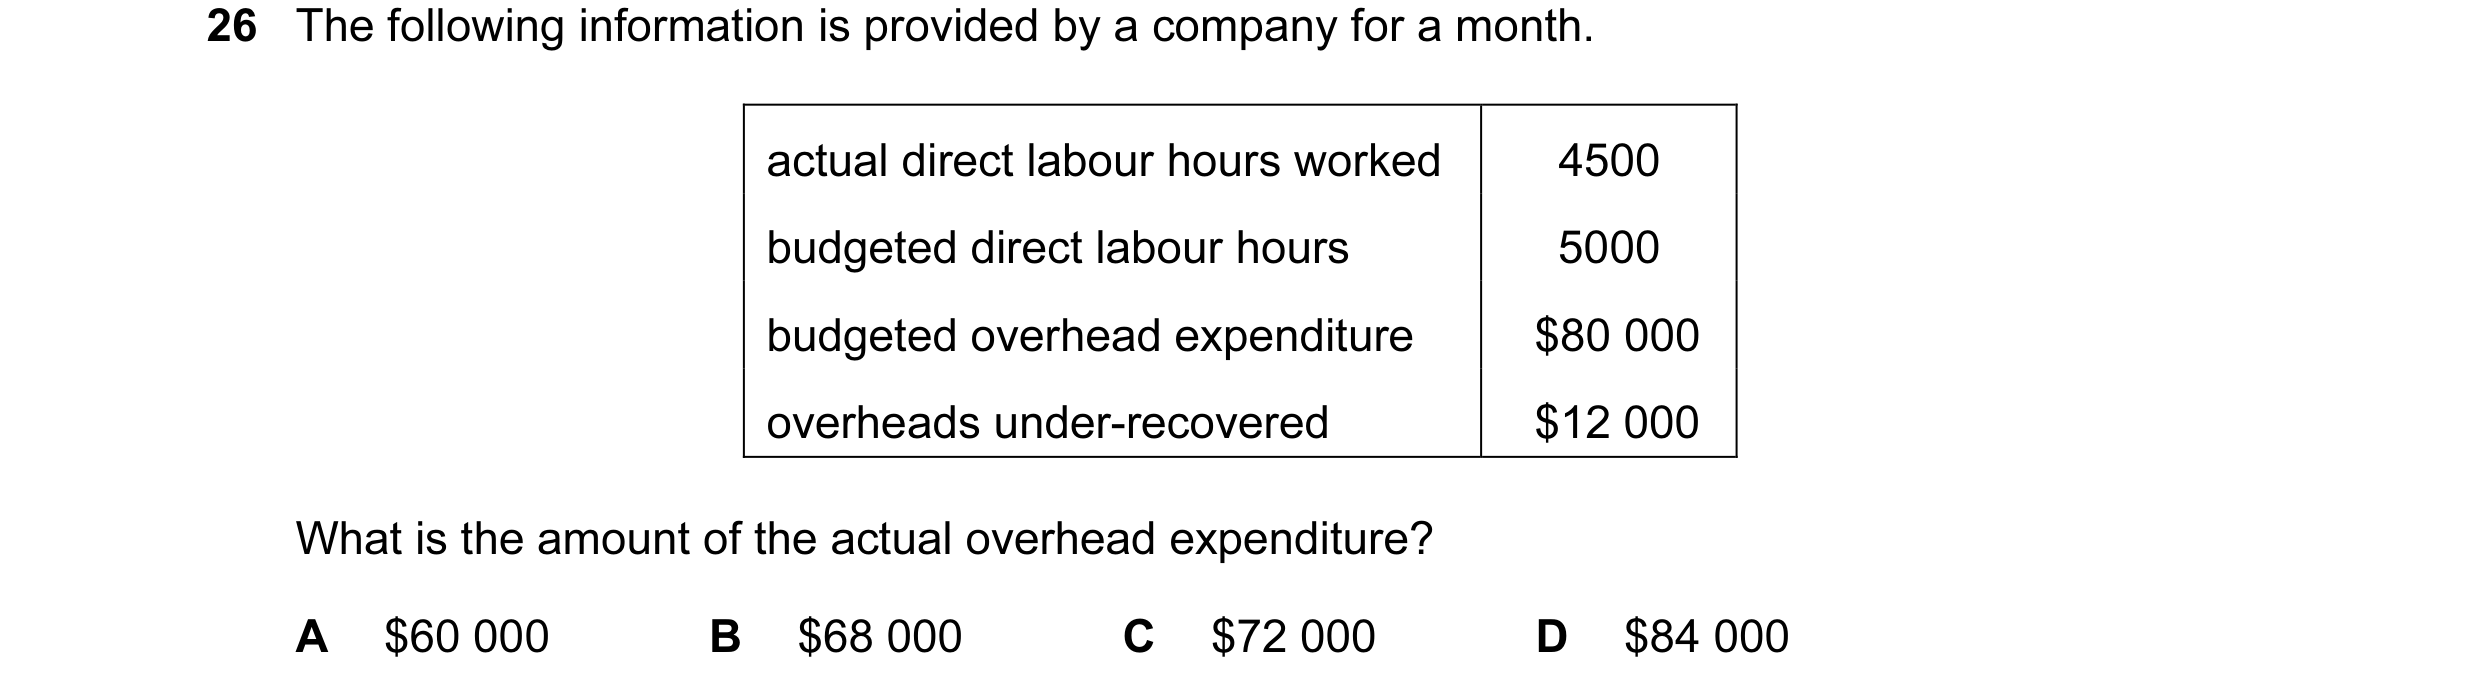
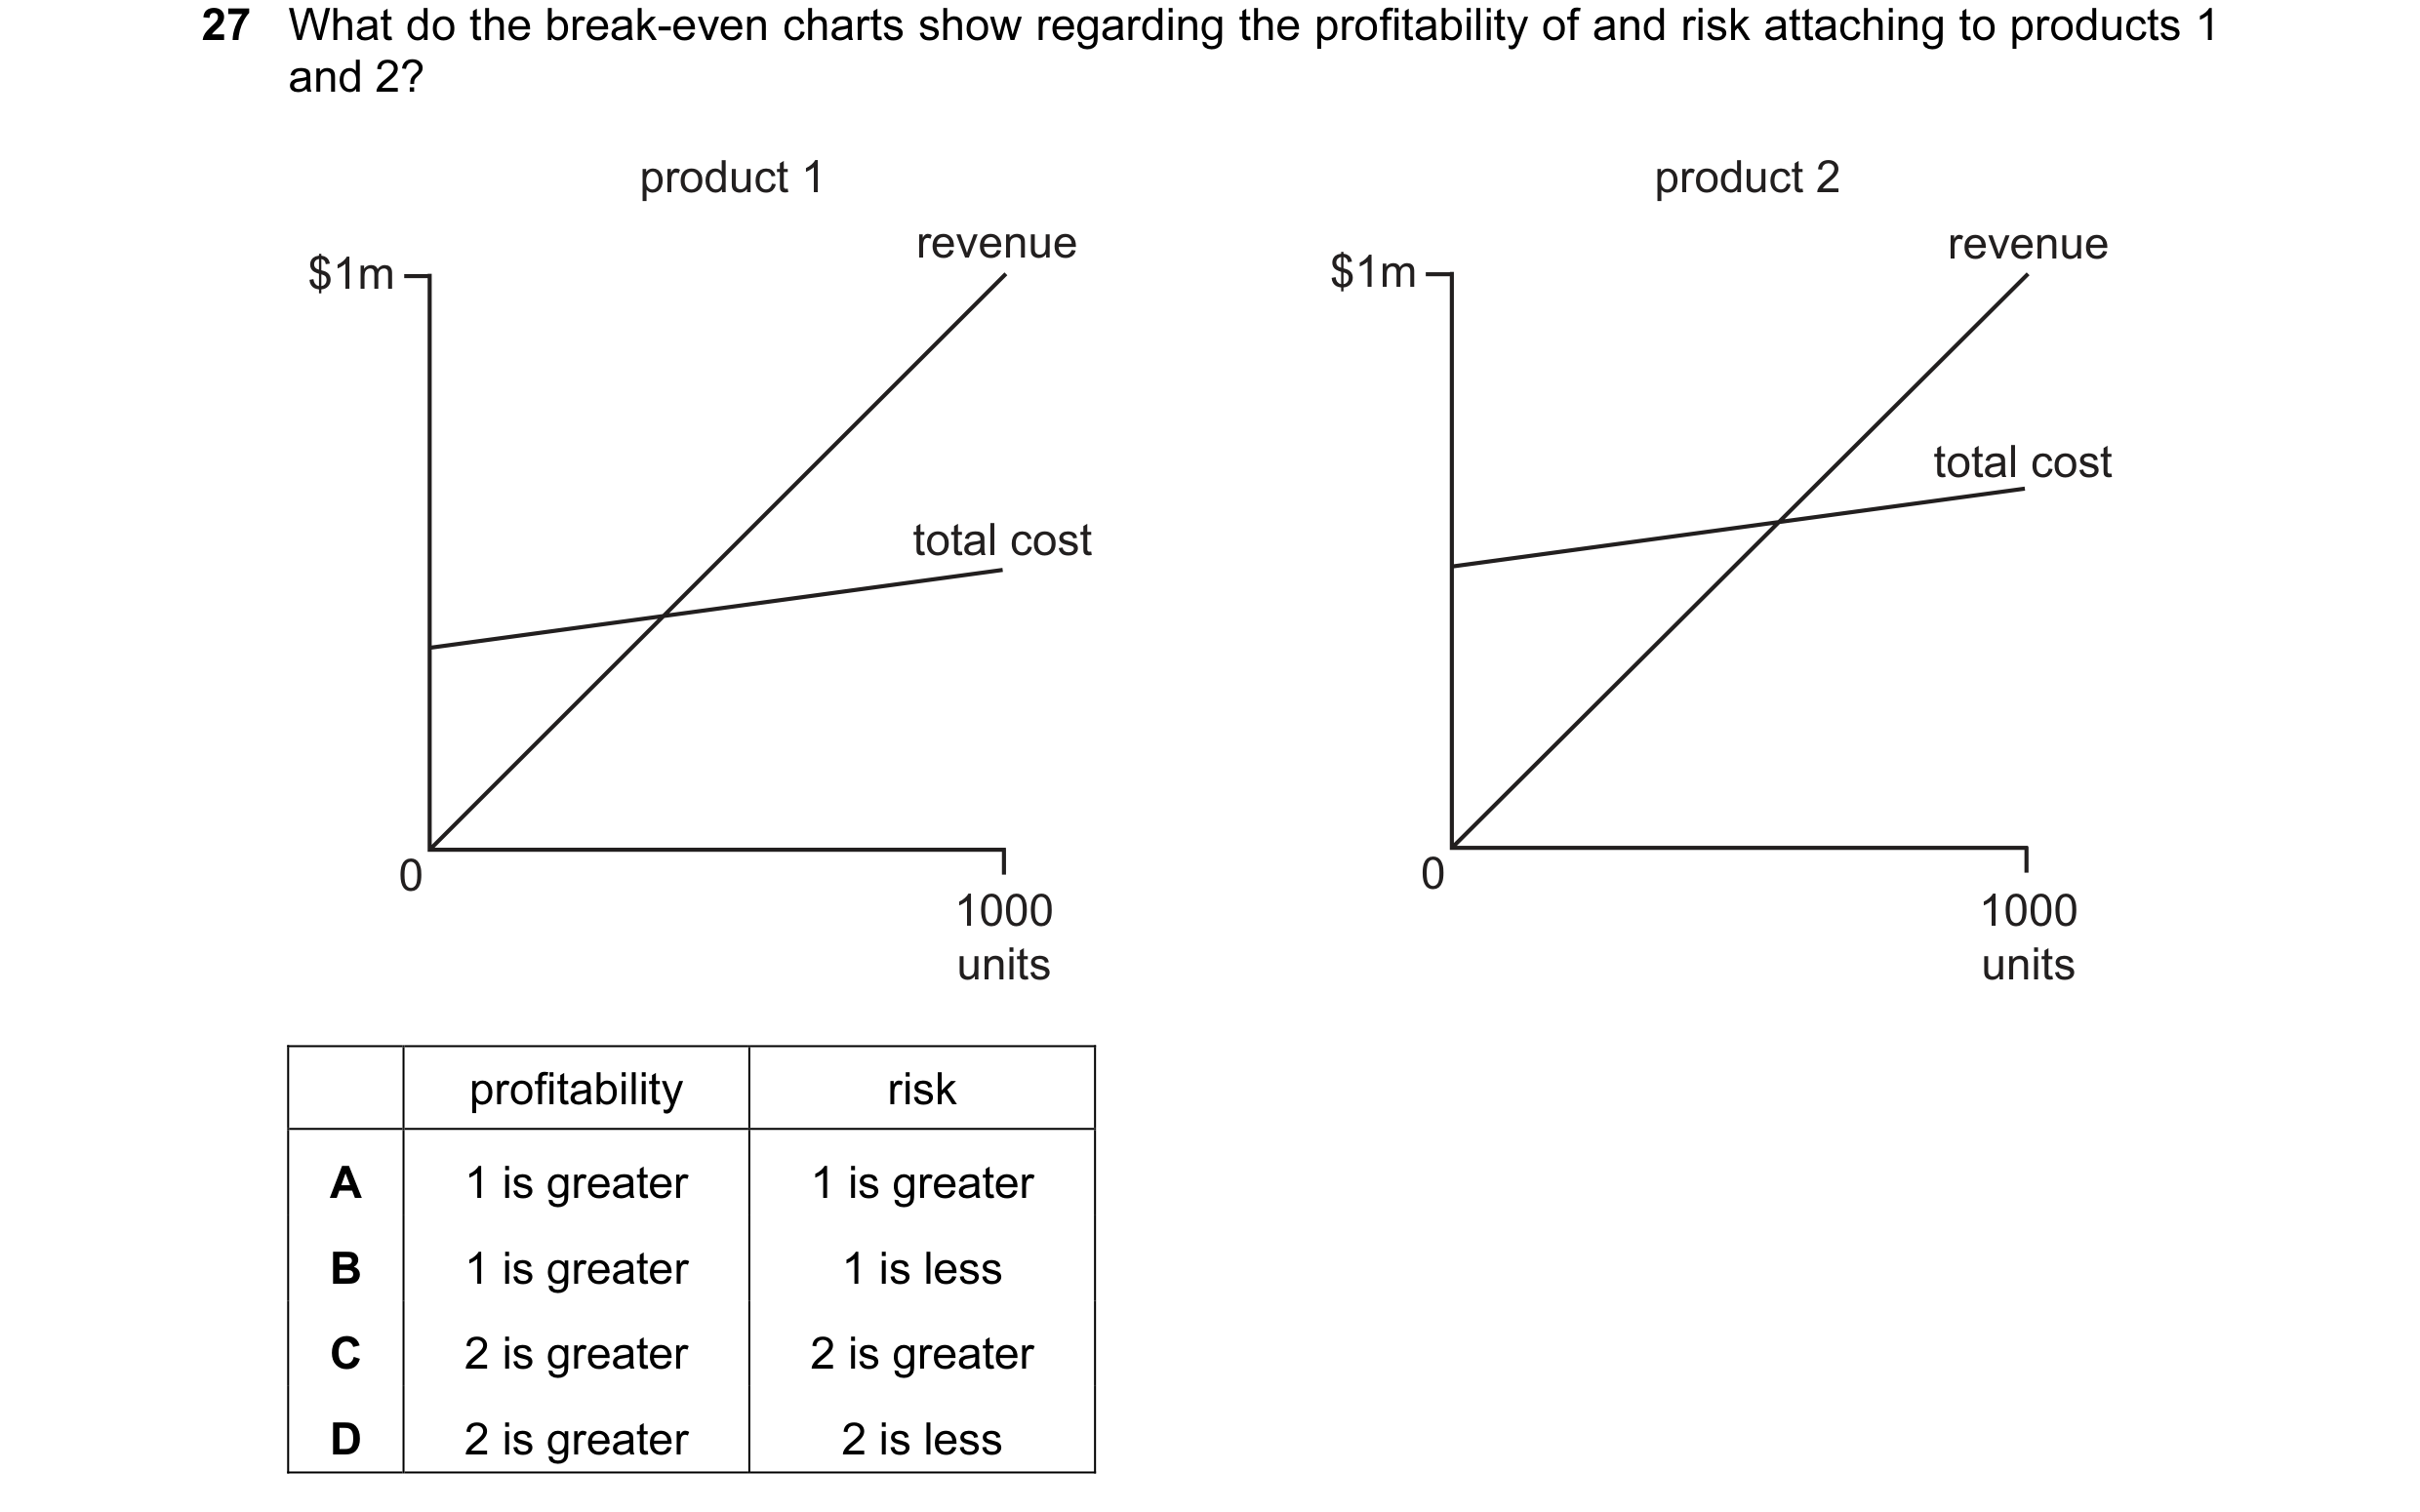 19 / 143
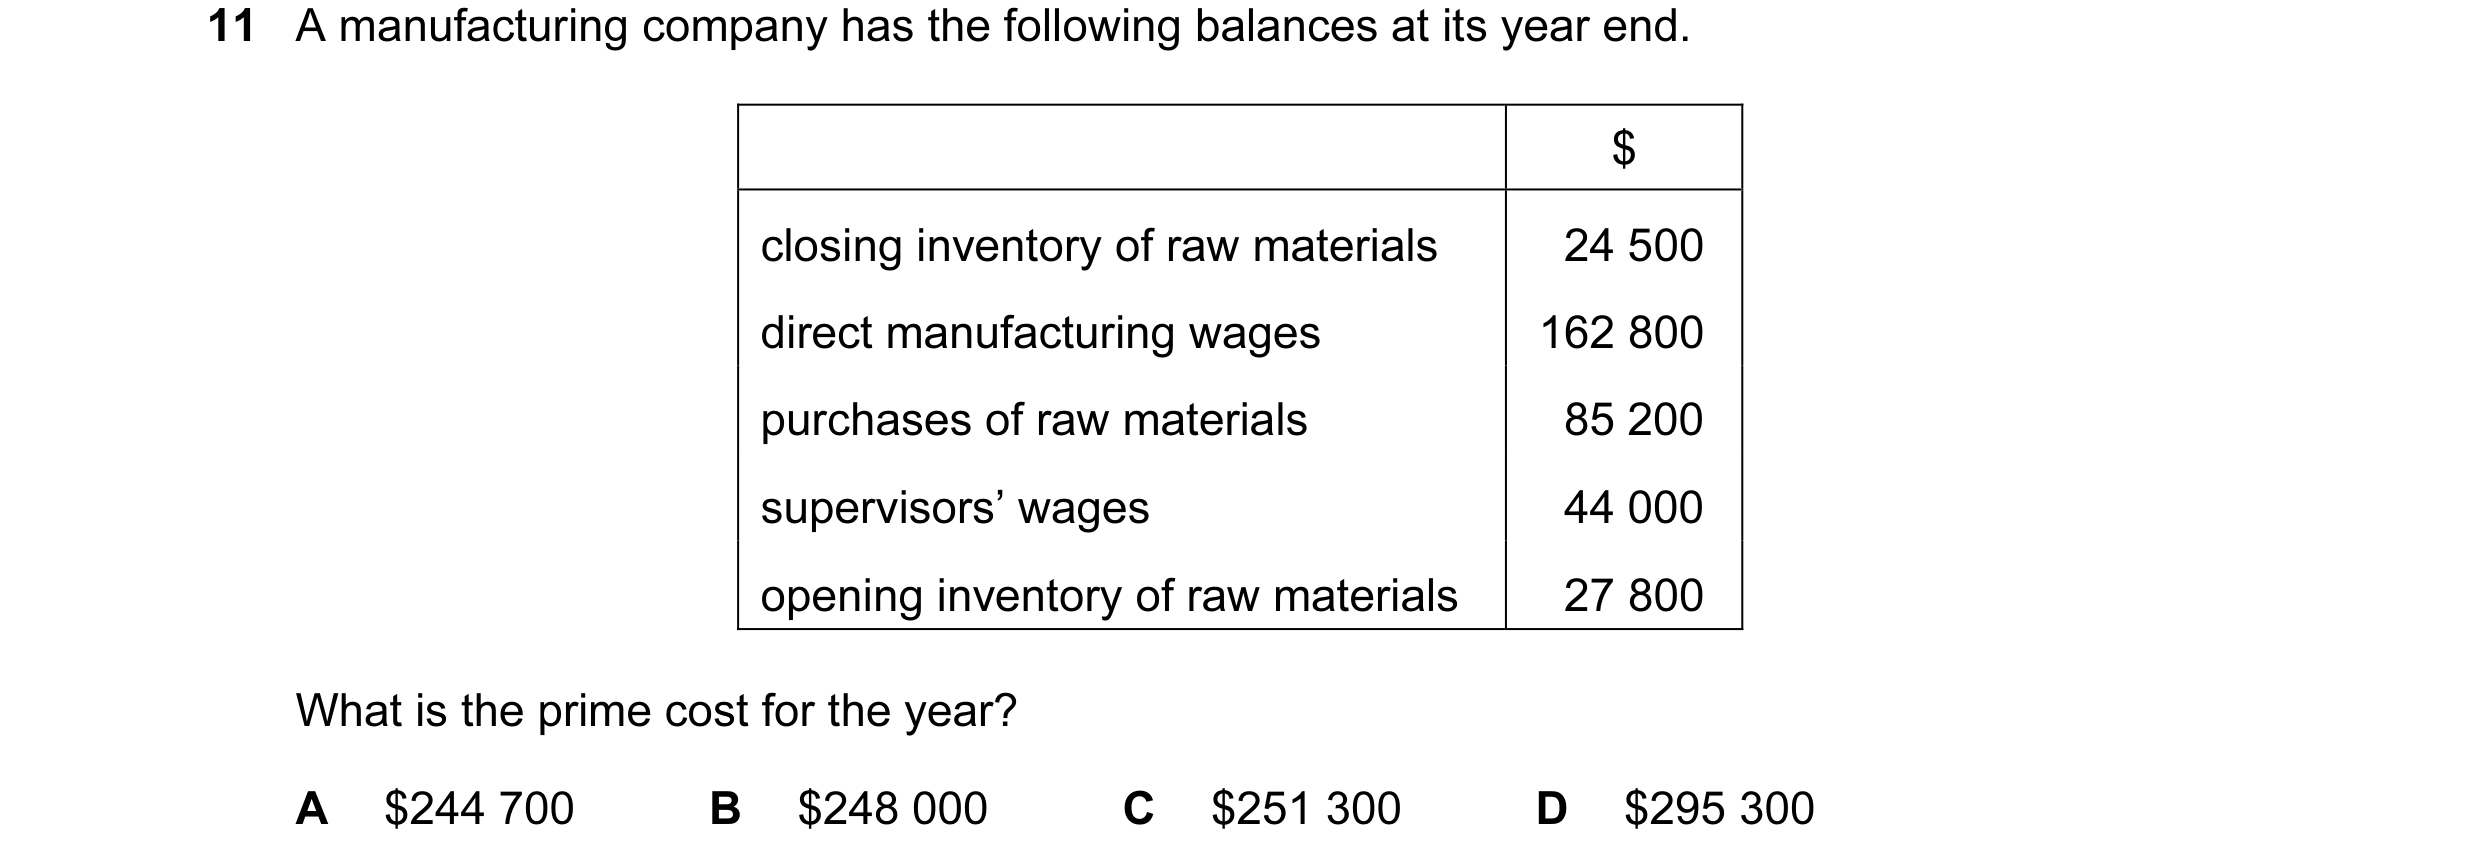
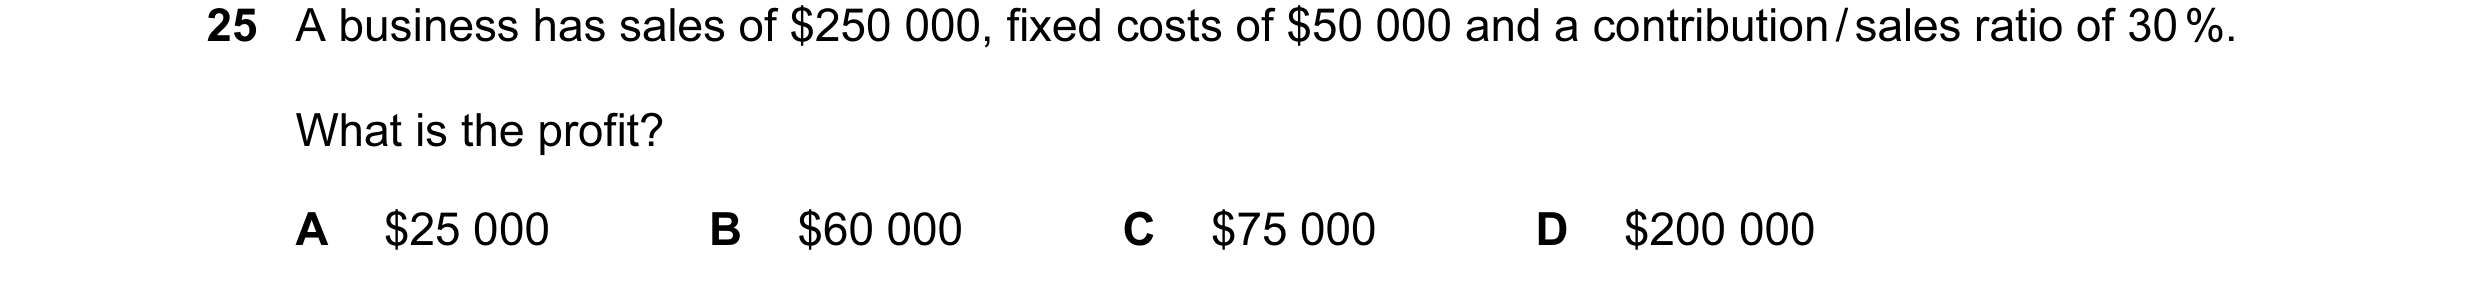
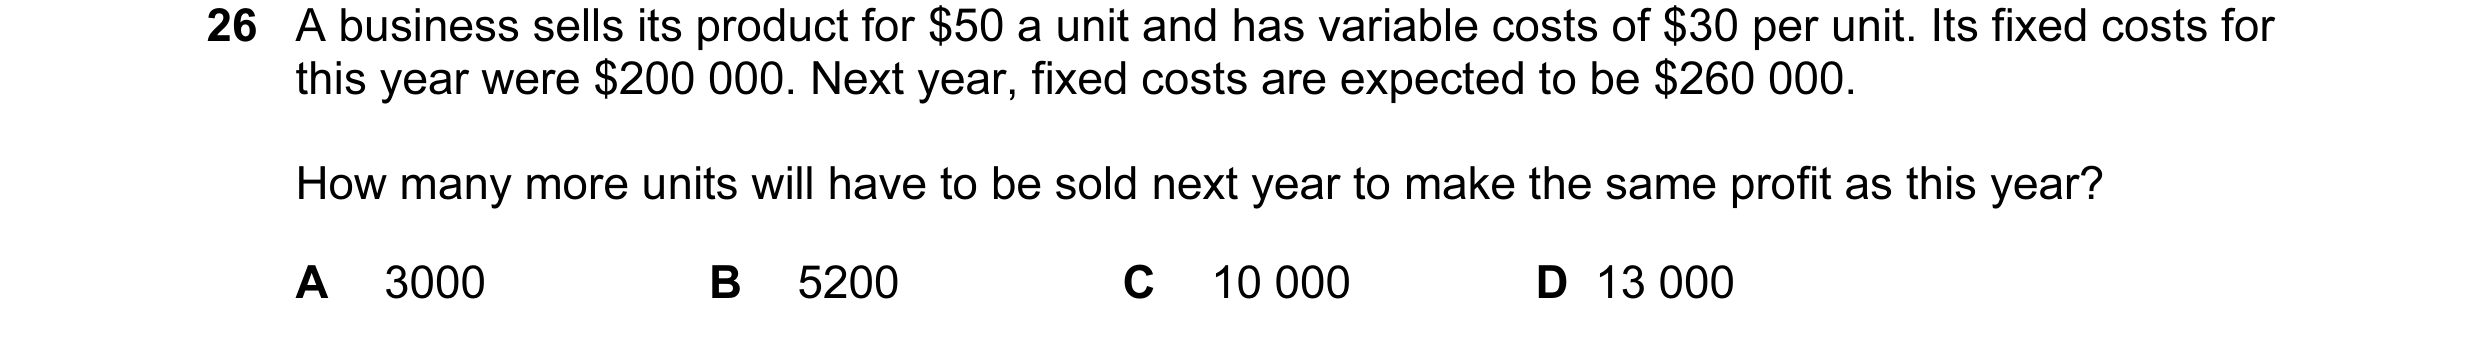
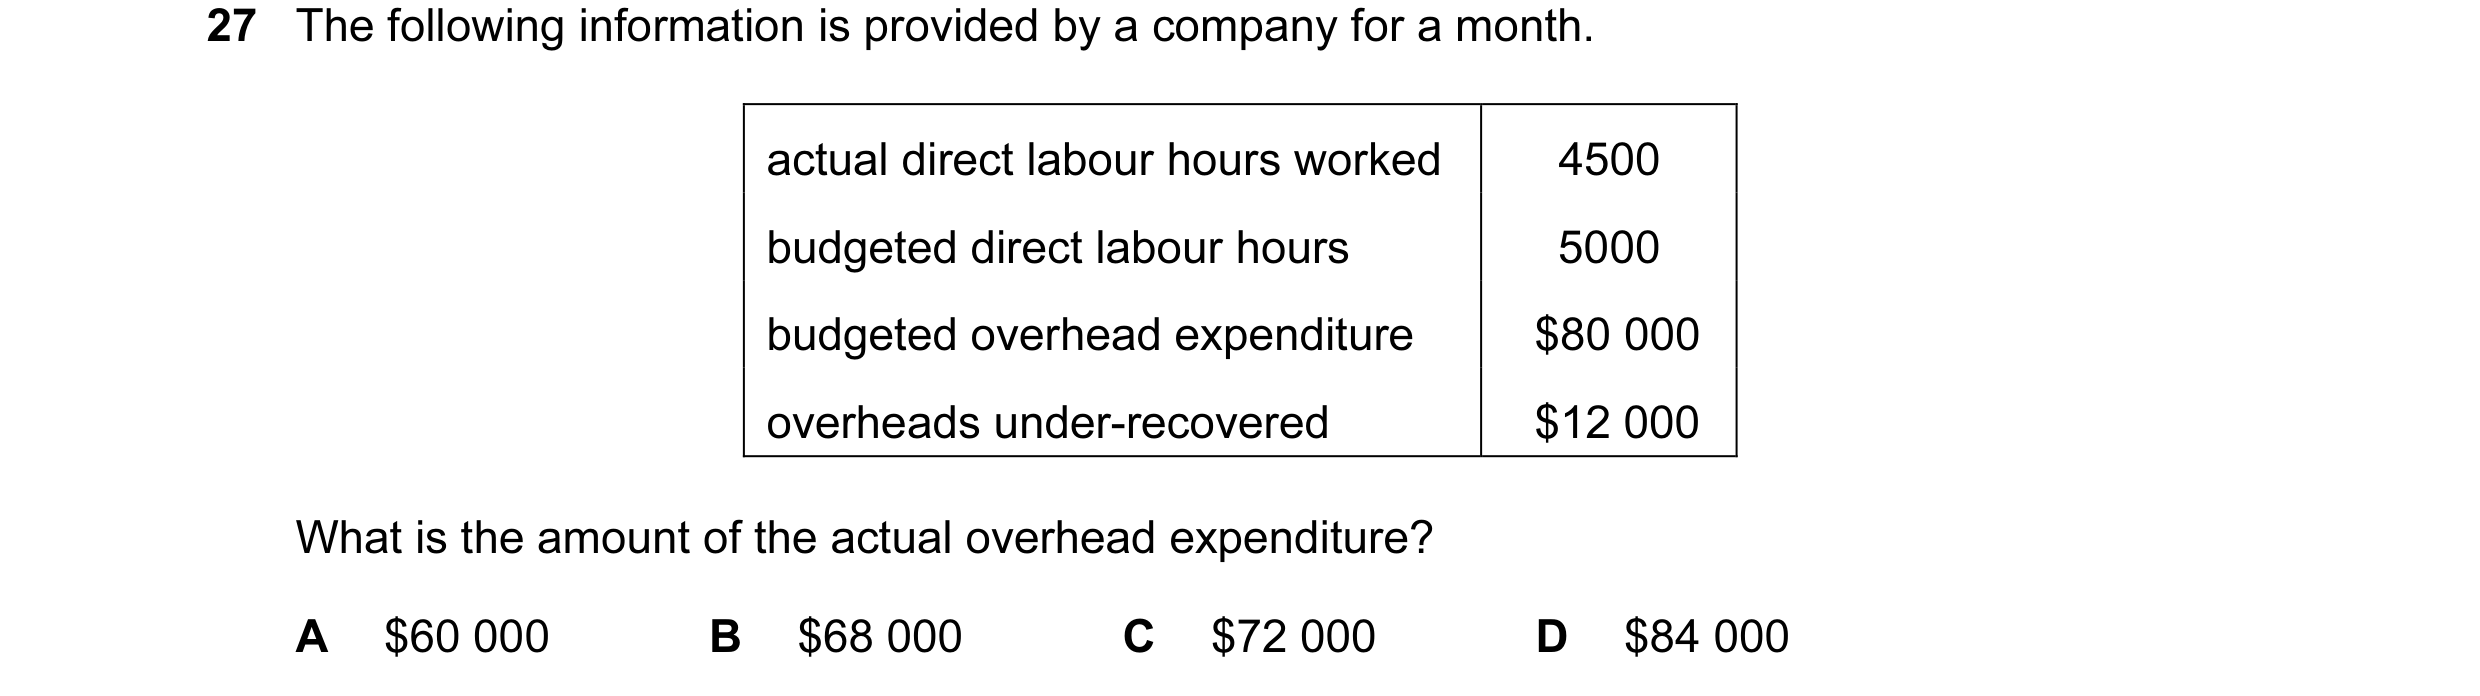
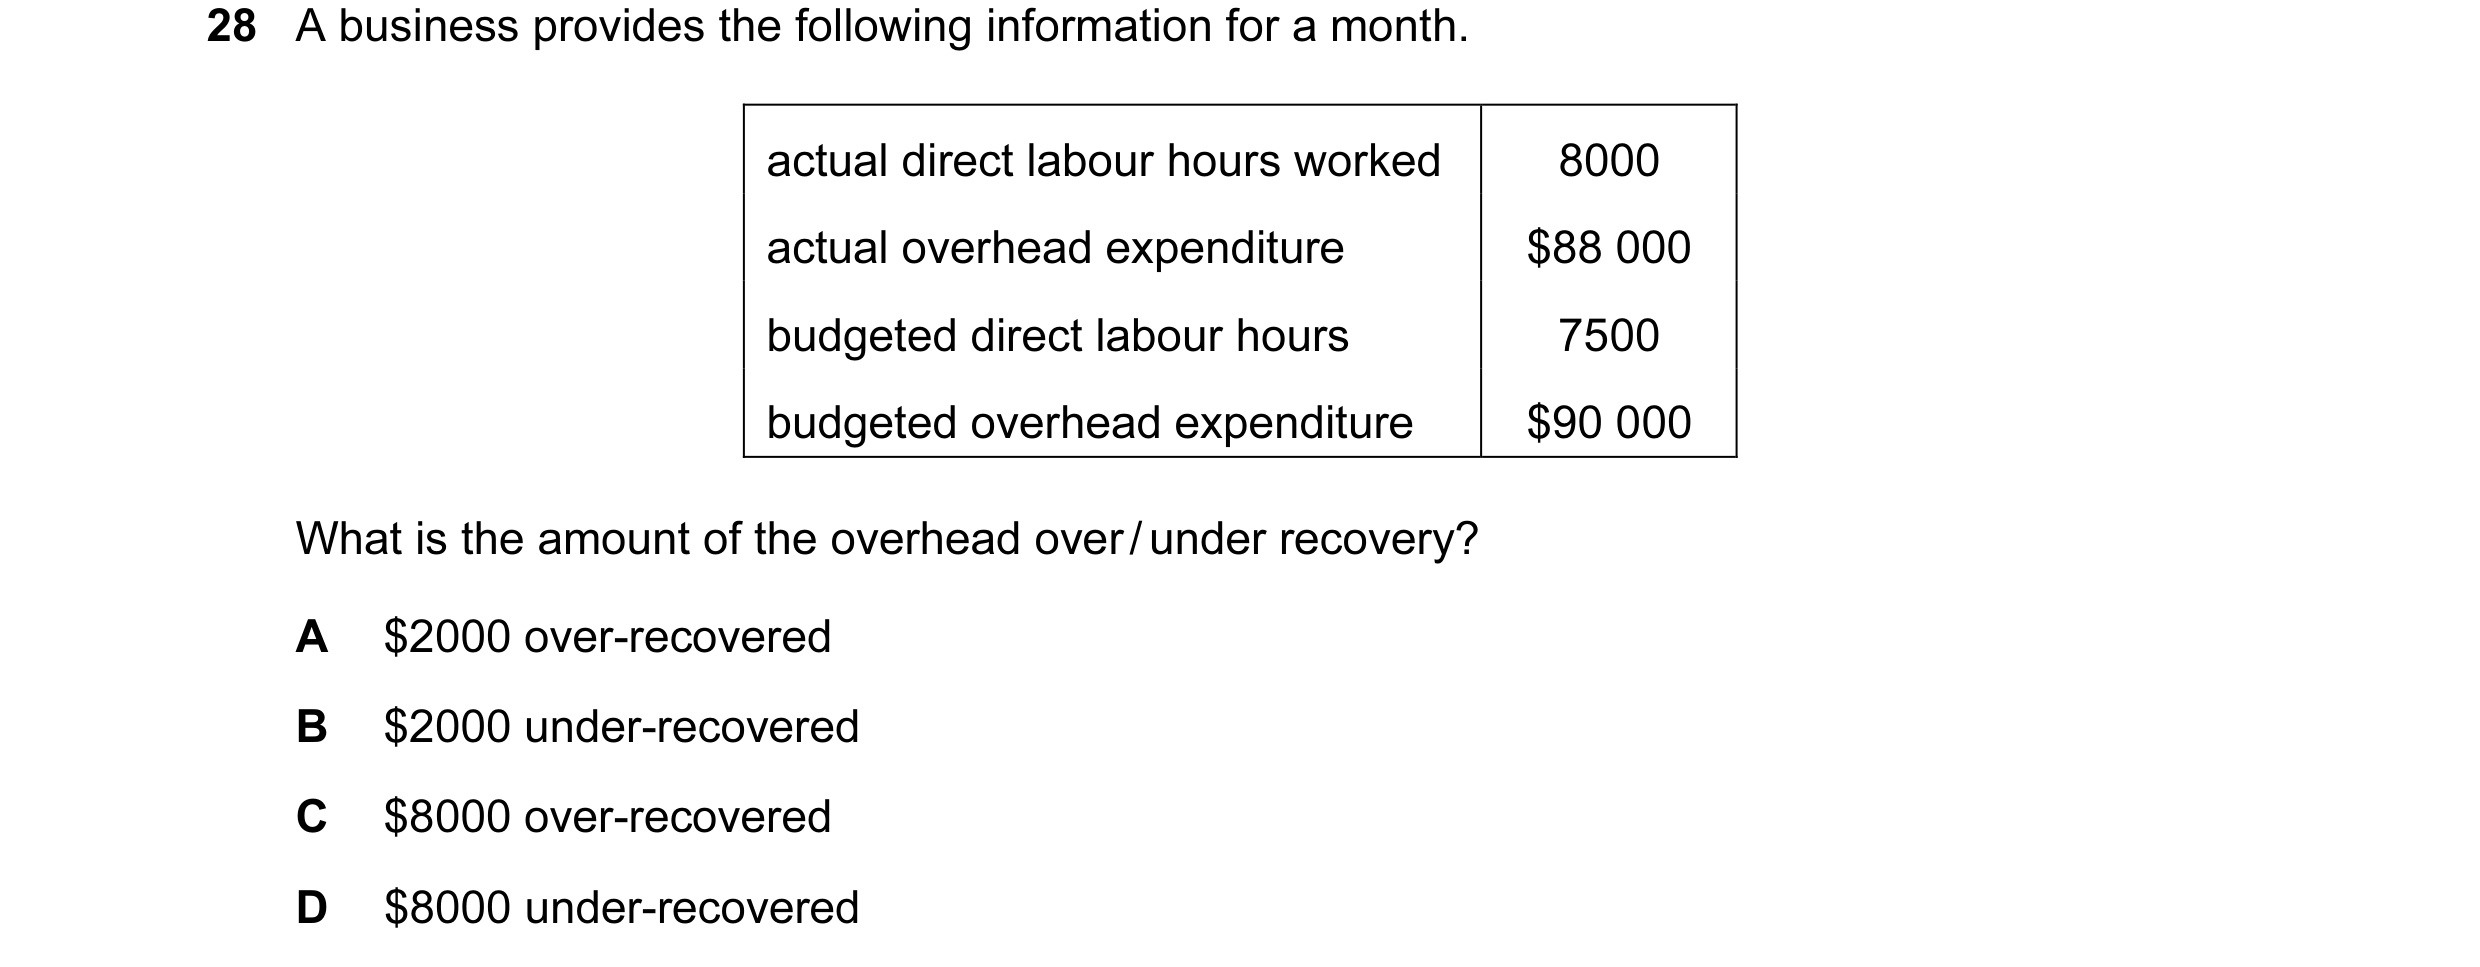 20 / 143
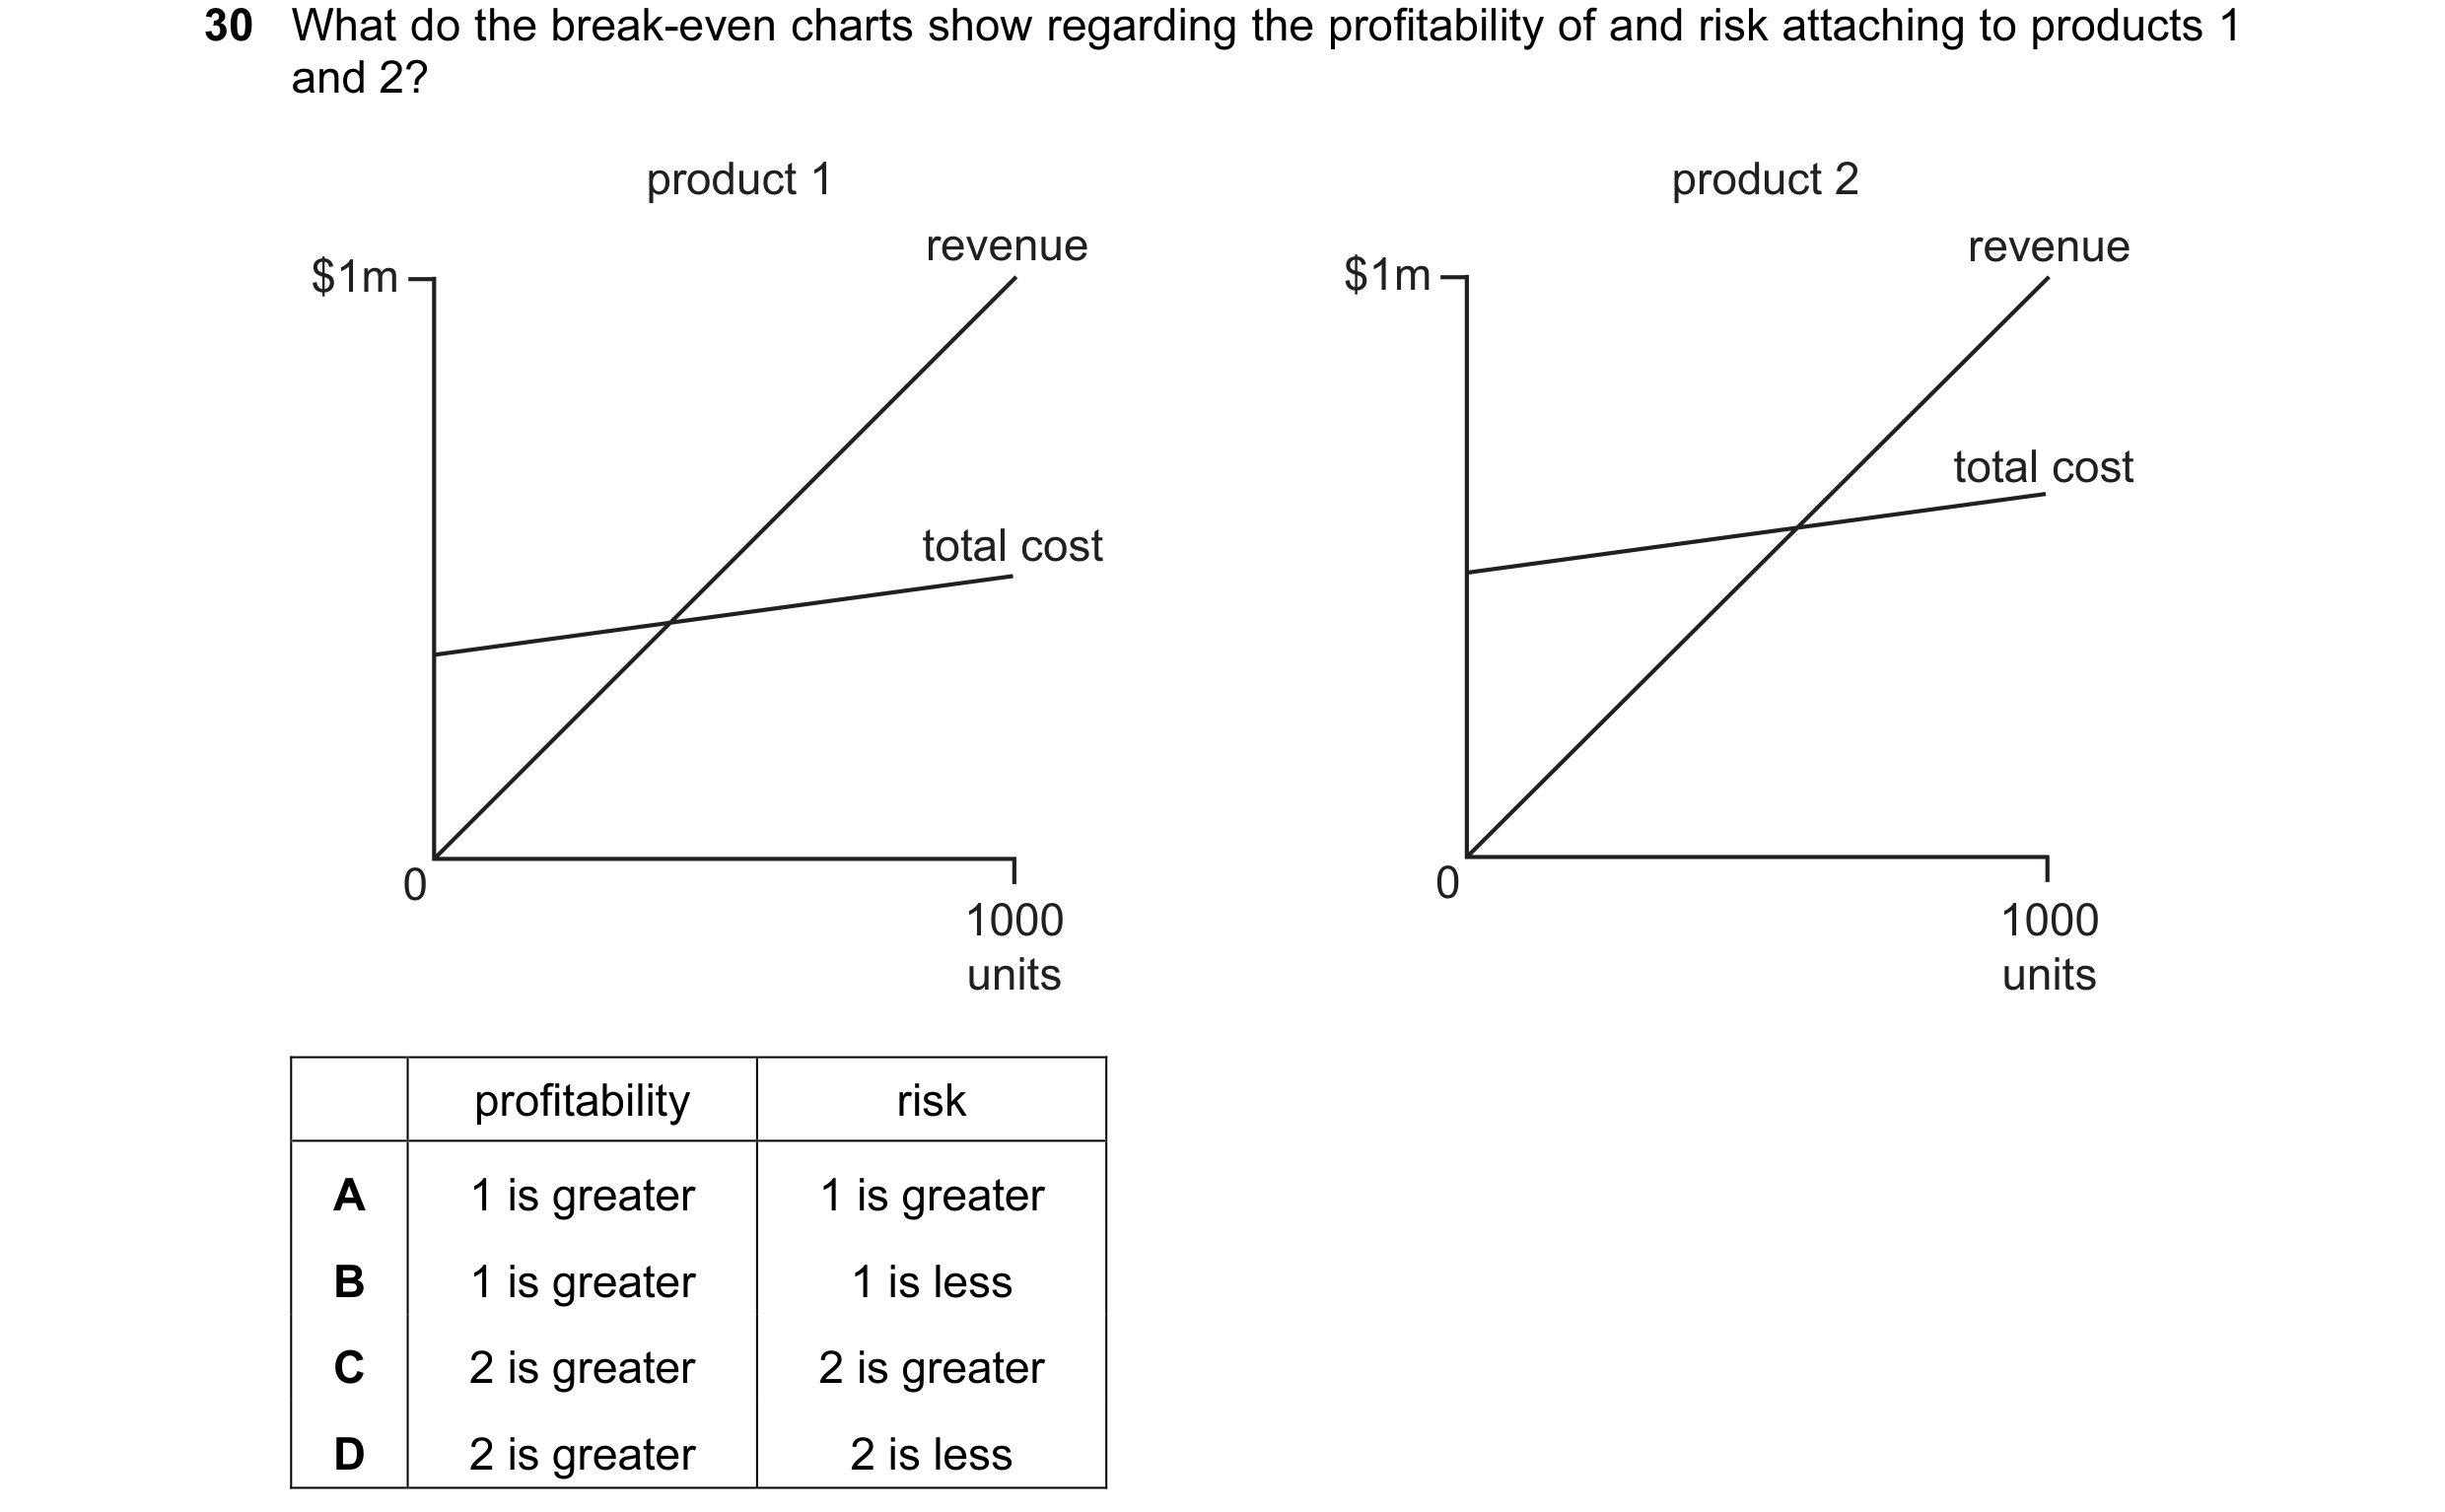
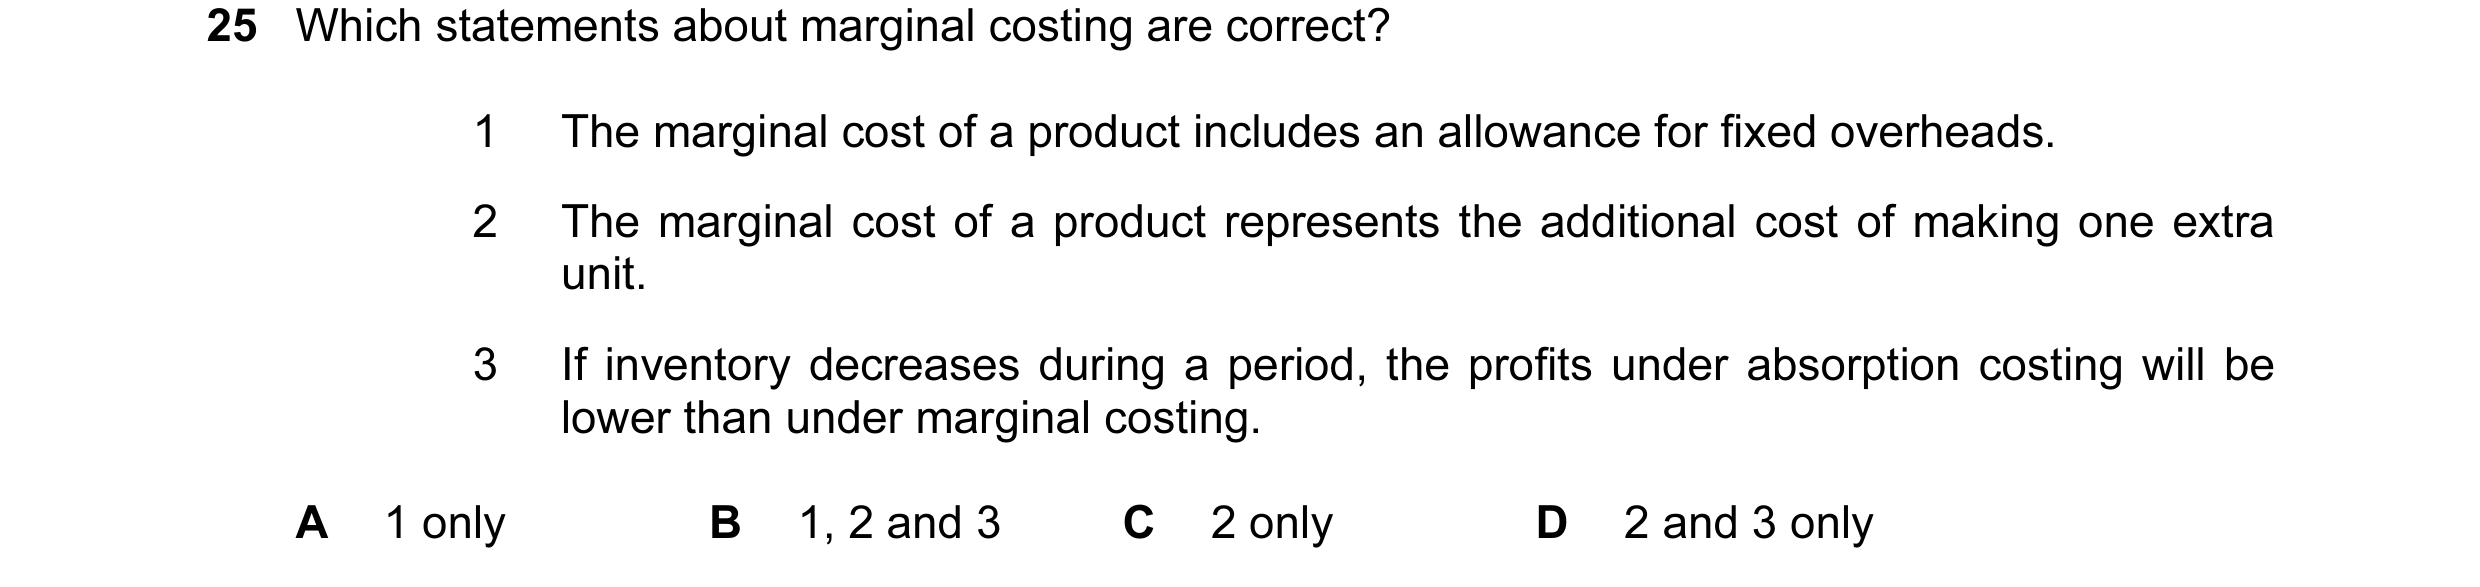
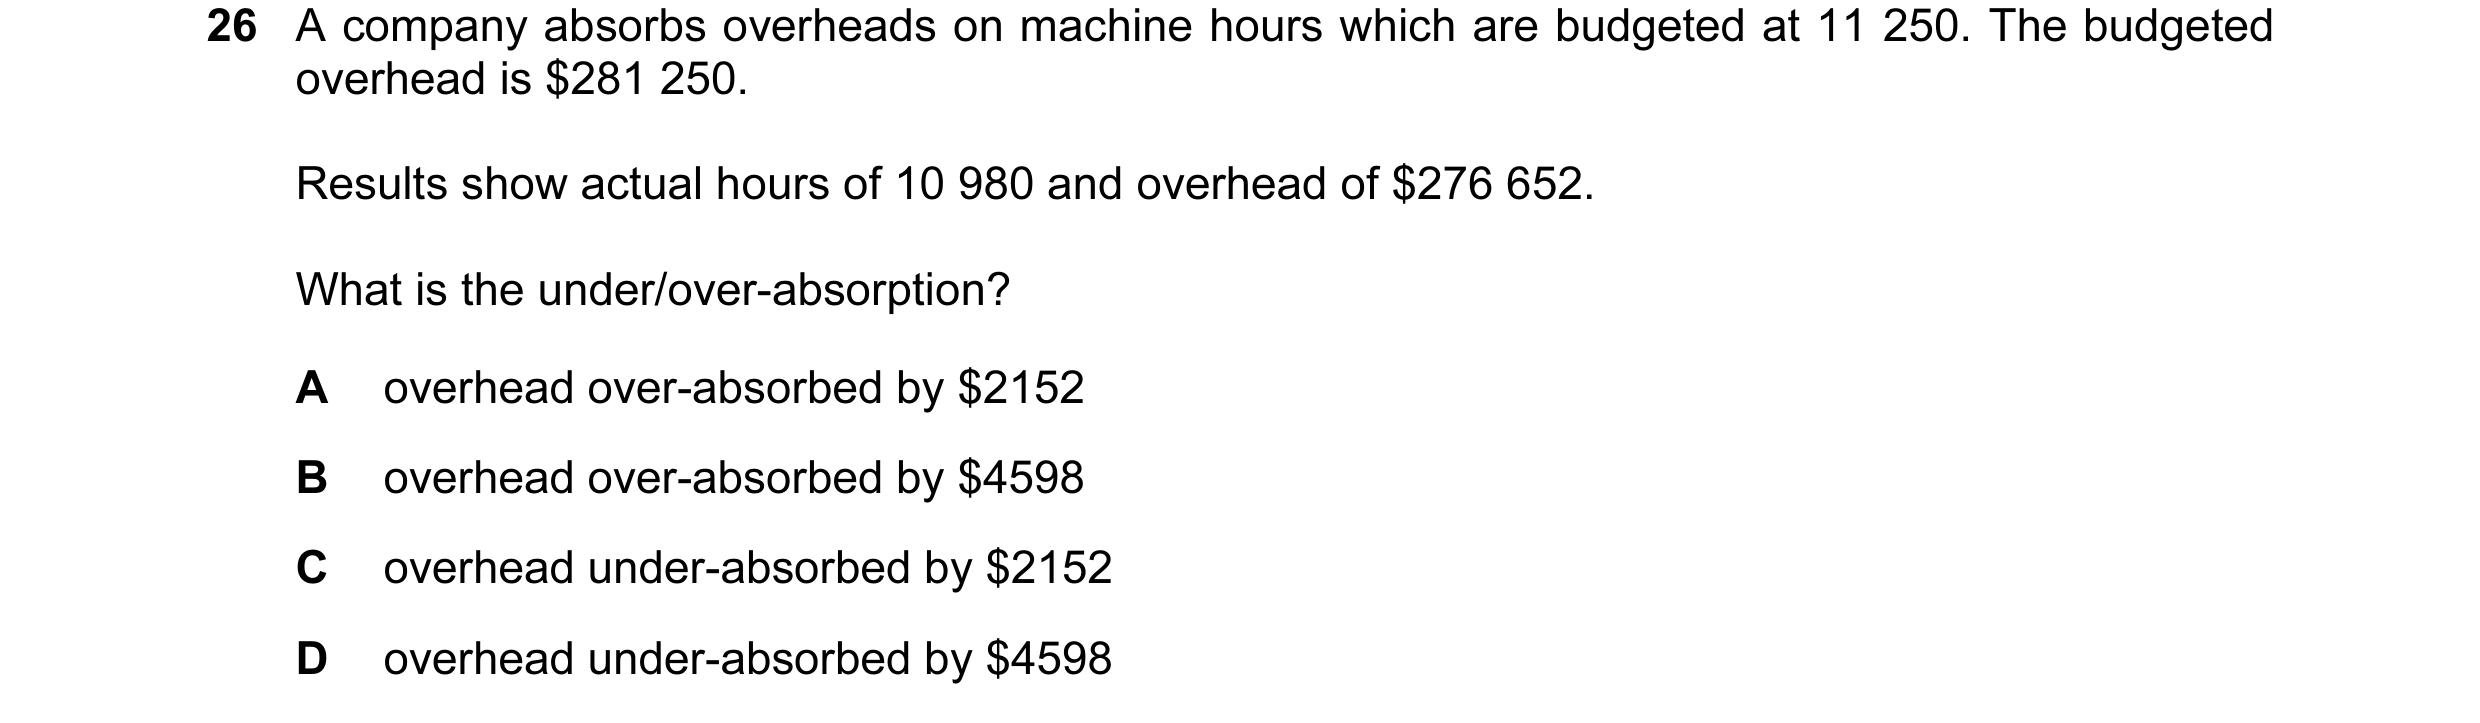 21 / 143
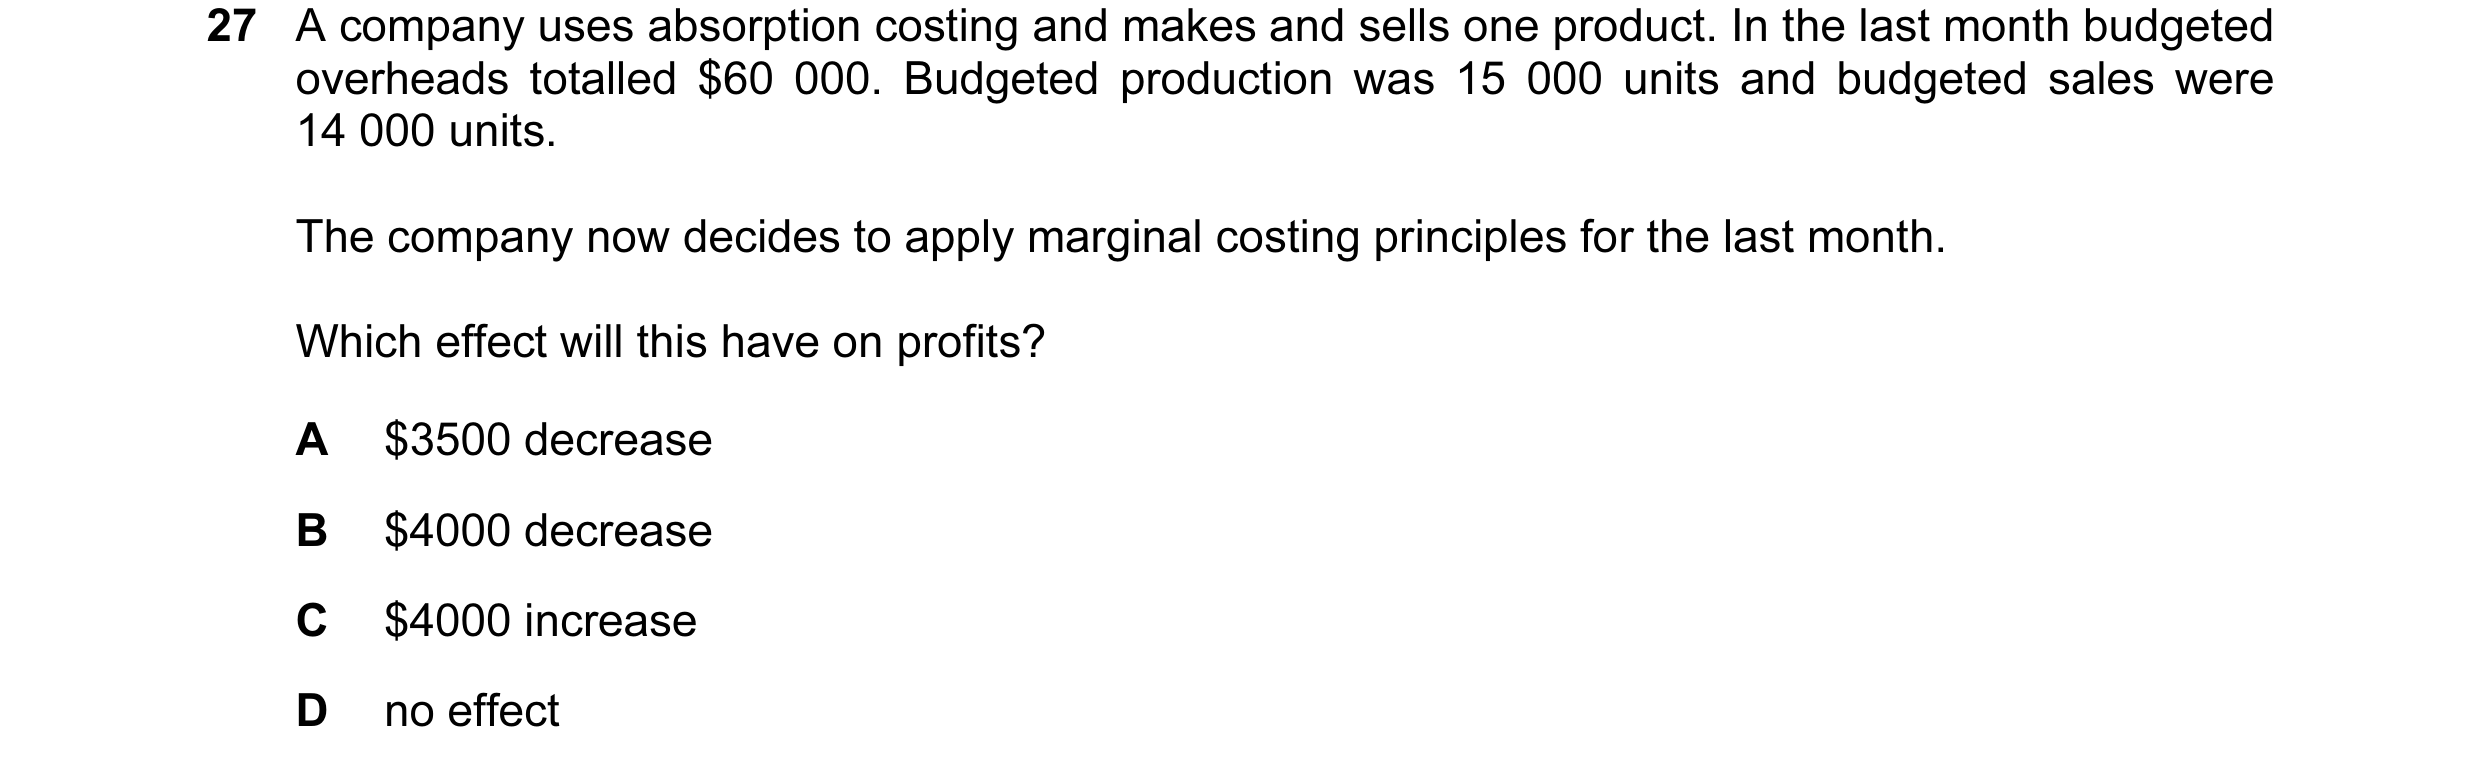
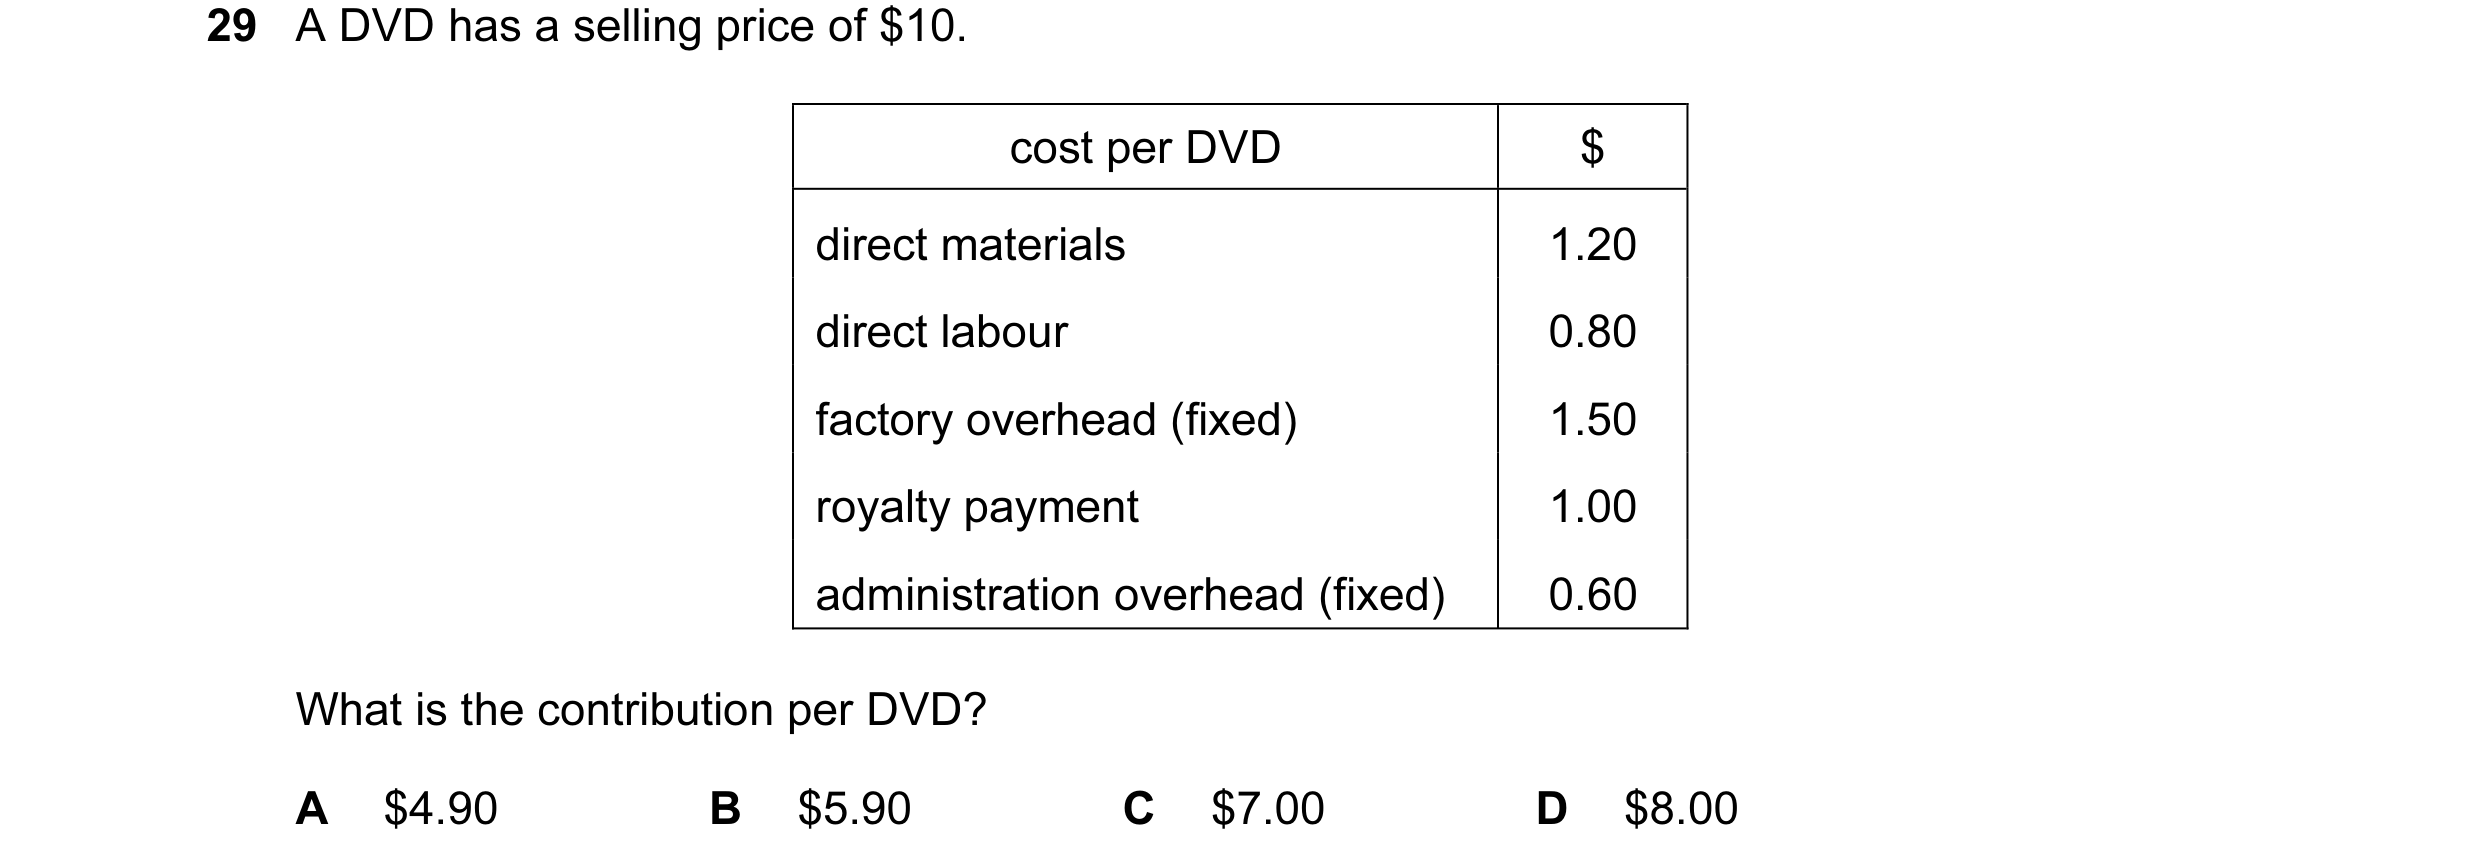
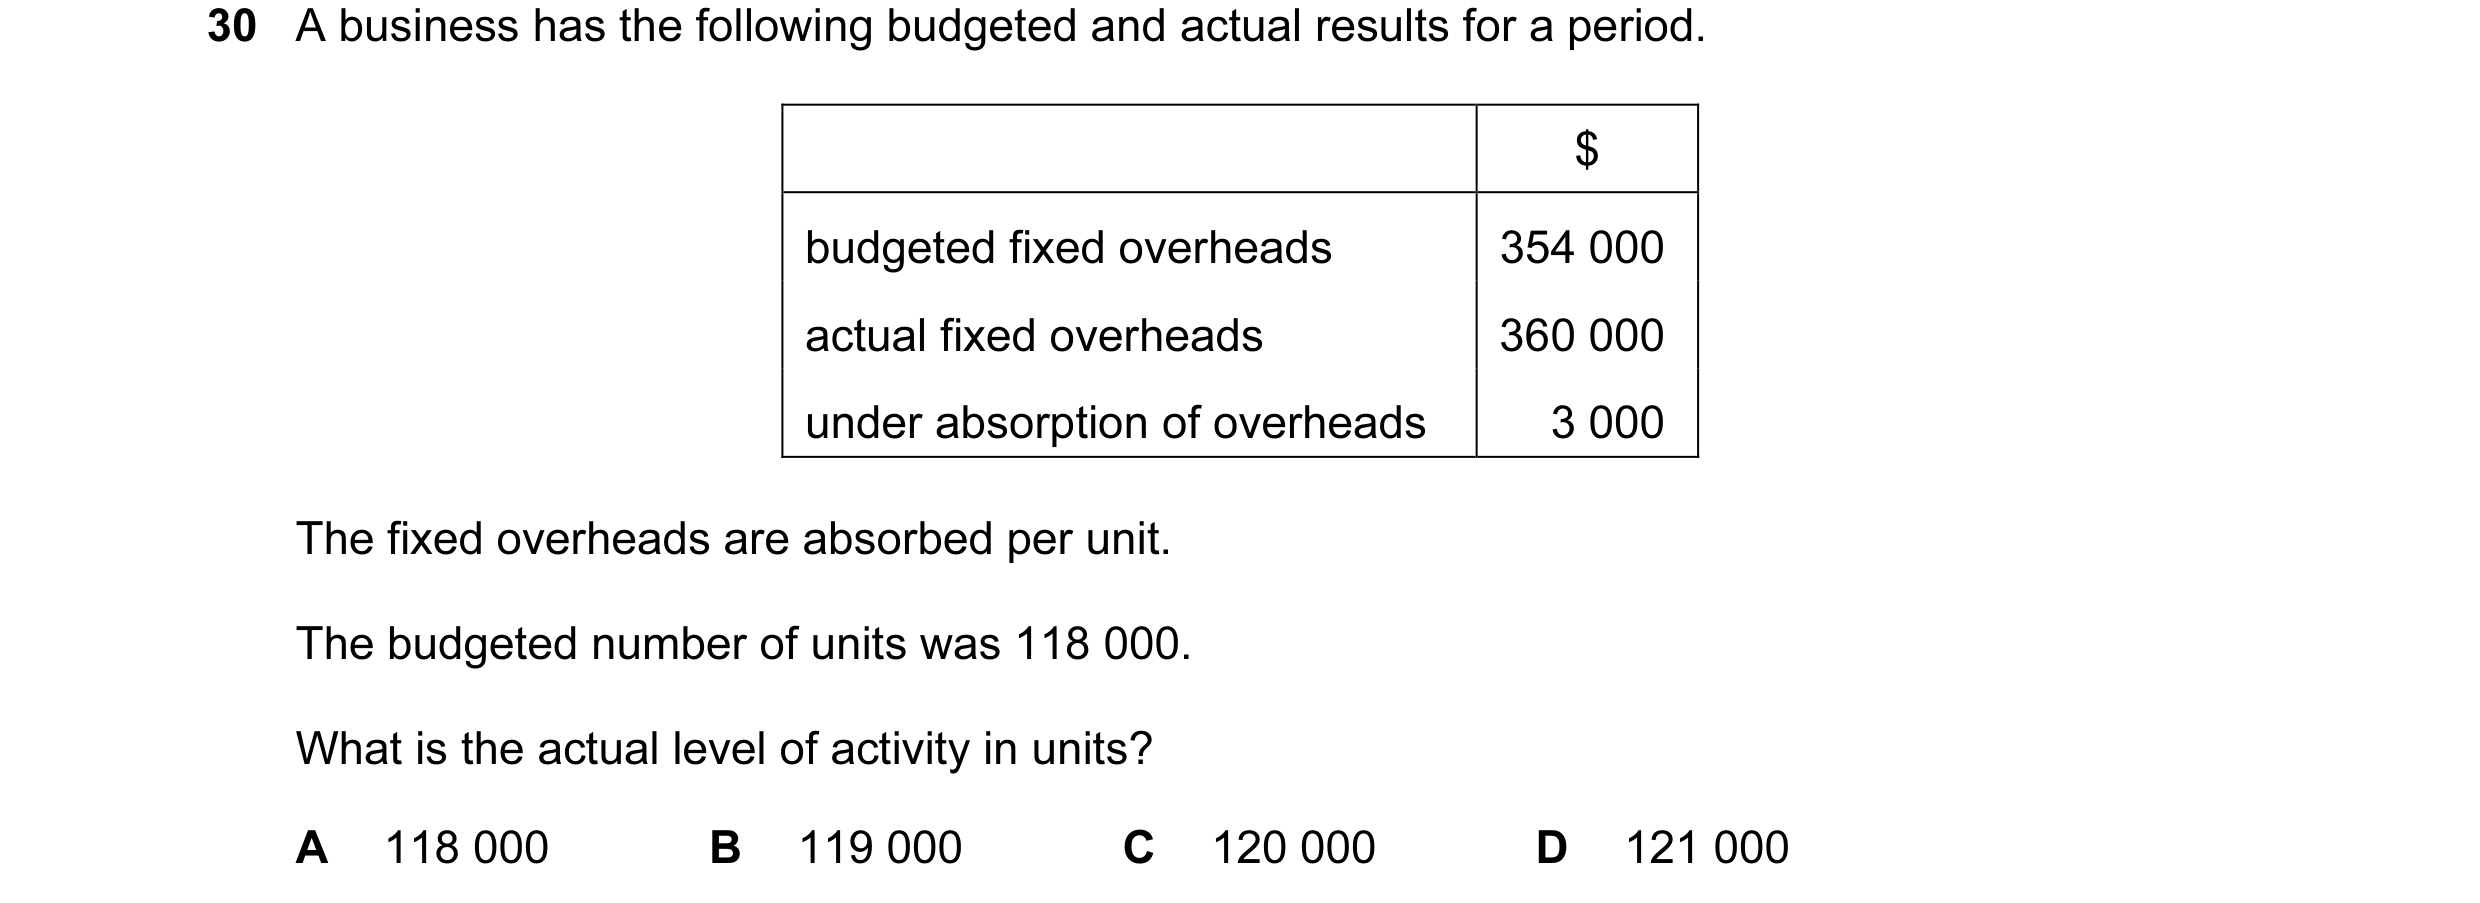 22 / 143
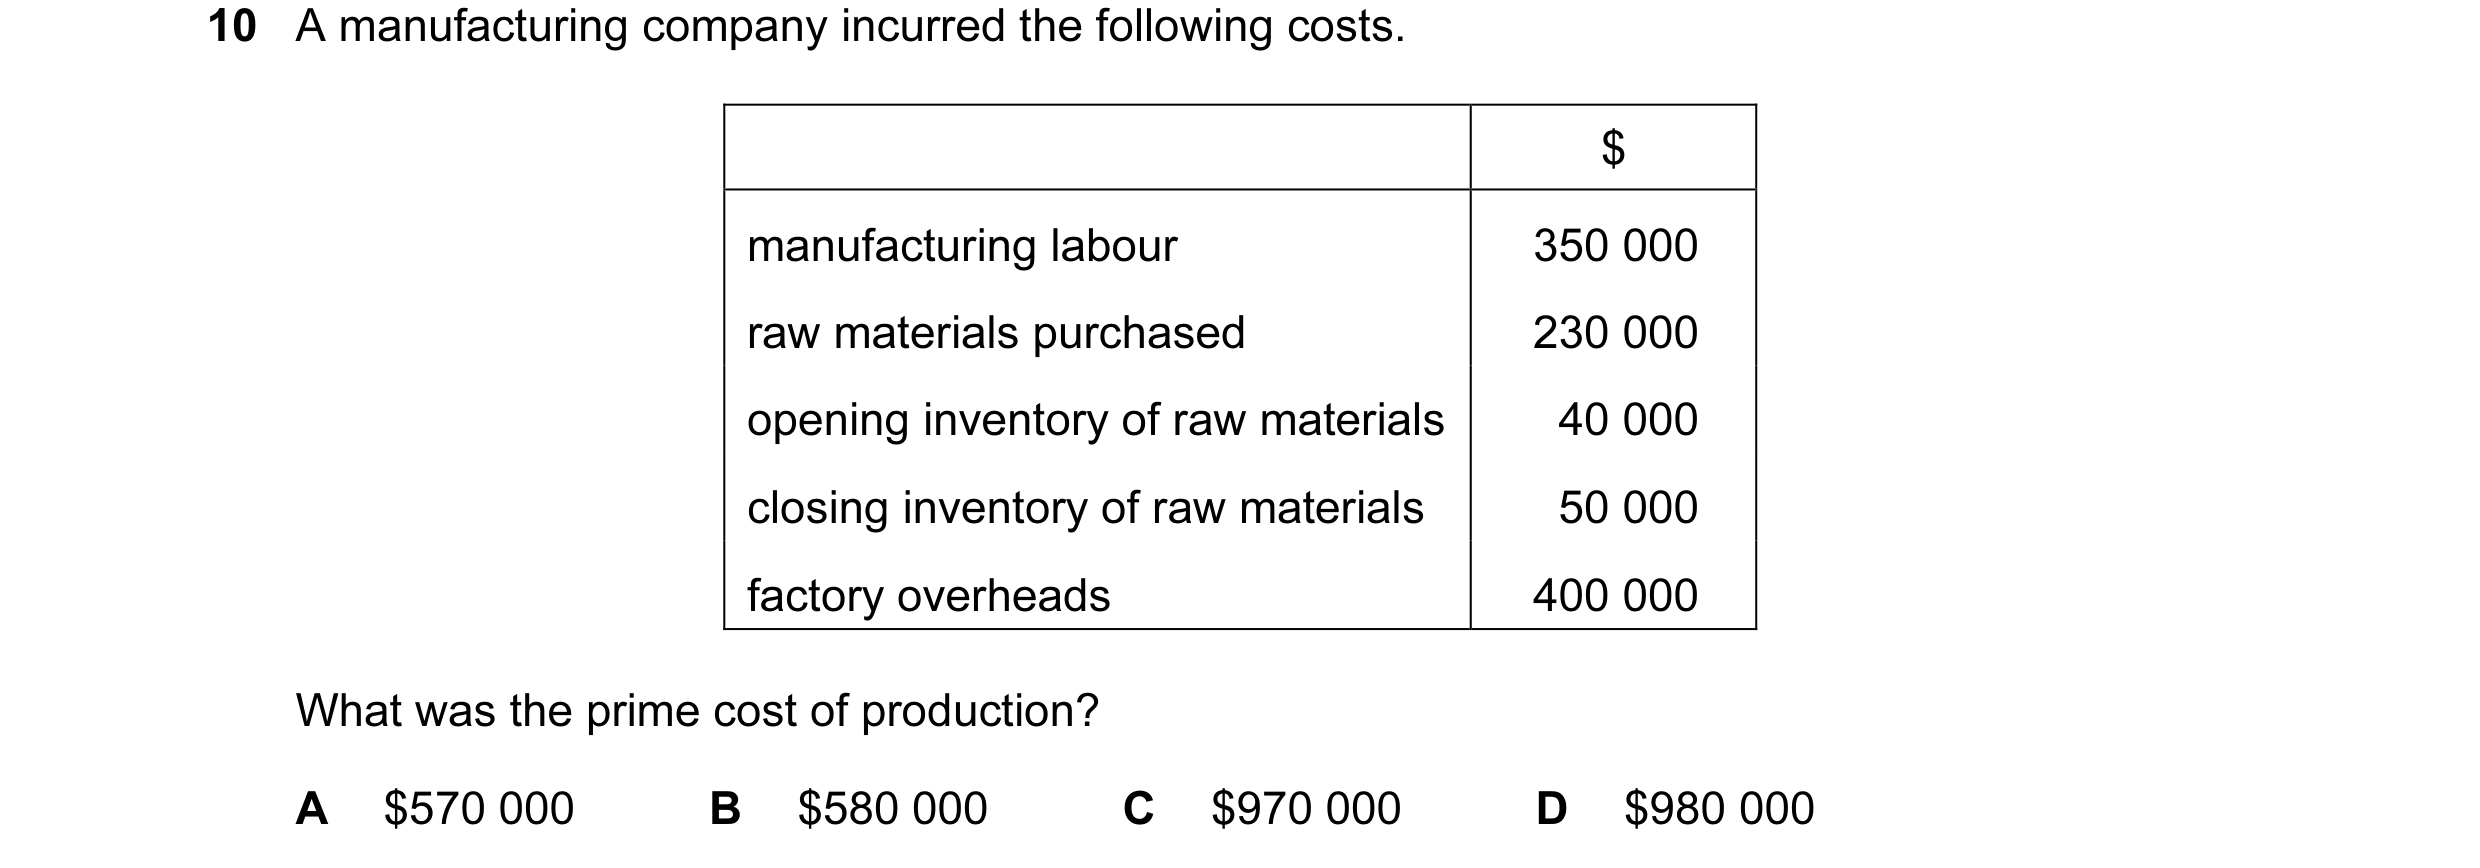
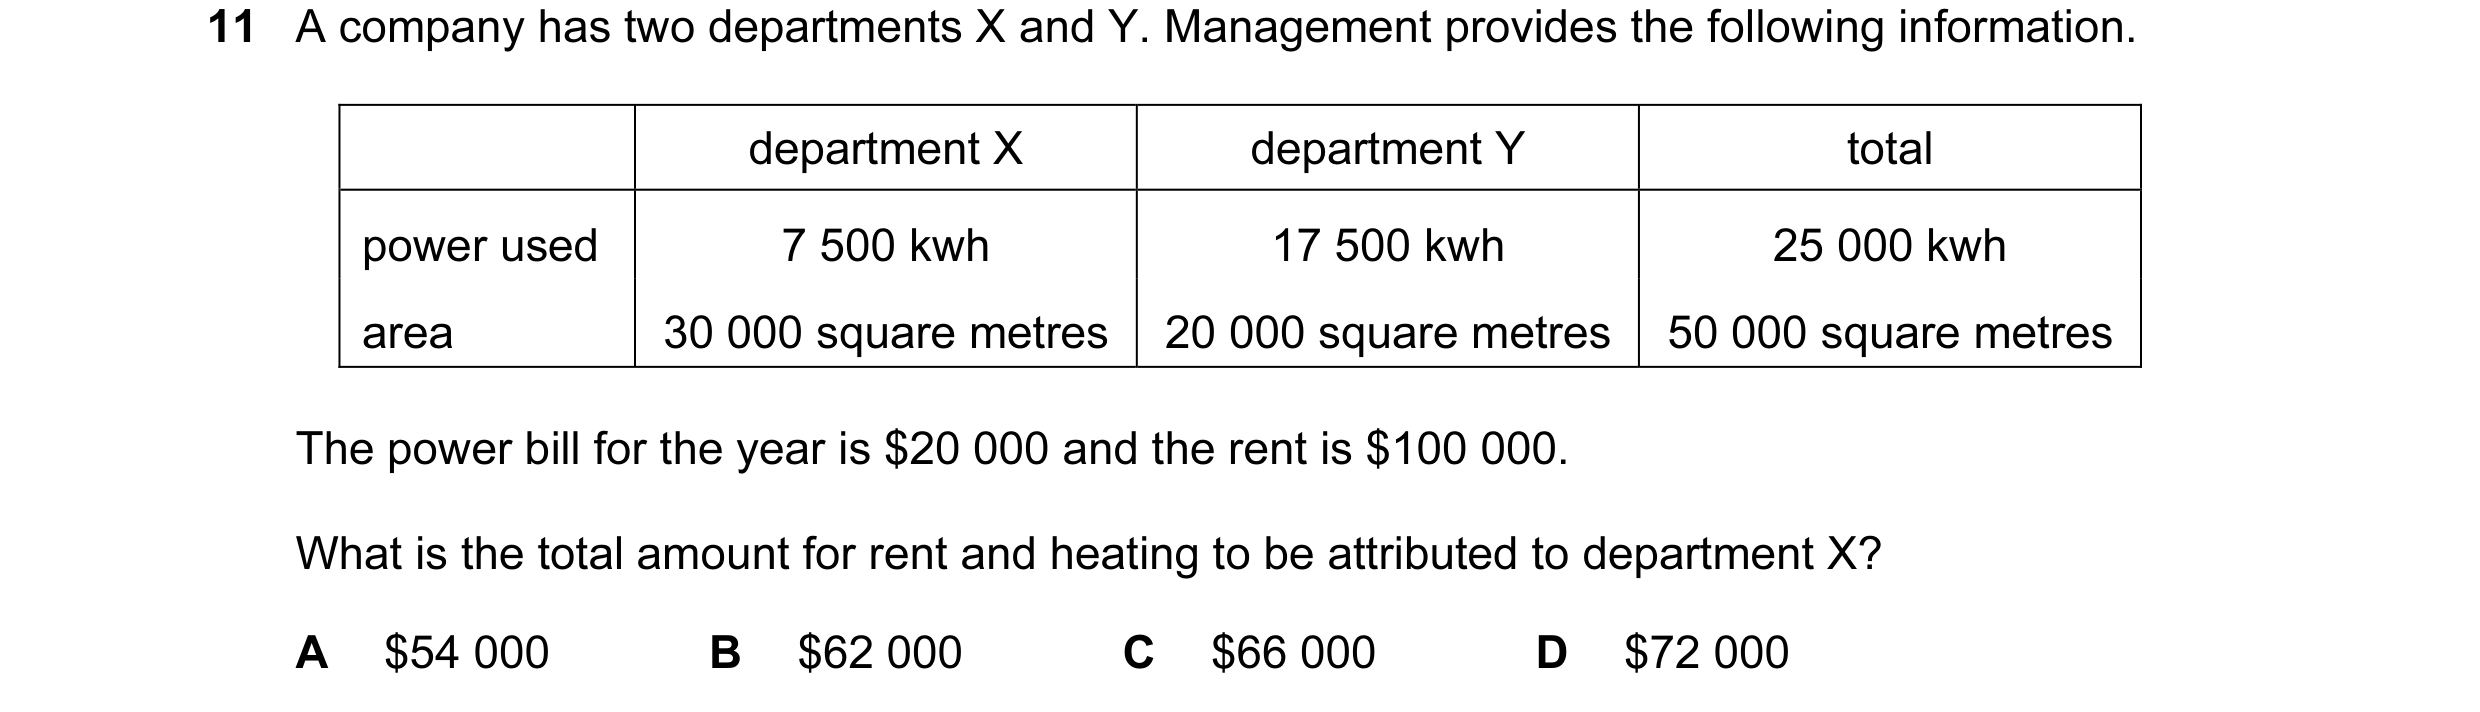
 23 / 143
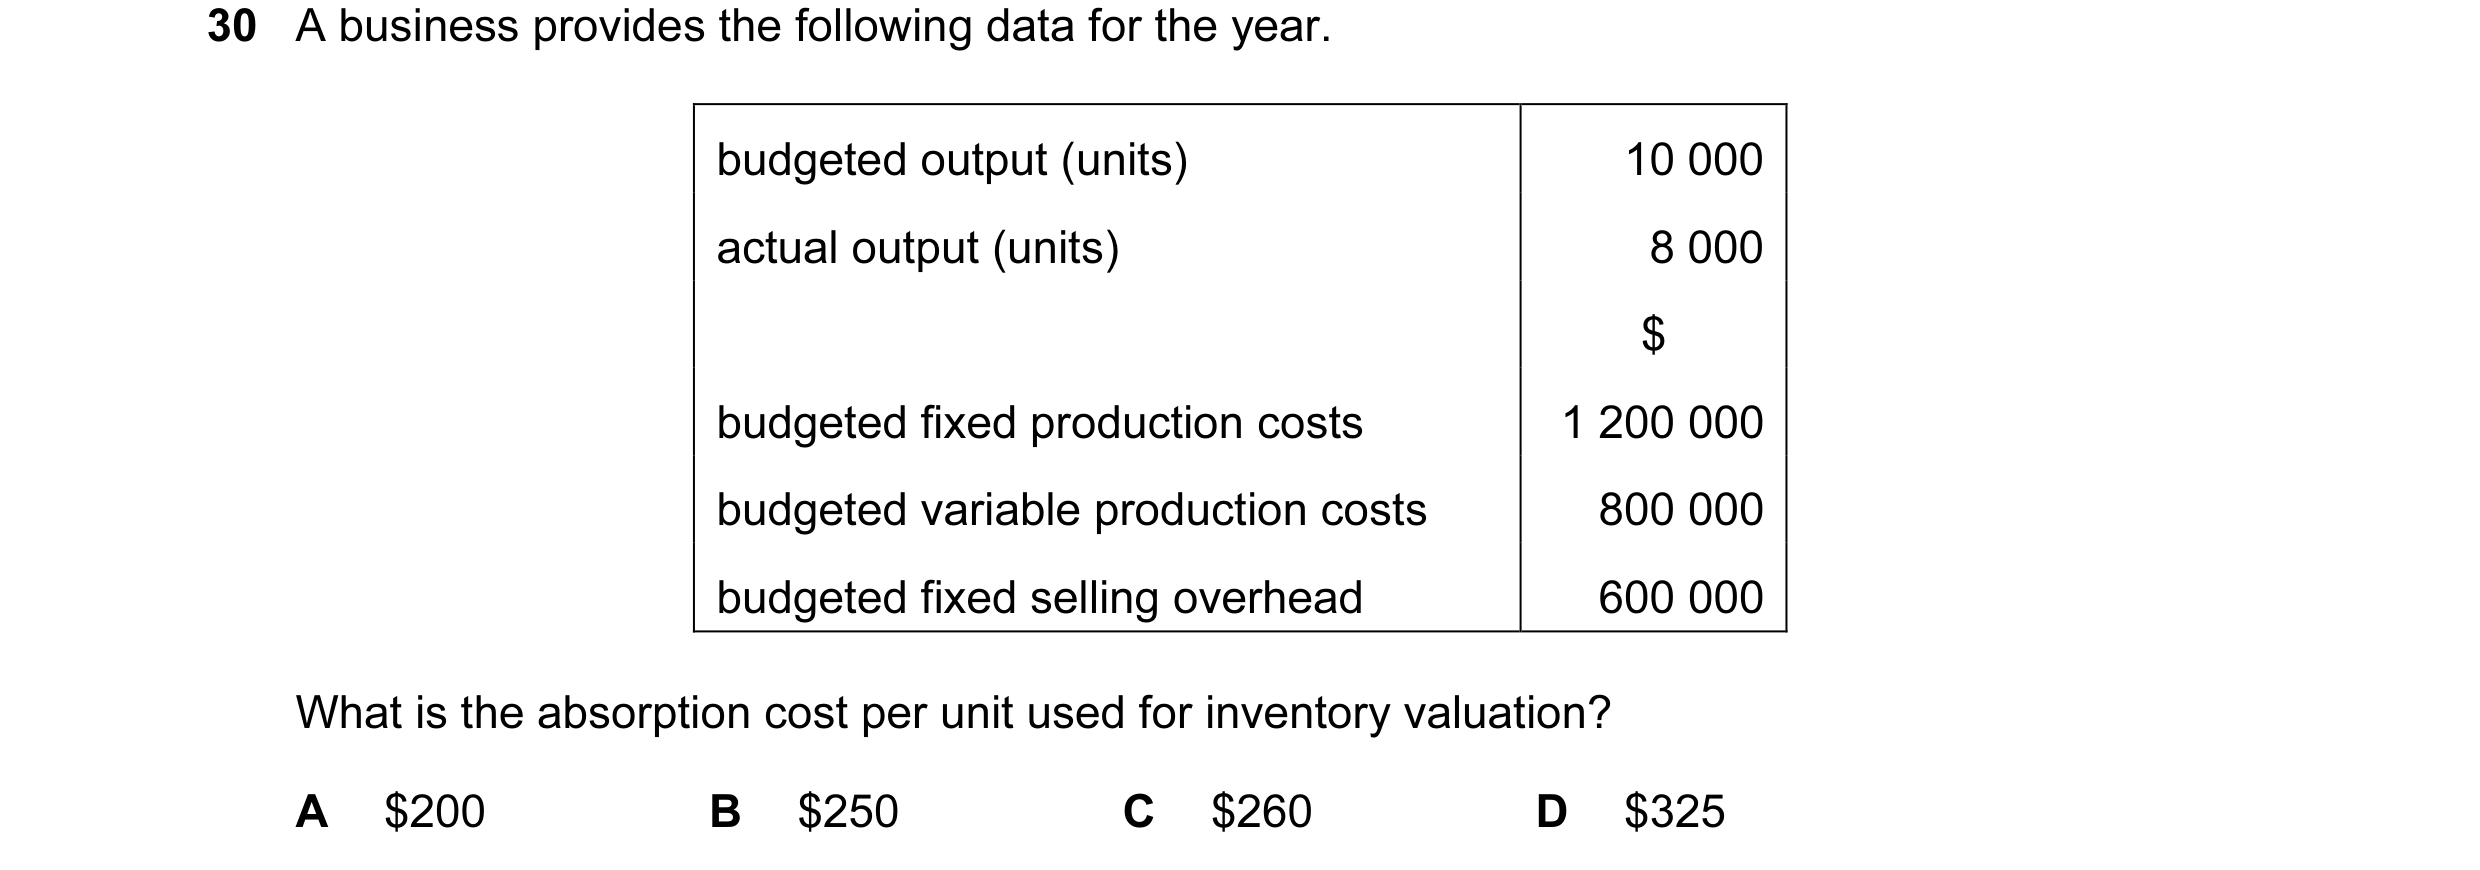
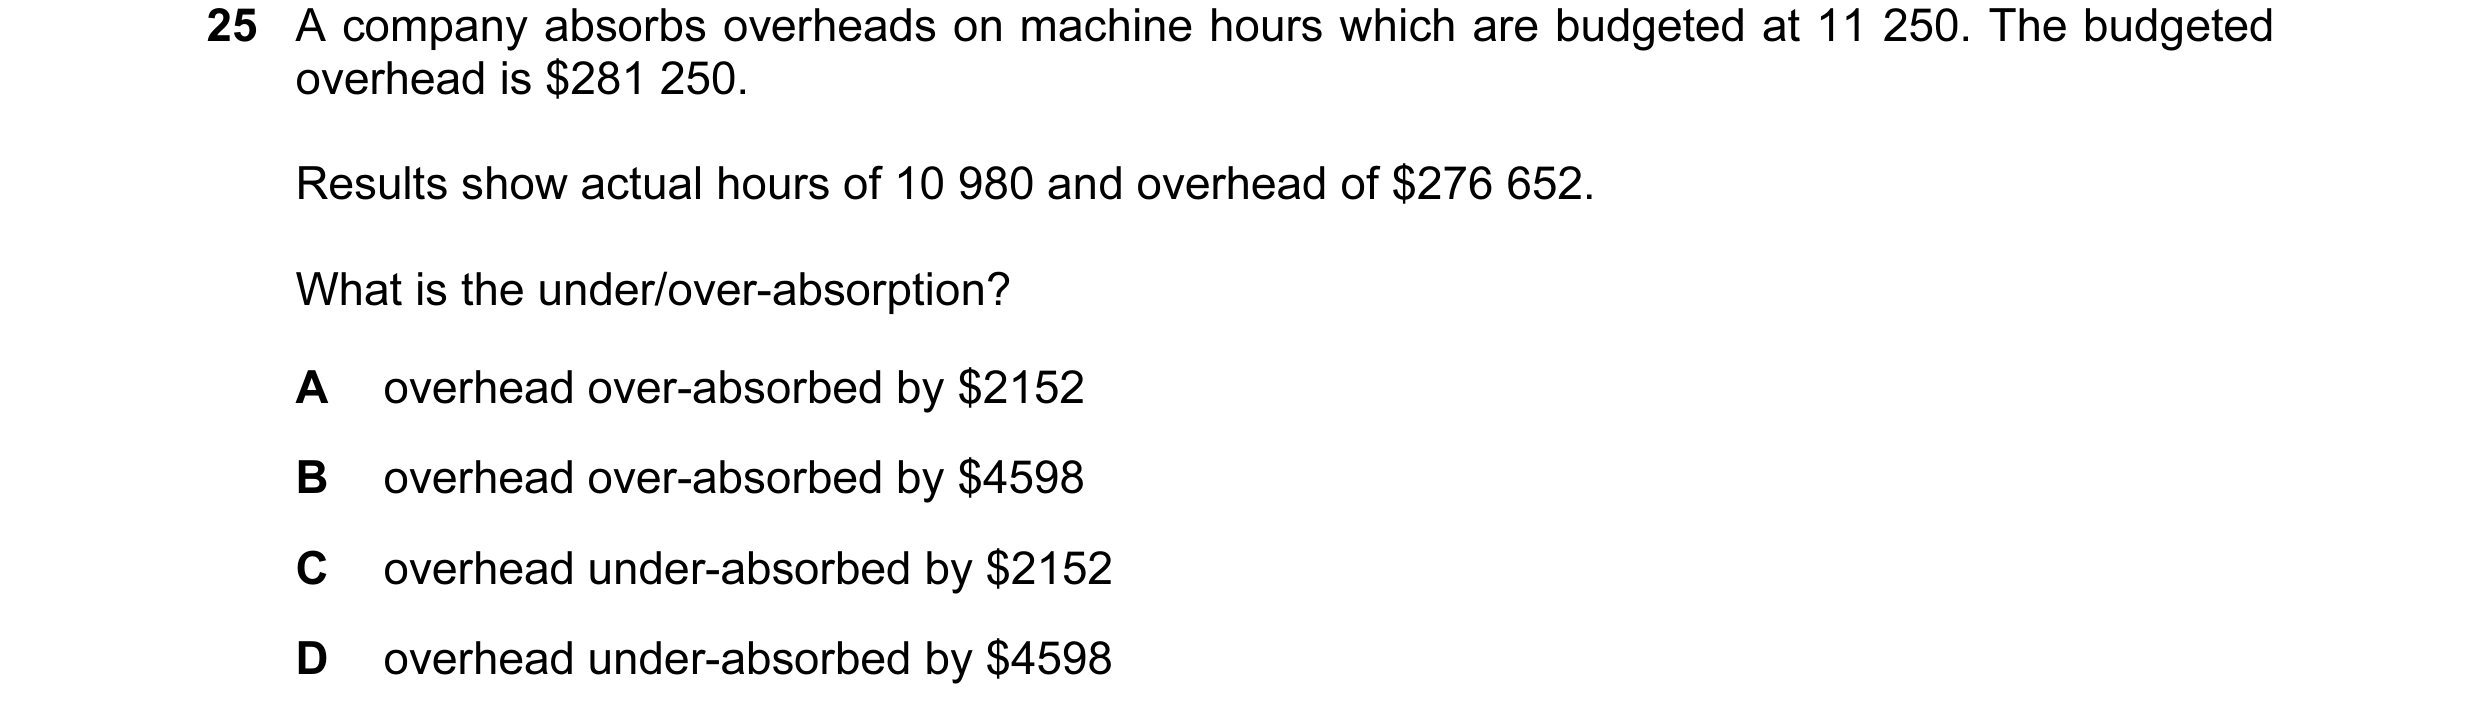 24 / 143
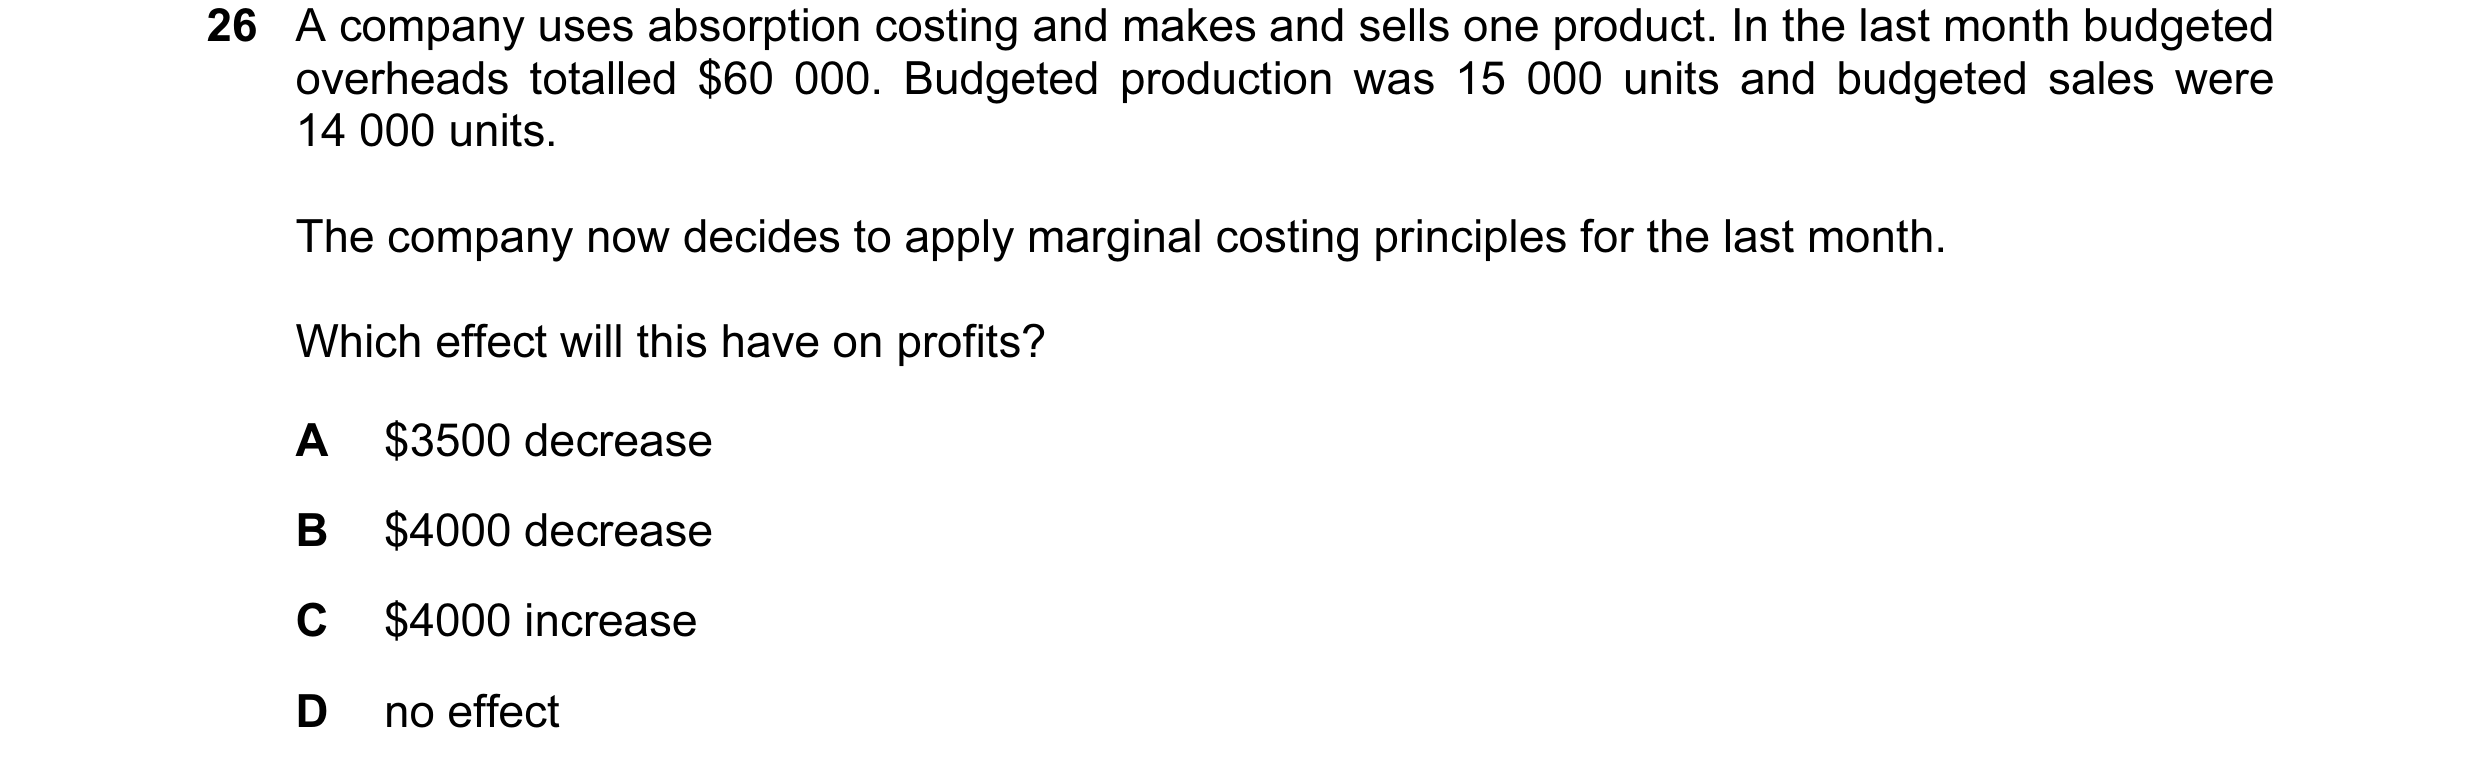
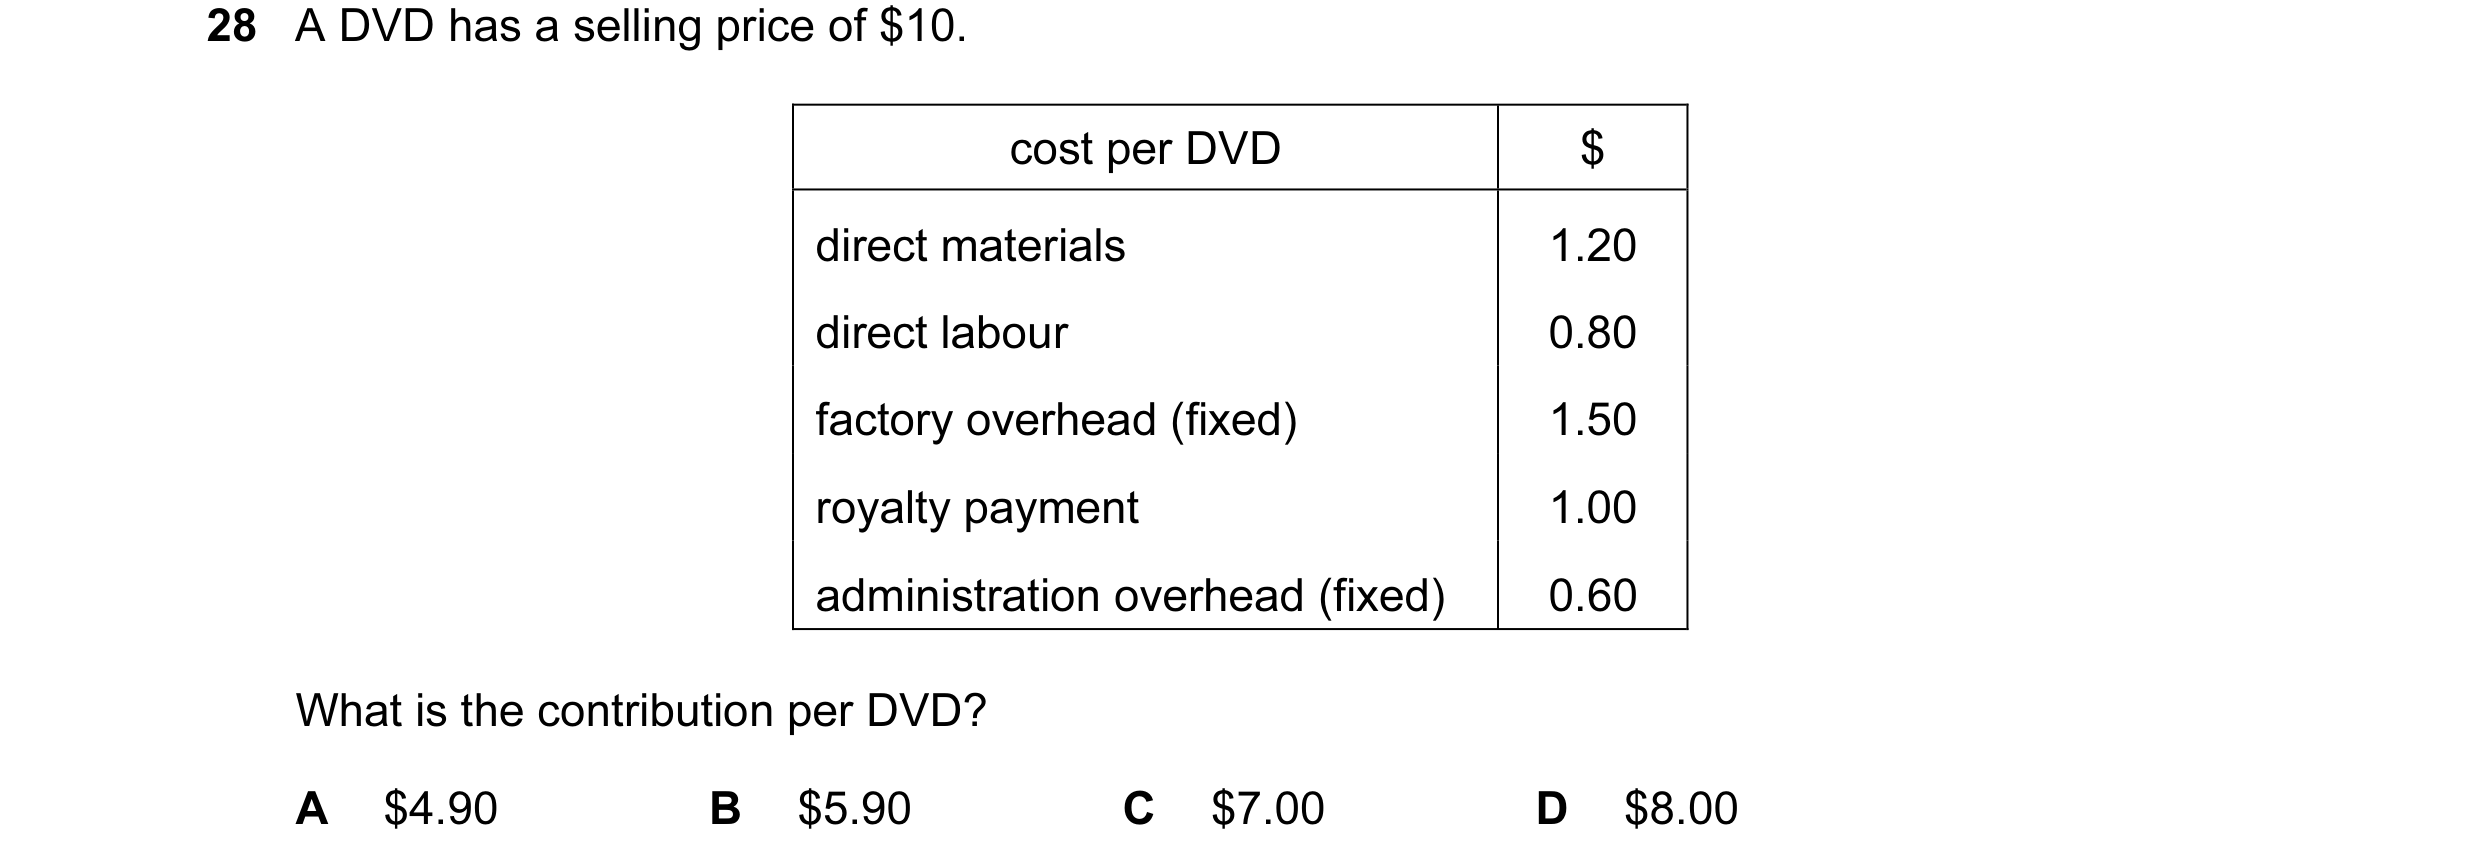
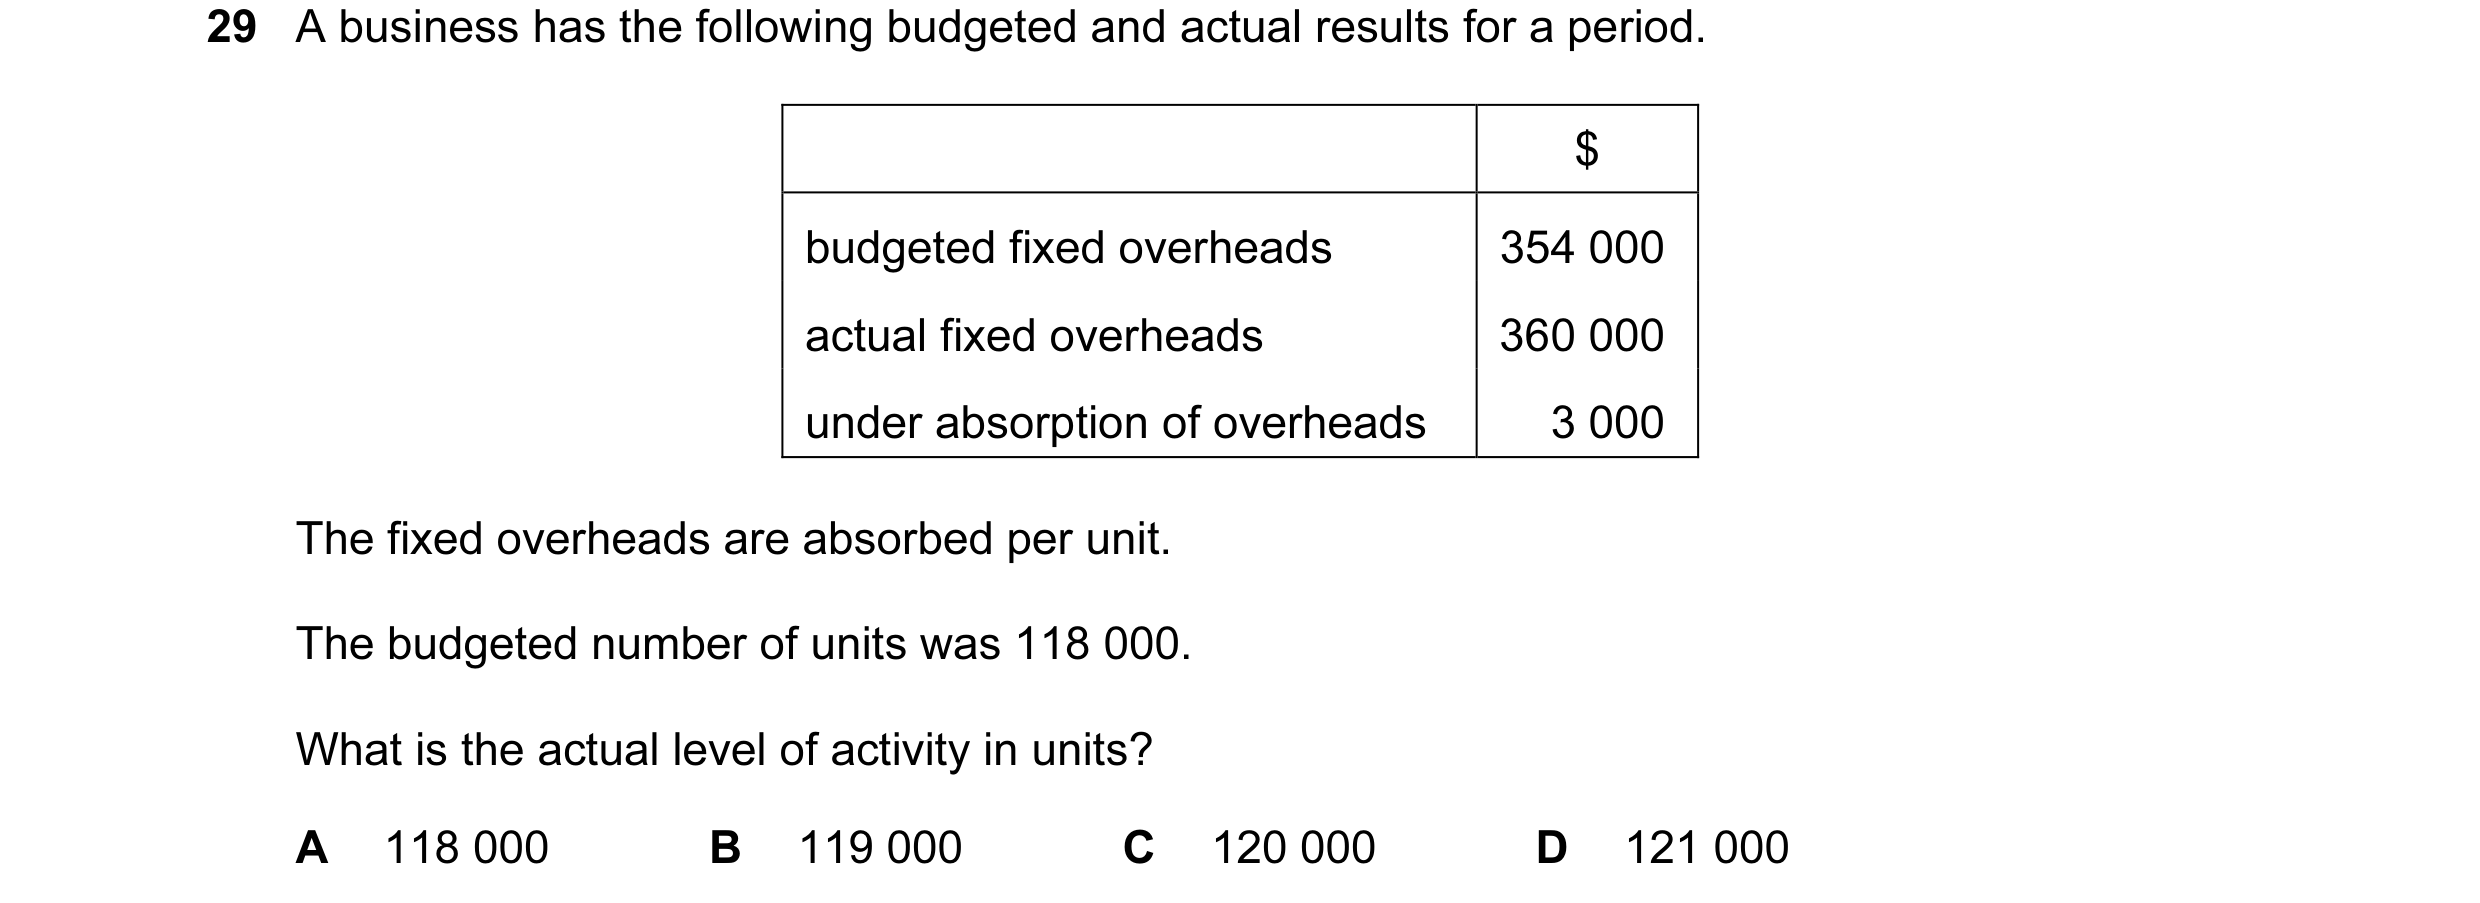
 25 / 143
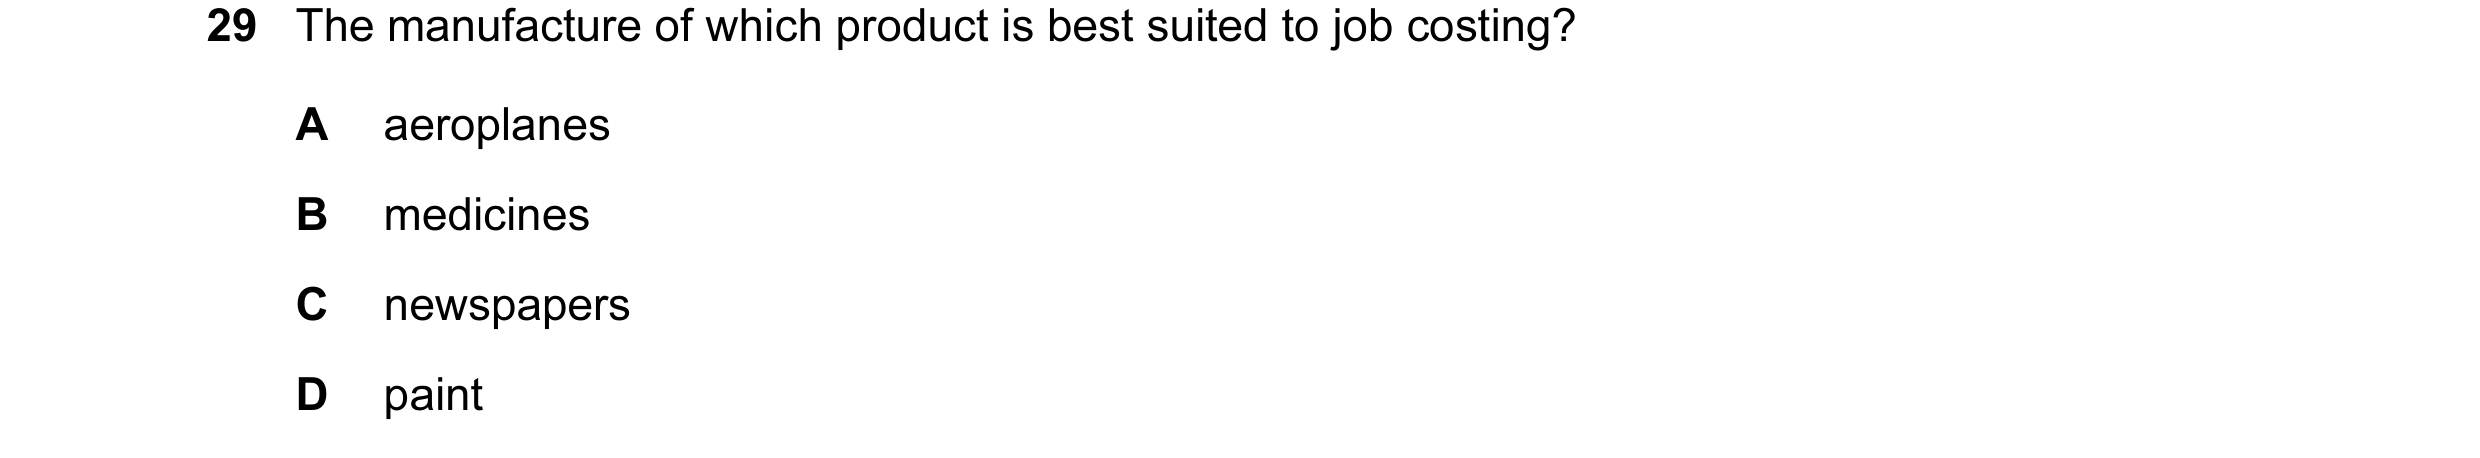
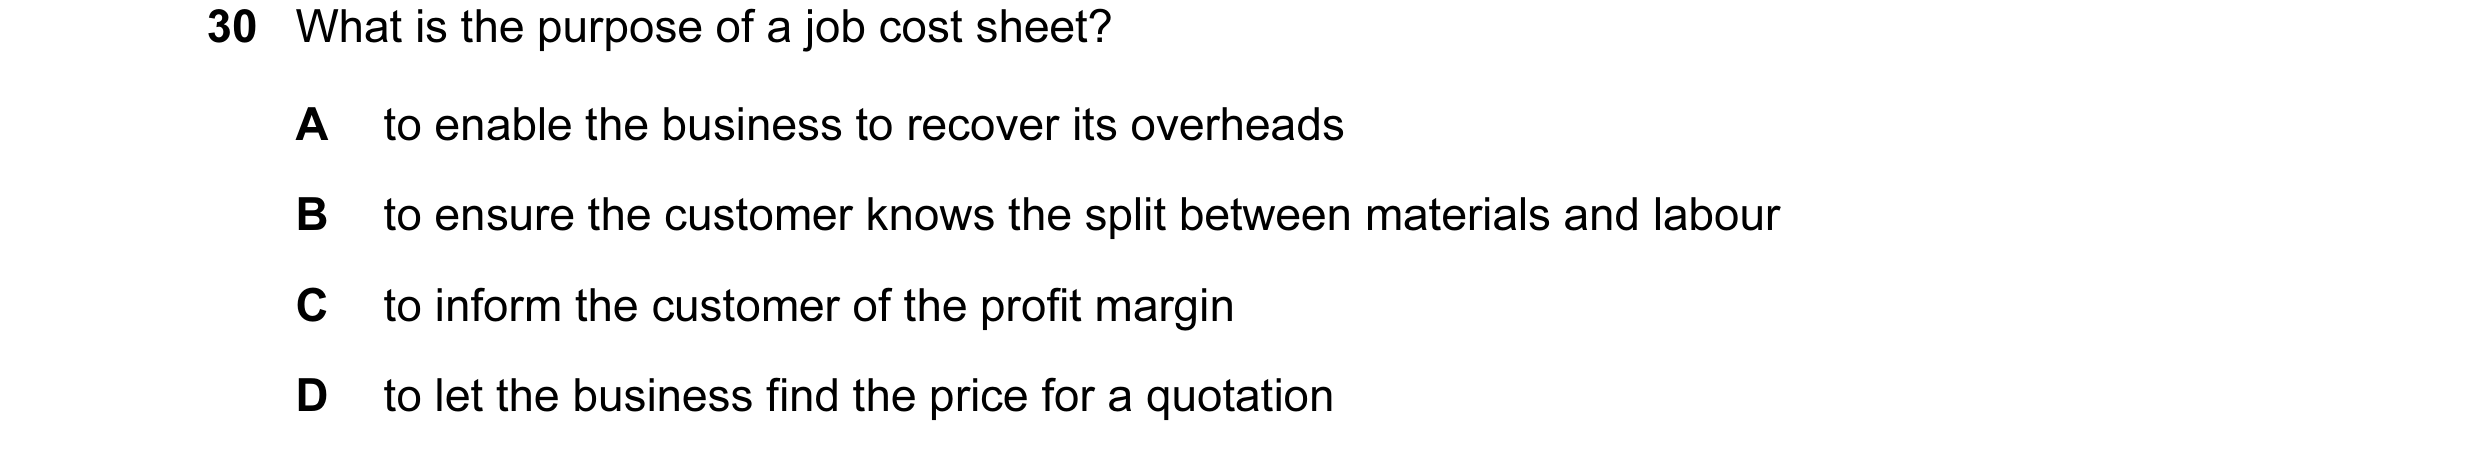 26 / 143
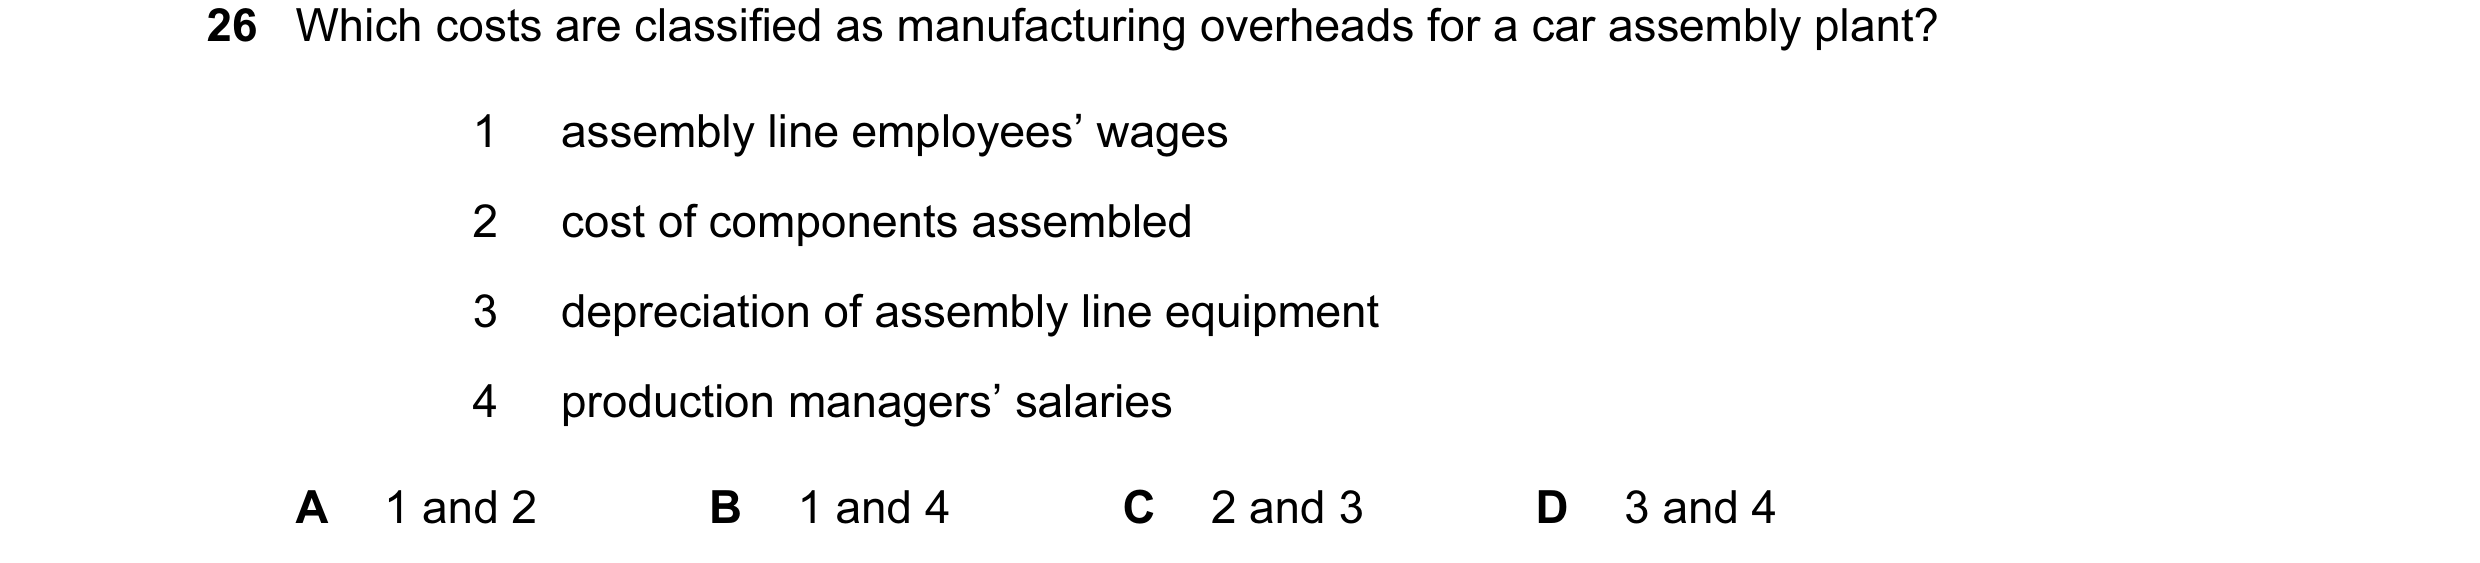
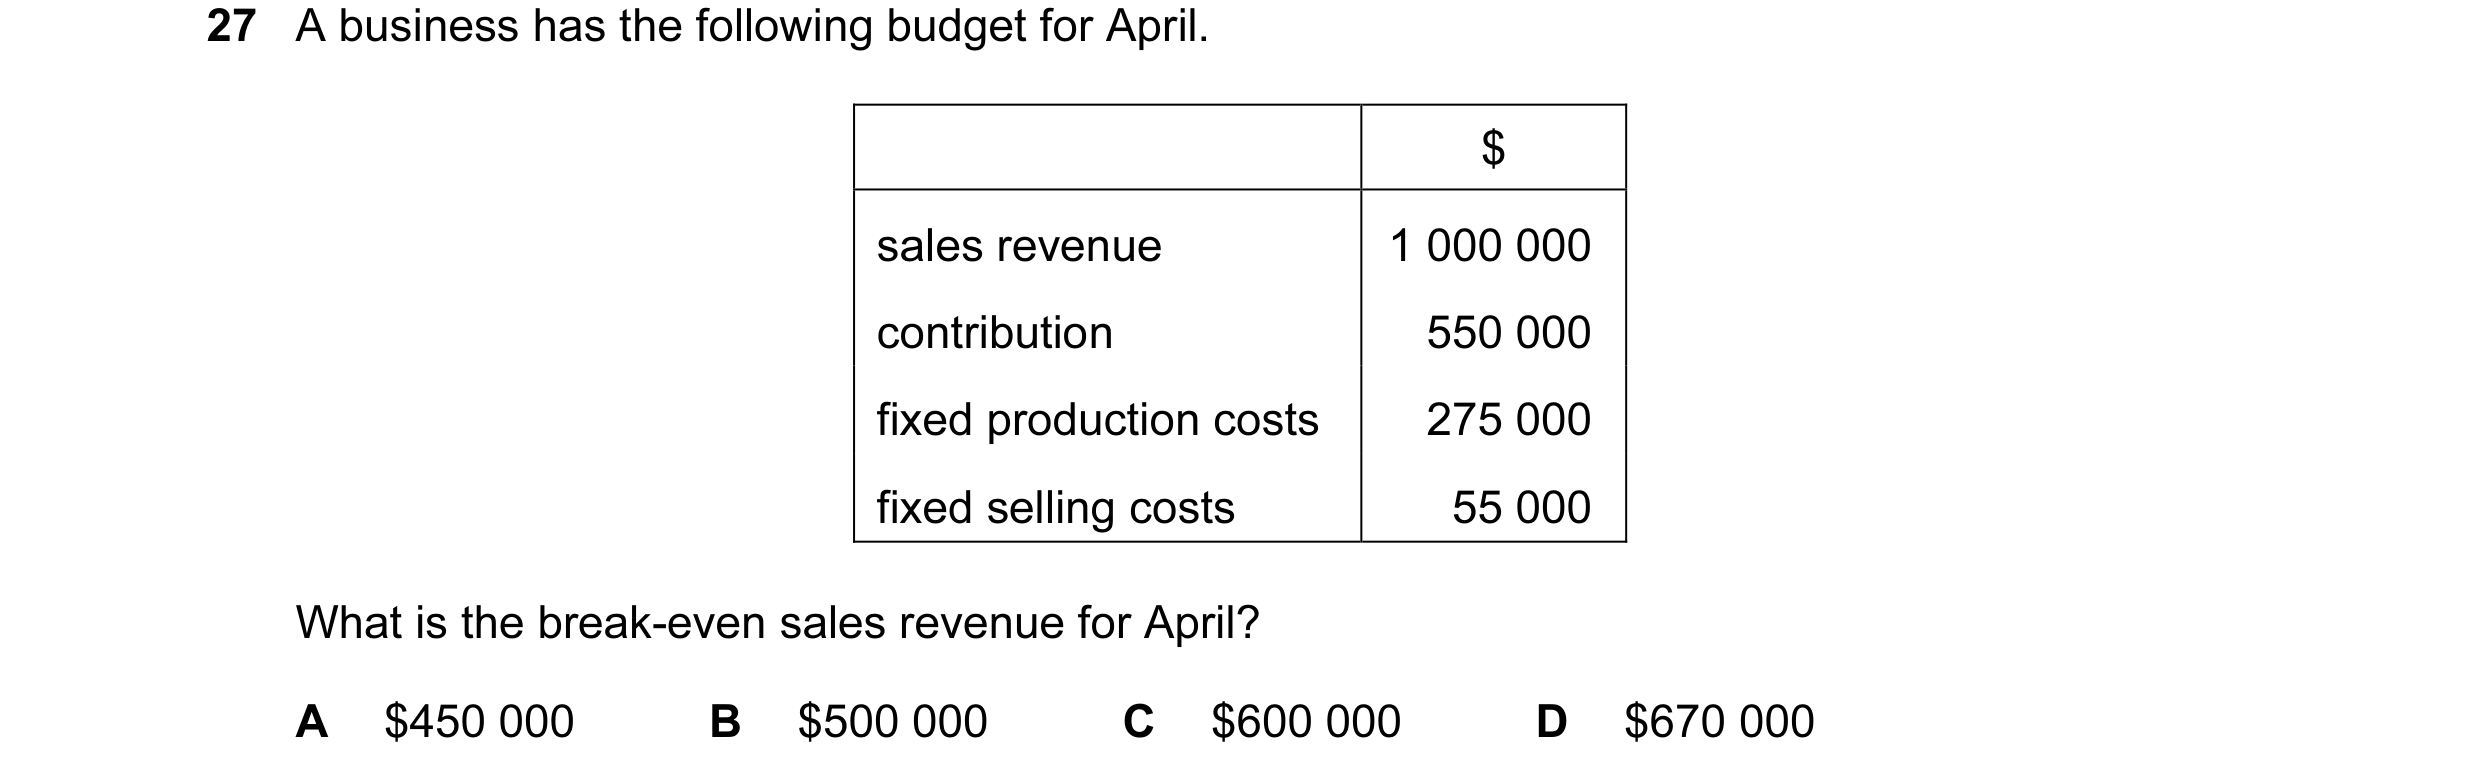
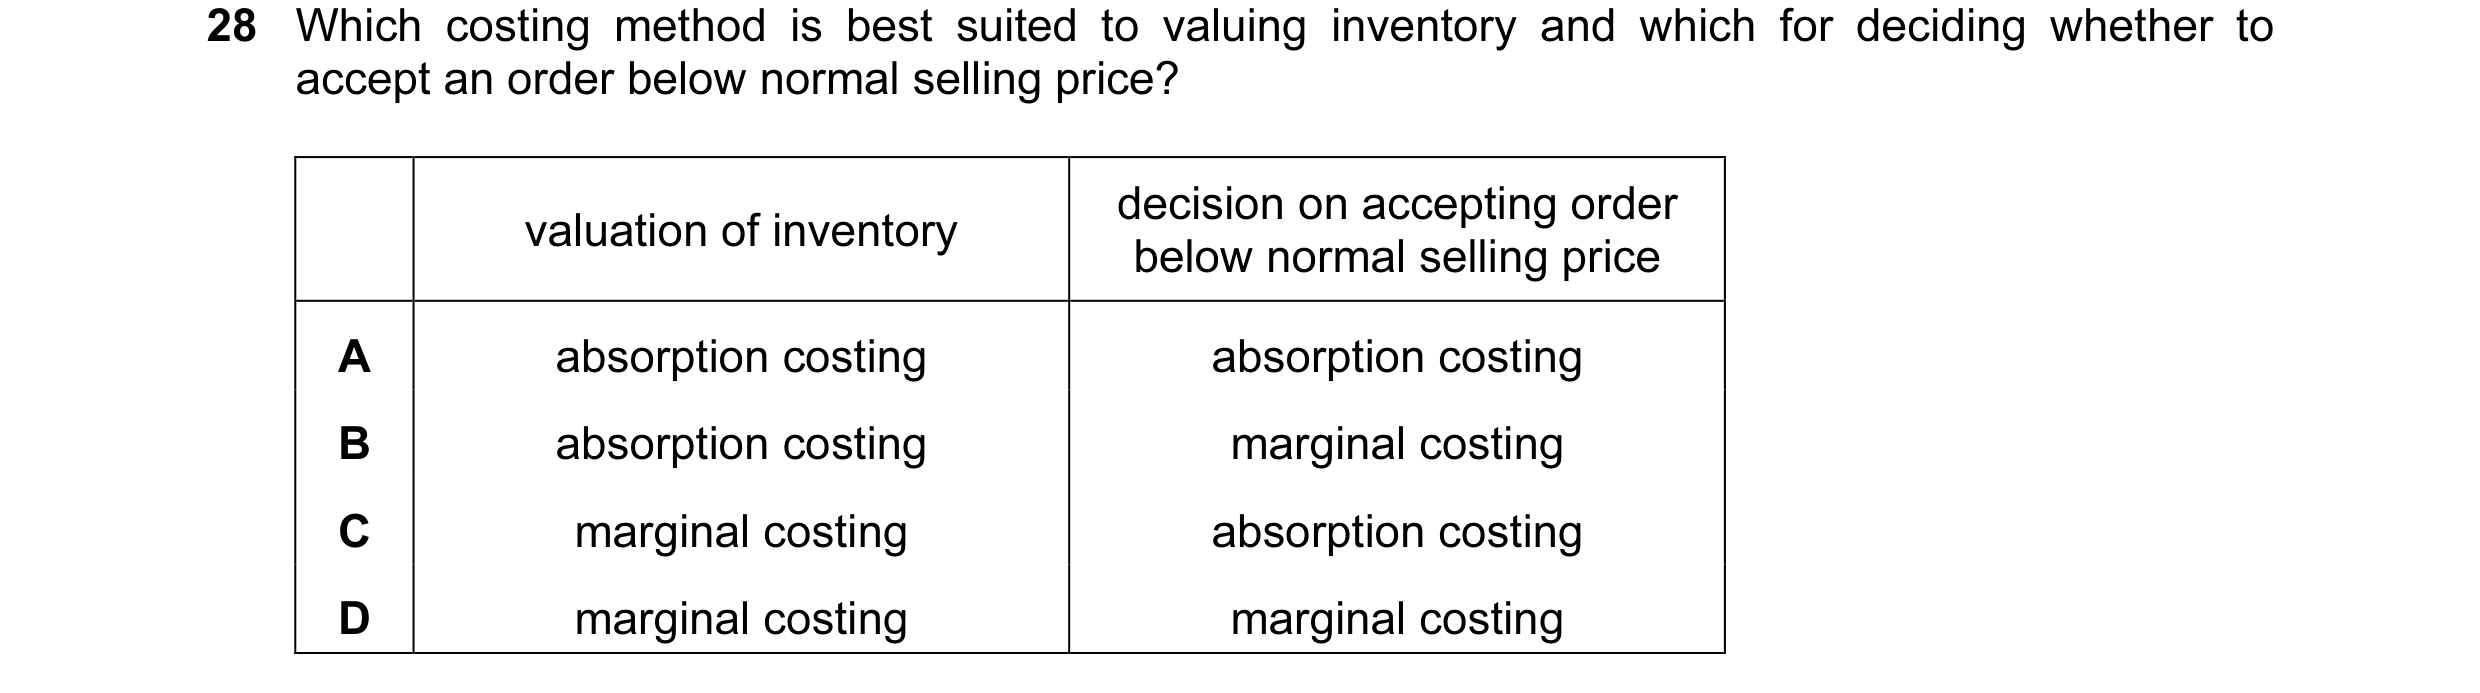
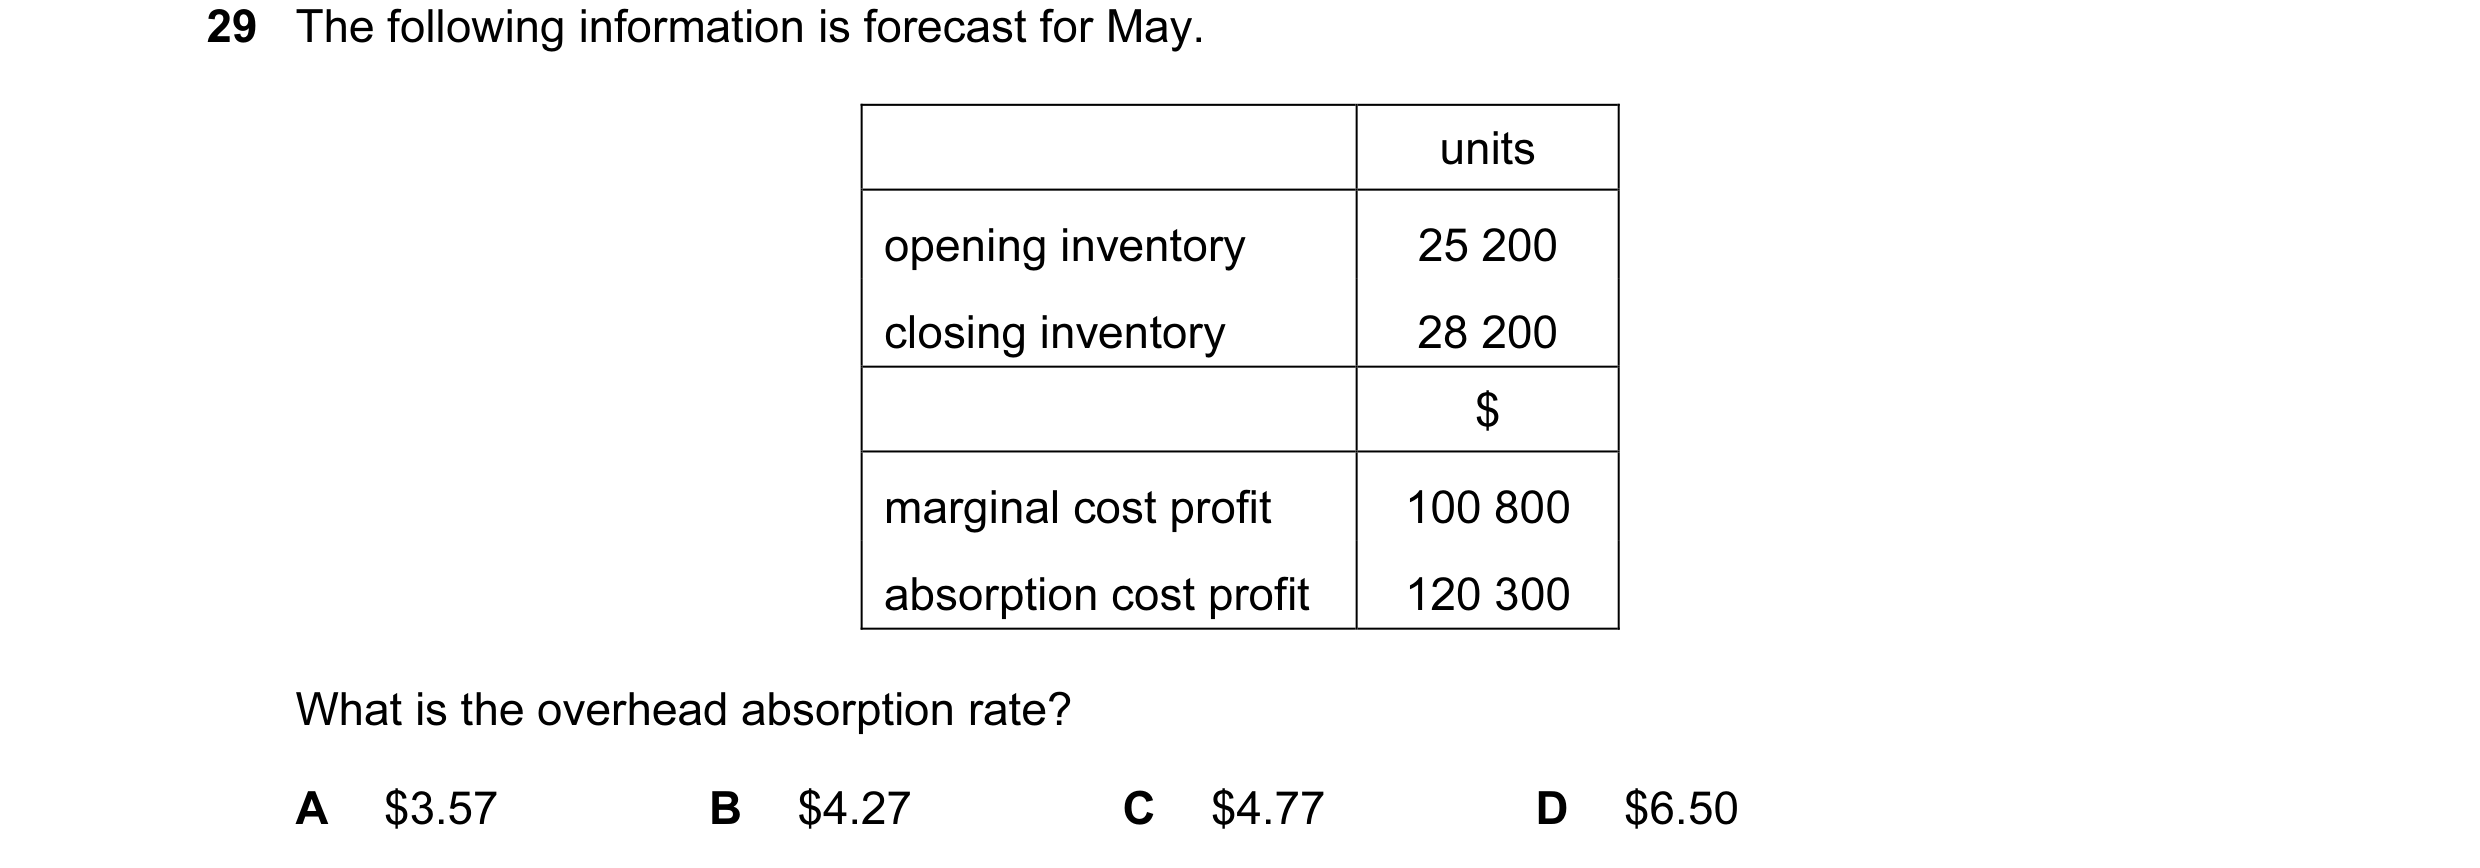 27 / 143
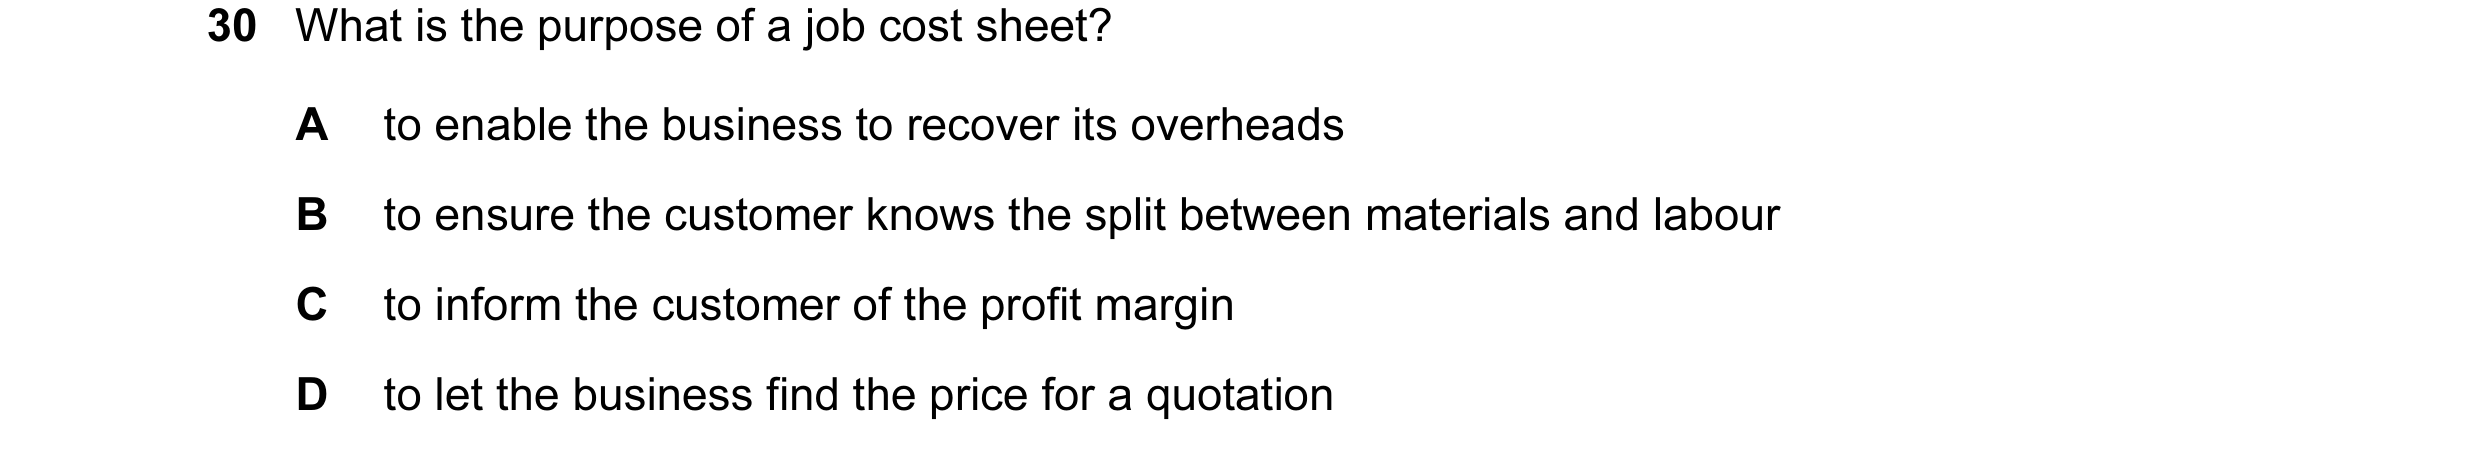
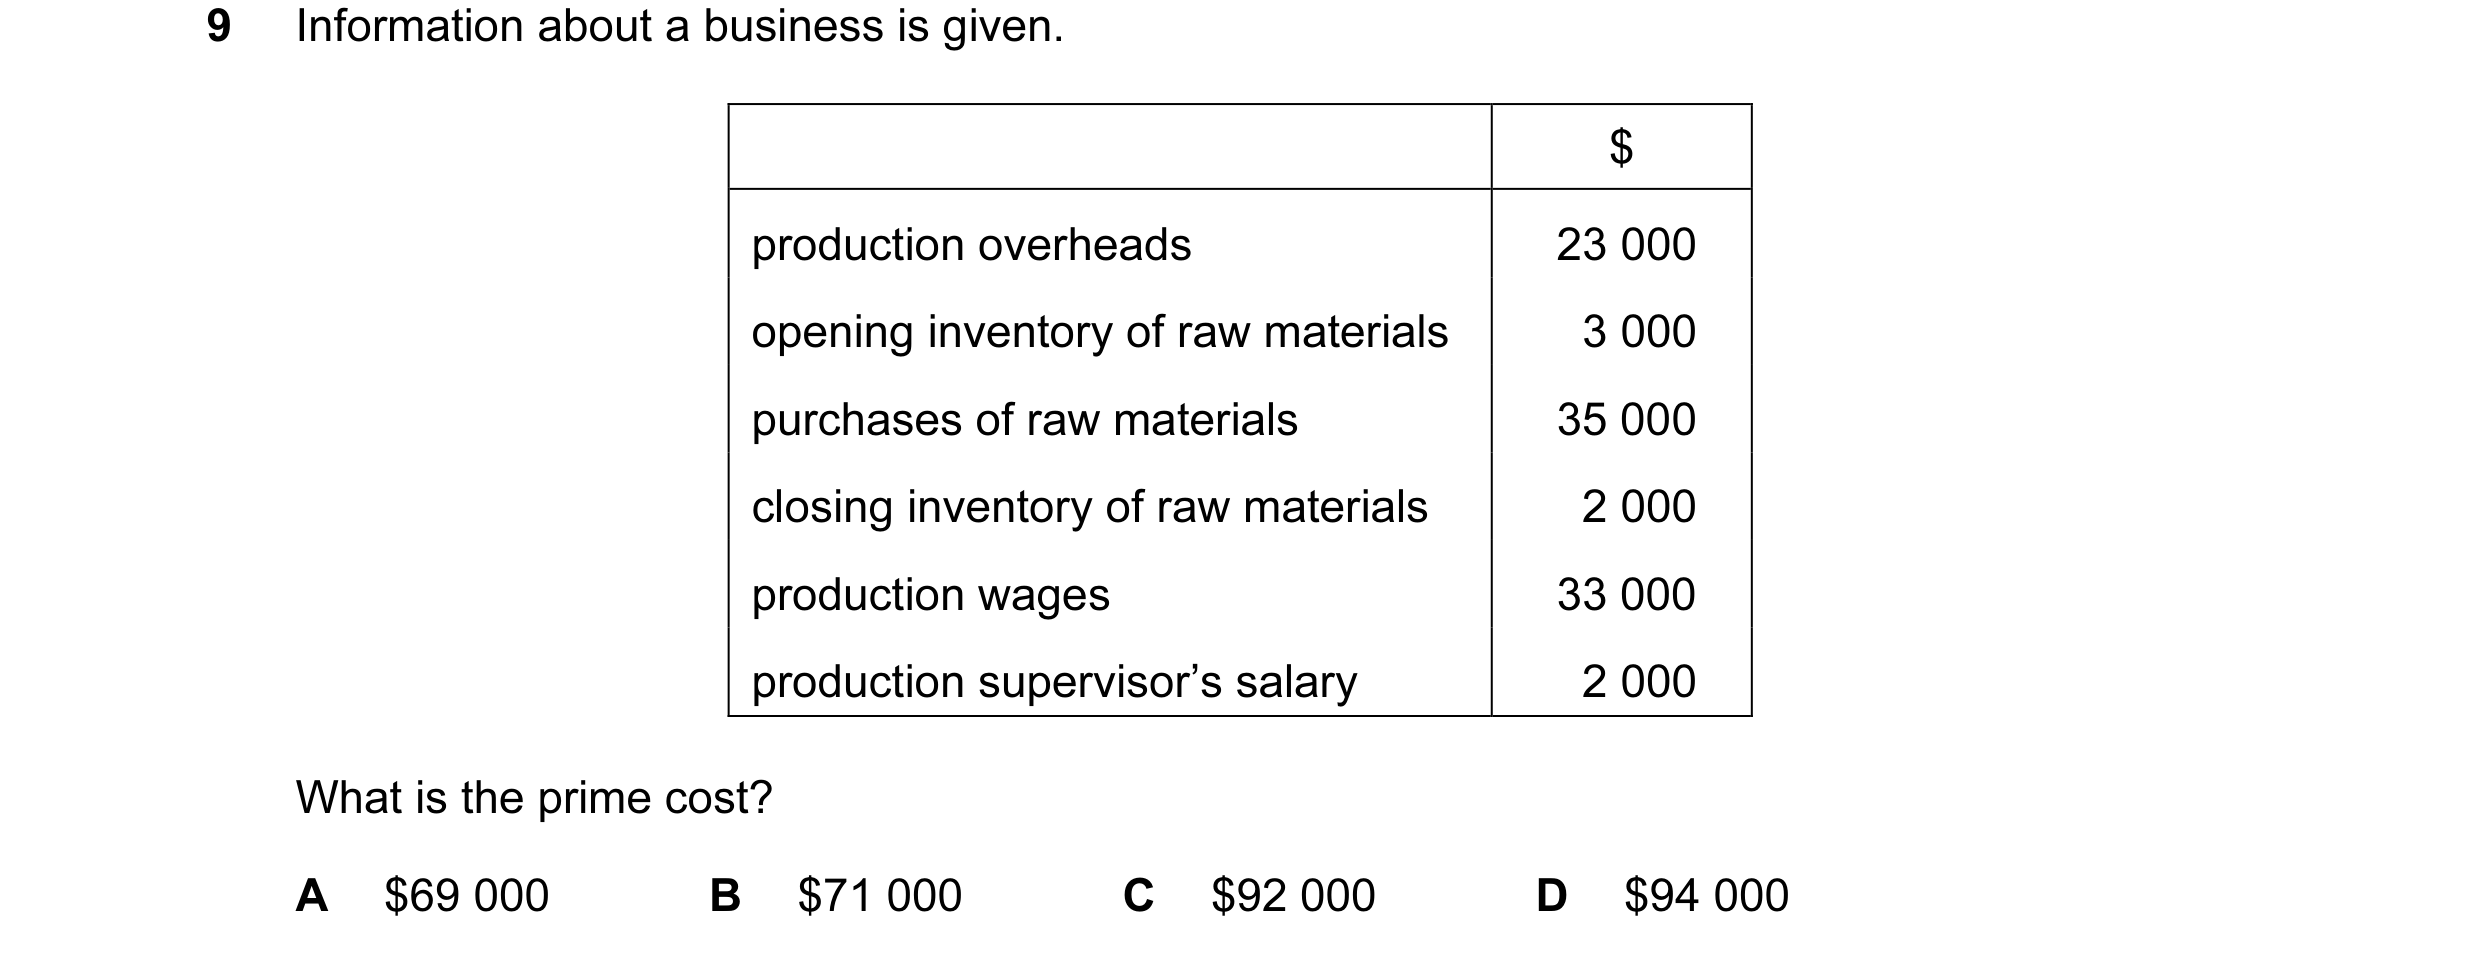
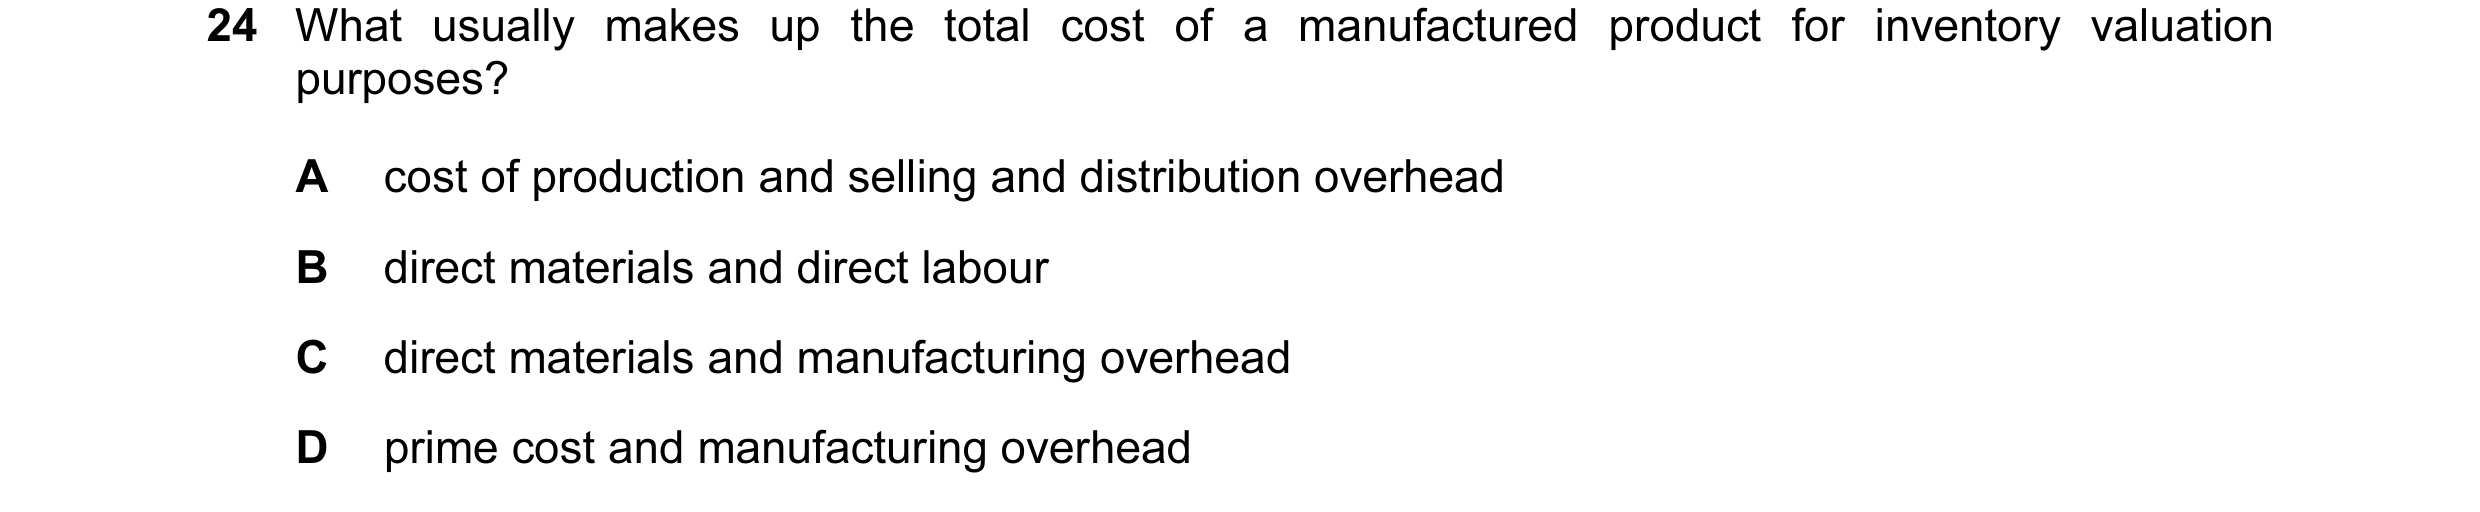
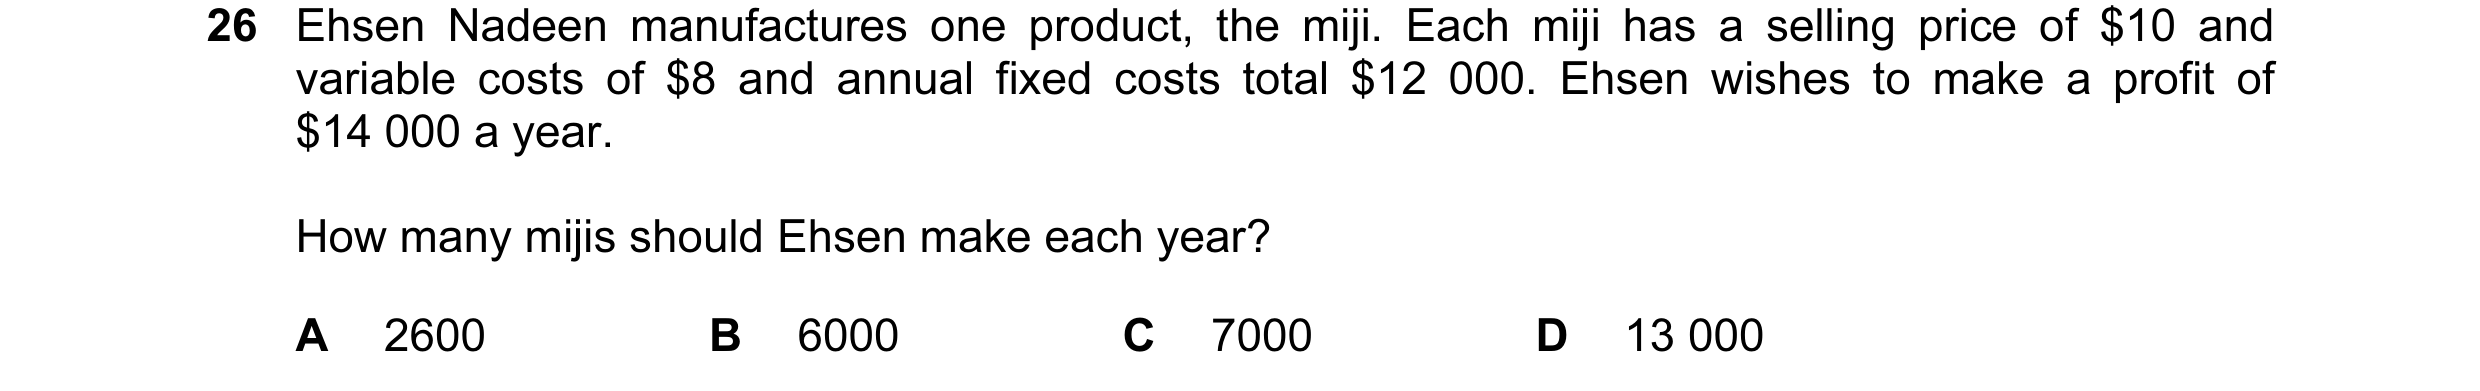
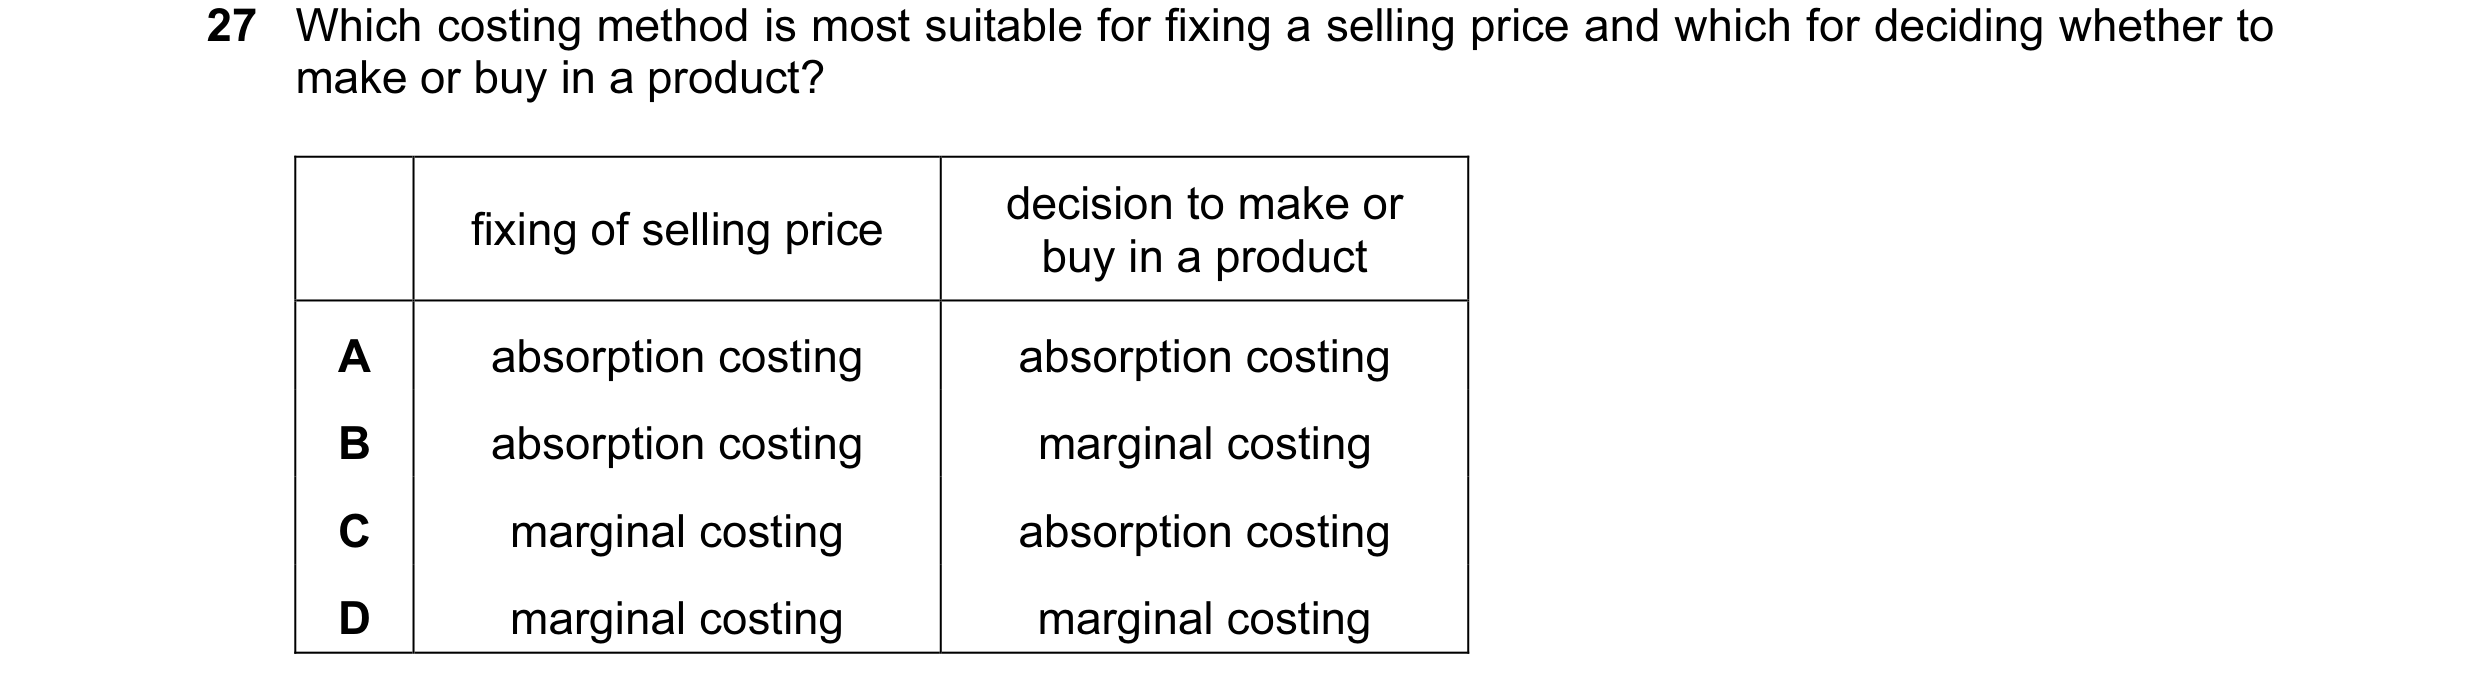 28 / 143
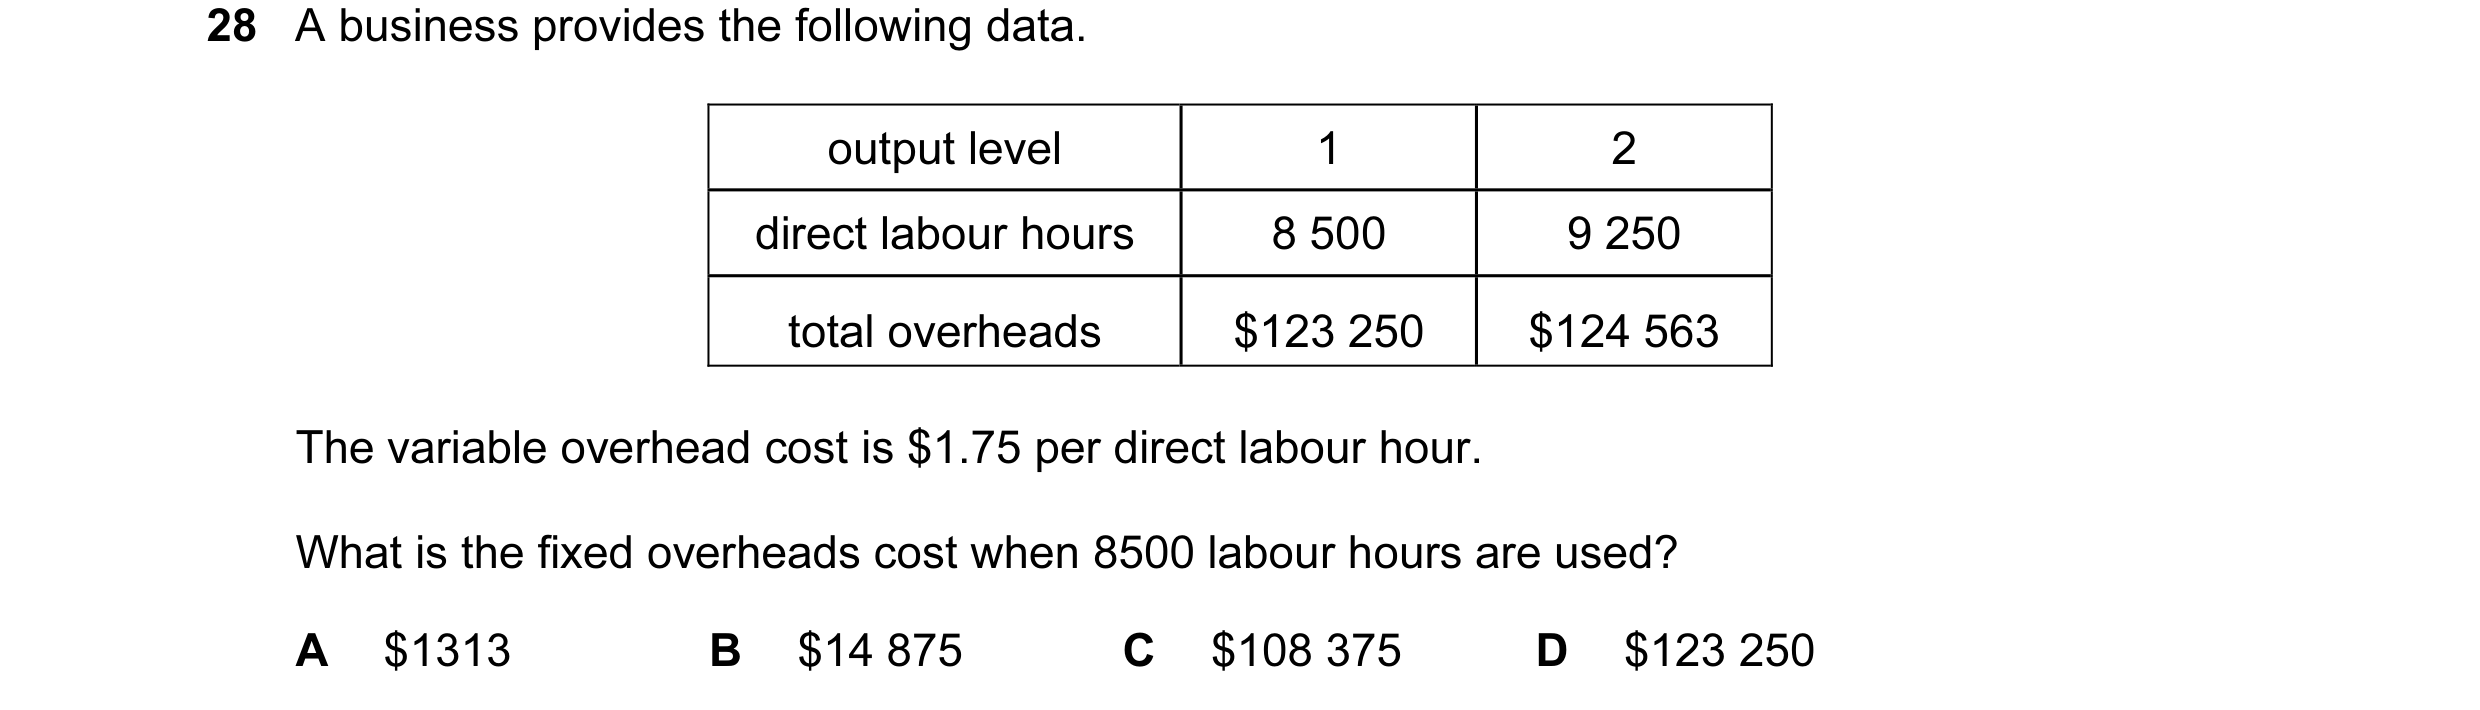
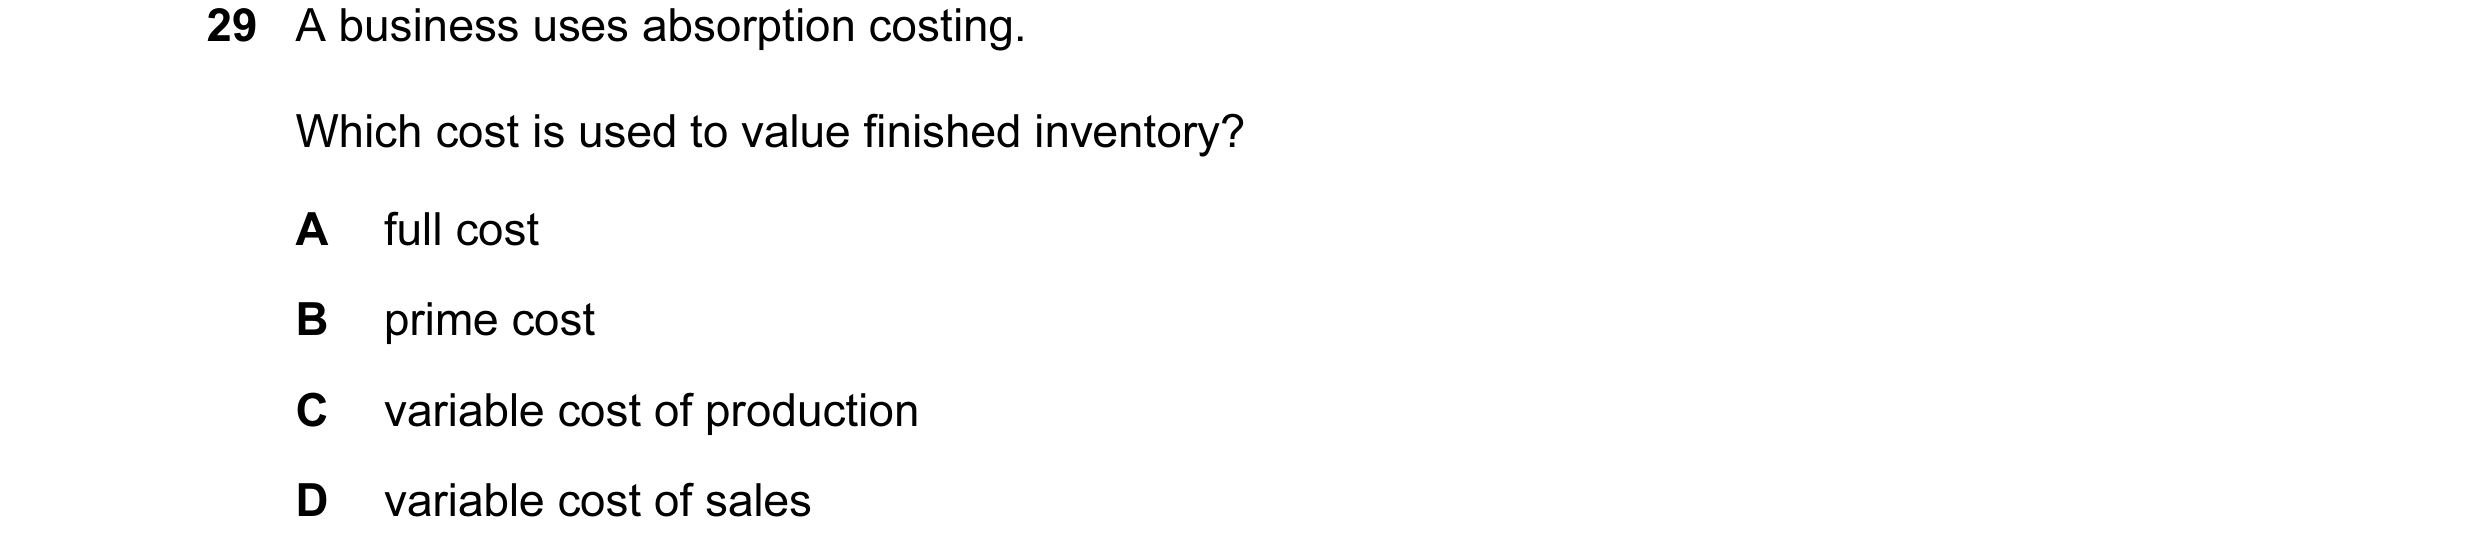
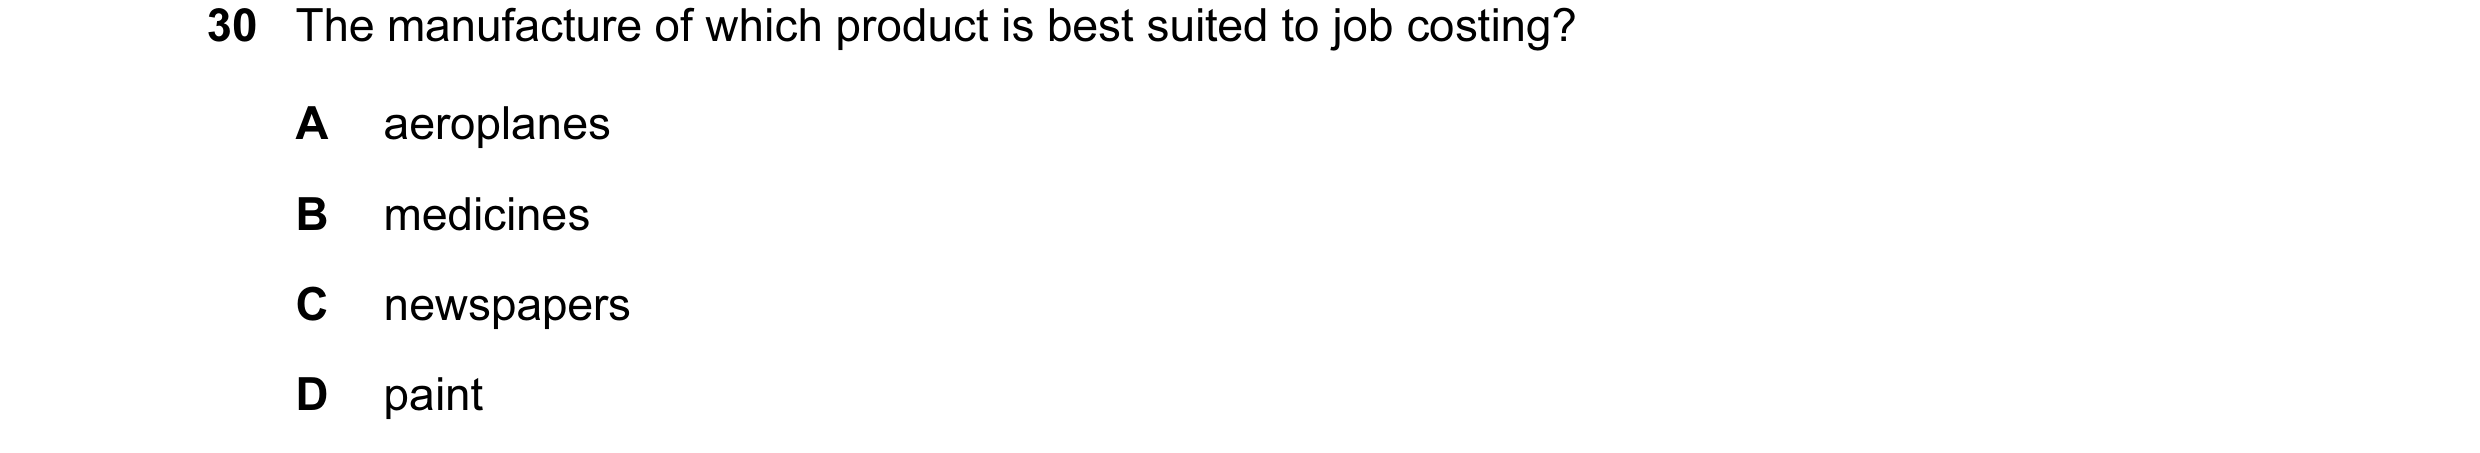
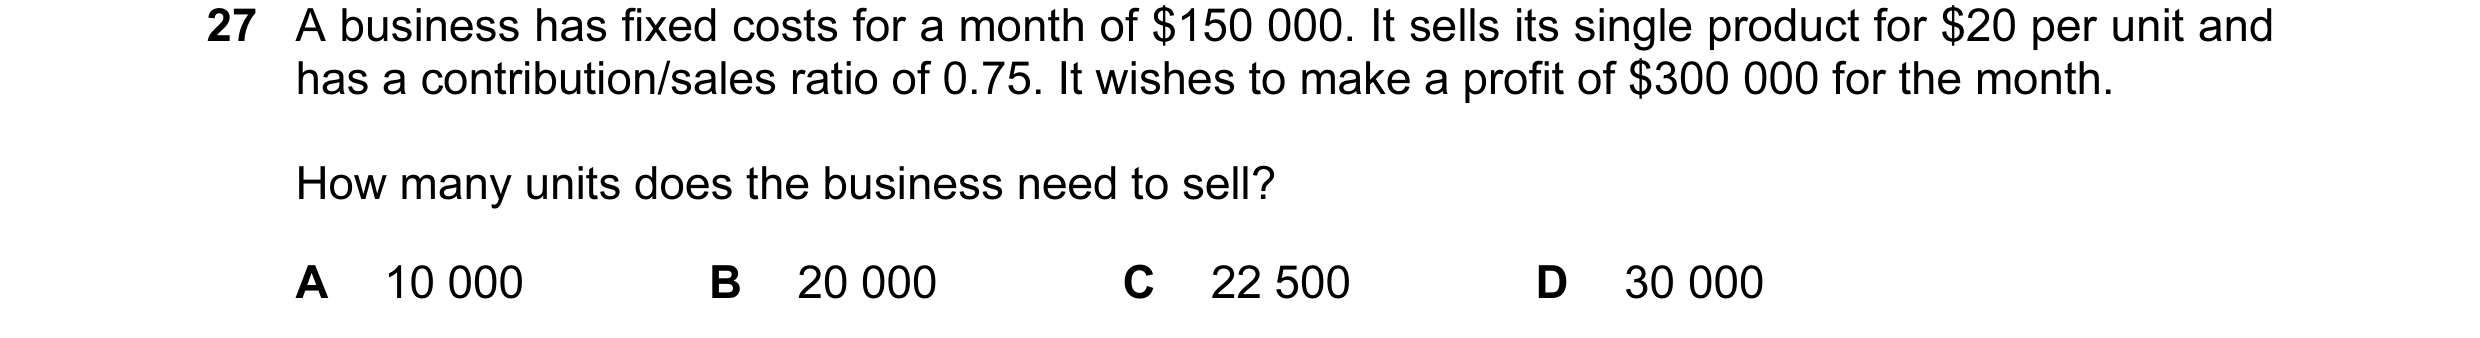
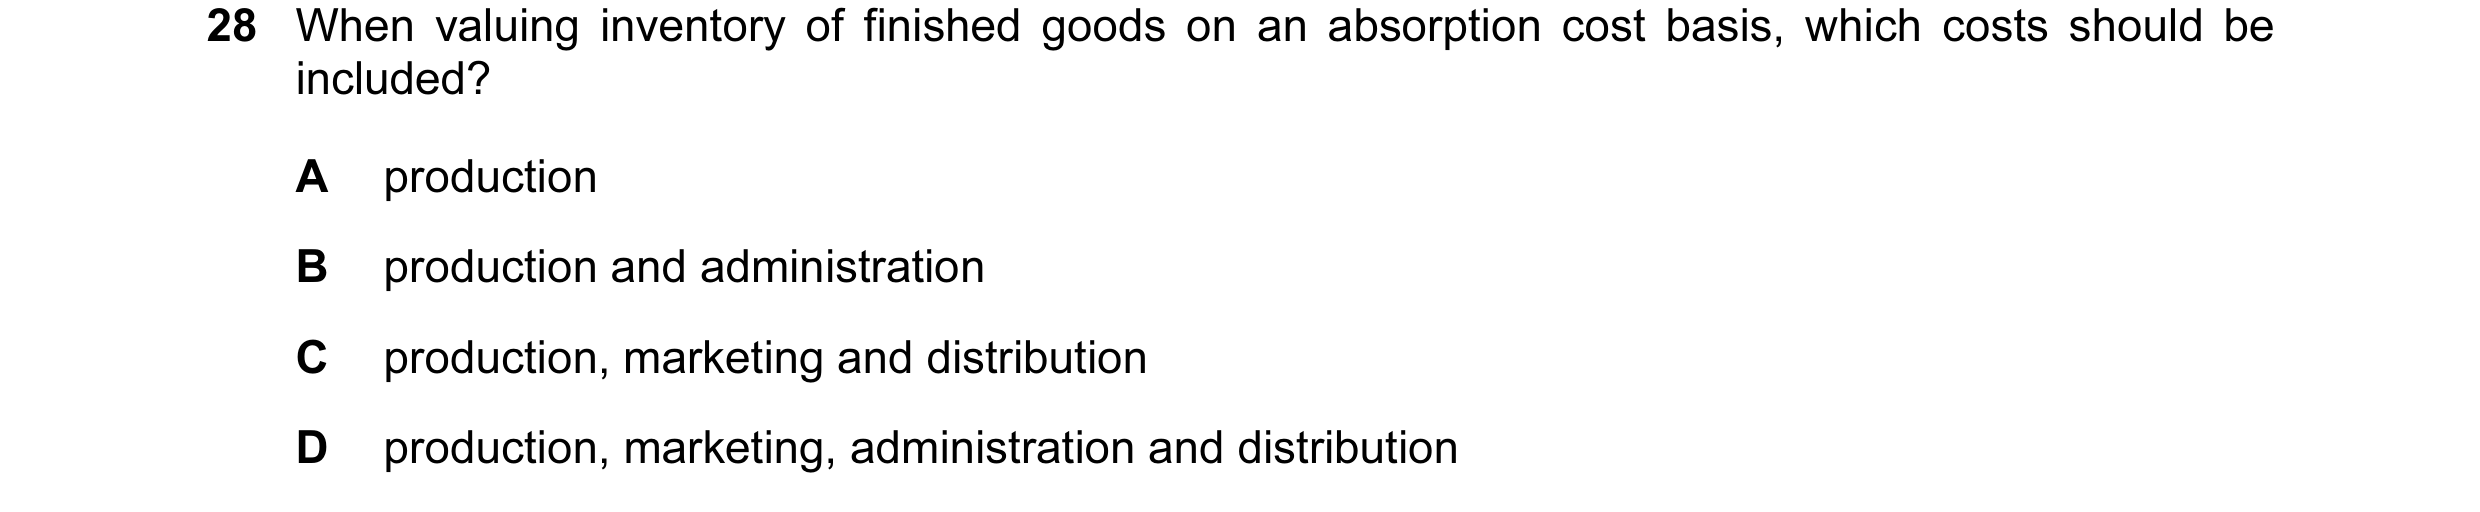
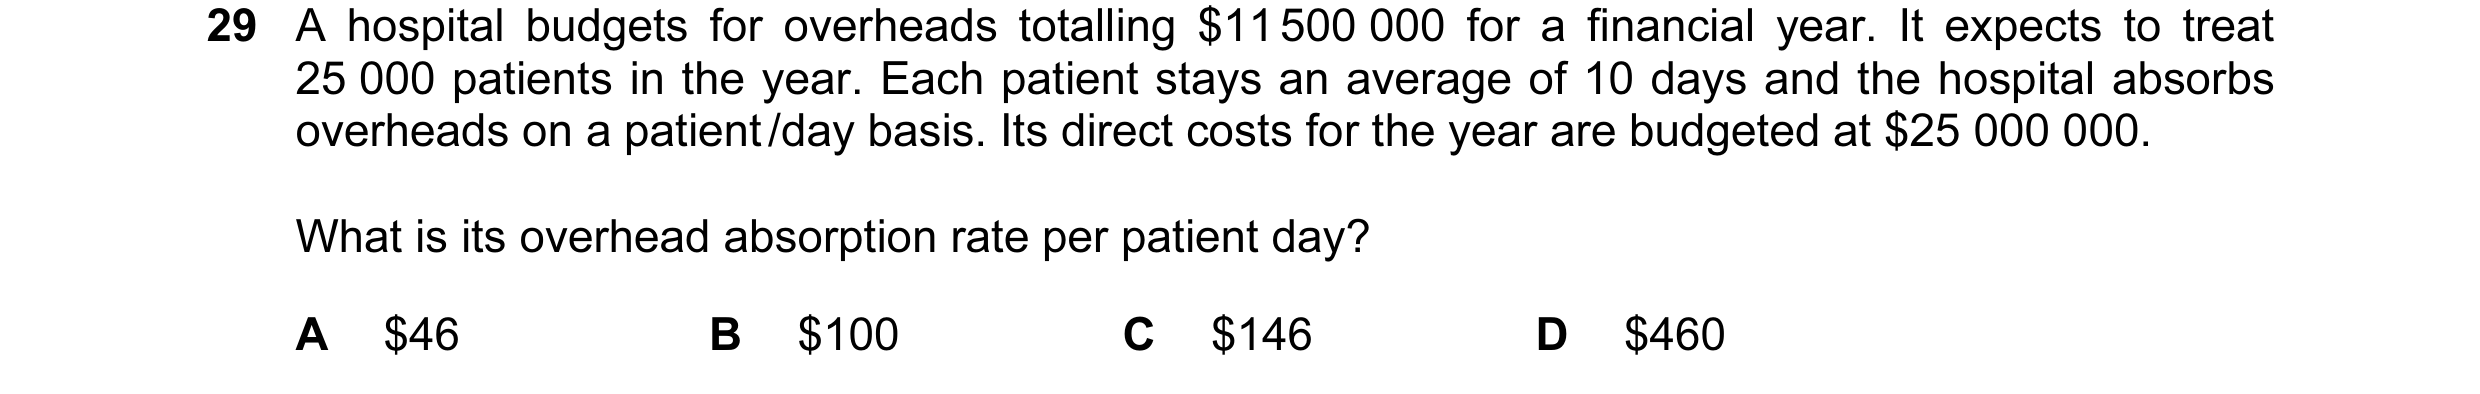 29 / 143
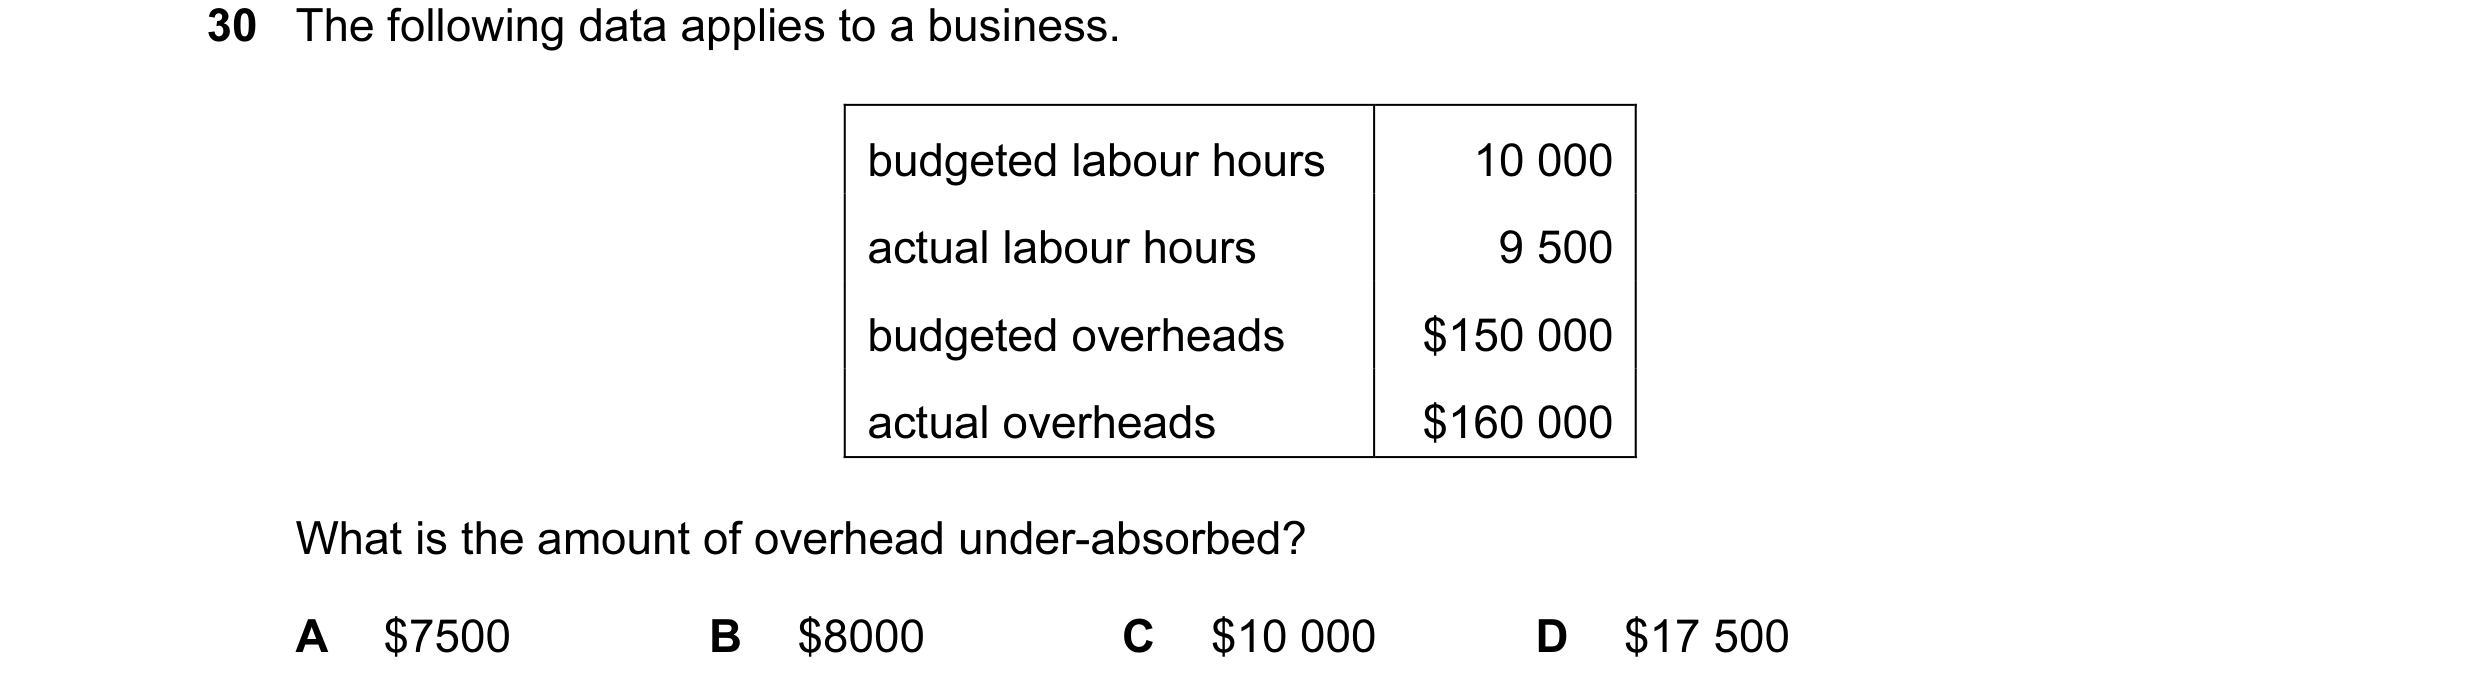
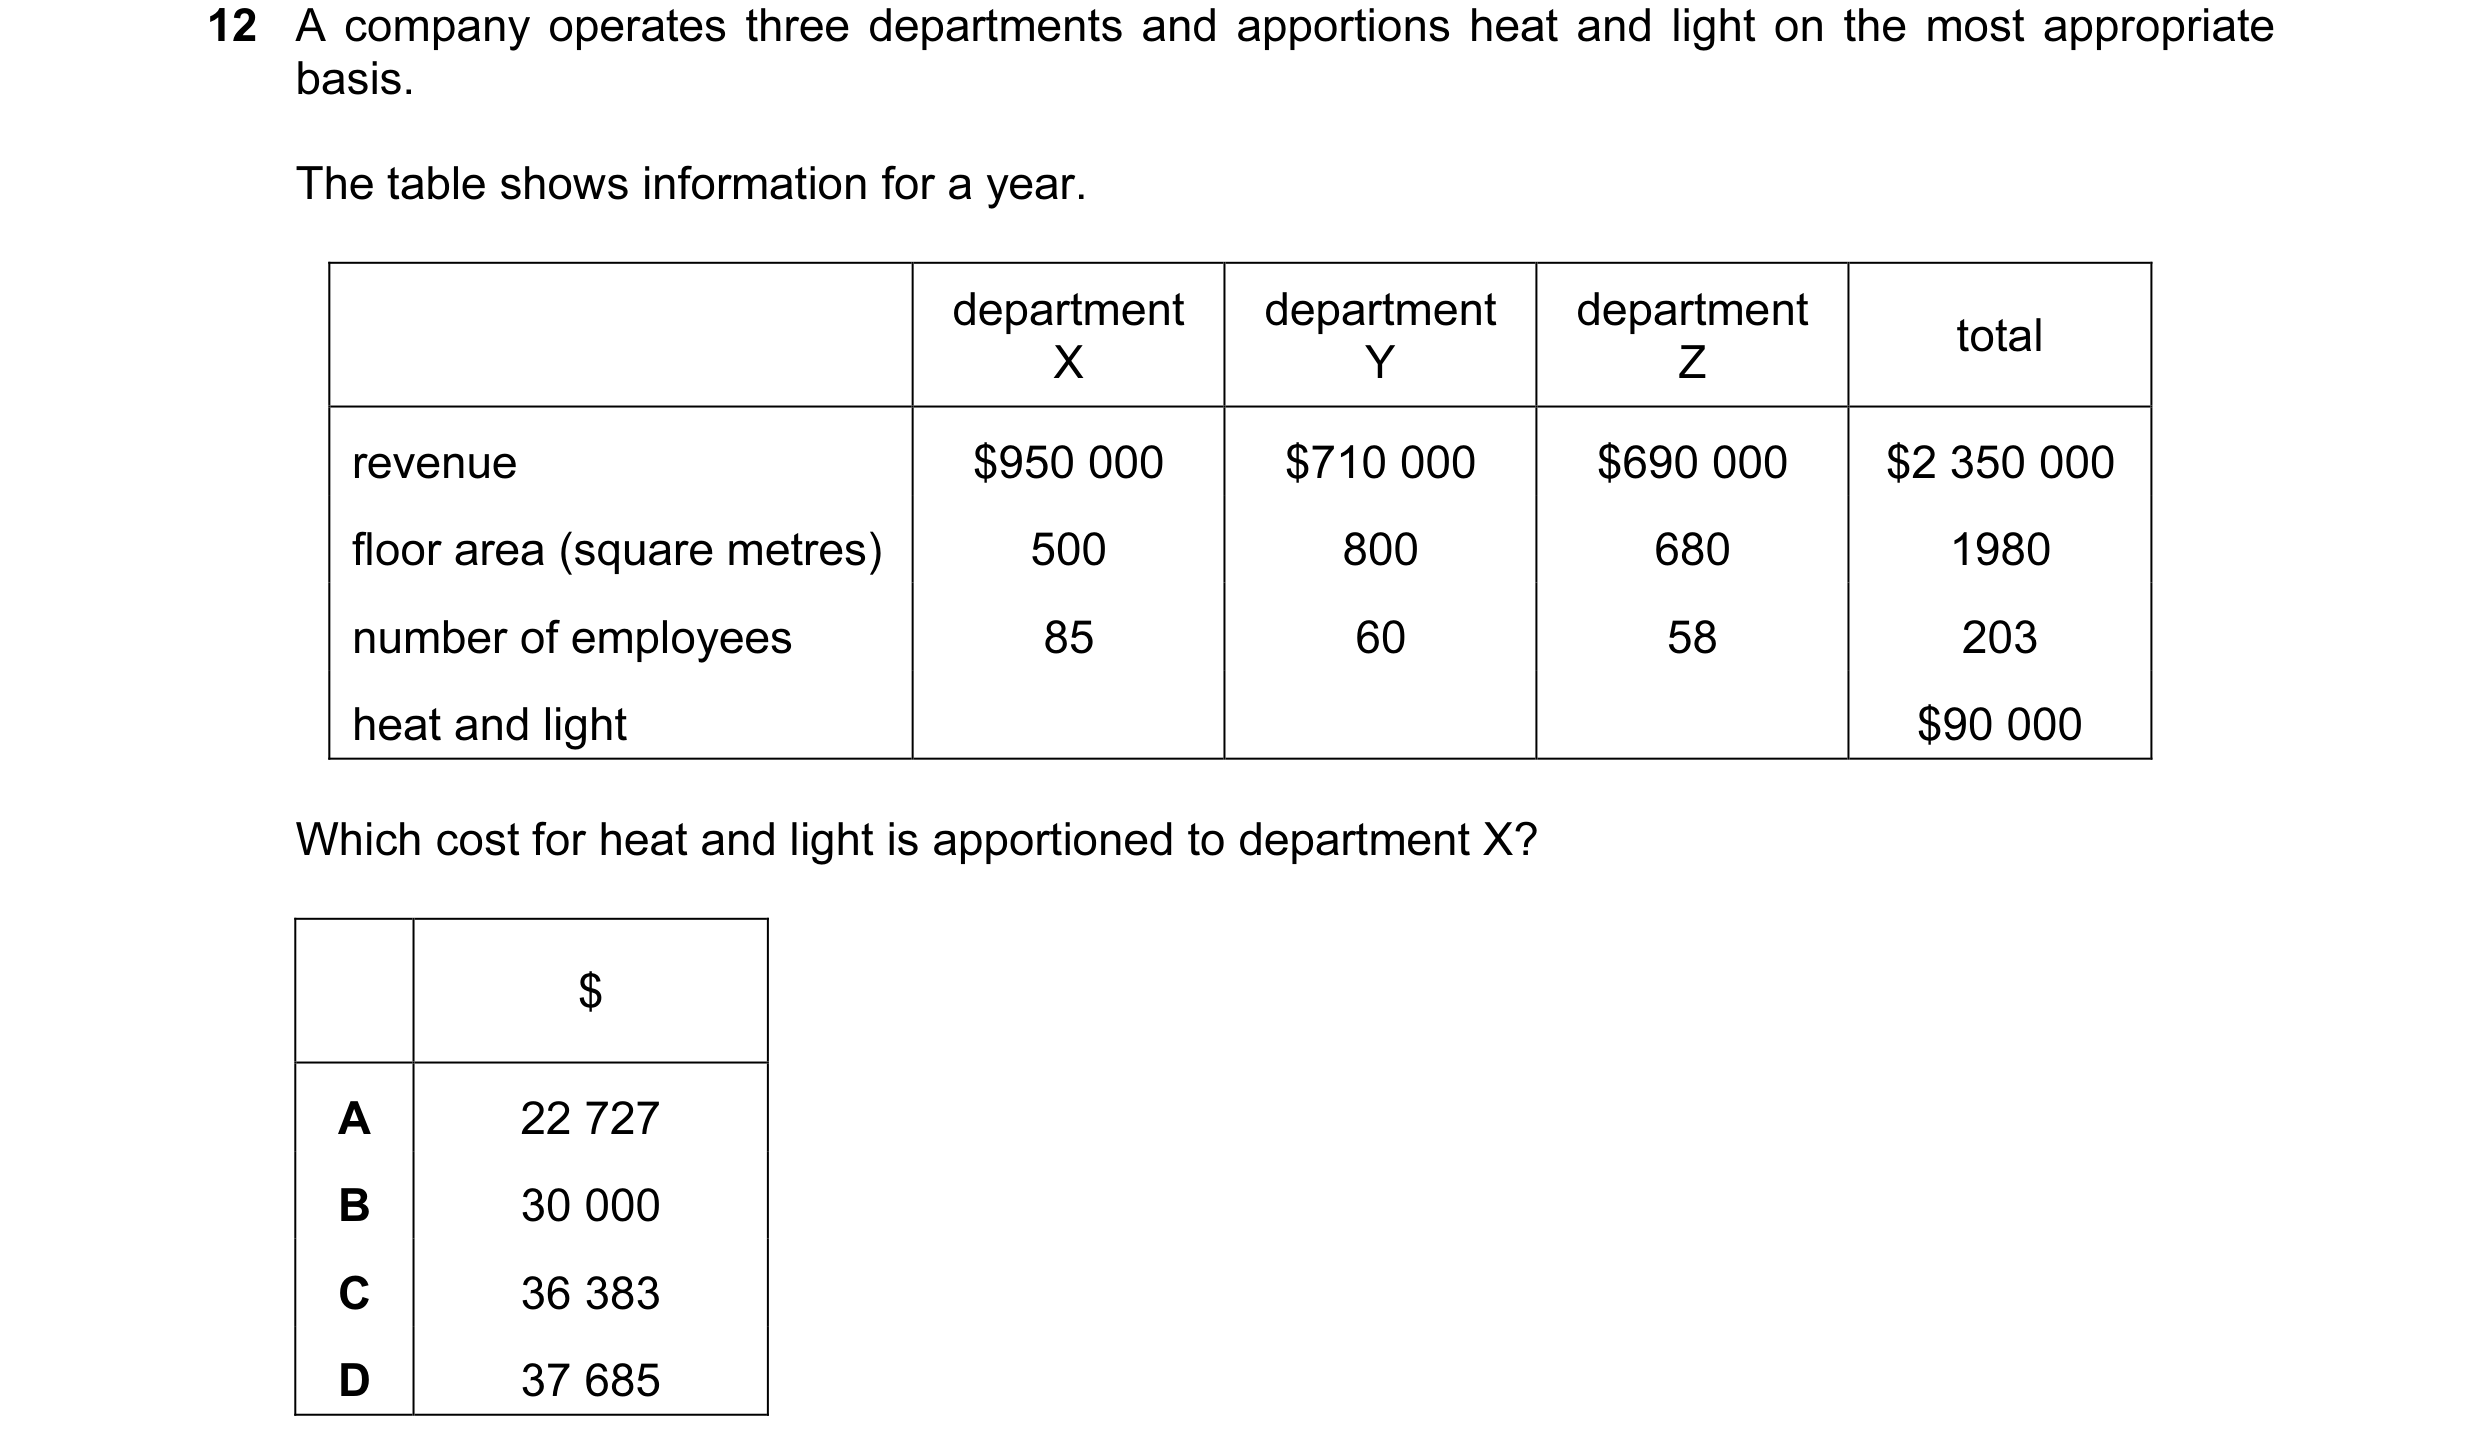
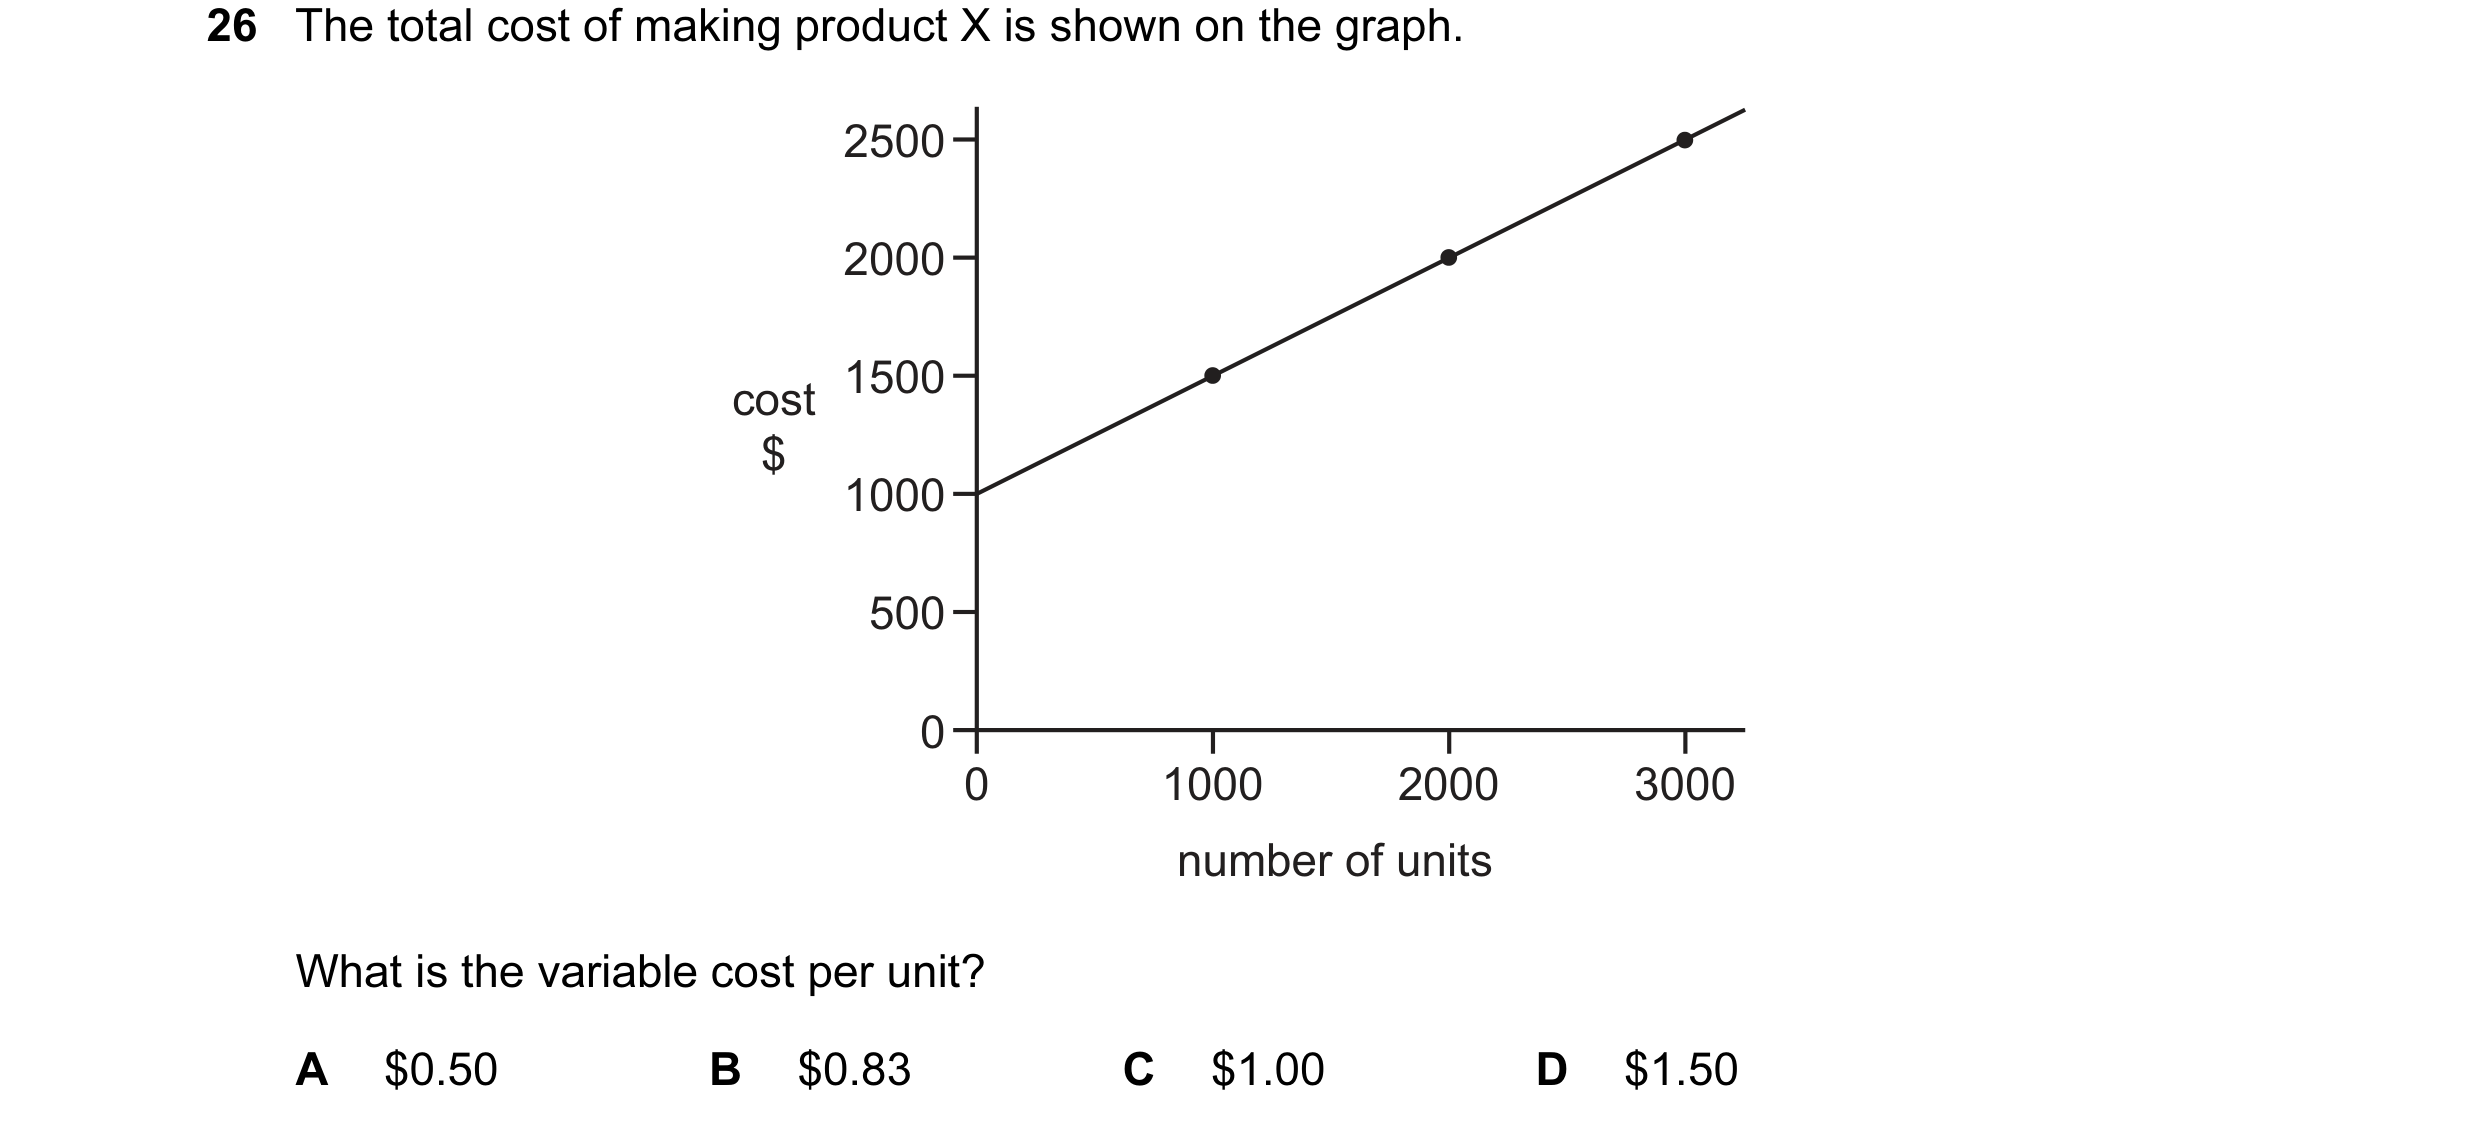 30 / 143
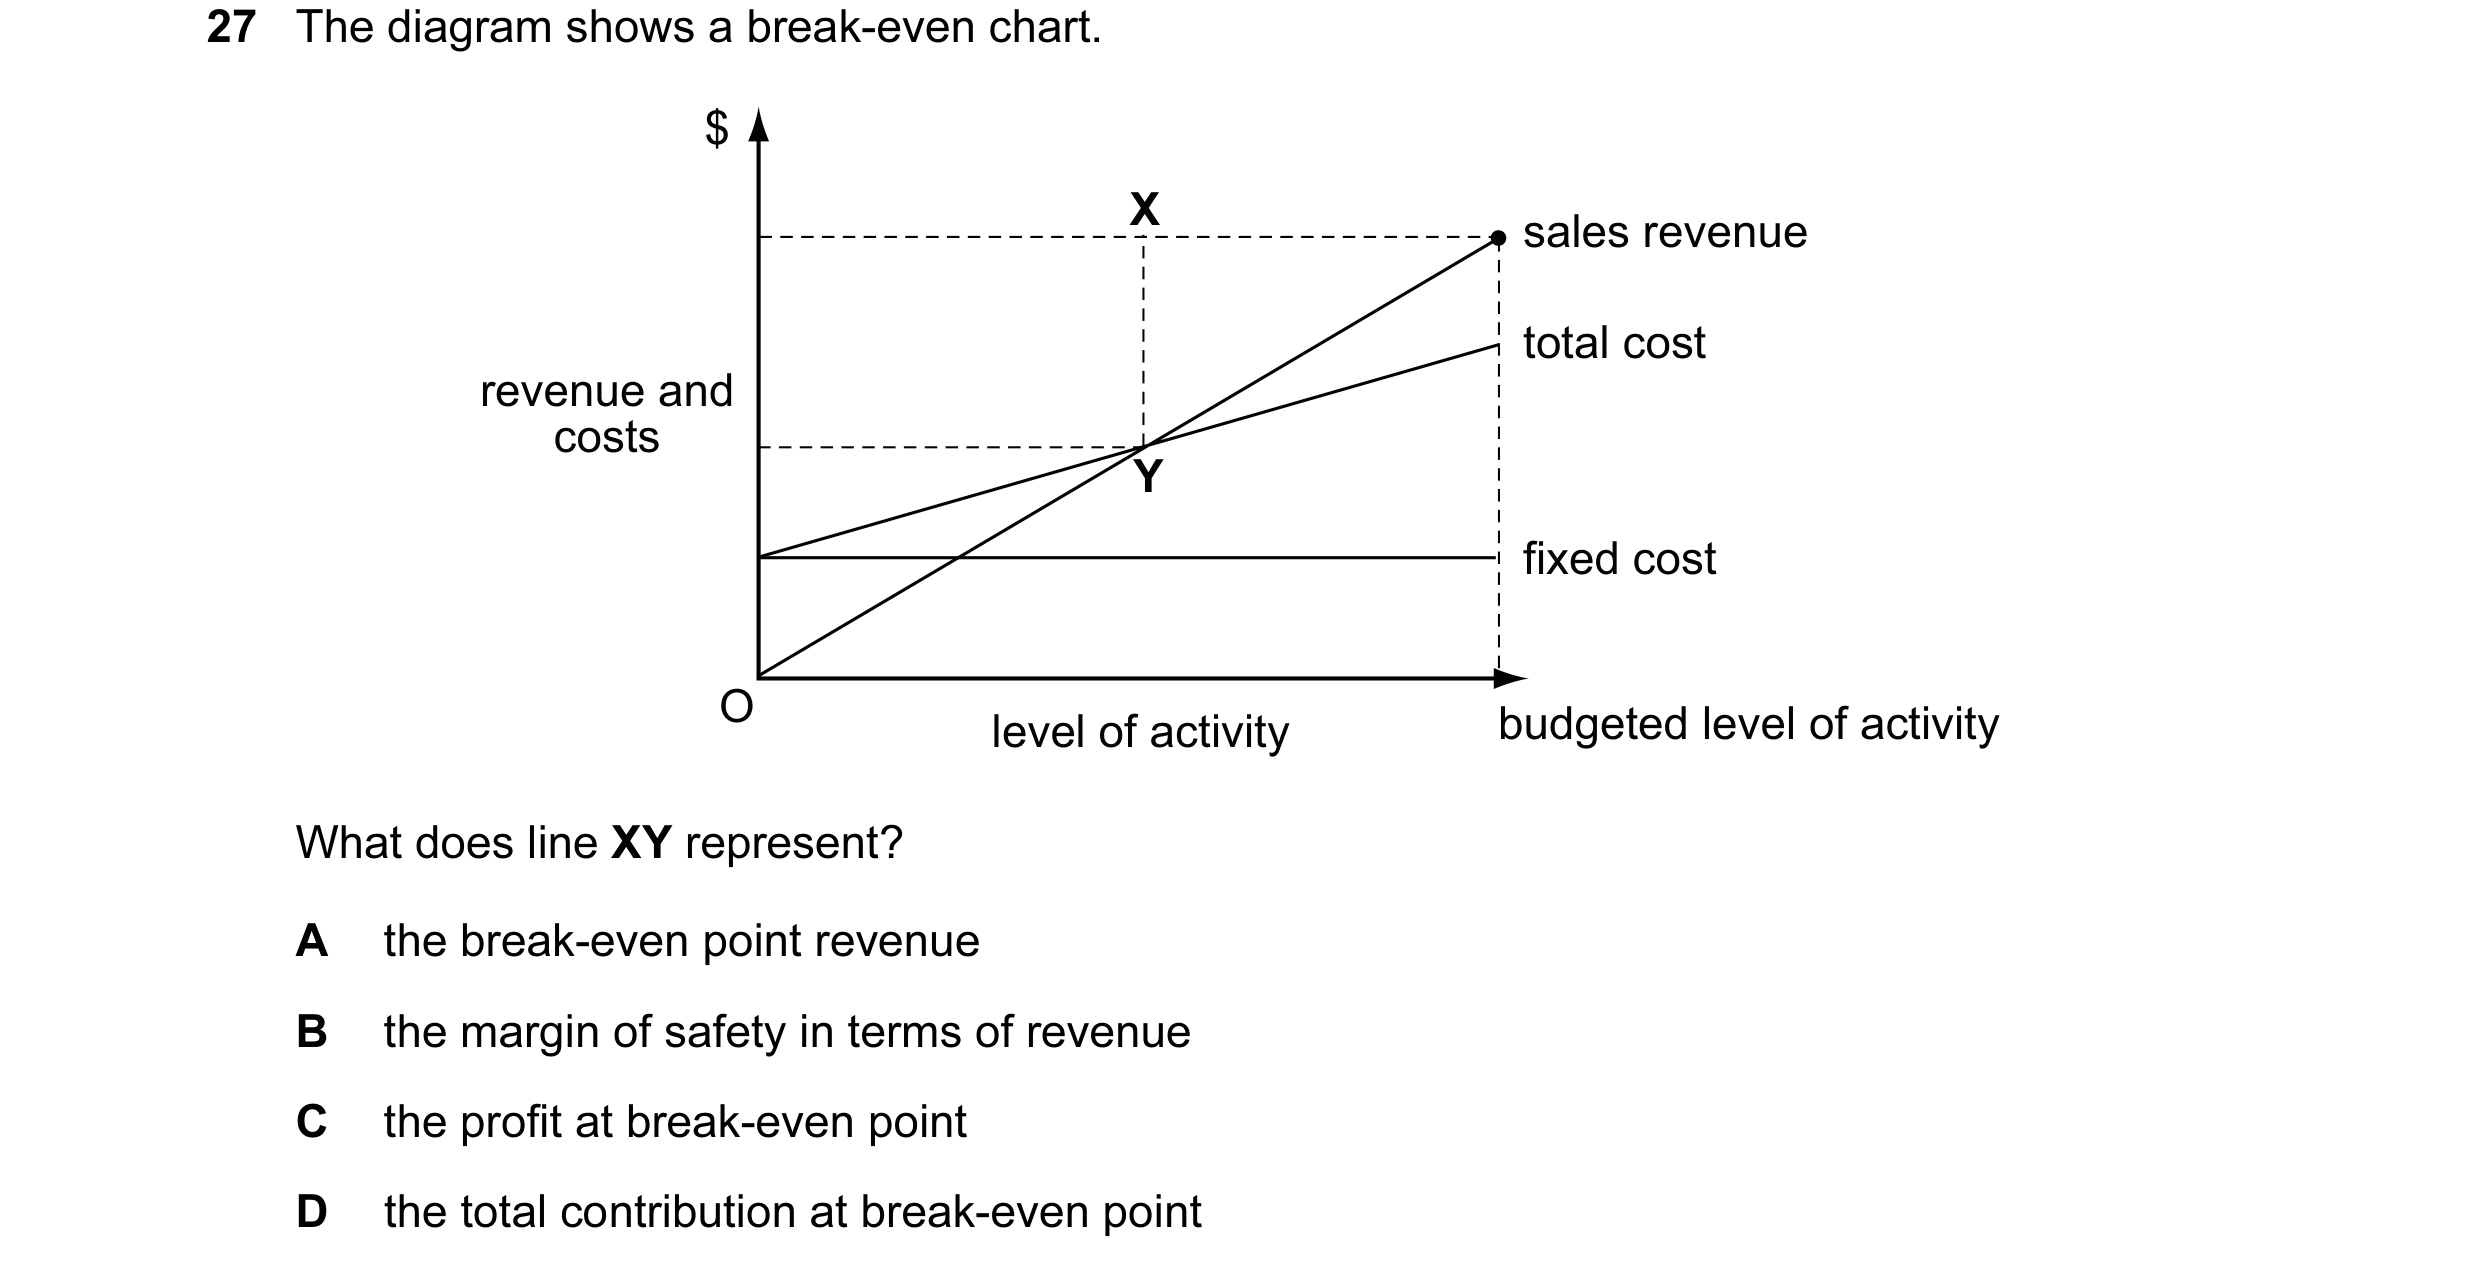
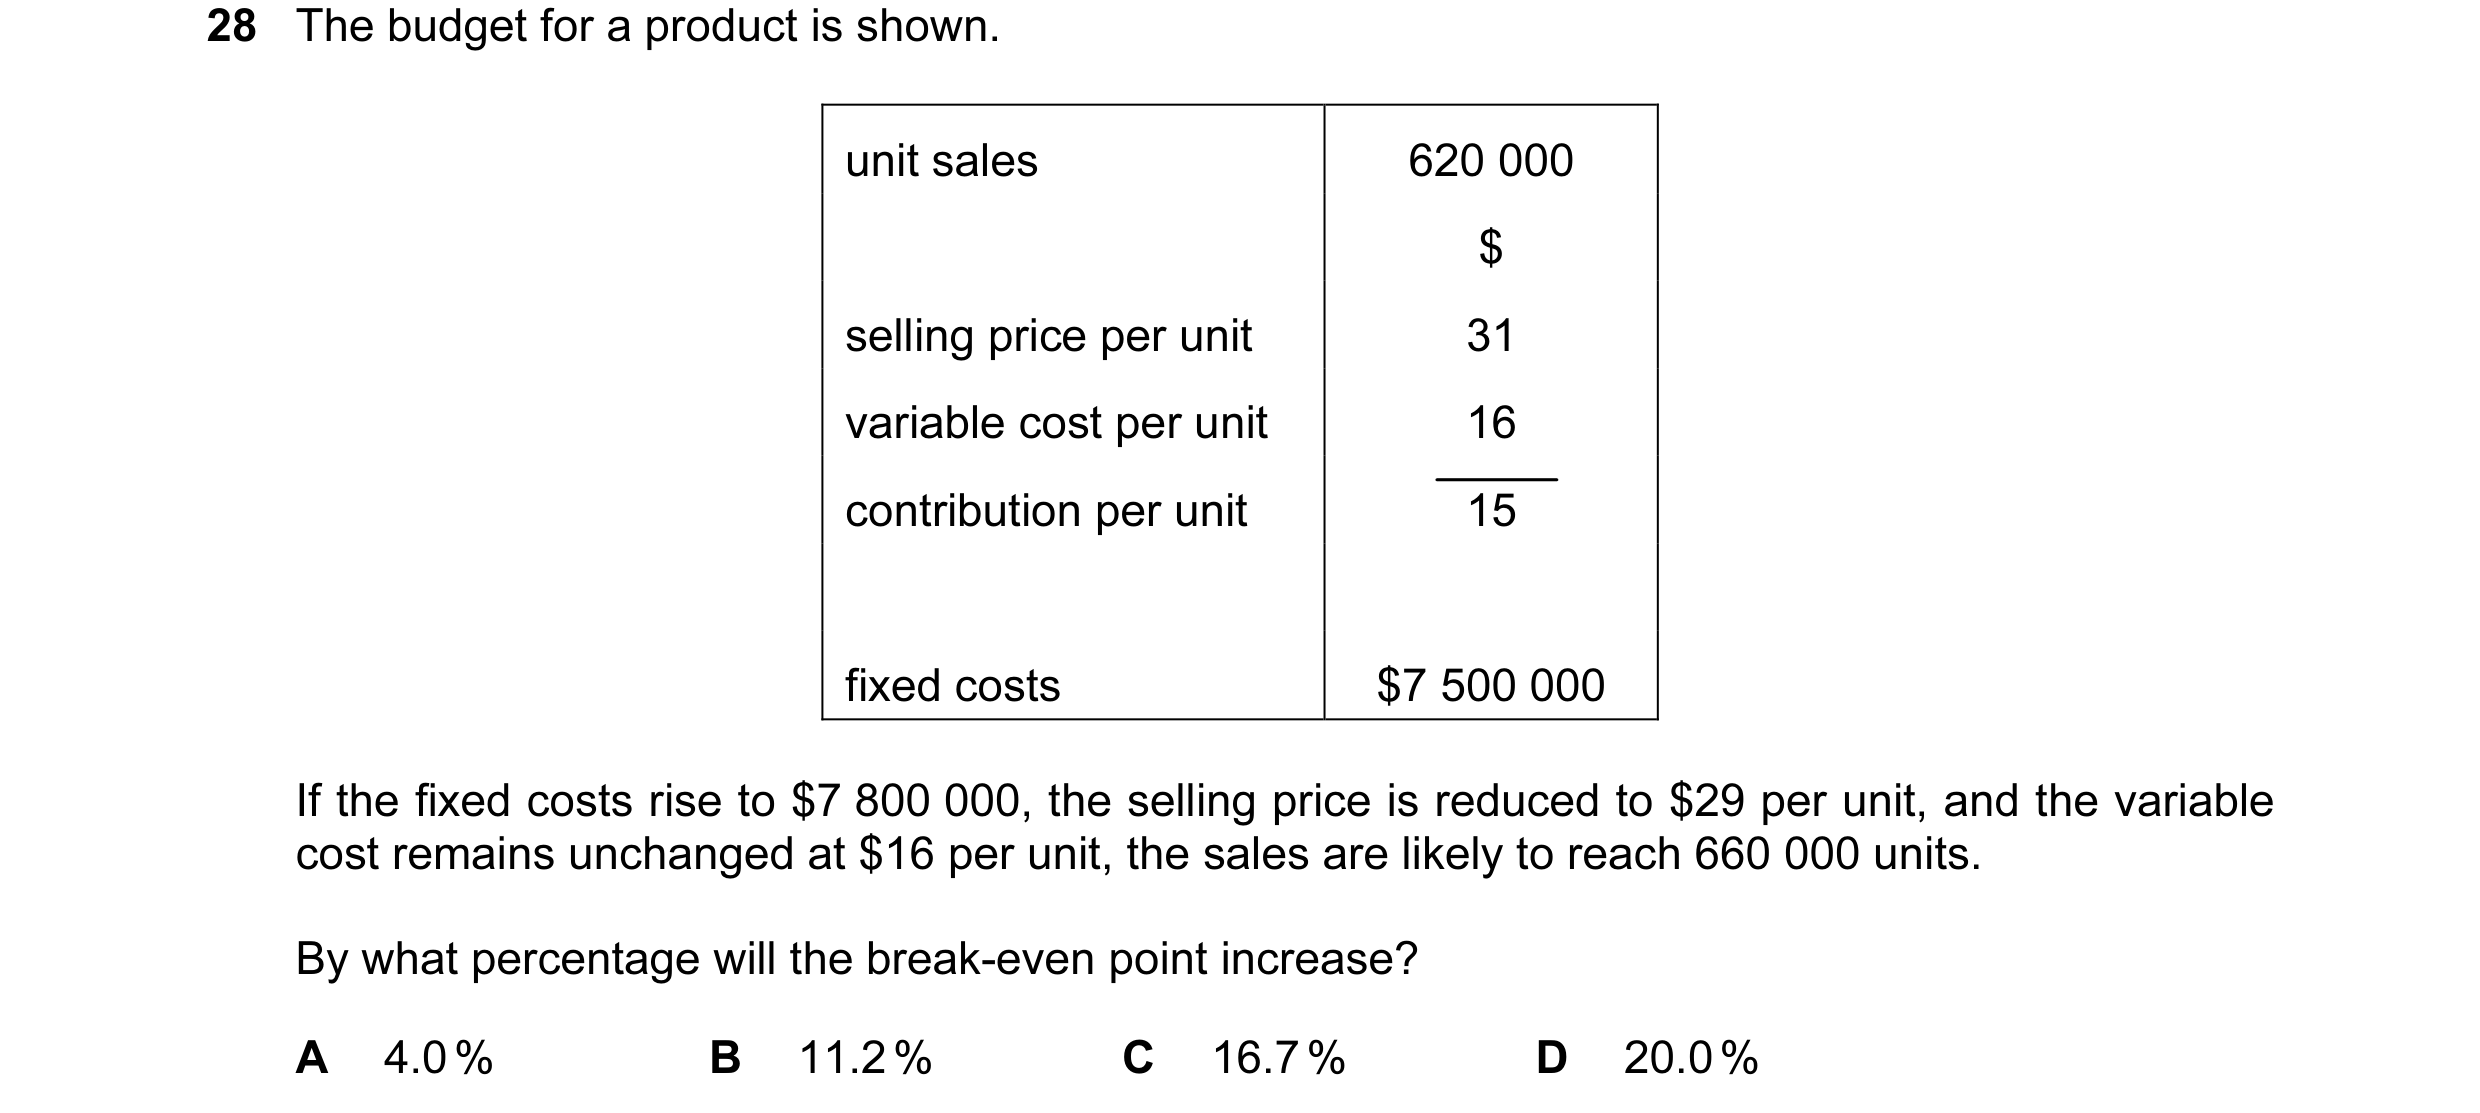
 31 / 143
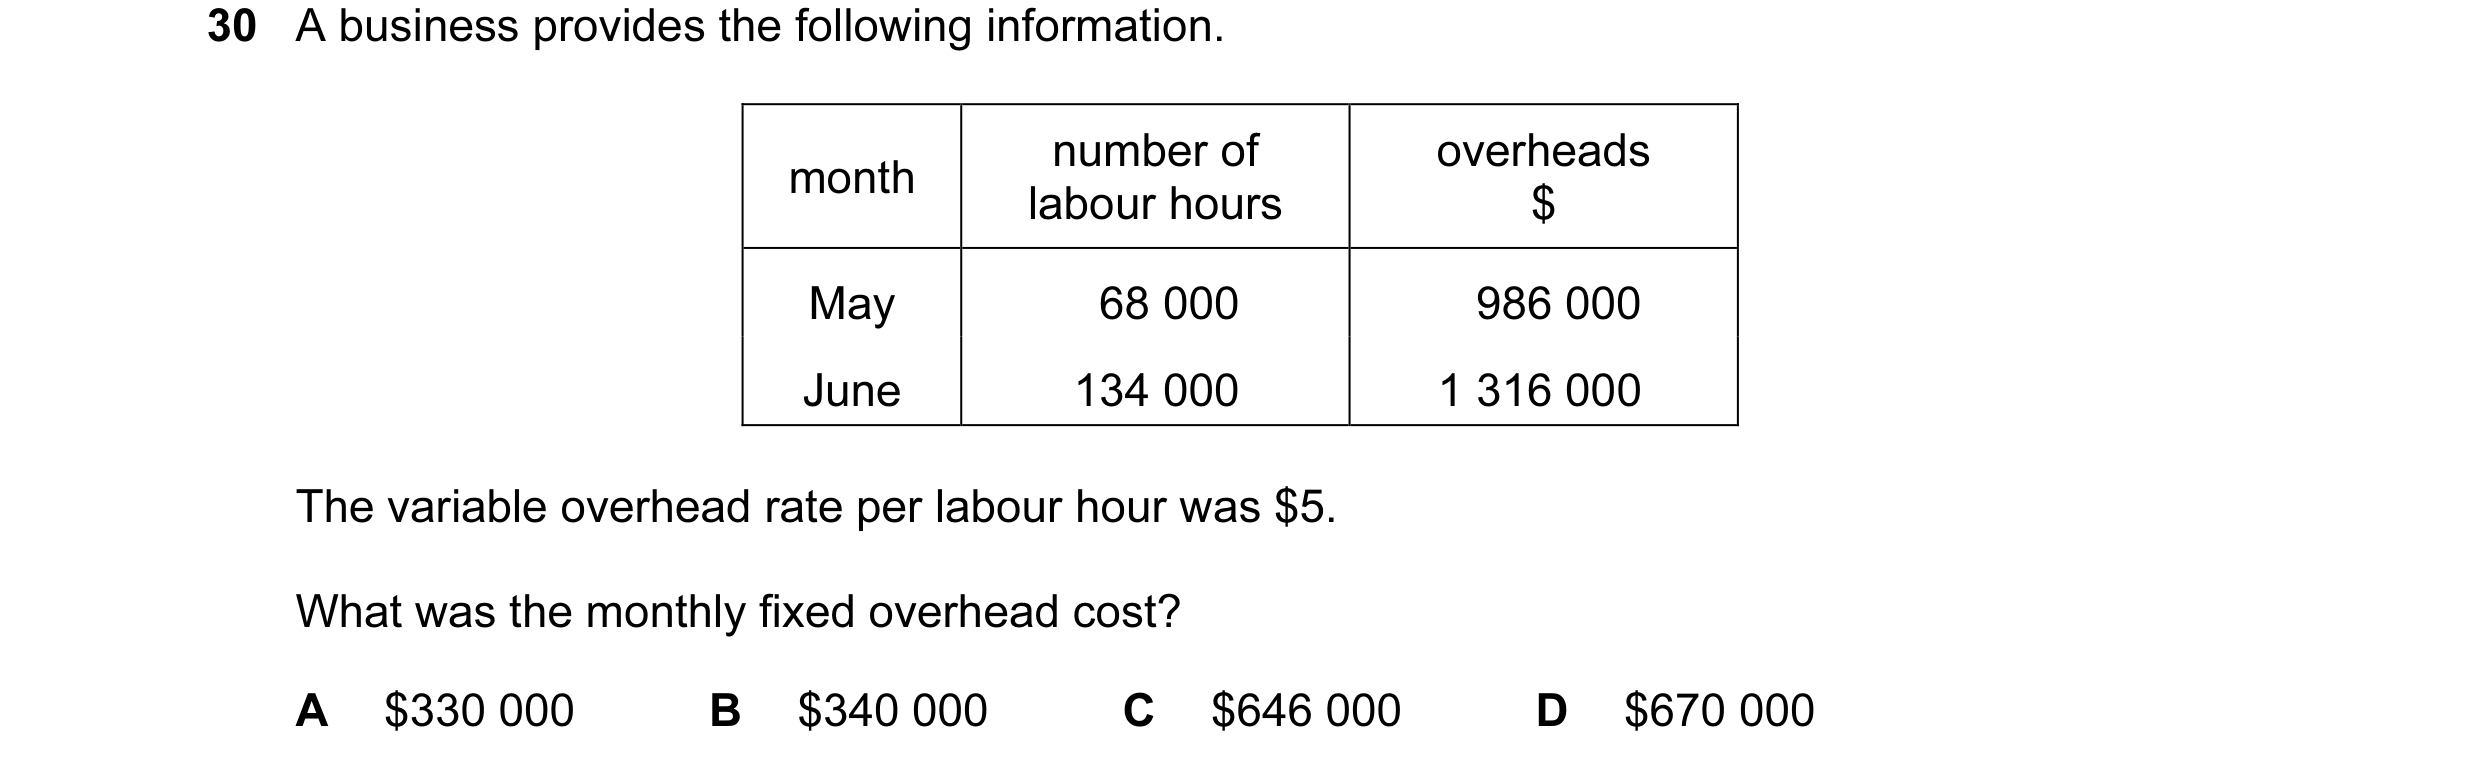
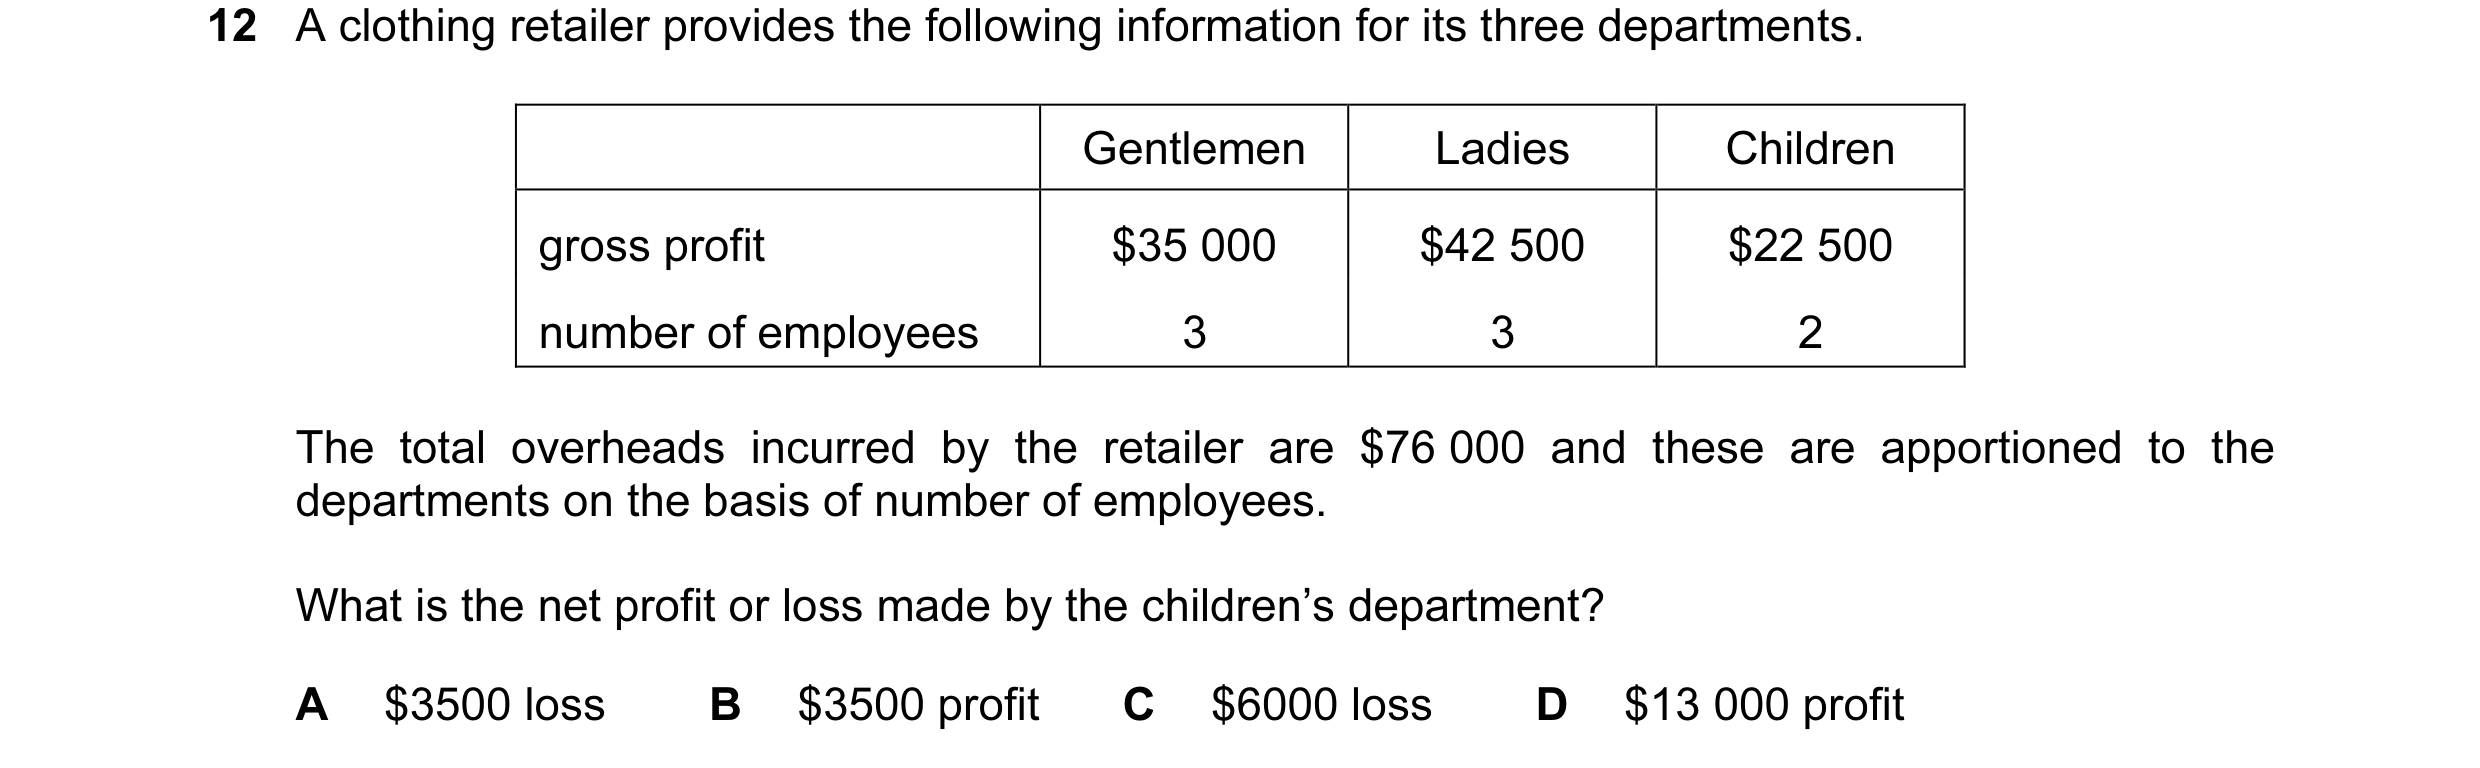
 32 / 143
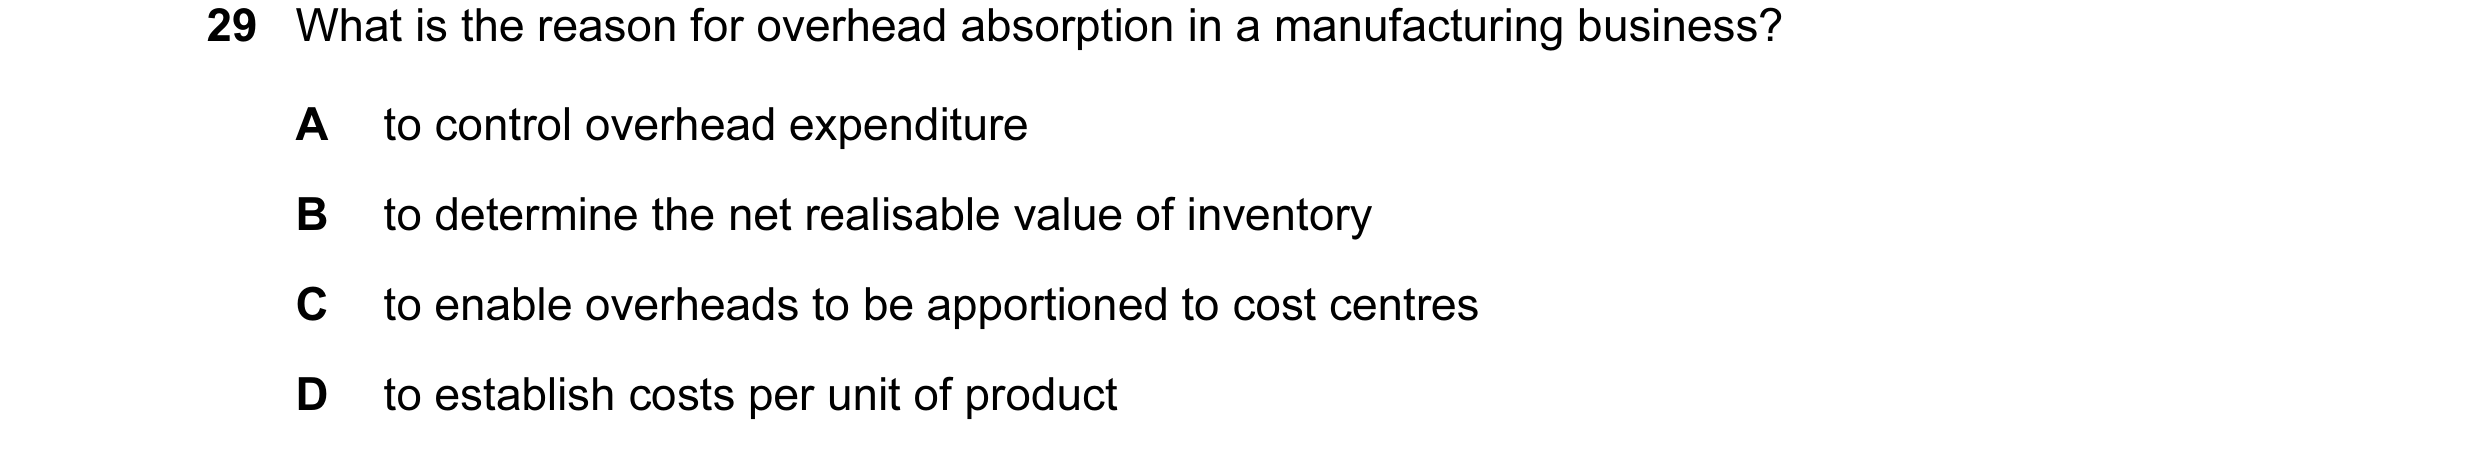
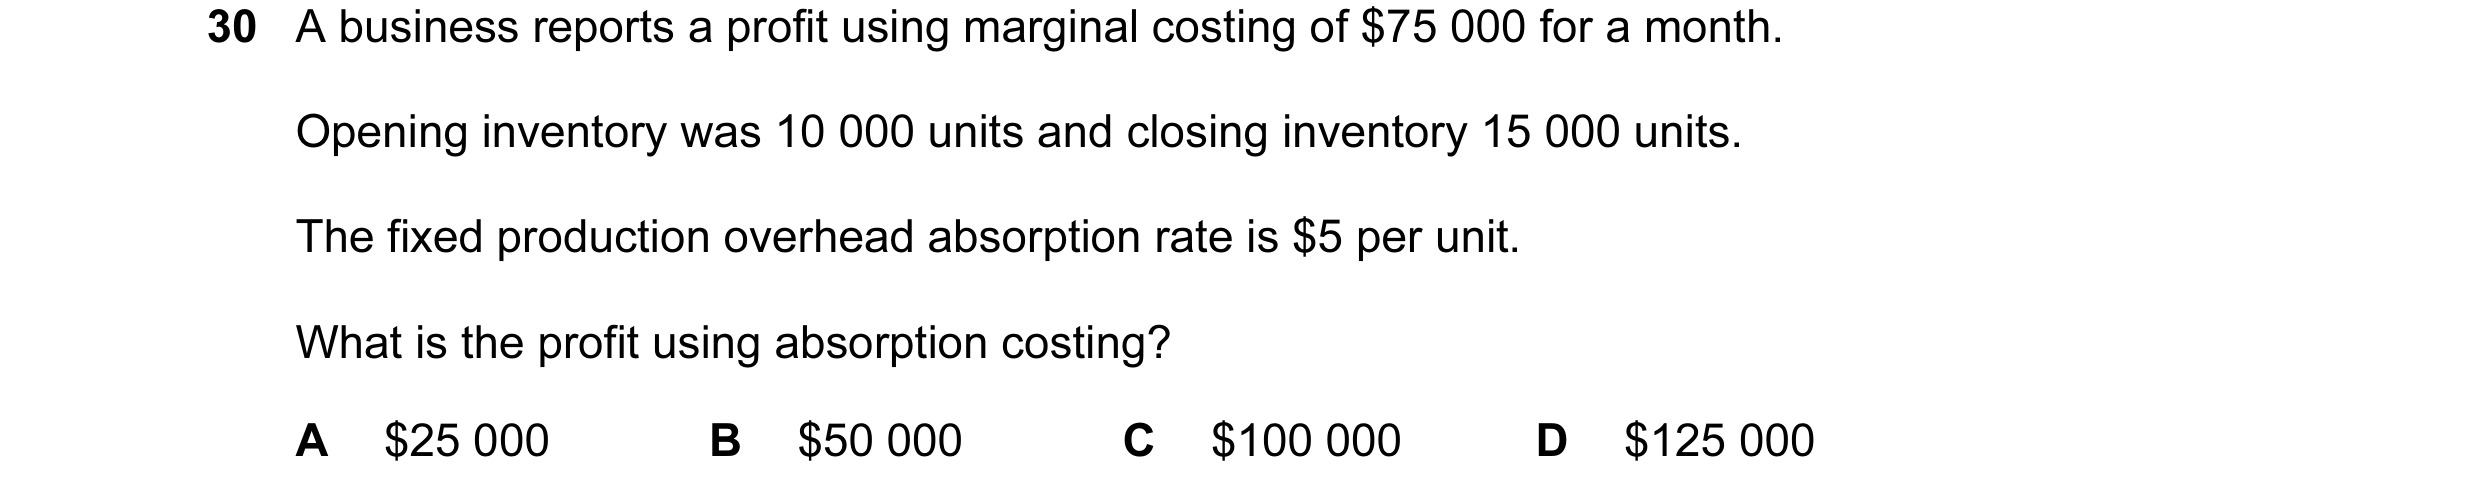
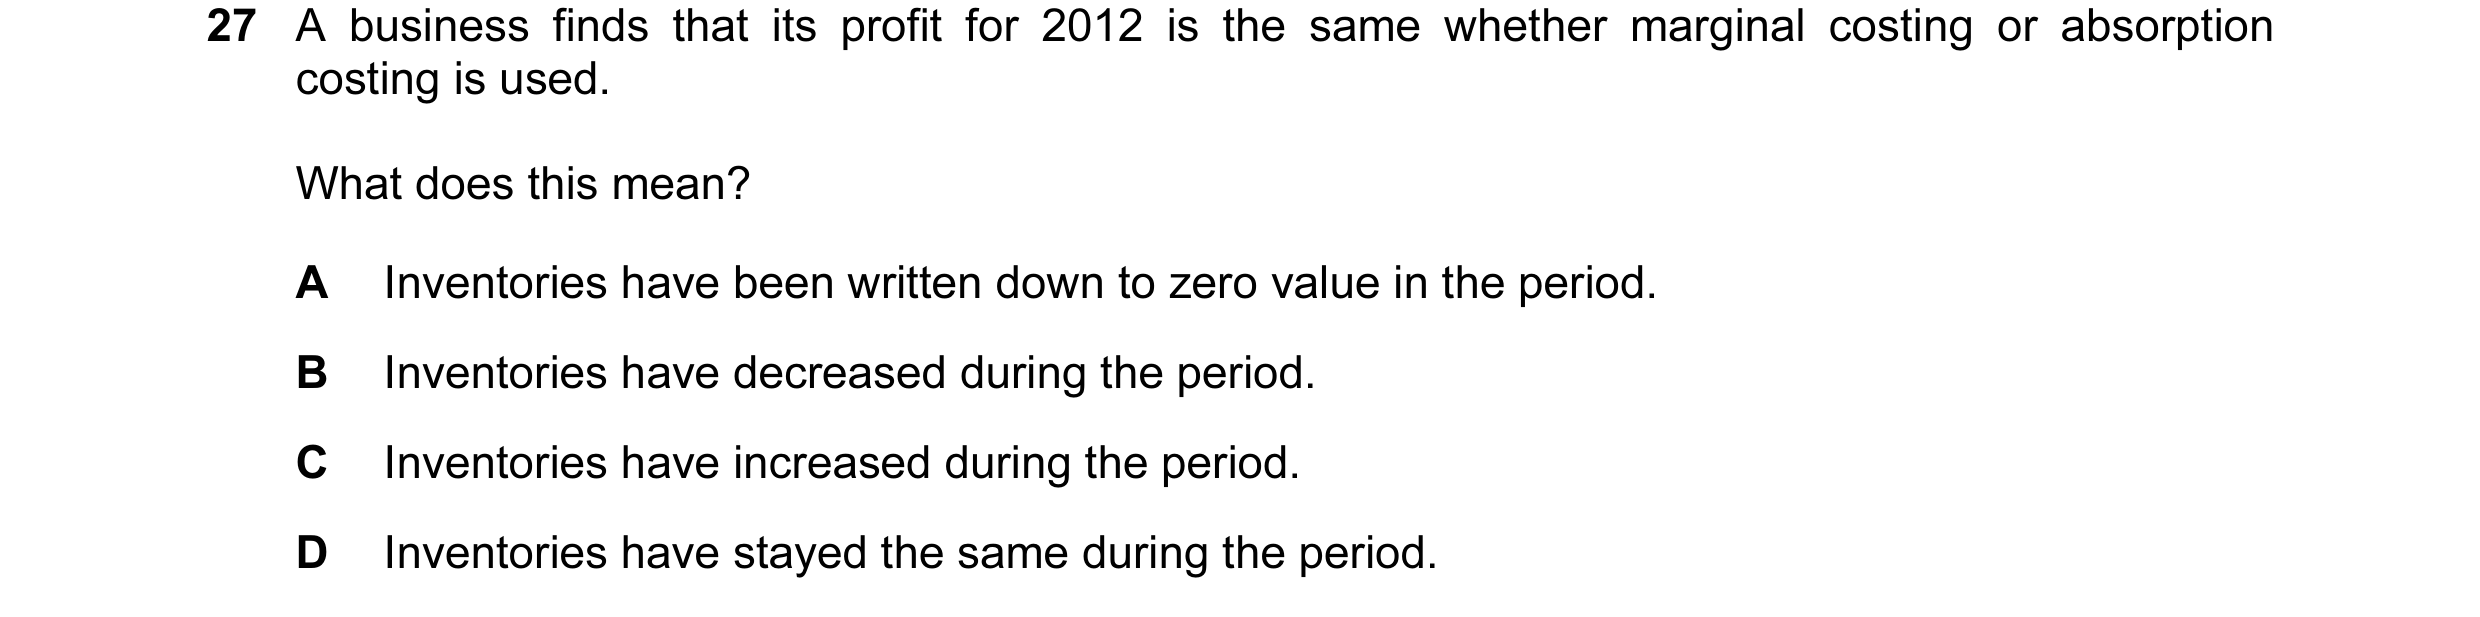
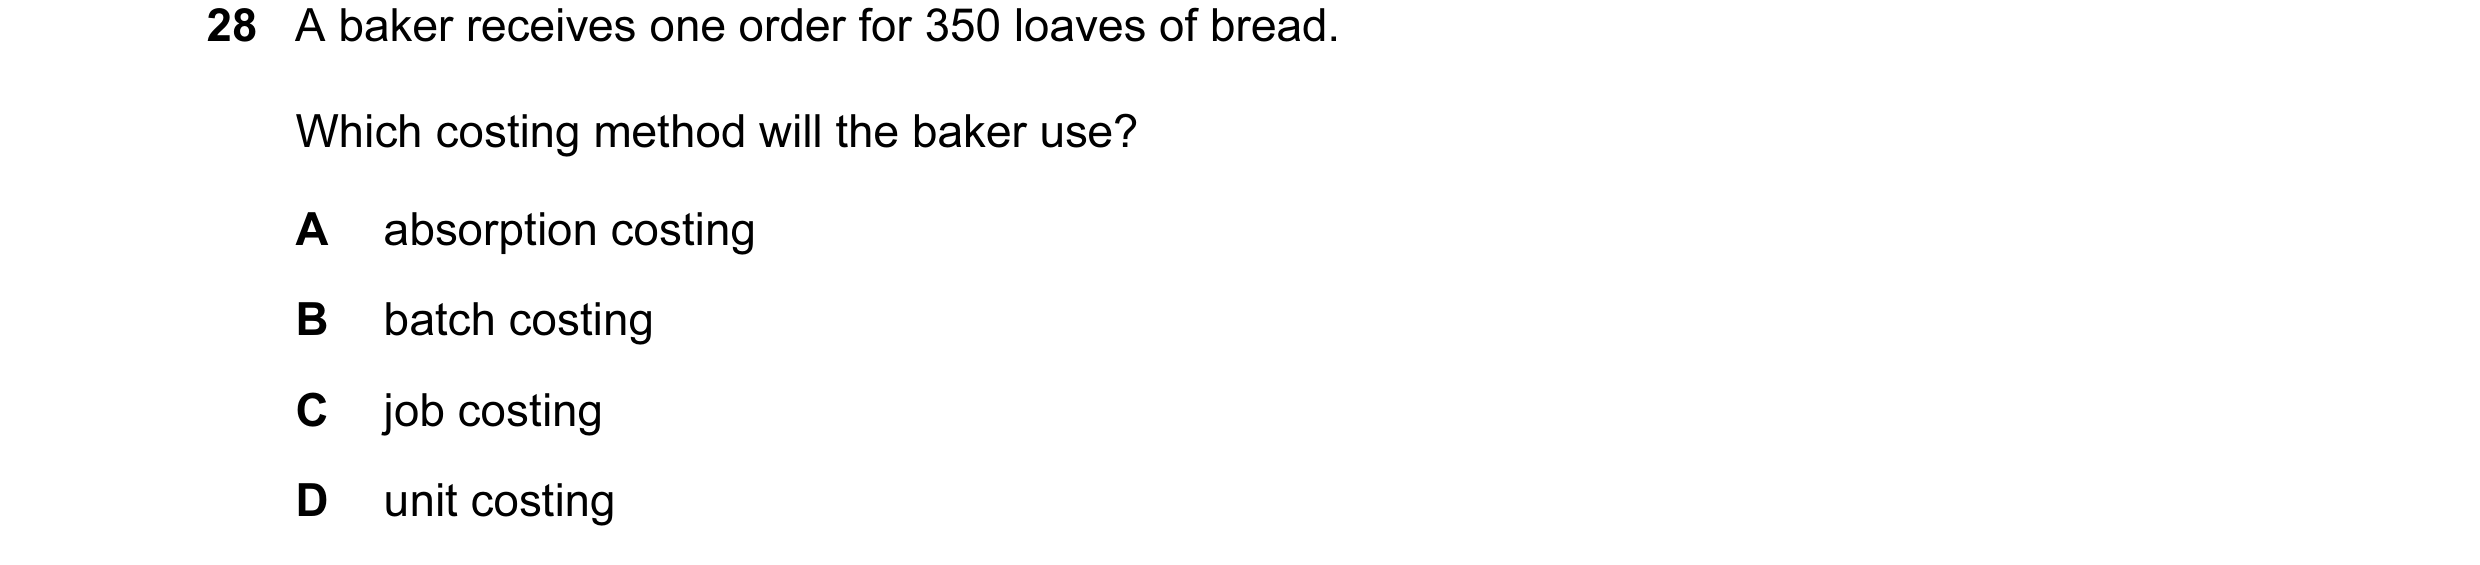
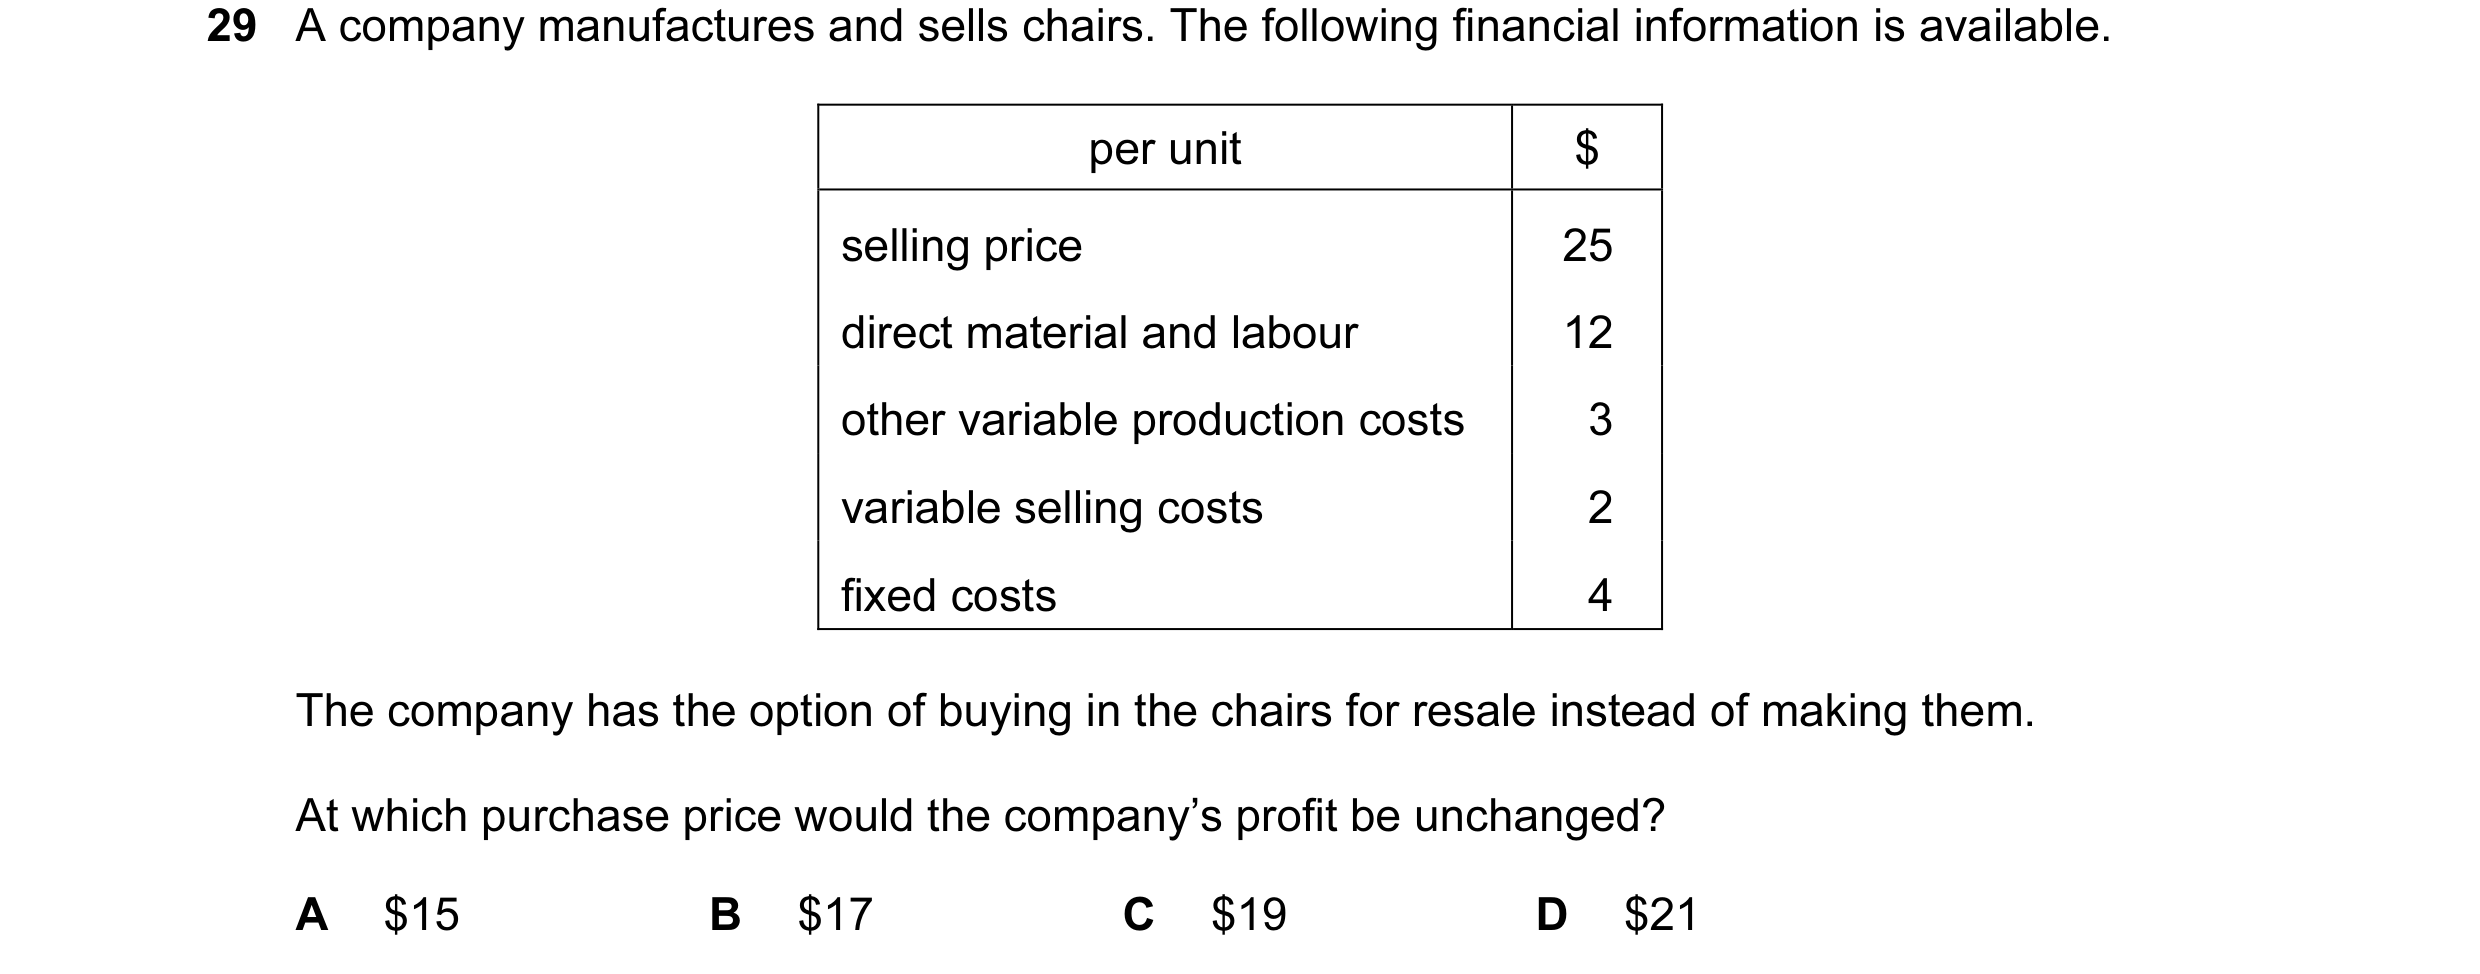 33 / 143
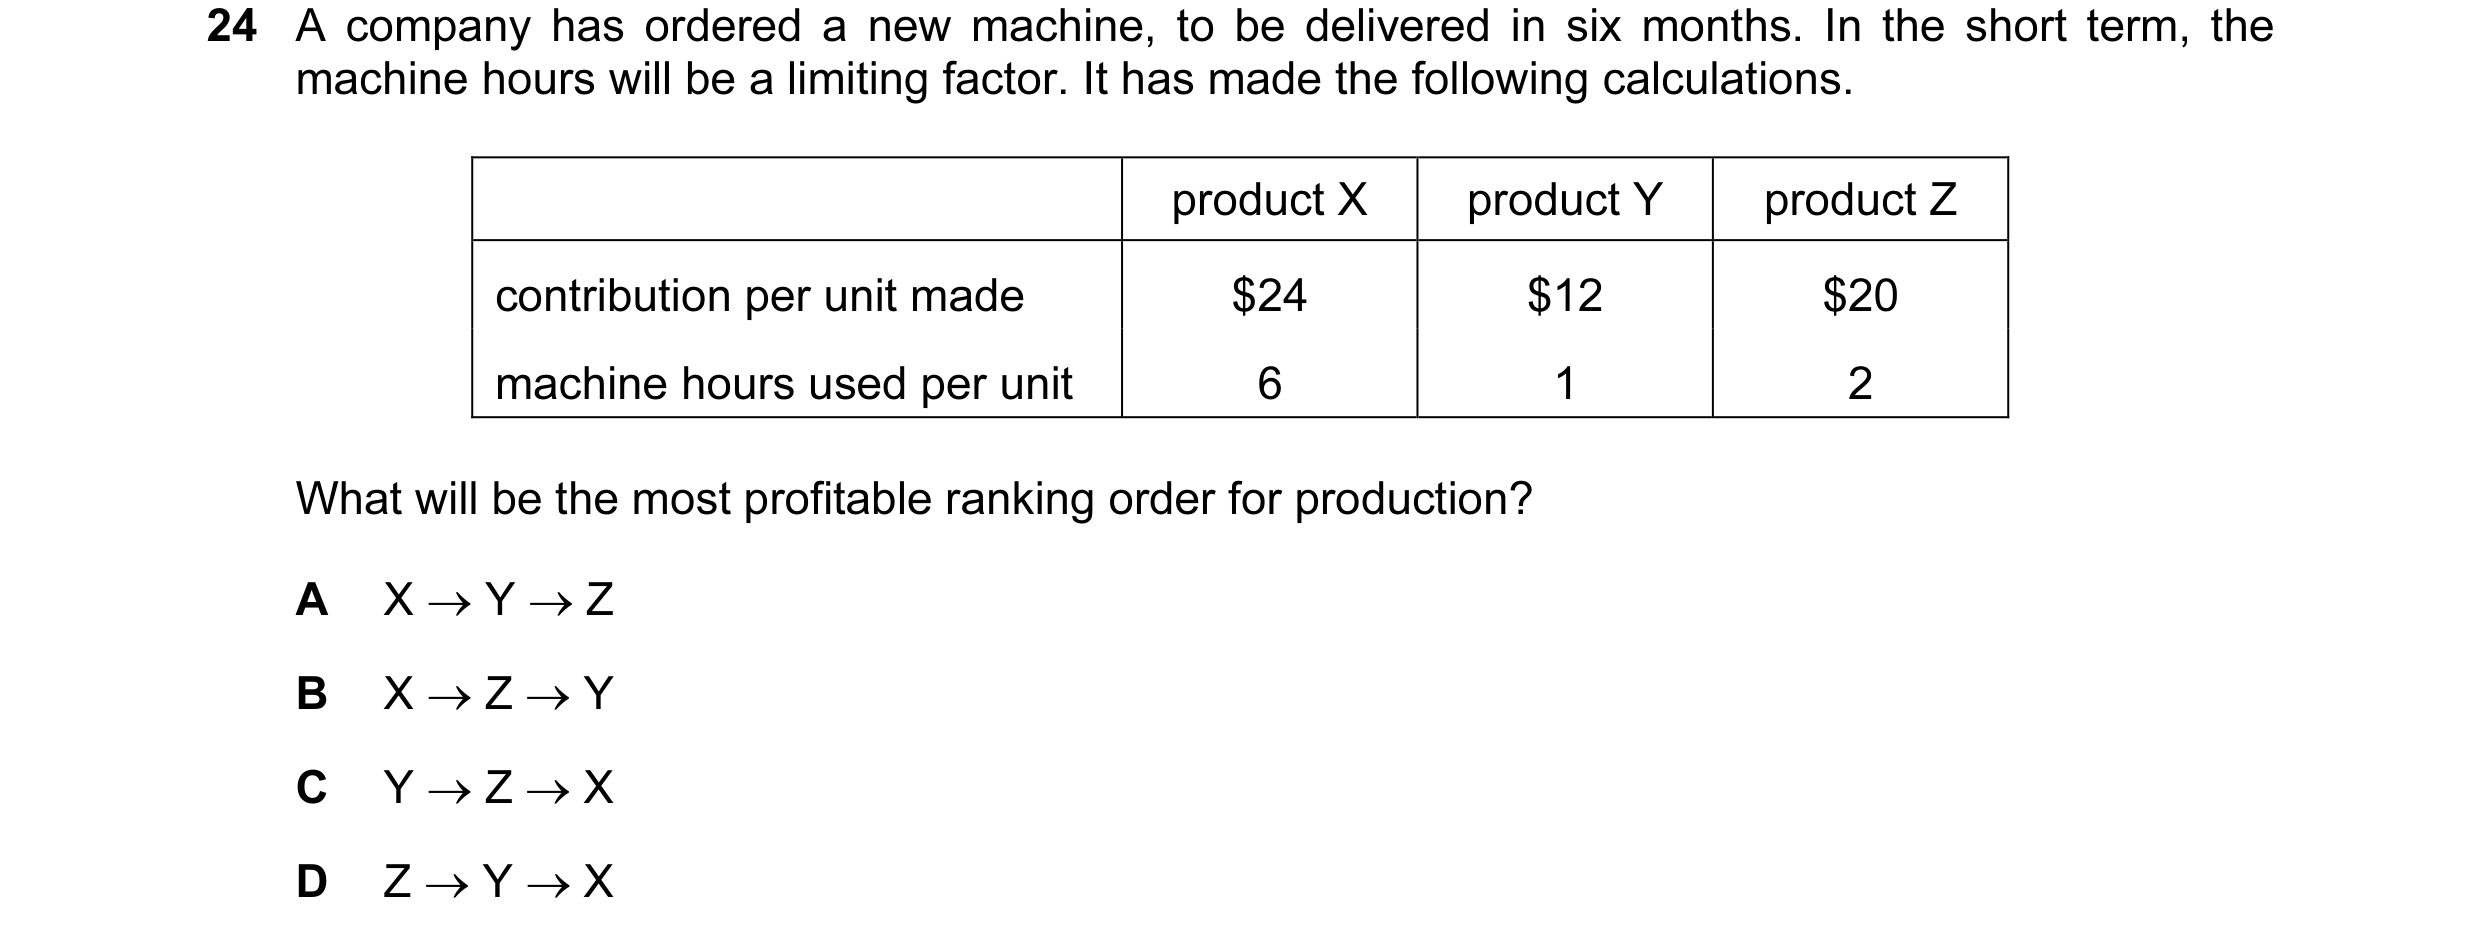
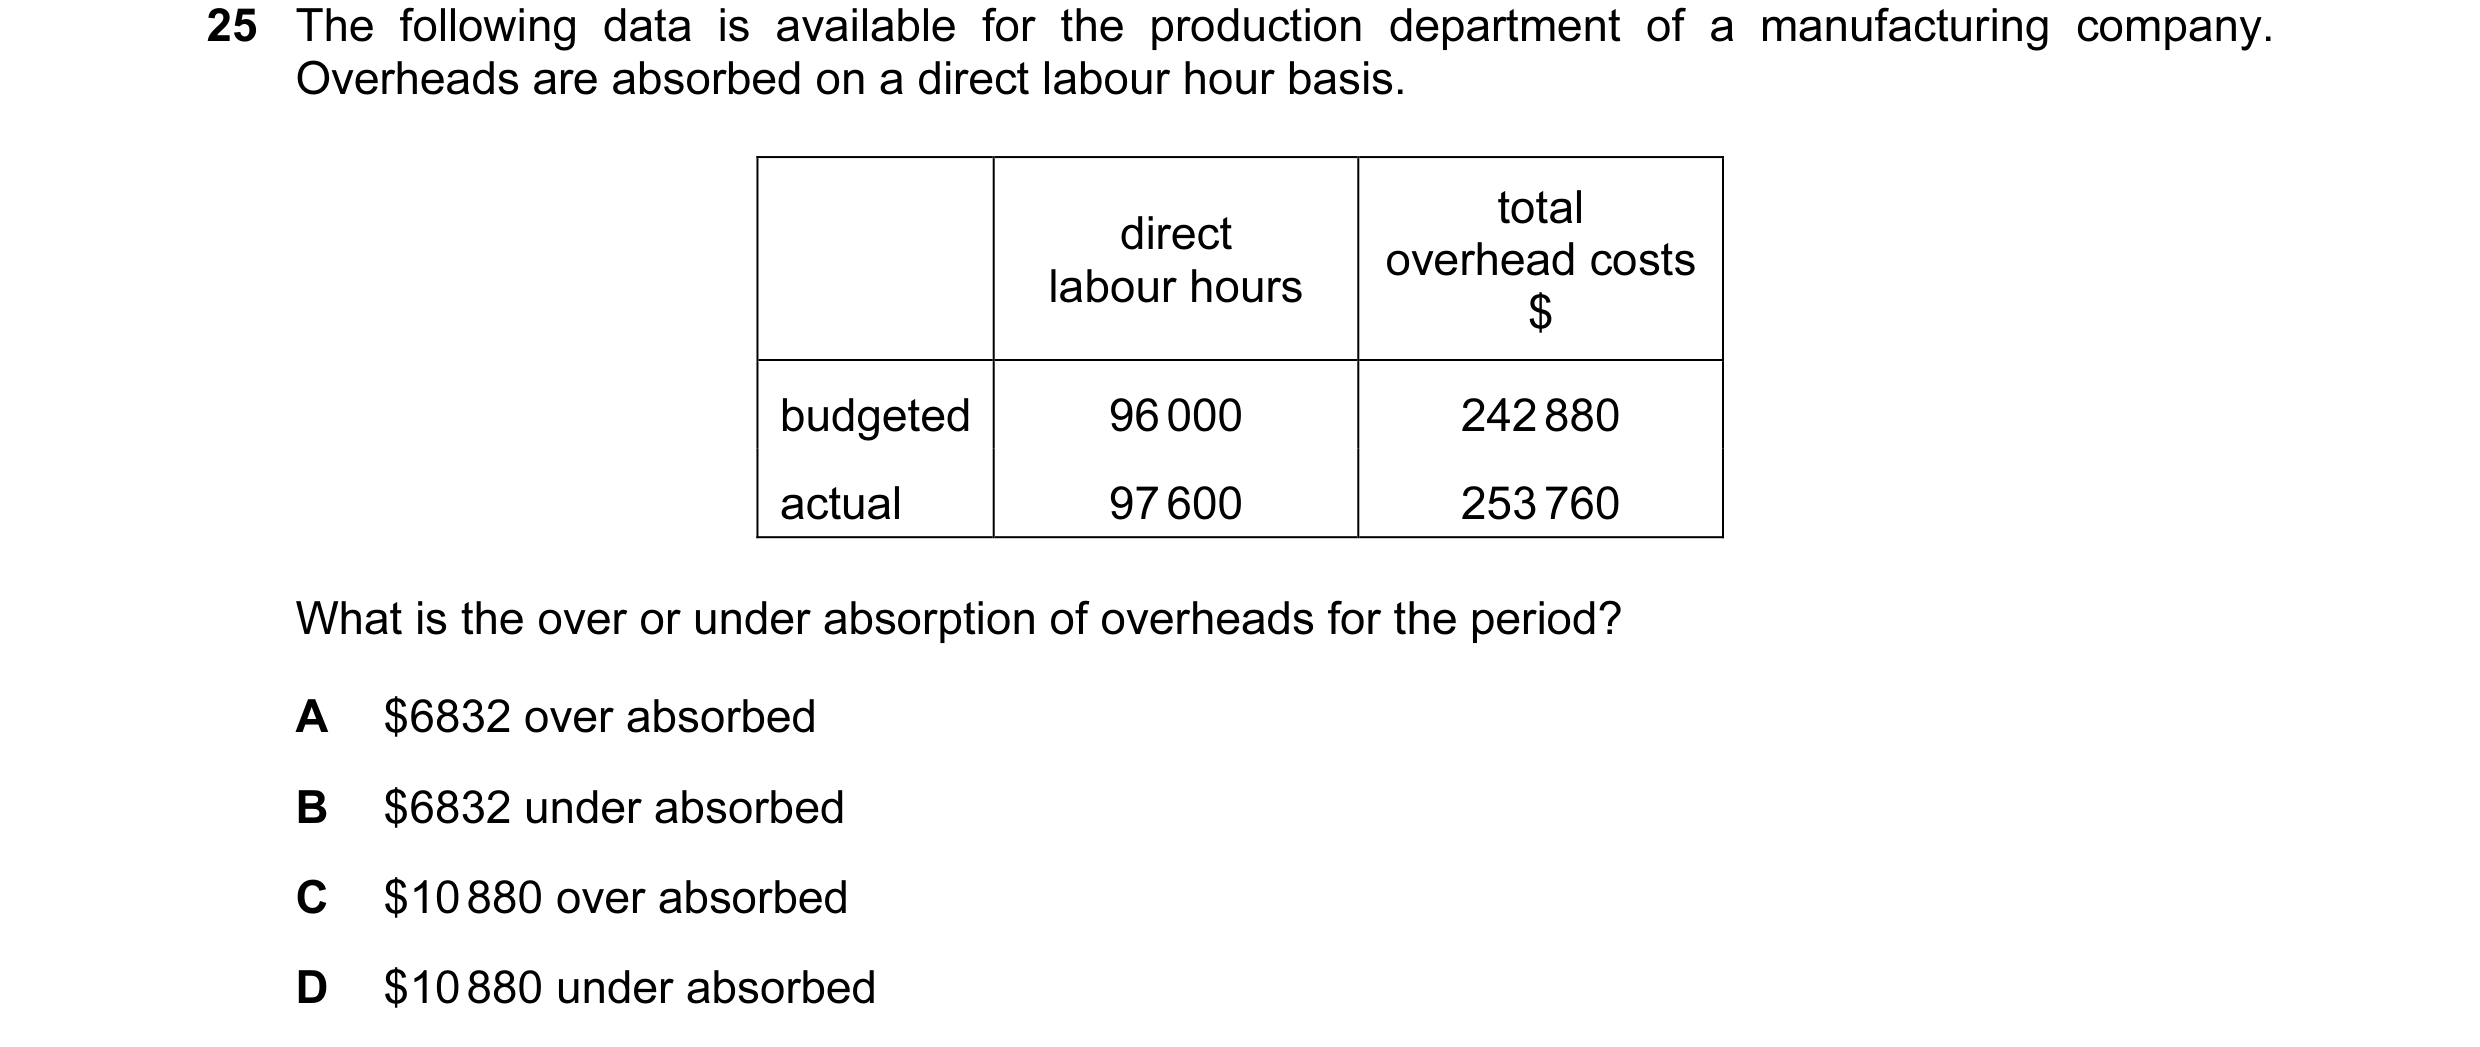
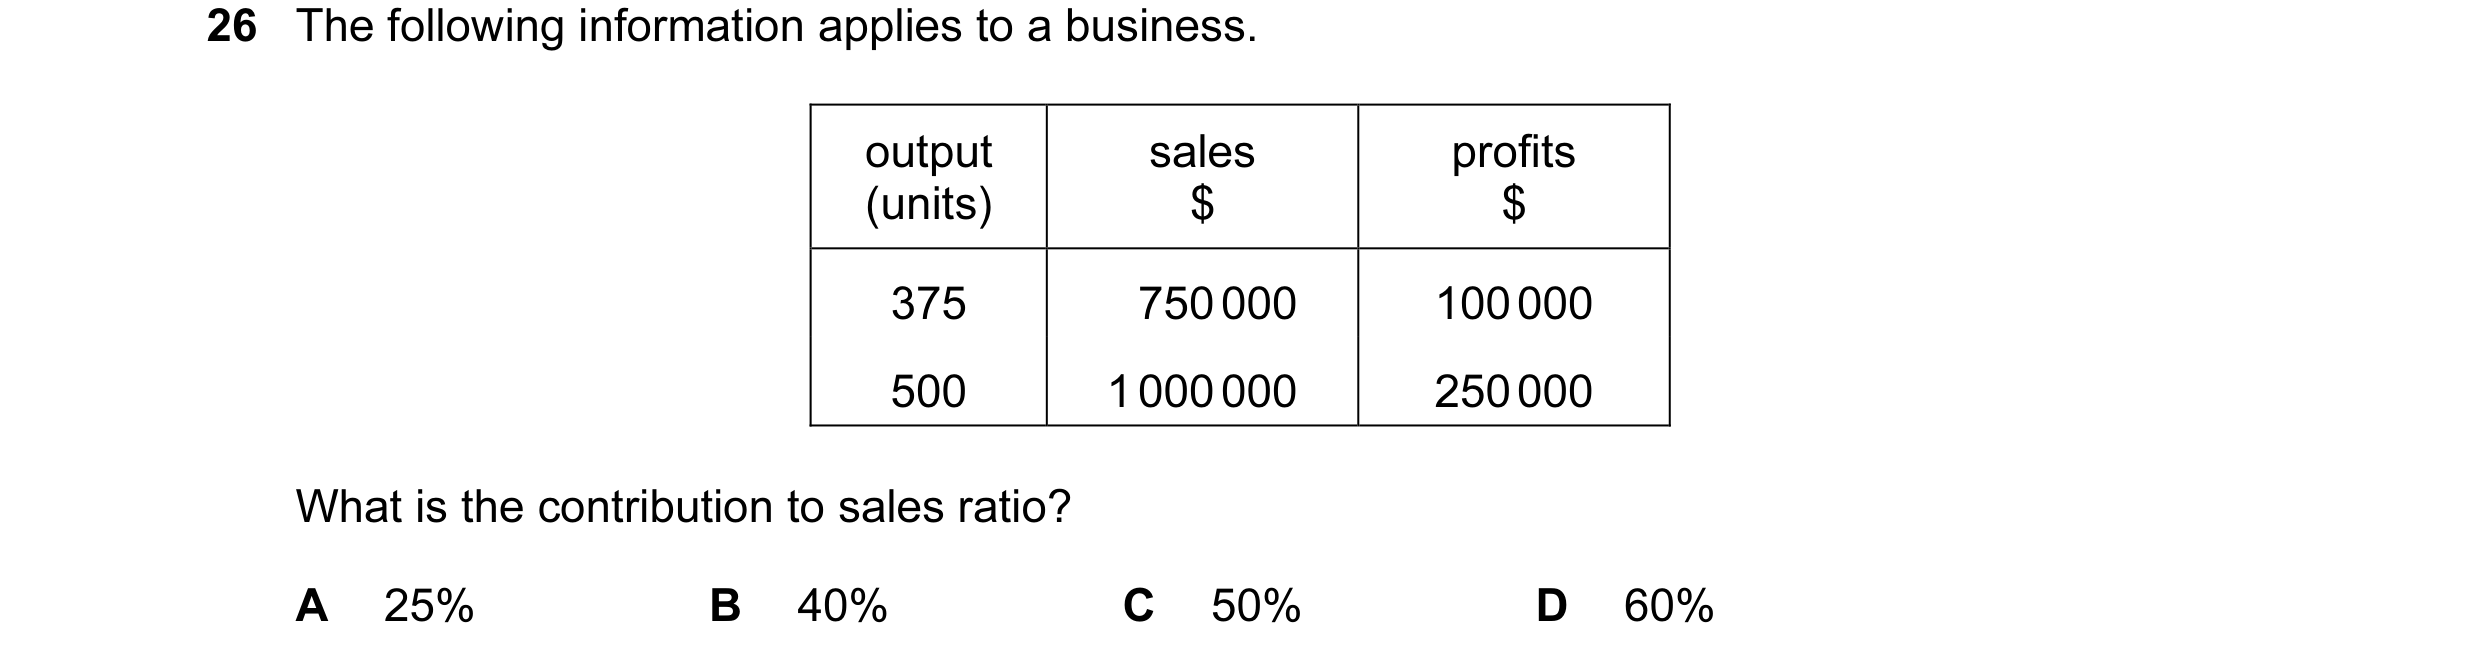 34 / 143
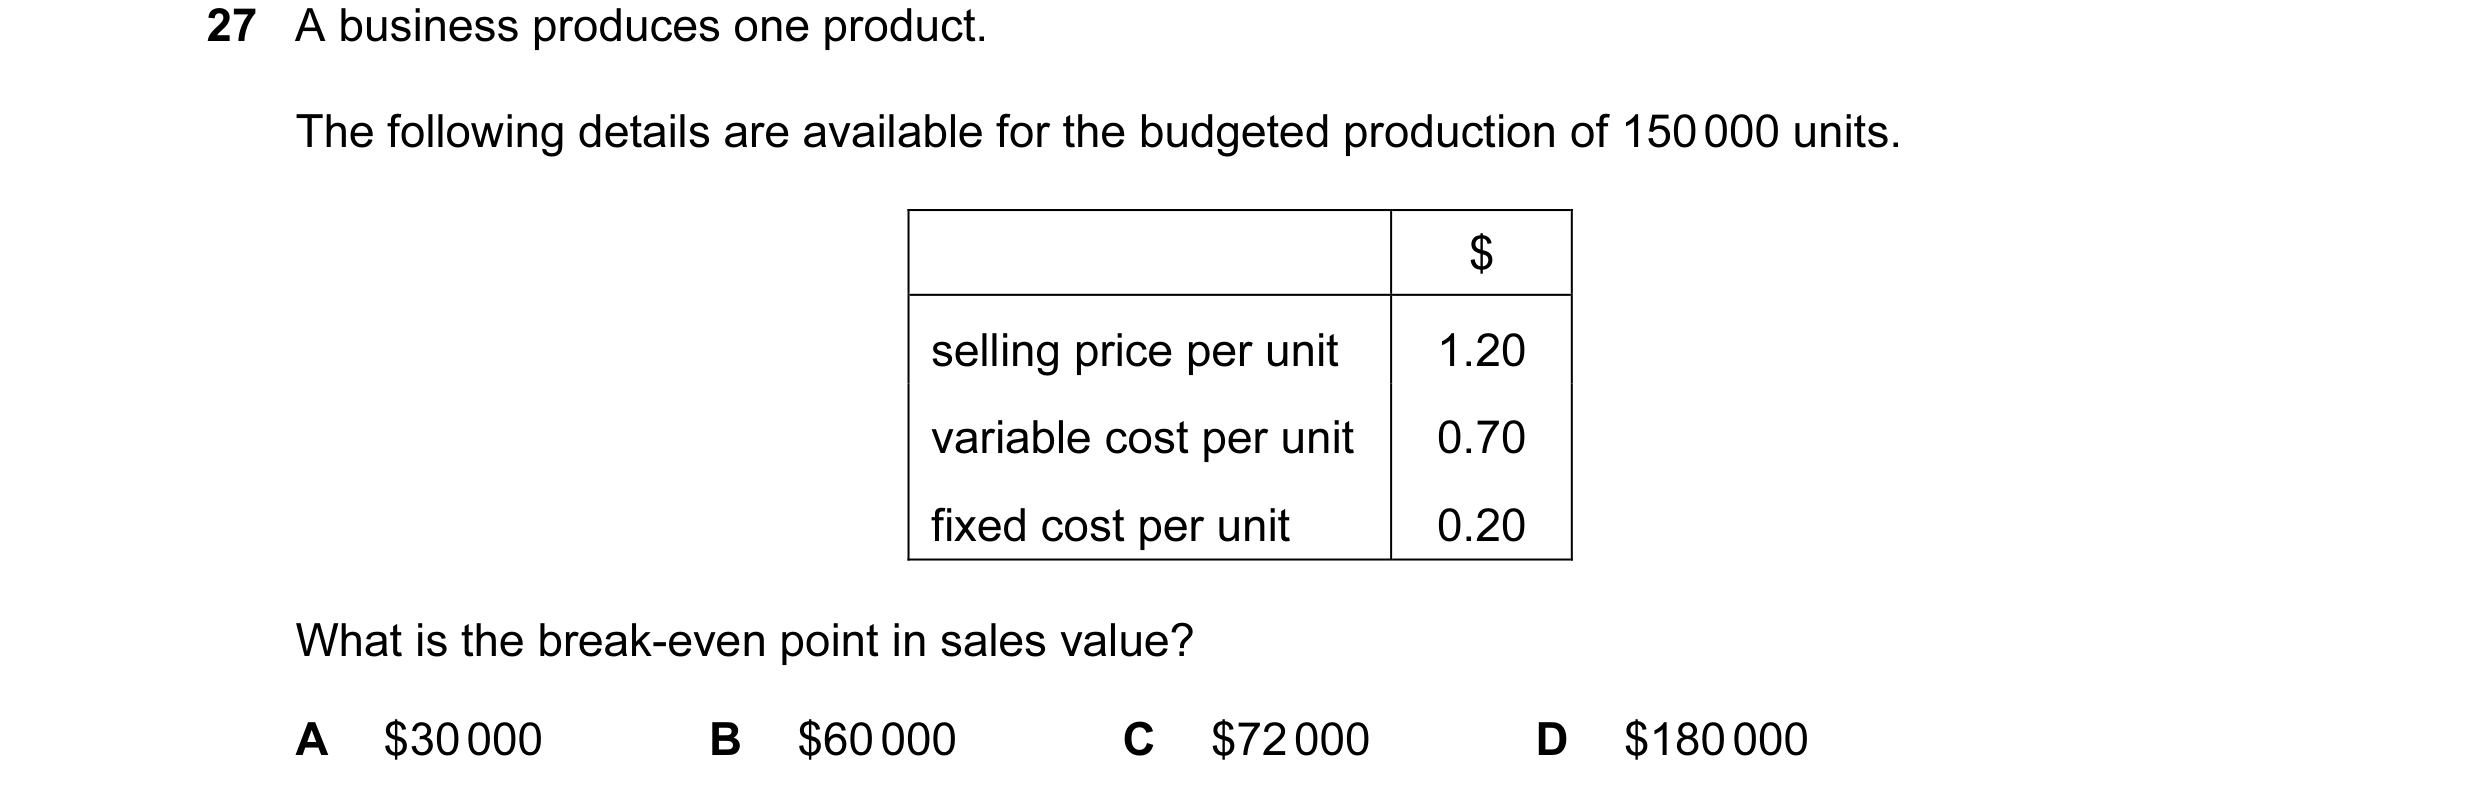
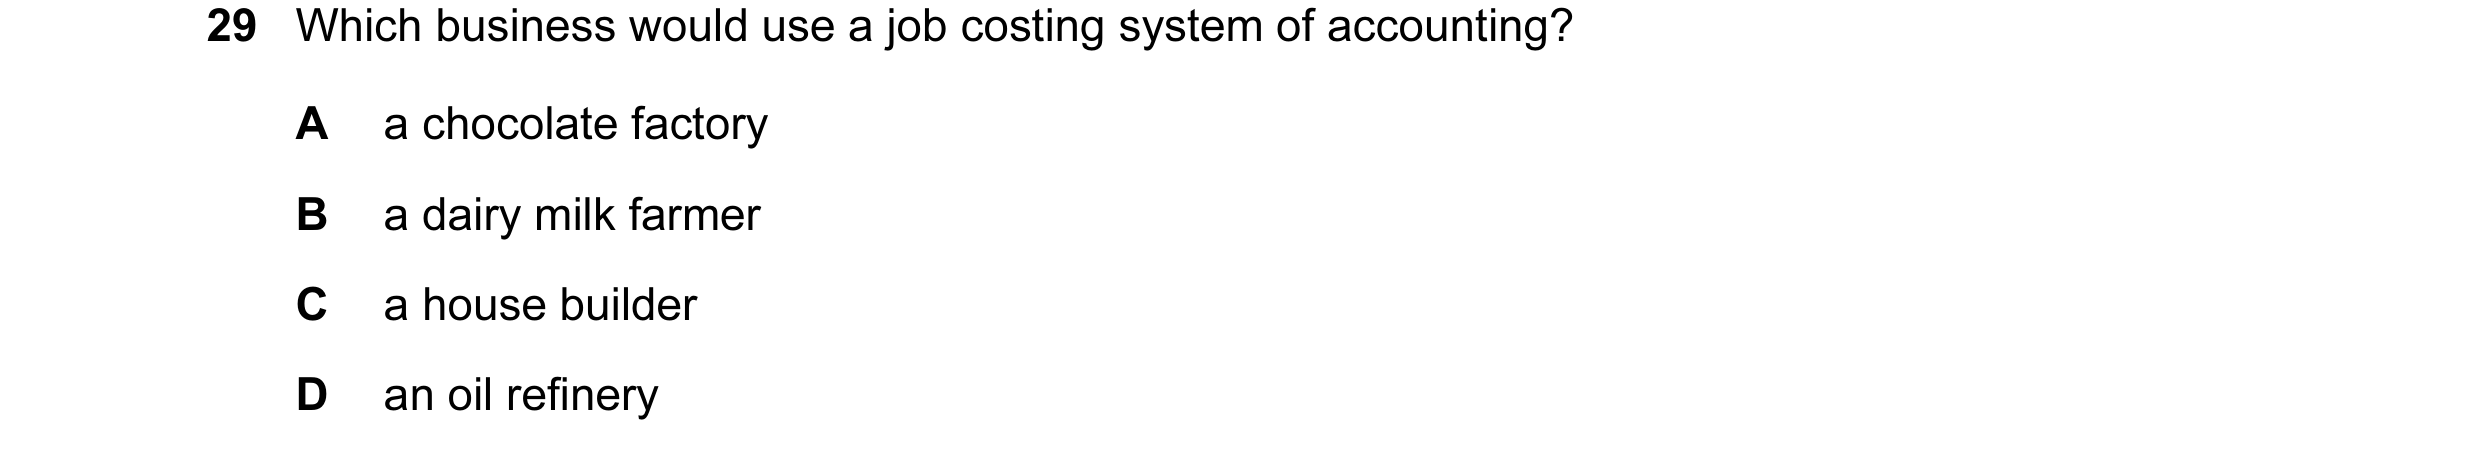
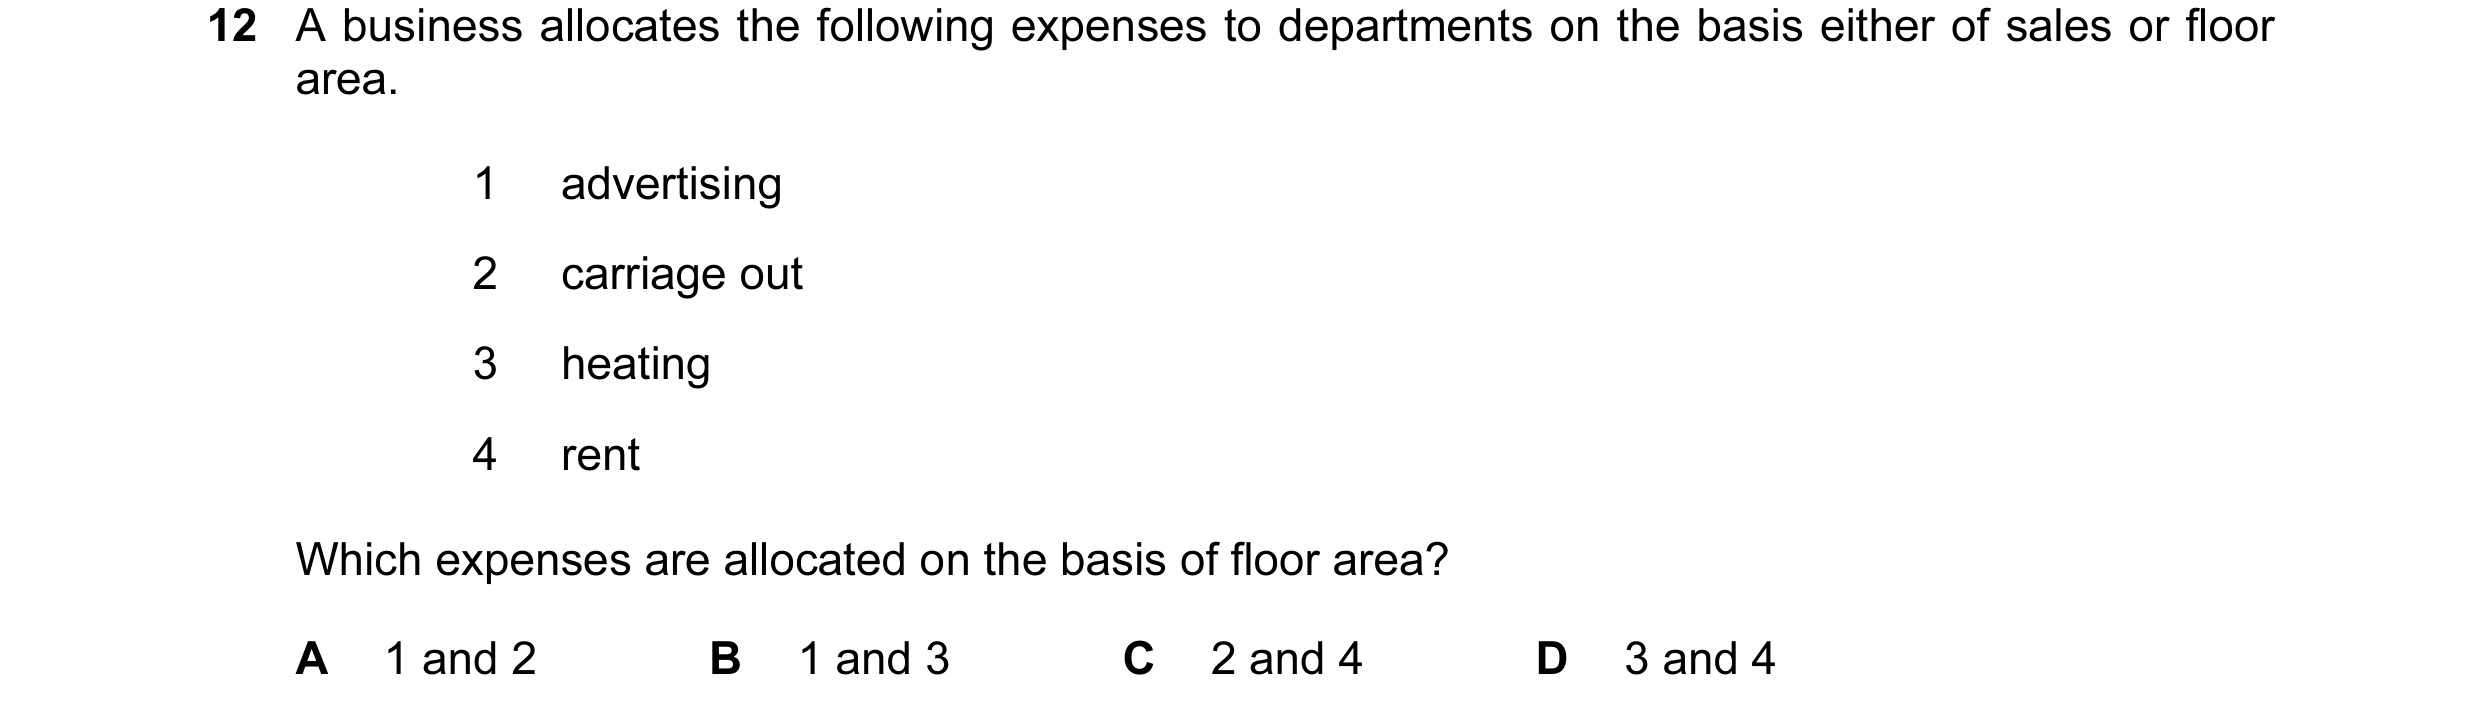
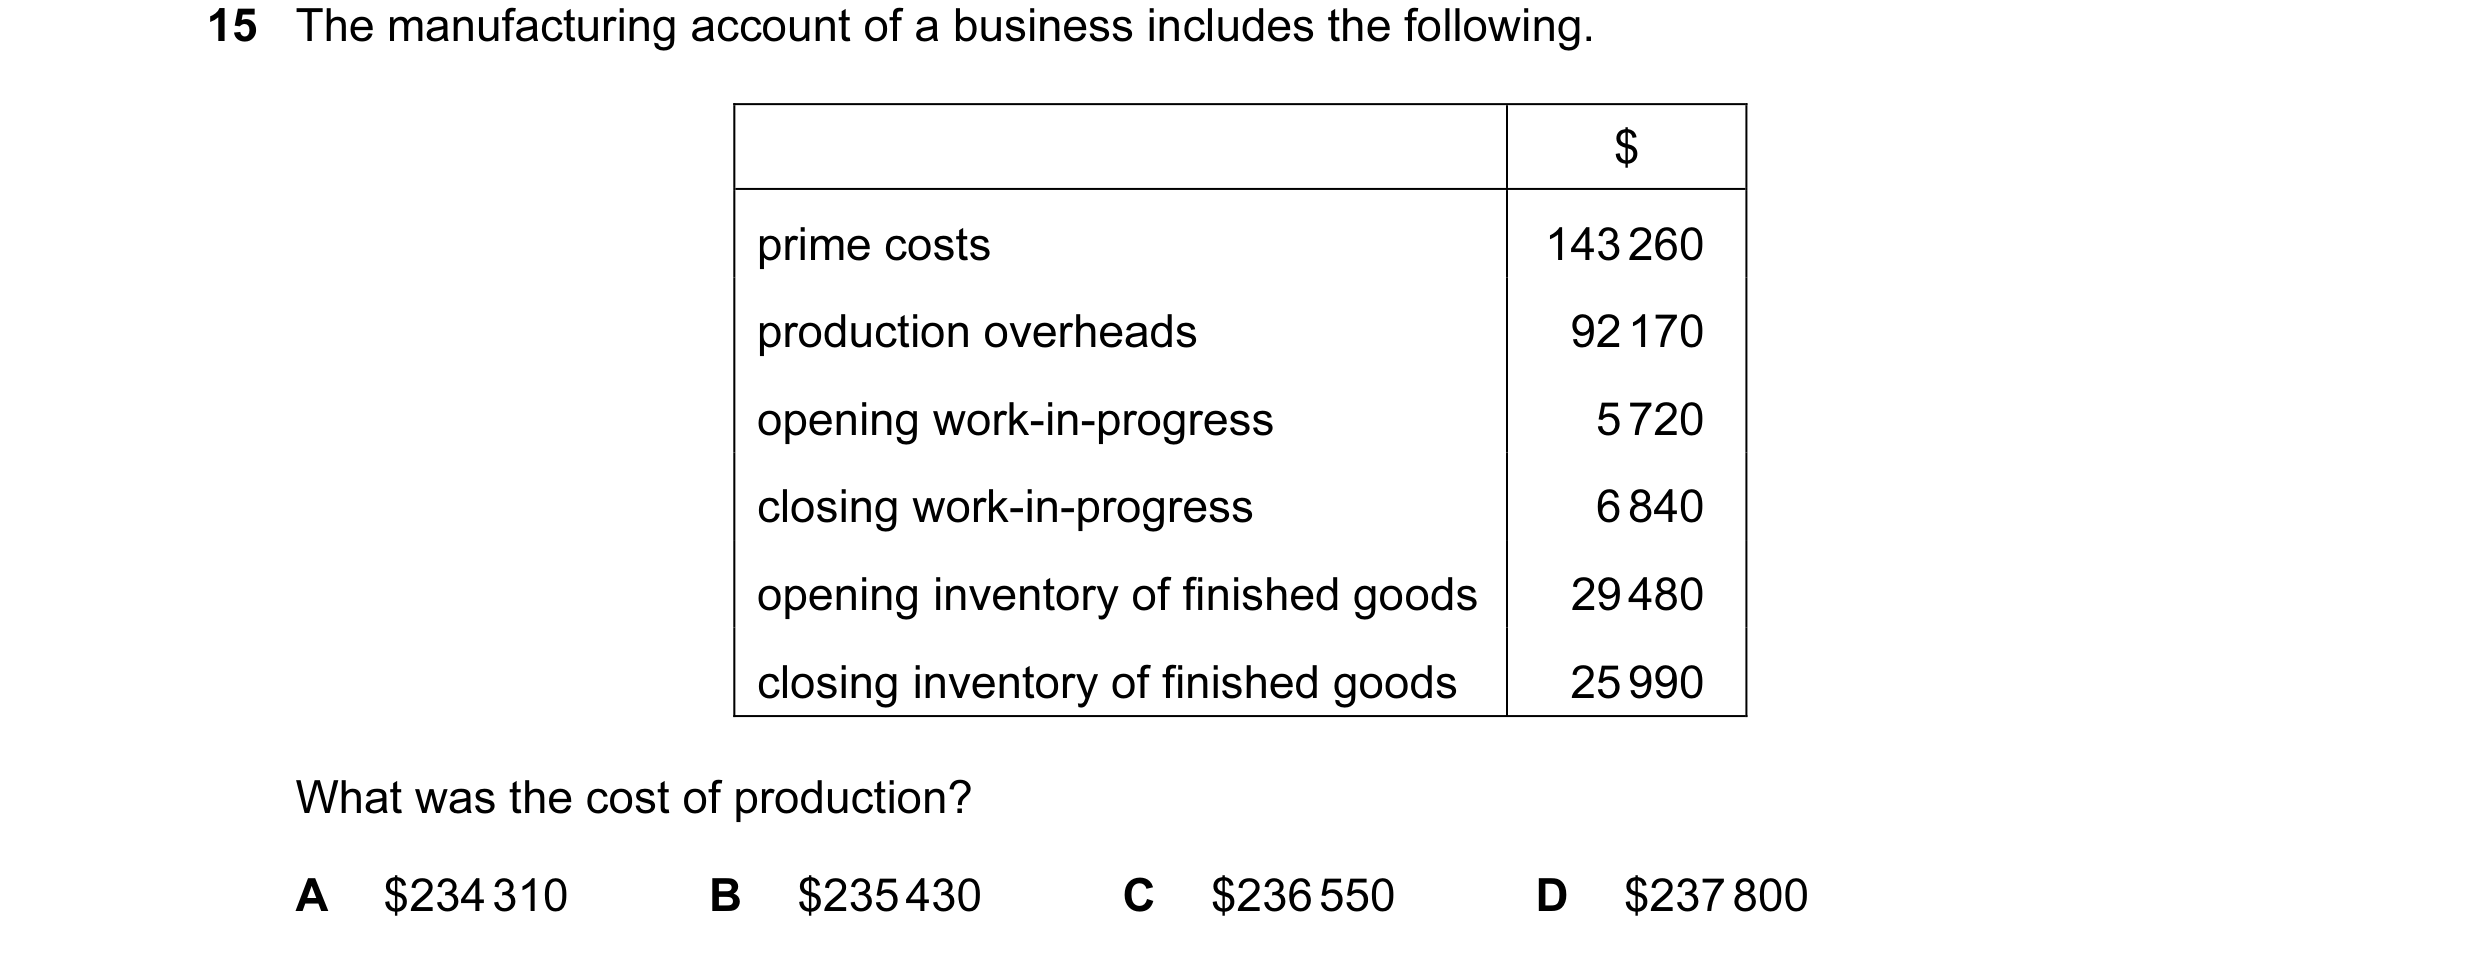 35 / 143
 36 / 143
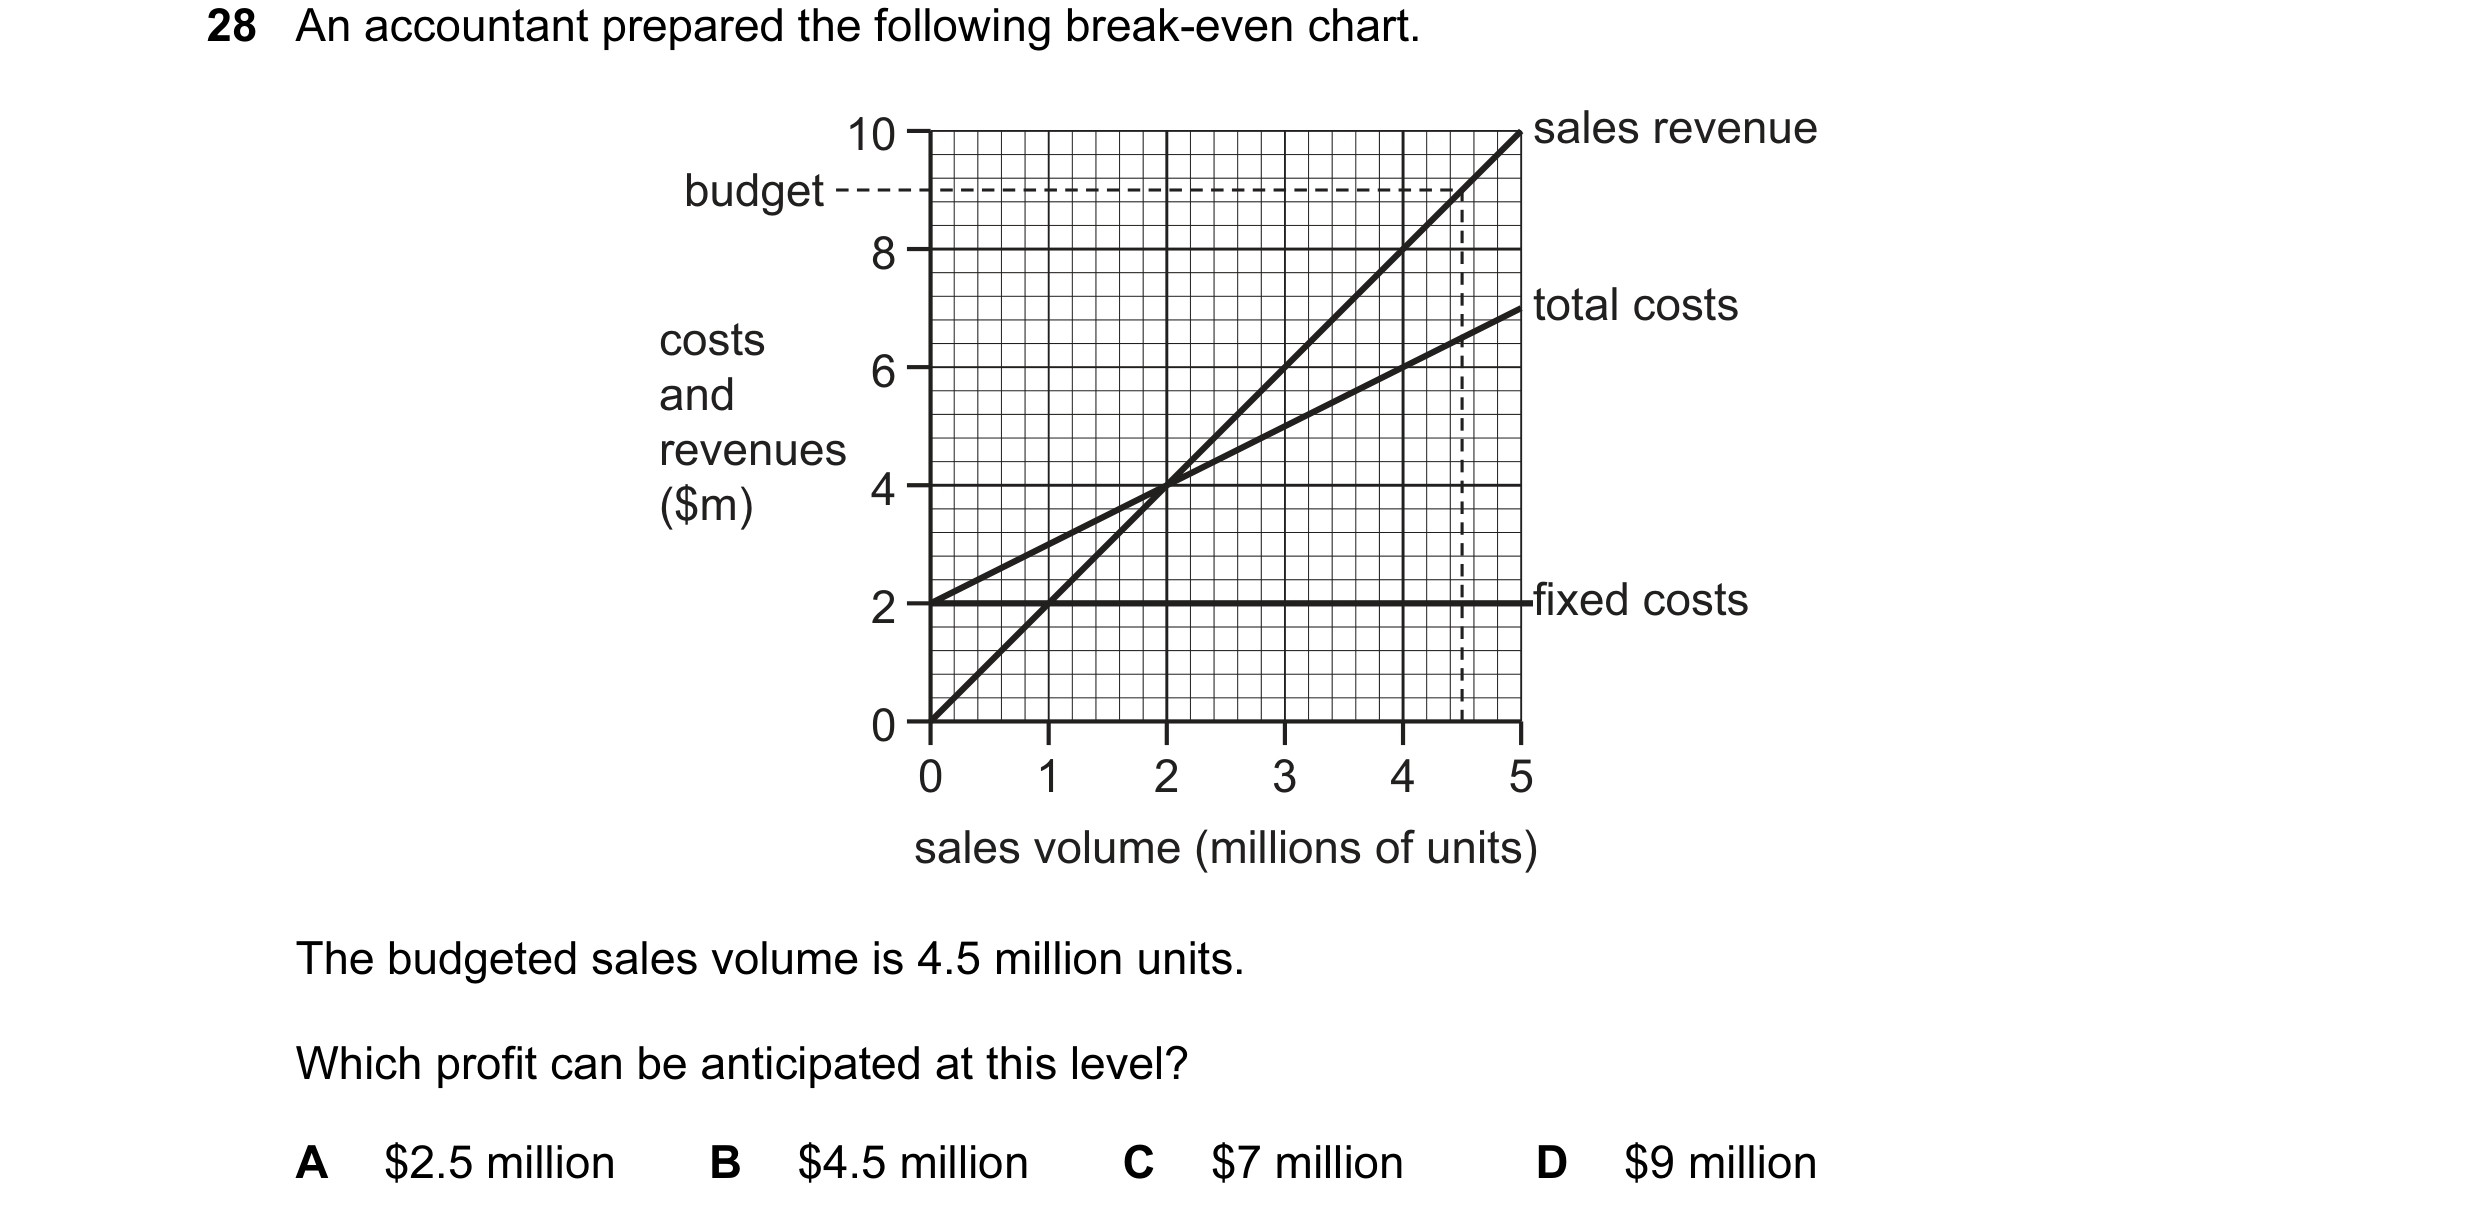
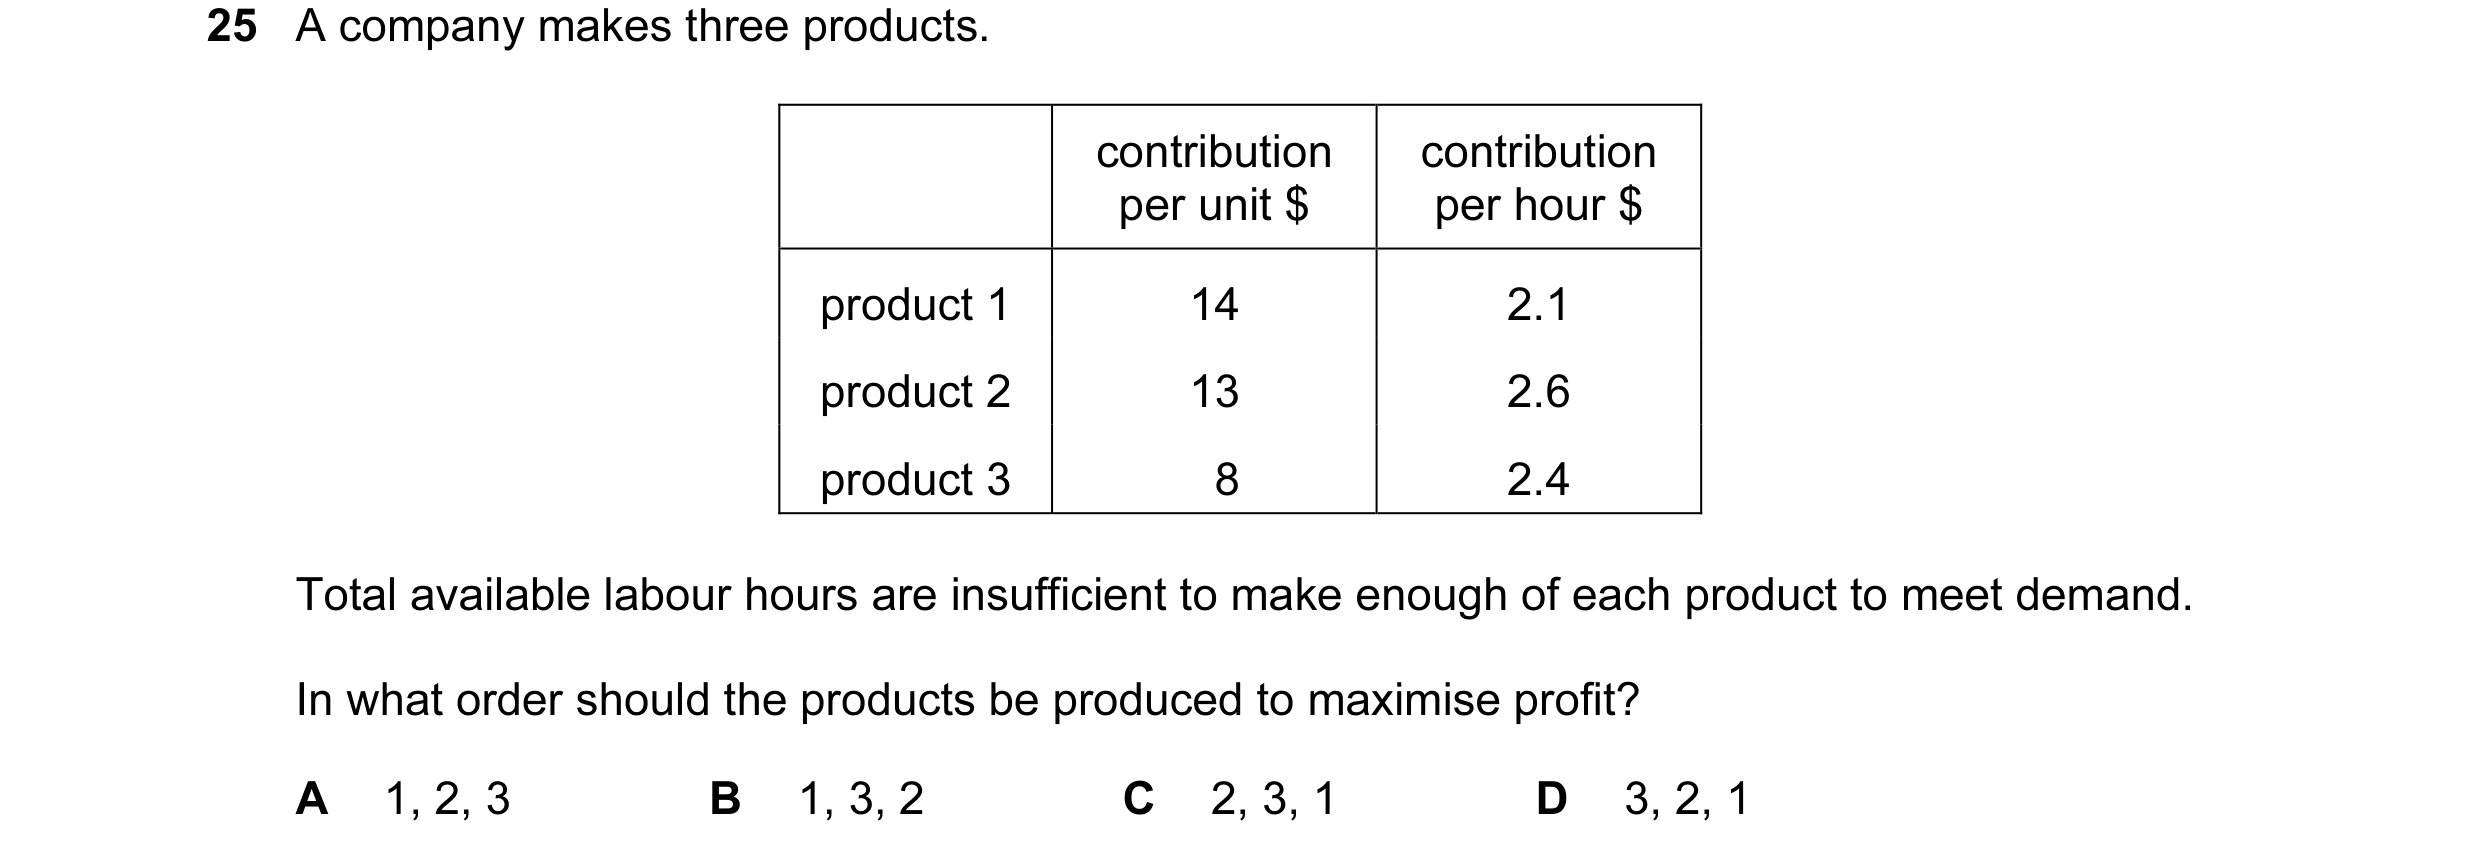
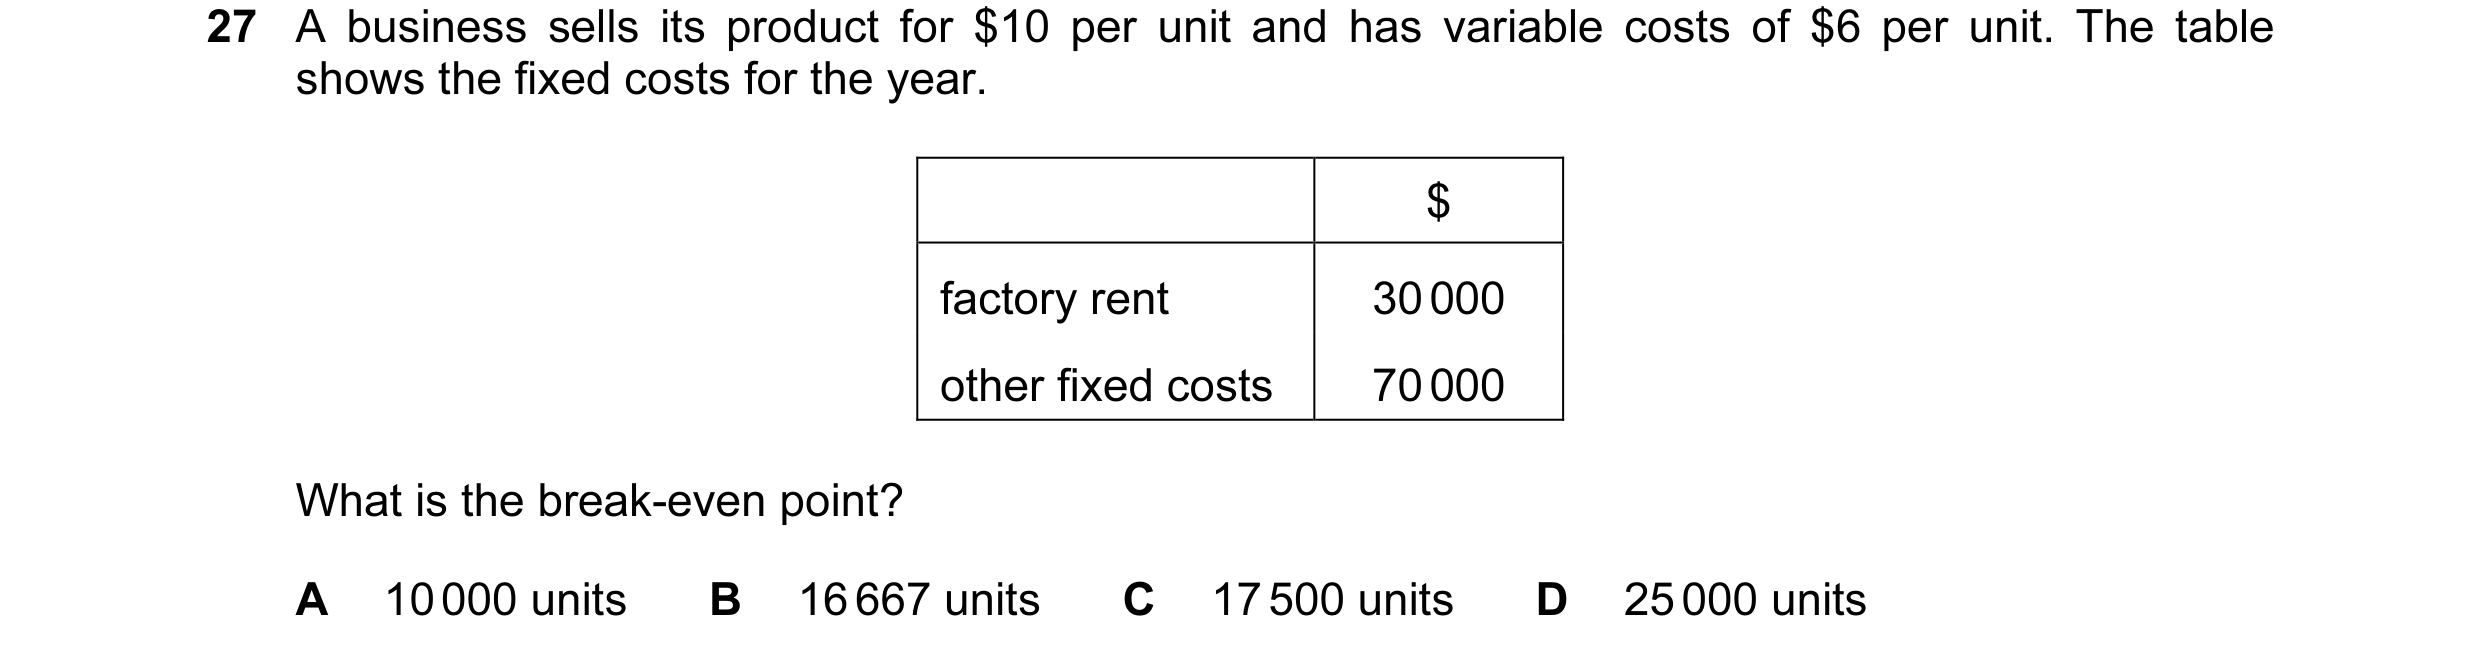 37 / 143
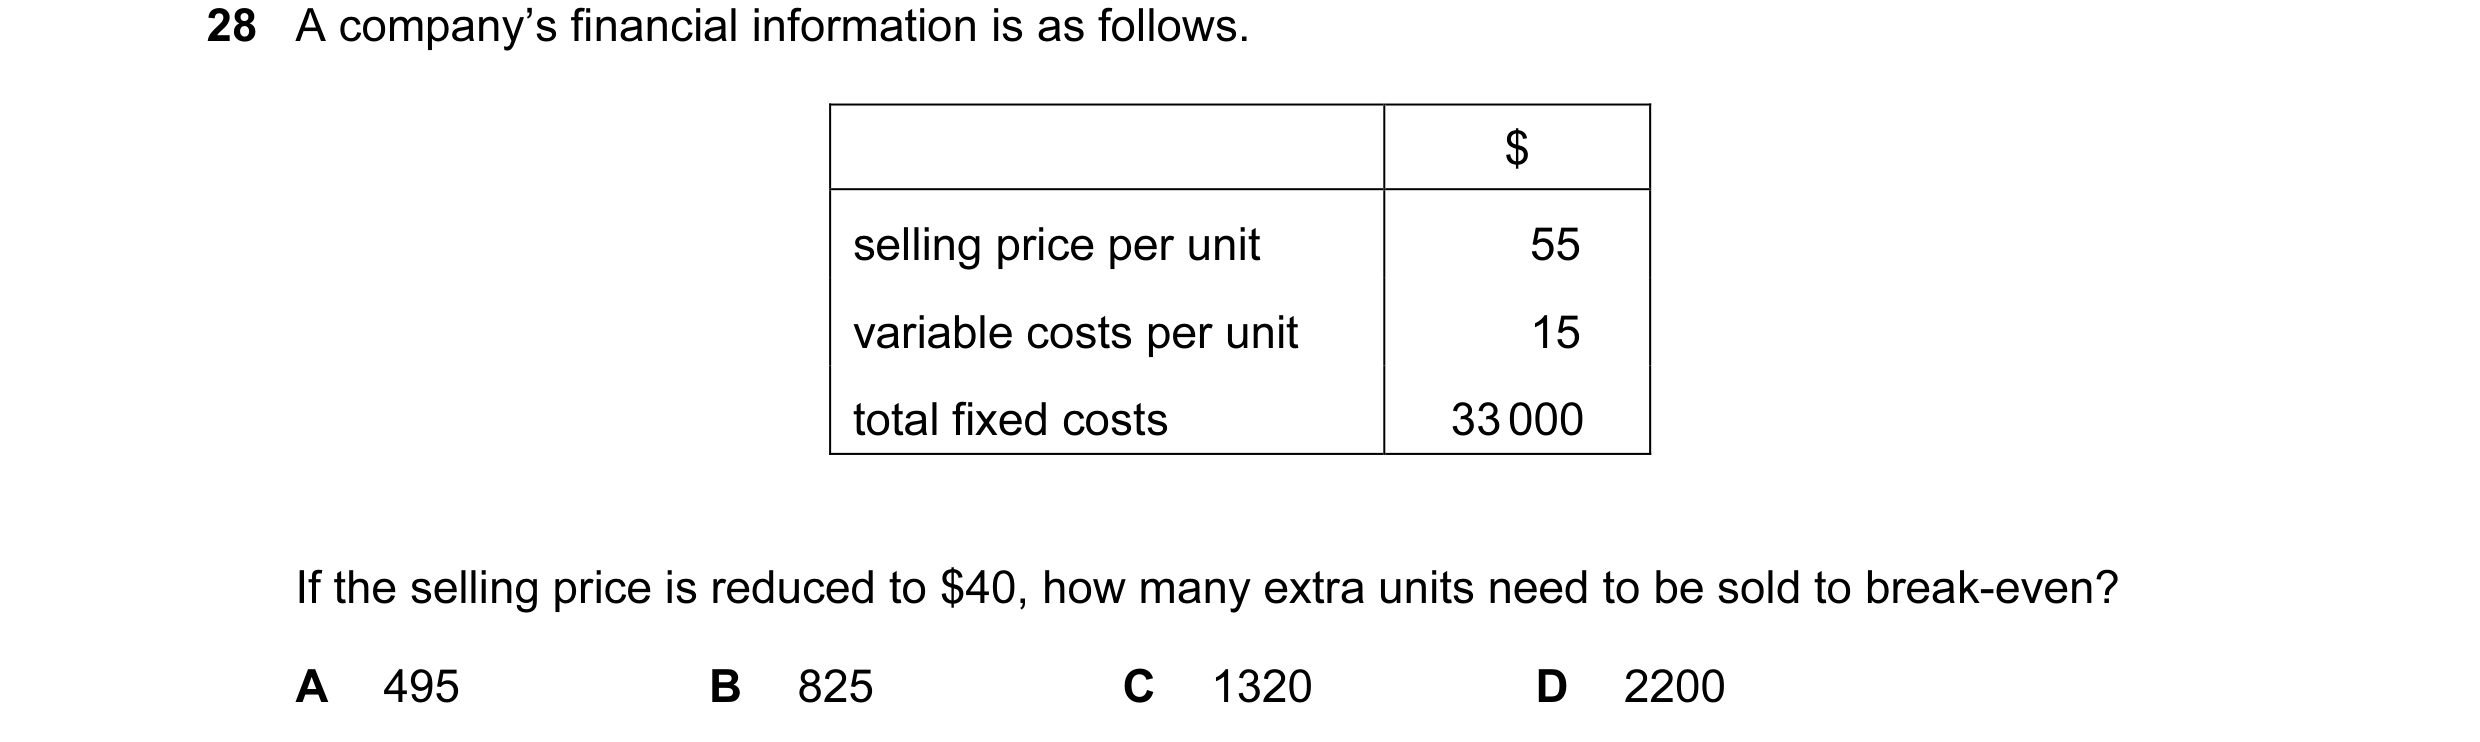
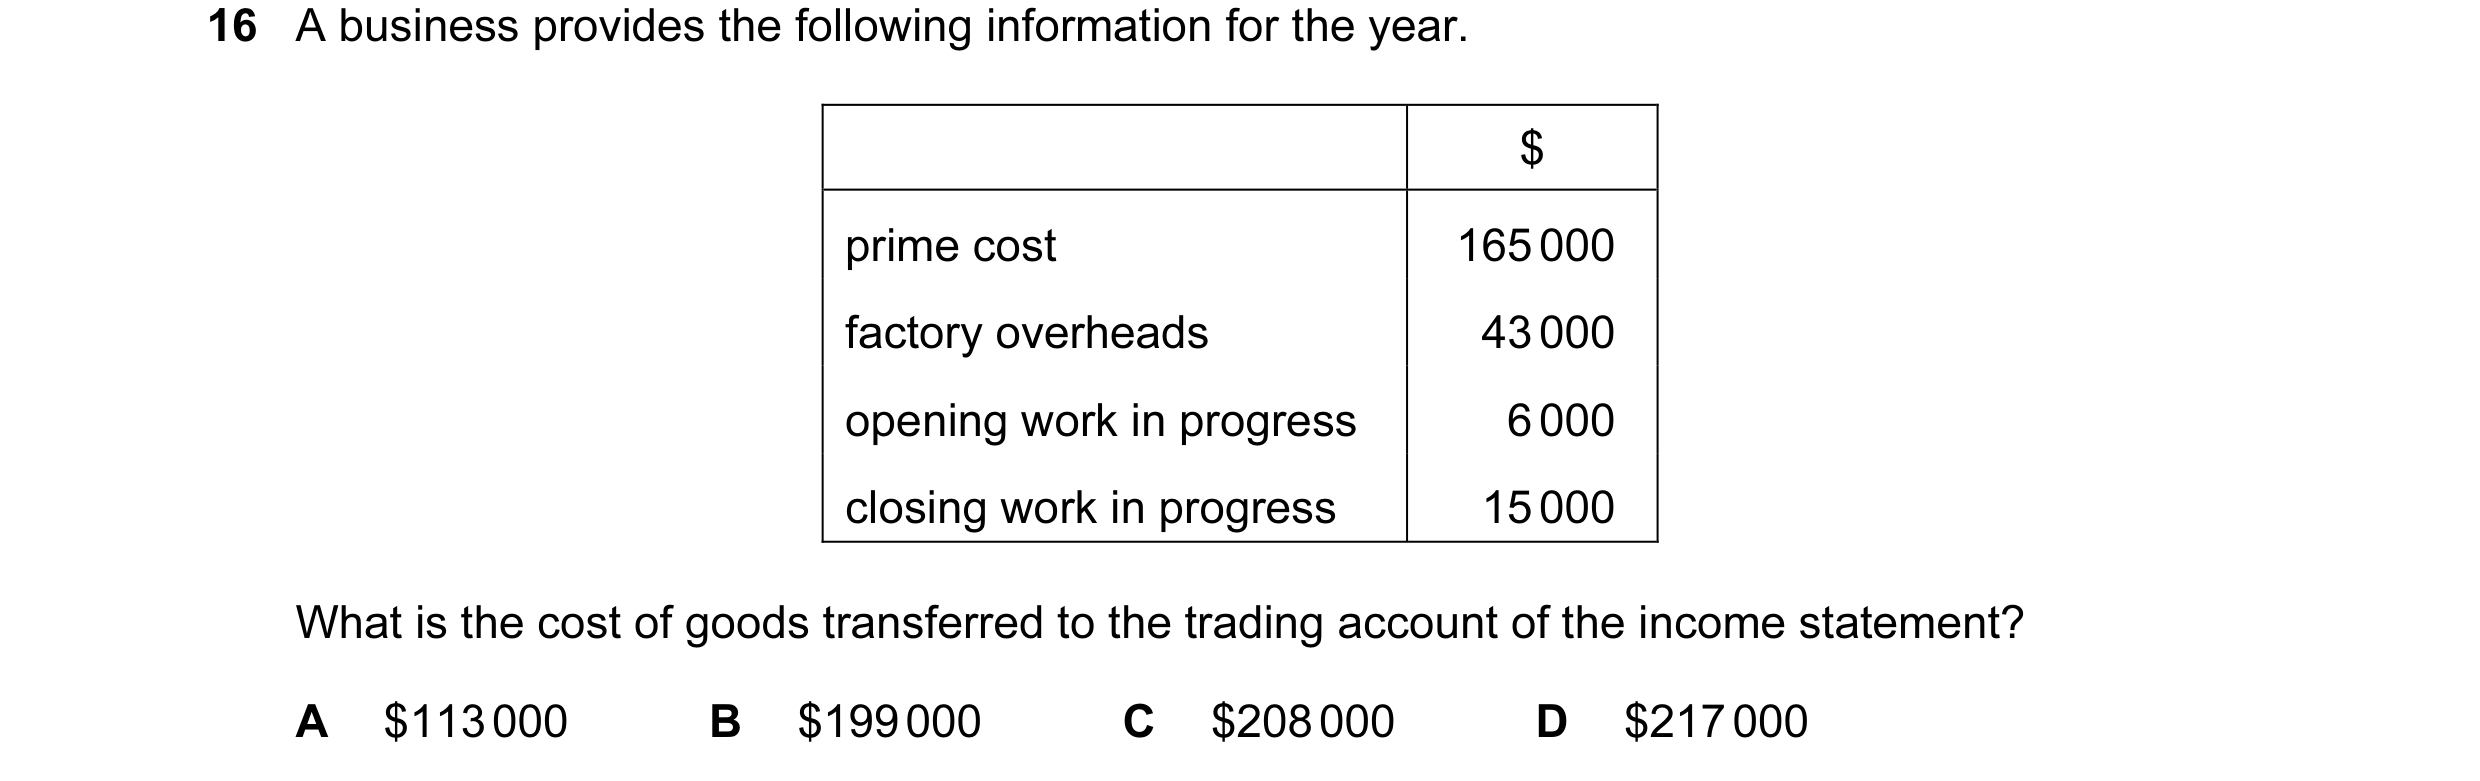
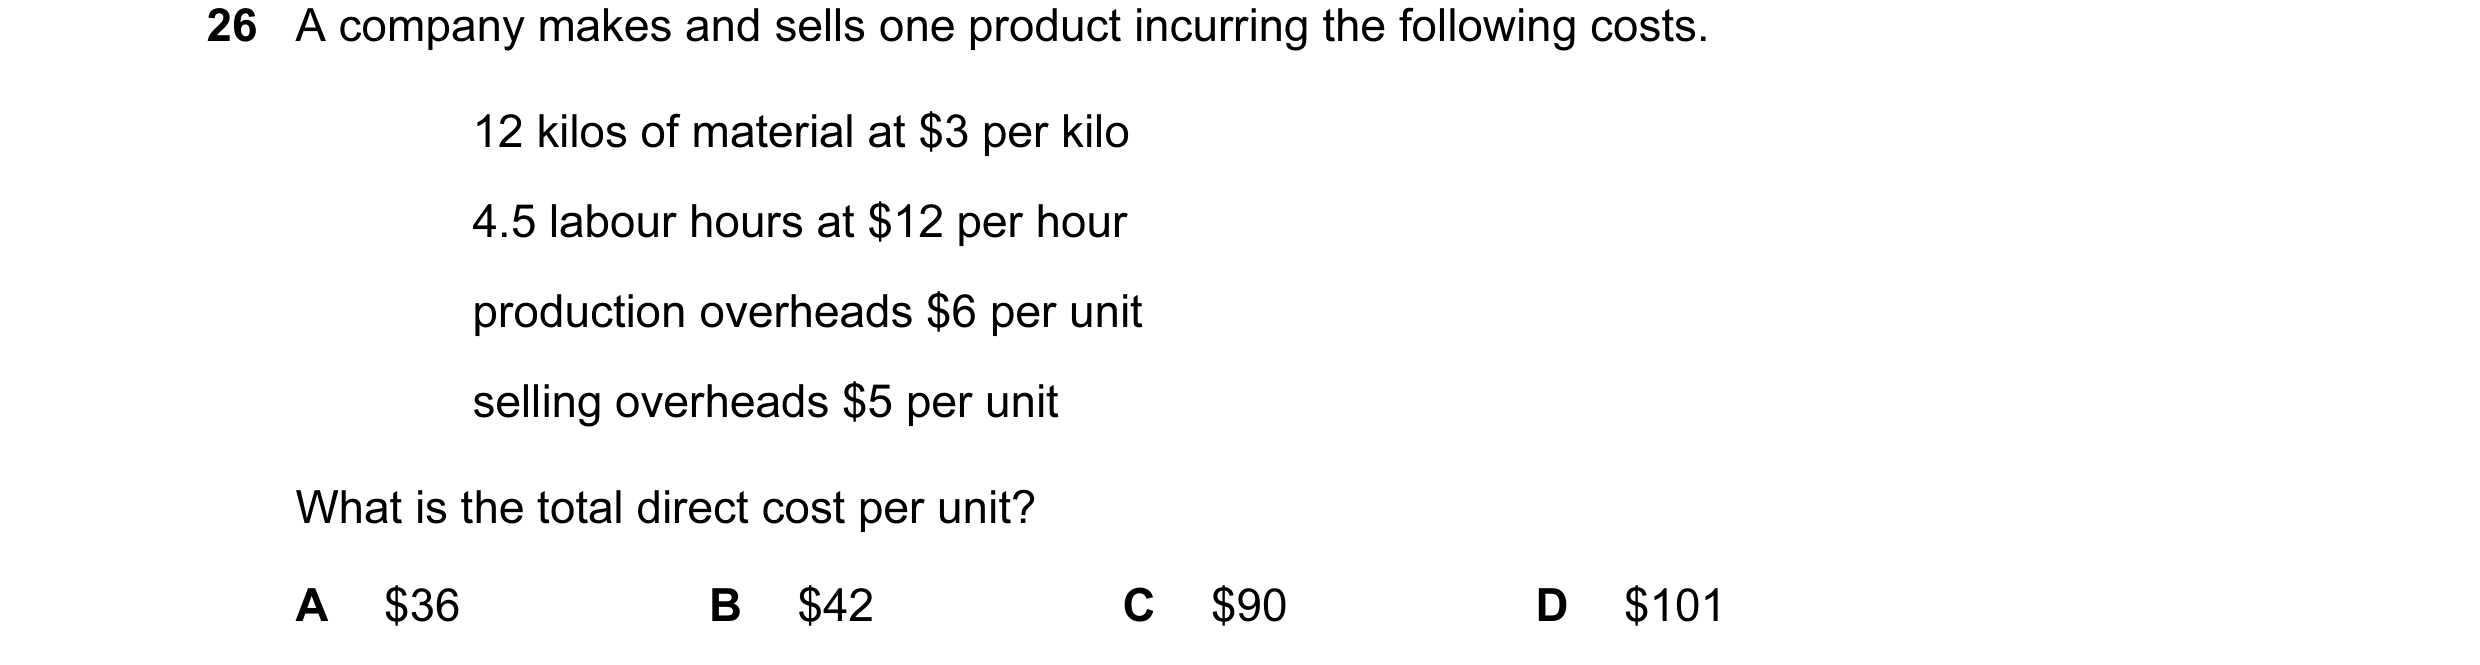 38 / 143
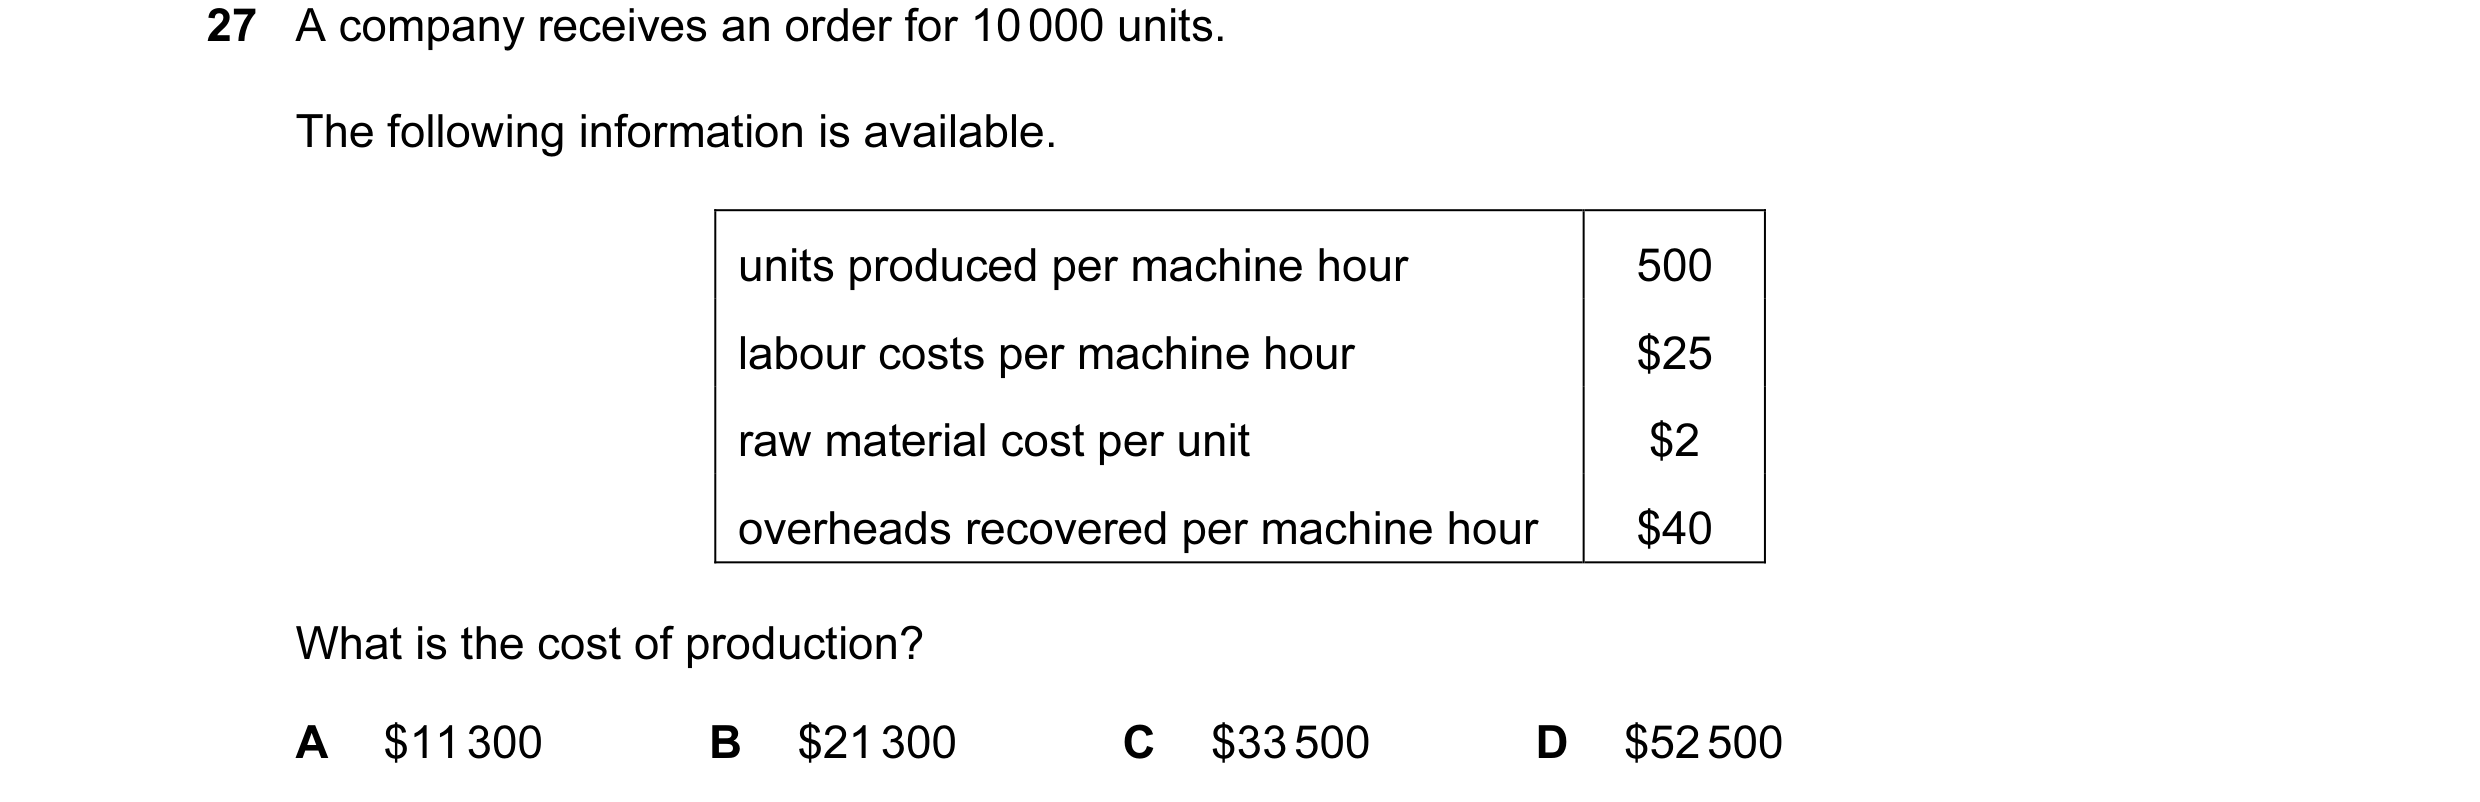
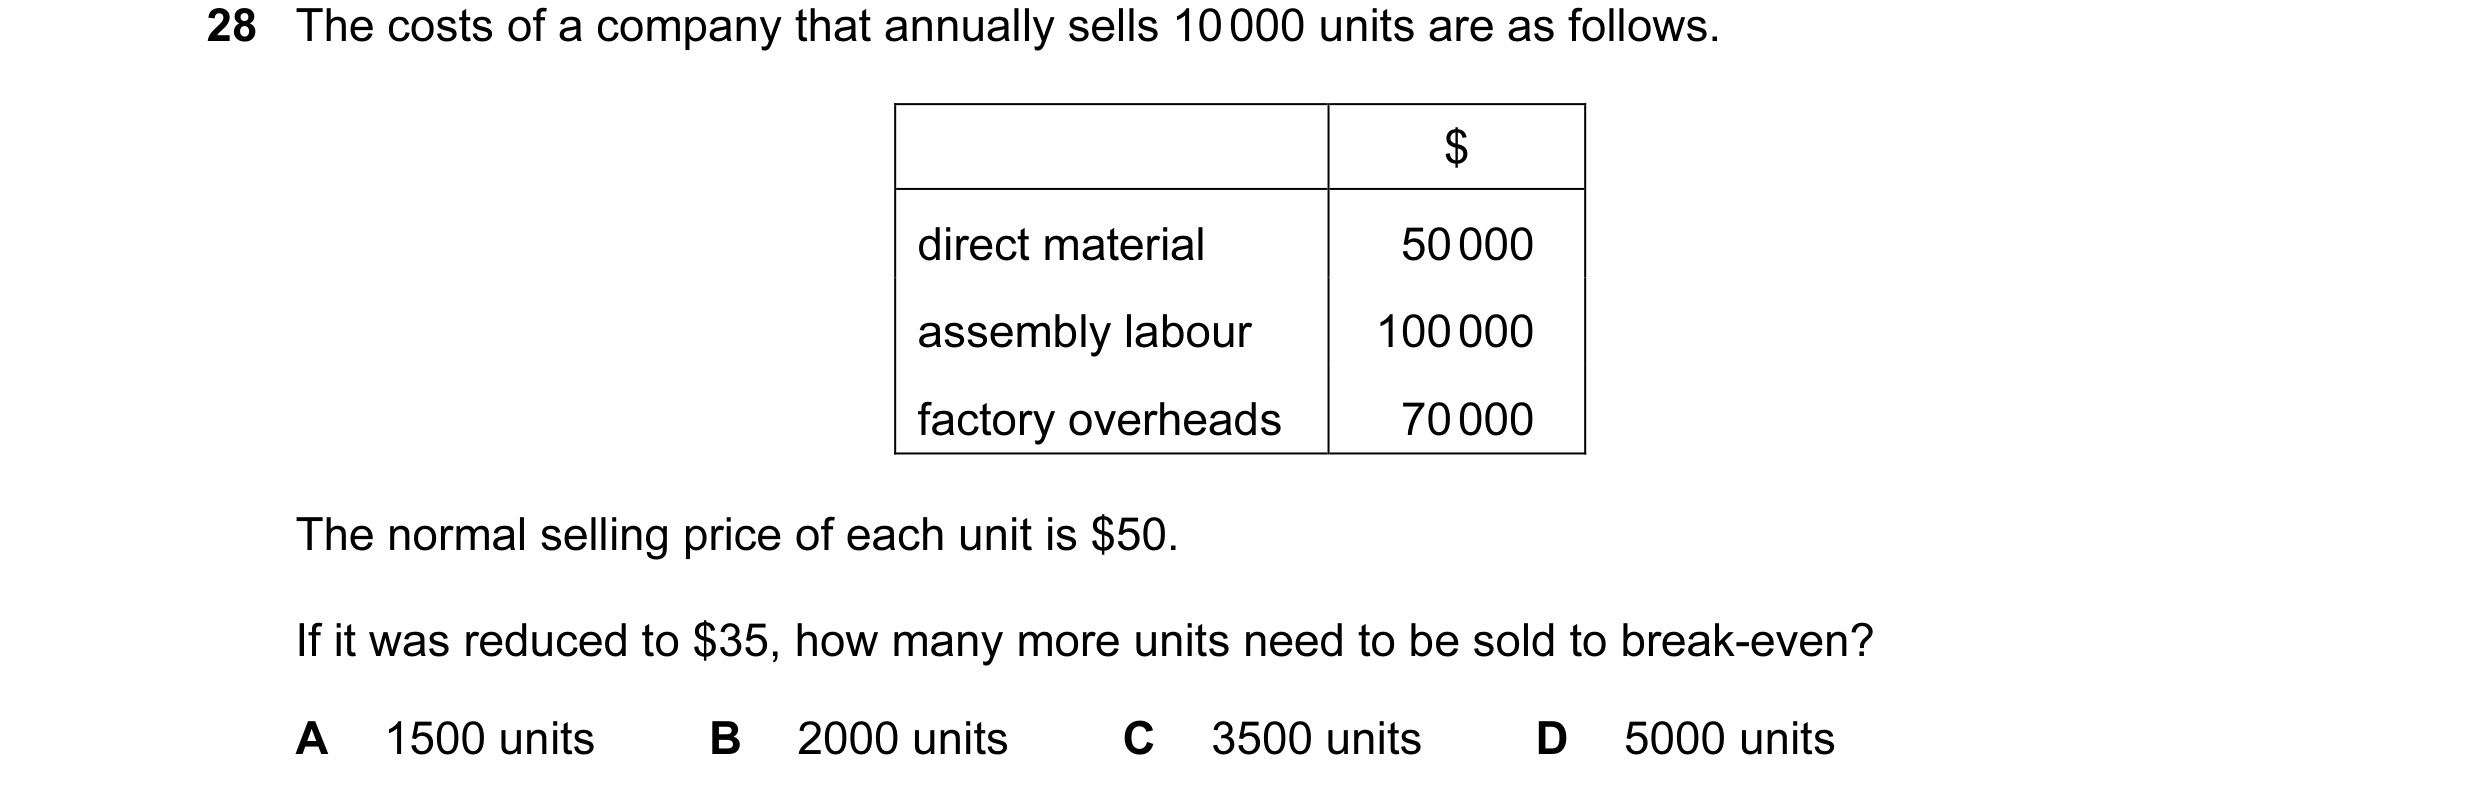
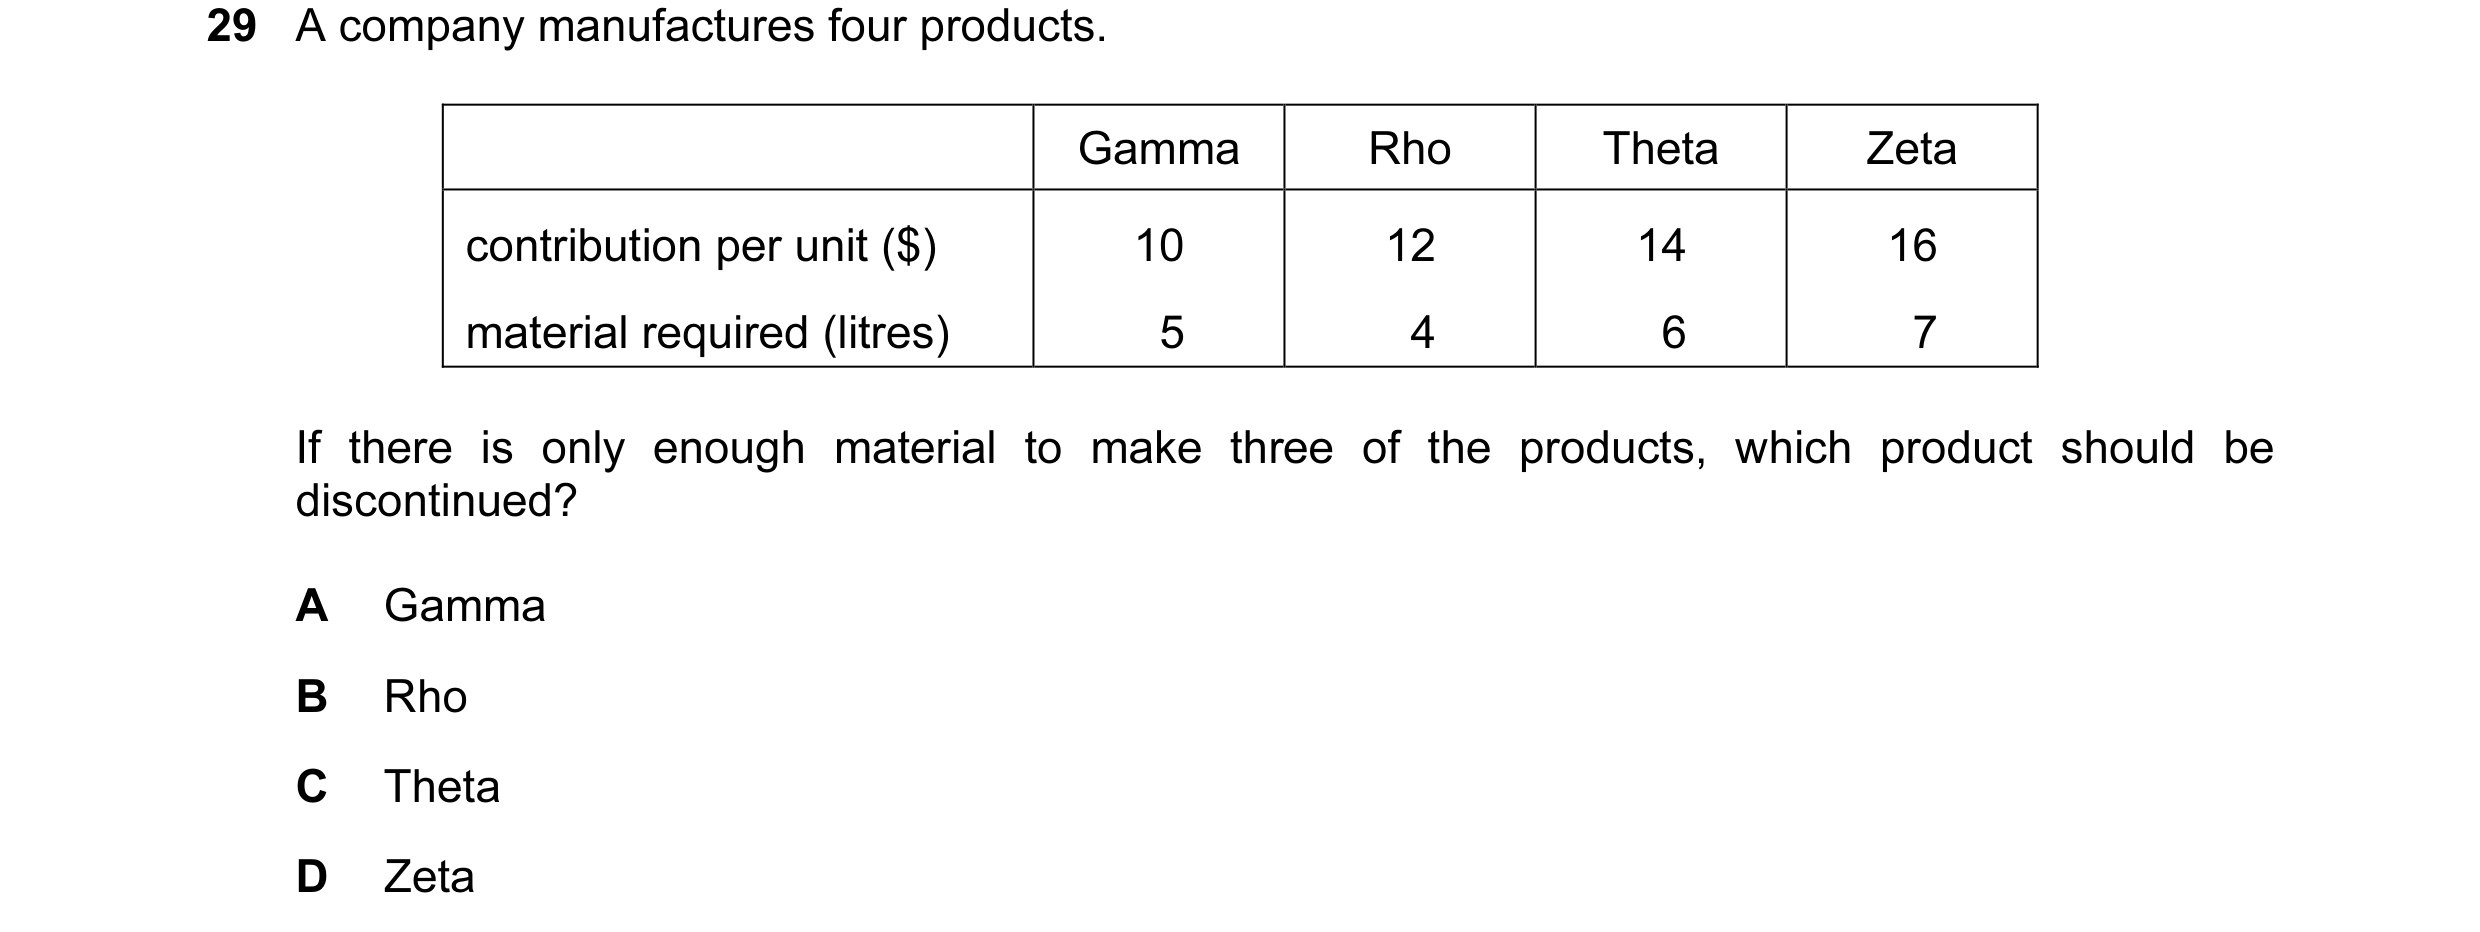 39 / 143
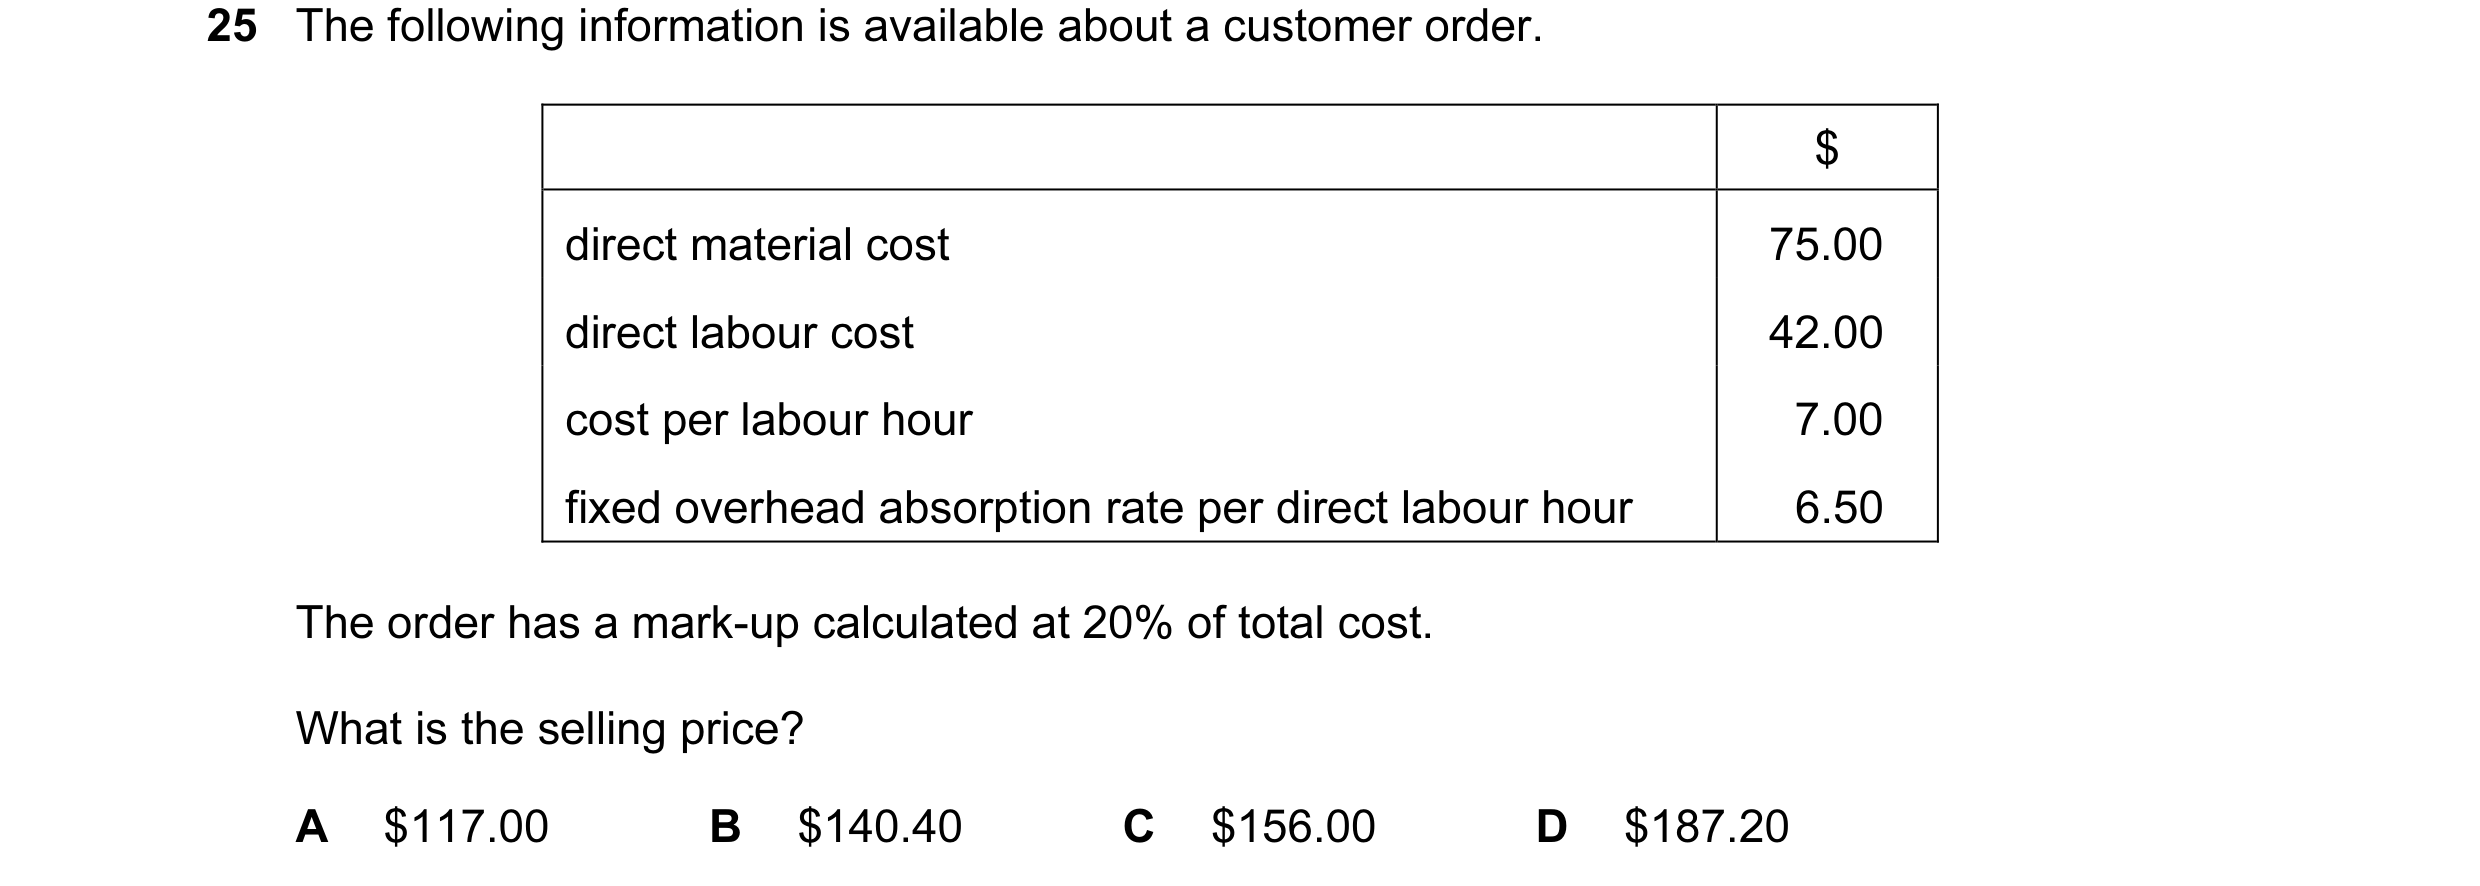
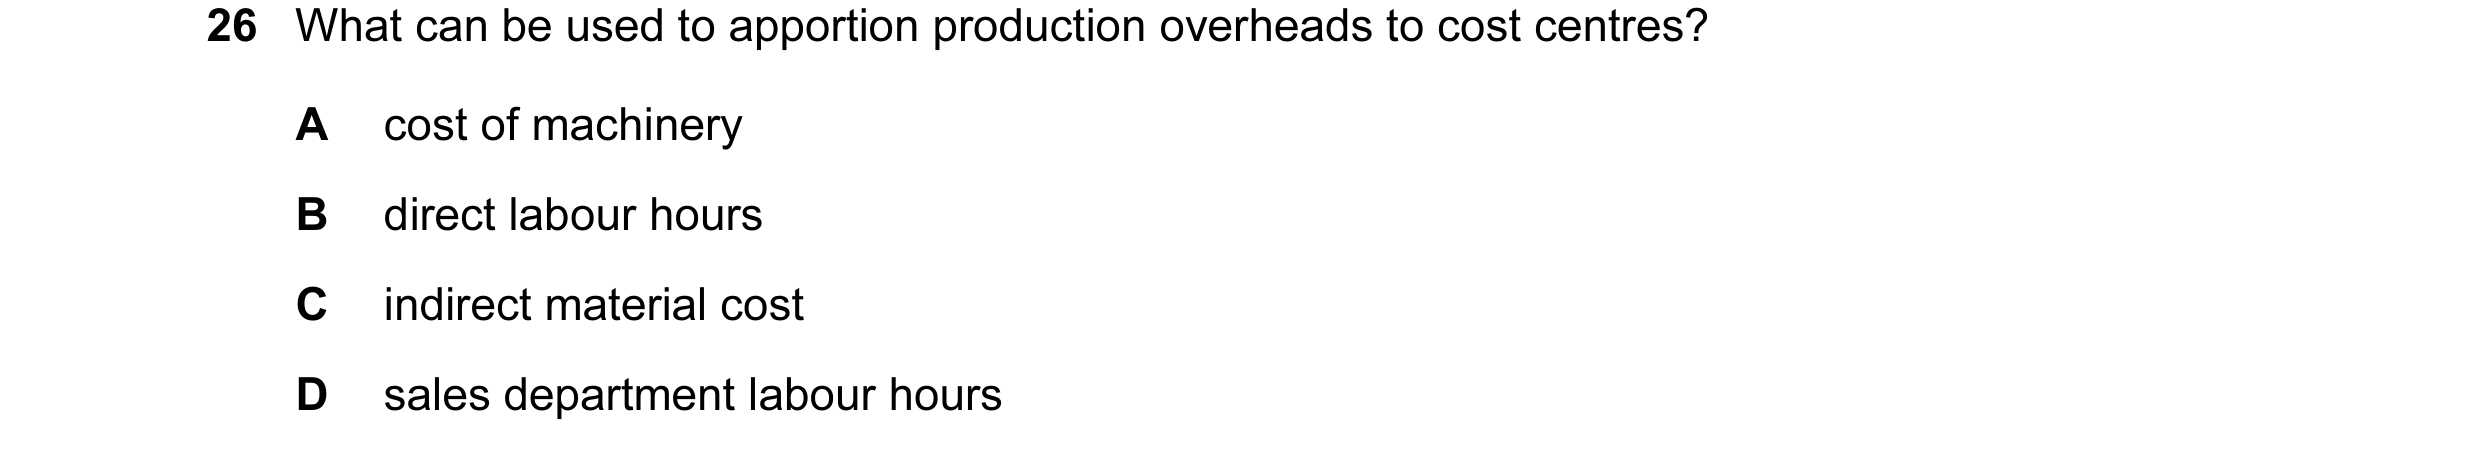
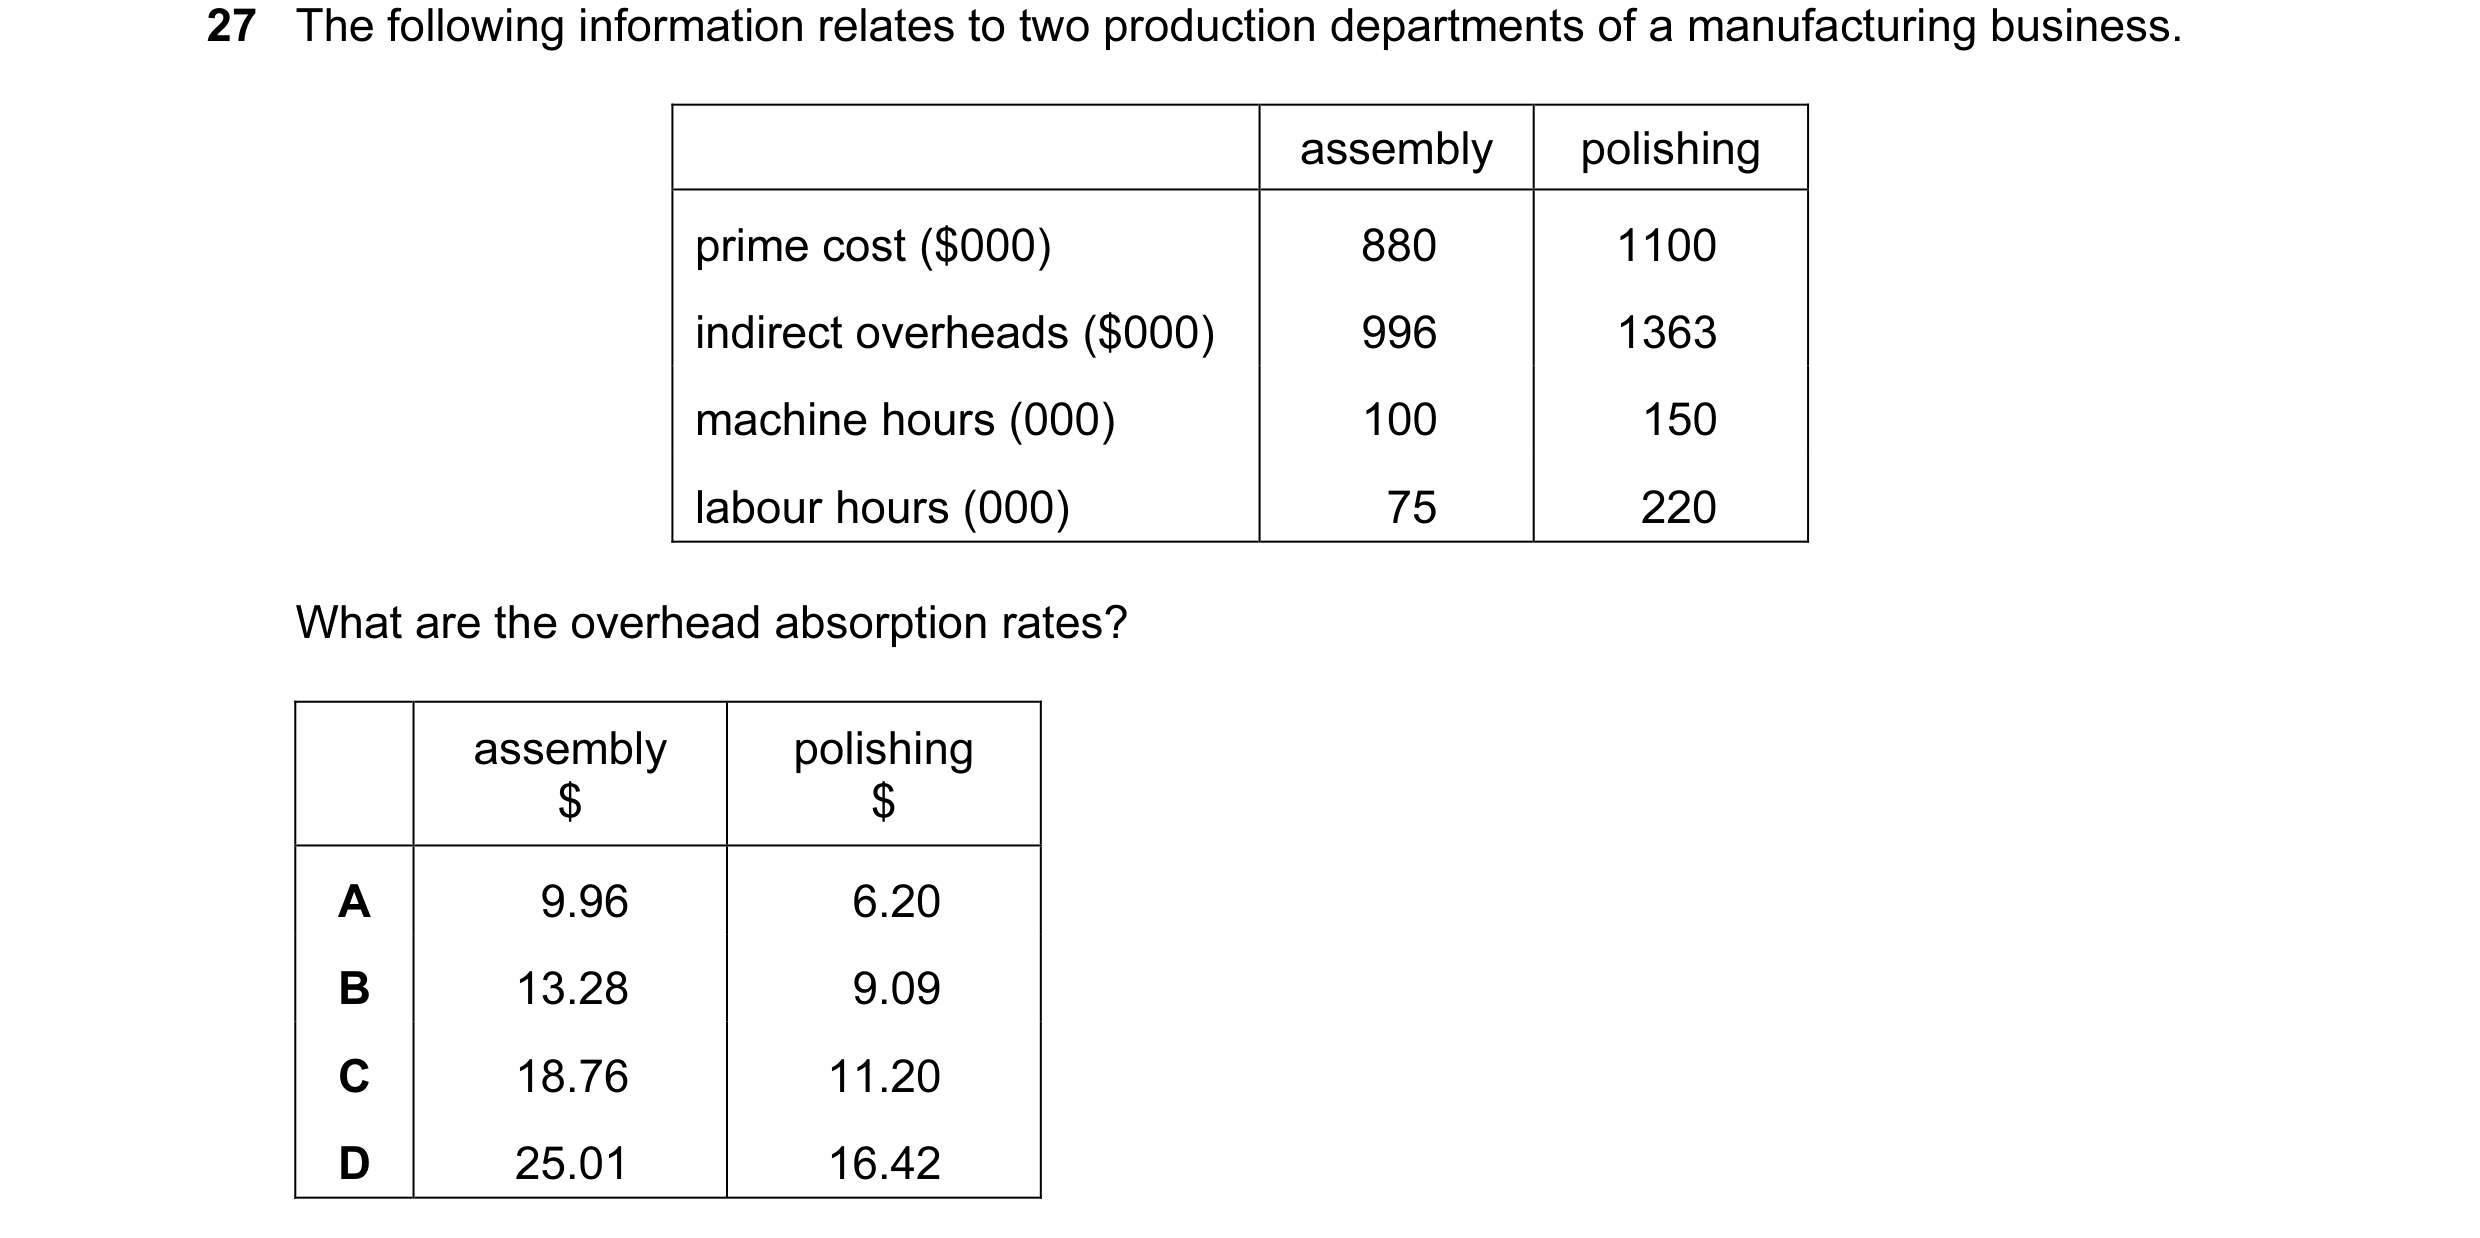
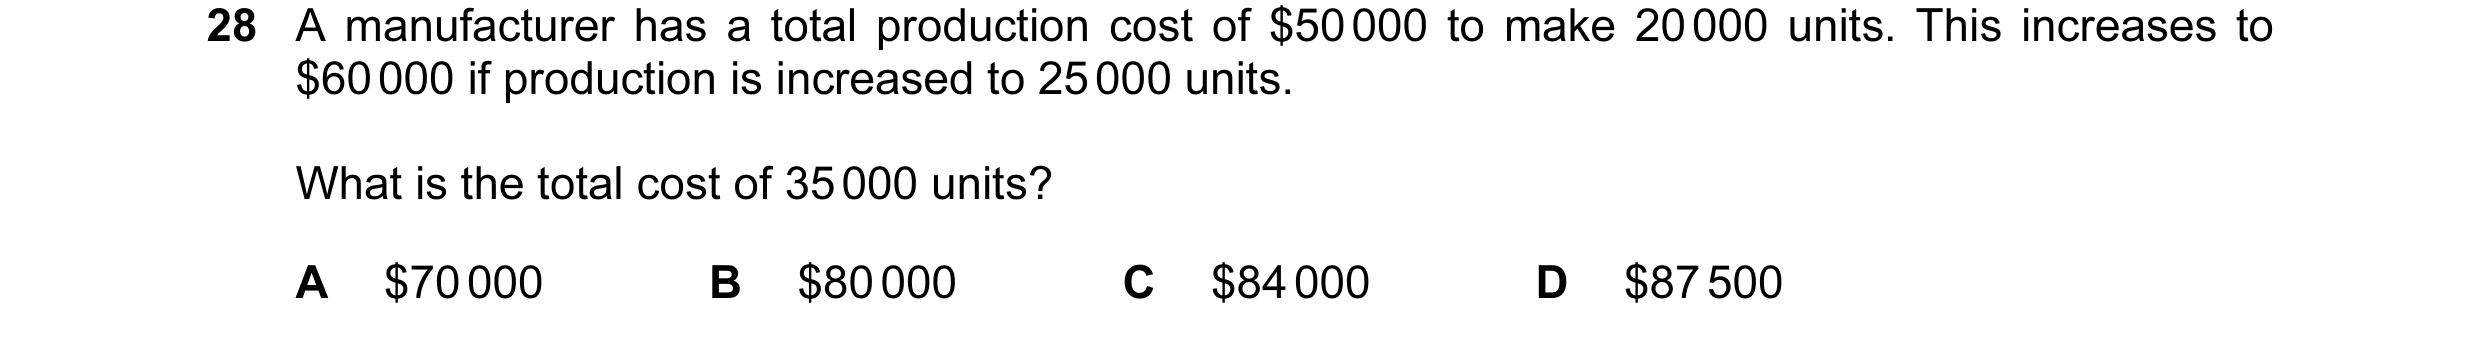 40 / 143
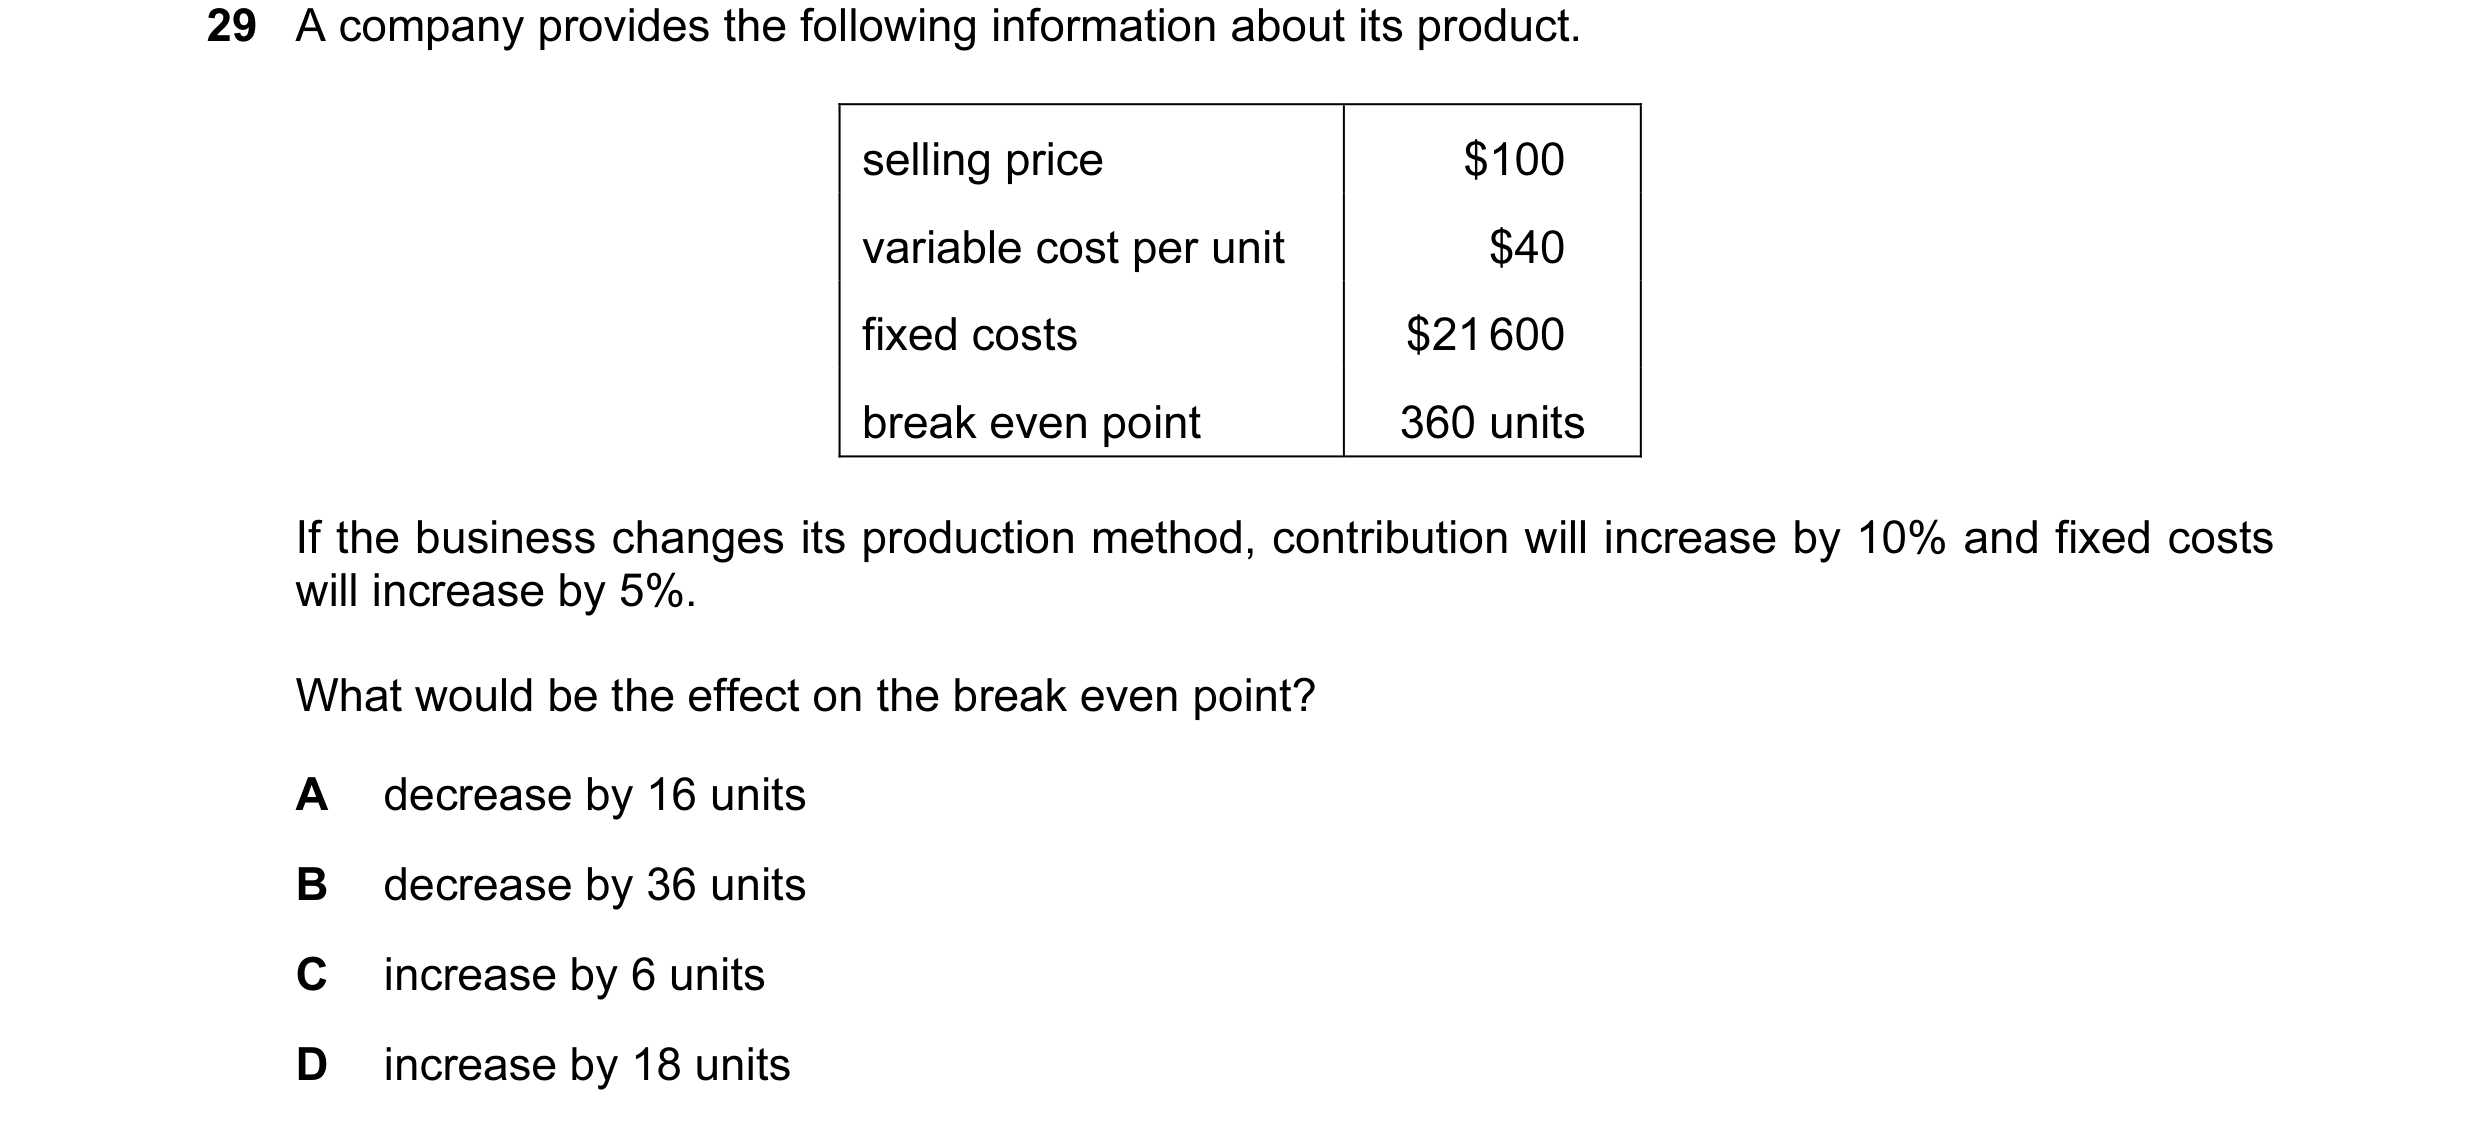
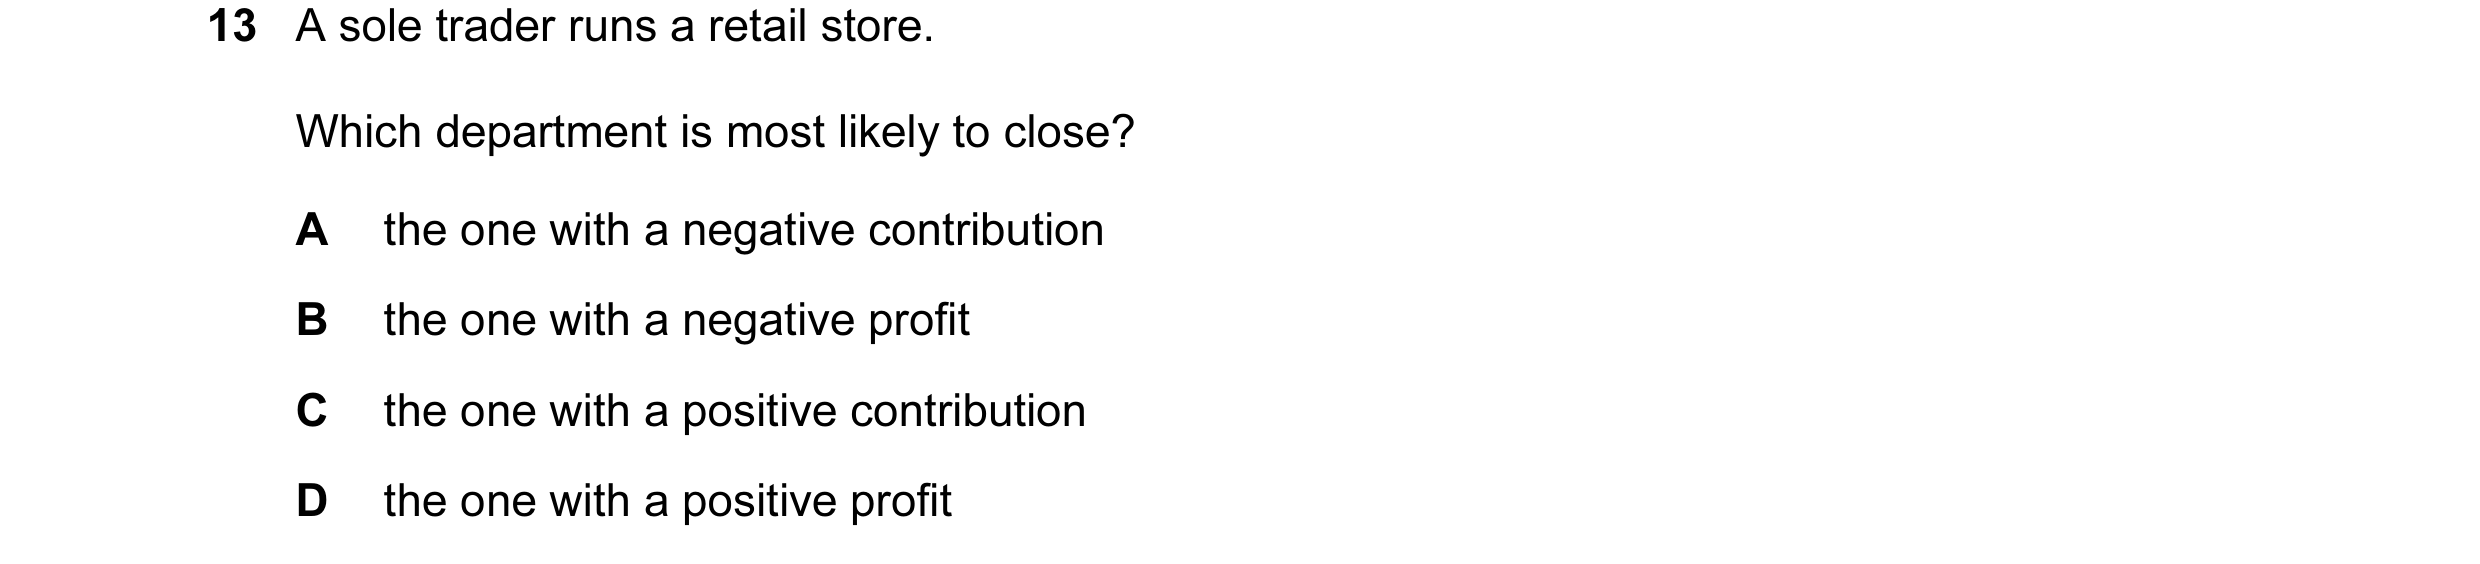
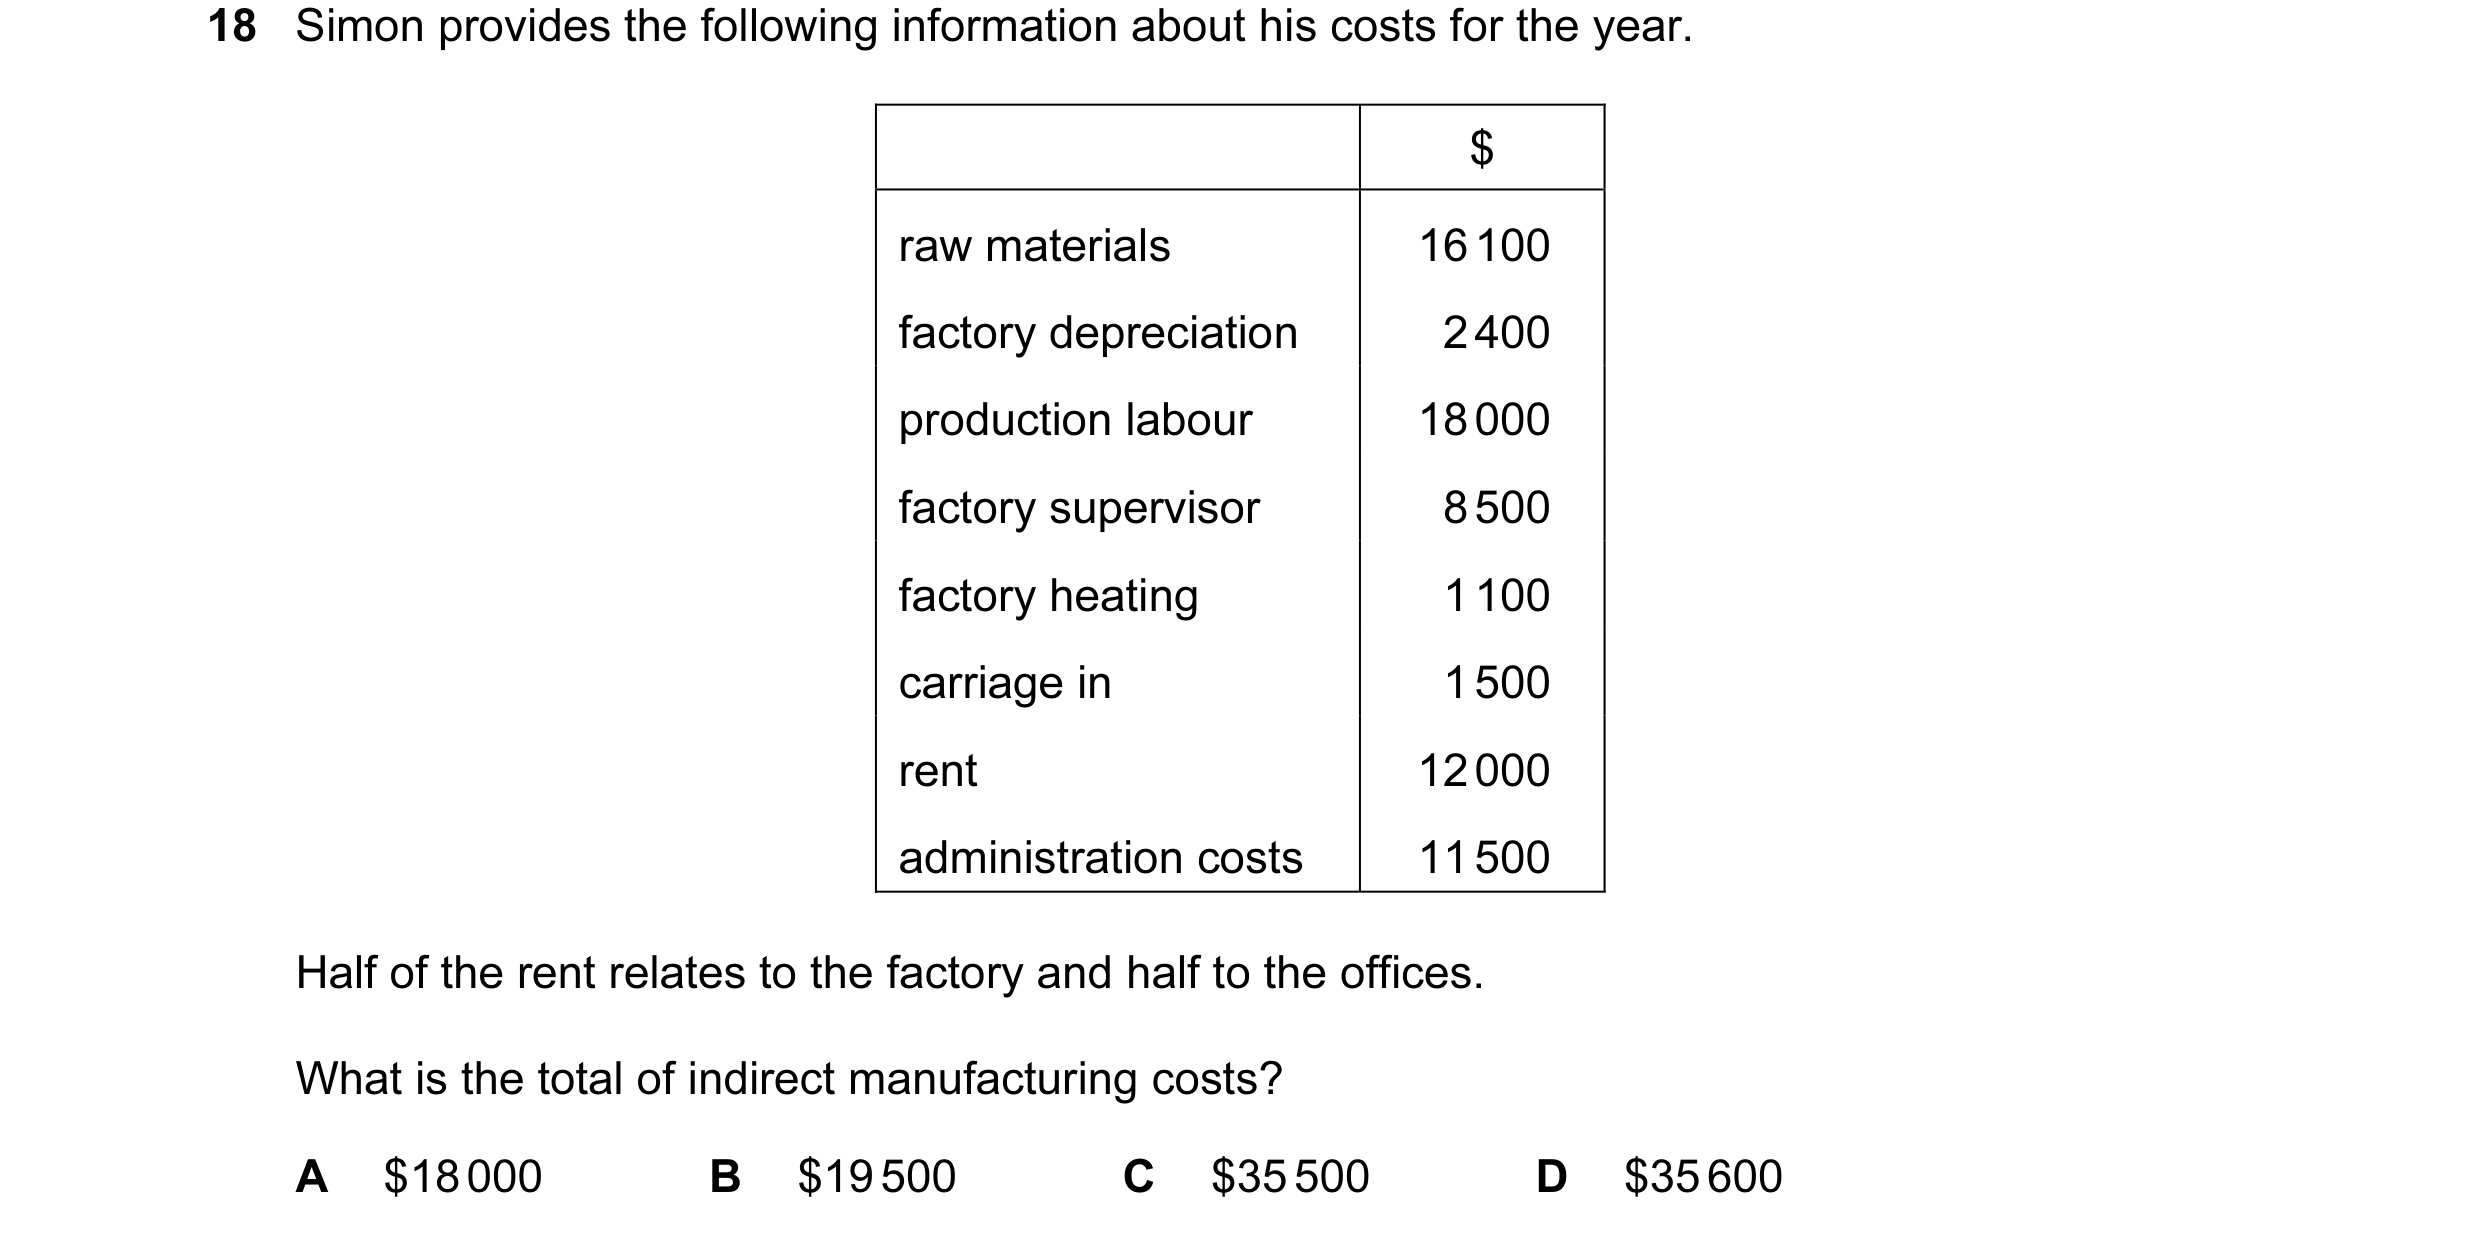 41 / 143
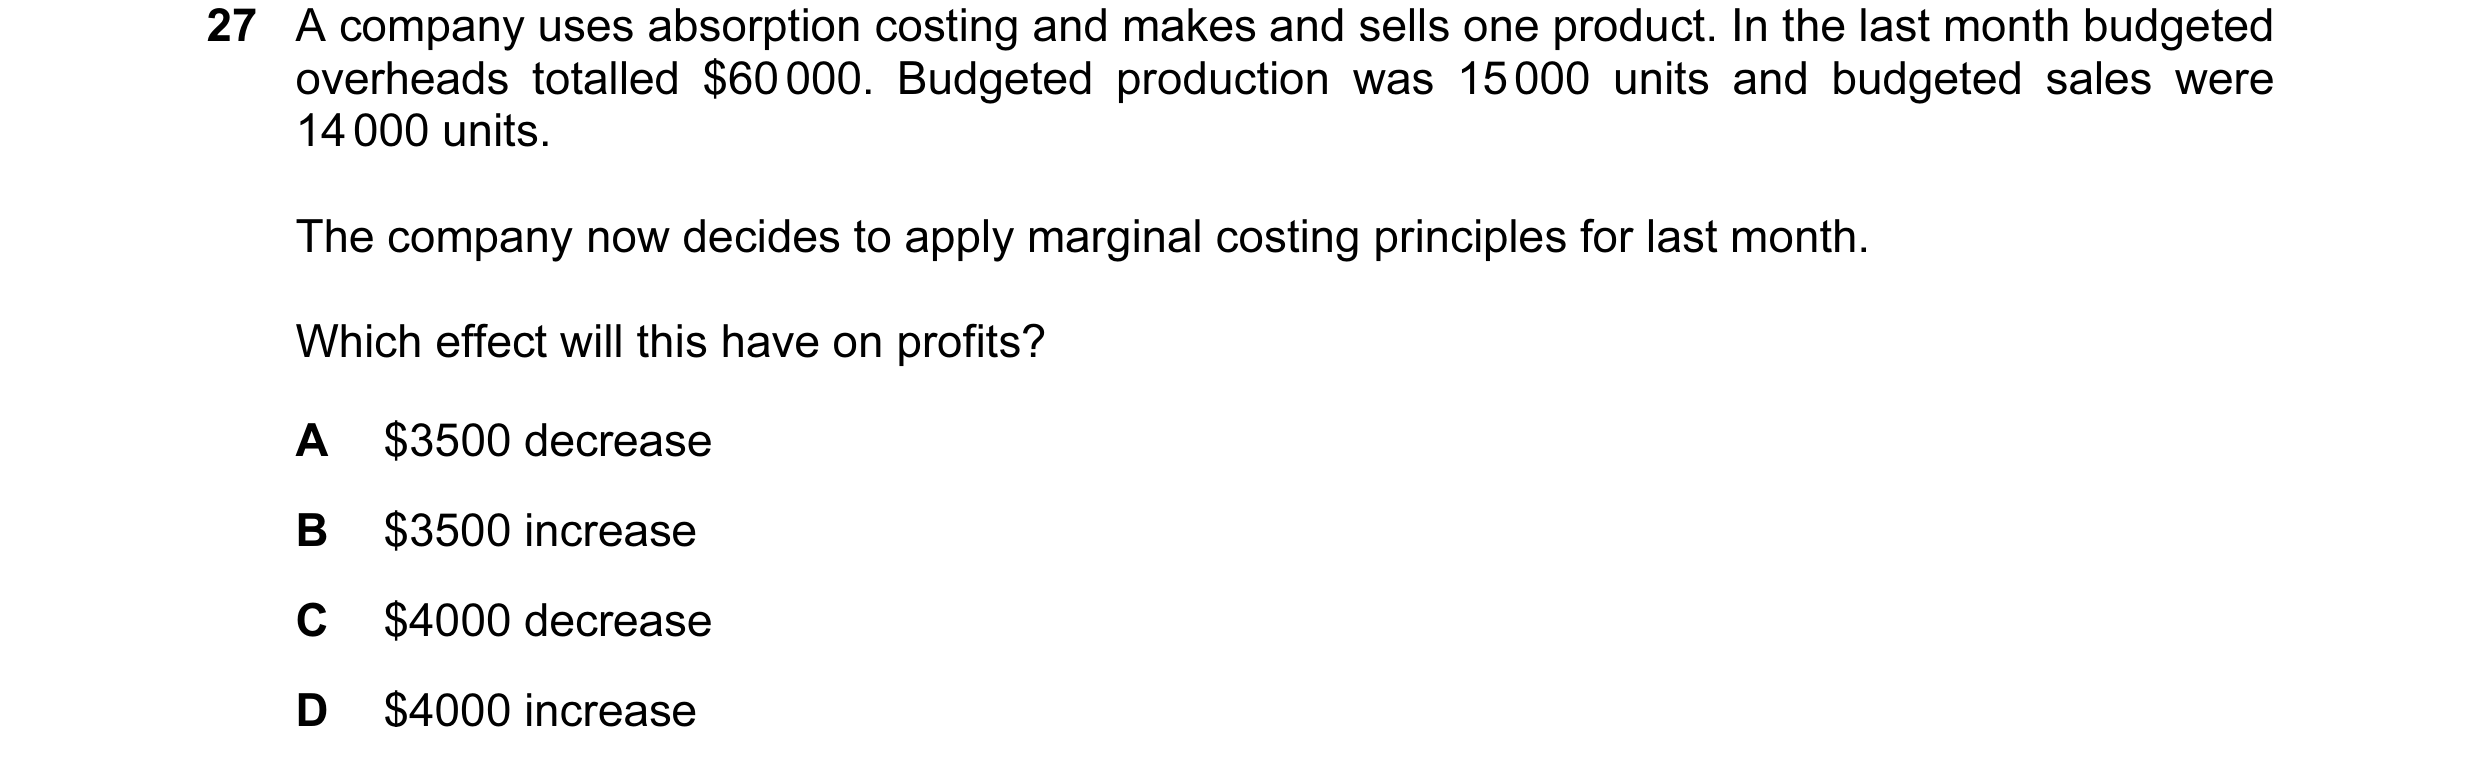
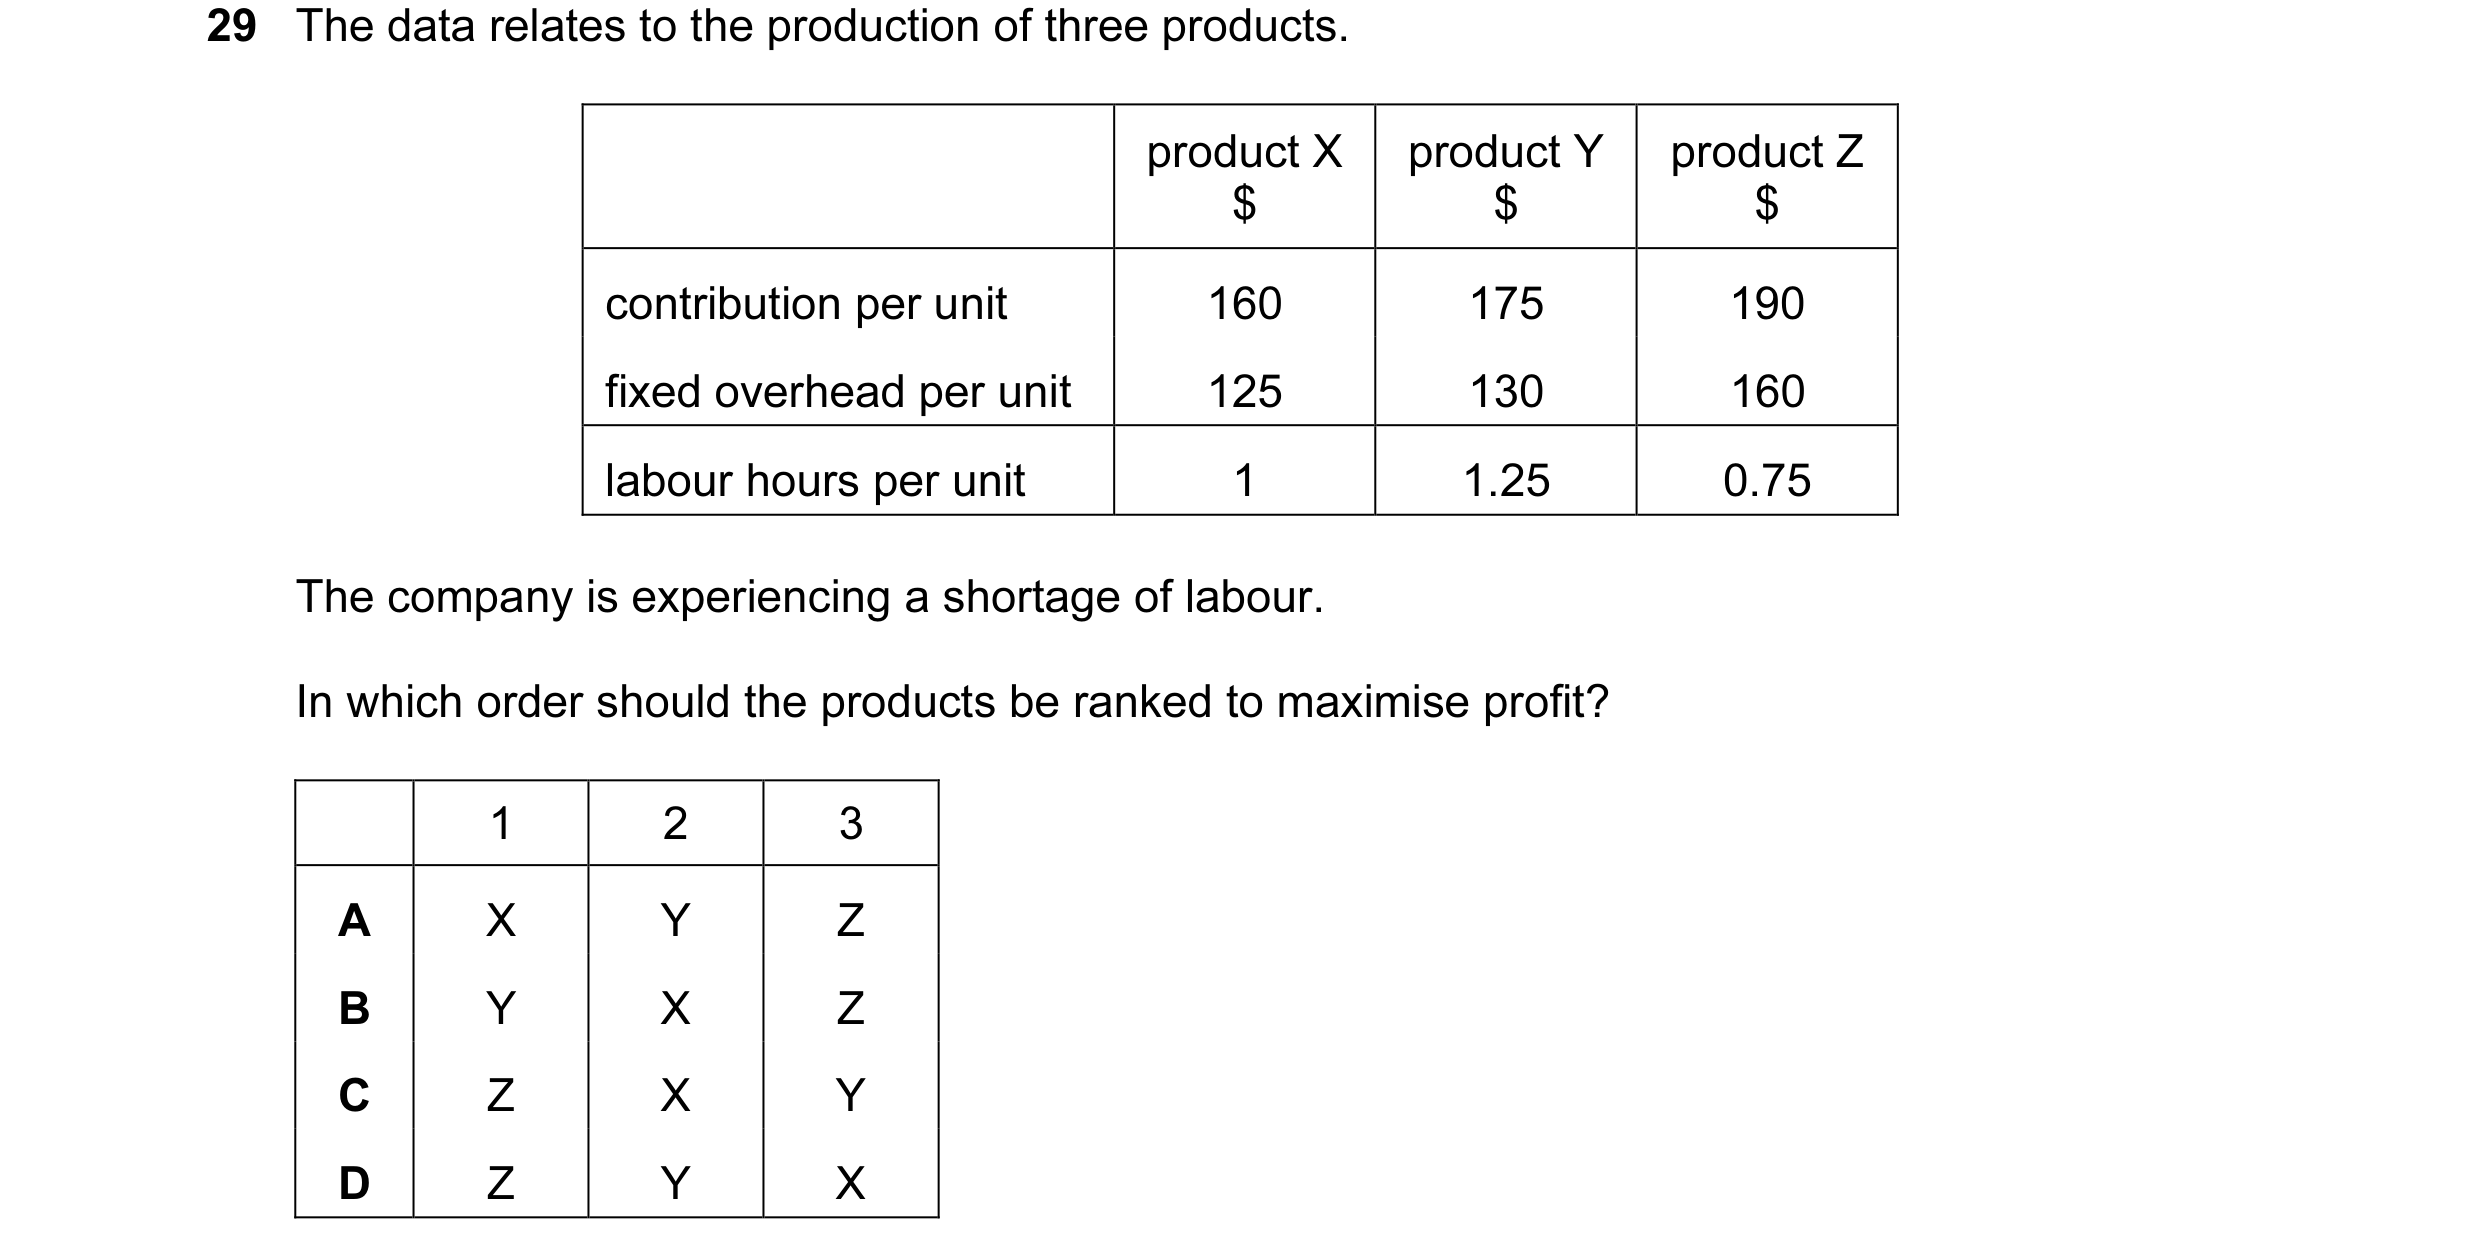
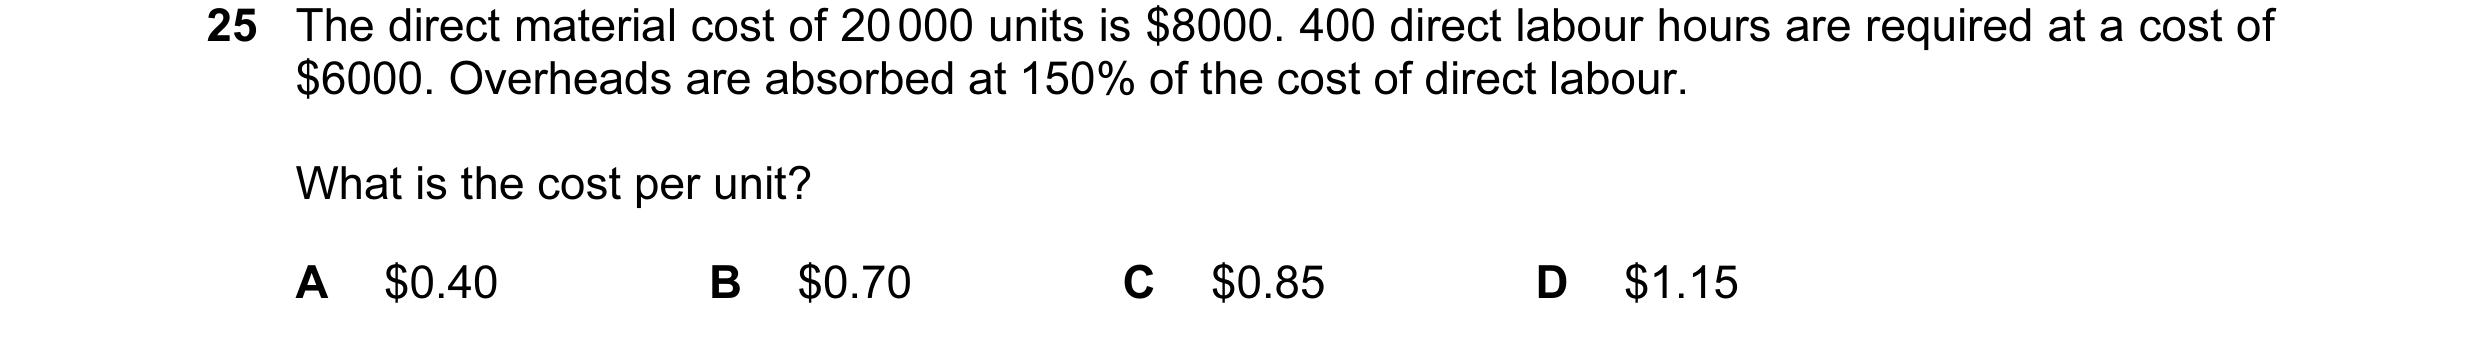
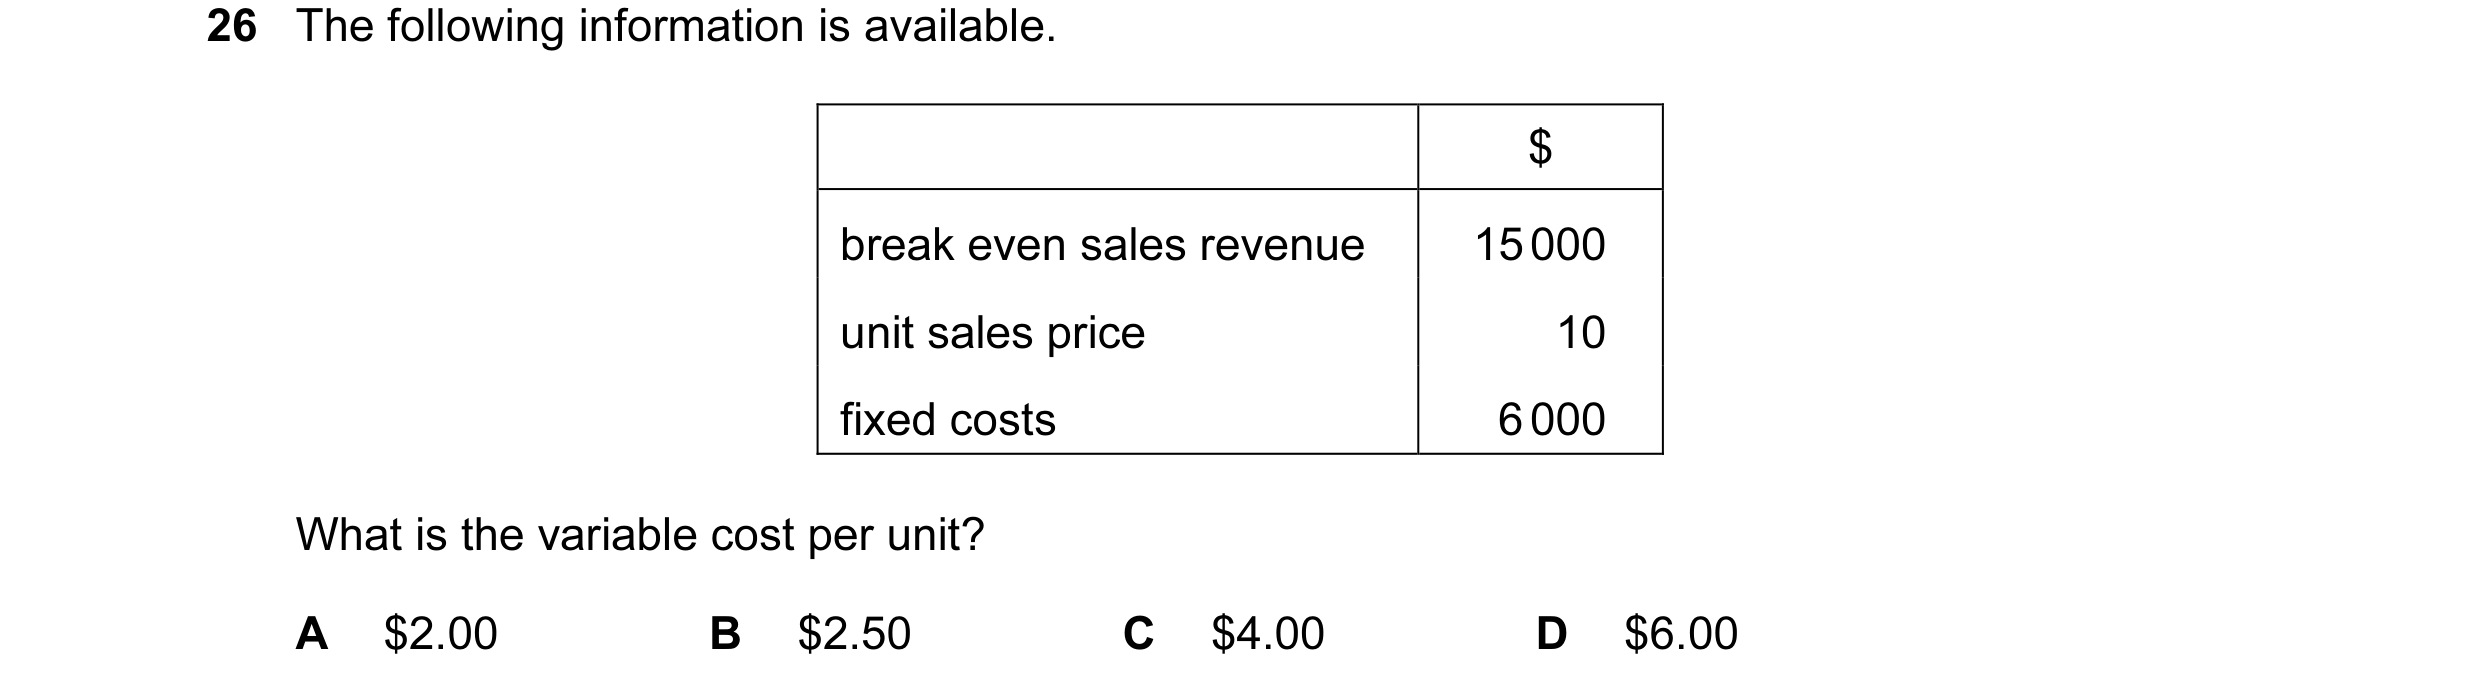 42 / 143
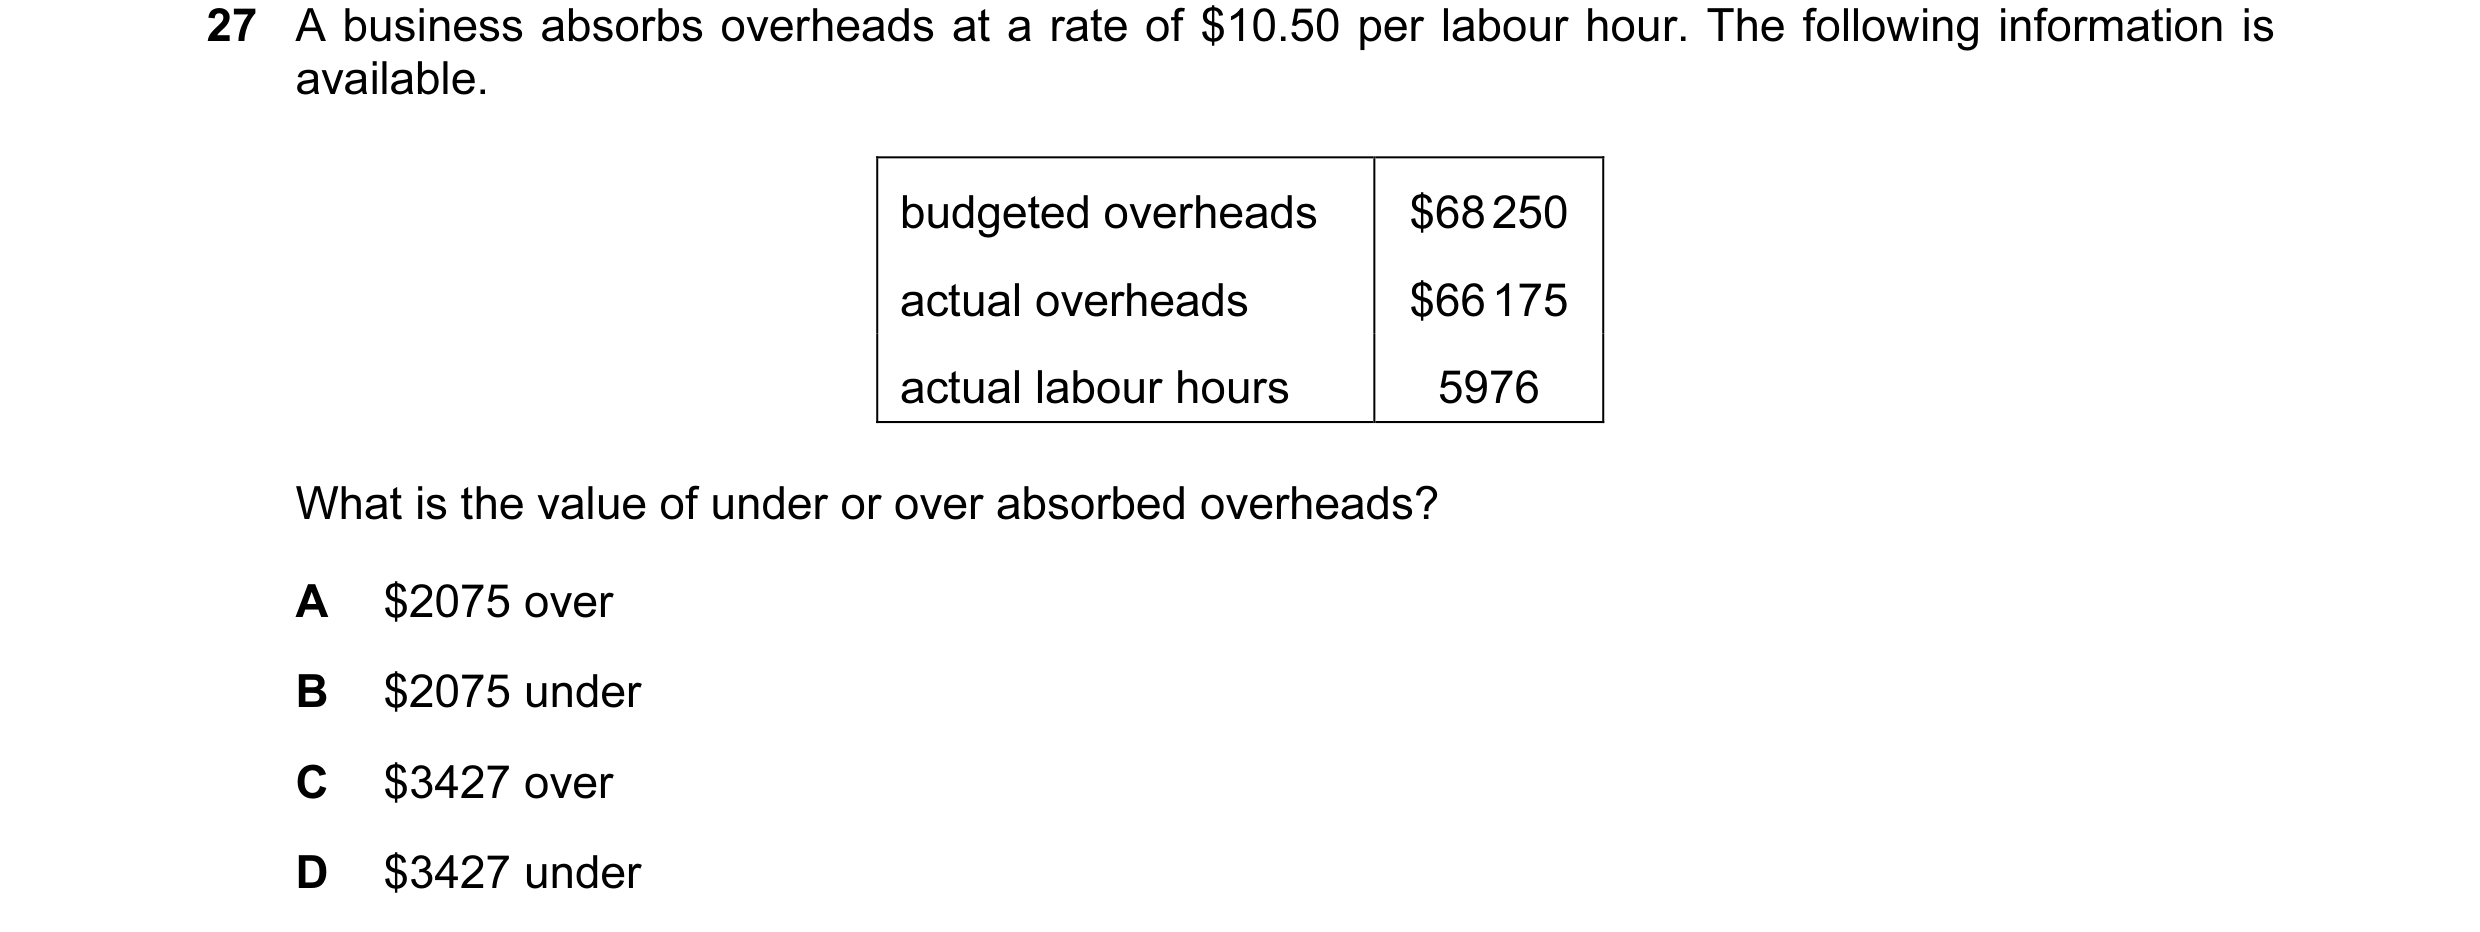
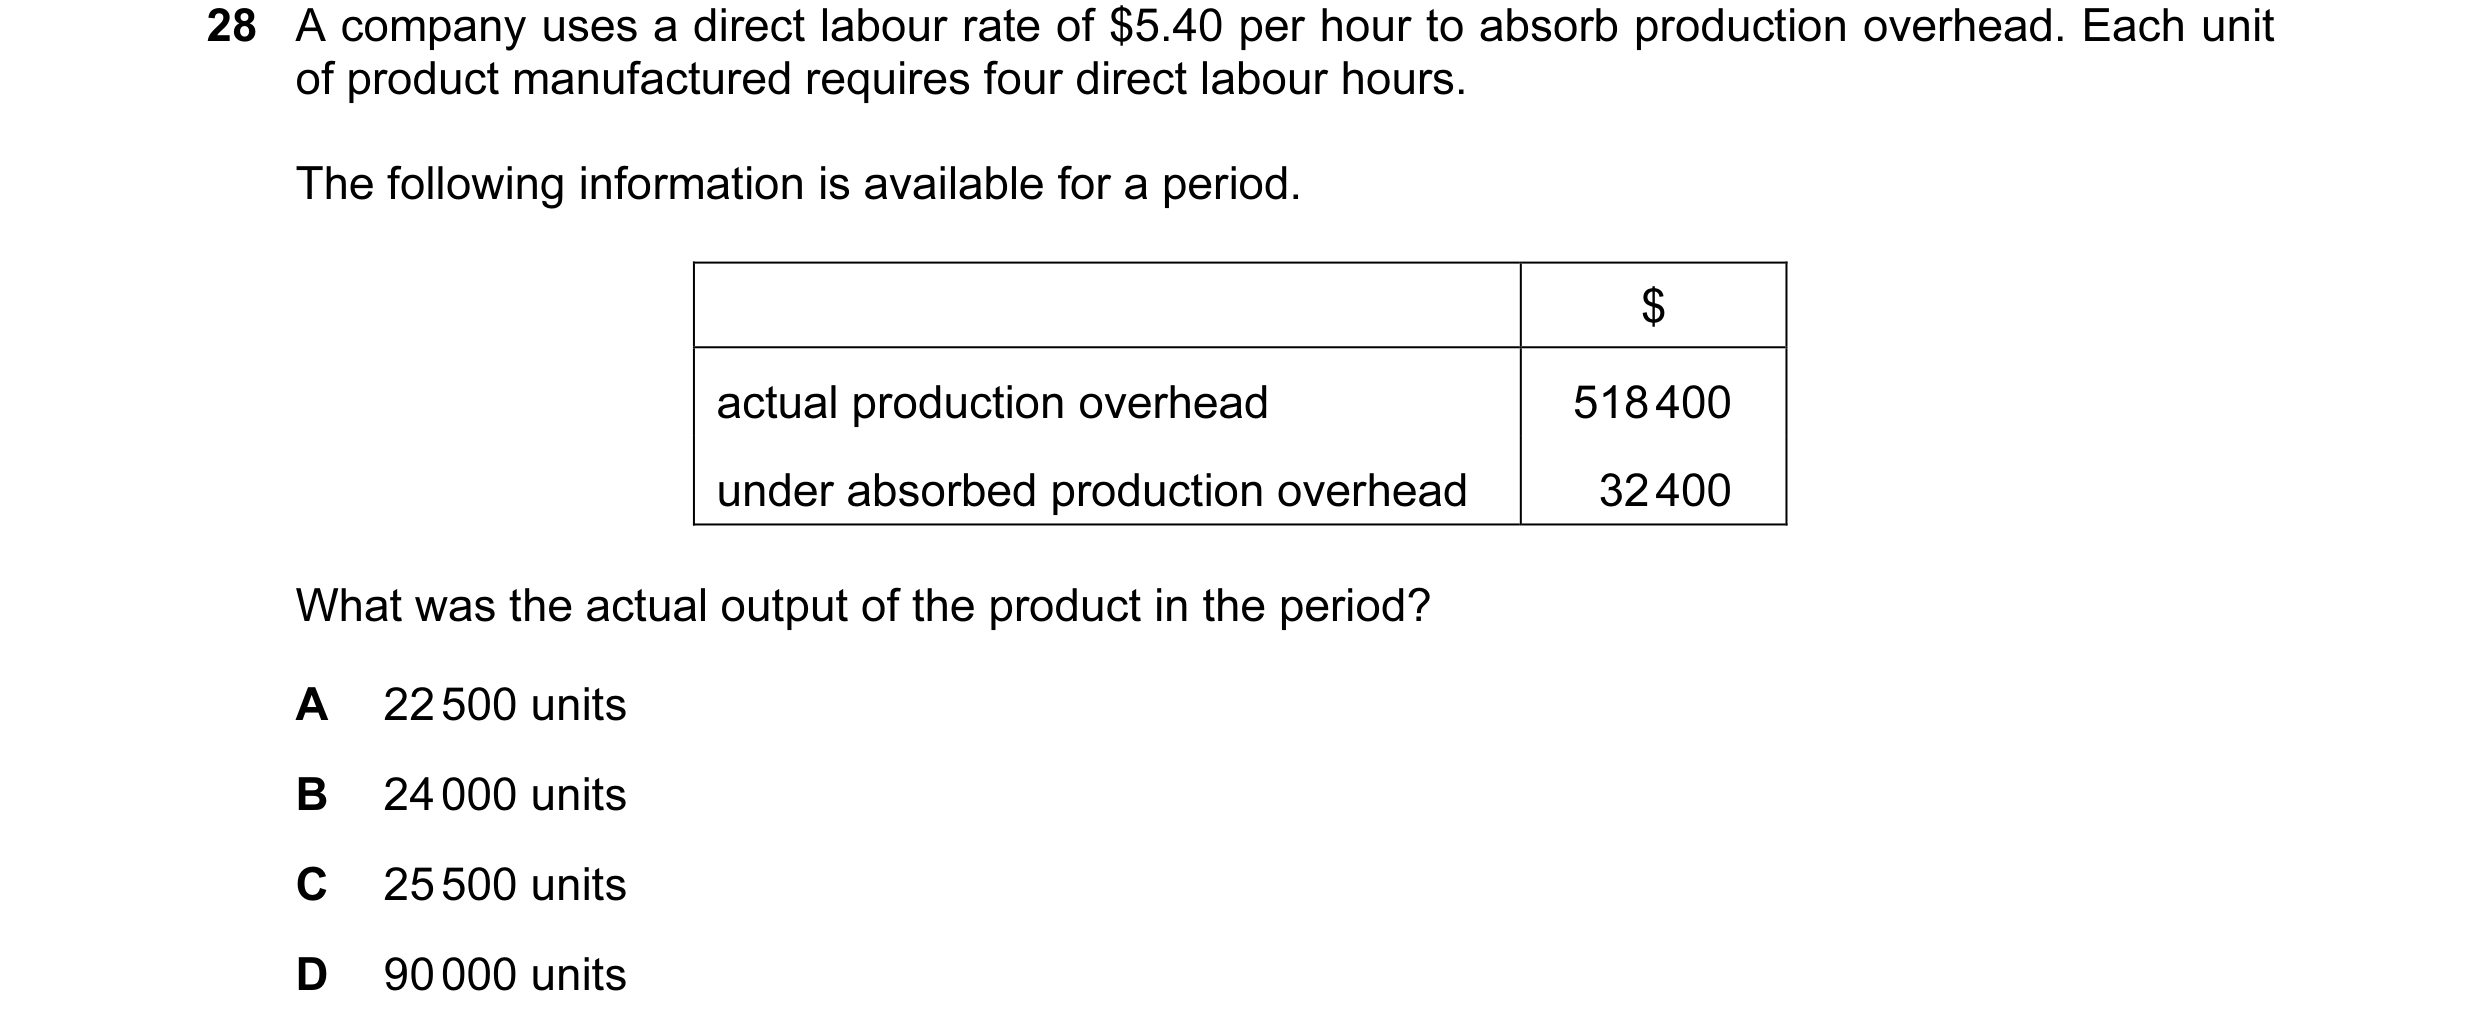
 43 / 143
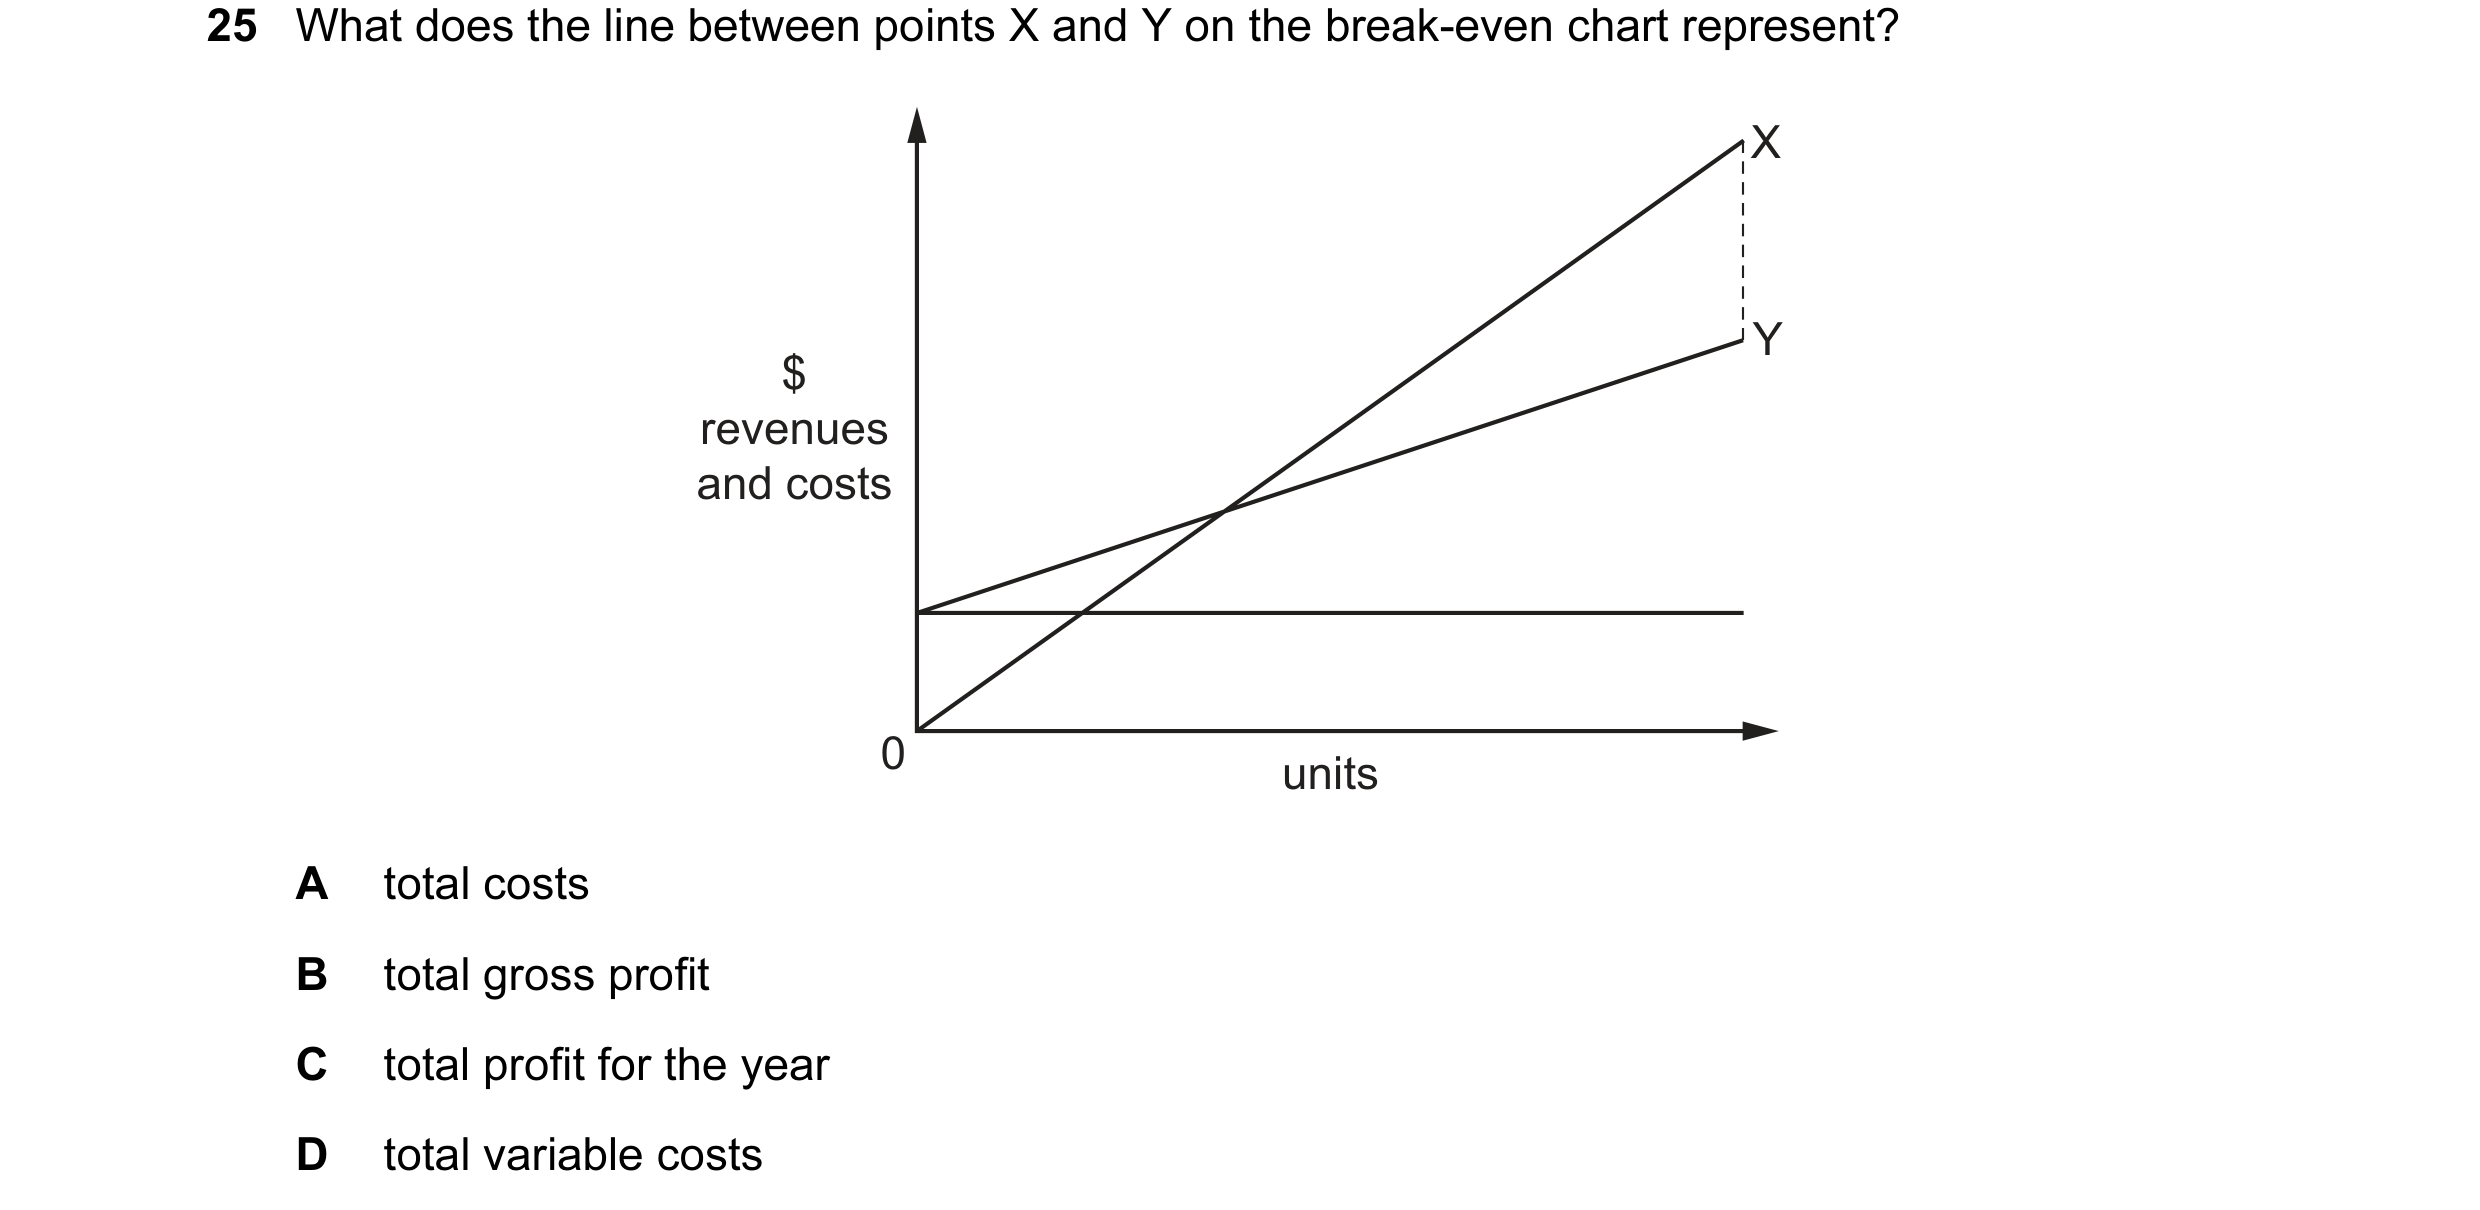
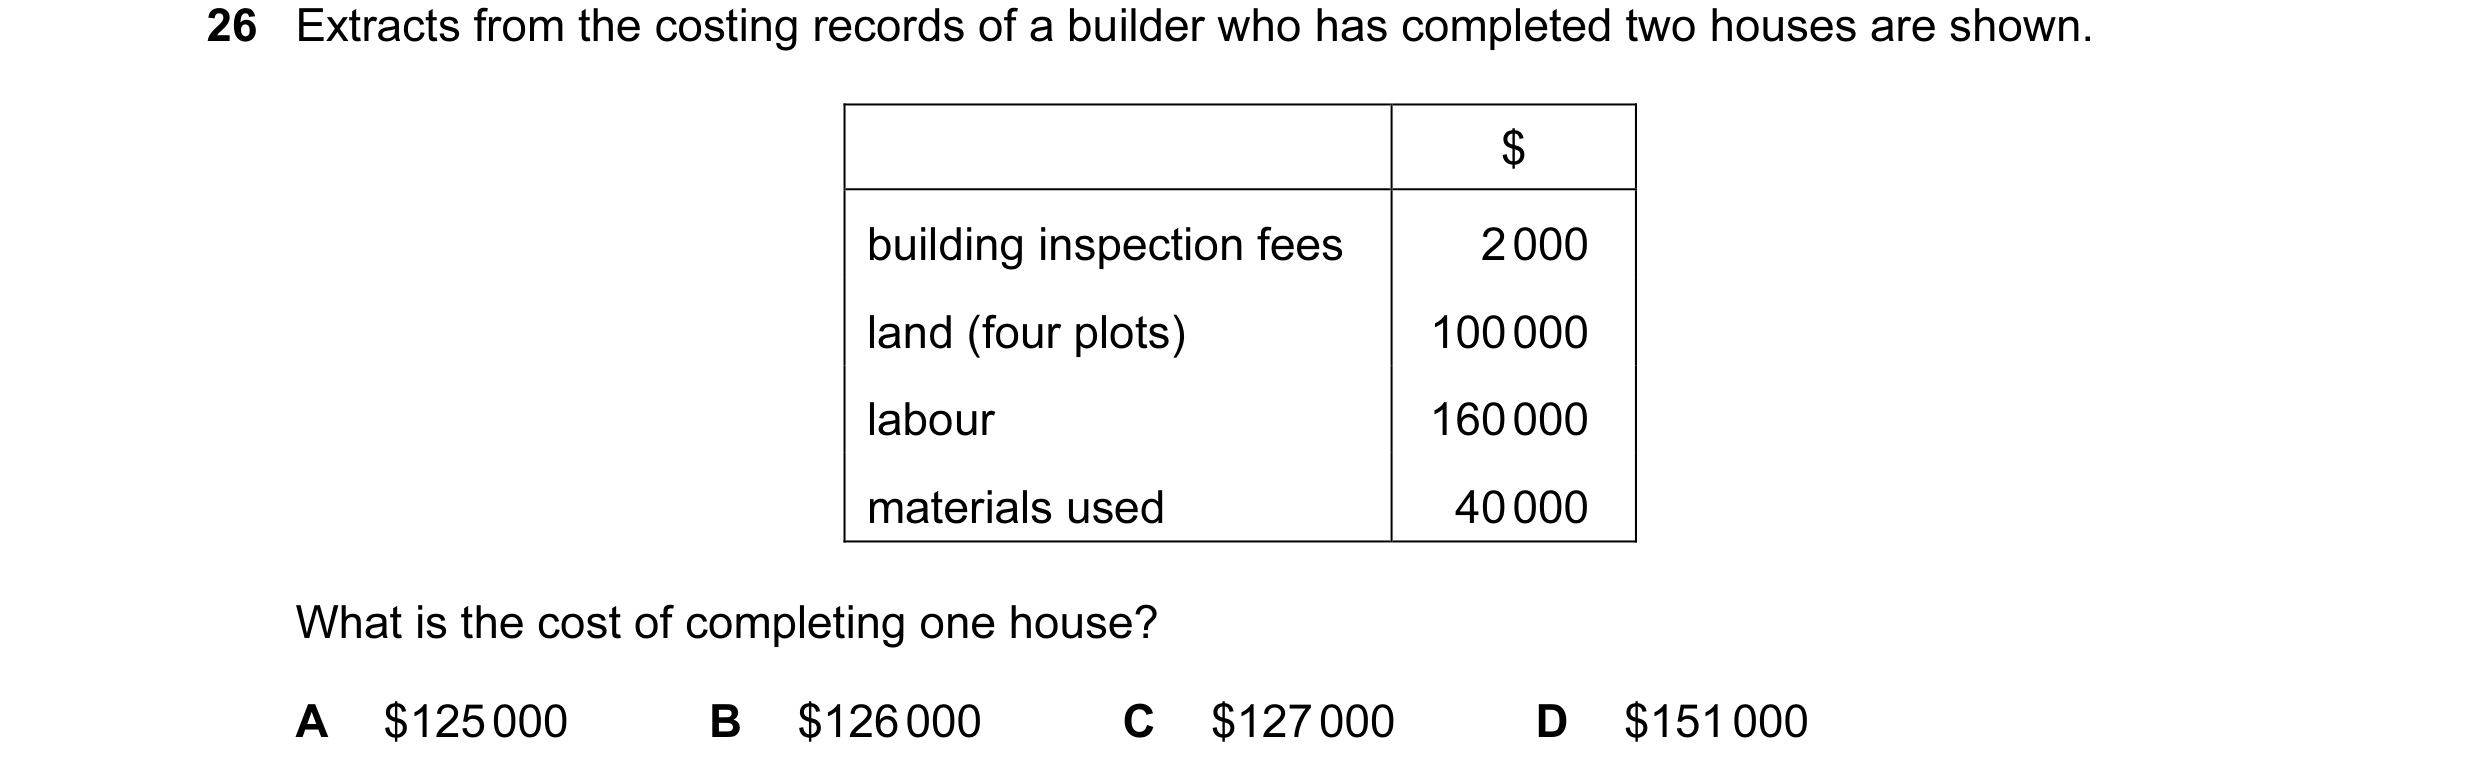 44 / 143
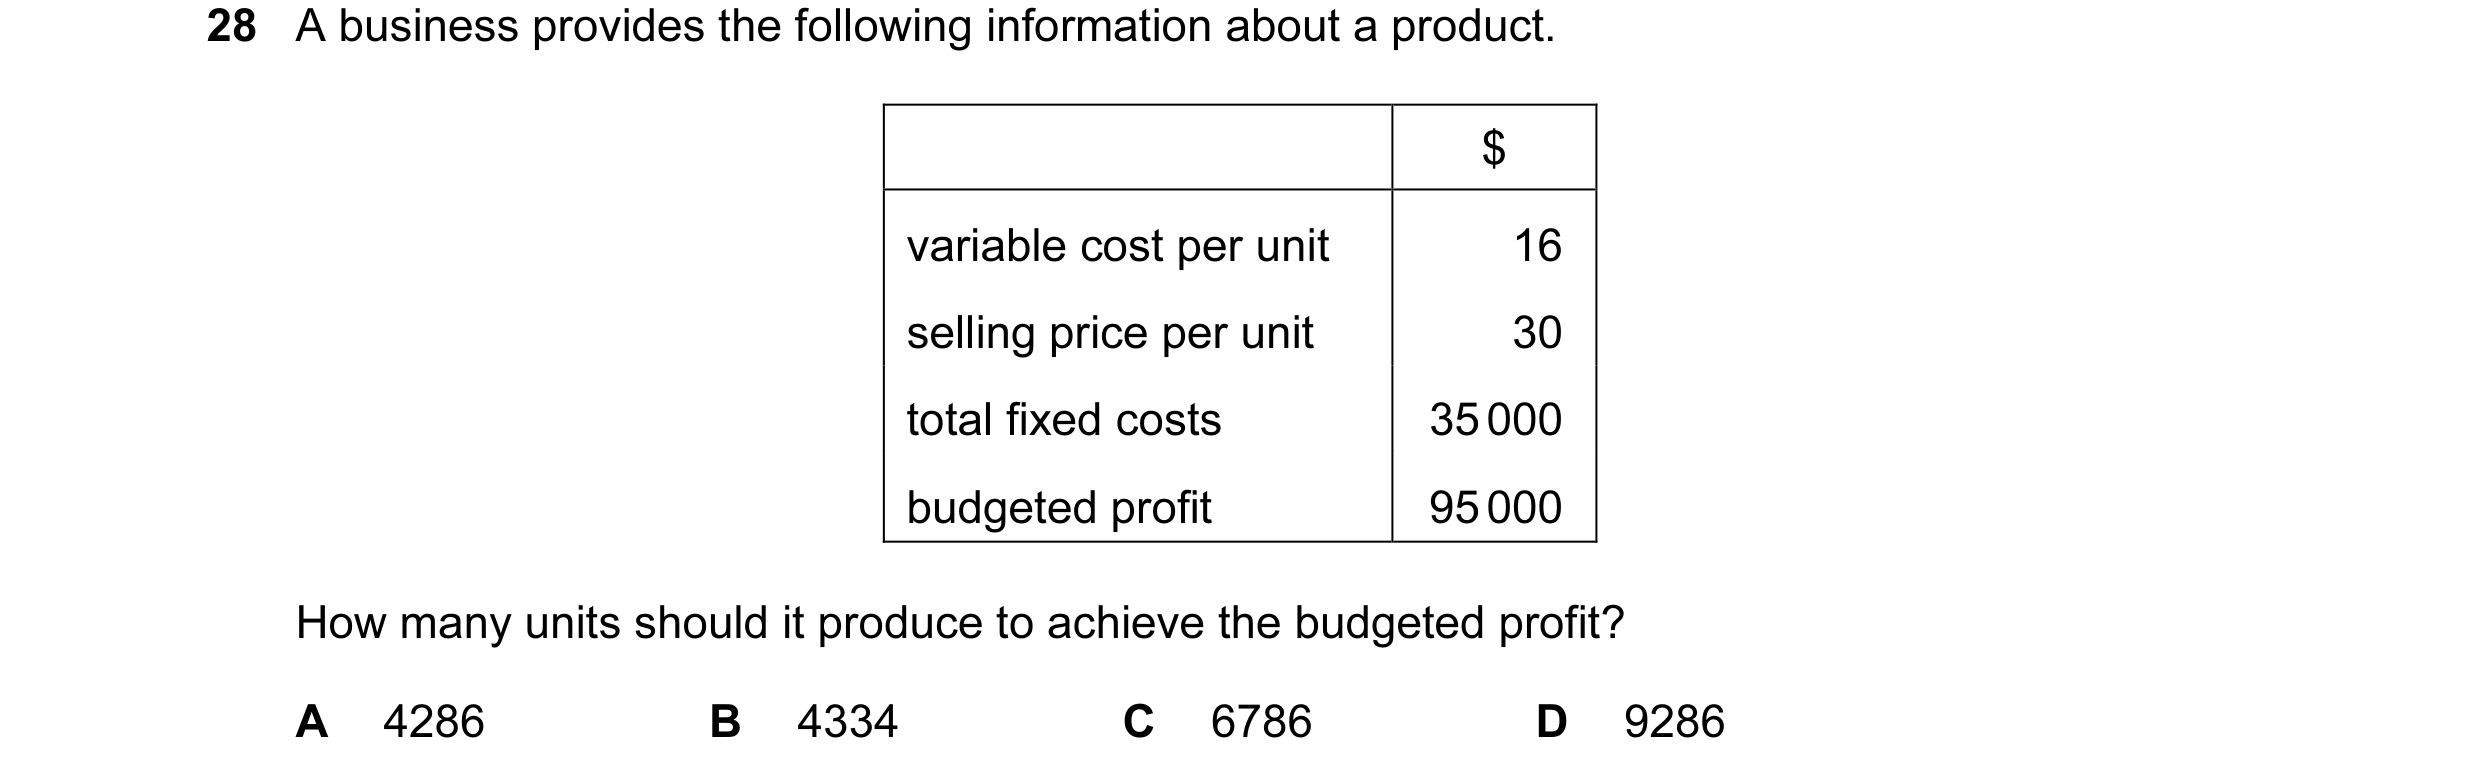
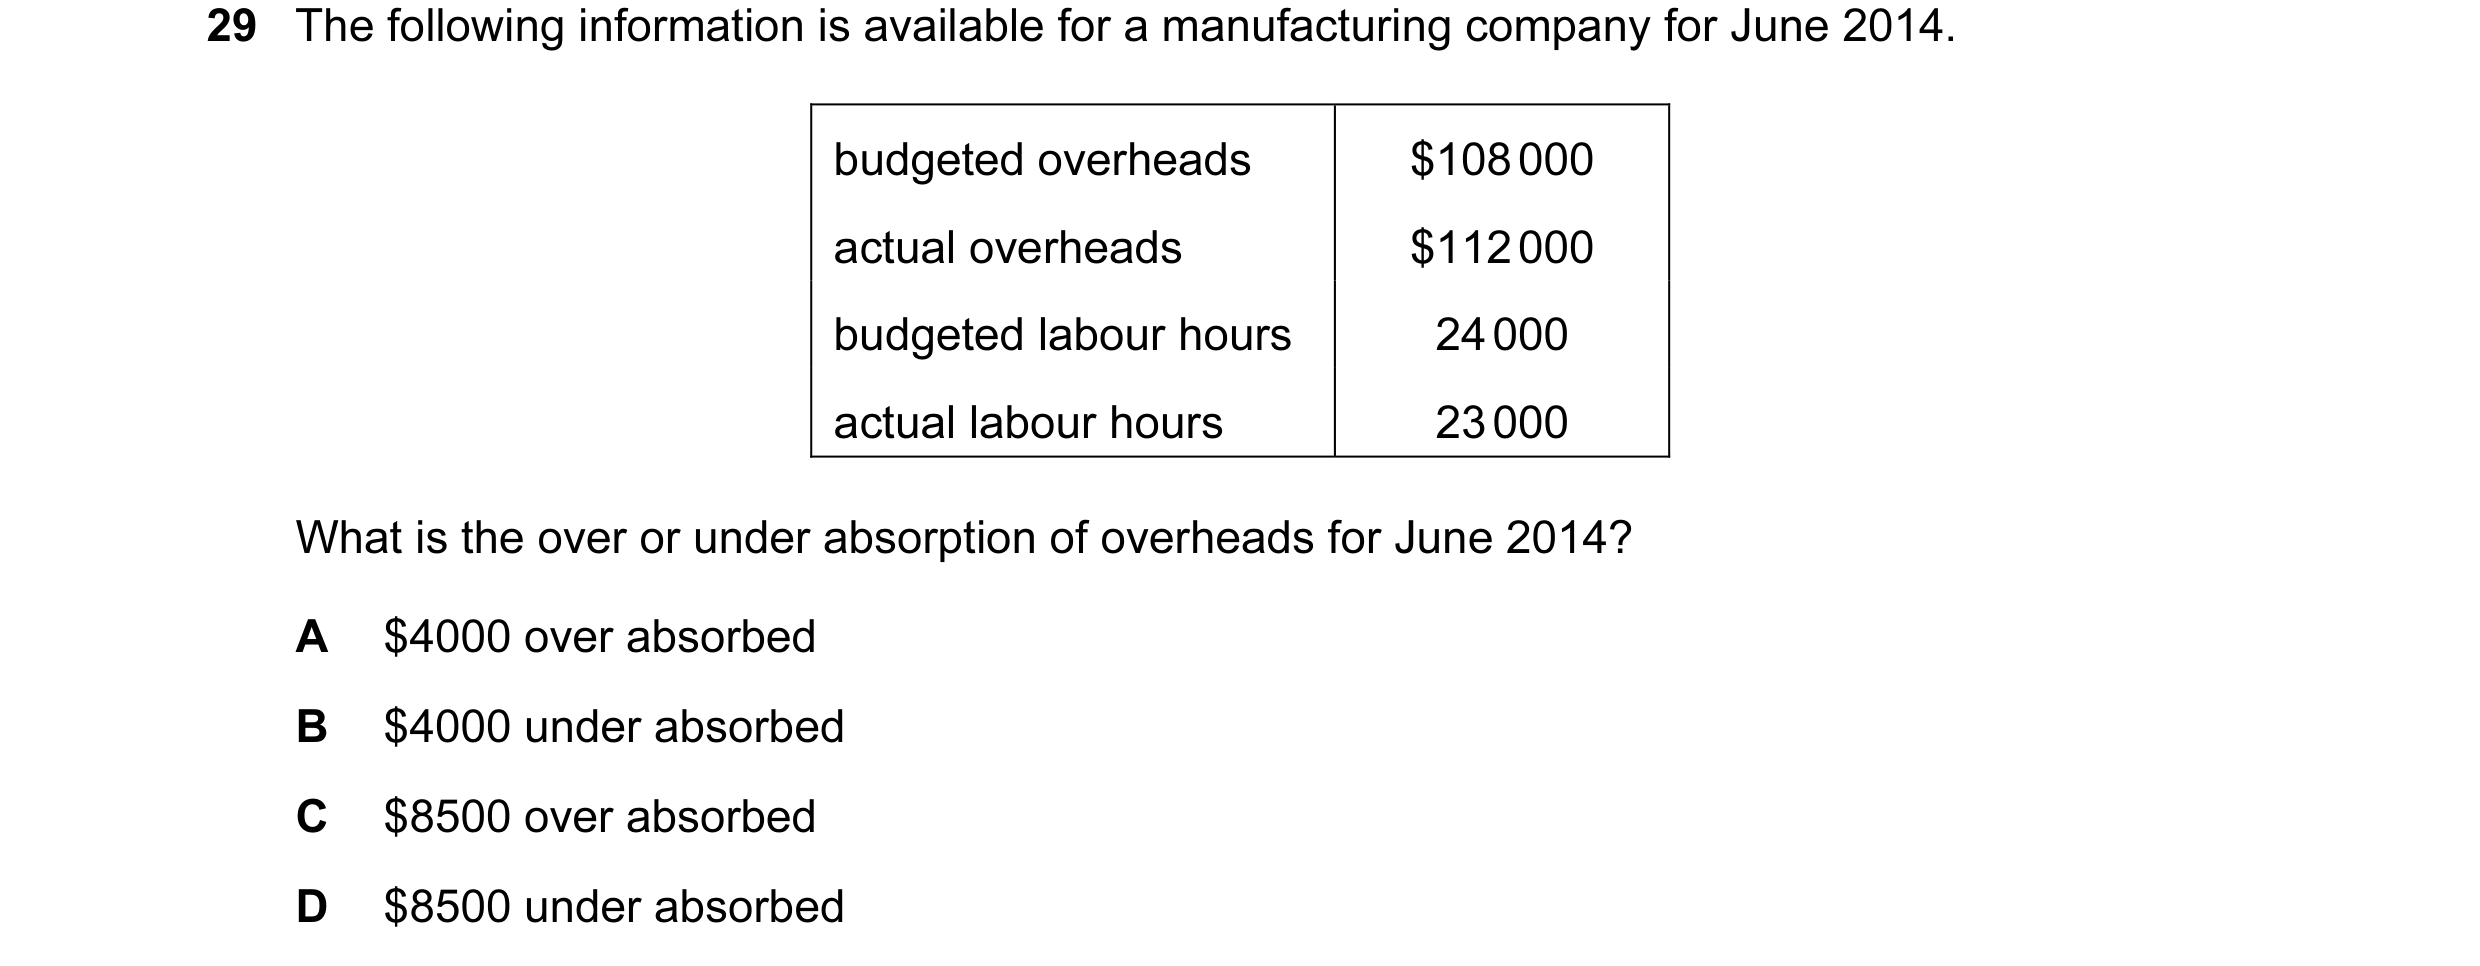
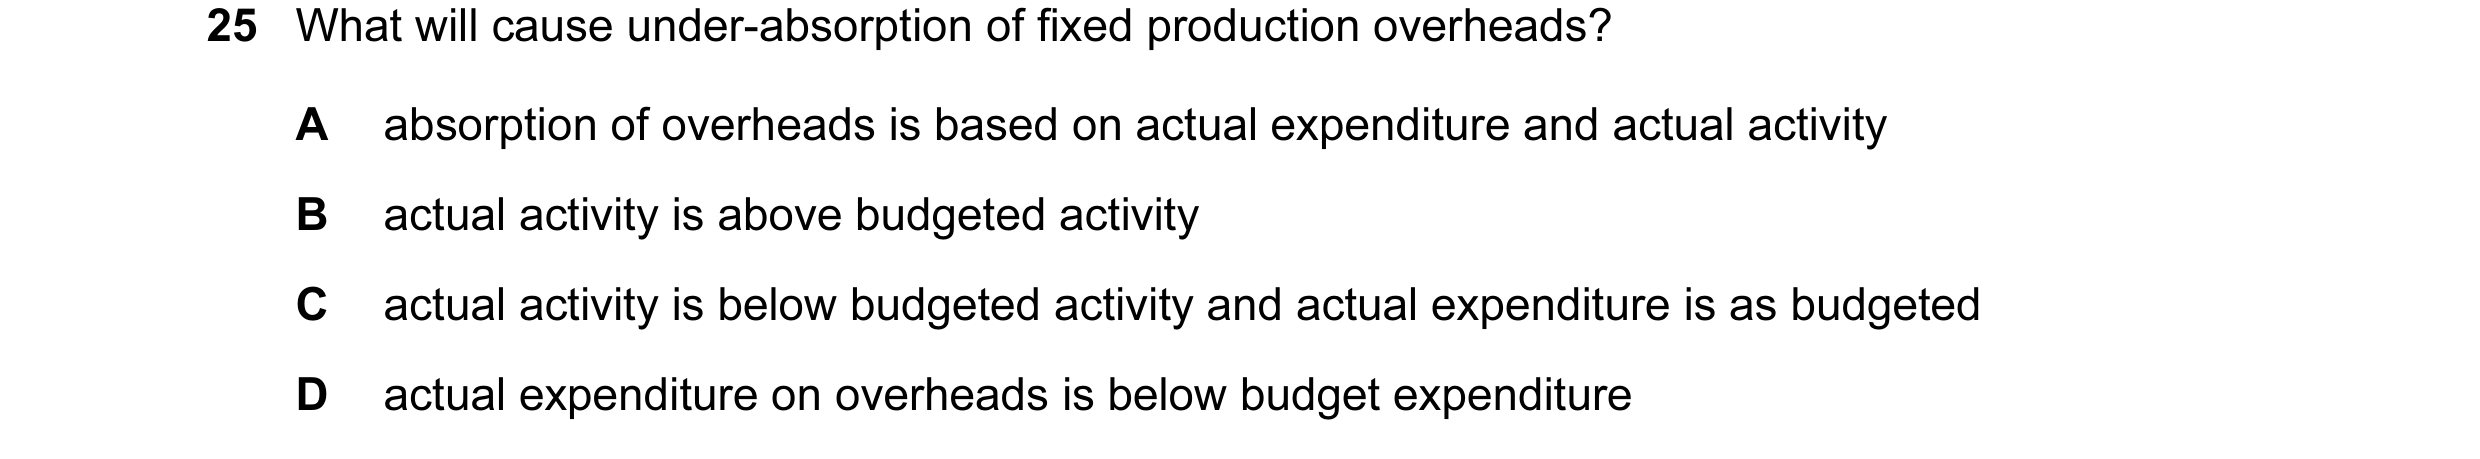
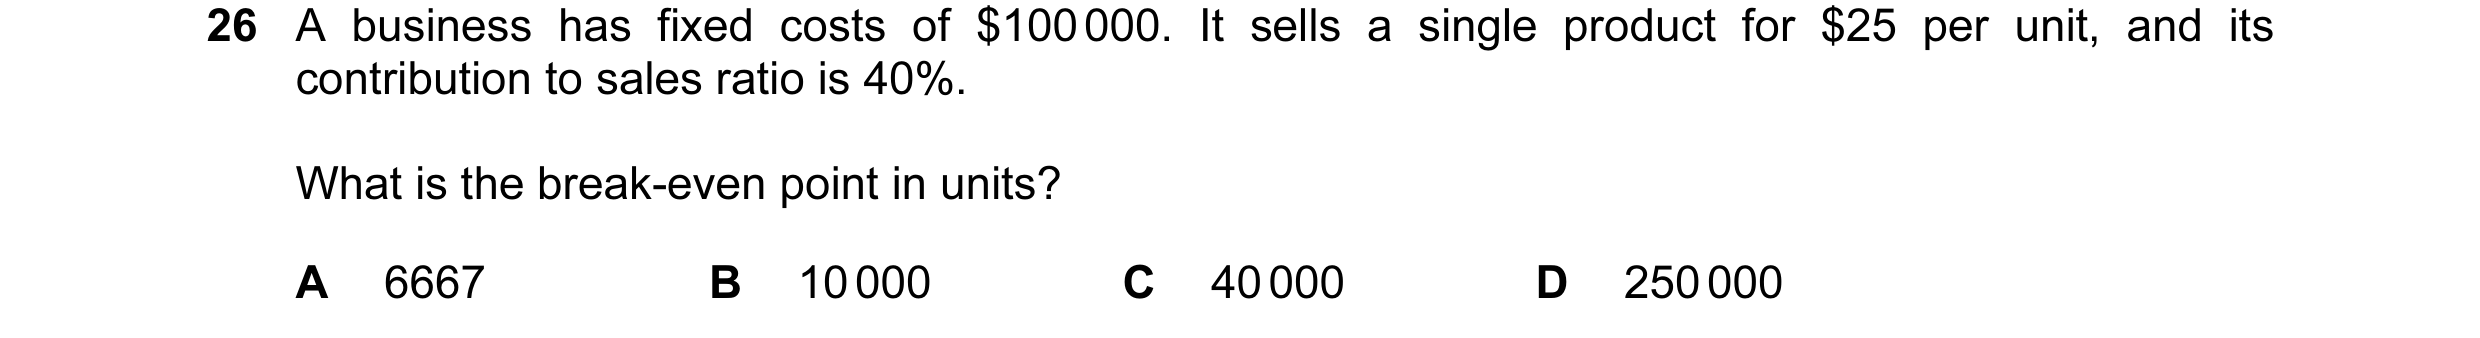 45 / 143
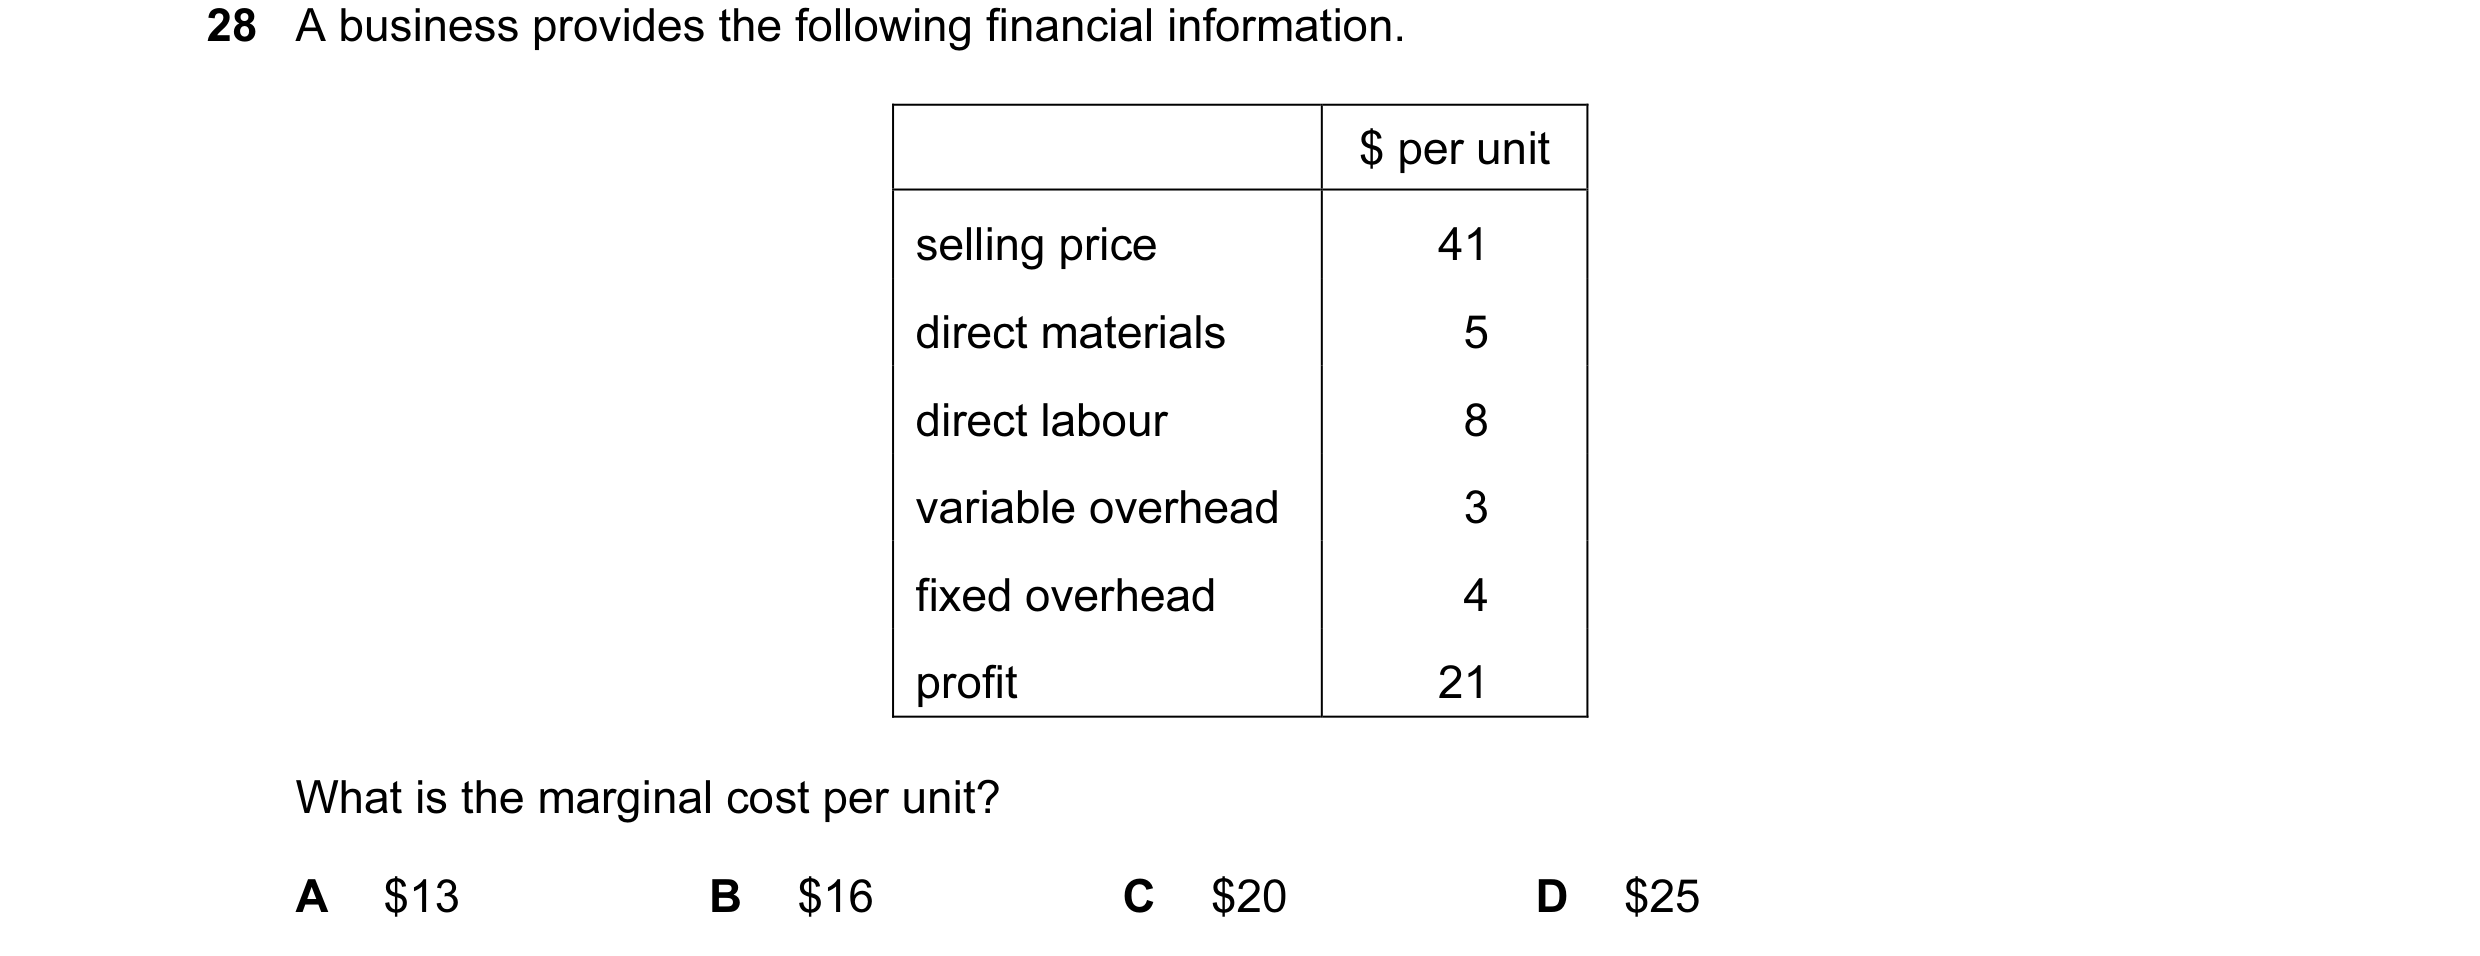
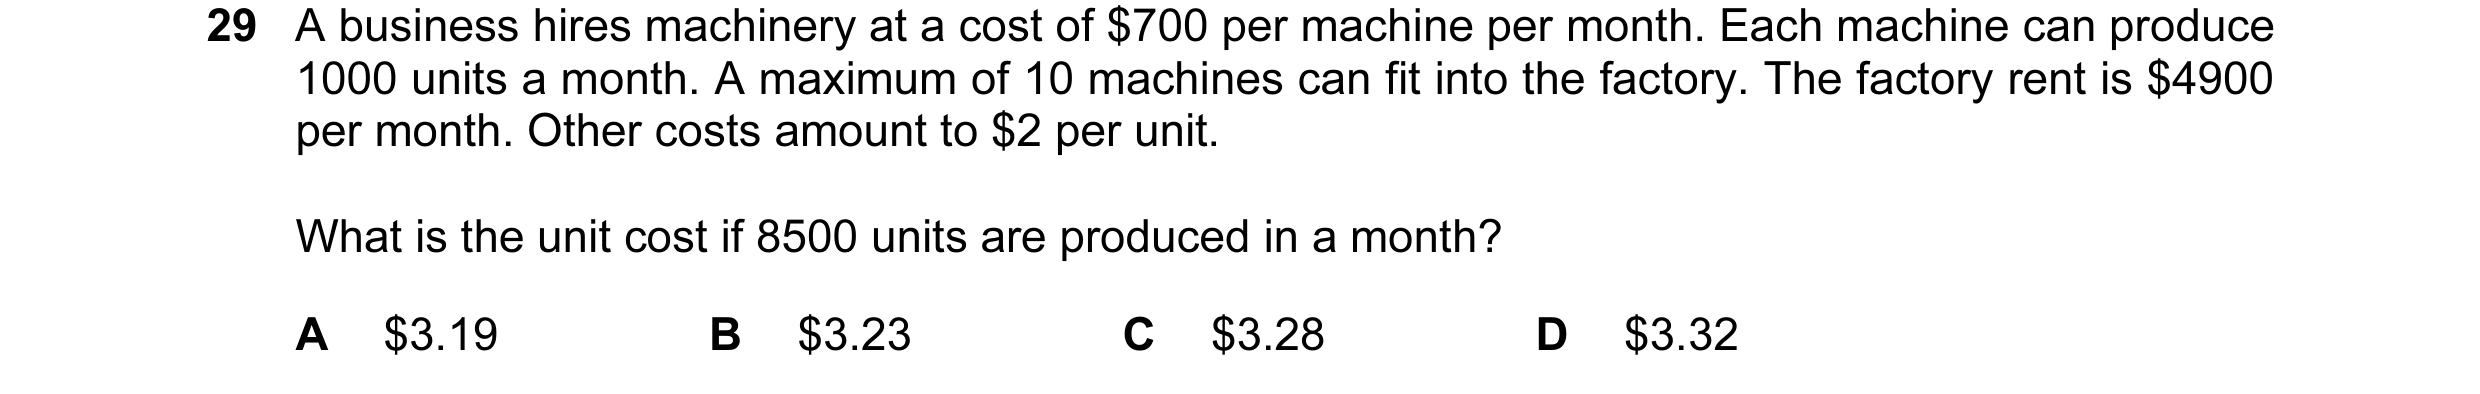
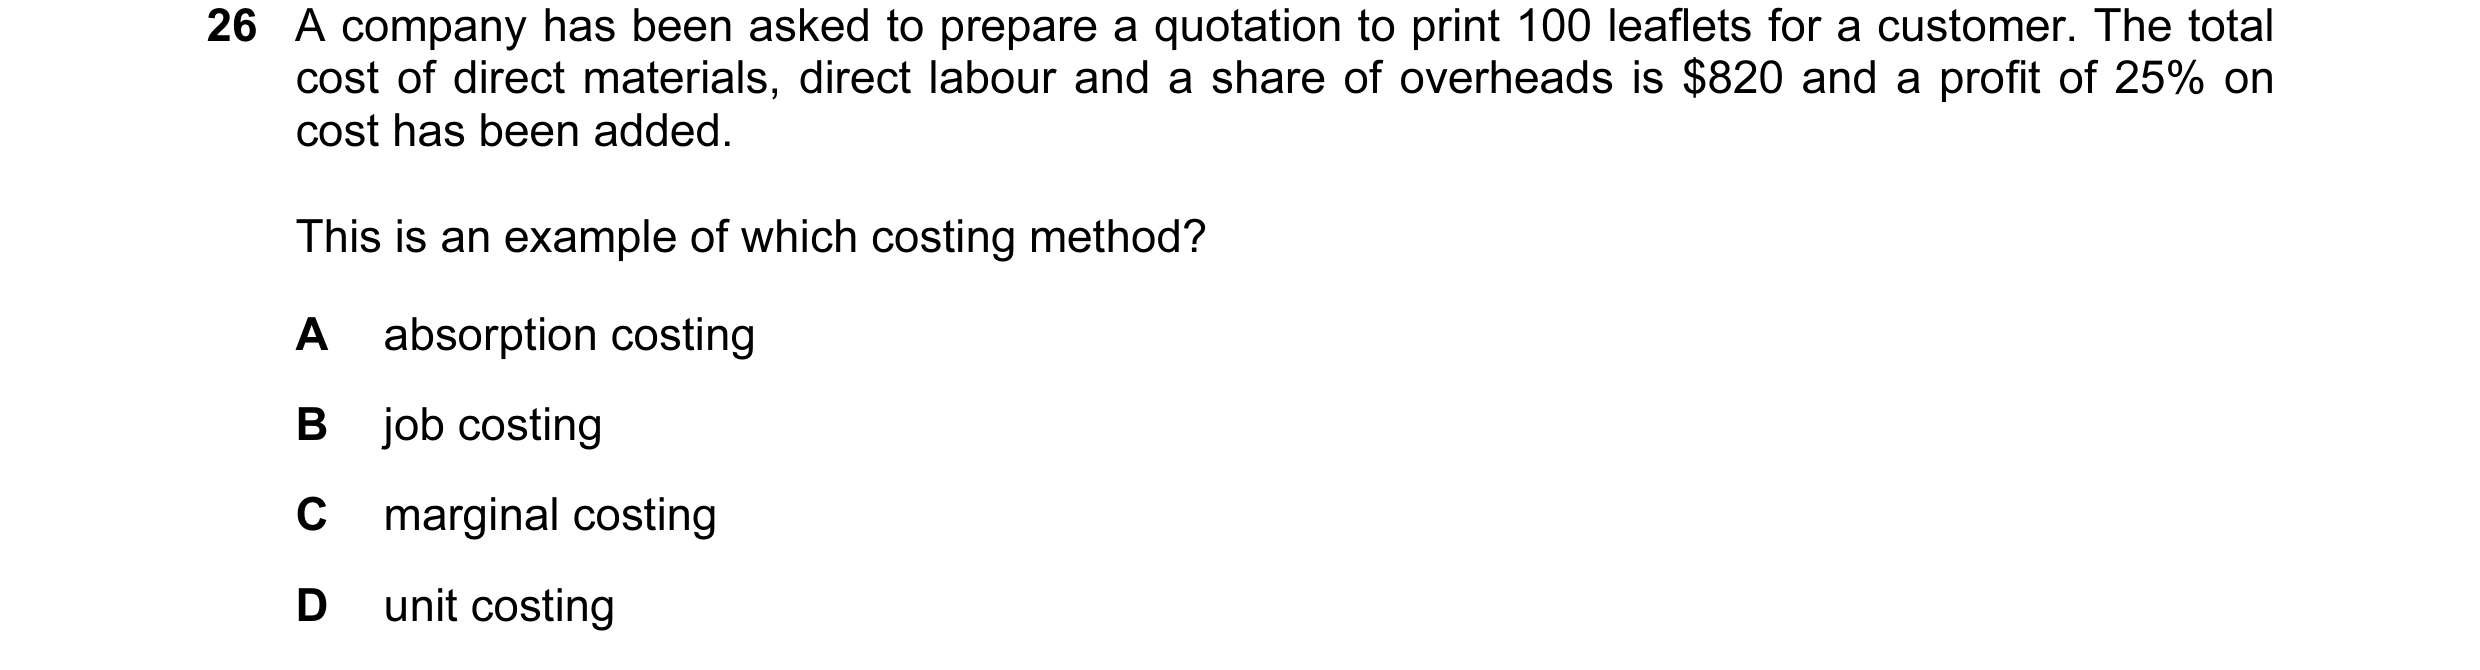
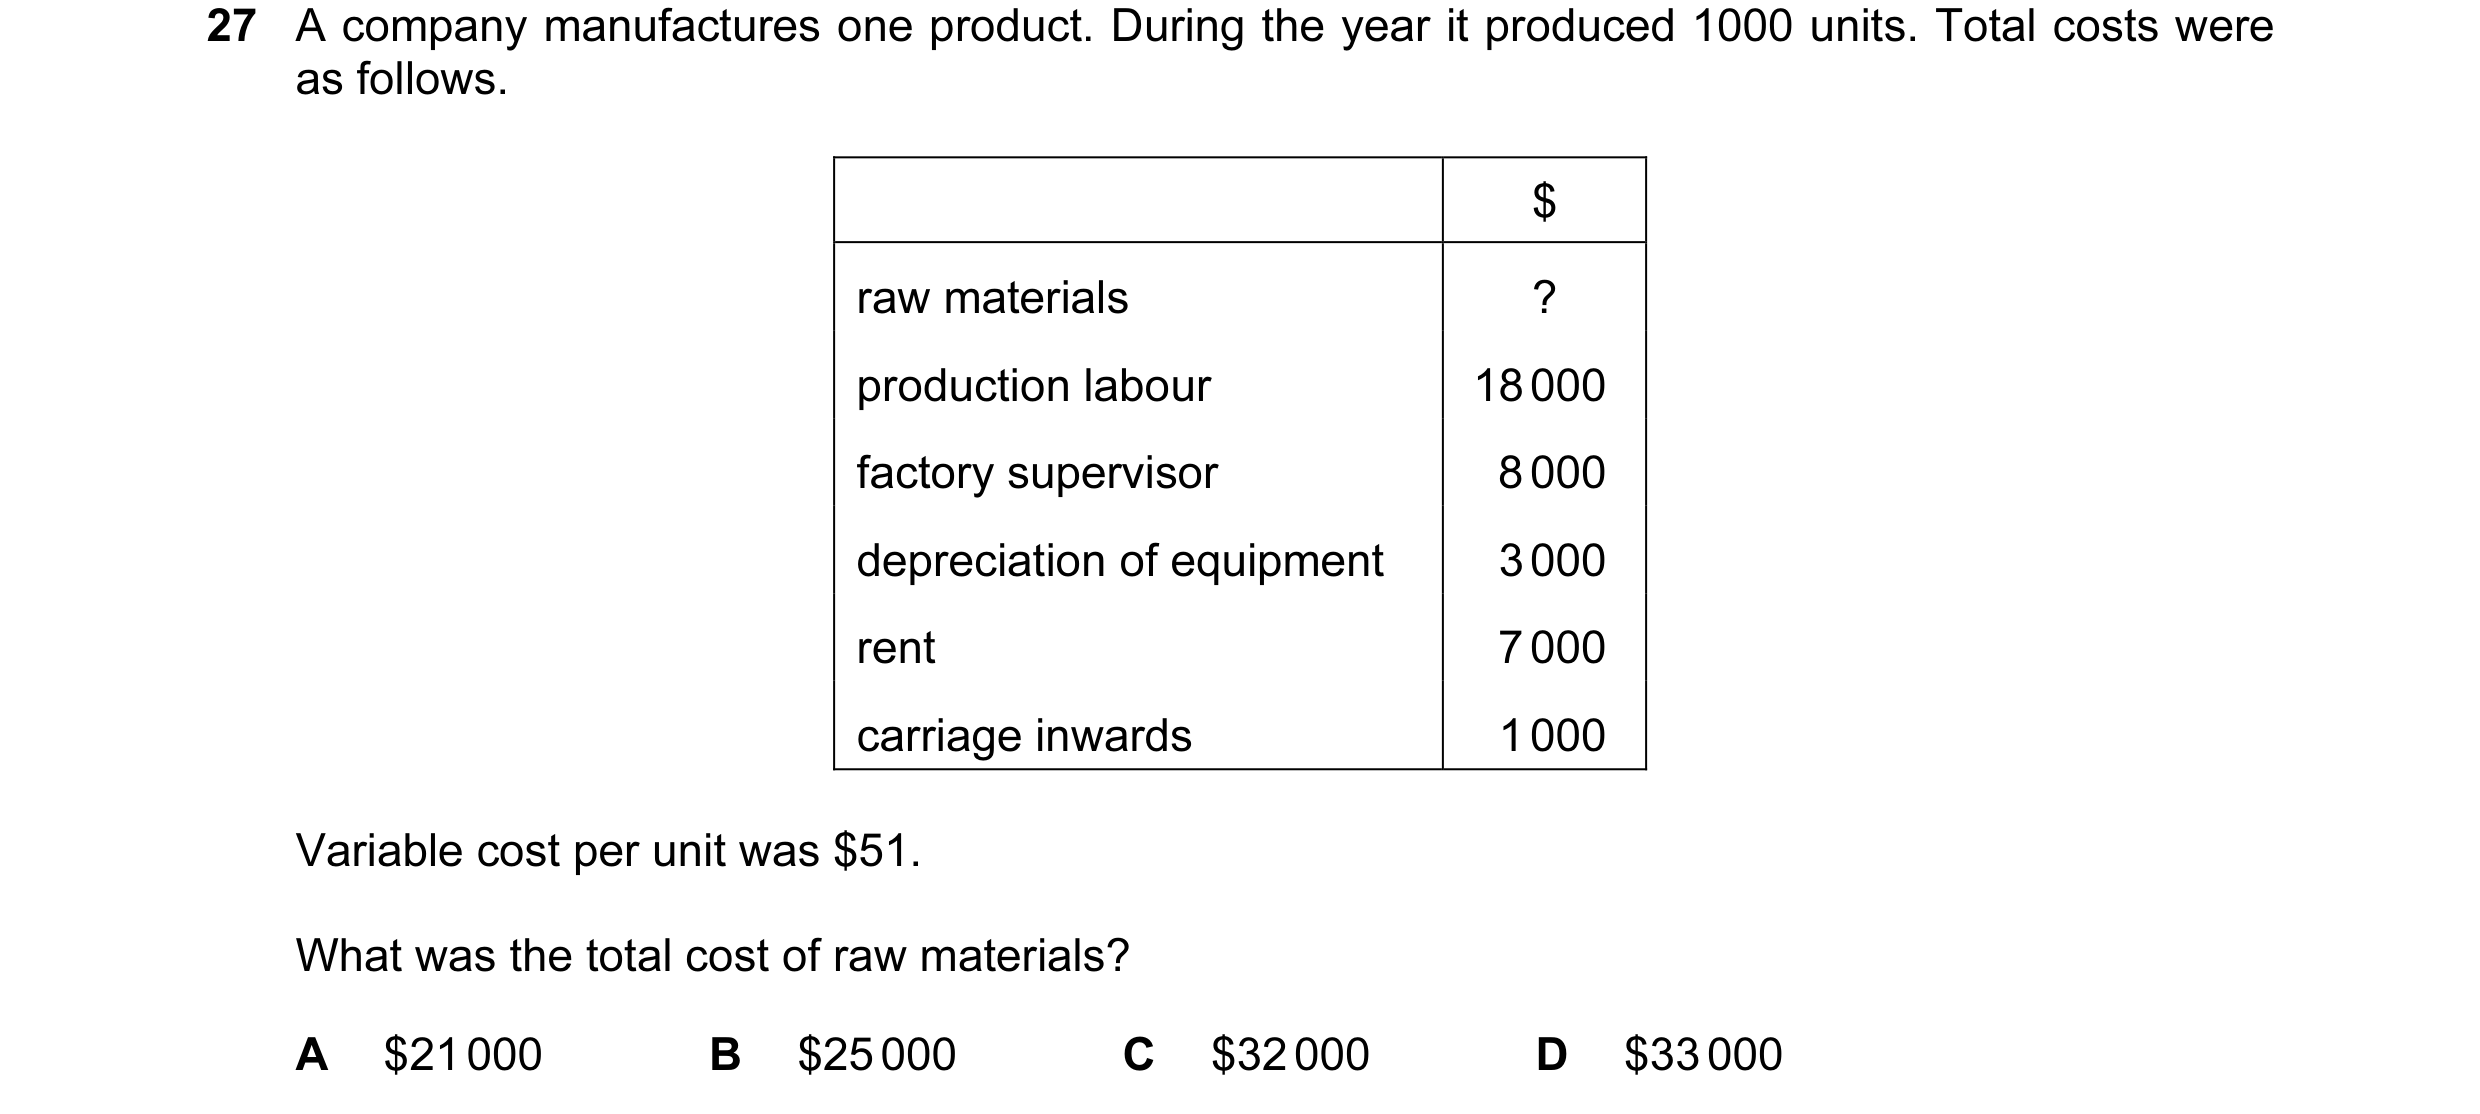 46 / 143
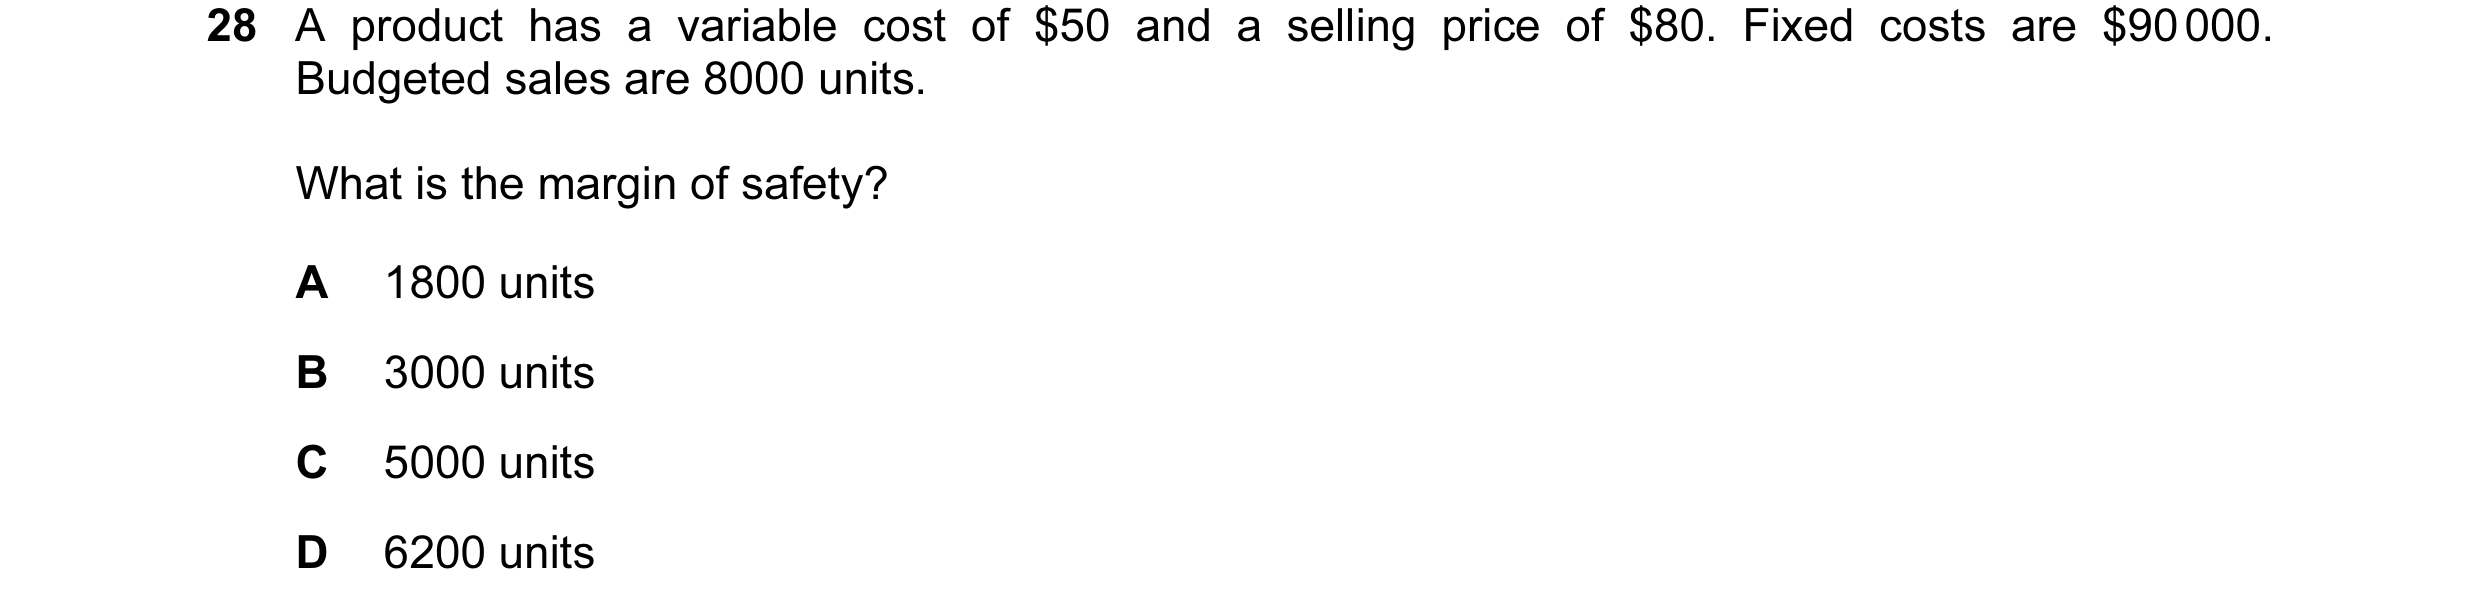
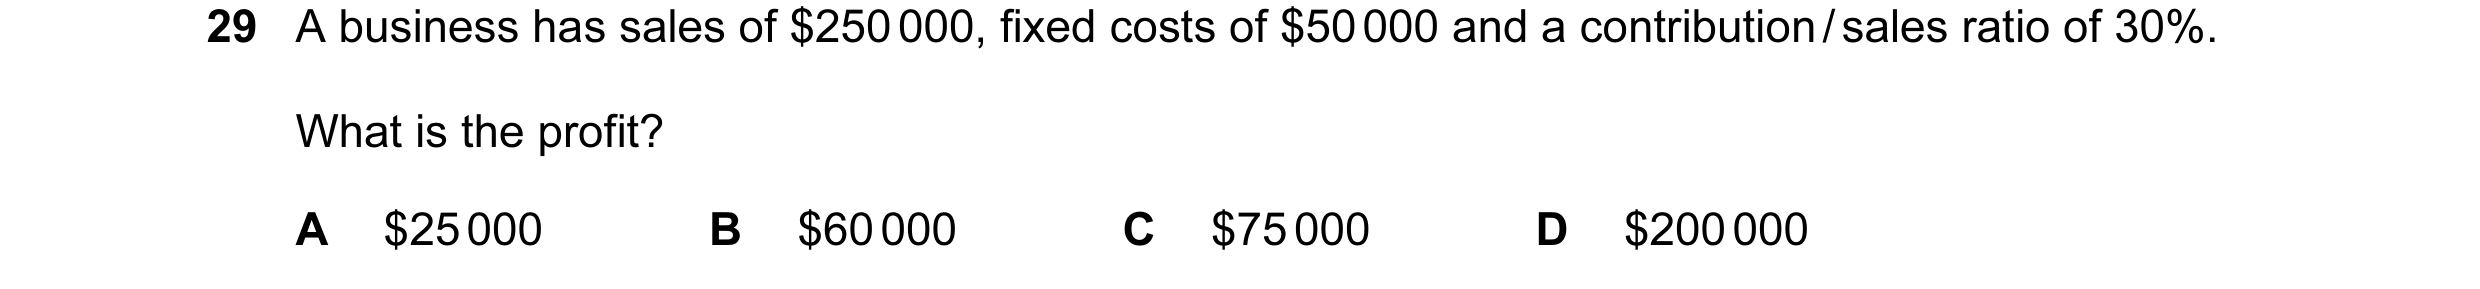
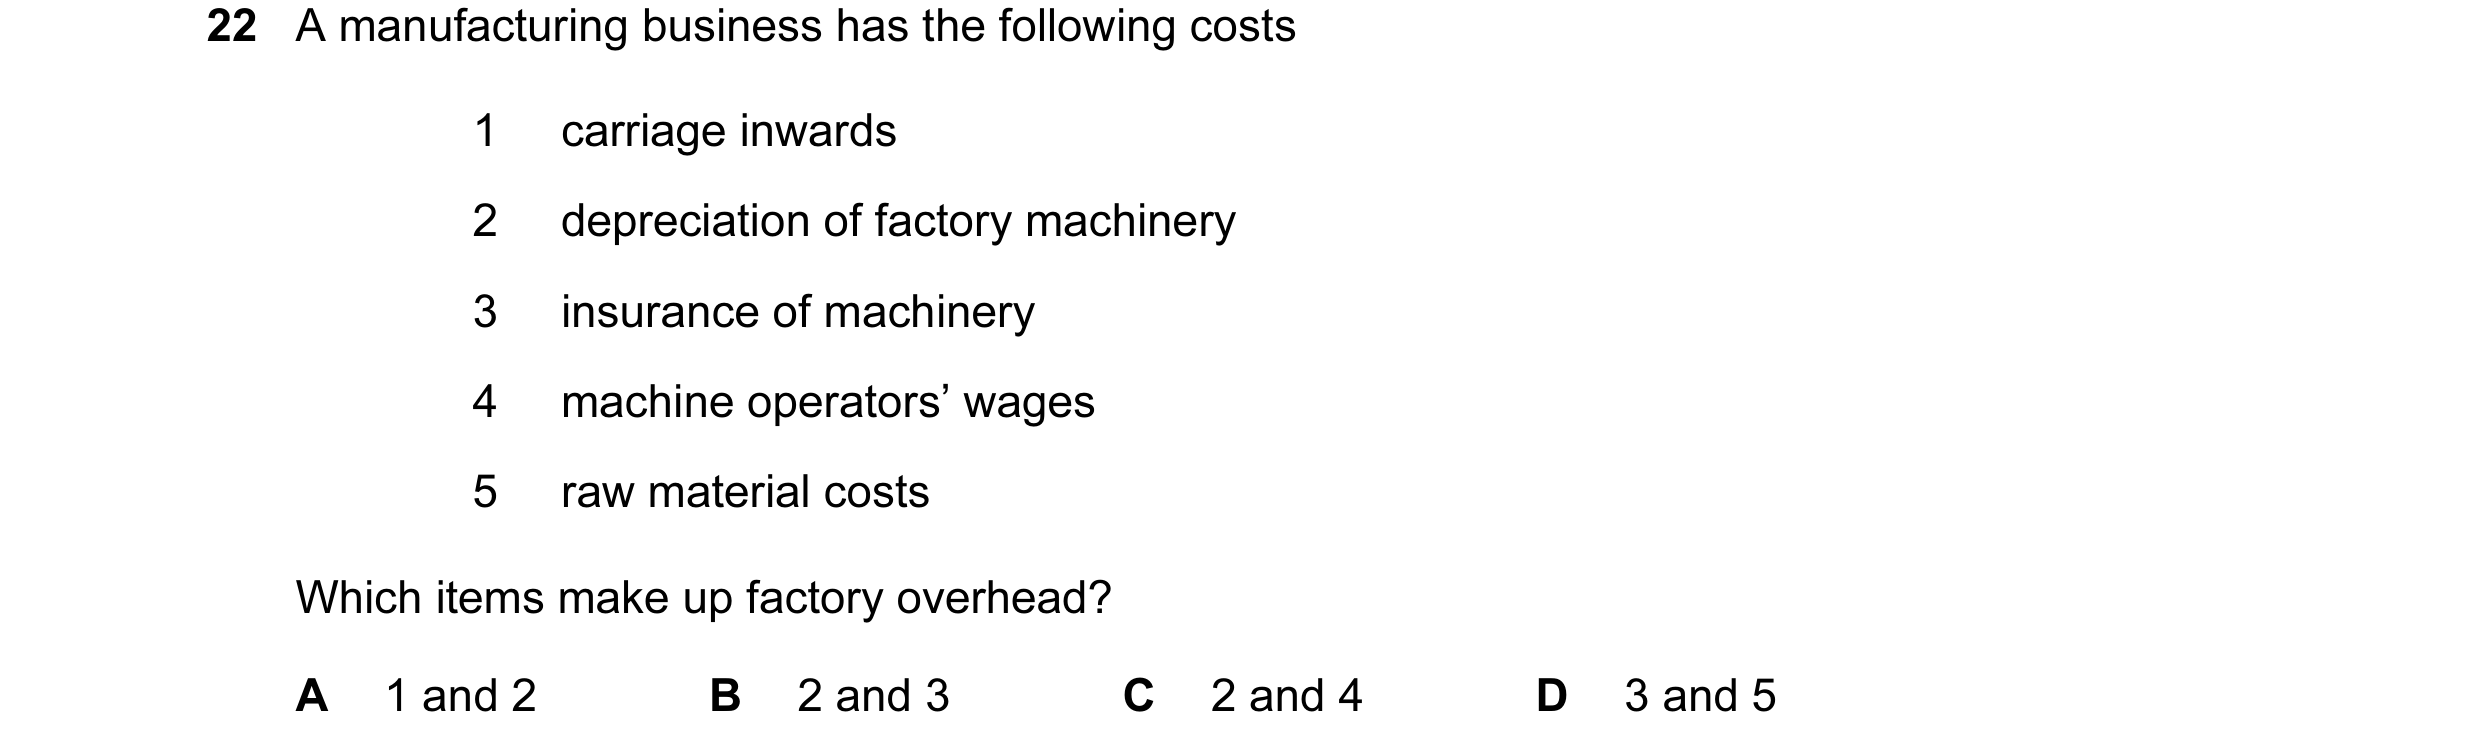
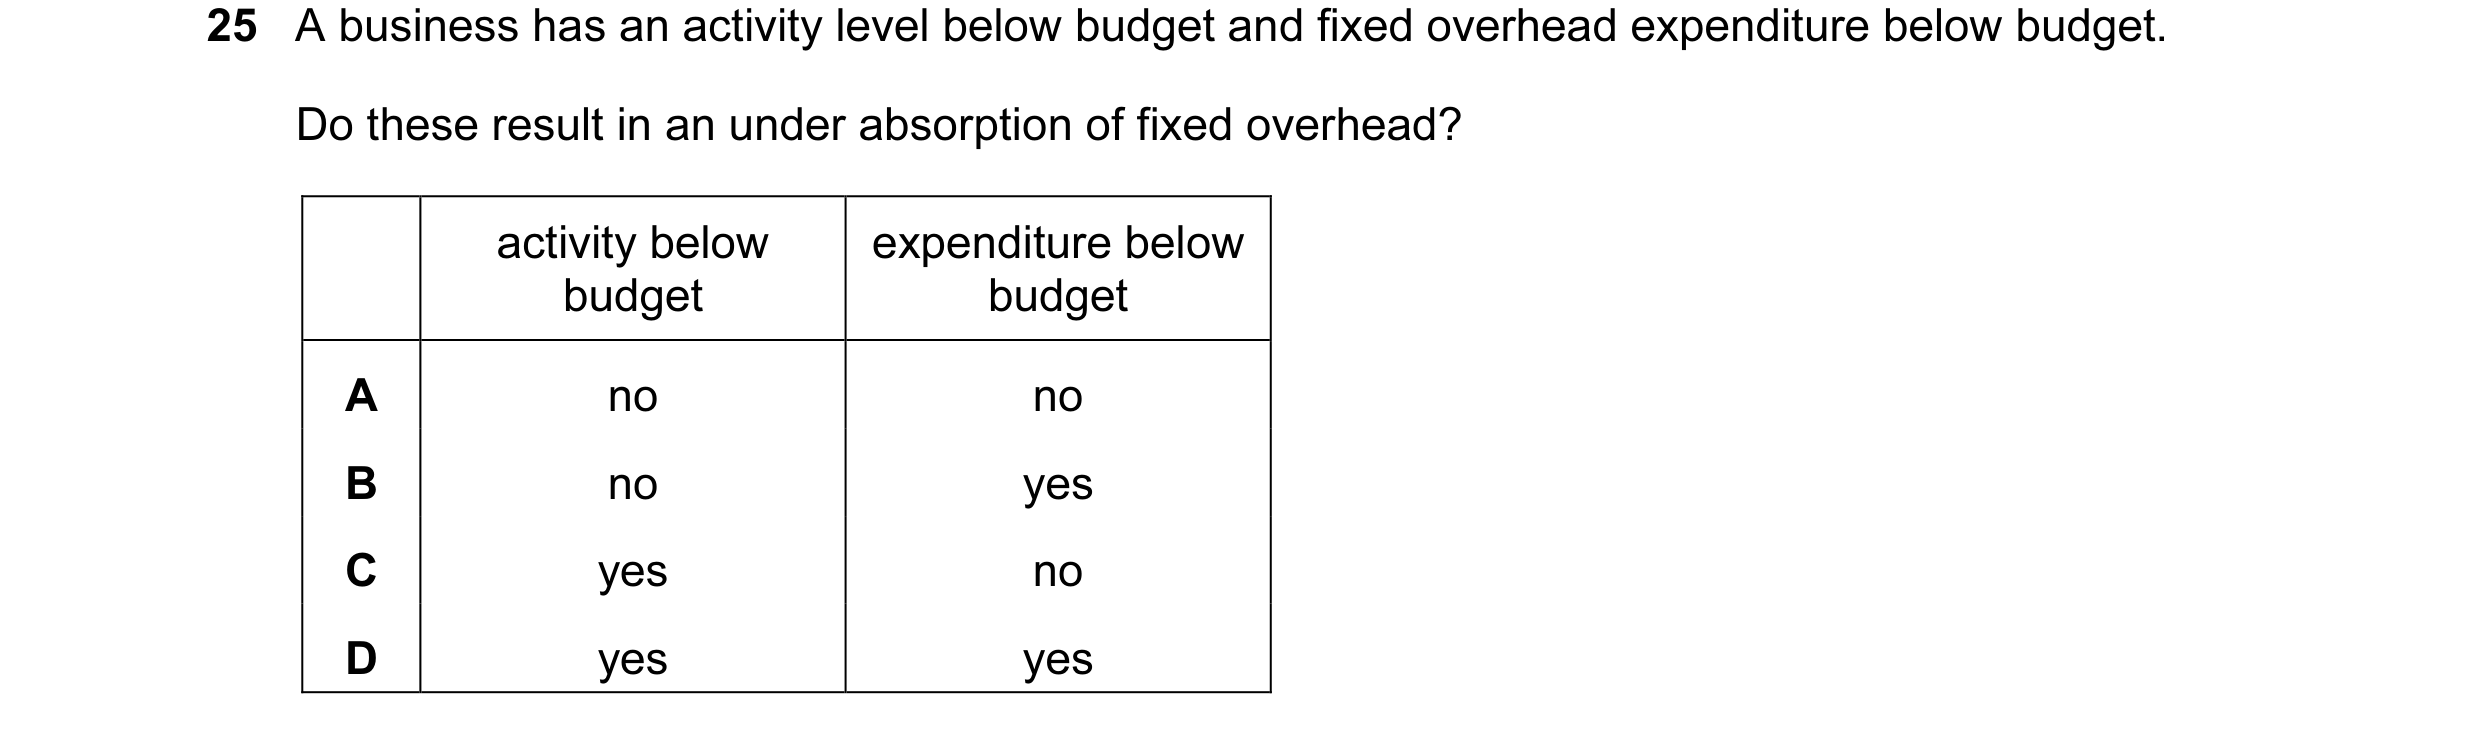
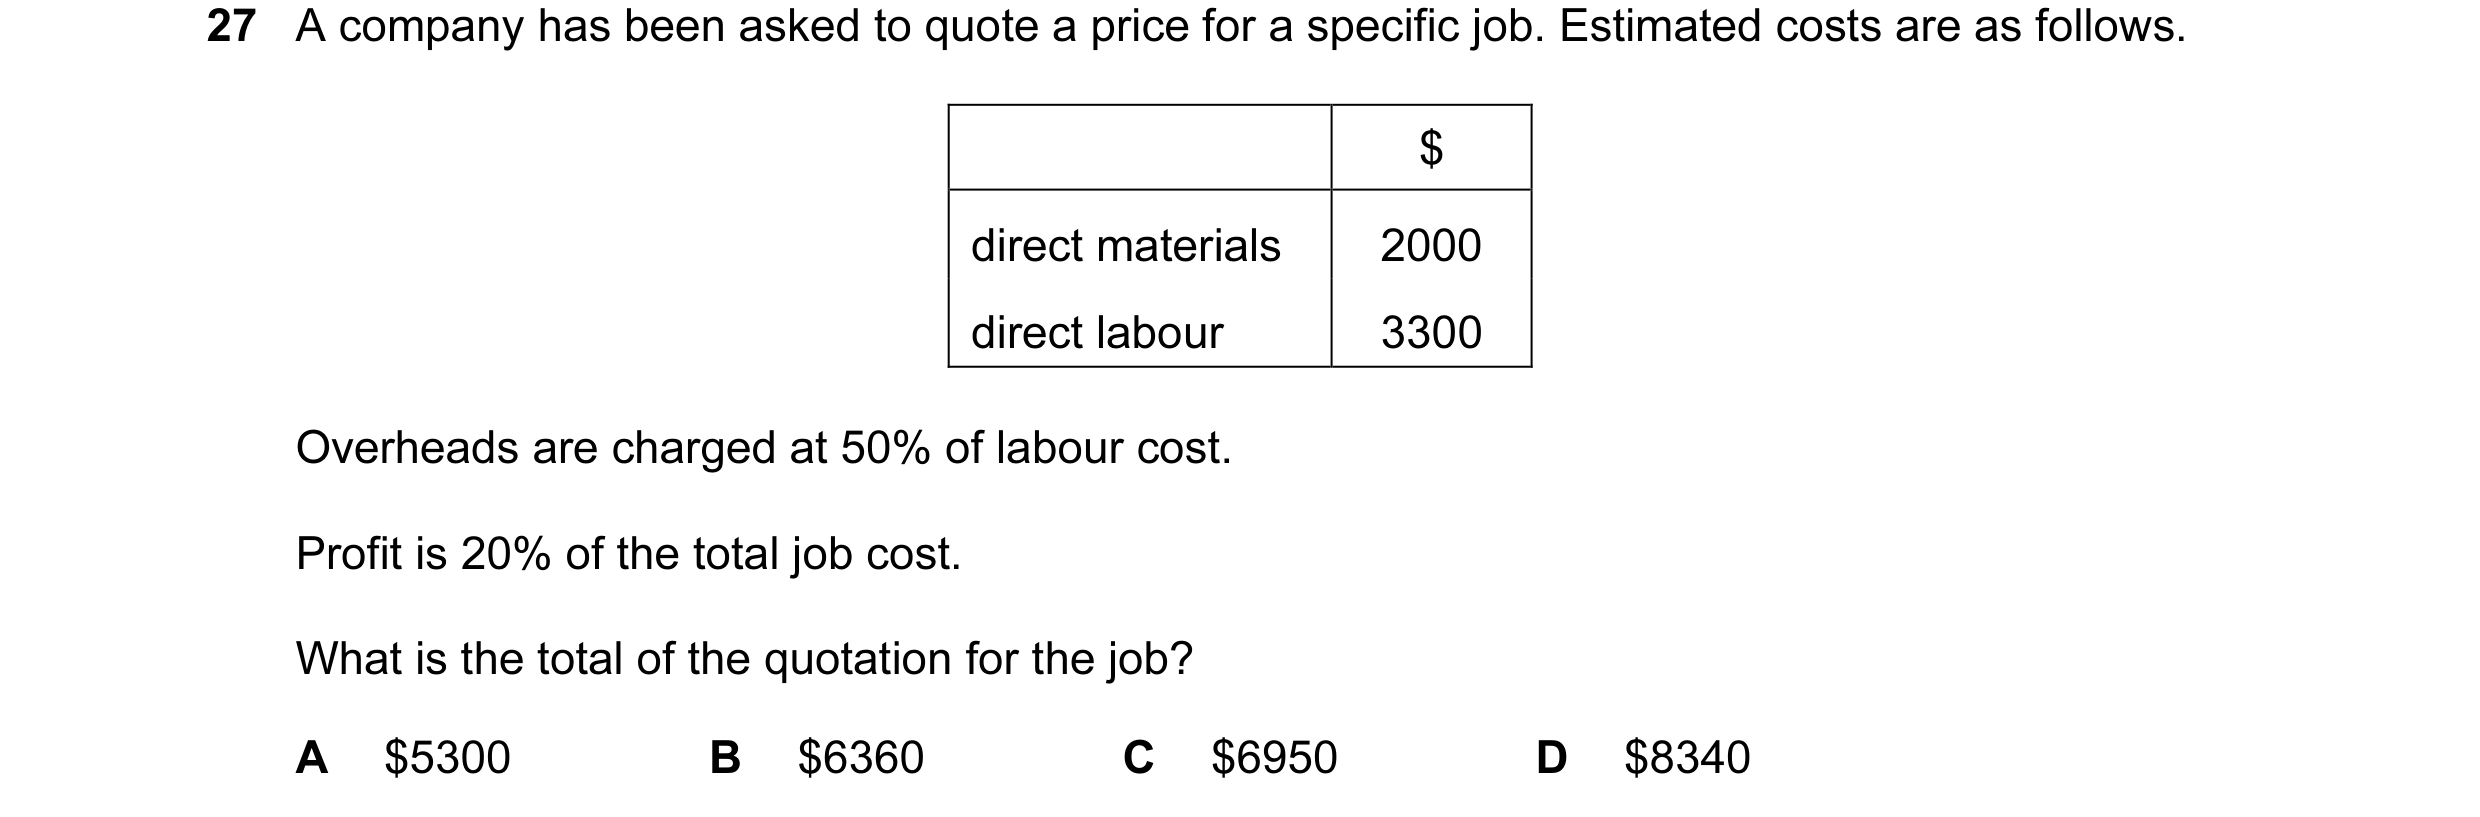 47 / 143
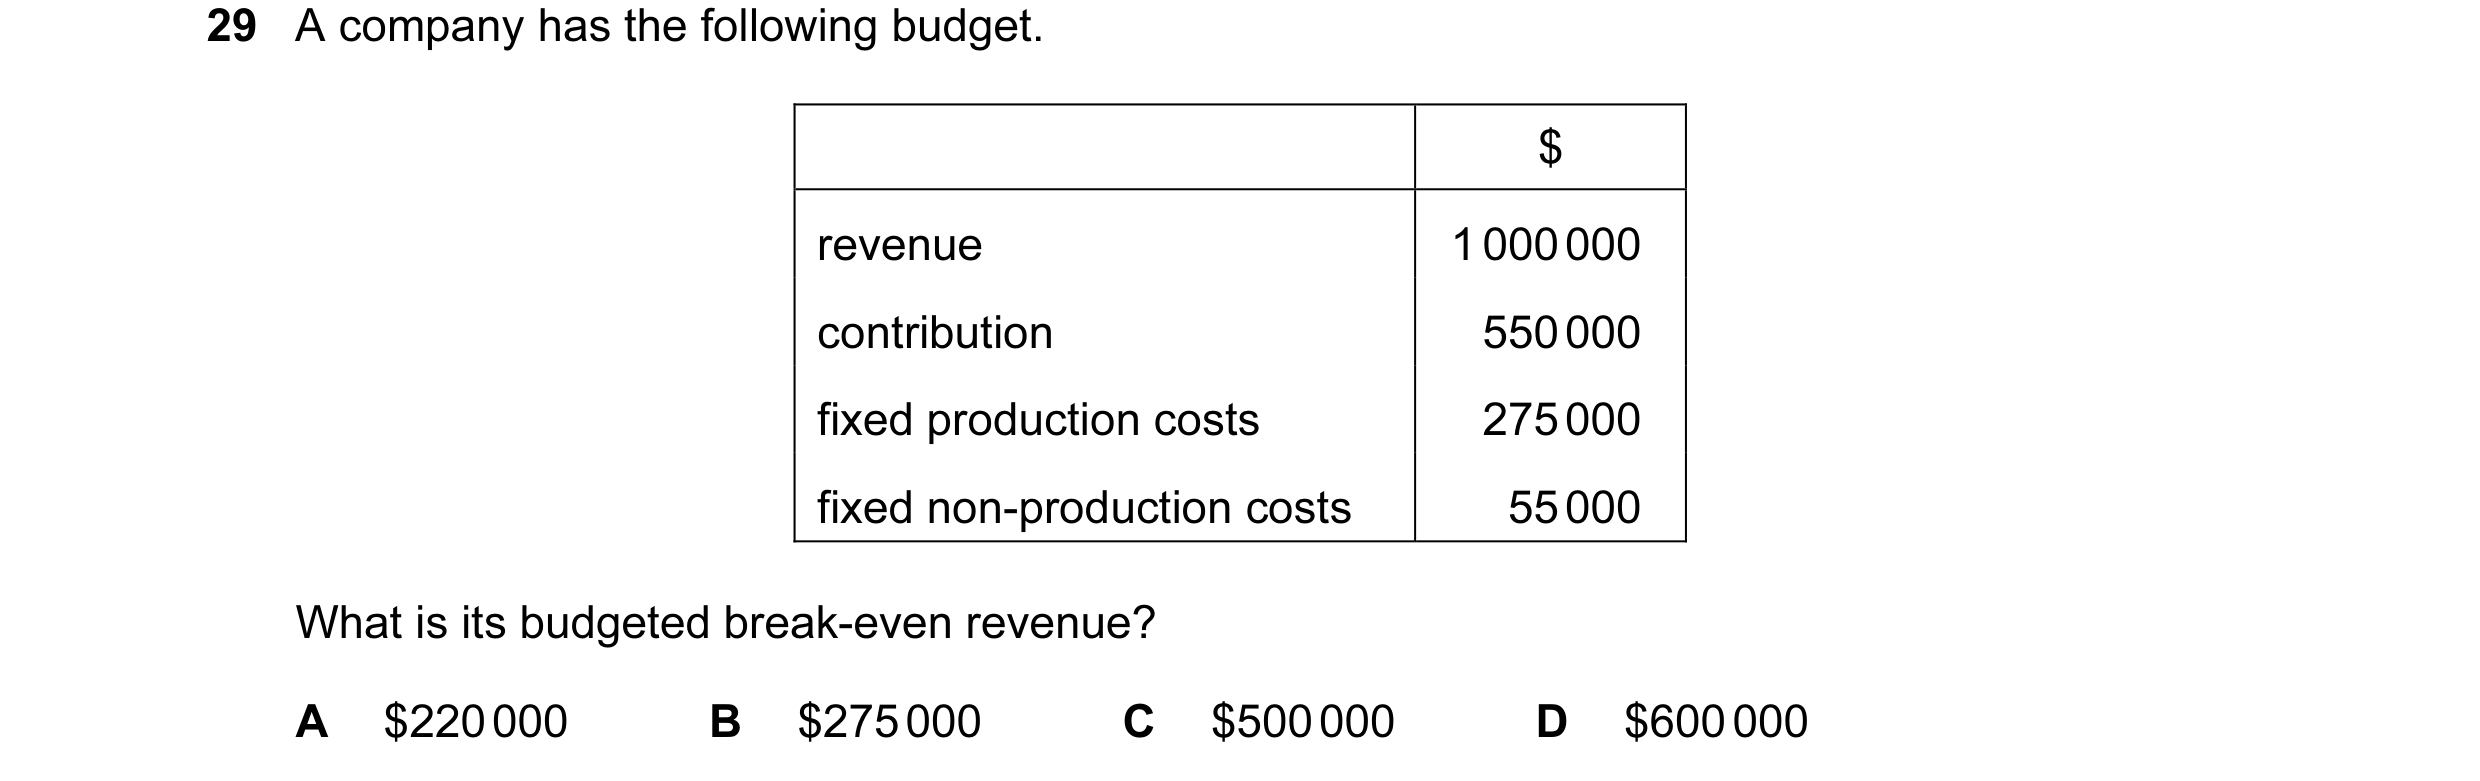
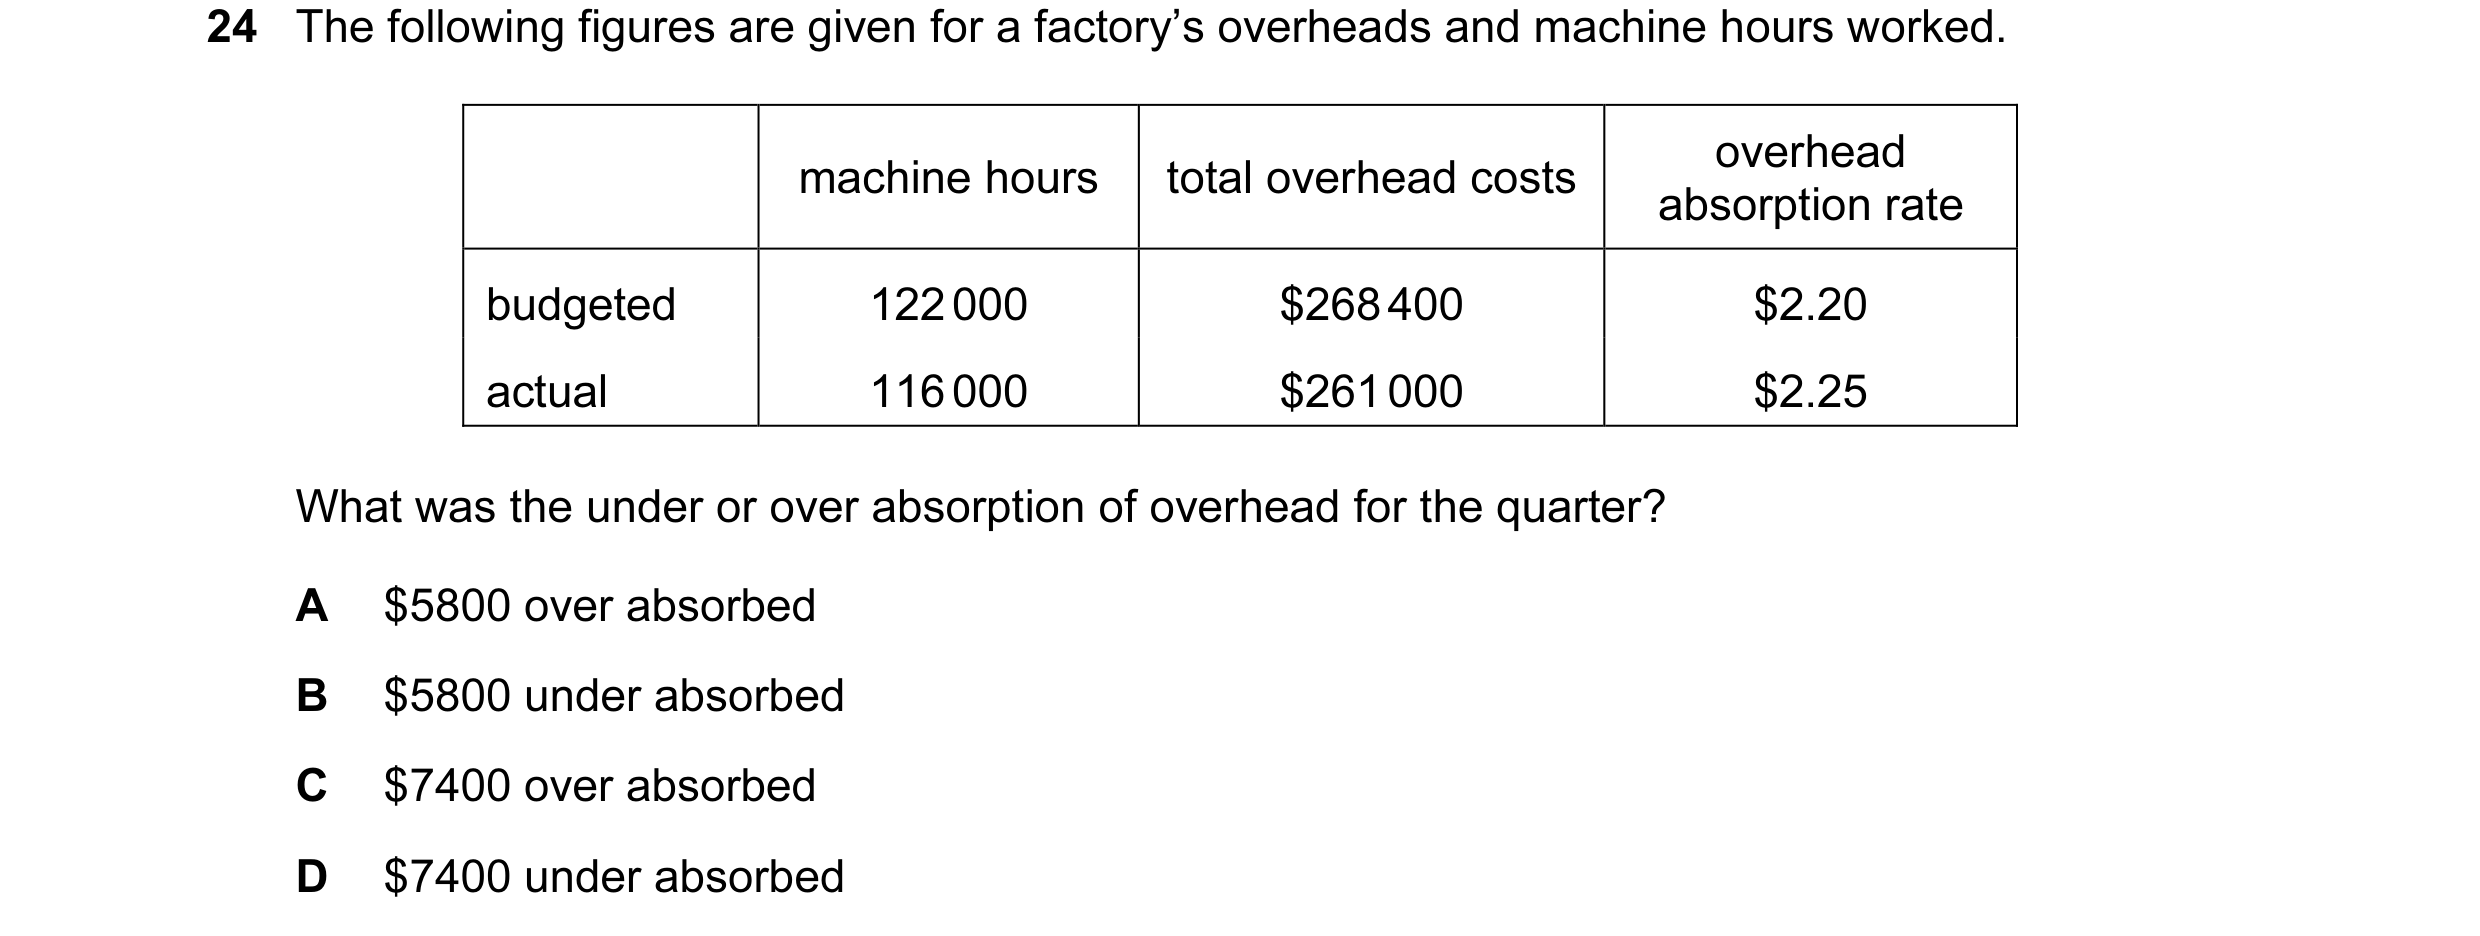
 48 / 143
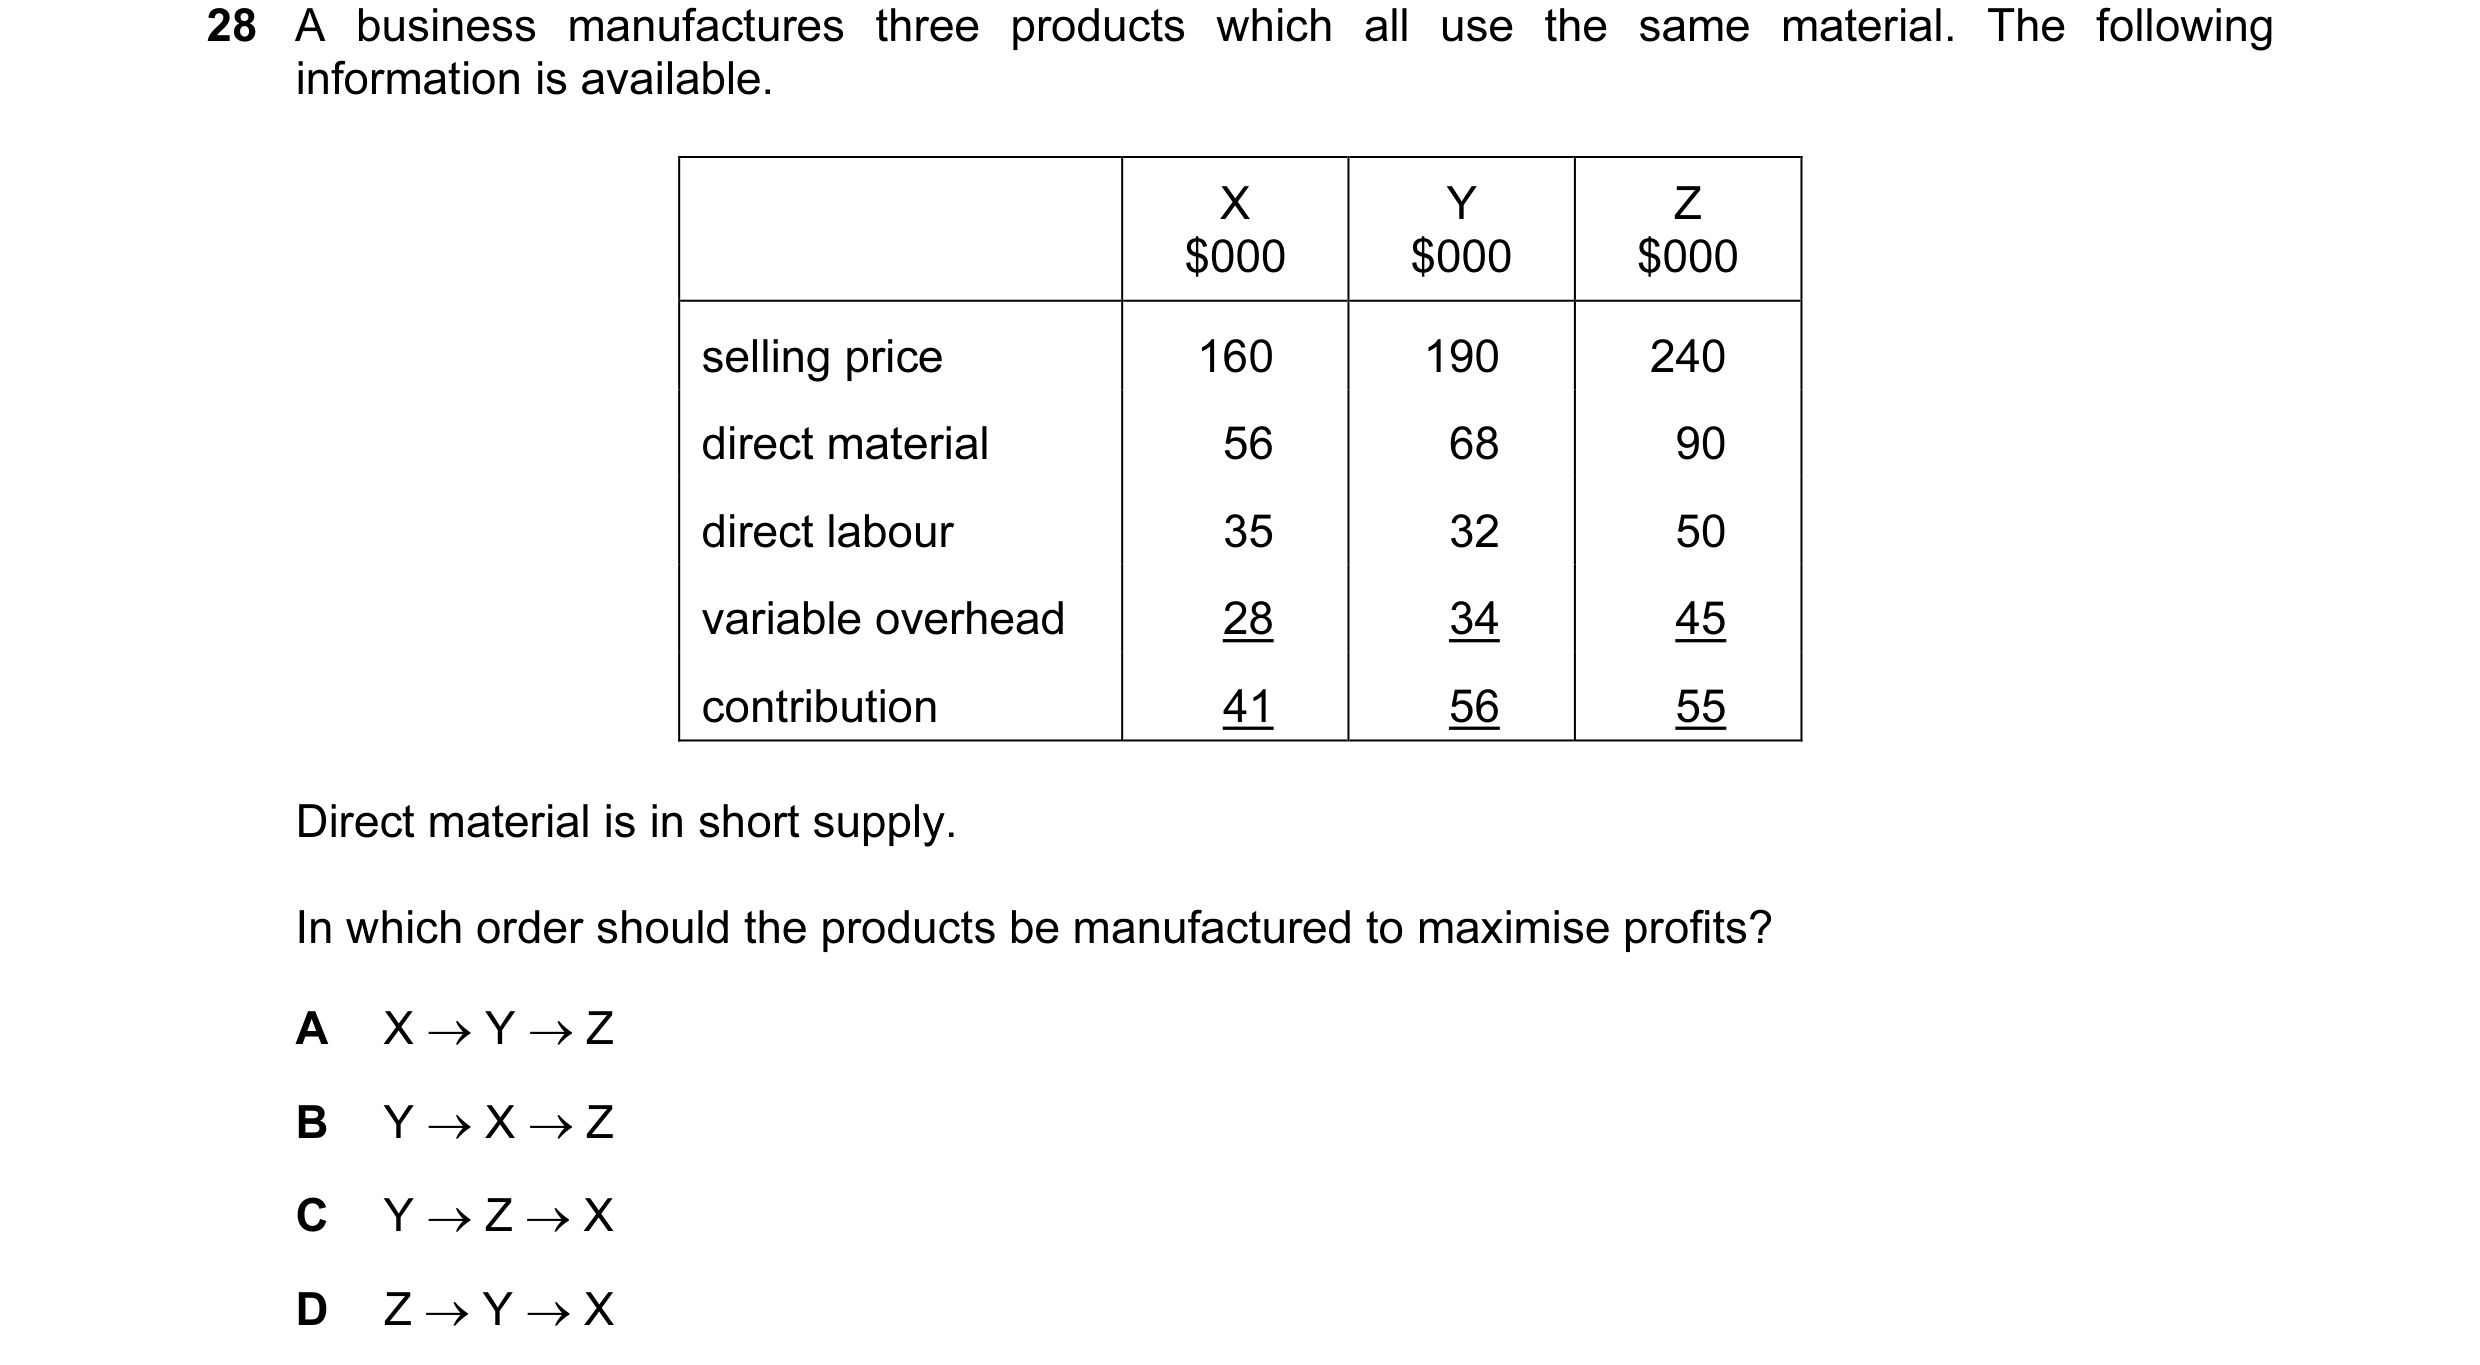
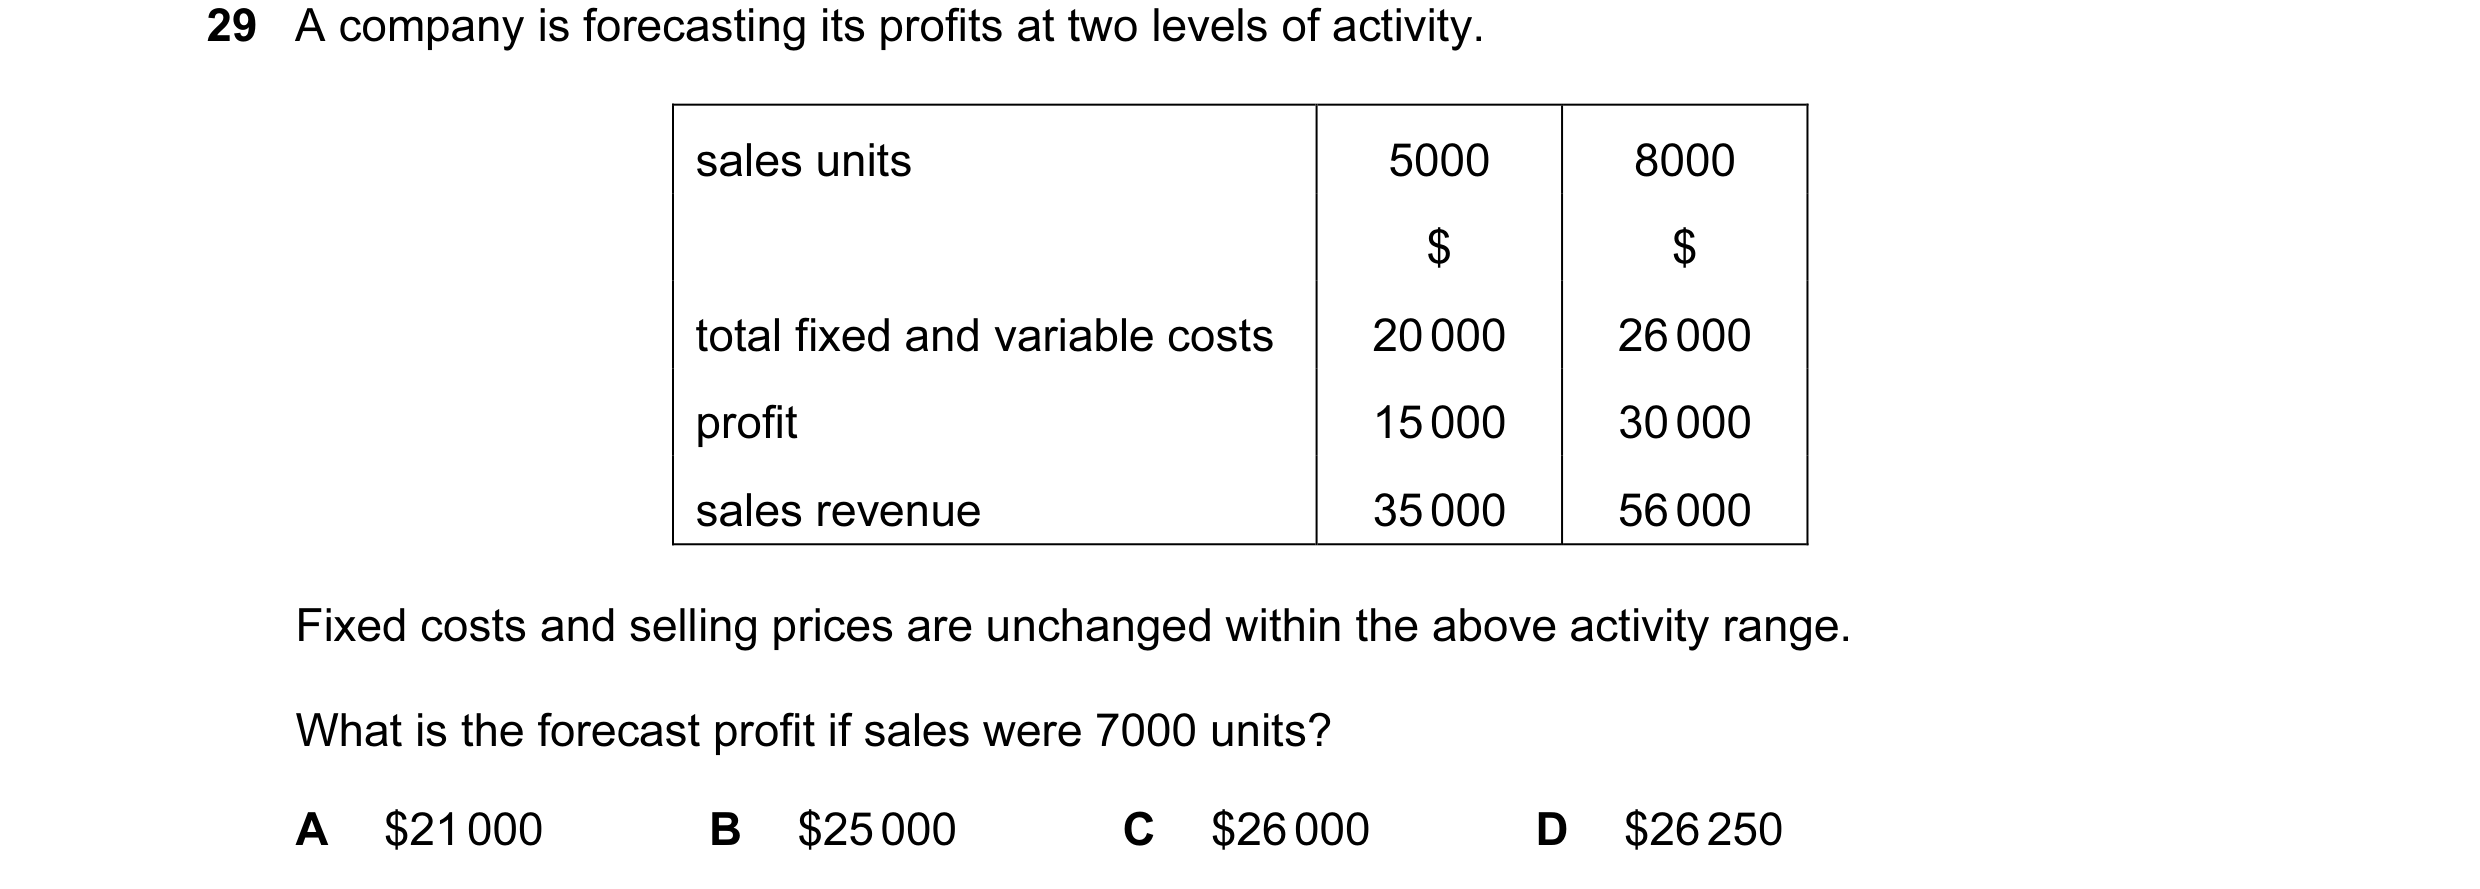 49 / 143
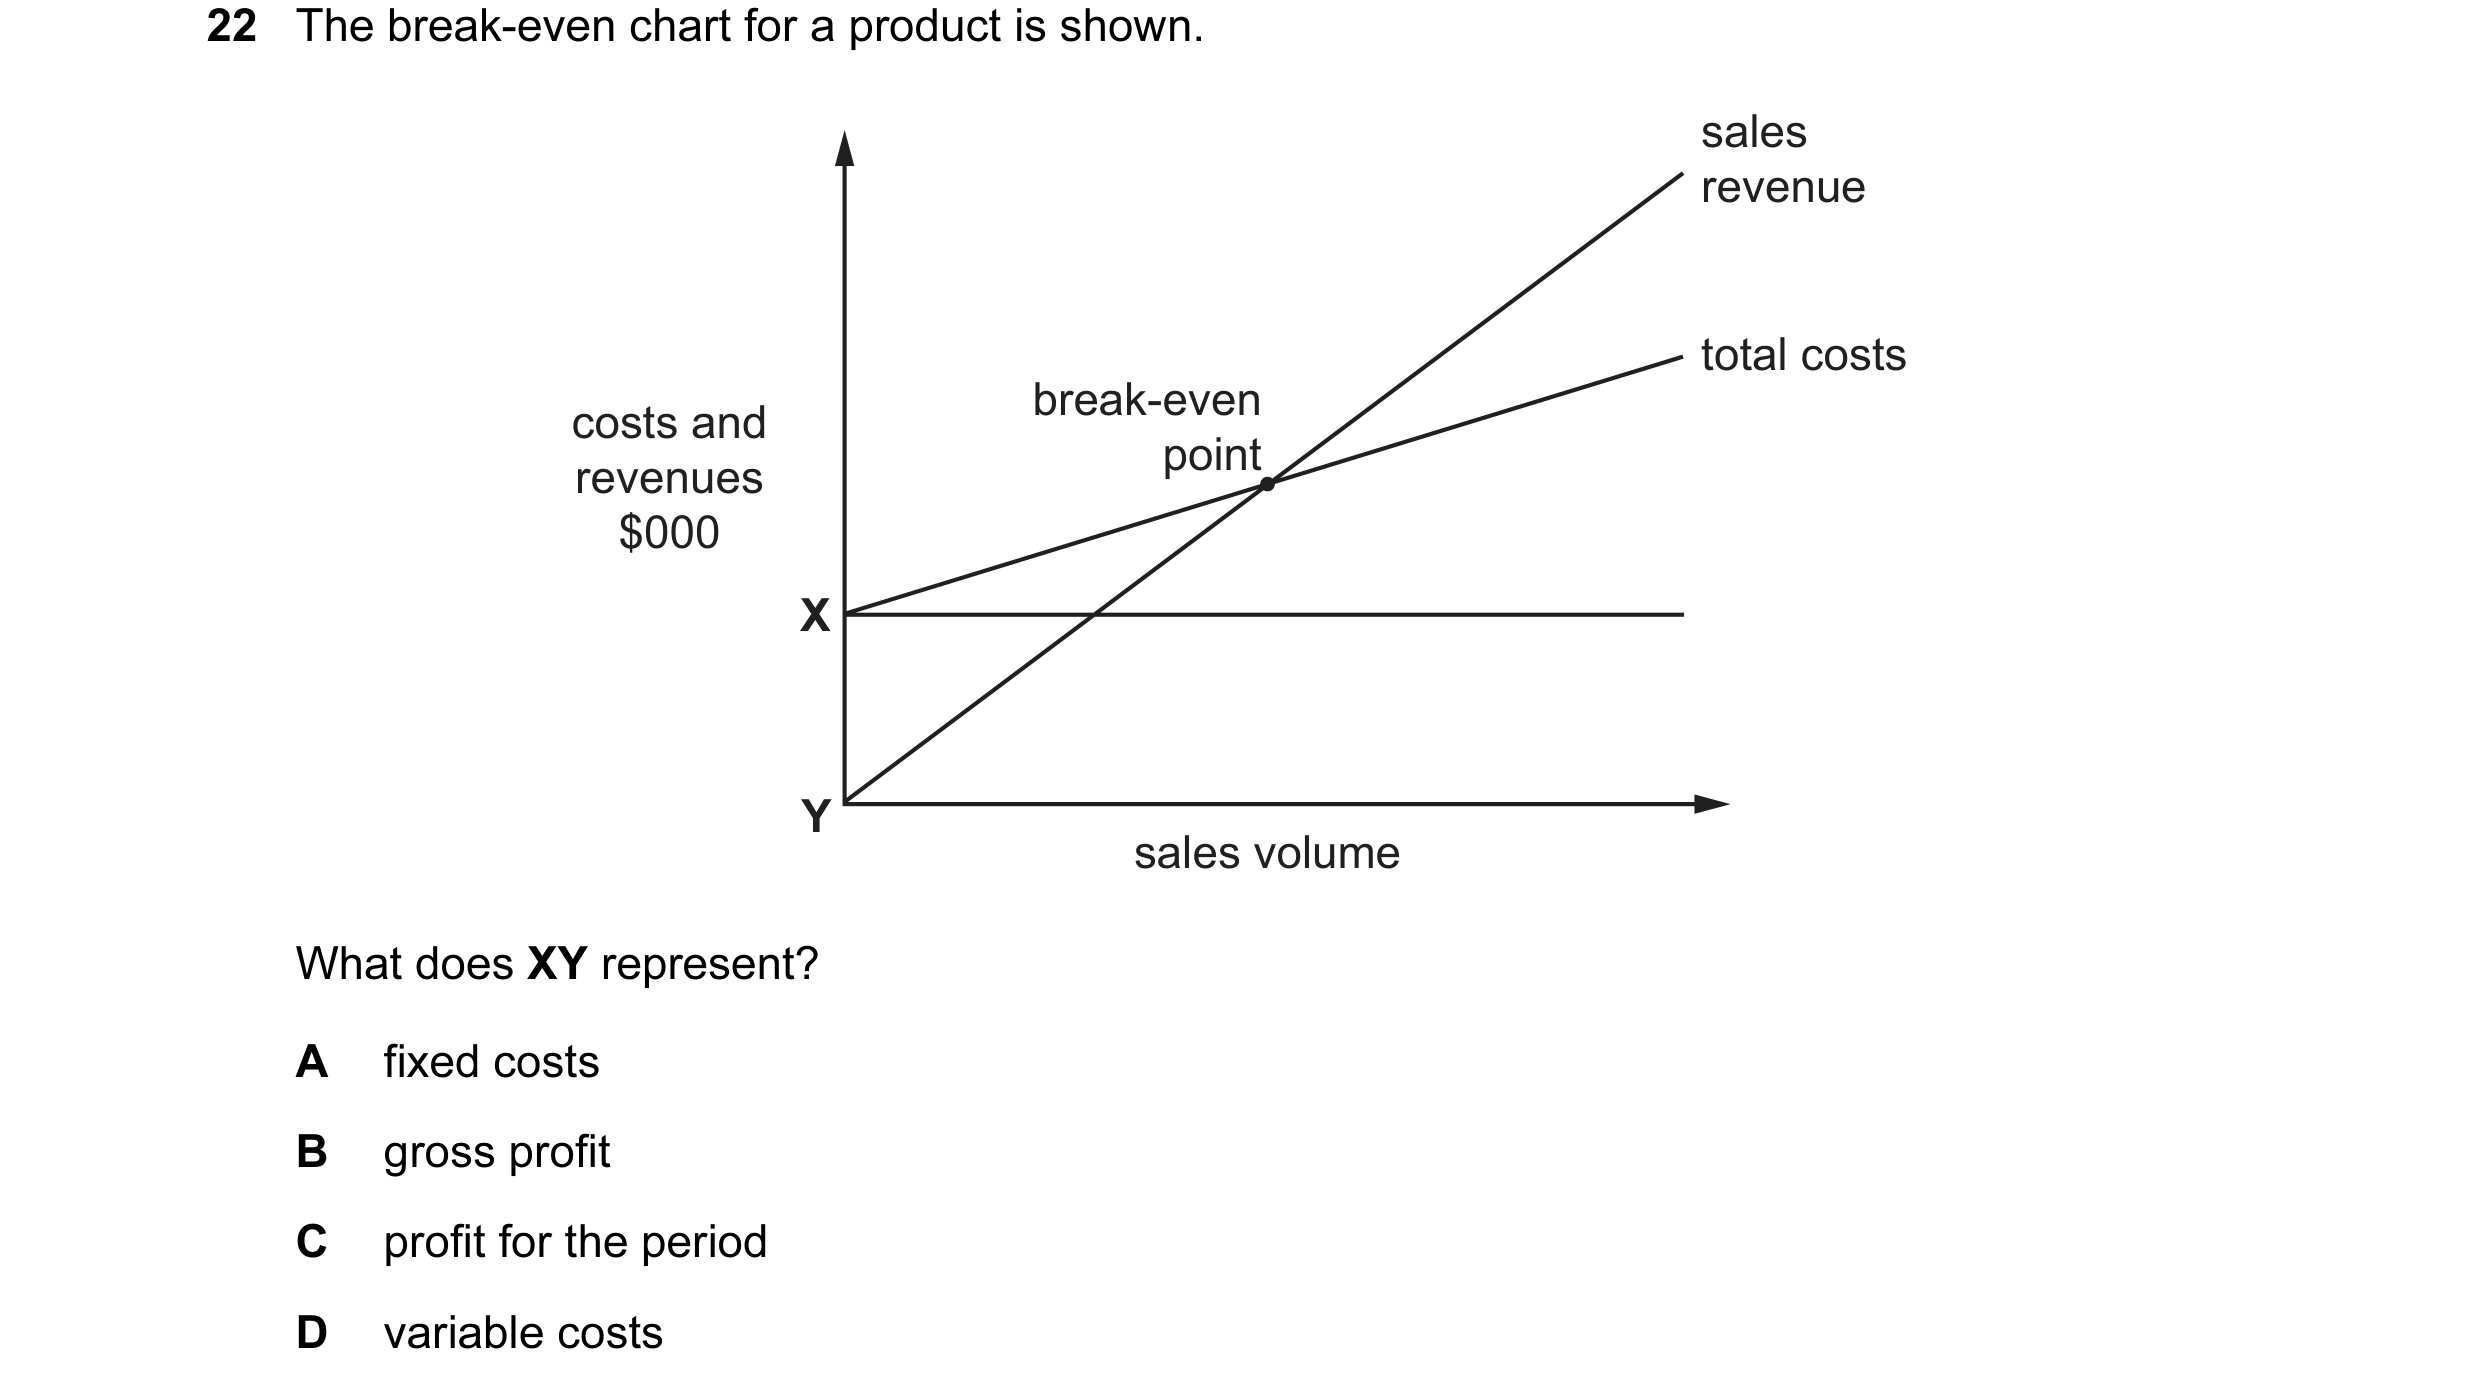
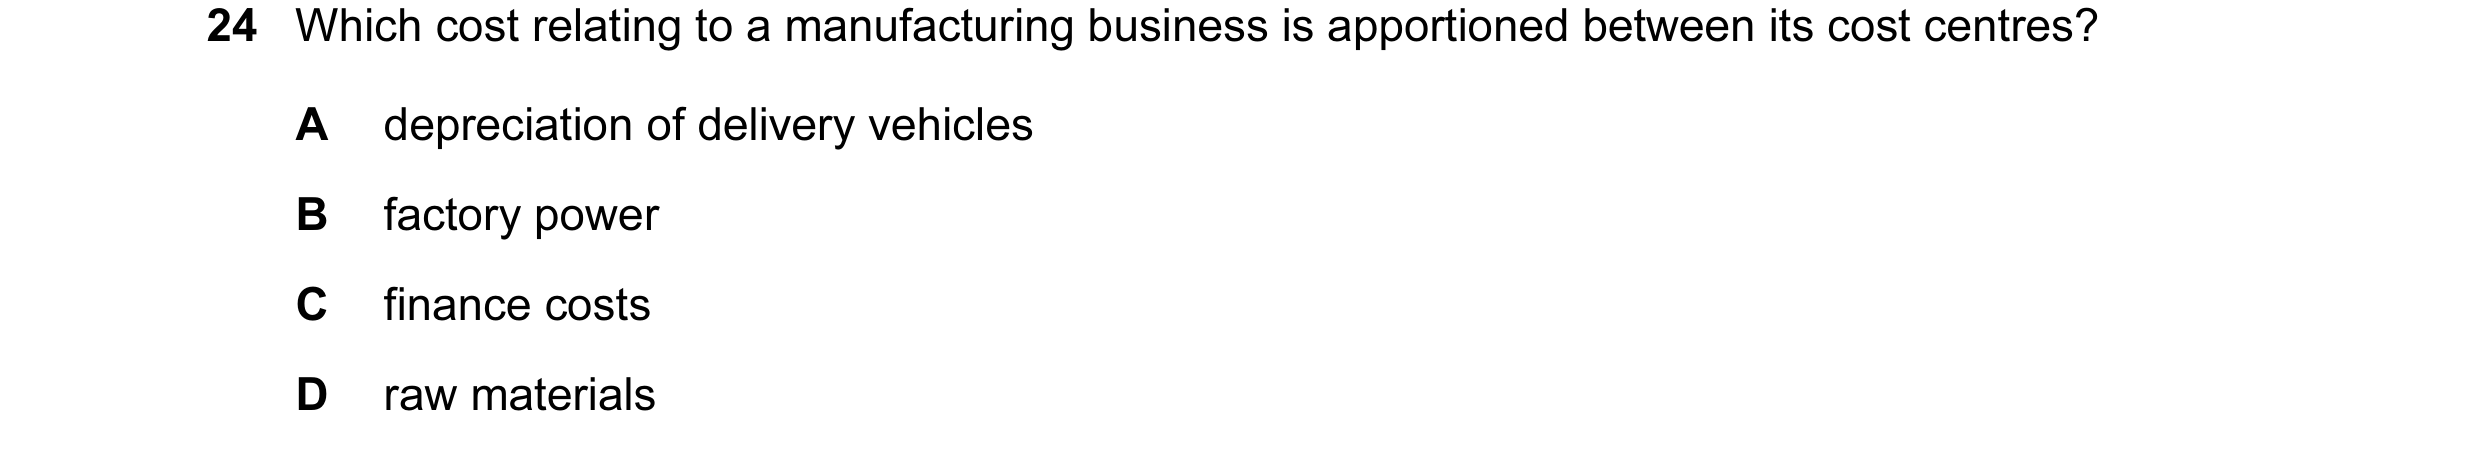
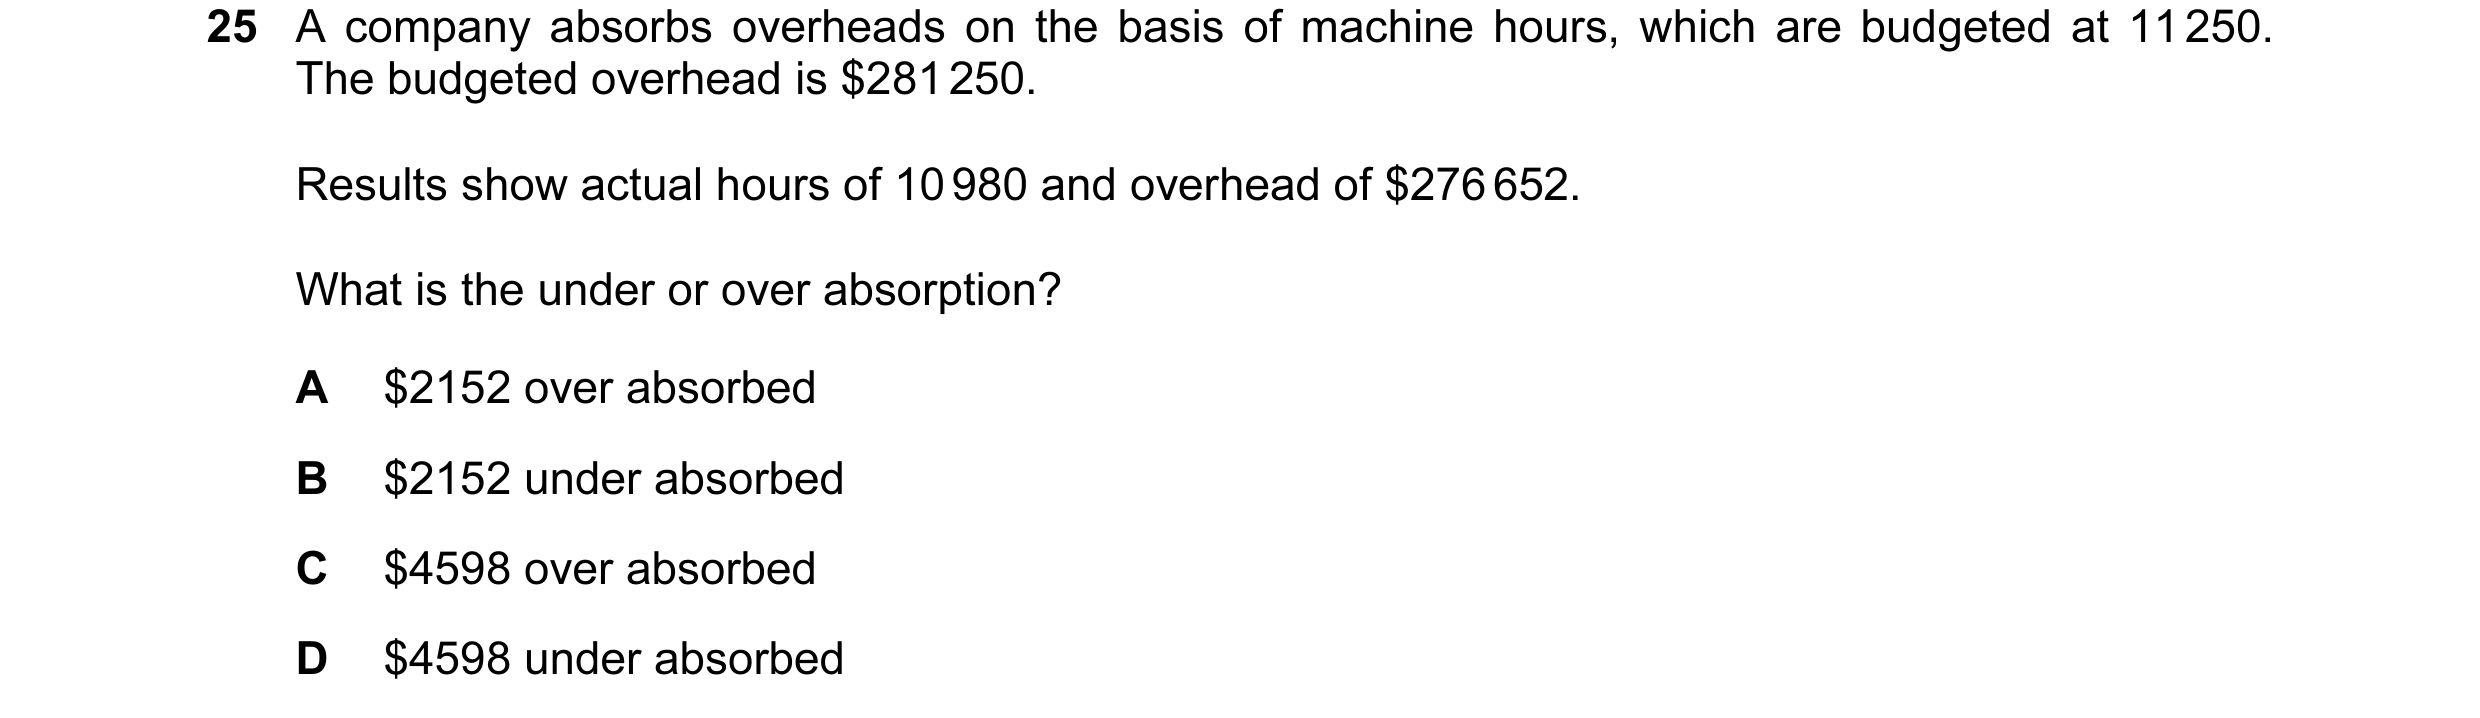 50 / 143
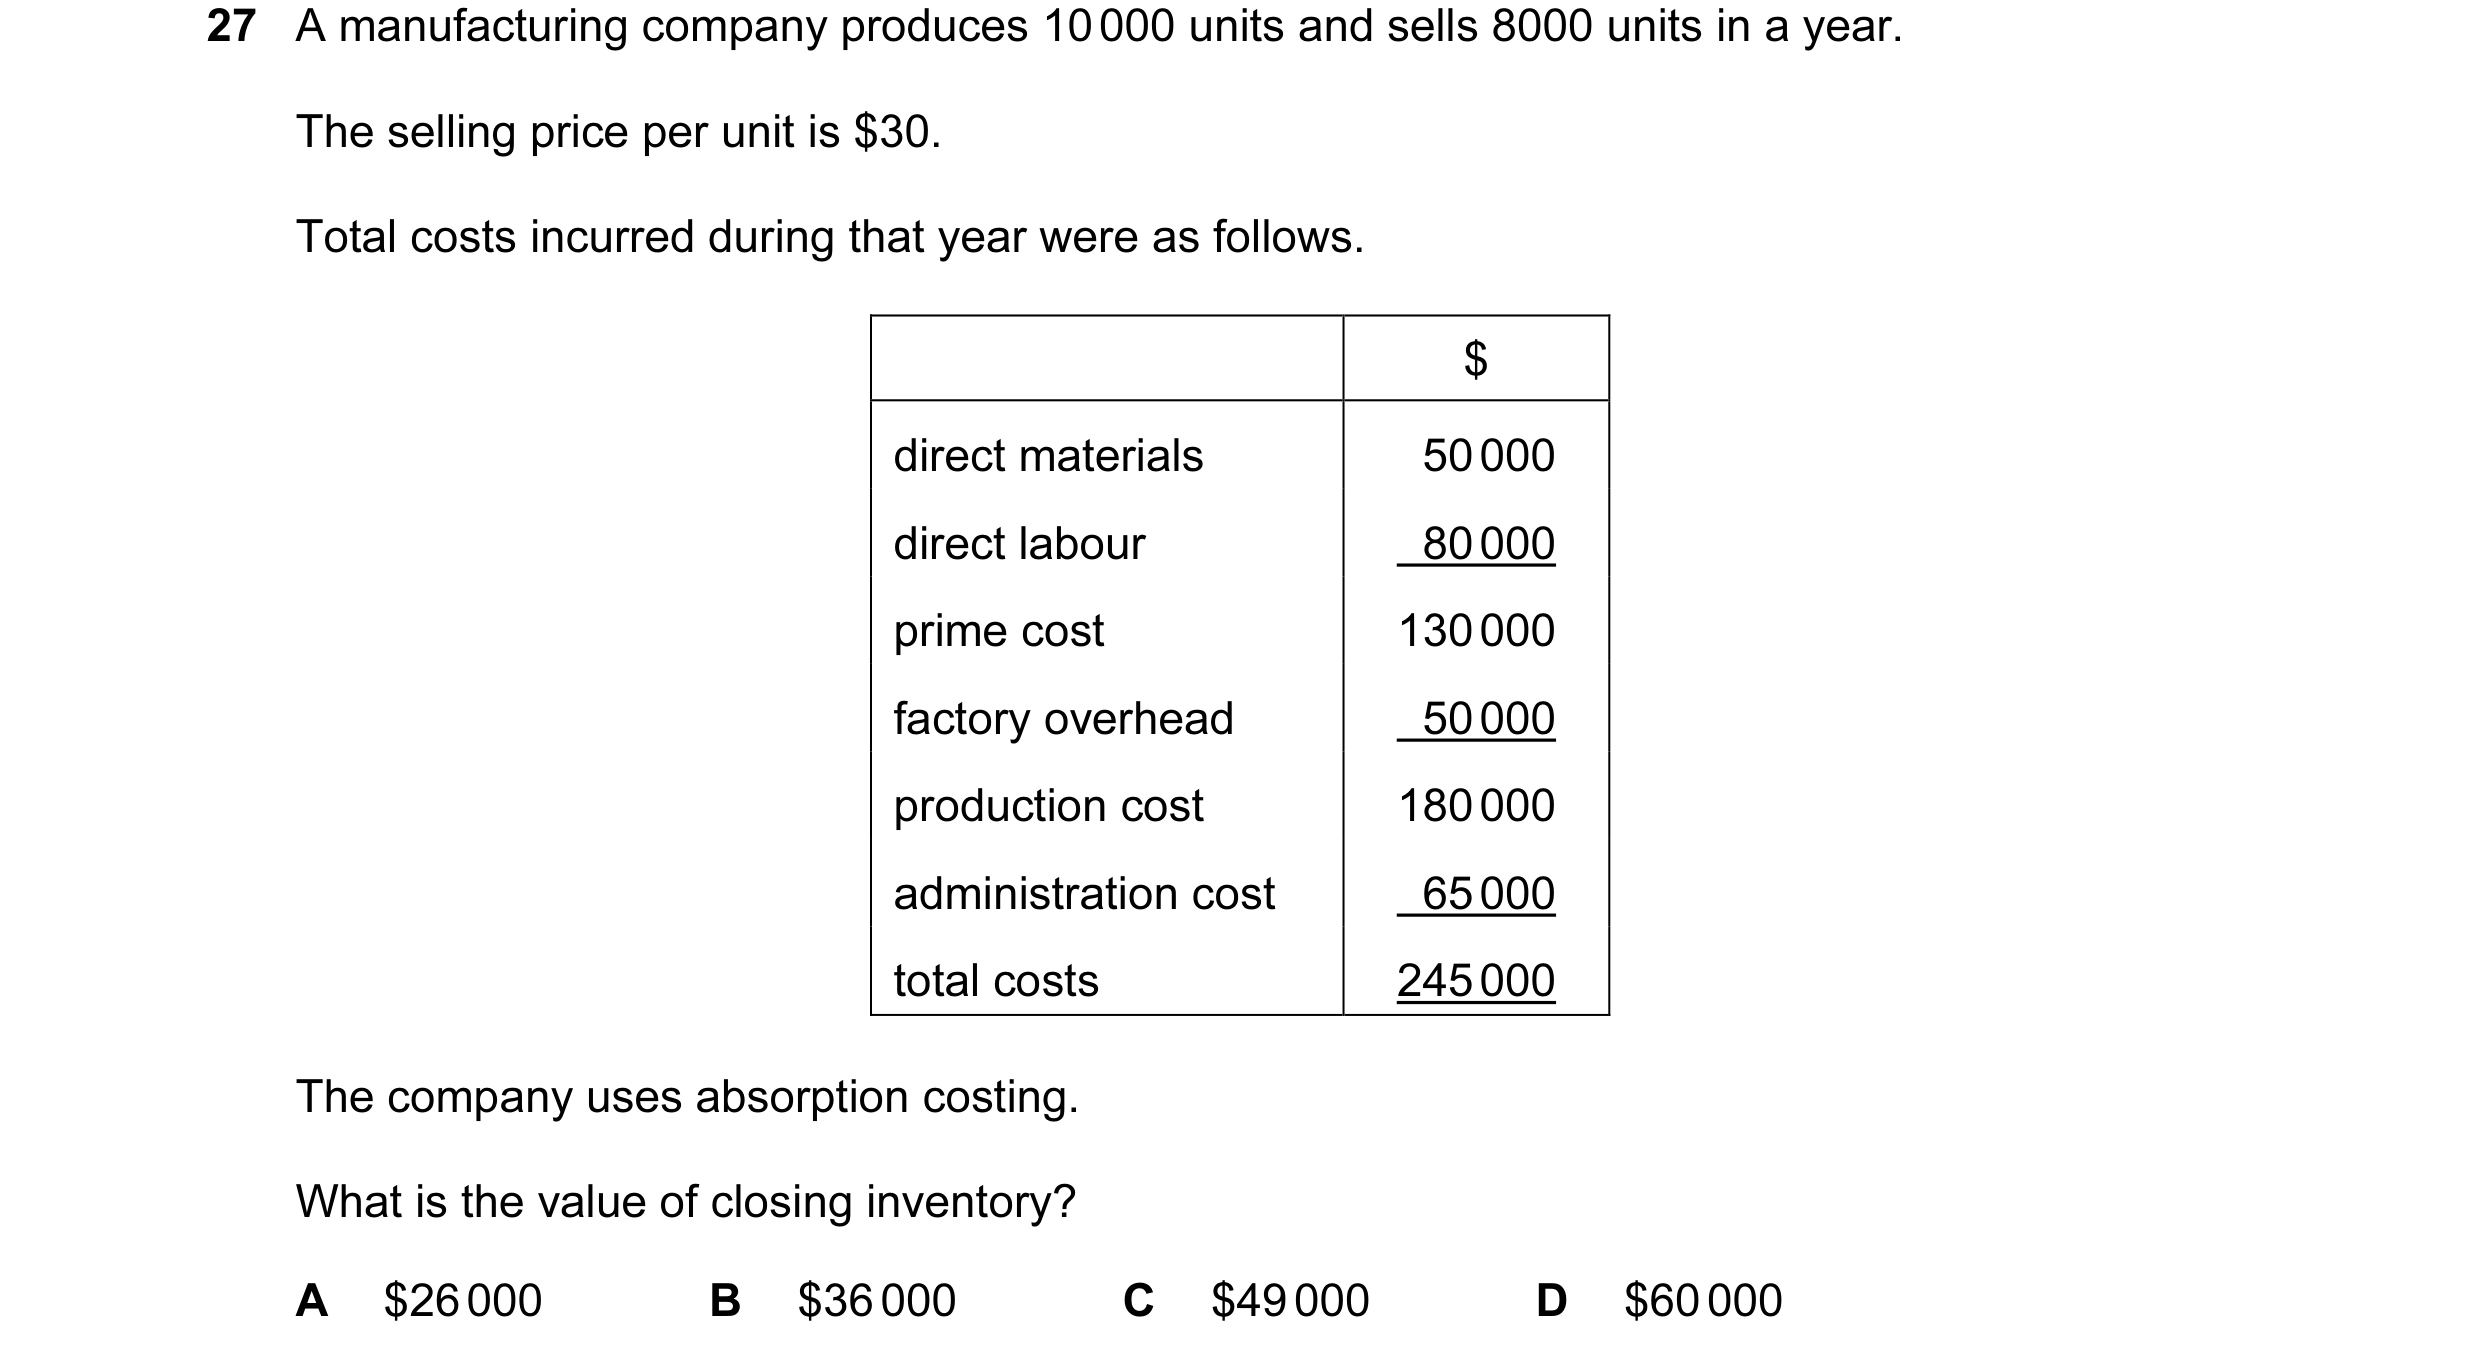
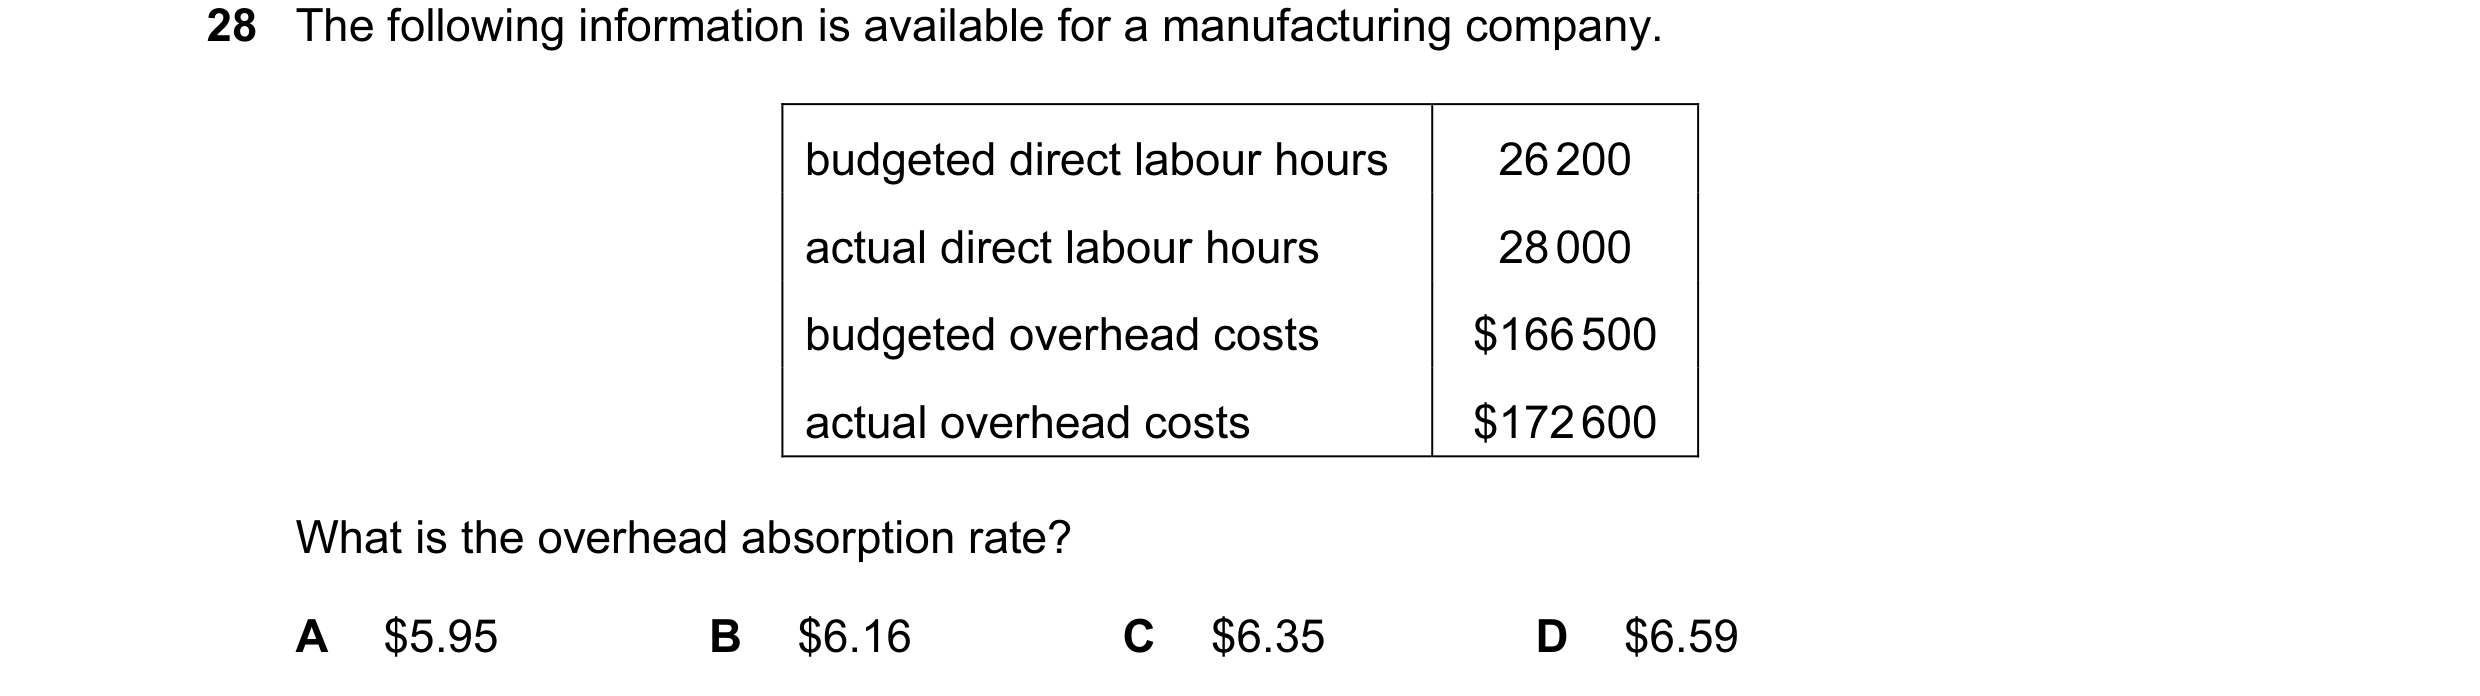
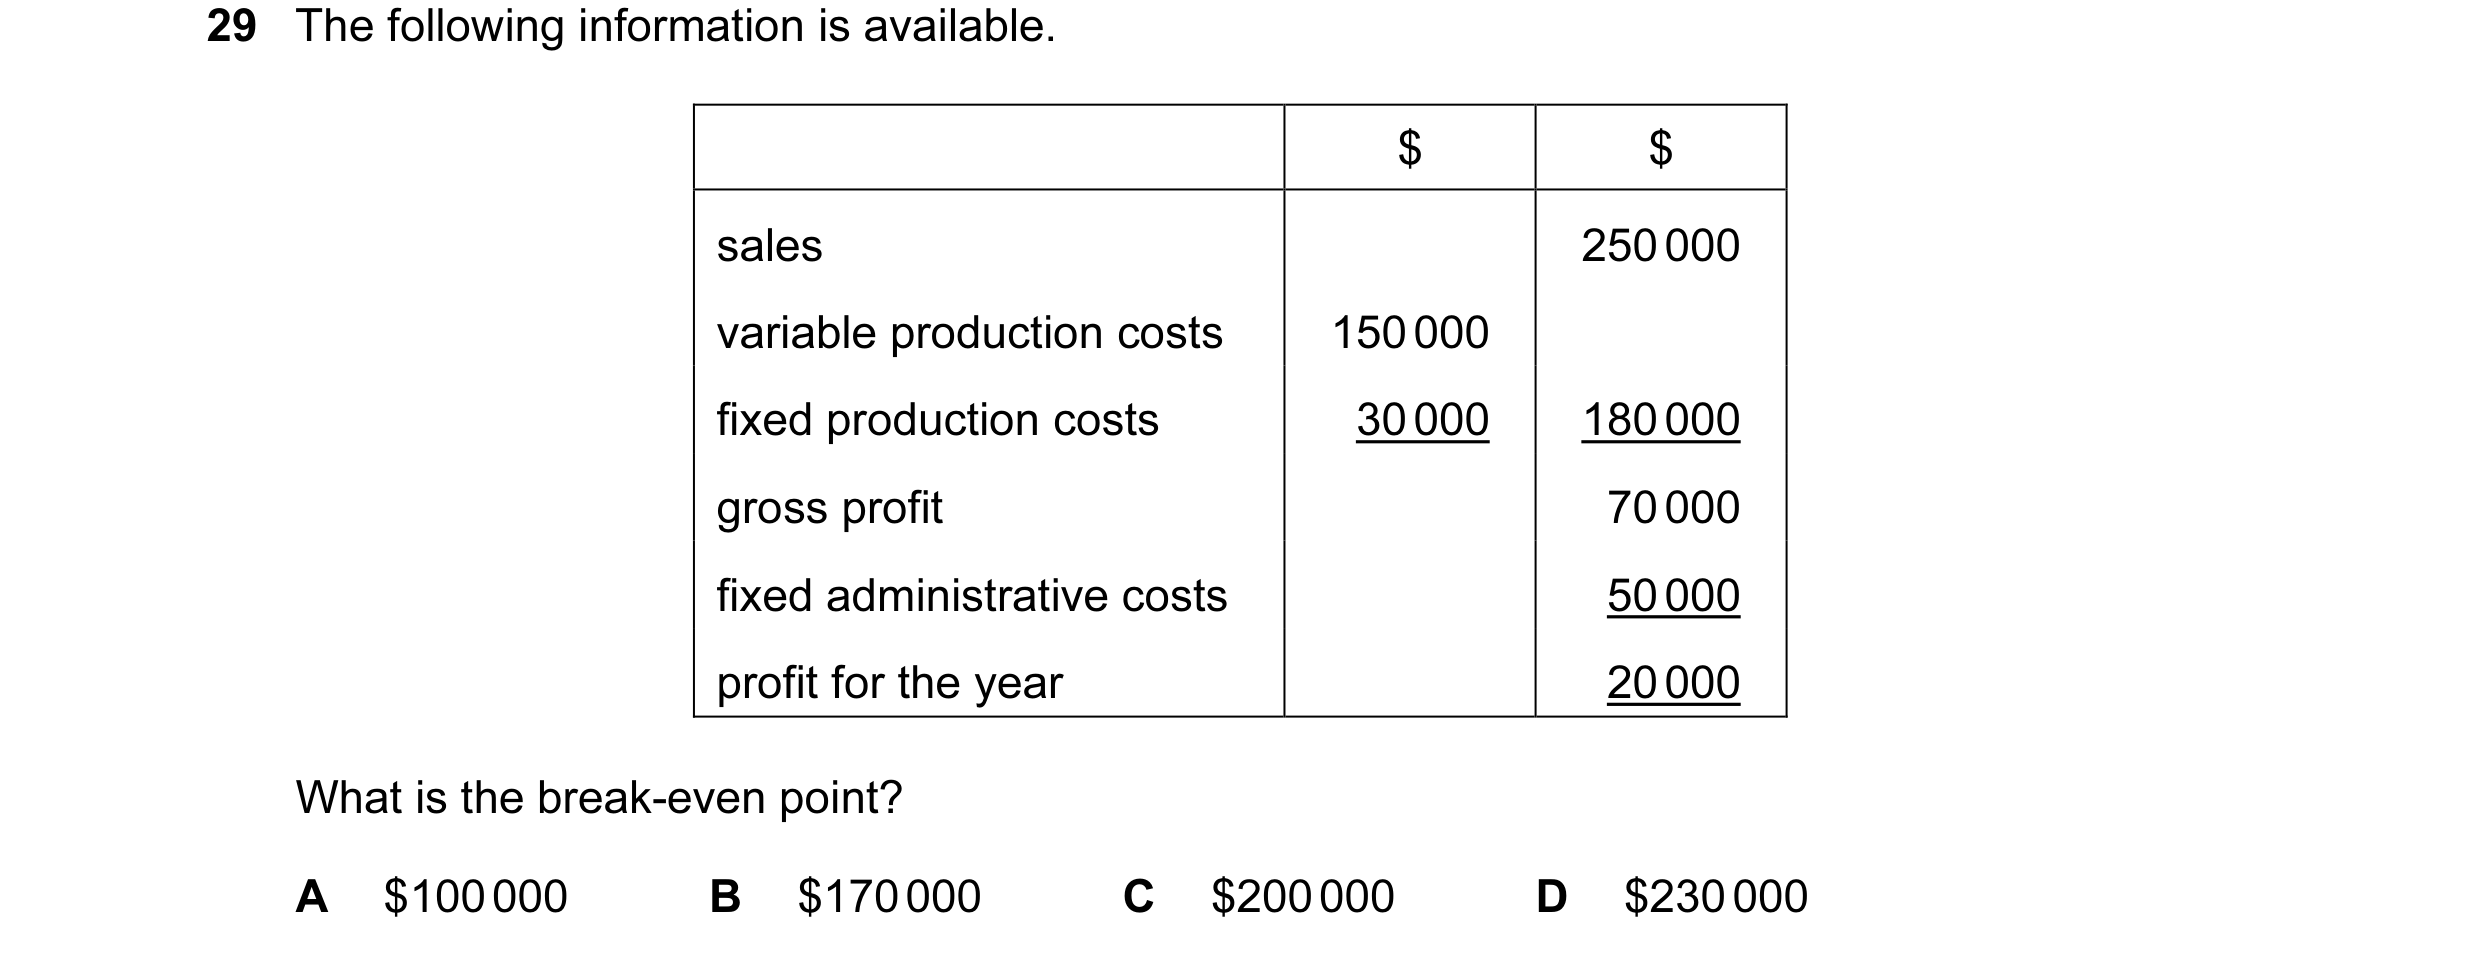 51 / 143
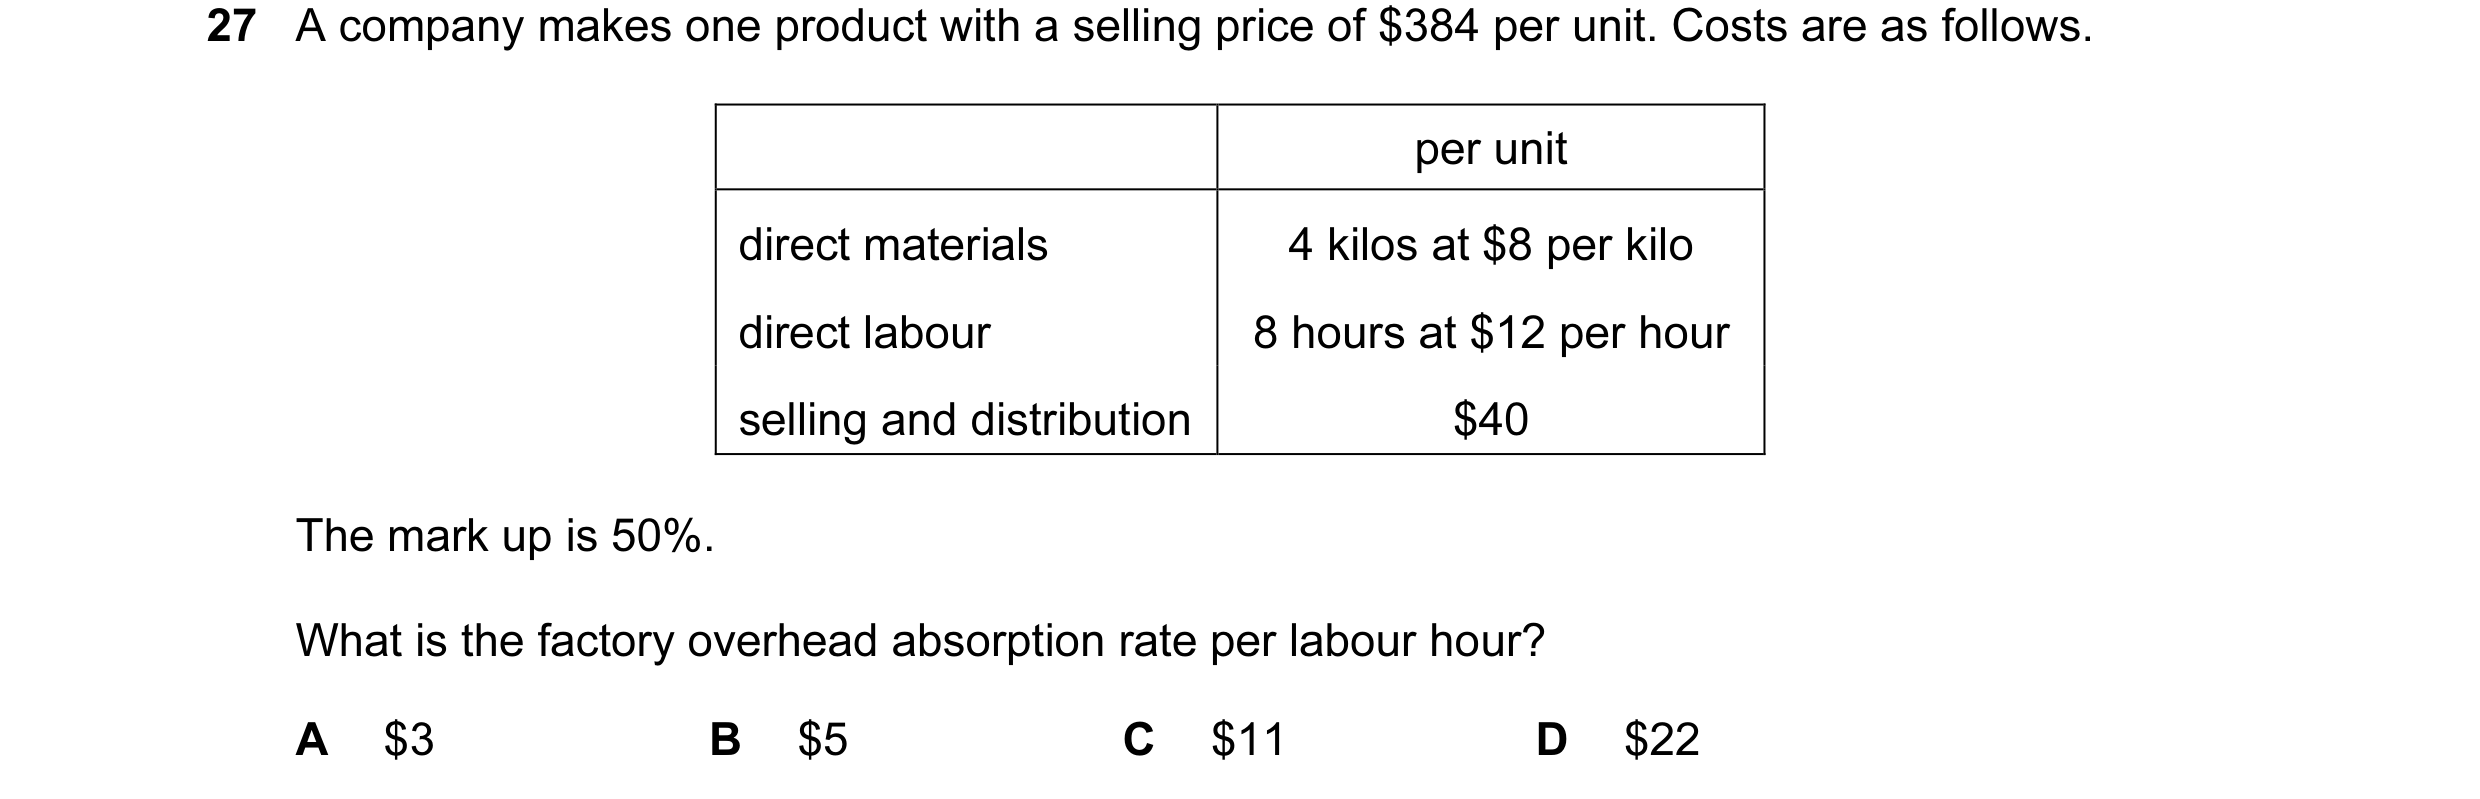
 52 / 143
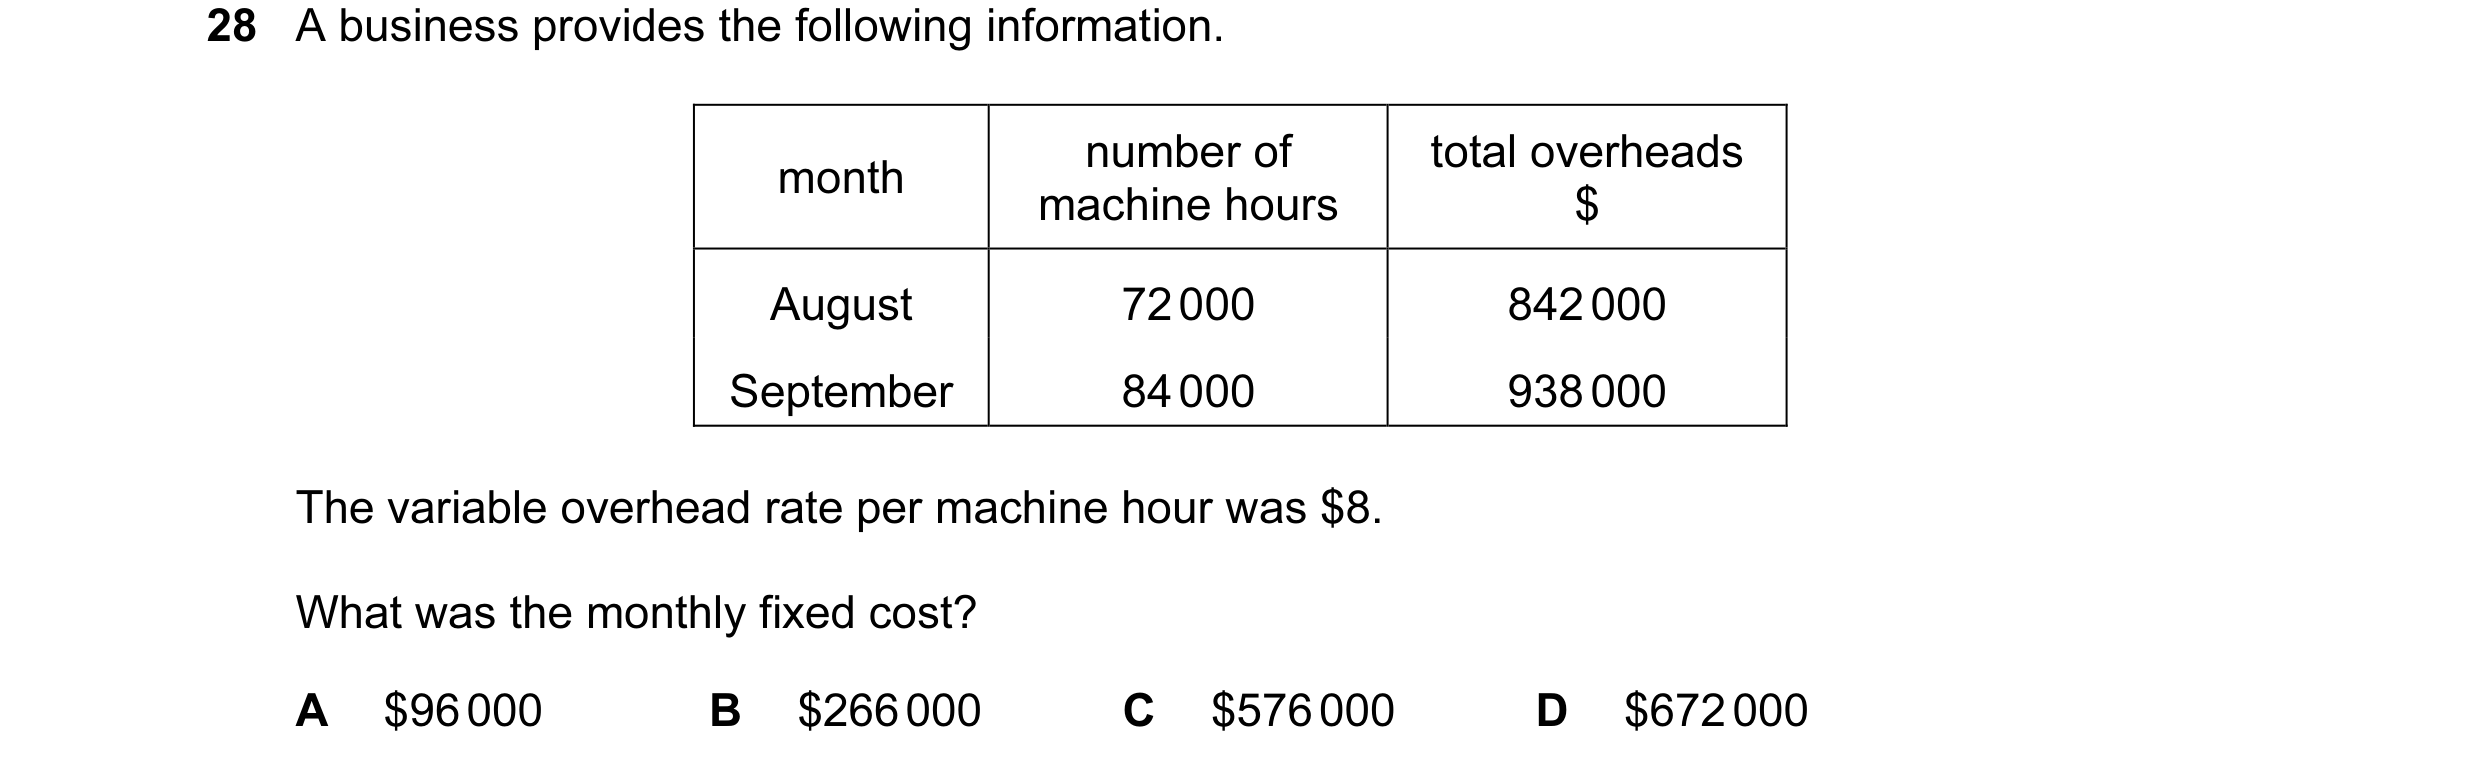
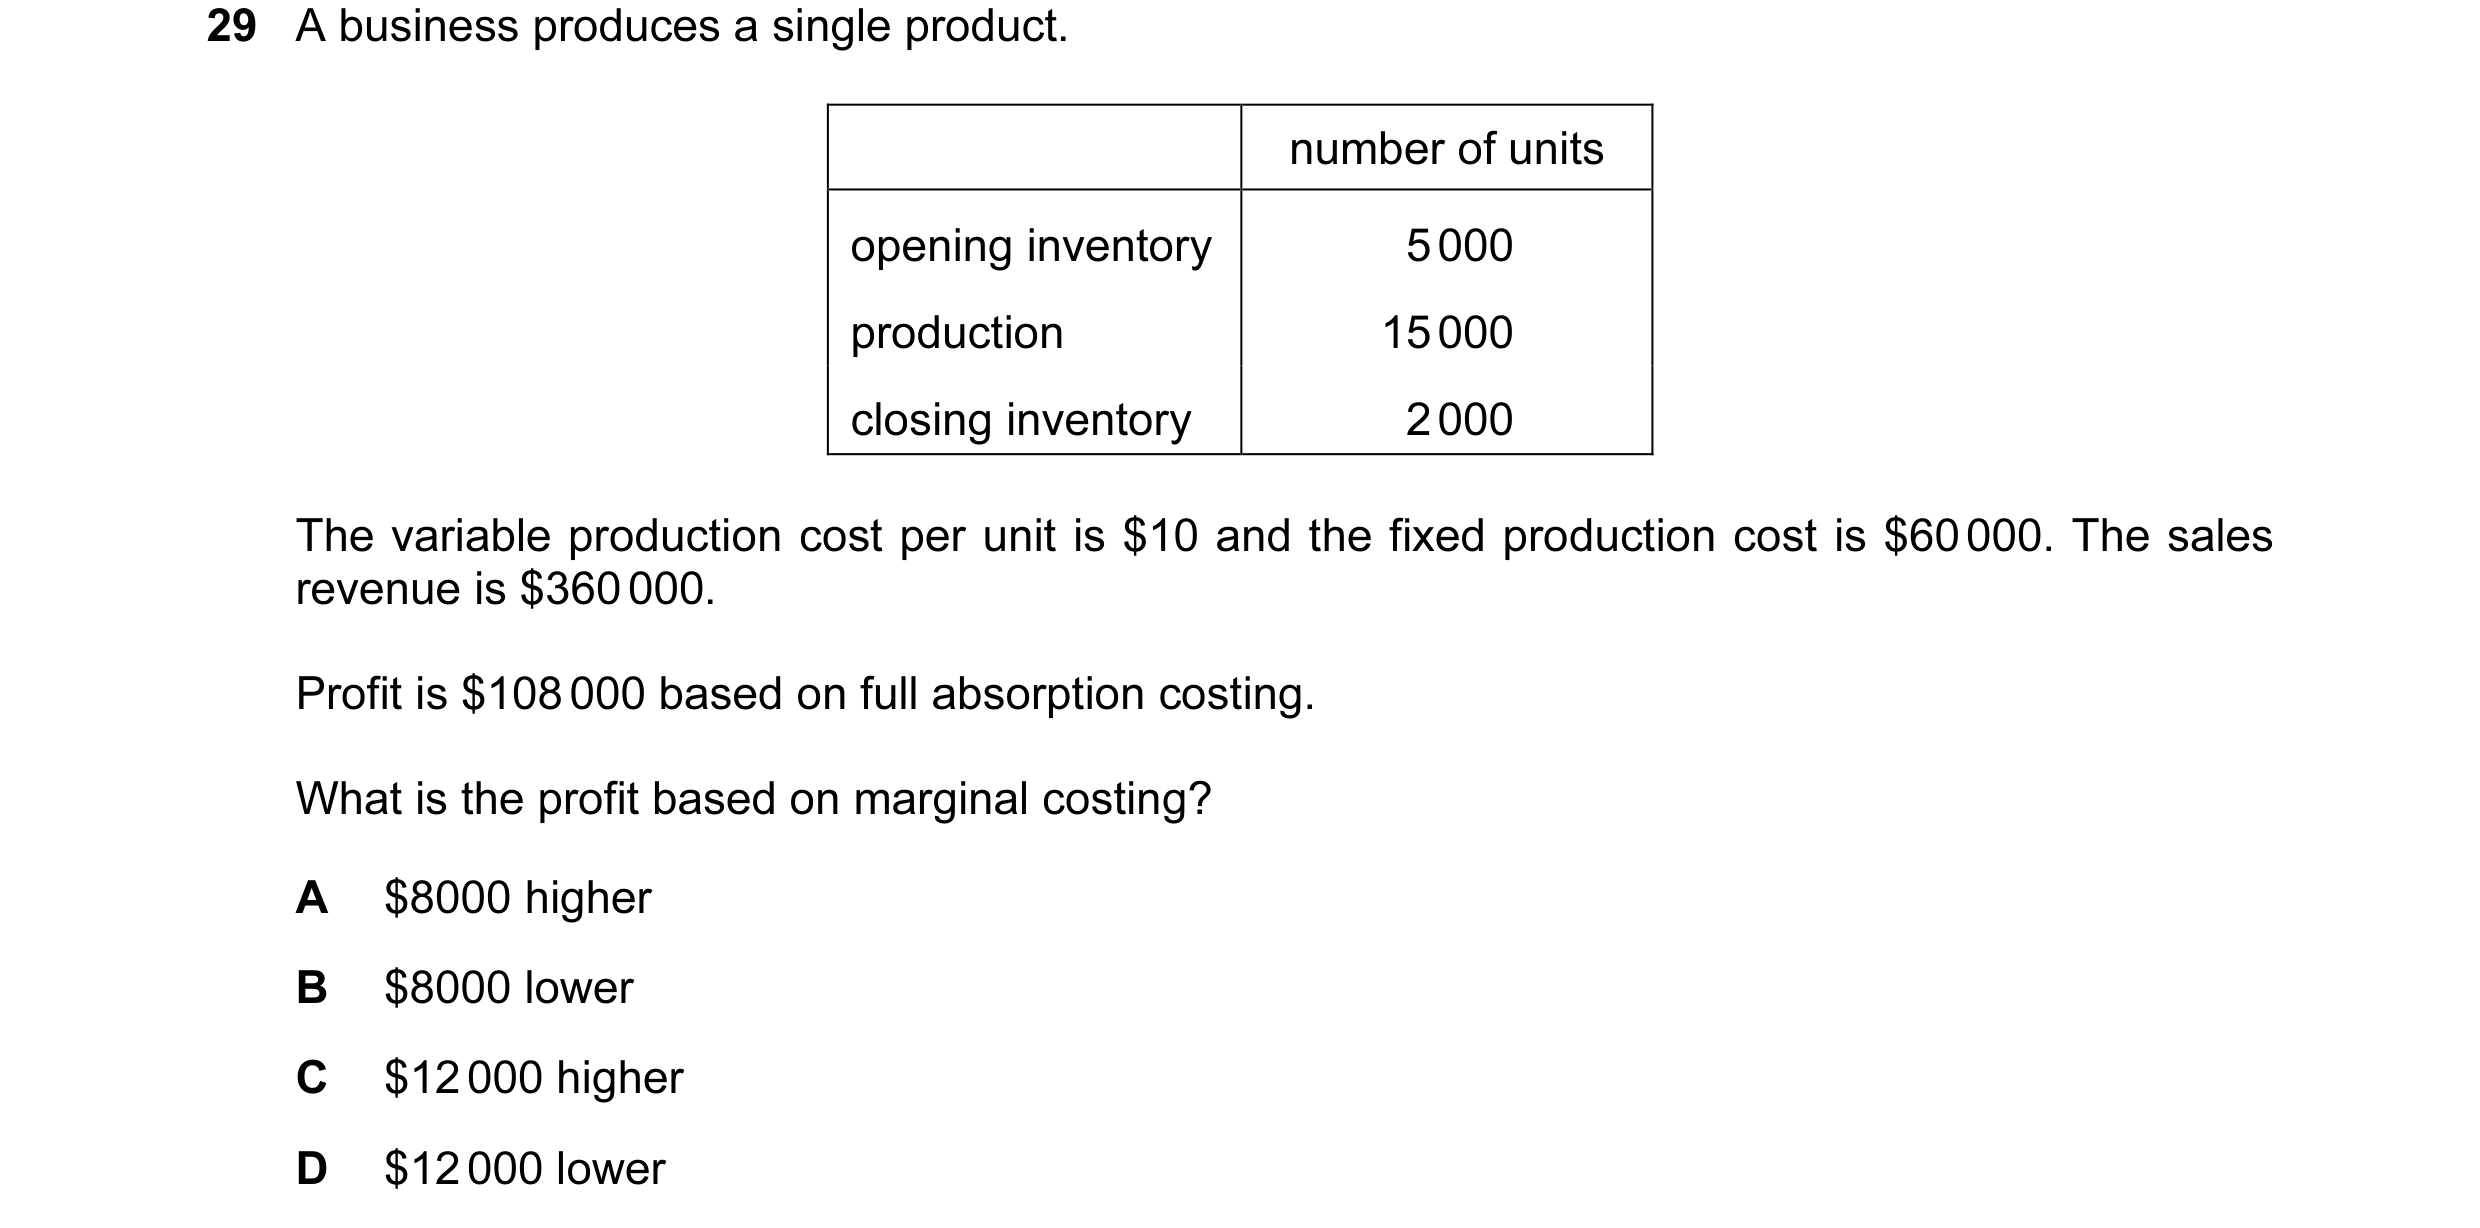 53 / 143
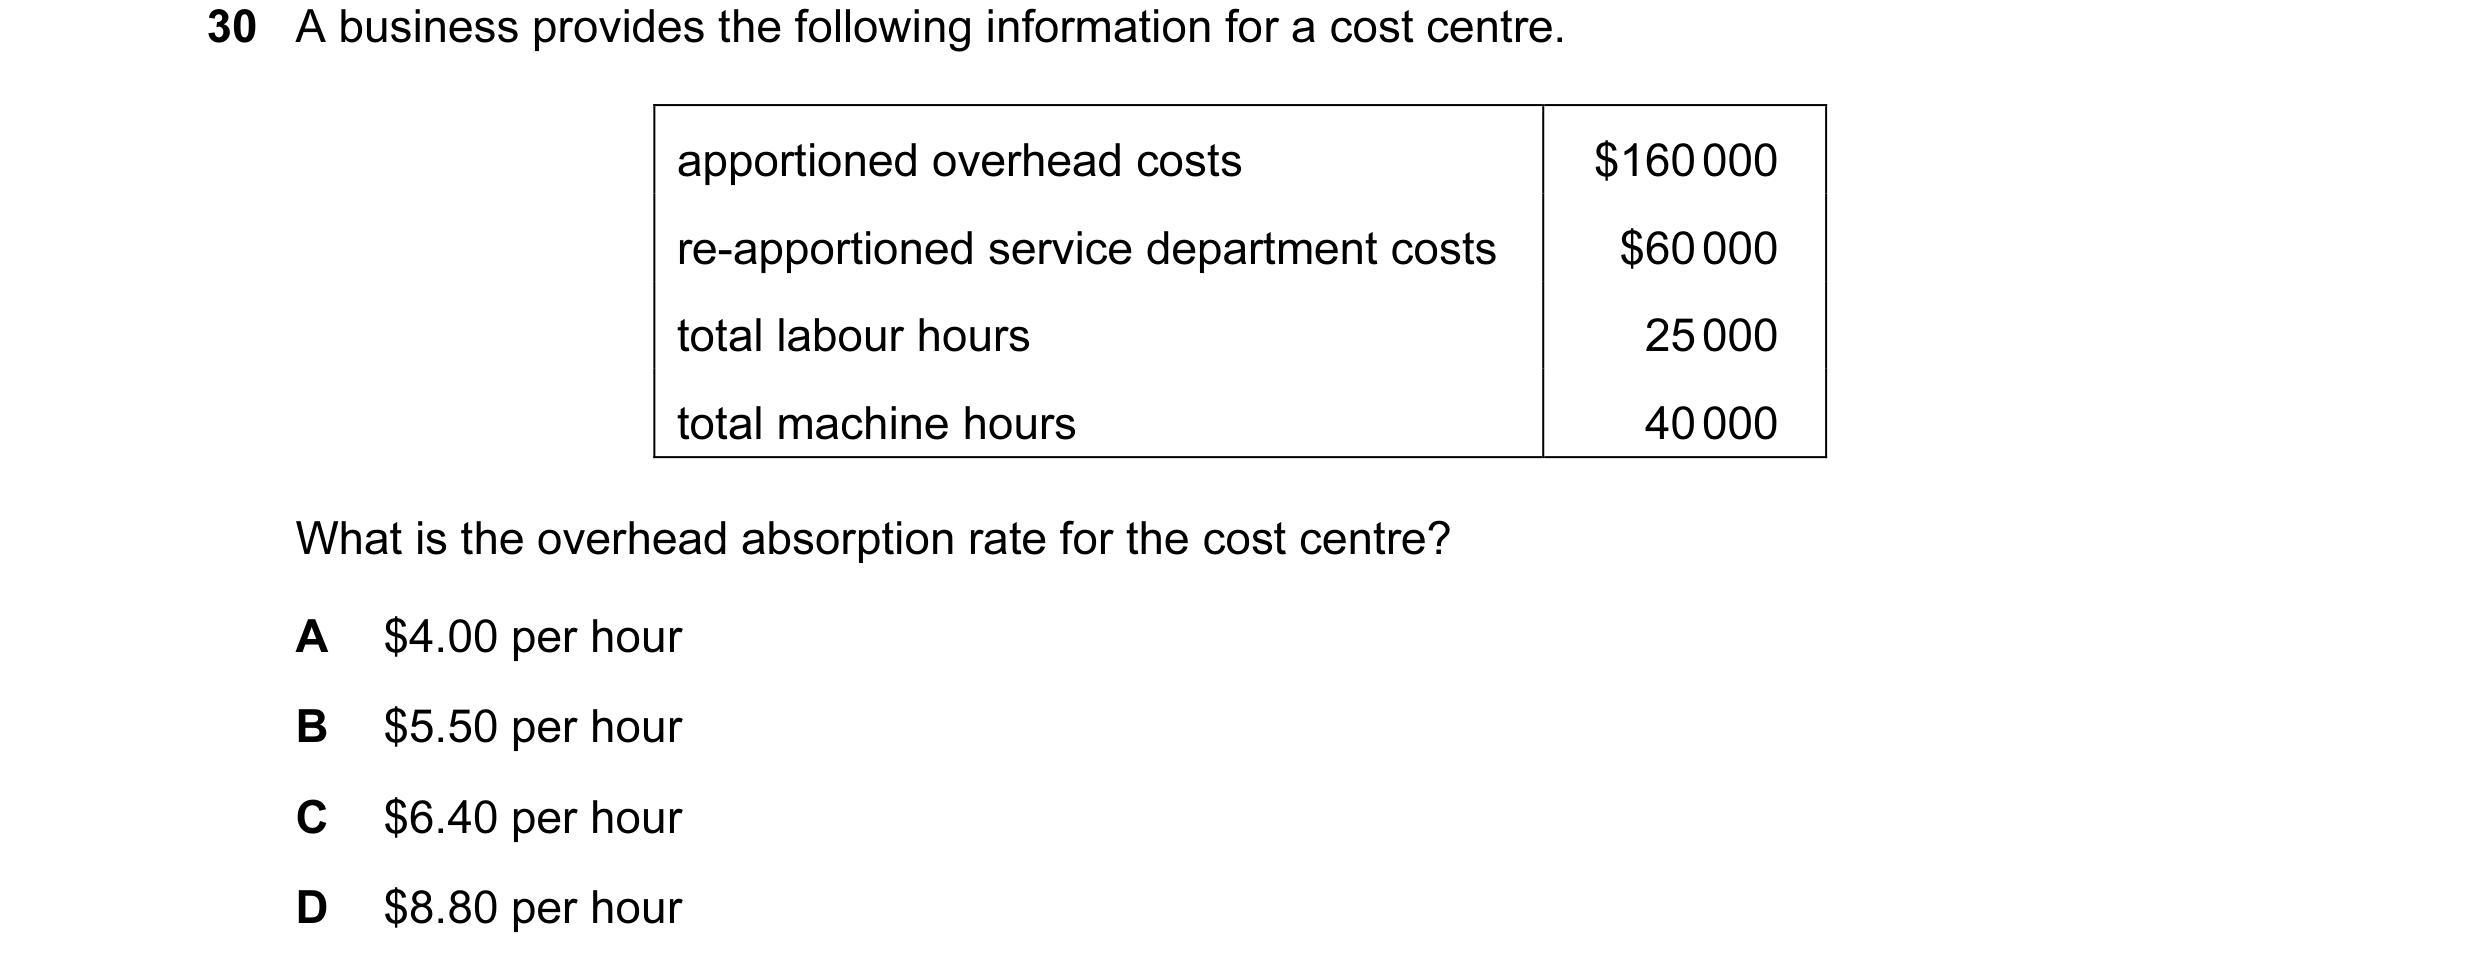
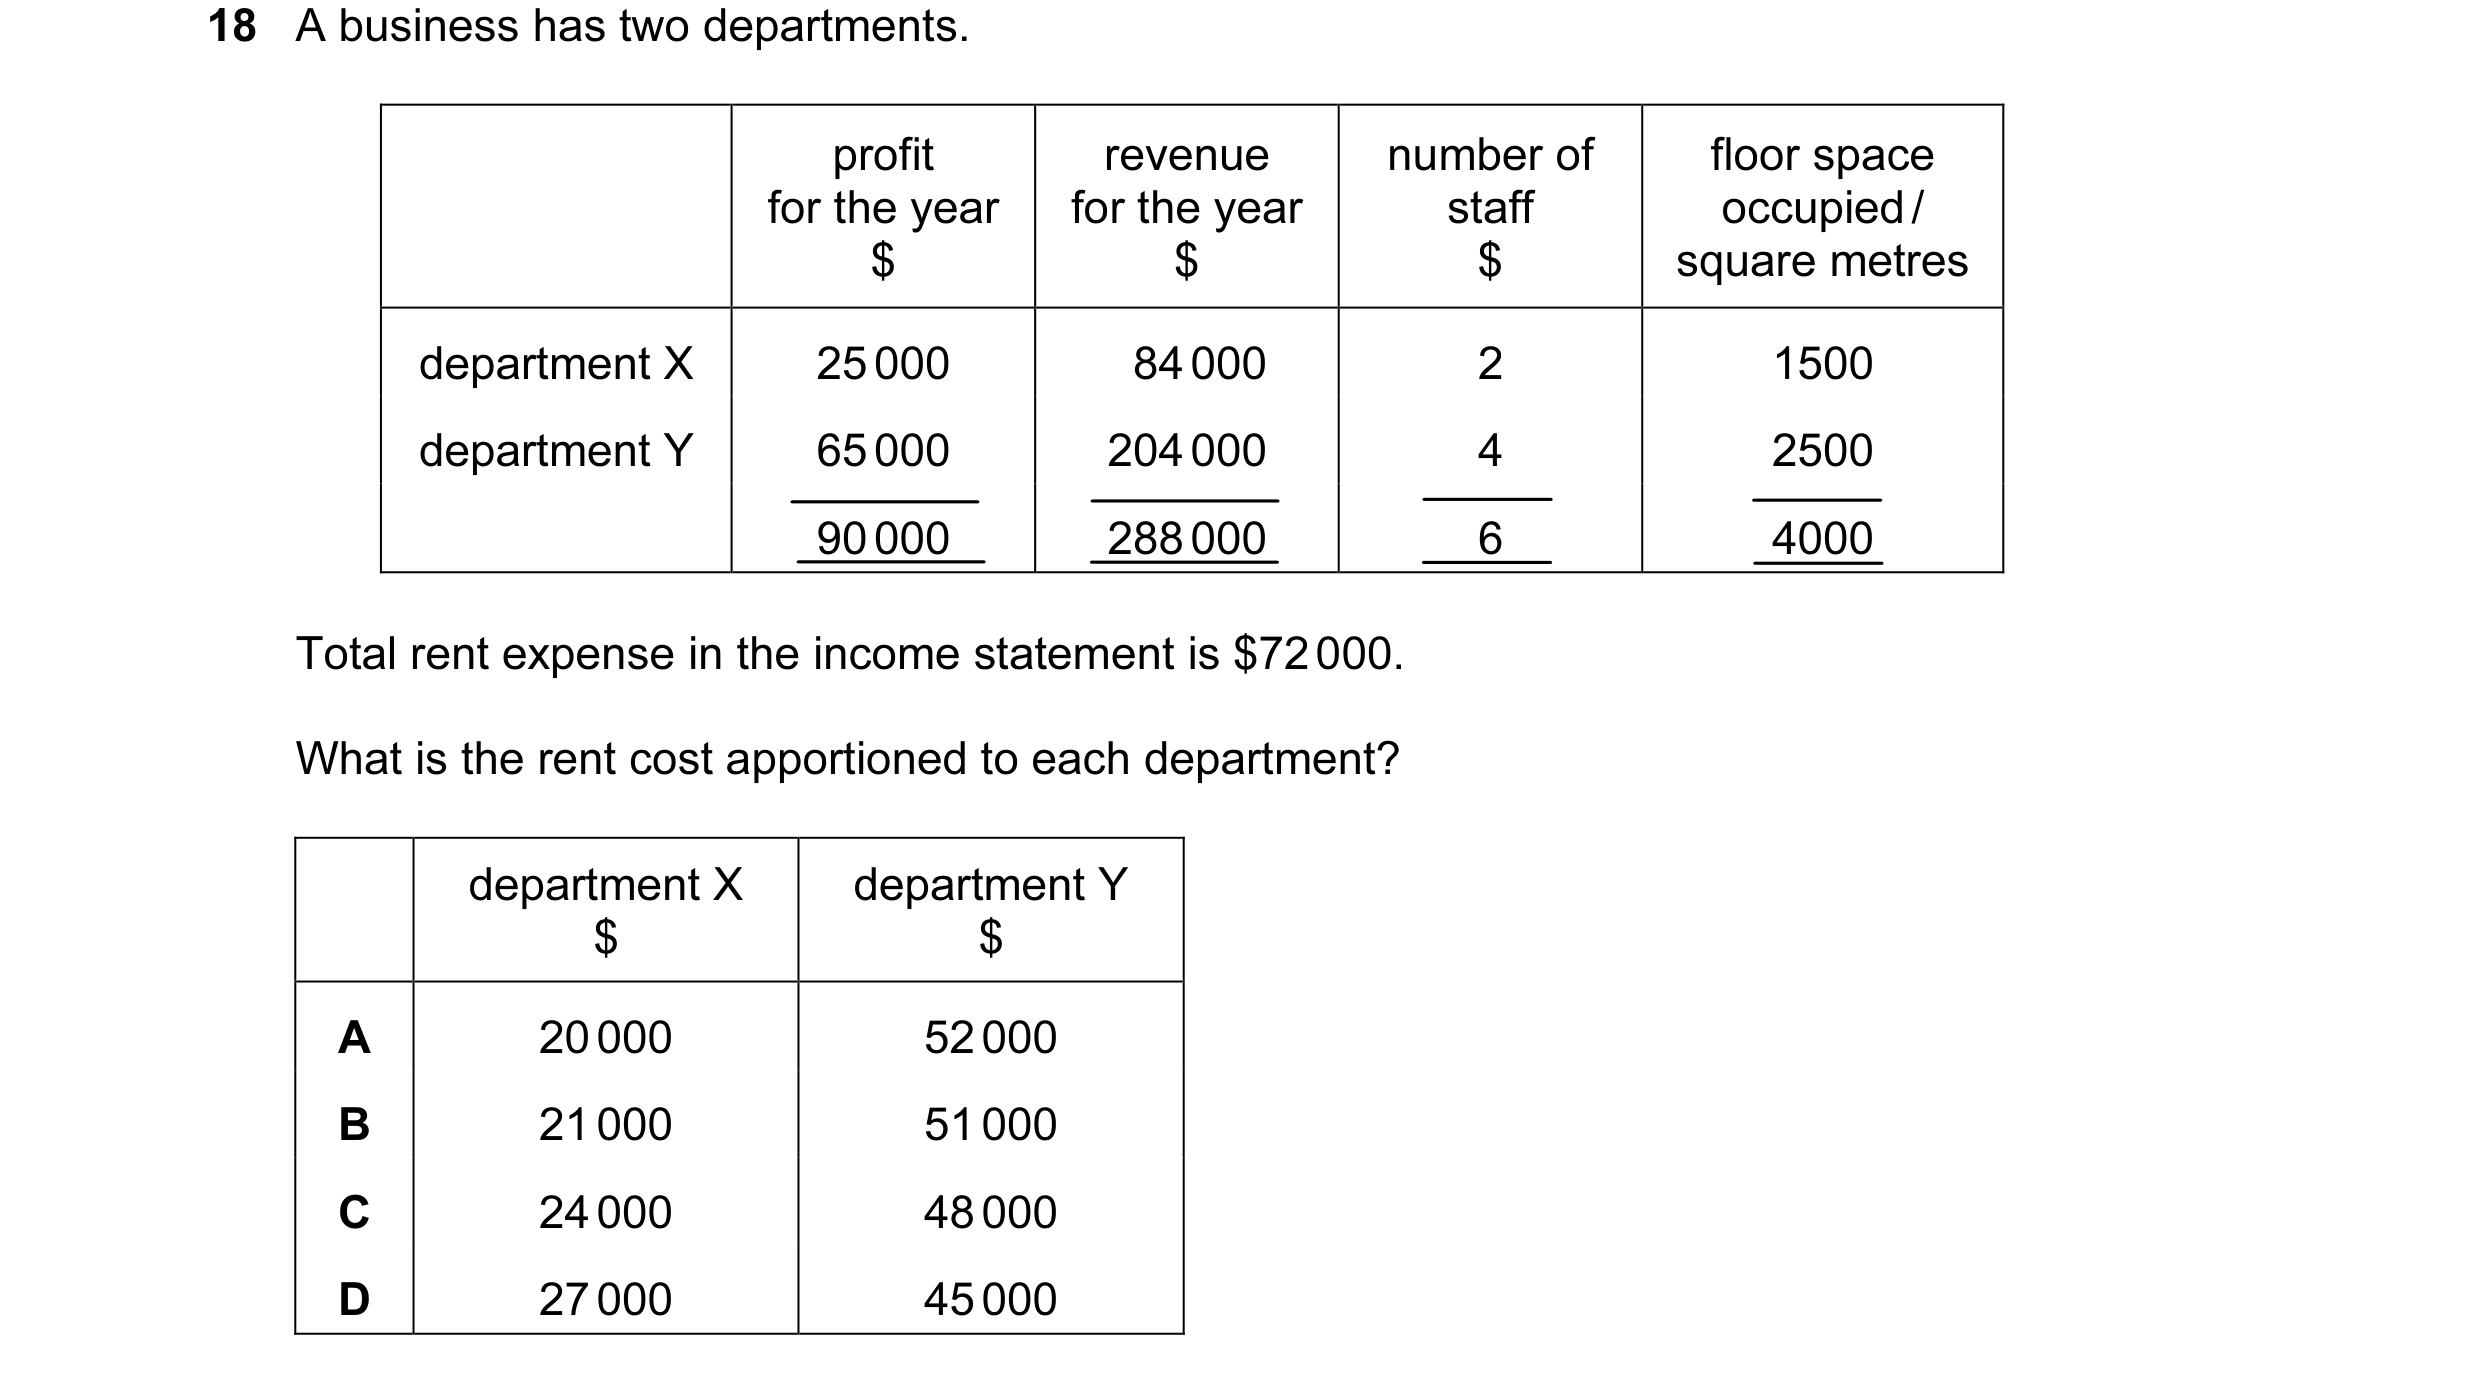
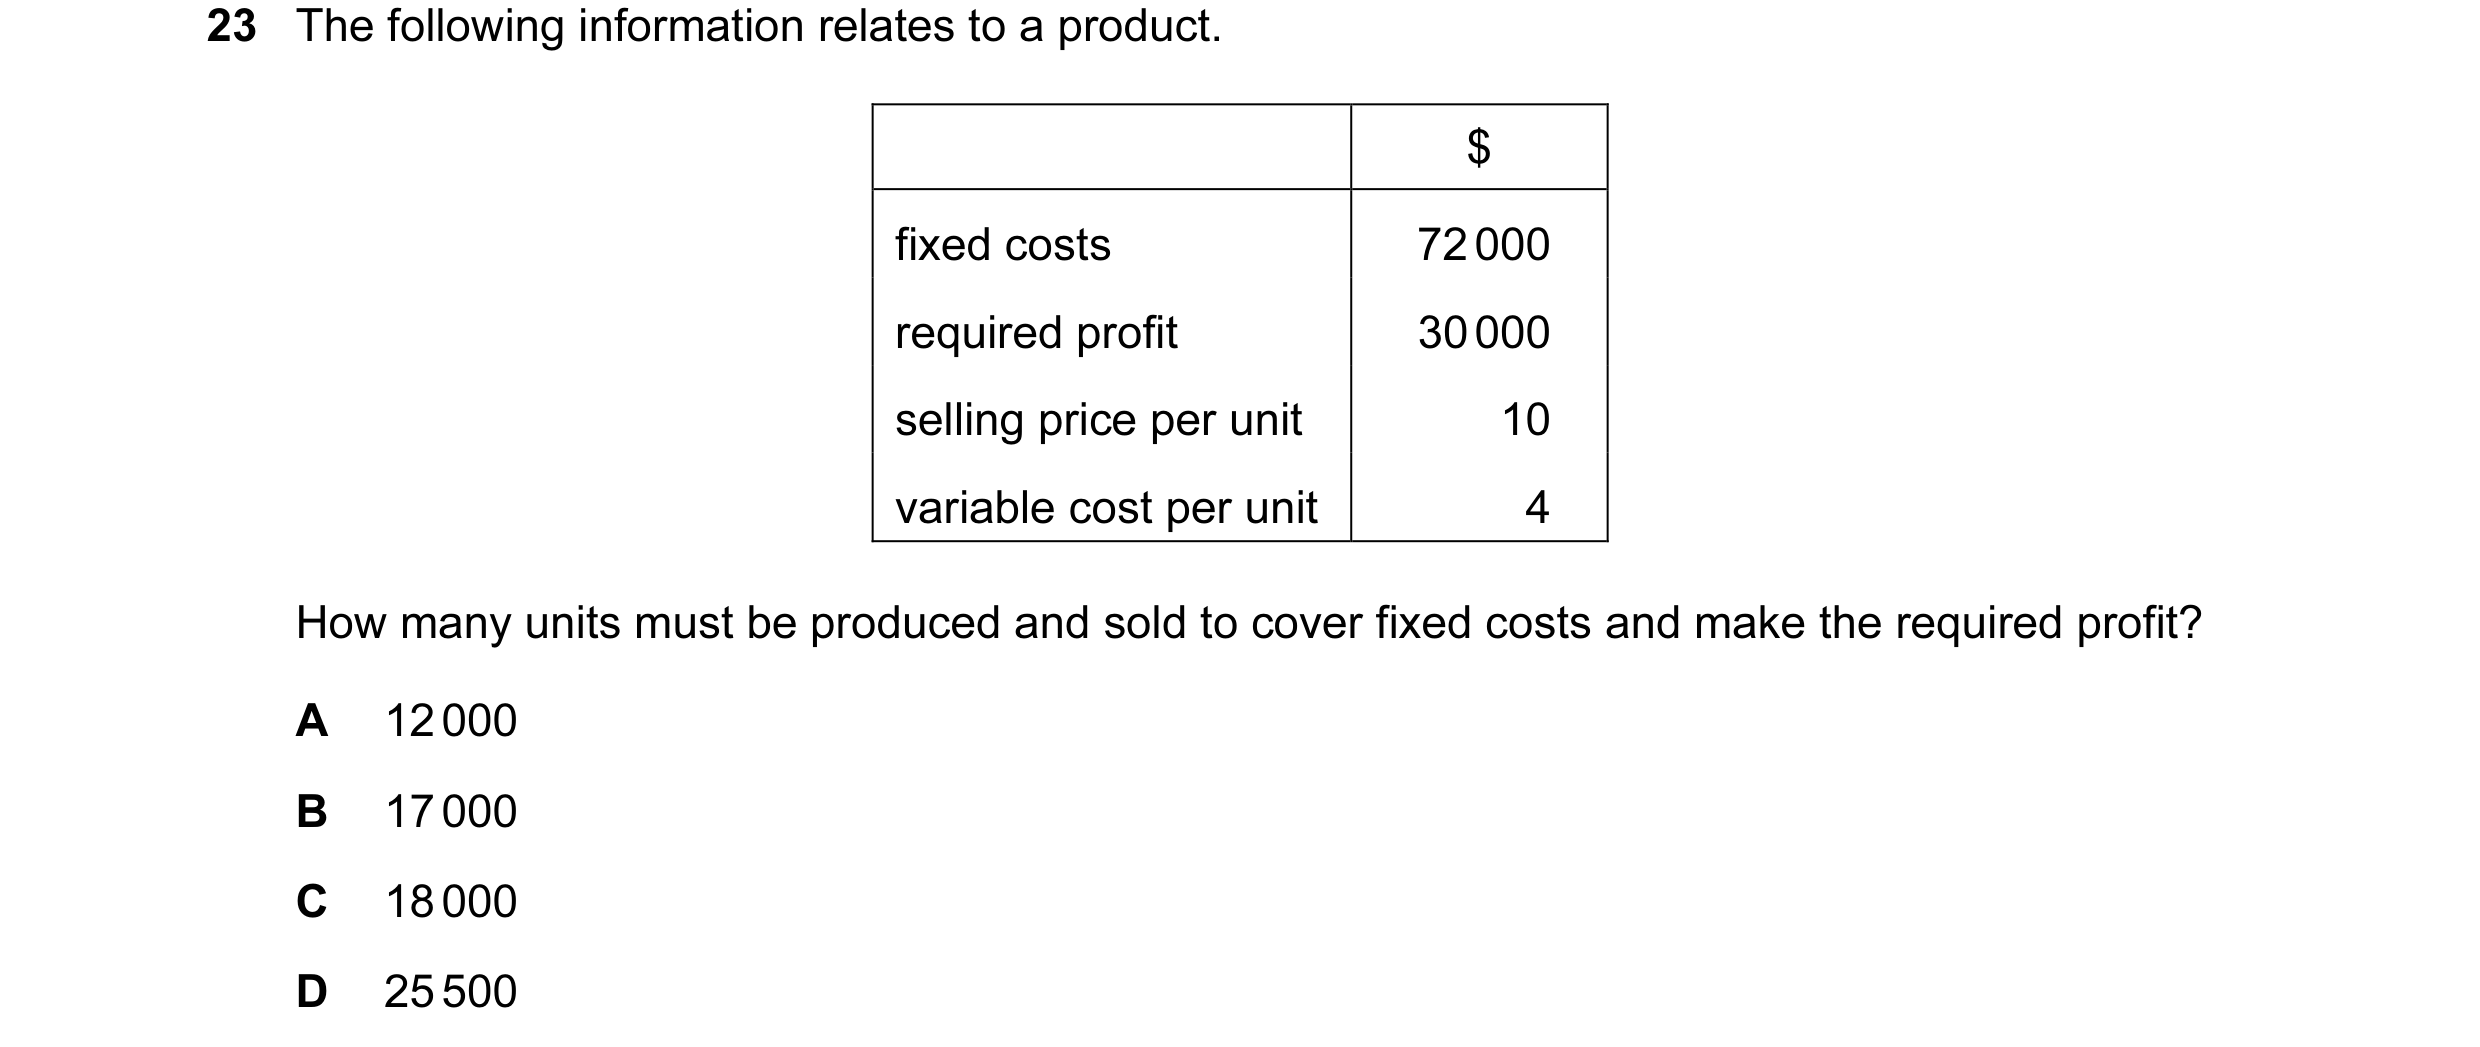 54 / 143
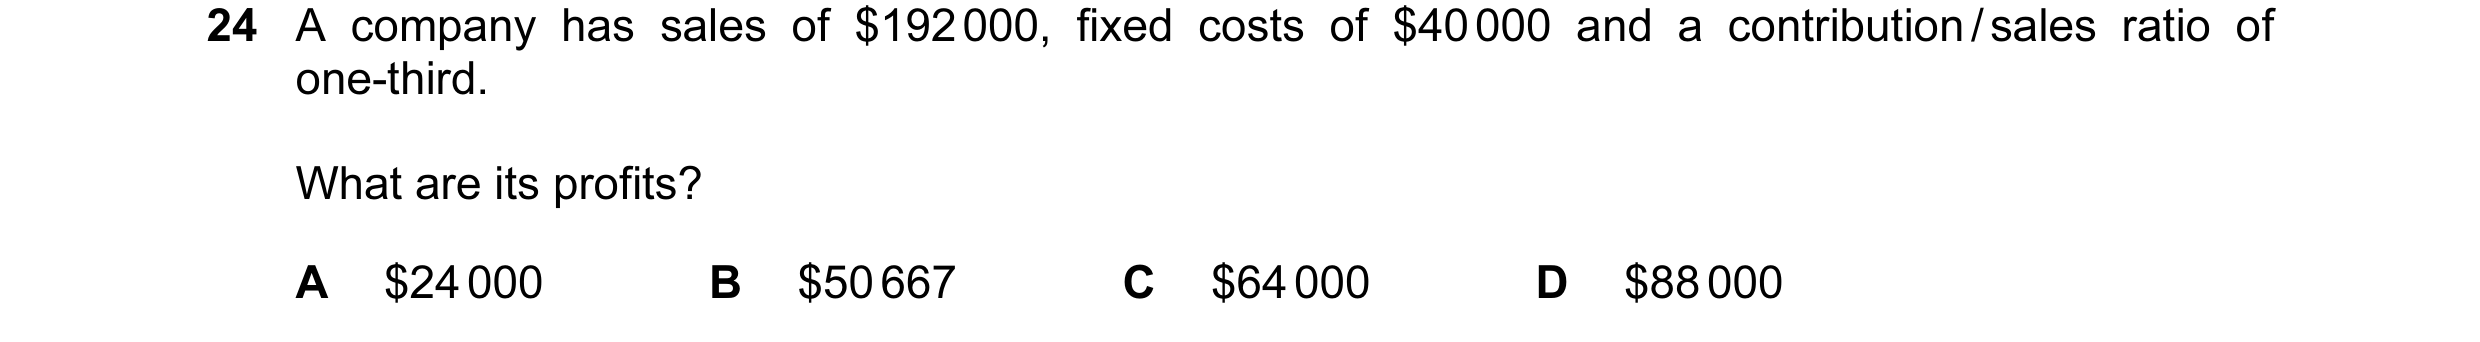
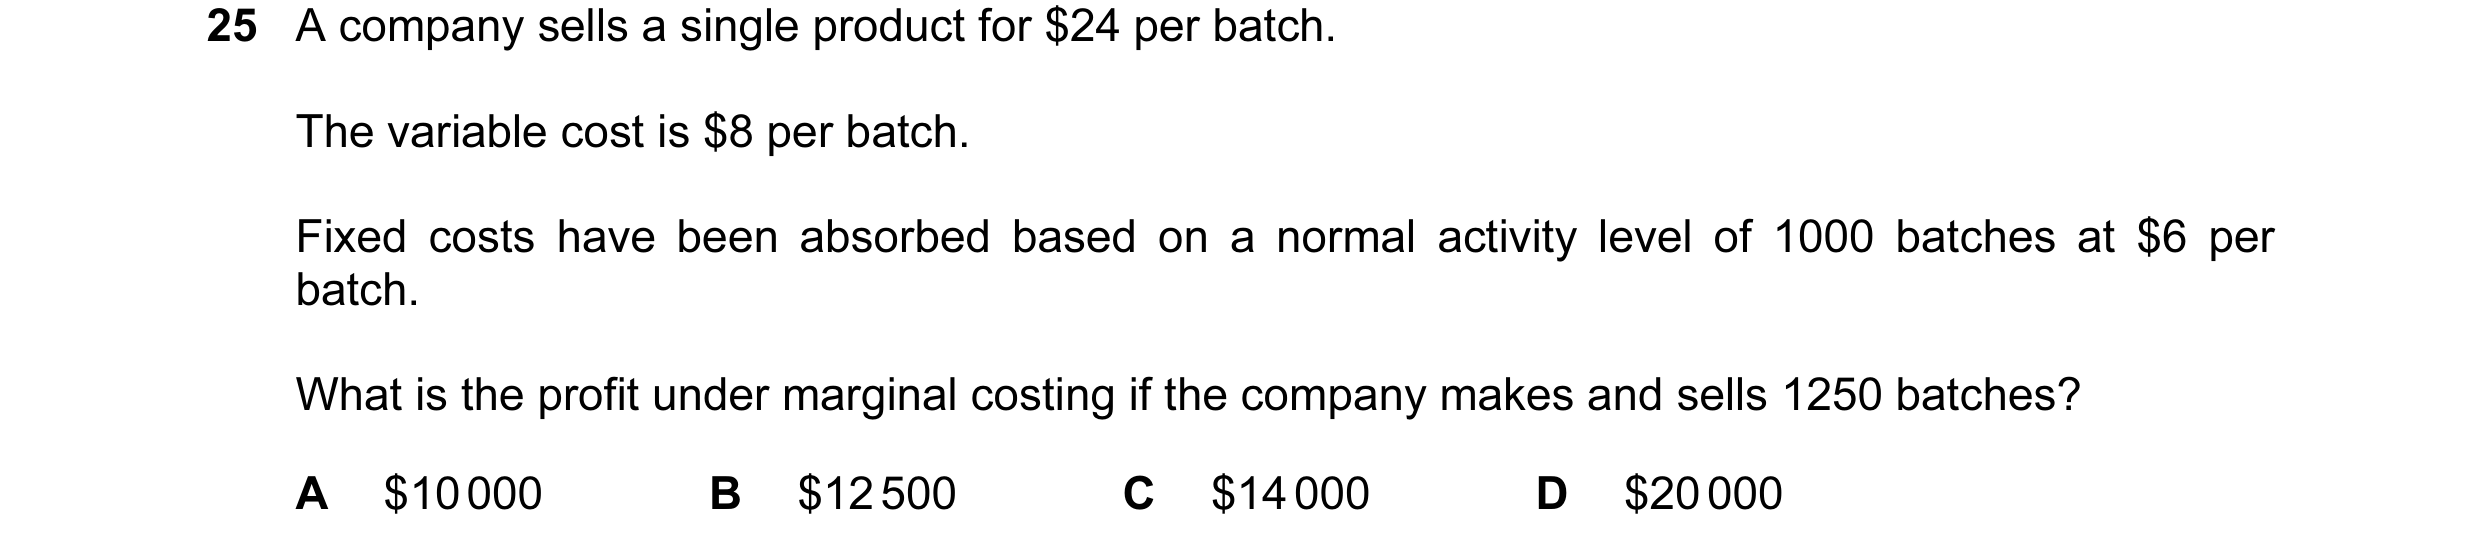
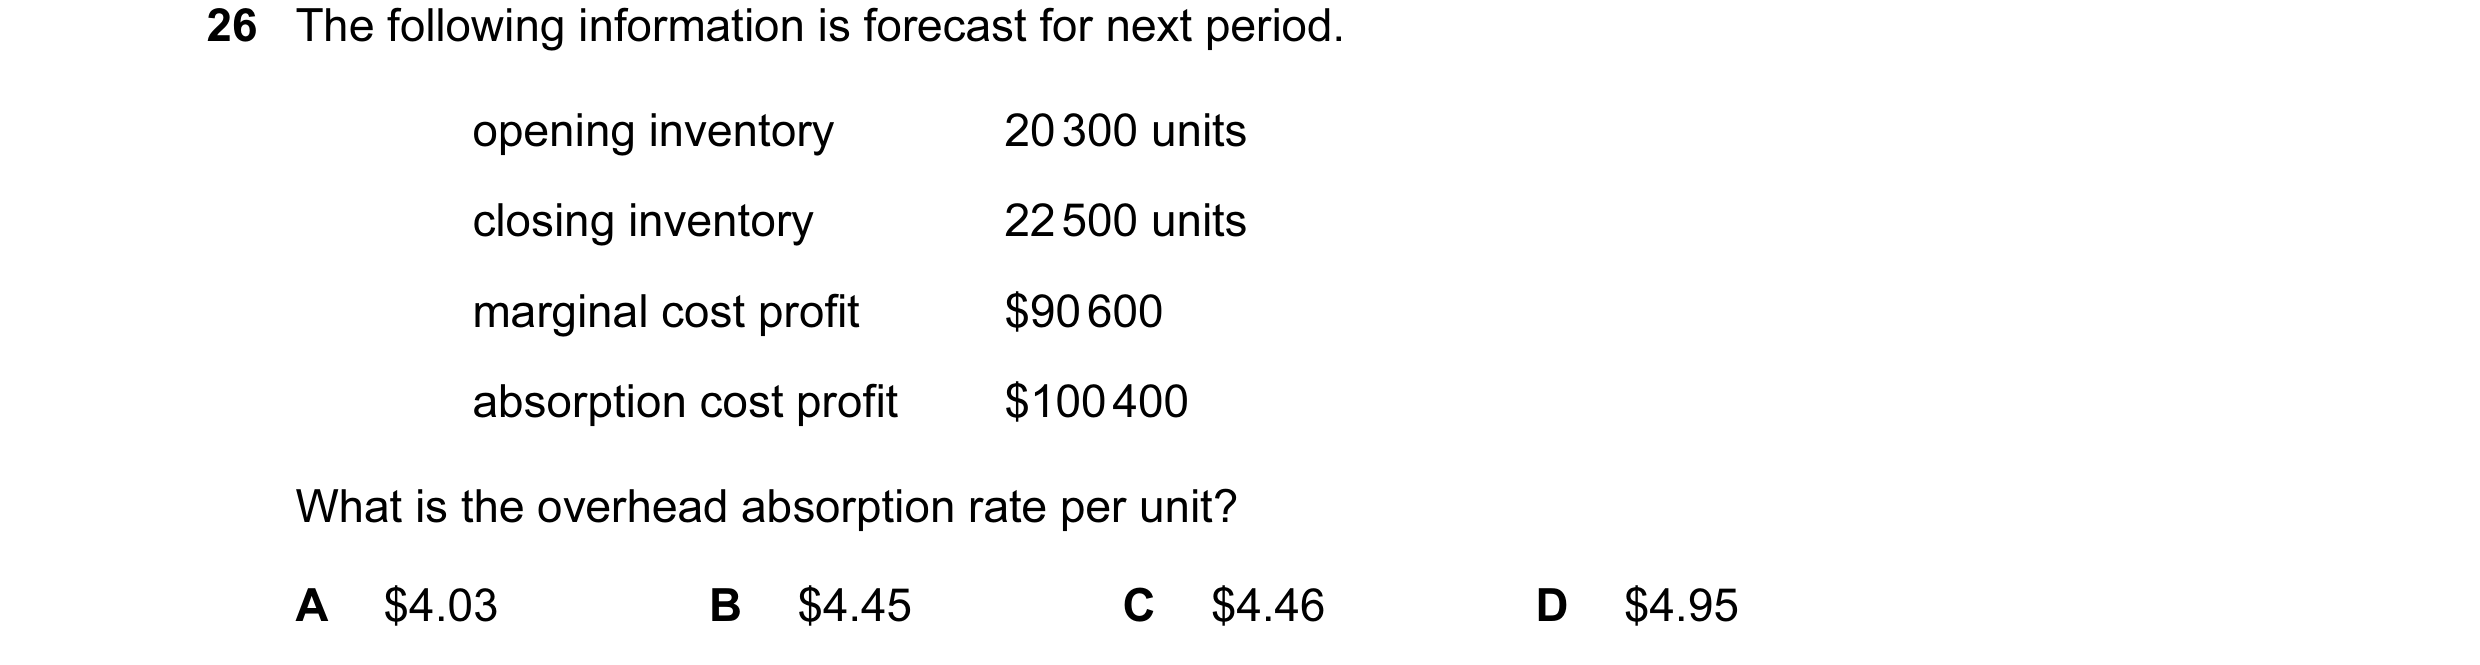
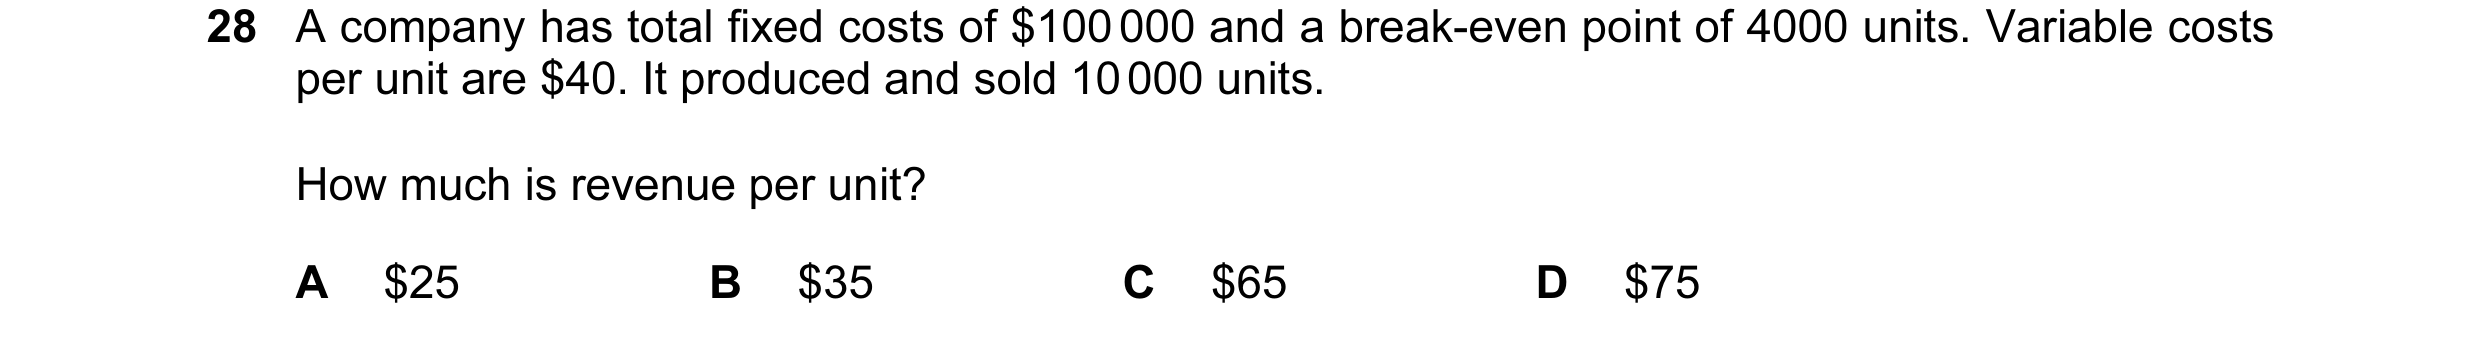
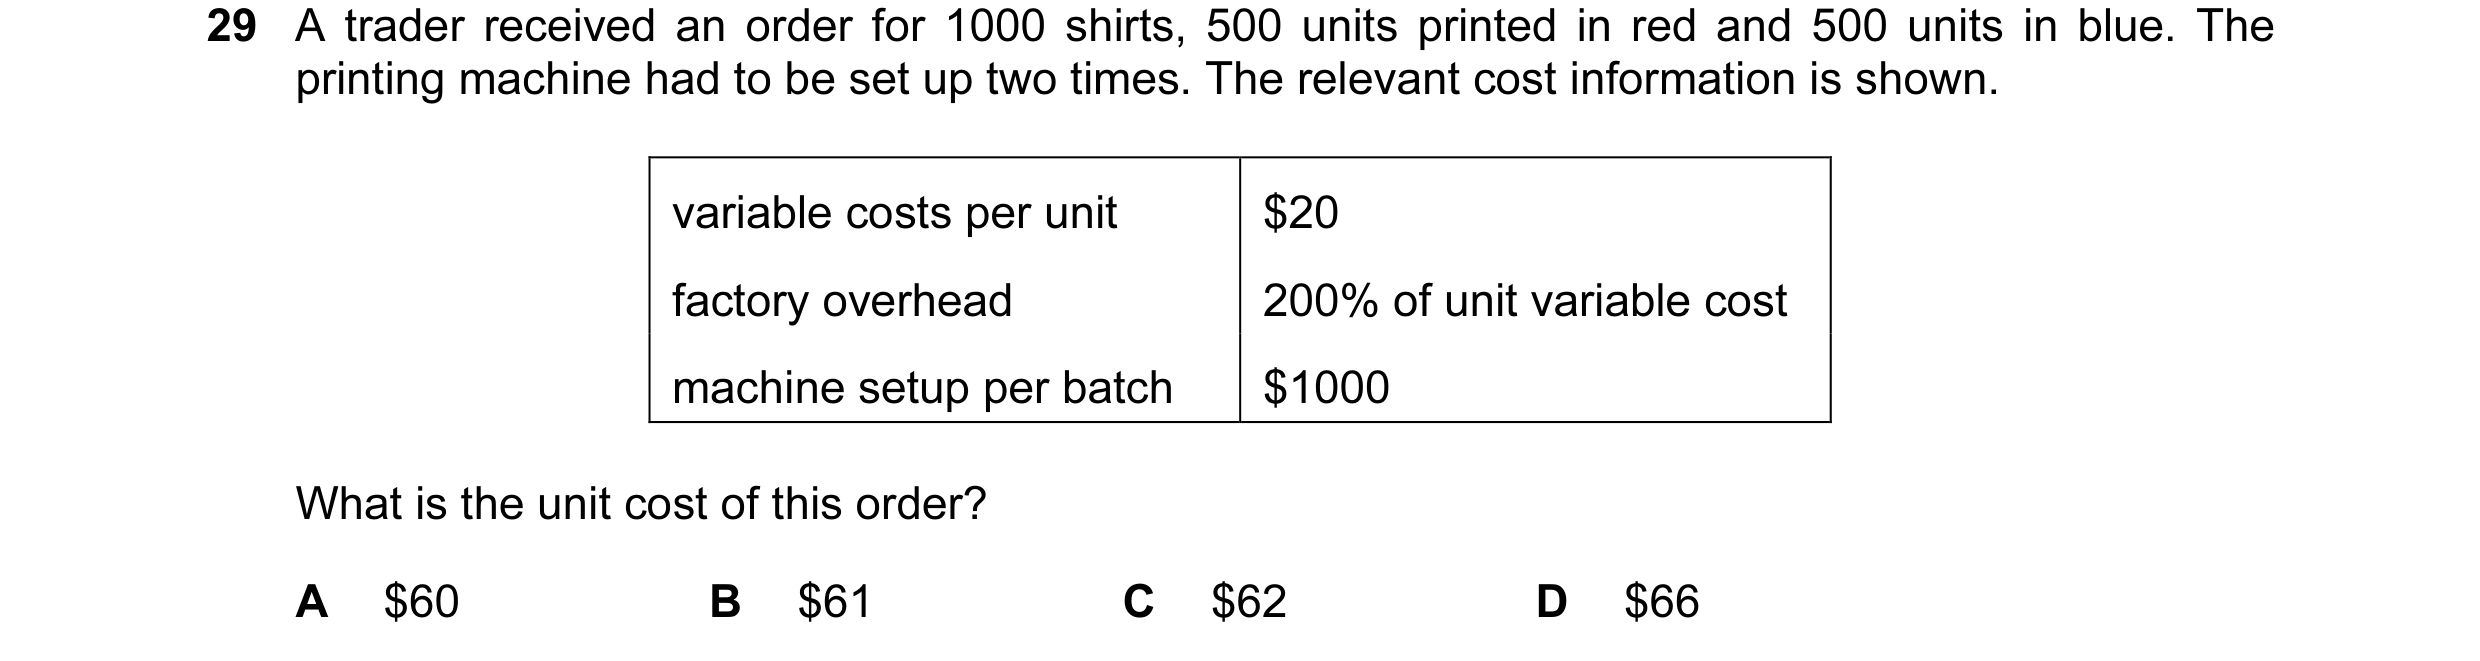 55 / 143
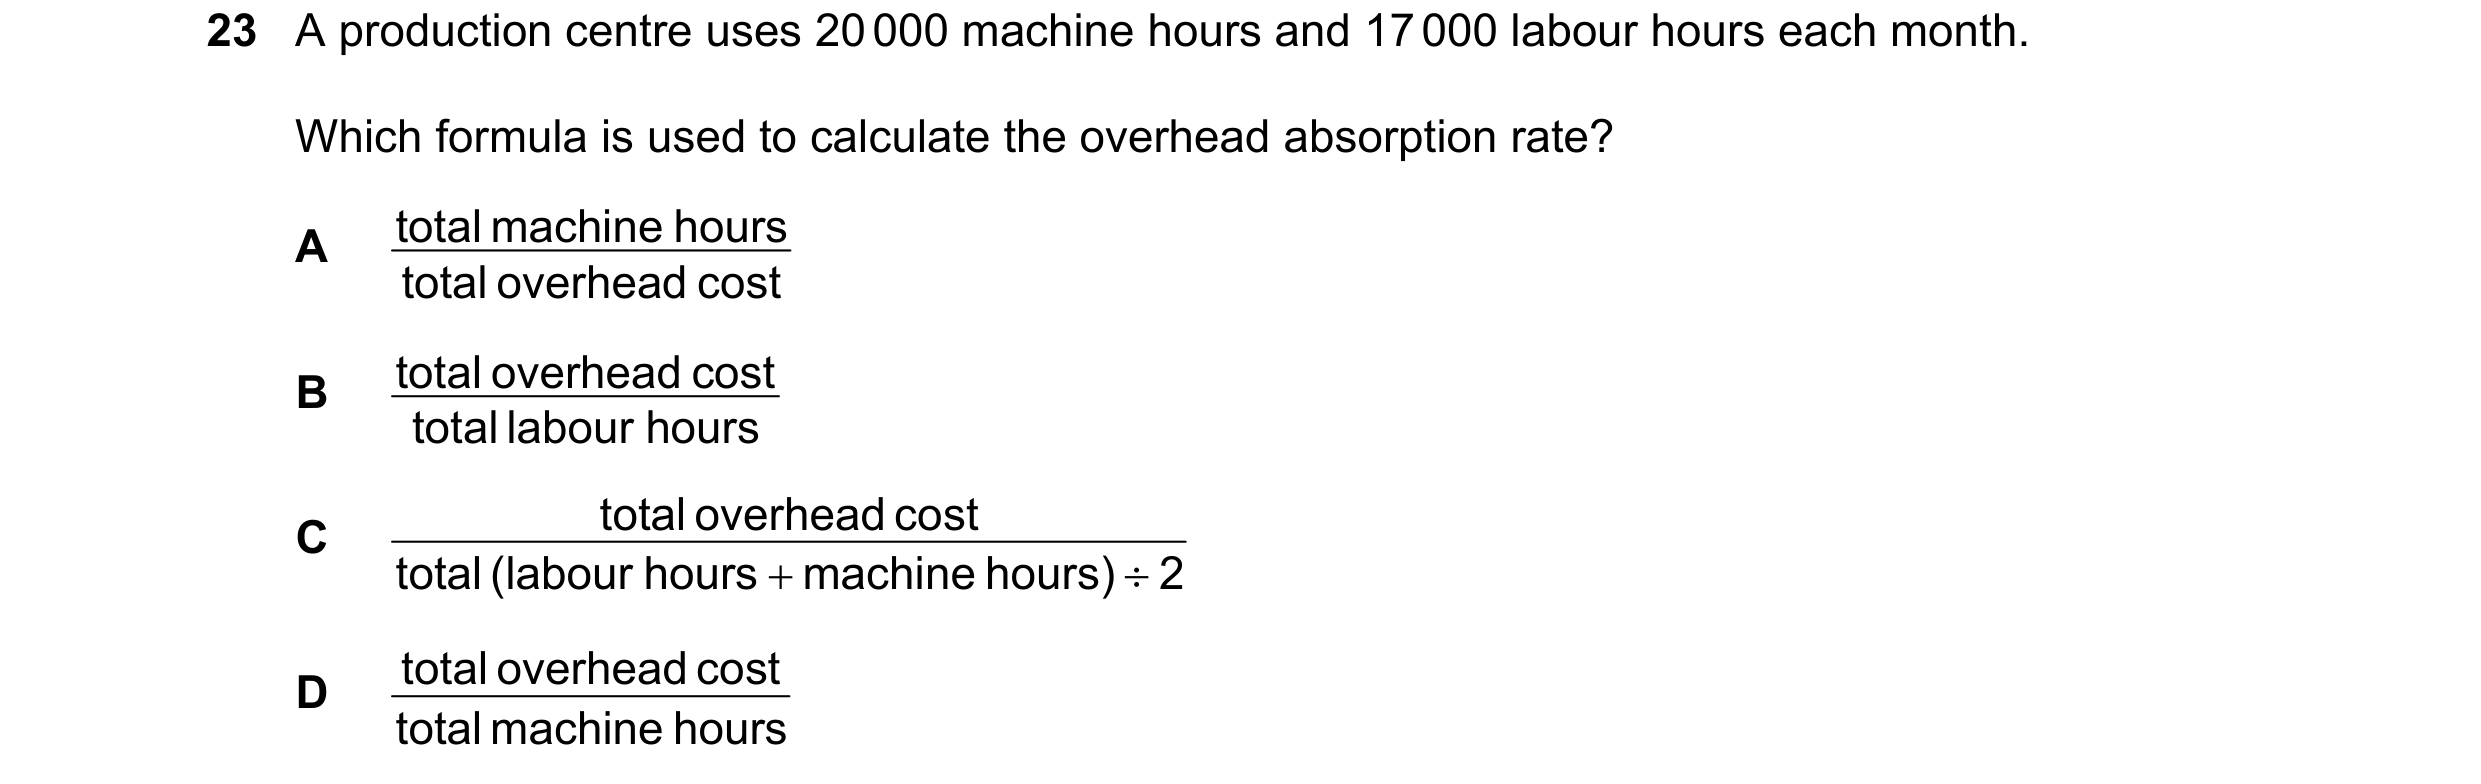
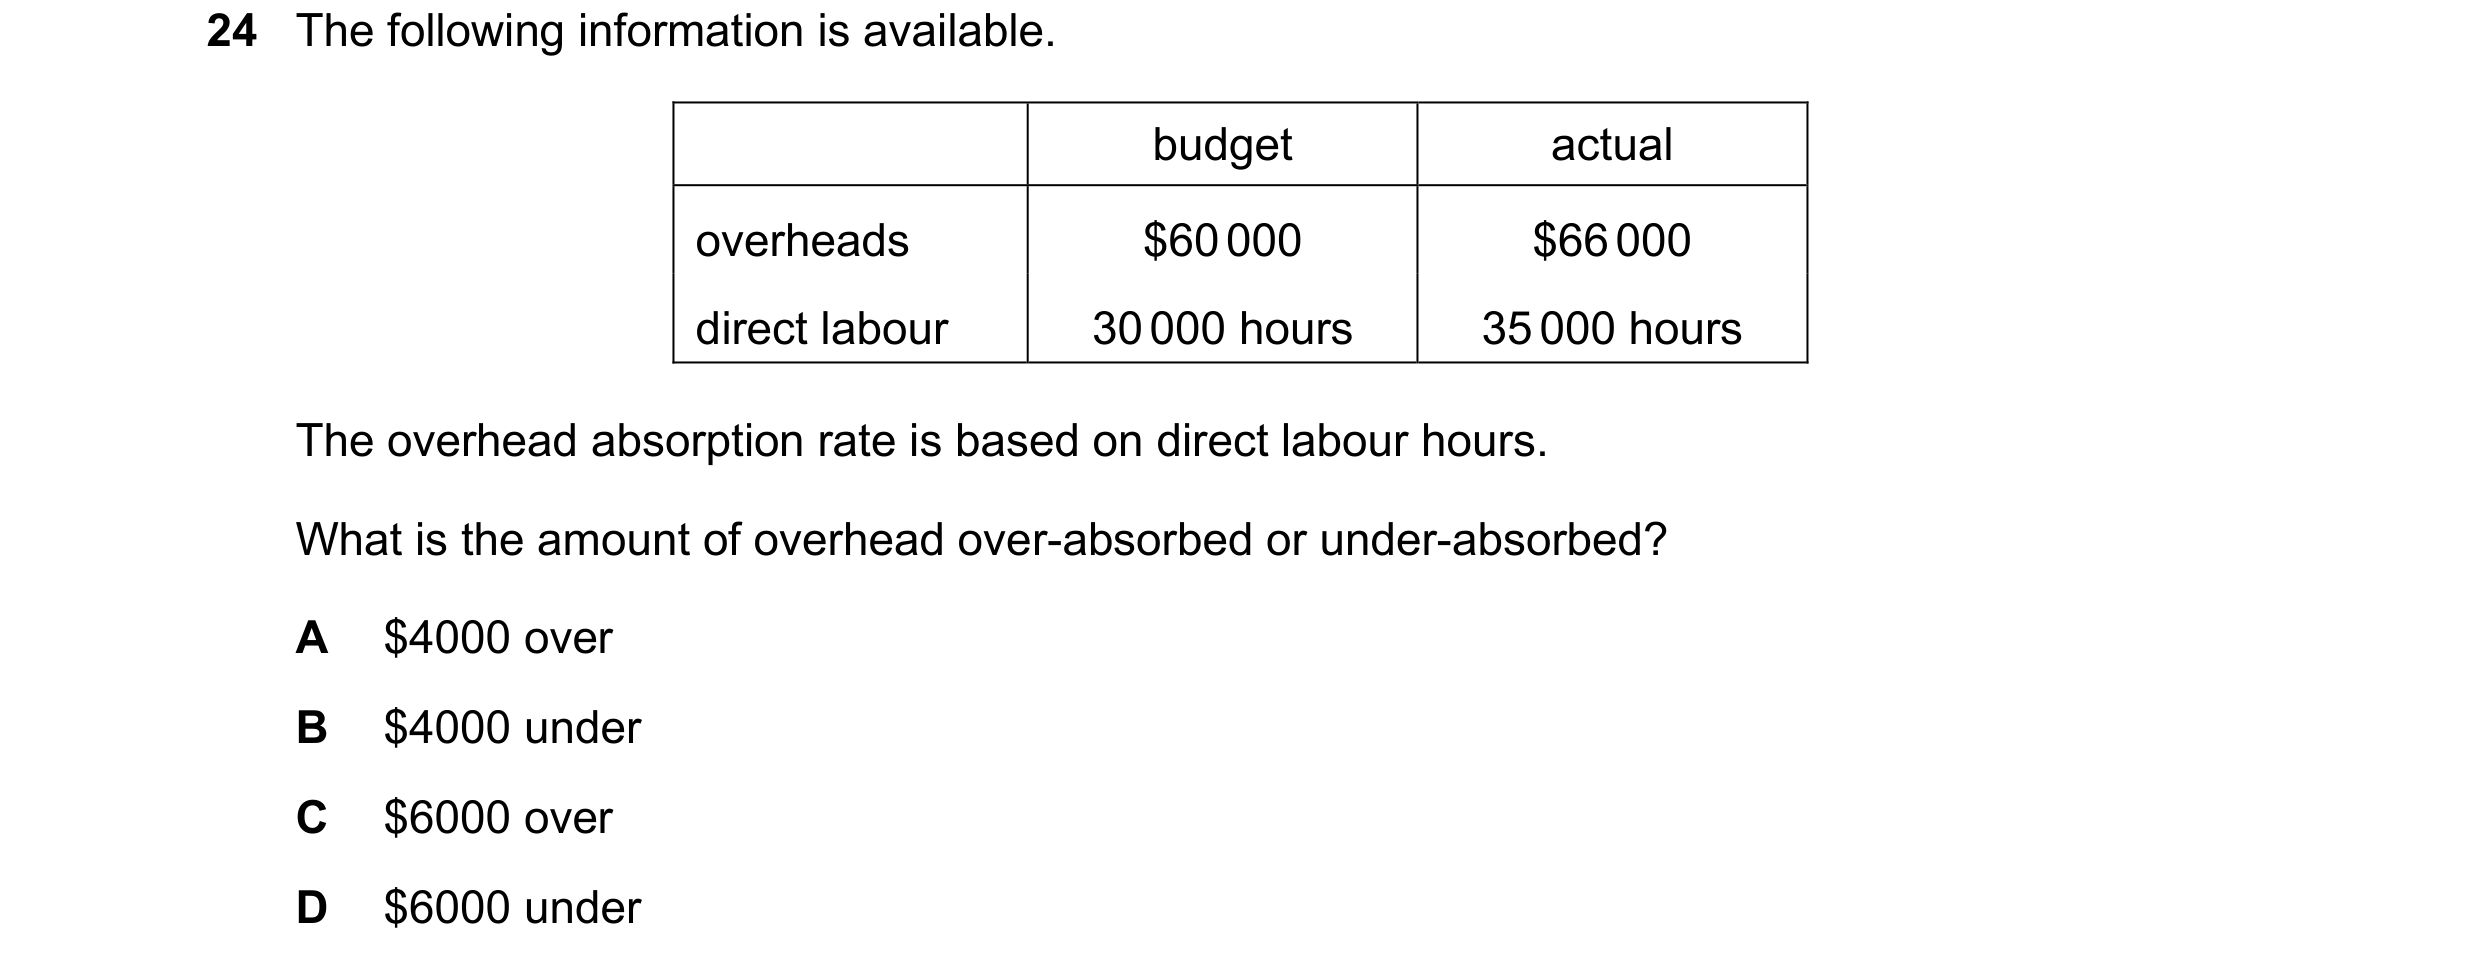
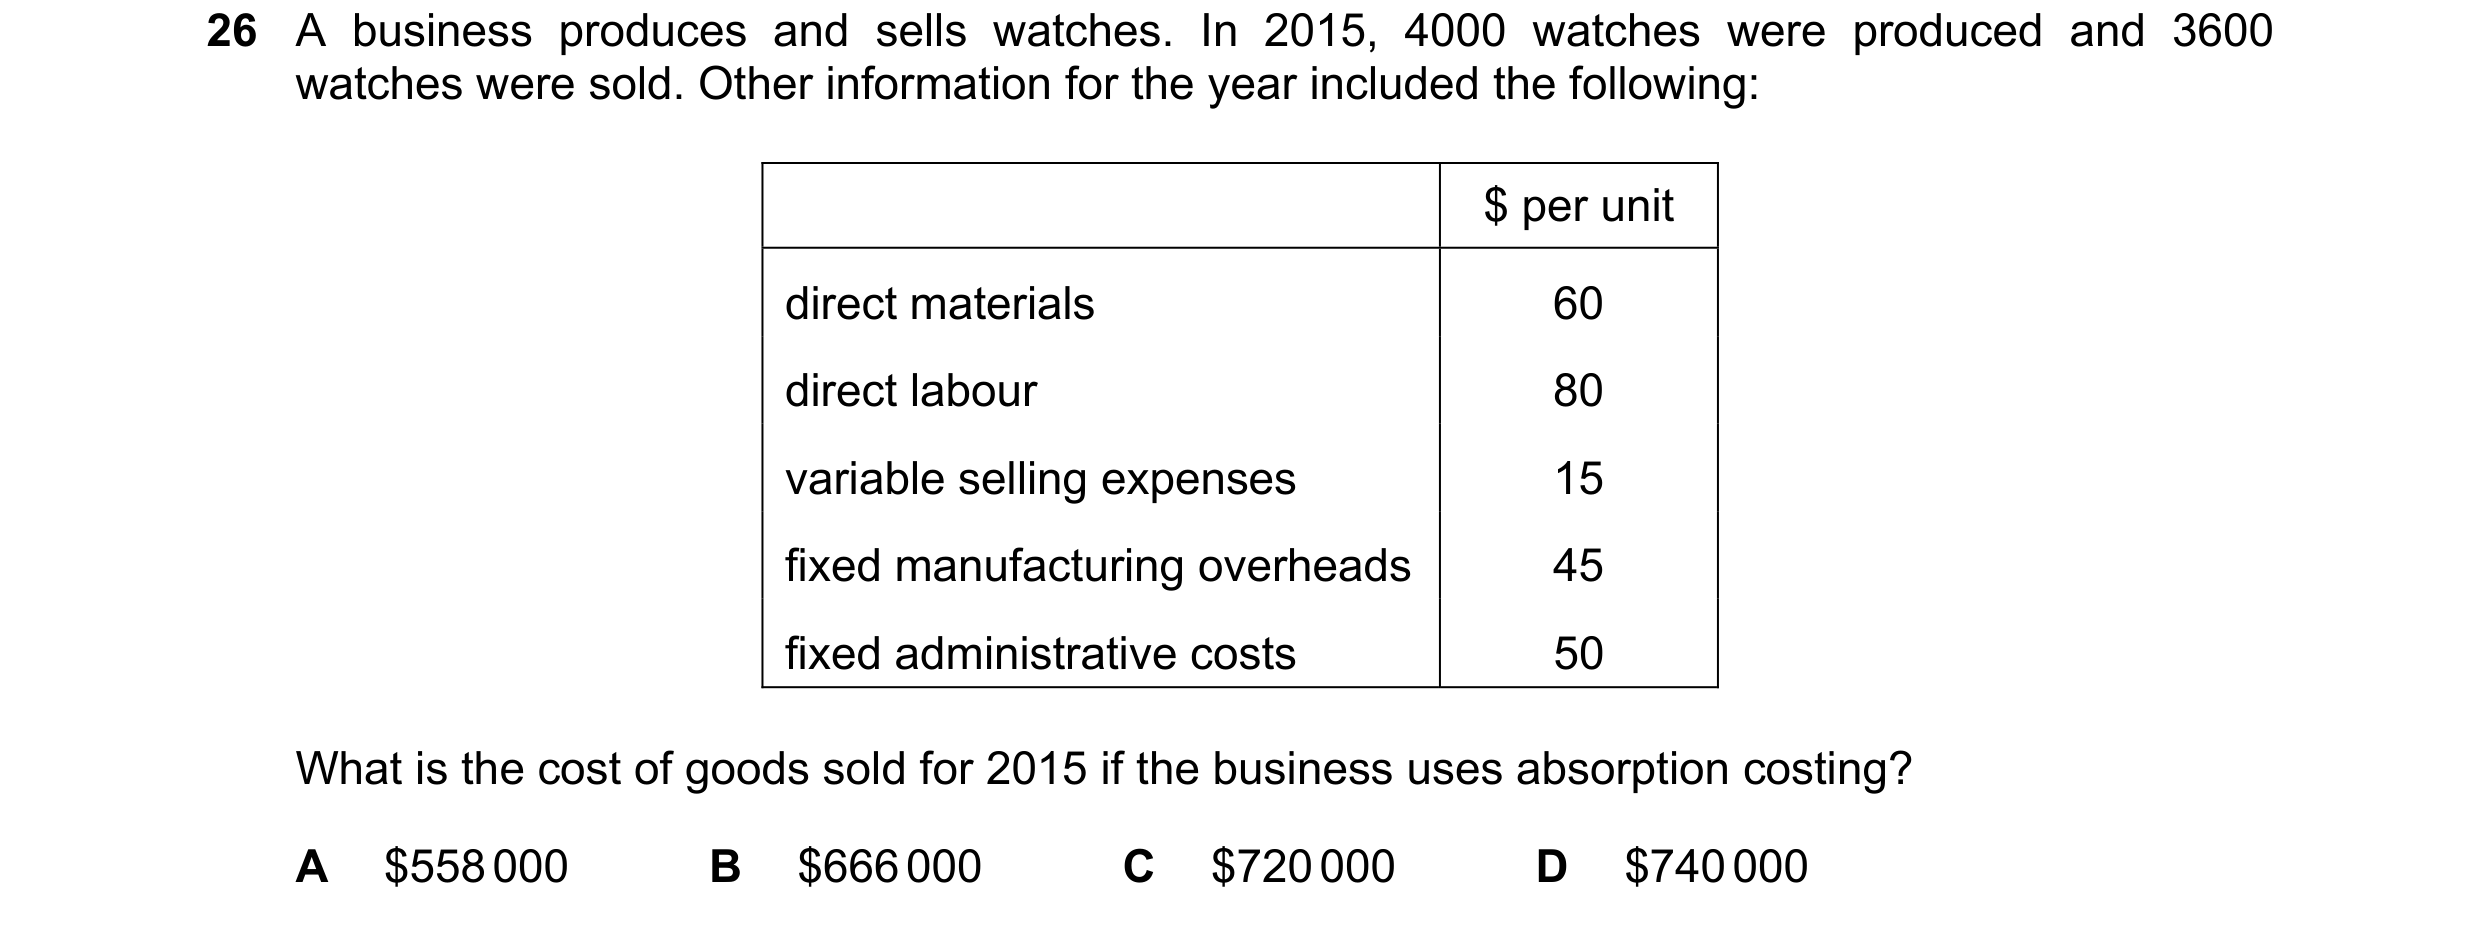
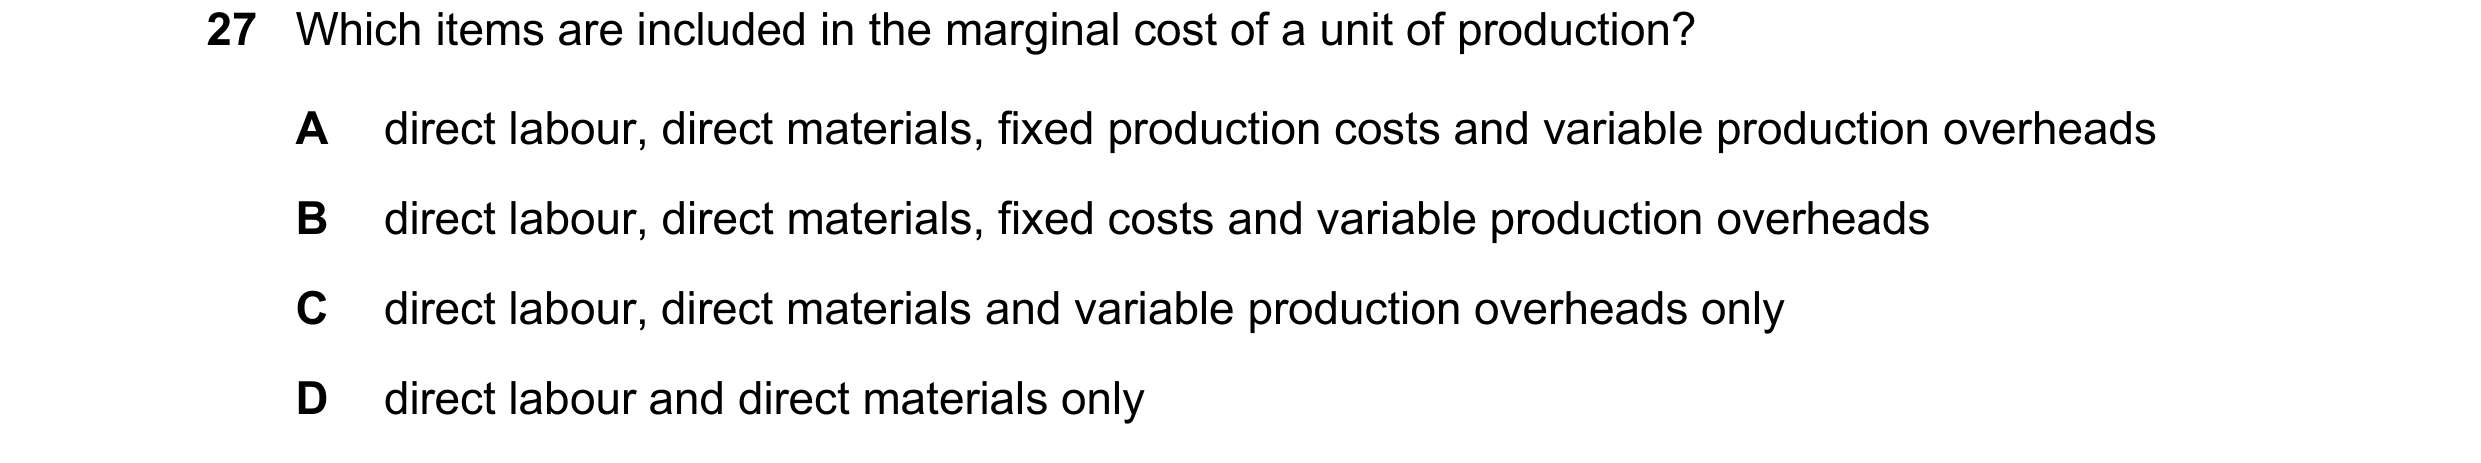 56 / 143
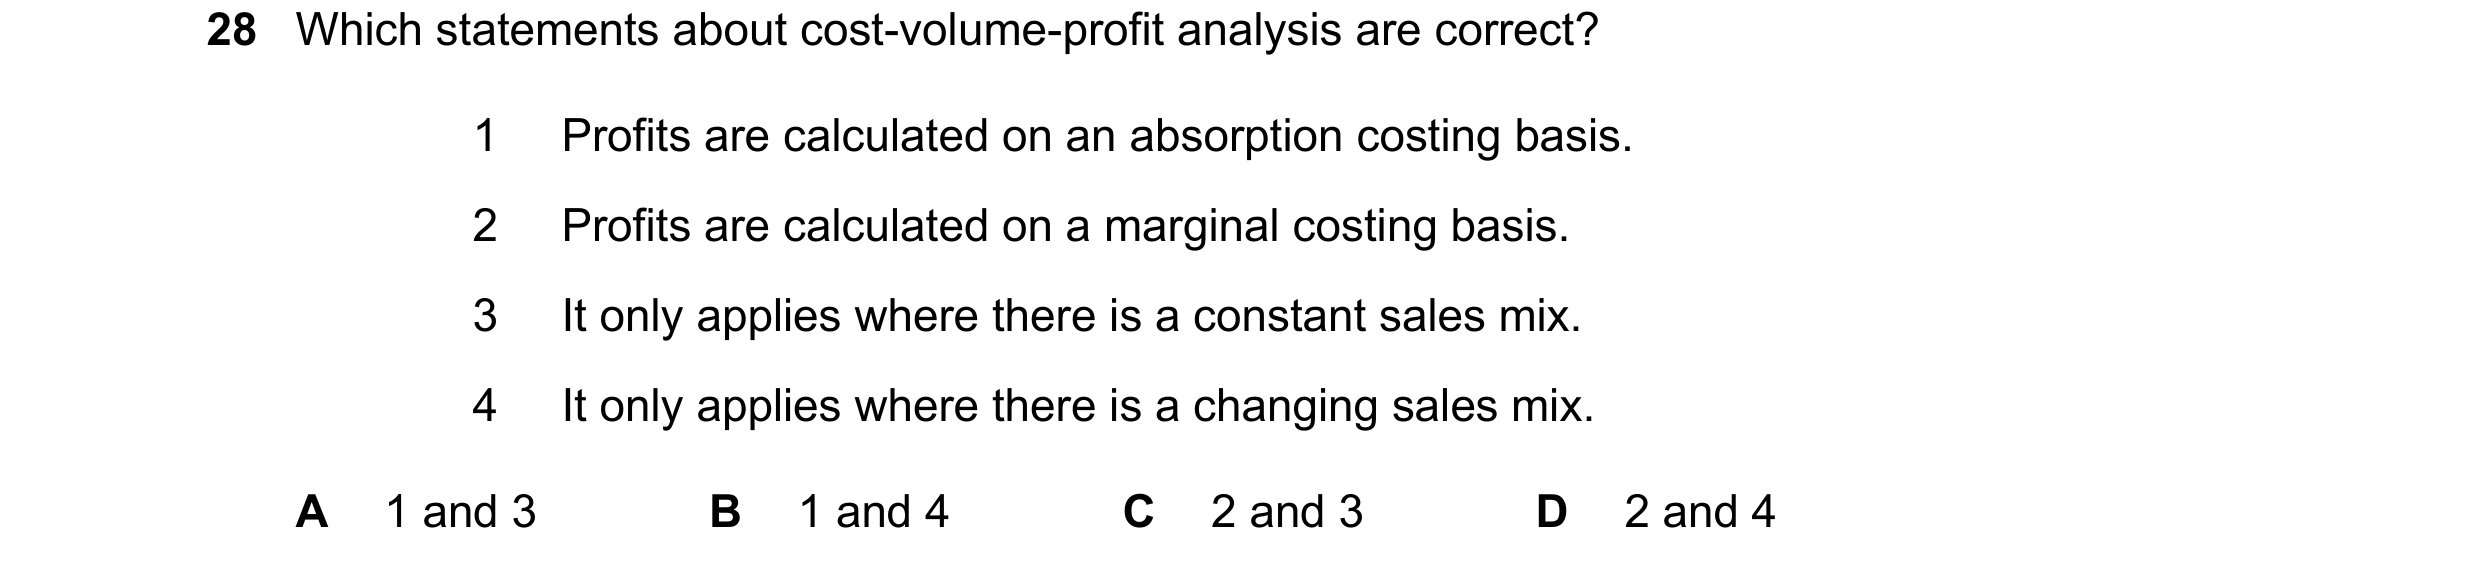
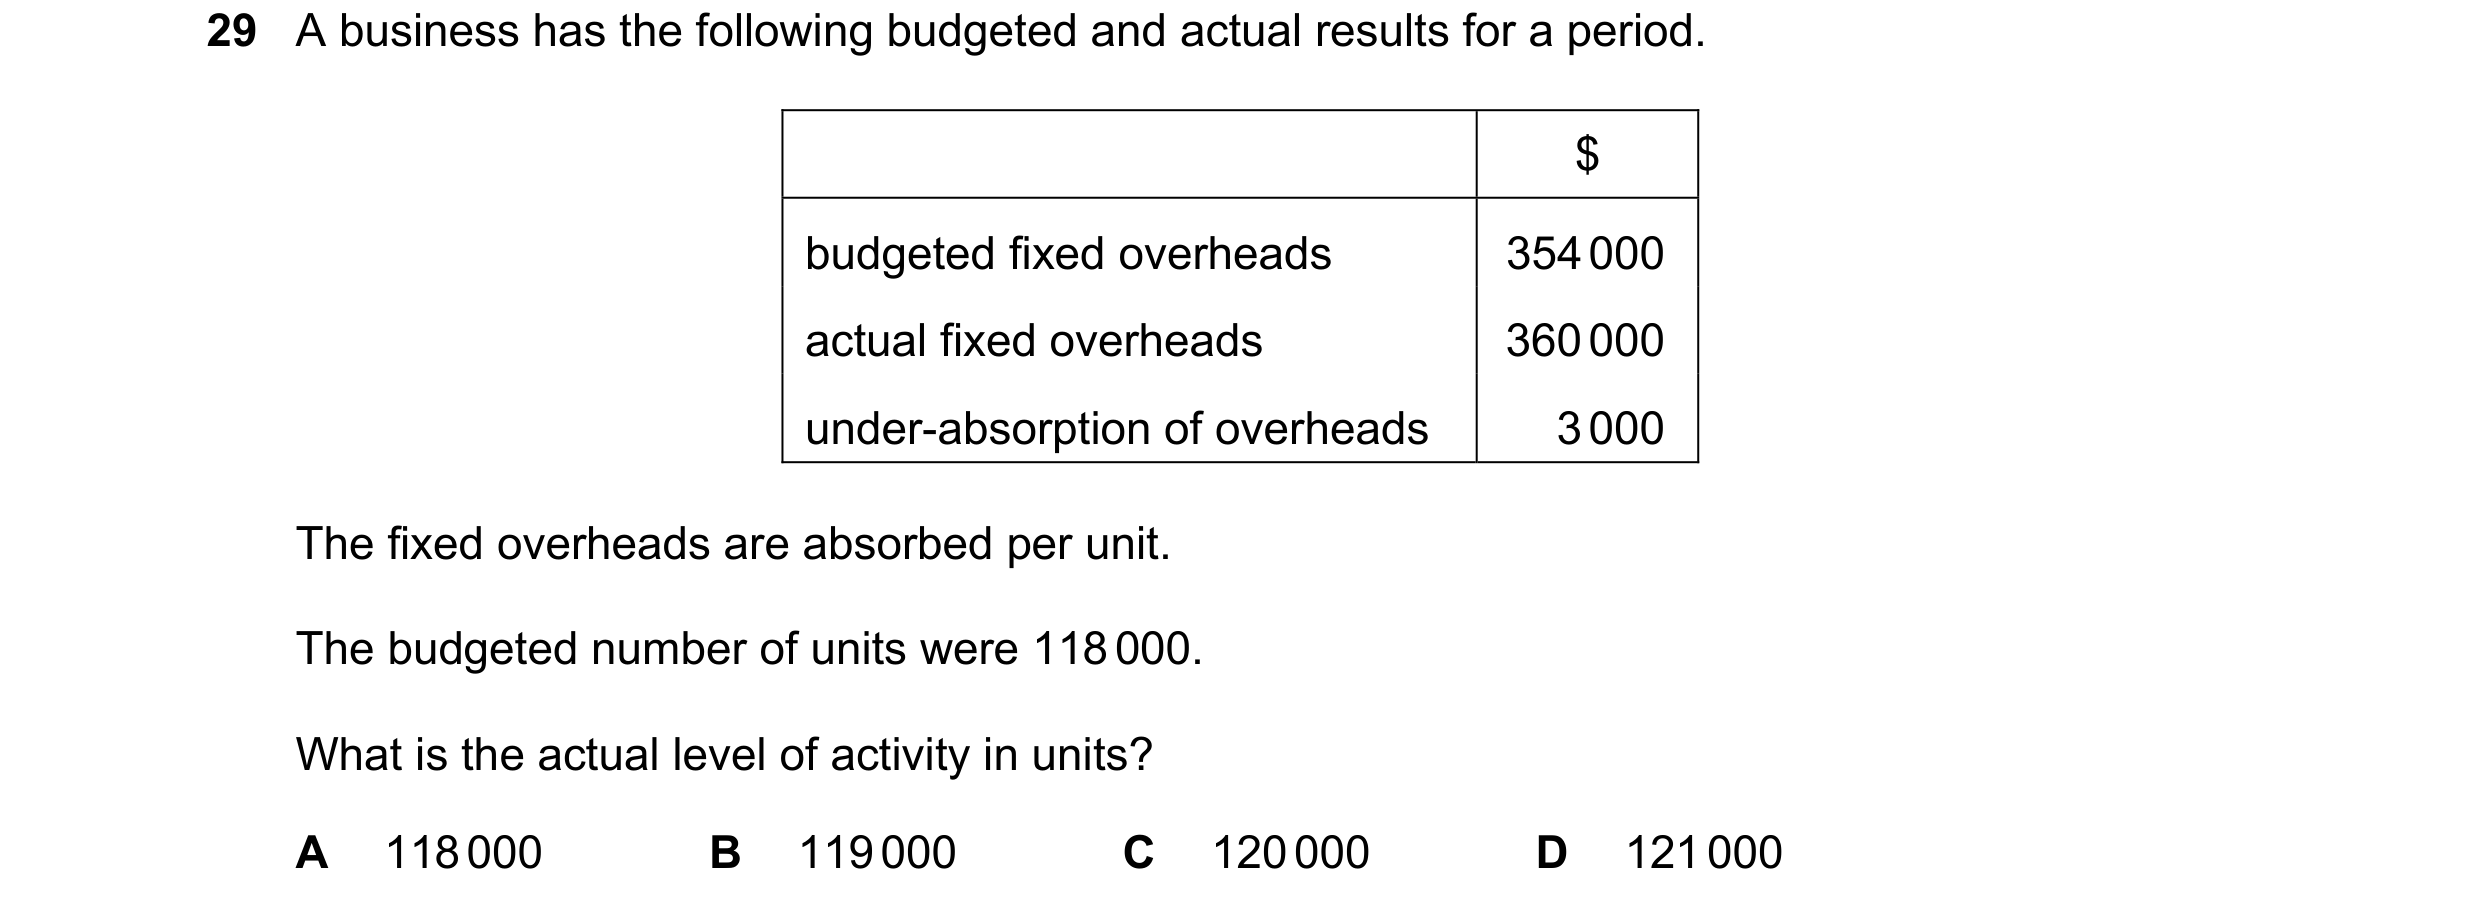
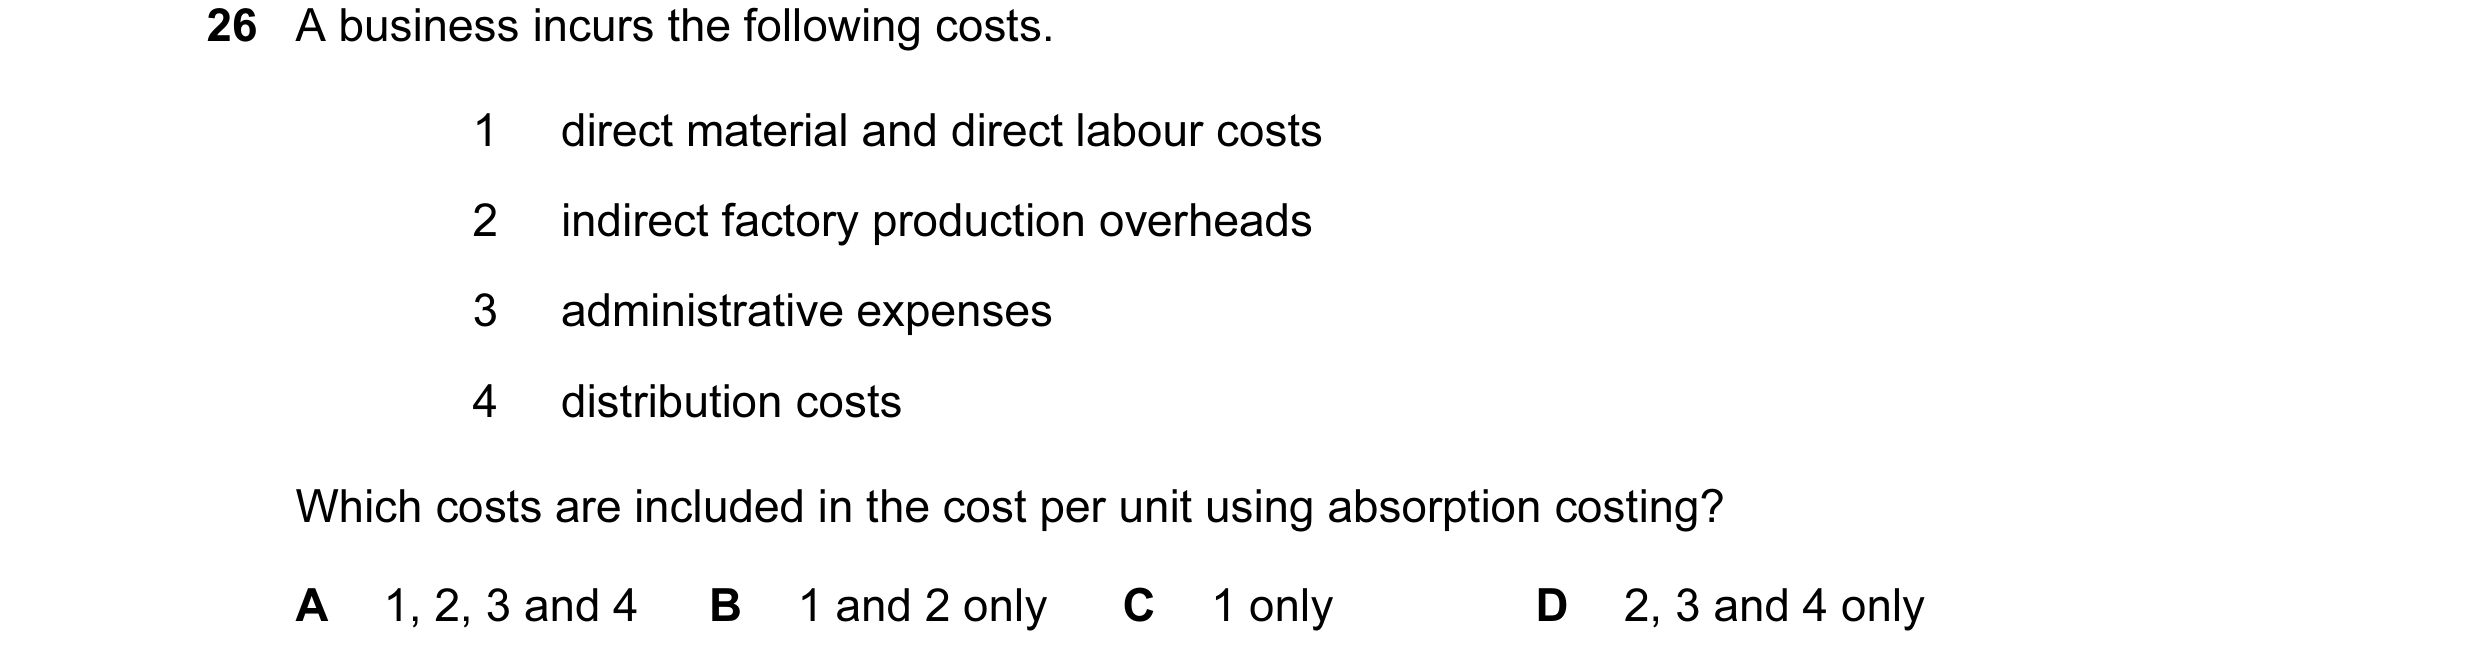
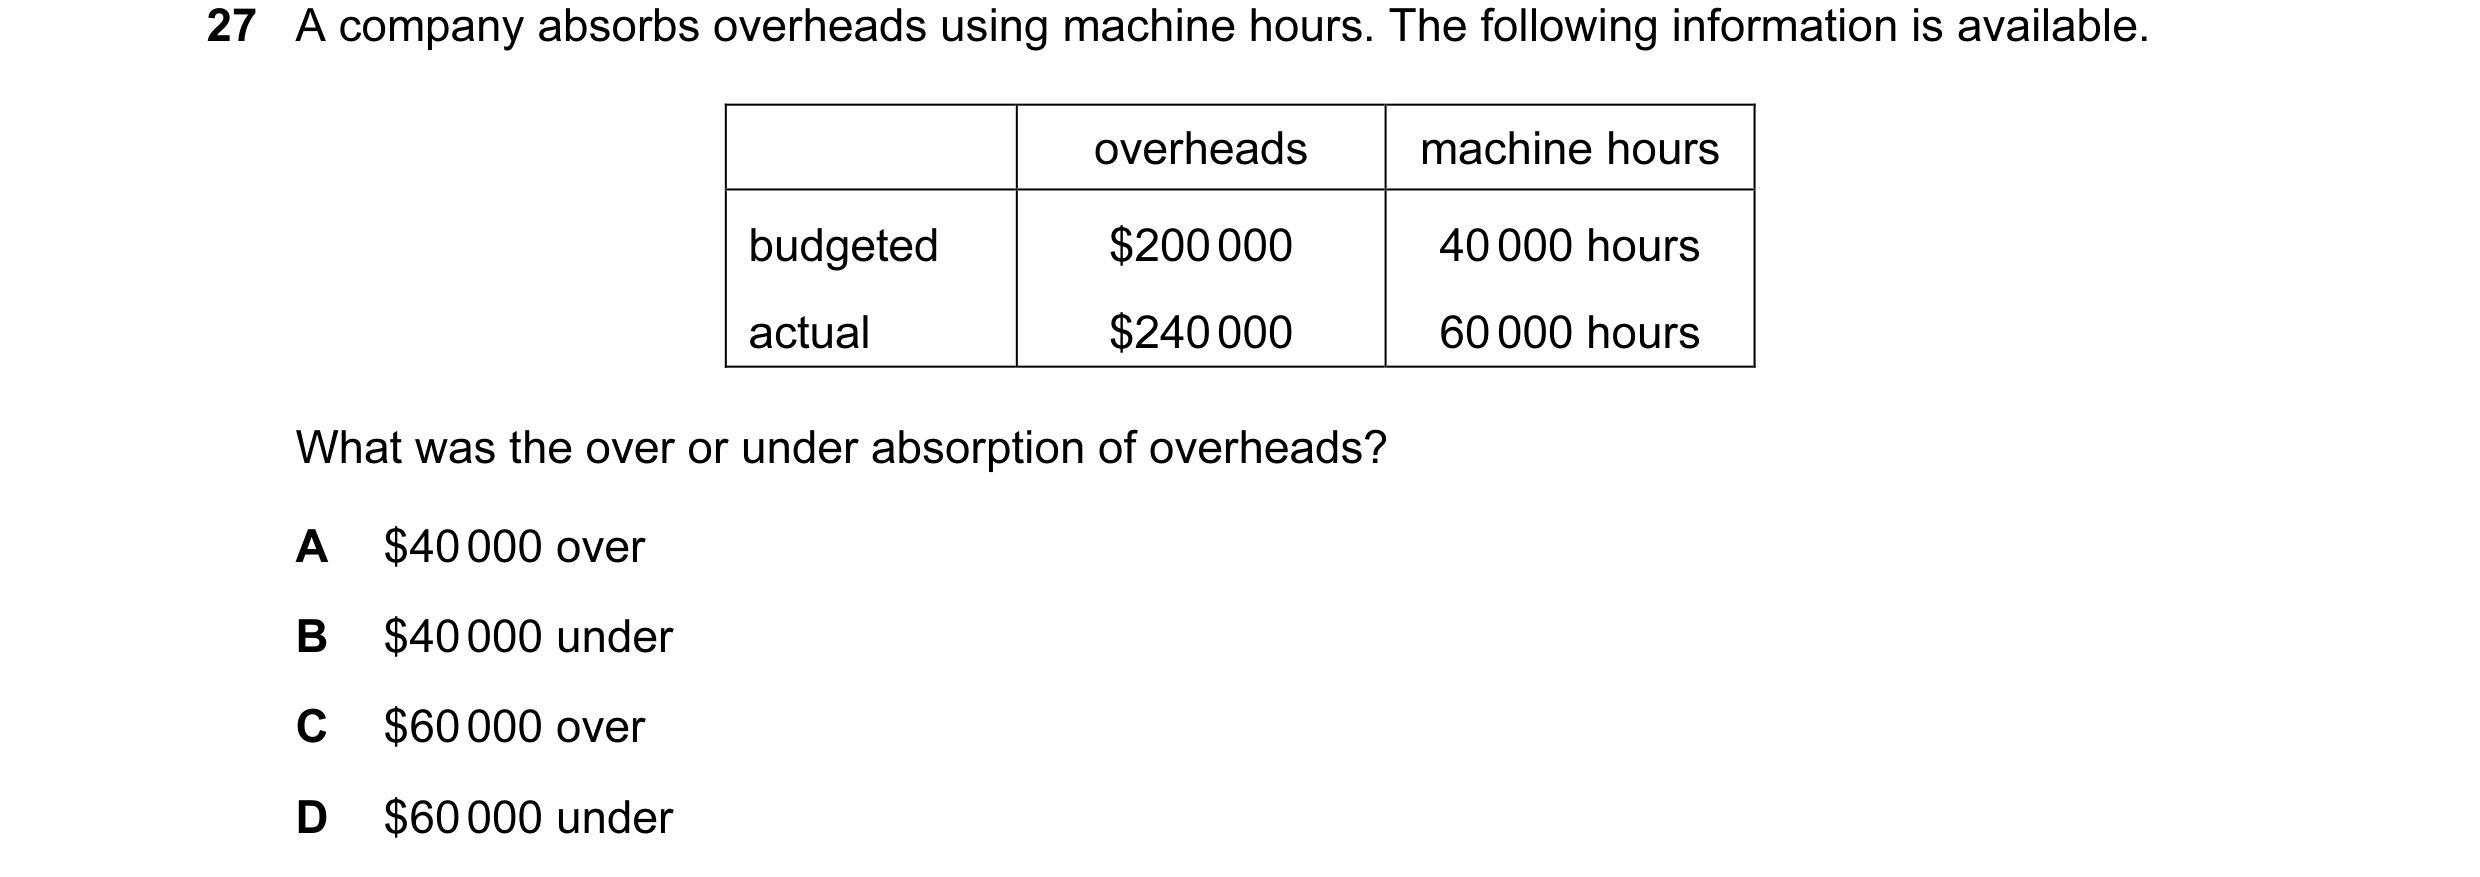 57 / 143
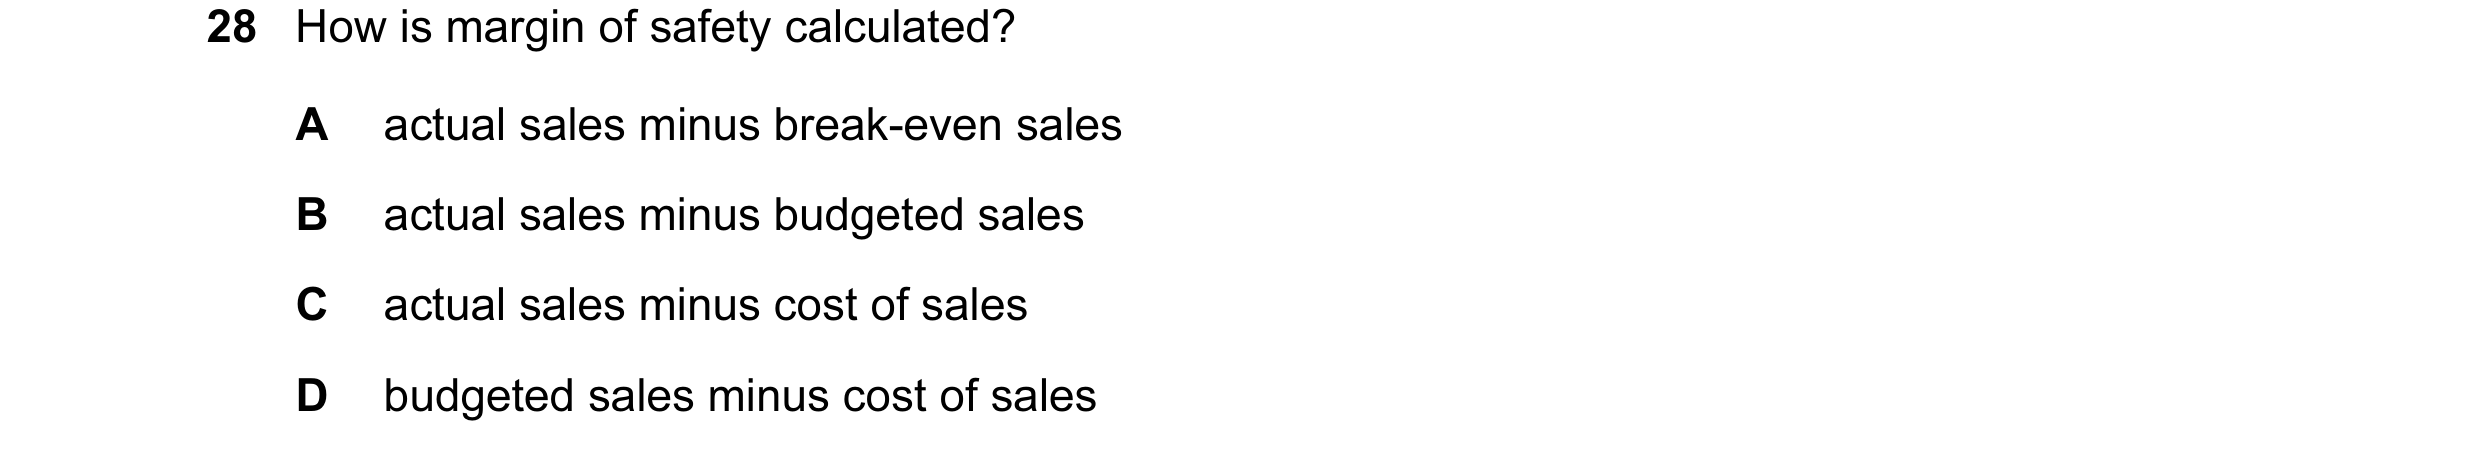
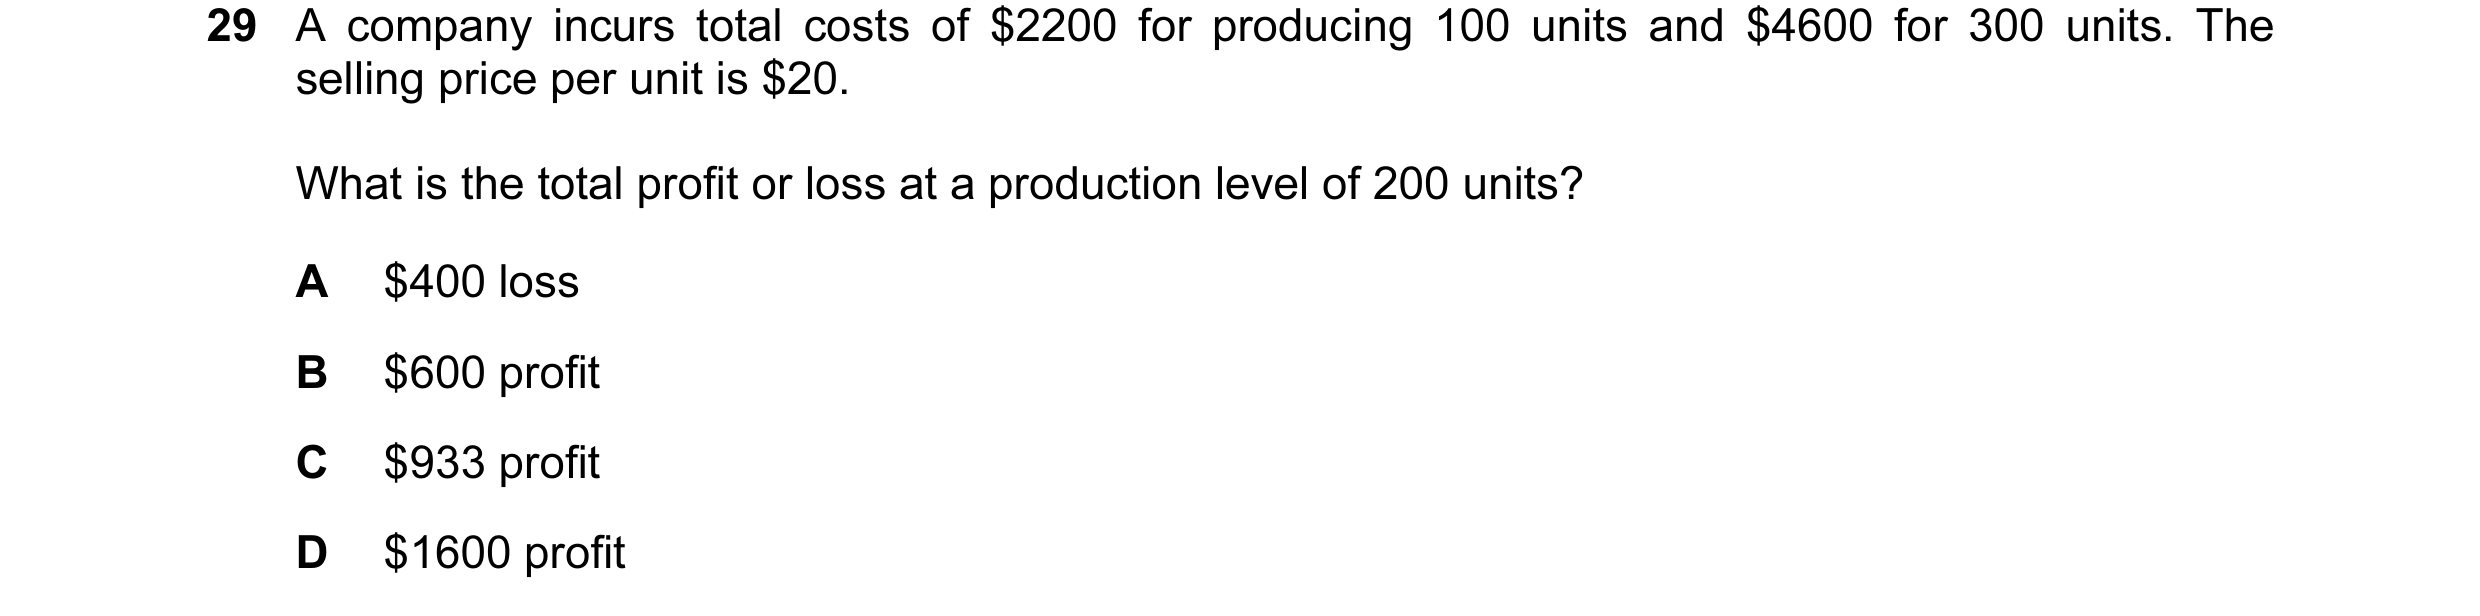
 58 / 143
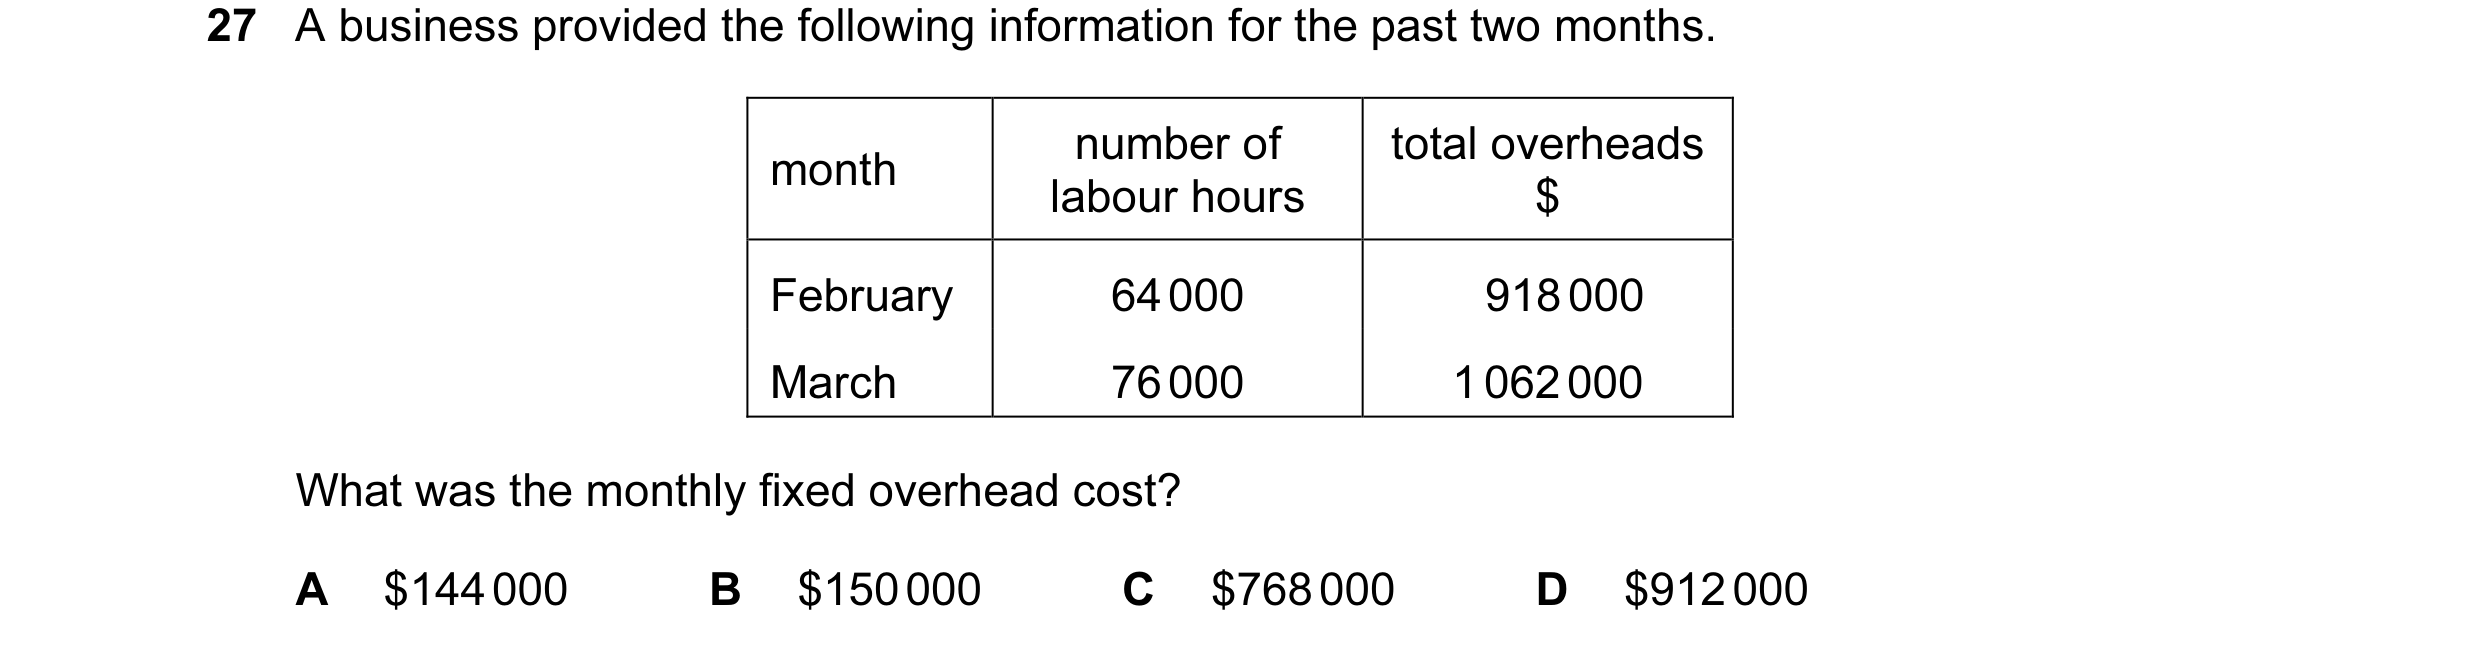
 59 / 143
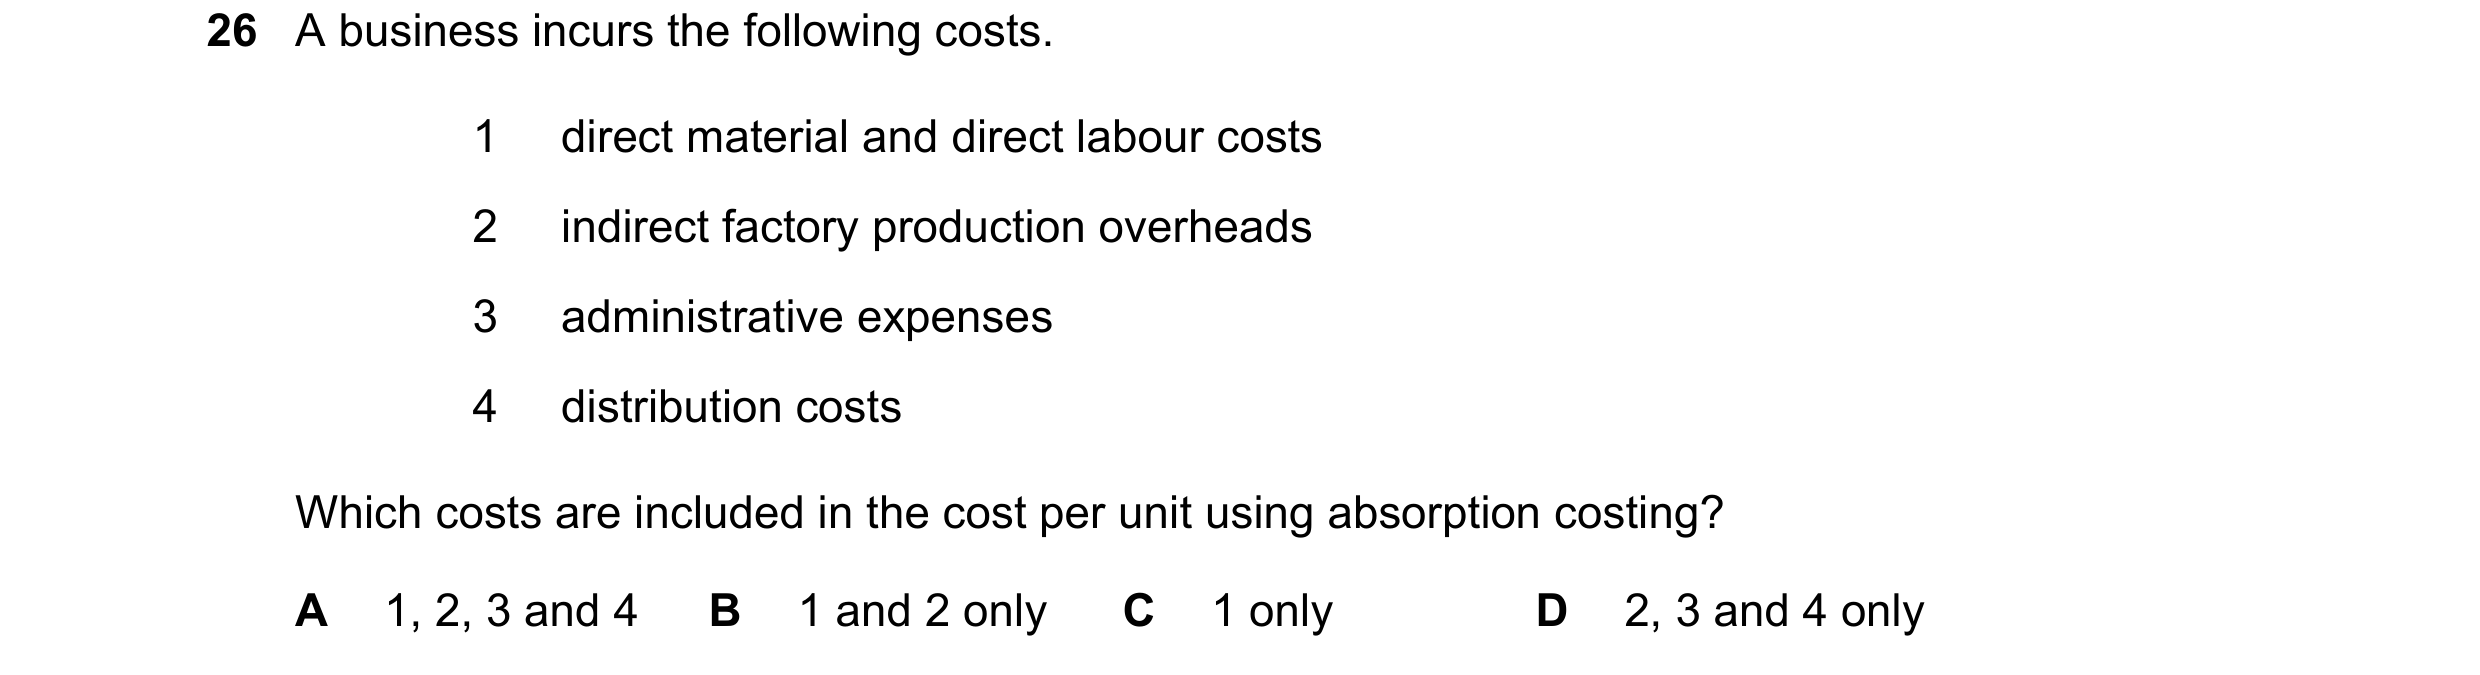
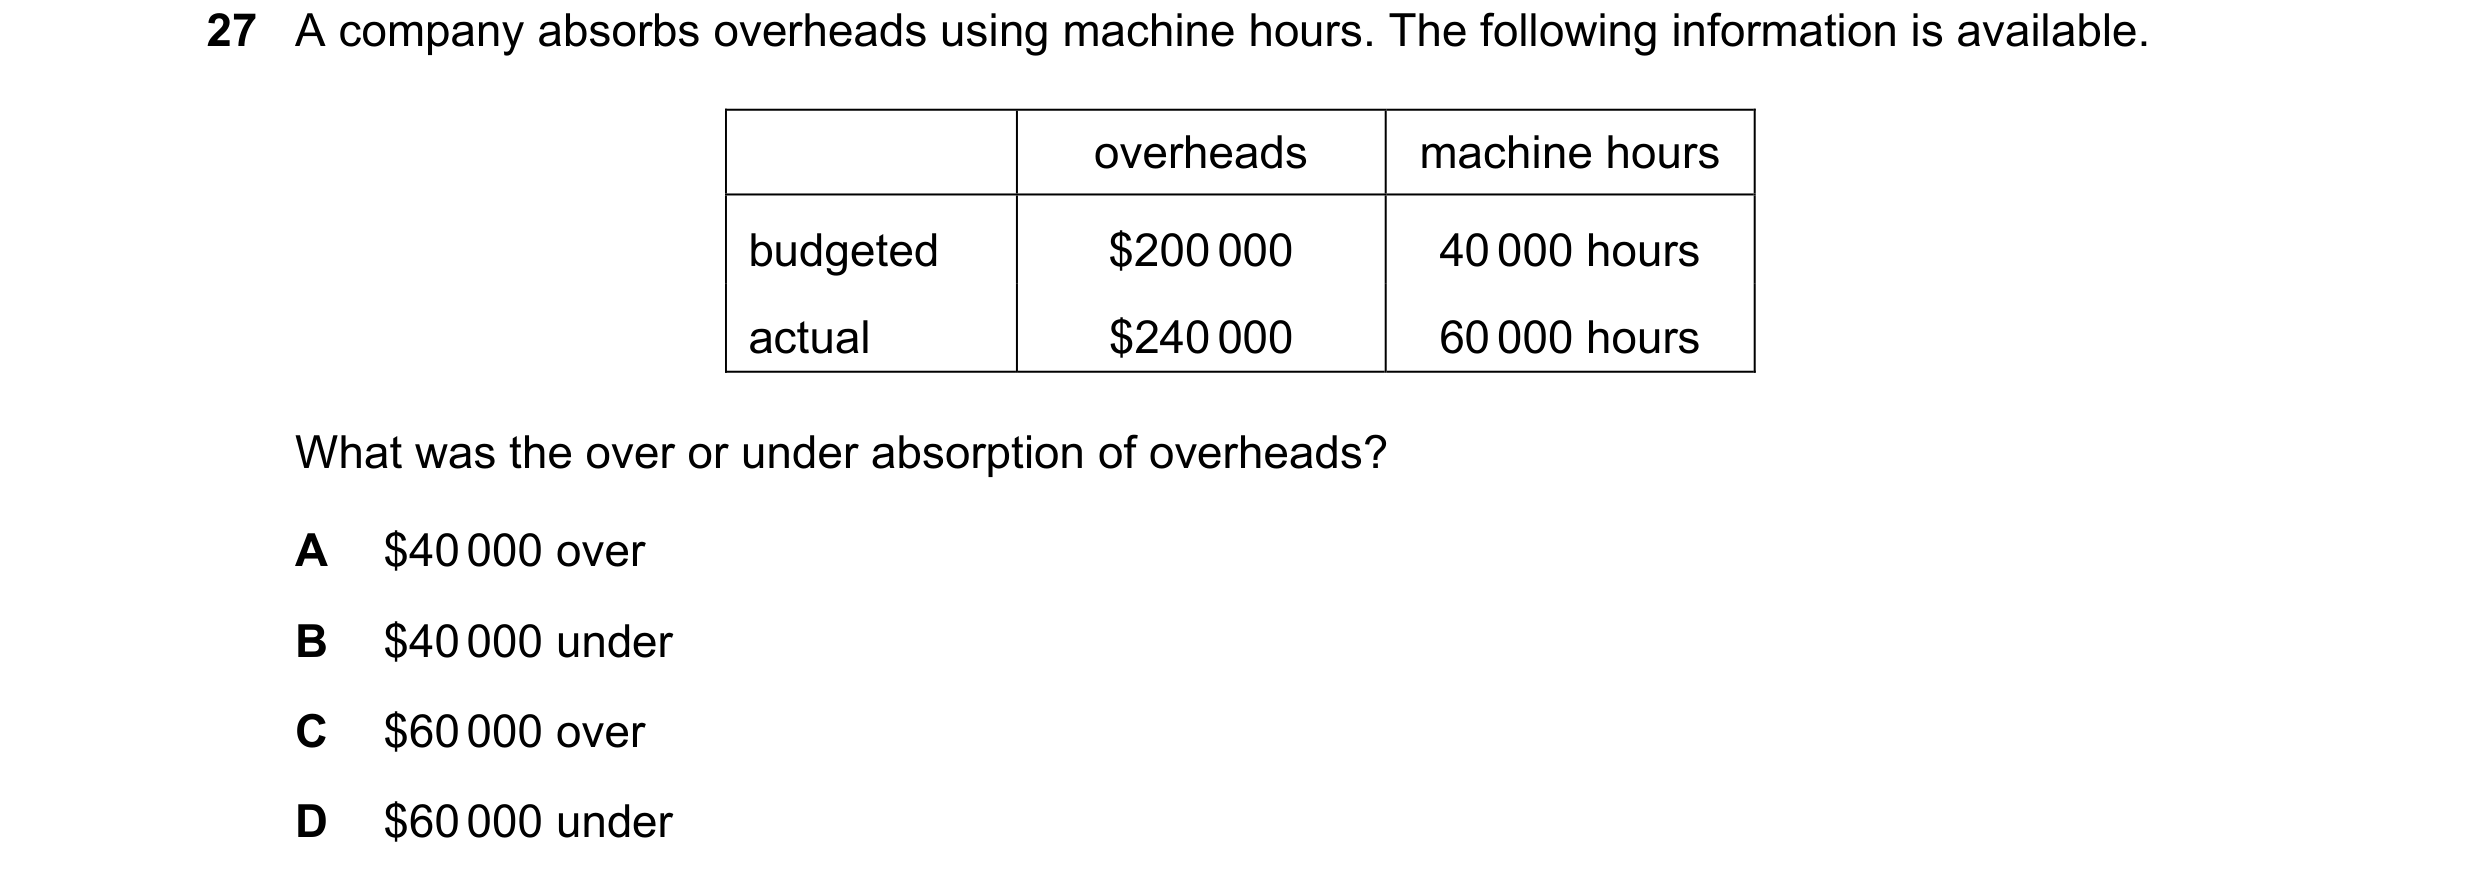
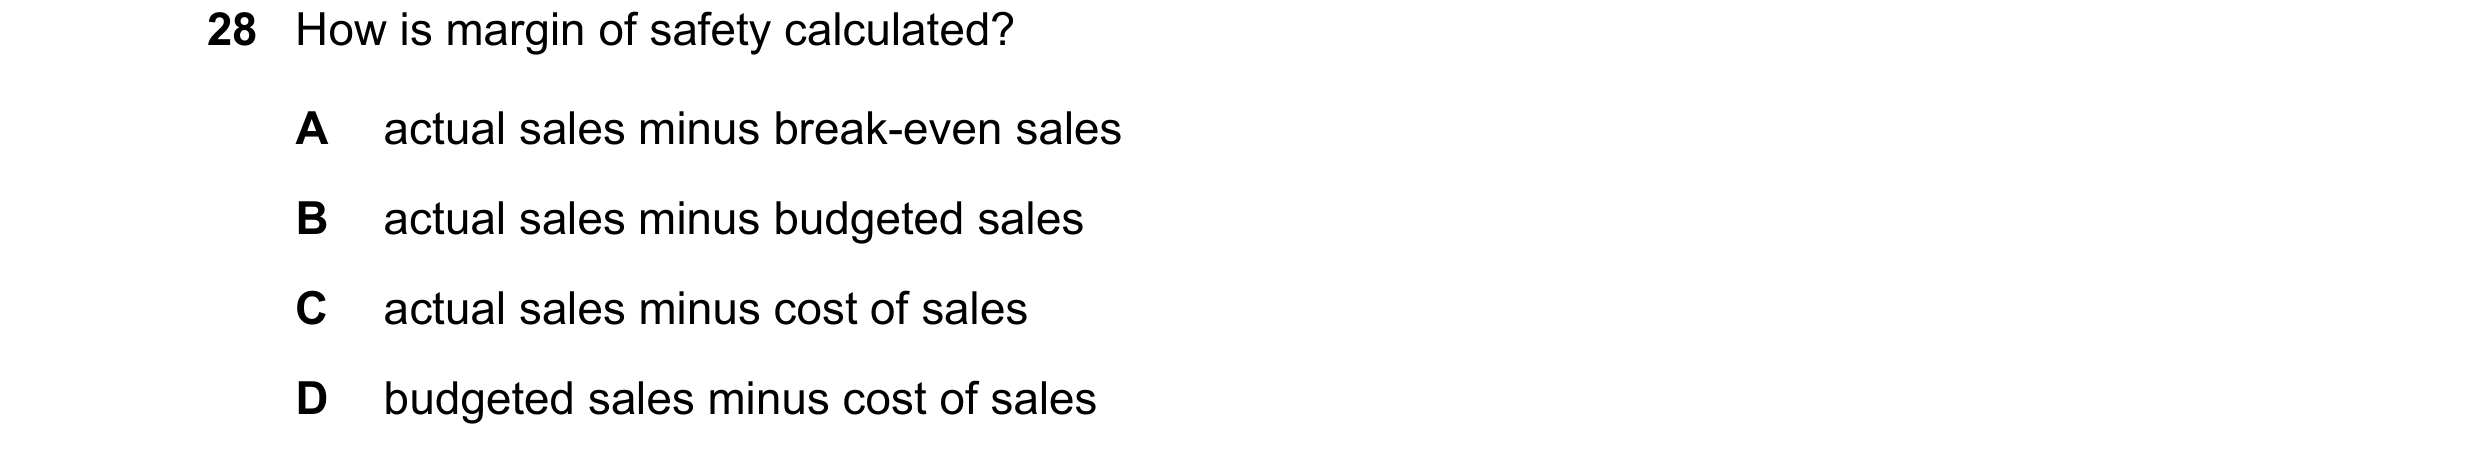
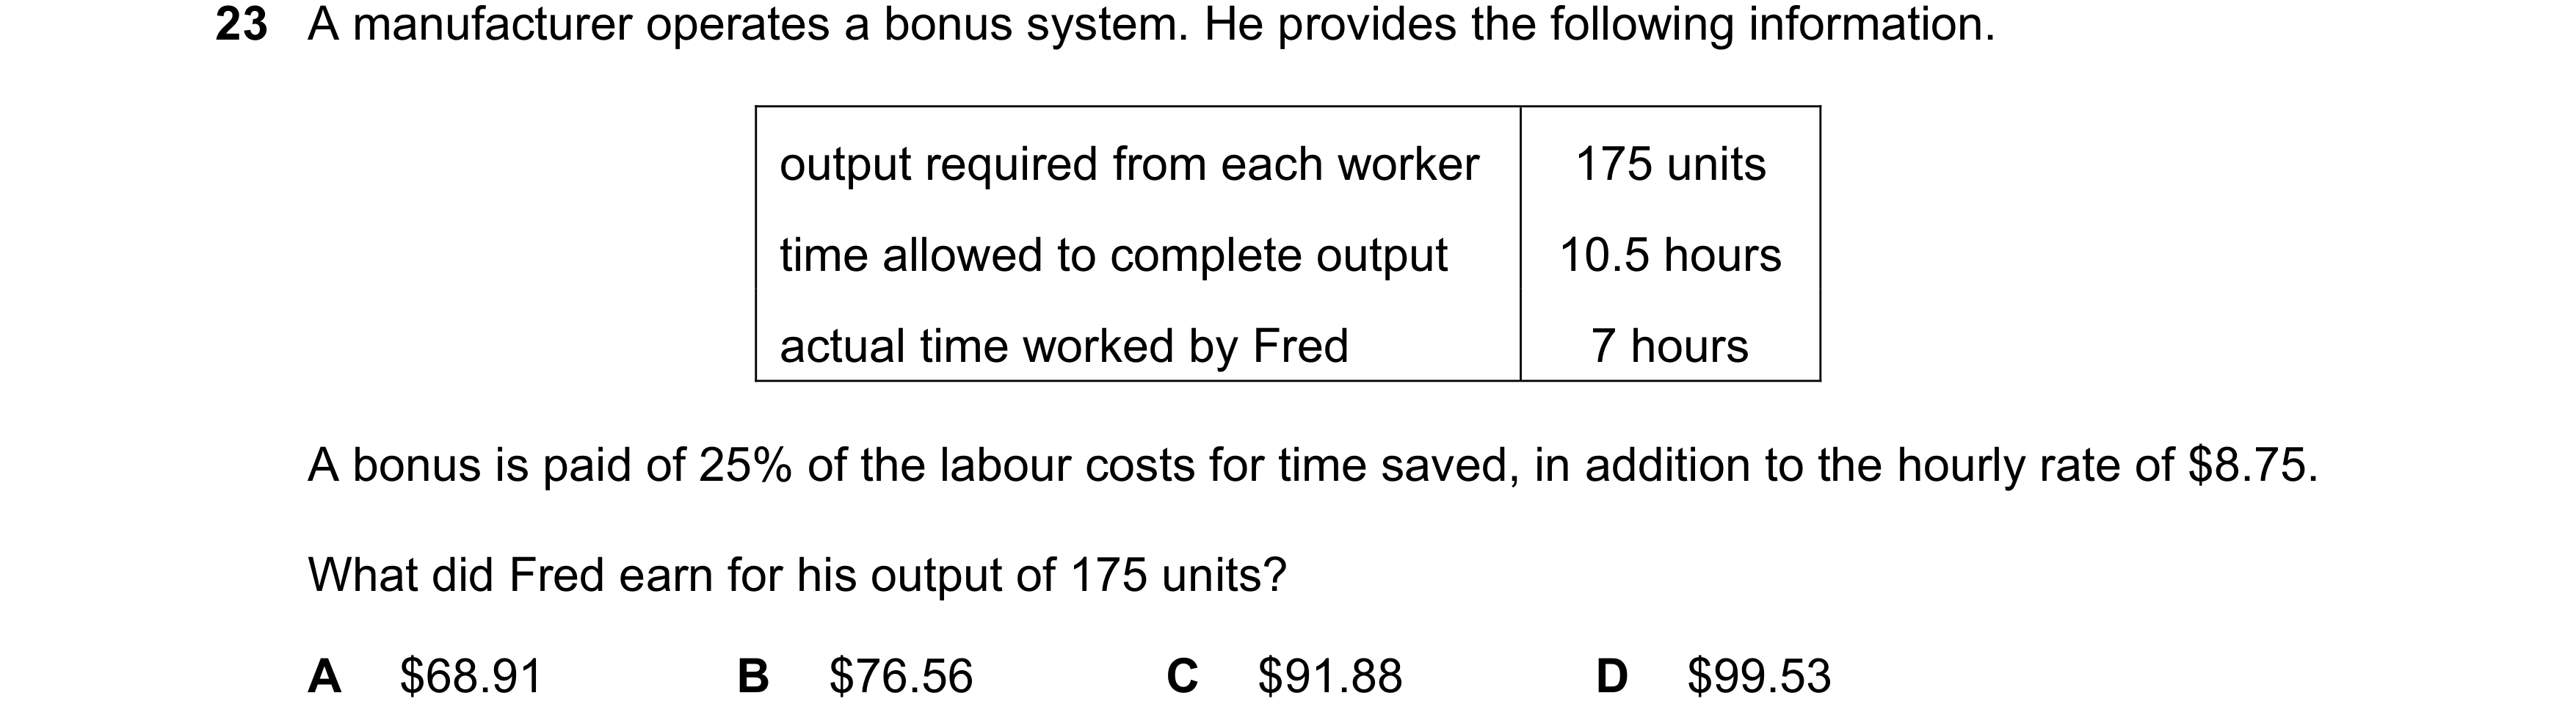 60 / 143
 61 / 143
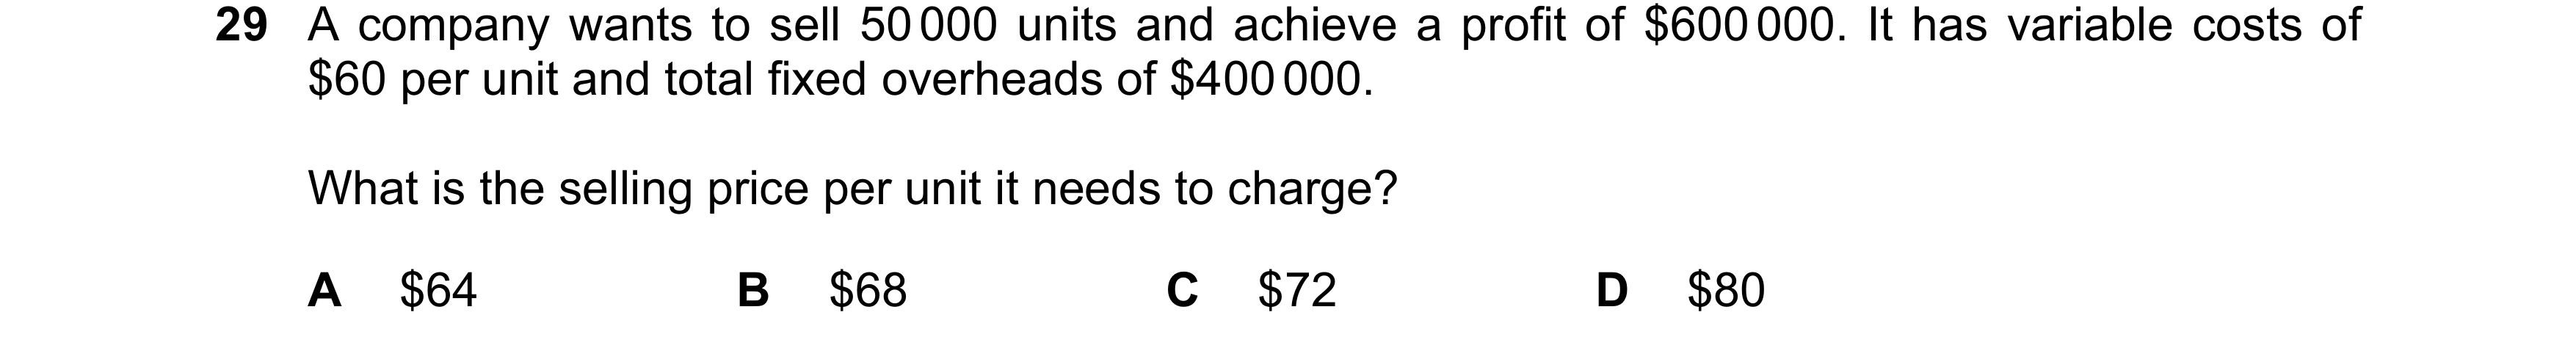
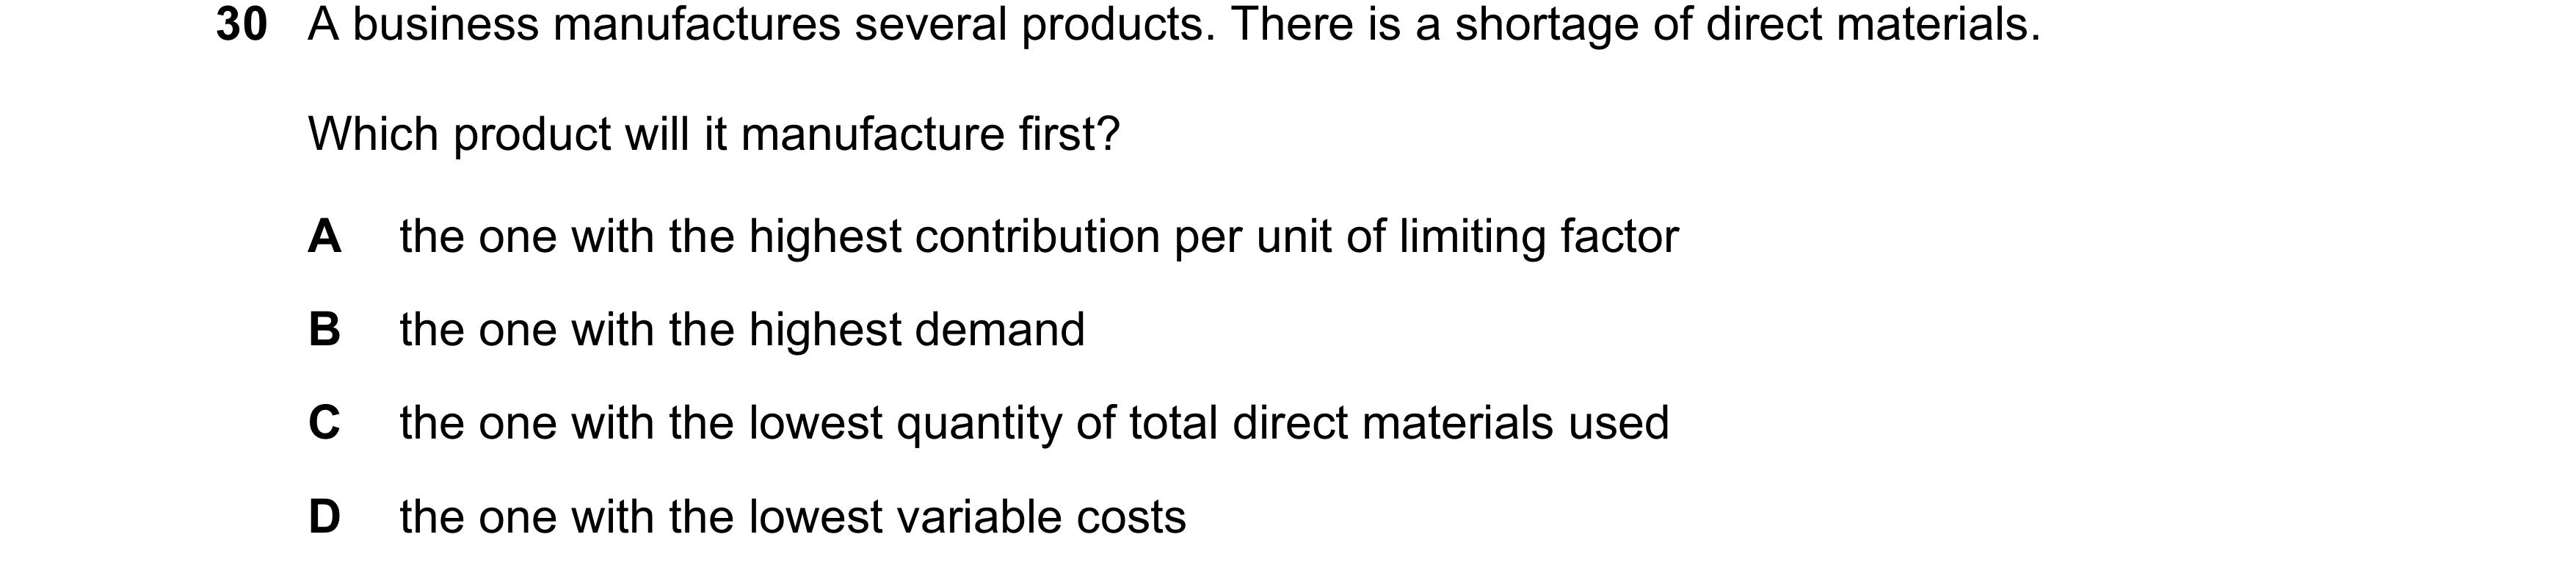
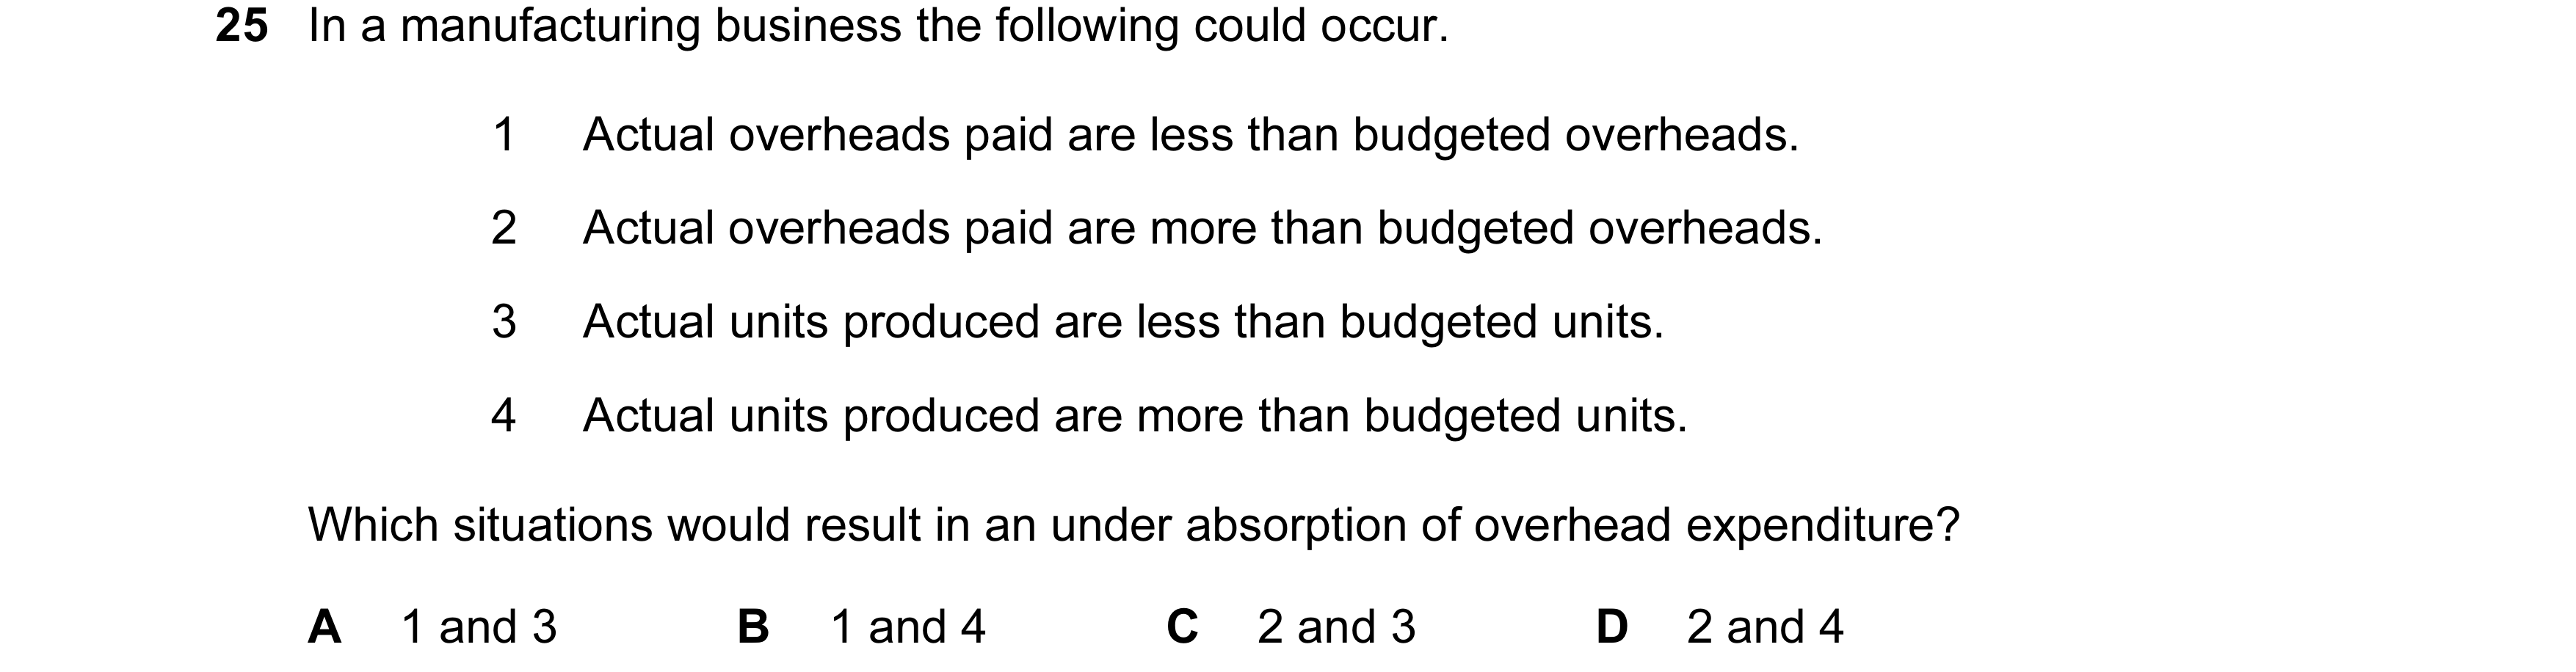
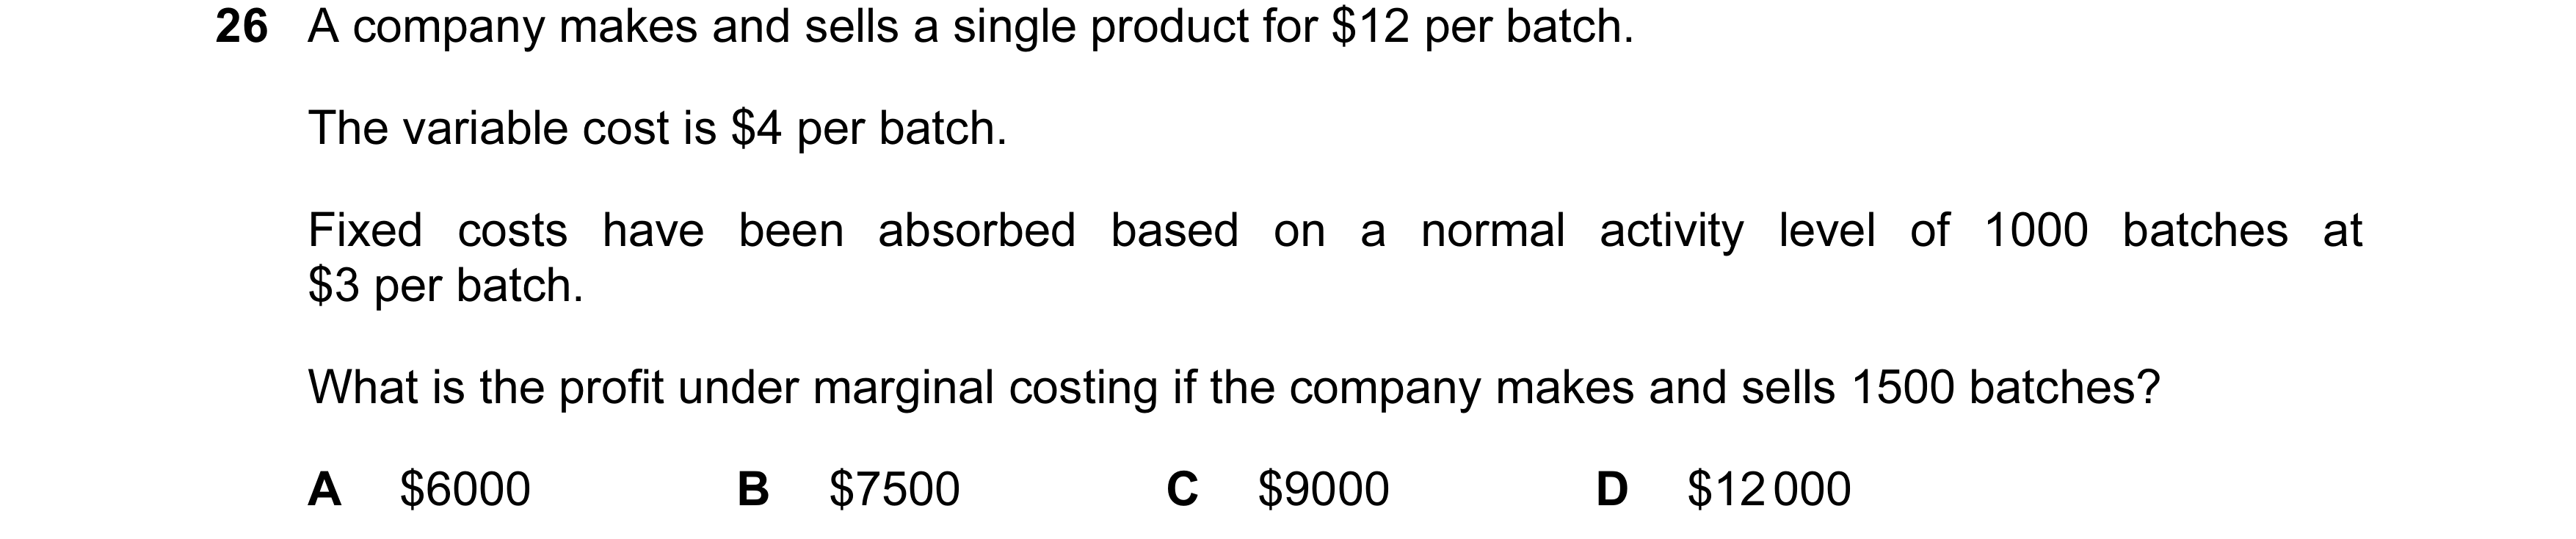
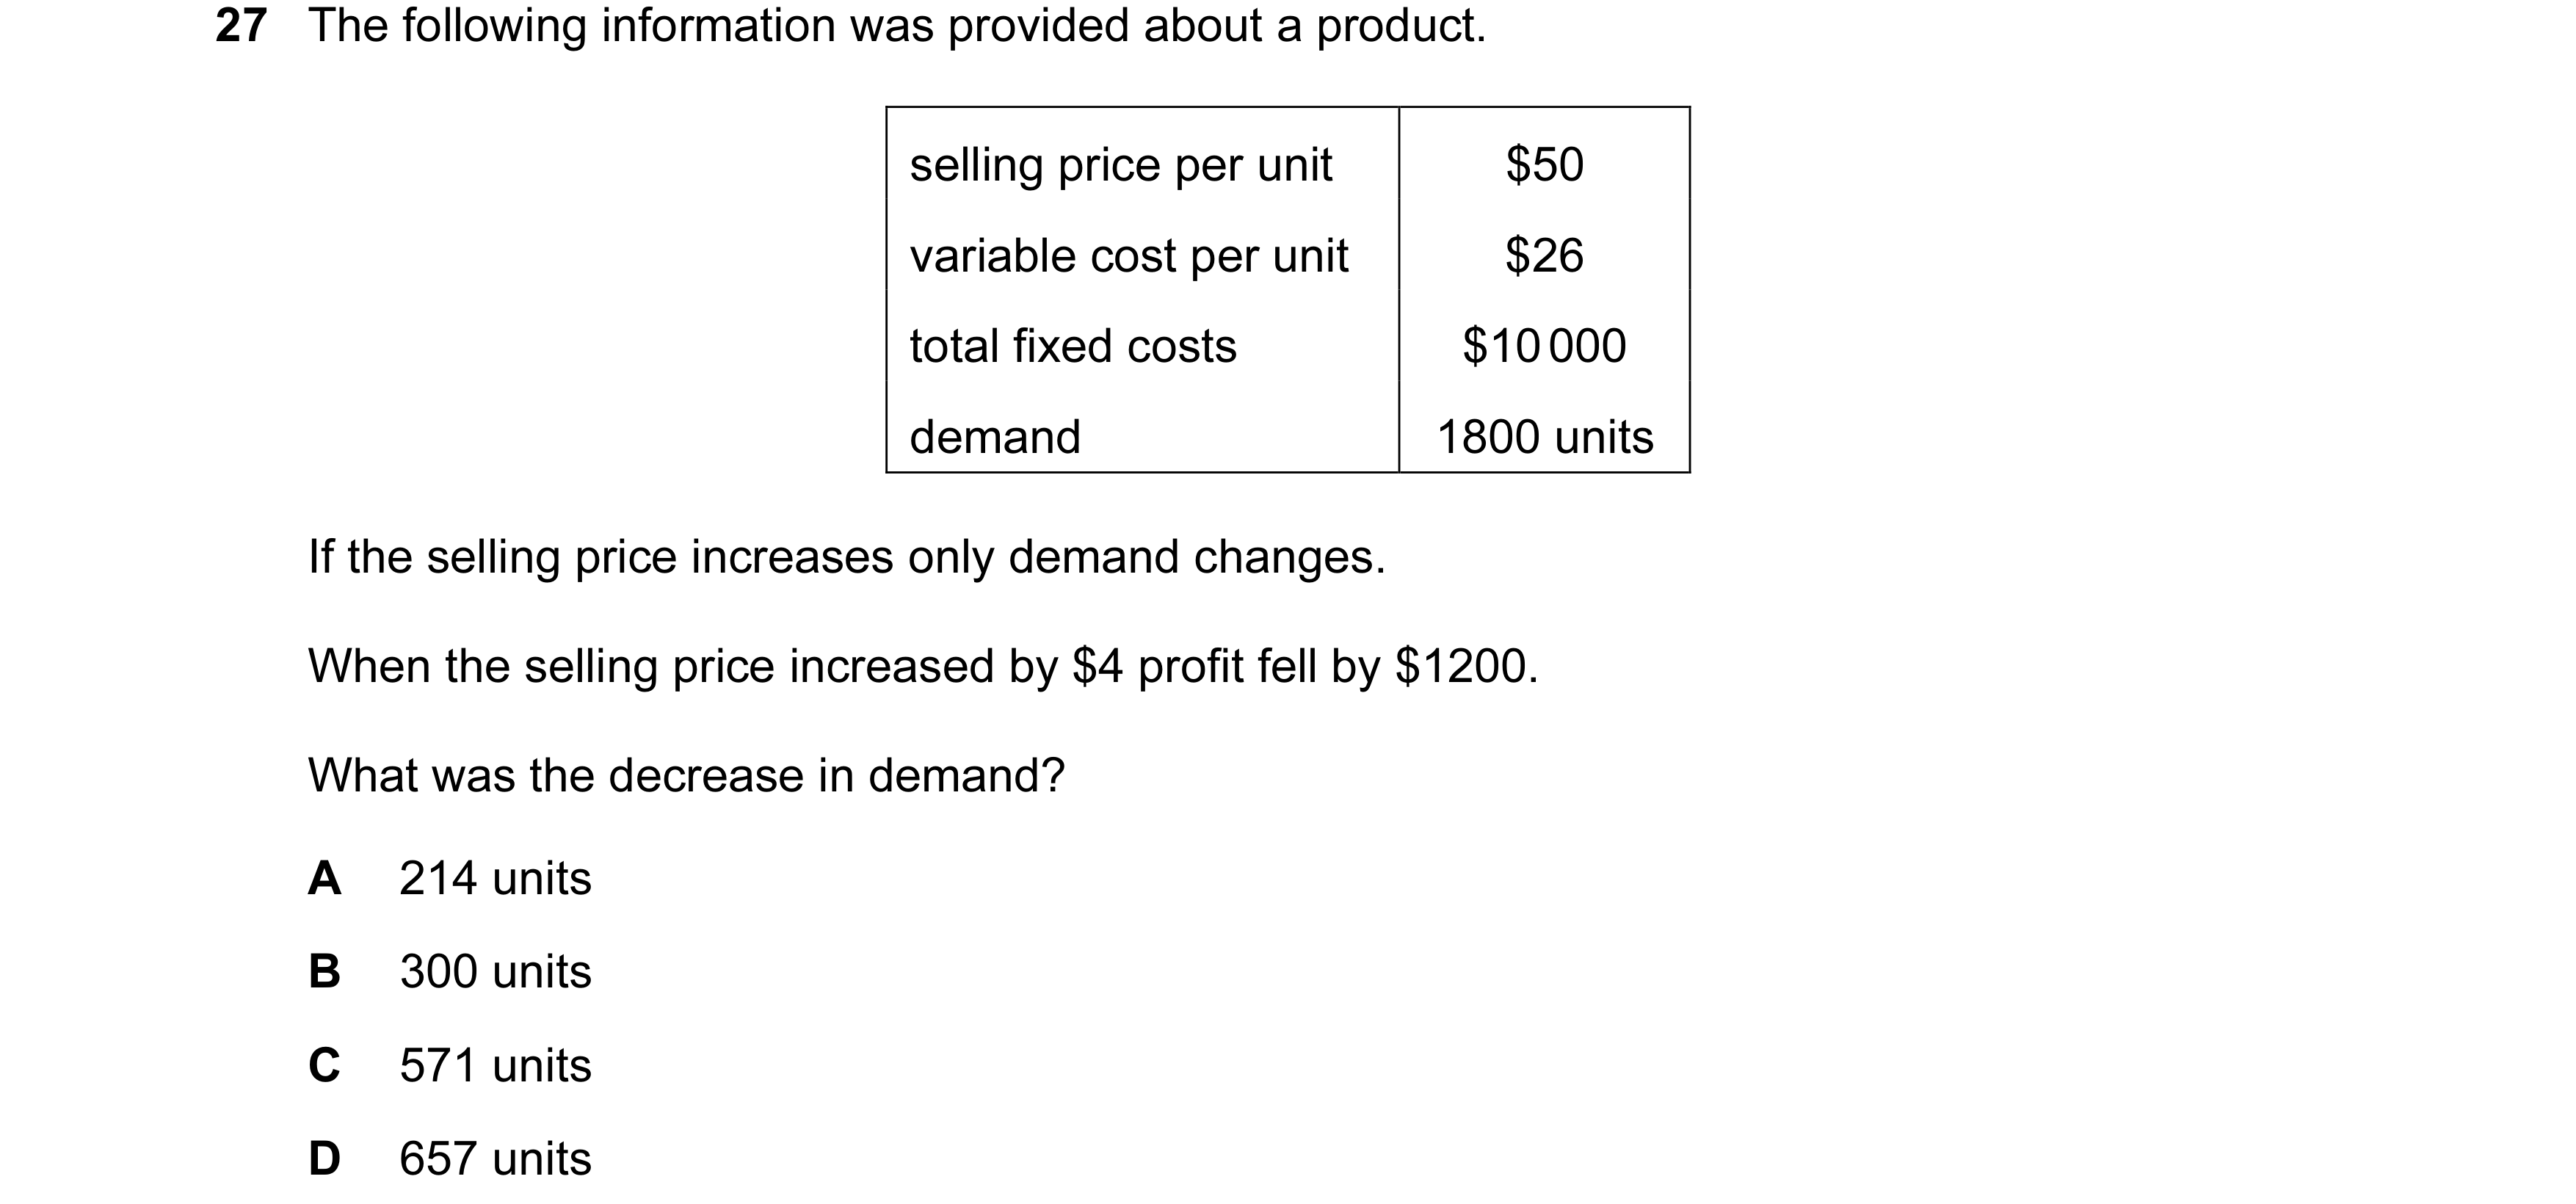 62 / 143
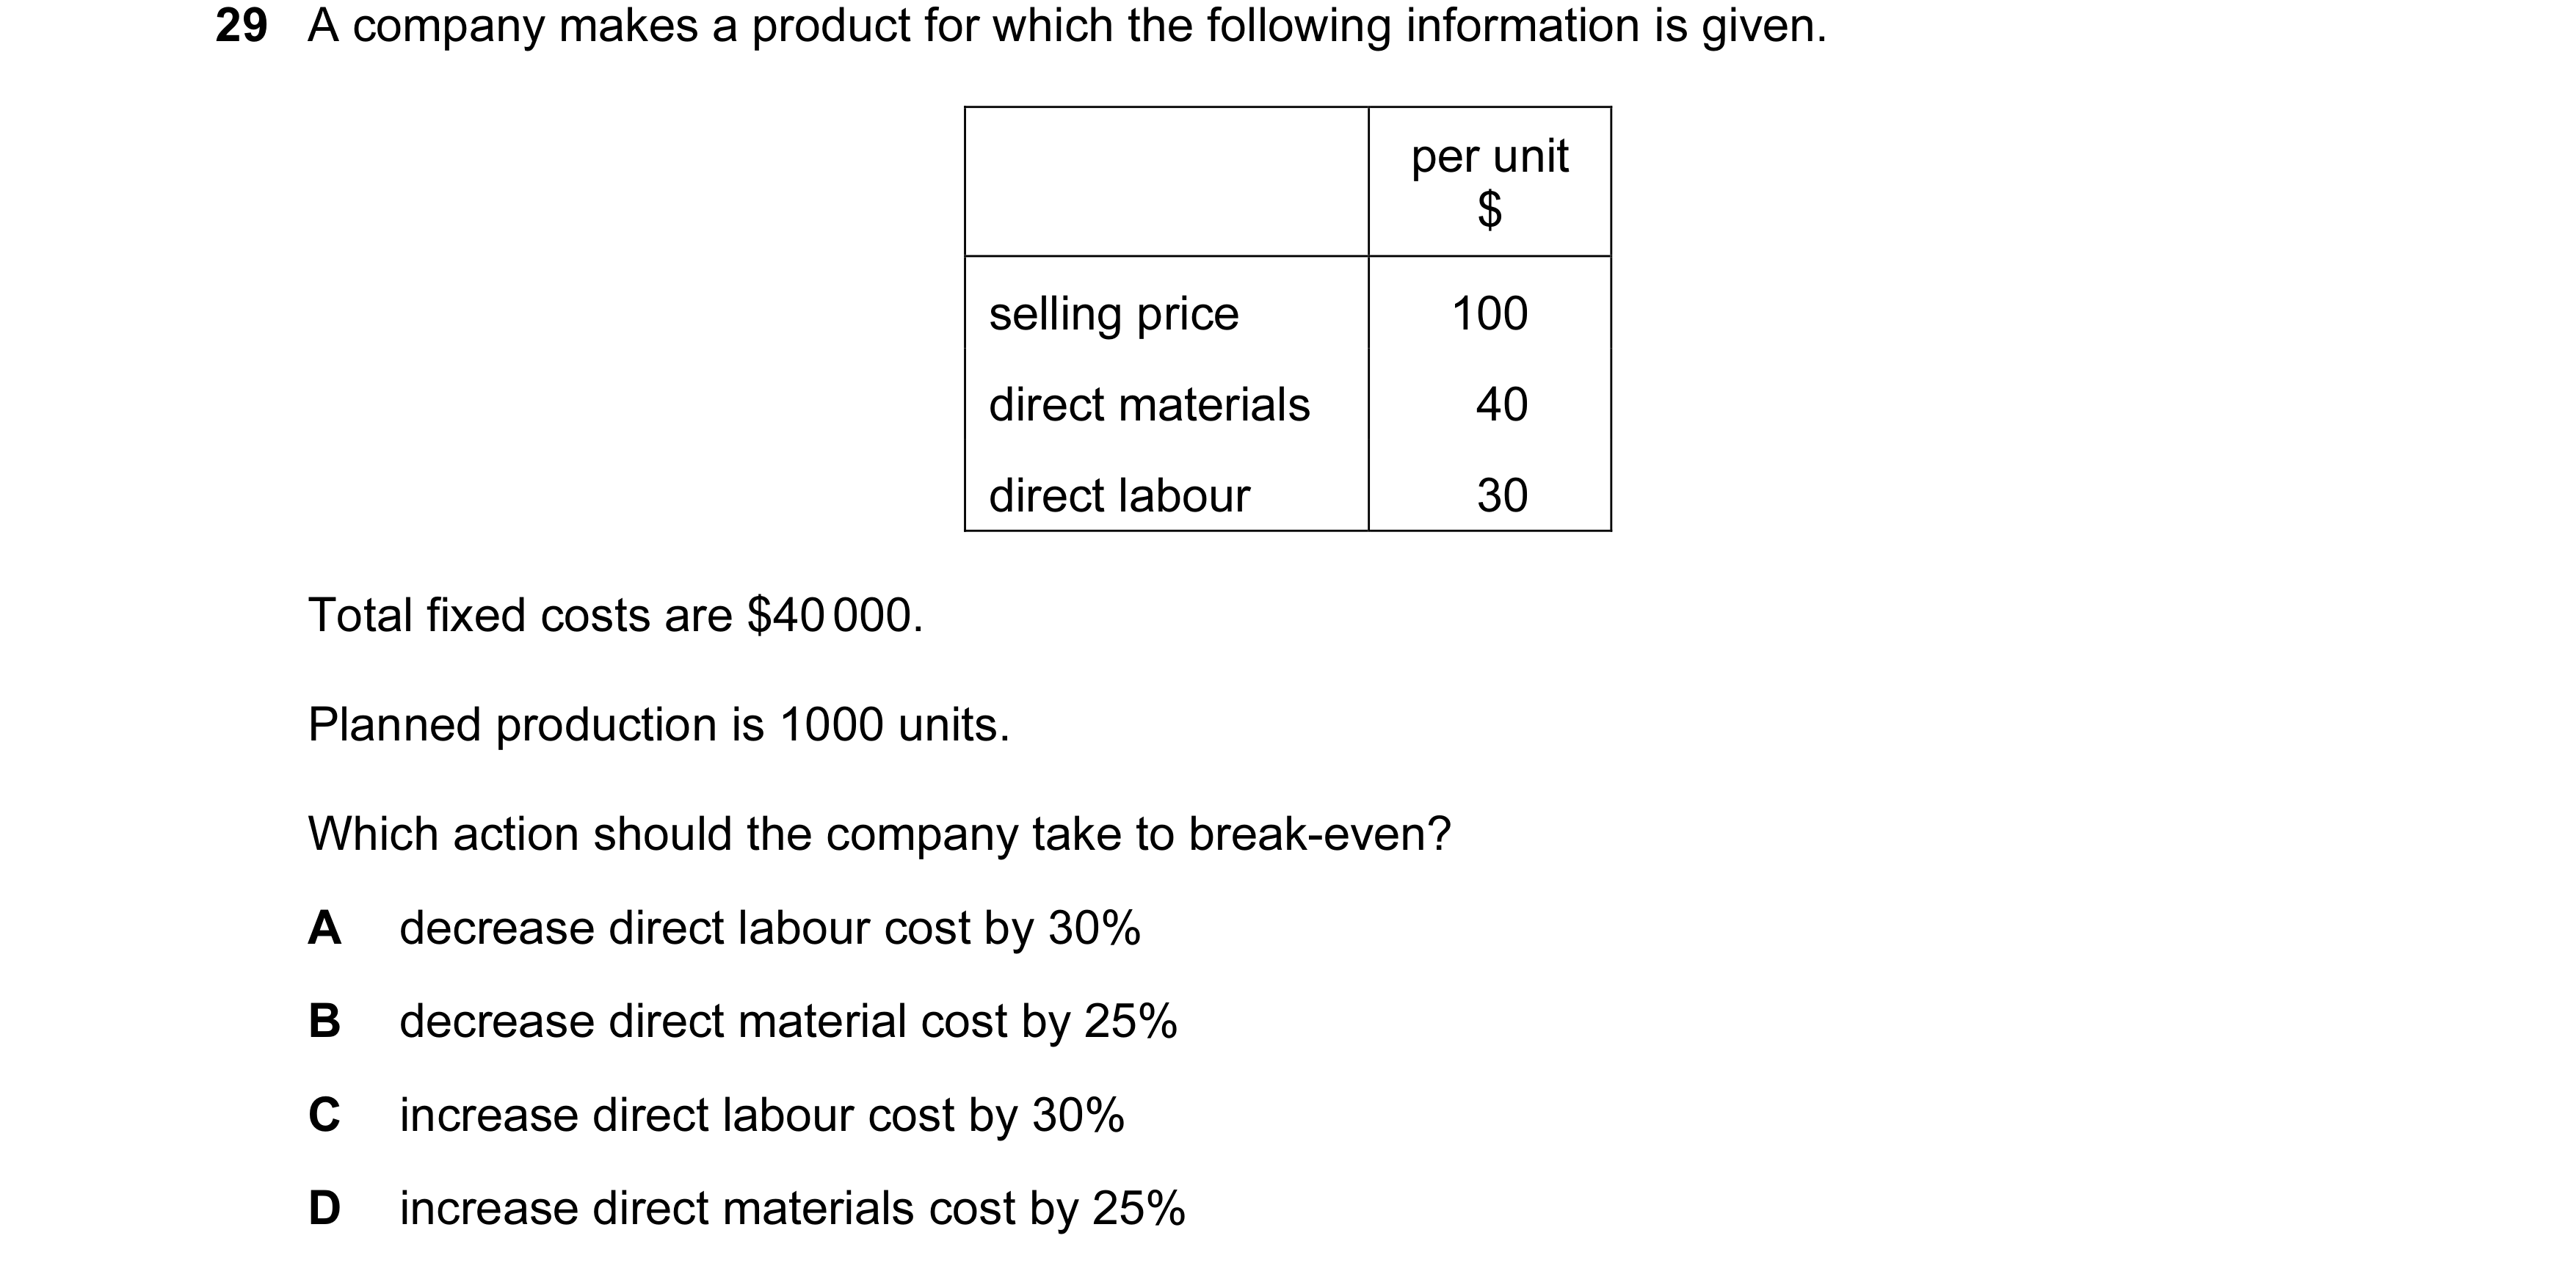
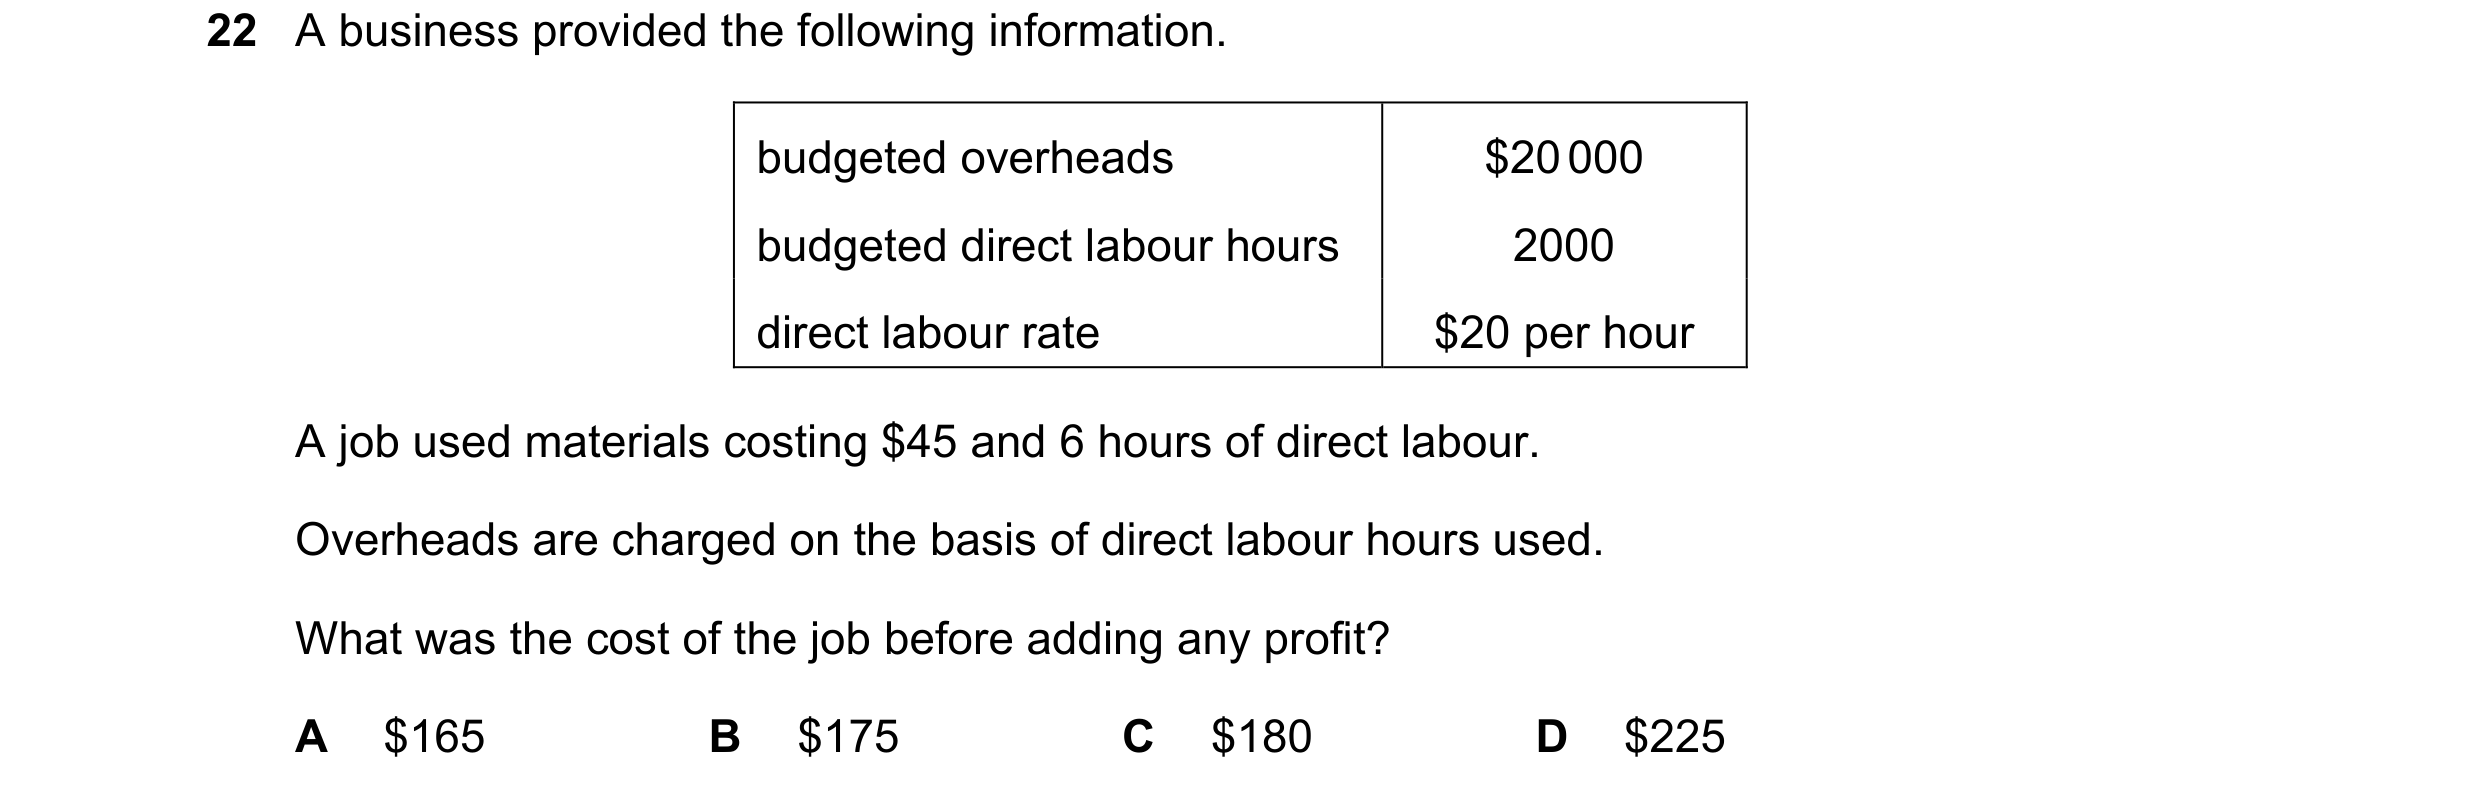
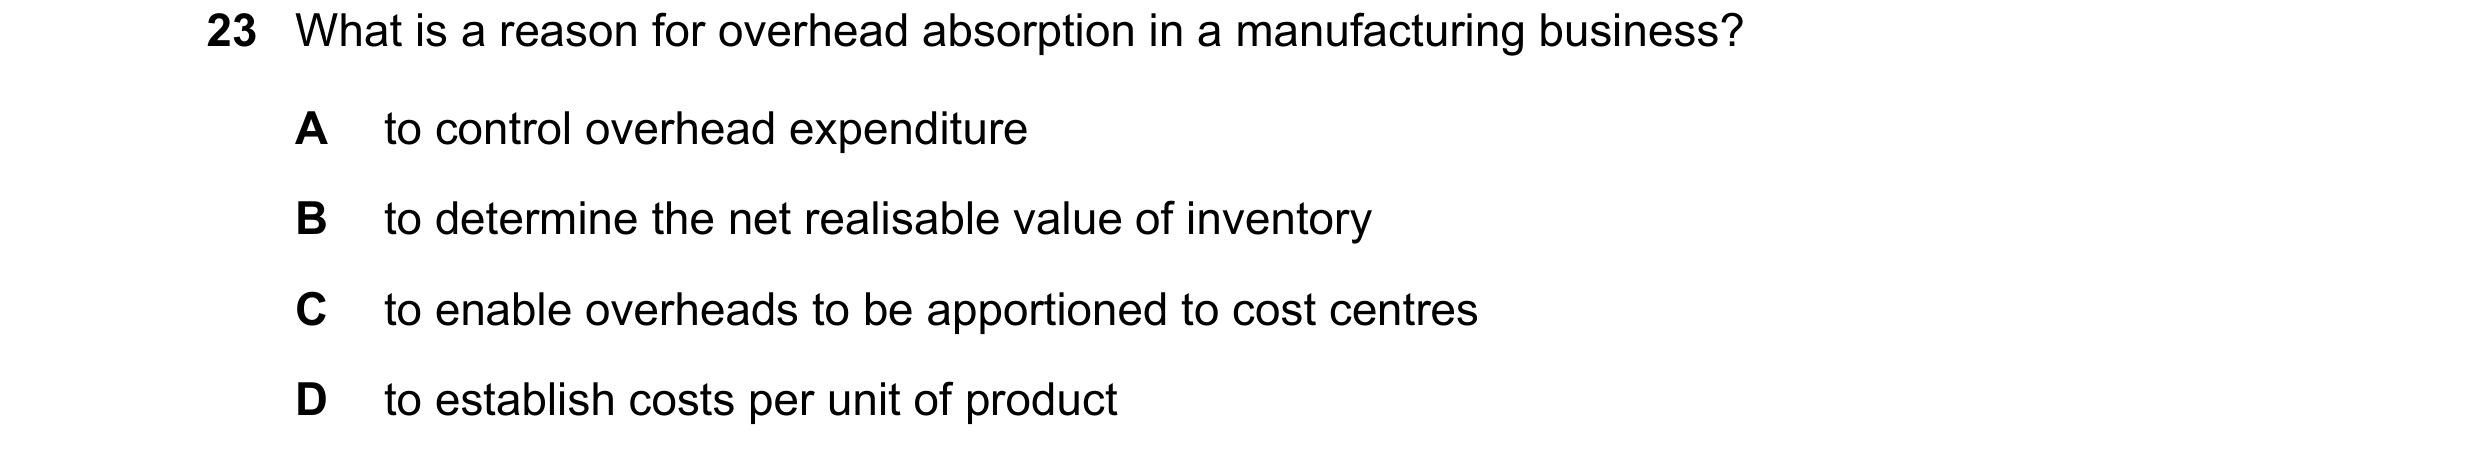
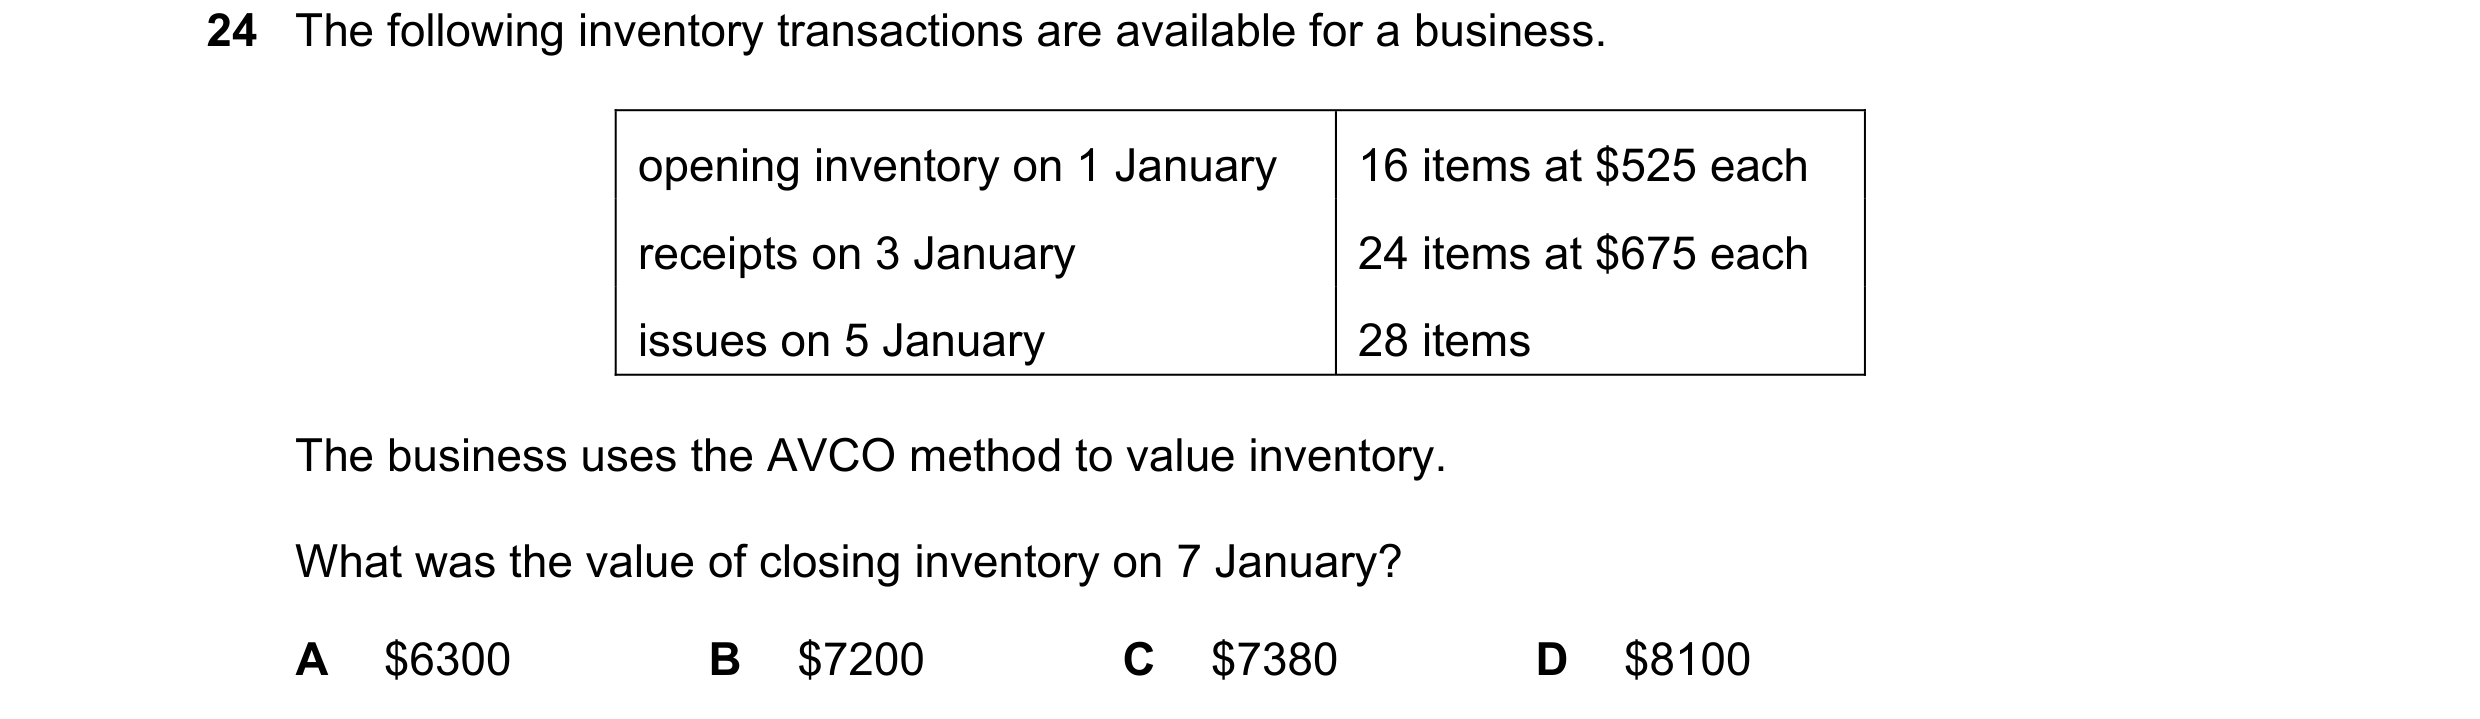 63 / 143
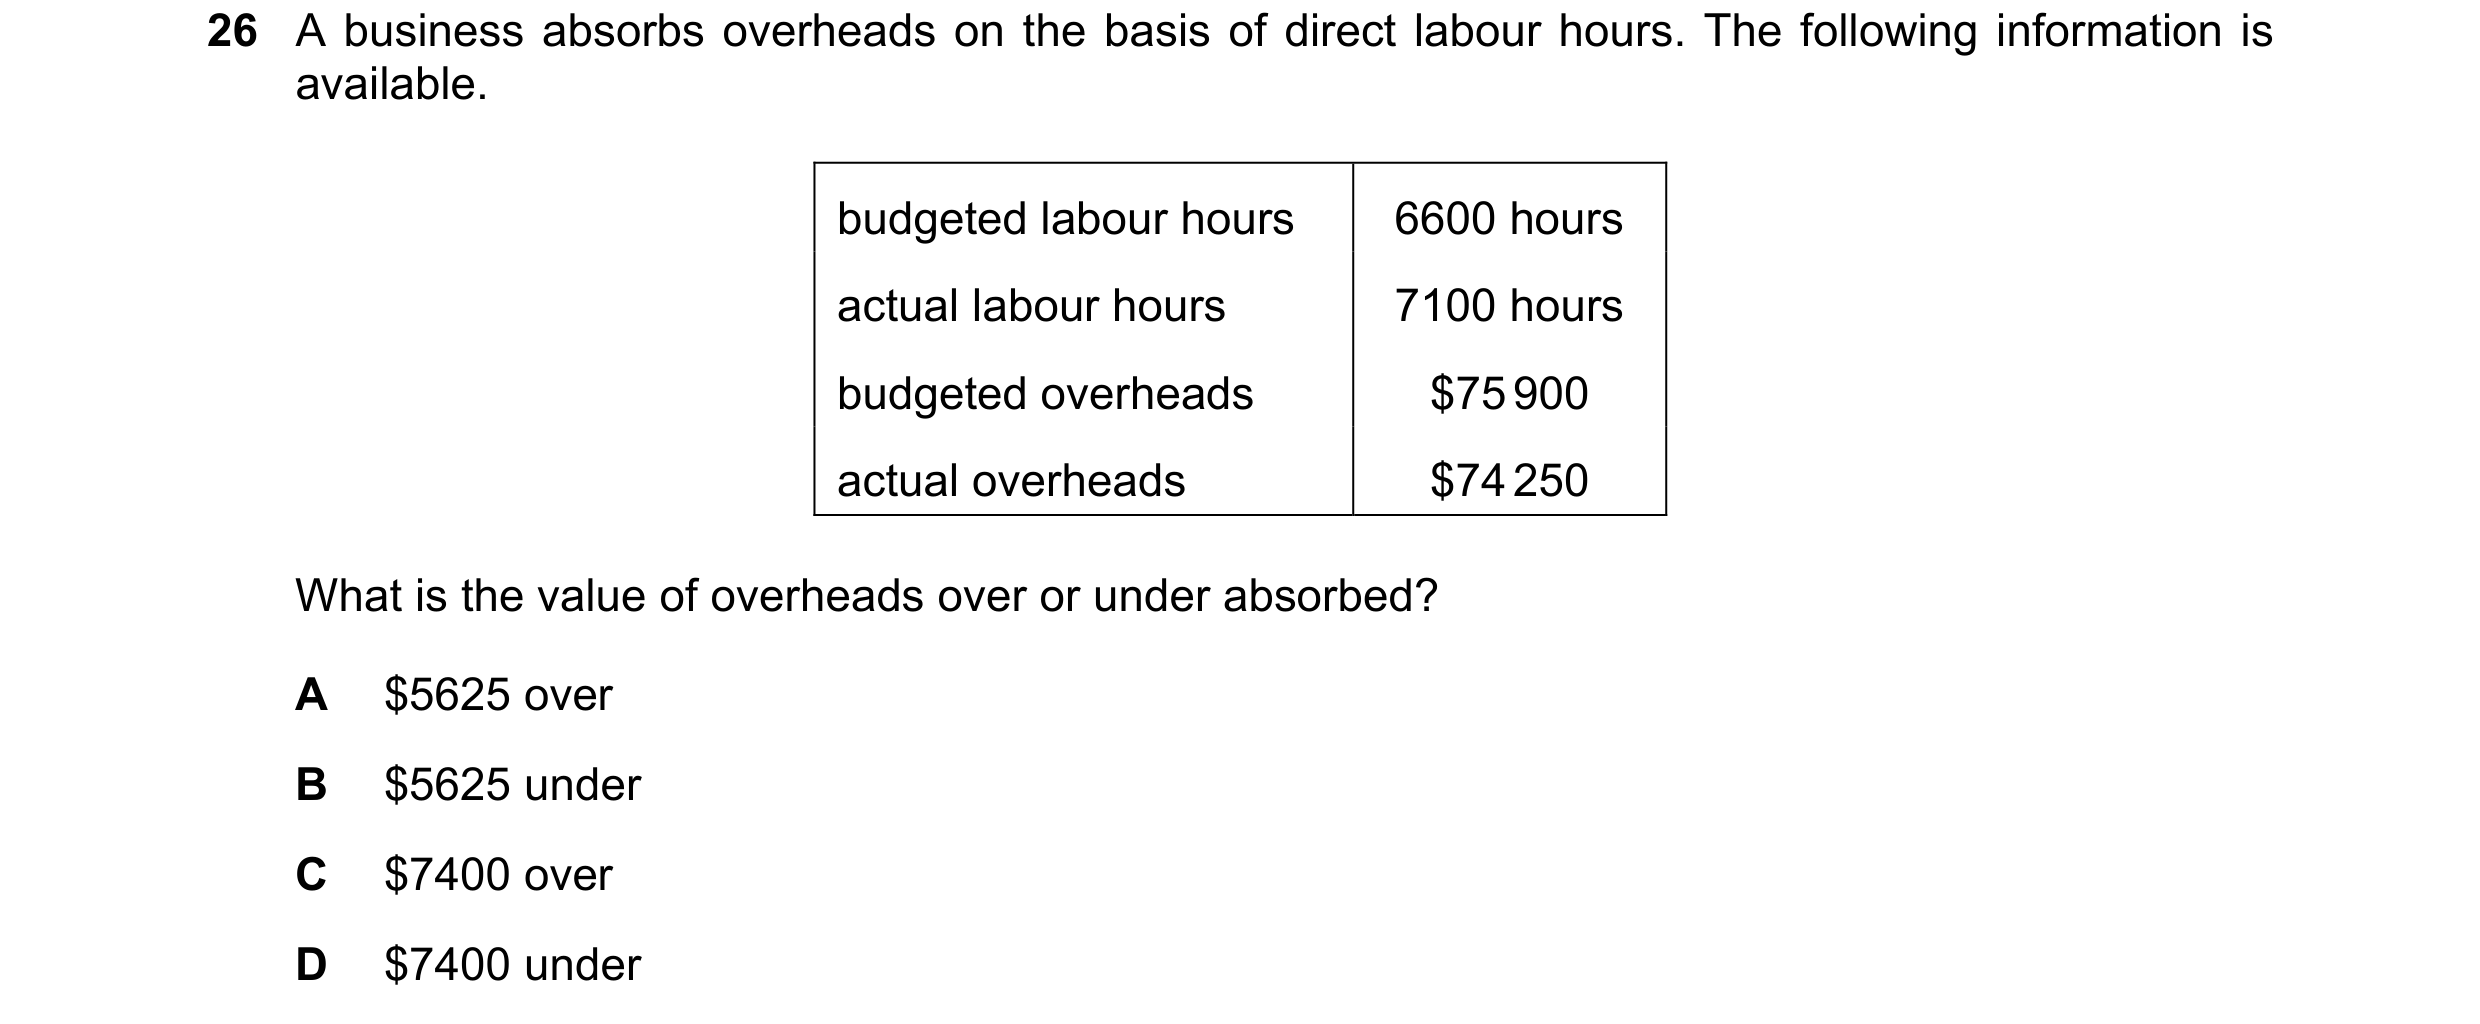
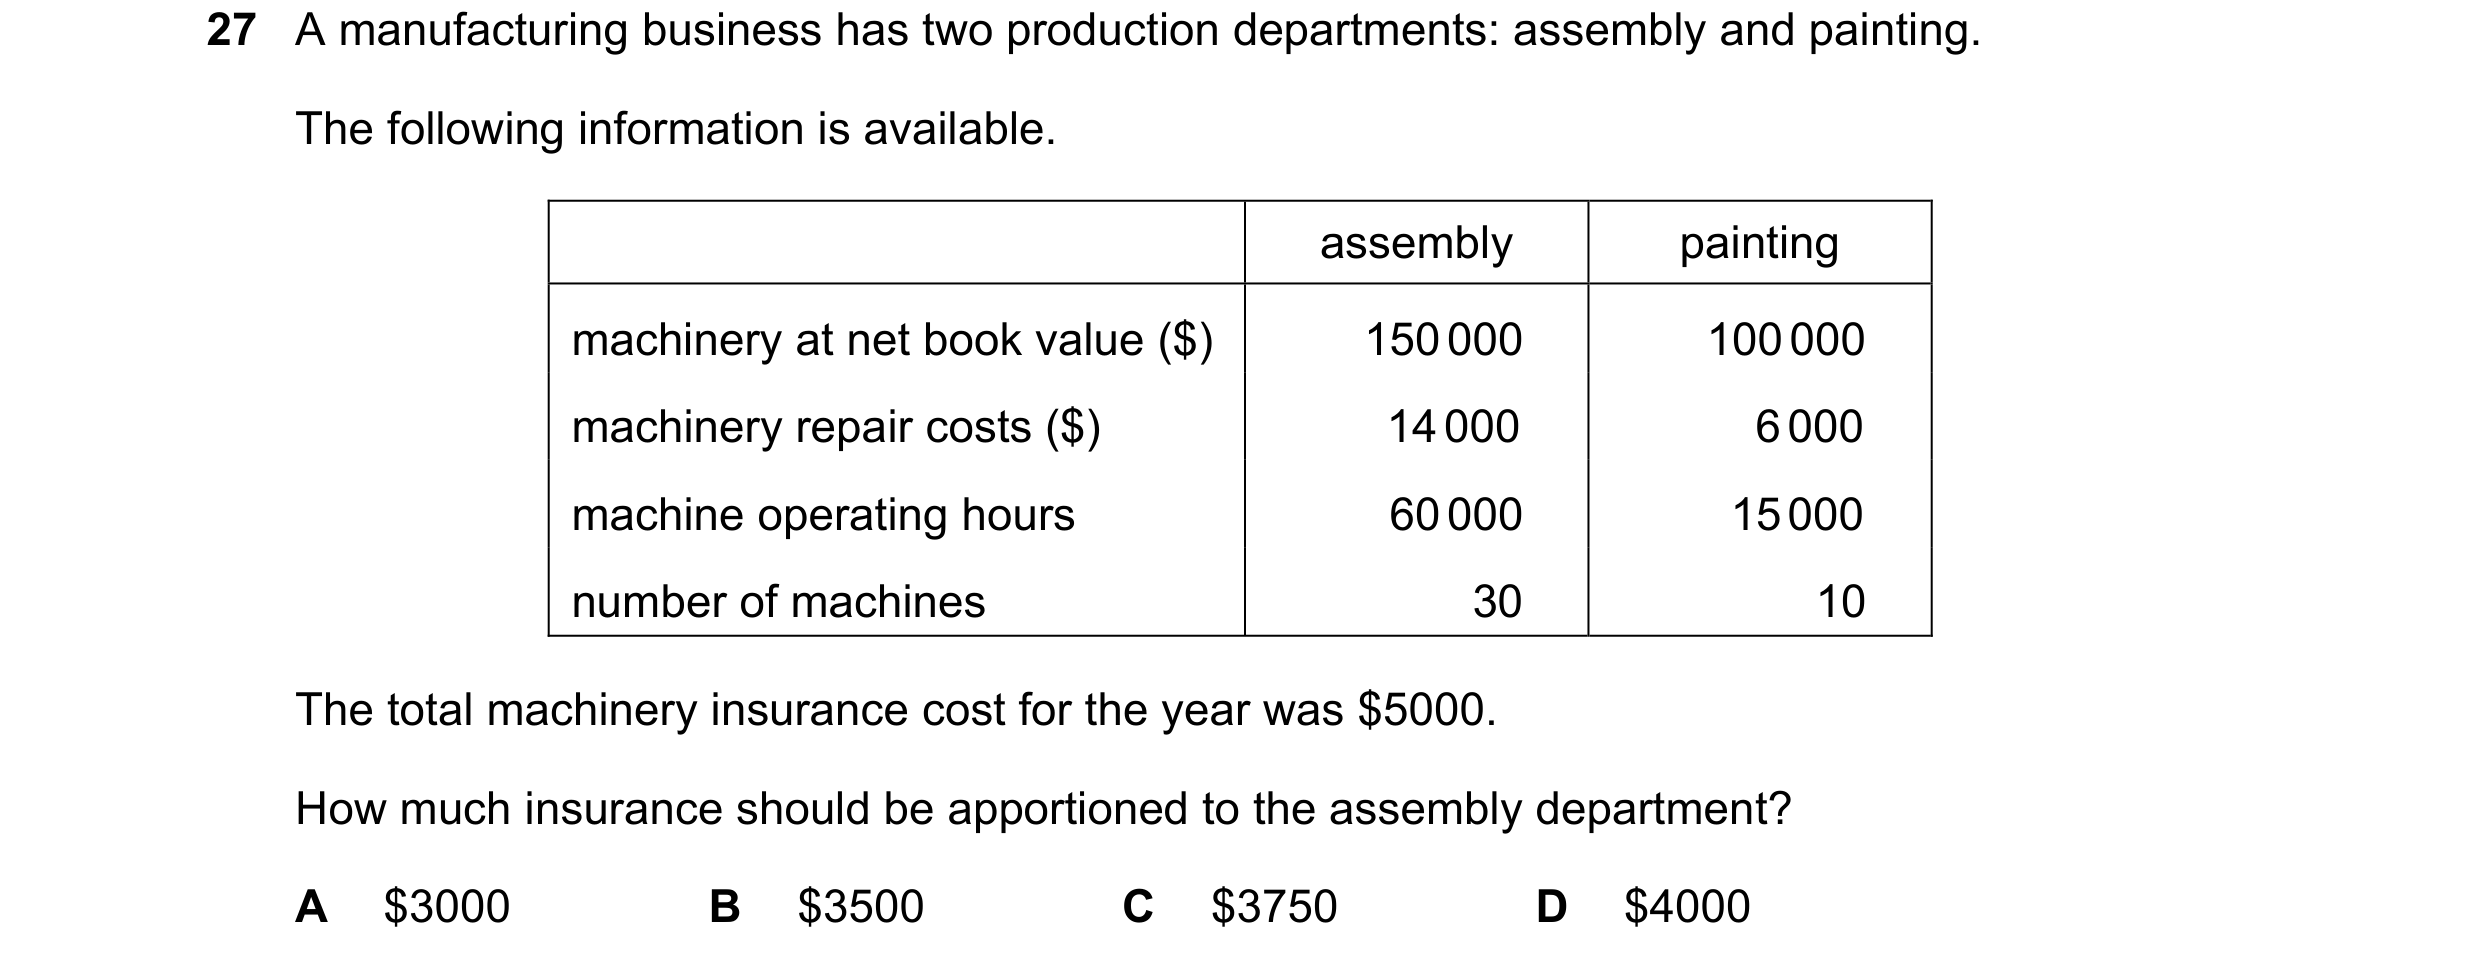
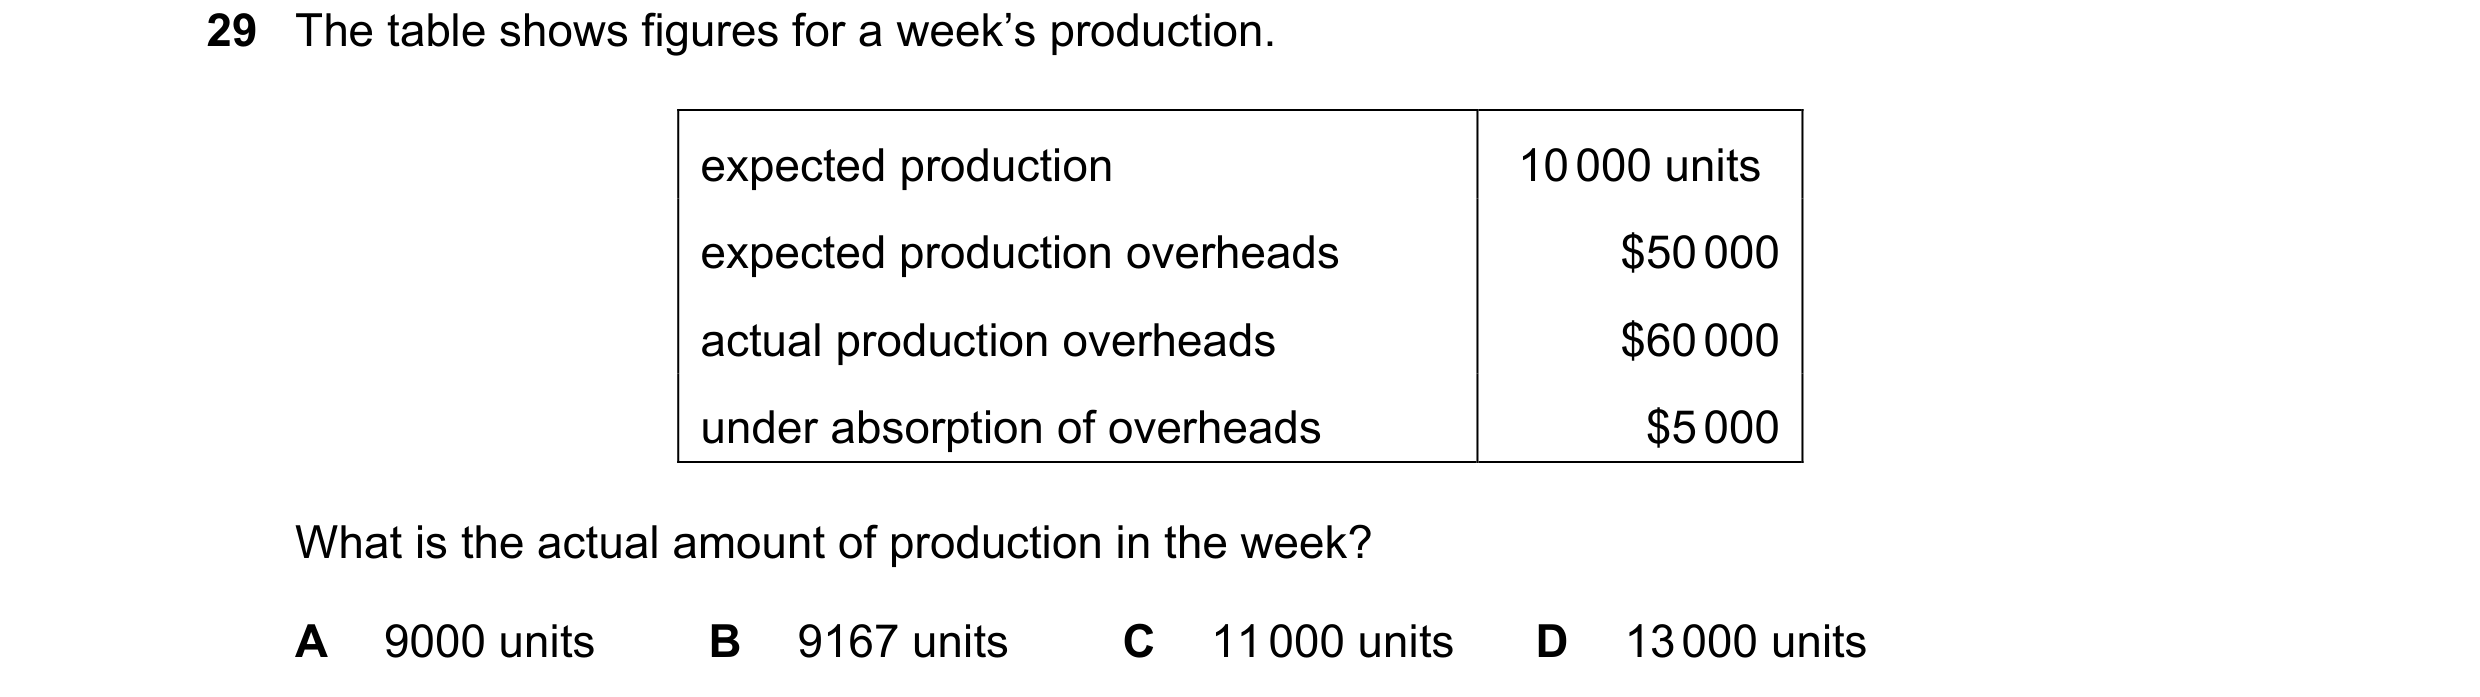 64 / 143
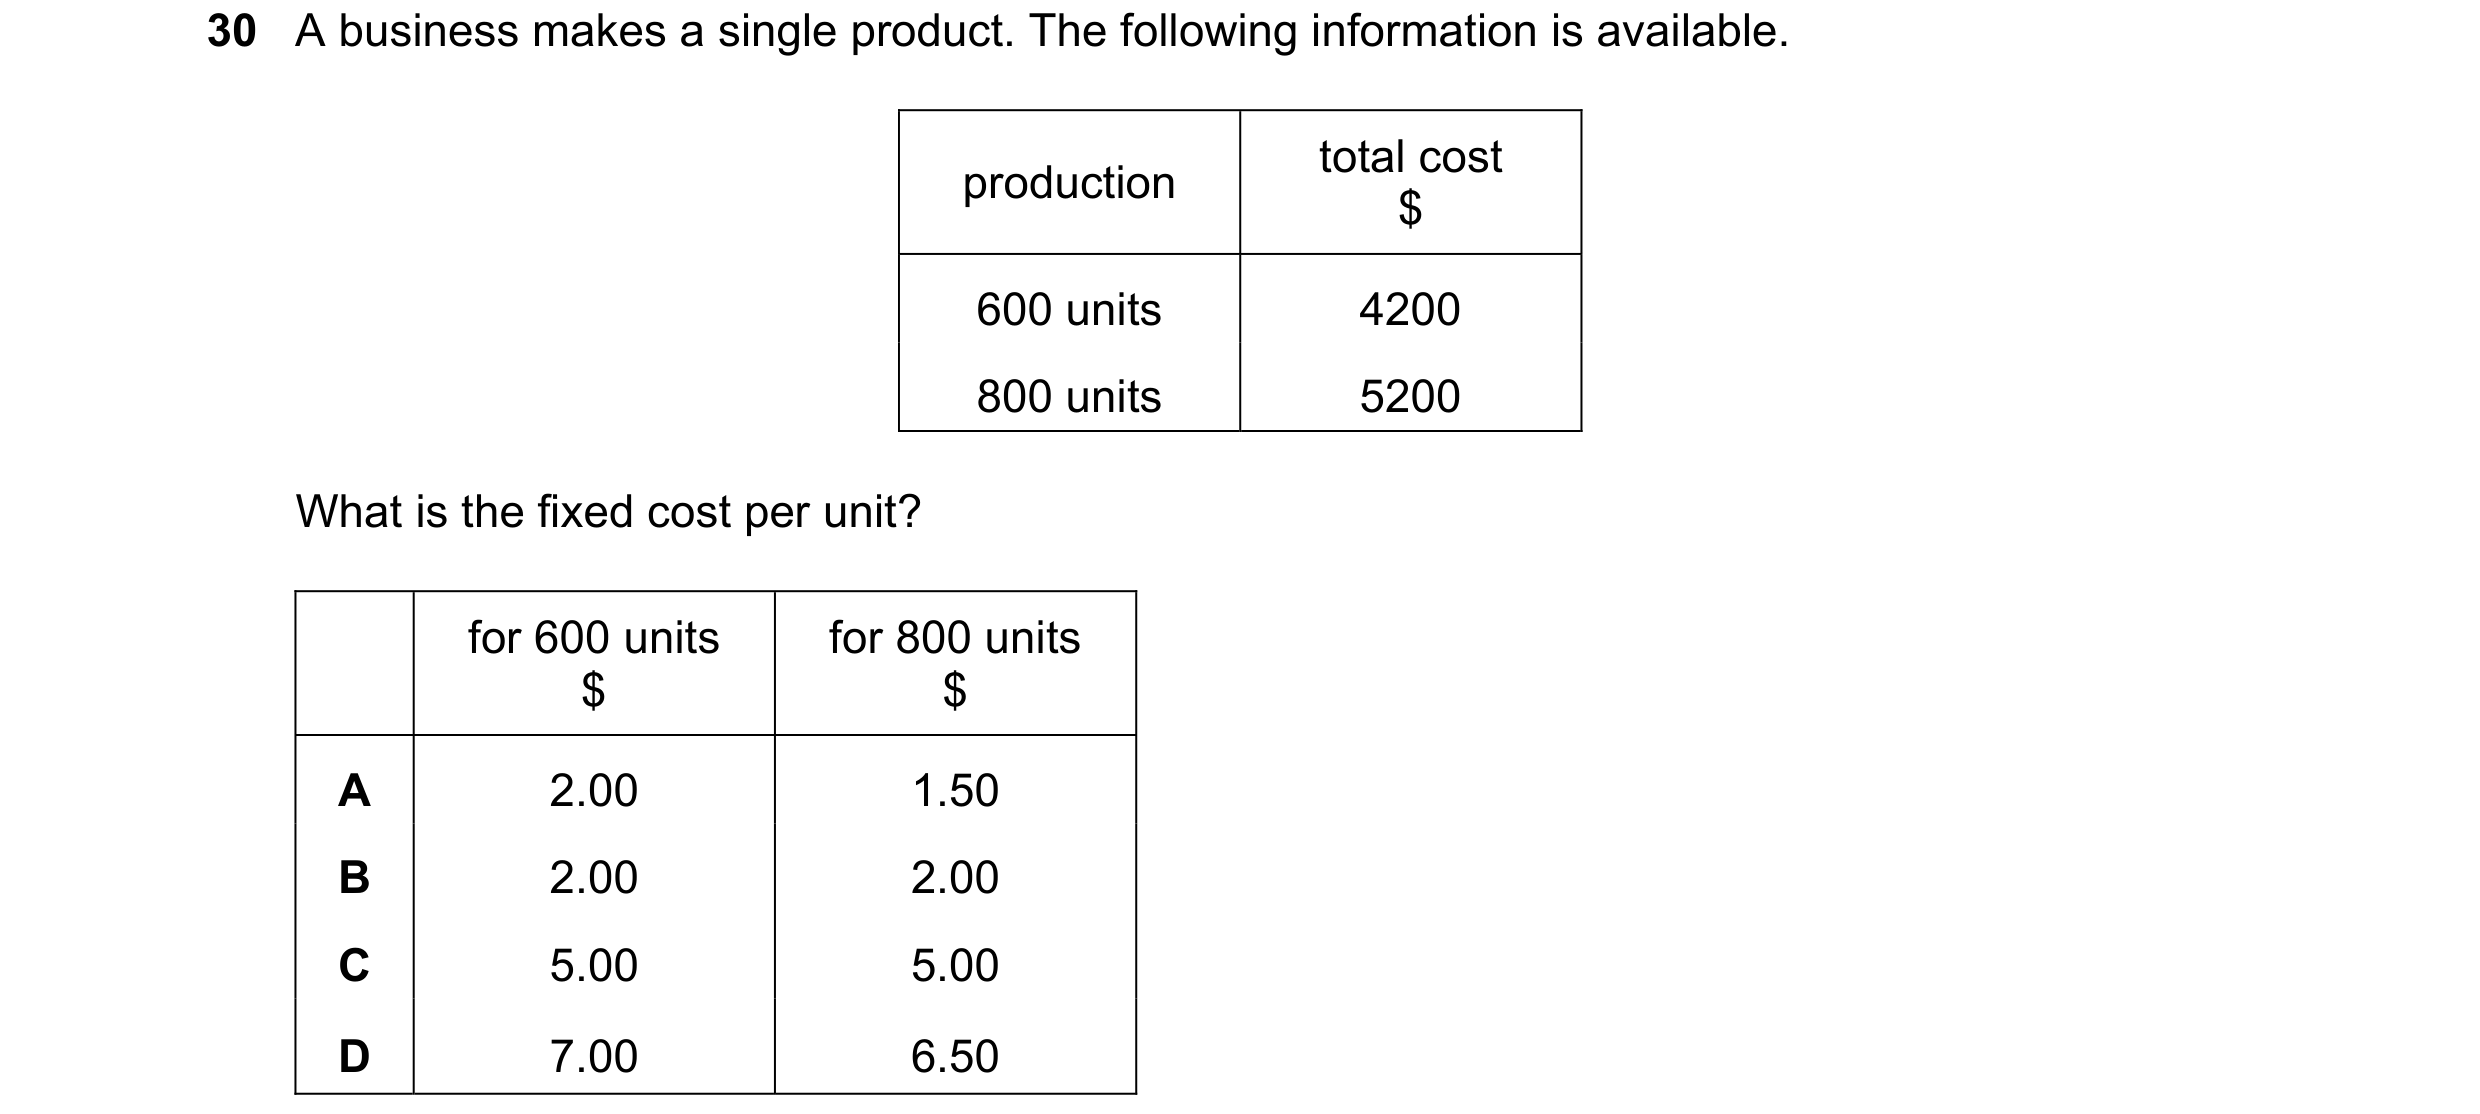
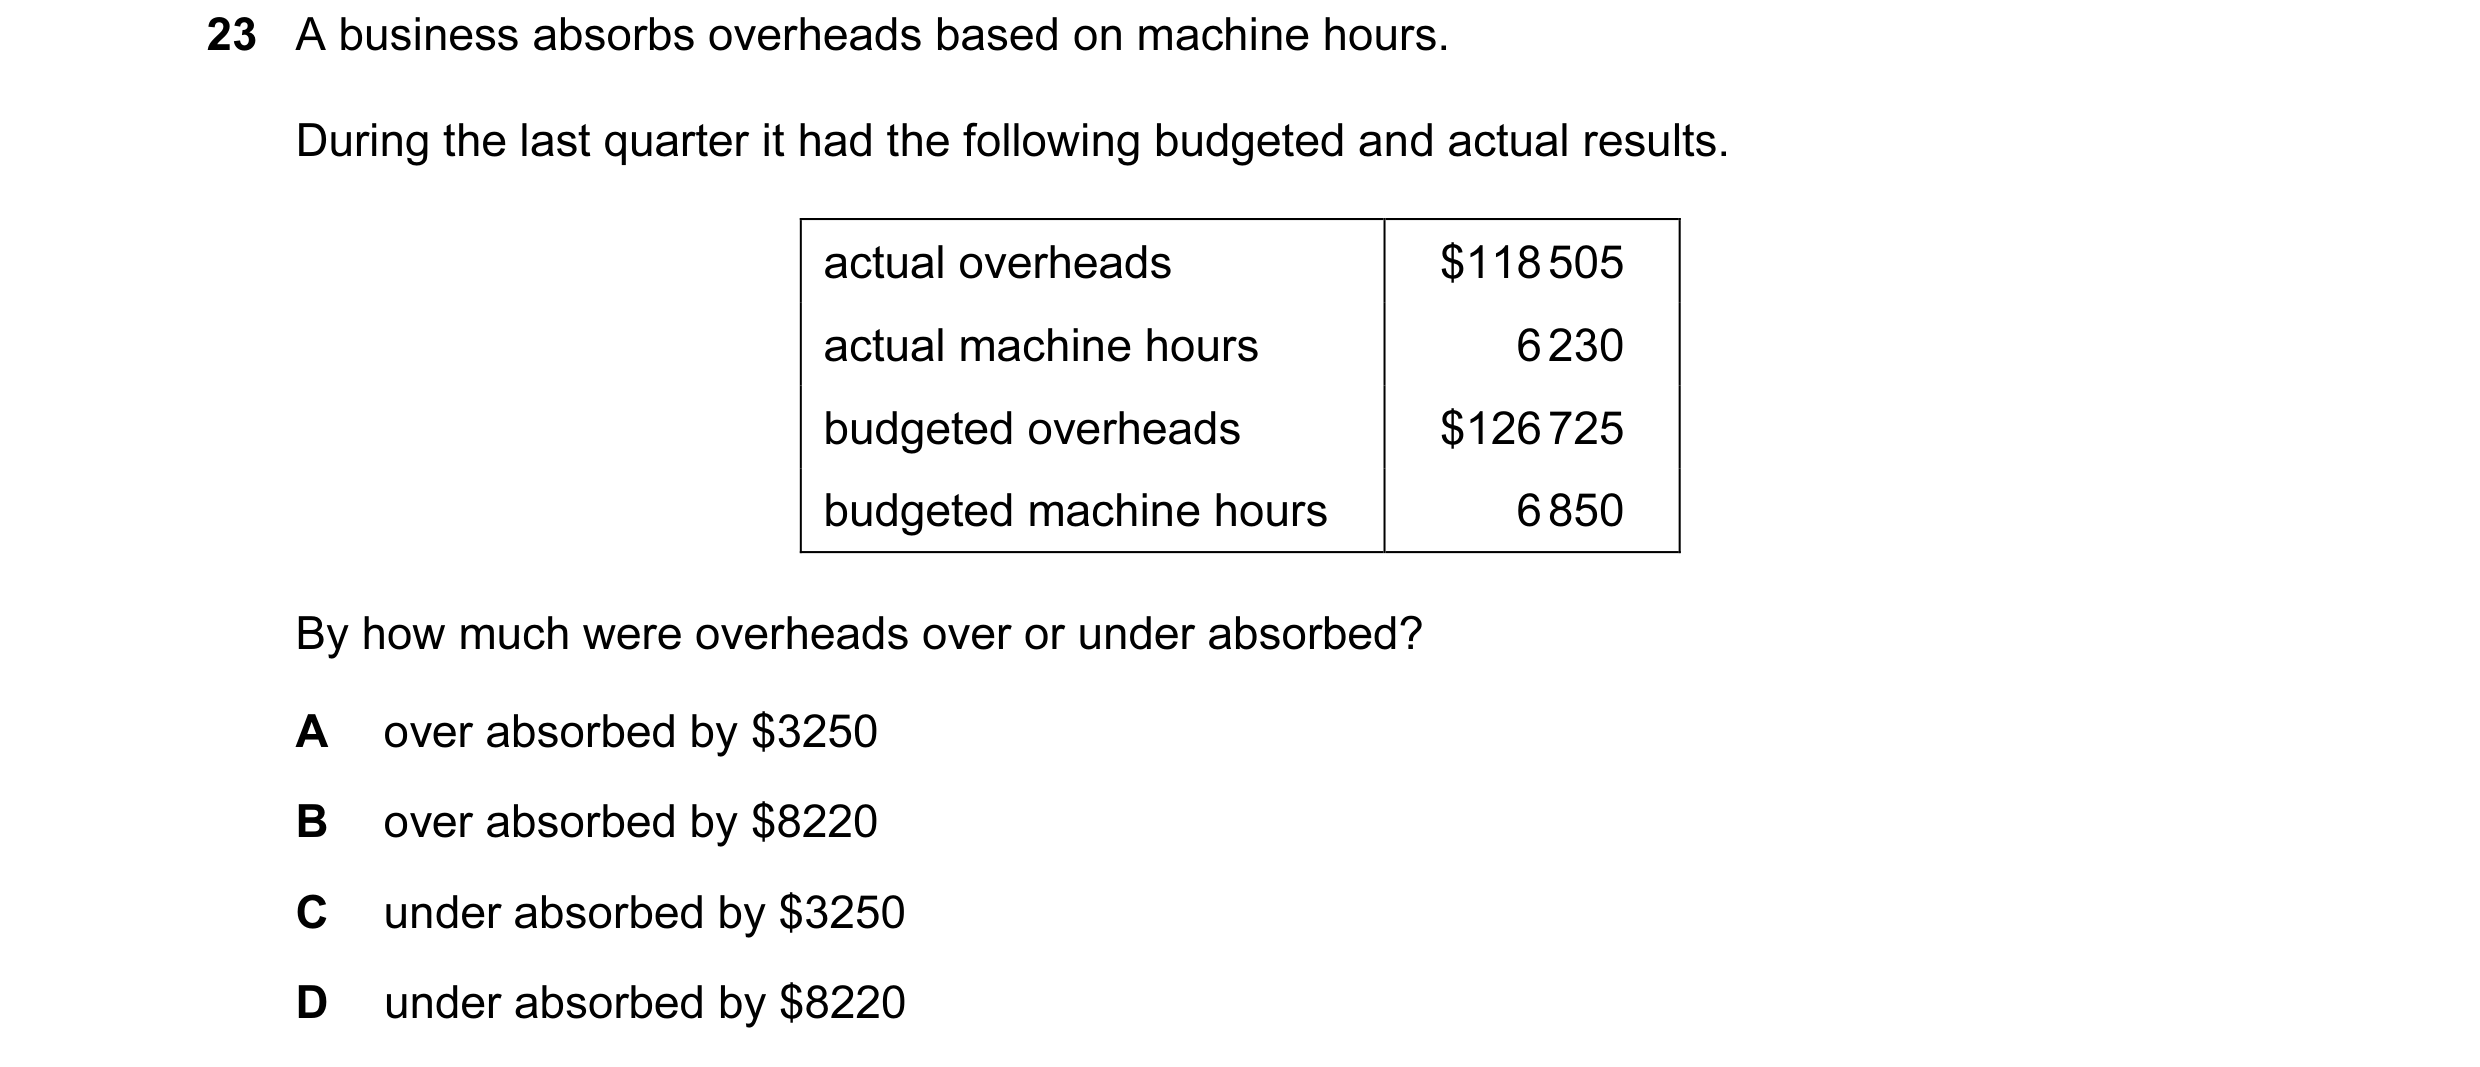
 65 / 143
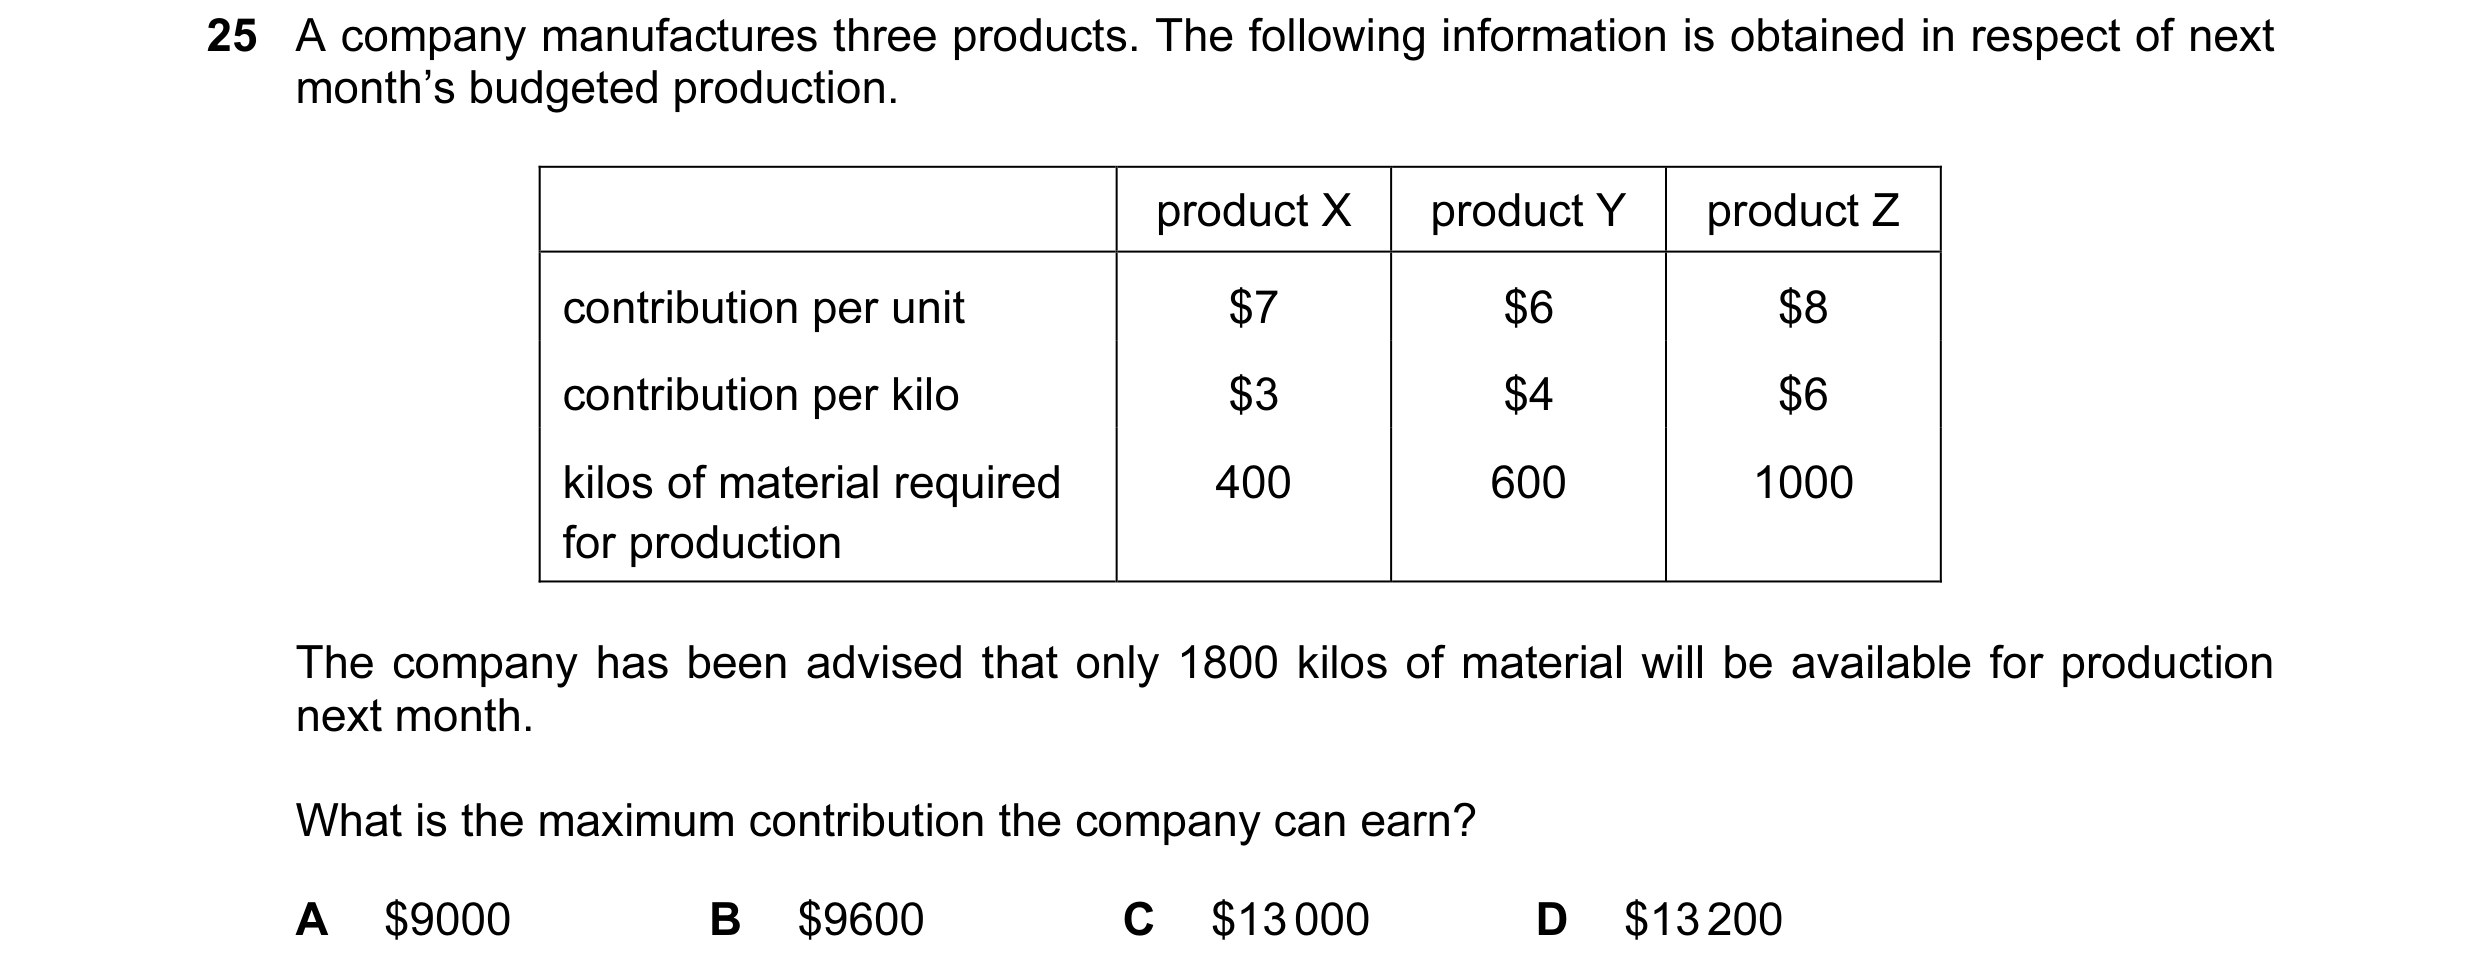
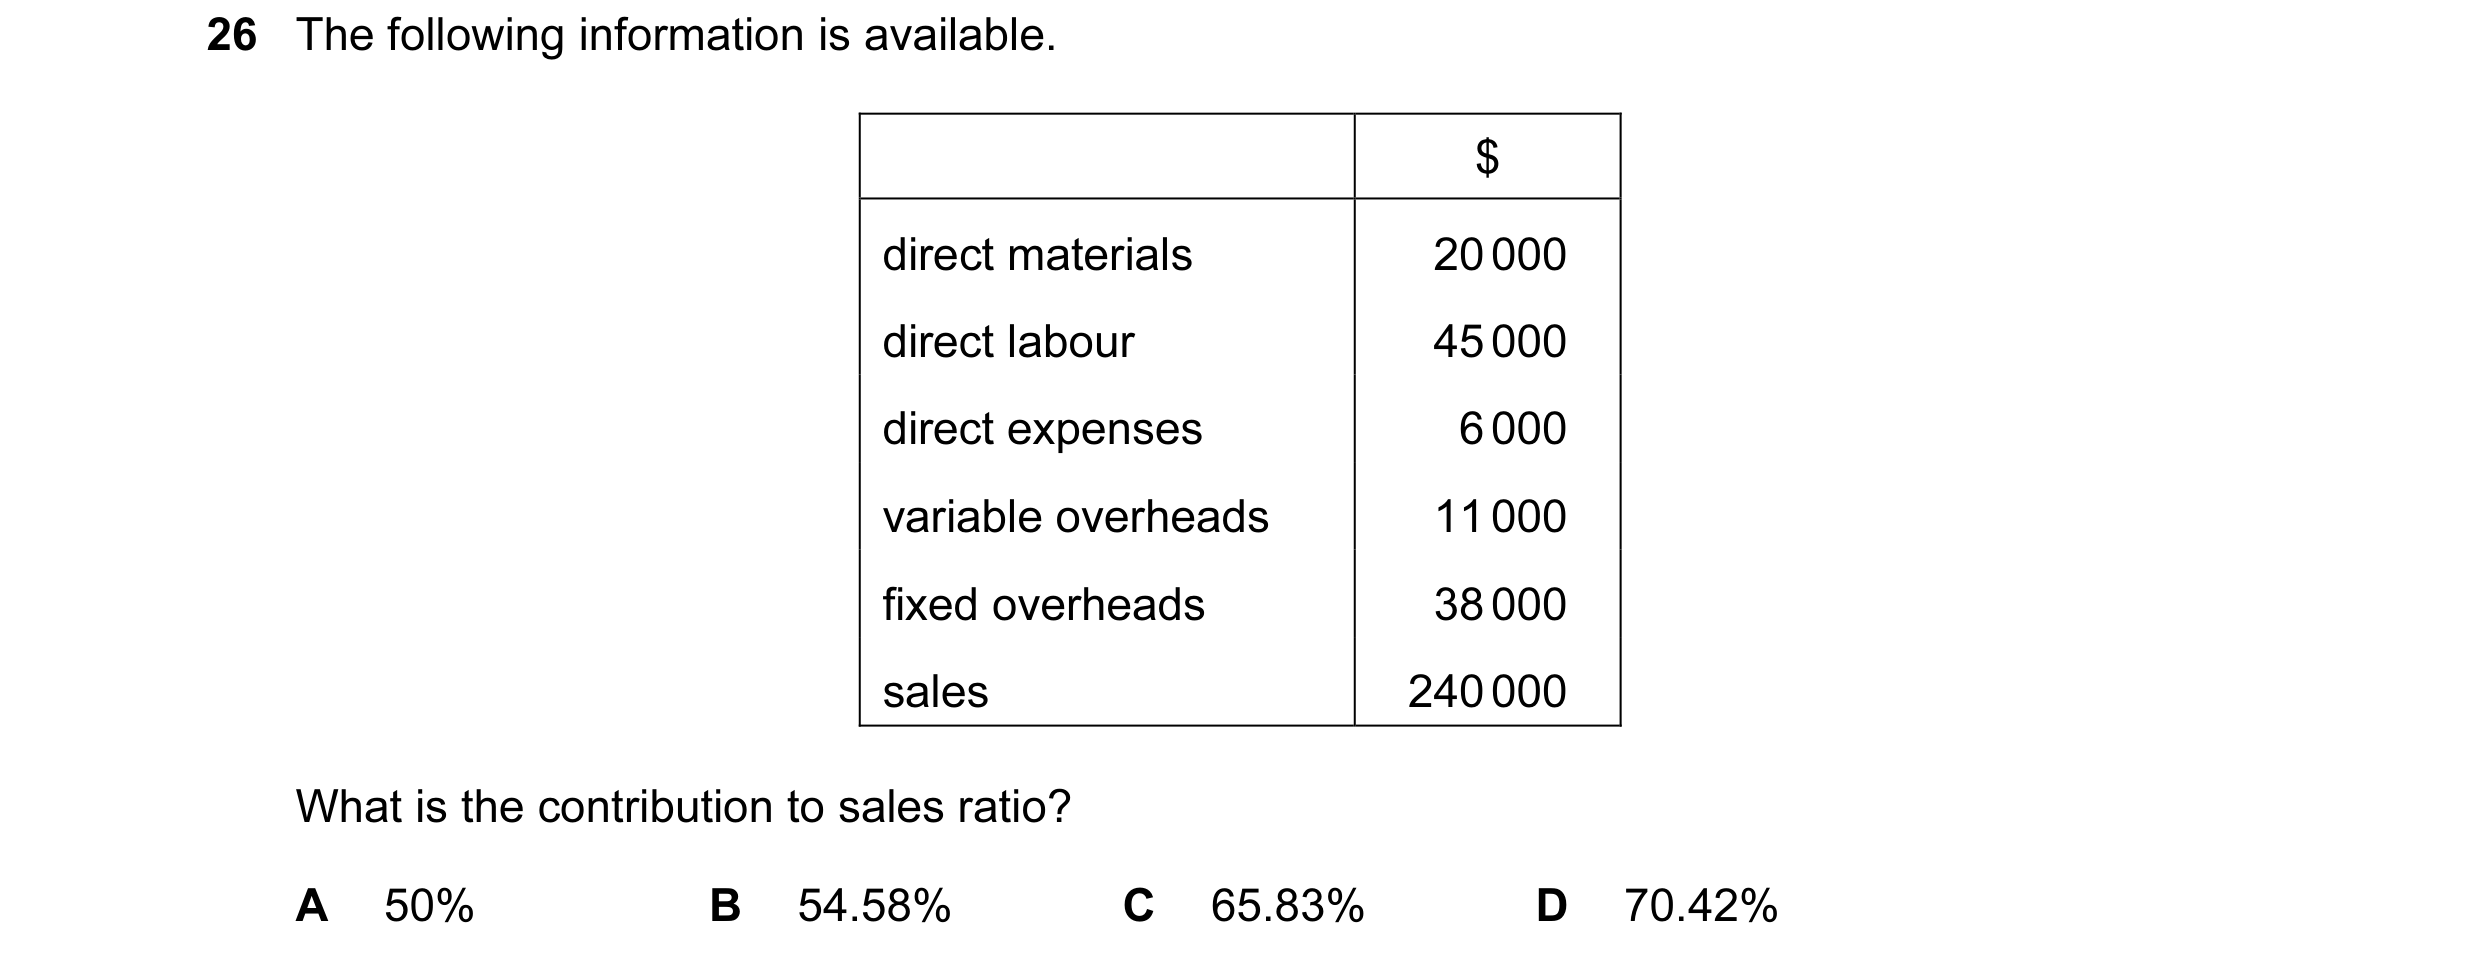
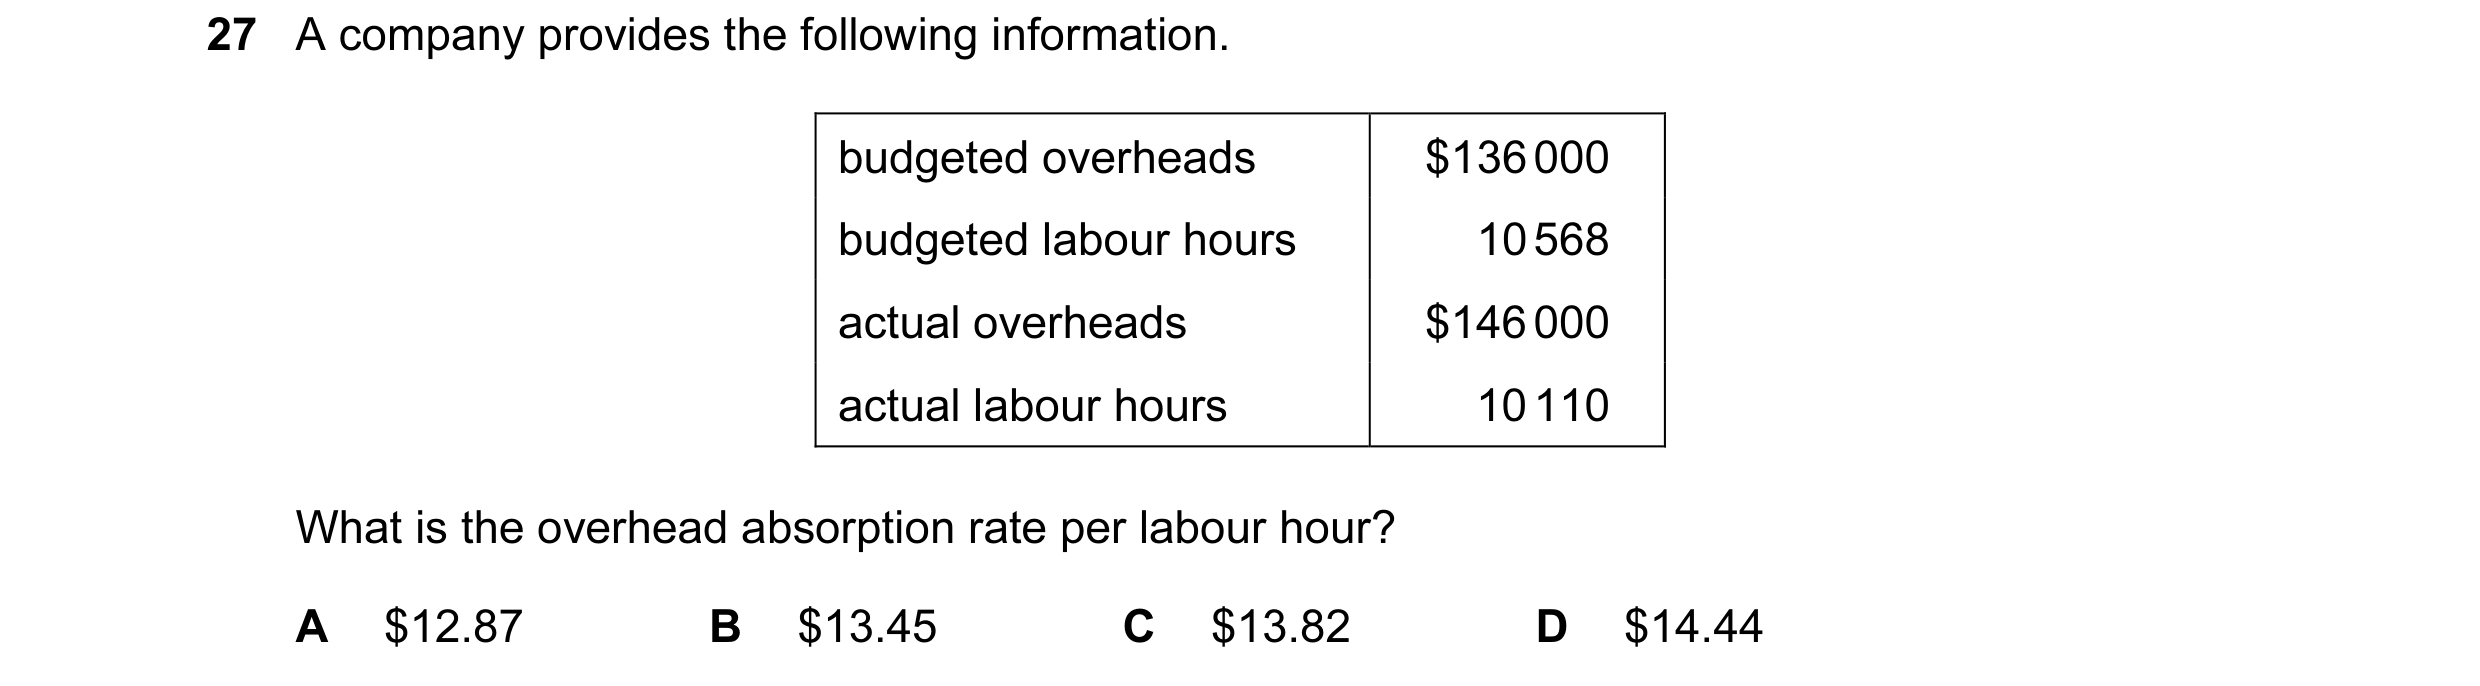 66 / 143
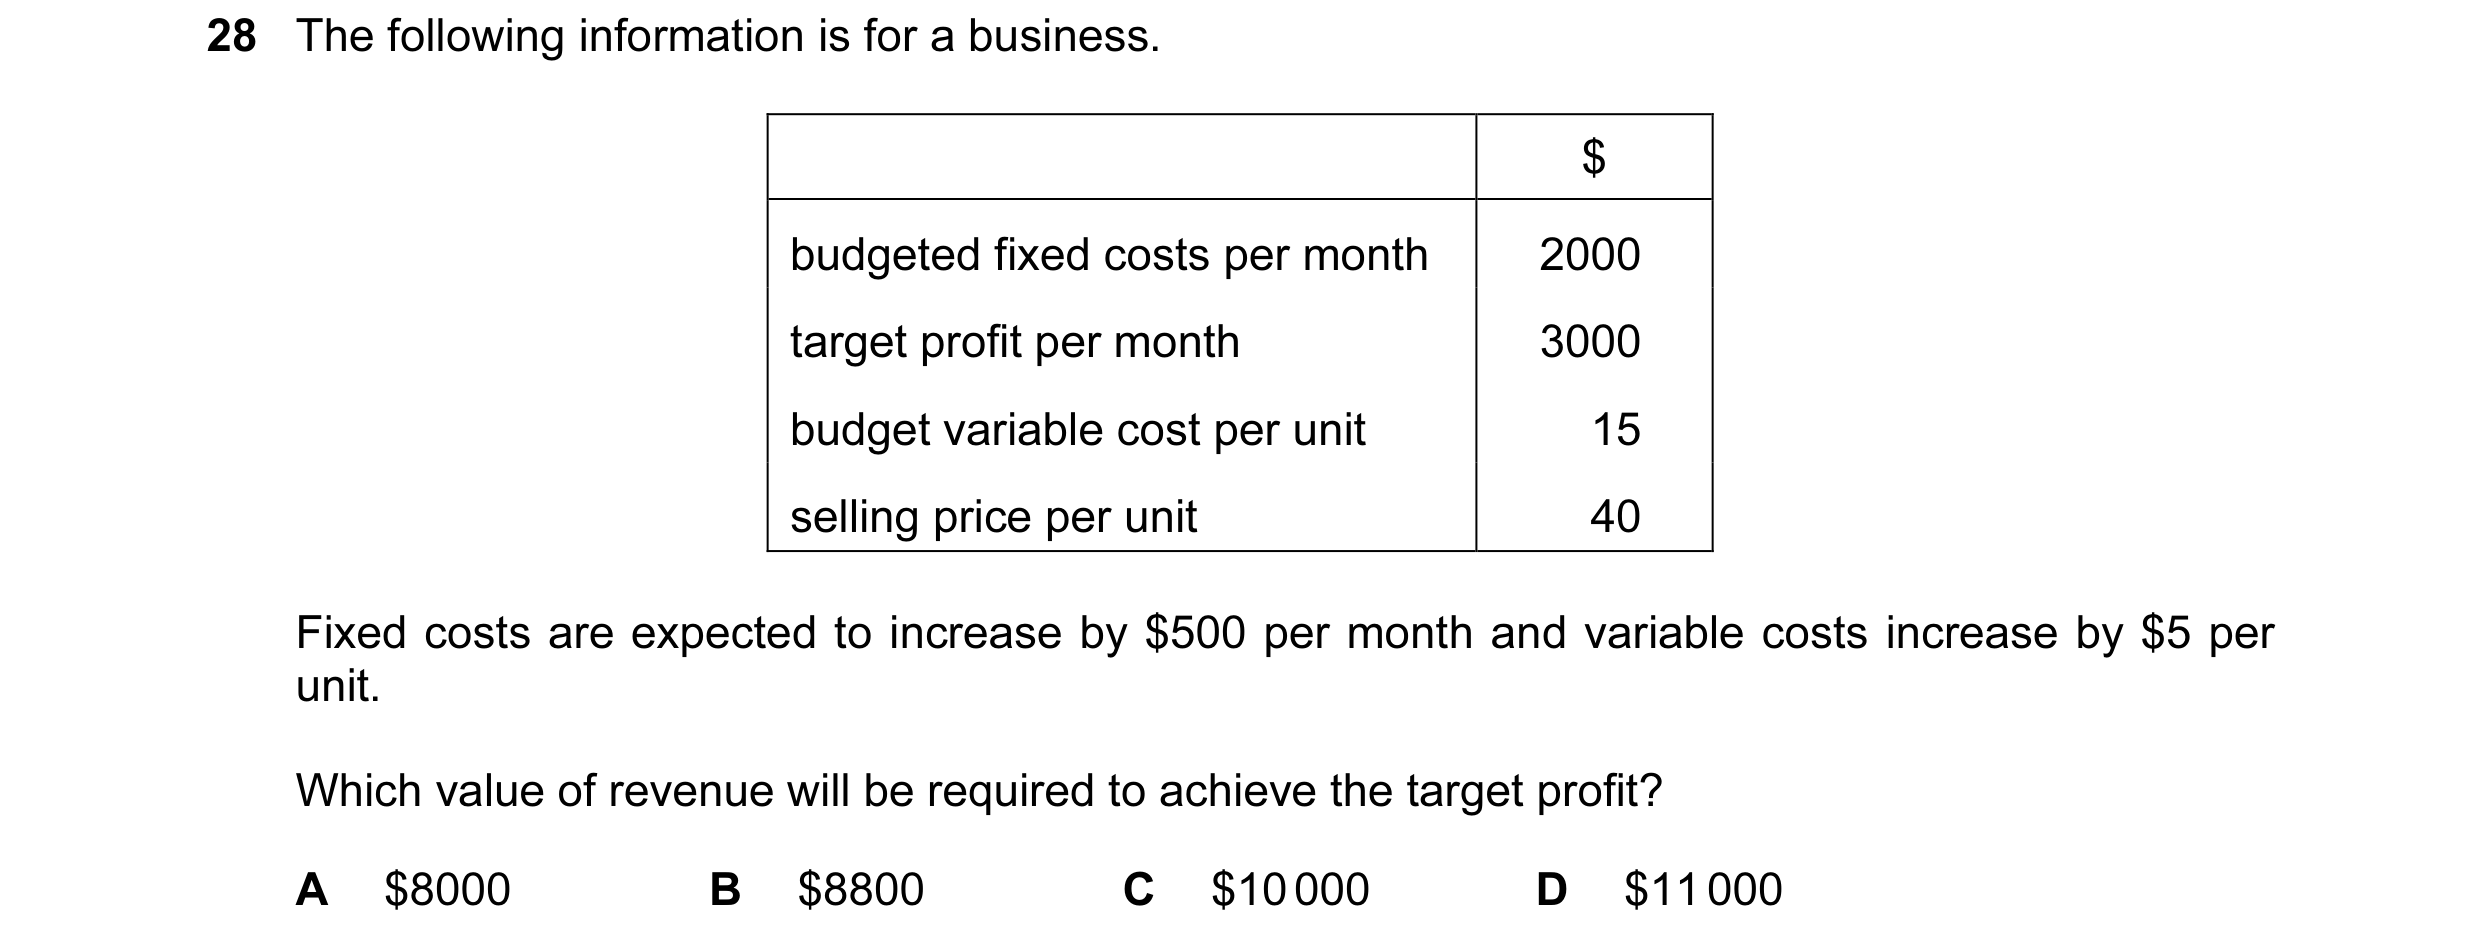
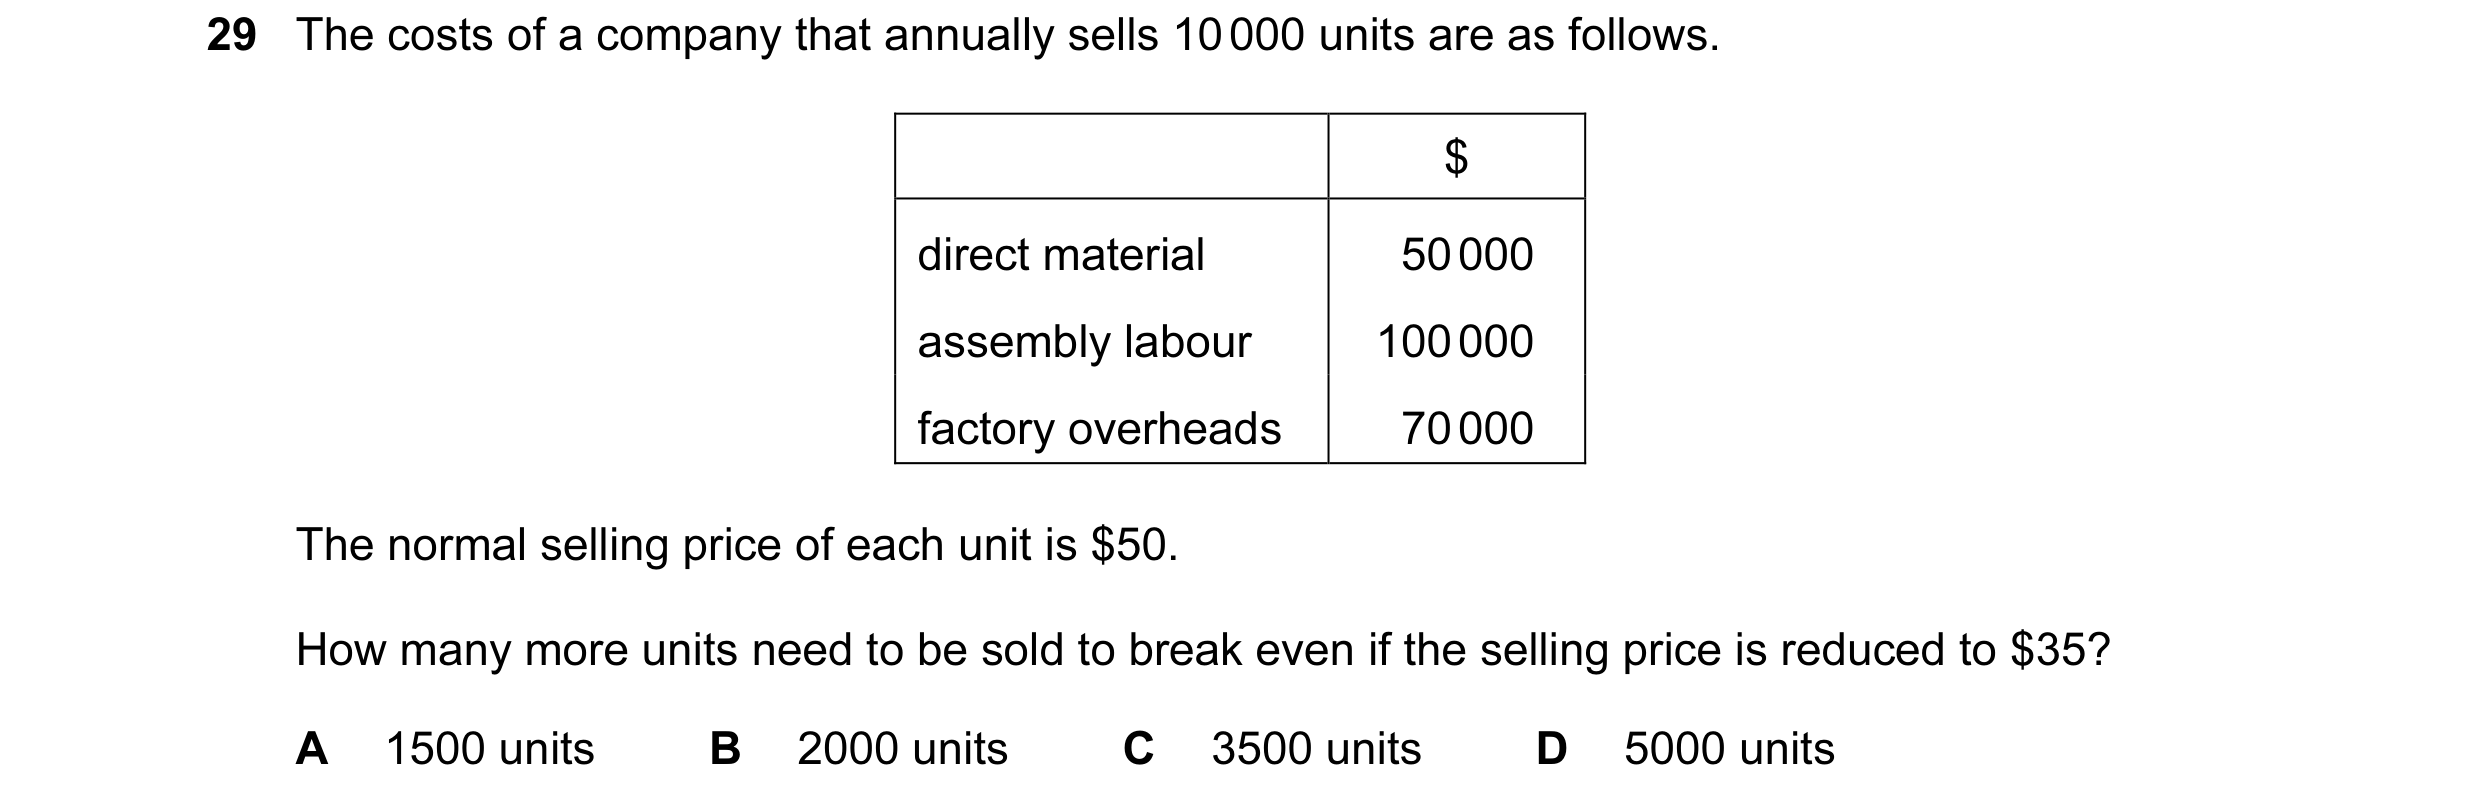
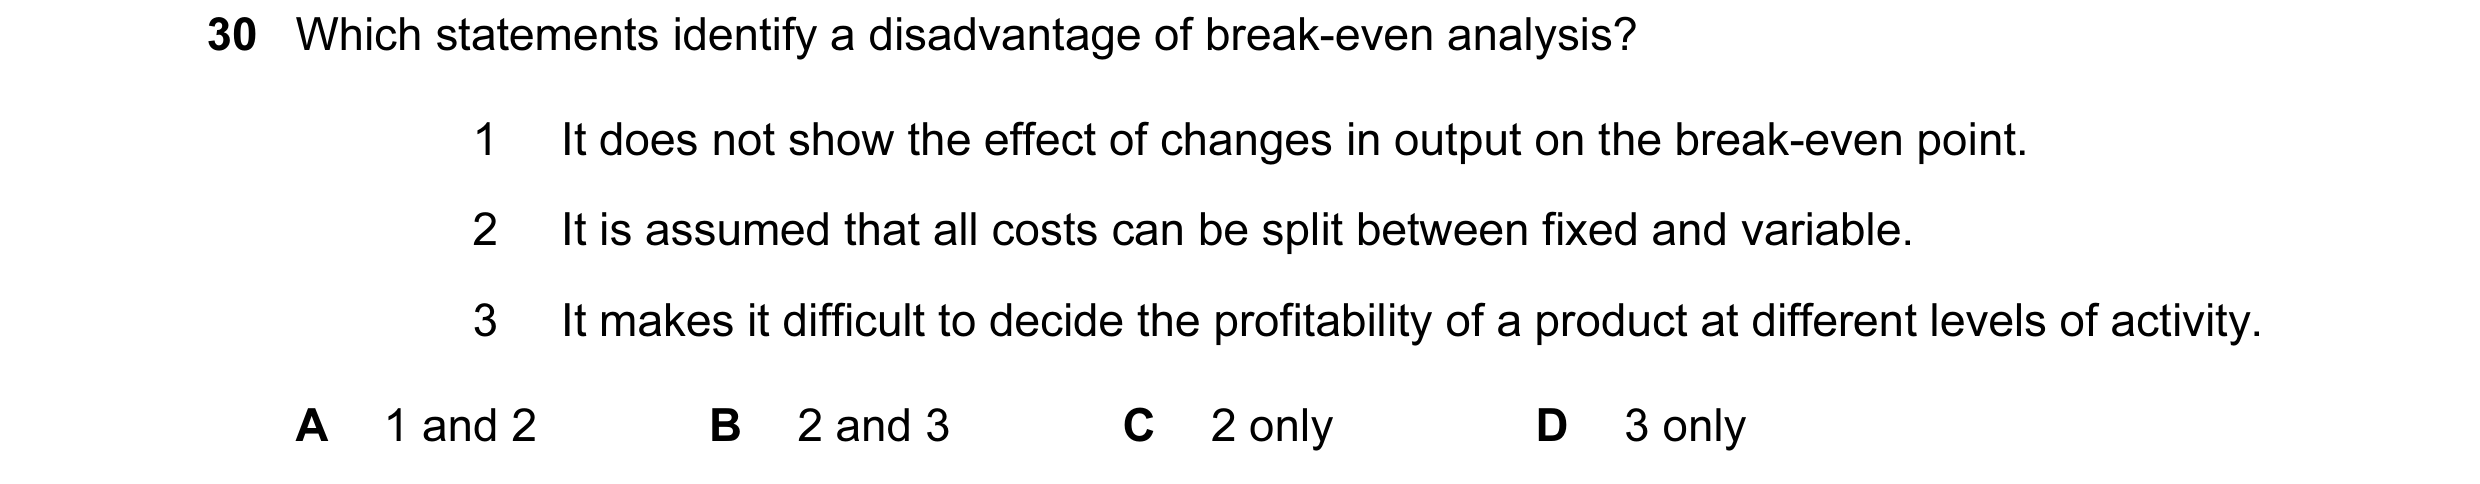
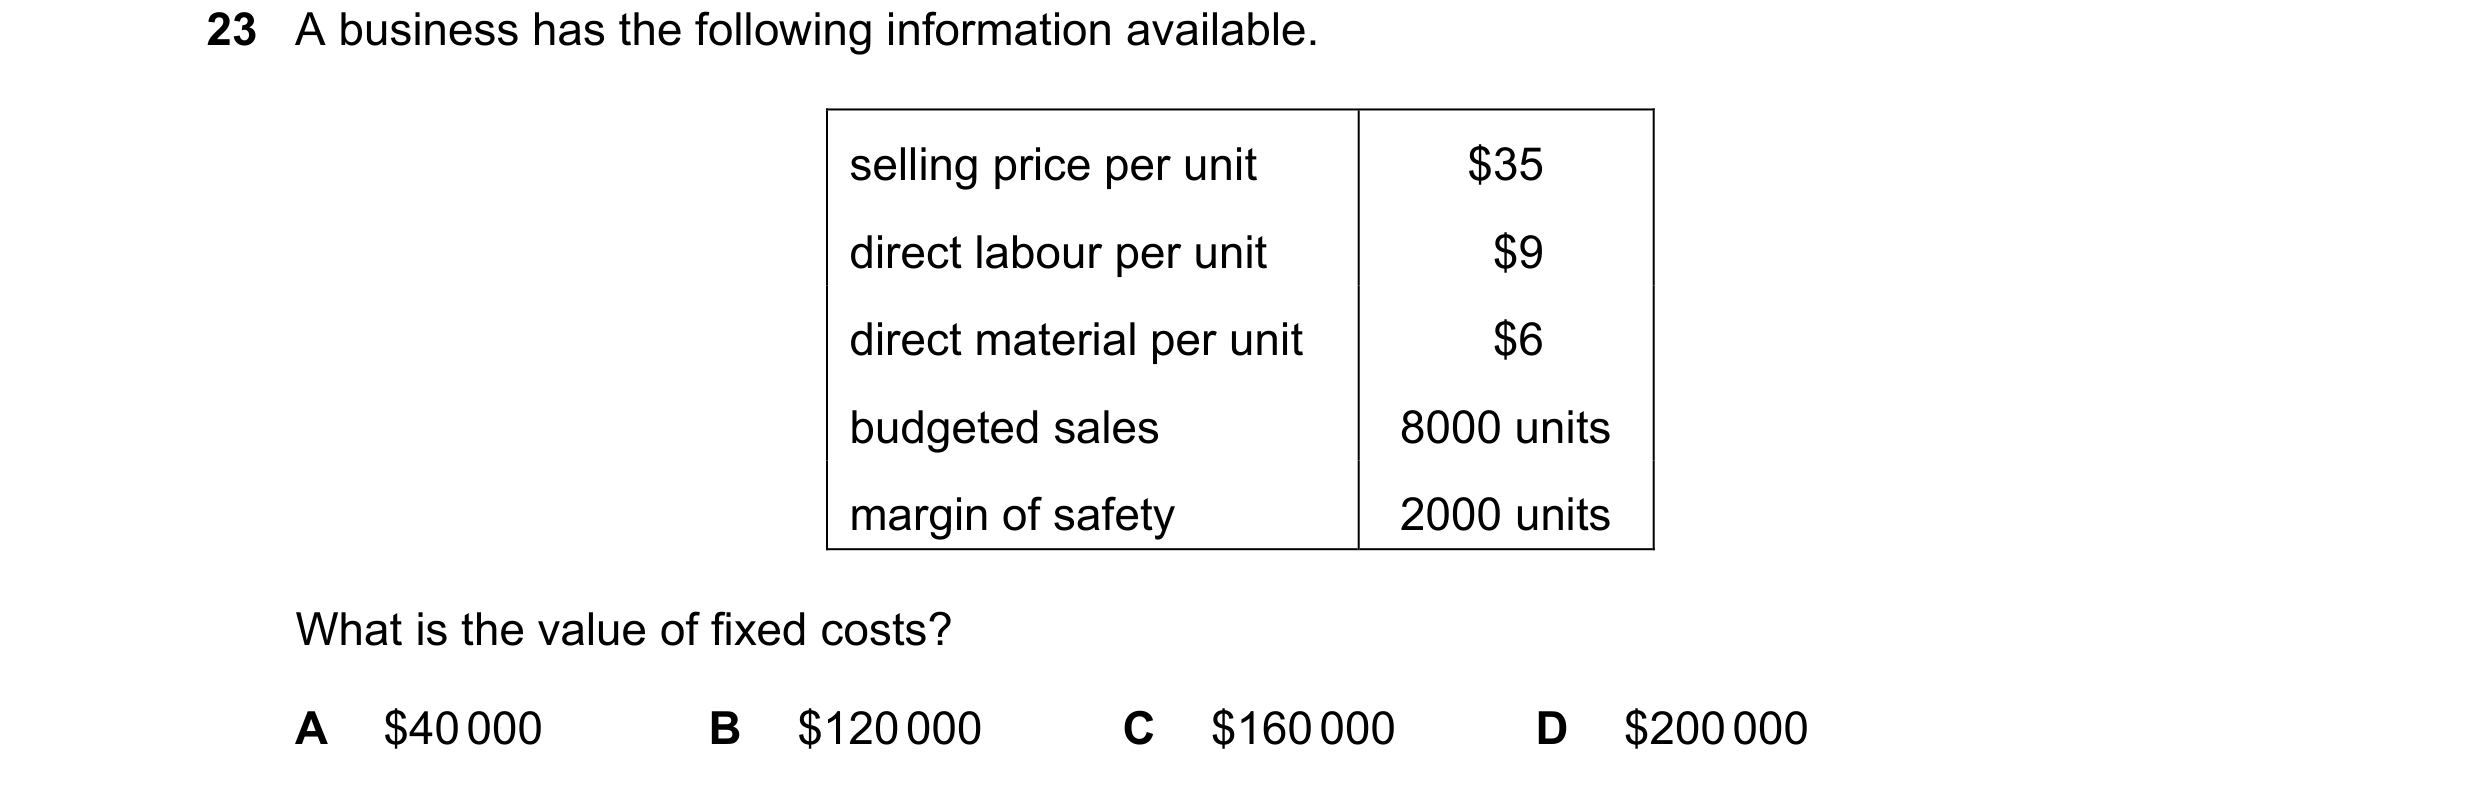 67 / 143
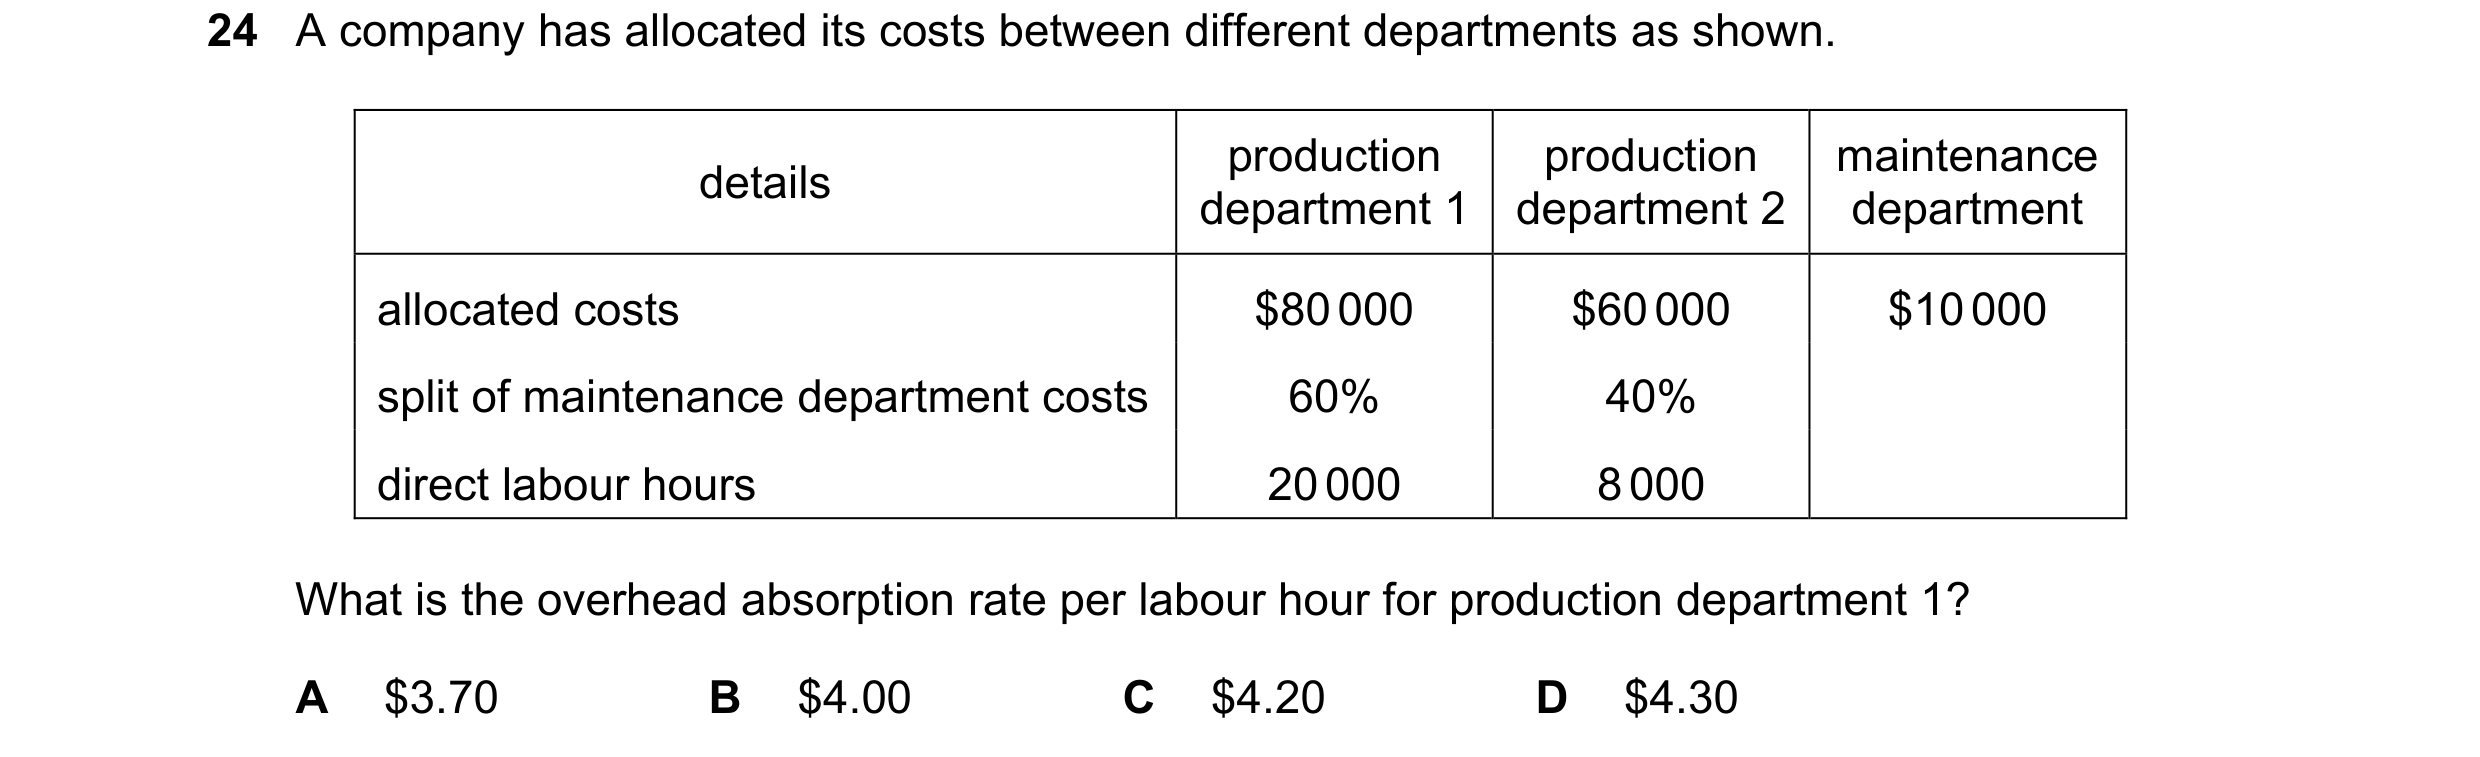
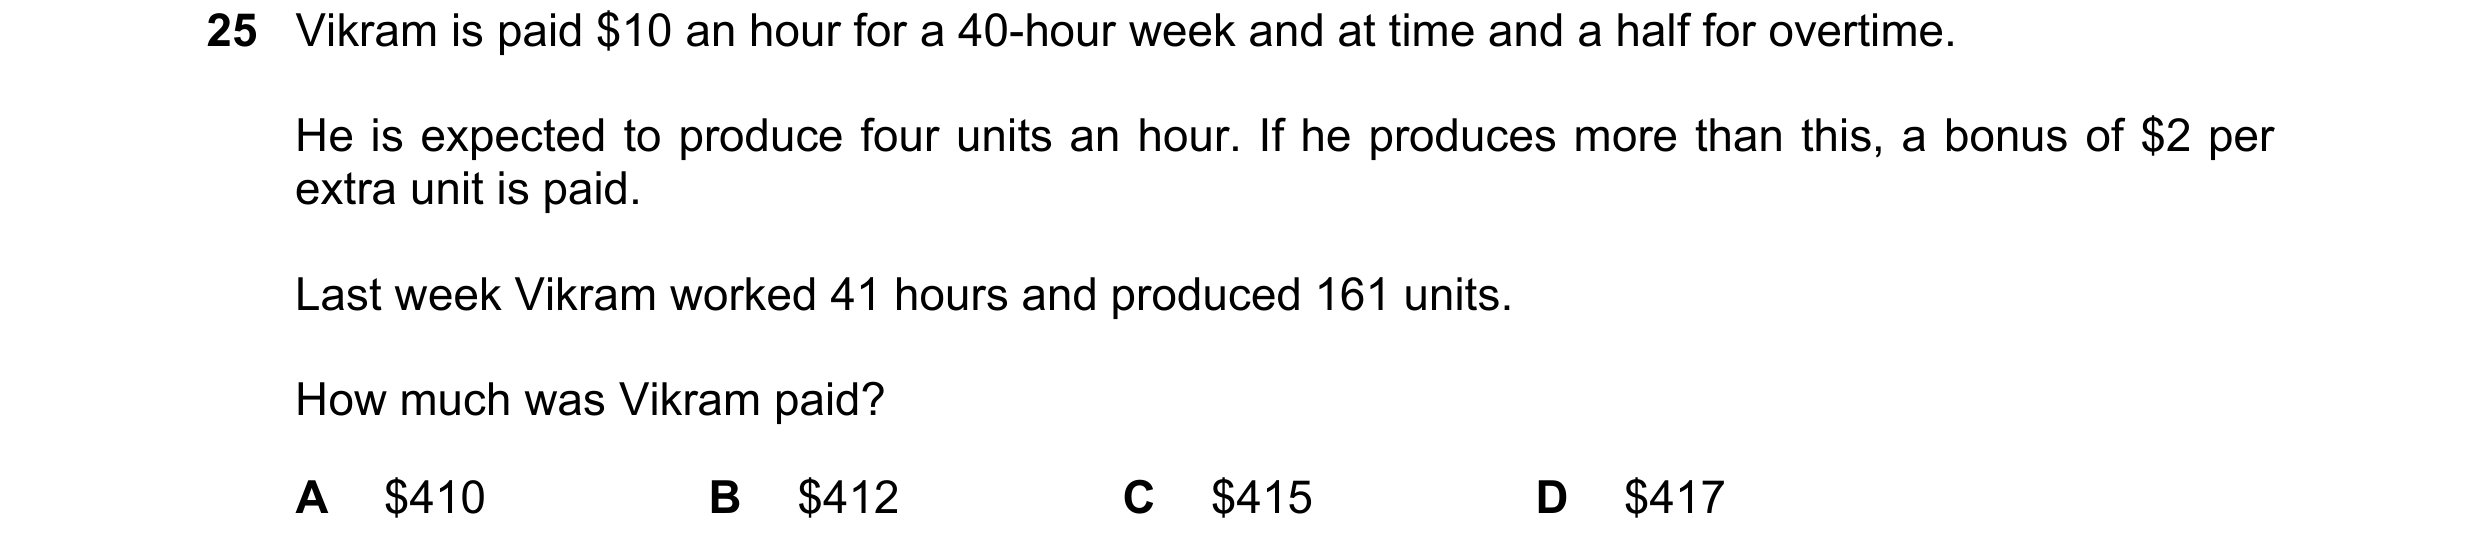
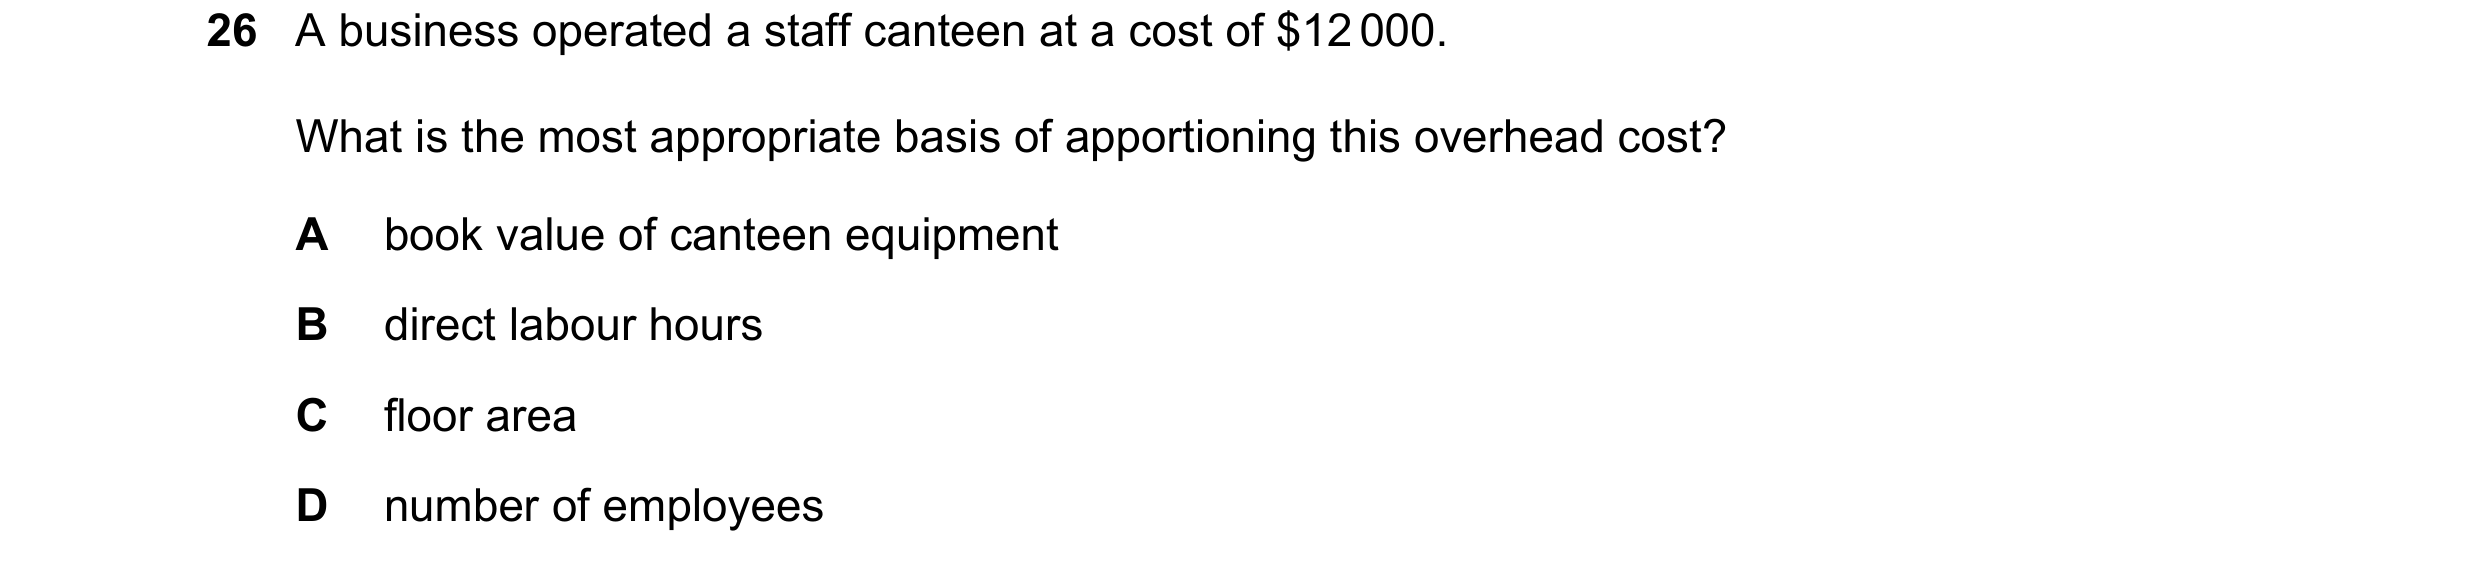
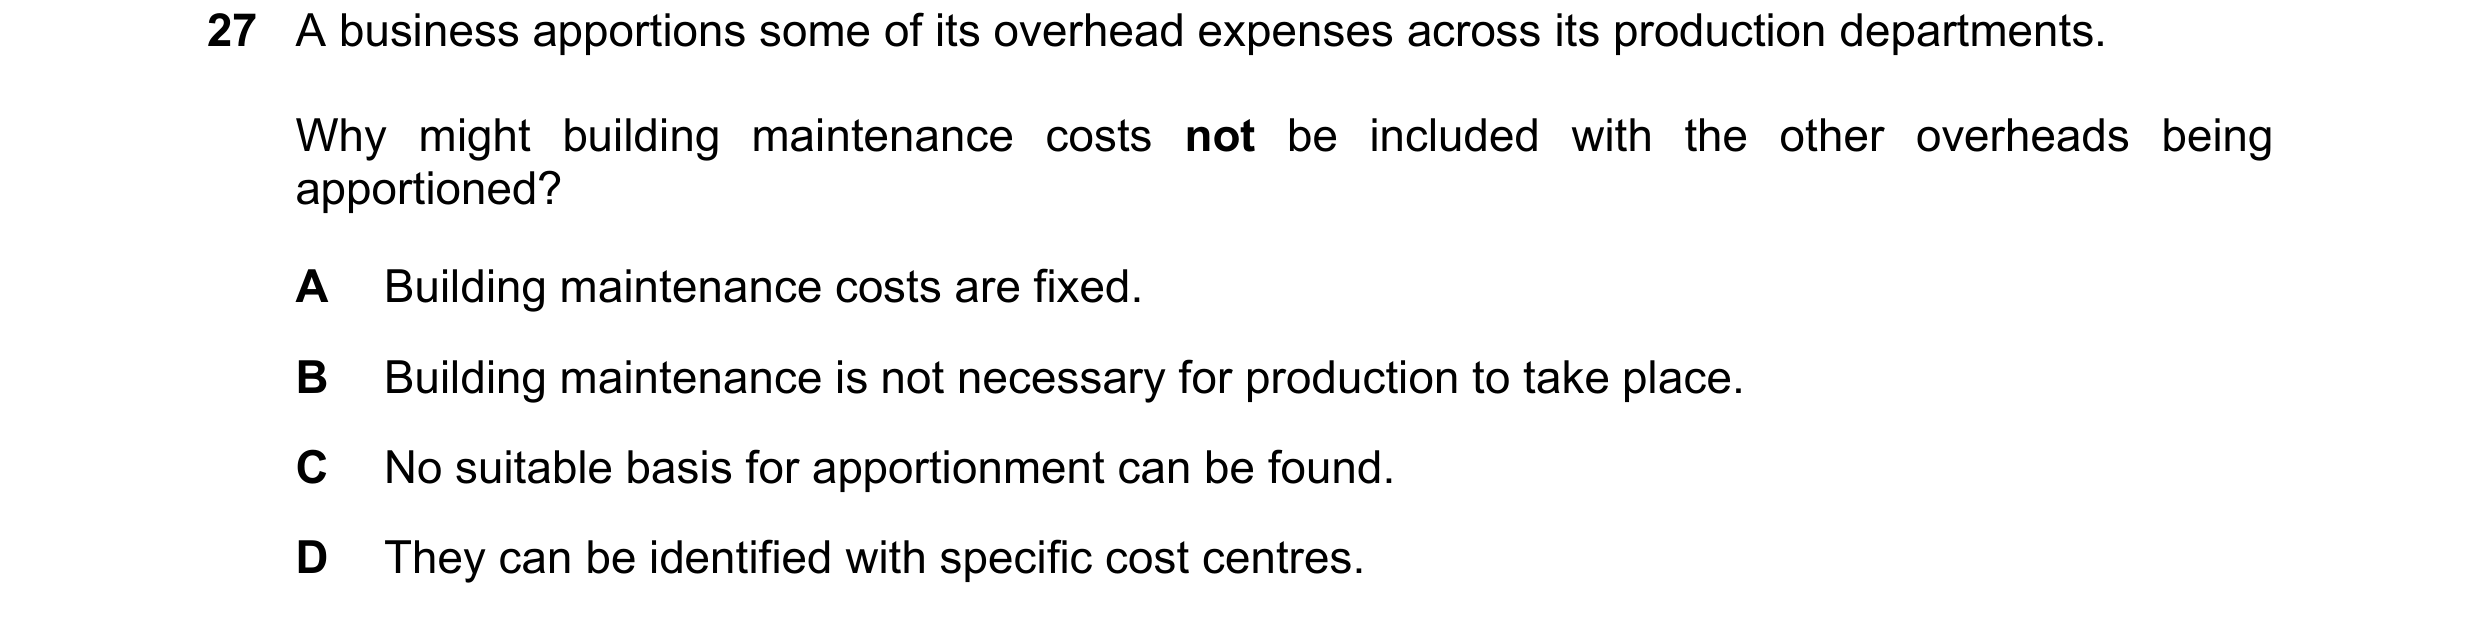 68 / 143
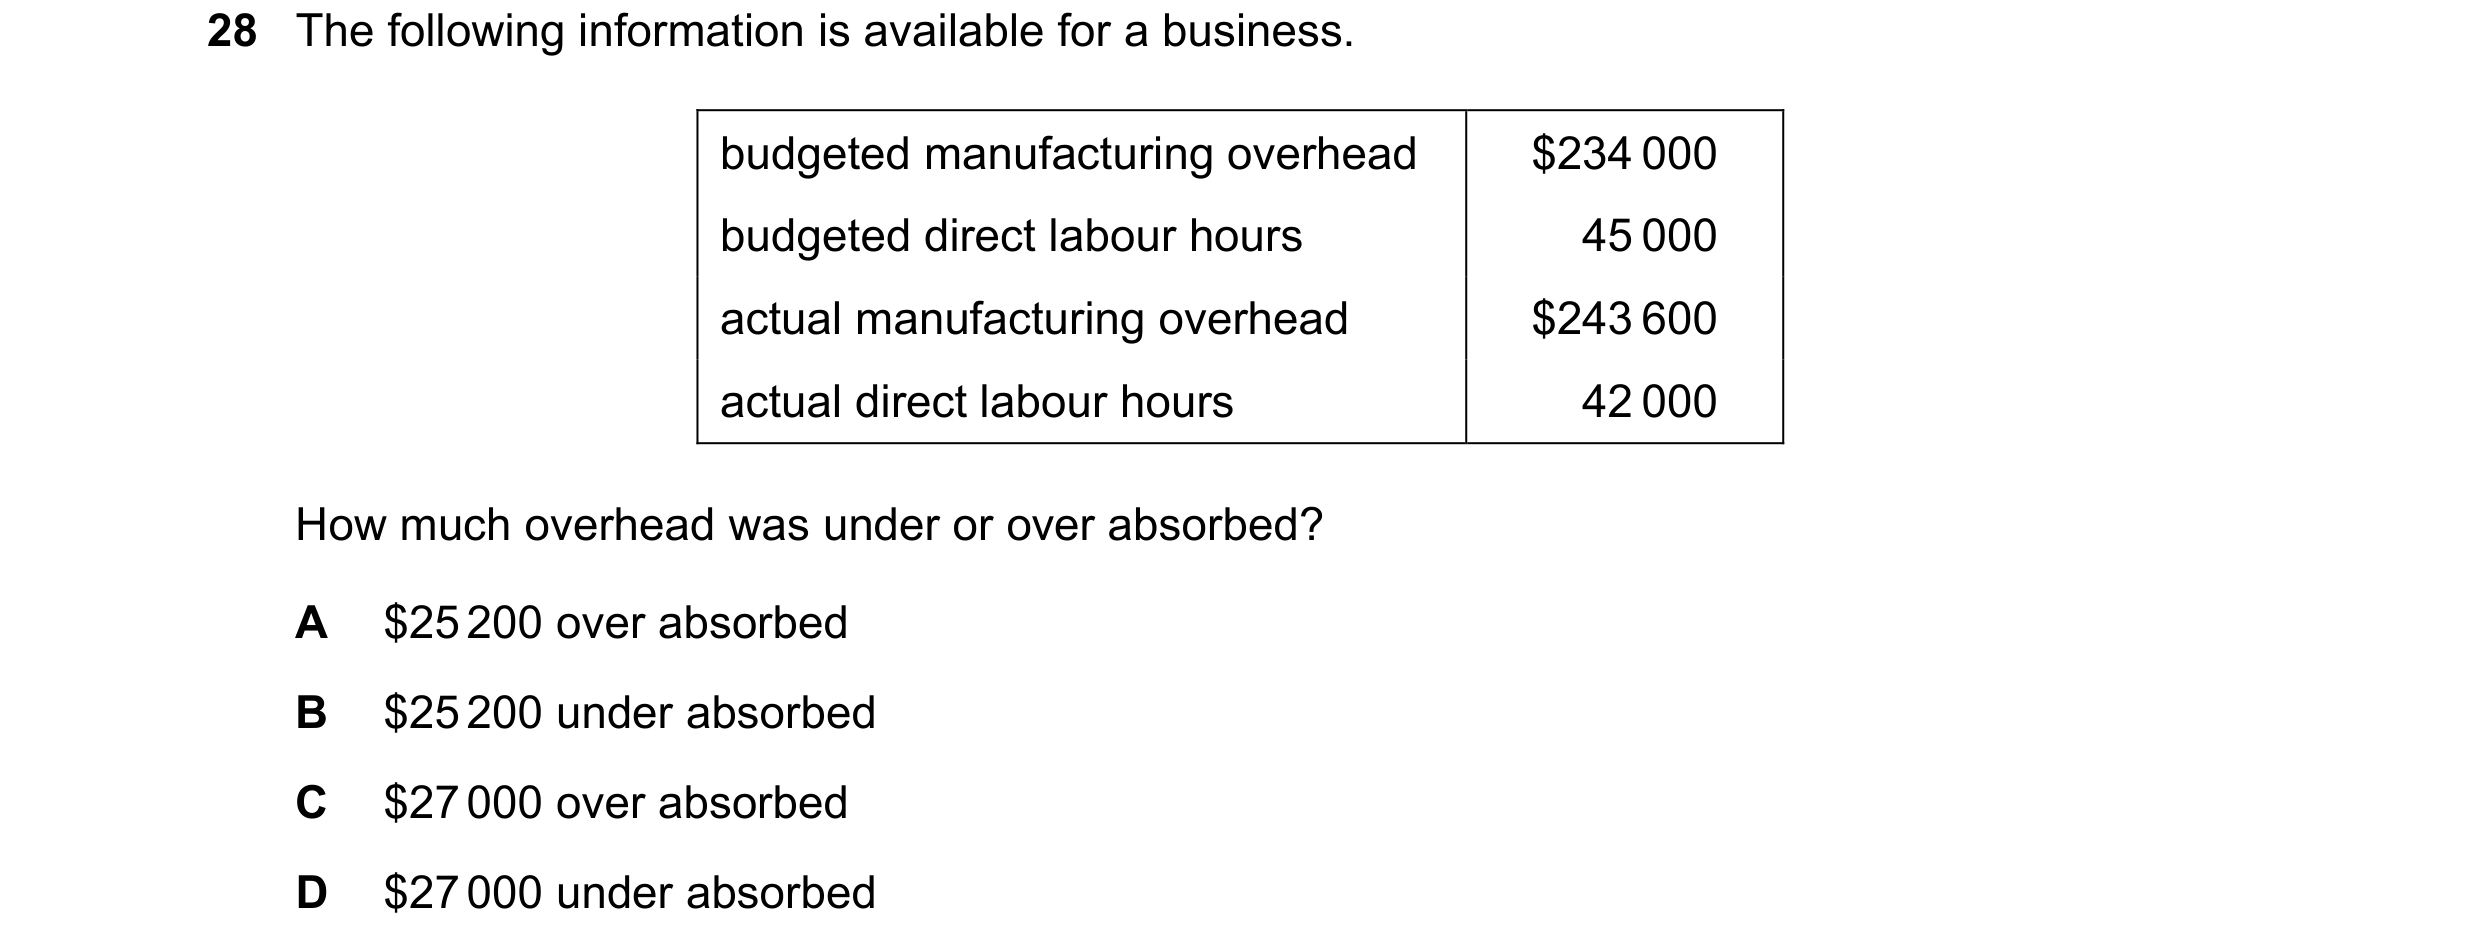
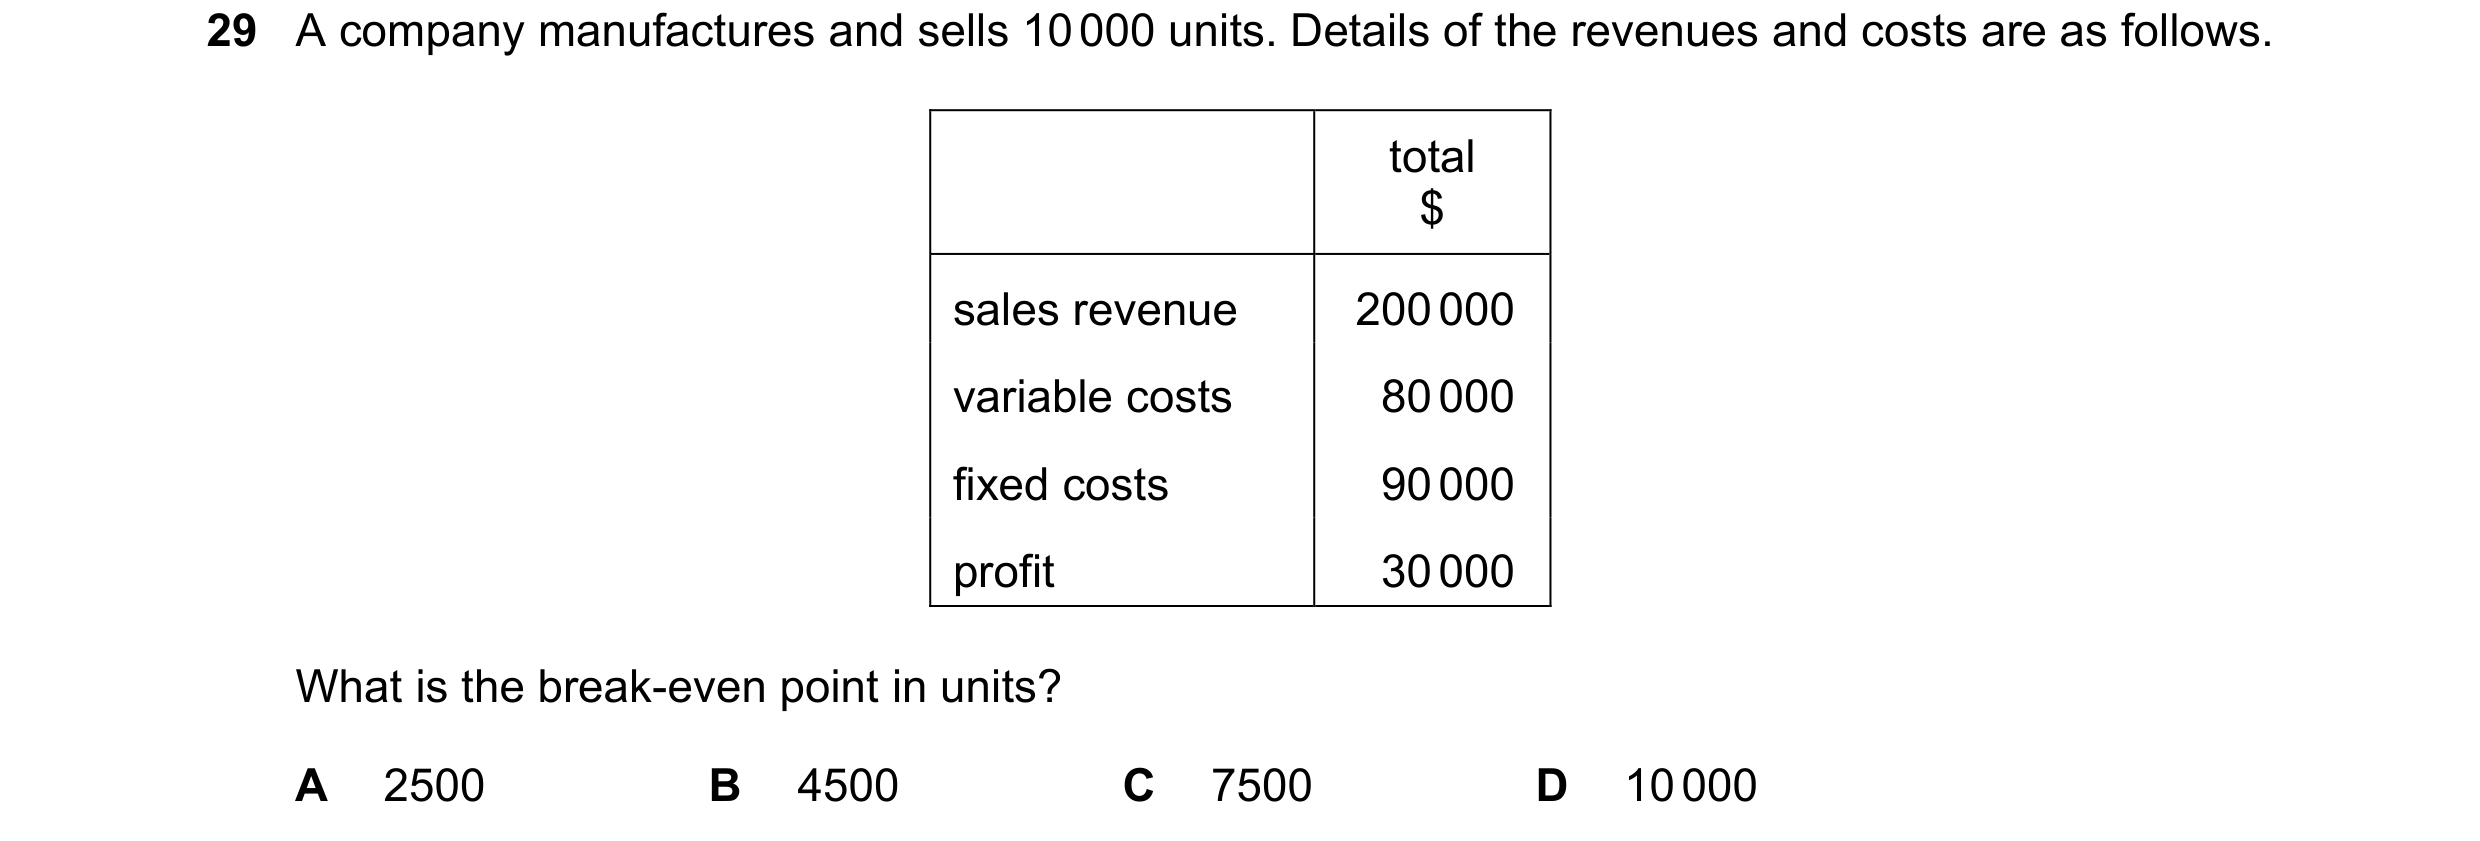
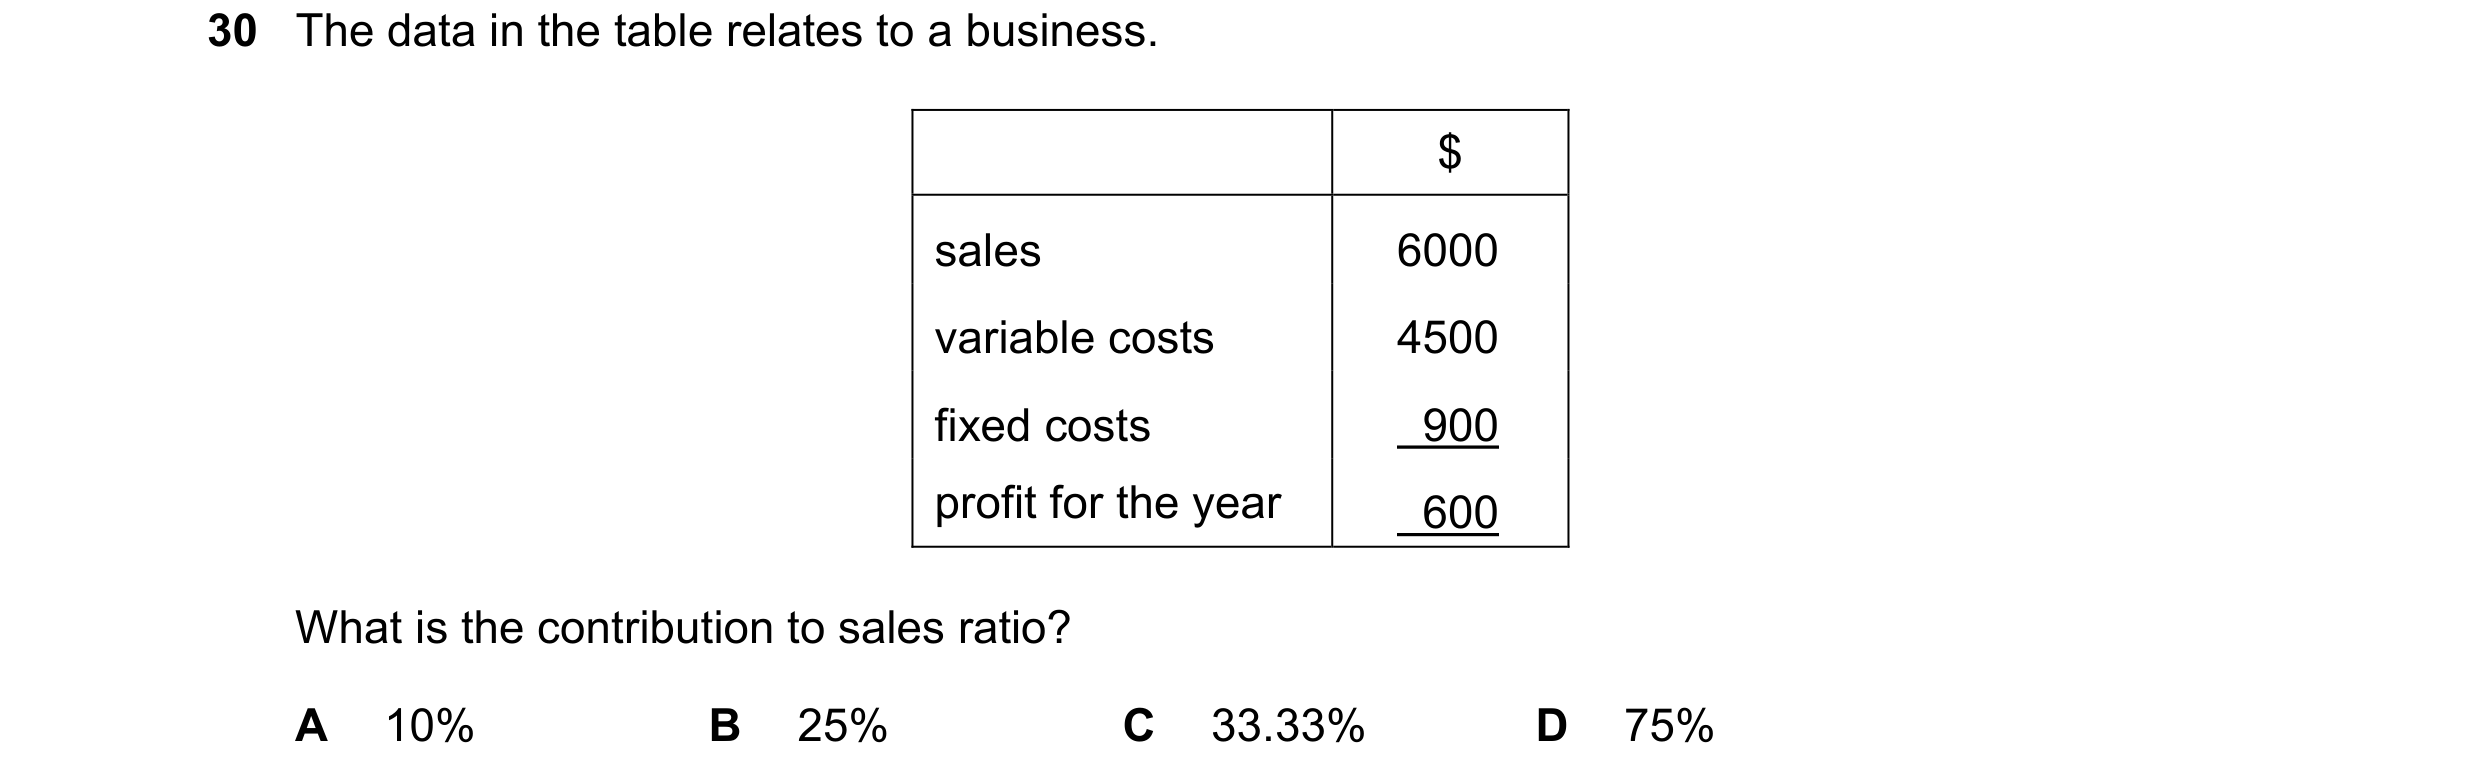
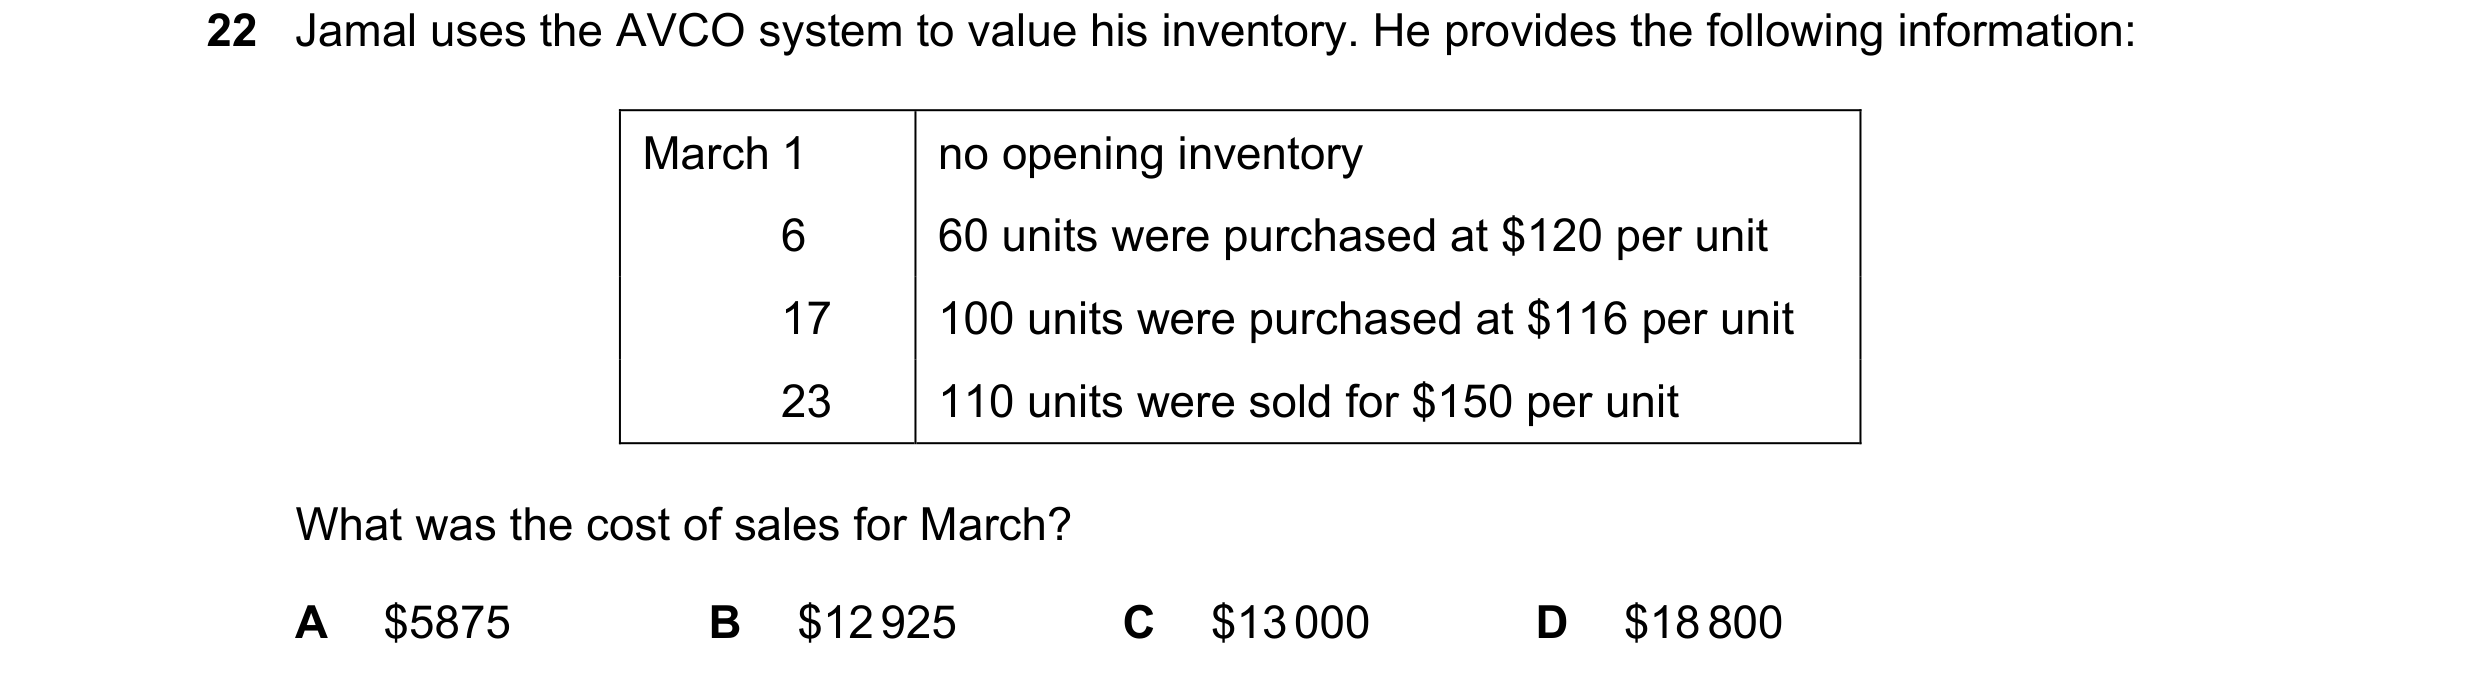 69 / 143
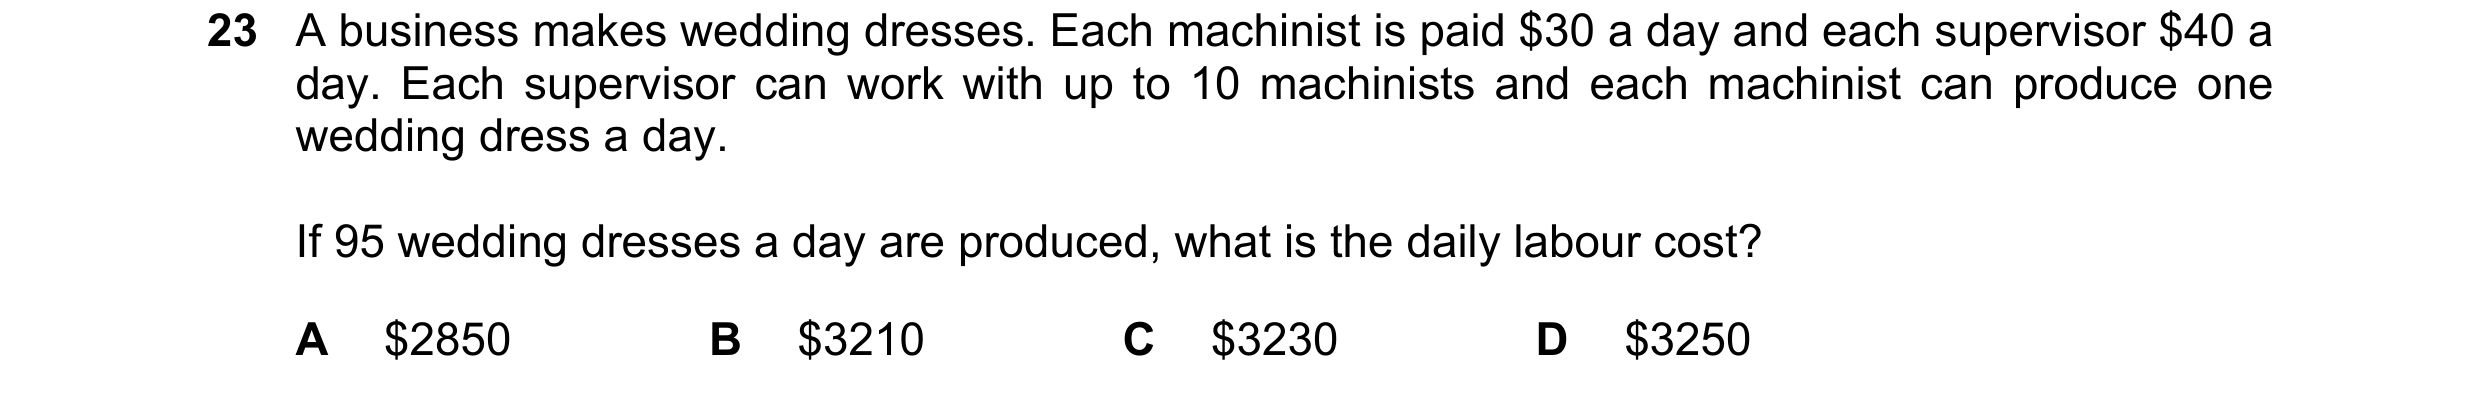
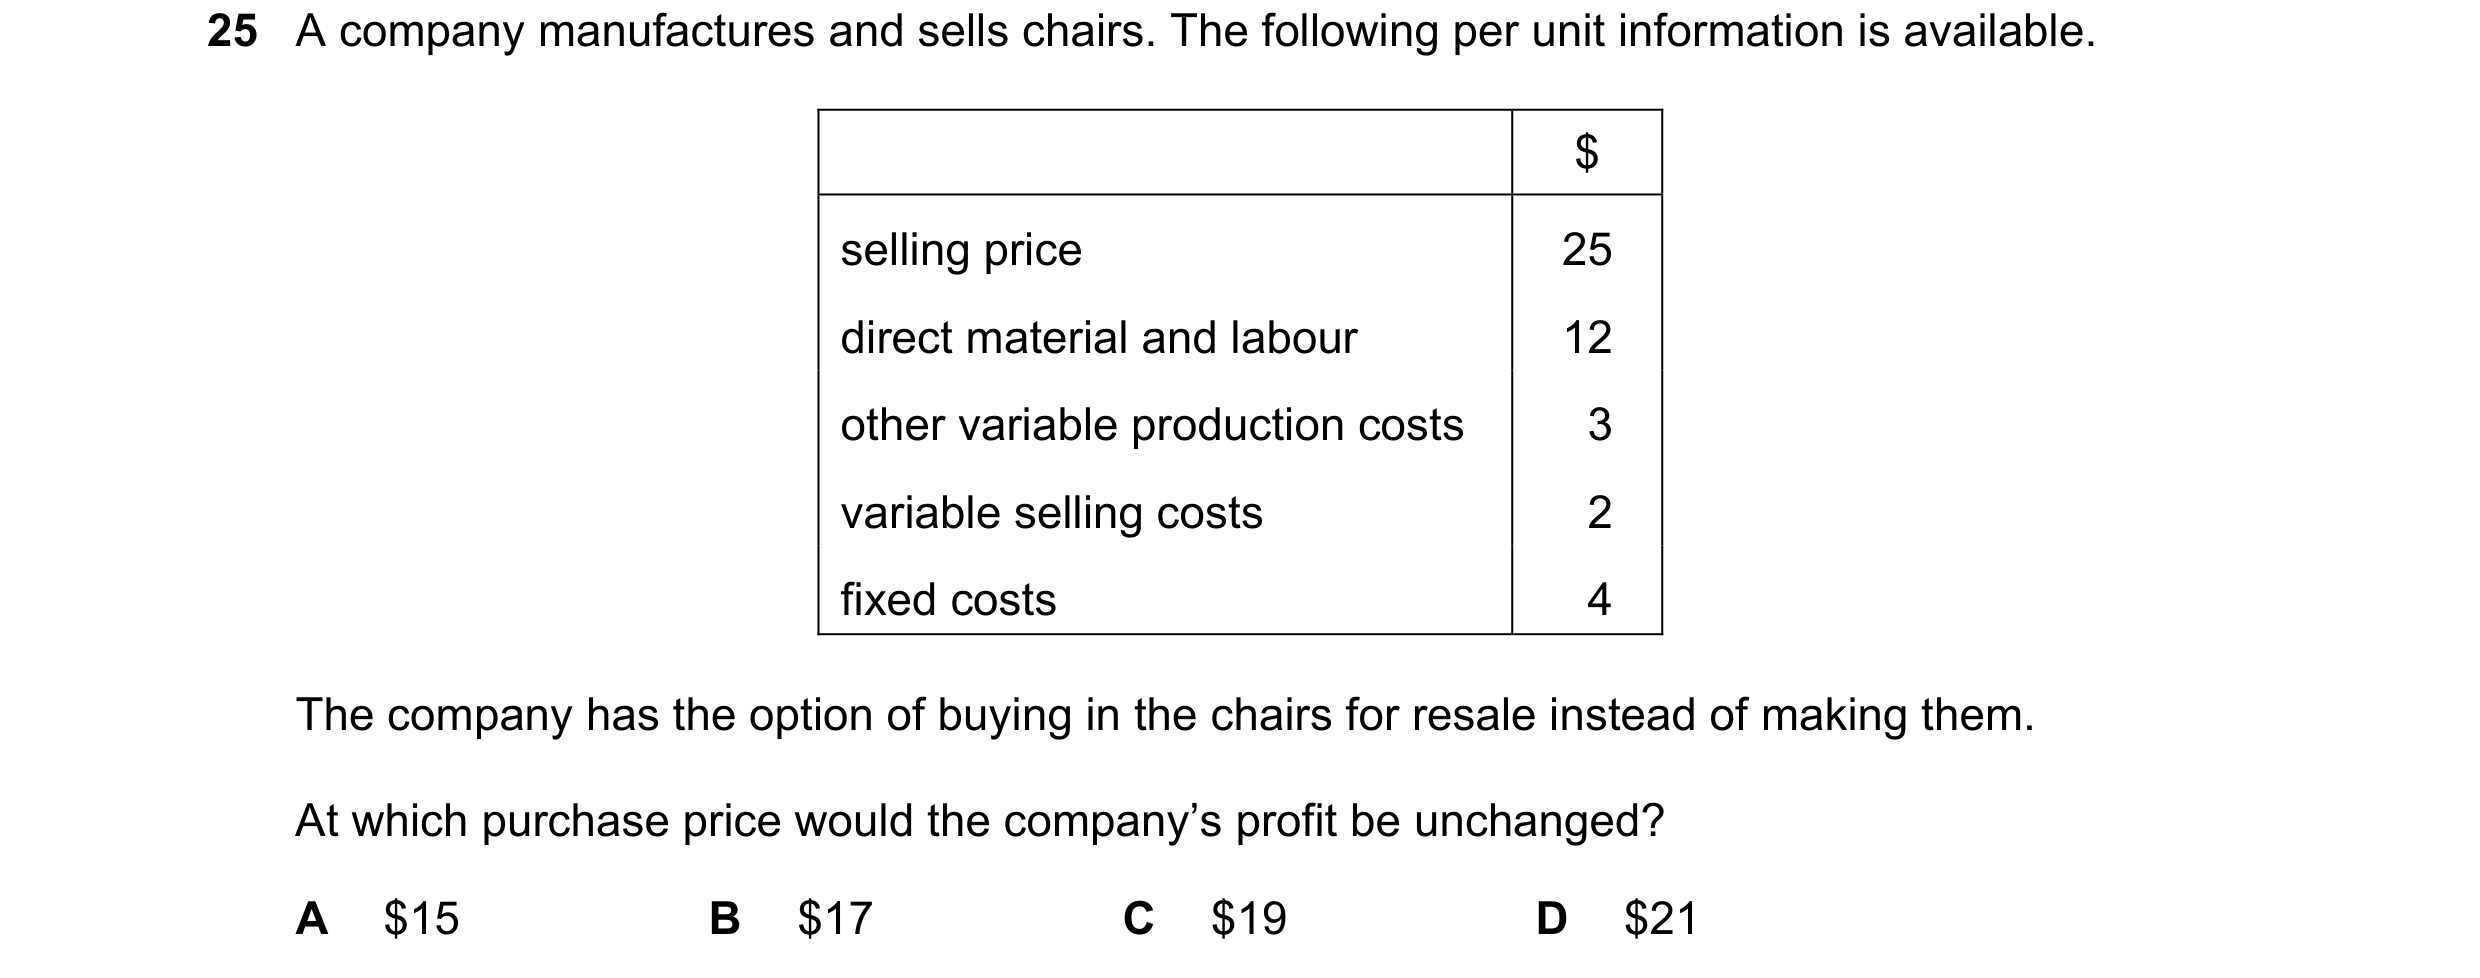
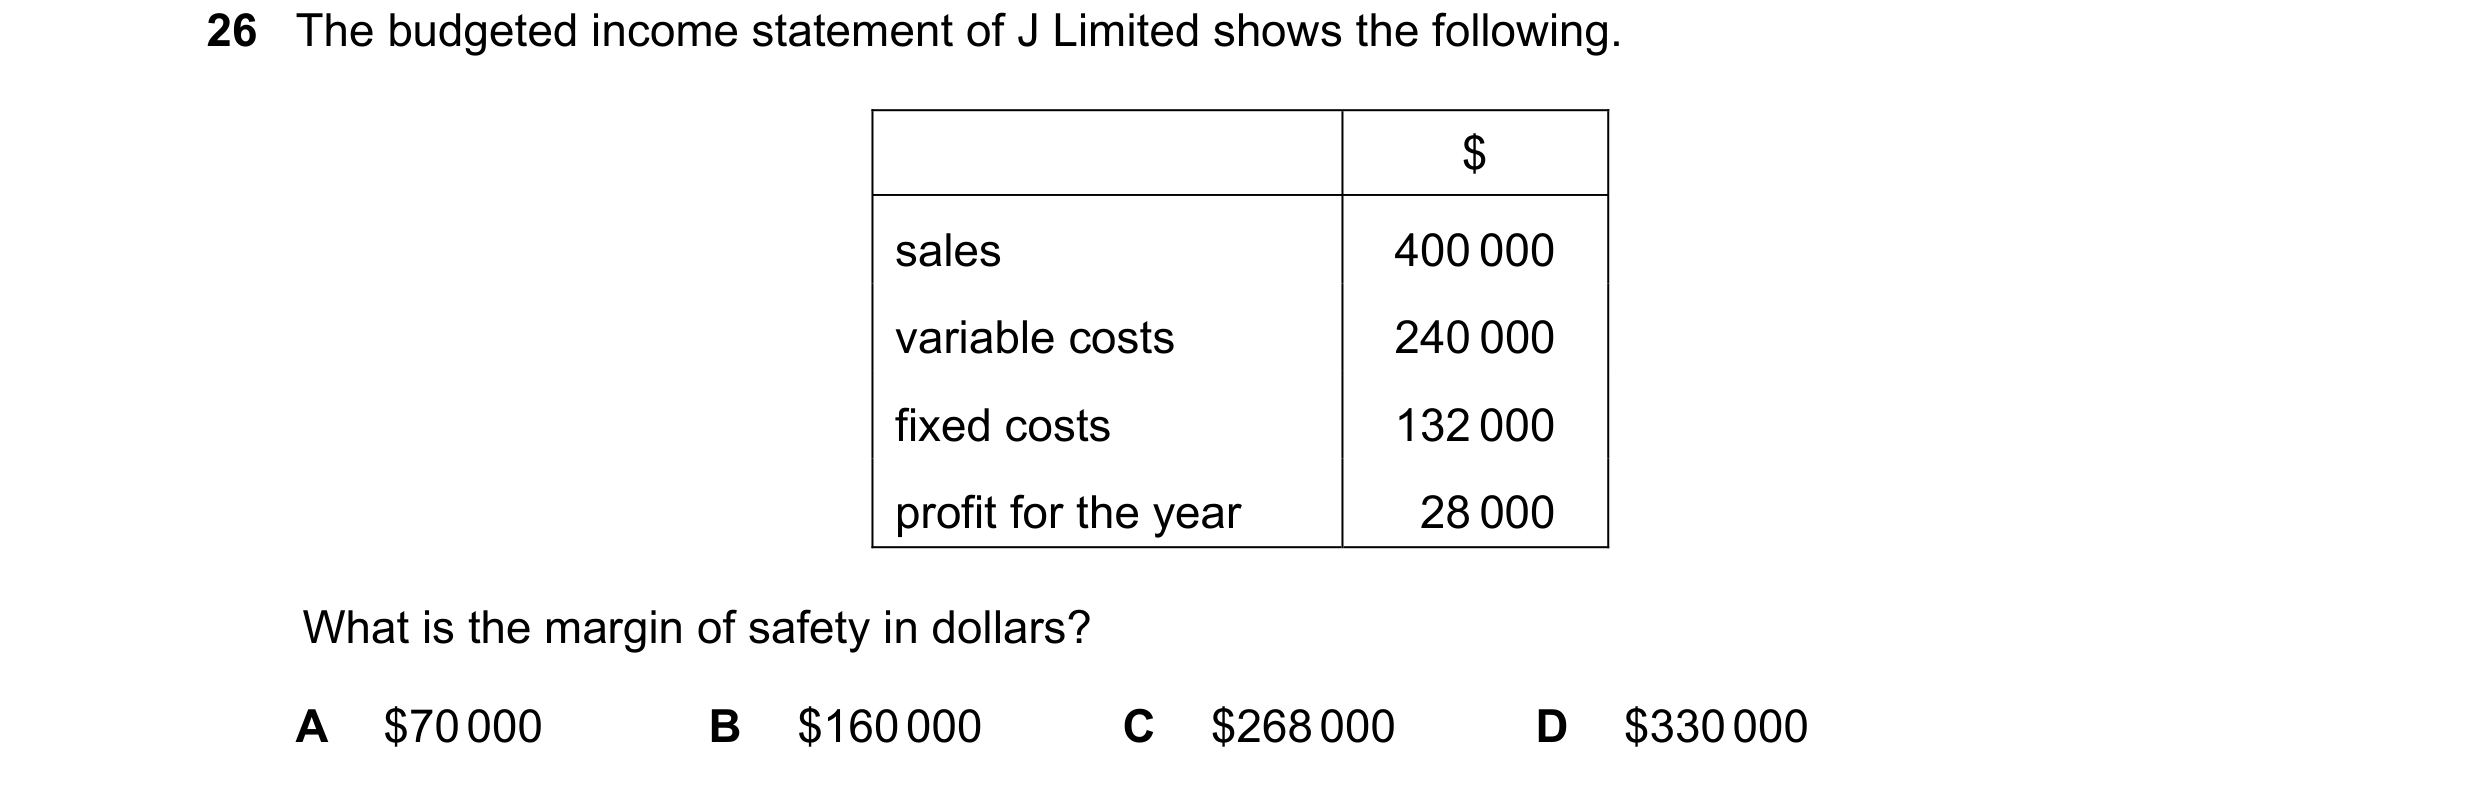
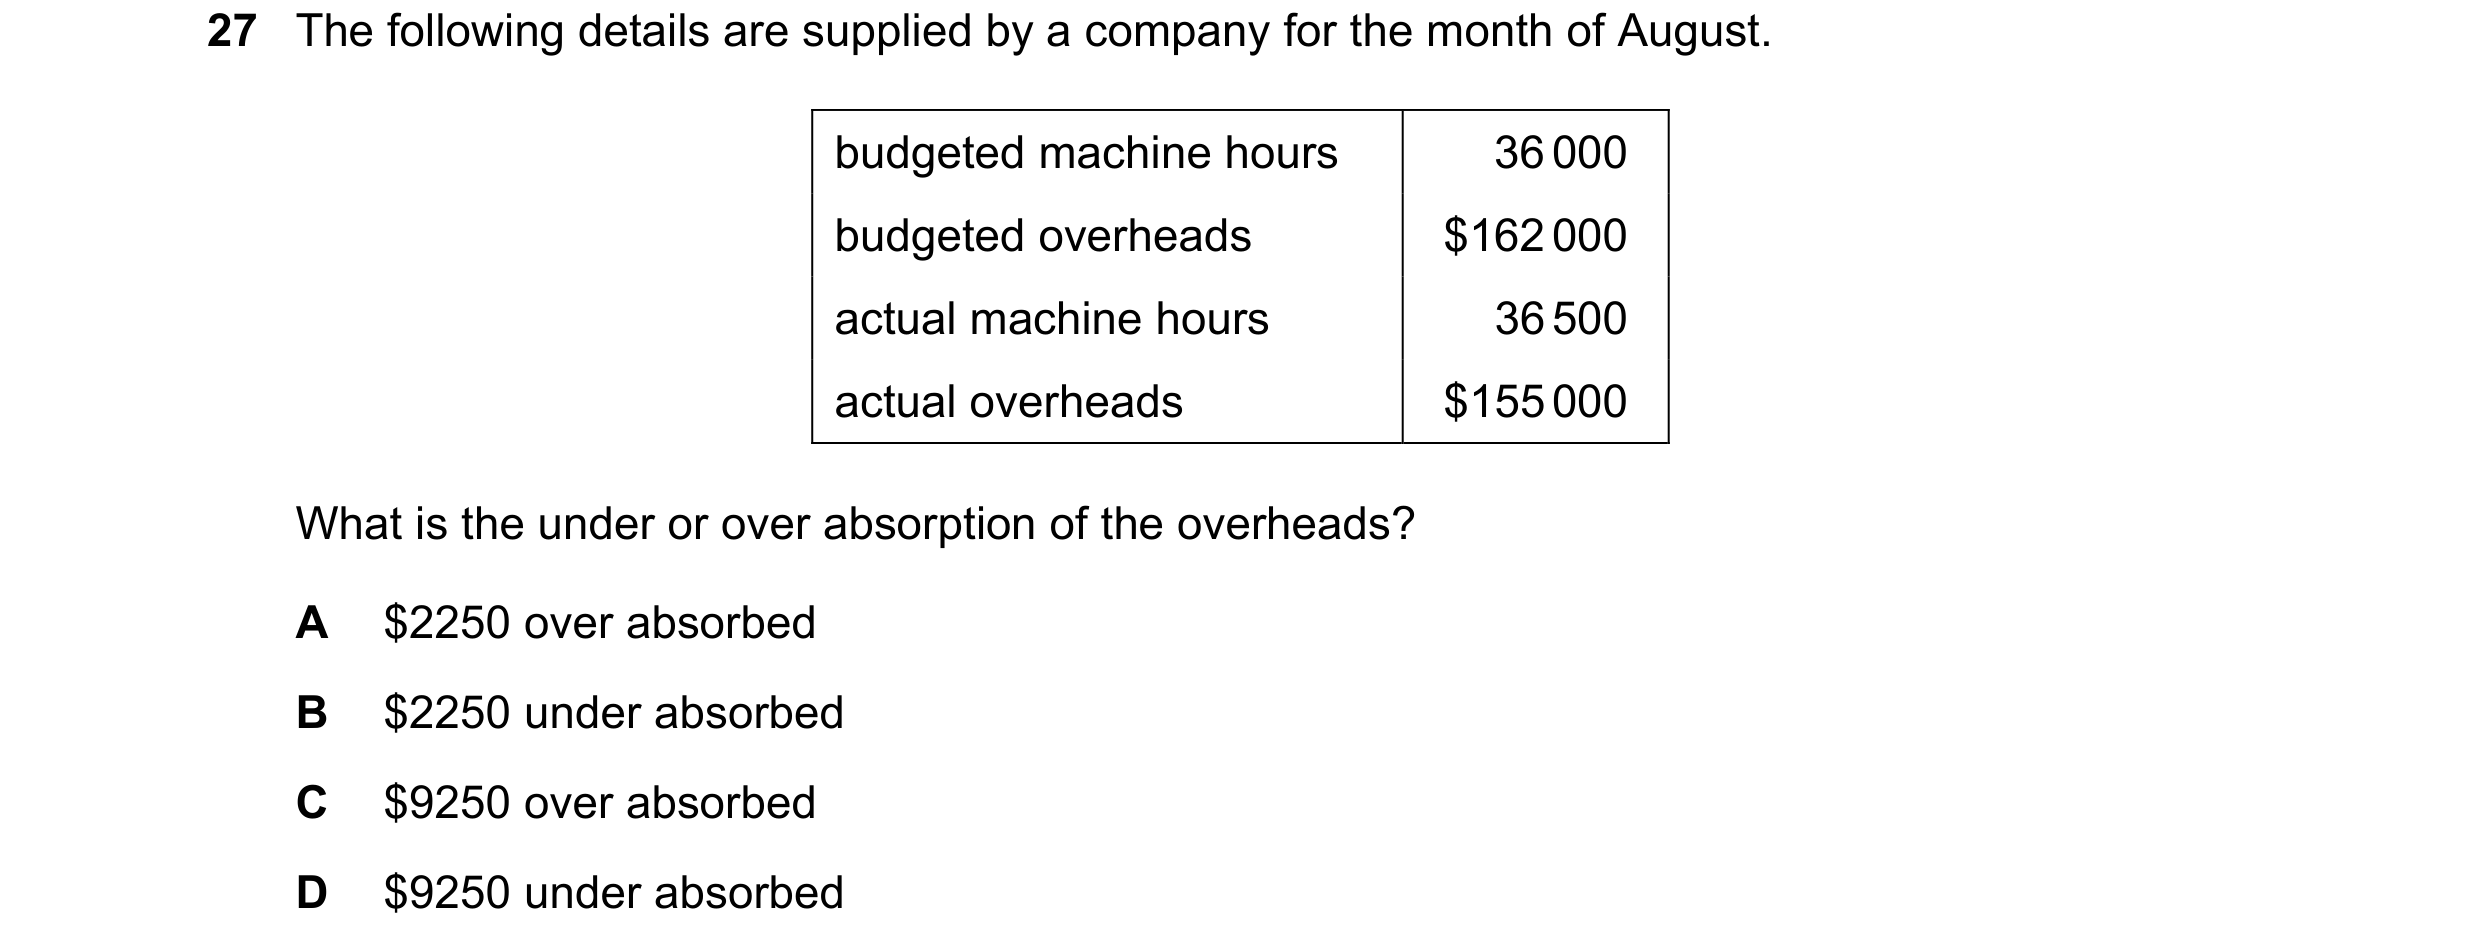 70 / 143
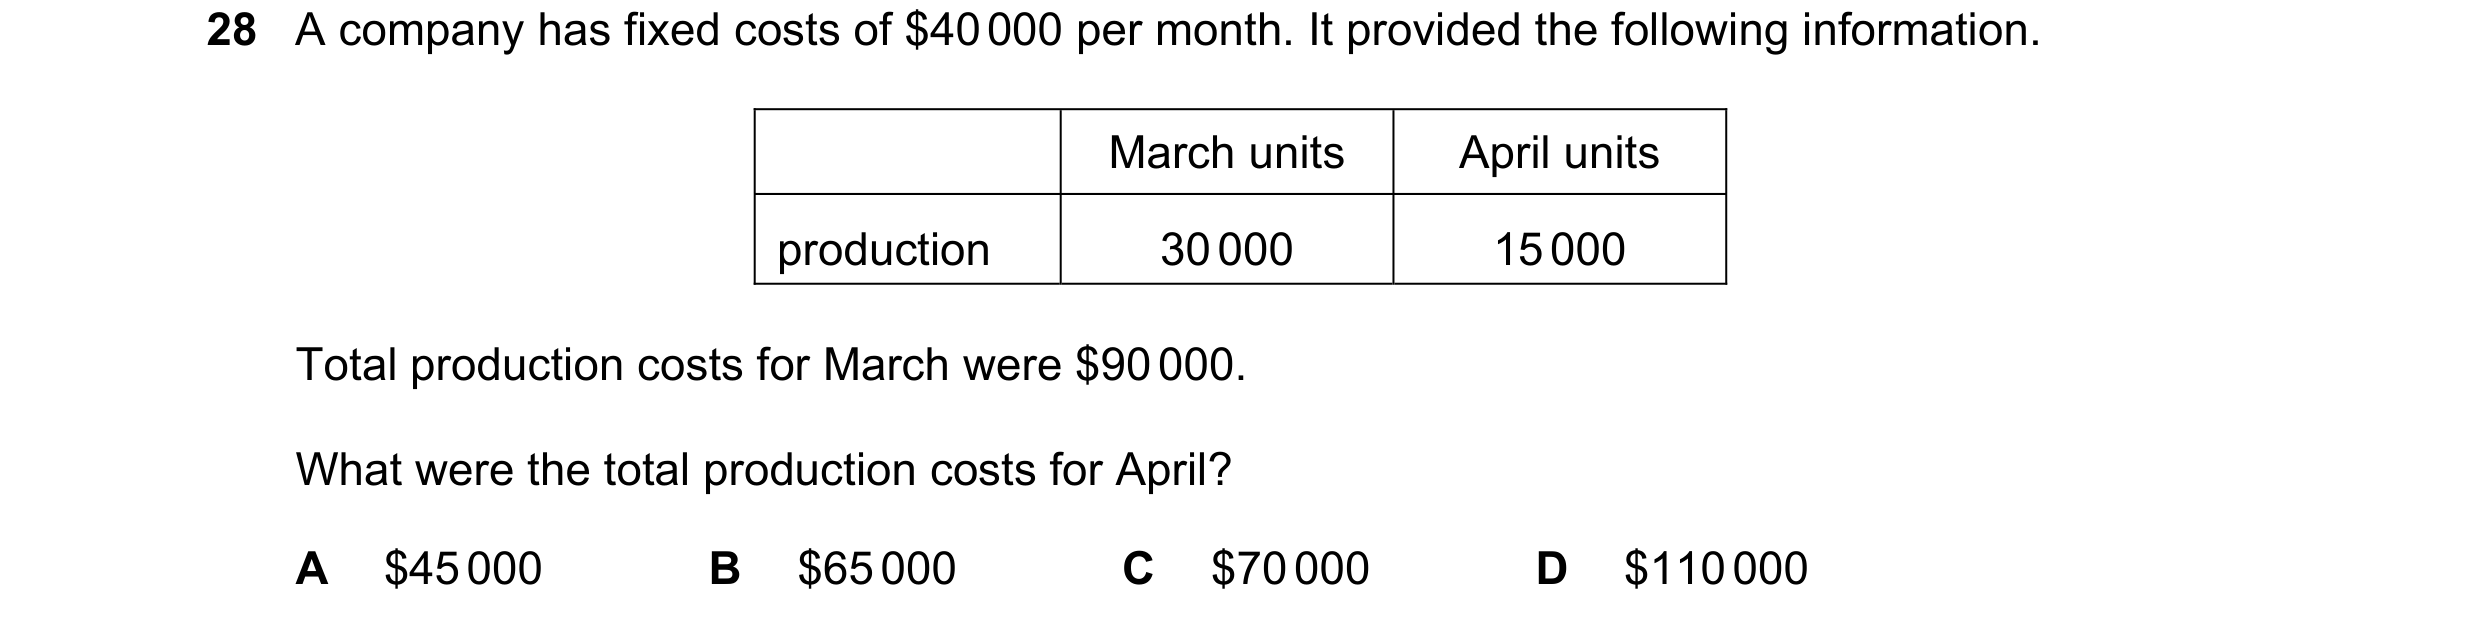
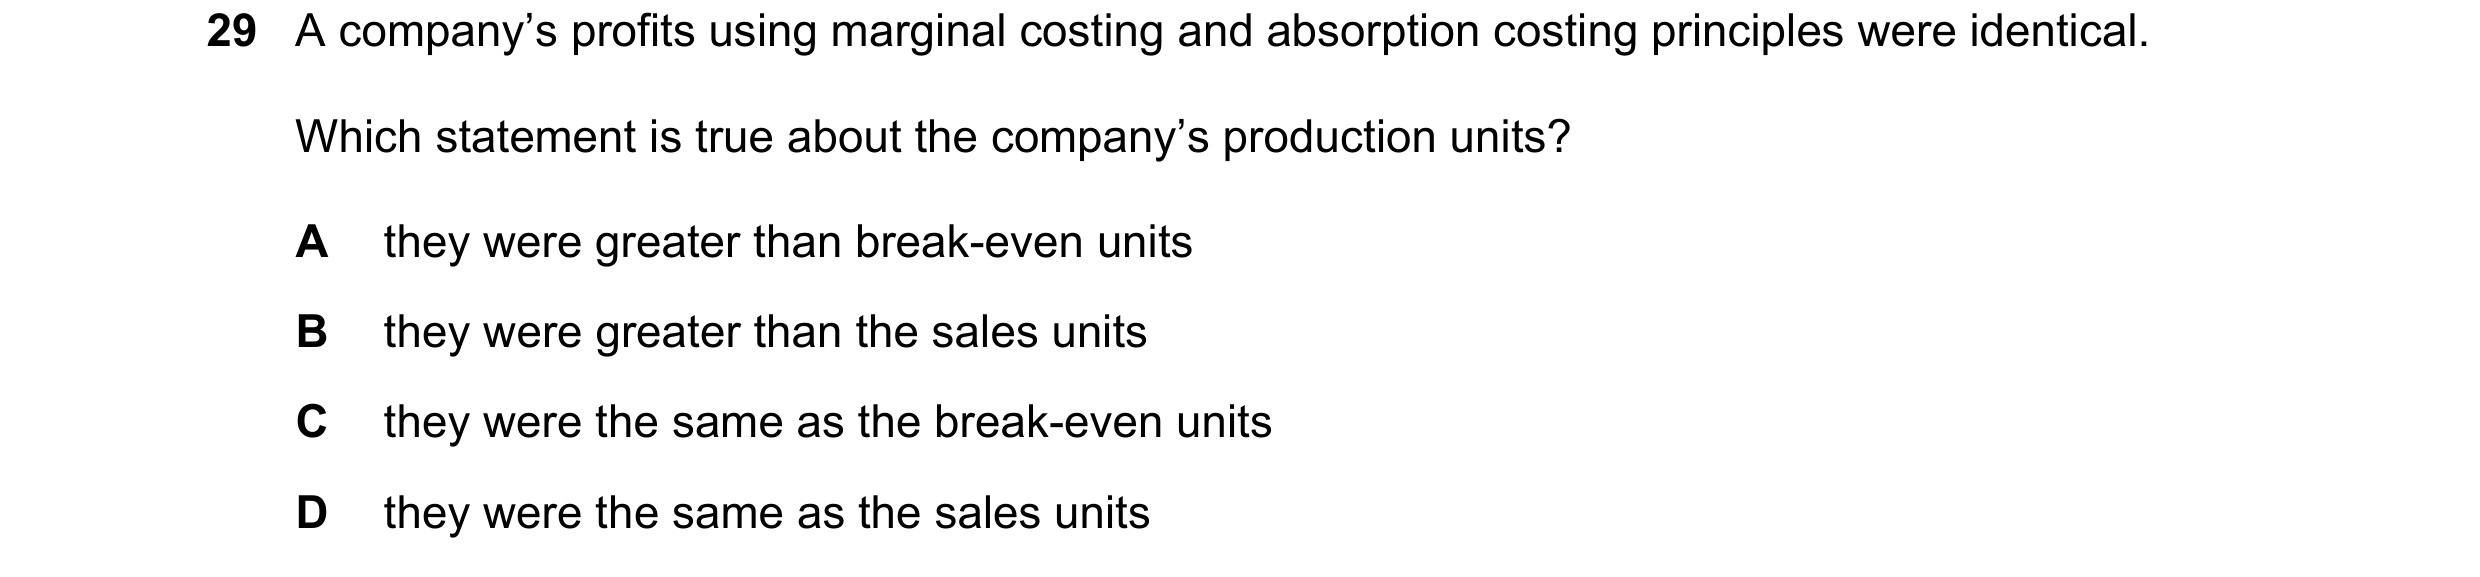
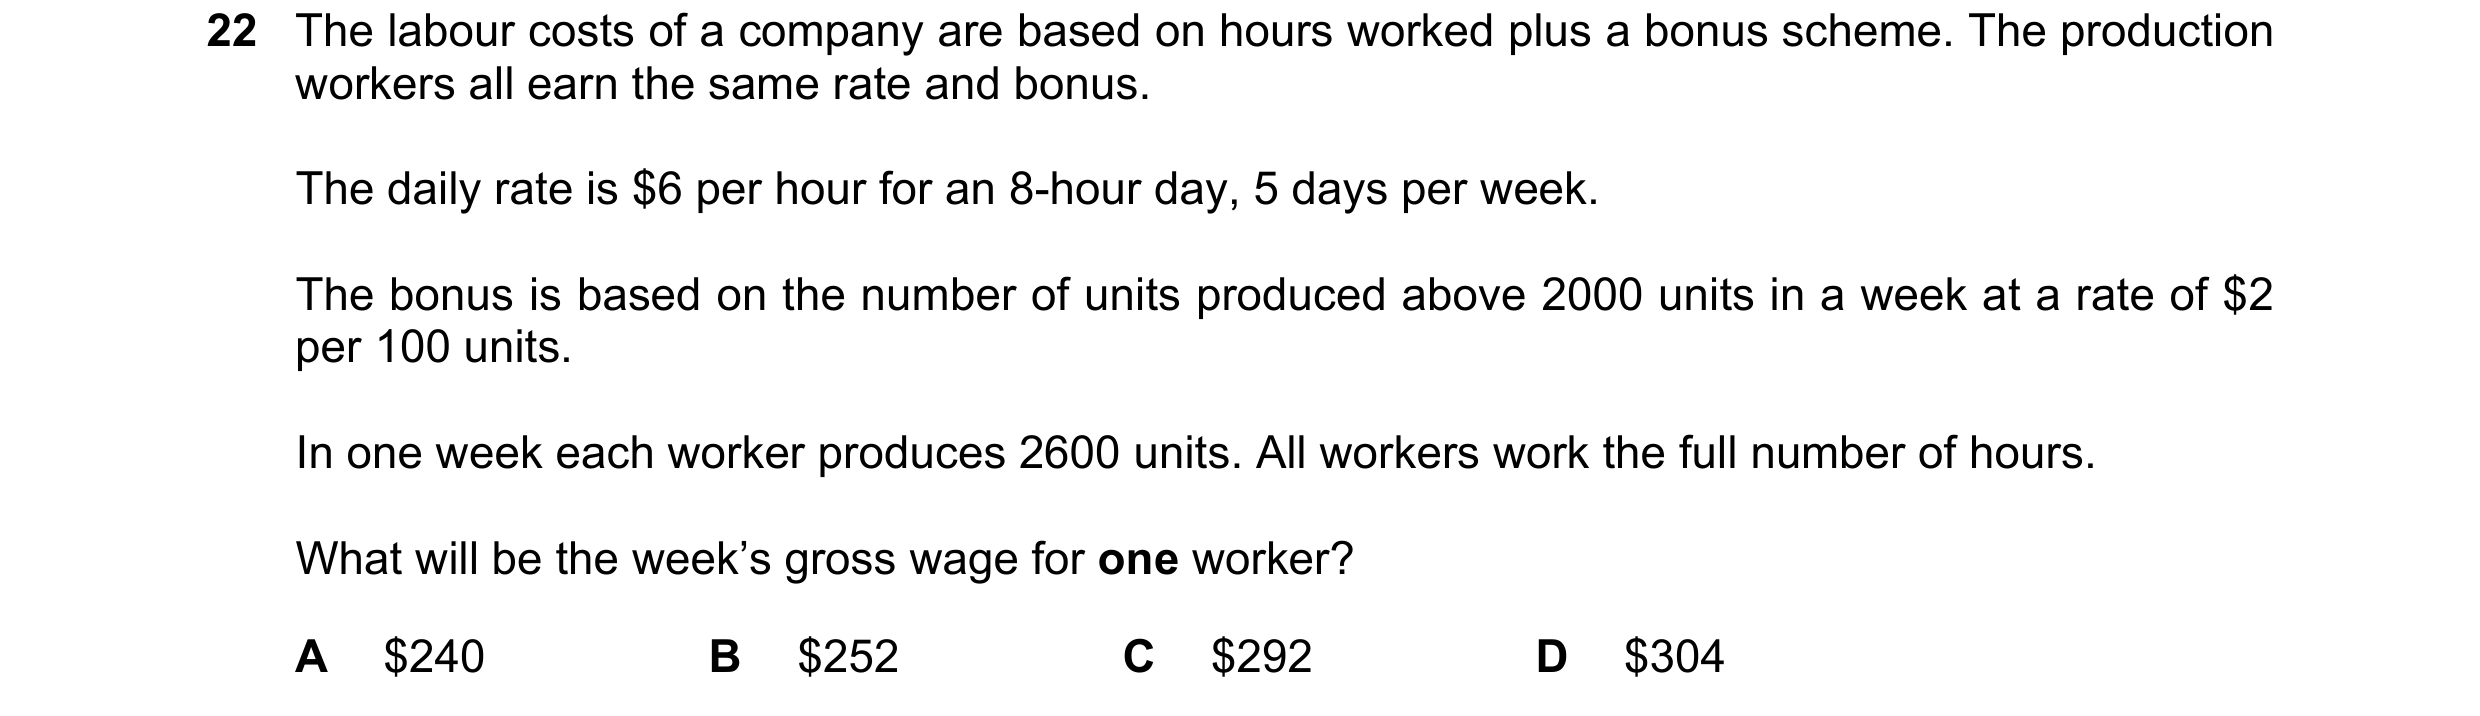
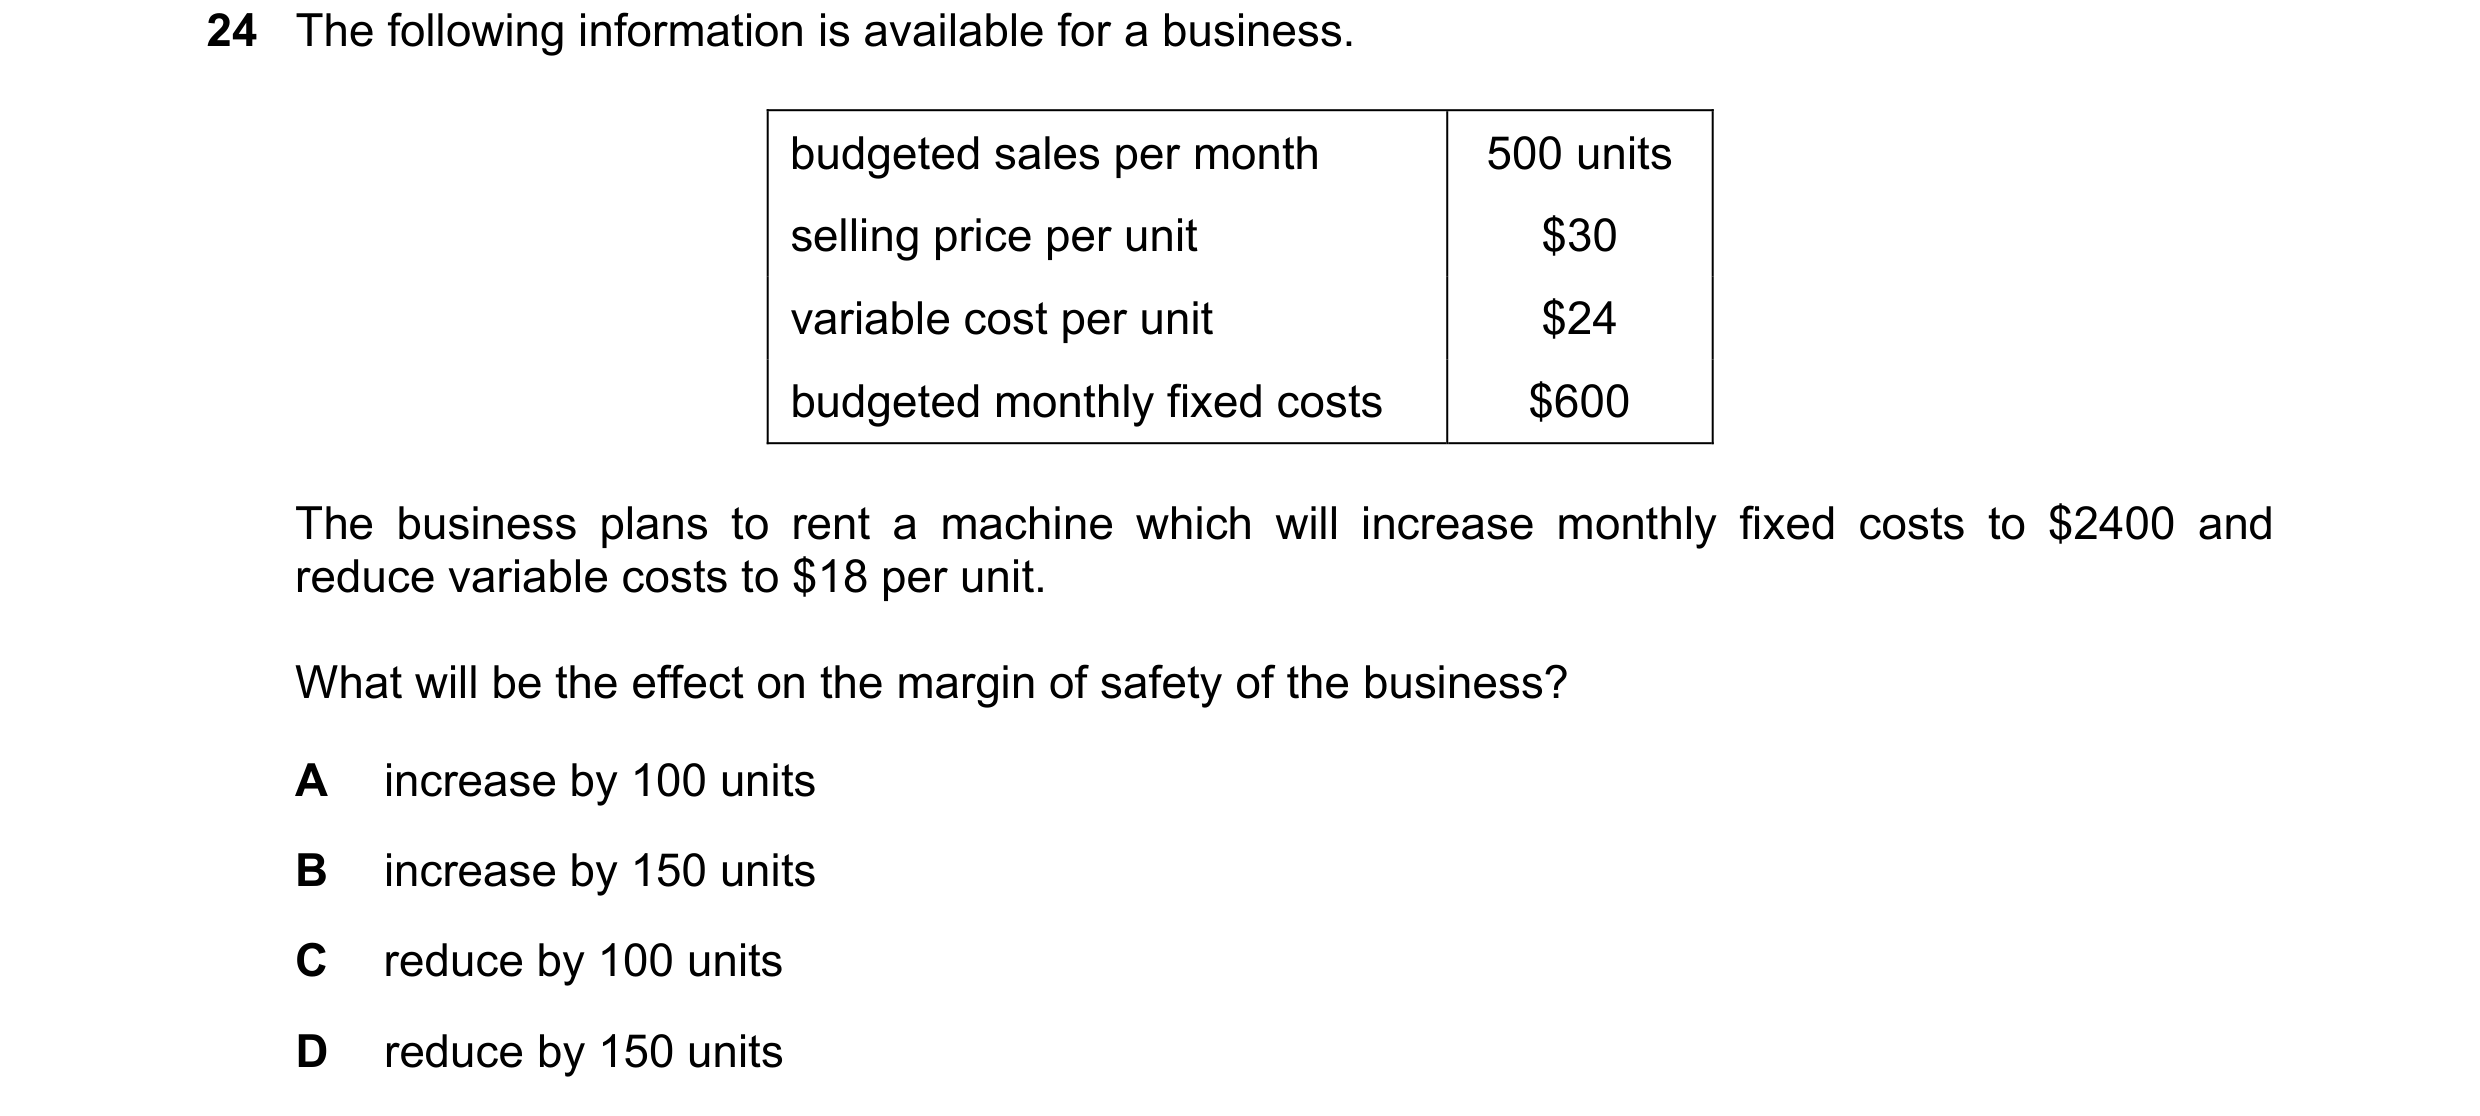 71 / 143
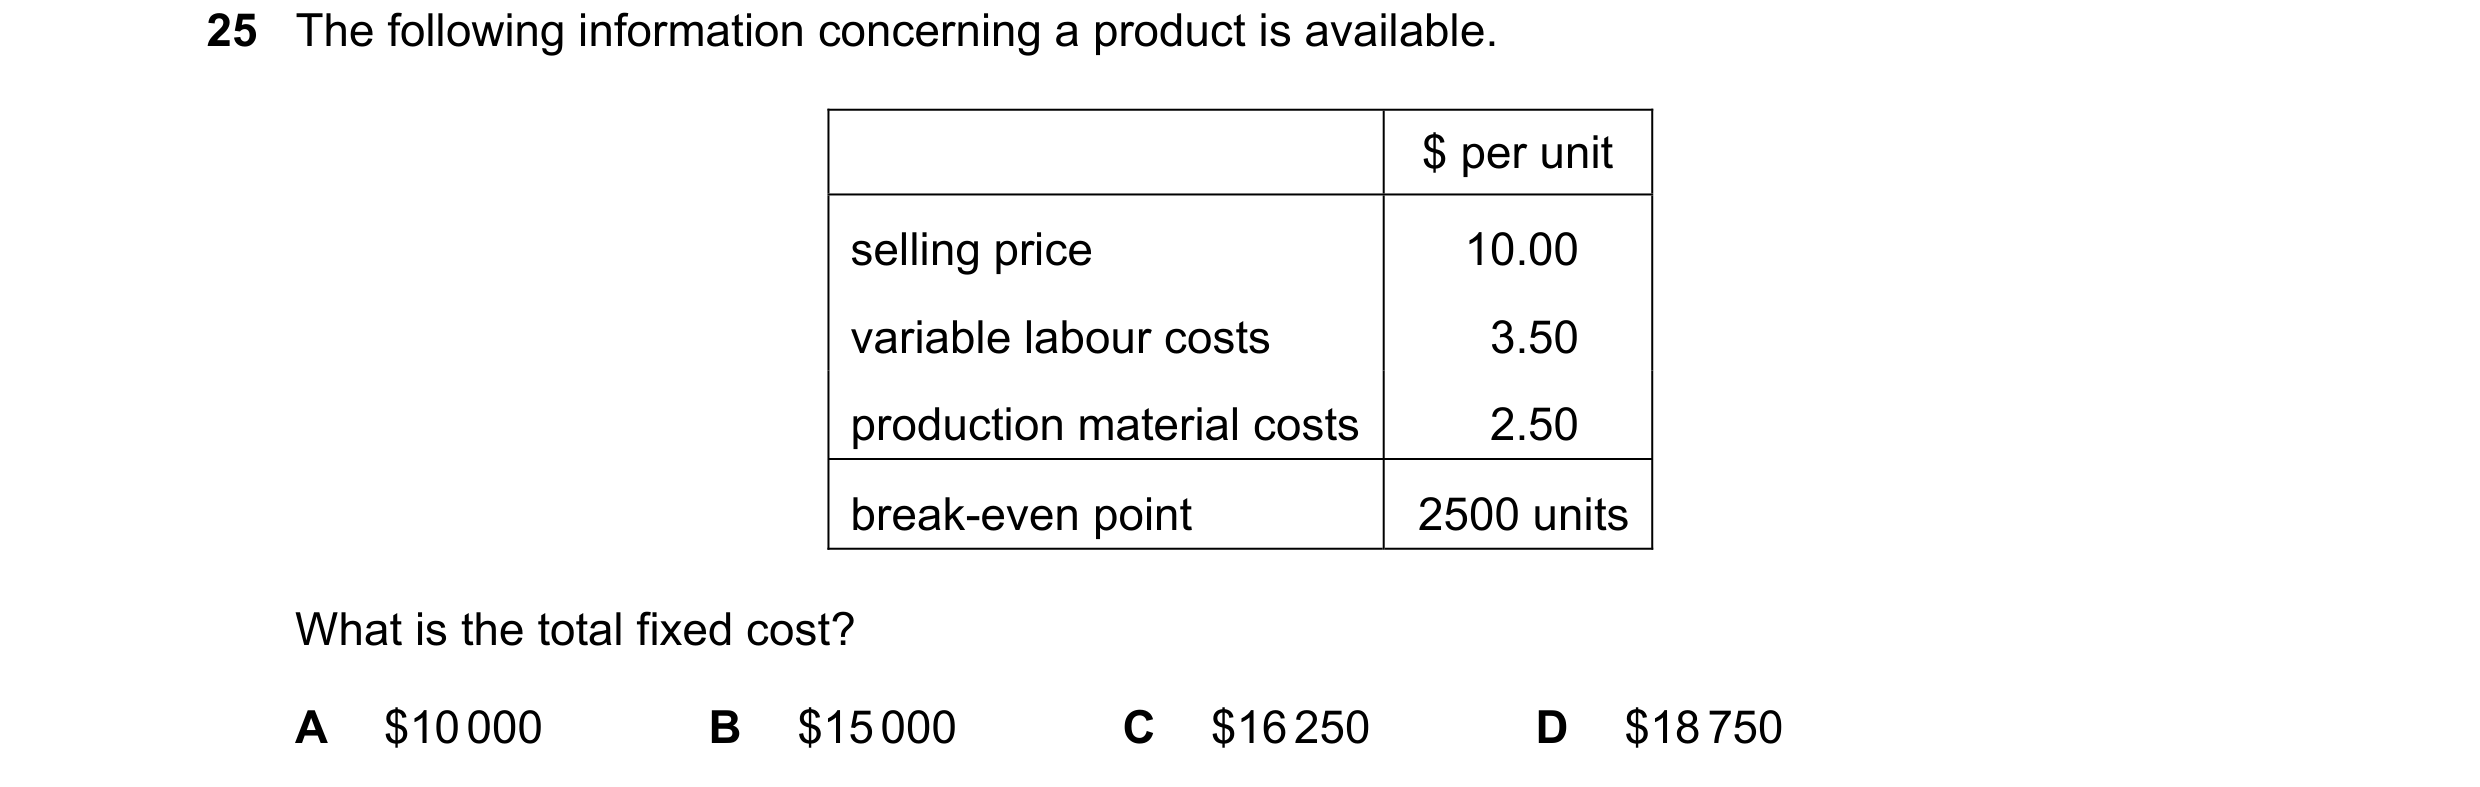
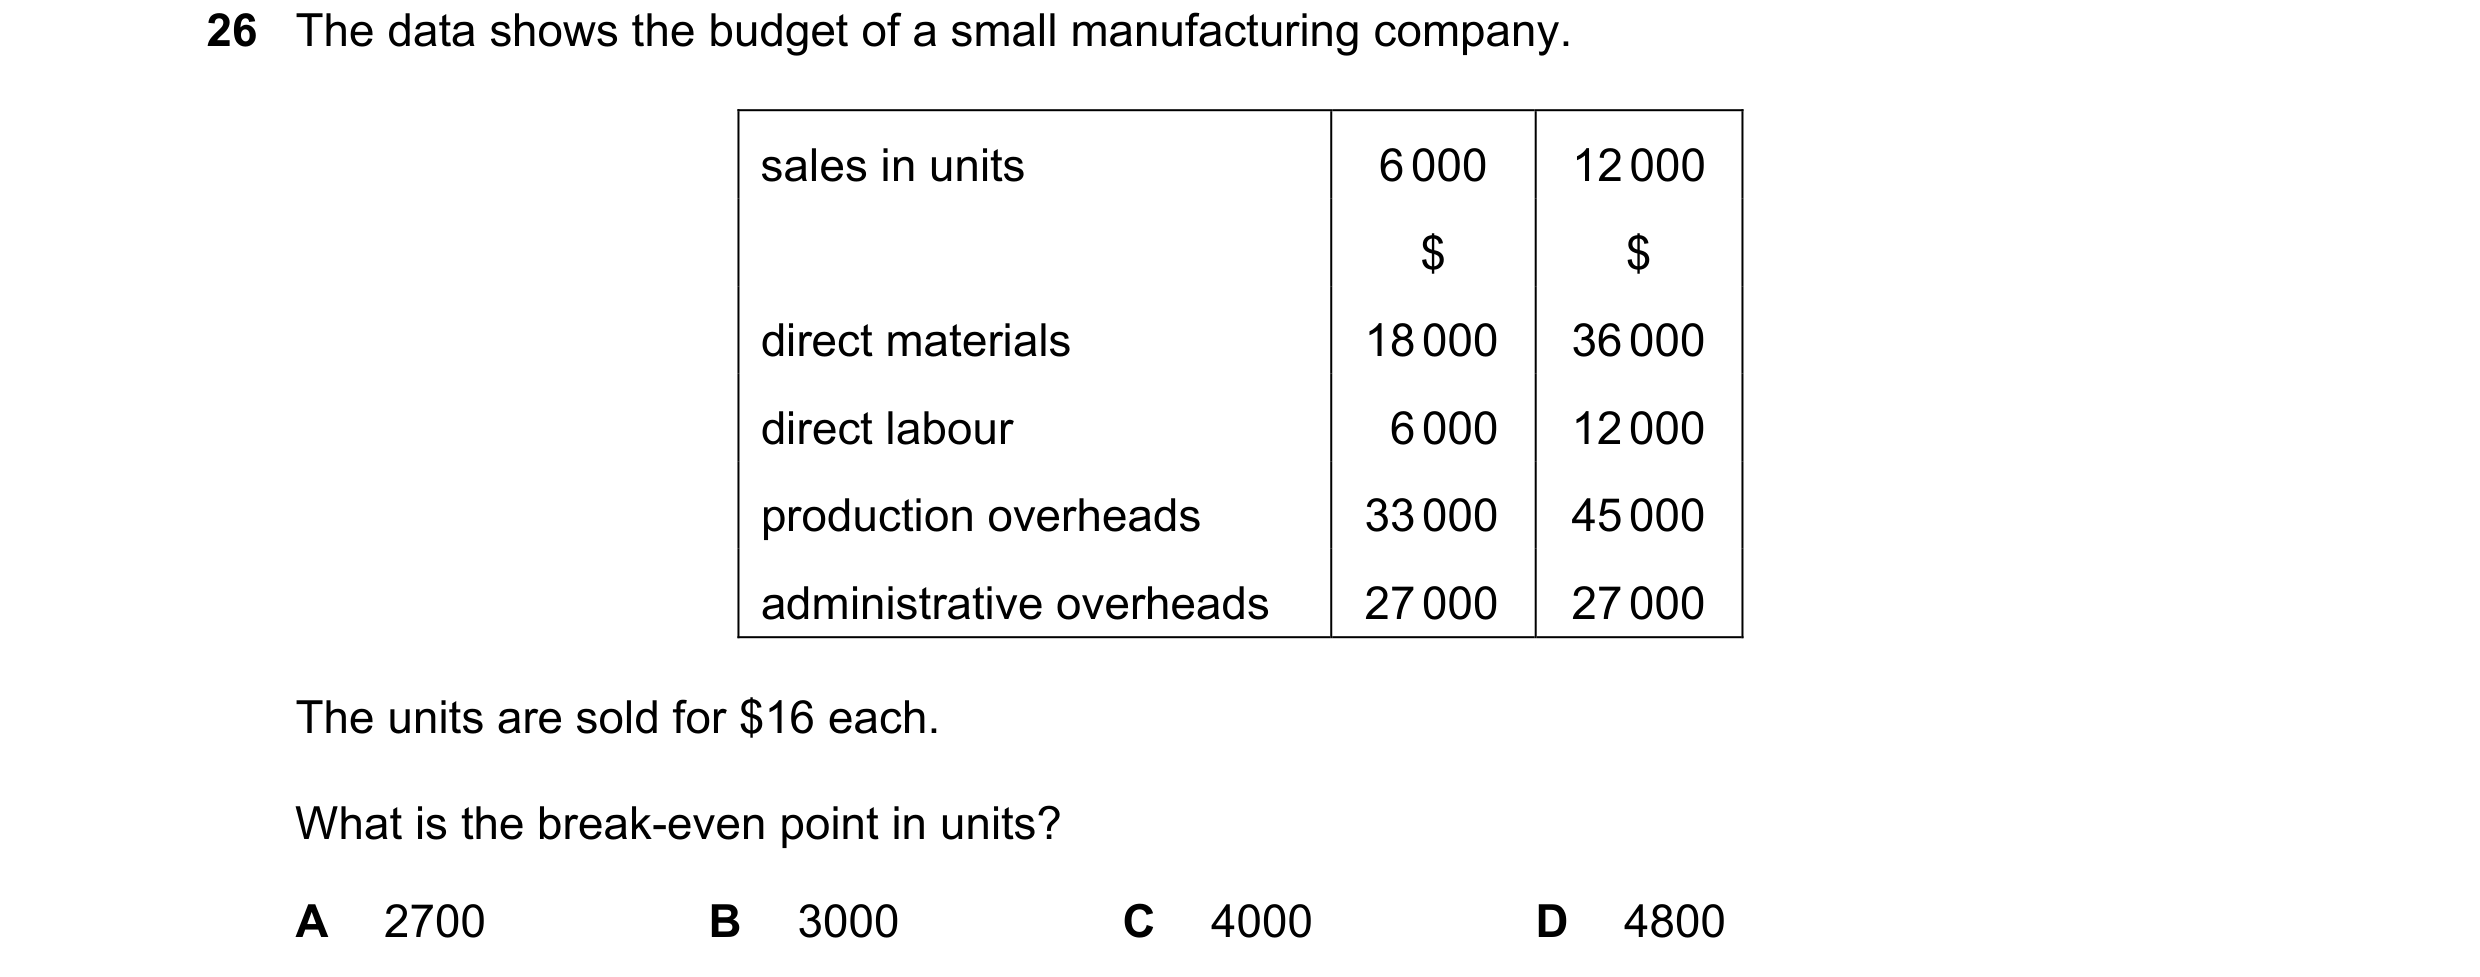
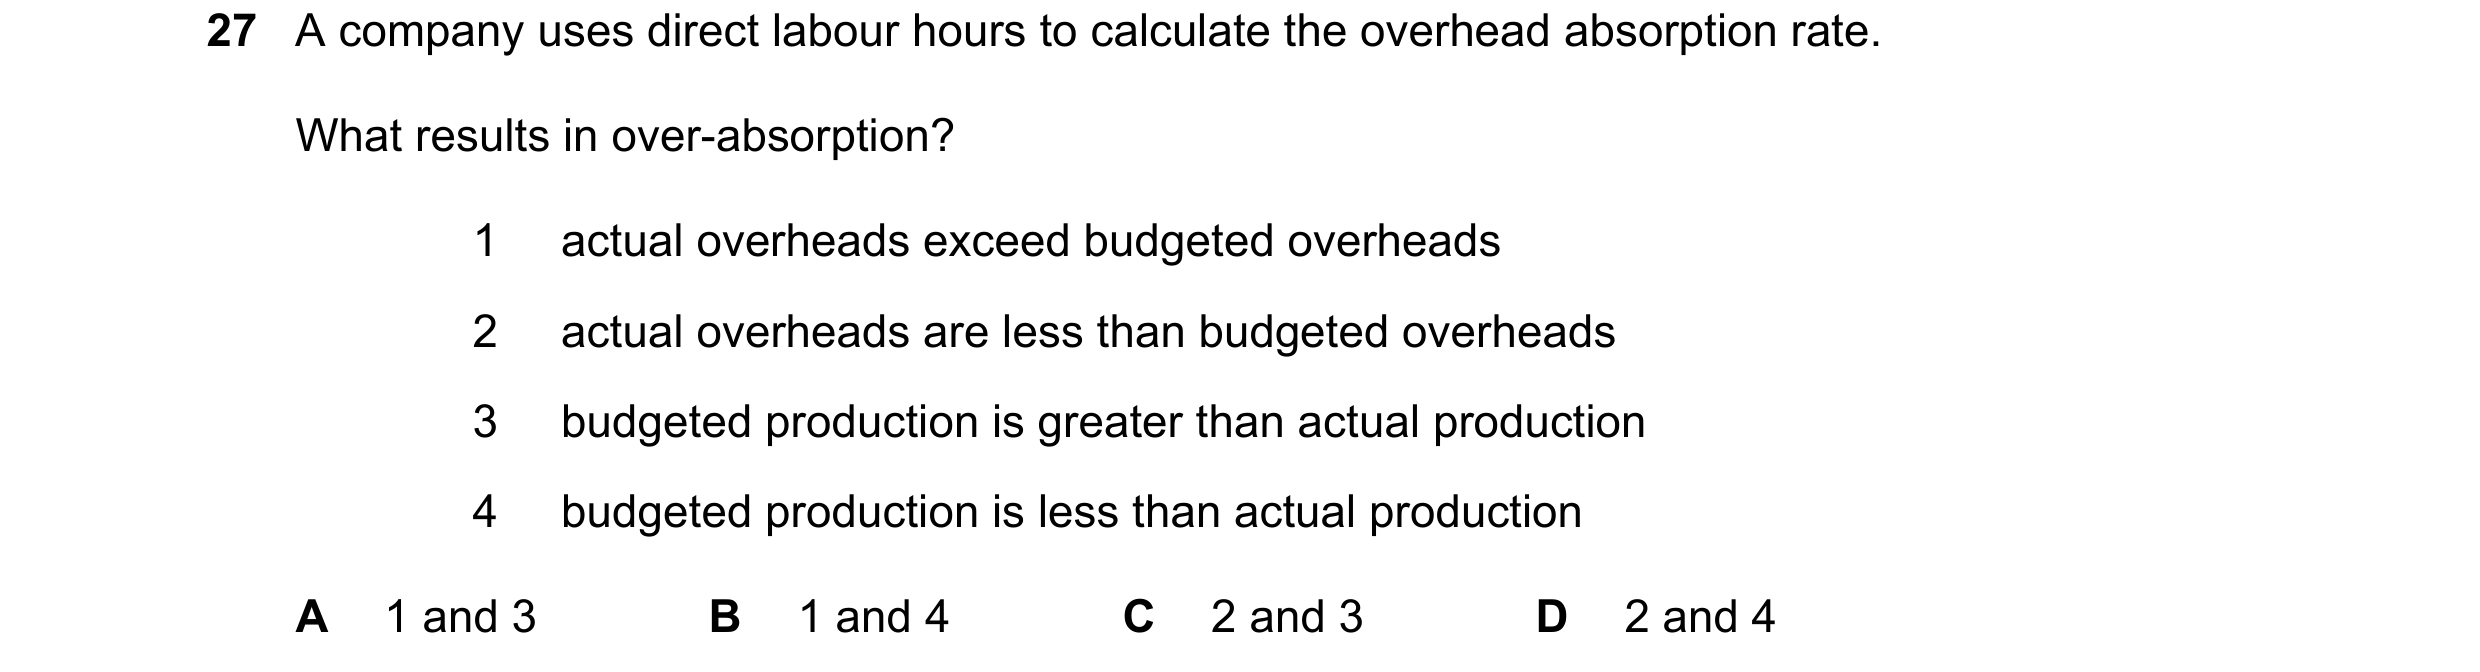
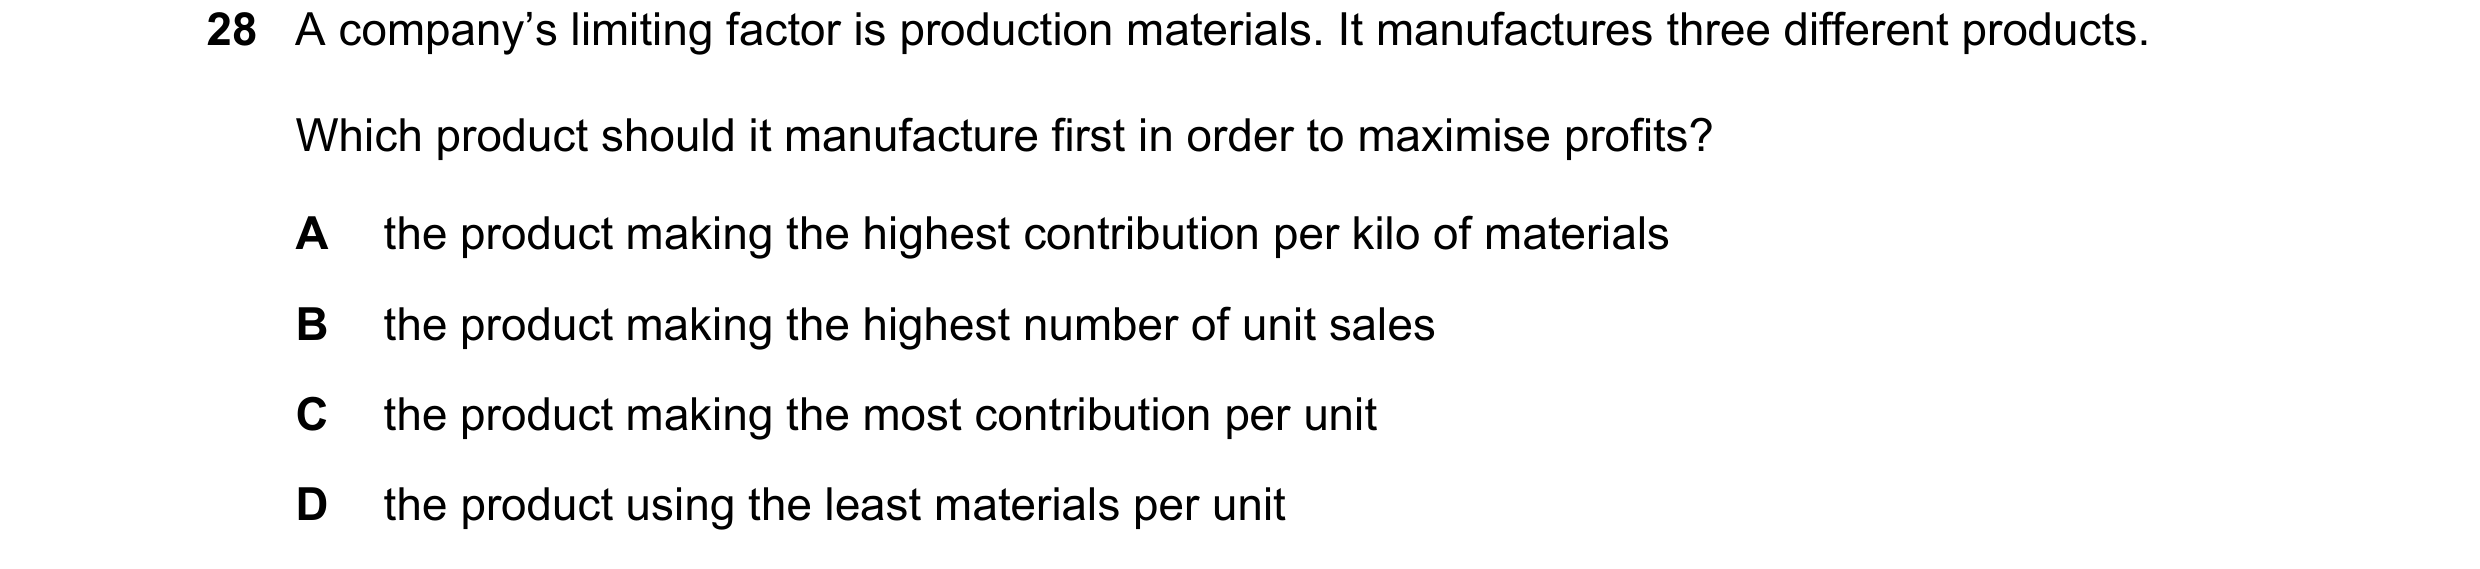 72 / 143
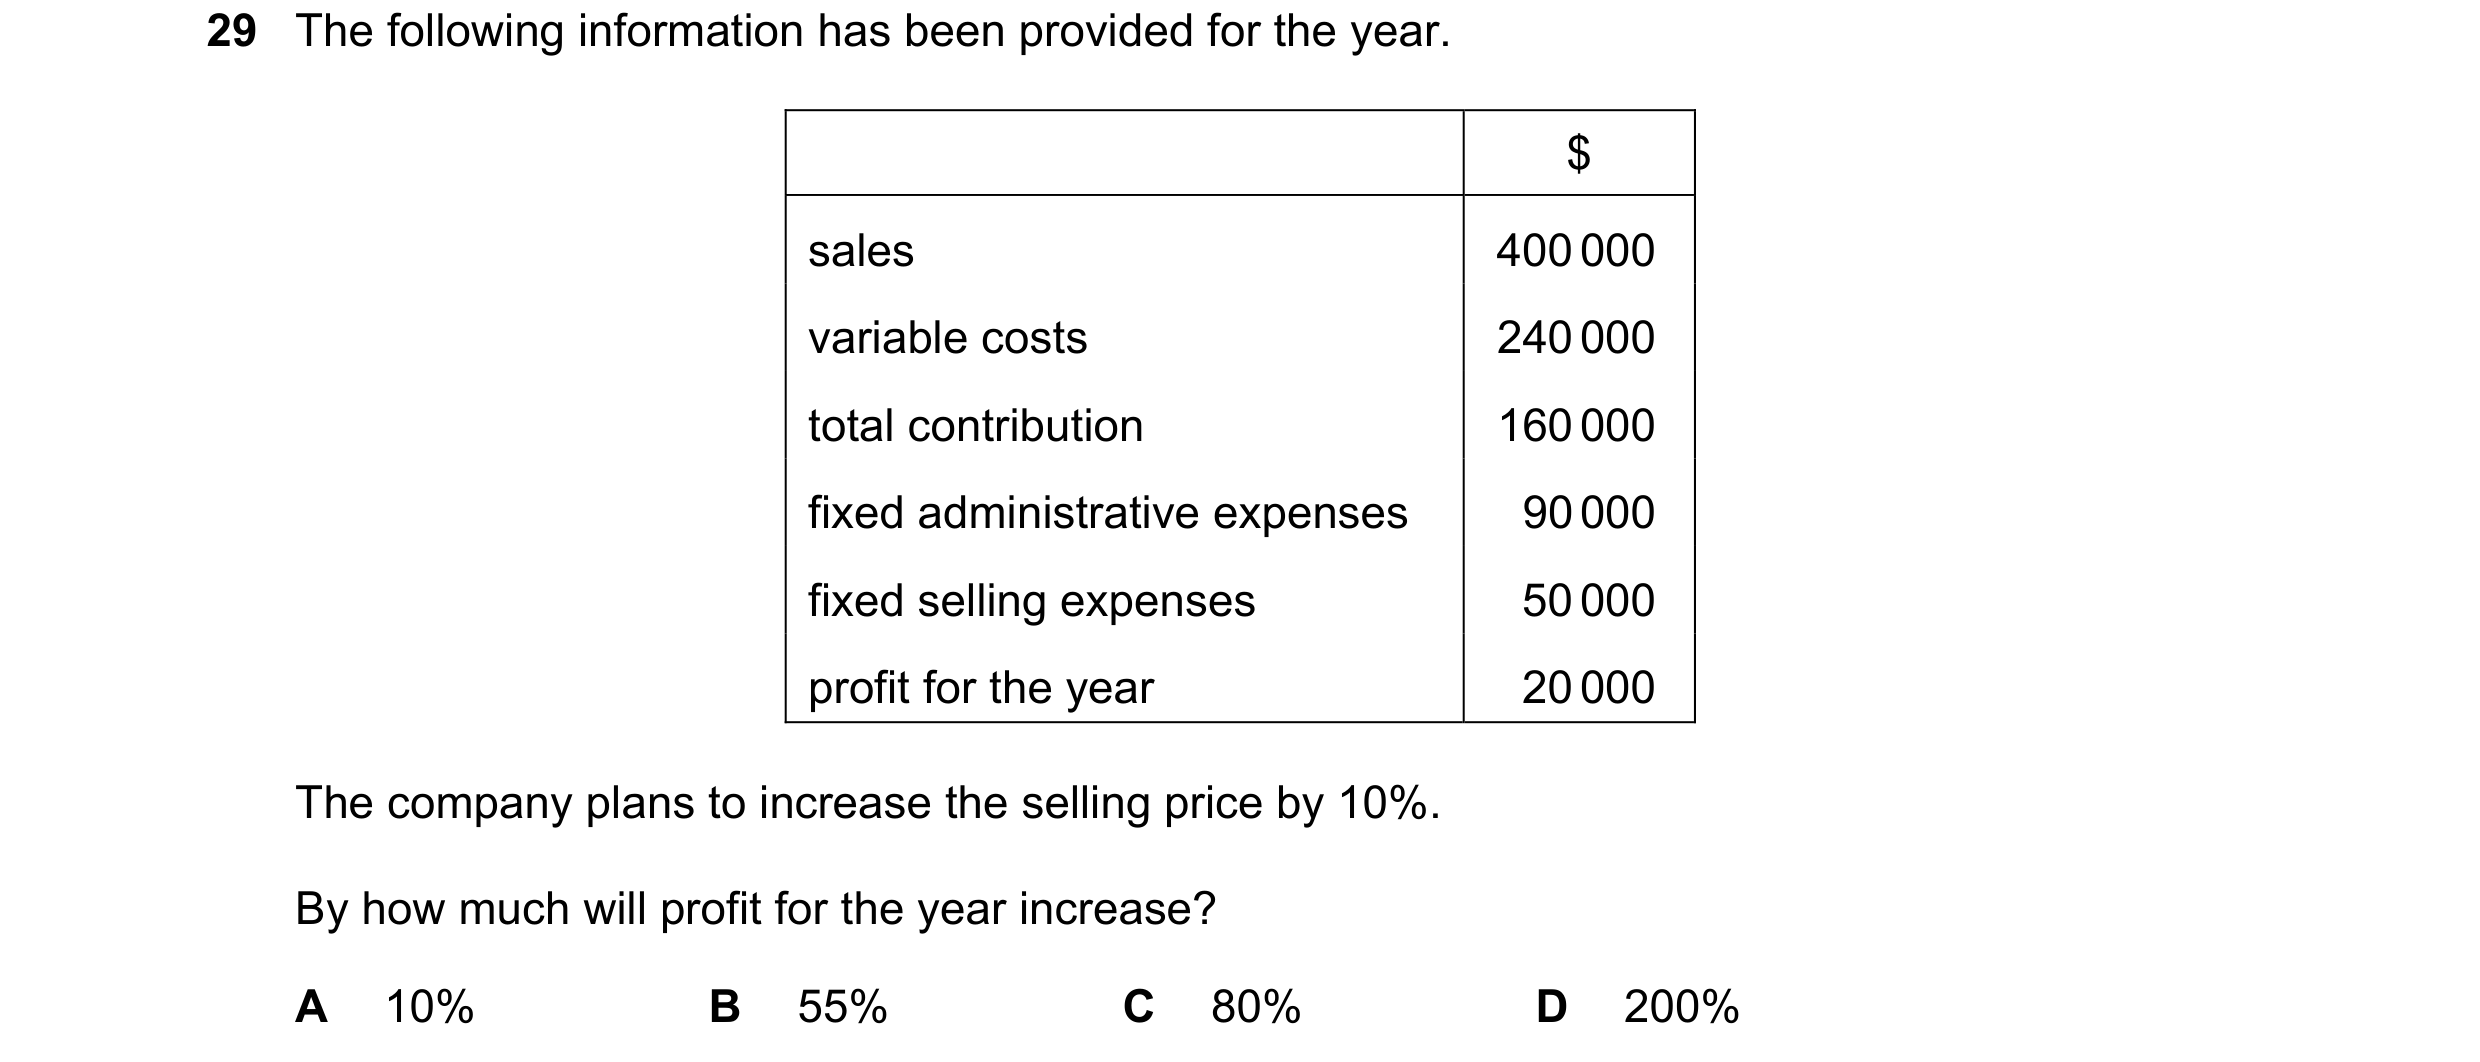
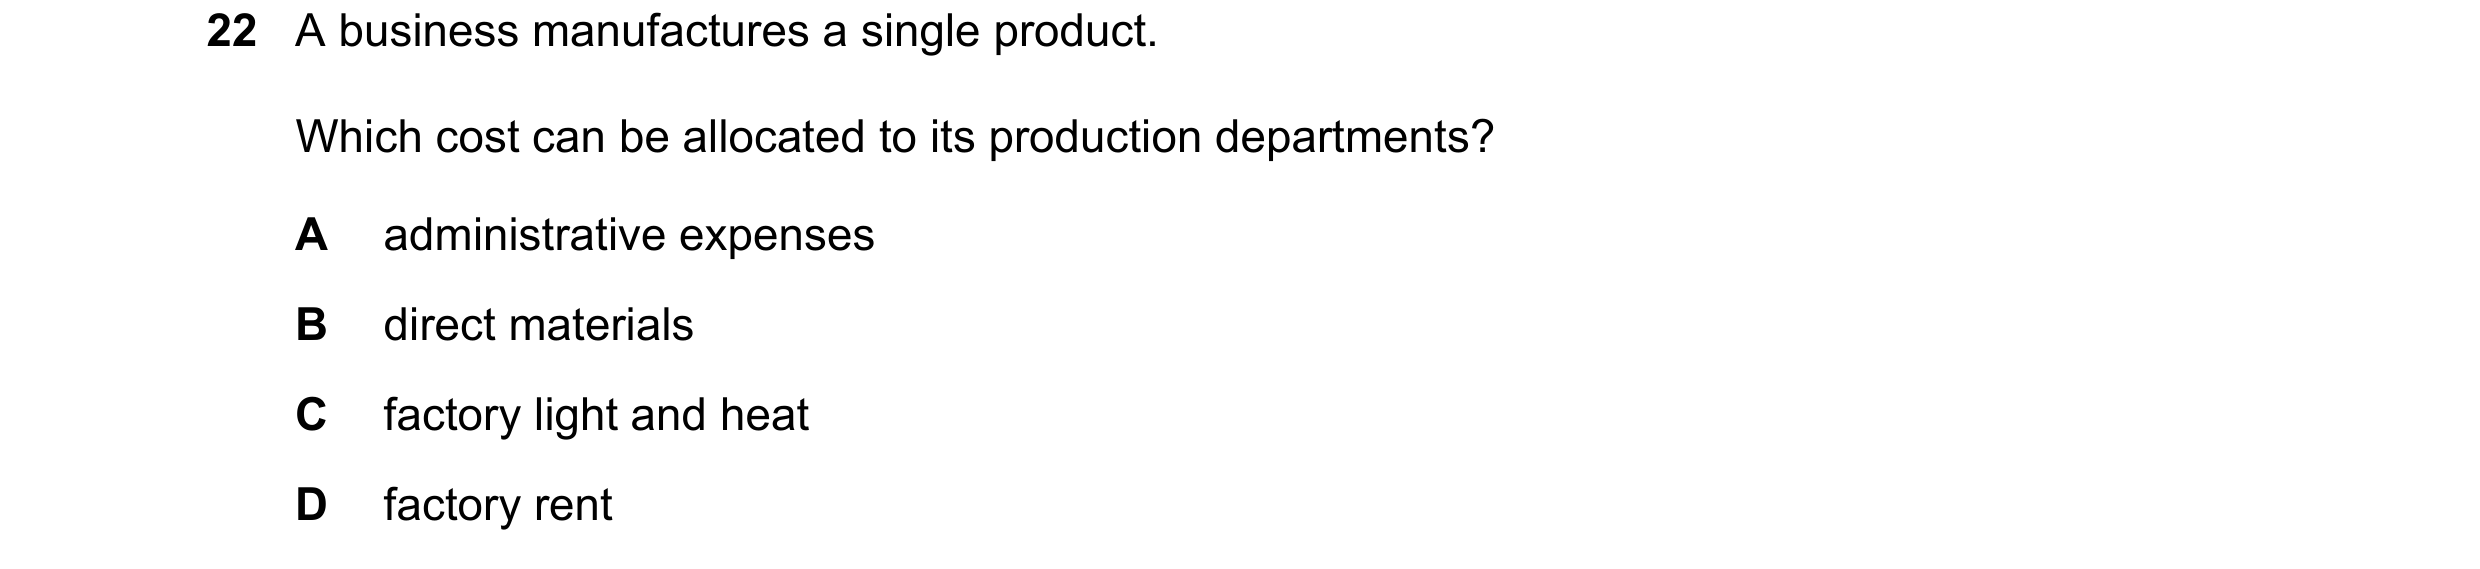
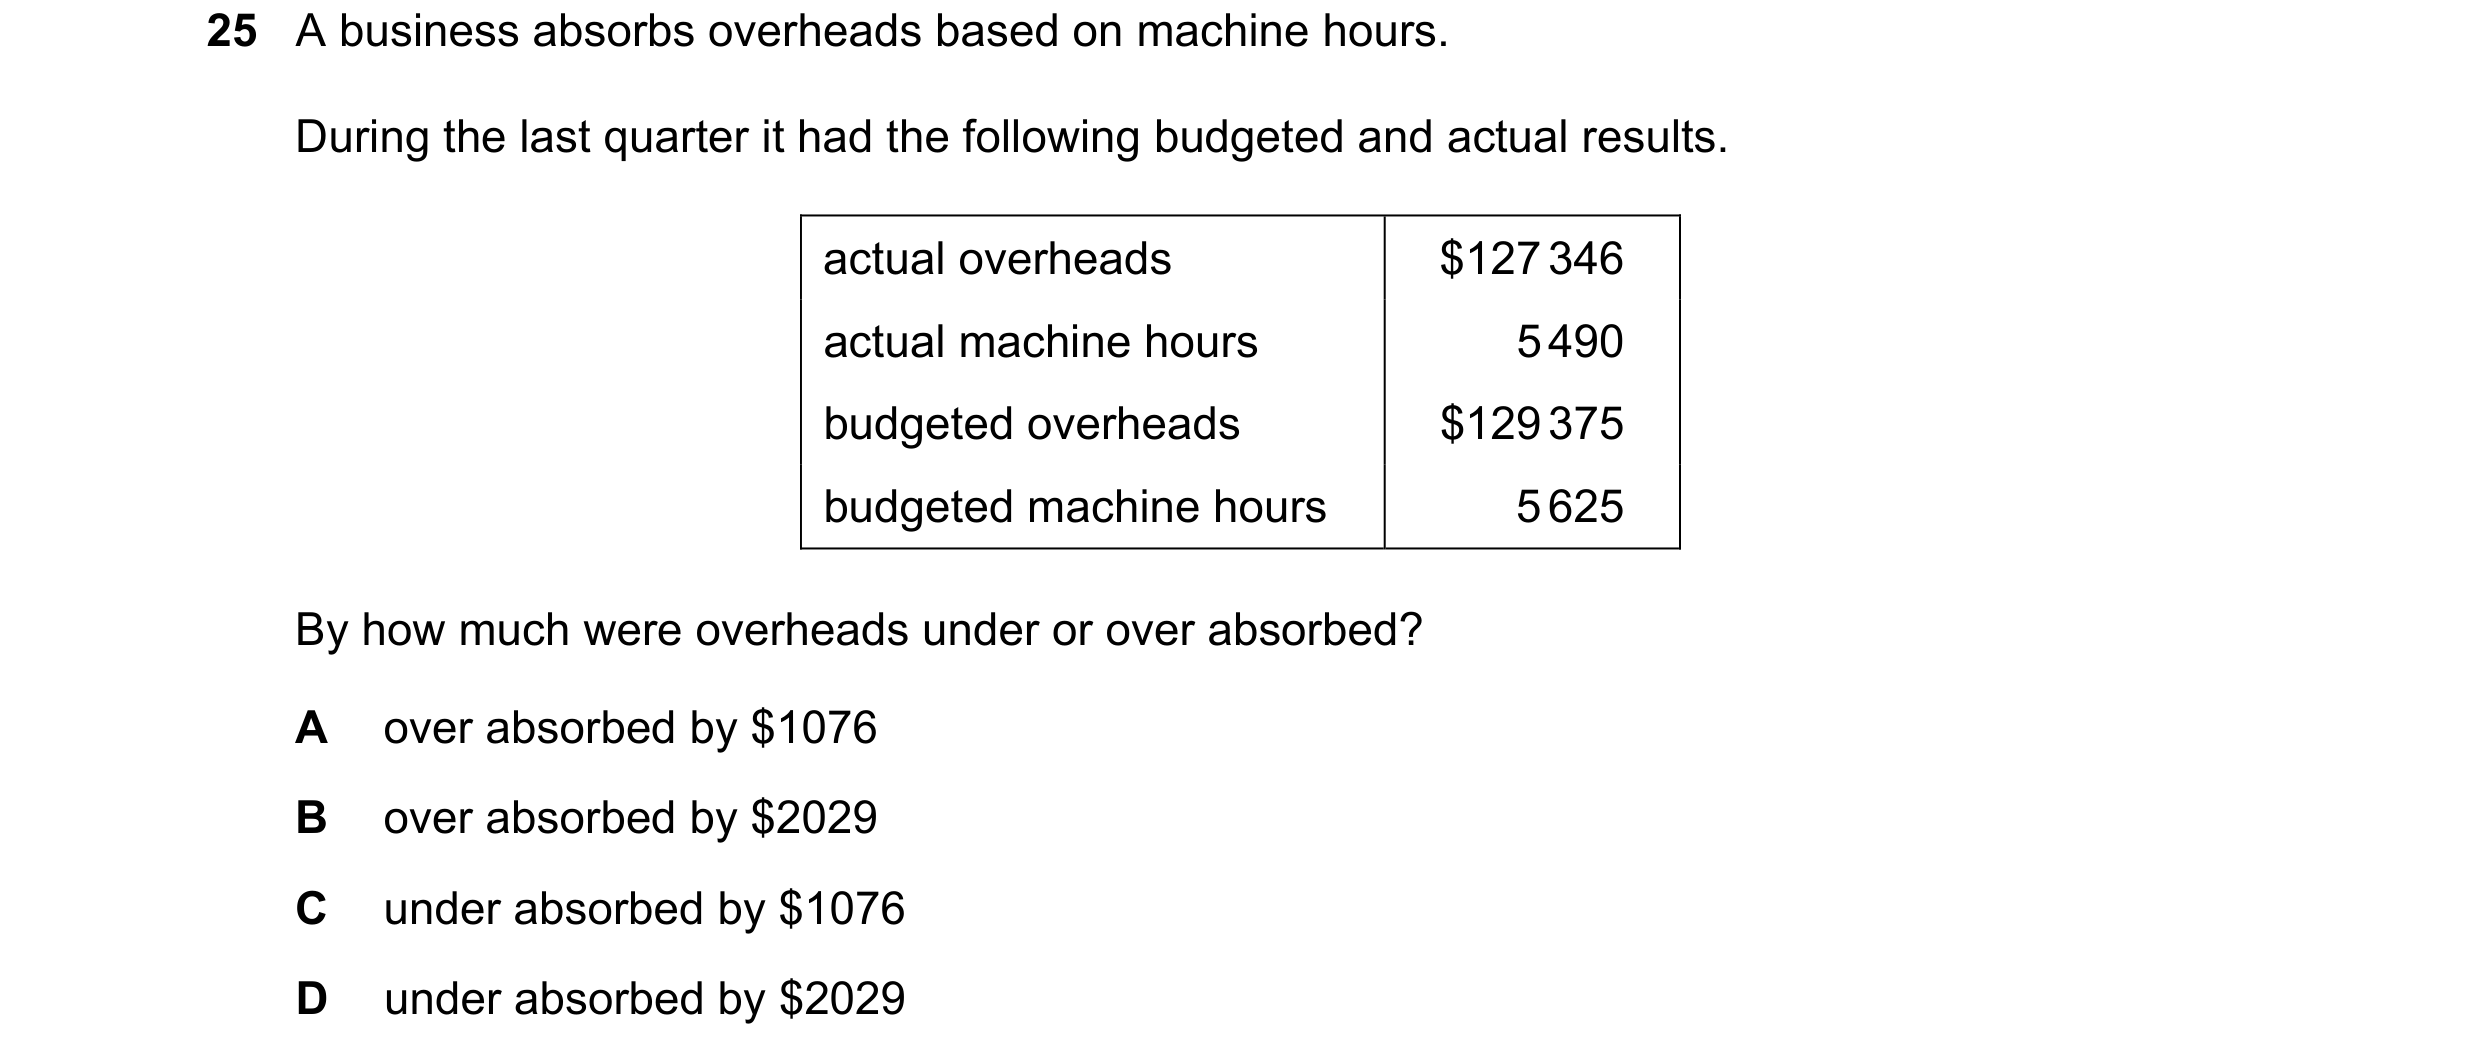
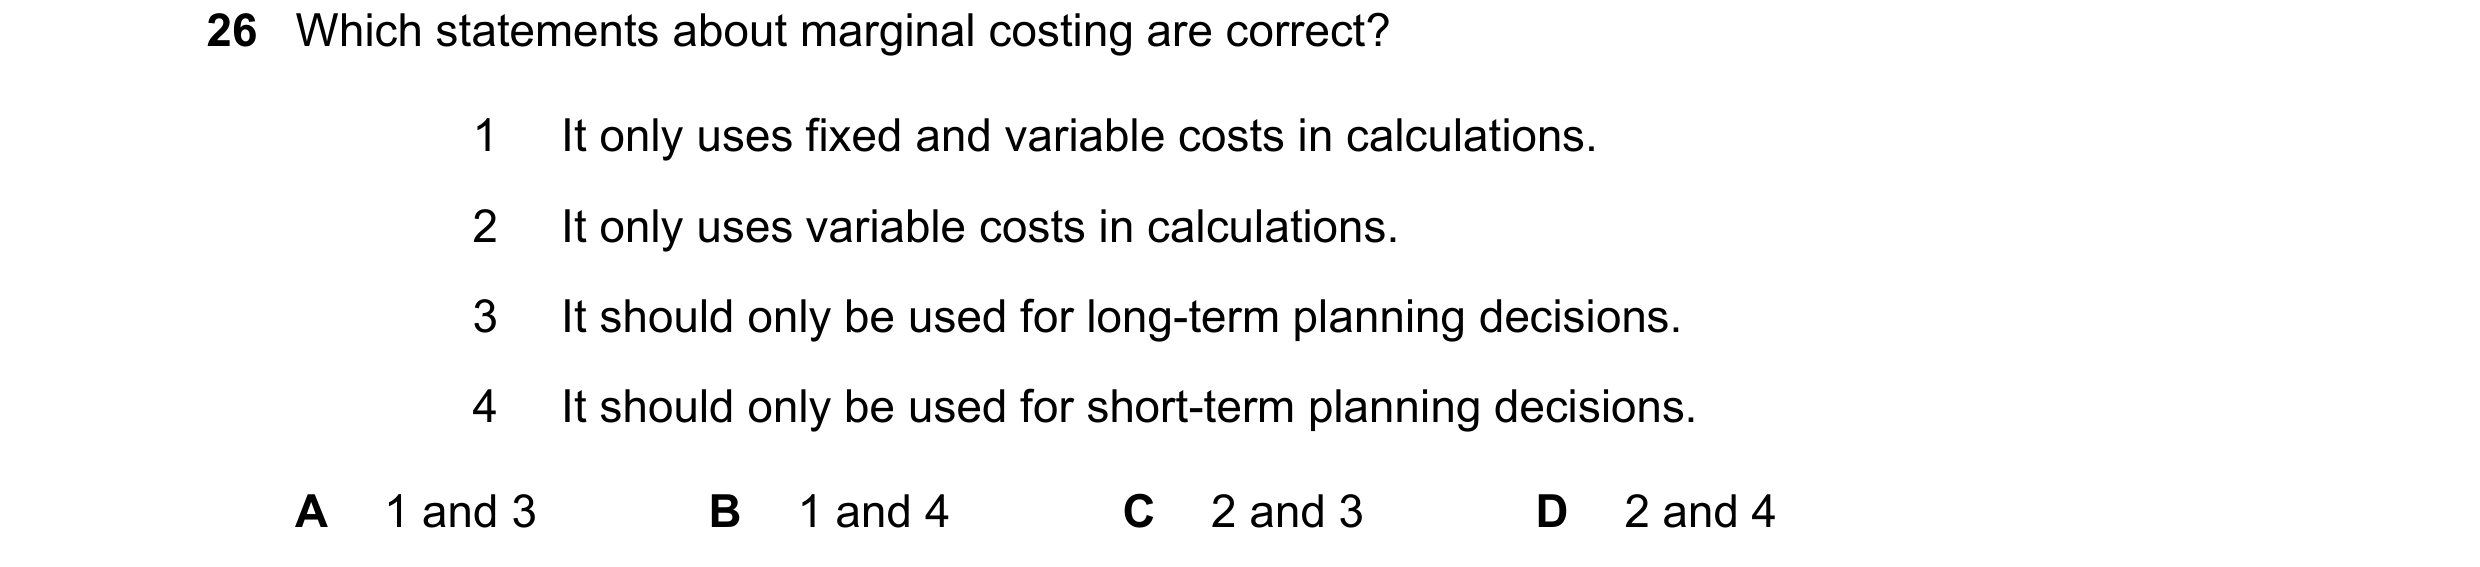 73 / 143
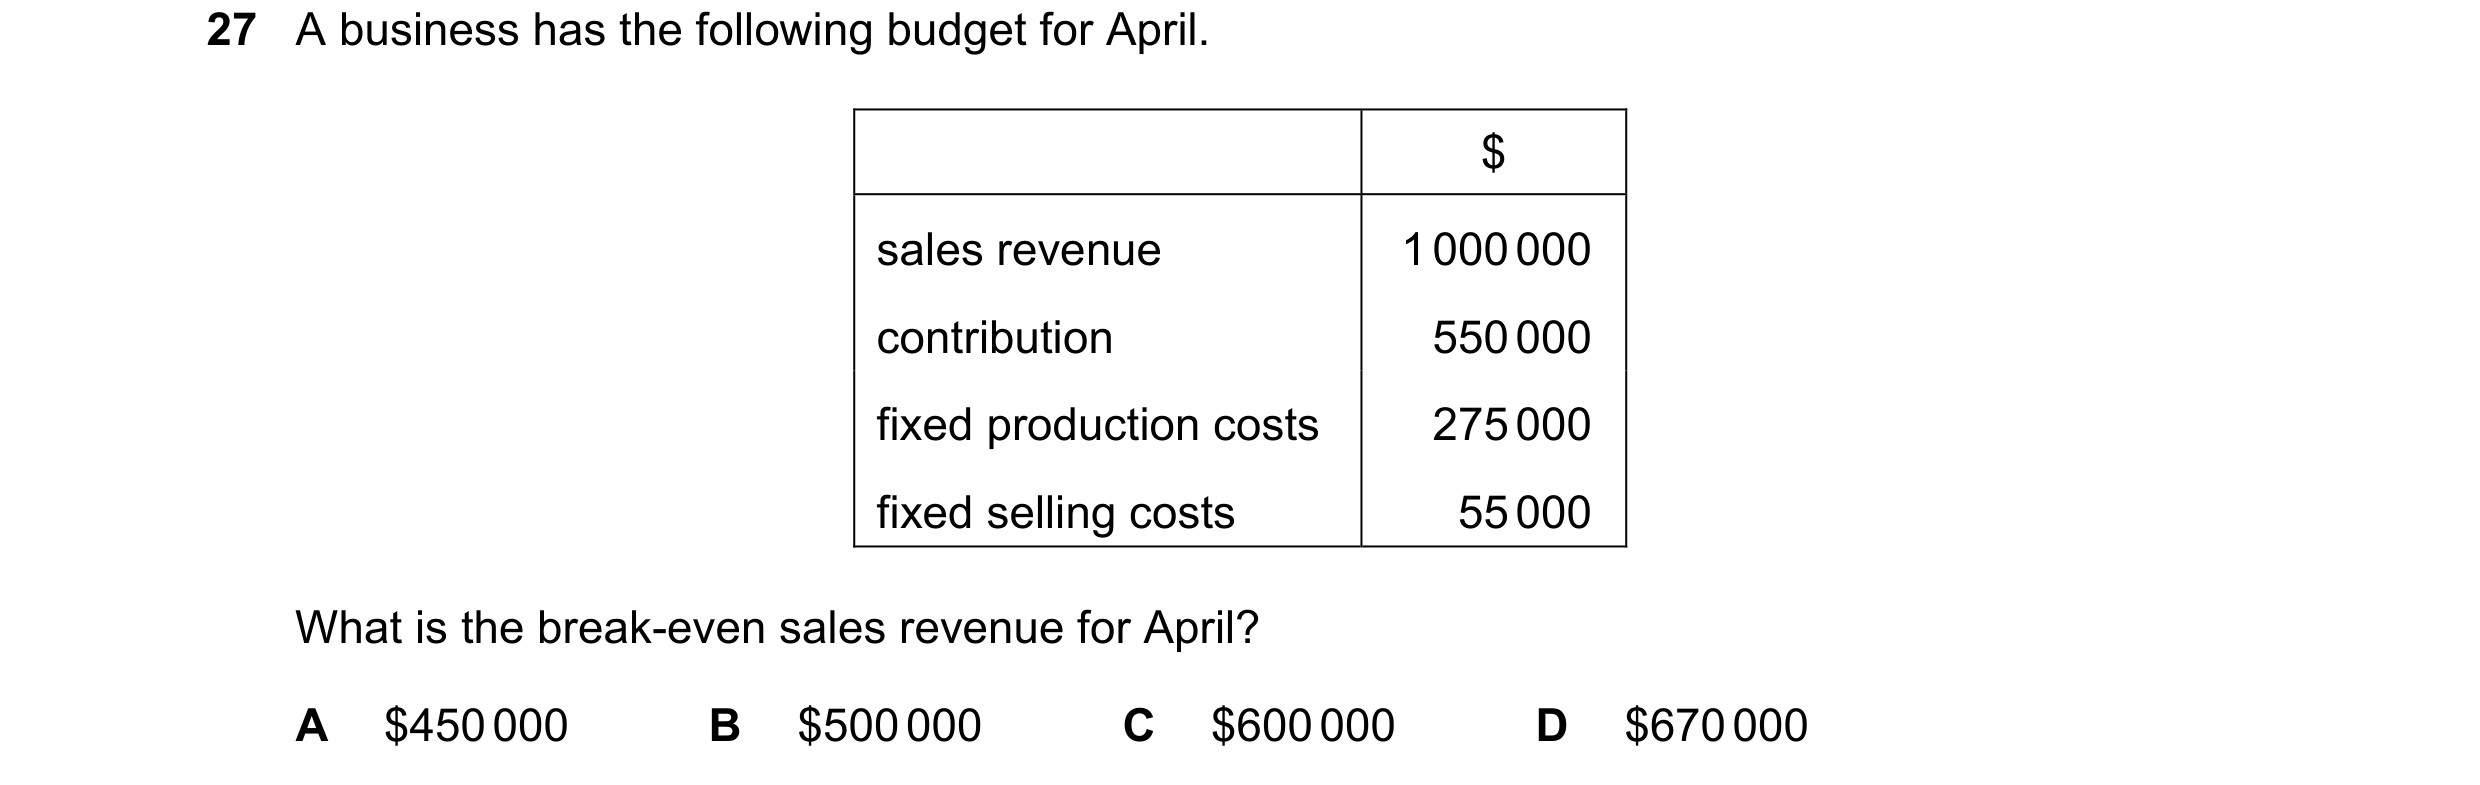
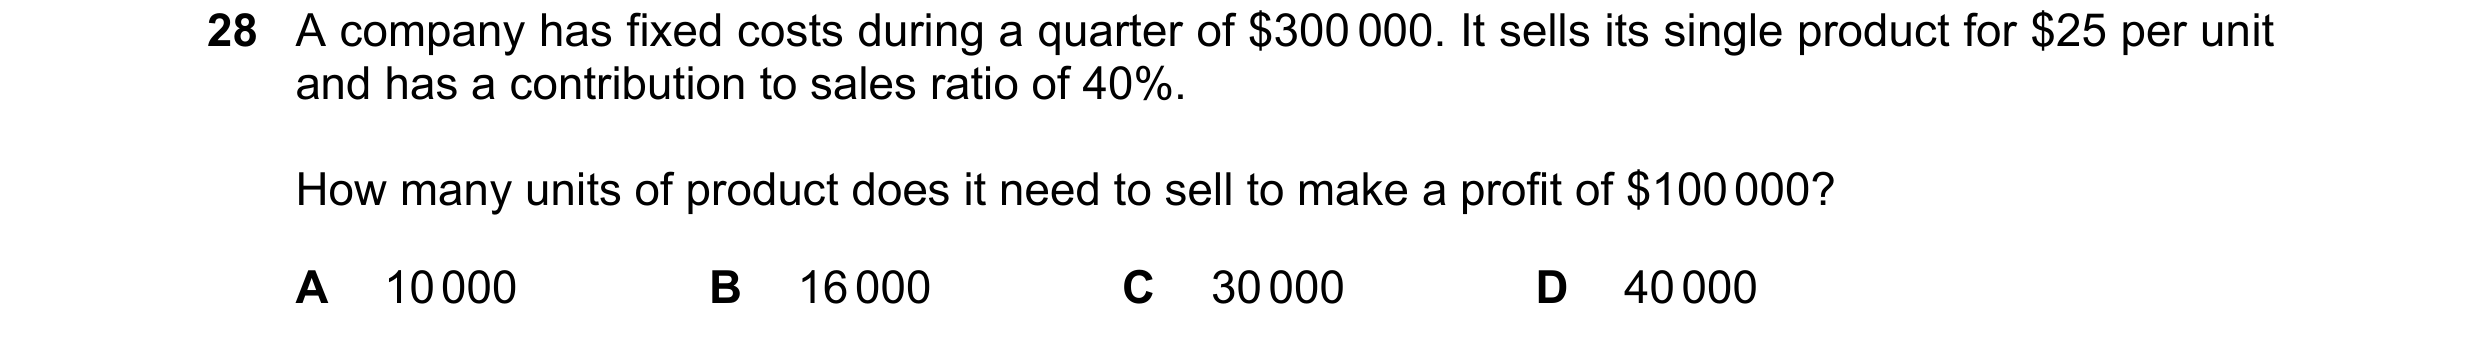
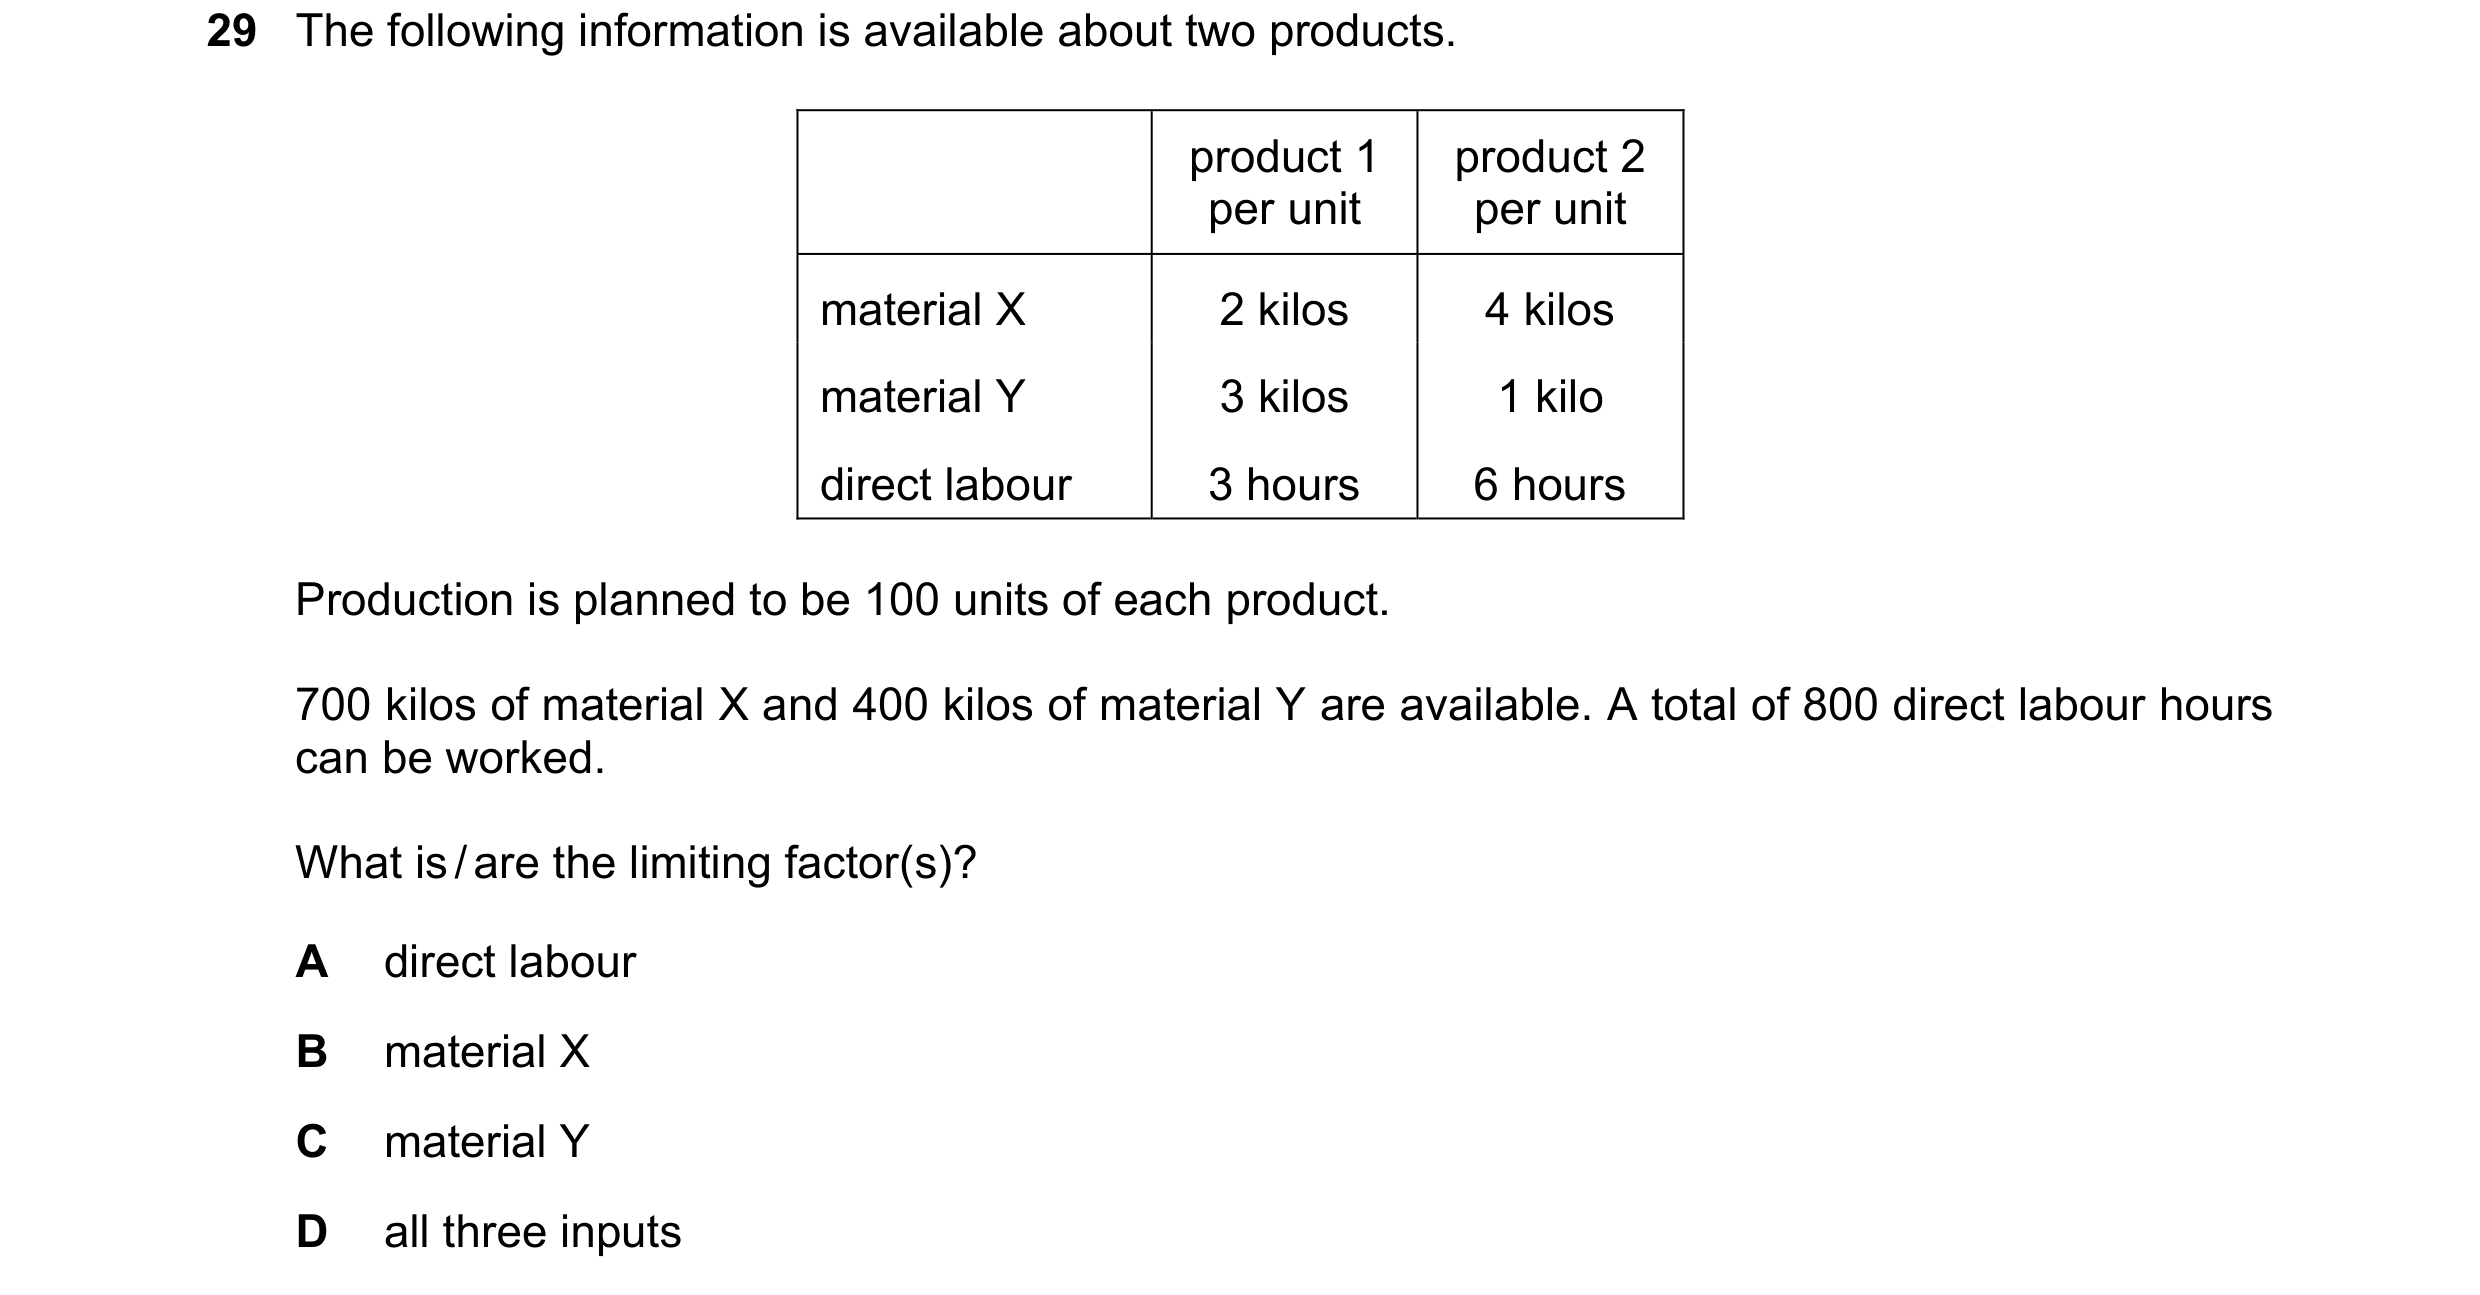
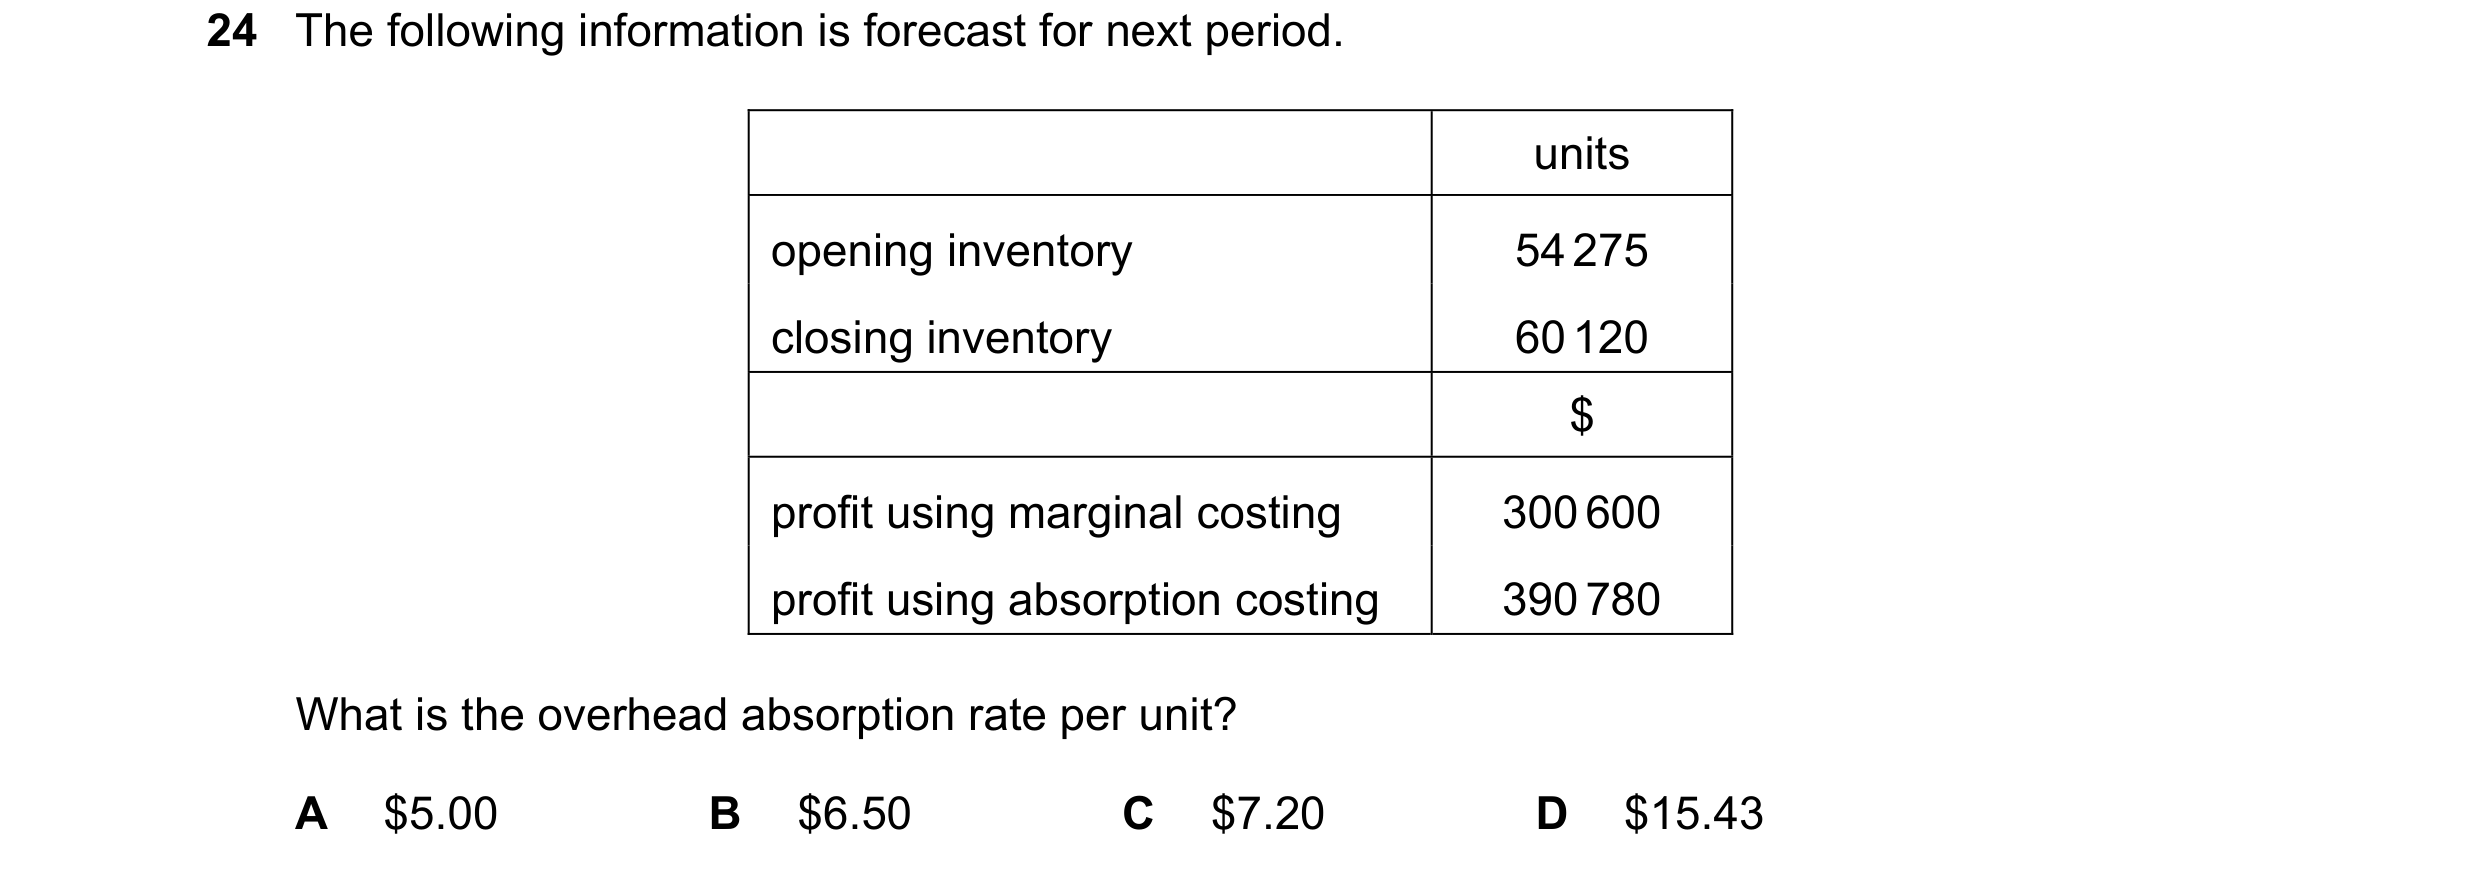 74 / 143
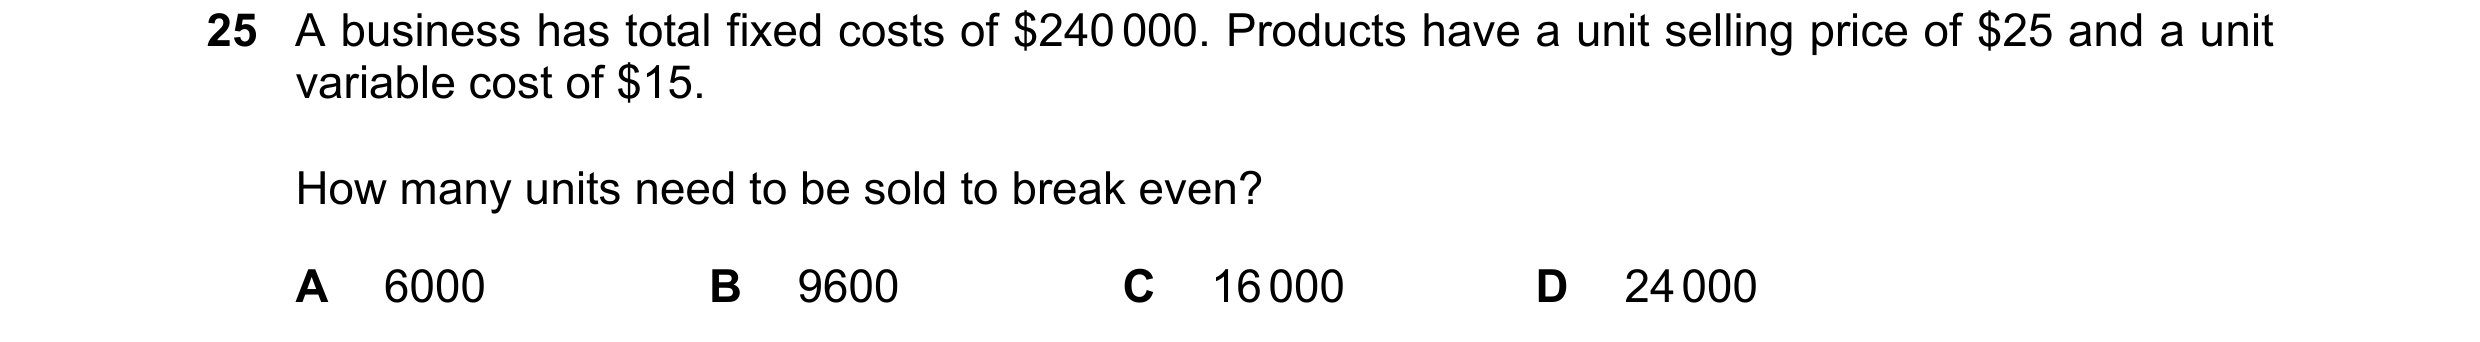
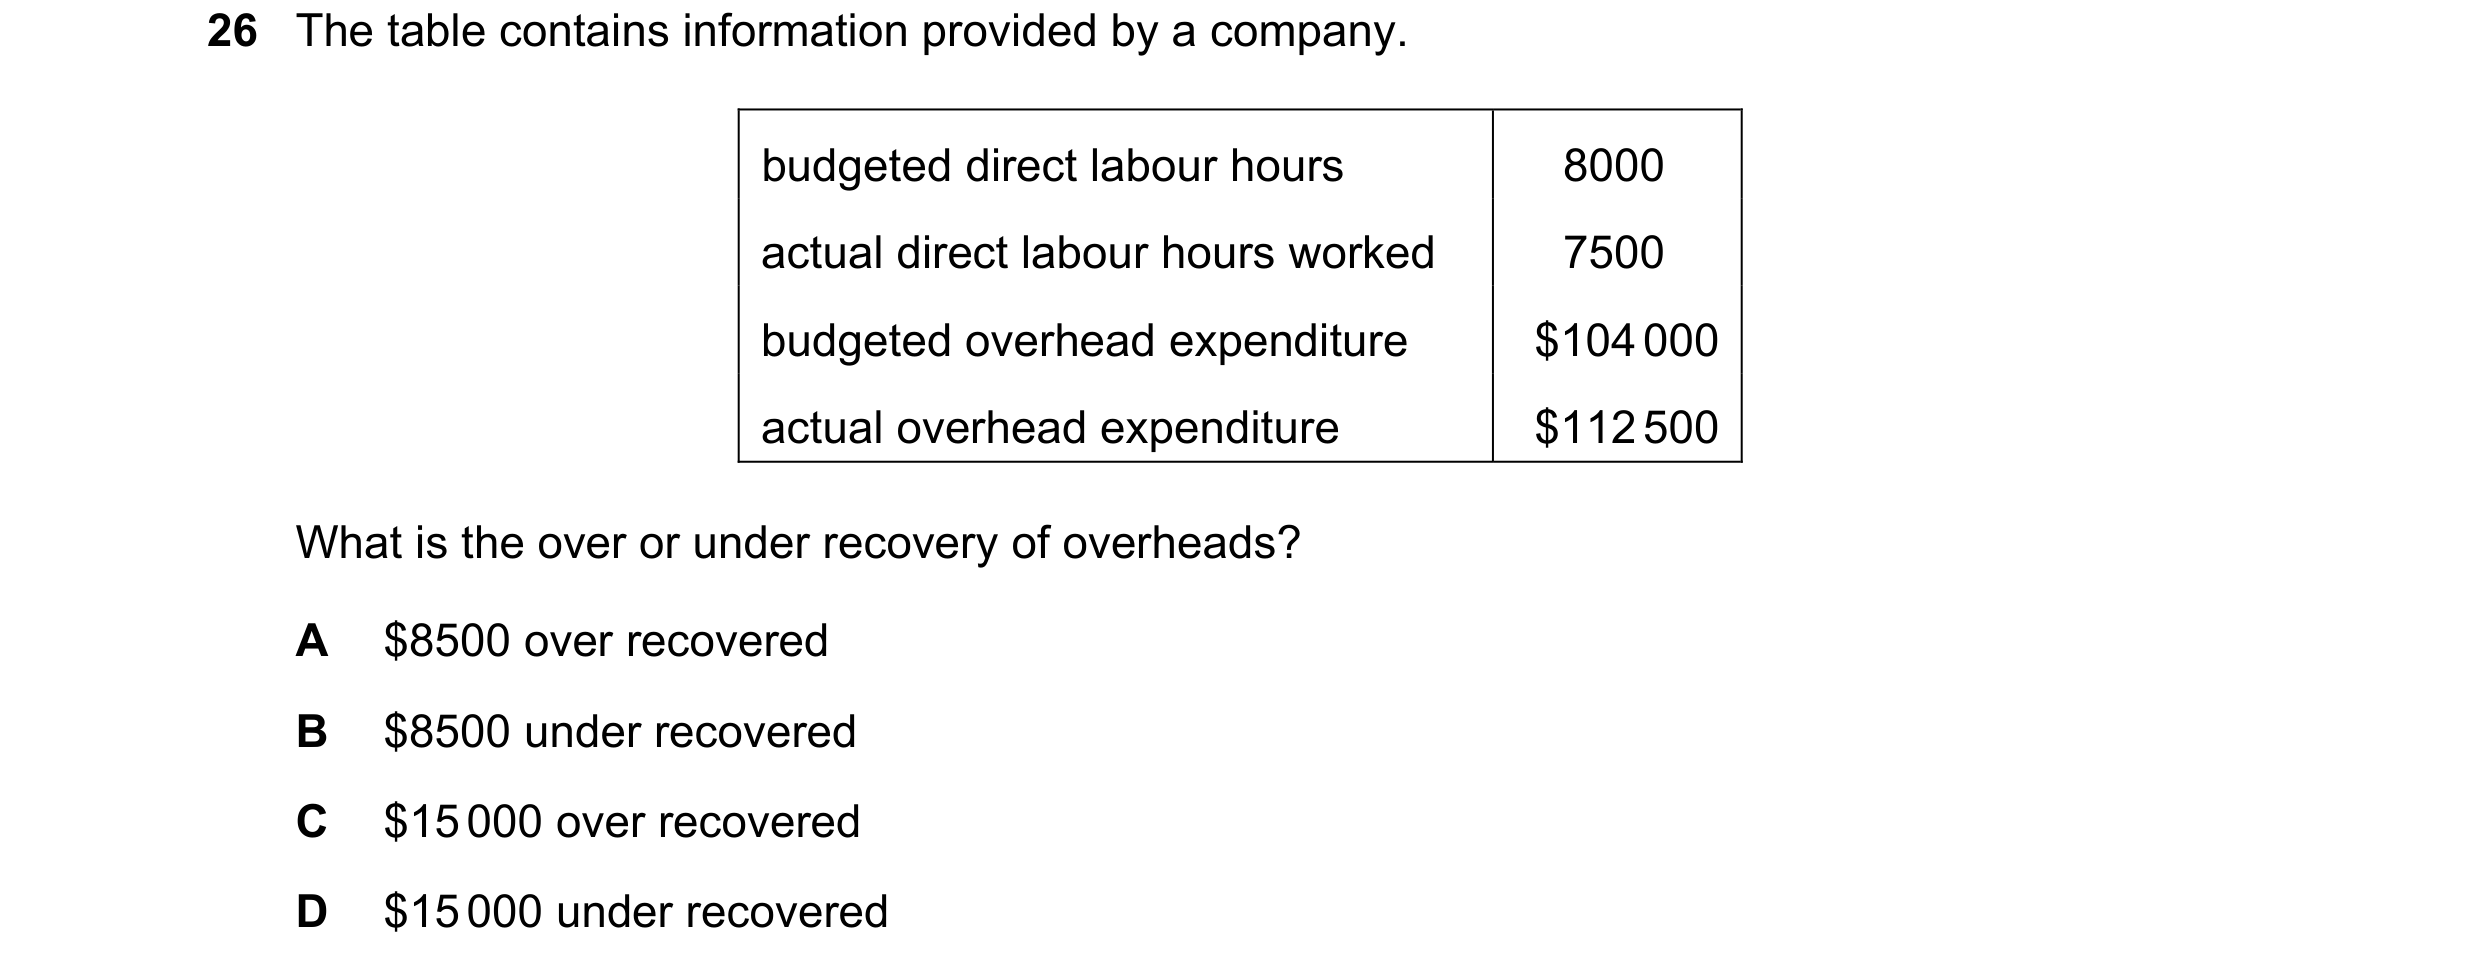
 75 / 143
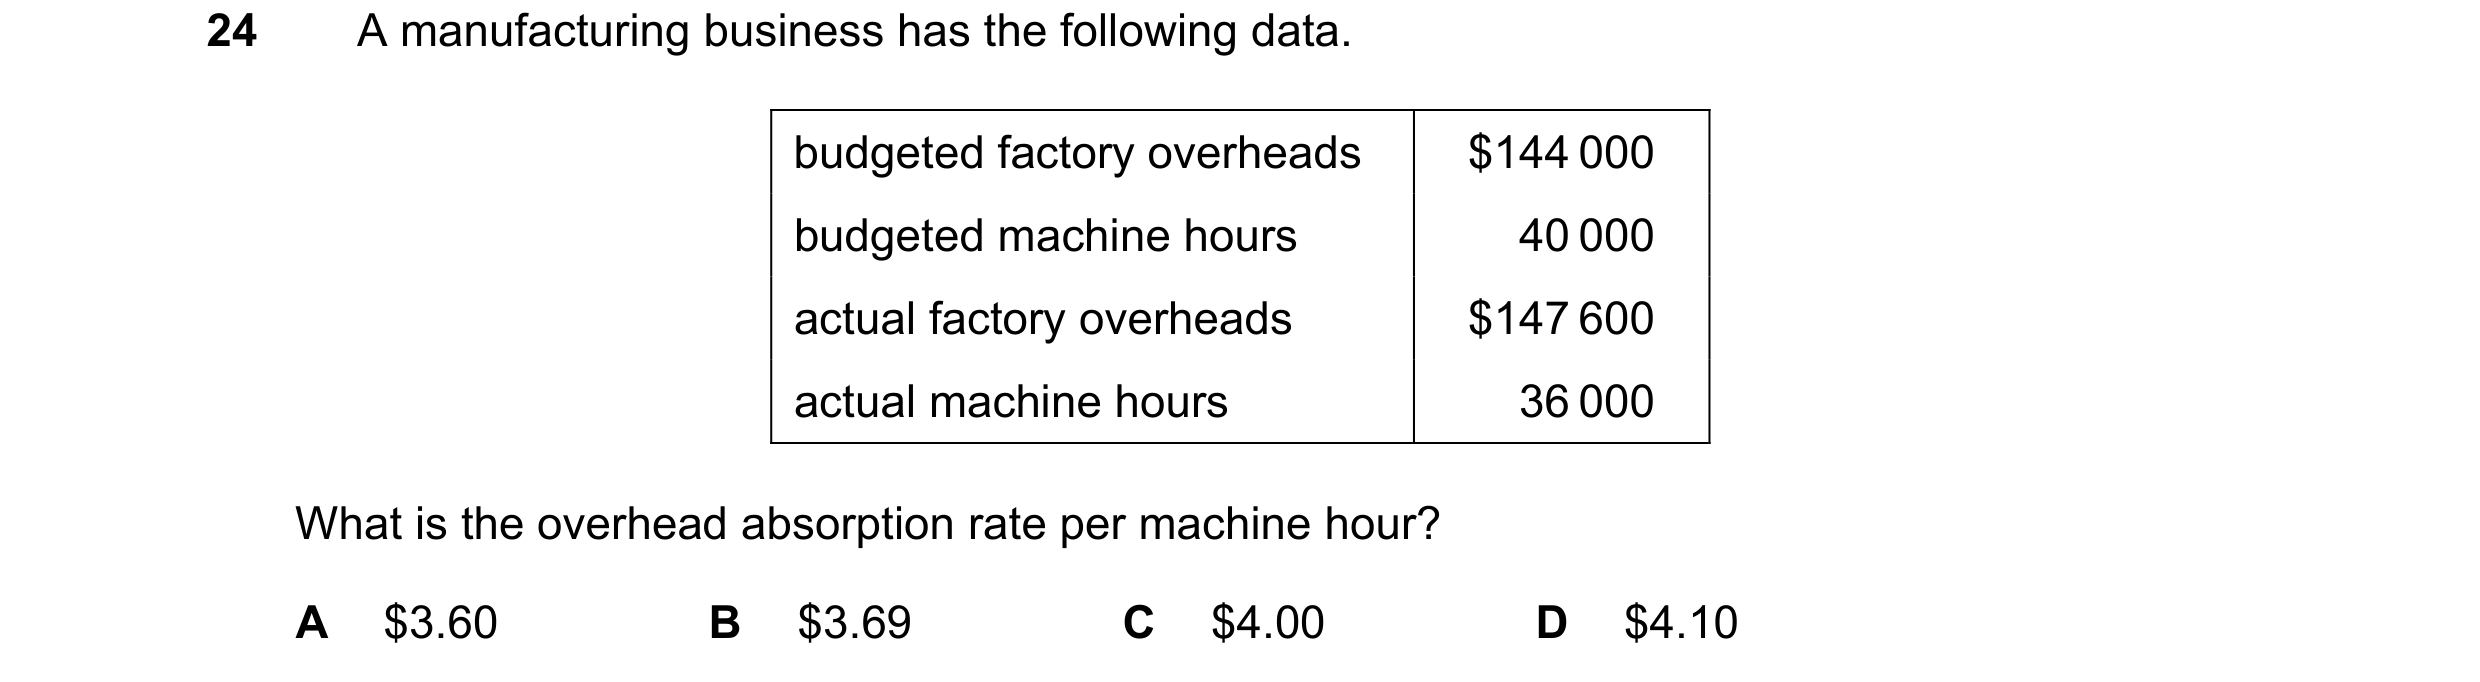
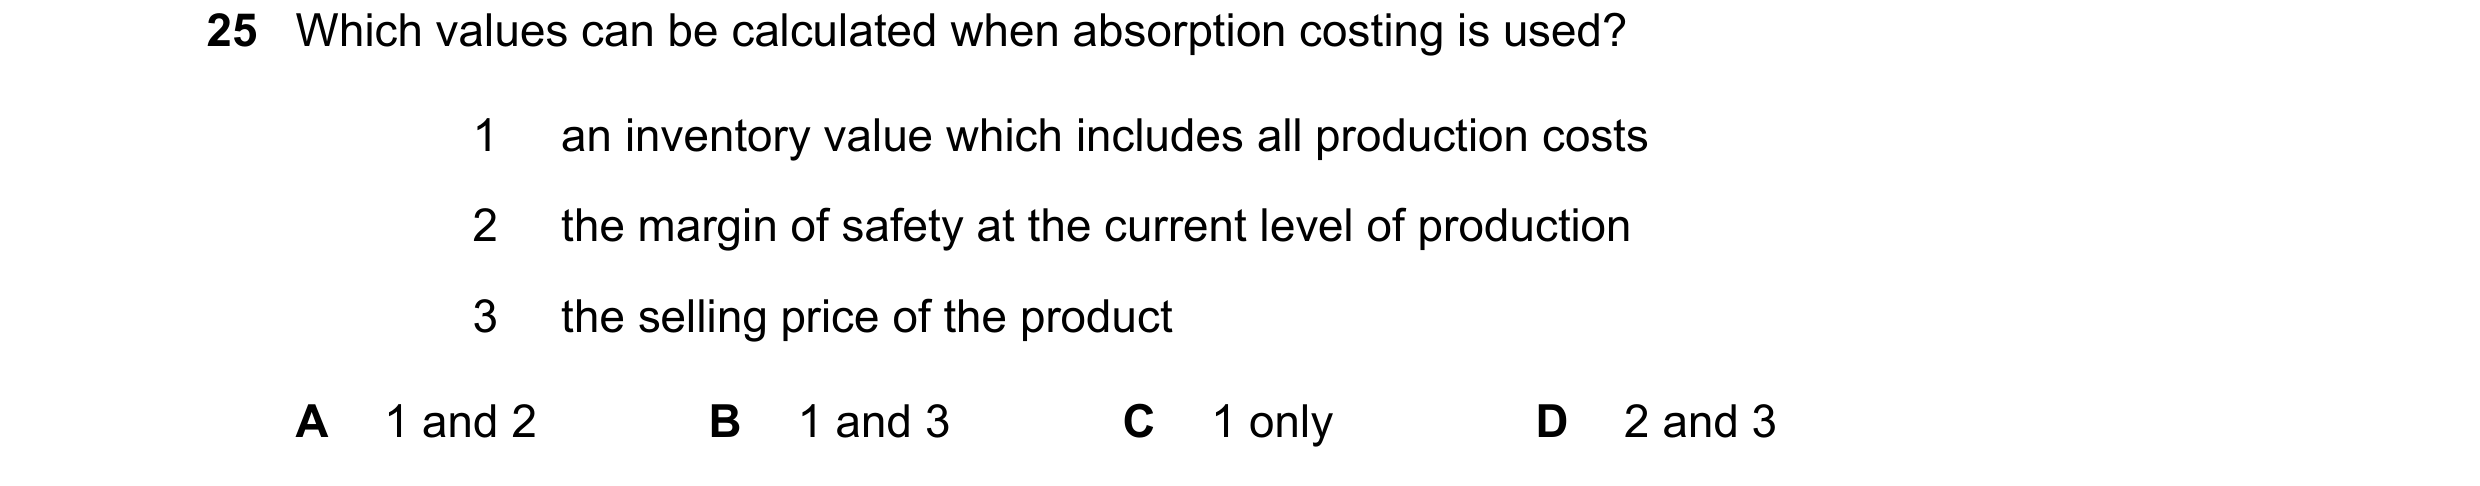
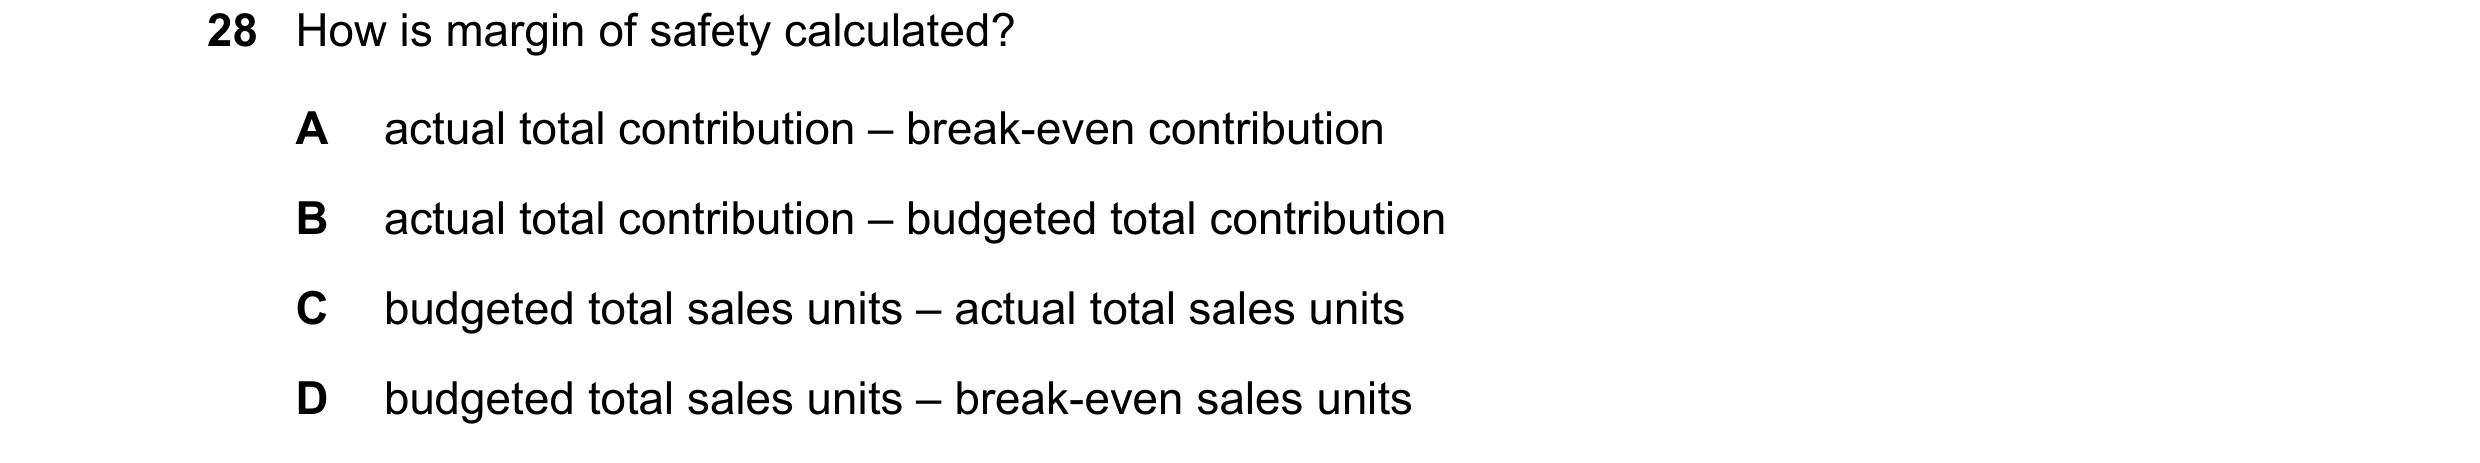
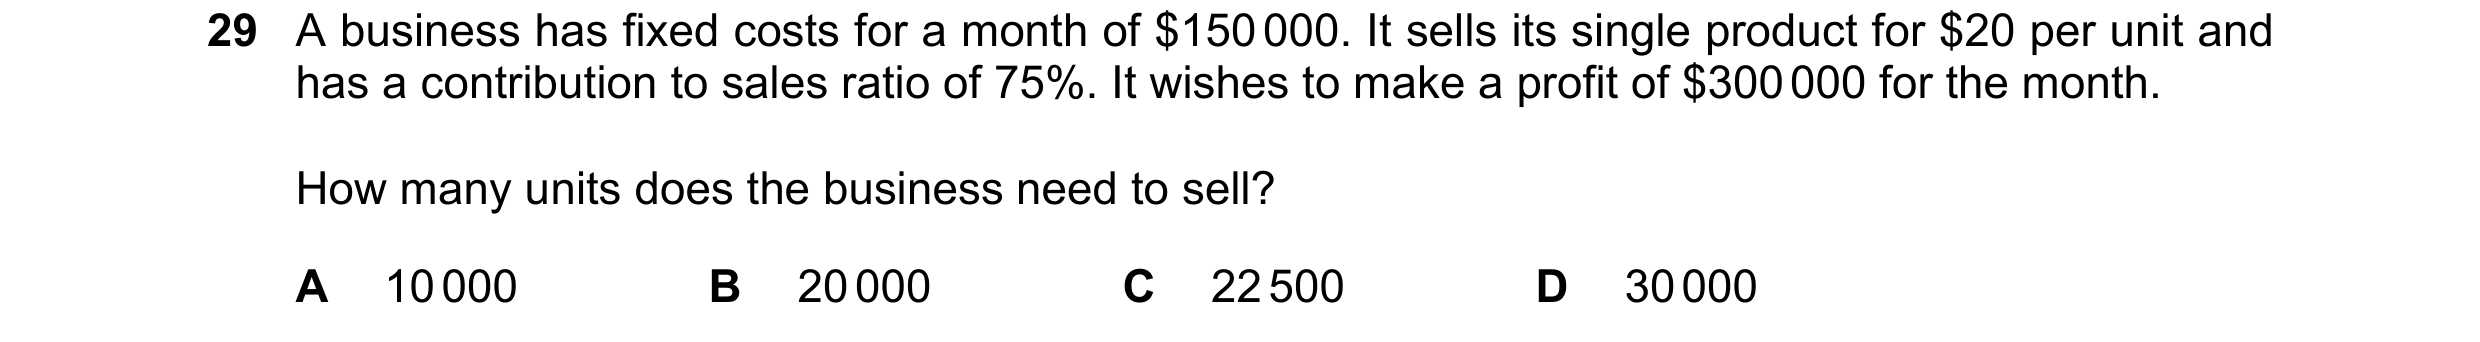
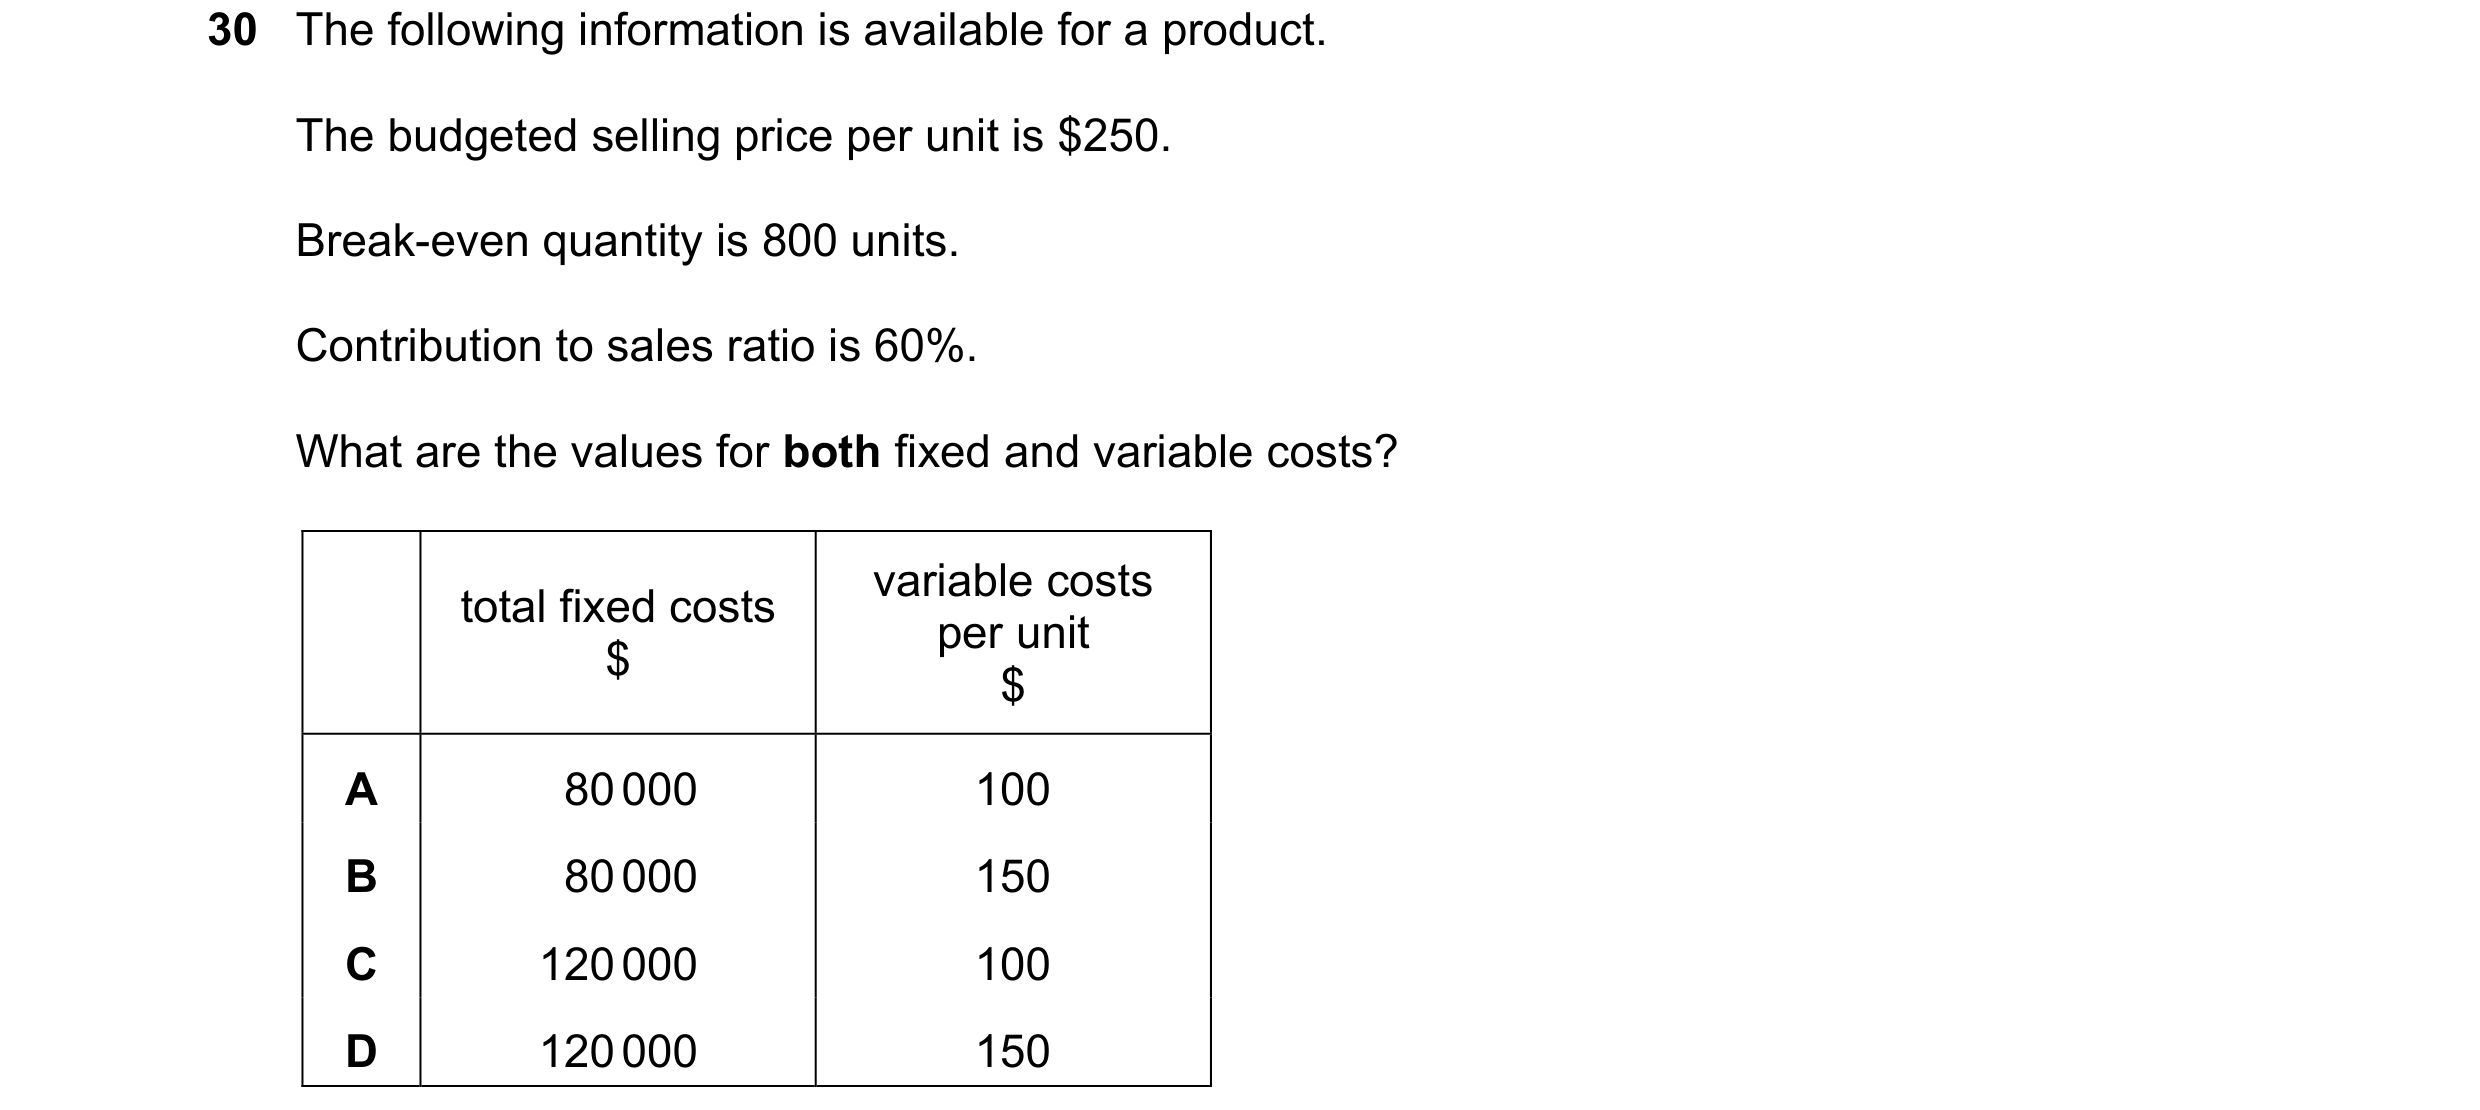 76 / 143
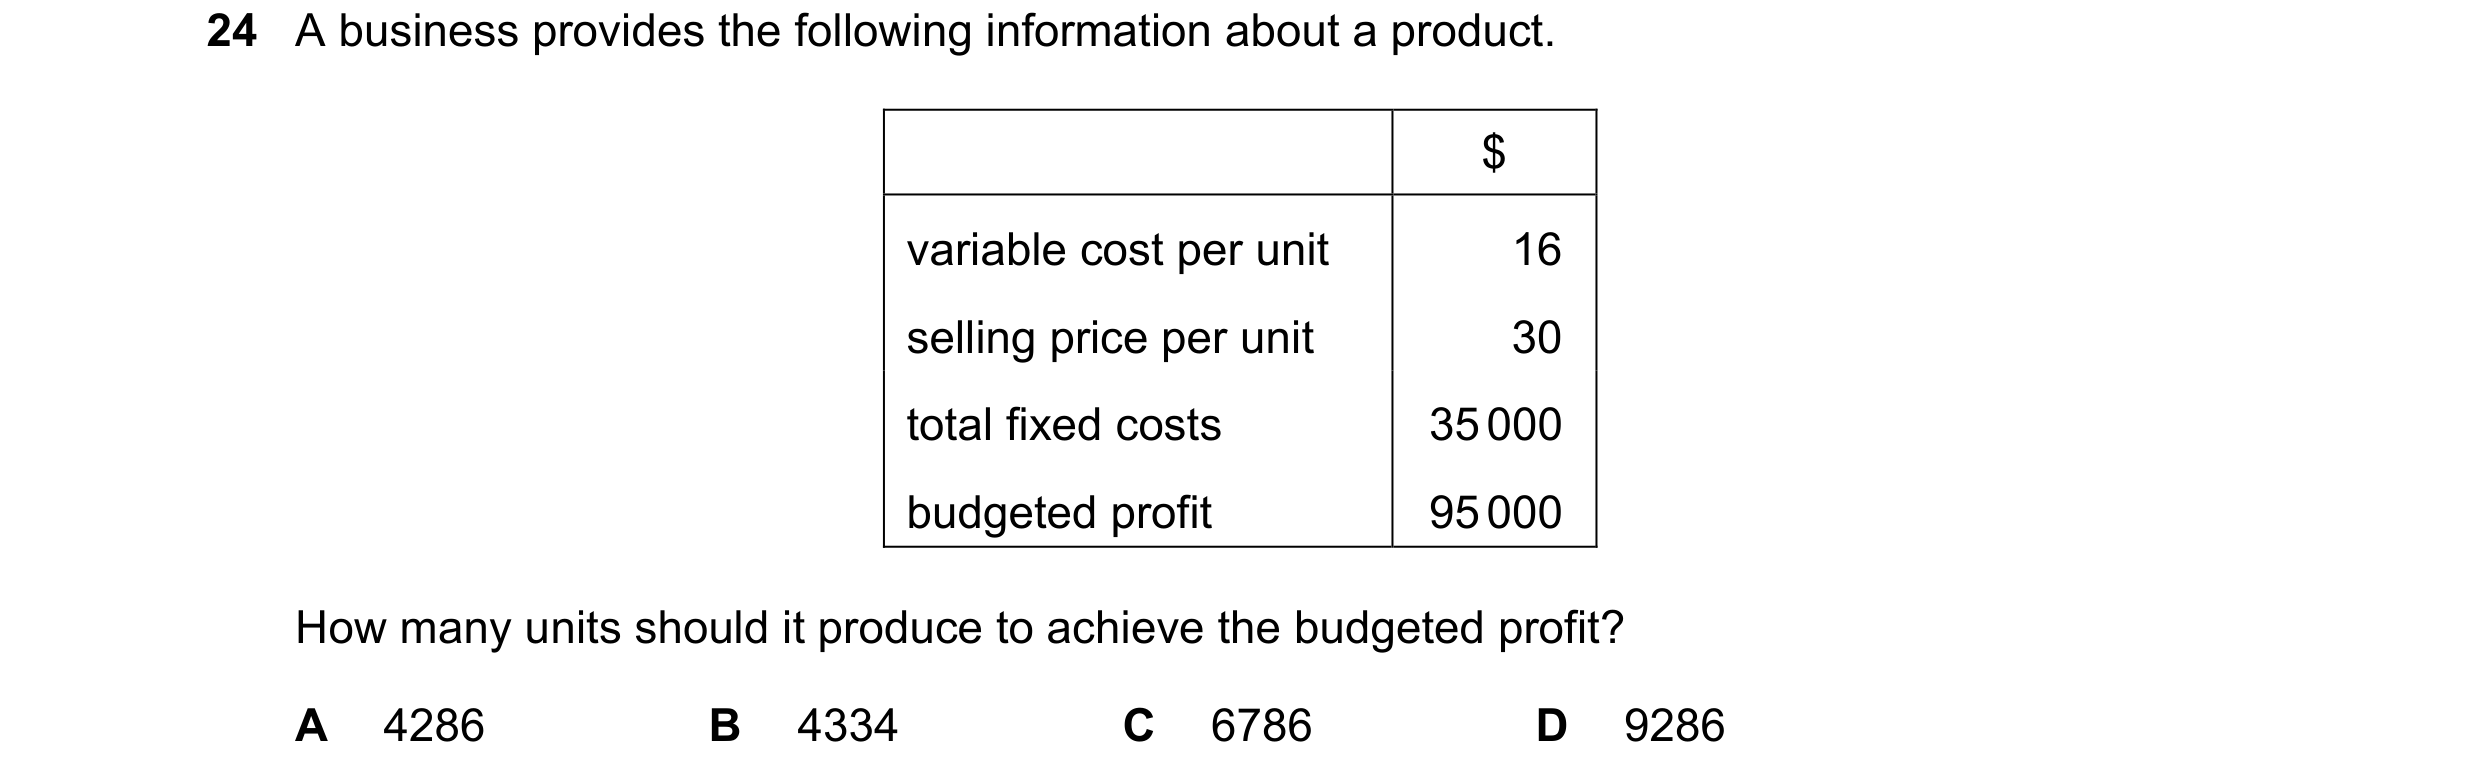
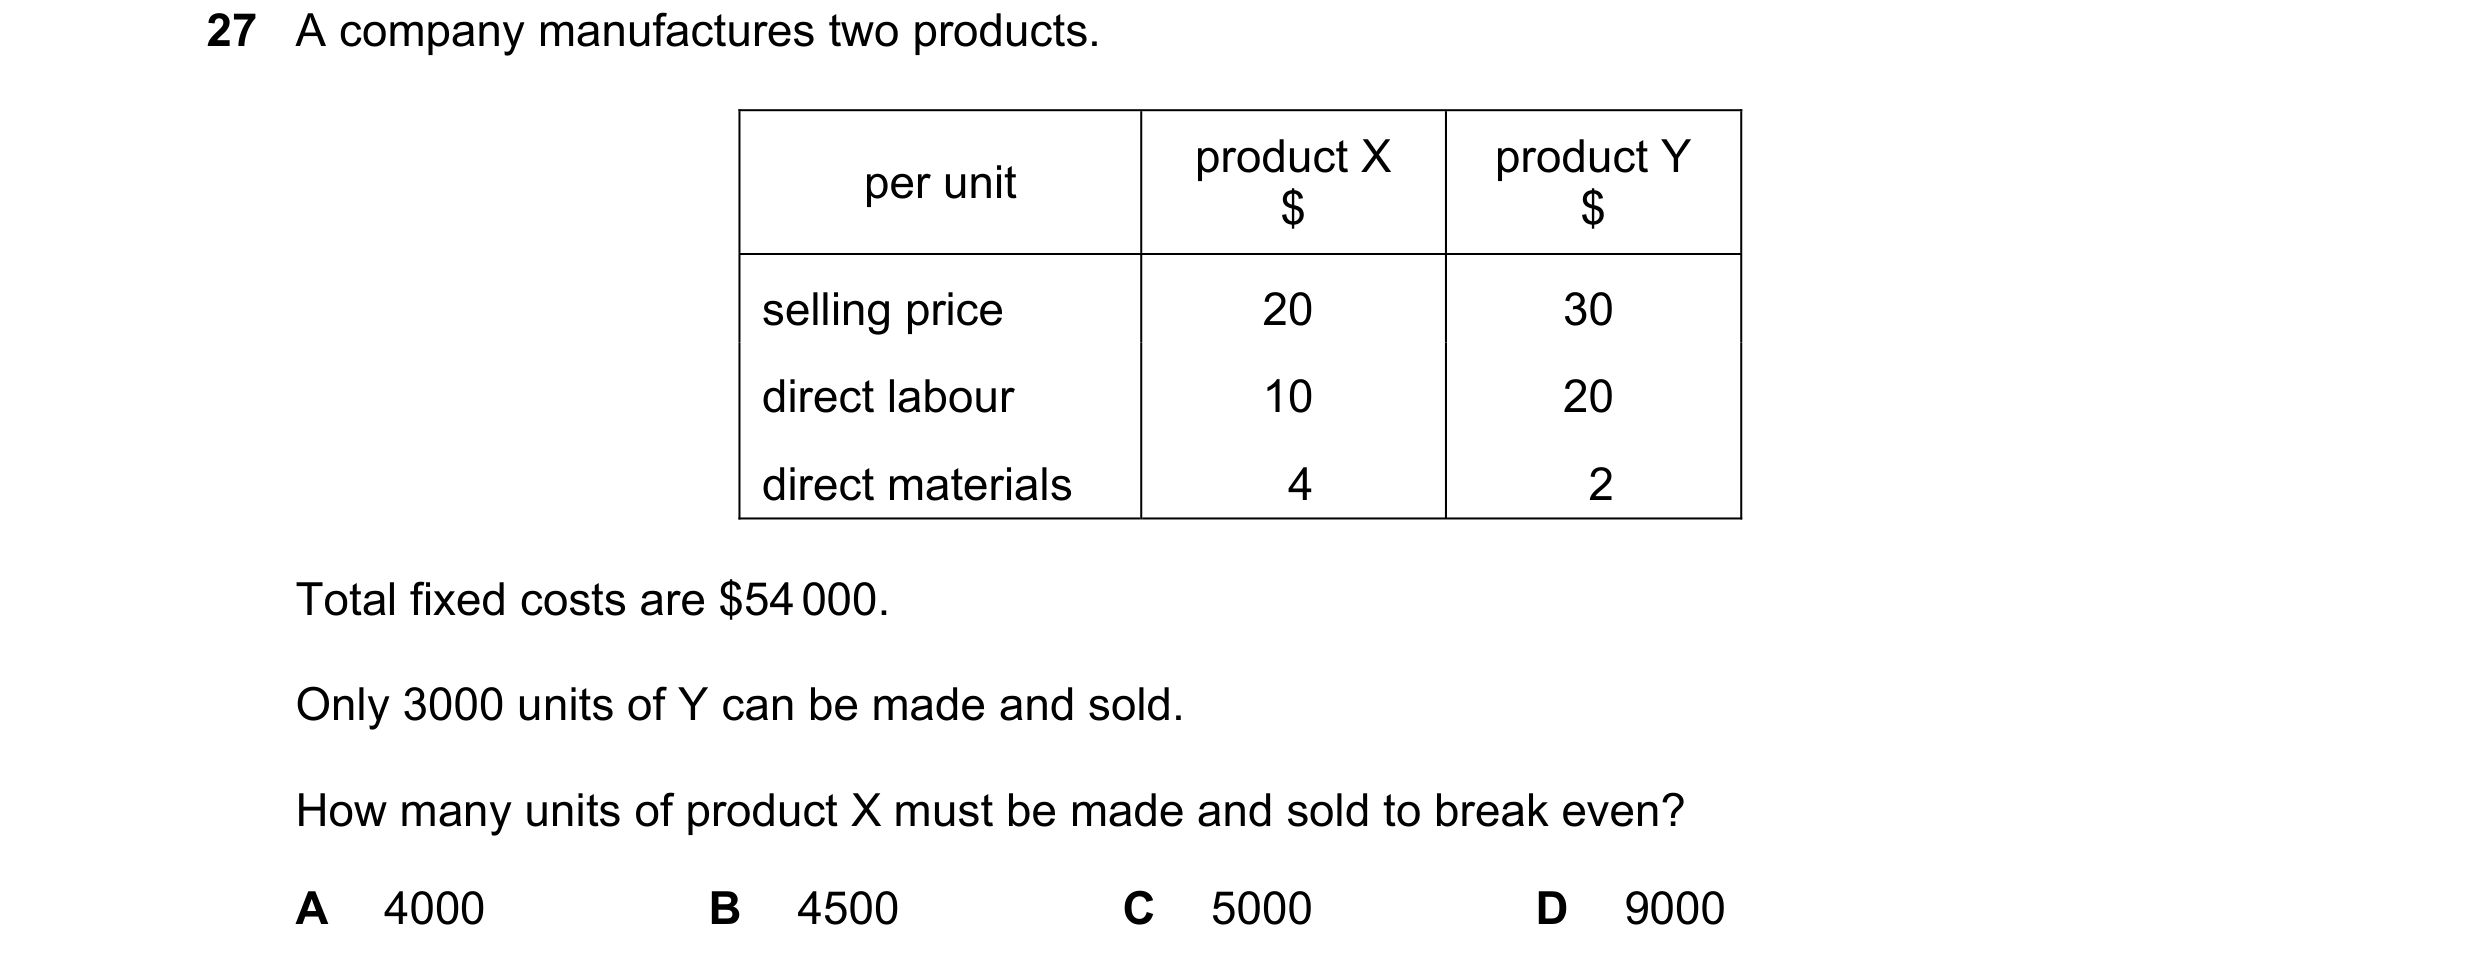 77 / 143
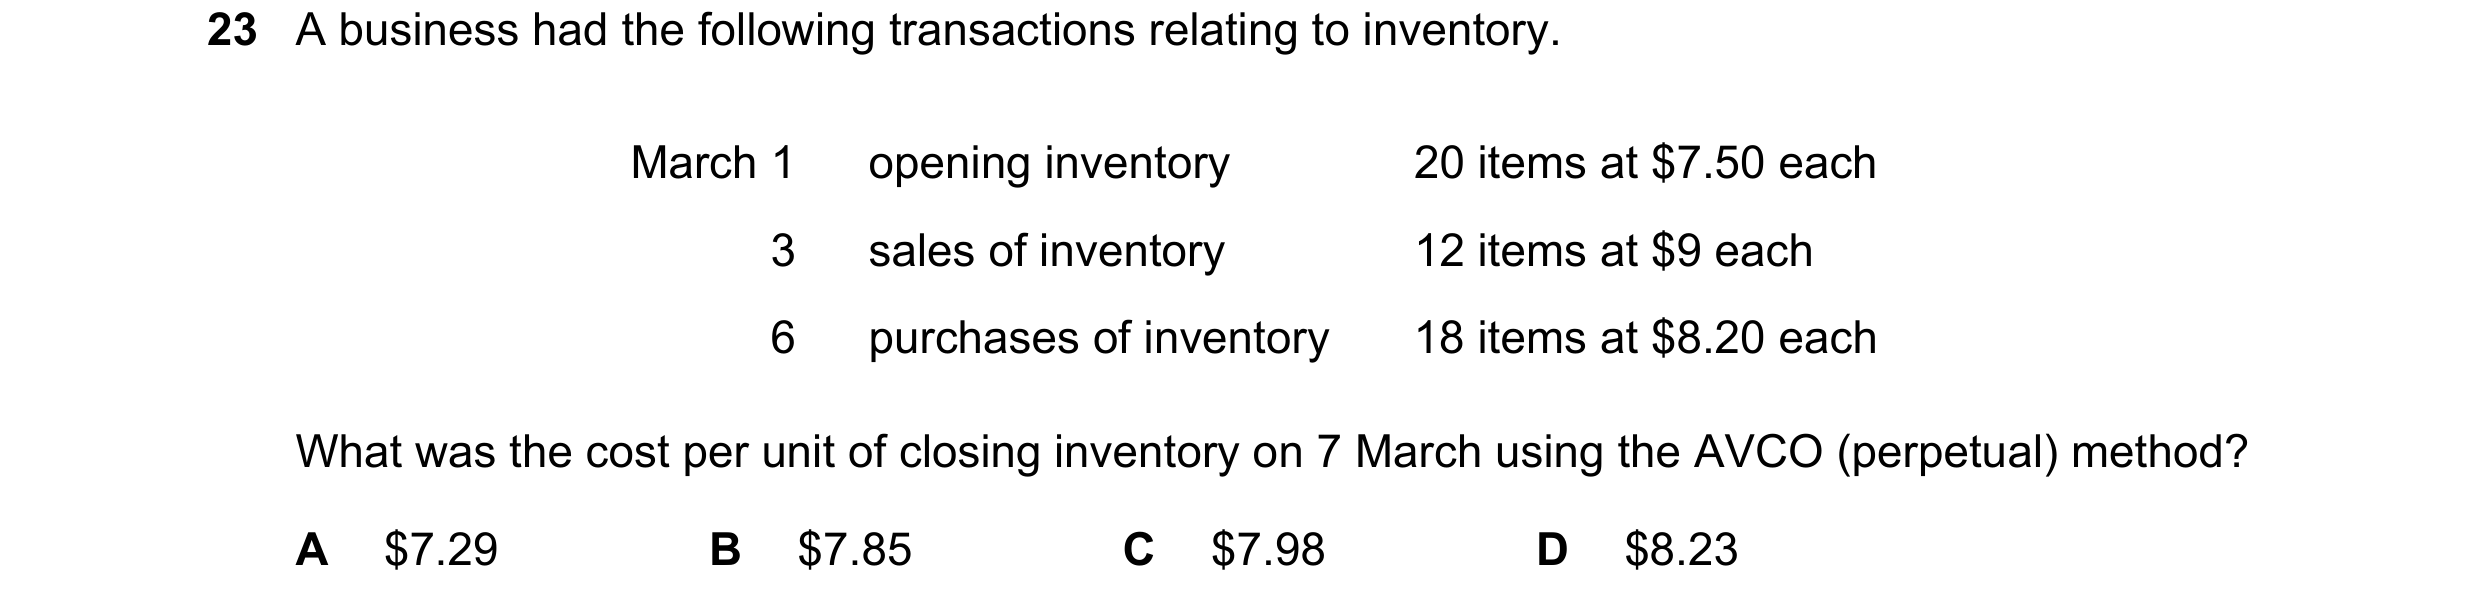
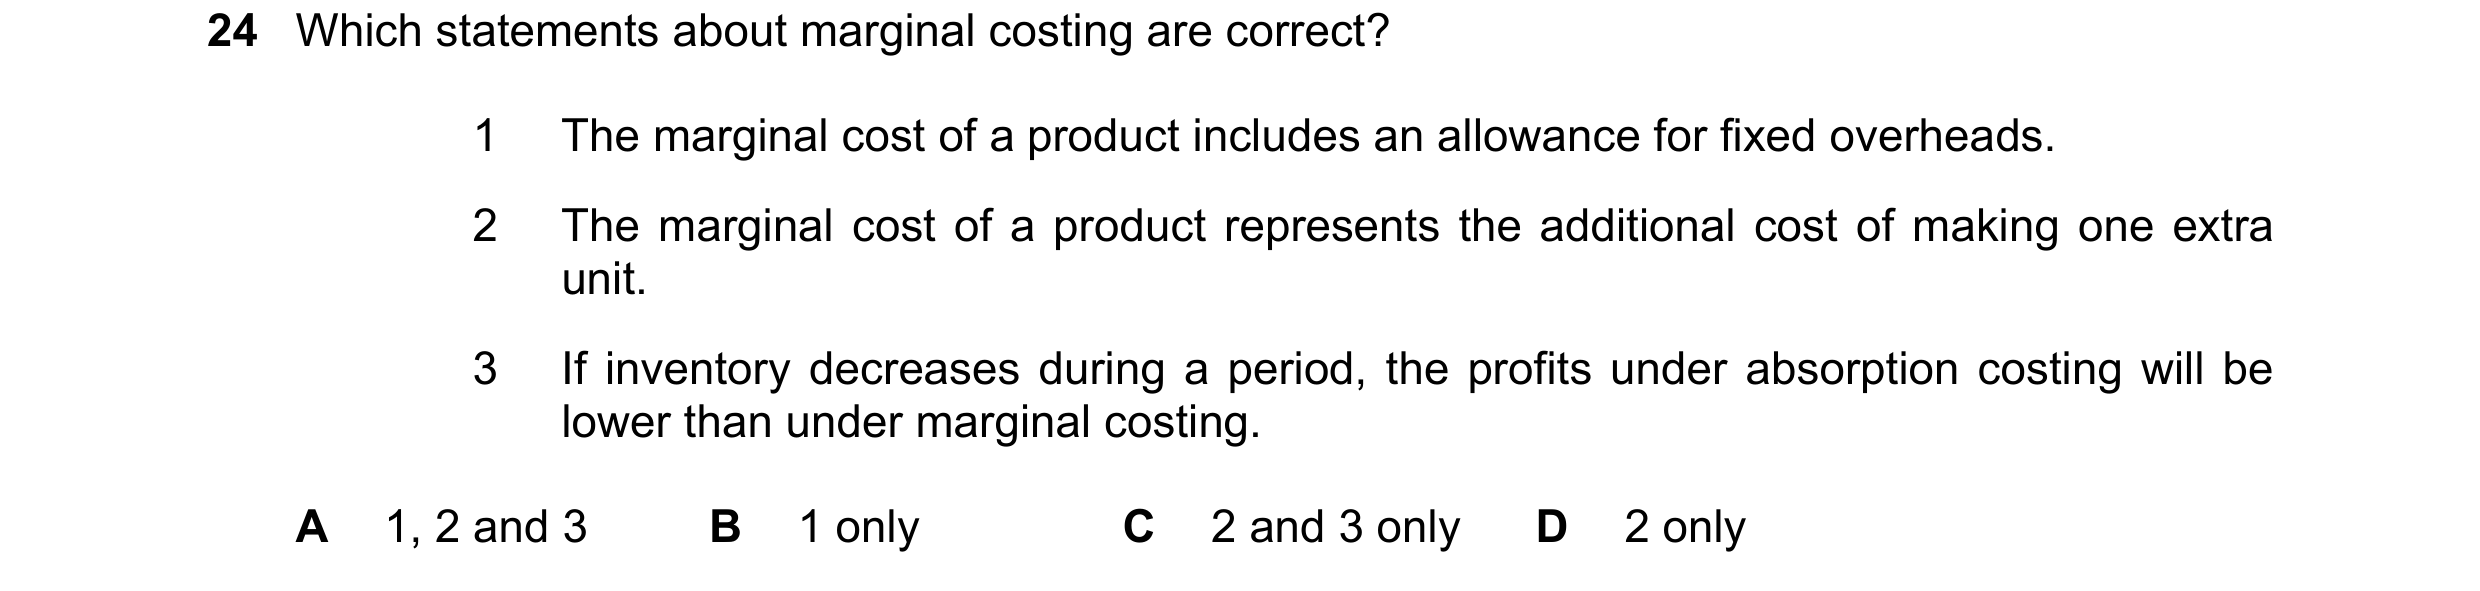
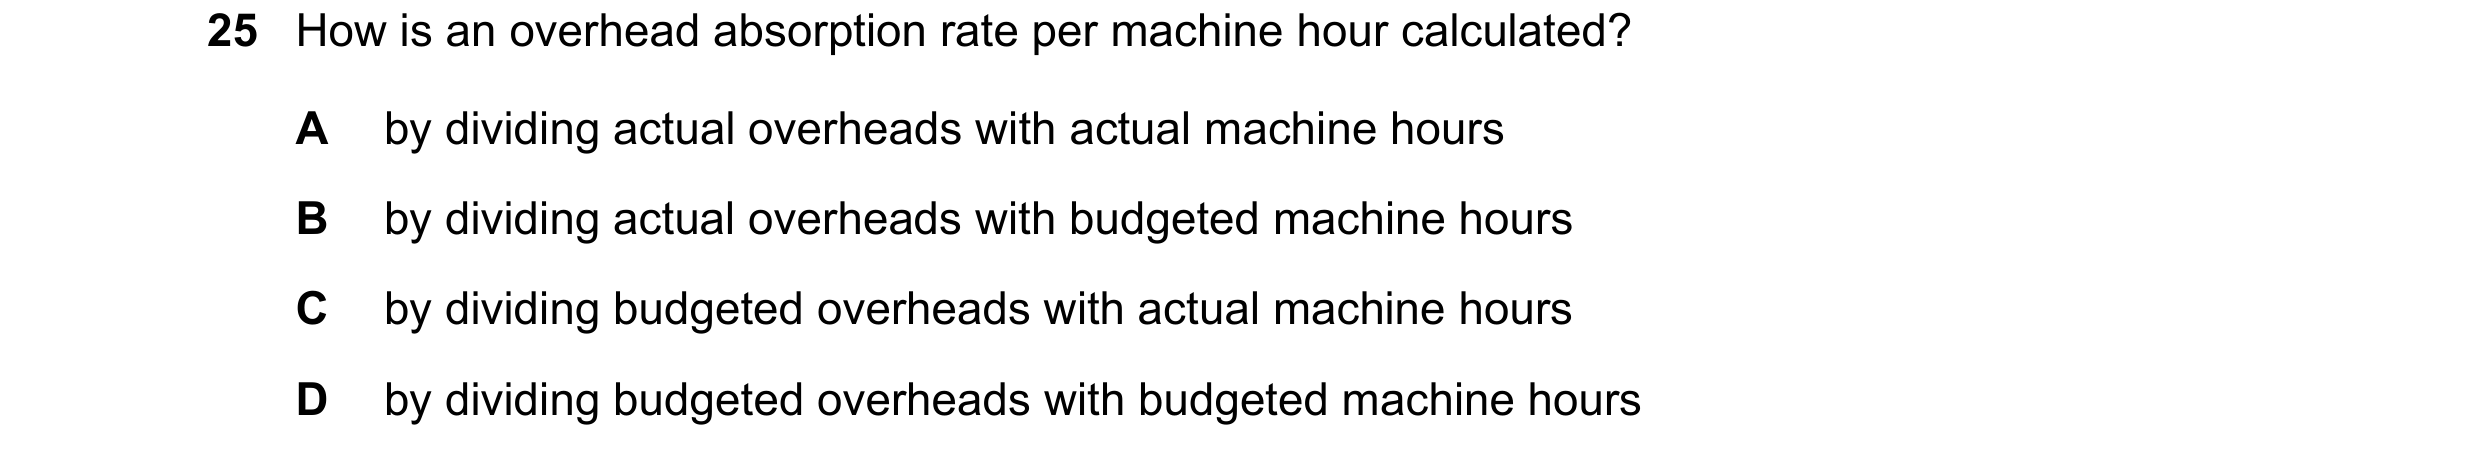
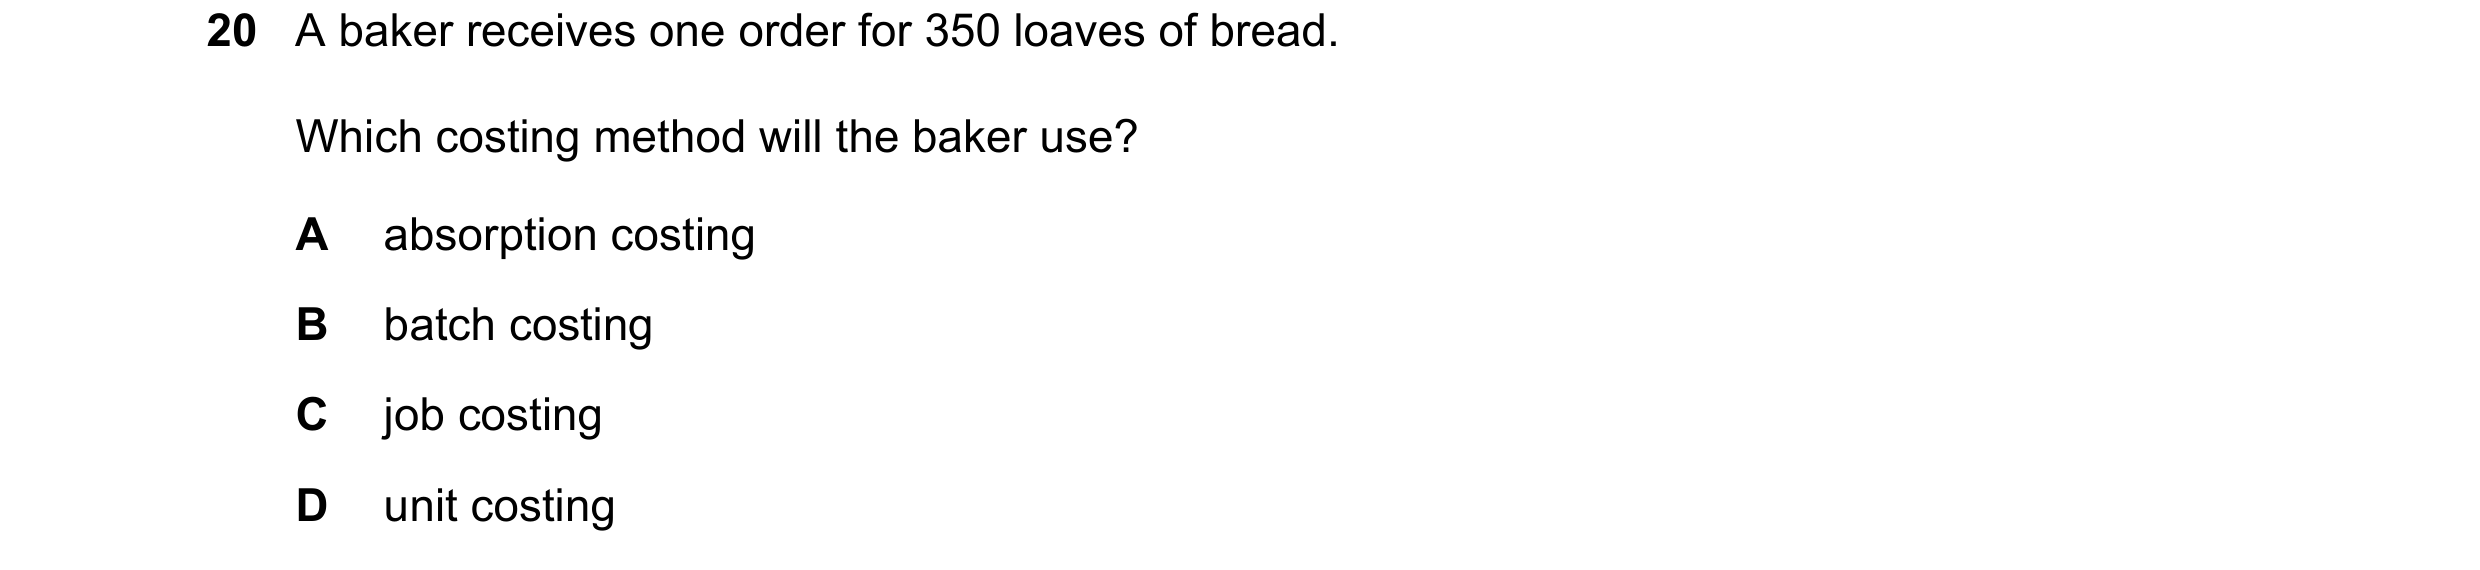 78 / 143
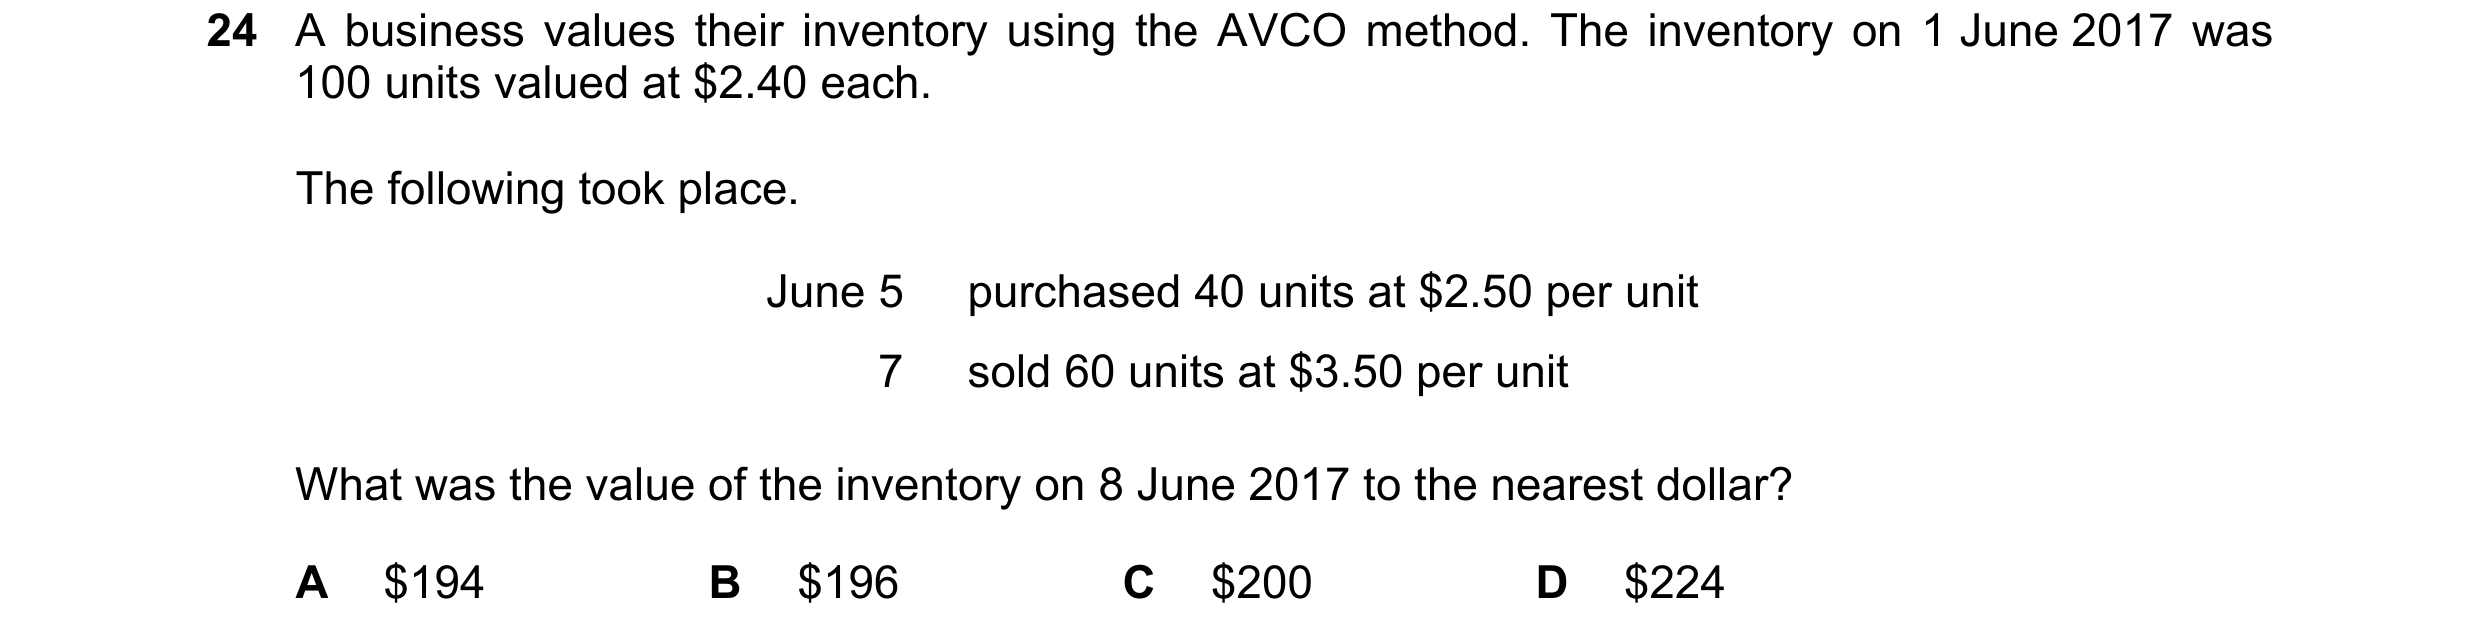
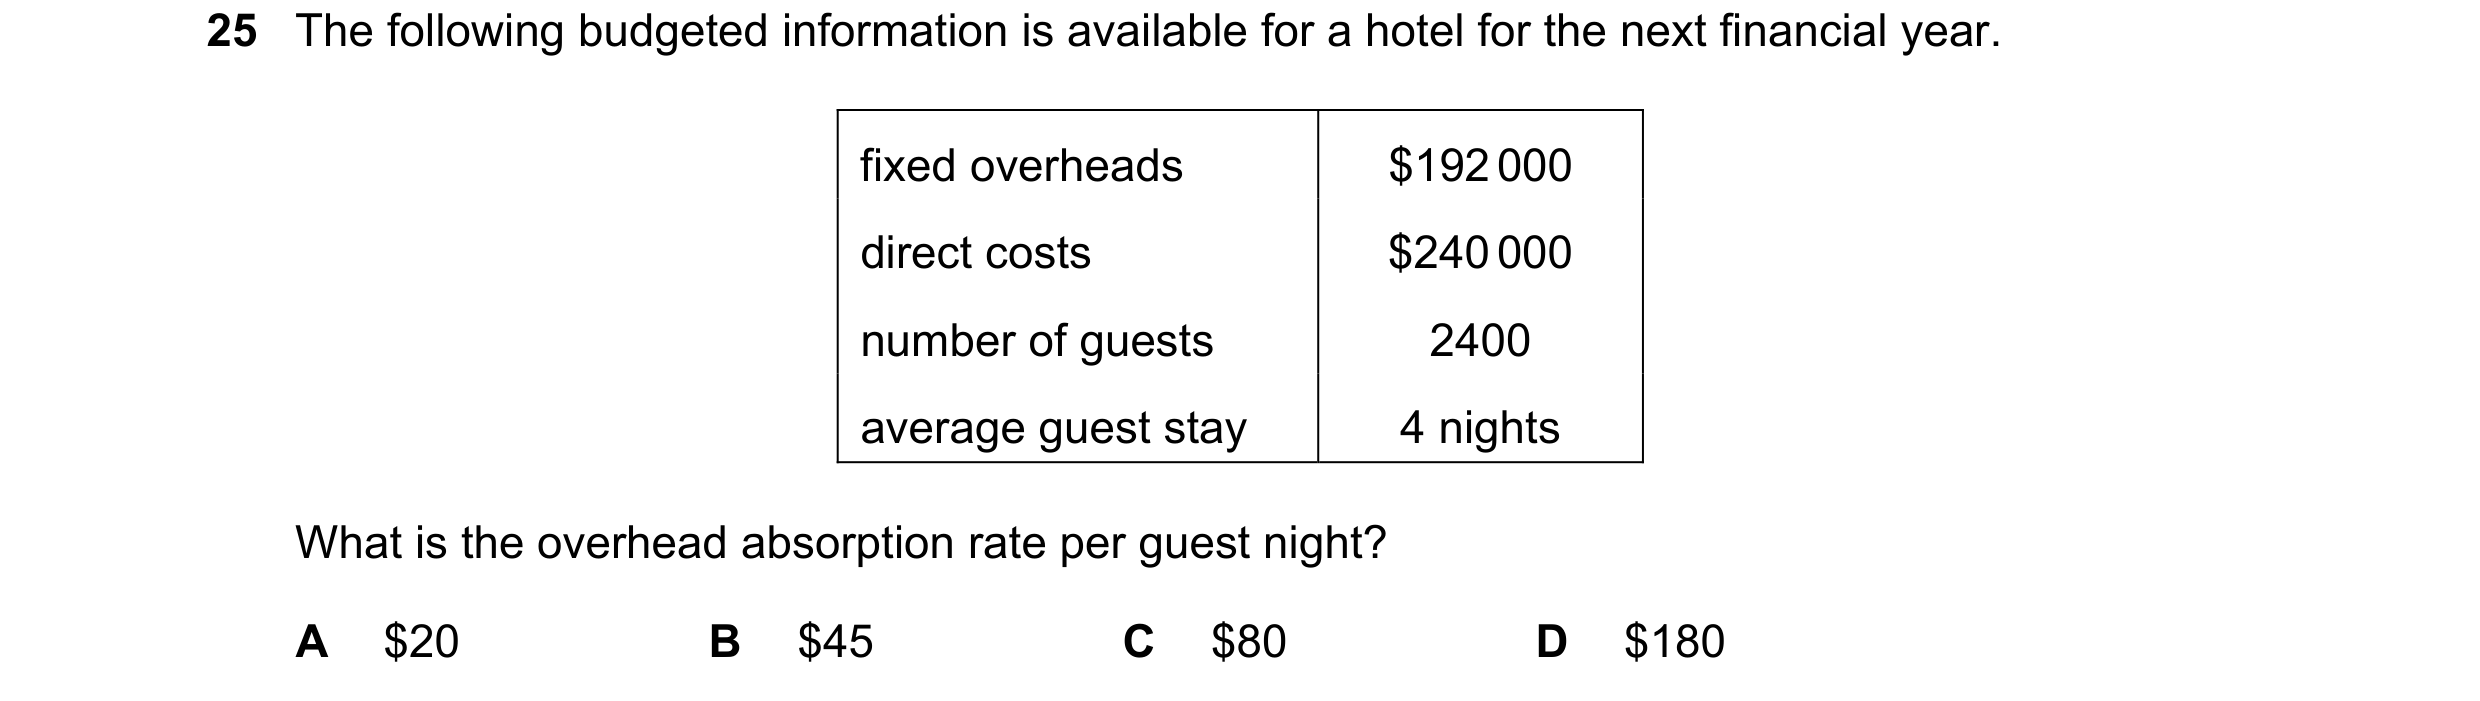
 79 / 143
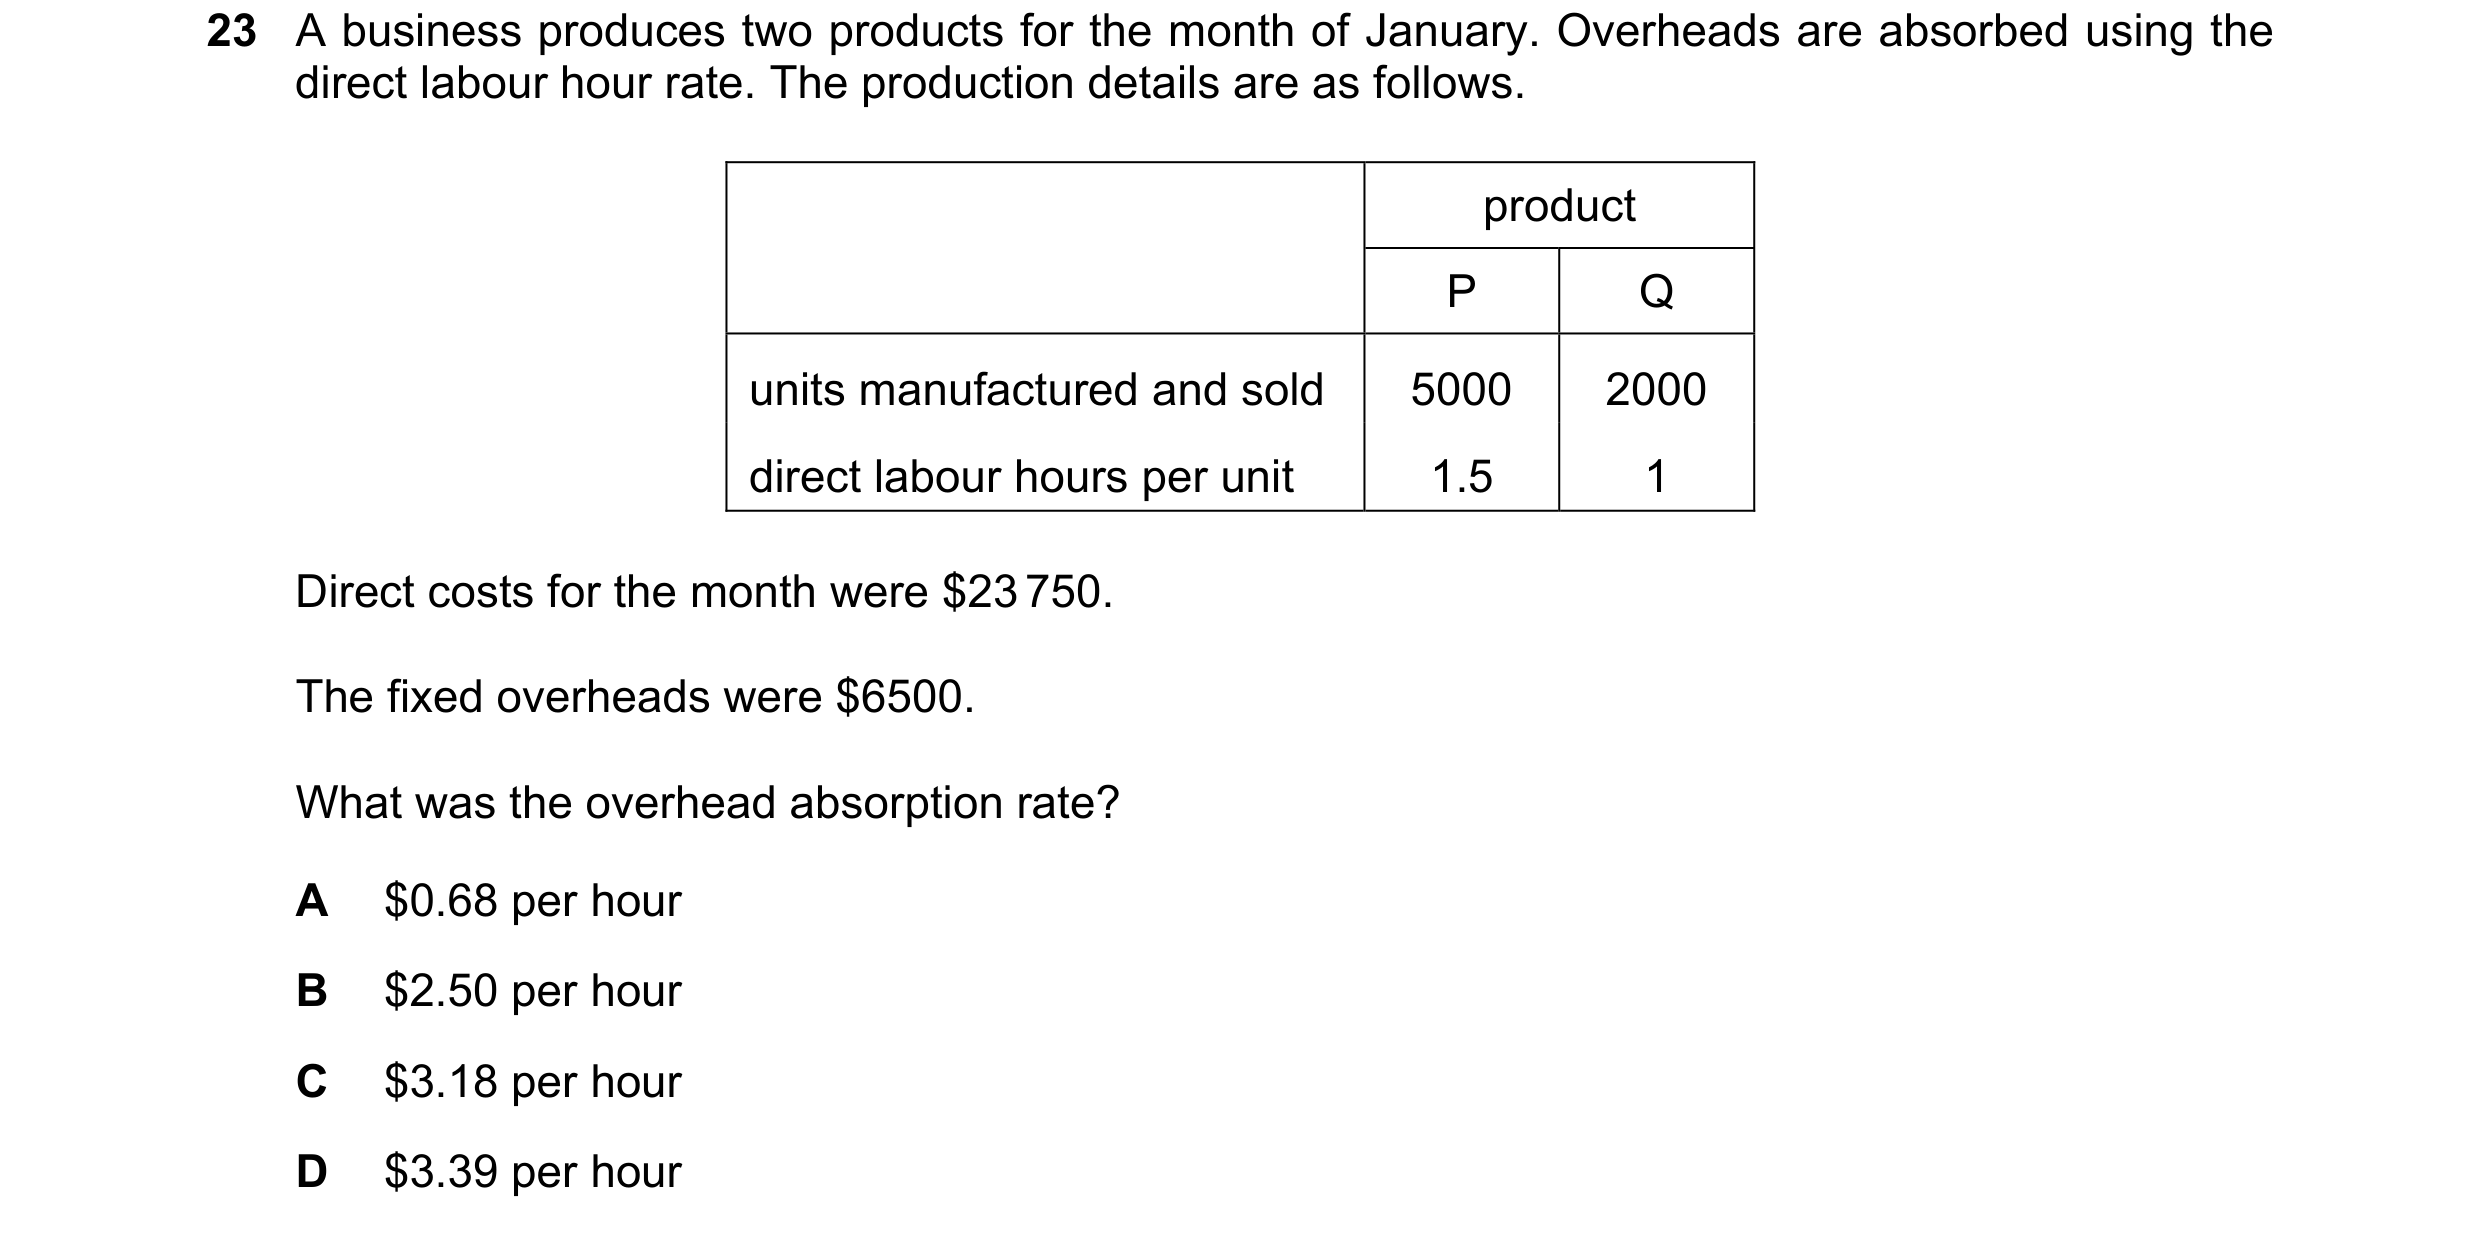
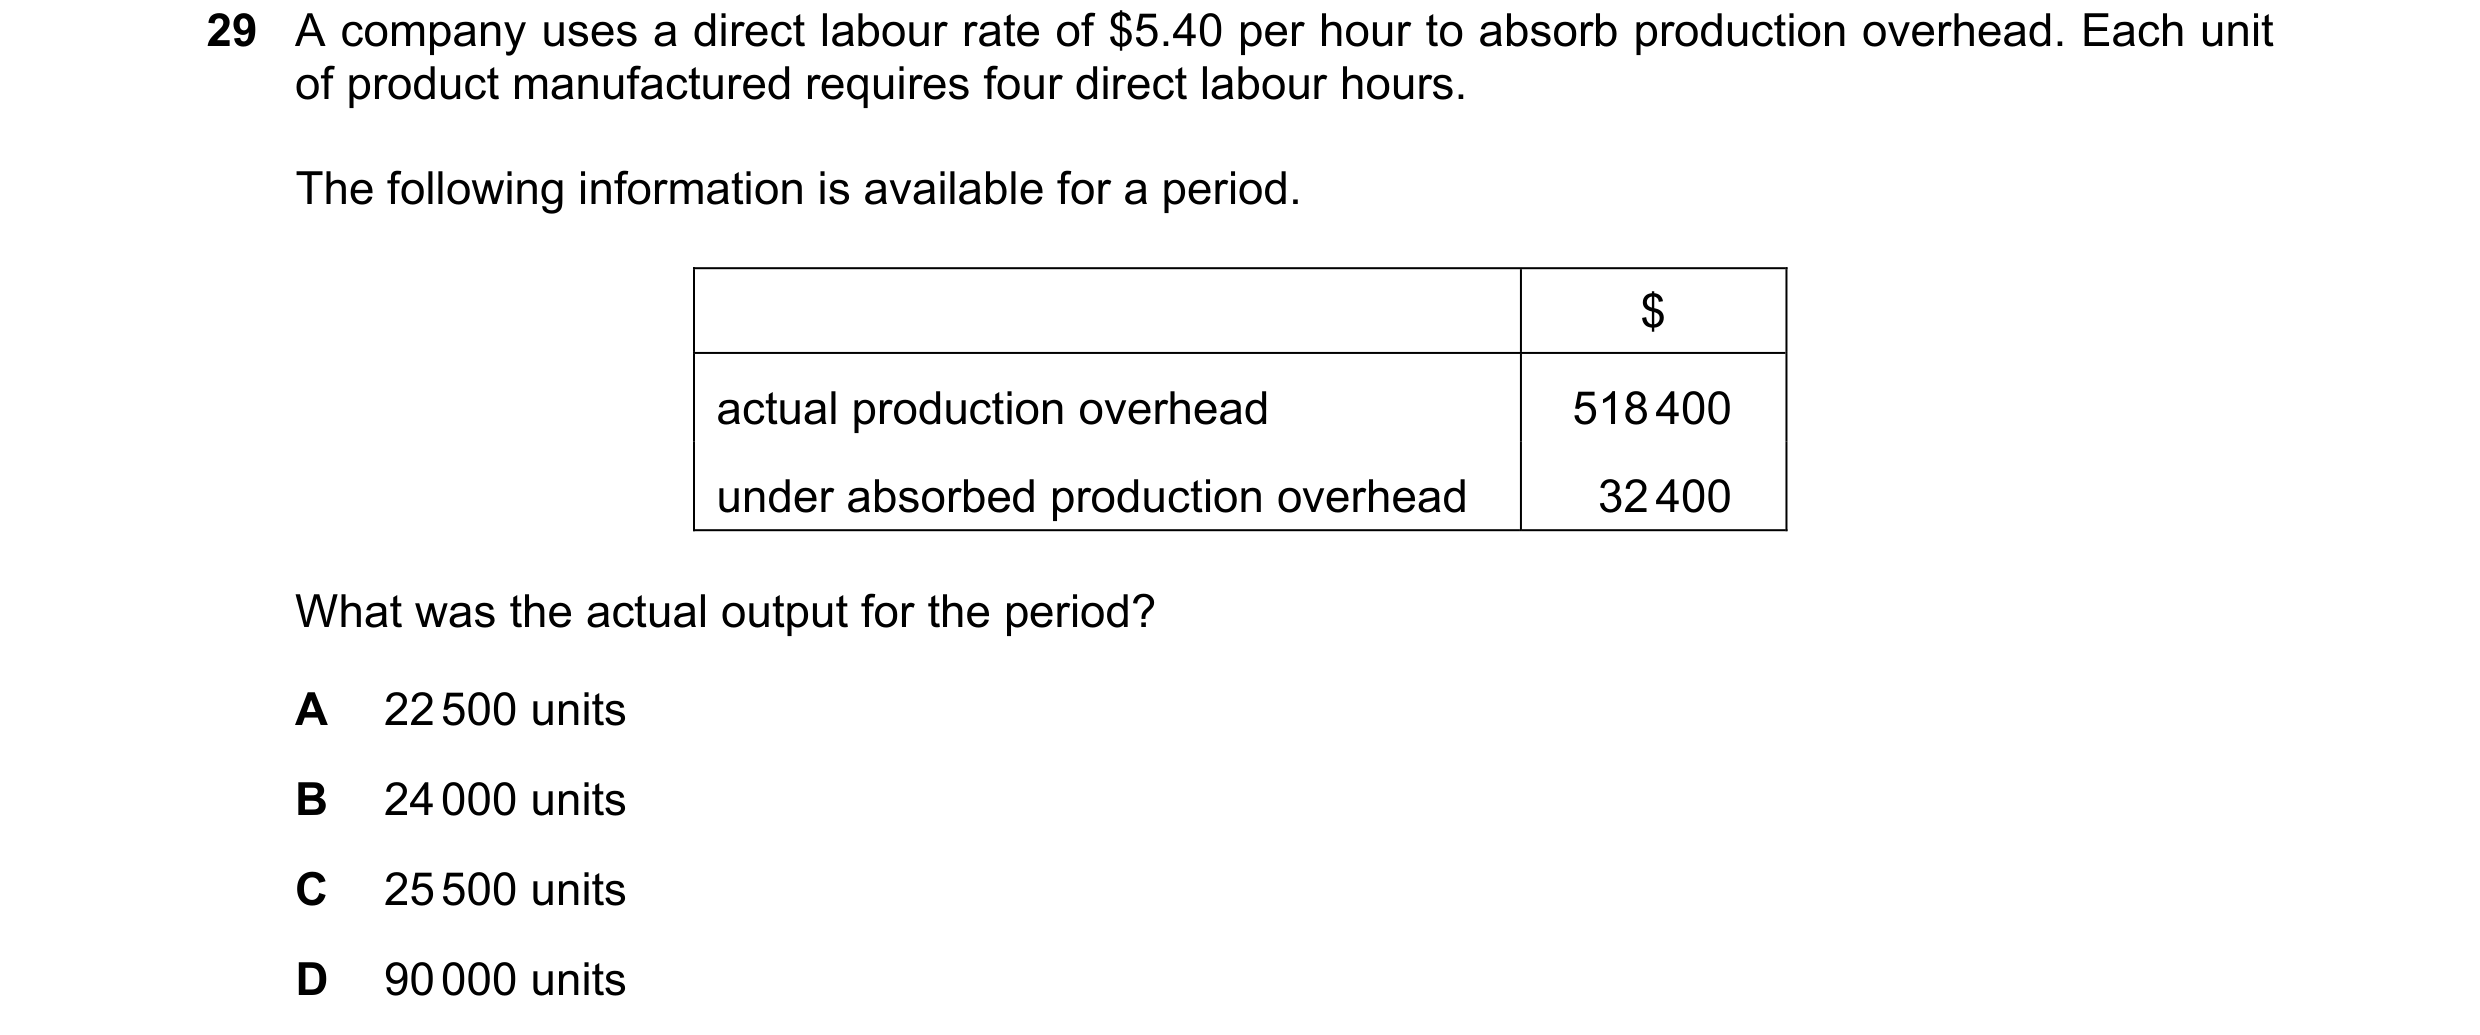 80 / 143
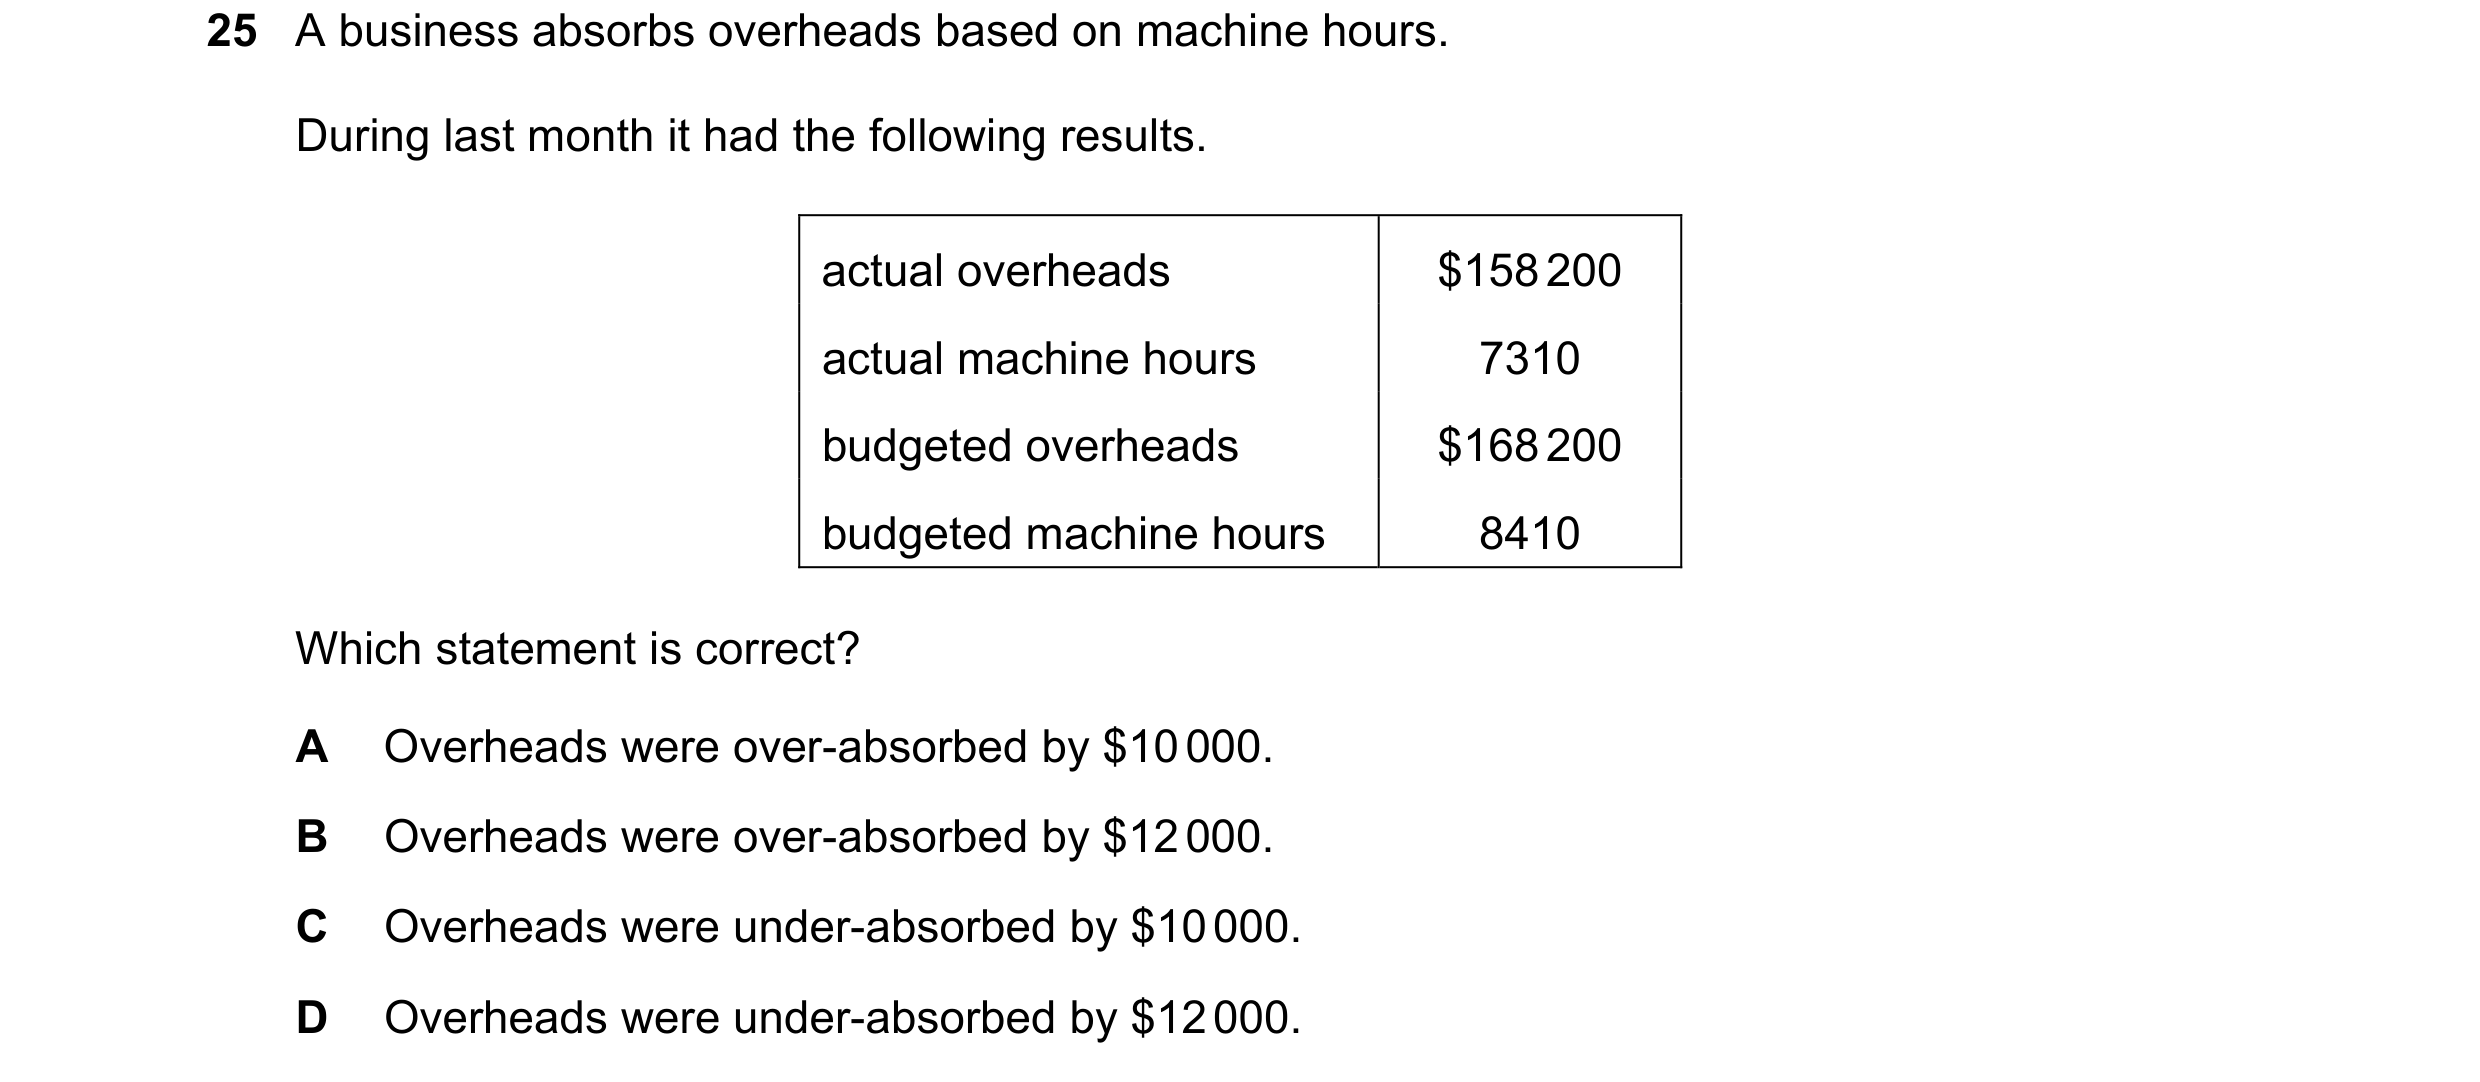
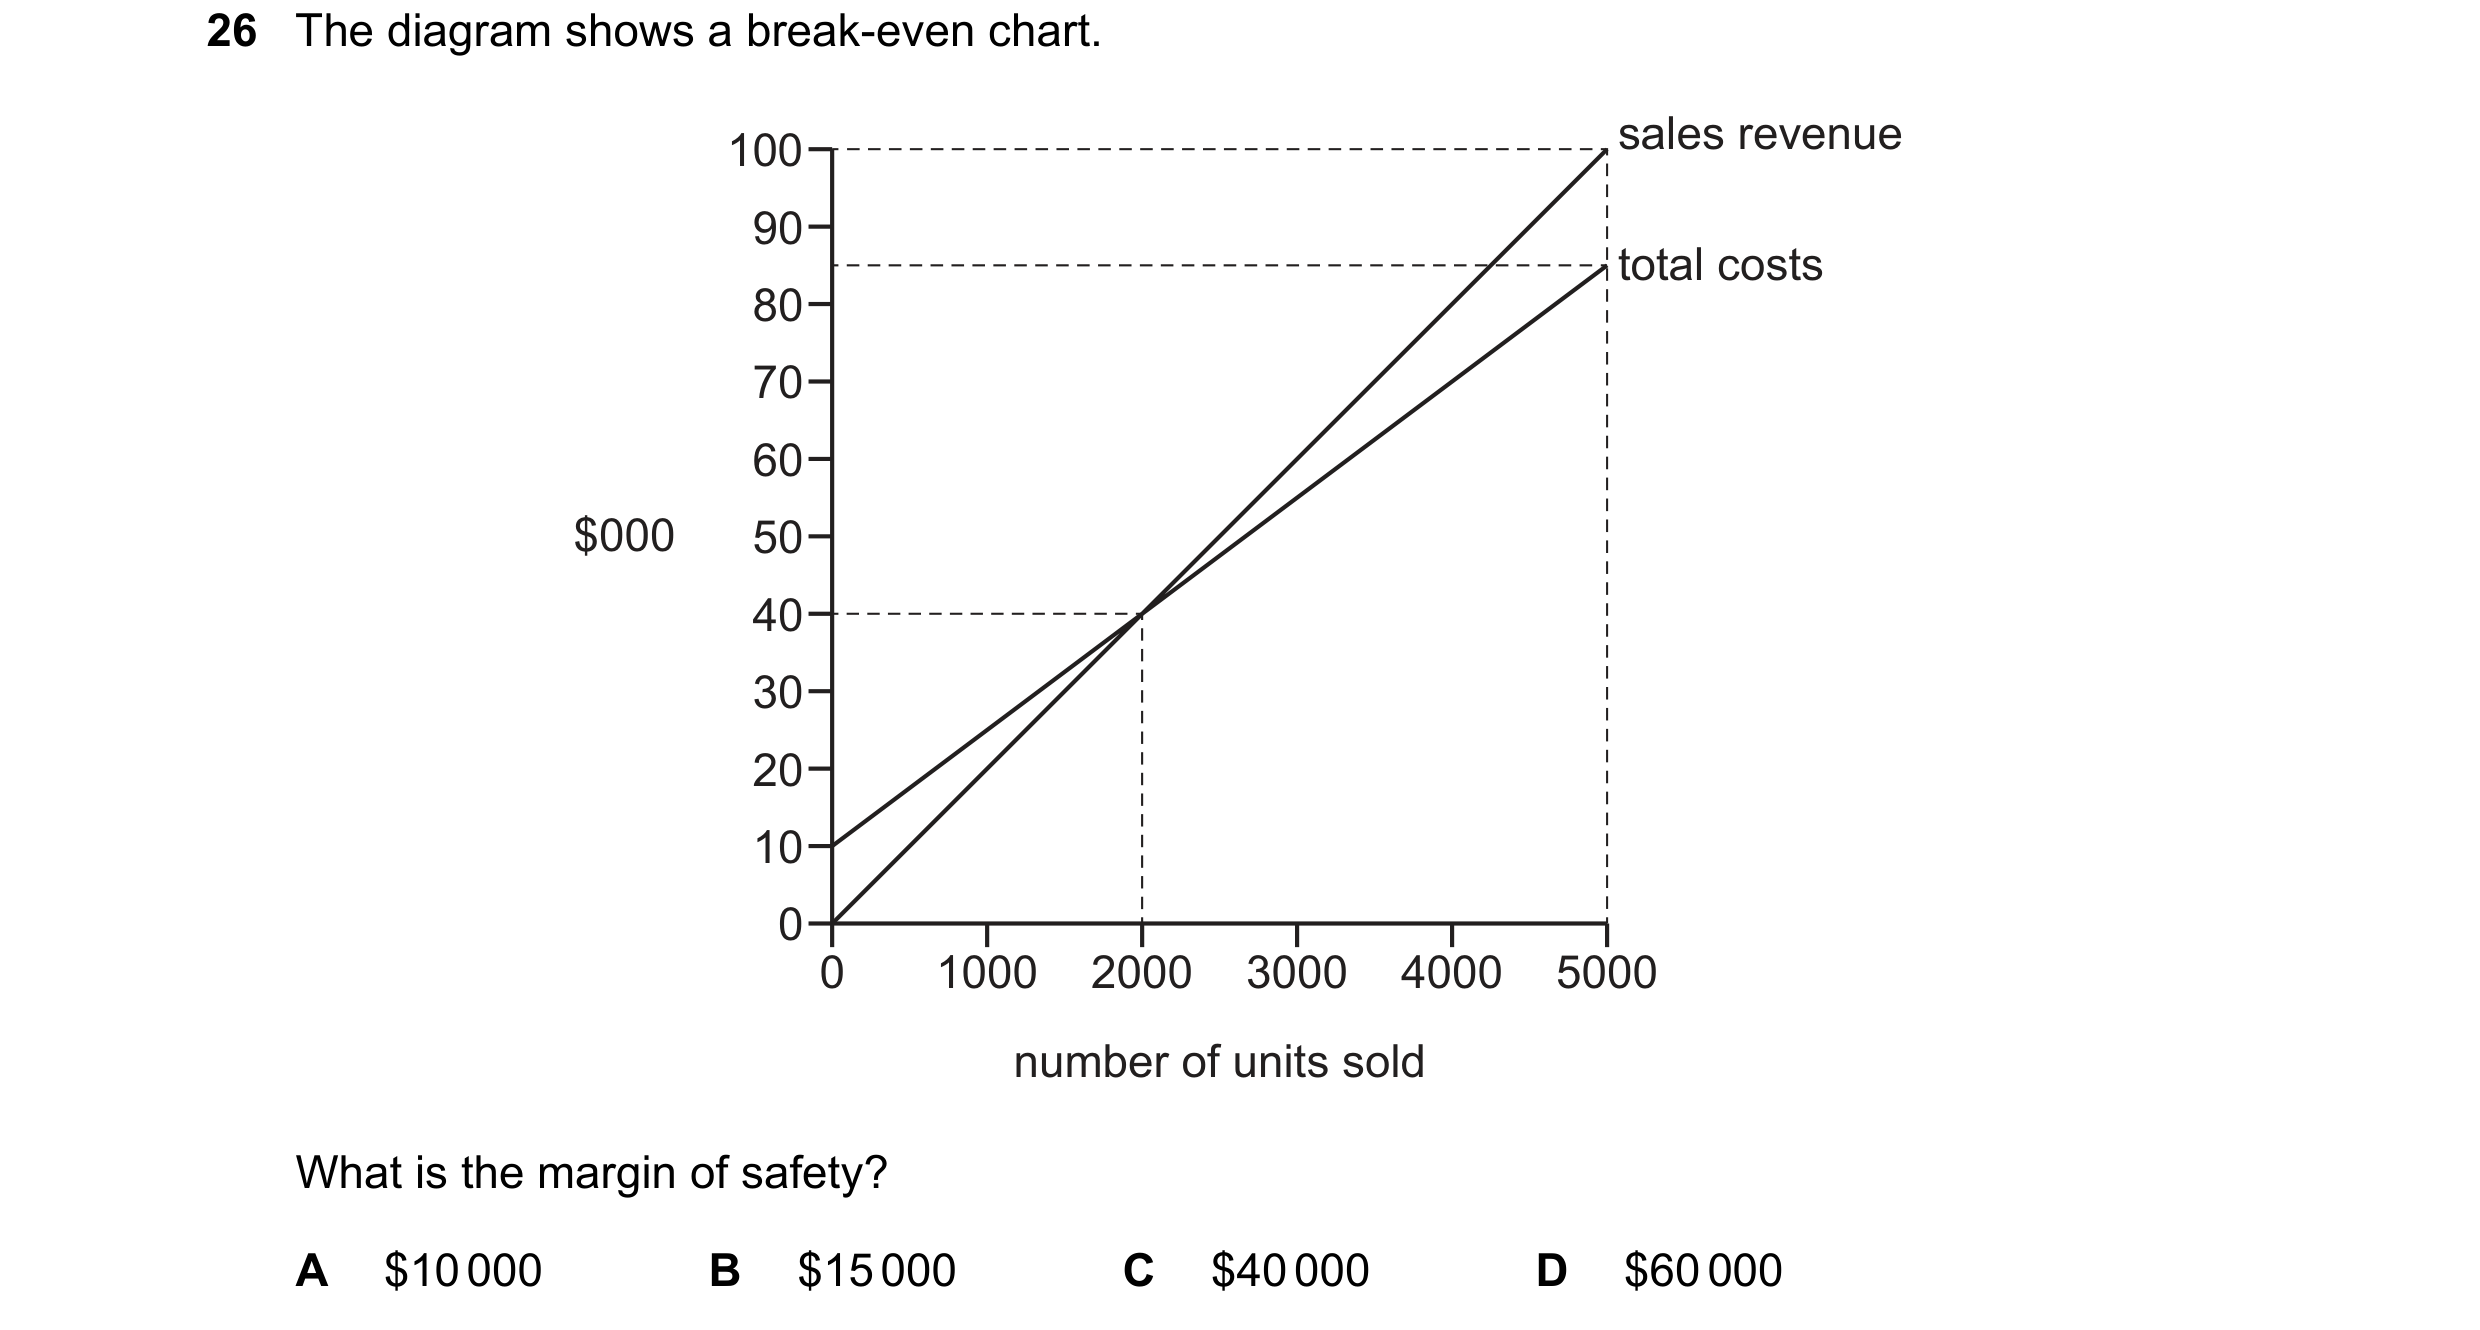
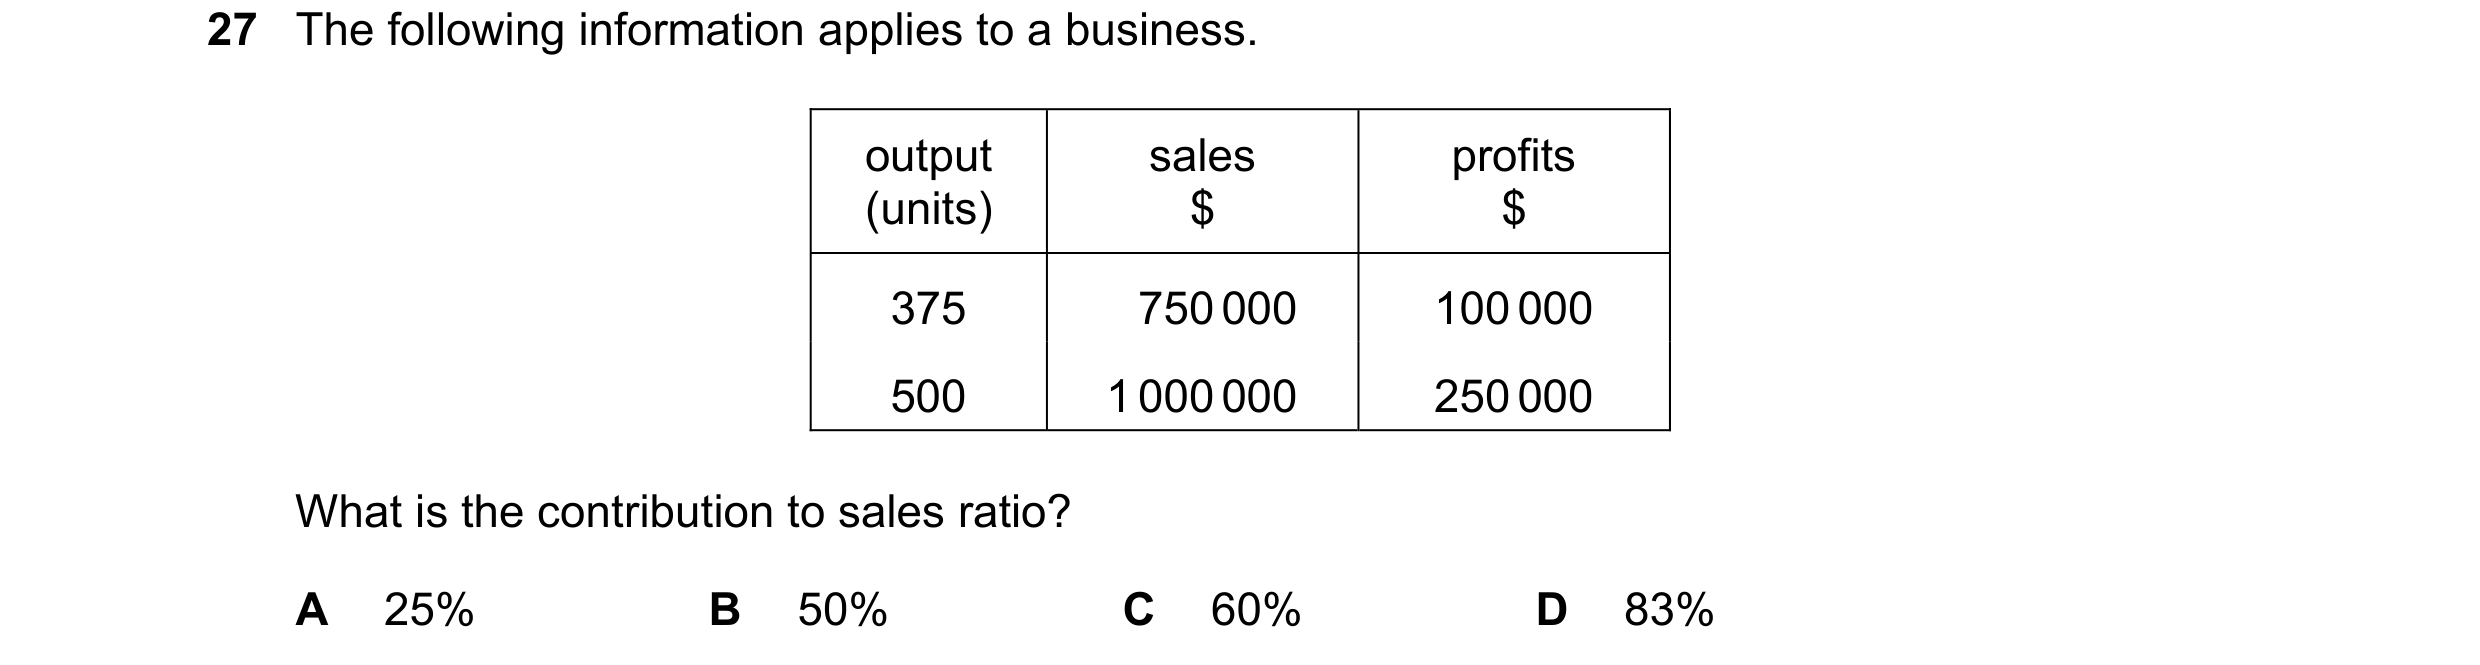 81 / 143
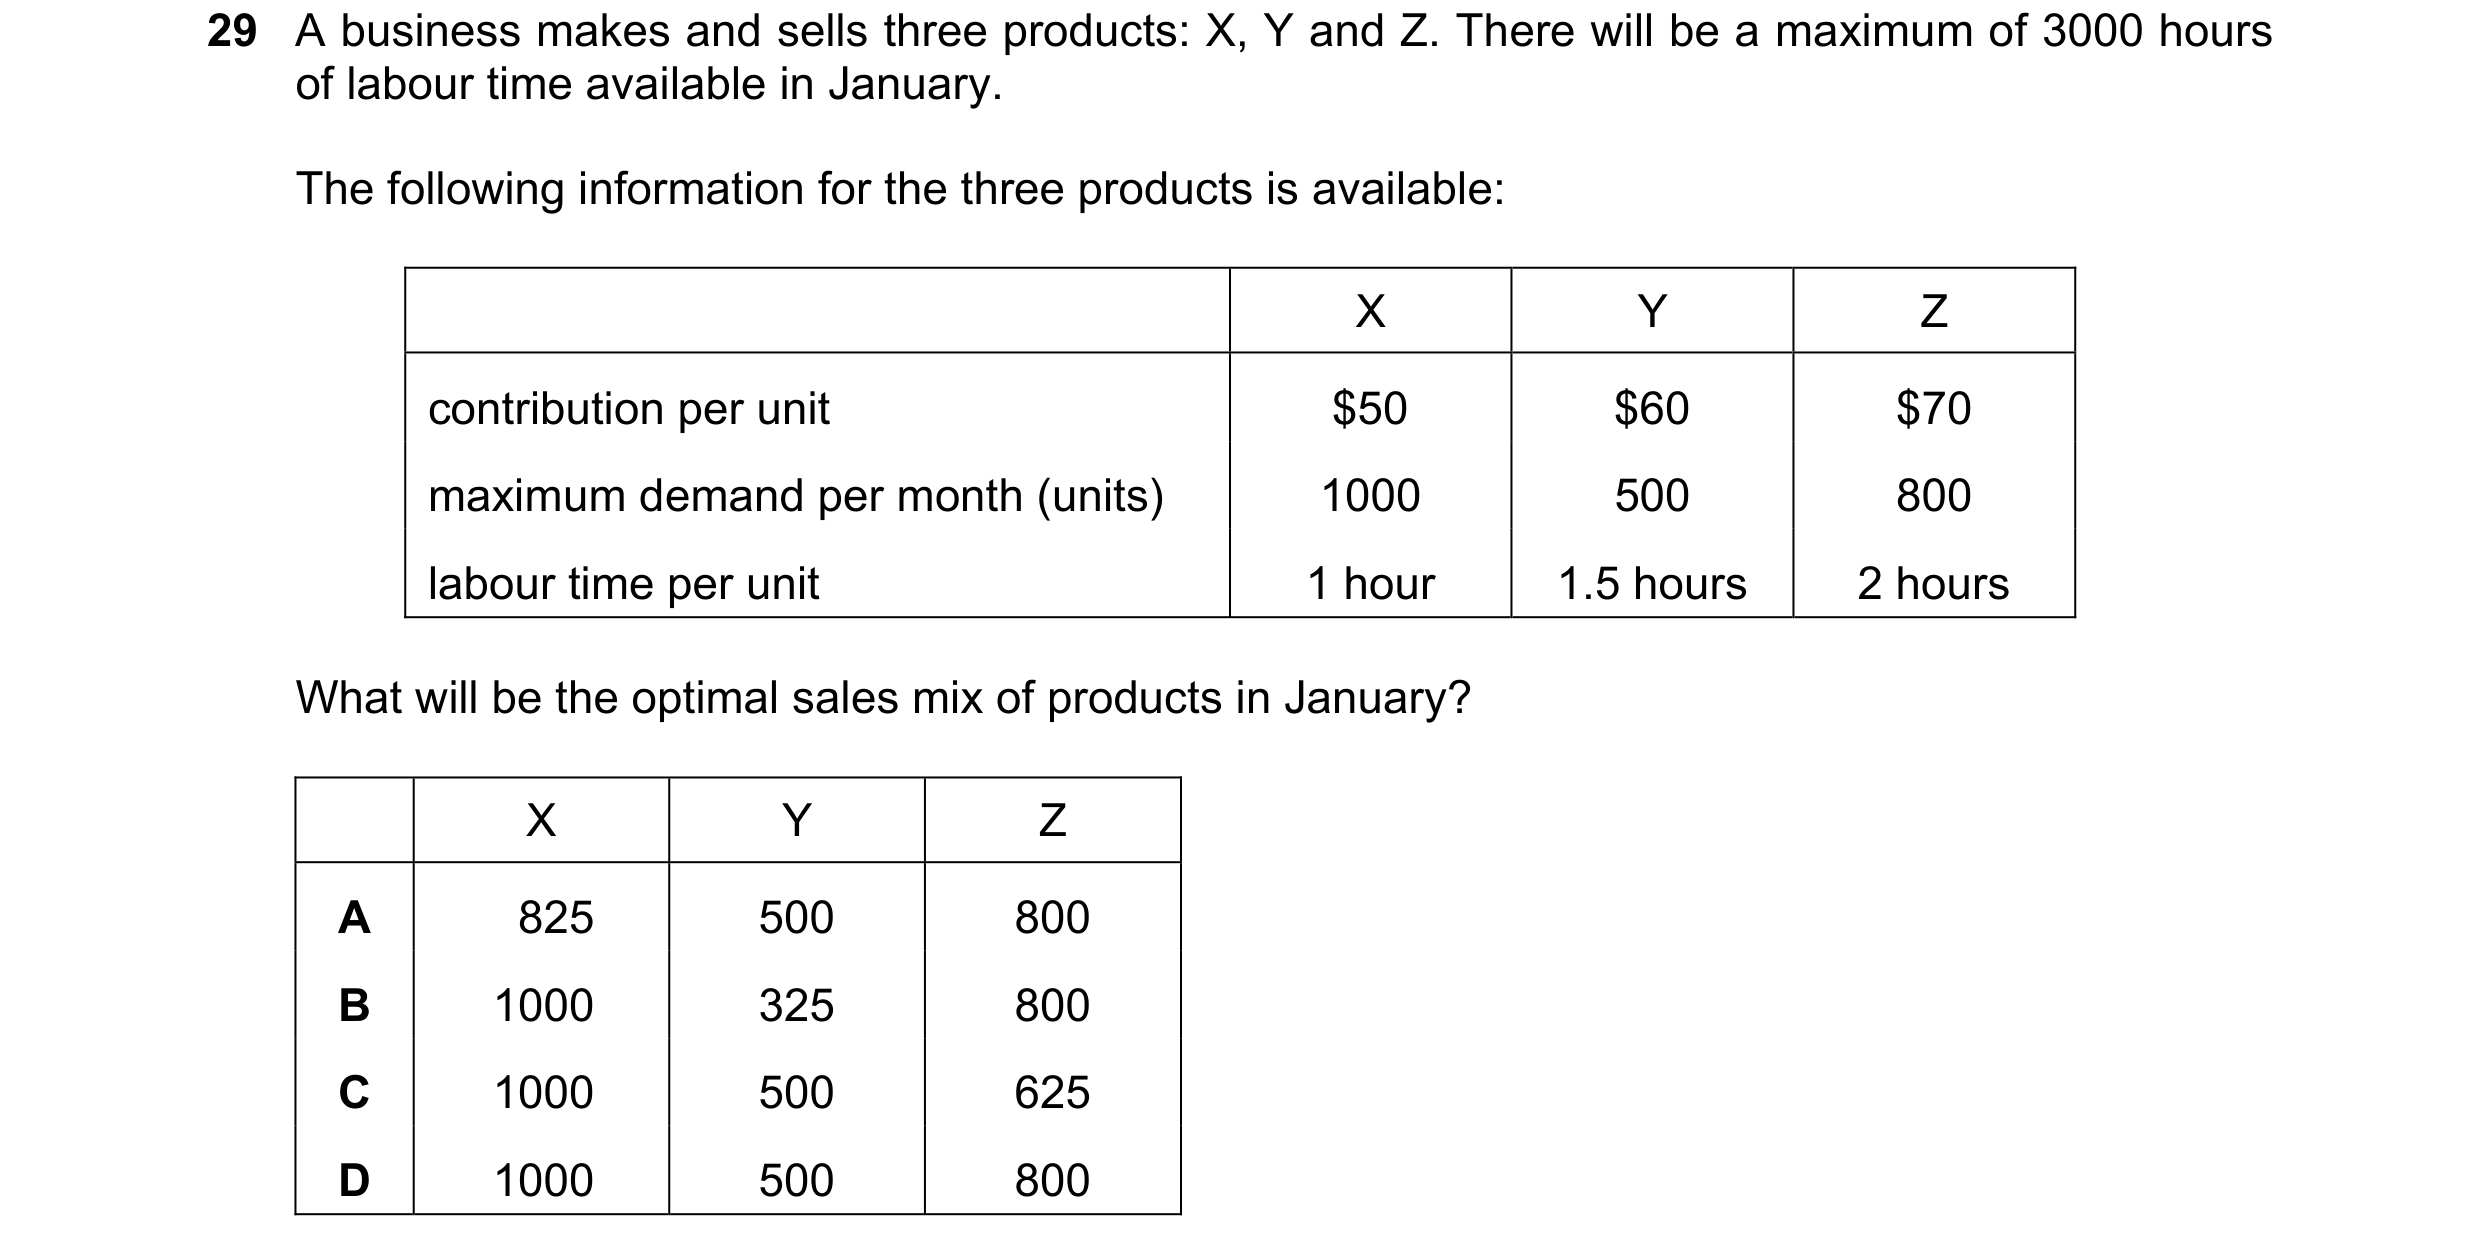
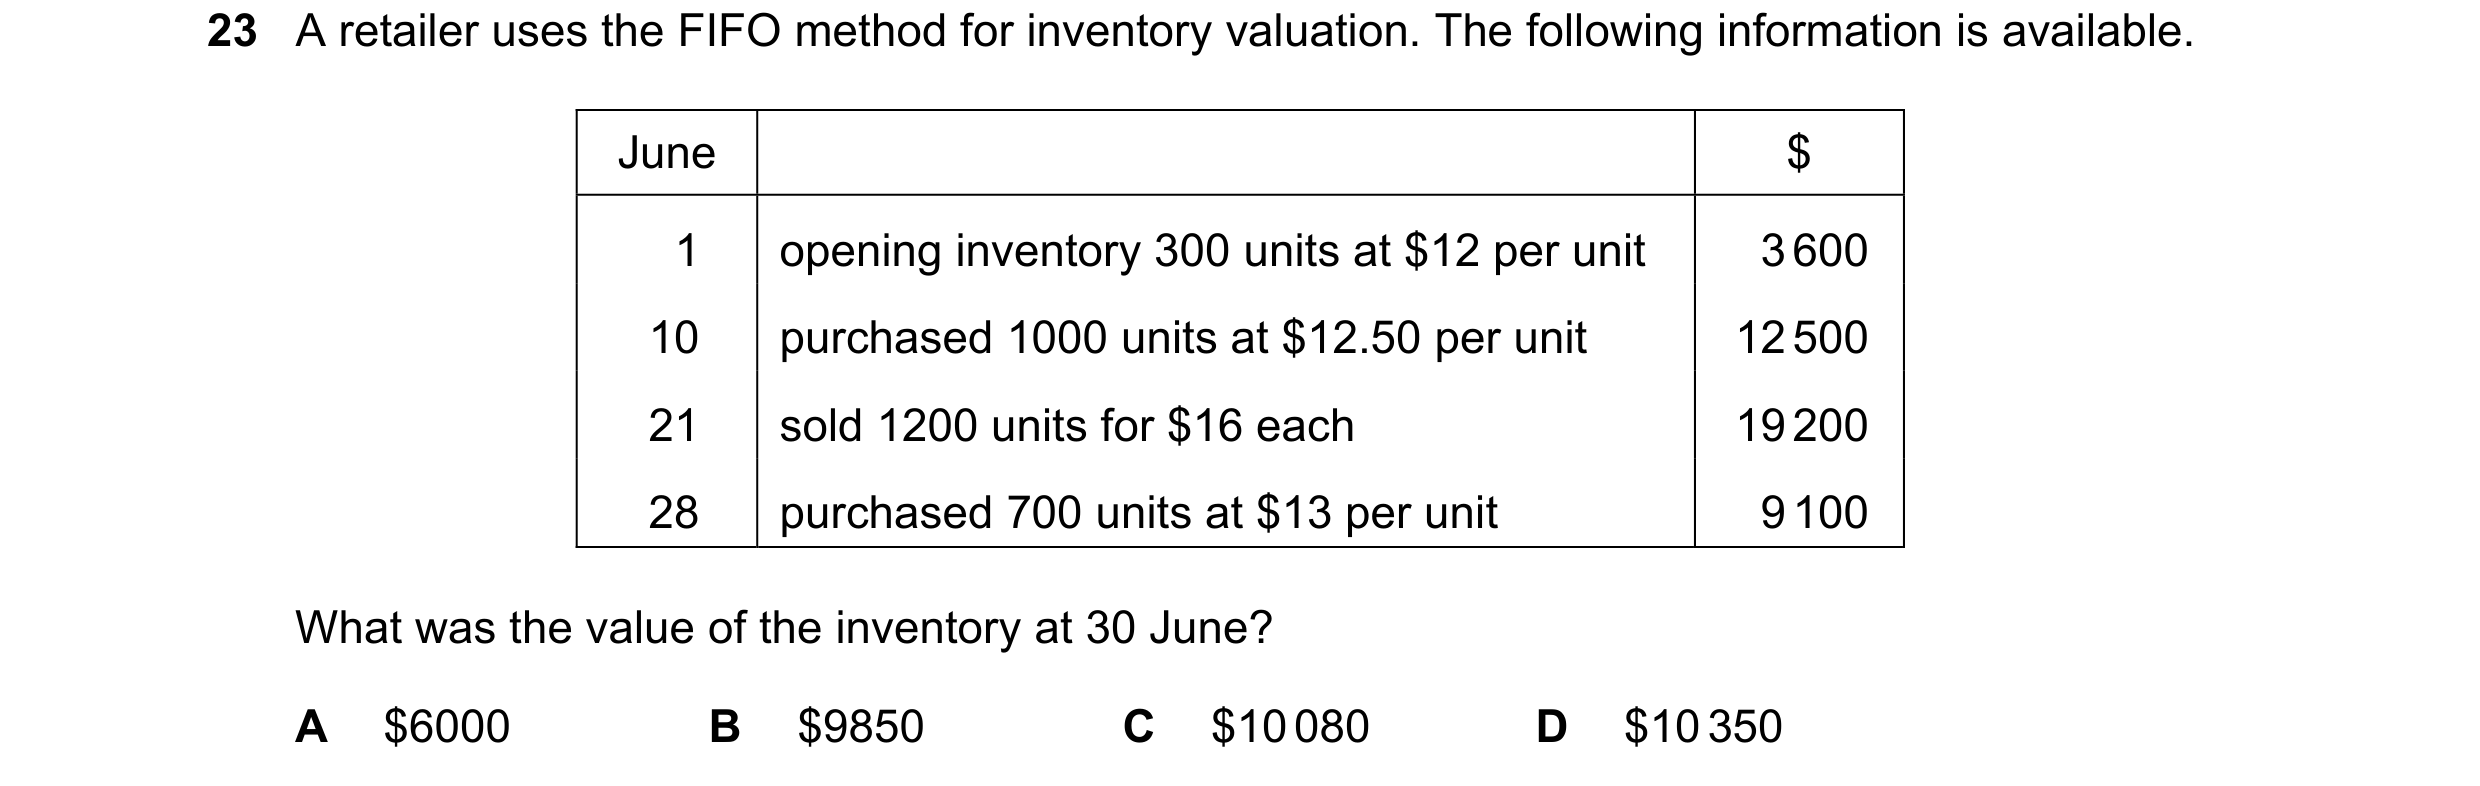
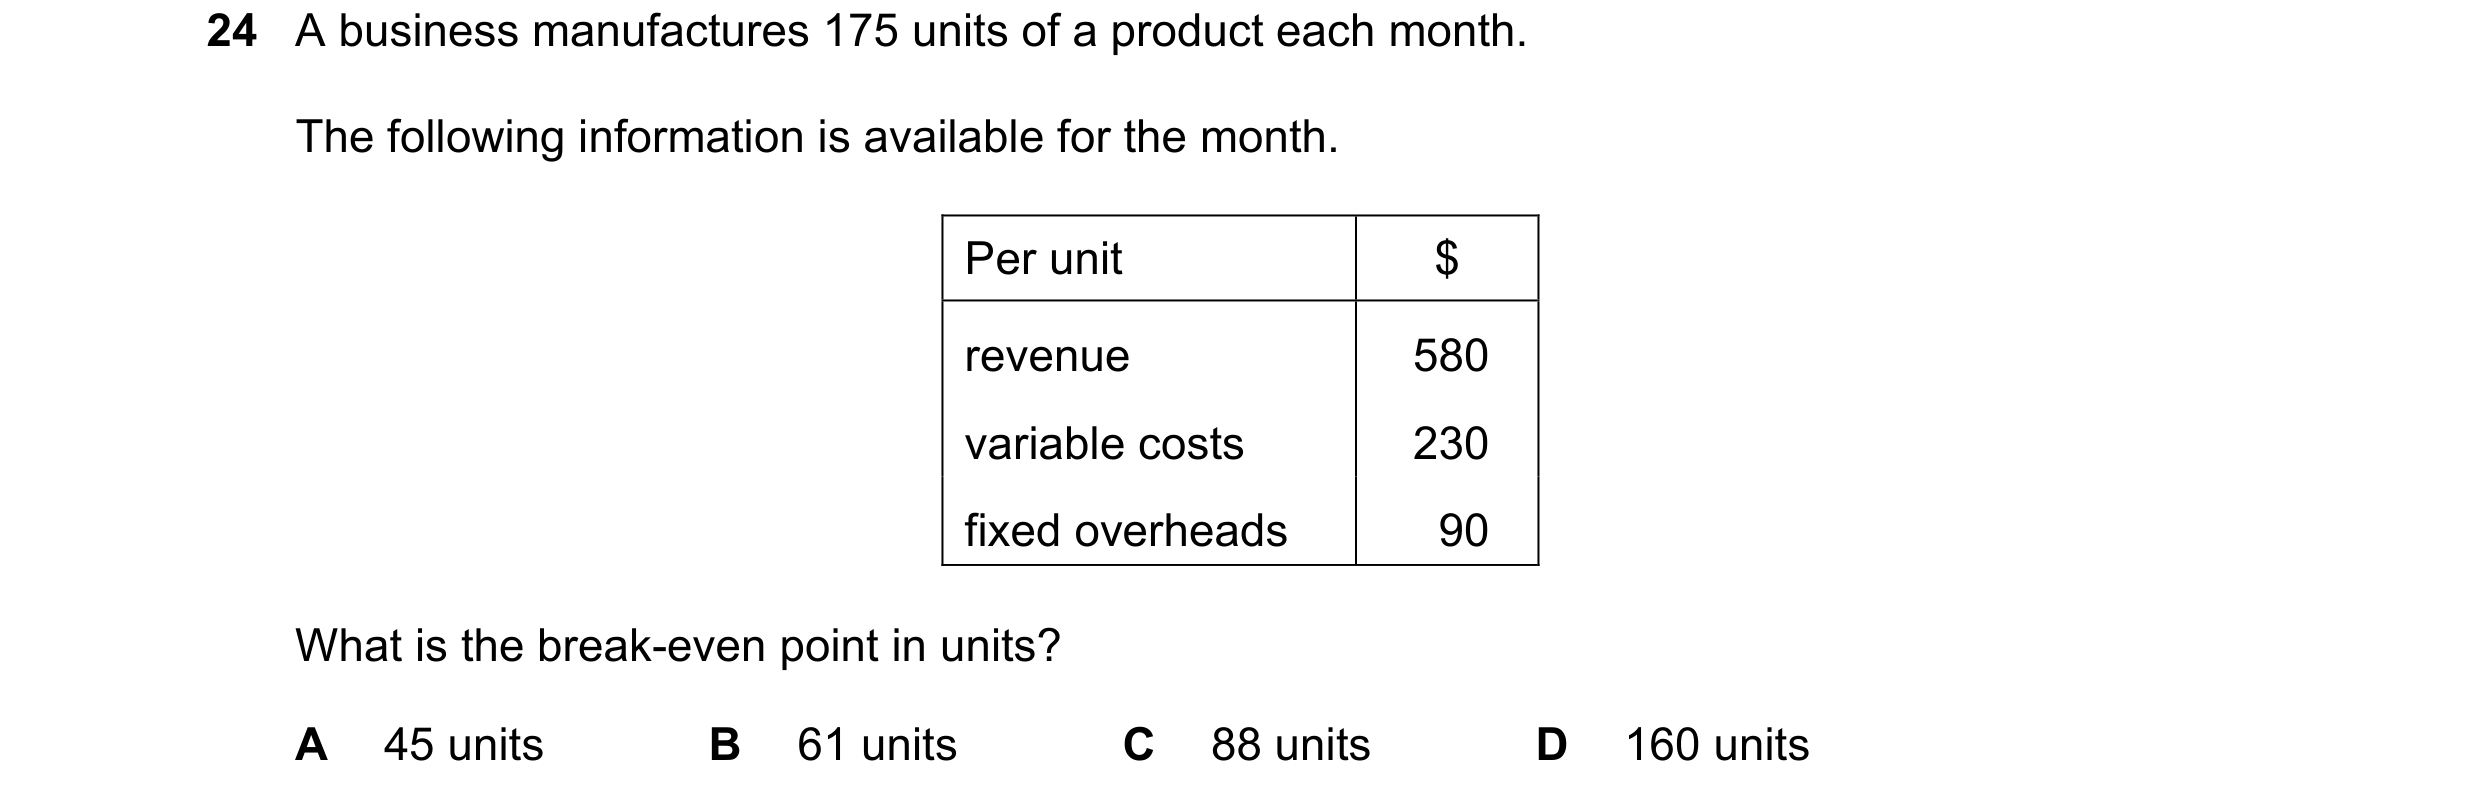
 82 / 143
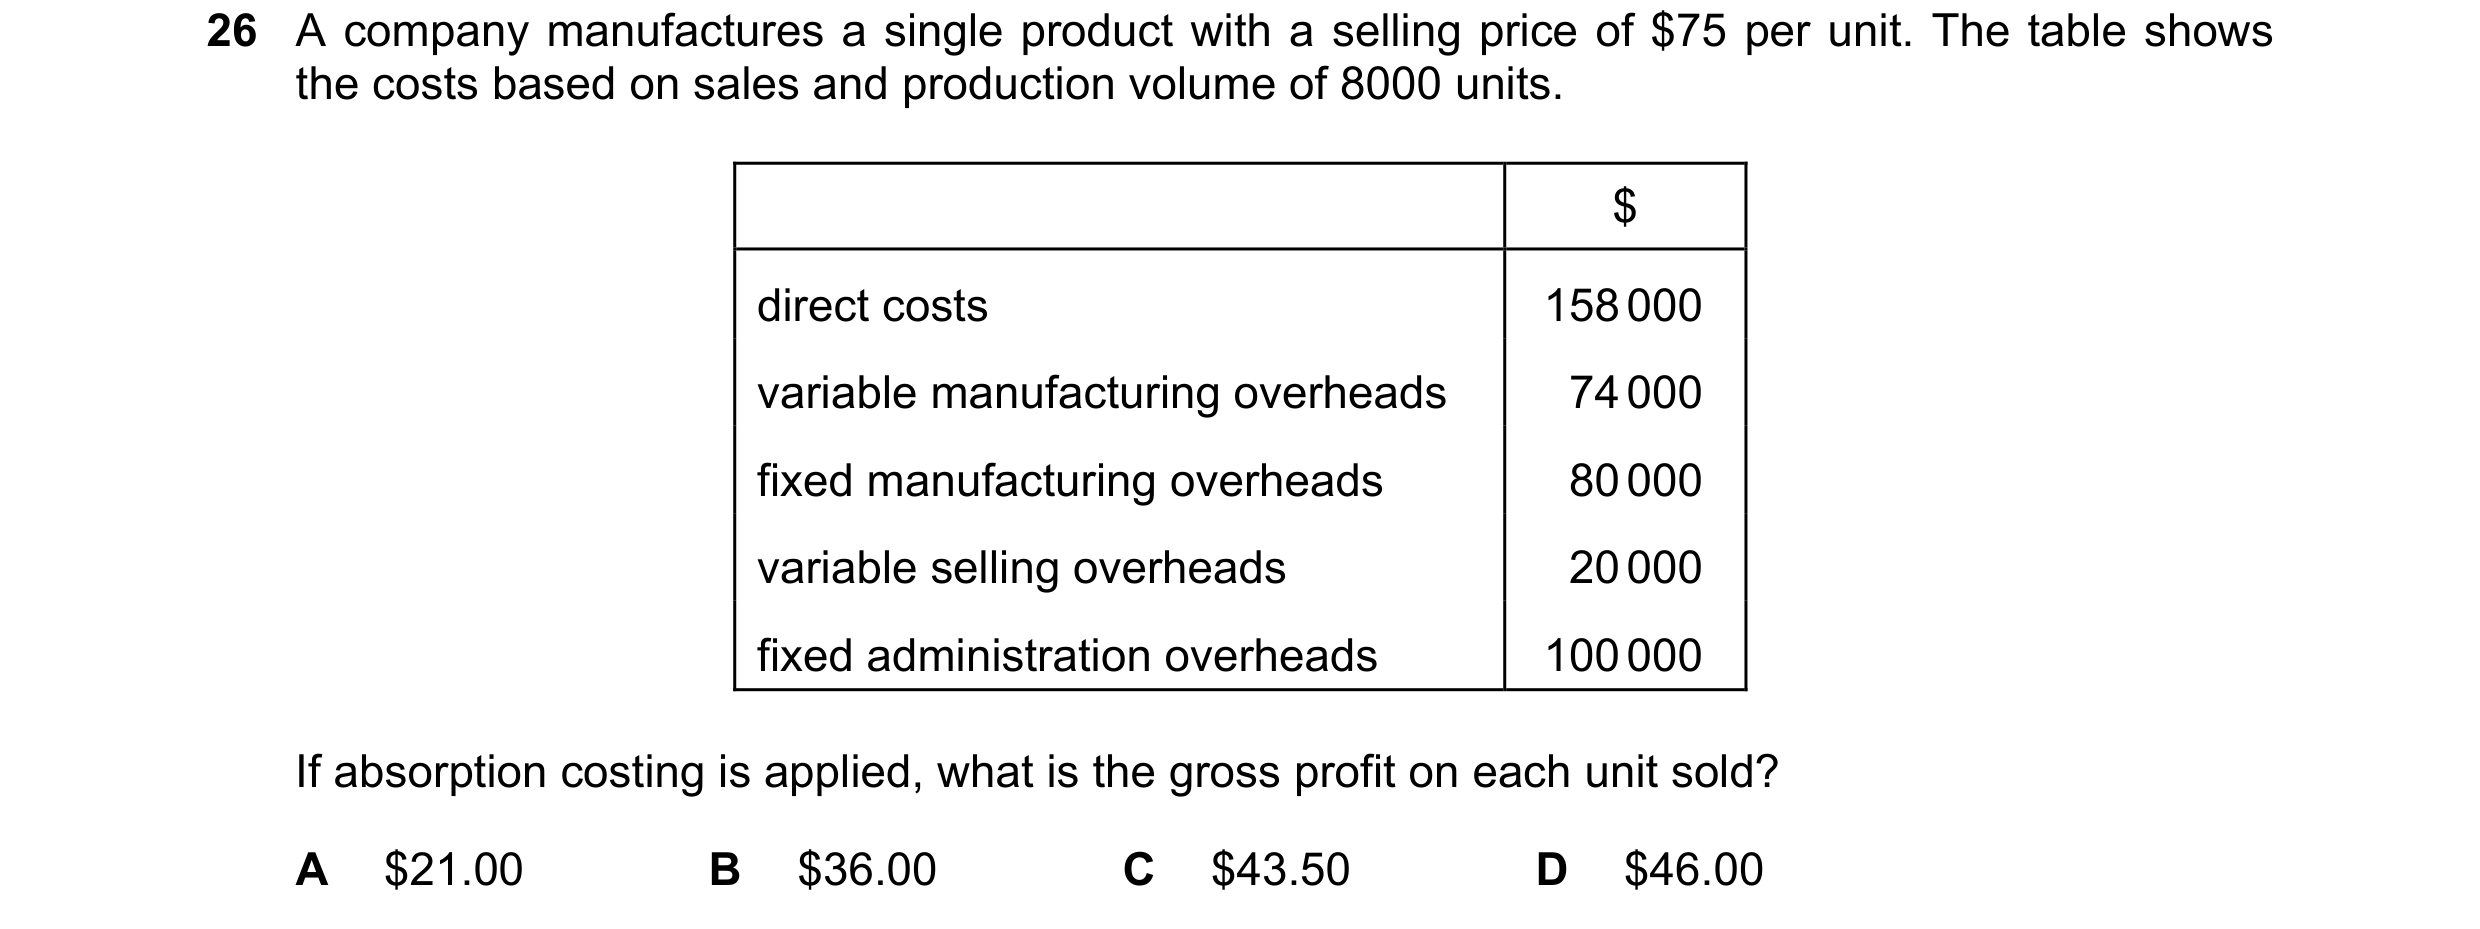
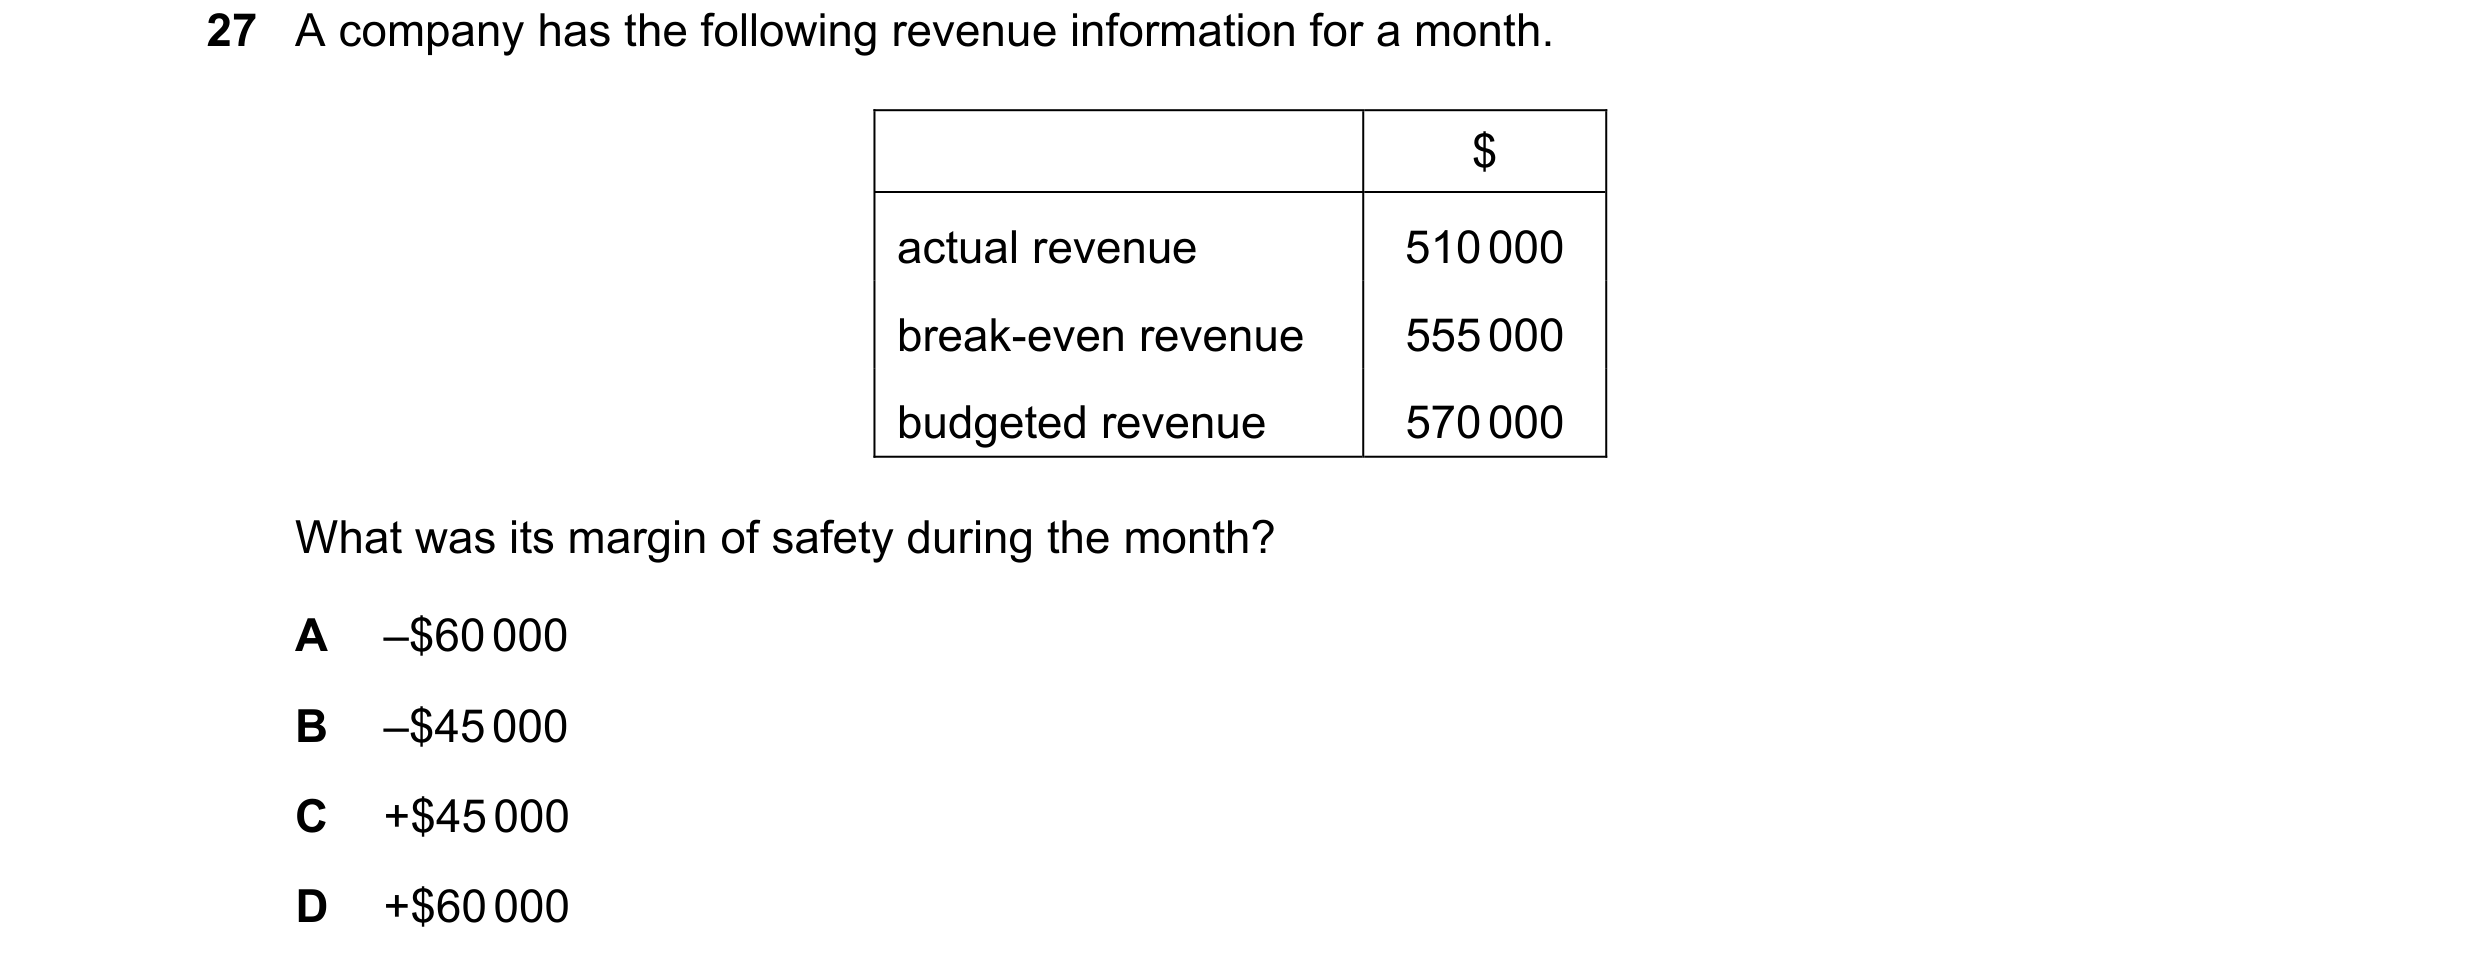
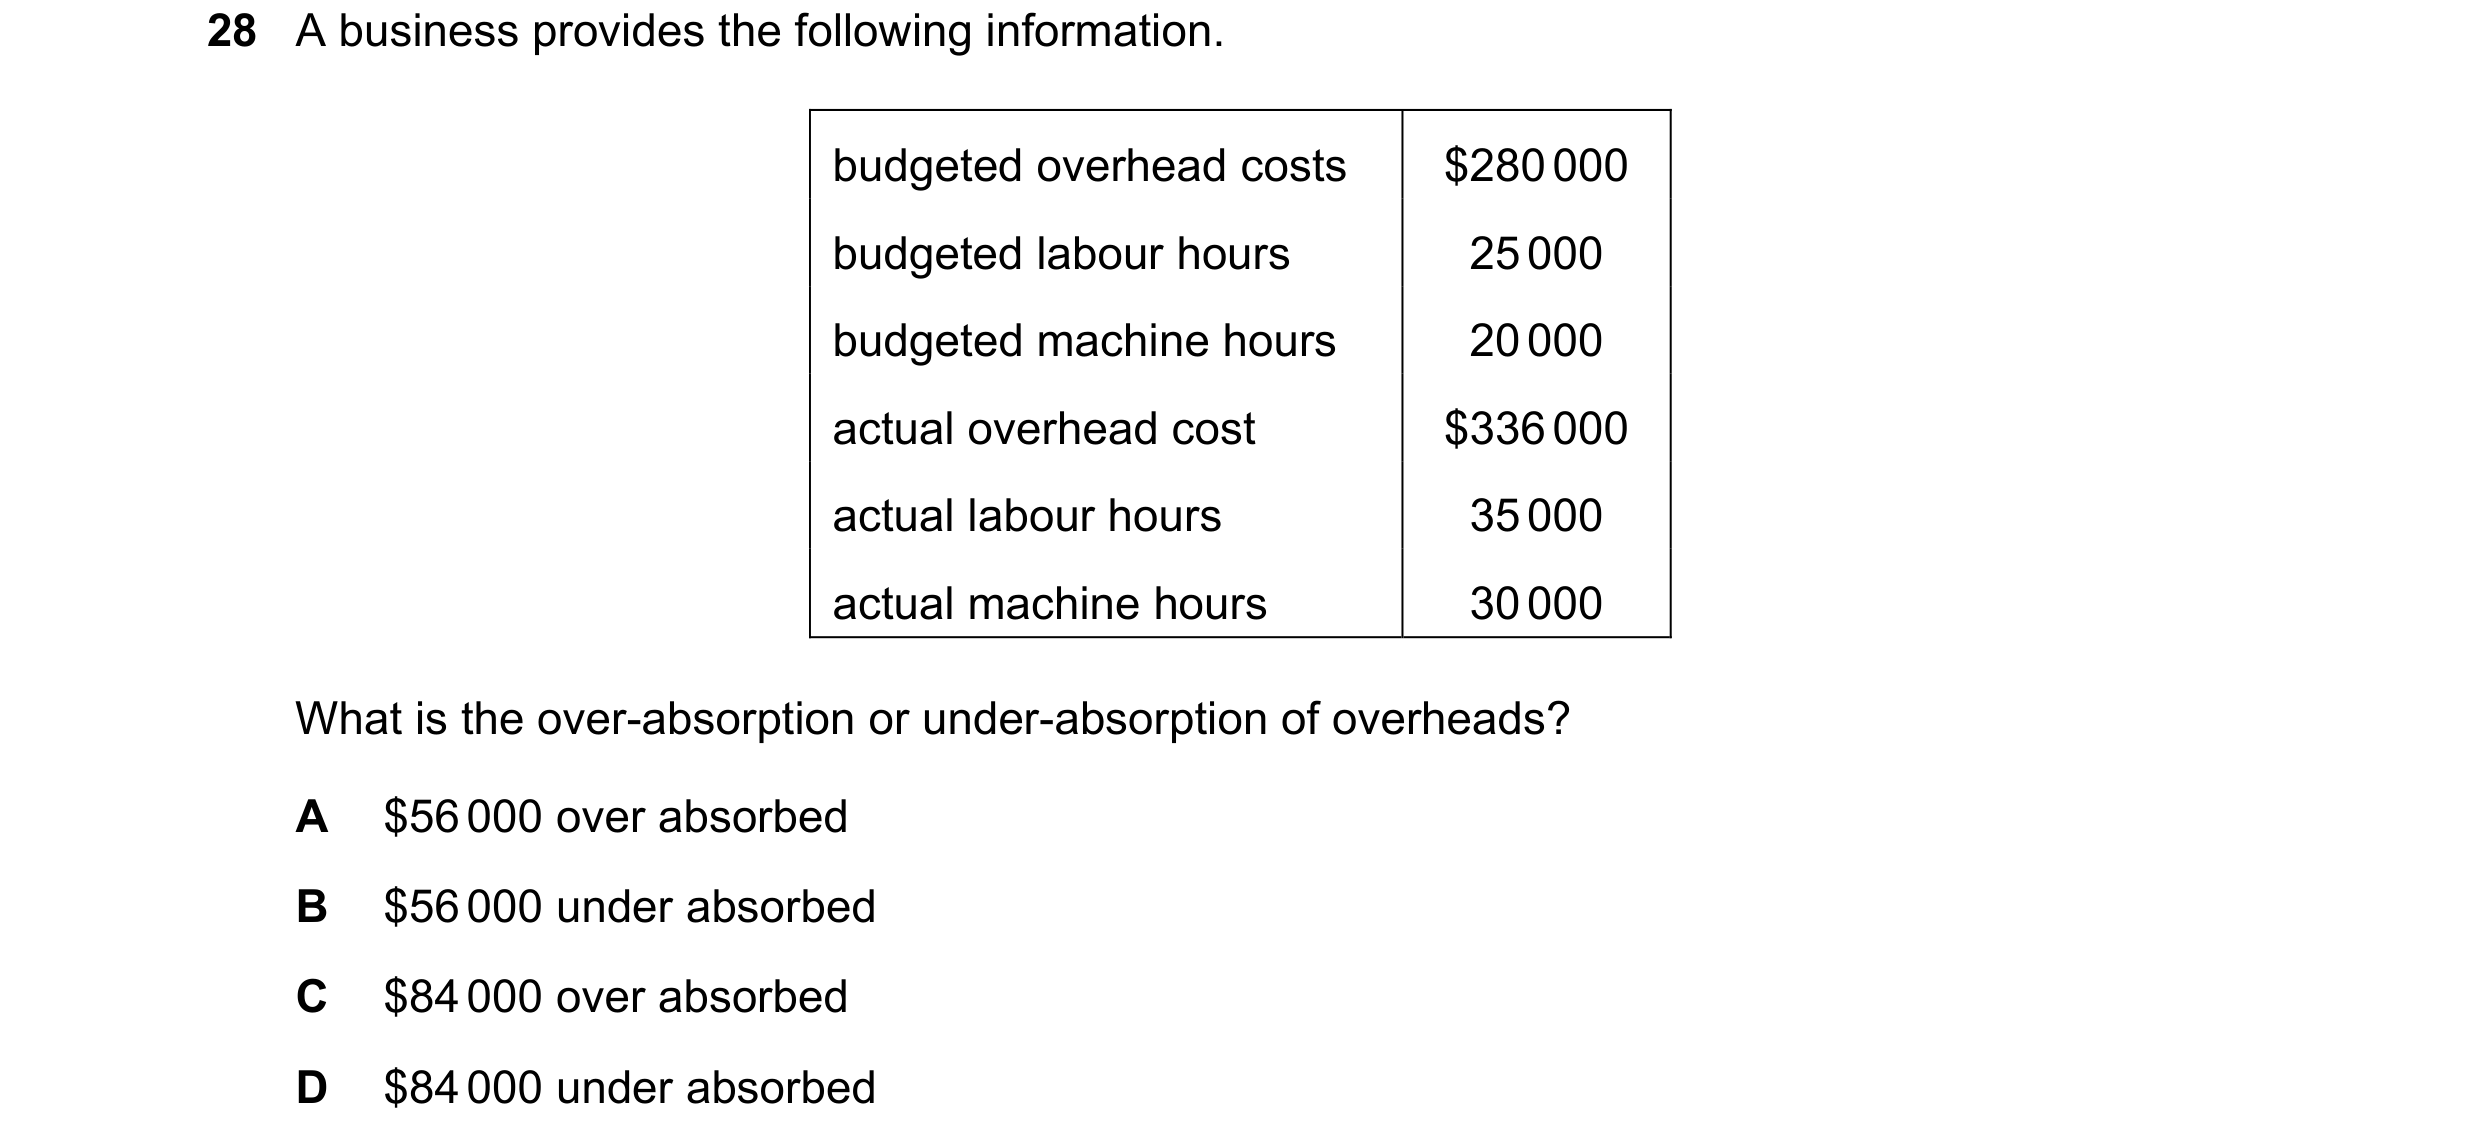 83 / 143
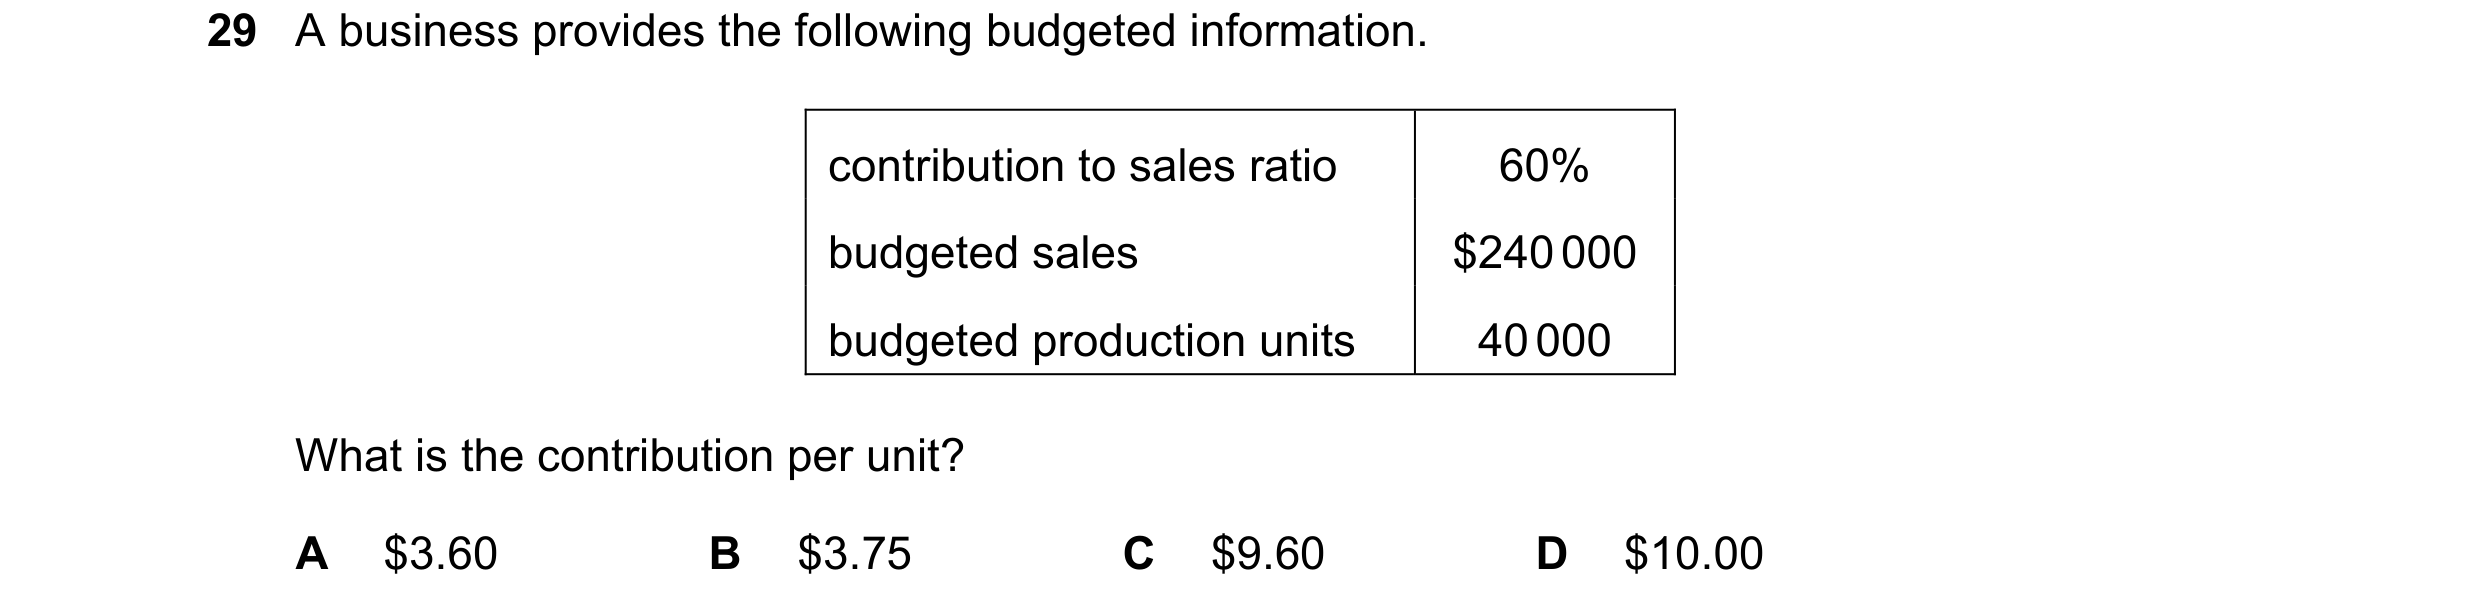
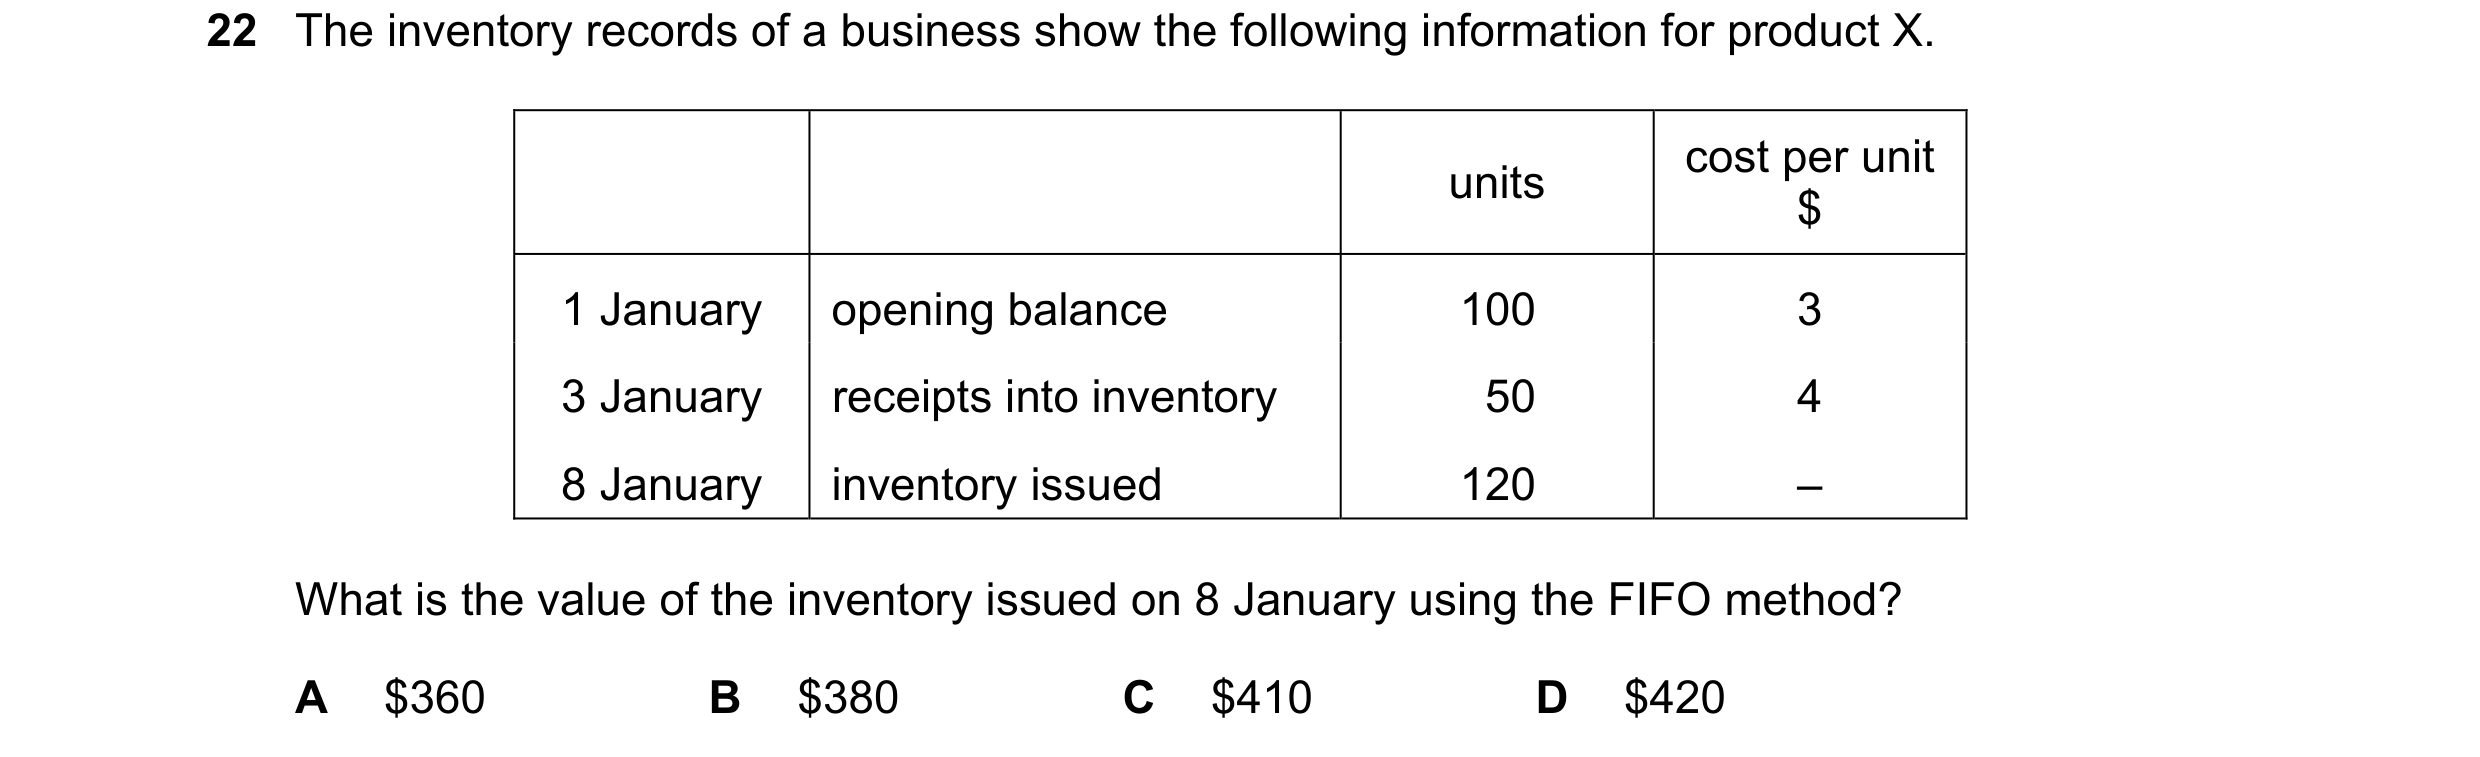
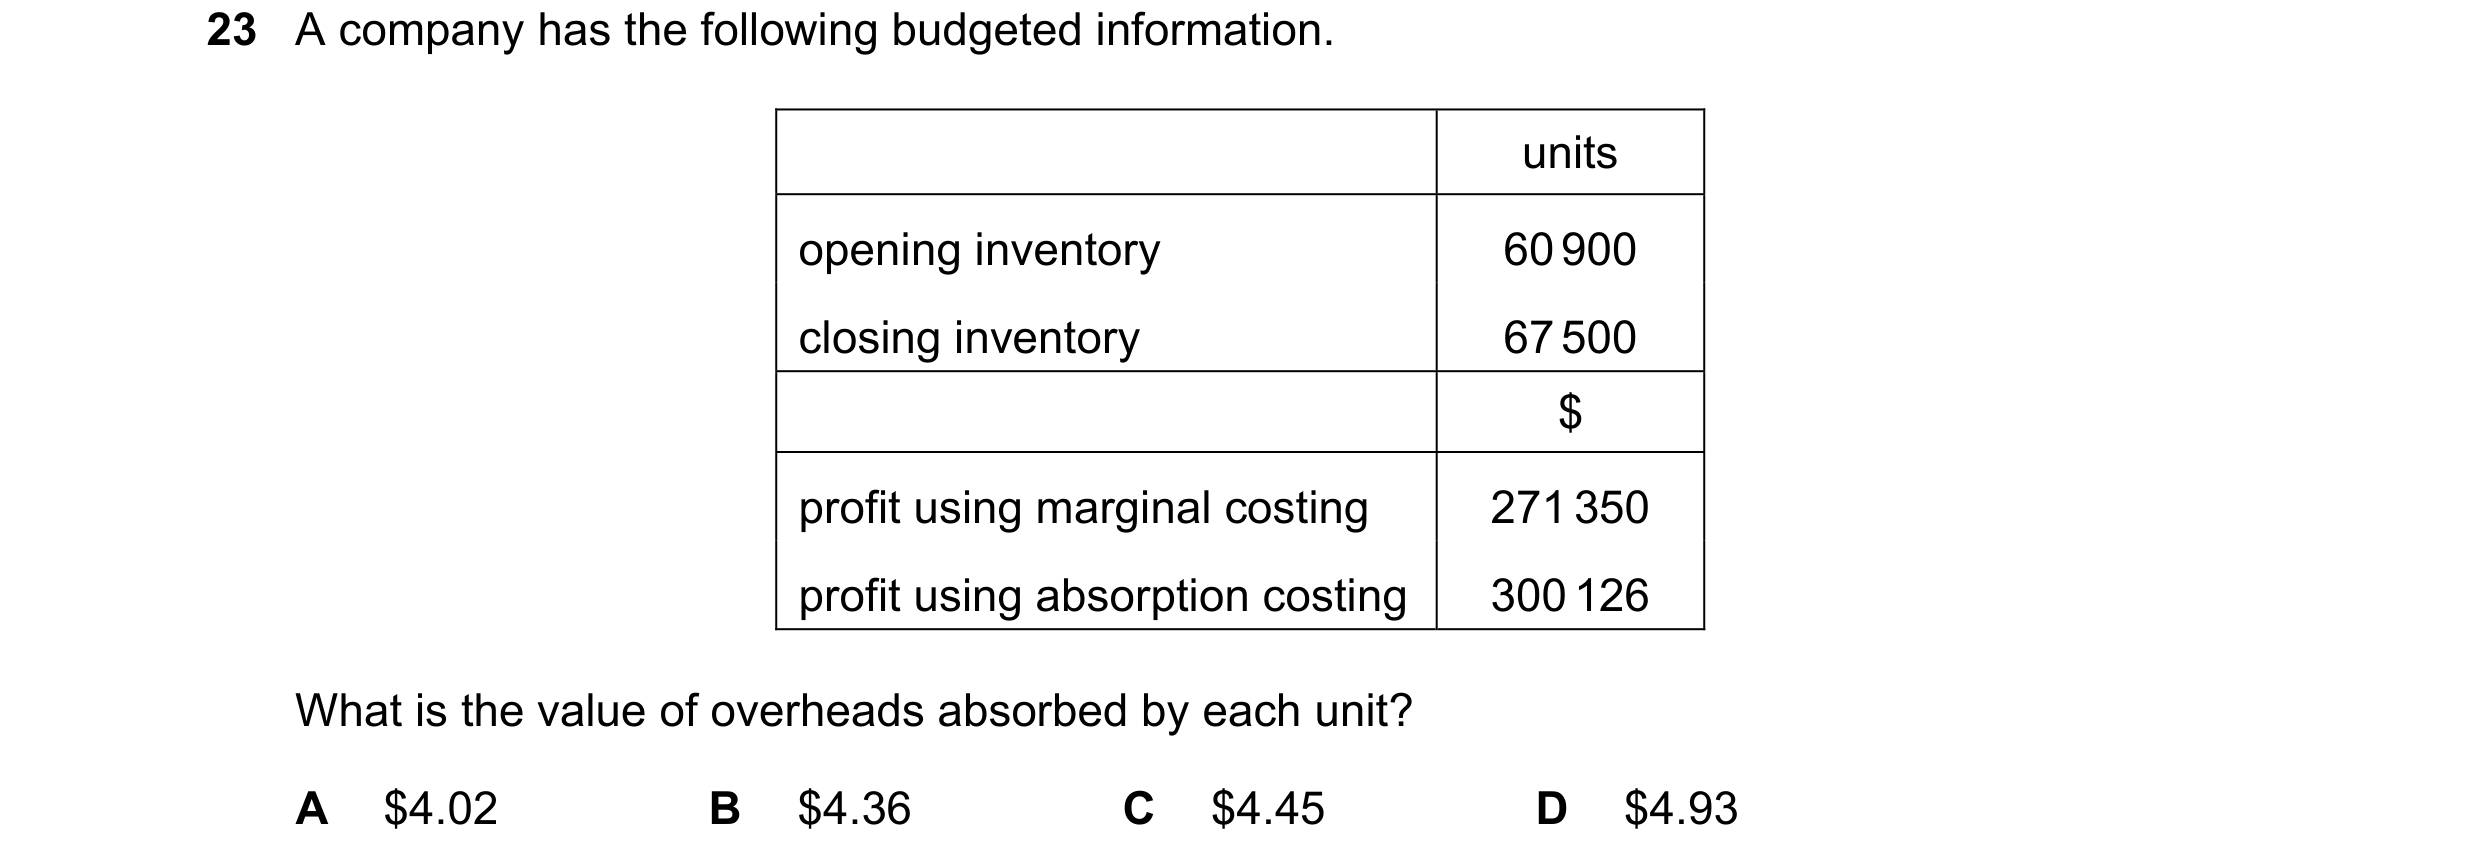
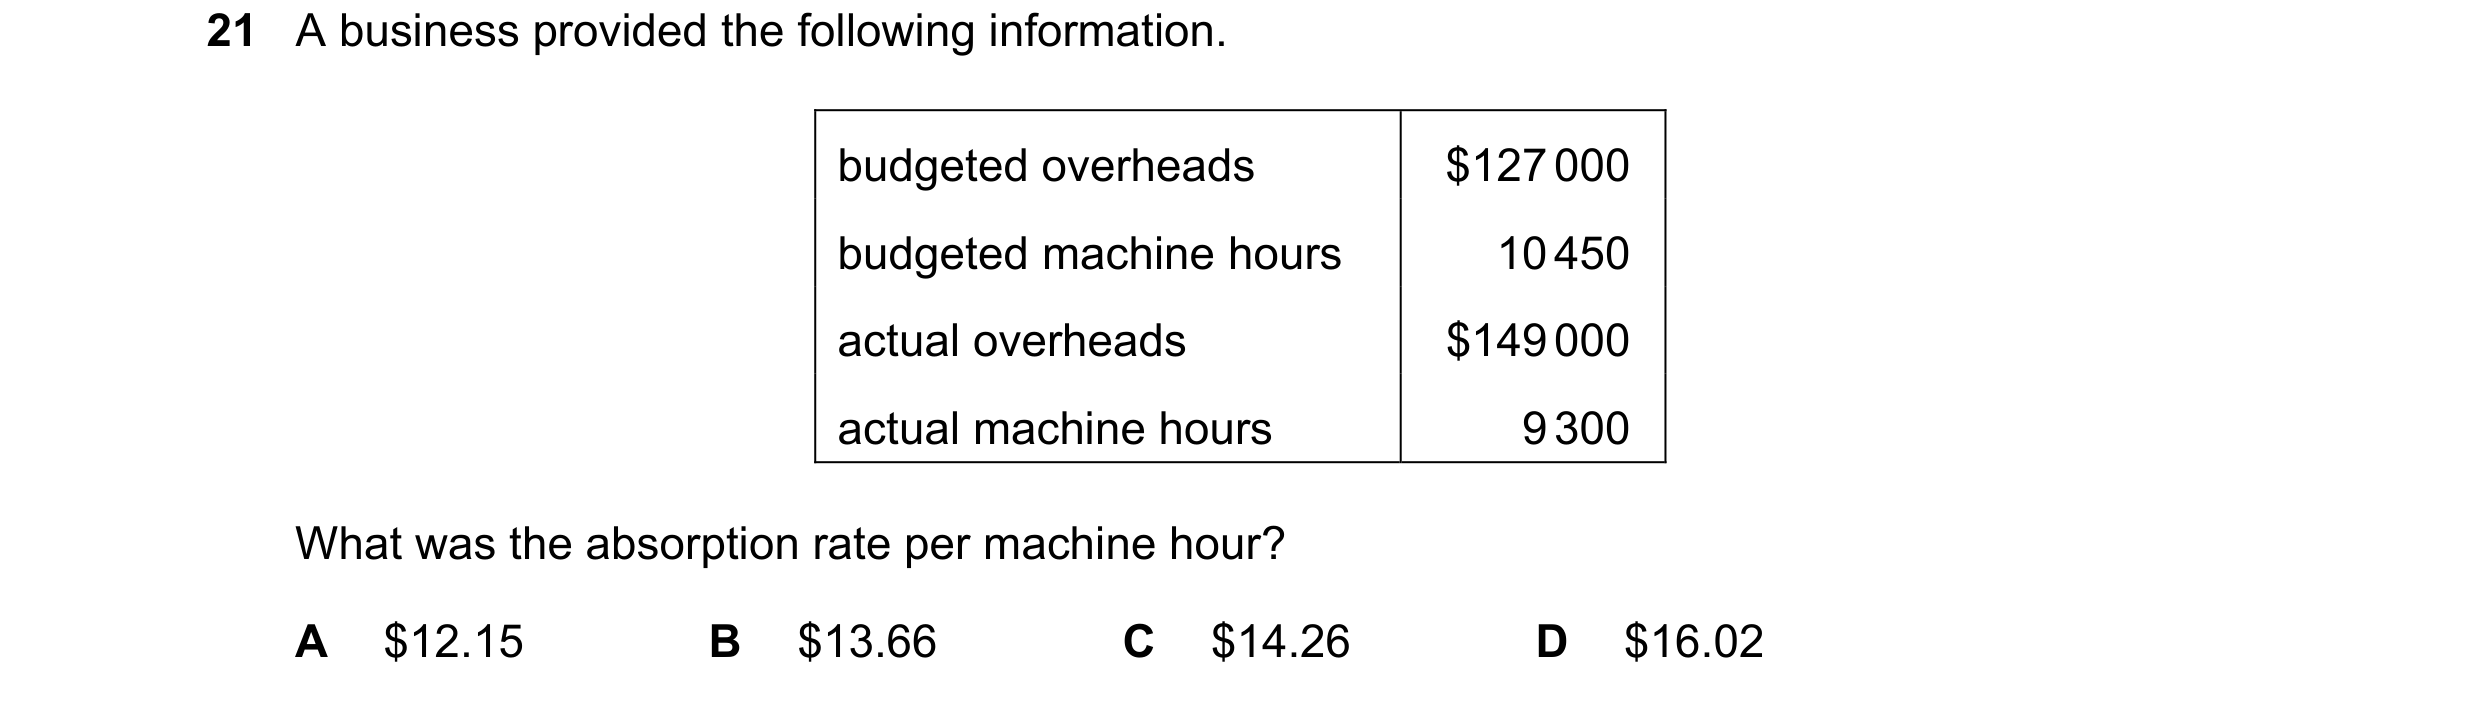 84 / 143
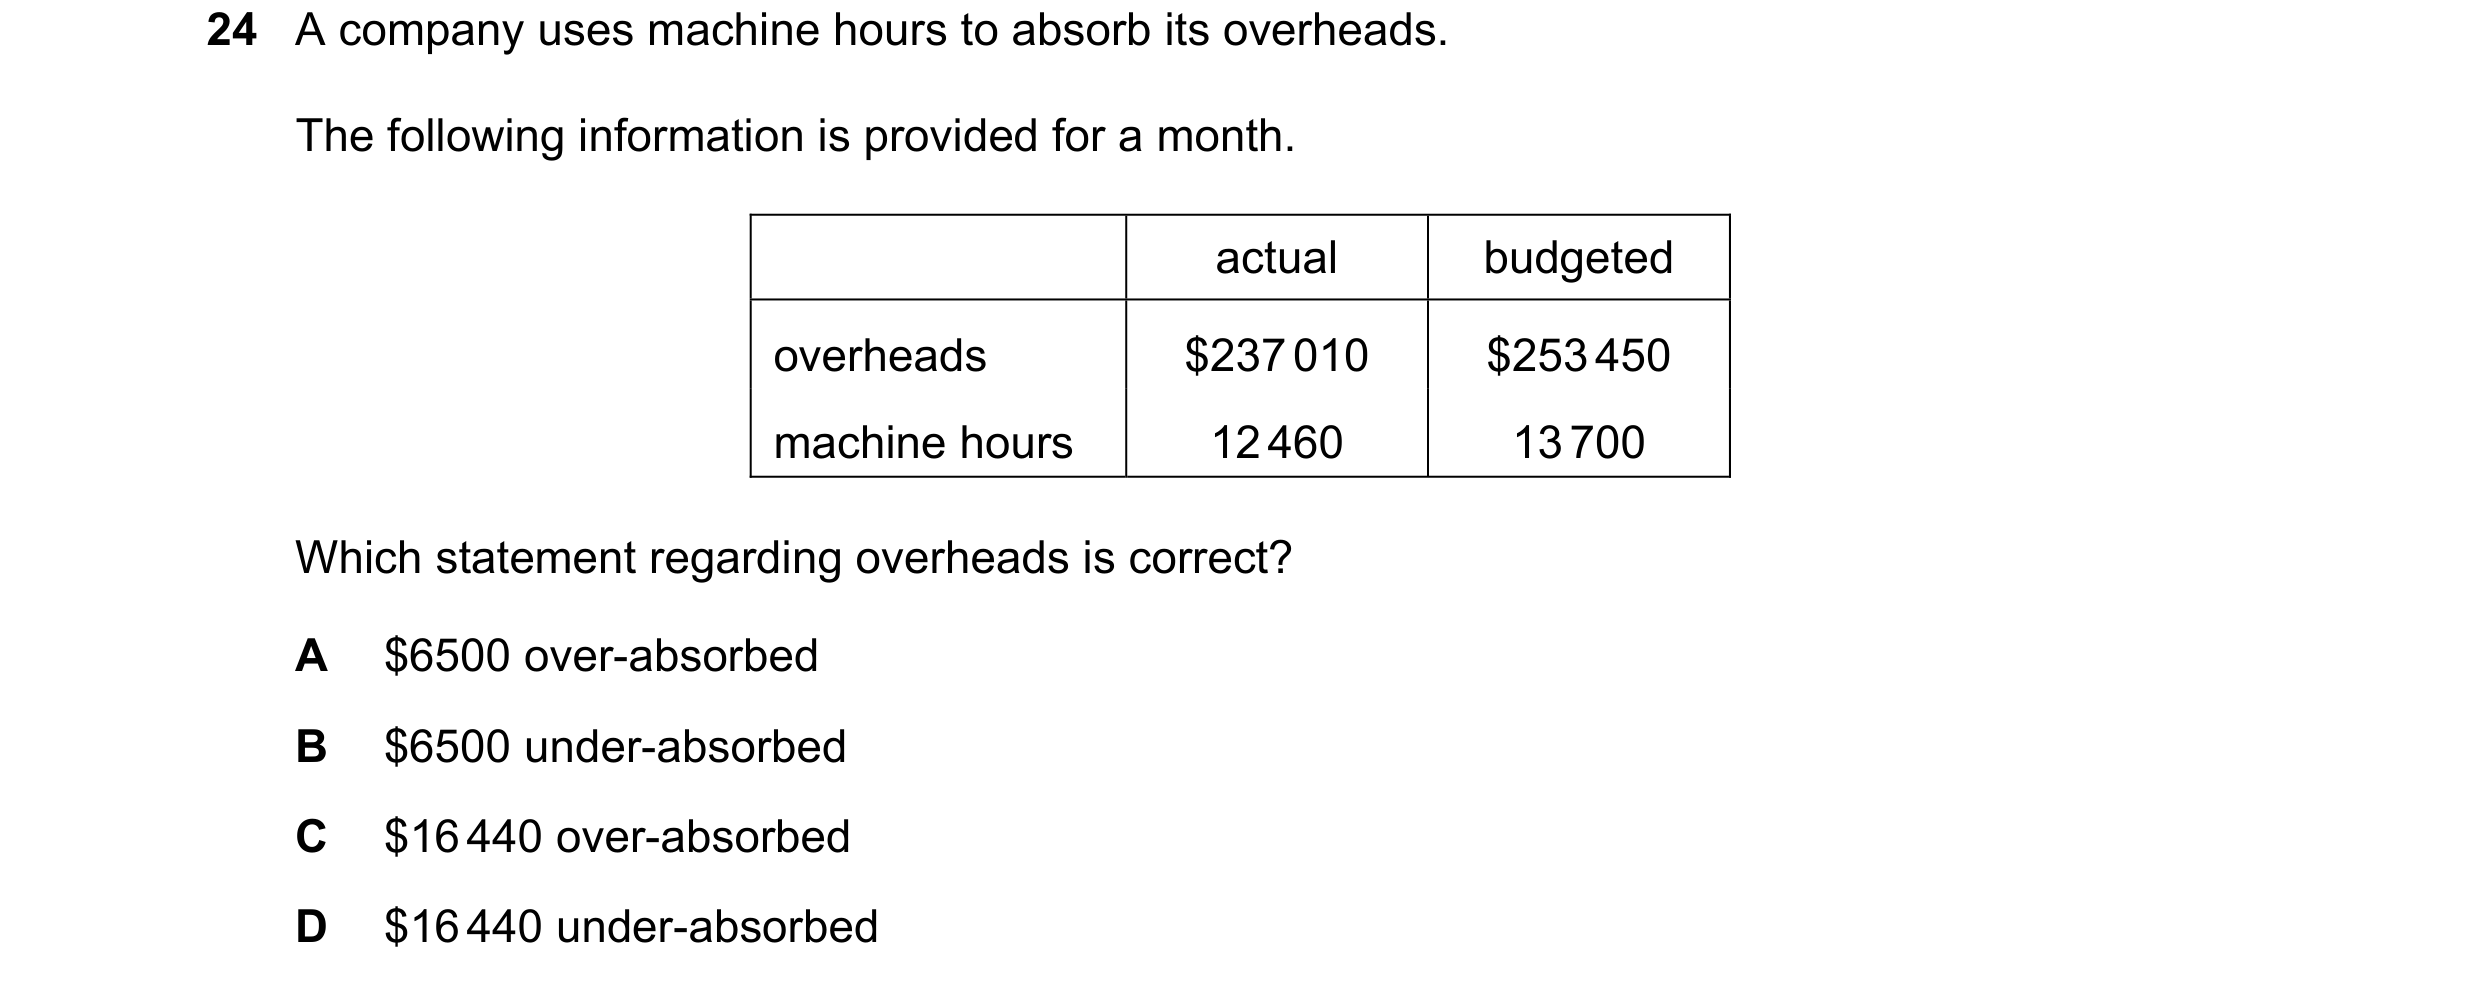
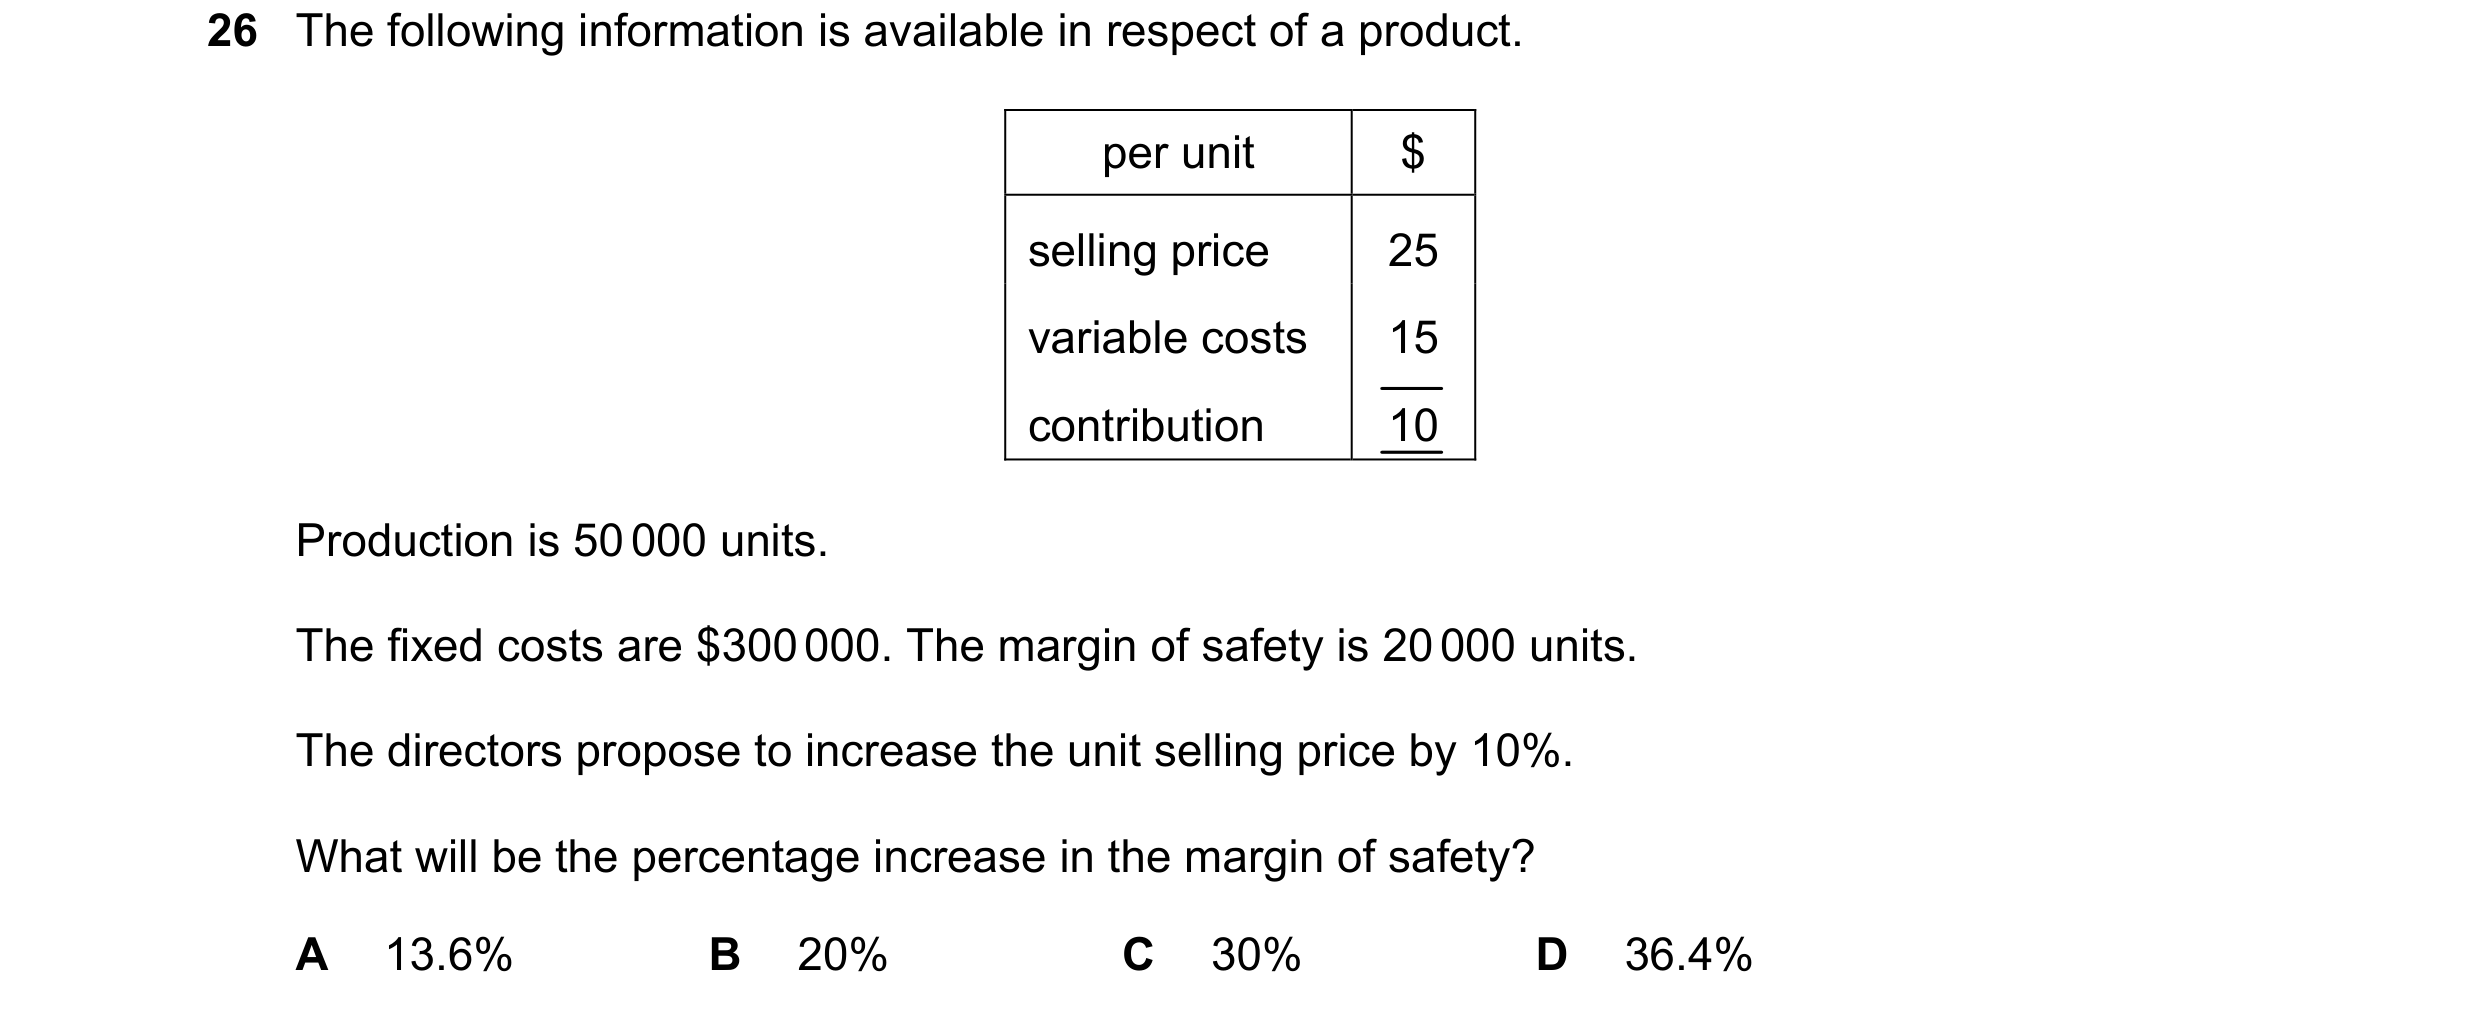
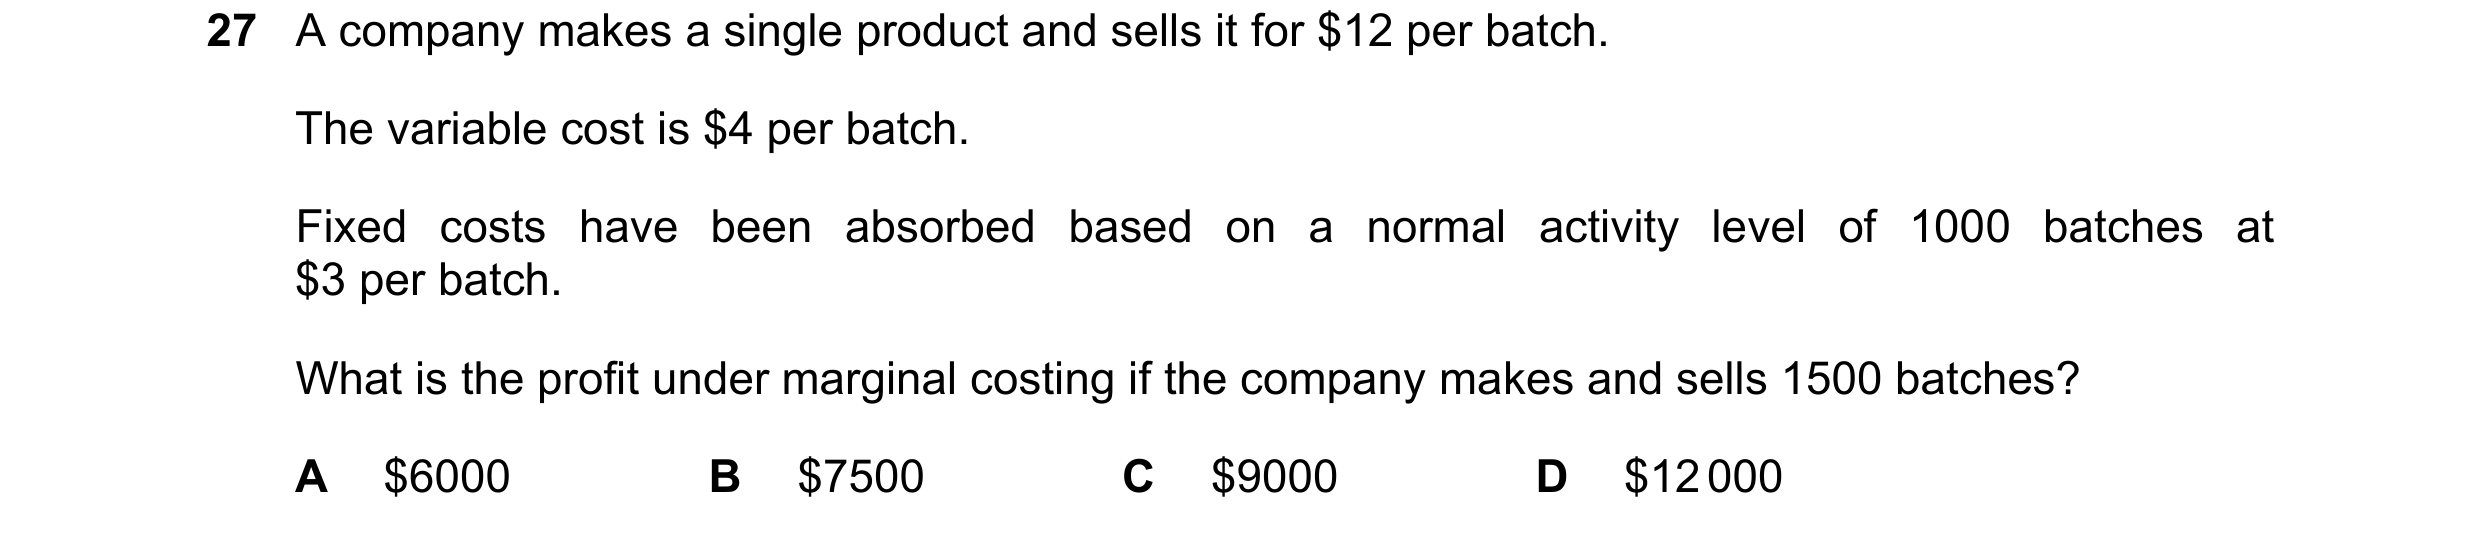
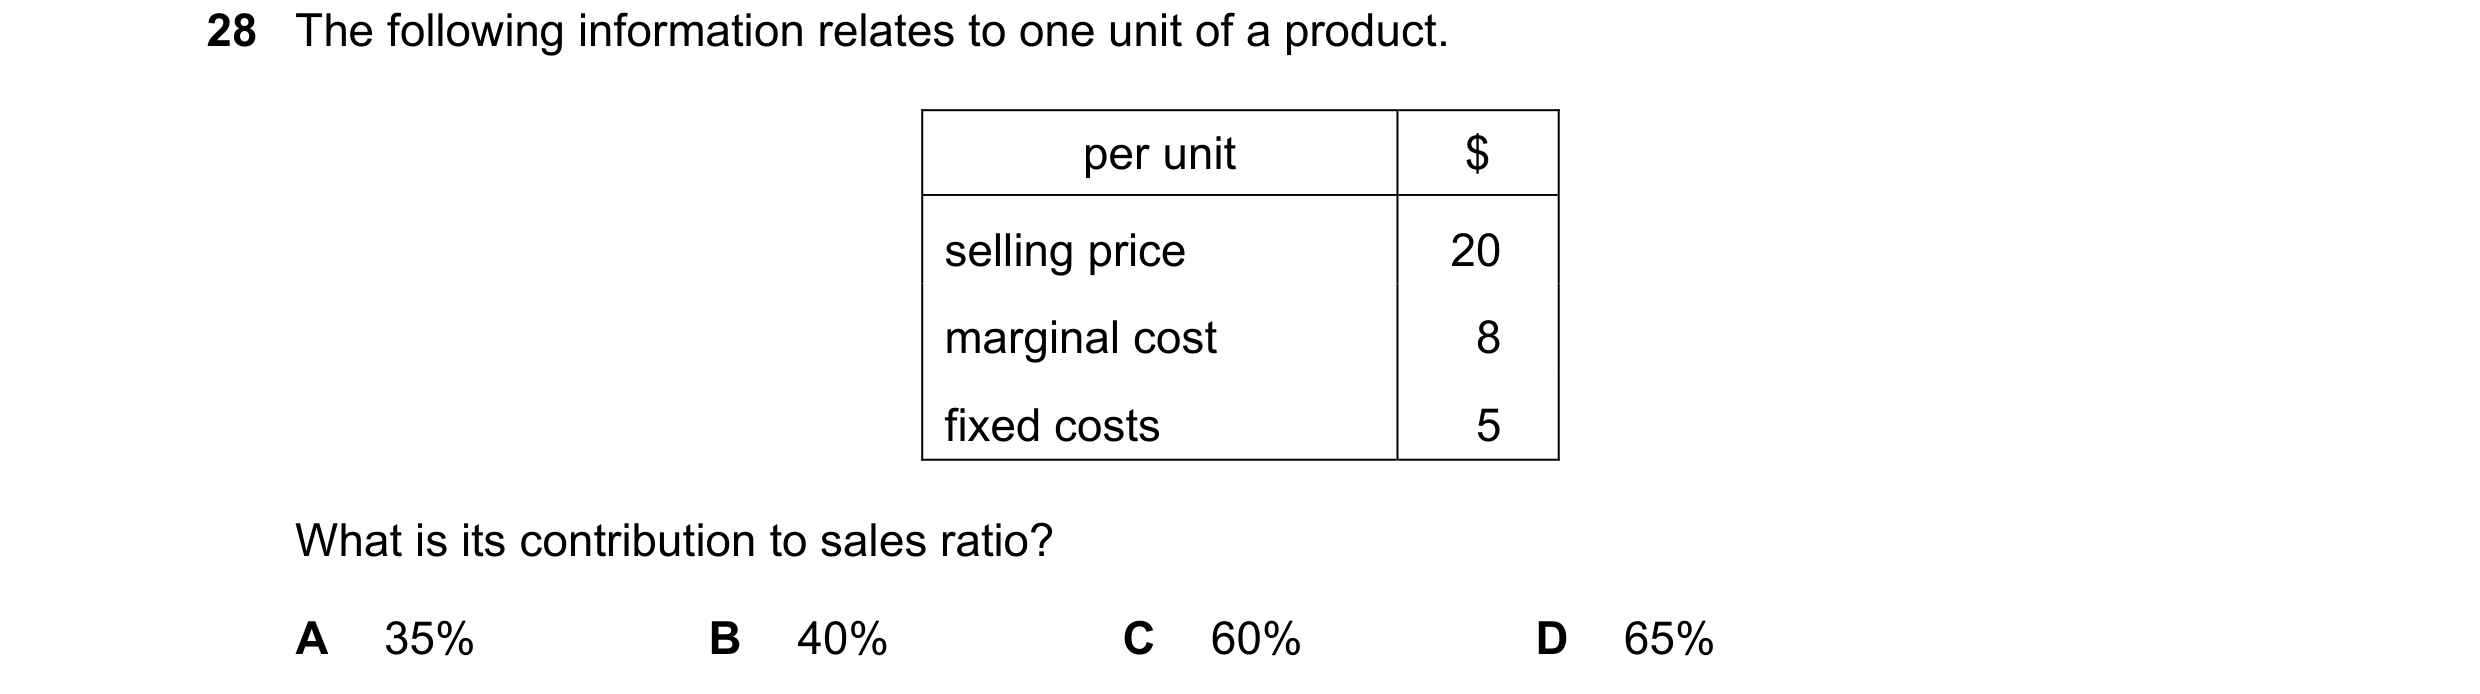 85 / 143
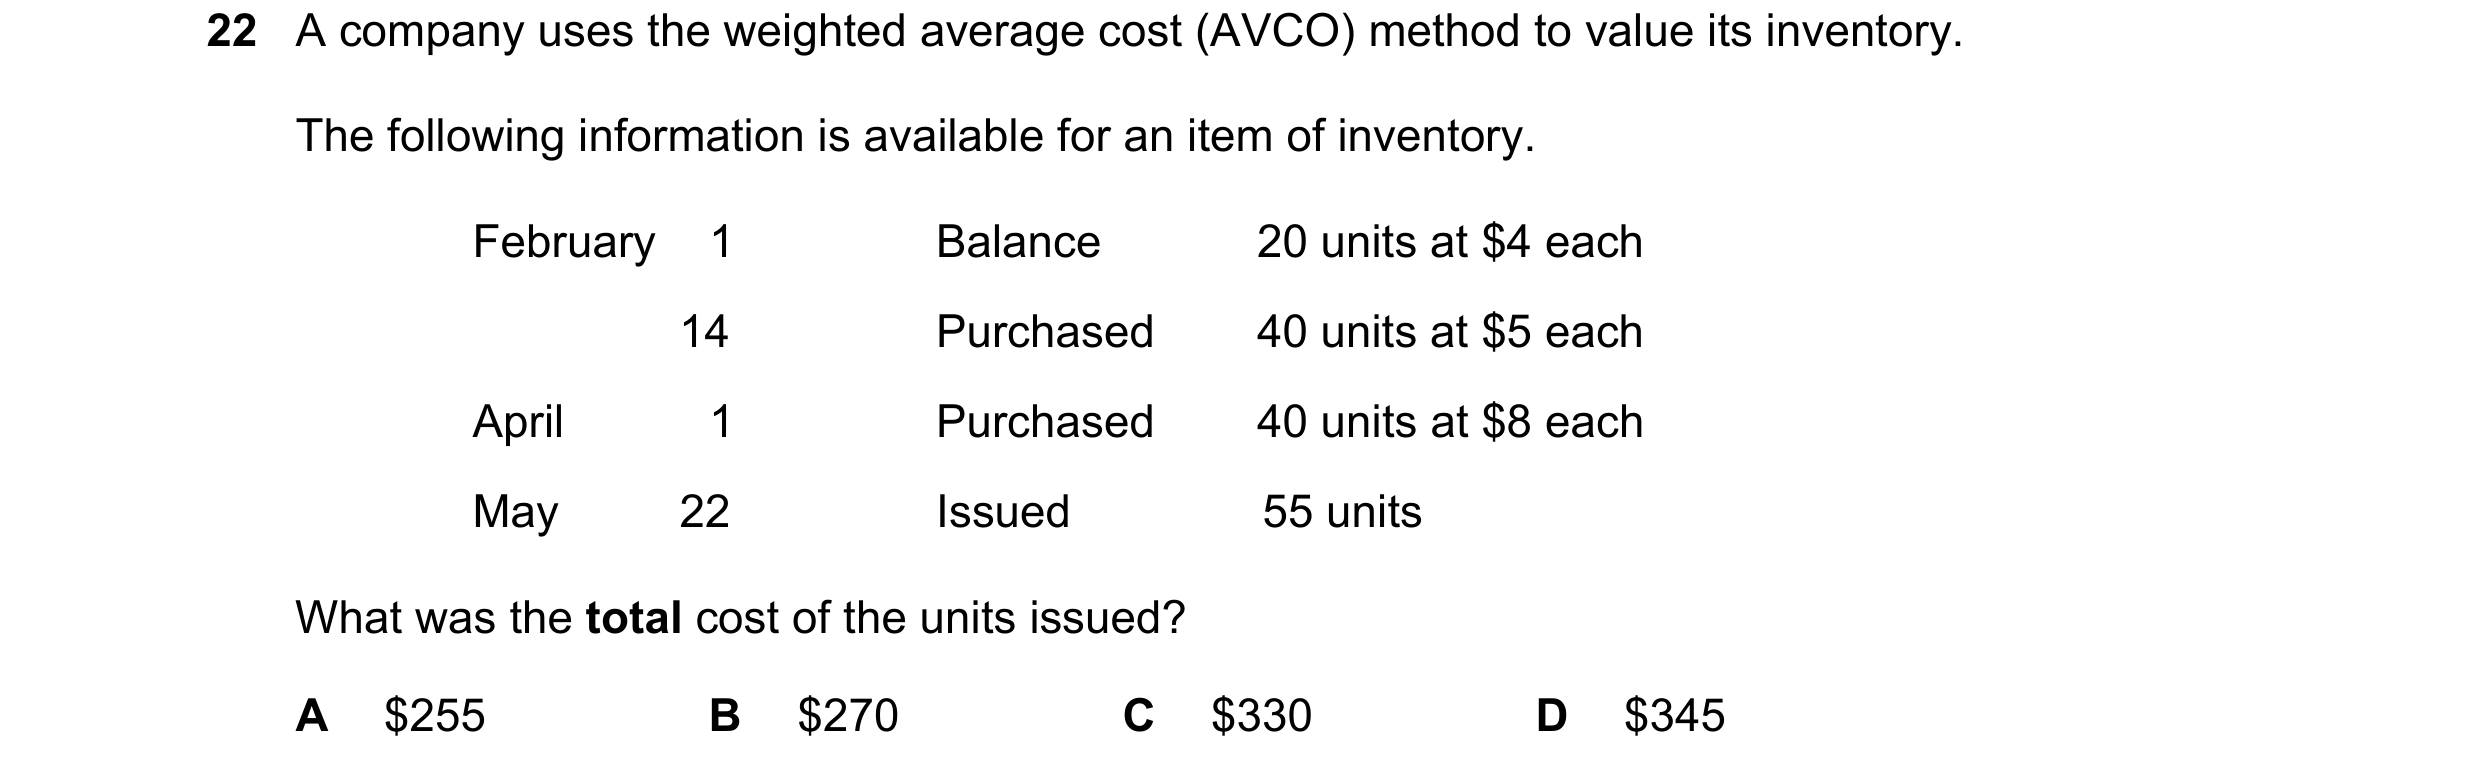
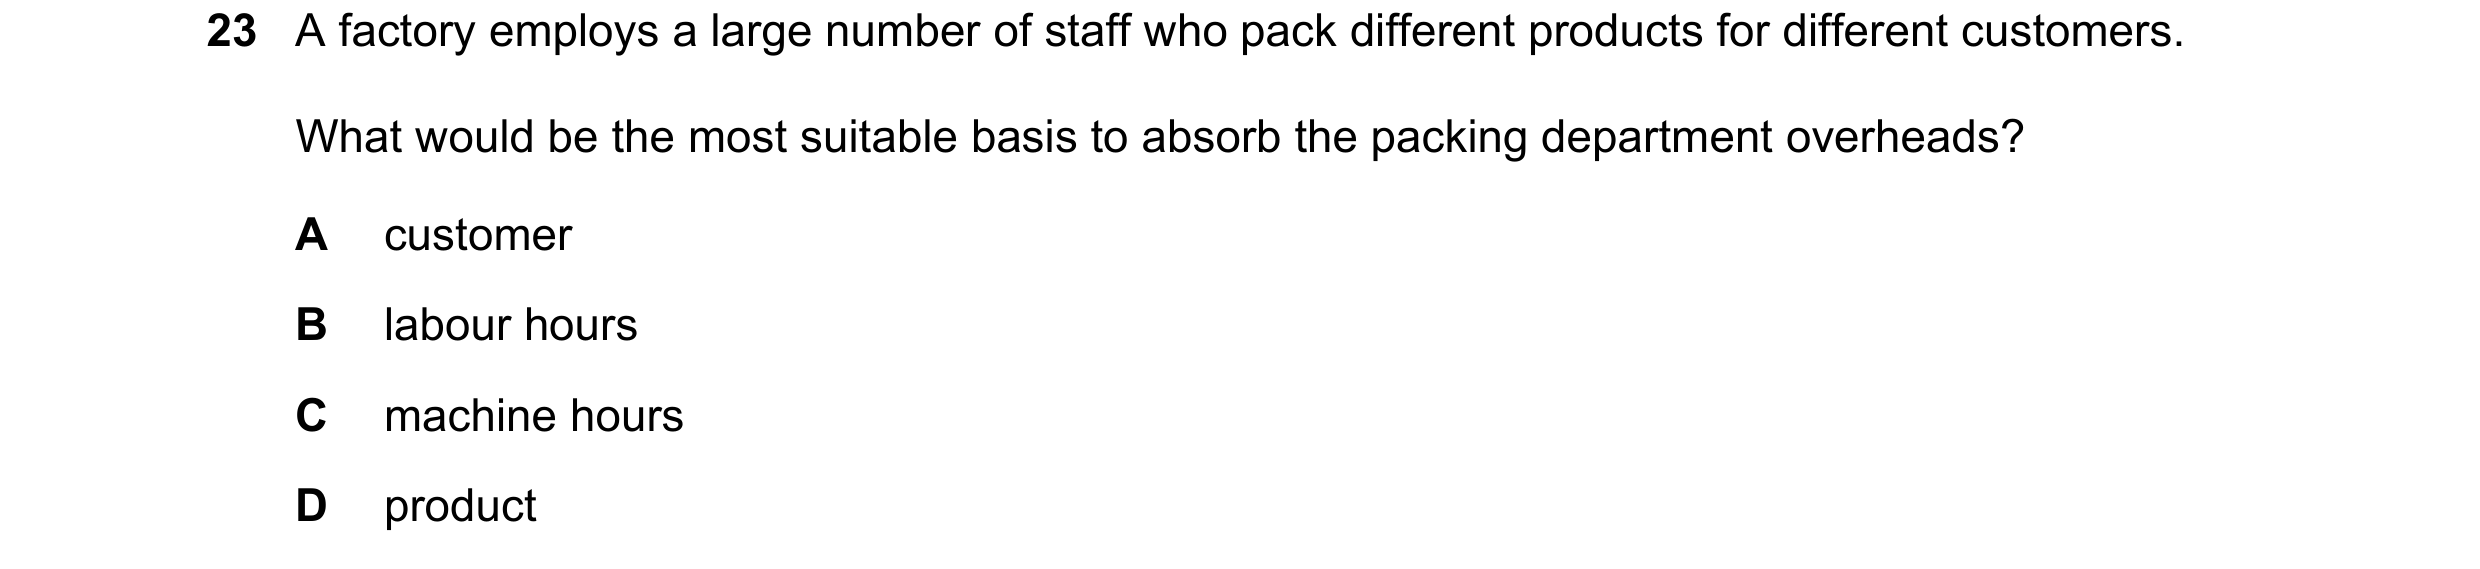
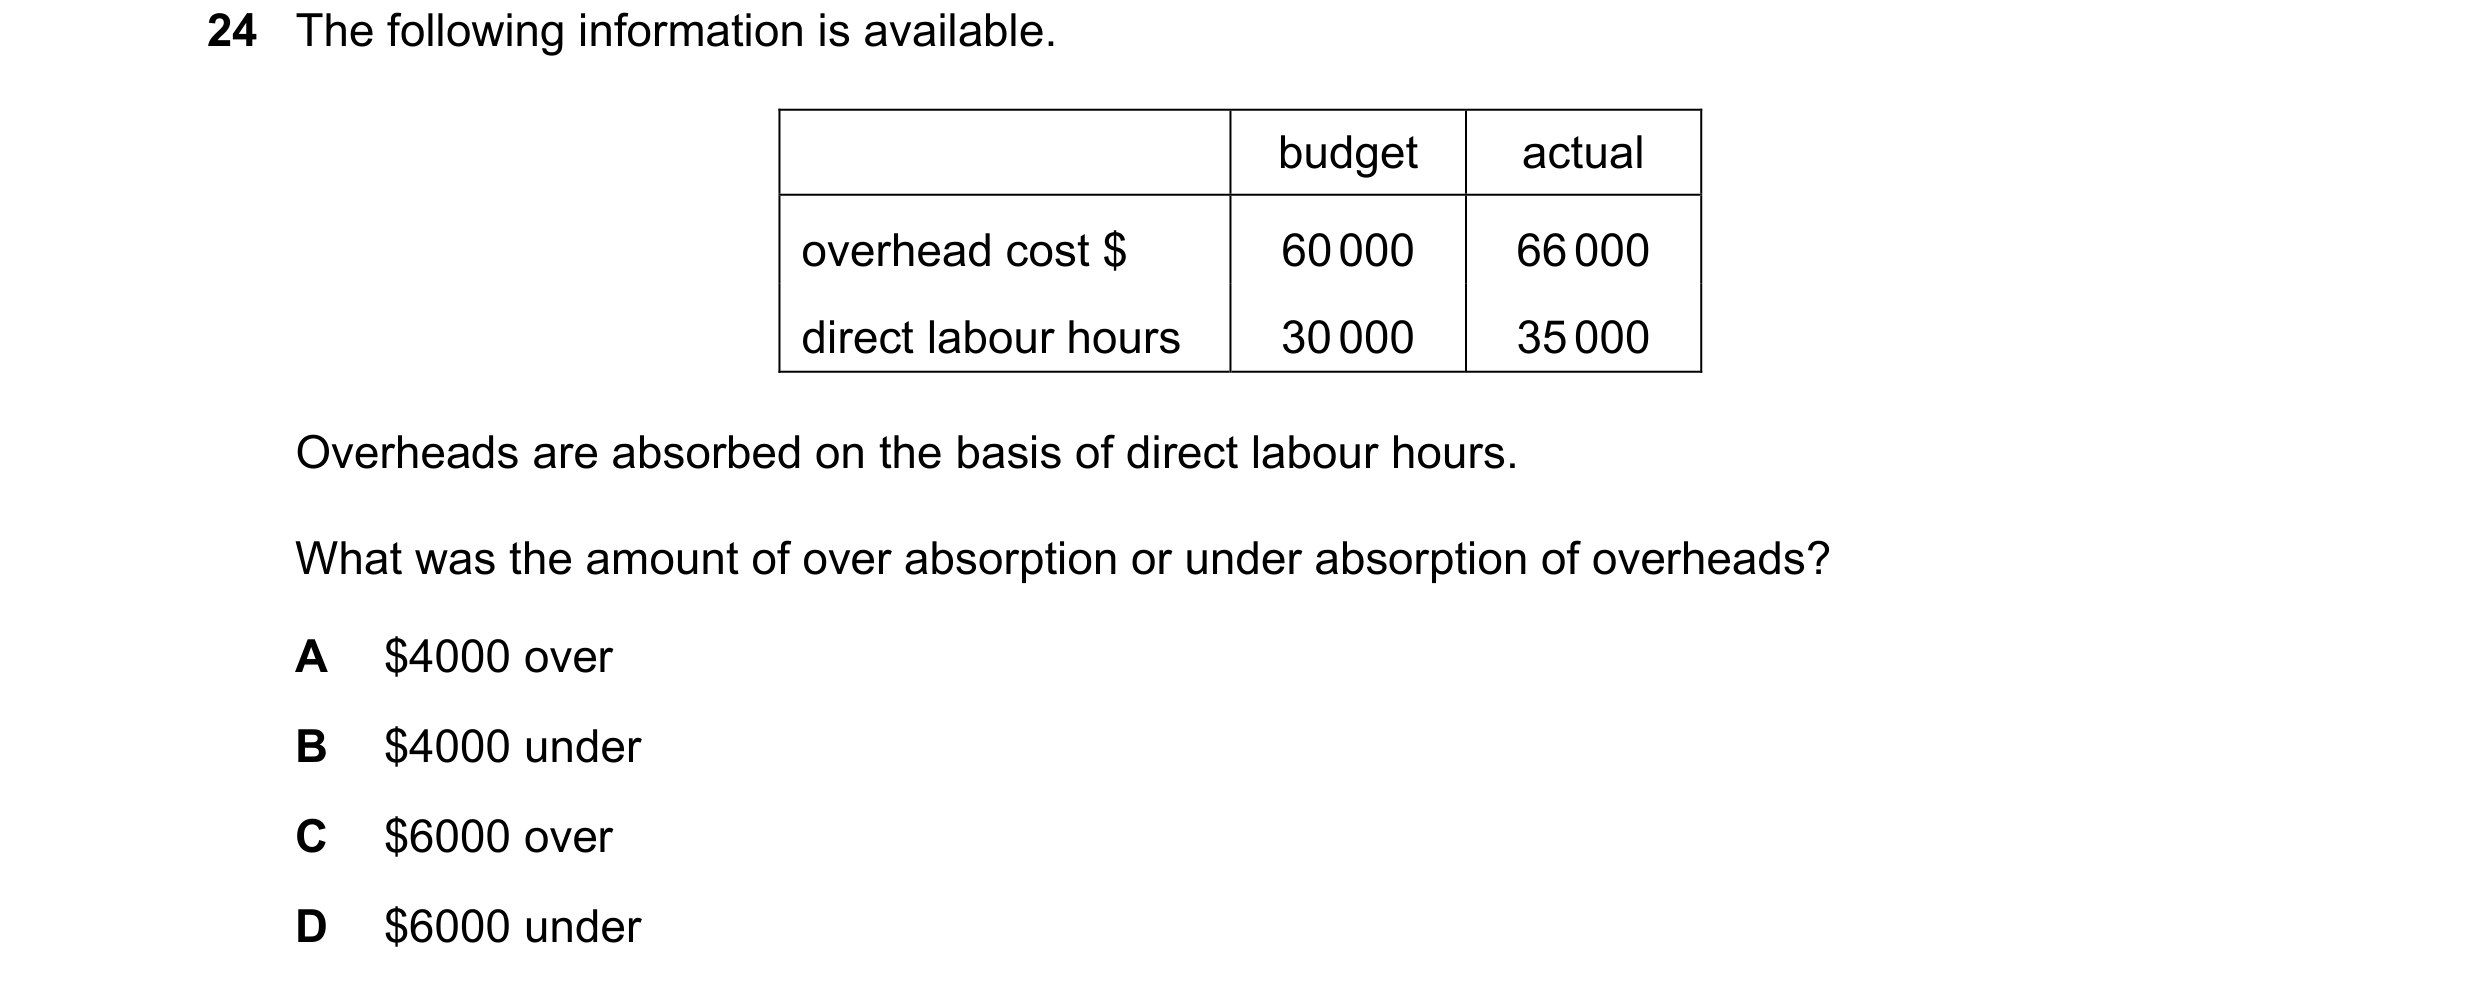
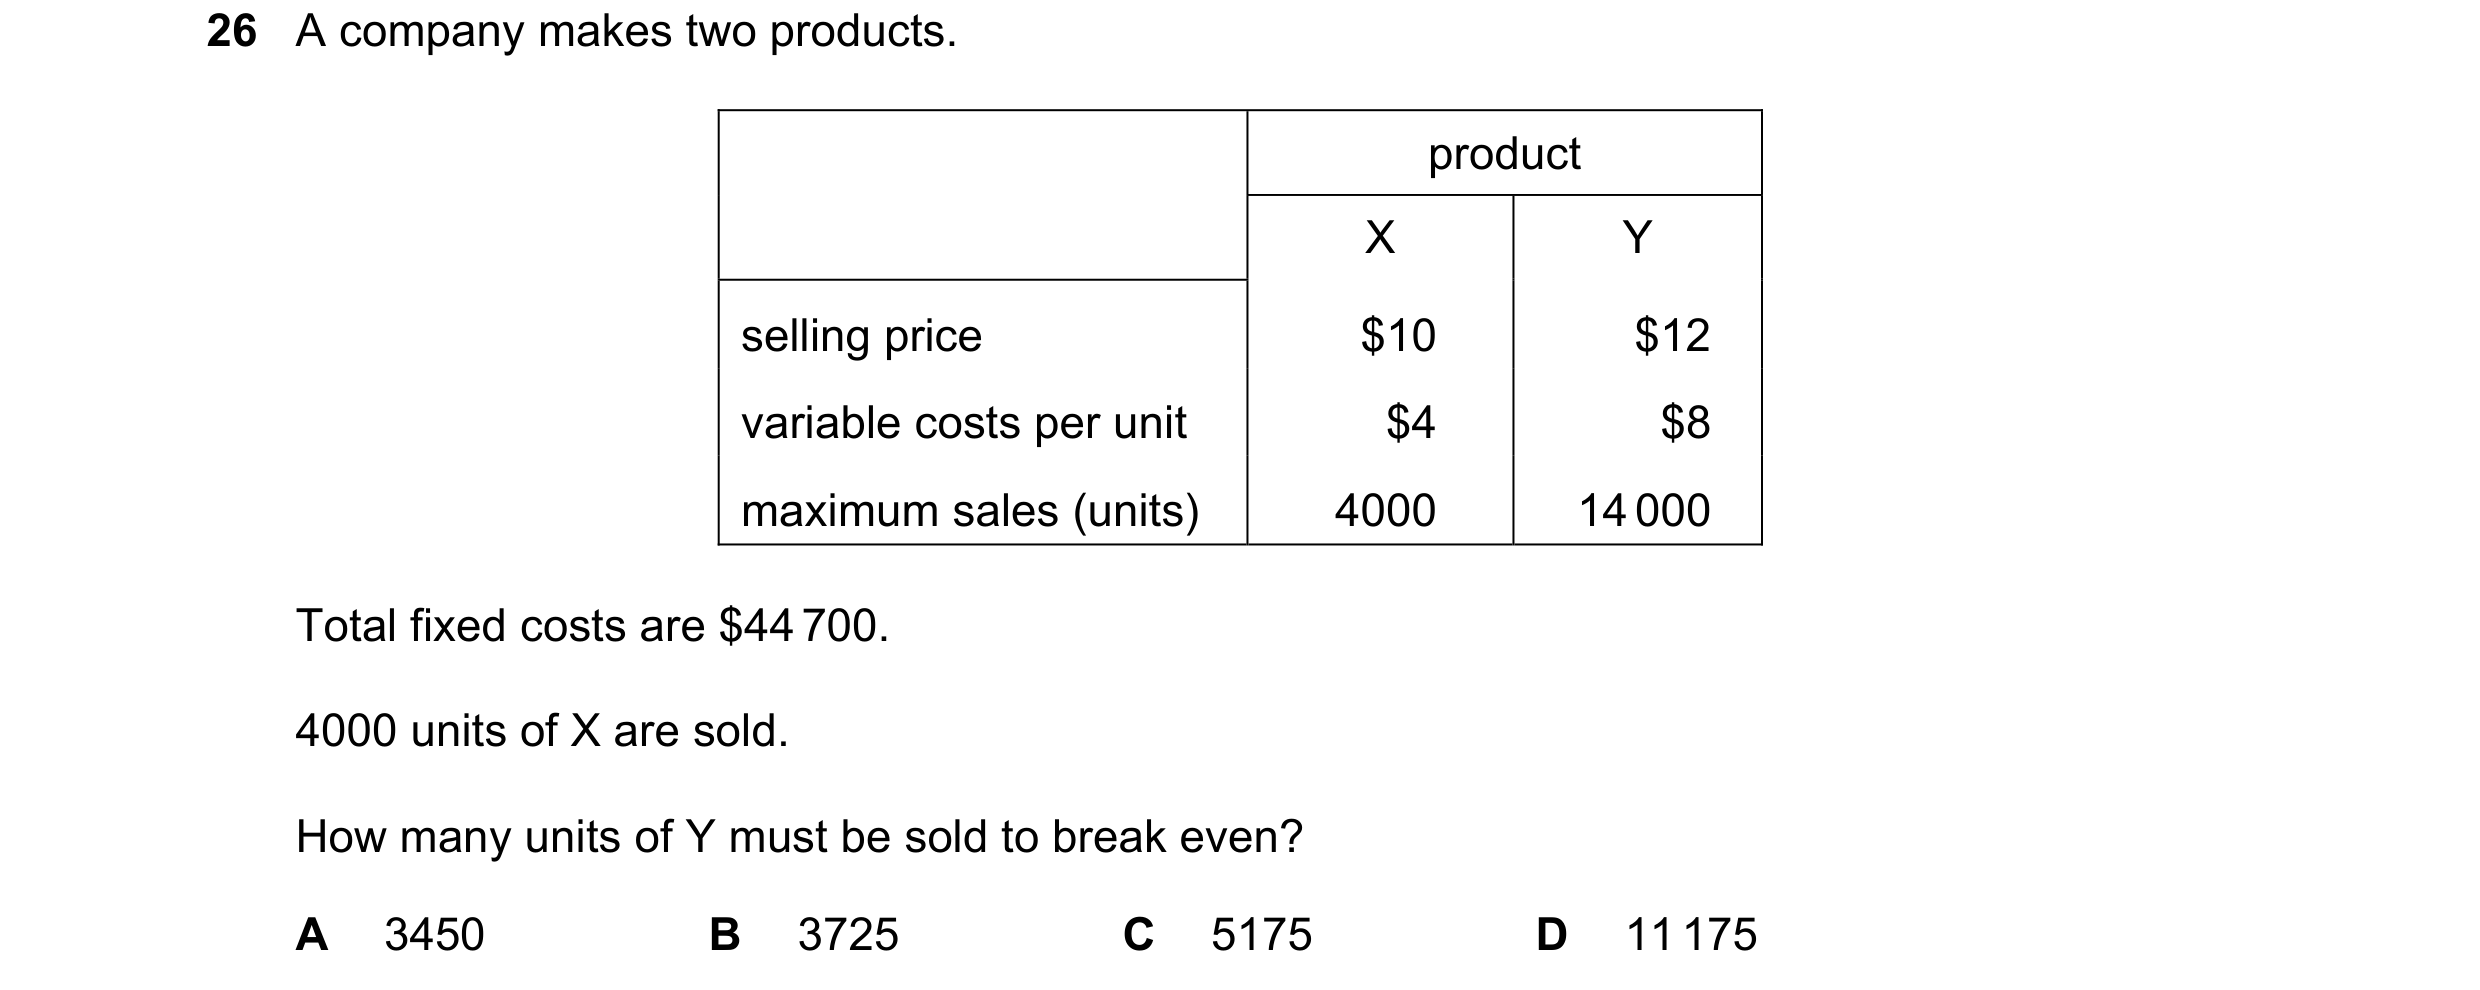 86 / 143
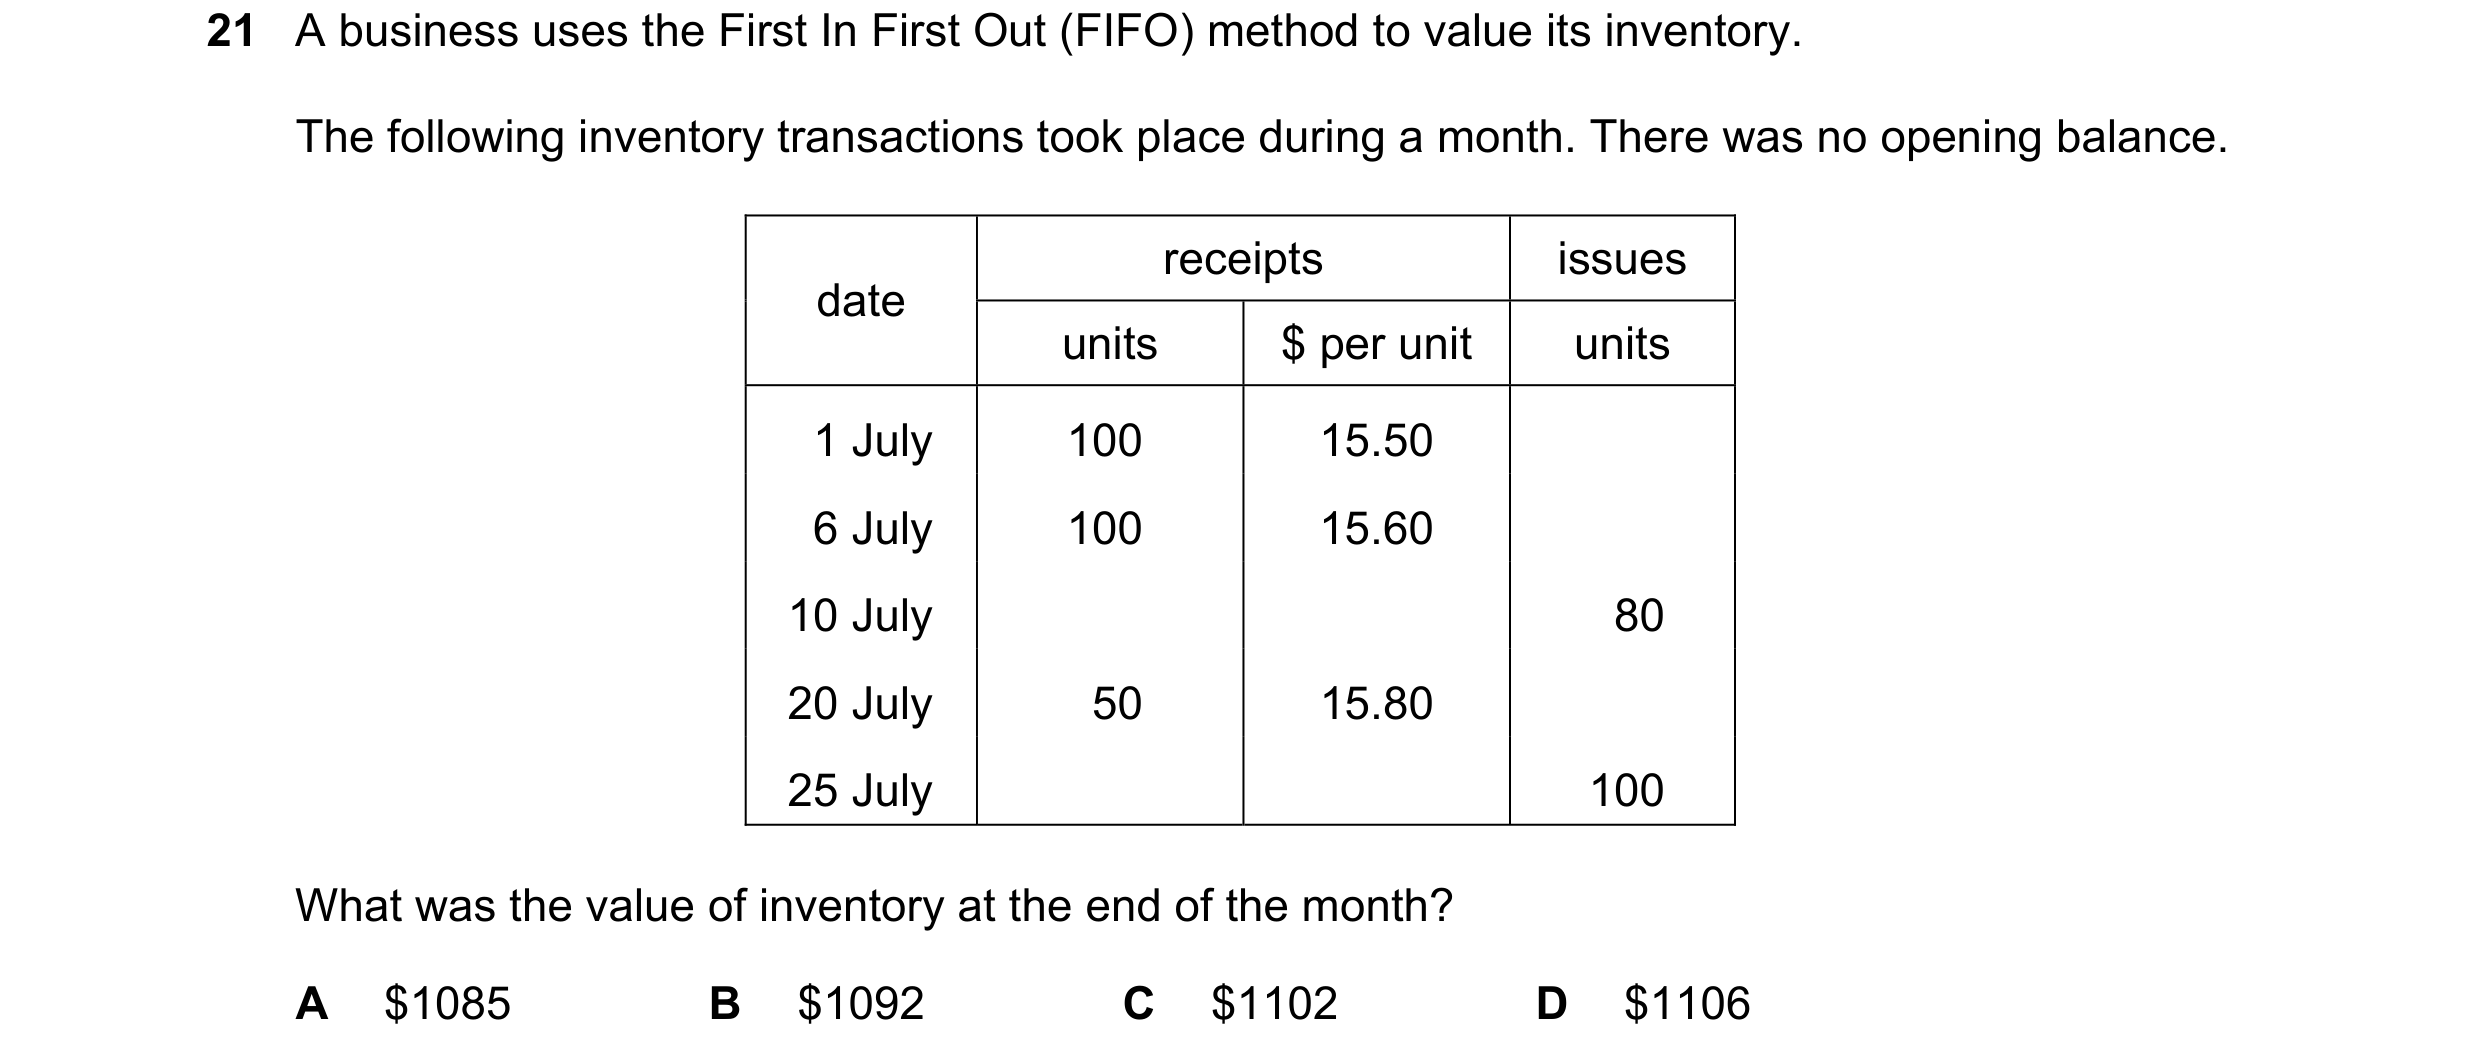
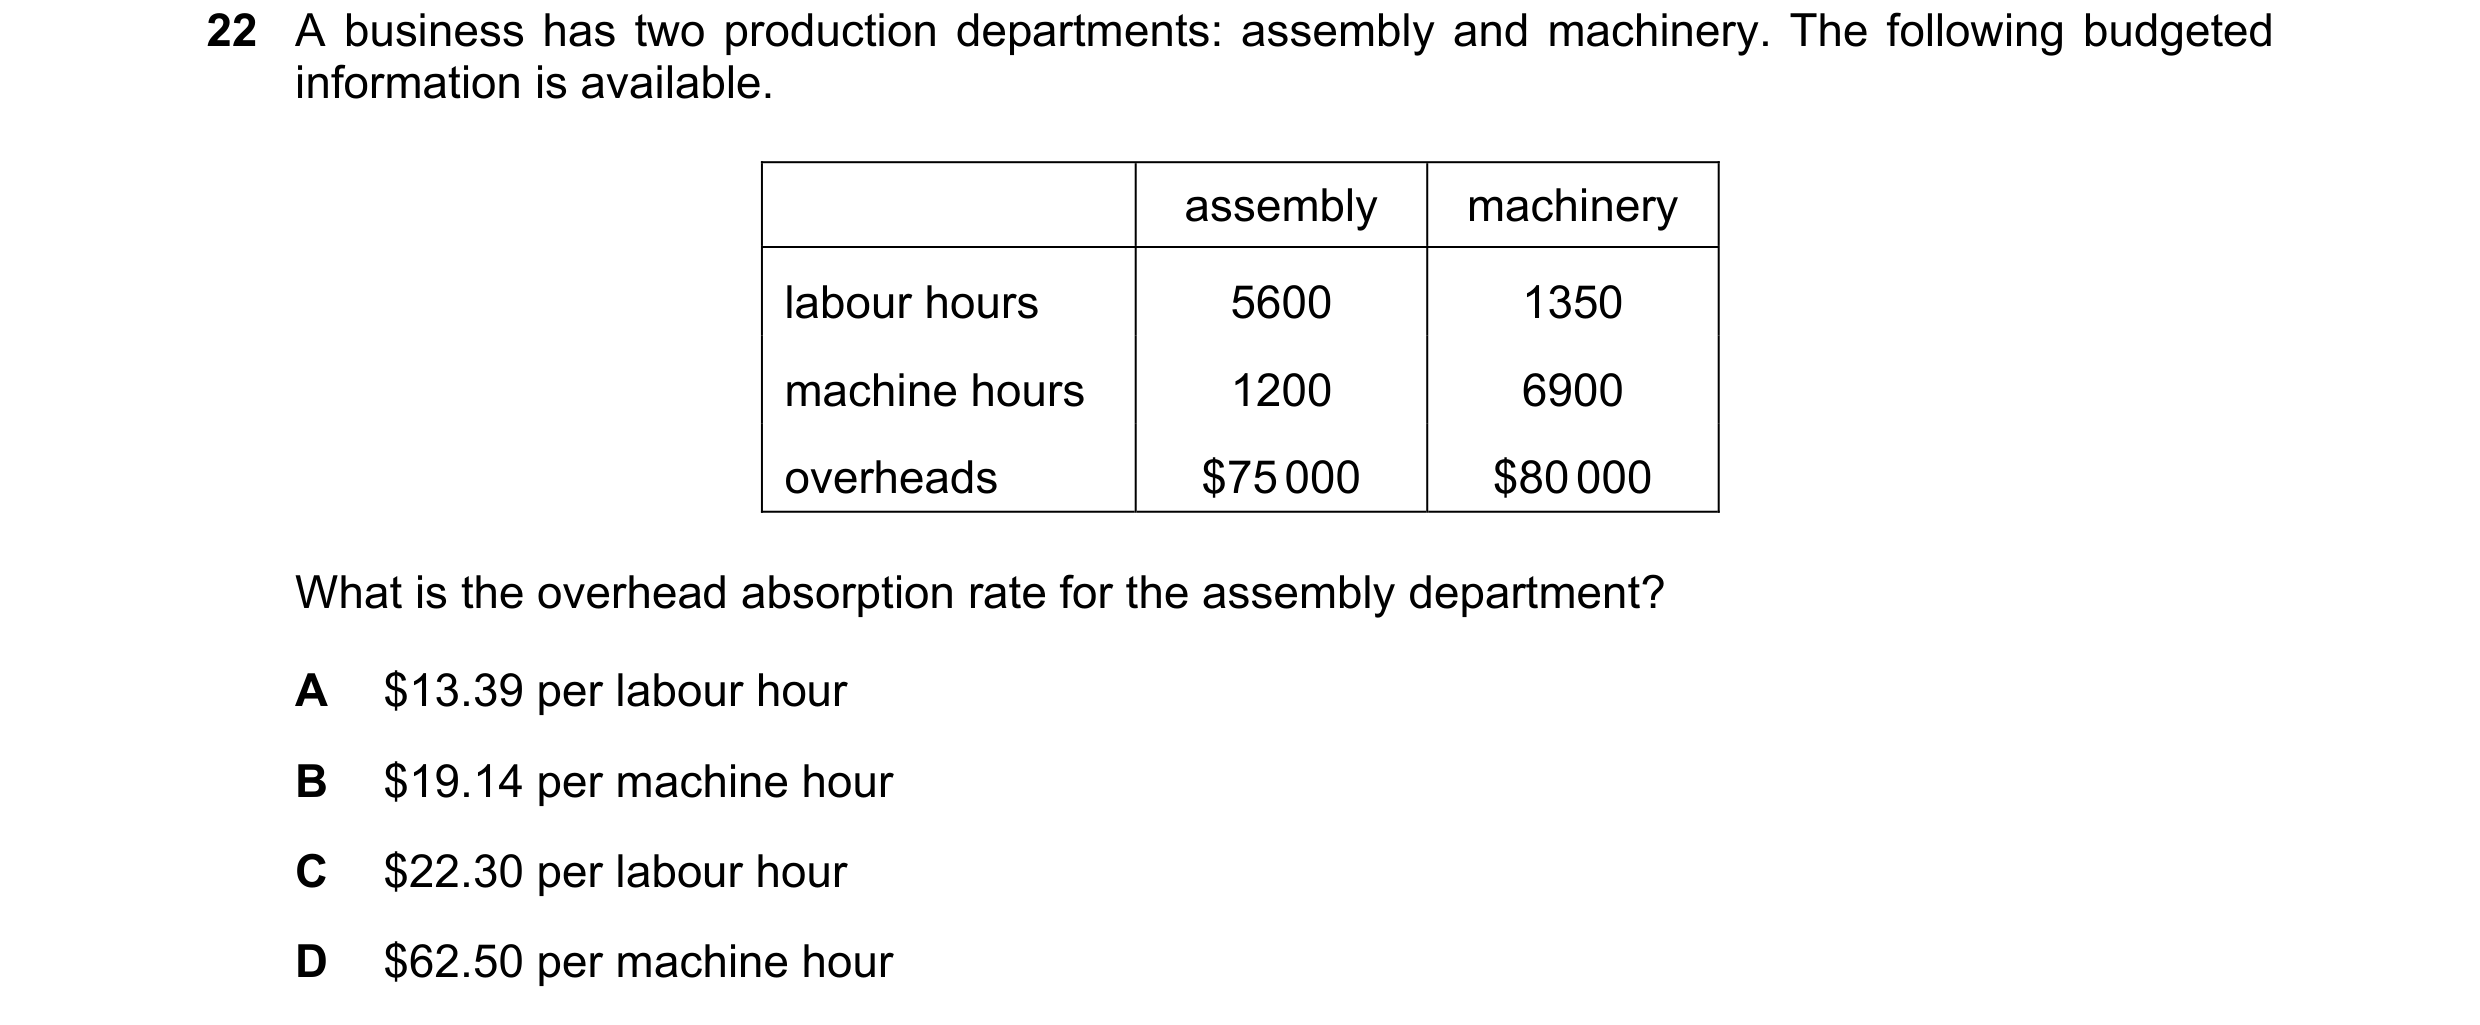
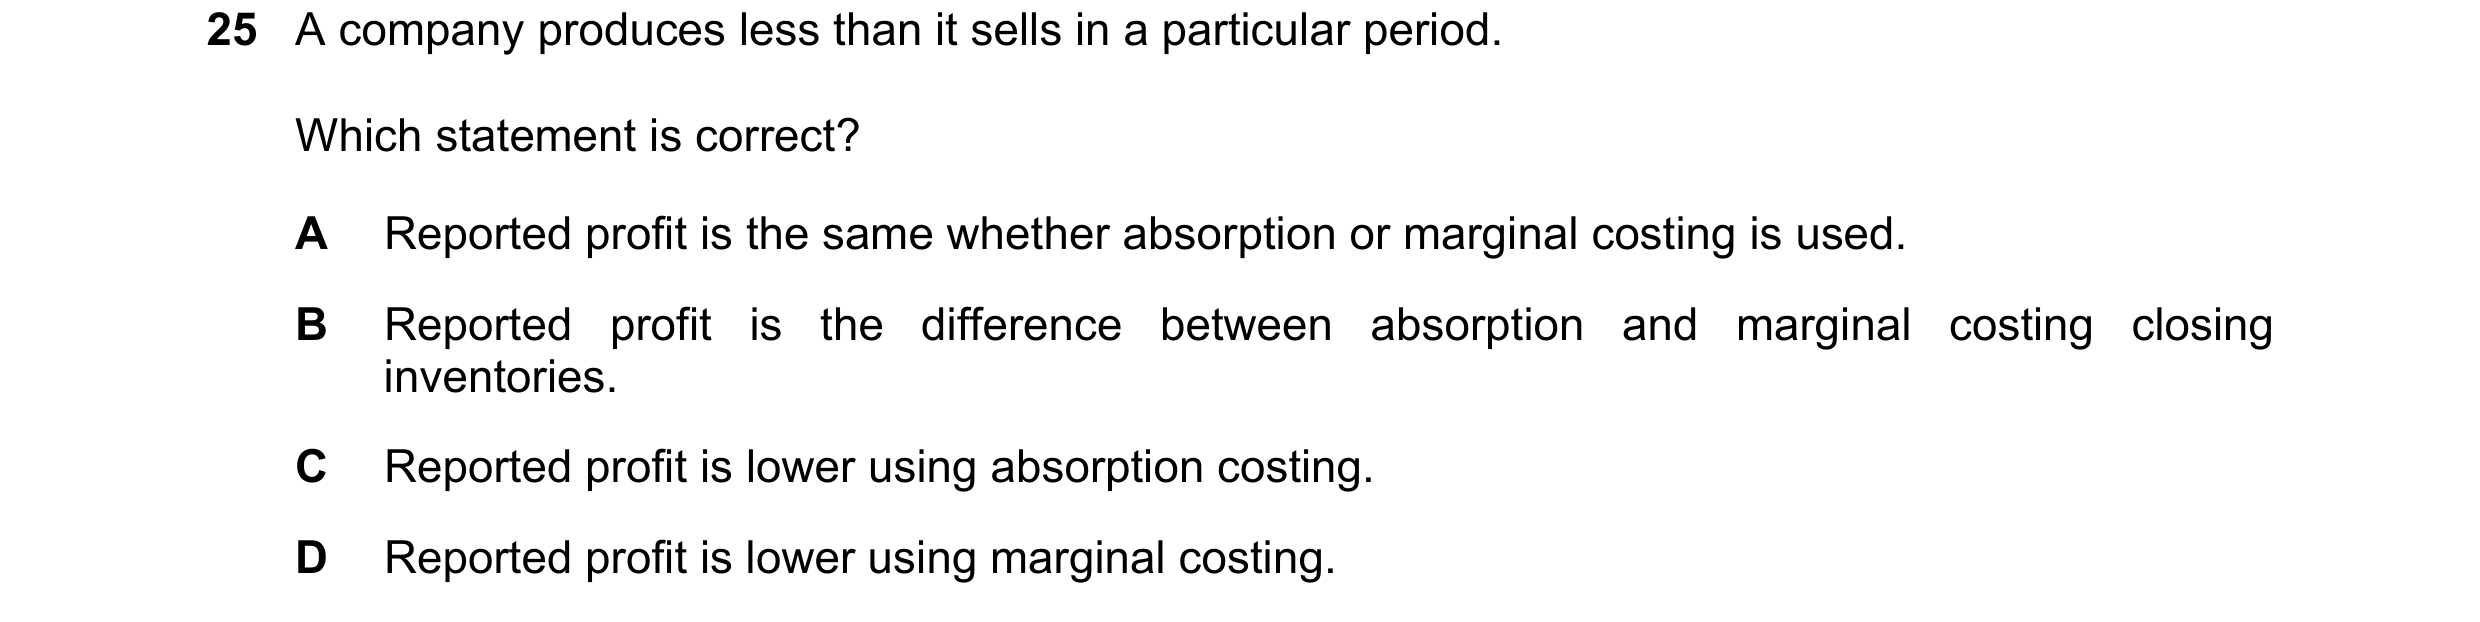 87 / 143
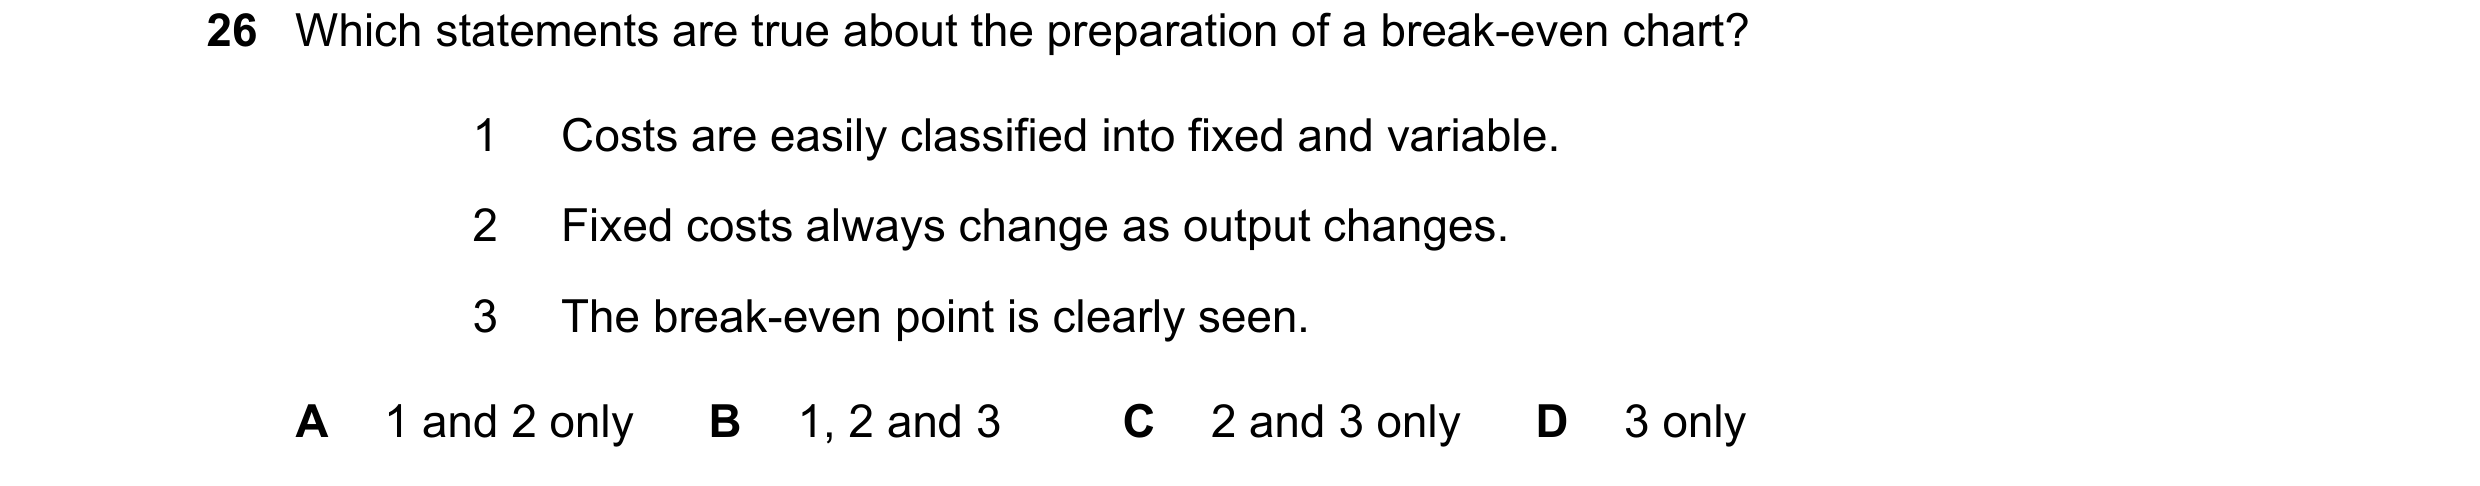
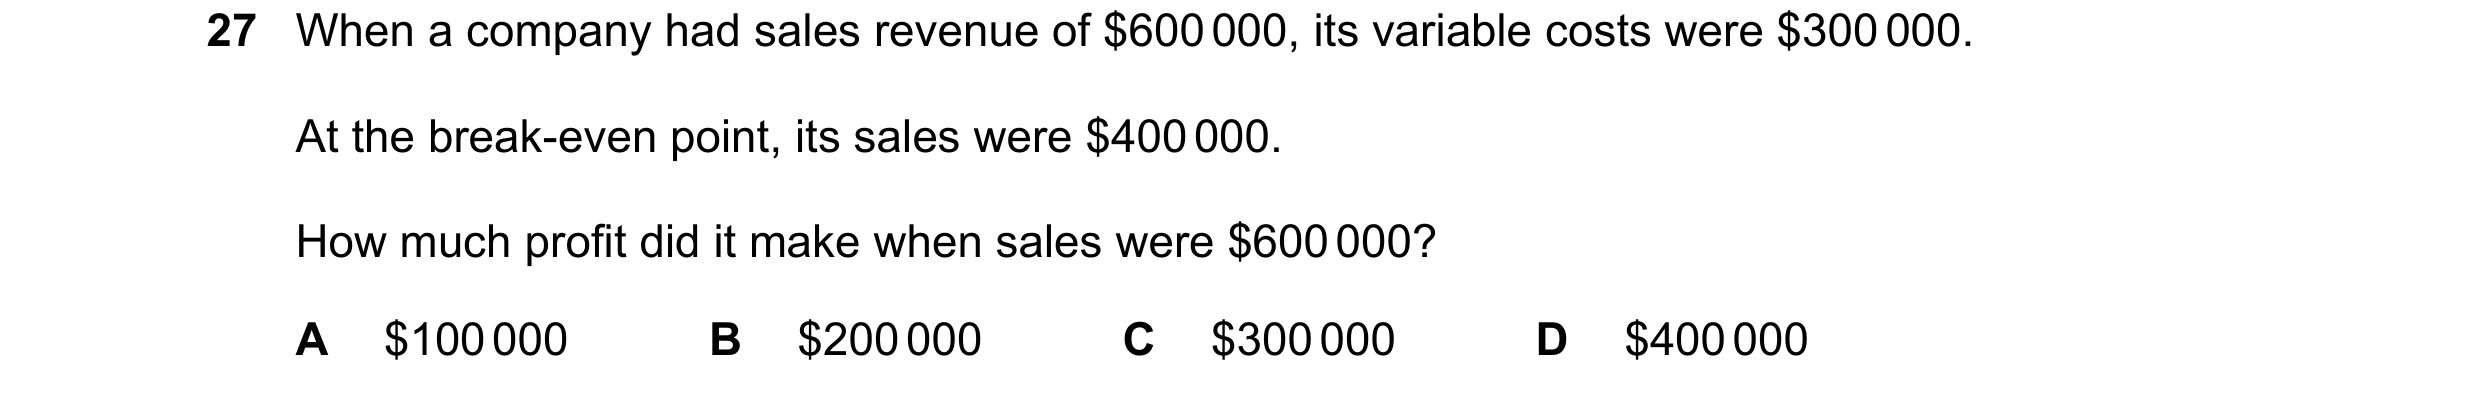
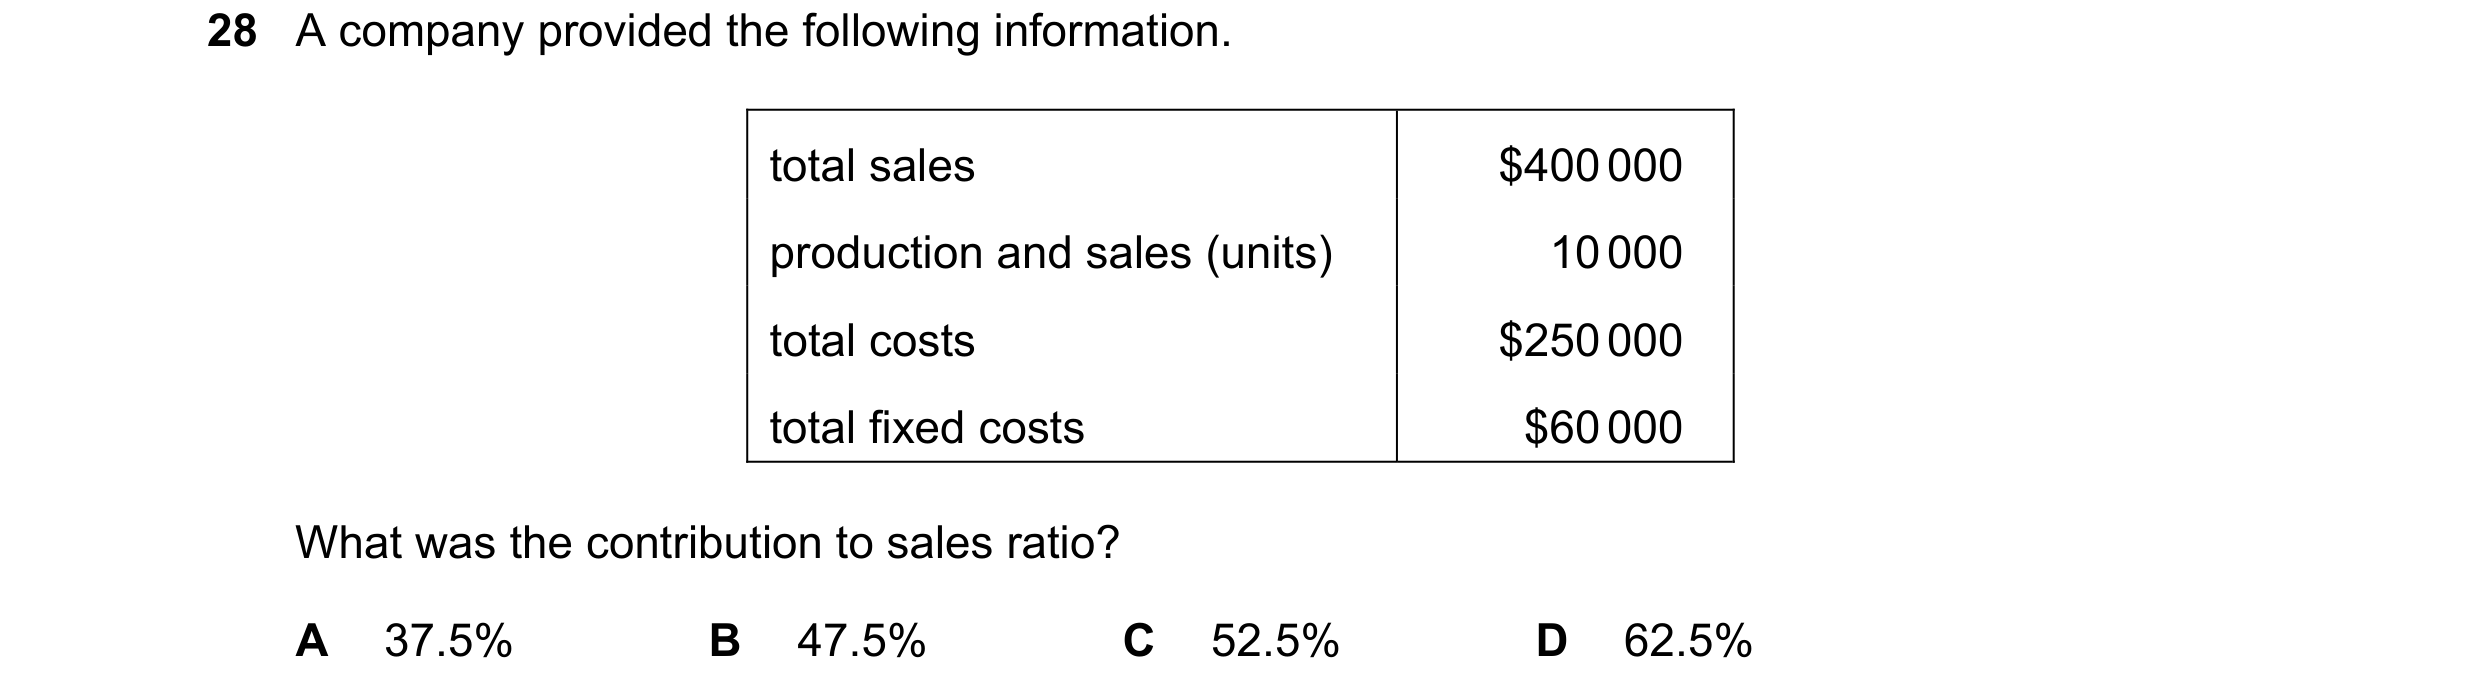
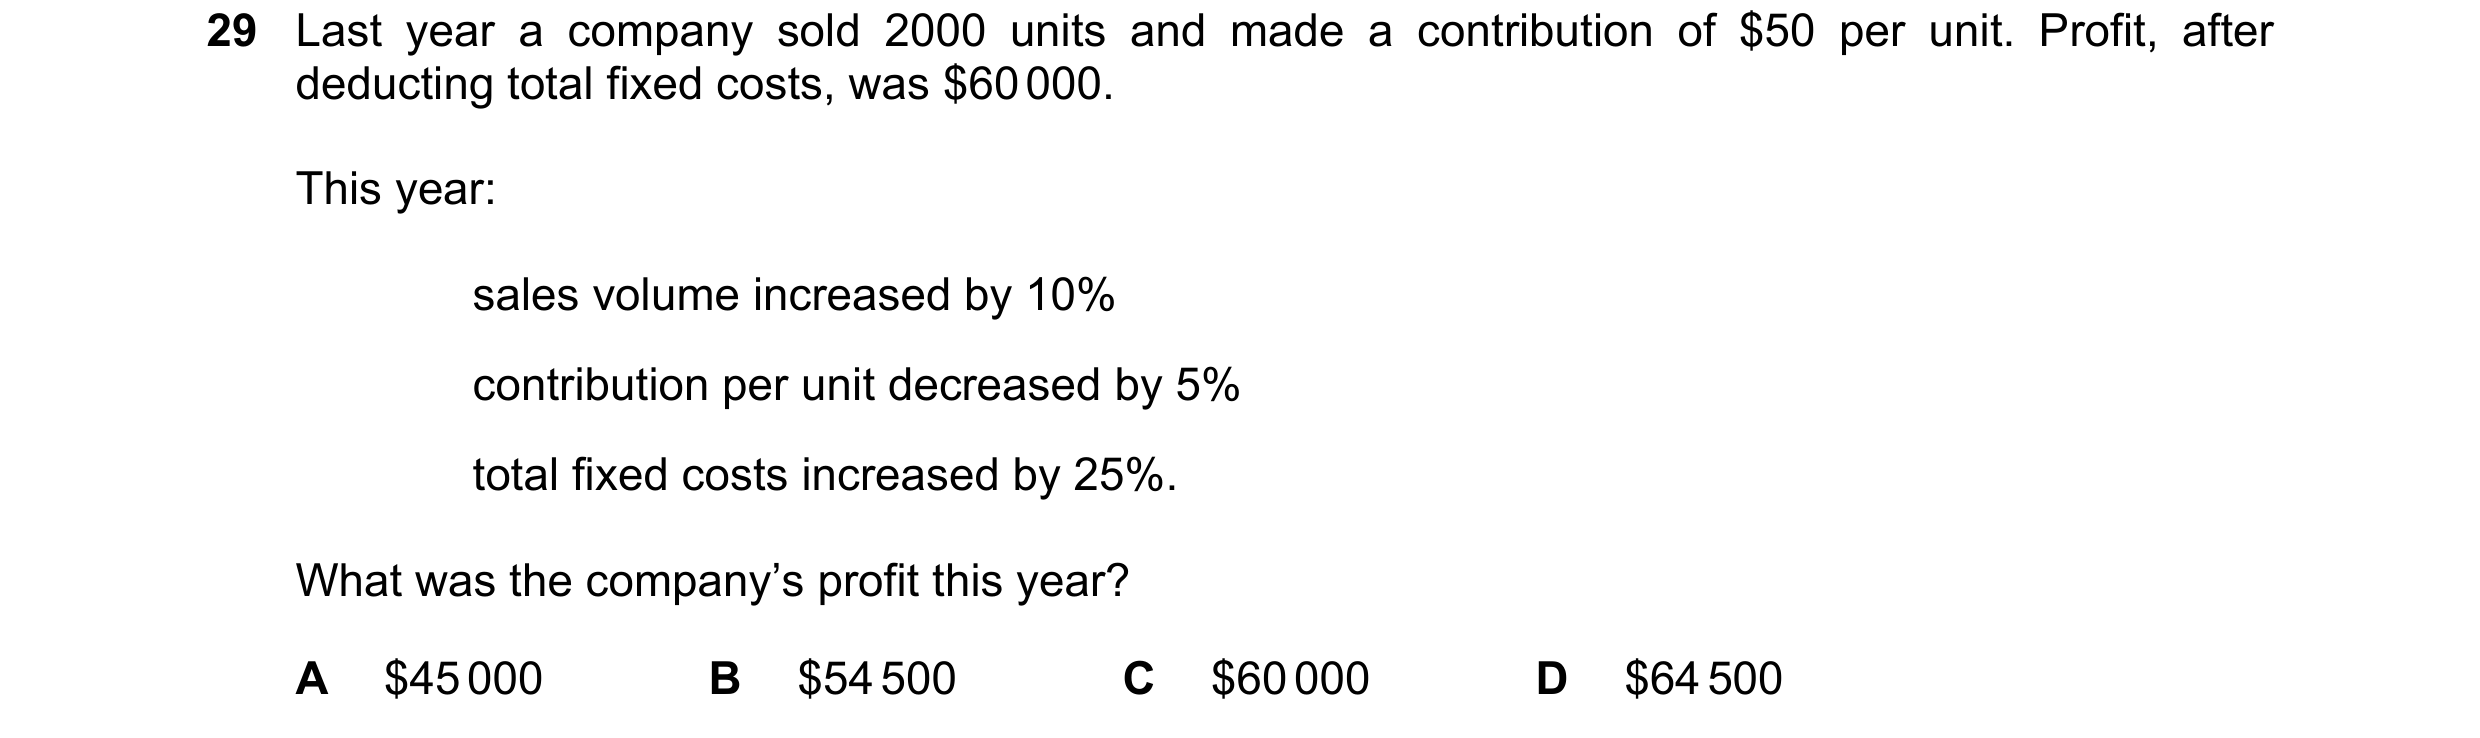
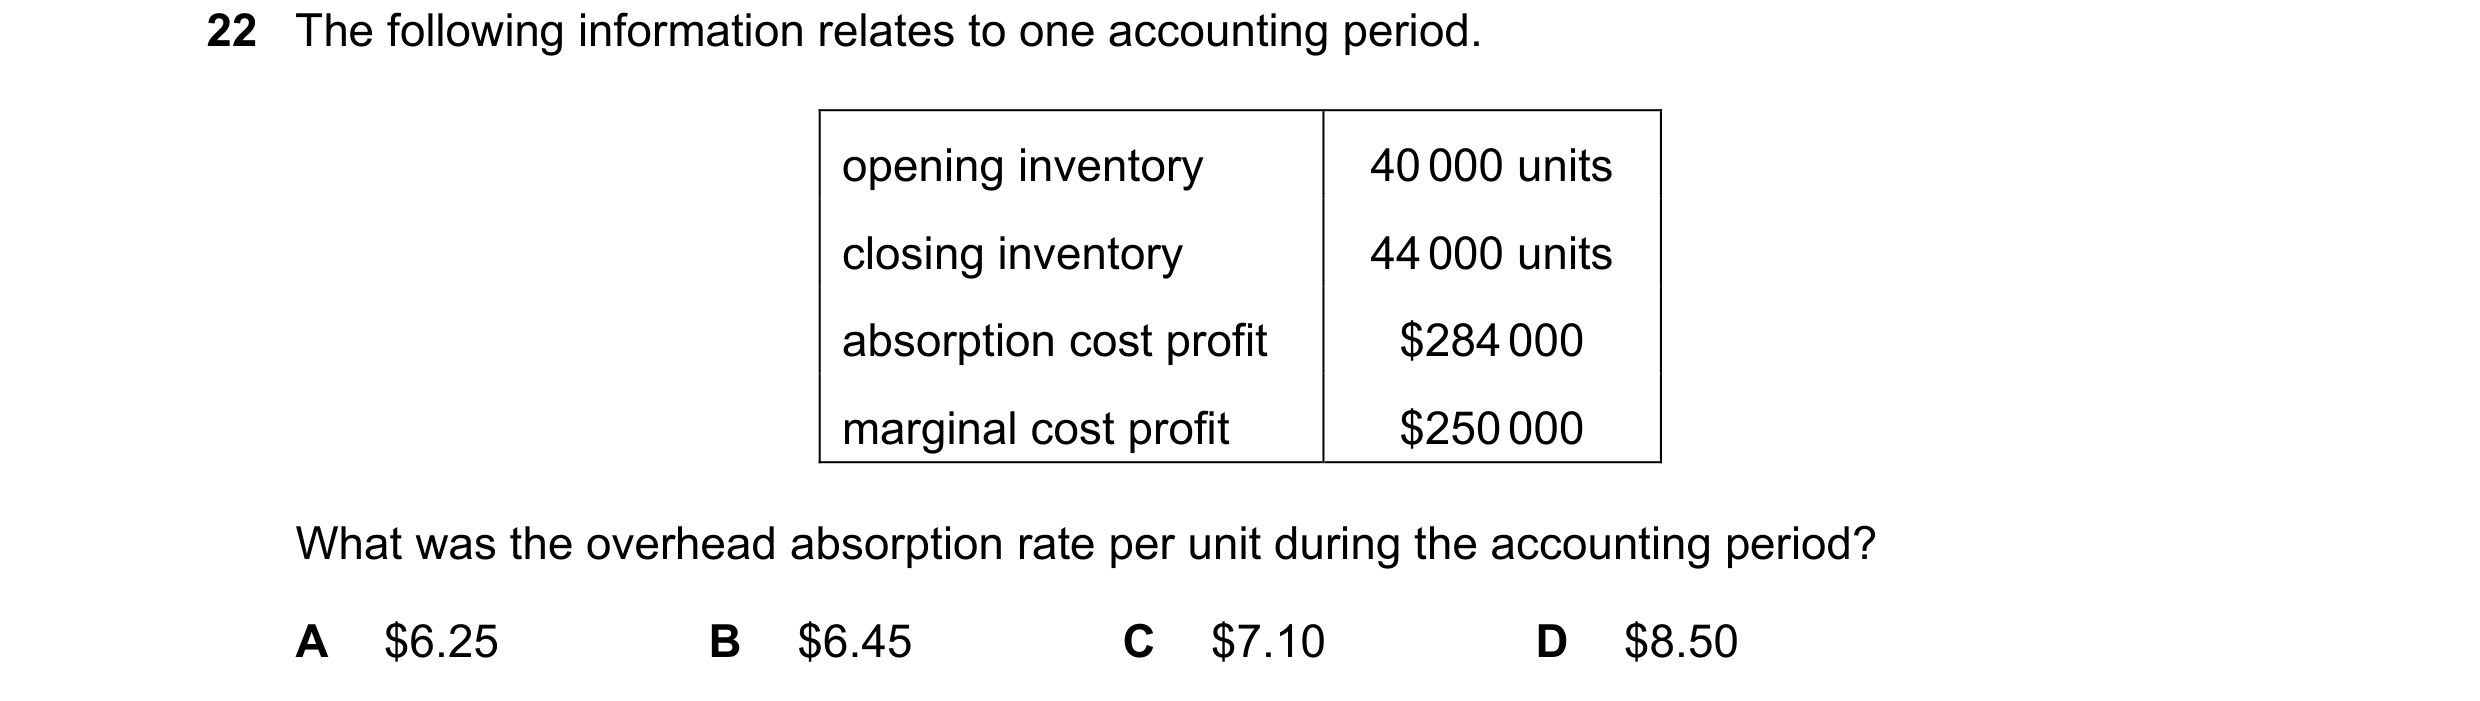 88 / 143
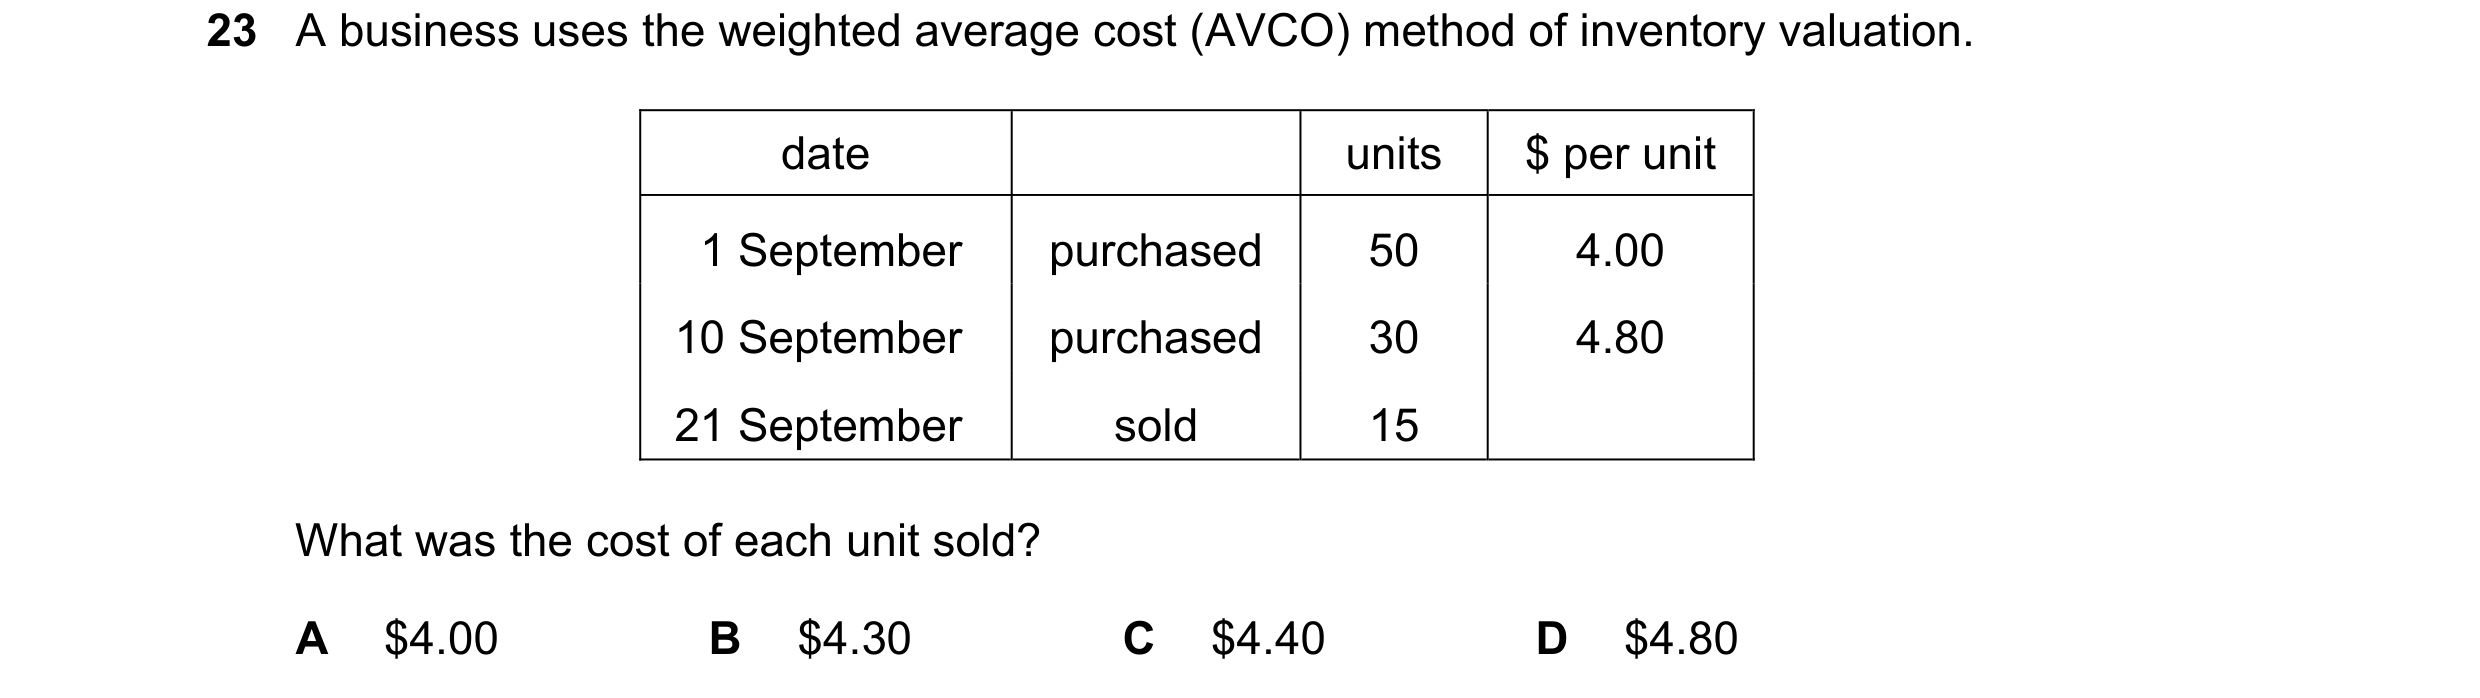
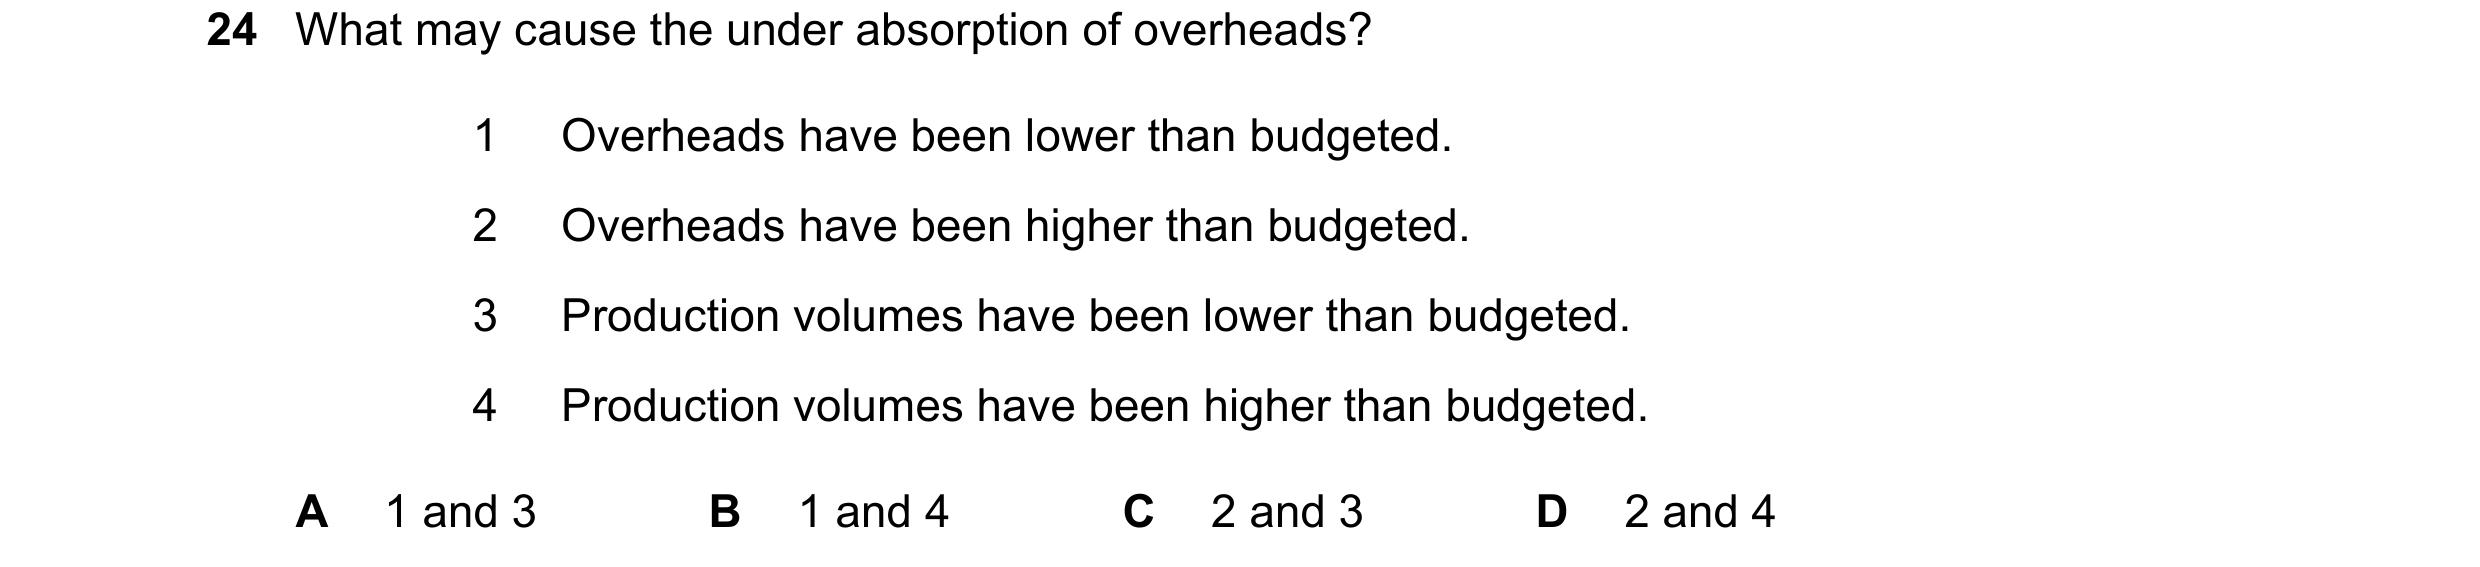
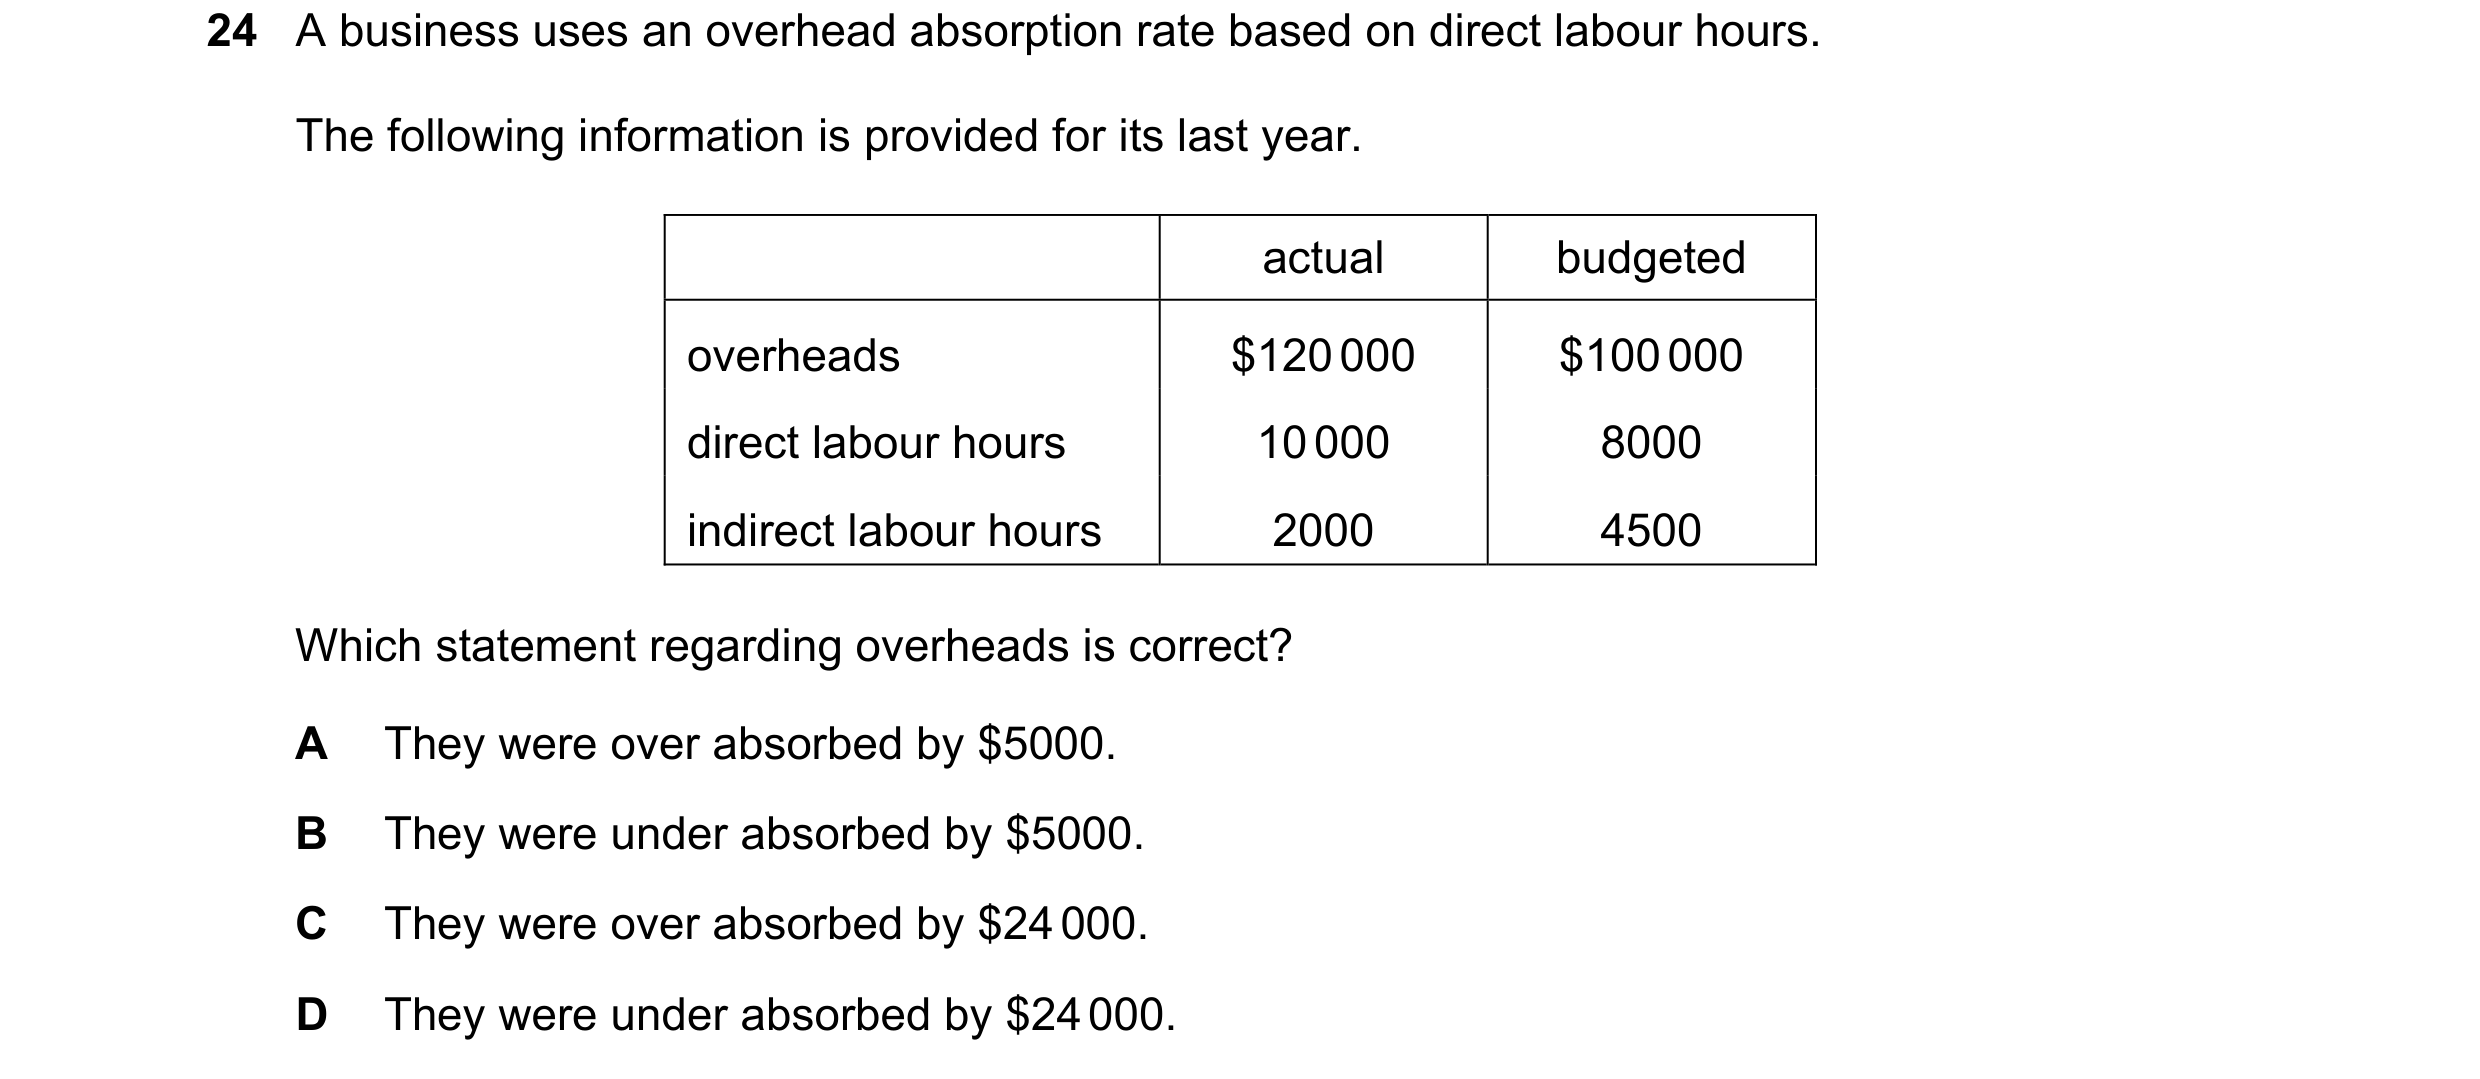 89 / 143
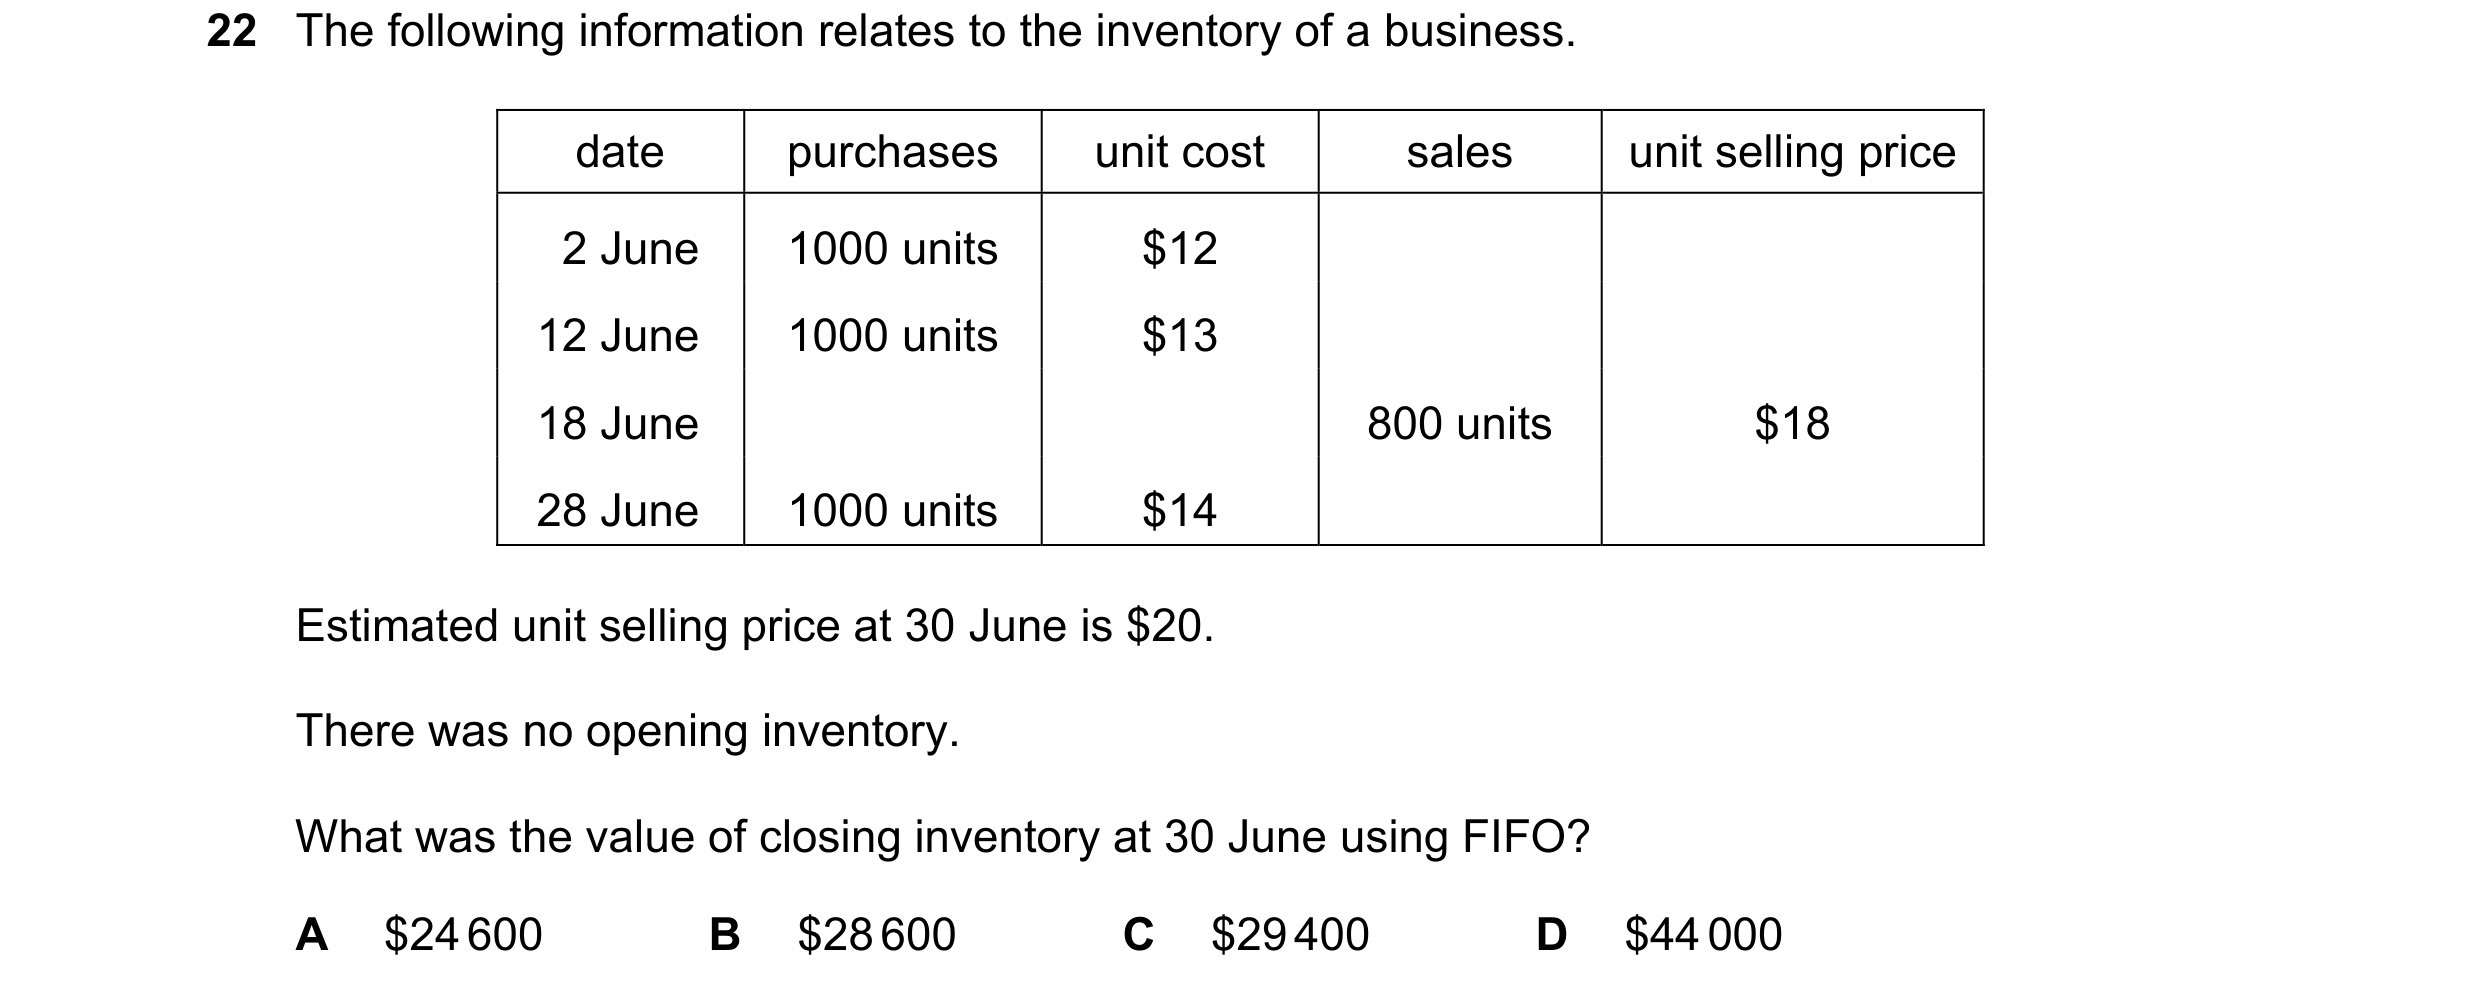
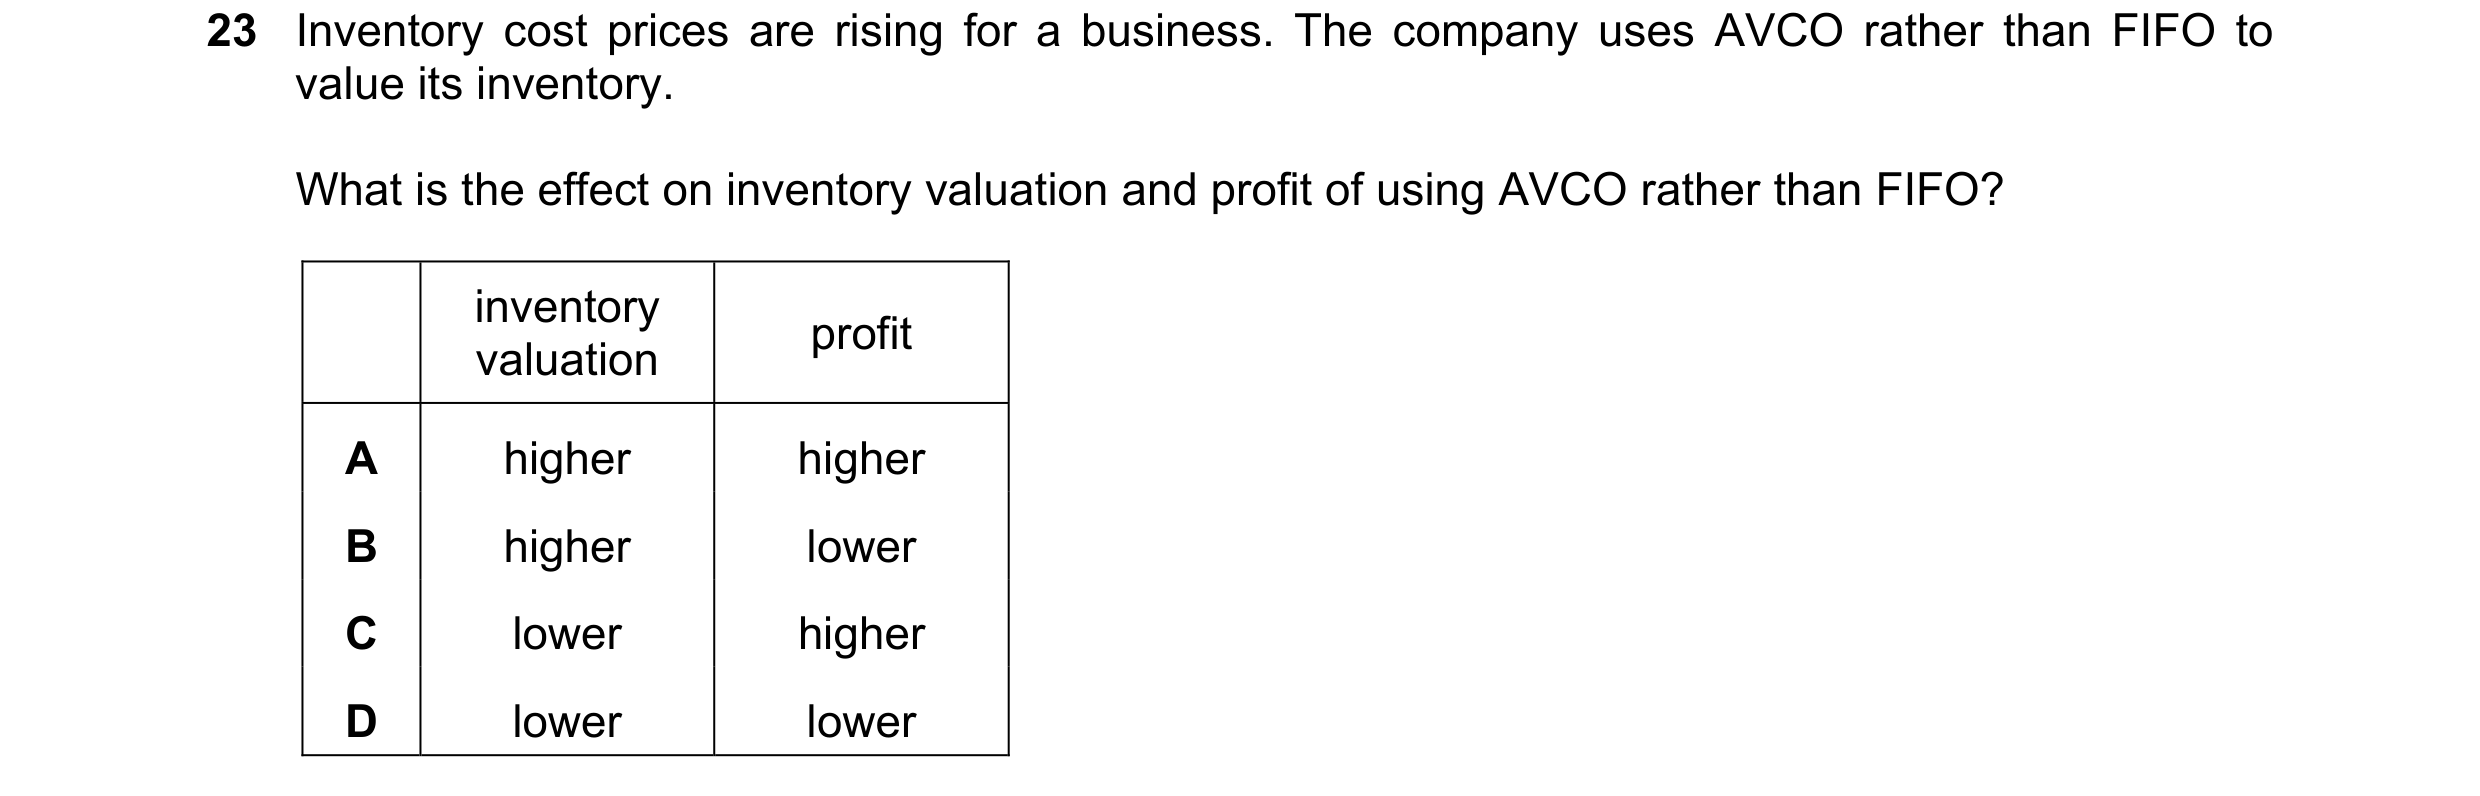
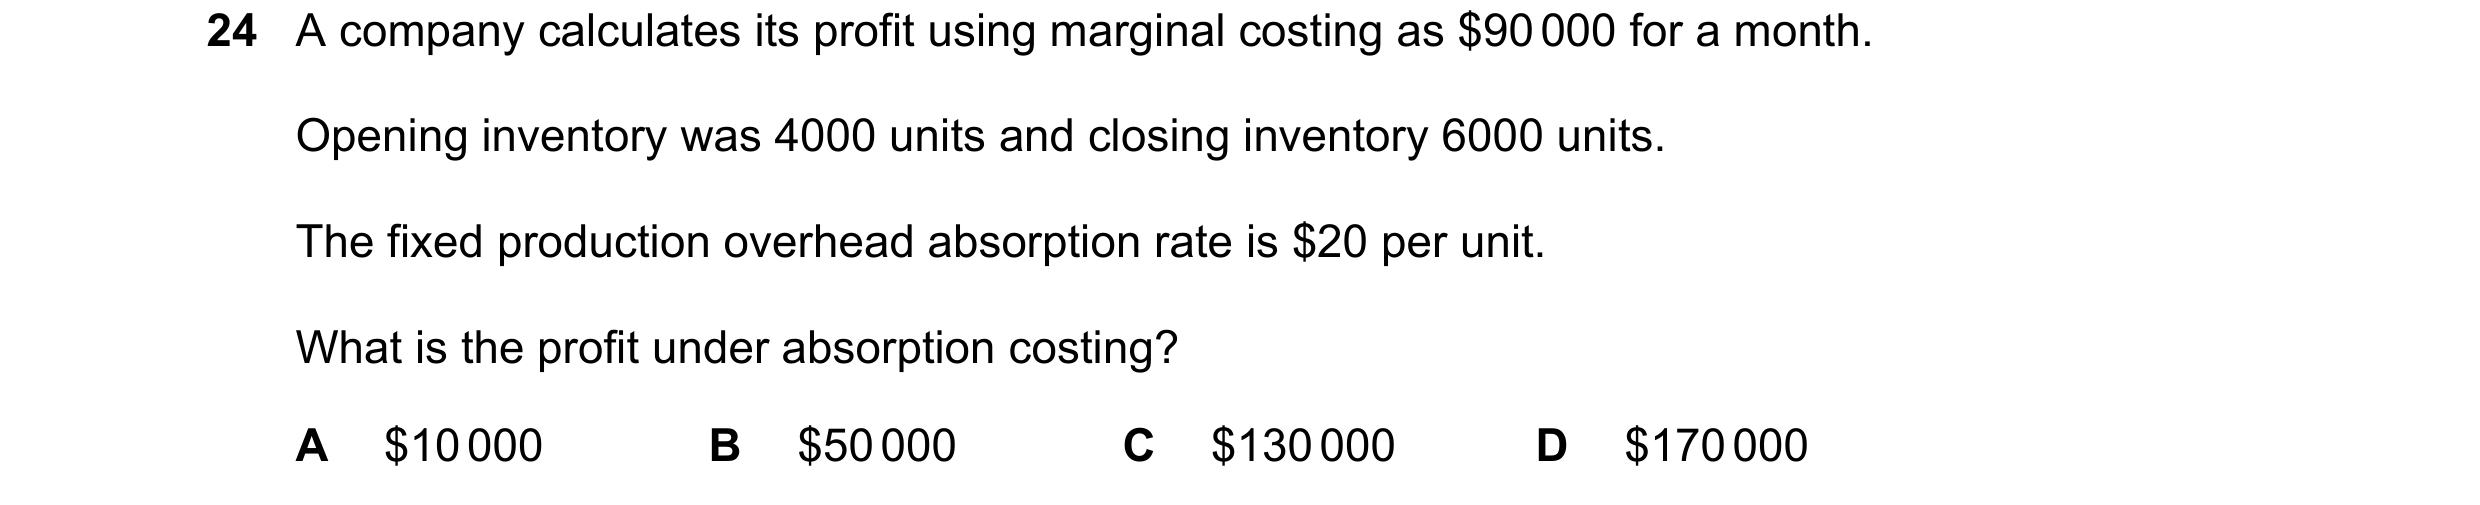
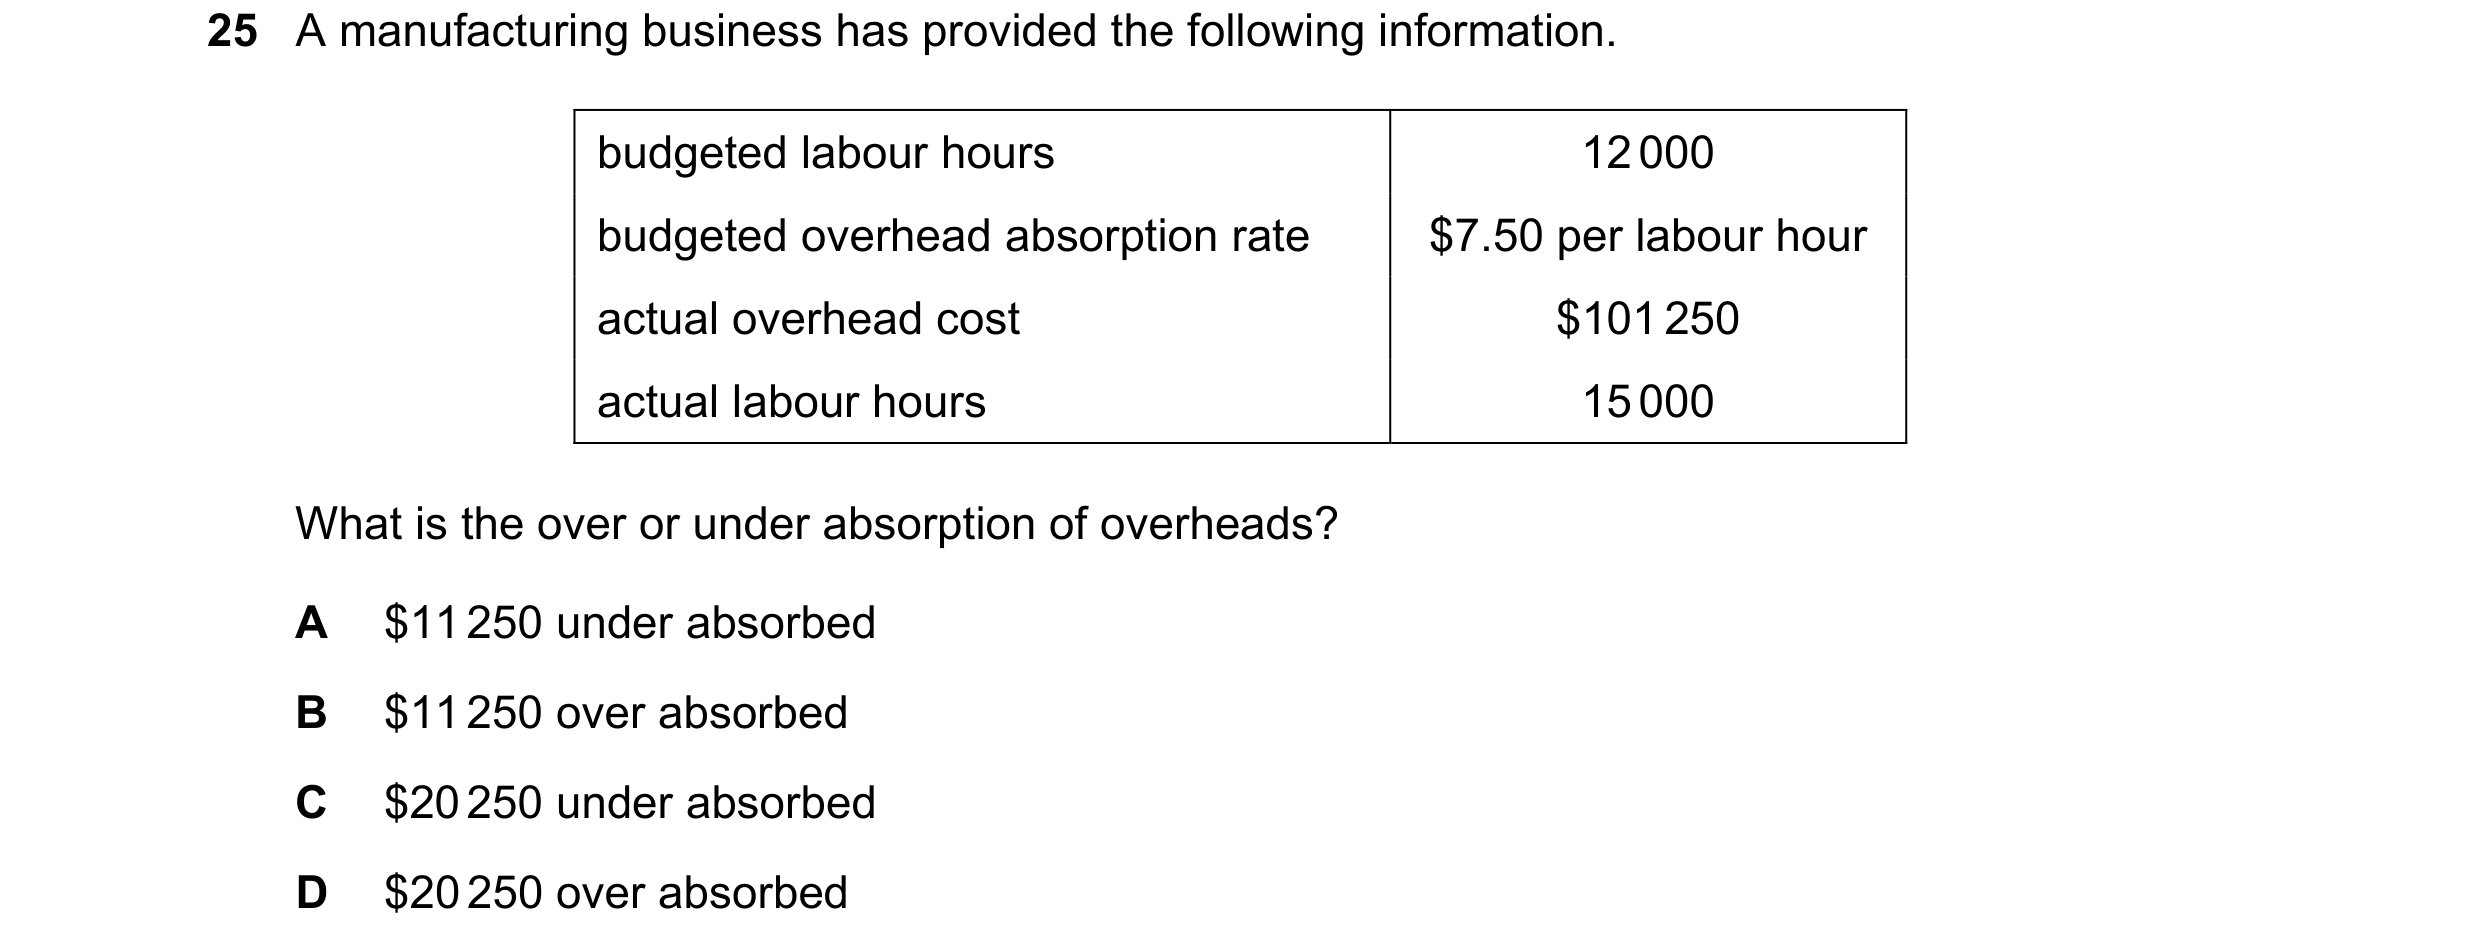 90 / 143
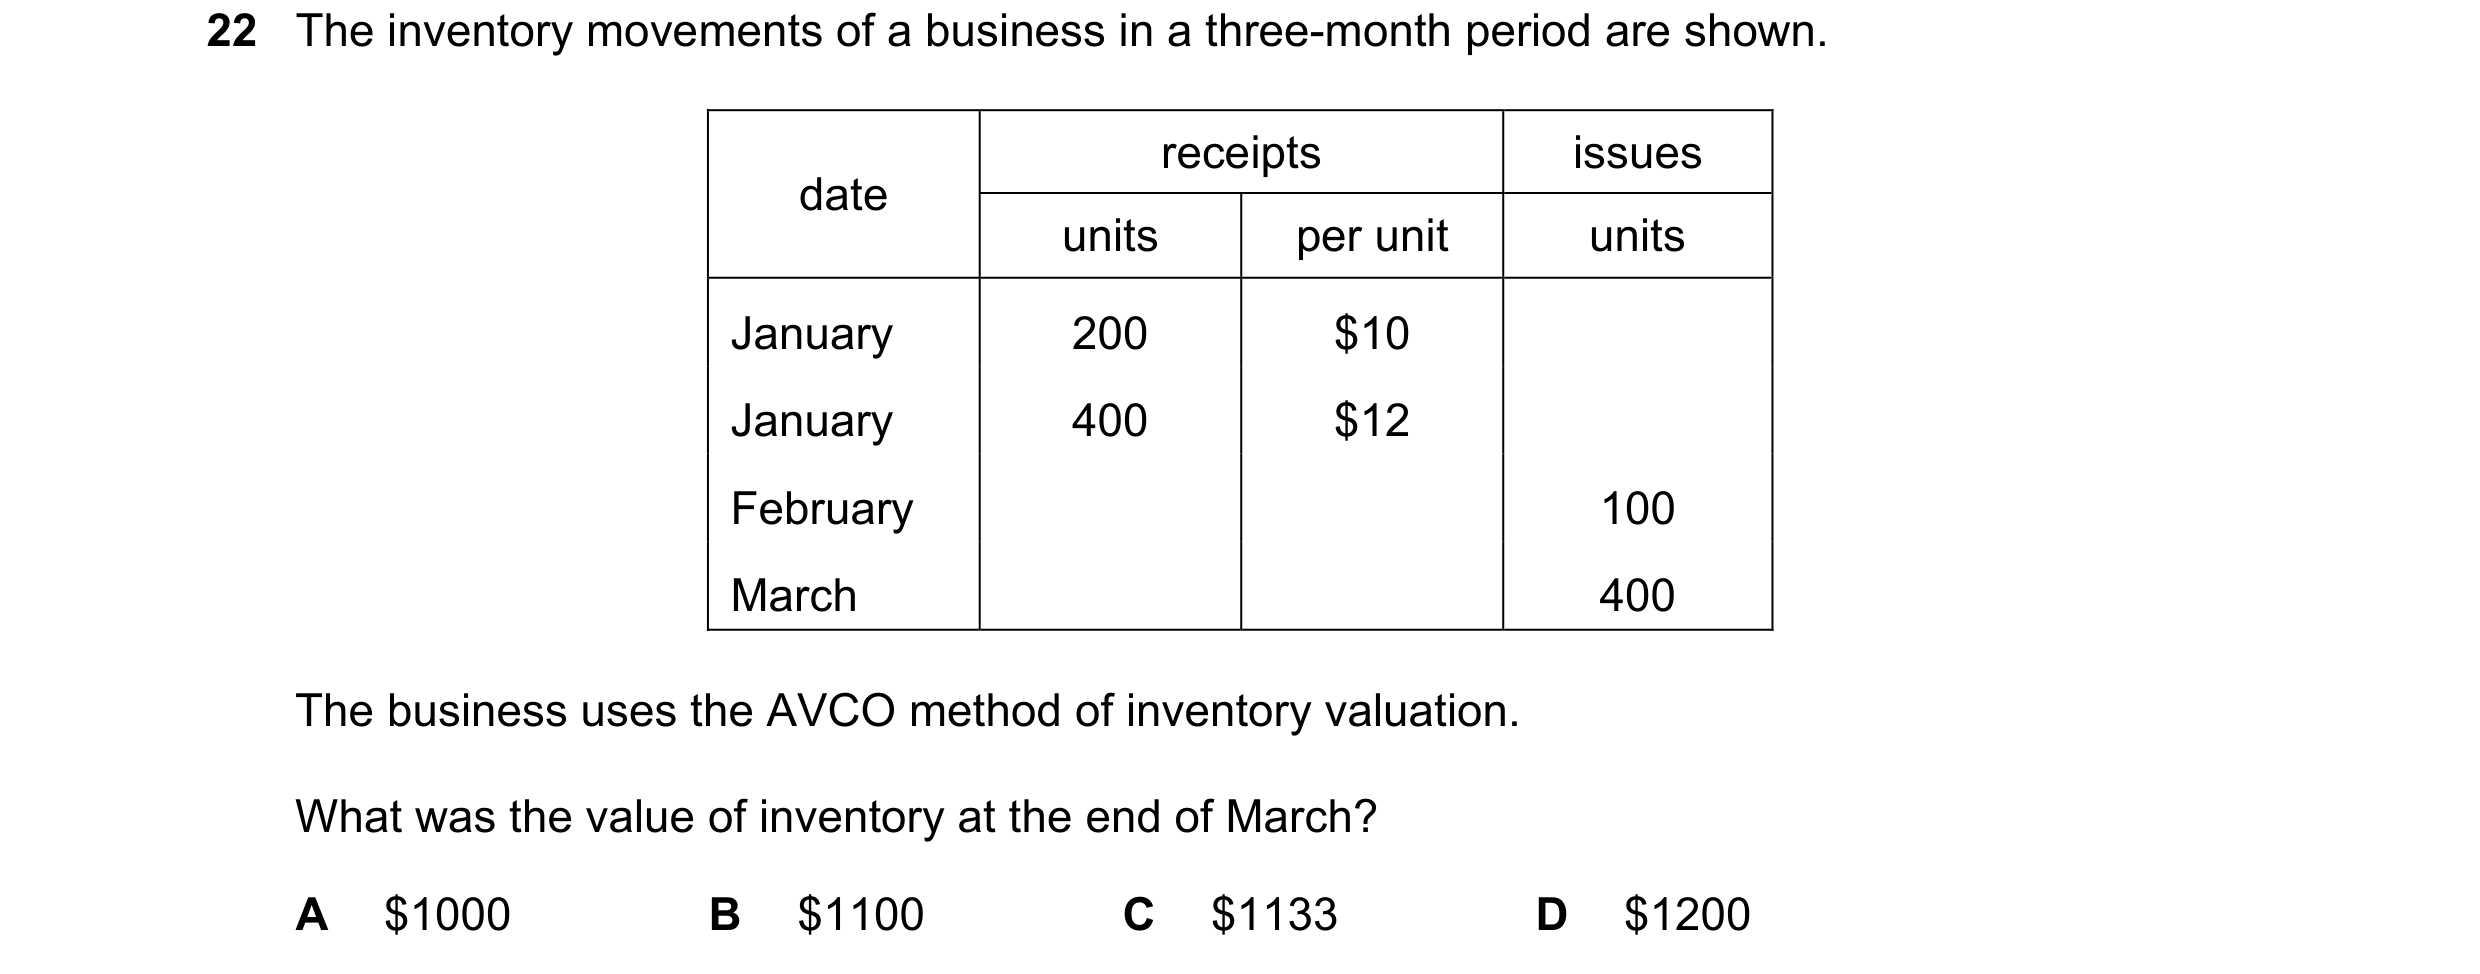
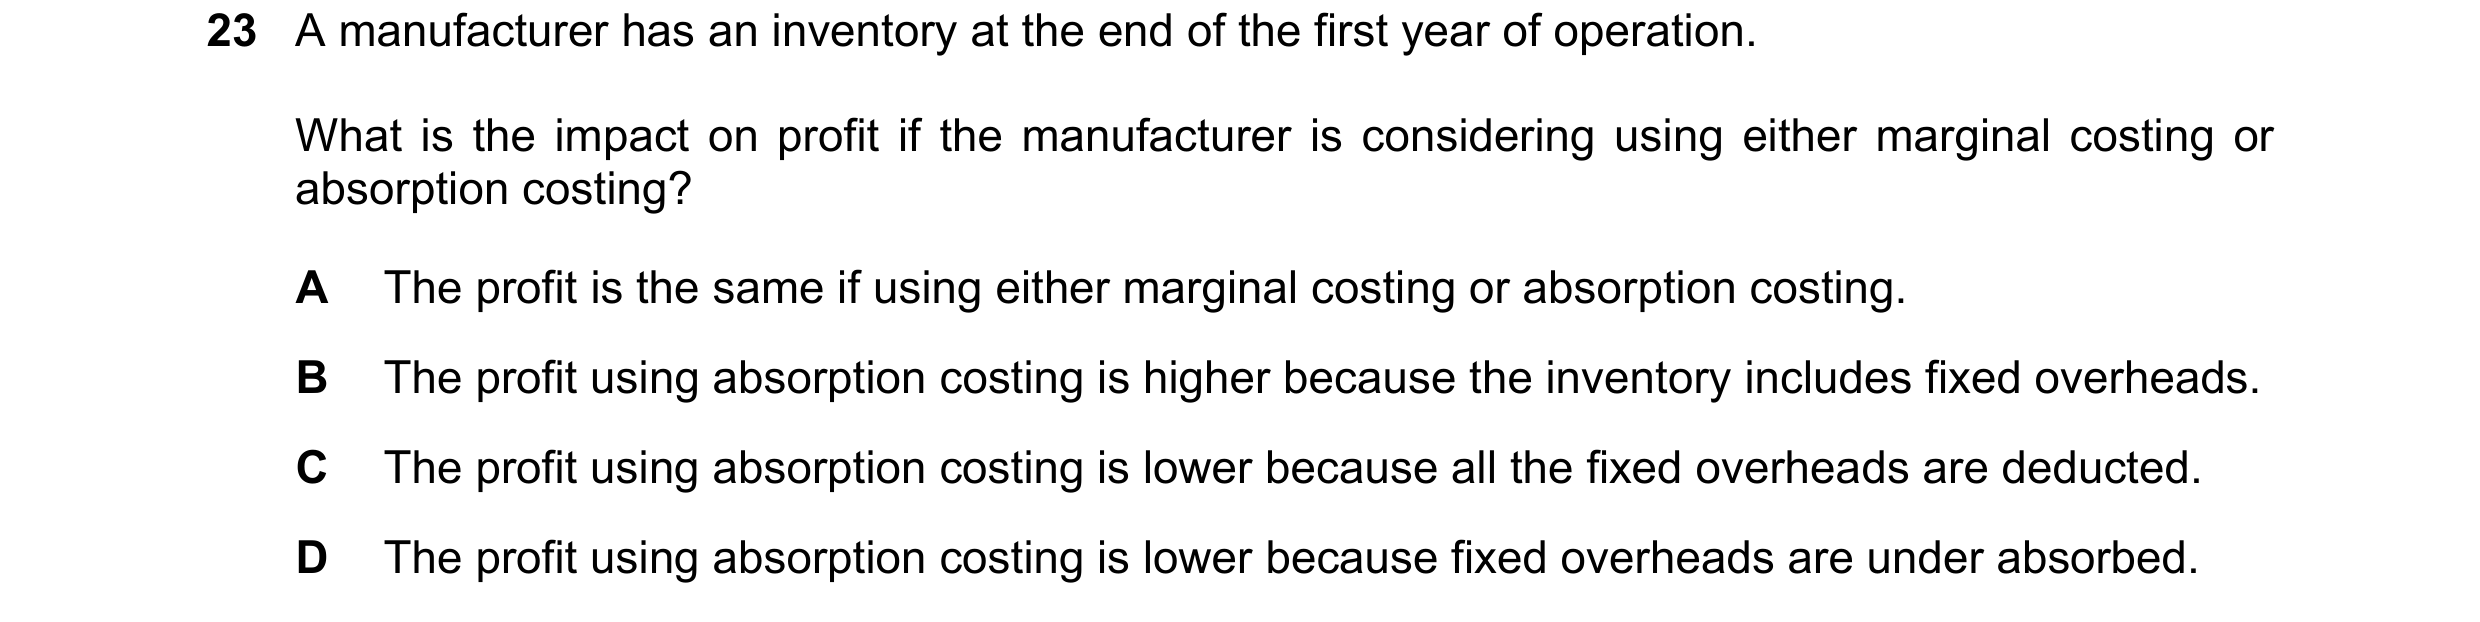
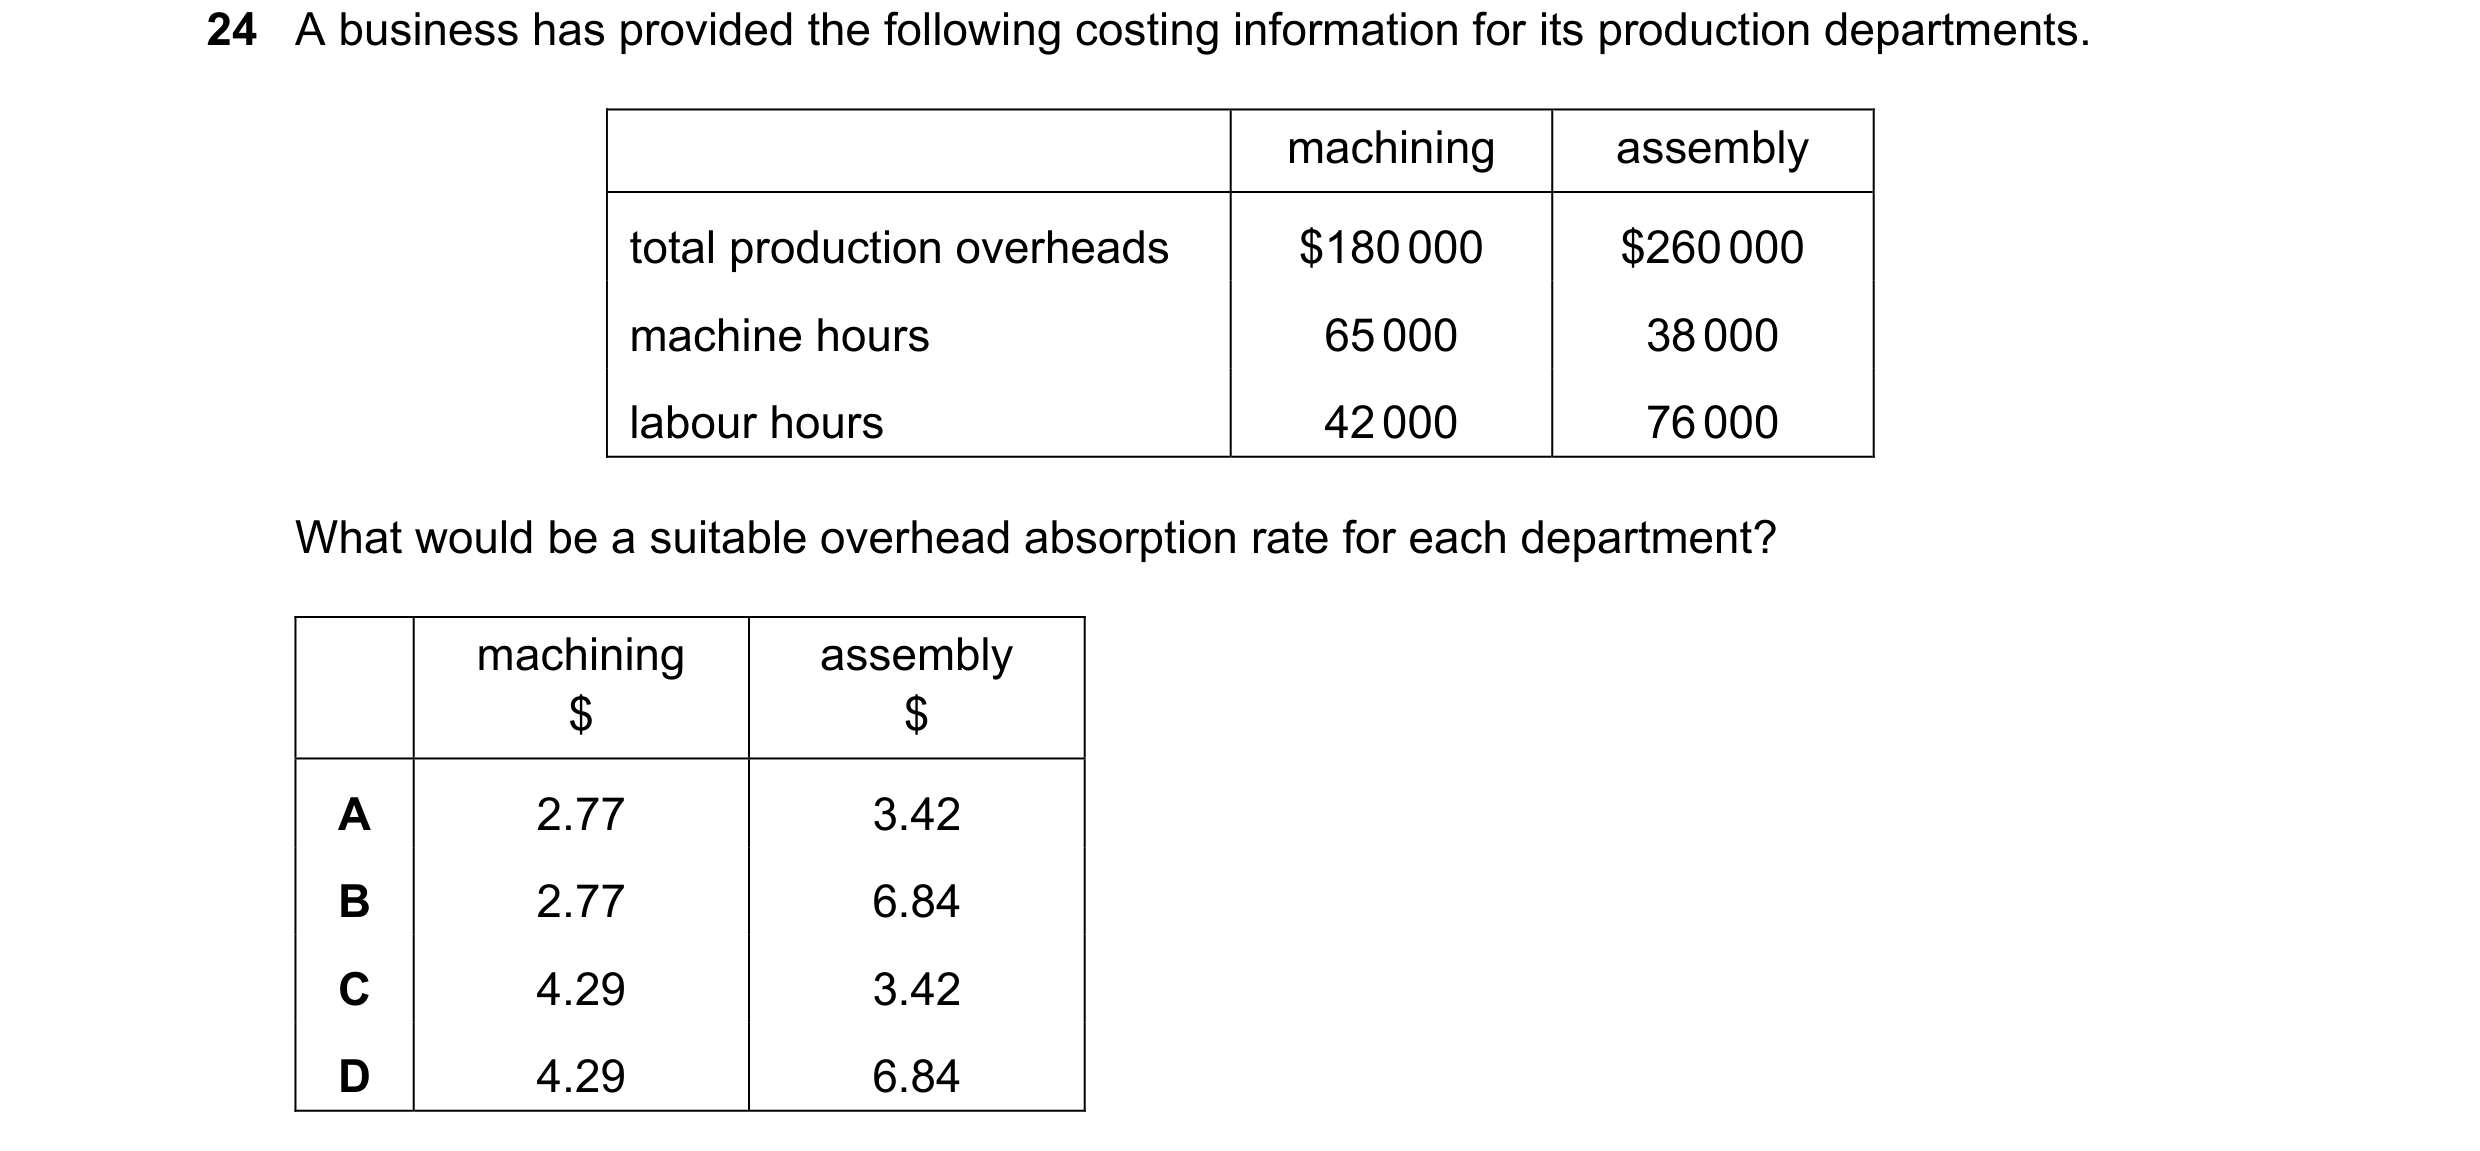 91 / 143
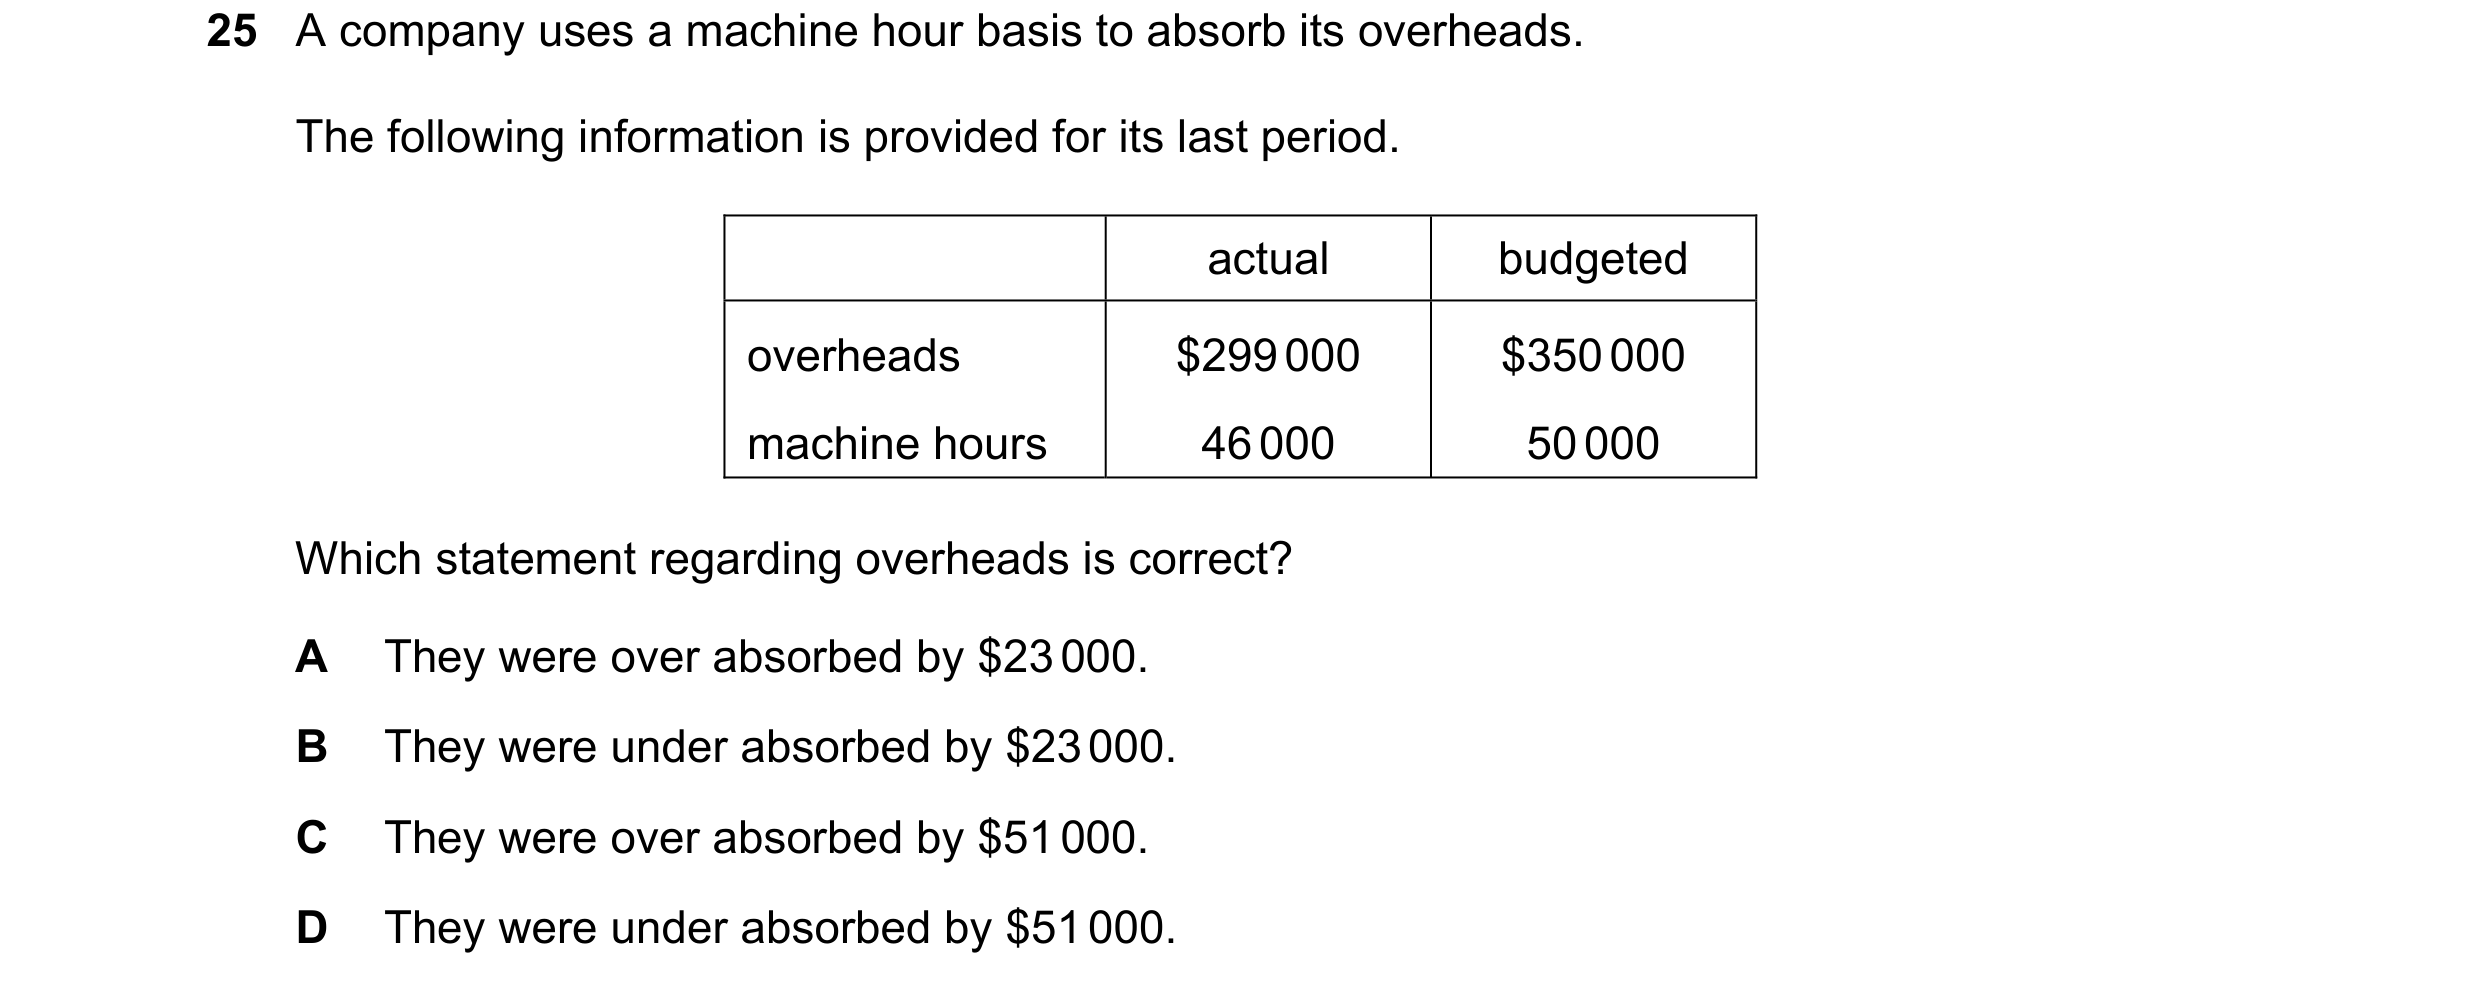
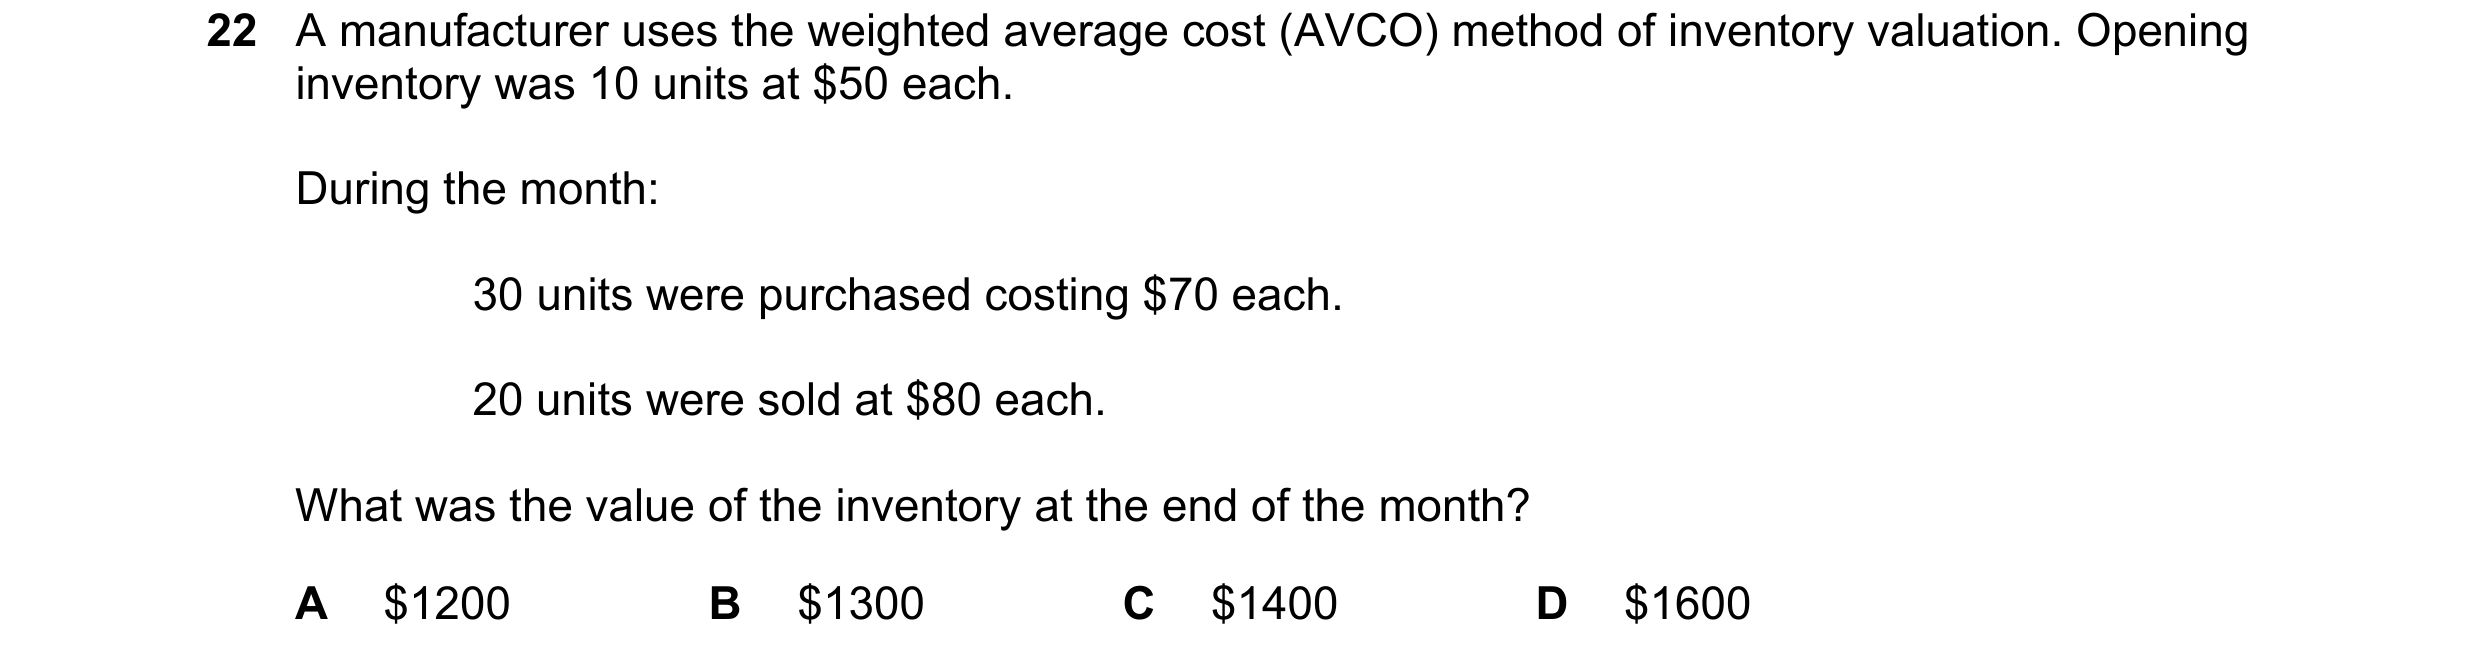
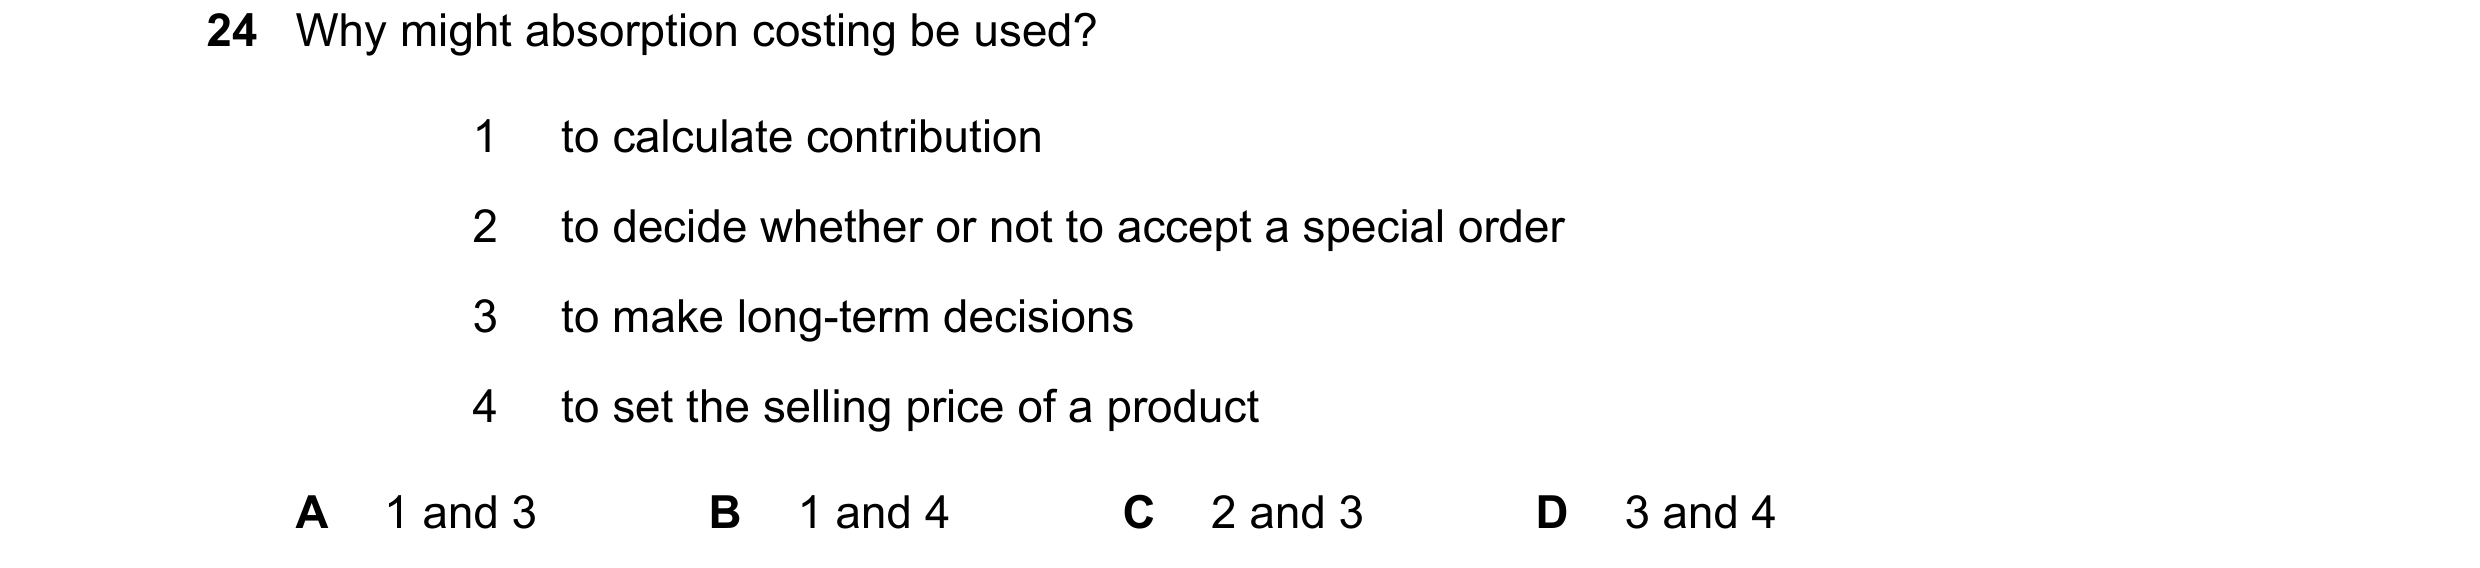
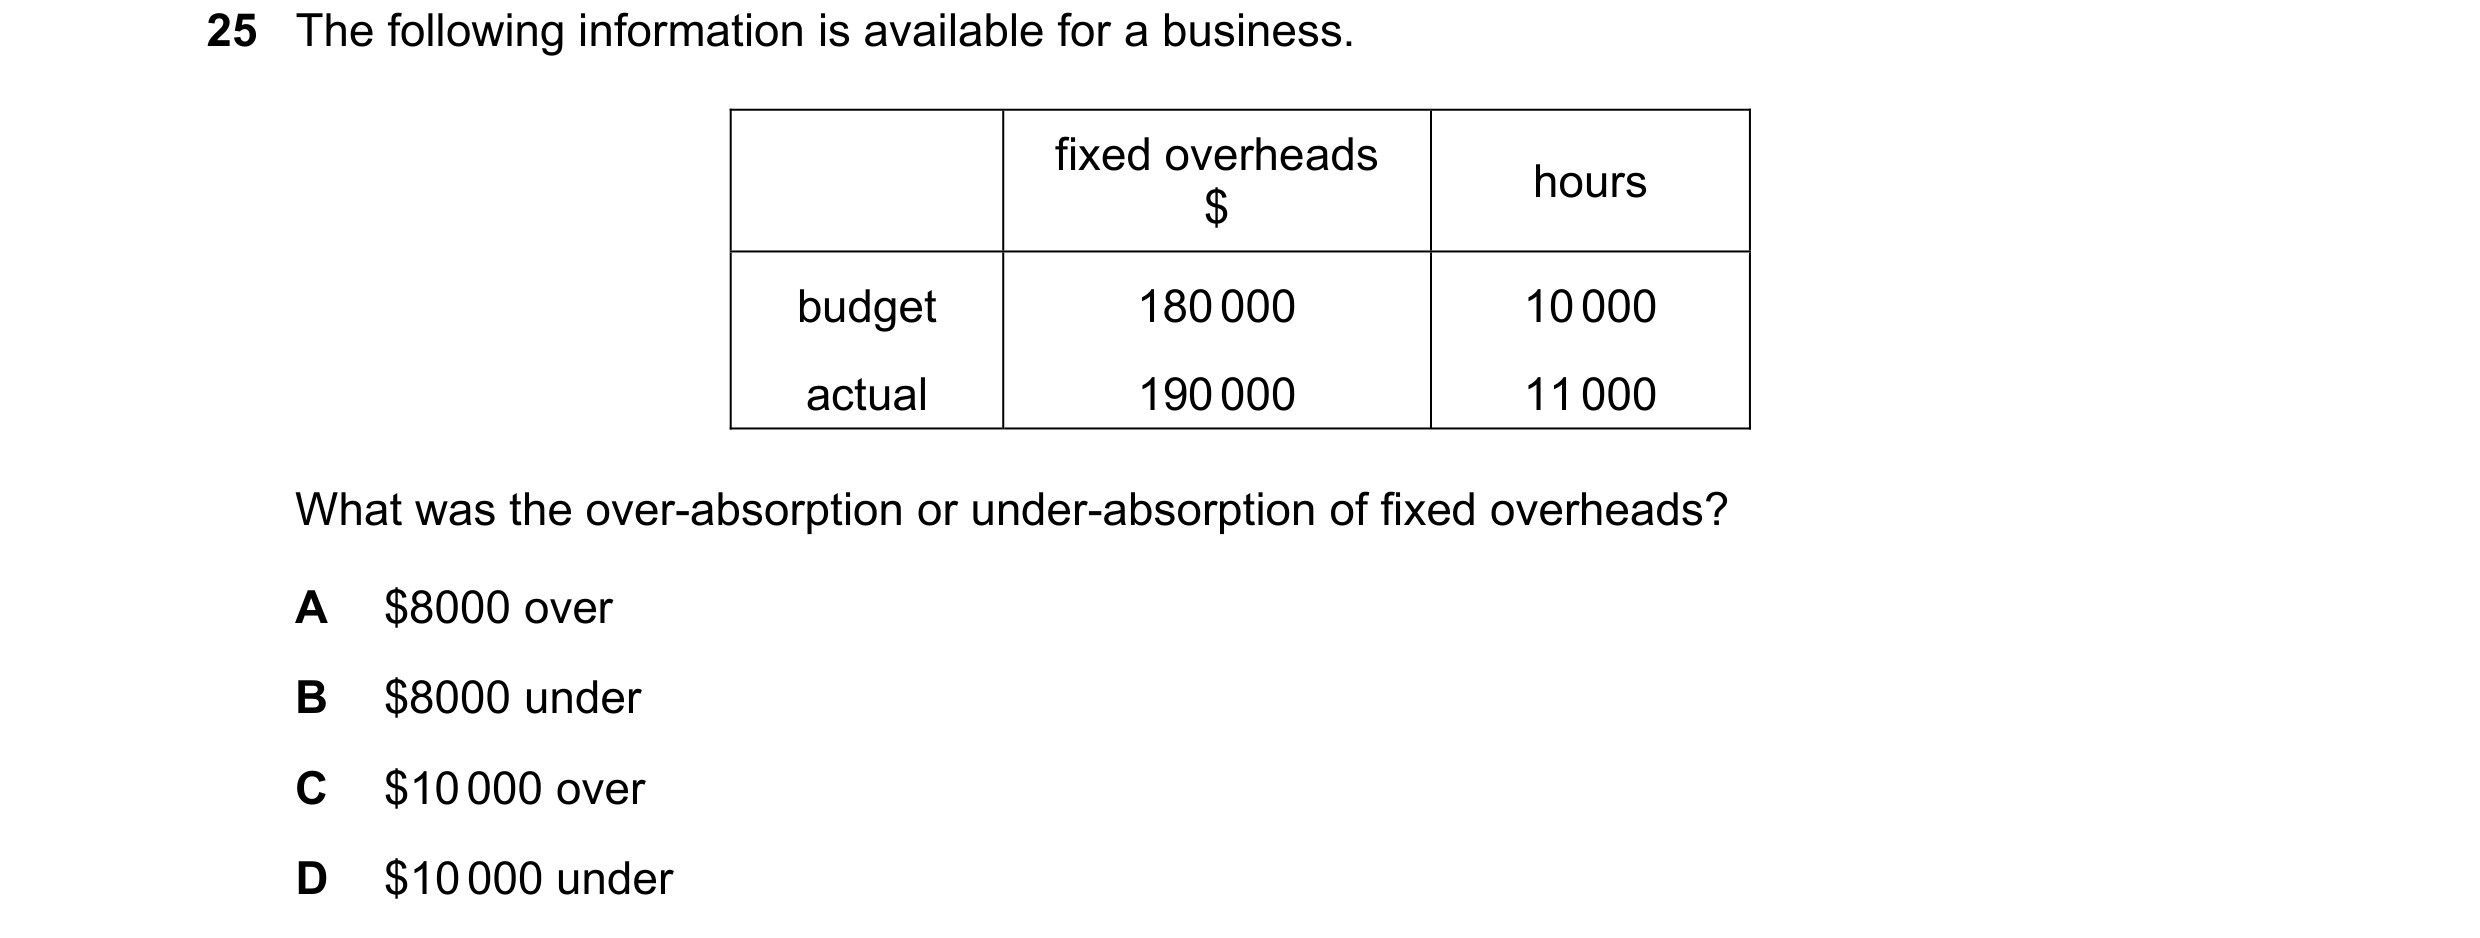 92 / 143
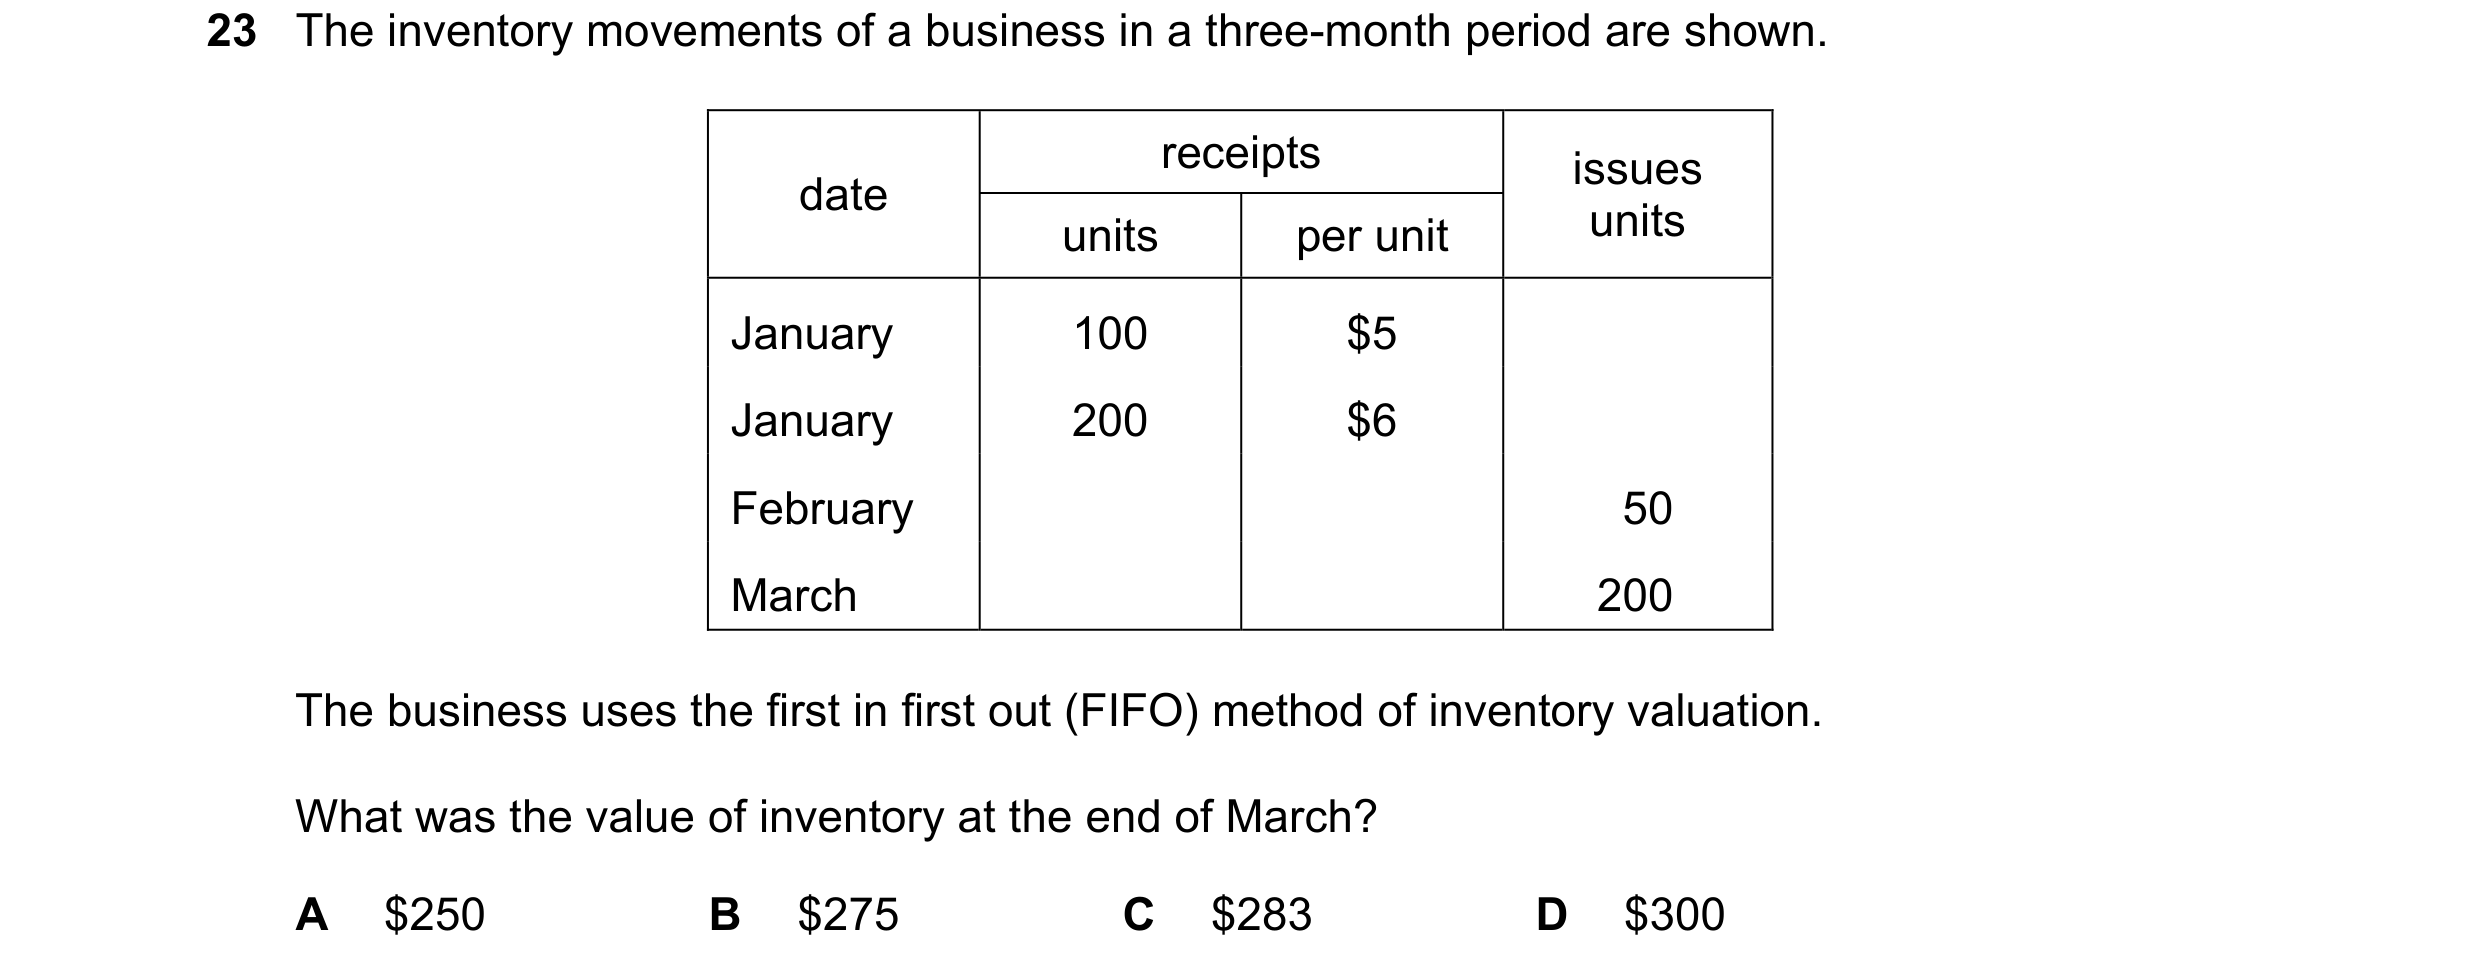
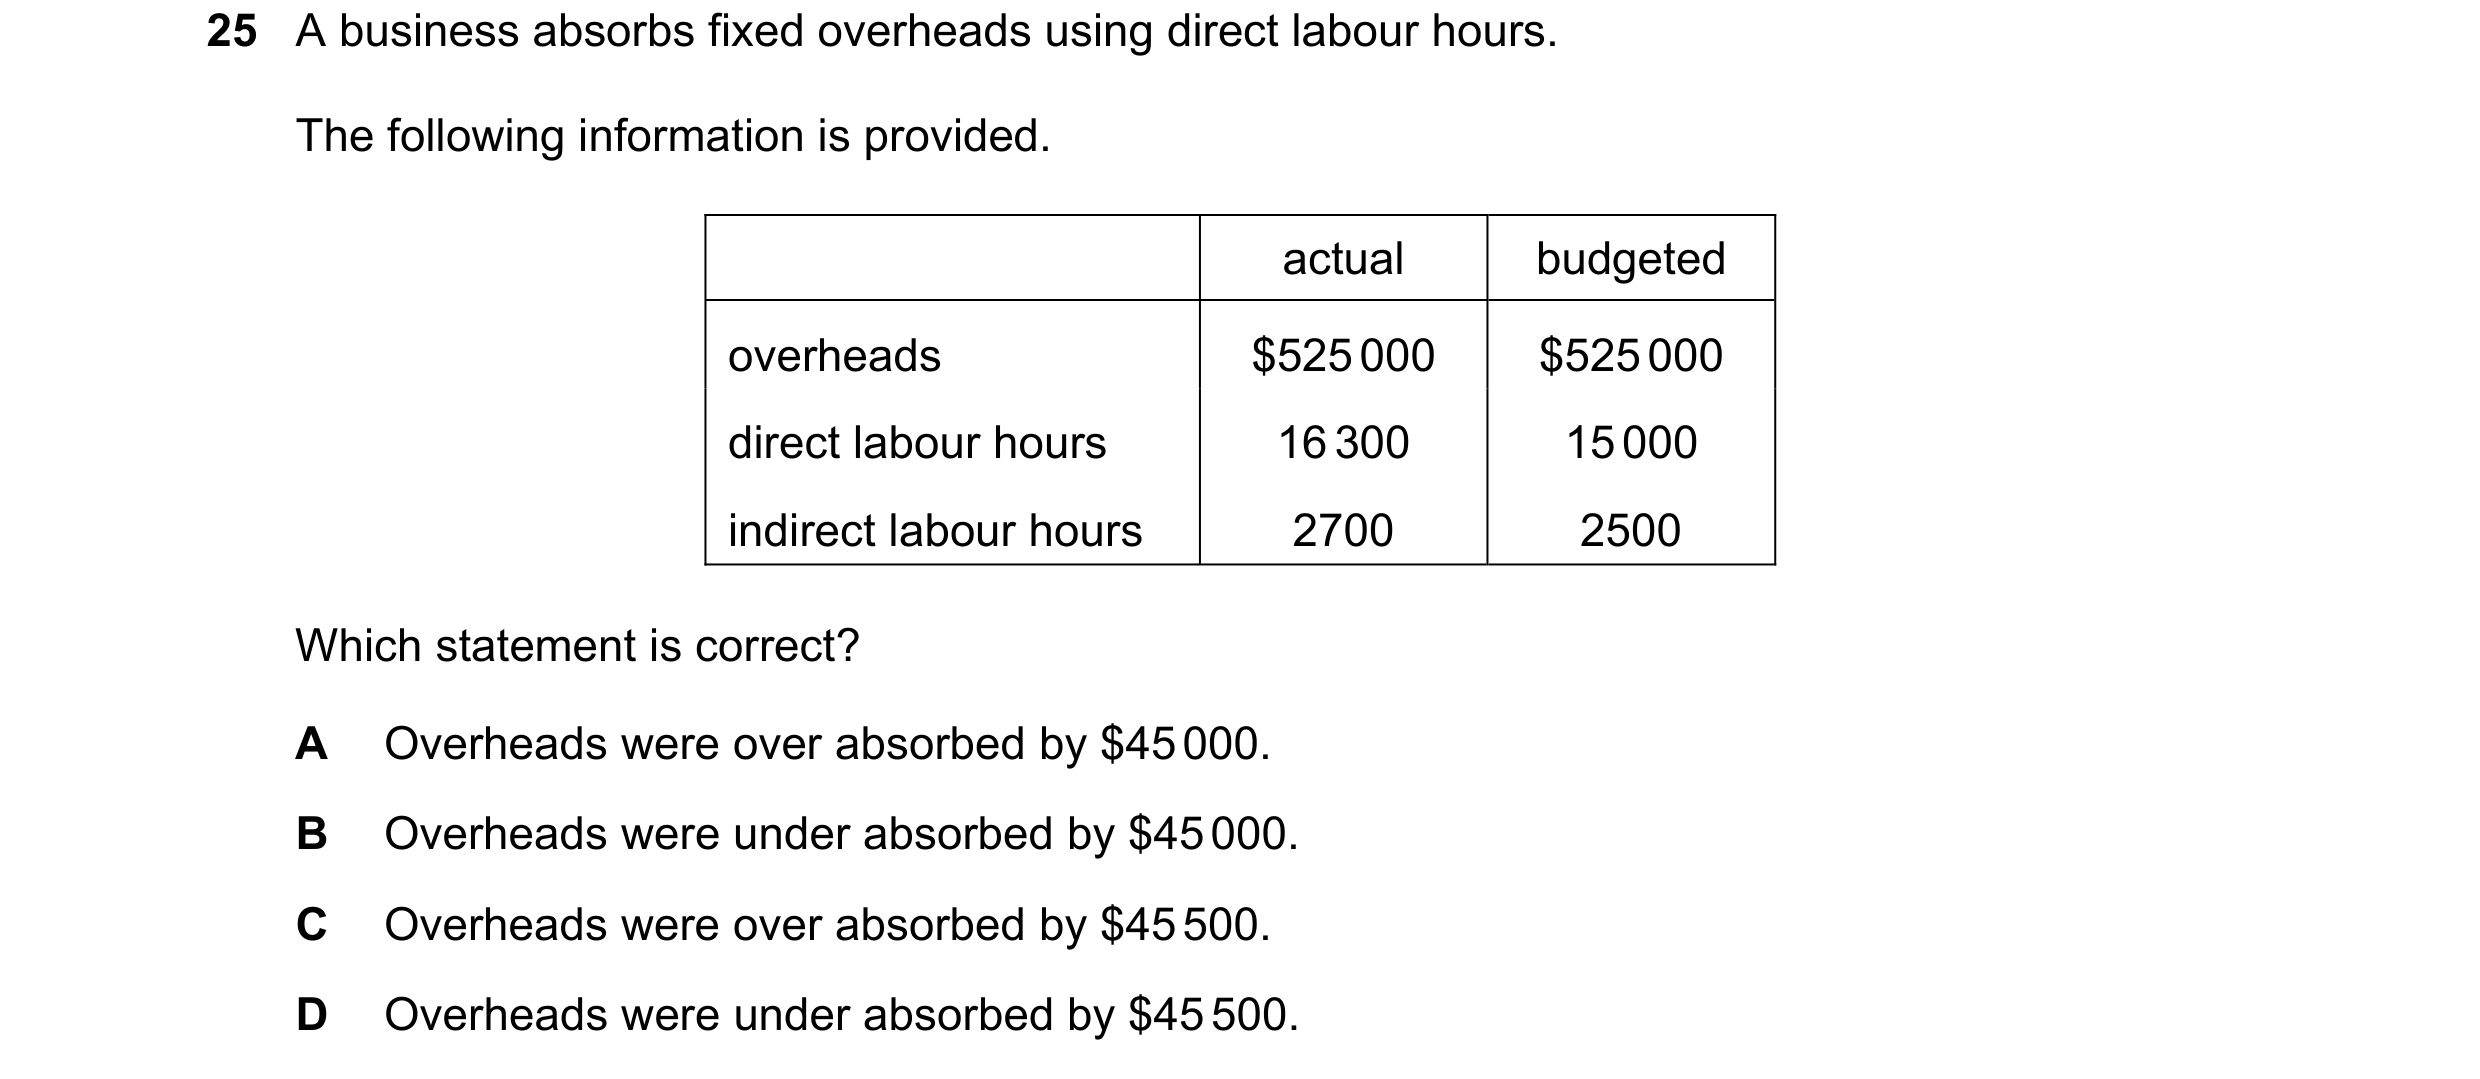 93 / 143
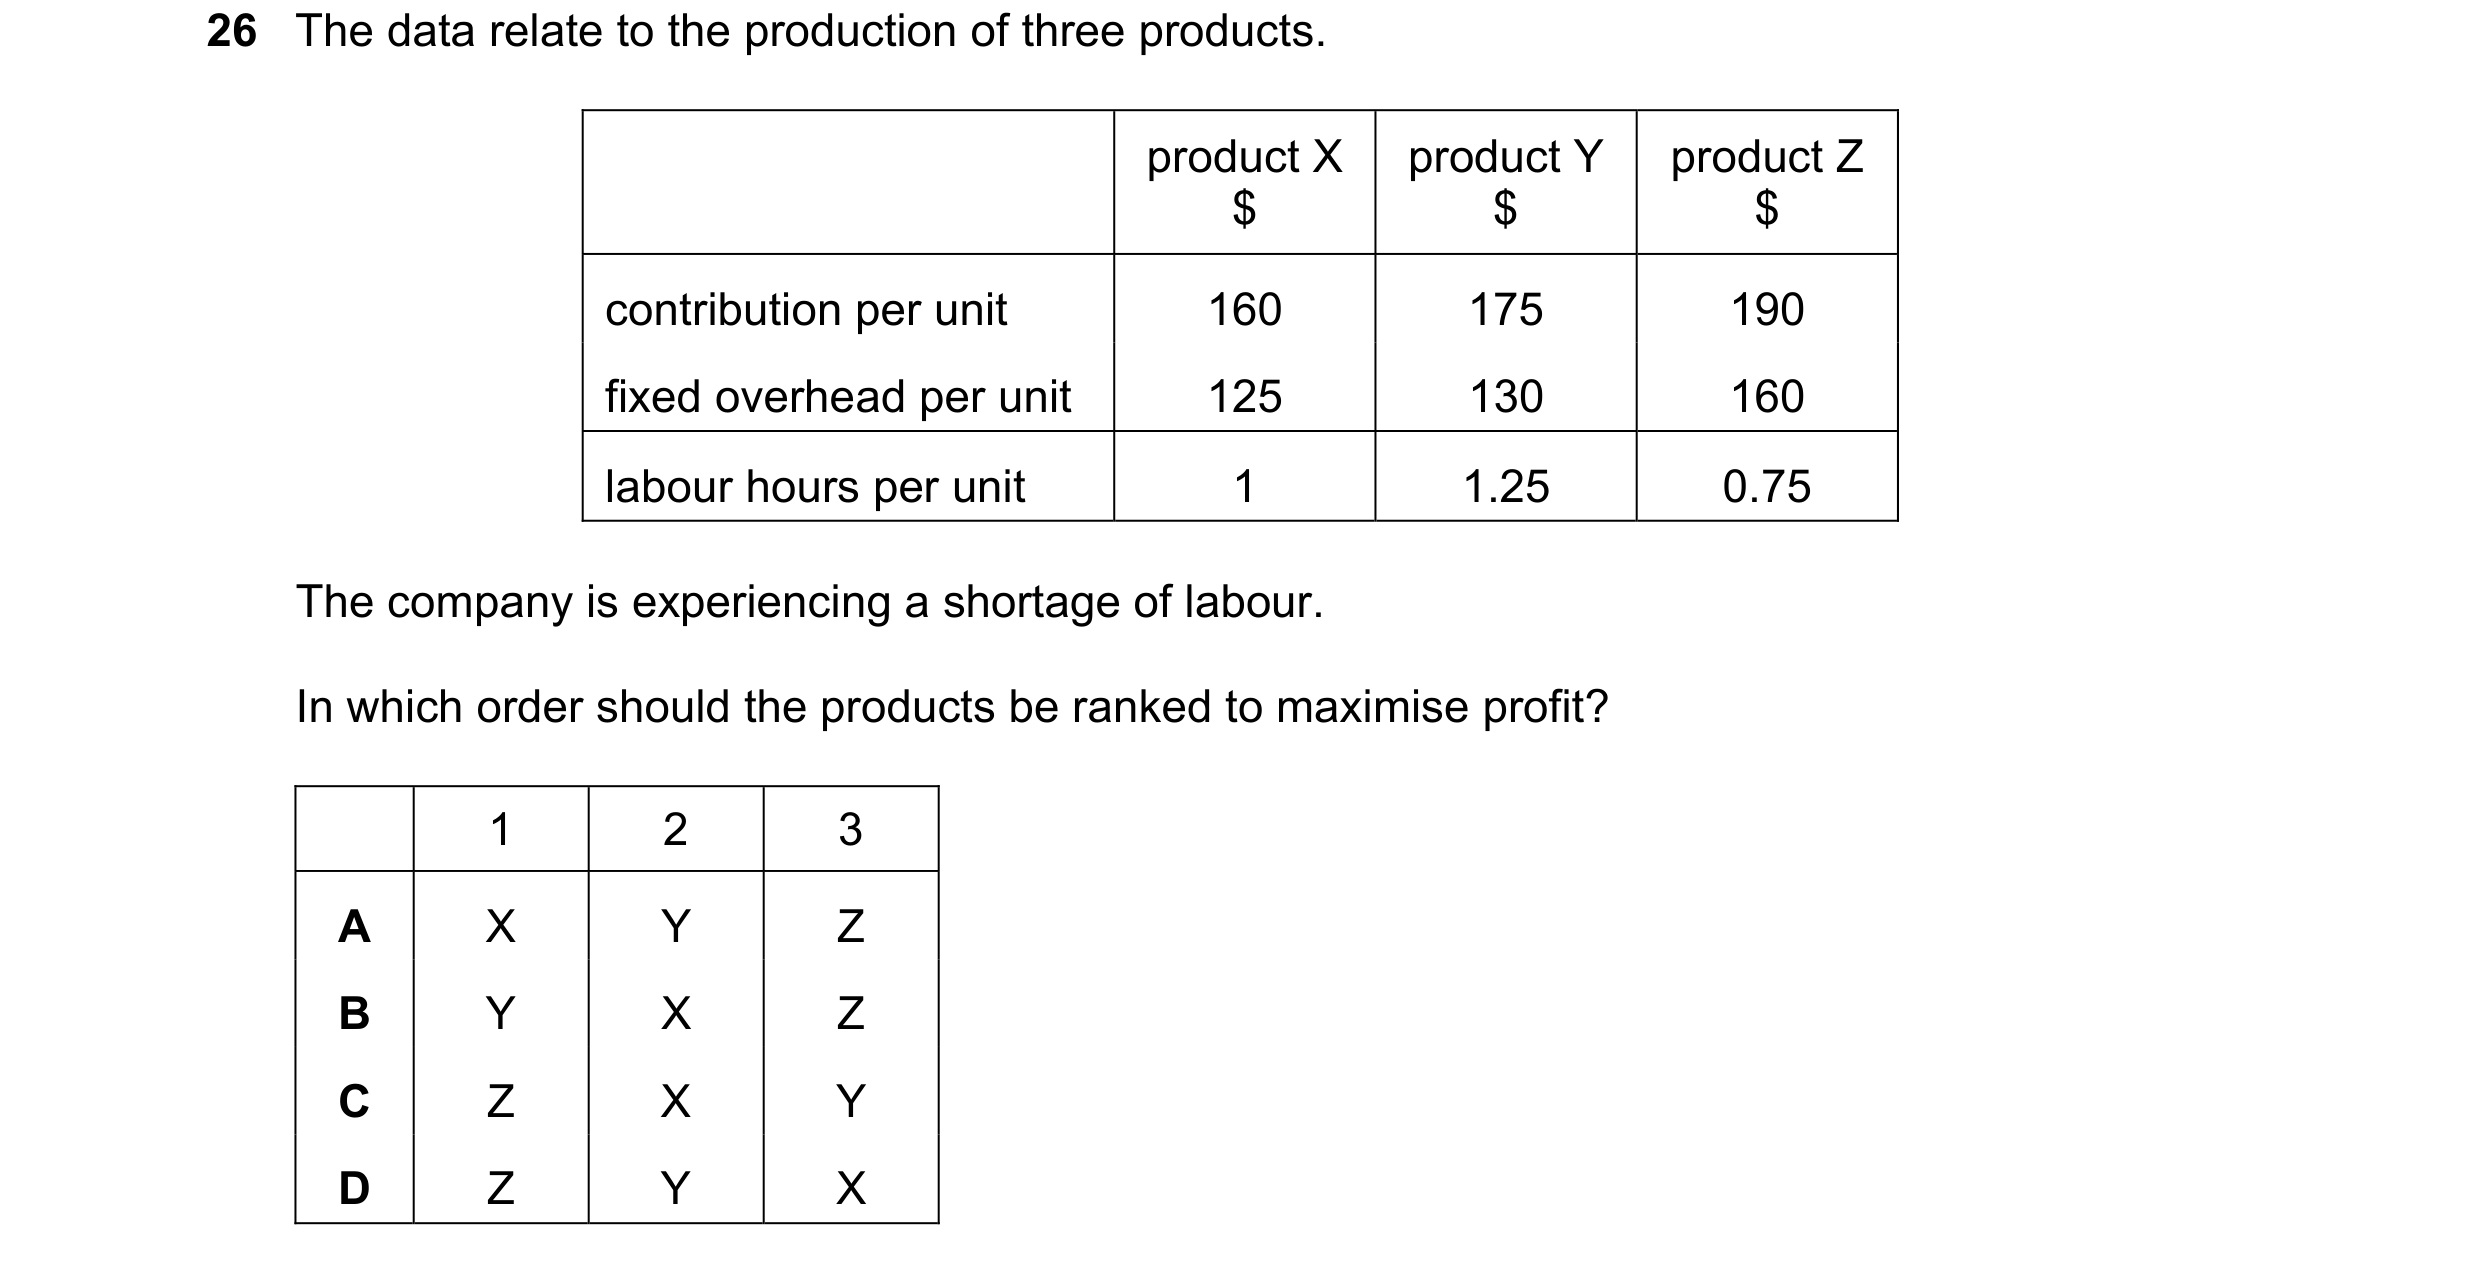
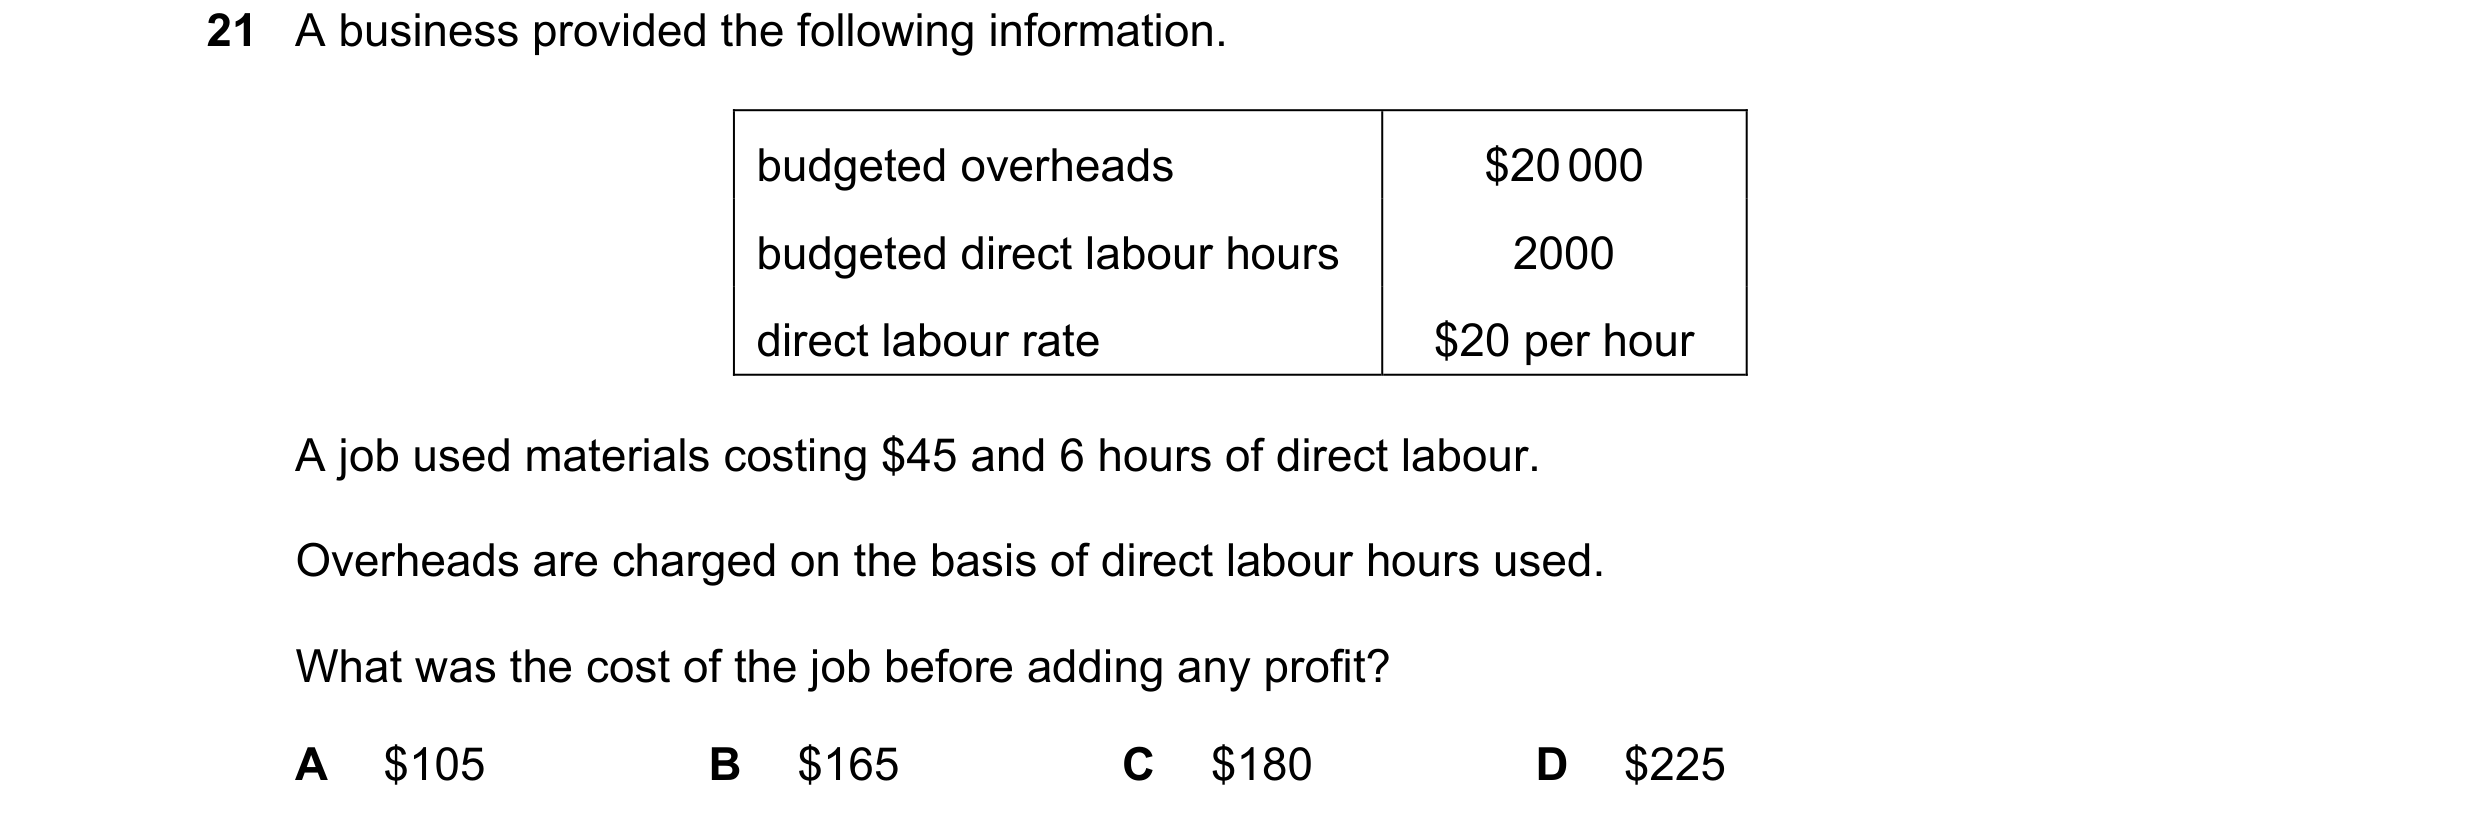
 94 / 143
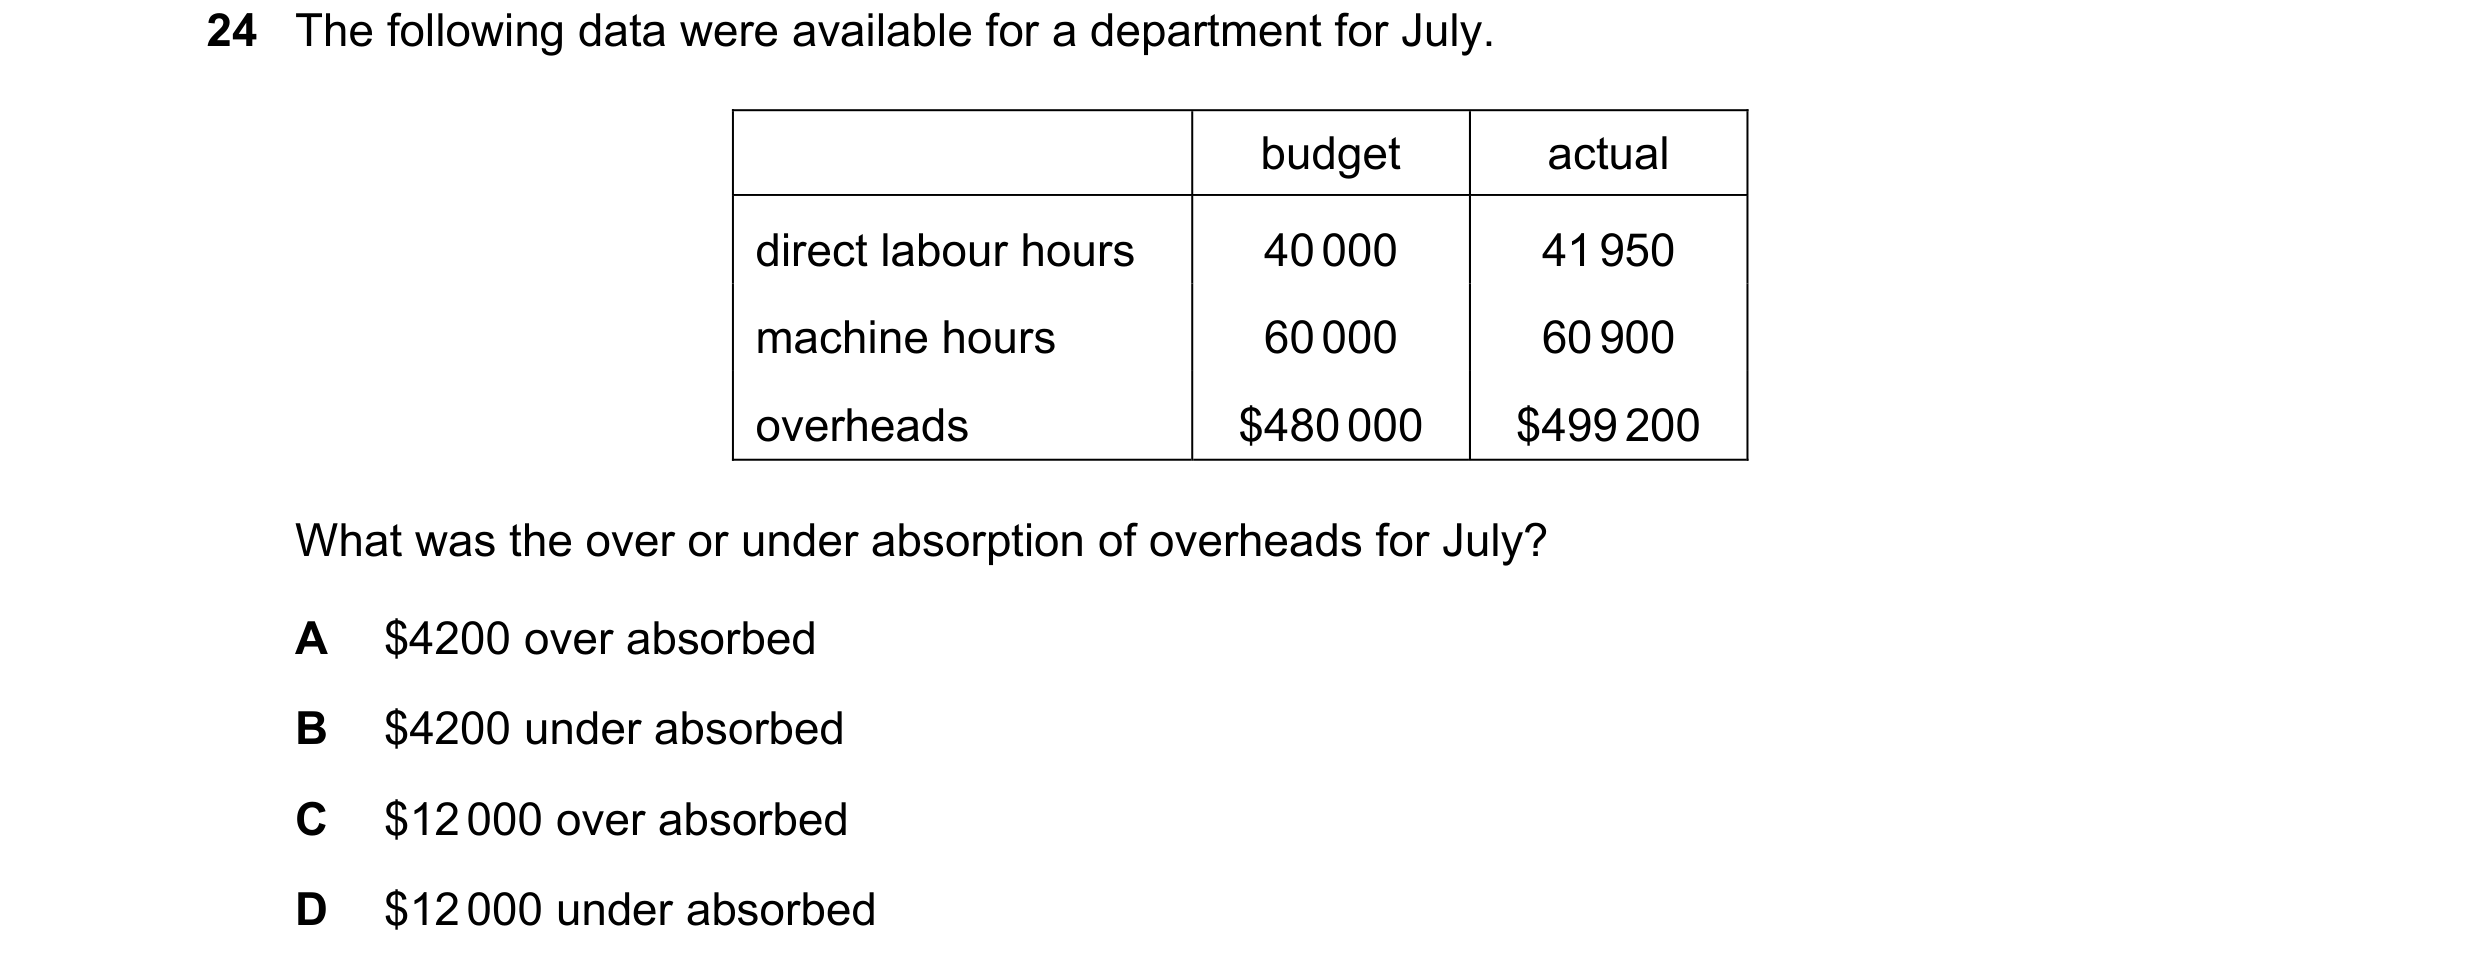
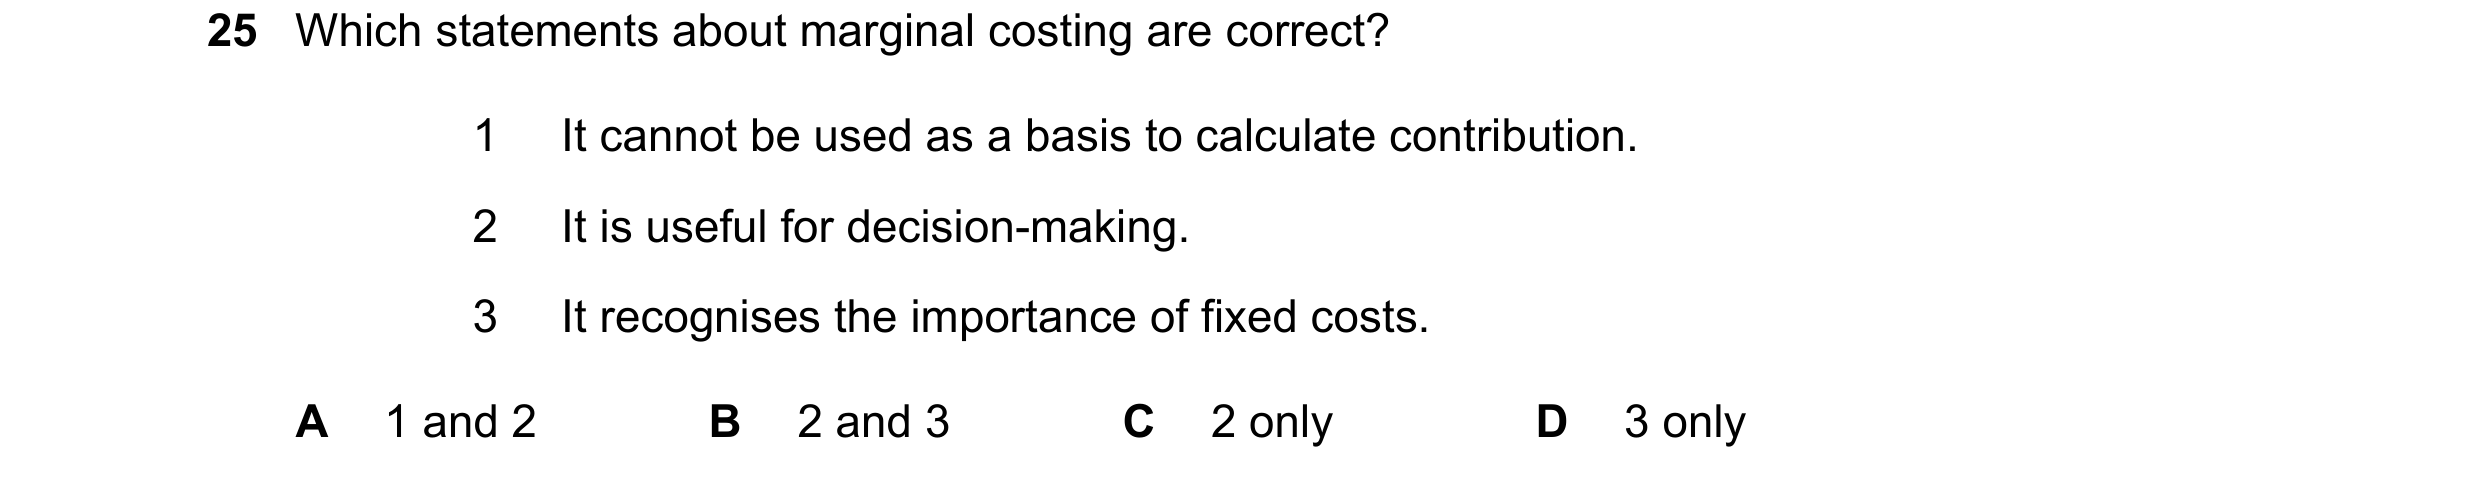
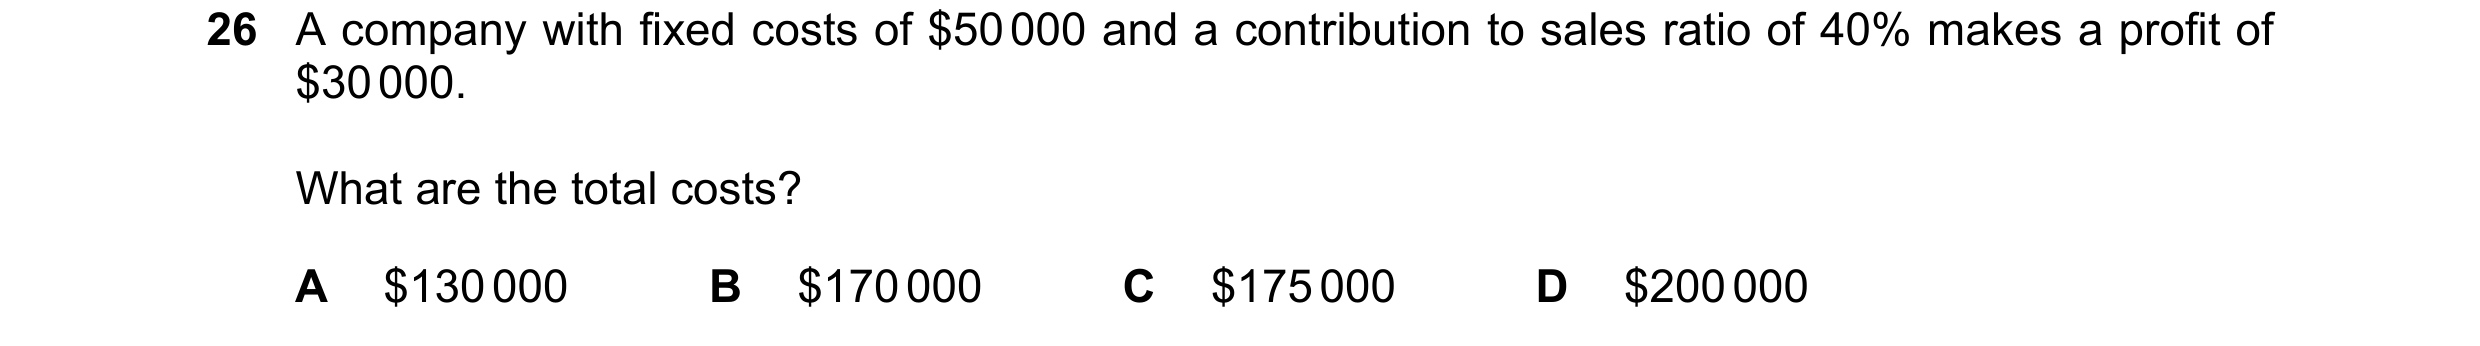
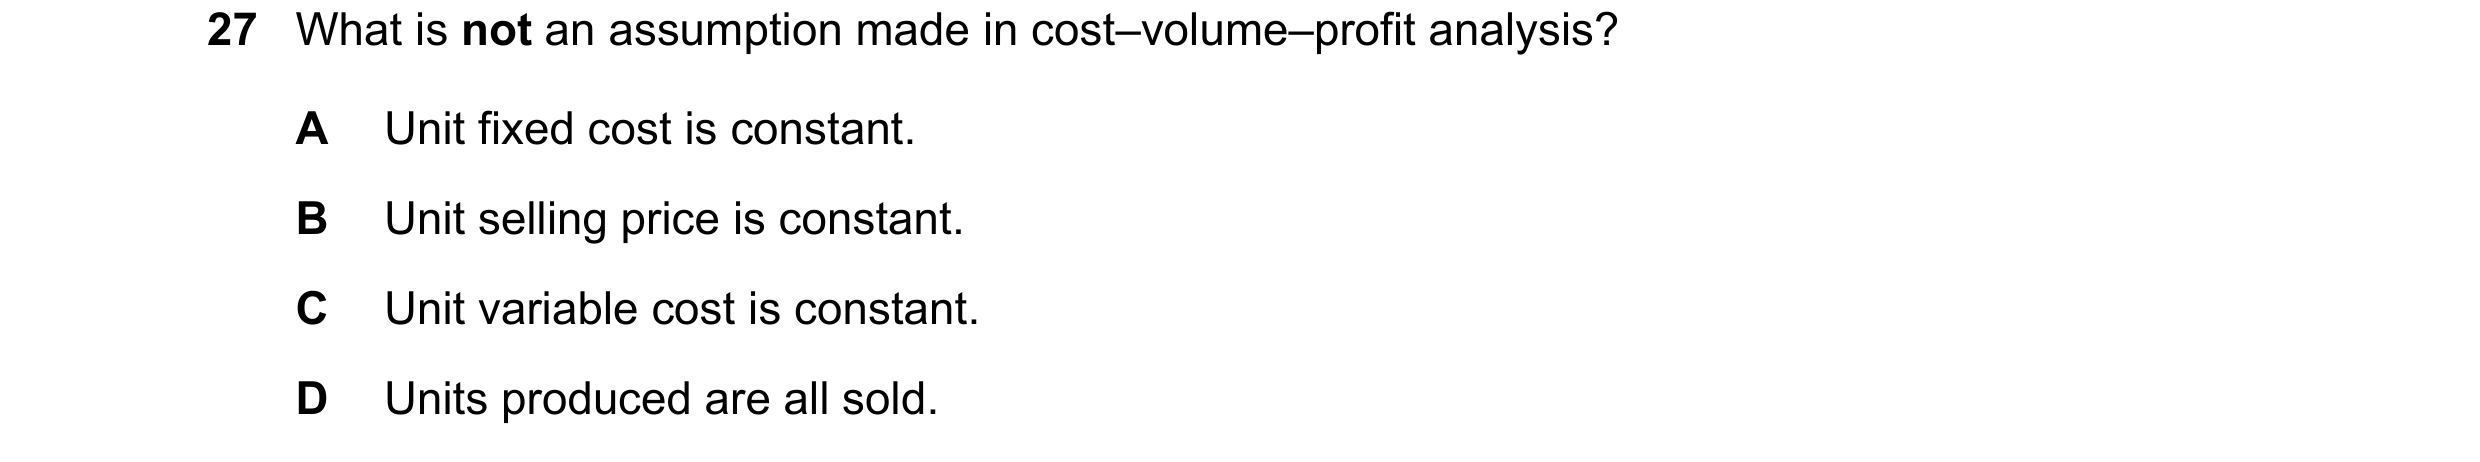 95 / 143
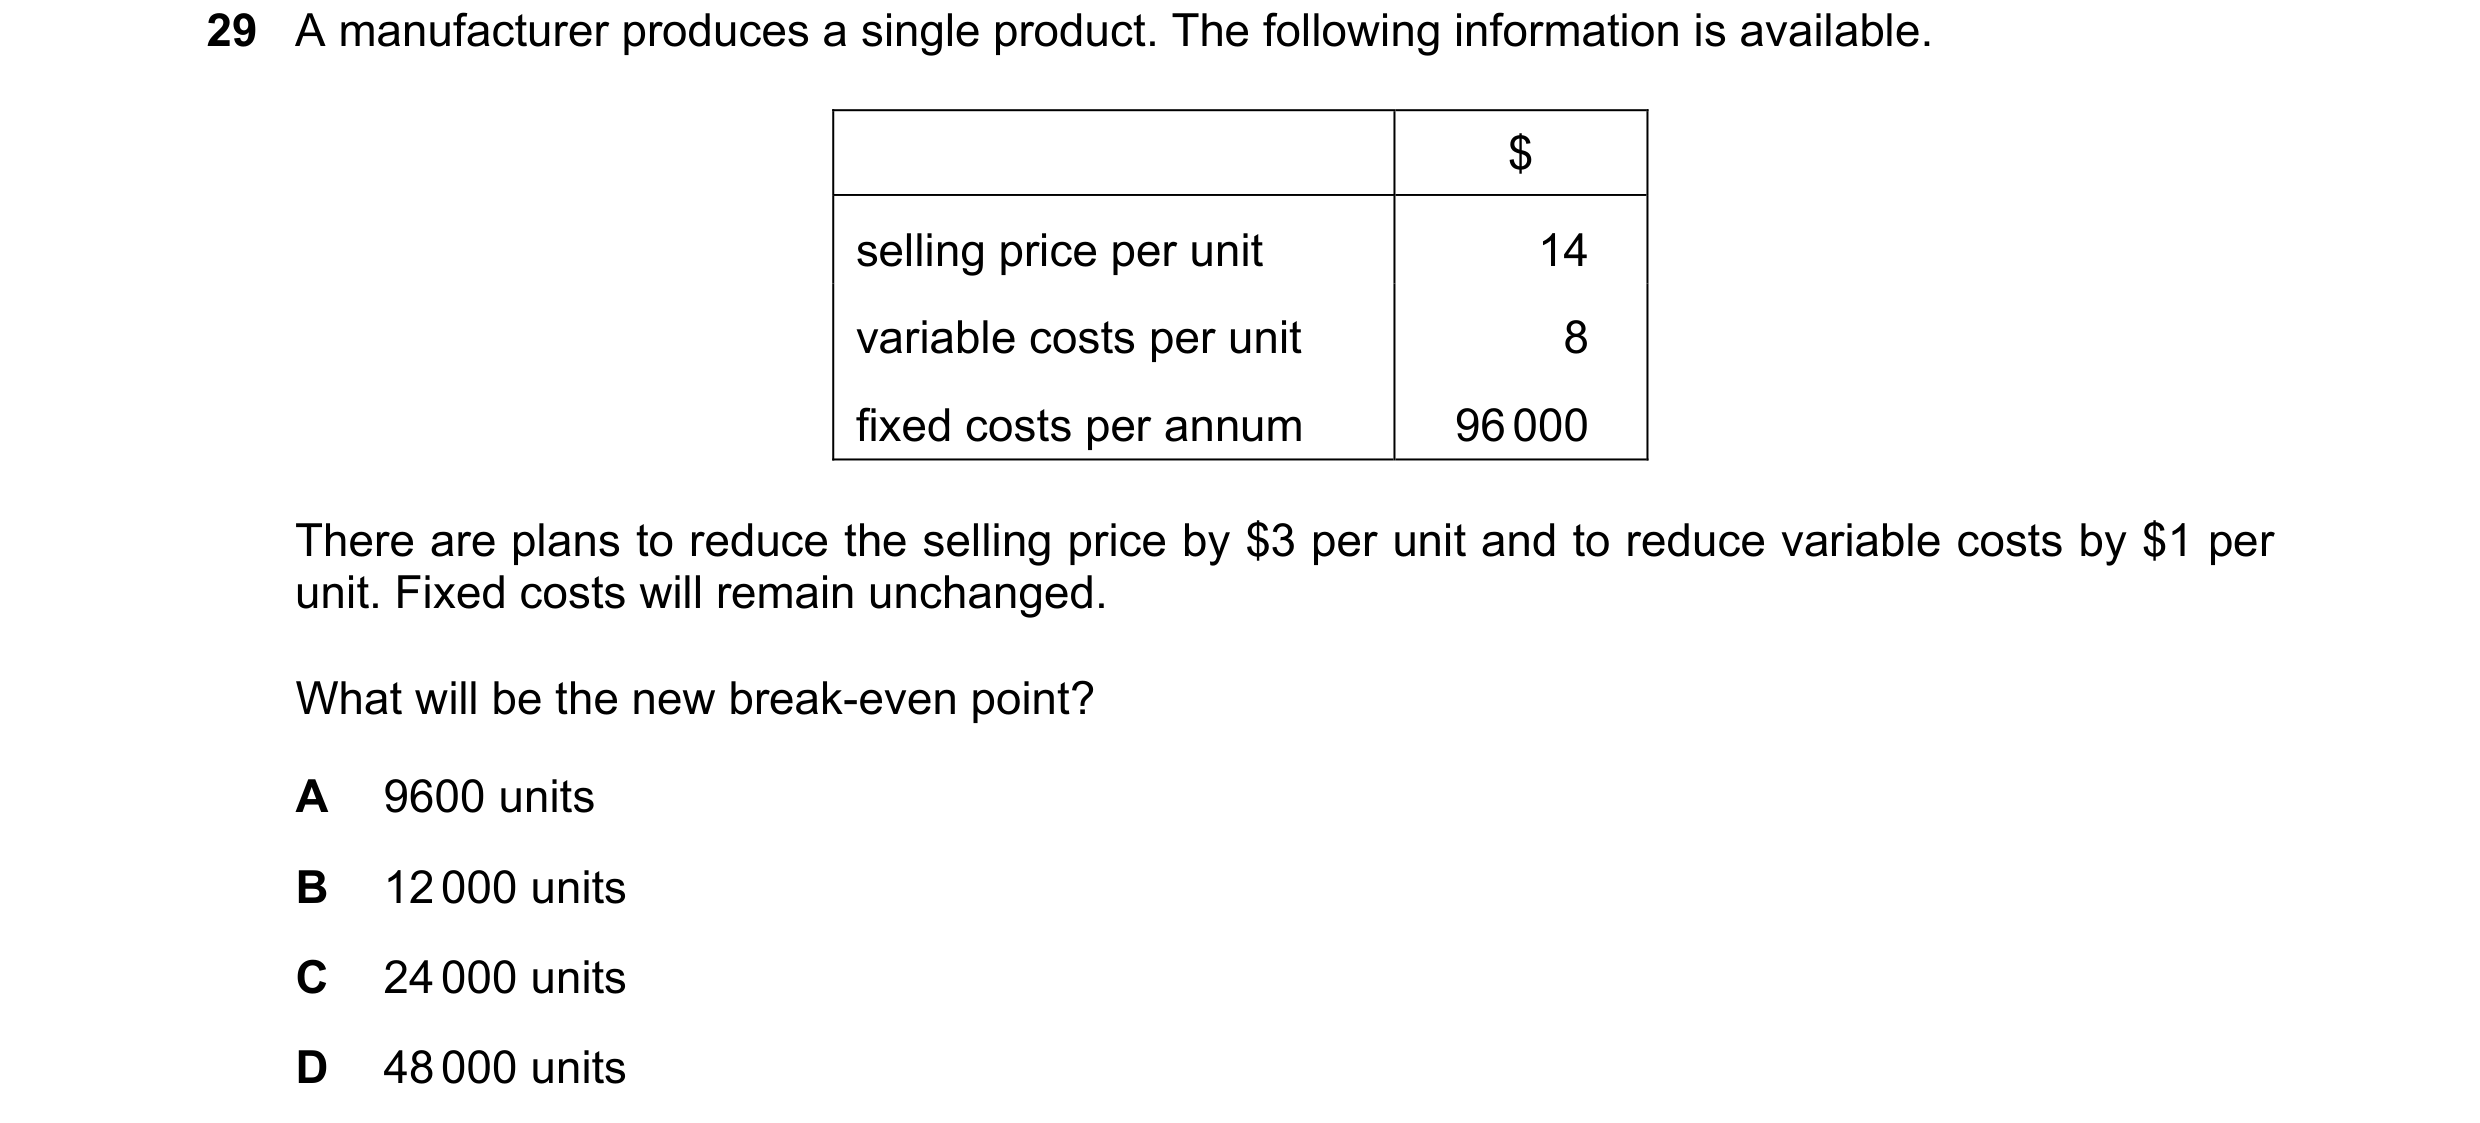
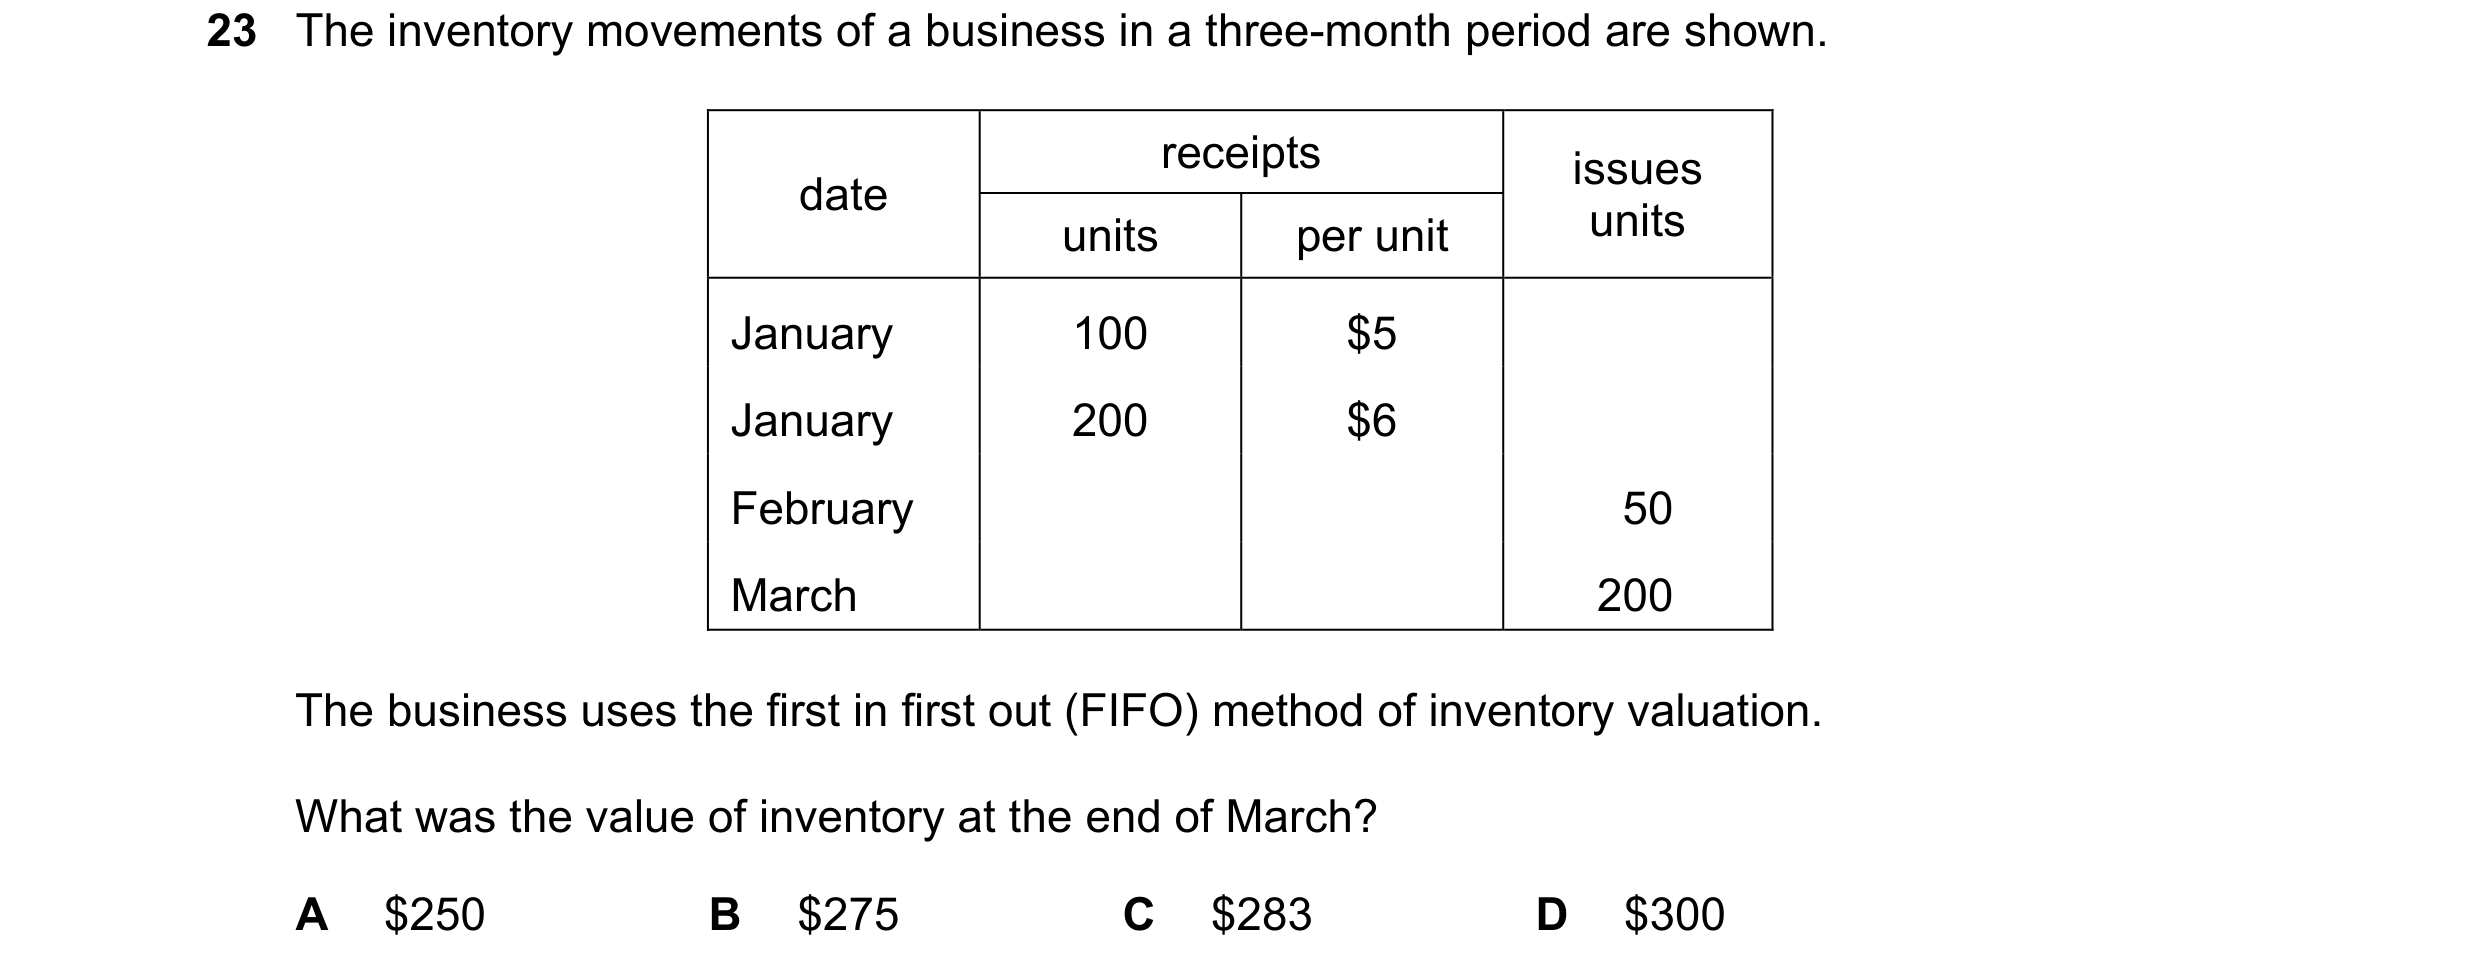
 96 / 143
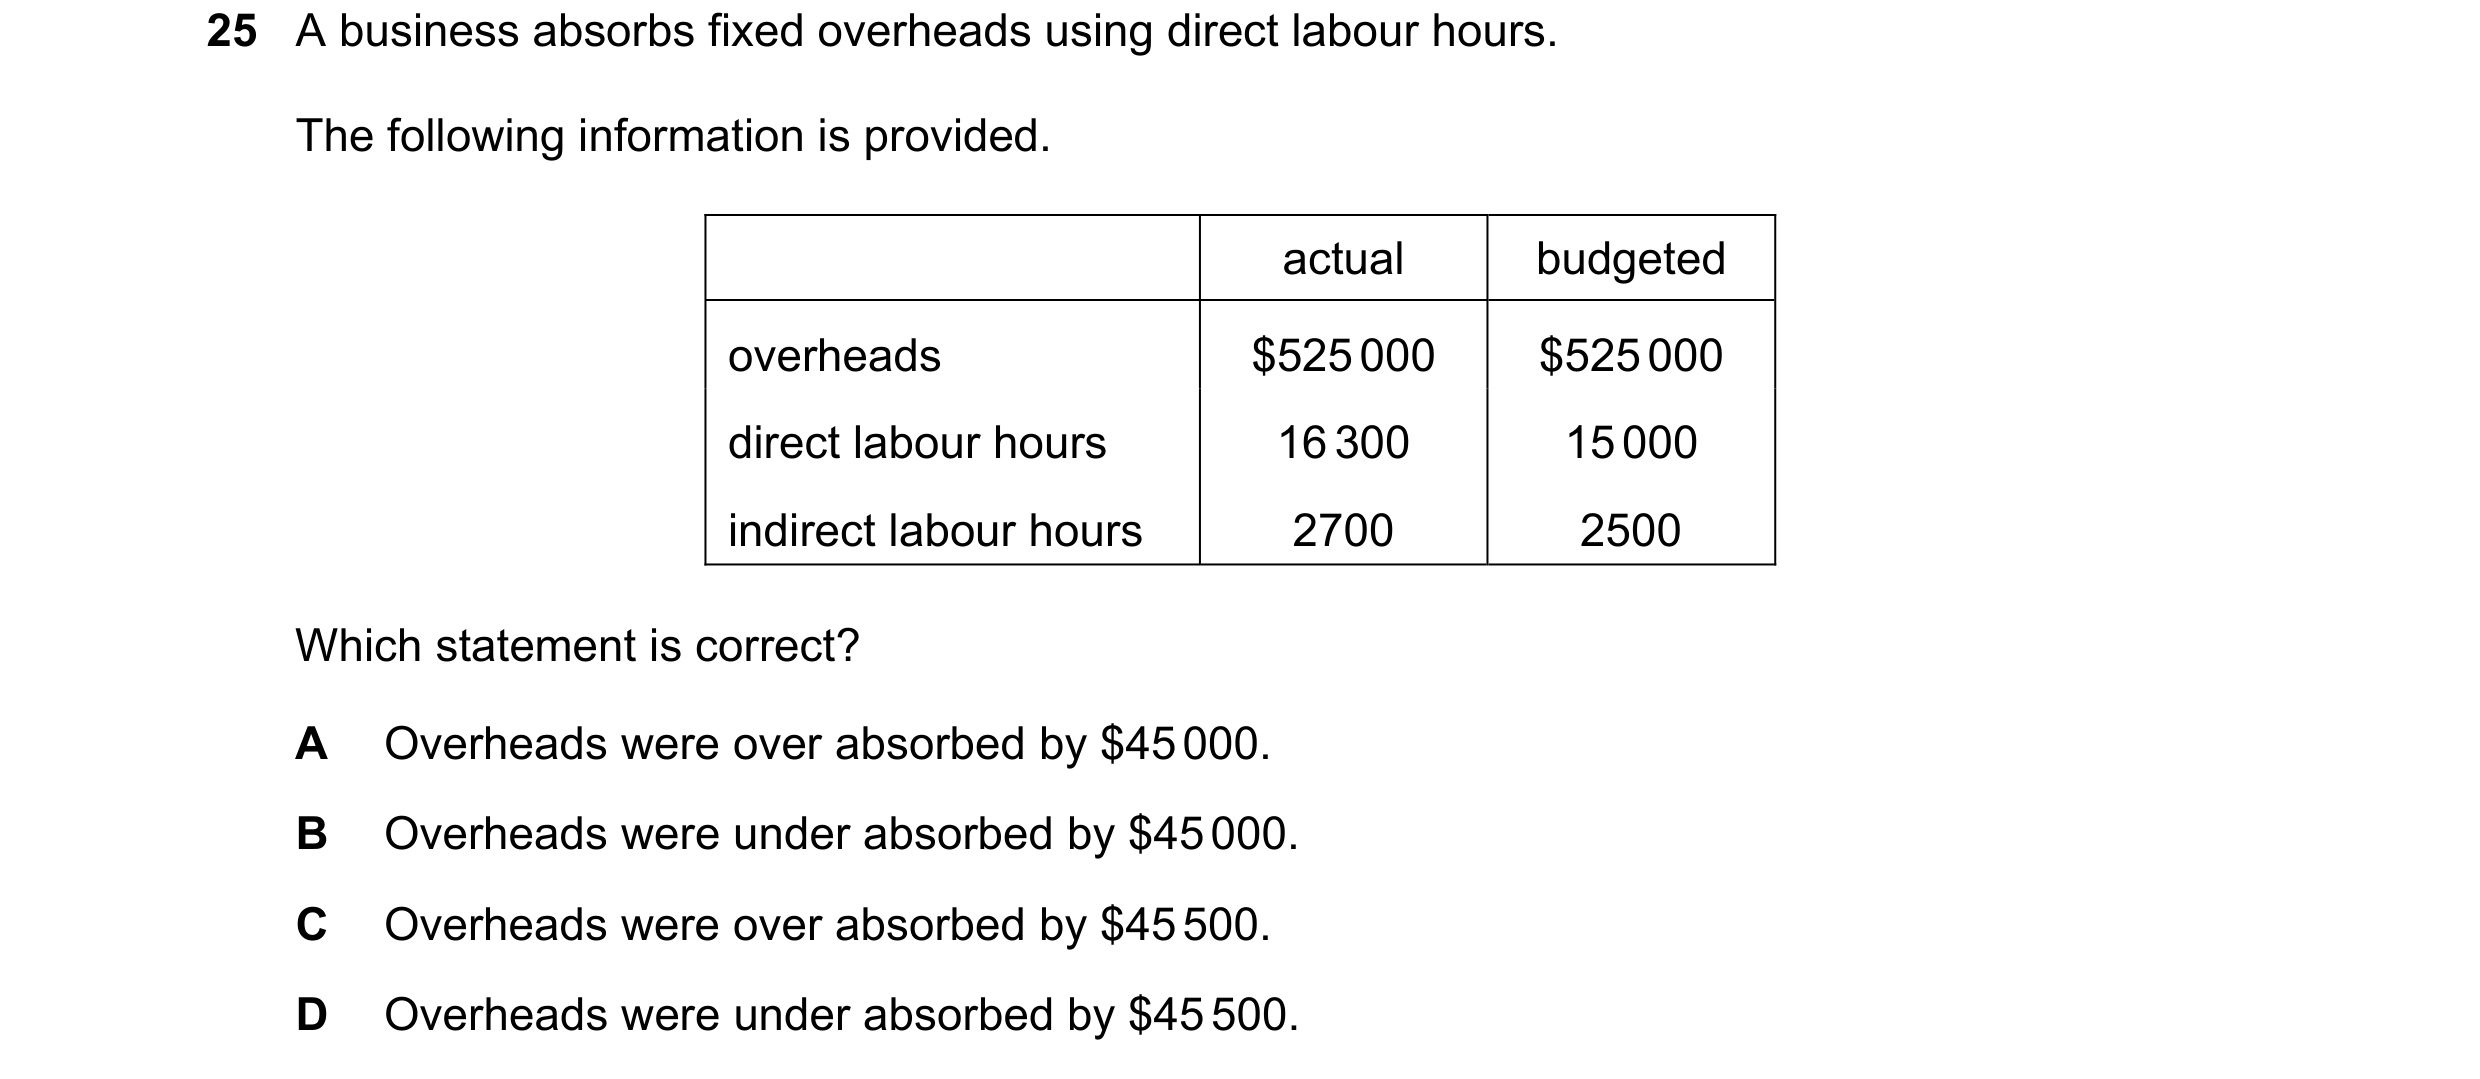
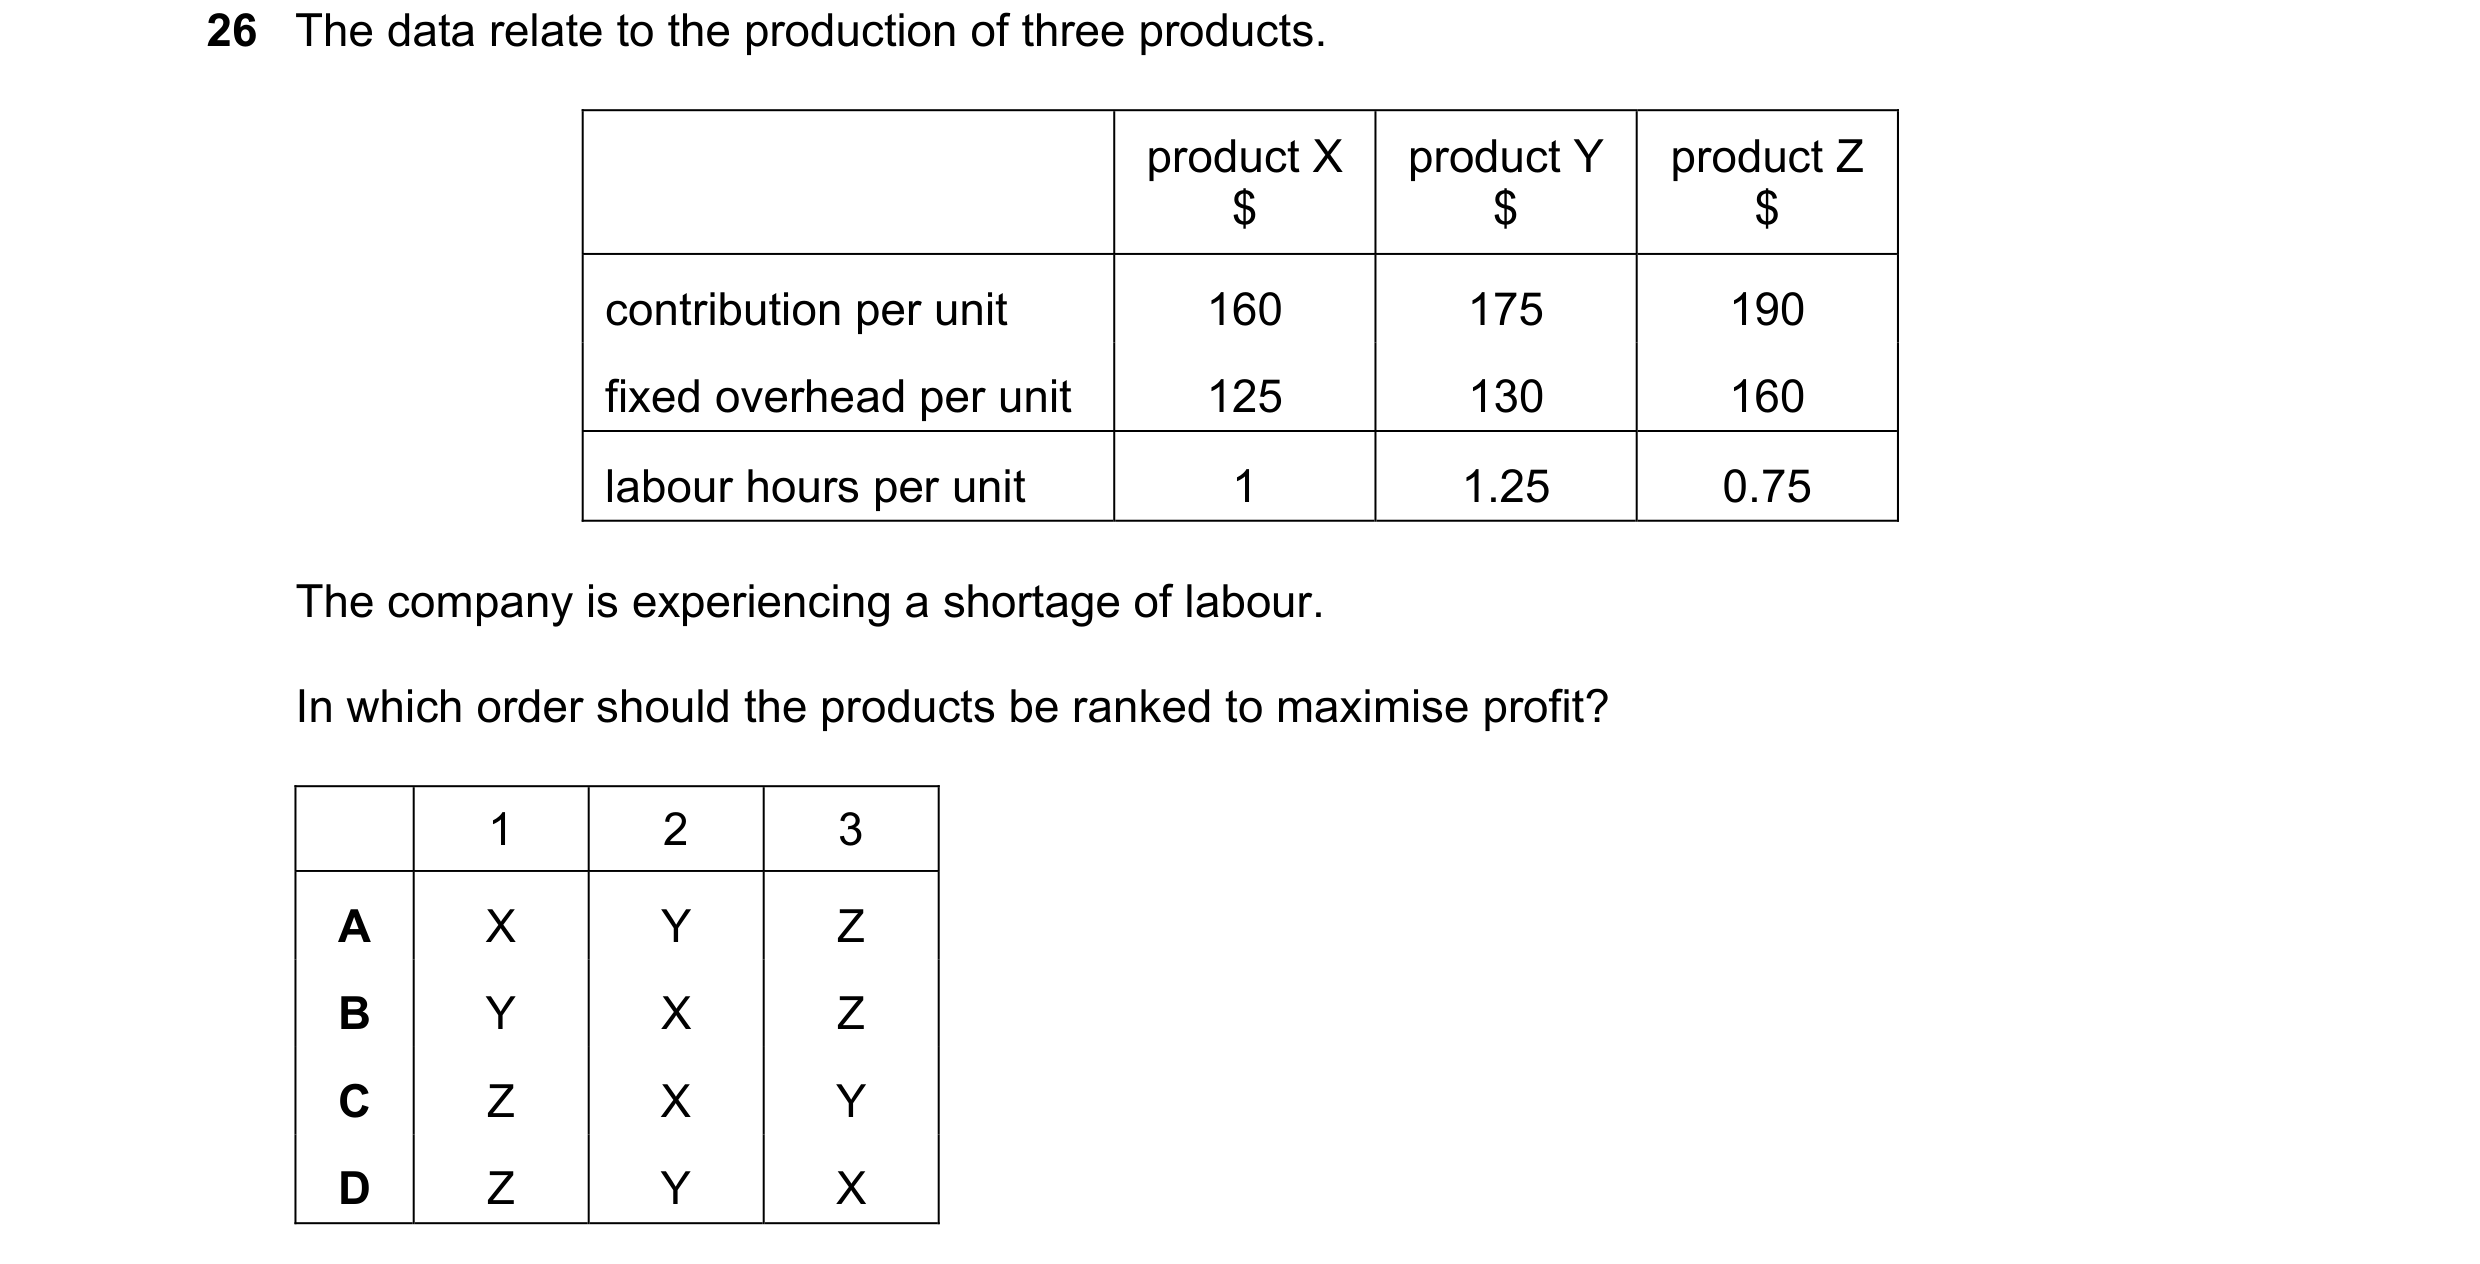
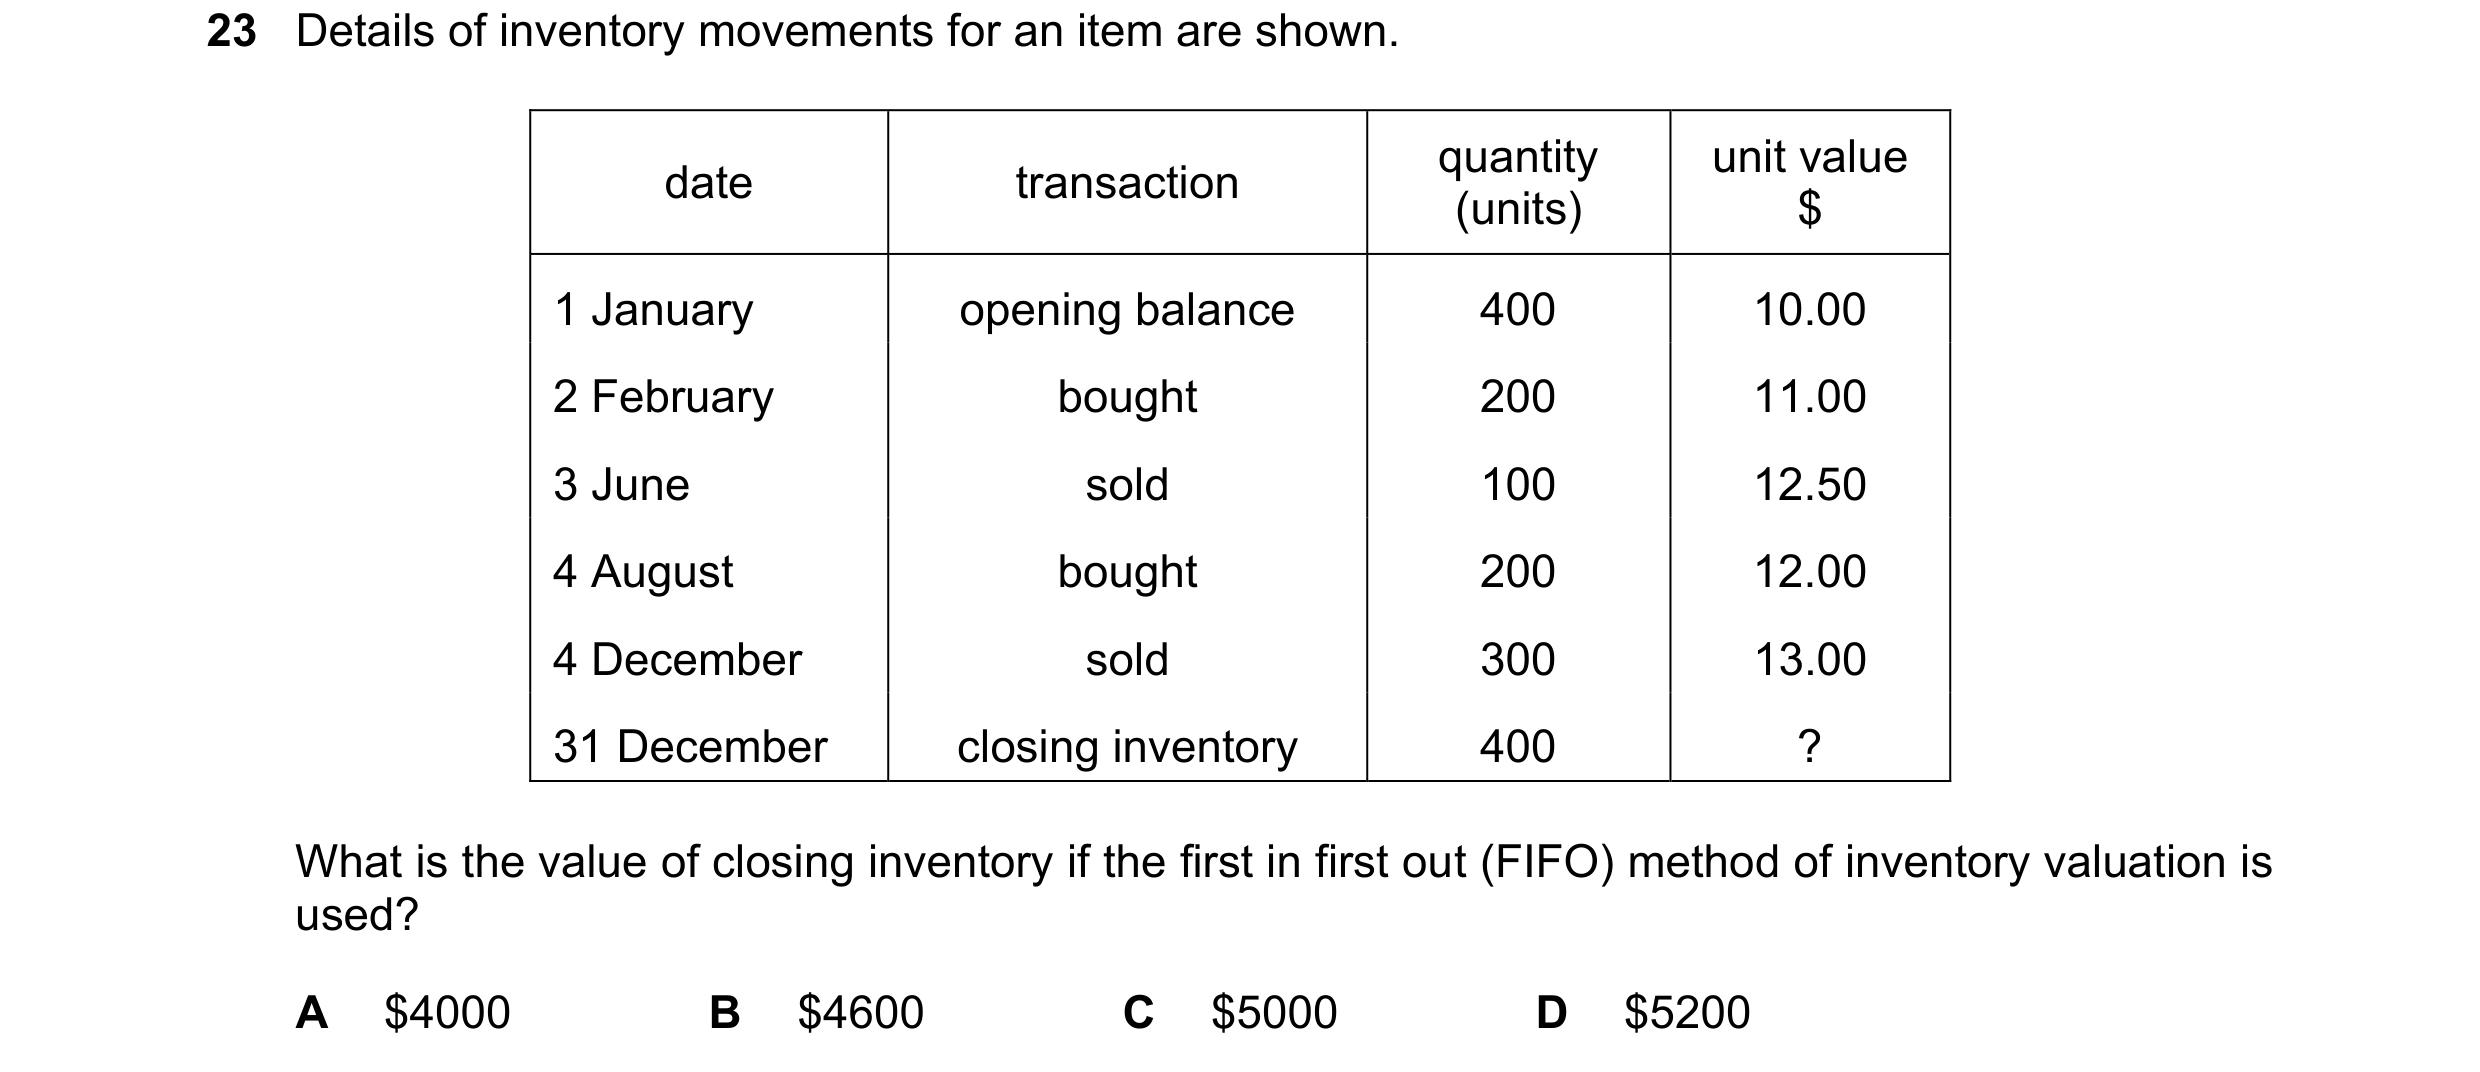 97 / 143
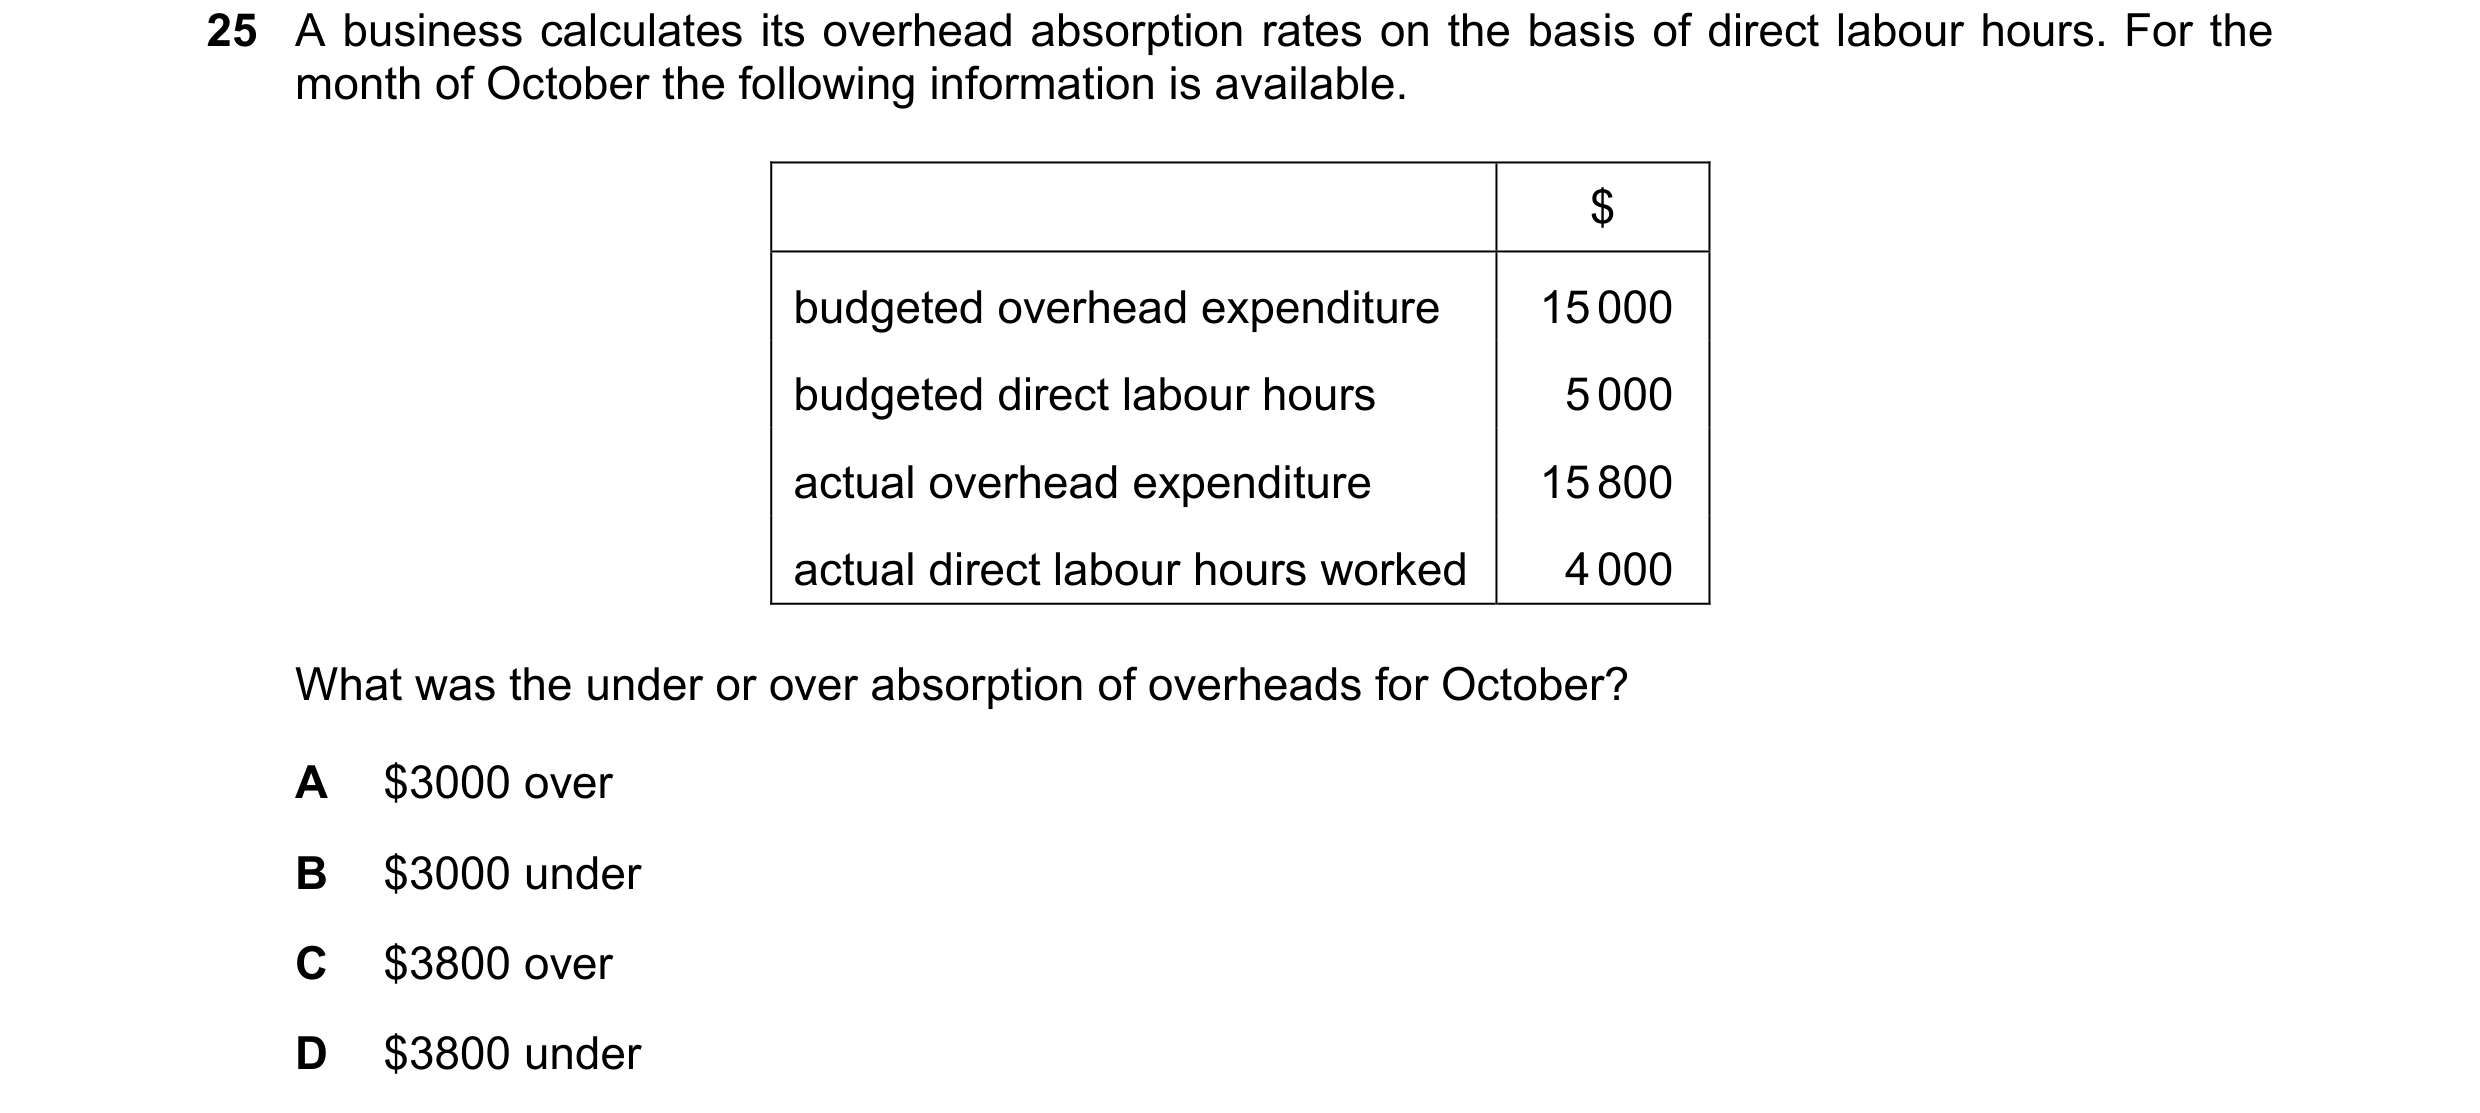
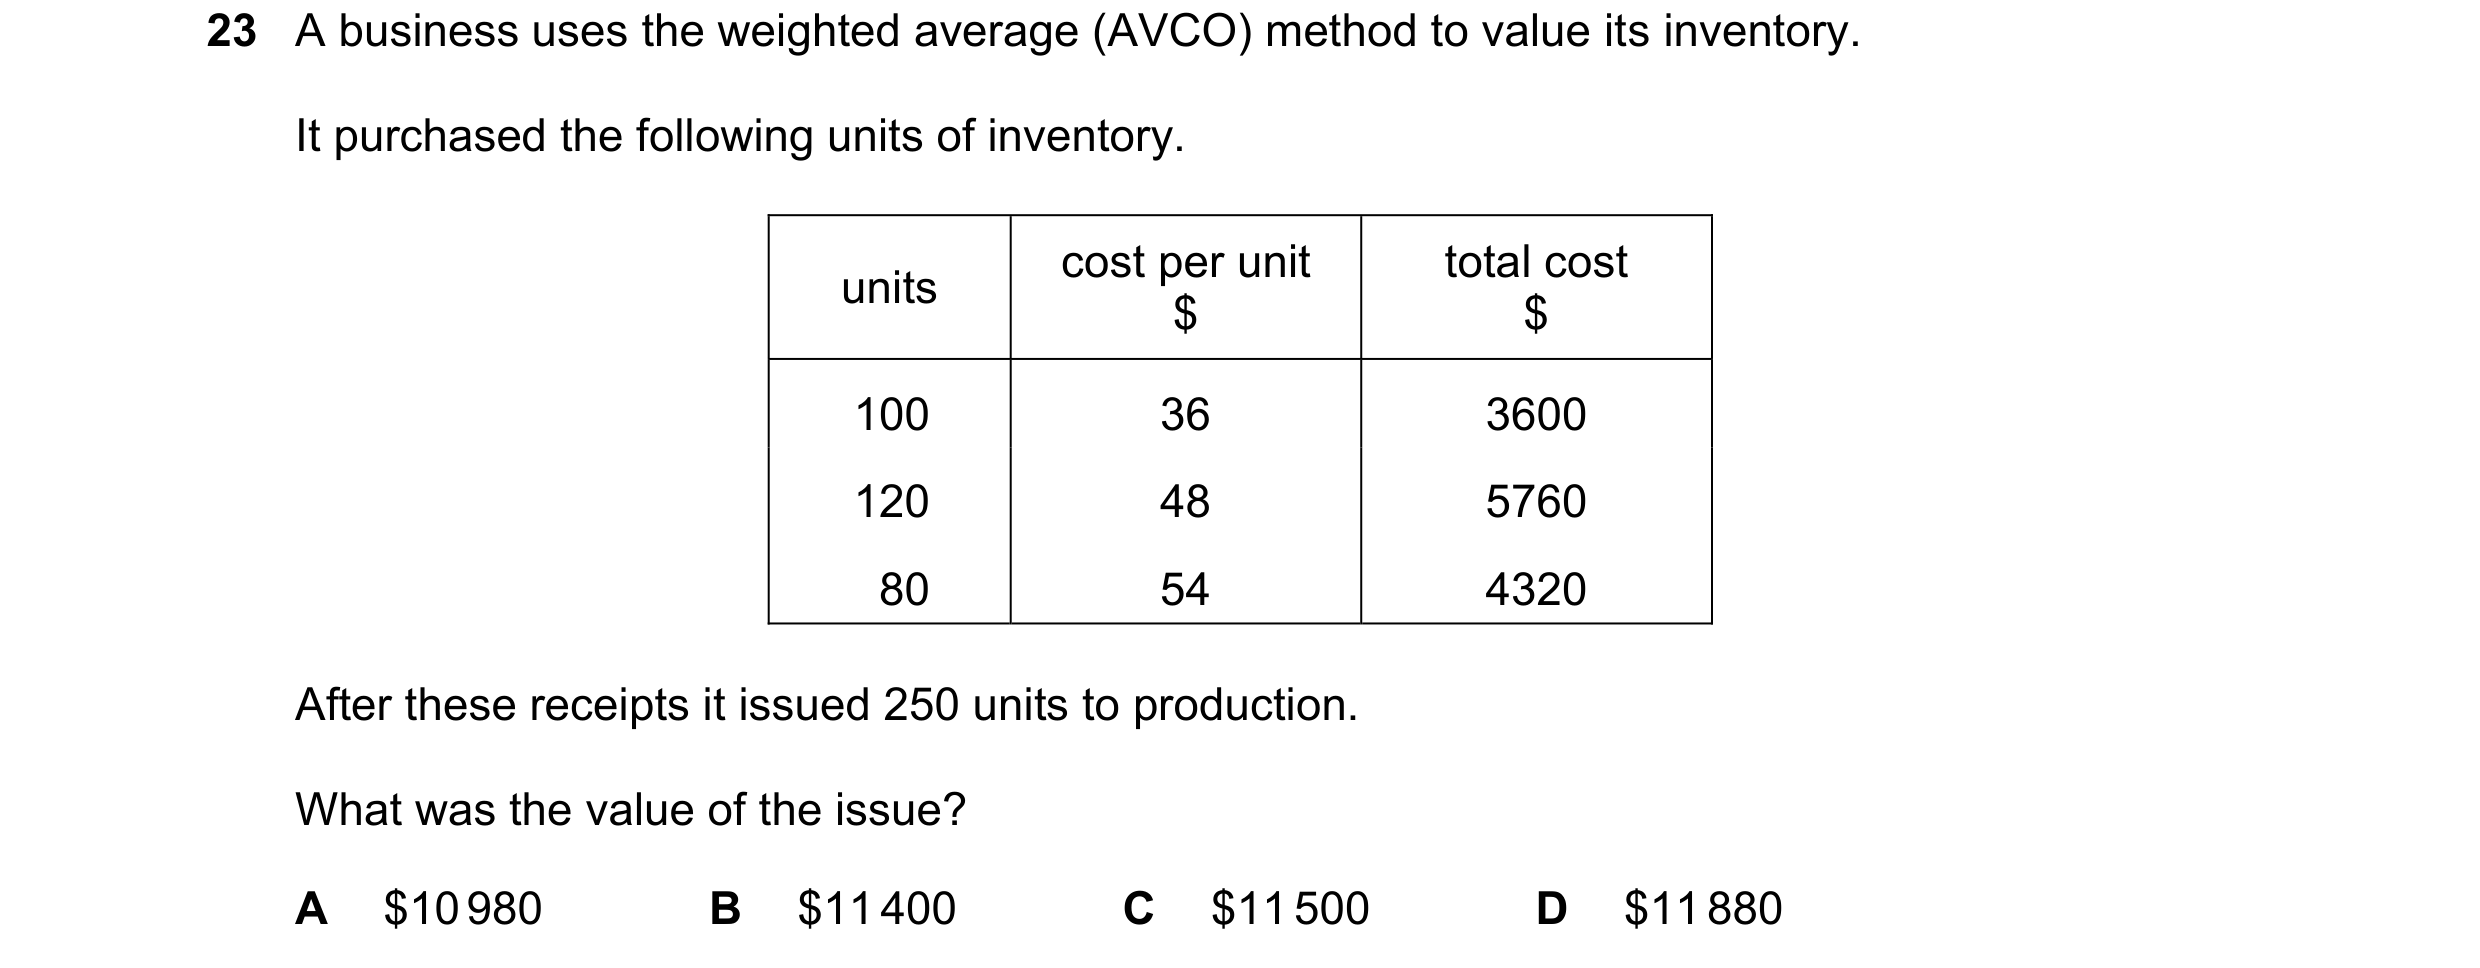 98 / 143
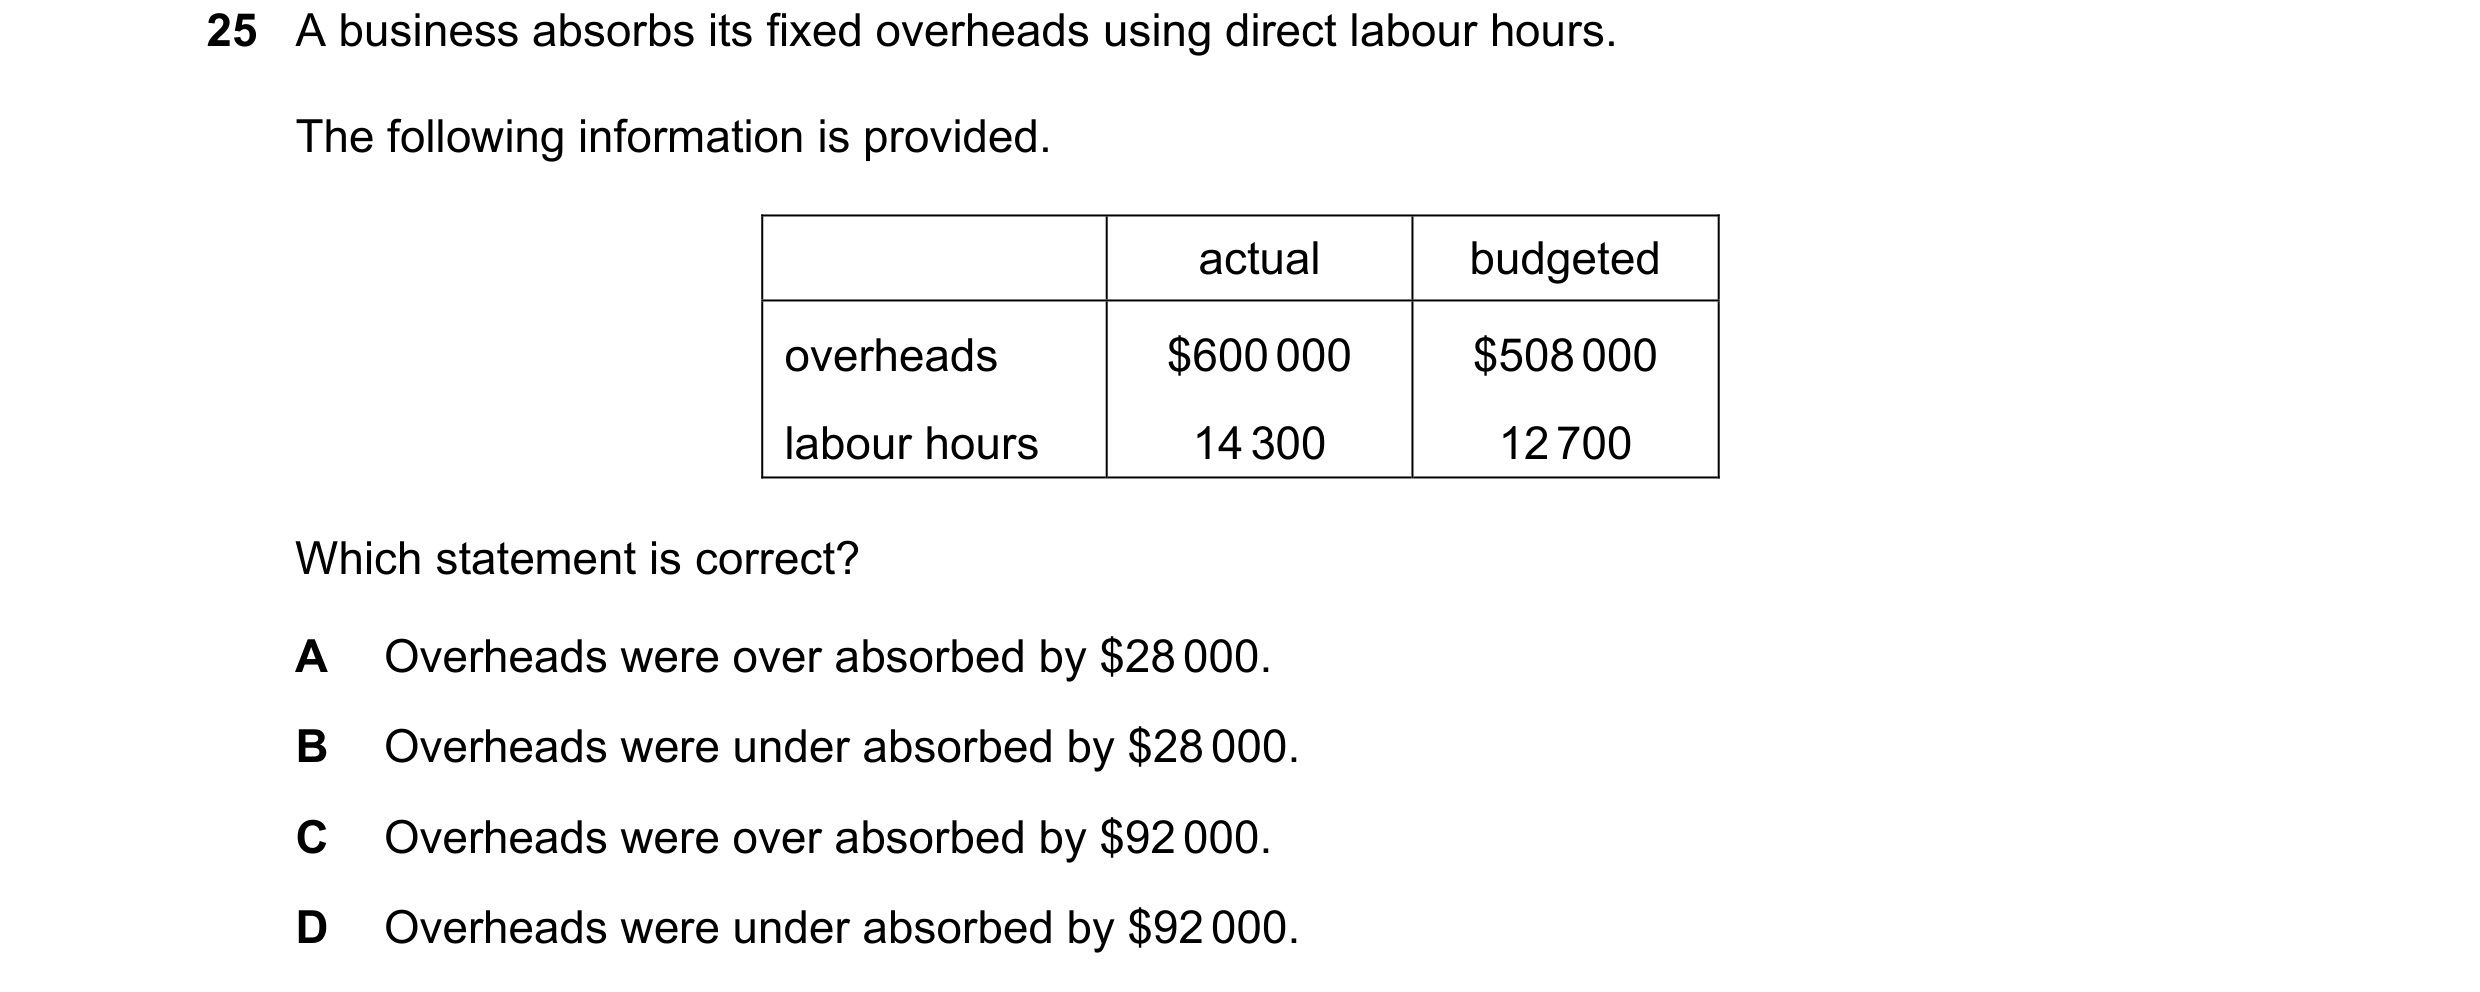
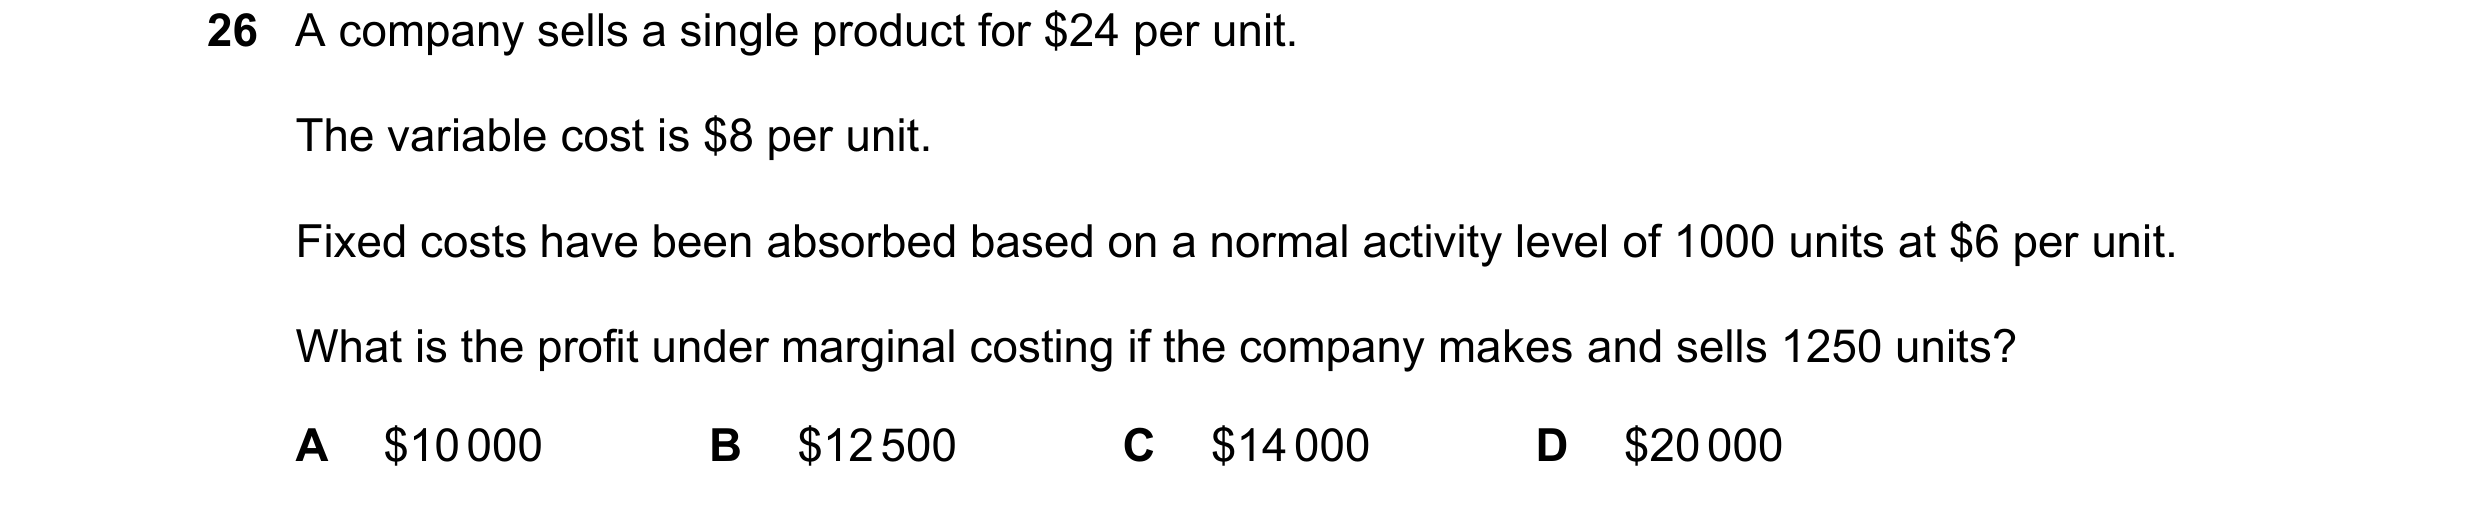
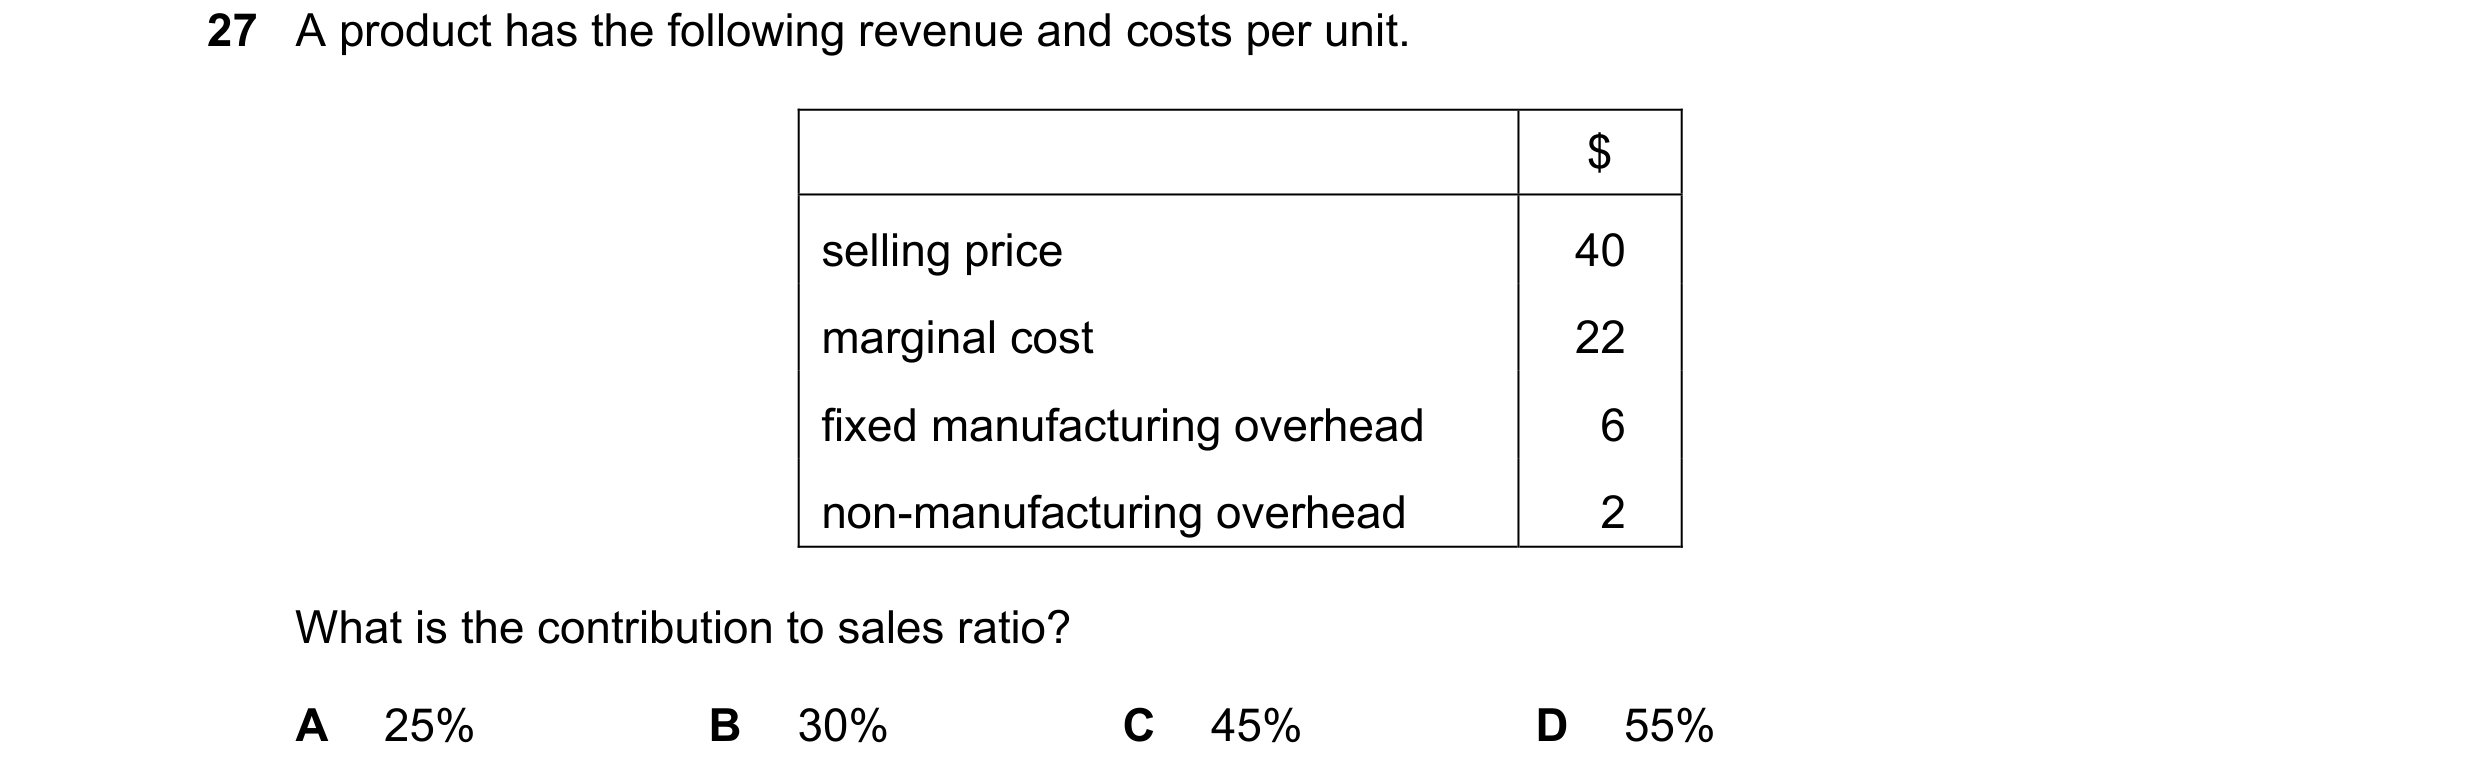
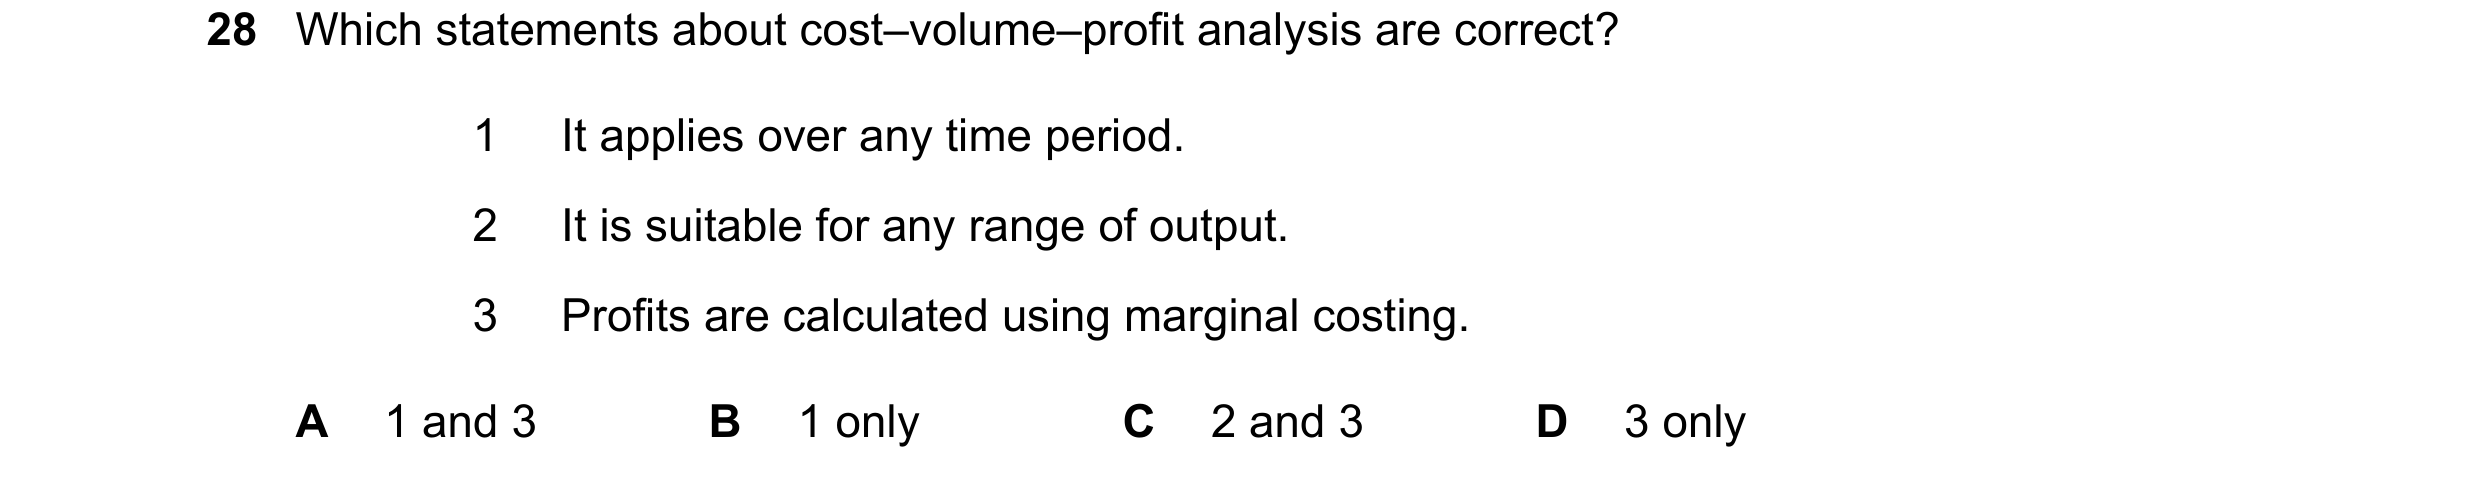 99 / 143
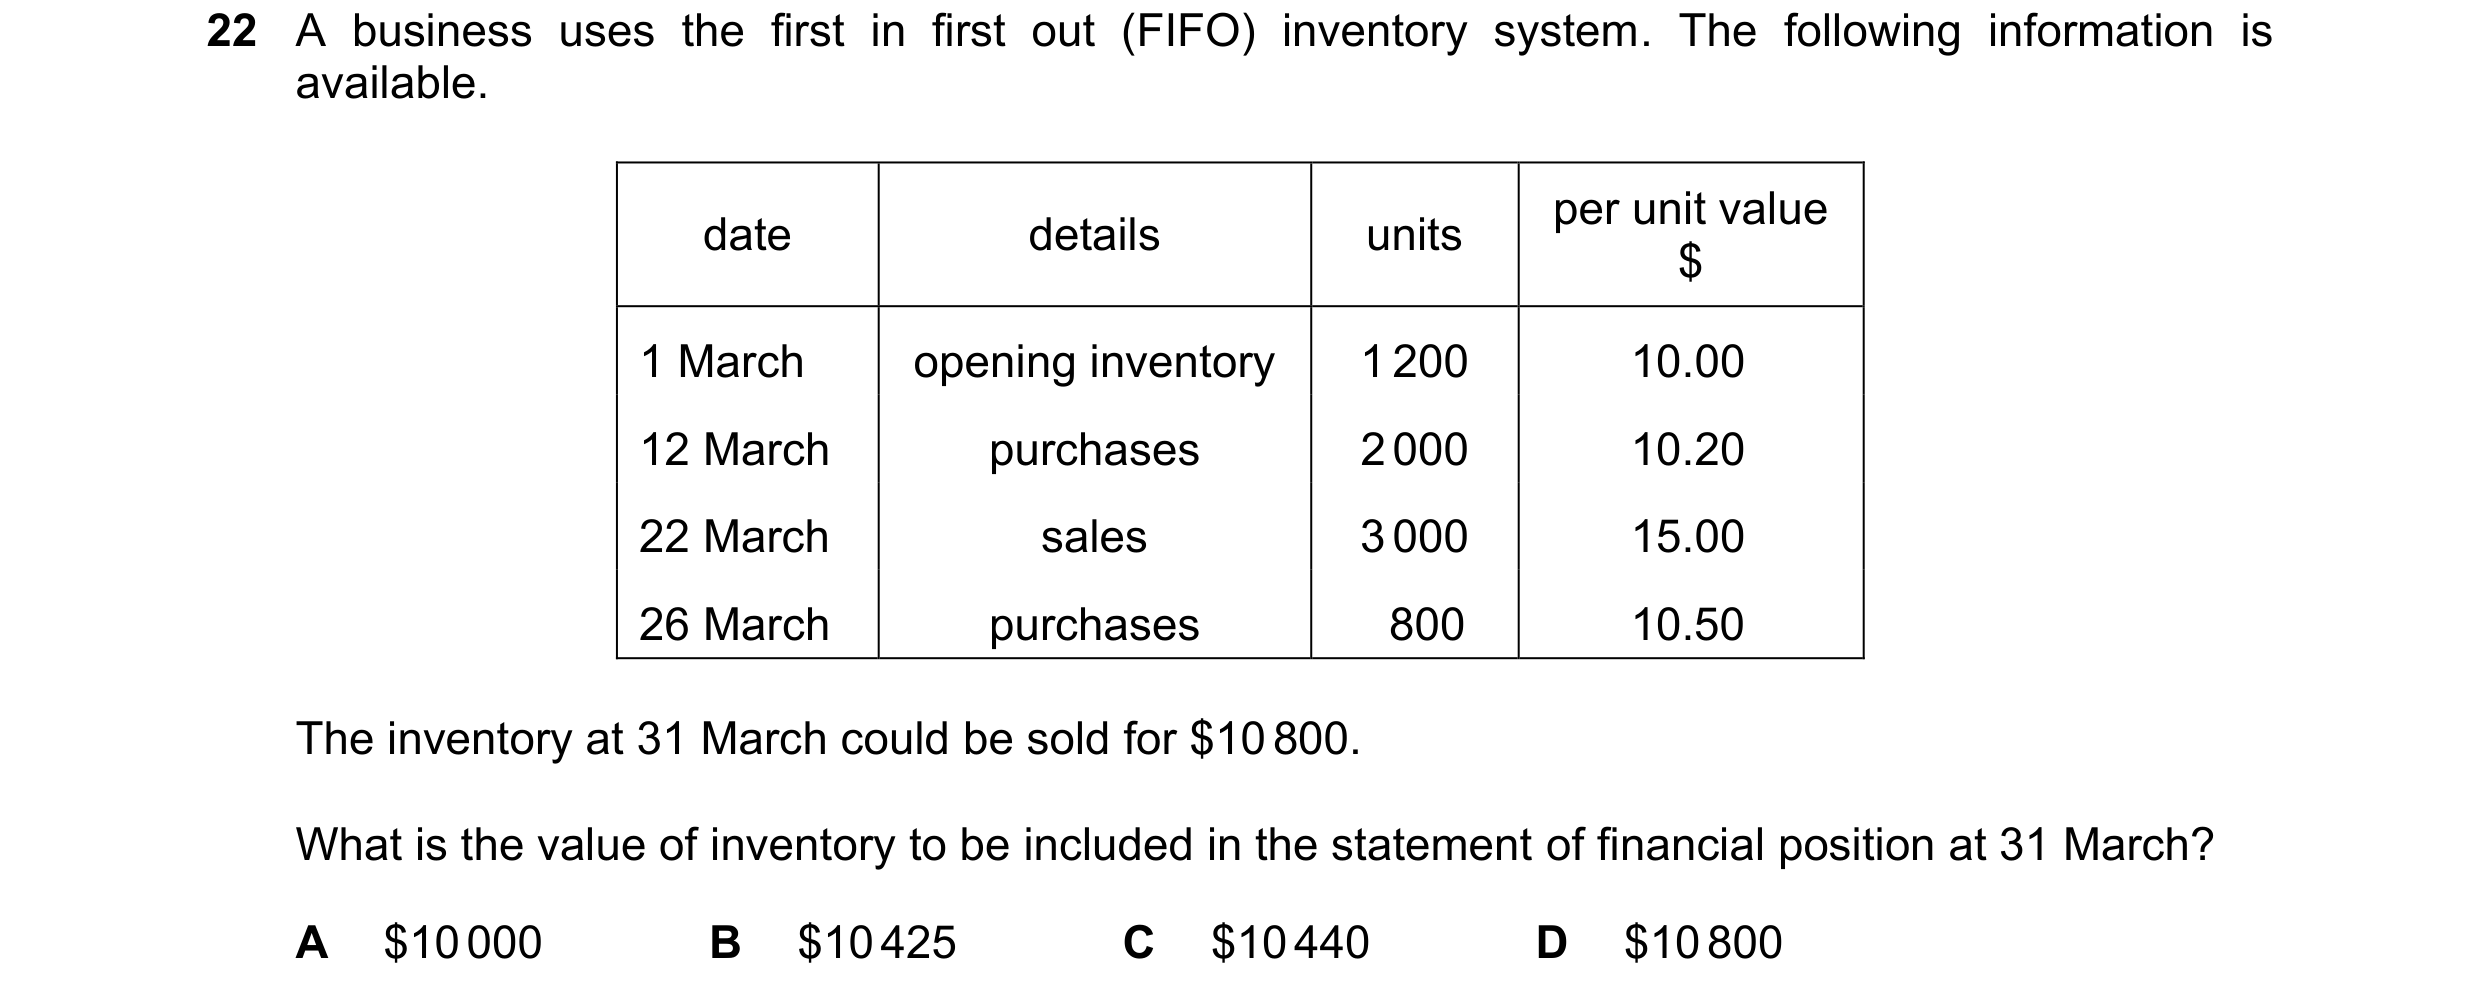
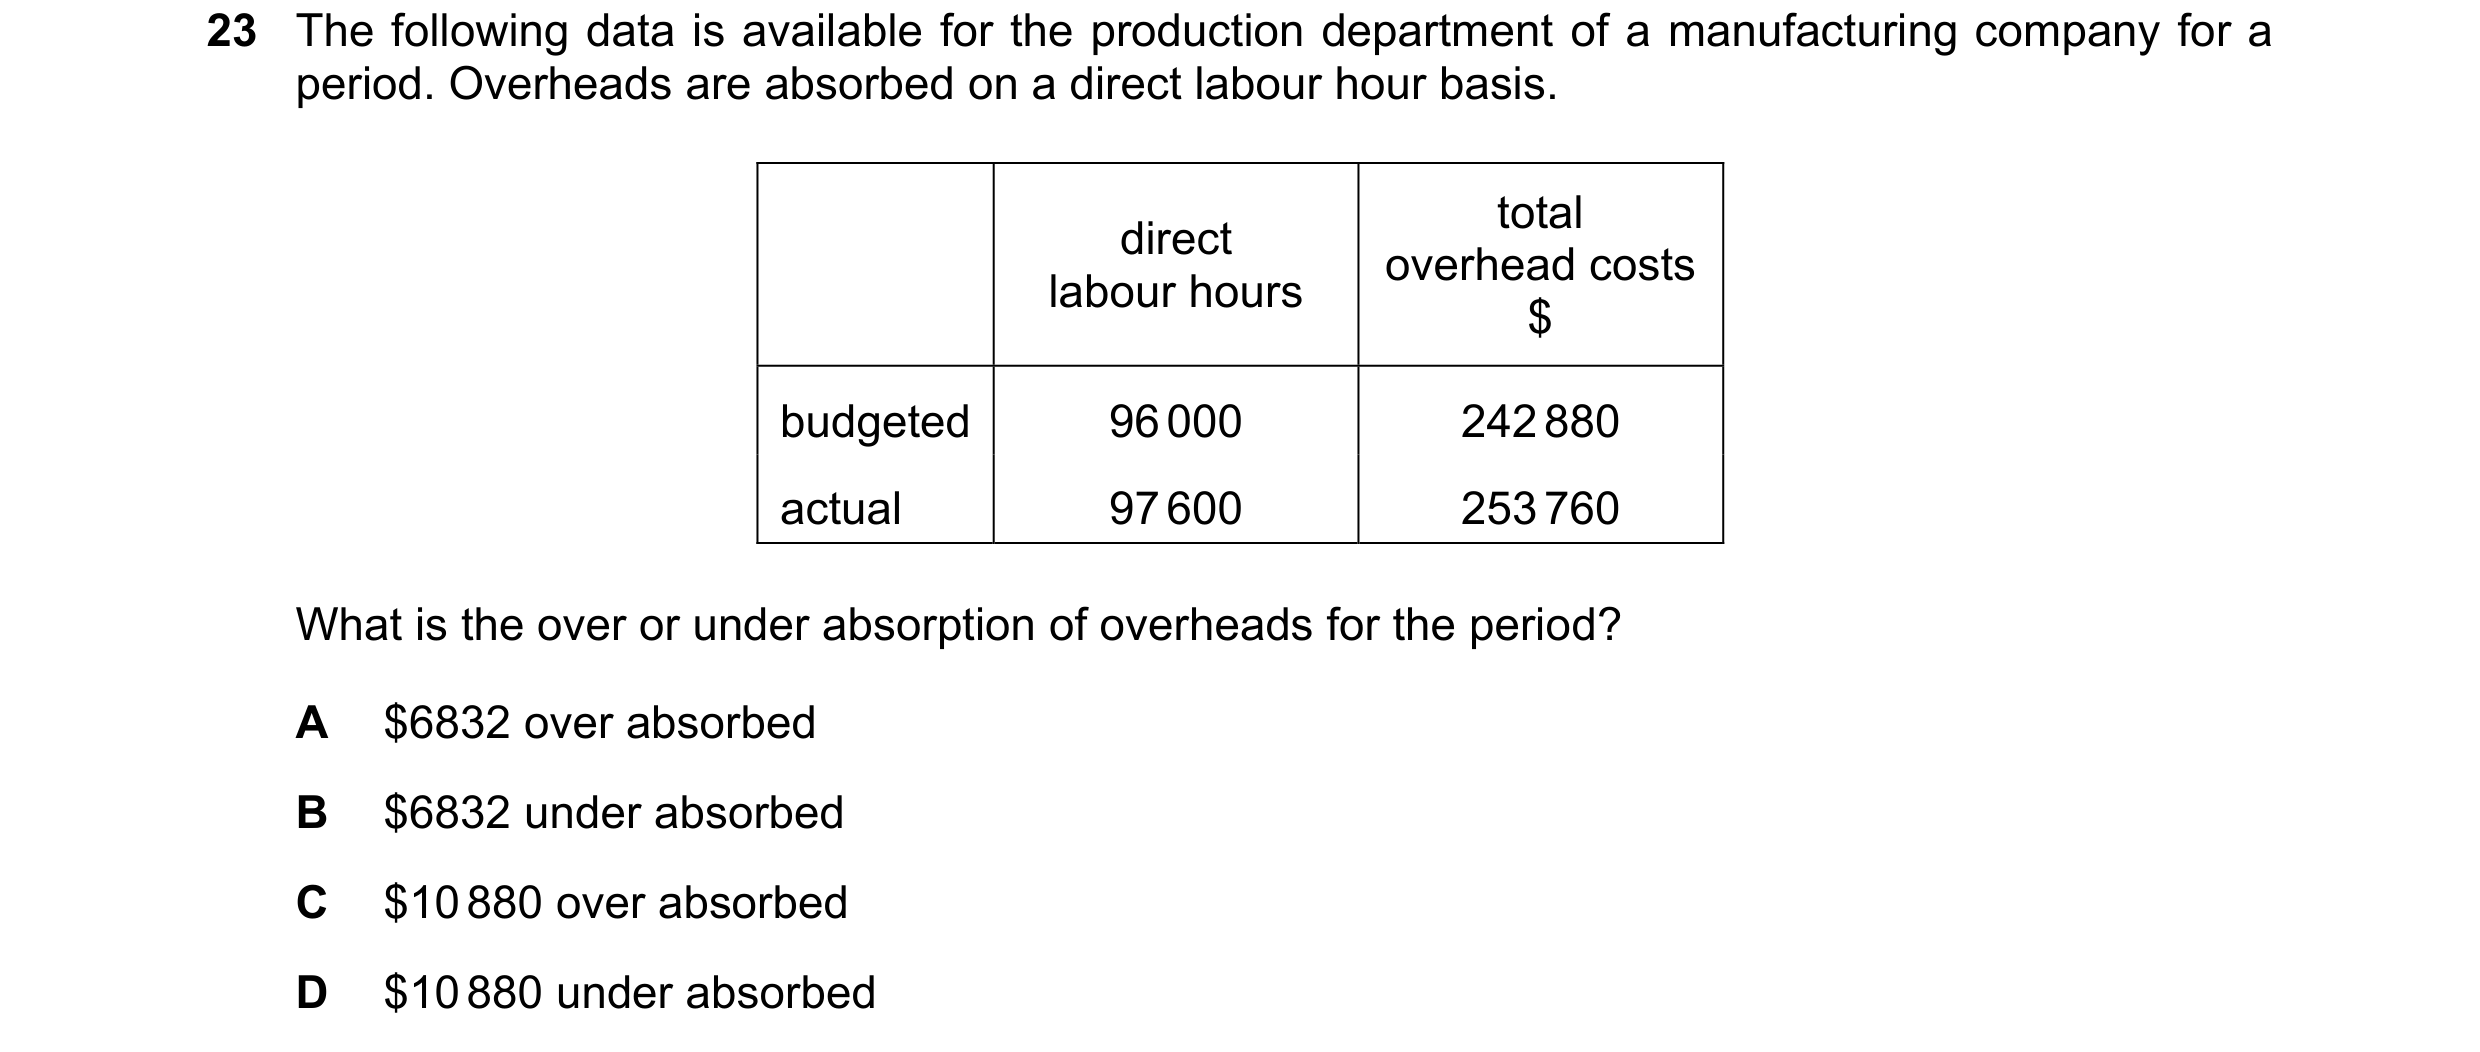
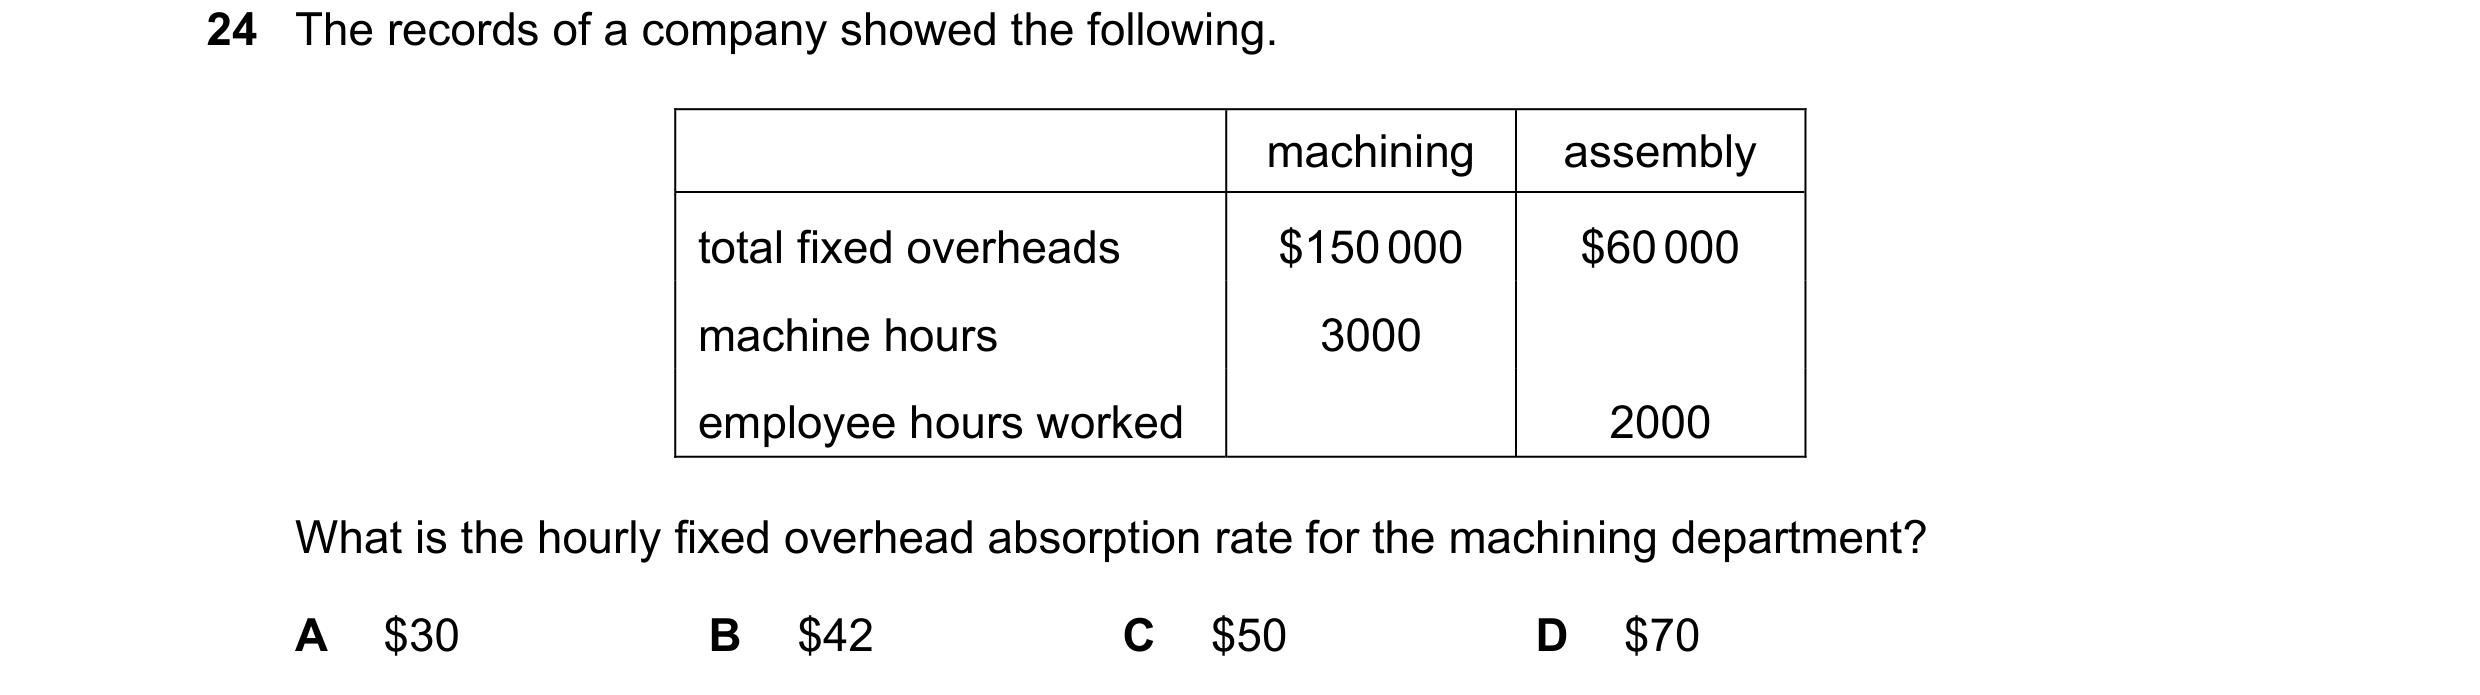
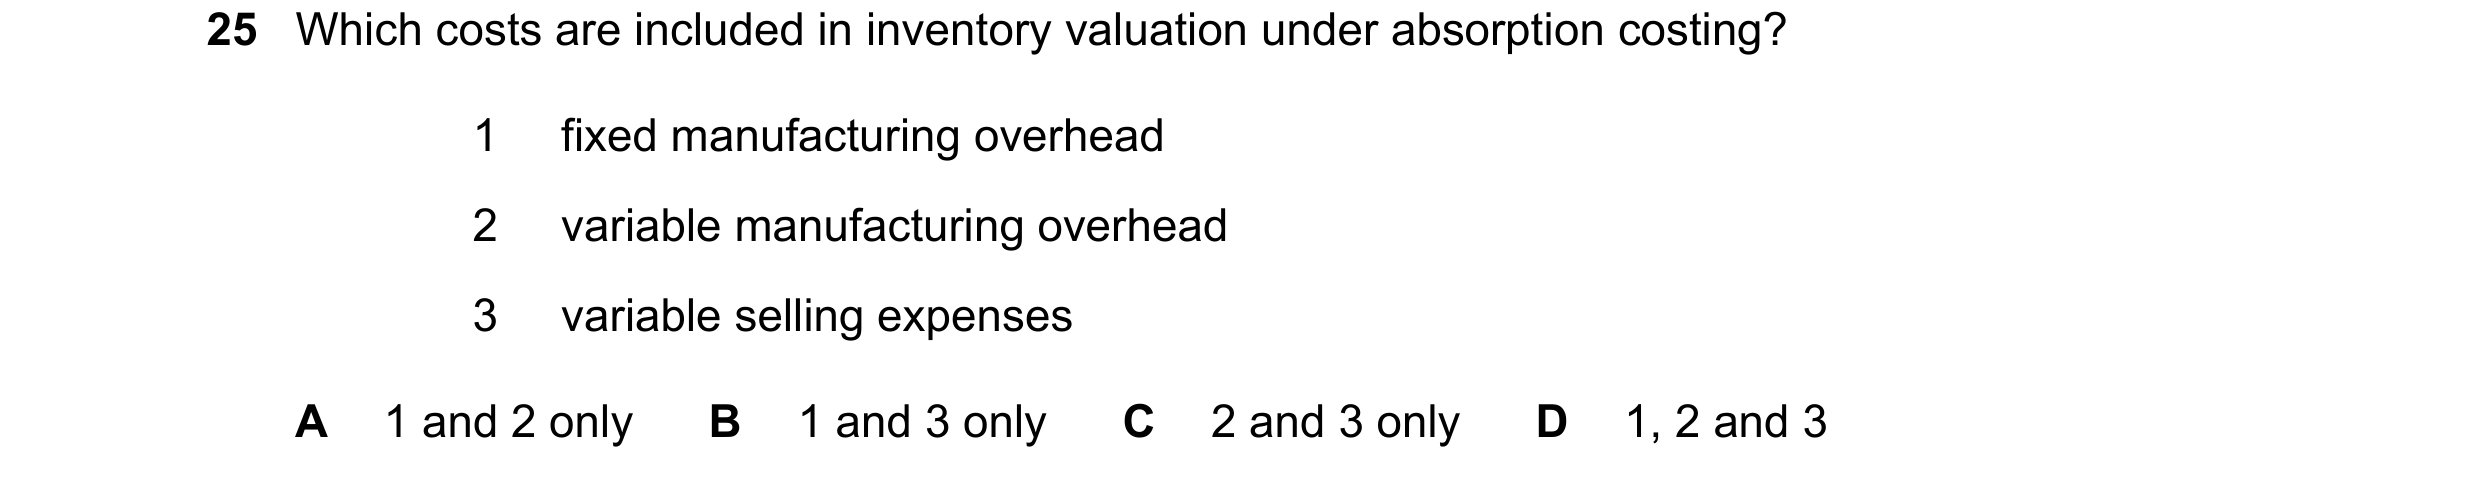 100 / 143
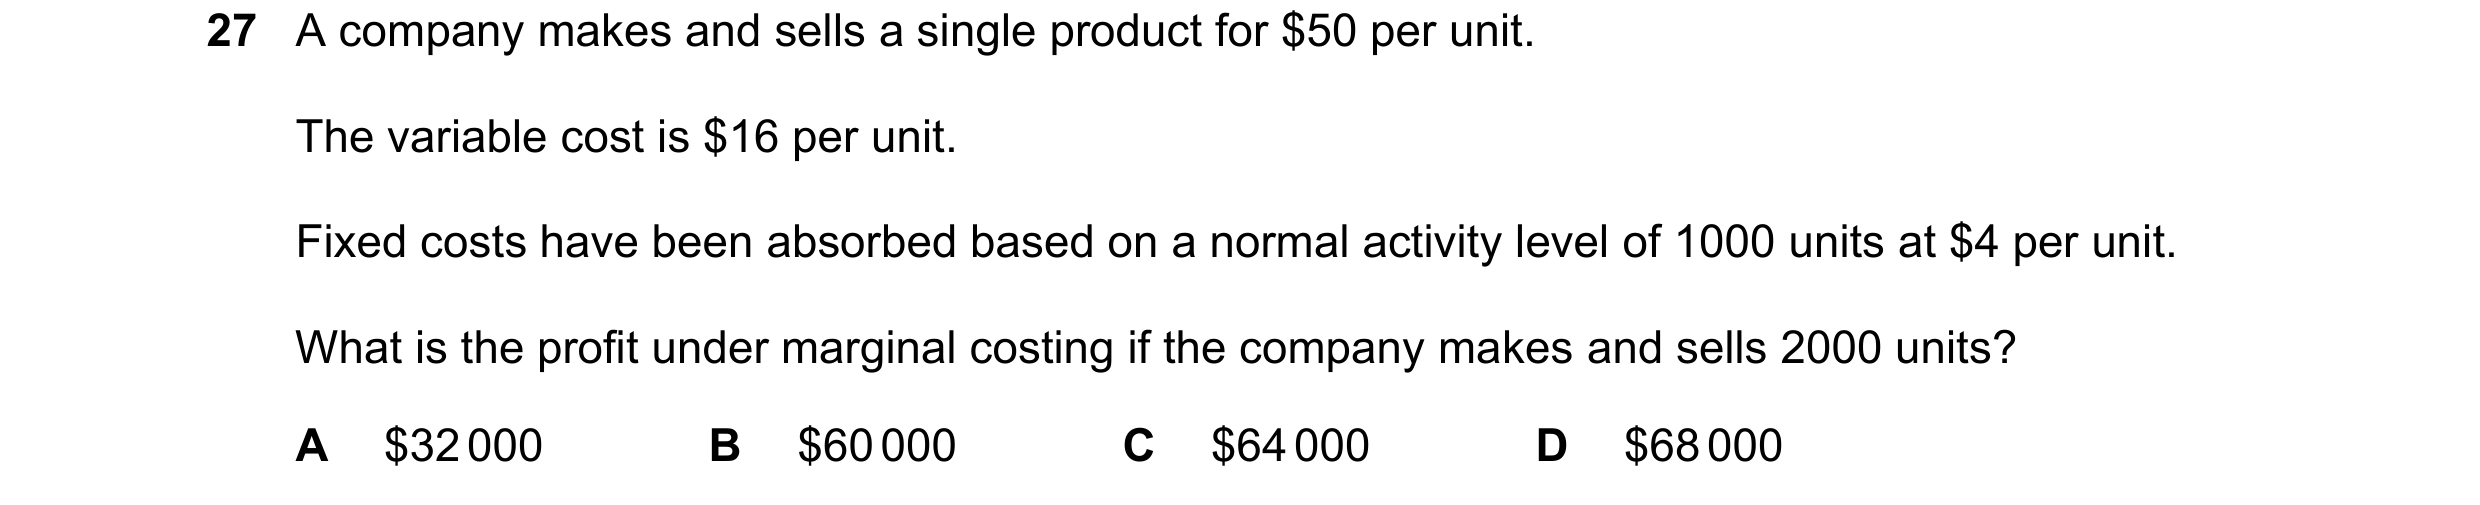
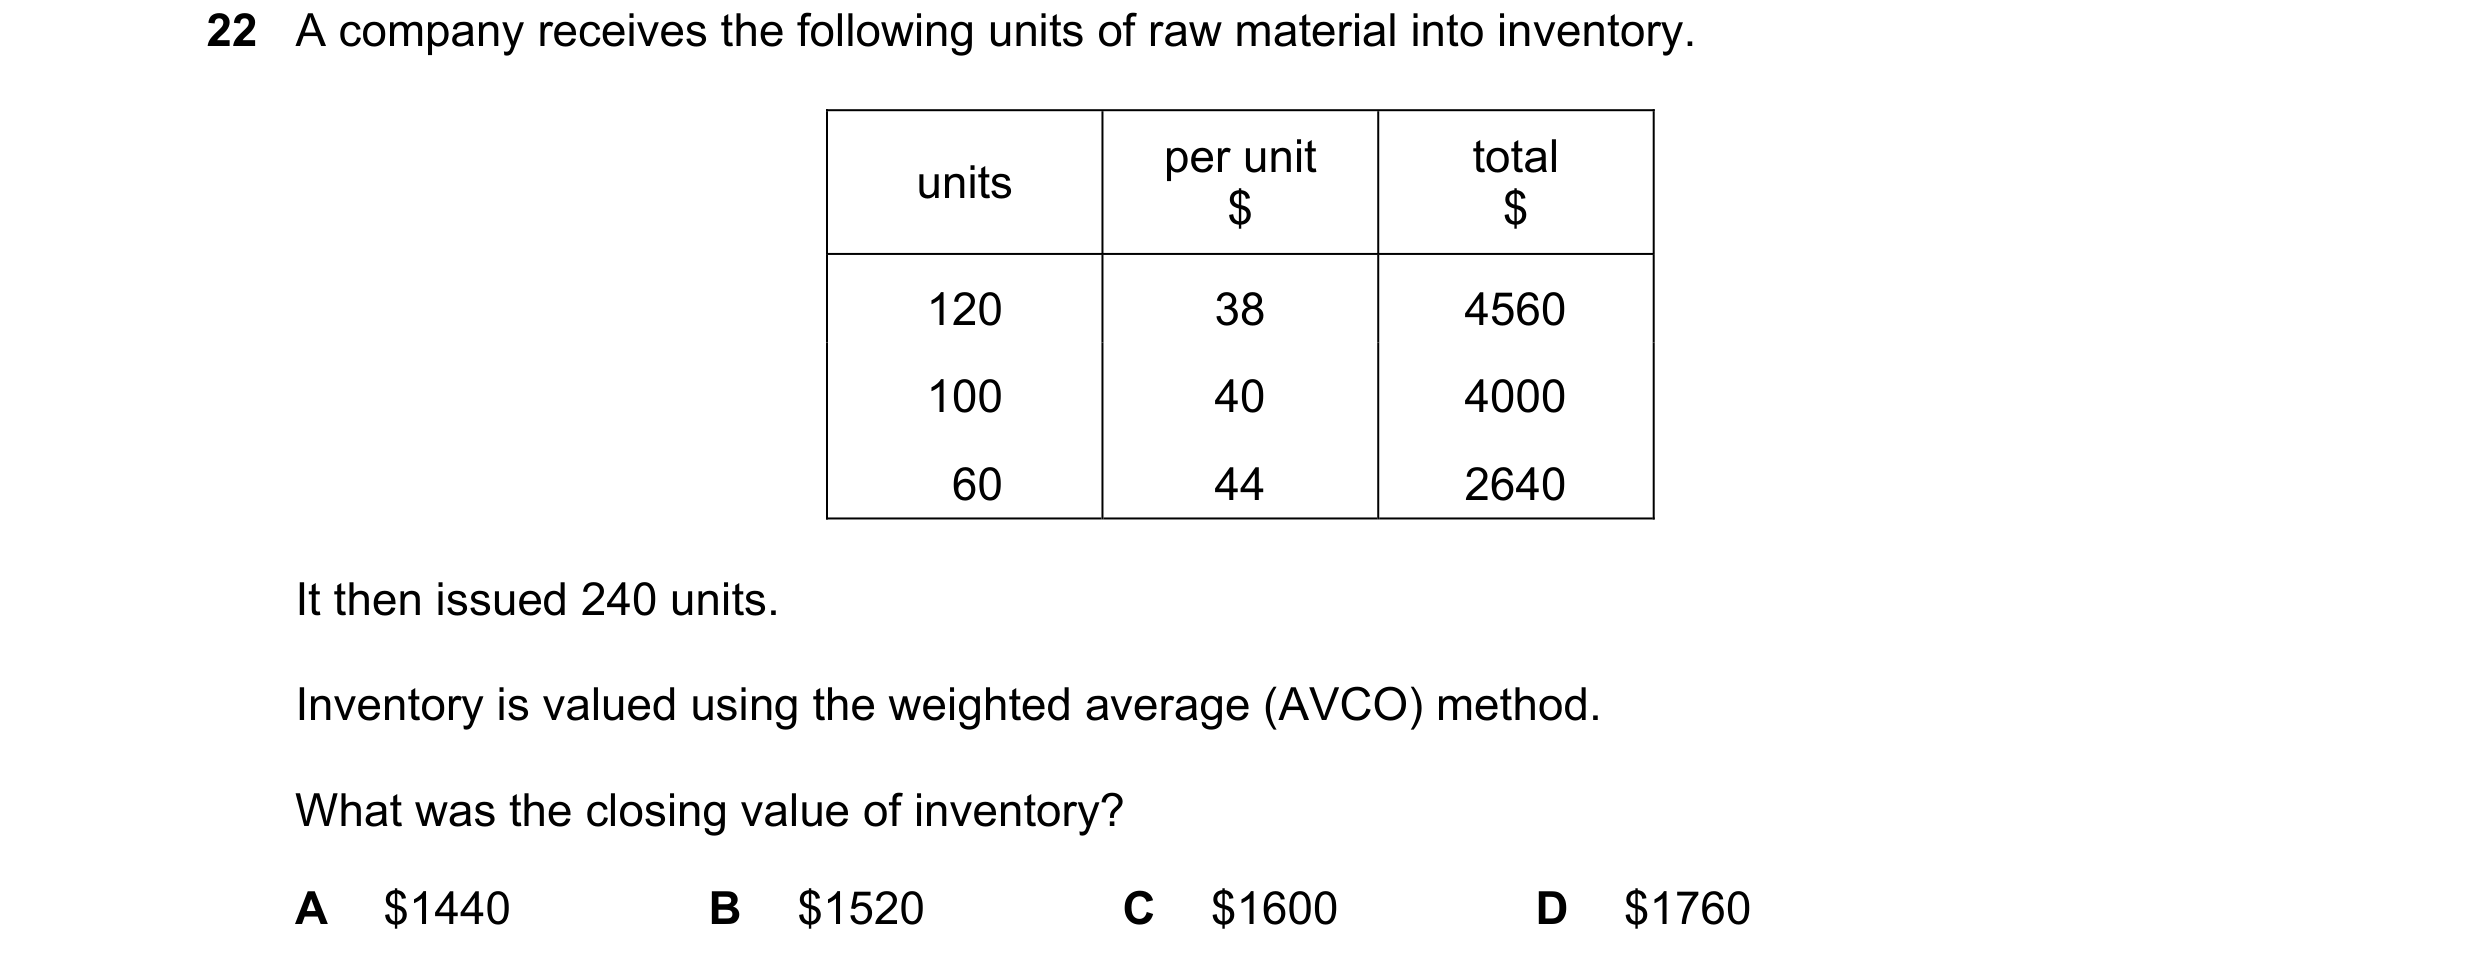
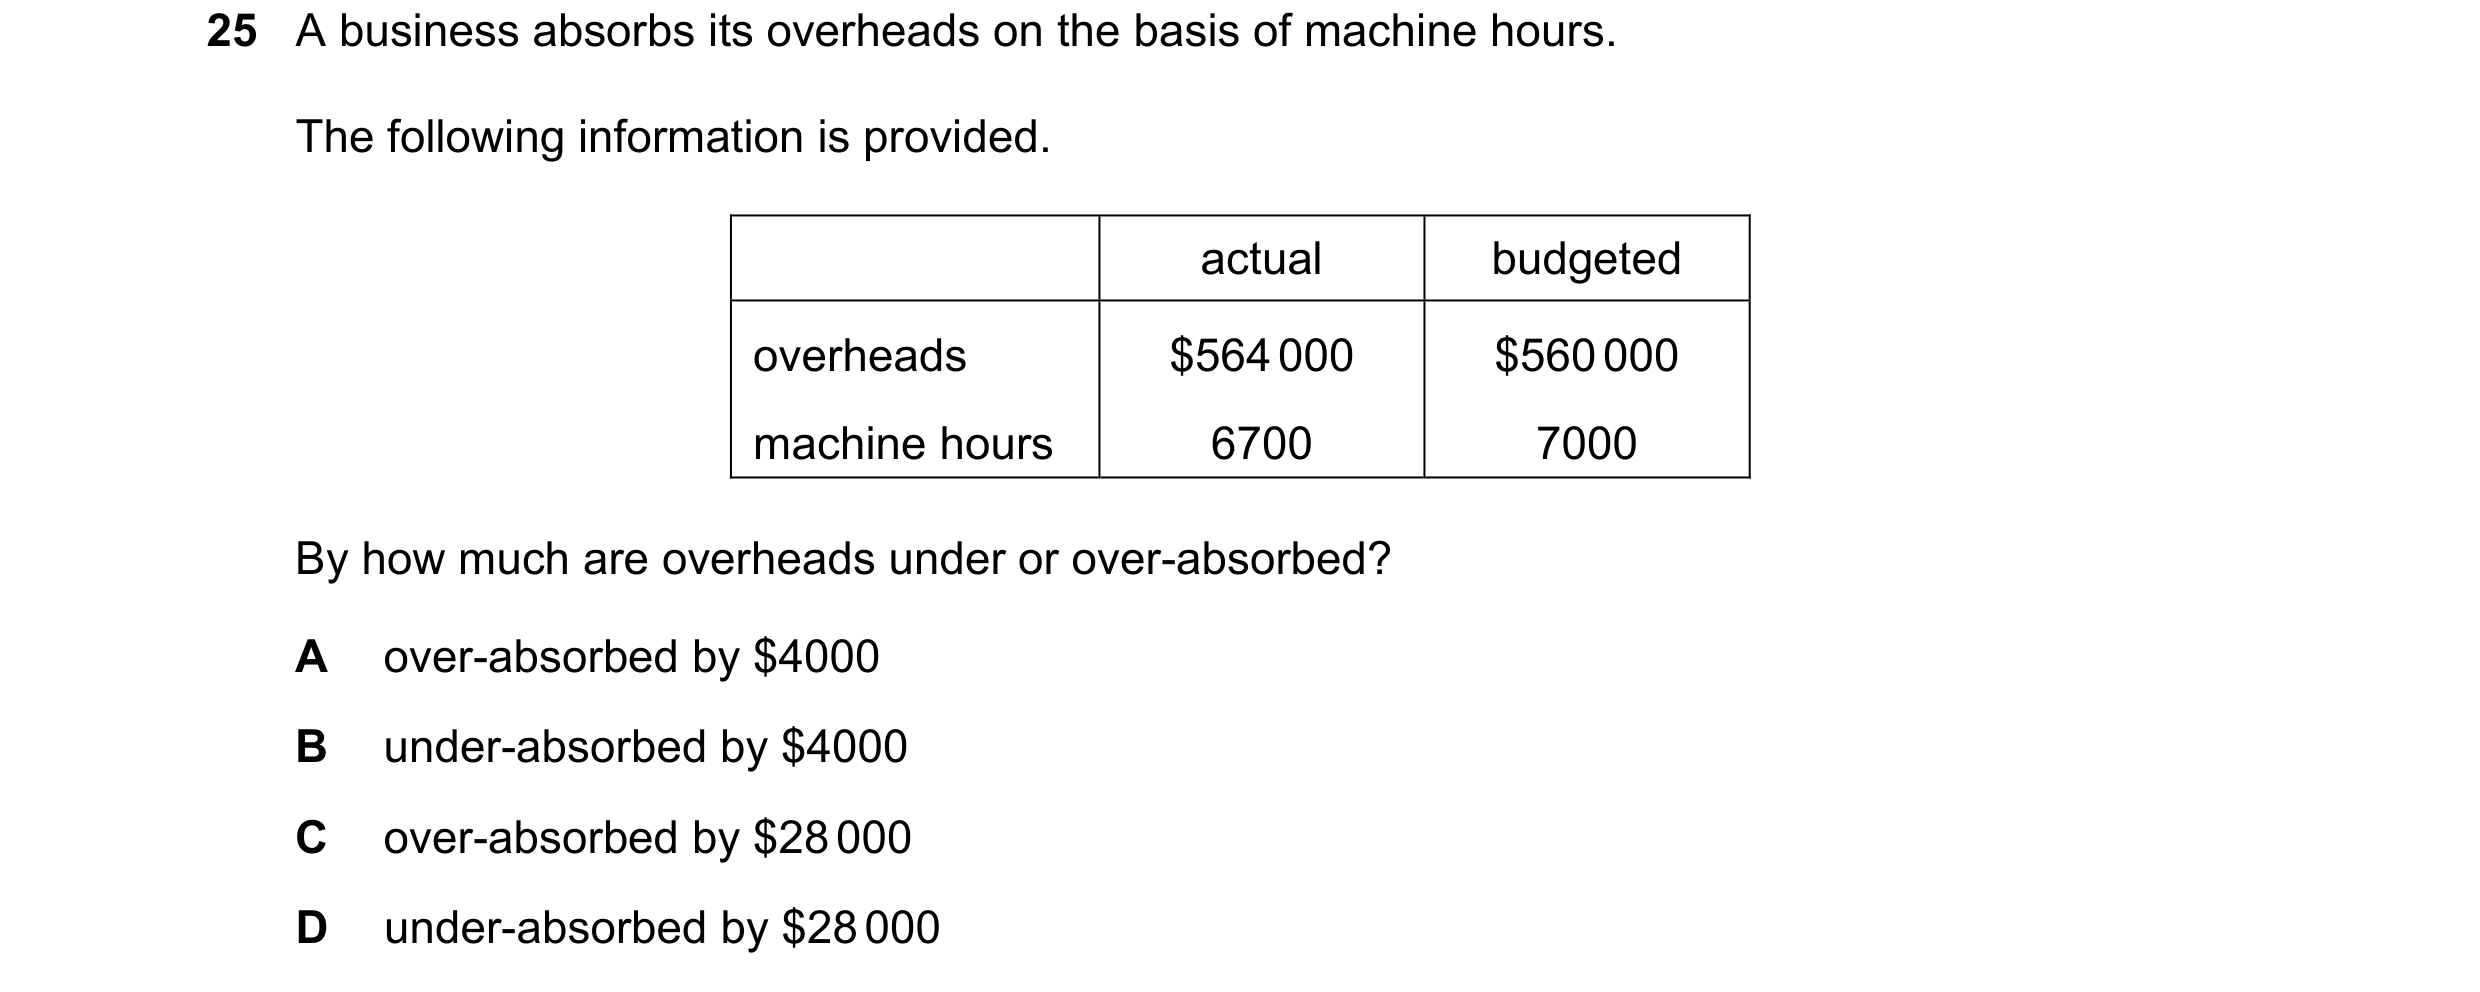 101 / 143
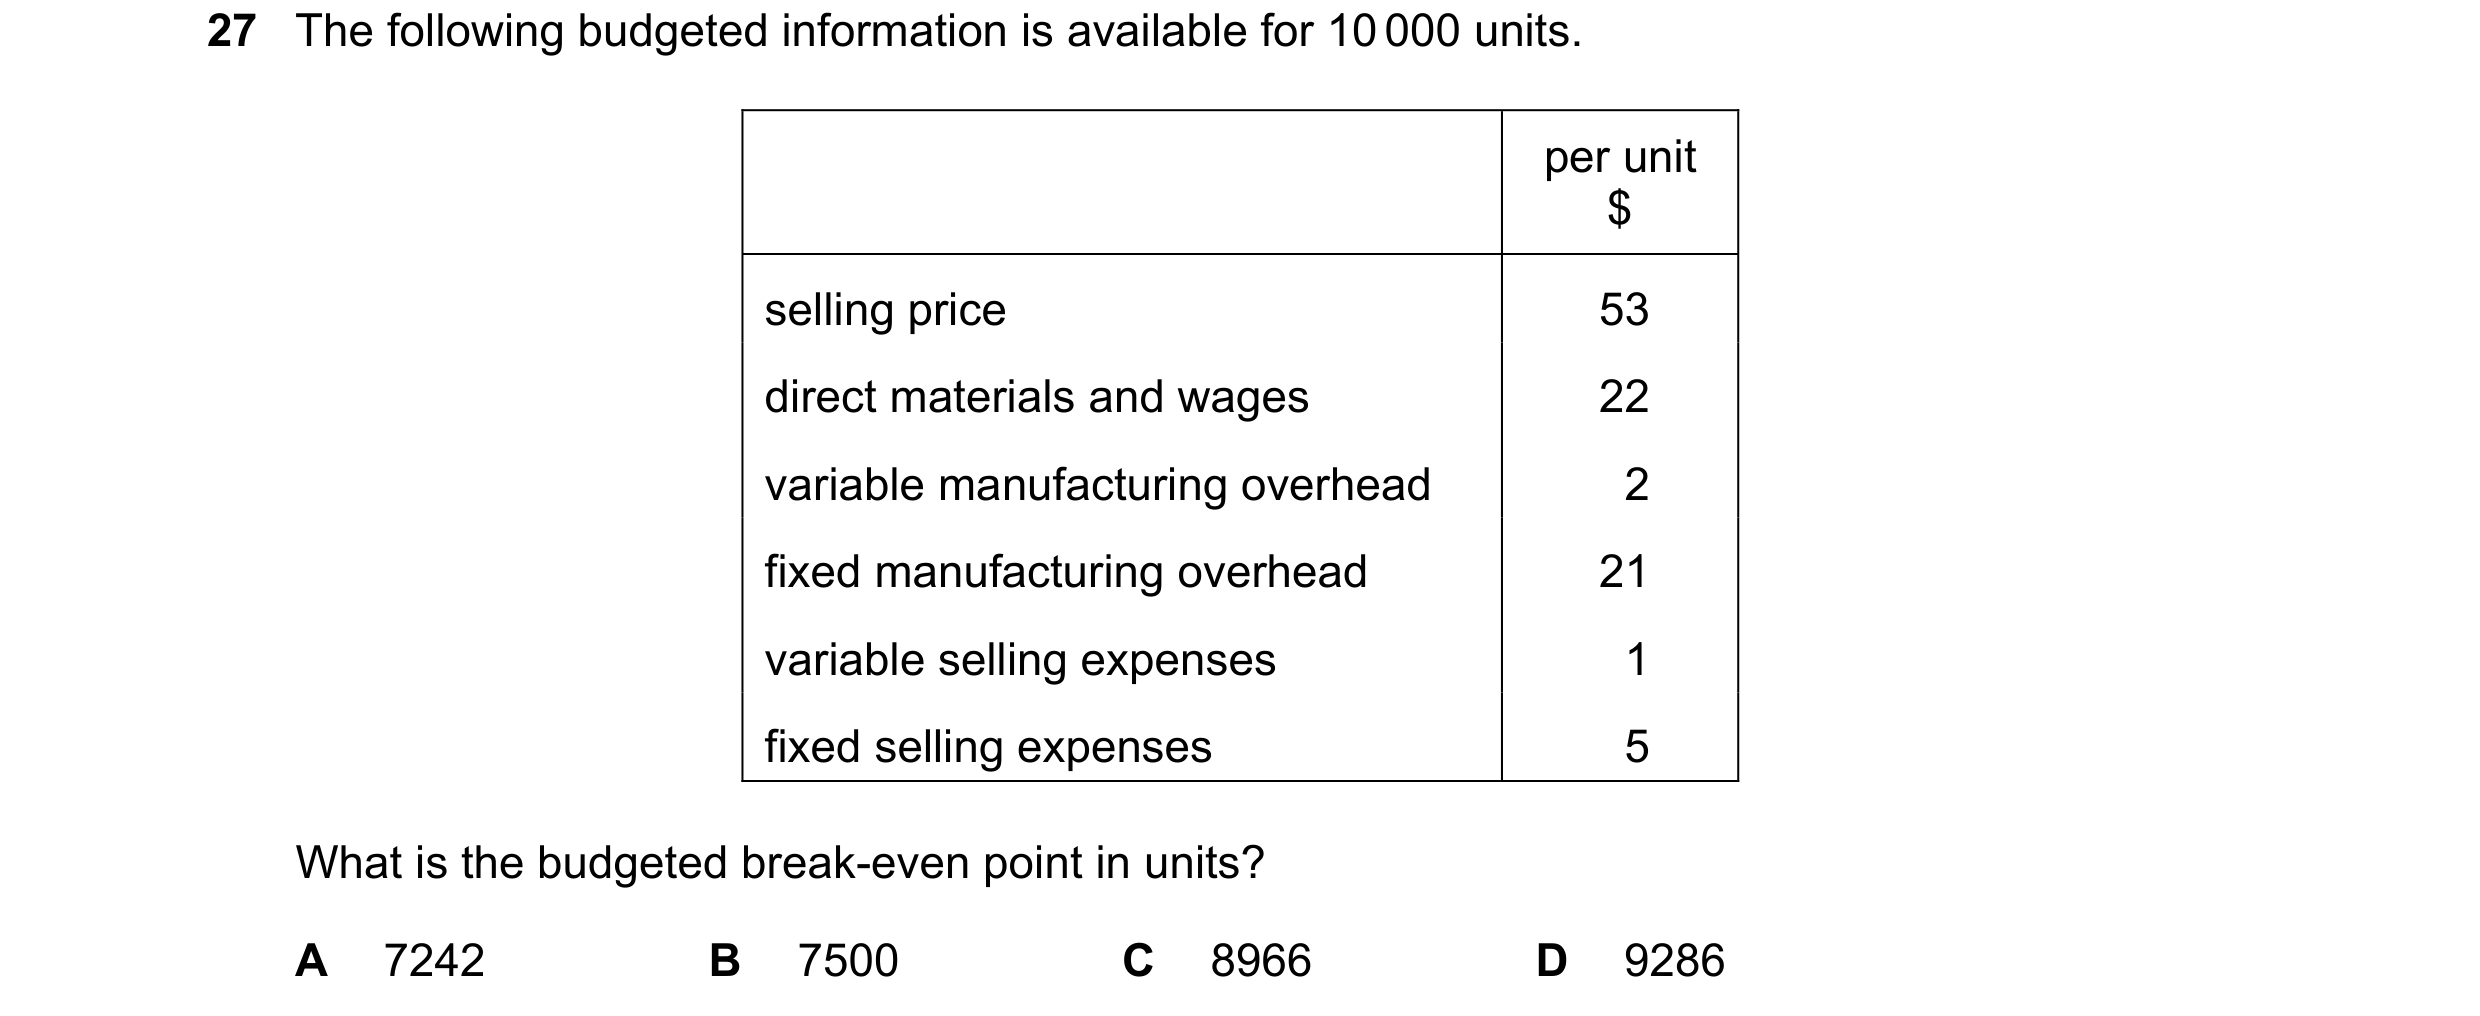
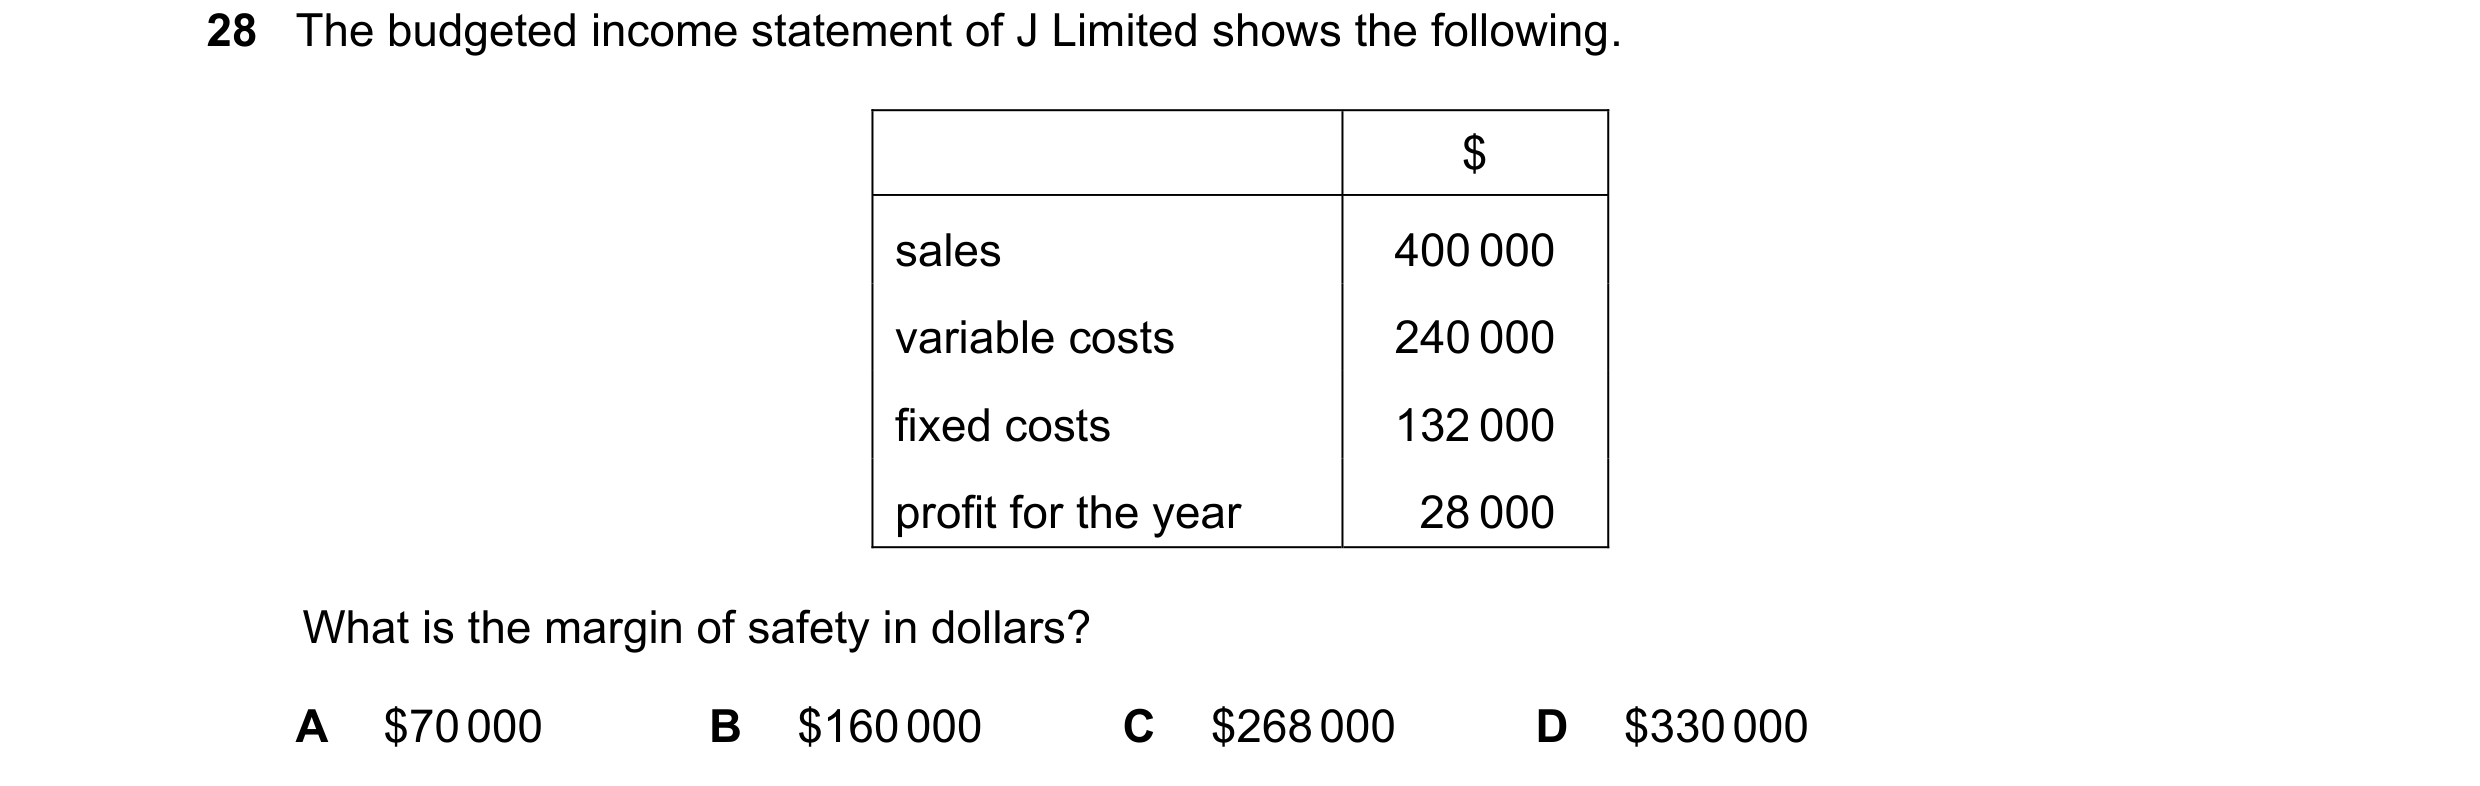
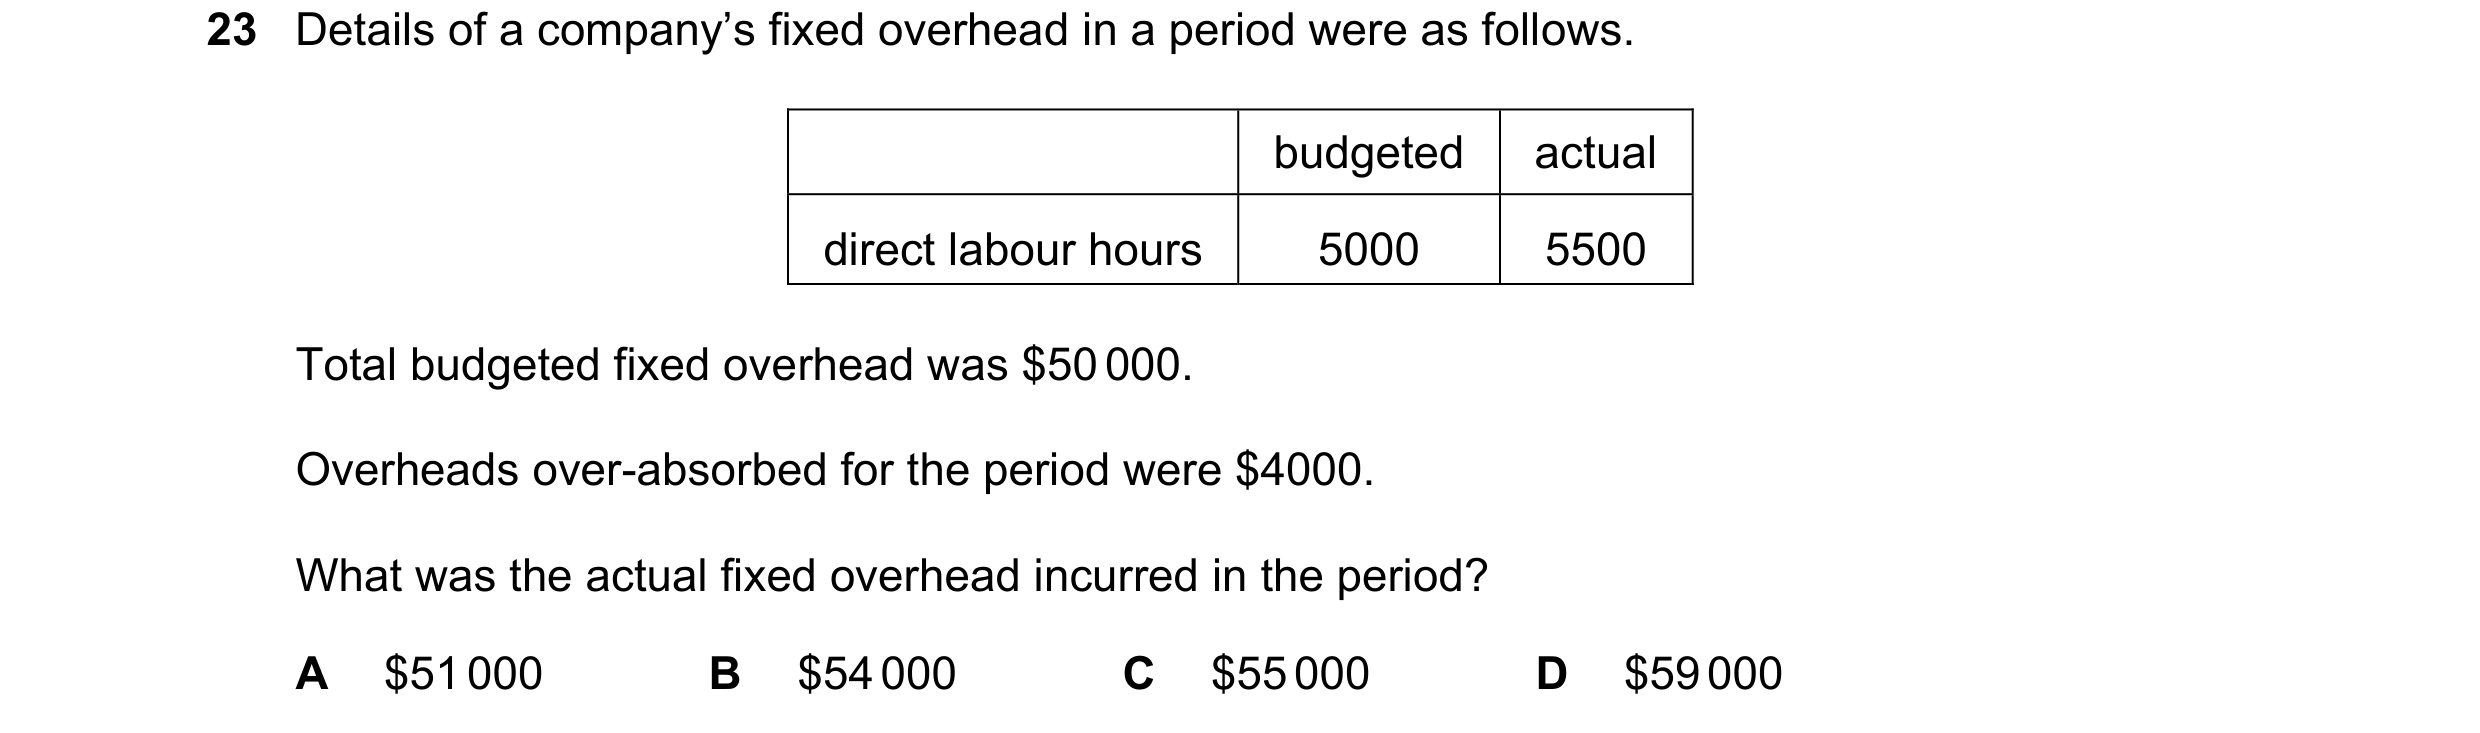 102 / 143
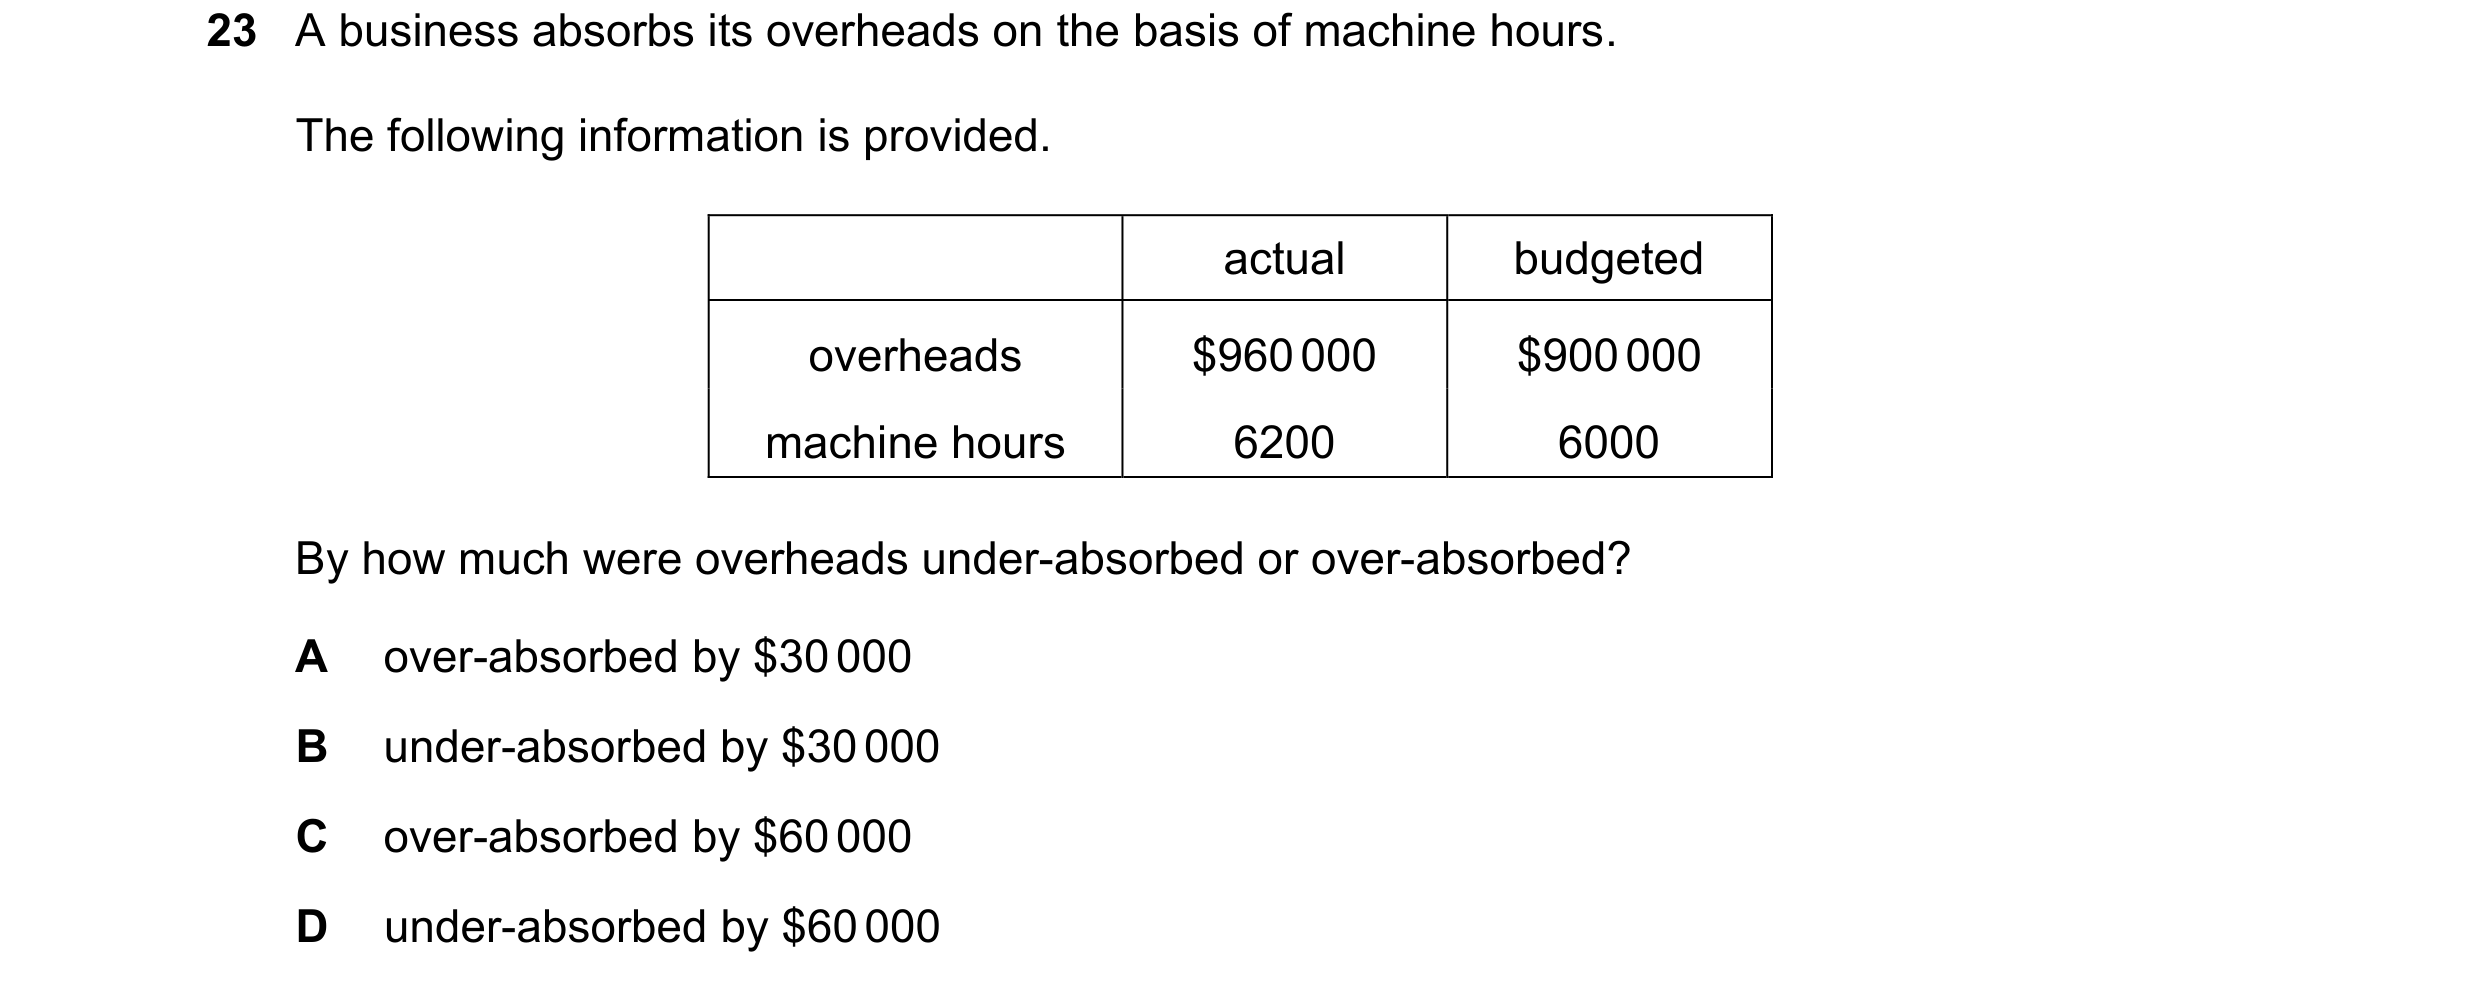
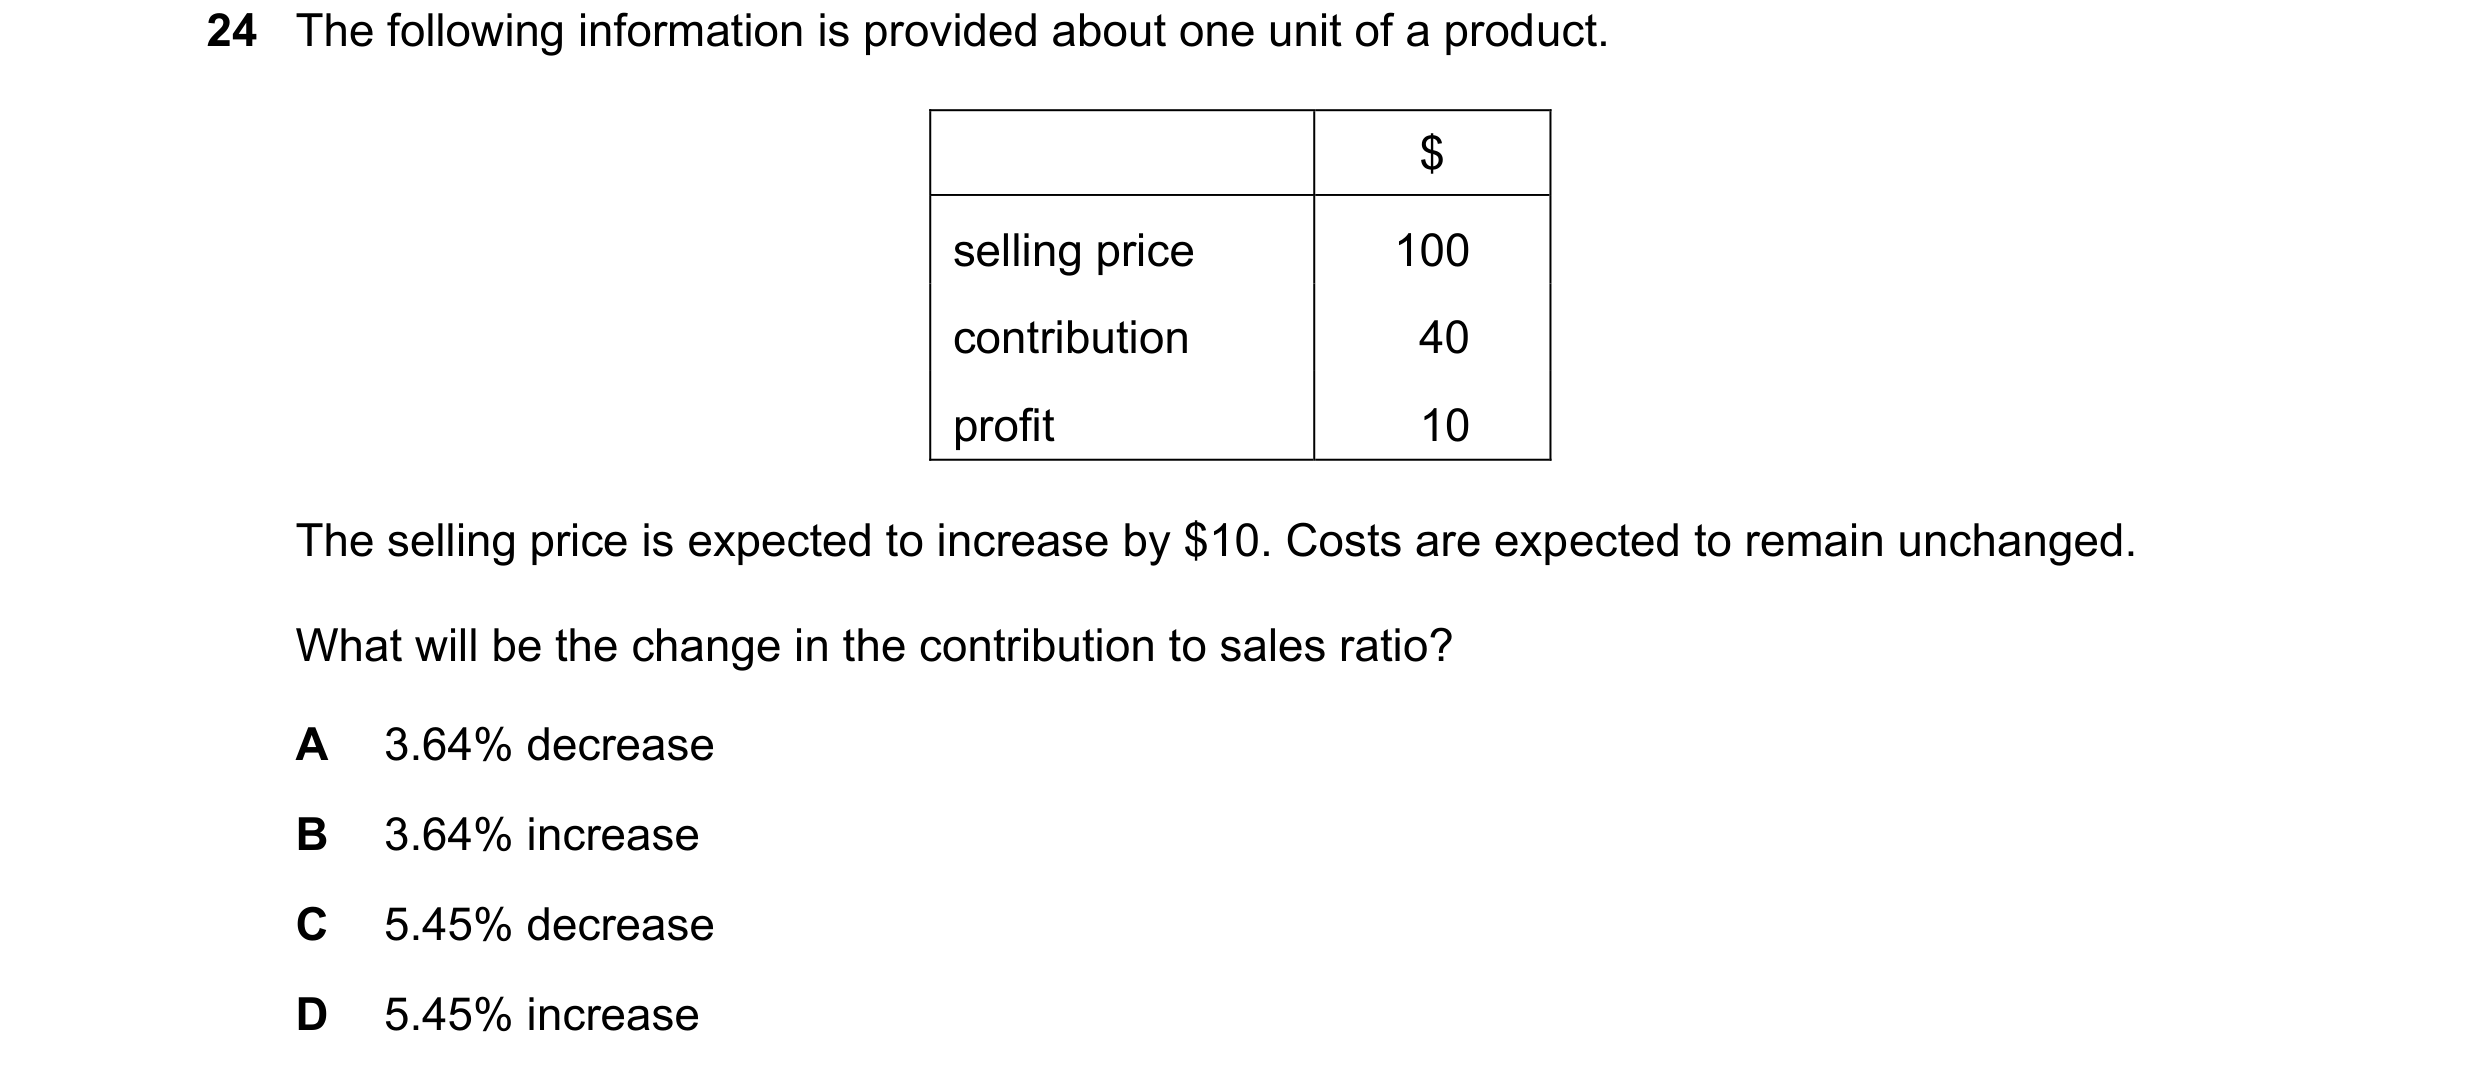 103 / 143
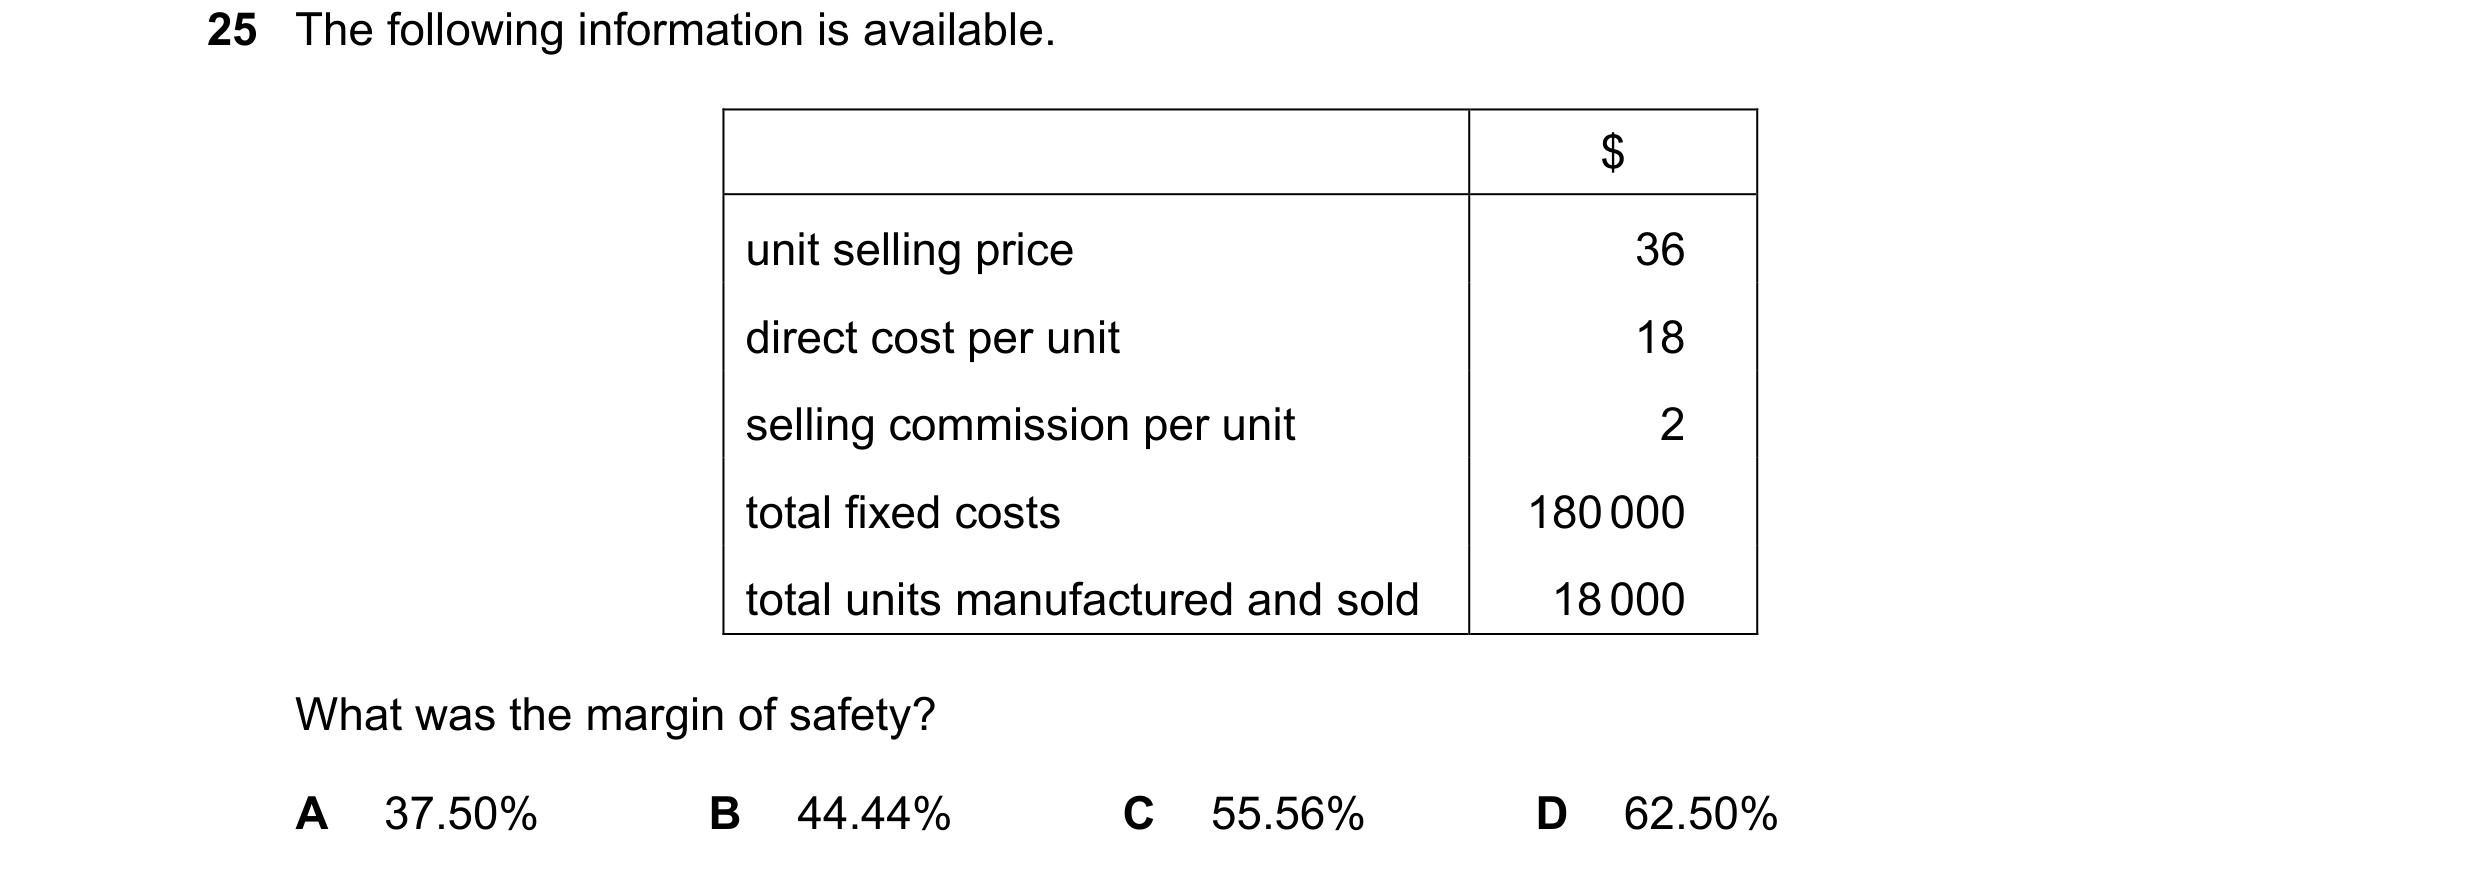
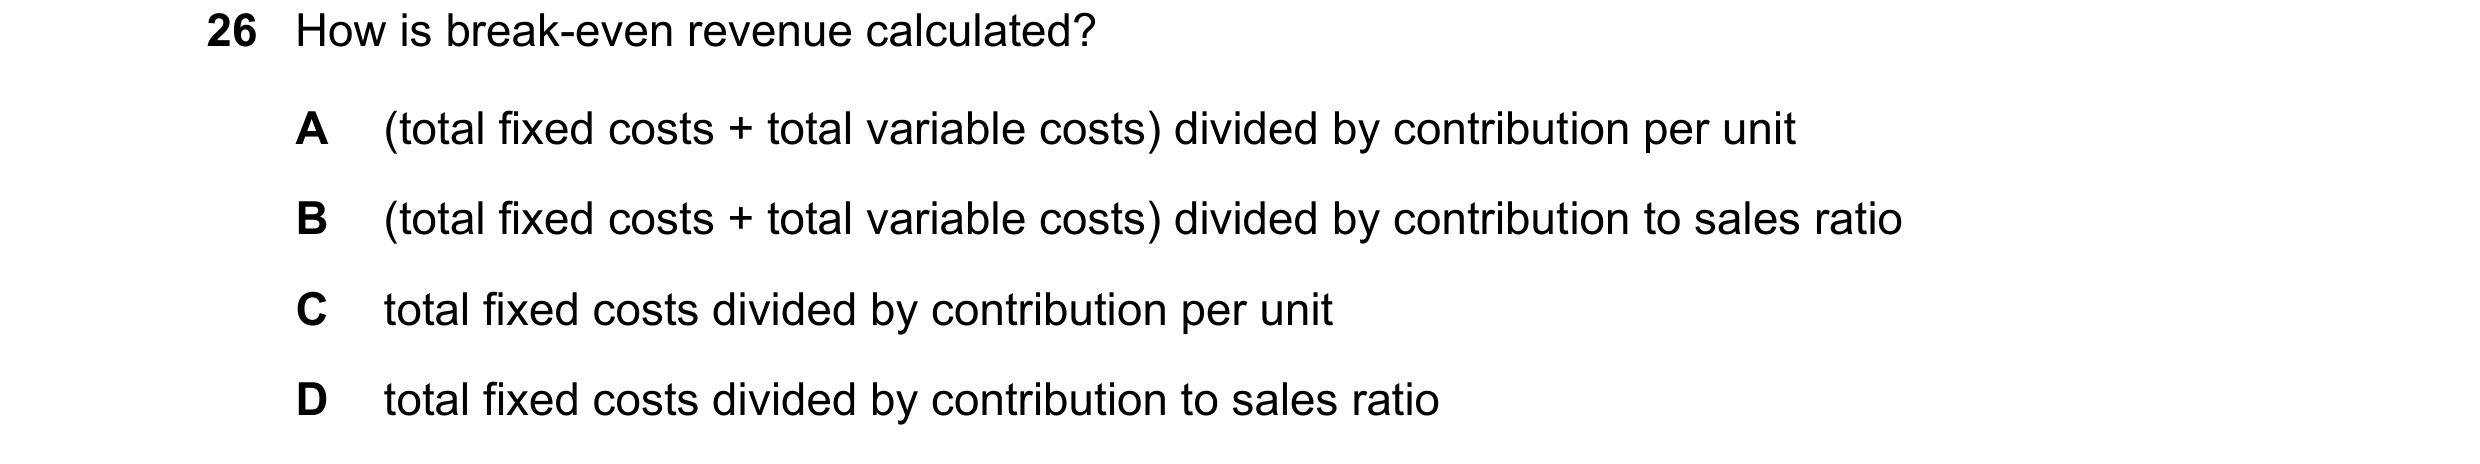
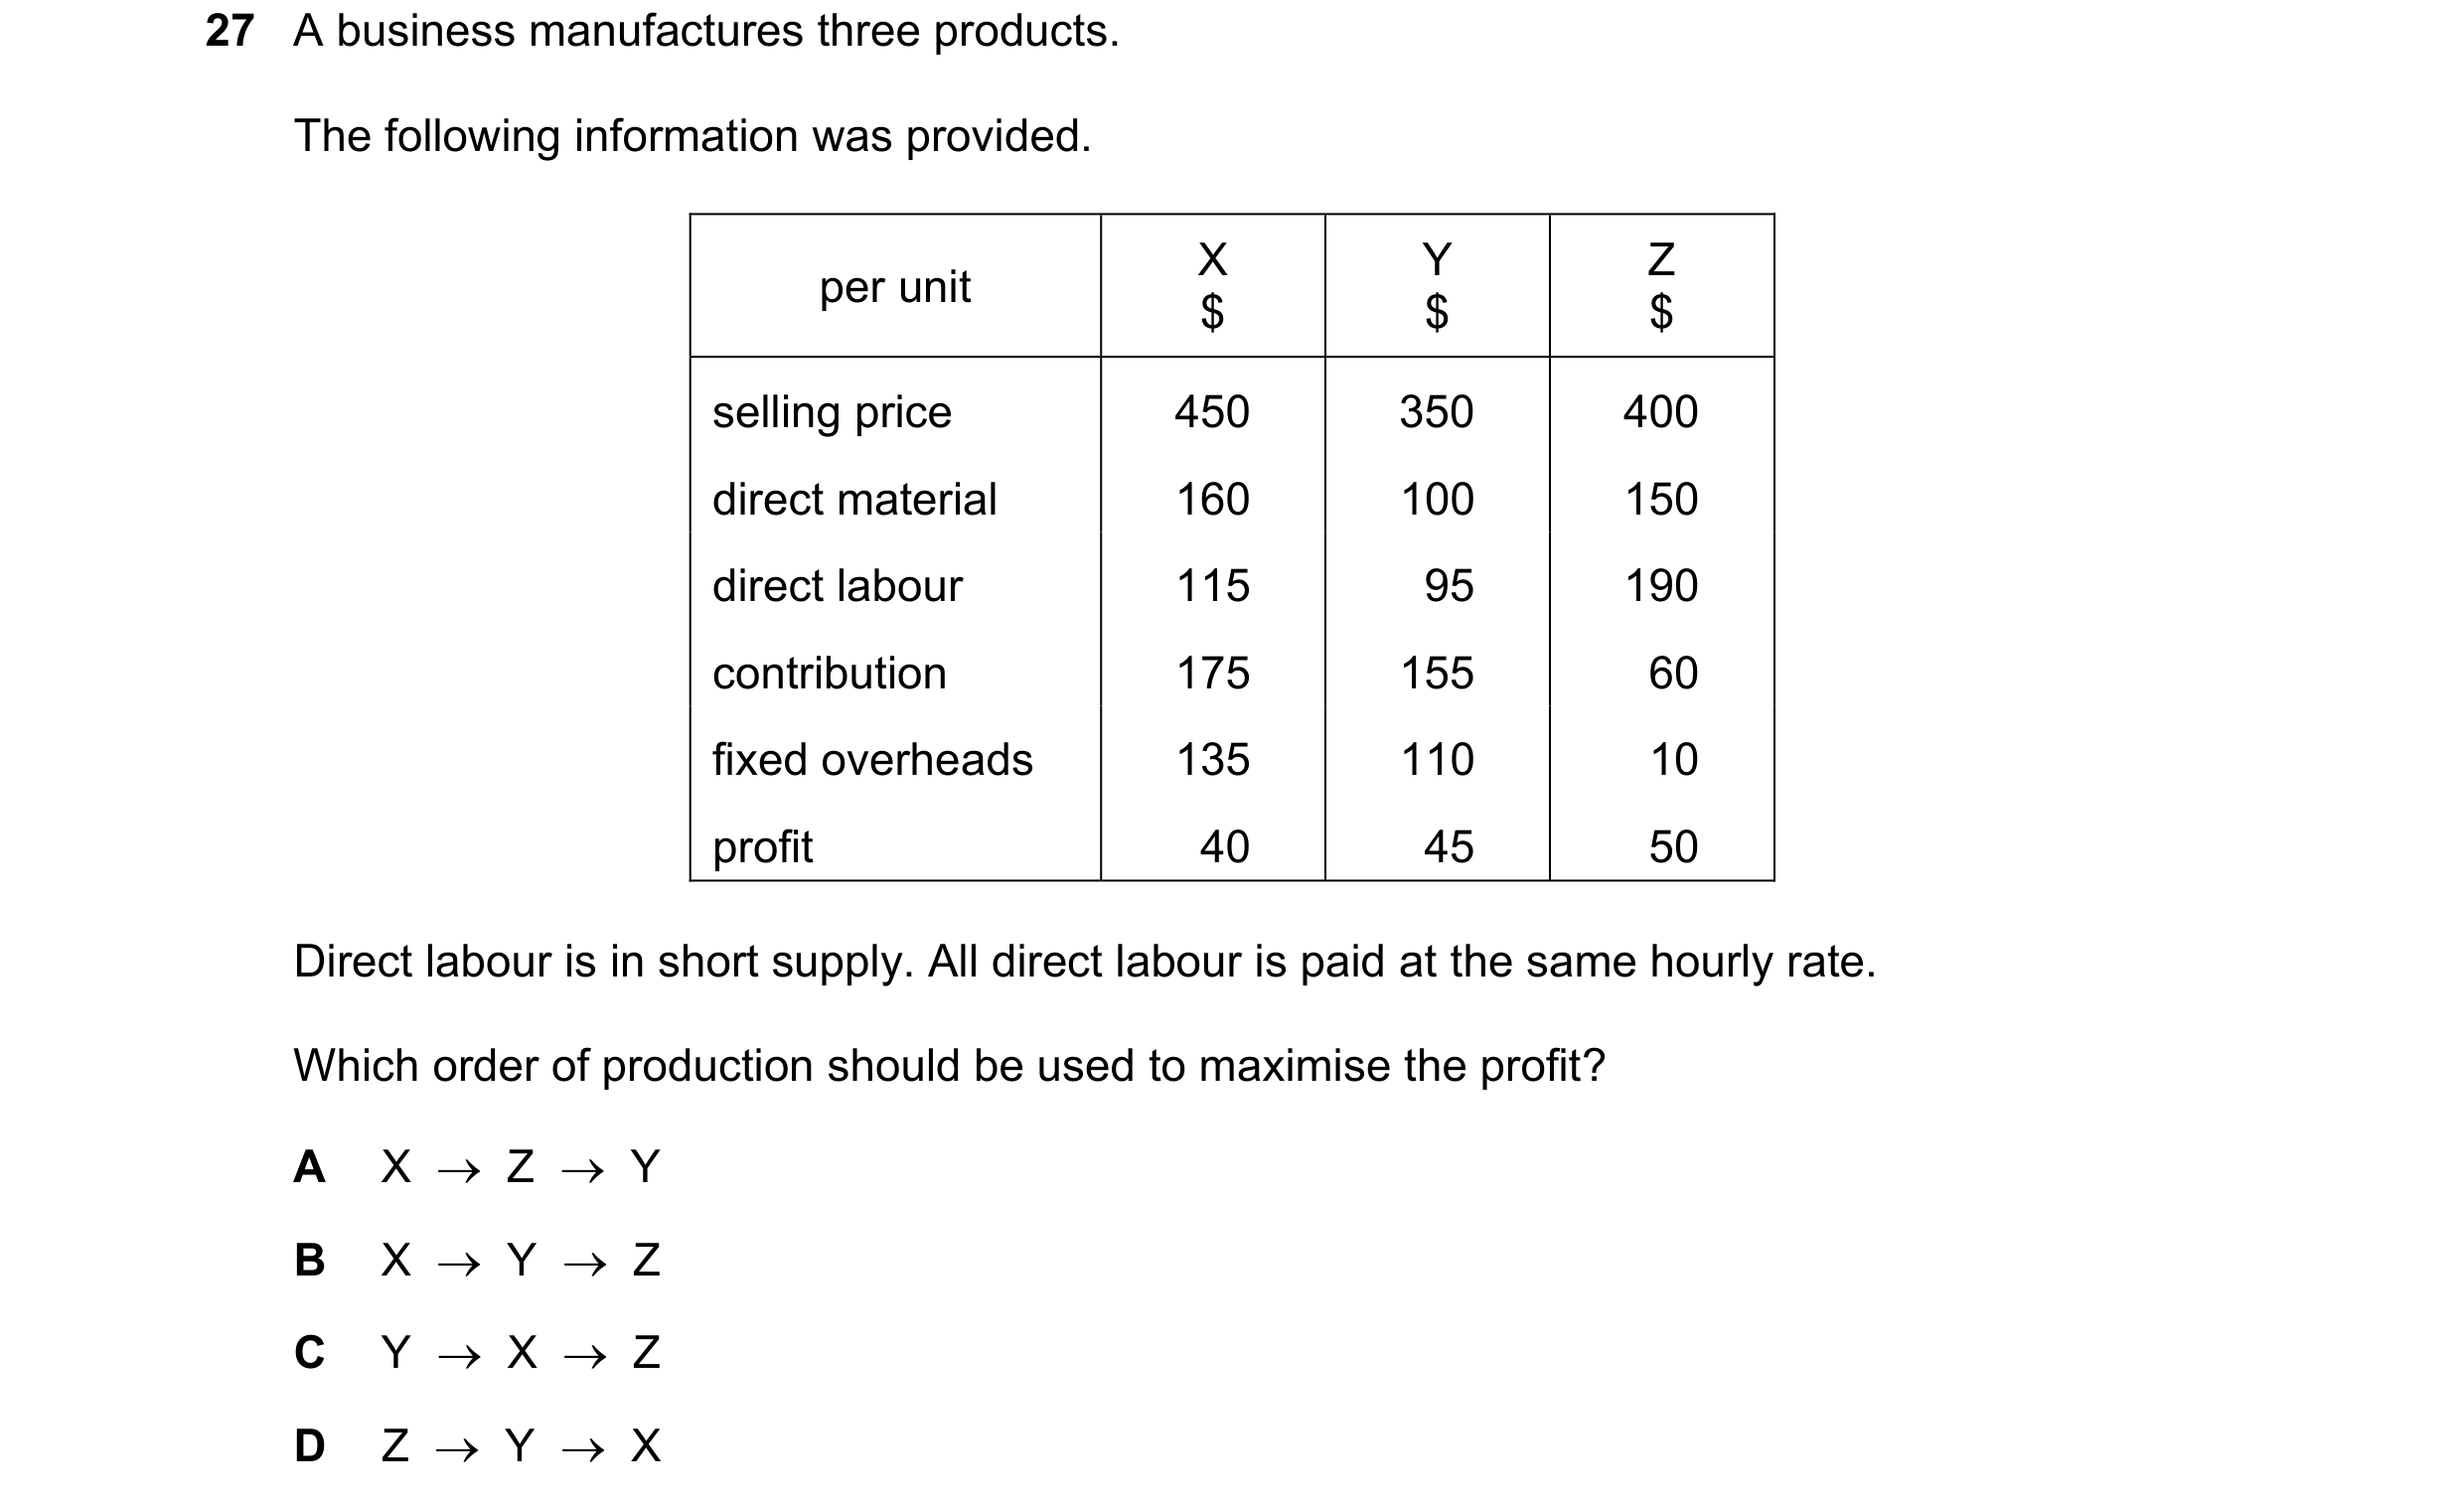 104 / 143
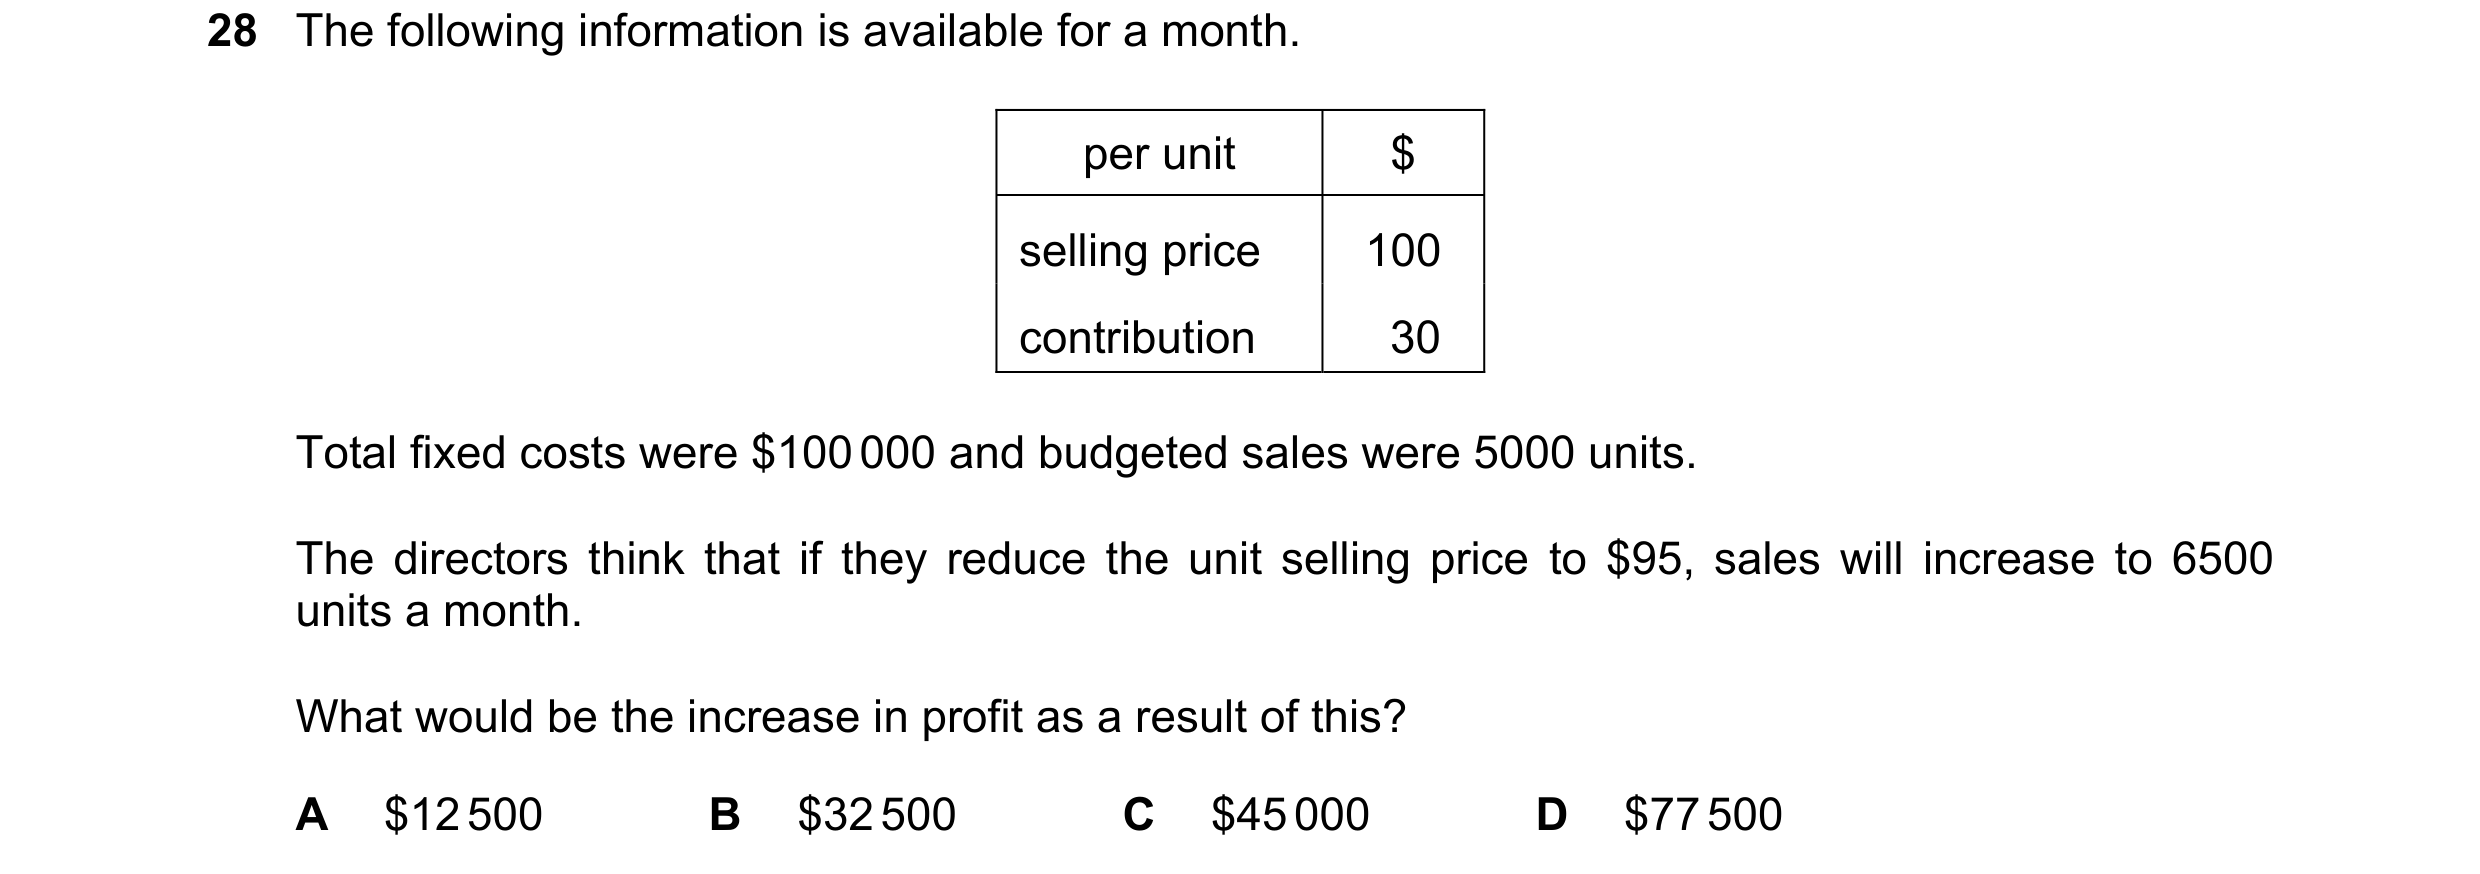
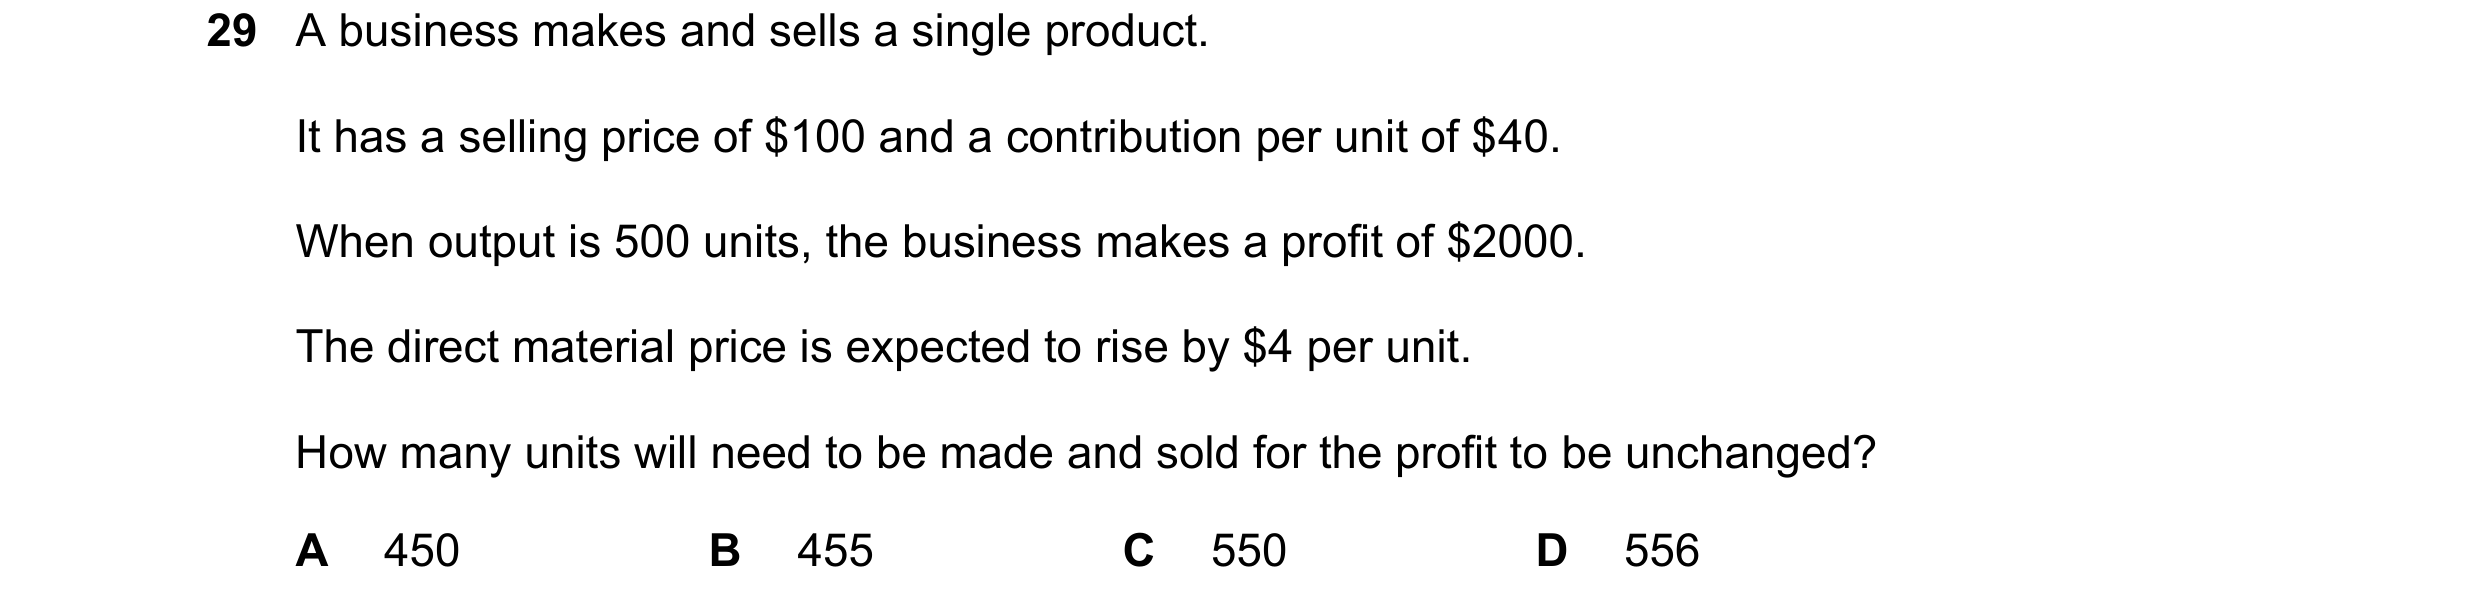
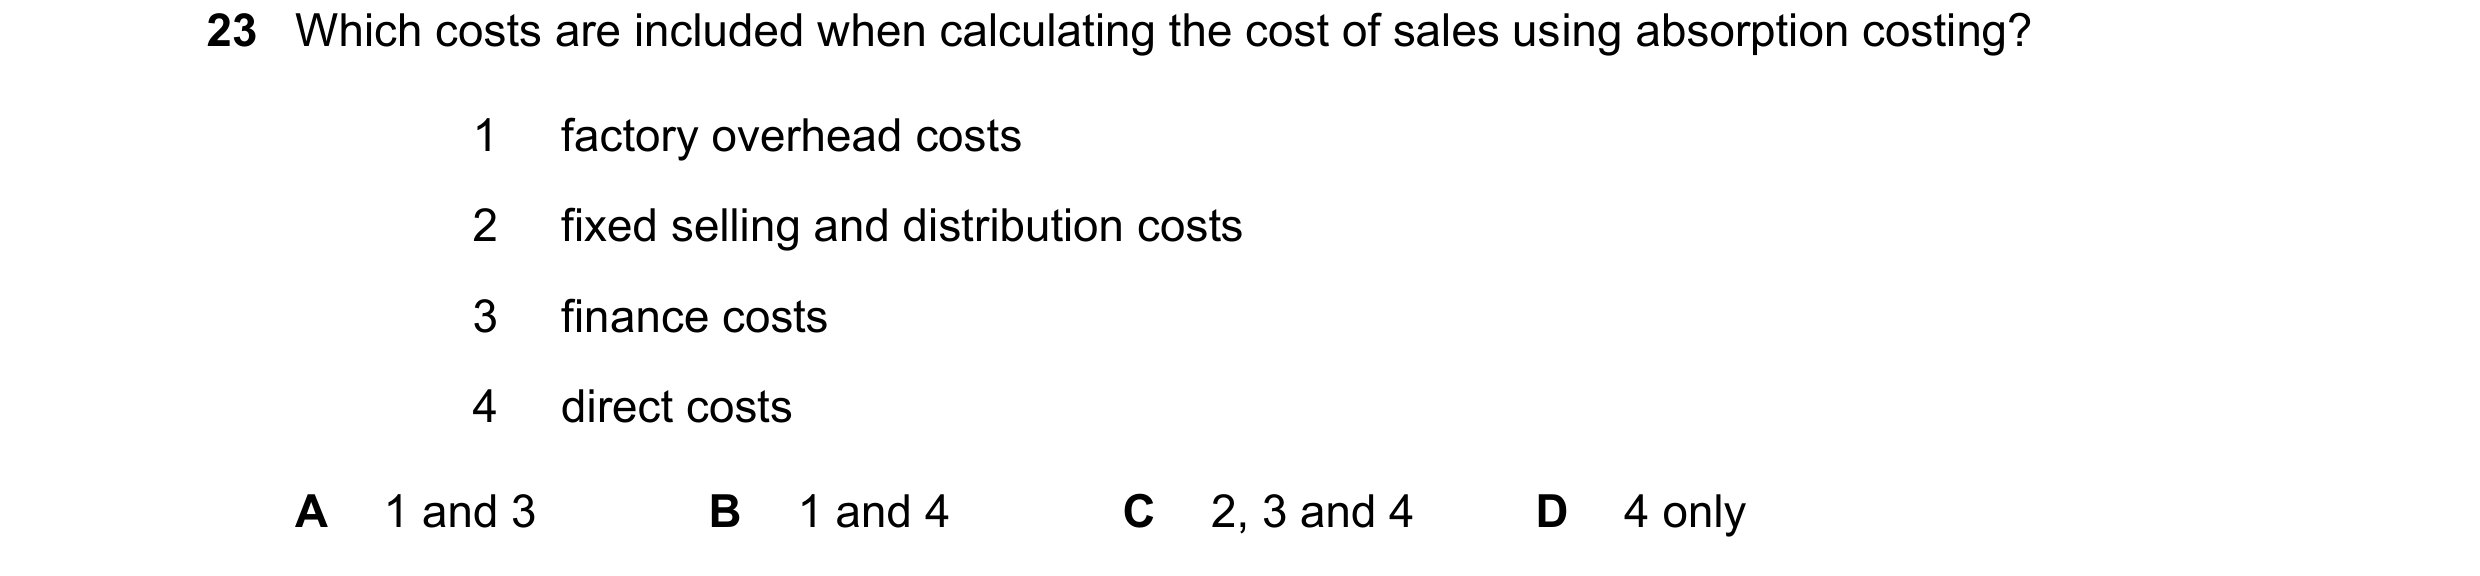
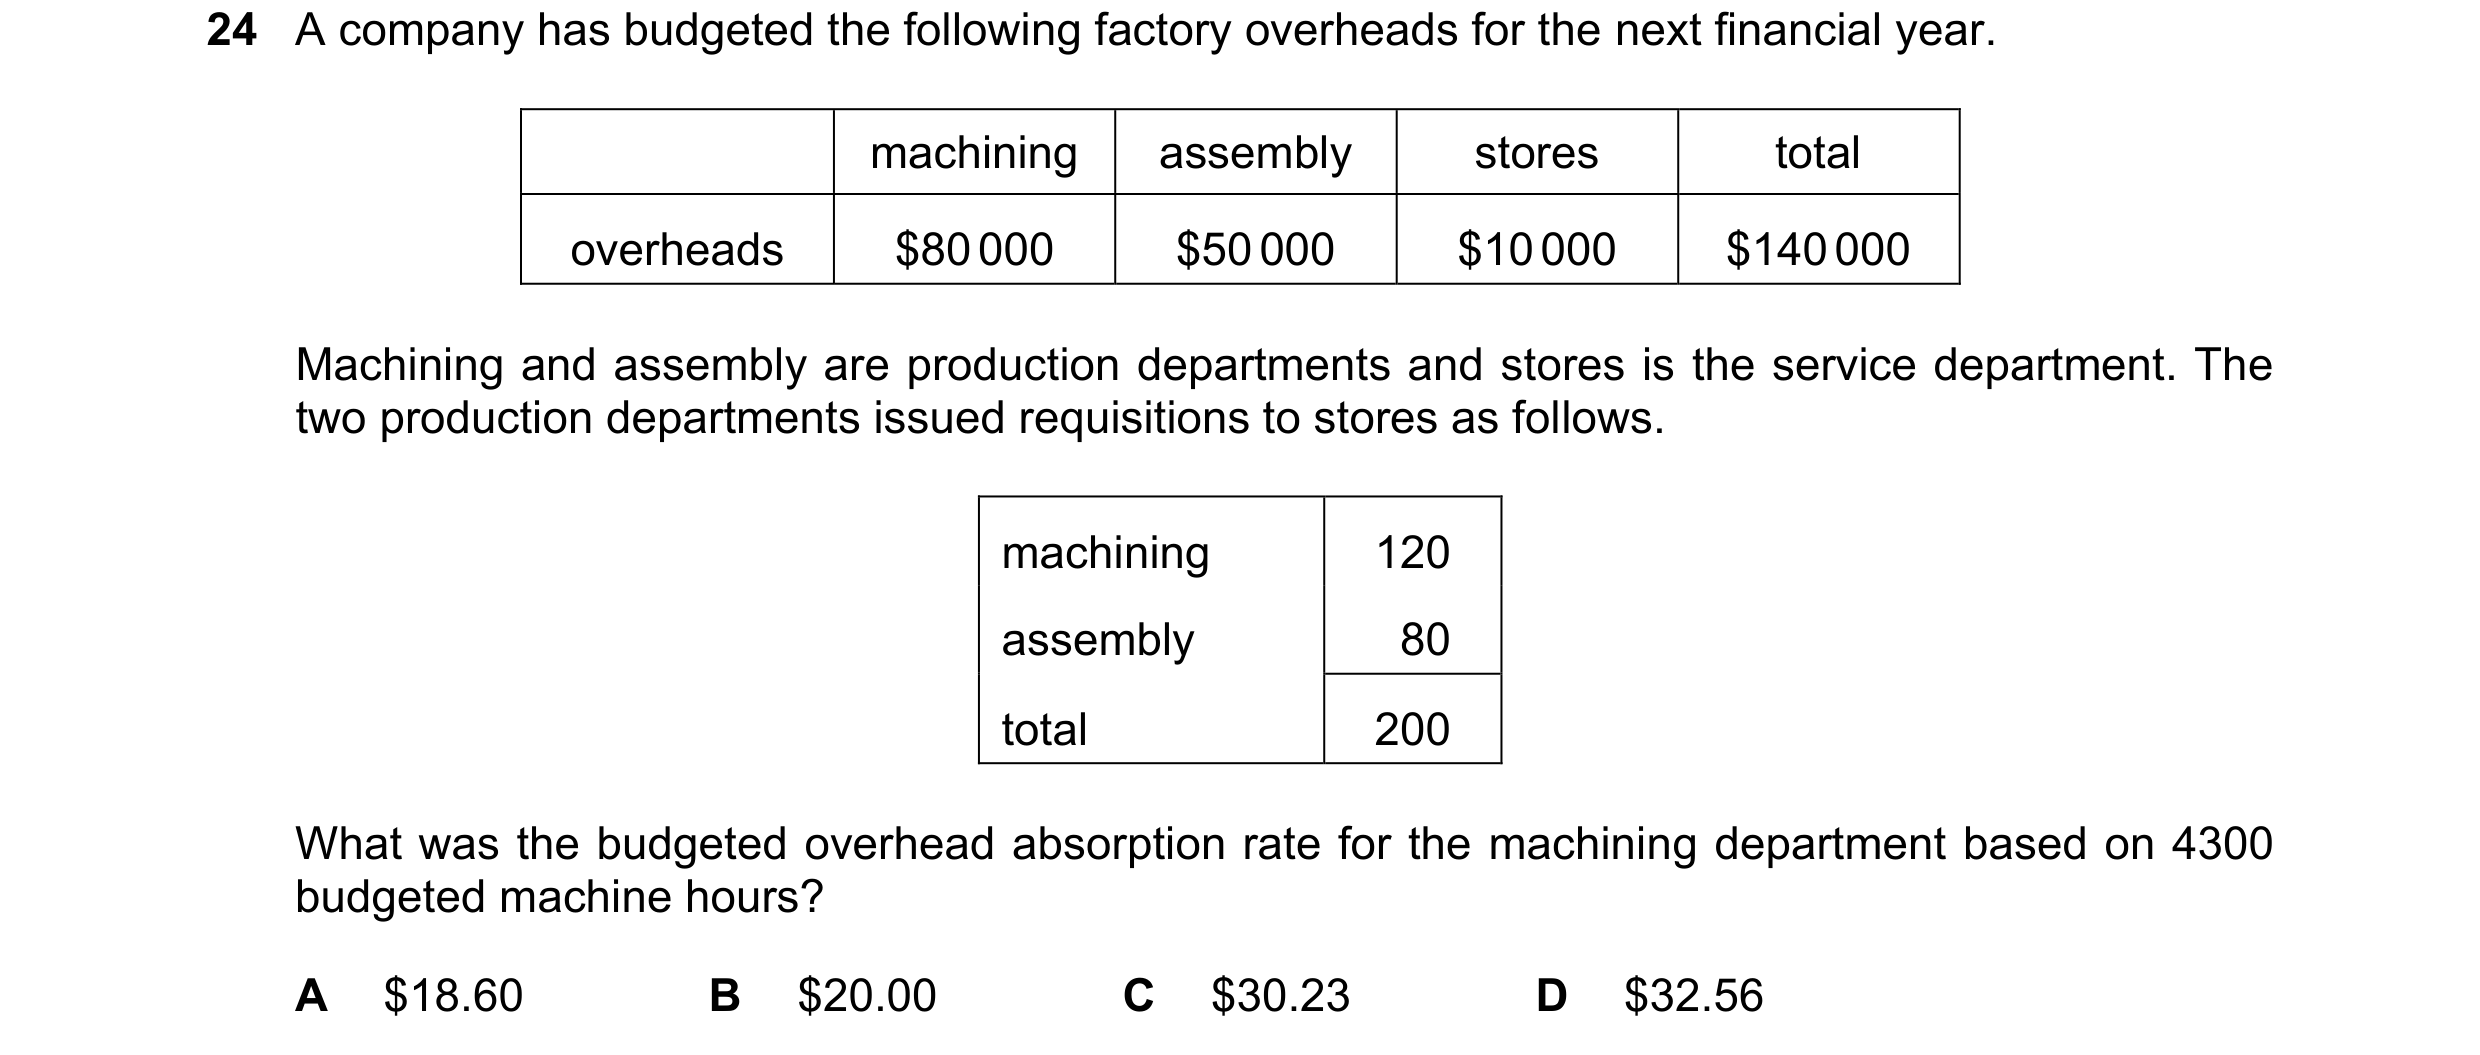 105 / 143
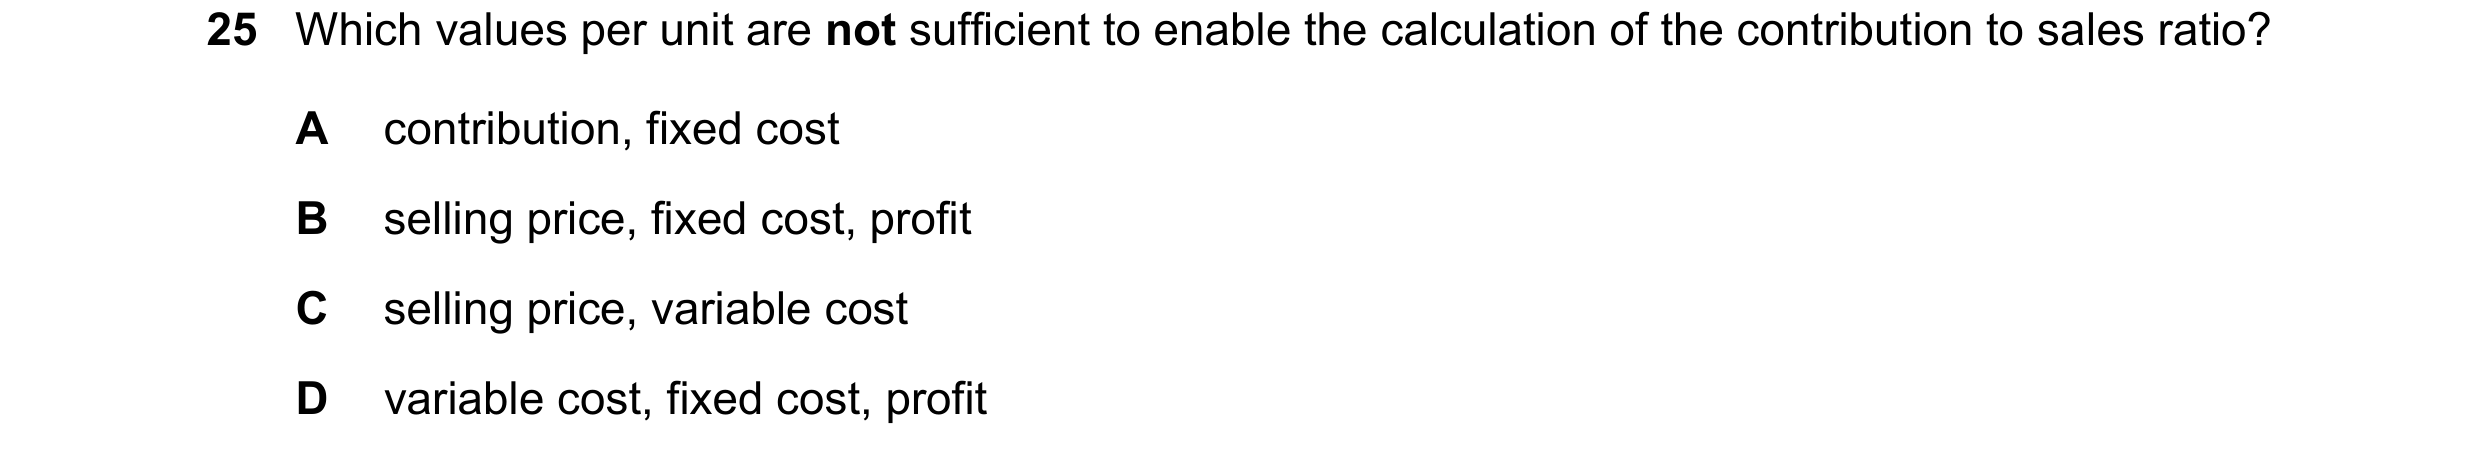
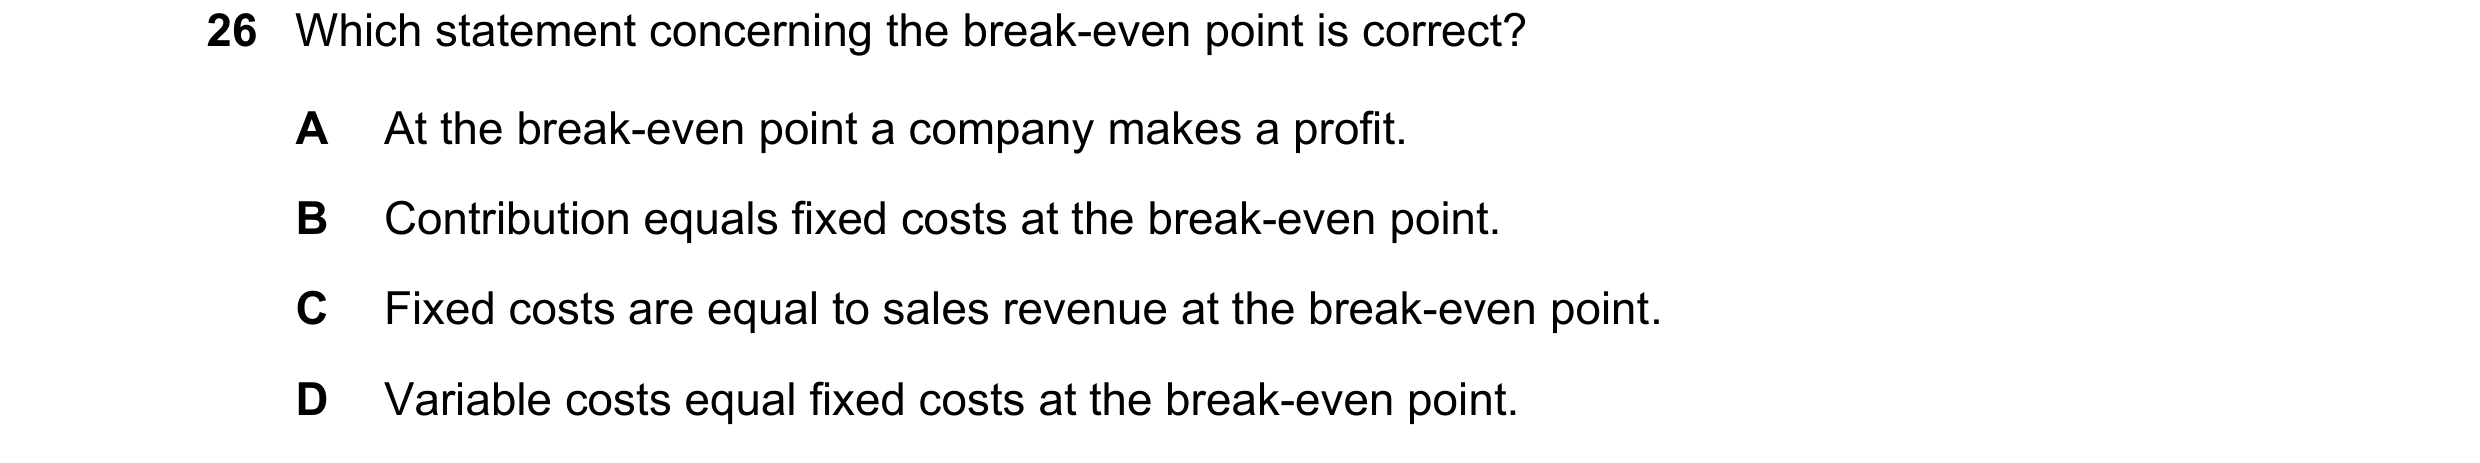
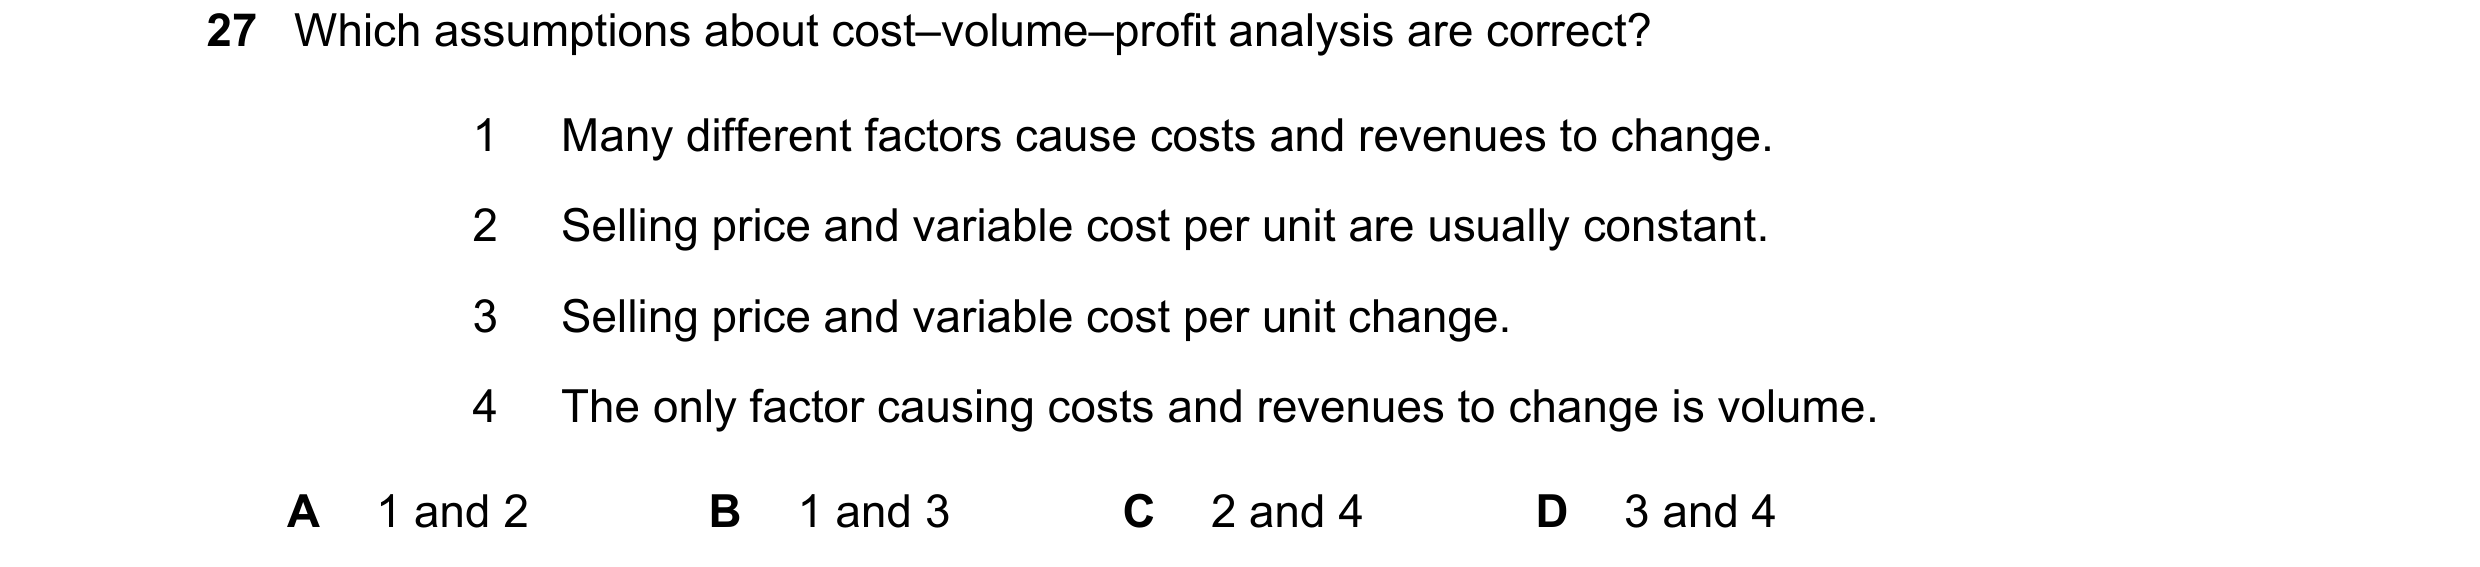
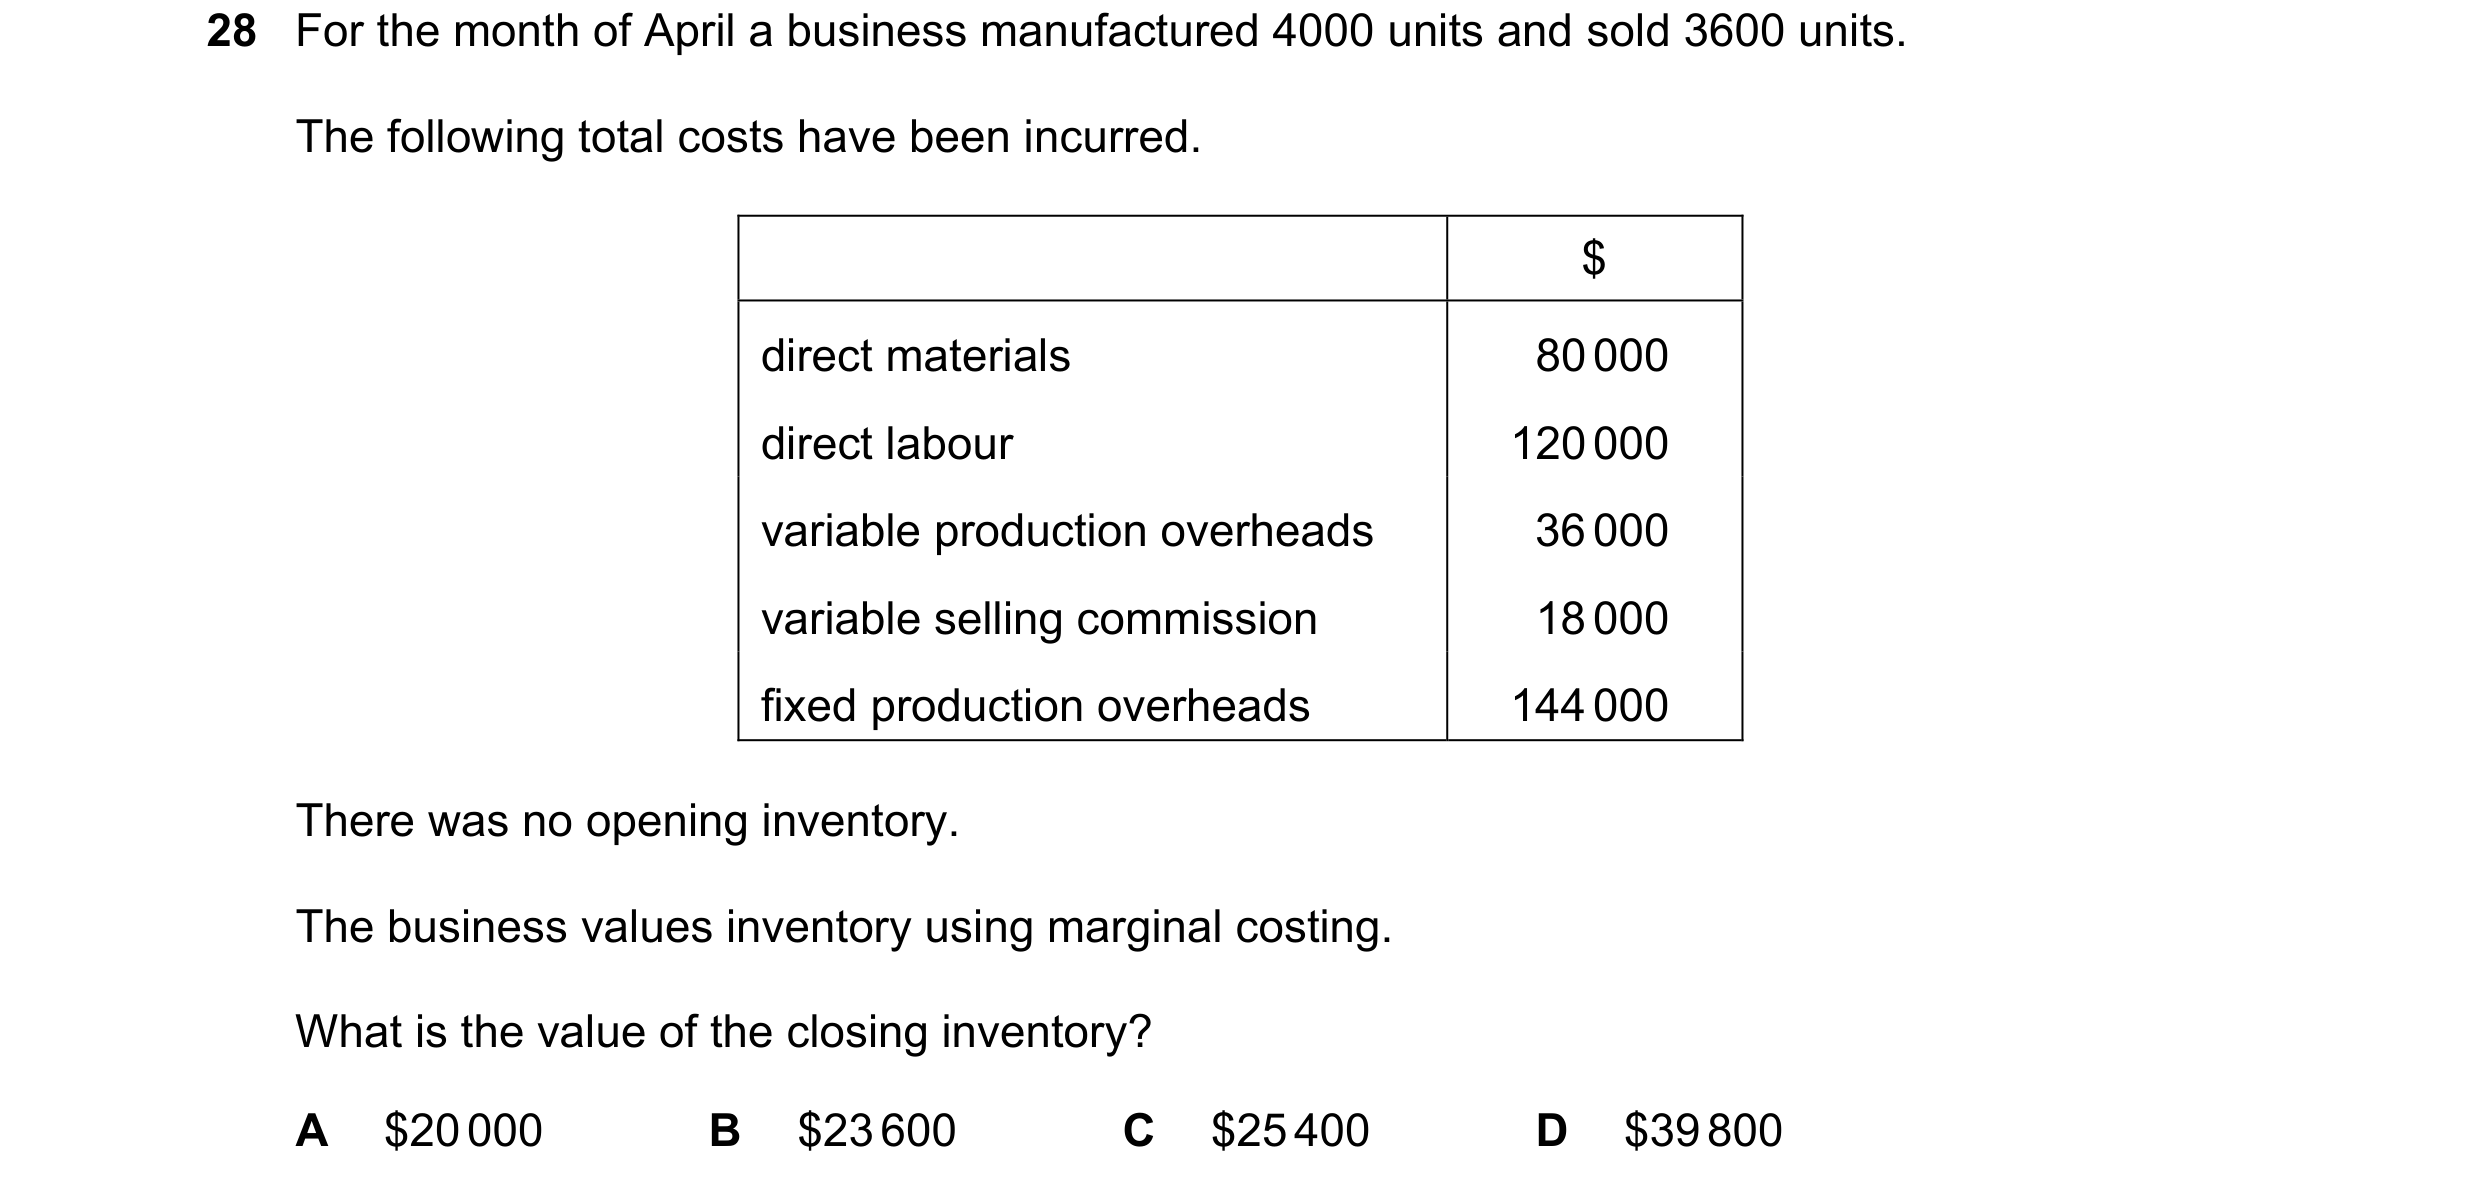
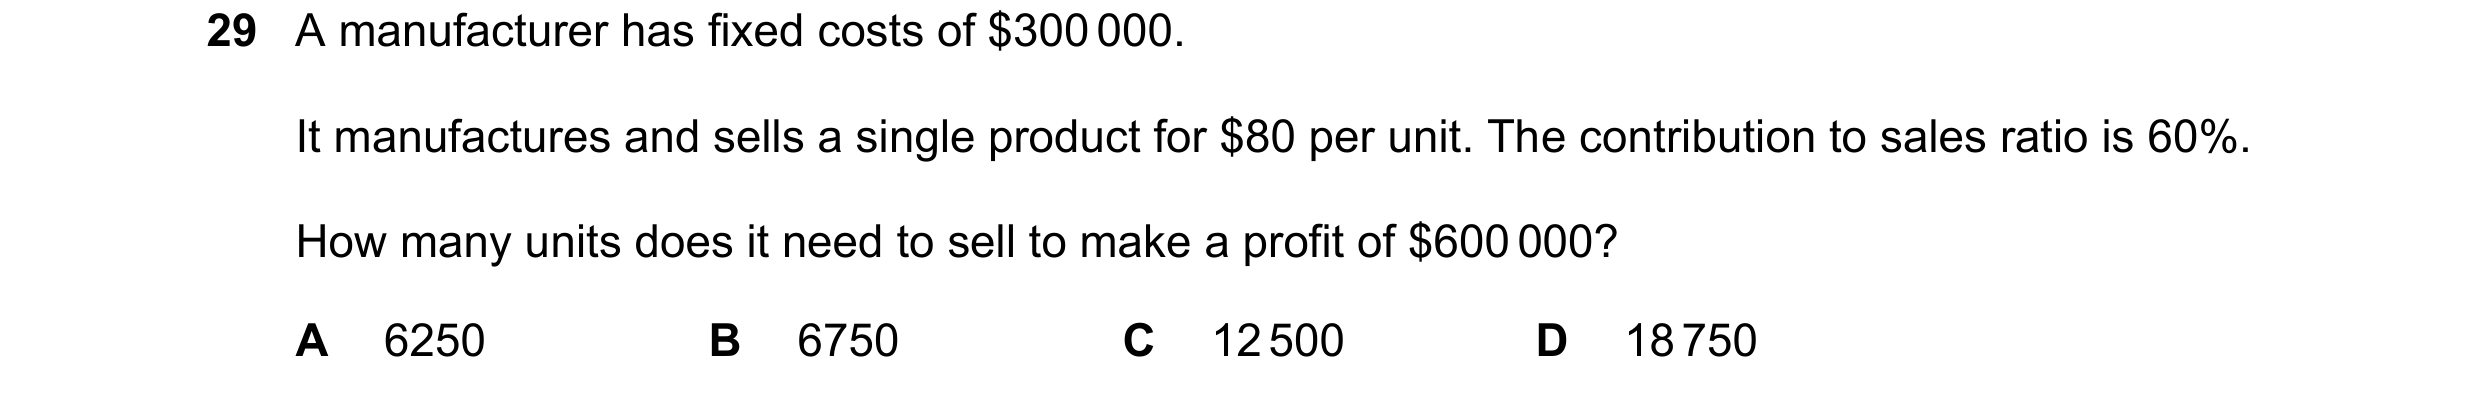 106 / 143
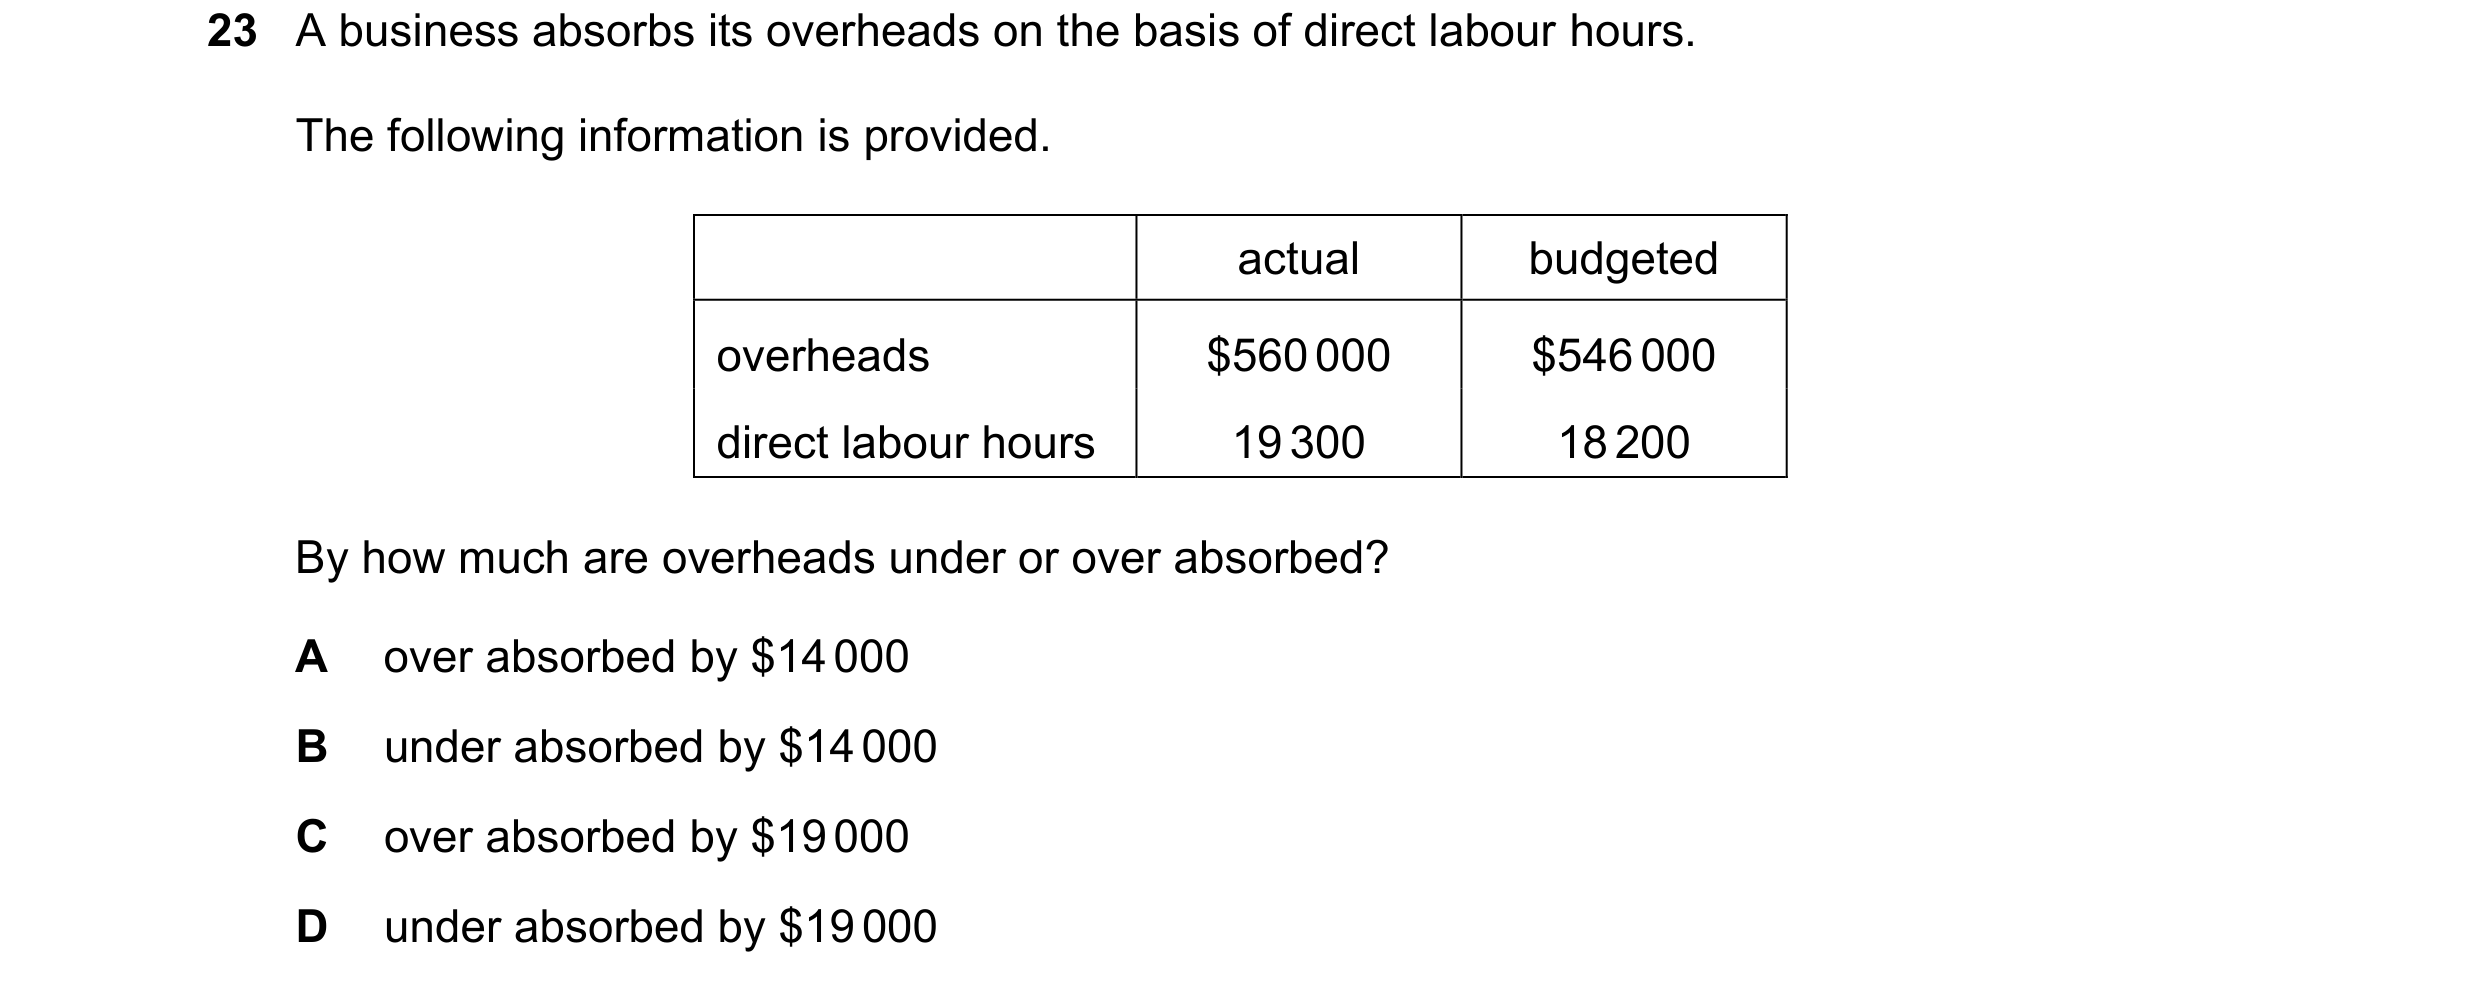
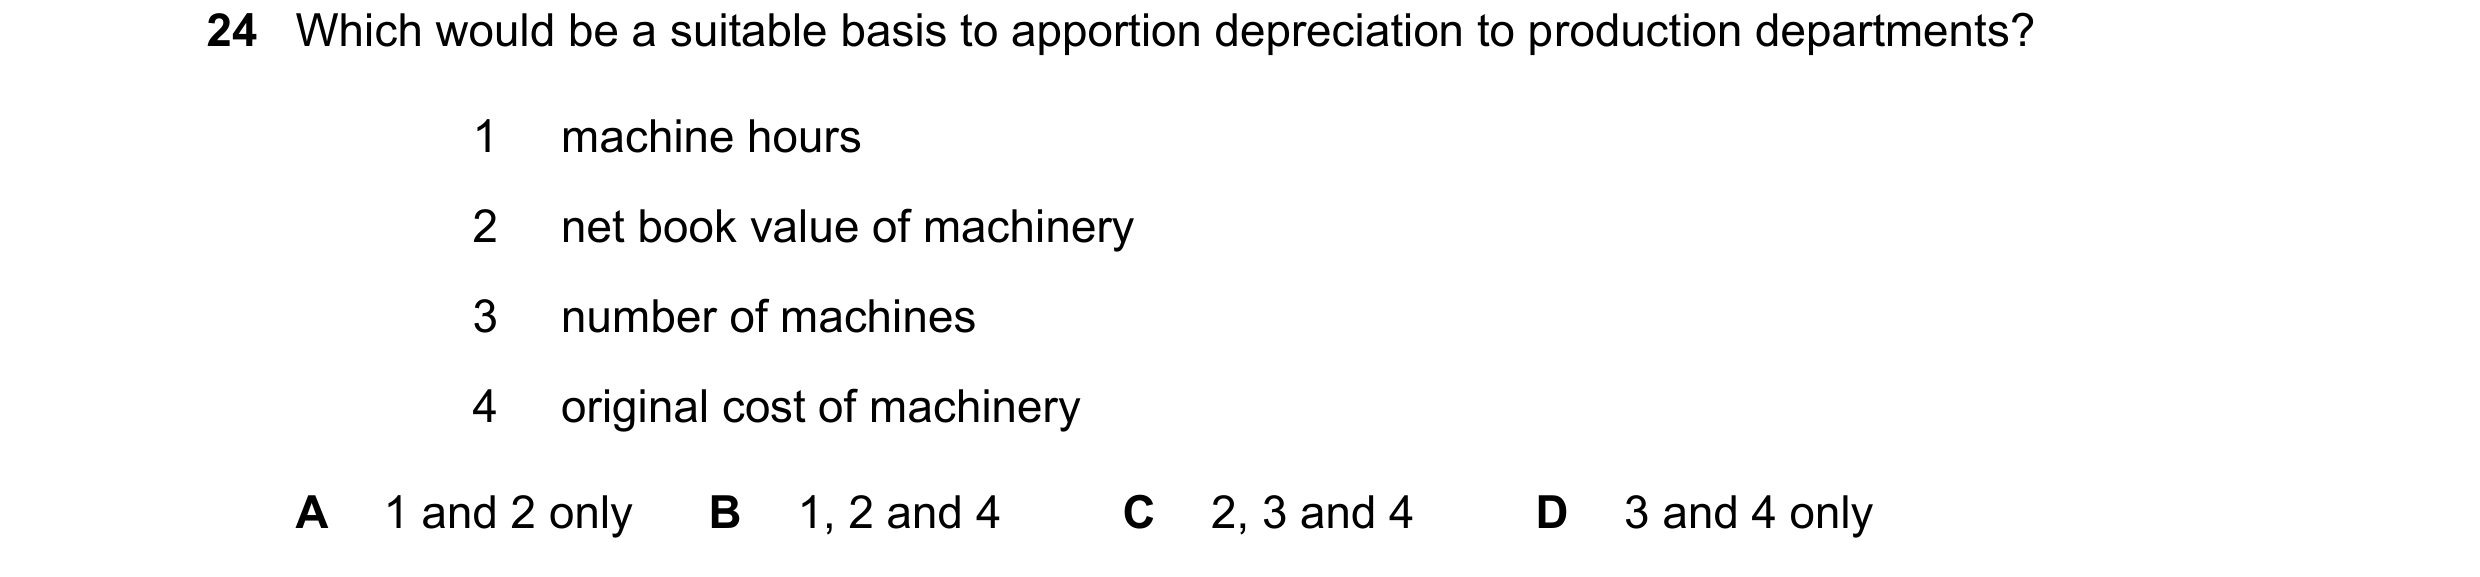
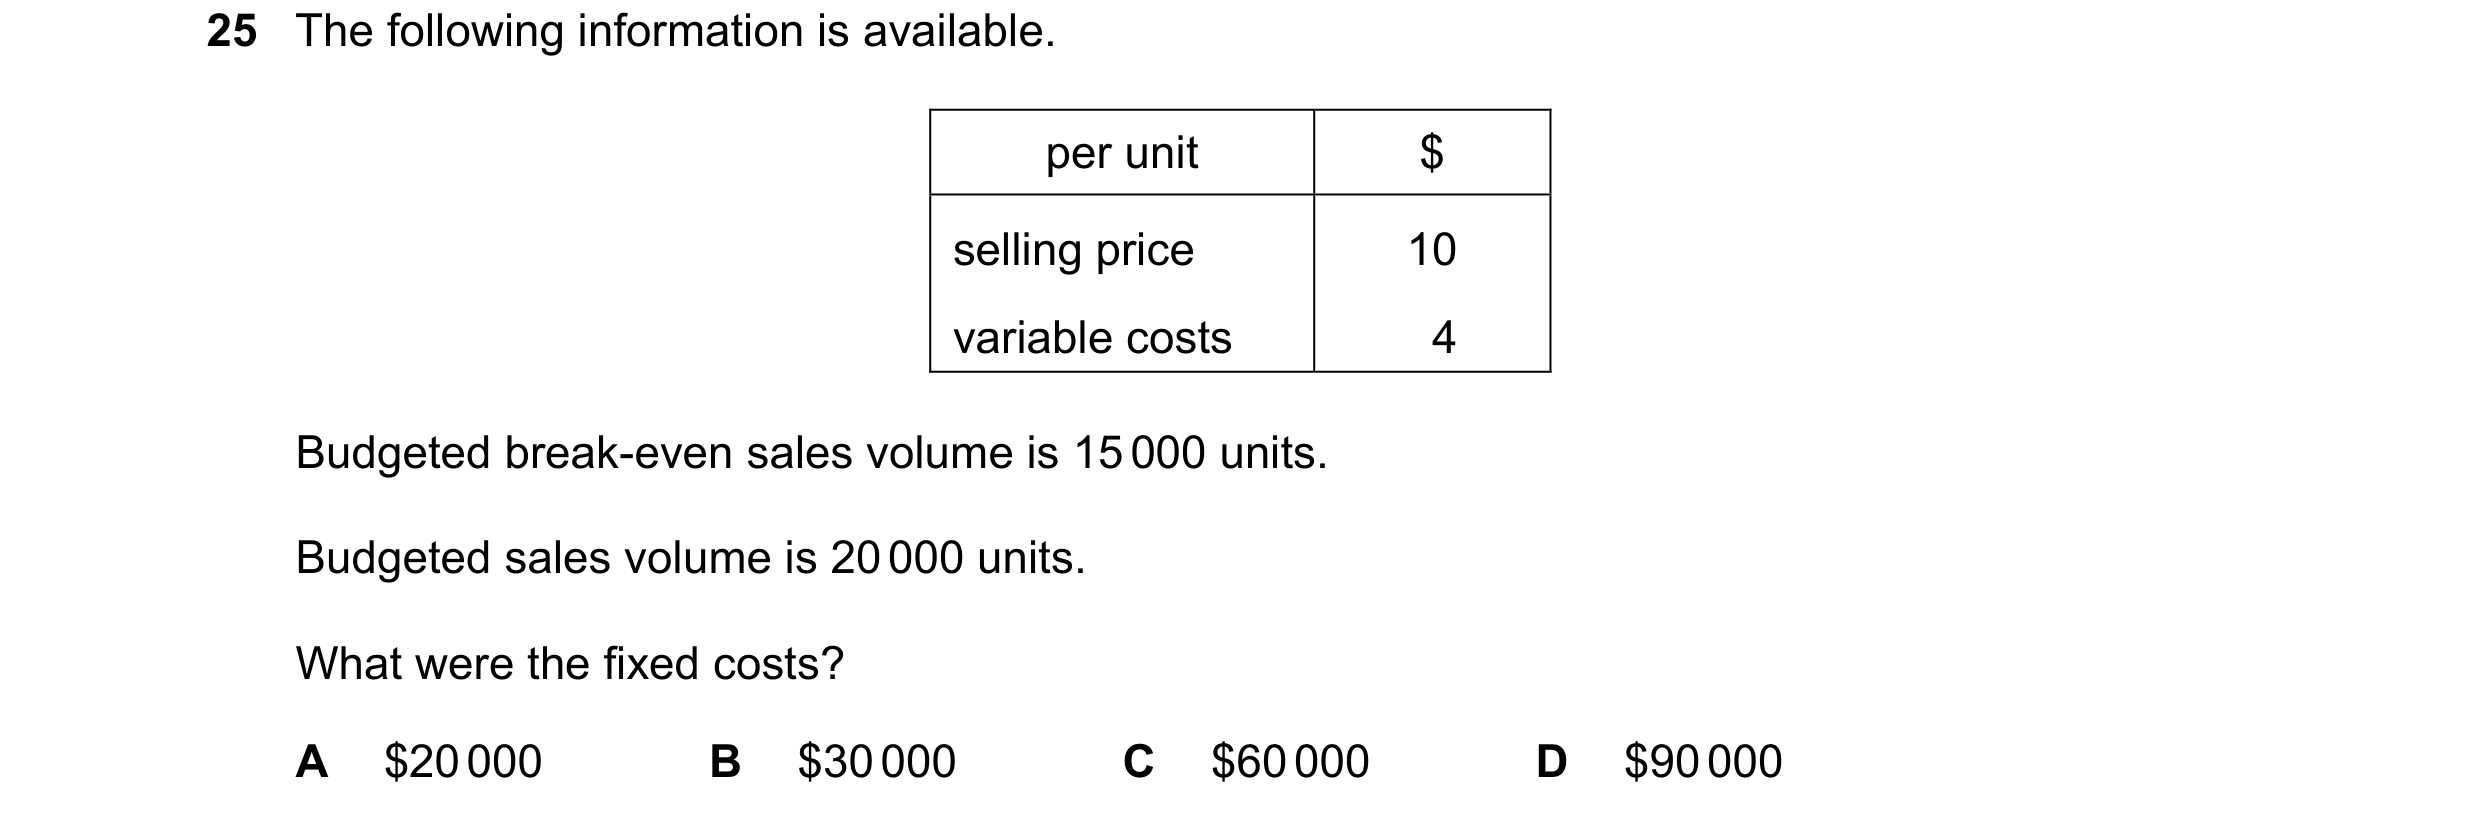
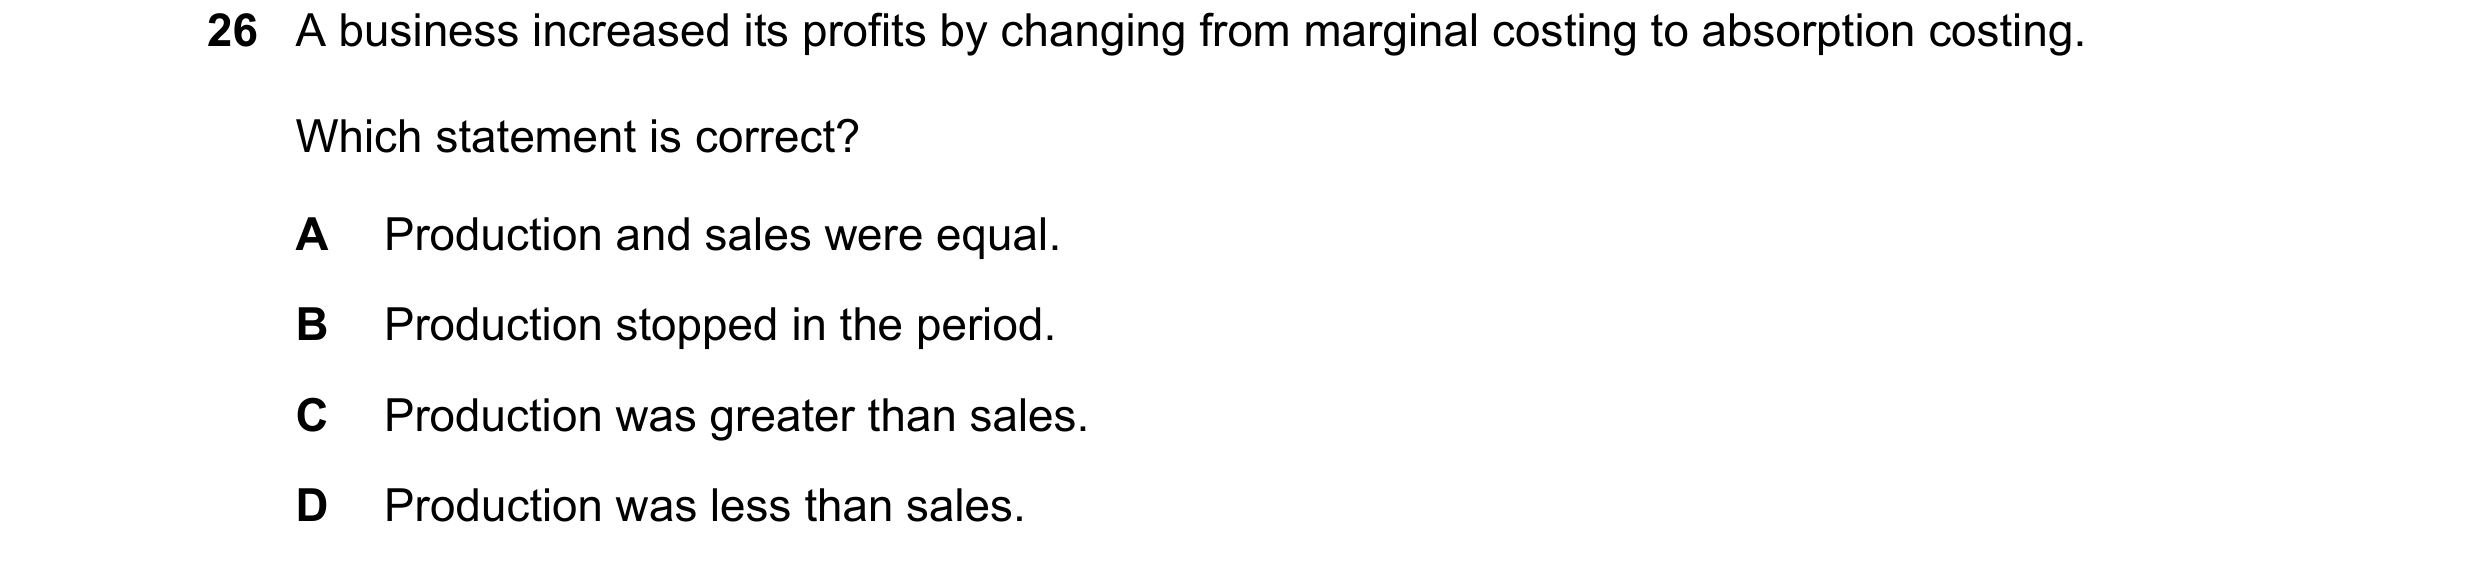 107 / 143
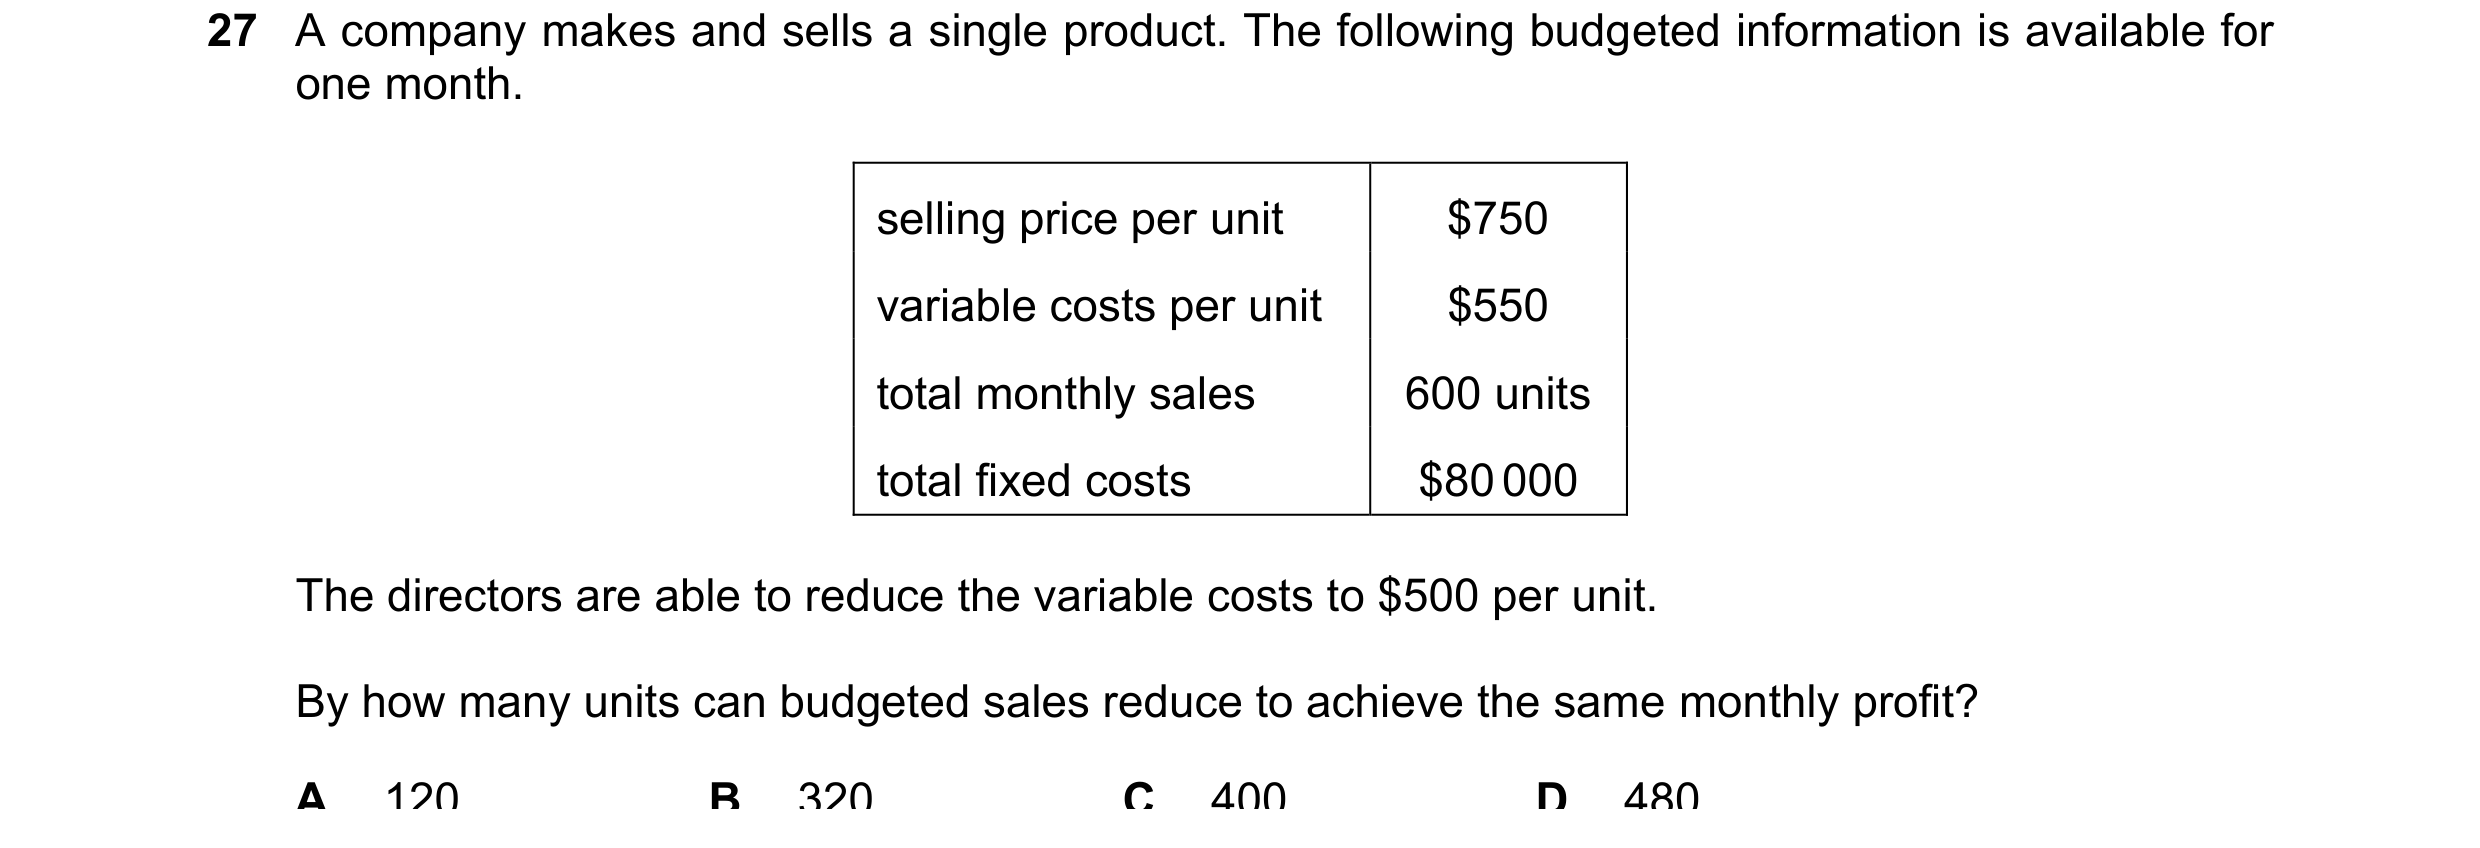
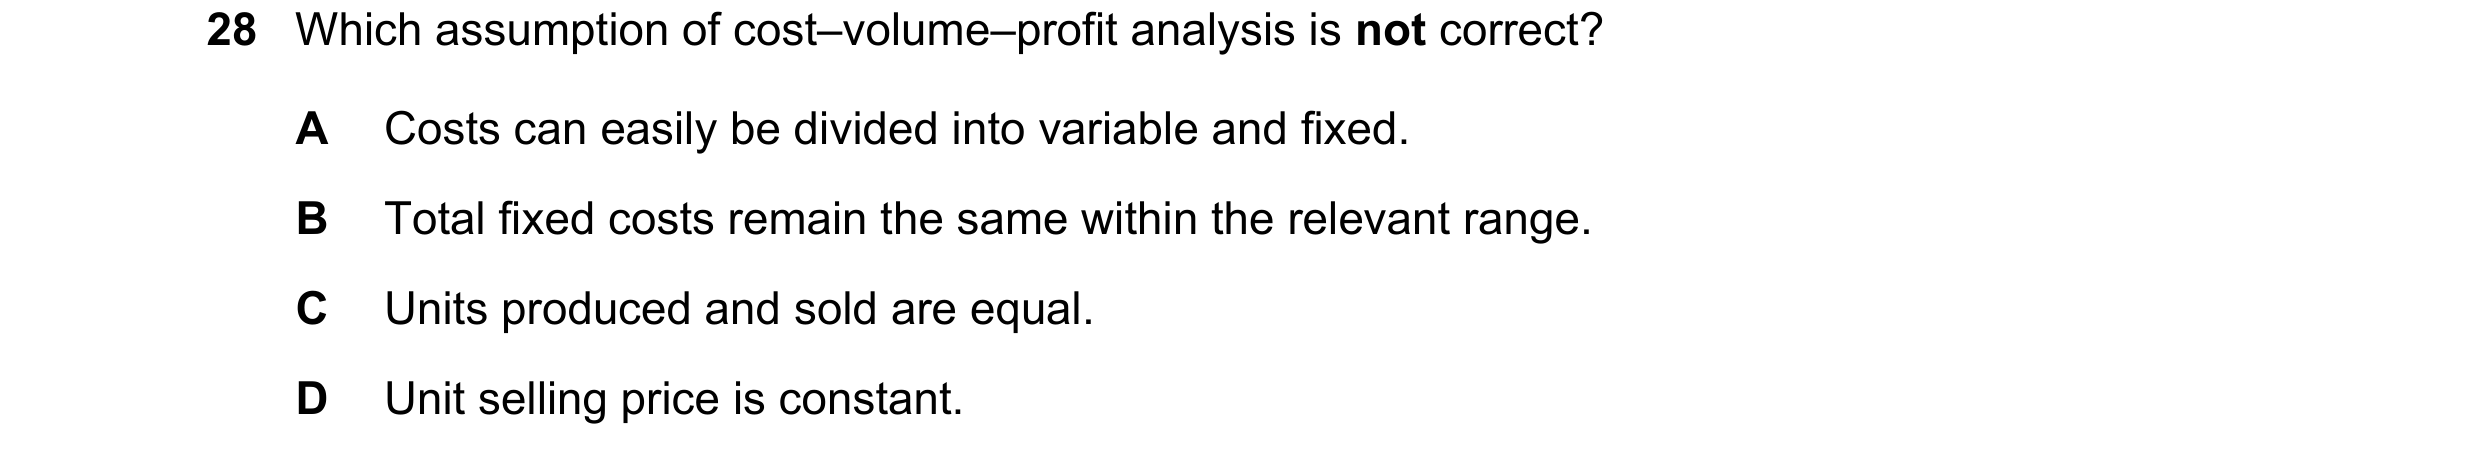
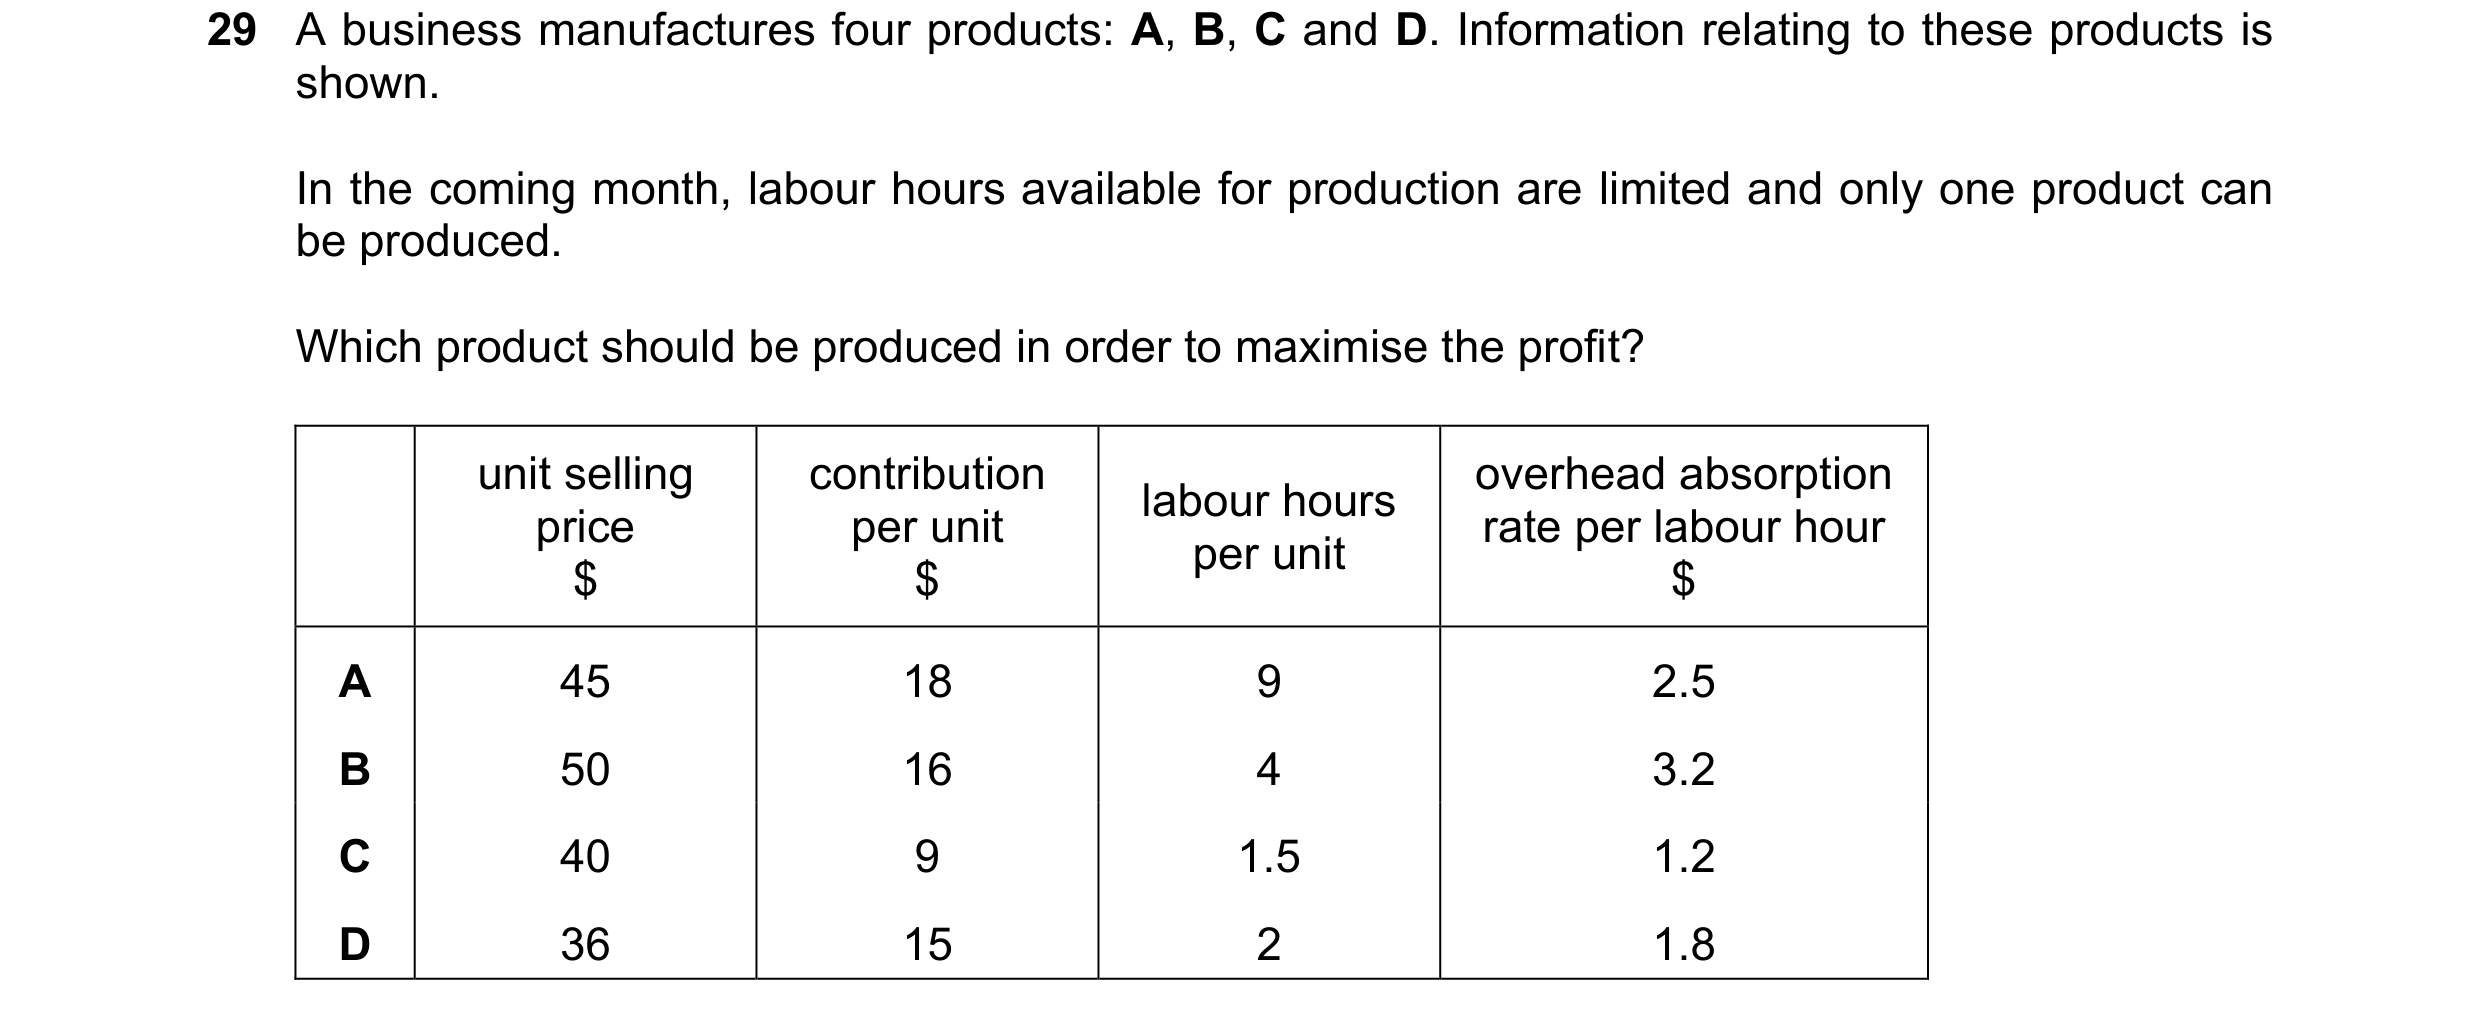
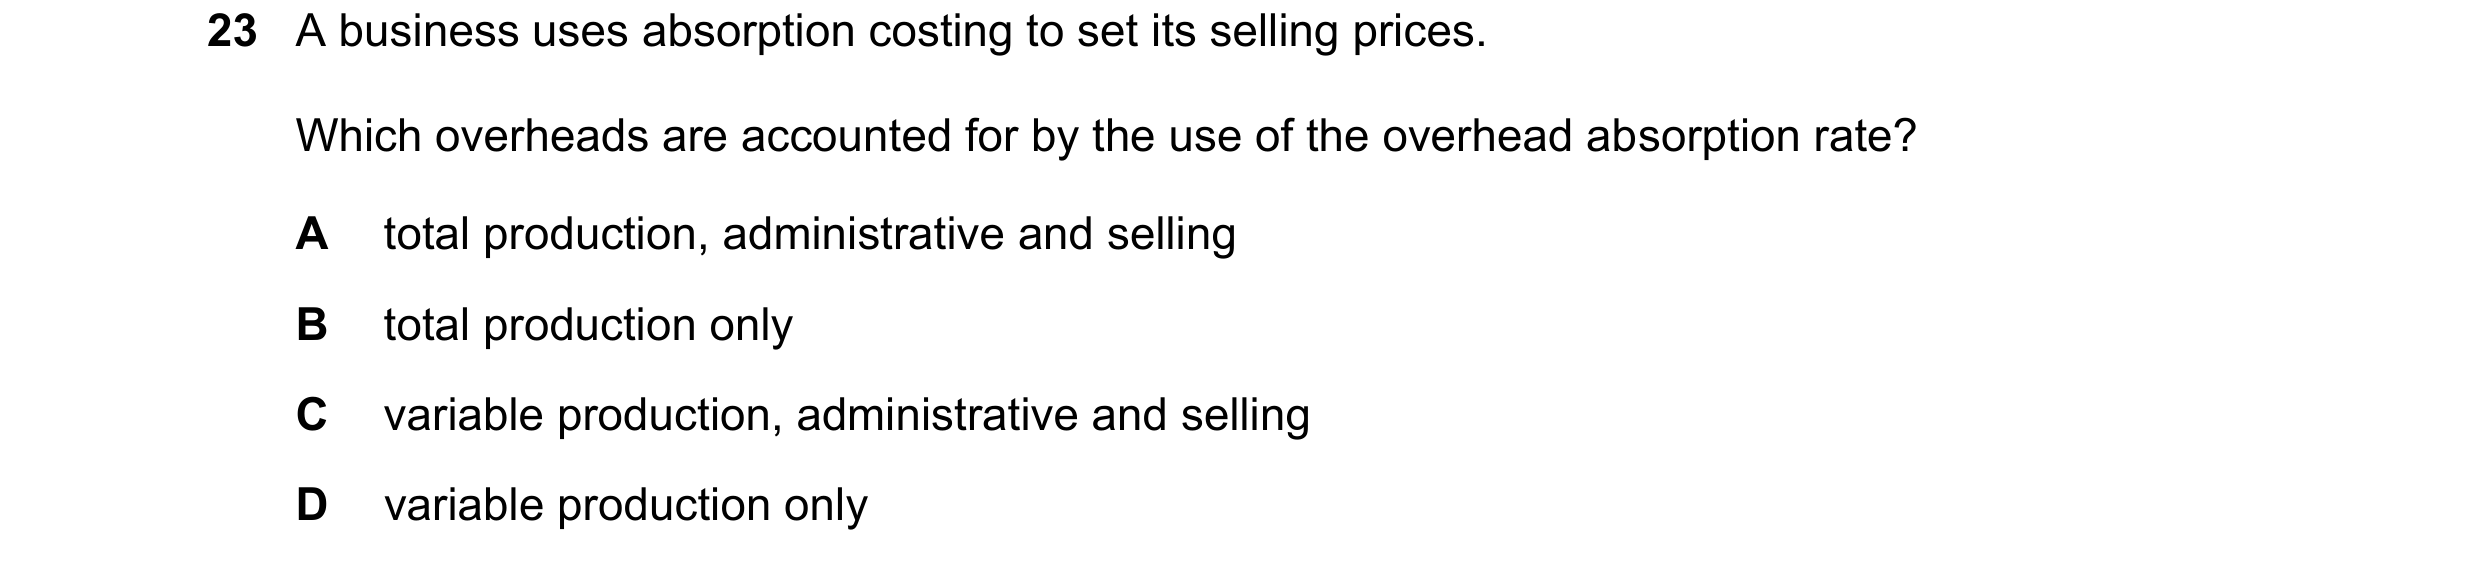 108 / 143
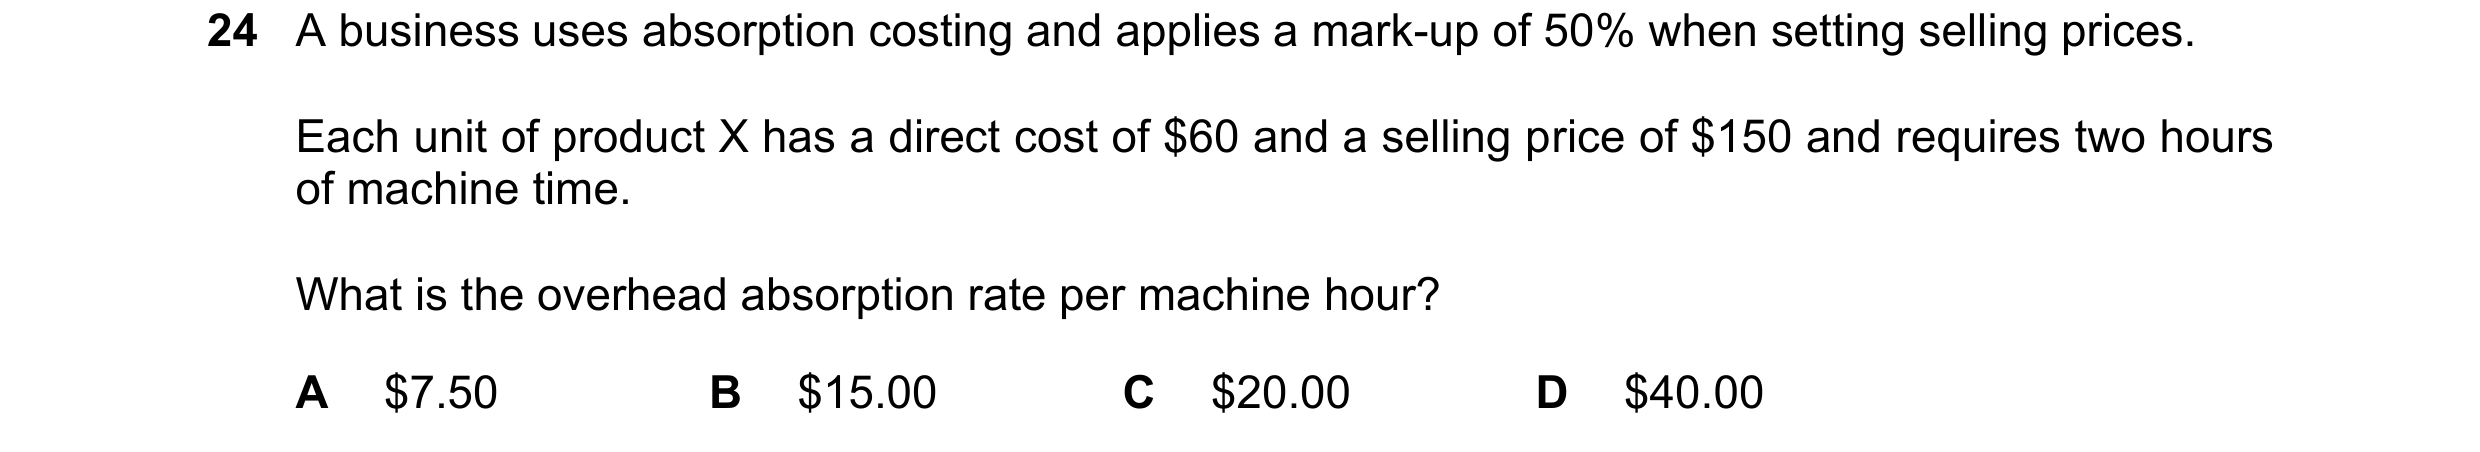
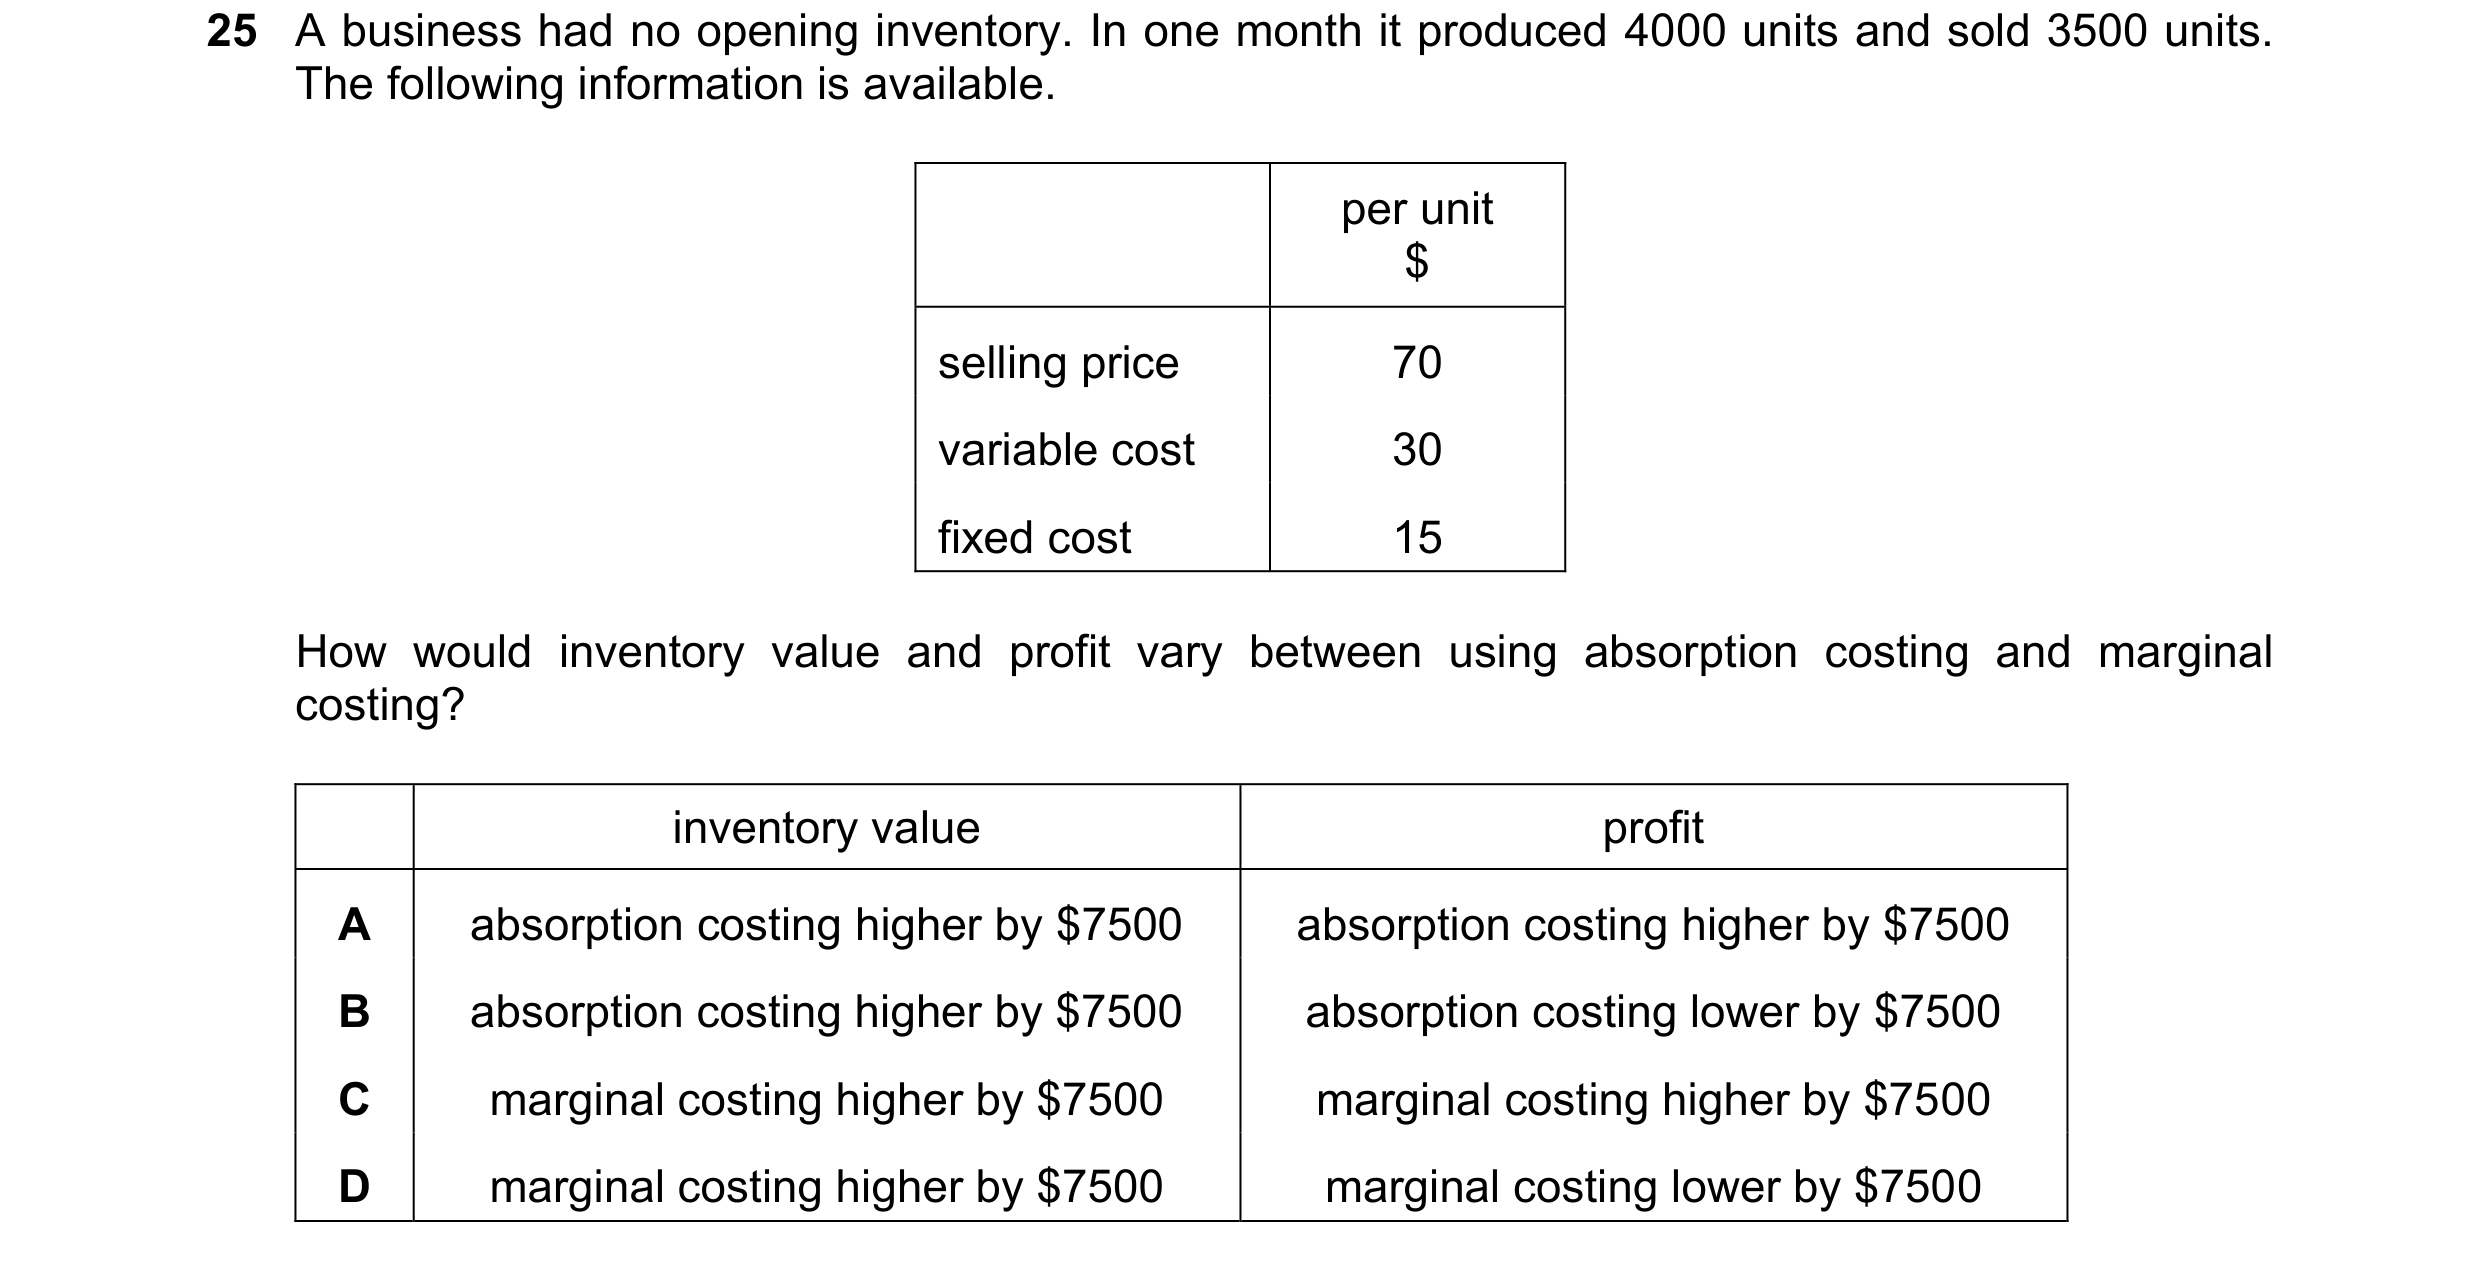
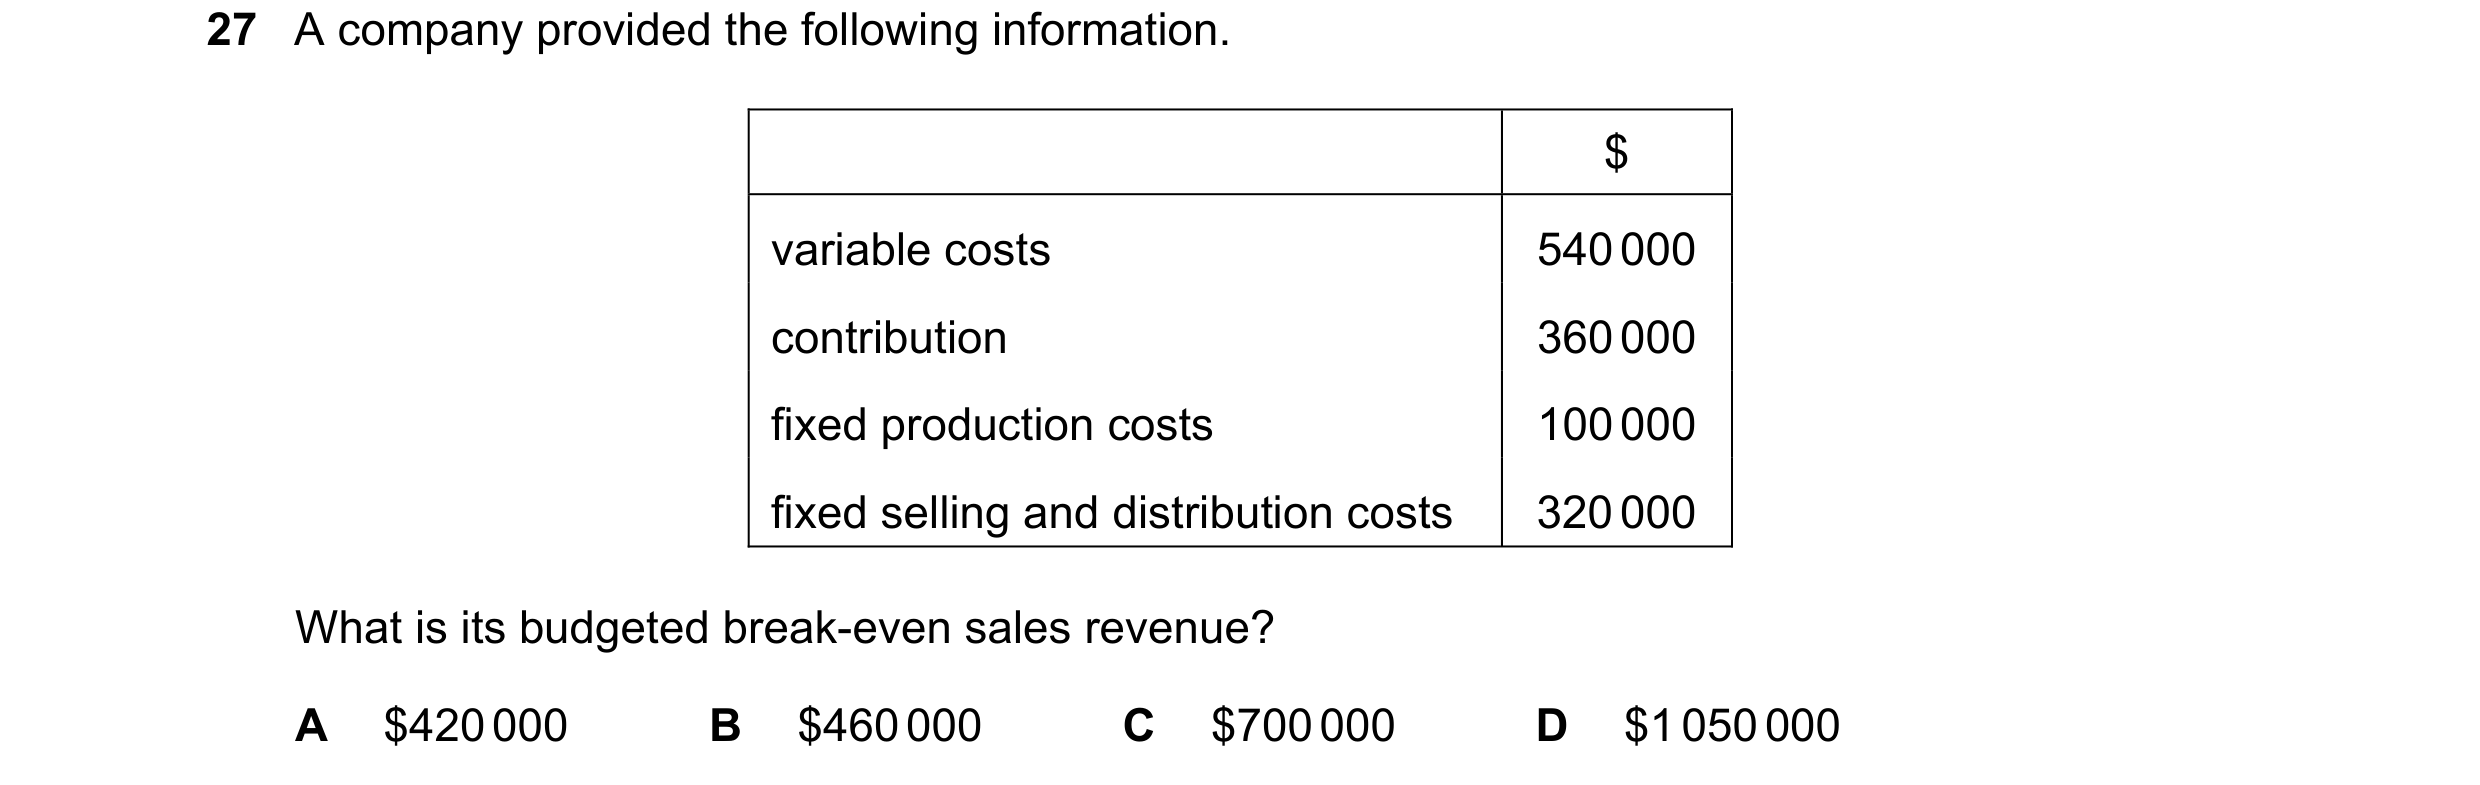 109 / 143
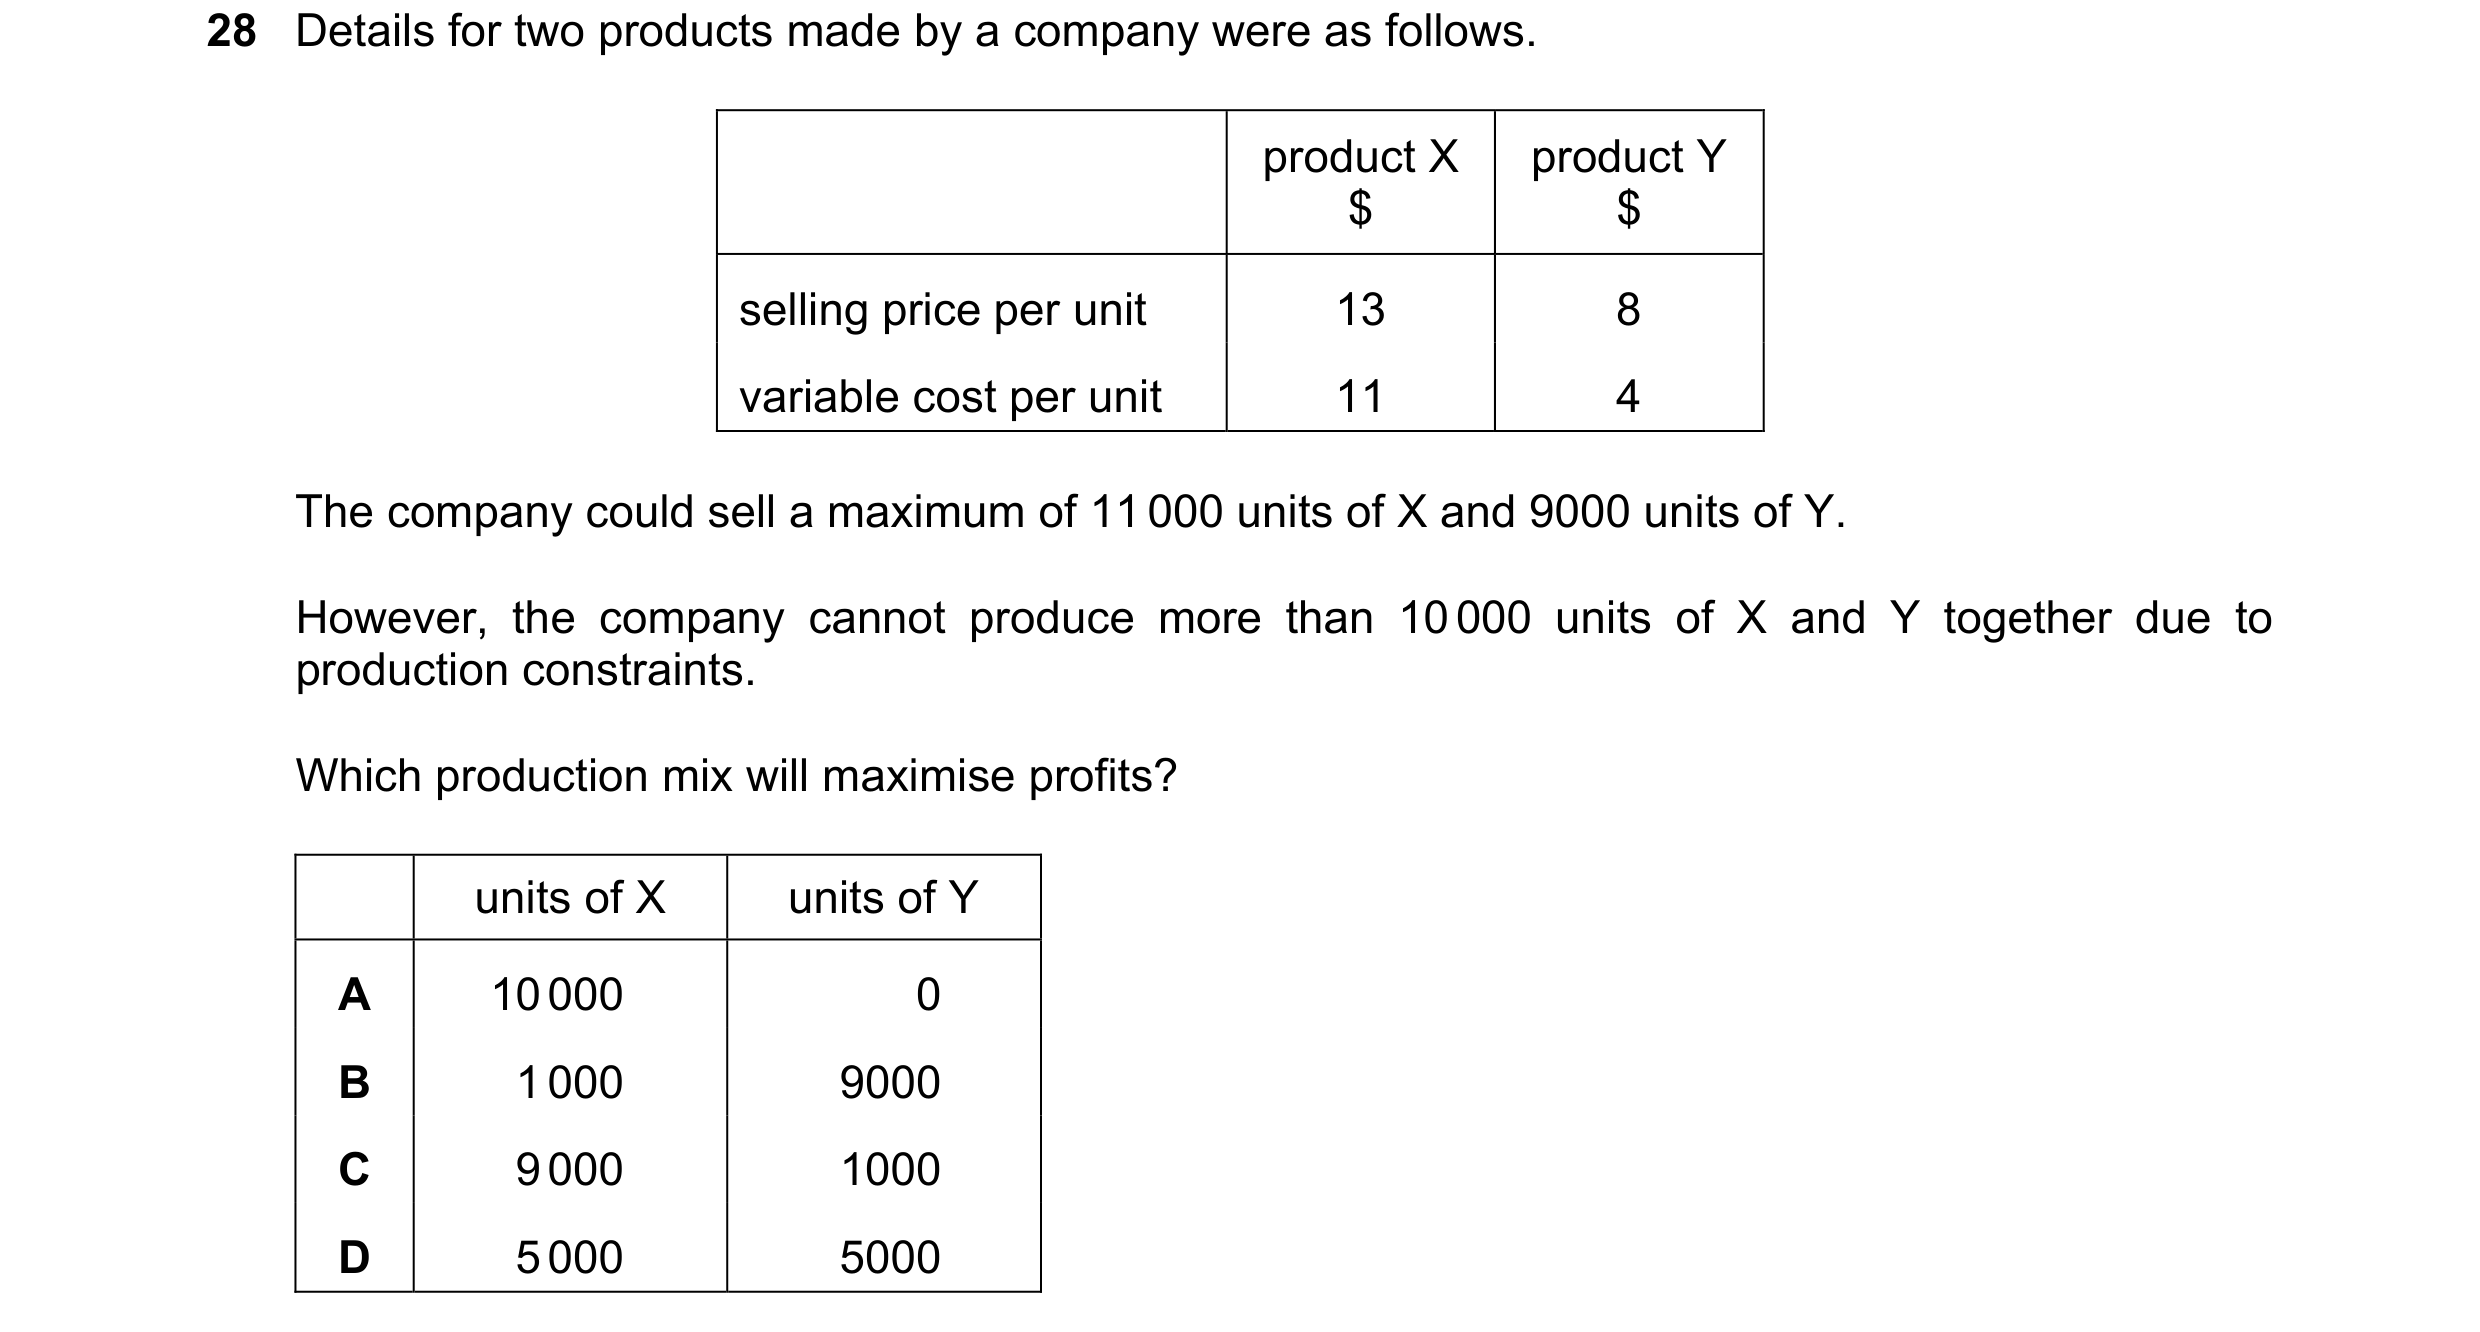
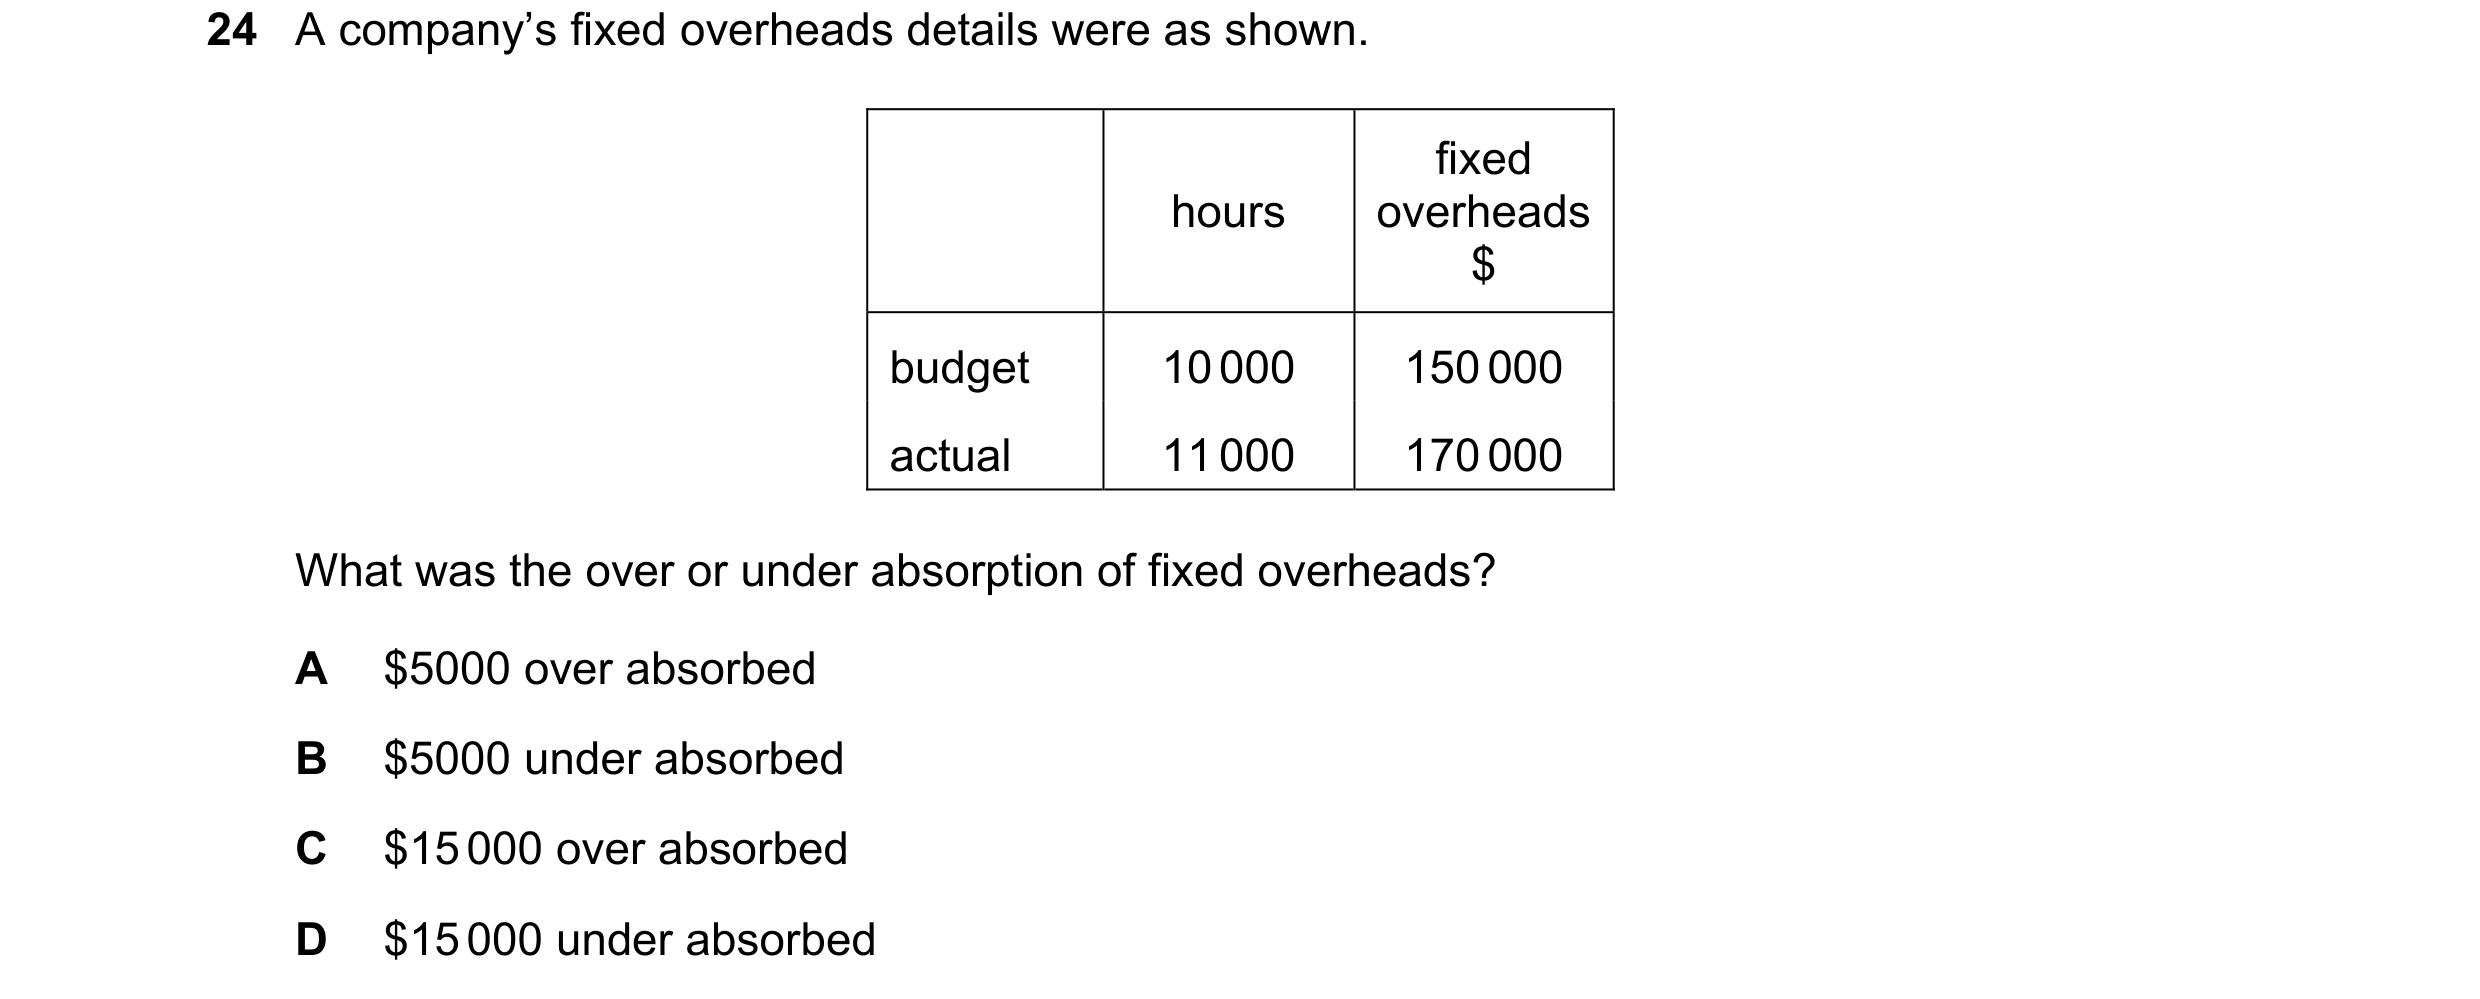
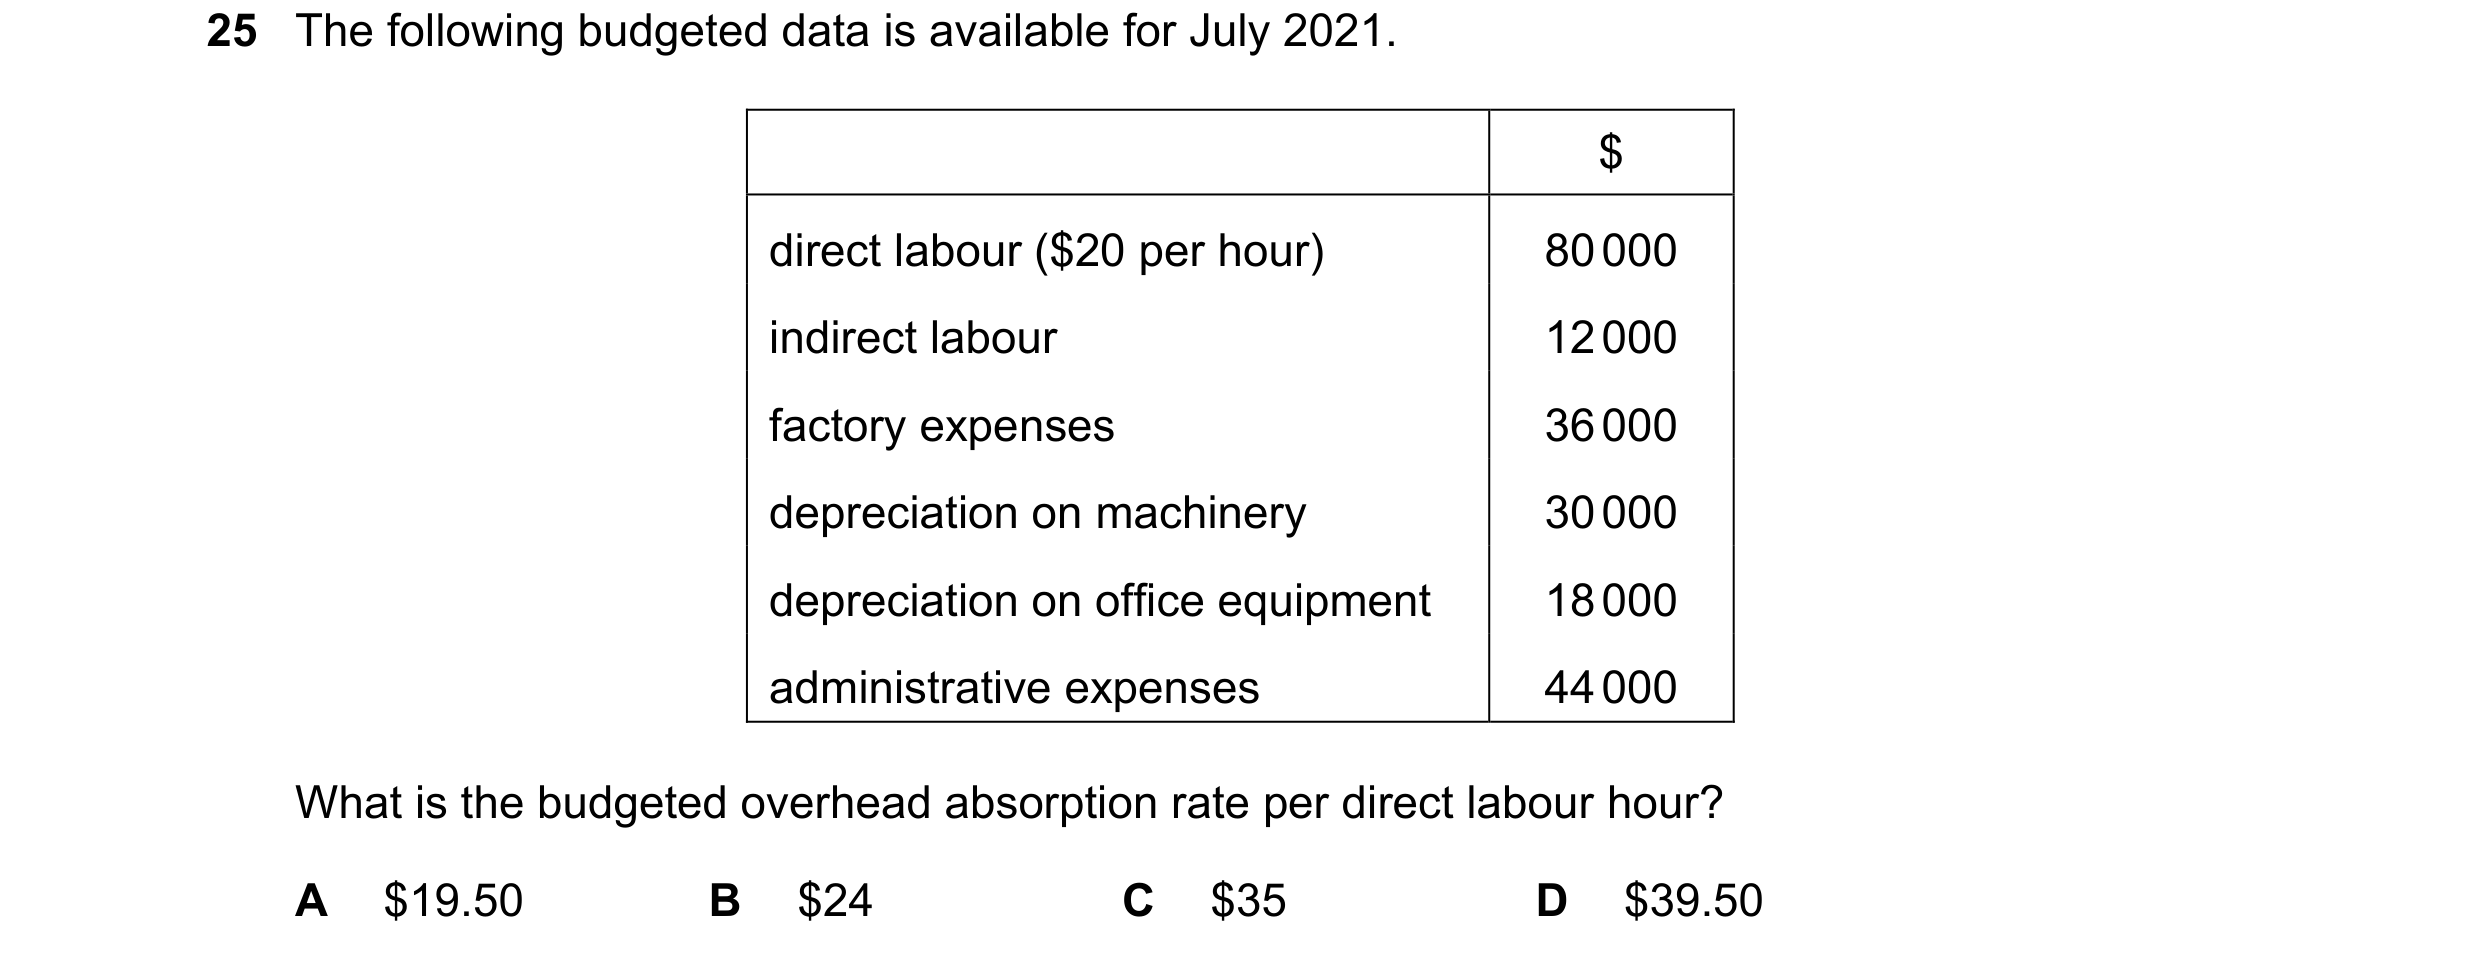 110 / 143
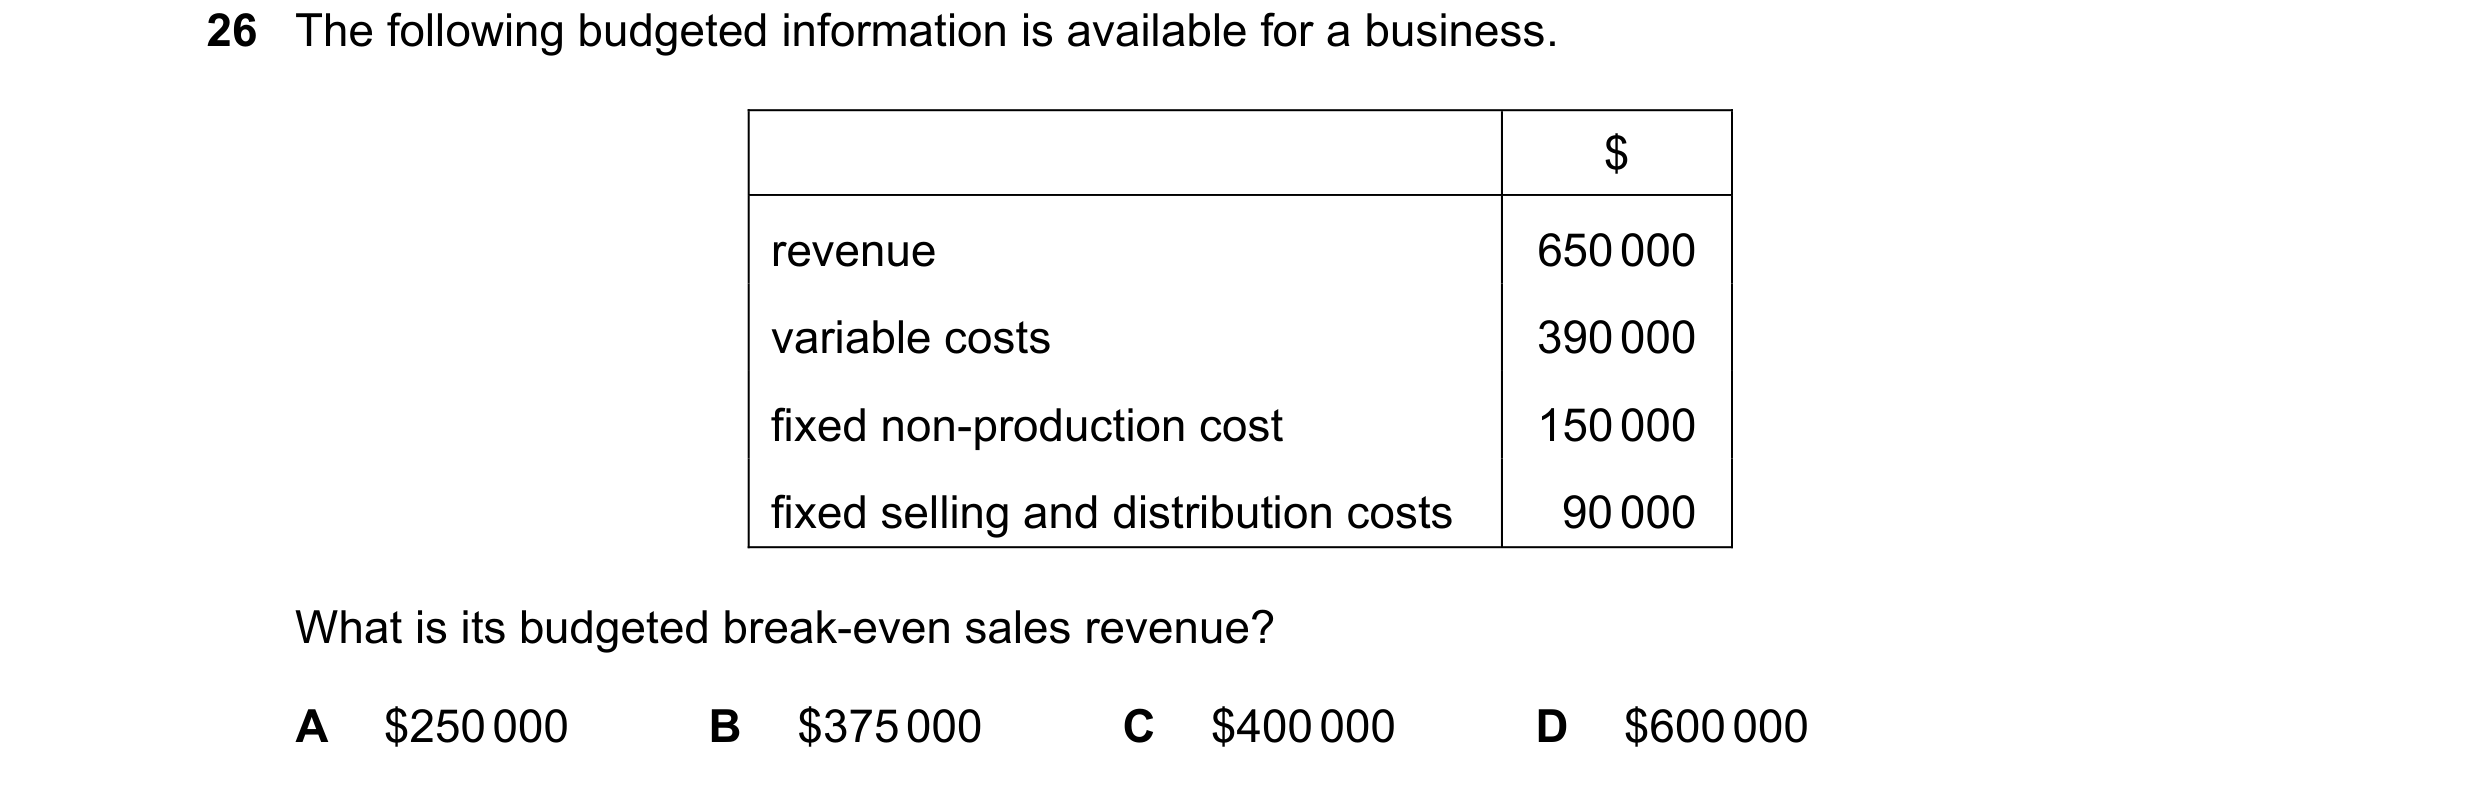
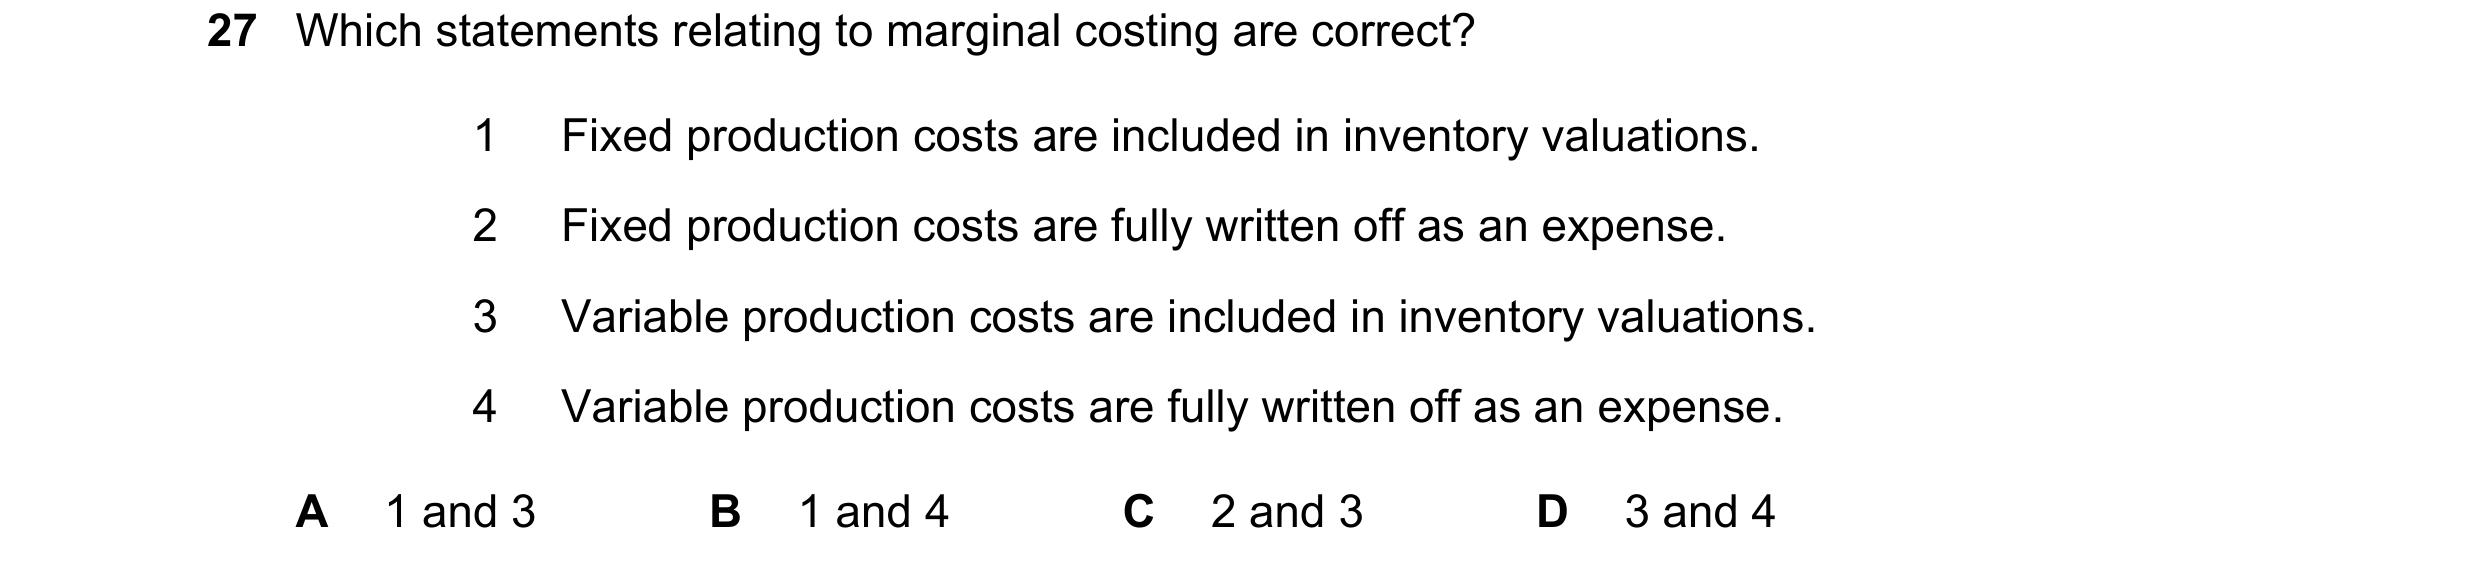
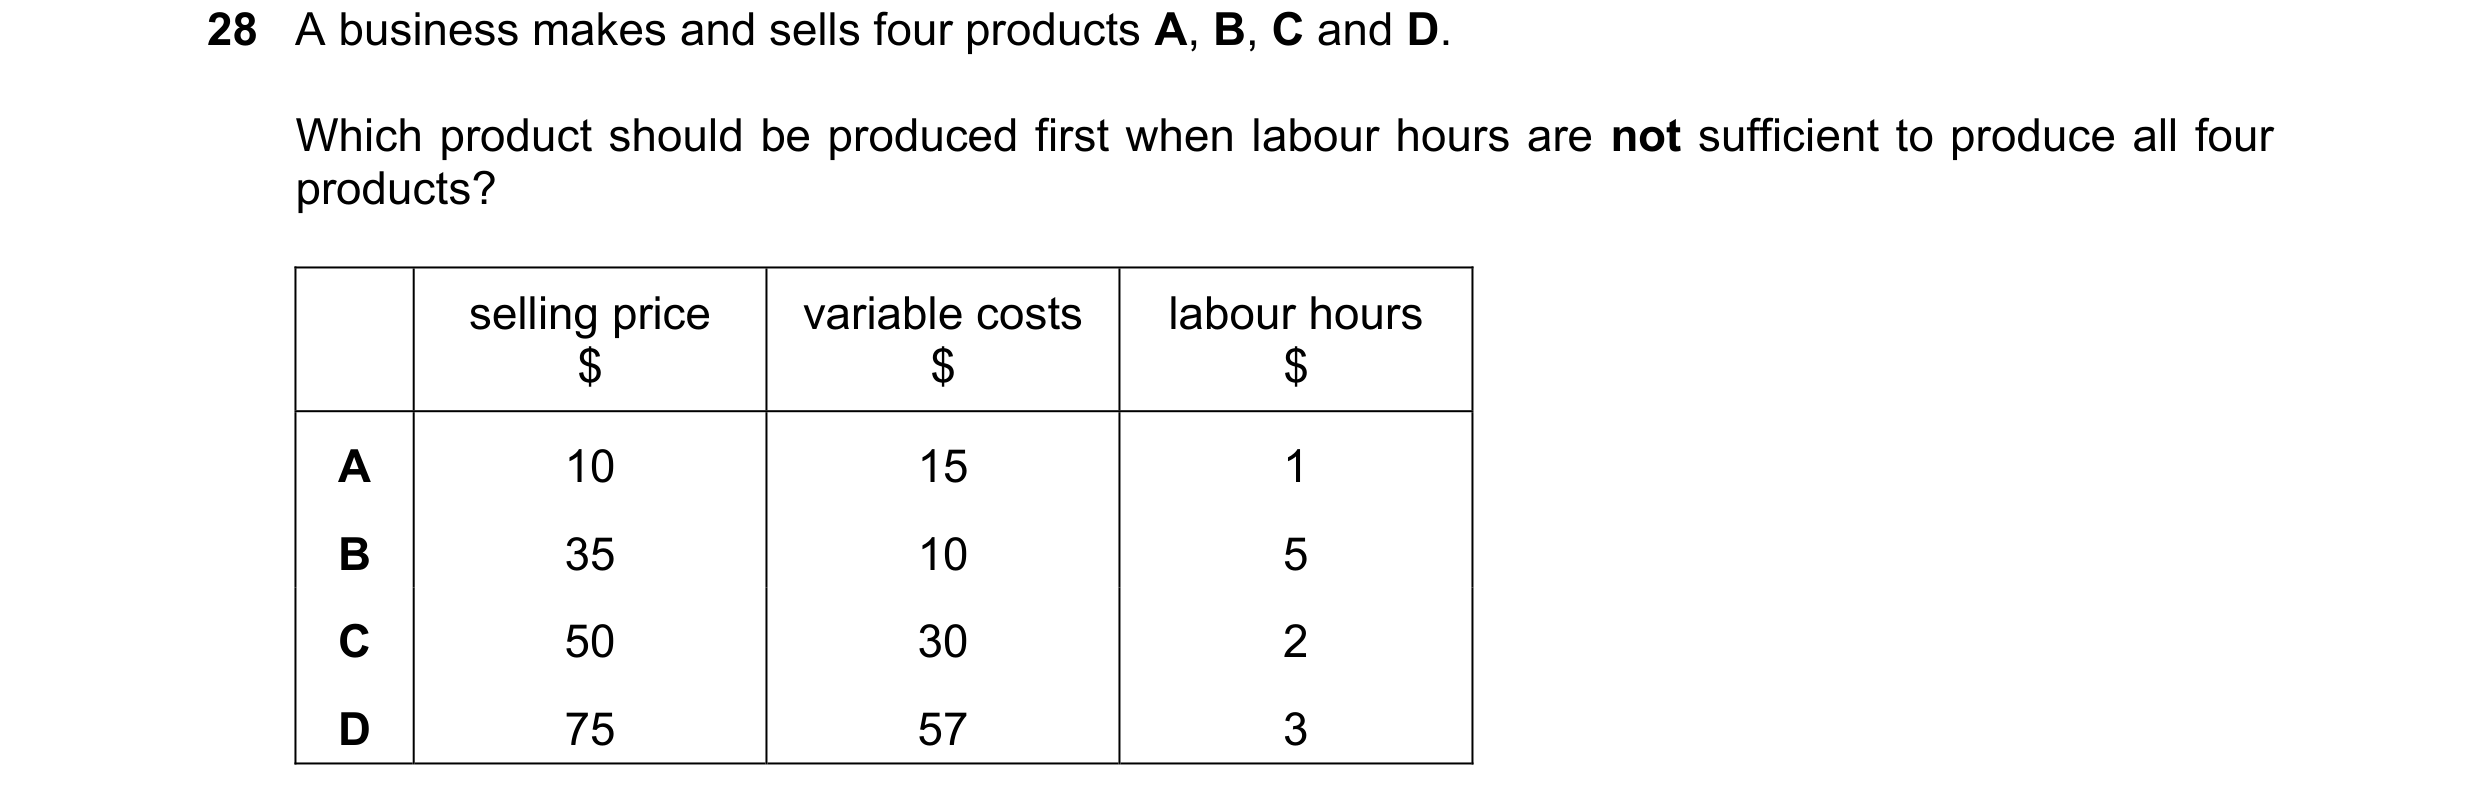
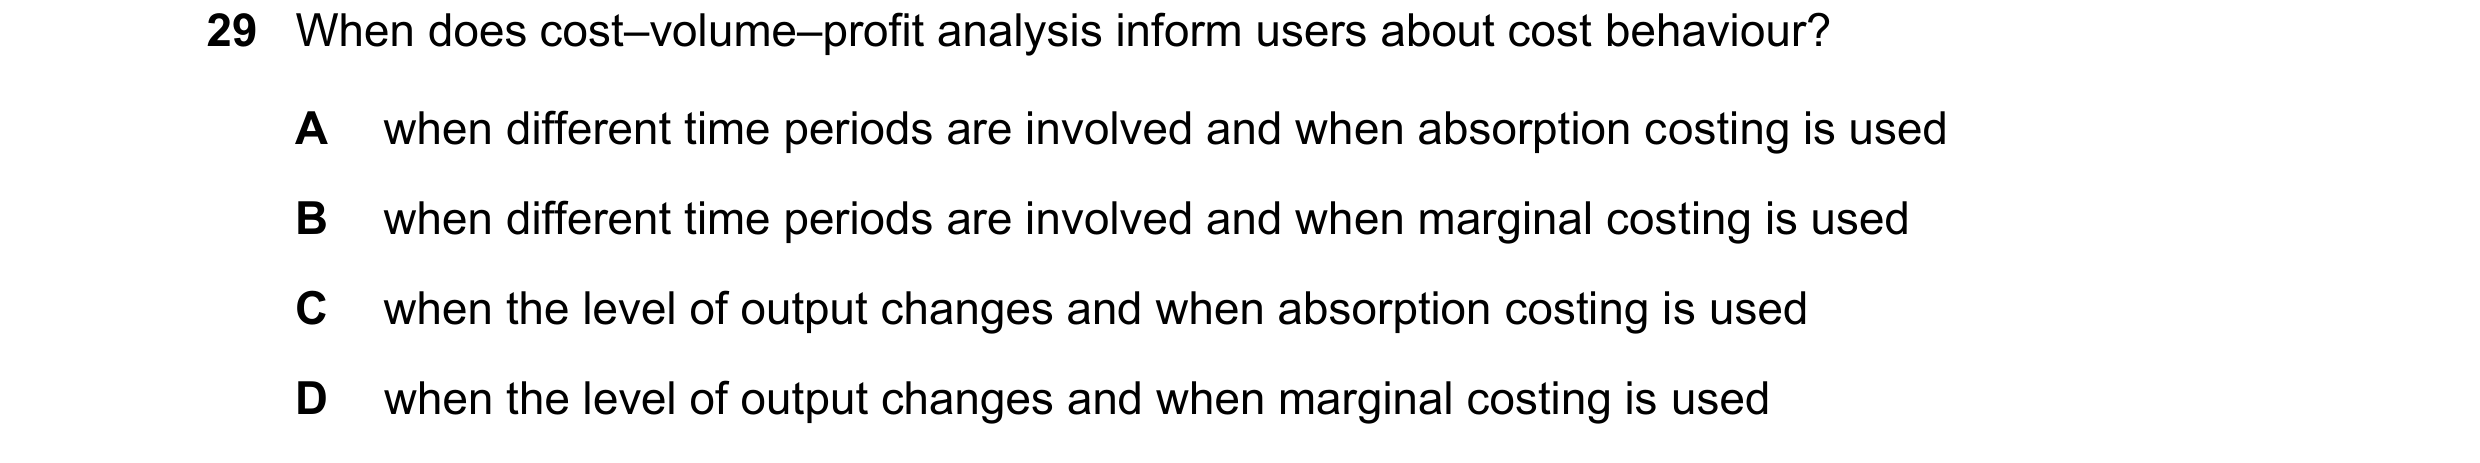 111 / 143
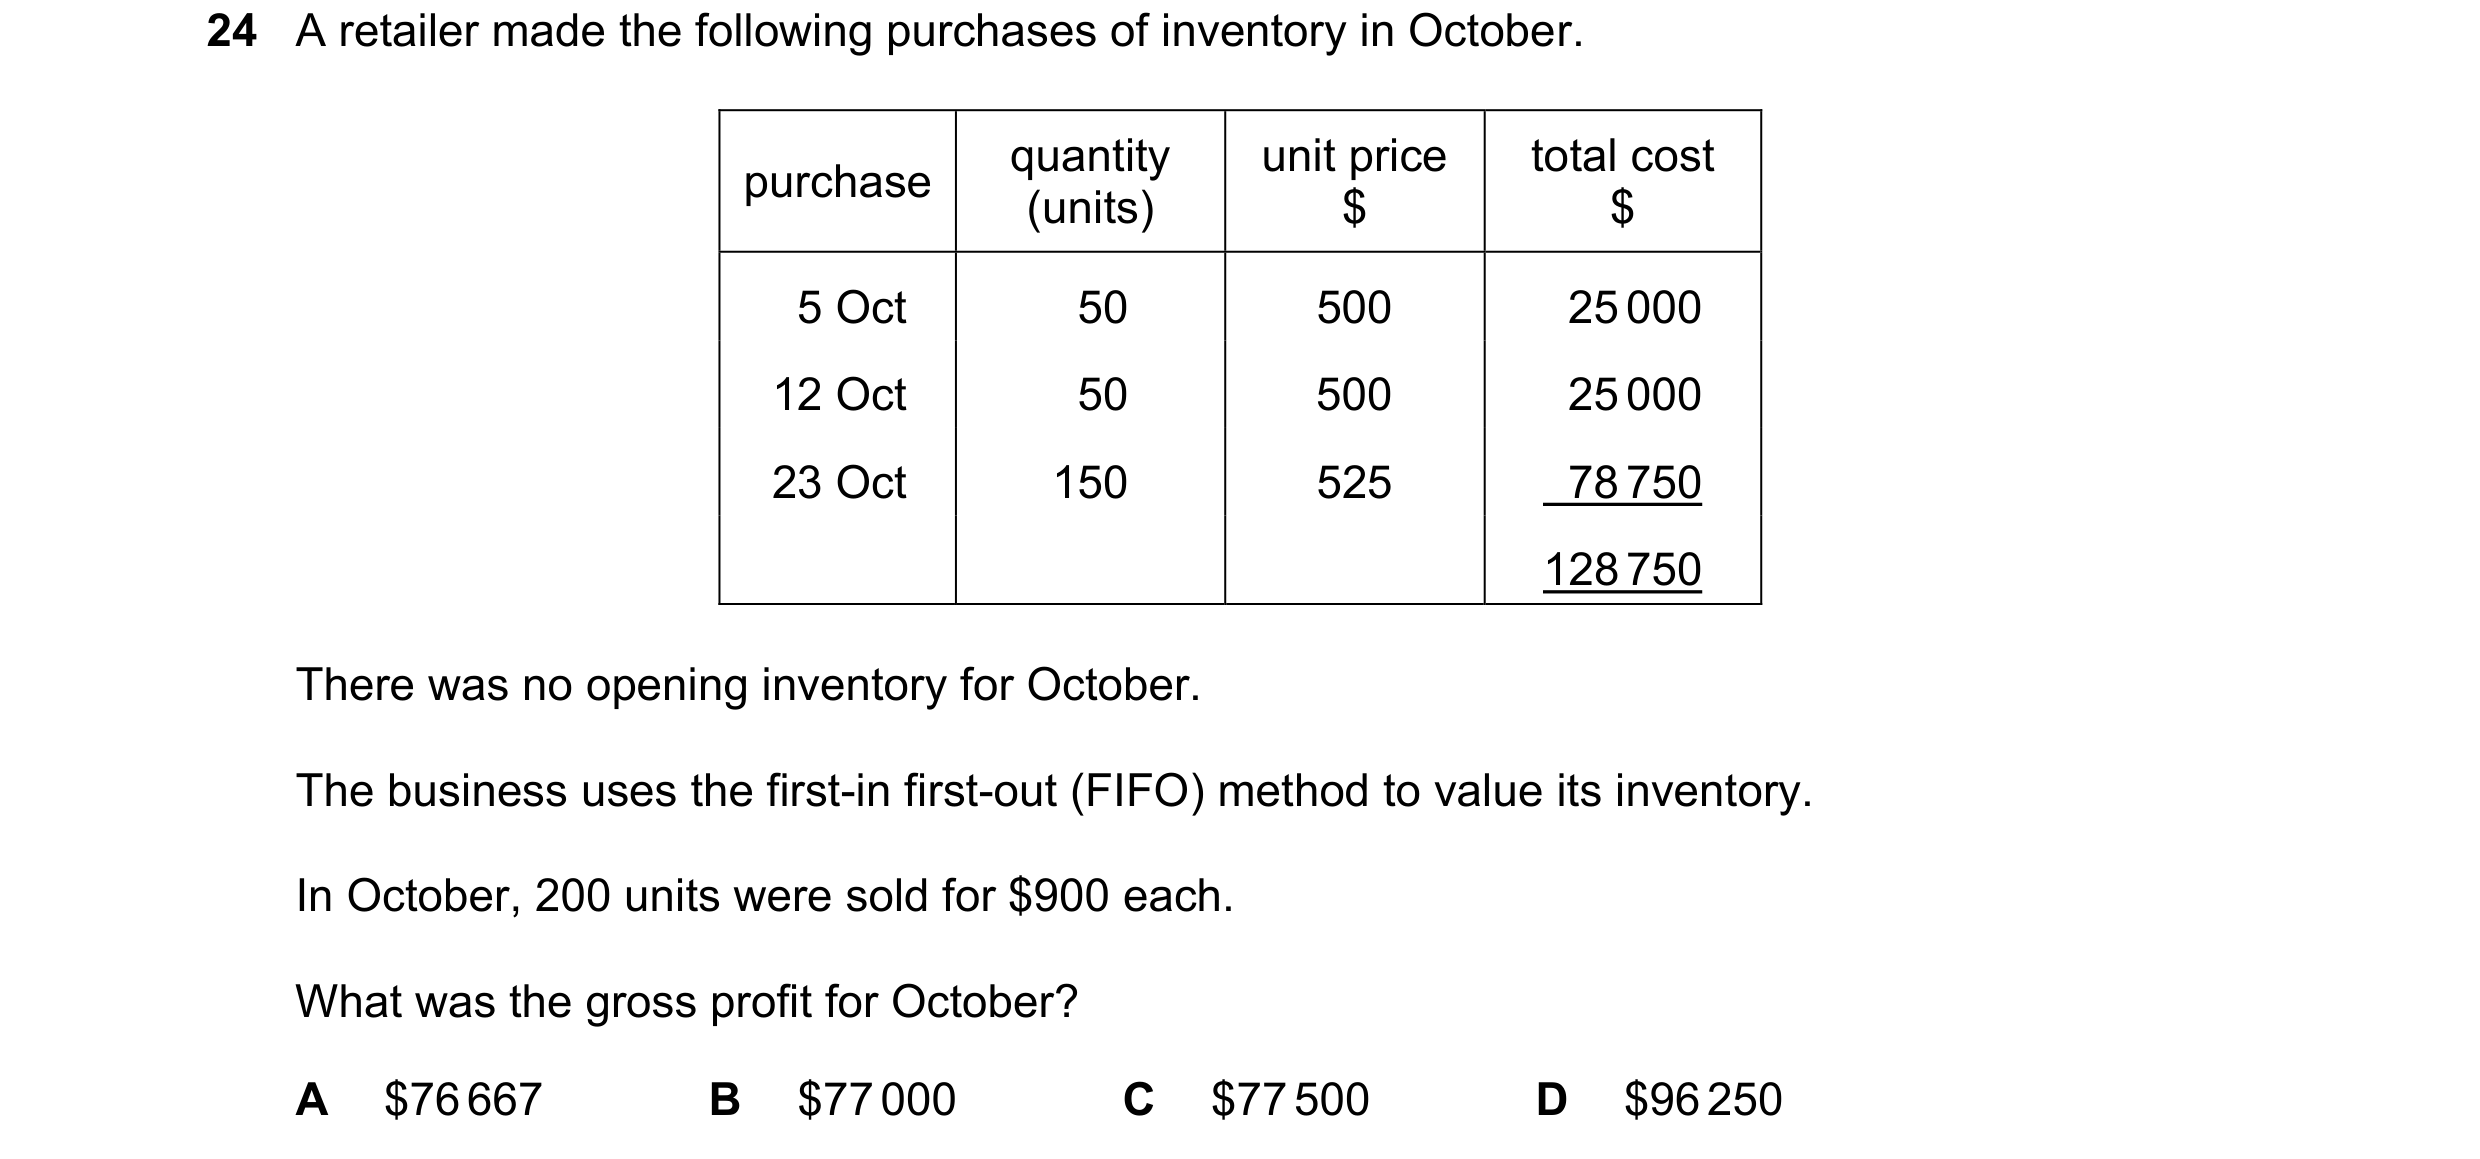
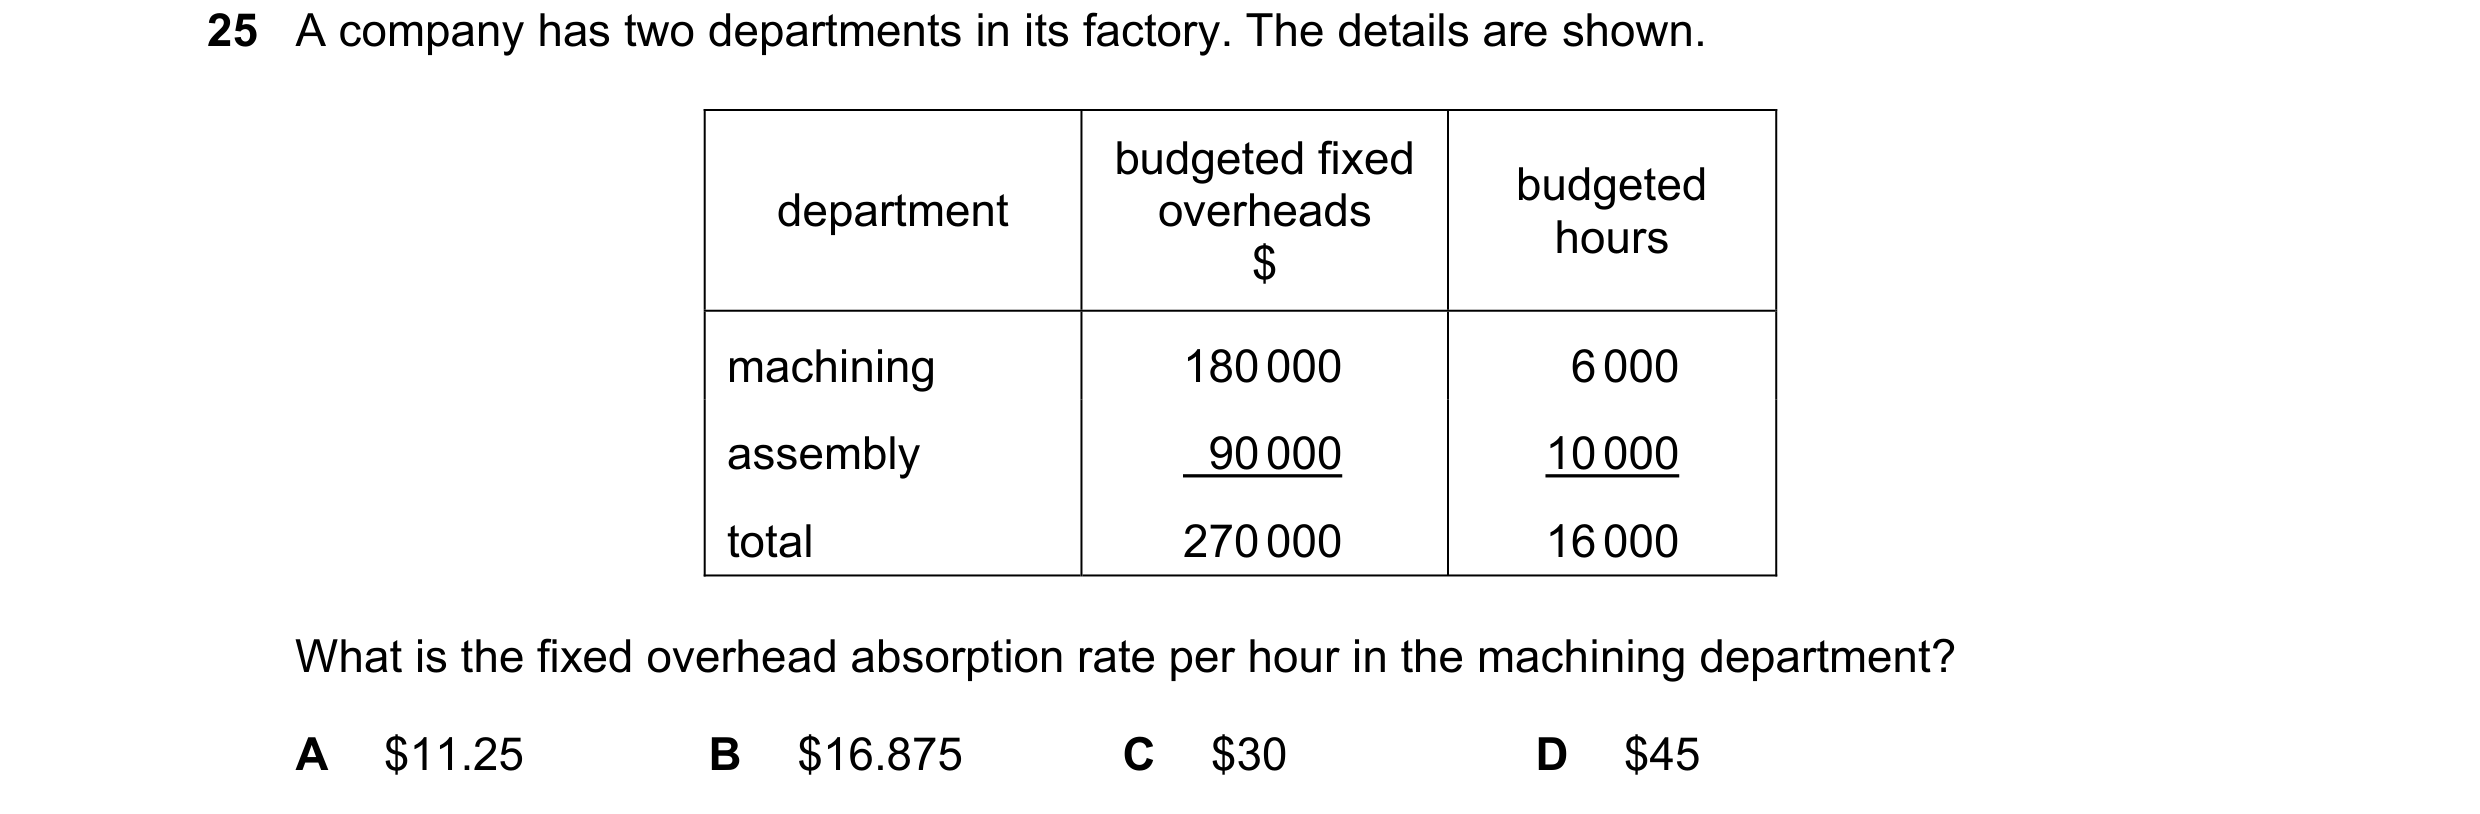
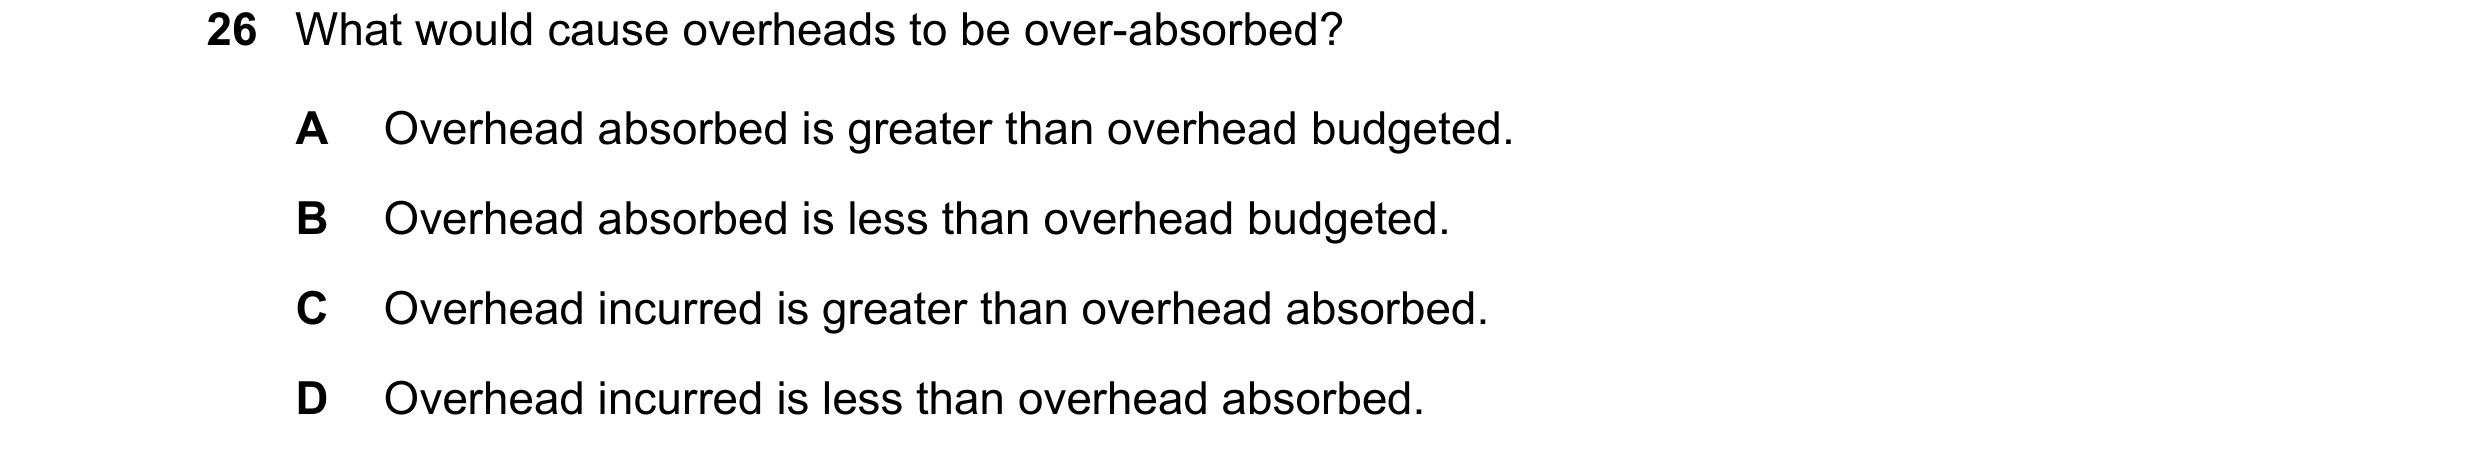 112 / 143
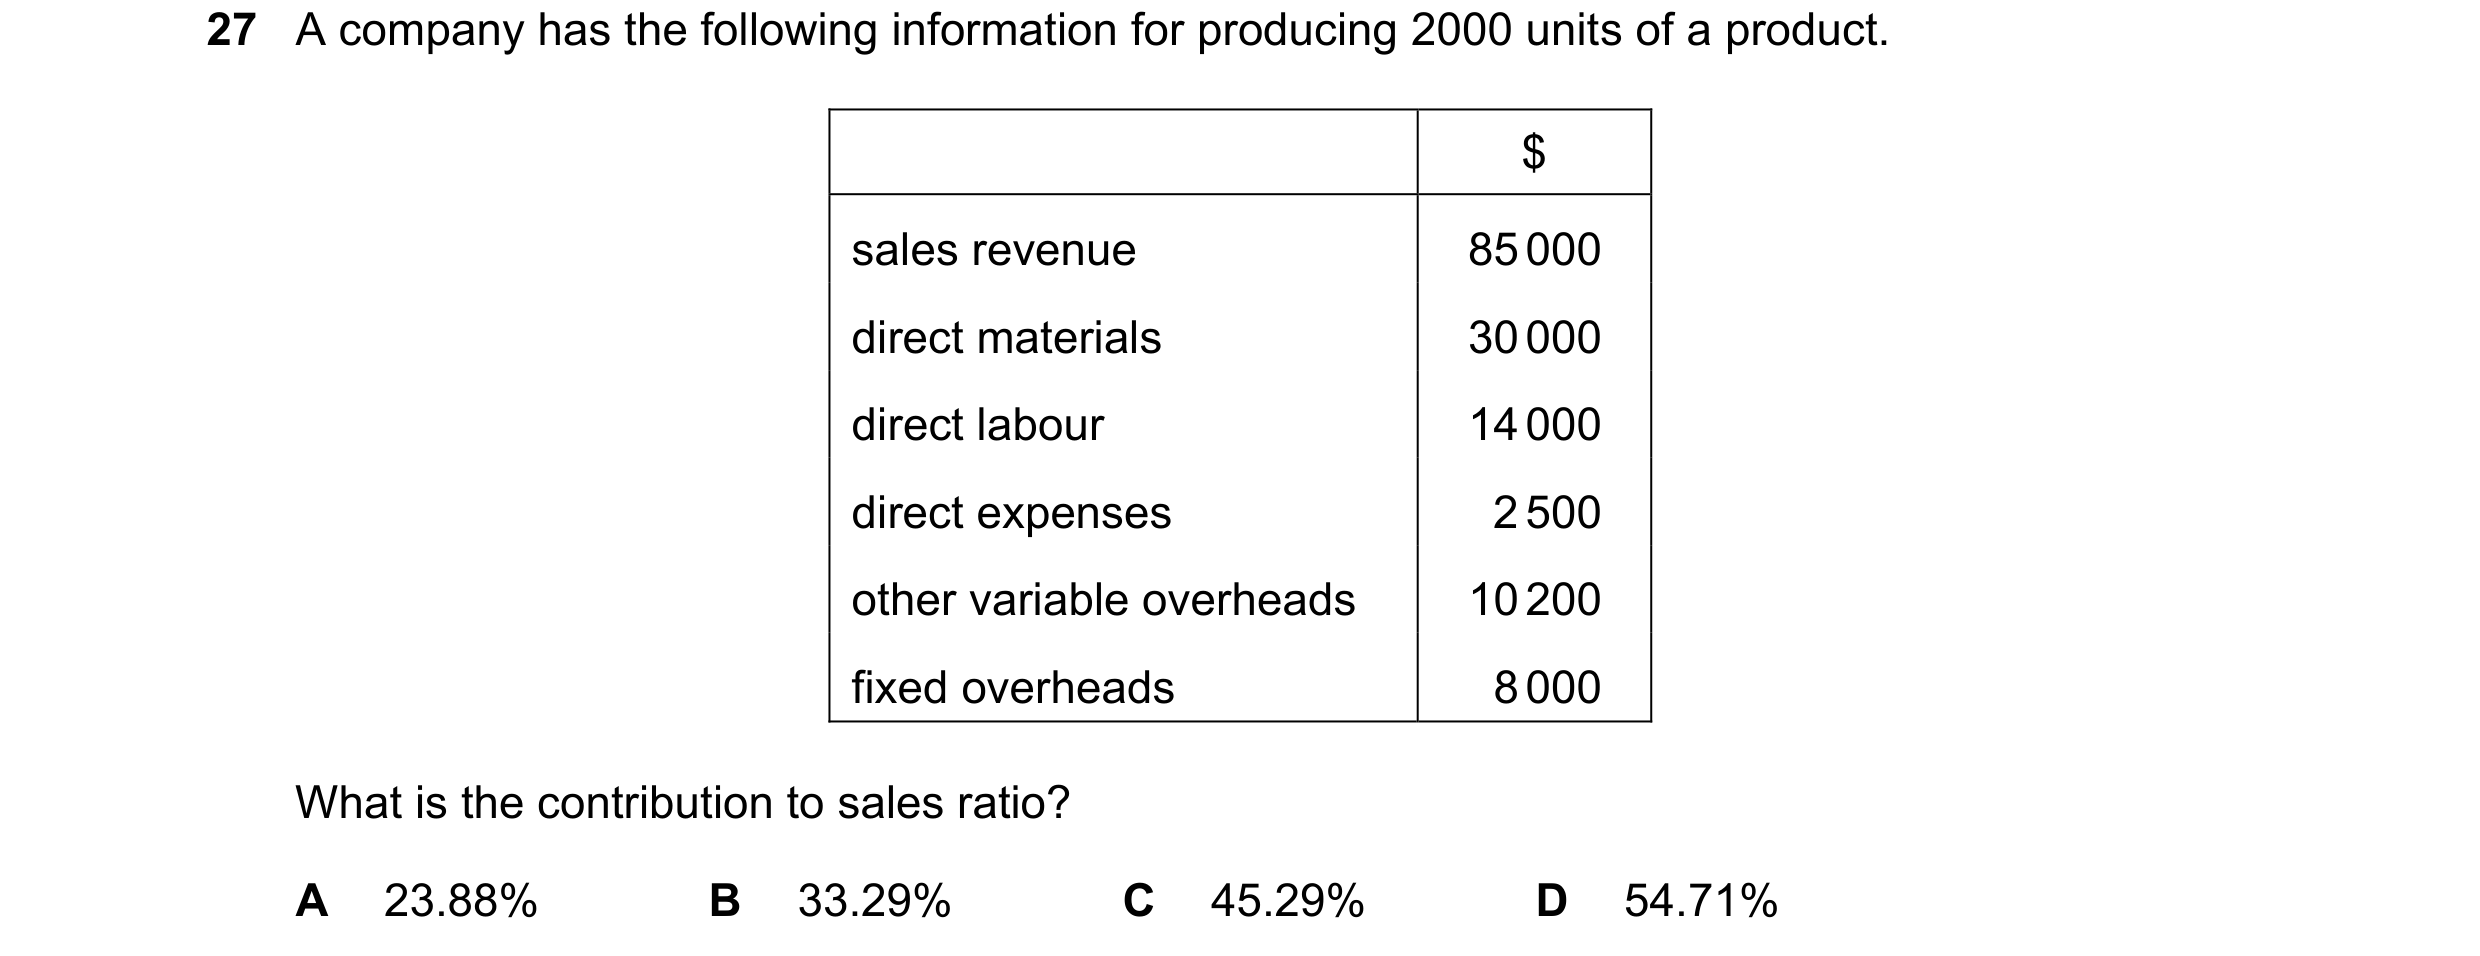
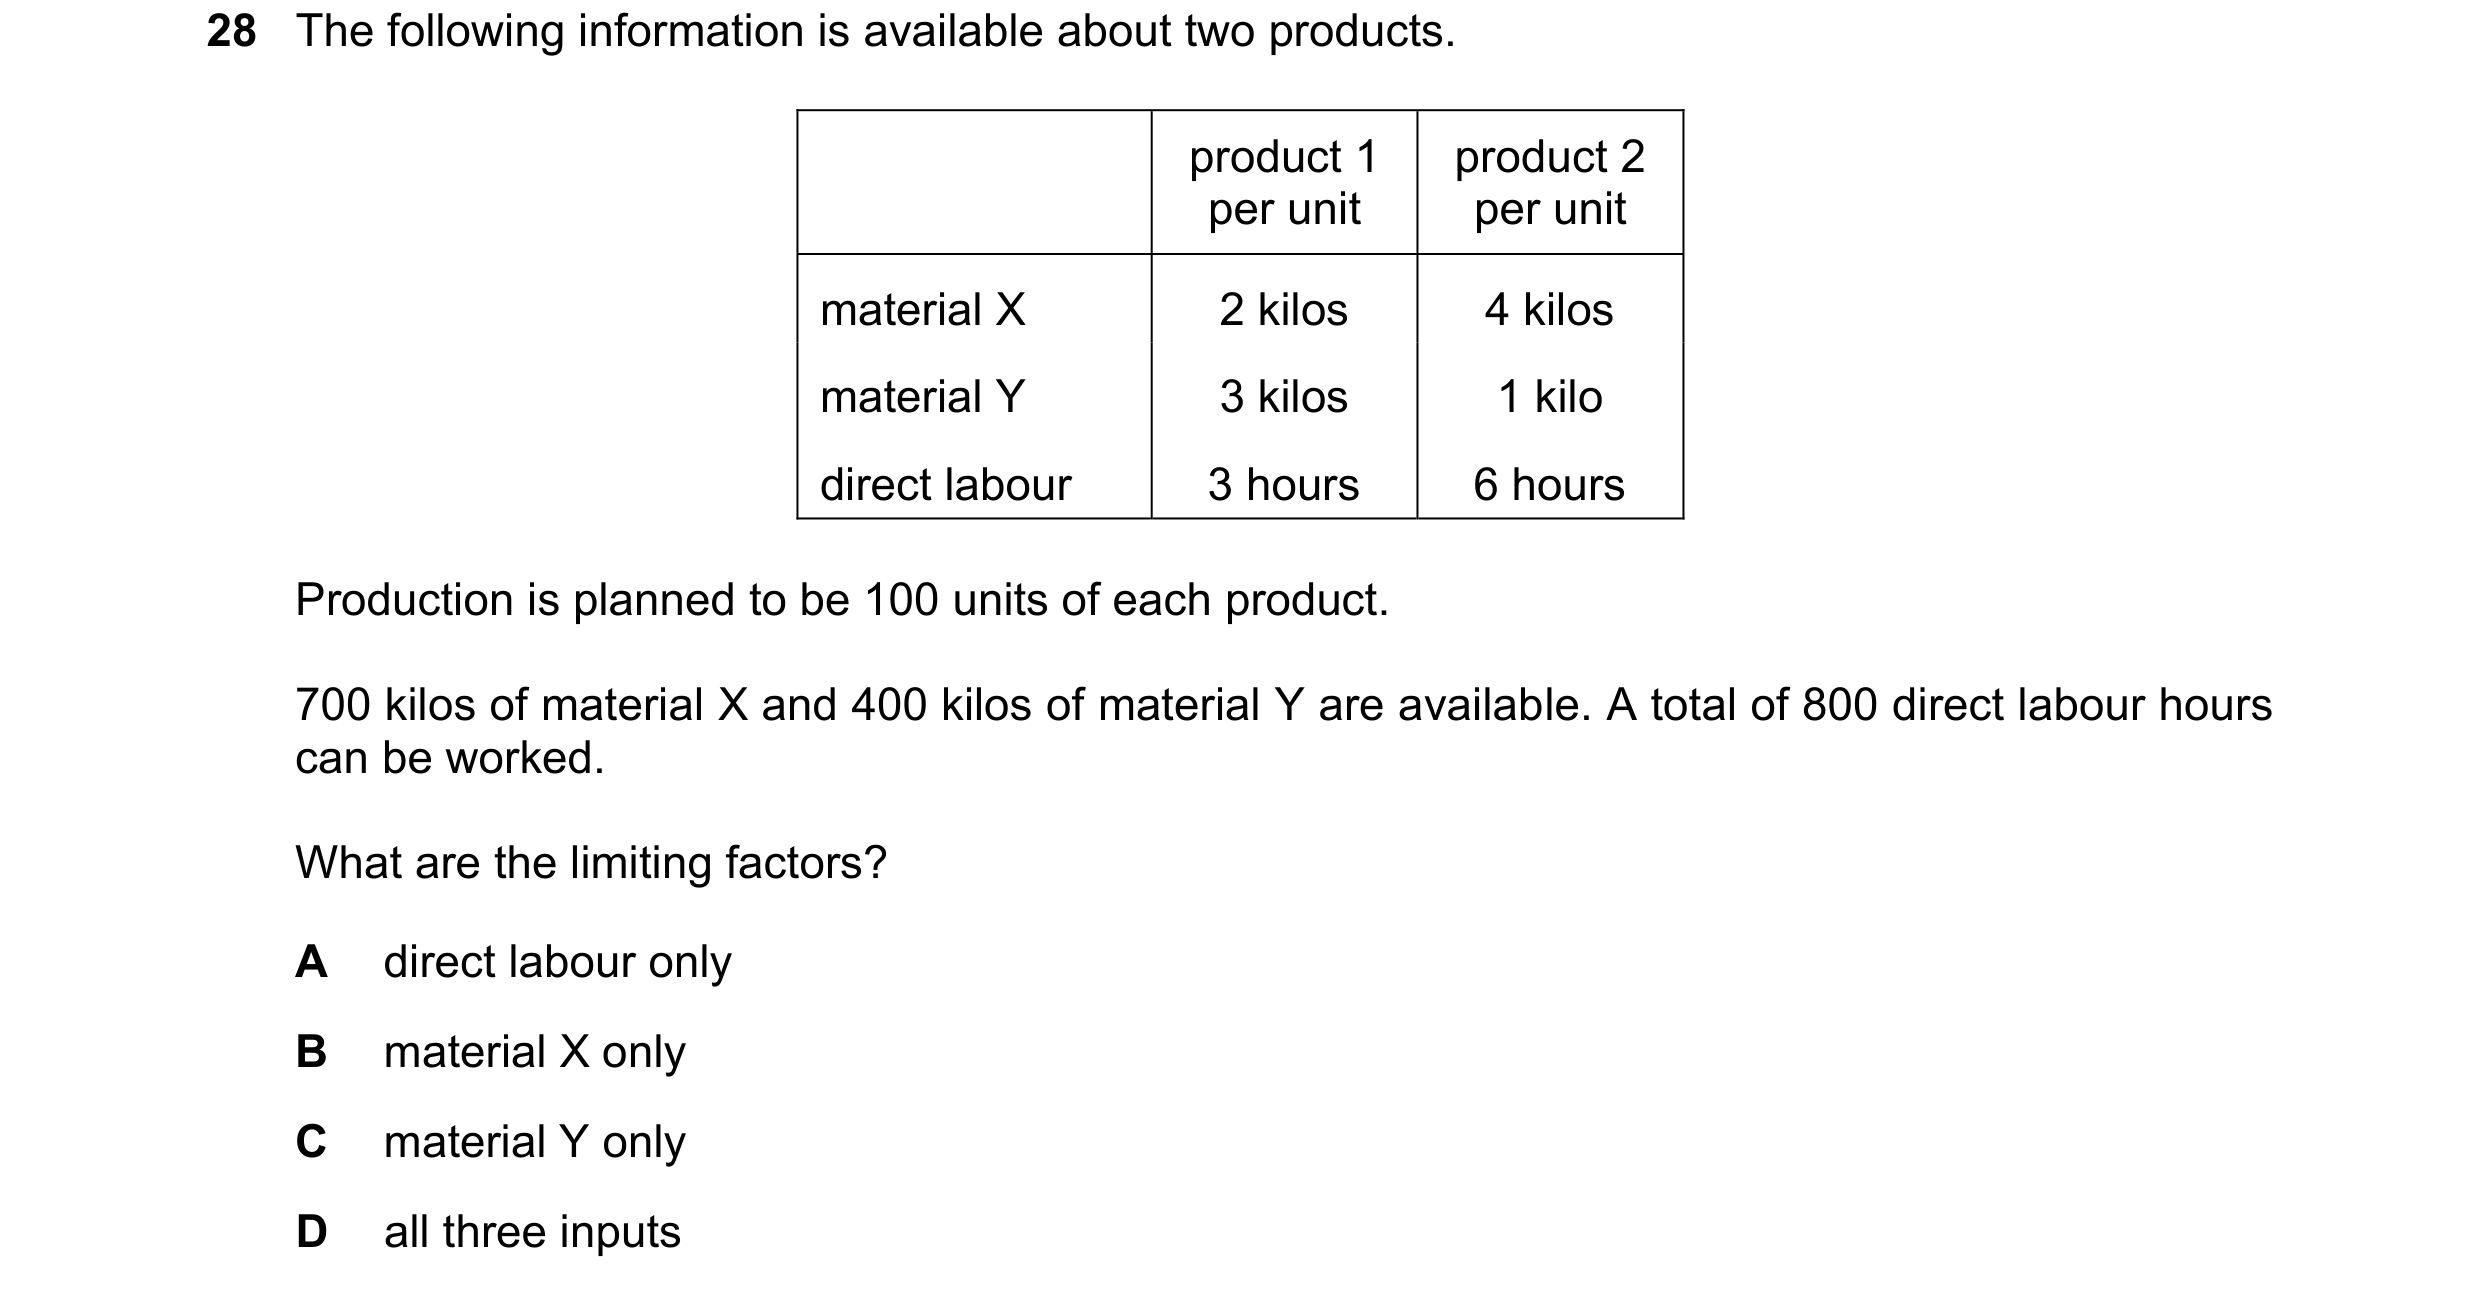
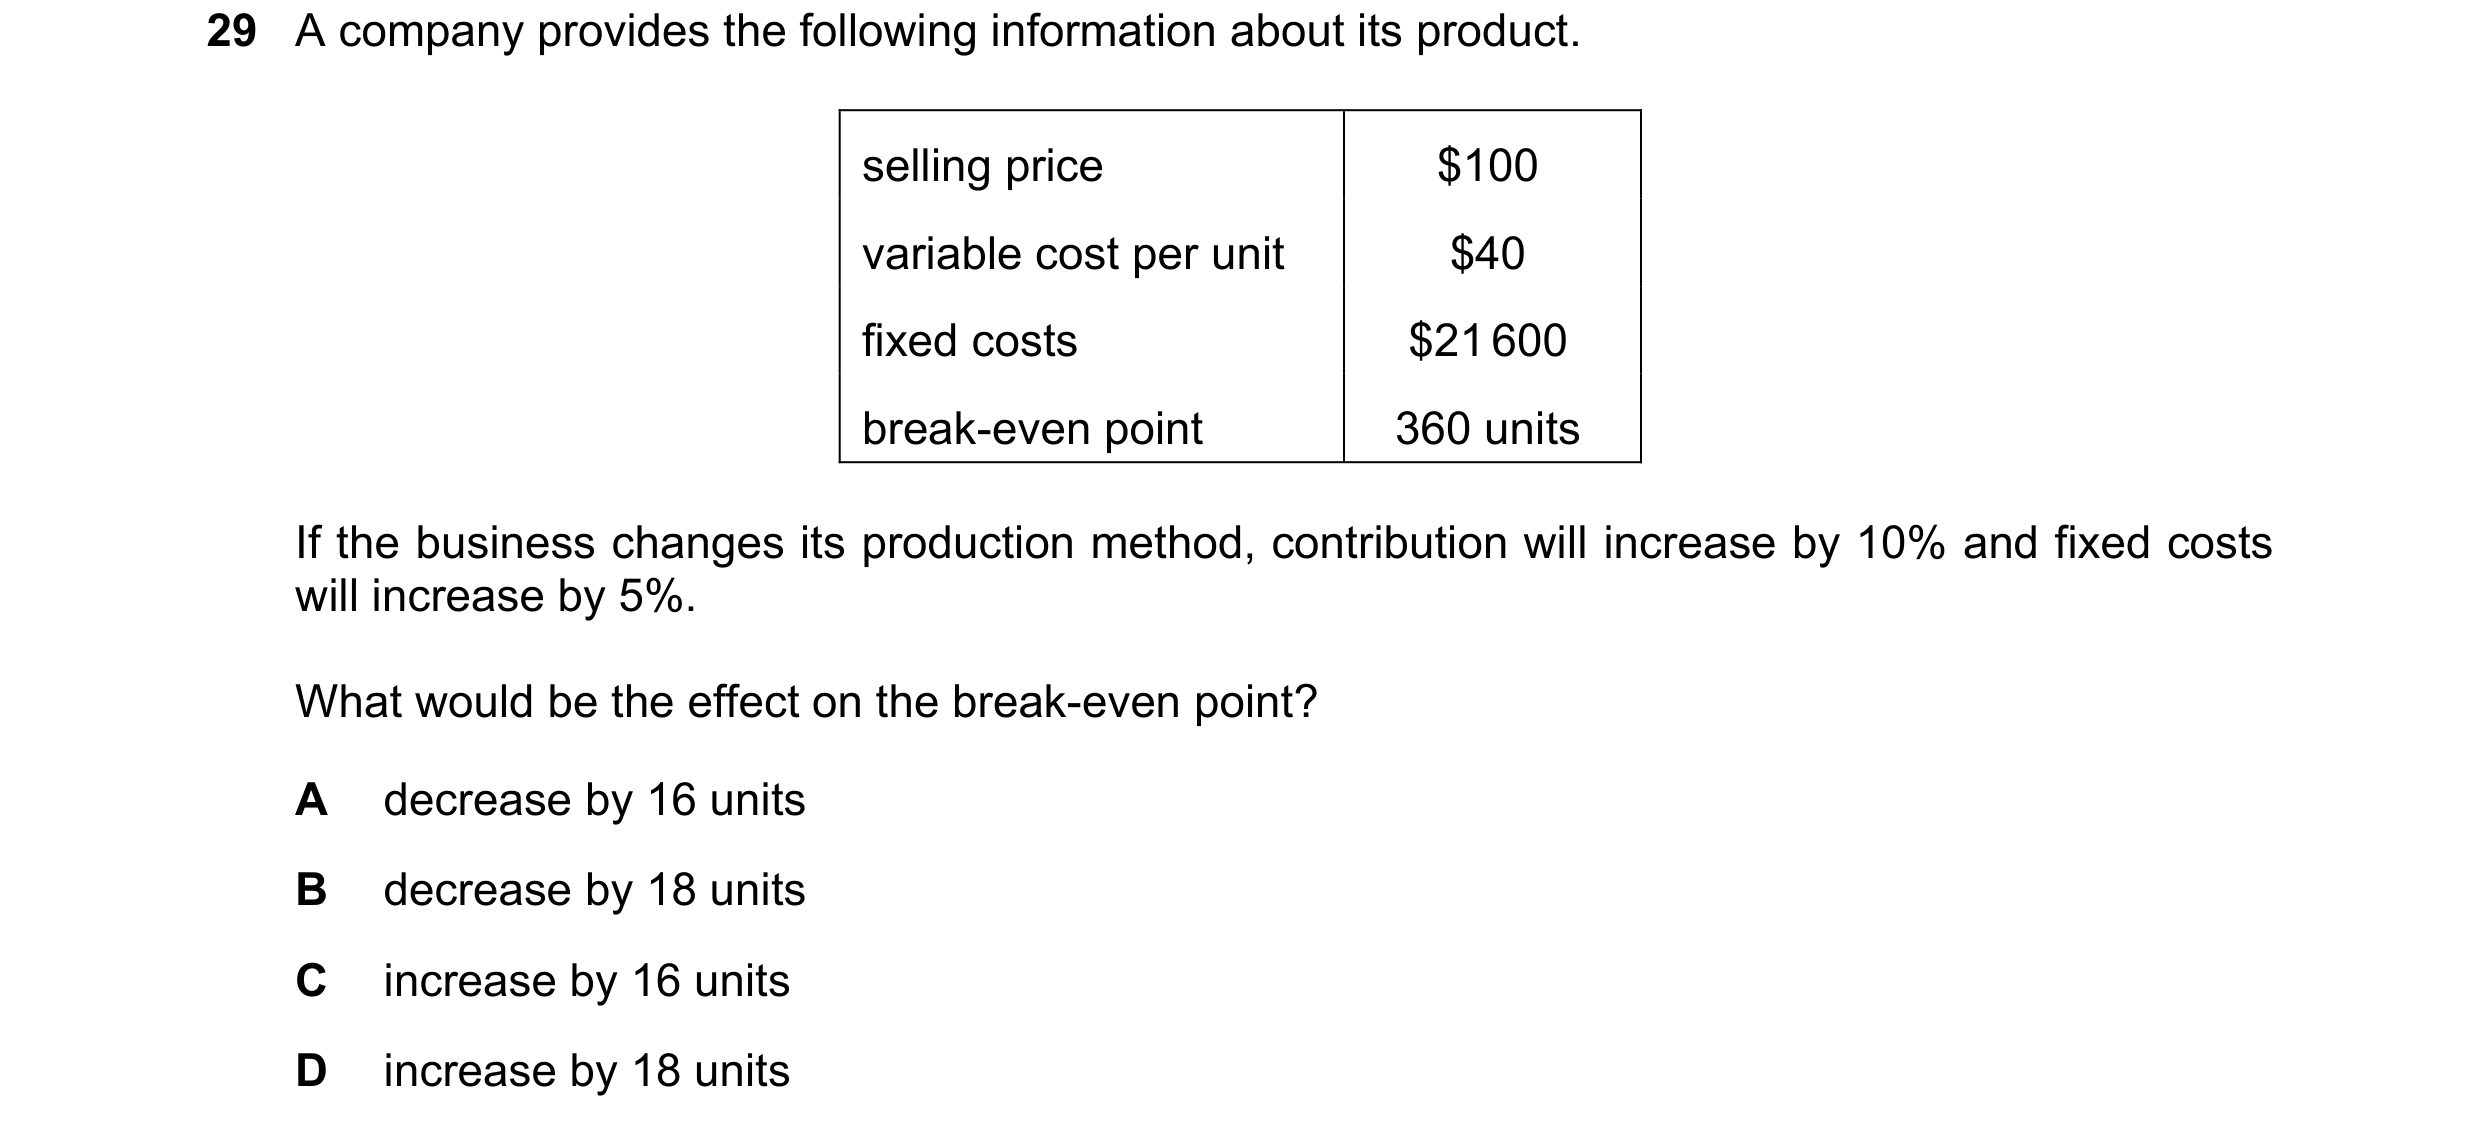 113 / 143
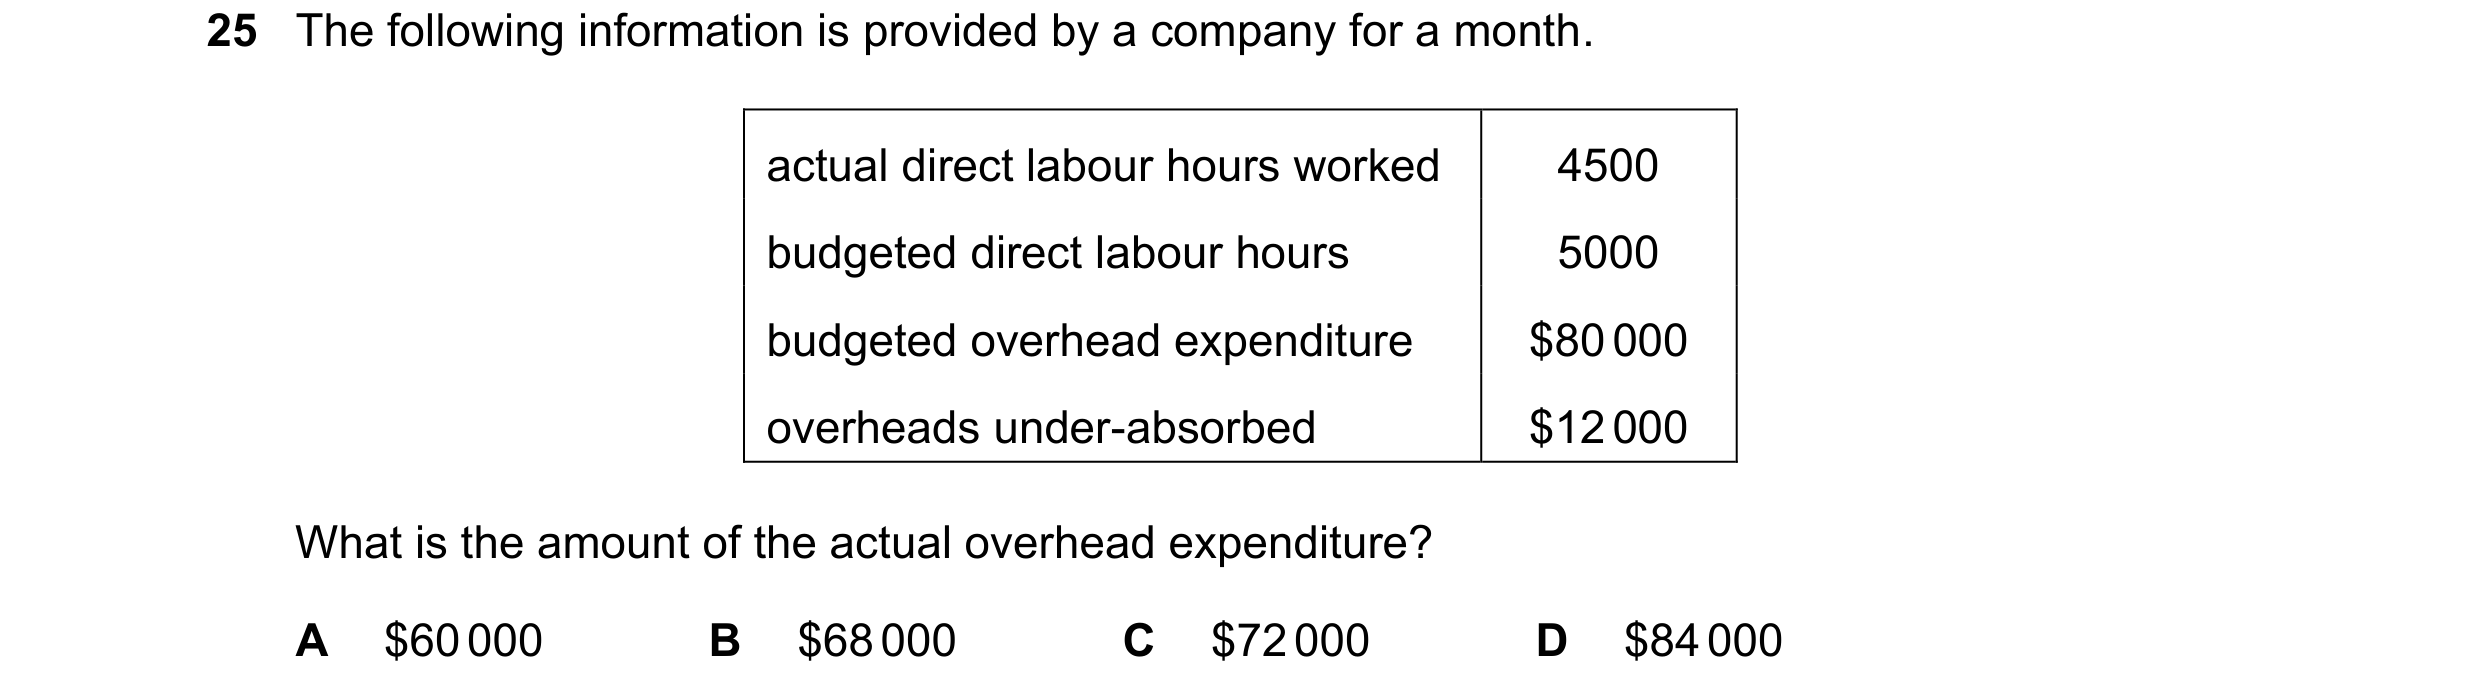
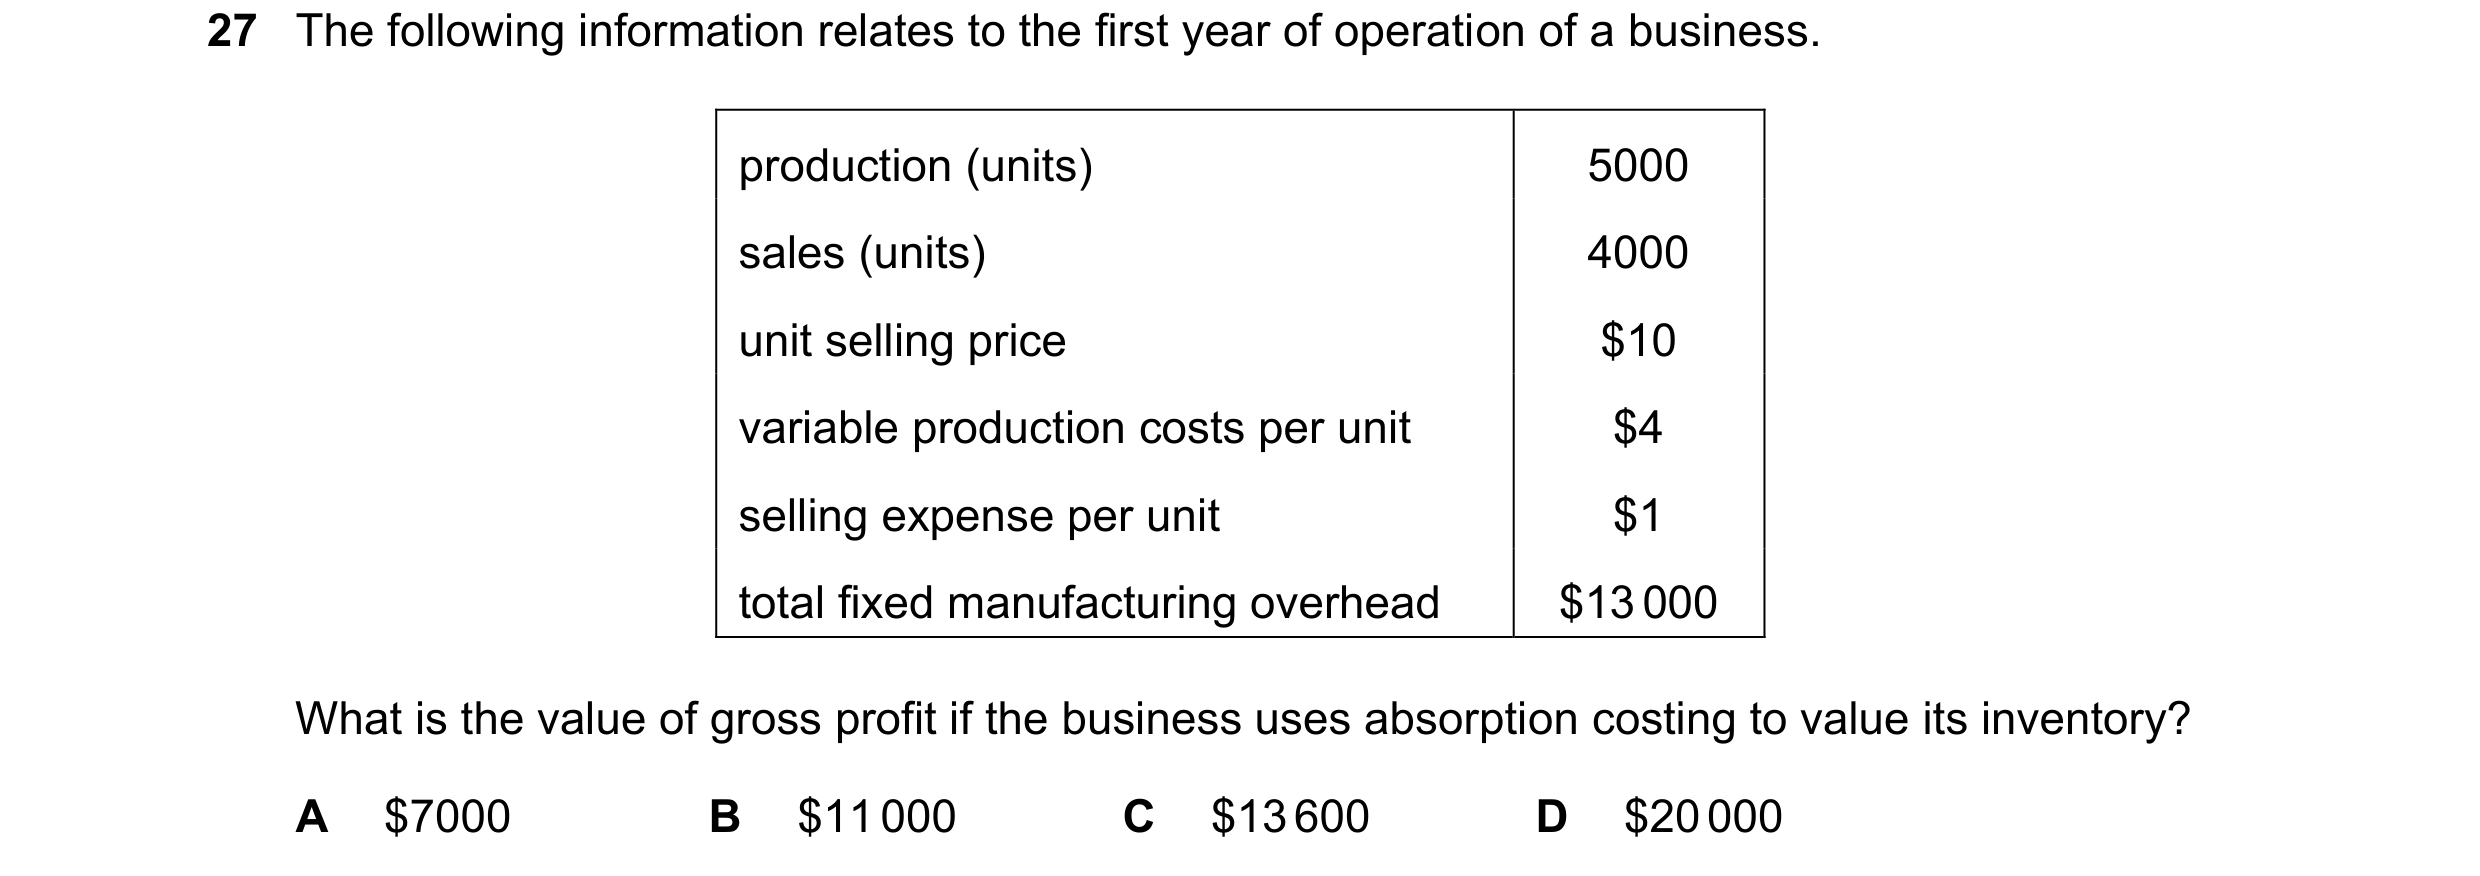
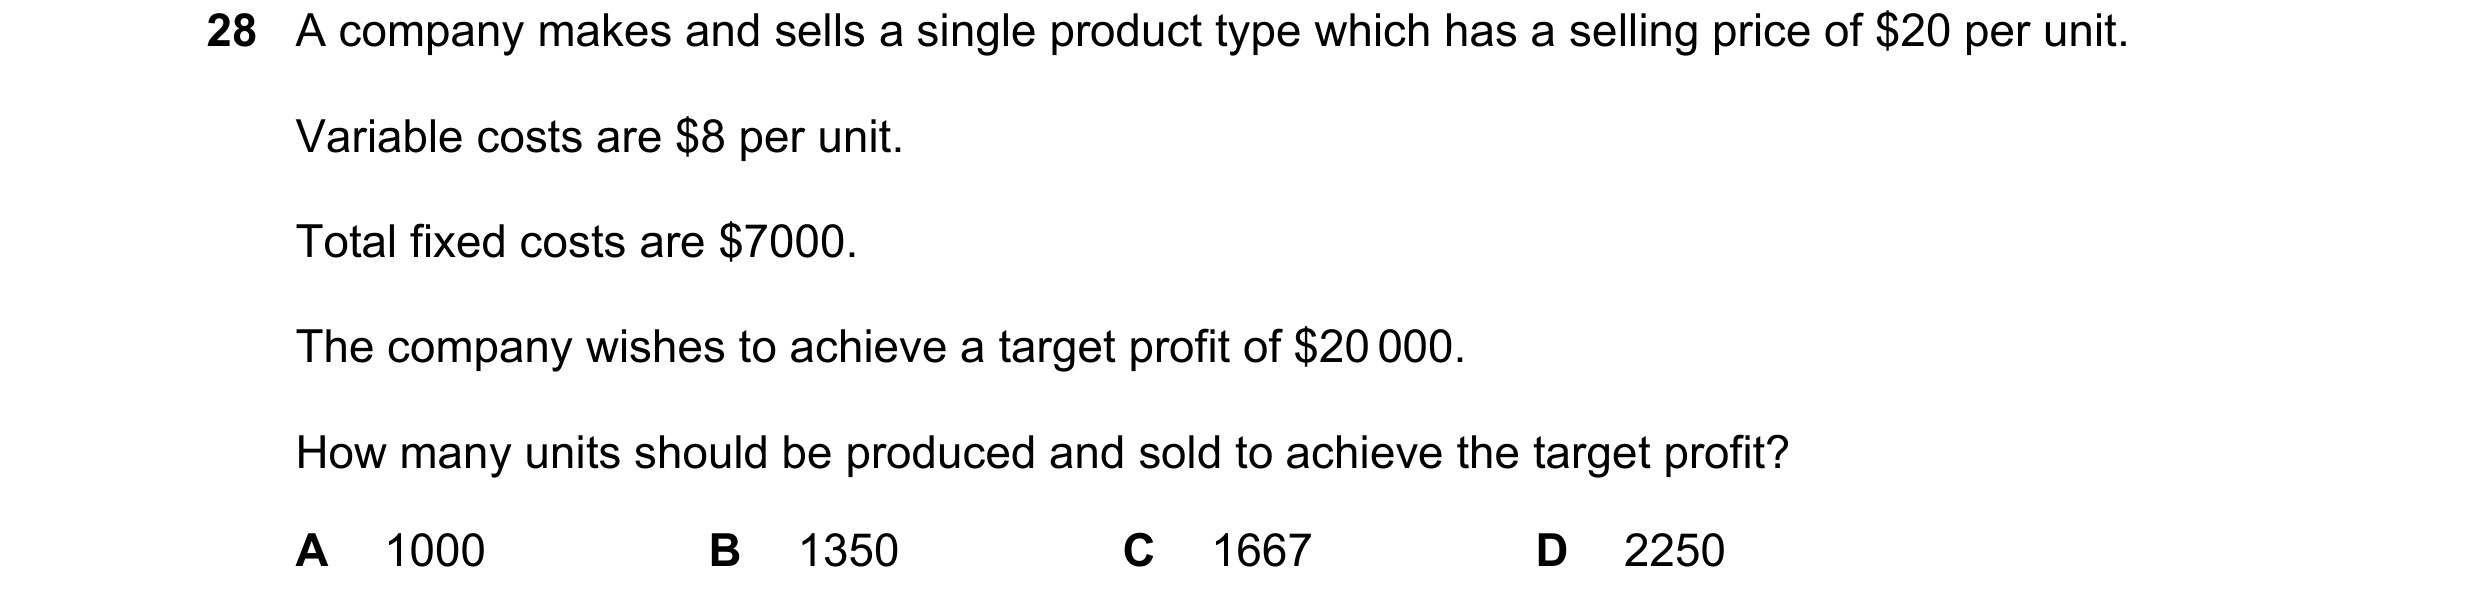 114 / 143
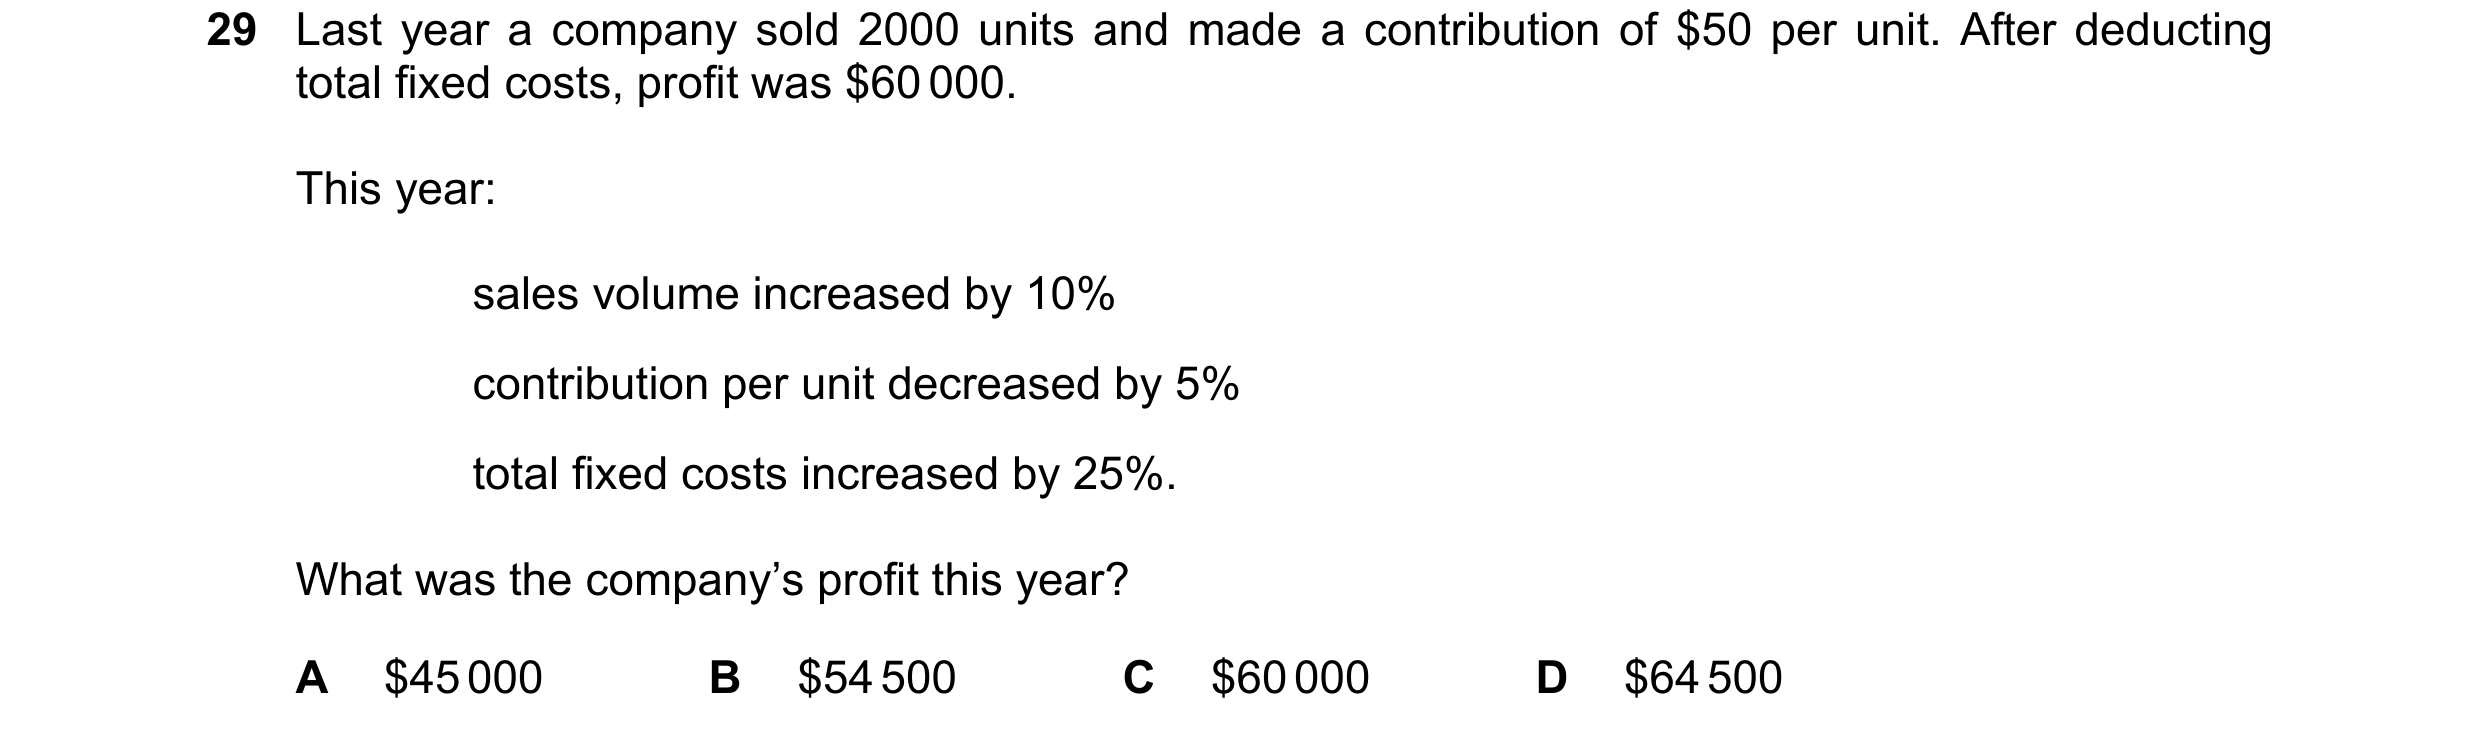
 115 / 143
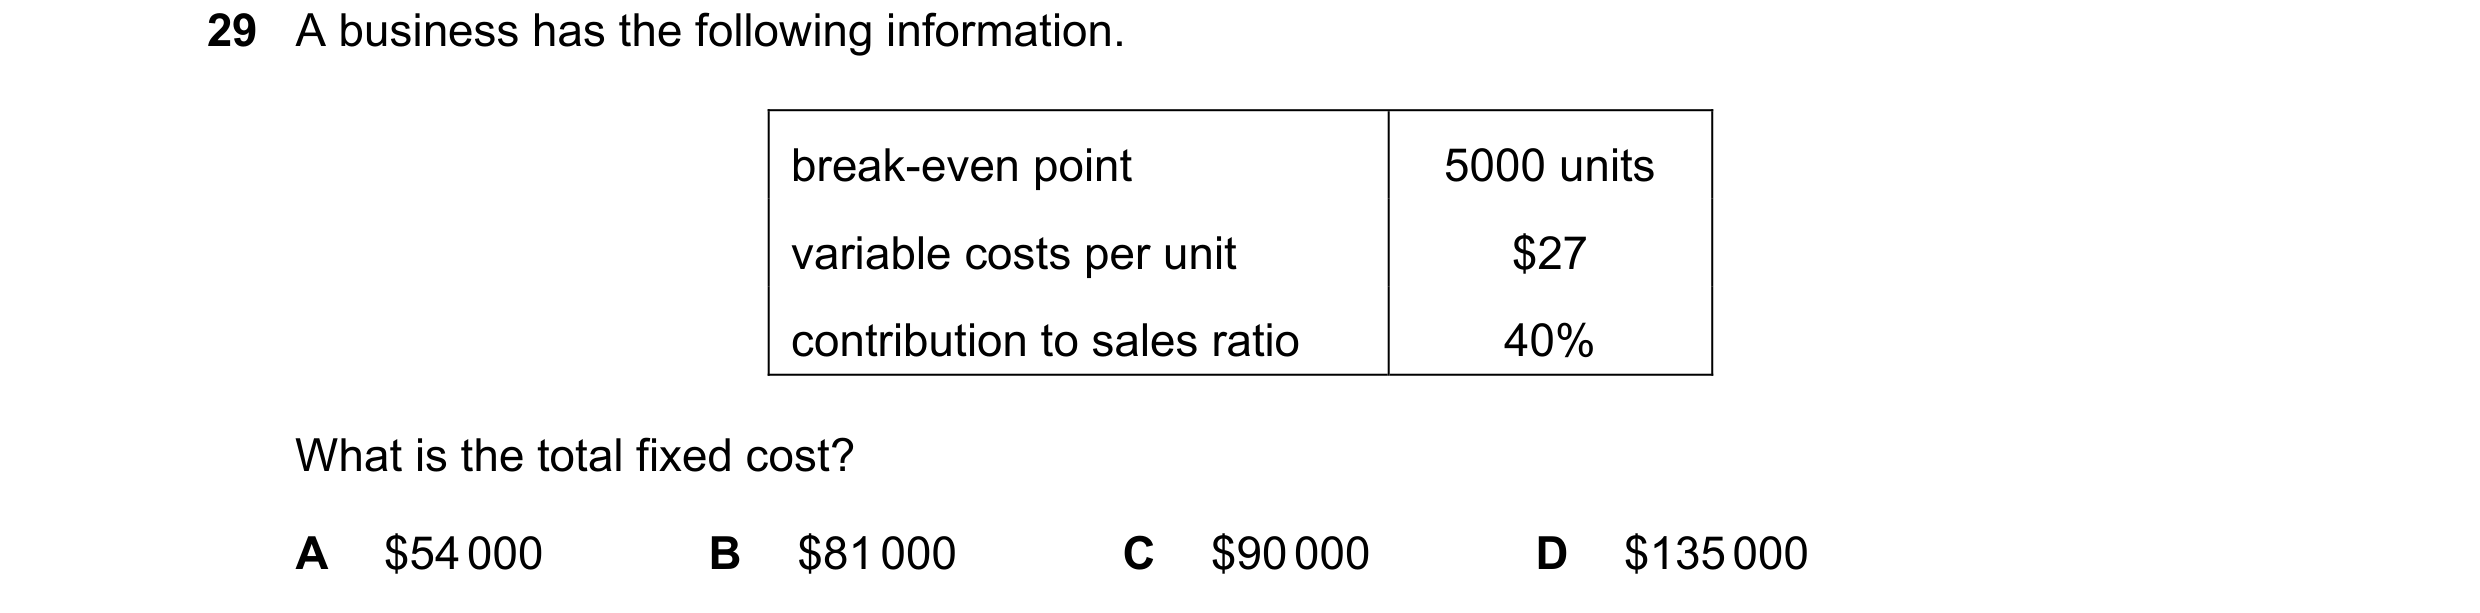
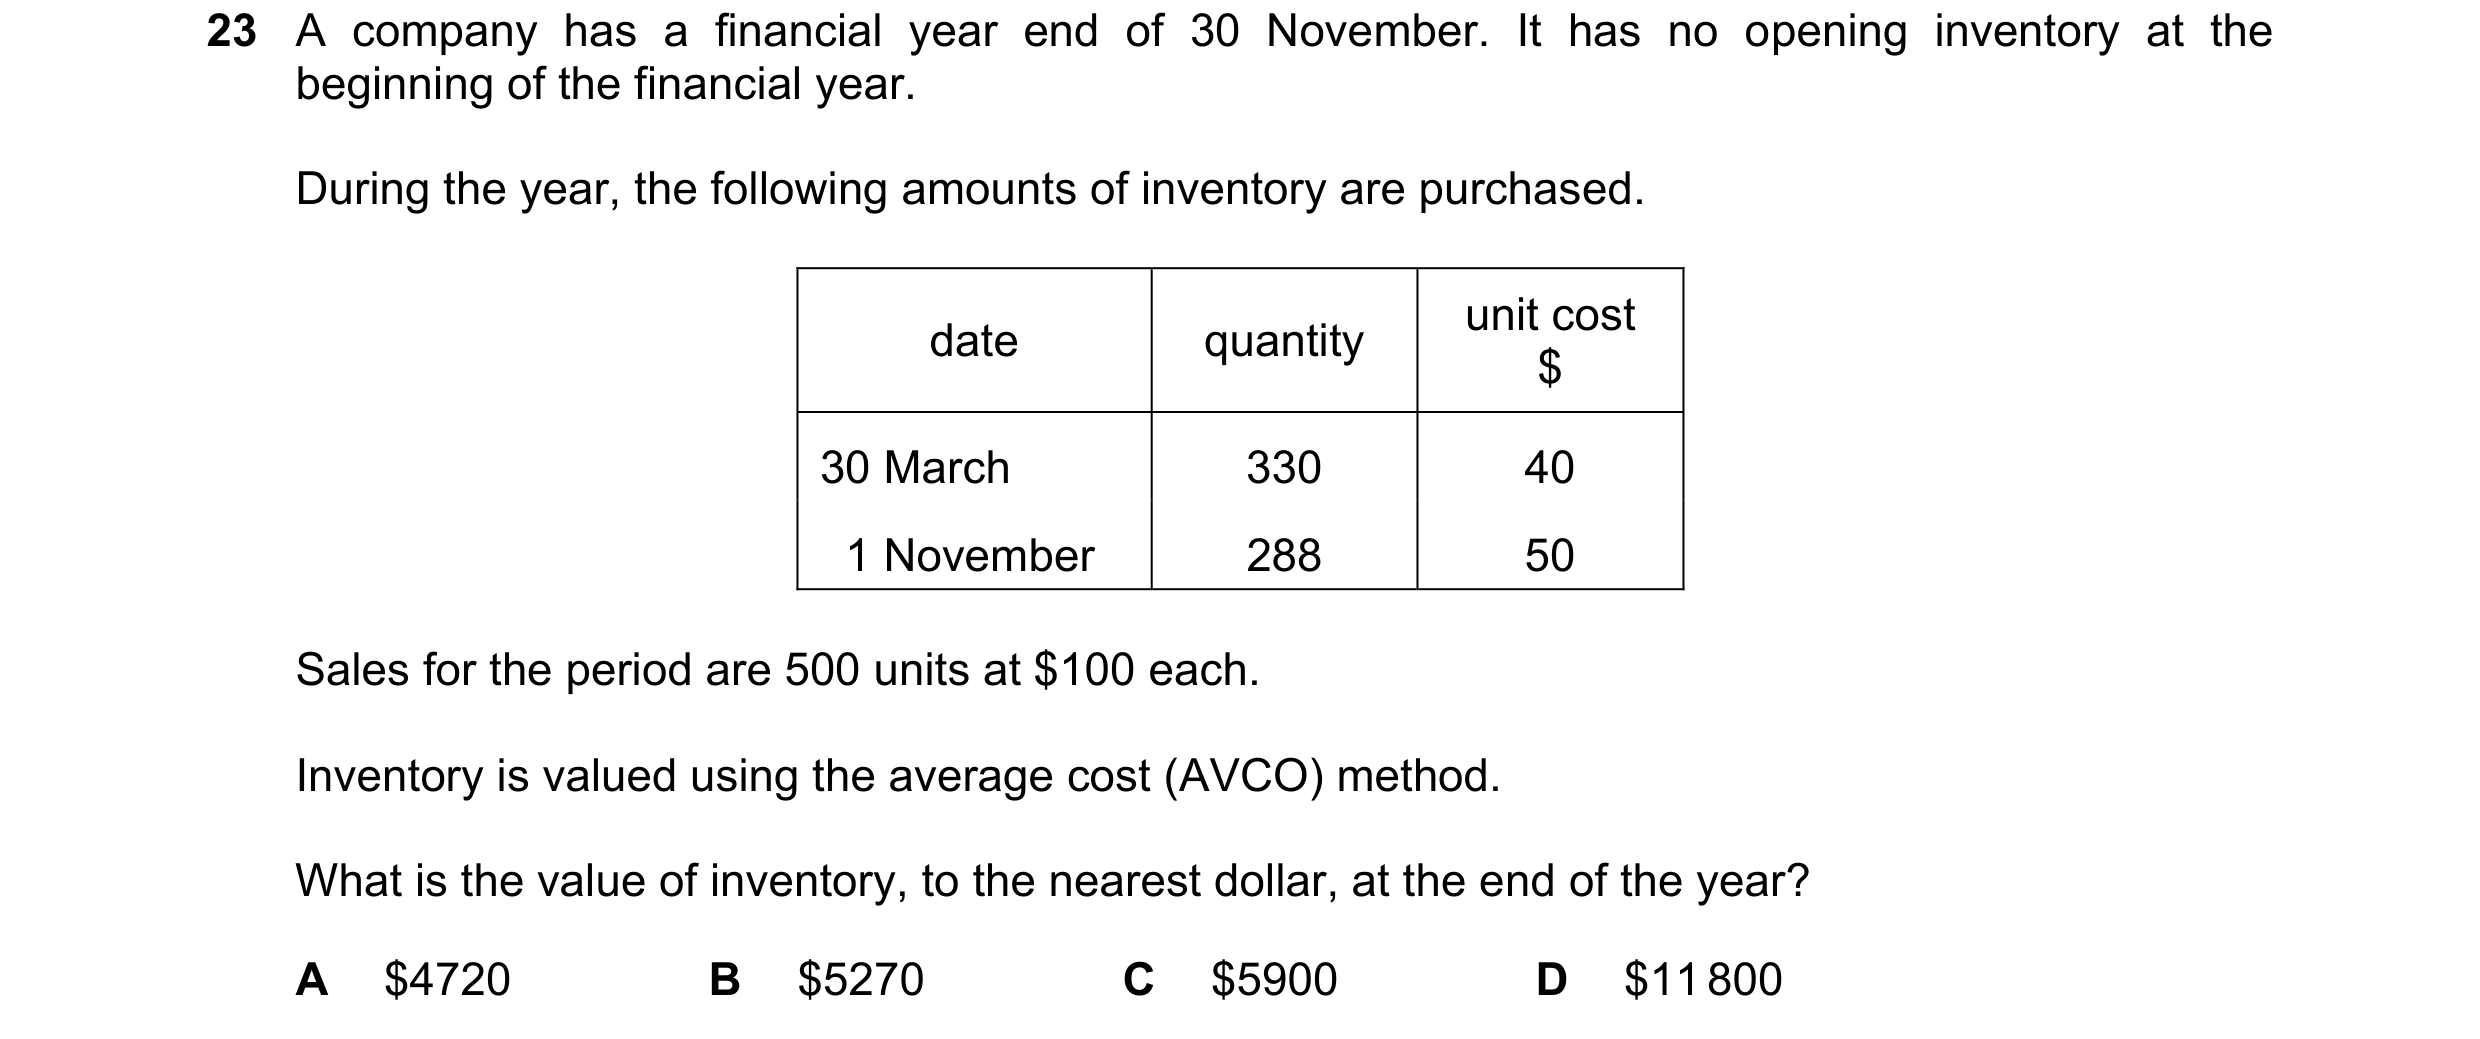 116 / 143
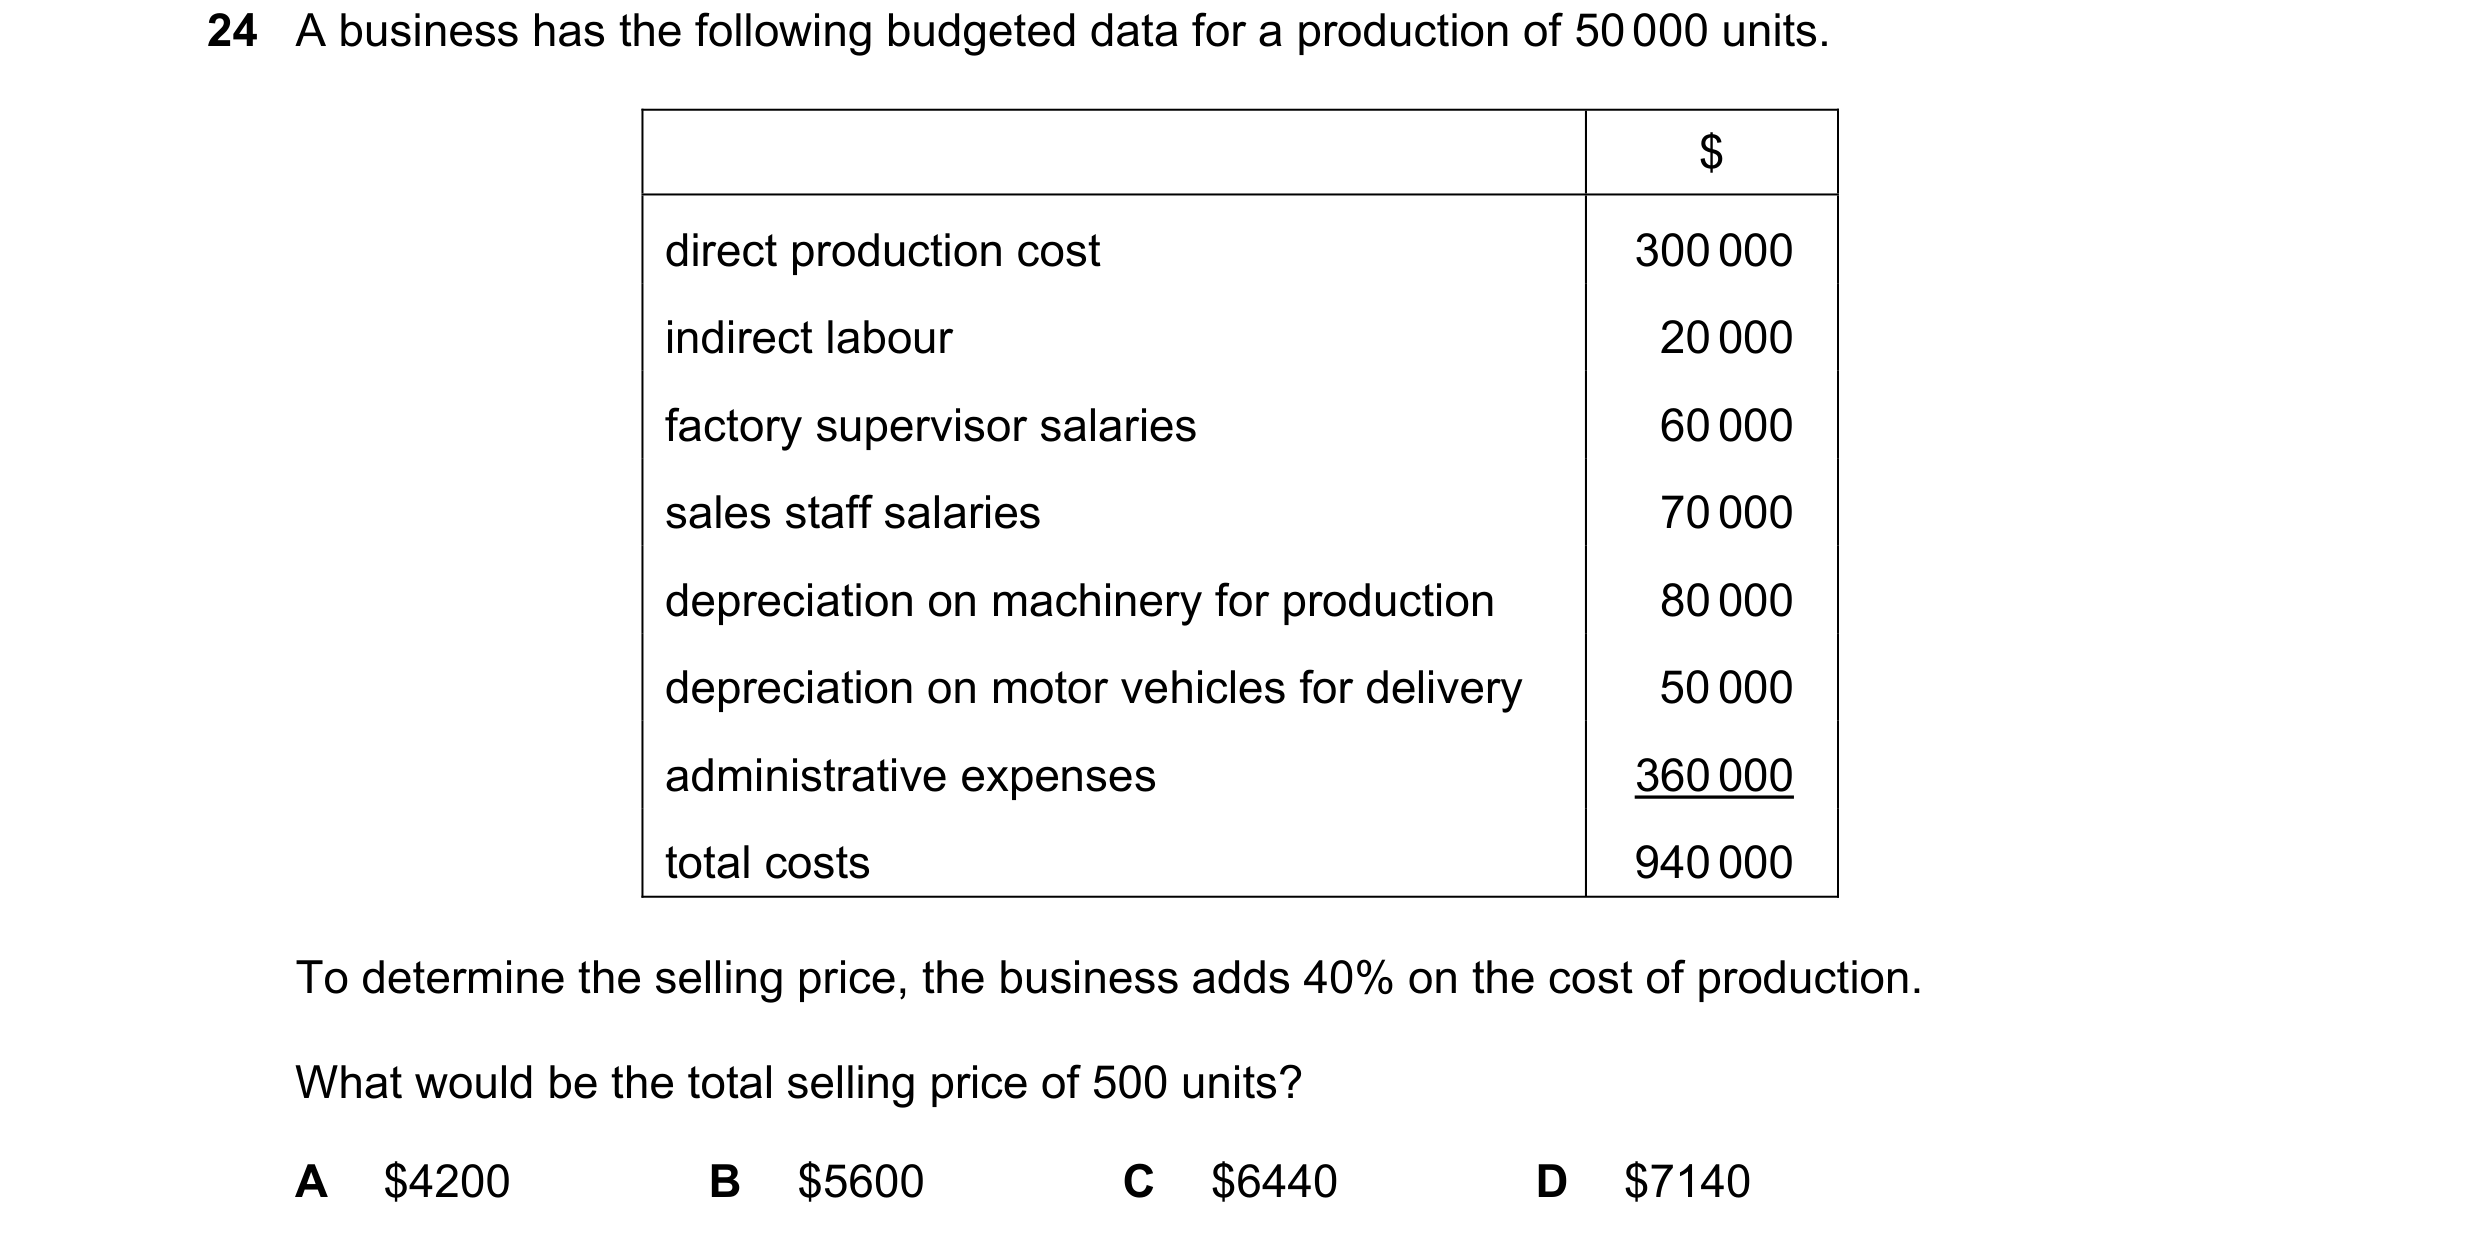
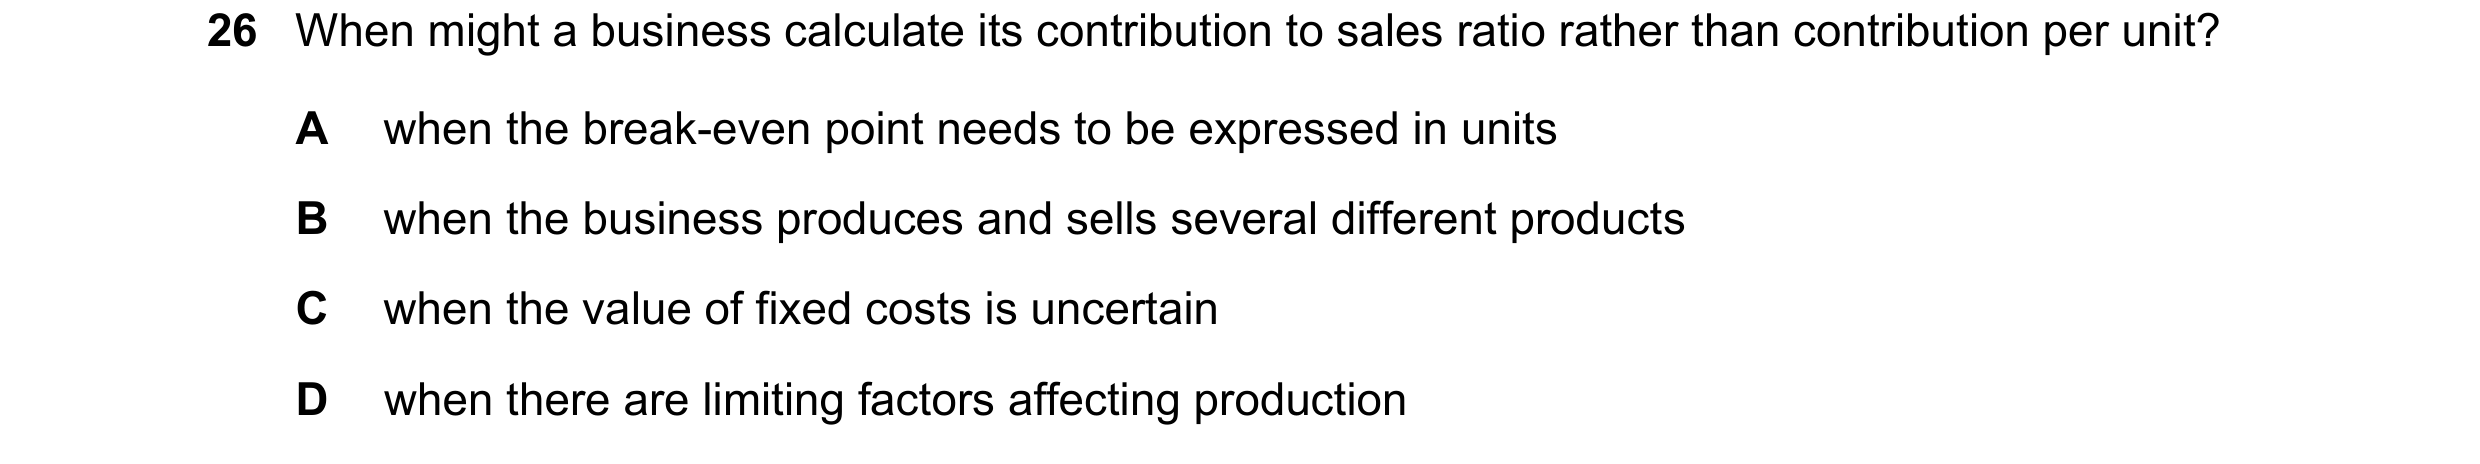
 117 / 143
 118 / 143
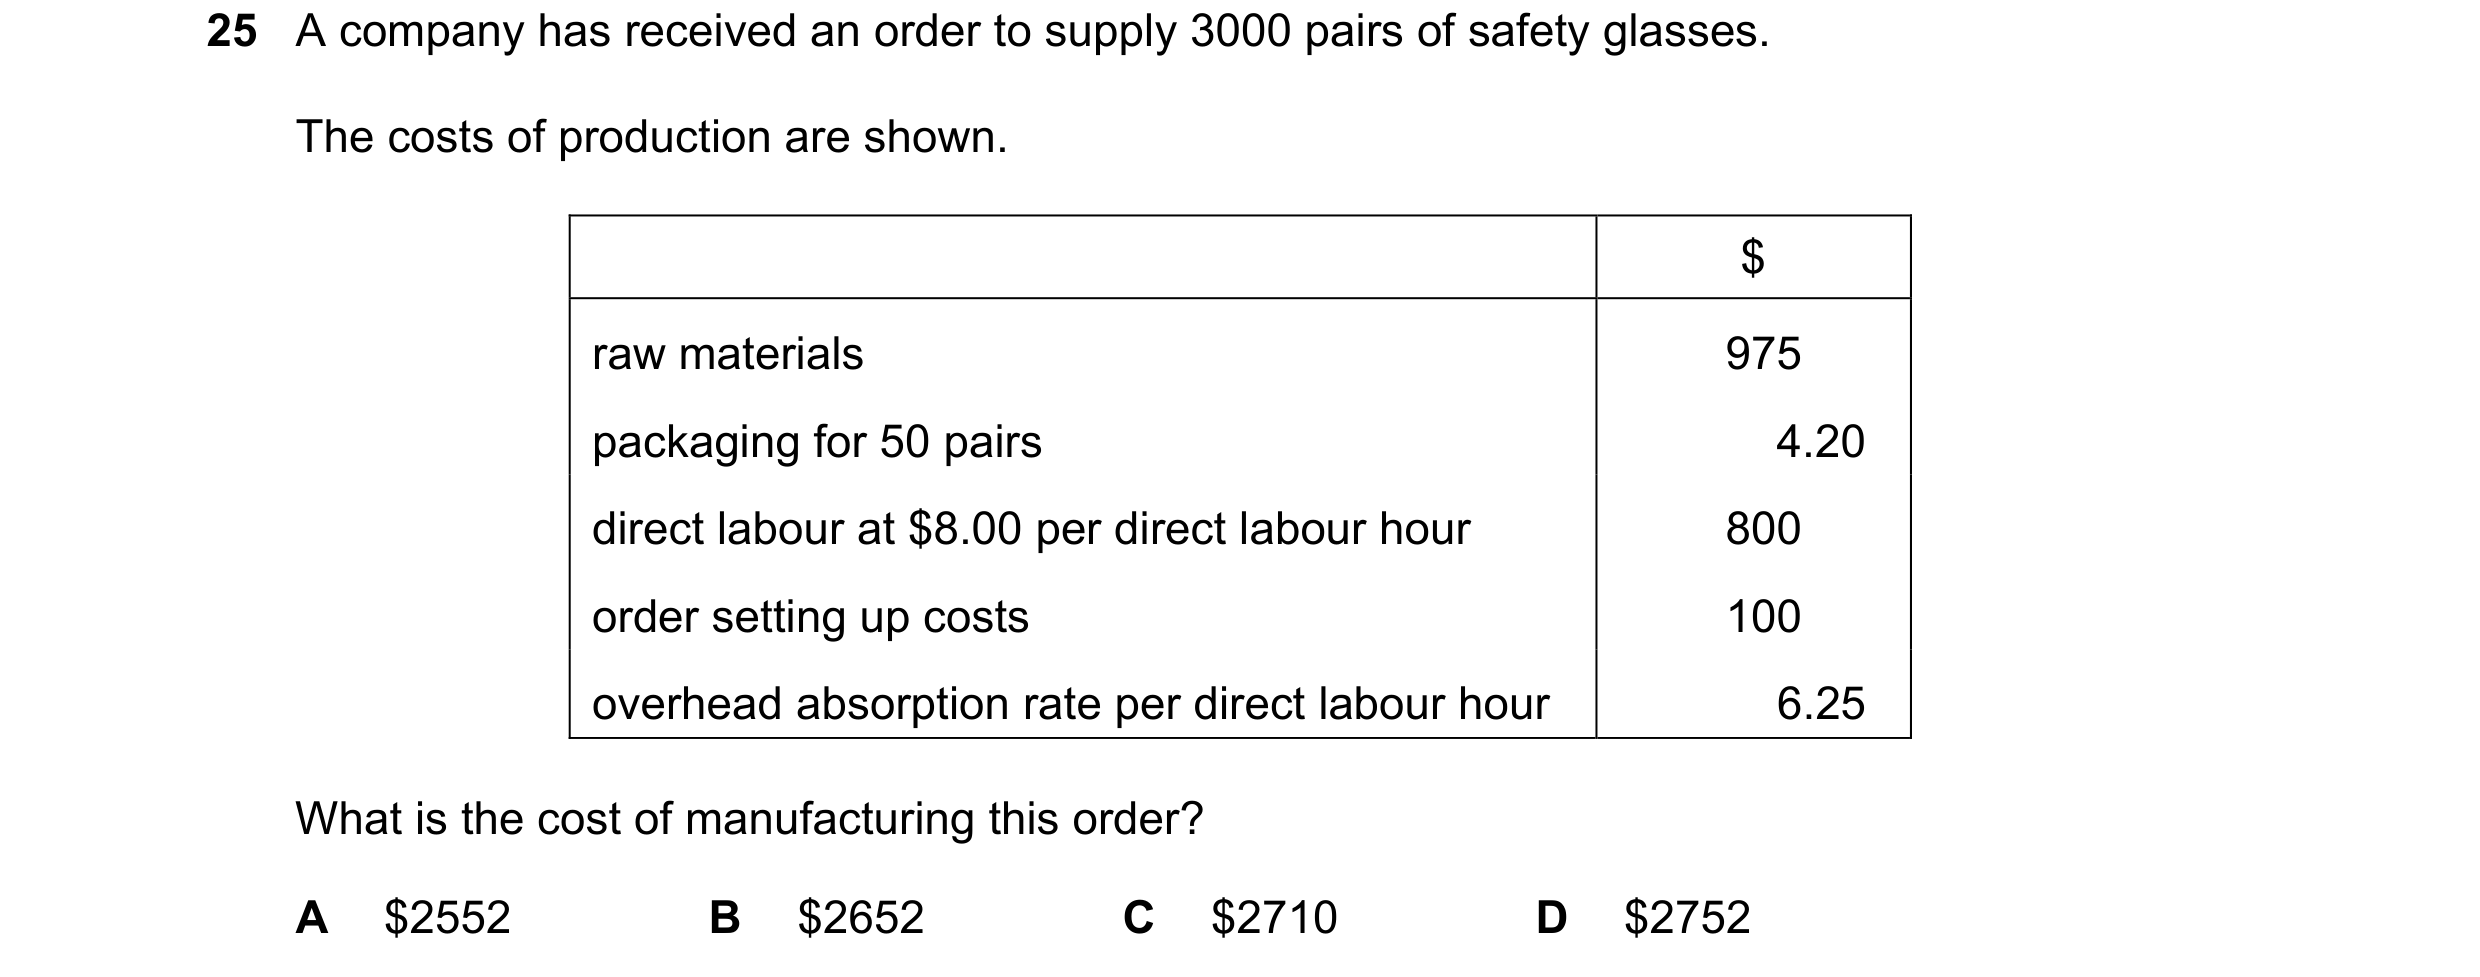
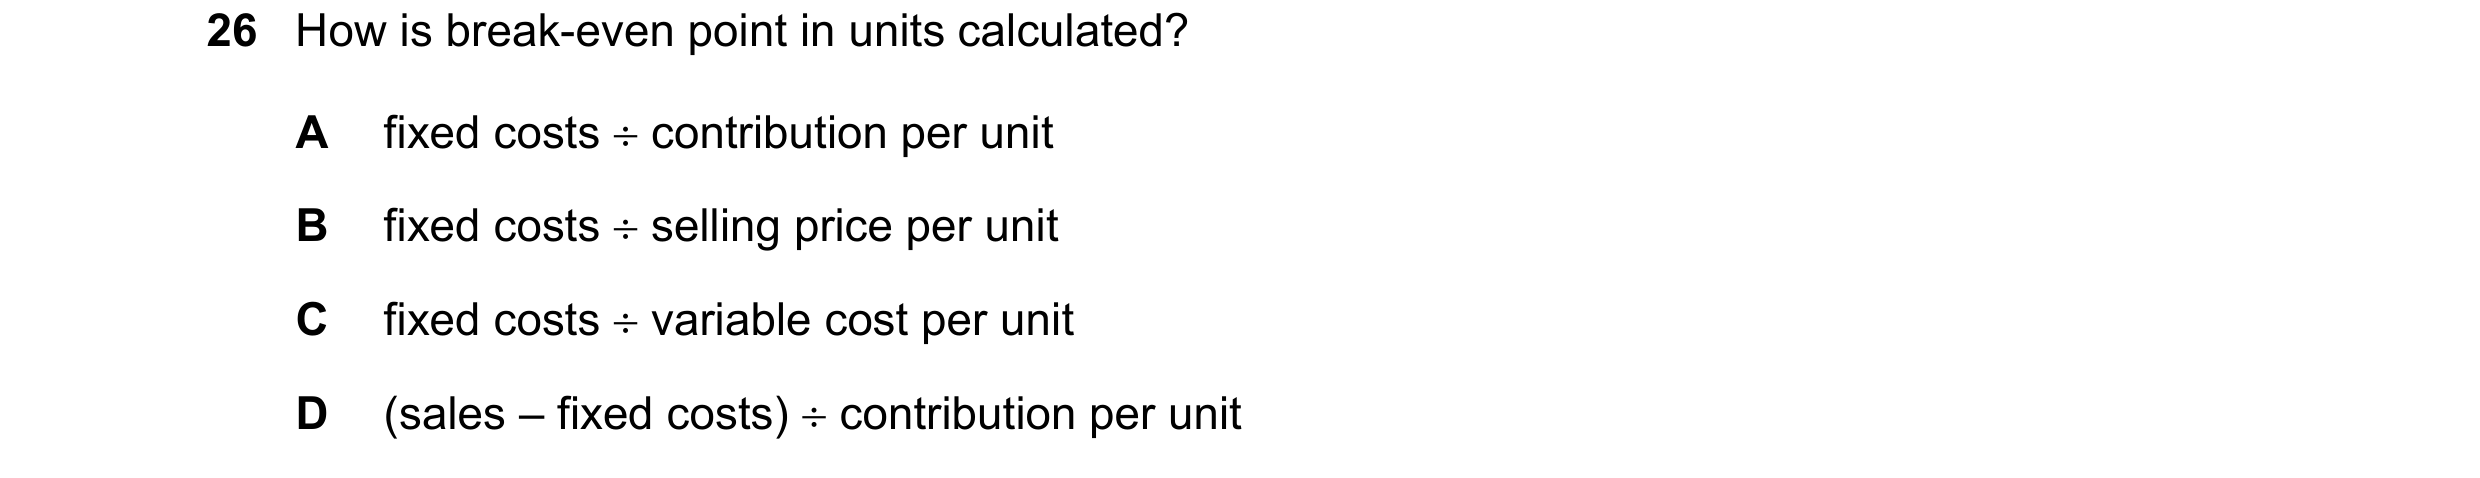
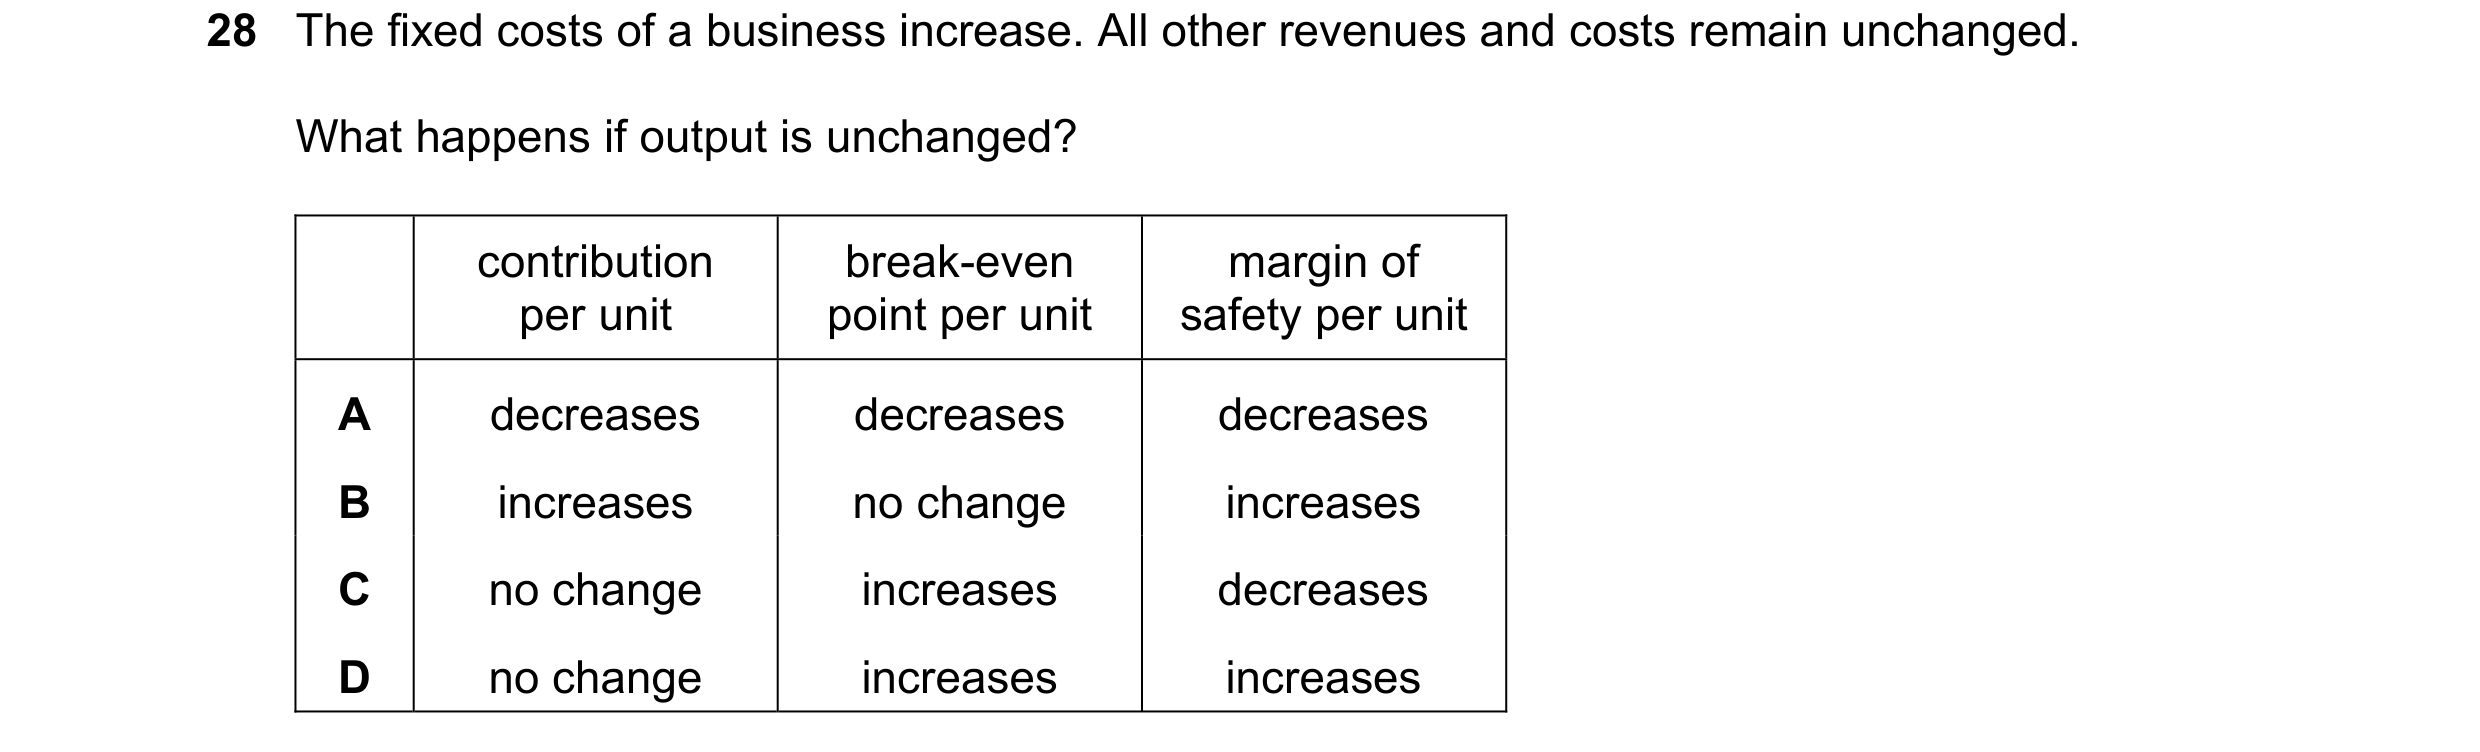 119 / 143
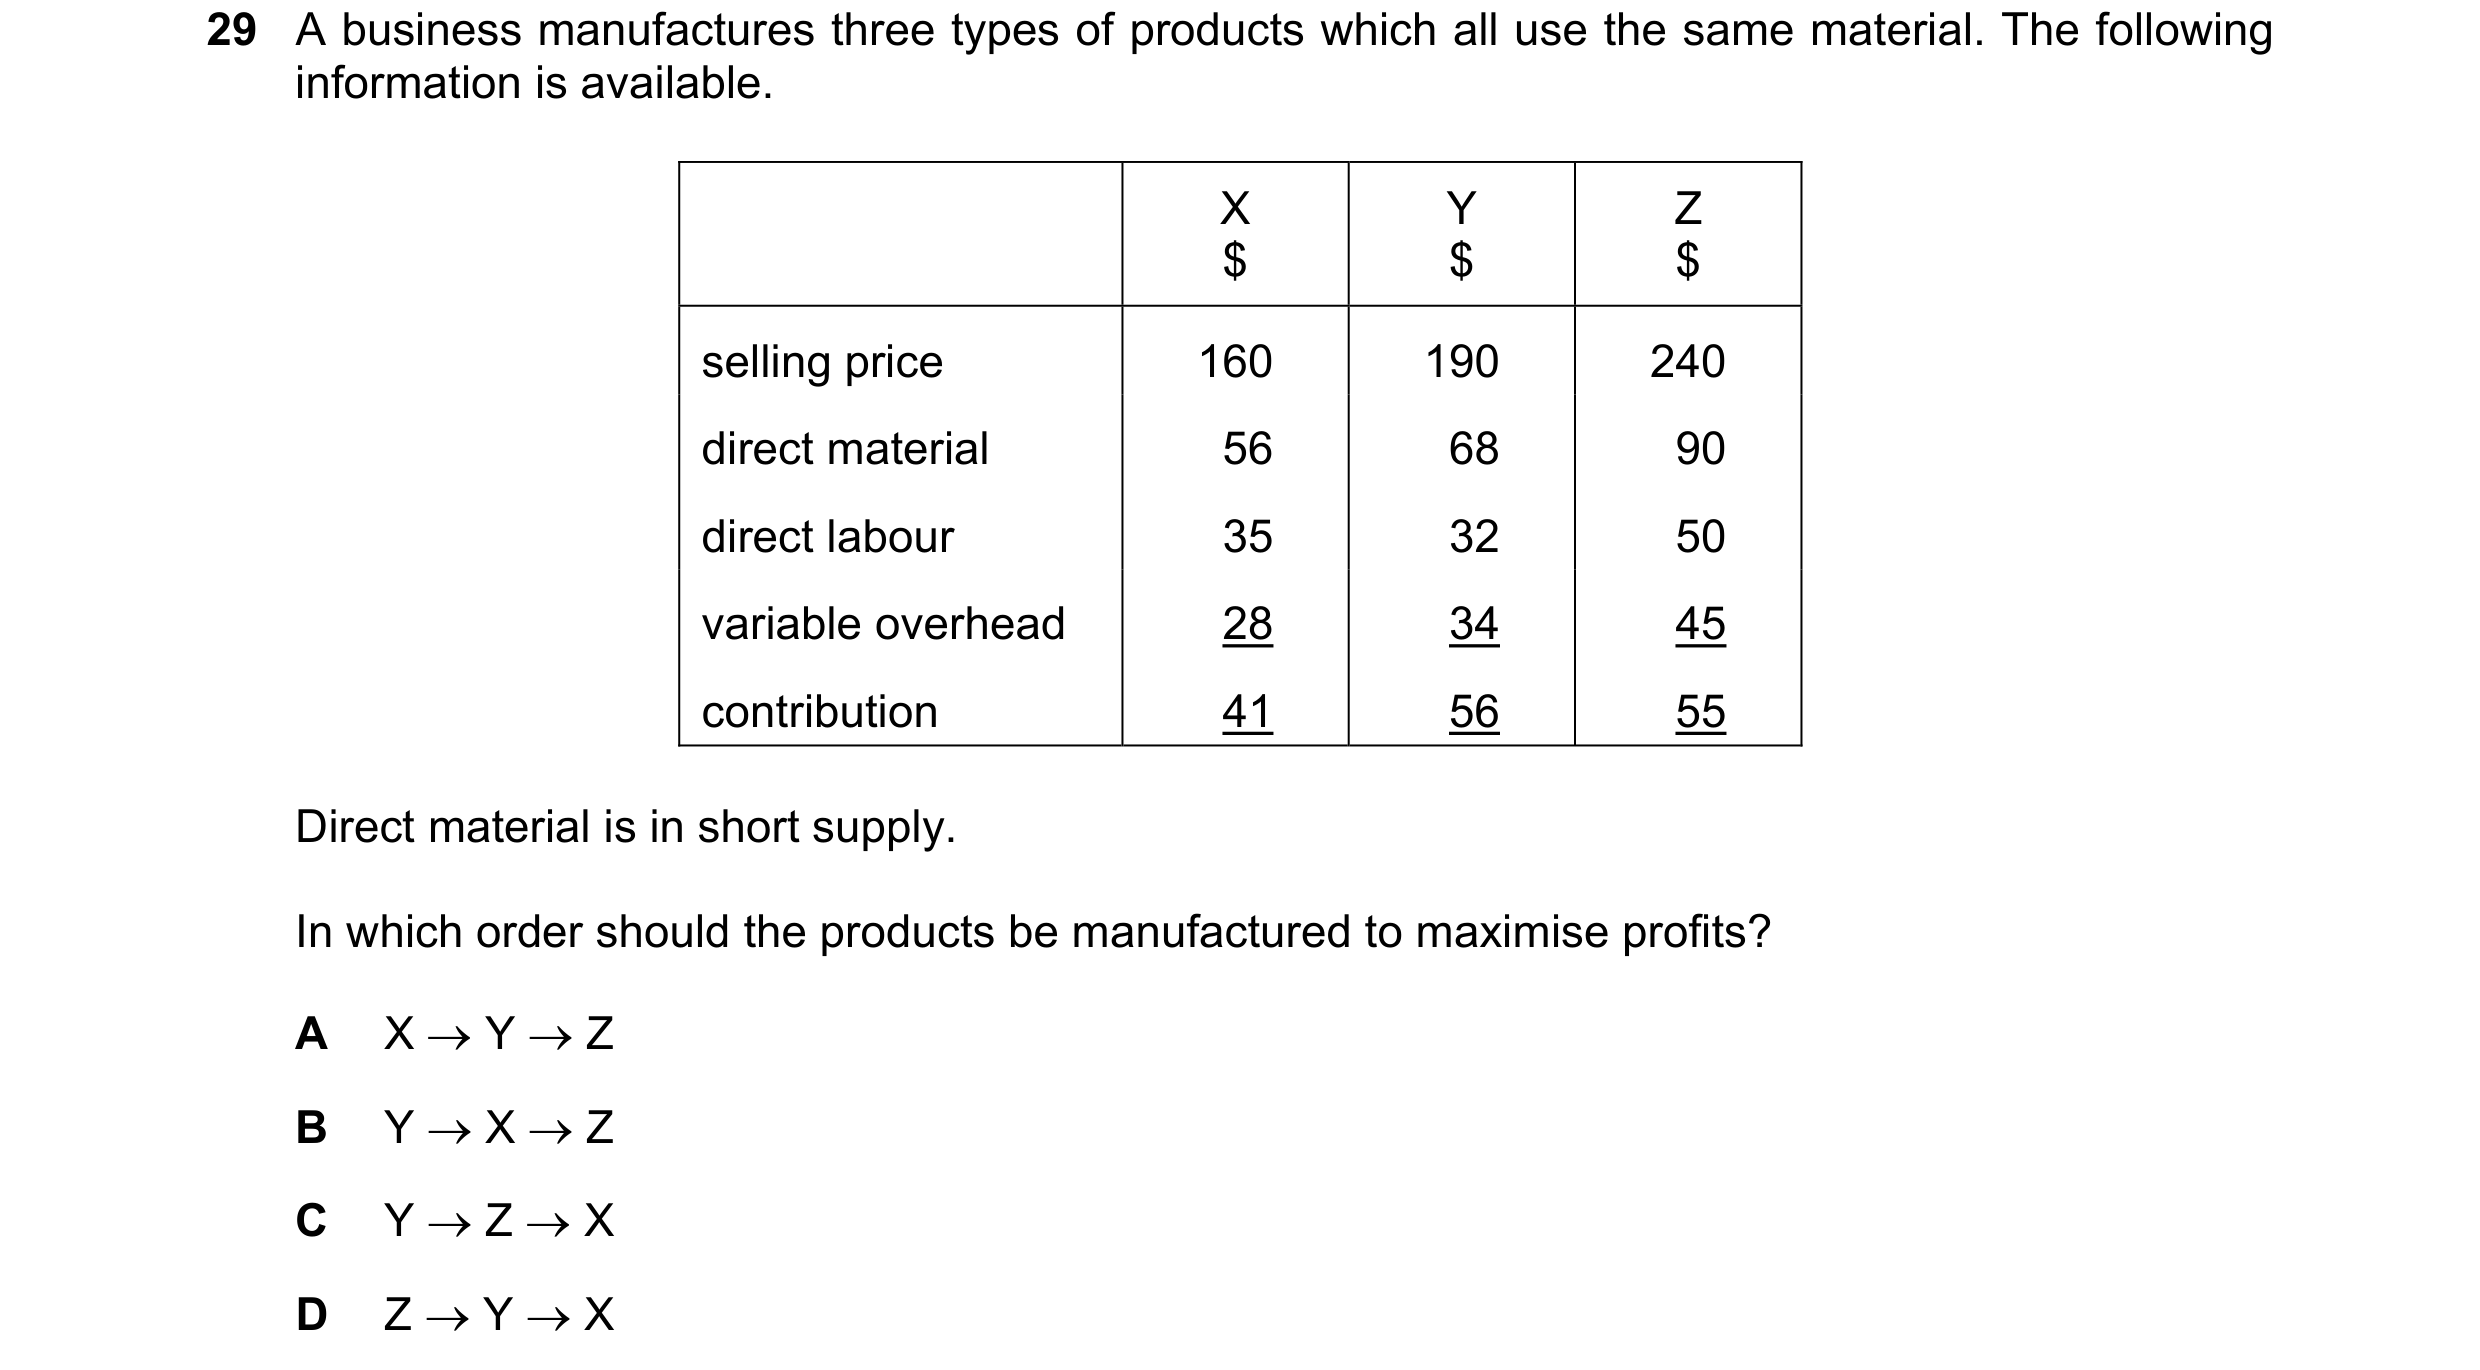
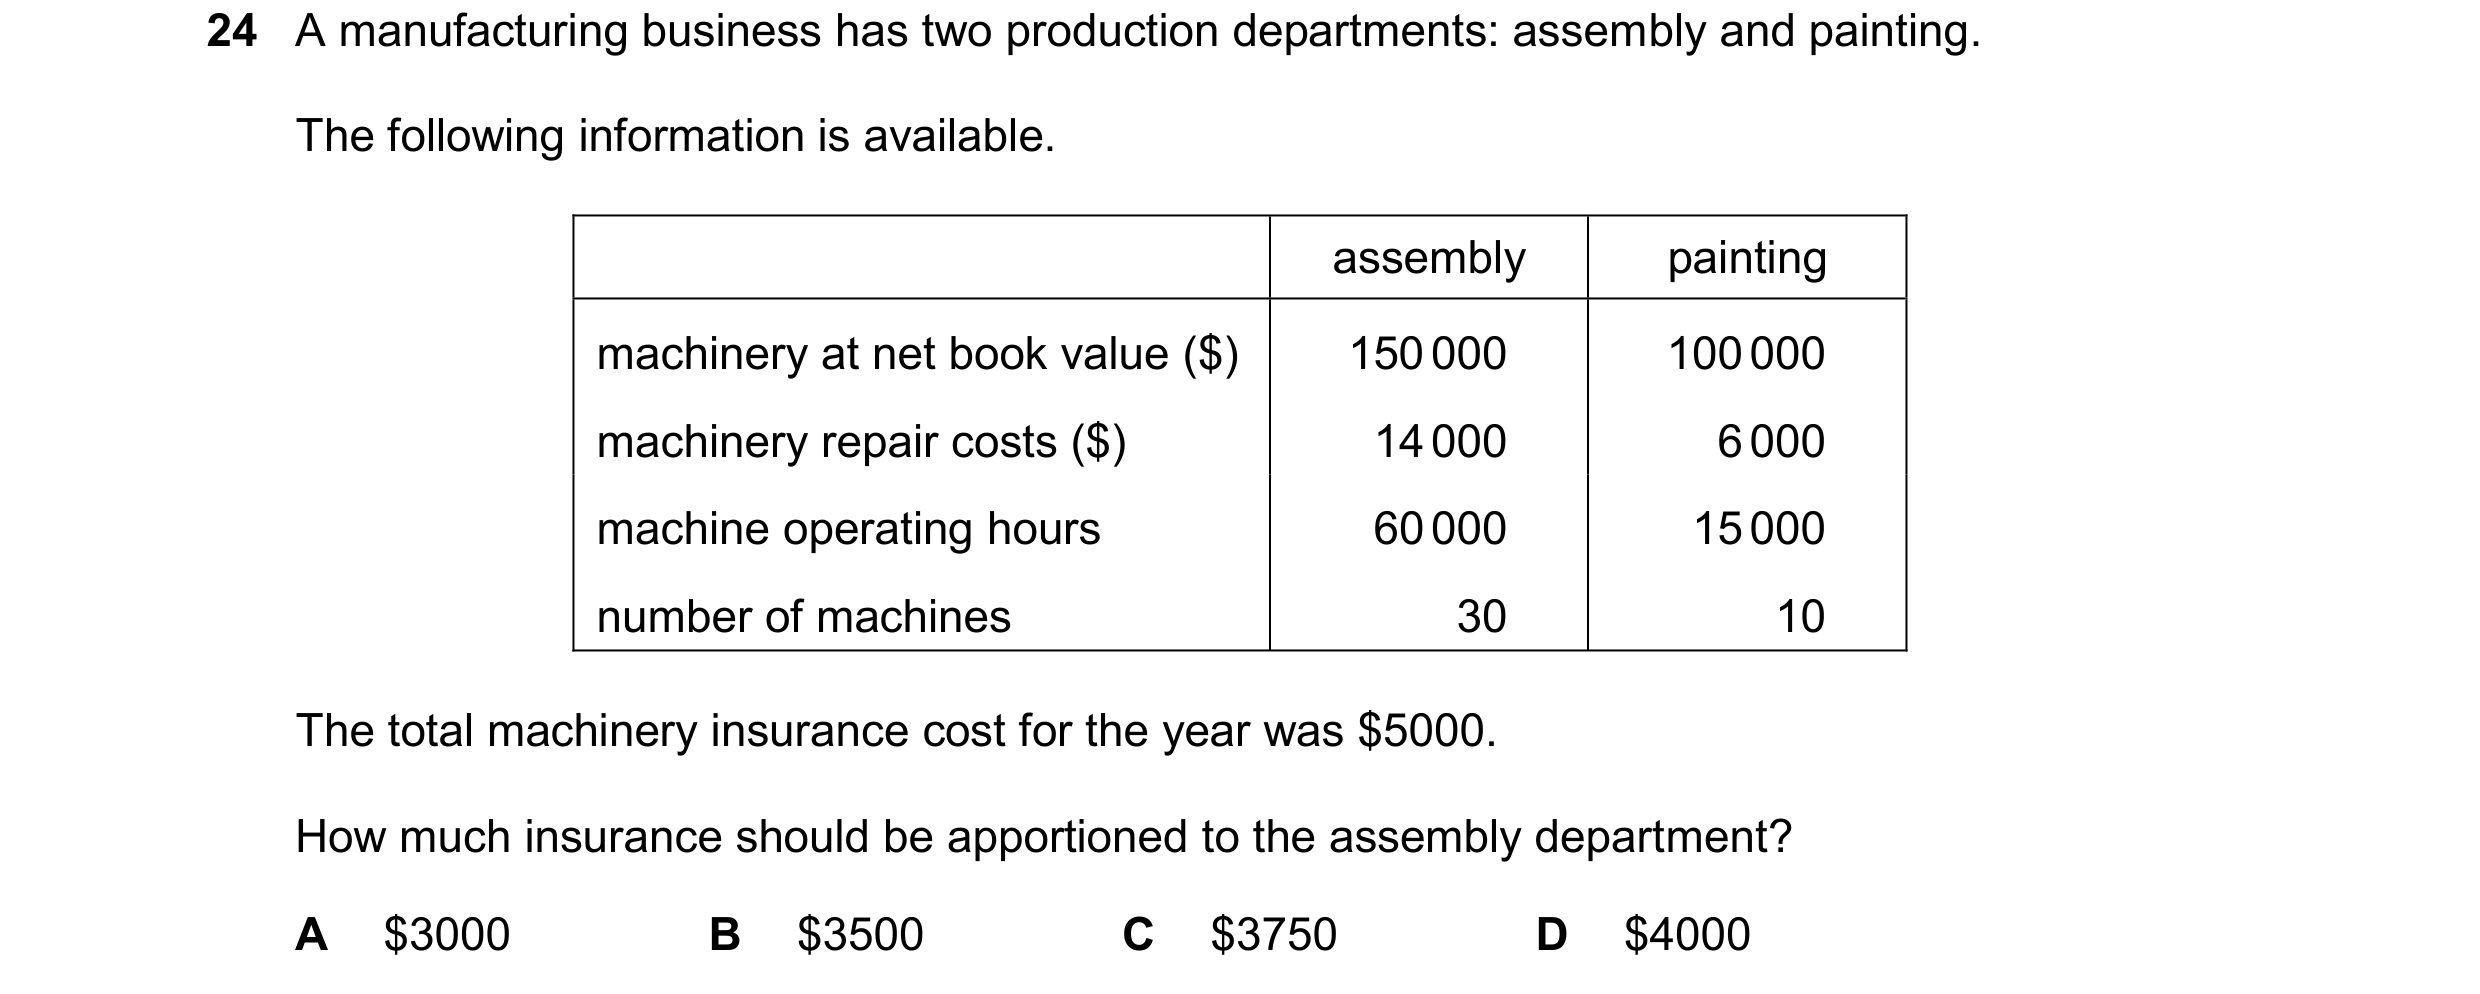 120 / 143
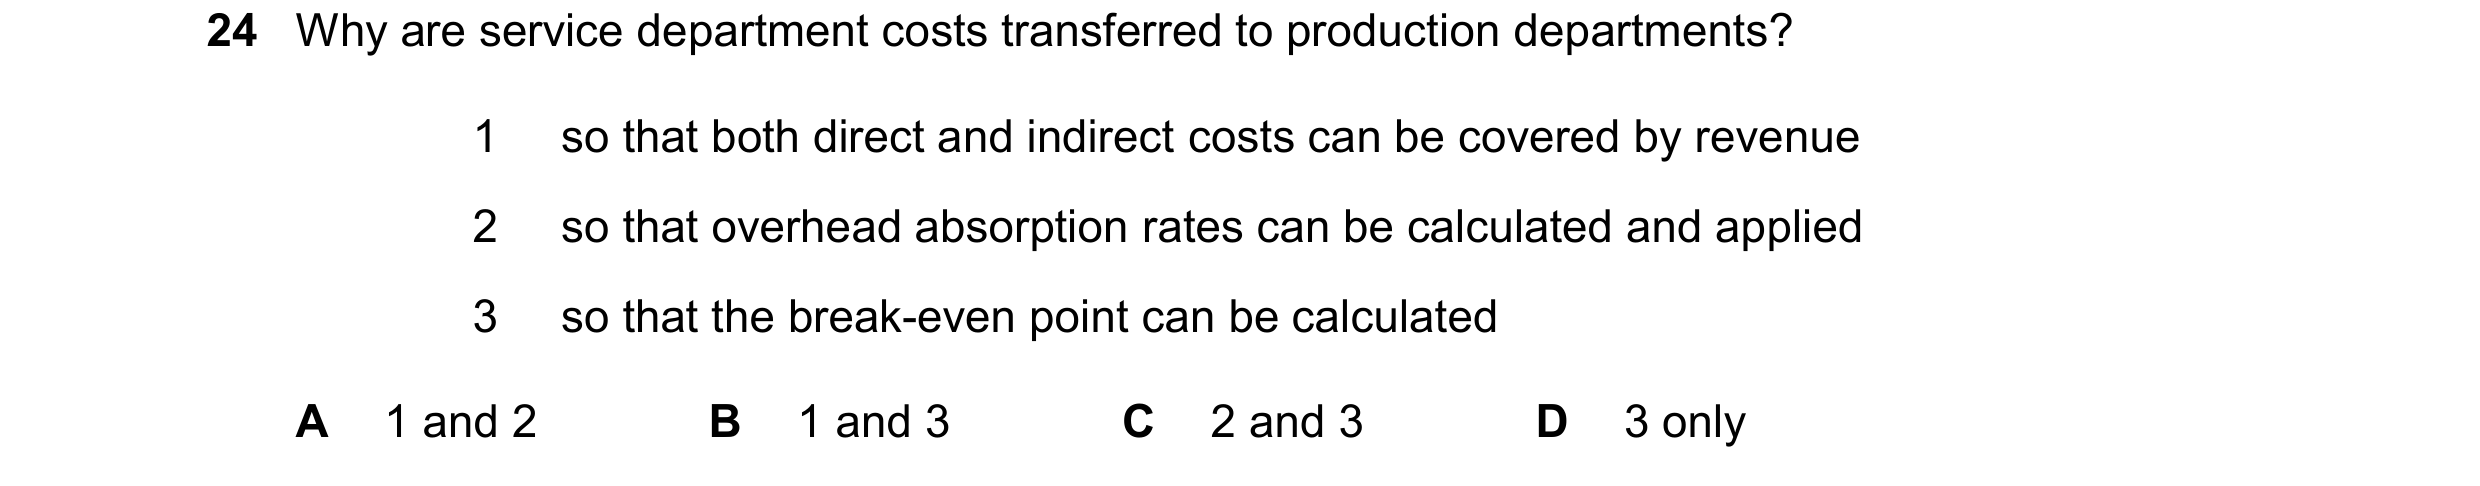
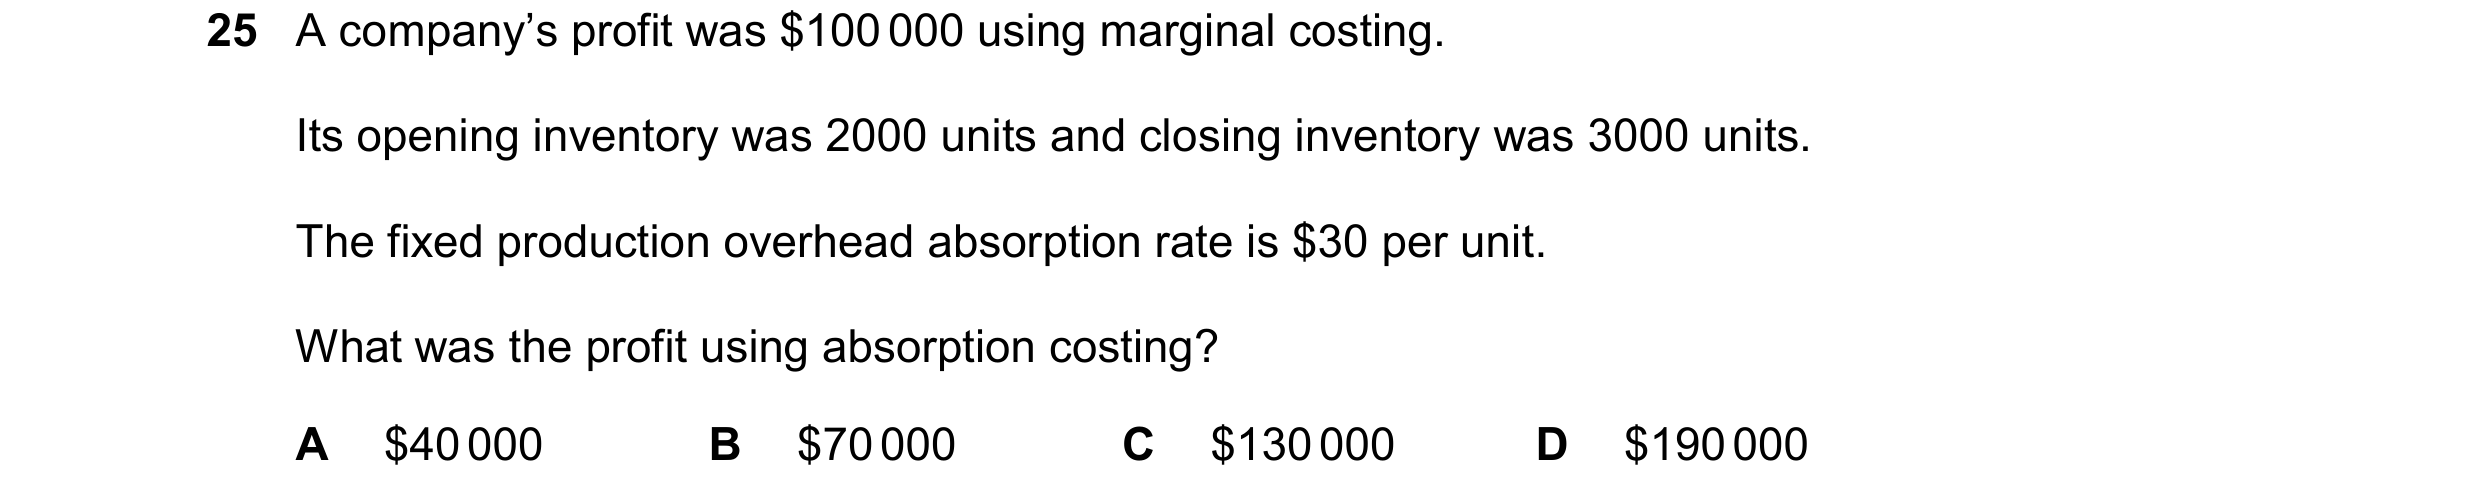
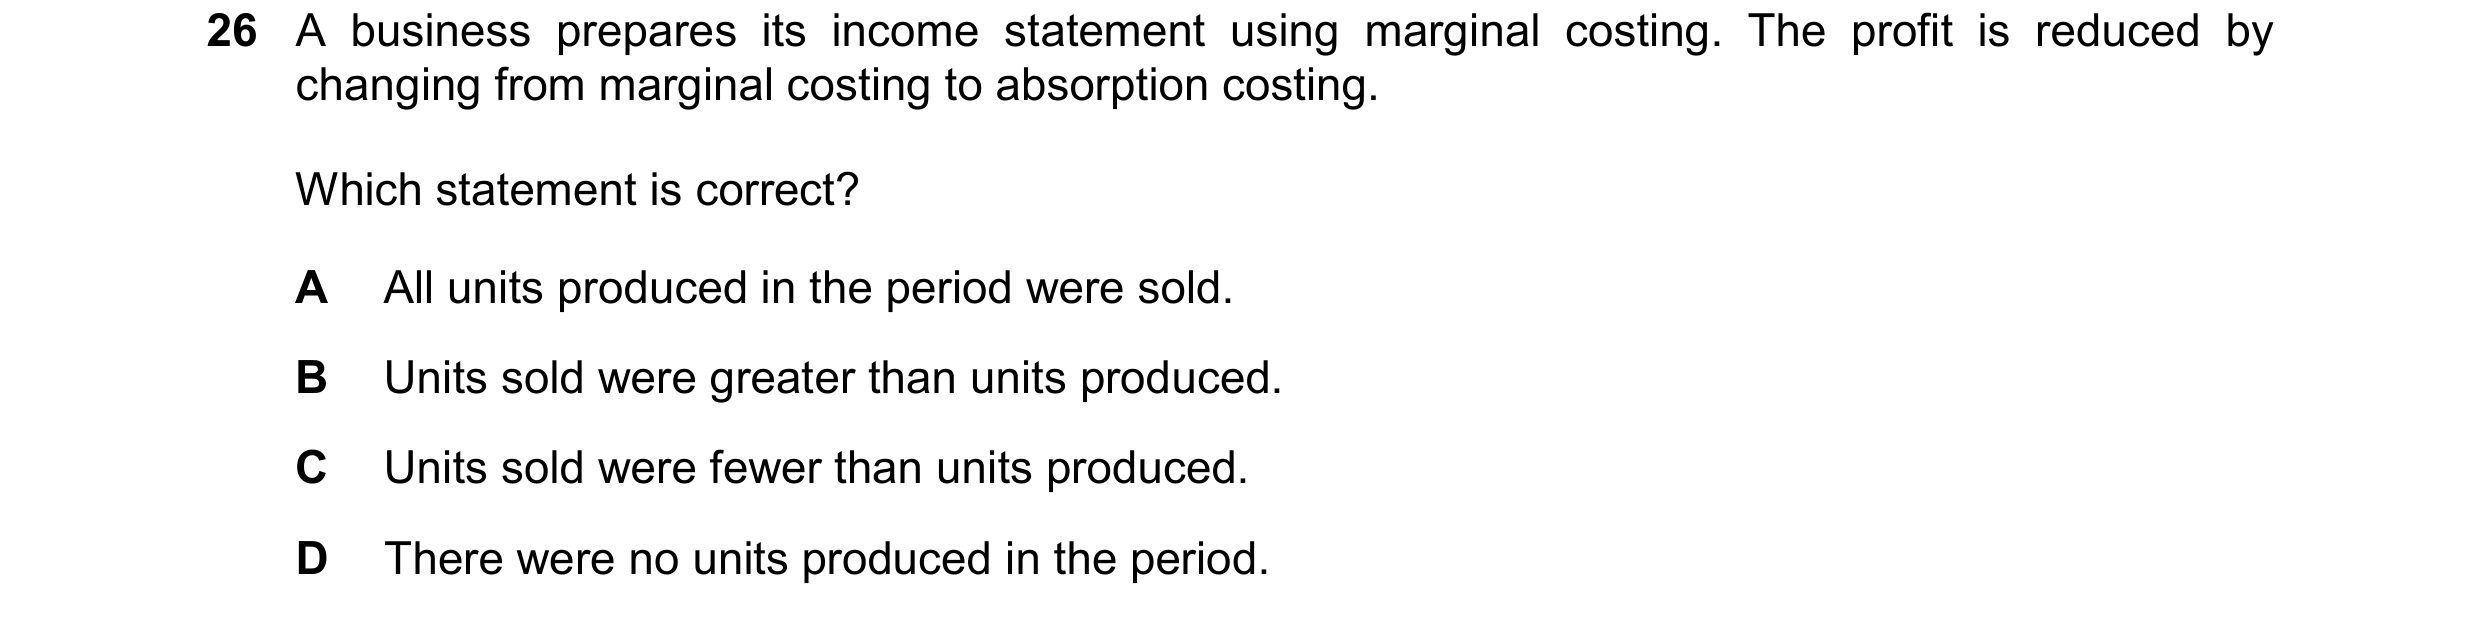 121 / 143
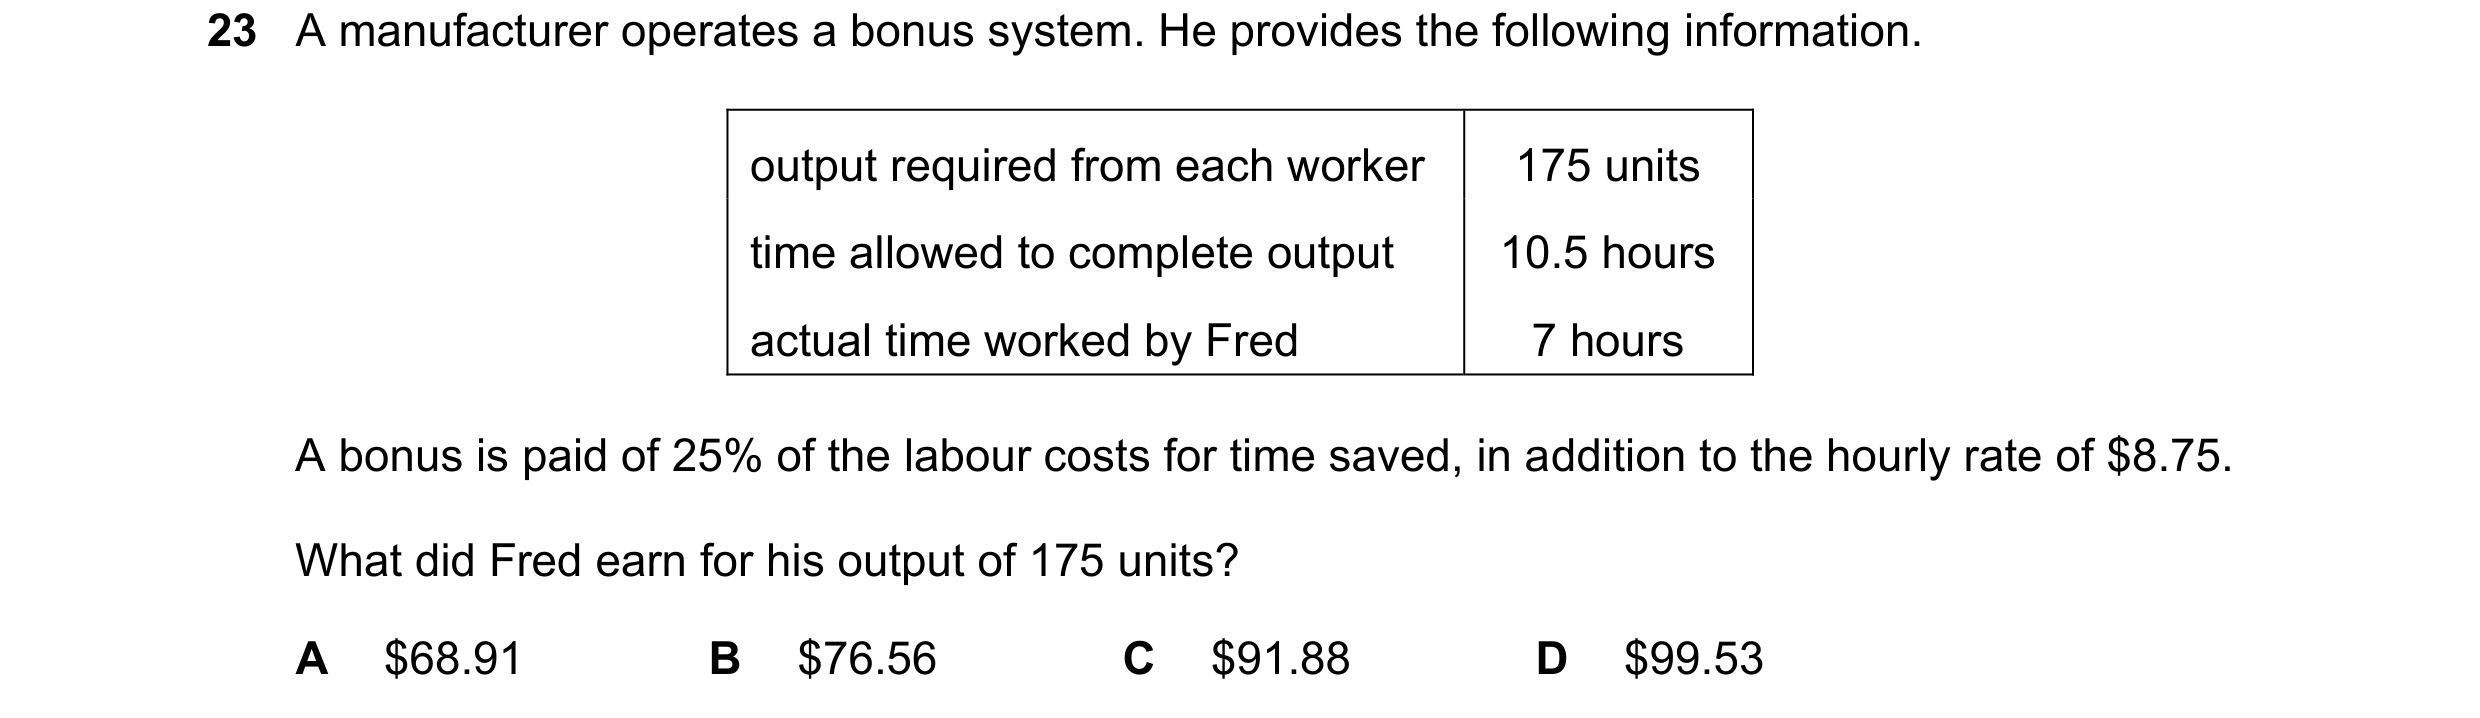
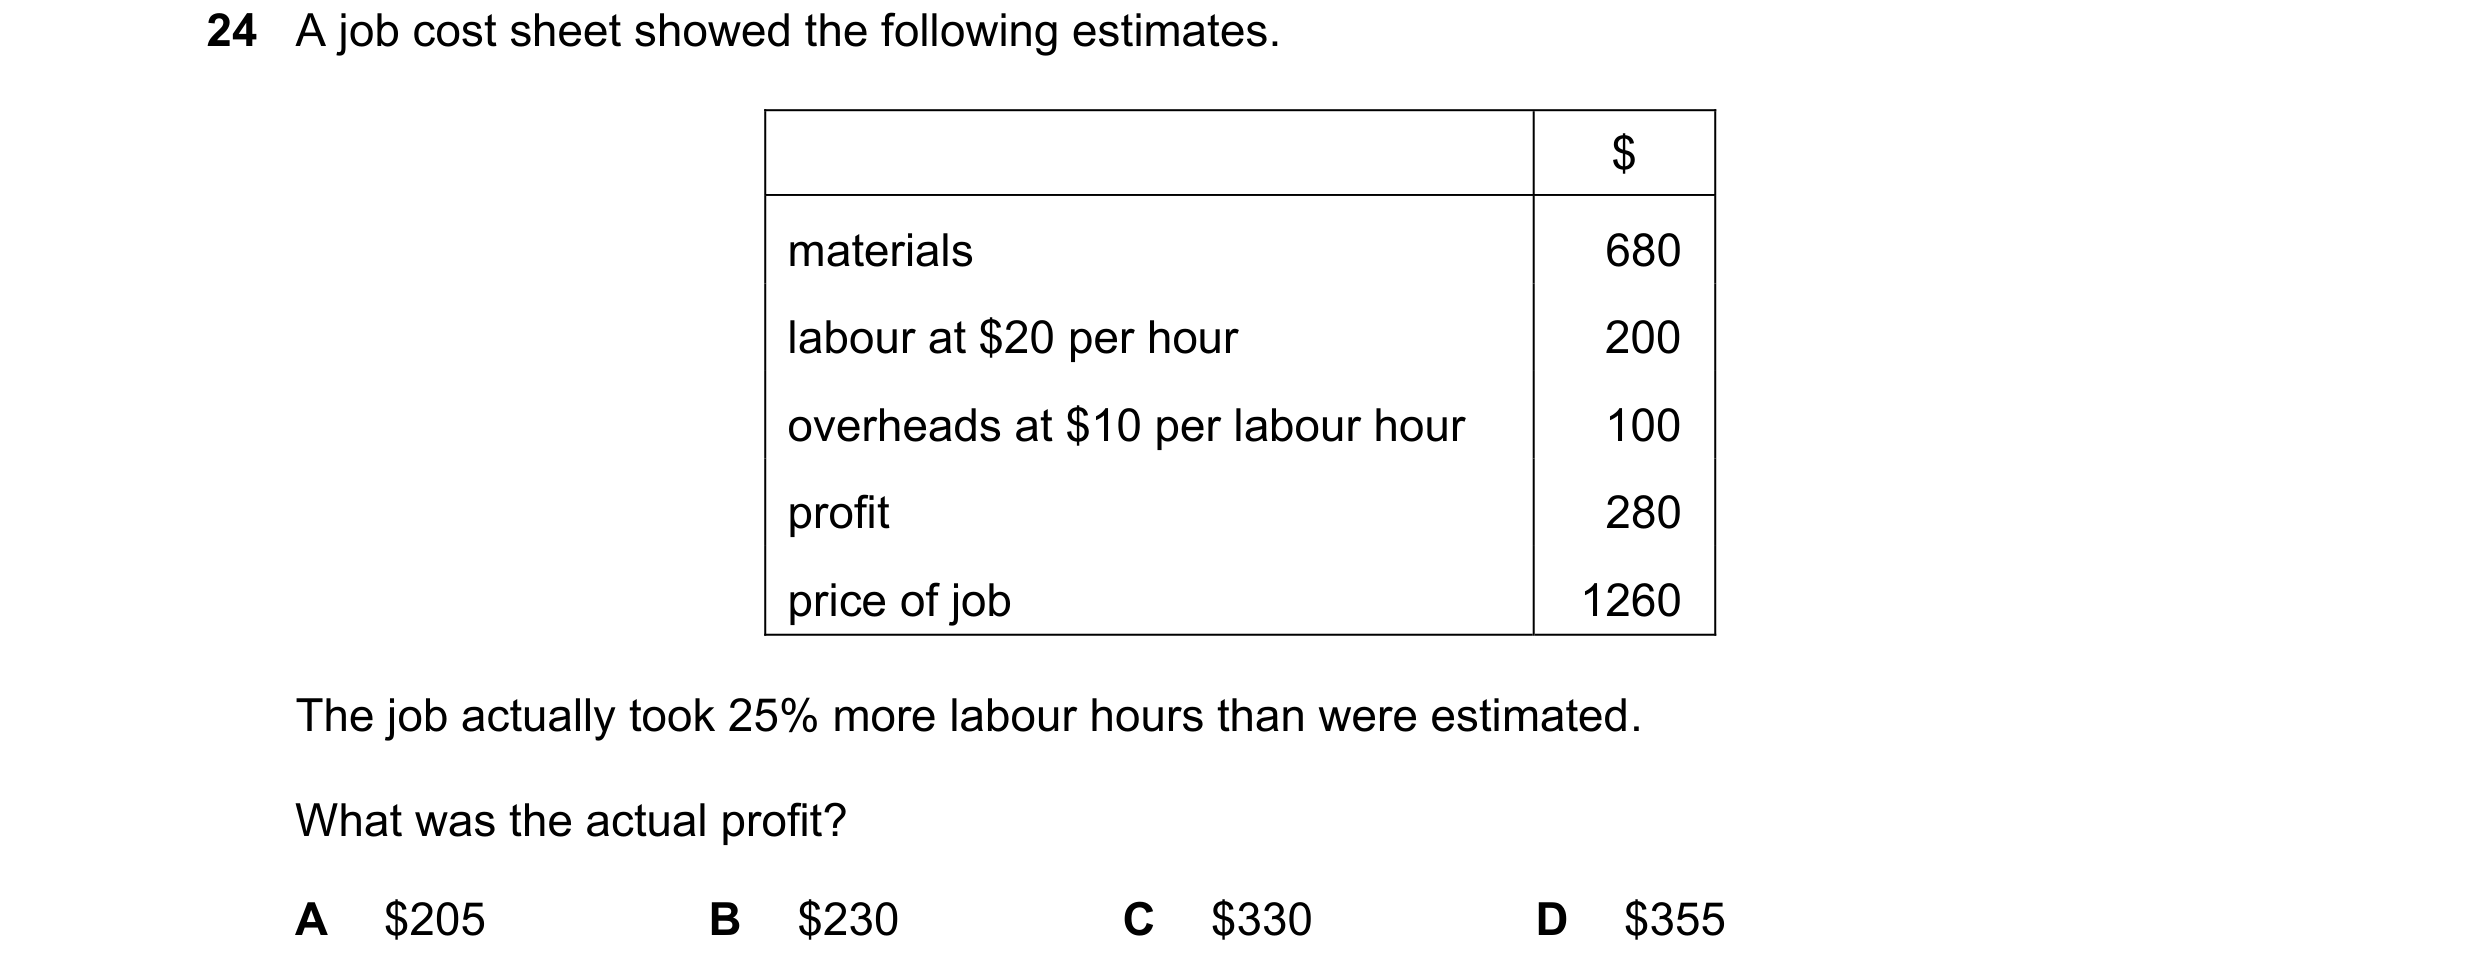
 122 / 143
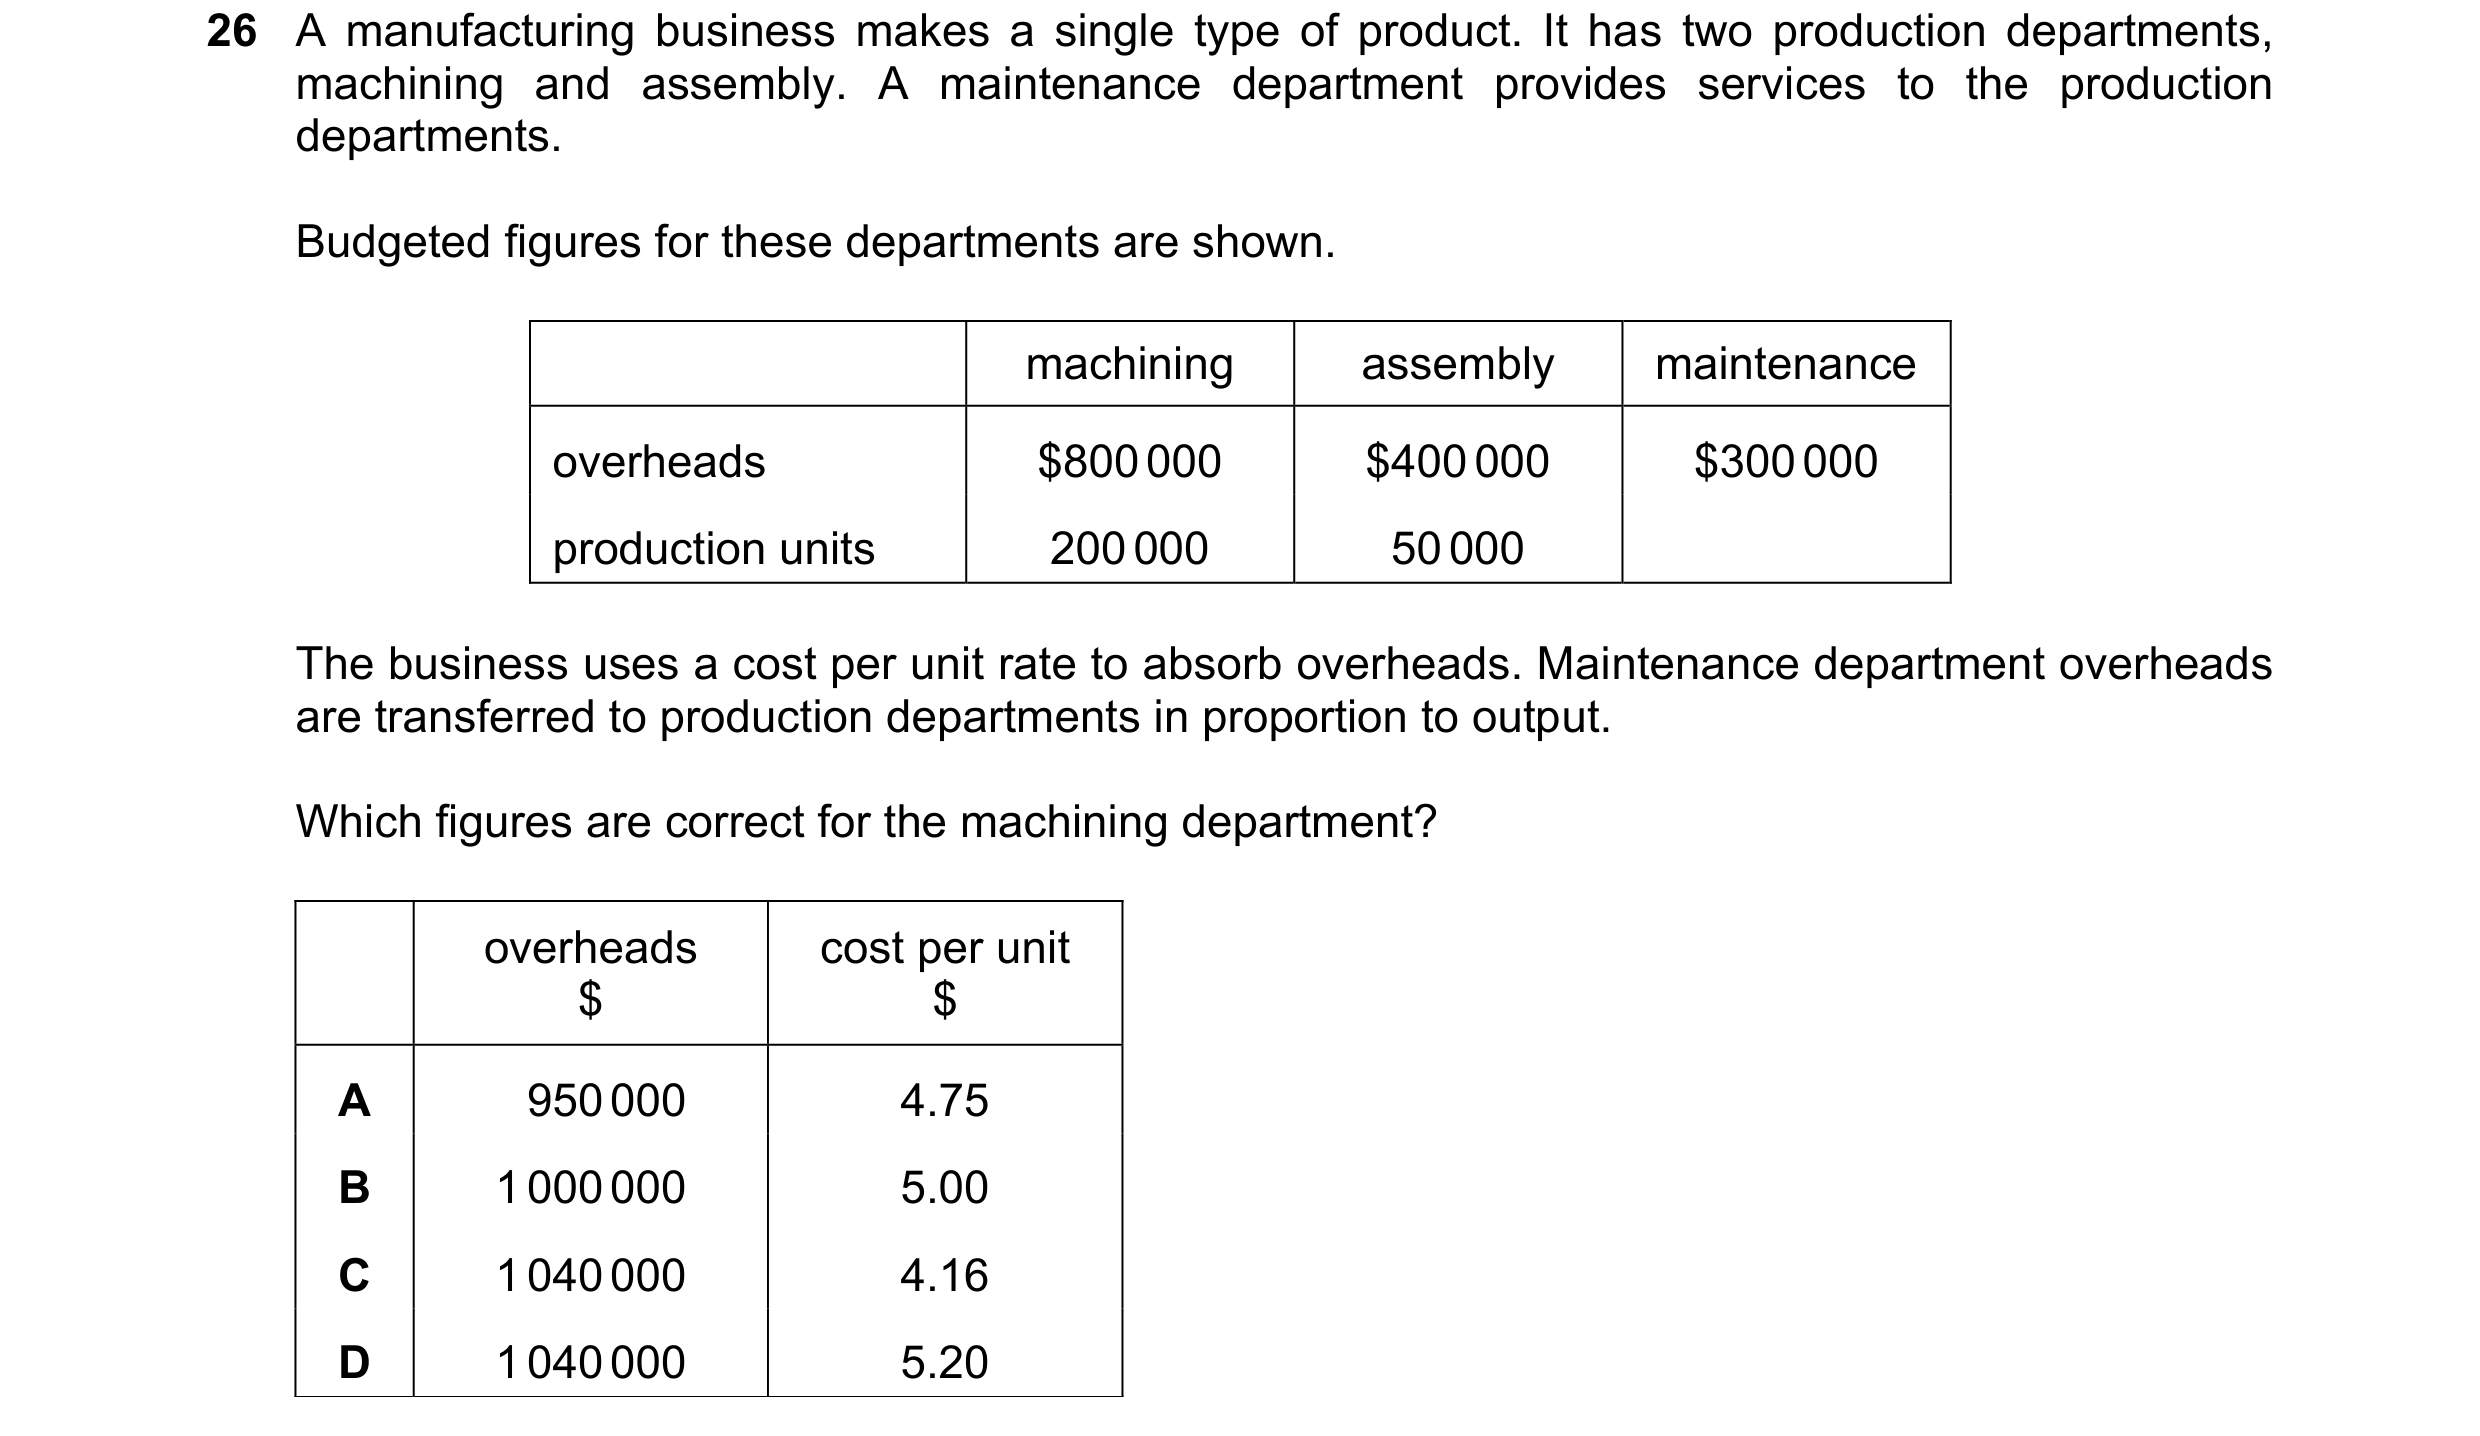
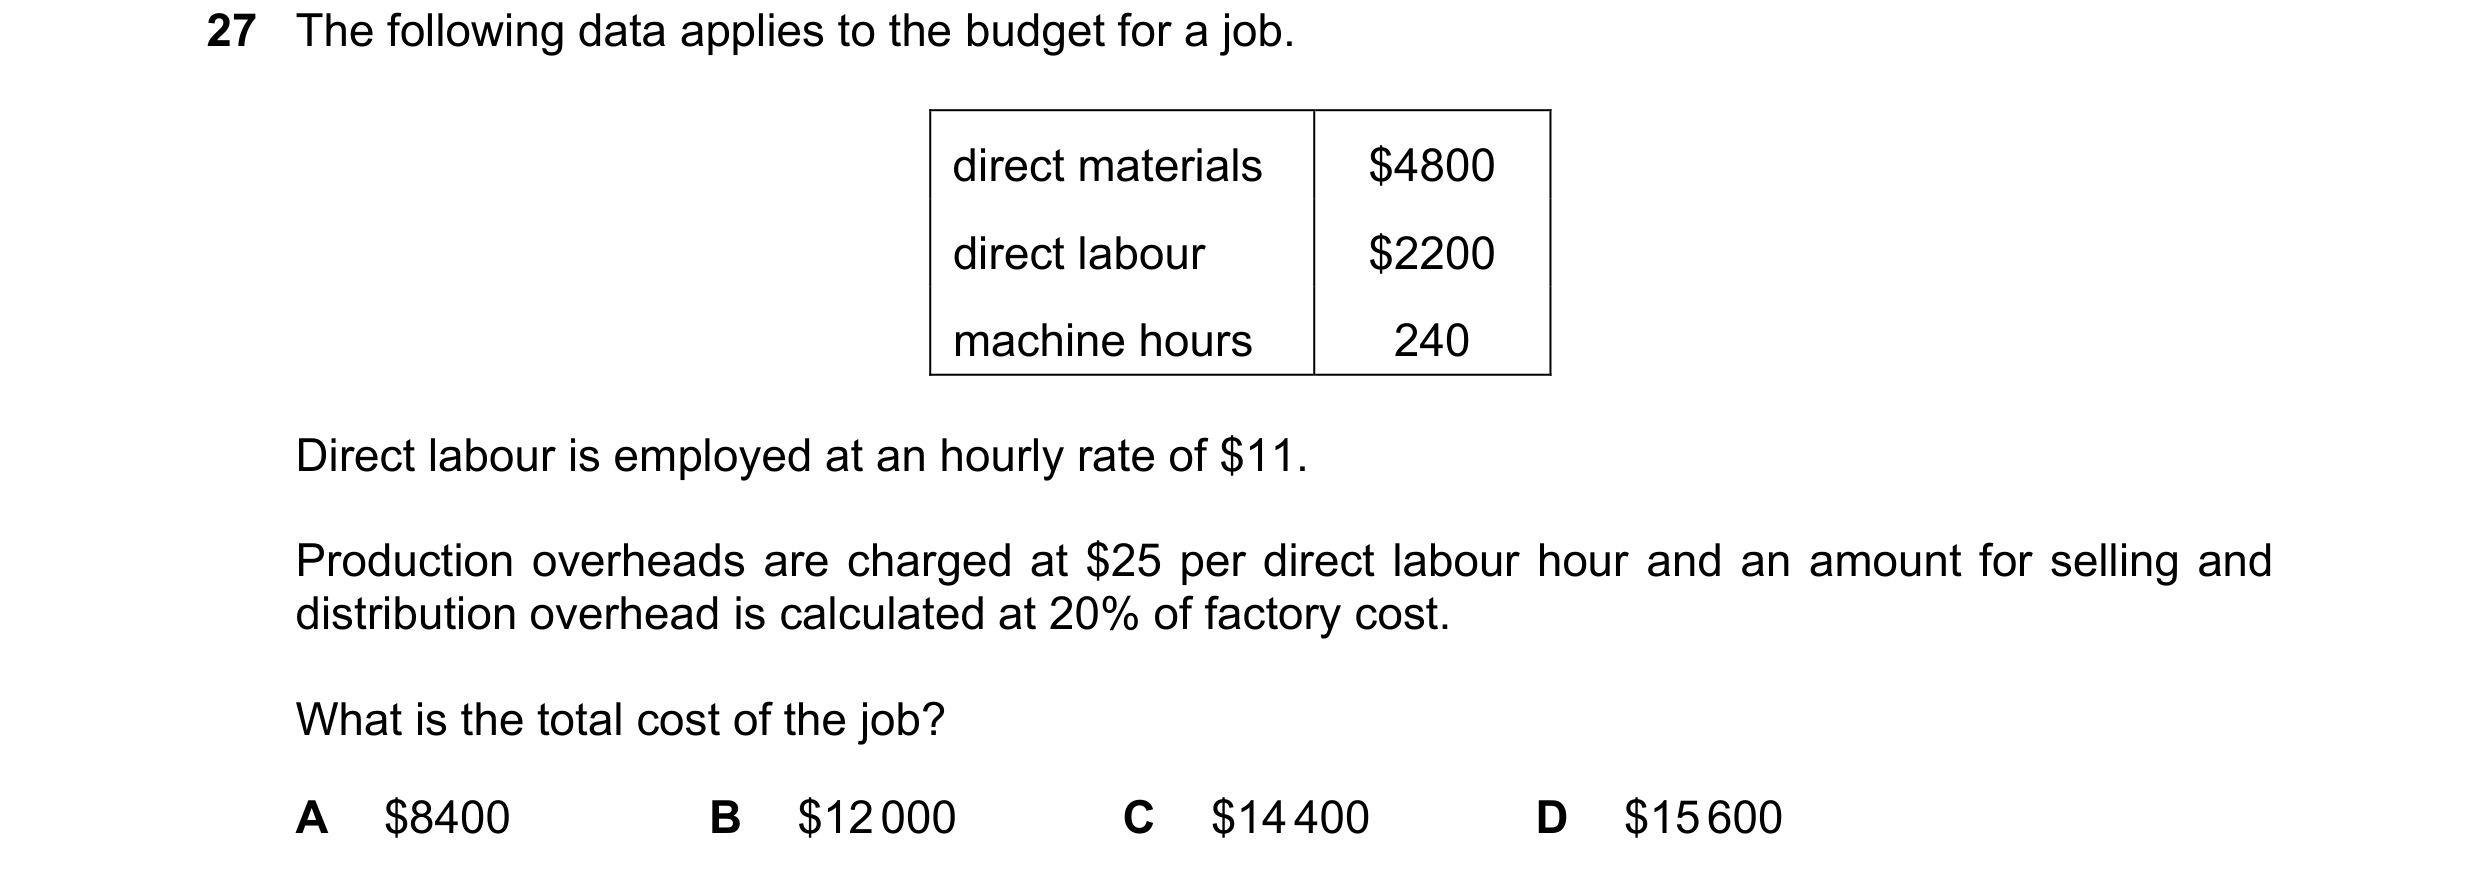 123 / 143
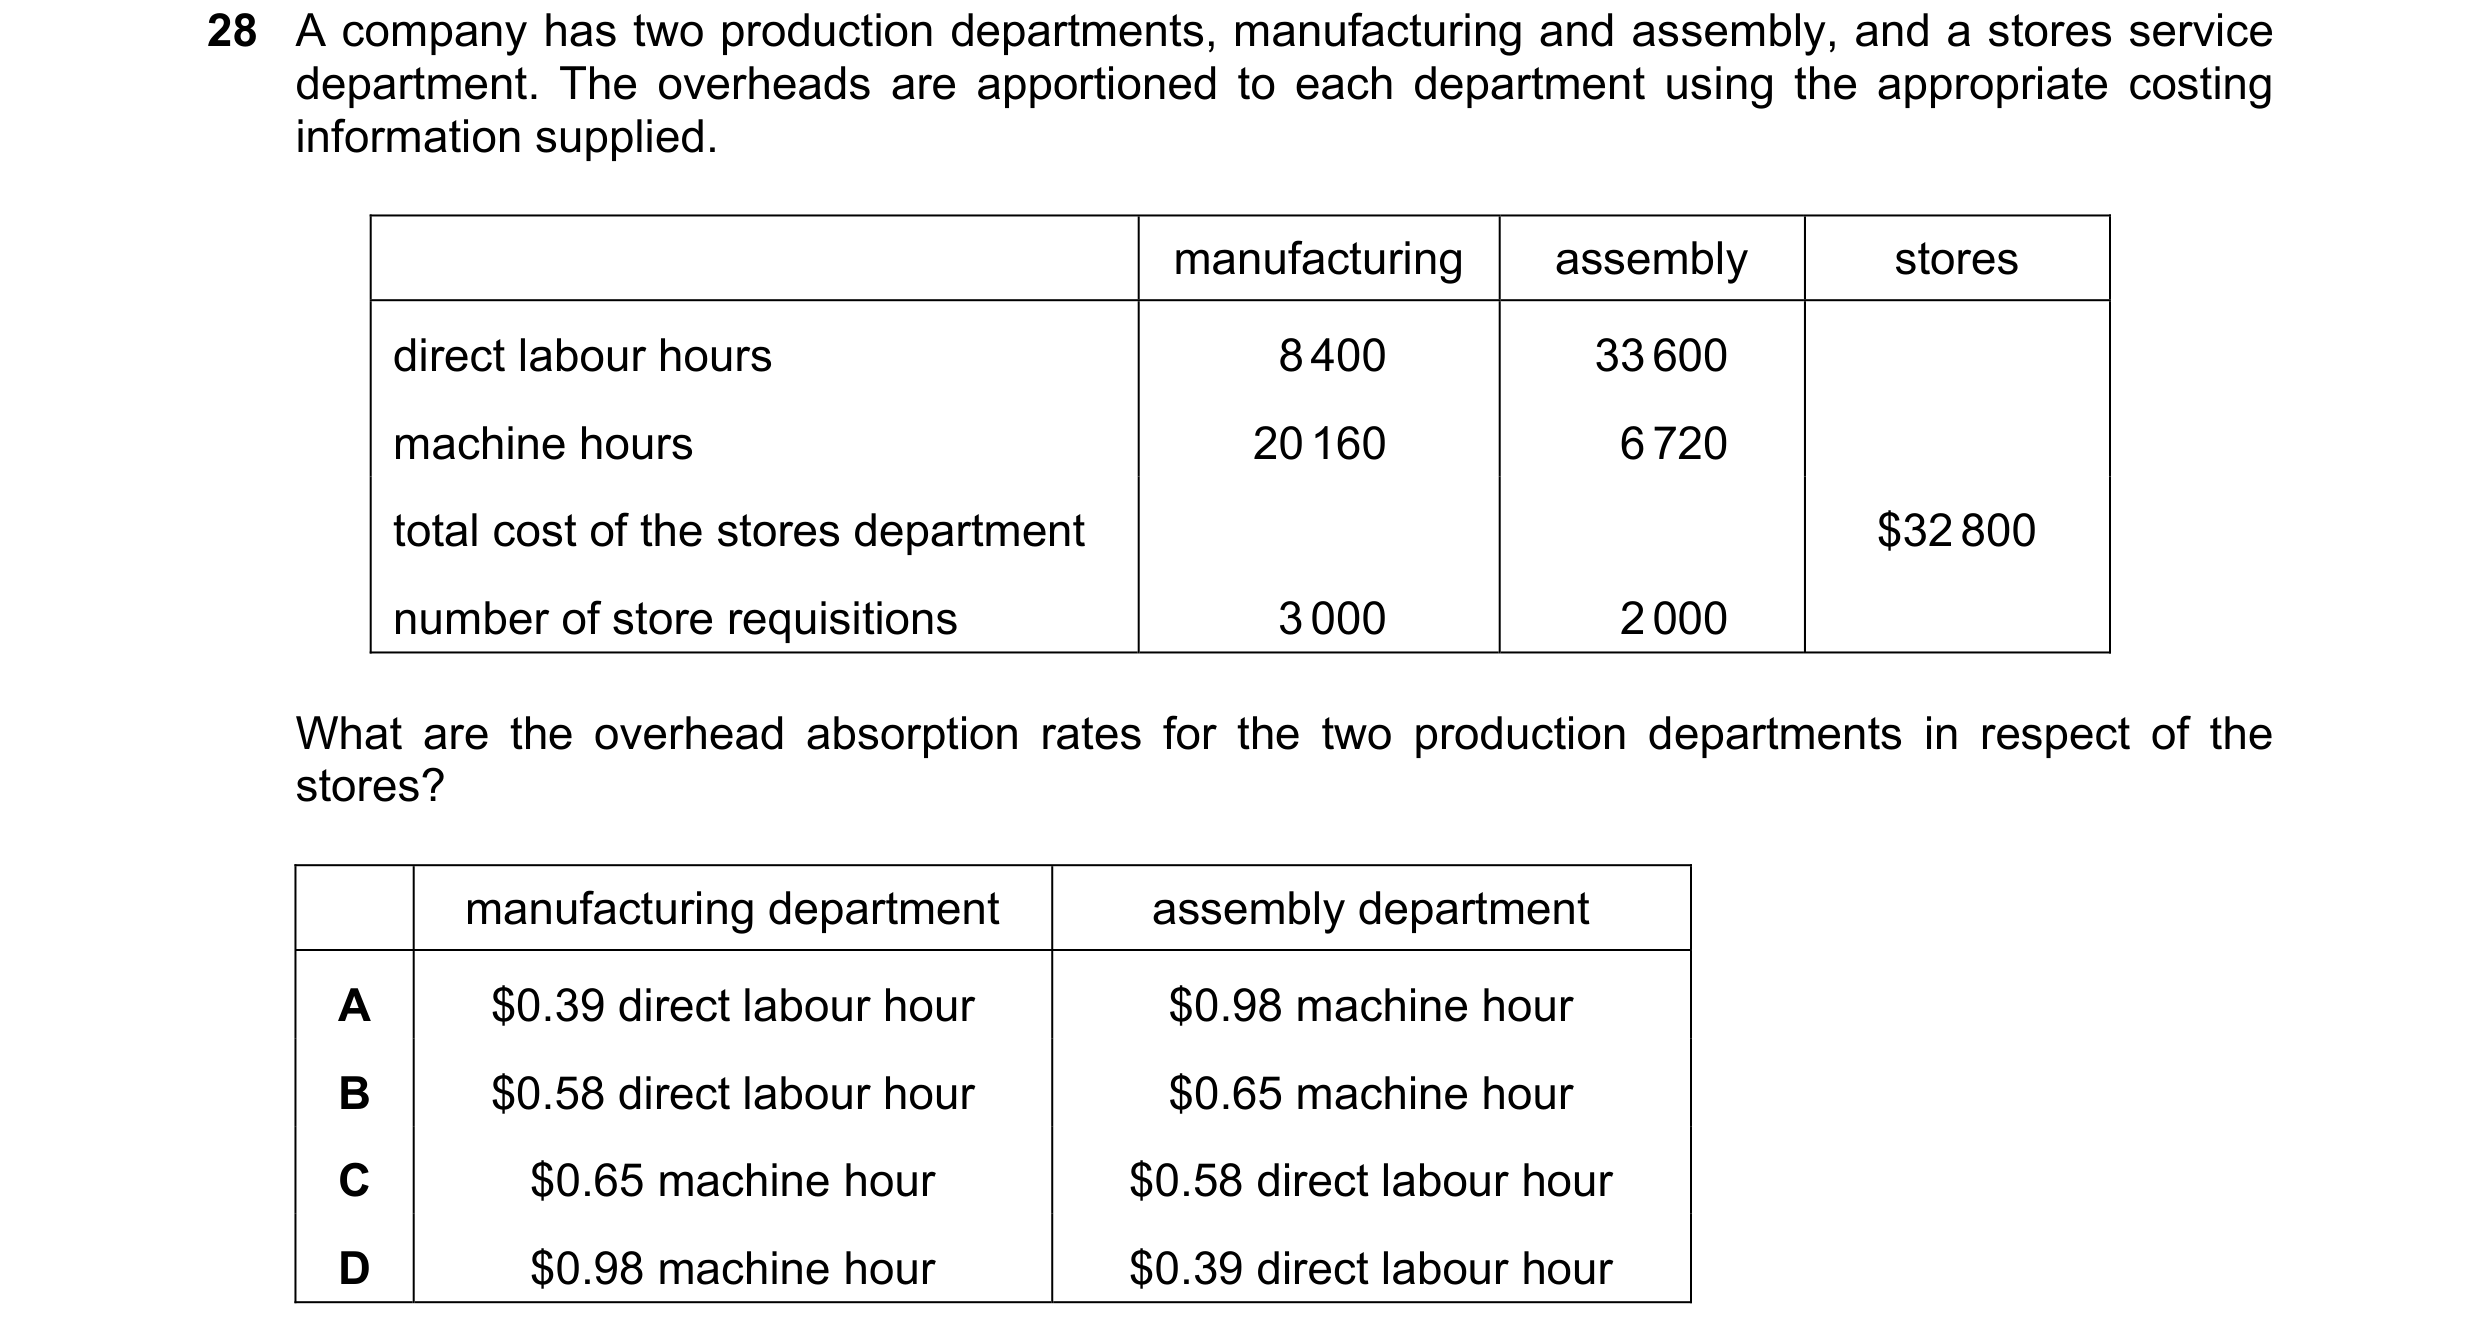
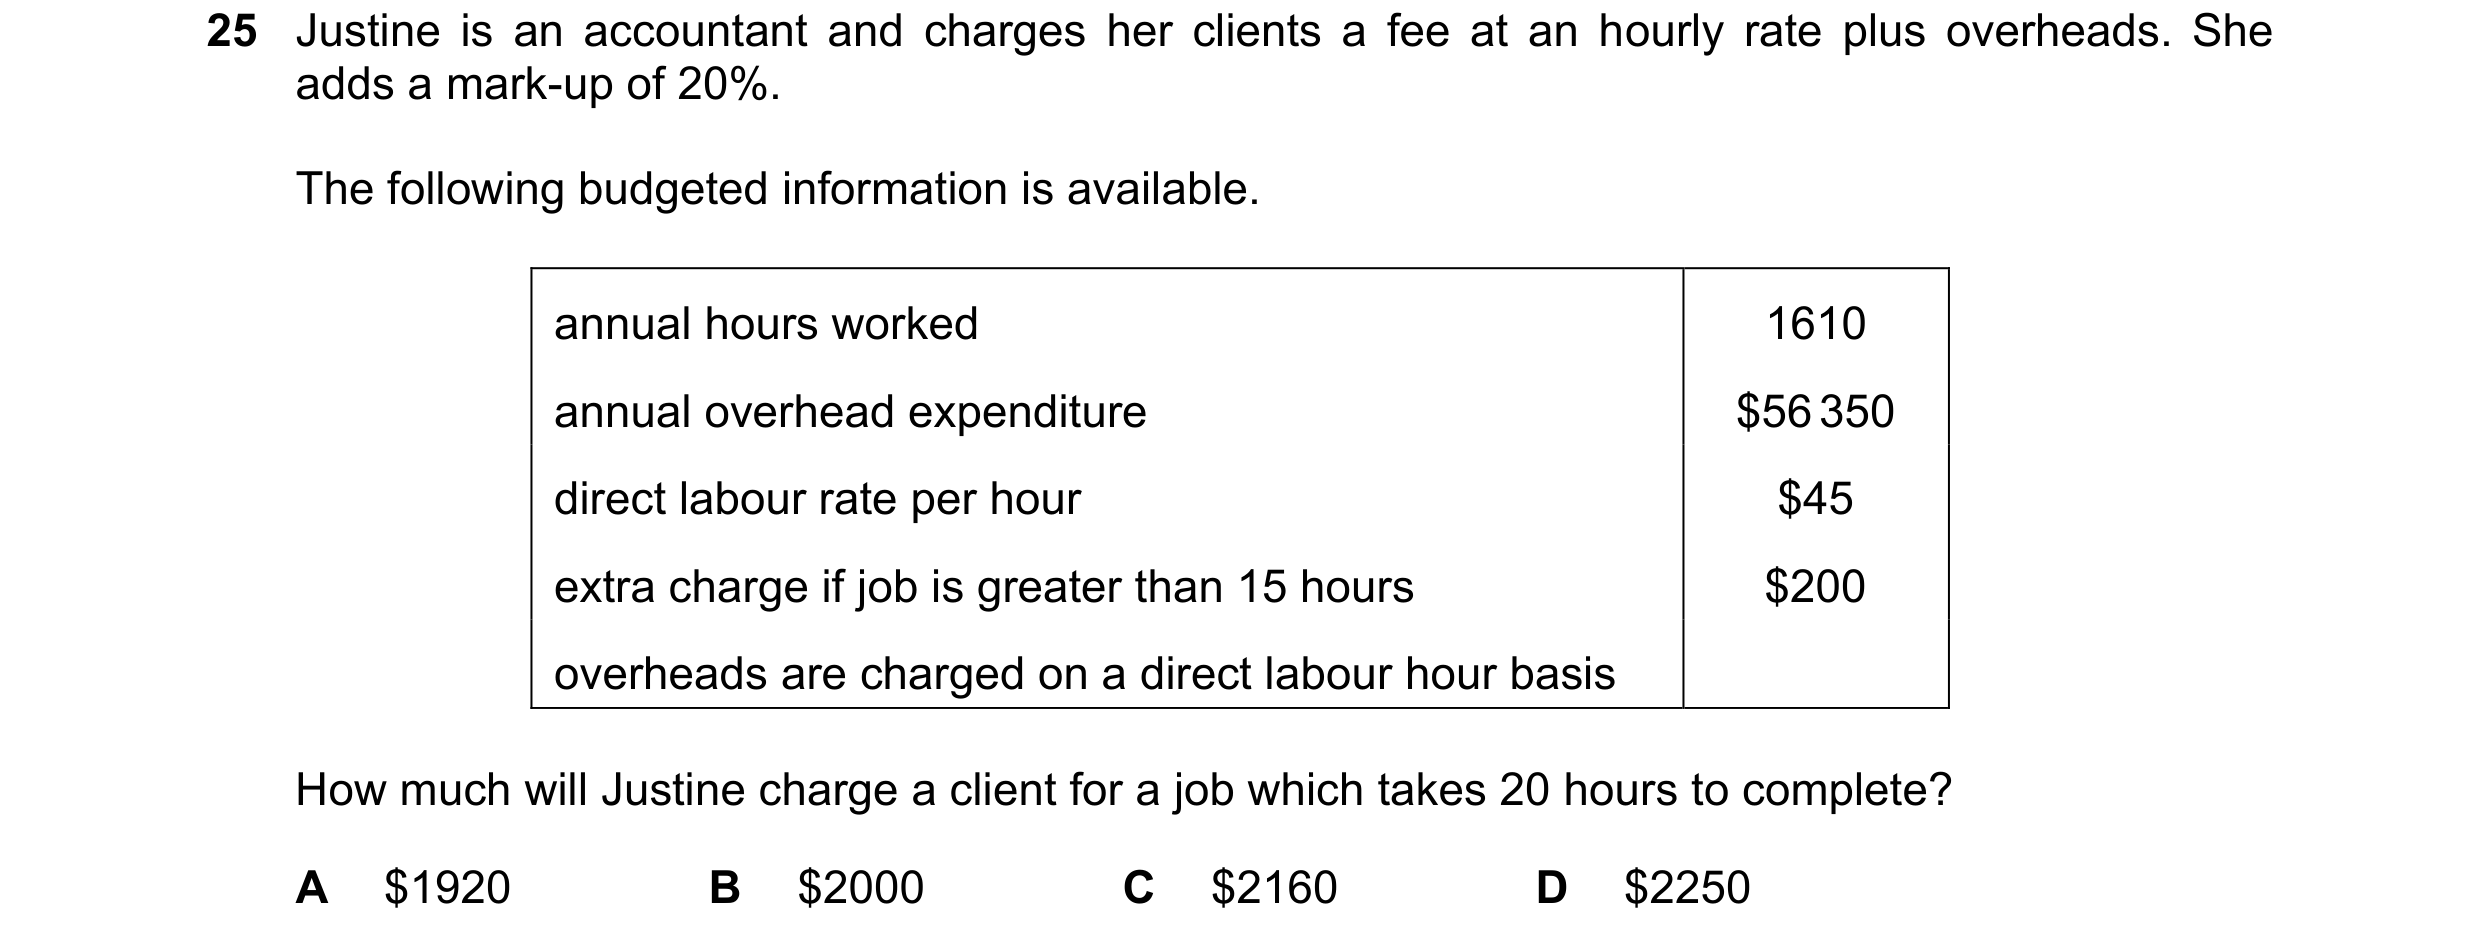
 124 / 143
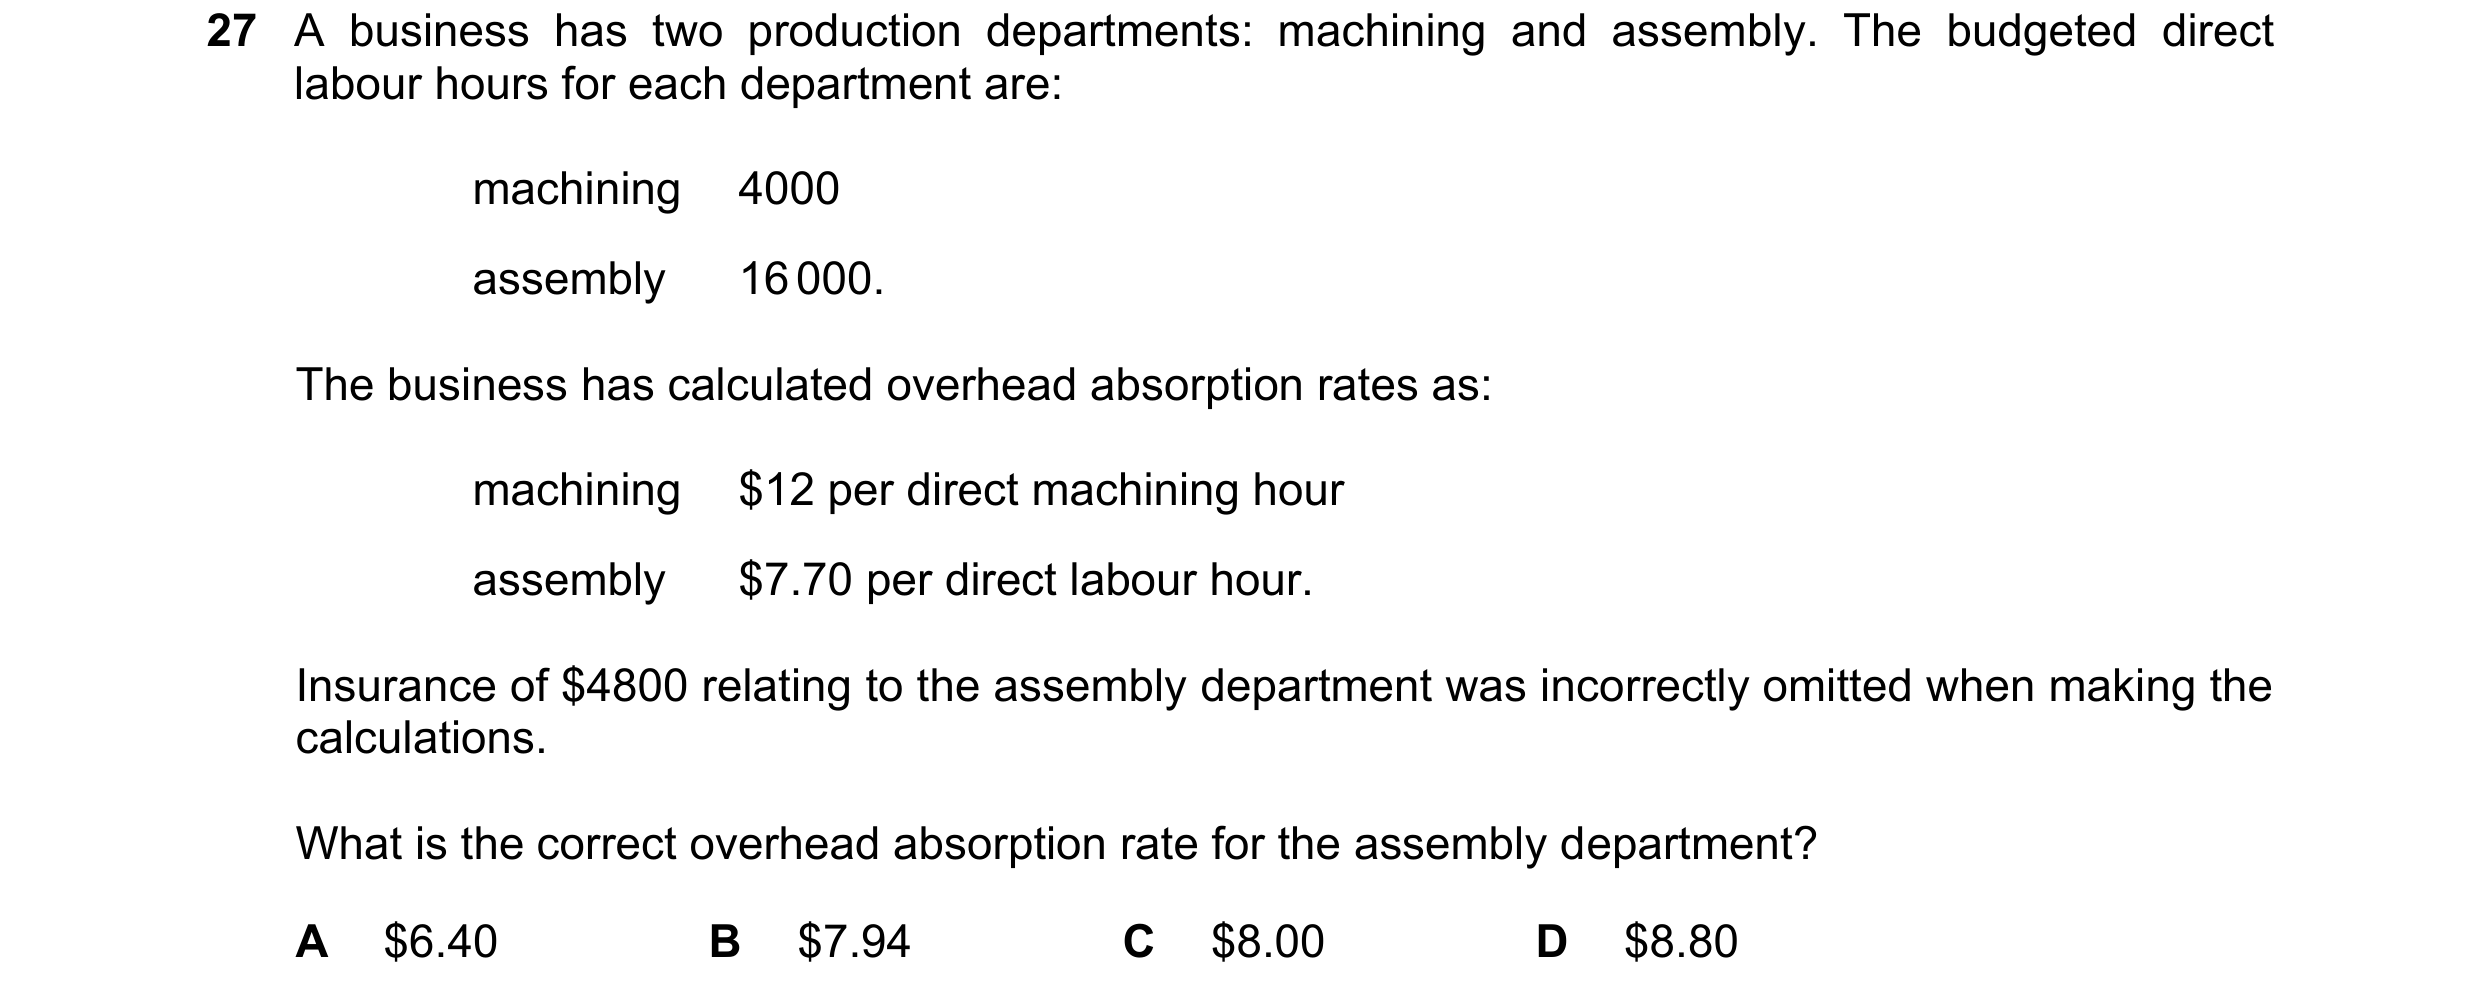
 125 / 143
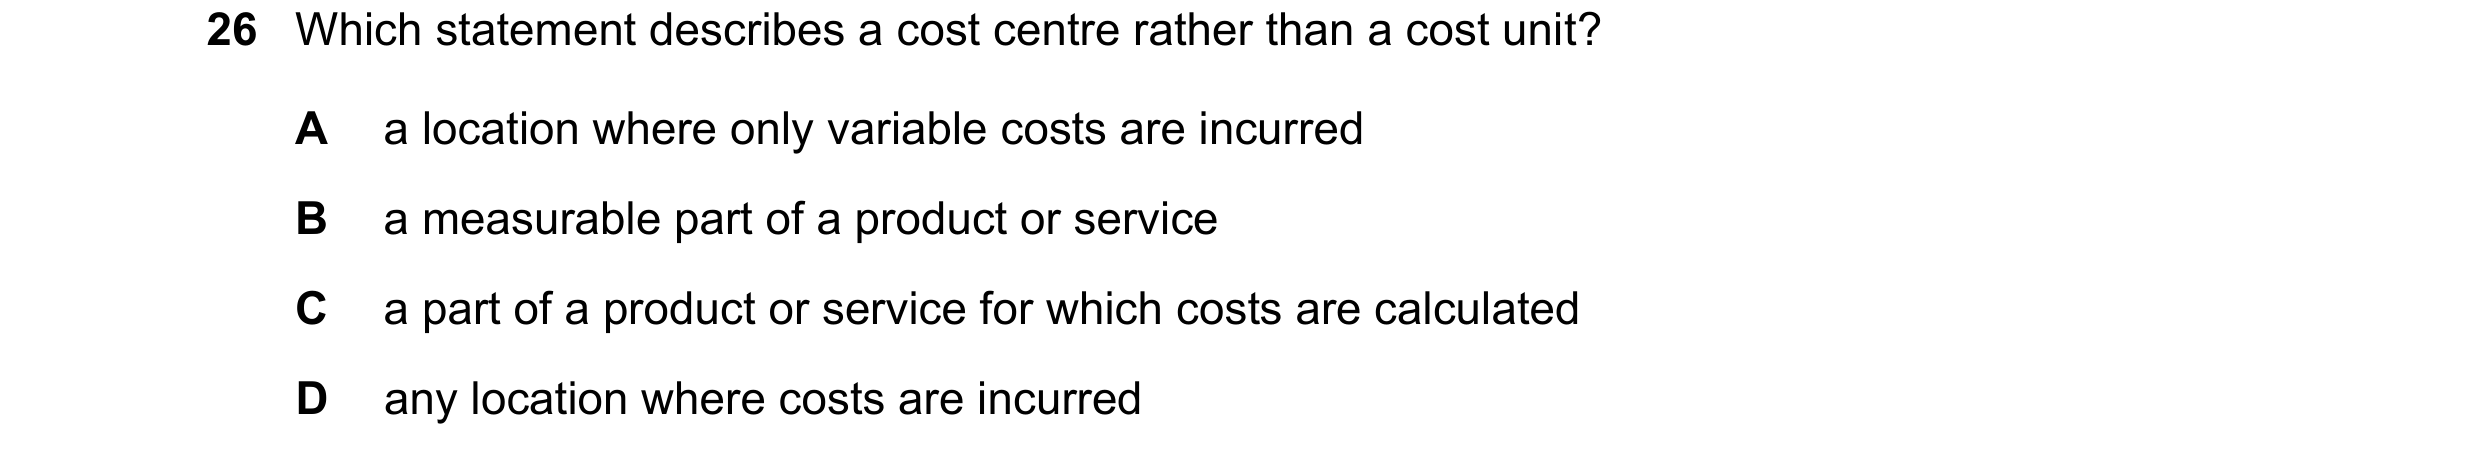
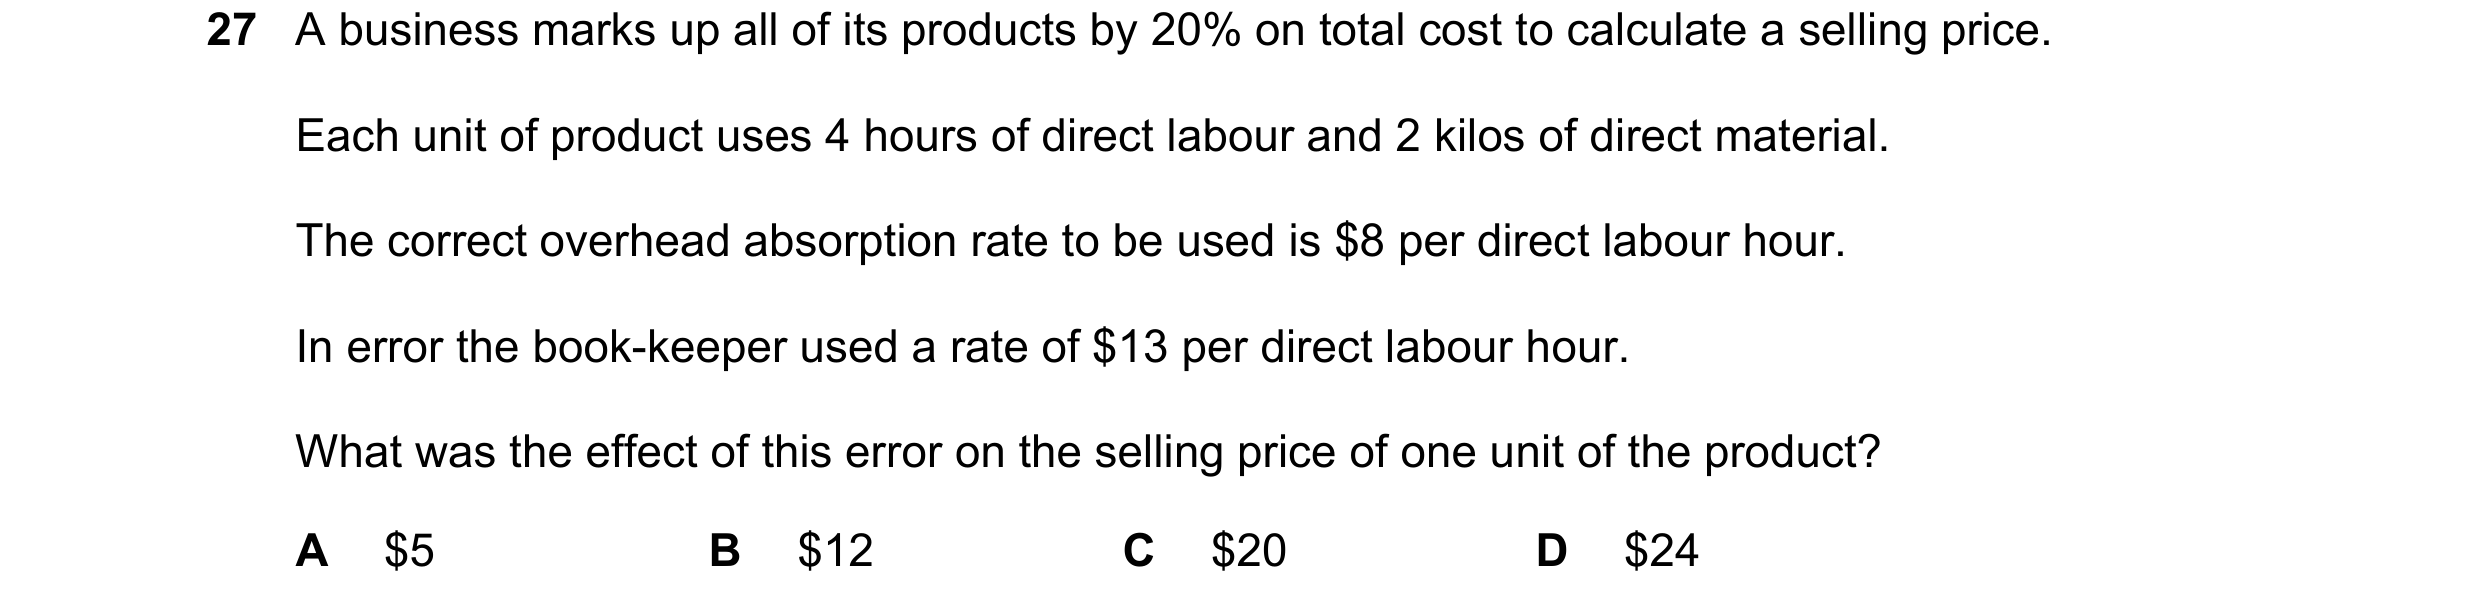
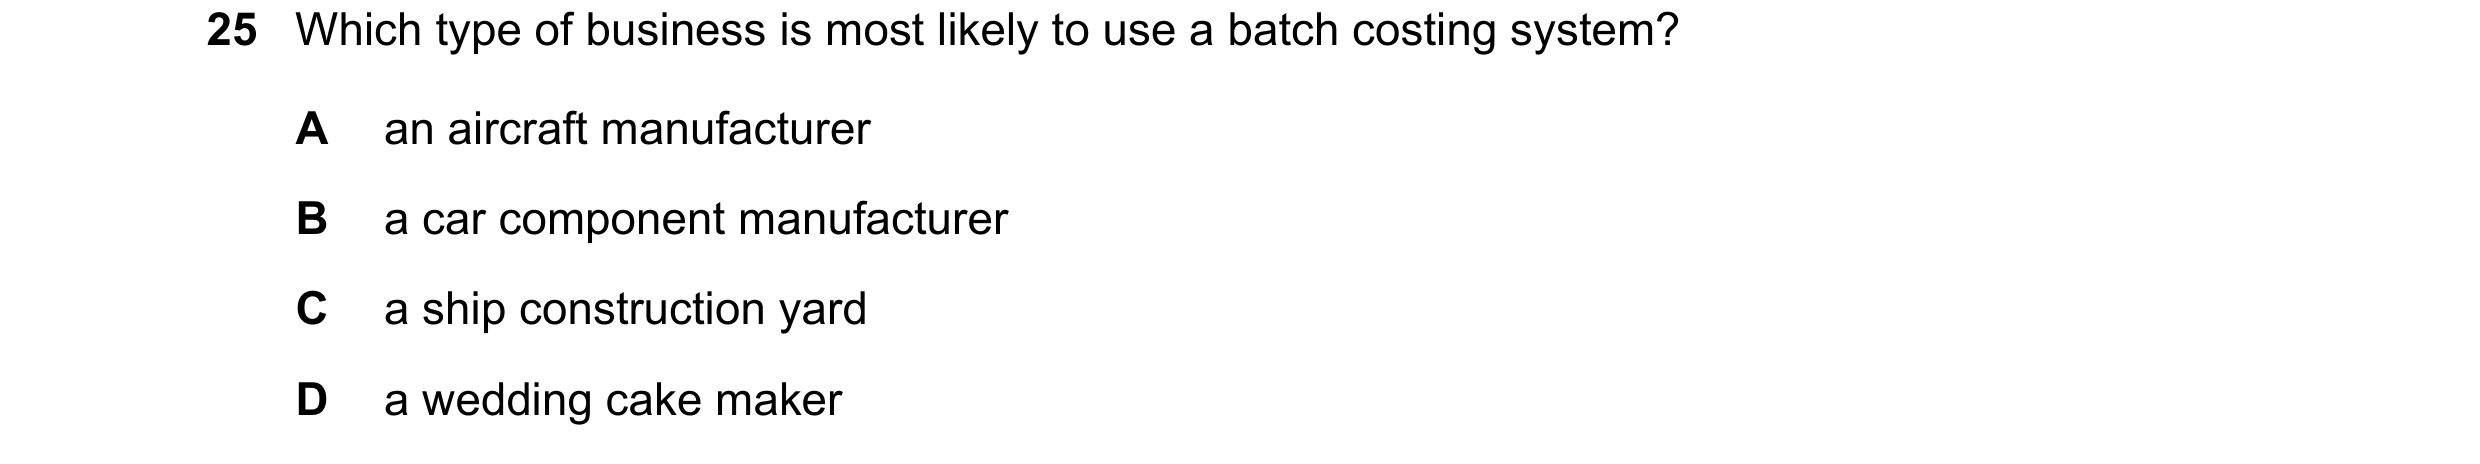
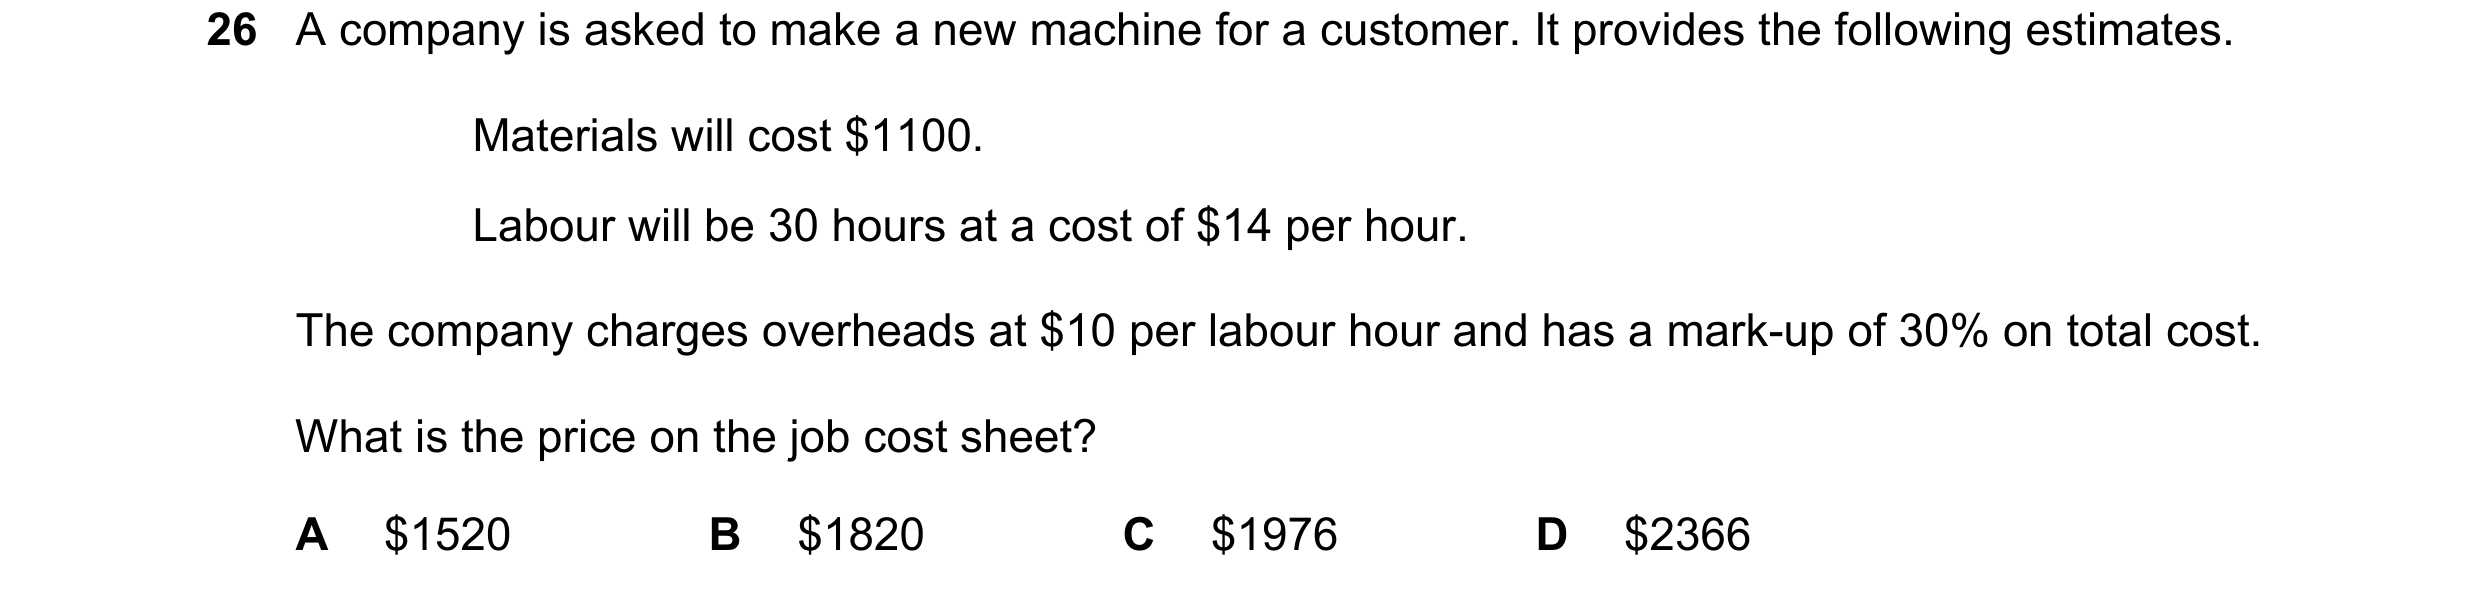 126 / 143
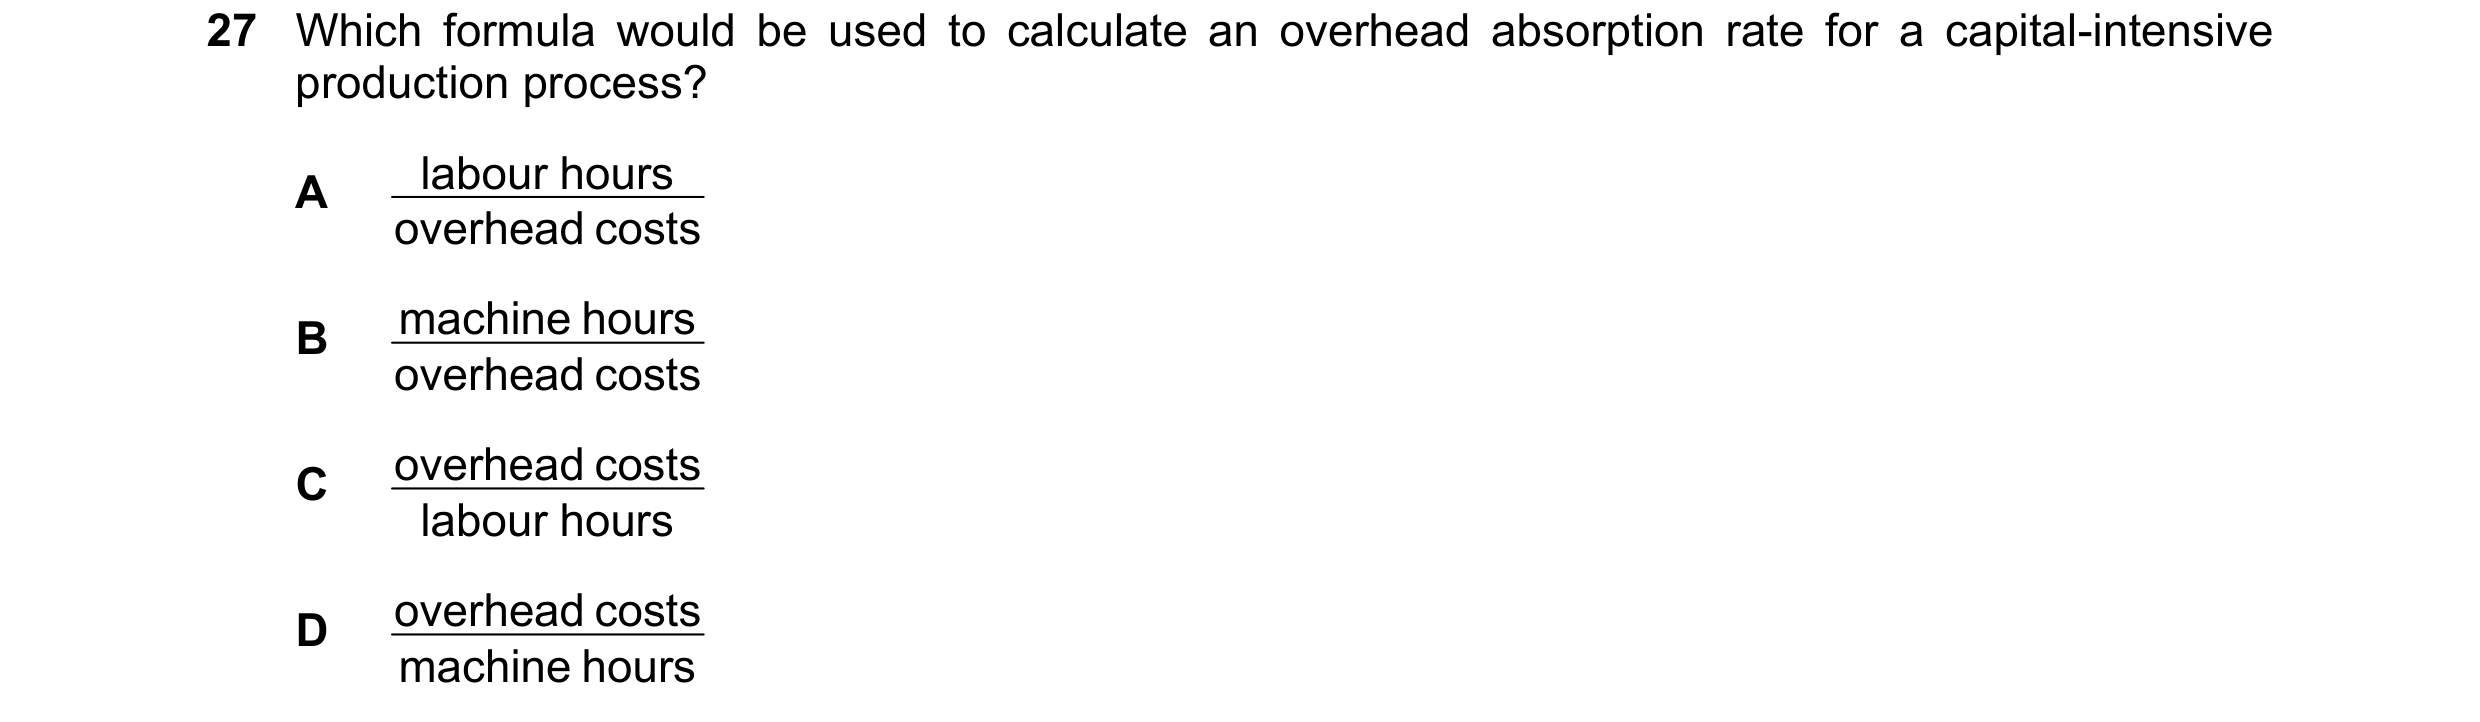
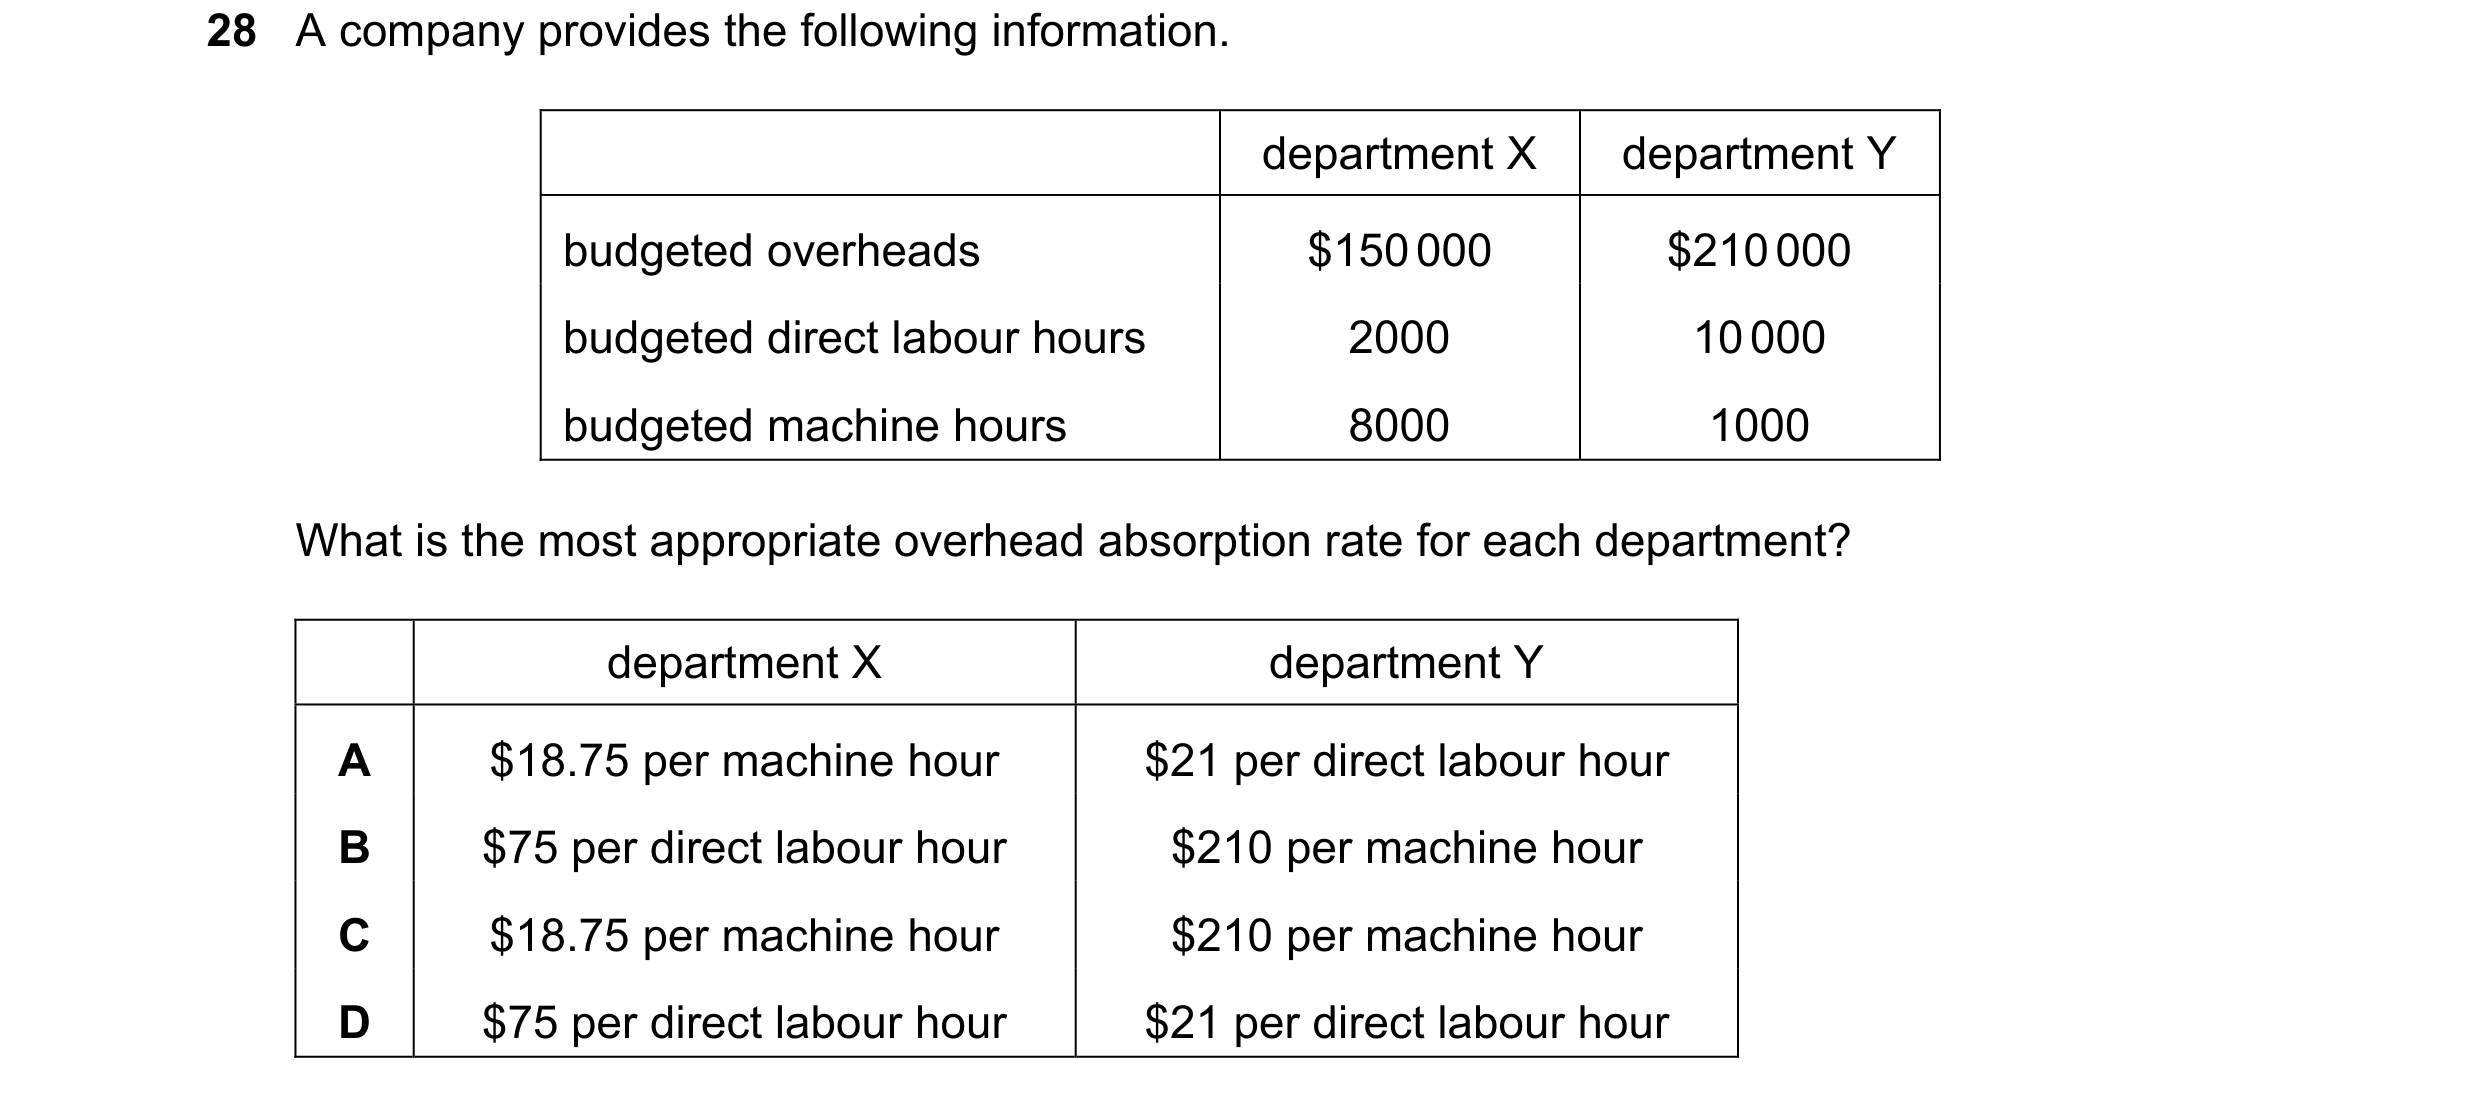
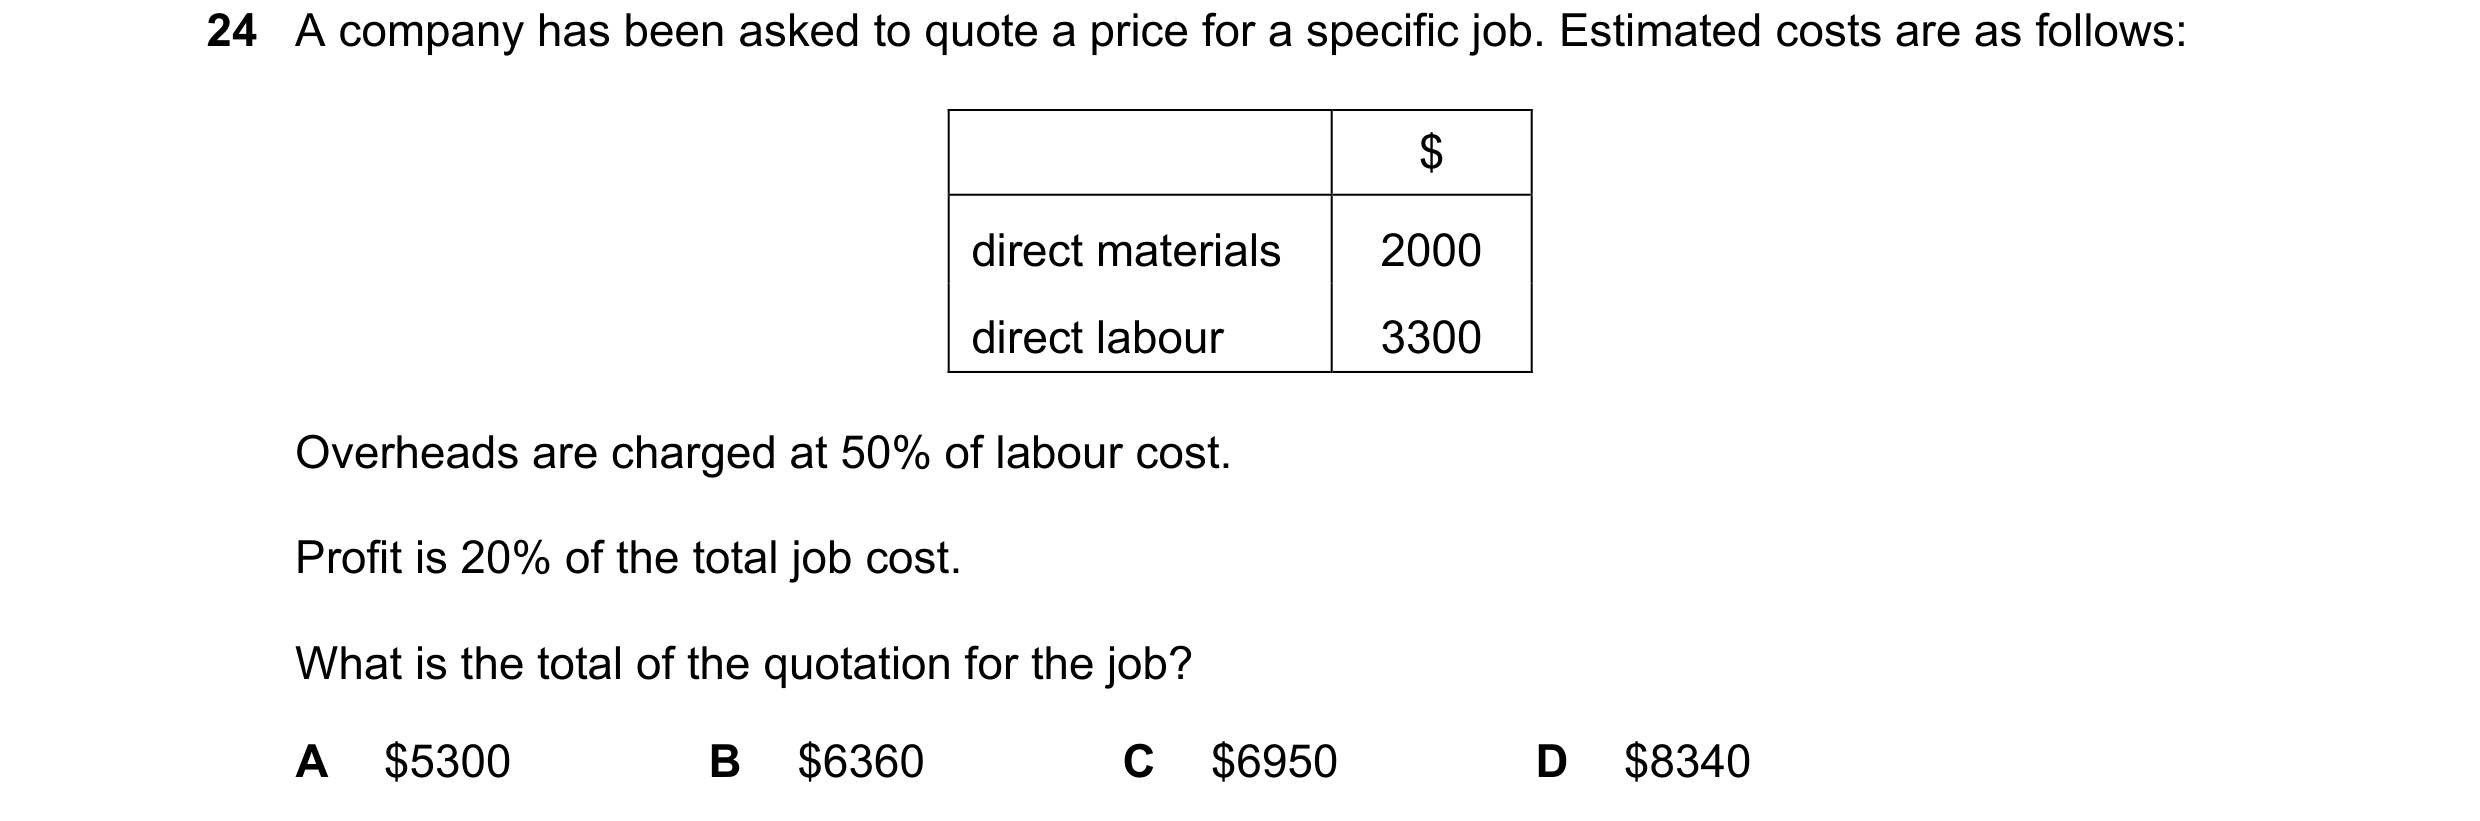 127 / 143
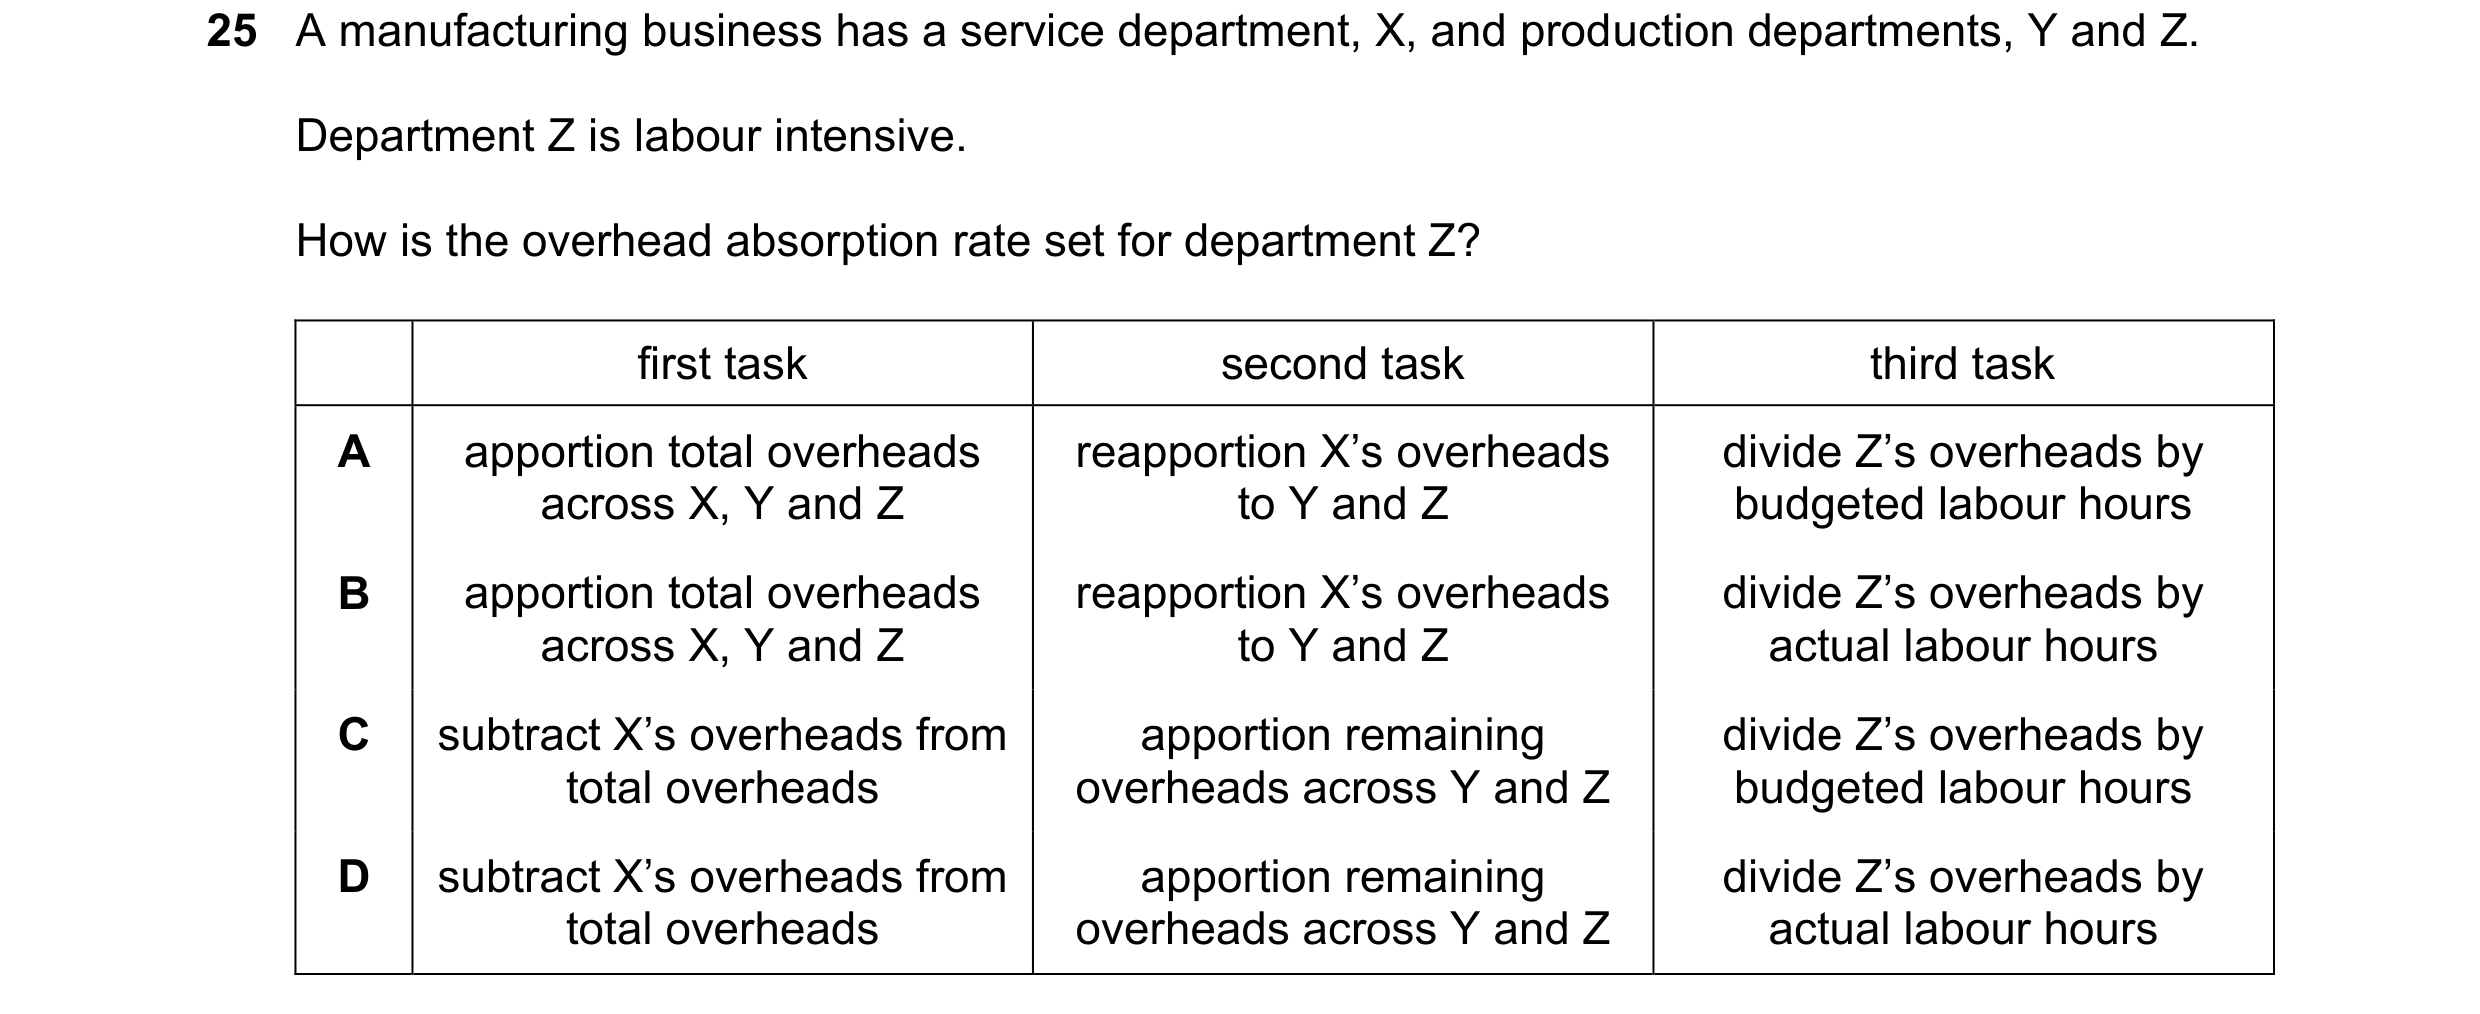
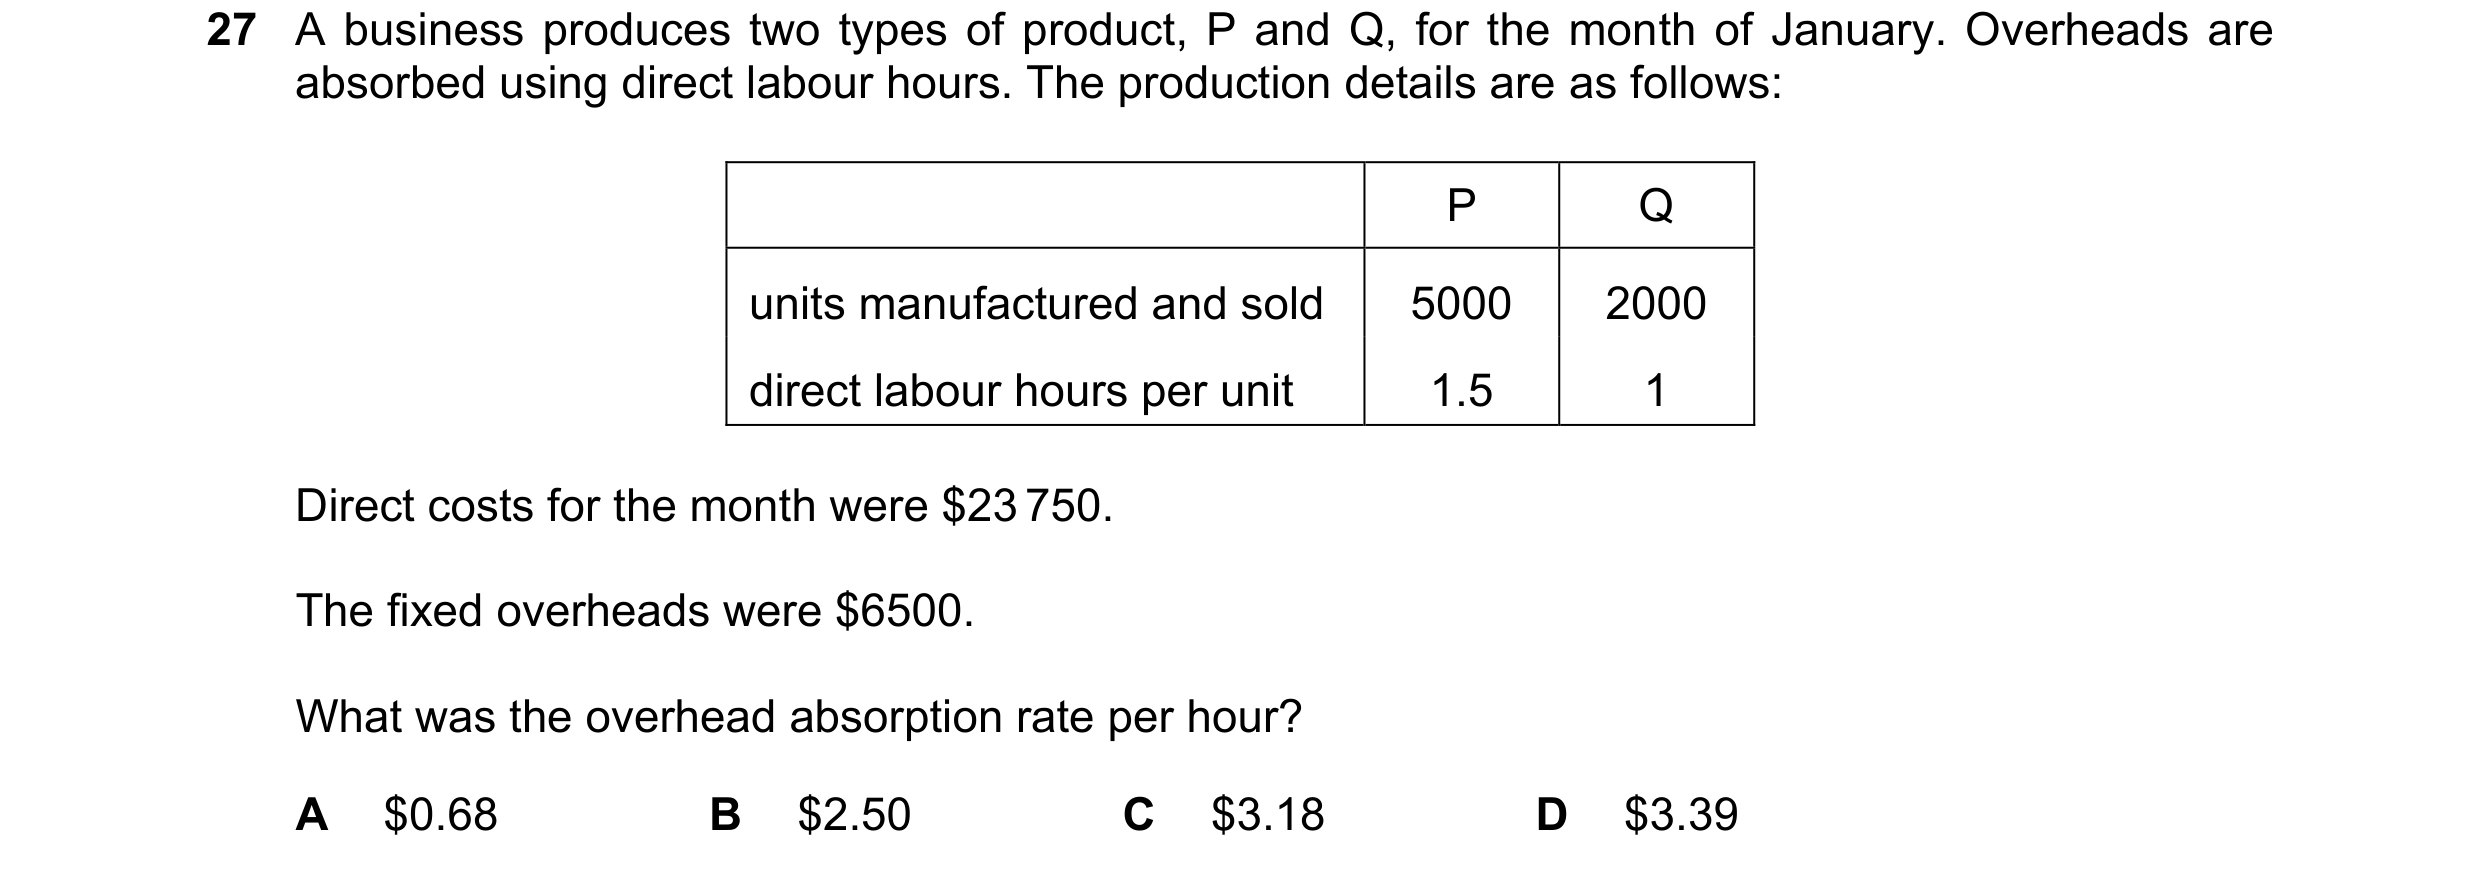
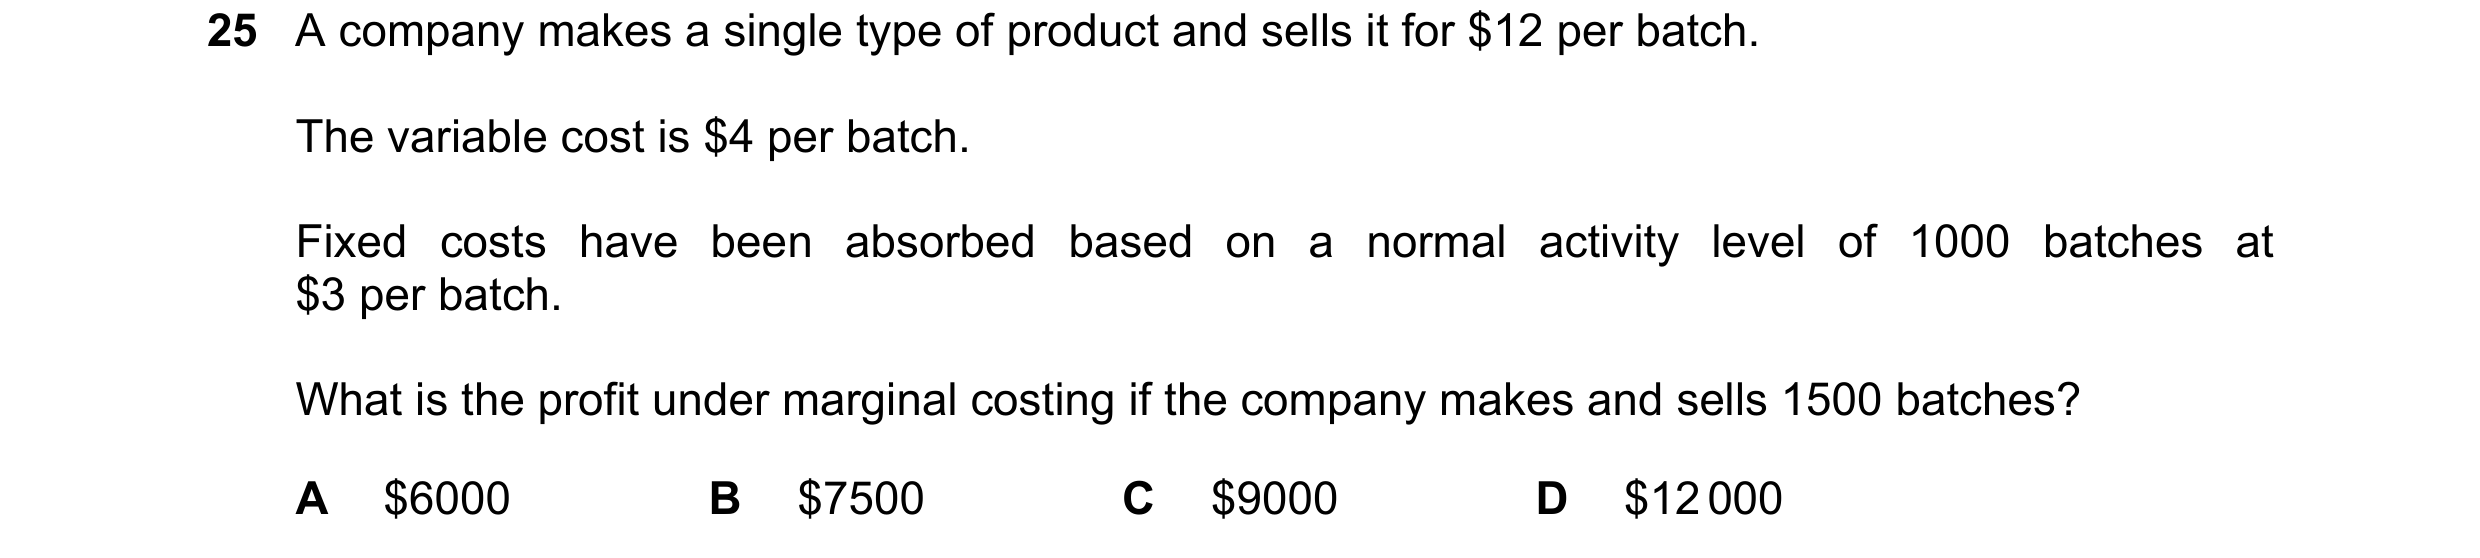 128 / 143
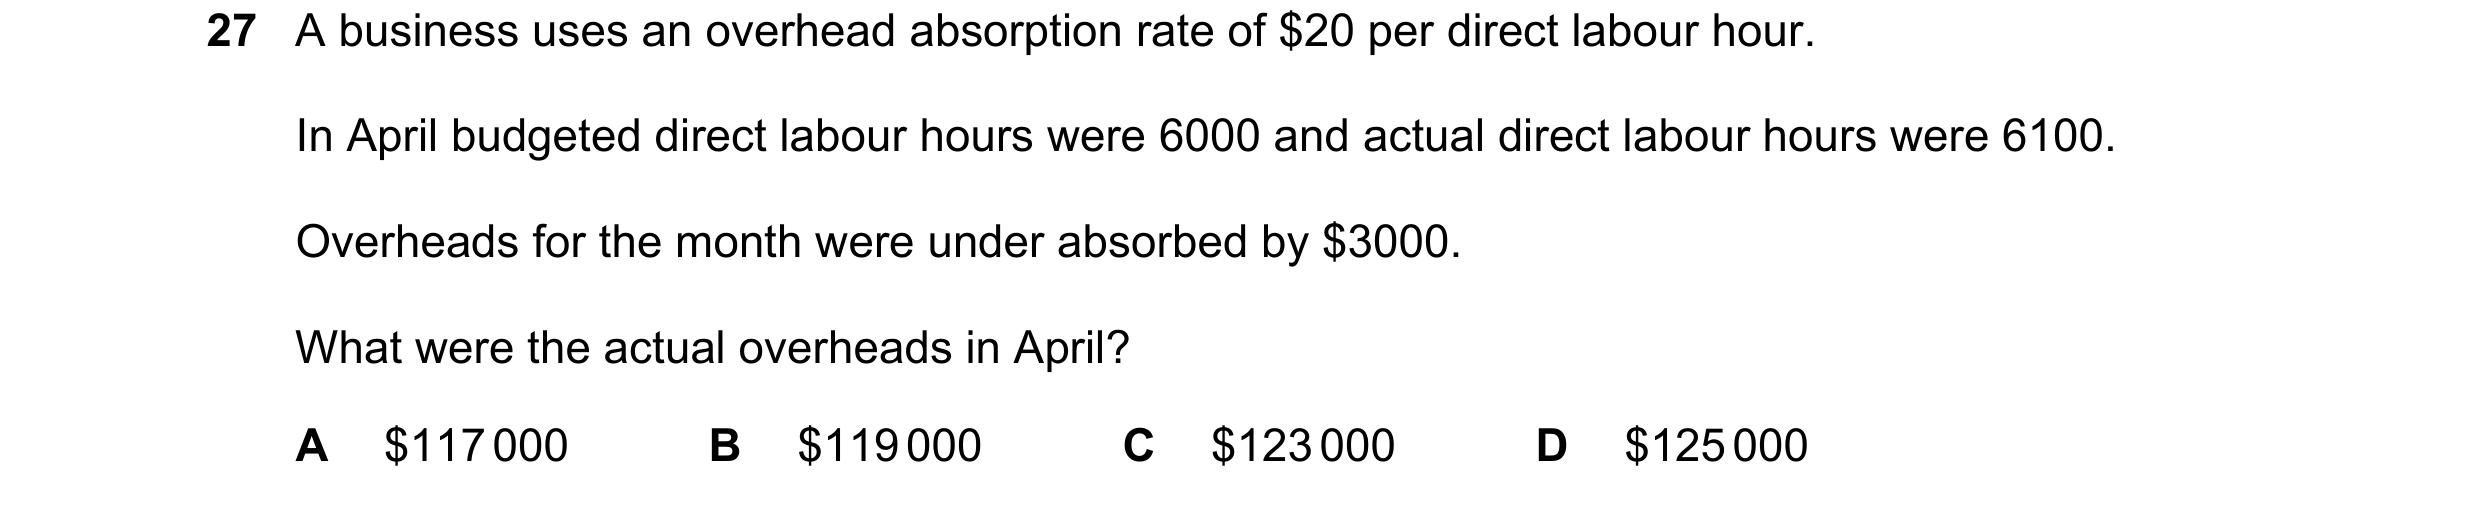
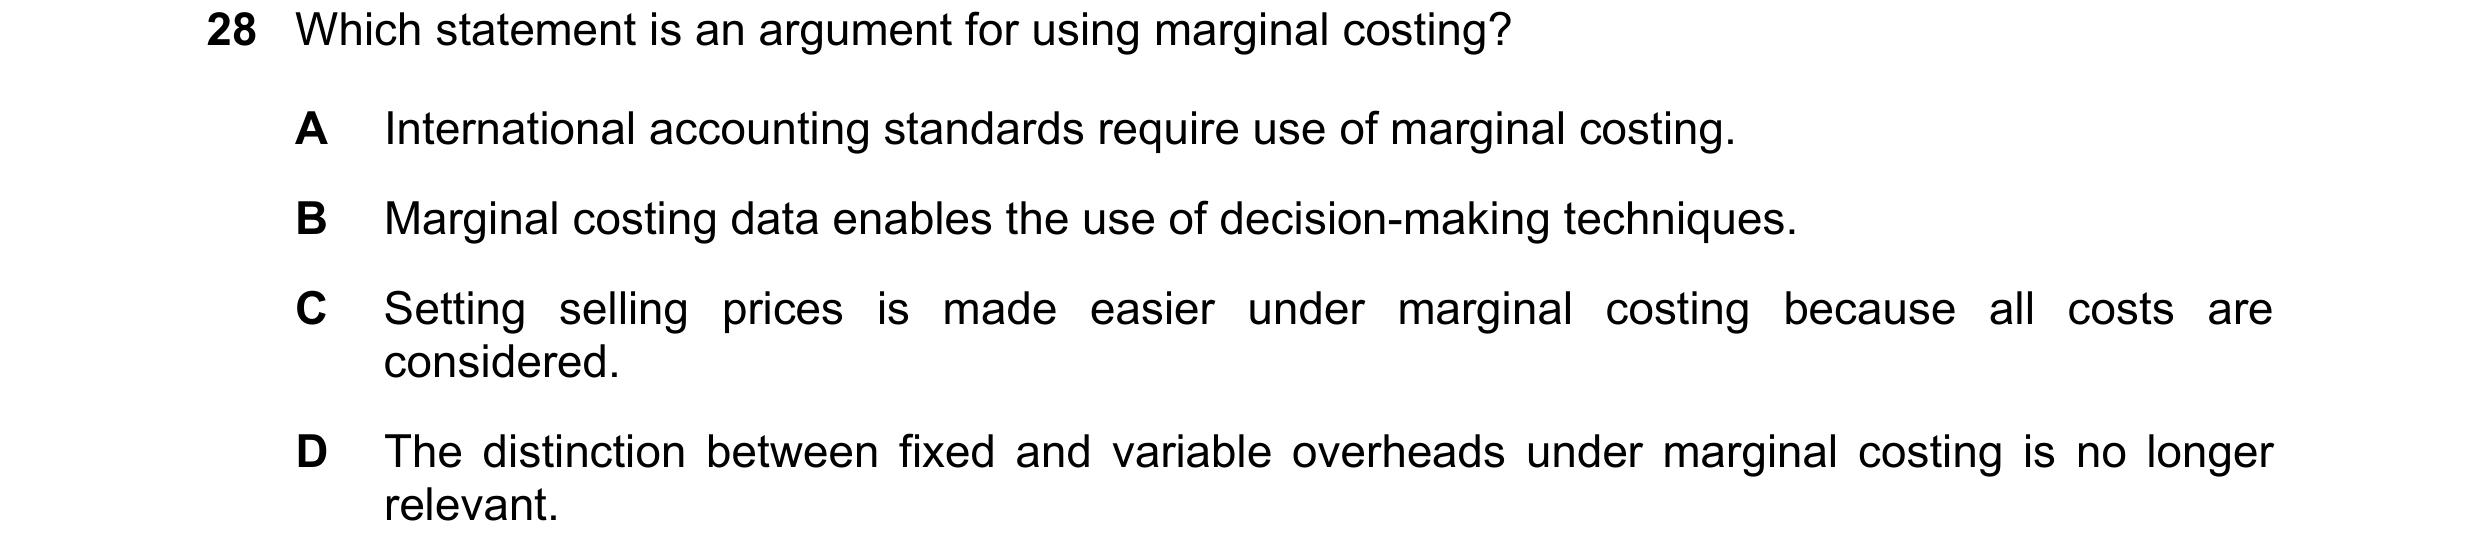
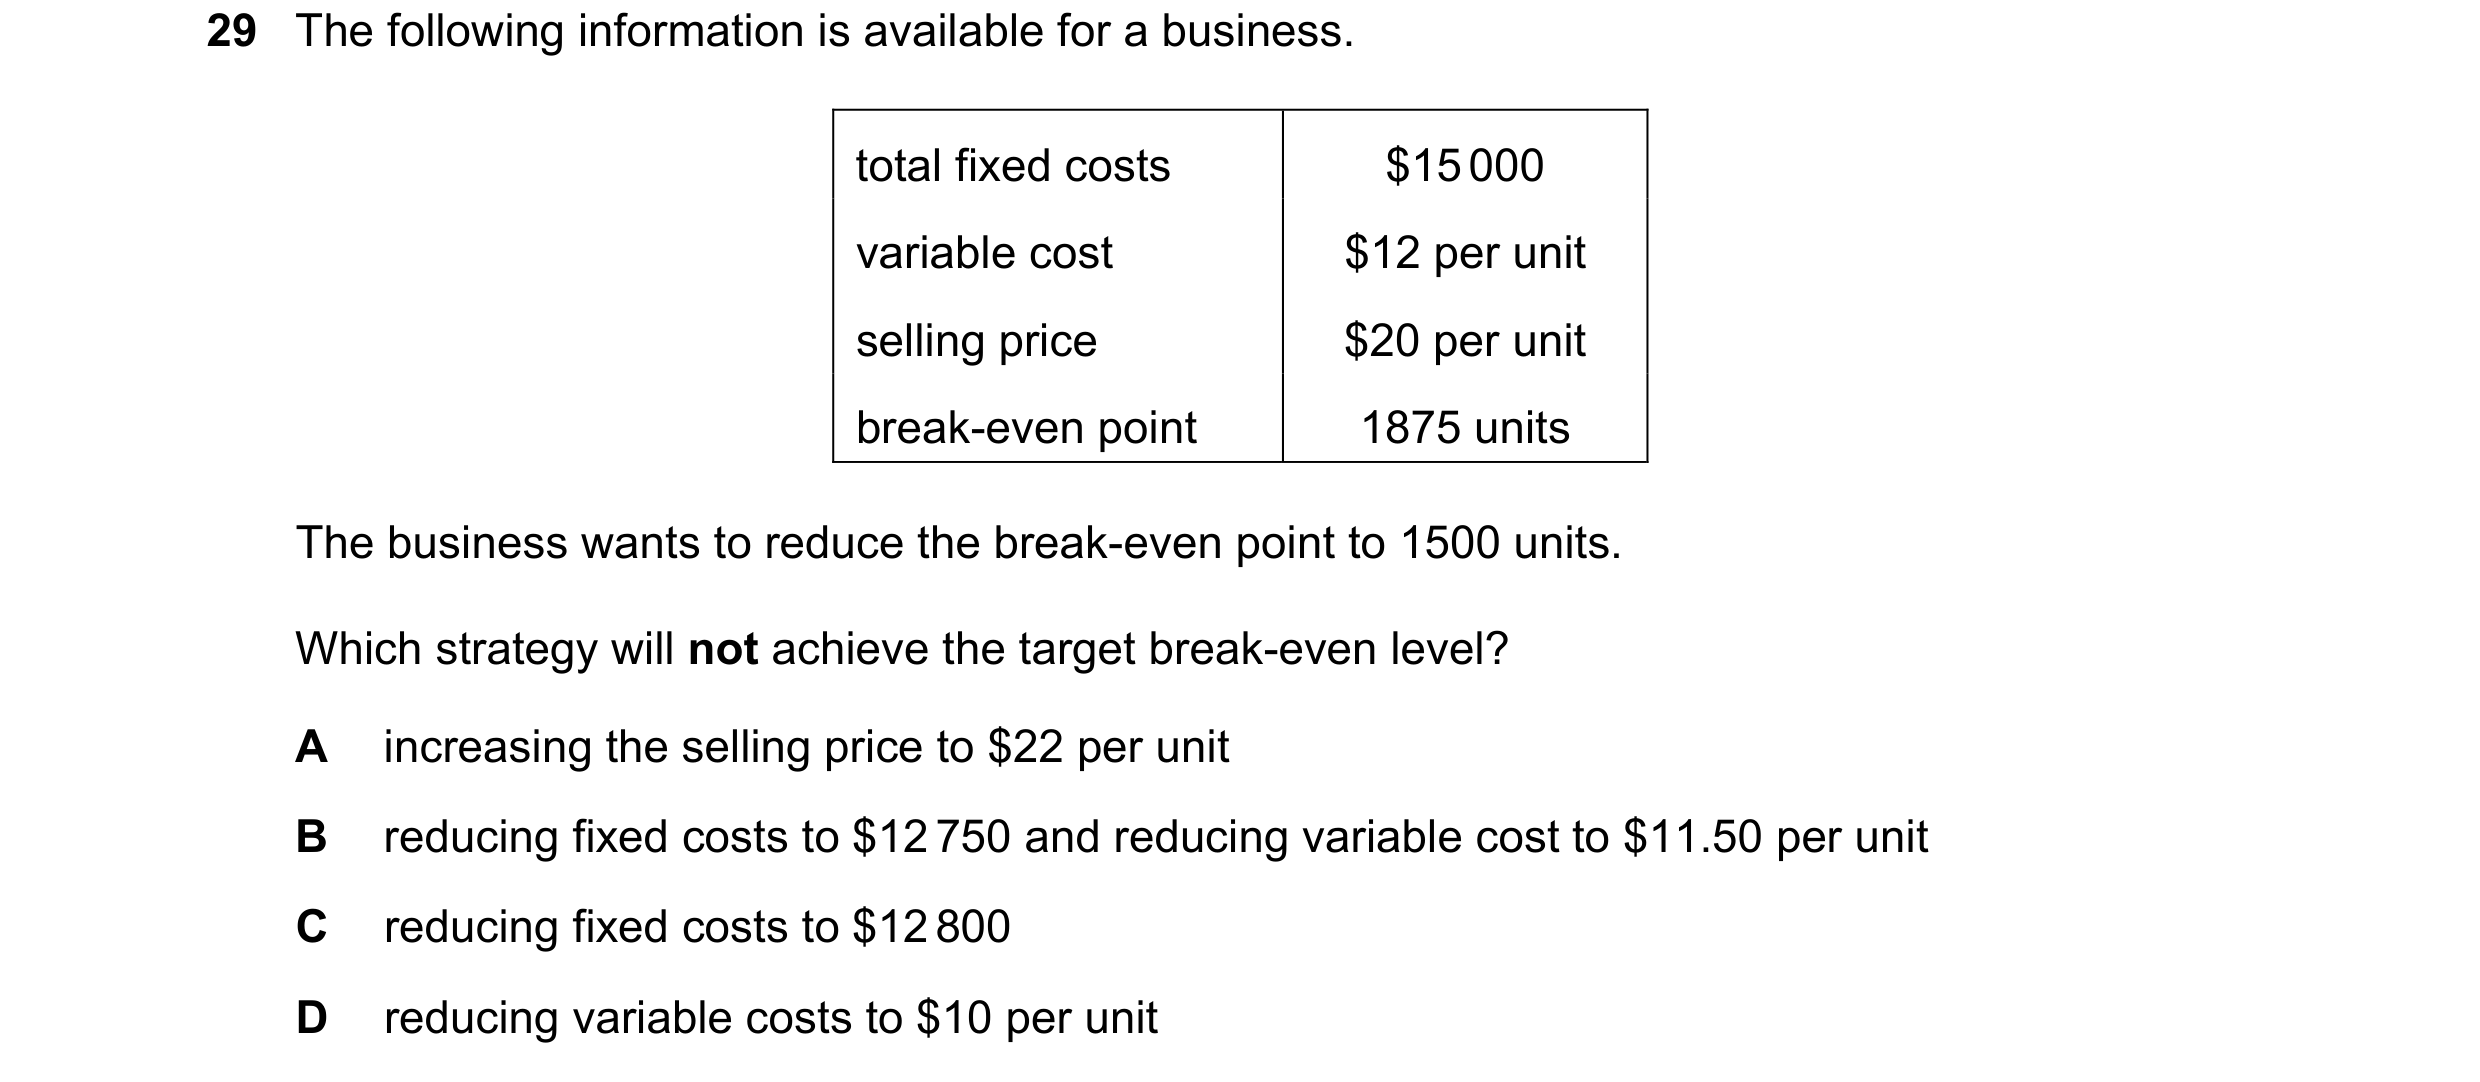 129 / 143
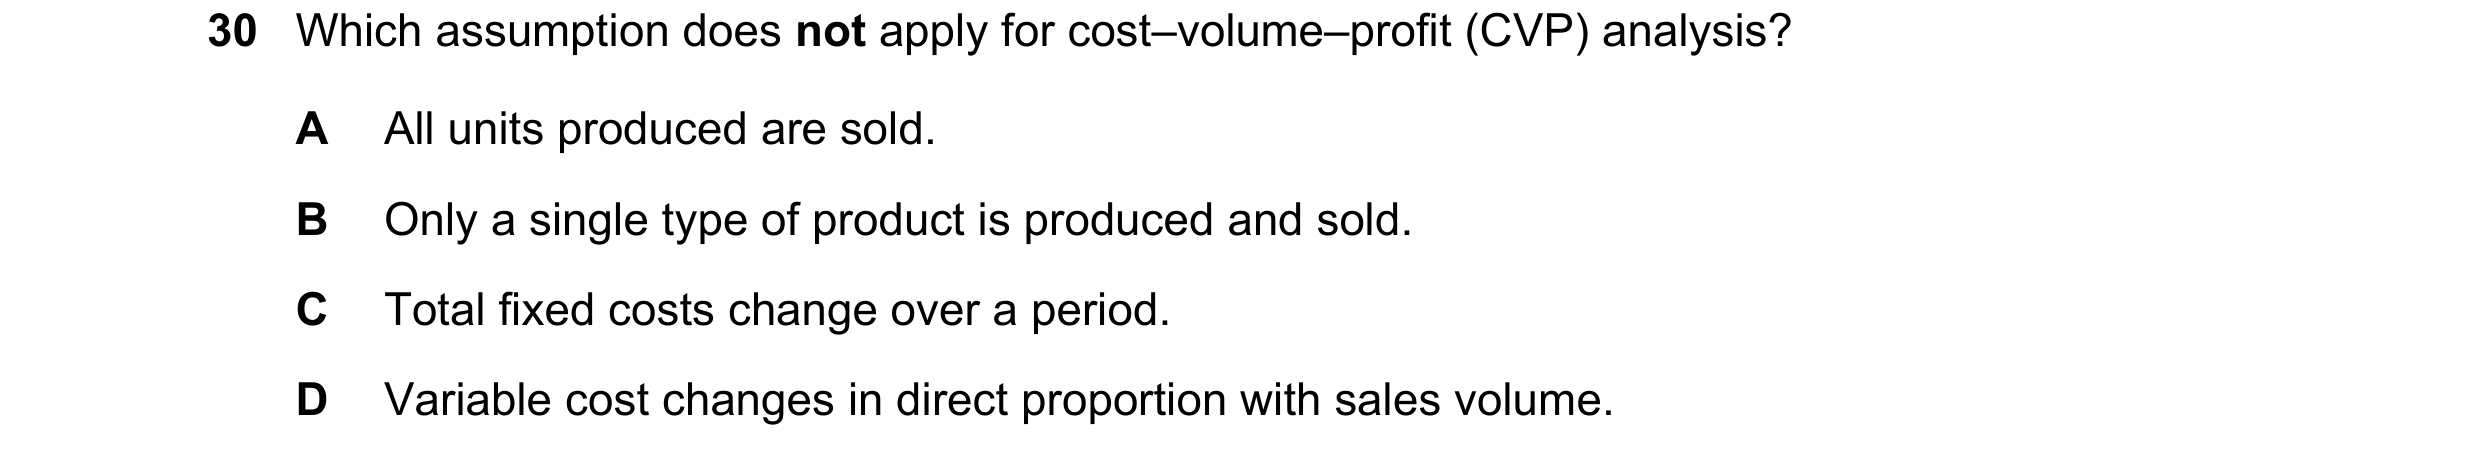
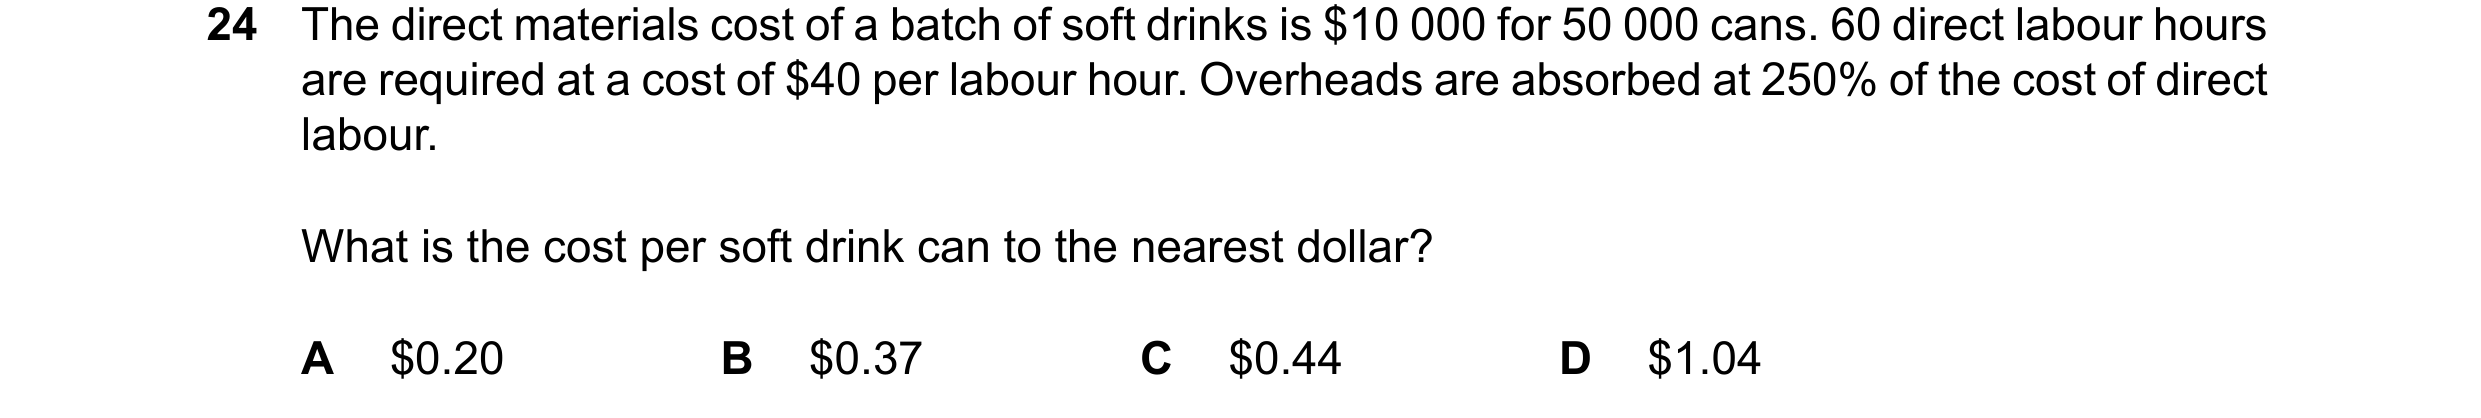
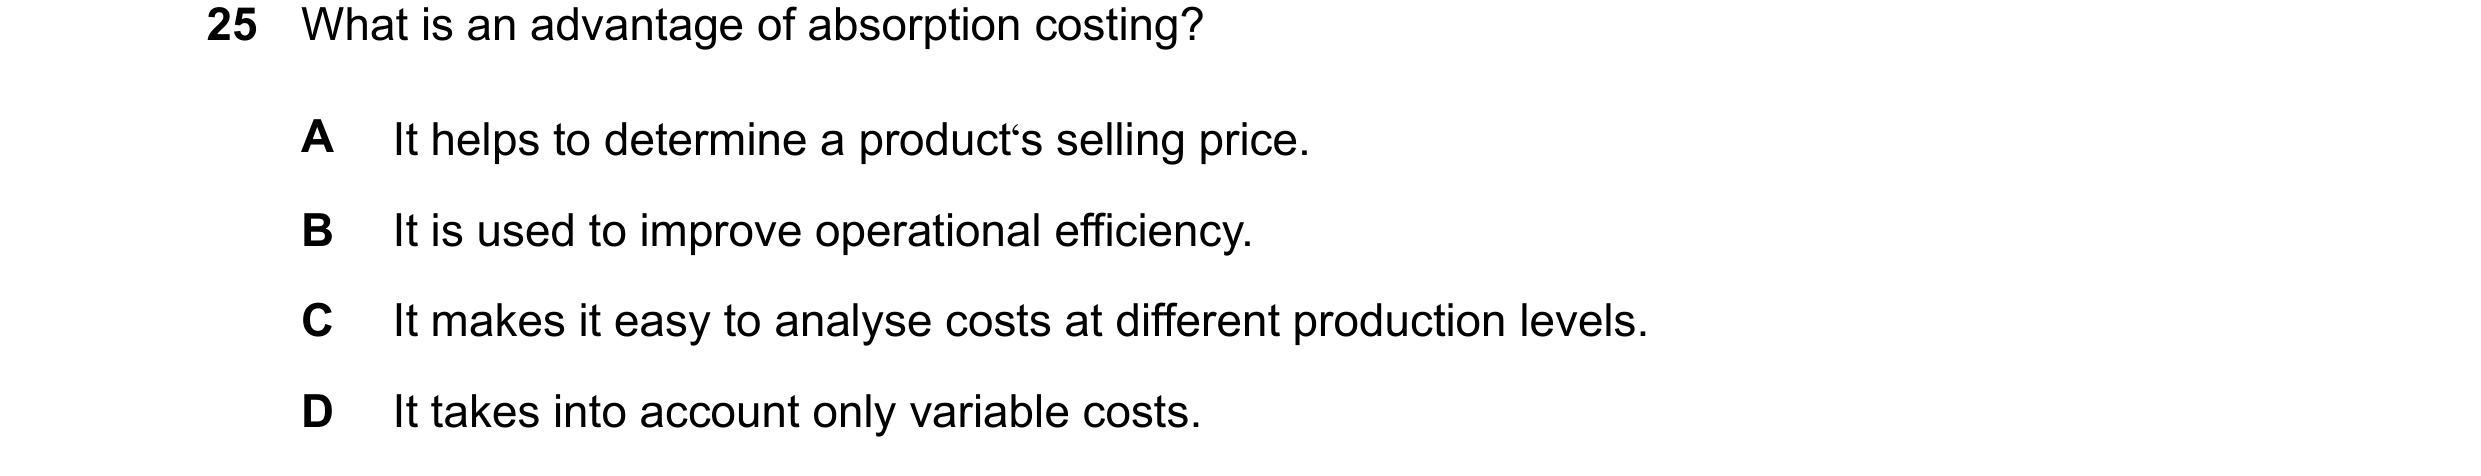
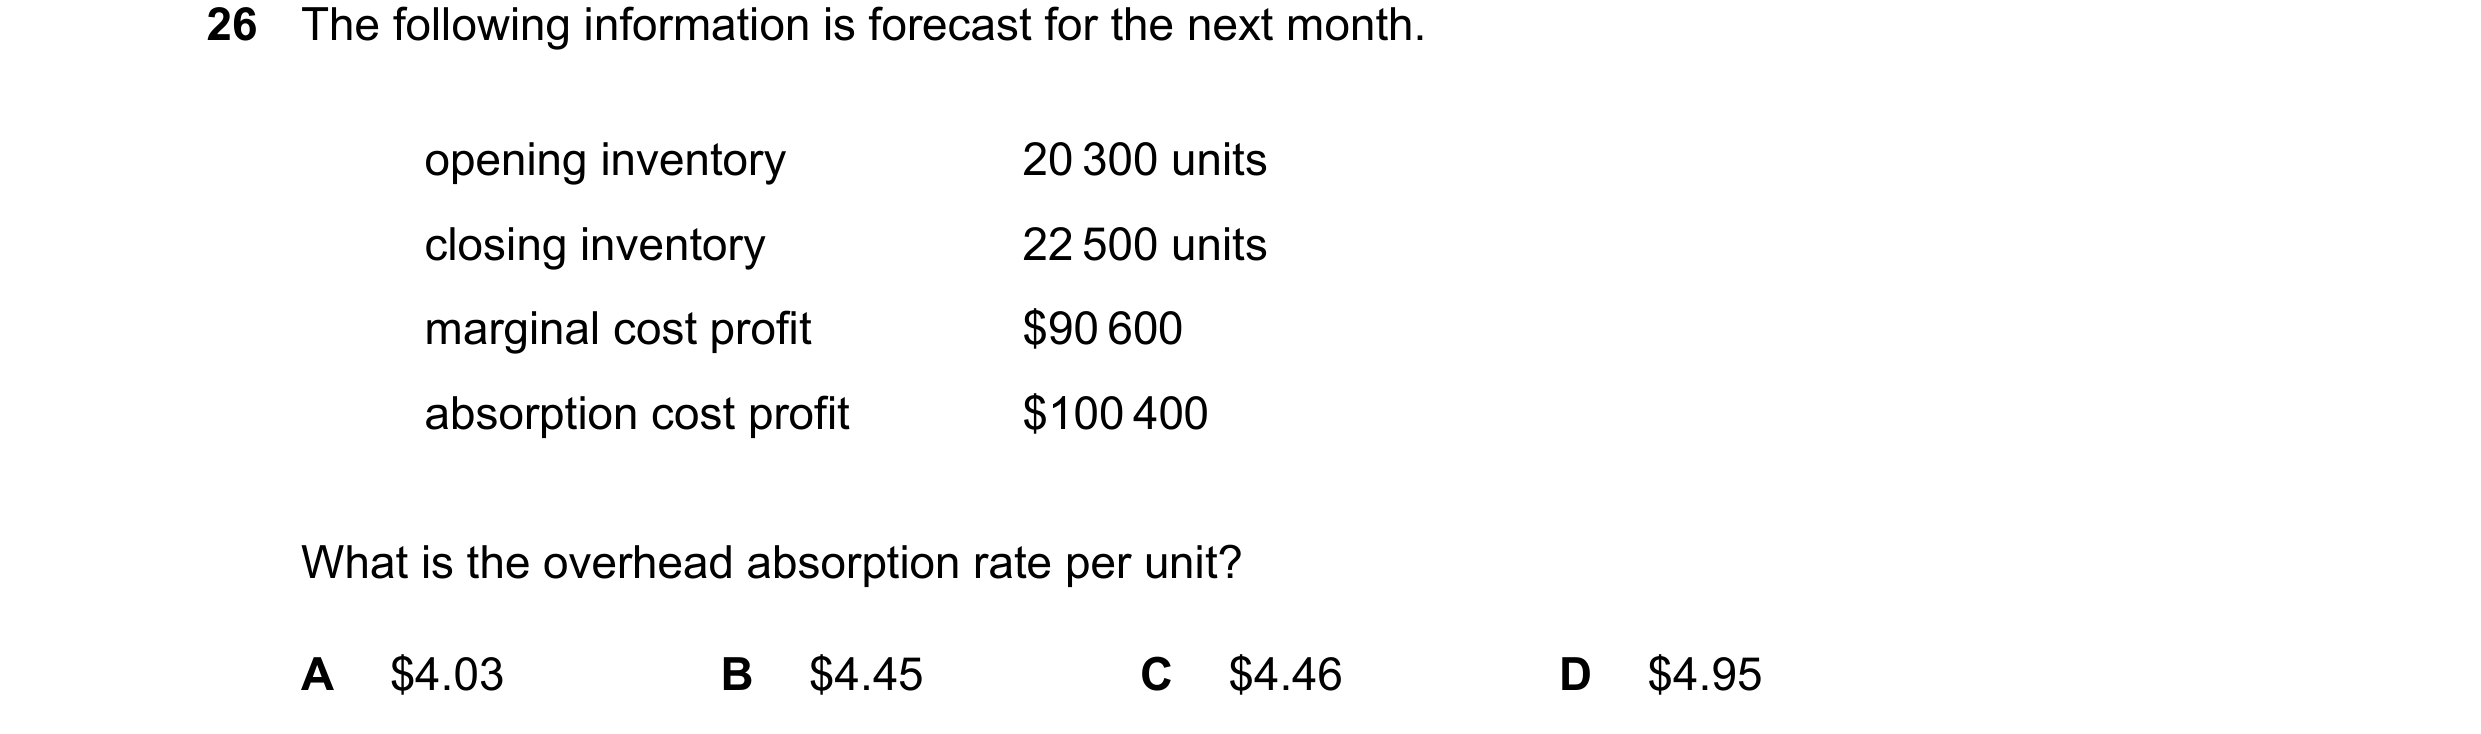
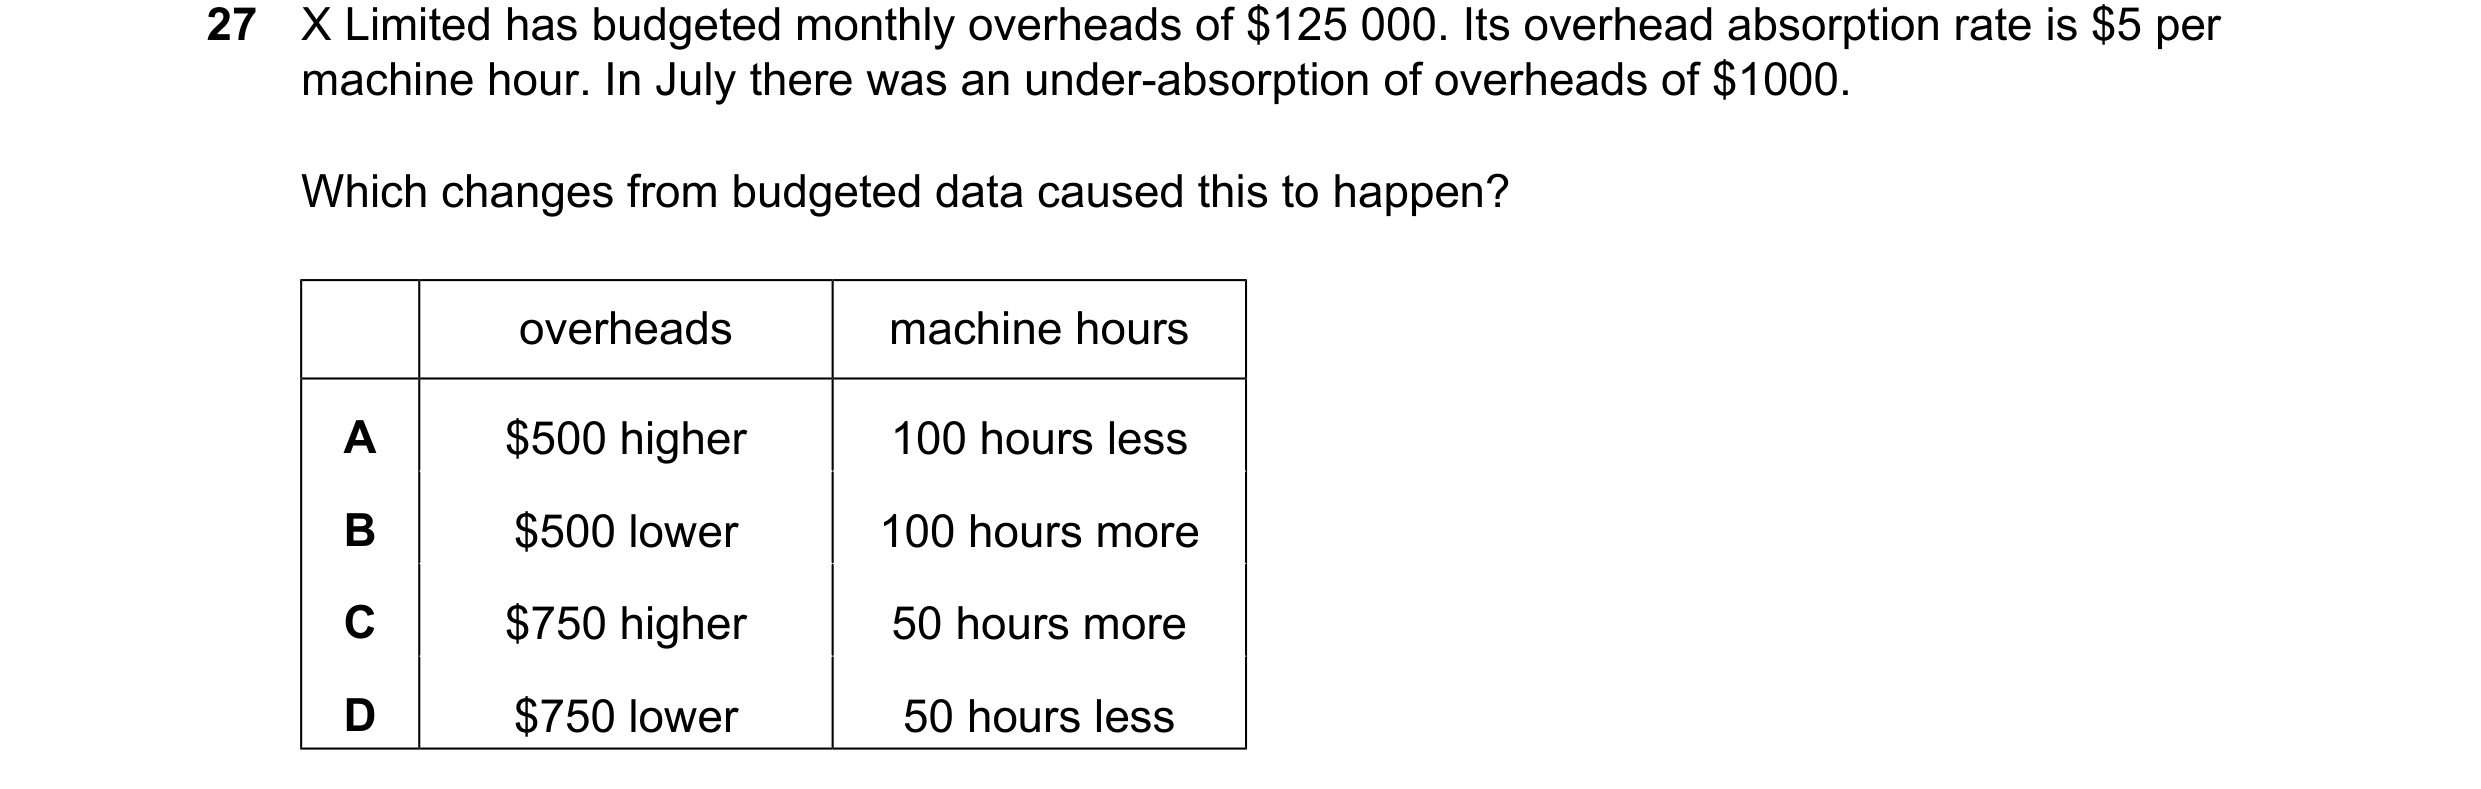 130 / 143
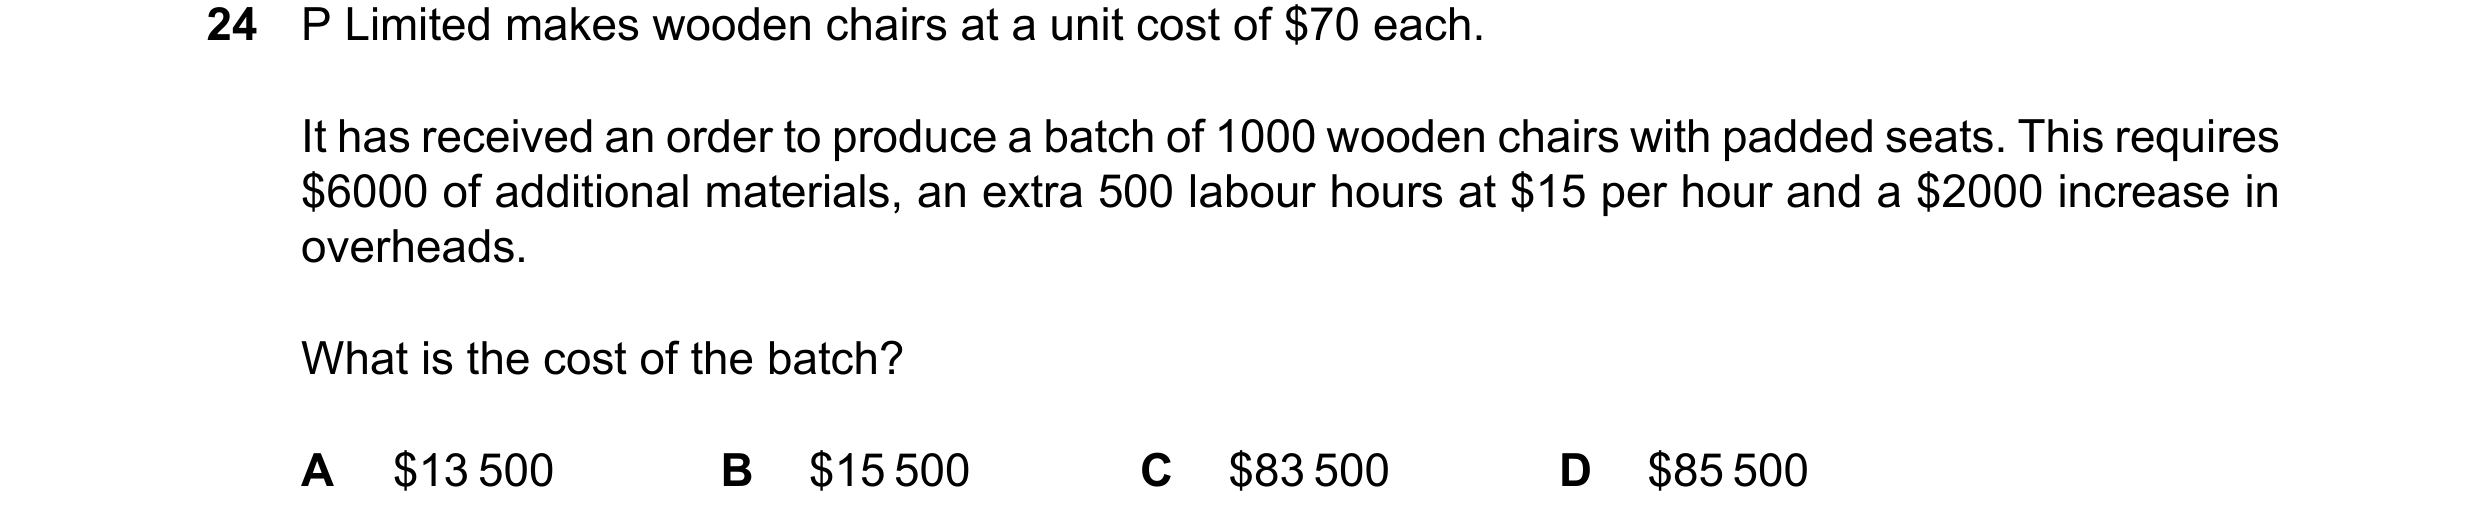
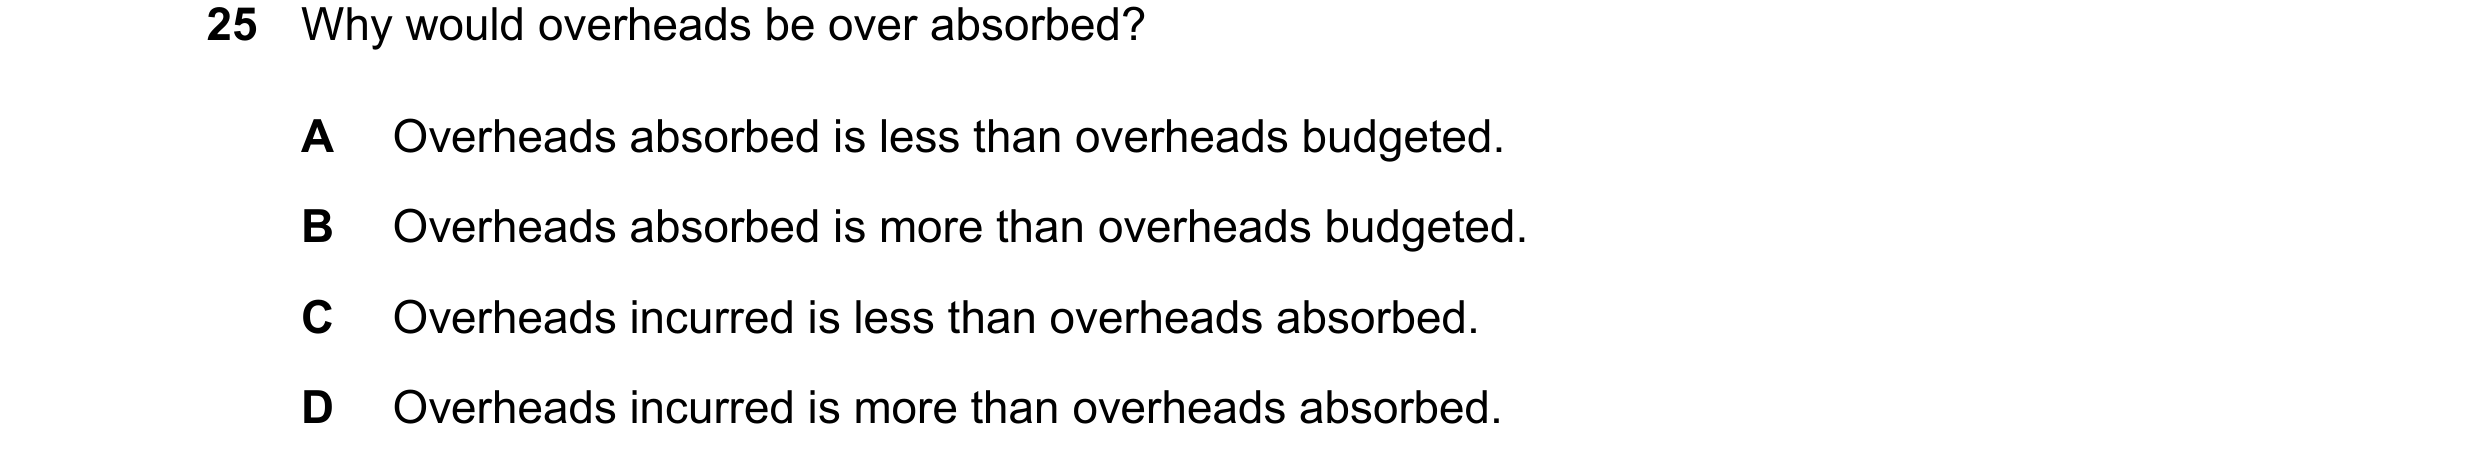
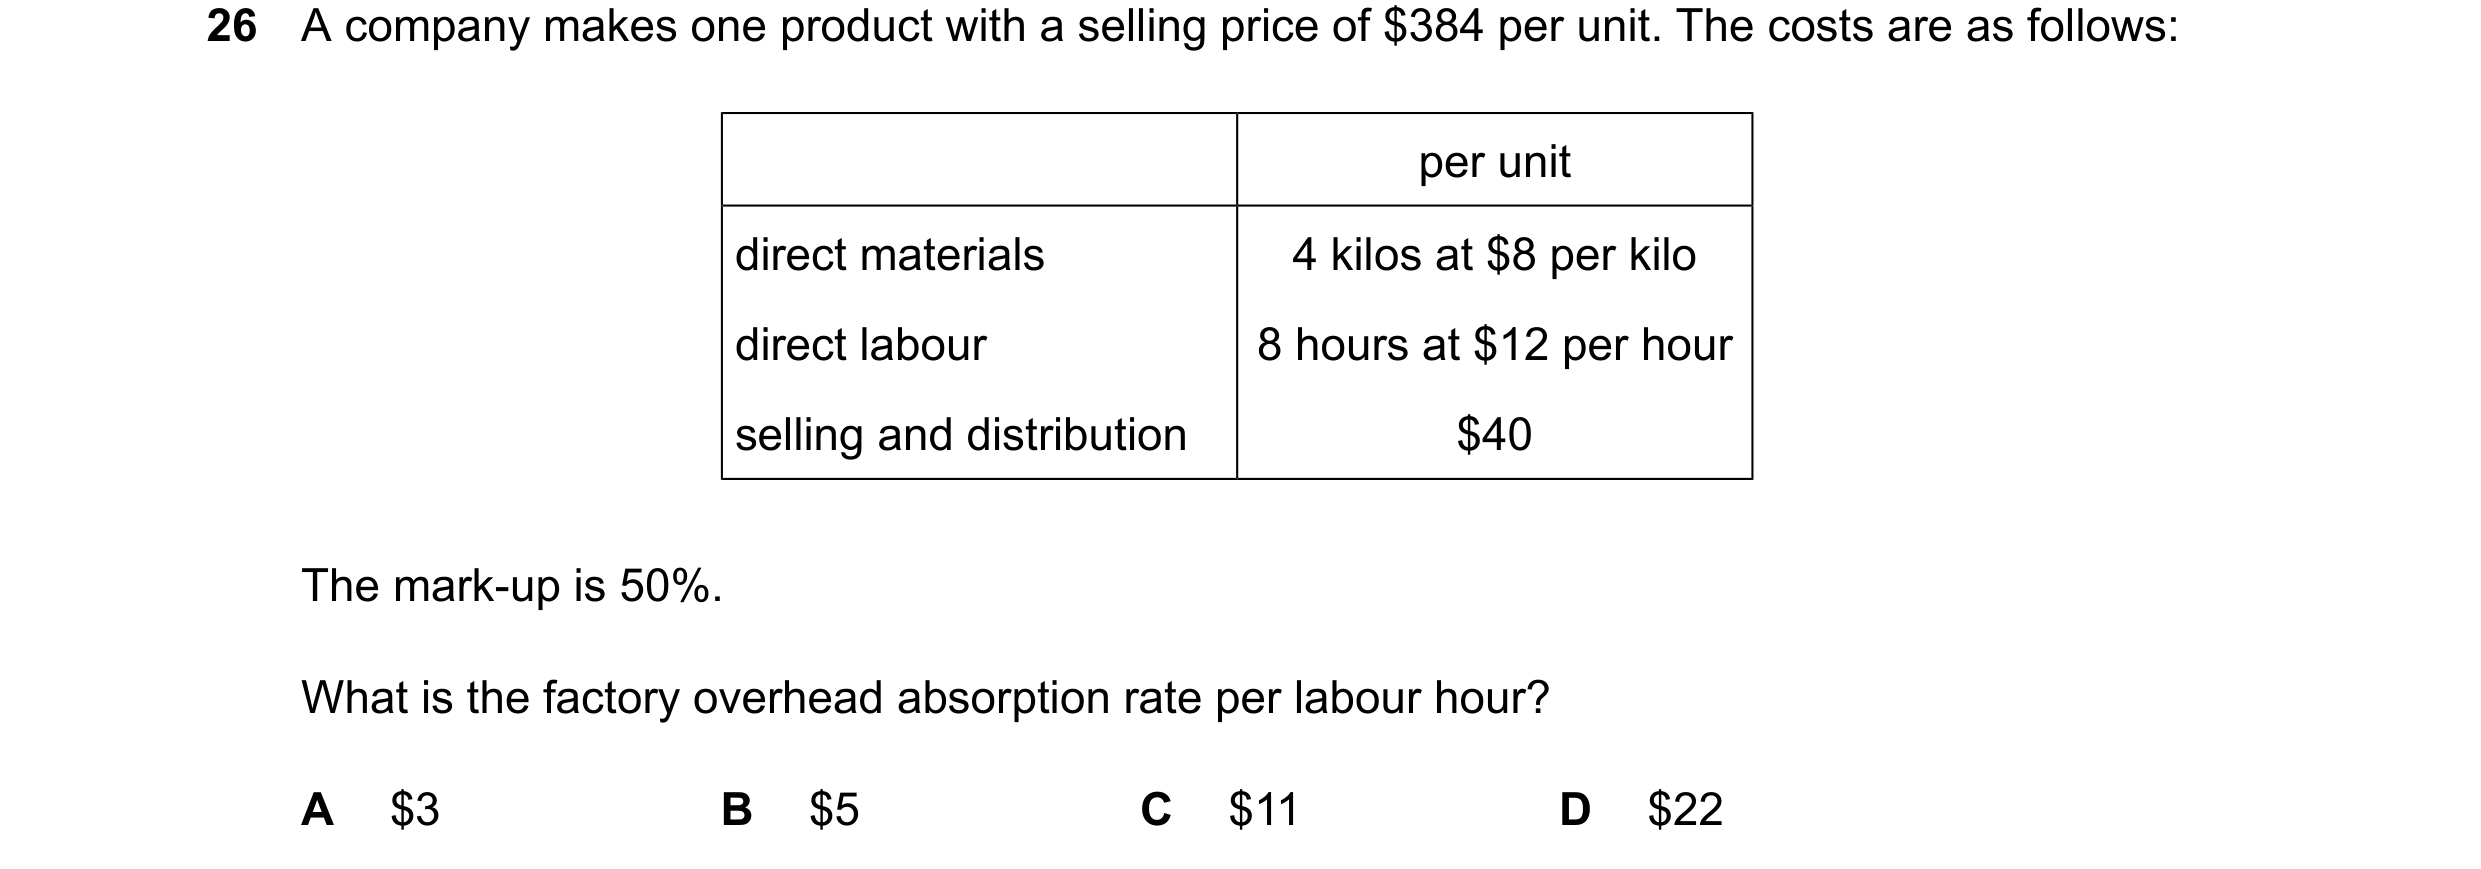
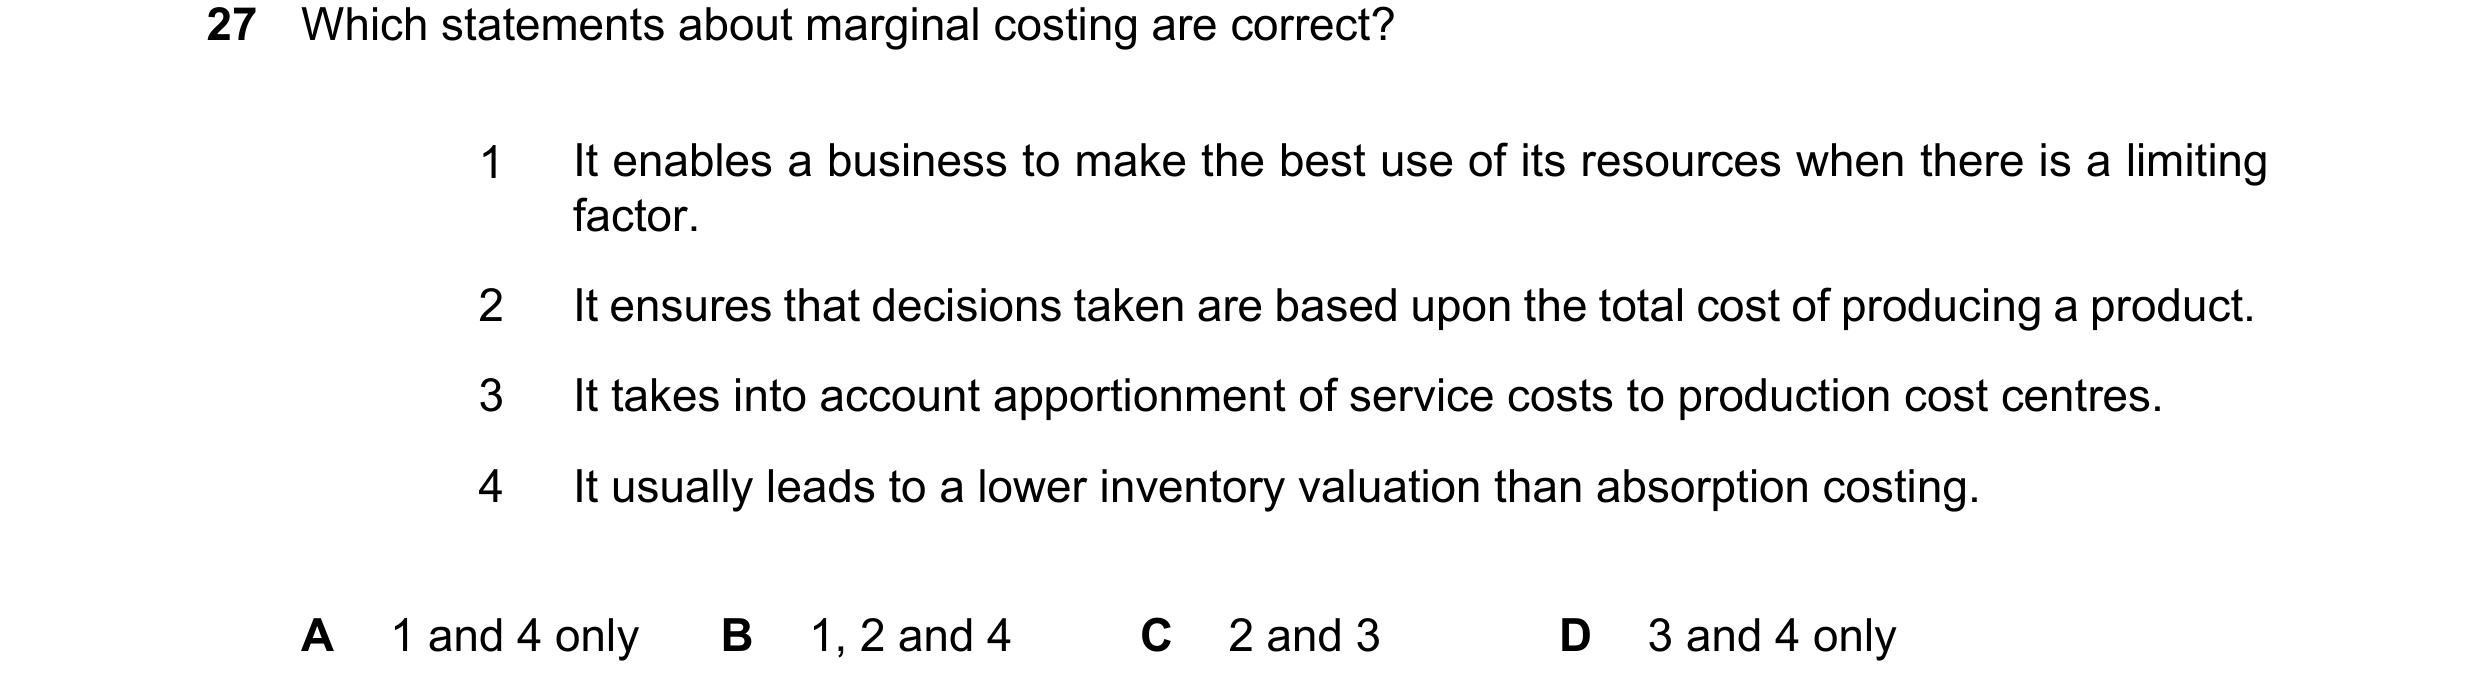 131 / 143
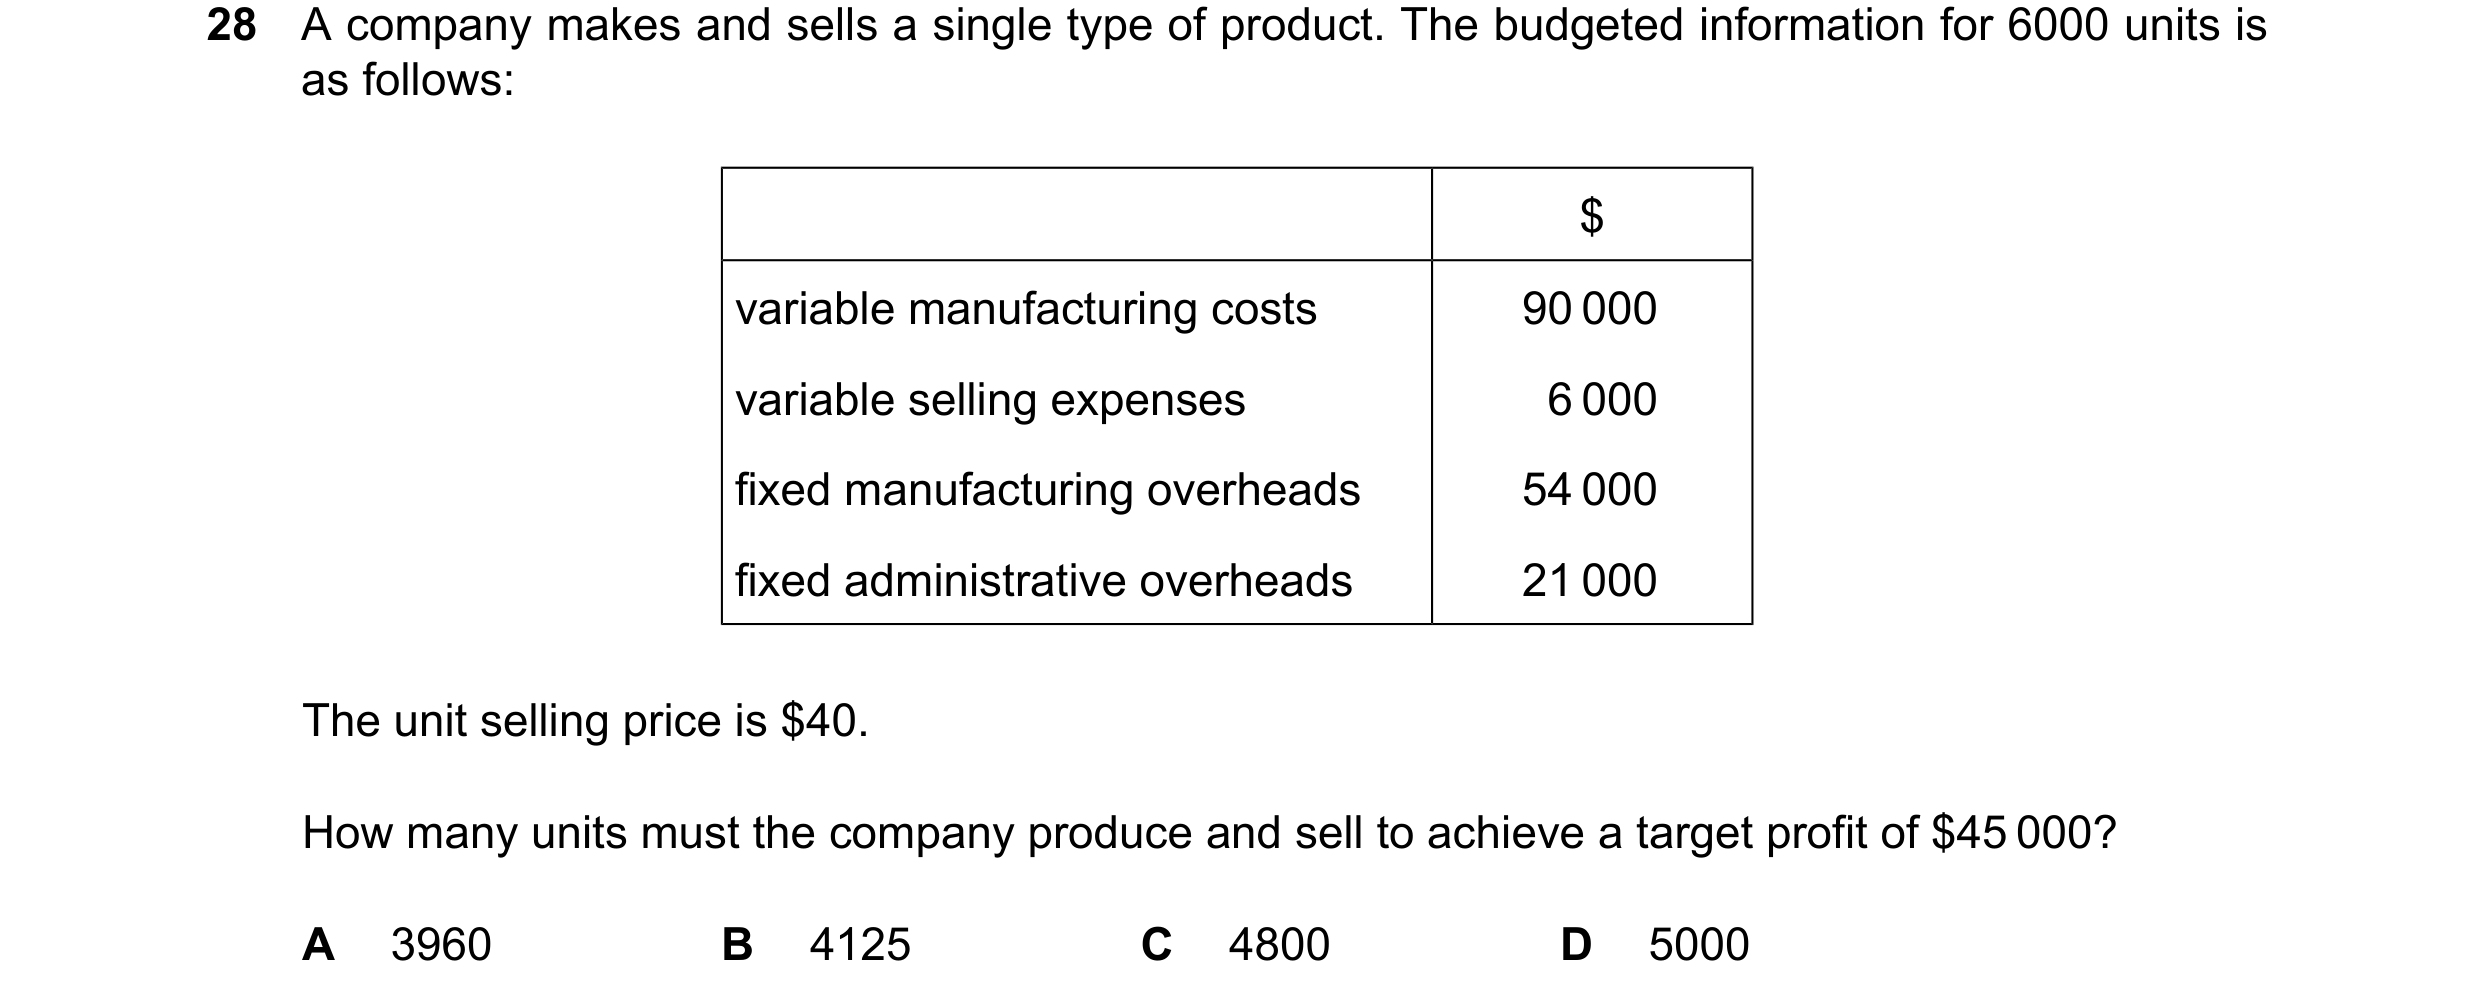
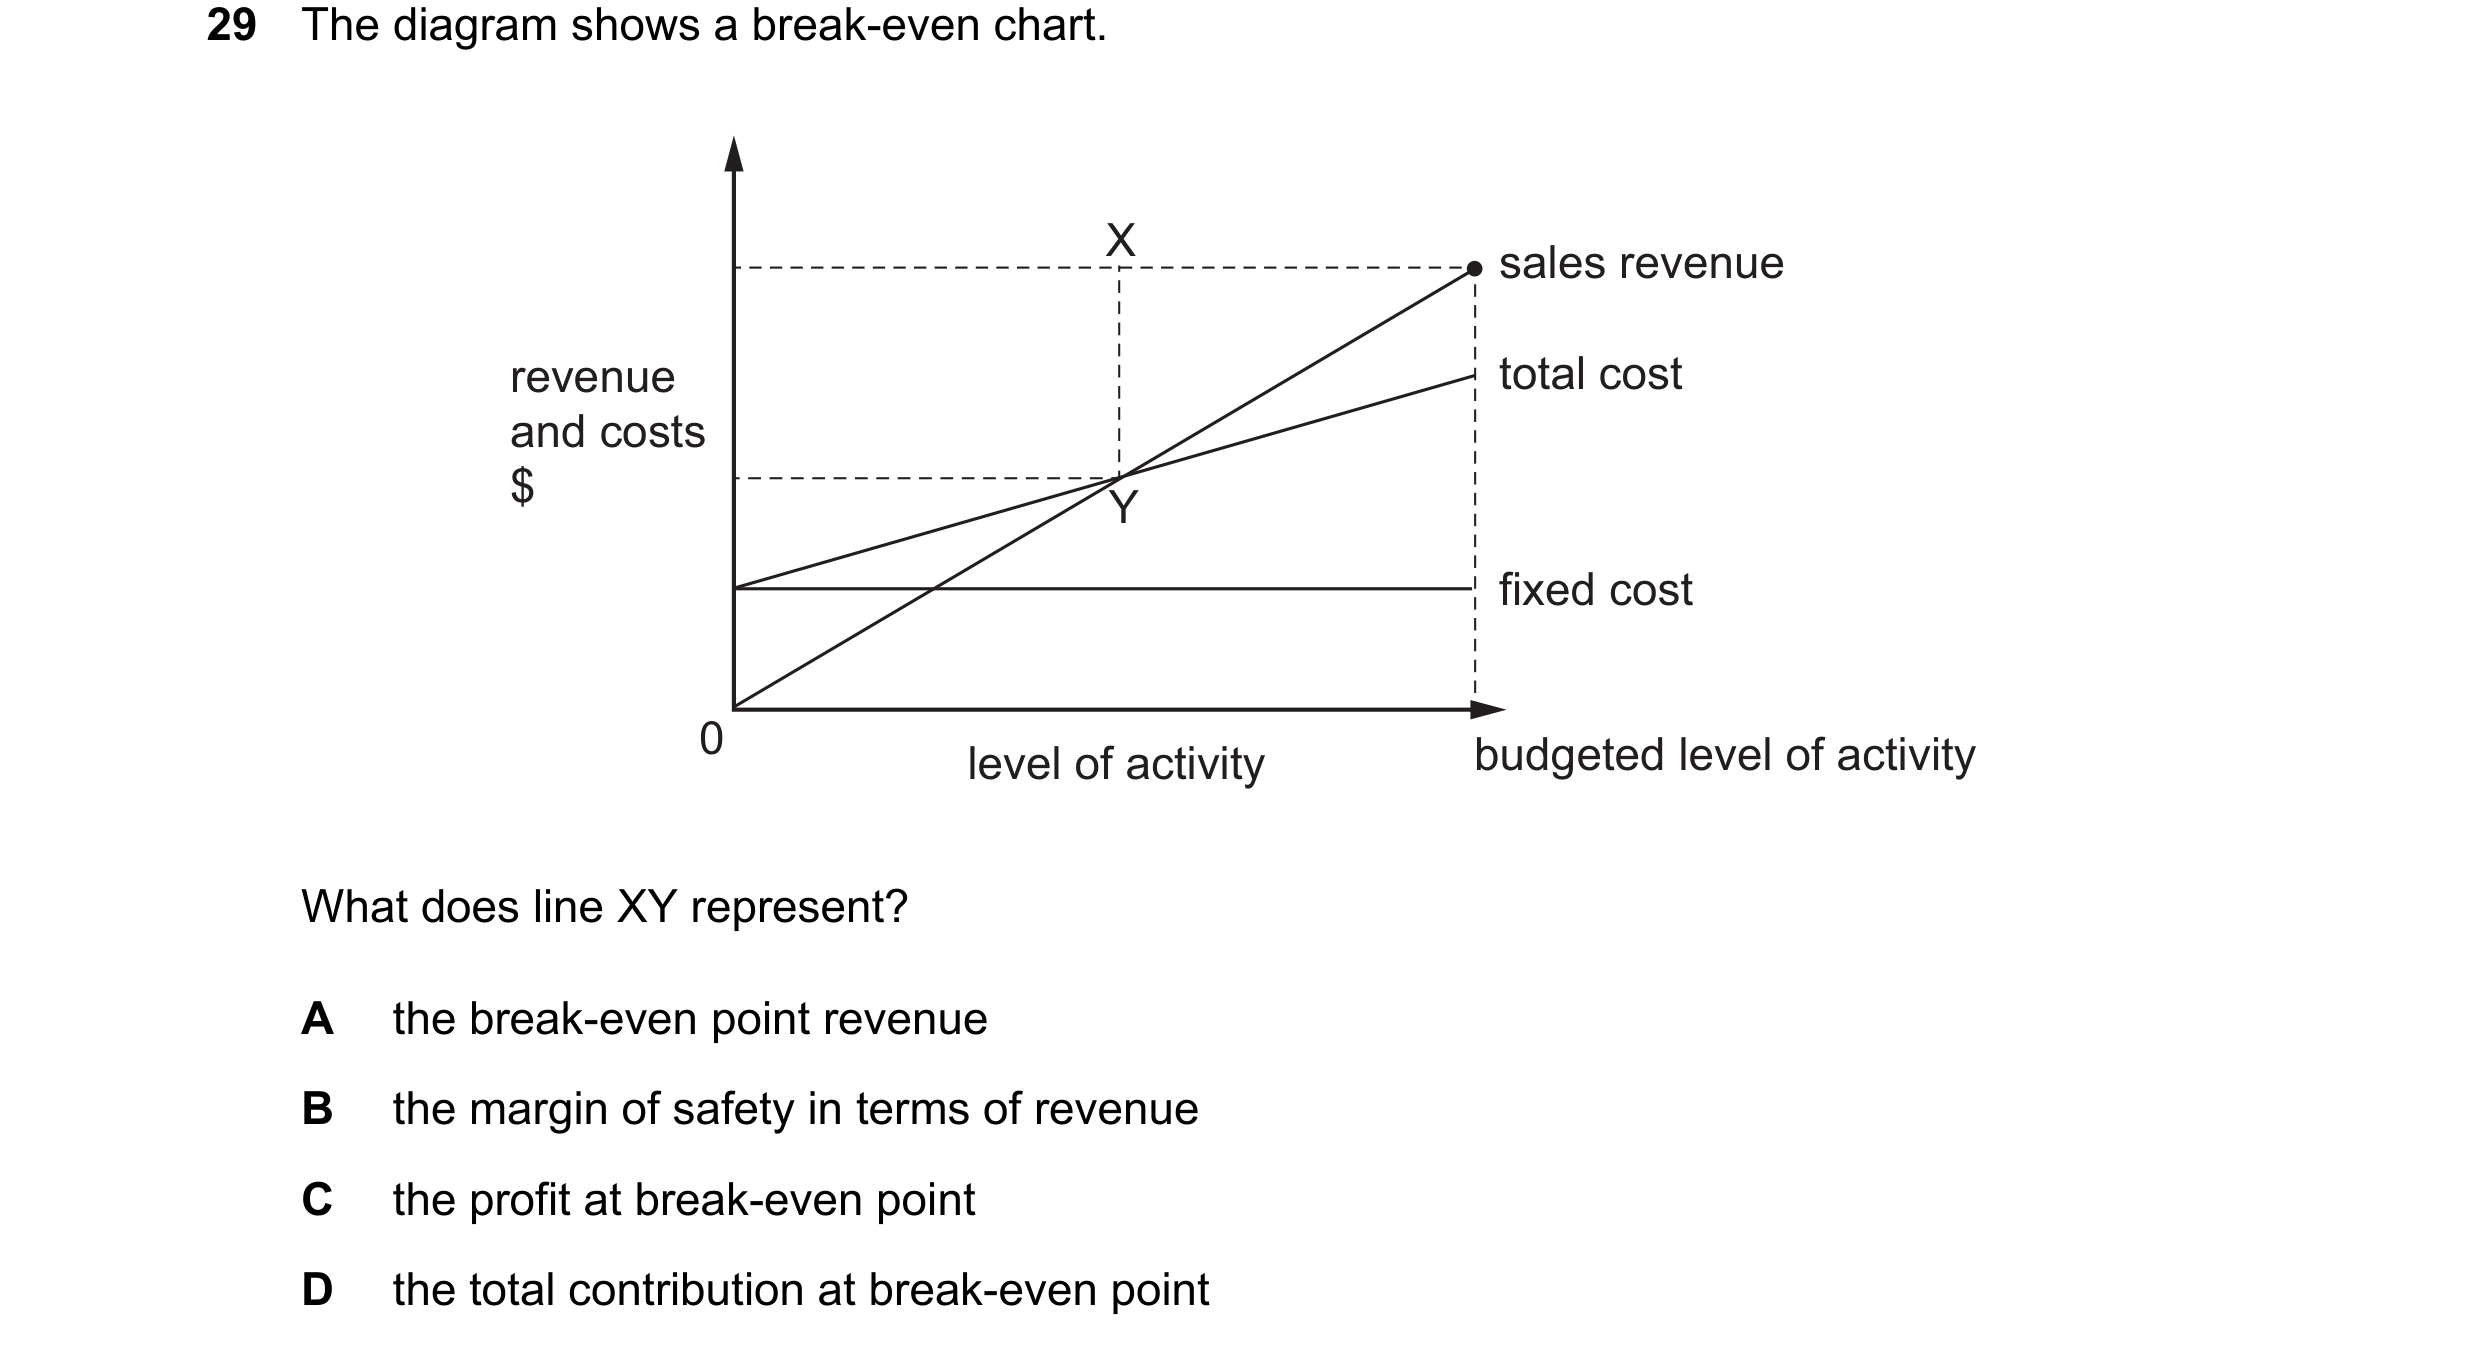
 132 / 143
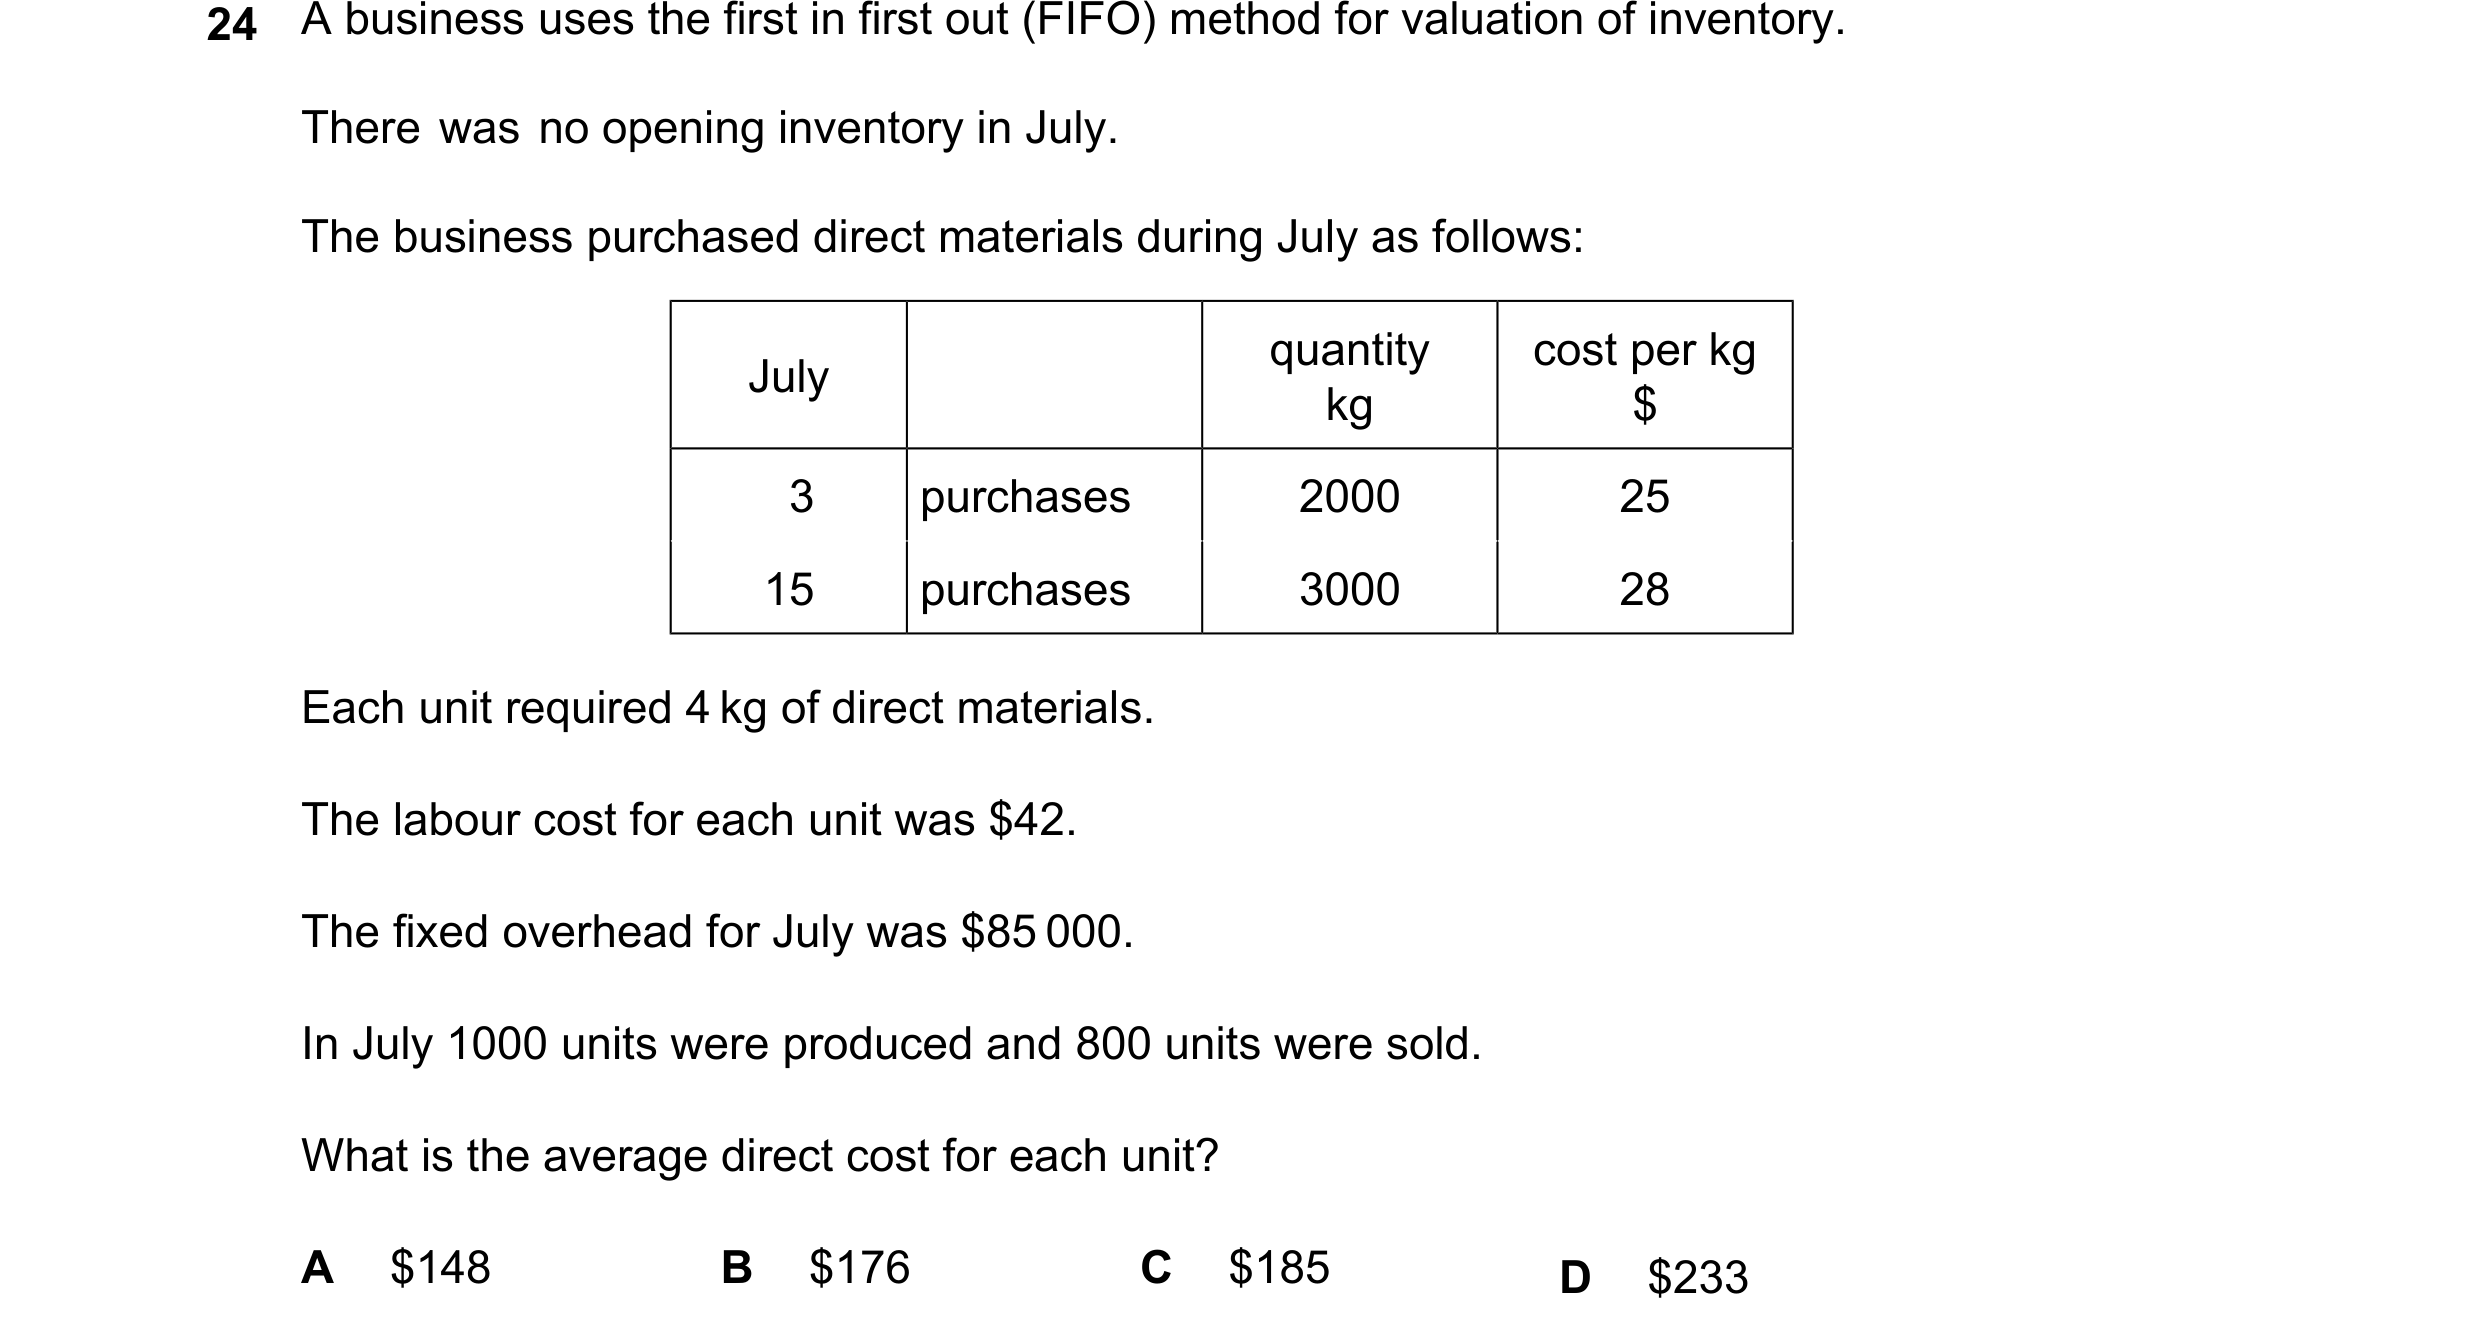
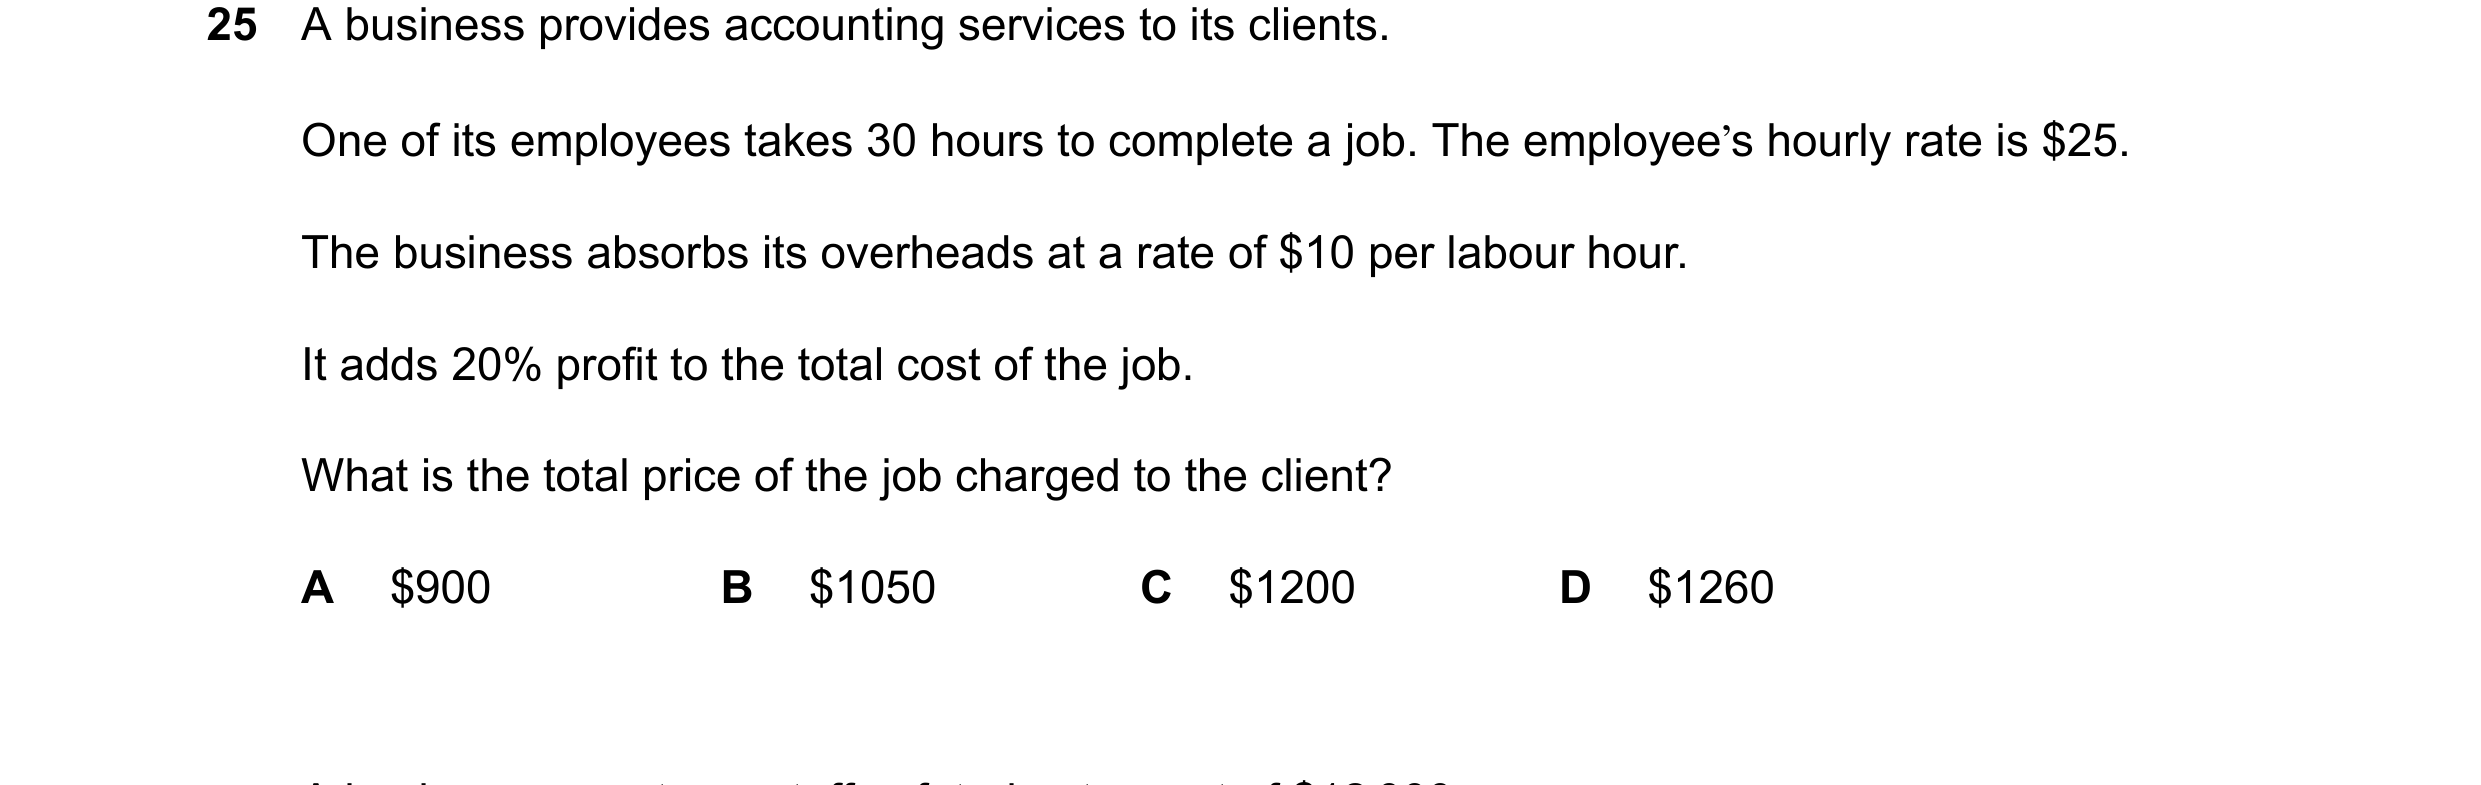
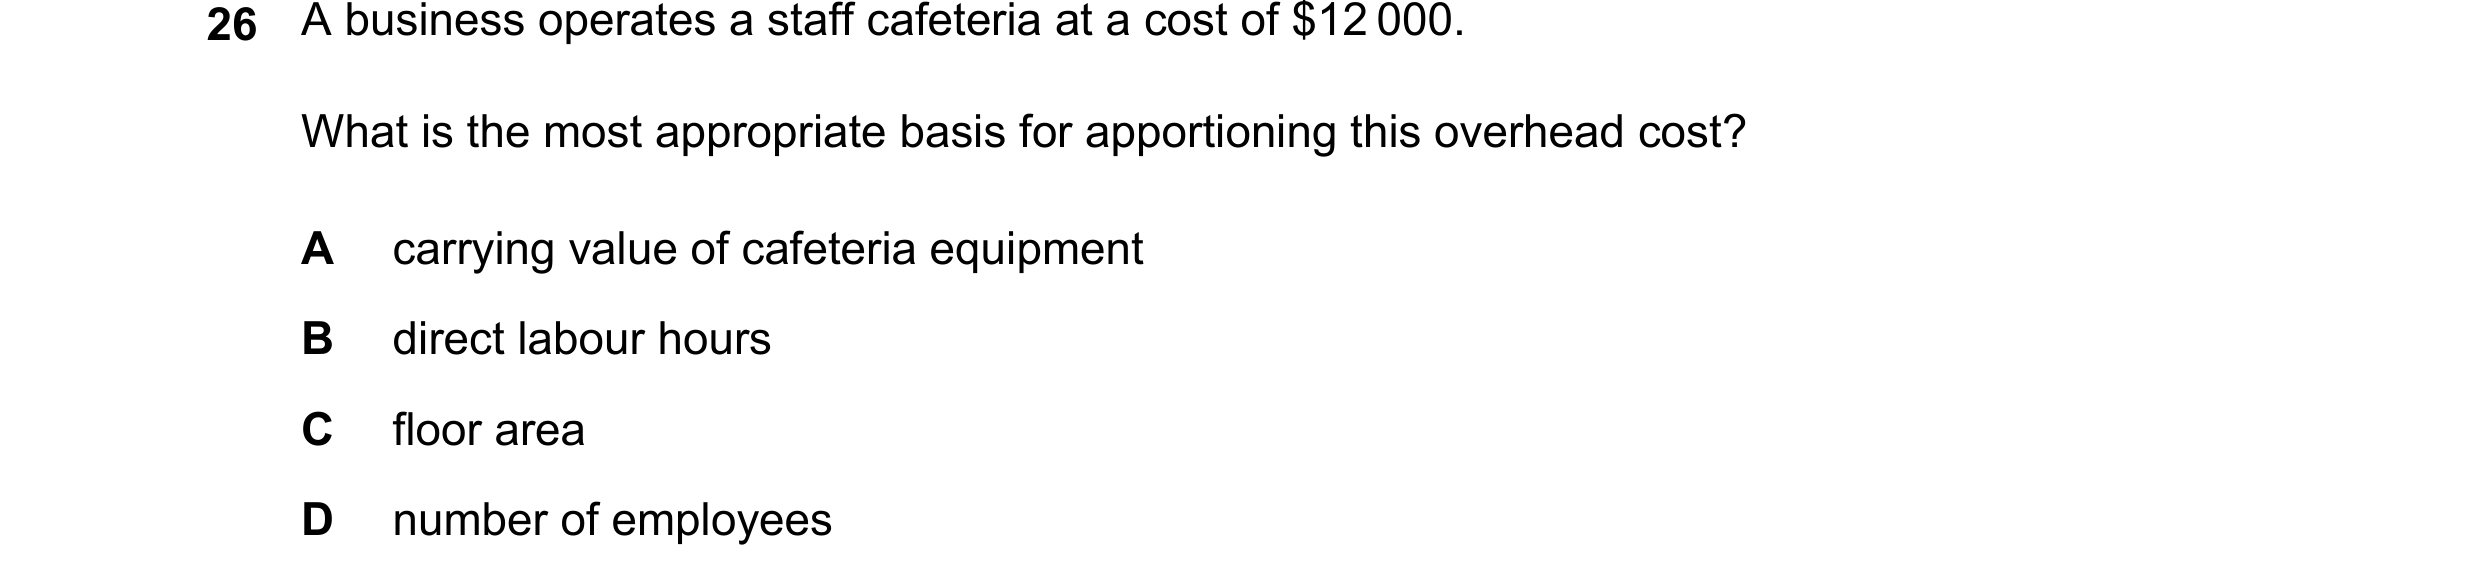 133 / 143
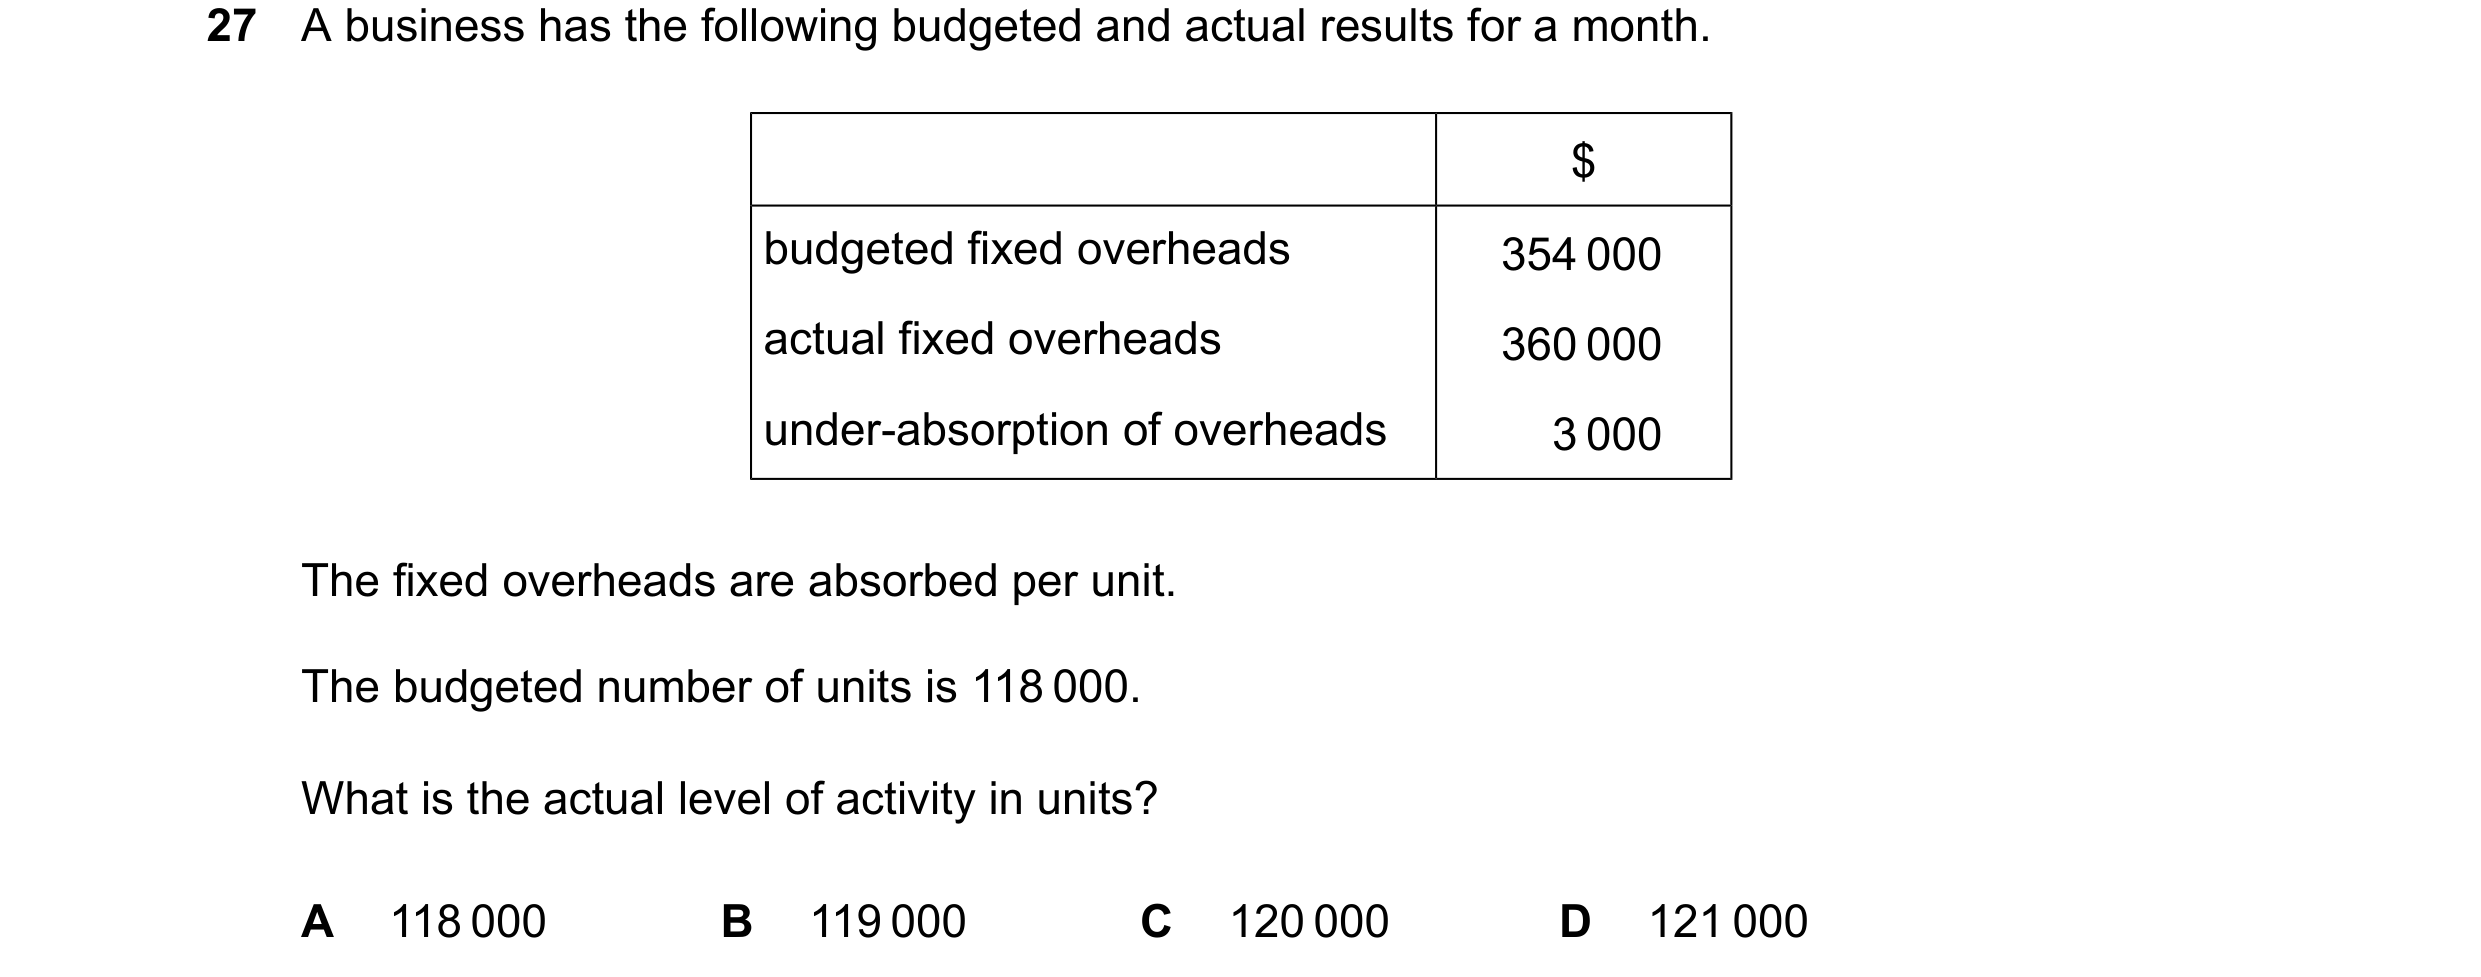
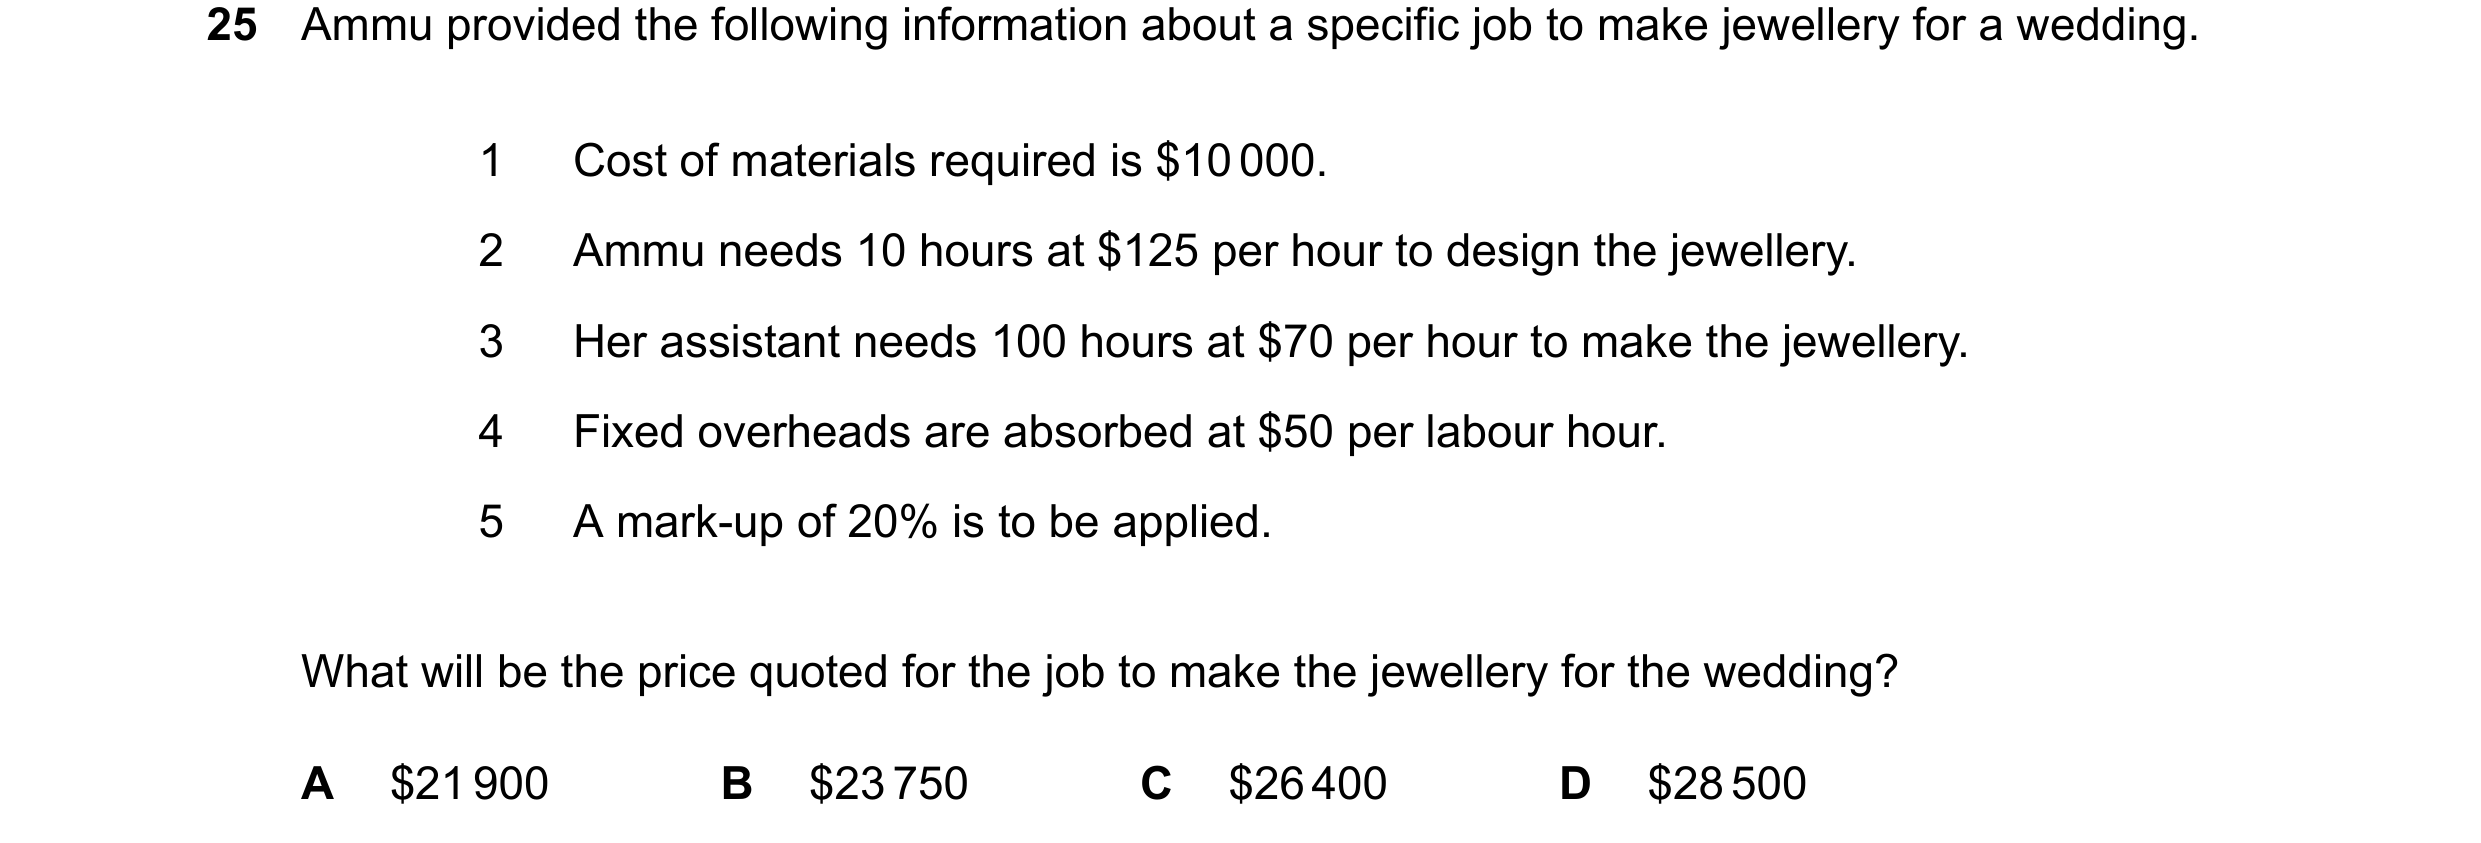
 134 / 143
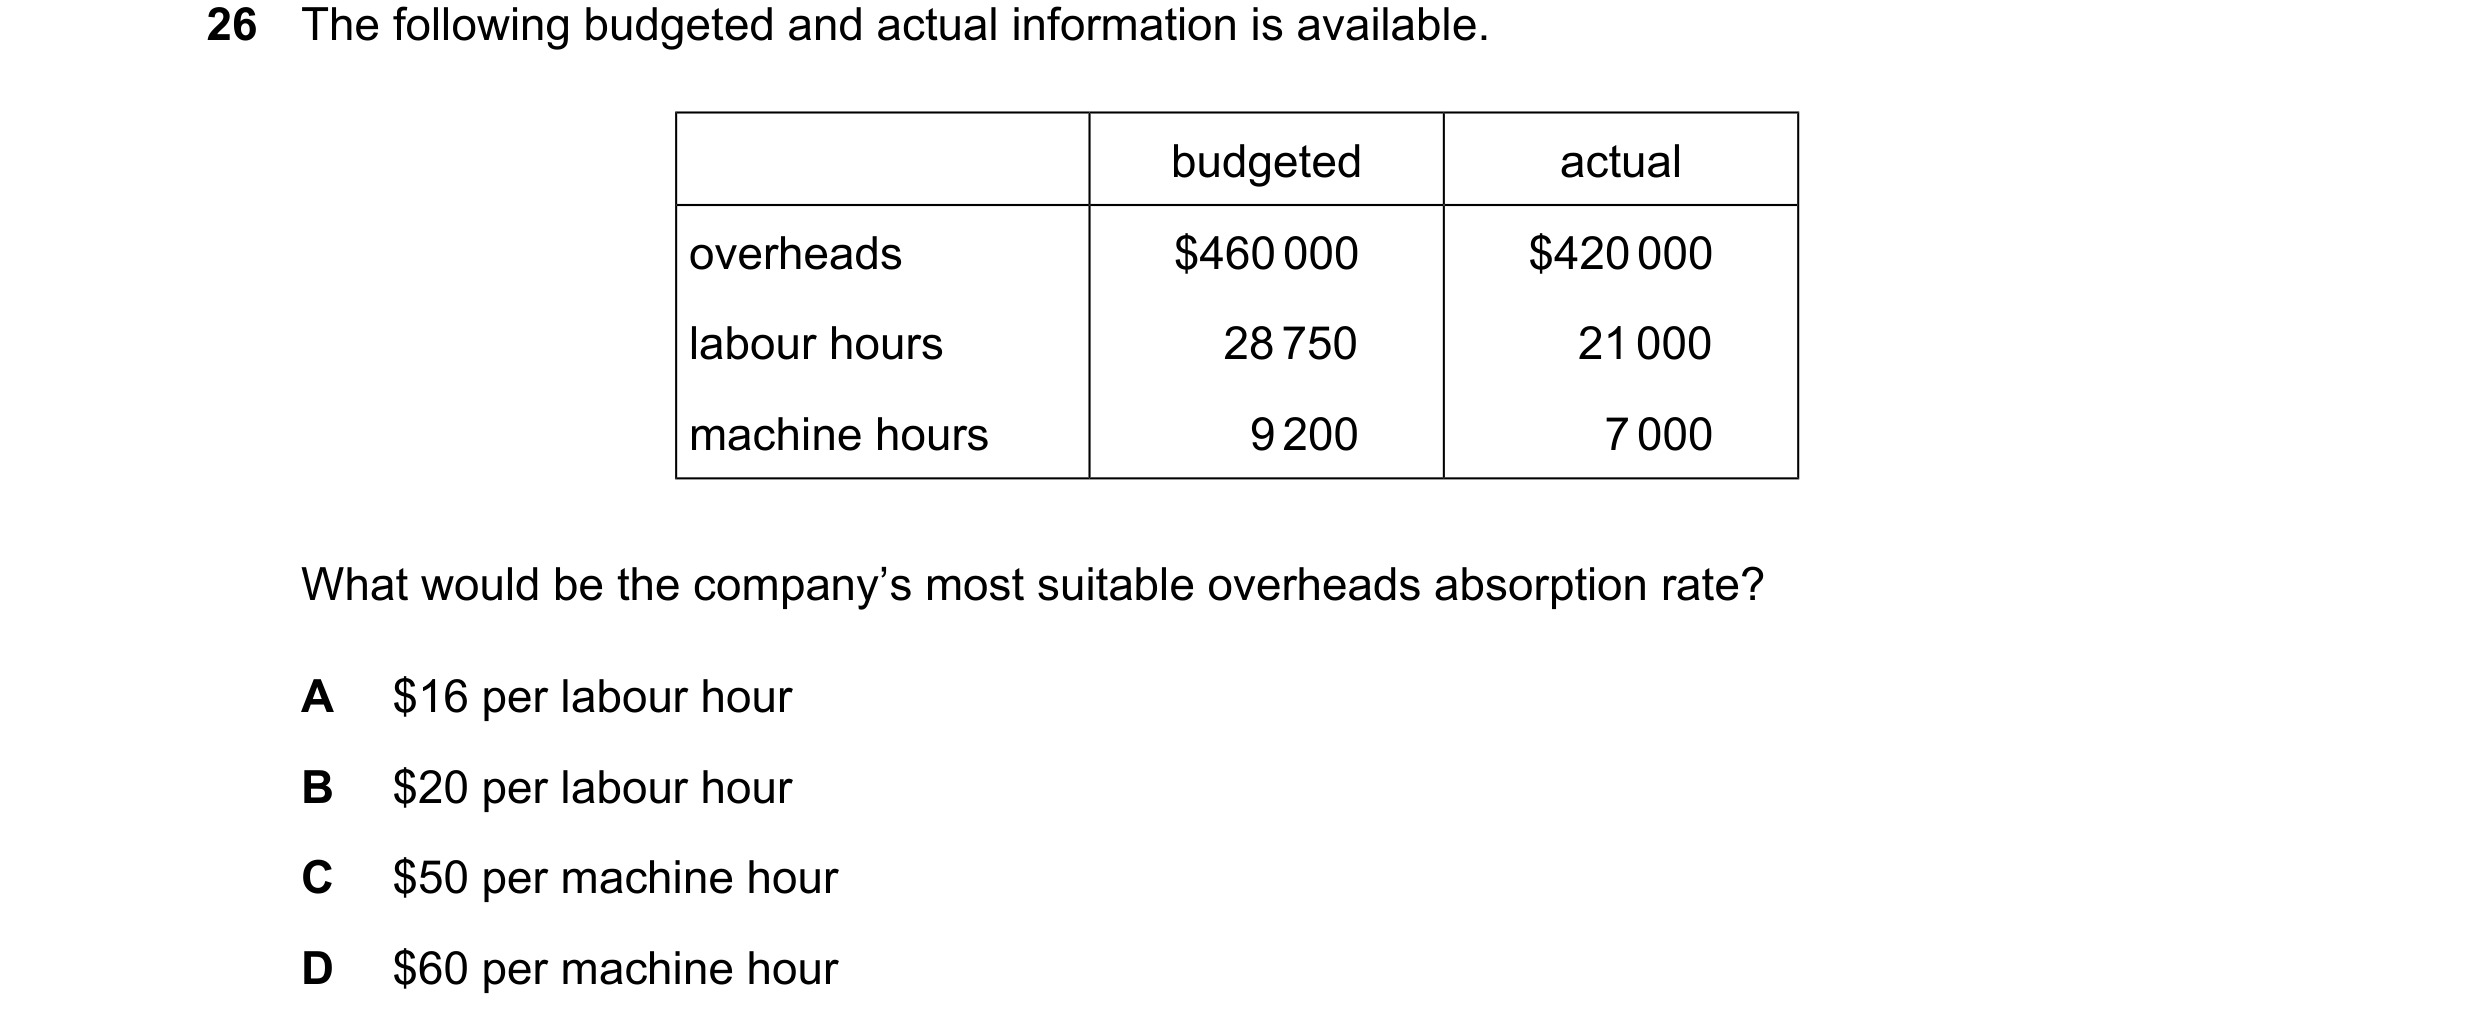 135 / 143
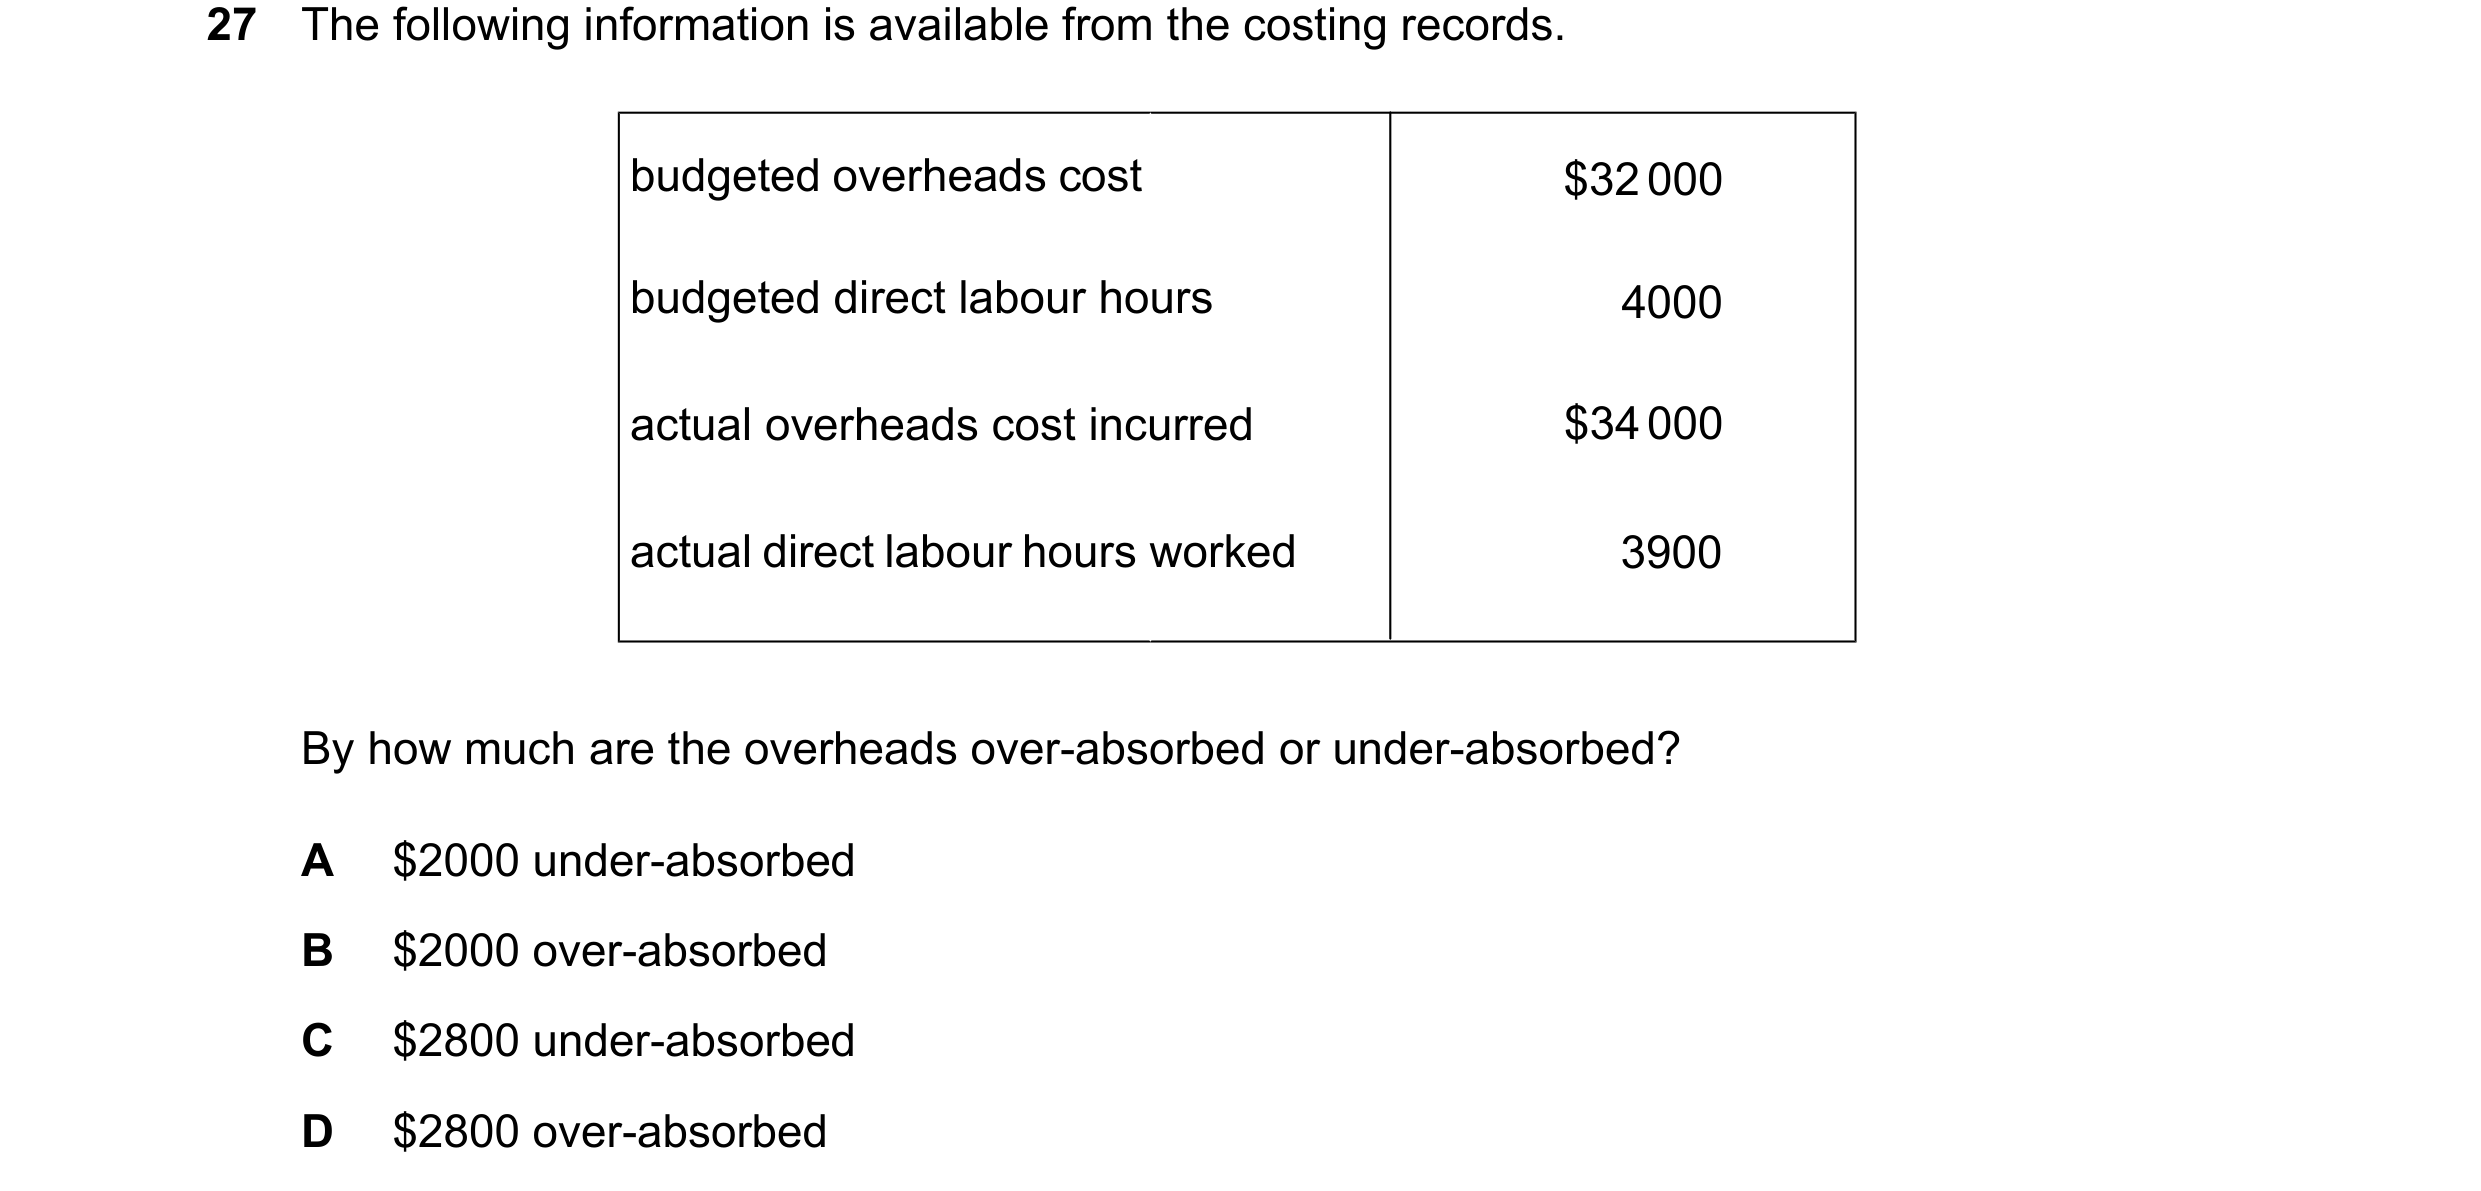
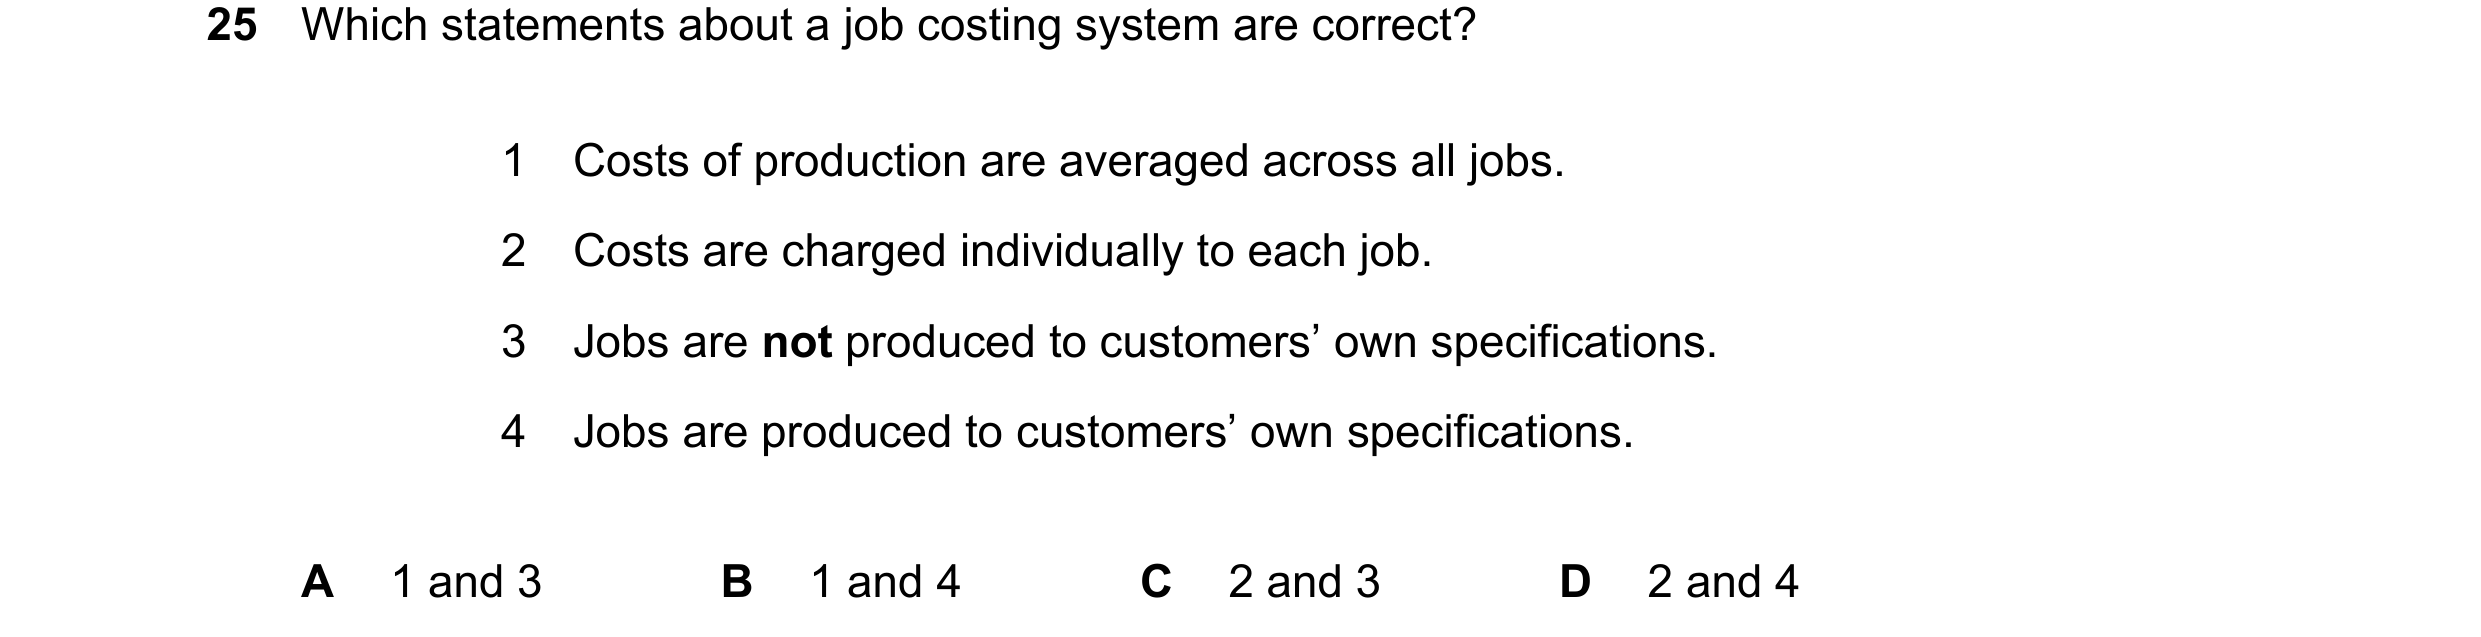
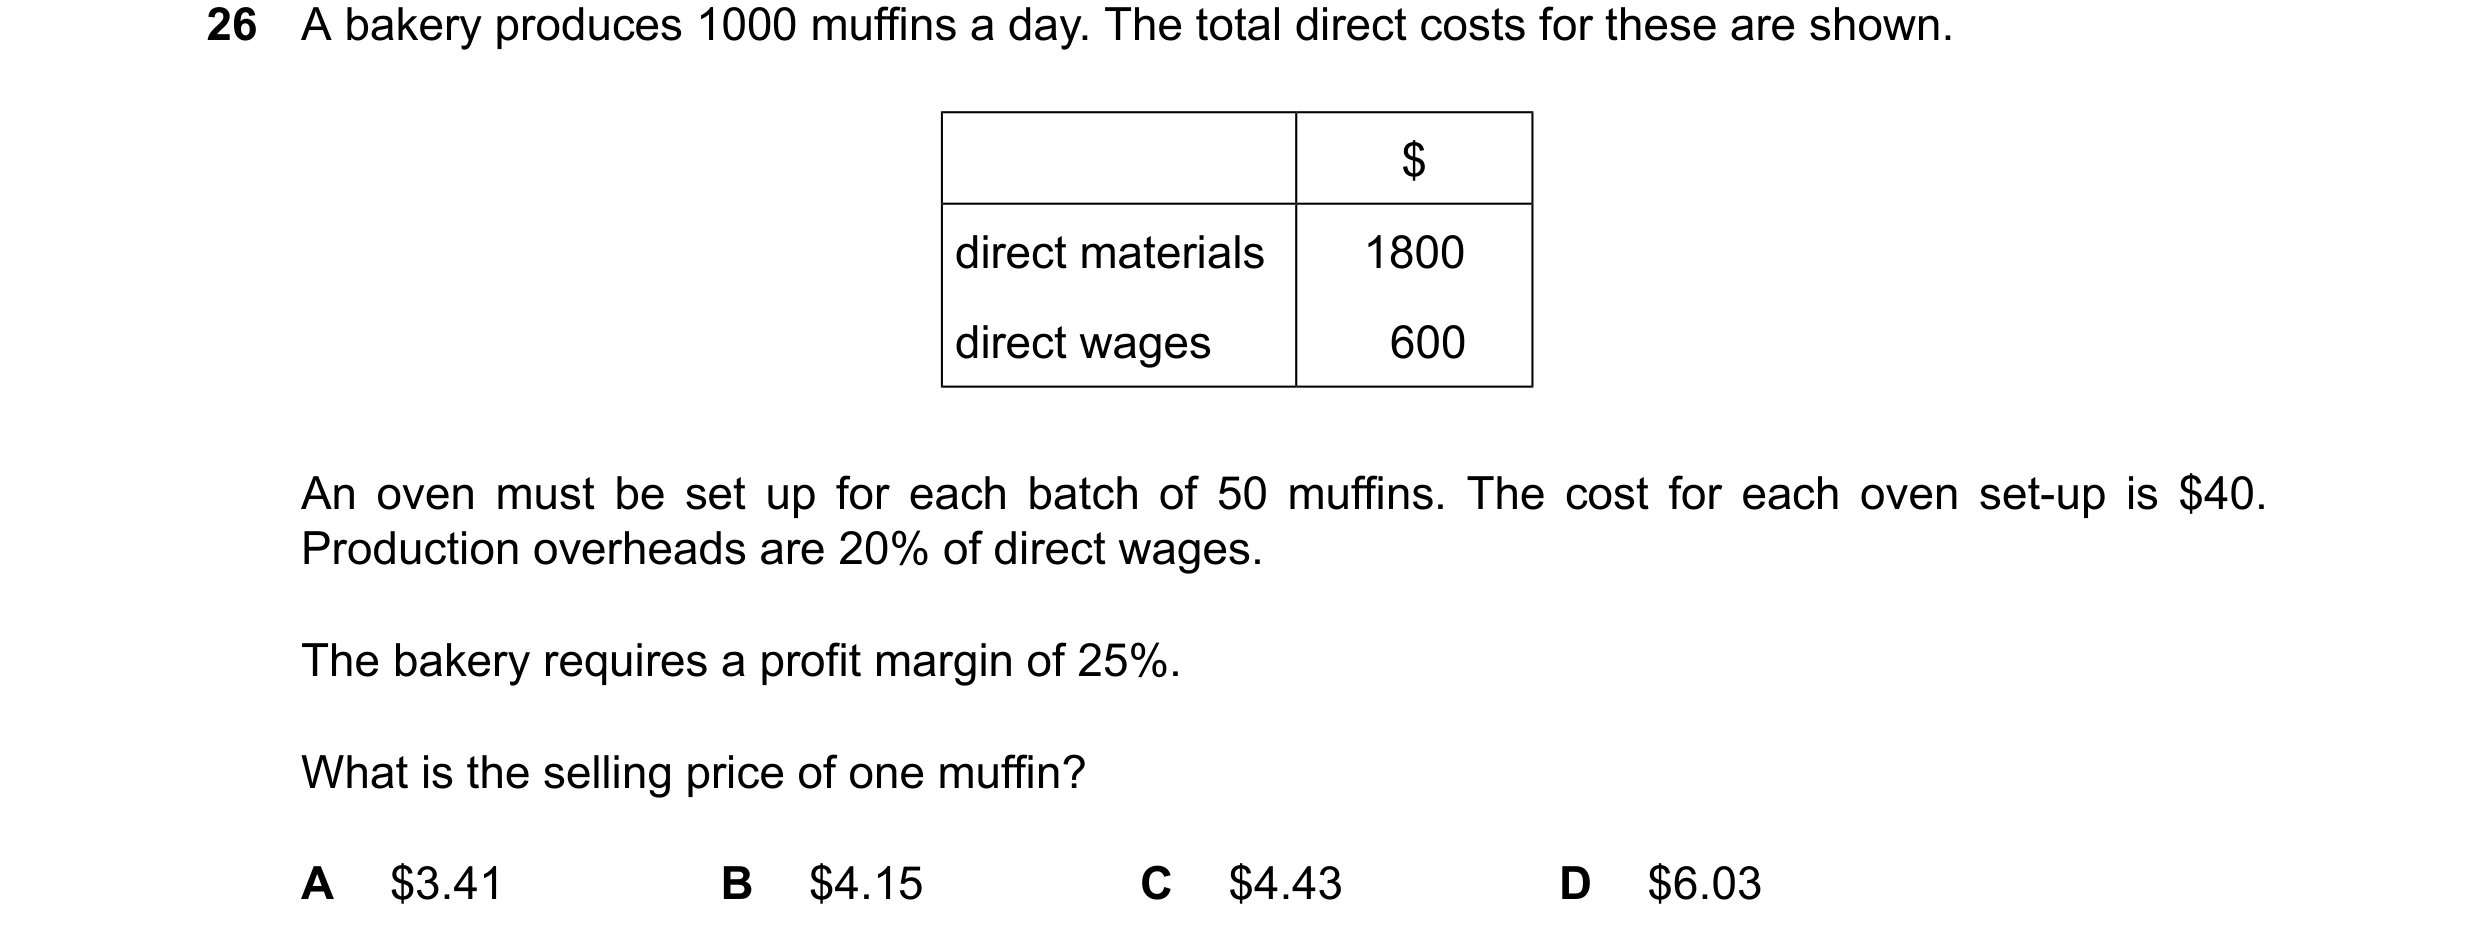 136 / 143
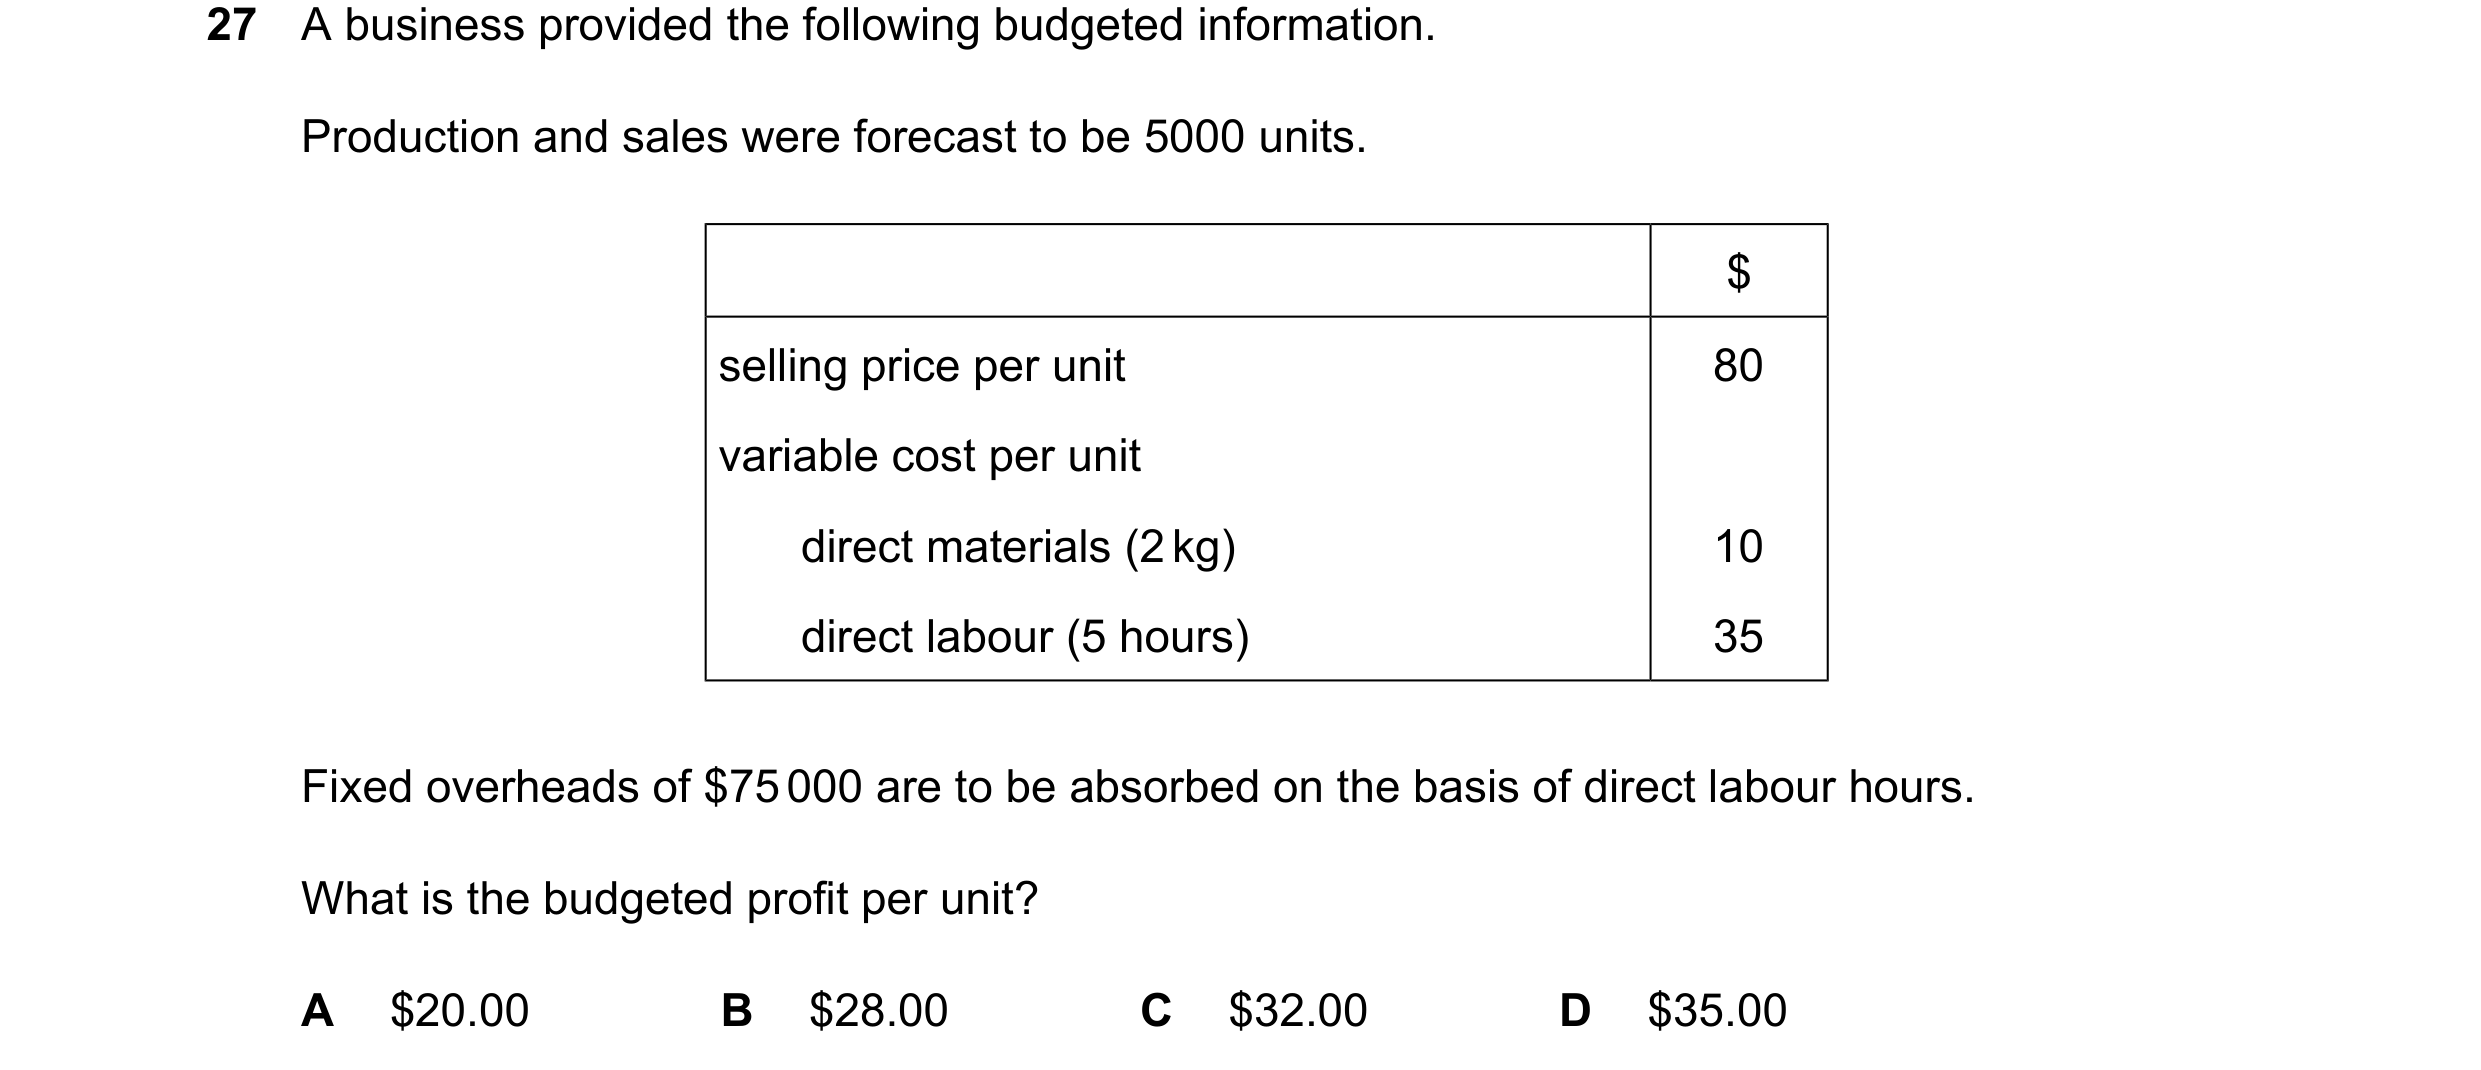
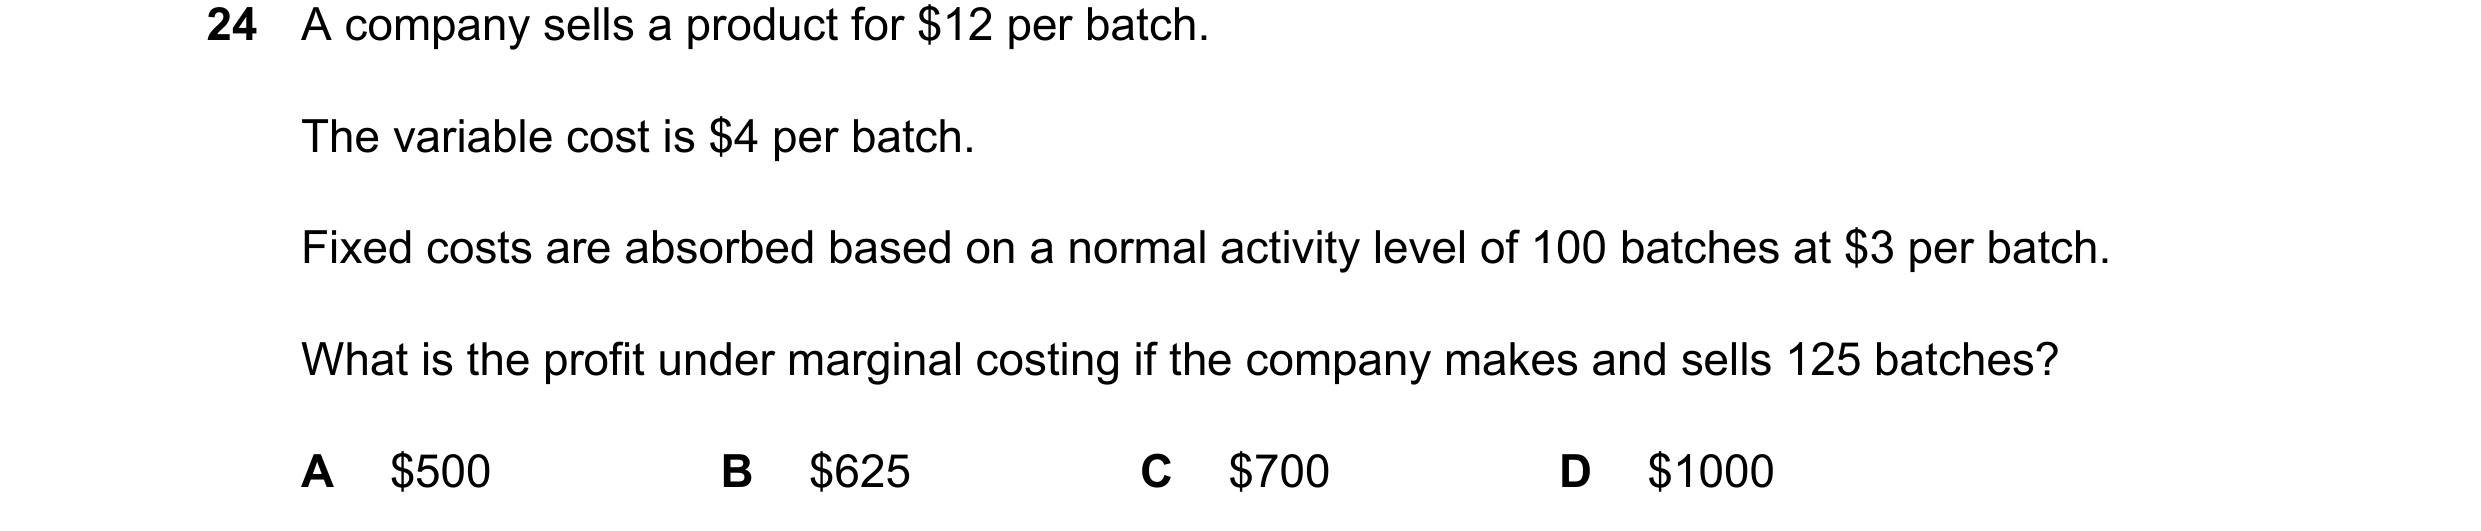
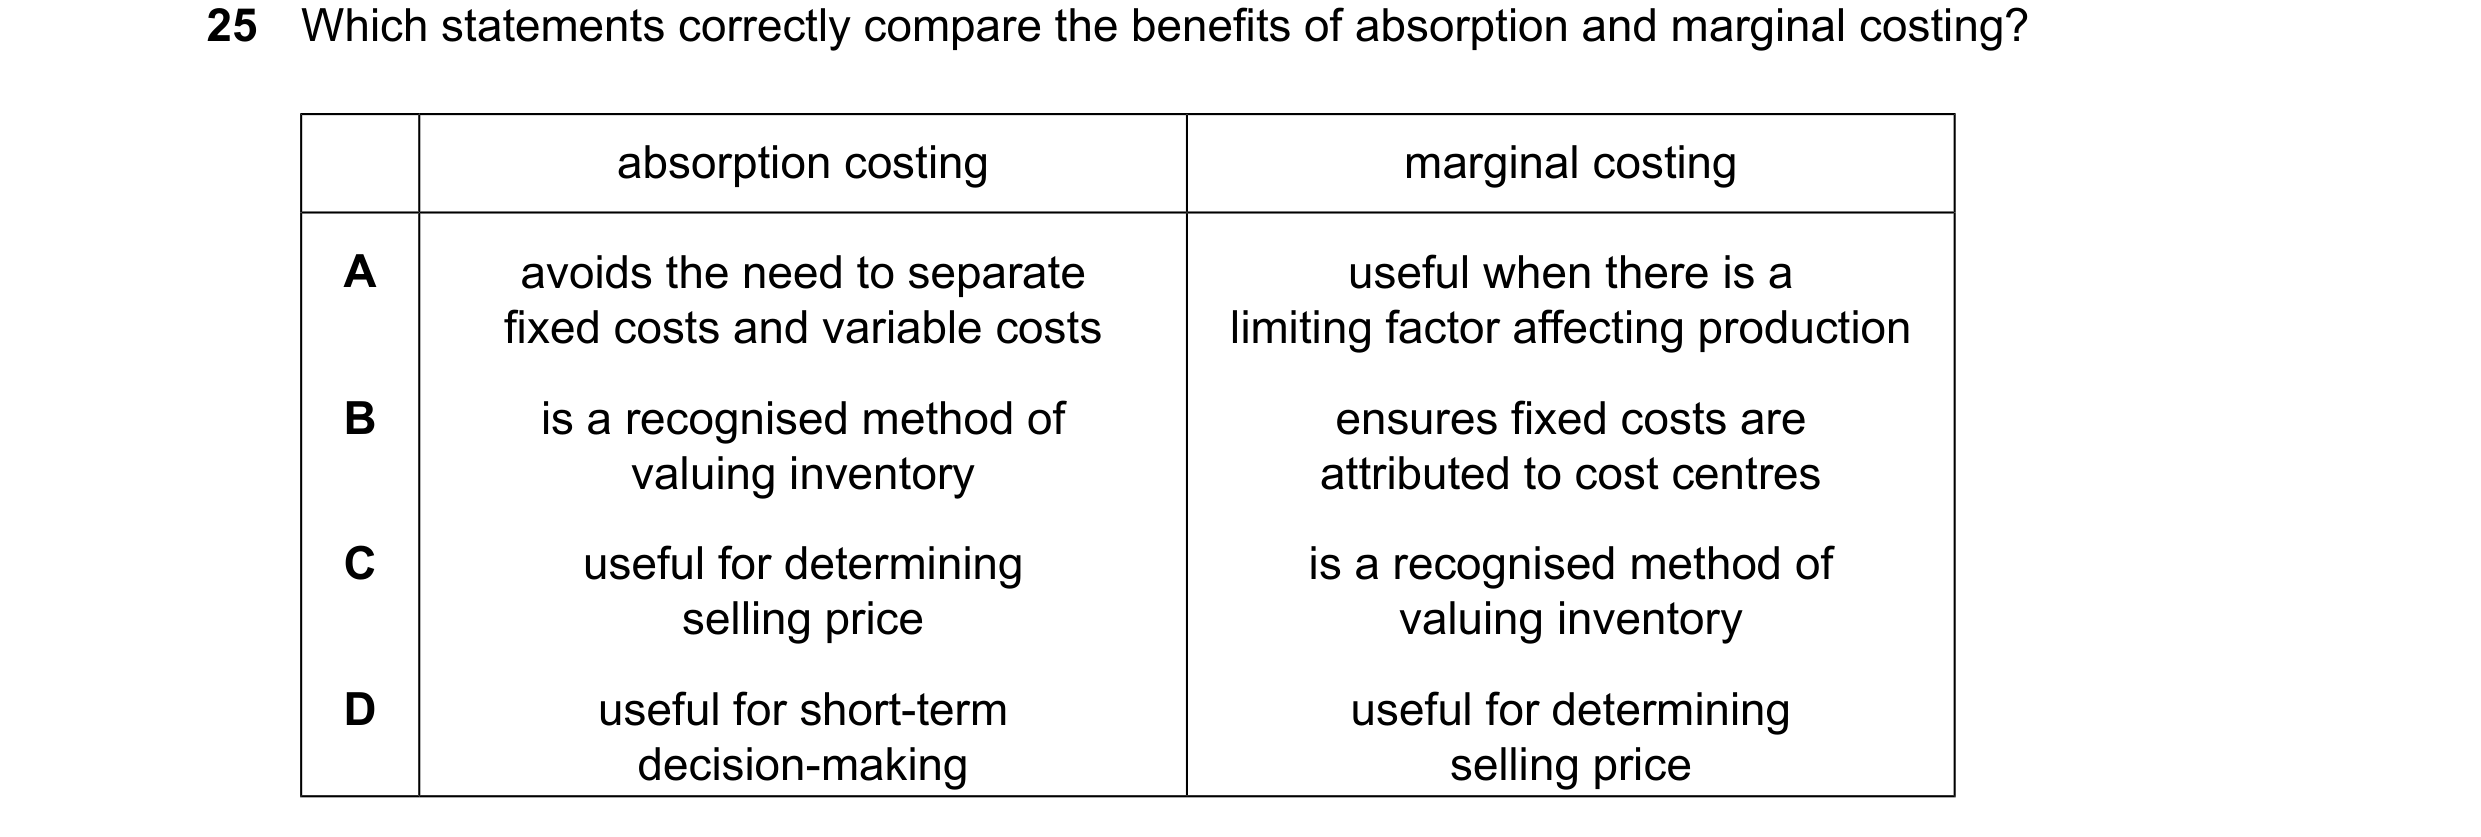
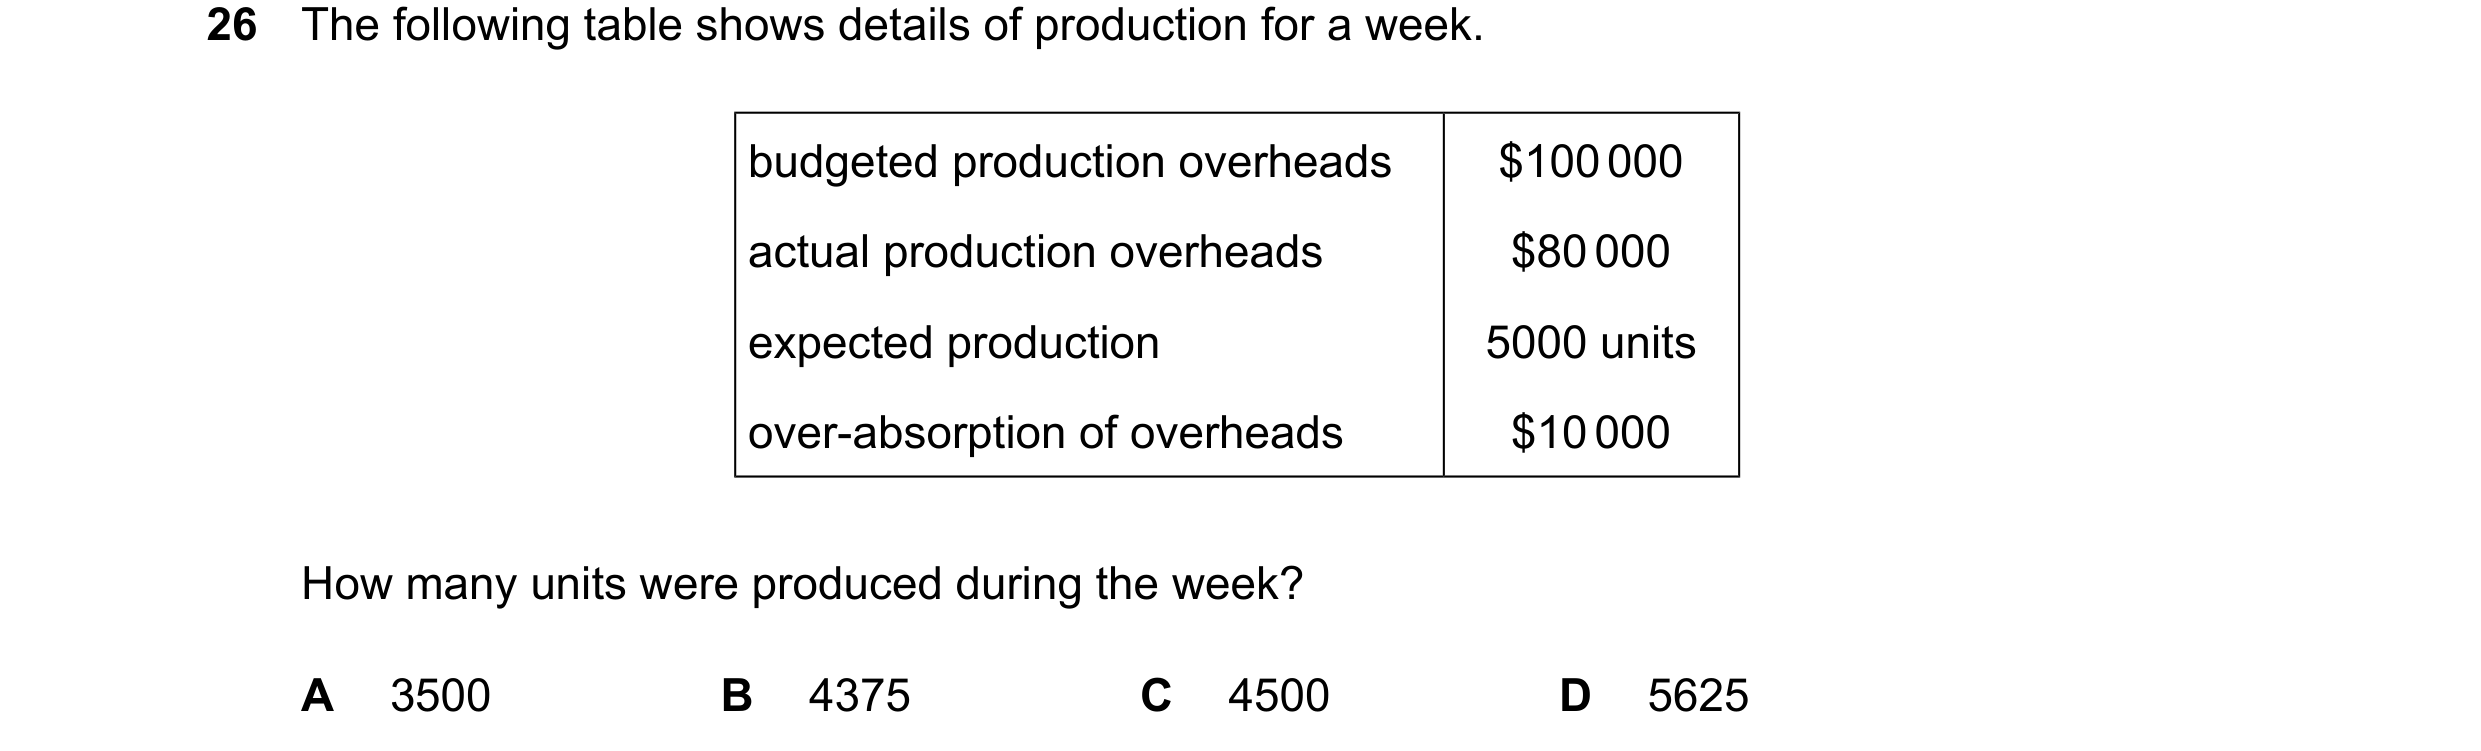 137 / 143
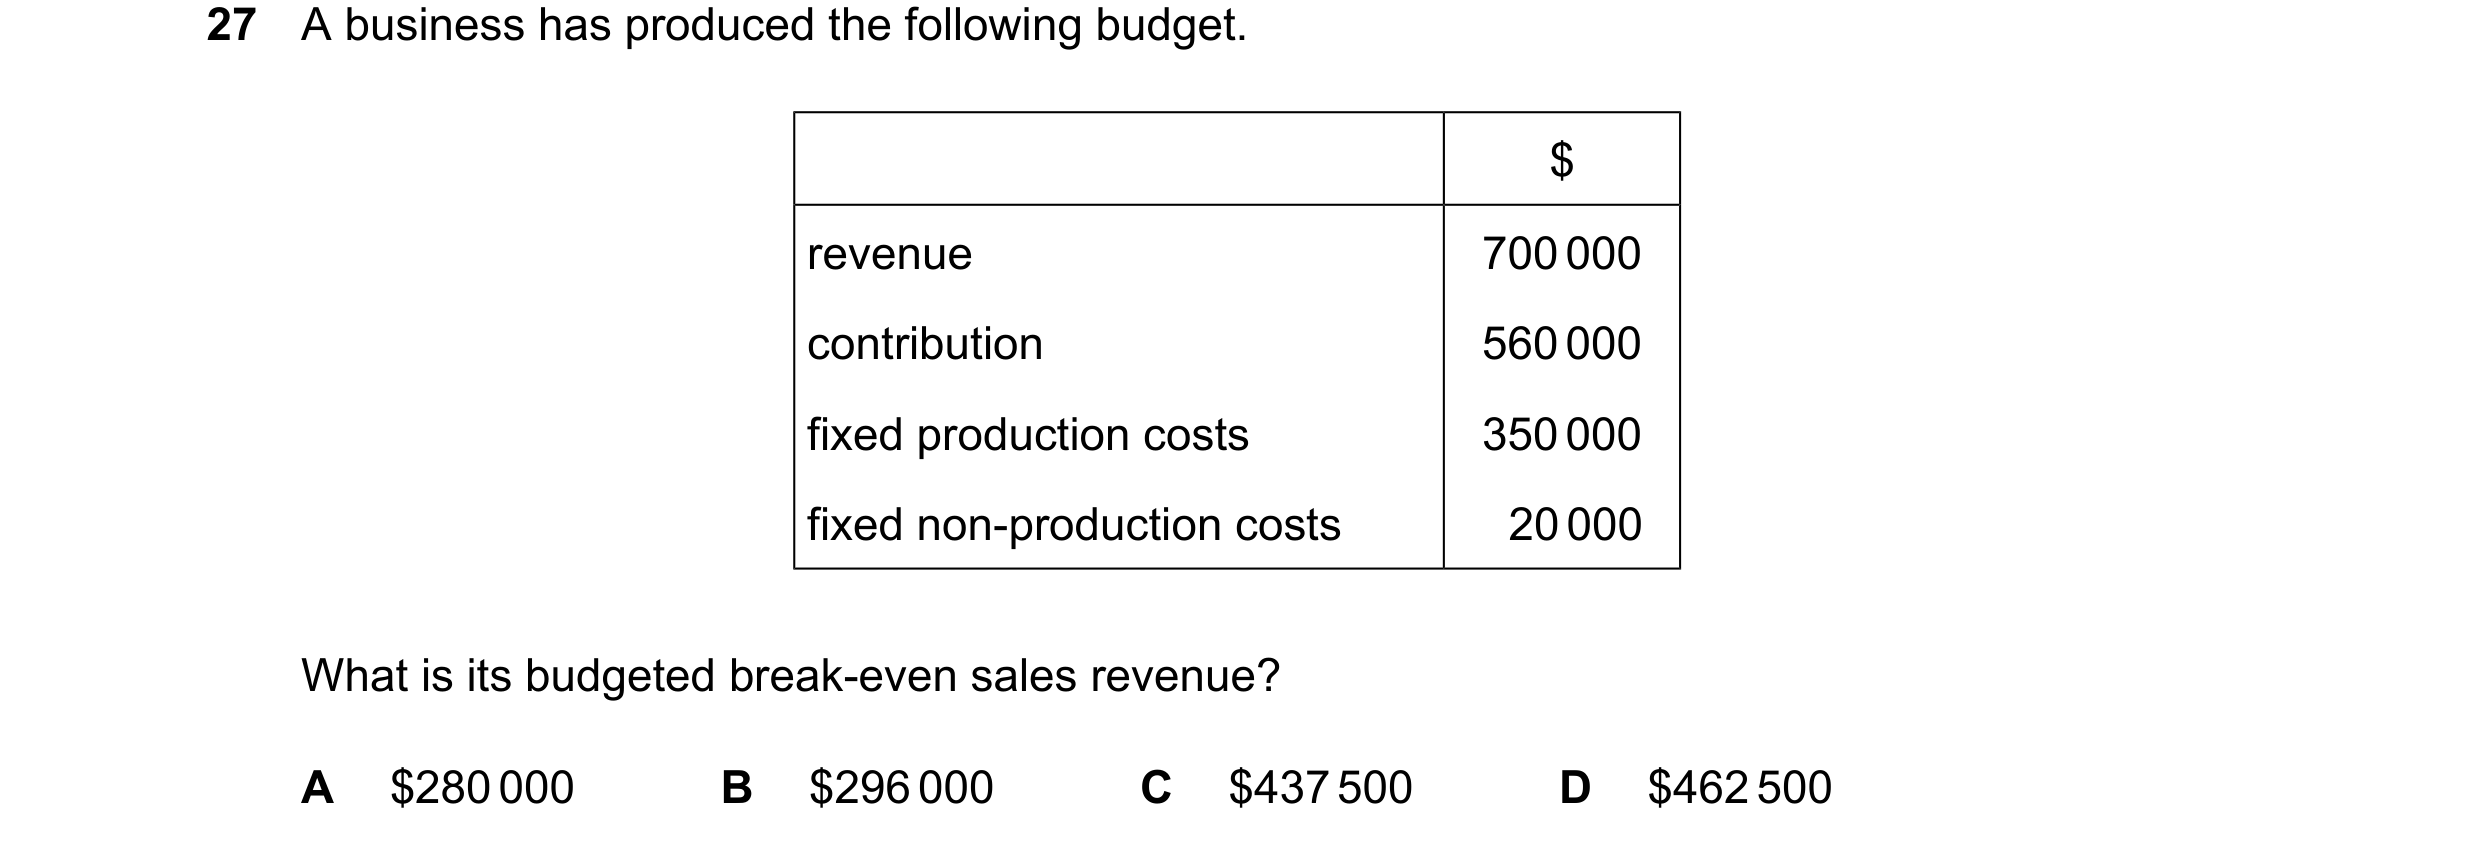
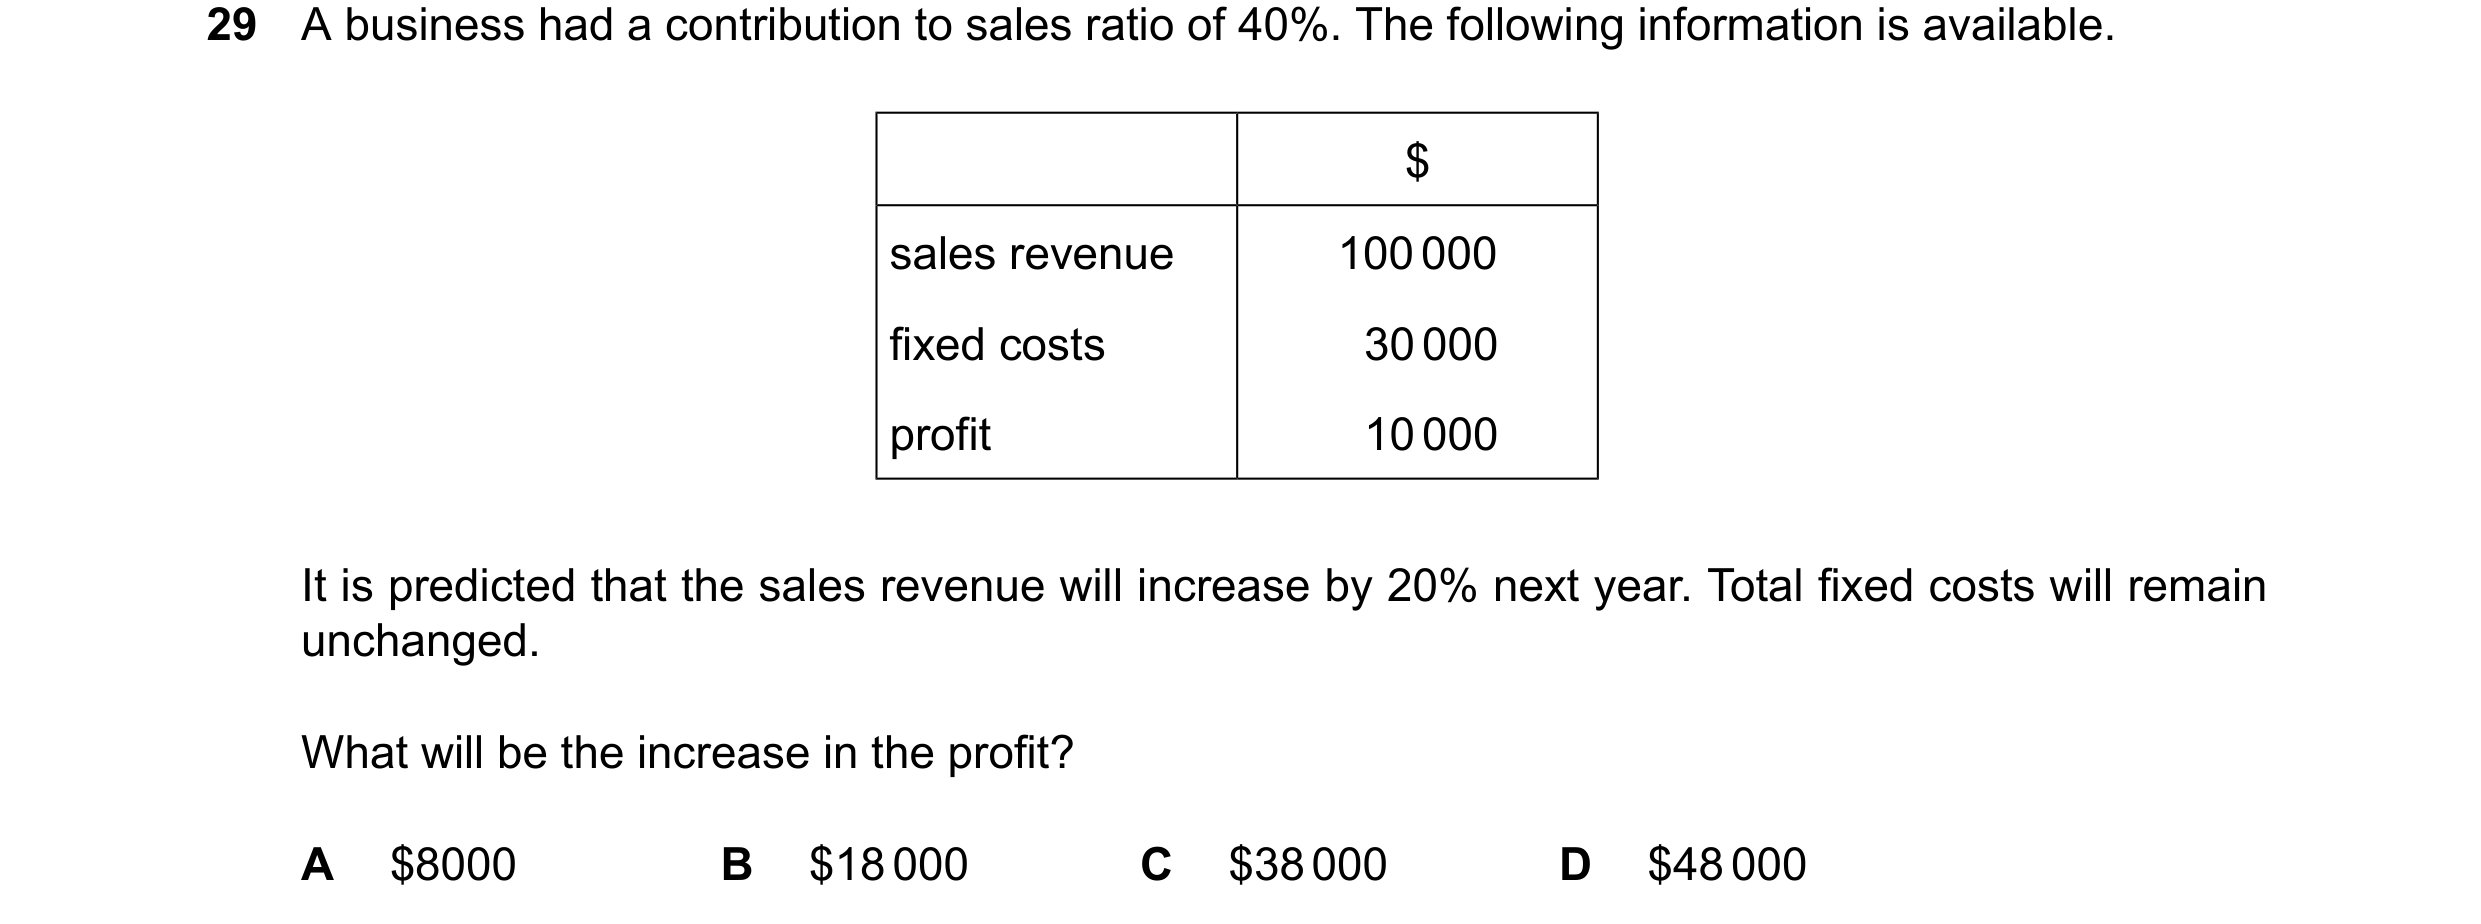
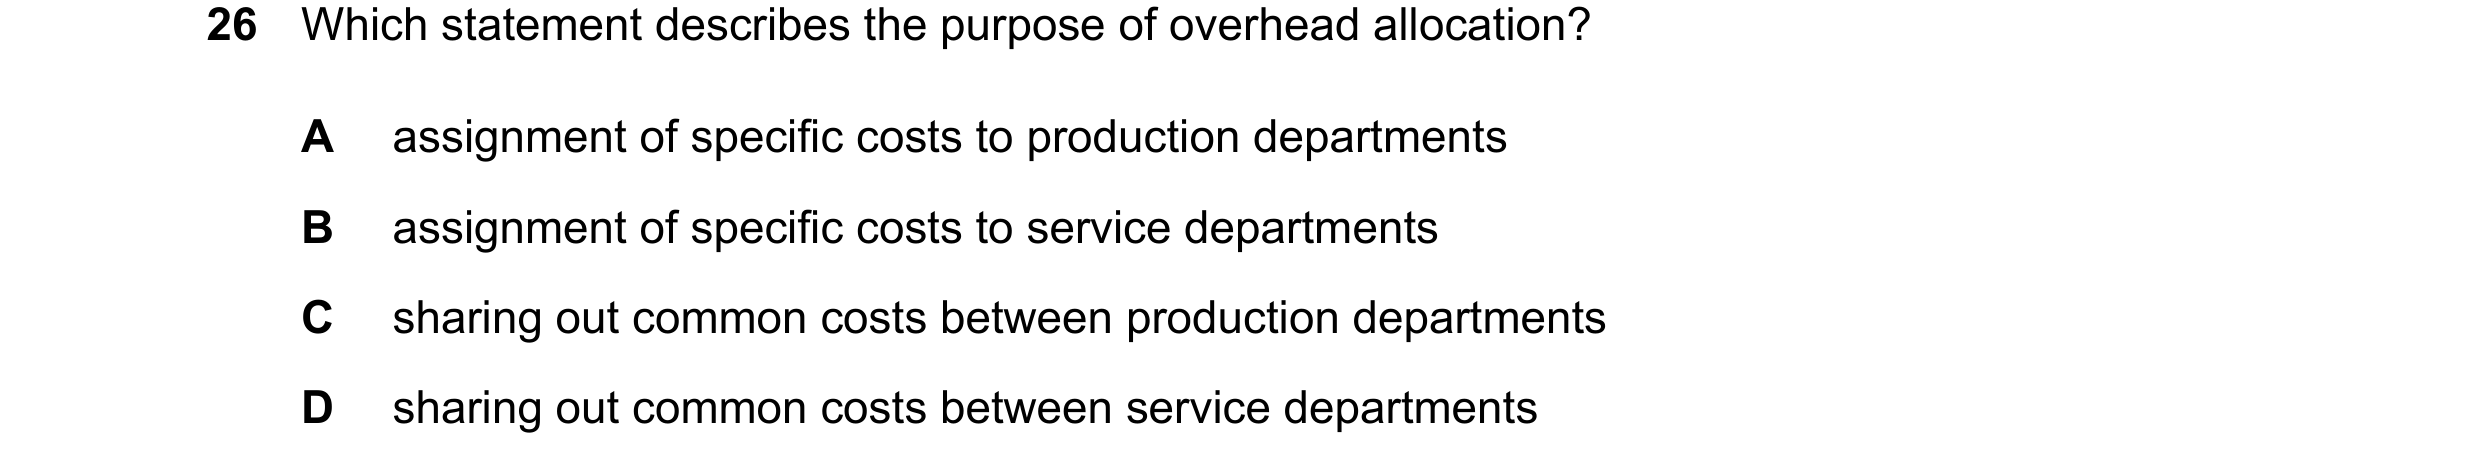 138 / 143
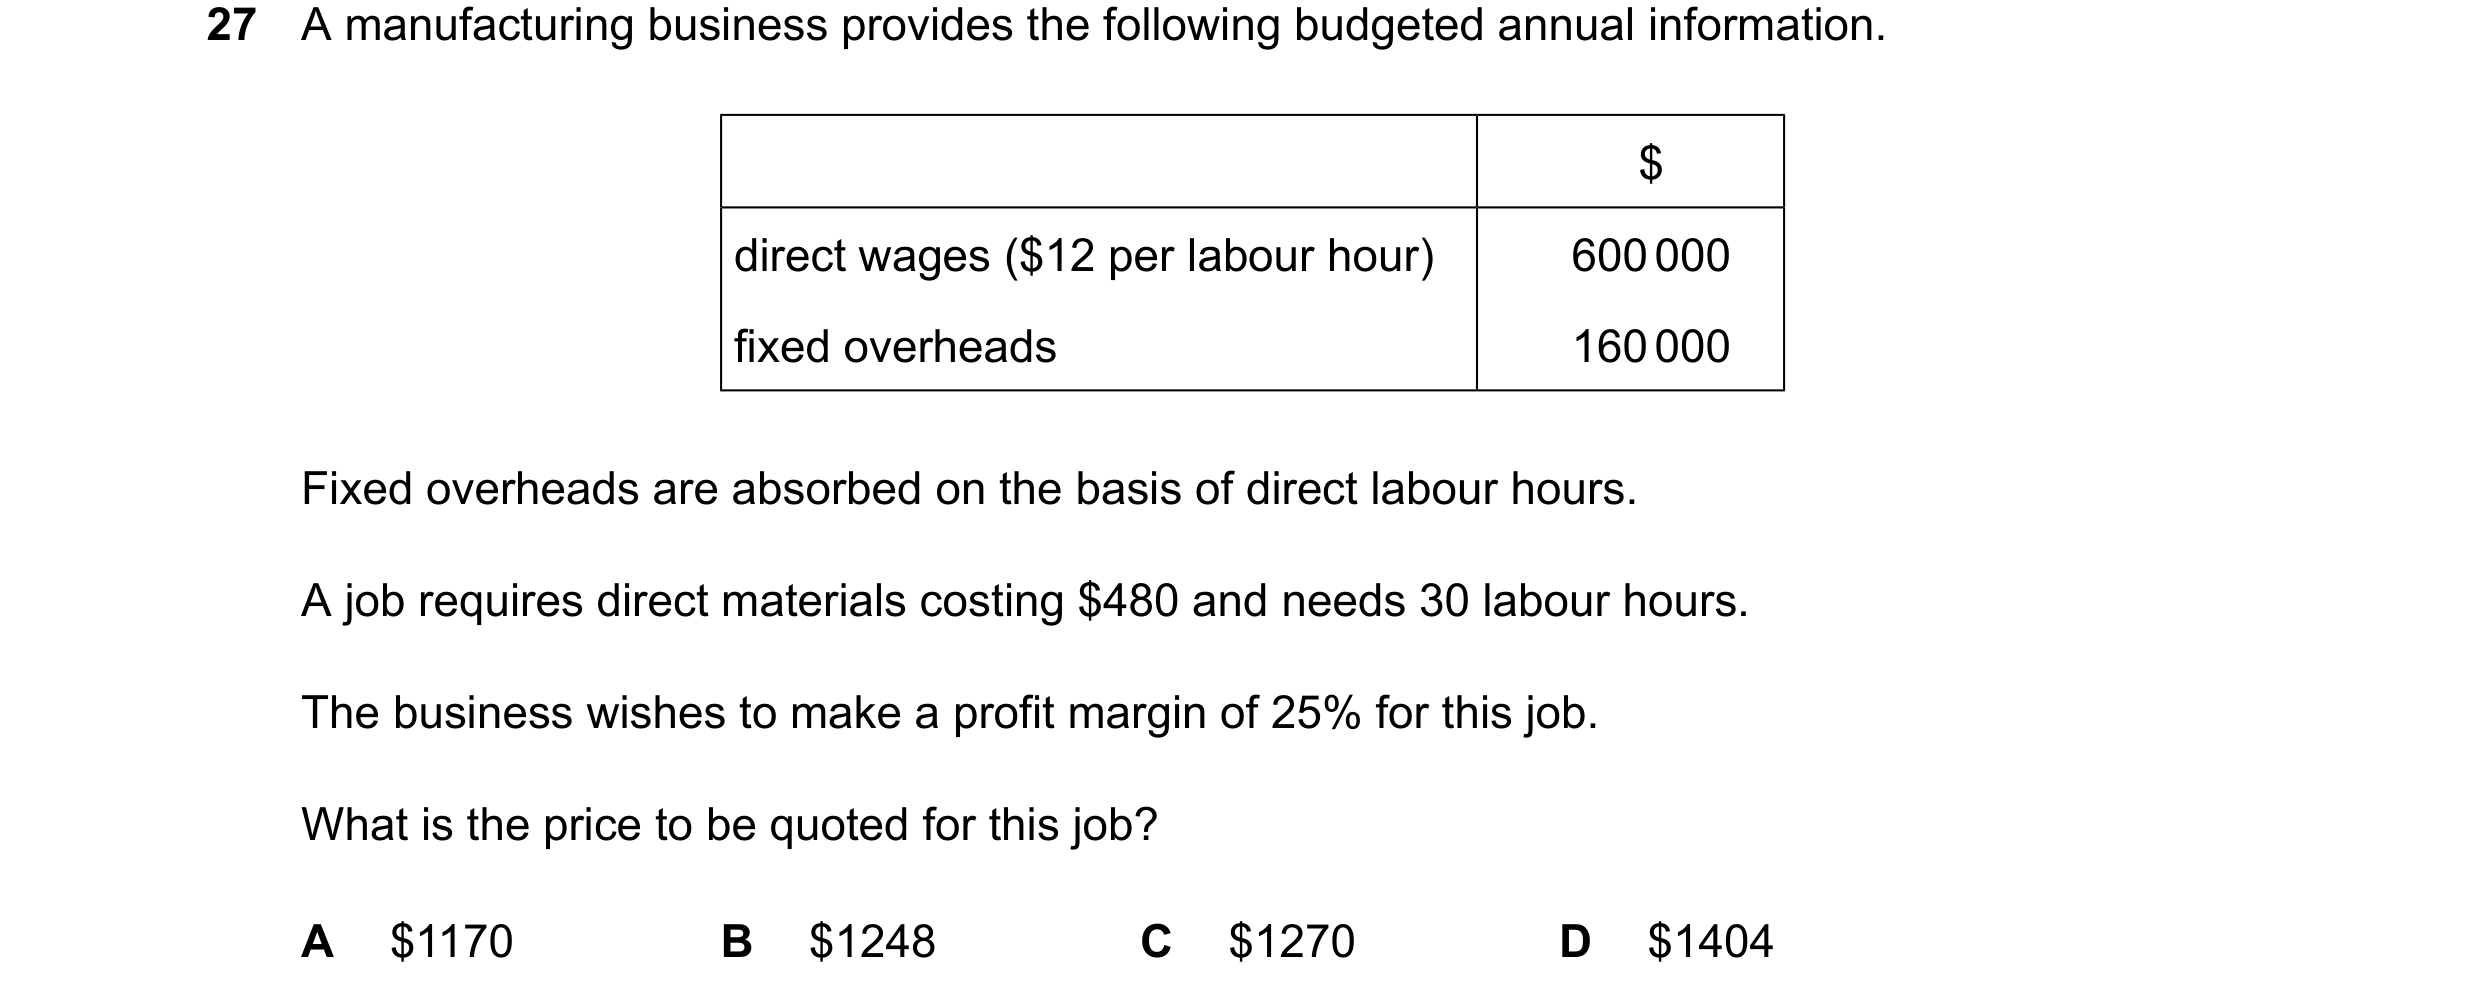
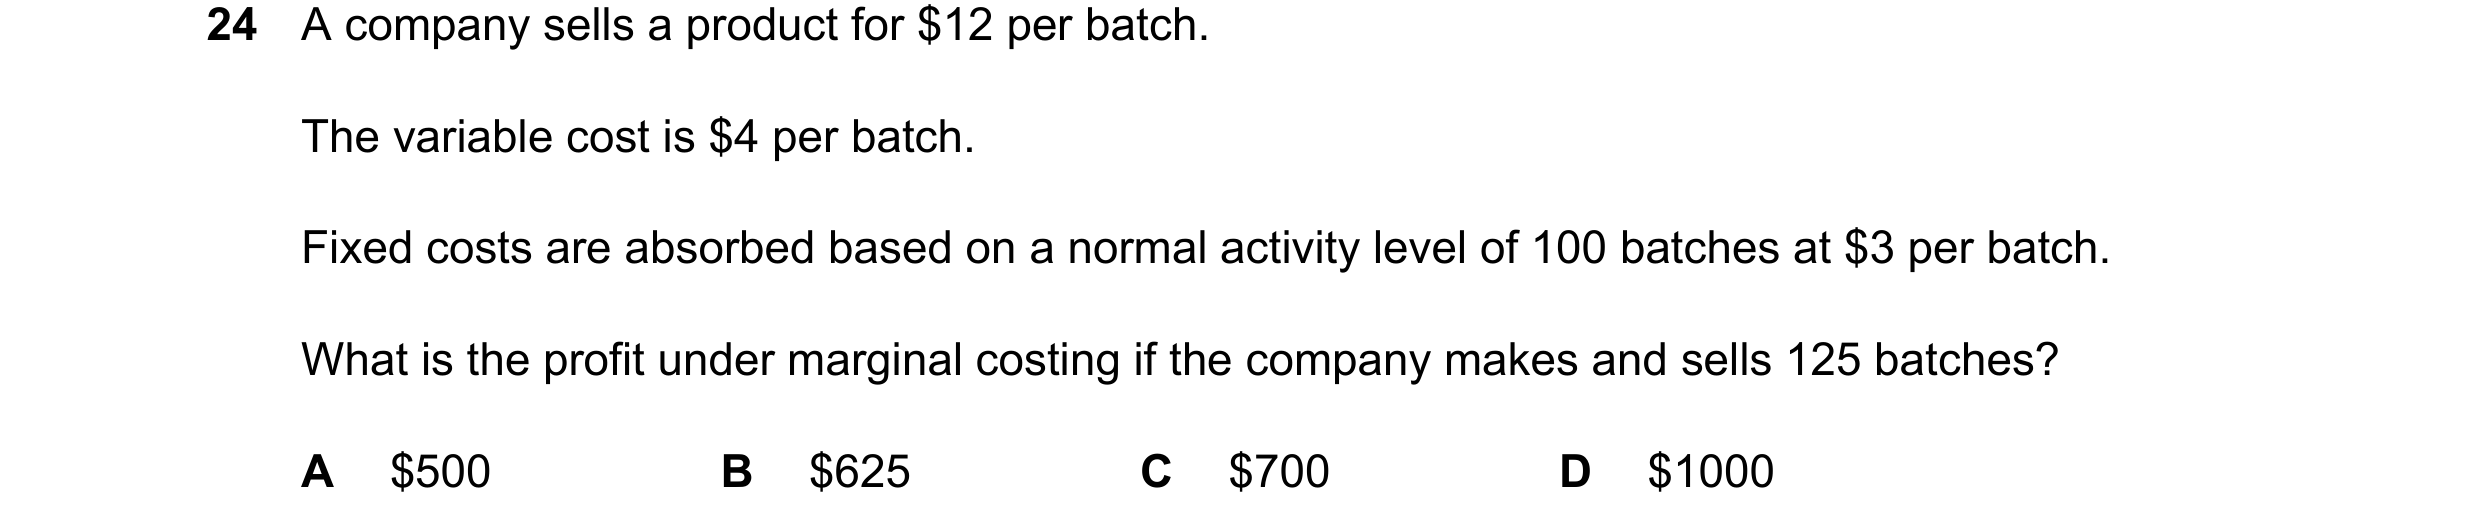
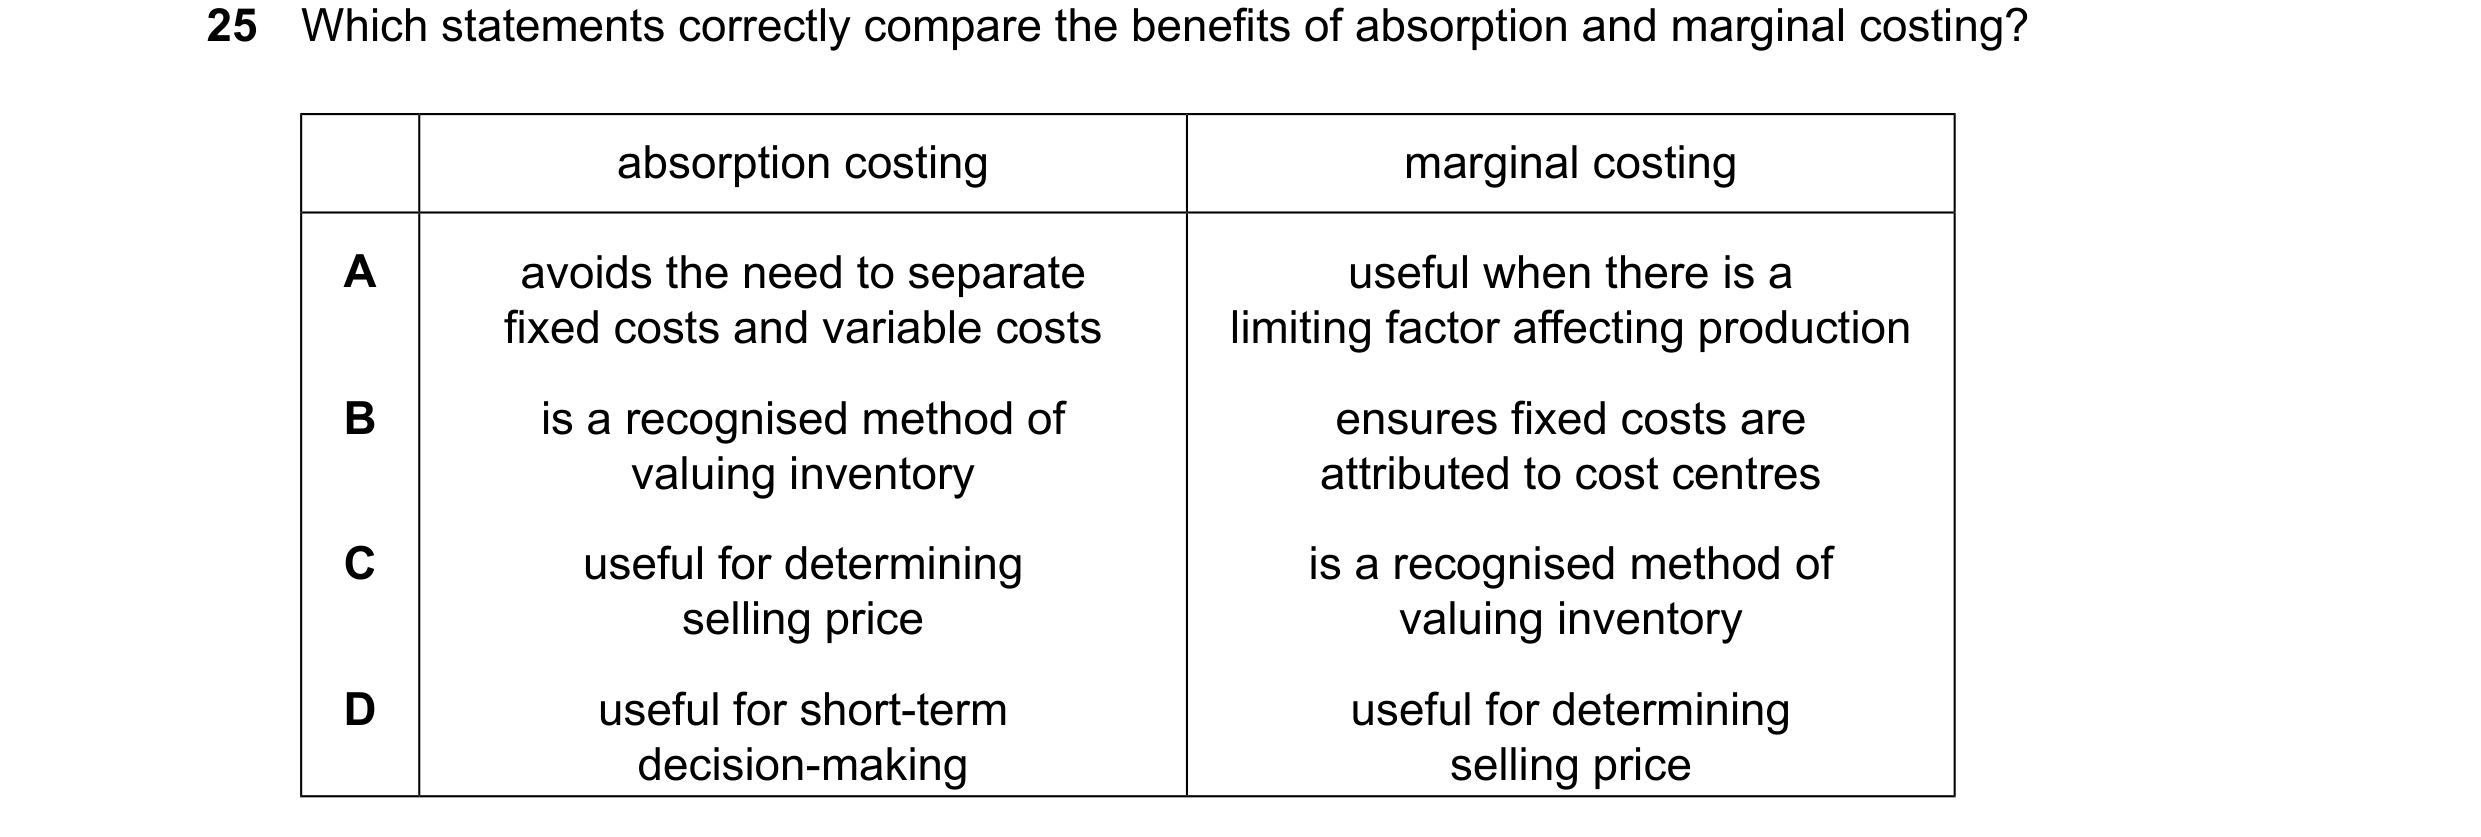
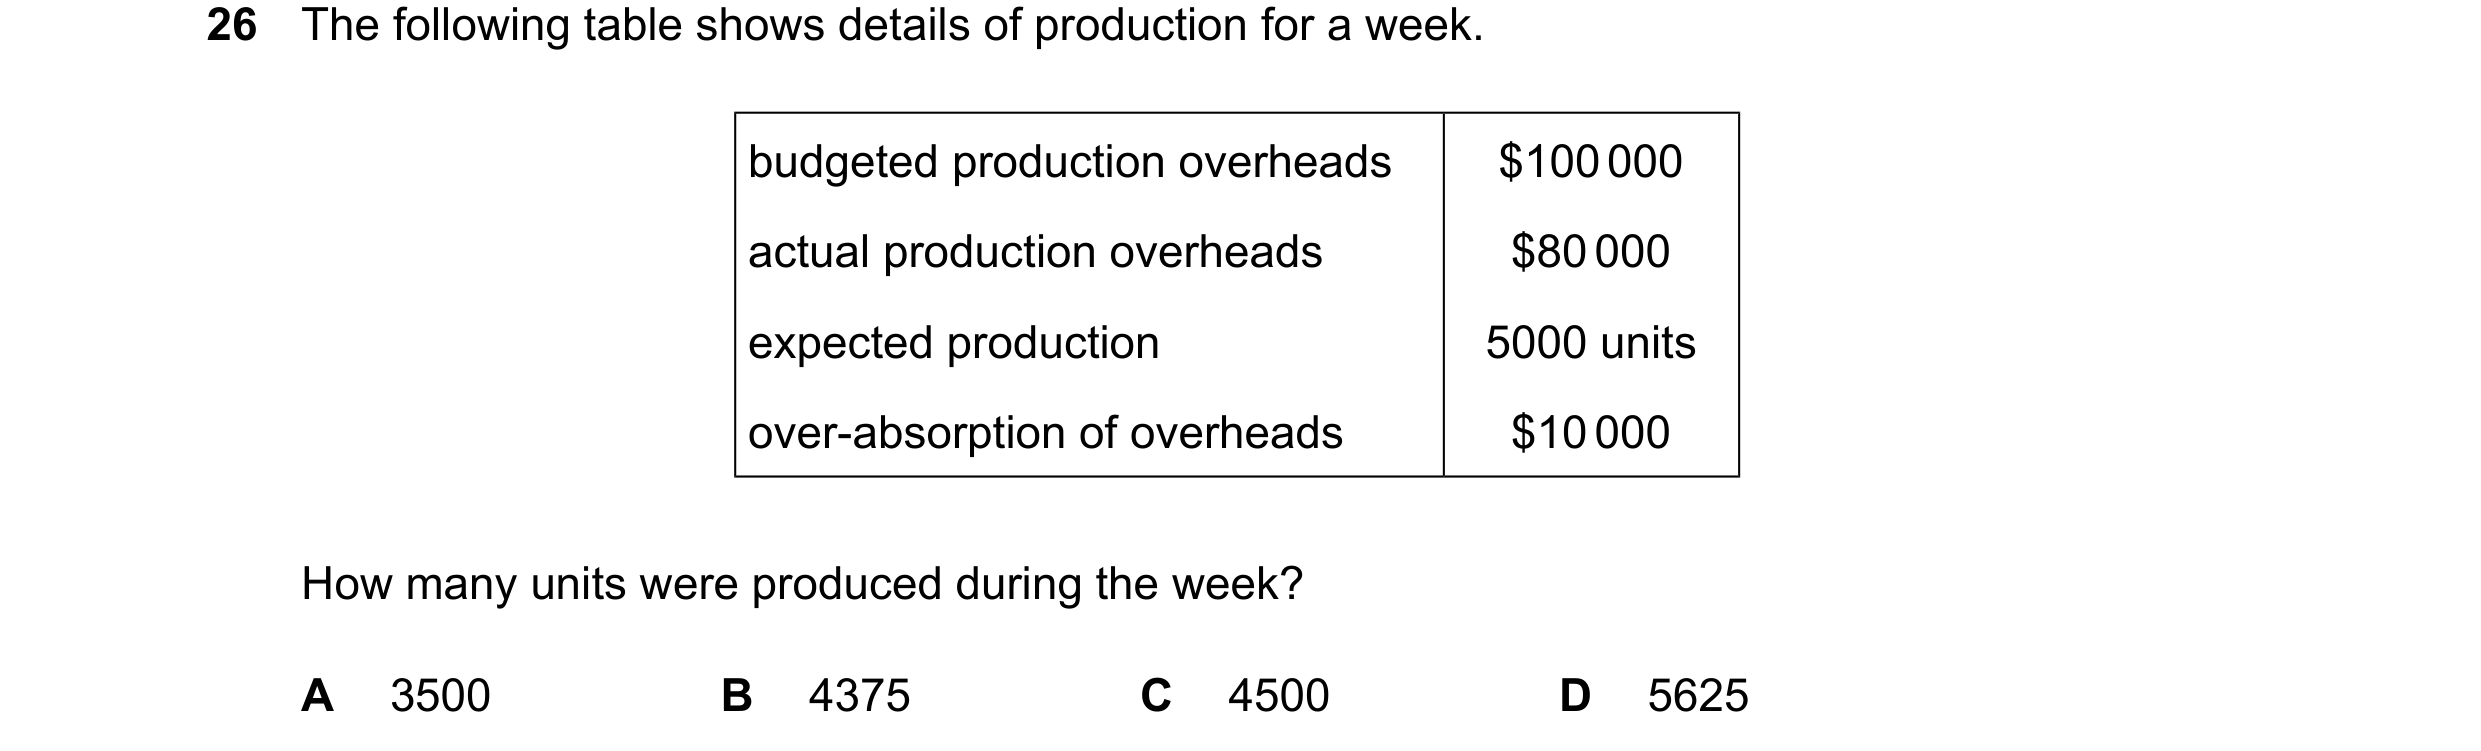 139 / 143
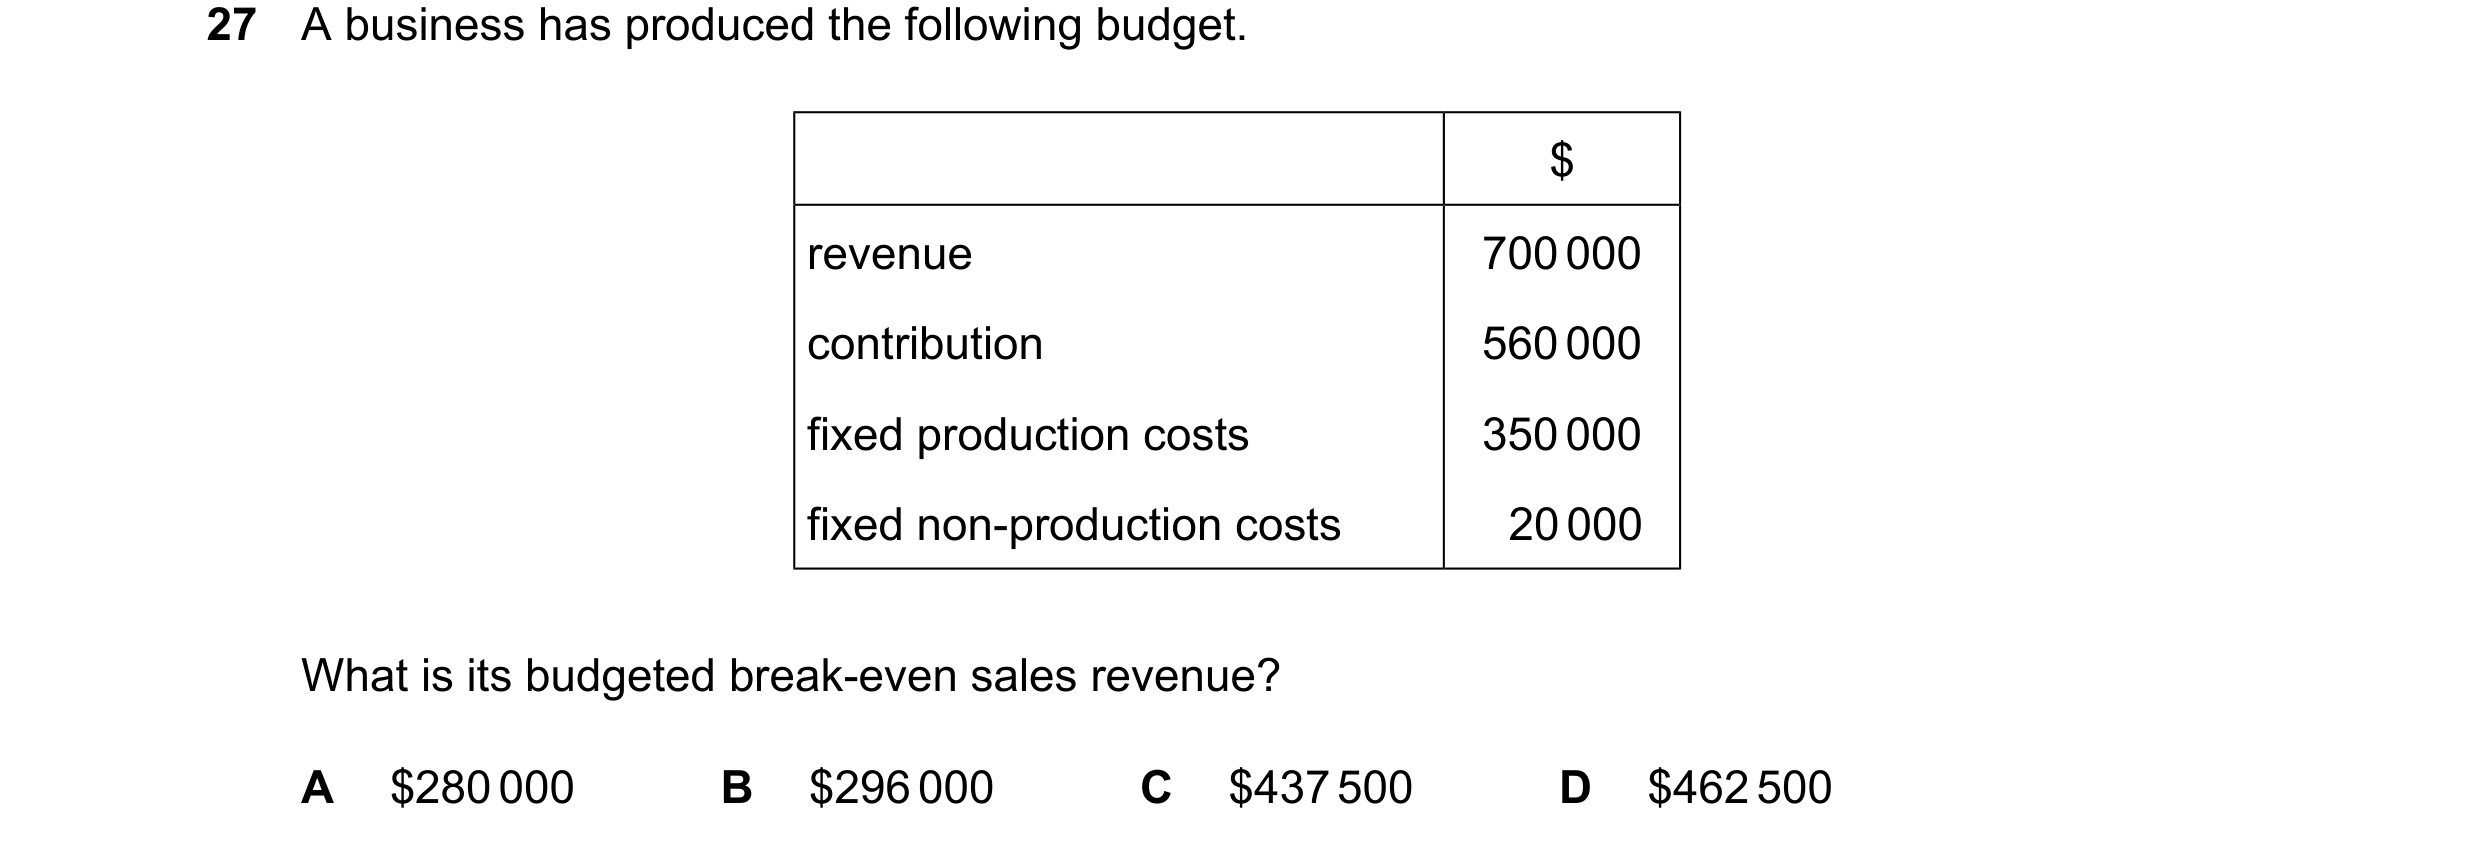
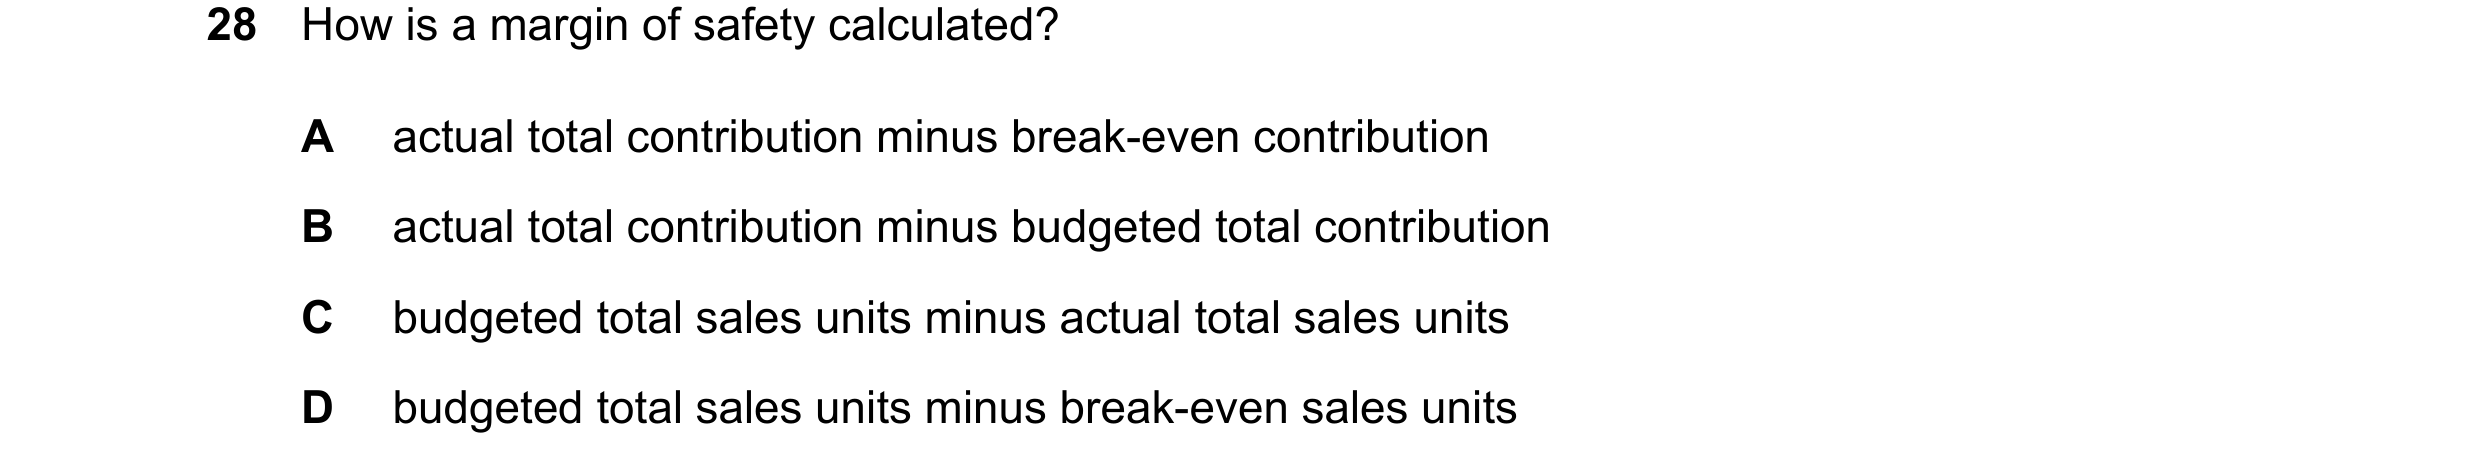
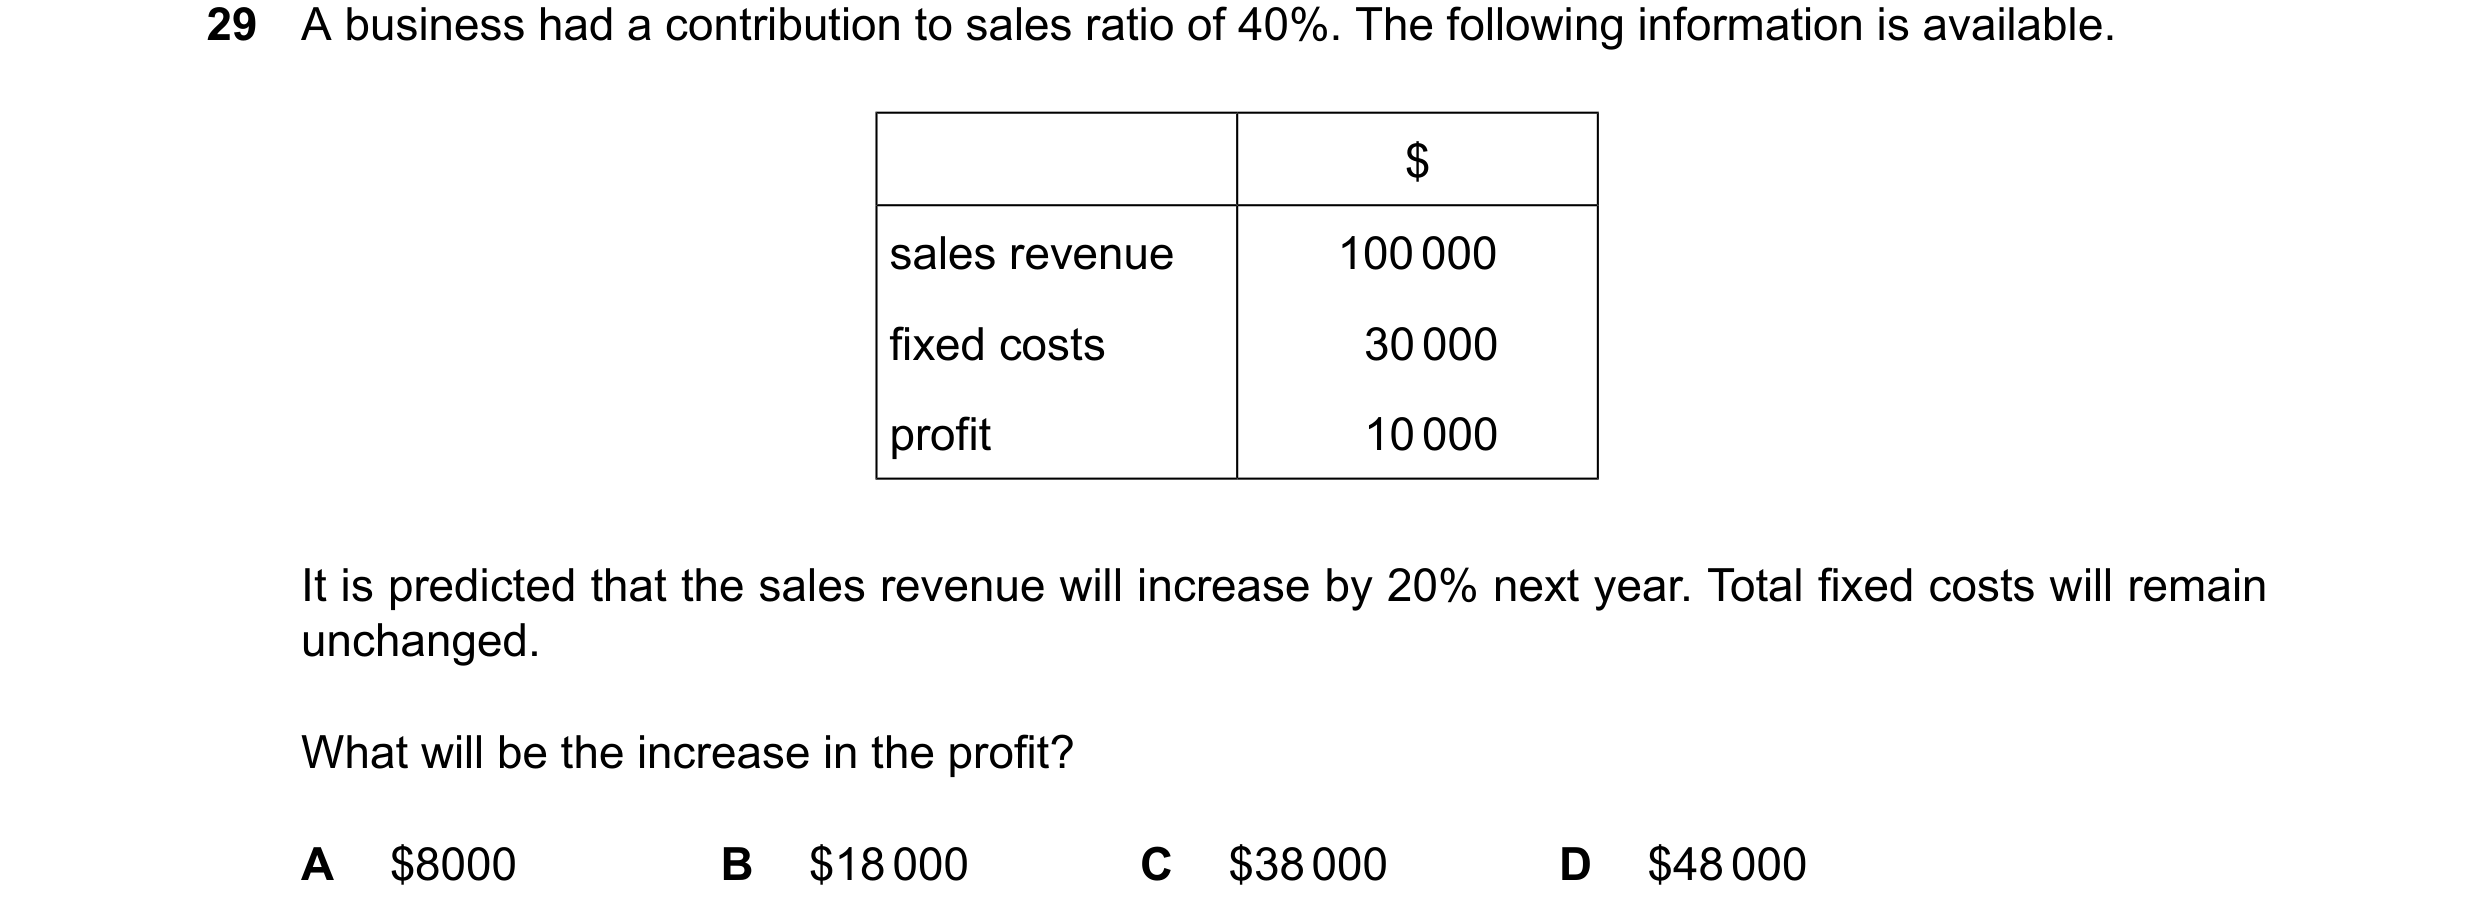
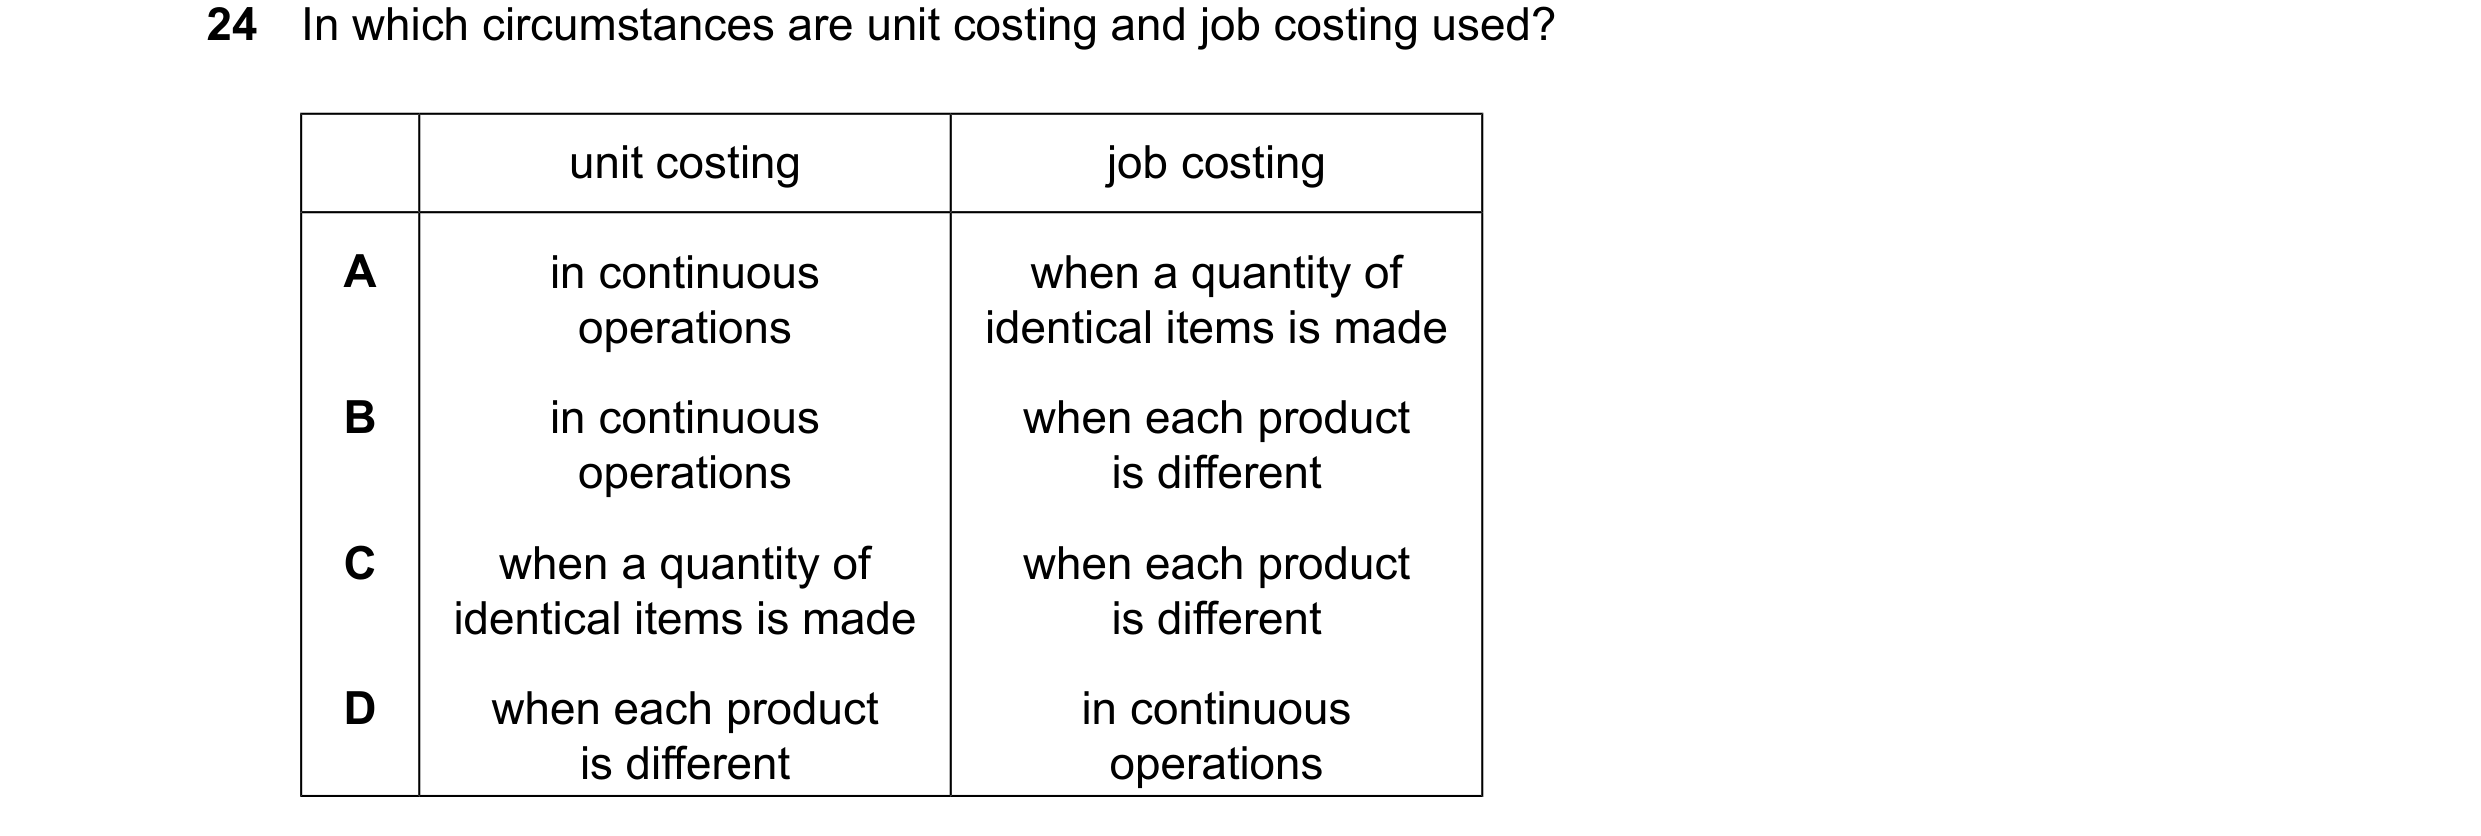 140 / 143
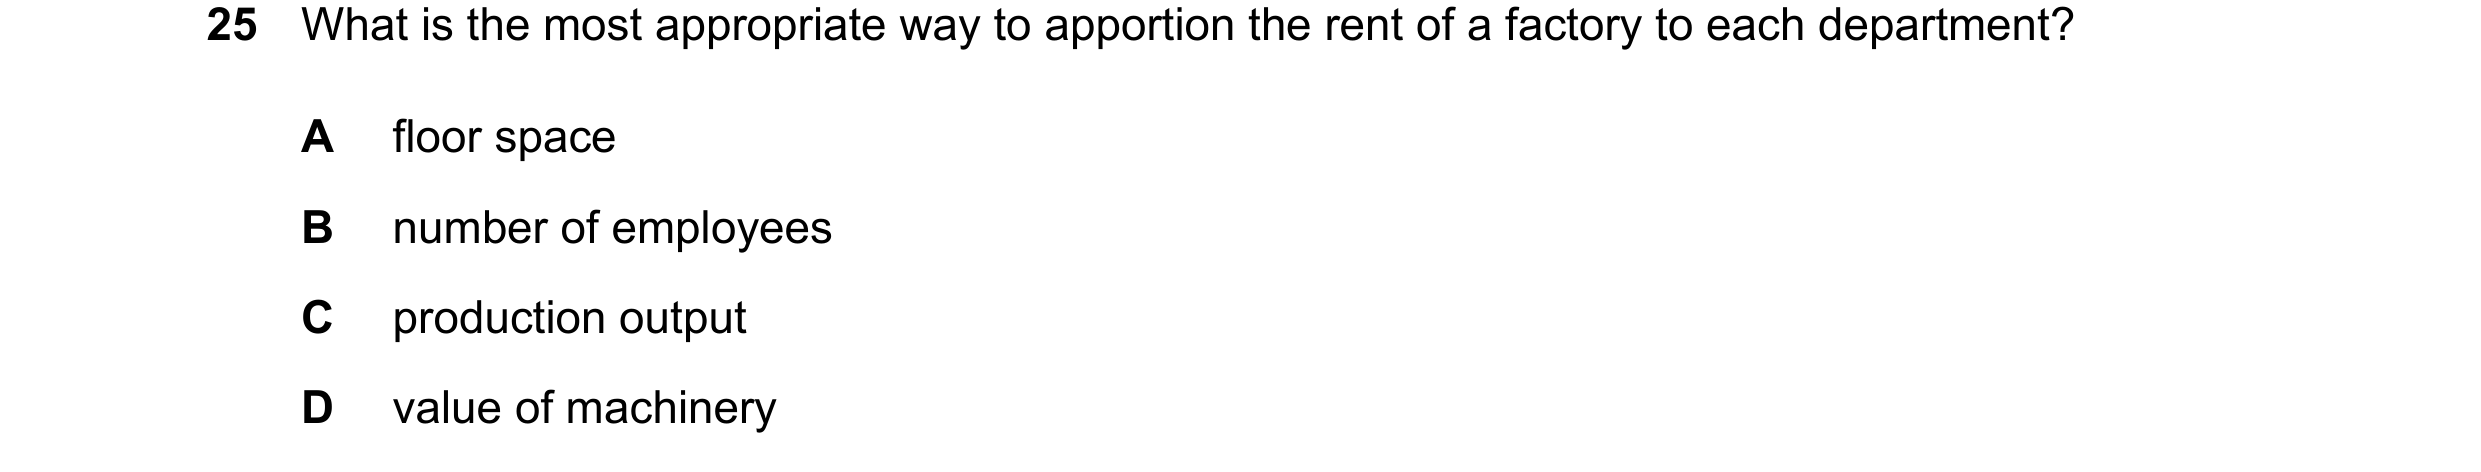
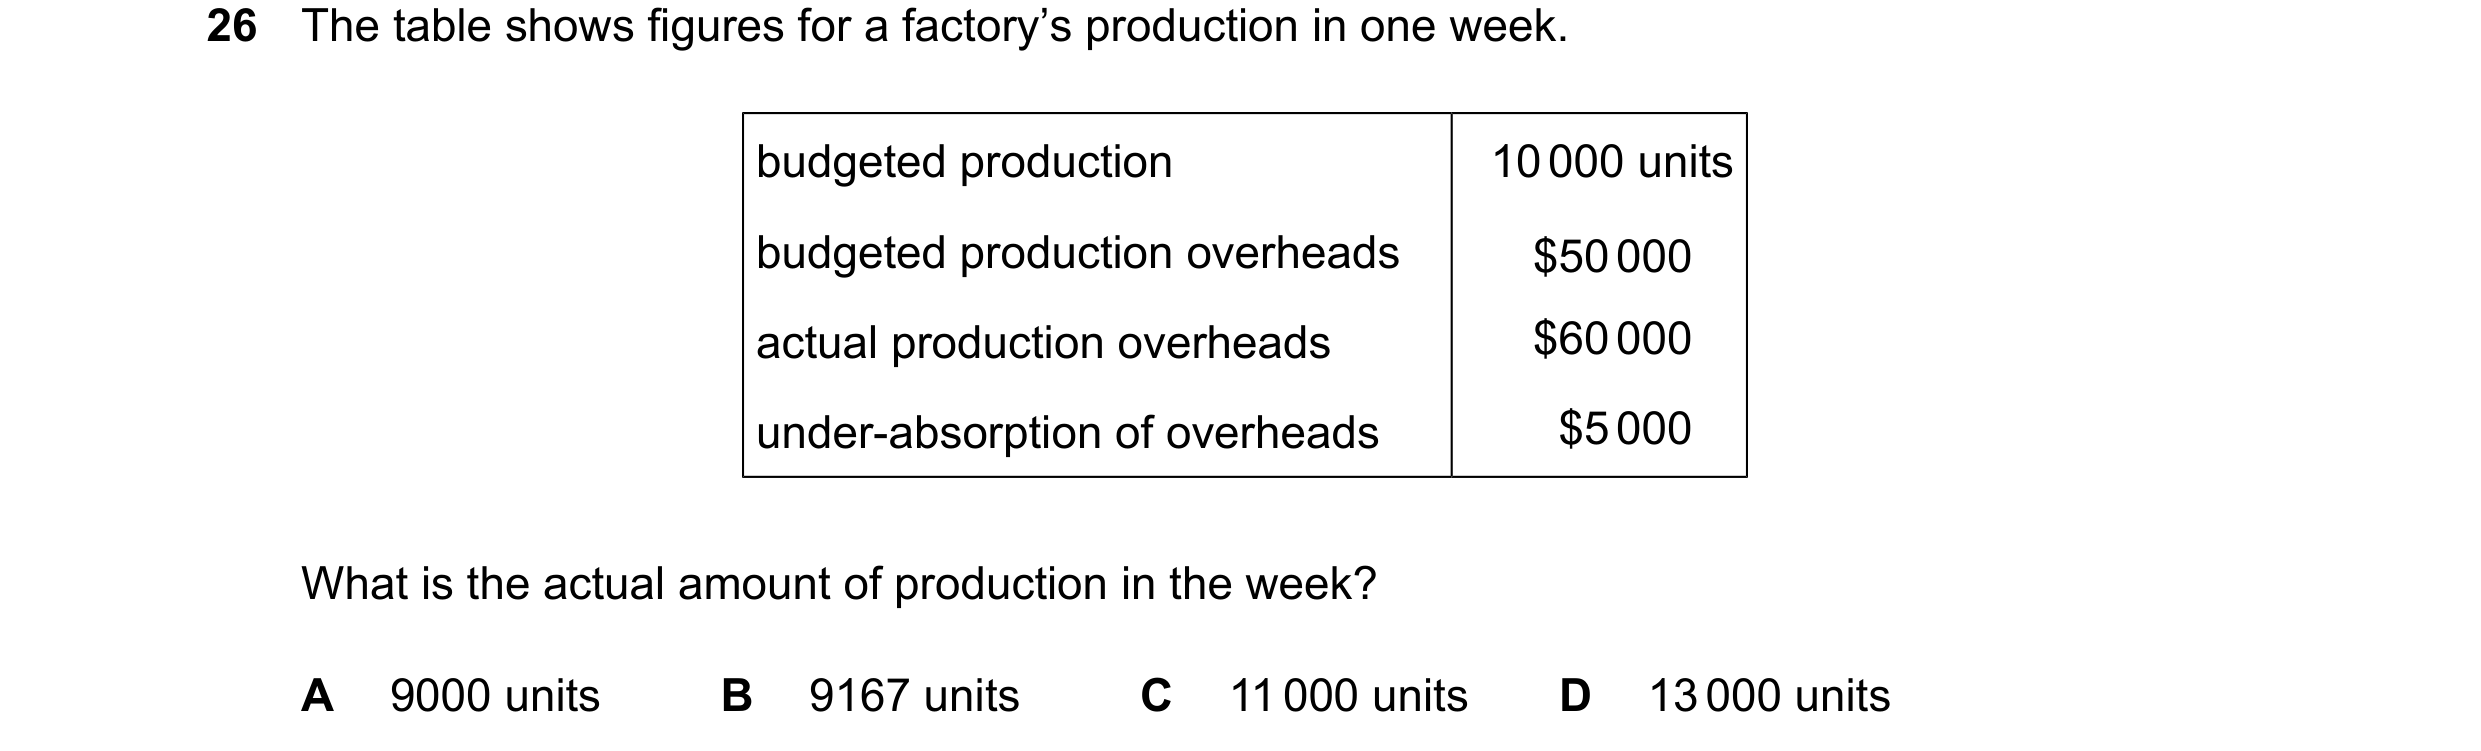
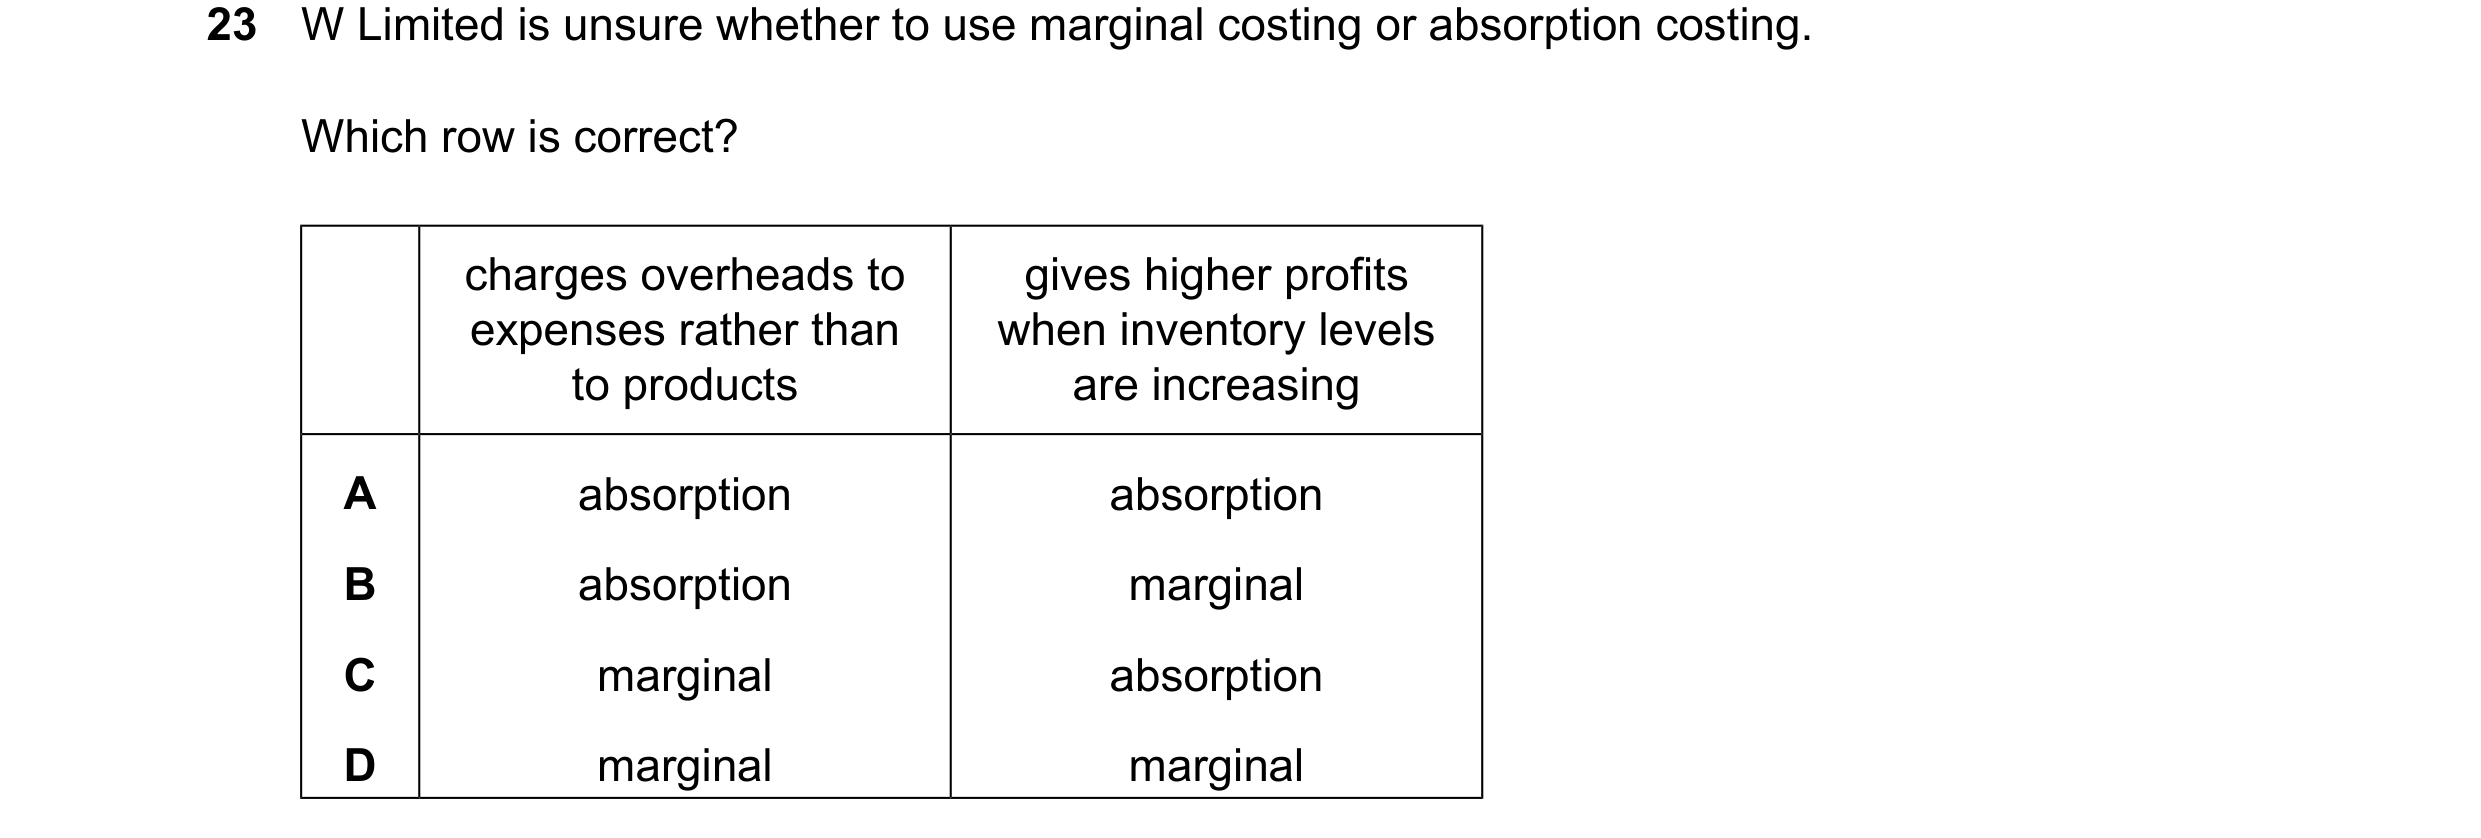
 141 / 143
 142 / 143
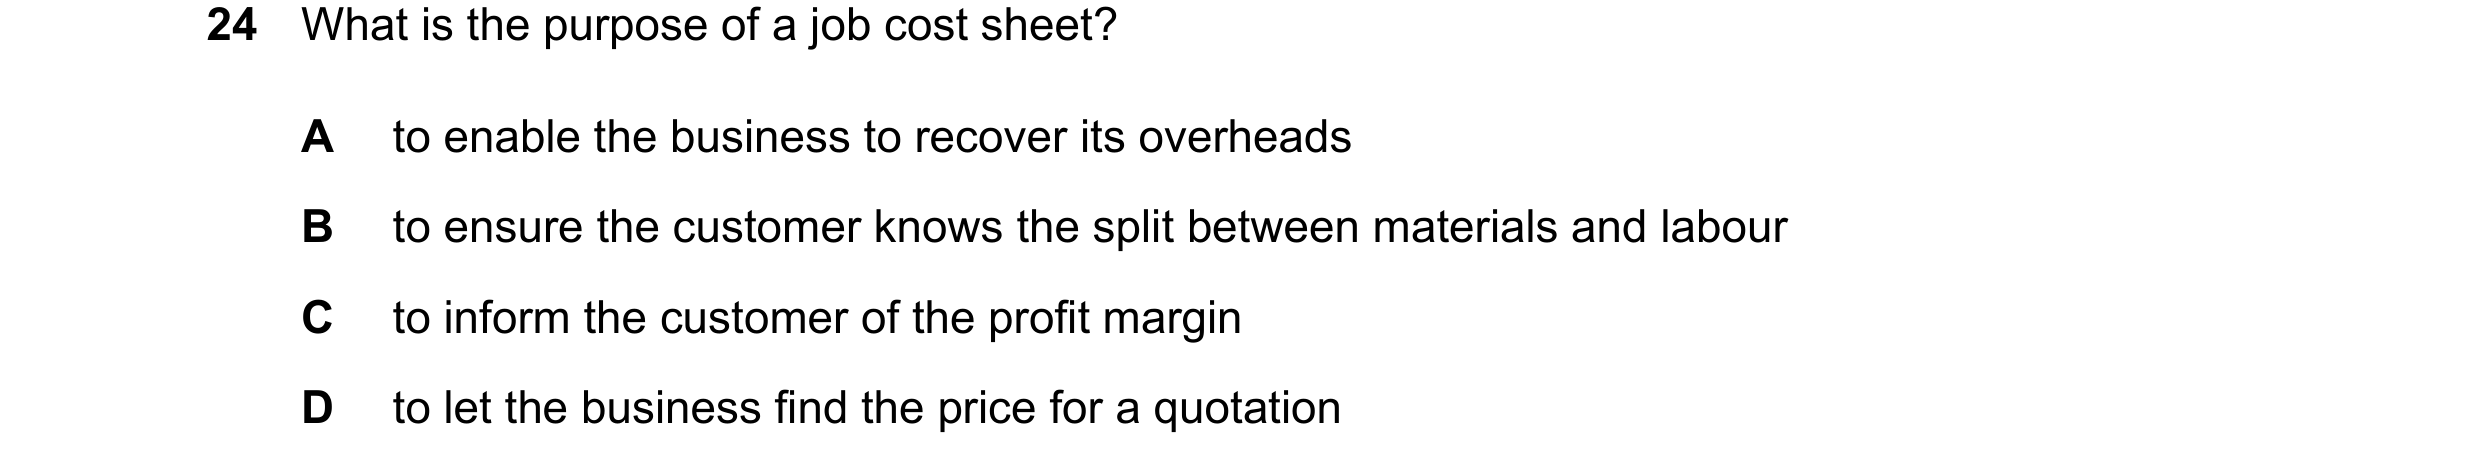
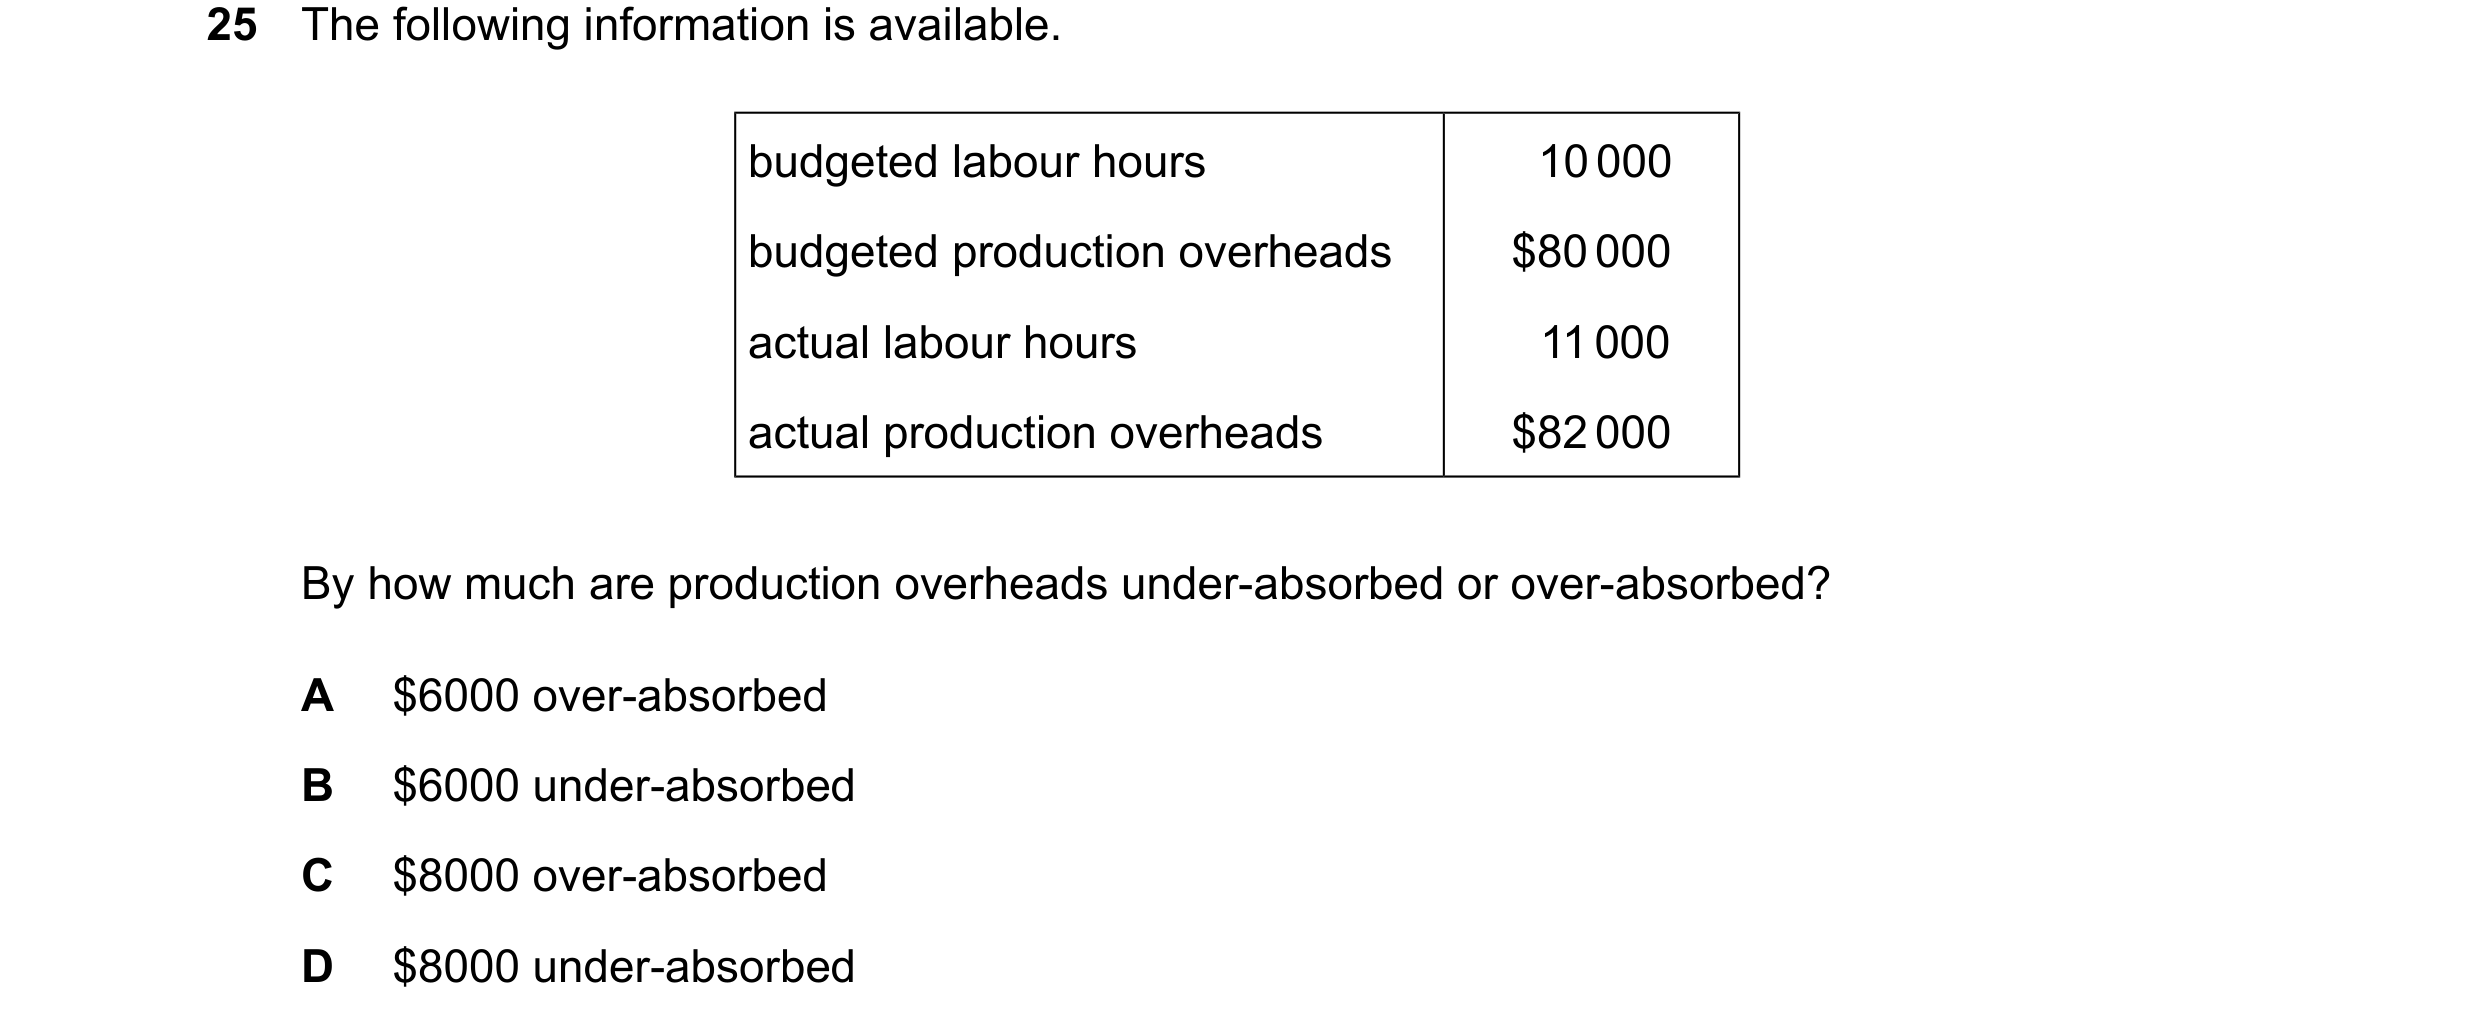
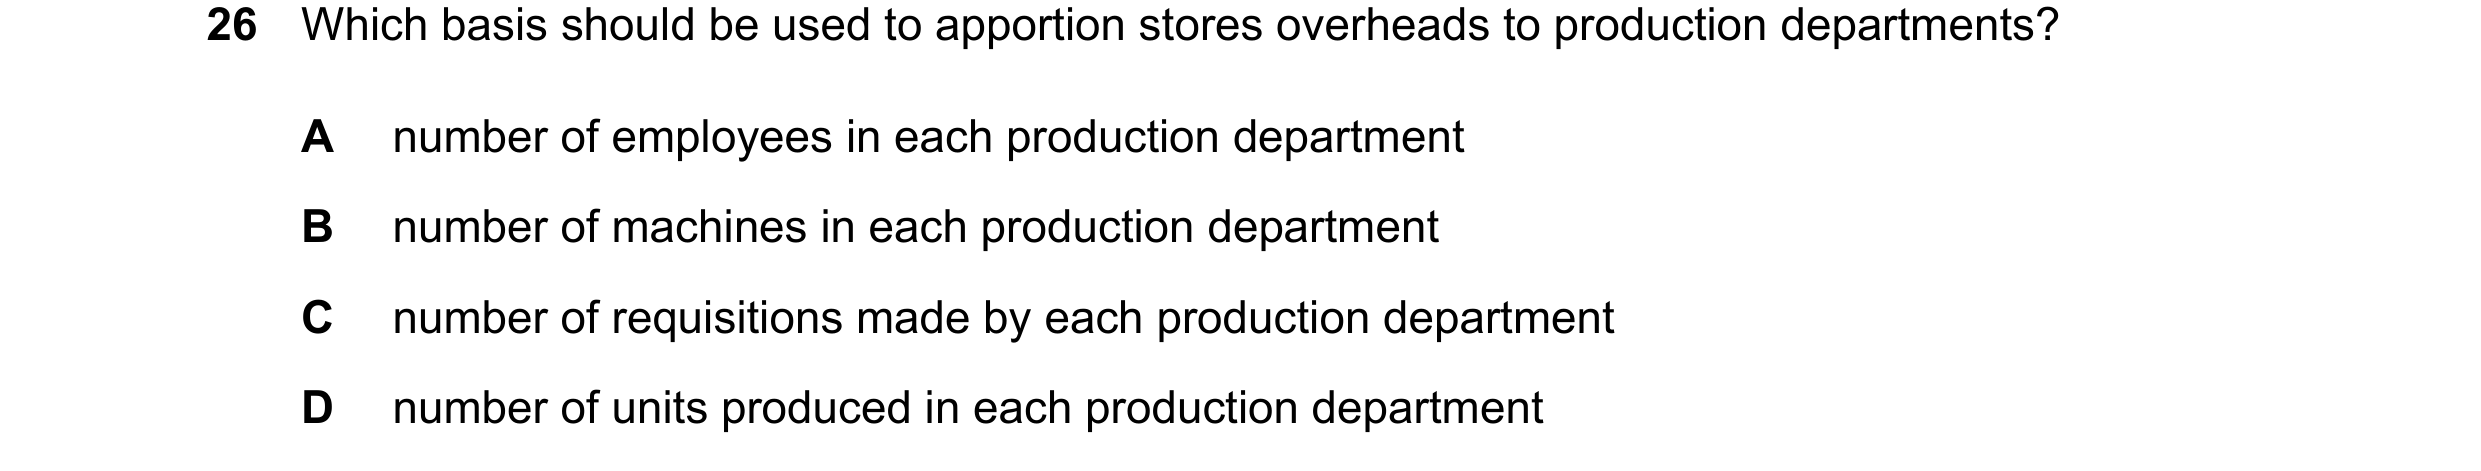
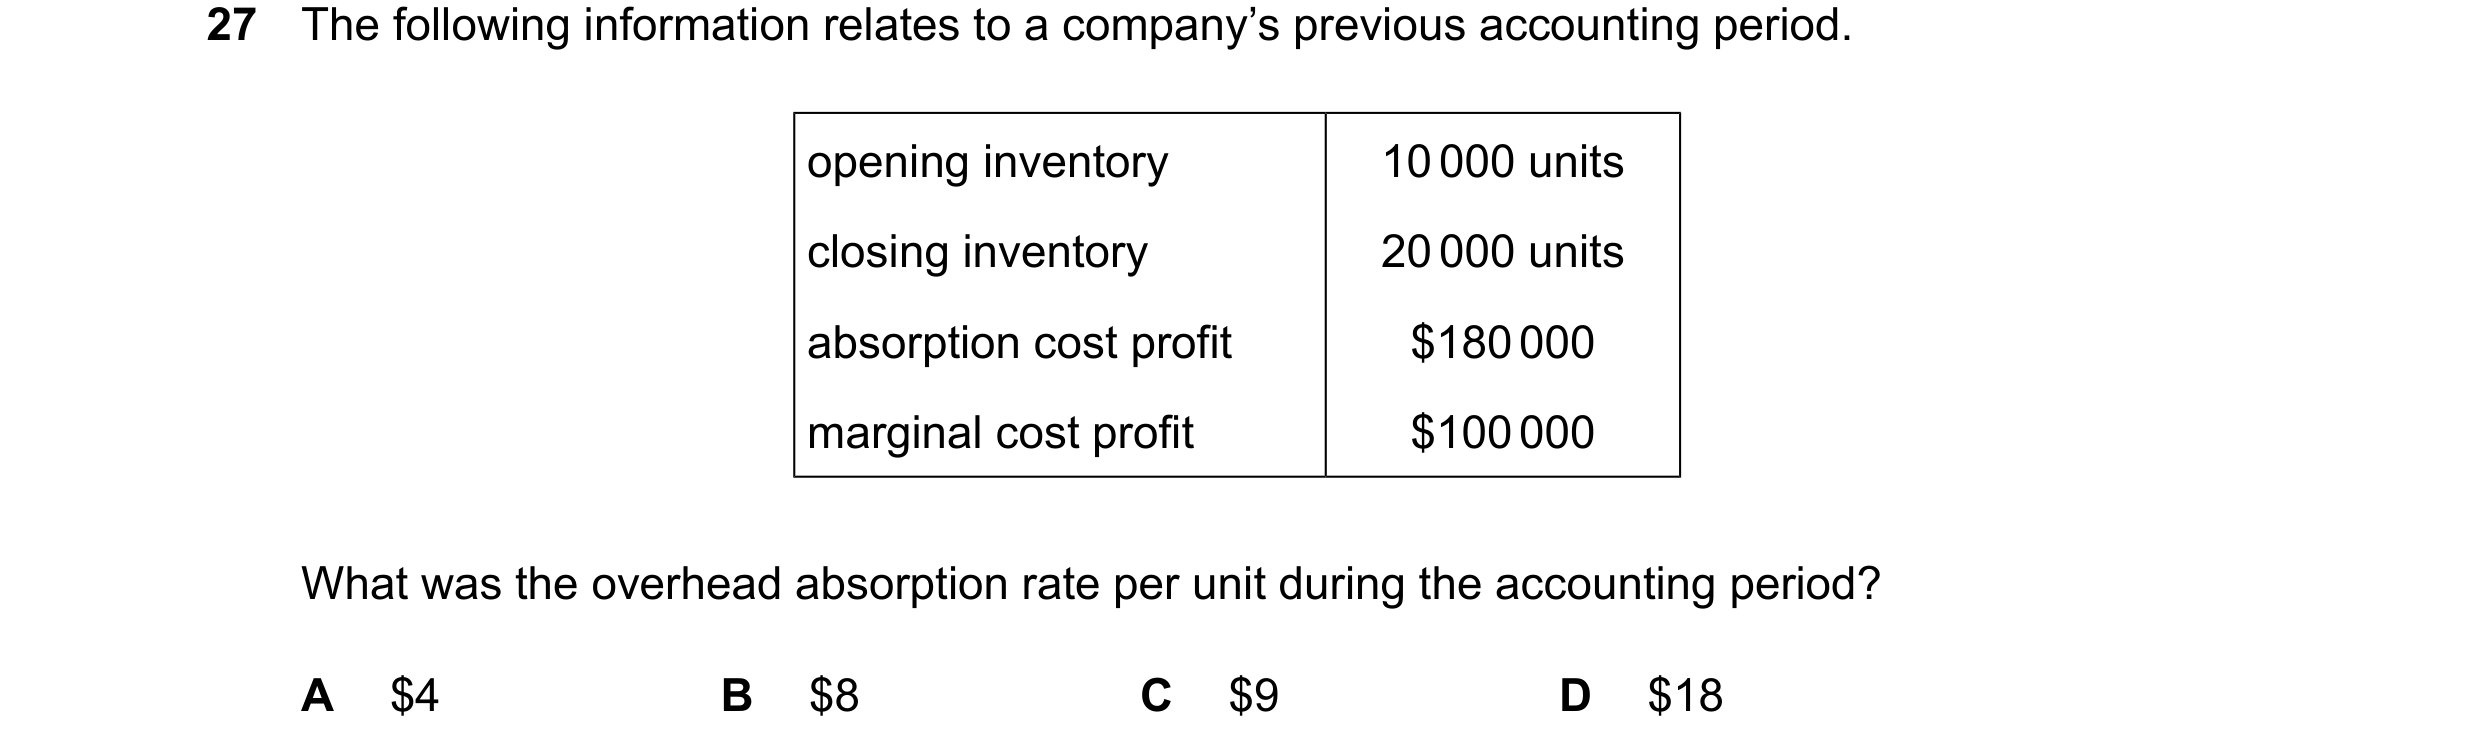 143 / 143