Cambridge A Level Accounting 9706 — 2022 Oct/Nov Paper 1 · Variant 3
9706/13/O/N/22 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
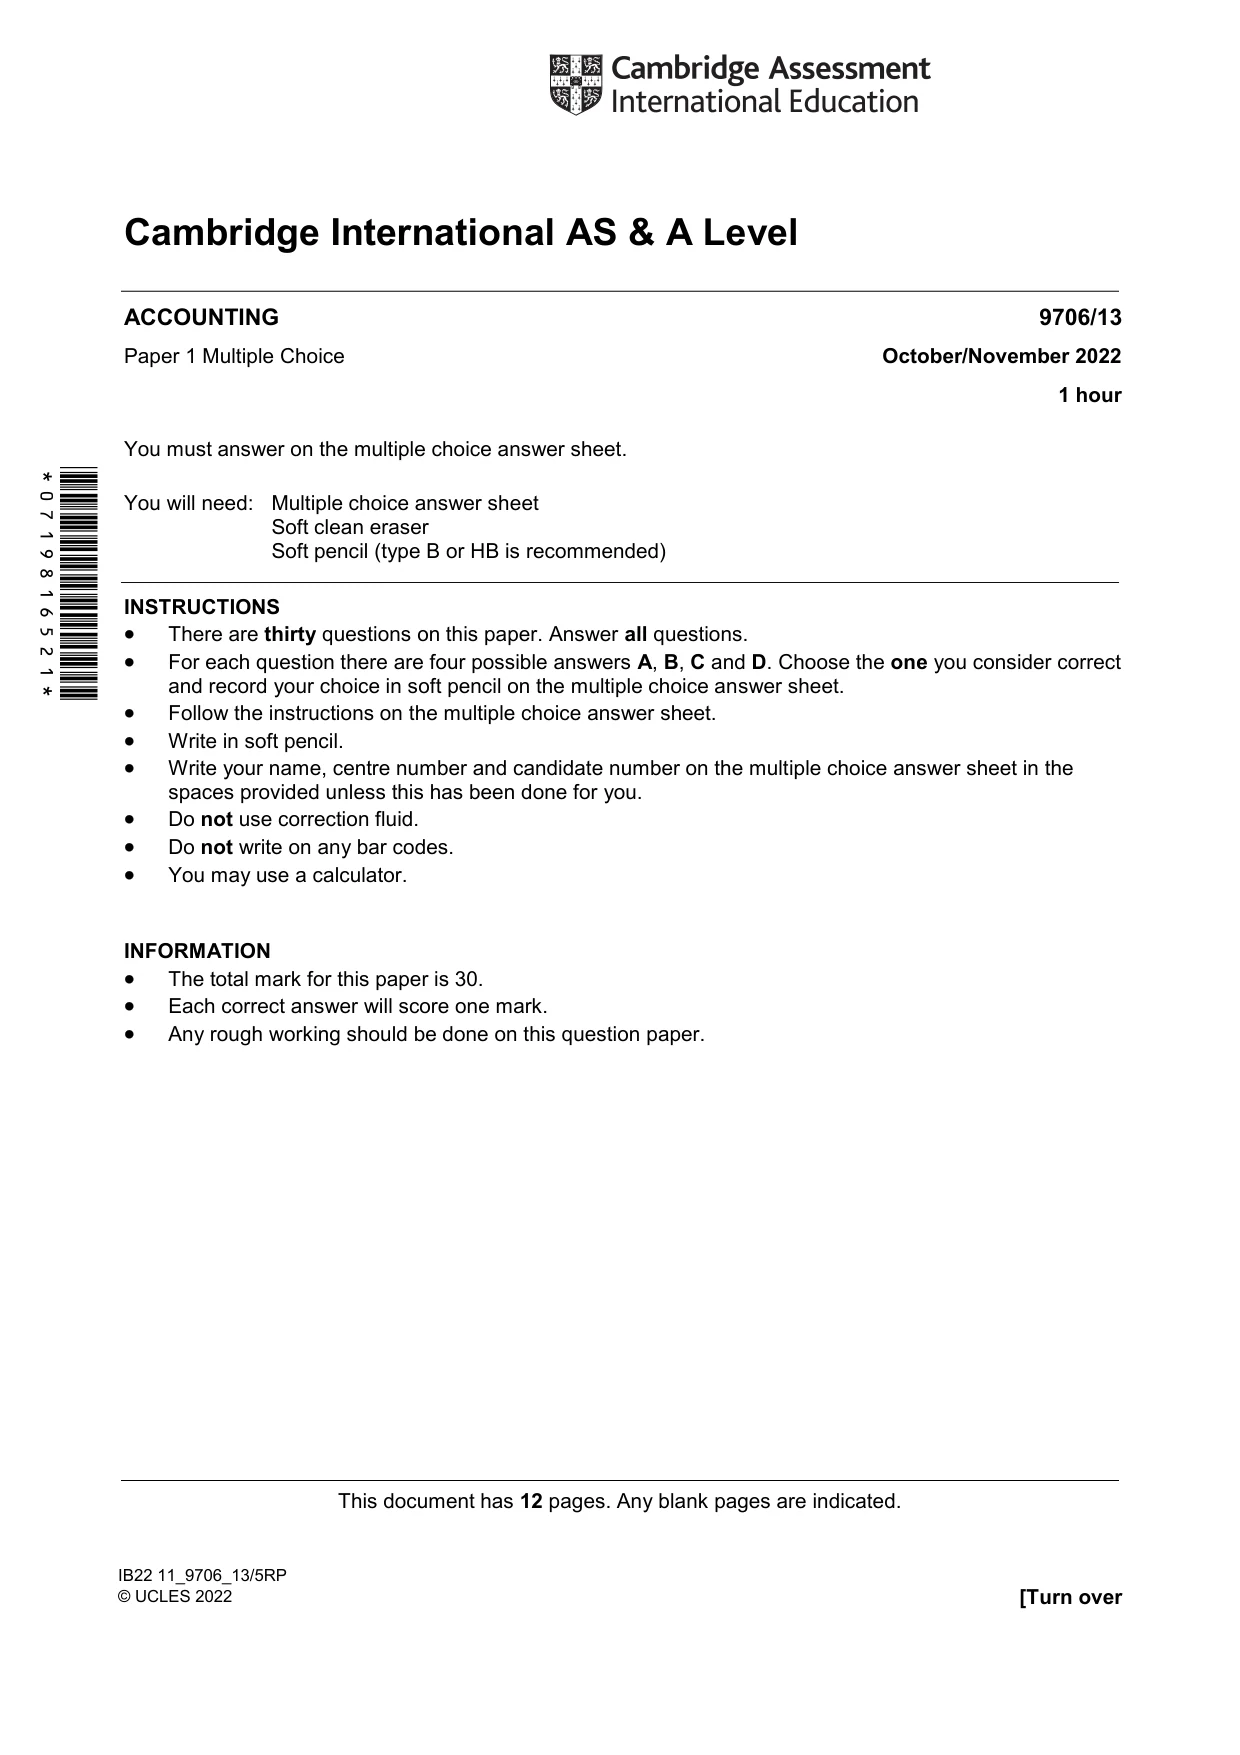
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Goods, $1200, sent to a customer on a sale or return basis have not been recorded in the…
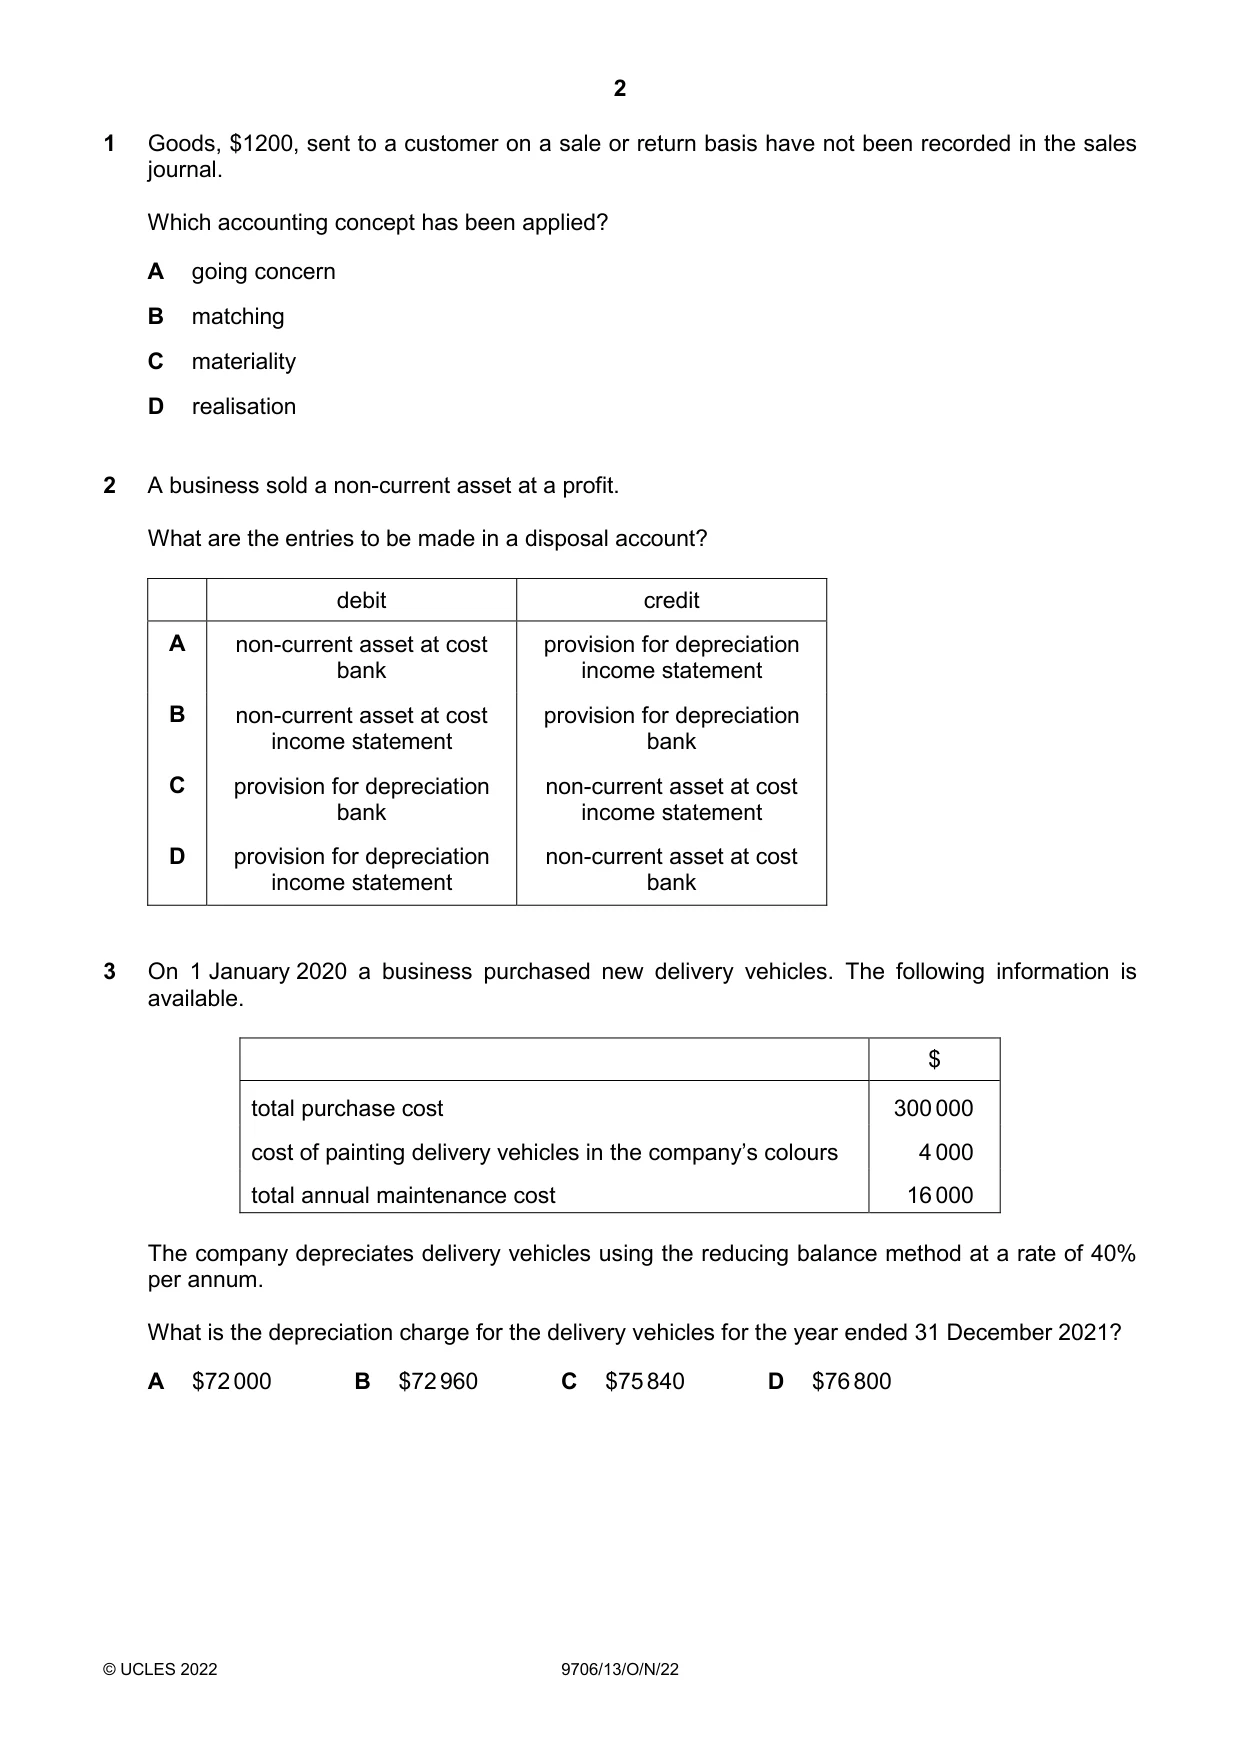
1 Goods, $1200, sent to a customer on a sale or return basis have not been recorded in the sales journal. Which accounting concept has been applied? A going concern B matching C materiality D realisation
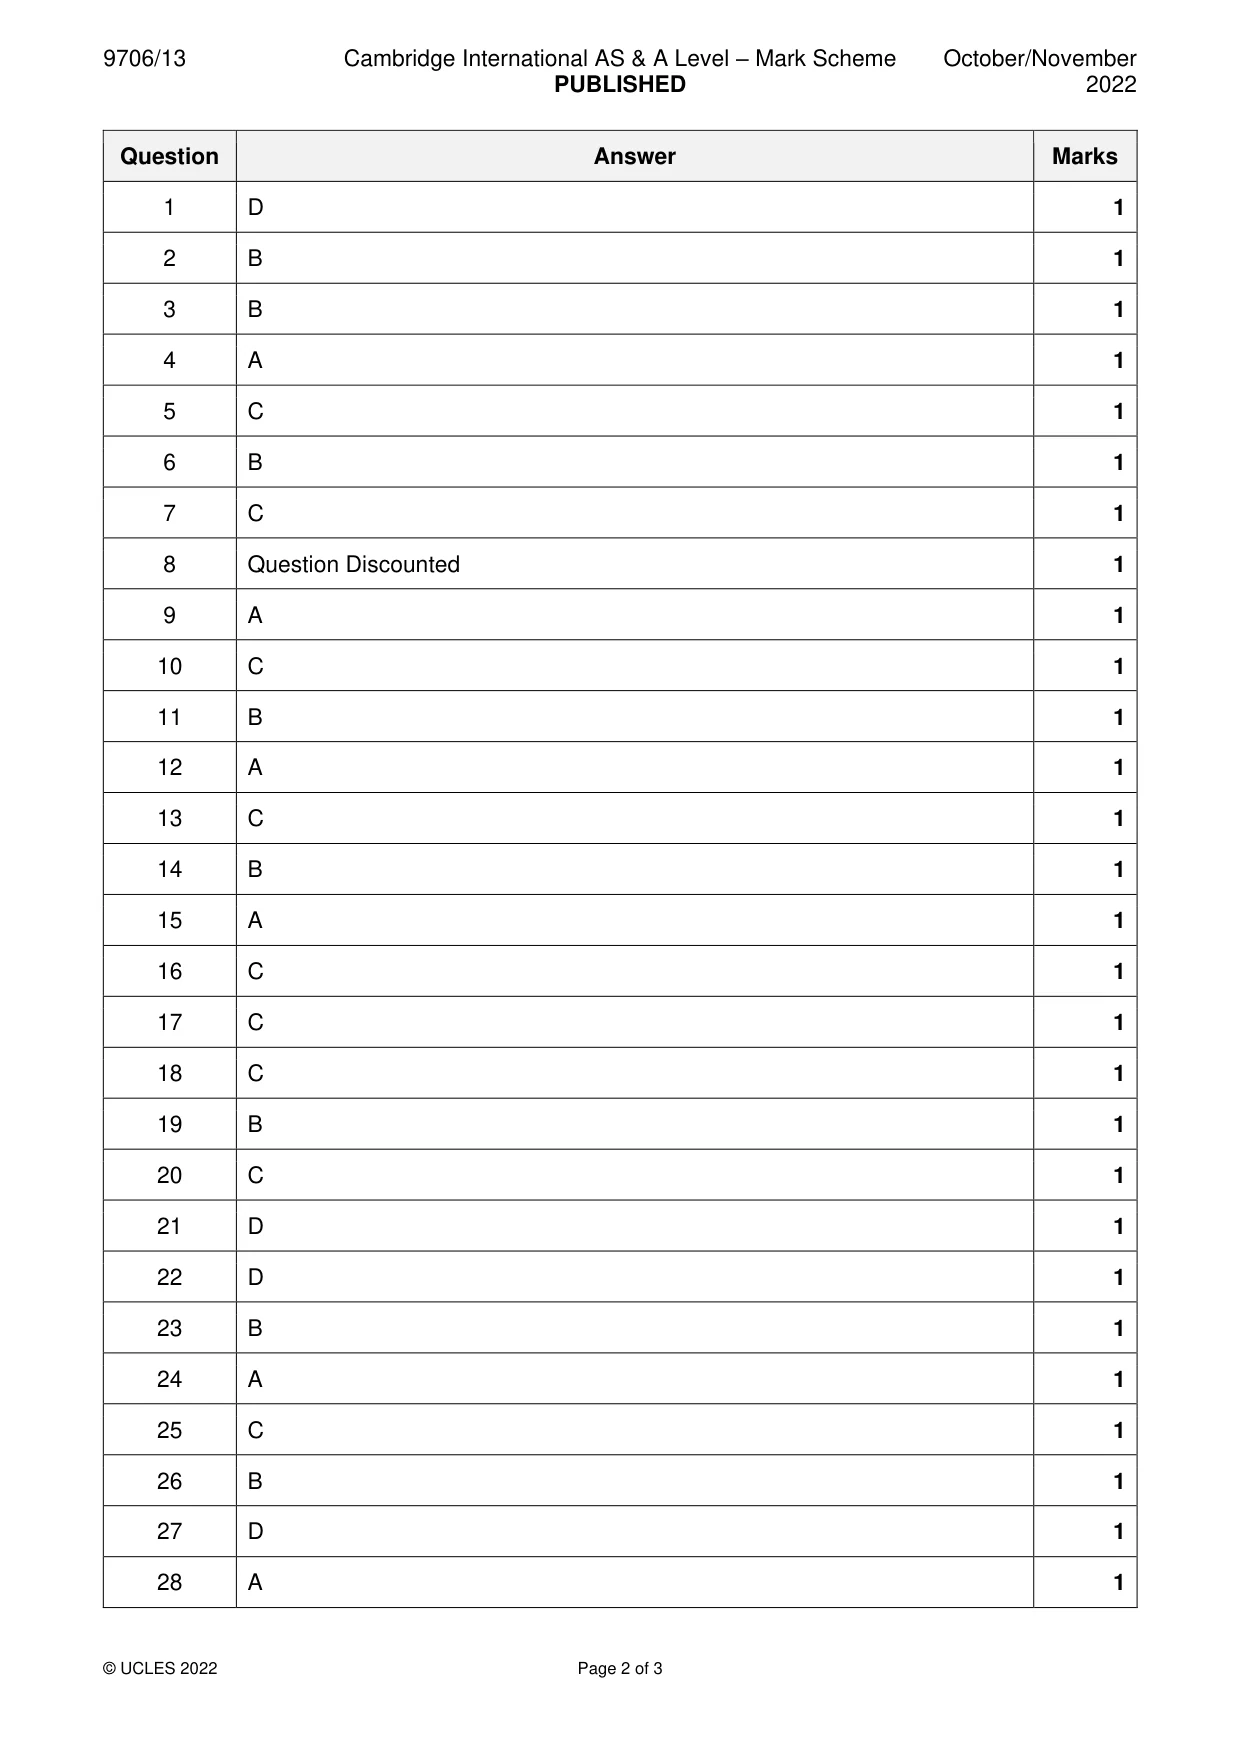
Mark scheme: D
Q2 · A business sold a non-current asset at a profit
2 A business sold a non-current asset at a profit. What are the entries to be made in a disposal account? debit credit A non-current asset at cost provision for depreciation bank income statement B non-current asset at cost provision for depreciation income statement bank C provision for depreciation non-current asset at cost bank income statement D provision for depreciation non-current asset at cost income statement bank
Mark scheme: B
Q3 · On 1 January 2020 a business purchased new delivery vehicles
3 On 1 January 2020 a business purchased new delivery vehicles. The following information is available. $ total purchase cost 300 000 cost of painting delivery vehicles in the company’s colours 4 000 total annual maintenance cost 16 000 The company depreciates delivery vehicles using the reducing balance method at a rate of 40% per annum. What is the depreciation charge for the delivery vehicles for the year ended 31 December 2021? A $72 000 B $72 960 C $75 840 D $76 800
Mark scheme: B
Q4 · The following information is available in respect of a trader’s non-current assets
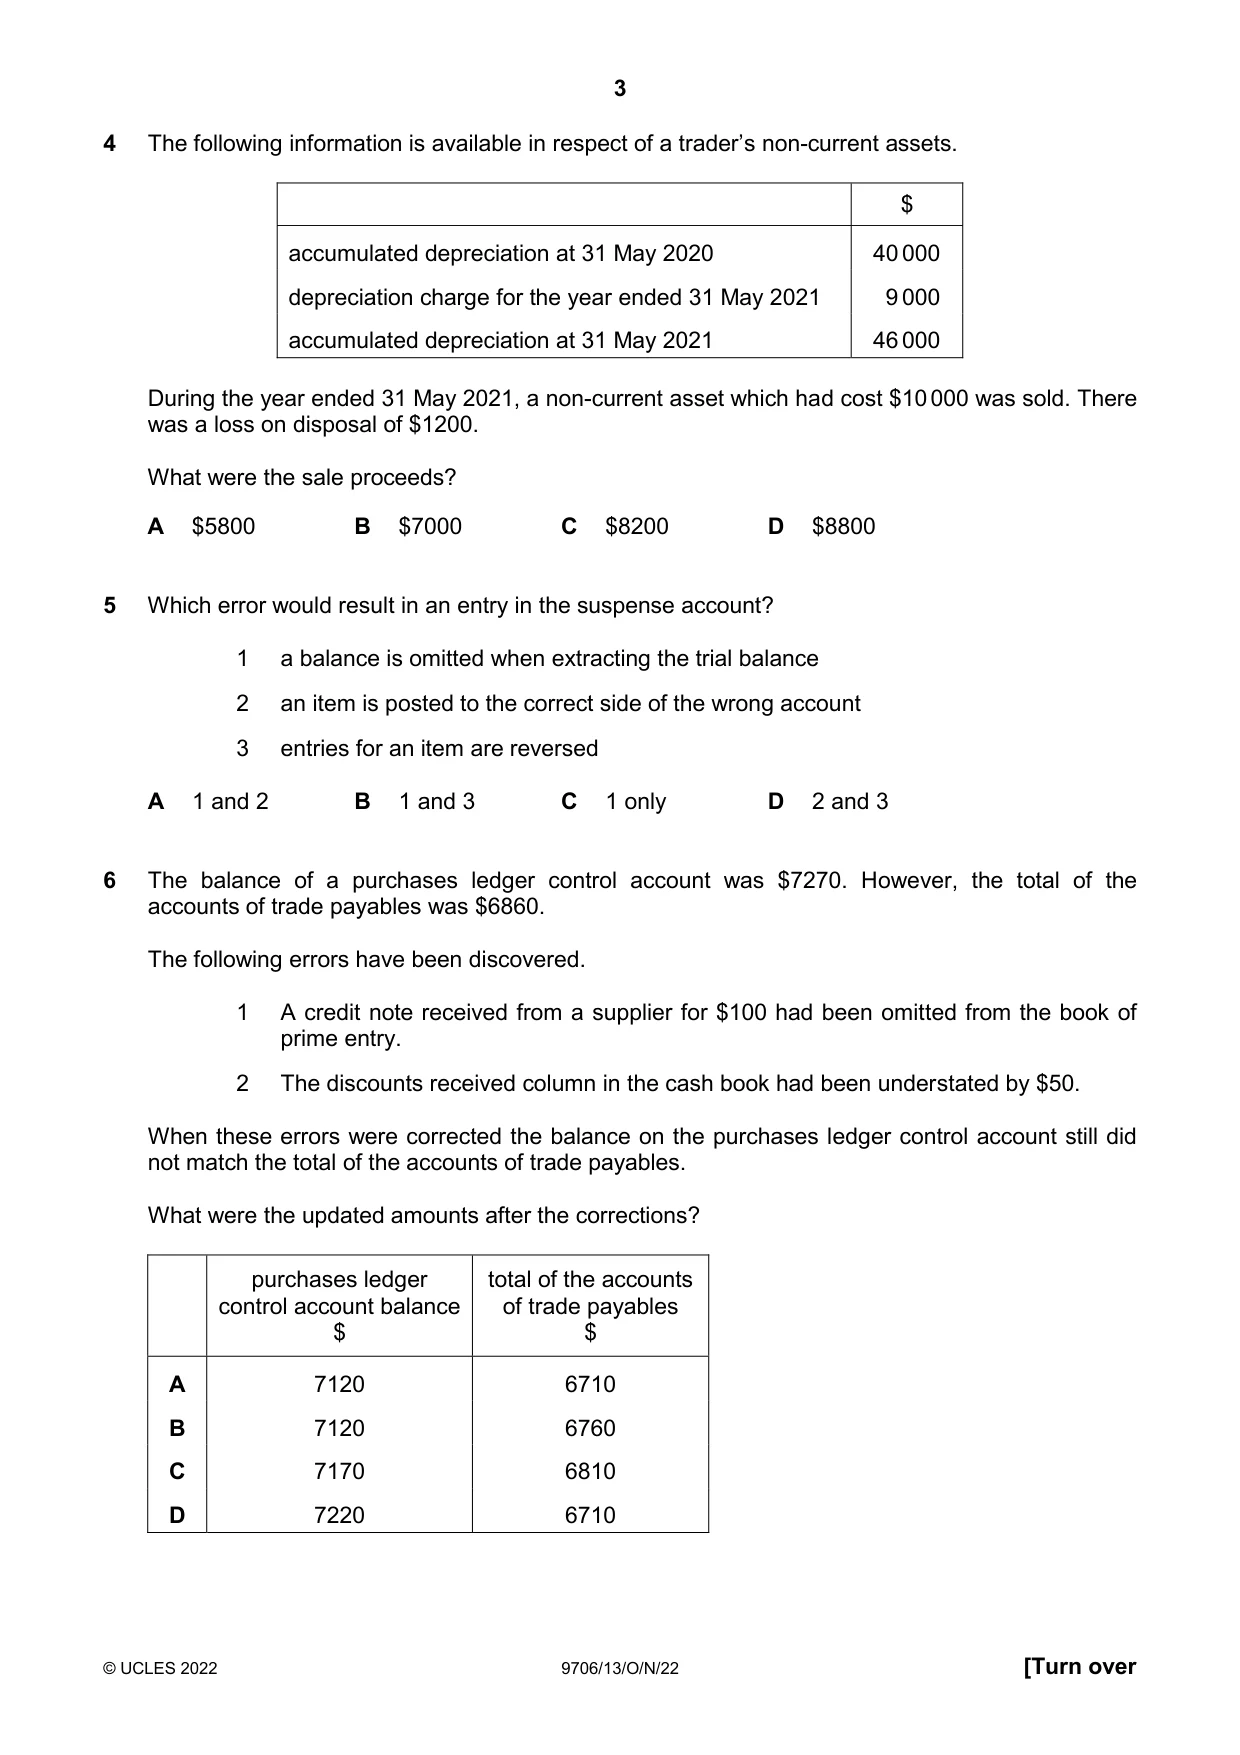
4 The following information is available in respect of a trader’s non-current assets. $ accumulated depreciation at 31 May 2020 40 000 depreciation charge for the year ended 31 May 2021 9 000 accumulated depreciation at 31 May 2021 46 000 During the year ended 31 May 2021, a non-current asset which had cost $10 000 was sold. There was a loss on disposal of $1200. What were the sale proceeds? A $5800 B $7000 C $8200 D $8800
Mark scheme: A
Q5 · Which error would result in an entry in the suspense account?
5 Which error would result in an entry in the suspense account? 1 a balance is omitted when extracting the trial balance 2 an item is posted to the correct side of the wrong account 3 entries for an item are reversed A 1 and 2 B 1 and 3 C 1 only D 2 and 3
Mark scheme: C
Q6 · The balance of a purchases ledger control account was $7270
6 The balance of a purchases ledger control account was $7270. However, the total of the accounts of trade payables was $6860. The following errors have been discovered. 1 A credit note received from a supplier for $100 had been omitted from the book of prime entry. 2 The discounts received column in the cash book had been understated by $50. When these errors were corrected the balance on the purchases ledger control account still did not match the total of the accounts of trade payables. What were the updated amounts after the corrections? purchases ledger total of the accounts control account balance of trade payables $ $ A 7120 6710 B 7120 6760 C 7170 6810 D 7220 6710
Mark scheme: B
Q7 · Which group would appear only on the credit side of a sales ledger control account?
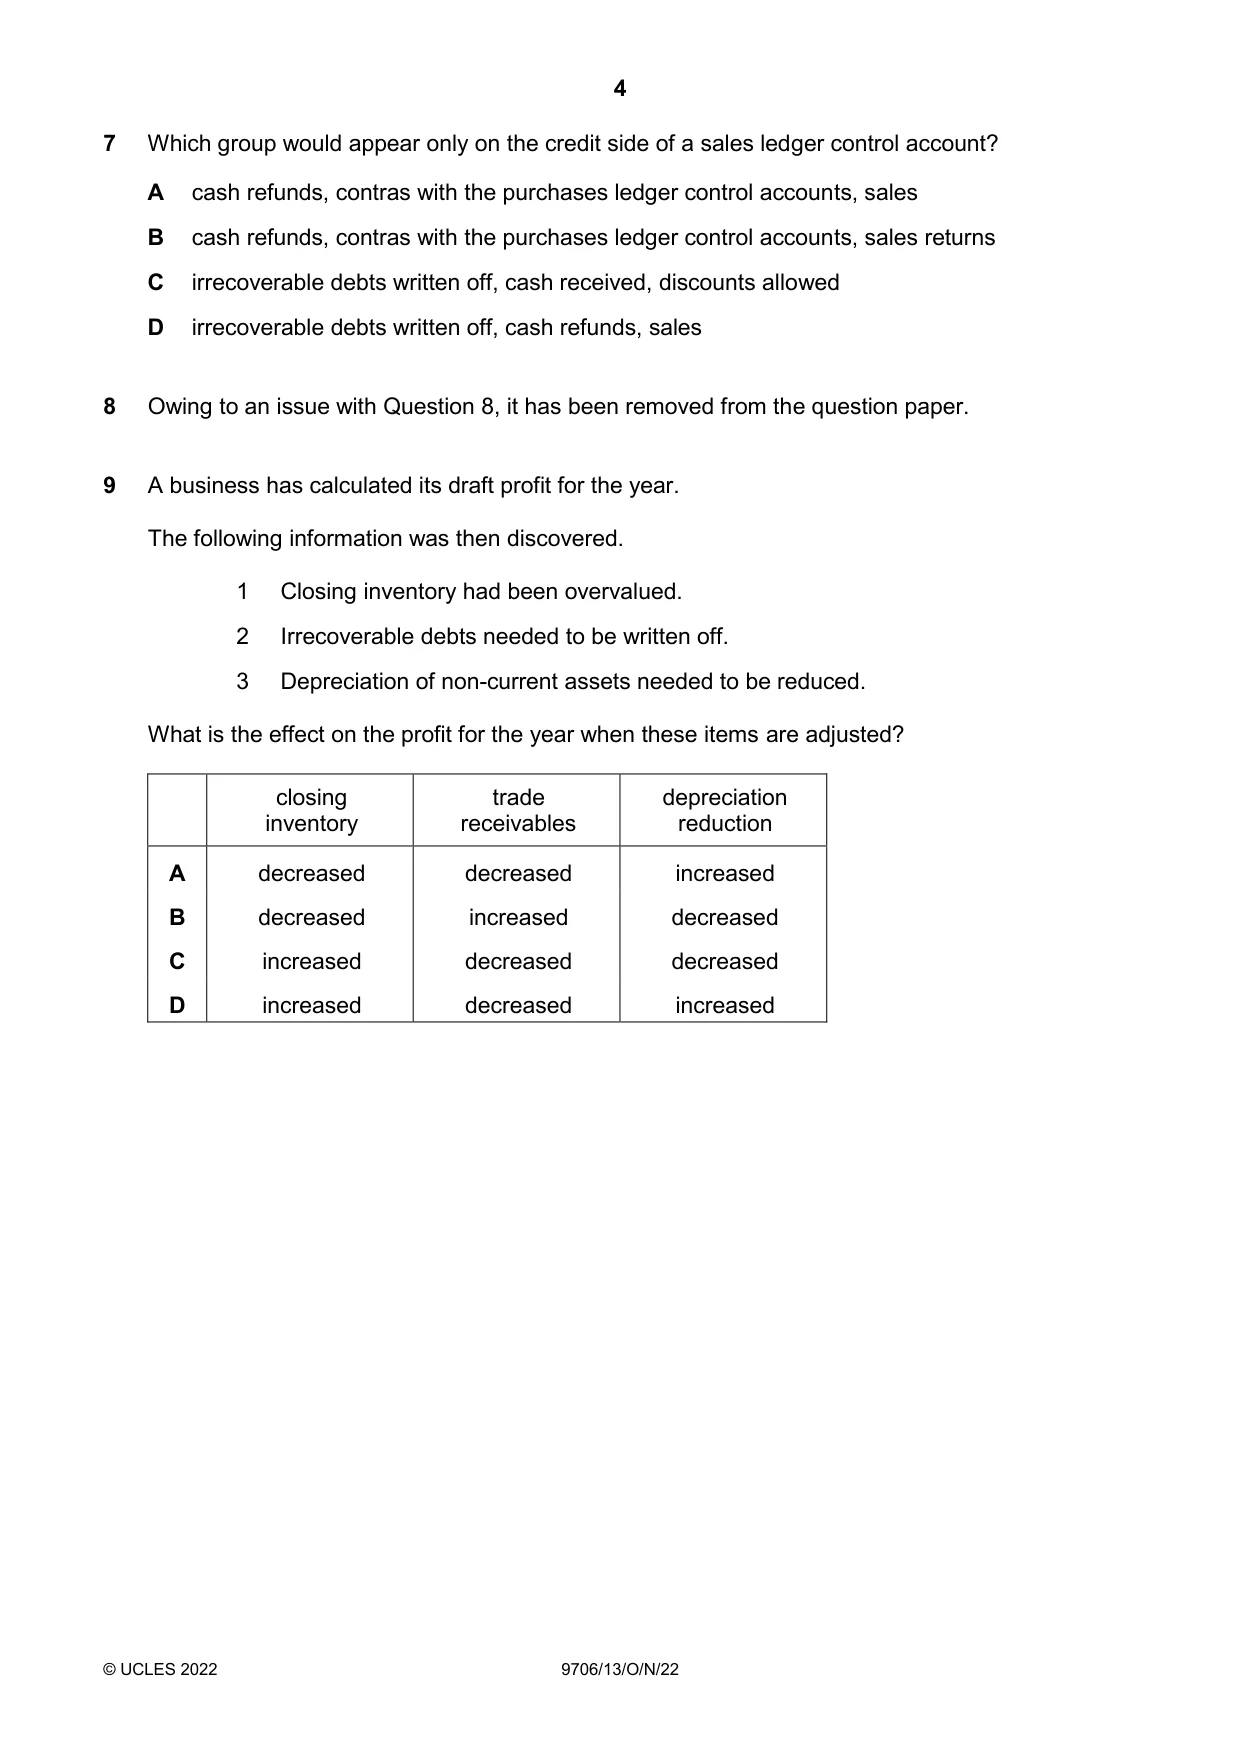
7 Which group would appear only on the credit side of a sales ledger control account? A cash refunds, contras with the purchases ledger control accounts, sales B cash refunds, contras with the purchases ledger control accounts, sales returns C irrecoverable debts written off, cash received, discounts allowed D irrecoverable debts written off, cash refunds, sales
Mark scheme: C
Q8 · Owing to an issue with Question 8, it has been removed from the question paper
8 Owing to an issue with Question 8, it has been removed from the question paper.
Q9 · A business has calculated its draft profit for the year
9 A business has calculated its draft profit for the year. The following information was then discovered. 1 Closing inventory had been overvalued. 2 Irrecoverable debts needed to be written off. 3 Depreciation of non-current assets needed to be reduced. What is the effect on the profit for the year when these items are adjusted? closing trade depreciation inventory receivables reduction A decreased decreased increased B decreased increased decreased C increased decreased decreased D increased decreased increased
Mark scheme: A
Q10 · A business makes a provision for doubtful debts of 4%
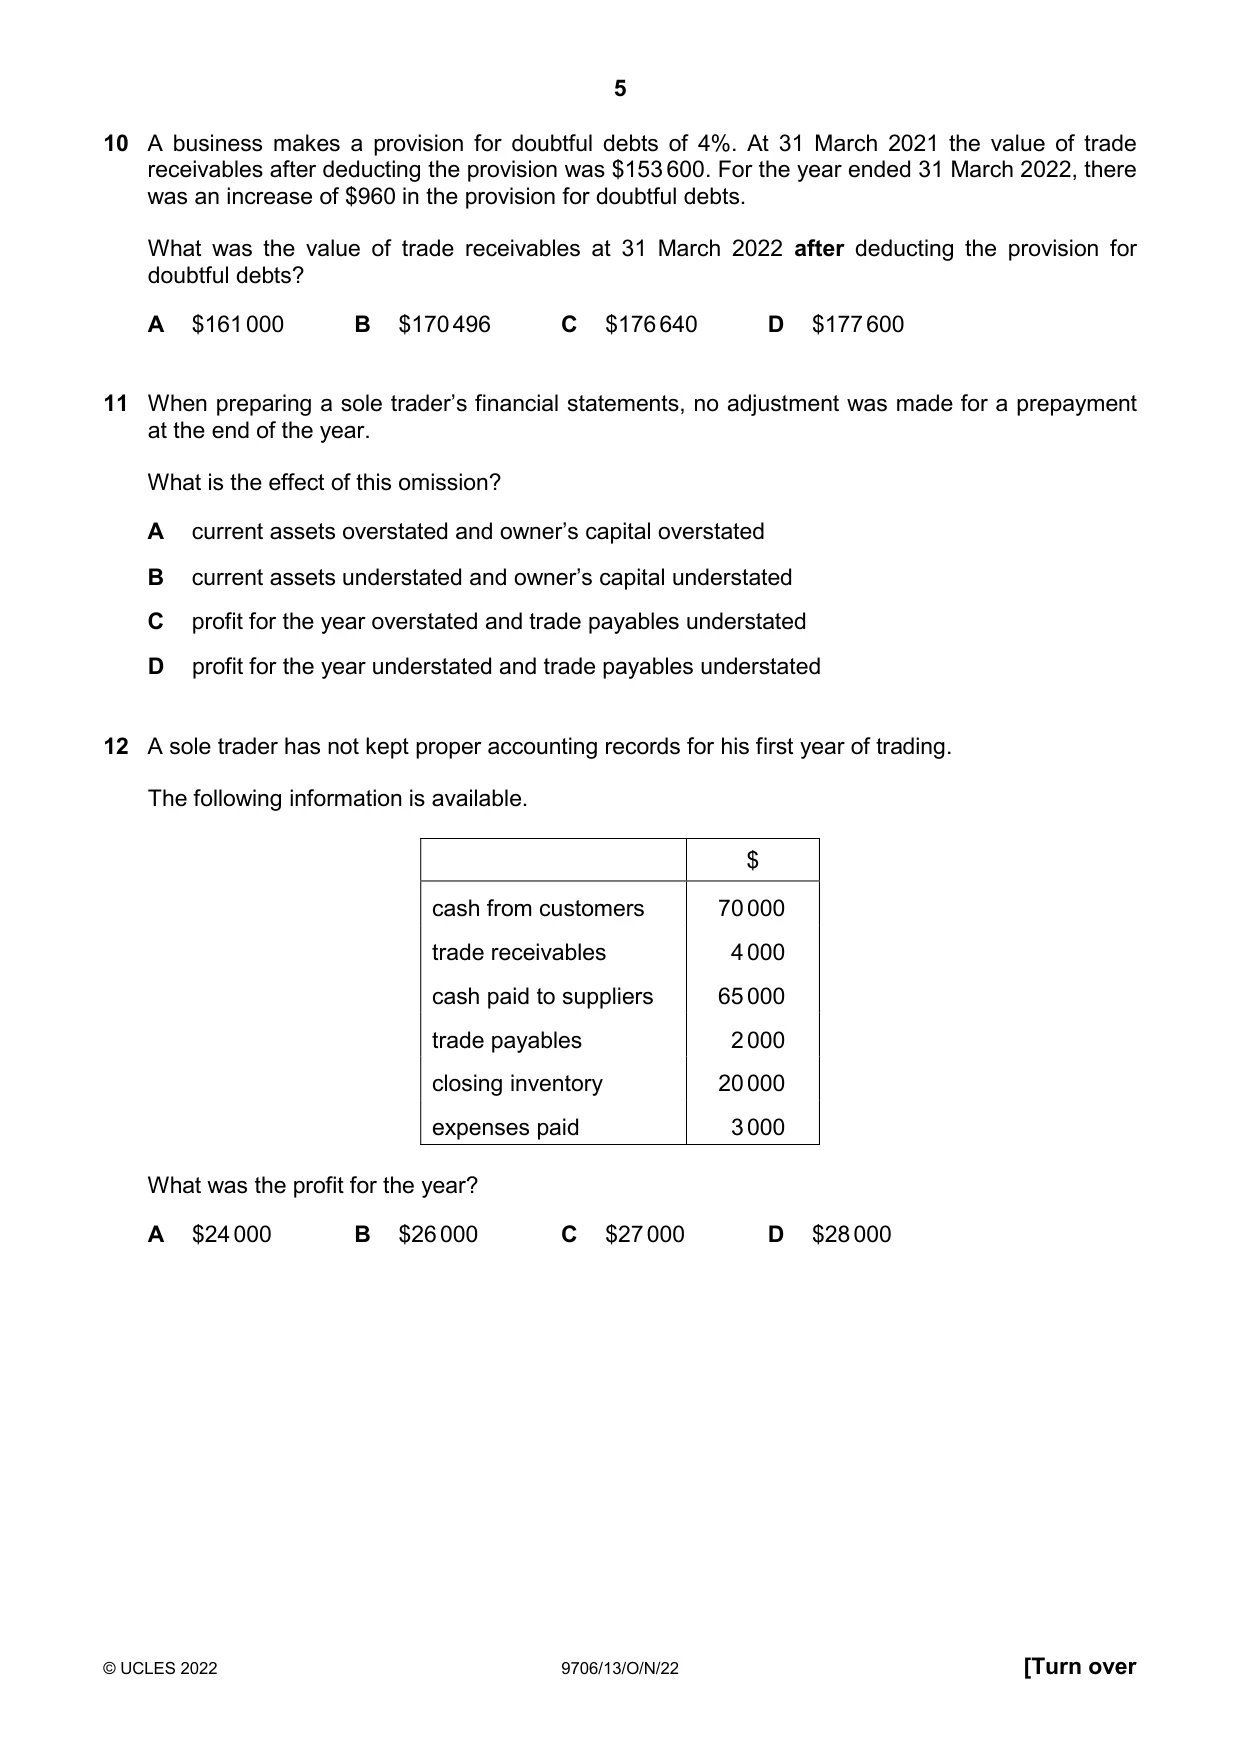
10 A business makes a provision for doubtful debts of 4%. At 31 March 2021 the value of trade receivables after deducting the provision was $153 600. For the year ended 31 March 2022, there was an increase of $960 in the provision for doubtful debts. What was the value of trade receivables at 31 March 2022 after deducting the provision for doubtful debts? A $161 000 B $170 496 C $176 640 D $177 600
Mark scheme: C
Q11 · When preparing a sole trader’s financial statements, no adjustment was made for a…
11 When preparing a sole trader’s financial statements, no adjustment was made for a prepayment at the end of the year. What is the effect of this omission? A current assets overstated and owner’s capital overstated B current assets understated and owner’s capital understated C profit for the year overstated and trade payables understated D profit for the year understated and trade payables understated
Mark scheme: B
Q12 · A sole trader has not kept proper accounting records for his first year of trading
12 A sole trader has not kept proper accounting records for his first year of trading. The following information is available. $ cash from customers 70 000 trade receivables 4 000 cash paid to suppliers 65 000 trade payables 2 000 closing inventory 20 000 expenses paid 3 000 What was the profit for the year? A $24 000 B $26 000 C $27 000 D $28 000
Mark scheme: A
Q13 · On 1 January 2022 a sole trader’s inventory was valued at $4500
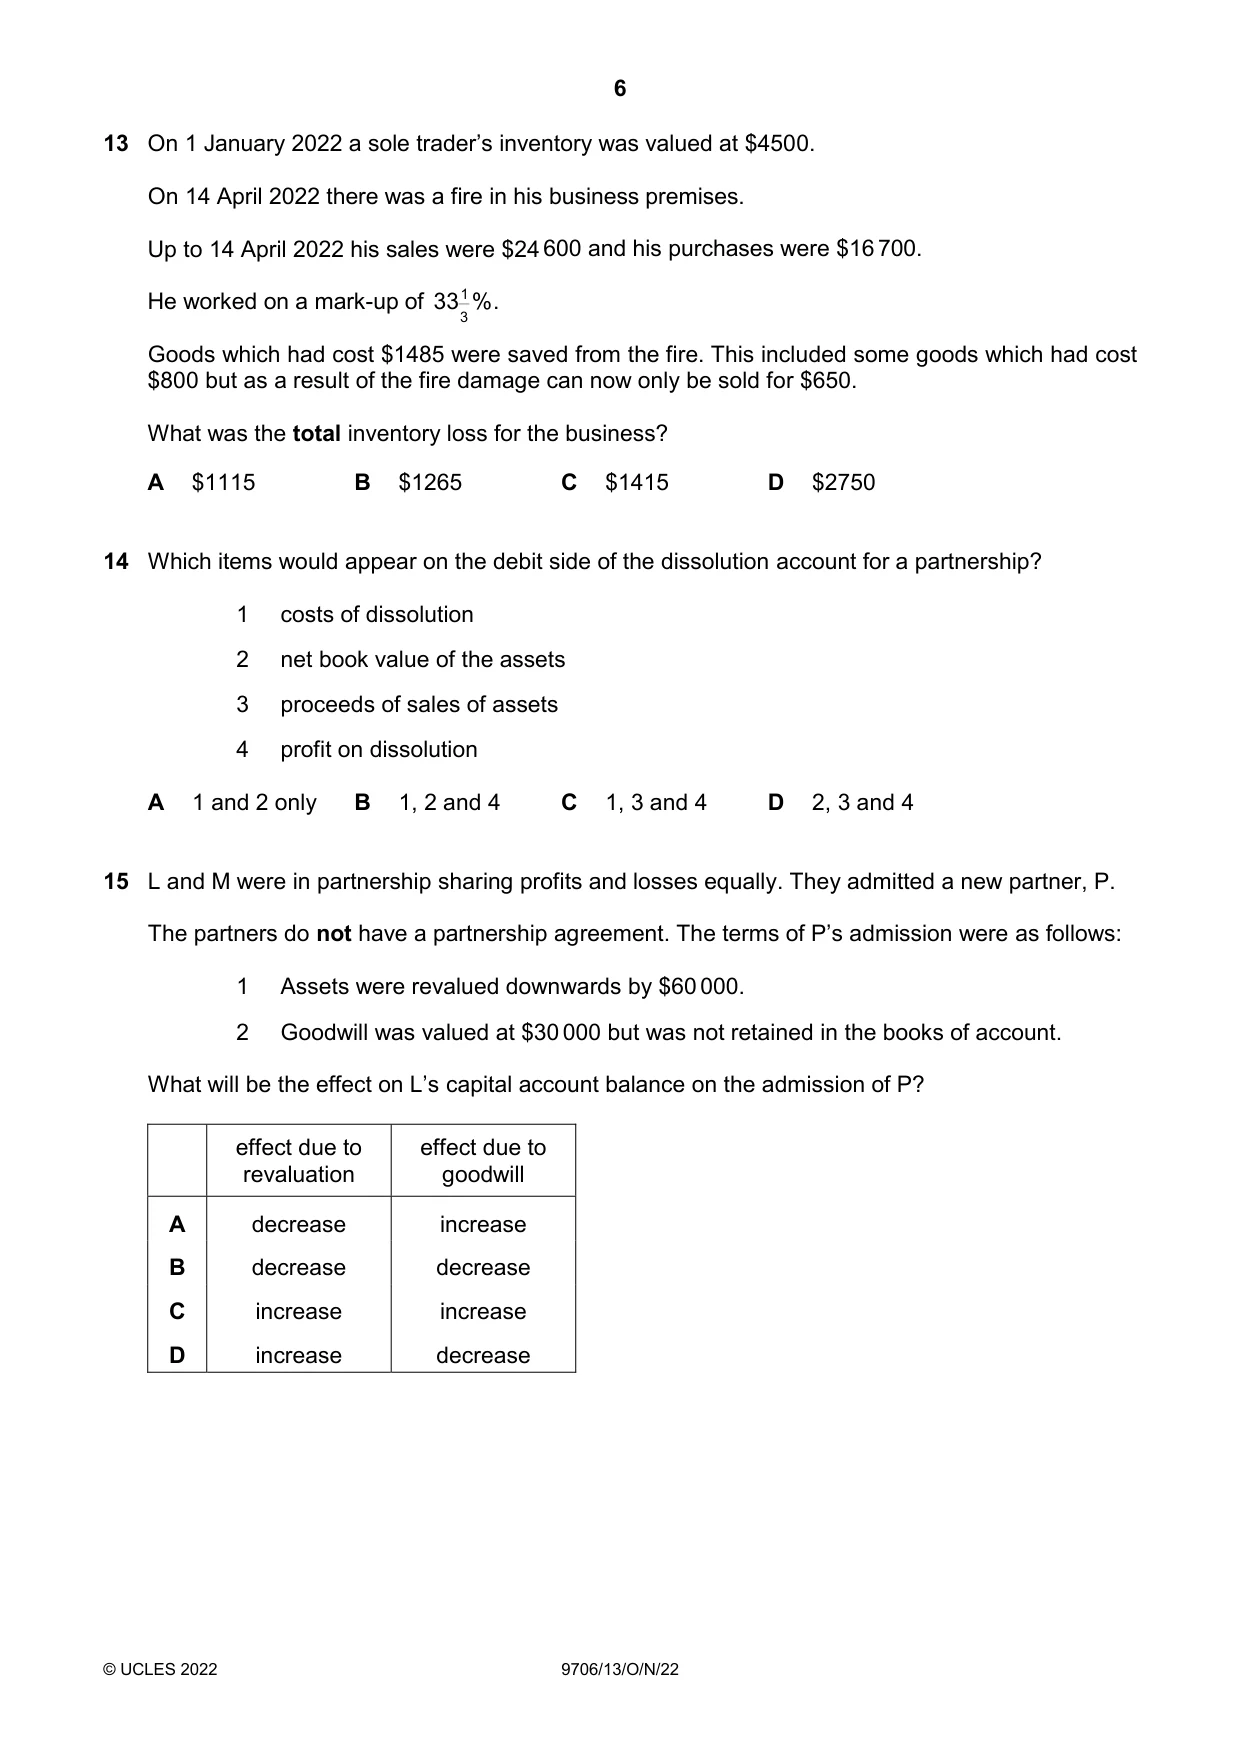
13 On 1 January 2022 a sole trader’s inventory was valued at $4500. On 14 April 2022 there was a fire in his business premises. Up to 14 April 2022 his sales were $24 600 and his purchases were $16 700. He worked on a mark-up of 33 %. 1 3 Goods which had cost $1485 were saved from the fire. This included some goods which had cost $800 but as a result of the fire damage can now only be sold for $650. What was the total inventory loss for the business? A $1115 B $1265 C $1415 D $2750
Mark scheme: C
Q14 · Which items would appear on the debit side of the dissolution account for a partnership?
14 Which items would appear on the debit side of the dissolution account for a partnership? 1 costs of dissolution 2 net book value of the assets 3 proceeds of sales of assets 4 profit on dissolution A 1 and 2 only B 1, 2 and 4 C 1, 3 and 4 D 2, 3 and 4
Mark scheme: B
Q15 · L and M were in partnership sharing profits and losses equally
15 L and M were in partnership sharing profits and losses equally. They admitted a new partner, P. The partners do not have a partnership agreement. The terms of P’s admission were as follows: 1 Assets were revalued downwards by $60 000. 2 Goodwill was valued at $30 000 but was not retained in the books of account. What will be the effect on L’s capital account balance on the admission of P? effect due to effect due to revaluation goodwill A decrease increase B decrease decrease C increase increase D increase decrease
Mark scheme: A
Q16 · J and K are in partnership sharing residual profits and losses in the ratio 7 : 3
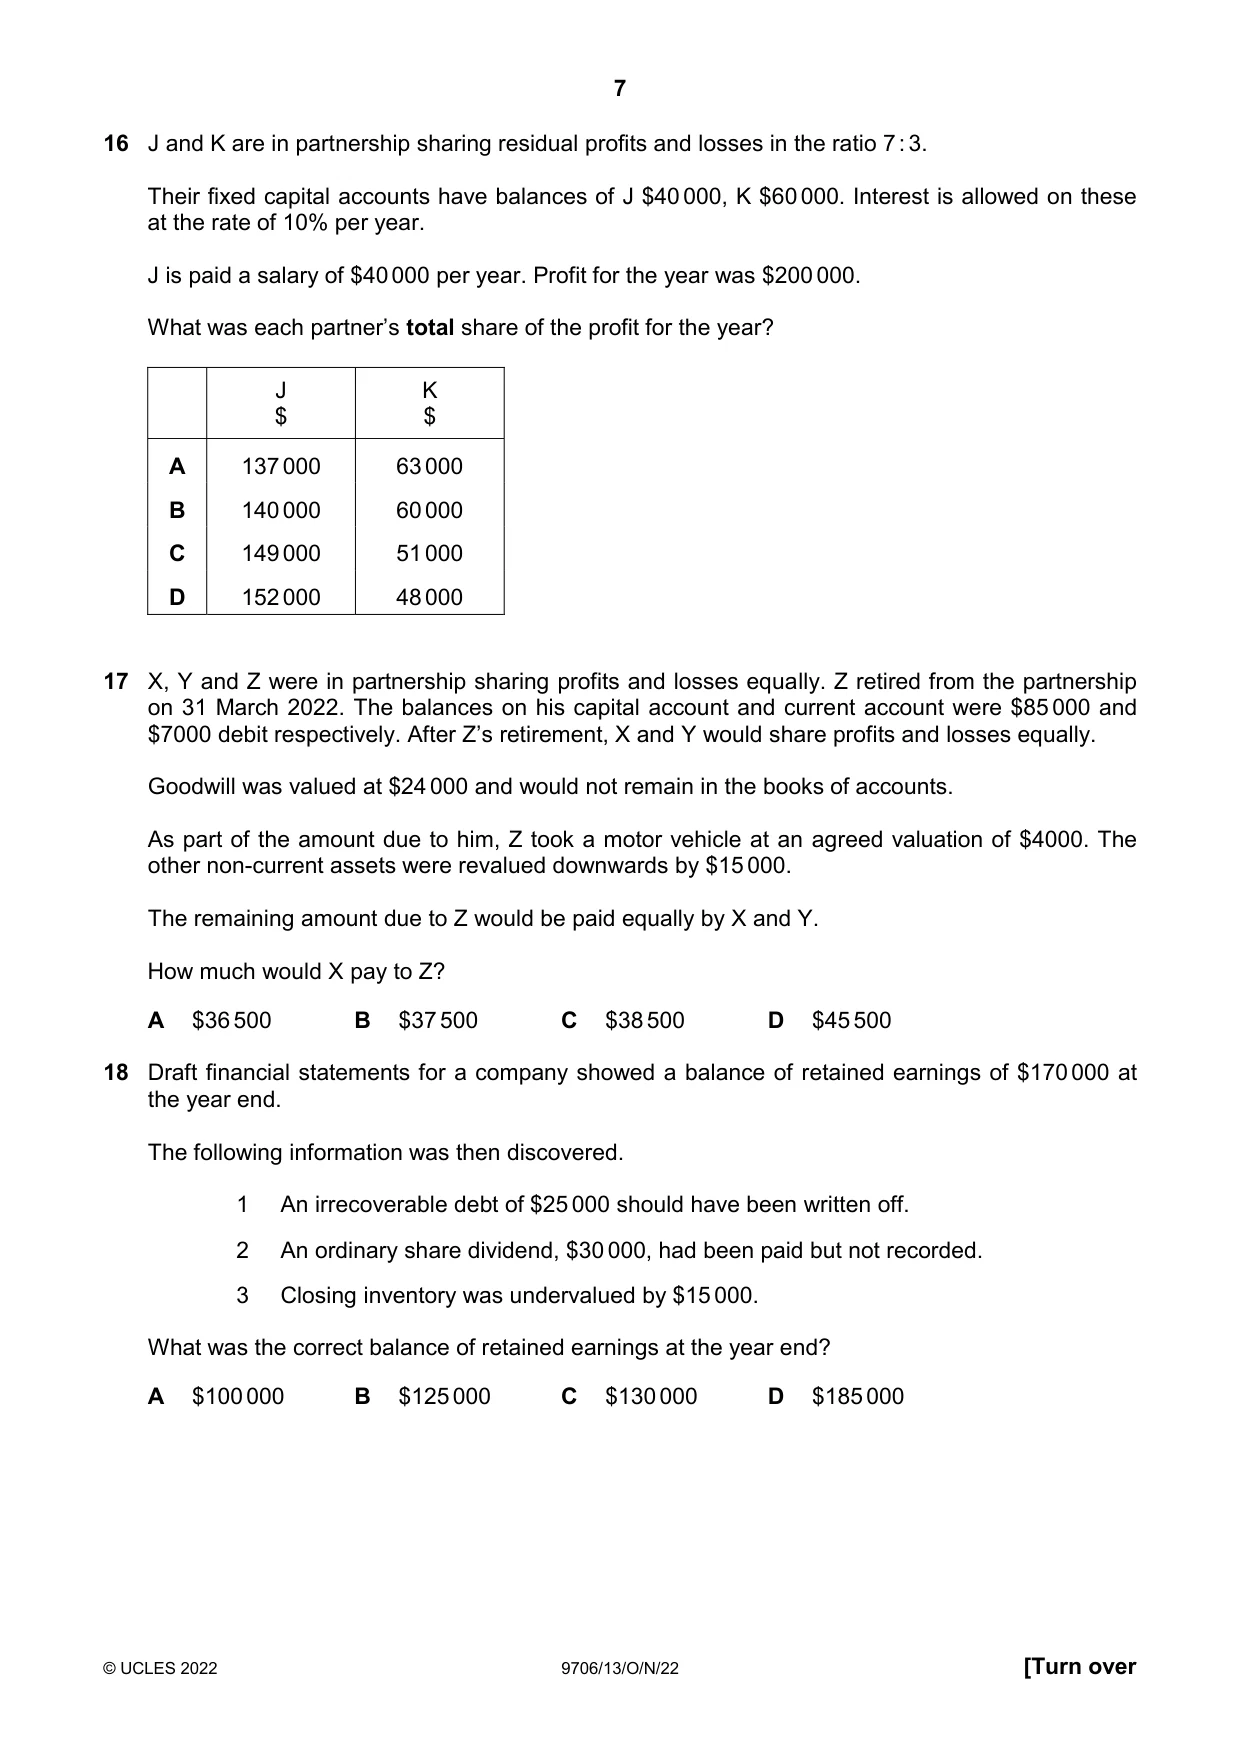
16 J and K are in partnership sharing residual profits and losses in the ratio 7 : 3. Their fixed capital accounts have balances of J $40 000, K $60 000. Interest is allowed on these at the rate of 10% per year. J is paid a salary of $40 000 per year. Profit for the year was $200 000. What was each partner’s total share of the profit for the year? J K $ $ A 137 000 63 000 B 140 000 60 000 C 149 000 51 000 D 152 000 48 000
Mark scheme: C
Q17 · X, Y and Z were in partnership sharing profits and losses equally
17 X, Y and Z were in partnership sharing profits and losses equally. Z retired from the partnership on 31 March 2022. The balances on his capital account and current account were $85 000 and $7000 debit respectively. After Z’s retirement, X and Y would share profits and losses equally. Goodwill was valued at $24 000 and would not remain in the books of accounts. As part of the amount due to him, Z took a motor vehicle at an agreed valuation of $4000. The other non-current assets were revalued downwards by $15 000. The remaining amount due to Z would be paid equally by X and Y. How much would X pay to Z? A $36 500 B $37 500 C $38 500 D $45 500
Mark scheme: C
Q18 · Draft financial statements for a company showed a balance of retained earnings of $170…
18 Draft financial statements for a company showed a balance of retained earnings of $170 000 at the year end. The following information was then discovered. 1 An irrecoverable debt of $25 000 should have been written off. 2 An ordinary share dividend, $30 000, had been paid but not recorded. 3 Closing inventory was undervalued by $15 000. What was the correct balance of retained earnings at the year end? A $100 000 B $125 000 C $130 000 D $185 000
Mark scheme: C
Q19 · A company provided the following information
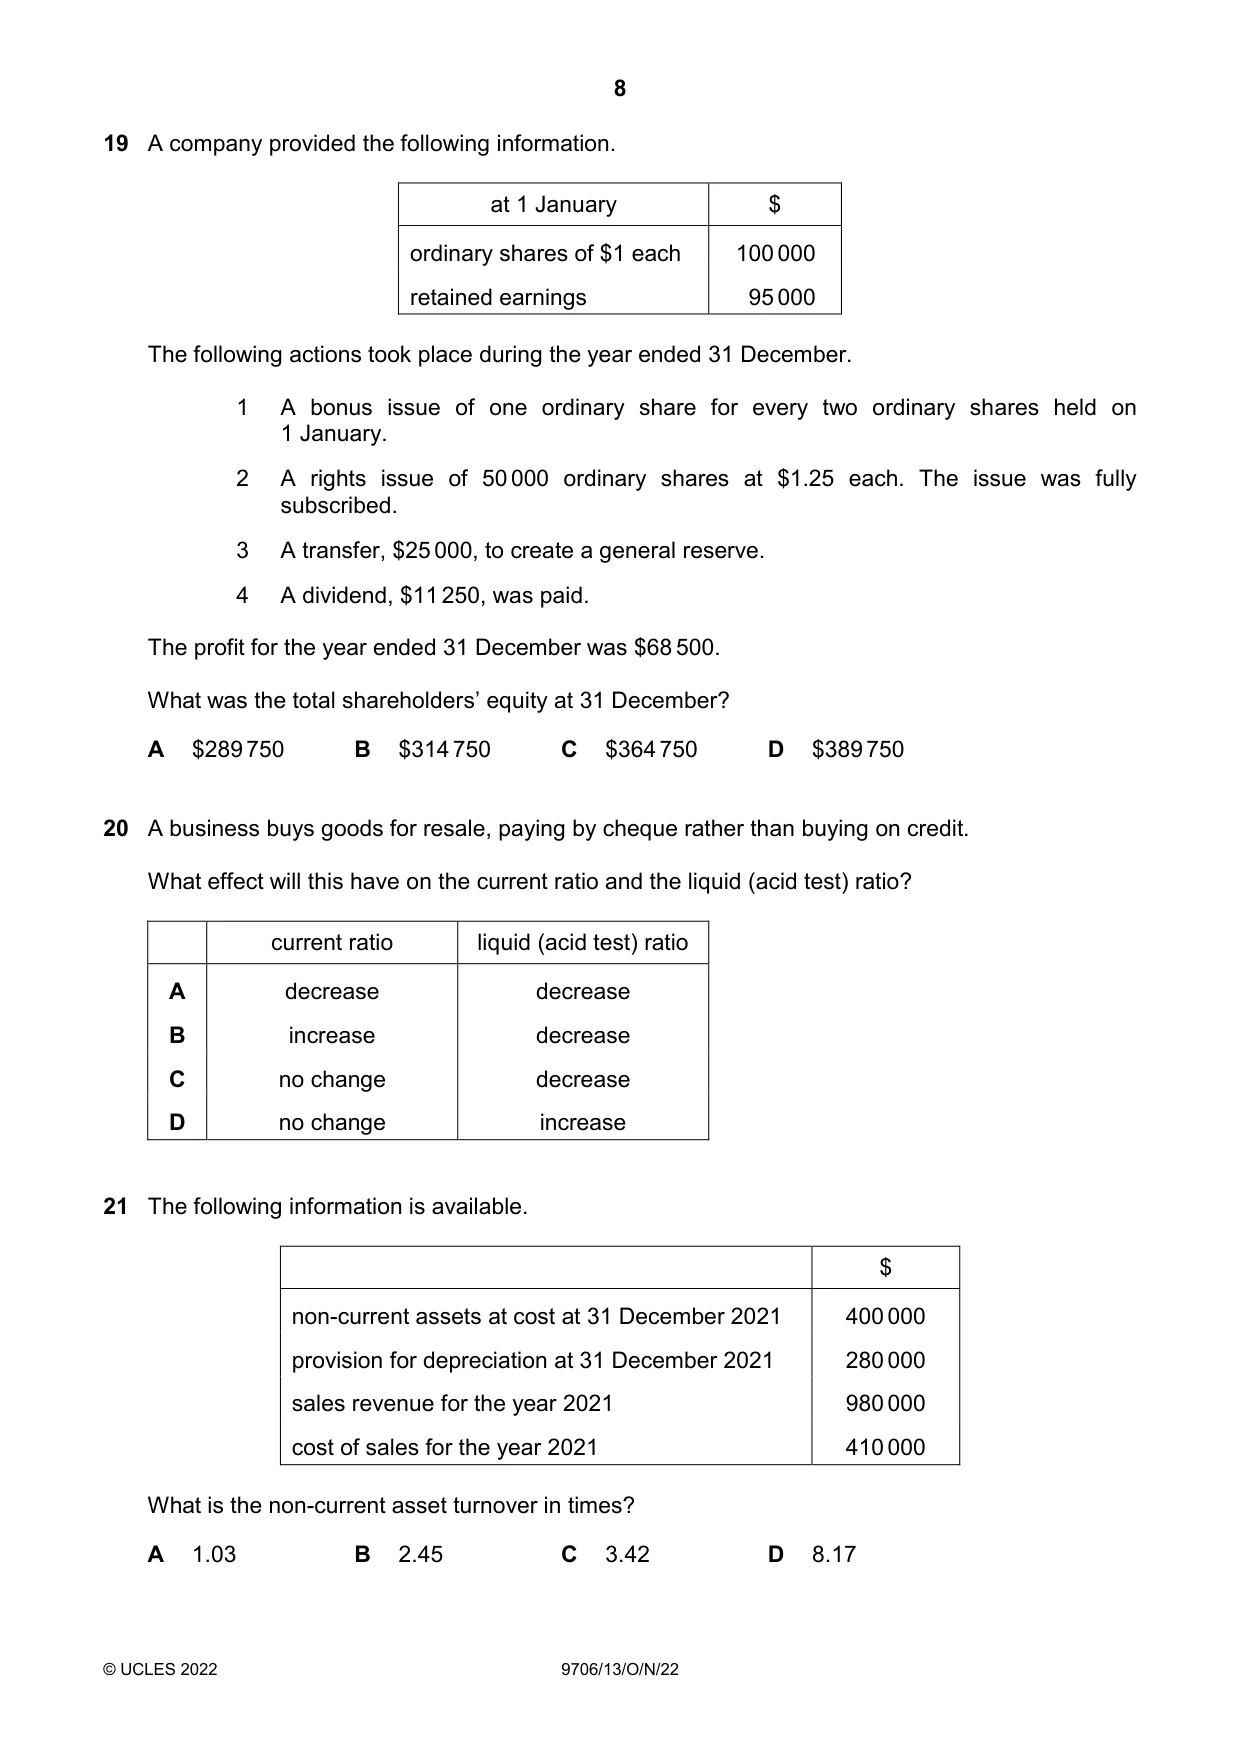
19 A company provided the following information. at 1 January $ ordinary shares of $1 each 100 000 retained earnings 95 000 The following actions took place during the year ended 31 December. 1 A bonus issue of one ordinary share for every two ordinary shares held on 1 January. 2 A rights issue of 50 000 ordinary shares at $1.25 each. The issue was fully subscribed. 3 A transfer, $25 000, to create a general reserve. 4 A dividend, $11 250, was paid. The profit for the year ended 31 December was $68 500. What was the total shareholders’ equity at 31 December? A $289 750 B $314 750 C $364 750 D $389 750
Mark scheme: B
Q20 · A business buys goods for resale, paying by cheque rather than buying on credit
20 A business buys goods for resale, paying by cheque rather than buying on credit. What effect will this have on the current ratio and the liquid (acid test) ratio? current ratio liquid (acid test) ratio A decrease decrease B increase decrease C no change decrease D no change increase
Mark scheme: C
More questions on Analysis and communication of accounting information
Q21 · The following information is available
21 The following information is available. $ non-current assets at cost at 31 December 2021 400 000 provision for depreciation at 31 December 2021 280 000 sales revenue for the year 2021 980 000 cost of sales for the year 2021 410 000 What is the non-current asset turnover in times? A 1.03 B 2.45 C 3.42 D 8.17
Mark scheme: D
More questions on Analysis and communication of accounting information
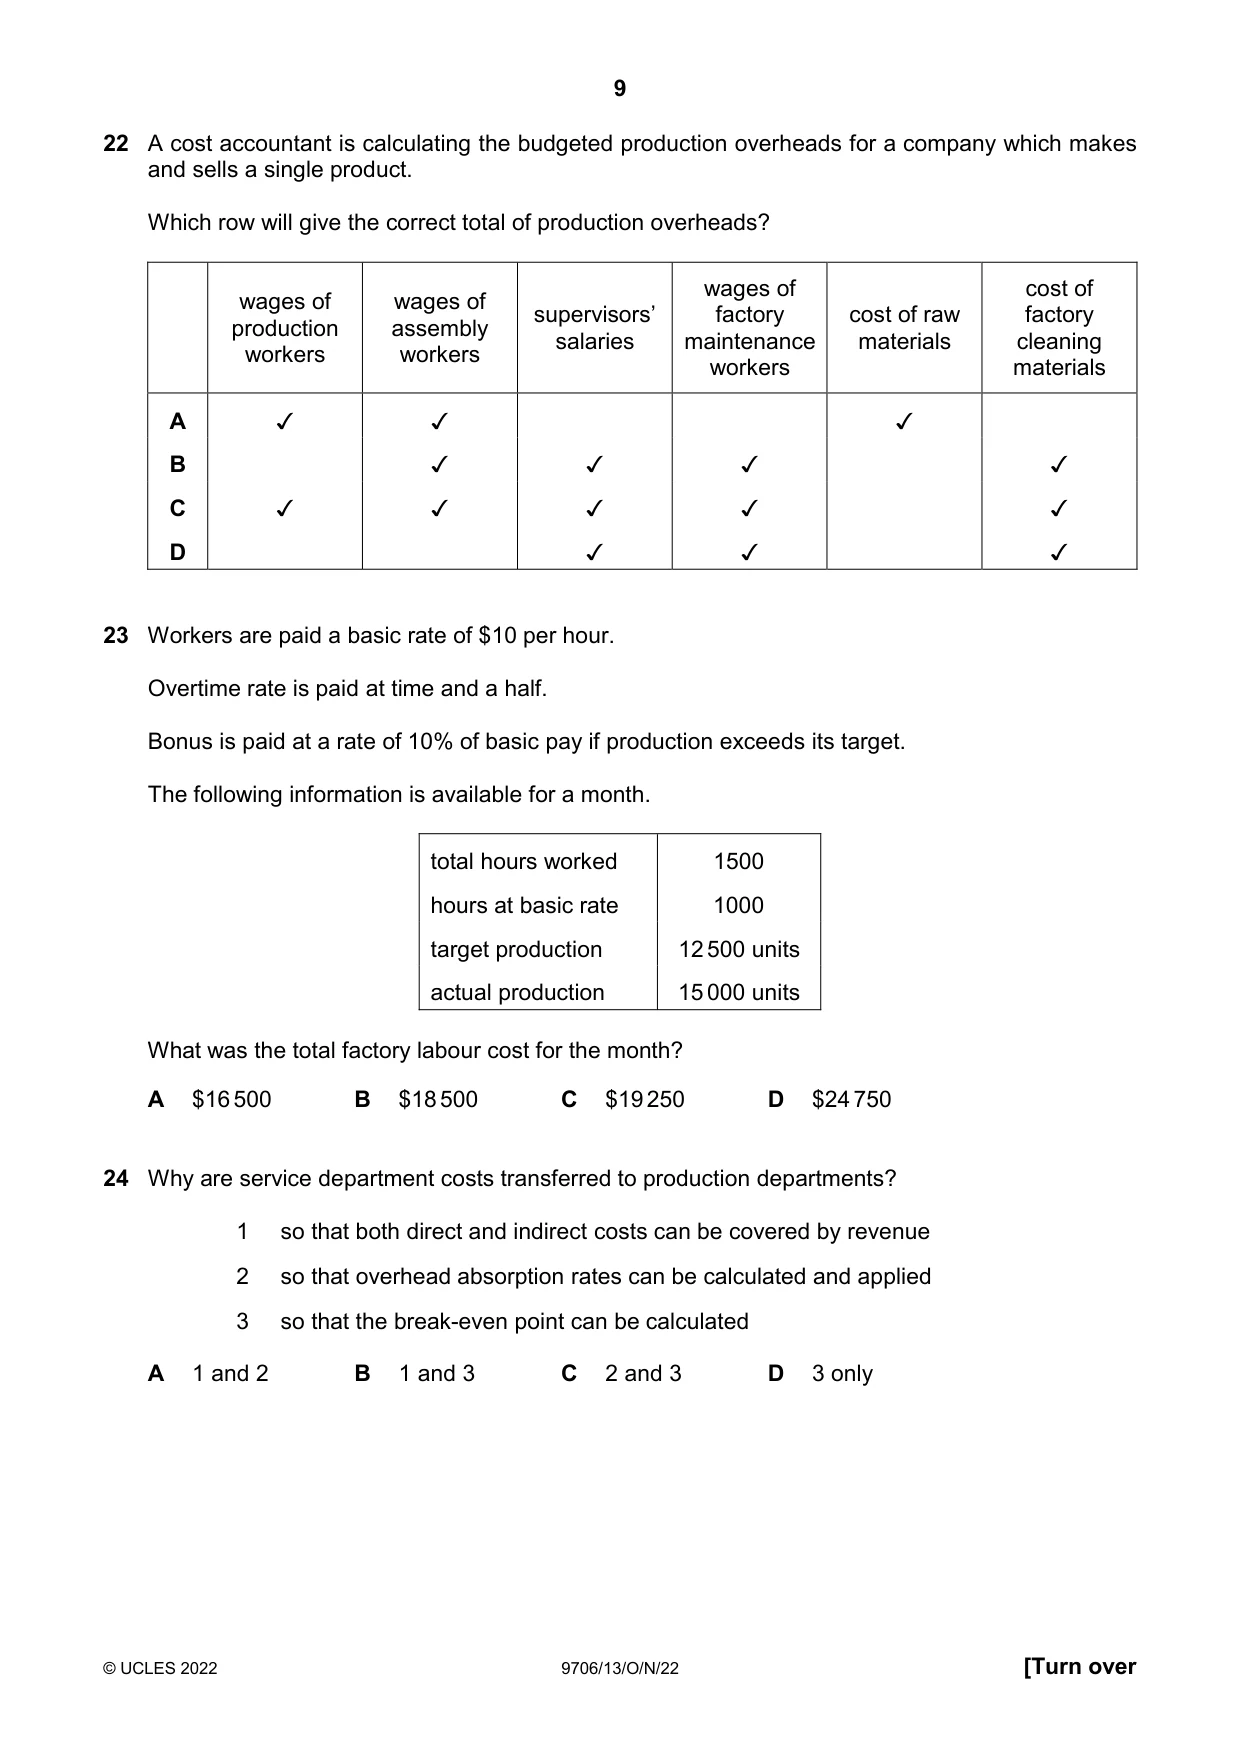
Q22 · Acost accountant is calculating the budgeted production overheads for a company which…
22 Acost accountant is calculating the budgeted production overheads for a company which makes and sells a single product. Which row will give the correct total of production overheads? wages of cost of wages of wages of ; , ; supervisors factory cost of raw factory production assembly lari int terial leani workers workers salaries maintenance | materials cleaning workers materials v v v v v v v v v v
Mark scheme: D
Q23 · Workers are paid a basic rate of $10 per hour
23 Workers are paid a basic rate of $10 per hour. Overtime rate is paid at time and a half. Bonus is paid at a rate of 10% of basic pay if production exceeds its target. The following information is available for a month. total hours worked 1500 hours at basic rate 1000 target production 12 500 units actual production 15 000 units What was the total factory labour cost for the month? A $16 500 B $18 500 C $19 250 D $24 750
Mark scheme: B
Q24 · Why are service department costs transferred to production departments?
24 Why are service department costs transferred to production departments? 1 so that both direct and indirect costs can be covered by revenue 2 so that overhead absorption rates can be calculated and applied 3 so that the break-even point can be calculated A 1 and 2 B 1 and 3 C 2 and 3 D 3 only
Mark scheme: A
Q25 · A company’s profit was $100 000 using marginal costing
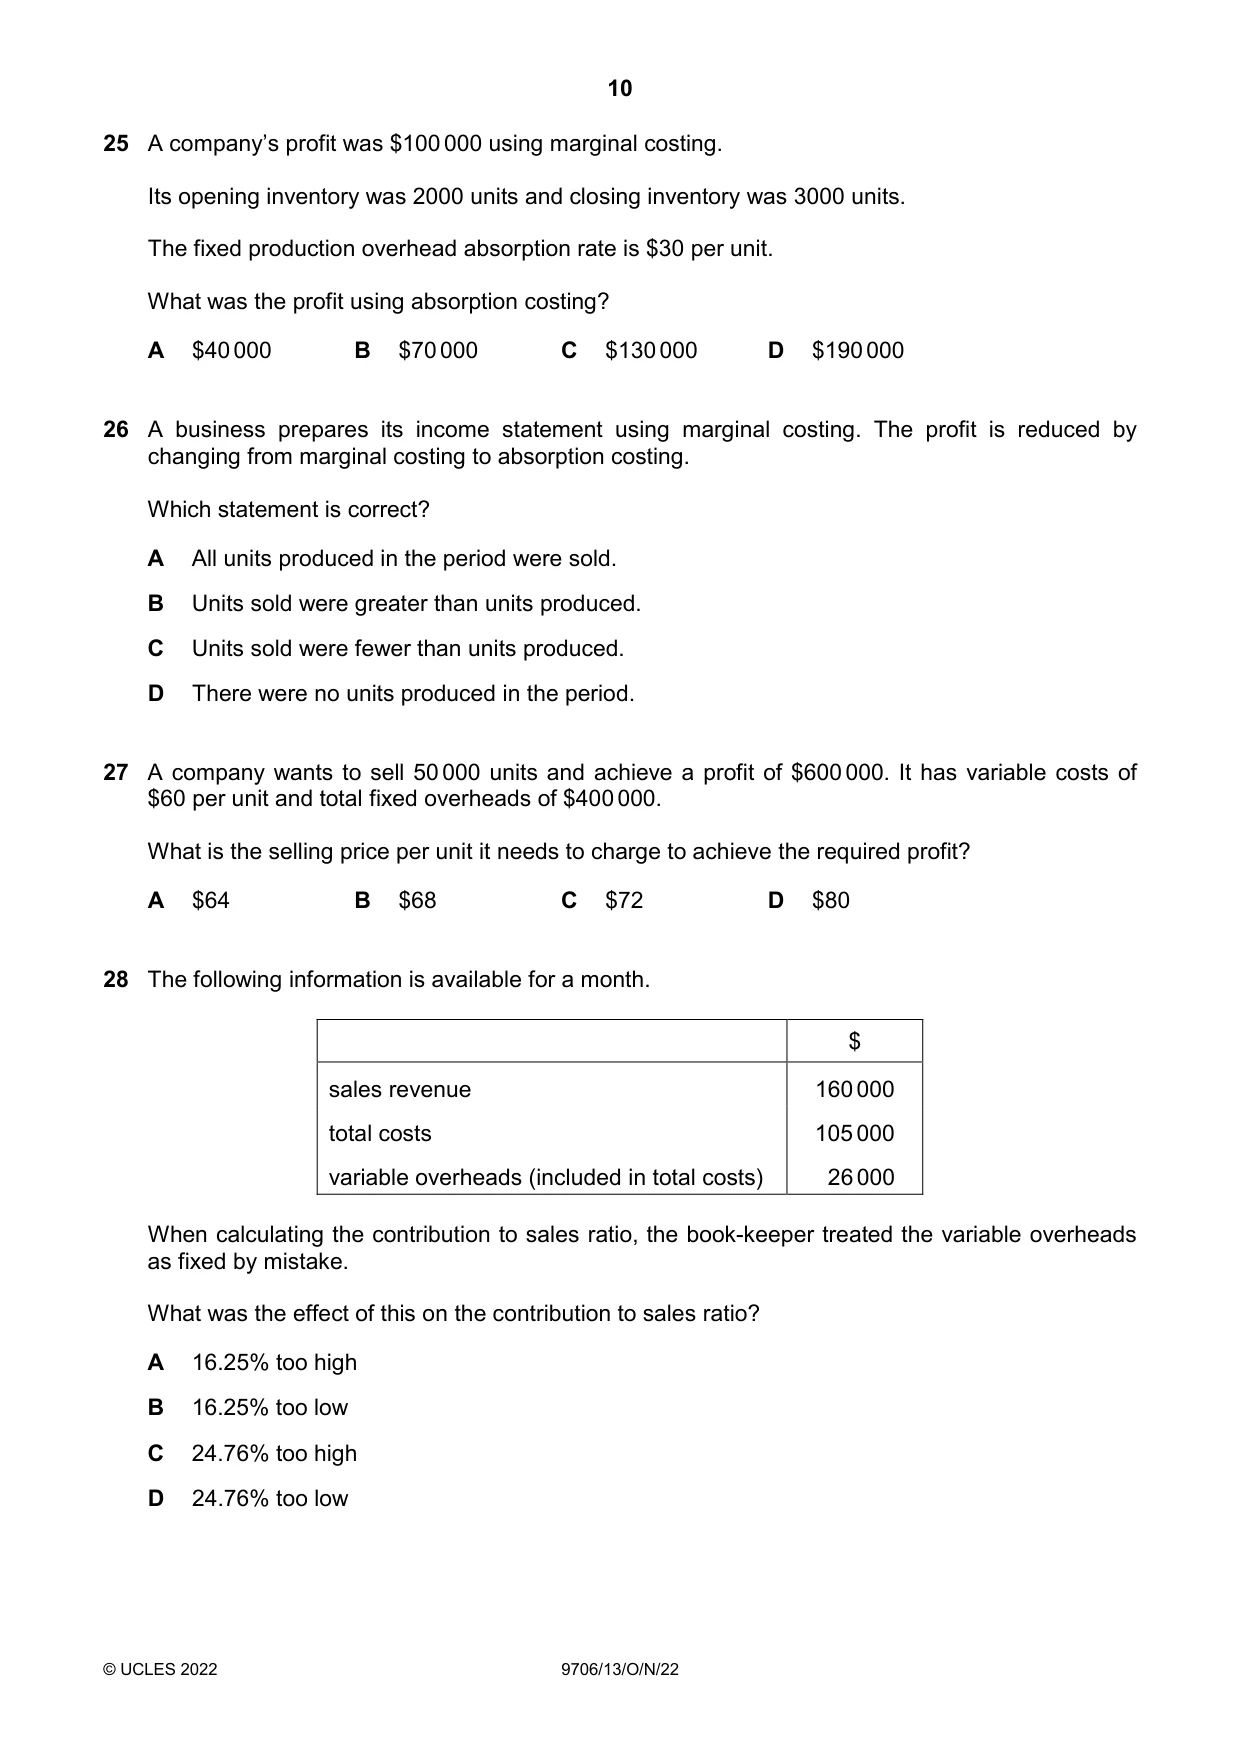
25 A company’s profit was $100 000 using marginal costing. Its opening inventory was 2000 units and closing inventory was 3000 units. The fixed production overhead absorption rate is $30 per unit. What was the profit using absorption costing? A $40 000 B $70 000 C $130 000 D $190 000
Mark scheme: C
Q26 · A business prepares its income statement using marginal costing
26 A business prepares its income statement using marginal costing. The profit is reduced by changing from marginal costing to absorption costing. Which statement is correct? A All units produced in the period were sold. B Units sold were greater than units produced. C Units sold were fewer than units produced. D There were no units produced in the period.
Mark scheme: B
Q27 · A company wants to sell 50 000 units and achieve a profit of $600 000
27 A company wants to sell 50 000 units and achieve a profit of $600 000. It has variable costs of $60 per unit and total fixed overheads of $400 000. What is the selling price per unit it needs to charge to achieve the required profit? A $64 B $68 C $72 D $80
Mark scheme: D
Q28 · The following information is available for a month
28 The following information is available for a month. $ sales revenue 160 000 total costs 105 000 variable overheads (included in total costs) 26 000 When calculating the contribution to sales ratio, the book-keeper treated the variable overheads as fixed by mistake. What was the effect of this on the contribution to sales ratio? A 16.25% too high B 16.25% too low C 24.76% too high D 24.76% too low
Mark scheme: A
Q29 · A business had the following results in April and May
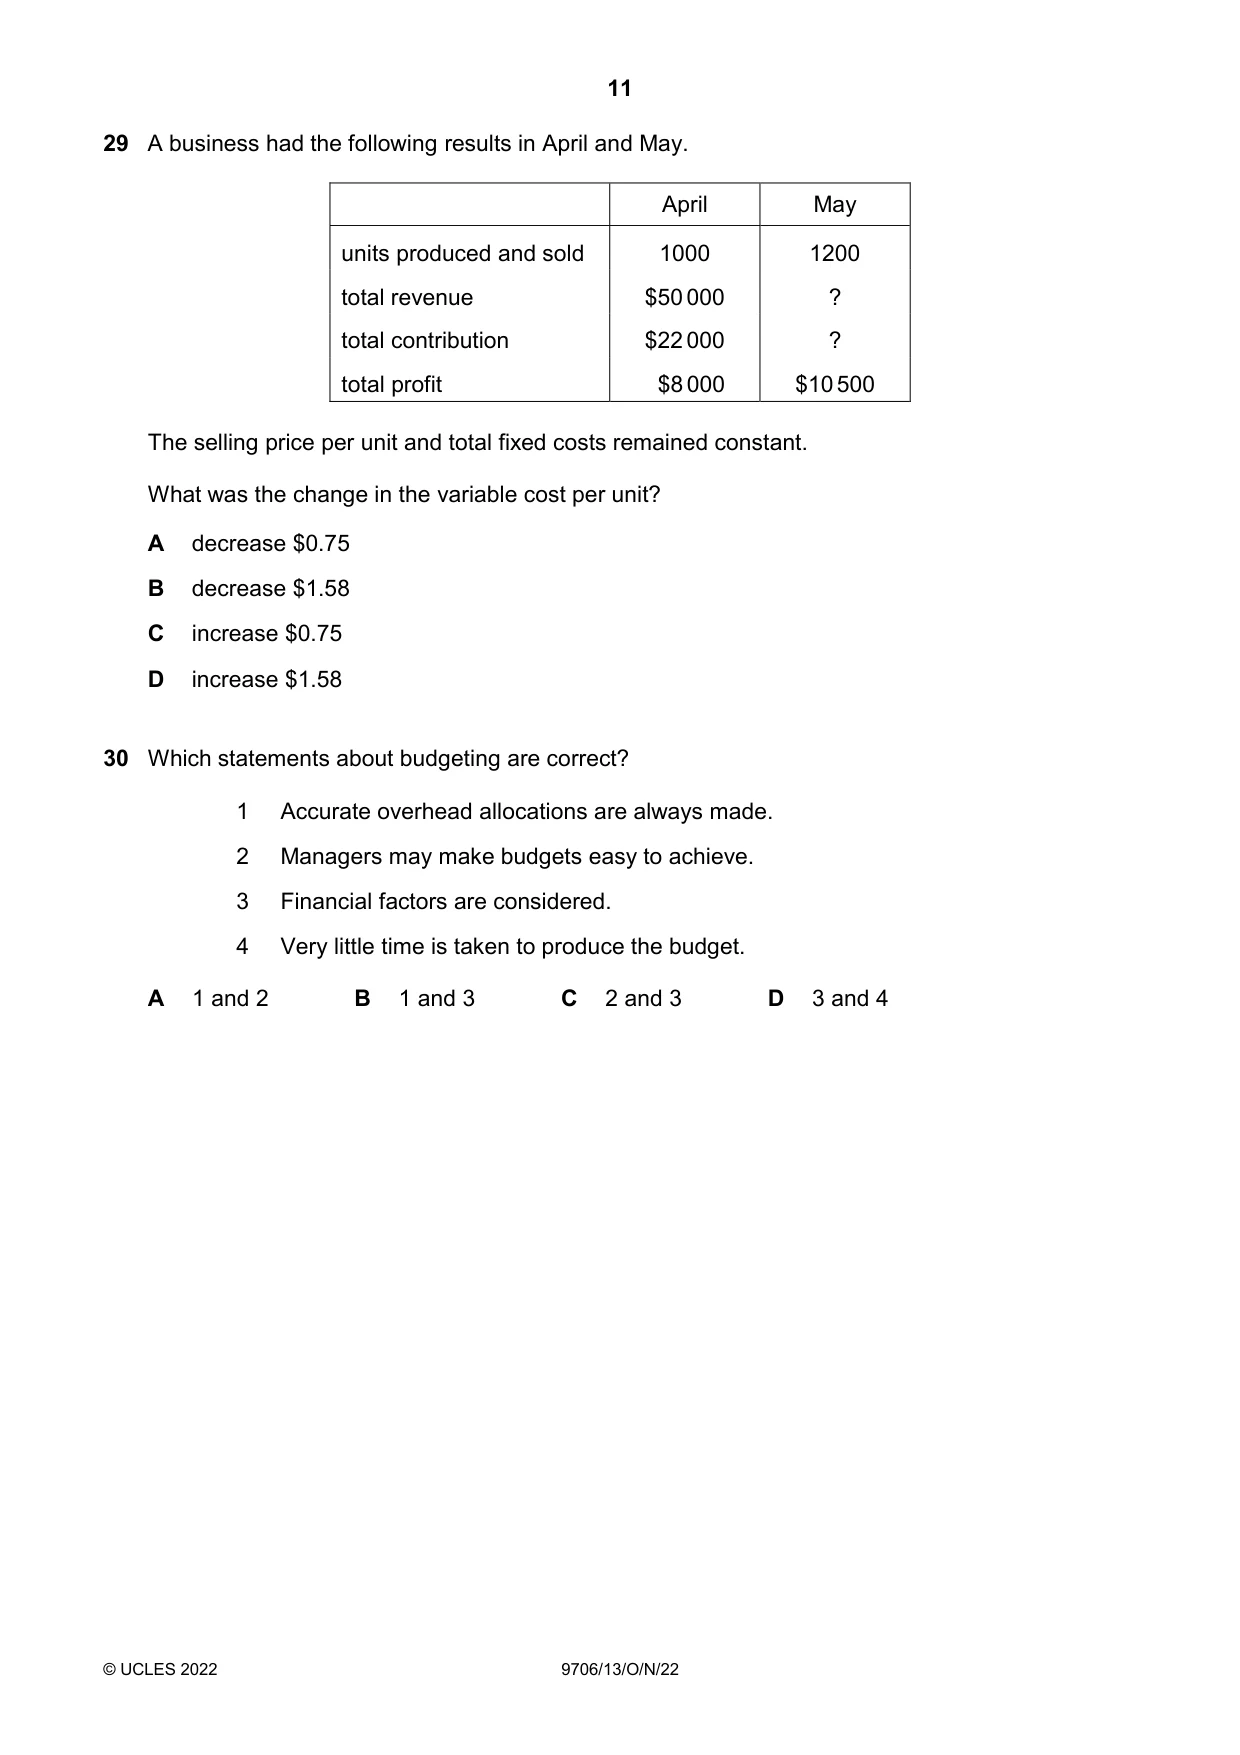
29 A business had the following results in April and May. April May units produced and sold 1000 1200 total revenue $50 000 ? total contribution $22 000 ? total profit $8 000 $10 500 The selling price per unit and total fixed costs remained constant. What was the change in the variable cost per unit? A decrease $0.75 B decrease $1.58 C increase $0.75 D increase $1.58
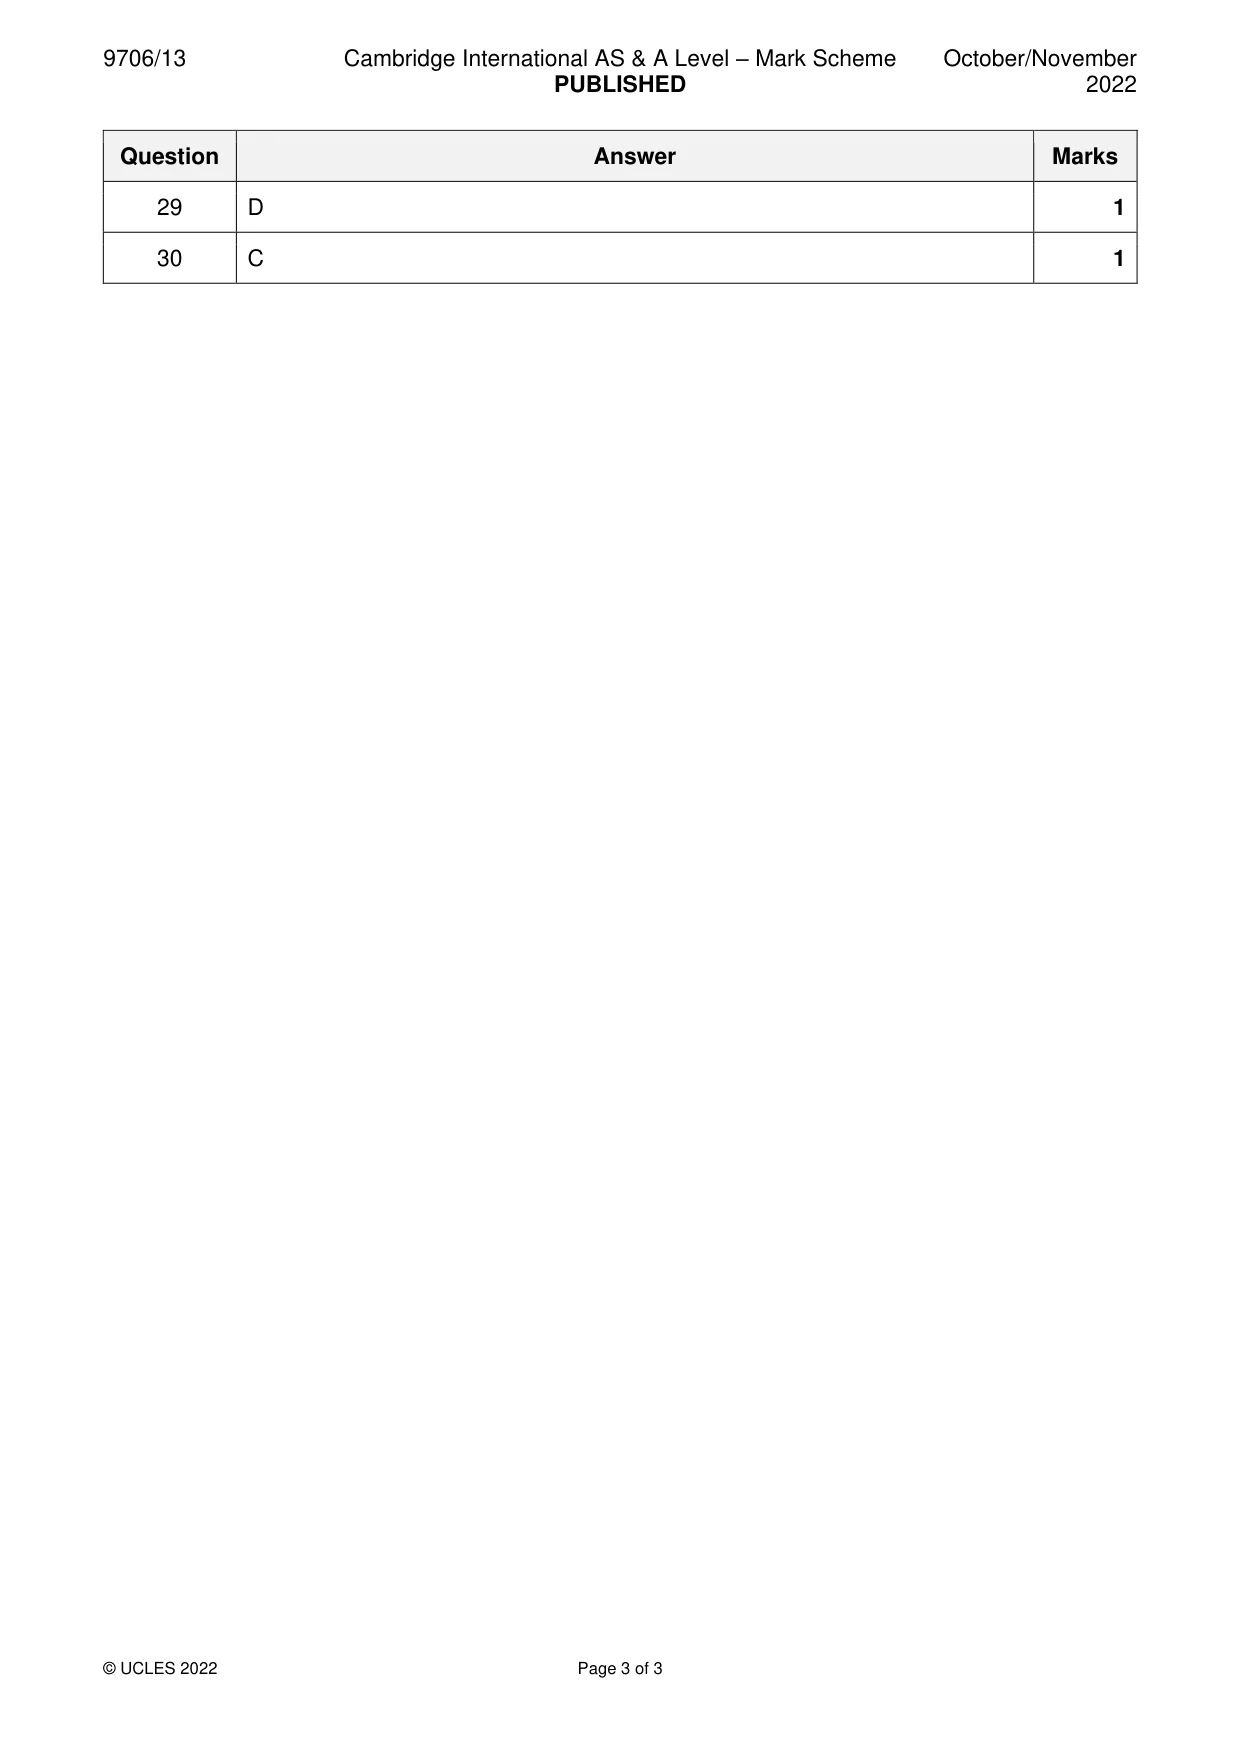
Mark scheme: D
Q30 · Which statements about budgeting are correct?
30 Which statements about budgeting are correct? 1 Accurate overhead allocations are always made. 2 Managers may make budgets easy to achieve. 3 Financial factors are considered. 4 Very little time is taken to produce the budget. A 1 and 2 B 1 and 3 C 2 and 3 D 3 and 4
Mark scheme: C
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
6Costs and cost behaviour5Preparation of financial statements5Accounting for non-current assets3Reconciliation and verification3Traditional costing methods3Analysis and communication of accounting information2Budgeting and budgetary control1The accounting system1Types of business entity1What you needed in this session
Cambridge’s own grade thresholds for 2022 Oct/Nov, Paper 1 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.