Cambridge A Level Accounting 9706 — 2025 Oct/Nov Paper 1 · Variant 2
9706/12/O/N/25 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
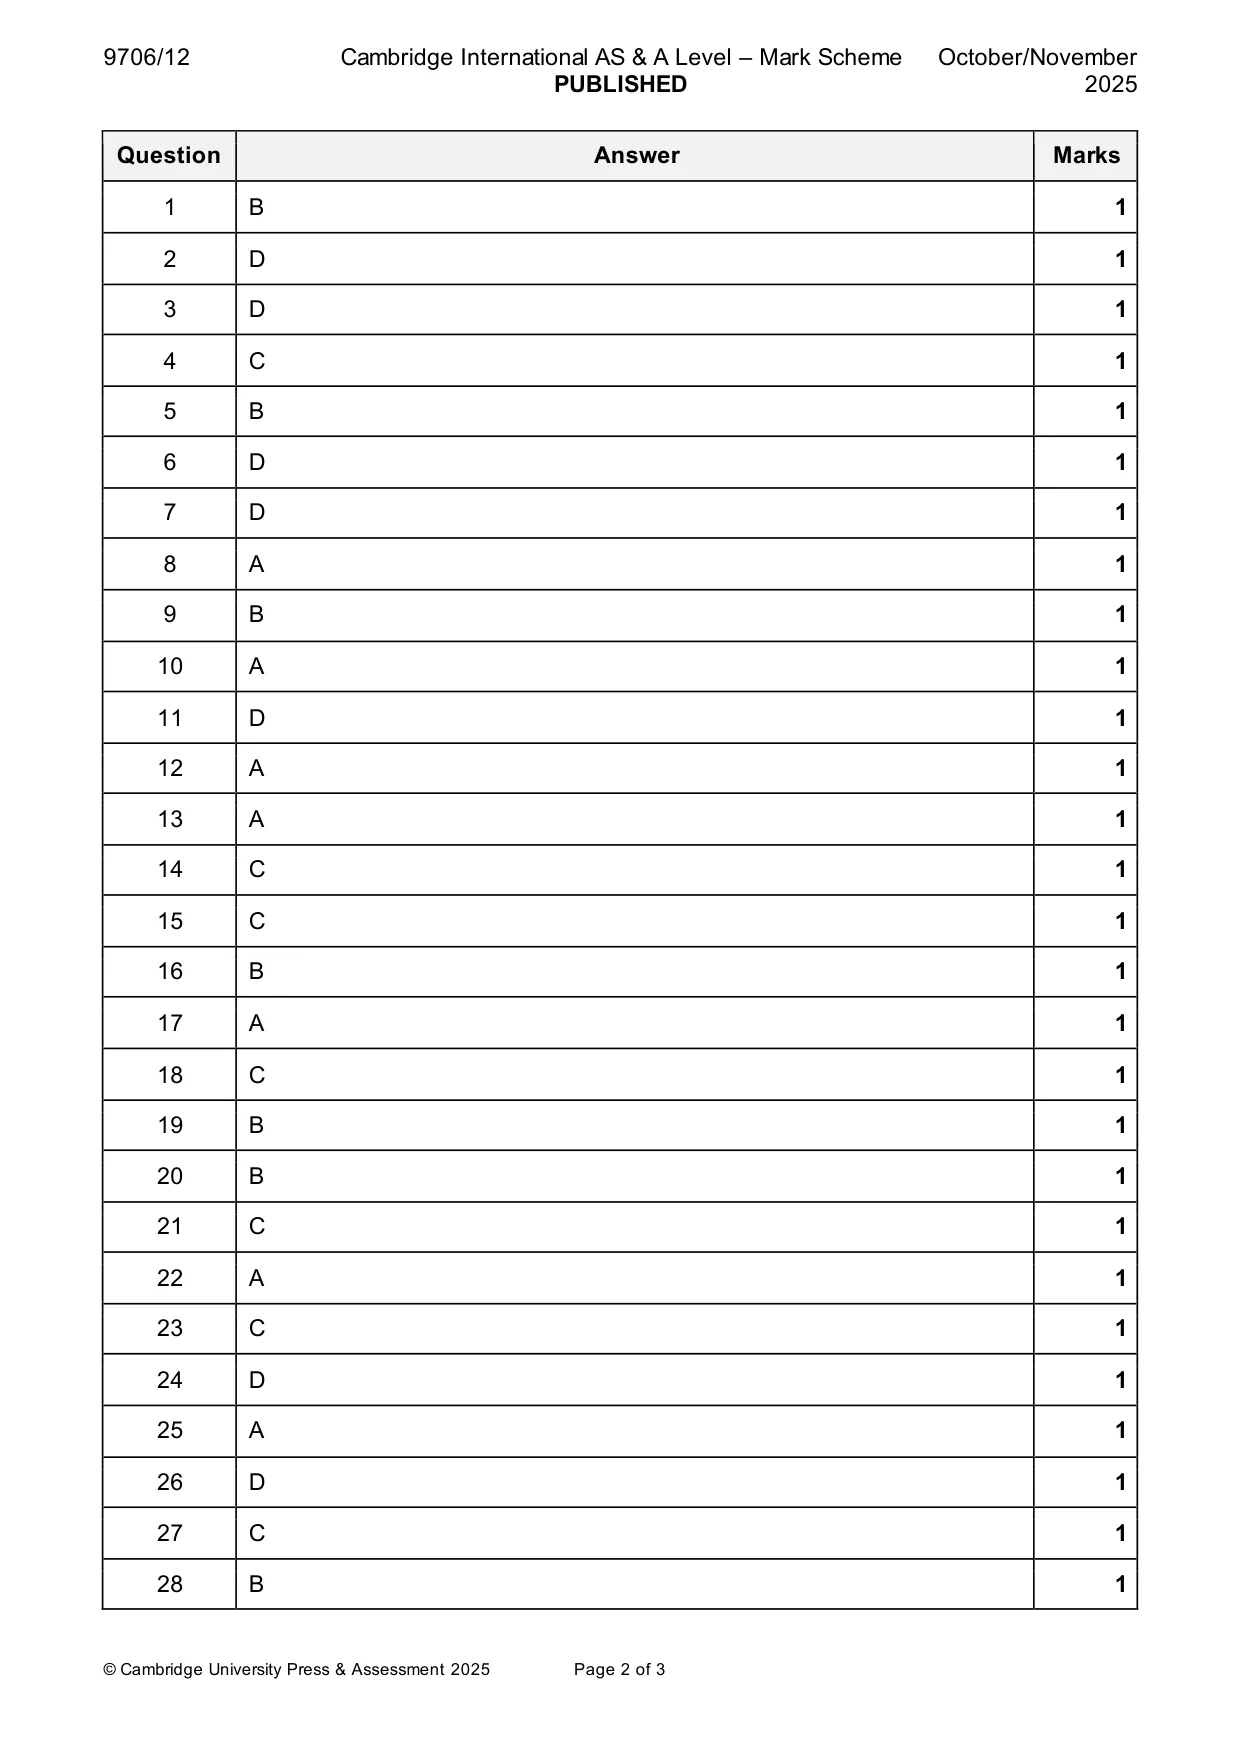
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · A company needs to raise finance to build a factory
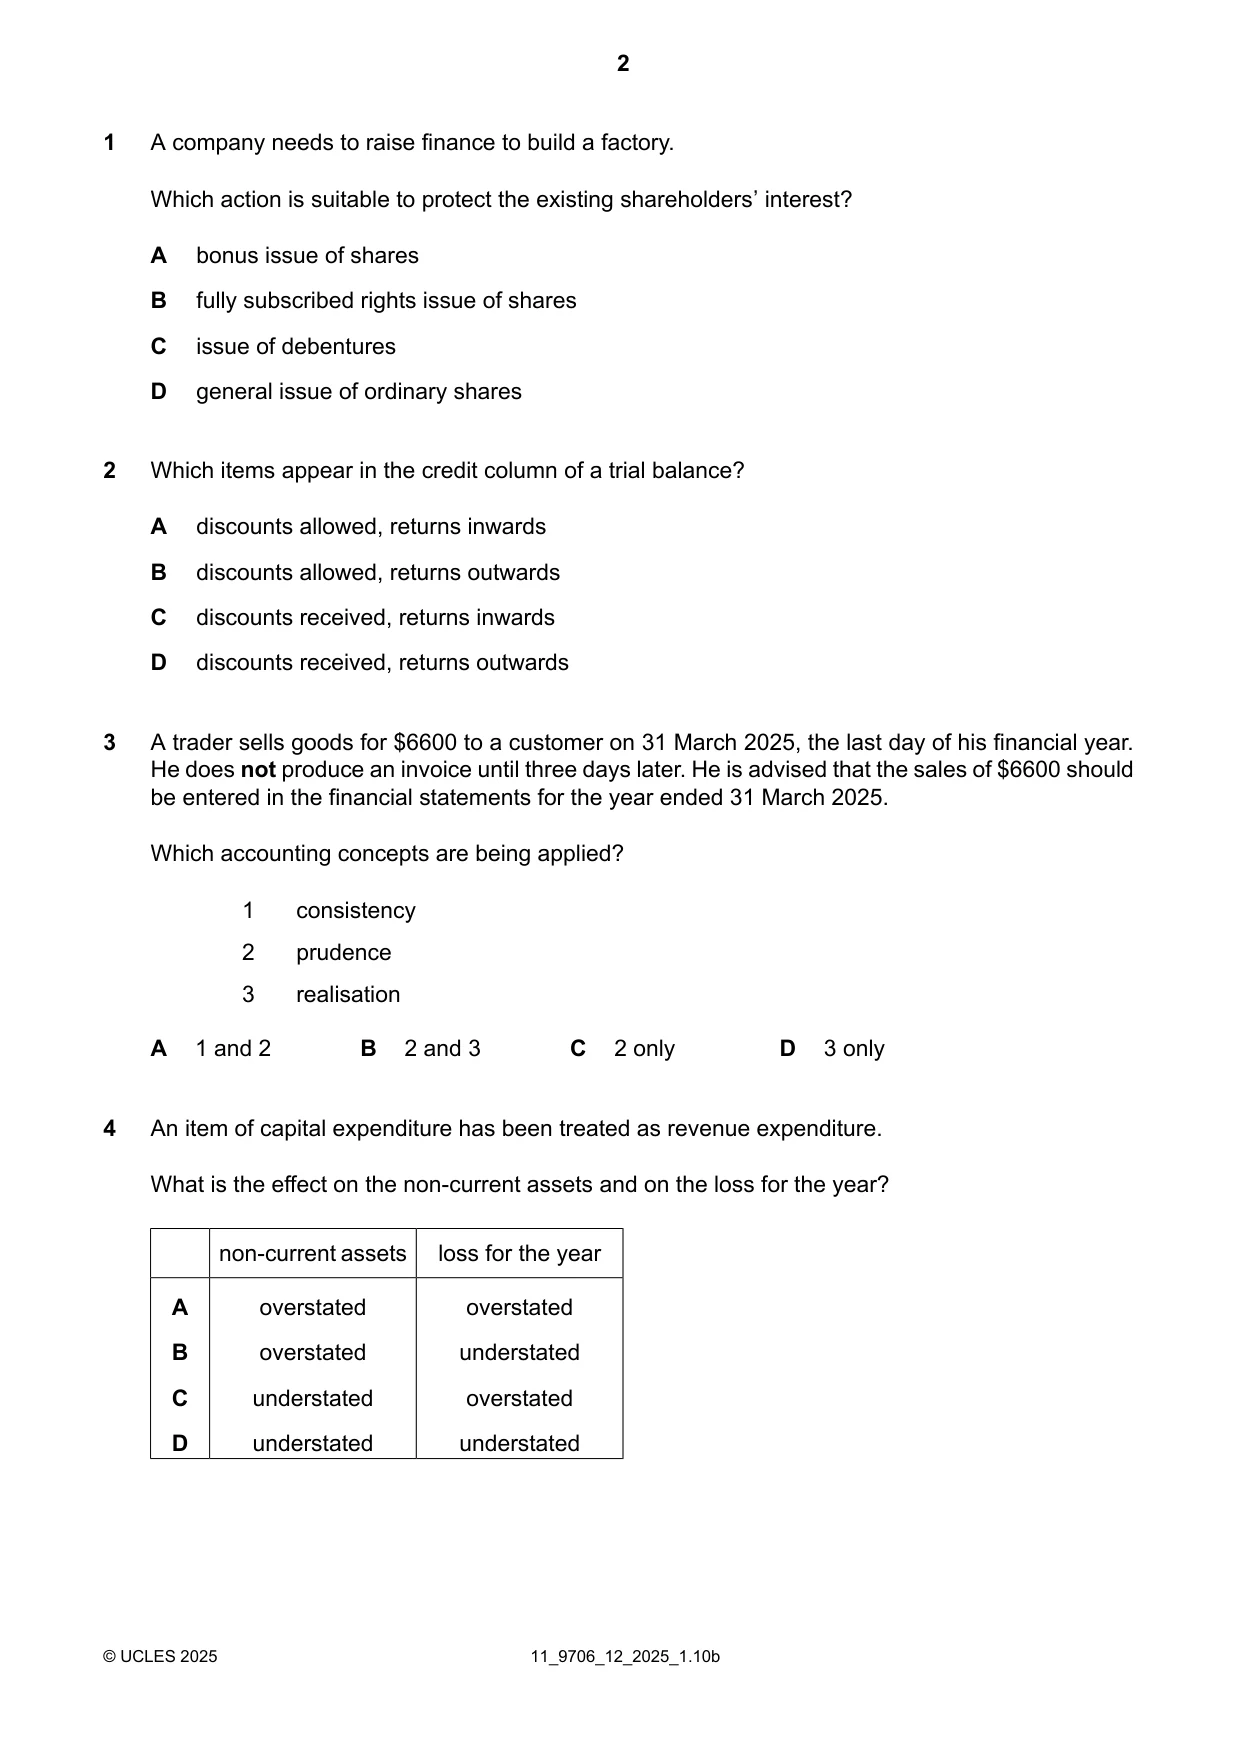
1 A company needs to raise finance to build a factory. Which action is suitable to protect the existing shareholders’ interest? A bonus issue of shares B fully subscribed rights issue of shares C issue of debentures D general issue of ordinary shares
Mark scheme: B
Q2 · Which items appear in the credit column of a trial balance?
2 Which items appear in the credit column of a trial balance? A discounts allowed, returns inwards B discounts allowed, returns outwards C discounts received, returns inwards D discounts received, returns outwards
Mark scheme: D
Q3 · A trader sells goods for $6600 to a customer on 31 March 2025, the last day of his…
3 A trader sells goods for $6600 to a customer on 31 March 2025, the last day of his financial year. He does not produce an invoice until three days later. He is advised that the sales of $6600 should be entered in the financial statements for the year ended 31 March 2025. Which accounting concepts are being applied? 1 consistency 2 prudence 3 realisation A 1 and 2 B 2 and 3 C 2 only D 3 only
Mark scheme: D
Q4 · An item of capital expenditure has been treated as revenue expenditure
4 An item of capital expenditure has been treated as revenue expenditure. What is the effect on the non-current assets and on the loss for the year? non-current assets loss for the year A overstated overstated B overstated understated C understated overstated D understated understated
Mark scheme: C
Q5 · Y Limited purchased a motor van and incurred the following expenditure at the beginning…
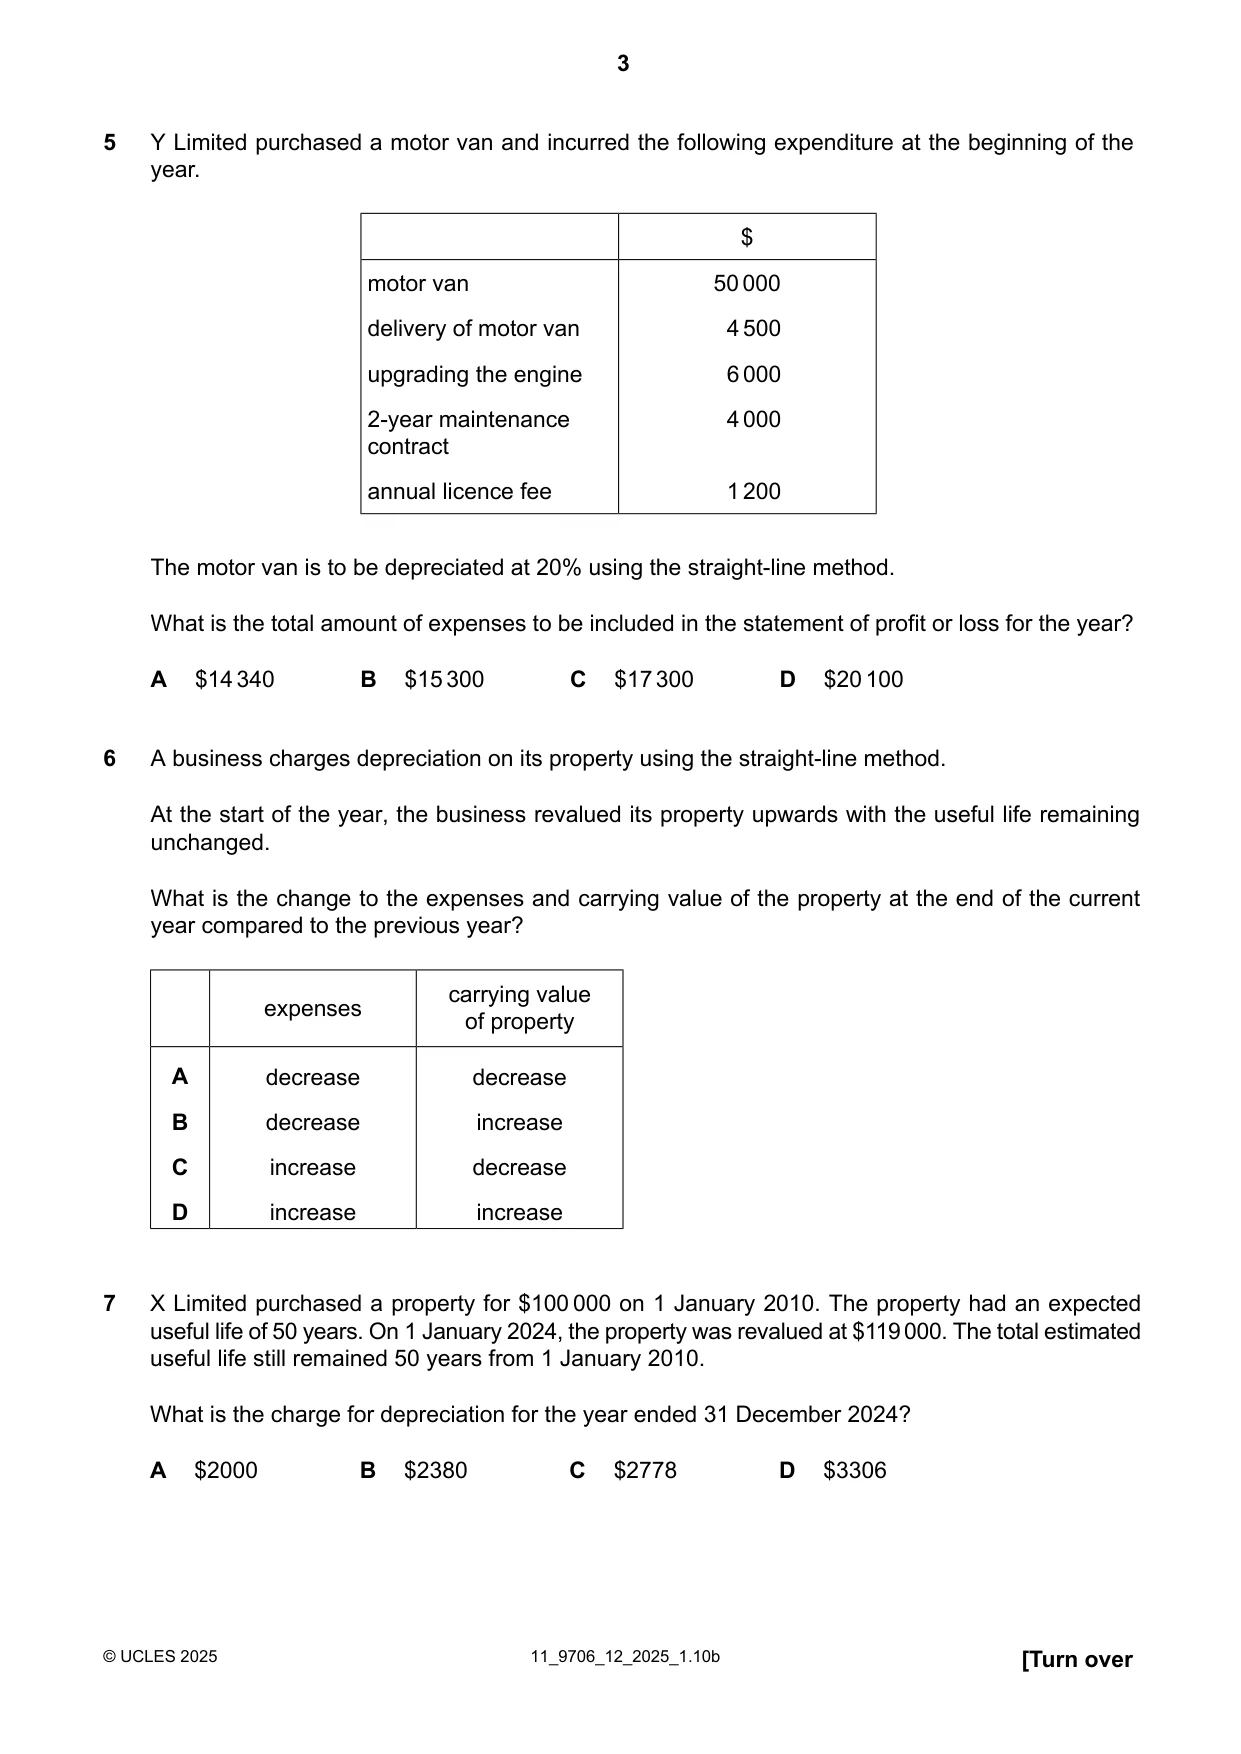
5 Y Limited purchased a motor van and incurred the following expenditure at the beginning of the year. $ motor van 50000 delivery of motor van 4500 upgrading the engine 6000 2-year maintenance 4000 contract annual licence fee 1200 The motor van is to be depreciated at 20% using the straight-line method. What is the total amount of expenses to be included in the statement of profit or loss for the year? A $14340 B $15300 C $17300 D $20100
Mark scheme: B
Q6 · A business charges depreciation on its property using the straight-line method
6 A business charges depreciation on its property using the straight-line method. At the start of the year, the business revalued its property upwards with the useful life remaining unchanged. What is the change to the expenses and carrying value of the property at the end of the current year compared to the previous year? carrying value expenses of property A decrease decrease B decrease increase C increase decrease D increase increase
Mark scheme: D
Q7 · X Limited purchased a property for $100 000 on 1 January 2010
7 X Limited purchased a property for $100 000 on 1 January 2010. The property had an expected useful life of 50 years. On 1 January 2024, the property was revalued at $119000. The total estimated useful life still remained 50 years from 1 January 2010. What is the charge for depreciation for the year ended 31 December 2024? A $2000 B $2380 C $2778 D $3306
Mark scheme: D
Q8 · The totals of a trial balance did not agree
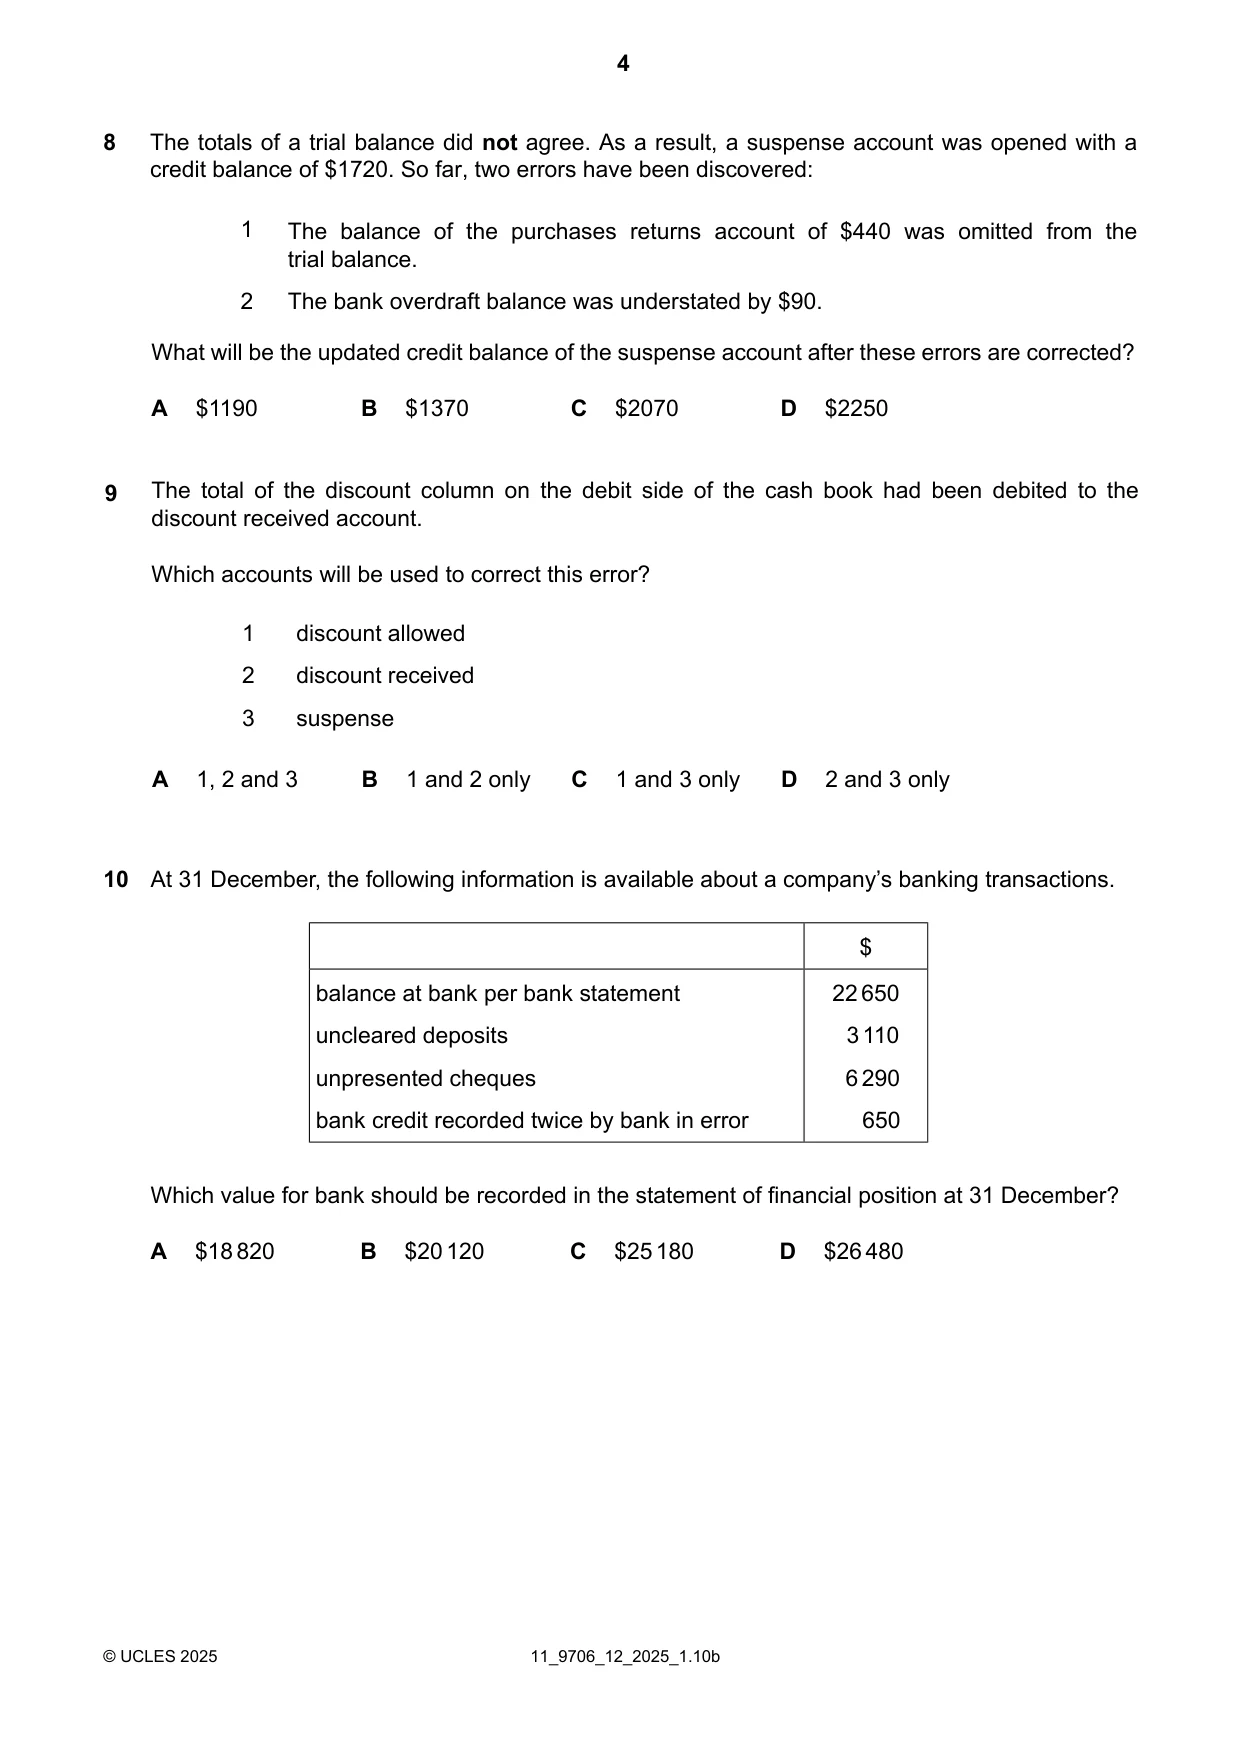
8 The totals of a trial balance did not agree. As a result, a suspense account was opened with a credit balance of $1720. So far, two errors have been discovered: 1 The balance of the purchases returns account of $440 was omitted from the trial balance. 2 The bank overdraft balance was understated by $90. What will be the updated credit balance of the suspense account after these errors are corrected? A $1190 B $1370 C $2070 D $2250
Mark scheme: A
Q9 · The total of the discount column on the debit side of the cash book had been debited to…
9 The total of the discount column on the debit side of the cash book had been debited to the discount received account. Which accounts will be used to correct this error? 1 discount allowed 2 discount received 3 suspense A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
Mark scheme: B
Q10 · At 31 December, the following information is available about a company’s banking…
10 At 31 December, the following information is available about a company’s banking transactions. $ balance at bank per bank statement 22650 uncleared deposits 3110 unpresented cheques 6290 bank credit recorded twice by bank in error 650 Which value for bank should be recorded in the statement of financial position at 31 December? A $18820 B $20120 C $25180 D $26480
Mark scheme: A
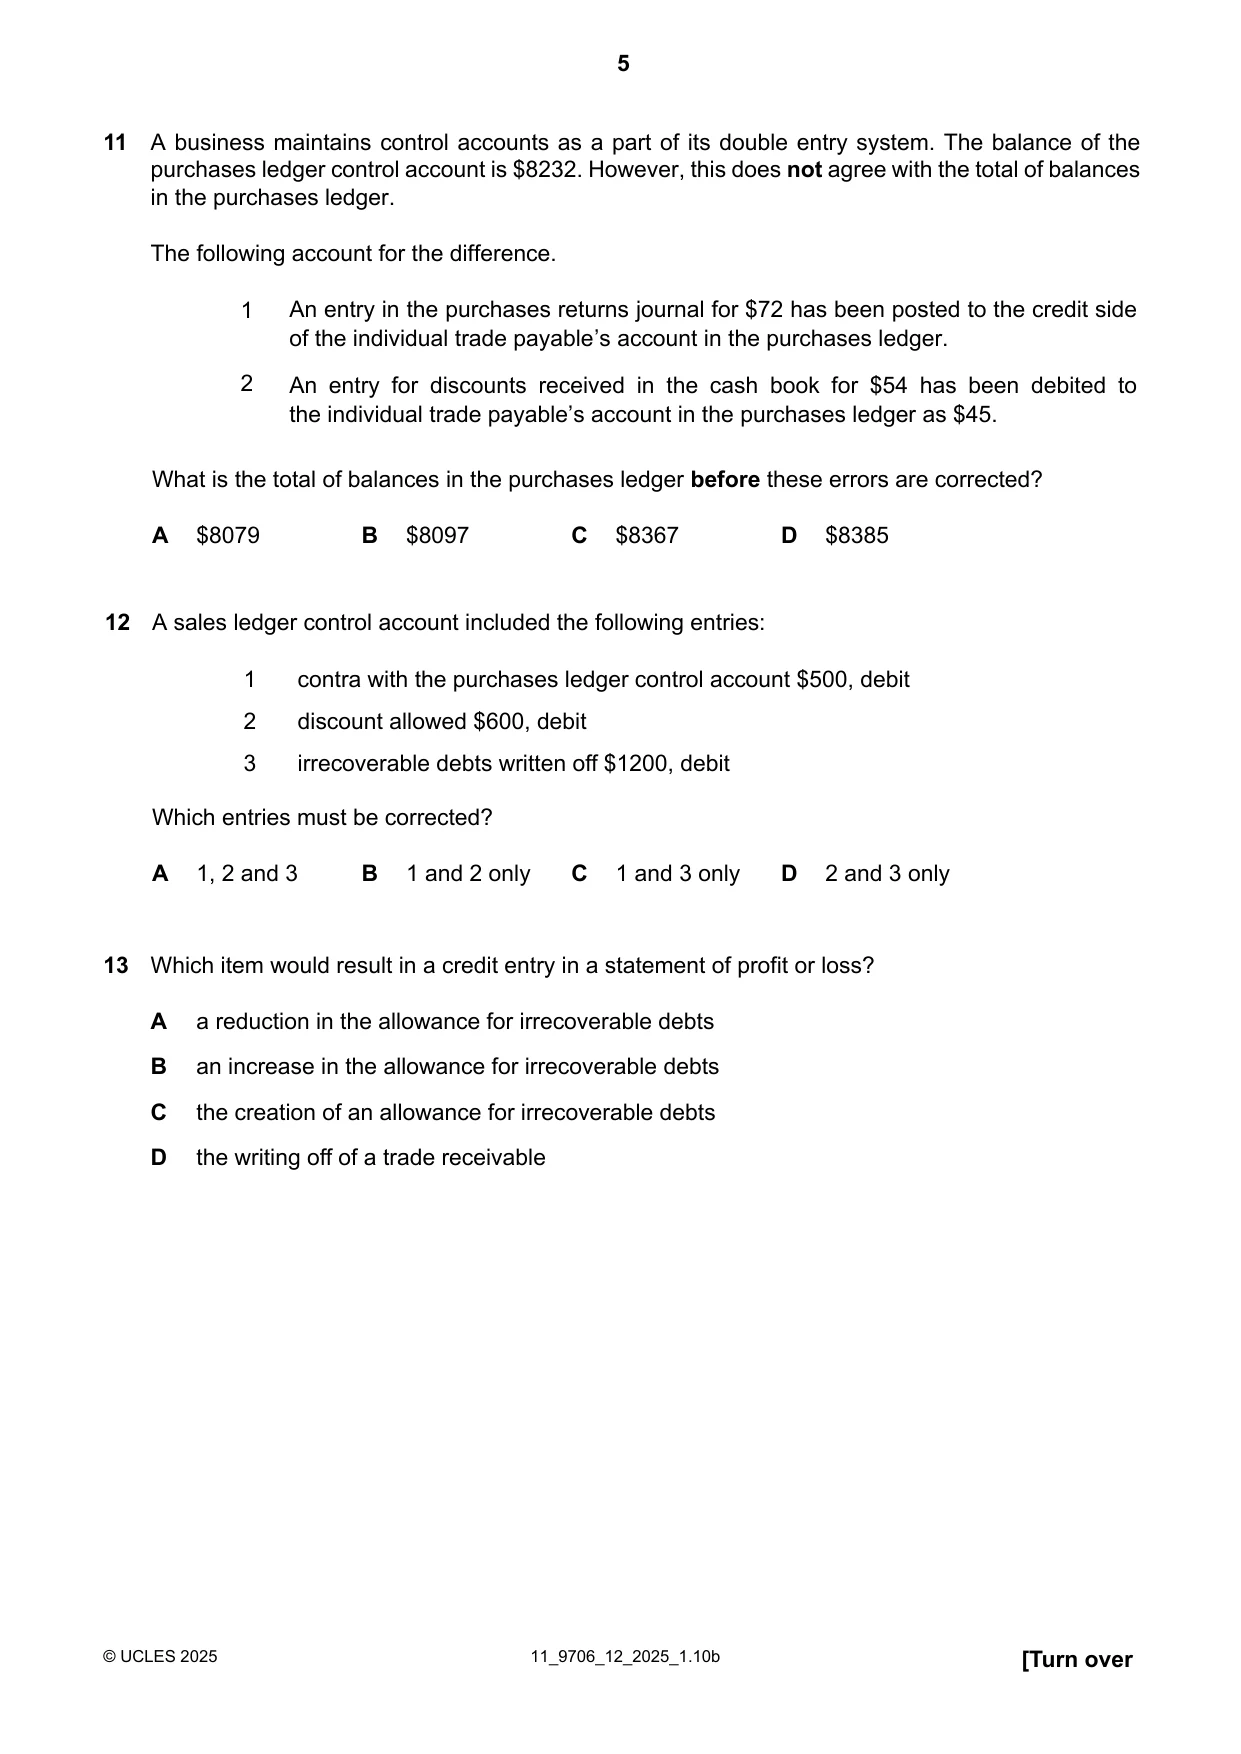
Q11 · A business maintains control accounts as a part of its double entry system
11 A business maintains control accounts as a part of its double entry system. The balance of the purchases ledger control account is $8232. However, this does not agree with the total of balances in the purchases ledger. The following account for the difference. 1 An entry in the purchases returns journal for $72 has been posted to the credit side of the individual trade payable’s account in the purchases ledger. 2 An entry for discounts received in the cash book for $54 has been debited to the individual trade payable’s account in the purchases ledger as $45. What is the total of balances in the purchases ledger before these errors are corrected? A $8079 B $8097 C $8367 D $8385
Mark scheme: D
Q12 · A sales ledger control account included the following entries: 1 contra with the…
12 A sales ledger control account included the following entries: 1 contra with the purchases ledger control account $500, debit 2 discount allowed $600, debit 3 irrecoverable debts written off $1200, debit Which entries must be corrected? A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
Mark scheme: A
Q13 · Which item would result in a credit entry in a statement of profit or loss?
13 Which item would result in a credit entry in a statement of profit or loss? A a reduction in the allowance for irrecoverable debts B an increase in the allowance for irrecoverable debts C the creation of an allowance for irrecoverable debts D the writing off of a trade receivable
Mark scheme: A
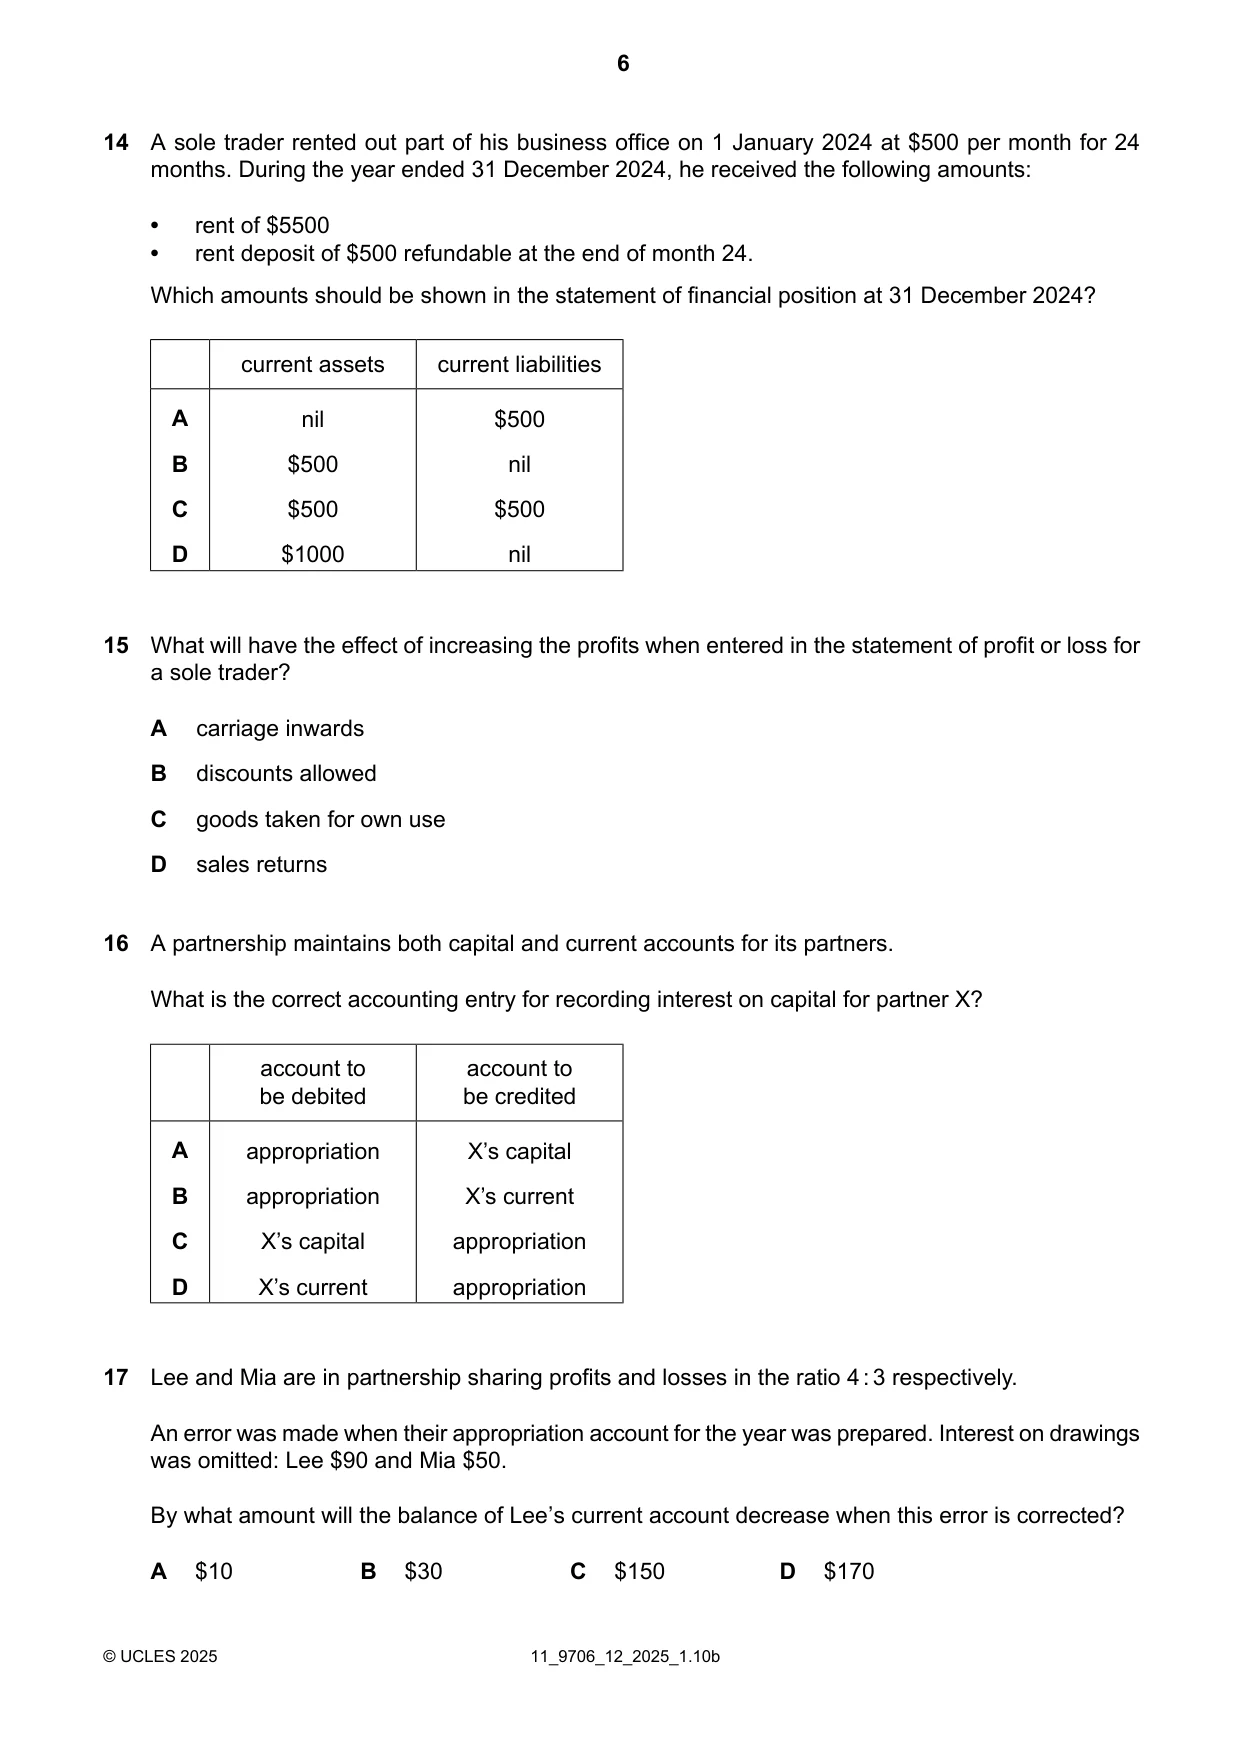
Q14 · A sole trader rented out part of his business office on 1 January 2024 at $500 per month…
14 A sole trader rented out part of his business office on 1 January 2024 at $500 per month for 24 months. During the year ended 31 December 2024, he received the following amounts: • rent of $5500 • rent deposit of $500 refundable at the end of month 24. Which amounts should be shown in the statement of financial position at 31 December 2024? current assets current liabilities A nil $500 B $500 nil C $500 $500 D $1000 nil
Mark scheme: C
Q15 · What will have the effect of increasing the profits when entered in the statement of…
15 What will have the effect of increasing the profits when entered in the statement of profit or loss for a sole trader? A carriage inwards B discounts allowed C goods taken for own use D sales returns
Mark scheme: C
Q16 · A partnership maintains both capital and current accounts for its partners
16 A partnership maintains both capital and current accounts for its partners. What is the correct accounting entry for recording interest on capital for partner X? account to account to be debited be credited A appropriation X’s capital B appropriation X’s current C X’s capital appropriation D X’s current appropriation
Mark scheme: B
Q17 · Lee and Mia are in partnership sharing profits and losses in the ratio 4 : 3 respectively
17 Lee and Mia are in partnership sharing profits and losses in the ratio 4 : 3 respectively. An error was made when their appropriation account for the year was prepared. Interest on drawings was omitted: Lee $90 and Mia $50. By what amount will the balance of Lee’s current account decrease when this error is corrected? A $10 B $30 C $150 D $170
Mark scheme: A
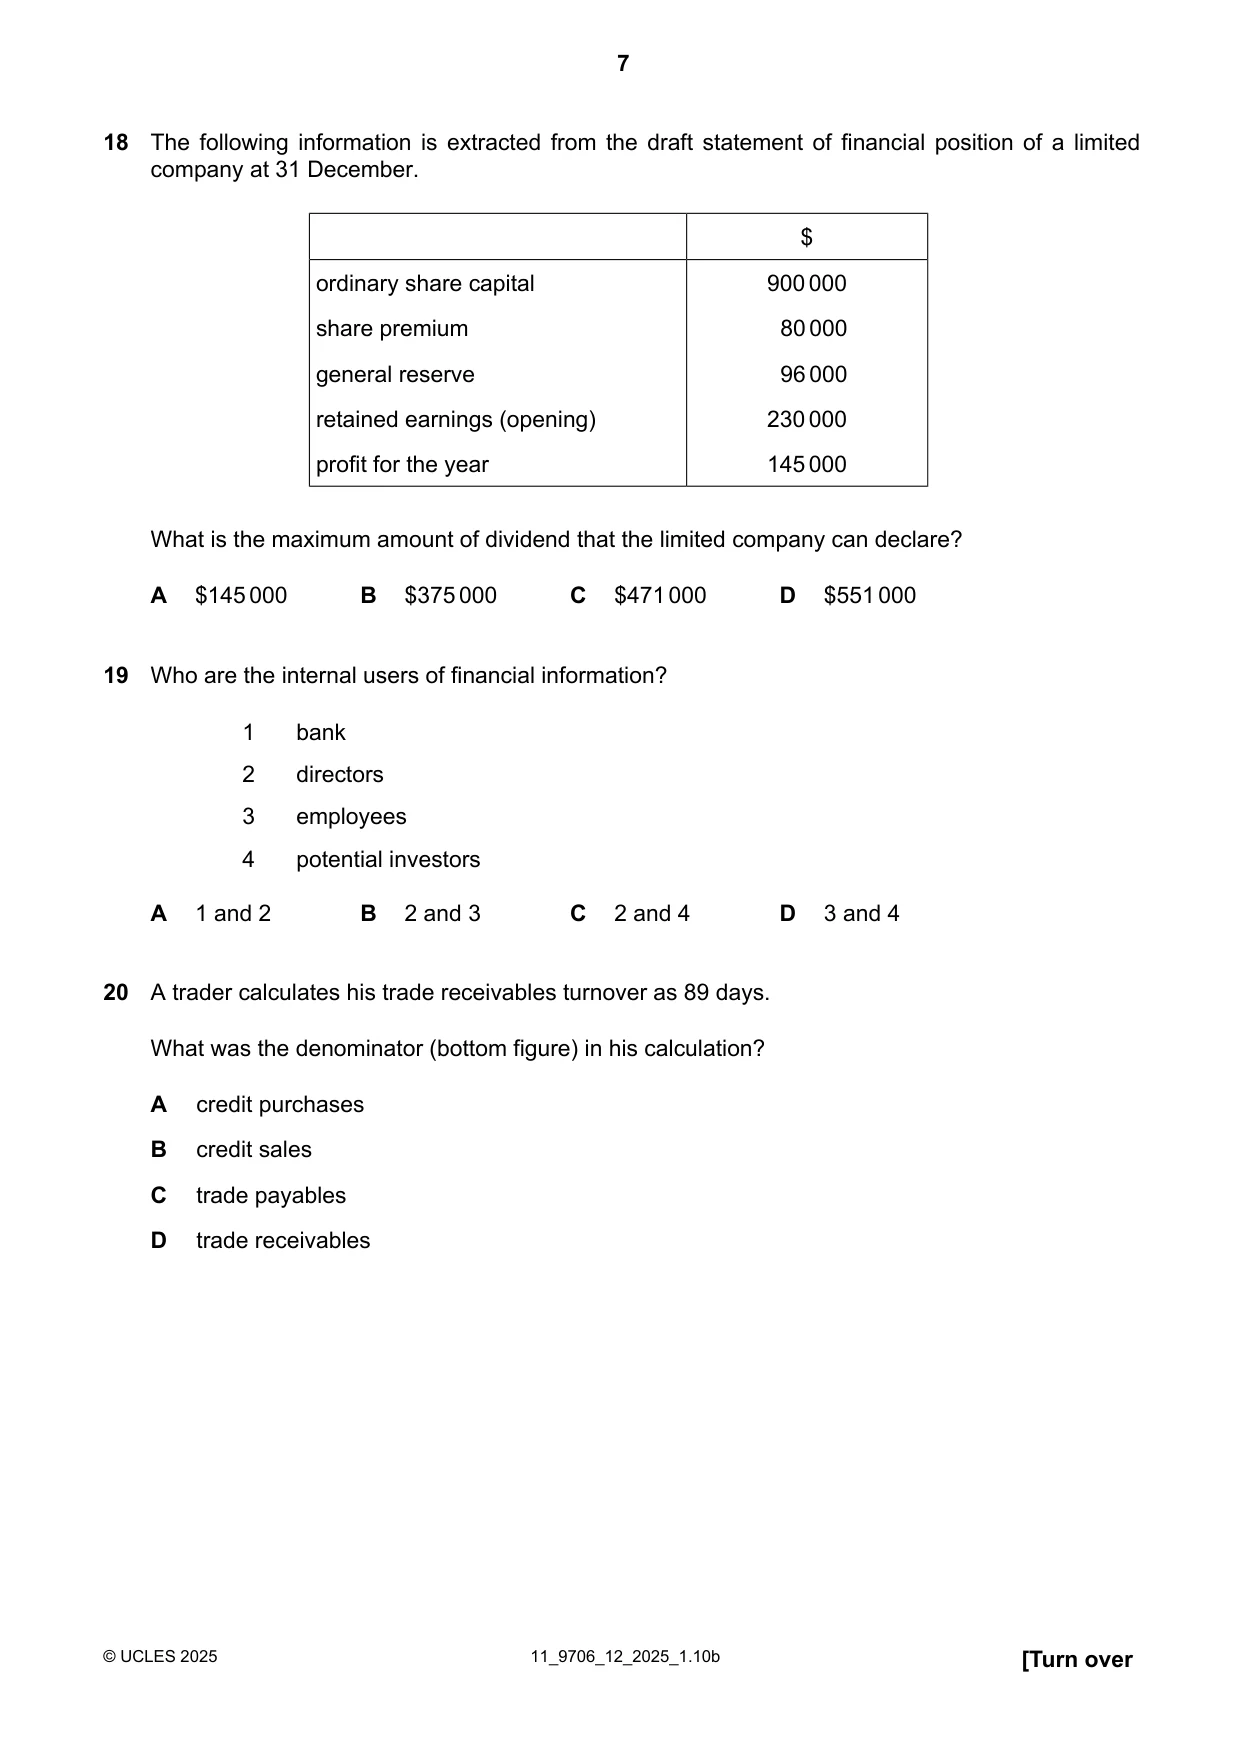
Q18 · The following information is extracted from the draft statement of financial position of…
18 The following information is extracted from the draft statement of financial position of a limited company at 31 December. $ ordinary share capital 900000 share premium 80000 general reserve 96000 retained earnings (opening) 230000 profit for the year 145000 What is the maximum amount of dividend that the limited company can declare? A $145000 B $375000 C $471000 D $551000
Mark scheme: C
Q19 · Who are the internal users of financial information?
19 Who are the internal users of financial information? 1 bank 2 directors 3 employees 4 potential investors A 1 and 2 B 2 and 3 C 2 and 4 D 3 and 4
Mark scheme: B
More questions on Analysis and communication of accounting information
Q20 · A trader calculates his trade receivables turnover as 89 days
20 A trader calculates his trade receivables turnover as 89 days. What was the denominator (bottom figure) in his calculation? A credit purchases B credit sales C trade payables D trade receivables
Mark scheme: B
More questions on Analysis and communication of accounting information
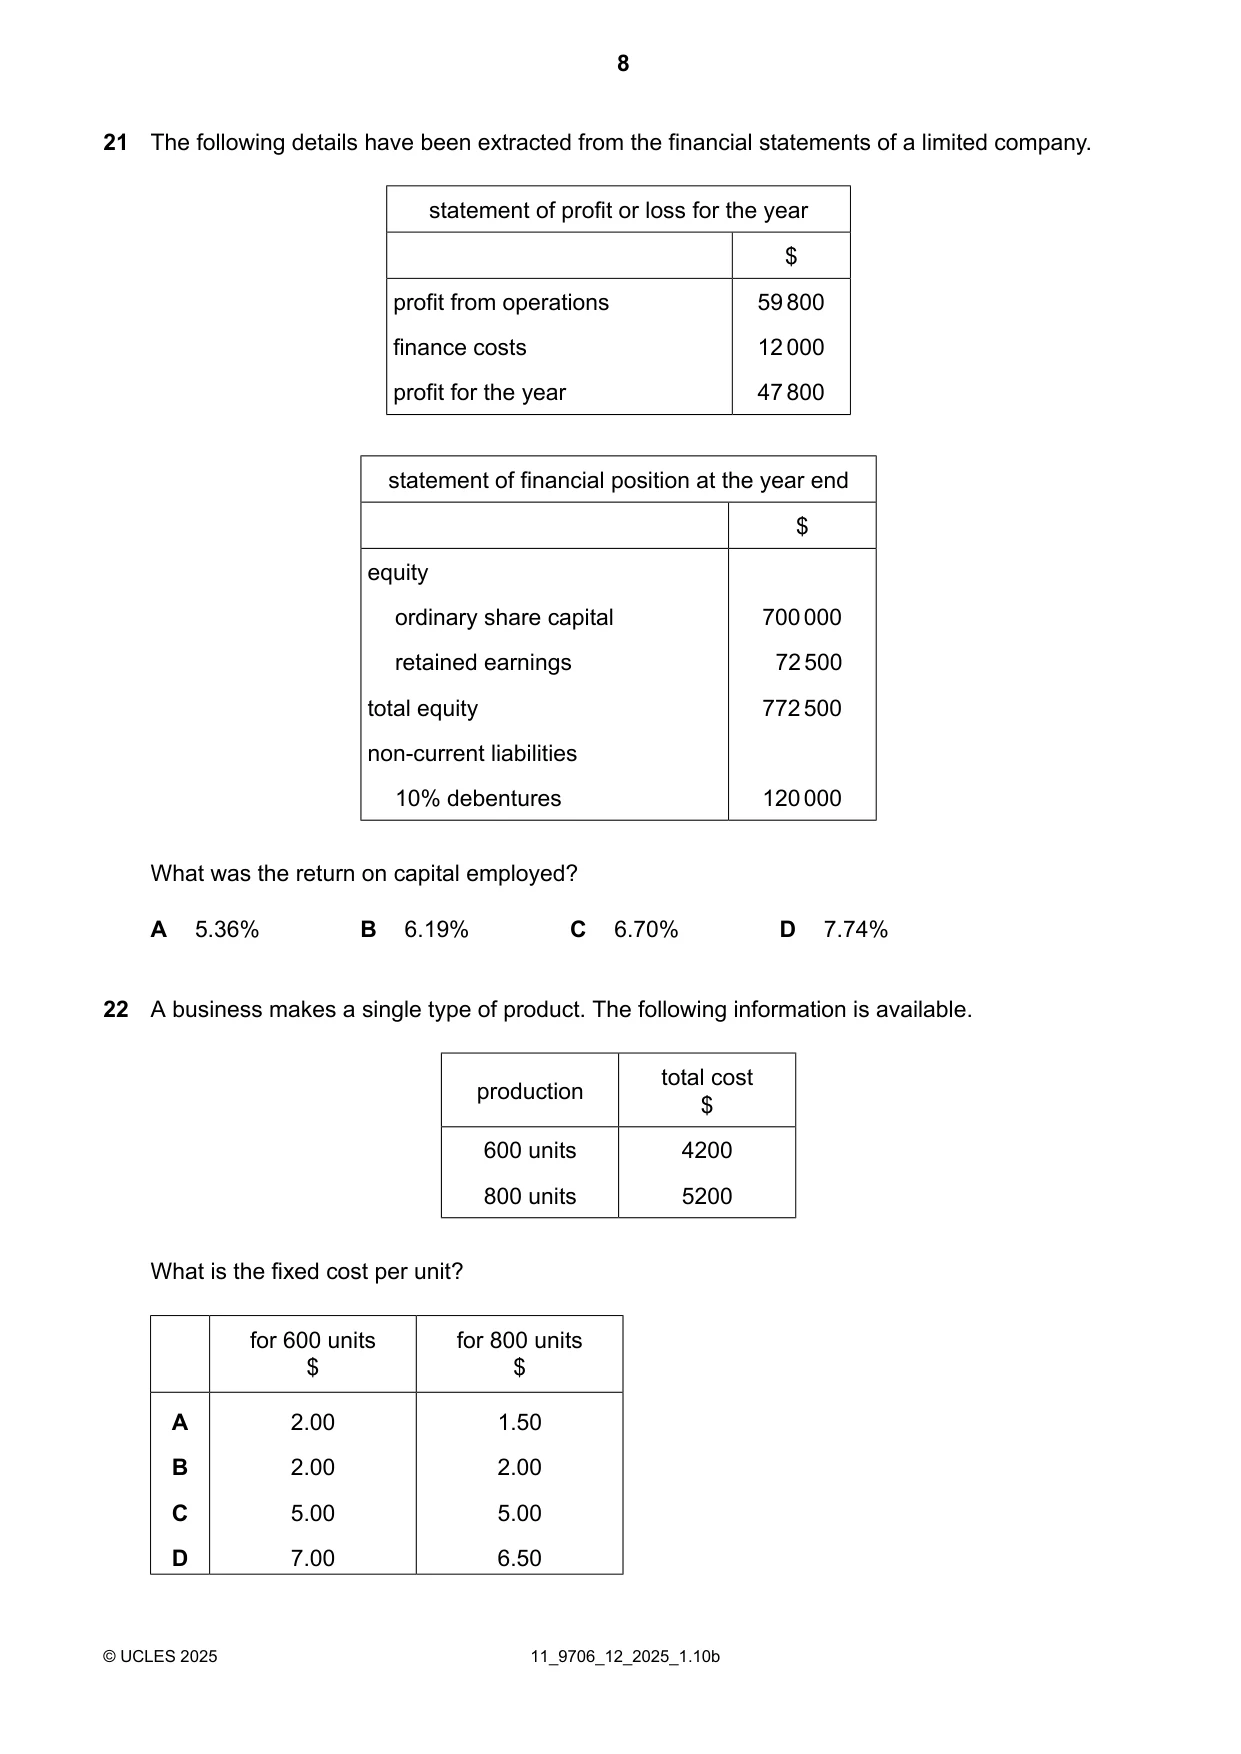
Q21 · The following details have been extracted from the financial statements of a limited…
21 The following details have been extracted from the financial statements of a limited company. statement of profit or loss for the year $ profit from operations 59800 finance costs 12000 profit for the year 47800 statement of financial position at the year end $ equity ordinary share capital 700000 retained earnings 72500 total equity 772500 non-current liabilities 10% debentures 120000 What was the return on capital employed? A 5.36% B 6.19% C 6.70% D 7.74%
Mark scheme: C
More questions on Analysis and communication of accounting information
Q22 · A business makes a single type of product
22 A business makes a single type of product. The following information is available. total cost production $ 600 units 4200 800 units 5200 What is the fixed cost per unit? for 600 units for 800 units $ $ A 2.00 1.50 B 2.00 2.00 C 5.00 5.00 D 7.00 6.50
Mark scheme: A
Q23 · W Limited is unsure whether to use marginal costing or absorption costing
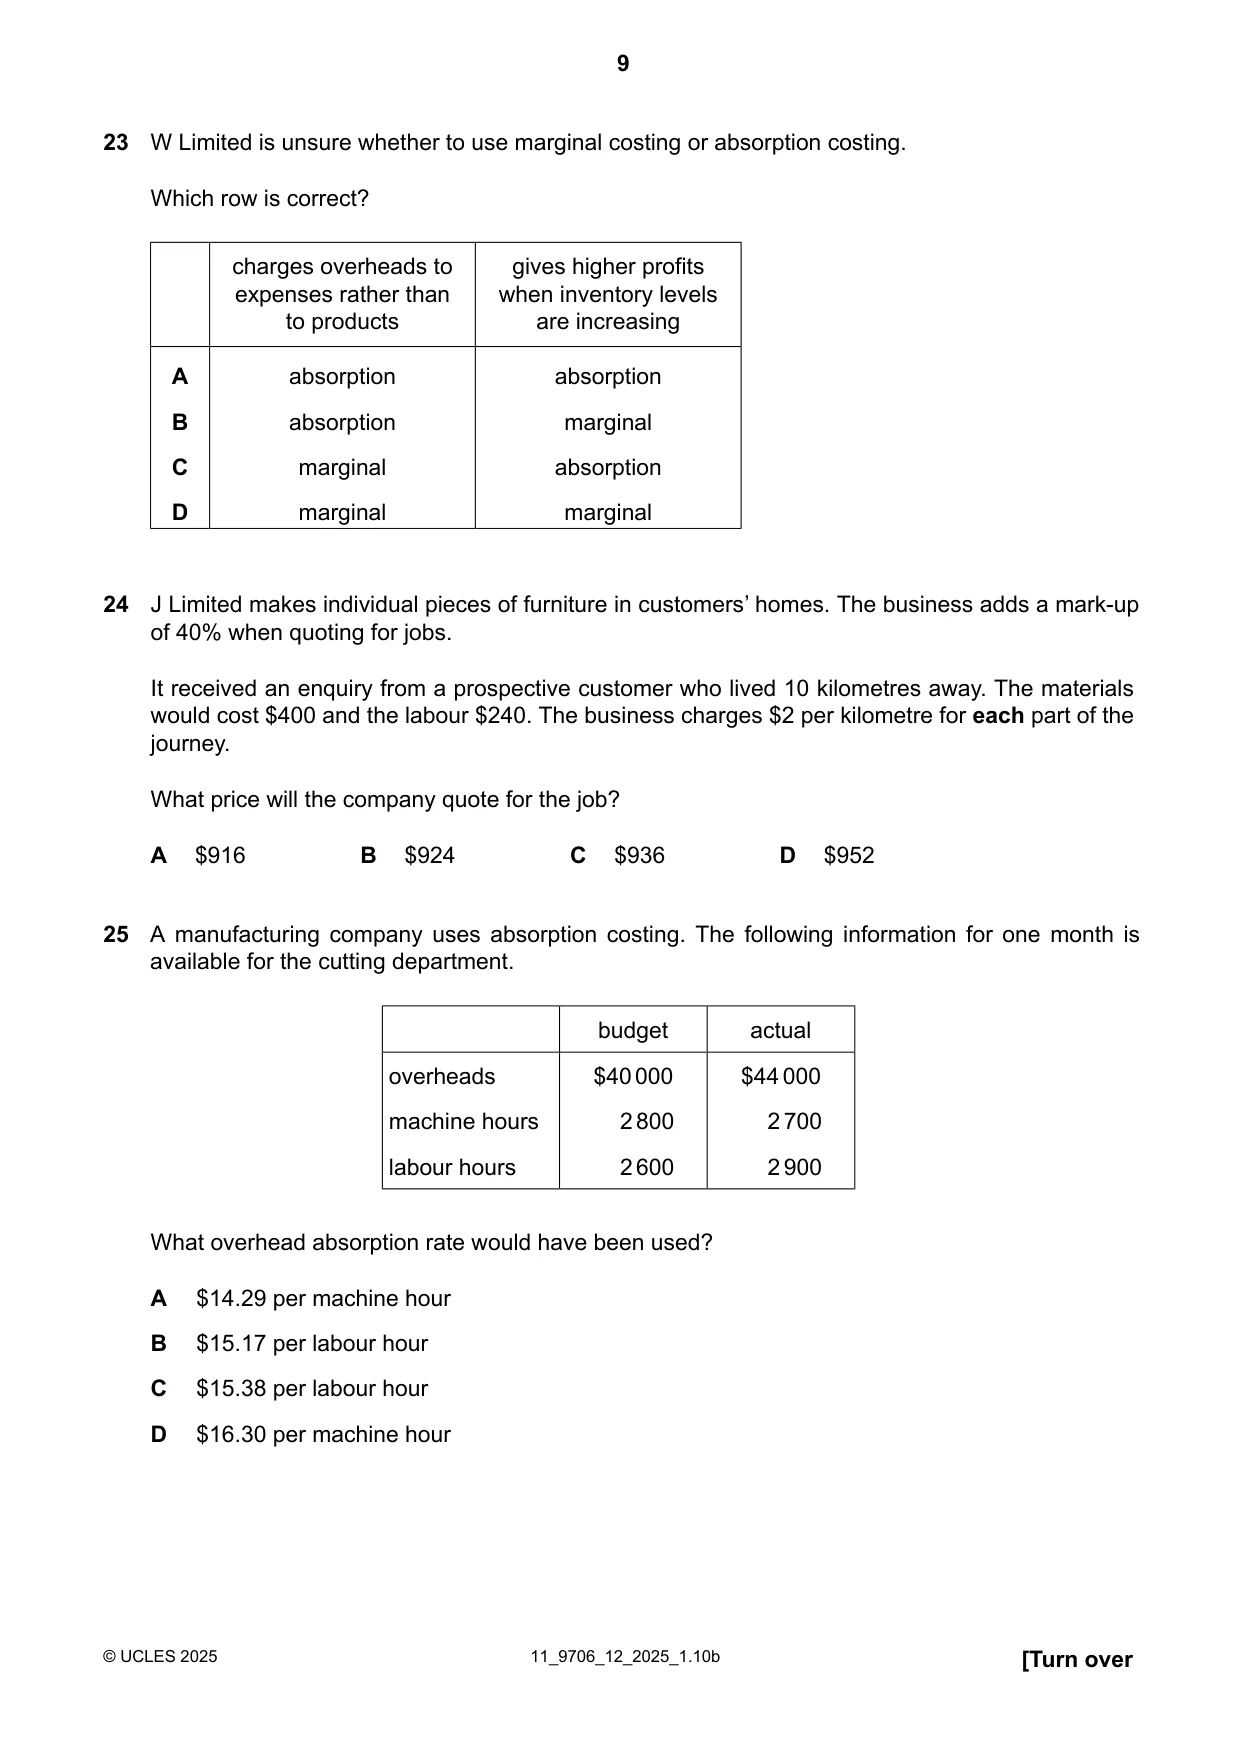
23 W Limited is unsure whether to use marginal costing or absorption costing. Which row is correct? charges overheads to gives higher profits expenses rather than when inventory levels to products are increasing A absorption absorption B absorption marginal C marginal absorption D marginal marginal
Mark scheme: C
Q24 · J Limited makes individual pieces of furniture in customers’ homes
24 J Limited makes individual pieces of furniture in customers’ homes. The business adds a mark-up of 40% when quoting for jobs. It received an enquiry from a prospective customer who lived 10 kilometres away. The materials would cost $400 and the labour $240. The business charges $2 per kilometre for each part of the journey. What price will the company quote for the job? A $916 B $924 C $936 D $952
Mark scheme: D
Q25 · A manufacturing company uses absorption costing
25 A manufacturing company uses absorption costing. The following information for one month is available for the cutting department. budget actual overheads $40000 $44000 machine hours 2800 2700 labour hours 2600 2900 What overhead absorption rate would have been used? A $14.29 per machine hour B $15.17 per labour hour C $15.38 per labour hour D $16.30 per machine hour
Mark scheme: A
Q26 · A business provides the following information
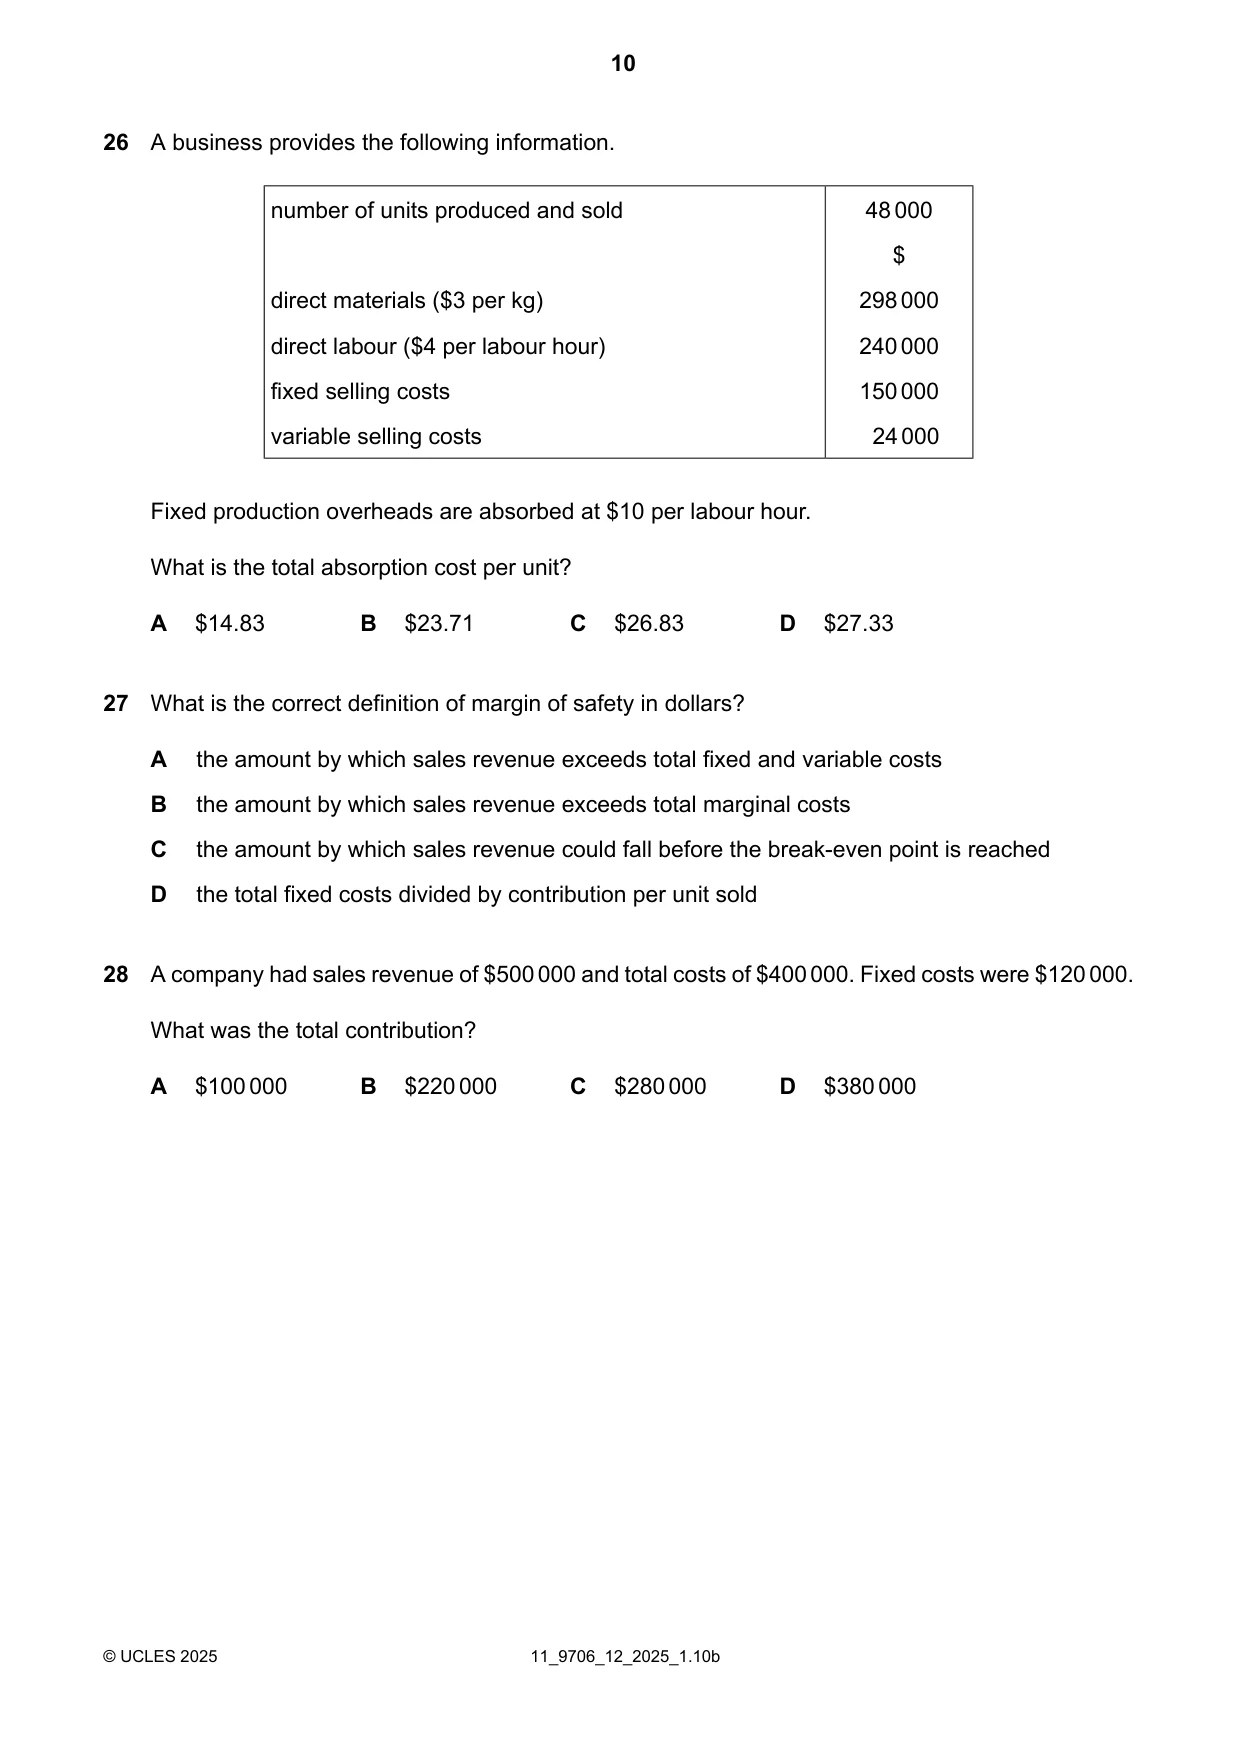
26 A business provides the following information. number of units produced and sold 48000 $ direct materials ($3 per kg) 298000 direct labour ($4 per labour hour) 240000 fixed selling costs 150000 variable selling costs 24000 Fixed production overheads are absorbed at $10 per labour hour. What is the total absorption cost per unit? A $14.83 B $23.71 C $26.83 D $27.33
Mark scheme: D
Q27 · What is the correct definition of margin of safety in dollars?
27 What is the correct definition of margin of safety in dollars? A the amount by which sales revenue exceeds total fixed and variable costs B the amount by which sales revenue exceeds total marginal costs C the amount by which sales revenue could fall before the break-even point is reached D the total fixed costs divided by contribution per unit sold
Mark scheme: C
Q28 · A company had sales revenue of $500000 and total costs of $400000
28 A company had sales revenue of $500000 and total costs of $400000. Fixed costs were $120000. What was the total contribution? A $100000 B $220000 C $280000 D $380000
Mark scheme: B
Q29 · The following information is available
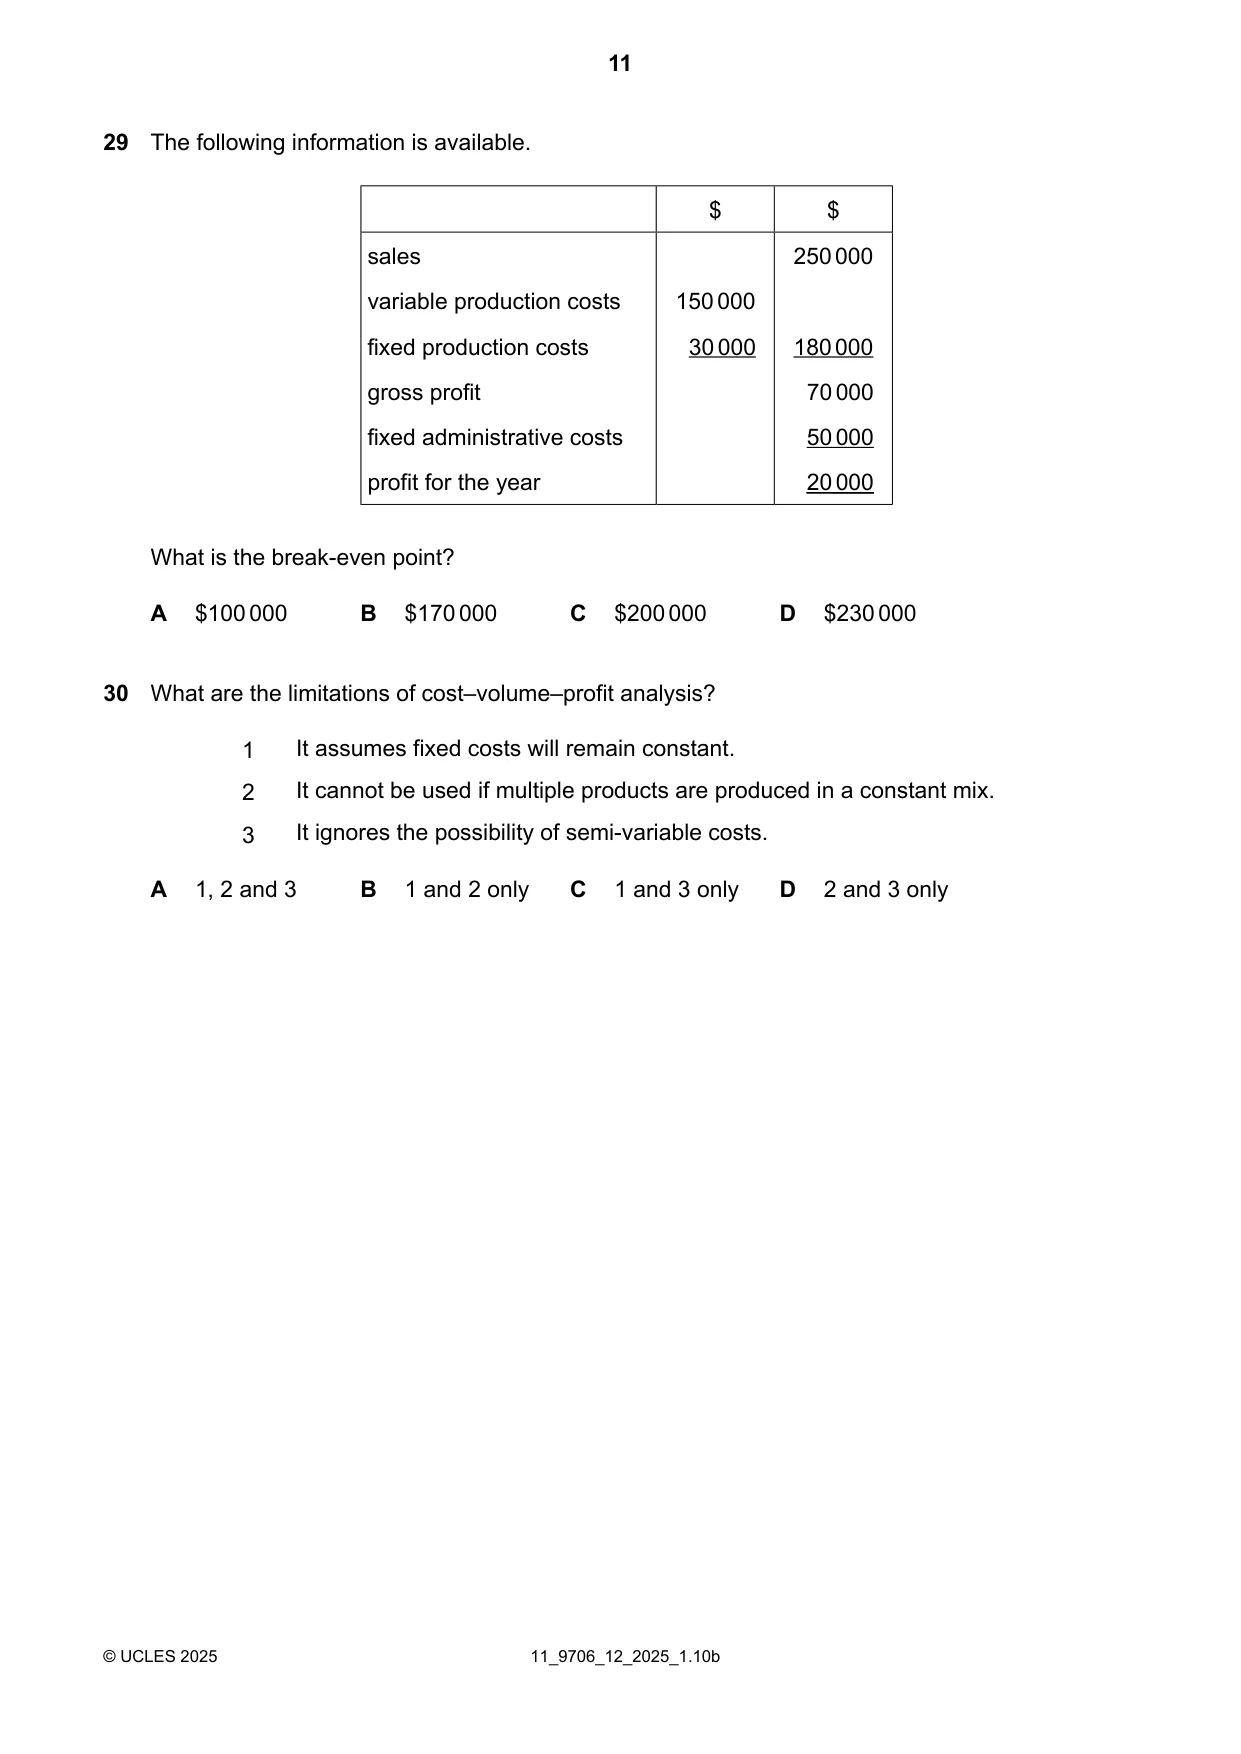
29 The following information is available. $ $ sales 250000 variable production costs 150000 fixed production costs 30000 180000 gross profit 70000 fixed administrative costs 50000 profit for the year 20000 What is the break-even point? A $100000 B $170000 C $200000 D $230000
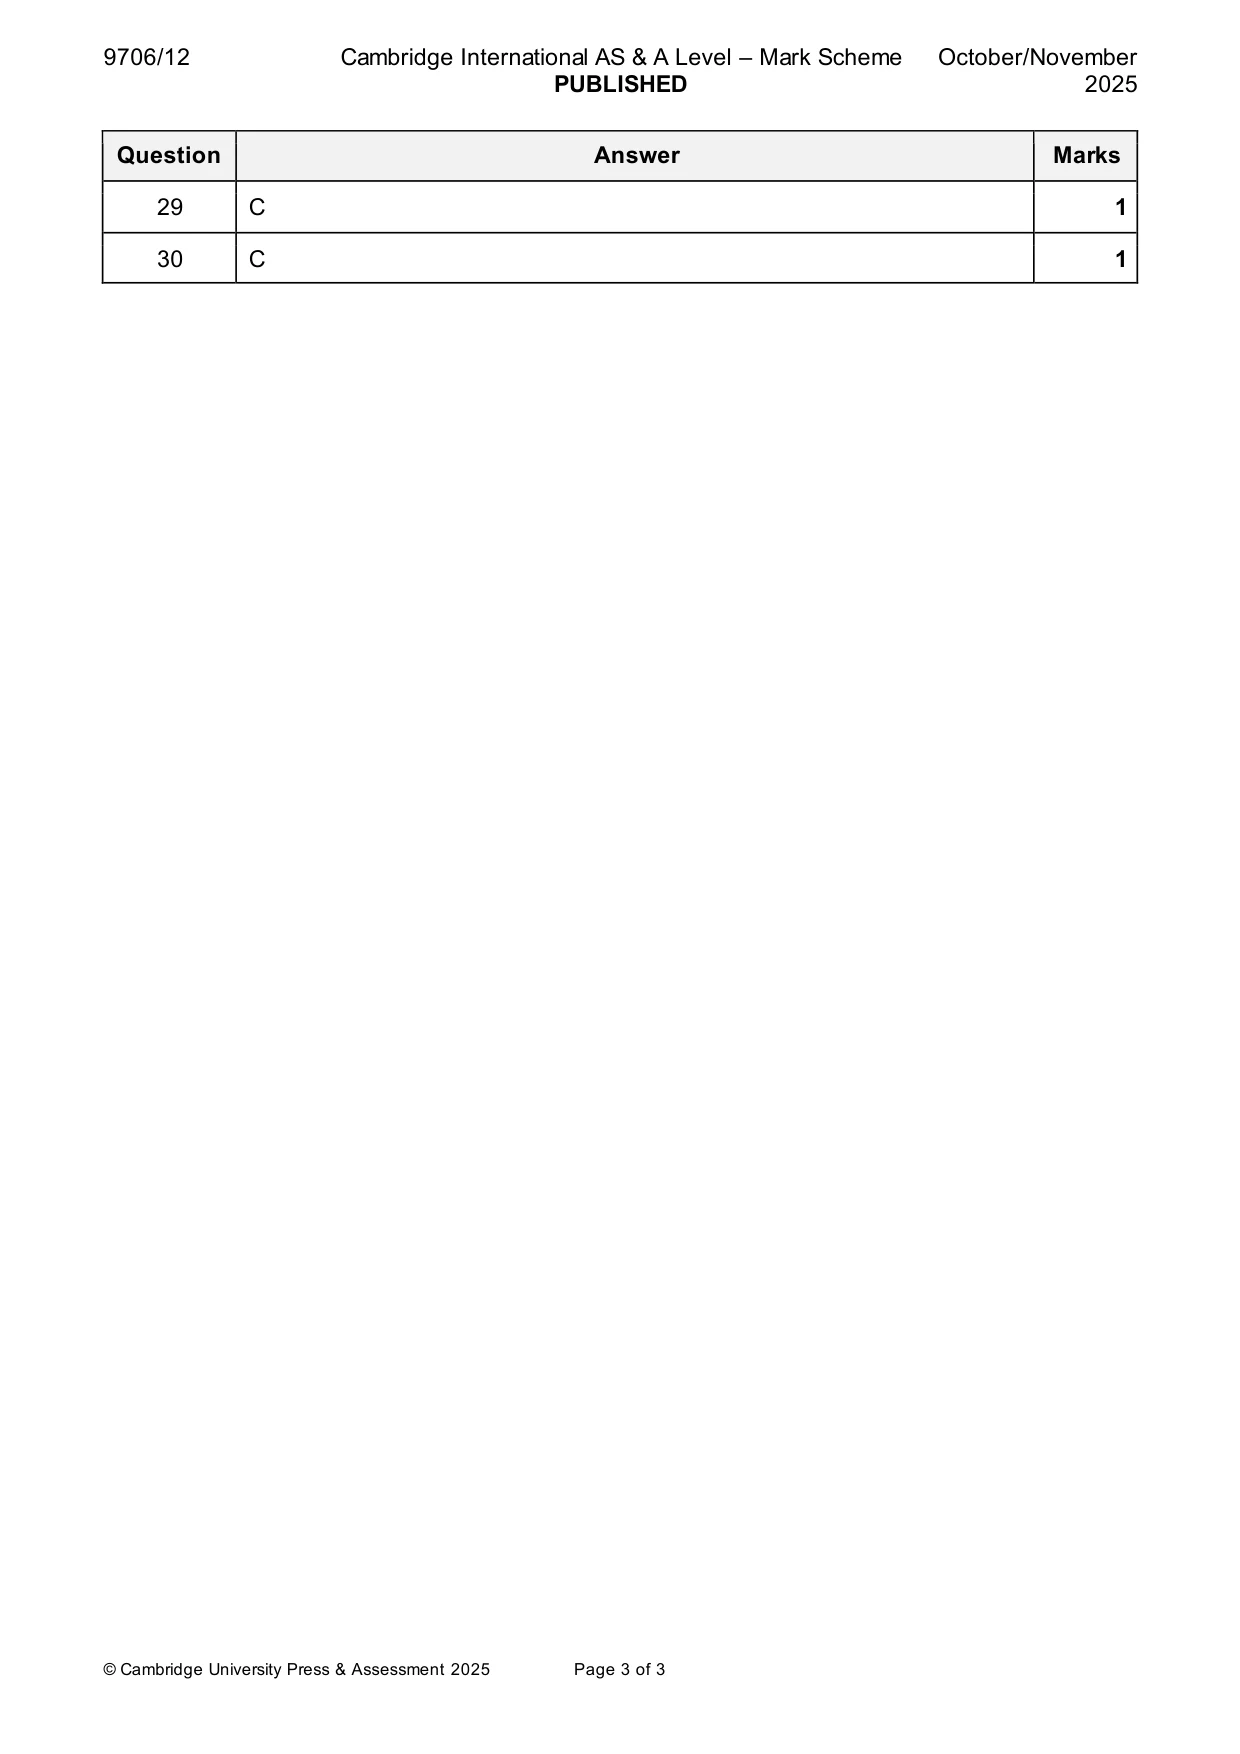
Mark scheme: C
Q30 · What are the limitations of cost–volume–profit analysis?
30 What are the limitations of cost–volume–profit analysis? 1 It assumes fixed costs will remain constant. 2 It cannot be used if multiple products are produced in a constant mix. 3 It ignores the possibility of semi-variable costs. A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
Mark scheme: C
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2025 Oct/Nov, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.