Cambridge A Level Accounting 9706 — 2023 Oct/Nov Paper 1 · Variant 1
9706/11/O/N/23 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
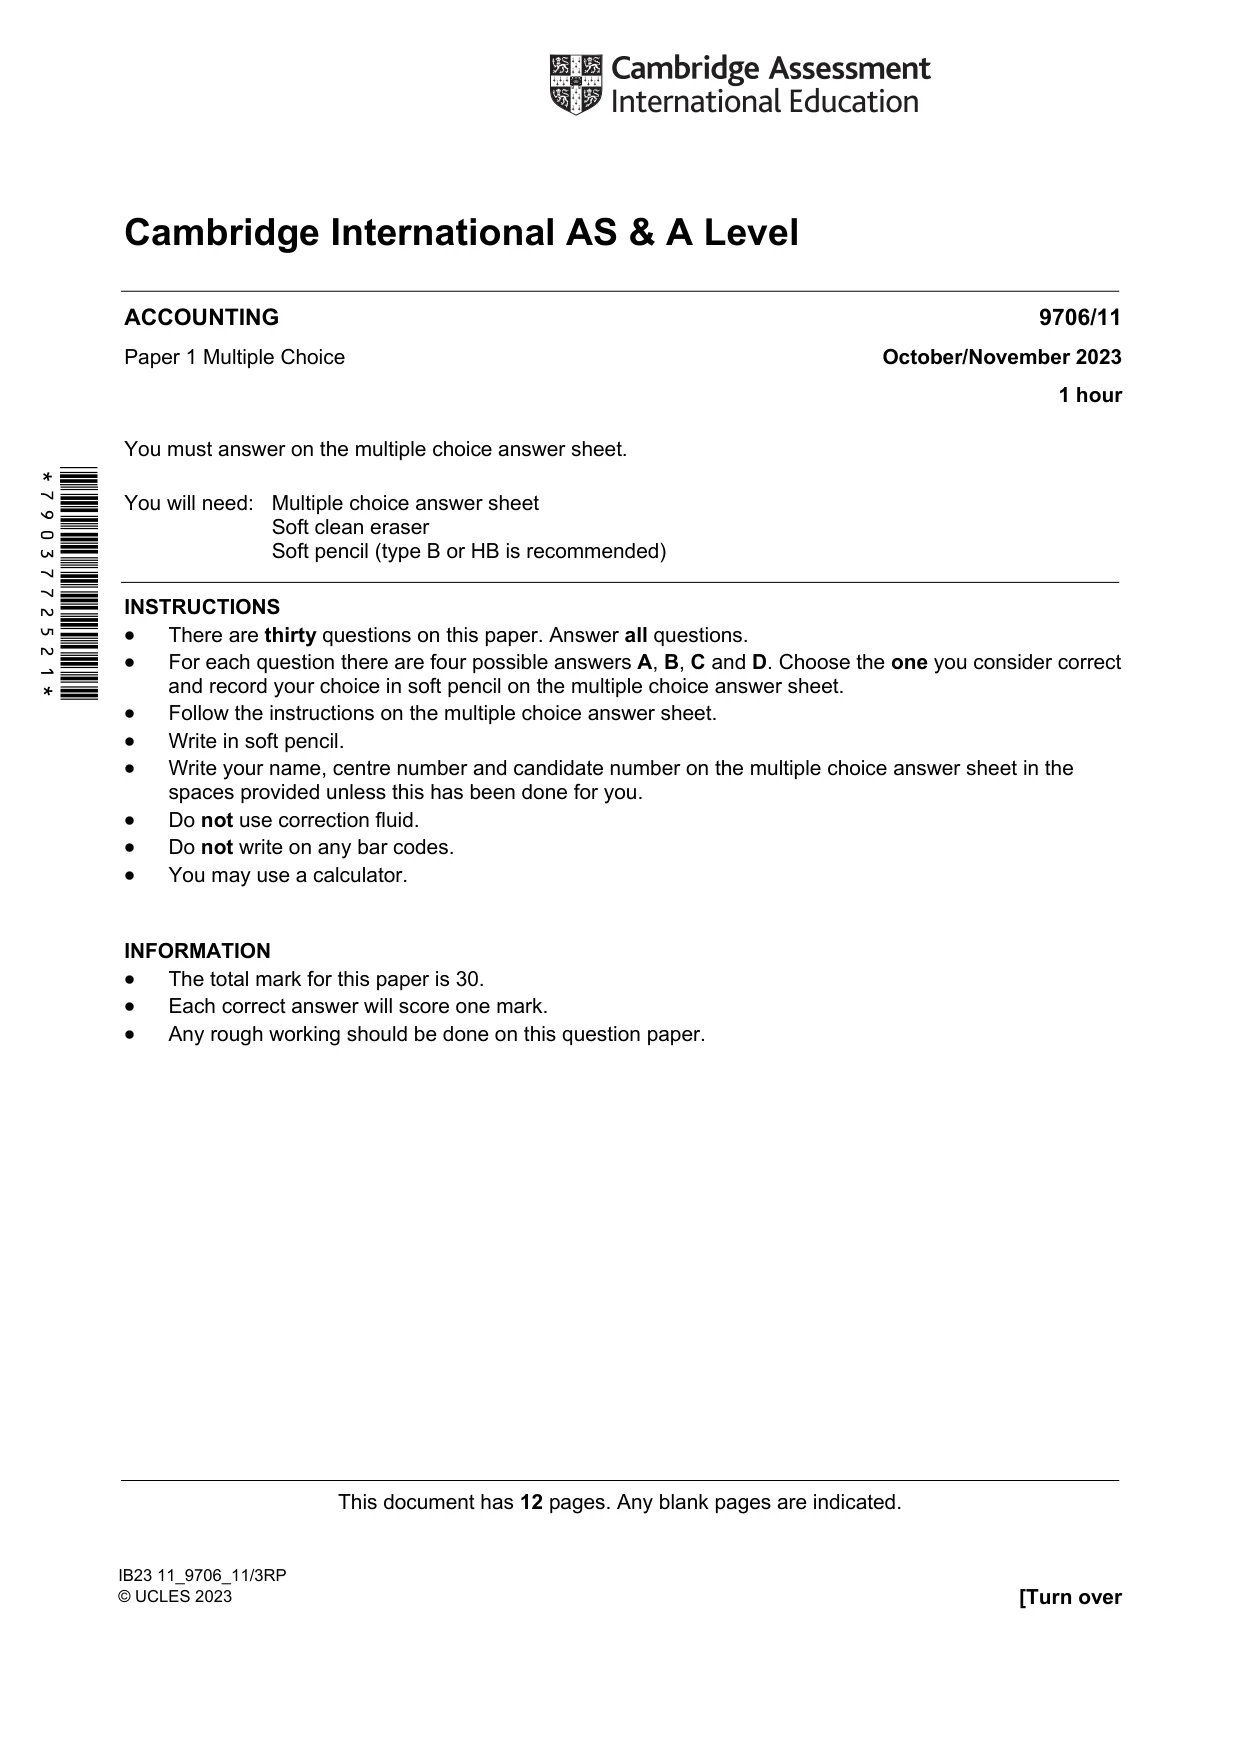
Question paper12 pages
Mark scheme3 pages
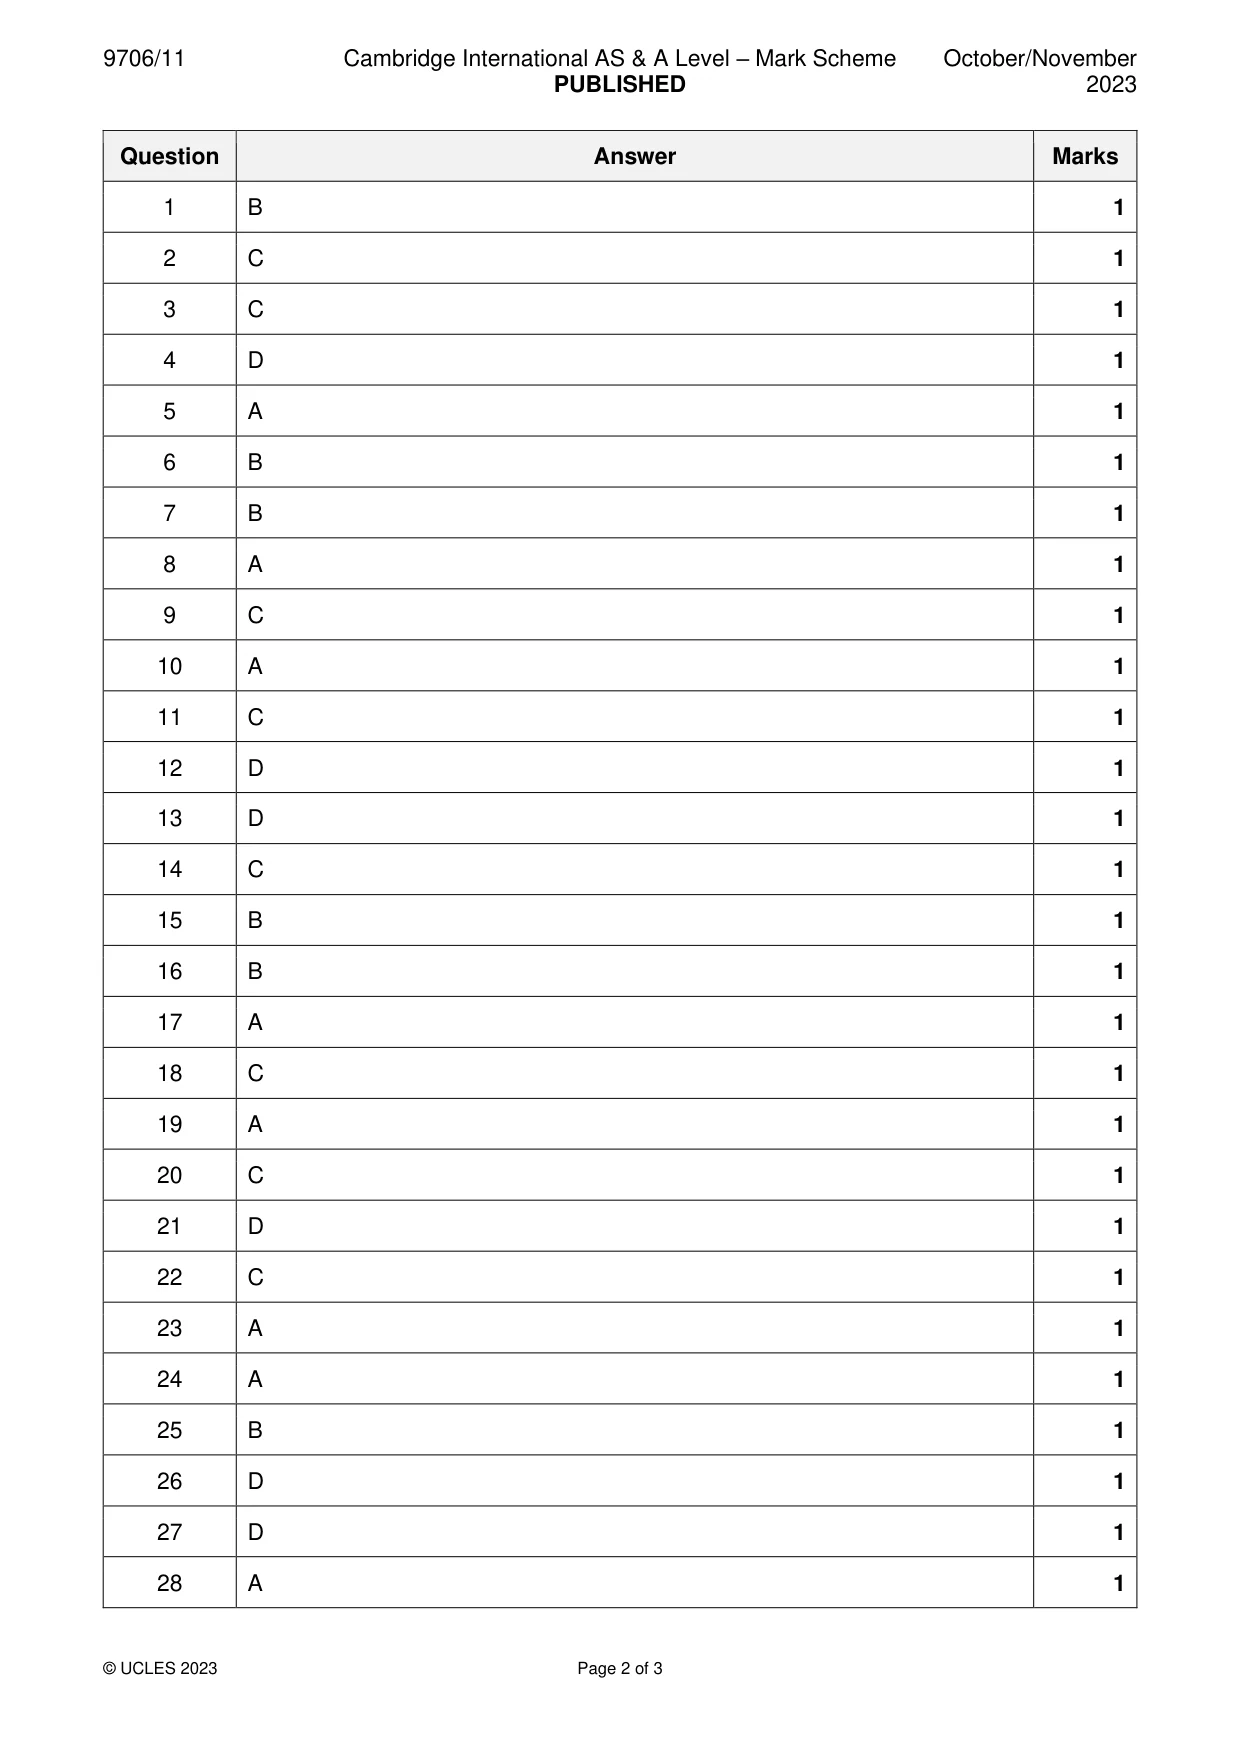
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Which sources are external short-term sources of finance for a limited company?
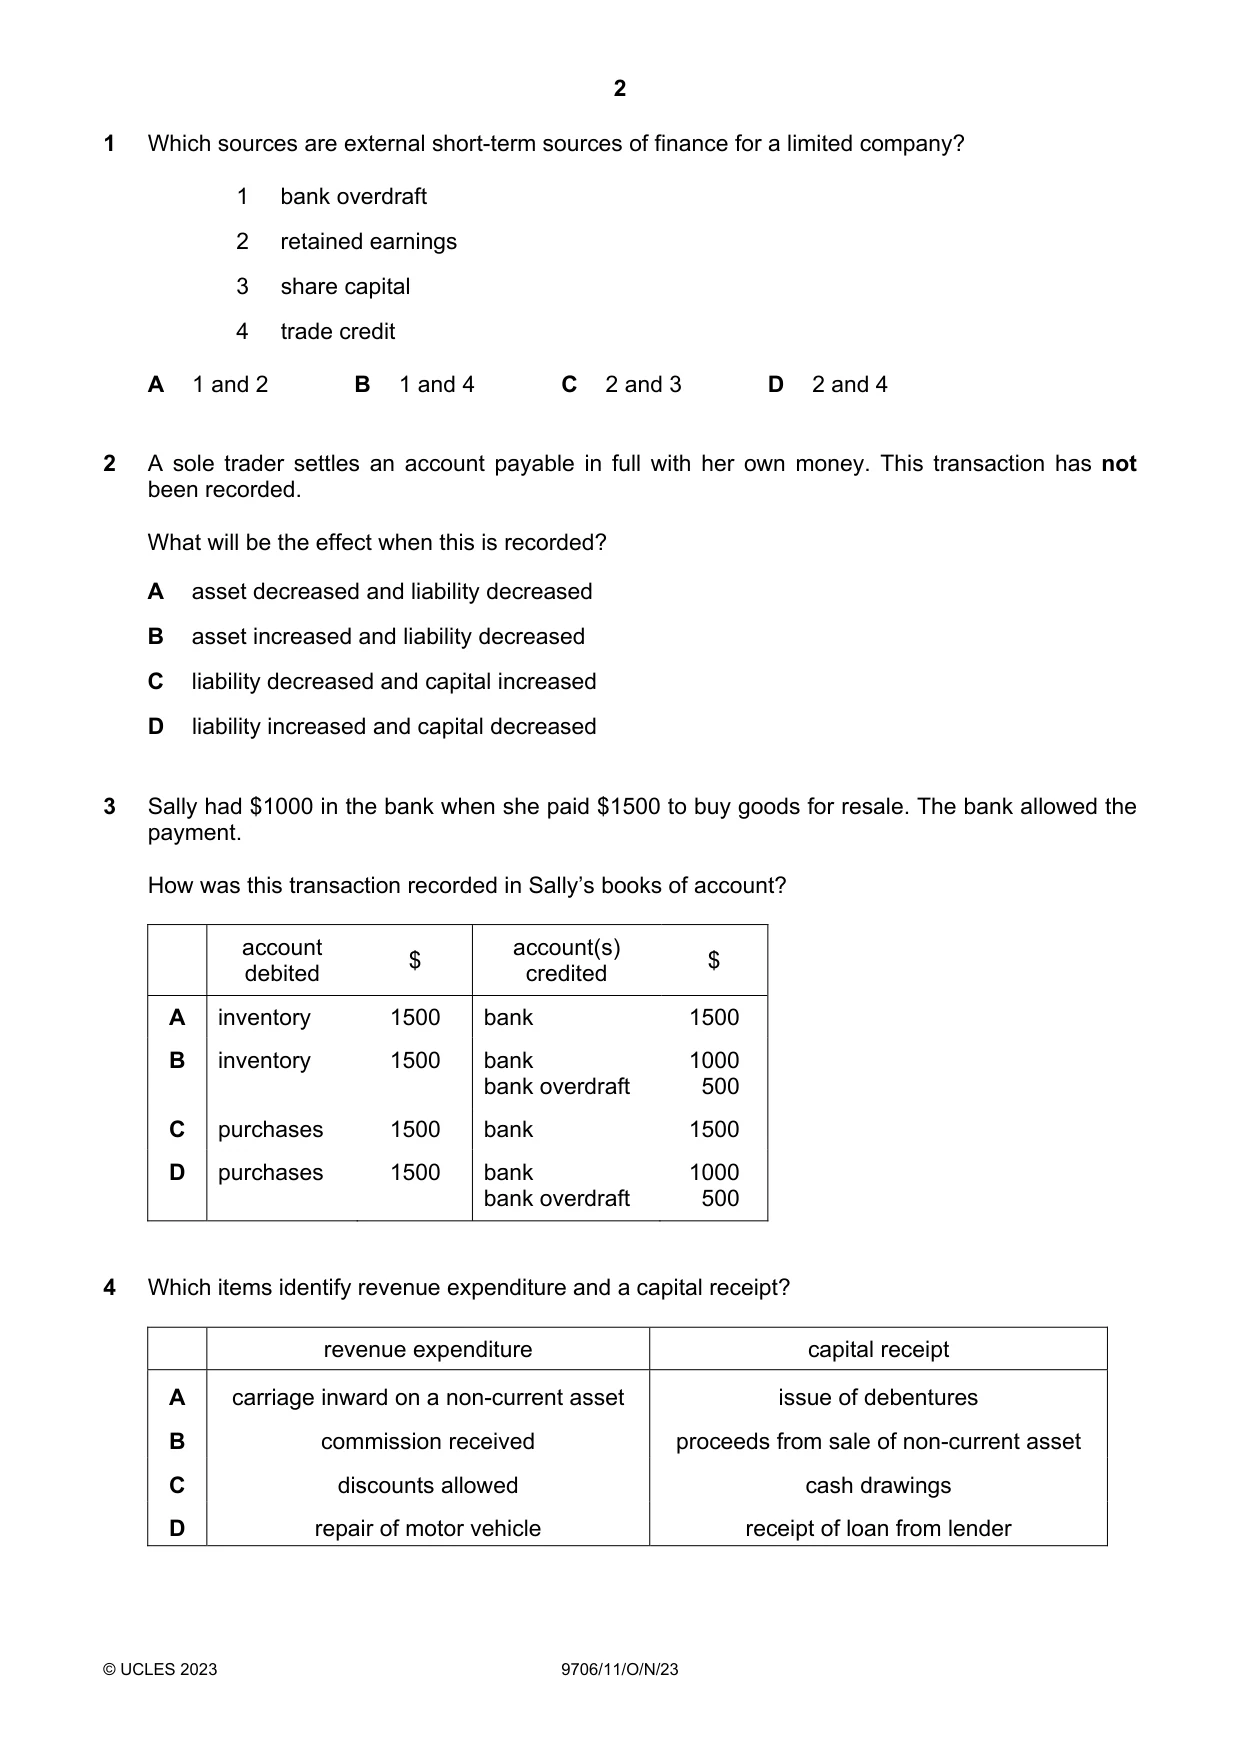
1 Which sources are external short-term sources of finance for a limited company? 1 bank overdraft 2 retained earnings 3 share capital 4 trade credit A 1 and 2 B 1 and 4 C 2 and 3 D 2 and 4
Mark scheme: B
Q2 · A sole trader settles an account payable in full with her own money
2 A sole trader settles an account payable in full with her own money. This transaction has not been recorded. What will be the effect when this is recorded? A asset decreased and liability decreased B asset increased and liability decreased C liability decreased and capital increased D liability increased and capital decreased
Mark scheme: C
Q3 · Sally had $1000 in the bank when she paid $1500 to buy goods for resale
3 Sally had $1000 in the bank when she paid $1500 to buy goods for resale. The bank allowed the payment. How was this transaction recorded in Sally’s books of account? account account(s) $ $ debited credited A inventory 1500 bank 1500 B inventory 1500 bank 1000 bank overdraft 500 C purchases 1500 bank 1500 D purchases 1500 bank 1000 bank overdraft 500
Mark scheme: C
Q4 · Which items identify revenue expenditure and a capital receipt?
4 Which items identify revenue expenditure and a capital receipt? revenue expenditure capital receipt A carriage inward on a non-current asset issue of debentures B commission received proceeds from sale of non-current asset C discounts allowed cash drawings D repair of motor vehicle receipt of loan from lender
Mark scheme: D
Q5 · Which statement identifies why depreciation is provided on non-current assets?
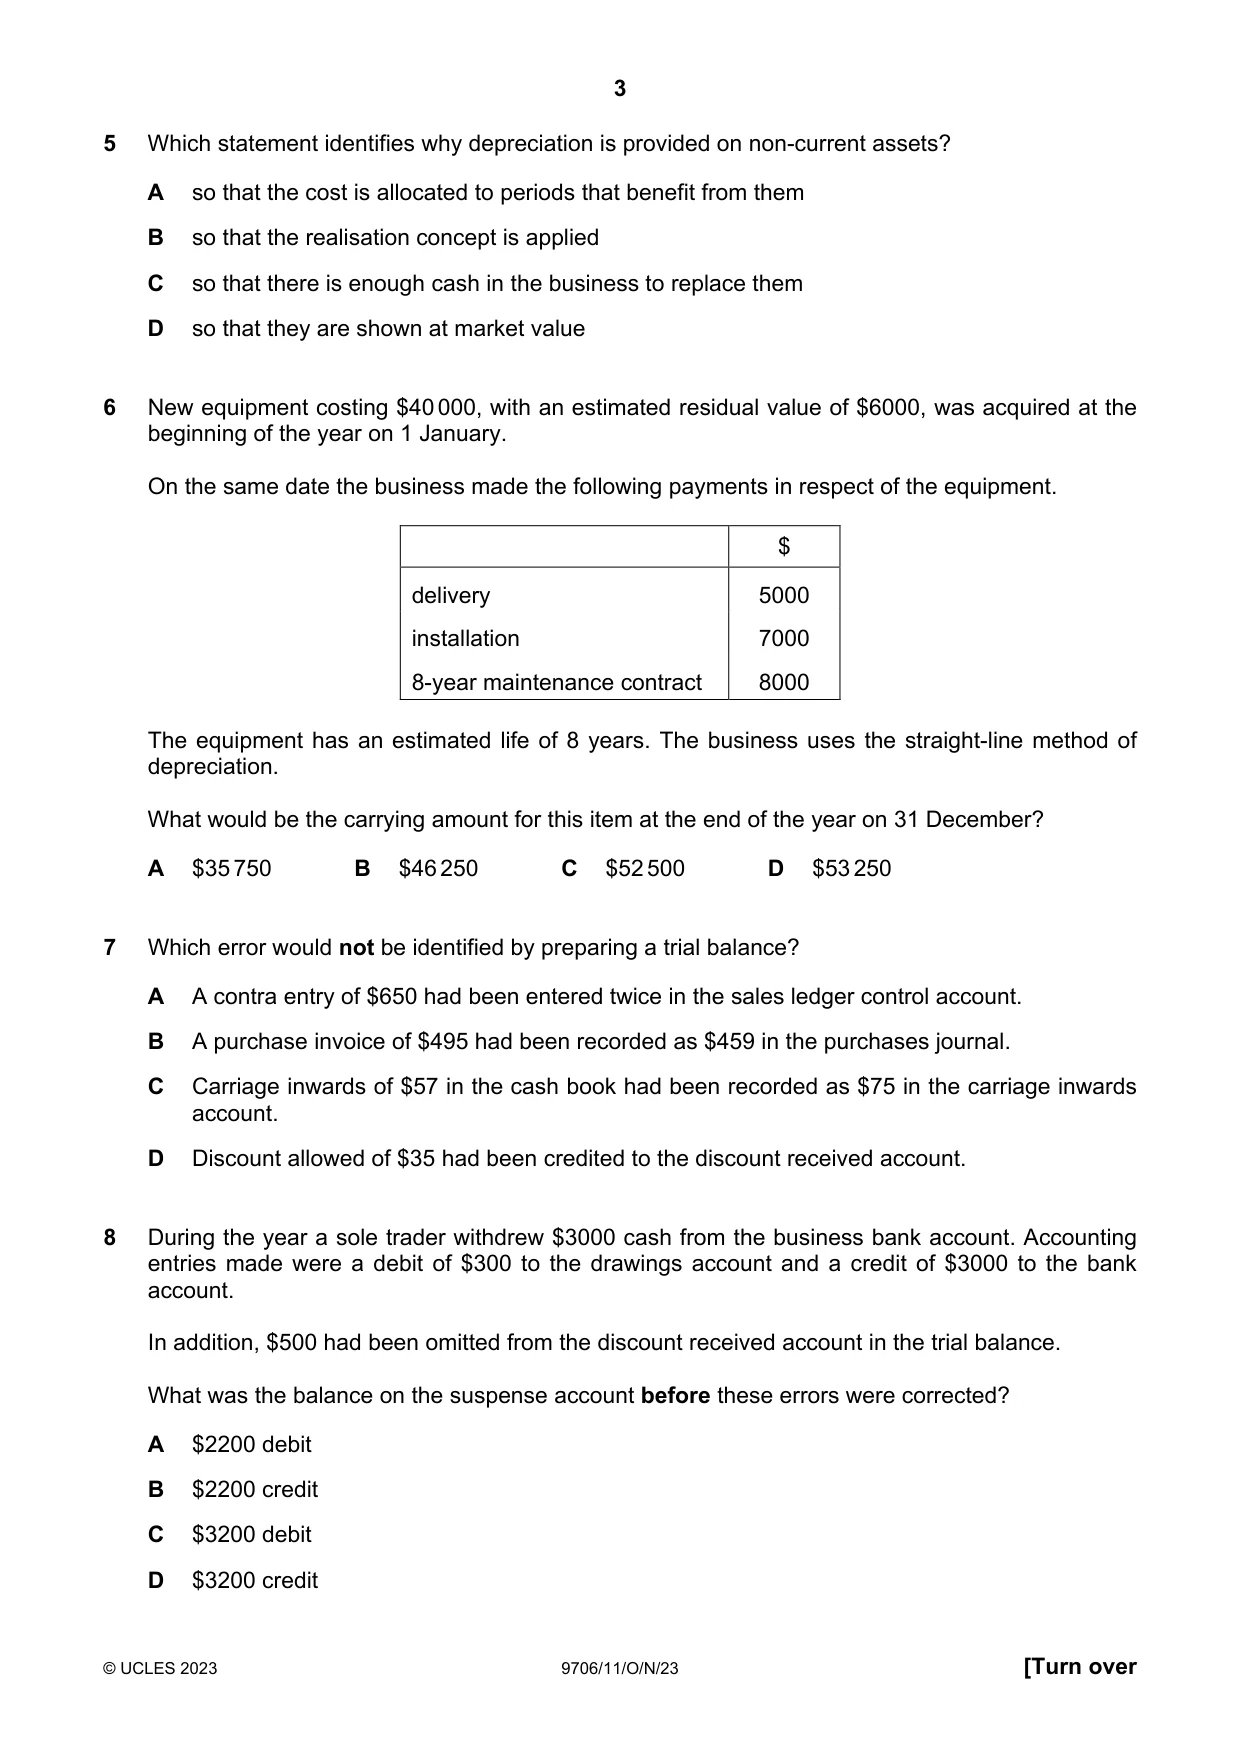
5 Which statement identifies why depreciation is provided on non-current assets? A so that the cost is allocated to periods that benefit from them B so that the realisation concept is applied C so that there is enough cash in the business to replace them D so that they are shown at market value
Mark scheme: A
Q6 · New equipment costing $40 000, with an estimated residual value of $6000, was acquired at…
6 New equipment costing $40 000, with an estimated residual value of $6000, was acquired at the beginning of the year on 1 January. On the same date the business made the following payments in respect of the equipment. $ delivery 5000 installation 7000 8-year maintenance contract 8000 The equipment has an estimated life of 8 years. The business uses the straight-line method of depreciation. What would be the carrying amount for this item at the end of the year on 31 December? A $35 750 B $46 250 C $52 500 D $53 250
Mark scheme: B
Q7 · Which error would not be identified by preparing a trial balance?
7 Which error would not be identified by preparing a trial balance? A A contra entry of $650 had been entered twice in the sales ledger control account. B A purchase invoice of $495 had been recorded as $459 in the purchases journal. C Carriage inwards of $57 in the cash book had been recorded as $75 in the carriage inwards account. D Discount allowed of $35 had been credited to the discount received account.
Mark scheme: B
Q8 · During the year a sole trader withdrew $3000 cash from the business bank account
8 During the year a sole trader withdrew $3000 cash from the business bank account. Accounting entries made were a debit of $300 to the drawings account and a credit of $3000 to the bank account. In addition, $500 had been omitted from the discount received account in the trial balance. What was the balance on the suspense account before these errors were corrected? A $2200 debit B $2200 credit C $3200 debit D $3200 credit
Mark scheme: A
Q9 · A company’s bank statement showed a credit balance of $2000
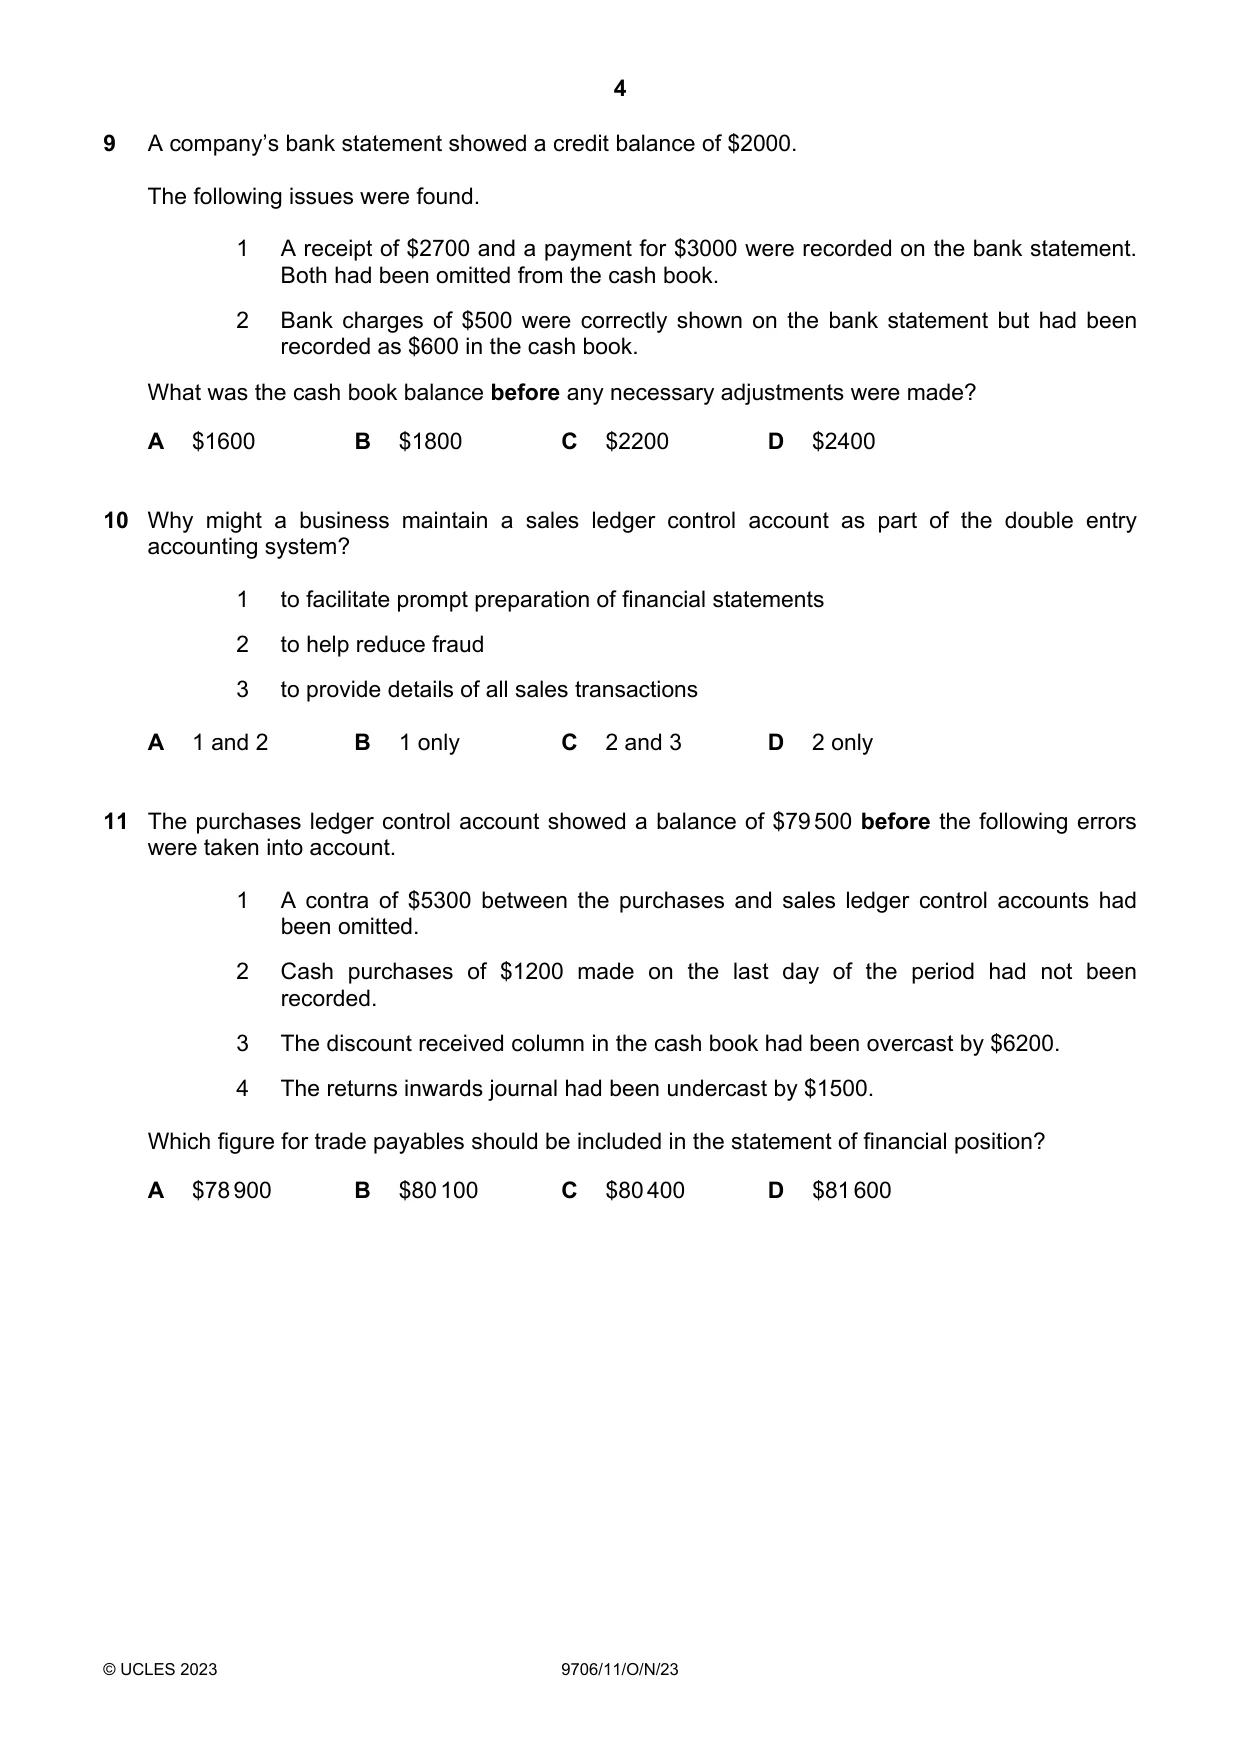
9 A company’s bank statement showed a credit balance of $2000. The following issues were found. 1 A receipt of $2700 and a payment for $3000 were recorded on the bank statement. Both had been omitted from the cash book. 2 Bank charges of $500 were correctly shown on the bank statement but had been recorded as $600 in the cash book. What was the cash book balance before any necessary adjustments were made? A $1600 B $1800 C $2200 D $2400
Mark scheme: C
Q10 · Why might a business maintain a sales ledger control account as part of the double entry…
10 Why might a business maintain a sales ledger control account as part of the double entry accounting system? 1 to facilitate prompt preparation of financial statements 2 to help reduce fraud 3 to provide details of all sales transactions A 1 and 2 B 1 only C 2 and 3 D 2 only
Mark scheme: A
Q11 · The purchases ledger control account showed a balance of $79 500 before the following…
11 The purchases ledger control account showed a balance of $79 500 before the following errors were taken into account. 1 A contra of $5300 between the purchases and sales ledger control accounts had been omitted. 2 Cash purchases of $1200 made on the last day of the period had not been recorded. 3 The discount received column in the cash book had been overcast by $6200. 4 The returns inwards journal had been undercast by $1500. Which figure for trade payables should be included in the statement of financial position? A $78 900 B $80 100 C $80 400 D $81 600
Mark scheme: C
Q12 · A business has trade receivables of $52 000 at the year-end
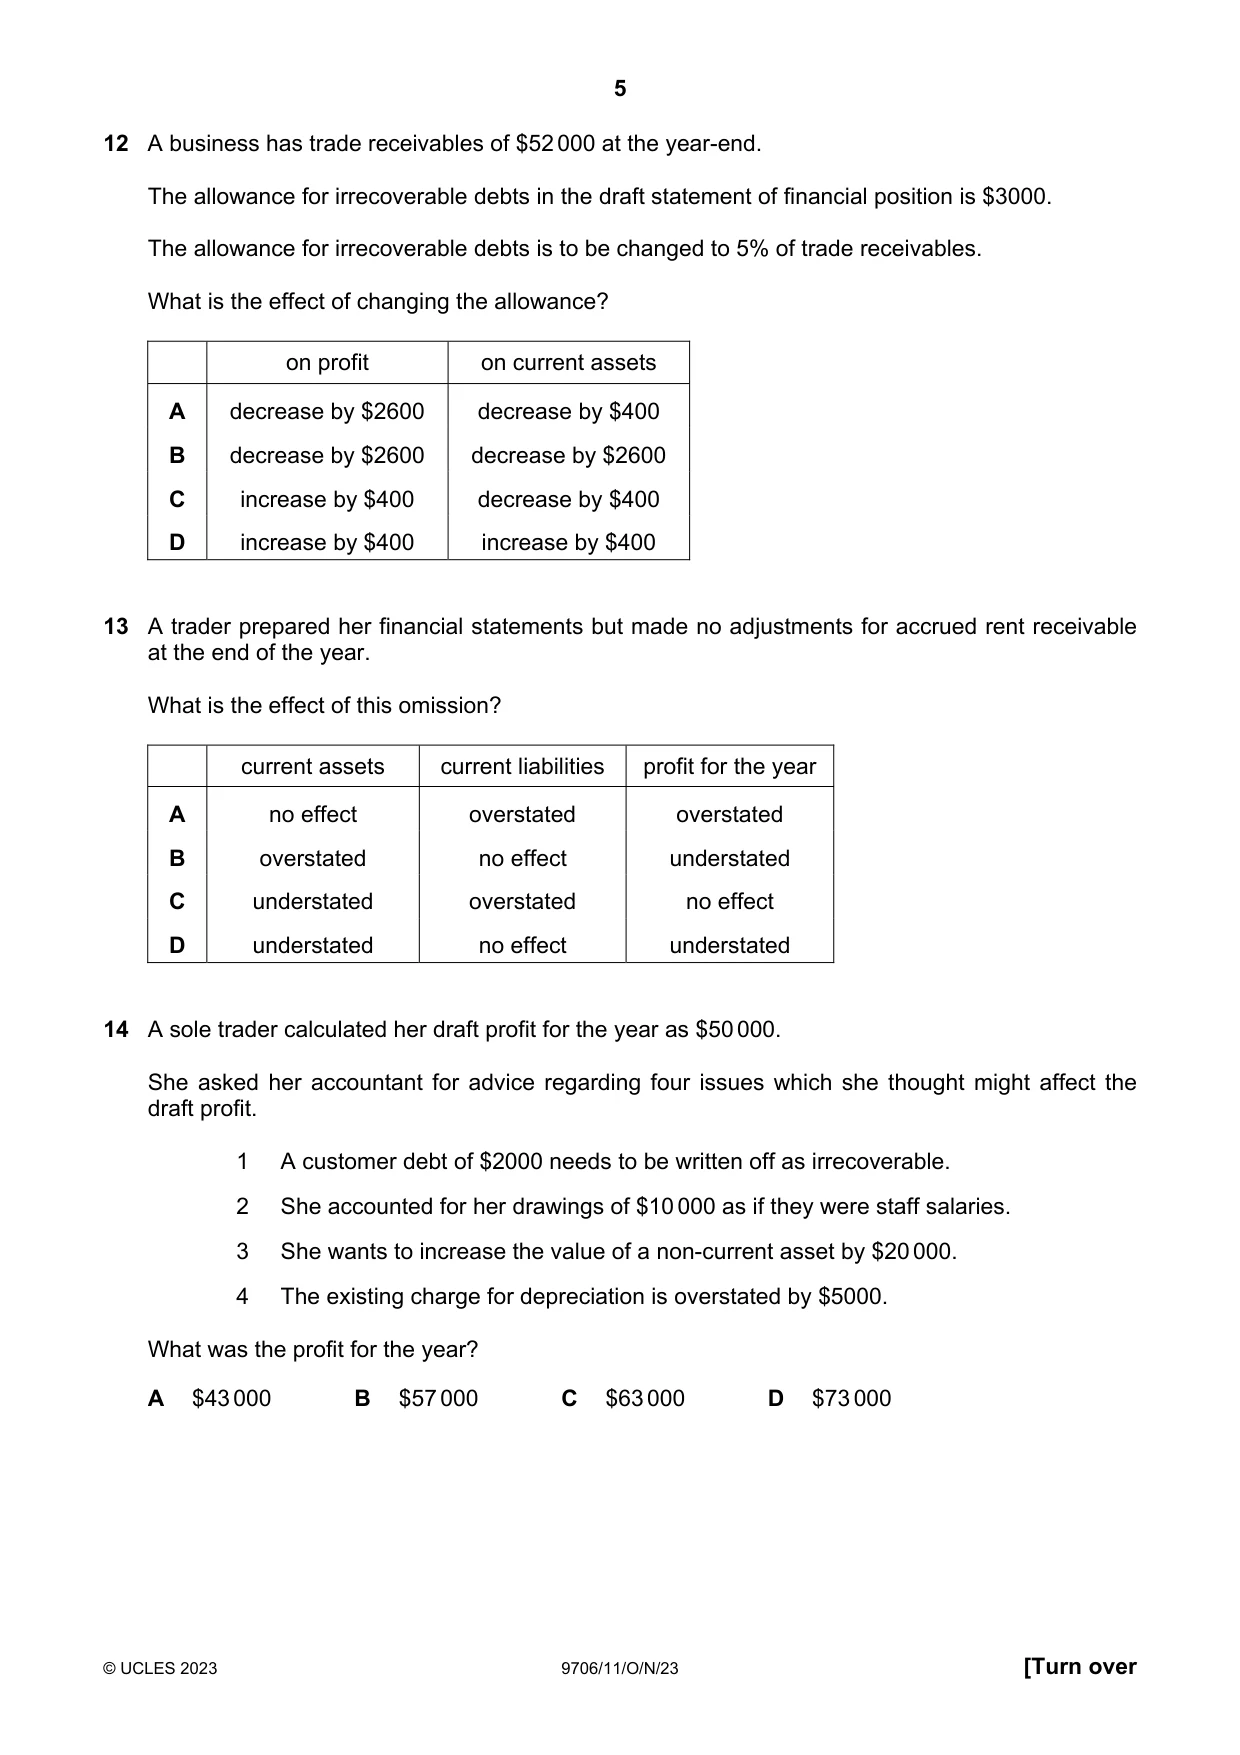
12 A business has trade receivables of $52 000 at the year-end. The allowance for irrecoverable debts in the draft statement of financial position is $3000. The allowance for irrecoverable debts is to be changed to 5% of trade receivables. What is the effect of changing the allowance? on profit on current assets A decrease by $2600 decrease by $400 B decrease by $2600 decrease by $2600 C increase by $400 decrease by $400 D increase by $400 increase by $400
Mark scheme: D
Q13 · A trader prepared her financial statements but made no adjustments for accrued rent…
13 A trader prepared her financial statements but made no adjustments for accrued rent receivable at the end of the year. What is the effect of this omission? current assets current liabilities profit for the year A no effect overstated overstated B overstated no effect understated C understated overstated no effect D understated no effect understated
Mark scheme: D
Q14 · A sole trader calculated her draft profit for the year as $50 000
14 A sole trader calculated her draft profit for the year as $50 000. She asked her accountant for advice regarding four issues which she thought might affect the draft profit. 1 A customer debt of $2000 needs to be written off as irrecoverable. 2 She accounted for her drawings of $10 000 as if they were staff salaries. 3 She wants to increase the value of a non-current asset by $20 000. 4 The existing charge for depreciation is overstated by $5000. What was the profit for the year? A $43 000 B $57 000 C $63 000 D $73 000
Mark scheme: C
Q15 · Which items in the books of a partnership would increase the profit available for…
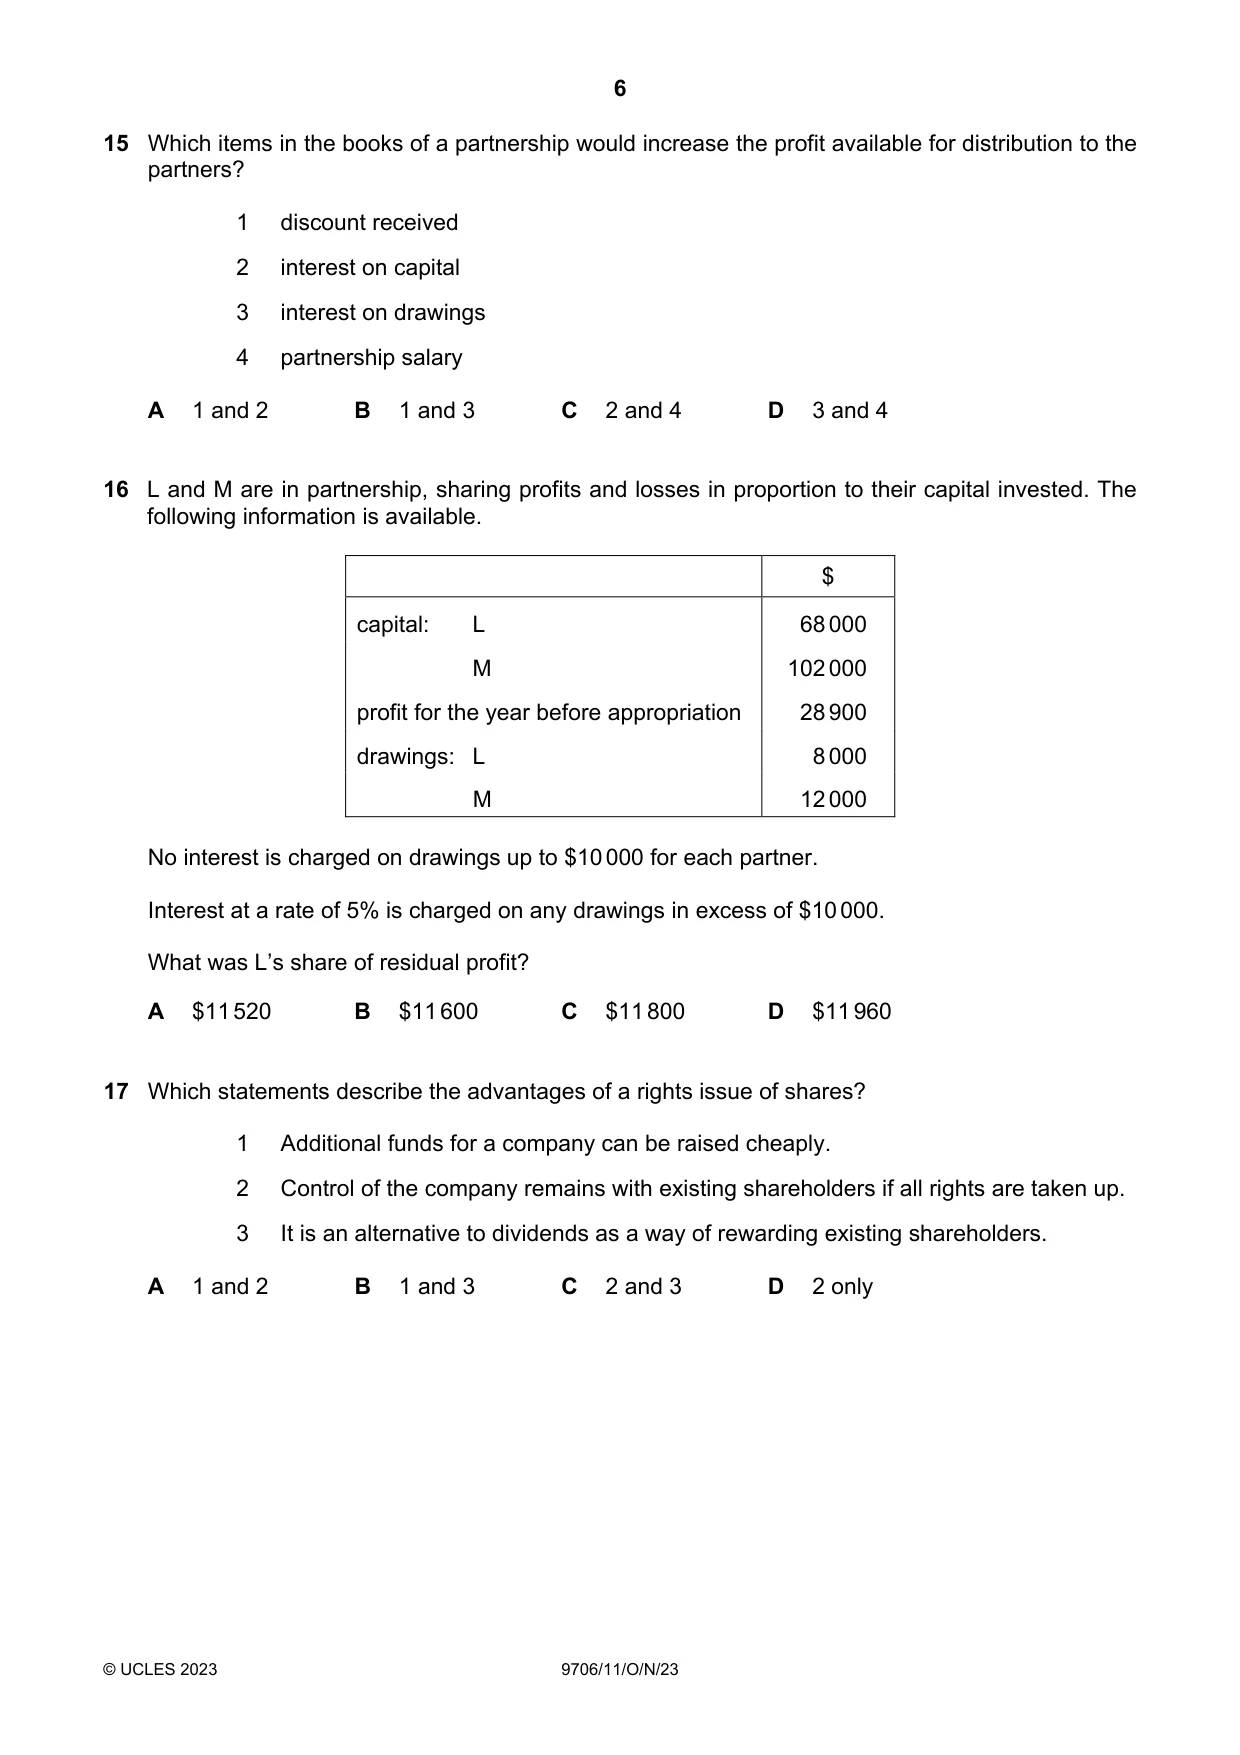
15 Which items in the books of a partnership would increase the profit available for distribution to the partners? 1 discount received 2 interest on capital 3 interest on drawings 4 partnership salary A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
Mark scheme: B
Q16 · L and M are in partnership, sharing profits and losses in proportion to their capital…
16 L and M are in partnership, sharing profits and losses in proportion to their capital invested. The following information is available. $ capital: L 68 000 M 102 000 profit for the year before appropriation 28 900 drawings: L 8 000 M 12 000 No interest is charged on drawings up to $10 000 for each partner. Interest at a rate of 5% is charged on any drawings in excess of $10 000. What was L’s share of residual profit? A $11 520 B $11 600 C $11 800 D $11 960
Mark scheme: B
Q17 · Which statements describe the advantages of a rights issue of shares?
17 Which statements describe the advantages of a rights issue of shares? 1 Additional funds for a company can be raised cheaply. 2 Control of the company remains with existing shareholders if all rights are taken up. 3 It is an alternative to dividends as a way of rewarding existing shareholders. A 1 and 2 B 1 and 3 C 2 and 3 D 2 only
Mark scheme: A
Q18 · The following information is available for a limited company’s financial year ended 31…
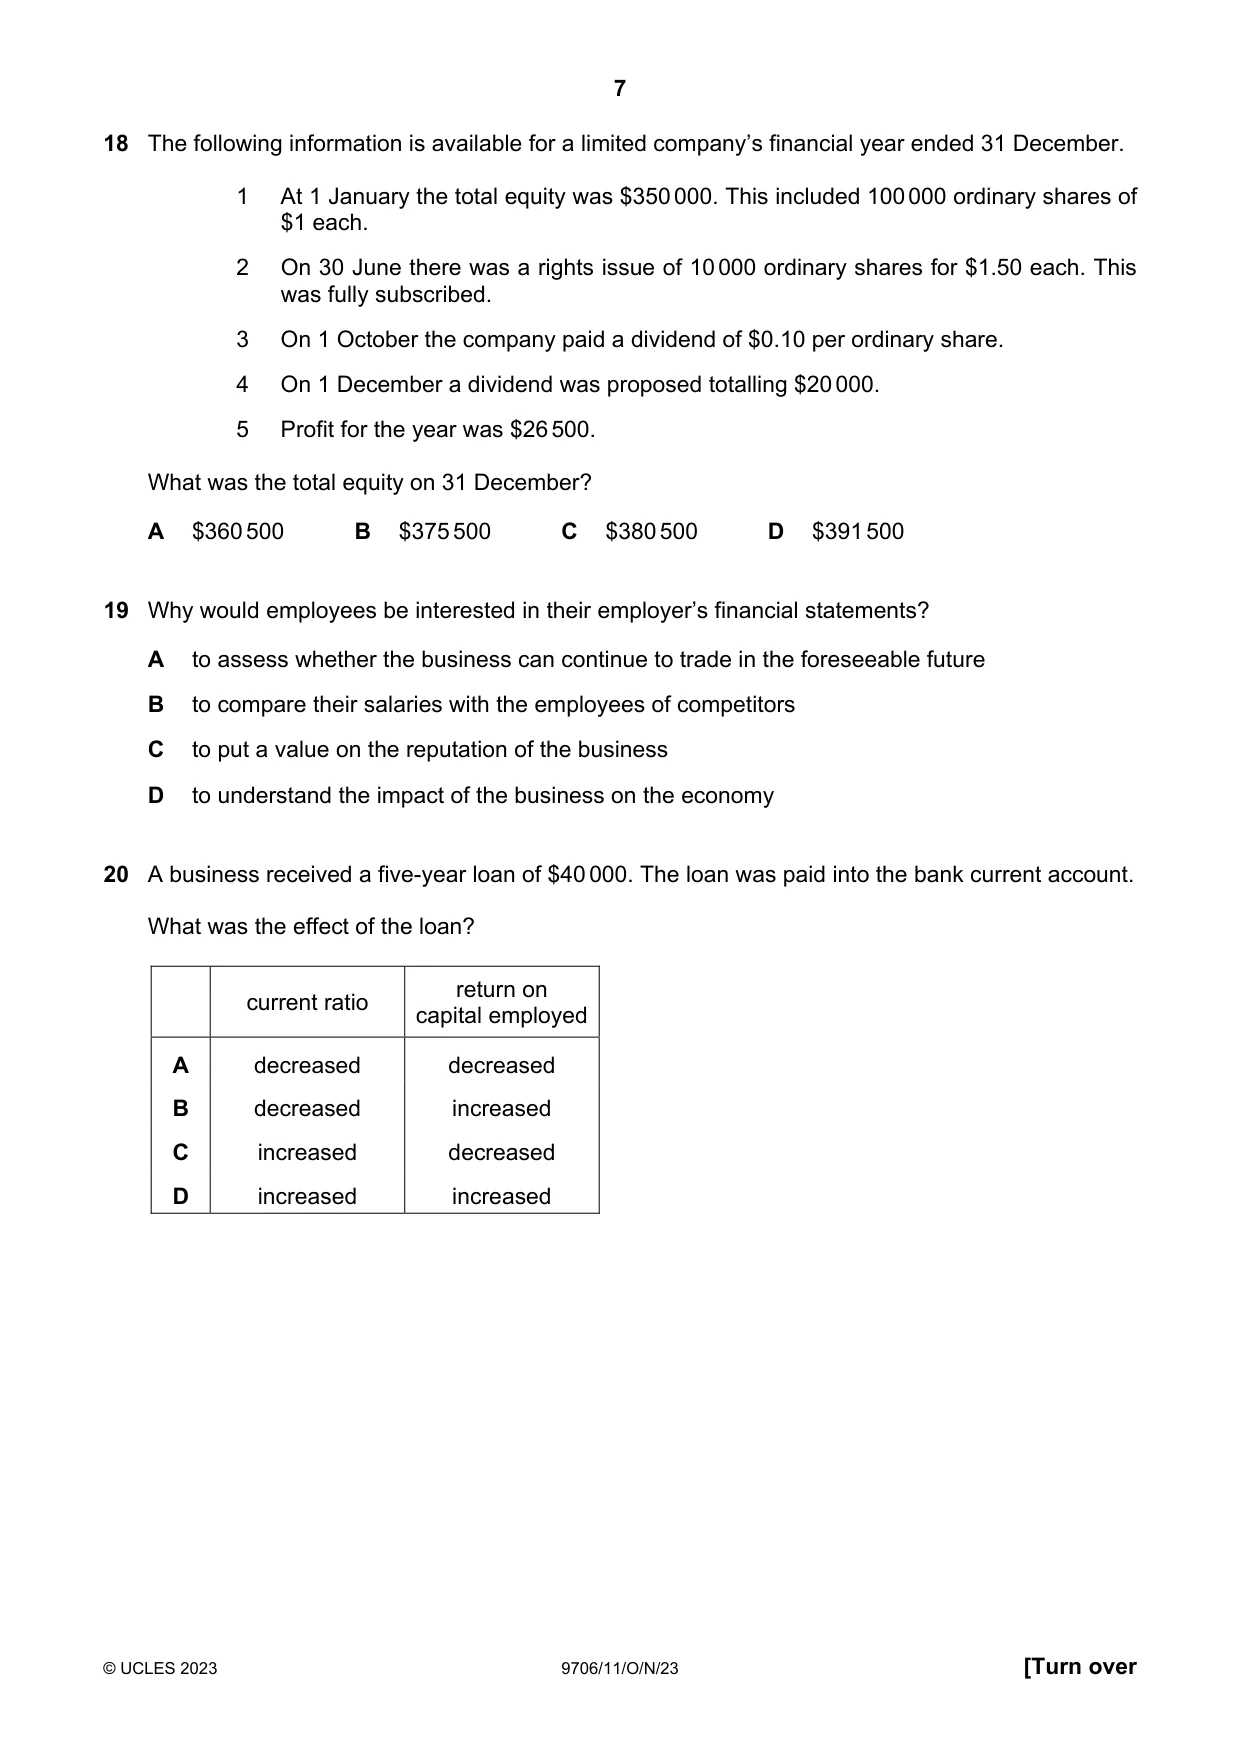
18 The following information is available for a limited company’s financial year ended 31 December. 1 At 1 January the total equity was $350 000. This included 100 000 ordinary shares of $1 each. 2 On 30 June there was a rights issue of 10 000 ordinary shares for $1.50 each. This was fully subscribed. 3 On 1 October the company paid a dividend of $0.10 per ordinary share. 4 On 1 December a dividend was proposed totalling $20 000. 5 Profit for the year was $26 500. What was the total equity on 31 December? A $360 500 B $375 500 C $380 500 D $391 500
Mark scheme: C
Q19 · Why would employees be interested in their employer’s financial statements?
19 Why would employees be interested in their employer’s financial statements? A to assess whether the business can continue to trade in the foreseeable future B to compare their salaries with the employees of competitors C to put a value on the reputation of the business D to understand the impact of the business on the economy
Mark scheme: A
More questions on Analysis and communication of accounting information
Q20 · A business received a five-year loan of $40 000
20 A business received a five-year loan of $40 000. The loan was paid into the bank current account. What was the effect of the loan? return on current ratio capital employed A decreased decreased B decreased increased C increased decreased D increased increased
Mark scheme: C
More questions on Analysis and communication of accounting information
Q21 · The draft financial statements of a business for the year ended 30 June included the…
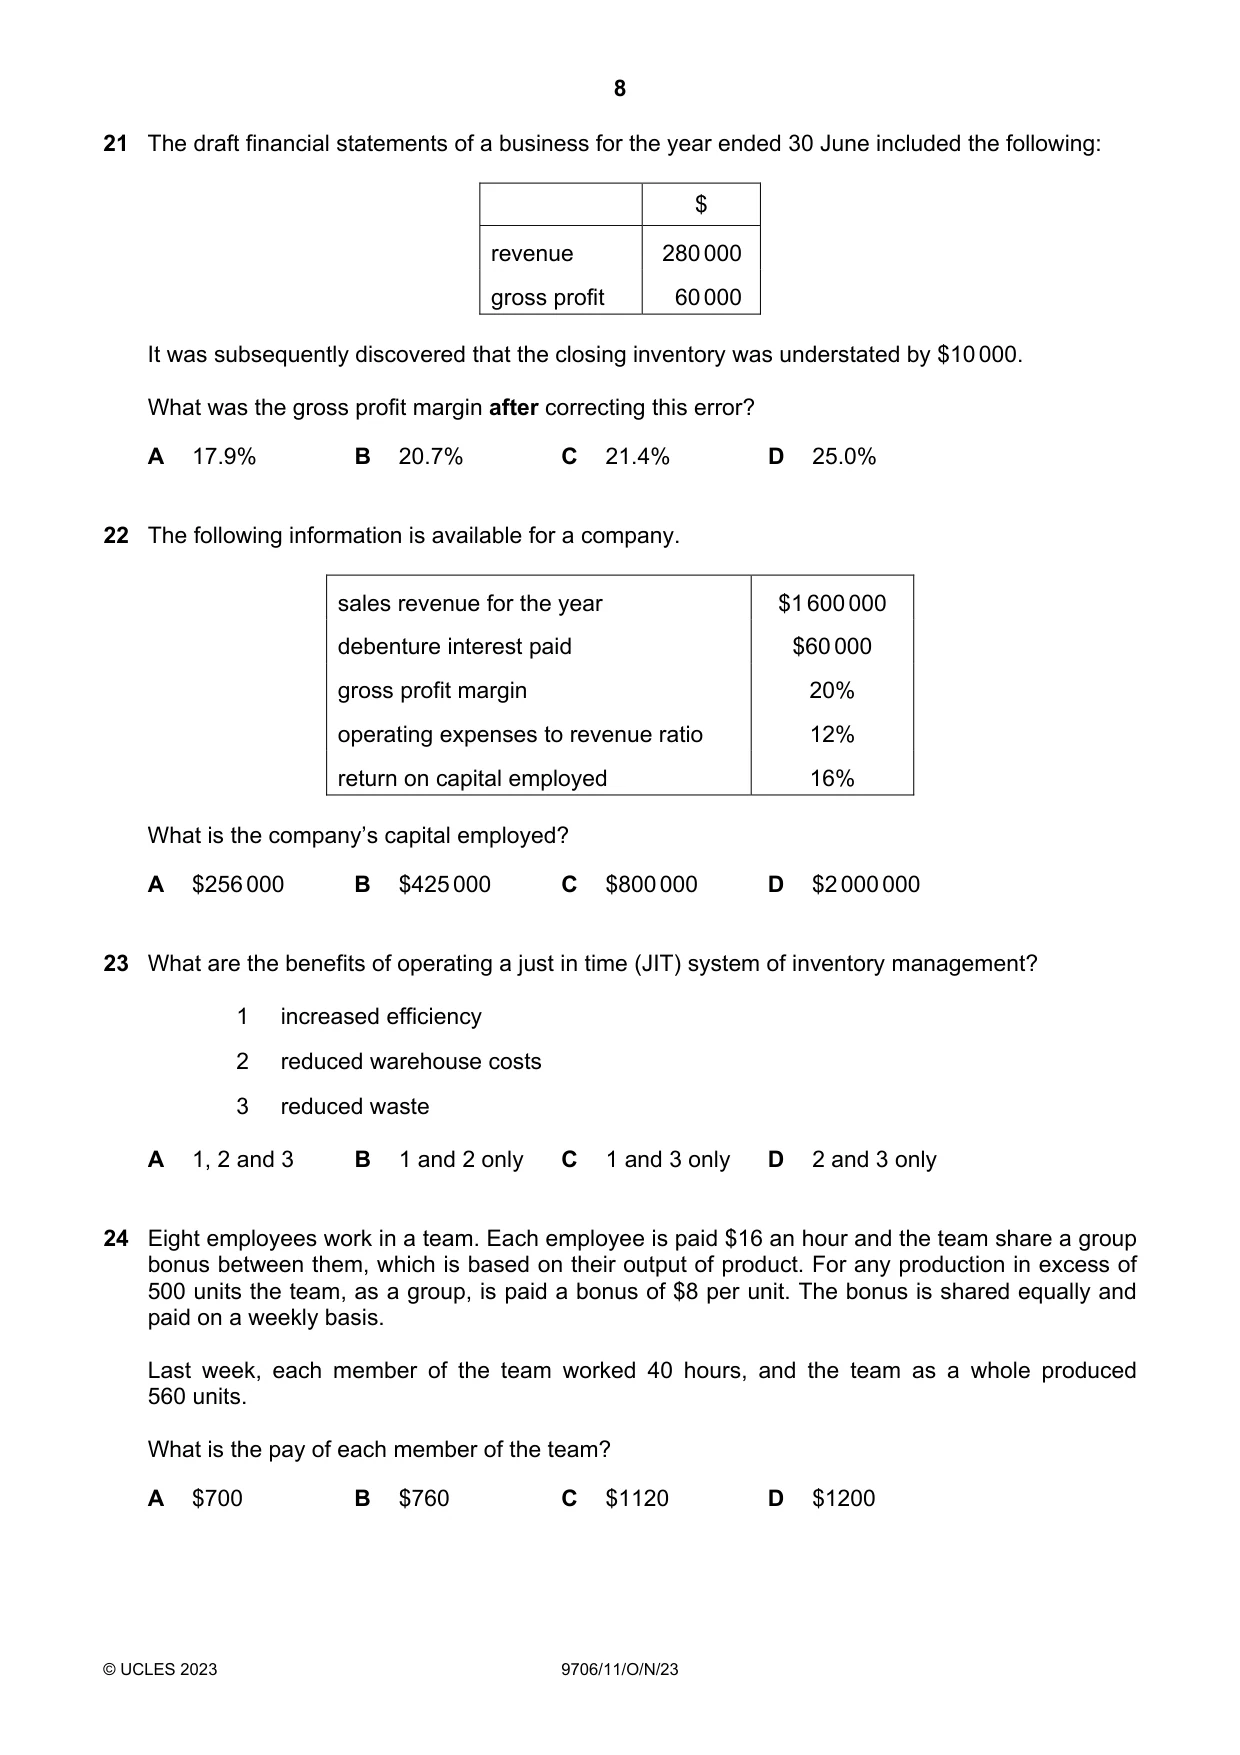
21 The draft financial statements of a business for the year ended 30 June included the following: $ revenue 280 000 gross profit 60 000 It was subsequently discovered that the closing inventory was understated by $10 000. What was the gross profit margin after correcting this error? A 17.9% B 20.7% C 21.4% D 25.0%
Mark scheme: D
More questions on Analysis and communication of accounting information
Q22 · The following information is available for a company
22 The following information is available for a company. sales revenue for the year $1 600 000 debenture interest paid $60 000 gross profit margin 20% operating expenses to revenue ratio 12% return on capital employed 16% What is the company’s capital employed? A $256 000 B $425 000 C $800 000 D $2 000 000
Mark scheme: C
More questions on Analysis and communication of accounting information
Q23 · What are the benefits of operating a just in time (JIT) system of inventory management?
23 What are the benefits of operating a just in time (JIT) system of inventory management? 1 increased efficiency 2 reduced warehouse costs 3 reduced waste A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
Mark scheme: A
Q24 · Eight employees work in a team
24 Eight employees work in a team. Each employee is paid $16 an hour and the team share a group bonus between them, which is based on their output of product. For any production in excess of 500 units the team, as a group, is paid a bonus of $8 per unit. The bonus is shared equally and paid on a weekly basis. Last week, each member of the team worked 40 hours, and the team as a whole produced 560 units. What is the pay of each member of the team? A $700 B $760 C $1120 D $1200
Mark scheme: A
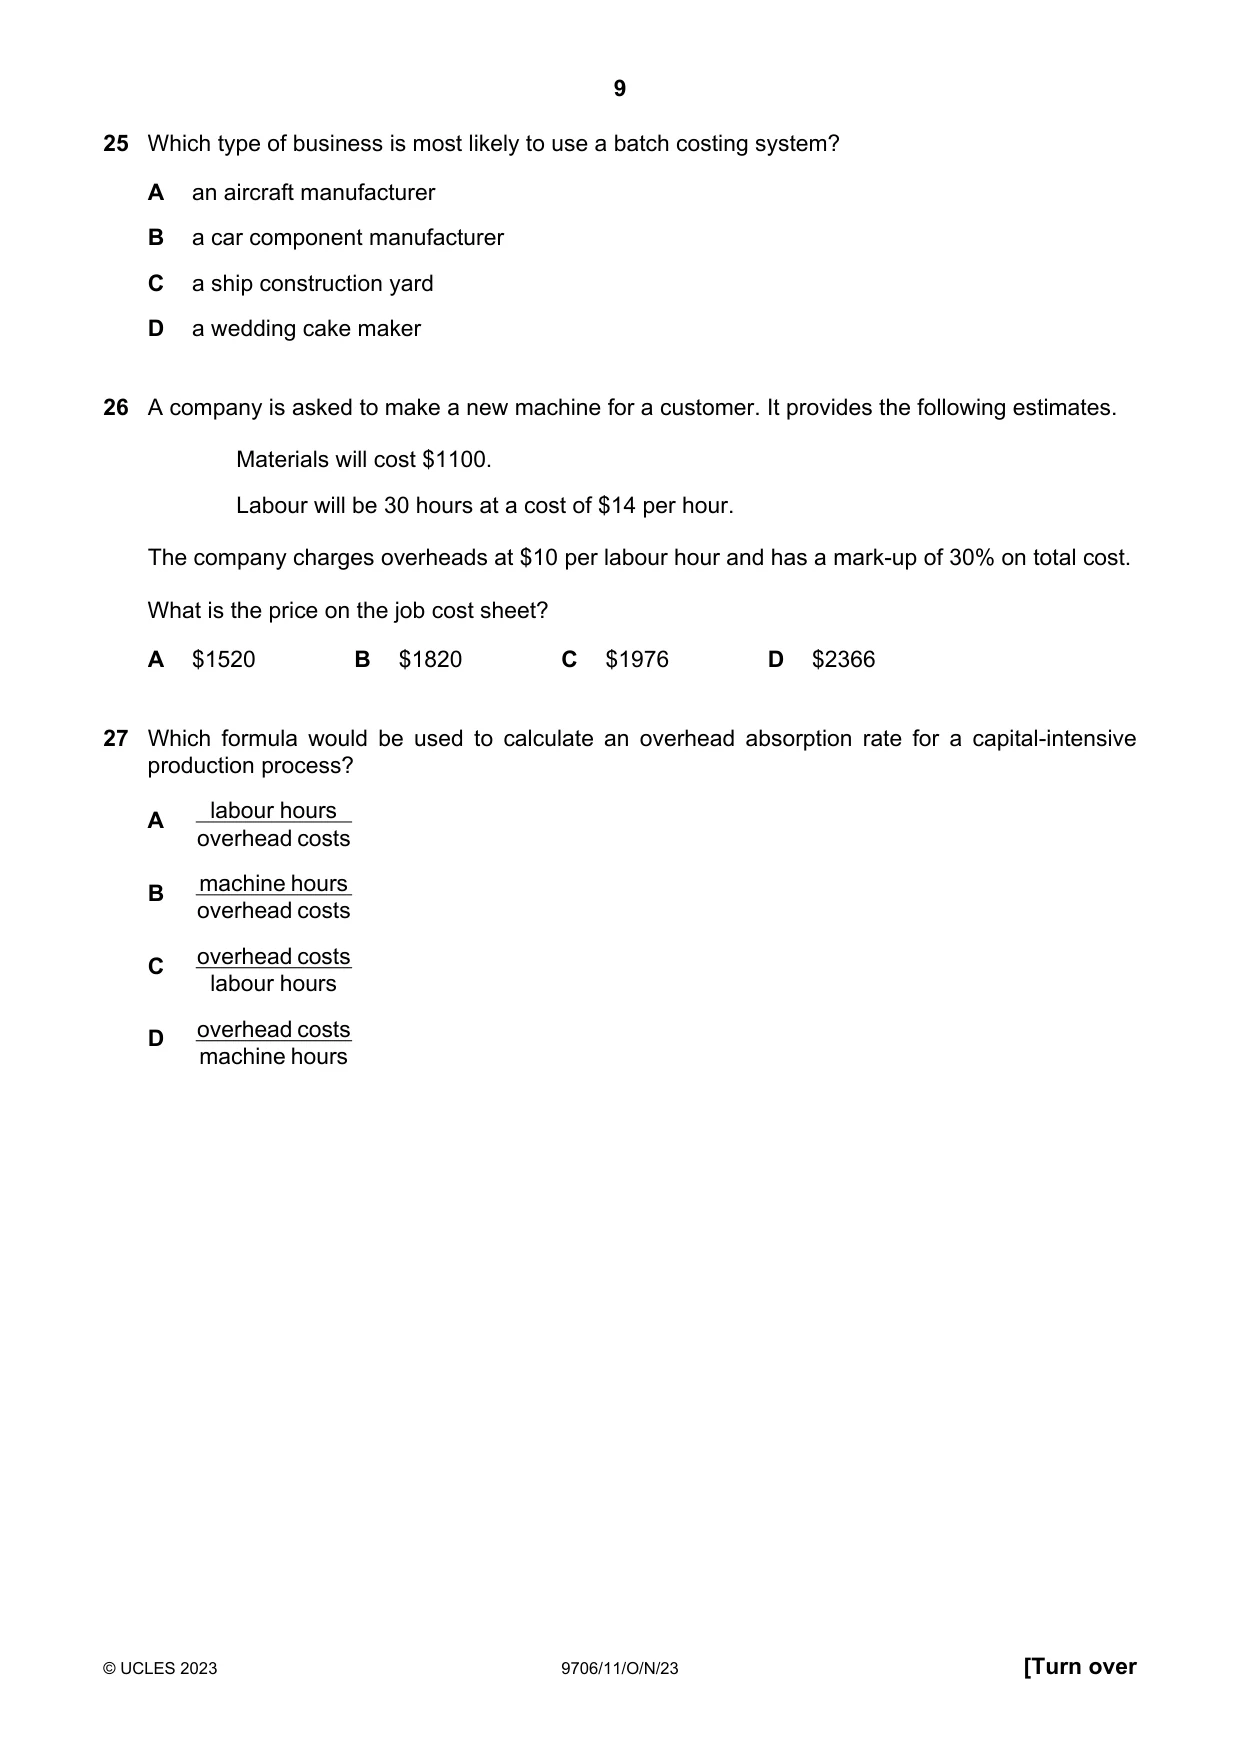
Q25 · Which type of business is most likely to use a batch costing system?
25 Which type of business is most likely to use a batch costing system? A an aircraft manufacturer B a car component manufacturer C a ship construction yard D a wedding cake maker
Mark scheme: B
Q26 · A company is asked to make a new machine for a customer
26 A company is asked to make a new machine for a customer. It provides the following estimates. Materials will cost $1100. Labour will be 30 hours at a cost of $14 per hour. The company charges overheads at $10 per labour hour and has a mark-up of 30% on total cost. What is the price on the job cost sheet? A $1520 B $1820 C $1976 D $2366
Mark scheme: D
Q27 · Which formula would be used to calculate an overhead absorption rate for a…
27 Which formula would be used to calculate an overhead absorption rate for a capital-intensive production process? A labour hours overhead costs B machine hours overhead costs C overhead costs labour hours D overhead costs machine hours
Mark scheme: D
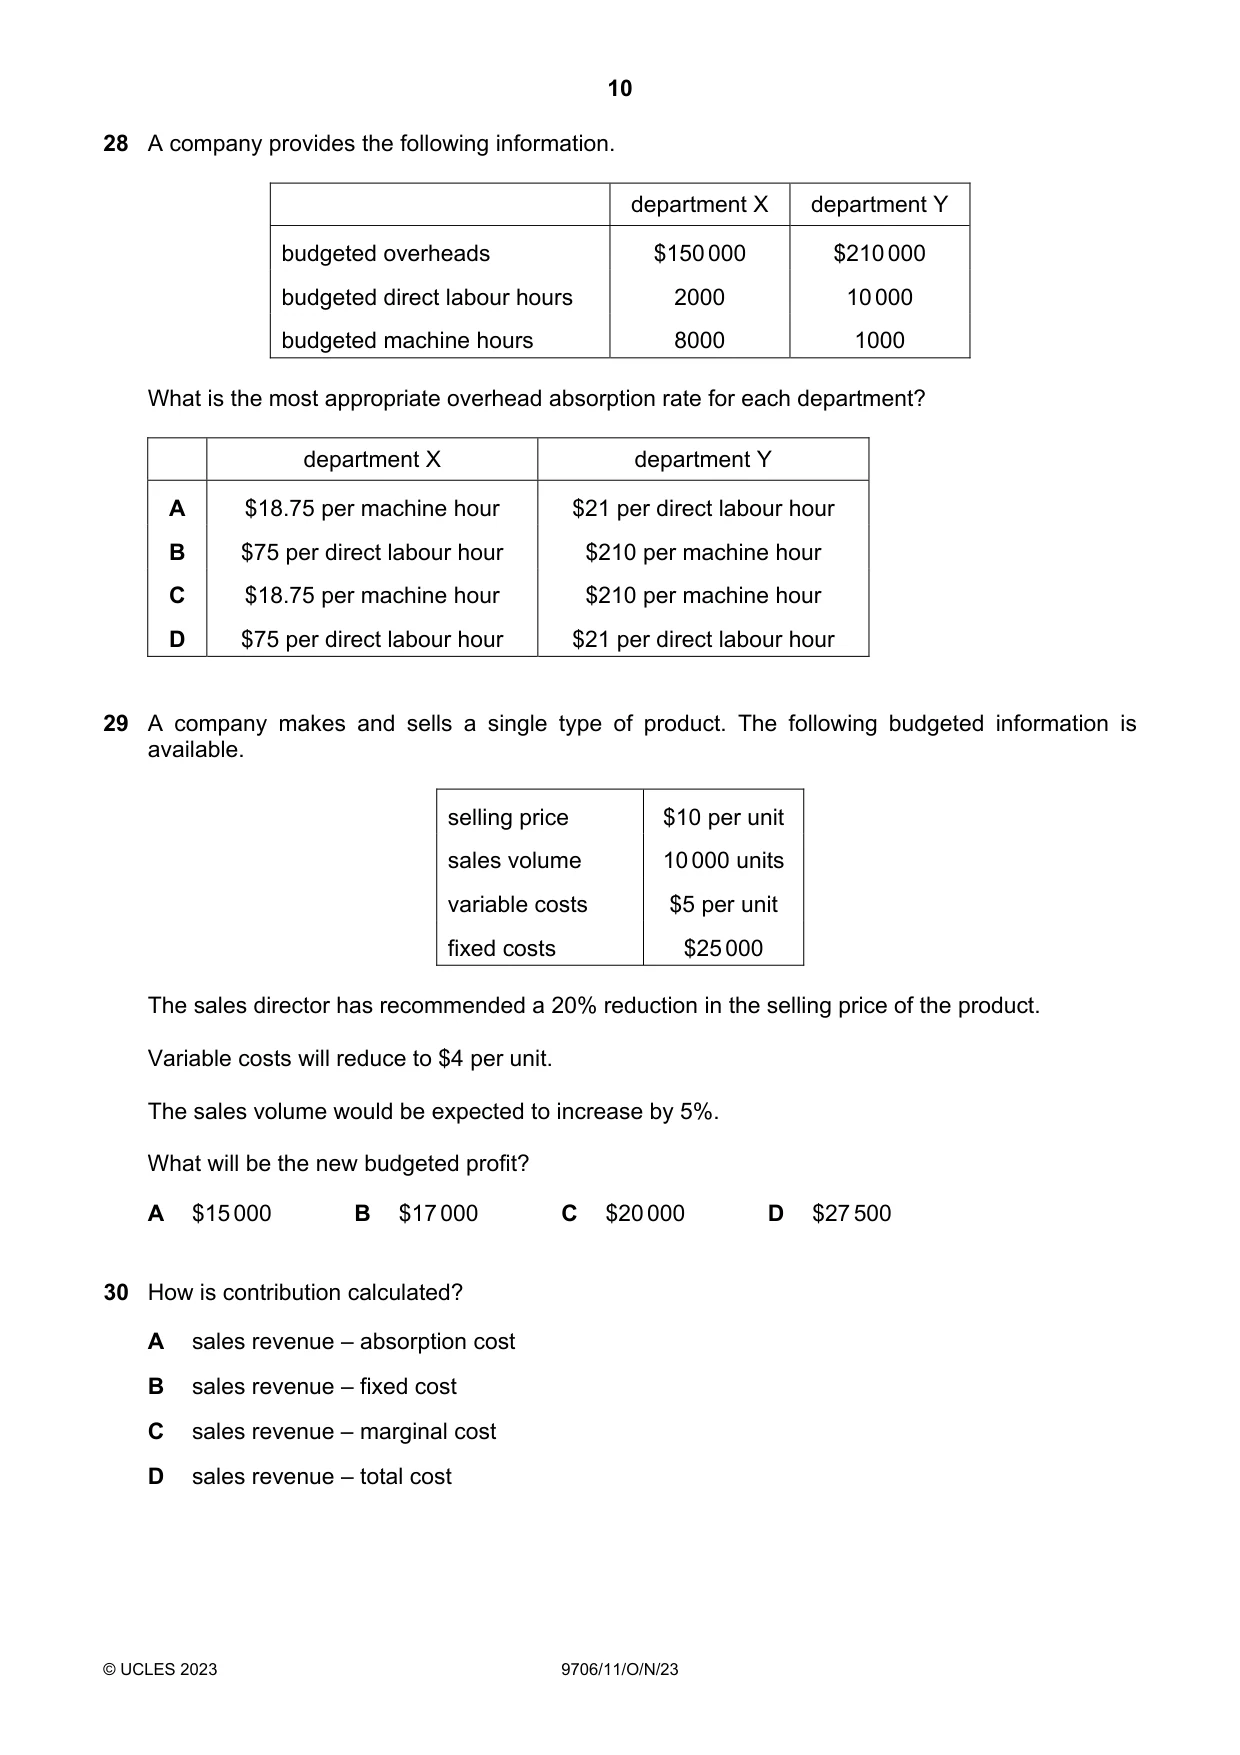
Q28 · A company provides the following information
28 A company provides the following information. department X department Y budgeted overheads $150 000 $210 000 budgeted direct labour hours 2000 10 000 budgeted machine hours 8000 1000 What is the most appropriate overhead absorption rate for each department? department X department Y A $18.75 per machine hour $21 per direct labour hour B $75 per direct labour hour $210 per machine hour C $18.75 per machine hour $210 per machine hour D $75 per direct labour hour $21 per direct labour hour
Mark scheme: A
Q29 · A company makes and sells a single type of product
29 A company makes and sells a single type of product. The following budgeted information is available. selling price $10 per unit sales volume 10 000 units variable costs $5 per unit fixed costs $25 000 The sales director has recommended a 20% reduction in the selling price of the product. Variable costs will reduce to $4 per unit. The sales volume would be expected to increase by 5%. What will be the new budgeted profit? A $15 000 B $17 000 C $20 000 D $27 500
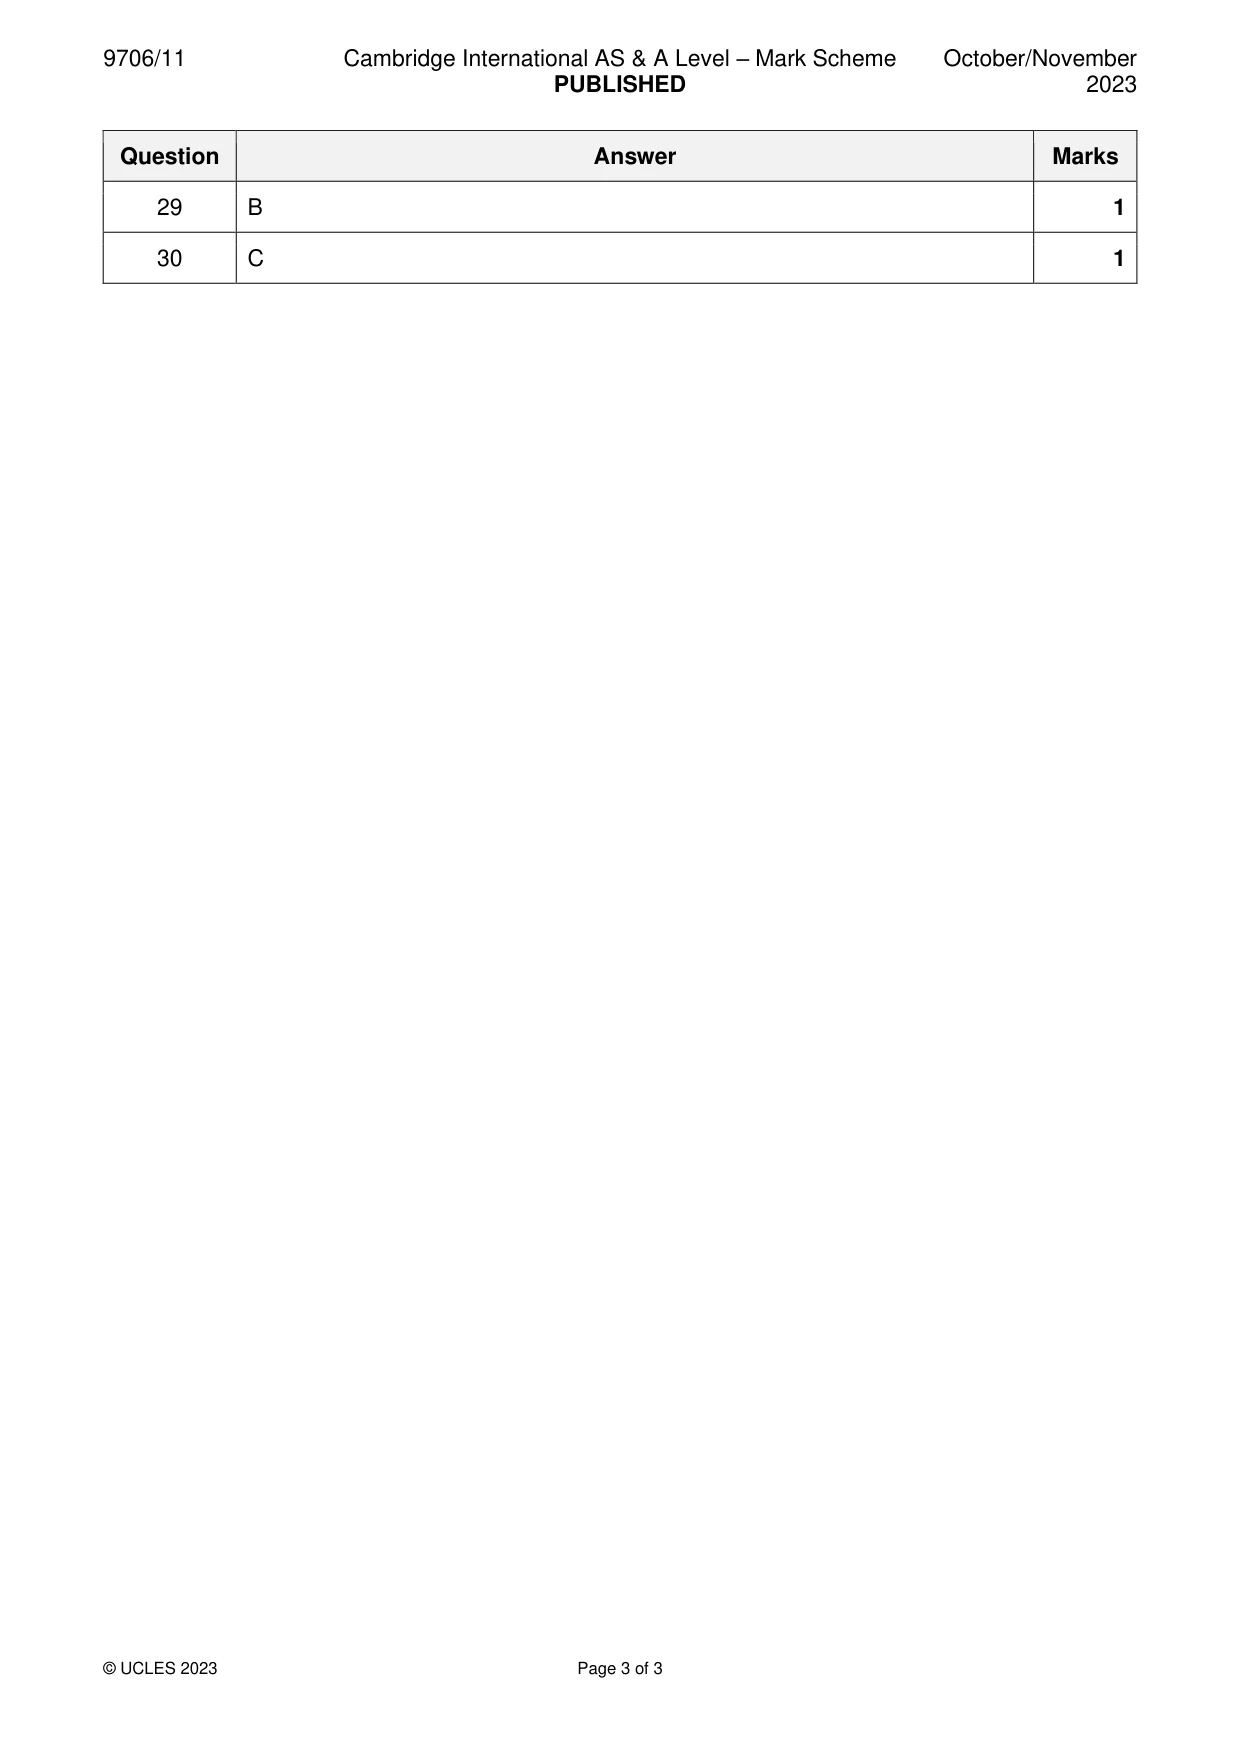
Mark scheme: B
Q30 · How is contribution calculated?
30 How is contribution calculated? A sales revenue – absorption cost B sales revenue – fixed cost C sales revenue – marginal cost D sales revenue – total cost
Mark scheme: C
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 Oct/Nov, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.