Cambridge A Level Accounting 9706 — 2024 Oct/Nov Paper 1 · Variant 1
9706/11/O/N/24 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
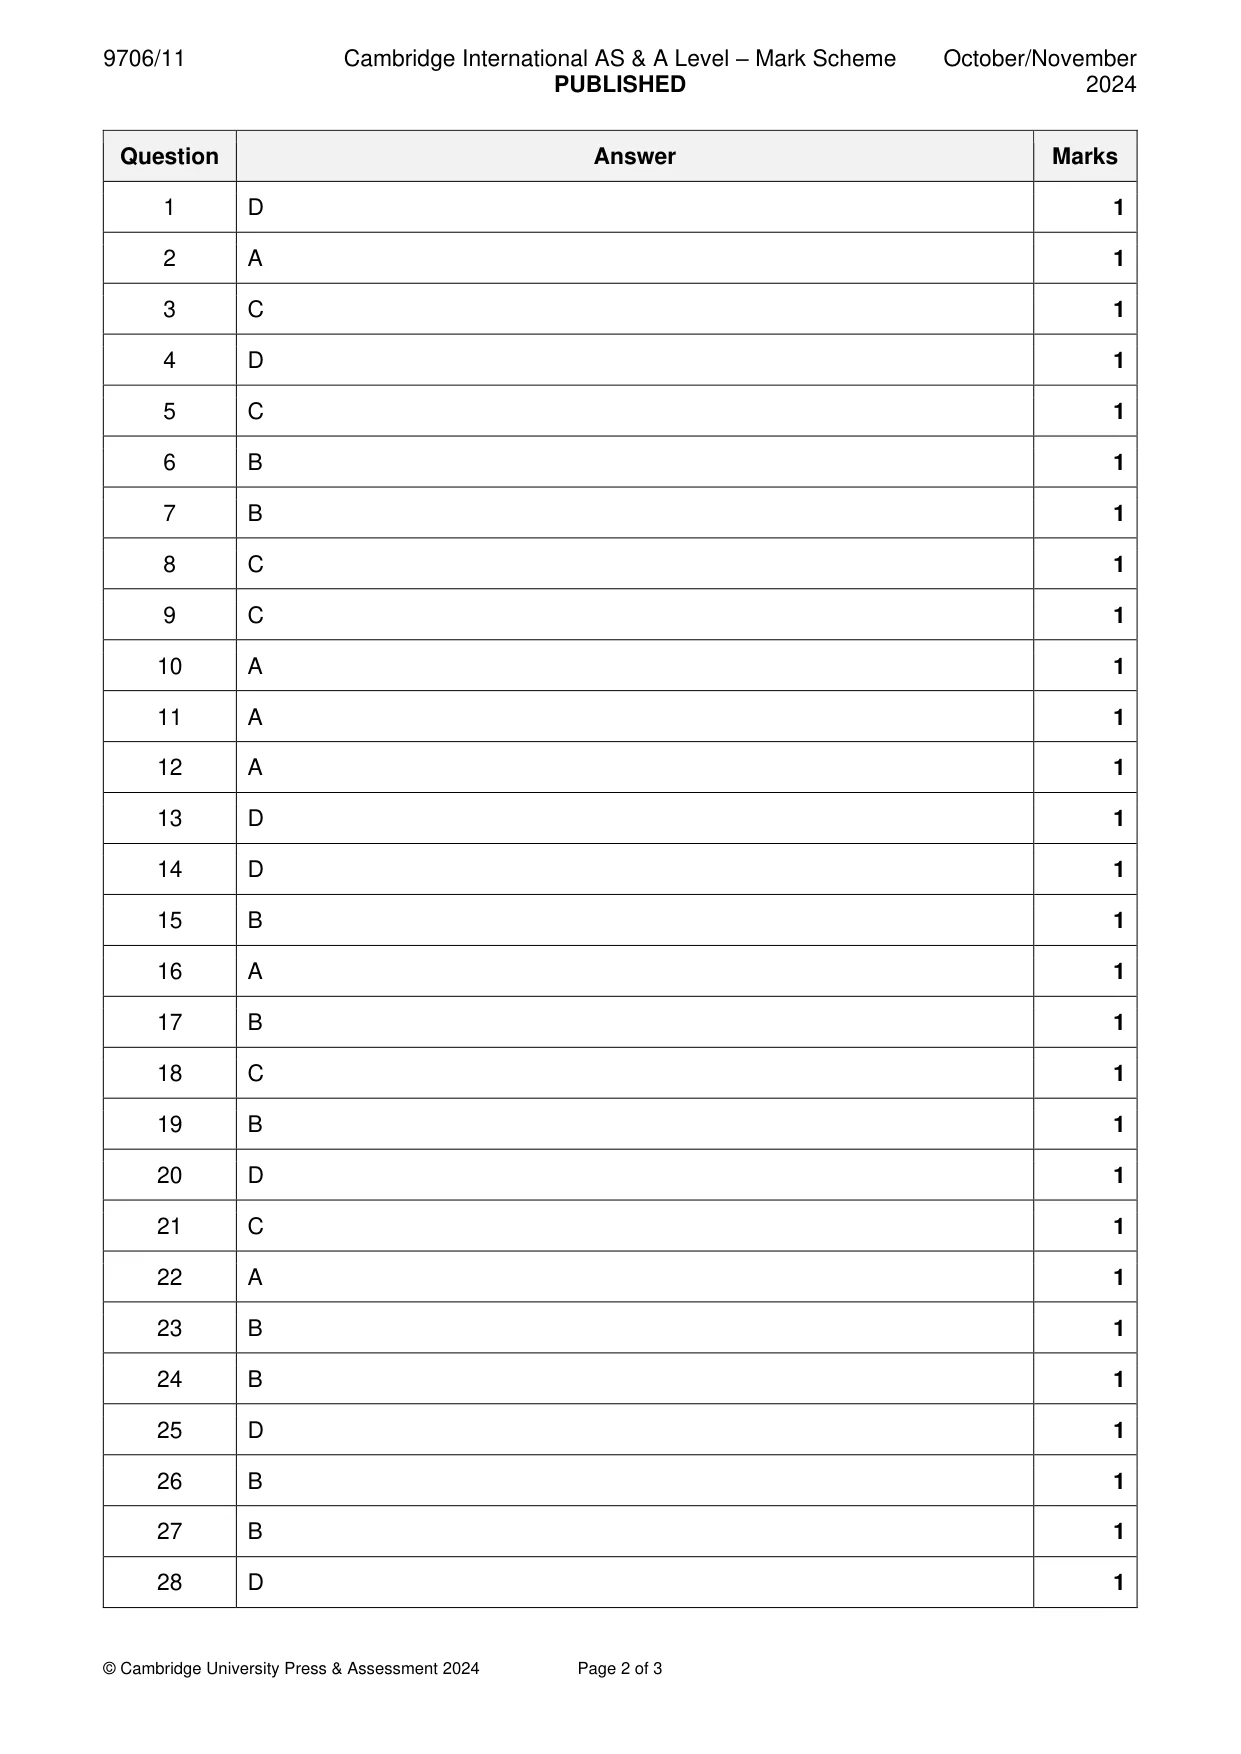
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
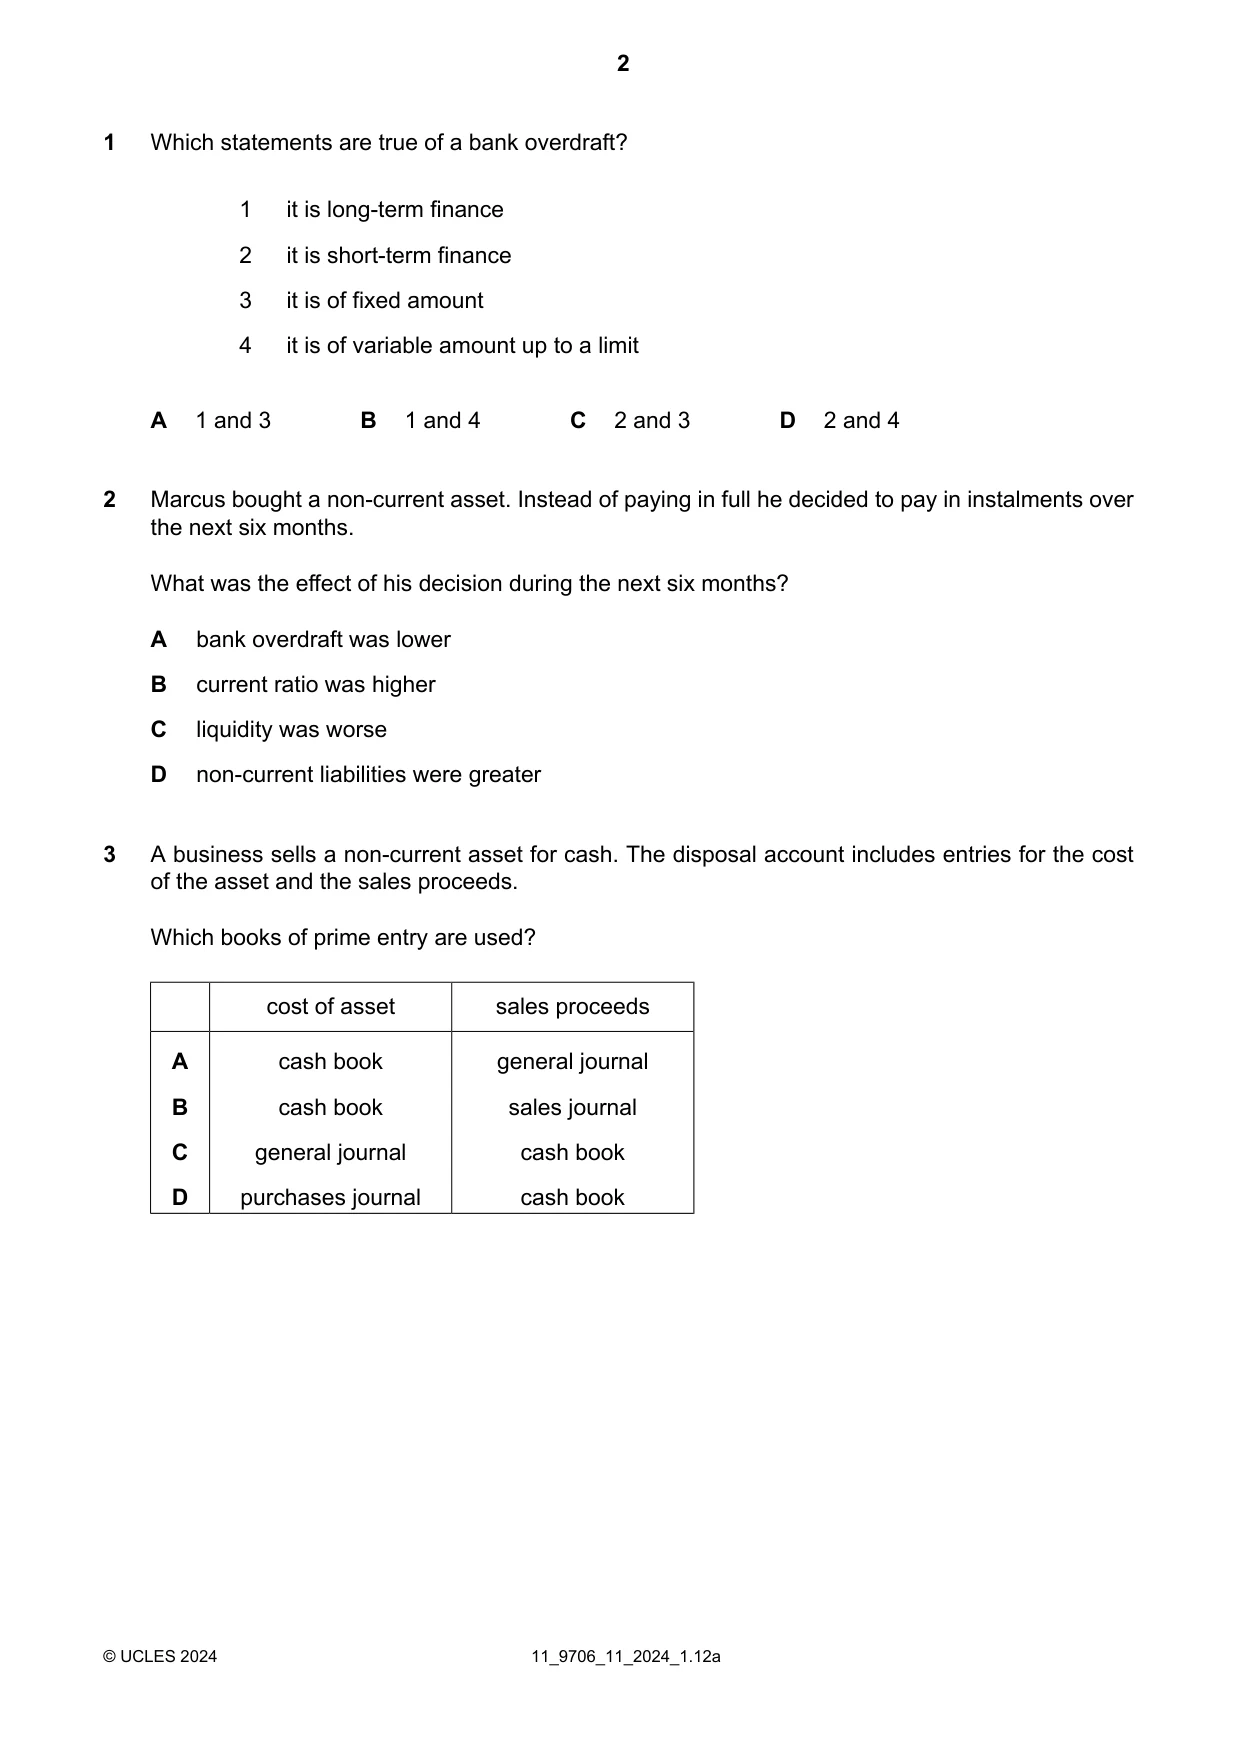
Q1 · Which statements are true of a bank overdraft?
1 Which statements are true of a bank overdraft? 1 it is long-term finance 2 it is short-term finance 3 it is of fixed amount 4 it is of variable amount up to a limit A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
Mark scheme: D
Q2 · Marcus bought a non-current asset
2 Marcus bought a non-current asset. Instead of paying in full he decided to pay in instalments over the next six months. What was the effect of his decision during the next six months? A bank overdraft was lower B current ratio was higher C liquidity was worse D non-current liabilities were greater
Mark scheme: A
More questions on Analysis and communication of accounting information
Q3 · A business sells a non-current asset for cash
3 A business sells a non-current asset for cash. The disposal account includes entries for the cost of the asset and the sales proceeds. Which books of prime entry are used? cost of asset sales proceeds A cash book general journal B cash book sales journal C general journal cash book D purchases journal cash book
Mark scheme: C
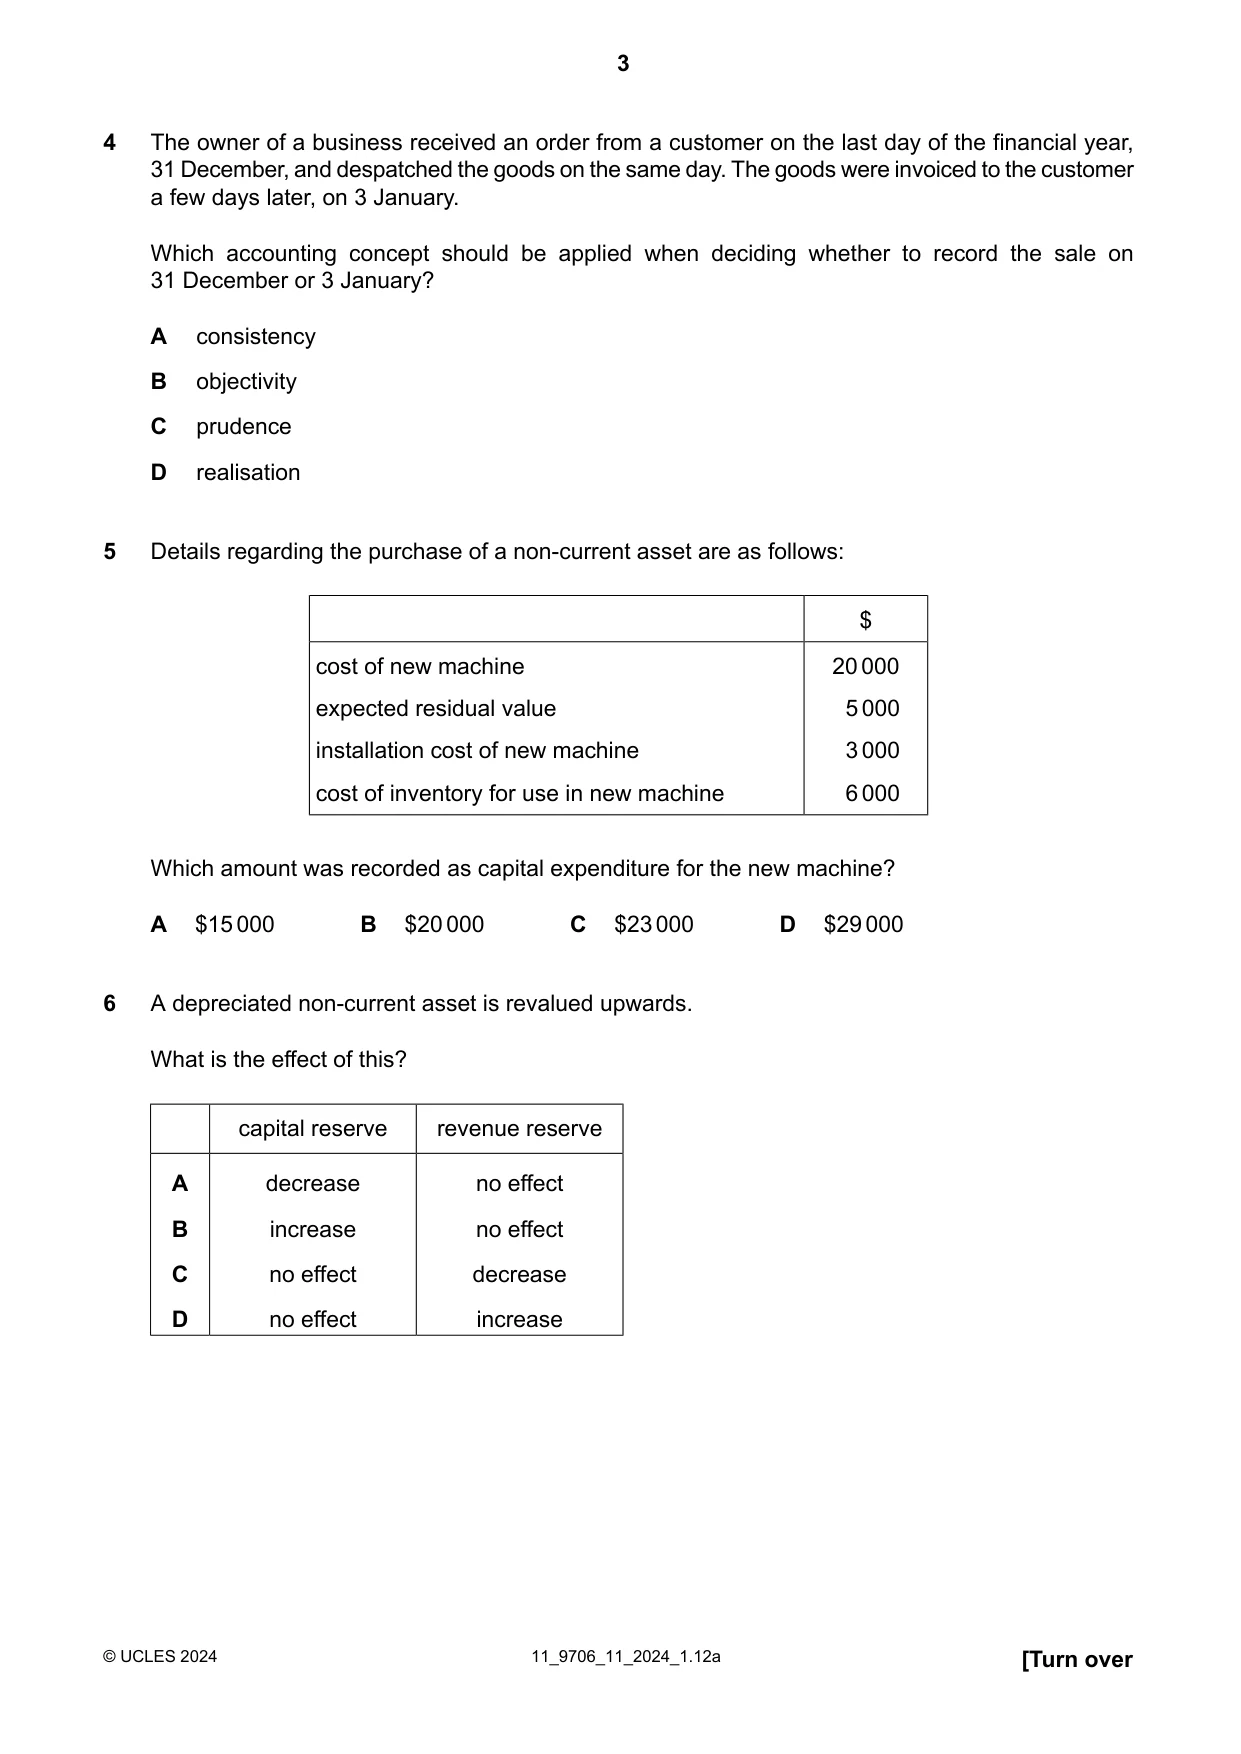
Q4 · The owner of a business received an order from a customer on the last day of the…
4 The owner of a business received an order from a customer on the last day of the financial year, 31 December, and despatched the goods on the same day. The goods were invoiced to the customer a few days later, on 3 January. Which accounting concept should be applied when deciding whether to record the sale on 31 December or 3 January? A consistency B objectivity C prudence D realisation
Mark scheme: D
Q5 · Details regarding the purchase of a non-current asset are as follows: $ cost of new…
5 Details regarding the purchase of a non-current asset are as follows: $ cost of new machine 20000 expected residual value 5000 installation cost of new machine 3000 cost of inventory for use in new machine 6000 Which amount was recorded as capital expenditure for the new machine? A $15000 B $20000 C $23000 D $29000
Mark scheme: C
Q6 · A depreciated non-current asset is revalued upwards
6 A depreciated non-current asset is revalued upwards. What is the effect of this? capital reserve revenue reserve A decrease no effect B increase no effect C no effect decrease D no effect increase
Mark scheme: B
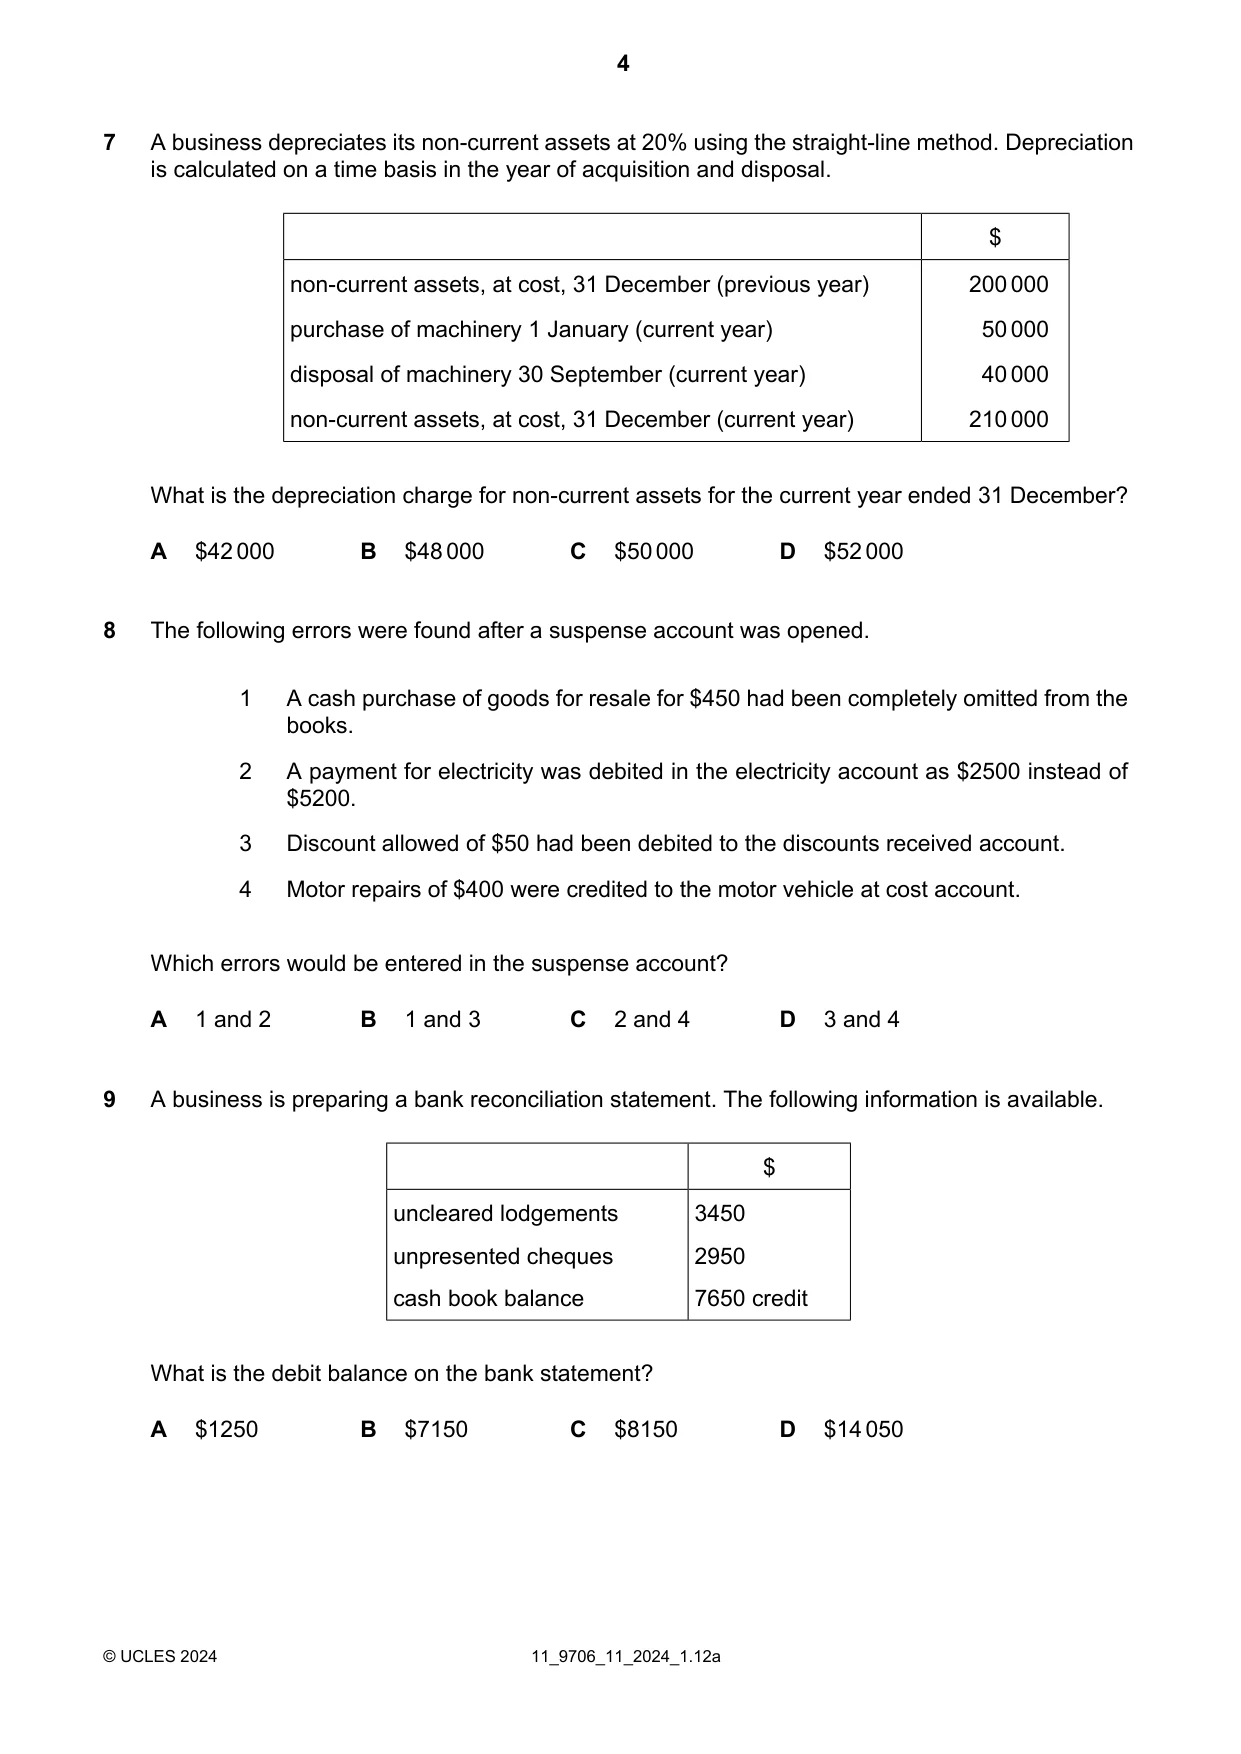
Q7 · A business depreciates its non-current assets at 20% using the straight-line method
7 A business depreciates its non-current assets at 20% using the straight-line method. Depreciation is calculated on a time basis in the year of acquisition and disposal. $ non-current assets, at cost, 31 December (previous year) 200000 purchase of machinery 1 January (current year) 50000 disposal of machinery 30 September (current year) 40000 non-current assets, at cost, 31 December (current year) 210000 What is the depreciation charge for non-current assets for the current year ended 31 December? A $42000 B $48000 C $50000 D $52000
Mark scheme: B
Q8 · The following errors were found after a suspense account was opened
8 The following errors were found after a suspense account was opened. 1 A cash purchase of goods for resale for $450 had been completely omitted from the books. 2 A payment for electricity was debited in the electricity account as $2500 instead of $5200. 3 Discount allowed of $50 had been debited to the discounts received account. 4 Motor repairs of $400 were credited to the motor vehicle at cost account. Which errors would be entered in the suspense account? A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
Mark scheme: C
Q9 · A business is preparing a bank reconciliation statement
9 A business is preparing a bank reconciliation statement. The following information is available. $ uncleared lodgements 3450 unpresented cheques 2950 cash book balance 7650 credit What is the debit balance on the bank statement? A $1250 B $7150 C $8150 D $14050
Mark scheme: C
Q10 · Which sources of information will be required to prepare a sales ledger control account?
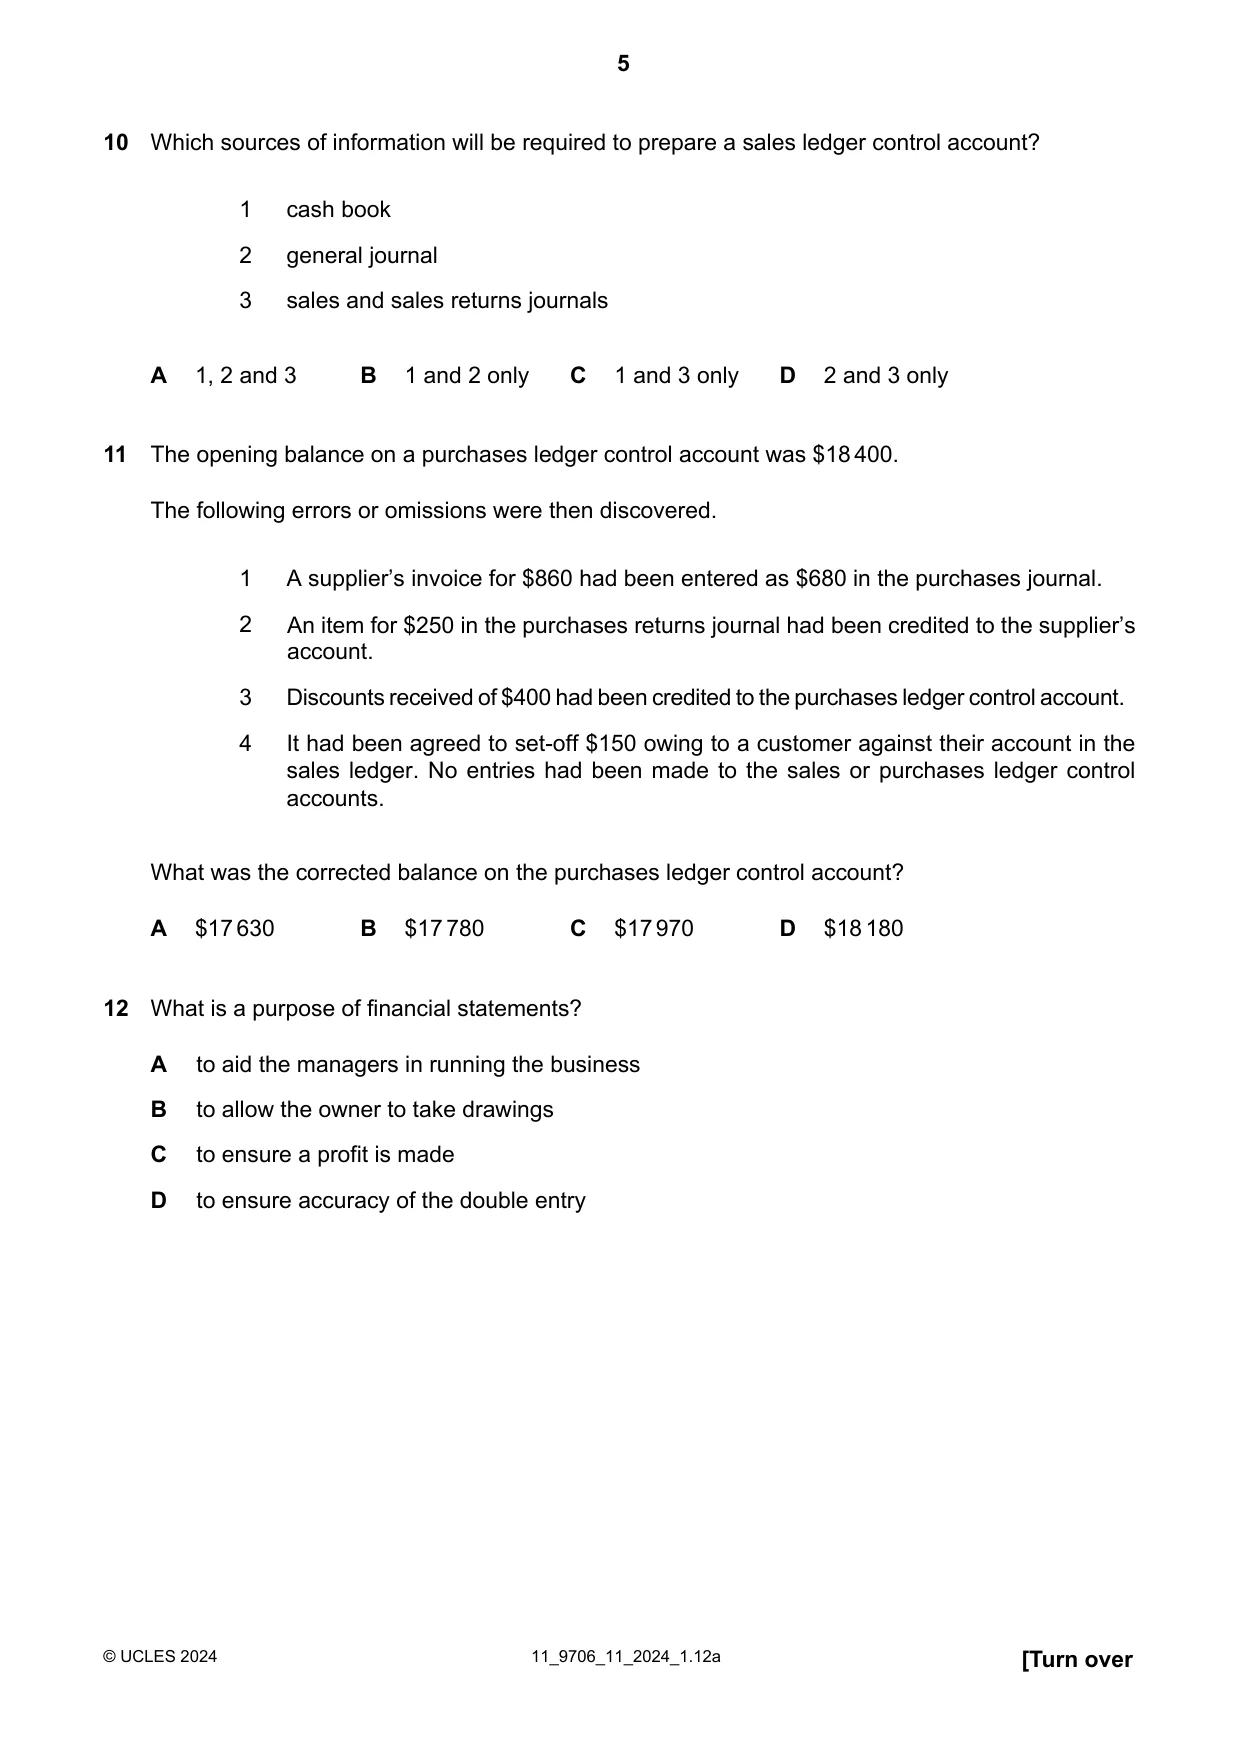
10 Which sources of information will be required to prepare a sales ledger control account? 1 cash book 2 general journal 3 sales and sales returns journals A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
Mark scheme: A
Q11 · The opening balance on a purchases ledger control account was $18400
11 The opening balance on a purchases ledger control account was $18400. The following errors or omissions were then discovered. 1 A supplier’s invoice for $860 had been entered as $680 in the purchases journal. 2 An item for $250 in the purchases returns journal had been credited to the supplier’s account. 3 Discounts received of $400 had been credited to the purchases ledger control account. 4 It had been agreed to set-off $150 owing to a customer against their account in the sales ledger. No entries had been made to the sales or purchases ledger control accounts. What was the corrected balance on the purchases ledger control account? A $17630 B $17780 C $17970 D $18180
Mark scheme: A
Q12 · What is a purpose of financial statements?
12 What is a purpose of financial statements? A to aid the managers in running the business B to allow the owner to take drawings C to ensure a profit is made D to ensure accuracy of the double entry
Mark scheme: A
Q13 · A business owner provided the following information at the end of his first year of…
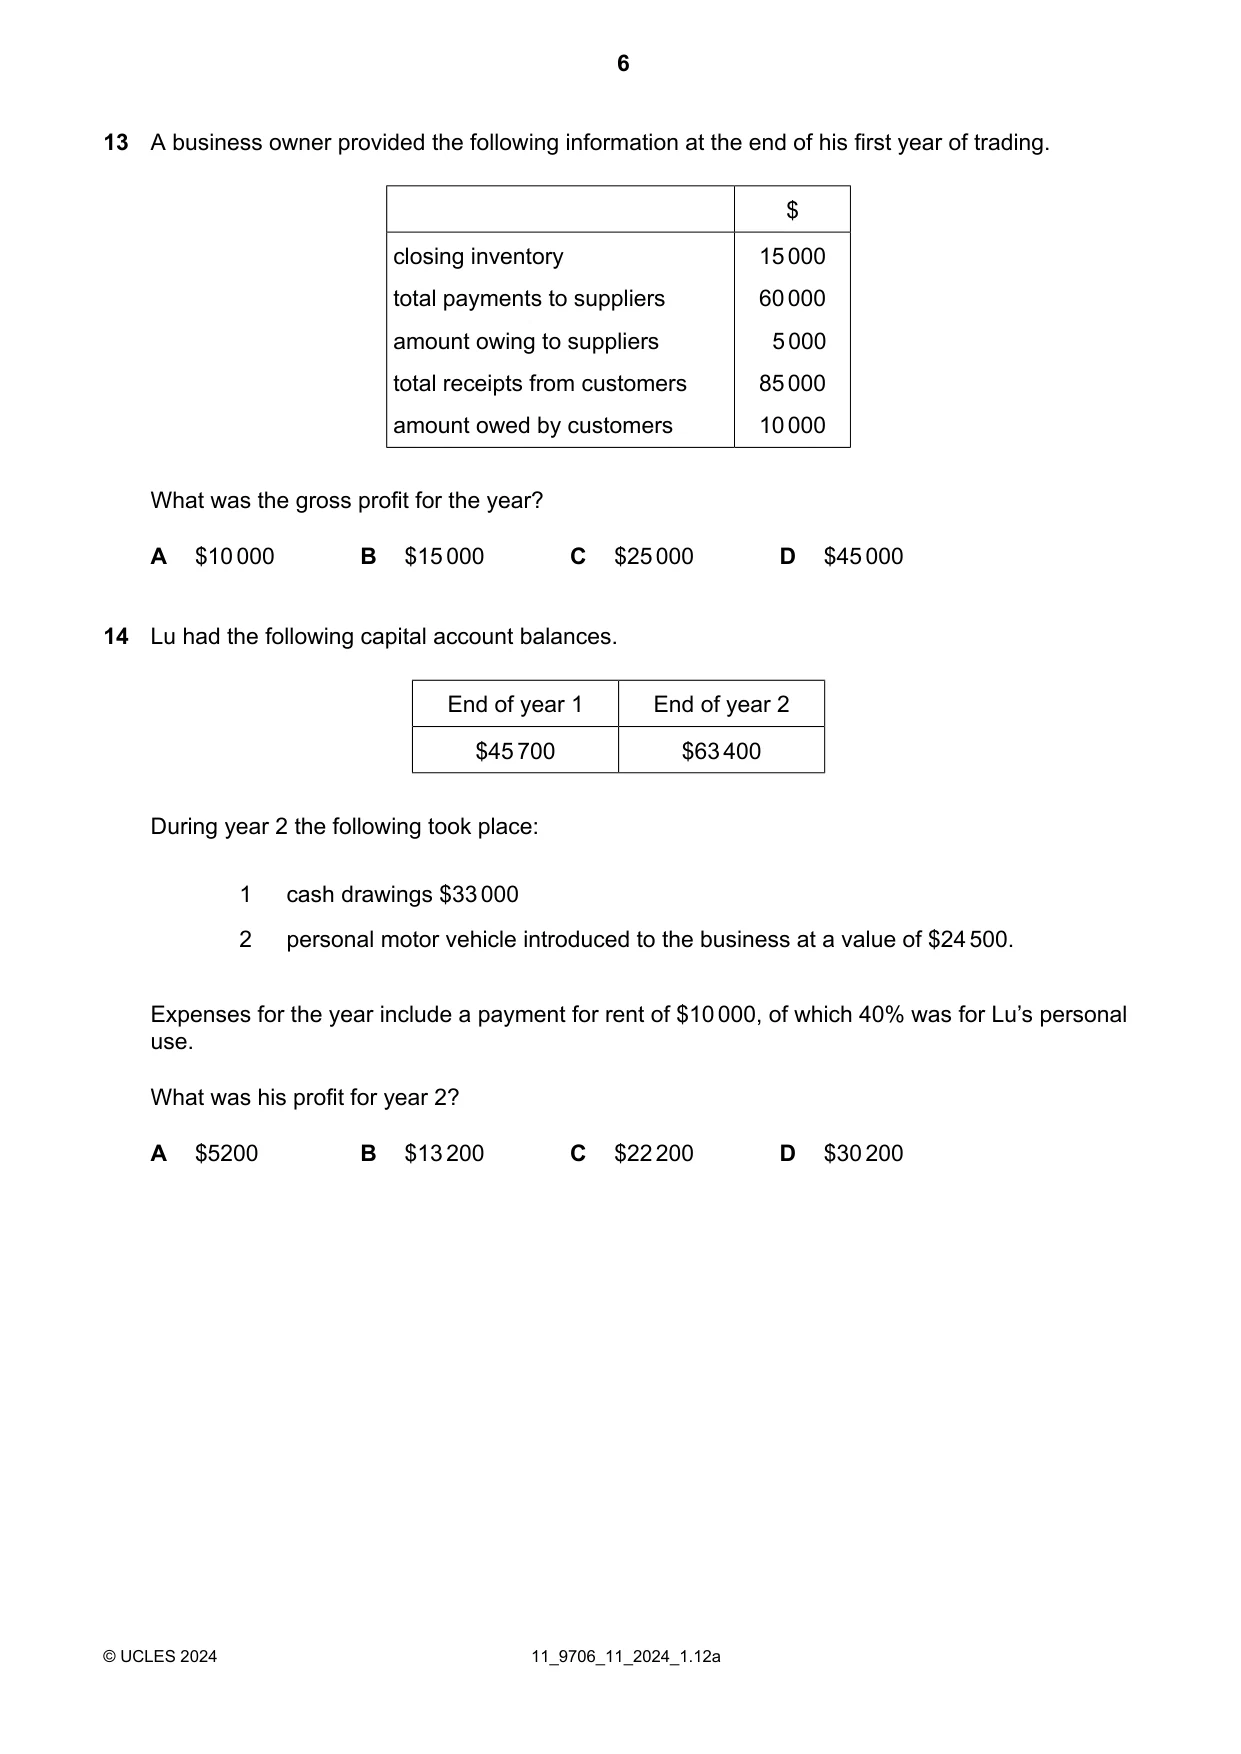
13 A business owner provided the following information at the end of his first year of trading. $ closing inventory 15000 total payments to suppliers 60000 amount owing to suppliers 5000 total receipts from customers 85000 amount owed by customers 10000 What was the gross profit for the year? A $10000 B $15000 C $25000 D $45000
Mark scheme: D
Q14 · Lu had the following capital account balances
14 Lu had the following capital account balances. End of year 1 End of year 2 $45700 $63400 During year 2 the following took place: 1 cash drawings $33000 2 personal motor vehicle introduced to the business at a value of $24500. Expenses for the year include a payment for rent of $10000, of which 40% was for Lu’s personal use. What was his profit for year 2? A $5200 B $13200 C $22200 D $30200
Mark scheme: D
Q15 · A business maintains an allowance for irrecoverable debts of 2% of trade receivables
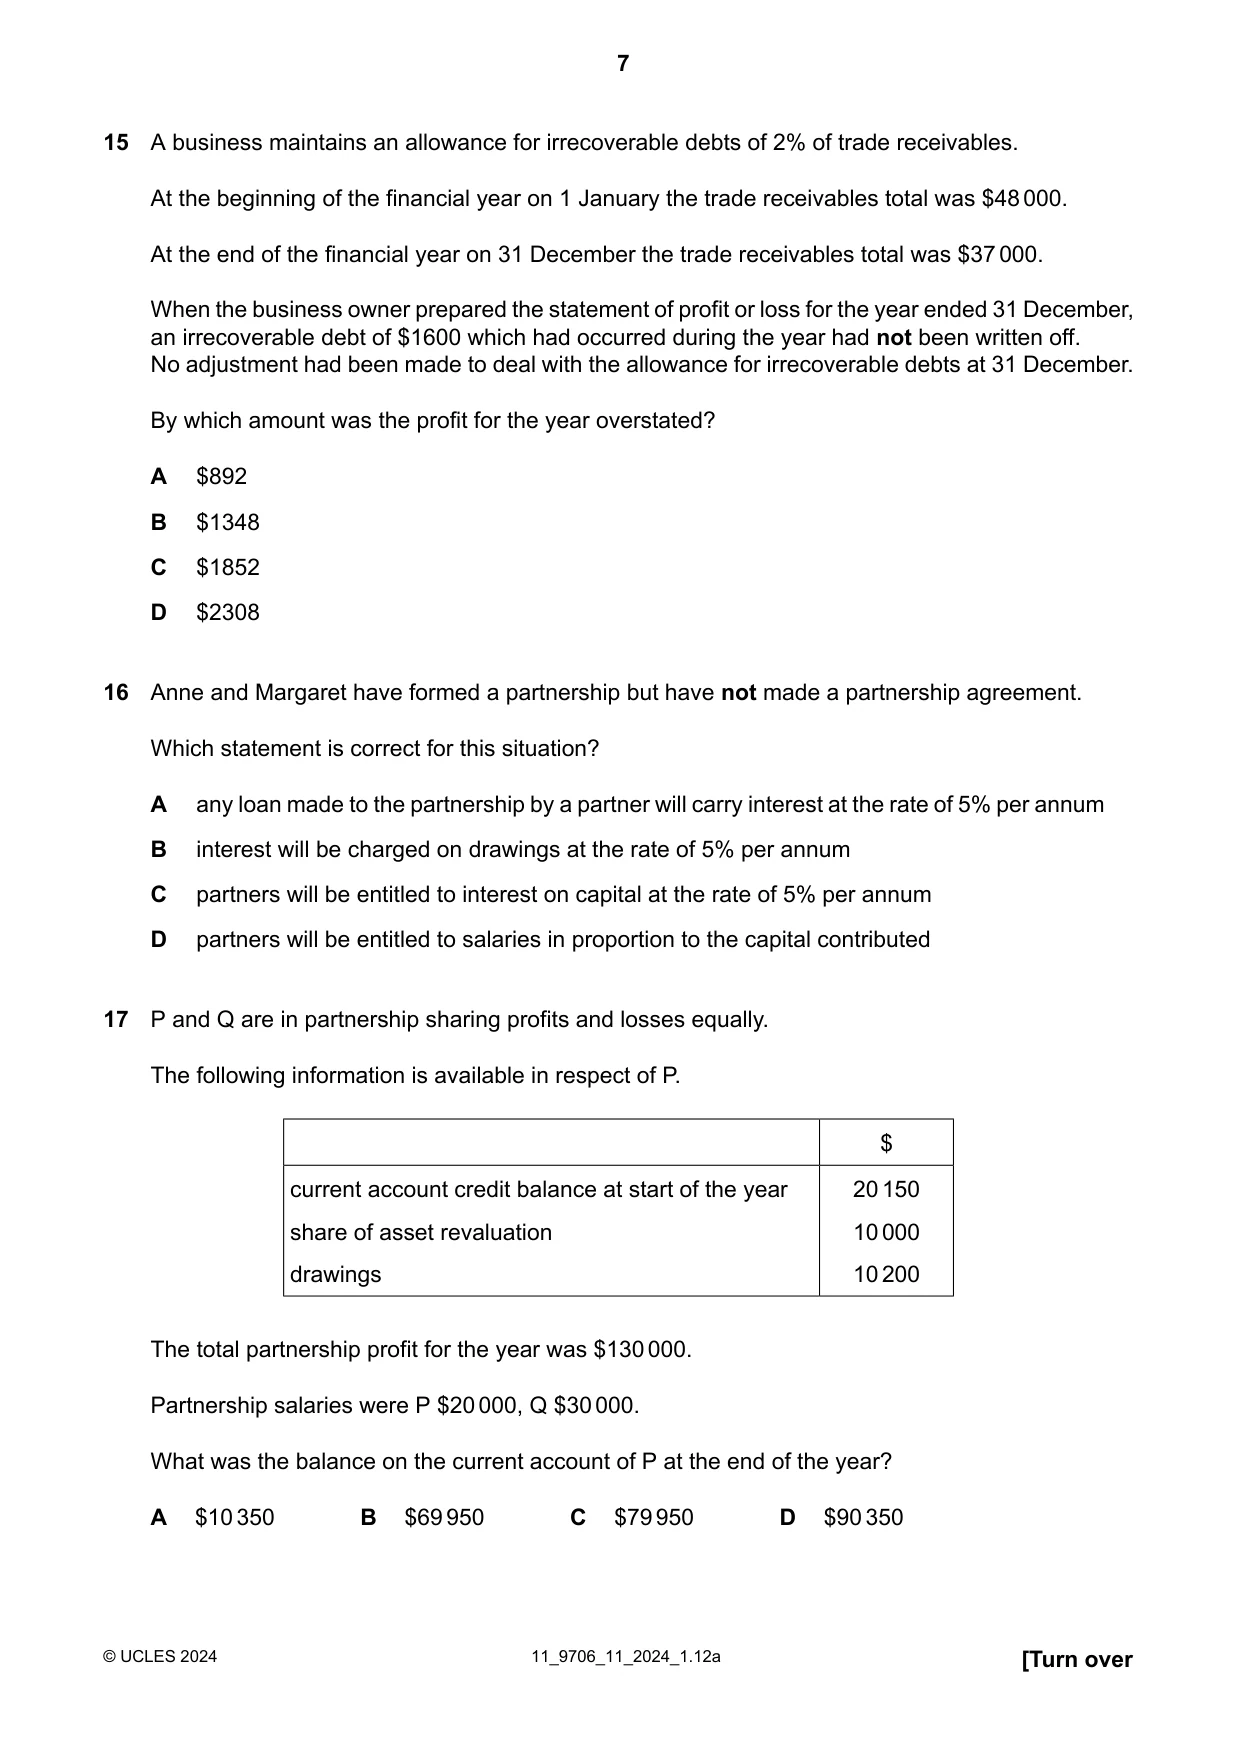
15 A business maintains an allowance for irrecoverable debts of 2% of trade receivables. At the beginning of the financial year on 1 January the trade receivables total was $48000. At the end of the financial year on 31 December the trade receivables total was $37000. When the business owner prepared the statement of profit or loss for the year ended 31 December, an irrecoverable debt of $1600 which had occurred during the year had not been written off. No adjustment had been made to deal with the allowance for irrecoverable debts at 31 December. By which amount was the profit for the year overstated? A $892 B $1348 C $1852 D $2308
Mark scheme: B
Q16 · Anne and Margaret have formed a partnership but have not made a partnership agreement
16 Anne and Margaret have formed a partnership but have not made a partnership agreement. Which statement is correct for this situation? A any loan made to the partnership by a partner will carry interest at the rate of 5% per annum B interest will be charged on drawings at the rate of 5% per annum C partners will be entitled to interest on capital at the rate of 5% per annum D partners will be entitled to salaries in proportion to the capital contributed
Mark scheme: A
Q17 · P and Q are in partnership sharing profits and losses equally
17 P and Q are in partnership sharing profits and losses equally. The following information is available in respect of P. $ current account credit balance at start of the year 20150 share of asset revaluation 10000 drawings 10200 The total partnership profit for the year was $130000. Partnership salaries were P $20000, Q $30000. What was the balance on the current account of P at the end of the year? A $10350 B $69950 C $79950 D $90350
Mark scheme: B
Q18 · Which statements are correct?
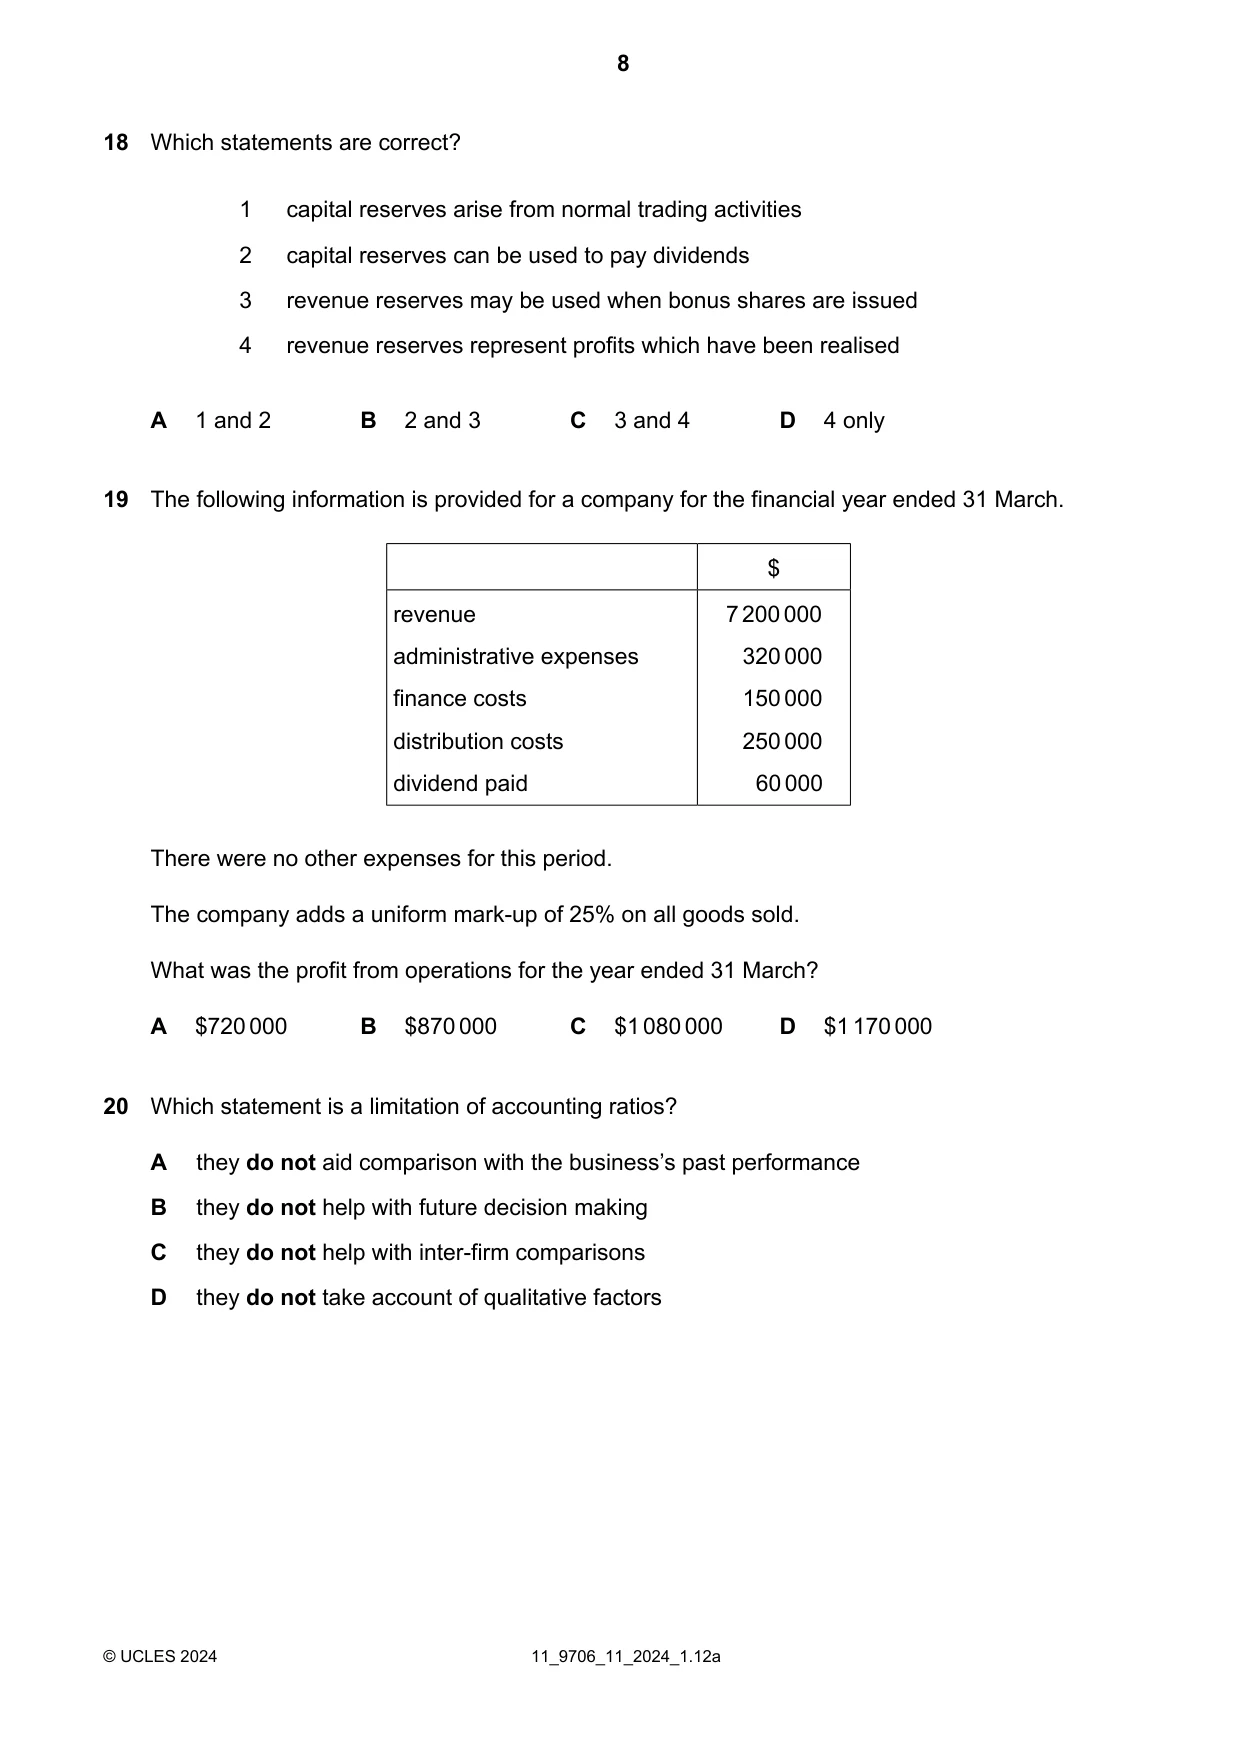
18 Which statements are correct? 1 capital reserves arise from normal trading activities 2 capital reserves can be used to pay dividends 3 revenue reserves may be used when bonus shares are issued 4 revenue reserves represent profits which have been realised A 1 and 2 B 2 and 3 C 3 and 4 D 4 only
Mark scheme: C
Q19 · The following information is provided for a company for the financial year ended 31 March
19 The following information is provided for a company for the financial year ended 31 March. $ revenue 7200000 administrative expenses 320000 finance costs 150000 distribution costs 250000 dividend paid 60000 There were no other expenses for this period. The company adds a uniform mark-up of 25% on all goods sold. What was the profit from operations for the year ended 31 March? A $720000 B $870000 C $1080000 D $1170000
Mark scheme: B
Q20 · Which statement is a limitation of accounting ratios?
20 Which statement is a limitation of accounting ratios? A they do not aid comparison with the business’s past performance B they do not help with future decision making C they do not help with inter-firm comparisons D they do not take account of qualitative factors
Mark scheme: D
More questions on Analysis and communication of accounting information
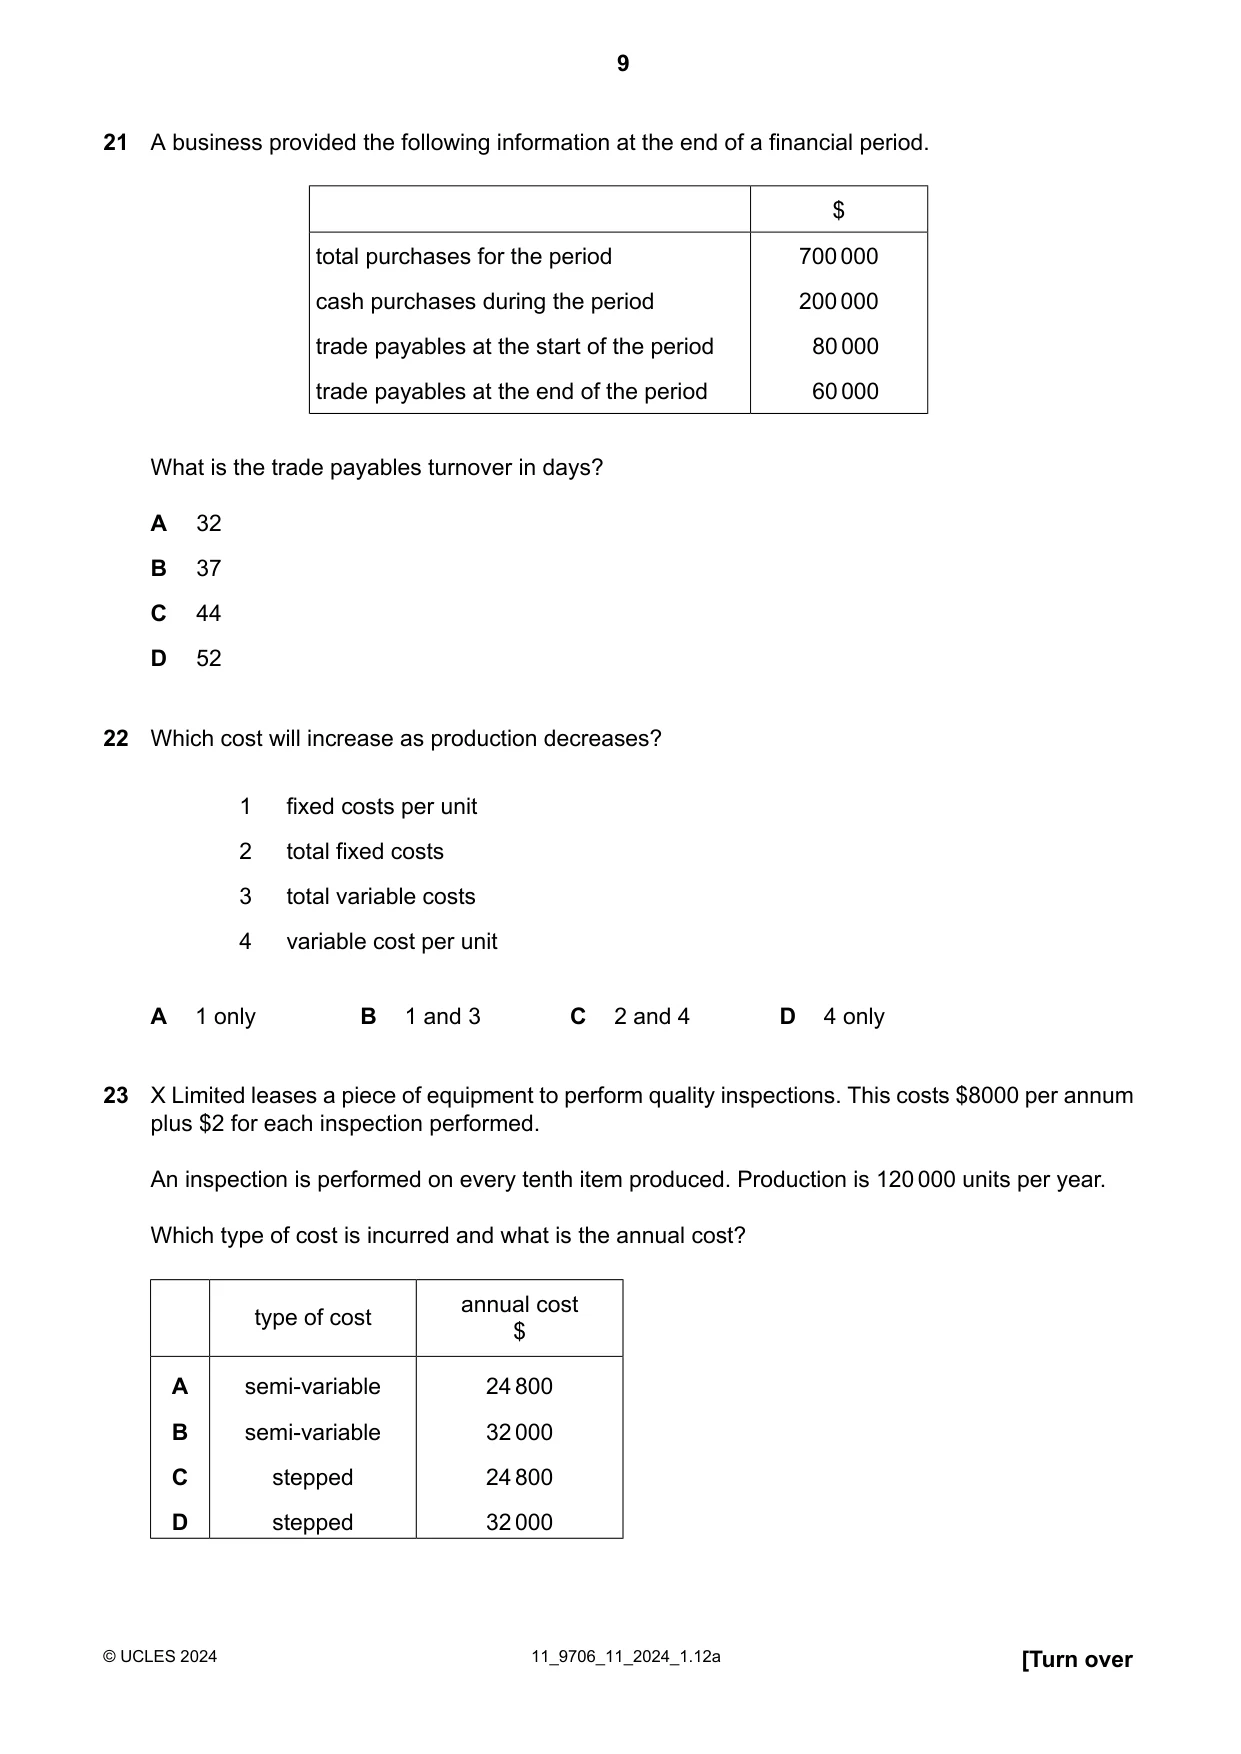
Q21 · A business provided the following information at the end of a financial period
21 A business provided the following information at the end of a financial period. $ total purchases for the period 700000 cash purchases during the period 200000 trade payables at the start of the period 80000 trade payables at the end of the period 60000 What is the trade payables turnover in days? A 32 B 37 C 44 D 52
Mark scheme: C
More questions on Analysis and communication of accounting information
Q22 · Which cost will increase as production decreases?
22 Which cost will increase as production decreases? 1 fixed costs per unit 2 total fixed costs 3 total variable costs 4 variable cost per unit A 1 only B 1 and 3 C 2 and 4 D 4 only
Mark scheme: A
Q23 · X Limited leases a piece of equipment to perform quality inspections
23 X Limited leases a piece of equipment to perform quality inspections. This costs $8000 per annum plus $2 for each inspection performed. An inspection is performed on every tenth item produced. Production is 120000 units per year. Which type of cost is incurred and what is the annual cost? annual cost type of cost $ A semi-variable 24800 B semi-variable 32000 C stepped 24800 D stepped 32000
Mark scheme: B
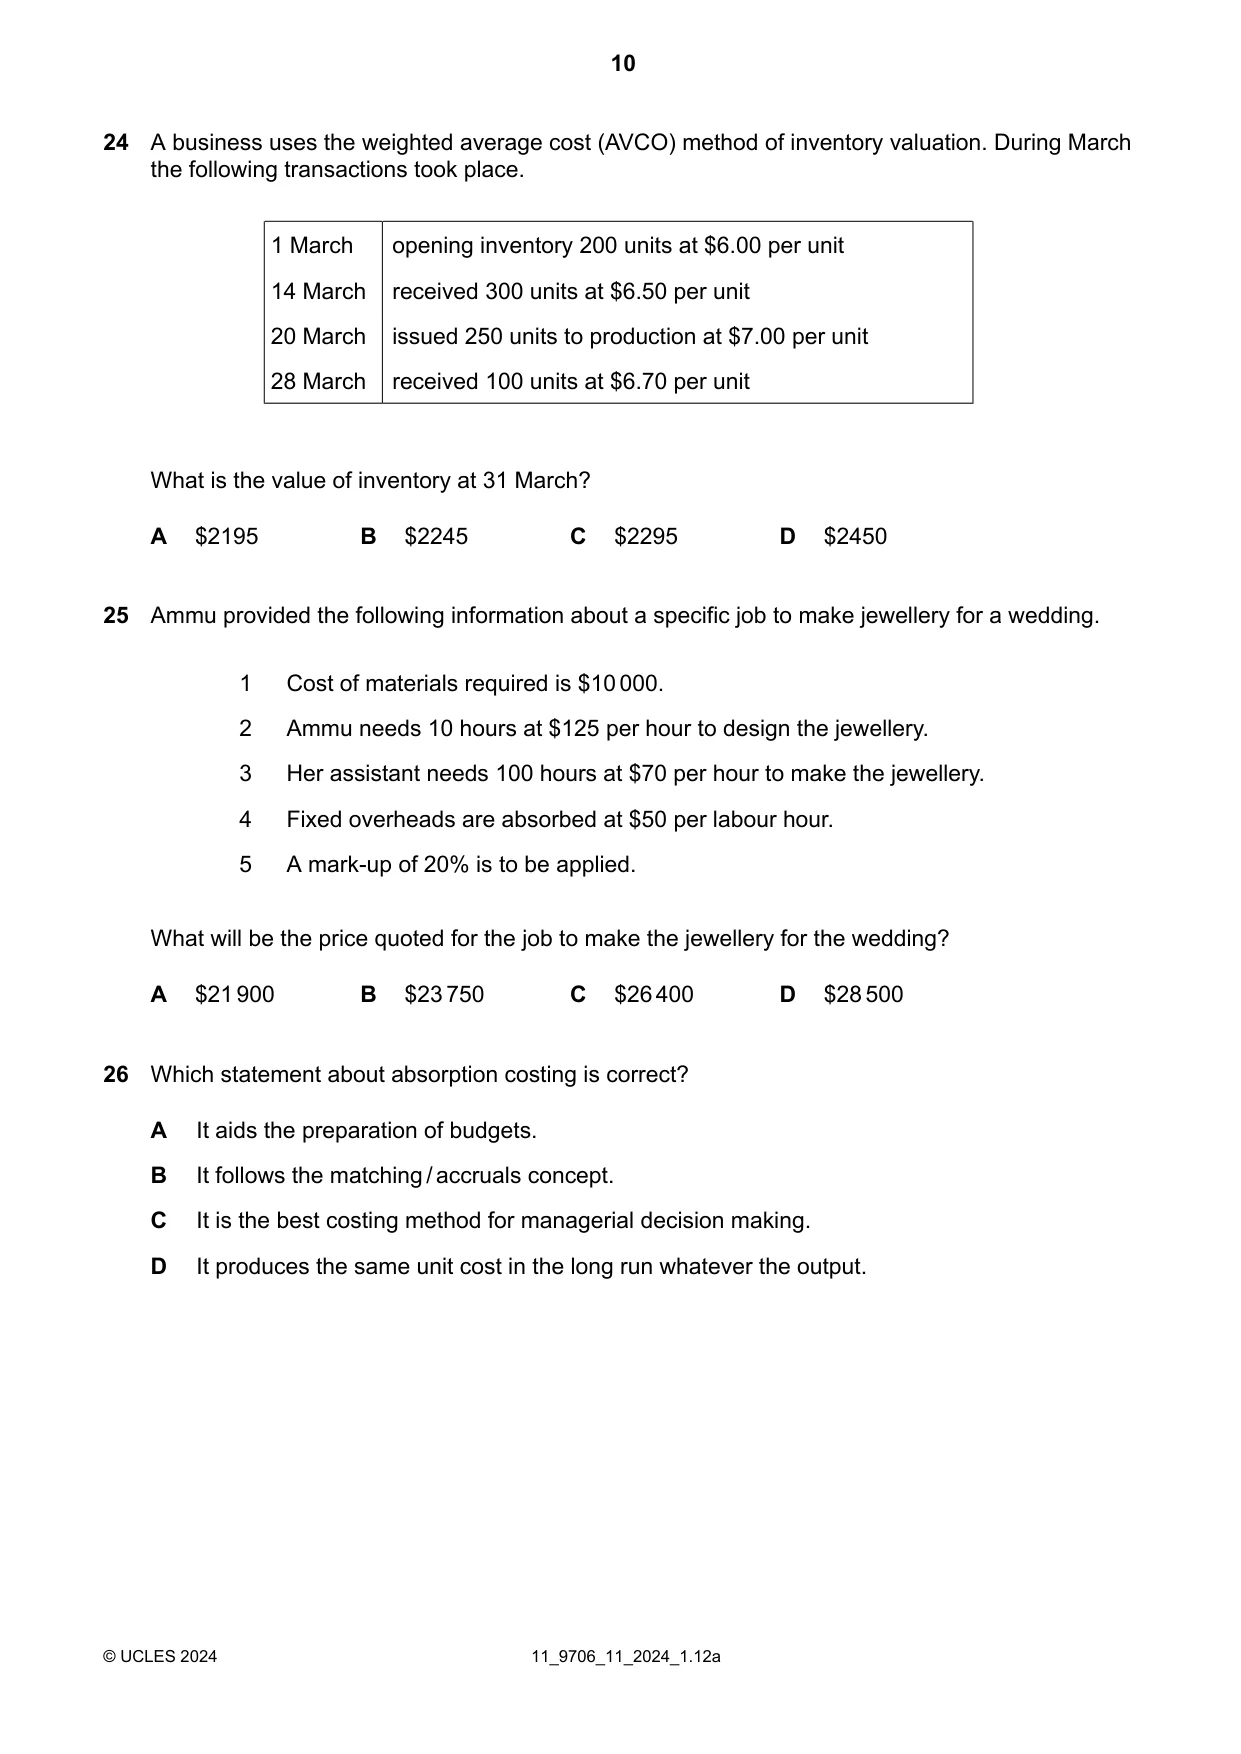
Q24 · A business uses the weighted average cost (AVCO) method of inventory valuation
24 A business uses the weighted average cost (AVCO) method of inventory valuation. During March the following transactions took place. 1 March opening inventory 200 units at $6.00 per unit 14 March received 300 units at $6.50 per unit 20 March issued 250 units to production at $7.00 per unit 28 March received 100 units at $6.70 per unit What is the value of inventory at 31 March? A $2195 B $2245 C $2295 D $2450
Mark scheme: B
Q25 · Ammu provided the following information about a specific job to make jewellery for a…
25 Ammu provided the following information about a specific job to make jewellery for a wedding. 1 Cost of materials required is $10000. 2 Ammu needs 10 hours at $125 per hour to design the jewellery. 3 Her assistant needs 100 hours at $70 per hour to make the jewellery. 4 Fixed overheads are absorbed at $50 per labour hour. 5 A mark-up of 20% is to be applied. What will be the price quoted for the job to make the jewellery for the wedding? A $21900 B $23750 C $26400 D $28500
Mark scheme: D
Q26 · Which statement about absorption costing is correct?
26 Which statement about absorption costing is correct? A It aids the preparation of budgets. B It follows the matching/accruals concept. C It is the best costing method for managerial decision making. D It produces the same unit cost in the long run whatever the output.
Mark scheme: B
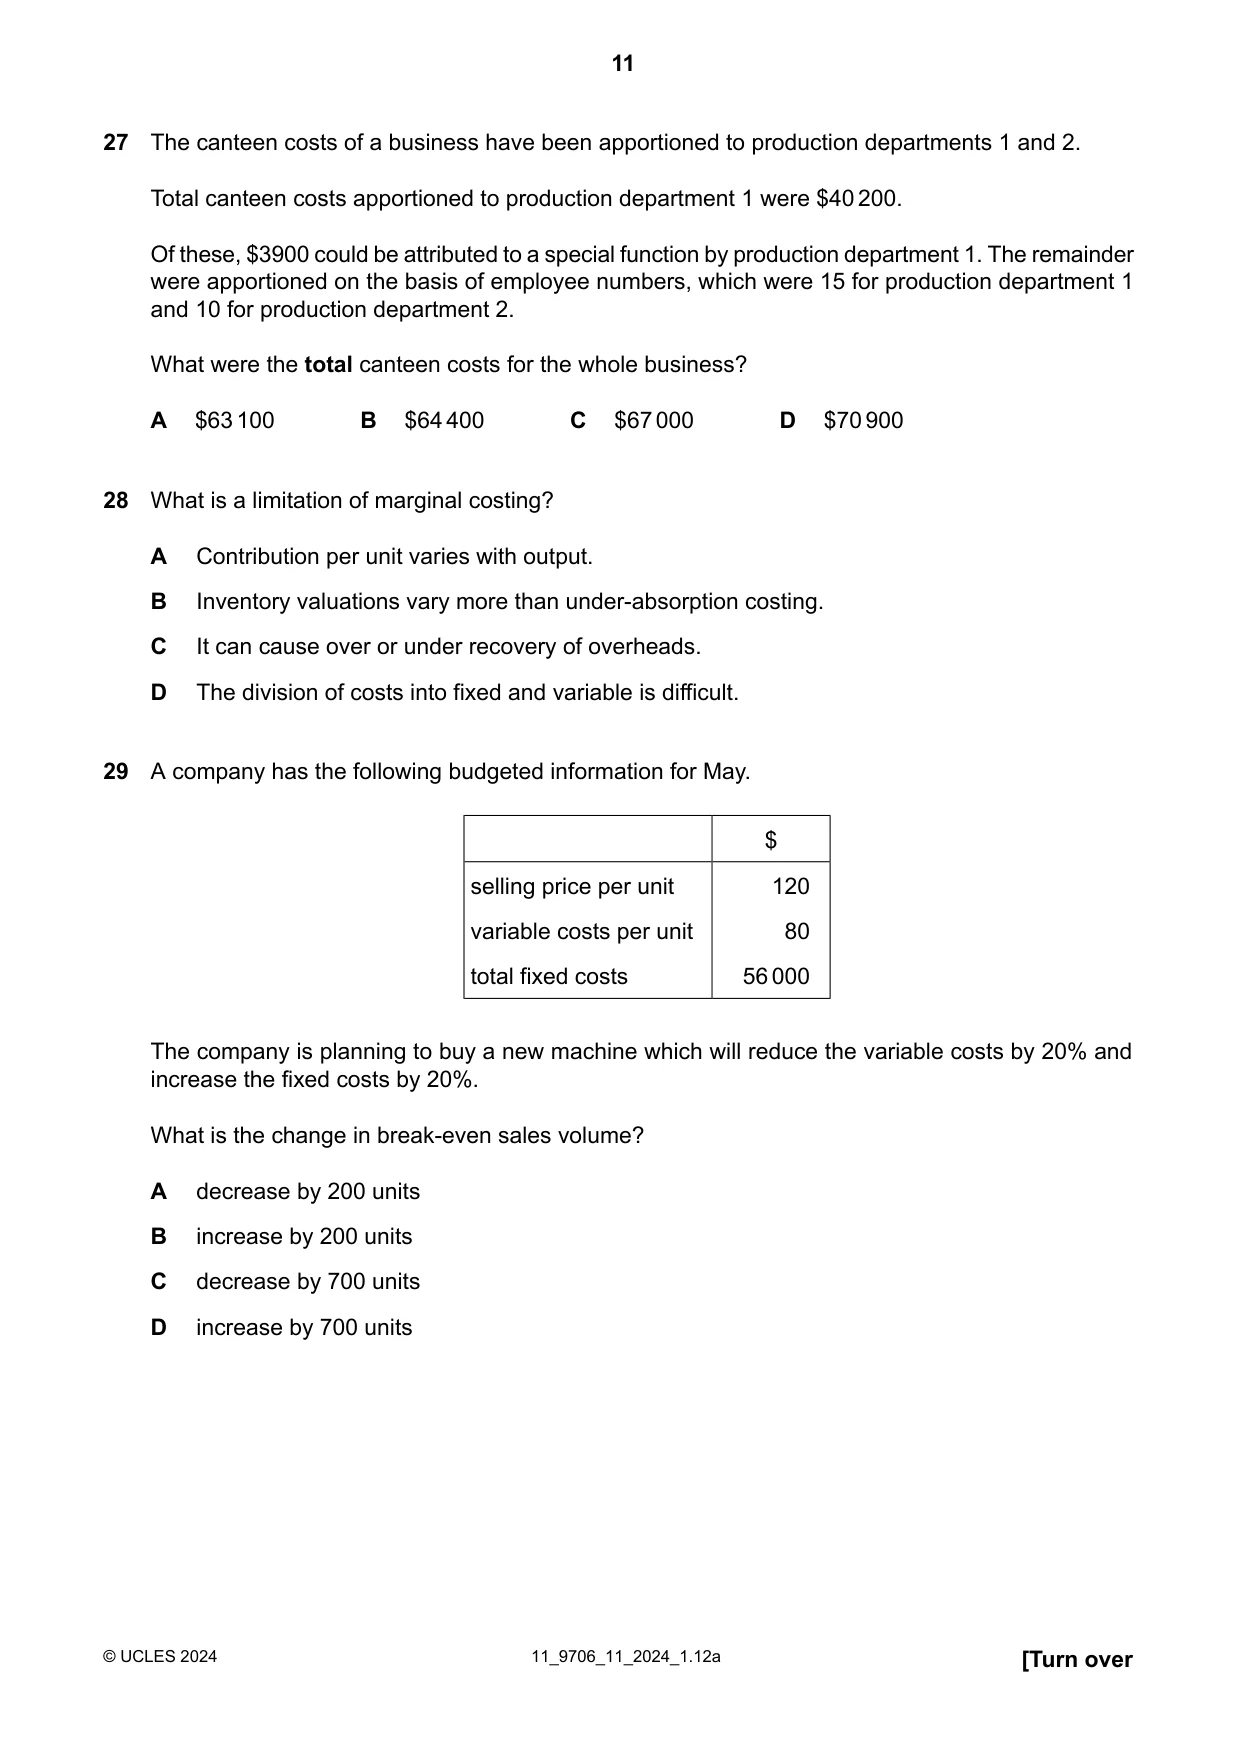
Q27 · The canteen costs of a business have been apportioned to production departments 1 and 2
27 The canteen costs of a business have been apportioned to production departments 1 and 2. Total canteen costs apportioned to production department 1 were $40200. Of these, $3900 could be attributed to a special function by production department 1. The remainder were apportioned on the basis of employee numbers, which were 15 for production department 1 and 10 for production department 2. What were the total canteen costs for the whole business? A $63100 B $64400 C $67000 D $70900
Mark scheme: B
Q28 · What is a limitation of marginal costing?
28 What is a limitation of marginal costing? A Contribution per unit varies with output. B Inventory valuations vary more than under-absorption costing. C It can cause over or under recovery of overheads. D The division of costs into fixed and variable is difficult.
Mark scheme: D
Q29 · A company has the following budgeted information for May
29 A company has the following budgeted information for May. $ selling price per unit 120 variable costs per unit 80 total fixed costs 56000 The company is planning to buy a new machine which will reduce the variable costs by 20% and increase the fixed costs by 20%. What is the change in break-even sales volume? A decrease by 200 units B increase by 200 units C decrease by 700 units D increase by 700 units
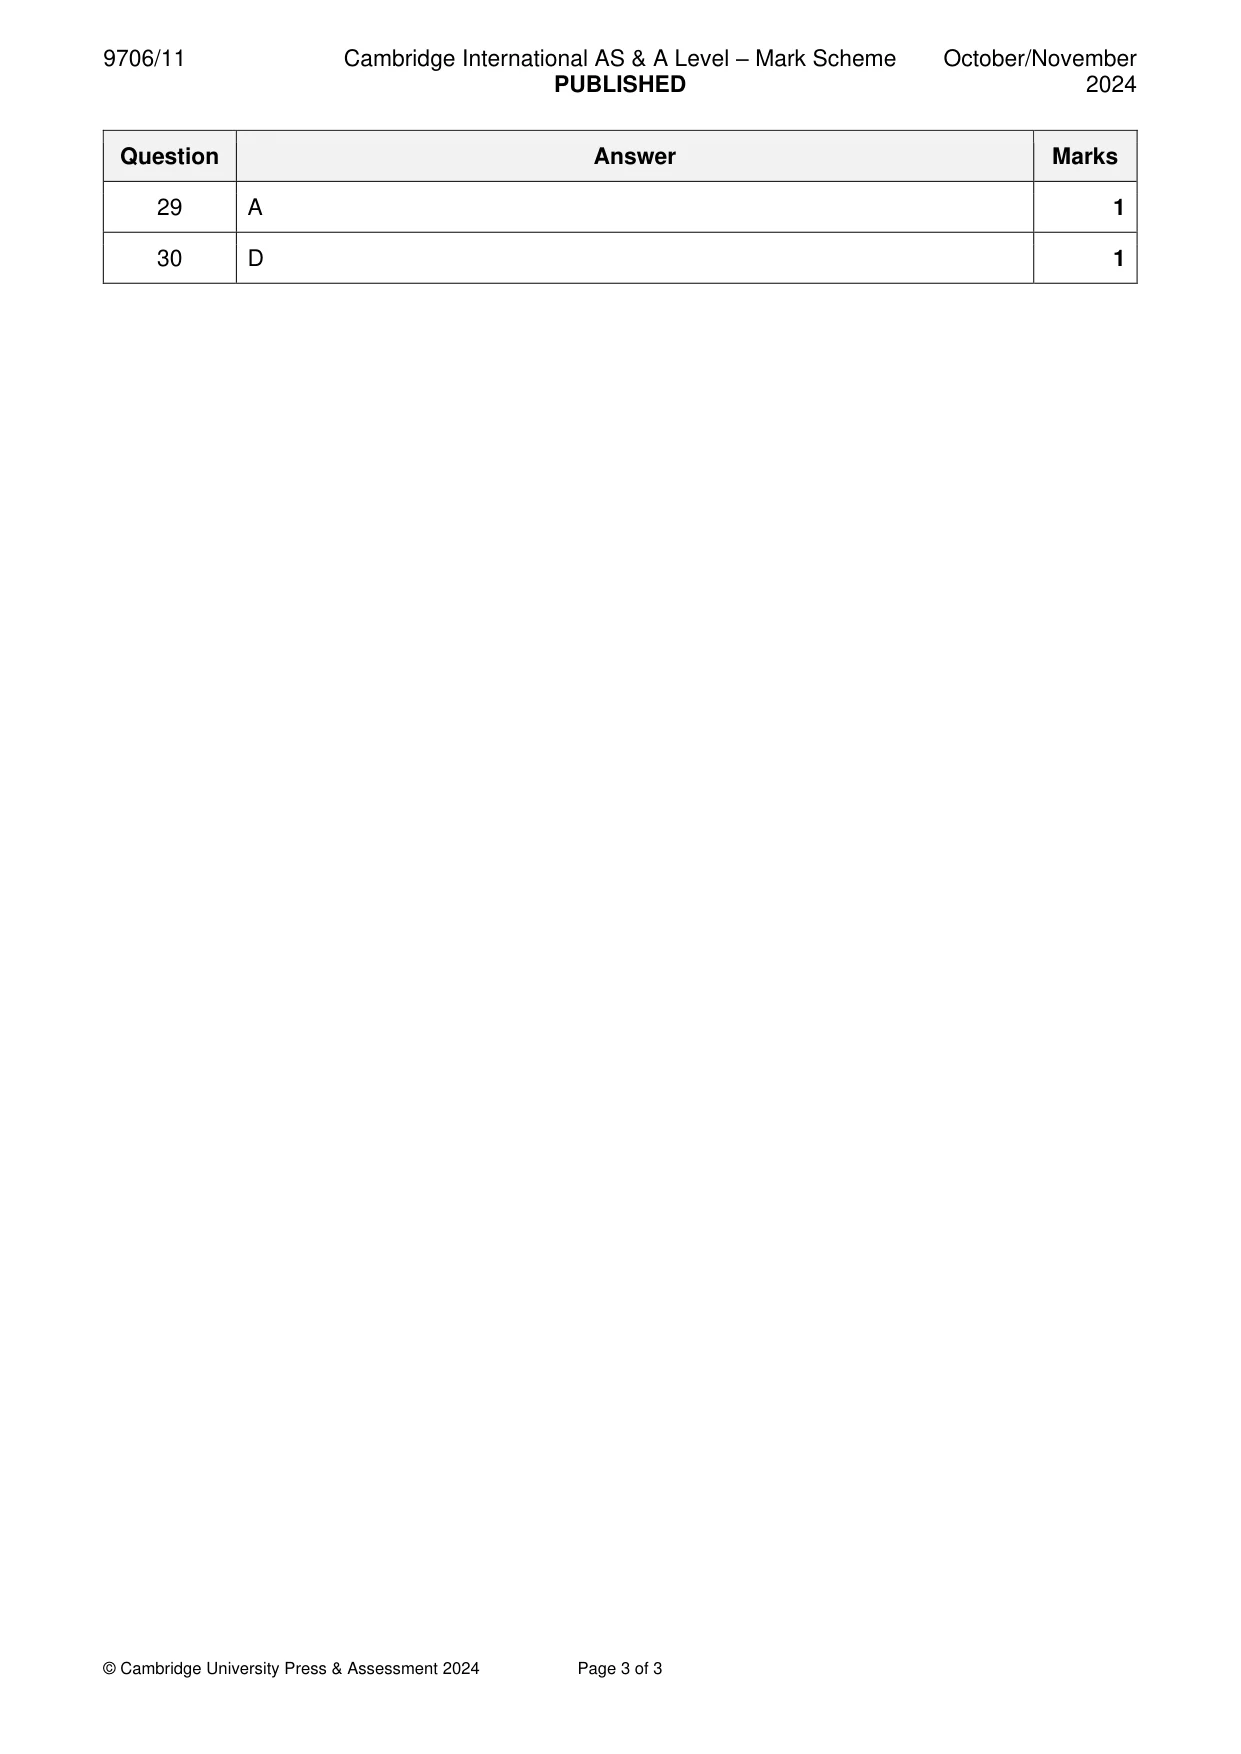
Mark scheme: A
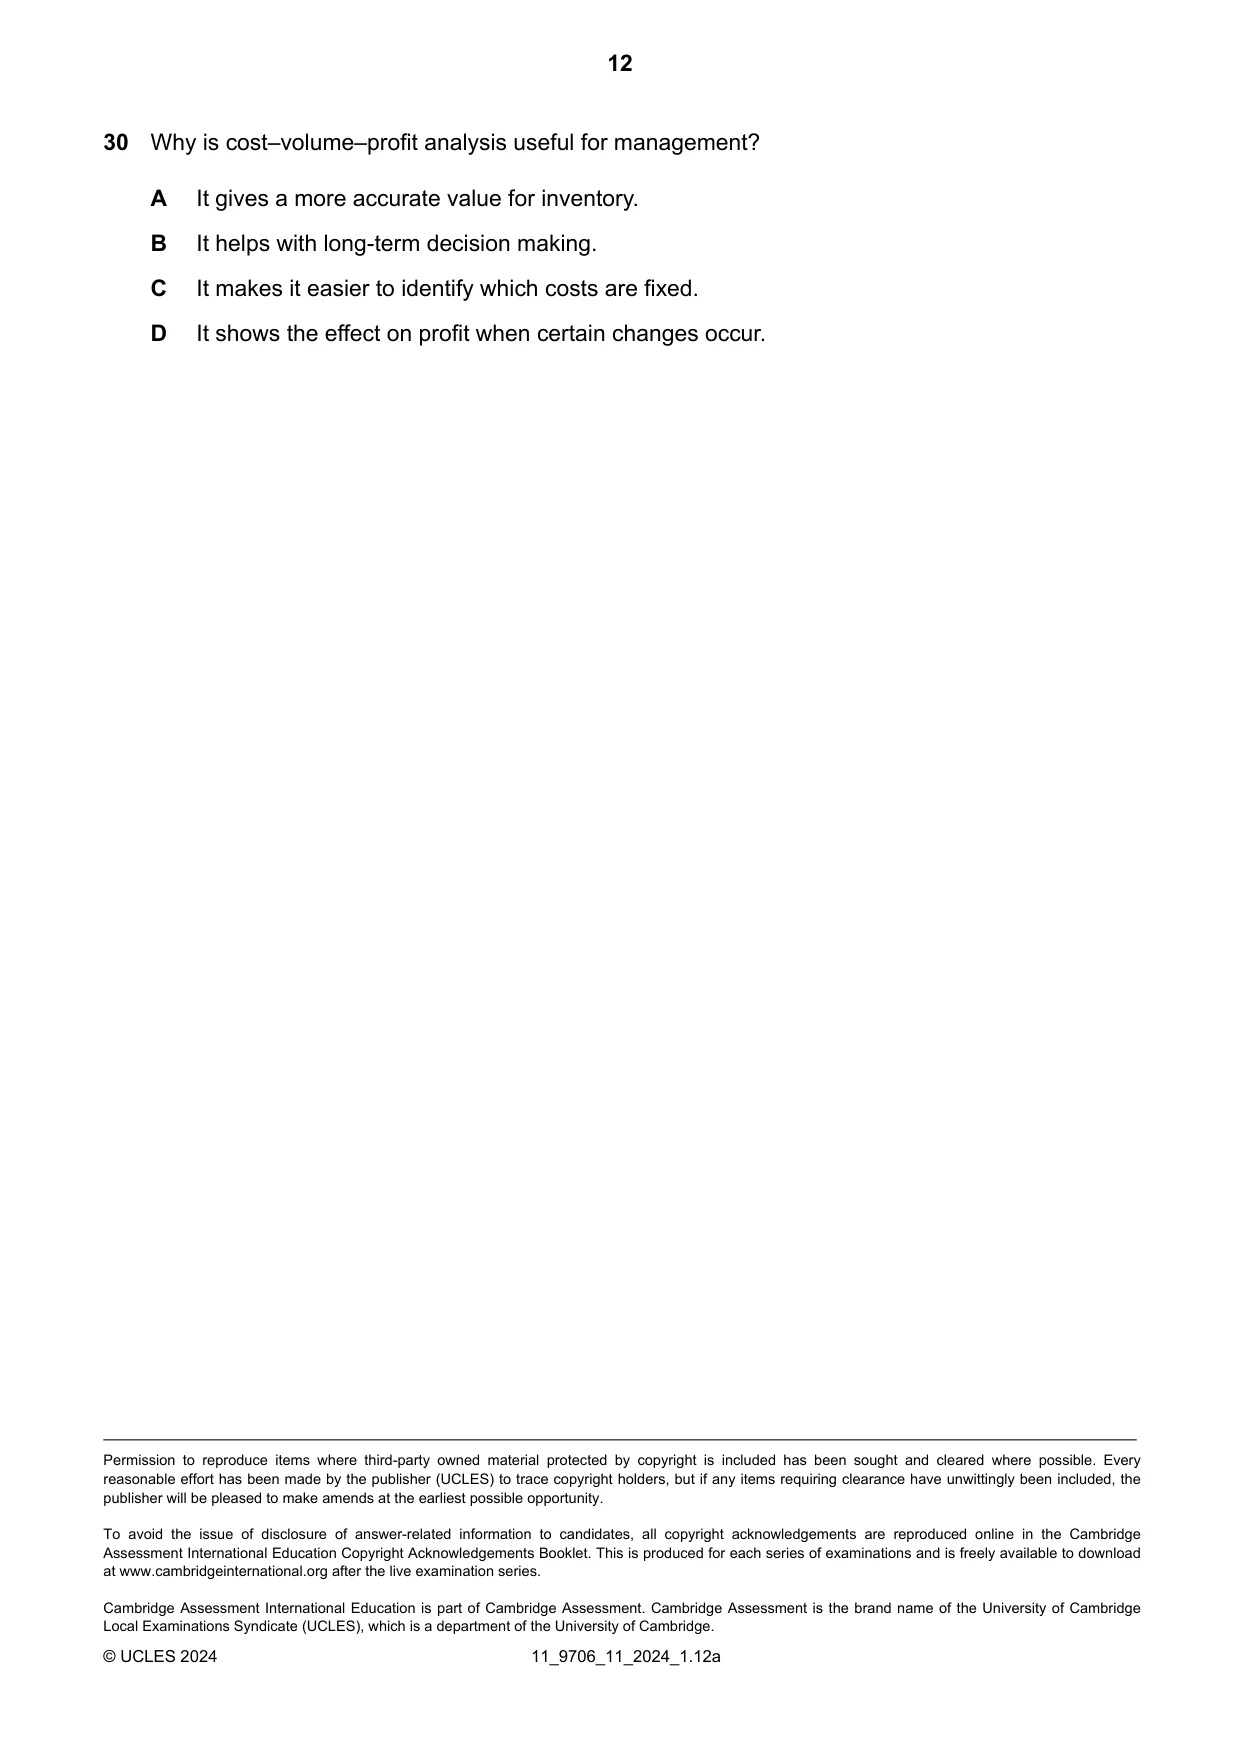
Q30 · Why is cost–volume–profit analysis useful for management?
30 Why is cost–volume–profit analysis useful for management? A It gives a more accurate value for inventory. B It helps with long-term decision making. C It makes it easier to identify which costs are fixed. D It shows the effect on profit when certain changes occur.
Mark scheme: D
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2024 Oct/Nov, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.