Cambridge A Level Accounting 9706 — 2024 Oct/Nov Paper 1 · Variant 2
9706/12/O/N/24 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
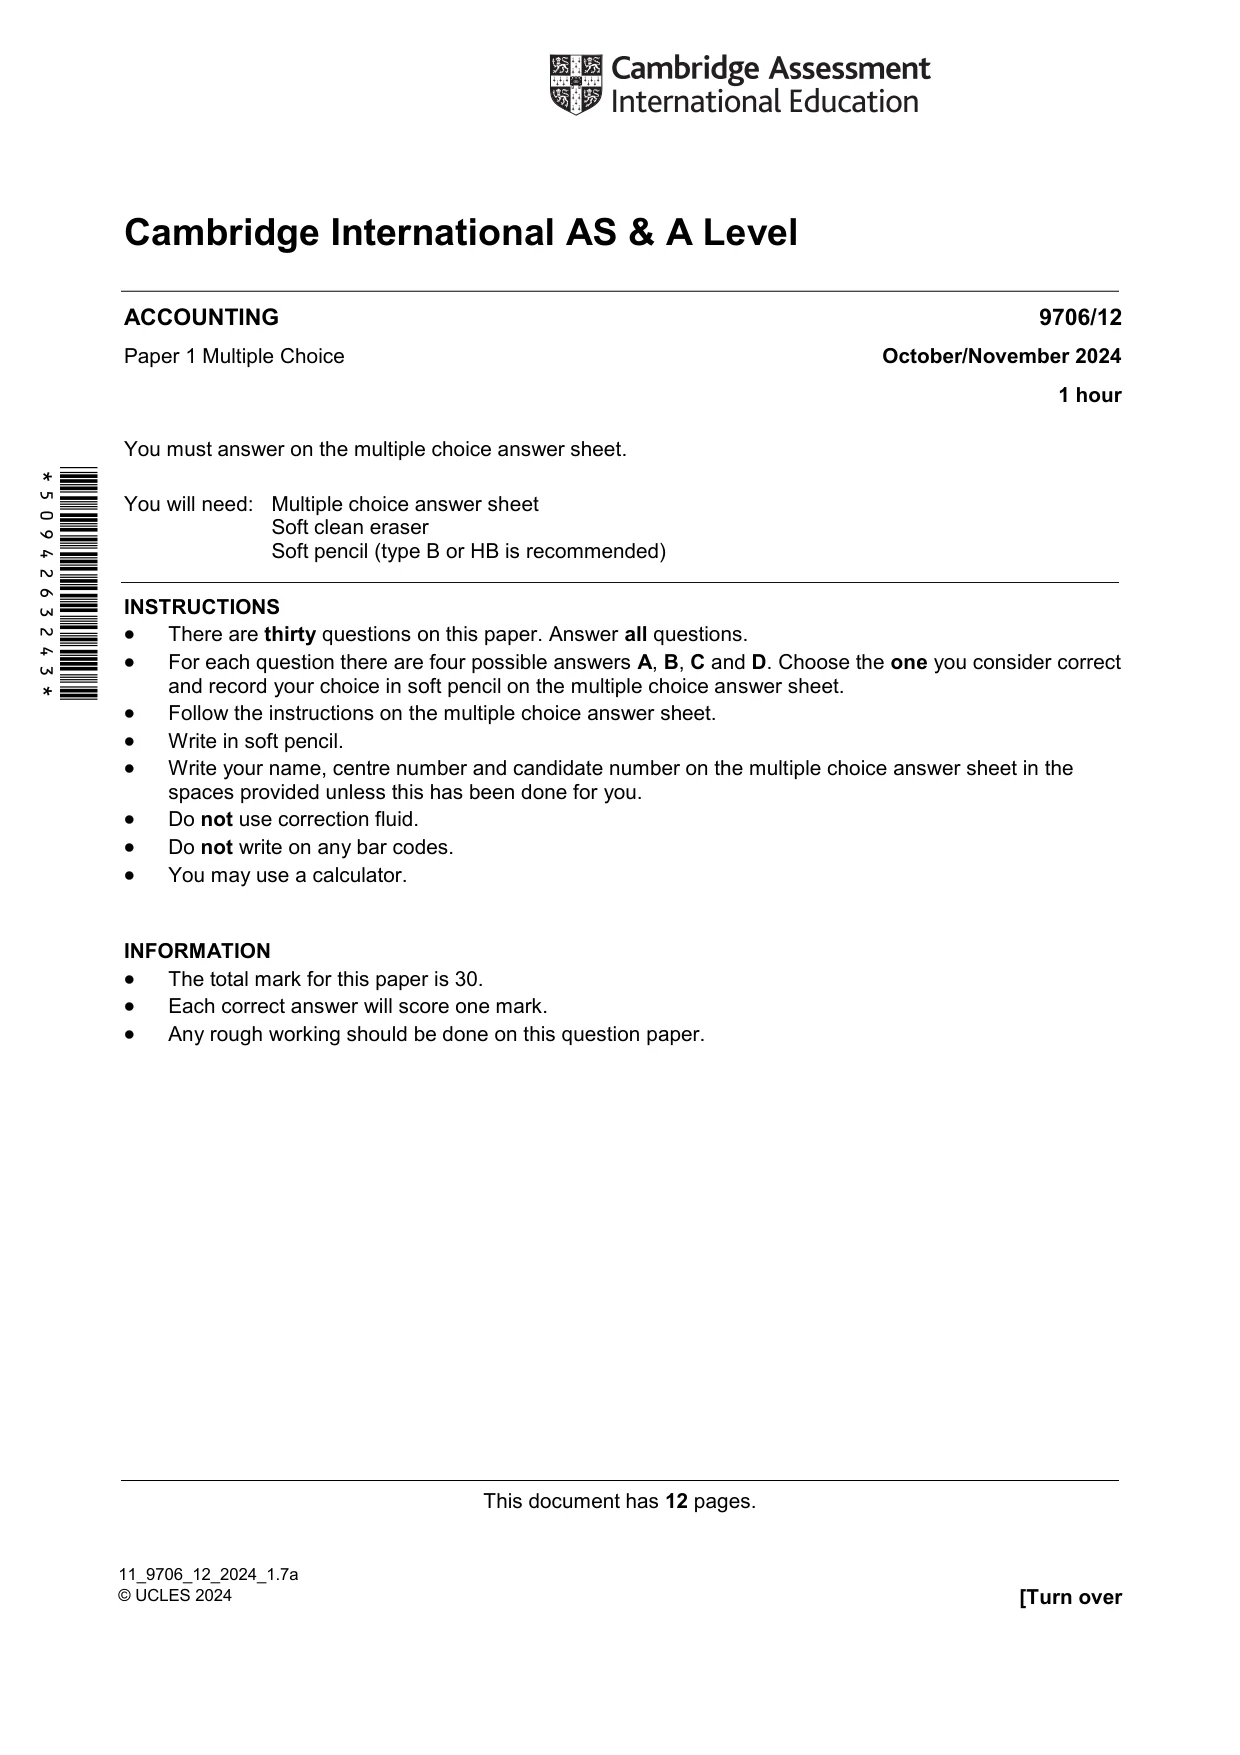
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · A business sells computers
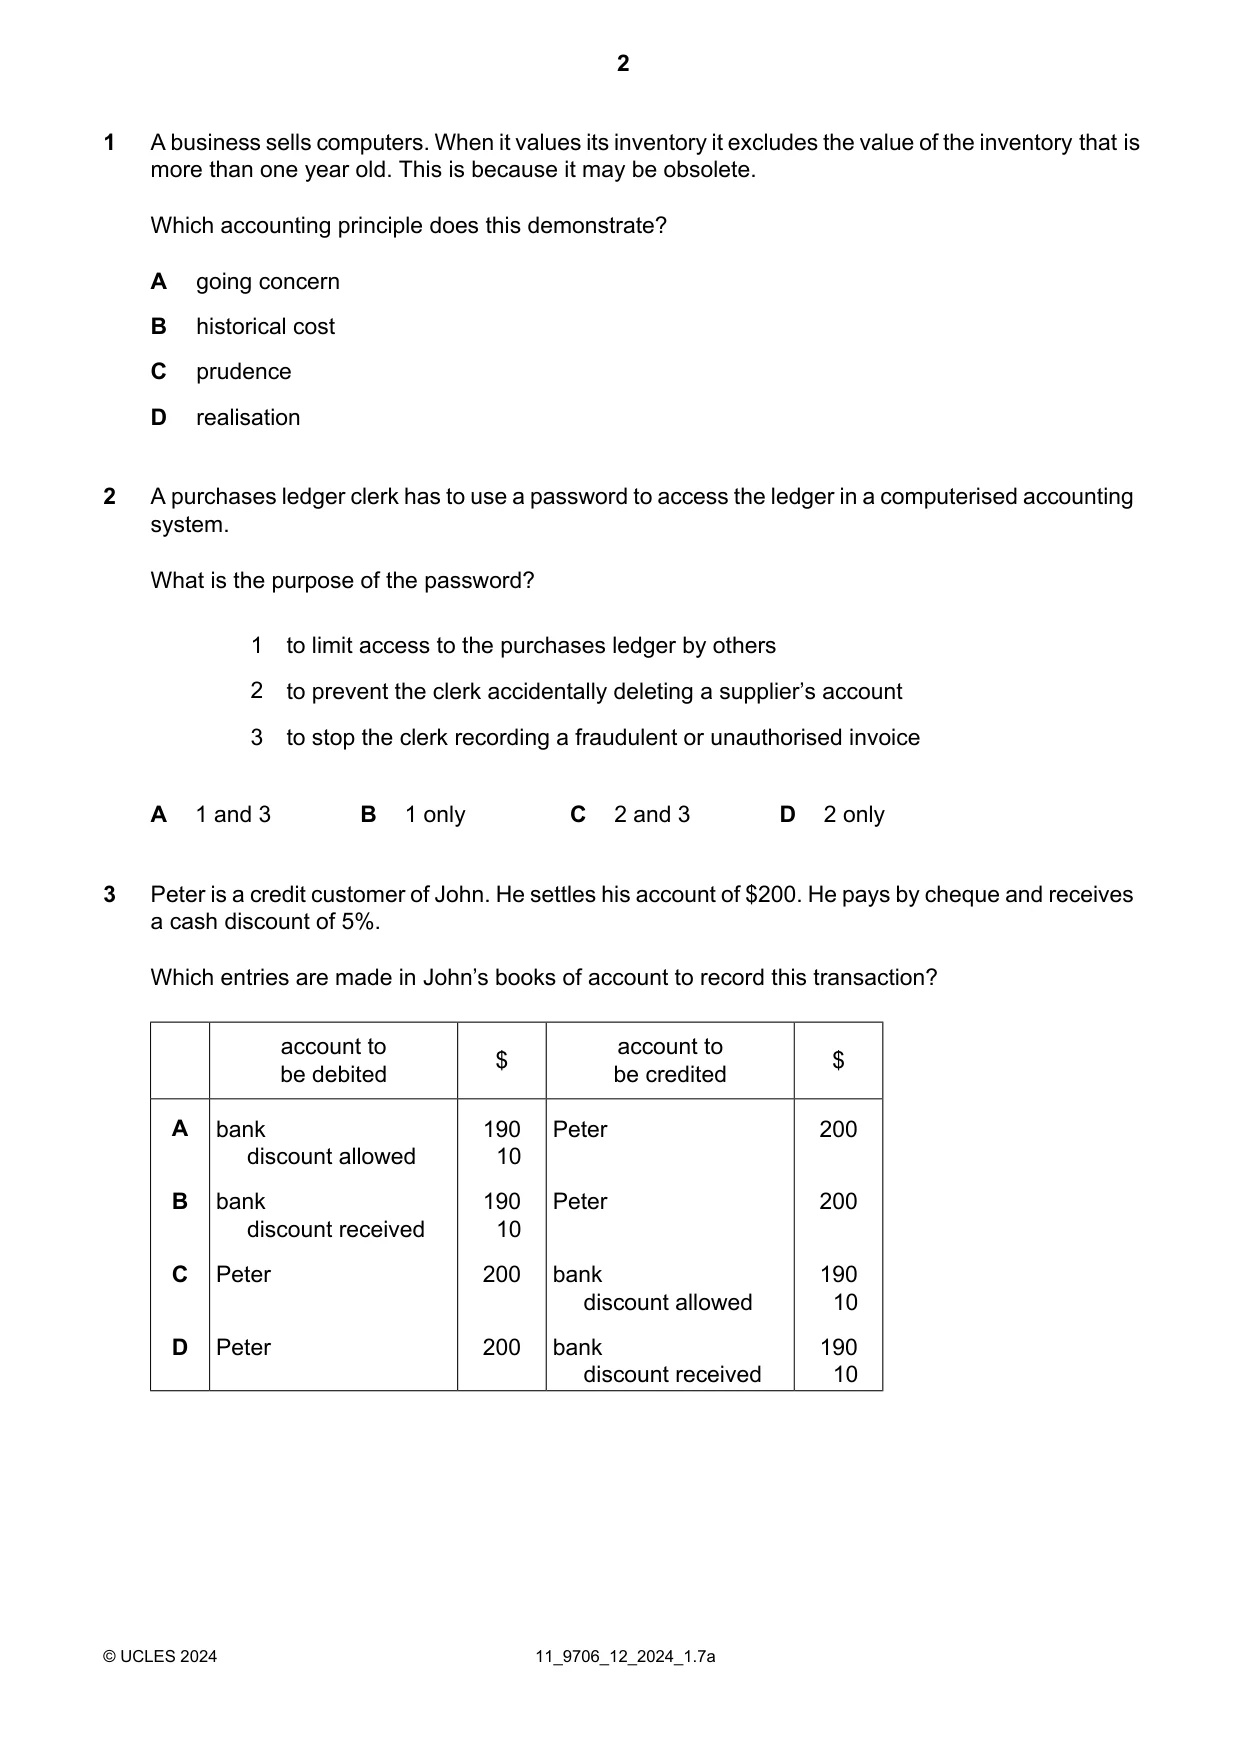
1 A business sells computers. When it values its inventory it excludes the value of the inventory that is more than one year old. This is because it may be obsolete. Which accounting principle does this demonstrate? A going concern B historical cost C prudence D realisation
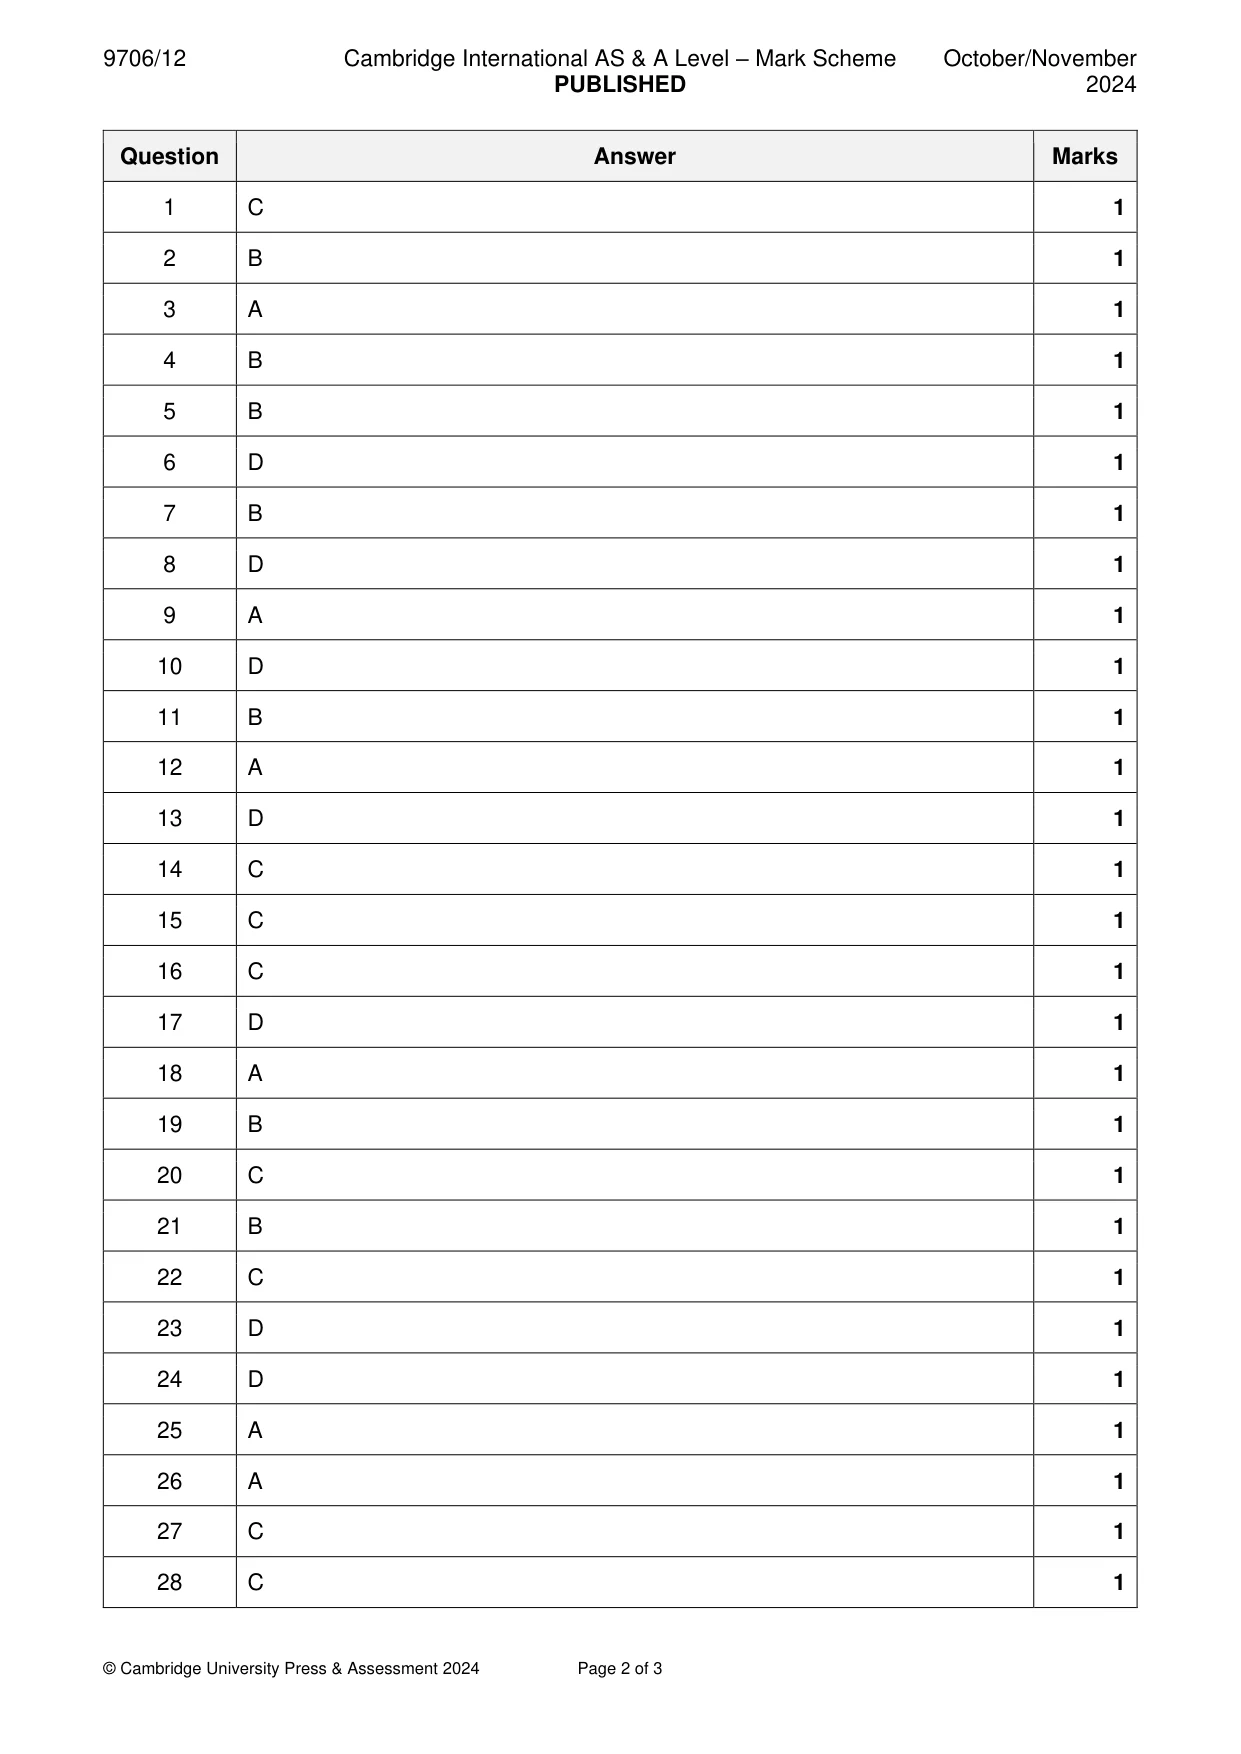
Mark scheme: C
Q2 · A purchases ledger clerk has to use a password to access the ledger in a computerised…
2 A purchases ledger clerk has to use a password to access the ledger in a computerised accounting system. What is the purpose of the password? 1 to limit access to the purchases ledger by others 2 to prevent the clerk accidentally deleting a supplier’s account 3 to stop the clerk recording a fraudulent or unauthorised invoice A 1 and 3 B 1 only C 2 and 3 D 2 only
Mark scheme: B
Q3 · Peter is a credit customer of John
3 Peter is a credit customer of John. He settles his account of $200. He pays by cheque and receives a cash discount of 5%. Which entries are made in John’s books of account to record this transaction? account to account to $ $ be debited be credited A bank 190 Peter 200 discount allowed 10 B bank 190 Peter 200 discount received 10 C Peter 200 bank 190 discount allowed 10 D Peter 200 bank 190 discount received 10
Mark scheme: A
Q4 · Which item is capital income?
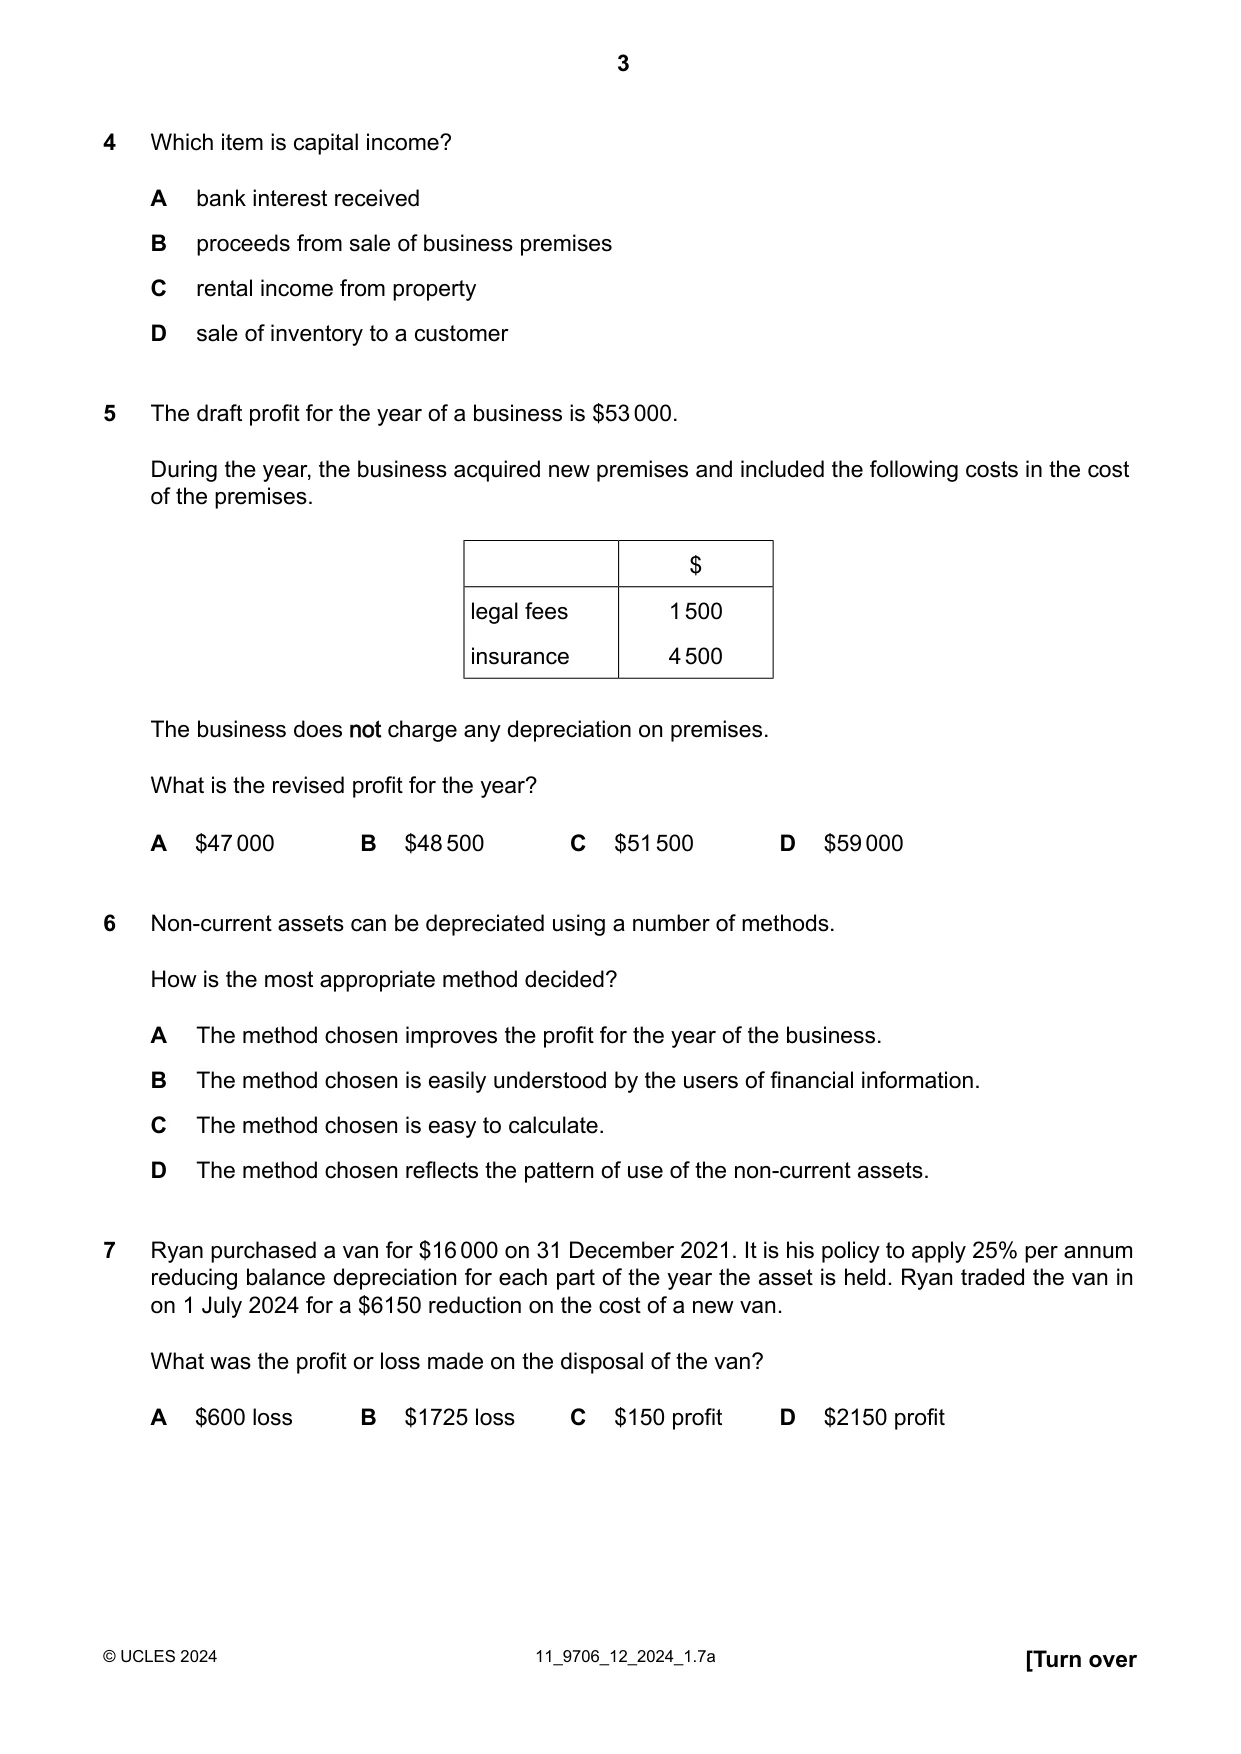
4 Which item is capital income? A bank interest received B proceeds from sale of business premises C rental income from property D sale of inventory to a customer
Mark scheme: B
Q5 · The draft profit for the year of a business is $53000
5 The draft profit for the year of a business is $53000. During the year, the business acquired new premises and included the following costs in the cost of the premises. $ legal fees 1500 insurance 4500 The business does not charge any depreciation on premises. What is the revised profit for the year? A $47000 B $48500 C $51500 D $59000
Mark scheme: B
Q6 · Non-current assets can be depreciated using a number of methods
6 Non-current assets can be depreciated using a number of methods. How is the most appropriate method decided? A The method chosen improves the profit for the year of the business. B The method chosen is easily understood by the users of financial information. C The method chosen is easy to calculate. D The method chosen reflects the pattern of use of the non-current assets.
Mark scheme: D
Q7 · Ryan purchased a van for $16000 on 31 December 2021
7 Ryan purchased a van for $16000 on 31 December 2021. It is his policy to apply 25% per annum reducing balance depreciation for each part of the year the asset is held. Ryan traded the van in on 1 July 2024 for a $6150 reduction on the cost of a new van. What was the profit or loss made on the disposal of the van? A $600 loss B $1725 loss C $150 profit D $2150 profit
Mark scheme: B
Q8 · The totals of the trial balance of a business did not agree
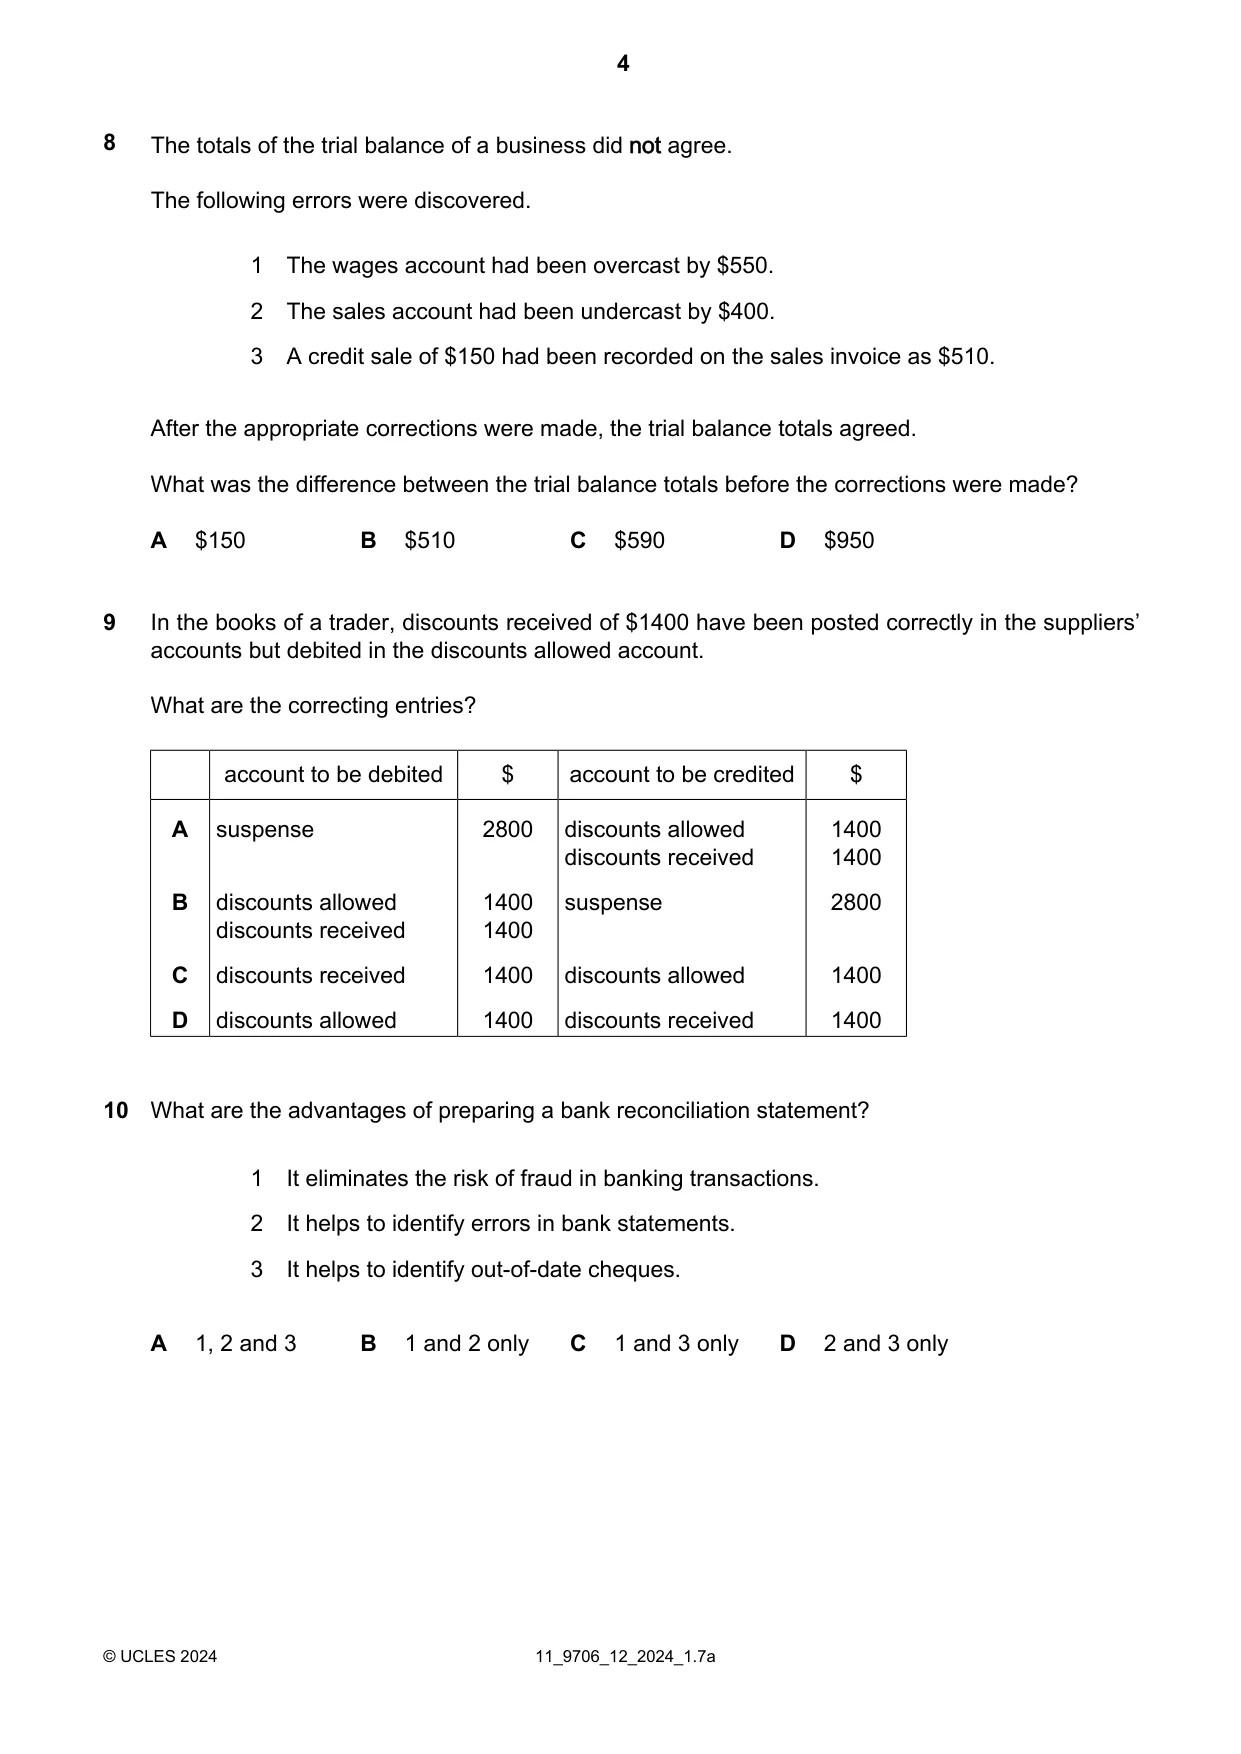
8 The totals of the trial balance of a business did not agree. The following errors were discovered. 1 The wages account had been overcast by $550. 2 The sales account had been undercast by $400. 3 A credit sale of $150 had been recorded on the sales invoice as $510. After the appropriate corrections were made, the trial balance totals agreed. What was the difference between the trial balance totals before the corrections were made? A $150 B $510 C $590 D $950
Mark scheme: D
Q9 · In the books of a trader, discounts received of $1400 have been posted correctly in the…
9 In the books of a trader, discounts received of $1400 have been posted correctly in the suppliers’ accounts but debited in the discounts allowed account. What are the correcting entries? account to be debited $ account to be credited $ A suspense 2800 discounts allowed 1400 discounts received 1400 B discounts allowed 1400 suspense 2800 discounts received 1400 C discounts received 1400 discounts allowed 1400 D discounts allowed 1400 discounts received 1400
Mark scheme: A
Q10 · What are the advantages of preparing a bank reconciliation statement?
10 What are the advantages of preparing a bank reconciliation statement? 1 It eliminates the risk of fraud in banking transactions. 2 It helps to identify errors in bank statements. 3 It helps to identify out-of-date cheques. A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
Mark scheme: D
Q11 · The cash book of a business showed a debit bank balance of $3900
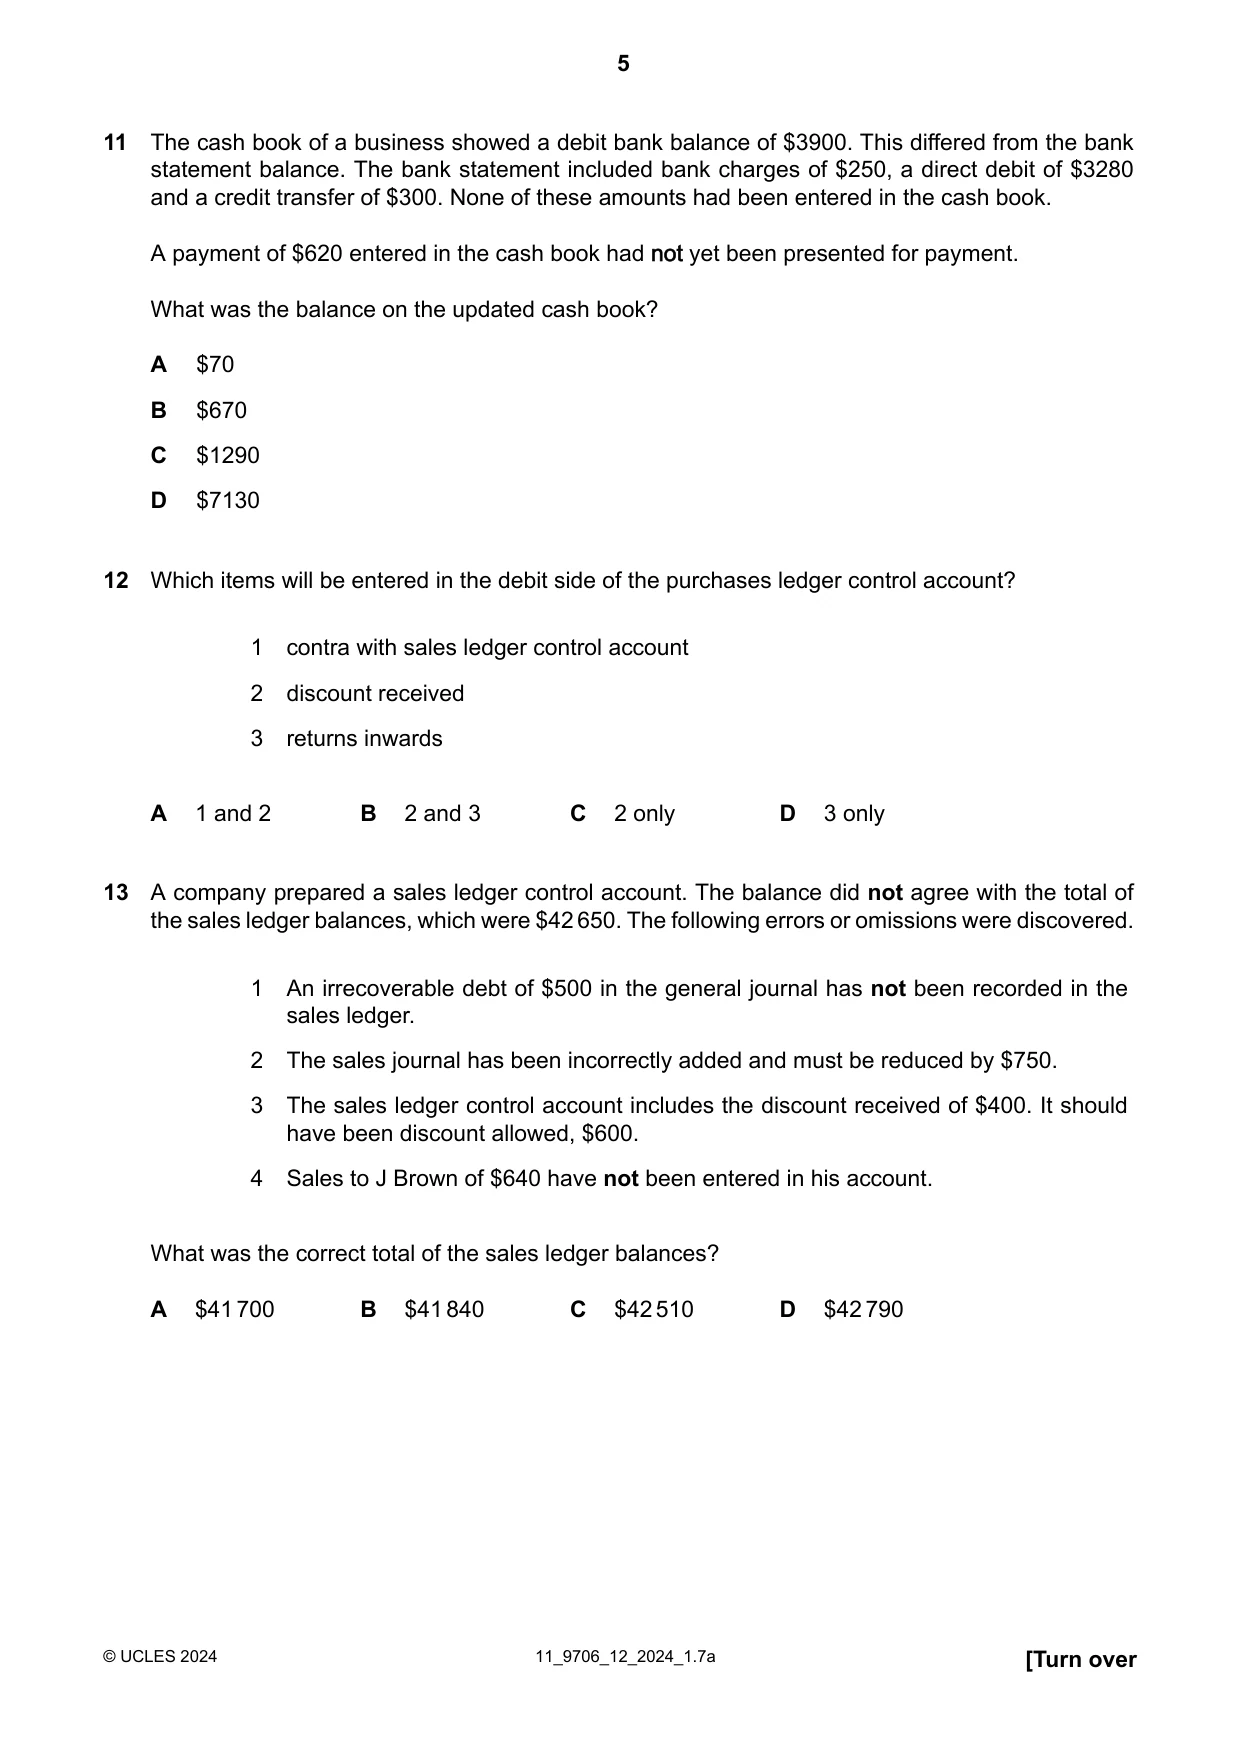
11 The cash book of a business showed a debit bank balance of $3900. This differed from the bank statement balance. The bank statement included bank charges of $250, a direct debit of $3280 and a credit transfer of $300. None of these amounts had been entered in the cash book. A payment of $620 entered in the cash book had not yet been presented for payment. What was the balance on the updated cash book? A $70 B $670 C $1290 D $7130
Mark scheme: B
Q12 · Which items will be entered in the debit side of the purchases ledger control account?
12 Which items will be entered in the debit side of the purchases ledger control account? 1 contra with sales ledger control account 2 discount received 3 returns inwards A 1 and 2 B 2 and 3 C 2 only D 3 only
Mark scheme: A
Q13 · A company prepared a sales ledger control account
13 A company prepared a sales ledger control account. The balance did not agree with the total of the sales ledger balances, which were $42 650. The following errors or omissions were discovered. 1 An irrecoverable debt of $500 in the general journal has not been recorded in the sales ledger. 2 The sales journal has been incorrectly added and must be reduced by $750. 3 The sales ledger control account includes the discount received of $400. It should have been discount allowed, $600. 4 Sales to J Brown of $640 have not been entered in his account. What was the correct total of the sales ledger balances? A $41700 B $41840 C $42510 D $42790
Mark scheme: D
Q14 · The current assets of a company include the balances on both the rent payable and rent…
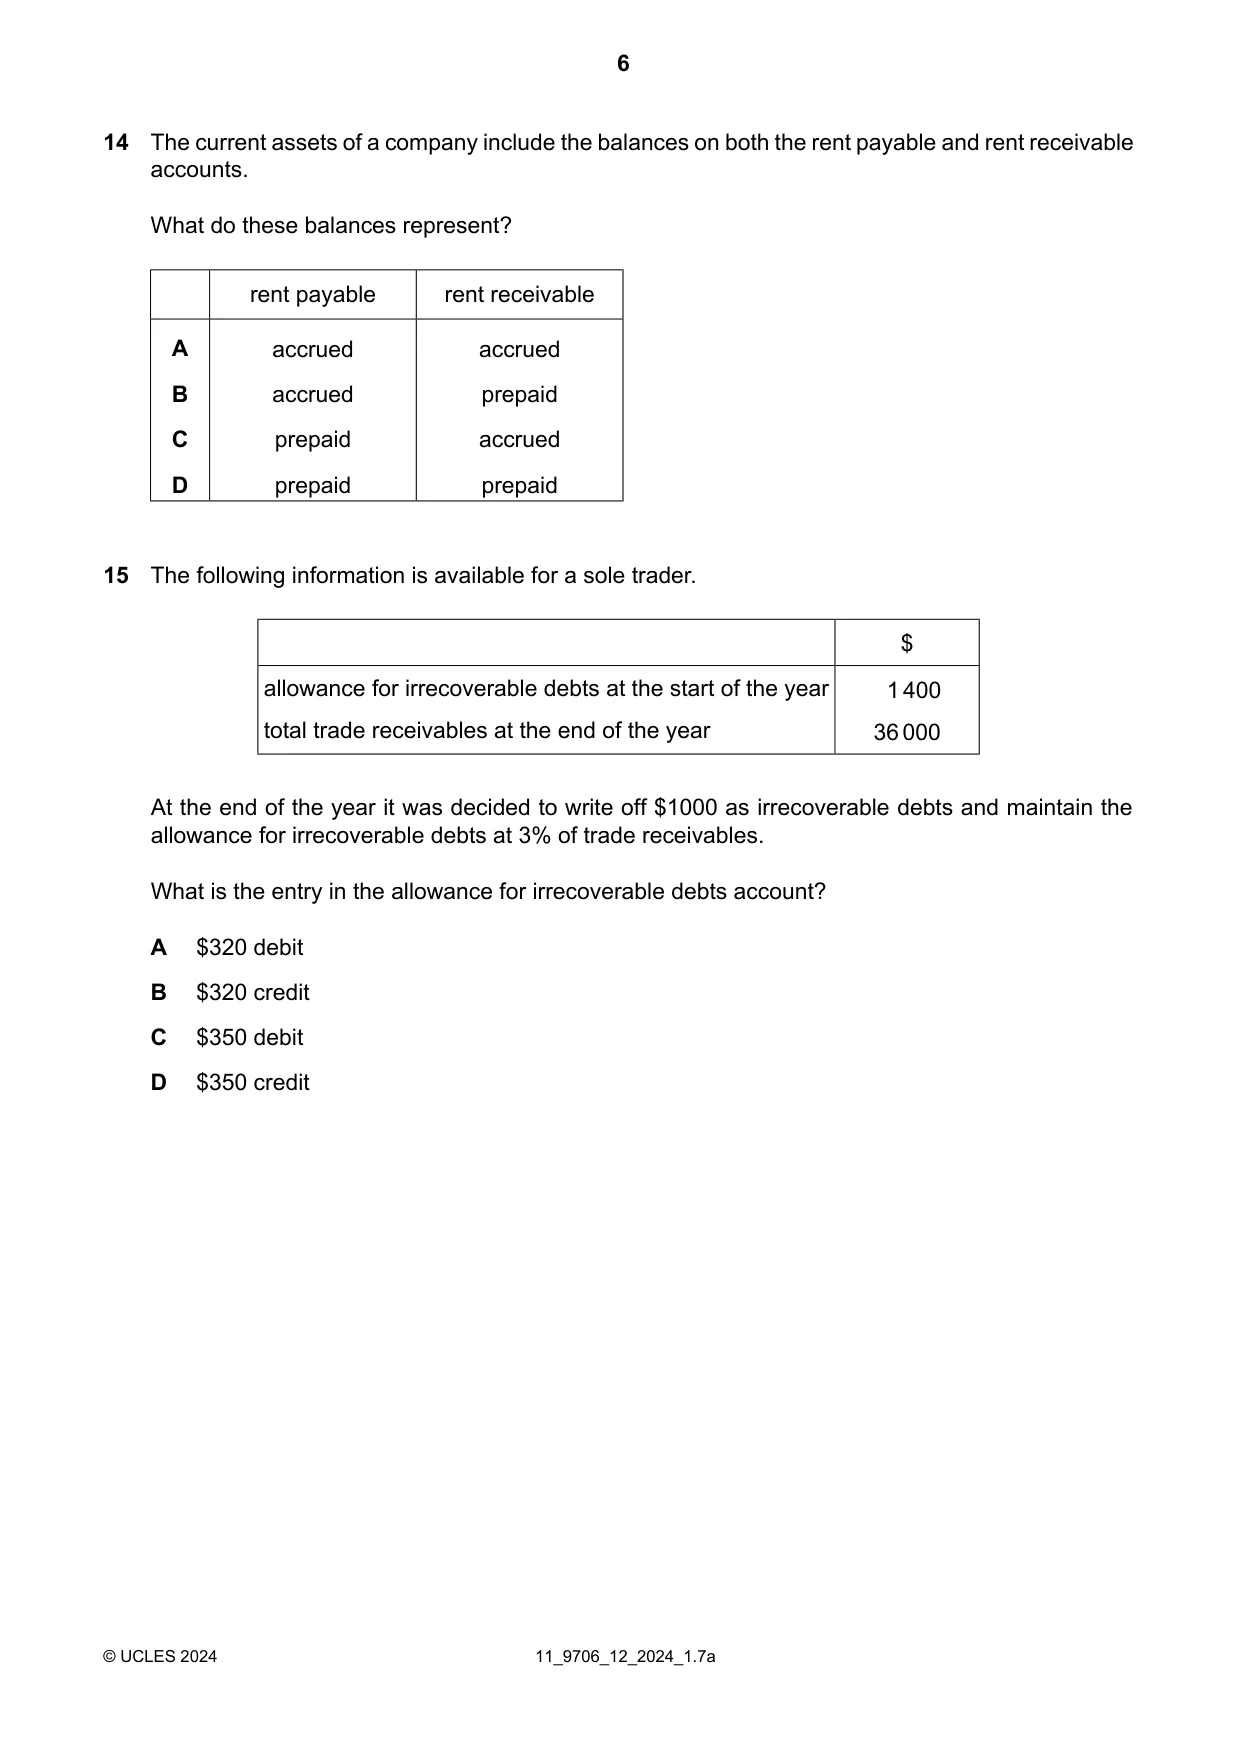
14 The current assets of a company include the balances on both the rent payable and rent receivable accounts. What do these balances represent? rent payable rent receivable A accrued accrued B accrued prepaid C prepaid accrued D prepaid prepaid
Mark scheme: C
Q15 · The following information is available for a sole trader
15 The following information is available for a sole trader. $ allowance for irrecoverable debts at the start of the year 1400 total trade receivables at the end of the year 36000 At the end of the year it was decided to write off $1000 as irrecoverable debts and maintain the allowance for irrecoverable debts at 3% of trade receivables. What is the entry in the allowance for irrecoverable debts account? A $320 debit B $320 credit C $350 debit D $350 credit
Mark scheme: C
Q16 · A sole trader’s statement of profit or loss shows the following information
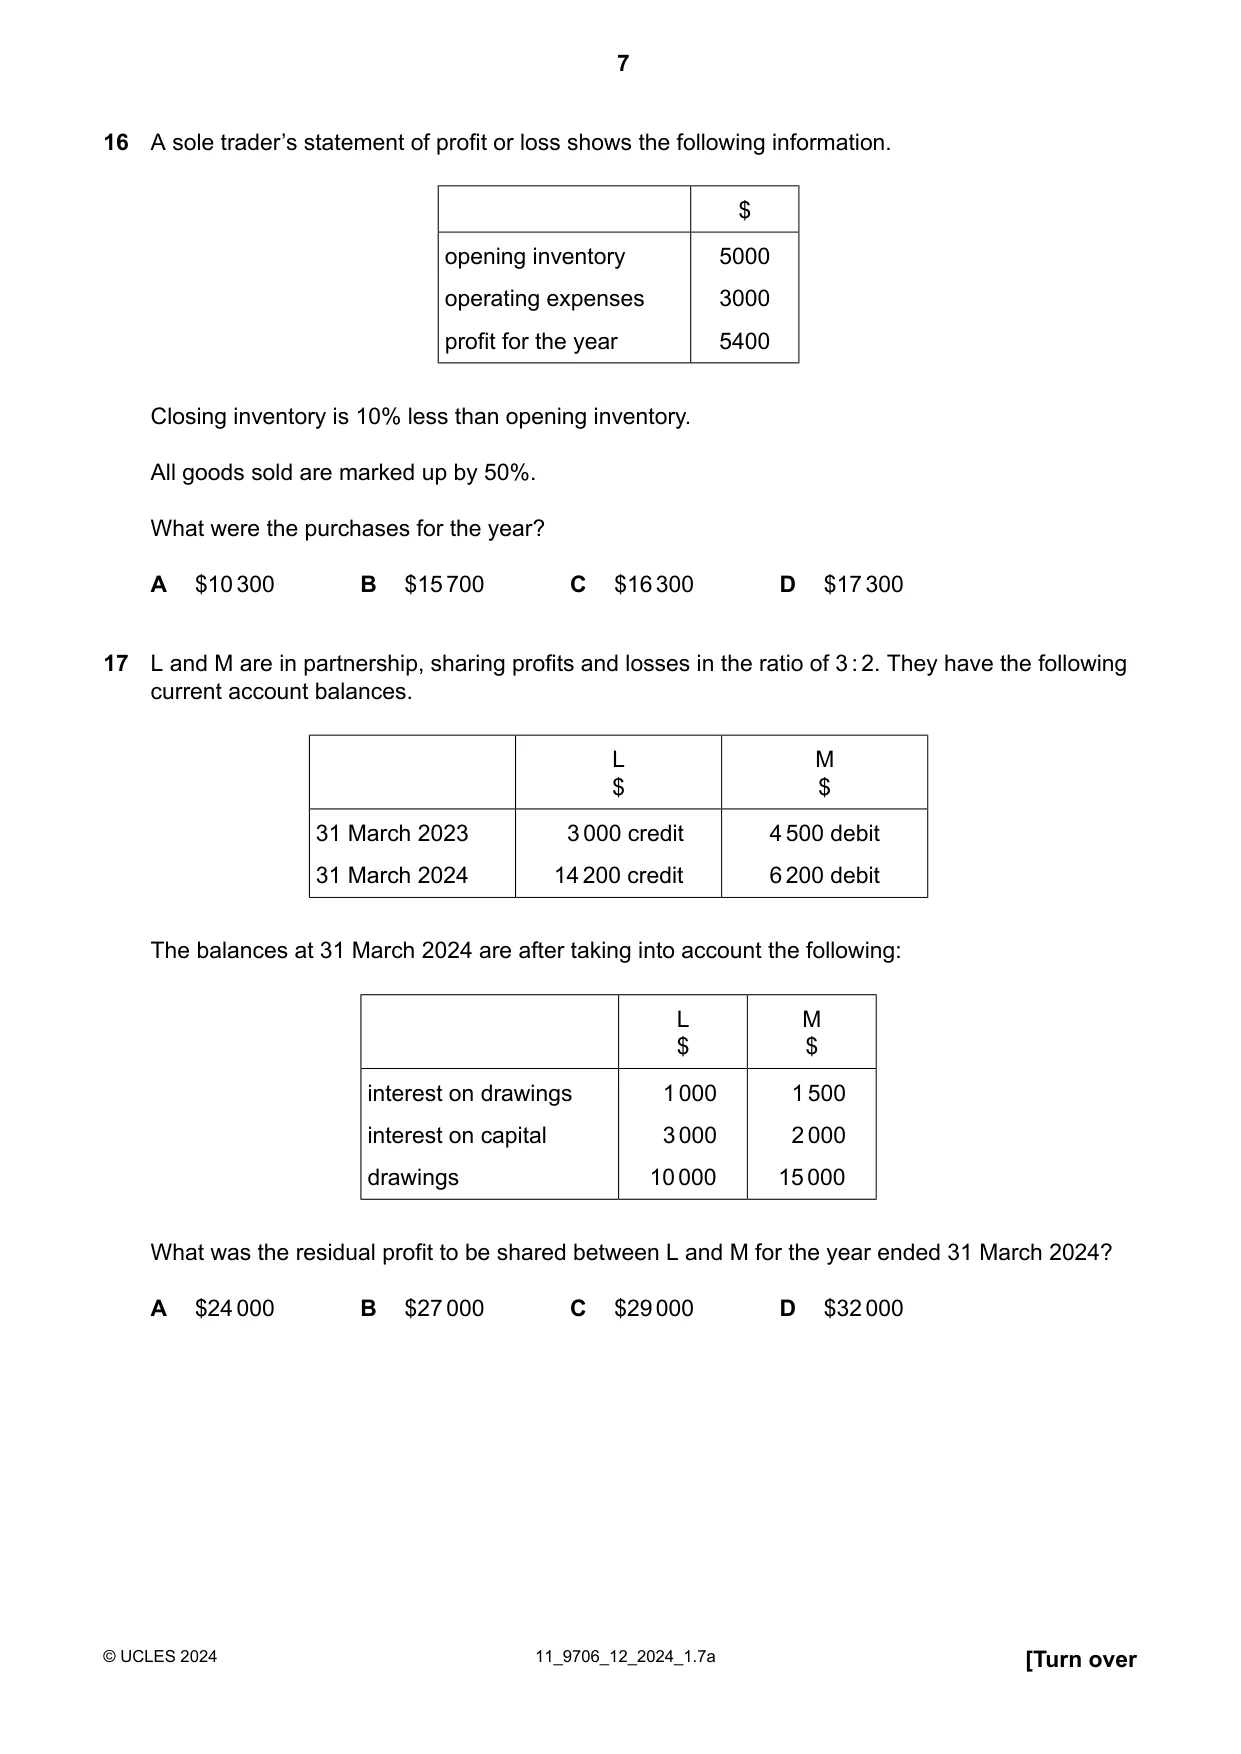
16 A sole trader’s statement of profit or loss shows the following information. $ opening inventory 5000 operating expenses 3000 profit for the year 5400 Closing inventory is 10% less than opening inventory. All goods sold are marked up by 50%. What were the purchases for the year? A $10300 B $15700 C $16300 D $17300
Mark scheme: C
Q17 · L and M are in partnership, sharing profits and losses in the ratio of 3:2
17 L and M are in partnership, sharing profits and losses in the ratio of 3:2. They have the following current account balances. L M $ $ 31 March 2023 3000 credit 4500 debit 31 March 2024 14200 credit 6200 debit The balances at 31 March 2024 are after taking into account the following: L M $ $ interest on drawings 1000 1500 interest on capital 3000 2000 drawings 10000 15000 What was the residual profit to be shared between L and M for the year ended 31 March 2024? A $24000 B $27000 C $29000 D $32000
Mark scheme: D
Q18 · A company issued shares at a premium
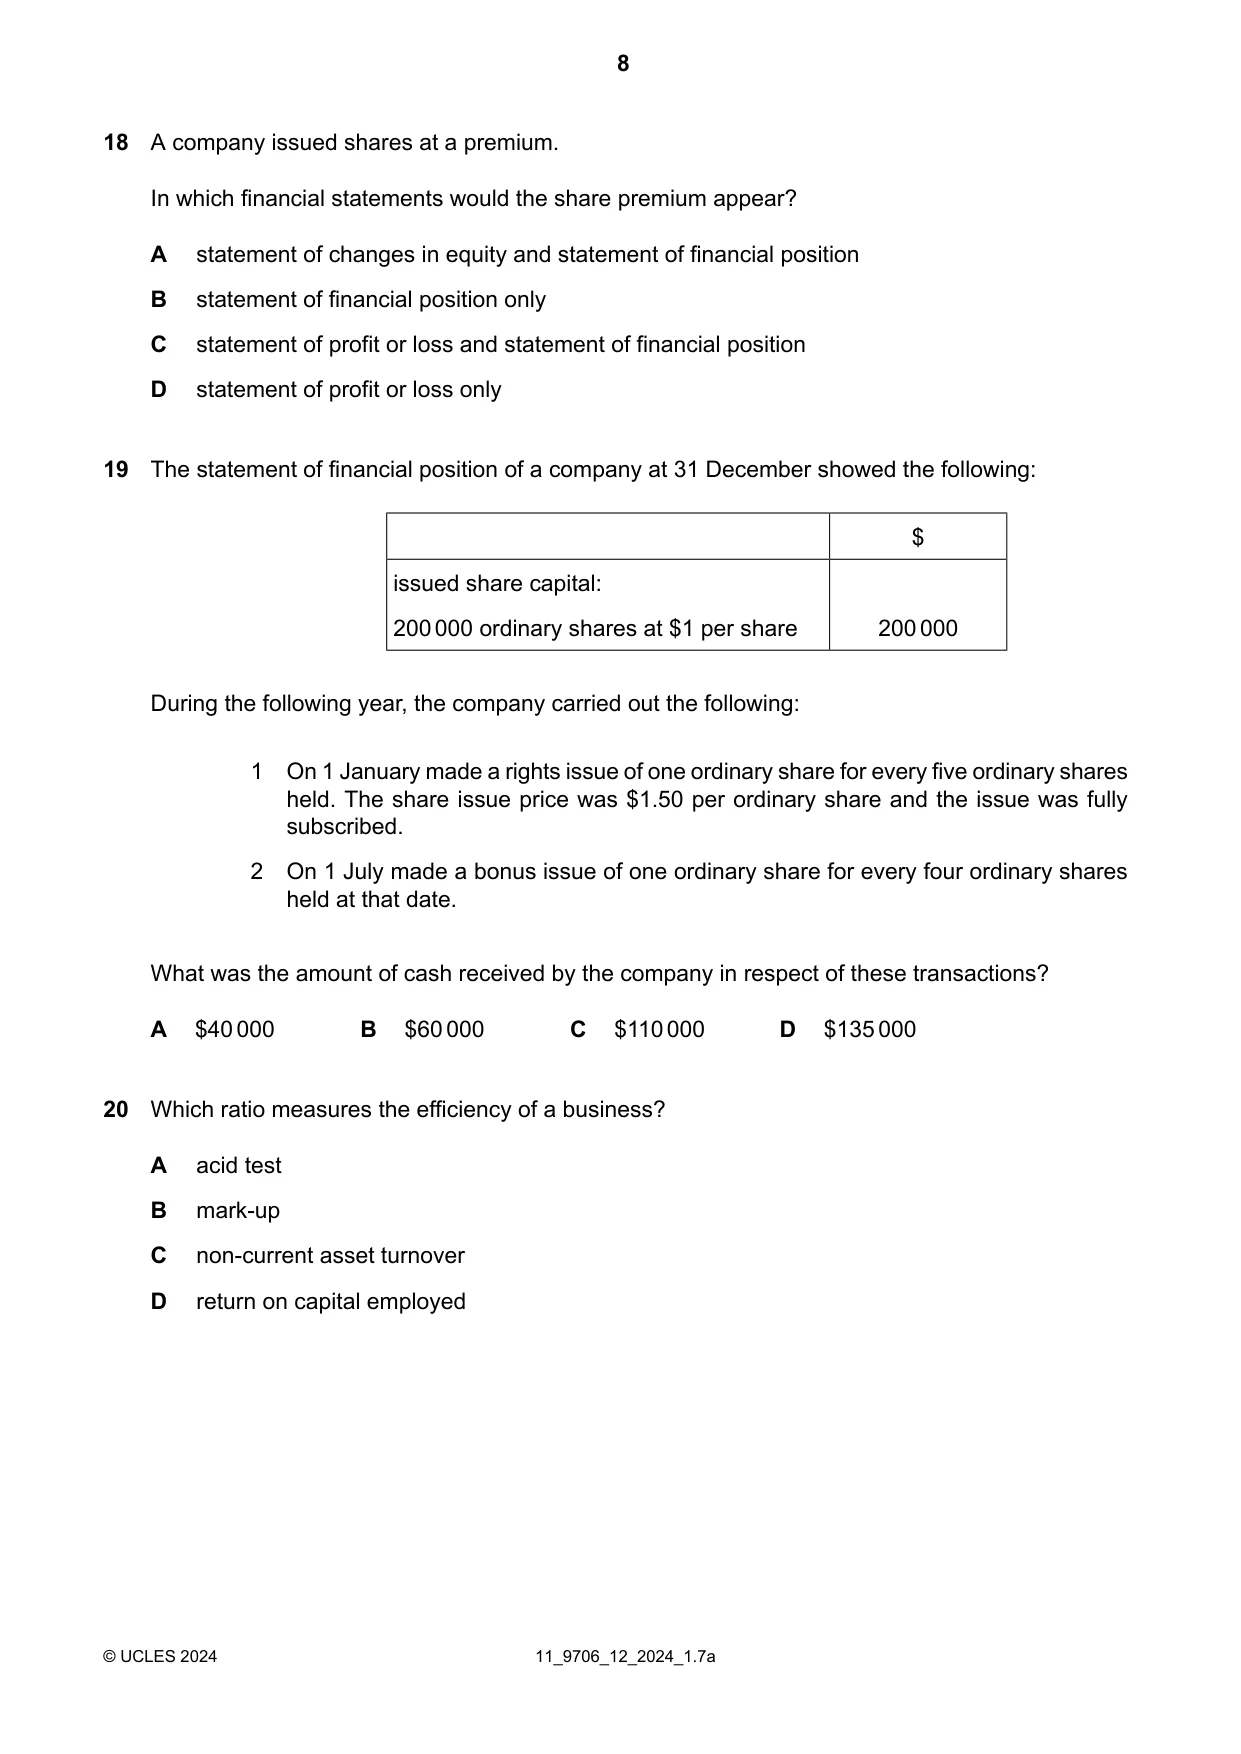
18 A company issued shares at a premium. In which financial statements would the share premium appear? A statement of changes in equity and statement of financial position B statement of financial position only C statement of profit or loss and statement of financial position D statement of profit or loss only
Mark scheme: A
Q19 · The statement of financial position of a company at 31 December showed the following: $…
19 The statement of financial position of a company at 31 December showed the following: $ issued share capital: 200000 ordinary shares at $1 per share 200000 During the following year, the company carried out the following: 1 On 1 January made a rights issue of one ordinary share for every five ordinary shares held. The share issue price was $1.50 per ordinary share and the issue was fully subscribed. 2 On 1 July made a bonus issue of one ordinary share for every four ordinary shares held at that date. What was the amount of cash received by the company in respect of these transactions? A $40000 B $60000 C $110000 D $135000
Mark scheme: B
Q20 · Which ratio measures the efficiency of a business?
20 Which ratio measures the efficiency of a business? A acid test B mark-up C non-current asset turnover D return on capital employed
Mark scheme: C
More questions on Analysis and communication of accounting information
Q21 · A company’s return on capital employed decreased to 10% in the current year from 15% in…
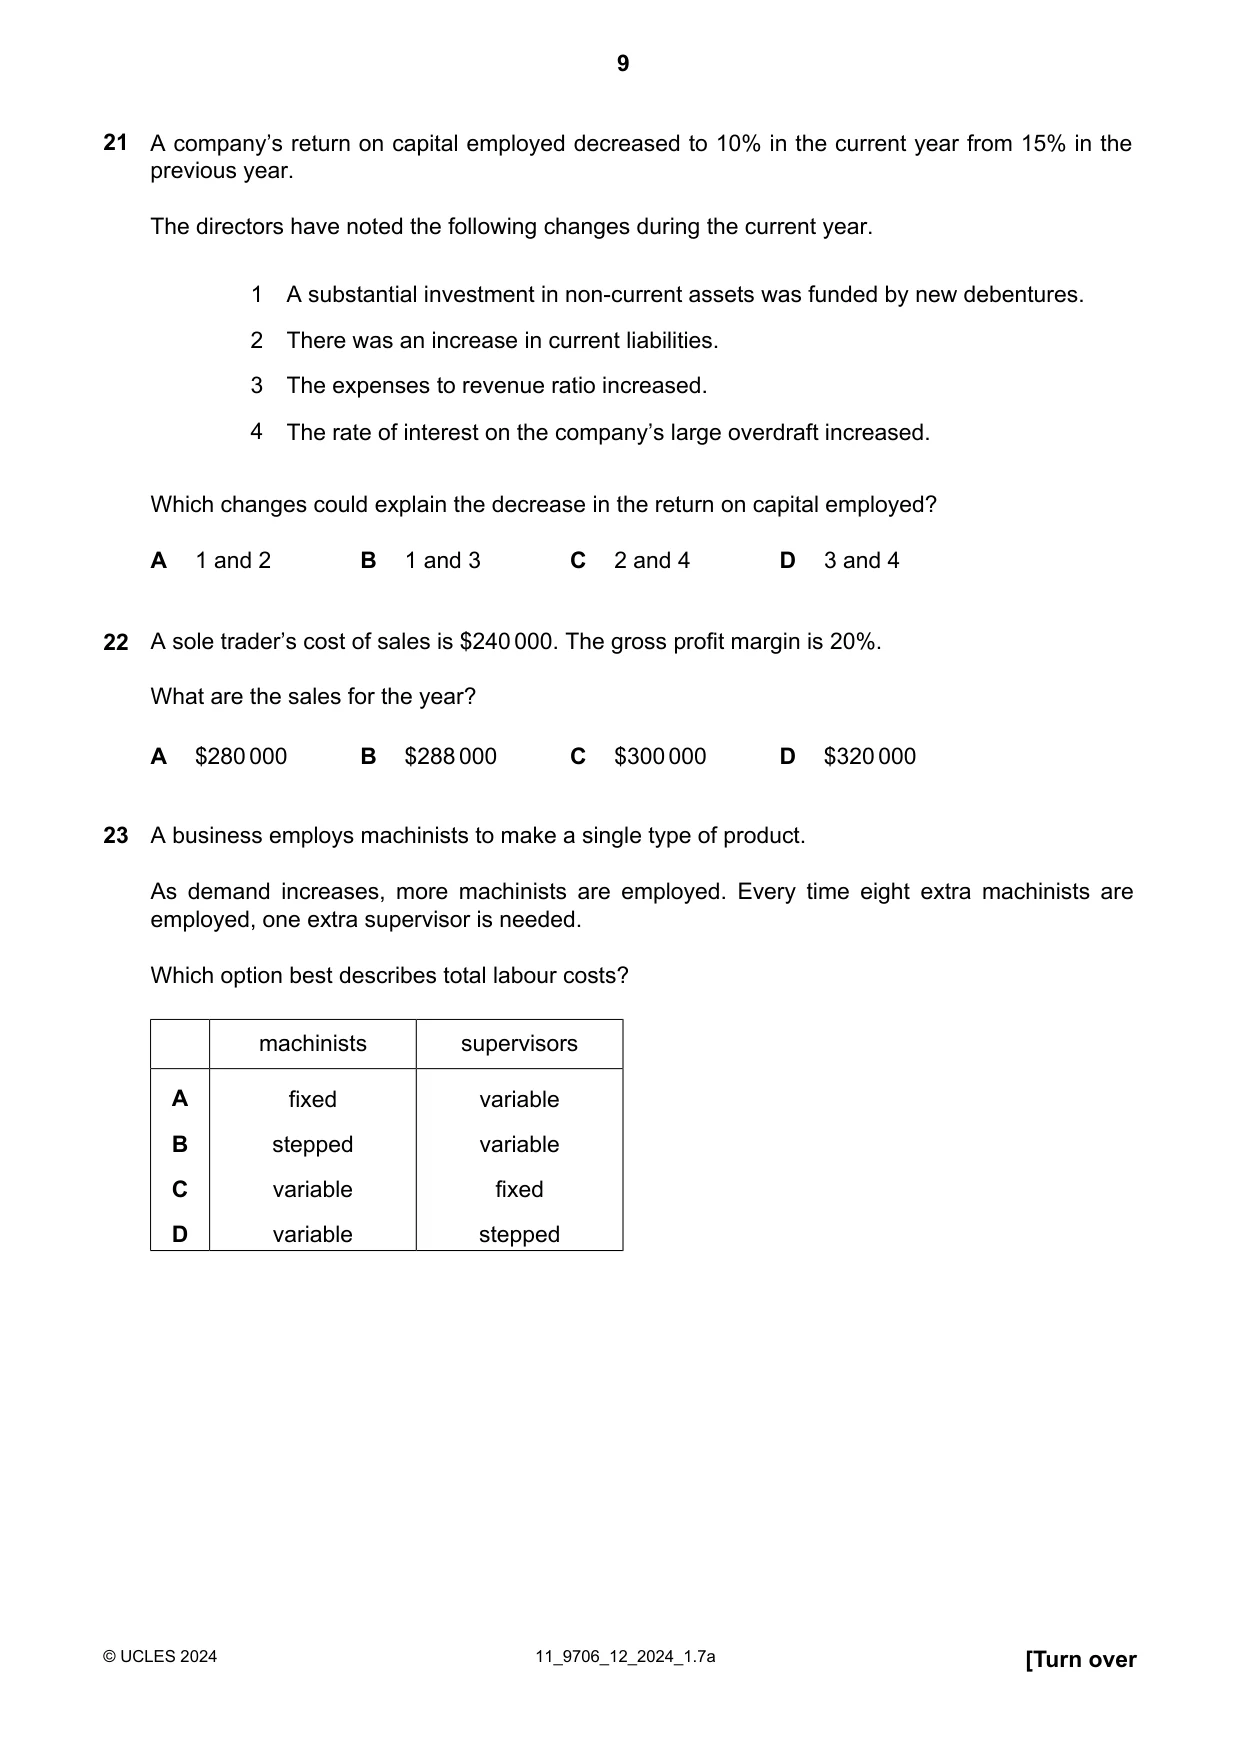
21 A company’s return on capital employed decreased to 10% in the current year from 15% in the previous year. The directors have noted the following changes during the current year. 1 A substantial investment in non-current assets was funded by new debentures. 2 There was an increase in current liabilities. 3 The expenses to revenue ratio increased. 4 The rate of interest on the company’s large overdraft increased. Which changes could explain the decrease in the return on capital employed? A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
Mark scheme: B
More questions on Analysis and communication of accounting information
Q22 · A sole trader’s cost of sales is $240 000
22 A sole trader’s cost of sales is $240 000. The gross profit margin is 20%. What are the sales for the year? A $280000 B $288000 C $300000 D $320000
Mark scheme: C
More questions on Analysis and communication of accounting information
Q23 · A business employs machinists to make a single type of product
23 A business employs machinists to make a single type of product. As demand increases, more machinists are employed. Every time eight extra machinists are employed, one extra supervisor is needed. Which option best describes total labour costs? machinists supervisors A fixed variable B stepped variable C variable fixed D variable stepped
Mark scheme: D
Q24 · The inventory movements of a business in a three-month period are shown
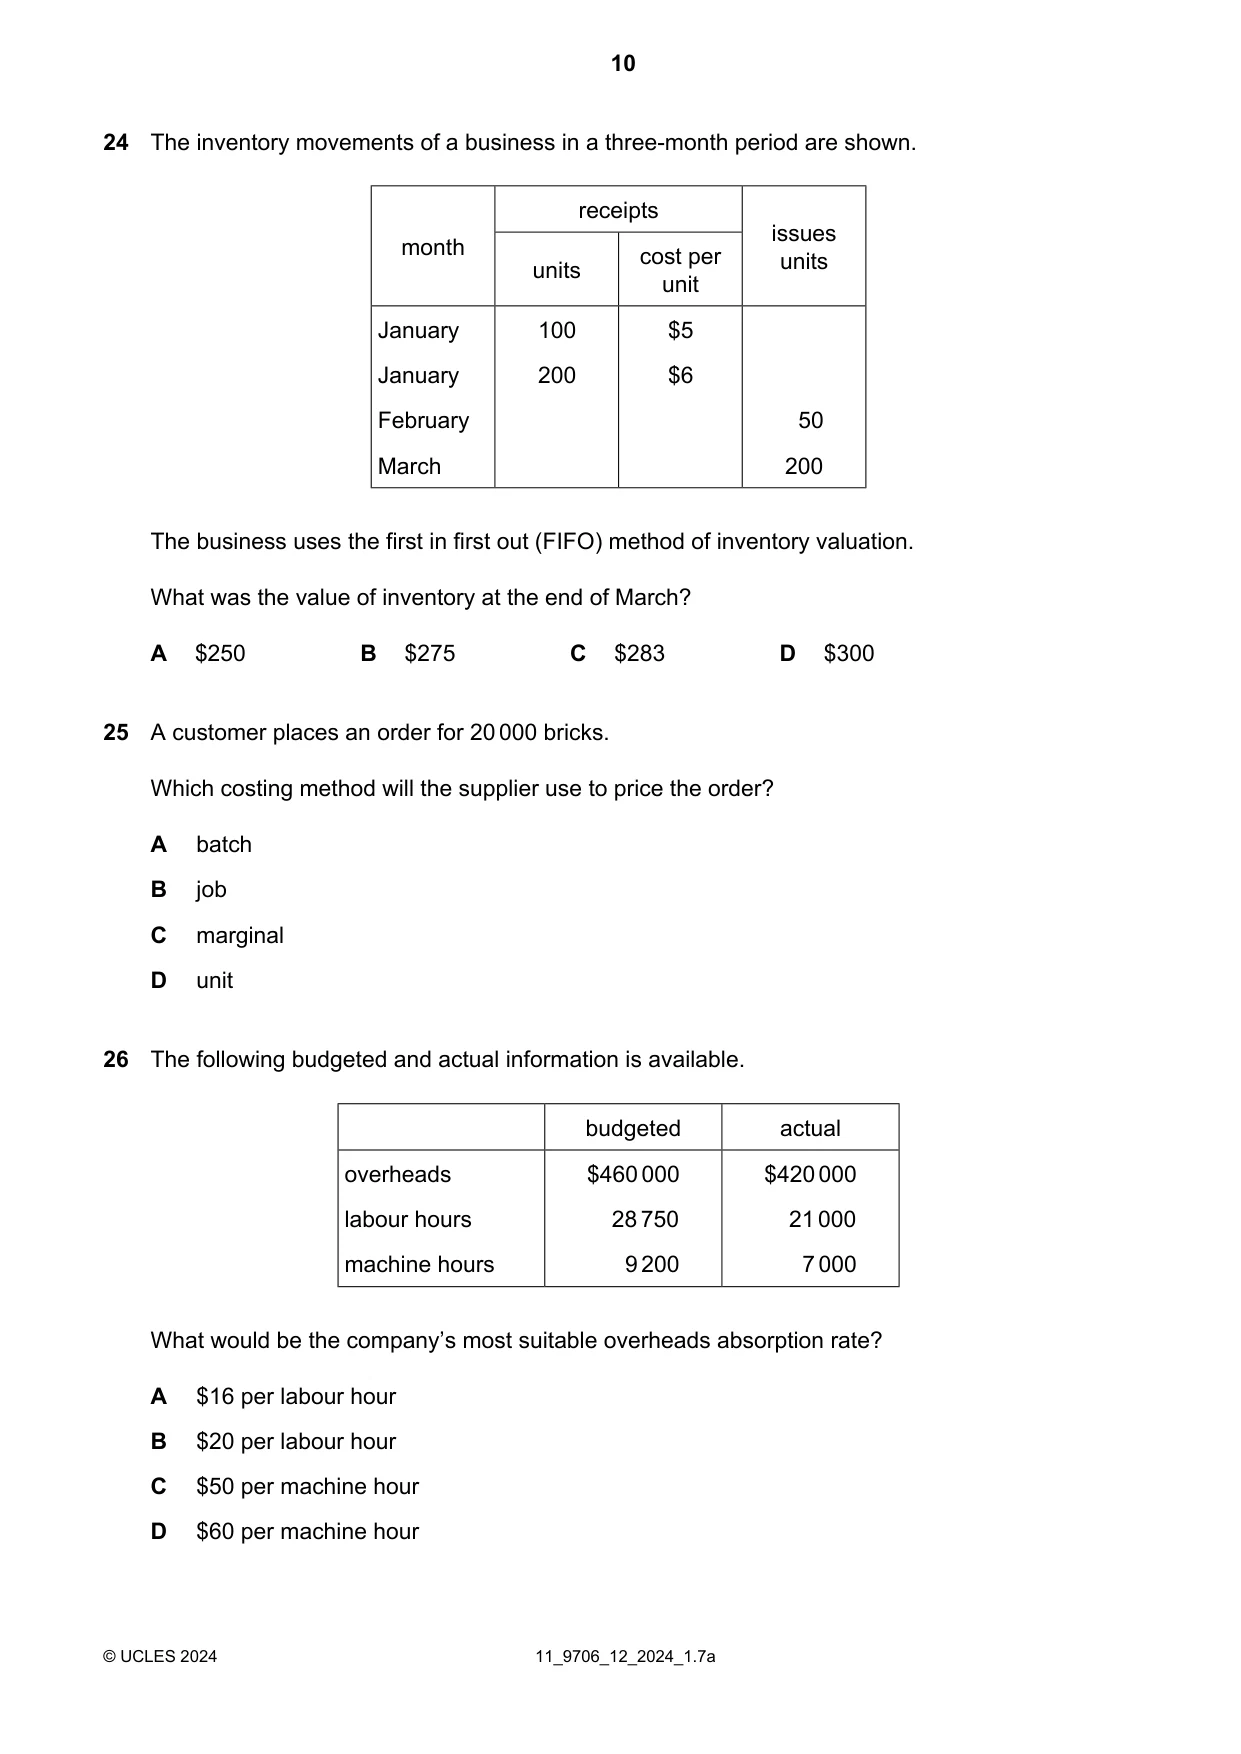
24 The inventory movements of a business in a three-month period are shown. receipts issues month cost per units units unit January 100 $5 January 200 $6 February 50 March 200 The business uses the first in first out (FIFO) method of inventory valuation. What was the value of inventory at the end of March? A $250 B $275 C $283 D $300
Mark scheme: D
Q25 · A customer places an order for 20000 bricks
25 A customer places an order for 20000 bricks. Which costing method will the supplier use to price the order? A batch B job C marginal D unit
Mark scheme: A
Q26 · The following budgeted and actual information is available
26 The following budgeted and actual information is available. budgeted actual overheads $460000 $420000 labour hours 28750 21000 machine hours 9200 7000 What would be the company’s most suitable overheads absorption rate? A $16 per labour hour B $20 per labour hour C $50 per machine hour D $60 per machine hour
Mark scheme: A
Q27 · The following information is available from the costing records
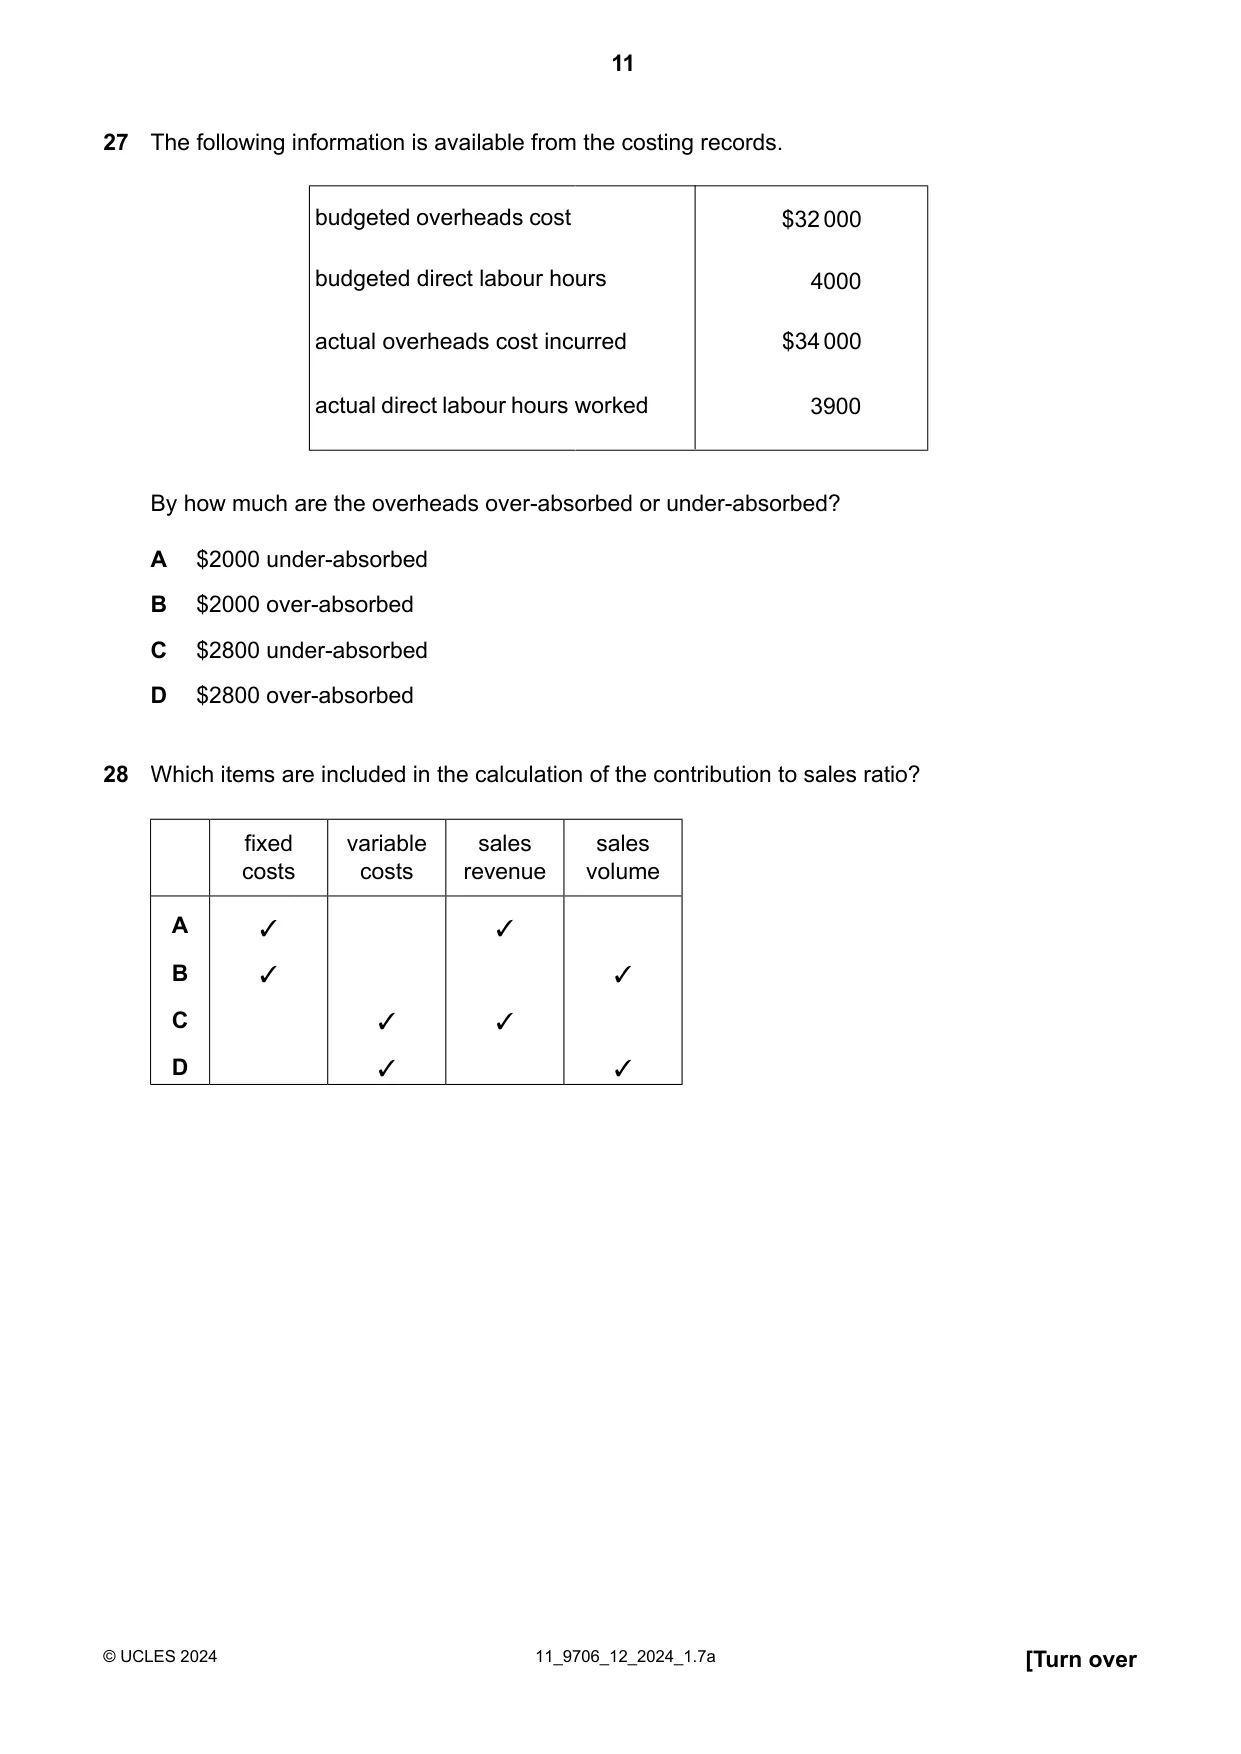
27 The following information is available from the costing records. budgeted overheads cost $32000 budgeted direct labour hours 4000 actual overheads cost incurred $34 000 actual direct labour hours worked 3900 By how much are the overheads over-absorbed or under-absorbed? A $2000 under-absorbed B $2000 over-absorbed C $2800 under-absorbed D $2800 over-absorbed
Mark scheme: C
Q28 · Which items are included in the calculation of the contribution to sales ratio?
28 Which items are included in the calculation of the contribution to sales ratio? fixed variable sales sales costs costs revenue volume A ✓ ✓ B ✓ ✓ C ✓ ✓ D ✓ ✓
Mark scheme: C
Q29 · The financial information for selling 6000 units in August was as follows: $ per unit…
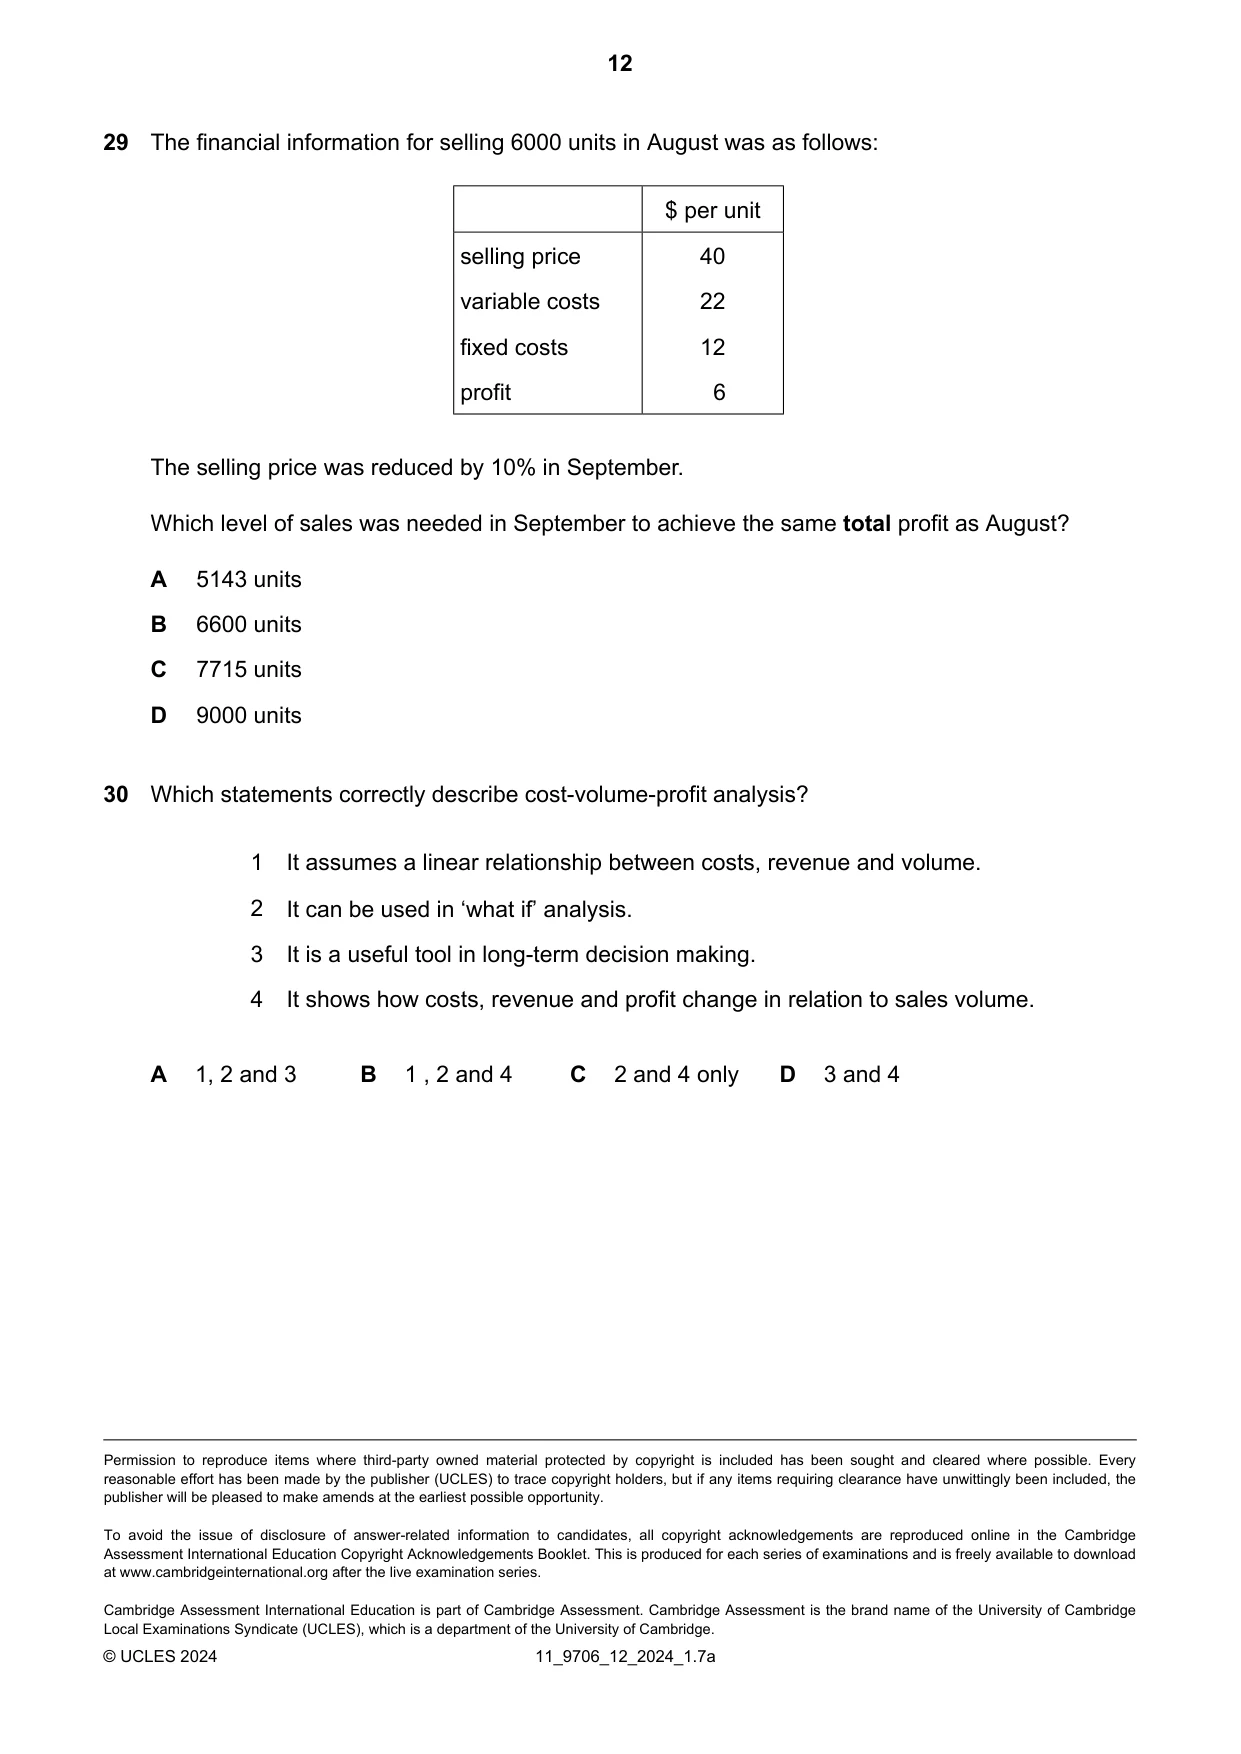
29 The financial information for selling 6000 units in August was as follows: $ per unit selling price 40 variable costs 22 fixed costs 12 profit 6 The selling price was reduced by 10% in September. Which level of sales was needed in September to achieve the same total profit as August? A 5143 units B 6600 units C 7715 units D 9000 units
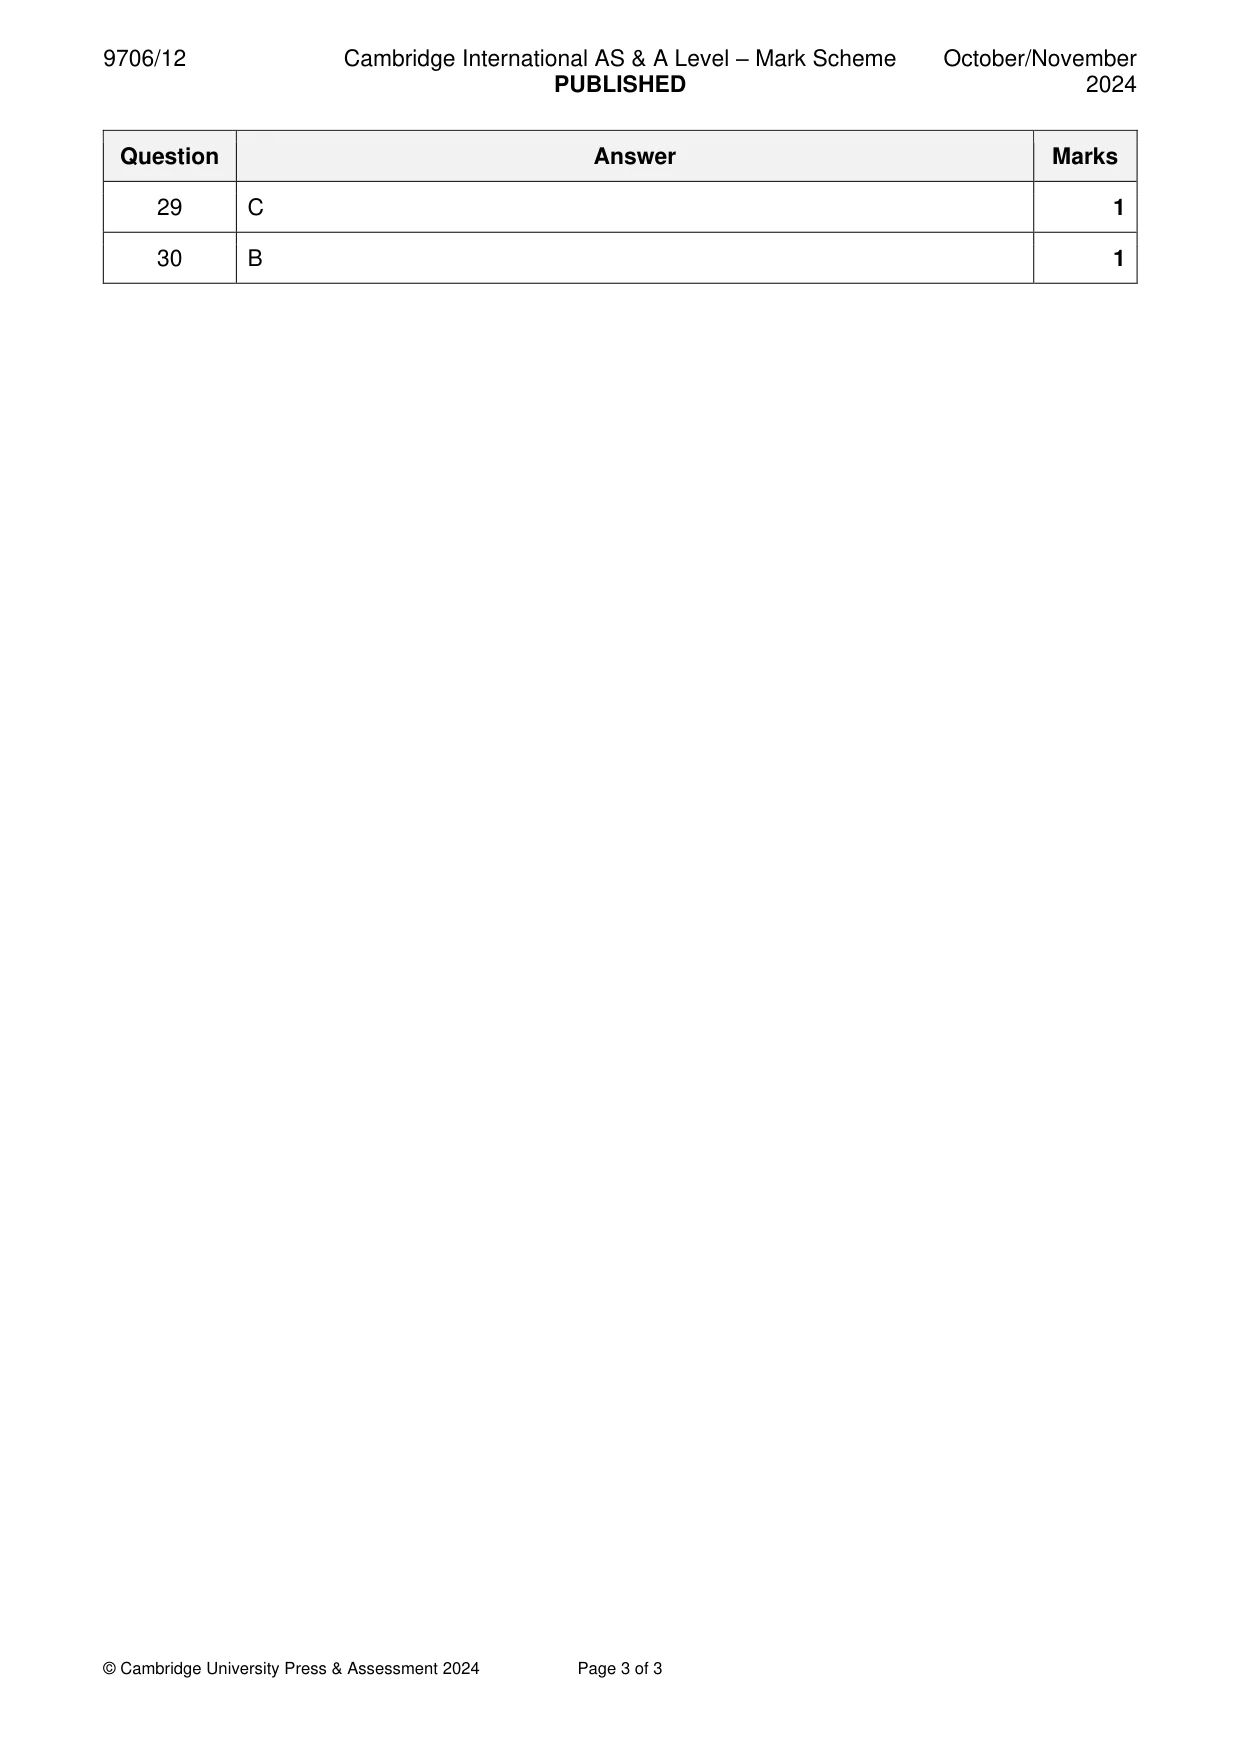
Mark scheme: C
Q30 · Which statements correctly describe cost-volume-profit analysis?
30 Which statements correctly describe cost-volume-profit analysis? 1 It assumes a linear relationship between costs, revenue and volume. 2 It can be used in ‘what if’ analysis. 3 It is a useful tool in long-term decision making. 4 It shows how costs, revenue and profit change in relation to sales volume. A 1, 2 and 3 B 1 , 2 and 4 C 2 and 4 only D 3 and 4
Mark scheme: B
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
6Reconciliation and verification6Costs and cost behaviour4Traditional costing methods4Accounting for non-current assets2Analysis and communication of accounting information2Preparation of financial statements2The accounting system2Analysis and communication of accounting information1Computerised accounting systems1What you needed in this session
Cambridge’s own grade thresholds for 2024 Oct/Nov, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.