Cambridge A Level Accounting 9706 — 2023 Oct/Nov Paper 1 · Variant 3
9706/13/O/N/23 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
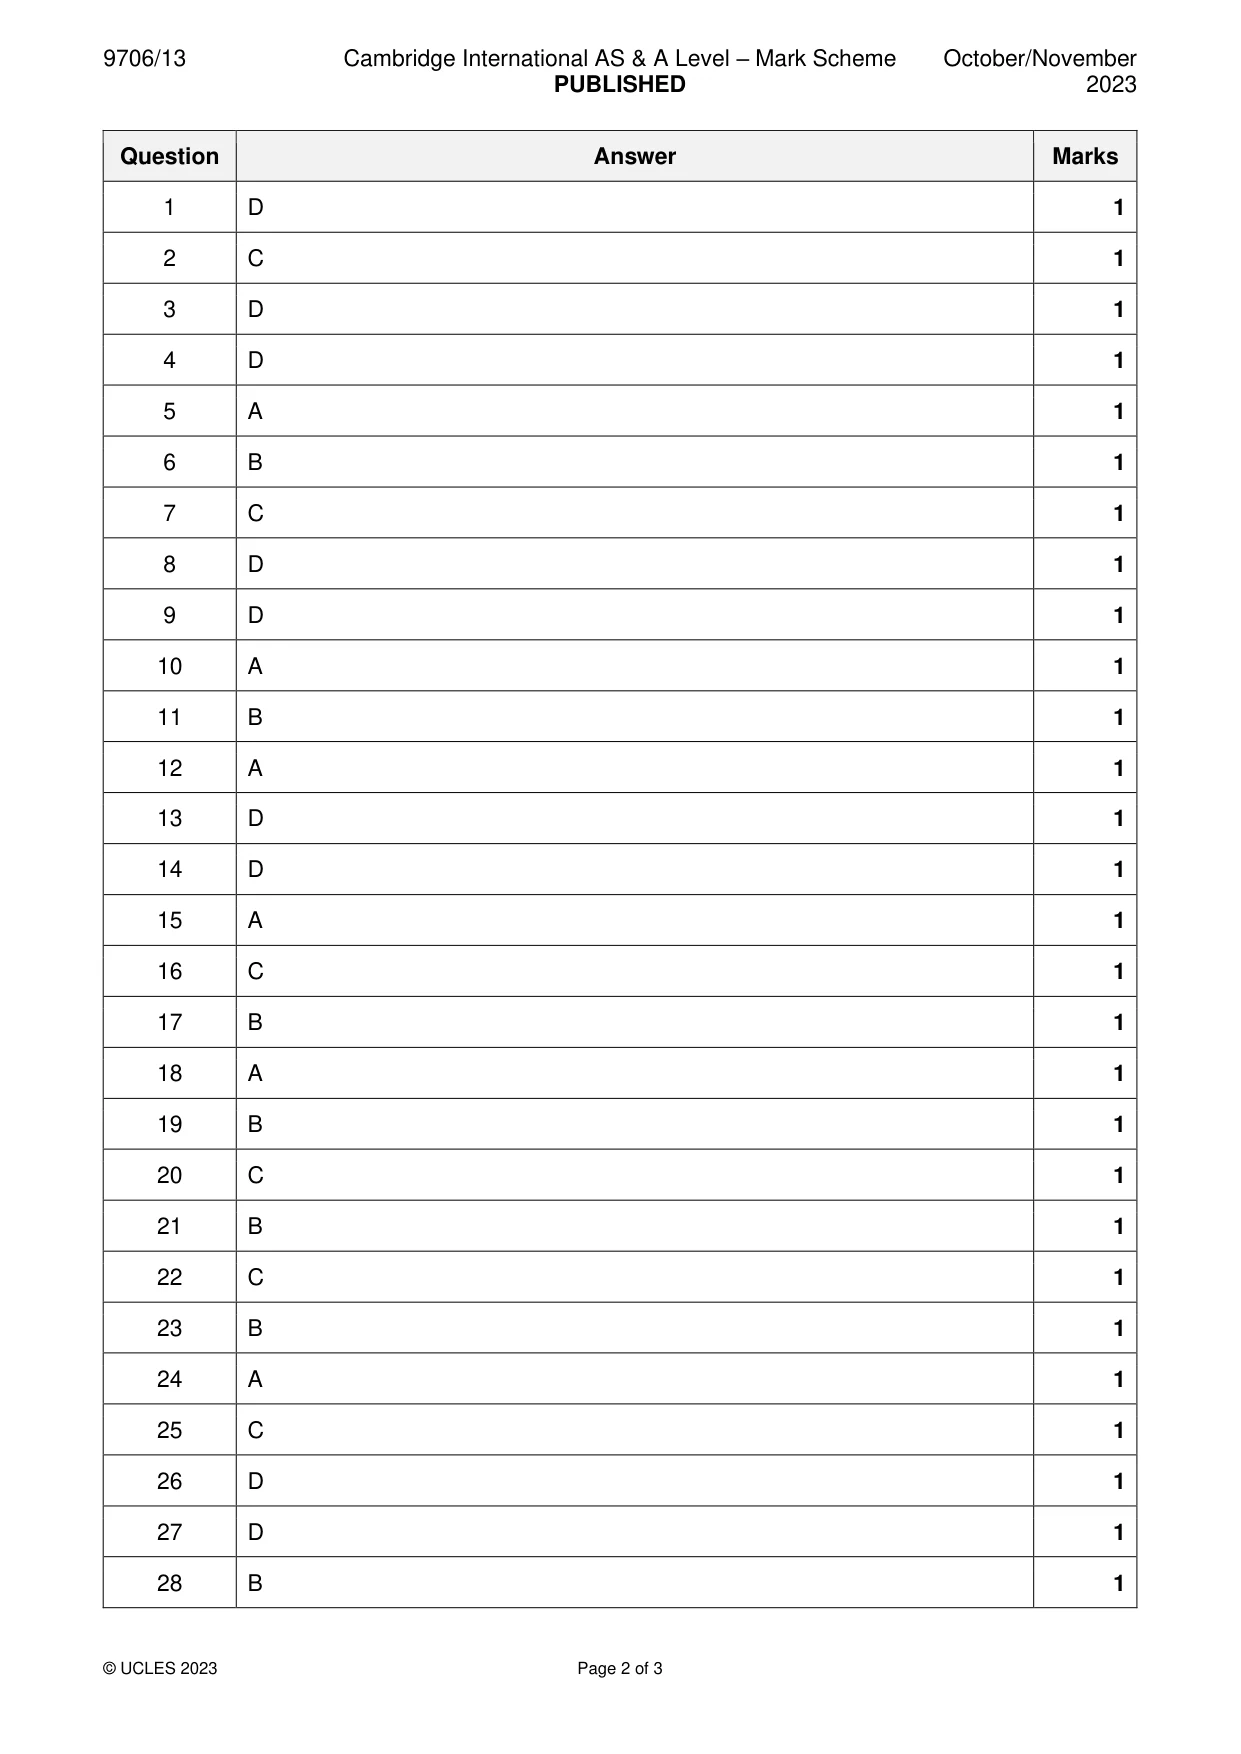
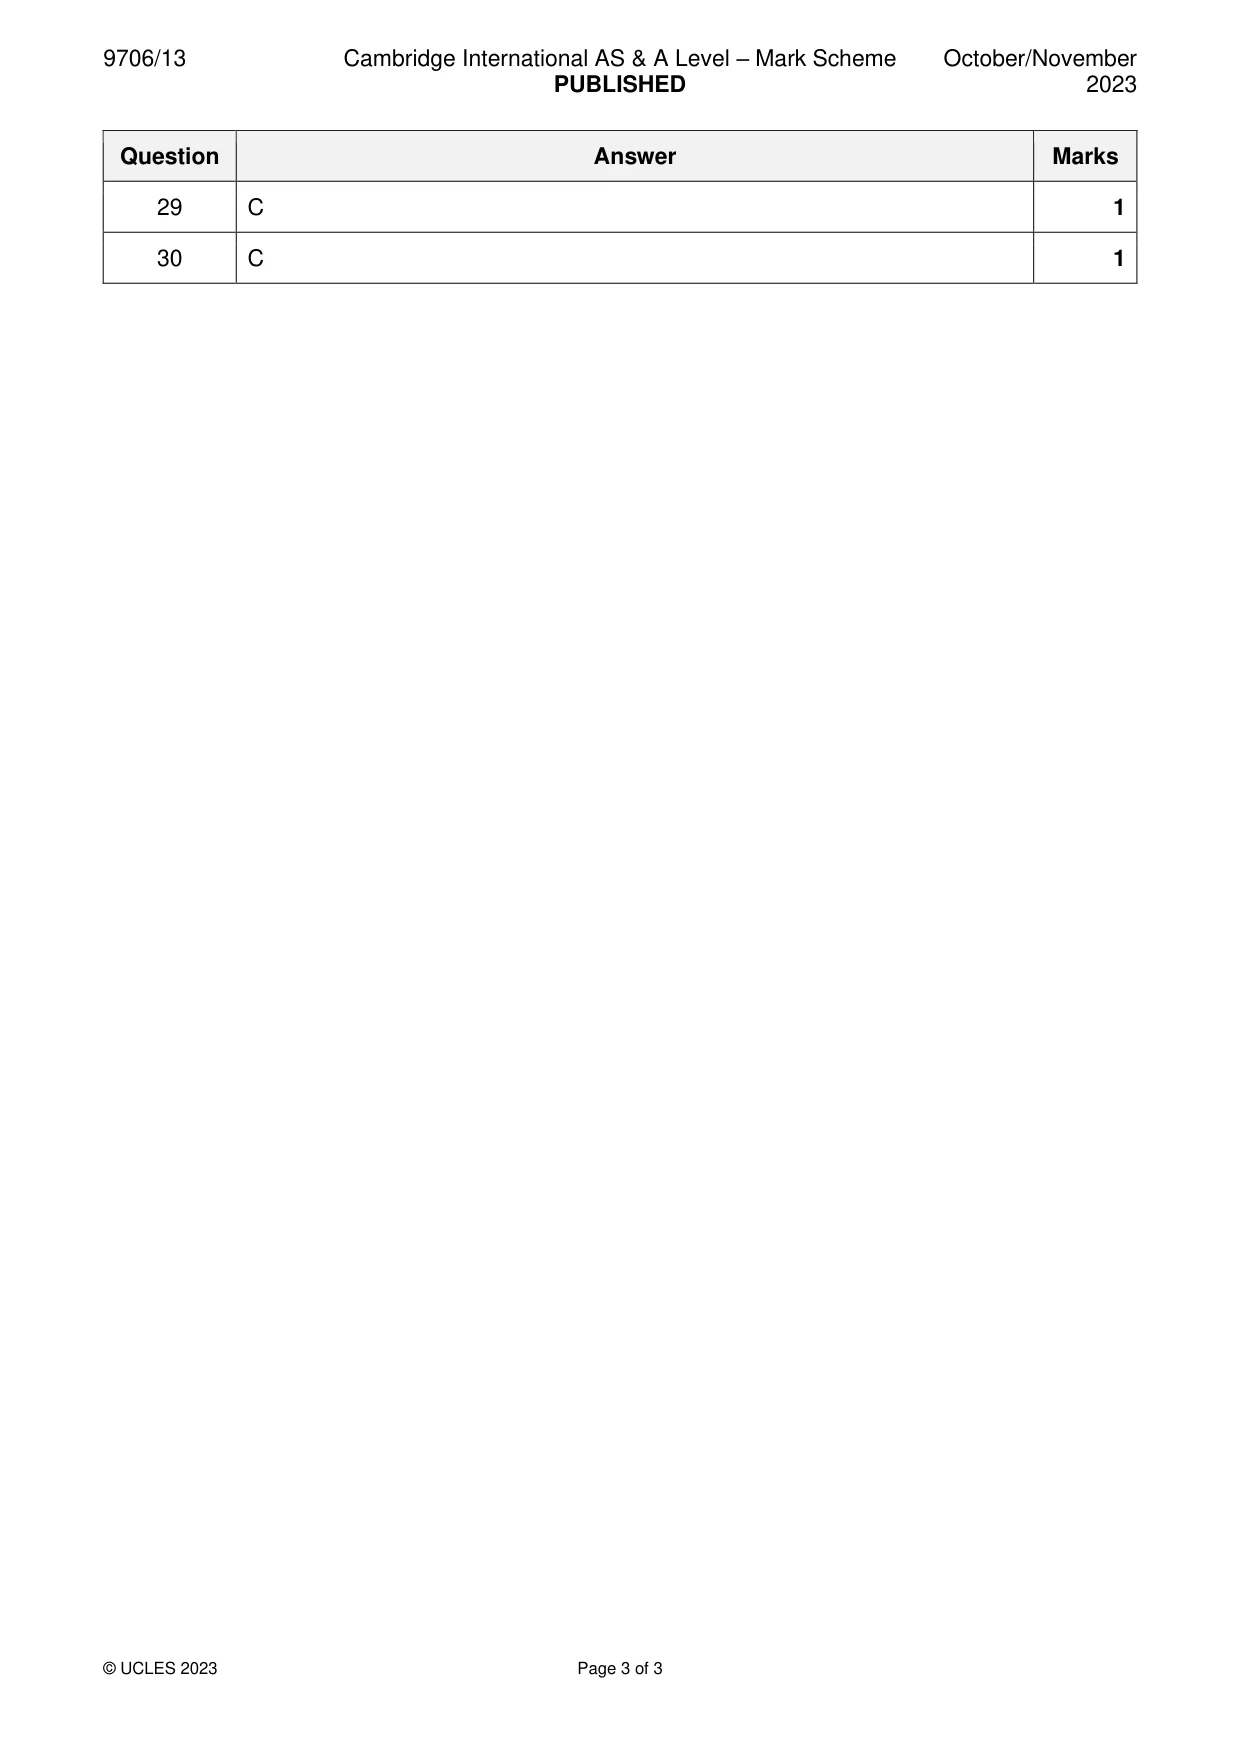
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Inventories are valued at the lower of cost and net realisable value in the statement of…
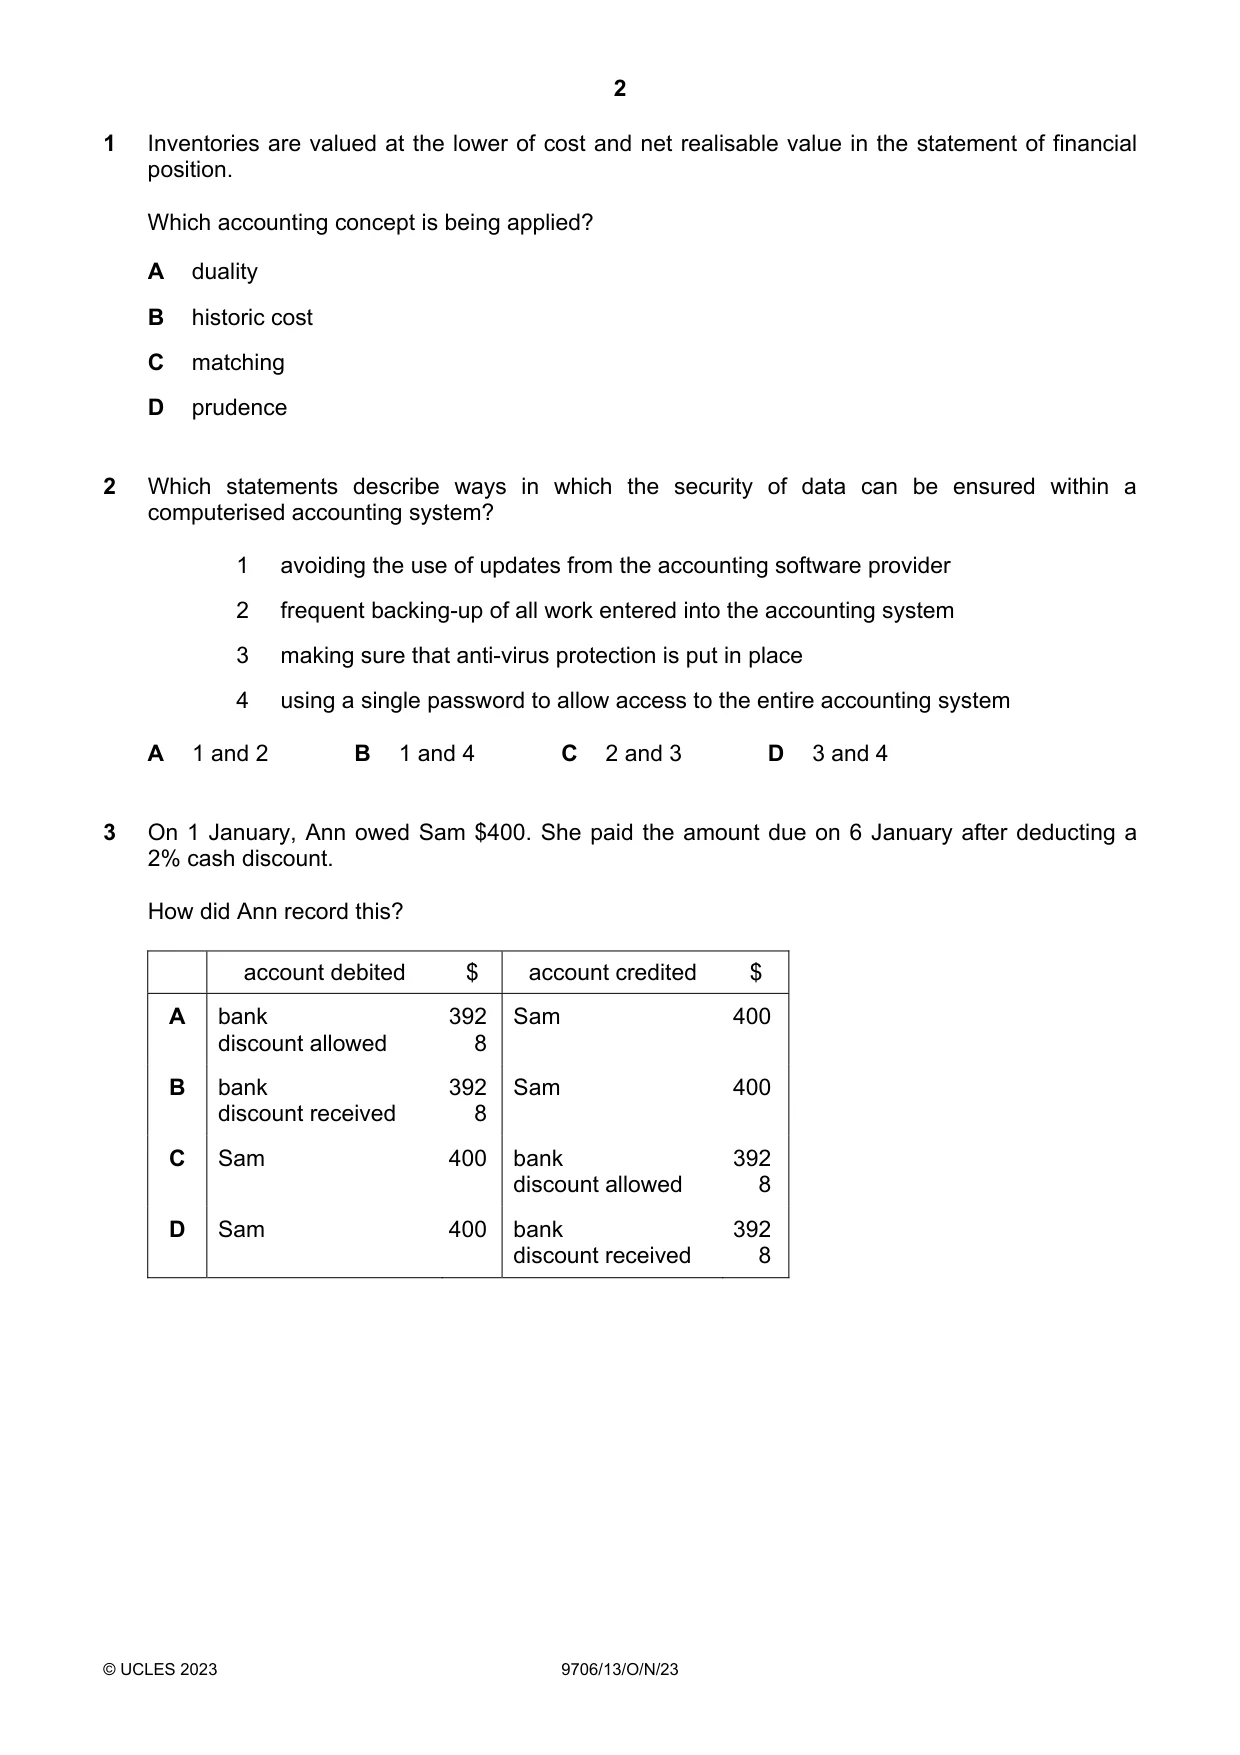
1 Inventories are valued at the lower of cost and net realisable value in the statement of financial position. Which accounting concept is being applied? A duality B historic cost C matching D prudence
Mark scheme: D
Q2 · Which statements describe ways in which the security of data can be ensured within a…
2 Which statements describe ways in which the security of data can be ensured within a computerised accounting system? 1 avoiding the use of updates from the accounting software provider 2 frequent backing-up of all work entered into the accounting system 3 making sure that anti-virus protection is put in place 4 using a single password to allow access to the entire accounting system A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
Mark scheme: C
Q3 · On 1 January, Ann owed Sam $400
3 On 1 January, Ann owed Sam $400. She paid the amount due on 6 January after deducting a 2% cash discount. How did Ann record this? account debited $ account credited $ A bank 392 Sam 400 discount allowed 8 B bank 392 Sam 400 discount received 8 C Sam 400 bank 392 discount allowed 8 D Sam 400 bank 392 discount received 8
Mark scheme: D
Q4 · An improvement to business premises has been incorrectly treated as an expense in the…
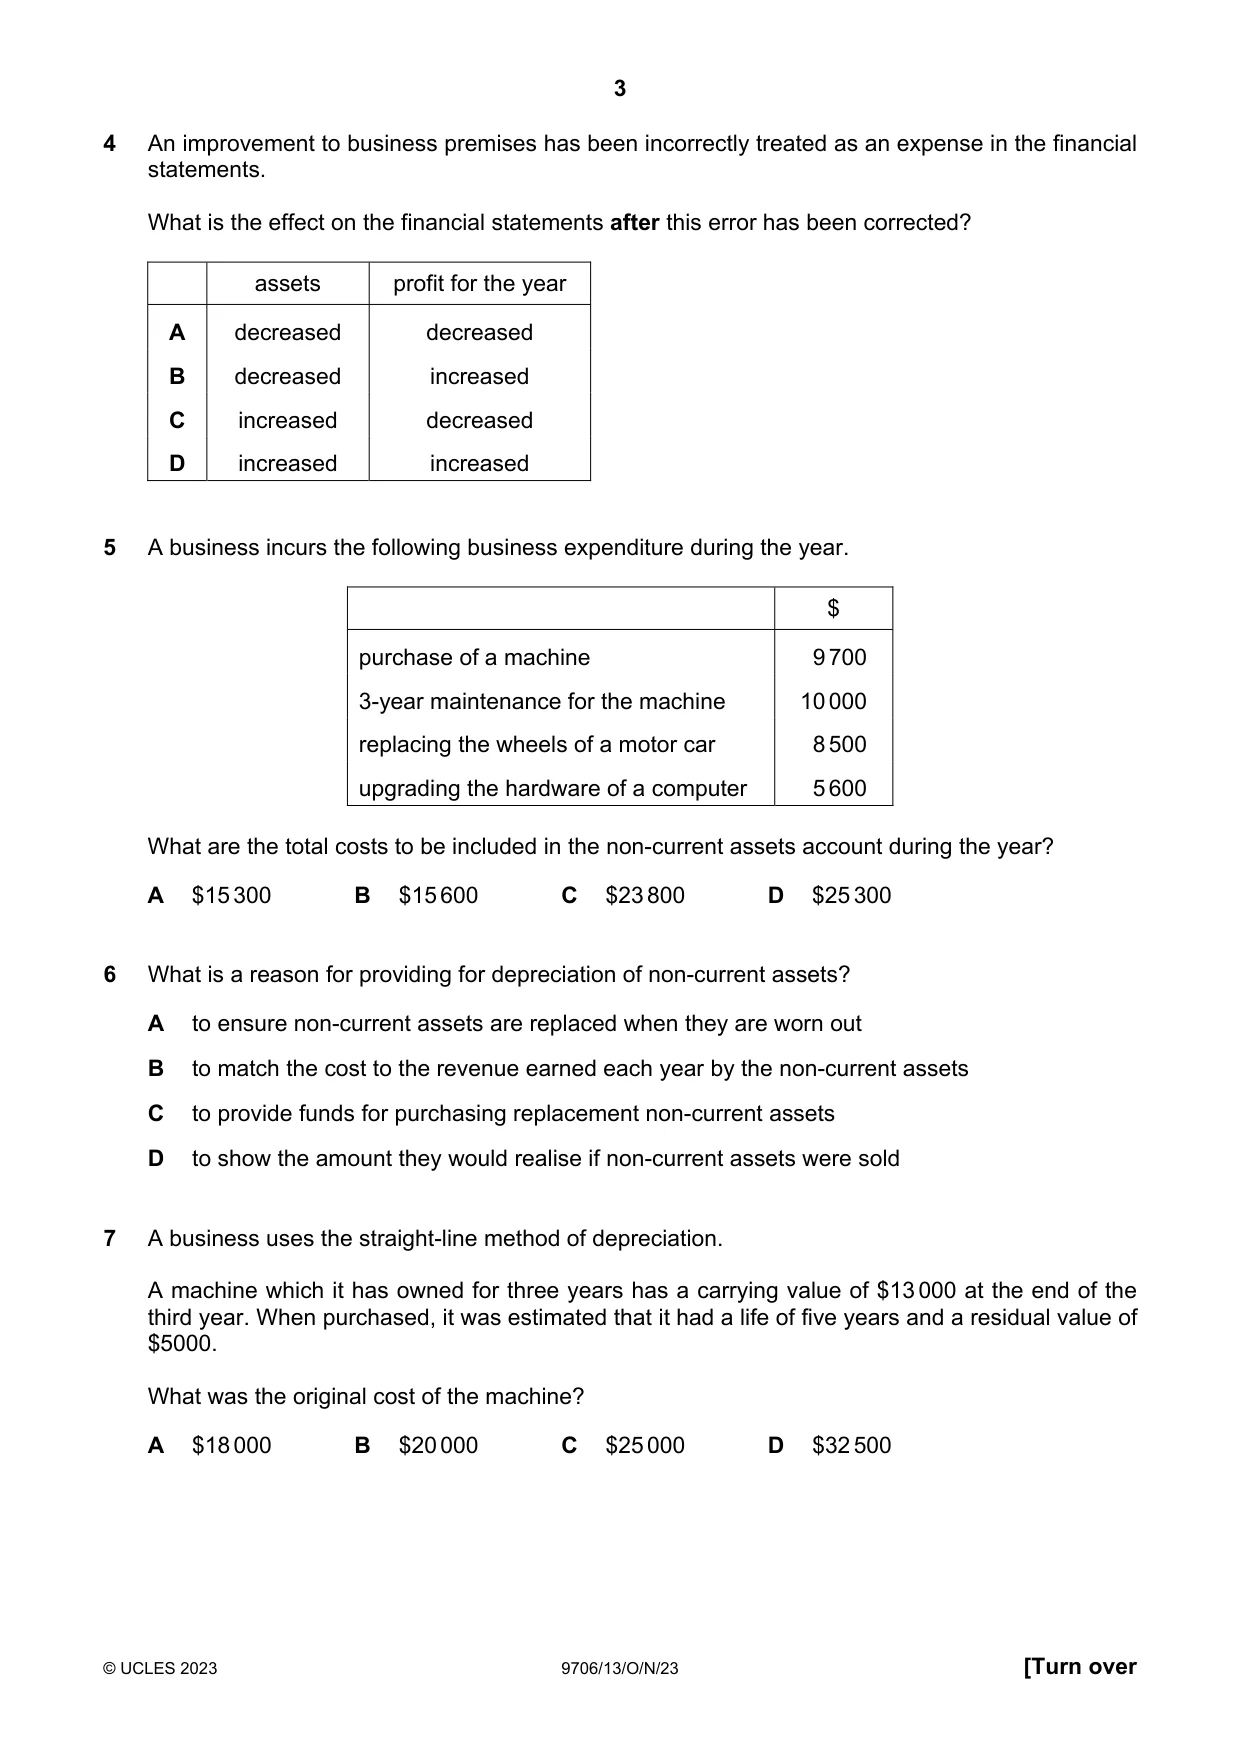
4 An improvement to business premises has been incorrectly treated as an expense in the financial statements. What is the effect on the financial statements after this error has been corrected? assets profit for the year A decreased decreased B decreased increased C increased decreased D increased increased
Mark scheme: D
Q5 · A business incurs the following business expenditure during the year
5 A business incurs the following business expenditure during the year. $ purchase of a machine 9 700 3-year maintenance for the machine 10 000 replacing the wheels of a motor car 8 500 upgrading the hardware of a computer 5 600 What are the total costs to be included in the non-current assets account during the year? A $15 300 B $15 600 C $23 800 D $25 300
Mark scheme: A
Q6 · What is a reason for providing for depreciation of non-current assets?
6 What is a reason for providing for depreciation of non-current assets? A to ensure non-current assets are replaced when they are worn out B to match the cost to the revenue earned each year by the non-current assets C to provide funds for purchasing replacement non-current assets D to show the amount they would realise if non-current assets were sold
Mark scheme: B
Q7 · A business uses the straight-line method of depreciation
7 A business uses the straight-line method of depreciation. A machine which it has owned for three years has a carrying value of $13 000 at the end of the third year. When purchased, it was estimated that it had a life of five years and a residual value of $5000. What was the original cost of the machine? A $18 000 B $20 000 C $25 000 D $32 500
Mark scheme: C
Q8 · Sammy paid a credit supplier $190 in full settlement of a debt of $200
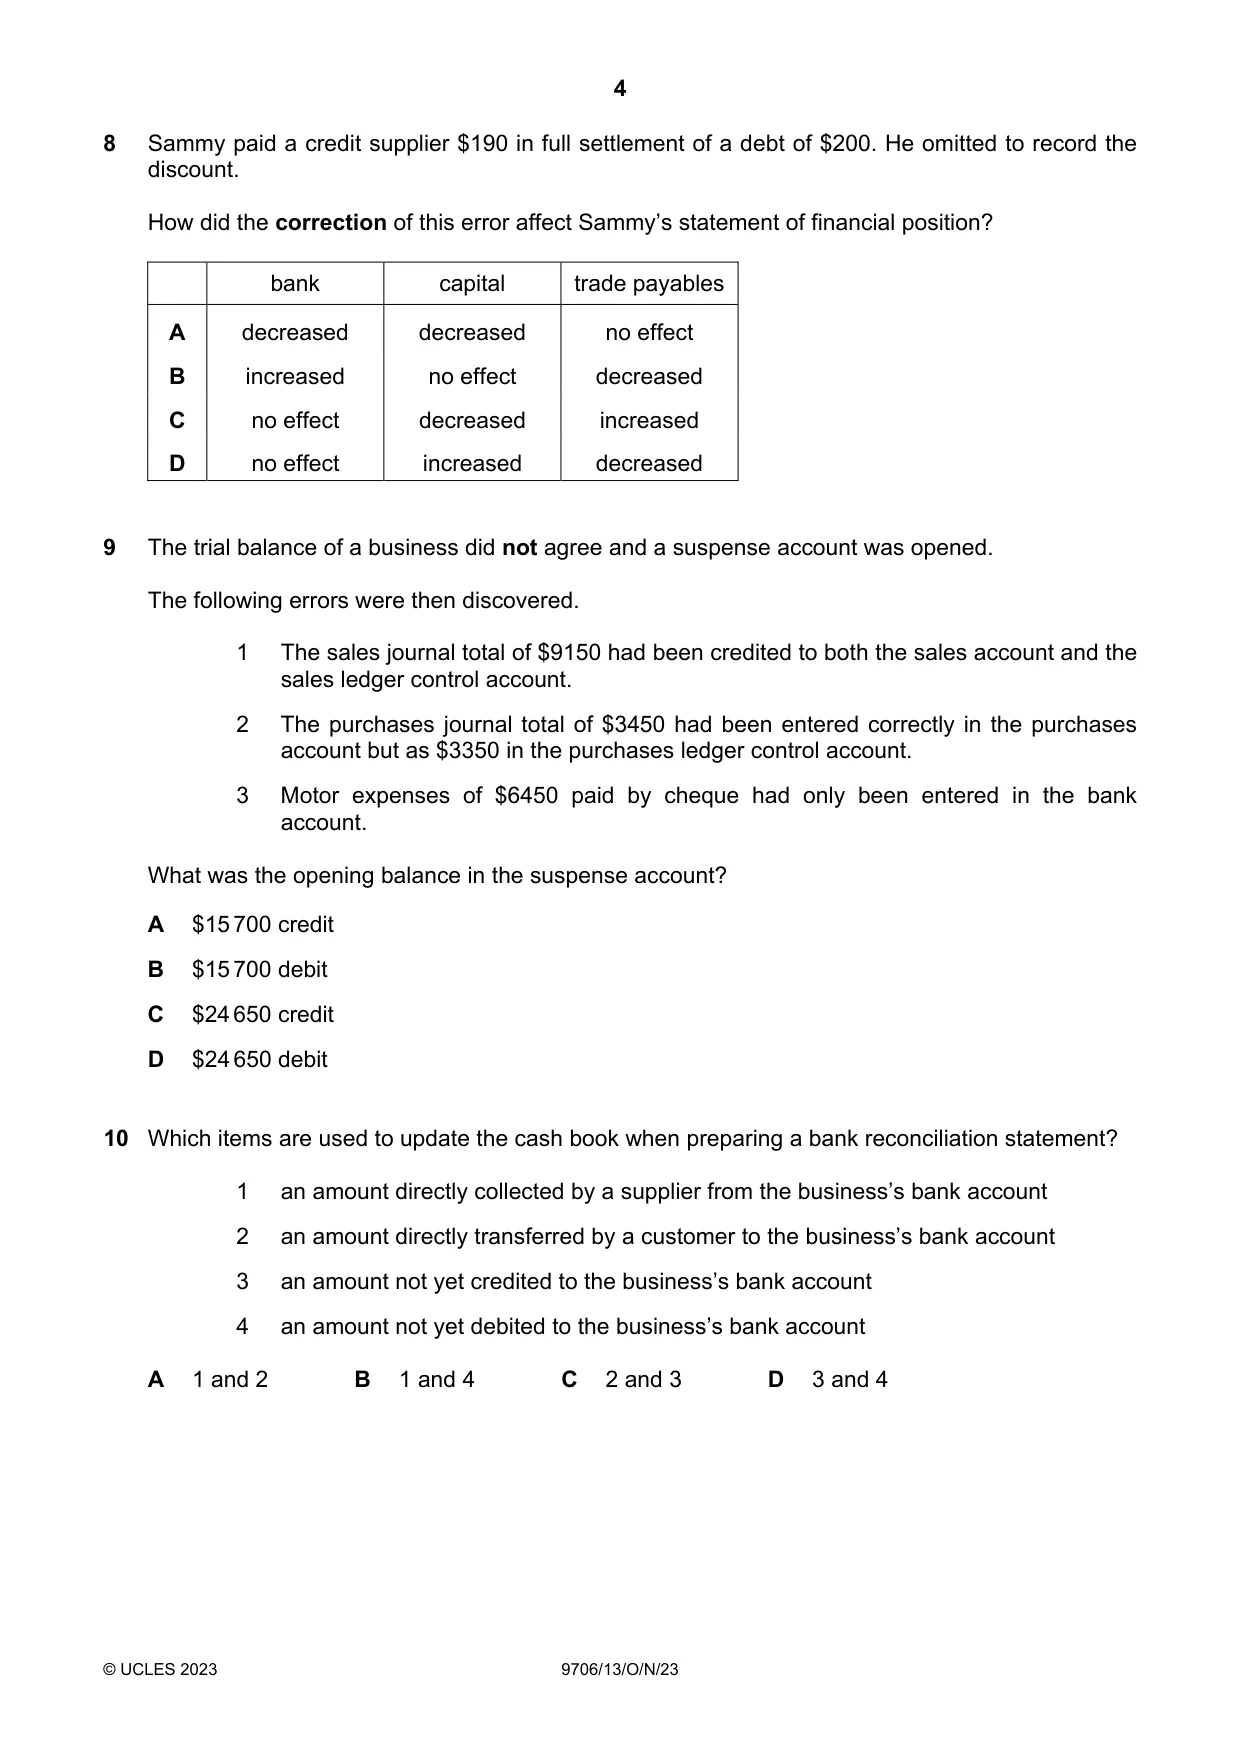
8 Sammy paid a credit supplier $190 in full settlement of a debt of $200. He omitted to record the discount. How did the correction of this error affect Sammy’s statement of financial position? bank capital trade payables A decreased decreased no effect B increased no effect decreased C no effect decreased increased D no effect increased decreased
Mark scheme: D
Q9 · The trial balance of a business did not agree and a suspense account was opened
9 The trial balance of a business did not agree and a suspense account was opened. The following errors were then discovered. 1 The sales journal total of $9150 had been credited to both the sales account and the sales ledger control account. 2 The purchases journal total of $3450 had been entered correctly in the purchases account but as $3350 in the purchases ledger control account. 3 Motor expenses of $6450 paid by cheque had only been entered in the bank account. What was the opening balance in the suspense account? A $15 700 credit B $15 700 debit C $24 650 credit D $24 650 debit
Mark scheme: D
Q10 · Which items are used to update the cash book when preparing a bank reconciliation…
10 Which items are used to update the cash book when preparing a bank reconciliation statement? 1 an amount directly collected by a supplier from the business’s bank account 2 an amount directly transferred by a customer to the business’s bank account 3 an amount not yet credited to the business’s bank account 4 an amount not yet debited to the business’s bank account A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
Mark scheme: A
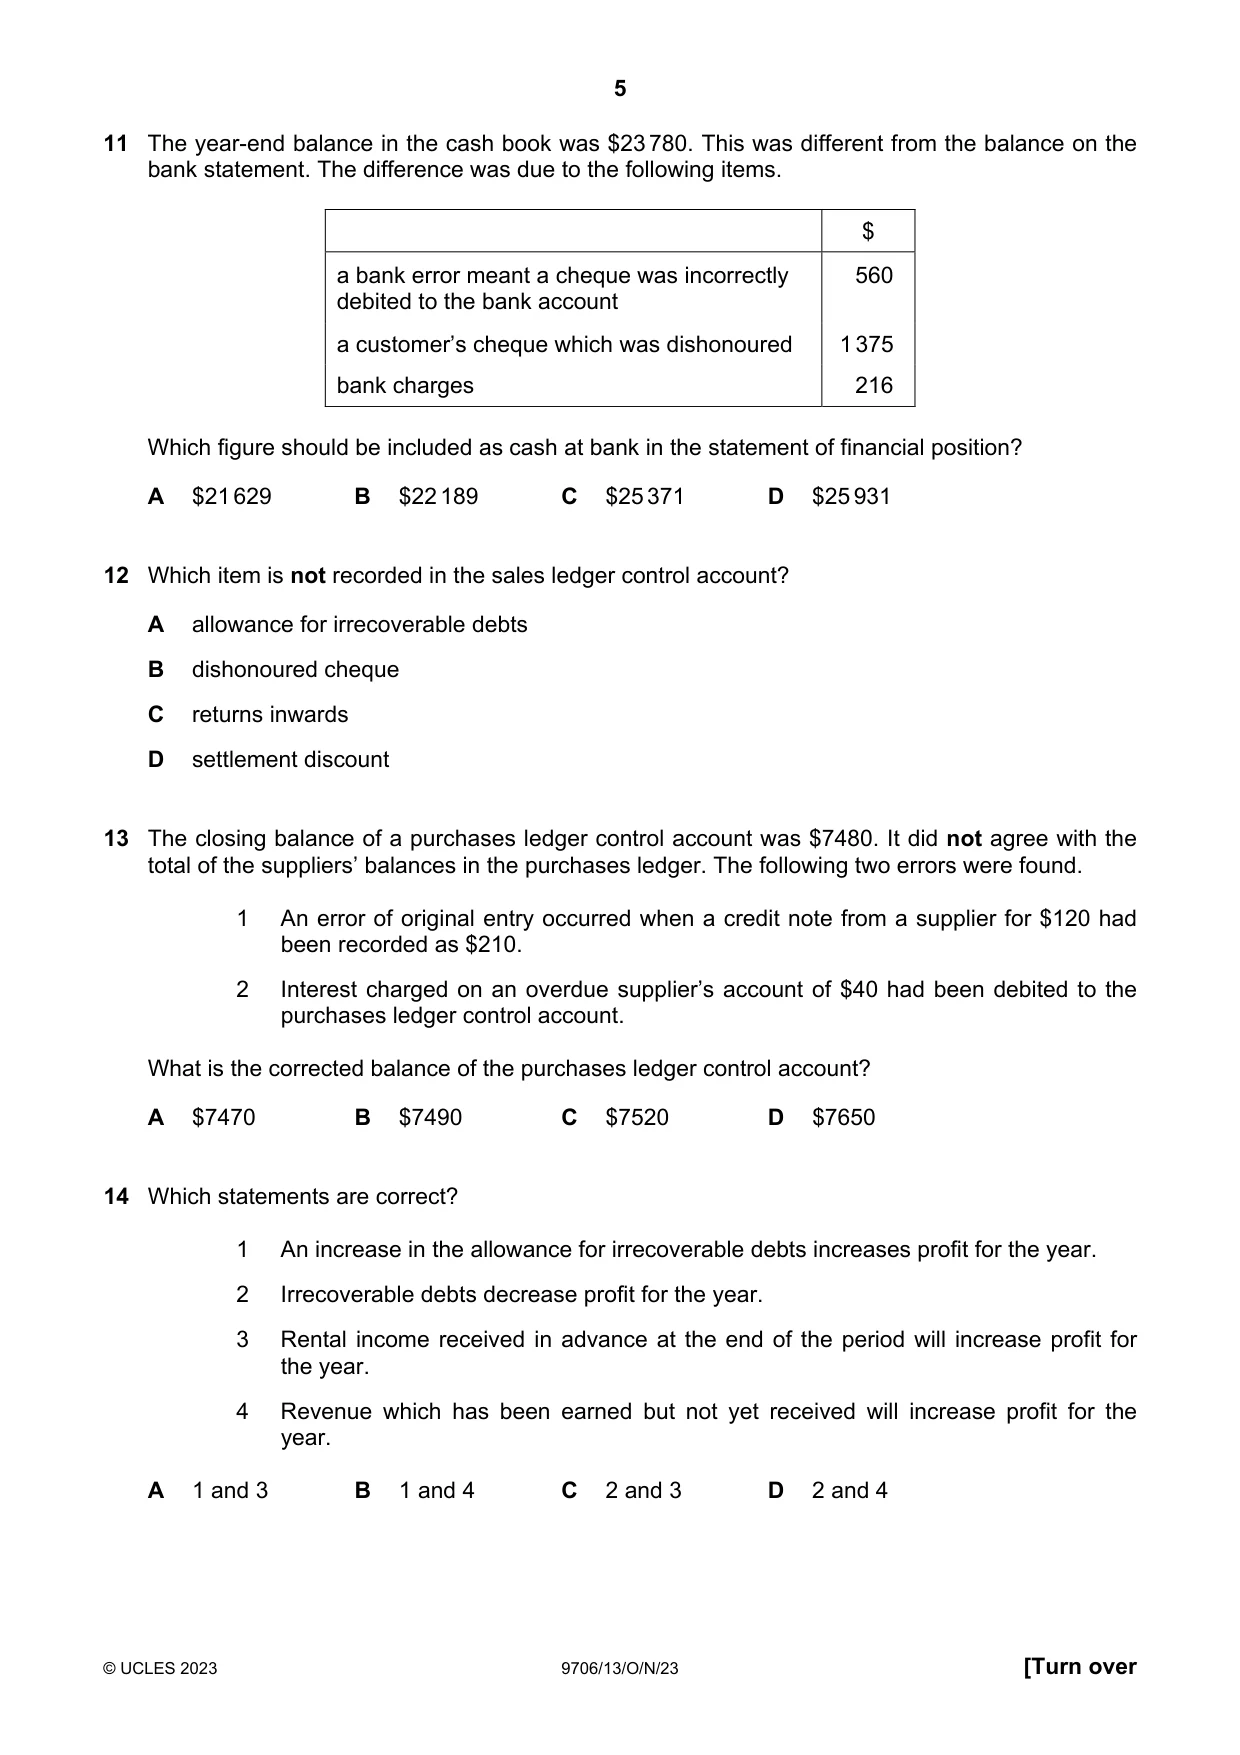
Q11 · The year-end balance in the cash book was $23 780
11 The year-end balance in the cash book was $23 780. This was different from the balance on the bank statement. The difference was due to the following items. $ a bank error meant a cheque was incorrectly 560 debited to the bank account a customer’s cheque which was dishonoured 1 375 bank charges 216 Which figure should be included as cash at bank in the statement of financial position? A $21 629 B $22 189 C $25 371 D $25 931
Mark scheme: B
Q12 · Which item is not recorded in the sales ledger control account?
12 Which item is not recorded in the sales ledger control account? A allowance for irrecoverable debts B dishonoured cheque C returns inwards D settlement discount
Mark scheme: A
Q13 · The closing balance of a purchases ledger control account was $7480
13 The closing balance of a purchases ledger control account was $7480. It did not agree with the total of the suppliers’ balances in the purchases ledger. The following two errors were found. 1 An error of original entry occurred when a credit note from a supplier for $120 had been recorded as $210. 2 Interest charged on an overdue supplier’s account of $40 had been debited to the purchases ledger control account. What is the corrected balance of the purchases ledger control account? A $7470 B $7490 C $7520 D $7650
Mark scheme: D
Q14 · Which statements are correct?
14 Which statements are correct? 1 An increase in the allowance for irrecoverable debts increases profit for the year. 2 Irrecoverable debts decrease profit for the year. 3 Rental income received in advance at the end of the period will increase profit for the year. 4 Revenue which has been earned but not yet received will increase profit for the year. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
Mark scheme: D
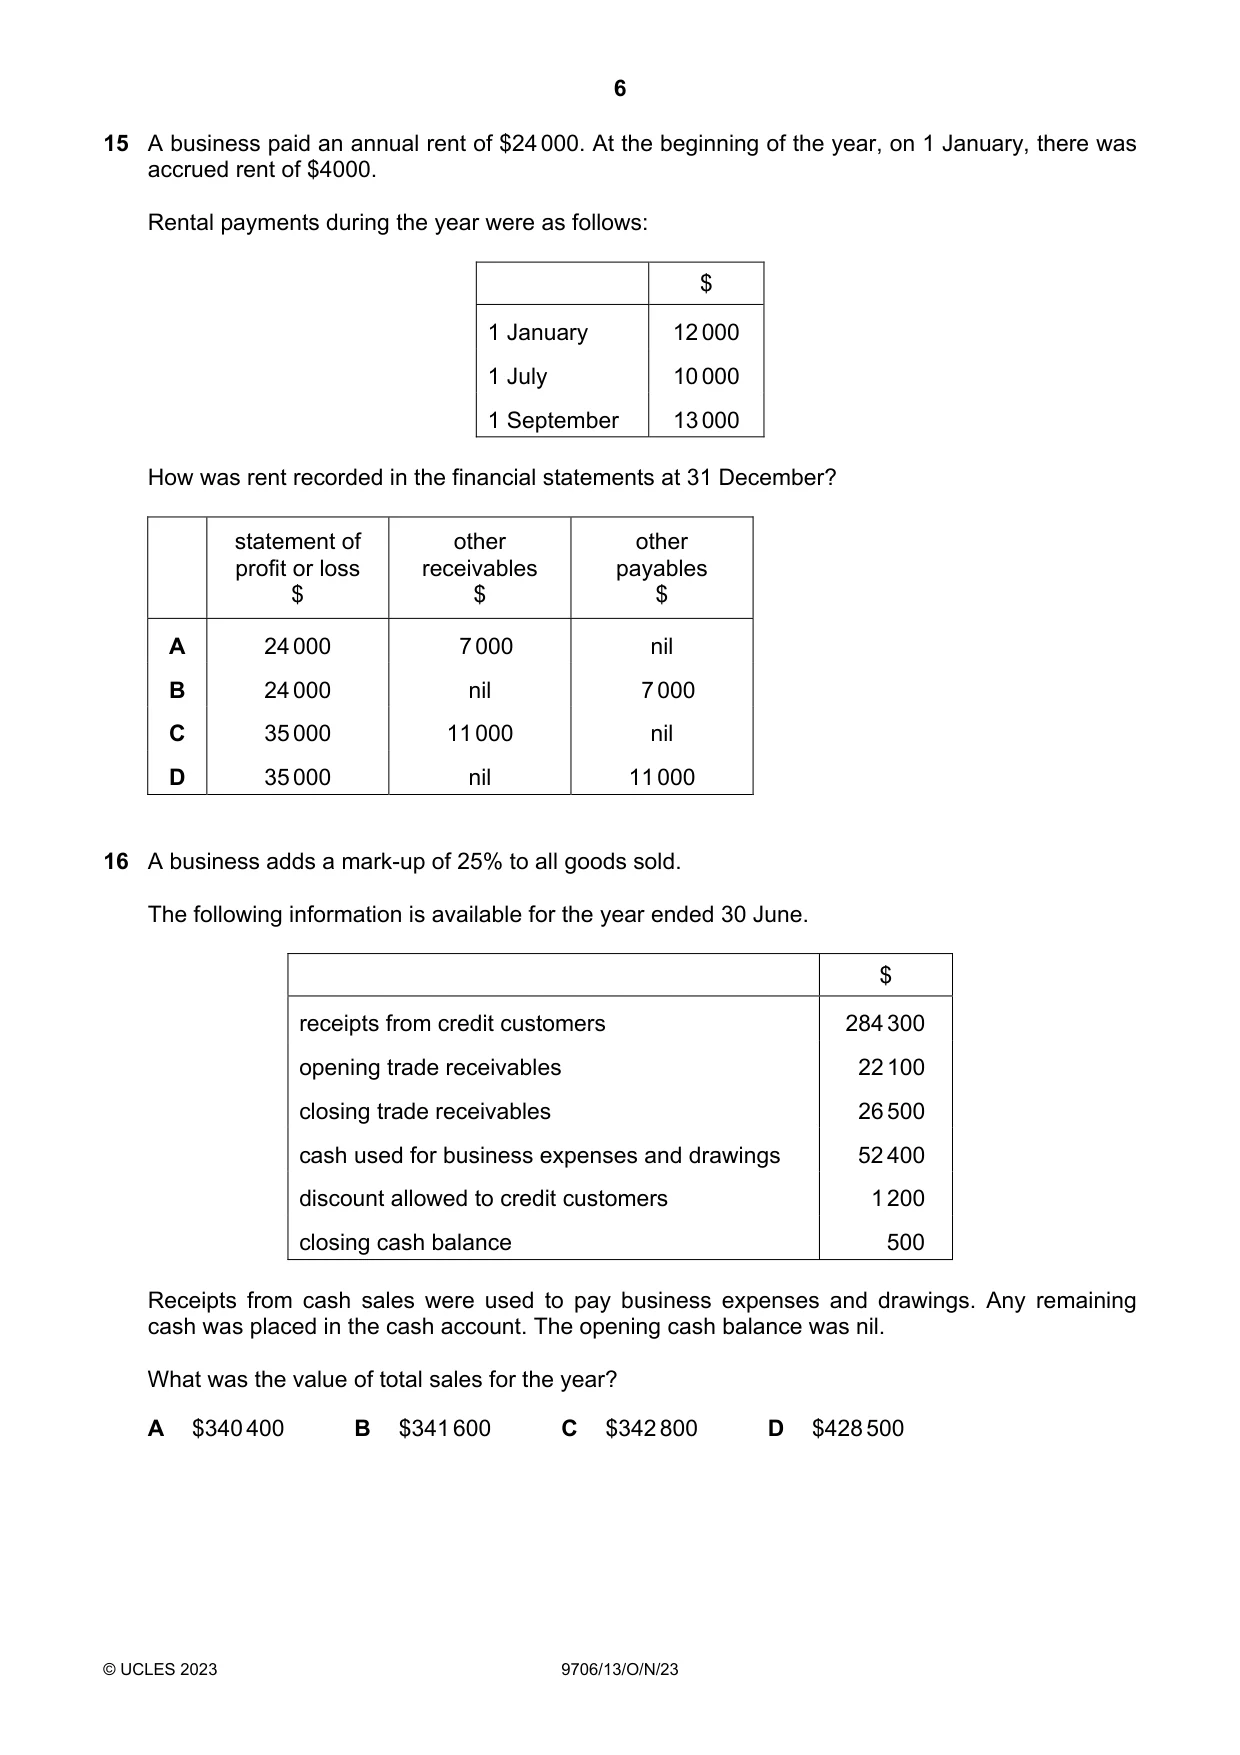
Q15 · A business paid an annual rent of $24 000
15 A business paid an annual rent of $24 000. At the beginning of the year, on 1 January, there was accrued rent of $4000. Rental payments during the year were as follows: $ 1 January 12 000 1 July 10 000 1 September 13 000 How was rent recorded in the financial statements at 31 December? statement of other other profit or loss receivables payables $ $ $ A 24 000 7 000 nil B 24 000 nil 7 000 C 35 000 11 000 nil D 35 000 nil 11 000
Mark scheme: A
Q16 · A business adds a mark-up of 25% to all goods sold
16 A business adds a mark-up of 25% to all goods sold. The following information is available for the year ended 30 June. $ receipts from credit customers 284 300 opening trade receivables 22 100 closing trade receivables 26 500 cash used for business expenses and drawings 52 400 discount allowed to credit customers 1 200 closing cash balance 500 Receipts from cash sales were used to pay business expenses and drawings. Any remaining cash was placed in the cash account. The opening cash balance was nil. What was the value of total sales for the year? A $340 400 B $341 600 C $342 800 D $428 500
Mark scheme: C
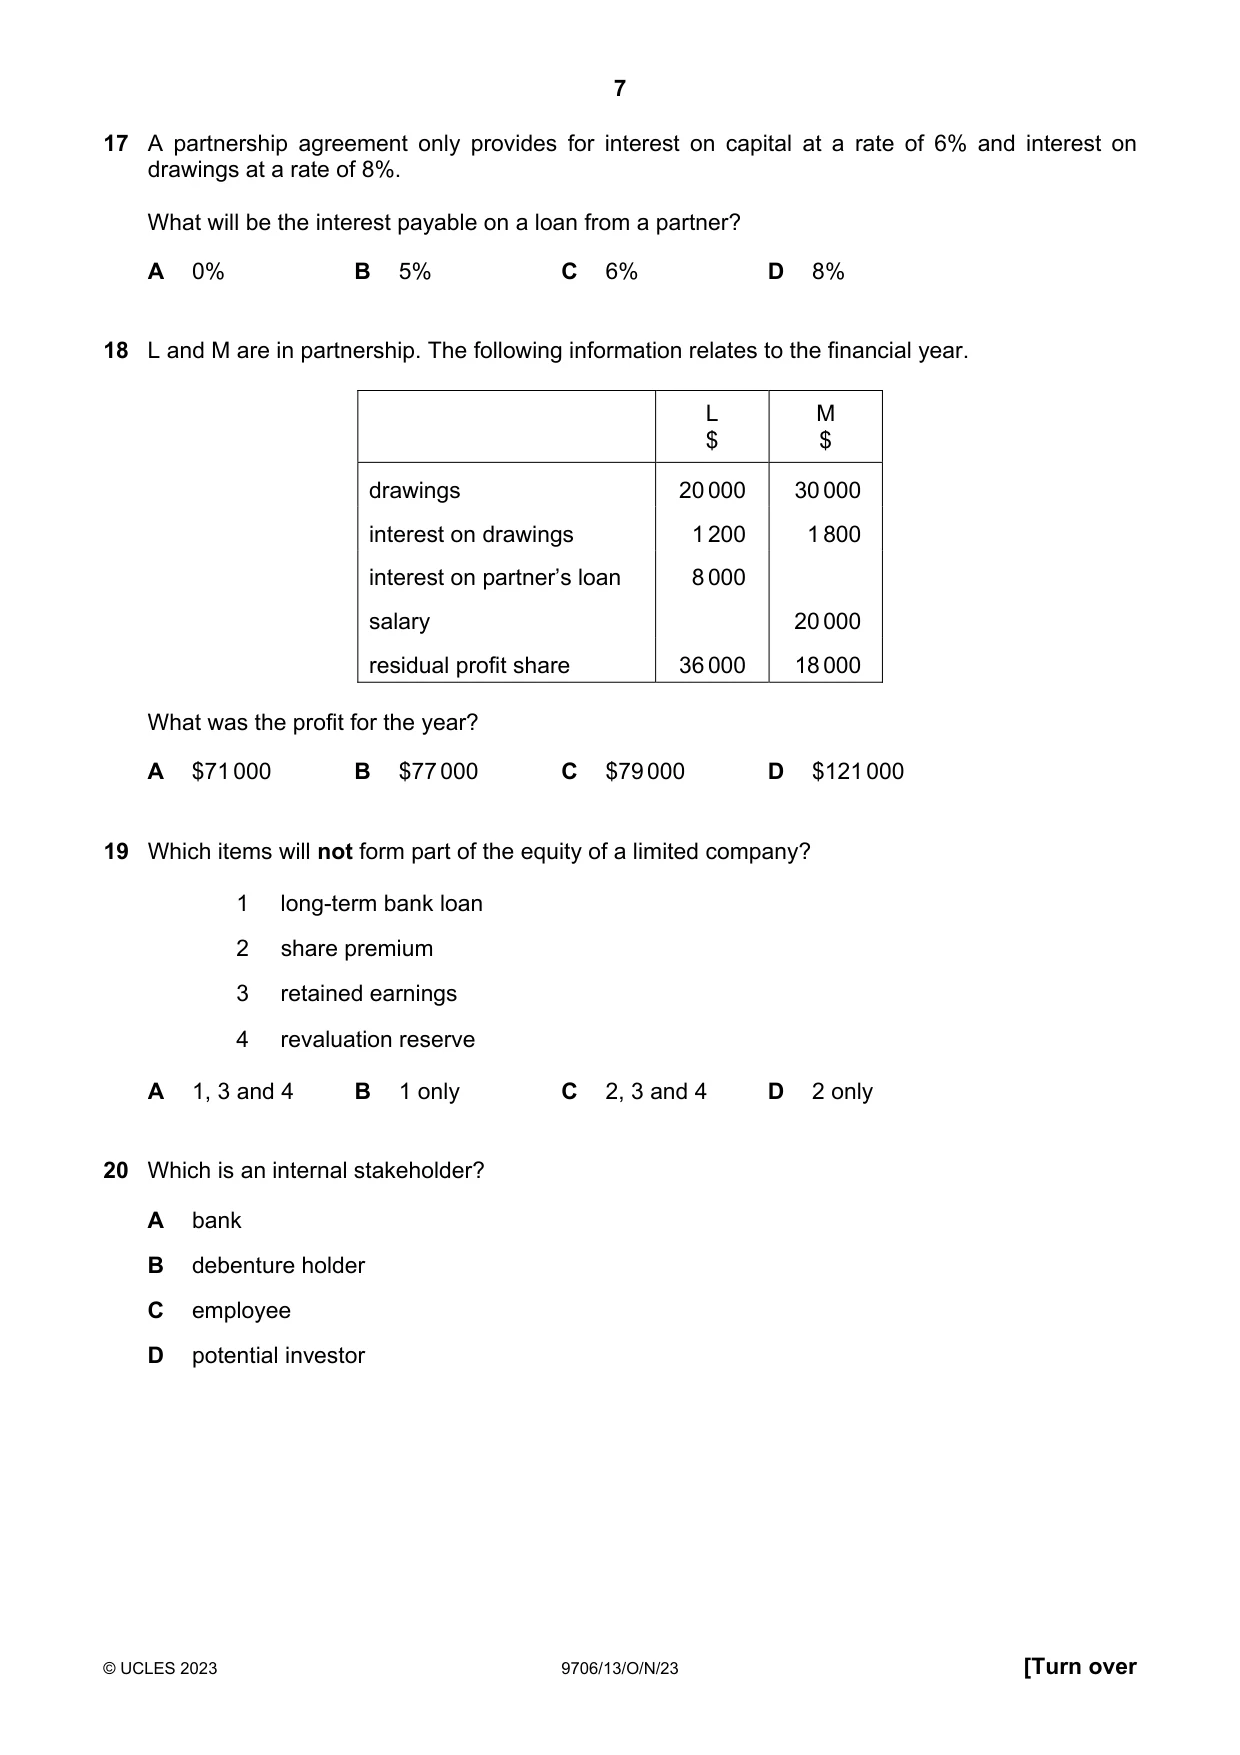
Q17 · A partnership agreement only provides for interest on capital at a rate of 6% and…
17 A partnership agreement only provides for interest on capital at a rate of 6% and interest on drawings at a rate of 8%. What will be the interest payable on a loan from a partner? A 0% B 5% C 6% D 8%
Mark scheme: B
Q18 · L and M are in partnership
18 L and M are in partnership. The following information relates to the financial year. L M $ $ drawings 20 000 30 000 interest on drawings 1 200 1 800 interest on partner’s loan 8 000 salary 20 000 residual profit share 36 000 18 000 What was the profit for the year? A $71 000 B $77 000 C $79 000 D $121 000
Mark scheme: A
Q19 · Which items will not form part of the equity of a limited company?
19 Which items will not form part of the equity of a limited company? 1 long-term bank loan 2 share premium 3 retained earnings 4 revaluation reserve A 1, 3 and 4 B 1 only C 2, 3 and 4 D 2 only
Mark scheme: B
Q20 · Which is an internal stakeholder?
20 Which is an internal stakeholder? A bank B debenture holder C employee D potential investor
Mark scheme: C
More questions on Analysis and communication of accounting information
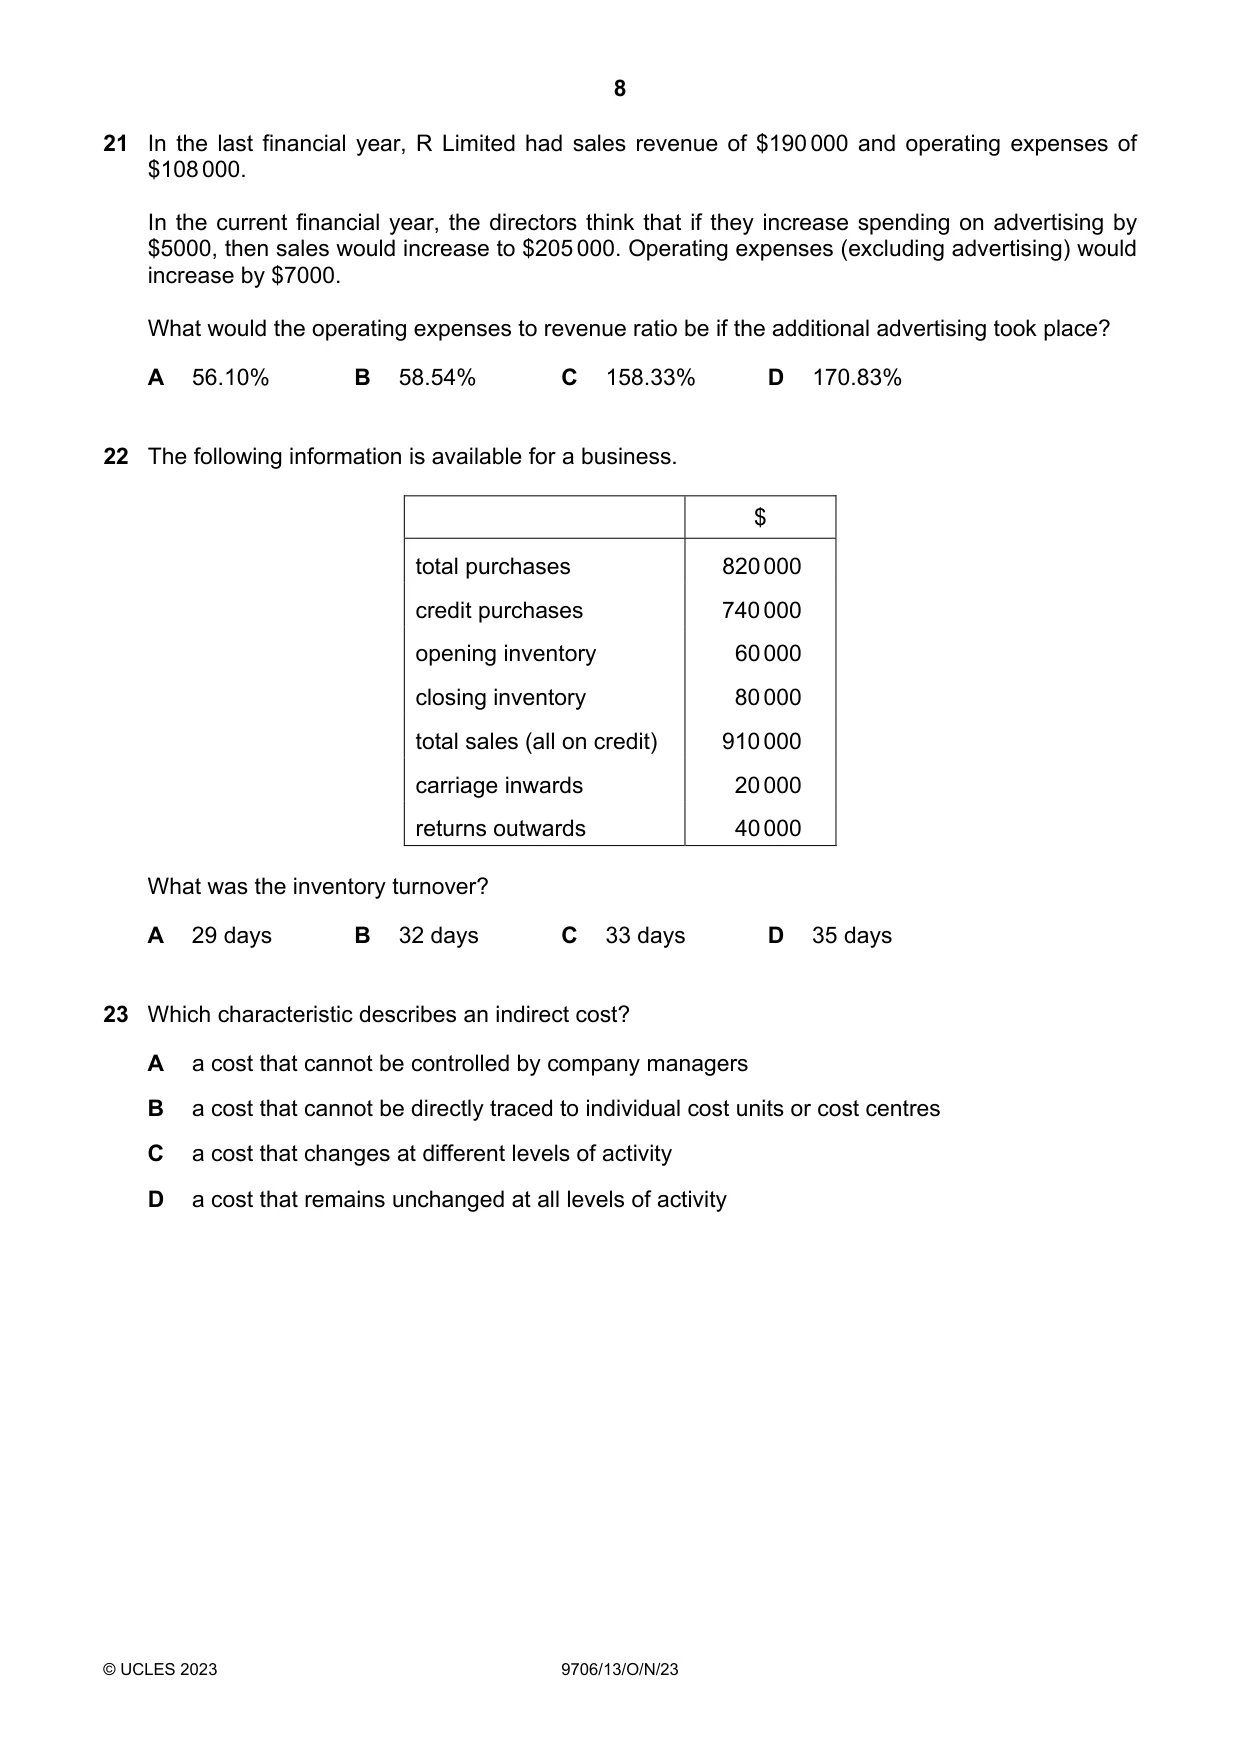
Q21 · In the last financial year, R Limited had sales revenue of $190 000 and operating…
21 In the last financial year, R Limited had sales revenue of $190 000 and operating expenses of $108 000. In the current financial year, the directors think that if they increase spending on advertising by $5000, then sales would increase to $205 000. Operating expenses (excluding advertising) would increase by $7000. What would the operating expenses to revenue ratio be if the additional advertising took place? A 56.10% B 58.54% C 158.33% D 170.83%
Mark scheme: B
More questions on Analysis and communication of accounting information
Q22 · The following information is available for a business
22 The following information is available for a business. $ total purchases 820 000 credit purchases 740 000 opening inventory 60 000 closing inventory 80 000 total sales (all on credit) 910 000 carriage inwards 20 000 returns outwards 40 000 What was the inventory turnover? A 29 days B 32 days C 33 days D 35 days
Mark scheme: C
More questions on Analysis and communication of accounting information
Q23 · Which characteristic describes an indirect cost?
23 Which characteristic describes an indirect cost? A a cost that cannot be controlled by company managers B a cost that cannot be directly traced to individual cost units or cost centres C a cost that changes at different levels of activity D a cost that remains unchanged at all levels of activity
Mark scheme: B
Q24 · The manufacture of product type X incurs a specific cost
24 The manufacture of product type X incurs a specific cost. Data relating to this is as follows: units produced 6000 9000 cost per unit $3 $2 Which type of cost is this? A fixed B semi-variable C stepped D variable
Mark scheme: A
Q25 · A company makes a single type of product and sells it for $12 per batch
25 A company makes a single type of product and sells it for $12 per batch. The variable cost is $4 per batch. Fixed costs have been absorbed based on a normal activity level of 1000 batches at $3 per batch. What is the profit under marginal costing if the company makes and sells 1500 batches? A $6000 B $7500 C $9000 D $12 000
Mark scheme: C
Q26 · A business operates a system of absorption costing
26 A business operates a system of absorption costing. Which statements are correct? 1 Overheads would be over absorbed if the actual activity level was below the budgeted level. 2 Overheads would be under absorbed if the actual activity level was below the budgeted level. 3 Overheads would be over absorbed if the actual overhead exceeded the budgeted overhead. 4 Overheads would be under absorbed if the actual overhead exceeded the budgeted overhead. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
Mark scheme: D
Q27 · A business uses an overhead absorption rate of $20 per direct labour hour
27 A business uses an overhead absorption rate of $20 per direct labour hour. In April budgeted direct labour hours were 6000 and actual direct labour hours were 6100. Overheads for the month were under absorbed by $3000. What were the actual overheads in April? A $117 000 B $119 000 C $123 000 D $125 000
Mark scheme: D
Q28 · Which statement is an argument for using marginal costing?
28 Which statement is an argument for using marginal costing? A International accounting standards require use of marginal costing. B Marginal costing data enables the use of decision-making techniques. C Setting selling prices is made easier under marginal costing because all costs are considered. D The distinction between fixed and variable overheads under marginal costing is no longer relevant.
Mark scheme: B
Q29 · The following information is available for a business
29 The following information is available for a business. total fixed costs $15 000 variable cost $12 per unit selling price $20 per unit break-even point 1875 units The business wants to reduce the break-even point to 1500 units. Which strategy will not achieve the target break-even level? A increasing the selling price to $22 per unit B reducing fixed costs to $12 750 and reducing variable cost to $11.50 per unit C reducing fixed costs to $12 800 D reducing variable costs to $10 per unit
Mark scheme: C
Q30 · Which assumption does not apply for cost–volume–profit (CVP) analysis?
30 Which assumption does not apply for cost–volume–profit (CVP) analysis? A All units produced are sold. B Only a single type of product is produced and sold. C Total fixed costs change over a period. D Variable cost changes in direct proportion with sales volume.
Mark scheme: C
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
6Traditional costing methods6Preparation of financial statements4Accounting for non-current assets3Analysis and communication of accounting information3Costs and cost behaviour2The accounting system2Types of business entity2Computerised accounting systems1Preparation of financial statements1What you needed in this session
Cambridge’s own grade thresholds for 2023 Oct/Nov, Paper 1 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.