Cambridge A Level Accounting 9706 — 2022 Oct/Nov Paper 1 · Variant 1
9706/11/O/N/22 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
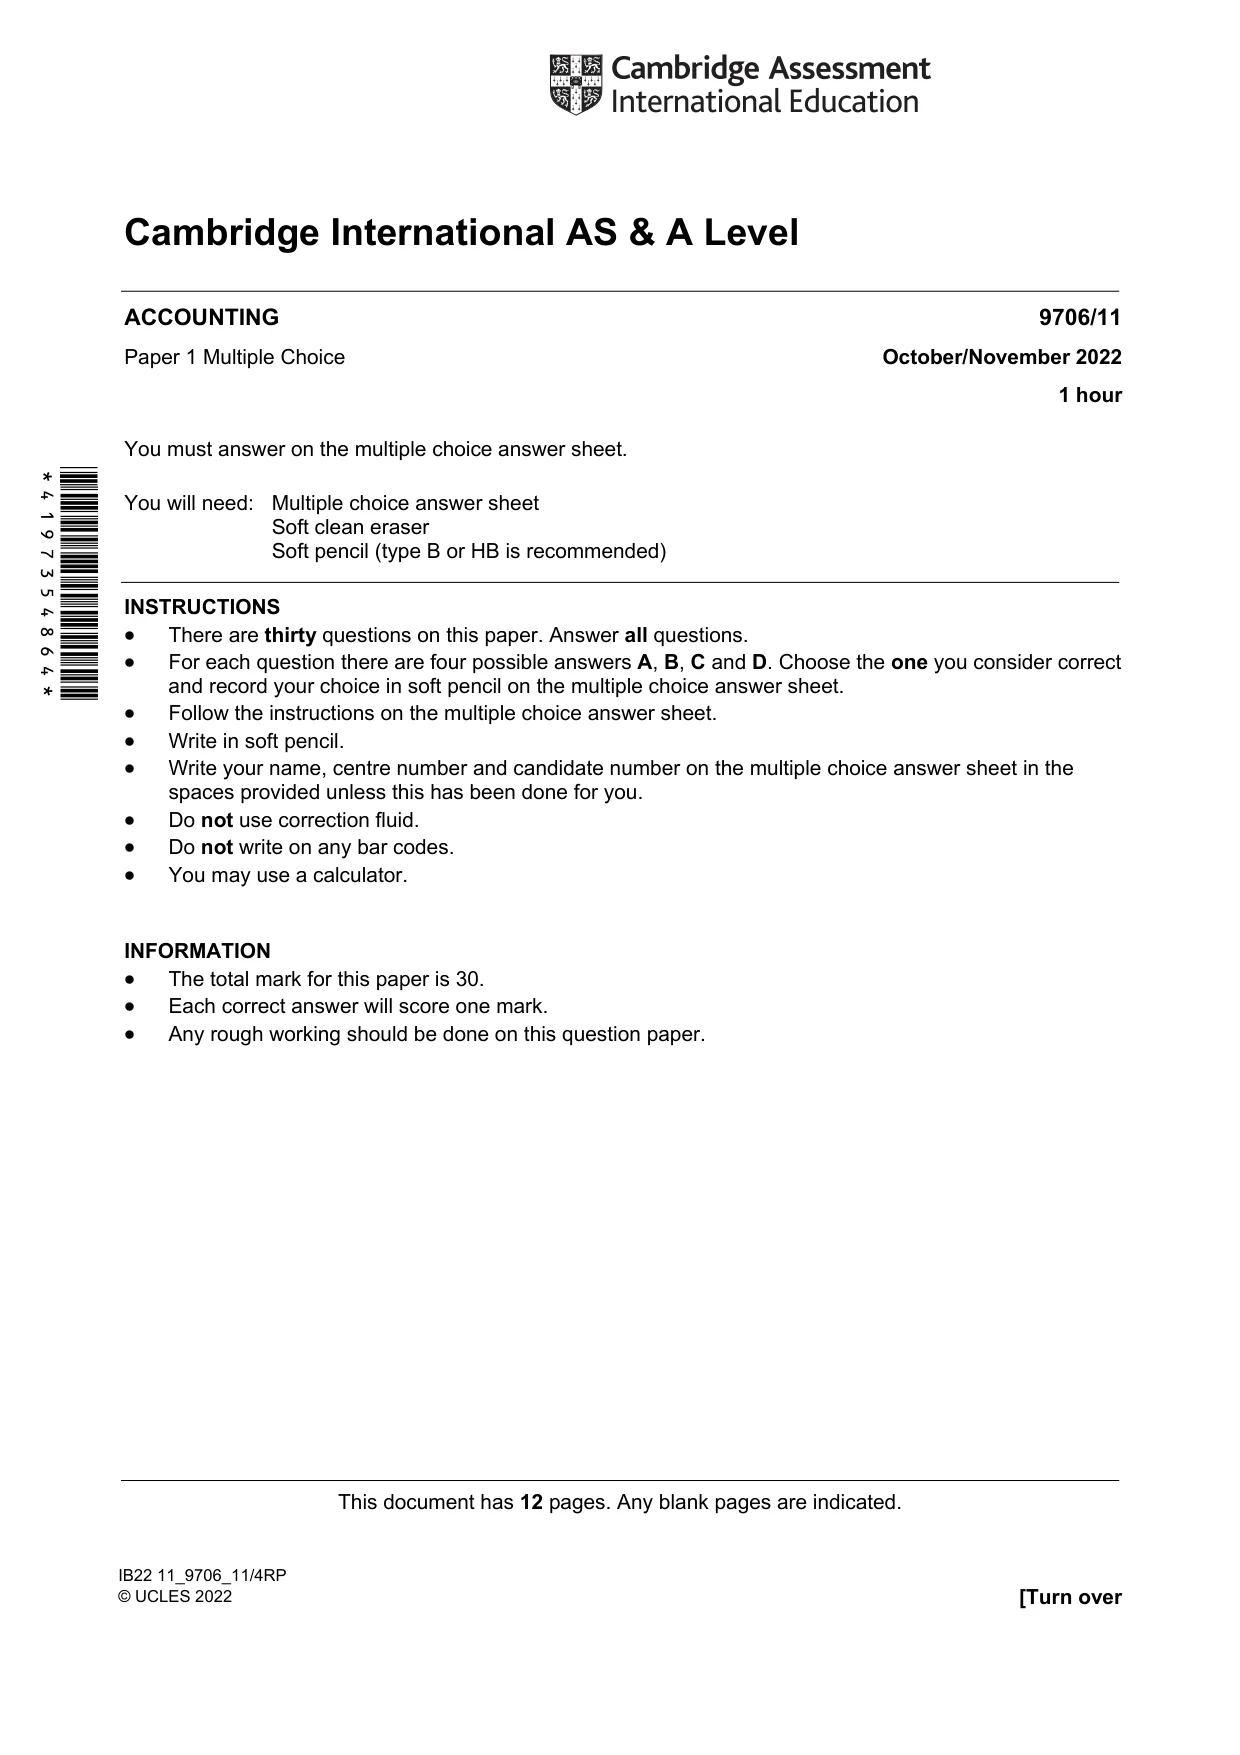
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · For which items does the cash book act as a book of prime entry?
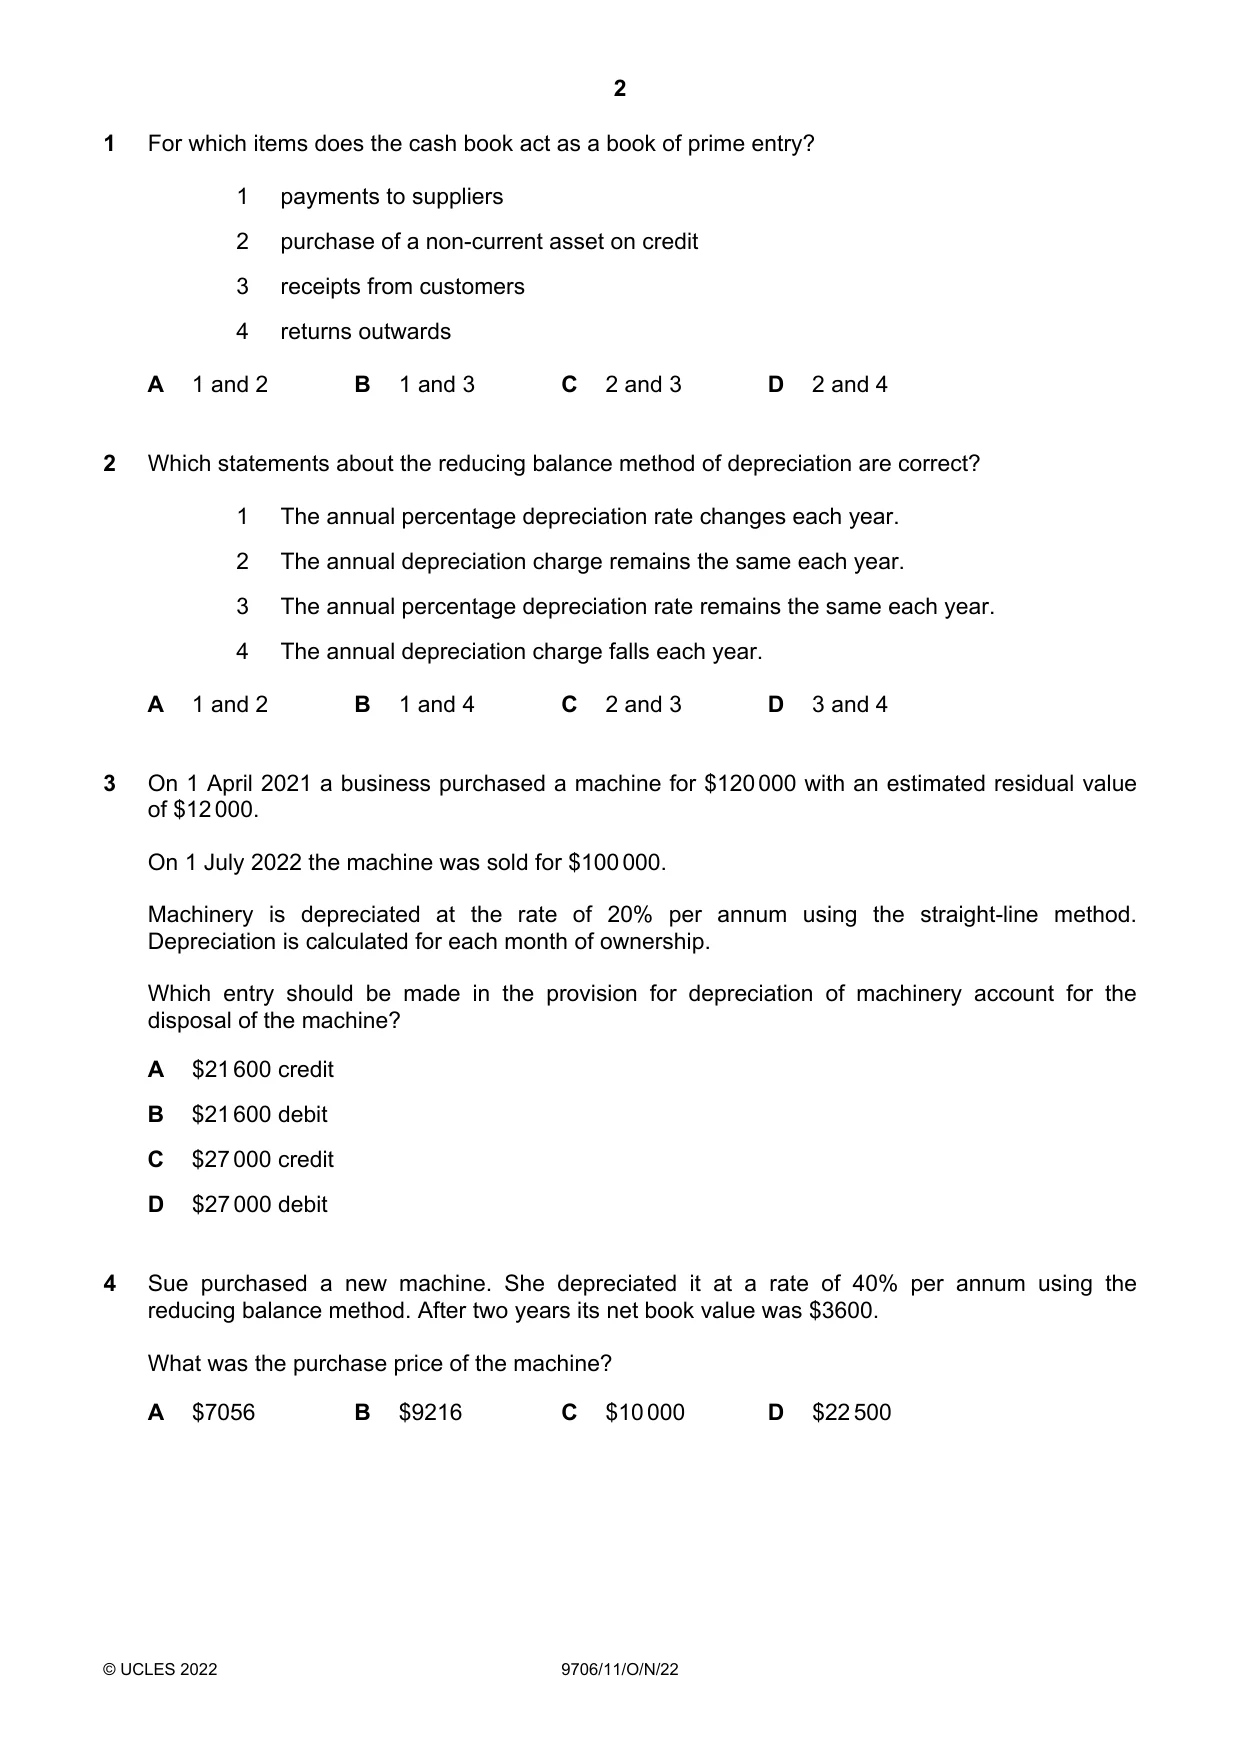
1 For which items does the cash book act as a book of prime entry? 1 payments to suppliers 2 purchase of a non-current asset on credit 3 receipts from customers 4 returns outwards A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
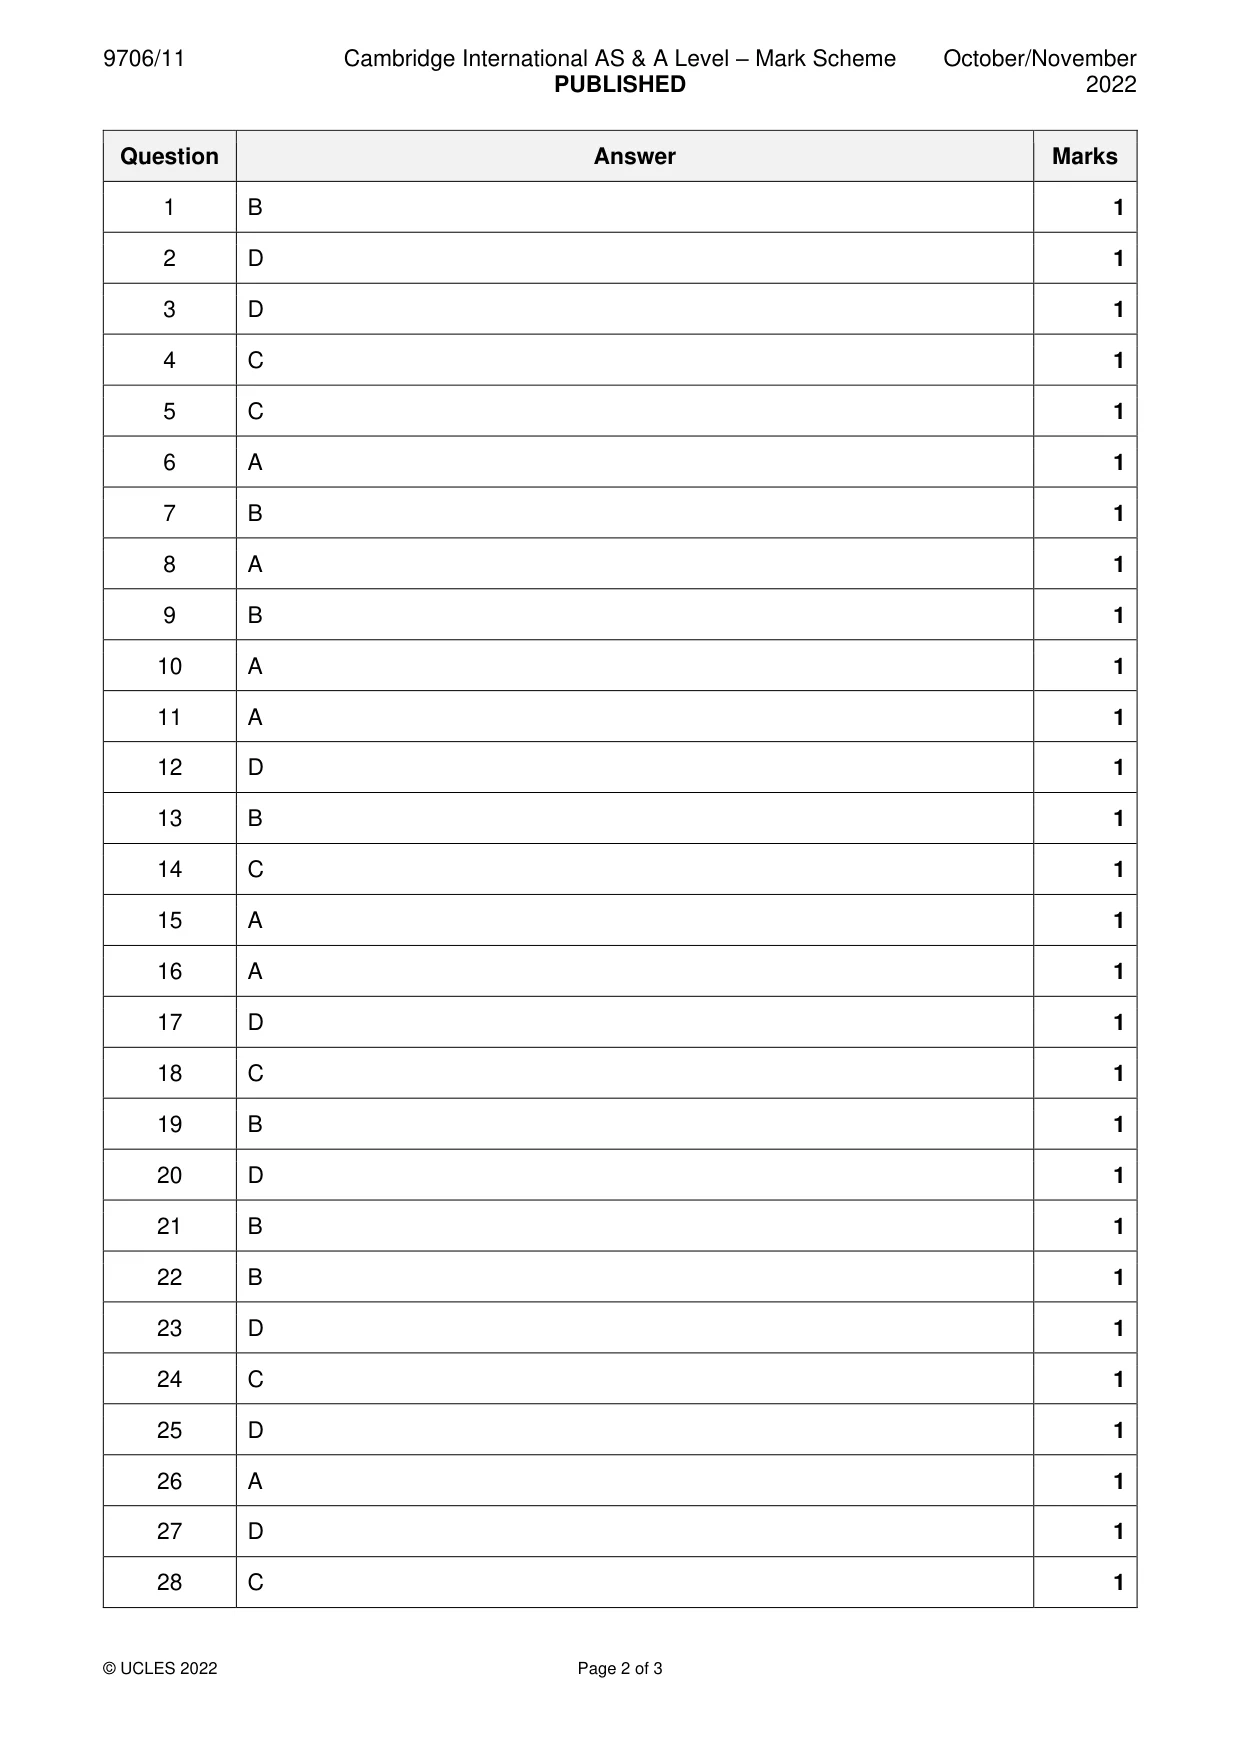
Mark scheme: B
Q2 · Which statements about the reducing balance method of depreciation are correct?
2 Which statements about the reducing balance method of depreciation are correct? 1 The annual percentage depreciation rate changes each year. 2 The annual depreciation charge remains the same each year. 3 The annual percentage depreciation rate remains the same each year. 4 The annual depreciation charge falls each year. A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
Mark scheme: D
Q3 · On 1 April 2021 a business purchased a machine for $120 000 with an estimated residual…
3 On 1 April 2021 a business purchased a machine for $120 000 with an estimated residual value of $12 000. On 1 July 2022 the machine was sold for $100 000. Machinery is depreciated at the rate of 20% per annum using the straight-line method. Depreciation is calculated for each month of ownership. Which entry should be made in the provision for depreciation of machinery account for the disposal of the machine? A $21 600 credit B $21 600 debit C $27 000 credit D $27 000 debit
Mark scheme: D
Q4 · Sue purchased a new machine
4 Sue purchased a new machine. She depreciated it at a rate of 40% per annum using the reducing balance method. After two years its net book value was $3600. What was the purchase price of the machine? A $7056 B $9216 C $10 000 D $22 500
Mark scheme: C
Q5 · Which items will be included in the sales ledger control account?
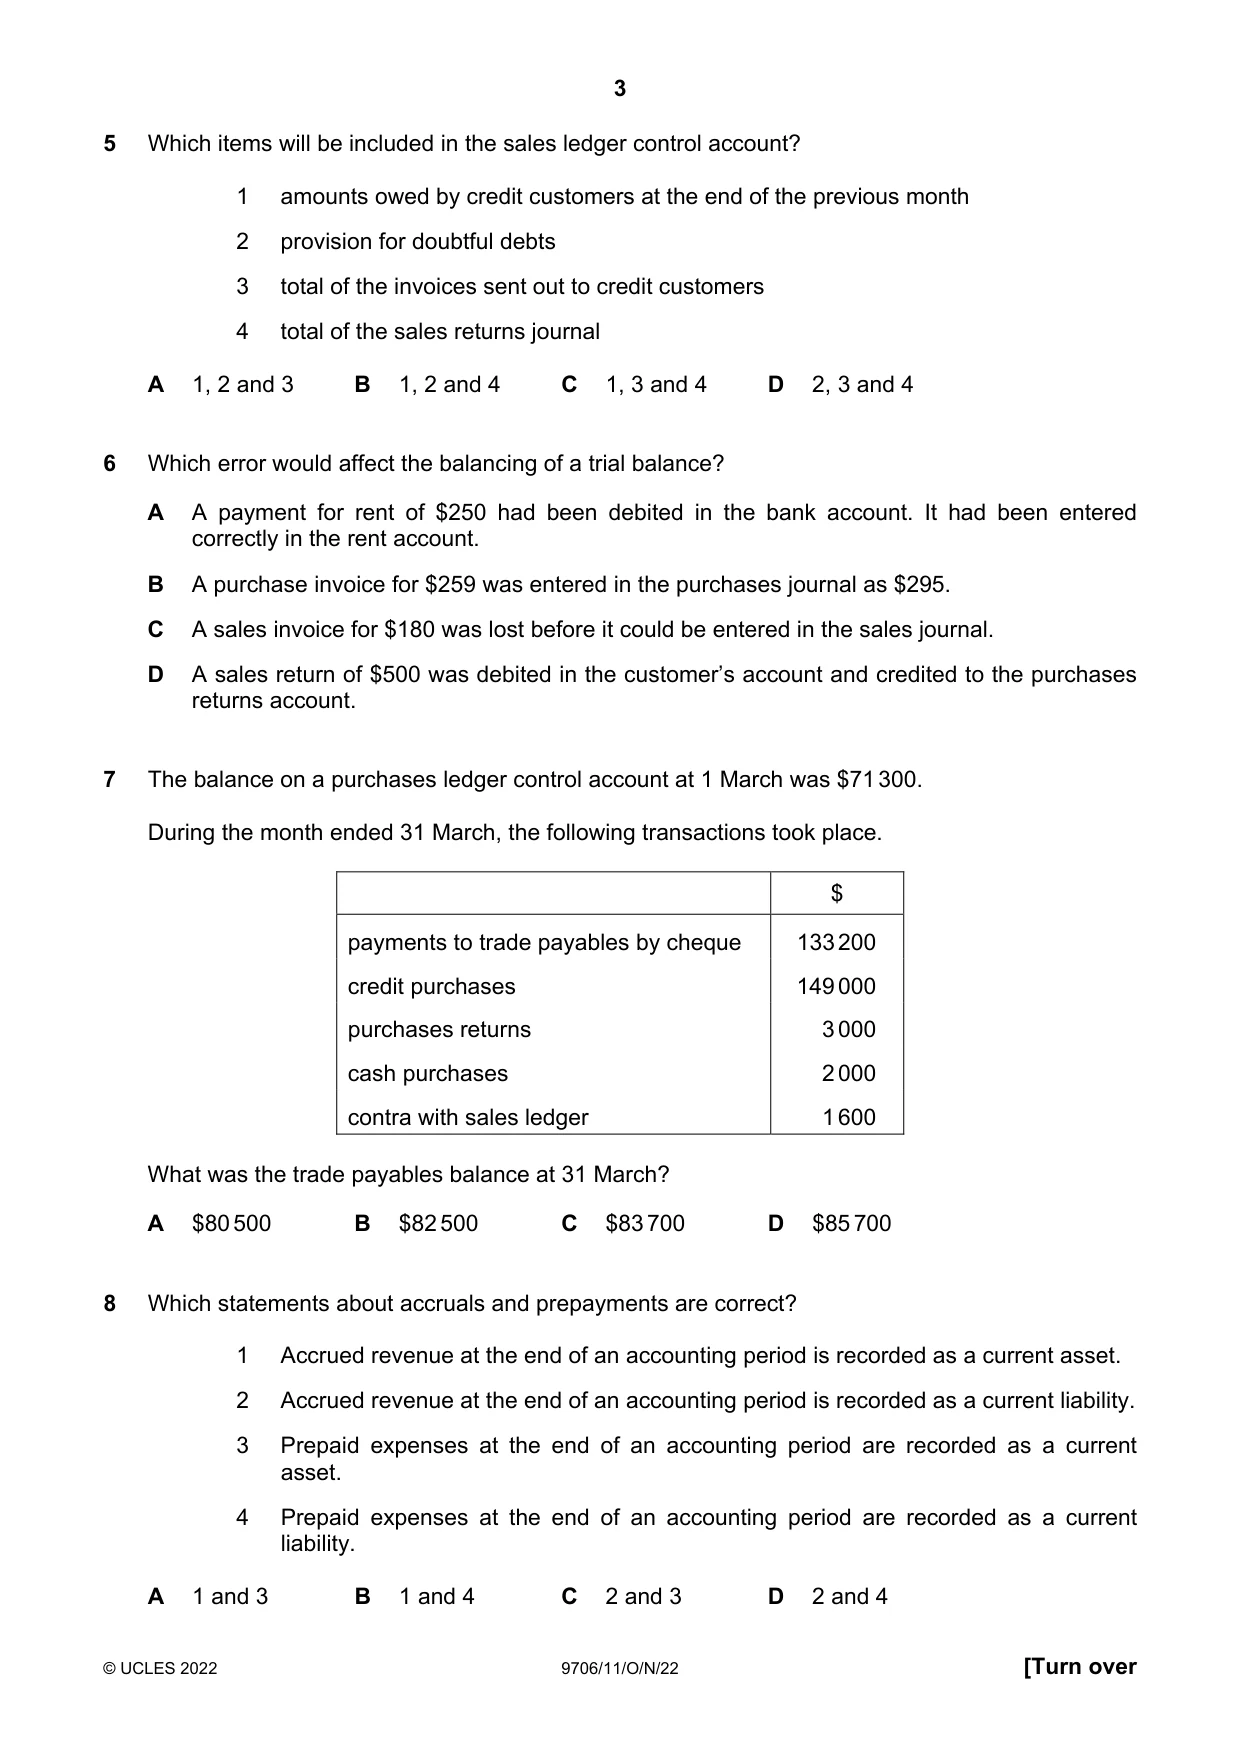
5 Which items will be included in the sales ledger control account? 1 amounts owed by credit customers at the end of the previous month 2 provision for doubtful debts 3 total of the invoices sent out to credit customers 4 total of the sales returns journal A 1, 2 and 3 B 1, 2 and 4 C 1, 3 and 4 D 2, 3 and 4
Mark scheme: C
Q6 · Which error would affect the balancing of a trial balance?
6 Which error would affect the balancing of a trial balance? A A payment for rent of $250 had been debited in the bank account. It had been entered correctly in the rent account. B A purchase invoice for $259 was entered in the purchases journal as $295. C A sales invoice for $180 was lost before it could be entered in the sales journal. D A sales return of $500 was debited in the customer’s account and credited to the purchases returns account.
Mark scheme: A
Q7 · The balance on a purchases ledger control account at 1 March was $71 300
7 The balance on a purchases ledger control account at 1 March was $71 300. During the month ended 31 March, the following transactions took place. $ payments to trade payables by cheque 133 200 credit purchases 149 000 purchases returns 3 000 cash purchases 2 000 contra with sales ledger 1 600 What was the trade payables balance at 31 March? A $80 500 B $82 500 C $83 700 D $85 700
Mark scheme: B
Q8 · Which statements about accruals and prepayments are correct?
8 Which statements about accruals and prepayments are correct? 1 Accrued revenue at the end of an accounting period is recorded as a current asset. 2 Accrued revenue at the end of an accounting period is recorded as a current liability. 3 Prepaid expenses at the end of an accounting period are recorded as a current asset. 4 Prepaid expenses at the end of an accounting period are recorded as a current liability. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
Mark scheme: A
Q9 · A business has a bank overdraft of $4800
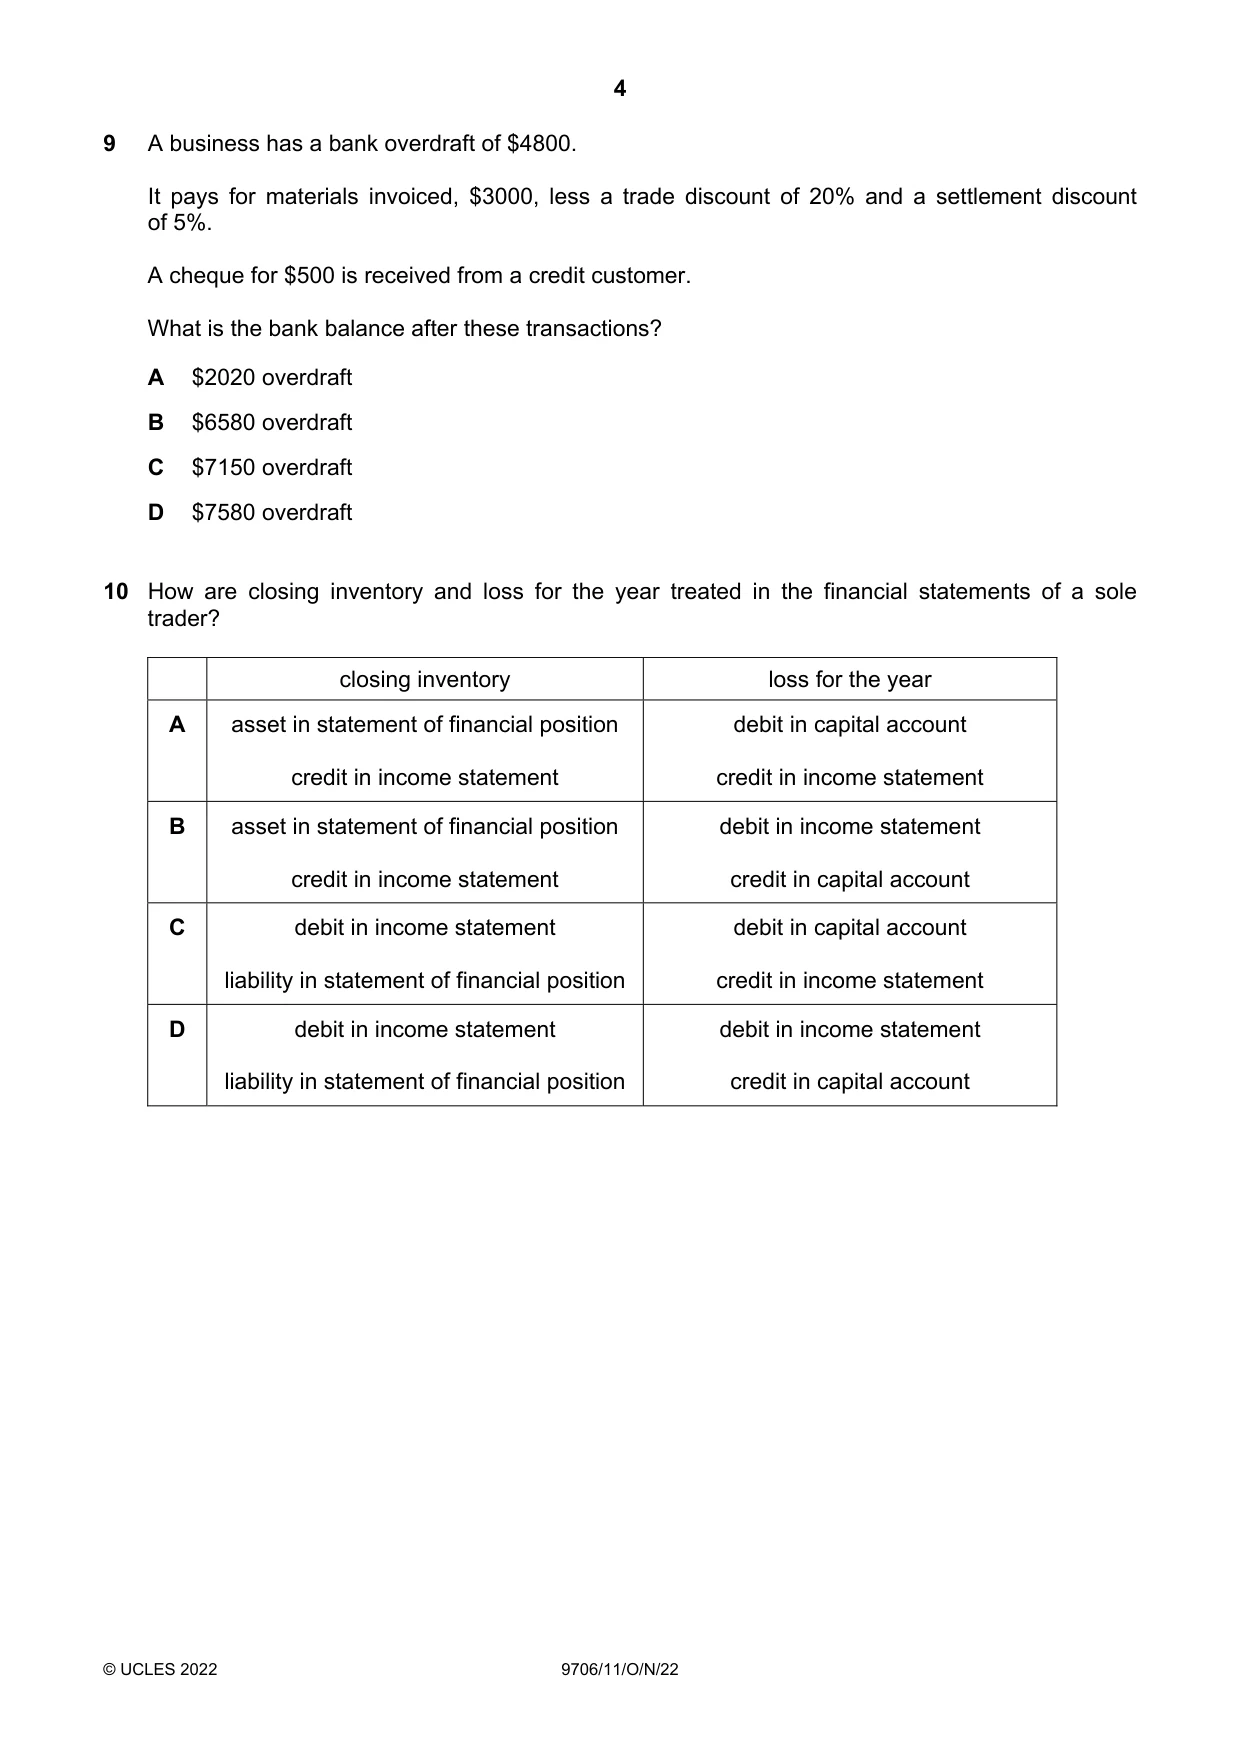
9 A business has a bank overdraft of $4800. It pays for materials invoiced, $3000, less a trade discount of 20% and a settlement discount of 5%. A cheque for $500 is received from a credit customer. What is the bank balance after these transactions? A $2020 overdraft B $6580 overdraft C $7150 overdraft D $7580 overdraft
Mark scheme: B
Q10 · How are closing inventory and loss for the year treated in the financial statements of a…
10 How are closing inventory and loss for the year treated in the financial statements of a sole trader? closing inventory loss for the year A asset in statement of financial position debit in capital account credit in income statement credit in income statement B asset in statement of financial position debit in income statement credit in income statement credit in capital account C debit in income statement debit in capital account liability in statement of financial position credit in income statement D debit in income statement debit in income statement liability in statement of financial position credit in capital account
Mark scheme: A
Q11 · A trader had the following closing trade receivables
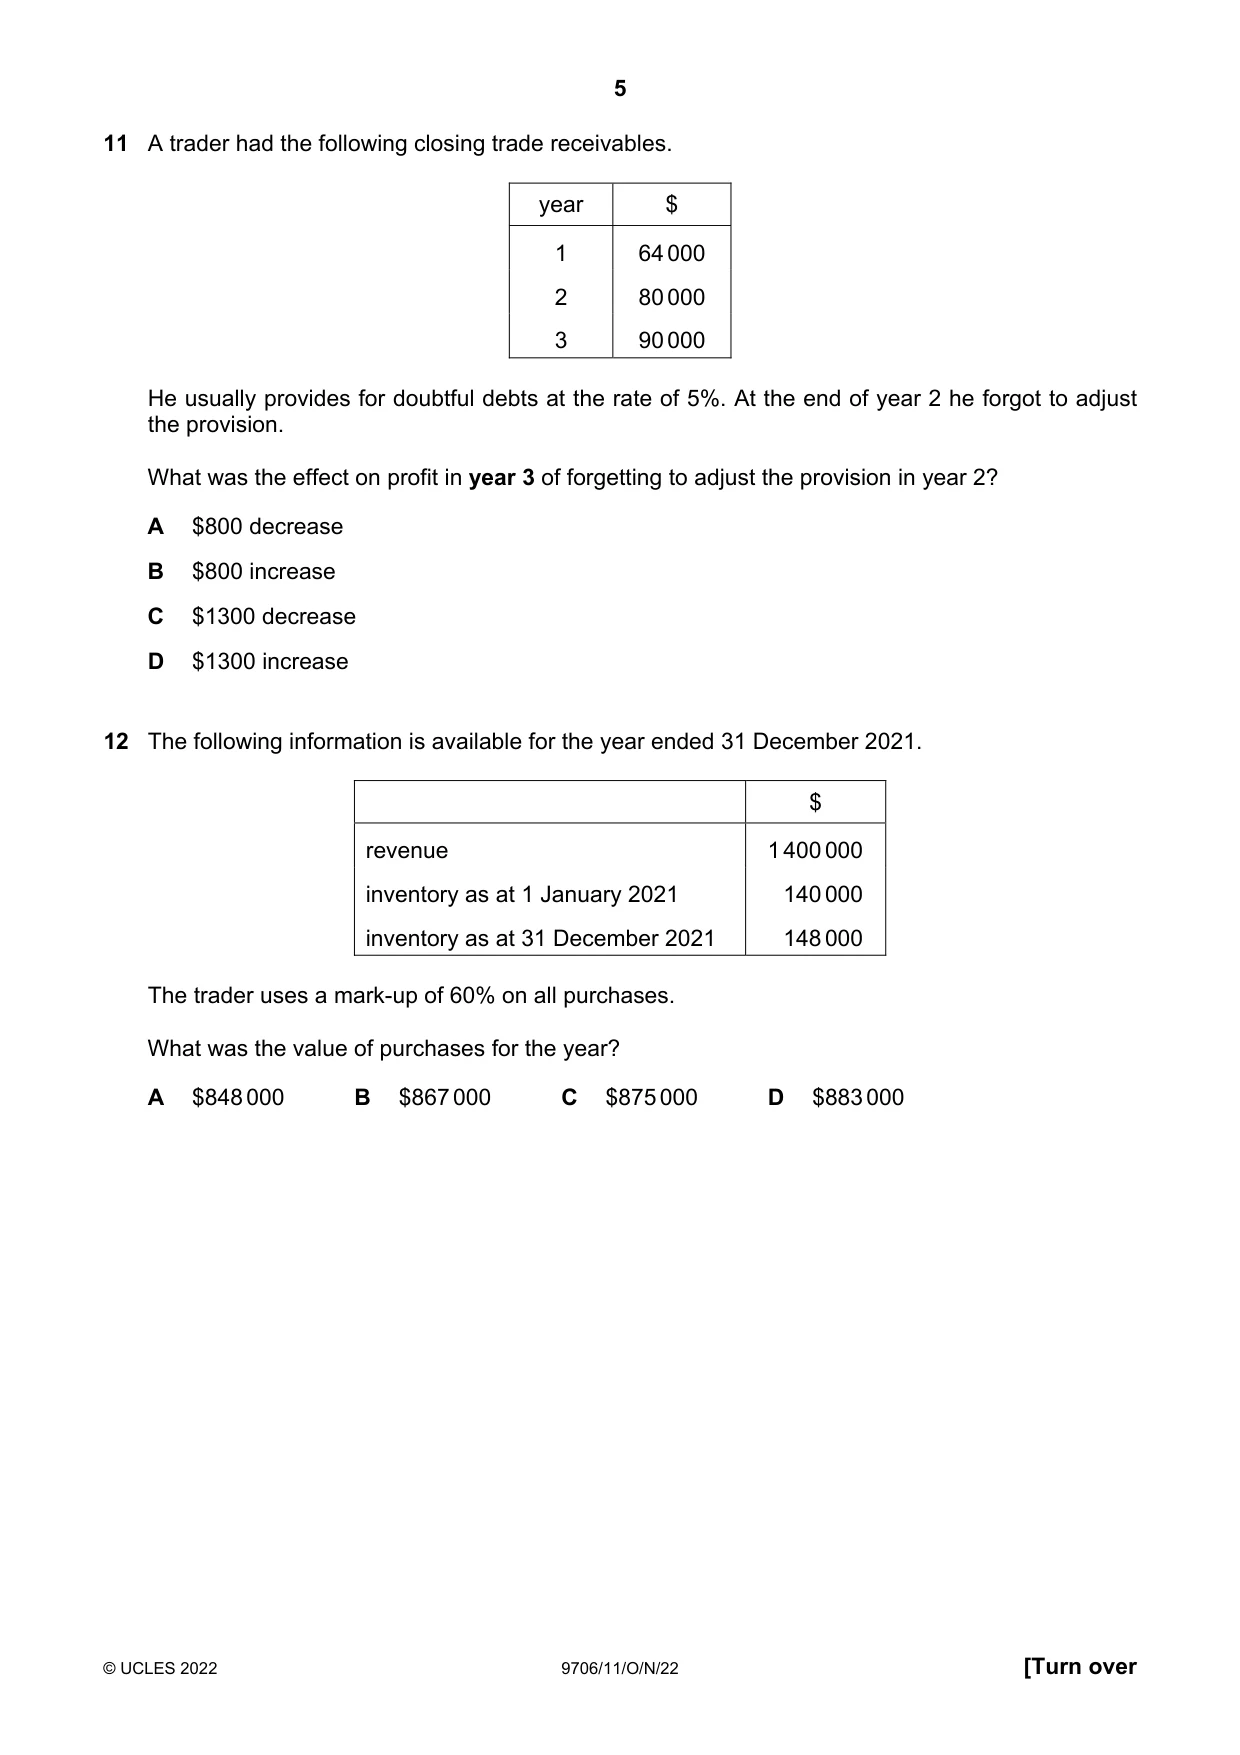
11 A trader had the following closing trade receivables. year $ 1 64 000 2 80 000 3 90 000 He usually provides for doubtful debts at the rate of 5%. At the end of year 2 he forgot to adjust the provision. What was the effect on profit in year 3 of forgetting to adjust the provision in year 2? A $800 decrease B $800 increase C $1300 decrease D $1300 increase
Mark scheme: A
Q12 · The following information is available for the year ended 31 December 2021
12 The following information is available for the year ended 31 December 2021. $ revenue 1 400 000 inventory as at 1 January 2021 140 000 inventory as at 31 December 2021 148 000 The trader uses a mark-up of 60% on all purchases. What was the value of purchases for the year? A $848 000 B $867 000 C $875 000 D $883 000
Mark scheme: D
Q13 · The following information is available for a business for the year ended 31 March 2022
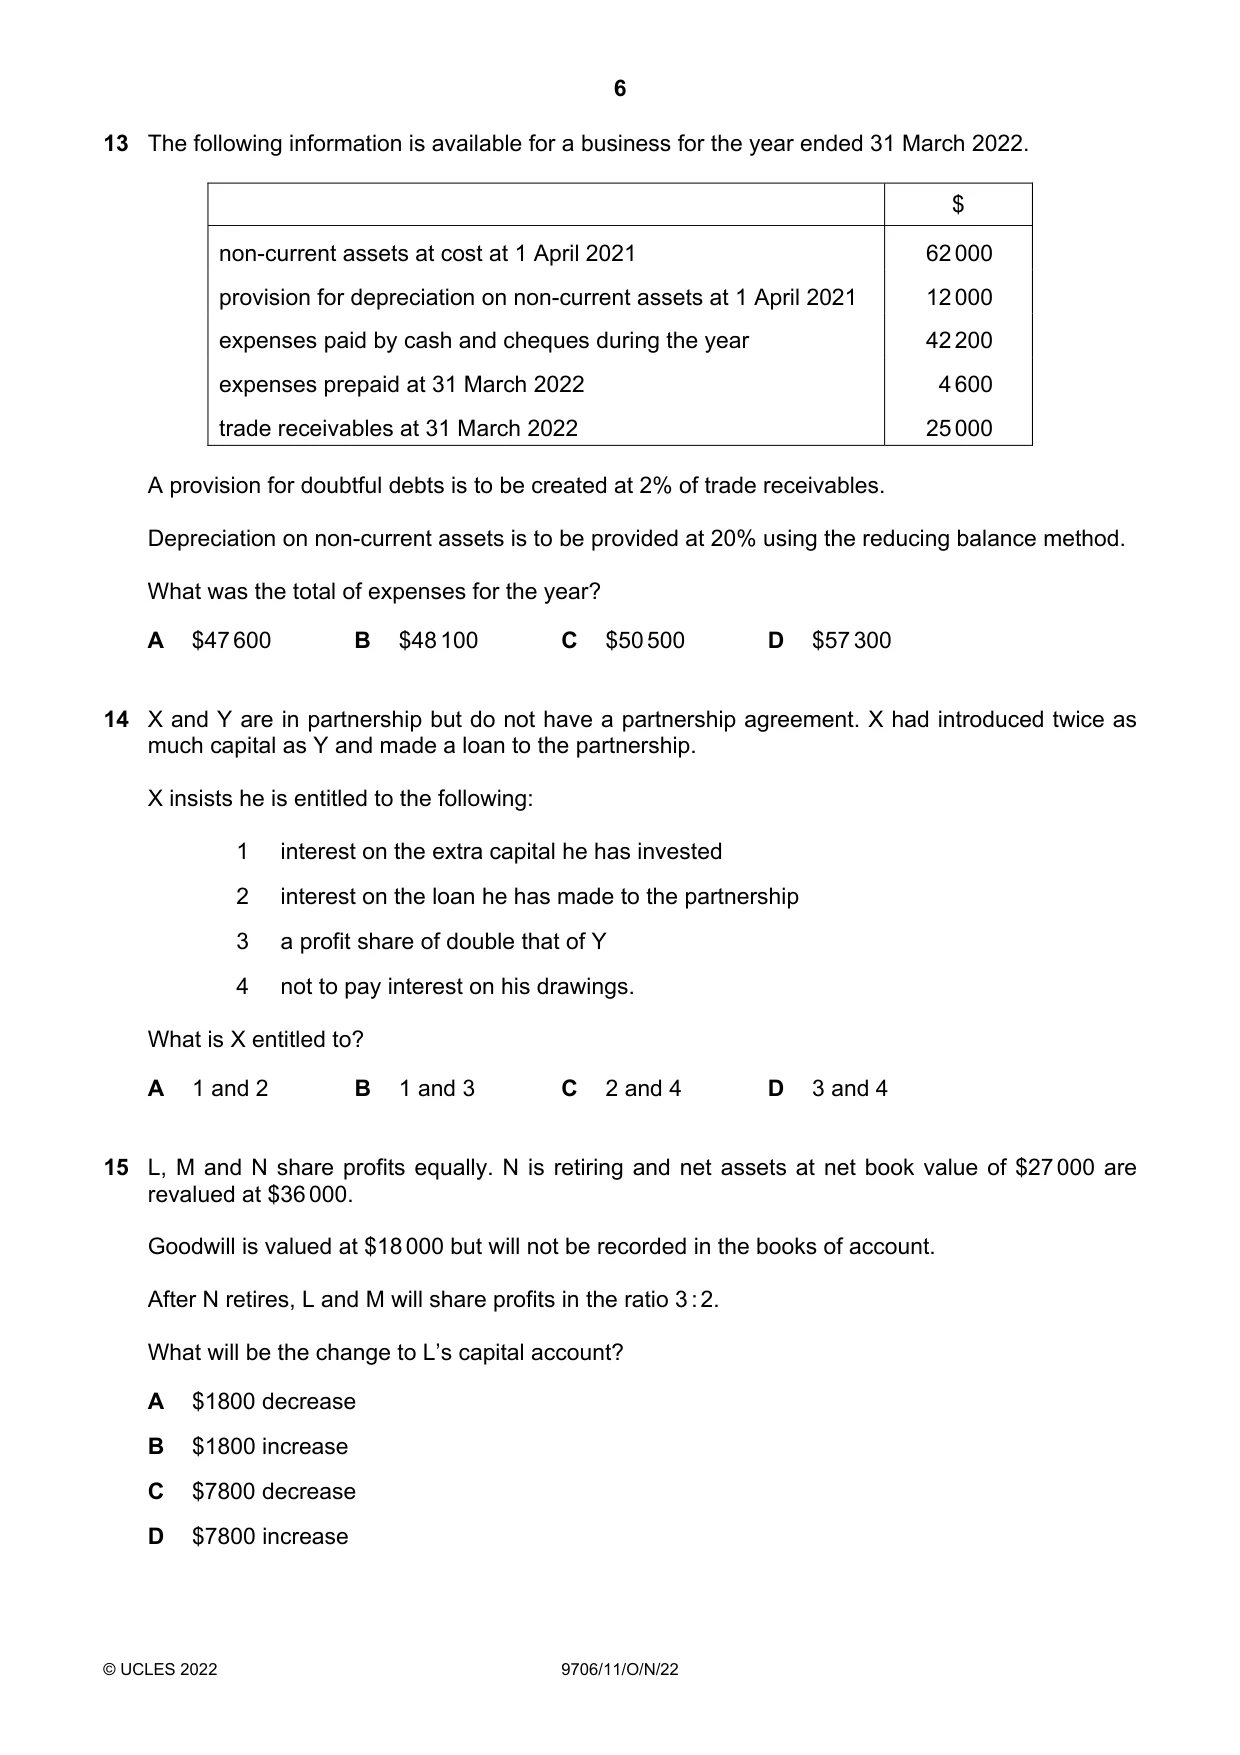
13 The following information is available for a business for the year ended 31 March 2022. $ non-current assets at cost at 1 April 2021 62 000 provision for depreciation on non-current assets at 1 April 2021 12 000 expenses paid by cash and cheques during the year 42 200 expenses prepaid at 31 March 2022 4 600 trade receivables at 31 March 2022 25 000 A provision for doubtful debts is to be created at 2% of trade receivables. Depreciation on non-current assets is to be provided at 20% using the reducing balance method. What was the total of expenses for the year? A $47 600 B $48 100 C $50 500 D $57 300
Mark scheme: B
Q14 · X and Y are in partnership but do not have a partnership agreement
14 X and Y are in partnership but do not have a partnership agreement. X had introduced twice as much capital as Y and made a loan to the partnership. X insists he is entitled to the following: 1 interest on the extra capital he has invested 2 interest on the loan he has made to the partnership 3 a profit share of double that of Y 4 not to pay interest on his drawings. What is X entitled to? A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
Mark scheme: C
Q15 · L, M and N share profits equally
15 L, M and N share profits equally. N is retiring and net assets at net book value of $27 000 are revalued at $36 000. Goodwill is valued at $18 000 but will not be recorded in the books of account. After N retires, L and M will share profits in the ratio 3 : 2. What will be the change to L’s capital account? A $1800 decrease B $1800 increase C $7800 decrease D $7800 increase
Mark scheme: A
Q16 · Dele and Iyabo are partners and share profits in the ratio of 3 : 1
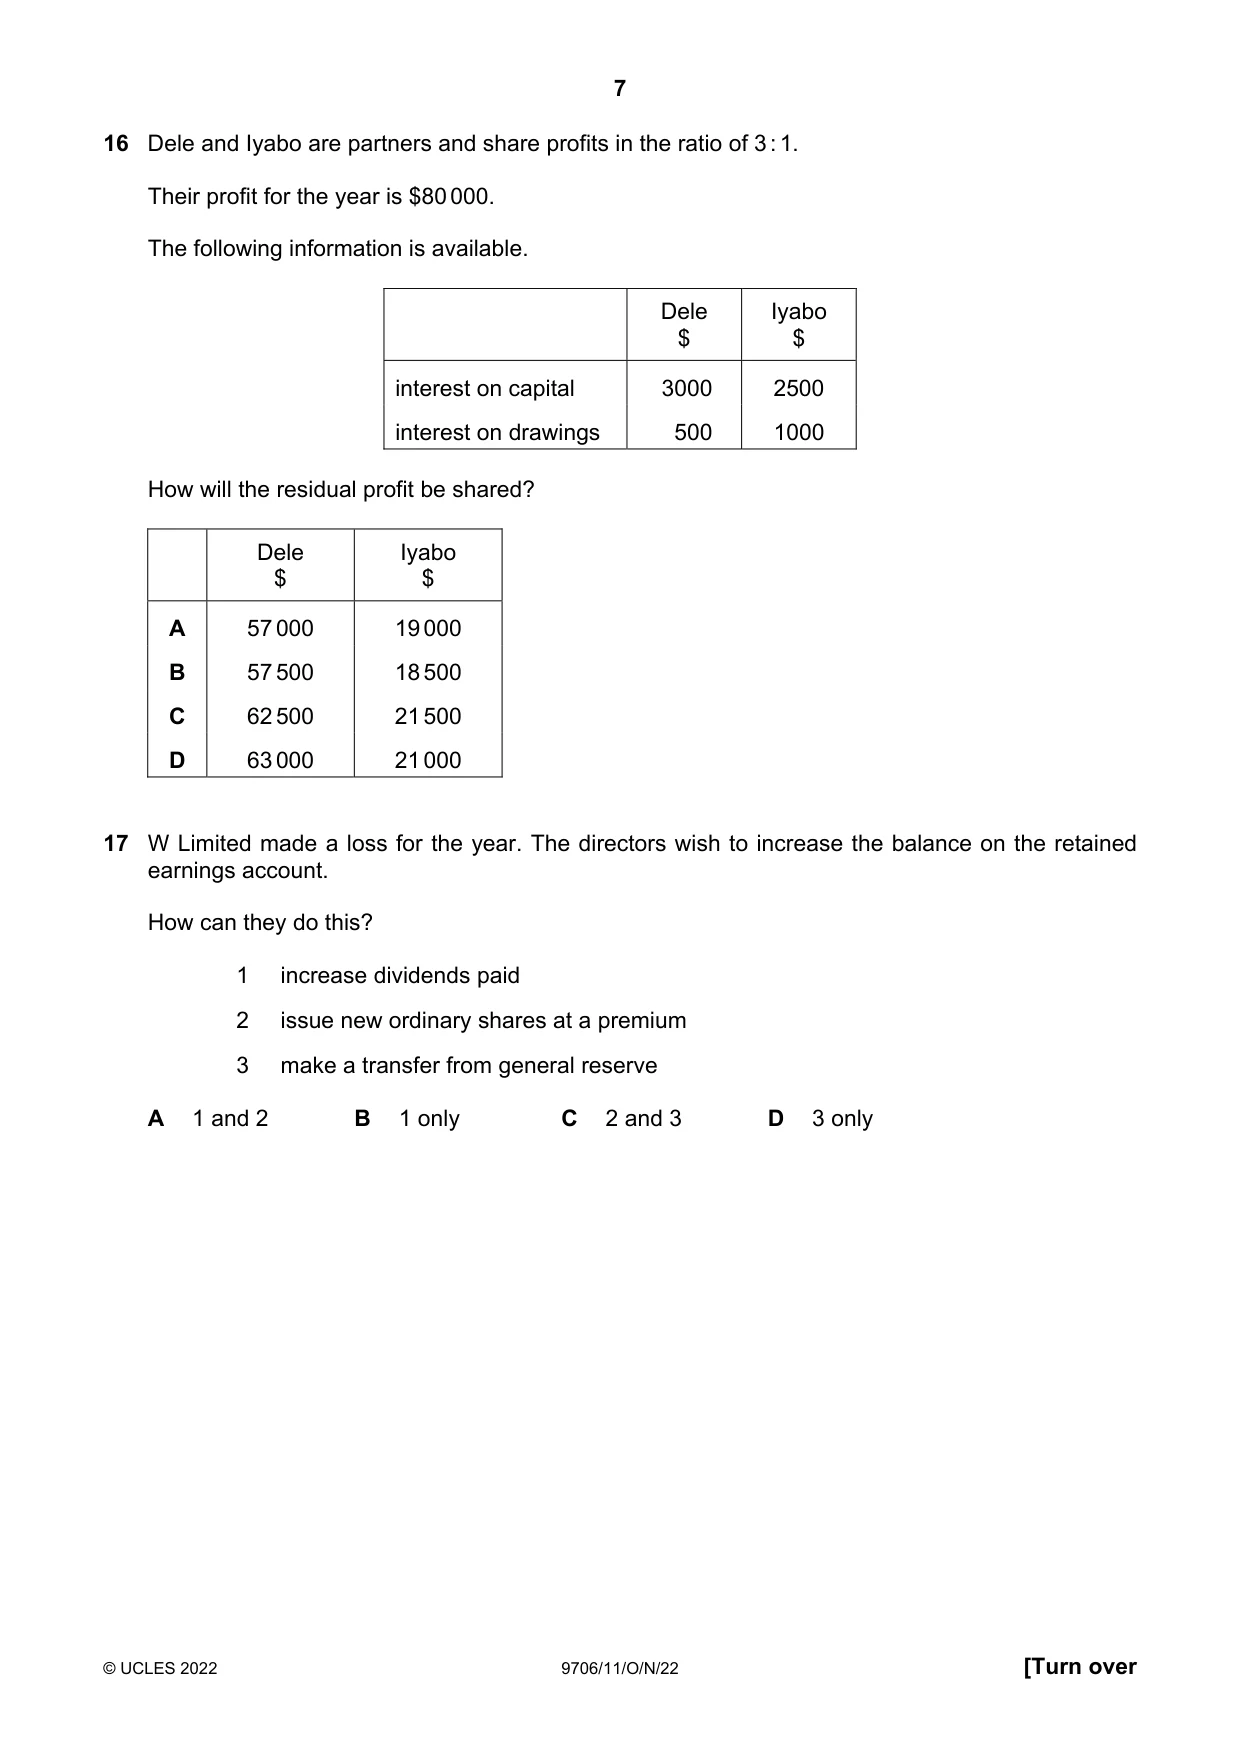
16 Dele and Iyabo are partners and share profits in the ratio of 3 : 1. Their profit for the year is $80 000. The following information is available. Dele Iyabo $ $ interest on capital 3000 2500 interest on drawings 500 1000 How will the residual profit be shared? Dele Iyabo $ $ A 57 000 19 000 B 57 500 18 500 C 62 500 21 500 D 63 000 21 000
Mark scheme: A
Q17 · W Limited made a loss for the year
17 W Limited made a loss for the year. The directors wish to increase the balance on the retained earnings account. How can they do this? 1 increase dividends paid 2 issue new ordinary shares at a premium 3 make a transfer from general reserve A 1 and 2 B 1 only C 2 and 3 D 3 only
Mark scheme: D
Q18 · The following items were taken from the financial statements of a limited company during…
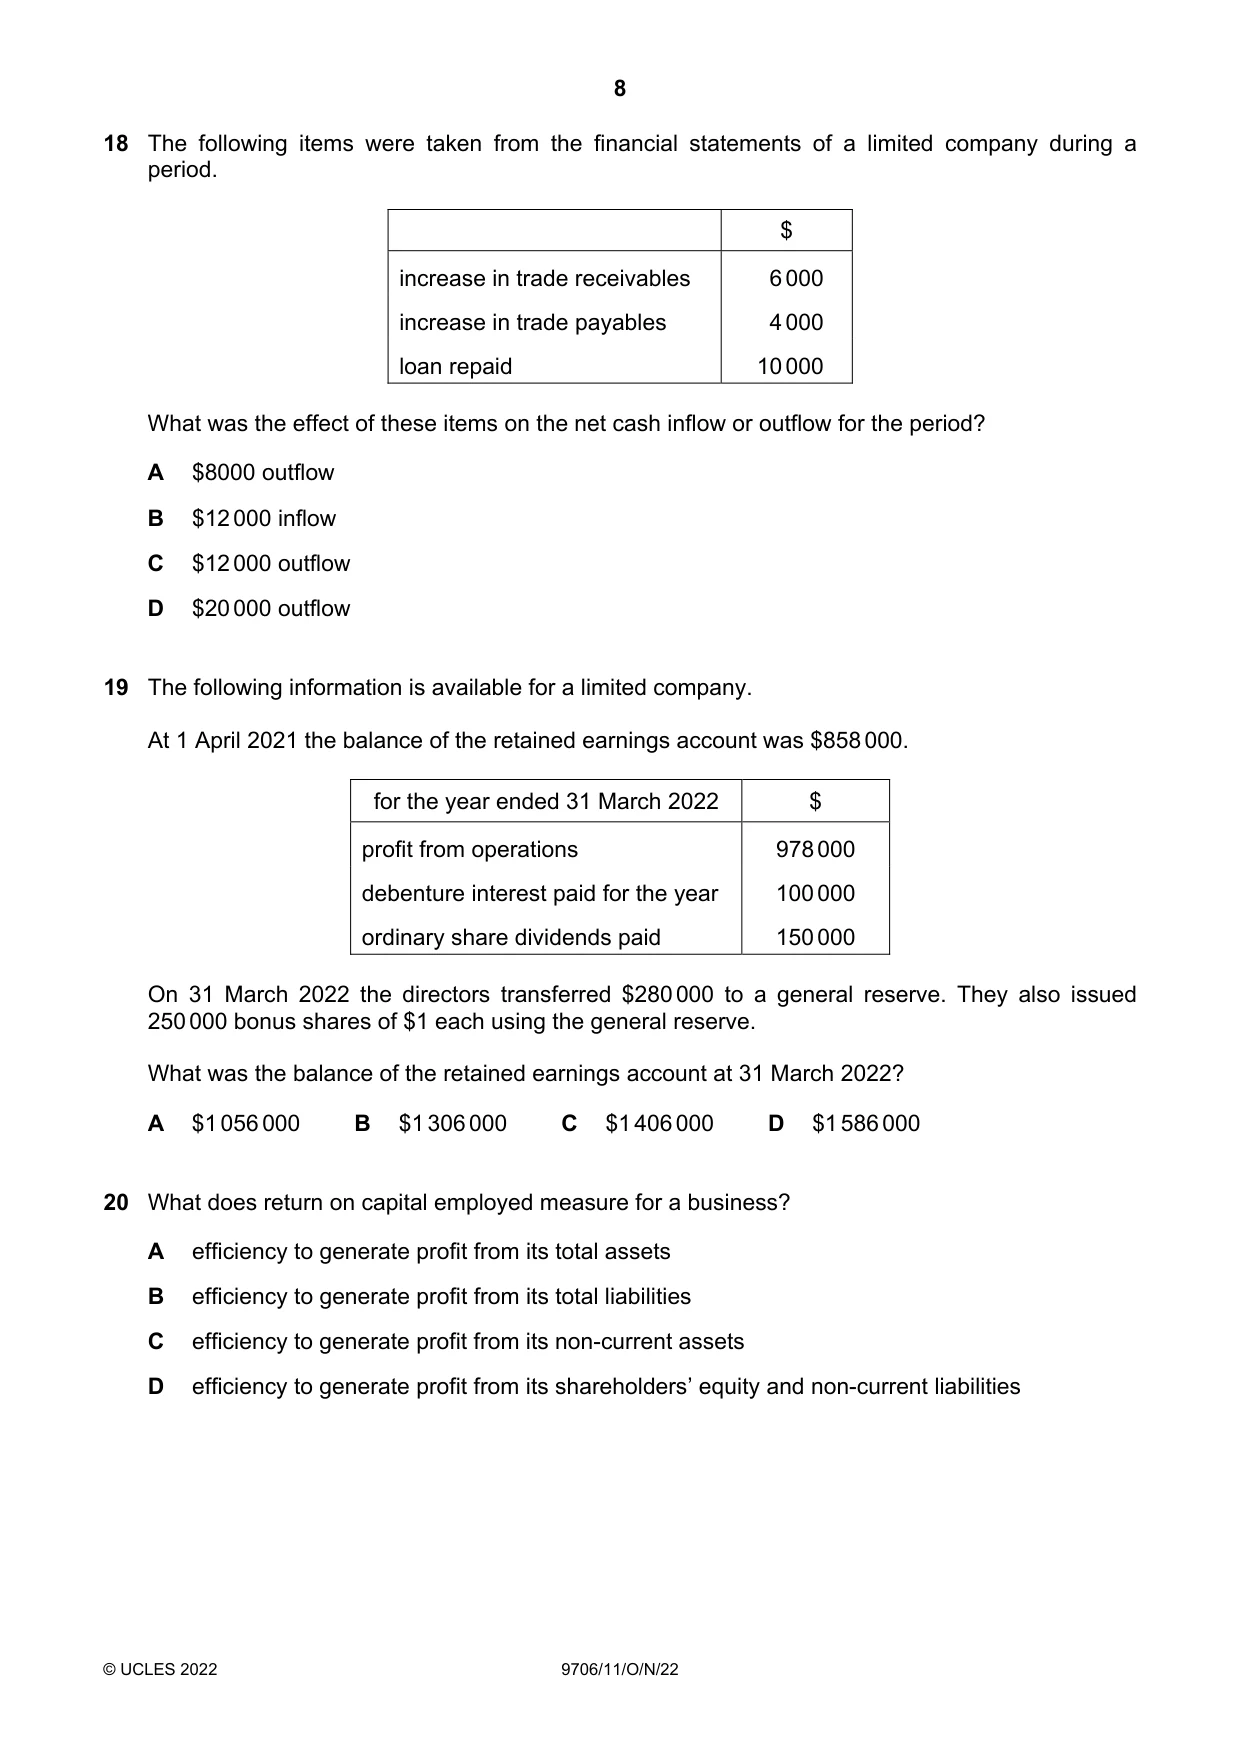
18 The following items were taken from the financial statements of a limited company during a period. $ increase in trade receivables 6 000 increase in trade payables 4 000 loan repaid 10 000 What was the effect of these items on the net cash inflow or outflow for the period? A $8000 outflow B $12 000 inflow C $12 000 outflow D $20 000 outflow
Mark scheme: C
Q19 · The following information is available for a limited company
19 The following information is available for a limited company. At 1 April 2021 the balance of the retained earnings account was $858 000. for the year ended 31 March 2022 $ profit from operations 978 000 debenture interest paid for the year 100 000 ordinary share dividends paid 150 000 On 31 March 2022 the directors transferred $280 000 to a general reserve. They also issued 250 000 bonus shares of $1 each using the general reserve. What was the balance of the retained earnings account at 31 March 2022? A $1 056 000 B $1 306 000 C $1 406 000 D $1 586 000
Mark scheme: B
Q20 · What does return on capital employed measure for a business?
20 What does return on capital employed measure for a business? A efficiency to generate profit from its total assets B efficiency to generate profit from its total liabilities C efficiency to generate profit from its non-current assets D efficiency to generate profit from its shareholders’ equity and non-current liabilities
Mark scheme: D
More questions on Analysis and communication of accounting information
Q21 · The following information was available for a business at the end of a financial year
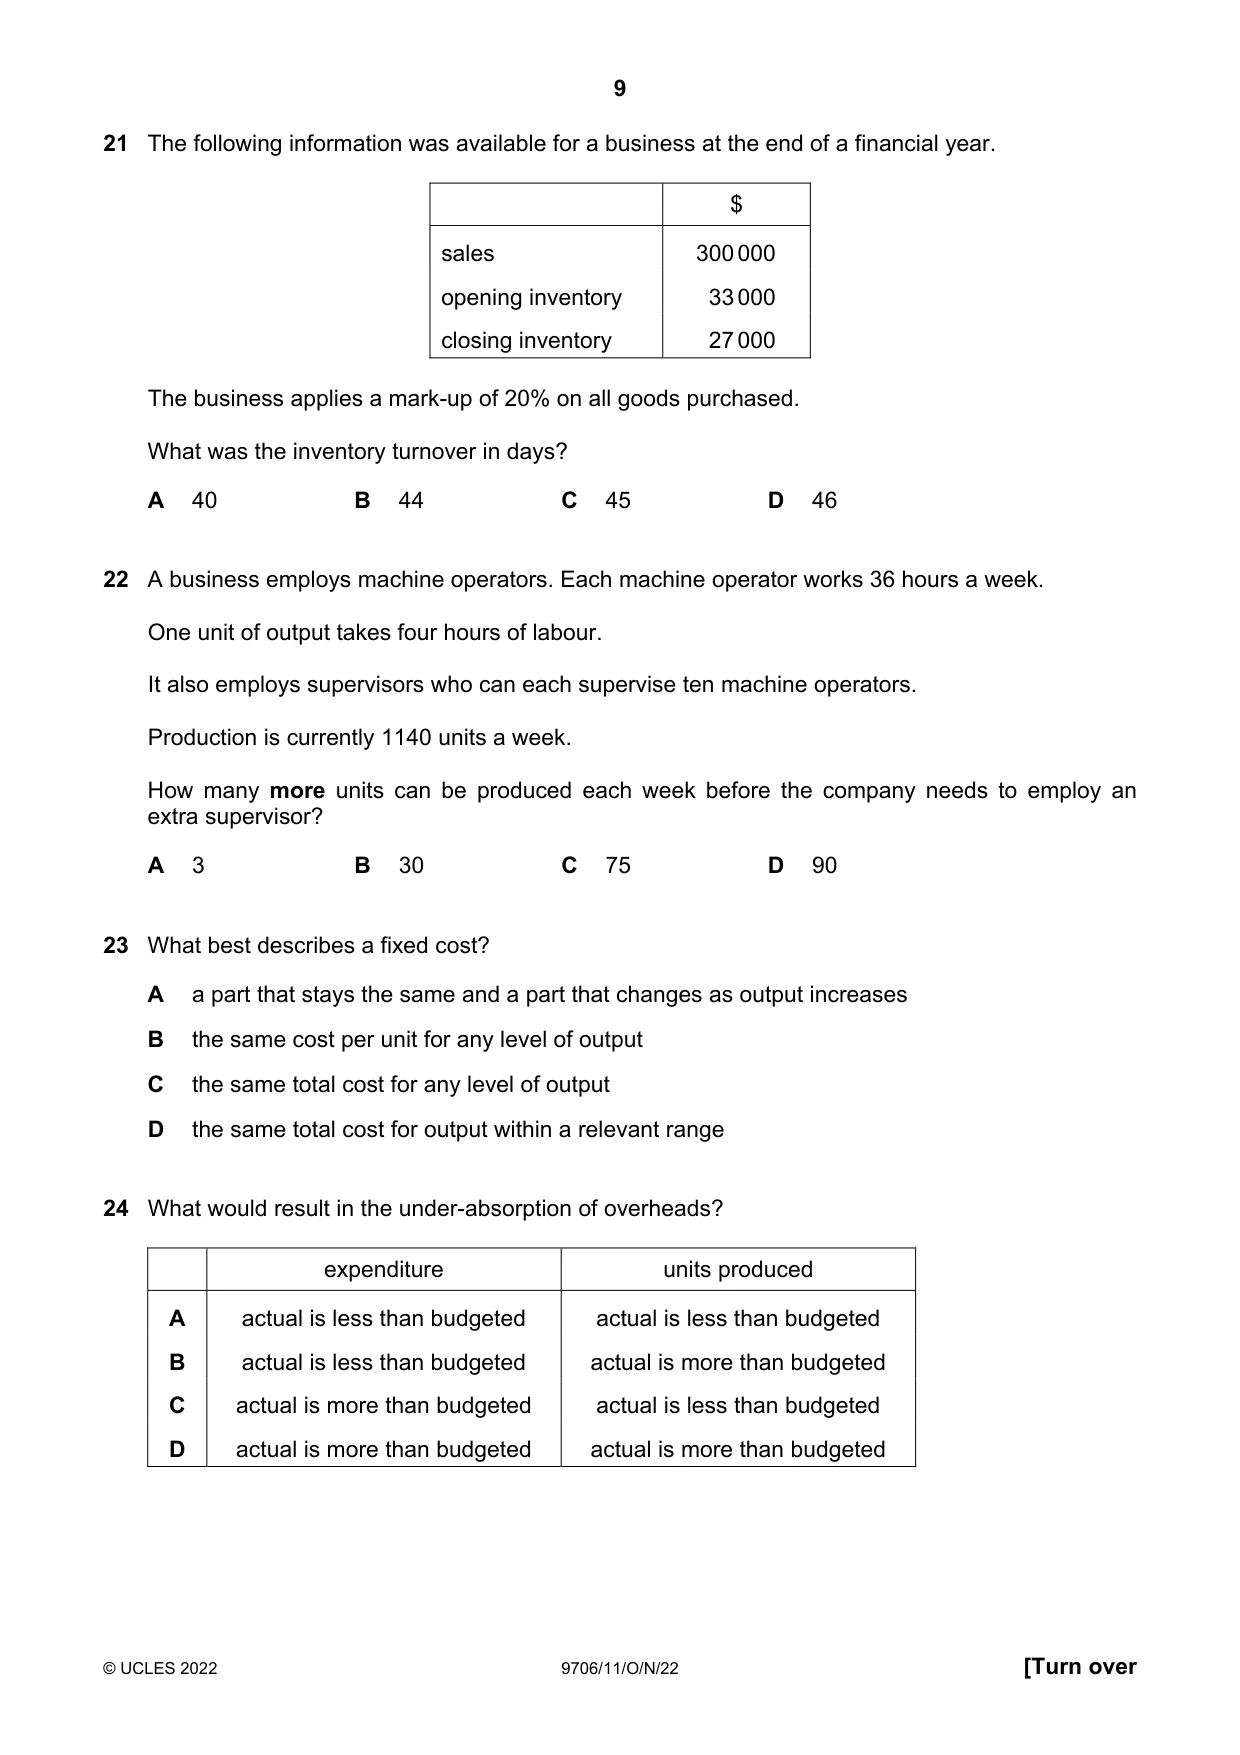
21 The following information was available for a business at the end of a financial year. $ sales 300 000 opening inventory 33 000 closing inventory 27 000 The business applies a mark-up of 20% on all goods purchased. What was the inventory turnover in days? A 40 B 44 C 45 D 46
Mark scheme: B
More questions on Analysis and communication of accounting information
Q22 · A business employs machine operators
22 A business employs machine operators. Each machine operator works 36 hours a week. One unit of output takes four hours of labour. It also employs supervisors who can each supervise ten machine operators. Production is currently 1140 units a week. How many more units can be produced each week before the company needs to employ an extra supervisor? A 3 B 30 C 75 D 90
Mark scheme: B
Q23 · What best describes a fixed cost?
23 What best describes a fixed cost? A a part that stays the same and a part that changes as output increases B the same cost per unit for any level of output C the same total cost for any level of output D the same total cost for output within a relevant range
Mark scheme: D
Q24 · What would result in the under-absorption of overheads?
24 What would result in the under-absorption of overheads? expenditure units produced A actual is less than budgeted actual is less than budgeted B actual is less than budgeted actual is more than budgeted C actual is more than budgeted actual is less than budgeted D actual is more than budgeted actual is more than budgeted
Mark scheme: C
Q25 · A company has received an order to supply 3000 pairs of safety glasses
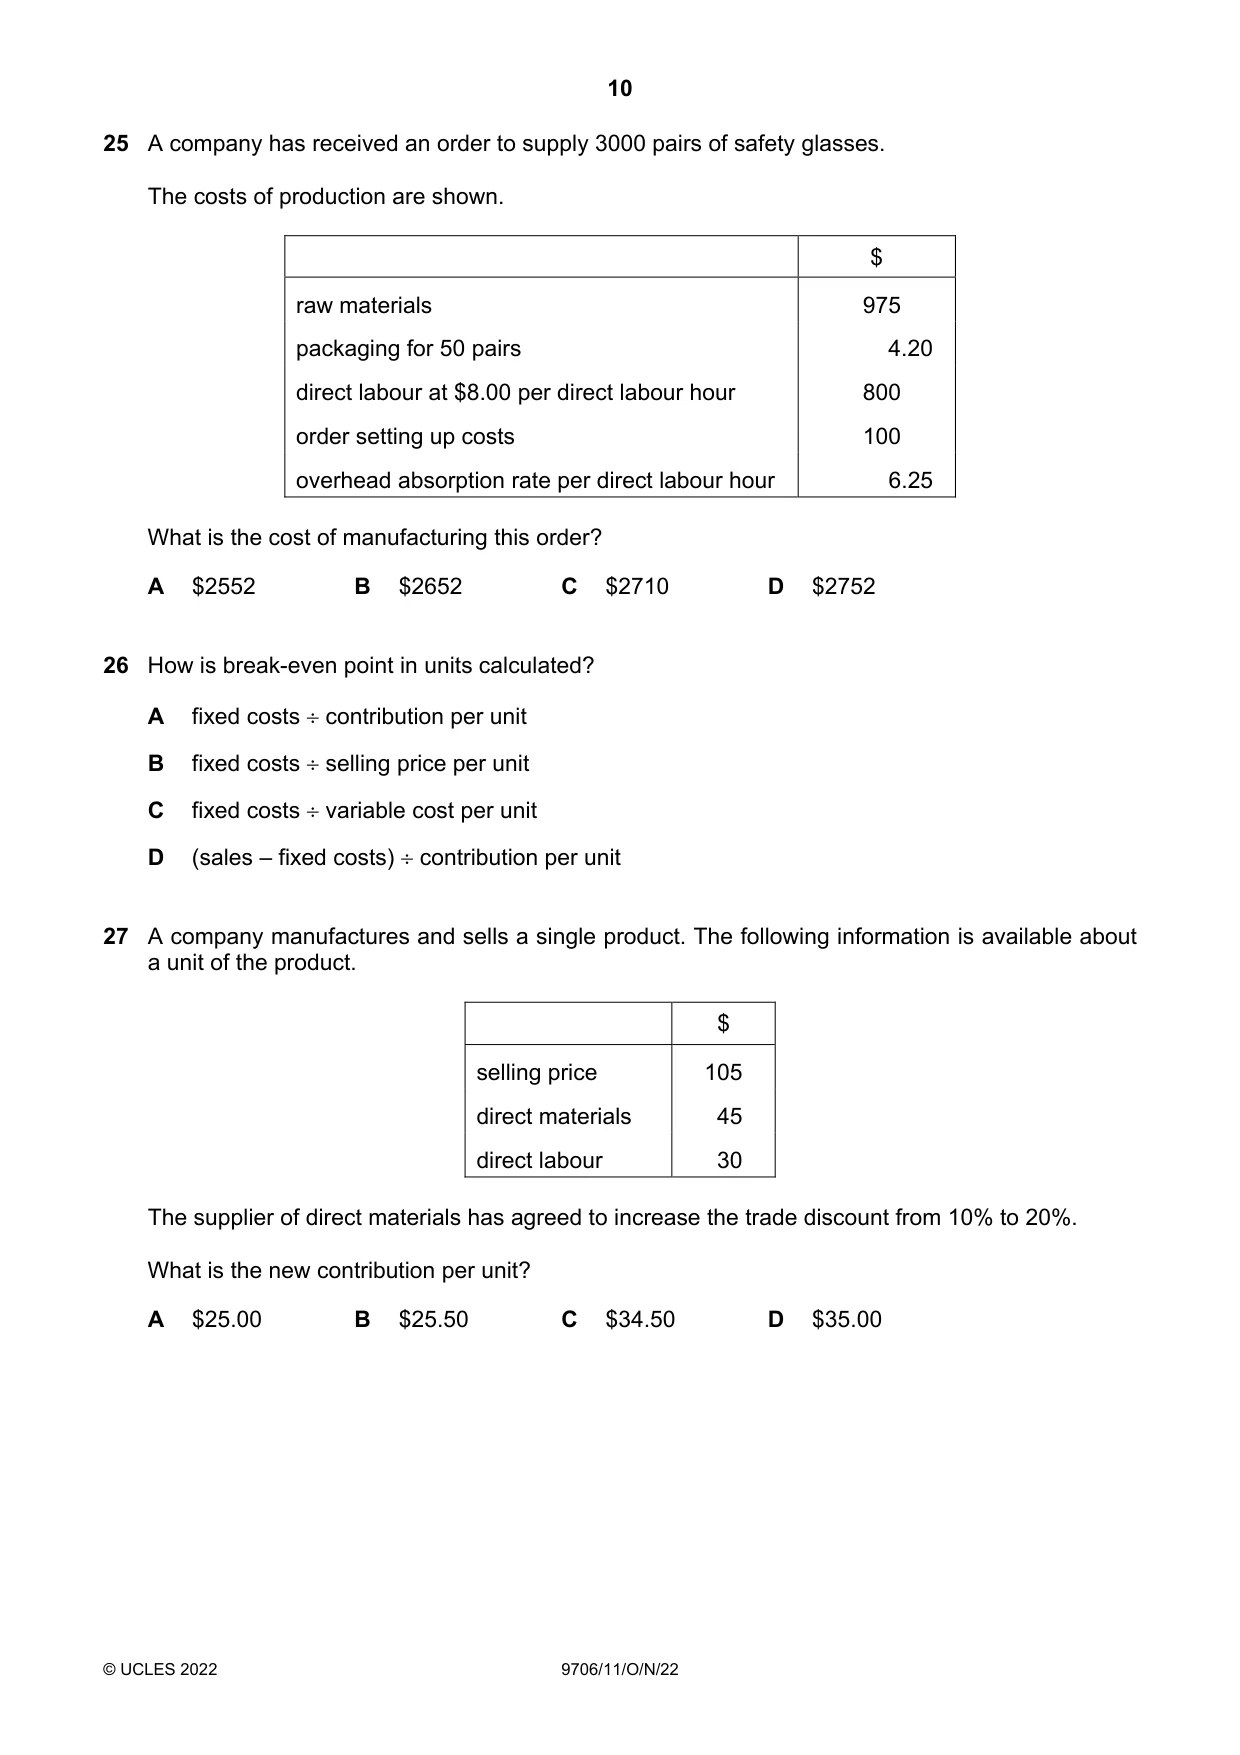
25 A company has received an order to supply 3000 pairs of safety glasses. The costs of production are shown. $ raw materials 975 packaging for 50 pairs 4.20 direct labour at $8.00 per direct labour hour 800 order setting up costs 100 overhead absorption rate per direct labour hour 6.25 What is the cost of manufacturing this order? A $2552 B $2652 C $2710 D $2752
Mark scheme: D
Q26 · How is break-even point in units calculated?
26 How is break-even point in units calculated? A fixed costs ÷ contribution per unit B fixed costs ÷ selling price per unit C fixed costs ÷ variable cost per unit D (sales – fixed costs) ÷ contribution per unit
Mark scheme: A
Q27 · A company manufactures and sells a single product
27 A company manufactures and sells a single product. The following information is available about a unit of the product. $ selling price 105 direct materials 45 direct labour 30 The supplier of direct materials has agreed to increase the trade discount from 10% to 20%. What is the new contribution per unit? A $25.00 B $25.50 C $34.50 D $35.00
Mark scheme: D
Q28 · The fixed costs of a business increase
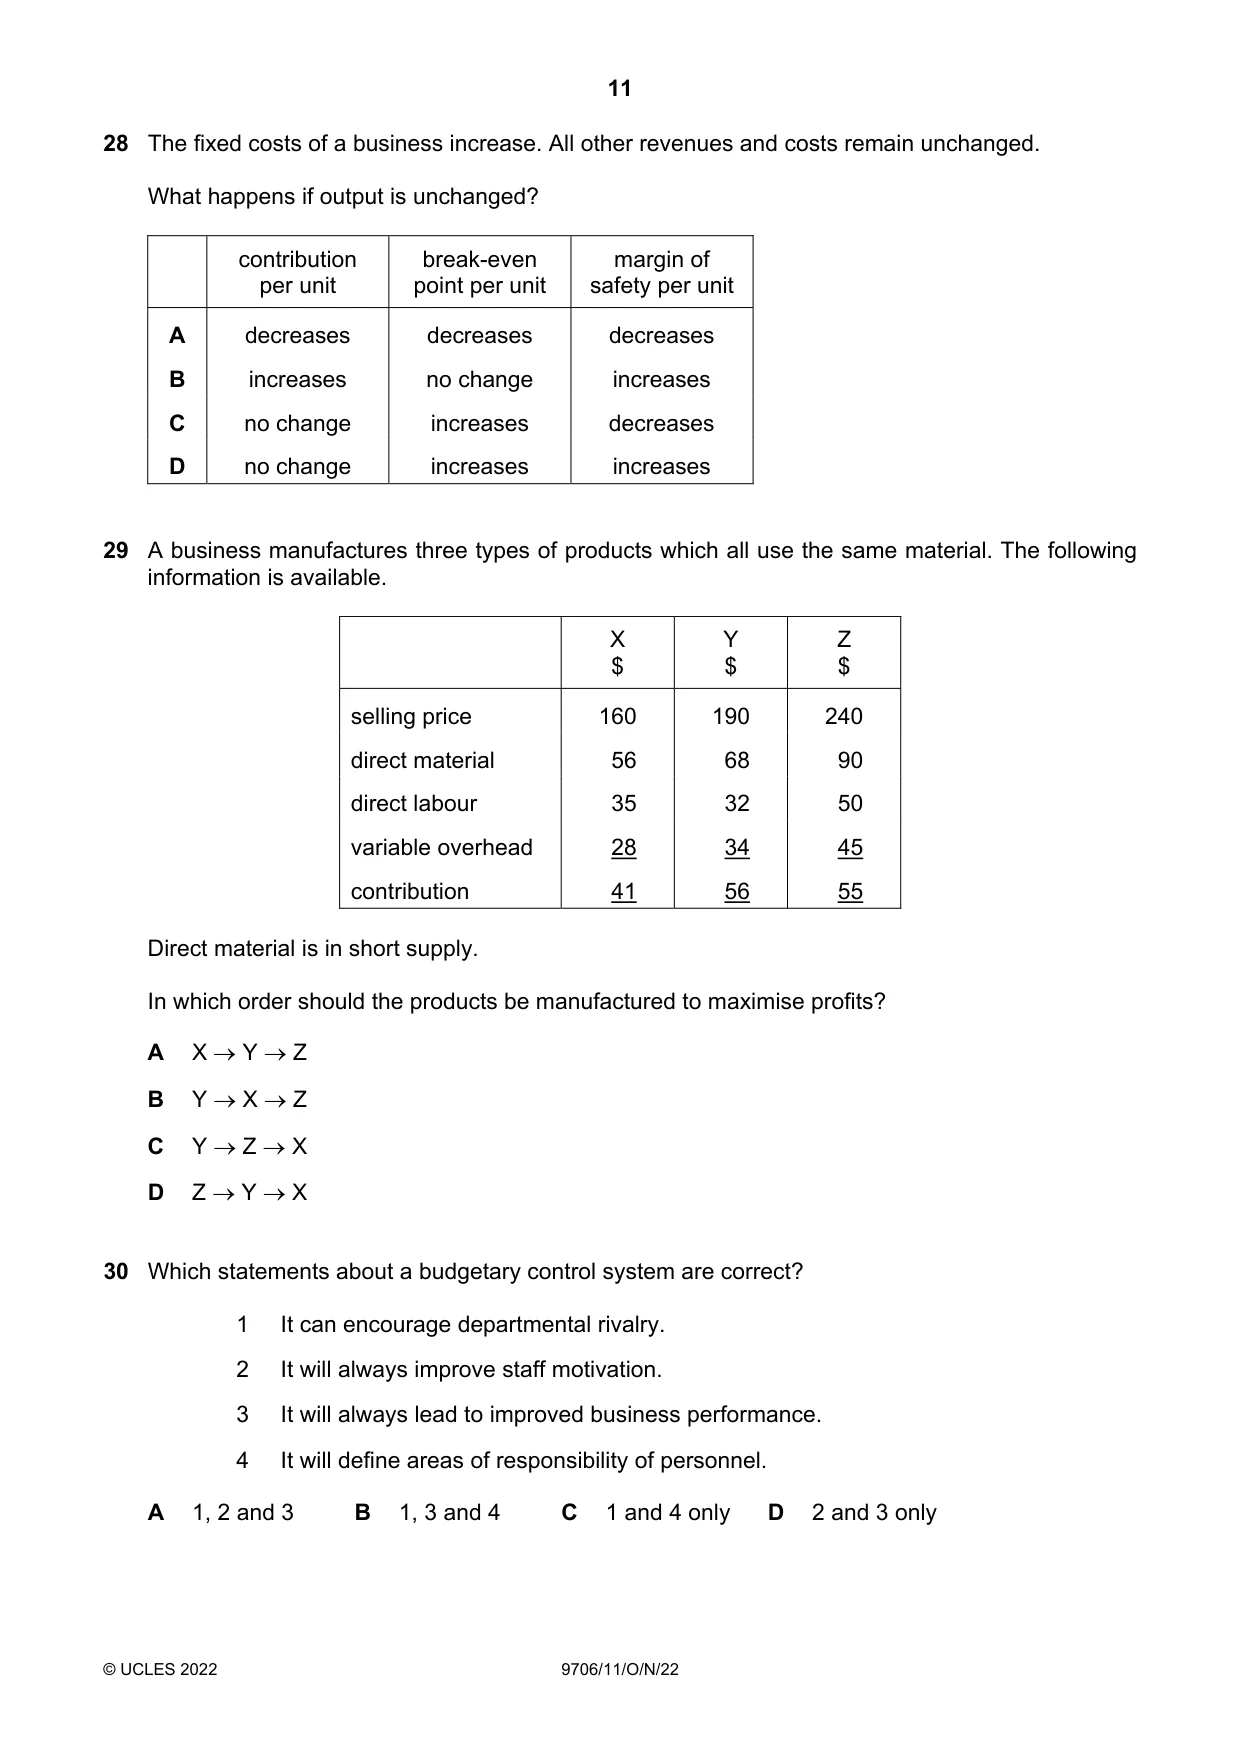
28 The fixed costs of a business increase. All other revenues and costs remain unchanged. What happens if output is unchanged? contribution break-even margin of per unit point per unit safety per unit A decreases decreases decreases B increases no change increases C no change increases decreases D no change increases increases
Mark scheme: C
Q29 · A business manufactures three types of products which all use the same material
29 A business manufactures three types of products which all use the same material. The following information is available. X Y Z $ $ $ selling price 160 190 240 direct material 56 68 90 direct labour 35 32 50 variable overhead 28 34 45 contribution 41 56 55 Direct material is in short supply. In which order should the products be manufactured to maximise profits? A X → Y → Z B Y → X → Z C Y → Z → X D Z → Y → X
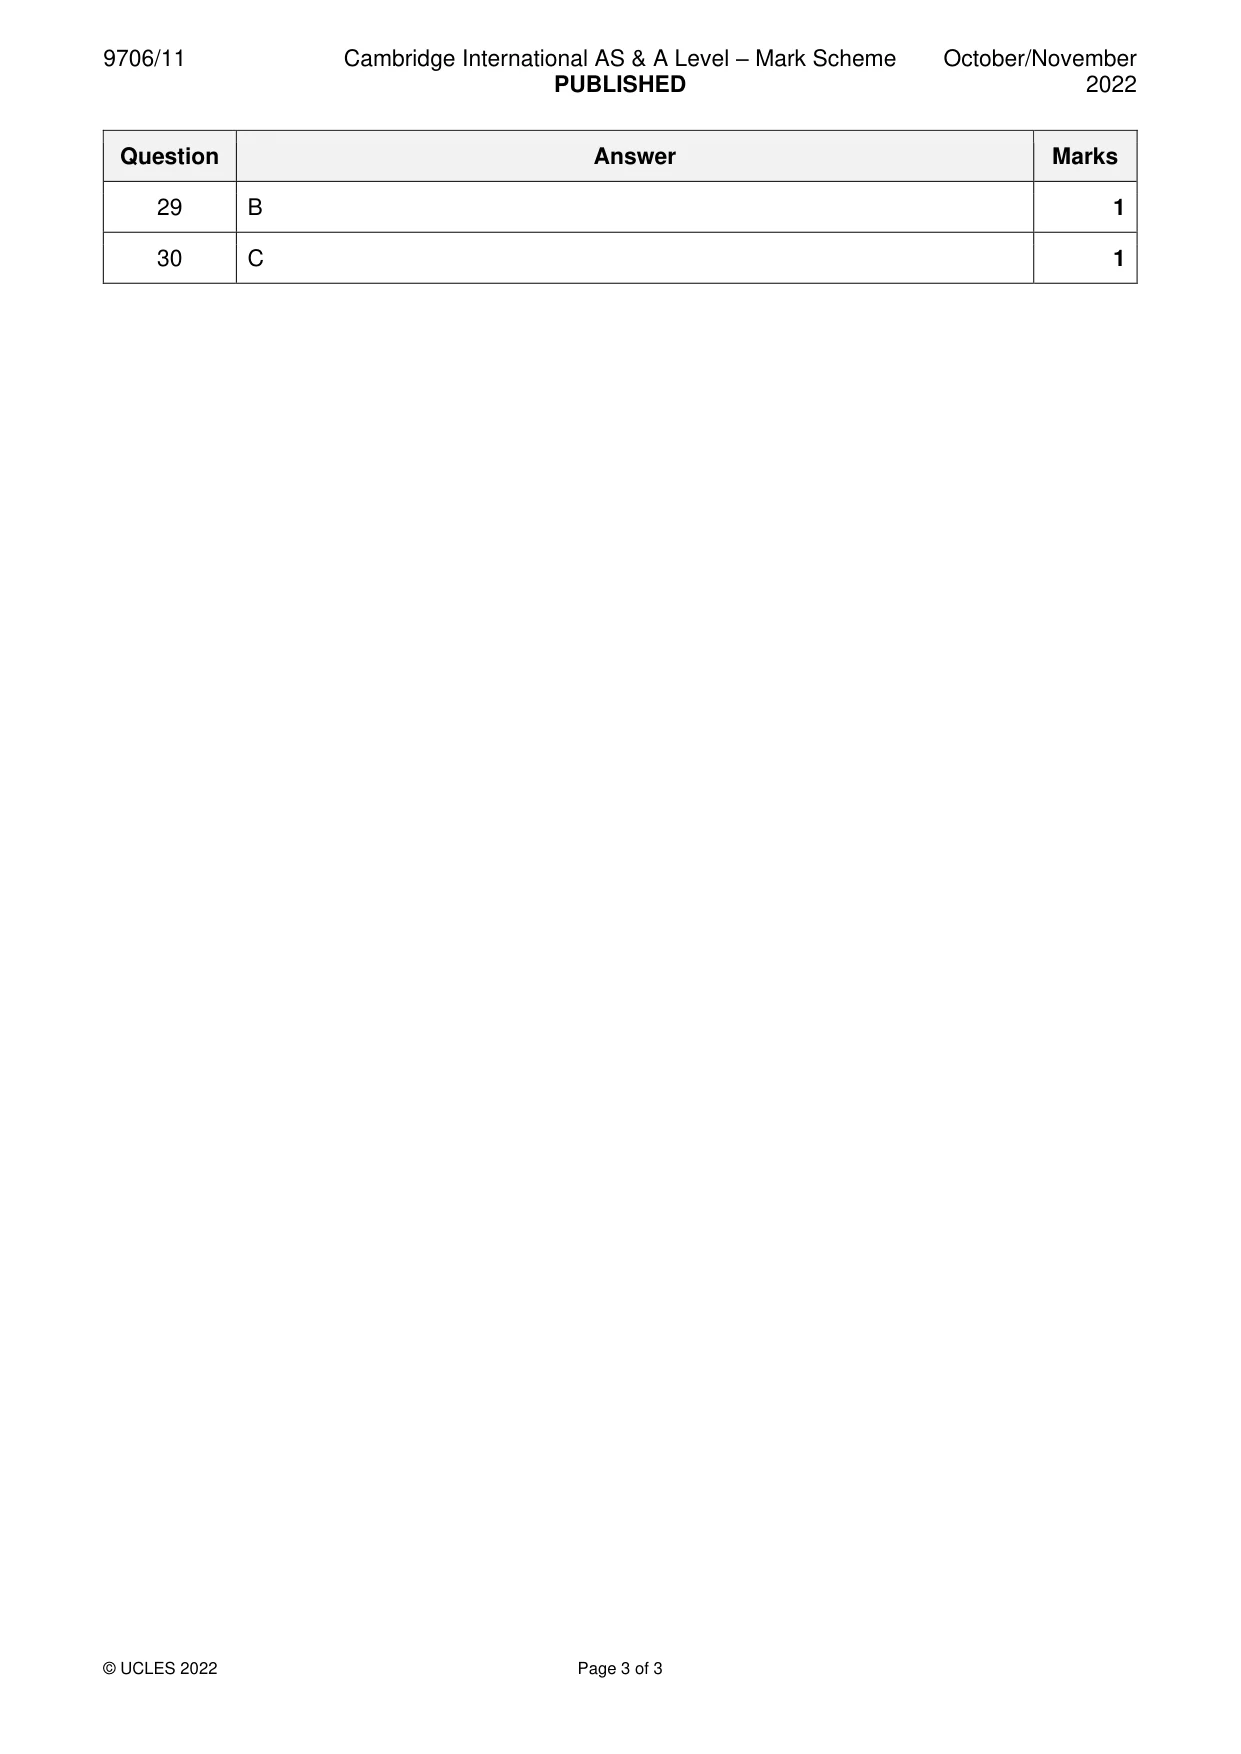
Mark scheme: B
Q30 · Which statements about a budgetary control system are correct?
30 Which statements about a budgetary control system are correct? 1 It can encourage departmental rivalry. 2 It will always improve staff motivation. 3 It will always lead to improved business performance. 4 It will define areas of responsibility of personnel. A 1, 2 and 3 B 1, 3 and 4 C 1 and 4 only D 2 and 3 only
Mark scheme: C
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
5Traditional costing methods5Preparation of financial statements4Accounting for non-current assets3Costs and cost behaviour3Reconciliation and verification3The accounting system3Analysis and communication of accounting information2Budgeting and budgetary control1Types of business entity1What you needed in this session
Cambridge’s own grade thresholds for 2022 Oct/Nov, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.