Cambridge A Level Accounting 9706 — 2014 Oct/Nov Paper 1 · Variant 1
9706/11/O/N/14 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
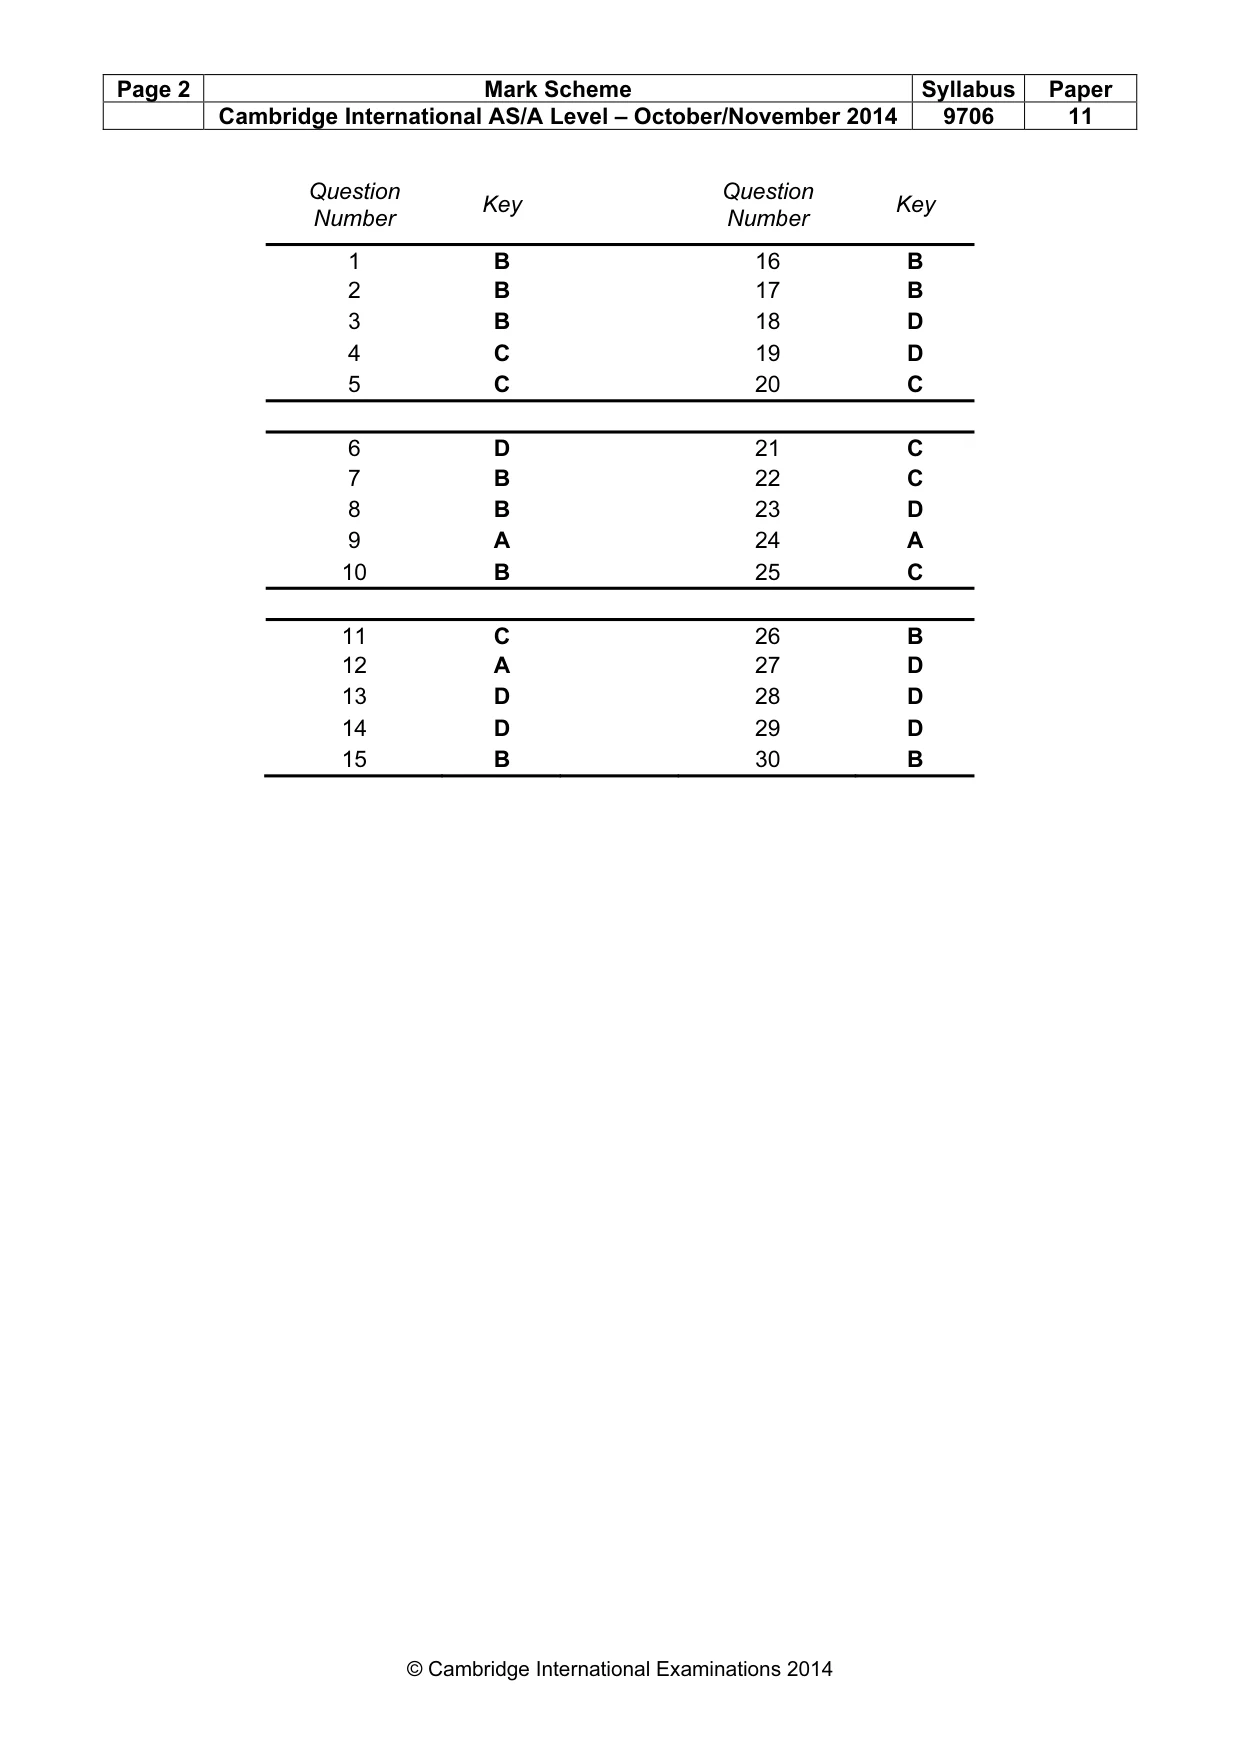
Mark scheme2 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · A non-current liability has been included as a current liability
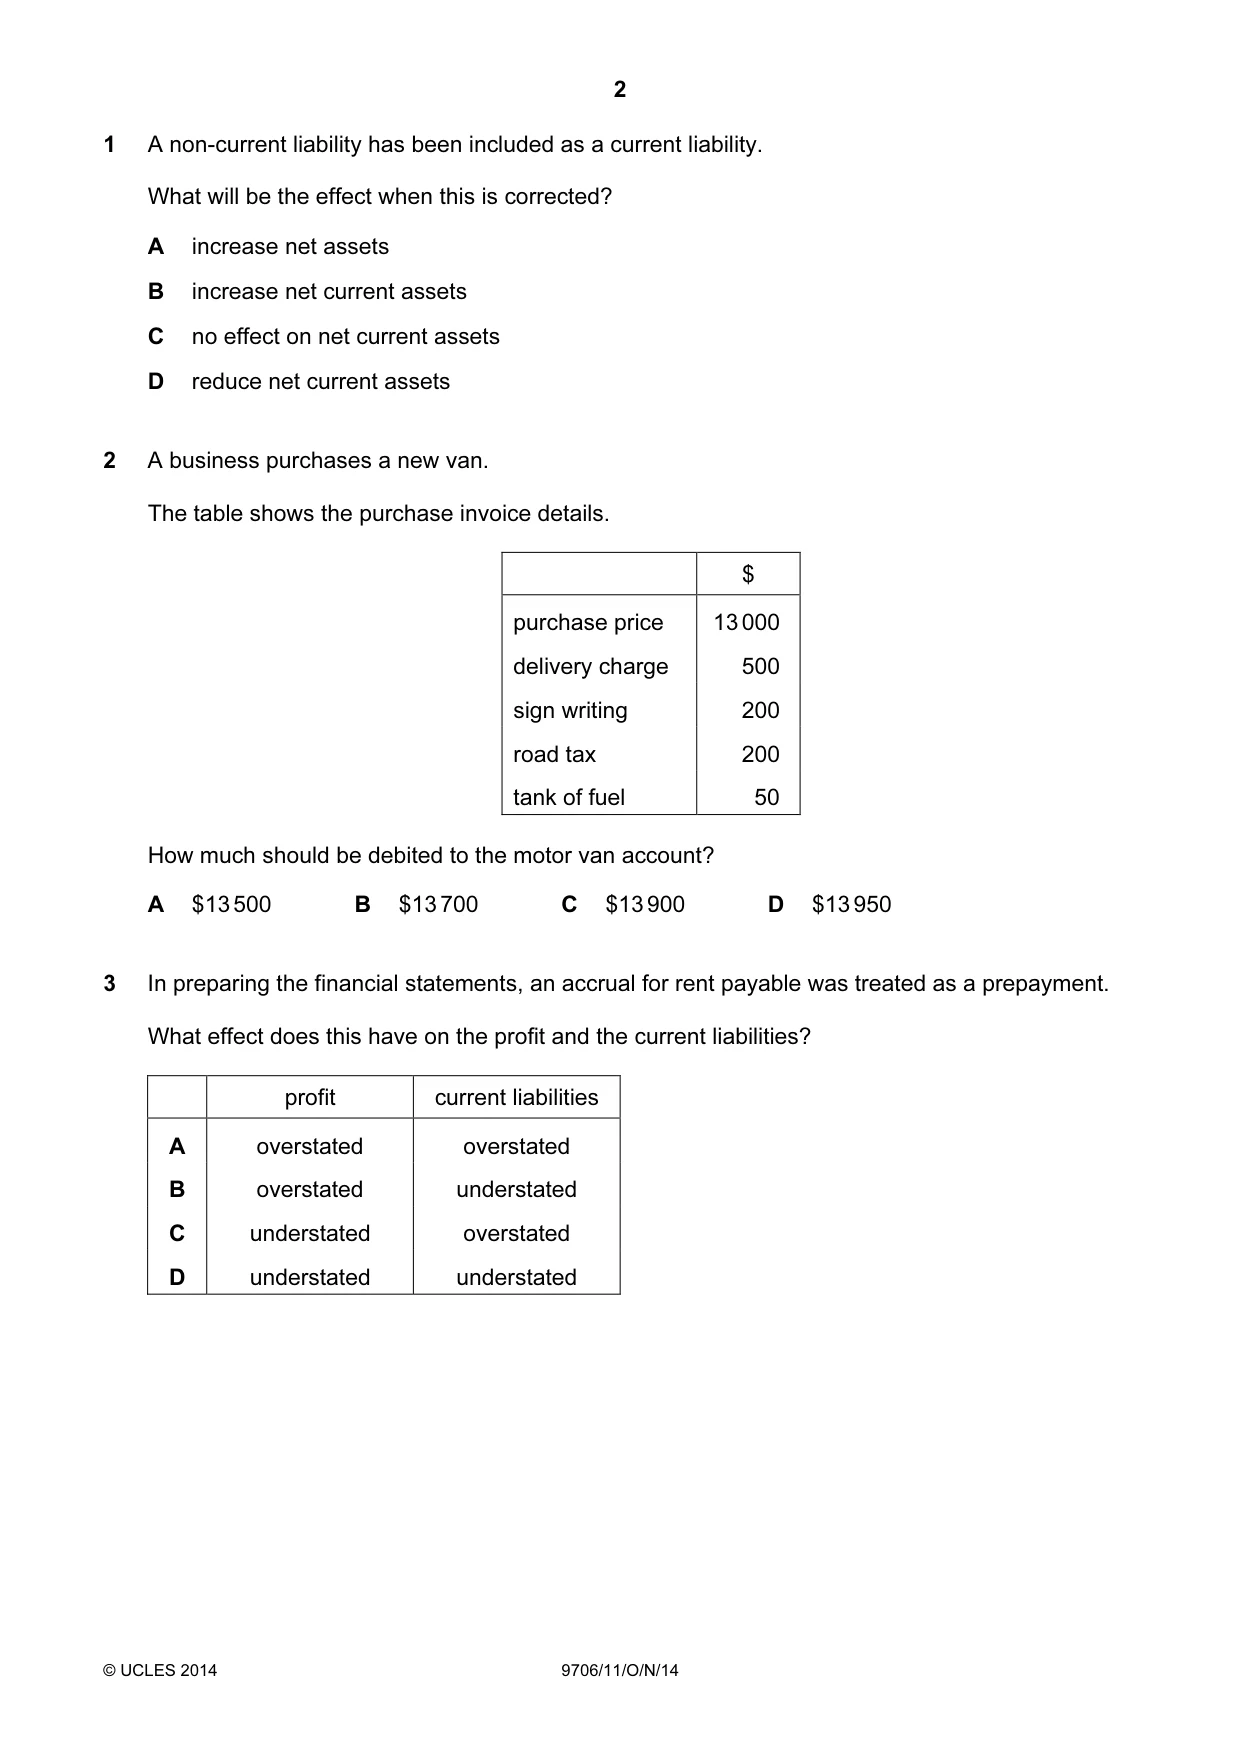
1 A non-current liability has been included as a current liability. What will be the effect when this is corrected? A increase net assets B increase net current assets C no effect on net current assets D reduce net current assets
Mark scheme: B
Q2 · A business purchases a new van
2 A business purchases a new van. The table shows the purchase invoice details. $ purchase price 13 000 delivery charge 500 sign writing 200 road tax 200 tank of fuel 50 How much should be debited to the motor van account? A $13 500 B $13 700 C $13 900 D $13 950
Mark scheme: B
Q3 · In preparing the financial statements, an accrual for rent payable was treated as a…
3 In preparing the financial statements, an accrual for rent payable was treated as a prepayment. What effect does this have on the profit and the current liabilities? profit current liabilities A overstated overstated B overstated understated C understated overstated D understated understated
Mark scheme: B
Q4 · The following information is available for a business
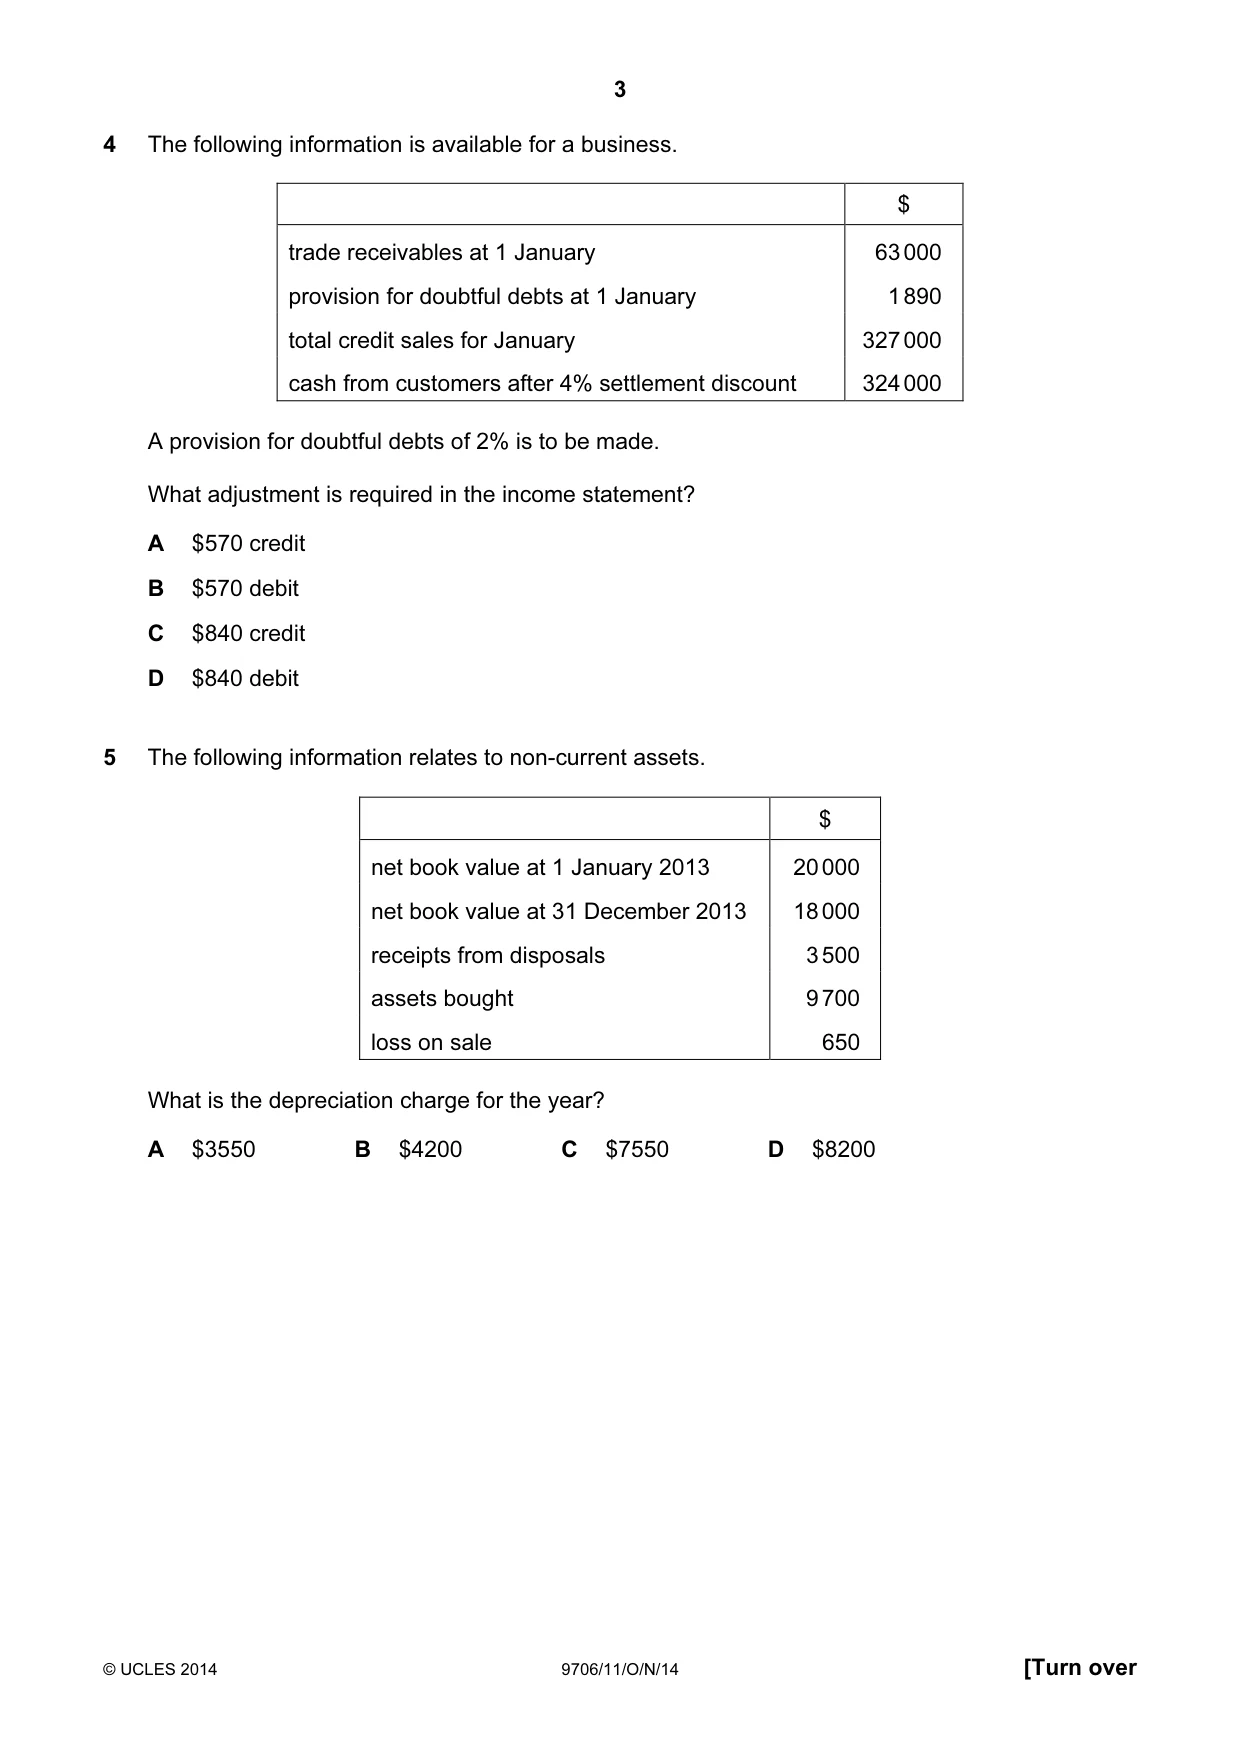
4 The following information is available for a business. $ trade receivables at 1 January 63 000 provision for doubtful debts at 1 January 1 890 total credit sales for January 327 000 cash from customers after 4% settlement discount 324 000 A provision for doubtful debts of 2% is to be made. What adjustment is required in the income statement? A $570 credit B $570 debit C $840 credit D $840 debit
Mark scheme: C
Q5 · The following information relates to non-current assets
5 The following information relates to non-current assets. $ net book value at 1 January 2013 20 000 net book value at 31 December 2013 18 000 receipts from disposals 3 500 assets bought 9 700 loss on sale 650 What is the depreciation charge for the year? A $3550 B $4200 C $7550 D $8200
Mark scheme: C
Q6 · The table shows information from a sales ledger control account
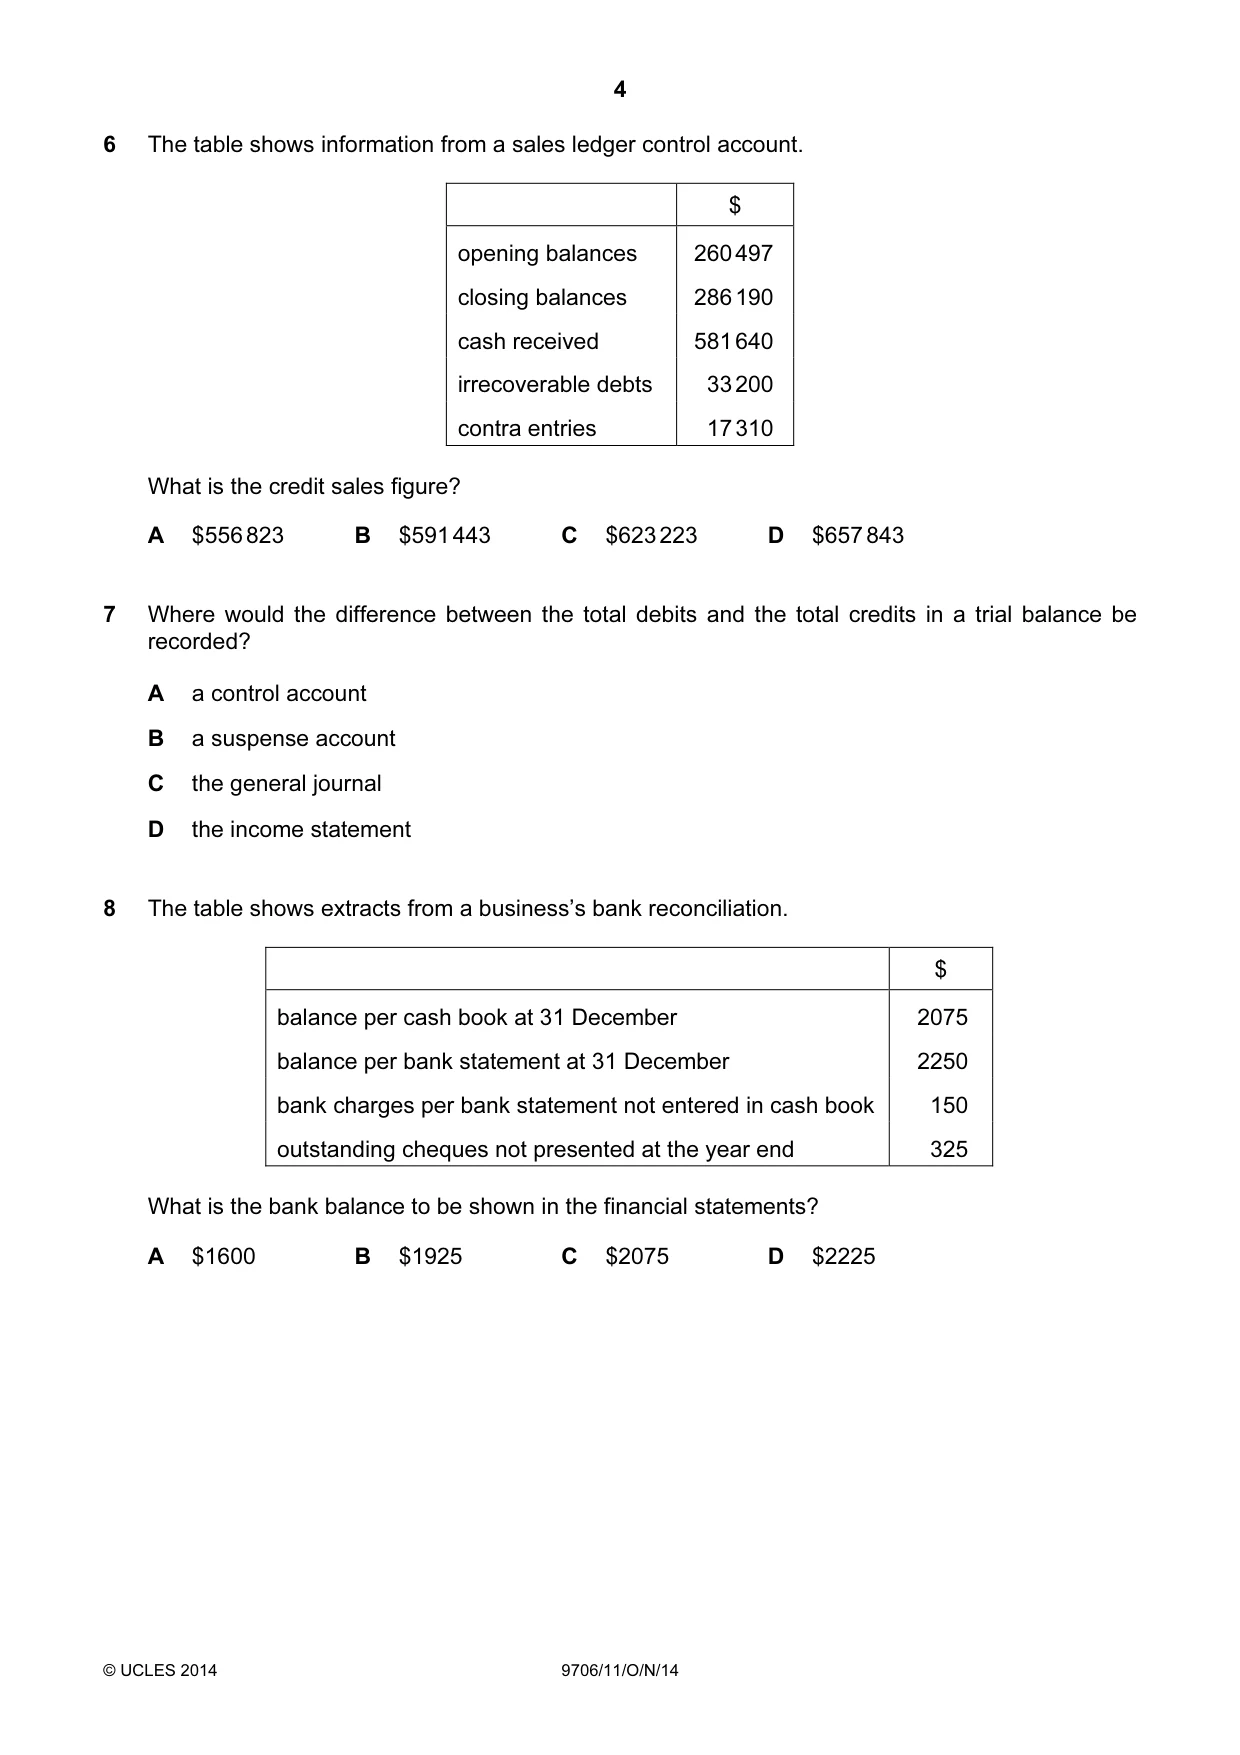
6 The table shows information from a sales ledger control account. $ opening balances 260 497 closing balances 286 190 cash received 581 640 irrecoverable debts 33 200 contra entries 17 310 What is the credit sales figure? A $556 823 B $591 443 C $623 223 D $657 843
Mark scheme: D
Q7 · Where would the difference between the total debits and the total credits in a trial…
7 Where would the difference between the total debits and the total credits in a trial balance be recorded? A a control account B a suspense account C the general journal D the income statement
Mark scheme: B
Q8 · The table shows extracts from a business’s bank reconciliation
8 The table shows extracts from a business’s bank reconciliation. $ balance per cash book at 31 December 2075 balance per bank statement at 31 December 2250 bank charges per bank statement not entered in cash book 150 outstanding cheques not presented at the year end 325 What is the bank balance to be shown in the financial statements? A $1600 B $1925 C $2075 D $2225
Mark scheme: B
Q9 · During the past month, a business lost some inventory because of theft
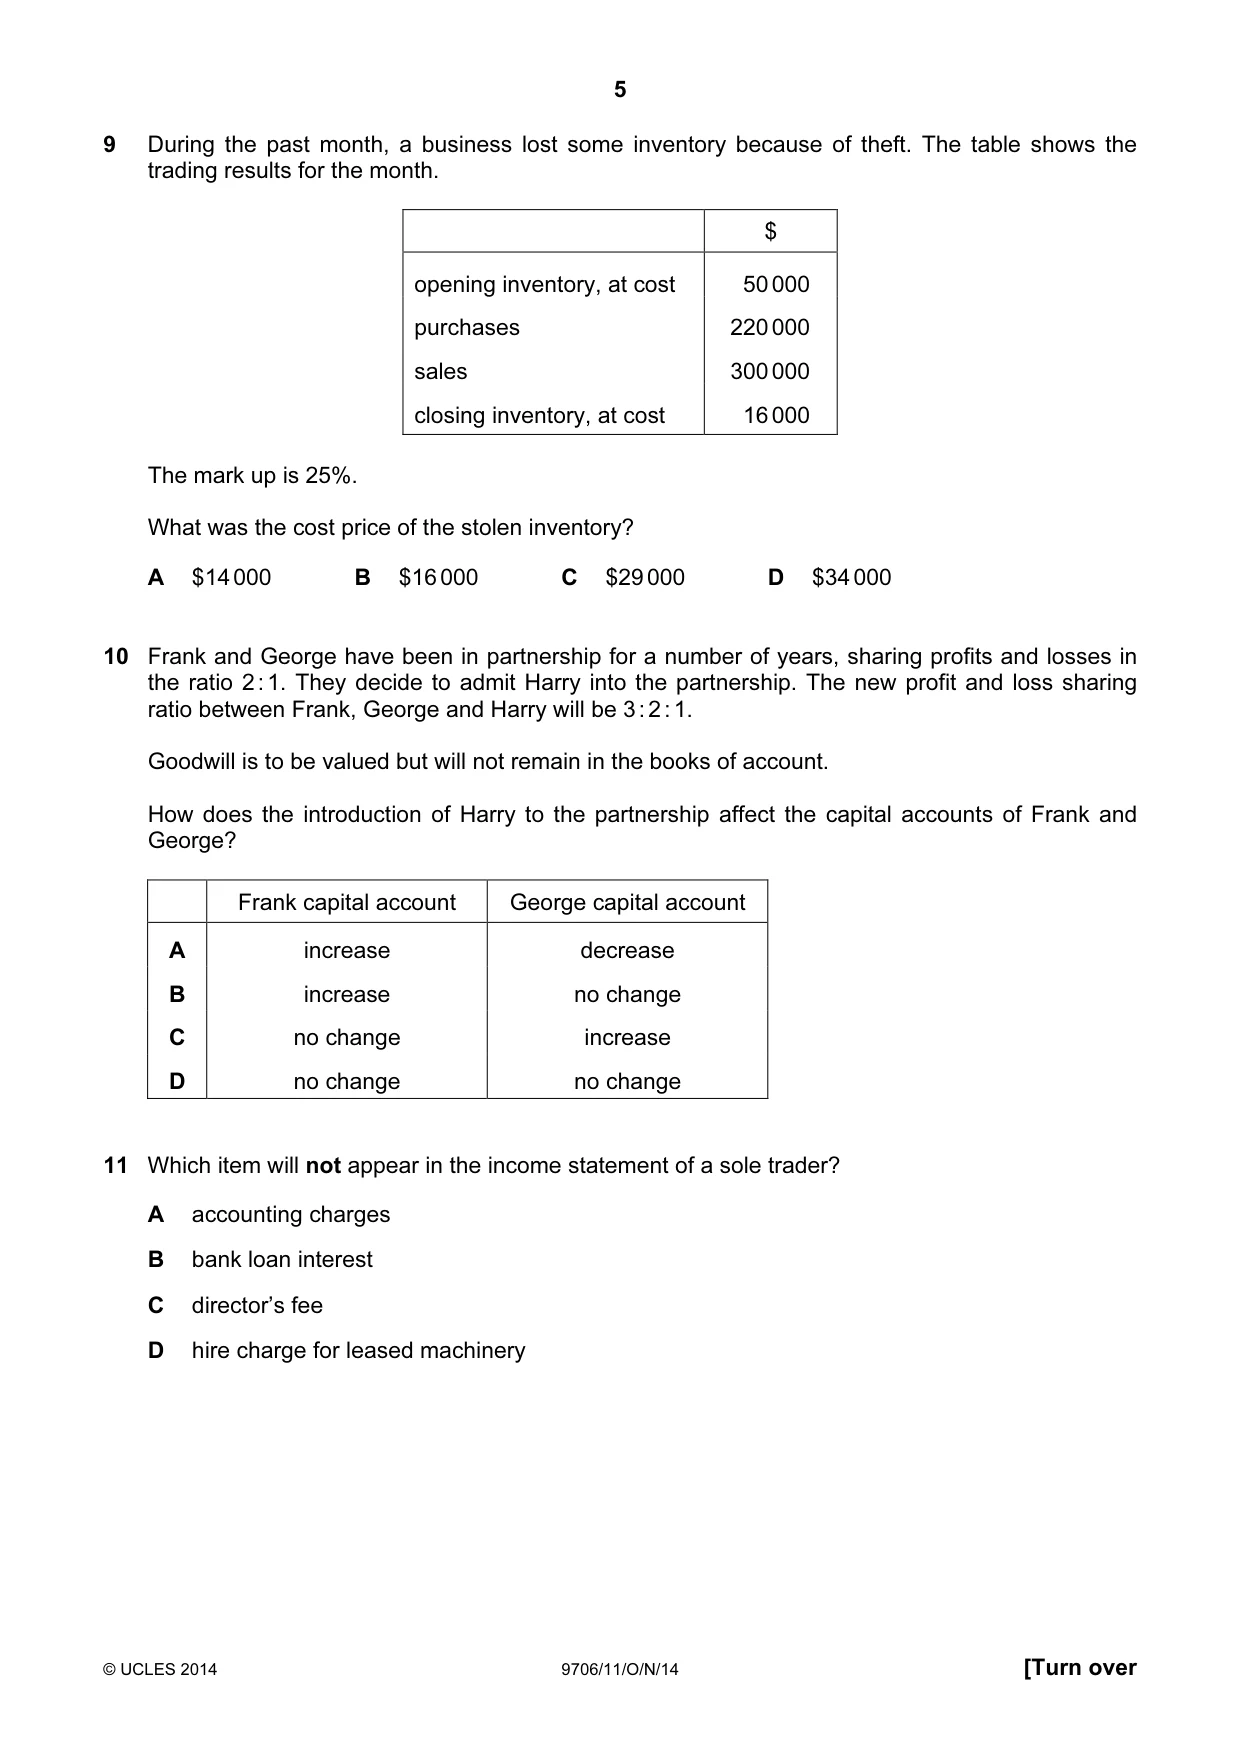
9 During the past month, a business lost some inventory because of theft. The table shows the trading results for the month. $ opening inventory, at cost 50 000 purchases 220 000 sales 300 000 closing inventory, at cost 16 000 The mark up is 25%. What was the cost price of the stolen inventory? A $14 000 B $16 000 C $29 000 D $34 000
Mark scheme: A
Q10 · Frank and George have been in partnership for a number of years, sharing profits and…
10 Frank and George have been in partnership for a number of years, sharing profits and losses in the ratio 2 : 1. They decide to admit Harry into the partnership. The new profit and loss sharing ratio between Frank, George and Harry will be 3 : 2 : 1. Goodwill is to be valued but will not remain in the books of account. How does the introduction of Harry to the partnership affect the capital accounts of Frank and George? Frank capital account George capital account A increase decrease B increase no change C no change increase D no change no change
Mark scheme: B
Q11 · Which item will not appear in the income statement of a sole trader?
11 Which item will not appear in the income statement of a sole trader? A accounting charges B bank loan interest C director’s fee D hire charge for leased machinery
Mark scheme: C
Q12 · What is not part of a company’s equity?
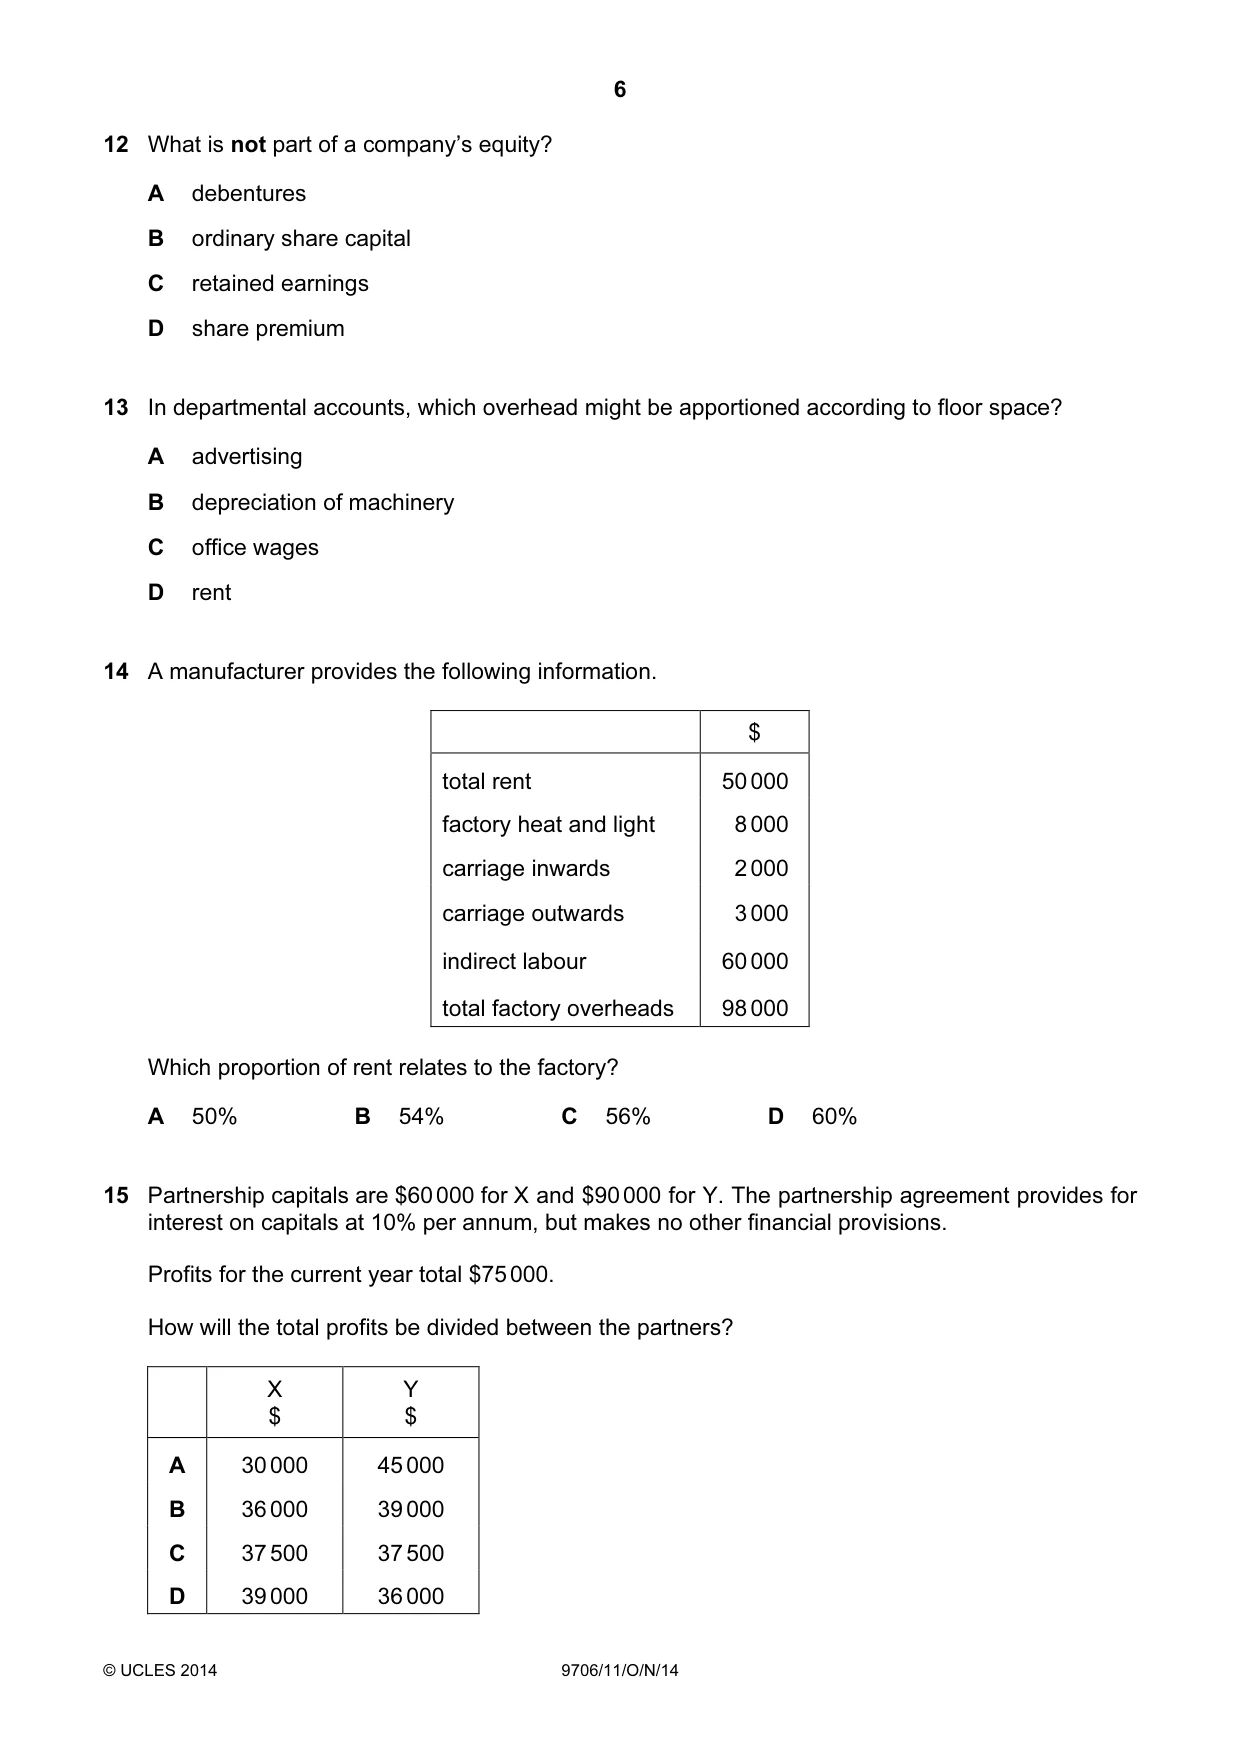
12 What is not part of a company’s equity? A debentures B ordinary share capital C retained earnings D share premium
Mark scheme: A
Q13 · In departmental accounts, which overhead might be apportioned according to floor space?
13 In departmental accounts, which overhead might be apportioned according to floor space? A advertising B depreciation of machinery C office wages D rent
Mark scheme: D
Q14 · A manufacturer provides the following information
14 A manufacturer provides the following information. $ total rent 50 000 factory heat and light 8 000 carriage inwards 2 000 carriage outwards 3 000 indirect labour 60 000 total factory overheads 98 000 Which proportion of rent relates to the factory? A 50% B 54% C 56% D 60%
Mark scheme: D
Q15 · Partnership capitals are $60 000 for X and $90 000 for Y
15 Partnership capitals are $60 000 for X and $90 000 for Y. The partnership agreement provides for interest on capitals at 10% per annum, but makes no other financial provisions. Profits for the current year total $75 000. How will the total profits be divided between the partners? X Y $ $ A 30 000 45 000 B 36 000 39 000 C 37 500 37 500 D 39 000 36 000
Mark scheme: B
Q16 · The following is an extract from the statement of financial position for a company at 31…
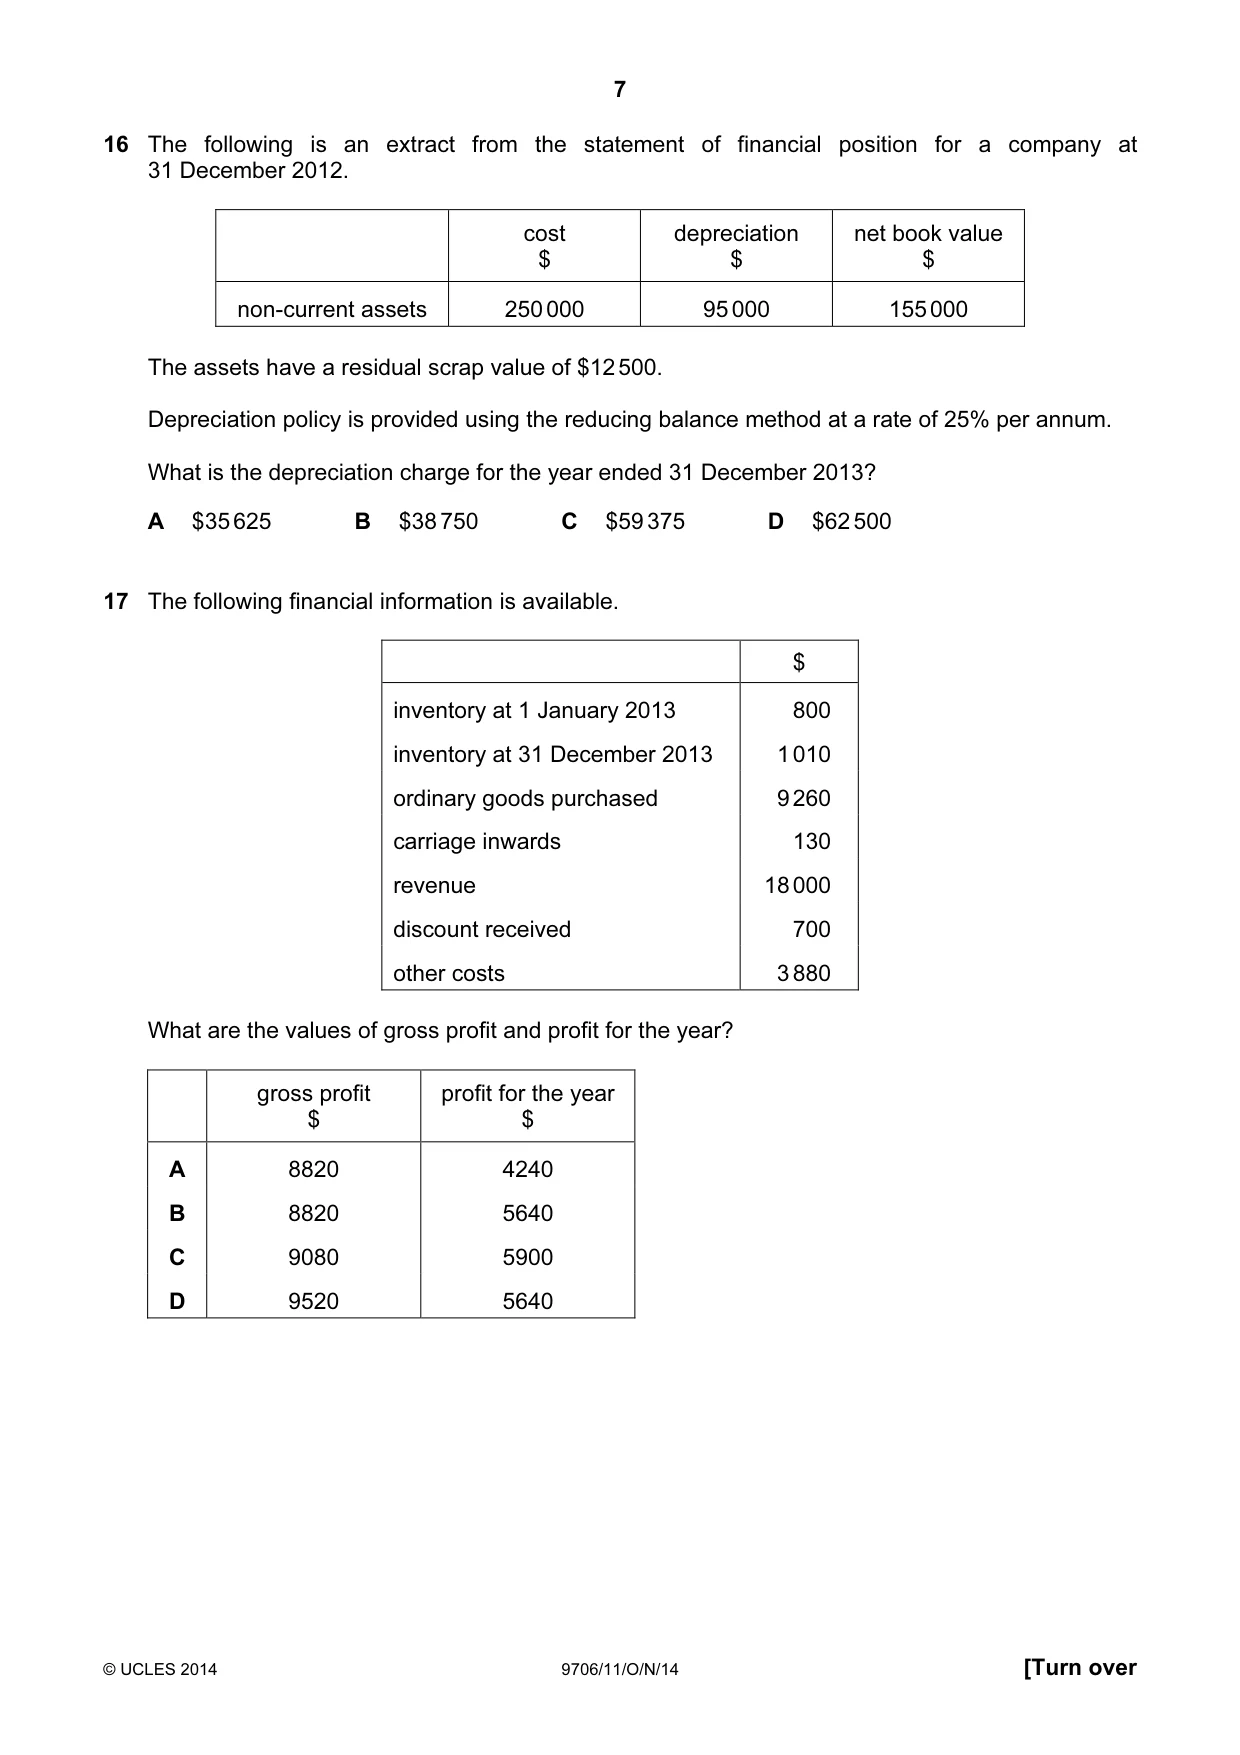
16 The following is an extract from the statement of financial position for a company at 31 December 2012. cost depreciation net book value $ $ $ non-current assets 250 000 95 000 155 000 The assets have a residual scrap value of $12 500. Depreciation policy is provided using the reducing balance method at a rate of 25% per annum. What is the depreciation charge for the year ended 31 December 2013? A $35 625 B $38 750 C $59 375 D $62 500
Mark scheme: B
Q17 · The following financial information is available
17 The following financial information is available. $ inventory at 1 January 2013 800 inventory at 31 December 2013 1 010 ordinary goods purchased 9 260 carriage inwards 130 revenue 18 000 discount received 700 other costs 3 880 What are the values of gross profit and profit for the year? gross profit profit for the year $ $ A 8820 4240 B 8820 5640 C 9080 5900 D 9520 5640
Mark scheme: B
Q18 · Z is admitted as a new partner in the partnership of X and Y
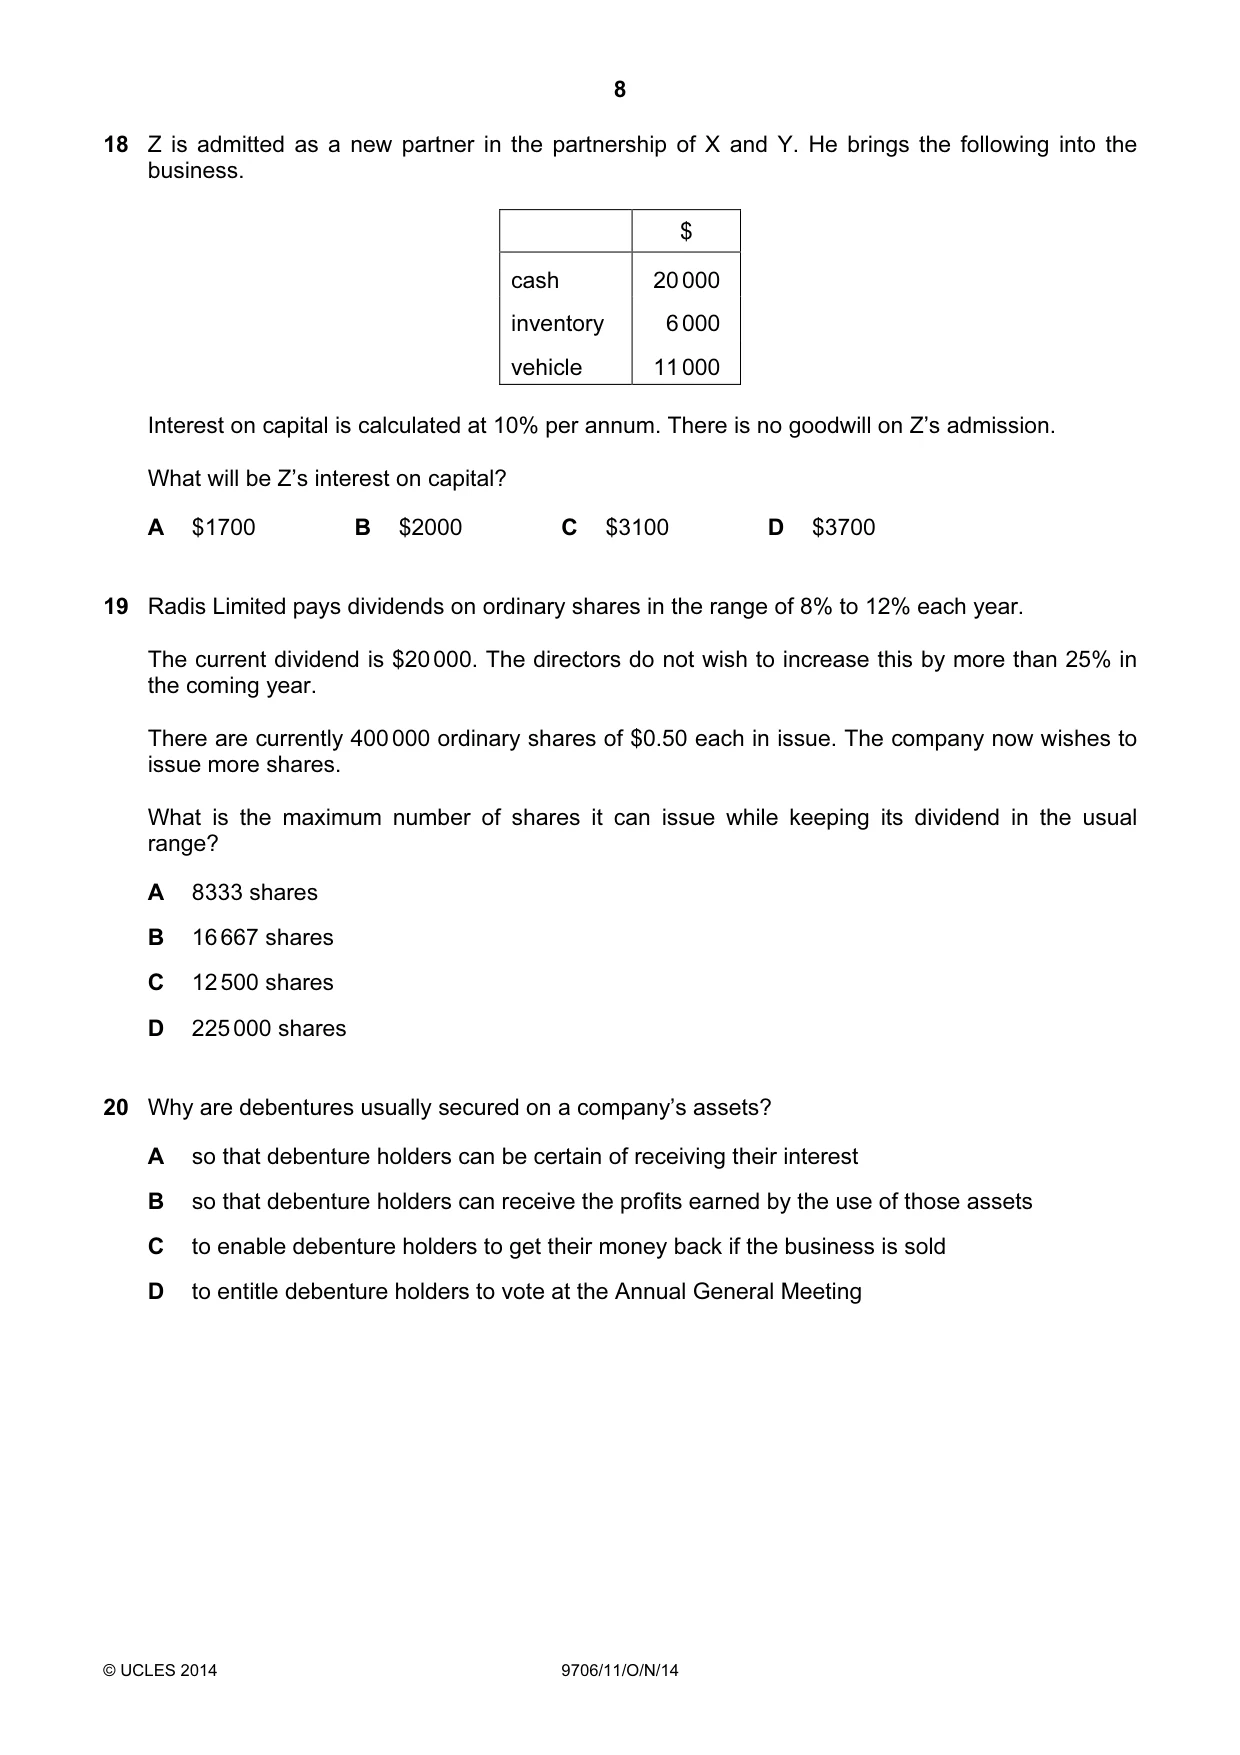
18 Z is admitted as a new partner in the partnership of X and Y. He brings the following into the business. $ cash 20 000 inventory 6 000 vehicle 11 000 Interest on capital is calculated at 10% per annum. There is no goodwill on Z’s admission. What will be Z’s interest on capital? A $1700 B $2000 C $3100 D $3700
Mark scheme: D
Q19 · Radis Limited pays dividends on ordinary shares in the range of 8% to 12% each year
19 Radis Limited pays dividends on ordinary shares in the range of 8% to 12% each year. The current dividend is $20 000. The directors do not wish to increase this by more than 25% in the coming year. There are currently 400 000 ordinary shares of $0.50 each in issue. The company now wishes to issue more shares. What is the maximum number of shares it can issue while keeping its dividend in the usual range? A 8333 shares B 16 667 shares C 12 500 shares D 225 000 shares
Mark scheme: D
Q20 · Why are debentures usually secured on a company’s assets?
20 Why are debentures usually secured on a company’s assets? A so that debenture holders can be certain of receiving their interest B so that debenture holders can receive the profits earned by the use of those assets C to enable debenture holders to get their money back if the business is sold D to entitle debenture holders to vote at the Annual General Meeting
Mark scheme: C
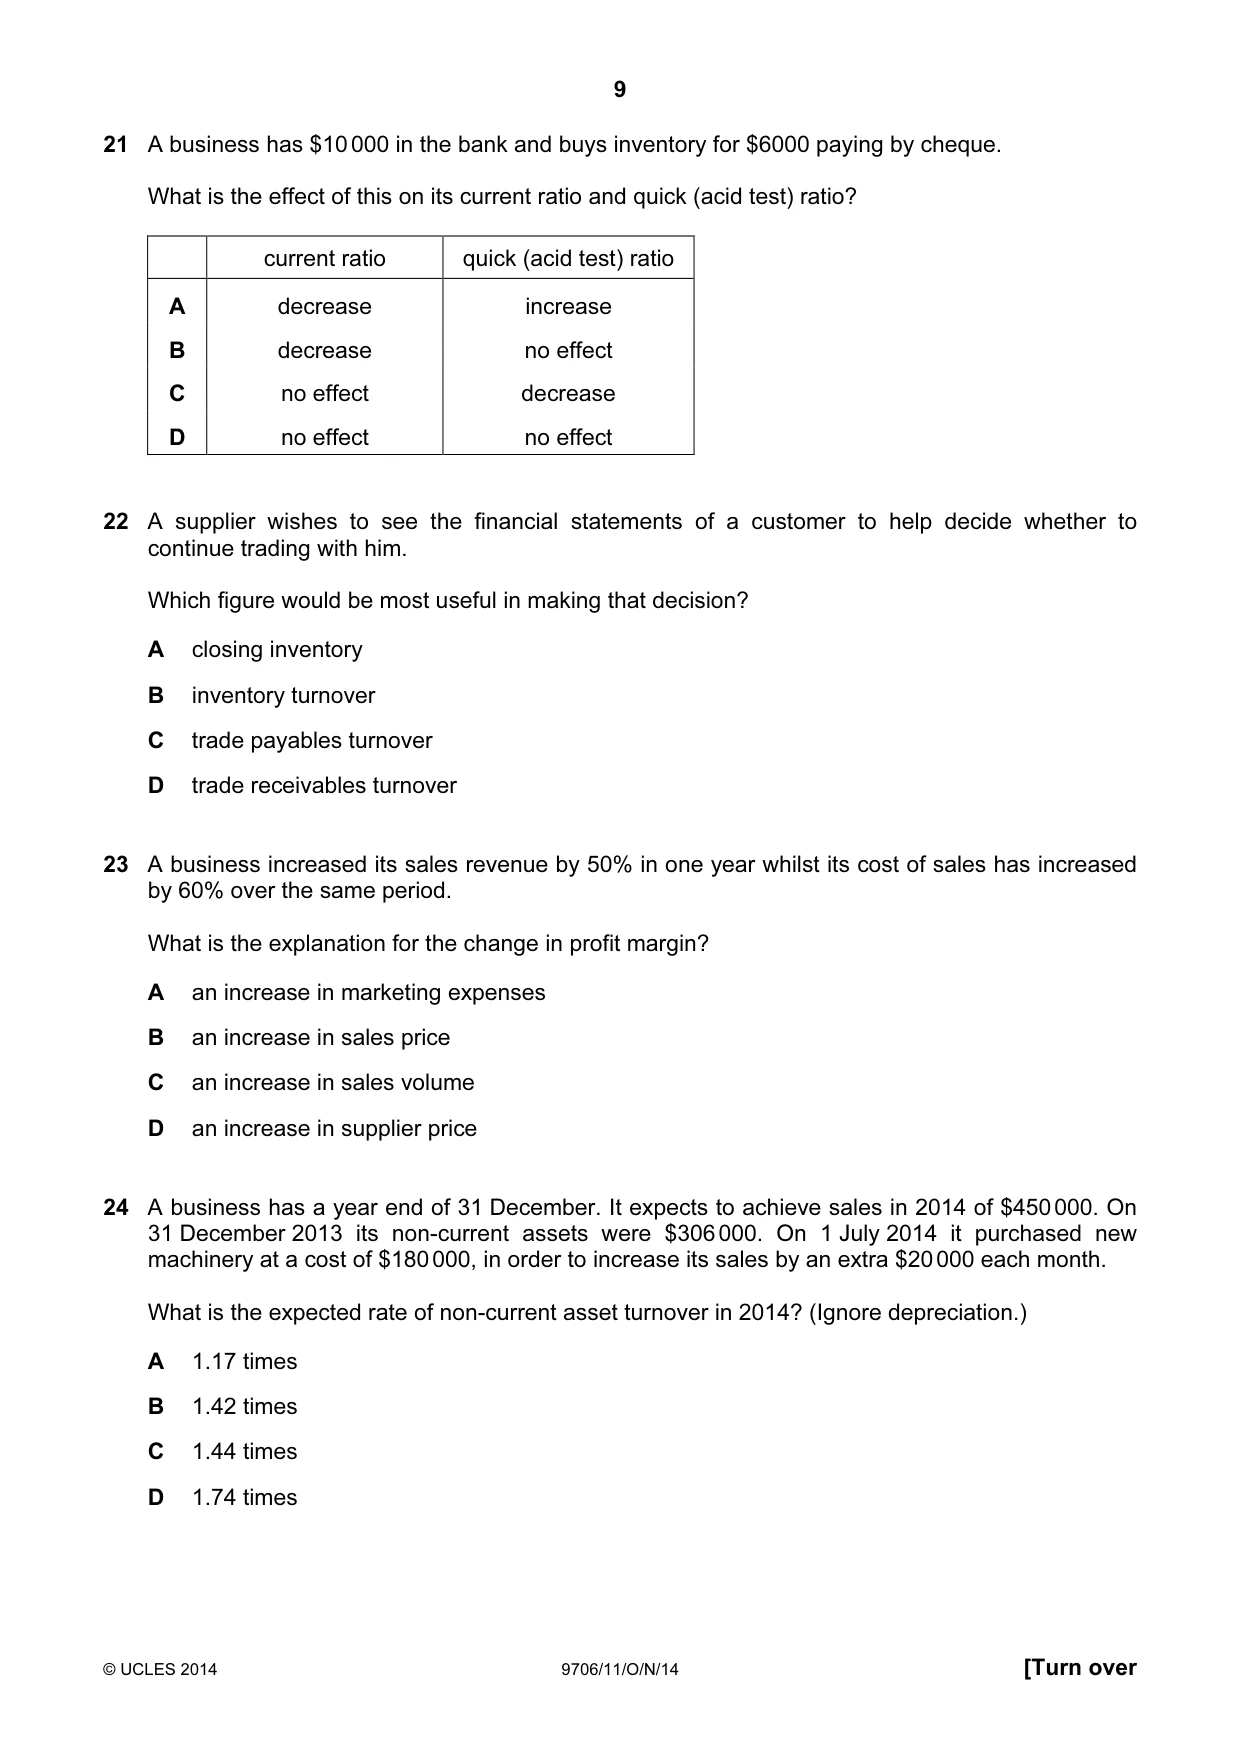
Q21 · A business has $10 000 in the bank and buys inventory for $6000 paying by cheque
21 A business has $10 000 in the bank and buys inventory for $6000 paying by cheque. What is the effect of this on its current ratio and quick (acid test) ratio? current ratio quick (acid test) ratio A decrease increase B decrease no effect C no effect decrease D no effect no effect
Mark scheme: C
More questions on Analysis and communication of accounting information
Q22 · A supplier wishes to see the financial statements of a customer to help decide whether to…
22 A supplier wishes to see the financial statements of a customer to help decide whether to continue trading with him. Which figure would be most useful in making that decision? A closing inventory B inventory turnover C trade payables turnover D trade receivables turnover
Mark scheme: C
More questions on Analysis and communication of accounting information
Q23 · A business increased its sales revenue by 50% in one year whilst its cost of sales has…
23 A business increased its sales revenue by 50% in one year whilst its cost of sales has increased by 60% over the same period. What is the explanation for the change in profit margin? A an increase in marketing expenses B an increase in sales price C an increase in sales volume D an increase in supplier price
Mark scheme: D
More questions on Analysis and communication of accounting information
Q24 · A business has a year end of 31 December
24 A business has a year end of 31 December. It expects to achieve sales in 2014 of $450 000. On 31 December 2013 its non-current assets were $306 000. On 1 July 2014 it purchased new machinery at a cost of $180 000, in order to increase its sales by an extra $20 000 each month. What is the expected rate of non-current asset turnover in 2014? (Ignore depreciation.) A 1.17 times B 1.42 times C 1.44 times D 1.74 times
Mark scheme: A
More questions on Analysis and communication of accounting information
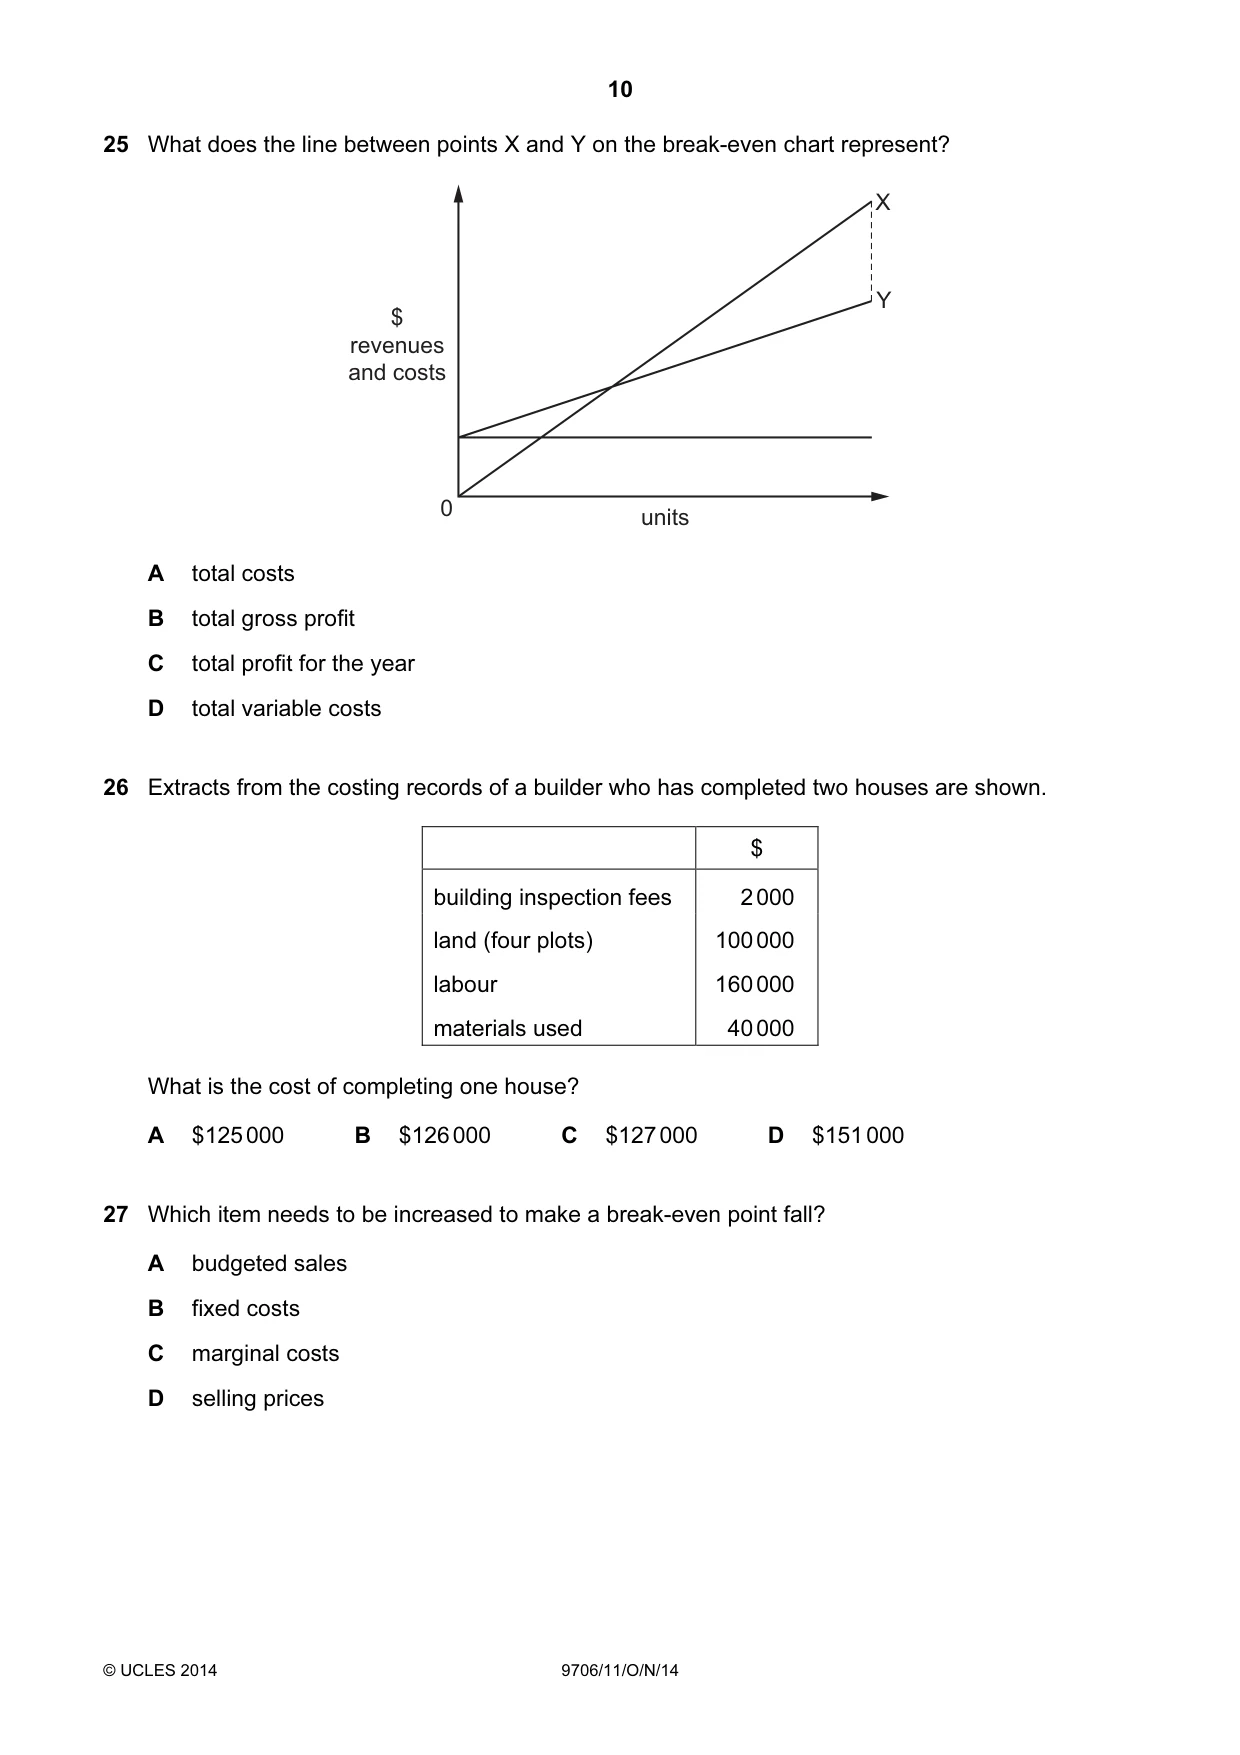
Q25 · What does the line between points X and Y on the break-even chart represent?
25 What does the line between points X and Y on the break-even chart represent? X Y $ revenues and costs 0 units A total costs B total gross profit C total profit for the year D total variable costs
Mark scheme: C
Q26 · Extracts from the costing records of a builder who has completed two houses are shown
26 Extracts from the costing records of a builder who has completed two houses are shown. $ building inspection fees 2 000 land (four plots) 100 000 labour 160 000 materials used 40 000 What is the cost of completing one house? A $125 000 B $126 000 C $127 000 D $151 000
Mark scheme: B
Q27 · Which item needs to be increased to make a break-even point fall?
27 Which item needs to be increased to make a break-even point fall? A budgeted sales B fixed costs C marginal costs D selling prices
Mark scheme: D
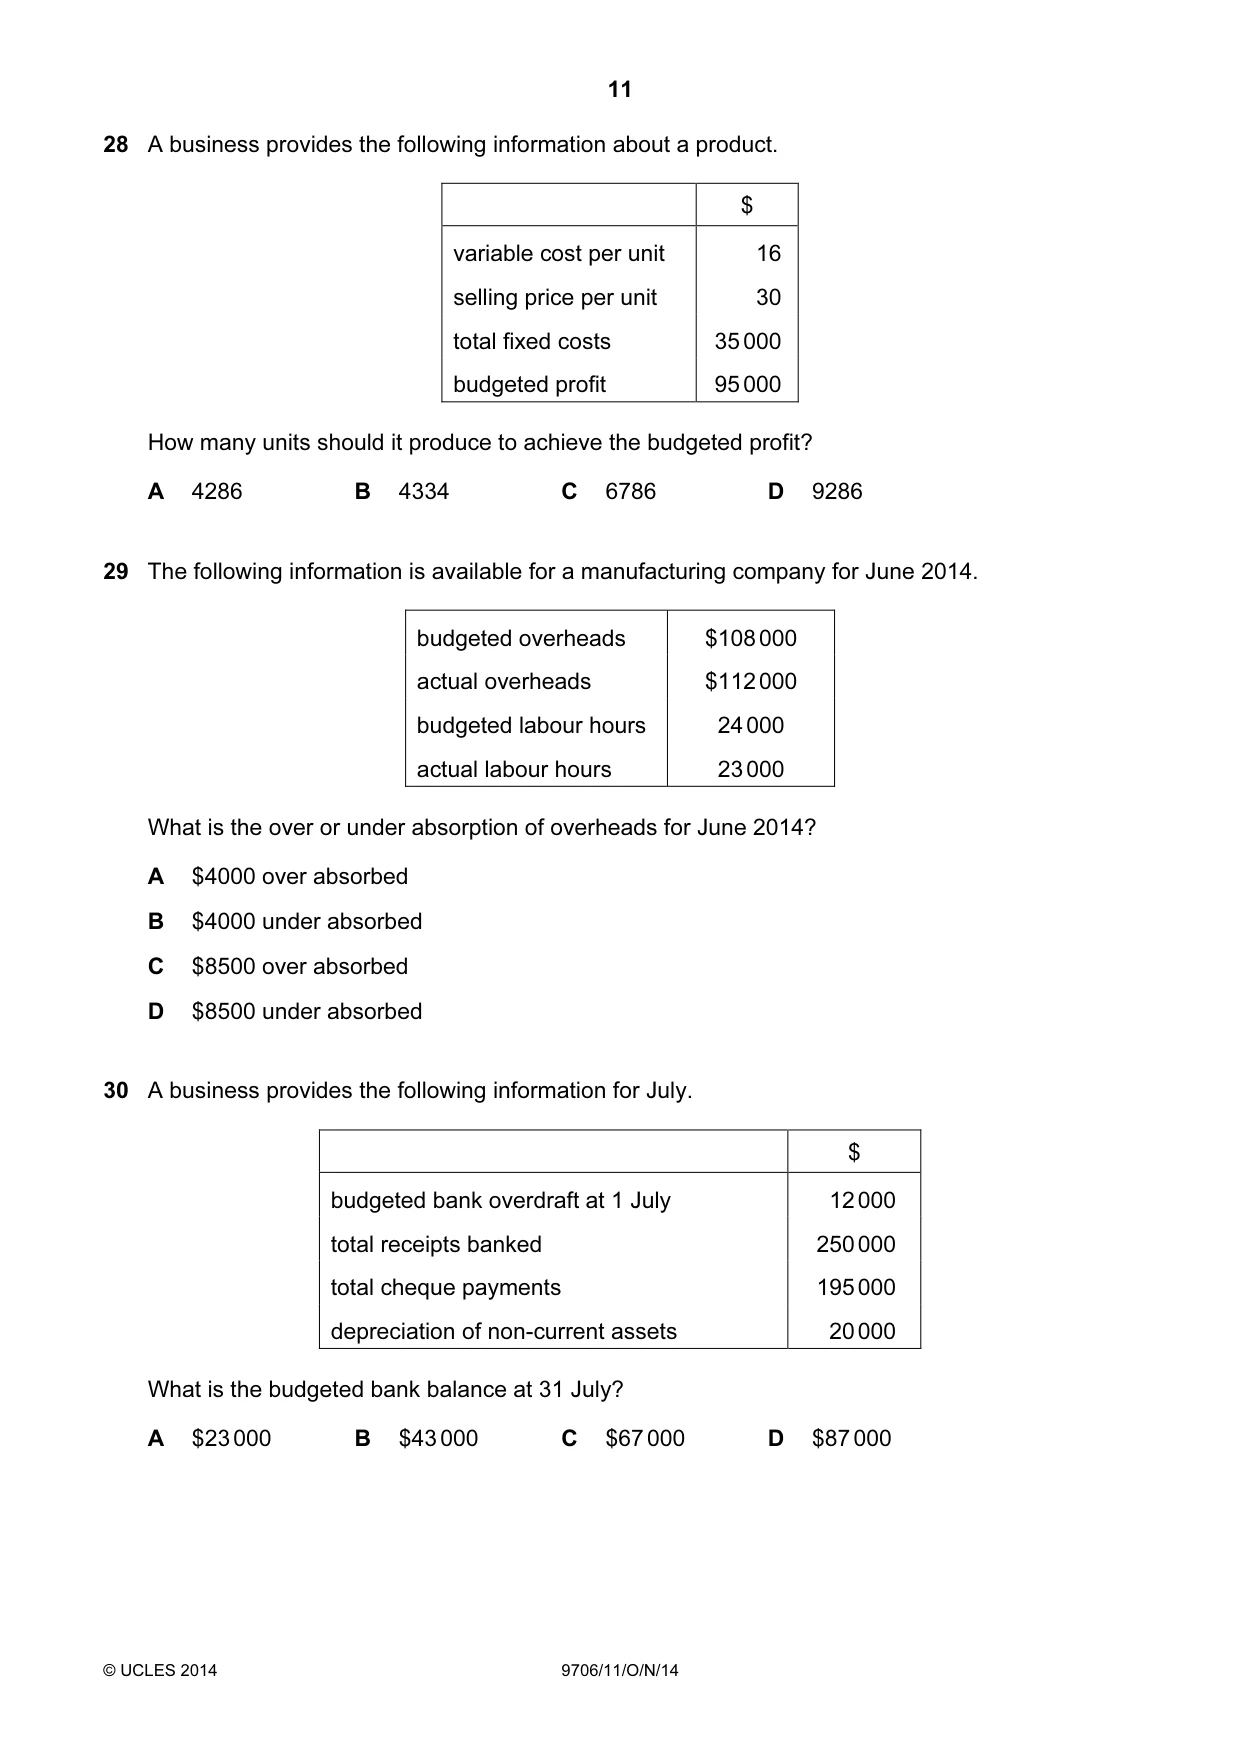
Q28 · A business provides the following information about a product
28 A business provides the following information about a product. $ variable cost per unit 16 selling price per unit 30 total fixed costs 35 000 budgeted profit 95 000 How many units should it produce to achieve the budgeted profit? A 4286 B 4334 C 6786 D 9286
Mark scheme: D
Q29 · The following information is available for a manufacturing company for June 2014
29 The following information is available for a manufacturing company for June 2014. budgeted overheads $108 000 actual overheads $112 000 budgeted labour hours 24 000 actual labour hours 23 000 What is the over or under absorption of overheads for June 2014? A $4000 over absorbed B $4000 under absorbed C $8500 over absorbed D $8500 under absorbed
Mark scheme: D
Q30 · A business provides the following information for July
30 A business provides the following information for July. $ budgeted bank overdraft at 1 July 12 000 total receipts banked 250 000 total cheque payments 195 000 depreciation of non-current assets 20 000 What is the budgeted bank balance at 31 July? A $23 000 B $43 000 C $67 000 D $87 000
Mark scheme: B
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2014 Oct/Nov, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.