Cambridge A Level Accounting 9706 — 2009 Oct/Nov Paper 1 · Variant 2
9706/12/O/N/09 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme2 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · The accounting year end of a business is 31 October
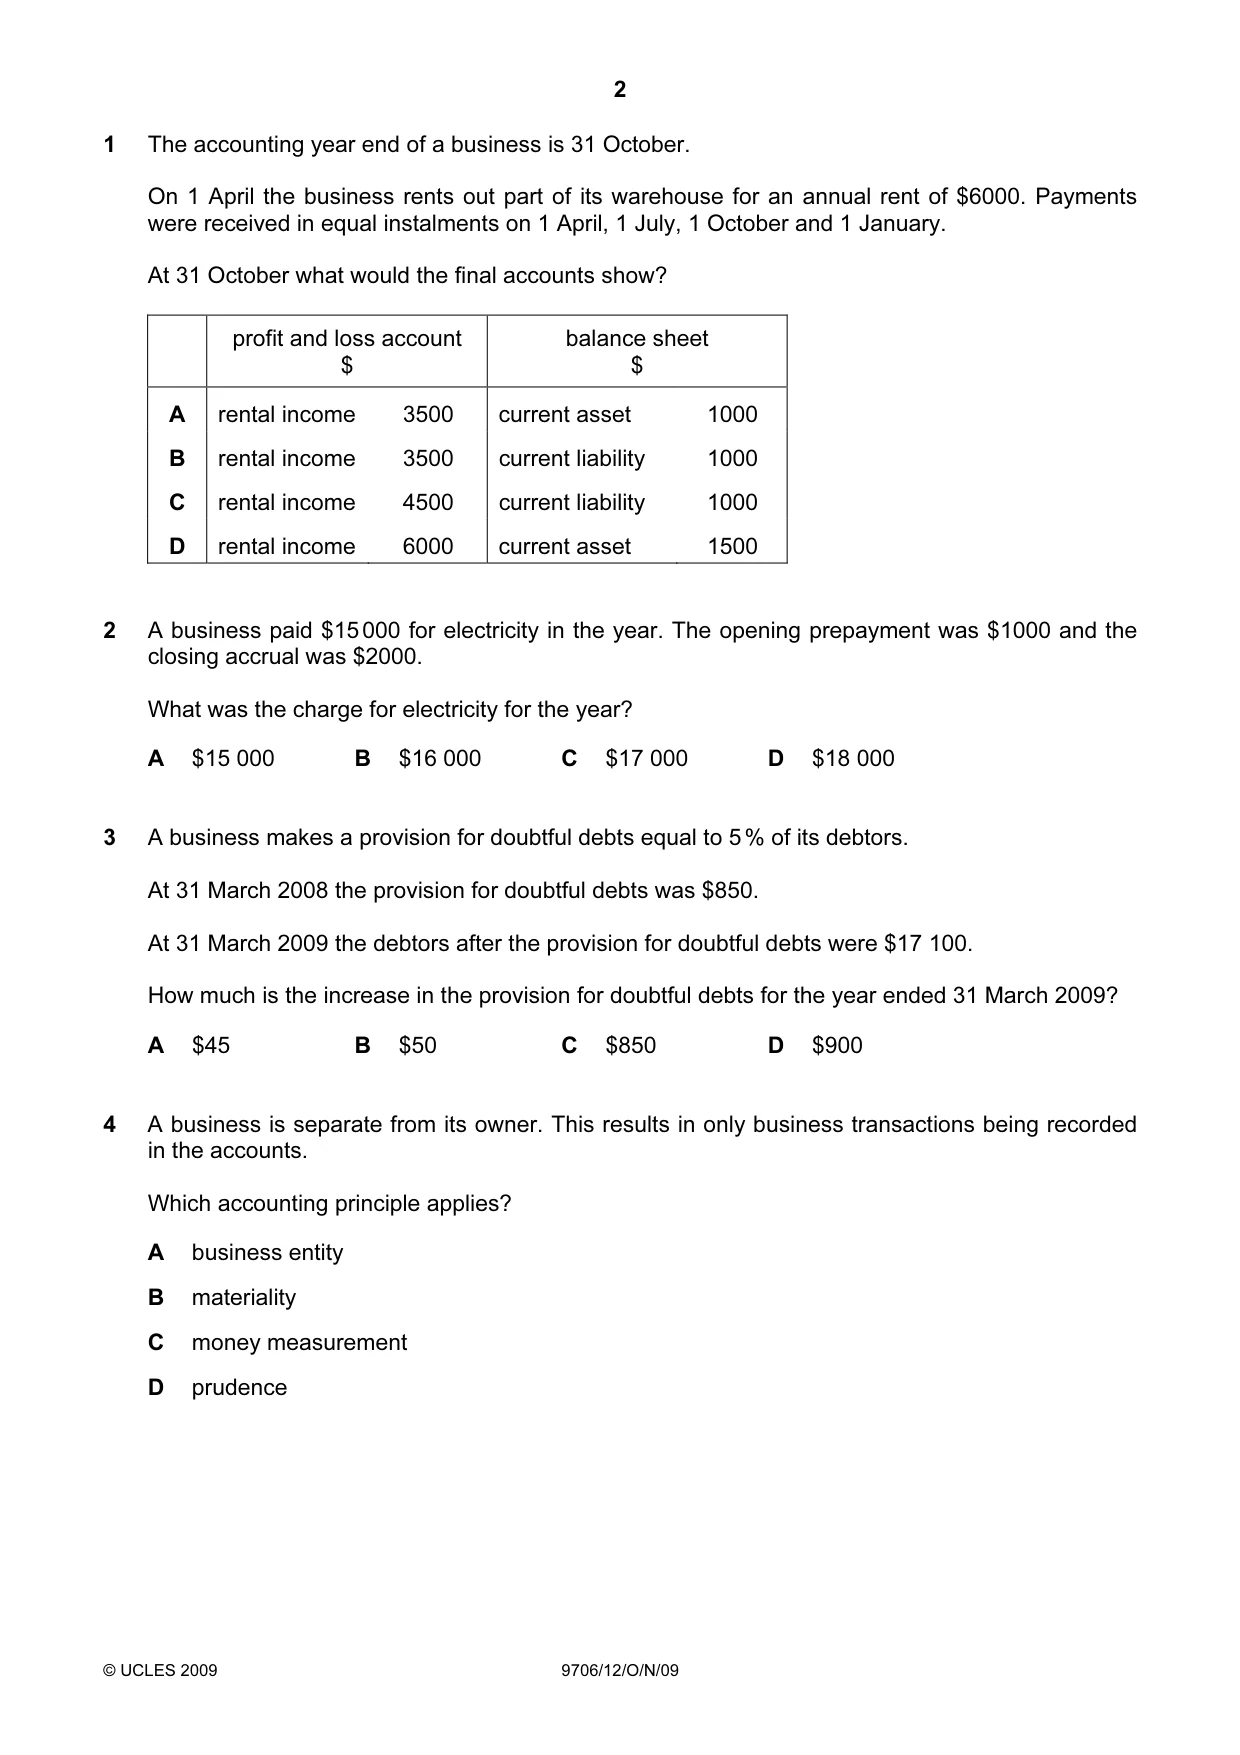
1 The accounting year end of a business is 31 October. On 1 April the business rents out part of its warehouse for an annual rent of $6000. Payments were received in equal instalments on 1 April, 1 July, 1 October and 1 January. At 31 October what would the final accounts show? profit and loss account balance sheet $ $ A rental income 3500 current asset 1000 B rental income 3500 current liability 1000 C rental income 4500 current liability 1000 D rental income 6000 current asset 1500
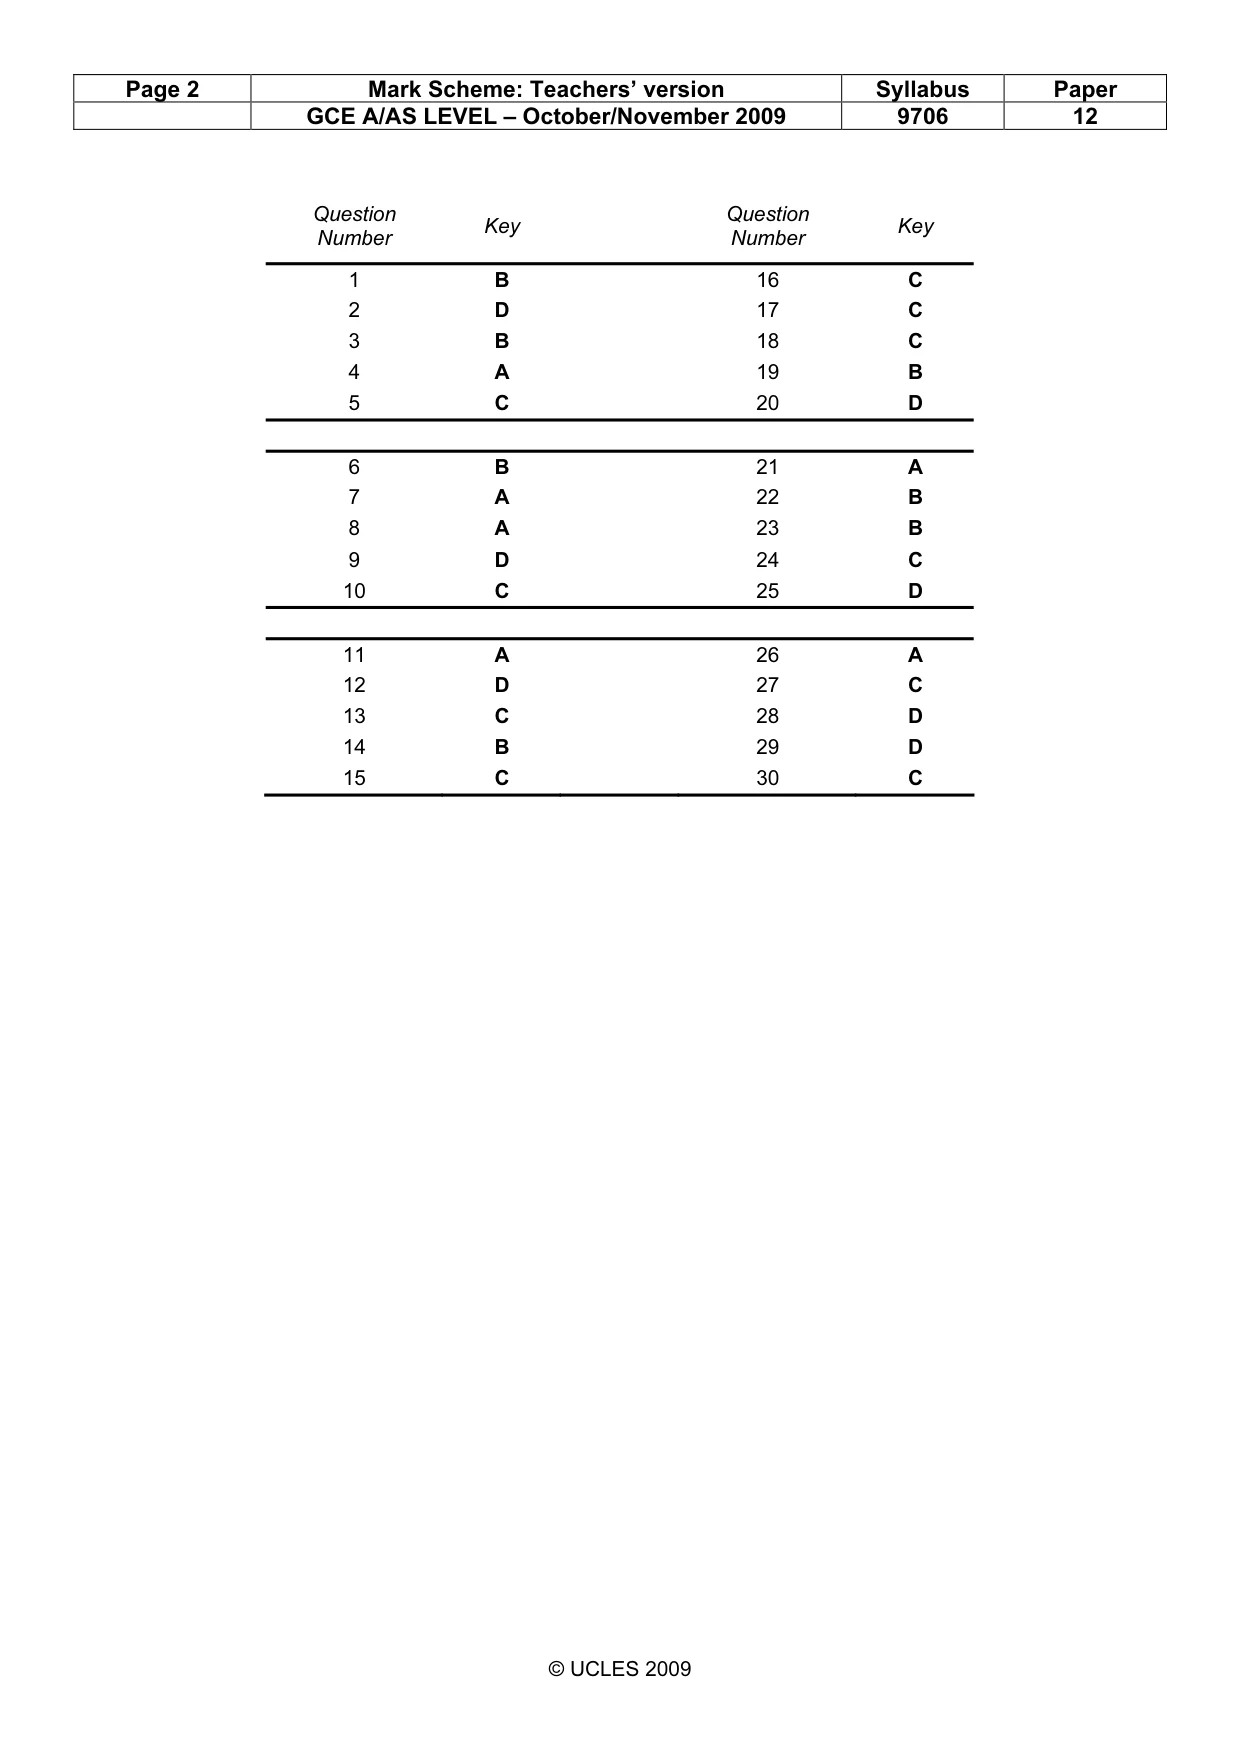
Mark scheme: B
Q2 · A business paid $15000 for electricity in the year
2 A business paid $15000 for electricity in the year. The opening prepayment was $1000 and the closing accrual was $2000. What was the charge for electricity for the year? A $15 000 B $16 000 C $17 000 D $18 000
Mark scheme: D
Q3 · A business makes a provision for doubtful debts equal to 5 % of its debtors
3 A business makes a provision for doubtful debts equal to 5 % of its debtors. At 31 March 2008 the provision for doubtful debts was $850. At 31 March 2009 the debtors after the provision for doubtful debts were $17 100. How much is the increase in the provision for doubtful debts for the year ended 31 March 2009? A $45 B $50 C $850 D $900
Mark scheme: B
Q4 · A business is separate from its owner
4 A business is separate from its owner. This results in only business transactions being recorded in the accounts. Which accounting principle applies? A business entity B materiality C money measurement D prudence
Mark scheme: A
Q5 · At 31 March the balance sheet of a company included the following
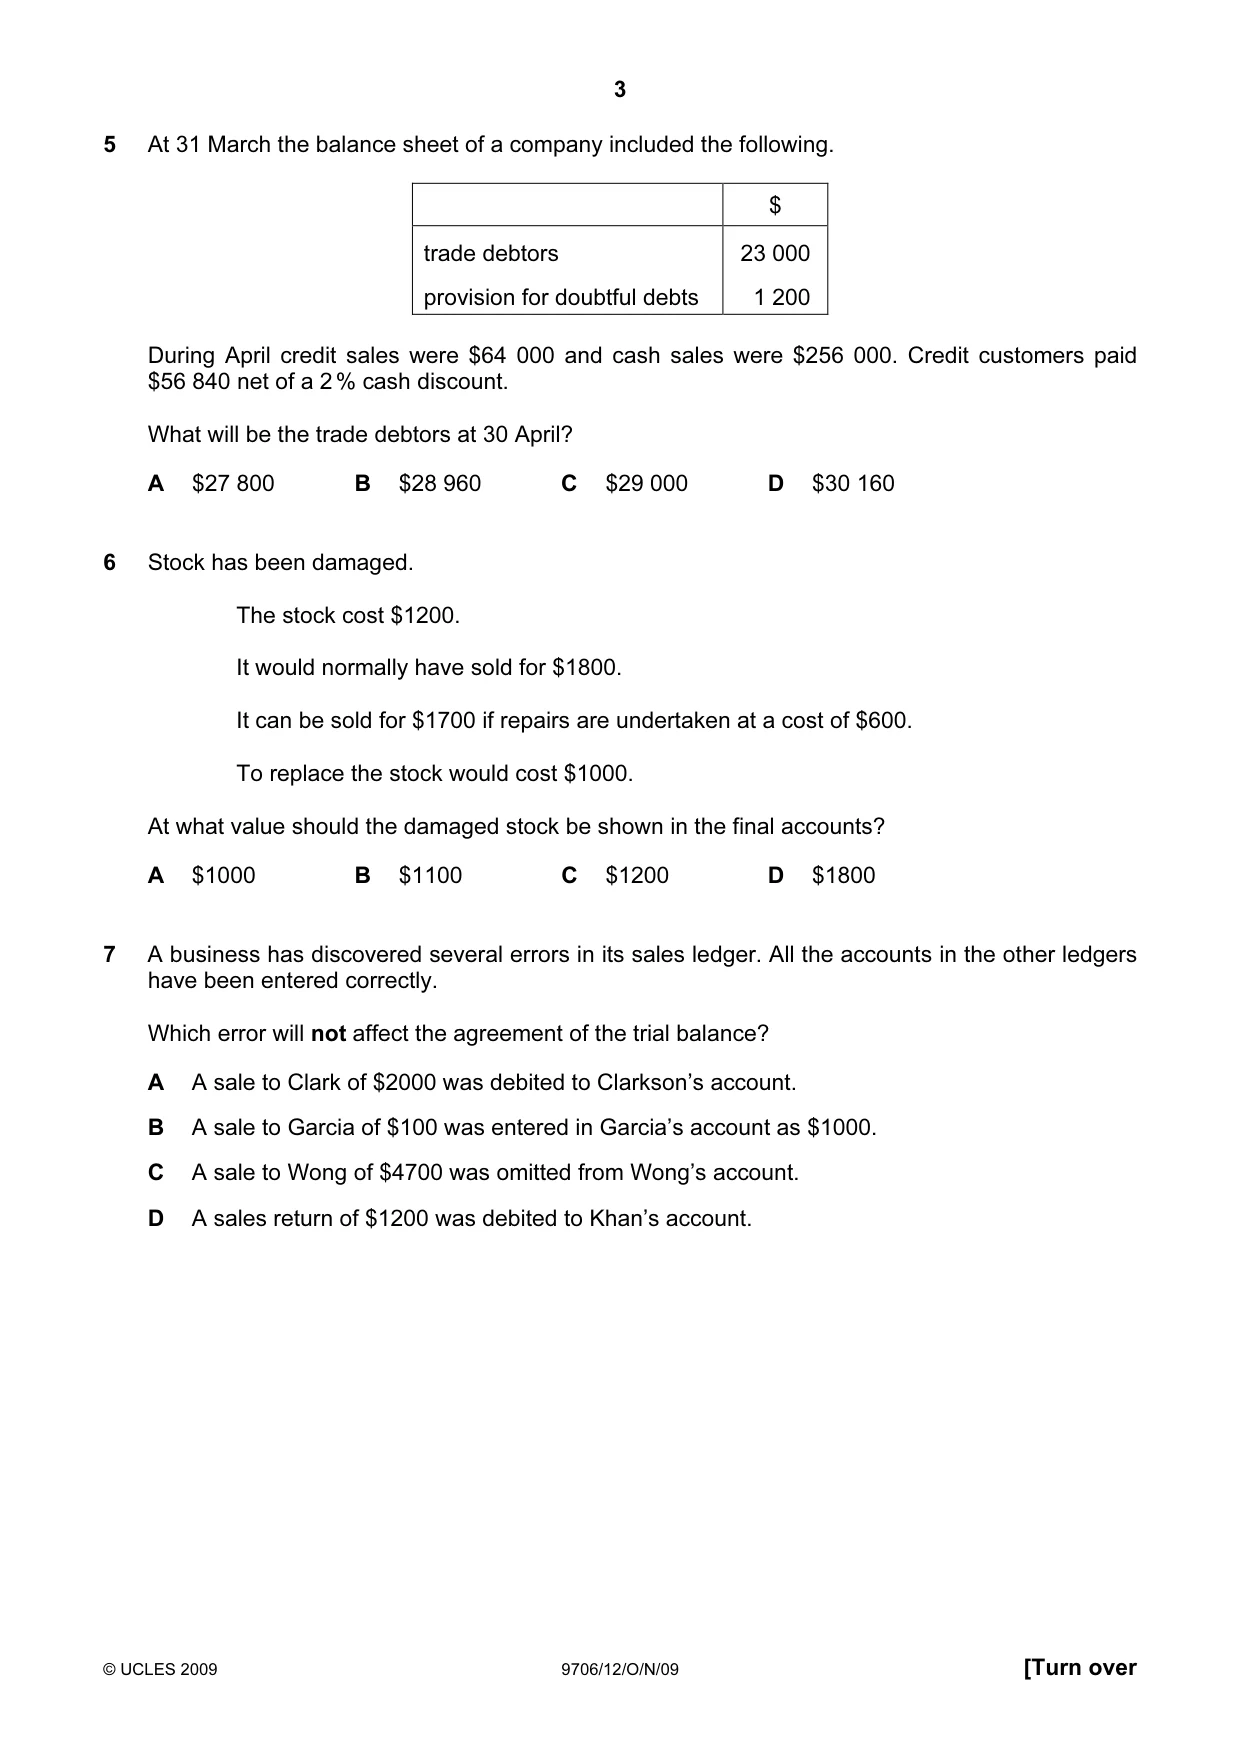
5 At 31 March the balance sheet of a company included the following. $ trade debtors 23 000 provision for doubtful debts 1 200 During April credit sales were $64 000 and cash sales were $256 000. Credit customers paid $56 840 net of a 2 % cash discount. What will be the trade debtors at 30 April? A $27 800 B $28 960 C $29 000 D $30 160
Mark scheme: C
Q6 · Stock has been damaged
6 Stock has been damaged. The stock cost $1200. It would normally have sold for $1800. It can be sold for $1700 if repairs are undertaken at a cost of $600. To replace the stock would cost $1000. At what value should the damaged stock be shown in the final accounts? A $1000 B $1100 C $1200 D $1800
Mark scheme: B
Q7 · A business has discovered several errors in its sales ledger
7 A business has discovered several errors in its sales ledger. All the accounts in the other ledgers have been entered correctly. Which error will not affect the agreement of the trial balance? A A sale to Clark of $2000 was debited to Clarkson’s account. B A sale to Garcia of $100 was entered in Garcia’s account as $1000. C A sale to Wong of $4700 was omitted from Wong’s account. D A sales return of $1200 was debited to Khan’s account.
Mark scheme: A
Q8 · A trial balance fails to agree and the bookkeeper finds the following errors
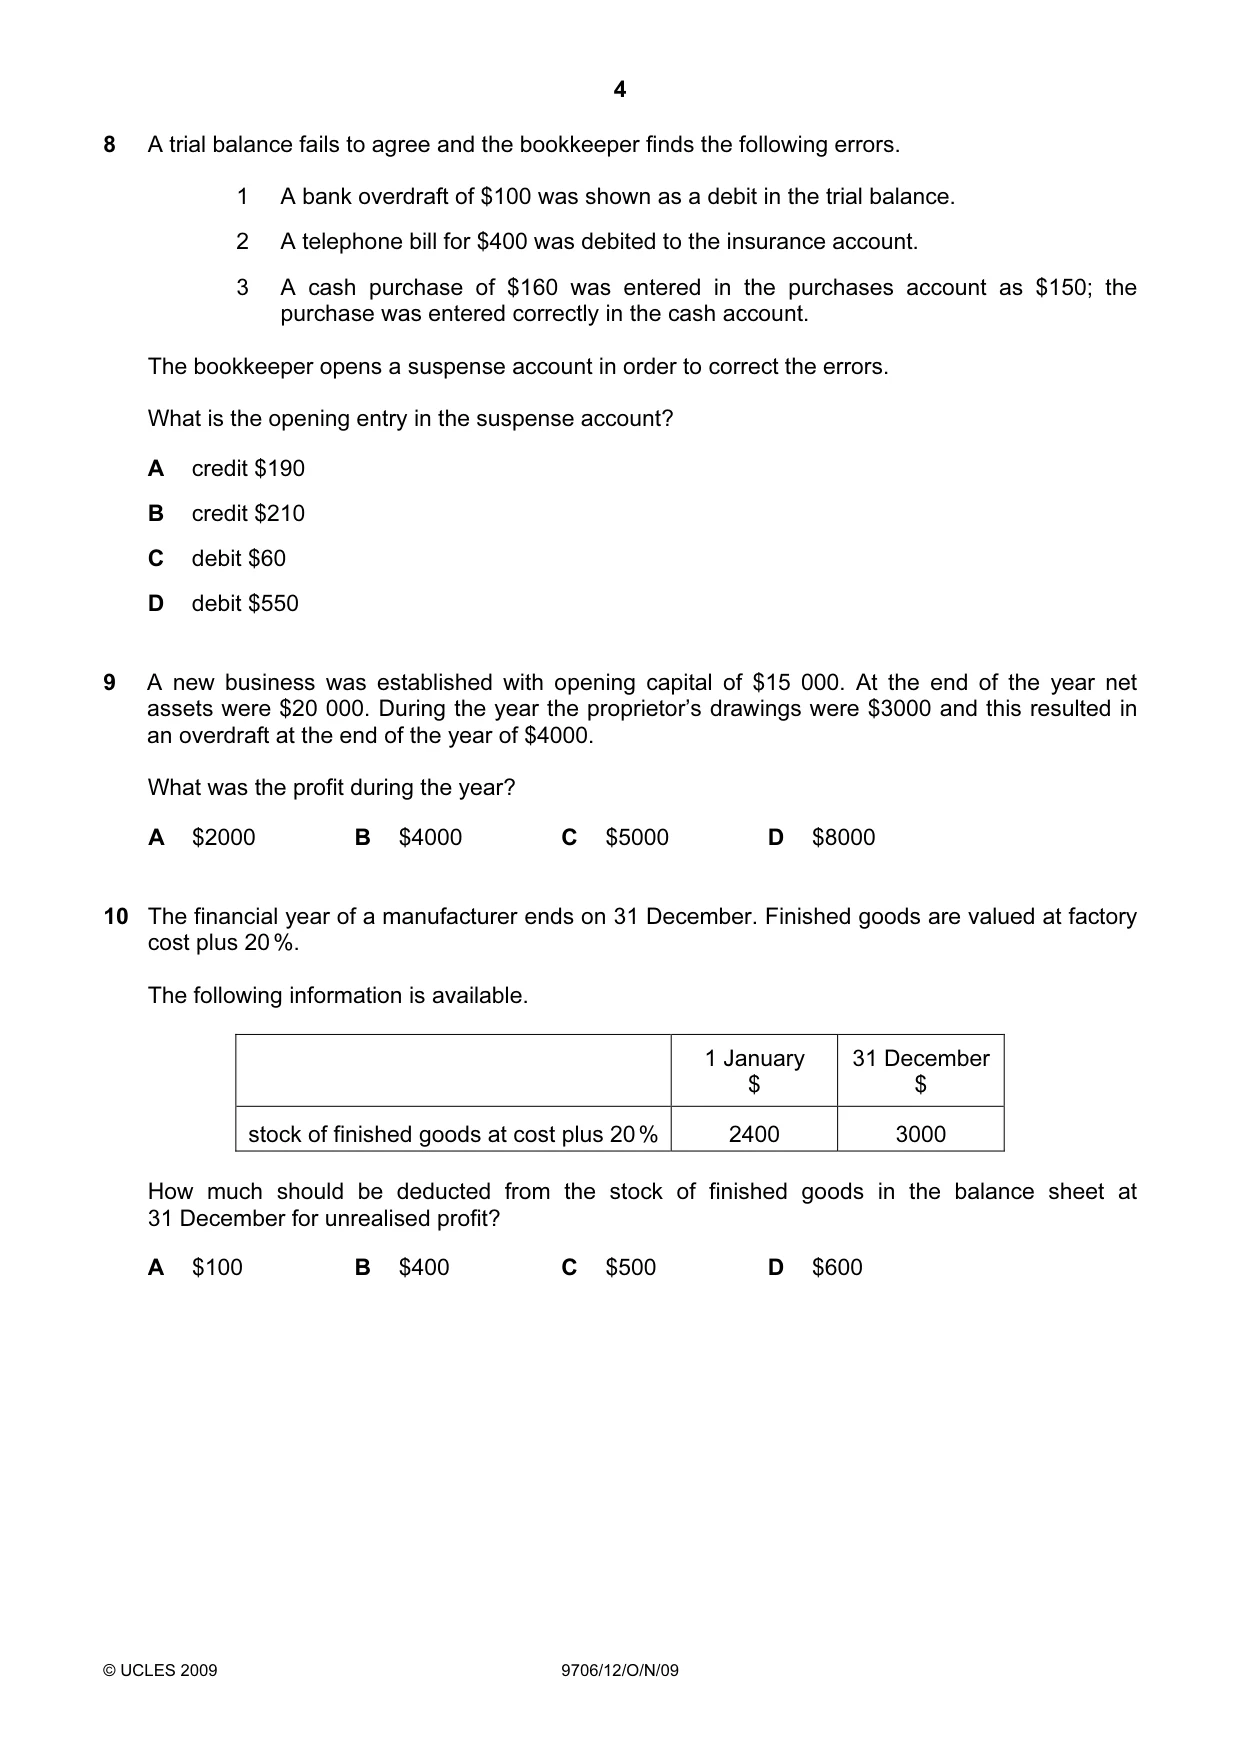
8 A trial balance fails to agree and the bookkeeper finds the following errors. 1 A bank overdraft of $100 was shown as a debit in the trial balance. 2 A telephone bill for $400 was debited to the insurance account. 3 A cash purchase of $160 was entered in the purchases account as $150; the purchase was entered correctly in the cash account. The bookkeeper opens a suspense account in order to correct the errors. What is the opening entry in the suspense account? A credit $190 B credit $210 C debit $60 D debit $550
Mark scheme: A
Q9 · A new business was established with opening capital of $15 000
9 A new business was established with opening capital of $15 000. At the end of the year net assets were $20 000. During the year the proprietor’s drawings were $3000 and this resulted in an overdraft at the end of the year of $4000. What was the profit during the year? A $2000 B $4000 C $5000 D $8000
Mark scheme: D
Q10 · The financial year of a manufacturer ends on 31 December
10 The financial year of a manufacturer ends on 31 December. Finished goods are valued at factory cost plus 20 %. The following information is available. 1 January 31 December $ $ stock of finished goods at cost plus 20 % 2400 3000 How much should be deducted from the stock of finished goods in the balance sheet at 31 December for unrealised profit? A $100 B $400 C $500 D $600
Mark scheme: C
Q11 · The stock records of a business show the following information for product X during…
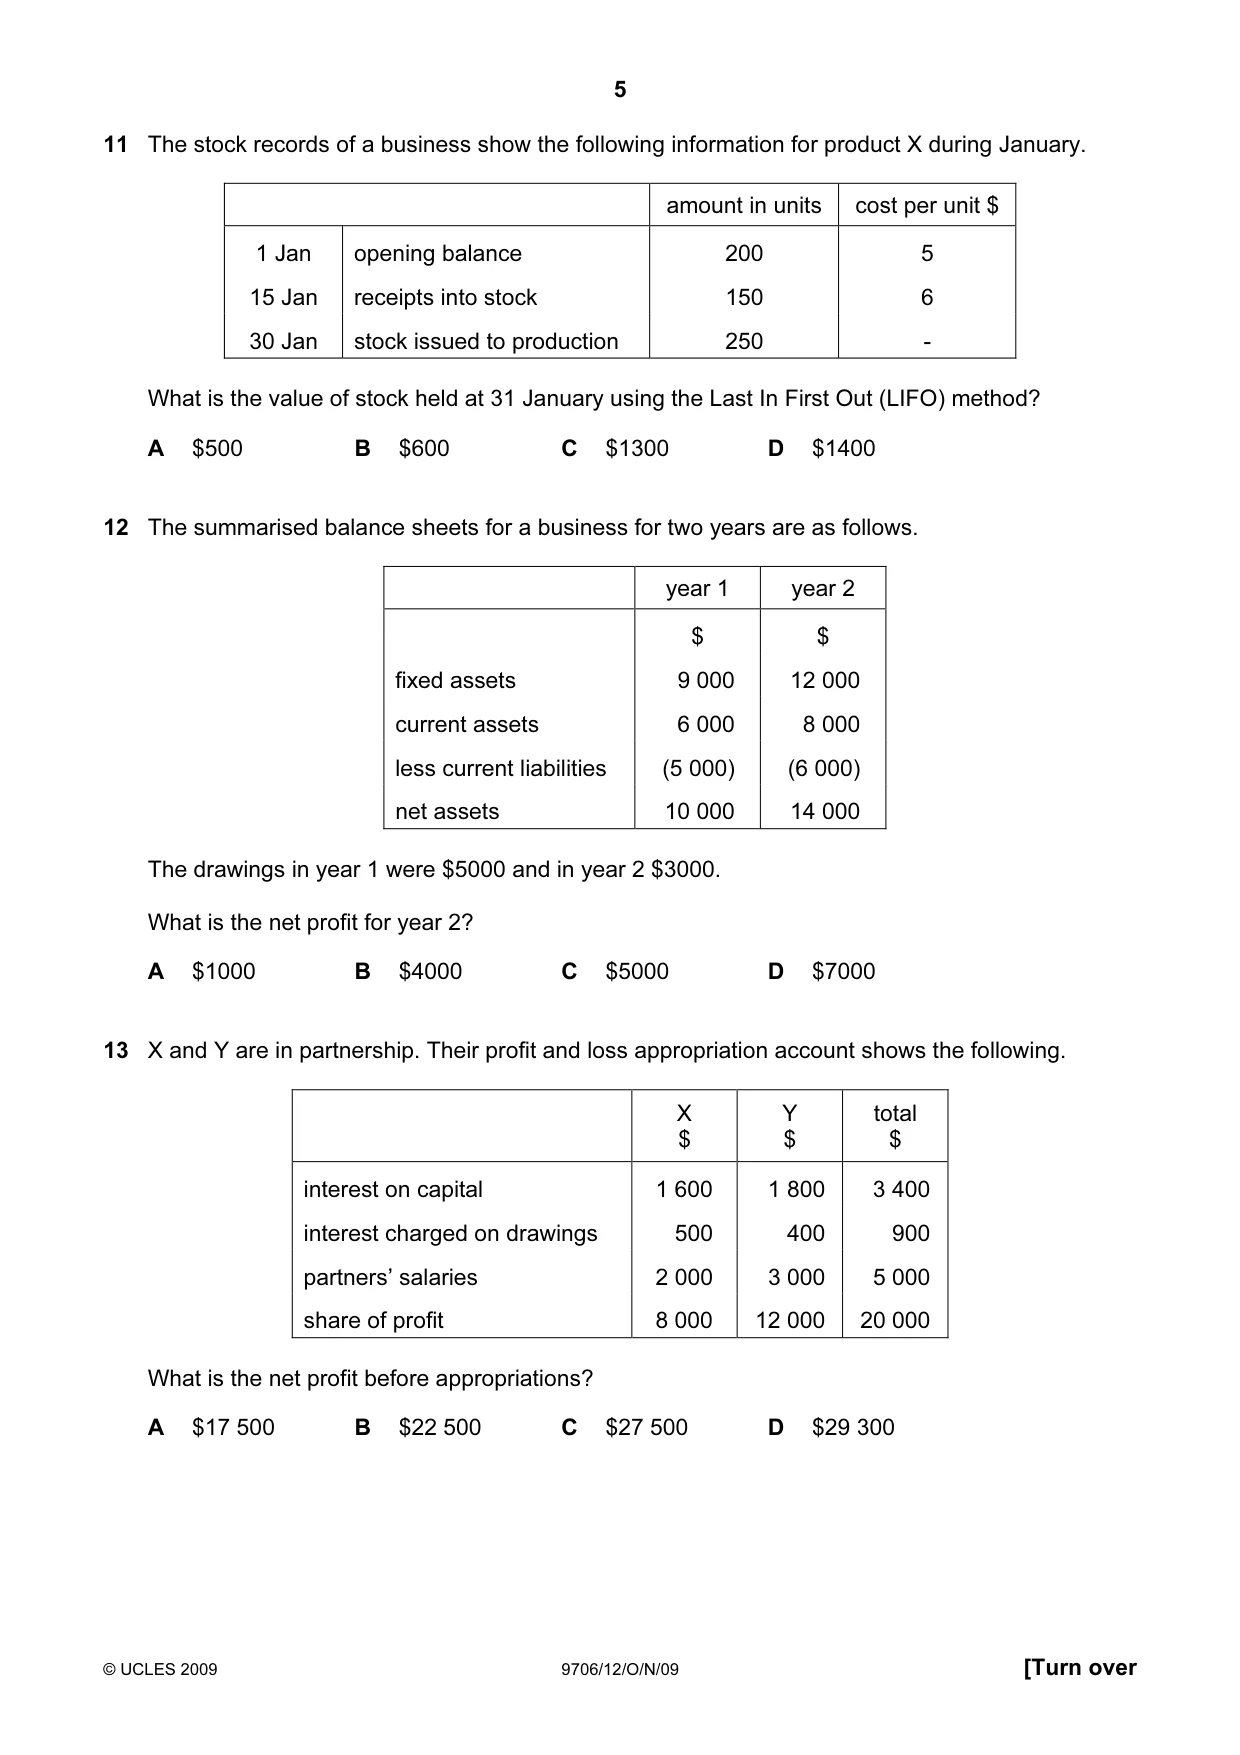
11 The stock records of a business show the following information for product X during January. amount in units cost per unit $ 1 Jan opening balance 200 5 15 Jan receipts into stock 150 6 30 Jan stock issued to production 250 - What is the value of stock held at 31 January using the Last In First Out (LIFO) method? A $500 B $600 C $1300 D $1400
Mark scheme: A
Q12 · The summarised balance sheets for a business for two years are as follows
12 The summarised balance sheets for a business for two years are as follows. year 1 year 2 $ $ fixed assets 9 000 12 000 current assets 6 000 8 000 less current liabilities (5 000) (6 000) net assets 10 000 14 000 The drawings in year 1 were $5000 and in year 2 $3000. What is the net profit for year 2? A $1000 B $4000 C $5000 D $7000
Mark scheme: D
Q13 · X and Y are in partnership
13 X and Y are in partnership. Their profit and loss appropriation account shows the following. X Y total $ $ $ interest on capital 1 600 1 800 3 400 interest charged on drawings 500 400 900 partners’ salaries 2 000 3 000 5 000 share of profit 8 000 12 000 20 000 What is the net profit before appropriations? A $17 500 B $22 500 C $27 500 D $29 300
Mark scheme: C
Q14 · An extract from the accounts of a manufacturing company shows the following
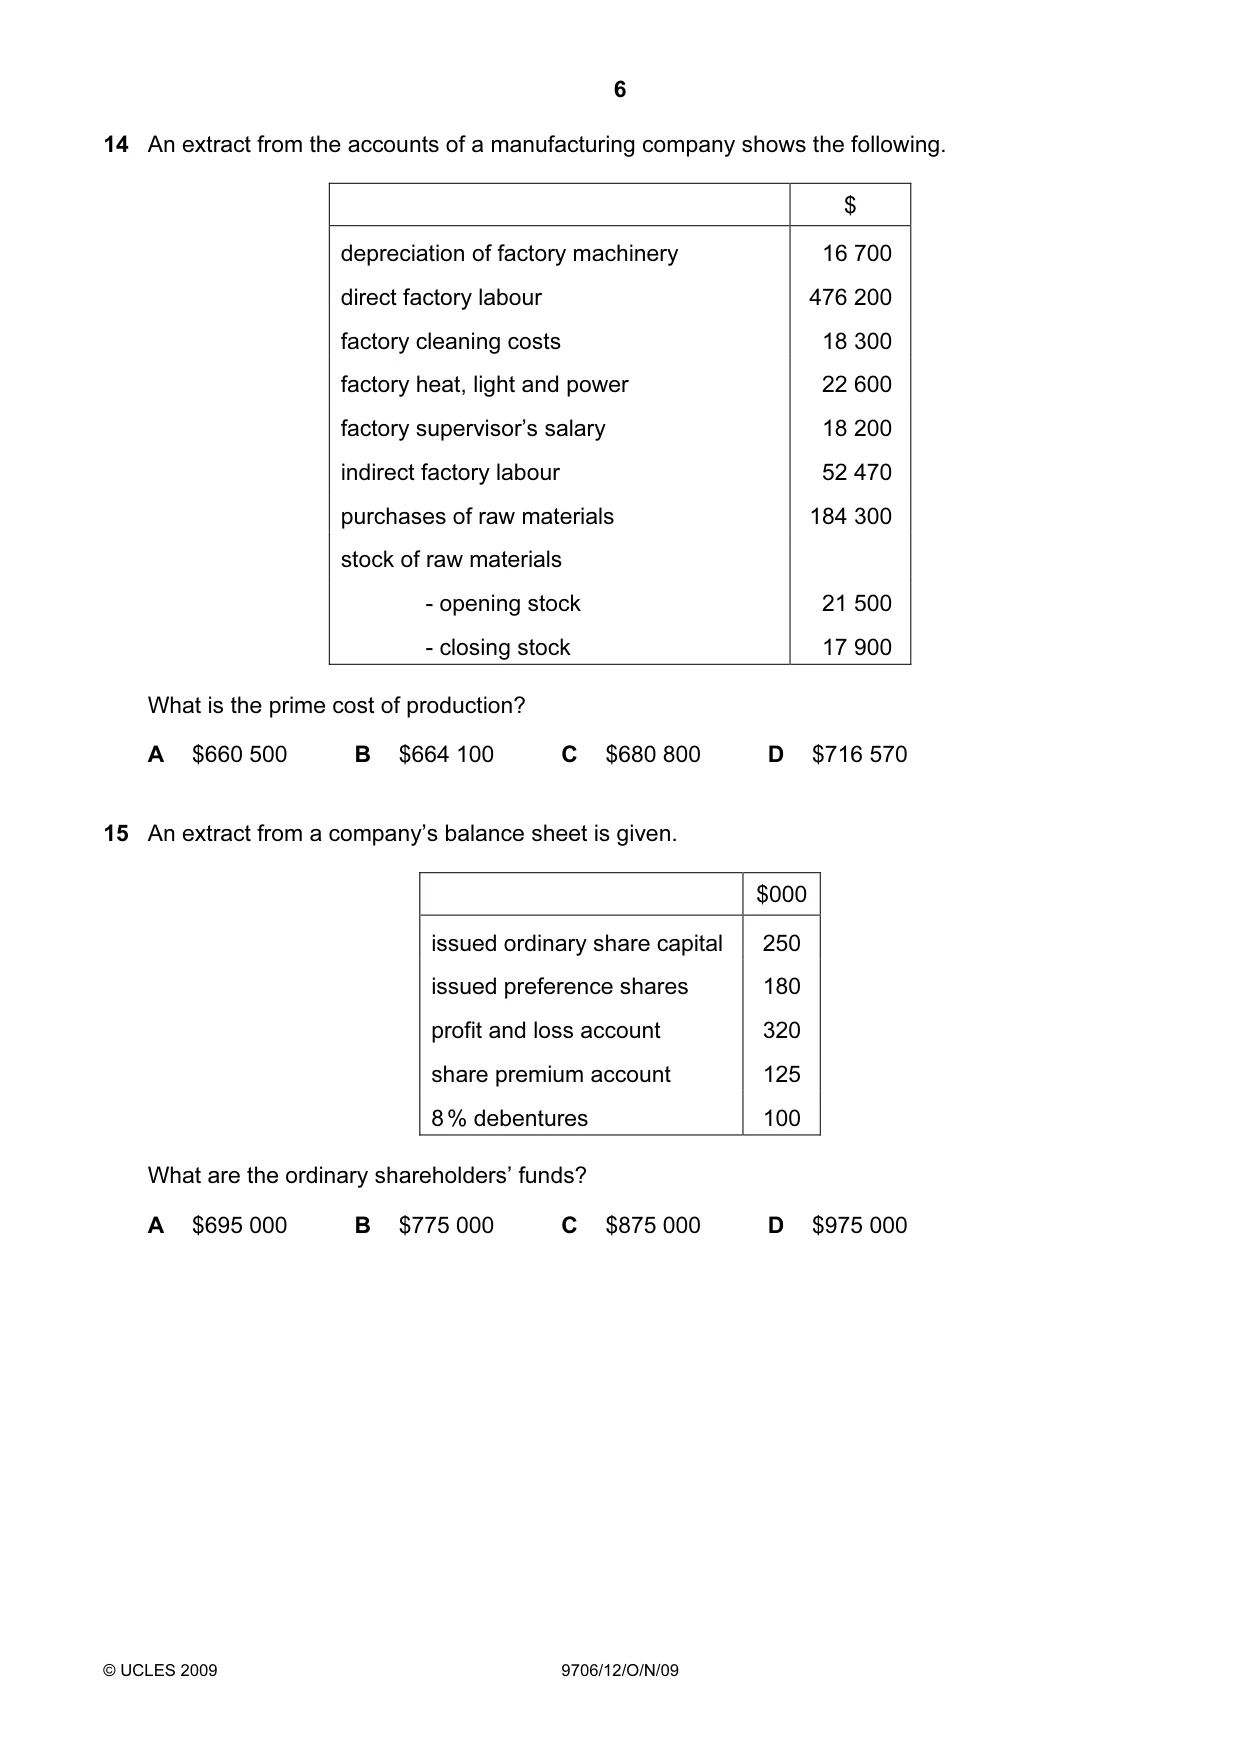
14 An extract from the accounts of a manufacturing company shows the following. $ depreciation of factory machinery 16 700 direct factory labour 476 200 factory cleaning costs 18 300 factory heat, light and power 22 600 factory supervisor’s salary 18 200 indirect factory labour 52 470 purchases of raw materials 184 300 stock of raw materials - opening stock 21 500 - closing stock 17 900 What is the prime cost of production? A $660 500 B $664 100 C $680 800 D $716 570
Mark scheme: B
Q15 · An extract from a company’s balance sheet is given
15 An extract from a company’s balance sheet is given. $000 issued ordinary share capital 250 issued preference shares 180 profit and loss account 320 share premium account 125 8 % debentures 100 What are the ordinary shareholders’ funds? A $695 000 B $775 000 C $875 000 D $975 000
Mark scheme: C
Q16 · An extract from a company’s balance sheet shows the following
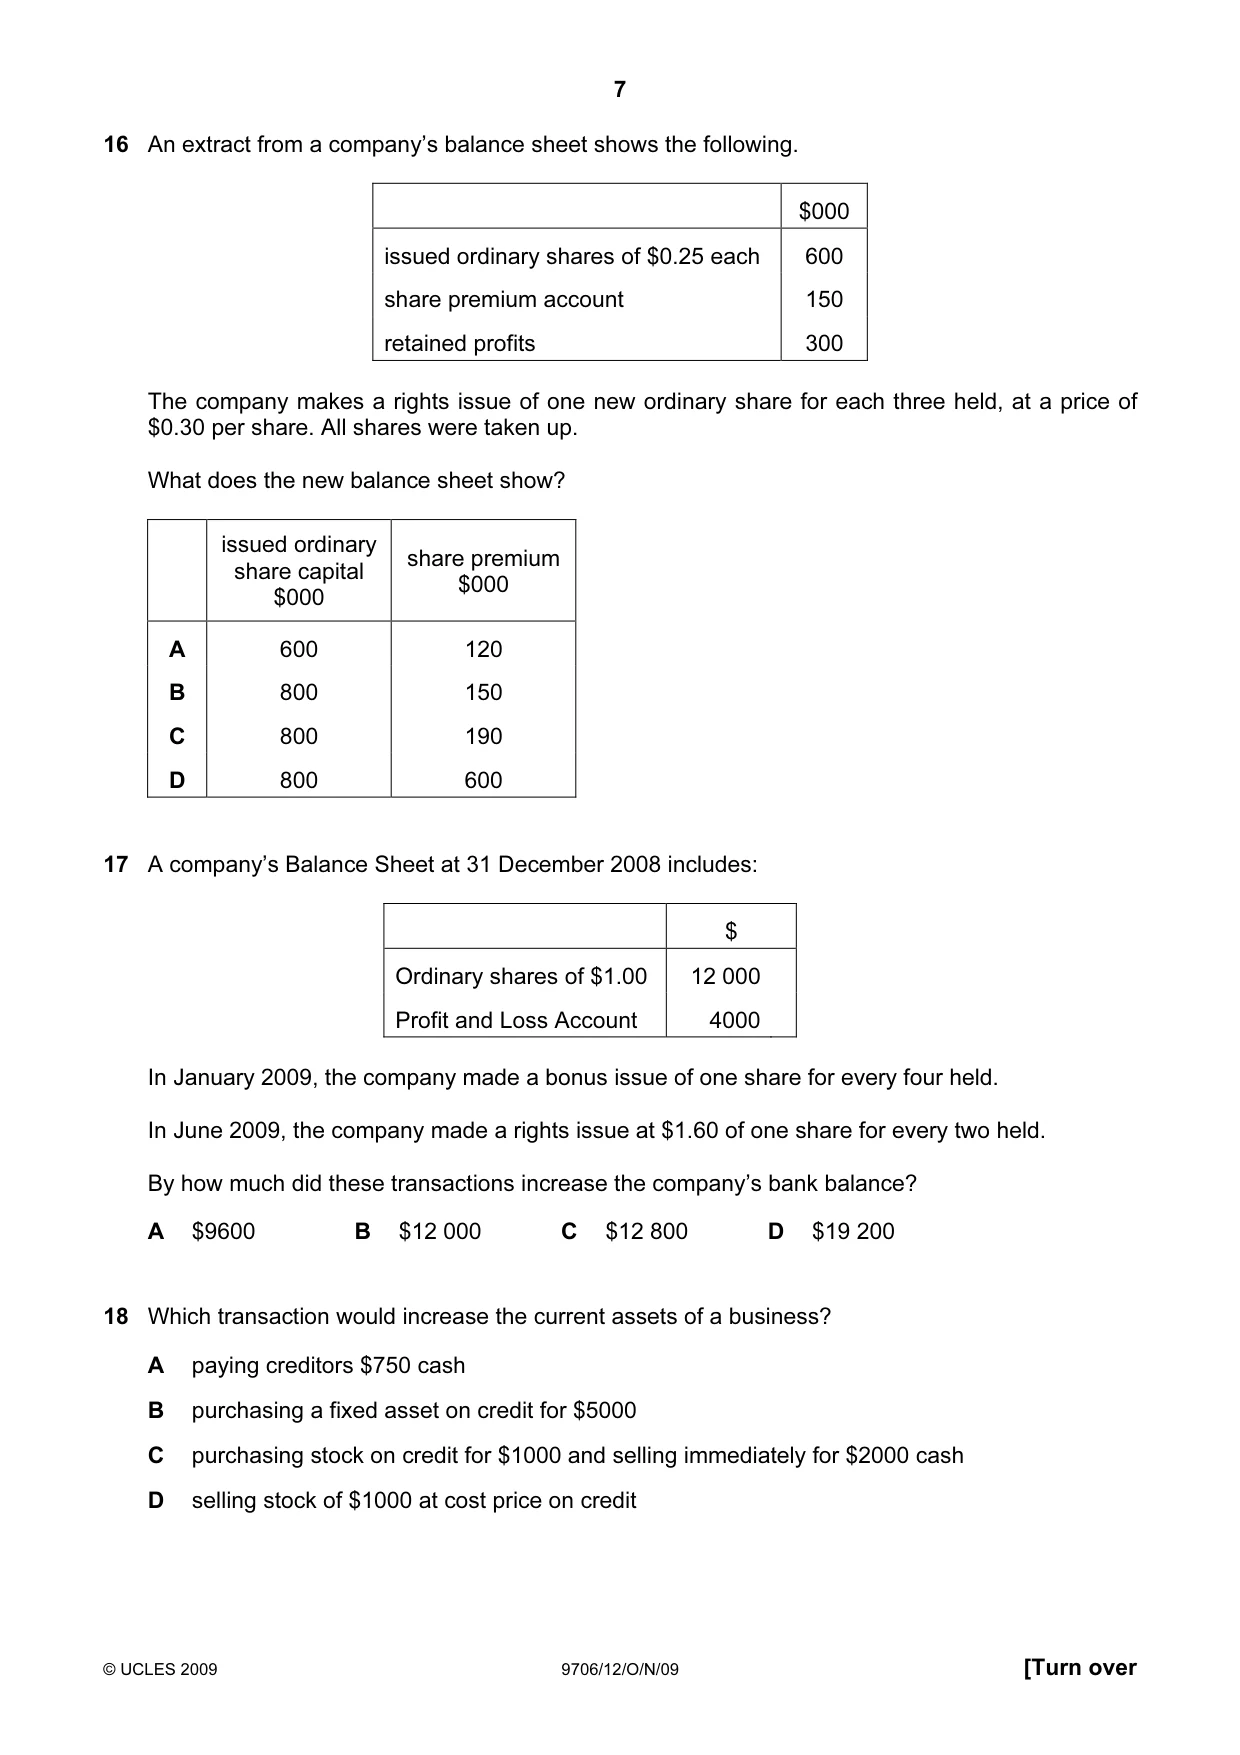
16 An extract from a company’s balance sheet shows the following. $000 issued ordinary shares of $0.25 each 600 share premium account 150 retained profits 300 The company makes a rights issue of one new ordinary share for each three held, at a price of $0.30 per share. All shares were taken up. What does the new balance sheet show? issued ordinary share premium share capital $000 $000 A 600 120 B 800 150 C 800 190 D 800 600
Mark scheme: C
Q17 · A company’s Balance Sheet at 31 December 2008 includes: $ Ordinary shares of $1.00 12 000…
17 A company’s Balance Sheet at 31 December 2008 includes: $ Ordinary shares of $1.00 12 000 Profit and Loss Account 4000 In January 2009, the company made a bonus issue of one share for every four held. In June 2009, the company made a rights issue at $1.60 of one share for every two held. By how much did these transactions increase the company’s bank balance? A $9600 B $12 000 C $12 800 D $19 200
Mark scheme: C
Q18 · Which transaction would increase the current assets of a business?
18 Which transaction would increase the current assets of a business? A paying creditors $750 cash B purchasing a fixed asset on credit for $5000 C purchasing stock on credit for $1000 and selling immediately for $2000 cash D selling stock of $1000 at cost price on credit
Mark scheme: C
Q19 · What will result in a reduction of working capital?
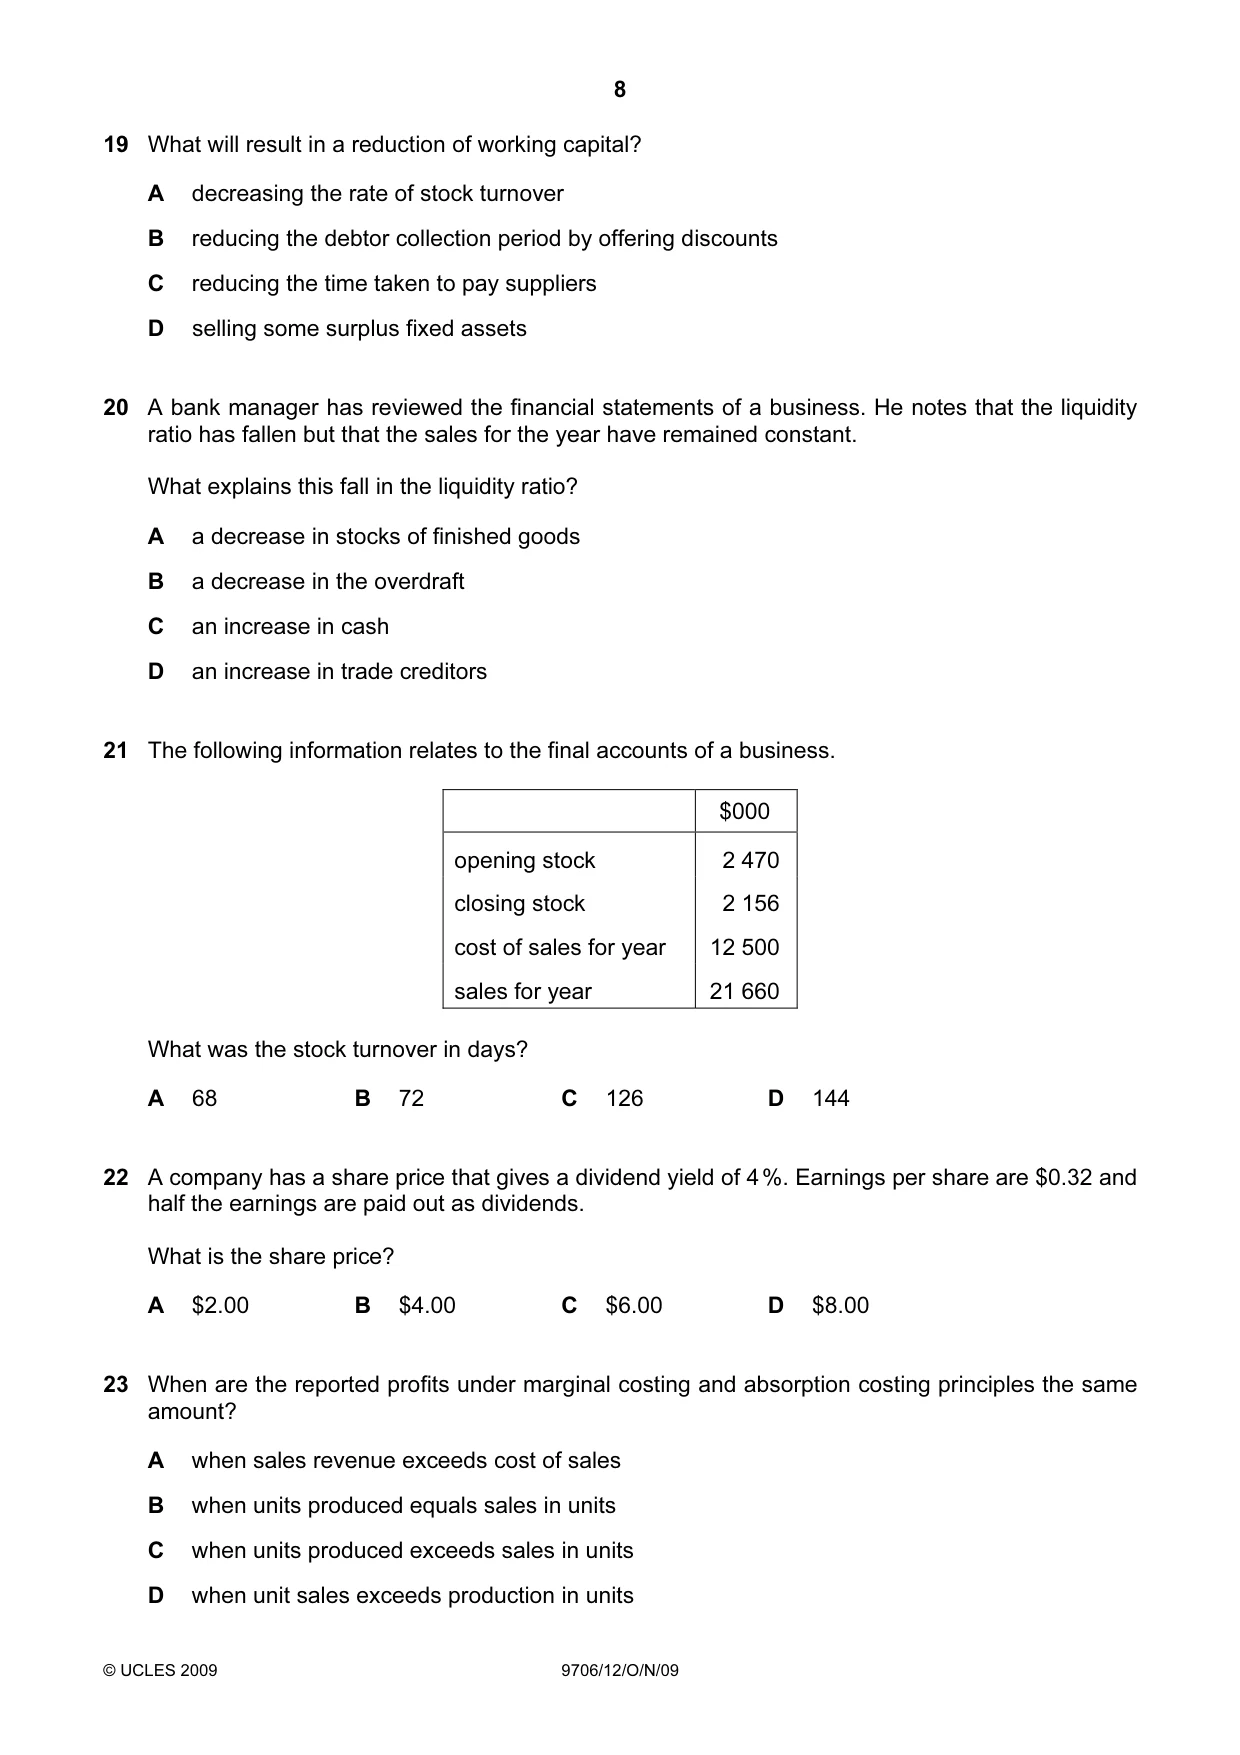
19 What will result in a reduction of working capital? A decreasing the rate of stock turnover B reducing the debtor collection period by offering discounts C reducing the time taken to pay suppliers D selling some surplus fixed assets
Mark scheme: B
More questions on Analysis and communication of accounting information
Q20 · A bank manager has reviewed the financial statements of a business
20 A bank manager has reviewed the financial statements of a business. He notes that the liquidity ratio has fallen but that the sales for the year have remained constant. What explains this fall in the liquidity ratio? A a decrease in stocks of finished goods B a decrease in the overdraft C an increase in cash D an increase in trade creditors
Mark scheme: D
More questions on Analysis and communication of accounting information
Q21 · The following information relates to the final accounts of a business
21 The following information relates to the final accounts of a business. $000 opening stock 2 470 closing stock 2 156 cost of sales for year 12 500 sales for year 21 660 What was the stock turnover in days? A 68 B 72 C 126 D 144
Mark scheme: A
More questions on Analysis and communication of accounting information
Q22 · A company has a share price that gives a dividend yield of 4 %
22 A company has a share price that gives a dividend yield of 4 %. Earnings per share are $0.32 and half the earnings are paid out as dividends. What is the share price? A $2.00 B $4.00 C $6.00 D $8.00
Mark scheme: B
More questions on Analysis and communication of accounting information
Q23 · When are the reported profits under marginal costing and absorption costing principles…
23 When are the reported profits under marginal costing and absorption costing principles the same amount? A when sales revenue exceeds cost of sales B when units produced equals sales in units C when units produced exceeds sales in units D when unit sales exceeds production in units
Mark scheme: B
Q24 · Which cost will fall as production is reduced?
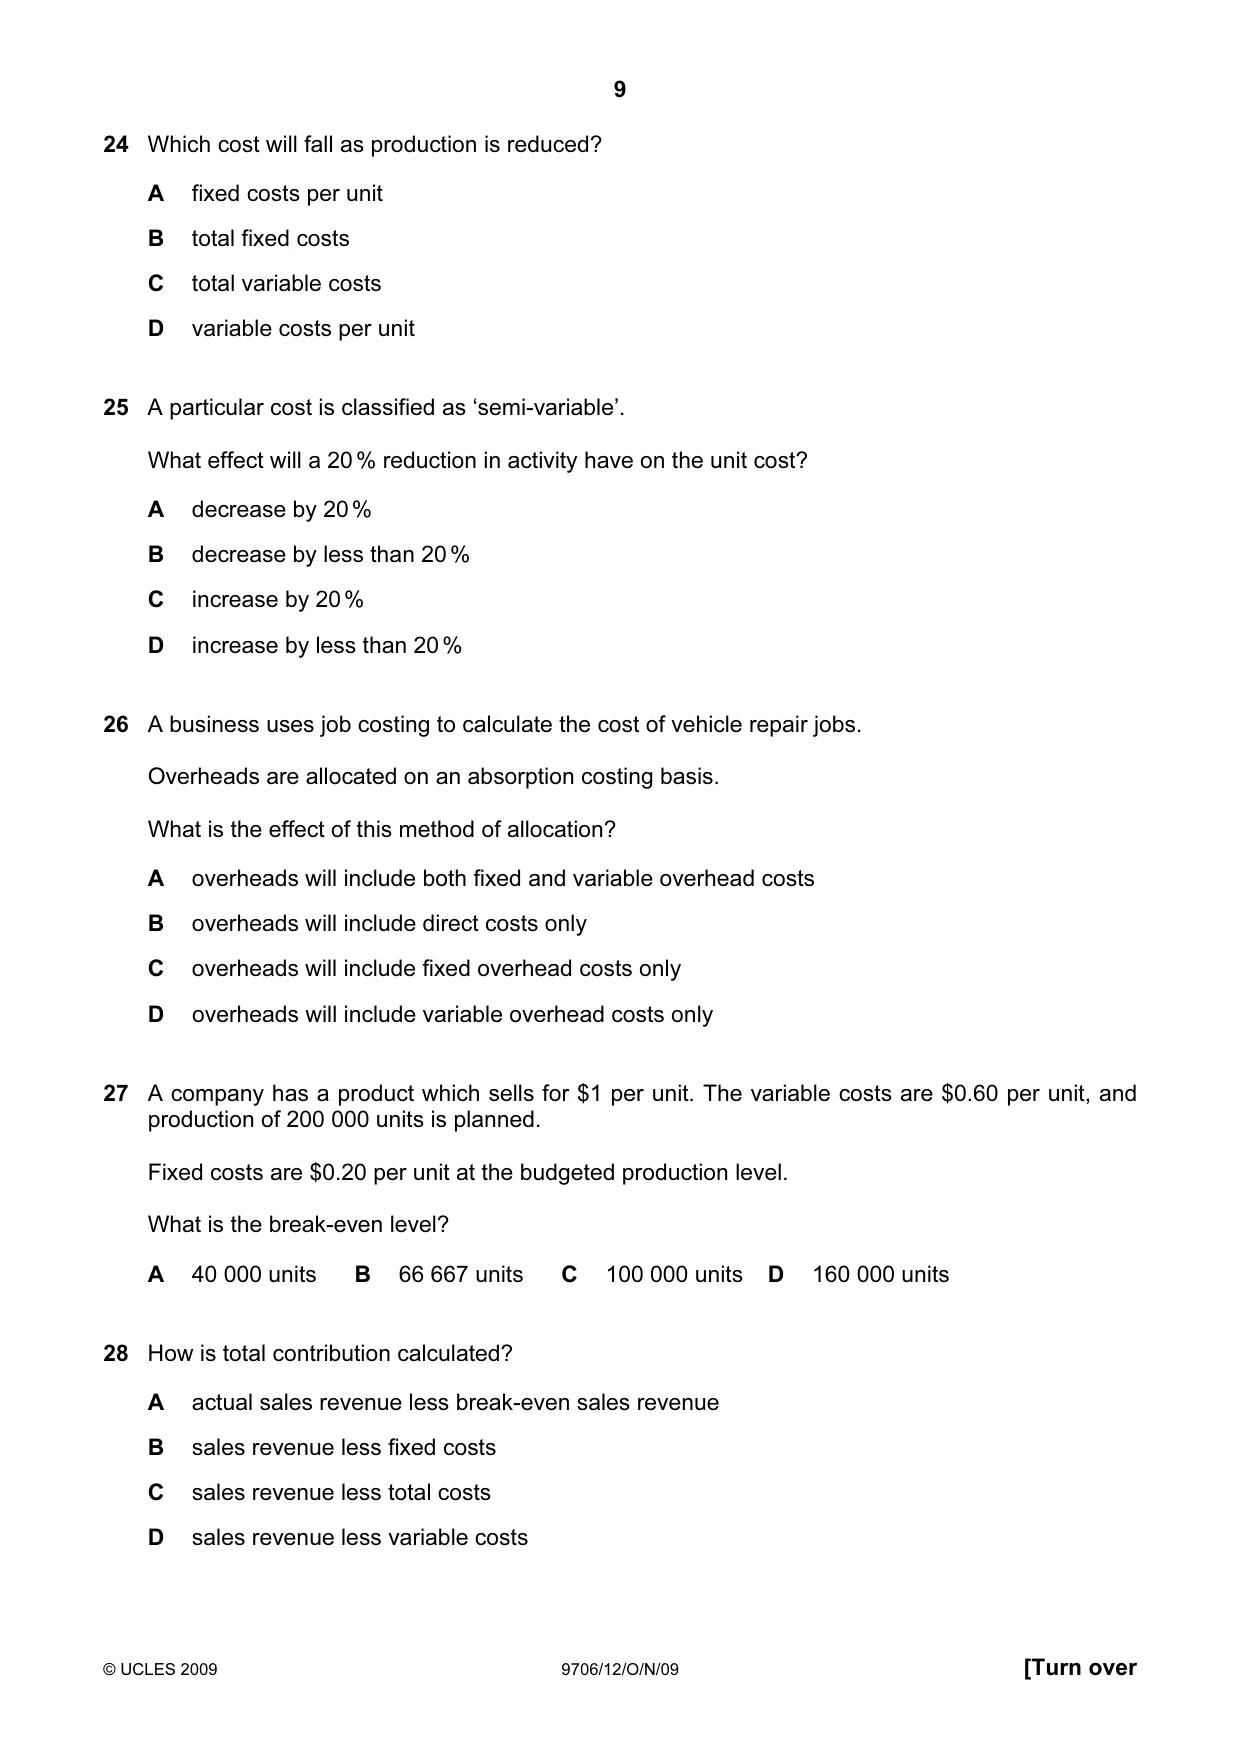
24 Which cost will fall as production is reduced? A fixed costs per unit B total fixed costs C total variable costs D variable costs per unit
Mark scheme: C
Q25 · A particular cost is classified as ‘semi-variable’
25 A particular cost is classified as ‘semi-variable’. What effect will a 20 % reduction in activity have on the unit cost? A decrease by 20 % B decrease by less than 20 % C increase by 20 % D increase by less than 20 %
Mark scheme: D
Q26 · A business uses job costing to calculate the cost of vehicle repair jobs
26 A business uses job costing to calculate the cost of vehicle repair jobs. Overheads are allocated on an absorption costing basis. What is the effect of this method of allocation? A overheads will include both fixed and variable overhead costs B overheads will include direct costs only C overheads will include fixed overhead costs only D overheads will include variable overhead costs only
Mark scheme: A
Q27 · A company has a product which sells for $1 per unit
27 A company has a product which sells for $1 per unit. The variable costs are $0.60 per unit, and production of 200 000 units is planned. Fixed costs are $0.20 per unit at the budgeted production level. What is the break-even level? A 40 000 units B 66 667 units C 100 000 units D 160 000 units
Mark scheme: C
Q28 · How is total contribution calculated?
28 How is total contribution calculated? A actual sales revenue less break-even sales revenue B sales revenue less fixed costs C sales revenue less total costs D sales revenue less variable costs
Mark scheme: D
Q29 · In January, a business had opening stocks of 25 200 units and closing stocks of 28 200…
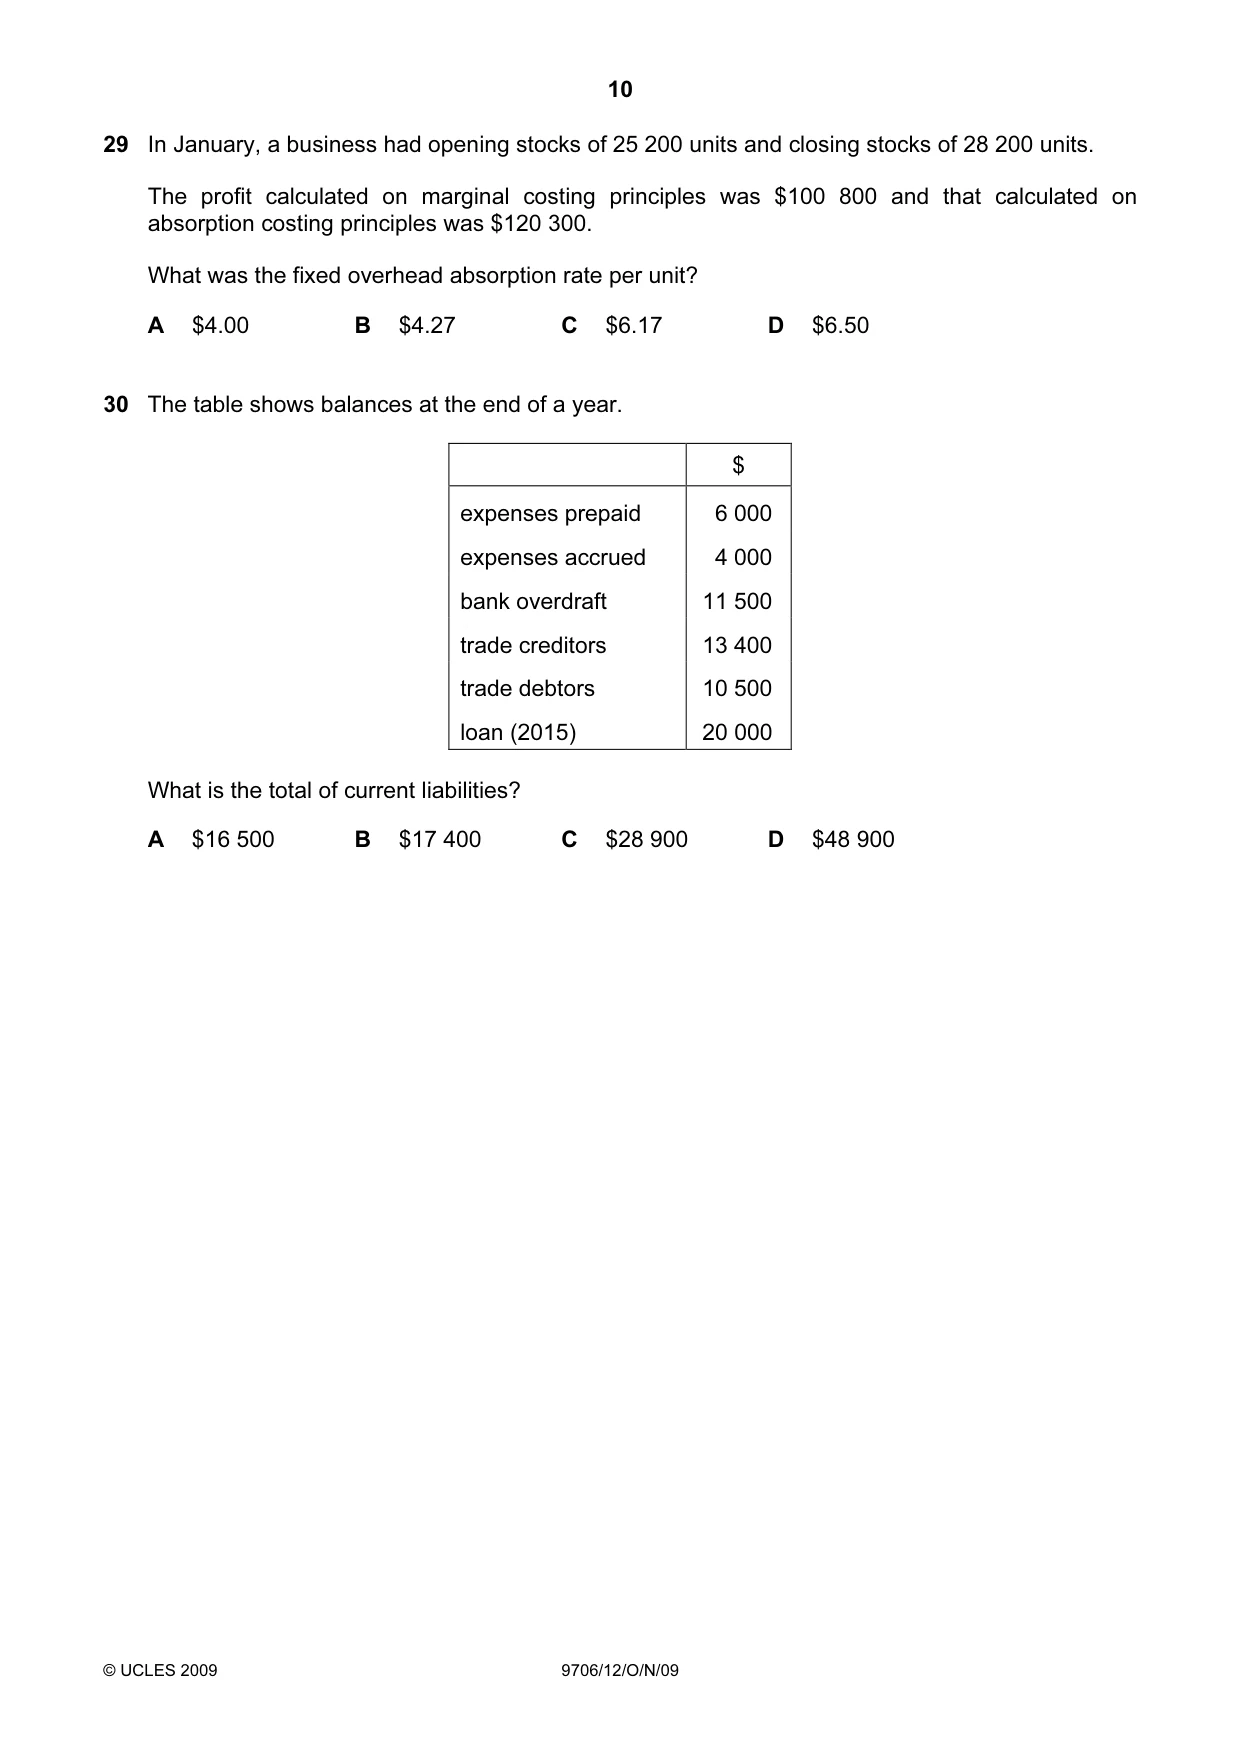
29 In January, a business had opening stocks of 25 200 units and closing stocks of 28 200 units. The profit calculated on marginal costing principles was $100 800 and that calculated on absorption costing principles was $120 300. What was the fixed overhead absorption rate per unit? A $4.00 B $4.27 C $6.17 D $6.50
Mark scheme: D
Q30 · The table shows balances at the end of a year
30 The table shows balances at the end of a year. $ expenses prepaid 6 000 expenses accrued 4 000 bank overdraft 11 500 trade creditors 13 400 trade debtors 10 500 loan (2015) 20 000 What is the total of current liabilities? A $16 500 B $17 400 C $28 900 D $48 900
Mark scheme: C
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2009 Oct/Nov, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.