Cambridge A Level Accounting 9706 — 2021 May/June Paper 1 · Variant 1
9706/11/M/J/21 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
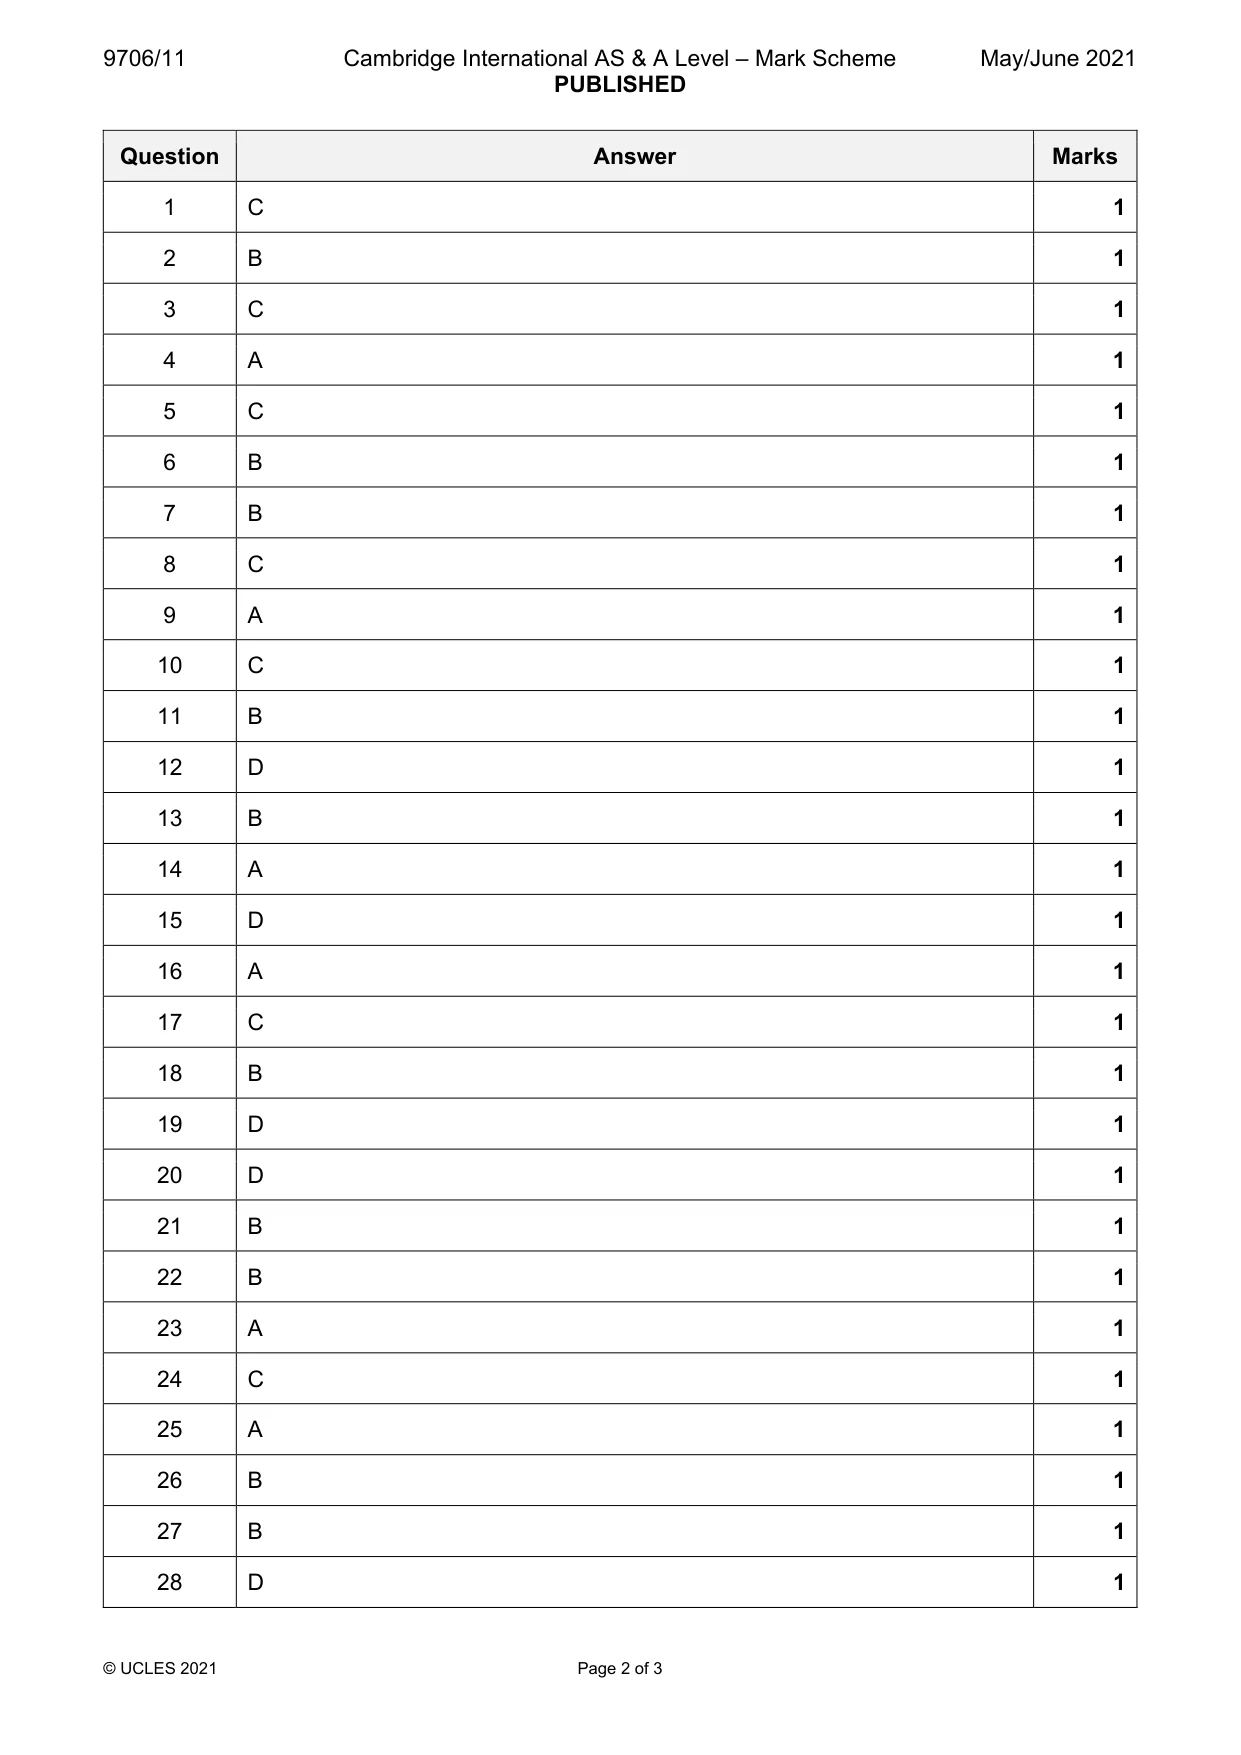
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · The skill and efficiency of the workforce of a business has increased during the…
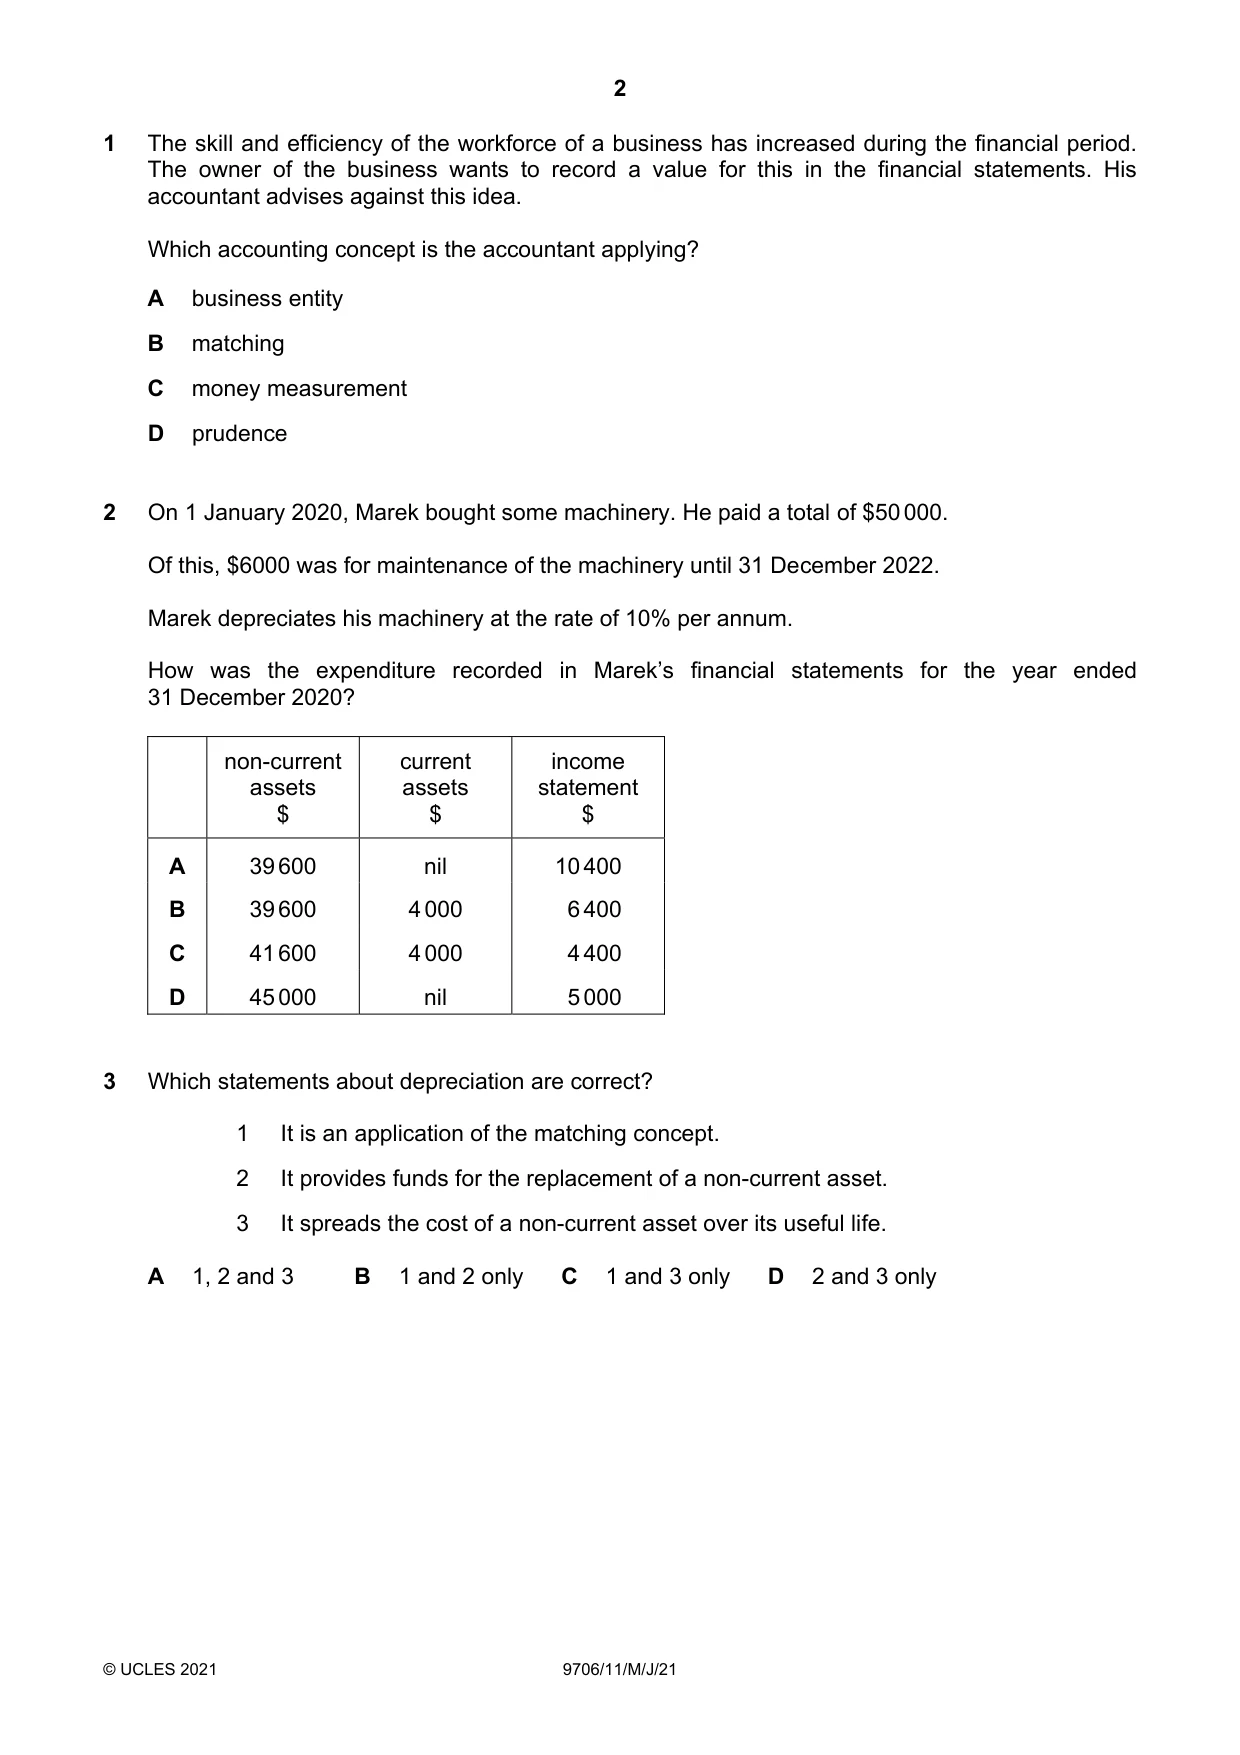
1 The skill and efficiency of the workforce of a business has increased during the financial period. The owner of the business wants to record a value for this in the financial statements. His accountant advises against this idea. Which accounting concept is the accountant applying? A business entity B matching C money measurement D prudence
Mark scheme: C
Q2 · On 1 January 2020, Marek bought some machinery
2 On 1 January 2020, Marek bought some machinery. He paid a total of $50 000. Of this, $6000 was for maintenance of the machinery until 31 December 2022. Marek depreciates his machinery at the rate of 10% per annum. How was the expenditure recorded in Marek’s financial statements for the year ended 31 December 2020? non-current current income assets assets statement $ $ $ A 39 600 nil 10 400 B 39 600 4 000 6 400 C 41 600 4 000 4 400 D 45 000 nil 5 000
Mark scheme: B
Q3 · Which statements about depreciation are correct?
3 Which statements about depreciation are correct? 1 It is an application of the matching concept. 2 It provides funds for the replacement of a non-current asset. 3 It spreads the cost of a non-current asset over its useful life. A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
Mark scheme: C
Q4 · An item of revenue expenditure is wrongly treated as capital expenditure
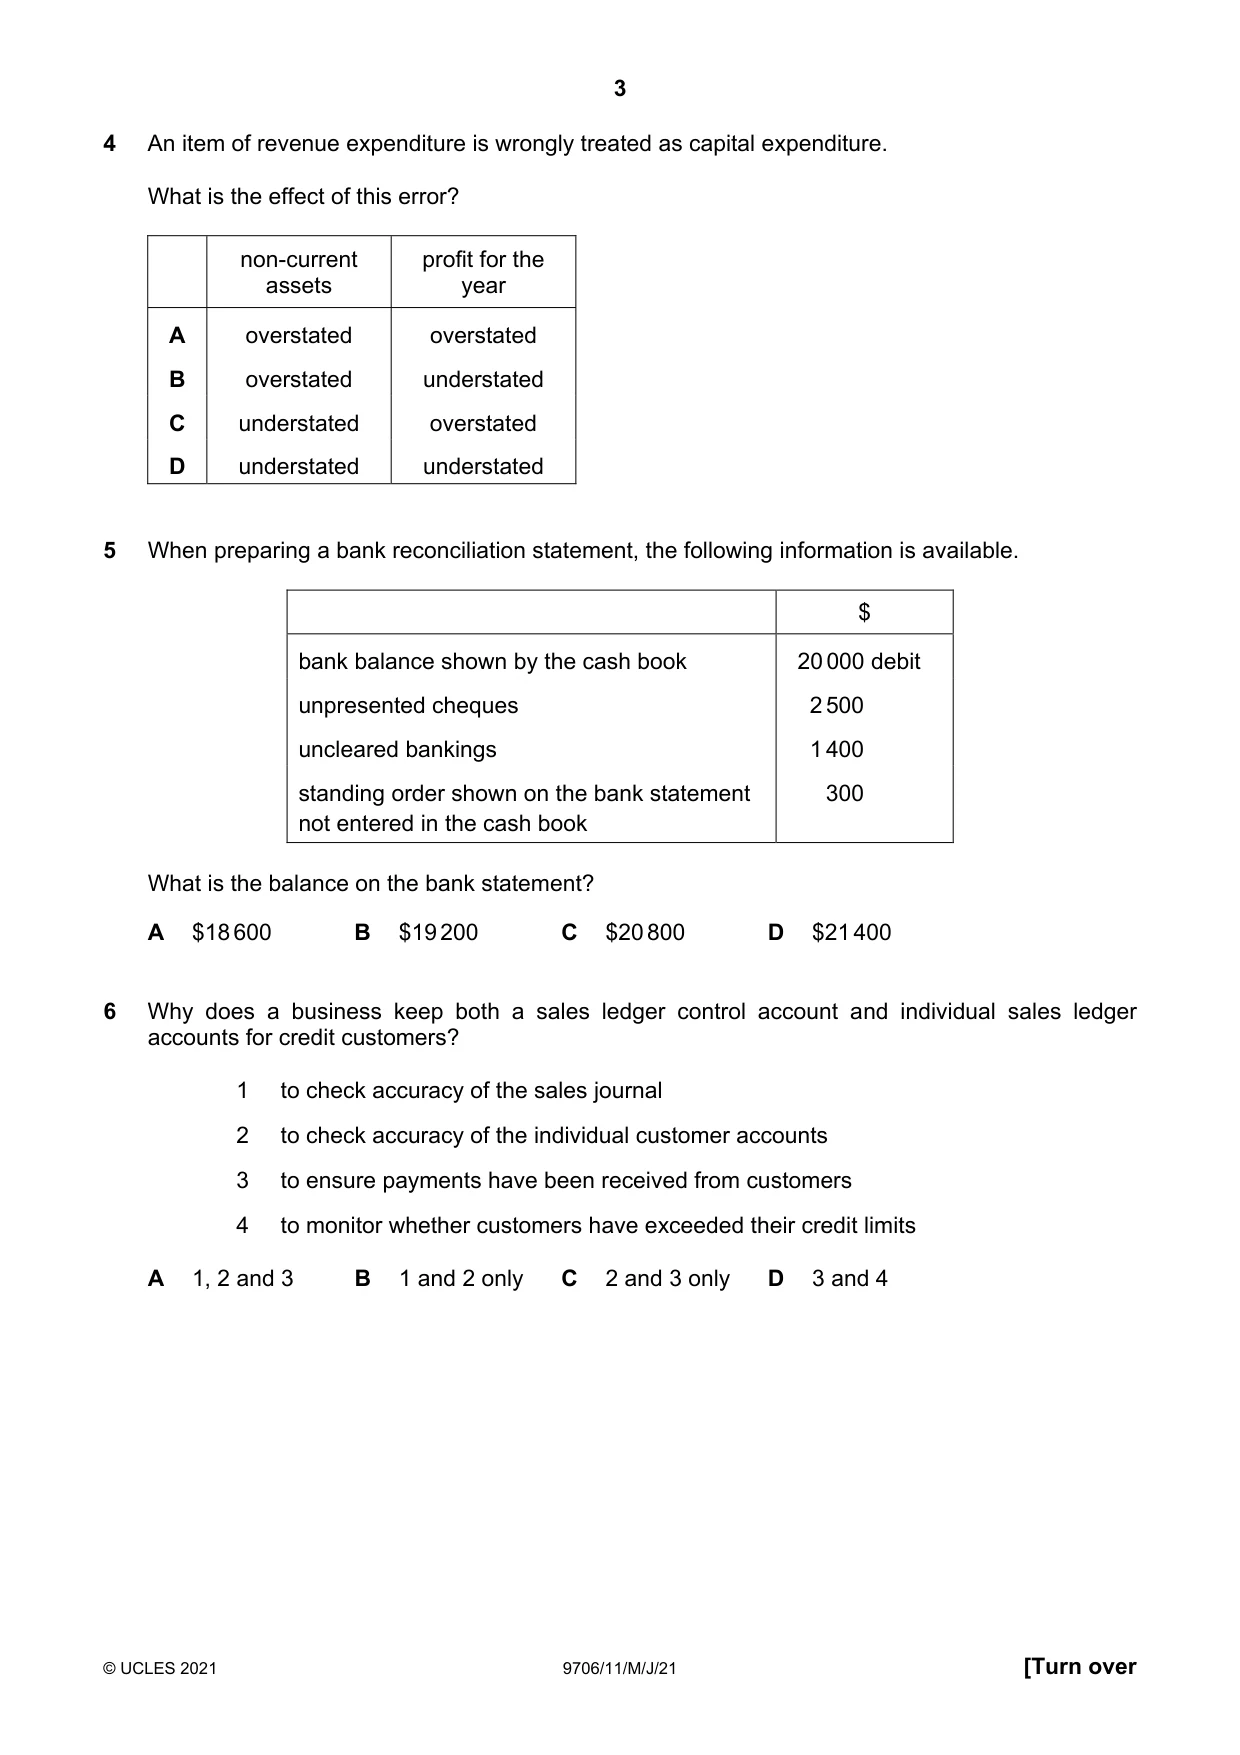
4 An item of revenue expenditure is wrongly treated as capital expenditure. What is the effect of this error? non-current profit for the assets year A overstated overstated B overstated understated C understated overstated D understated understated
Mark scheme: A
Q5 · When preparing a bank reconciliation statement, the following information is available
5 When preparing a bank reconciliation statement, the following information is available. $ bank balance shown by the cash book 20 000 debit unpresented cheques 2 500 uncleared bankings 1 400 standing order shown on the bank statement 300 not entered in the cash book What is the balance on the bank statement? A $18 600 B $19 200 C $20 800 D $21 400
Mark scheme: C
Q6 · Why does a business keep both a sales ledger control account and individual sales ledger…
6 Why does a business keep both a sales ledger control account and individual sales ledger accounts for credit customers? 1 to check accuracy of the sales journal 2 to check accuracy of the individual customer accounts 3 to ensure payments have been received from customers 4 to monitor whether customers have exceeded their credit limits A 1, 2 and 3 B 1 and 2 only C 2 and 3 only D 3 and 4
Mark scheme: B
Q7 · A businessman suspects some of his inventory has been stolen
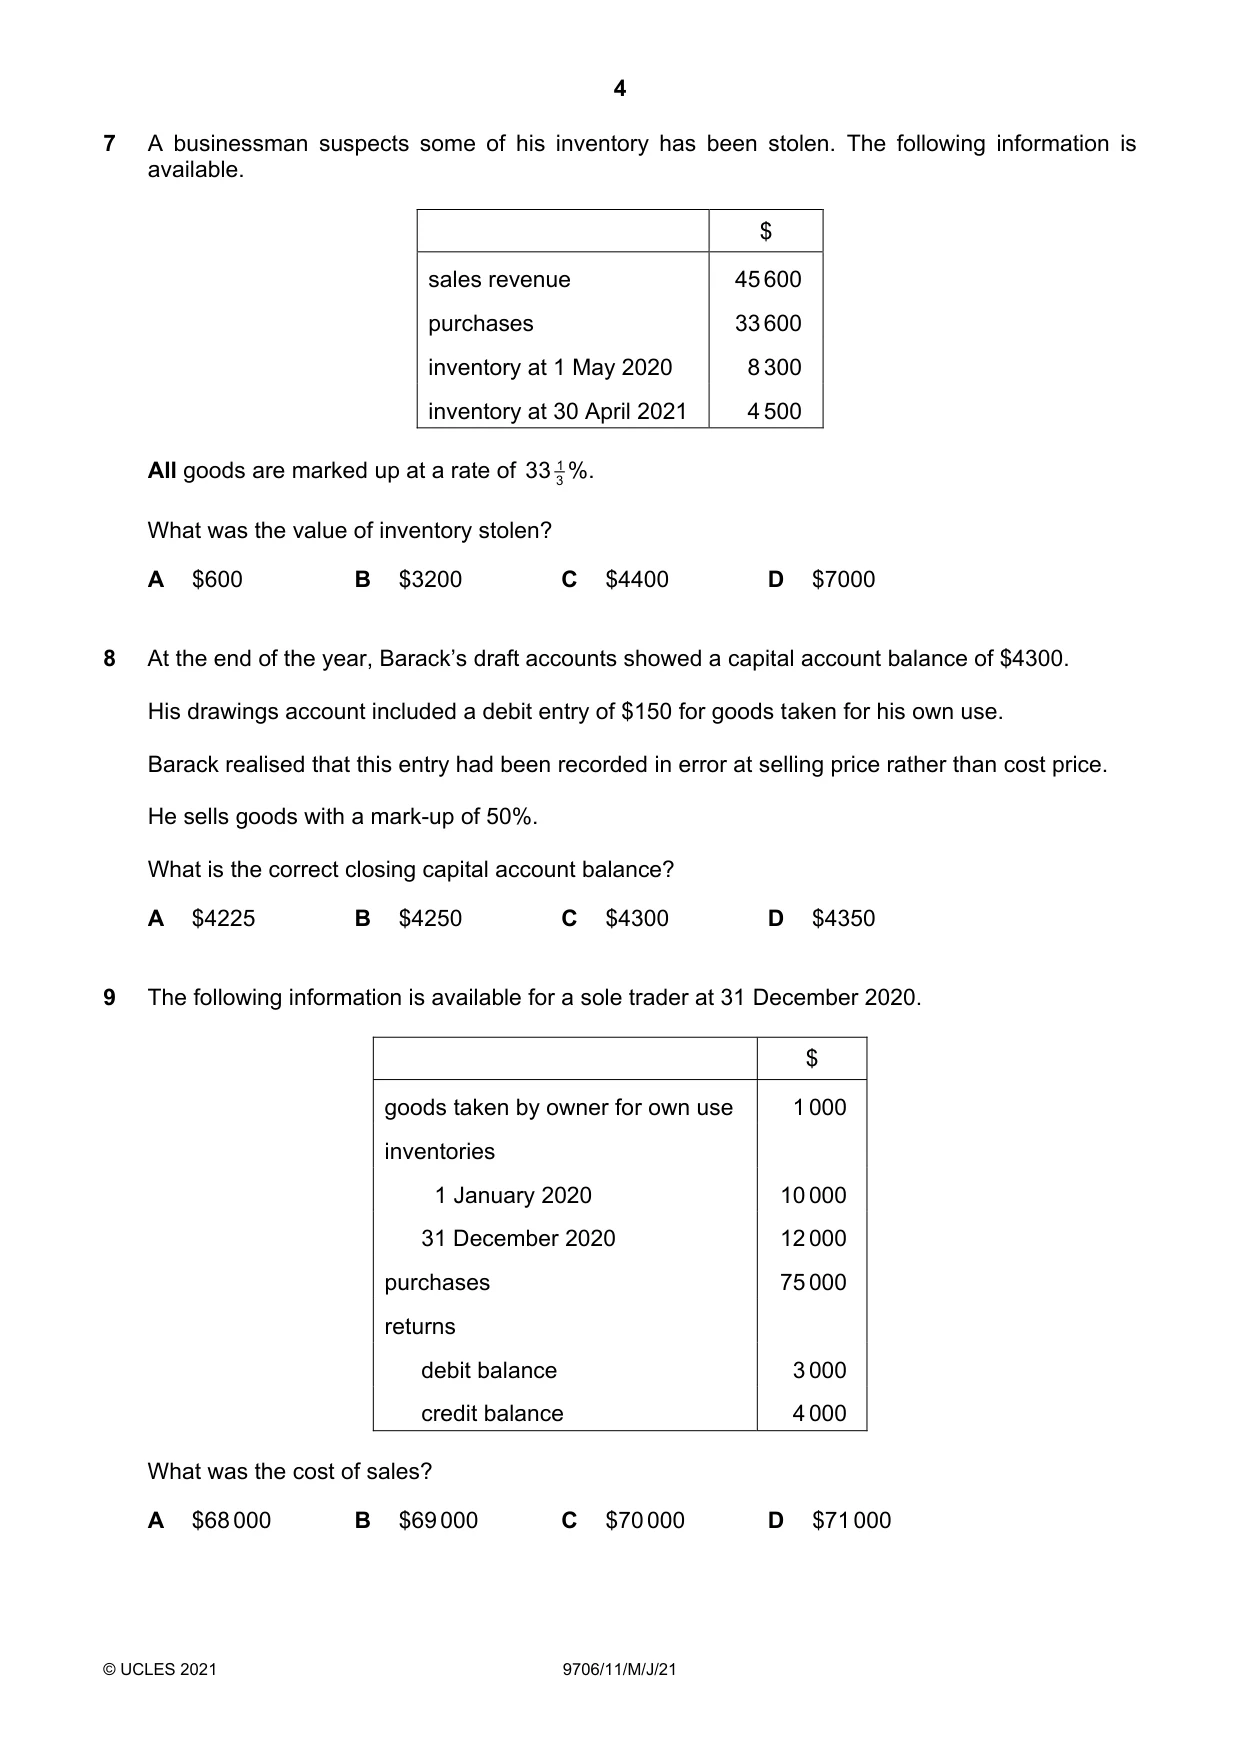
7 A businessman suspects some of his inventory has been stolen. The following information is available. $ sales revenue 45 600 purchases 33 600 inventory at 1 May 2020 8 300 inventory at 30 April 2021 4 500 All goods are marked up at a rate of 33 %. 1 3 What was the value of inventory stolen? A $600 B $3200 C $4400 D $7000
Mark scheme: B
Q8 · At the end of the year, Barack’s draft accounts showed a capital account balance of $4300
8 At the end of the year, Barack’s draft accounts showed a capital account balance of $4300. His drawings account included a debit entry of $150 for goods taken for his own use. Barack realised that this entry had been recorded in error at selling price rather than cost price. He sells goods with a mark-up of 50%. What is the correct closing capital account balance? A $4225 B $4250 C $4300 D $4350
Mark scheme: C
Q9 · The following information is available for a sole trader at 31 December 2020
9 The following information is available for a sole trader at 31 December 2020. $ goods taken by owner for own use 1 000 inventories 1 January 2020 10 000 31 December 2020 12 000 purchases 75 000 returns debit balance 3 000 credit balance 4 000 What was the cost of sales? A $68 000 B $69 000 C $70 000 D $71 000
Mark scheme: A
Q10 · Which items only appear on the credit side of a partner’s capital account?
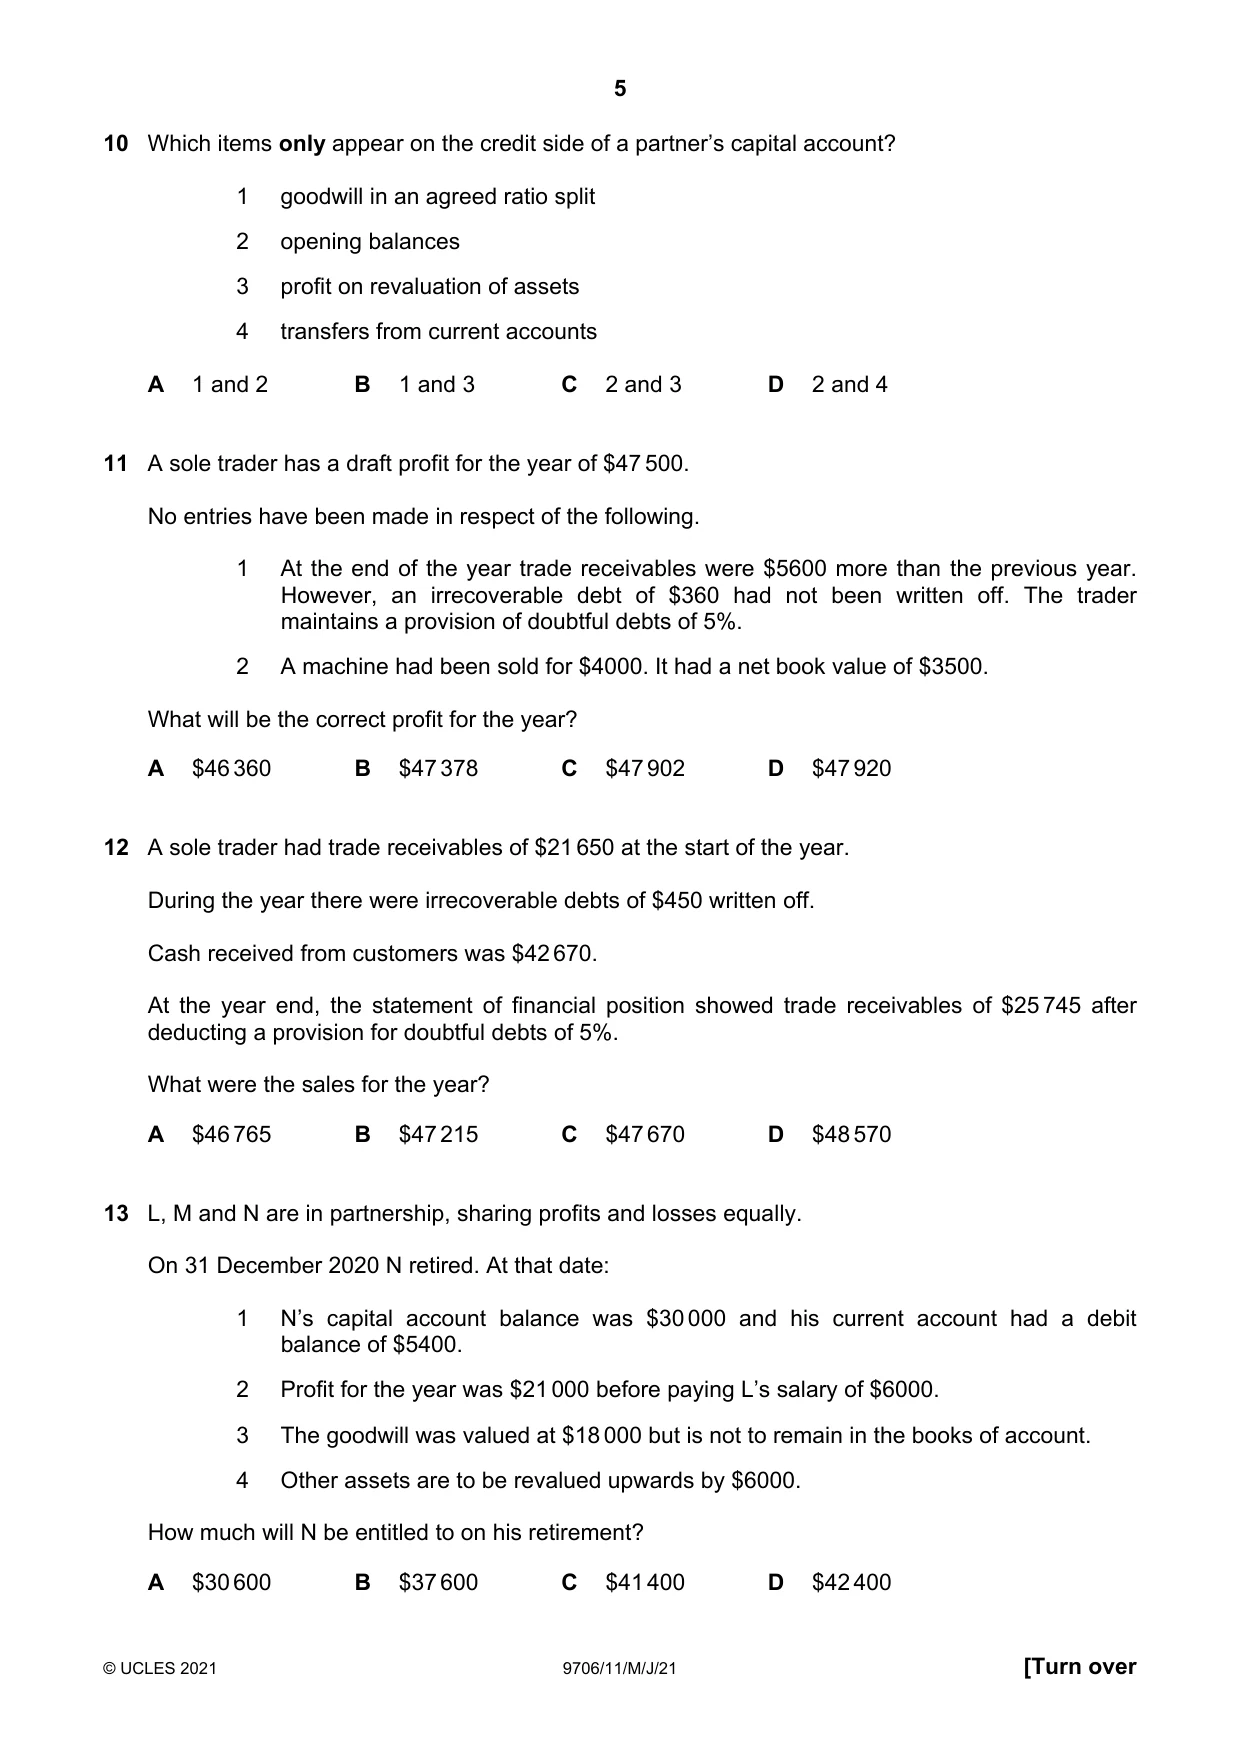
10 Which items only appear on the credit side of a partner’s capital account? 1 goodwill in an agreed ratio split 2 opening balances 3 profit on revaluation of assets 4 transfers from current accounts A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
Mark scheme: C
Q11 · A sole trader has a draft profit for the year of $47 500
11 A sole trader has a draft profit for the year of $47 500. No entries have been made in respect of the following. 1 At the end of the year trade receivables were $5600 more than the previous year. However, an irrecoverable debt of $360 had not been written off. The trader maintains a provision of doubtful debts of 5%. 2 A machine had been sold for $4000. It had a net book value of $3500. What will be the correct profit for the year? A $46 360 B $47 378 C $47 902 D $47 920
Mark scheme: B
Q12 · A sole trader had trade receivables of $21 650 at the start of the year
12 A sole trader had trade receivables of $21 650 at the start of the year. During the year there were irrecoverable debts of $450 written off. Cash received from customers was $42 670. At the year end, the statement of financial position showed trade receivables of $25 745 after deducting a provision for doubtful debts of 5%. What were the sales for the year? A $46 765 B $47 215 C $47 670 D $48 570
Mark scheme: D
Q13 · L, M and N are in partnership, sharing profits and losses equally
13 L, M and N are in partnership, sharing profits and losses equally. On 31 December 2020 N retired. At that date: 1 N’s capital account balance was $30 000 and his current account had a debit balance of $5400. 2 Profit for the year was $21 000 before paying L’s salary of $6000. 3 The goodwill was valued at $18 000 but is not to remain in the books of account. 4 Other assets are to be revalued upwards by $6000. How much will N be entitled to on his retirement? A $30 600 B $37 600 C $41 400 D $42 400
Mark scheme: B
Q14 · Charlie and Daphne are in partnership, sharing profits and losses in the ratio 2 : 1
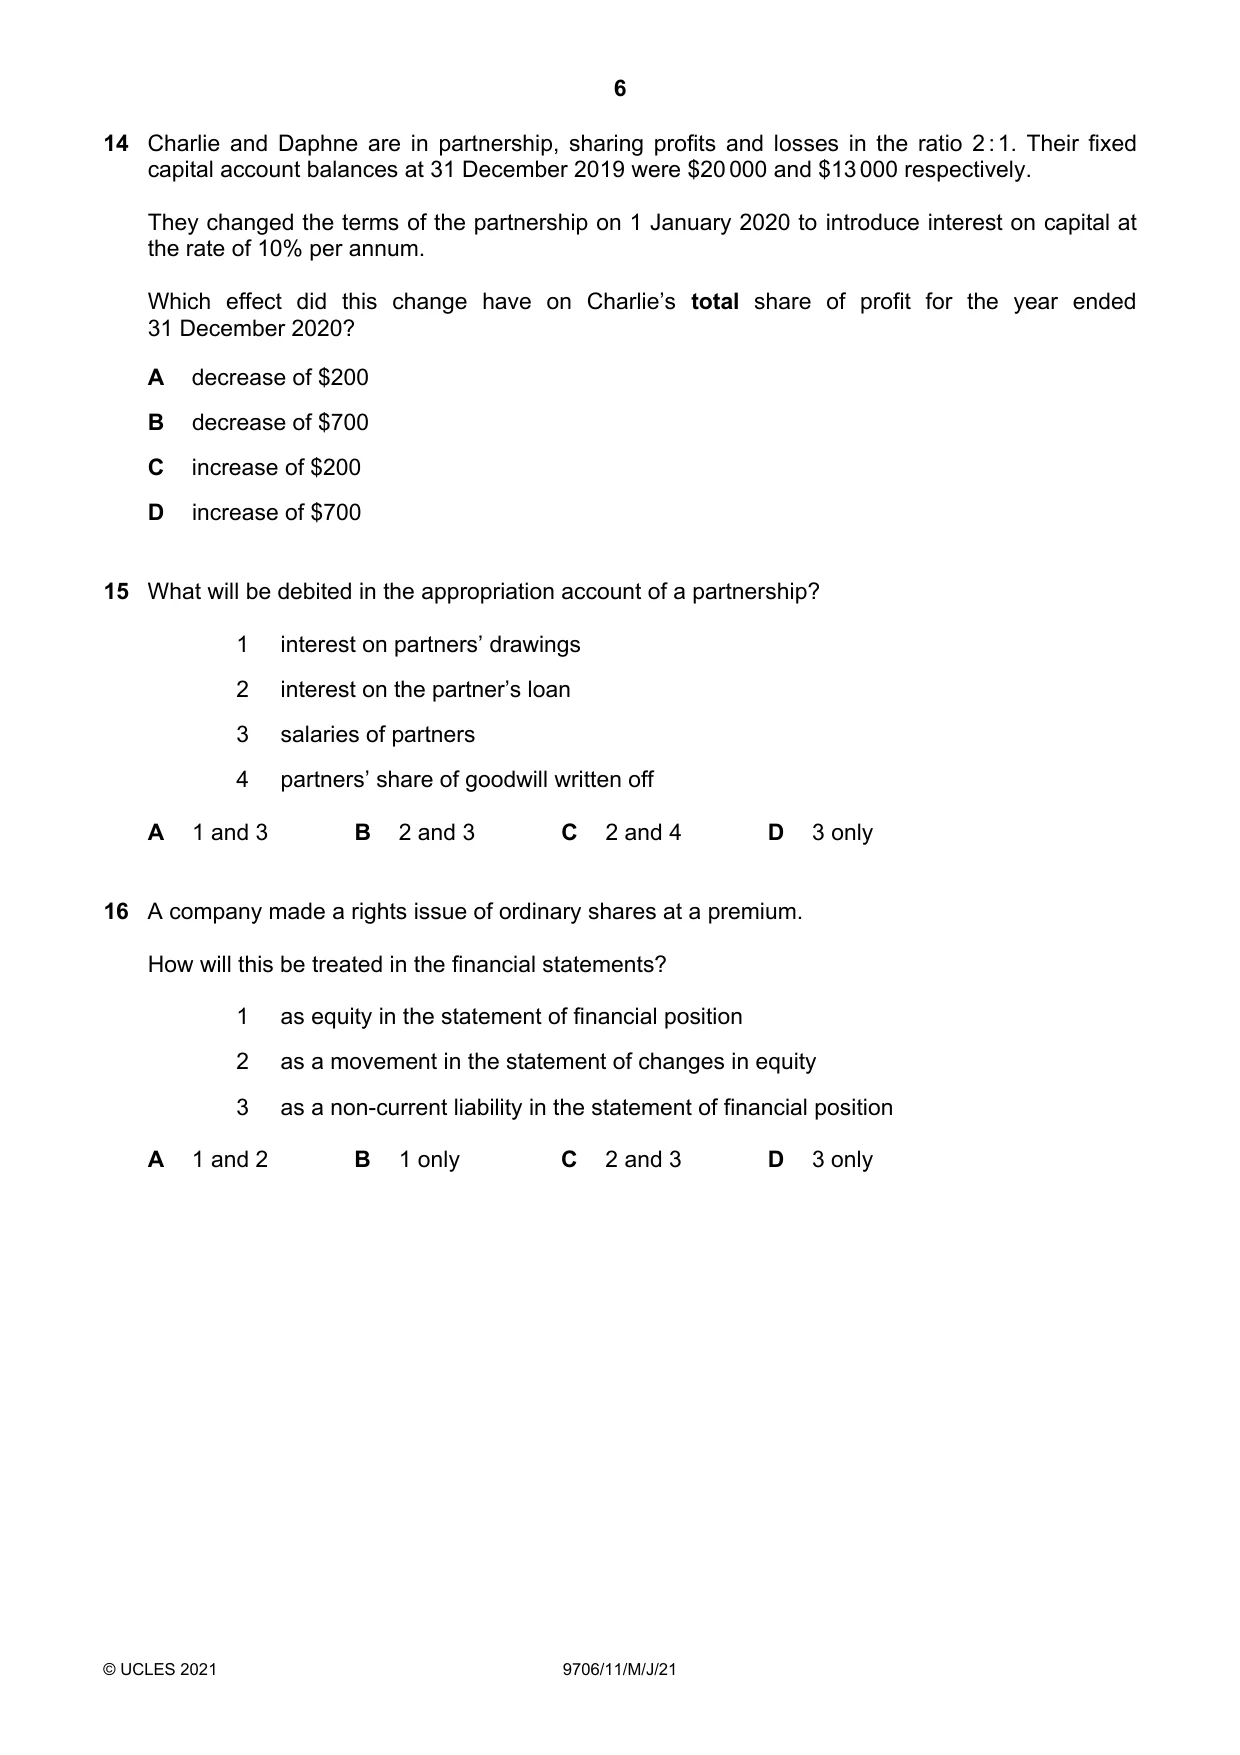
14 Charlie and Daphne are in partnership, sharing profits and losses in the ratio 2 : 1. Their fixed capital account balances at 31 December 2019 were $20 000 and $13 000 respectively. They changed the terms of the partnership on 1 January 2020 to introduce interest on capital at the rate of 10% per annum. Which effect did this change have on Charlie’s total share of profit for the year ended 31 December 2020? A decrease of $200 B decrease of $700 C increase of $200 D increase of $700
Mark scheme: A
Q15 · What will be debited in the appropriation account of a partnership?
15 What will be debited in the appropriation account of a partnership? 1 interest on partners’ drawings 2 interest on the partner’s loan 3 salaries of partners 4 partners’ share of goodwill written off A 1 and 3 B 2 and 3 C 2 and 4 D 3 only
Mark scheme: D
Q16 · A company made a rights issue of ordinary shares at a premium
16 A company made a rights issue of ordinary shares at a premium. How will this be treated in the financial statements? 1 as equity in the statement of financial position 2 as a movement in the statement of changes in equity 3 as a non-current liability in the statement of financial position A 1 and 2 B 1 only C 2 and 3 D 3 only
Mark scheme: A
Q17 · The income statement of X Limited for 2020 showed an incorrect profit figure because $10…
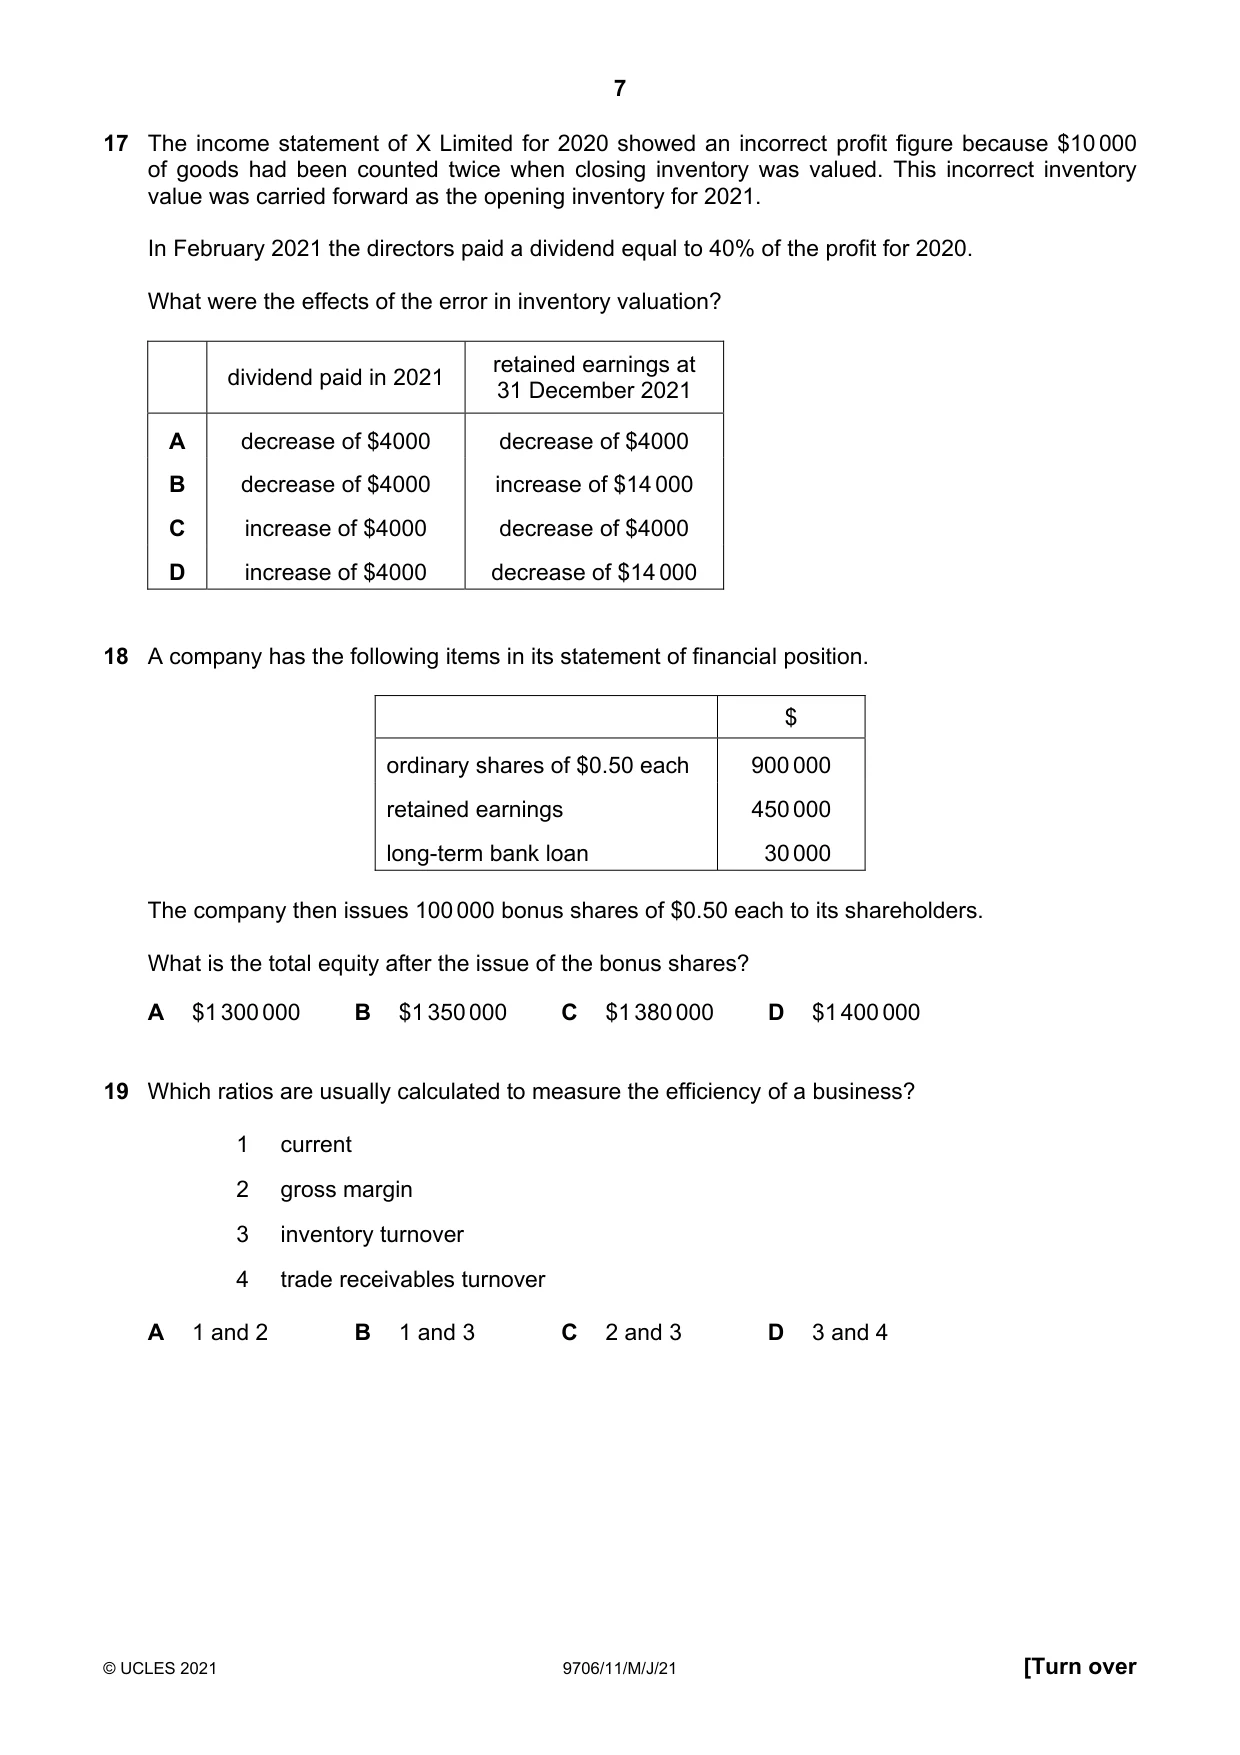
17 The income statement of X Limited for 2020 showed an incorrect profit figure because $10 000 of goods had been counted twice when closing inventory was valued. This incorrect inventory value was carried forward as the opening inventory for 2021. In February 2021 the directors paid a dividend equal to 40% of the profit for 2020. What were the effects of the error in inventory valuation? retained earnings at dividend paid in 2021 31 December 2021 A decrease of $4000 decrease of $4000 B decrease of $4000 increase of $14 000 C increase of $4000 decrease of $4000 D increase of $4000 decrease of $14 000
Mark scheme: C
Q18 · A company has the following items in its statement of financial position
18 A company has the following items in its statement of financial position. $ ordinary shares of $0.50 each 900 000 retained earnings 450 000 long-term bank loan 30 000 The company then issues 100 000 bonus shares of $0.50 each to its shareholders. What is the total equity after the issue of the bonus shares? A $1 300 000 B $1 350 000 C $1 380 000 D $1 400 000
Mark scheme: B
Q19 · Which ratios are usually calculated to measure the efficiency of a business?
19 Which ratios are usually calculated to measure the efficiency of a business? 1 current 2 gross margin 3 inventory turnover 4 trade receivables turnover A 1 and 2 B 1 and 3 C 2 and 3 D 3 and 4
Mark scheme: D
More questions on Analysis and communication of accounting information
Q20 · The following information is available for a limited company at the end of its financial…
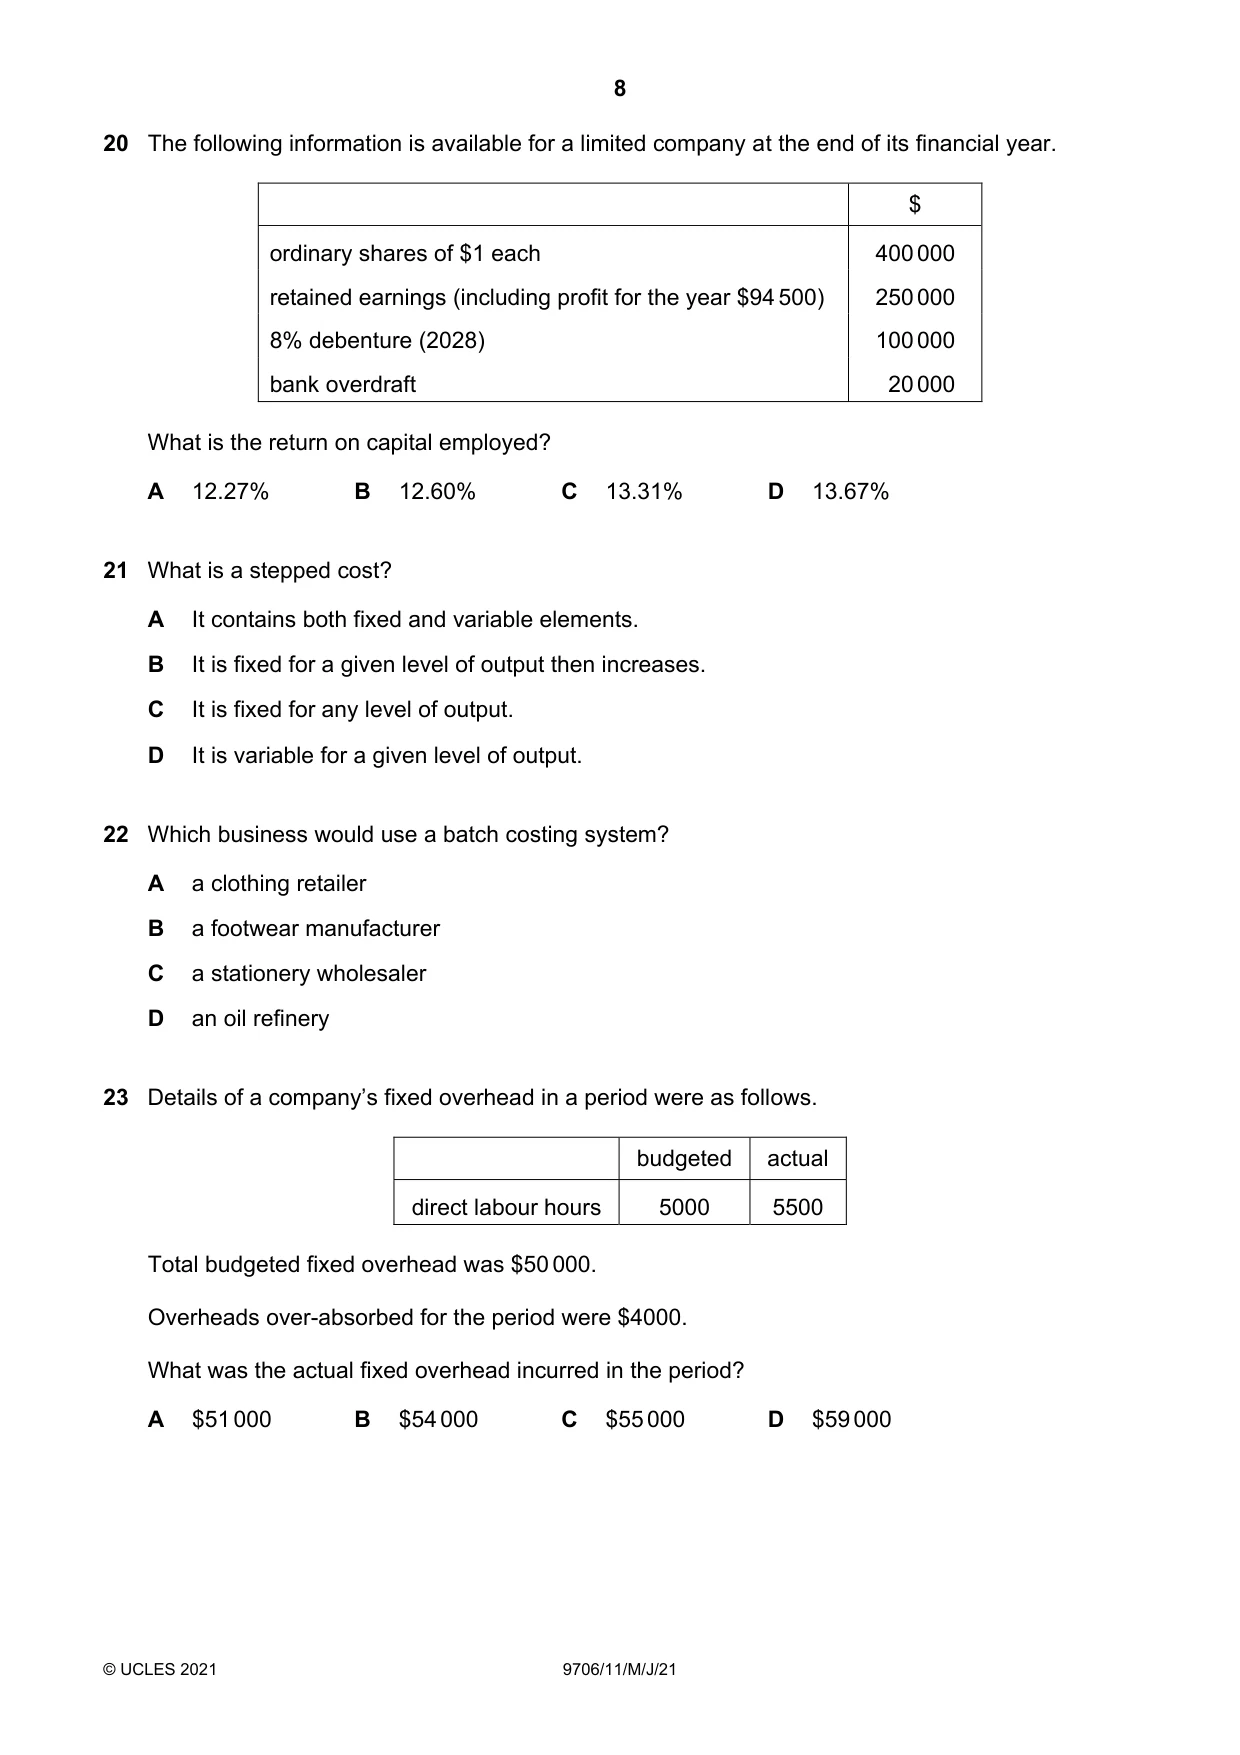
20 The following information is available for a limited company at the end of its financial year. $ ordinary shares of $1 each 400 000 retained earnings (including profit for the year $94 500) 250 000 8% debenture (2028) 100 000 bank overdraft 20 000 What is the return on capital employed? A 12.27% B 12.60% C 13.31% D 13.67%
Mark scheme: D
More questions on Analysis and communication of accounting information
Q21 · What is a stepped cost?
21 What is a stepped cost? A It contains both fixed and variable elements. B It is fixed for a given level of output then increases. C It is fixed for any level of output. D It is variable for a given level of output.
Mark scheme: B
Q22 · Which business would use a batch costing system?
22 Which business would use a batch costing system? A a clothing retailer B a footwear manufacturer C a stationery wholesaler D an oil refinery
Mark scheme: B
Q23 · Details of a company’s fixed overhead in a period were as follows
23 Details of a company’s fixed overhead in a period were as follows. budgeted actual direct labour hours 5000 5500 Total budgeted fixed overhead was $50 000. Overheads over-absorbed for the period were $4000. What was the actual fixed overhead incurred in the period? A $51 000 B $54 000 C $55 000 D $59 000
Mark scheme: A
Q24 · How might an under-absorption of overheads arise?
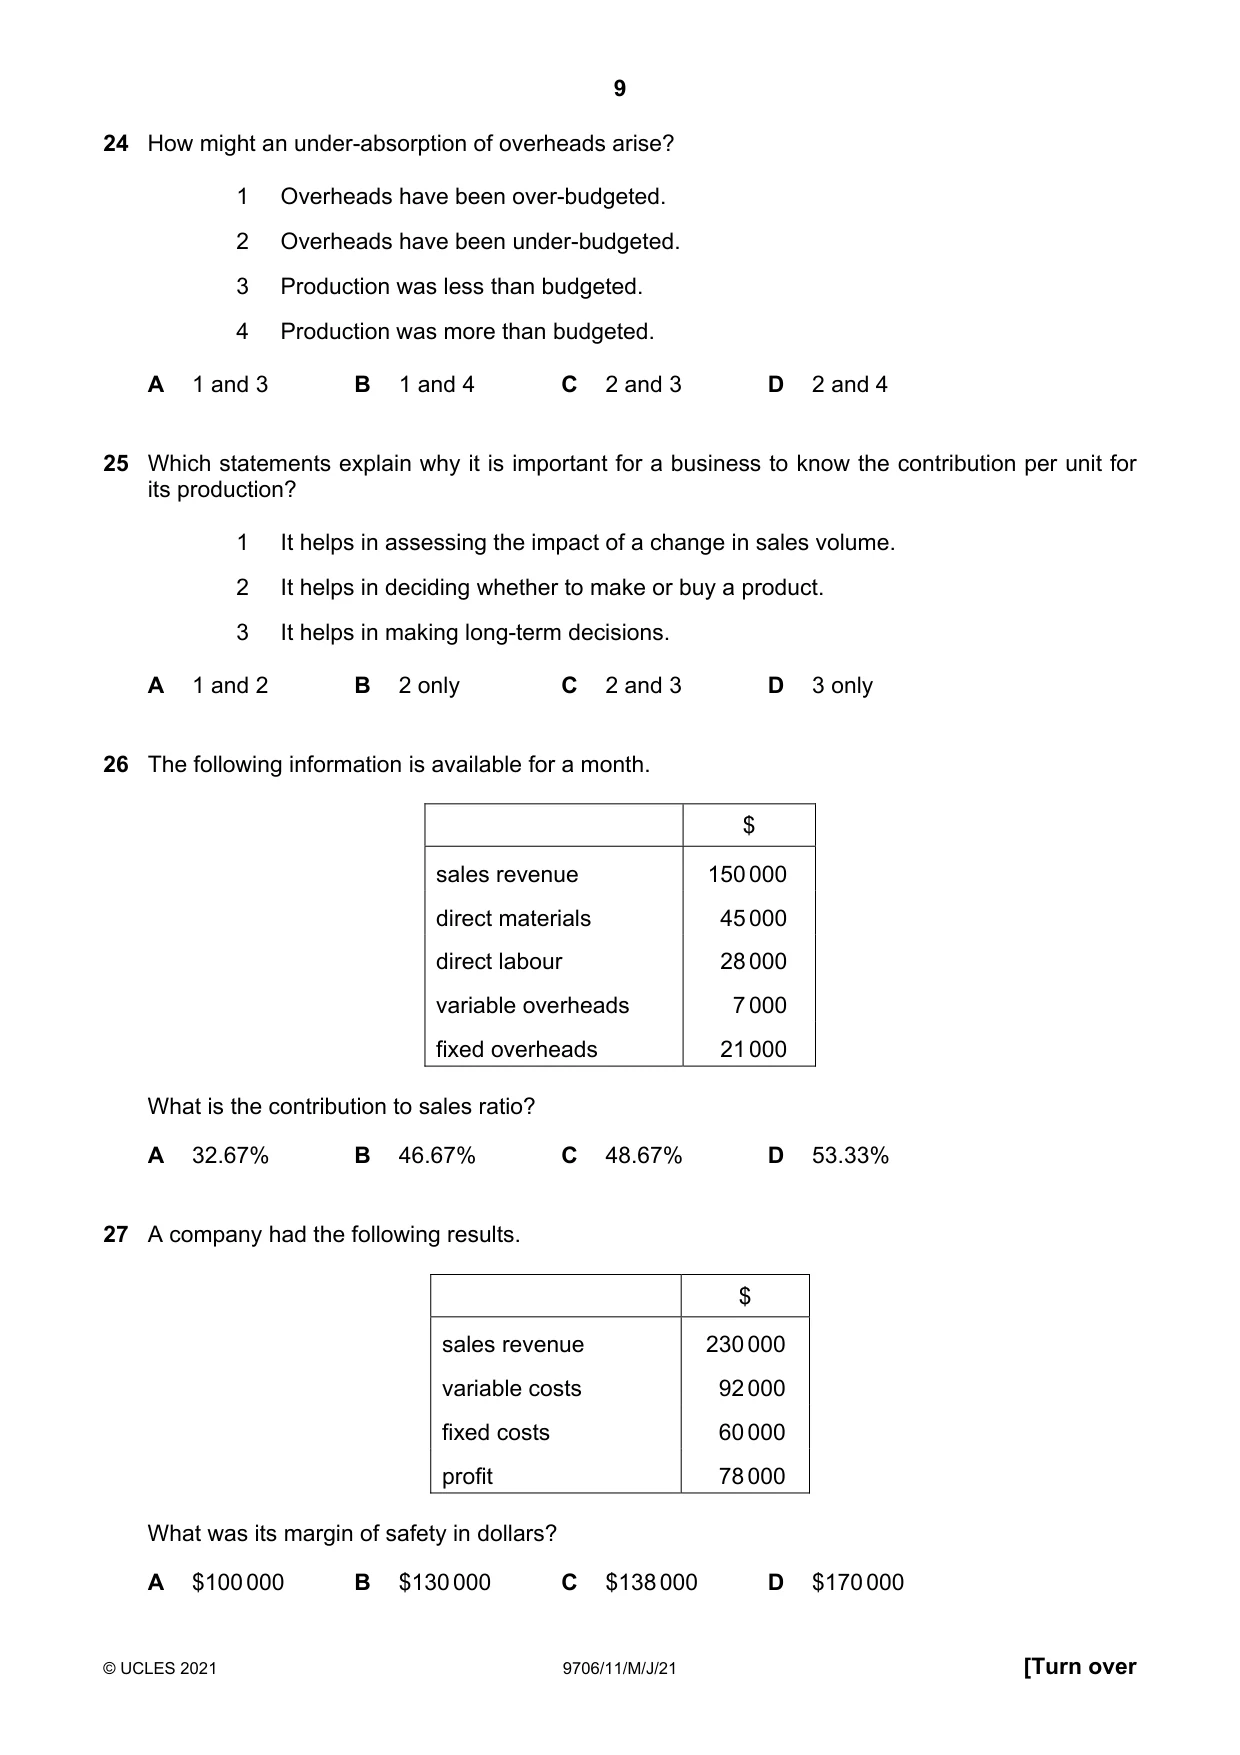
24 How might an under-absorption of overheads arise? 1 Overheads have been over-budgeted. 2 Overheads have been under-budgeted. 3 Production was less than budgeted. 4 Production was more than budgeted. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
Mark scheme: C
Q25 · Which statements explain why it is important for a business to know the contribution per…
25 Which statements explain why it is important for a business to know the contribution per unit for its production? 1 It helps in assessing the impact of a change in sales volume. 2 It helps in deciding whether to make or buy a product. 3 It helps in making long-term decisions. A 1 and 2 B 2 only C 2 and 3 D 3 only
Mark scheme: A
Q26 · The following information is available for a month
26 The following information is available for a month. $ sales revenue 150 000 direct materials 45 000 direct labour 28 000 variable overheads 7 000 fixed overheads 21 000 What is the contribution to sales ratio? A 32.67% B 46.67% C 48.67% D 53.33%
Mark scheme: B
Q27 · A company had the following results
27 A company had the following results. $ sales revenue 230 000 variable costs 92 000 fixed costs 60 000 profit 78 000 What was its margin of safety in dollars? A $100 000 B $130 000 C $138 000 D $170 000
Mark scheme: B
Q28 · A company has total fixed costs of $400 000
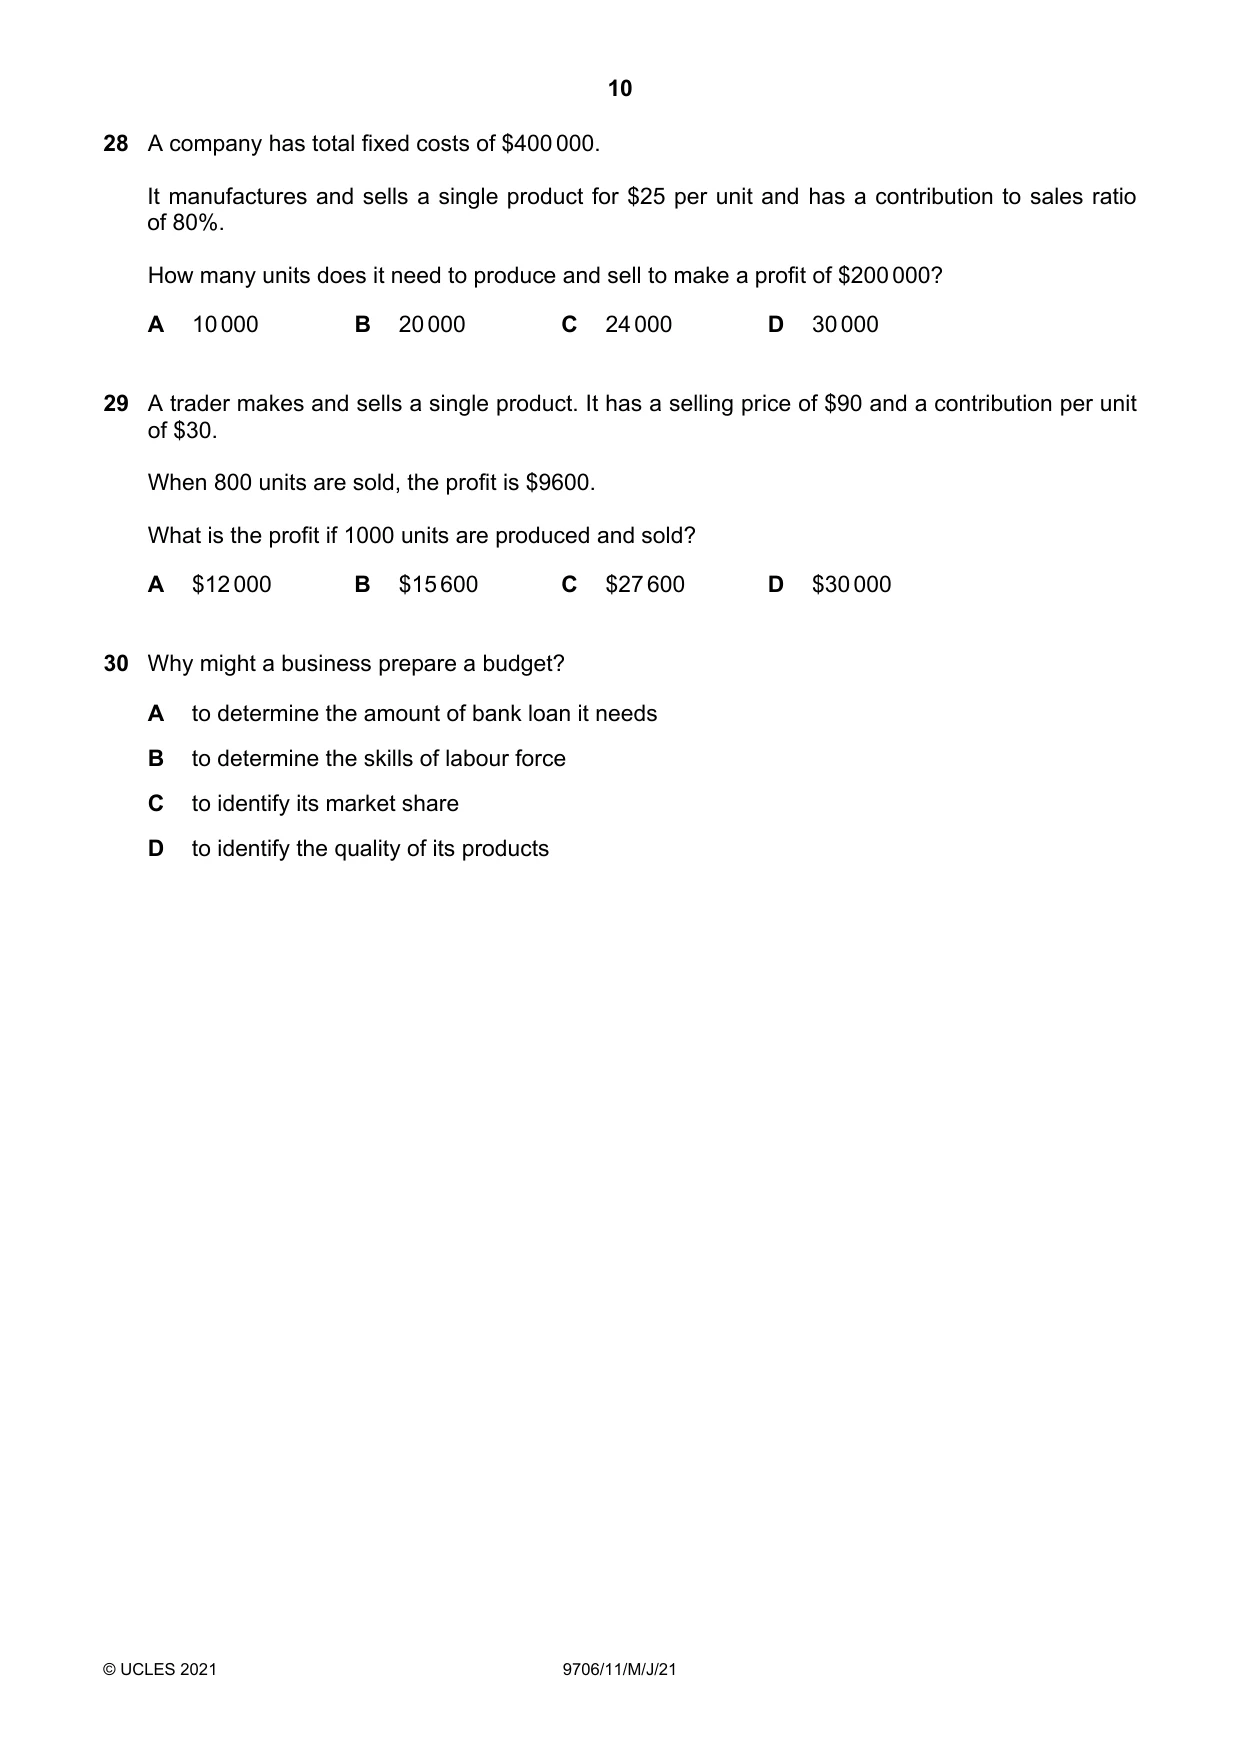
28 A company has total fixed costs of $400 000. It manufactures and sells a single product for $25 per unit and has a contribution to sales ratio of 80%. How many units does it need to produce and sell to make a profit of $200 000? A 10 000 B 20 000 C 24 000 D 30 000
Mark scheme: D
Q29 · A trader makes and sells a single product
29 A trader makes and sells a single product. It has a selling price of $90 and a contribution per unit of $30. When 800 units are sold, the profit is $9600. What is the profit if 1000 units are produced and sold? A $12 000 B $15 600 C $27 600 D $30 000
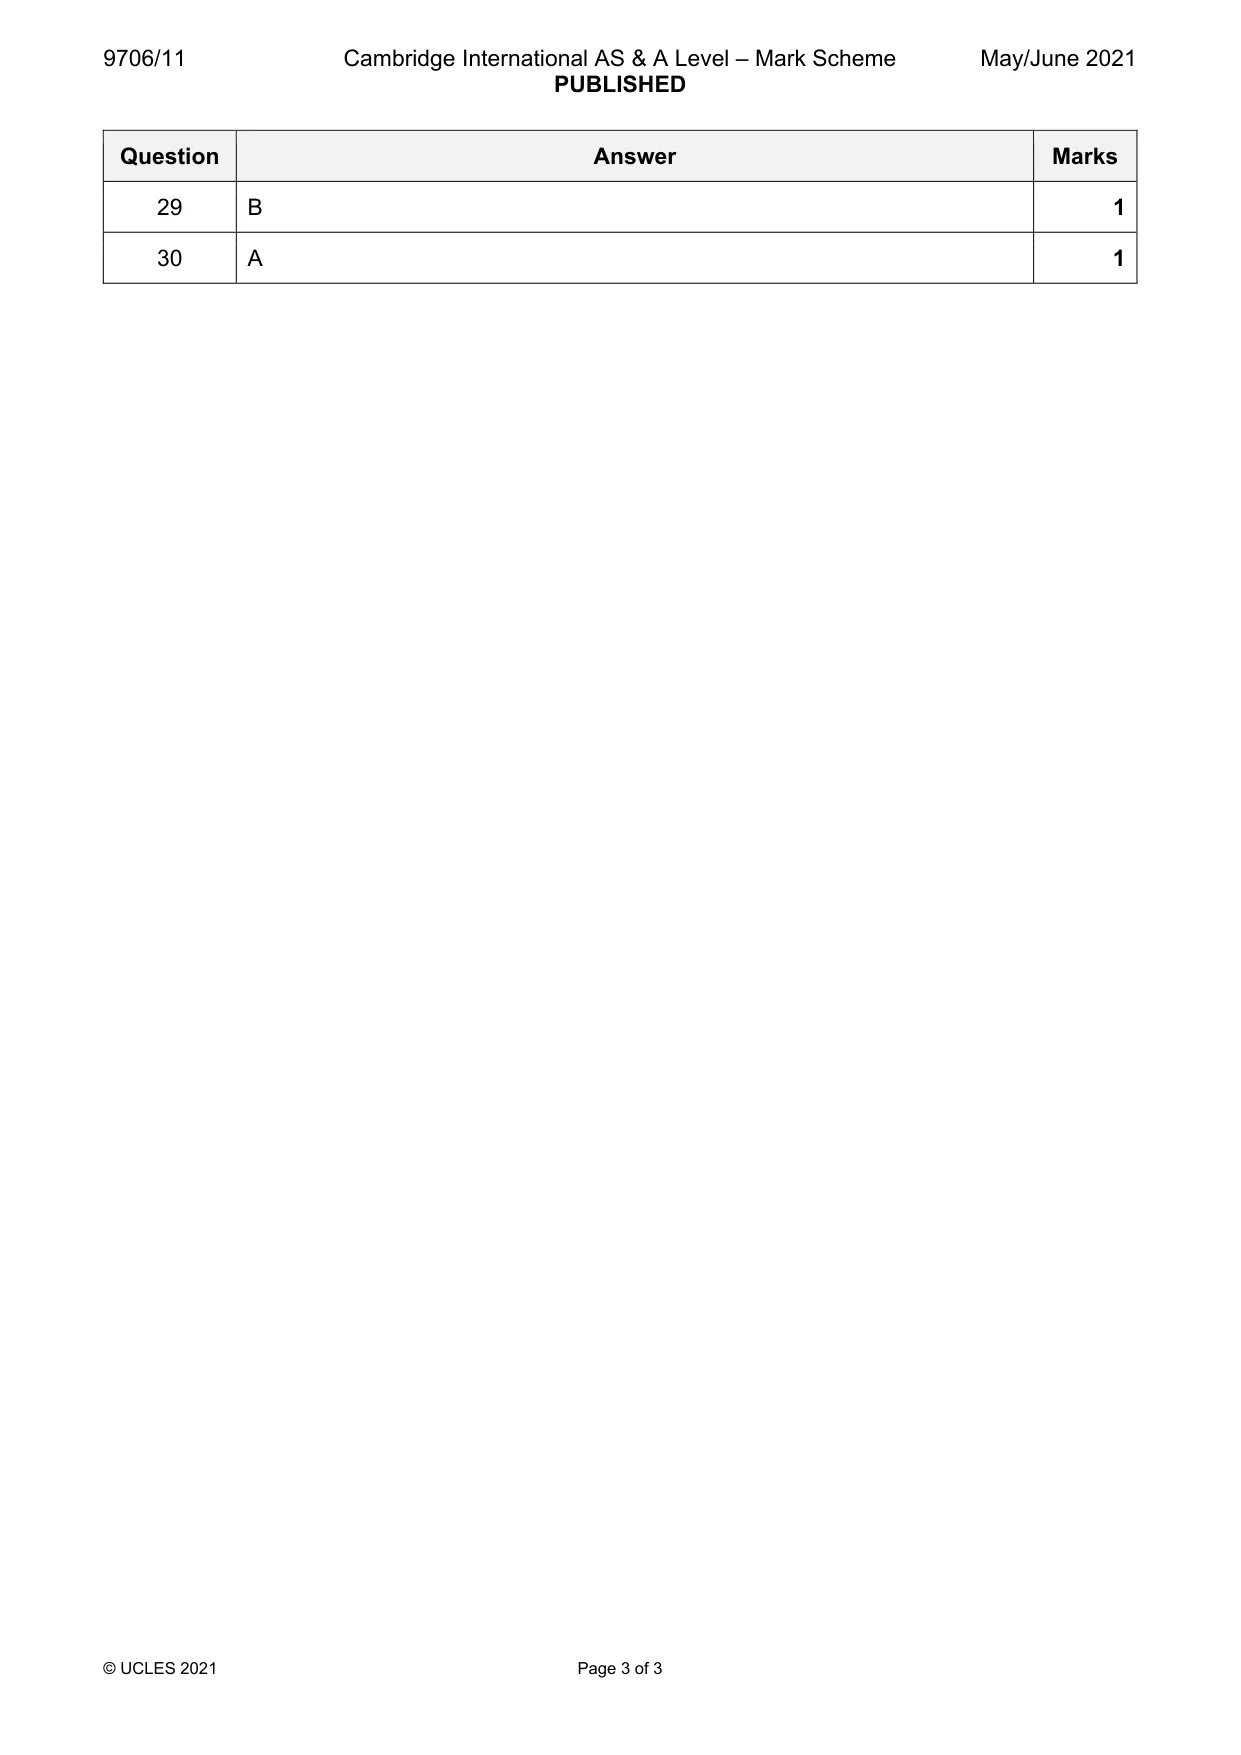
Mark scheme: B
Q30 · Why might a business prepare a budget?
30 Why might a business prepare a budget? A to determine the amount of bank loan it needs B to determine the skills of labour force C to identify its market share D to identify the quality of its products
Mark scheme: A
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 May/June, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.