Questions as text
Q1 · The accounting year end of a business is 31 October 9706/11 May/June 2006
2 The accounting year end of a business is 31 October. On 1 April the business rents out part of its warehouse for an annual rent of $6000 receivable in equal instalments on 1 April, 1 July, 1 October and 1 January. At 31 October what would the final accounts show? Profit and Loss Account Balance Sheet $ $ A rental income 3500 current asset 1000 B rental income 3500 current liability 1000 C rental income 4500 current liability 1000 D rental income 6000 current asset 1500
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q2 · The following information is taken from the stationery account of a business 9706/11 May/June 2006
3 The following information is taken from the stationery account of a business. $ stock of stationery at beginning of the year 600 cash paid for stationery during the year 7000 invoice not yet received for stationery 480 stock of stationery at end of year 800 How much should be debited to the Profit and Loss Account for stationery? A $6680 B $6800 C $7280 D $8080
1 marks
Answer: C
This question in 9706/11 May/June 2006
Q3 · On 30 September 2005 a manufacturer’s current assets totalled $28 000 9706/11 May/June 2006
4 On 30 September 2005 a manufacturer’s current assets totalled $28 000. The next day only two transactions took place. 1 Stock bought for cash. The list price of $2000 was subject to a trade discount of 20 % and a cash discount of 5 %. Payment was made immediately. 2 A bad debt of $400 was written off. What was the total of current assets on 2 October 2005? A $27 680 B $28 080 C $29 520 D $29 600
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q4 · Stock has been damaged 9706/11 May/June 2006
6 Stock has been damaged. The stock cost $1200. It would have sold for $1800 when perfect. It can be sold for $1700 if repairs are undertaken at a cost of $600. To replace the stock would cost $1000. At what value should the damaged stock be shown in the final accounts? A $1000 B $1100 C $1200 D $1800
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q5 · The following information is extracted from the records of a business 9706/11 May/June 2006
8 The following information is extracted from the records of a business. $ At 31 December 2004: Rent paid in advance 4 000 During the year ended 31 December 2005: Rent paid 41 000 At 31 December 2005: Rent paid in advance 7 000 How much will be debited for rent in the Profit and Loss Account for the year ended 31 December 2005? A $34 000 B $38 000 C $41 000 D $44 000
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q6 · A sole trader has calculated a draft net profit of $56 750 9706/11 May/June 2006
10 A sole trader has calculated a draft net profit of $56 750. He then discovers the following mistakes: Discounts Received of $580 and Discounts Allowed of $665 have been recorded on the wrong sides of the Discounts Received and Allowed accounts. What is the corrected draft net profit? A $56 580 B $56 665 C $56 835 D $56 920
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q7 · How should goodwill be treated in the accounts of a limited company? 9706/11 May/June 2006
13 How should goodwill be treated in the accounts of a limited company? A Goodwill should always be written off immediately. B Non-purchased goodwill is shown in the balance sheet. C Purchased goodwill remains on the balance sheet as a permanent item. D Purchased goodwill is shown in the balance sheet and written off over its useful life.
1 marks
Answer: D
This question in 9706/11 May/June 2006
Q8 · Stocks should be valued at the lower of cost and net realisable value 9706/11 May/June 2006
14 Stocks should be valued at the lower of cost and net realisable value. The table shows data about four products. W X Y Z product $ $ $ $ cost 18 19 17 23 realisable value 15 28 17 26 selling expenses 3 2 3 At how much should the total stocks be valued? A $72 B $77 C $78 D $86
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q9 · A partnership maintains both capital and current accounts for its partners 9706/11 May/June 2006
15 A partnership maintains both capital and current accounts for its partners. What is the correct accounting entry for recording interest on capital for partner X? account to be debited account to be credited A Profit and Loss Appropriation X’s Capital B Profit and Loss Appropriation X’s Current C X’s Capital Profit and Loss Appropriation D X’s Current Profit and Loss Appropriation
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q10 · At the end of a financial year the following information is available 9706/11 May/June 2006
16 At the end of a financial year the following information is available. $ sales 200 000 opening stock 15 000 closing stock 18 000 If the business makes a standard mark-up of 25 %, what were the purchases? A $147 000 B $153 000 C $157 000 D $163 000
1 marks
Answer: D
This question in 9706/11 May/June 2006
Q11 · A trader does not keep double-entry records 9706/11 May/June 2006
17 A trader does not keep double-entry records. At the beginning of a period, suppliers are owed $43 600. Payments of $197 320 were made in the period. Suppliers are owed $35 390 at the end of the period. What are the total purchases for the period? A $118 330 B $189 110 C $205 530 D $276 310
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q12 · Dele and Iyabo are partners in a business and share profits in the ratio of 3:1 9706/11 May/June 2006
18 Dele and Iyabo are partners in a business and share profits in the ratio of 3:1. Their net profit is $80 000. The following information is available: Dele Iyabo $ $ interest on capitals 3 000 2 500 interest on drawings 500 1 000 How will the residual net profit be shared? Dele Iyabo $ $ A 57 000 19 000 B 58 875 21 125 C 59 500 20 500 D 60 500 19 500
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q13 · What will increase the working capital and net assets and reserves of a company? 9706/11 May/June 2006
19 What will increase the working capital and net assets and reserves of a company? A a bonus issue of shares B a debenture issue C an issue of shares at a premium D an issue of shares at nominal value
1 marks
Answer: C
This question in 9706/11 May/June 2006
Q14 · At 1 January 2005 the capital structure of S Limited was as follows 9706/11 May/June 2006
20 At 1 January 2005 the capital structure of S Limited was as follows. $ issued share capital 100 000 ordinary shares of $1 each 100 000 share premium account 30 000 On 1 April 2005 the company made an issue of 20 000 shares for $36 000. On 1 June 2005 a bonus issue of one share for every six in issue was made. The share premium account was used for the purpose. What is the balance on the share premium account at 31 December 2005? A $26 000 B $34 000 C $46 000 D $56 000
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q15 · A newly formed company issues 1 000 000 ordinary shares of $1 at $2.50 each $300 000 5 %… 9706/11 May/June 2006
21 A newly formed company issues 1 000 000 ordinary shares of $1 at $2.50 each $300 000 5 % debentures. Operating profit for the year was $465 000. The directors recommend an 8 % ordinary dividend for the year. What is the retained profit for the year? A $250 000 B $370 000 C $385 000 D $400 000
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q16 · A company has issued 80 000 shares of $0.50 each 9706/11 May/June 2006
22 A company has issued 80 000 shares of $0.50 each. These are quoted on the stock exchange at $1.60 each. The company makes a rights issue on a 1 for 4 basis at a price of $1.20 each. What is the balance on the Share Capital account after the rights issue? A $50 000 B $100 000 C $120 000 D $160 000
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q17 · A company’s net profit is $20 000 9706/11 Oct/Nov 2006
3 A company’s net profit is $20 000. Capital receipts of $5000 have been treated as revenue receipts. Capital expenditure of $4000 has been treated as revenue expenditure. What is the correct net profit figure? A $11 000 B $19 000 C $21 000 D $29 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2006
Q18 · At the beginning of the year a business has a provision for doubtful debts of $2600 9706/11 Oct/Nov 2006
4 At the beginning of the year a business has a provision for doubtful debts of $2600. At the year end the provision is to be 5 % of trade debtors. The balance on the debtors’ control account at the year end is $69 200, before writing off a bad debt of $480. The business operates a separate bad debts account. What is the entry in the Profit and Loss Account for the provision for doubtful debts? A $836 debit B $860 debit C $836 credit D $860 credit
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2006
Q19 · The following information relates to a company’s fixed assets at 31 December: cost price… 9706/11 Oct/Nov 2006
6 The following information relates to a company’s fixed assets at 31 December: cost price disposal value $ $ motor vehicles 25 000 18 000 equipment 48 000 36 000 fixtures and fittings 12 000 5 000 The company has a serious cash shortage and will cease to trade within the next two months. What is the total value for fixed assets in the company’s Balance Sheet at 31 December? A $26 000 B $59 000 C $85 000 D $144 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2006
Q20 · What is the normal treatment of life membership subscriptions? 9706/11 Oct/Nov 2006
13 What is the normal treatment of life membership subscriptions? A credit the income and expenditure account in the year of receipt B credit the life membership fund with the year’s receipts and transfer a proportion each year to the income and expenditure account C debit the income and expenditure account in the year of receipt D debit the life membership fund with the year’s receipts and transfer a proportion each year to the income and expenditure account
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2006
Q21 · A club’s treasurer has calculated that there is a deficit in the Income and Expenditure… 9706/11 Oct/Nov 2006
15 A club’s treasurer has calculated that there is a deficit in the Income and Expenditure account. How is this described in the Income and Expenditure account? A an excess of expenditure over income B an excess of income over expenditure C an excess of payments over receipts D an excess of receipts over payments
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2006
Q22 · X has not kept proper records for his business 9706/11 Oct/Nov 2006
16 X has not kept proper records for his business. Between 31 December 2004 and 31 December 2005 his net assets had increased by $30 000. On 1 January 2005, X brought into the business his private car which had cost $12 000 but now has a re-sale value of $8000. Drawings for the year ended 31 December 2005 were $16 000. What was X’s profit for the year ended 31 December 2005? A $22 000 B $26 000 C $34 000 D $38 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2006
Q23 · Hilary and Lee commenced in partnership on 1 January 2005 9706/11 Oct/Nov 2006
17 Hilary and Lee commenced in partnership on 1 January 2005. There was no partnership agreement concerning the division of interest on the loan or of profits. Hilary Lee $ $ capital contributions 5000 600 loan to partnership – 1000 At the year end, 31 December 2005, net profit before the loan interest was $8850. What would be Hilary’s share of the profit? A $4400 B $4425 C $4800 D $4827
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2006
Q24 · An extract from the accounts of a manufacturing company shows: $ direct factory labour… 9706/11 Oct/Nov 2006
18 An extract from the accounts of a manufacturing company shows: $ direct factory labour 476 200 indirect factory labour 52 470 factory supervisor’s salary 18 200 opening stock of raw materials 21 500 heat, light and power 22 600 purchases of raw materials 184 300 depreciation charge for factory machinery 16 700 factory cleaning costs 18 300 closing stock of raw materials 17 900 What is the prime cost of production? A $660 500 B $664 100 C $680 800 D $716 570
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2006
Q25 · Which statement is correct? 9706/11 Oct/Nov 2006
20 Which statement is correct? A A bonus issue of shares will increase the amount of cash available to the company. B A rights issue of shares is always made at the nominal value of the shares. C A rights issue of shares will increase the amount of cash available to the company. D If shares are issued at an amount that is more than the nominal value of the shares, the excess must be debited to the share premium account.
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2006
Q26 · A company balance sheet shows the following: $000 $1 ordinary shares 500 retained… 9706/11 Oct/Nov 2006
21 A company balance sheet shows the following: $000 $1 ordinary shares 500 retained earnings 400 10 % debentures 300 1 200 net assets 1 200 A fully subscribed 1 for 4 rights issue at $2 per share is made and 50 % of the debentures are repaid at par. What are the net assets following these changes? A $1 100 000 B $1 175 000 C $1 225 000 D $1 300 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2006
Q27 · The table shows extracts from a company’s Balance Sheets at 31 December 2004 and at 31… 9706/11 Oct/Nov 2006
22 The table shows extracts from a company’s Balance Sheets at 31 December 2004 and at 31 December 2005. 31 December 2004 31 December 2005 $m $m ordinary shares of $1 each 100 130 share premium account 50 80 On 1 July 2005 there was a bonus issue of 1 ordinary share for every 10 held. On 1 October 2005 there was a rights issue. There were no other reserve balances. How much cash was received from the issue of shares in the year ended 31 December 2005? A $20 m B $30 m C $50 m D $60 m
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2006
Q28 · A trial balance shows: Dr Cr $ $ provision for doubtful debts 1200 debtors 28 000 $2100… 9706/11 May/June 2007
4 A trial balance shows: Dr Cr $ $ provision for doubtful debts 1200 debtors 28 000 $2100 of the debtors are irrecoverable and are to be written off. The owner of the business wishes to make the provision for doubtful debts equal to 5 % of his outstanding debtors. What is the amount debited to the profit and loss account for the provision for doubtful debts? A $95 B $1295 C $1400 D $2600
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q29 · An item of stock originally cost $5000, but has deteriorated badly and is written down to… 9706/11 May/June 2007
5 An item of stock originally cost $5000, but has deteriorated badly and is written down to its estimated net realisable value of $2000. Which accounting principle has been applied? A consistency B materiality C prudence D substance over form
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q30 · A company changes from the straight-line method of depreciation to the reducing balance… 9706/11 May/June 2007
6 A company changes from the straight-line method of depreciation to the reducing balance method. Which accounting principle has not been applied? A consistency B going concern C historic cost D materiality
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q31 · The following information relates to a business: $ opening debtors 280 000 cash received… 9706/11 May/June 2007
8 The following information relates to a business: $ opening debtors 280 000 cash received during the year 520 000 discounts allowed during the year 30 000 bad debts written off during the year 15 000 closing debtors 265 000 What were the sales during the year? A $490 000 B $535 000 C $550 000 D $580 000
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q32 · A trader, whose purchases are all on credit, does not keep double entry records 9706/11 May/June 2007
11 A trader, whose purchases are all on credit, does not keep double entry records. The following information is available: $ opening creditors 51 660 payments to suppliers during the year 212 760 closing creditors 56 340 The discount received for the year amounted to $1000. What were the purchases for the period? A $209 080 B $214 940 C $217 440 D $218 440
1 marks
Answer: D
This question in 9706/11 May/June 2007
Q33 · A business has two items in stock which need to be repaired before sale 9706/11 May/June 2007
12 A business has two items in stock which need to be repaired before sale. cost selling price repair costs $ $ $ item 1 2 160 2 450 190 item 2 3 190 3 060 320 What is the total stock value of these items? A $4900 B $5000 C $5510 D $5640
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q34 · A business does not keep complete accounting records 9706/11 May/June 2007
13 A business does not keep complete accounting records. The following information is known: $ capital at start of year 52 000 capital at end of year 55 000 owner’s drawings in year 13 000 capital introduced during the year 25 000 What is the net profit/loss for the year? A net loss $9 000 B net profit $9 000 C net loss $15 000 D net profit $15 000
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q35 · The following information is available for the partnership of Atul and Mansoor at 31… 9706/11 May/June 2007
14 The following information is available for the partnership of Atul and Mansoor at 31 December: $ net profit before appropriations 60 000 salary of Atul 9 000 drawings: Atul 12 000 Mansoor 13 000 interest on capital: Atul 400 Mansoor 500 Residual profits are shared between Atul and Mansoor in the ratio 2 : 1. What is Mansoor’s share of total profit for the year? A $16 200 B $17 000 C $17 100 D $17 200
1 marks
Answer: D
This question in 9706/11 May/June 2007
Q36 · At the beginning of the financial year stock was valued at $15 000 9706/11 May/June 2007
15 At the beginning of the financial year stock was valued at $15 000. During the year, sales of $21 000 and purchases of $18 000 were made. Unfortunately, all stock was stolen on the last day of the financial year. Goods are marked up by 50 % to calculate selling price. What is the cost of the stolen stock? A $7 500 B $11 000 C $19 000 D $22 500
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q37 · A company transfers manufactured items from factory to warehouse at cost plus 10 % 9706/11 May/June 2007
16 A company transfers manufactured items from factory to warehouse at cost plus 10 %. This year the transfer value was $93 500 and at the end of the year the closing stock was 20 % of the year’s production. How will the stock of finished goods be shown? Trading Account Balance Sheet $ $ A 17 000 17 000 B 18 700 16 830 C 18 700 17 000 D 18 700 18 700
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q38 · A company receives payment for 20 % of its sales in the month of sale, 50 % in the… 9706/11 May/June 2007
17 A company receives payment for 20 % of its sales in the month of sale, 50 % in the following month and 30 % two months after the month of sale. The table shows sales for four months. $ January 180 000 February 240 000 March 270 000 April 220 000 How much were total cash receipts in April? A $220 000 B $228 000 C $249 000 D $251 000
1 marks
Answer: D
This question in 9706/11 May/June 2007
Q39 · A company makes a bonus issue of shares 9706/11 May/June 2007
18 A company makes a bonus issue of shares. What is the effect on the net assets and the reserves in the balance sheet? net assets reserves A increase decrease B increase unchanged C unchanged decrease D unchanged increase
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q40 · The capital structure of a company is shown 9706/11 May/June 2007
19 The capital structure of a company is shown. $ 700 000 ordinary shares of $0.25 each 175 000 8 % loan stocks 160 000 During the year the company made profits before interest of $105 000. The directors wish to distribute as much of the profits as possible by way of dividend. What is the dividend per share? A $0.1317 B $0.15 C $0.5268 D $0.60
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q41 · A trial balance at 30 June, before making end of year adjustments, showed: debit credit $… 9706/11 May/June 2008
4 A trial balance at 30 June, before making end of year adjustments, showed: debit credit $ $ trade debtors 35 600 - provision for doubtful debts - 1 160 At 30 June, it was decided to write off a bad debt of $1600 and to make a provision for doubtful debts equal to 2 % of trade debtors. What was the total expense in the profit and loss account for bad and doubtful debts for the year ended 30 June? A $680 B $1120 C $2080 D $2280
1 marks
Answer: B
This question in 9706/11 May/June 2008
Q42 · Which transaction applies the matching concept? 9706/11 May/June 2008
6 Which transaction applies the matching concept? A a machine acquired on long-term rental is included in fixed assets B computer equipment is depreciated over two years C a building is revalued following a fall in property prices D a waste-paper basket is treated as revenue expenditure
1 marks
Answer: B
This question in 9706/11 May/June 2008
Q43 · The following debit balance appears on a trial balance after preparing the manufacturing… 9706/11 May/June 2008
7 The following debit balance appears on a trial balance after preparing the manufacturing account for the year. loose tools $18 000 What is this item? A a creditor for loose tools B the annual charge for loose tools C a prepayment for loose tools D stock of loose tools
1 marks
Answer: D
This question in 9706/11 May/June 2008
Q44 · At the year-end a cash book shows a credit balance of $4800 9706/11 May/June 2008
8 At the year-end a cash book shows a credit balance of $4800. The bank statement included bank charges of $25 which had not been included in the cash book. Cheque payments entered in the cash book before the year end to the value of $250 had not yet cleared the bank. How would the bank balance be shown in the balance sheet? $ A current asset 4775 B current liability 4825 C current asset 5025 D current liability 5075
1 marks
Answer: B
This question in 9706/11 May/June 2008
Q45 · The information relates to the subscriptions of a club 9706/11 May/June 2008
12 The information relates to the subscriptions of a club. in advance in arrears $ $ at the start of the year 50 75 at the end of the year 150 120 Cash received during the year was $3750. What was the subscription income for the year? A $3695 B $3750 C $3755 D $3805
1 marks
Answer: A
This question in 9706/11 May/June 2008
Q46 · How should stocks be valued in published accounts? 9706/11 May/June 2008
14 How should stocks be valued in published accounts? A cost B net realisable value C replacement cost D the lower of cost and net realisable value
1 marks
Answer: D
This question in 9706/11 May/June 2008
Q47 · Which item would not be found in the accounts of clubs and societies? 9706/11 May/June 2008
15 Which item would not be found in the accounts of clubs and societies? A accumulated fund B income and expenditure C drawings D surpluses and deficits
1 marks
Answer: C
This question in 9706/11 May/June 2008
Q48 · What appears as a credit entry in the appropriation account of a partnership? 9706/11 May/June 2008
16 What appears as a credit entry in the appropriation account of a partnership? A goodwill B interest on capital C net trading profit D partnership salaries
1 marks
Answer: C
This question in 9706/11 May/June 2008
Q49 · The wages of staff employed in manufacturing goods have been debited in the profit and… 9706/11 May/June 2008
17 The wages of staff employed in manufacturing goods have been debited in the profit and loss account. What is the effect of this error? gross profit net profit A overstated no effect B overstated overstated C understated no effect D understated understated
1 marks
Answer: A
This question in 9706/11 May/June 2008
Q50 · The table shows extracts from the trial balance of a business at 31 December 2007 9706/11 May/June 2008
18 The table shows extracts from the trial balance of a business at 31 December 2007. $ ordinary share capital 20 000 share premium 40 000 long term loan (repayable 2017) 30 000 bank overdraft 60 000 4 % preference share capital 50 000 7 % debentures 2012 70 000 What is the total of ‘creditors: amounts falling due after more than one year’ in the balance sheet? A $100 000 B $150 000 C $160 000 D $210 000
1 marks
Answer: A
This question in 9706/11 May/June 2008
Q51 · A company’s capital is $ ordinary shares of $1.00 each 200 000 share premium account 80… 9706/11 May/June 2008
19 A company’s capital is $ ordinary shares of $1.00 each 200 000 share premium account 80 000 revenue reserves 160 000 Changes now to be made (in the order given) • A one for one bonus issue • A rights issue of 100 000 ordinary shares of $1.00 each at $1.40 per share The company wishes to maximise the amounts available to pay dividends. What will be the ordinary capital and reserves of the company? ordinary share capital share premium revenue reserves $ $ $ A 500 000 40 000 40 000 B 500 000 80 000 nil C 540 000 nil 40 000 D 540 000 40 000 40 000
1 marks
Answer: A
This question in 9706/11 May/June 2008
Q52 · Interest receivable account shows interest of $17 500 received during the year 9706/11 Oct/Nov 2008
4 Interest receivable account shows interest of $17 500 received during the year. Interest of $1600 is due at the year-end. How will this be shown in the final accounts? profit and loss $ balance sheet $ account A credit 17 500 sundry debtors 1600 B credit 19 100 sundry debtors 1600 C debit 17 500 sundry creditors 1600 D debit 19 100 sundry creditors 1600
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2008
Q53 · Closing stock has been undervalued 9706/11 Oct/Nov 2008
9 Closing stock has been undervalued. What is the effect on the financial statements? net current assets net profit A no effect understated B overstated overstated C understated no effect D understated understated
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2008
Q54 · A company’s capital expenditure of $200 000 has been debited in error to the purchases… 9706/11 Oct/Nov 2008
12 A company’s capital expenditure of $200 000 has been debited in error to the purchases account. Depreciation is provided at the rate of 15 % per annum on the cost of all fixed assets held at each year end. How will this affect the net profit? A $170 000 understated B $200 000 overstated C $200 000 understated D $230 000 overstated
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2008
Q55 · A business sells some of its stock for $80 on credit to a customer 9706/11 Oct/Nov 2008
13 A business sells some of its stock for $80 on credit to a customer. The stock originally cost $50. Which statement reflects the effect of this transaction on the balance sheet? current assets owner’s capital A decrease by $30 decreases by $30 B decrease by $30 increases by $30 C increase by $30 decreases by $30 D increase by $30 increases by $30
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2008
Q56 · The stock records of a business show the following information for product X 9706/11 Oct/Nov 2008
15 The stock records of a business show the following information for product X. cost per unit amount in units $ 1 January opening balance 100 3 3 January receipts into stock 50 4 8 January stock issued 120 - What is the value of the stock issued on 8 January using the First In First Out (FIFO) method? A $360 B $380 C $410 D $420
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2008
Q57 · A business uses the weighted average cost (AVCO) method of stock valuation 9706/11 Oct/Nov 2008
16 A business uses the weighted average cost (AVCO) method of stock valuation. During March the following transactions took place. $ 1 March opening stock 200 units at $6.00 per unit 1200 14 March received 300 units at $6.50 per unit 1950 20 March issued 250 units to production at $7.00 per unit 1750 28 March received 100 units at $6.70 per unit 670 What is the value of stock at 31 March? A $2195 B $2245 C $2295 D $2450
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2008
Q58 · A business has the following assets and liabilities 9706/11 Oct/Nov 2008
17 A business has the following assets and liabilities. $ short-term investment 6 000 loan interest owing 1 500 loan repayable within one year 12 000 deposits from customers for orders 4 500 creditors 27 000 debtors 39 000 pre-payments 3 500 What is the amount of net current assets? A $3500 B $4500 C $8000 D $15 500
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2008
Q59 · Information about the final accounts of a partnership is given 9706/11 Oct/Nov 2008
18 Information about the final accounts of a partnership is given. $ net profit before interest 160 000 interest on bank loan 14 000 interest credited to capital accounts 15 000 drawings 70 000 partnership salaries 24 000 What is the remaining balance of profits to be appropriated amongst the partners? A $66 000 B $107 000 C $121 000 D $137 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2008
Q60 · The following information is taken from the stationery account of a business 9706/11 May/June 2009
4 The following information is taken from the stationery account of a business. $ stock of stationery at beginning of the year 600 cash paid for stationery during the year 7000 amount owing for stationery at end of year 480 stock of stationery at end of year 800 How much should be debited to the profit and loss account for stationery? A $6680 B $6800 C $7280 D $8080
1 marks
Answer: C
This question in 9706/11 May/June 2009
Q61 · The table shows information from a business at 30 November 2008 9706/11 May/June 2009
6 The table shows information from a business at 30 November 2008. $ Credit sales invoiced during financial year 80 000 Goods despatched to customers in November 2008 and invoiced in December 2008 5 000 Goods included in sales for November 2008 on a sale or return basis, but only sold in December 2008 – at invoice price 10 000 – at cost price 8 000 Which amount will appear in the trading account as sales for the year ended 30 November 2008? A $75 000 B $77 000 C $83 000 D $85 000
1 marks
Answer: A
This question in 9706/11 May/June 2009
Q62 · X and Y are partners in a business 9706/11 May/June 2009
15 X and Y are partners in a business. X receives an annual salary of $5000 from the partnership and the balance of profits and losses is shared between X and Y in the ratio of 3 : 2 respectively. In the last financial year, the net profit was $30 000. How much was credited to each partner for the year? X Y $ $ A 10 000 15 000 B 12 000 18 000 C 20 000 10 000 D 21 000 14 000
1 marks
Answer: C
This question in 9706/11 May/June 2009
Q63 · An extract from a company’s trial balance is shown 9706/11 May/June 2009
16 An extract from a company’s trial balance is shown. debit credit $ $ debtors’ control account – debit balances 225 000 debtors’ control account – credit balances 2 800 creditors’ control account – debit balances 3 200 creditors’ control account – credit balances 261 000 investment in another company 12 000 How much should be shown as trade debtors in the company’s financial statements? A $222 200 B $228 200 C $237 400 D $240 200
1 marks
Answer: B
This question in 9706/11 May/June 2009
Q64 · The following items appear in the subscriptions account of a club for a financial year 9706/11 May/June 2009
17 The following items appear in the subscriptions account of a club for a financial year. $ subscriptions received owed from the previous year 3 000 subscriptions paid in advance for next year 1 000 subscriptions income transferred to the income and expenditure account 50 000 subscriptions outstanding at year end 2 000 How much cash was received from members in the year? A $46 000 B $50 000 C $52 000 D $56 000
1 marks
Answer: C
This question in 9706/11 May/June 2009
Q65 · The directors of a company provide the following information 9706/11 May/June 2009
18 The directors of a company provide the following information. $ bank overdraft 1 200 equipment 12 000 long term loan 8 000 petty cash 900 stocks 2 500 trade creditors 3 000 trade debtors 2 000 What is the amount of the net current assets? A $1200 B $2400 C $3600 D $5200
1 marks
Answer: A
This question in 9706/11 May/June 2009
Q66 · A company profit and loss account includes: $000 dividend 300 increase in stock 200… 9706/11 May/June 2009
19 A company profit and loss account includes: $000 dividend 300 increase in stock 200 overheads 400 purchases 800 If the net profit percentage is 20 %, what is the figure for sales? A $1 120 000 B $1 250 000 C $1 625 000 D $1 750 000
1 marks
Answer: B
This question in 9706/11 May/June 2009
Q67 · A shareholder sells some ordinary shares for more than he paid for them 9706/11 May/June 2009
20 A shareholder sells some ordinary shares for more than he paid for them. What is the effect on the company balance sheet? ordinary share capital share premium account A decrease decrease B decrease increase C no effect decrease D no effect no effect
1 marks
Answer: D
This question in 9706/11 May/June 2009
Q68 · At the beginning of the year a company has authorised share capital of 800 000 ordinary… 9706/11 May/June 2009
21 At the beginning of the year a company has authorised share capital of 800 000 ordinary shares of $0.25 each and an issued share capital of 400 000 ordinary shares of $0.25. During the year the company makes a further issue of 200 000 ordinary shares at a price of $0.60. What is the balance on the share capital account at the end of the year? A $150 000 B $220 000 C $250 000 D $350 000
1 marks
Answer: A
This question in 9706/11 May/June 2009
Q69 · The table shows balances at the end of a year 9706/11 Oct/Nov 2009
1 The table shows balances at the end of a year. $ expenses prepaid 6 000 expenses accrued 4 000 bank overdraft 11 500 trade creditors 13 400 trade debtors 10 500 loan (2015) 20 000 What is the total of current liabilities? A $16 500 B $17 400 C $28 900 D $48 900
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2009
Q70 · The accounting year end of a business is 31 October 9706/11 Oct/Nov 2009
2 The accounting year end of a business is 31 October. On 1 April the business rents out part of its warehouse for an annual rent of $6000. Payments were received in equal instalments on 1 April, 1 July, 1 October and 1 January. At 31 October what would the final accounts show? profit and loss account balance sheet $ $ A rental income 3500 current asset 1000 B rental income 3500 current liability 1000 C rental income 4500 current liability 1000 D rental income 6000 current asset 1500
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2009
Q71 · A business paid $15000 for electricity in the year 9706/11 Oct/Nov 2009
3 A business paid $15000 for electricity in the year. The opening prepayment was $1000 and the closing accrual was $2000. What was the charge for electricity for the year? A $15 000 B $16 000 C $17 000 D $18 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2009
Q72 · A business makes a provision for doubtful debts equal to 5 % of its debtors 9706/11 Oct/Nov 2009
4 A business makes a provision for doubtful debts equal to 5 % of its debtors. At 31 March 2008 the provision for doubtful debts was $850. At 31 March 2009 the debtors after the provision for doubtful debts were $17 100. How much is the increase in the provision for doubtful debts for the year ended 31 March 2009? A $45 B $50 C $850 D $900
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2009
Q73 · At 31 March the balance sheet of a company included the following 9706/11 Oct/Nov 2009
6 At 31 March the balance sheet of a company included the following. $ trade debtors 23 000 provision for doubtful debts 1 200 During April credit sales were $64 000 and cash sales were $256 000. Credit customers paid $56 840 net of a 2 % cash discount. What will be the trade debtors at 30 April? A $27 800 B $28 960 C $29 000 D $30 160
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2009
Q74 · Stock has been damaged 9706/11 Oct/Nov 2009
7 Stock has been damaged. The stock cost $1200. It would normally have sold for $1800. It can be sold for $1700 if repairs are undertaken at a cost of $600. To replace the stock would cost $1000. At what value should the damaged stock be shown in the final accounts? A $1000 B $1100 C $1200 D $1800
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2009
Q75 · A new business was established with opening capital of $15 000 9706/11 Oct/Nov 2009
10 A new business was established with opening capital of $15 000. At the end of the year net assets were $20 000. During the year the proprietor’s drawings were $3000 and this resulted in an overdraft at the end of the year of $4000. What was the profit during the year? A $2000 B $4000 C $5000 D $8000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2009
Q76 · The financial year of a manufacturer ends on 31 December 9706/11 Oct/Nov 2009
11 The financial year of a manufacturer ends on 31 December. Finished goods are valued at factory cost plus 20 %. The following information is available. 1 January 31 December $ $ stock of finished goods at cost plus 20 % 2400 3000 How much should be deducted from the stock of finished goods in the balance sheet at 31 December for unrealised profit? A $100 B $400 C $500 D $600
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2009
Q77 · The stock records of a business show the following information for product X during… 9706/11 Oct/Nov 2009
12 The stock records of a business show the following information for product X during January. amount in units cost per unit $ 1 Jan opening balance 200 5 15 Jan receipts into stock 150 6 30 Jan stock issued to production 250 - What is the value of stock held at 31 January using the Last In First Out (LIFO) method? A $500 B $600 C $1300 D $1400
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2009
Q78 · The summarised balance sheets for a business for two years are as follows 9706/11 Oct/Nov 2009
13 The summarised balance sheets for a business for two years are as follows. year 1 year 2 $ $ fixed assets 9 000 12 000 current assets 6 000 8 000 less current liabilities (5 000) (6 000) net assets 10 000 14 000 The drawings in year 1 were $5000 and in year 2 $3000. What is the net profit for year 2? A $1000 B $4000 C $5000 D $7000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2009
Q79 · X and Y are in partnership 9706/11 Oct/Nov 2009
14 X and Y are in partnership. Their profit and loss appropriation account shows the following. X Y total $ $ $ interest on capital 1 600 1 800 3 400 interest charged on drawings 500 400 900 partners’ salaries 2 000 3 000 5 000 share of profit 8 000 12 000 20 000 What is the net profit before appropriations? A $17 500 B $22 500 C $27 500 D $29 300
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2009
Q80 · An extract from the accounts of a manufacturing company shows the following 9706/11 Oct/Nov 2009
15 An extract from the accounts of a manufacturing company shows the following. $ depreciation of factory machinery 16 700 direct factory labour 476 200 factory cleaning costs 18 300 factory heat, light and power 22 600 factory supervisor’s salary 18 200 indirect factory labour 52 470 purchases of raw materials 184 300 stock of raw materials - opening stock 21 500 - closing stock 17 900 What is the prime cost of production? A $660 500 B $664 100 C $680 800 D $716 570
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2009
Q81 · An extract from a company’s balance sheet is given 9706/11 Oct/Nov 2009
16 An extract from a company’s balance sheet is given. $000 issued ordinary share capital 250 issued preference shares 180 profit and loss account 320 share premium account 125 8 % debentures 100 What are the ordinary shareholders’ funds? A $695 000 B $775 000 C $875 000 D $975 000
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2009
Q82 · An extract from a company’s balance sheet shows the following 9706/11 Oct/Nov 2009
17 An extract from a company’s balance sheet shows the following. $000 issued ordinary shares of $0.25 each 600 share premium account 150 retained profits 300 The company makes a rights issue of one new ordinary share for each three held, at a price of $0.30 per share. All shares were taken up. What does the new balance sheet show? issued ordinary share premium share capital $000 $000 A 600 120 B 800 150 C 800 190 D 800 600
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2009
Q83 · A company’s Balance Sheet at 31 December 2008 includes: $ Ordinary shares of $1.00 12 000… 9706/11 Oct/Nov 2009
18 A company’s Balance Sheet at 31 December 2008 includes: $ Ordinary shares of $1.00 12 000 Profit and Loss Account 4000 In January 2009, the company made a bonus issue of one share for every four held. In June 2009, the company made a rights issue at $1.60 of one share for every two held. By how much did these transactions increase the company’s bank balance? A $9600 B $12 000 C $12 800 D $19 200
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2009
Q84 · Which transaction would increase the current assets of a business? 9706/11 Oct/Nov 2009
19 Which transaction would increase the current assets of a business? A paying creditors $750 cash B purchasing a fixed asset on credit for $5000 C purchasing stock on credit for $1000 and selling immediately for $2000 cash D selling stock of $1000 at cost price on credit
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2009
Q85 · The accounting year end of a business is 31 October 9706/12 Oct/Nov 2009
1 The accounting year end of a business is 31 October. On 1 April the business rents out part of its warehouse for an annual rent of $6000. Payments were received in equal instalments on 1 April, 1 July, 1 October and 1 January. At 31 October what would the final accounts show? profit and loss account balance sheet $ $ A rental income 3500 current asset 1000 B rental income 3500 current liability 1000 C rental income 4500 current liability 1000 D rental income 6000 current asset 1500
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q86 · A business paid $15000 for electricity in the year 9706/12 Oct/Nov 2009
2 A business paid $15000 for electricity in the year. The opening prepayment was $1000 and the closing accrual was $2000. What was the charge for electricity for the year? A $15 000 B $16 000 C $17 000 D $18 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2009
Q87 · A business makes a provision for doubtful debts equal to 5 % of its debtors 9706/12 Oct/Nov 2009
3 A business makes a provision for doubtful debts equal to 5 % of its debtors. At 31 March 2008 the provision for doubtful debts was $850. At 31 March 2009 the debtors after the provision for doubtful debts were $17 100. How much is the increase in the provision for doubtful debts for the year ended 31 March 2009? A $45 B $50 C $850 D $900
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q88 · At 31 March the balance sheet of a company included the following 9706/12 Oct/Nov 2009
5 At 31 March the balance sheet of a company included the following. $ trade debtors 23 000 provision for doubtful debts 1 200 During April credit sales were $64 000 and cash sales were $256 000. Credit customers paid $56 840 net of a 2 % cash discount. What will be the trade debtors at 30 April? A $27 800 B $28 960 C $29 000 D $30 160
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q89 · Stock has been damaged 9706/12 Oct/Nov 2009
6 Stock has been damaged. The stock cost $1200. It would normally have sold for $1800. It can be sold for $1700 if repairs are undertaken at a cost of $600. To replace the stock would cost $1000. At what value should the damaged stock be shown in the final accounts? A $1000 B $1100 C $1200 D $1800
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q90 · A new business was established with opening capital of $15 000 9706/12 Oct/Nov 2009
9 A new business was established with opening capital of $15 000. At the end of the year net assets were $20 000. During the year the proprietor’s drawings were $3000 and this resulted in an overdraft at the end of the year of $4000. What was the profit during the year? A $2000 B $4000 C $5000 D $8000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2009
Q91 · The financial year of a manufacturer ends on 31 December 9706/12 Oct/Nov 2009
10 The financial year of a manufacturer ends on 31 December. Finished goods are valued at factory cost plus 20 %. The following information is available. 1 January 31 December $ $ stock of finished goods at cost plus 20 % 2400 3000 How much should be deducted from the stock of finished goods in the balance sheet at 31 December for unrealised profit? A $100 B $400 C $500 D $600
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q92 · The stock records of a business show the following information for product X during… 9706/12 Oct/Nov 2009
11 The stock records of a business show the following information for product X during January. amount in units cost per unit $ 1 Jan opening balance 200 5 15 Jan receipts into stock 150 6 30 Jan stock issued to production 250 - What is the value of stock held at 31 January using the Last In First Out (LIFO) method? A $500 B $600 C $1300 D $1400
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2009
Q93 · The summarised balance sheets for a business for two years are as follows 9706/12 Oct/Nov 2009
12 The summarised balance sheets for a business for two years are as follows. year 1 year 2 $ $ fixed assets 9 000 12 000 current assets 6 000 8 000 less current liabilities (5 000) (6 000) net assets 10 000 14 000 The drawings in year 1 were $5000 and in year 2 $3000. What is the net profit for year 2? A $1000 B $4000 C $5000 D $7000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2009
Q94 · X and Y are in partnership 9706/12 Oct/Nov 2009
13 X and Y are in partnership. Their profit and loss appropriation account shows the following. X Y total $ $ $ interest on capital 1 600 1 800 3 400 interest charged on drawings 500 400 900 partners’ salaries 2 000 3 000 5 000 share of profit 8 000 12 000 20 000 What is the net profit before appropriations? A $17 500 B $22 500 C $27 500 D $29 300
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q95 · An extract from the accounts of a manufacturing company shows the following 9706/12 Oct/Nov 2009
14 An extract from the accounts of a manufacturing company shows the following. $ depreciation of factory machinery 16 700 direct factory labour 476 200 factory cleaning costs 18 300 factory heat, light and power 22 600 factory supervisor’s salary 18 200 indirect factory labour 52 470 purchases of raw materials 184 300 stock of raw materials - opening stock 21 500 - closing stock 17 900 What is the prime cost of production? A $660 500 B $664 100 C $680 800 D $716 570
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q96 · An extract from a company’s balance sheet is given 9706/12 Oct/Nov 2009
15 An extract from a company’s balance sheet is given. $000 issued ordinary share capital 250 issued preference shares 180 profit and loss account 320 share premium account 125 8 % debentures 100 What are the ordinary shareholders’ funds? A $695 000 B $775 000 C $875 000 D $975 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q97 · An extract from a company’s balance sheet shows the following 9706/12 Oct/Nov 2009
16 An extract from a company’s balance sheet shows the following. $000 issued ordinary shares of $0.25 each 600 share premium account 150 retained profits 300 The company makes a rights issue of one new ordinary share for each three held, at a price of $0.30 per share. All shares were taken up. What does the new balance sheet show? issued ordinary share premium share capital $000 $000 A 600 120 B 800 150 C 800 190 D 800 600
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q98 · A company’s Balance Sheet at 31 December 2008 includes: $ Ordinary shares of $1.00 12 000… 9706/12 Oct/Nov 2009
17 A company’s Balance Sheet at 31 December 2008 includes: $ Ordinary shares of $1.00 12 000 Profit and Loss Account 4000 In January 2009, the company made a bonus issue of one share for every four held. In June 2009, the company made a rights issue at $1.60 of one share for every two held. By how much did these transactions increase the company’s bank balance? A $9600 B $12 000 C $12 800 D $19 200
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q99 · Which transaction would increase the current assets of a business? 9706/12 Oct/Nov 2009
18 Which transaction would increase the current assets of a business? A paying creditors $750 cash B purchasing a fixed asset on credit for $5000 C purchasing stock on credit for $1000 and selling immediately for $2000 cash D selling stock of $1000 at cost price on credit
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q100 · What will result in a reduction of working capital? 9706/12 Oct/Nov 2009
19 What will result in a reduction of working capital? A decreasing the rate of stock turnover B reducing the debtor collection period by offering discounts C reducing the time taken to pay suppliers D selling some surplus fixed assets
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q101 · A bank manager has reviewed the financial statements of a business 9706/12 Oct/Nov 2009
20 A bank manager has reviewed the financial statements of a business. He notes that the liquidity ratio has fallen but that the sales for the year have remained constant. What explains this fall in the liquidity ratio? A a decrease in stocks of finished goods B a decrease in the overdraft C an increase in cash D an increase in trade creditors
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2009
Q102 · The following information relates to the final accounts of a business 9706/12 Oct/Nov 2009
21 The following information relates to the final accounts of a business. $000 opening stock 2 470 closing stock 2 156 cost of sales for year 12 500 sales for year 21 660 What was the stock turnover in days? A 68 B 72 C 126 D 144
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2009
Q103 · A company has a share price that gives a dividend yield of 4 % 9706/12 Oct/Nov 2009
22 A company has a share price that gives a dividend yield of 4 %. Earnings per share are $0.32 and half the earnings are paid out as dividends. What is the share price? A $2.00 B $4.00 C $6.00 D $8.00
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q104 · The table shows balances at the end of a year 9706/12 Oct/Nov 2009
30 The table shows balances at the end of a year. $ expenses prepaid 6 000 expenses accrued 4 000 bank overdraft 11 500 trade creditors 13 400 trade debtors 10 500 loan (2015) 20 000 What is the total of current liabilities? A $16 500 B $17 400 C $28 900 D $48 900
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q105 · An item of capital expenditure has been incorrectly treated as revenue expenditure in the… 9706/11 May/June 2010
2 An item of capital expenditure has been incorrectly treated as revenue expenditure in the accounts of a business. What is the effect of this error on the accounts of the business? assets profit A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: D
This question in 9706/11 May/June 2010
Q106 · The table shows information from the books of a business at 30 April 2010 9706/11 May/June 2010
7 The table shows information from the books of a business at 30 April 2010. details $ credit sales invoiced during financial year 79 000 goods sent to customers on 28 April 2010 and invoiced 4 May 2010 6 100 goods sent to customers during April 2010 on sale or return basis but 8 300 not sold by 30 April 2010 What is the amount of sales for the year ended 30 April 2010? A $76 800 B $85 100 C $85 300 D $93 400
1 marks
Answer: B
This question in 9706/11 May/June 2010
Q107 · A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors)… 9706/11 May/June 2010
11 A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors) control account 48 500 2 900 trade payables (creditors) control account 3 600 34 800 It is then found that an invoice, $900, issued to a debtor on 27 December, has not been entered in the accounting records. What is the correct figure for trade receivables (debtors) in the balance sheet at 31 December? A $46 500 B $49 400 C $51 200 D $53 000
1 marks
Answer: D
This question in 9706/11 May/June 2010
Q108 · During the year ended 31 December, a sports club received $10 860 for subscriptions 9706/11 May/June 2010
12 During the year ended 31 December, a sports club received $10 860 for subscriptions. The following further information is available. year ended 31 December start of year end of year $ $ subscriptions owing 580 870 subscriptions received in advance 1 640 1 220 What is the figure for subscriptions in the Income and Expenditure Account for the year ended 31 December? A $10 150 B $10 510 C $11 570 D $12 270
1 marks
Answer: C
This question in 9706/11 May/June 2010
Q109 · A firm has incomplete accounting records 9706/11 May/June 2010
13 A firm has incomplete accounting records. The following figures are known. $ capital at start of year 20 000 owner’s drawings 7 000 capital at end of year 30 000 How much profit has the firm made during the year? A $7000 B $17 000 C $27 000 D $30 000
1 marks
Answer: B
This question in 9706/11 May/June 2010
Q110 · A company calculates factory profit at a mark-up of 20 % on the cost of production 9706/11 May/June 2010
14 A company calculates factory profit at a mark-up of 20 % on the cost of production. The following information is available. $ inventory (stock) of finished goods at cost at 31 December 2007 40 000 cost of goods produced for the year to 31 December 2008 240 000 closing inventory (stock) of finished goods at cost plus factory profit at 54 000 31 December 2008 How much will be shown as factory profit in the accounts for the year ended 31 December 2008? A $39 000 B $40 000 C $47 000 D $48 000
1 marks
Answer: C
This question in 9706/11 May/June 2010
Q111 · The table shows transactions relating to an inventory (stock) item during a period 9706/11 May/June 2010
15 The table shows transactions relating to an inventory (stock) item during a period. number of units per unit bought 100 cost $16 sold 60 selling price $25 Of the remaining units, 20 are damaged and can only be sold for $10 each. What is the profit for the period? A $220 B $300 C $420 D $540
1 marks
Answer: C
This question in 9706/11 May/June 2010
Q112 · X, Y and Z are in partnership sharing profits and losses in the ratio 5 : 2 : 3 9706/11 May/June 2010
16 X, Y and Z are in partnership sharing profits and losses in the ratio 5 : 2 : 3. Y is entitled to a salary of $18 000 per annum. Partners receive interest at 6 % per annum on their capital account balances at the start of the year. At the beginning of the year, capital account balances were: X $30 000 Y $22 000 Z $20 000 The net profit before salary and interest for the year is $140 000. What is Y’s share of the total profits? A $23 536 B $28 000 C $42 856 D $46 000
1 marks
Answer: C
This question in 9706/11 May/June 2010
Q113 · L and M are in partnership 9706/11 May/June 2010
17 L and M are in partnership. Which item should appear in the partnership appropriation account? A additional capital contributed by M B cash drawings of L and M during the year C salary due to L D salary paid to M’s wife
1 marks
Answer: C
This question in 9706/11 May/June 2010
Q114 · A company is set up with an authorised share capital of $3 million 9706/11 May/June 2010
18 A company is set up with an authorised share capital of $3 million. It plans to purchase immediately a factory for $1 million. Preliminary expenses will be $100 000 and the immediate requirement for working capital will be $800 000. It will also require new equipment costing $600 000 in 12 months time. What is the minimum amount the company needs to raise now? A $1 000 000 B $1 900 000 C $2 500 000 D $3 000 000
1 marks
Answer: B
This question in 9706/11 May/June 2010
Q115 · At 1 January 2009 the capital structure of a company was as follows 9706/11 May/June 2010
19 At 1 January 2009 the capital structure of a company was as follows. $ issued share capital 100 000 ordinary shares of $1 each 100 000 share premium account 30 000 On 1 April 2009 the company made a rights issue of 20 000 shares of $1 each for $36 000. On 1 June 2009 a bonus issue of one share for every six in issue was made. The share premium account was used for this purpose. What is the balance on the share premium account at 31 December 2009? A $26 000 B $34 000 C $46 000 D $56 000
1 marks
Answer: A
This question in 9706/11 May/June 2010
Q116 · When is a share premium account opened? 9706/11 May/June 2010
20 When is a share premium account opened? A when shares are issued at a price above nominal value B when shares are redeemed by the company at a premium C when shares are sold by a shareholder at a price above their nominal value D when the company issues bonus shares
1 marks
Answer: A
This question in 9706/11 May/June 2010
Q117 · An item of capital expenditure has been incorrectly treated as revenue expenditure in the… 9706/12 May/June 2010
1 An item of capital expenditure has been incorrectly treated as revenue expenditure in the accounts of a business. What is the effect of this error on the accounts of the business? assets profit A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: D
This question in 9706/12 May/June 2010
Q118 · The table shows information from the books of a business at 30 April 2010 9706/12 May/June 2010
6 The table shows information from the books of a business at 30 April 2010. details $ credit sales invoiced during financial year 79 000 goods sent to customers on 28 April 2010 and invoiced 4 May 2010 6 100 goods sent to customers during April 2010 on sale or return basis but 8 300 not sold by 30 April 2010 What is the amount of sales for the year ended 30 April 2010? A $76 800 B $85 100 C $85 300 D $93 400
1 marks
Answer: B
This question in 9706/12 May/June 2010
Q119 · A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors)… 9706/12 May/June 2010
10 A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors) control account 48 500 2 900 trade payables (creditors) control account 3 600 34 800 It is then found that an invoice, $900, issued to a debtor on 27 December, has not been entered in the accounting records. What is the correct figure for trade receivables (debtors) in the balance sheet at 31 December? A $46 500 B $49 400 C $51 200 D $53 000
1 marks
Answer: D
This question in 9706/12 May/June 2010
Q120 · During the year ended 31 December, a sports club received $10 860 for subscriptions 9706/12 May/June 2010
11 During the year ended 31 December, a sports club received $10 860 for subscriptions. The following further information is available. year ended 31 December start of year end of year $ $ subscriptions owing 580 870 subscriptions received in advance 1 640 1 220 What is the figure for subscriptions in the Income and Expenditure Account for the year ended 31 December? A $10 150 B $10 510 C $11 570 D $12 270
1 marks
Answer: C
This question in 9706/12 May/June 2010
Q121 · A firm has incomplete accounting records 9706/12 May/June 2010
12 A firm has incomplete accounting records. The following figures are known. $ capital at start of year 20 000 owner’s drawings 7 000 capital at end of year 30 000 How much profit has the firm made during the year? A $7000 B $17 000 C $27 000 D $30 000
1 marks
Answer: B
This question in 9706/12 May/June 2010
Q122 · A company calculates factory profit at a mark-up of 20 % on the cost of production 9706/12 May/June 2010
13 A company calculates factory profit at a mark-up of 20 % on the cost of production. The following information is available. $ inventory (stock) of finished goods at cost at 31 December 2007 40 000 cost of goods produced for the year to 31 December 2008 240 000 closing inventory (stock) of finished goods at cost plus factory profit at 54 000 31 December 2008 How much will be shown as factory profit in the accounts for the year ended 31 December 2008? A $39 000 B $40 000 C $47 000 D $48 000
1 marks
Answer: C
This question in 9706/12 May/June 2010
Q123 · The table shows transactions relating to an inventory (stock) item during a period 9706/12 May/June 2010
14 The table shows transactions relating to an inventory (stock) item during a period. number of units per unit bought 100 cost $16 sold 60 selling price $25 Of the remaining units, 20 are damaged and can only be sold for $10 each. What is the profit for the period? A $220 B $300 C $420 D $540
1 marks
Answer: C
This question in 9706/12 May/June 2010
Q124 · X, Y and Z are in partnership sharing profits and losses in the ratio 5 : 2 : 3 9706/12 May/June 2010
15 X, Y and Z are in partnership sharing profits and losses in the ratio 5 : 2 : 3. Y is entitled to a salary of $18 000 per annum. Partners receive interest at 6 % per annum on their capital account balances at the start of the year. At the beginning of the year, capital account balances were: X $30 000 Y $22 000 Z $20 000 The net profit before salary and interest for the year is $140 000. What is Y’s share of the total profits? A $23 536 B $28 000 C $42 856 D $46 000
1 marks
Answer: C
This question in 9706/12 May/June 2010
Q125 · L and M are in partnership 9706/12 May/June 2010
16 L and M are in partnership. Which item should appear in the partnership appropriation account? A additional capital contributed by M B cash drawings of L and M during the year C salary due to L D salary paid to M’s wife
1 marks
Answer: C
This question in 9706/12 May/June 2010
Q126 · The table shows information from the books of a business at 30 April 2010 9706/13 May/June 2010
5 The table shows information from the books of a business at 30 April 2010. details $ credit sales invoiced during financial year 79 000 goods sent to customers on 28 April 2010 and invoiced 4 May 2010 6 100 goods sent to customers during April 2010 on sale or return basis but 8 300 not sold by 30 April 2010 What is the amount of sales for the year ended 30 April 2010? A $76 800 B $85 100 C $85 300 D $93 400
1 marks
Answer: B
This question in 9706/13 May/June 2010
Q127 · During the year ended 31 December, a sports club received $10 860 for subscriptions 9706/13 May/June 2010
10 During the year ended 31 December, a sports club received $10 860 for subscriptions. The following further information is available. year ended 31 December start of year end of year $ $ subscriptions owing 580 870 subscriptions received in advance 1 640 1 220 What is the figure for subscriptions in the Income and Expenditure Account for the year ended 31 December? A $10 150 B $10 510 C $11 570 D $12 270
1 marks
Answer: C
This question in 9706/13 May/June 2010
Q128 · A firm has incomplete accounting records 9706/13 May/June 2010
11 A firm has incomplete accounting records. The following figures are known. $ capital at start of year 20 000 owner’s drawings 7 000 capital at end of year 30 000 How much profit has the firm made during the year? A $7000 B $17 000 C $27 000 D $30 000
1 marks
Answer: B
This question in 9706/13 May/June 2010
Q129 · A company calculates factory profit at a mark-up of 20 % on the cost of production 9706/13 May/June 2010
12 A company calculates factory profit at a mark-up of 20 % on the cost of production. The following information is available. $ inventory (stock) of finished goods at cost at 31 December 2007 40 000 cost of goods produced for the year to 31 December 2008 240 000 closing inventory (stock) of finished goods at cost plus factory profit at 54 000 31 December 2008 How much will be shown as factory profit in the accounts for the year ended 31 December 2008? A $39 000 B $40 000 C $47 000 D $48 000
1 marks
Answer: C
This question in 9706/13 May/June 2010
Q130 · The table shows transactions relating to an inventory (stock) item during a period 9706/13 May/June 2010
13 The table shows transactions relating to an inventory (stock) item during a period. number of units per unit bought 100 cost $16 sold 60 selling price $25 Of the remaining units, 20 are damaged and can only be sold for $10 each. What is the profit for the period? A $220 B $300 C $420 D $540
1 marks
Answer: C
This question in 9706/13 May/June 2010
Q131 · X, Y and Z are in partnership sharing profits and losses in the ratio 5 : 2 : 3 9706/13 May/June 2010
14 X, Y and Z are in partnership sharing profits and losses in the ratio 5 : 2 : 3. Y is entitled to a salary of $18 000 per annum. Partners receive interest at 6 % per annum on their capital account balances at the start of the year. At the beginning of the year, capital account balances were: X $30 000 Y $22 000 Z $20 000 The net profit before salary and interest for the year is $140 000. What is Y’s share of the total profits? A $23 536 B $28 000 C $42 856 D $46 000
1 marks
Answer: C
This question in 9706/13 May/June 2010
Q132 · L and M are in partnership 9706/13 May/June 2010
15 L and M are in partnership. Which item should appear in the partnership appropriation account? A additional capital contributed by M B cash drawings of L and M during the year C salary due to L D salary paid to M’s wife
1 marks
Answer: C
This question in 9706/13 May/June 2010
Q133 · A company is set up with an authorised share capital of $3 million 9706/13 May/June 2010
16 A company is set up with an authorised share capital of $3 million. It plans to purchase immediately a factory for $1 million. Preliminary expenses will be $100 000 and the immediate requirement for working capital will be $800 000. It will also require new equipment costing $600 000 in 12 months time. What is the minimum amount the company needs to raise now? A $1 000 000 B $1 900 000 C $2 500 000 D $3 000 000
1 marks
Answer: B
This question in 9706/13 May/June 2010
Q134 · At 1 January 2009 the capital structure of a company was as follows 9706/13 May/June 2010
17 At 1 January 2009 the capital structure of a company was as follows. $ issued share capital 100 000 ordinary shares of $1 each 100 000 share premium account 30 000 On 1 April 2009 the company made a rights issue of 20 000 shares of $1 each for $36 000. On 1 June 2009 a bonus issue of one share for every six in issue was made. The share premium account was used for this purpose. What is the balance on the share premium account at 31 December 2009? A $26 000 B $34 000 C $46 000 D $56 000
1 marks
Answer: A
This question in 9706/13 May/June 2010
Q135 · Closing inventory (stock) has been overvalued 9706/11 Oct/Nov 2010
7 Closing inventory (stock) has been overvalued. What is the effect on the financial statements? net current assets net profit A no effect understated B overstated no effect C overstated overstated D understated understated
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2010
Q136 · For the eleven months ended 31 August 2009, snack bar takings were correctly recorded at… 9706/11 Oct/Nov 2010
11 For the eleven months ended 31 August 2009, snack bar takings were correctly recorded at $109 340. For September 2009, the snack bar takings were mixed up with other income. The snack bar profit margin was 30.%. The table shows figures for the snack bar for September 2009. $ opening inventory (stock) at cost 6 303 purchases 8 844 closing inventory (stock) at cost 7 370 What was the gross profit of the snack bar for the year ended 30 September 2009? A $27 566 B $36 135 C $36 593 D $43 912
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2010
Q137 · The table shows data for a manufacturing company for a year 9706/11 Oct/Nov 2010
14 The table shows data for a manufacturing company for a year. $ office salaries 34 500 factory wages 115 000 depreciation on plant 3 700 depreciation on office equipment 1 500 cost of raw materials 89 600 royalties paid 4 200 closing inventory (stock) of completed goods 5 100 What is the production cost of completed goods for the year? A $203 000 B $208 300 C $212 500 D $214 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2010
Q138 · A company has the following current assets and current liabilities 9706/11 Oct/Nov 2010
15 A company has the following current assets and current liabilities. $ bank deposit account 6 000 bank overdraft 4 500 loan interest payable 2 500 deposits from customers (for orders) 1 500 loans to employees 4 000 trade payables (creditors) 9 000 trade receivables (debtors) 12 000 What is the amount of the net current assets? A $(3500) B $4500 C $7500 D $13 500
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2010
Q139 · A business has two departments, men’s clothing and ladies’ clothing 9706/11 Oct/Nov 2010
17 A business has two departments, men’s clothing and ladies’ clothing. The following information is available. men’s department ladies’ department sales assistants 7 9 floor space 160 m2 200 m2 value of non current (fixed) assets $59 000 $61 000 annual sales $450 000 $750 000 The cost of heating and lighting is $17 692. What is the cost of heating and lighting for the men’s department? A $6634.50 B $7740.25 C $7863.11 D $8698.57
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2010
Q140 · The table shows extracts from the trial balance of a company at 31 December 2009 9706/11 Oct/Nov 2010
19 The table shows extracts from the trial balance of a company at 31 December 2009. $ ordinary share capital 750 000 8 % preference shares 250 000 6 % debentures (2015) 150 000 bank loan repayable (2012) 75 000 bank overdraft 110 000 mortgage on buildings (repayable 2010) 120 000 What is the total of non current liabilities in the balance sheet at 31 December 2009? A $195 000 B $225 000 C $345 000 D $595 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2010
Q141 · Closing inventory (stock) has been overvalued 9706/12 Oct/Nov 2010
7 Closing inventory (stock) has been overvalued. What is the effect on the financial statements? net current assets net profit A no effect understated B overstated no effect C overstated overstated D understated understated
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2010
Q142 · At the end of a financial year the following information is available 9706/12 Oct/Nov 2010
10 At the end of a financial year the following information is available. $ sales 200 000 opening inventory (stock) 15 000 closing inventory (stock) 18 000 If the business makes a standard mark-up of 25 %, what were the purchases? A $147 000 B $153 000 C $157 000 D $163 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2010
Q143 · For the eleven months ended 31 August 2009, snack bar takings were correctly recorded at… 9706/12 Oct/Nov 2010
11 For the eleven months ended 31 August 2009, snack bar takings were correctly recorded at $109 340. For September 2009, the snack bar takings were mixed up with other income. The snack bar profit margin was 30.%. The table shows figures for the snack bar for September 2009. $ opening inventory (stock) at cost 6 303 purchases 8 844 closing inventory (stock) at cost 7 370 What was the gross profit of the snack bar for the year ended 30 September 2009? A $27 566 B $36 135 C $36 593 D $43 912
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2010
Q144 · Information relating to a club’s subscription is: $ received during the year 20 000 paid… 9706/12 Oct/Nov 2010
12 Information relating to a club’s subscription is: $ received during the year 20 000 paid in advance in the previous year 2 000 paid in advance during the current year 1 000 There were no subscriptions in arrears at the start or end of the year. Individual subscriptions have remained constant at $500 per annum for the last two years. How many members does the club have? A 38 B 40 C 42 D 44
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2010
Q145 · The table shows data for a manufacturing company for a year 9706/12 Oct/Nov 2010
14 The table shows data for a manufacturing company for a year. $ office salaries 34 500 factory wages 115 000 depreciation on plant 3 700 depreciation on office equipment 1 500 cost of raw materials 89 600 royalties paid 4 200 closing inventory (stock) of completed goods 5 100 What is the production cost of completed goods for the year? A $203 000 B $208 300 C $212 500 D $214 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2010
Q146 · A company has the following current assets and current liabilities 9706/12 Oct/Nov 2010
15 A company has the following current assets and current liabilities. $ bank deposit account 6 000 bank overdraft 4 500 loan interest payable 2 500 deposits from customers (for orders) 1 500 loans to employees 4 000 trade payables (creditors) 9 000 trade receivables (debtors) 12 000 What is the amount of the net current assets? A $(3500) B $4500 C $7500 D $13 500
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2010
Q147 · A customer paid a deposit in advance for goods to be supplied at a later date 9706/13 Oct/Nov 2010
1 A customer paid a deposit in advance for goods to be supplied at a later date. How should this be recorded in the seller’s books? debit credit A cash customer B cash sales C customer prepayment D customer sales
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2010
Q148 · At 30 June the balance sheet of a business includes the following 9706/13 Oct/Nov 2010
4 At 30 June the balance sheet of a business includes the following. $ trade receivables (debtors) 46 000 provision for doubtful debts 5 % 2 300 During July, sales of $350 000 were made of which 20 % were in cash. Credit customers paid $303 800 after deducting a 2 % cash discount. How much did the trade receivables (debtors) owe to the business at 31 July? A $15 200 B $16 000 C $22 200 D $76 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2010
Q149 · Closing inventory (stock) has been overvalued 9706/13 Oct/Nov 2010
6 Closing inventory (stock) has been overvalued. What is the effect on the financial statements? net current assets net profit A no effect understated B overstated no effect C overstated overstated D understated understated
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q150 · An electricity accrual of $375 was treated as a prepayment in preparing a trader’s income… 9706/13 Oct/Nov 2010
8 An electricity accrual of $375 was treated as a prepayment in preparing a trader’s income (profit and loss) account. What was the effect on profit? A overstated by $375 B overstated by $750 C understated by $375 D understated by $750
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2010
Q151 · At the end of a financial year the following information is available 9706/13 Oct/Nov 2010
9 At the end of a financial year the following information is available. $ sales 200 000 opening inventory (stock) 15 000 closing inventory (stock) 18 000 If the business makes a standard mark-up of 25 %, what were the purchases? A $147 000 B $153 000 C $157 000 D $163 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2010
Q152 · For the eleven months ended 31 August 2009, snack bar takings were correctly recorded at… 9706/13 Oct/Nov 2010
10 For the eleven months ended 31 August 2009, snack bar takings were correctly recorded at $109 340. For September 2009, the snack bar takings were mixed up with other income. The snack bar profit margin was 30.%. The table shows figures for the snack bar for September 2009. $ opening inventory (stock) at cost 6 303 purchases 8 844 closing inventory (stock) at cost 7 370 What was the gross profit of the snack bar for the year ended 30 September 2009? A $27 566 B $36 135 C $36 593 D $43 912
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2010
Q153 · Information relating to a club’s subscription is: $ received during the year 20 000 paid… 9706/13 Oct/Nov 2010
11 Information relating to a club’s subscription is: $ received during the year 20 000 paid in advance in the previous year 2 000 paid in advance during the current year 1 000 There were no subscriptions in arrears at the start or end of the year. Individual subscriptions have remained constant at $500 per annum for the last two years. How many members does the club have? A 38 B 40 C 42 D 44
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q154 · X and Y are in partnership, sharing residual profits and losses equally after the… 9706/13 Oct/Nov 2010
12 X and Y are in partnership, sharing residual profits and losses equally after the payments below are made. 1 2 % interest is charged on partners’ drawings 2 salary to Y of $10 000 The partners’ drawings for the year were: X $12 000 Y $8000 The net profit for the current year is $52 000. How much will each partner receive in share of residual profits? A $10 800 B $11 200 C $20 800 D $21 200
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2010
Q155 · The table shows data for a manufacturing company for a year 9706/13 Oct/Nov 2010
13 The table shows data for a manufacturing company for a year. $ office salaries 34 500 factory wages 115 000 depreciation on plant 3 700 depreciation on office equipment 1 500 cost of raw materials 89 600 royalties paid 4 200 closing inventory (stock) of completed goods 5 100 What is the production cost of completed goods for the year? A $203 000 B $208 300 C $212 500 D $214 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q156 · A company has the following current assets and current liabilities 9706/13 Oct/Nov 2010
14 A company has the following current assets and current liabilities. $ bank deposit account 6 000 bank overdraft 4 500 loan interest payable 2 500 deposits from customers (for orders) 1 500 loans to employees 4 000 trade payables (creditors) 9 000 trade receivables (debtors) 12 000 What is the amount of the net current assets? A $(3500) B $4500 C $7500 D $13 500
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2010
Q157 · X started a business 3 years ago and now has a capital of $175 000 9706/13 Oct/Nov 2010
15 X started a business 3 years ago and now has a capital of $175 000. Over that period his profits have been $73 000 and his drawings $52 000. In year 2 he introduced cash of $35 000 and in year 3 he took out of the business, for his own use, a non current (fixed) asset with a net book value of $4000. How much capital did he start the business with? A $67 000 B $115 000 C $123 000 D $158 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q158 · A business has two departments, men’s clothing and ladies’ clothing 9706/13 Oct/Nov 2010
16 A business has two departments, men’s clothing and ladies’ clothing. The following information is available. men’s department ladies’ department sales assistants 7 9 floor space 160 m2 200 m2 value of non current (fixed) assets $59 000 $61 000 annual sales $450 000 $750 000 The cost of heating and lighting is $17 692. What is the cost of heating and lighting for the men’s department? A $6634.50 B $7740.25 C $7863.11 D $8698.57
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q159 · A company makes a bonus issue of shares 9706/13 Oct/Nov 2010
17 A company makes a bonus issue of shares. What is the effect on the net assets and the reserves in the balance sheet? net assets reserves A increase decrease B increase unchanged C unchanged decrease D unchanged increase
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q160 · The table shows extracts from the trial balance of a company at 31 December 2009 9706/13 Oct/Nov 2010
18 The table shows extracts from the trial balance of a company at 31 December 2009. $ ordinary share capital 750 000 8 % preference shares 250 000 6 % debentures (2015) 150 000 bank loan repayable (2012) 75 000 bank overdraft 110 000 mortgage on buildings (repayable 2010) 120 000 What is the total of non current liabilities in the balance sheet at 31 December 2009? A $195 000 B $225 000 C $345 000 D $595 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2010
Q161 · A company’s share capital and reserves are: $ non current (fixed) assets 250 000 net… 9706/13 Oct/Nov 2010
19 A company’s share capital and reserves are: $ non current (fixed) assets 250 000 net current assets 125 000 375 000 share capital and reserves 150 000 shares $1 each 150 000 share premium 75 000 general reserve 125 000 profits retained 25 000 375 000 The directors propose to issue bonus shares on the basis of one $1 share for every three already held. Following this the directors intend to make a rights issue on the basis of one new $1 share for every four shares held, at a premium of $0.20 per share. What will the total net assets of the company be after the share issues? A $425 000 B $435 000 C $475 000 D $485 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2010
Q162 · On 1 January 2009 a business had prepaid rent of $50 9706/13 Oct/Nov 2010
30 On 1 January 2009 a business had prepaid rent of $50. During 2009, three rent payments were made of $250 each. On 31 December 2009, the business still owes $200 rent on account for 2009. The business owner has charged the rent payments made during 2009 in his income (profit and loss) account. What is the effect on net profit? A $200 too high B $200 too low C $250 too high D $250 too low
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2010
Q163 · A business paid $10 000 for waste disposal in the year 9706/11 May/June 2011
1 A business paid $10 000 for waste disposal in the year. The opening prepayment was $1500 and the closing accrual was $2000. What was the charge for waste disposal for the year? A $6500 B $9500 C $10 500 D $13 500
1 marks
Answer: D
This question in 9706/11 May/June 2011
Q164 · The non-current assets of a business are shown 9706/11 May/June 2011
2 The non-current assets of a business are shown. end of year start of year $ $ cost 360 000 300 000 accumulated depreciation 120 000 75 000 net book value 240 000 225 000 During the year, non-current assets costing $110 000 were bought and non-current assets with a net book value of $20 000 were sold. What was the depreciation charge for the year? A $35 000 B $45 000 C $50 000 D $75 000
1 marks
Answer: D
This question in 9706/11 May/June 2011
Q165 · Which transaction would increase the current assets of a business? 9706/11 May/June 2011
3 Which transaction would increase the current assets of a business? A paying invoices $950, after receiving $50 cash discount B purchasing a machine on credit for $1200 C purchasing inventory for $1100 cash and selling it on credit for $1500 D selling inventory with an original cost of $800 at below cost price
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q166 · The following summarised information has been taken from the balance sheet of a… 9706/11 May/June 2011
4 The following summarised information has been taken from the balance sheet of a partnership. $ non-current assets 42 000 capital accounts 36 000 current accounts (debit) 5 000 current liabilities 7 000 non-current liabilities 15 000 What is the amount of current assets? A $6000 B $11 000 C $17 000 D $21 000
1 marks
Answer: B
This question in 9706/11 May/June 2011
Q167 · Closing inventory has been overvalued 9706/11 May/June 2011
8 Closing inventory has been overvalued. What is the effect on the financial statements? net current assets profit from operations A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/11 May/June 2011
Q168 · A manufacturing company has the following balances at its year end 9706/11 May/June 2011
10 A manufacturing company has the following balances at its year end. $ closing inventory of raw materials 24 500 direct manufacturing wages 162 800 purchases of raw materials 85 200 supervisors’ wages 44 000 opening inventory of raw materials 27 800 What is the prime cost for the year? A $244 700 B $248 000 C $251 300 D $295 300
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q169 · A partnership provides the following financial information for the year ended 30 June 2011 9706/11 May/June 2011
11 A partnership provides the following financial information for the year ended 30 June 2011. $000 profit from operations 240 bank interest payable 21 interest credited to current accounts 15 drawings 100 partnership salaries 95 What is the residual balance of profits to be appropriated between the partners? A $9000 B $104 000 C $109 000 D $204 000
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q170 · A new business was established with opening capital of $20 000 9706/11 May/June 2011
12 A new business was established with opening capital of $20 000. At the end of the first year, assets less liabilities were $26 000. The owner withdrew $7000 as drawings during the year and this resulted in a bank overdraft of $5000 at the end of the year. What was the profit during the first year? A $8000 B $12 000 C $13 000 D $18 000
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q171 · At the year end a company discovers that some inventory is damaged 9706/11 May/June 2011
13 At the year end a company discovers that some inventory is damaged. This inventory originally cost $2000 and to replace it would now cost $1900. It would normally sell for $2400 but can now only be sold for $2200 if repairs costing $400 are undertaken. At what value should the damaged inventory be shown in the financial statements? A $1800 B $1900 C $2000 D $2200
1 marks
Answer: A
This question in 9706/11 May/June 2011
Q172 · A club charges each of its 100 members an annual subscription of $12 9706/11 May/June 2011
14 A club charges each of its 100 members an annual subscription of $12. At the end of a year four members had not paid their annual subscription. What will be the entries in the financial statements for subscriptions? income and expenditure account balance sheet $ A 1152 current asset $48 B 1152 current liability $48 C 1200 current asset $48 D 1200 current liability $48
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q173 · A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000… 9706/11 May/June 2011
16 A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000 4 % debentures. By what amount will the net assets of the company increase? A $250 000 B $550 000 C $1 000 000 D $1 300 000
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q174 · An extract from Bumble Ltd's balance sheet shows the following 9706/11 May/June 2011
17 An extract from Bumble Ltd's balance sheet shows the following. $000 ordinary shares of $0.25 each 500 share premium 100 retained earnings 300 The company makes a rights issue of 1 share for each 4 held at a price of $0.30 per share. All shares are taken up. What will the new balance sheet show? A B C D $000 $000 $000 $000 ordinary shares of $0.25 each 625 500 625 625 rights issue – 125 – – share premium 100 125 125 100 retained earnings 300 275 300 325
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q175 · The following data is available at the end of a financial year 9706/11 May/June 2011
18 The following data is available at the end of a financial year. opening inventory $60 000 purchases $420 000 closing inventory $80 000 mark up 25 % trade receivables turnover 50 days Sales are all on credit and accrue evenly over the year. What is the amount of trade receivables at the end of the year (to the nearest $500)? A $55 000 B $57 500 C $68 500 D $72 000
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q176 · The annual accounts of a business include the following 9706/11 May/June 2011
19 The annual accounts of a business include the following. $ revenue 160 000 opening inventory 10 000 closing inventory 14 000 Inventory turnover is 10 times. What is the gross profit? A $20 000 B $40 000 C $60 000 D $120 000
1 marks
Answer: B
This question in 9706/11 May/June 2011
Q177 · A business sells goods at a mark up of 33.3 % 9706/11 May/June 2011
23 A business sells goods at a mark up of 33.3 %. Information for a year is given. $ revenue 600 000 opening inventory 53 000 closing inventory 68 000 What are the total purchases for the year? A $415 000 B $435 000 C $450 000 D $465 000
1 marks
Answer: D
This question in 9706/11 May/June 2011
Q178 · Closing inventory has been overvalued 9706/12 May/June 2011
4 Closing inventory has been overvalued. What is the effect on the financial statements? net current assets profit from operations A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/12 May/June 2011
Q179 · At the year end a company discovers that some inventory is damaged 9706/12 May/June 2011
5 At the year end a company discovers that some inventory is damaged. This inventory originally cost $2000 and to replace it would now cost $1900. It would normally sell for $2400 but can now only be sold for $2200 if repairs costing $400 are undertaken. At what value should the damaged inventory be shown in the financial statements? A $1800 B $1900 C $2000 D $2200
1 marks
Answer: A
This question in 9706/12 May/June 2011
Q180 · A club charges each of its 100 members an annual subscription of $12 9706/12 May/June 2011
6 A club charges each of its 100 members an annual subscription of $12. At the end of a year four members had not paid their annual subscription. What will be the entries in the financial statements for subscriptions? income and expenditure account balance sheet $ A 1152 current asset $48 B 1152 current liability $48 C 1200 current asset $48 D 1200 current liability $48
1 marks
Answer: C
This question in 9706/12 May/June 2011
Q181 · The following summarised information has been taken from the balance sheet of a… 9706/12 May/June 2011
13 The following summarised information has been taken from the balance sheet of a partnership. $ non-current assets 42 000 capital accounts 36 000 current accounts (debit) 5 000 current liabilities 7 000 non-current liabilities 15 000 What is the amount of current assets? A $6000 B $11 000 C $17 000 D $21 000
1 marks
Answer: B
This question in 9706/12 May/June 2011
Q182 · A partnership provides the following financial information for the year ended 30 June 2011 9706/12 May/June 2011
16 A partnership provides the following financial information for the year ended 30 June 2011. $000 profit from operations 240 bank interest payable 21 interest credited to current accounts 15 drawings 100 partnership salaries 95 What is the residual balance of profits to be appropriated between the partners? A $9000 B $104 000 C $109 000 D $204 000
1 marks
Answer: C
This question in 9706/12 May/June 2011
Q183 · A new business was established with opening capital of $20 000 9706/12 May/June 2011
17 A new business was established with opening capital of $20 000. At the end of the first year, assets less liabilities were $26 000. The owner withdrew $7000 as drawings during the year and this resulted in a bank overdraft of $5000 at the end of the year. What was the profit during the first year? A $8000 B $12 000 C $13 000 D $18 000
1 marks
Answer: C
This question in 9706/12 May/June 2011
Q184 · A business sells goods at a mark up of 33.3 % 9706/12 May/June 2011
30 A business sells goods at a mark up of 33.3 %. Information for a year is given. $ revenue 600 000 opening inventory 53 000 closing inventory 68 000 What are the total purchases for the year? A $415 000 B $435 000 C $450 000 D $465 000
1 marks
Answer: D
This question in 9706/12 May/June 2011
Q185 · The following summarised information has been taken from the balance sheet of a… 9706/13 May/June 2011
5 The following summarised information has been taken from the balance sheet of a partnership. $ non-current assets 42 000 capital accounts 36 000 current accounts (debit) 5 000 current liabilities 7 000 non-current liabilities 15 000 What is the amount of current assets? A $6000 B $11 000 C $17 000 D $21 000
1 marks
Answer: B
This question in 9706/13 May/June 2011
Q186 · Closing inventory has been overvalued 9706/13 May/June 2011
9 Closing inventory has been overvalued. What is the effect on the financial statements? net current assets profit from operations A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/13 May/June 2011
Q187 · A partnership provides the following financial information for the year ended 30 June 2011 9706/13 May/June 2011
12 A partnership provides the following financial information for the year ended 30 June 2011. $000 profit from operations 240 bank interest payable 21 interest credited to current accounts 15 drawings 100 partnership salaries 95 What is the residual balance of profits to be appropriated between the partners? A $9000 B $104 000 C $109 000 D $204 000
1 marks
Answer: C
This question in 9706/13 May/June 2011
Q188 · A new business was established with opening capital of $20 000 9706/13 May/June 2011
13 A new business was established with opening capital of $20 000. At the end of the first year, assets less liabilities were $26 000. The owner withdrew $7000 as drawings during the year and this resulted in a bank overdraft of $5000 at the end of the year. What was the profit during the first year? A $8000 B $12 000 C $13 000 D $18 000
1 marks
Answer: C
This question in 9706/13 May/June 2011
Q189 · At the year end a company discovers that some inventory is damaged 9706/13 May/June 2011
14 At the year end a company discovers that some inventory is damaged. This inventory originally cost $2000 and to replace it would now cost $1900. It would normally sell for $2400 but can now only be sold for $2200 if repairs costing $400 are undertaken. At what value should the damaged inventory be shown in the financial statements? A $1800 B $1900 C $2000 D $2200
1 marks
Answer: A
This question in 9706/13 May/June 2011
Q190 · A club charges each of its 100 members an annual subscription of $12 9706/13 May/June 2011
15 A club charges each of its 100 members an annual subscription of $12. At the end of a year four members had not paid their annual subscription. What will be the entries in the financial statements for subscriptions? income and expenditure account balance sheet $ A 1152 current asset $48 B 1152 current liability $48 C 1200 current asset $48 D 1200 current liability $48
1 marks
Answer: C
This question in 9706/13 May/June 2011
Q191 · A company pays rates annually in advance on 1 April each year 9706/11 Oct/Nov 2011
3 A company pays rates annually in advance on 1 April each year. $4000 is paid by them on 1 April 2009 and $4800 on 1 April 2010. The company’s accounting year end is 31 December. What is the charge for rates in the 2010 income statement? A $4000 B $4200 C $4600 D $4800
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2011
Q192 · At the end of its financial year a business had accounts receivable of $16 000 and had a… 9706/11 Oct/Nov 2011
4 At the end of its financial year a business had accounts receivable of $16 000 and had a bad debts provision of $640. The provision is to be maintained at 5 % of accounts receivable. Which amount is shown in the income statement? A $160 credit B $160 debit C $800 credit D $800 debit
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2011
Q193 · An analysis of a business’s record of inventory for an item shows the following: On 1… 9706/11 Oct/Nov 2011
10 An analysis of a business’s record of inventory for an item shows the following: On 1 January the business had an inventory of 100 units at a cost of $10 each. units purchased units sold February 50 units March 60 units at $11 each April 70 units at $12 each 100 units May 30 units All sales are made at $13 per unit. The business values its inventory on a FIFO basis. What is the value of the inventory at the end of May? A $500 B $550 C $600 D $650
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2011
Q194 · X, Y and Z are in partnership, sharing profits in the ratio 2 : 2 : 1 9706/11 Oct/Nov 2011
11 X, Y and Z are in partnership, sharing profits in the ratio 2 : 2 : 1. X is allowed an annual salary of $10 000. Y has made a loan to the partnership on which the partnership pays interest of $5000 each year. Profit for the year before appropriations is $150 000. What is Z’s total appropriation of profit for the year? A $27 000 B $28 000 C $29 000 D $30 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2011
Q195 · There are 75 members of a tennis club, paying an annual subscription of $95 each 9706/11 Oct/Nov 2011
12 There are 75 members of a tennis club, paying an annual subscription of $95 each. The treasurer has provided the following information for the year. $ subscriptions received 7 305 overheads: tennis balls - purchased 850 - opening inventory 110 - closing inventory 95 other overheads 4 700 How much surplus will the club’s income and expenditure account for the year show? A $1560 B $1670 C $1740 D $1850
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2011
Q196 · A businessman marks up his cost of sales by 50 % 9706/11 Oct/Nov 2011
13 A businessman marks up his cost of sales by 50 %. At the end of his trading year the following data is available. $ opening inventory 5 000 closing inventory 4 000 ordinary goods purchased 35 000 What is his sales figure for the year? A $51 000 B $52 500 C $54 000 D $66 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2011
Q197 · The financial year of a manufacturer ends on 31 December 9706/11 Oct/Nov 2011
14 The financial year of a manufacturer ends on 31 December. Finished goods are valued at factory cost plus 20 %. The following information is available: 1 January 31 December $ $ inventory of finished goods 2400 3000 What is the amount to be deducted for the provision for unrealised profit in the income statement? A $100 B $120 C $500 D $600
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2011
Q198 · The following information relates to the non-current assets of a business formed three… 9706/11 Oct/Nov 2011
15 The following information relates to the non-current assets of a business formed three years ago. $ cost at start of year 1 10 000 accumulated depreciation at end of year 3 6 000 profit for year 3 18 000 Depreciation has been consistently charged using the straight line method. What would the profit be in year 3 if the method of depreciation for that year is changed to the reducing balance method at a rate of 25 %? A $16 500 B $17 500 C $18 500 D $19 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2011
Q199 · The table gives data about rental income for the year ended 31 March 2011 9706/12 Oct/Nov 2011
1 The table gives data about rental income for the year ended 31 March 2011. $ rents owing 31 March 2010 1 400 rents received in advance 31 March 2010 1 300 cash received 13 700 rents written off 560 rents owing at 31 March 2011 1 750 rents paid in advance at 31 March 2011 1 600 Which value of rental income will appear in the income statement for the year ended 31 March 2011? A $14 010 B $14 210 C $14 310 D $14 510
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2011
Q200 · The table shows information for a business at 31 March in Year 1 9706/12 Oct/Nov 2011
5 The table shows information for a business at 31 March in Year 1. $ inventory 16 100 trade payables 5 200 other payables 2 000 The information excludes the purchase of $3700 of goods. These goods were delivered on 31 March Year 1, but the invoice states that legal title to the goods does not pass until payment is received. Which values should appear in the balance sheet on 31 March Year 1? inventory trade payables other payables $ $ $ A 16 100 5200 2000 B 16 100 5200 5700 C 19 800 5200 5700 D 19 800 8900 2000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2011
Q201 · Subscriptions received by a sports club were as follows 9706/12 Oct/Nov 2011
14 Subscriptions received by a sports club were as follows. received year ended 31 December 2008 2009 2010 $ $ $ for membership in the year ended 31 December 2008 1900 100 – 2009 300 2100 400 2010 – 200 2500 Note: all subscriptions for 2009 are included above. A receipts and payments account and an income and expenditure account have been prepared for the year ended 31 December 2009. What are the amounts of membership subscriptions shown in the receipts and payments account and the income and expenditure account for 2009? receipts and income and payments account expenditure account $ $ A 2100 2100 B 2400 2100 C 2400 2800 D 2800 2400
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2011
Q202 · The treasurer has provided the following information relating to a golf club’s financial… 9706/12 Oct/Nov 2011
15 The treasurer has provided the following information relating to a golf club’s financial position at the year end. $ cash at bank 2 500 non-current assets 120 000 prepaid expenses 80 inventory of refreshments 500 subscriptions in advance 50 subscriptions in arrears 100 unpaid bills 200 What is the accumulated fund at the year end? A $122 780 B $122 930 C $123 130 D $123 180
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2011
Q203 · A trader buys and sells garden fertiliser in 50 kilo units 9706/12 Oct/Nov 2011
16 A trader buys and sells garden fertiliser in 50 kilo units. Inventory at 1 July was 250 units valued at $16 per unit. Purchases and sales during the month were as follows. purchases sales date (units) (units) 3 July sales 100 11 July purchases ($13 per unit) 200 14 July sales 200 25 July purchases ($14 per unit) 200 29 July sales 200 The FIFO method is used to value inventory. What is the value of the closing inventory at 31 July? A $1950 B $2100 C $2400 D $4000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2011
Q204 · A company pays rates annually in advance on 1 April each year 9706/13 Oct/Nov 2011
2 A company pays rates annually in advance on 1 April each year. $4000 is paid by them on 1 April 2009 and $4800 on 1 April 2010. The company’s accounting year end is 31 December. What is the charge for rates in the 2010 income statement? A $4000 B $4200 C $4600 D $4800
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2011
Q205 · At the end of its financial year a business had accounts receivable of $16 000 and had a… 9706/13 Oct/Nov 2011
3 At the end of its financial year a business had accounts receivable of $16 000 and had a bad debts provision of $640. The provision is to be maintained at 5 % of accounts receivable. Which amount is shown in the income statement? A $160 credit B $160 debit C $800 credit D $800 debit
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2011
Q206 · What might stop financial statements showing a true and fair view? 9706/13 Oct/Nov 2011
4 What might stop financial statements showing a true and fair view? A changes in depreciation methods from year to year B changes in dividend policy C creation of an asset revaluation reserve D inclusion of purchased goodwill in a balance sheet
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2011
Q207 · An analysis of a business’s record of inventory for an item shows the following: On 1… 9706/13 Oct/Nov 2011
9 An analysis of a business’s record of inventory for an item shows the following: On 1 January the business had an inventory of 100 units at a cost of $10 each. units purchased units sold February 50 units March 60 units at $11 each April 70 units at $12 each 100 units May 30 units All sales are made at $13 per unit. The business values its inventory on a FIFO basis. What is the value of the inventory at the end of May? A $500 B $550 C $600 D $650
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2011
Q208 · X, Y and Z are in partnership, sharing profits in the ratio 2 : 2 : 1 9706/13 Oct/Nov 2011
10 X, Y and Z are in partnership, sharing profits in the ratio 2 : 2 : 1. X is allowed an annual salary of $10 000. Y has made a loan to the partnership on which the partnership pays interest of $5000 each year. Profit for the year before appropriations is $150 000. What is Z’s total appropriation of profit for the year? A $27 000 B $28 000 C $29 000 D $30 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2011
Q209 · There are 75 members of a tennis club, paying an annual subscription of $95 each 9706/13 Oct/Nov 2011
11 There are 75 members of a tennis club, paying an annual subscription of $95 each. The treasurer has provided the following information for the year. $ subscriptions received 7 305 overheads: tennis balls - purchased 850 - opening inventory 110 - closing inventory 95 other overheads 4 700 How much surplus will the club’s income and expenditure account for the year show? A $1560 B $1670 C $1740 D $1850
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2011
Q210 · A businessman marks up his cost of sales by 50 % 9706/13 Oct/Nov 2011
12 A businessman marks up his cost of sales by 50 %. At the end of his trading year the following data is available. $ opening inventory 5 000 closing inventory 4 000 ordinary goods purchased 35 000 What is his sales figure for the year? A $51 000 B $52 500 C $54 000 D $66 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2011
Q211 · The financial year of a manufacturer ends on 31 December 9706/13 Oct/Nov 2011
13 The financial year of a manufacturer ends on 31 December. Finished goods are valued at factory cost plus 20 %. The following information is available: 1 January 31 December $ $ inventory of finished goods 2400 3000 What is the amount to be deducted for the provision for unrealised profit in the income statement? A $100 B $120 C $500 D $600
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2011
Q212 · The following information relates to the non-current assets of a business formed three… 9706/13 Oct/Nov 2011
14 The following information relates to the non-current assets of a business formed three years ago. $ cost at start of year 1 10 000 accumulated depreciation at end of year 3 6 000 profit for year 3 18 000 Depreciation has been consistently charged using the straight line method. What would the profit be in year 3 if the method of depreciation for that year is changed to the reducing balance method at a rate of 25 %? A $16 500 B $17 500 C $18 500 D $19 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2011
Q213 · What could be used to fund a bonus issue of shares? 9706/13 Oct/Nov 2011
15 What could be used to fund a bonus issue of shares? 1 asset revaluation reserve 2 general reserve 3 retained earnings 4 share premium A 1 and 2 only B 1, 2 and 3 only C 1, 2, 3 and 4 D 2 and 3 only
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2011
Q214 · The following data is available for a business for the year ended 30 September 2010 9706/13 Oct/Nov 2011
19 The following data is available for a business for the year ended 30 September 2010. opening inventory $1 000 000 purchases for the year $2 500 000 closing inventory $1 500 000 mark up 50 % trade receivables collection period 60 days Sales are on credit and accrue evenly over a 360-day accounting period. What is the value of trade receivables at 30 September 2010? A $500 000 B $625 000 C $666 667 D $750 000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2011
Q215 · The principle of prudence in the preparation of financial statements is practised through… 9706/11 May/June 2012
3 The principle of prudence in the preparation of financial statements is practised through the application of which action? A create additional reserves B exclude unpaid credit sales C overstate the liabilities D provide for anticipated losses
1 marks
Answer: D
This question in 9706/11 May/June 2012
Q216 · What is evidence that a company’s financial statements are true and fair? 9706/11 May/June 2012
4 What is evidence that a company’s financial statements are true and fair? A The directors have signed off the financial statements. B The profit has been agreed with the tax authorities. C They are filed on time. D They follow generally accepted accounting principles.
1 marks
Answer: D
This question in 9706/11 May/June 2012
Q217 · The following items appear in the books of a builder 9706/11 May/June 2012
5 The following items appear in the books of a builder. $ rent of own home 3 000 rent of builder’s yard 2 500 housekeeping expenses 2 000 overalls 100 loose tools 300 equipment 3 000 lorries 1 500 rates on business premises 650 rent of business premises 3 500 assistant’s wages 3 000 What is the total business expenditure? A $11 250 B $14 550 C $16 550 D $19 550
1 marks
Answer: B
This question in 9706/11 May/June 2012
Q218 · A company’s accounts showed a gross profit for the year of $32 500 9706/11 May/June 2012
7 A company’s accounts showed a gross profit for the year of $32 500. After the draft financial statements were prepared it was found that the opening inventory had been overstated by $2400 and the closing inventory had been understated by $3400. What is the corrected gross profit for the year? A $26 700 B $31 500 C $33 500 D $38 300
1 marks
Answer: D
This question in 9706/11 May/June 2012
Q219 · A manufacturing company has the following information for the year ended 31 December 9706/11 May/June 2012
8 A manufacturing company has the following information for the year ended 31 December. $ purchase of raw materials 58 000 wages of machine operators 97 000 depreciation on factory plant 15 000 opening inventory of raw materials 10 000 closing inventory of raw materials 8 000 wages of factory supervisor 18 000 factory light and heating costs 22 000 What is the prime cost for the year? A $153 000 B $157 000 C $175 000 D $212 000
1 marks
Answer: B
This question in 9706/11 May/June 2012
Q220 · The table shows the assets and liabilities of a club 9706/11 May/June 2012
11 The table shows the assets and liabilities of a club. $ non-current assets 10 000 cash at bank 6 400 electricity owing 600 rent prepaid 900 subscriptions: in arrears 5 700 in advance 3 800 How much is the accumulated fund? A $14 200 B $14 800 C $18 000 D $18 600
1 marks
Answer: D
This question in 9706/11 May/June 2012
Q221 · The inventory records of a business show the following information for product X 9706/11 May/June 2012
13 The inventory records of a business show the following information for product X. cost per unit units $ 1 January opening balance 100 3 3 January receipts into inventory 50 4 8 January inventory issued 120 – What is the value of the inventory issued on 8 January using the first in first out (FIFO) method? A $360 B $380 C $410 D $420
1 marks
Answer: B
This question in 9706/11 May/June 2012
Q222 · The table shows opening and closing balances for the rent receivable account 9706/12 May/June 2012
2 The table shows opening and closing balances for the rent receivable account. start of year end of year $ $ rent received in advance 4200 1600 rent due in arrears 2000 2400 During the year, $111 000 rental income was received. What is the total rent receivable for the year? A $110 600 B $111 000 C $113 200 D $114 000
1 marks
Answer: D
This question in 9706/12 May/June 2012
Q223 · A company’s accounts showed a gross profit for the year of $32 500 9706/12 May/June 2012
8 A company’s accounts showed a gross profit for the year of $32 500. After the draft financial statements were prepared it was found that the opening inventory had been overstated by $2400 and the closing inventory had been understated by $3400. What is the corrected gross profit for the year? A $26 700 B $31 500 C $33 500 D $38 300
1 marks
Answer: D
This question in 9706/12 May/June 2012
Q224 · A manufacturing company has the following information for the year ended 31 December 9706/12 May/June 2012
9 A manufacturing company has the following information for the year ended 31 December. $ purchase of raw materials 58 000 wages of machine operators 97 000 depreciation on factory plant 15 000 opening inventory of raw materials 10 000 closing inventory of raw materials 8 000 wages of factory supervisor 18 000 factory light and heating costs 22 000 What is the prime cost for the year? A $153 000 B $157 000 C $175 000 D $212 000
1 marks
Answer: B
This question in 9706/12 May/June 2012
Q225 · Which statements about non-profit making organisations are correct? 9706/12 May/June 2012
12 Which statements about non-profit making organisations are correct? 1 A club or society may engage in trading activities. 2 A club or society may suffer bad debts. 3 Subscriptions are credited to the income and expenditure account in the year in which they are received. 4 The term ‘excess of expenditure over income’ replaces ‘profit for the year’. A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: A
This question in 9706/12 May/June 2012
Q226 · A business sells goods at cost plus 25 % 9706/12 May/June 2012
13 A business sells goods at cost plus 25 %. Information for a year is shown. $ revenue 240 000 opening inventory 42 000 closing inventory 48 000 What is the total of purchases for the year? A $180 000 B $186 000 C $192 000 D $198 000
1 marks
Answer: D
This question in 9706/12 May/June 2012
Q227 · A company has an issued share capital of 200 000 6 % cumulative preference shares of $1… 9706/12 May/June 2012
15 A company has an issued share capital of 200 000 6 % cumulative preference shares of $1 each fully paid and 800 000 ordinary shares of $1 each fully paid. Assuming that the company earns no profit in the year, which statement is correct? A Both preference and ordinary shares are paid a dividend in the year. B The unpaid dividends for both preference and ordinary shares are carried forward to a future year. C The unpaid preference dividend is carried forward to a future year. D The preference shares are paid a total dividend of $12 000 in the year.
1 marks
Answer: C
This question in 9706/12 May/June 2012
Q228 · The journal entry ‘Debit Subscription Income, Credit Creditors’ was made in the… 9706/13 May/June 2012
1 The journal entry ‘Debit Subscription Income, Credit Creditors’ was made in the accounting records of a club. What does this represent? A subscriptions owed by members B subscriptions received by cheque C subscriptions received in advance D subscriptions refunded to members
1 marks
Answer: C
This question in 9706/13 May/June 2012
Q229 · A business starts trading on 1 May 2011 9706/13 May/June 2012
2 A business starts trading on 1 May 2011. The table shows rent paid on the premises. date period $ 2 May 2011 1 May – 30 Jun 1 000 3 Jul 2011 1 Jul – 30 Sep 1 500 2 Oct 2011 1 Oct – 31 Dec 1 500 4 Jan 2012 1 Jan – 31 Mar 1 560 1 Apr 2012 1 Apr – 30 Jun 1 560 Which figure should be shown in the financial statements for prepaid rent on 30 April 2012? A $520 B $1 000 C $1 040 D $1 560
1 marks
Answer: C
This question in 9706/13 May/June 2012
Q230 · The following items appear in the books of a builder 9706/13 May/June 2012
6 The following items appear in the books of a builder. $ rent of own home 3 000 rent of builder’s yard 2 500 housekeeping expenses 2 000 overalls 100 loose tools 300 equipment 3 000 lorries 1 500 rates on business premises 650 rent of business premises 3 500 assistant’s wages 3 000 What is the total business expenditure? A $11 250 B $14 550 C $16 550 D $19 550
1 marks
Answer: B
This question in 9706/13 May/June 2012
Q231 · A business has a draft profit for the year of $84 000 9706/13 May/June 2012
8 A business has a draft profit for the year of $84 000. It is discovered that the closing inventory was overvalued by $4000 and that discounts received of $1500 were treated as an expense. What is the corrected profit for the year? A $81 500 B $83 000 C $89 500 D $91 000
1 marks
Answer: B
This question in 9706/13 May/June 2012
Q232 · What appears as a credit entry in the appropriation account of a partnership? 9706/13 May/June 2012
10 What appears as a credit entry in the appropriation account of a partnership? A goodwill B interest on capital C partnership salaries D trading profit for the year
1 marks
Answer: D
This question in 9706/13 May/June 2012
Q233 · In which account should a partner’s drawings appear in the partnership’s end-of-year… 9706/13 May/June 2012
11 In which account should a partner’s drawings appear in the partnership’s end-of-year financial statements? A appropriation account B income statement C partner’s capital account D partner’s current account
1 marks
Answer: D
This question in 9706/13 May/June 2012
Q234 · The table shows the assets and liabilities of a club 9706/13 May/June 2012
12 The table shows the assets and liabilities of a club. $ non-current assets 10 000 cash at bank 6 400 electricity owing 600 rent prepaid 900 subscriptions: in arrears 5 700 in advance 3 800 How much is the accumulated fund? A $14 200 B $14 800 C $18 000 D $18 600
1 marks
Answer: D
This question in 9706/13 May/June 2012
Q235 · The table shows transactions relating to a product during July 9706/13 May/June 2012
14 The table shows transactions relating to a product during July. units $ (per unit) purchased 50 4 sold 30 10 Of the remaining units, 8 are damaged and therefore worthless. What is the profit for July? A $68 B $100 C $148 D $180
1 marks
Answer: C
This question in 9706/13 May/June 2012
Q236 · A business makes up its financial statements to 30 April each year 9706/11 Oct/Nov 2012
1 A business makes up its financial statements to 30 April each year. Included in the ledger account balances on 1 May 2011 was insurance (debit) $800. On 31 October 2011 an insurance premium of $2100 was paid for the year ending 31 October 2012. Which amount was charged for insurance in the income statement for the year ended 30 April 2012? A $1050 B $1850 C $2100 D $2900
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2012
Q237 · A business increases its provision for doubtful debts by $1600 9706/11 Oct/Nov 2012
2 A business increases its provision for doubtful debts by $1600. What will be the effect of this adjustment on the financial statements? profit for the year trade receivables (net) A decrease by $1600 decrease by $1600 B decrease by $1600 increase by $1600 C increase by $1600 decrease by $1600 D increase by $1600 increase by $1600
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2012
Q238 · The dividends receivable account shows dividends of $7500 received during the year 9706/11 Oct/Nov 2012
3 The dividends receivable account shows dividends of $7500 received during the year. Dividends of $1200 are due at the year end. How will dividends be shown in the financial statements? statement of income statement $ $ financial position A credit 7500 other receivables 1200 B credit 8700 other receivables 1200 C debit 7500 other payables 1200 D debit 8700 other payables 1200
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2012
Q239 · Which statement is correct? 9706/11 Oct/Nov 2012
4 Which statement is correct? A All reserves are created by a transfer from retained earnings. B Revaluation reserves appear in the non-current assets section of the statement of financial position. C Some reserves are treated as current liabilities at the financial year end. D Total reserves form part of shareholders’ equity.
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2012
Q240 · A trader provided the following information 9706/11 Oct/Nov 2012
6 A trader provided the following information. $ gross profit 3 000 motor expenses for repairs to private motor car 500 wages paid to staff 1 000 rent paid for premises 600 interest on home loan 700 What is the profit for the year? A $200 B $700 C $900 D $1400
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2012
Q241 · Alfredo received his bank statement which showed a balance of $937 overdrawn 9706/11 Oct/Nov 2012
8 Alfredo received his bank statement which showed a balance of $937 overdrawn. This did not agree with his cash book. On investigation he noted the following. • Bank charges of $76 had not been entered in the cash book. • There was an unpresented cheque of $214. • Alfredo had paid $35 cash into his bank account but this was not showing on the statement. At which value was the bank overdraft shown in the statement of financial position? A $758 B $937 C $1116 D $1192
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2012
Q242 · A manufacturer has inventories of 1 finished goods 2 work-in-progress 3 raw materials… 9706/11 Oct/Nov 2012
11 A manufacturer has inventories of 1 finished goods 2 work-in-progress 3 raw materials Which inventories appear in the manufacturing account? A 1 and 2 only B 1 and 3 only C 1, 2 and 3 D 2 and 3 only
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2012
Q243 · A company discovers that its opening inventory was overvalued by $30 000 9706/11 Oct/Nov 2012
12 A company discovers that its opening inventory was overvalued by $30 000. Which effect will the correction of this error have on the financial statements for the year? profit for closing the year inventory A – $30 000 nil B nil – $30 000 C + $30 000 nil D + $30 000 – $30 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2012
Q244 · X and Y are in partnership 9706/11 Oct/Nov 2012
14 X and Y are in partnership. Their income statement and appropriation account shows the following. $ depreciation of non-current assets 5 000 interest on loan from Y 600 interest on capital 2 400 interest charged on drawings 900 partners’ salaries 5 000 residual profit 12 000 What is the profit for the year before any appropriations? A $18 500 B $19 100 C $20 300 D $25 900
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2012
Q245 · The committee of a sports club decided to introduce a life membership scheme 9706/11 Oct/Nov 2012
15 The committee of a sports club decided to introduce a life membership scheme. The cost of life membership was $200, to be transferred to the income and expenditure account over a twenty–year period. Seven members took up life membership in the first year. Which values would be shown in the financial statements at the end of year 1? income and current deferred expenditure account liabilities income $ $ $ A nil nil 1400 B 70 nil 1330 C 70 70 1260 D 1400 nil nil
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2012
Q246 · A company commences business on 1 April 9706/11 Oct/Nov 2012
16 A company commences business on 1 April. It buys the following units of inventory. date quantity unit cost 1 April 200 $250 1 September 400 $200 1 December 200 $300 During the year, it sells 500 units at $550 each. What is the gross profit for the year using the FIFO method of inventory valuation? A $85 000 B $155 000 C $156 250 D $165 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2012
Q247 · A business buys a vehicle for $10 000 on 1 January Year 1 and sells it for $6500 on 1… 9706/11 Oct/Nov 2012
18 A business buys a vehicle for $10 000 on 1 January Year 1 and sells it for $6500 on 1 January Year 3, having depreciated it at 10 % a year using the straight line method. The company provides a full year’s depreciation in the year of purchase and none in the year of disposal. Which amount for profit or loss will appear in the disposal account and on what side of the disposal account will it be shown? A $1500 on the credit side B $1500 on the debit side C $2500 on the credit side D $2500 on the debit side
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2012
Q248 · A company raises cash by issuing 8 % debentures 9706/11 Oct/Nov 2012
19 A company raises cash by issuing 8 % debentures. What is the effect on the company’s profits and net current assets in the year of issue? profits net current assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2012
Q249 · A company is financed by 25 000 $1 ordinary shares 9706/11 Oct/Nov 2012
20 A company is financed by 25 000 $1 ordinary shares. The company wishes to finance expansion by issuing 5000 $1 ordinary shares at a premium of $0.20 and $10 000 debentures. What will be the new equity figure in the statement of financial position? A $30 000 B $31 000 C $40 000 D $41 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2012
Q250 · Rent for premises is paid monthly in advance on the first day of each month 9706/12 Oct/Nov 2012
1 Rent for premises is paid monthly in advance on the first day of each month. The payments during the last financial year were as follows. up to and including 1 January $1000 per month from 1 February $1200 per month Which amount(s) will appear in the financial statements for the year ended 30 April? statement of income statement financial position A $12 400 – B $12 600 – C $12 600 $1200 accrual D $12 600 $1200 prepaid
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2012
Q251 · The following items appear in a statement of financial position 9706/12 Oct/Nov 2012
3 The following items appear in a statement of financial position. • an estimate of a liability in a court case, the outcome of which is uncertain • an unrealised surplus from the revaluation of a non-current asset • accumulated depreciation on non-current assets • an estimate of future loss arising from bad debts How many of these are provisions and how many are reserves? provisions reserves A 1 3 B 2 2 C 3 1 D 4 0
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2012
Q252 · A trial balance shows the following information 9706/12 Oct/Nov 2012
4 A trial balance shows the following information. $ premises at cost 150 000 accumulated depreciation on premises 25 000 On 1 January the premises are revalued at $270 000. At the same time 200 000 shares of $1 each are issued for $300 000. What is the value of the reserves created on 1 January? A $120 000 B $145 000 C $220 000 D $245 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2012
Q253 · Draft financial statements show revenue of $106 000 and closing inventory of $2100 9706/12 Oct/Nov 2012
6 Draft financial statements show revenue of $106 000 and closing inventory of $2100. There were 100 items which had cost $10 an item but which were for sale at $6 an item. At the year end these were with a customer on a sale or return basis. These items were treated as having been sold although no sale had been agreed. What are the values of revenue and inventory when the principle of prudence is applied? revenue inventory $ $ A 105 000 2700 B 105 000 3100 C 105 400 2700 D 105 400 3100
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2012
Q254 · A draft income statement shows a profit for the year of $360 000 9706/12 Oct/Nov 2012
10 A draft income statement shows a profit for the year of $360 000. Interest received for the year of $1200 has been treated as interest paid. What is the correct profit? A $357 600 B $358 800 C $361 200 D $362 400
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2012
Q255 · Which item appears in the financial statements of a limited company but not in those of a… 9706/12 Oct/Nov 2012
13 Which item appears in the financial statements of a limited company but not in those of a sole trader or partnership? A dividends paid B other payables C other receivables D trade payables
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2012
Q256 · Which items would appear in a partnership’s appropriation account? 9706/12 Oct/Nov 2012
14 Which items would appear in a partnership’s appropriation account? 1 partners’ interest on capital 2 partners’ introduction of new capital 3 salaries of employees 4 salaries of partners A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2012
Q257 · The following information relates to the annual membership subscriptions of a cricket… 9706/12 Oct/Nov 2012
15 The following information relates to the annual membership subscriptions of a cricket club for the year ended 31 December. 1 January 31 December $ $ subscriptions in arrears 7200 7800 subscriptions paid in advance 2800 4200 Cash received during the year for subscriptions totalled $81 000. Which amount should be shown in the income and expenditure account for membership subscriptions? A $80 200 B $81 000 C $81 600 D $81 800
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2012
Q258 · A business does not keep complete accounting records 9706/12 Oct/Nov 2012
16 A business does not keep complete accounting records. The following information is known: $ capital at start of year 52 000 capital at end of year 55 000 owner’s drawings in year 13 000 capital introduced during the year 25 000 What is the profit/loss for the year? A loss $9000 B profit $9000 C loss $15 000 D profit $15 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2012
Q259 · The table shows information relating to closing inventory 9706/12 Oct/Nov 2012
17 The table shows information relating to closing inventory. $ cost 50 000 realisable value 45 000 costs of realisation 5 000 replacement cost 35 000 What is the value of the closing inventory? A $35 000 B $40 000 C $45 000 D $50 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2012
Q260 · A company has issued non-cumulative preference shares and ordinary shares 9706/12 Oct/Nov 2012
19 A company has issued non-cumulative preference shares and ordinary shares. Which statement is correct? A If no preference dividend is paid, it is carried forward to a future year. B Preference shareholders always get a dividend. C Preference shareholders and ordinary shareholders always get a dividend. D Preference shareholders may get a dividend.
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2012
Q261 · A company has an authorised share capital of 1 000 000 $0.50 ordinary shares 9706/12 Oct/Nov 2012
20 A company has an authorised share capital of 1 000 000 $0.50 ordinary shares. Its issued share capital is 800 000 shares. An ordinary dividend of 7½ % is declared. How much is payable to the shareholders? A $30 000 B $37 500 C $60 000 D $75 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2012
Q262 · Which of these statements are correct? 9706/13 Oct/Nov 2012
4 Which of these statements are correct? 1 A share premium account is classified as a reserve. 2 A revaluation reserve may be negative if a non-current asset decreases in value. A 1 only B 2 only C both 1 and 2 D neither 1 nor 2
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2012
Q263 · A company’s income statement includes the following 9706/13 Oct/Nov 2012
13 A company’s income statement includes the following. $000 dividend 300 increase in inventory 200 overheads 400 ordinary goods purchased 800 If the net profit percentage is 20 %, what is the figure for revenue? A $1 120 000 B $1 250 000 C $1 625 000 D $1 750 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2012
Q264 · Details of a company’s inventory are shown in the table 9706/13 Oct/Nov 2012
16 Details of a company’s inventory are shown in the table. inventory item X Y Z $ $ $ cost 500 600 800 selling expenses 100 200 300 sales value 700 700 700 Which figure for inventory should be shown in the accounts? A $1400 B $1700 C $1800 D $1900
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2012
Q265 · A business was started on 1 January 9706/13 Oct/Nov 2012
17 A business was started on 1 January. The purchases and sales of inventory for January were: date purchases sales 4 January 3 @ $200 – 13 January – 2 @ $400 26 January 3 @ $250 – 28 January – 2 @ $400 The business used the first in first out (FIFO) method of inventory valuation. What was the gross profit for January? A $250 B $650 C $700 D $750
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2012
Q266 · The profits of Bronte Ltd are: Year ended 31 December 2010 nil Year ended 31 December… 9706/13 Oct/Nov 2012
19 The profits of Bronte Ltd are: Year ended 31 December 2010 nil Year ended 31 December 2011 $60 000 Bronte Ltd has in issue 200 000 5% preference shares of $1 each. What is the profit available for distribution to ordinary shareholders for the year ended 31 December 2011, if the preference shares are (i) cumulative or (ii) non-cumulative? (ii) Non - (i) Cumulative cumulative A $40 000 $40 000 B $40 000 $50 000 C $50 000 $40 000 D $50 000 $50 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2012
Q267 · A club’s income and expenditure account for 2012 showed rent and rates of $4000 9706/11 May/June 2013
4 A club’s income and expenditure account for 2012 showed rent and rates of $4000. On 31 December 2012 rent owing was $600 and rates paid in advance was $800. What was the amount shown in the receipts and payments account for rent and rates for the year ended 31 December 2012? A $3800 B $4000 C $4200 D $5400
1 marks
Answer: C
This question in 9706/11 May/June 2013
Q268 · At the beginning of the year a business has a provision for doubtful debts of $2600 9706/11 May/June 2013
5 At the beginning of the year a business has a provision for doubtful debts of $2600. At the year end the provision is to be 5% of trade receivables. The balance on the sales ledger control account at the year end is $69 200, before writing off a bad debt of $480. The business operates a separate bad debts account. What is the entry in the income statement for the provision for doubtful debts? A $836 credit B $836 debit C $860 credit D $860 debit
1 marks
Answer: B
This question in 9706/11 May/June 2013
Q269 · A trader has two departments in his clothes store – men’s and women’s 9706/11 May/June 2013
16 A trader has two departments in his clothes store – men’s and women’s. The following information is available. men’s women’s sales staff (number) 7 13 floor space 81 m2 99 m2 value of non-current assets $90 000 $135 000 annual sales $247 000 $403 000 The cost of advertising and distribution is $68 100. What is the cost for advertising and distribution for the men’s department? A $23 835 B $25 878 C $27 240 D $30 645
1 marks
Answer: B
This question in 9706/11 May/June 2013
Q270 · What do the reserves of limited companies include? 9706/11 May/June 2013
20 What do the reserves of limited companies include? A debentures B ordinary shares C preference shares D share premium
1 marks
Answer: D
This question in 9706/11 May/June 2013
Q271 · The following information has been extracted from the statement of financial position of… 9706/11 May/June 2013
24 The following information has been extracted from the statement of financial position of a limited company. $ 6% debenture (2016 – 2018) 20 000 ordinary share capital issued – 400 000 ordinary shares of $1 each 400 000 5% preference shares of $1 each 200 000 share premium account 50 000 retained earnings 75 000 What is the value of the shareholders’ equity? A $525 000 B $545 000 C $695 000 D $725 000
1 marks
Answer: A
This question in 9706/11 May/June 2013
Q272 · A business paid $5750 during its trading year for advertising 9706/12 May/June 2013
2 A business paid $5750 during its trading year for advertising. Part of this amount included $500 in respect of the next financial year. Which effects would the correct treatment of the $500 have on the financial statements? profit for net current the year assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: D
This question in 9706/12 May/June 2013
Q273 · A rents its building to B 9706/12 May/June 2013
3 A rents its building to B. At 31 December 2011, B owed $4500 for rent. At 31 December 2012, B had paid $3200 in advance. During the year A had received $17 100 in rental from B. What is the rental income to be shown in A’s income statement for the year ended 31 December 2012? A $9400 B $15 800 C $18 400 D $24 800
1 marks
Answer: A
This question in 9706/12 May/June 2013
Q274 · The draft financial statements of a business show a profit for the year of $64 000 before… 9706/12 May/June 2013
4 The draft financial statements of a business show a profit for the year of $64 000 before taking account of the following. 1 the reduction of the provision for doubtful debts by $300 2 the purchase of office stationery costing $2400 which has not been entered in the records; only one sixth of this stationery was used by the year end What is the corrected profit for the year? A $61 900 B $63 900 C $64 100 D $64 300
1 marks
Answer: B
This question in 9706/12 May/June 2013
Q275 · The summarised statements of financial position for a business for two years are as… 9706/12 May/June 2013
12 The summarised statements of financial position for a business for two years are as follows. year 1 year 2 $ $ non-current assets 9 000 12 000 current assets 6 000 8 000 less current liabilities (5 000) (6 000) net assets 10 000 14 000 The drawings in year 1 were $5000 and in year 2 $3000. What is the profit for year 2? A $1000 B $4000 C $5000 D $7000
1 marks
Answer: D
This question in 9706/12 May/June 2013
Q276 · The wages of staff employed in manufacturing goods have been debited in the income… 9706/12 May/June 2013
13 The wages of staff employed in manufacturing goods have been debited in the income statement. What is the effect of this error? gross profit profit for the year A overstated no effect B overstated overstated C understated no effect D understated understated
1 marks
Answer: A
This question in 9706/12 May/June 2013
Q277 · During the year ended 31 December 2012 a business made a profit of $31 000 9706/12 May/June 2013
14 During the year ended 31 December 2012 a business made a profit of $31 000. A dividend of 8% was paid on the 200 000 ordinary shares of $0.50 each, and $12 000 was transferred to general reserve. The retained earnings of the business on 31 December 2012 amounted to $68 000. What was the balance of retained earnings on 1 January 2012? A $41 000 B $57 000 C $65 000 D $79 000
1 marks
Answer: B
This question in 9706/12 May/June 2013
Q278 · A business sells some inventory for $80 on credit 9706/12 May/June 2013
17 A business sells some inventory for $80 on credit. This originally cost $50. How does this affect the statement of financial position? current assets owner’s capital A decrease by $30 decreases by $30 B decrease by $30 increases by $30 C increase by $30 decreases by $30 D increase by $30 increases by $30
1 marks
Answer: D
This question in 9706/12 May/June 2013
Q279 · An extract from a statement of financial position is as follows 9706/12 May/June 2013
20 An extract from a statement of financial position is as follows. $ ordinary share capital 50 000 general reserve 10 000 retained earnings 4 000 10% debentures 20 000 What is the value of the shareholders’ funds? A $50 000 B $54 000 C $64 000 D $80 000
1 marks
Answer: C
This question in 9706/12 May/June 2013
Q280 · Which item would result in a credit entry in an income statement? 9706/13 May/June 2013
1 Which item would result in a credit entry in an income statement? A an increase in the provision for doubtful debts B a reduction in the provision for doubtful debts C the creation of a provision for doubtful debts D the writing off of a trade receivable
1 marks
Answer: B
This question in 9706/13 May/June 2013
Q281 · A business prepares its financial statements on 31 December 9706/13 May/June 2013
2 A business prepares its financial statements on 31 December. Insurance premiums paid were as follows. date period covered $ January 2012 1 July 2011 to 31 December 2011 940 July 2012 1 January 2012 to 30 June 2012 1120 January 2013 1 July 2012 to 31 December 2012 1245 March 2013 1 January 2013 to 30 June 2013 1880 Which amount should be shown in the income statement for the year ended 31 December 2012? A $1120 B $2060 C $2365 D $3305
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q282 · A company has the following balances 9706/13 May/June 2013
3 A company has the following balances. $ trade receivables at 31 December 2012 125 400 provision for doubtful debts at 1 January 2012 1 800 During the year ended 31 December 2012 bad debts of $20 500 had been written off. The company provides for 5% of trade receivables at each year end. What is the doubtful debts expense for the year ended 31 December 2012? A $3445 B $4470 C $5245 D $6270
1 marks
Answer: B
This question in 9706/13 May/June 2013
Q283 · The table shows information relating to the non-current assets of a business 9706/13 May/June 2013
4 The table shows information relating to the non-current assets of a business. $ net book value at the beginning of year 28 000 net book value at end of year 25 000 depreciation charge for the year 4 000 disposals at net book value 9 000 What is the cost of non-current asset additions? A $2000 B $6000 C $10 000 D $16 000
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q284 · The table shows balances at the end of a year 9706/13 May/June 2013
5 The table shows balances at the end of a year. $ expenses prepaid 6 000 expenses accrued 4 000 bank overdraft 11 500 trade payables 13 400 trade receivables 10 500 loan (2017) 20 000 What is the total of current liabilities? A $16 500 B $17 400 C $28 900 D $48 900
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q285 · On 1 July 2012, a business shows an accrual on the rent account of $600 9706/13 May/June 2013
6 On 1 July 2012, a business shows an accrual on the rent account of $600. During the following year, payments were made for rent as detailed below. $ 26 July 2012 paid 3 months rent to 31 July 2012 900 11 November 2012 paid 4 months rent to 30 November 2012 1 200 15 March 2013 paid 4 months rent to 31 March 2013 1 200 In preparing the rent account for the year ending 30 June 2013, which amount is to be shown as a prepayment or accrual for rent at that date? A $600 accrual B $600 prepayment C $900 accrual D $900 prepayment
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q286 · Closing inventory has been overvalued 9706/13 May/June 2013
7 Closing inventory has been overvalued. What is the effect on the financial statements? net current assets profit for the year A no effect understated B overstated no effect C overstated overstated D understated understated
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q287 · A draft income statement shows a profit for the year of $75 000 9706/13 May/June 2013
11 A draft income statement shows a profit for the year of $75 000. Discounts allowed of $4000 have been treated as discounts received and discounts received of $7000 have been treated as discounts allowed. What is the correct profit? A $69 000 B $72 000 C $78 000 D $81 000
1 marks
Answer: D
This question in 9706/13 May/June 2013
Q288 · L and M are in partnership 9706/13 May/June 2013
13 L and M are in partnership. Which item should appear in the partnership appropriation account? A additional capital contributed by M B cash drawings of L and M during the year C salary due to L D salary paid to M’s wife
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q289 · A new business was established with opening capital of $15 000 9706/13 May/June 2013
14 A new business was established with opening capital of $15 000. At the end of the year net assets were $20 000. During the year the proprietor’s drawings were $3000 and this resulted in an overdraft at the end of the year of $4000. What was the profit for the year? A $2000 B $5000 C $7000 D $8000
1 marks
Answer: D
This question in 9706/13 May/June 2013
Q290 · The manufacturing account of a business includes the following 9706/13 May/June 2013
15 The manufacturing account of a business includes the following. $ prime costs 143 260 production overheads 92 170 opening work-in-progress 5 720 closing work-in-progress 6 840 opening inventory of finished goods 29 480 closing inventory of finished goods 25 990 What was the cost of production? A $234 310 B $235 430 C $236 550 D $237 800
1 marks
Answer: A
This question in 9706/13 May/June 2013
Q291 · S and T are in partnership sharing profits and losses in the ratio 3 : 2 9706/13 May/June 2013
16 S and T are in partnership sharing profits and losses in the ratio 3 : 2. Their fixed capital accounts have balances of S $80 000 and T $60 000. Interest is allowed on these at the rate of 6% per year. Profit for the year was $100 000. What is the division of profits between the partners? S T $ $ A 49 400 50 600 B 50 600 49 400 C 59 760 40 240 D 60 000 40 000
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q292 · A business sells inventory at a mark up of 20% 9706/13 May/June 2013
18 A business sells inventory at a mark up of 20%. Some inventory has been stolen. The following information is available. 1 January 2012 31 December 2012 $ $ inventory 6 000 5 000 purchases for the year 101 000 revenue 120 000 What was the value of the inventory stolen? A $1000 B $1200 C $2000 D $6000
1 marks
Answer: C
This question in 9706/13 May/June 2013
Q293 · ABC Ltd purchased a non-current asset for $35 000 on 1 April 2009 and sold it on 1… 9706/13 May/June 2013
19 ABC Ltd purchased a non-current asset for $35 000 on 1 April 2009 and sold it on 1 October 2012 for $14 500. The company’s year end is 31 December and their policy is to make no charge for depreciation in the year of disposal but a full year’s charge in the year of purchase. The company uses the reducing balance method at the rate of 25% per annum. What is the profit or loss made, to the nearest $, on the disposal of the asset? A $265 loss B $265 profit C $5188 loss D $5188 profit
1 marks
Answer: A
This question in 9706/13 May/June 2013
Q294 · The following is an extract from the statement of financial position of a company 9706/13 May/June 2013
20 The following is an extract from the statement of financial position of a company. $ ordinary shares of $0.25 each 35 000 6% cumulative preference shares 40 000 No dividend was paid on the preference shares last year but the directors propose to pay a dividend this year. The directors also propose a final ordinary share dividend of $0.05 per share. What is the amount of dividends to be paid? cumulative ordinary shares preference shares $ $ A 1750 2400 B 1750 4800 C 7000 2400 D 7000 4800
1 marks
Answer: D
This question in 9706/13 May/June 2013
Q295 · On 1 January 2012 a business had prepaid rent of $50 9706/11 Oct/Nov 2013
3 On 1 January 2012 a business had prepaid rent of $50. During 2012, it made three rent payments of $250 each. On 31 December 2012, the business owed $200 rent for 2012. The business owner only charged the rent payments made during 2012 in the income statement. What is the effect on profit for the year? A $200 overstated B $200 understated C $250 overstated D $250 understated
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2013
Q296 · The following information is extracted from the statement of financial position of a… 9706/11 Oct/Nov 2013
6 The following information is extracted from the statement of financial position of a business. $ bank loan (repayable 2019) 16 200 bank loan interest owing 1 880 bank overdraft 11 600 capital 20 710 drawings 19 100 inventory 14 610 prepayments 1 420 trade payables 14 110 trade receivables 9 050 What is the value of the net current liabilities? A $1590 B $2510 C $18 710 D $20 320
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2013
Q297 · A trader provides the following financial information for the year 9706/11 Oct/Nov 2013
11 A trader provides the following financial information for the year. $ direct costs 210 000 indirect costs 55 000 increase in work in progress 7 000 raw materials taken for own use 2 000 Which figures should appear in the manufacturing account? transfer to trading account prime cost overheads of income statement $ $ $ A 208 000 55 000 256 000 B 208 000 55 000 270 000 C 210 000 53 000 256 000 D 210 000 53 000 270 000
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2013
Q298 · Which item appears in a company’s income statement? 9706/11 Oct/Nov 2013
12 Which item appears in a company’s income statement? A dividends B inventory C trade payables D transfer to reserves
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2013
Q299 · The table shows the following balances for a business 9706/11 Oct/Nov 2013
13 The table shows the following balances for a business. start end of year of year $ $ inventory 6 000 9 000 trade payables 8 000 10 000 Total payments to trade payables were $20 000. What is the cost of sales for the year? A $15 000 B $19 000 C $21 000 D $25 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2013
Q300 · X and Y are in partnership sharing residual profits and losses in the ratio 7 : 3 9706/11 Oct/Nov 2013
14 X and Y are in partnership sharing residual profits and losses in the ratio 7 : 3. Their fixed capital accounts have balances of X $40 000; Y $60 000. Interest is allowed on these at the rate of 10% per year. X is paid a salary of $40 000 per year. Profit for the year was $200 000. What was the division of profits between the partners? X Y $ $ A 137 000 63 000 B 140 000 60 000 C 149 000 51 000 D 152 000 48 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2013
Q301 · A trader provides the following information 9706/11 Oct/Nov 2013
16 A trader provides the following information. $ opening inventory 6 000 closing inventory 4 000 purchases 15 000 He uses a uniform gross profit margin of 20%. What was the sales figure for the trading period? A $16 250 B $18 750 C $20 400 D $21 250
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2013
Q302 · A club supplies refreshments for its members at a uniform gross profit margin of 30% 9706/11 Oct/Nov 2013
17 A club supplies refreshments for its members at a uniform gross profit margin of 30%. The following information is available. $ receipts 62 000 opening inventory 10 000 purchases 45 000 What is the value of closing inventory? A $10 000 B $11 600 C $16 500 D $18 600
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2013
Q303 · The following information has been taken from the books of accounts of a limited company… 9706/11 Oct/Nov 2013
19 The following information has been taken from the books of accounts of a limited company for the year ended 31 December 2012. $ bank loan interest for the year 1 650 bank overdraft interest for the year 2 150 ordinary dividends paid during the year 900 8% debenture taken out on 1 October 2012 30 000 What are the total finance costs in the income statement for the year ended 31 December 2012? A $4400 B $4700 C $5300 D $6200
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2013
Q304 · A company has 1 000 000 ordinary shares of $1 issued at $2.50 9706/11 Oct/Nov 2013
20 A company has 1 000 000 ordinary shares of $1 issued at $2.50. It also has a 5% debenture of $300 000. Profit from operations for the year was $465 000. The directors paid an 8% ordinary dividend during the year. What is the retained profit for the year? A $250 000 B $370 000 C $385 000 D $400 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2013
Q305 · The following information is taken from a trader’s statement of financial position 9706/12 Oct/Nov 2013
1 The following information is taken from a trader’s statement of financial position. $ non-current assets 80 000 capital at start of year 75 000 drawings 16 000 profit for the year 13 000 non-current liability 6 000 current assets 12 700 What is the amount of trade payables? A $8700 B $11 700 C $14 700 D $26 700
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2013
Q306 · A business wishes to create a new provision for doubtful debts 9706/12 Oct/Nov 2013
2 A business wishes to create a new provision for doubtful debts. Which effect will this have in the financial statements of the business? in the income in the statement of statement financial position A increase profit increase current assets B increase profit reduce current liabilities C reduce profit increase current liabilities D reduce profit reduce current assets
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2013
Q307 · An item can be converted easily into cash 9706/12 Oct/Nov 2013
6 An item can be converted easily into cash. In which section of the statement of financial position would this item appear? A capital B current assets C current liabilities D non-current assets
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2013
Q308 · During the month a company lost a quantity of inventory in a burglary 9706/12 Oct/Nov 2013
11 During the month a company lost a quantity of inventory in a burglary. The table shows the company’s results for the month. $ opening trading inventory, at cost 30 000 purchases 210 000 revenue 330 000 closing trading inventory, at cost 4 000 A gross profit on all sales of 30% has been achieved. What was the cost of the inventory lost in the burglary? A $4000 B $5000 C $9000 D $13 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2013
Q309 · During the financial year a business receives $620 000 from its trade receivables after… 9706/12 Oct/Nov 2013
12 During the financial year a business receives $620 000 from its trade receivables after allowing cash discounts of $30 000. At the start of the year trade receivables owed $47 000. At the end of the year trade receivables owed $40 000. What was the amount of credit sales made during the year? A $613 000 B $627 000 C $643 000 D $657 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2013
Q310 · A business had a profit for the year of $450 000 before correcting the following errors 9706/12 Oct/Nov 2013
13 A business had a profit for the year of $450 000 before correcting the following errors. 1 Closing inventory was undervalued by $15 000. 2 Sales returns of $5000 had been recorded as purchases returns. 3 The charge for depreciation was overstated by $20 000. What was the corrected profit? A $435 000 B $445 000 C $475 000 D $495 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2013
Q311 · The following departmental accounts have been prepared for a limited company for the year… 9706/12 Oct/Nov 2013
14 The following departmental accounts have been prepared for a limited company for the year ended 30 September 2013. department X department Y $ $ revenue 810 000 515 000 cost of sales 470 000 265 000 gross profit 340 000 250 000 overheads 210 000 295 000 profit / (loss) for the year 130 000 (45 000) The following errors have been found. 1 Department X overheads include $10 000 for the purchase of goods for resale of department X. 2 Revenue of $40 000 has been credited to department X when it should have been credited to department Y. What is the corrected profit for the year for department X? A $80 000 B $90 000 C $100 000 D $170 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2013
Q312 · A company has the following expenses for the year 9706/12 Oct/Nov 2013
15 A company has the following expenses for the year. $ directors’ salaries 140 000 depreciation of delivery vehicles 87 000 office salaries 90 000 loan interest 33 000 discounts allowed 12 000 What is the total of the administration overheads? A $242 000 B $263 000 C $329 000 D $362 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2013
Q313 · Which items appear in the manufacturing account of a business? 9706/12 Oct/Nov 2013
16 Which items appear in the manufacturing account of a business? 1 closing inventory of finished goods 2 closing inventory of work in progress 3 carriage inwards 4 carriage outwards A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2013
Q314 · A club has 190 members 9706/12 Oct/Nov 2013
18 A club has 190 members. The club charges an annual subscription of $240 per member. At the start of the year, 11 members had paid their subscriptions for the current year in advance. At the end of the year, 8 members had paid their subscriptions for the next year in advance, but 3 members had not yet paid their current year subscriptions. Which figures are recorded in the current year? income and receipts and expenditure account payments account $ $ A 44 160 45 600 B 45 600 44 160 C 45 600 41 760 D 41 760 45 600
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2013
Q315 · The following financial information was provided at 31 December 2012 9706/12 Oct/Nov 2013
19 The following financial information was provided at 31 December 2012. $ purchases 95 000 returns inwards 3 300 returns outwards 2 100 inventory withdrawn for personal use 5 000 Inventory on 31 December 2012 was valued at $1000 more than on 1 January 2012. What was the cost of sales? A $85 700 B $86 900 C $89 000 D $97 100
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2013
Q316 · The table shows extracts from the trial balance of a business at 31 December 2012 9706/12 Oct/Nov 2013
22 The table shows extracts from the trial balance of a business at 31 December 2012. $ ordinary share capital 20 000 share premium 40 000 long-term loan (repayable 2022) 30 000 bank overdraft 60 000 4% non-redeemable preference share capital 50 000 7% debentures 2017 70 000 What is the total of non-current liabilities in the statement of financial position? A $100 000 B $150 000 C $160 000 D $210 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2013
Q317 · A company calculates a draft profit for the year of $98 000 9706/13 Oct/Nov 2013
2 A company calculates a draft profit for the year of $98 000. This includes the profit margin of $3000 on goods sold on credit but not yet paid for. It also includes $500 profit taken on goods sold to a customer on a sale or return basis. What is the correct gross profit? A $94 500 B $95 000 C $97 500 D $98 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2013
Q318 · A trader provides the following information 9706/13 Oct/Nov 2013
3 A trader provides the following information. $ prepaid rates at 1 October 2012 400 rent and rates paid during the year 16 200 accrued rates at 30 September 2013 600 prepaid rent at 30 September 2013 1 200 Which charge for rent and rates appears in the income statement for the year ended 30 September 2013? A $15 200 B $16 000 C $16 400 D $17 200
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2013
Q319 · At the beginning of the year a company has a provision for doubtful debts of $1000 9706/13 Oct/Nov 2013
5 At the beginning of the year a company has a provision for doubtful debts of $1000. At the end of the year the required provision is $2500. During the year debts of $1500 are written off and $100 is received in respect of a debt written off many years ago. What is the net amount charged to the income statement for bad and doubtful debts? A $1500 B $2500 C $2900 D $3000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2013
Q320 · On 30 September 2012 a manufacturer’s current assets totalled $28 000 9706/13 Oct/Nov 2013
8 On 30 September 2012 a manufacturer’s current assets totalled $28 000. The next day, only two transactions took place. 1 Inventory was bought for cash. The price of $2000 was subject to a trade discount of 20% and a cash discount of 5%. Payment was made immediately. 2 A bad debt of $400 was written off. What was the total of current assets on 2 October 2012? A $27 680 B $28 080 C $29 520 D $29 600
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2013
Q321 · The table shows information from the books of a business at 30 April 2013 9706/13 Oct/Nov 2013
9 The table shows information from the books of a business at 30 April 2013. details $ credit sales invoiced during financial year 79 000 goods sent to customers on 28 April 2013 and invoiced 4 May 2013 6 100 goods sent to customers during April 2013 on sale or return basis but 8 300 not sold by 30 April 2013 What is the value of sales for the year ended 30 April 2013? A $76 800 B $85 100 C $87 300 D $93 400
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2013
Q322 · The following information relates to a company’s non-current assets at 31 December 9706/13 Oct/Nov 2013
10 The following information relates to a company’s non-current assets at 31 December. cost price disposal value $ $ motor vehicles 25 000 18 000 equipment 48 000 36 000 fixtures and fittings 12 000 5 000 The company has a serious cash shortage and will cease to trade within the next two months. What is the total value for non-current assets in the company’s statement of financial position at 31 December? A $26 000 B $59 000 C $85 000 D $144 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2013
Q323 · Which group of items are included in the prime cost? 9706/13 Oct/Nov 2013
15 Which group of items are included in the prime cost? A inventories of finished goods, purchases of raw materials, direct wages B inventories of raw materials, purchases of raw materials, direct wages C inventories of raw materials, purchases of raw materials, indirect wages D inventories of work in progress, purchases of raw materials, indirect wages
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2013
Q324 · A business provides the following information for the year 9706/13 Oct/Nov 2013
16 A business provides the following information for the year. $ prime cost 165 000 factory overheads 43 000 opening work in progress 6 000 closing work in progress 15 000 What is the cost of goods transferred to the trading account of the income statement? A $113 000 B $199 000 C $208 000 D $217 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2013
Q325 · W, X, Y and Z are in partnership 9706/13 Oct/Nov 2013
18 W, X, Y and Z are in partnership. What would be shown in the partnership appropriation account? A drawings made by W B goods taken for the personal use of Y C interest on a loan made by Z D interest on drawings made by X
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2013
Q326 · A trader uses the revaluation method of depreciation for loose tools 9706/13 Oct/Nov 2013
19 A trader uses the revaluation method of depreciation for loose tools. On 1 January loose tools were valued at $4620 and on 31 December at $5740. During the year $2010 was spent on purchasing new loose tools. Which amount was charged to the income statement? A $890 B $1120 C $2010 D $3130
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2013
Q327 · The accounting year end of a business is 31 October 9706/11 May/June 2014
2 The accounting year end of a business is 31 October. On 1 April the business rents out part of its warehouse for an annual rent of $6000. Payments were received in equal instalments on 1 April, 1 July, 1 October and 1 January. At 31 October what would the financial statements show? statement of income statement financial position $ $ A rental income 3500 current asset 1000 B rental income 3500 current liability 1000 C rental income 4500 current liability 1000 D rental income 6000 current asset 1500
1 marks
Answer: B
This question in 9706/11 May/June 2014
Q328 · Which transaction would increase the current assets of a business? 9706/11 May/June 2014
3 Which transaction would increase the current assets of a business? A paying invoices $950, after receiving $50 cash discount B purchasing a machine on credit for $1200 C purchasing inventory for $1100 cash and selling it on credit for $1500 D selling inventory with an original cost of $800 at below cost price
1 marks
Answer: C
This question in 9706/11 May/June 2014
Q329 · A new machine is purchased at a price of $75 000 9706/11 May/June 2014
4 A new machine is purchased at a price of $75 000. In addition, delivery and installation cost is $2500. The business depreciates all non-current assets at a rate of 20% per annum using the straight line method. By how much would this transaction decrease the profit for the year? A $14 500 B $15 000 C $15 500 D $17 500
1 marks
Answer: C
This question in 9706/11 May/June 2014
Q330 · A business had current assets and current liabilities as follows 9706/11 May/June 2014
6 A business had current assets and current liabilities as follows. $ inventories 1600 trade receivables 3200 trade payables 2700 rent receivable 800 A fire destroyed the inventories, but 75% of the loss is covered by an agreed insurance claim. What are the net current assets after the fire? A $900 B $1300 C $2500 D $2900
1 marks
Answer: C
This question in 9706/11 May/June 2014
Q331 · The accounting year end for a company is 31 October 9706/11 May/June 2014
7 The accounting year end for a company is 31 October. The table shows the company’s telephone bill received on 2 December for the three months ended 30 November. $ telephone calls to 30 November 1041 rental of equipment for the period from 1 September to 30 November 156 Which accrual should the company make in the financial statements for the year ended 31 October? A $503 B $798 C $1093 D $1197
1 marks
Answer: B
This question in 9706/11 May/June 2014
Q332 · Trade receivables at 31 December 2013 were $350 000 9706/11 May/June 2014
10 Trade receivables at 31 December 2013 were $350 000. It is later found that $33 000 should be written off as bad debt. The provision for doubtful debts at the year end includes a specific provision of $2500 and a general provision of 4%. What is the net amount of trade receivables at 31 December 2013? A $300 500 B $301 820 C $301 920 D 303 000
1 marks
Answer: C
This question in 9706/11 May/June 2014
Q333 · A business has a draft profit for the year of $182 750 9706/11 May/June 2014
11 A business has a draft profit for the year of $182 750. The following adjustments have not yet been included in the financial statements. 1 a decrease of $2800 in the provision for doubtful debts 2 a prepayment of $3900 for rent receivable What is the actual profit for the year? A $176 050 B $181 650 C $183 850 D $189 450
1 marks
Answer: B
This question in 9706/11 May/June 2014
Q334 · The following information relates to the motor vehicles of a business 9706/11 May/June 2014
14 The following information relates to the motor vehicles of a business. 1 January 2013 31 December 2013 $ $ net book value 398 000 480 000 During 2013 the following occurred. 1 Additional motor vehicles costing $195 000 were purchased. 2 A motor vehicle (original cost $80 000) was sold for $24 000 at a profit of $2000. What was the depreciation charge for 2013? A $87 000 B $89 000 C $91 000 D $113 000
1 marks
Answer: C
This question in 9706/11 May/June 2014
Q335 · What is the treatment of life membership subscriptions? 9706/11 May/June 2014
16 What is the treatment of life membership subscriptions? A Credit the income and expenditure account in the year of receipt. B Credit the life membership fund with the year’s receipts and transfer a proportion each year to the income and expenditure account. C Debit the income and expenditure account in the year of receipt. D Debit the life membership fund with the year’s receipts and transfer a proportion each year to the income and expenditure account.
1 marks
Answer: B
This question in 9706/11 May/June 2014
Q336 · Hedley has 100 items of inventory in his warehouse and five more with a customer on a… 9706/12 May/June 2014
1 Hedley has 100 items of inventory in his warehouse and five more with a customer on a sale or return basis. He provides the following information. $ per unit historic cost paid 60 selling price 85 current replacement cost 65 Which value should appear in the statement of financial position for inventory? A $6000 B $6300 C $6825 D $8500
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q337 · When preparing a sole trader’s annual accounts, no adjustment was made for a prepayment… 9706/12 May/June 2014
2 When preparing a sole trader’s annual accounts, no adjustment was made for a prepayment at the end of the year. What is the effect of this omission? A current assets overstated owner’s capital overstated B current assets understated owner’s capital understated C profit for the year overstated trade payables understated D profit for the year understated trade payables understated
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q338 · A trader took out a 6% bank loan of $30 000 on 1 November 2013, to be repaid in full in… 9706/12 May/June 2014
4 A trader took out a 6% bank loan of $30 000 on 1 November 2013, to be repaid in full in 10 years’ time. Interest is to be paid annually. No interest had been paid by 30 April 2014. How should this be recorded in the statement of financial position at 30 April 2014? current liabilities non-current liabilities $ $ A 0 30 000 B 900 30 000 C 1 800 30 000 D 30 900 0
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q339 · A business provides the following information 9706/12 May/June 2014
11 A business provides the following information. $ revenue 140 000 opening inventory 22 000 closing inventory 24 500 purchases 120 000 Goods are sold at cost plus 25%. The owner has taken goods for own use but has not recorded these as drawings. What is the value of the goods taken for own use? A $5500 B $10 500 C $12 500 D $17 500
1 marks
Answer: A
This question in 9706/12 May/June 2014
Q340 · For the eleven months ended 31 August 2013, snack bar takings were correctly recorded at… 9706/12 May/June 2014
12 For the eleven months ended 31 August 2013, snack bar takings were correctly recorded at $109 340. For September 2013, the snack bar takings were mixed up with other income. The snack bar profit margin was 30%. The table shows figures for the snack bar for September 2013. $ opening inventory at cost 6303 purchases 8844 closing inventory at cost 7370 What was the gross profit of the snack bar for the year ended 30 September 2013? A $27 566 B $36 135 C $36 593 D $43 912
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q341 · Which items would appear in a partnership’s appropriation account, in the absence of a… 9706/12 May/June 2014
15 Which items would appear in a partnership’s appropriation account, in the absence of a partnership agreement? 1 profit for the year 2 partners’ interest on drawings 3 partners’ salaries 4 partners’ share of profits A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q342 · A partnership makes a profit for the year of $108 000 before taking account of… 9706/12 May/June 2014
16 A partnership makes a profit for the year of $108 000 before taking account of appropriations. Other financial information is as follows. X Y Z salary – – $10 000 capital balance $50 000 $40 000 $10 000 profit sharing ratio 5 3 2 Interest on capital is allowed at 8% per annum. What is Z’s share of the profit for the year? A $18 000 B $18 800 C $28 000 D $28 800
1 marks
Answer: D
This question in 9706/12 May/June 2014
Q343 · A business has settled a legal dispute with a customer and expects to pay him $10 000… 9706/12 May/June 2014
17 A business has settled a legal dispute with a customer and expects to pay him $10 000 before the end of the next financial year. Which heading is this amount included under in the company’s statement of financial position for this financial year? A capital and reserves B current liabilities C non-current assets D non-current liabilities
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q344 · A company issues shares at a premium 9706/12 May/June 2014
21 A company issues shares at a premium. Which effect does the issue have on the company’s statement of financial position? net assets share capital A decrease decrease B decrease no effect C increase increase D increase no effect
1 marks
Answer: C
This question in 9706/12 May/June 2014
Q345 · A business sells a single product 9706/12 May/June 2014
23 A business sells a single product. This year the gross profit margin and net profit margin were both lower than last year. What is the reason for this change? A decrease in carriage out B decrease in sales returns C increase in carriage in D increase in purchases returns
1 marks
Answer: C
This question in 9706/12 May/June 2014
Q346 · The following information is given about four products 9706/12 May/June 2014
24 The following information is given about four products. Which product makes the most gross profit? inventory turnover average inventory mark up on cost (per annum) in units % A 8 times 1000 15 B 6 times 1000 30 C 7 times 1000 25 D 10 times 1000 20
1 marks
Answer: D
This question in 9706/12 May/June 2014
Q347 · The interest receivable account shows interest of $17 500 received during the year 9706/13 May/June 2014
2 The interest receivable account shows interest of $17 500 received during the year. Interest of $1600 is due at the year end. How will this be shown in the income statement? income $ statement A credit 17 500 B credit 19 100 C debit 17 500 D debit 19 100
1 marks
Answer: B
This question in 9706/13 May/June 2014
Q348 · A company sells goods at a mark up of 25% 9706/13 May/June 2014
4 A company sells goods at a mark up of 25%. The following information is available at the end of the financial year. goods in warehouse $300 000 (cost) goods sent on sale or return $200 000 (at invoice price) What was the value of closing inventory in the financial statements? A $300 000 B $450 000 C $460 000 D $500 000
1 marks
Answer: C
This question in 9706/13 May/June 2014
Q349 · After draft financial statements had been prepared, the following errors were discovered 9706/13 May/June 2014
5 After draft financial statements had been prepared, the following errors were discovered. Opening inventory was overvalued by $2000. Closing inventory was undervalued by $3000. The original gross profit was $90 000. What was the gross profit after the errors were corrected? A $85 000 B $89 000 C $91 000 D $95 000
1 marks
Answer: D
This question in 9706/13 May/June 2014
Q350 · A new business decided to value inventory using AVCO 9706/13 May/June 2014
10 A new business decided to value inventory using AVCO. During the first week of trading they received the following deliveries. 1000 litres at $2.00 per litre 500 litres at $2.75 per litre What is the value of an issue of 1250 litres to production? A $2687.50 B $2812.50 C $2875.00 D $2968.75
1 marks
Answer: B
This question in 9706/13 May/June 2014
Q351 · A sports club maintains a life subscriptions account 9706/13 May/June 2014
13 A sports club maintains a life subscriptions account. How should the balance on the account appear in the financial statements? A asset in the statement of financial position B expenditure in the income and expenditure account C income in the income and expenditure account D liability in the statement of financial position
1 marks
Answer: D
This question in 9706/13 May/June 2014
Q352 · A sole trader withdraws goods for his own use 9706/13 May/June 2014
15 A sole trader withdraws goods for his own use. How does this affect his financial statements? income statement statement of financial position A increase closing inventories decrease drawings B increase cost of goods sold decrease drawings C decrease closing inventories increase drawings D decrease cost of goods sold increase drawings
1 marks
Answer: D
This question in 9706/13 May/June 2014
Q353 · Which items appear in a manufacturing account? 9706/13 May/June 2014
16 Which items appear in a manufacturing account? 1 closing inventory of work in progress 2 closing inventory of finished goods 3 depreciation of production machinery 4 depreciation of office equipment A 1 and 2 B 1 and 3 C 2 and 3 D 3 and 4
1 marks
Answer: B
This question in 9706/13 May/June 2014
Q354 · A company has ordinary share capital of $80 000 9706/13 May/June 2014
17 A company has ordinary share capital of $80 000. Each share has a nominal value of $0.25. A dividend of $0.06 per share is paid. What is the total dividend paid? A $1200 B $4800 C $15 200 D $19 200
1 marks
Answer: D
This question in 9706/13 May/June 2014
Q355 · Daphne buys a non-current asset for $10 000 9706/13 May/June 2014
18 Daphne buys a non-current asset for $10 000. It has an estimated life of two years and a scrap value of $2000. She is considering whether to depreciate it using the straight line method or to use the reducing balance method at a rate of 60% per annum. Which statements are correct? 1 The profit for the year in Year 1 is higher if the reducing balance method is chosen. 2 The profit for the year in Year 1 is higher if the straight line method is chosen. 3 The profit on disposal at the end of Year 2 is higher if the reducing balance method is chosen. 4 The profit on disposal at the end of Year 2 is higher if the straight line method is chosen. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/13 May/June 2014
Q356 · A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000… 9706/13 May/June 2014
19 A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000 4% debentures. By which amount will the net assets of the company increase? A $250 000 B $550 000 C $1 000 000 D $1 300 000
1 marks
Answer: C
This question in 9706/13 May/June 2014
Q357 · In preparing the financial statements, an accrual for rent payable was treated as a… 9706/11 Oct/Nov 2014
3 In preparing the financial statements, an accrual for rent payable was treated as a prepayment. What effect does this have on the profit and the current liabilities? profit current liabilities A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2014
Q358 · The following information is available for a business 9706/11 Oct/Nov 2014
4 The following information is available for a business. $ trade receivables at 1 January 63 000 provision for doubtful debts at 1 January 1 890 total credit sales for January 327 000 cash from customers after 4% settlement discount 324 000 A provision for doubtful debts of 2% is to be made. What adjustment is required in the income statement? A $570 credit B $570 debit C $840 credit D $840 debit
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2014
Q359 · During the past month, a business lost some inventory because of theft 9706/11 Oct/Nov 2014
9 During the past month, a business lost some inventory because of theft. The table shows the trading results for the month. $ opening inventory, at cost 50 000 purchases 220 000 sales 300 000 closing inventory, at cost 16 000 The mark up is 25%. What was the cost price of the stolen inventory? A $14 000 B $16 000 C $29 000 D $34 000
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2014
Q360 · Which item will not appear in the income statement of a sole trader? 9706/11 Oct/Nov 2014
11 Which item will not appear in the income statement of a sole trader? A accounting charges B bank loan interest C director’s fee D hire charge for leased machinery
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2014
Q361 · What is not part of a company’s equity? 9706/11 Oct/Nov 2014
12 What is not part of a company’s equity? A debentures B ordinary share capital C retained earnings D share premium
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2014
Q362 · Partnership capitals are $60 000 for X and $90 000 for Y 9706/11 Oct/Nov 2014
15 Partnership capitals are $60 000 for X and $90 000 for Y. The partnership agreement provides for interest on capitals at 10% per annum, but makes no other financial provisions. Profits for the current year total $75 000. How will the total profits be divided between the partners? X Y $ $ A 30 000 45 000 B 36 000 39 000 C 37 500 37 500 D 39 000 36 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2014
Q363 · The following financial information is available 9706/11 Oct/Nov 2014
17 The following financial information is available. $ inventory at 1 January 2013 800 inventory at 31 December 2013 1 010 ordinary goods purchased 9 260 carriage inwards 130 revenue 18 000 discount received 700 other costs 3 880 What are the values of gross profit and profit for the year? gross profit profit for the year $ $ A 8820 4240 B 8820 5640 C 9080 5900 D 9520 5640
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2014
Q364 · At the end of its financial year a business had trade receivables of $16 000 and had… 9706/12 Oct/Nov 2014
1 At the end of its financial year a business had trade receivables of $16 000 and had provision for doubtful debts of $640. The provision is to be maintained at 5%. Which amount is shown in the income statement? A $160 credit B $160 debit C $800 credit D $800 debit
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2014
Q365 · The non-current assets of a business are shown in the table 9706/12 Oct/Nov 2014
2 The non-current assets of a business are shown in the table. end of year start of year $ $ cost 360 000 300 000 accumulated depreciation 120 000 75 000 net book value 240 000 225 000 During the year, non-current assets costing $110 000 were bought and non-current assets with a net book value of $20 000 were sold. What was the depreciation charge for the year? A $35 000 B $45 000 C $50 000 D $75 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2014
Q366 · A sole trader calculated a draft profit for the year of $56 750 9706/12 Oct/Nov 2014
3 A sole trader calculated a draft profit for the year of $56 750. He then discovers that discounts received of $580 and discounts allowed of $665 had been recorded on the wrong sides of their respective accounts. What is the correct profit for the year? A $56 580 B $56 665 C $56 835 D $56 920
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2014
Q367 · Opening inventory is found to be overstated by $8000 and closing inventory is overstated… 9706/12 Oct/Nov 2014
4 Opening inventory is found to be overstated by $8000 and closing inventory is overstated by $6500. What is the effect of the correction of these errors on profit for the year? A decrease of $1500 B decrease of $14 500 C increase of $1500 D increase of $14 500
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2014
Q368 · A business sells some of its inventory for $500 on credit to a customer 9706/12 Oct/Nov 2014
8 A business sells some of its inventory for $500 on credit to a customer. The inventory originally cost $600. What is the effect of this transaction on the statement of financial position? current assets owner’s capital A decrease by $100 decrease by $100 B decrease by $100 increase by $100 C increase by $100 decrease by $100 D increase by $100 increase by $100
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2014
Q369 · A trader decides to prepare departmental accounts 9706/12 Oct/Nov 2014
11 A trader decides to prepare departmental accounts. Which statements explain the reason for his decision? 1 To be able to calculate inventory for each department. 2 To establish how to improve service to customers. 3 To have a basis for calculating staff bonuses. 4 To know the profit for each department. A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2014
Q370 · A sports club provides the following information at the year end 9706/12 Oct/Nov 2014
12 A sports club provides the following information at the year end. The bank balance had increased by $5000. The depreciation charge for the year was $600. Subscriptions in arrears had increased by $100. What was the surplus for the year? A $4300 B $4400 C $4500 D $4900
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2014
Q371 · The following information is available for a partnership at 31 December 2013 9706/12 Oct/Nov 2014
13 The following information is available for a partnership at 31 December 2013. $ residual loss 3 000 total salaries to partners 5 000 total interest on capital 27 000 total drawings 14 000 total interest on drawings 700 How much is the profit for the year? A $14 300 B $20 300 C $28 300 D $34 300
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2014
Q372 · The manufacturing account and income statement of a trader show the following: $… 9706/12 Oct/Nov 2014
14 The manufacturing account and income statement of a trader show the following: $ purchases of raw materials 70 000 direct costs and overheads 54 000 increase in inventory of raw materials 8 000 decrease in work in progress 3 000 increase in inventory of finished goods 14 000 What are the values of cost of production and cost of sales? cost of production cost of sales $ $ A 119 000 105 000 B 124 000 105 000 C 124 000 143 000 D 129 000 143 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2014
Q373 · The following balances are extracted from the books of Juno Limited 9706/12 Oct/Nov 2014
15 The following balances are extracted from the books of Juno Limited. 30 April 2014 30 April 2013 $ $ ordinary shares of $0.50 each 700 000 500 000 share premium 90 000 50 000 How many ordinary shares have been issued during the year ended 30 April 2014? A 200 000 B 240 000 C 400 000 D 480 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2014
Q374 · A company issues 1 000 000 ordinary shares of $1 each at a premium of 20% 9706/12 Oct/Nov 2014
16 A company issues 1 000 000 ordinary shares of $1 each at a premium of 20%. Which value will be shown for ordinary shares in the statement of financial position? A $200 000 B $800 000 C $1 000 000 D $1 200 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2014
Q375 · Which items increase when a company issues new shares? 9706/12 Oct/Nov 2014
17 Which items increase when a company issues new shares? A equity and bank B equity and current liabilities C intangible assets and current liabilities D intangible assets and equity
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2014
Q376 · The draft accounts of a business for the year ended 30 June 2013 include the following: $… 9706/12 Oct/Nov 2014
19 The draft accounts of a business for the year ended 30 June 2013 include the following: $ revenue 280 000 gross profit 60 000 It was subsequently discovered that the closing inventory was understated by $10 000. What was the gross profit percentage after correcting this error? A 17.9% B 20.7% C 21.4% D 25.0%
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2014
Q377 · The following financial information is available 9706/12 Oct/Nov 2014
20 The following financial information is available. $ trade payables 10 000 bank overdraft 4 400 trade receivables 20 000 other receivables 600 other payables 1 600 non-current liabilities 5 000 The business has a current ratio of 2.5 : 1. What is the value of inventory? A $15 900 B $16 900 C $19 400 D $31 900
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2014
Q378 · A business provides the following information 9706/13 Oct/Nov 2014
1 A business provides the following information. debit credit $ $ prepaid expenses 4 620 accrued expenses 8 125 bank balances 14 920 3 612 trade payables 18 148 loan (10 years) 15 000 What is the total for current liabilities? A $26 273 B $26 380 C $29 885 D $44 885
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q379 · The provision for doubtful debts at 1 January 2013 was $1580 9706/13 Oct/Nov 2014
2 The provision for doubtful debts at 1 January 2013 was $1580. Trade receivables at 31 December 2013 were $44 750. An irrecoverable debt of $12 500 had not been written off. The provision for doubtful debts was 5%. Which entry for doubtful debts was included in the income statement for the year ended 31 December 2013? A credit $32.50 B credit $657.50 C debit $32.50 D debit $657.50
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q380 · On 1 January a business has prepaid $800 for four months’ motor insurance 9706/13 Oct/Nov 2014
4 On 1 January a business has prepaid $800 for four months’ motor insurance. It also has an outstanding invoice for fuel of $140. During January it pays the fuel invoice and a further $600 for fuel. At 31 January it has an outstanding fuel invoice of $160. What is the charge for motor expenses in the income statement for January? A $760 B $960 C $1100 D $1560
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2014
Q381 · A business provides the following information 9706/13 Oct/Nov 2014
6 A business provides the following information. $ cheque paid in 2013 for equipment bought in 2012 15 000 equipment purchased on credit in 2013 42 000 net book value of equipment at 1 January 2013 83 000 net book value of equipment at 31 December 2013 67 000 What was the depreciation charge in the income statement for the year ended 31 December 2013? A $16 000 B $31 000 C $43 000 D $58 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2014
Q382 · When preparing the financial statements for the year the following errors are discovered 9706/13 Oct/Nov 2014
7 When preparing the financial statements for the year the following errors are discovered. 1 The sales journal was undercast by $300. 2 No provision had been made for accrued wages of $200. 3 No account had been taken of prepaid rent of $400. The draft profit for the year is $8050. What will be the profit when the errors are corrected? A $8150 B $8550 C $8750 D $8950
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2014
Q383 · How are subscriptions in arrears recorded in the statement of financial position for a… 9706/13 Oct/Nov 2014
13 How are subscriptions in arrears recorded in the statement of financial position for a club? A as a current asset B as a current liability C as a non-current asset D as a non-current liability
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2014
Q384 · The following items appear in the subscriptions account of a club for a financial year 9706/13 Oct/Nov 2014
14 The following items appear in the subscriptions account of a club for a financial year. $ subscriptions received owed from the previous year 3 080 subscriptions paid in advance for next year 1 050 subscriptions income transferred to the income and expenditure account 50 000 subscriptions outstanding at year end 2 000 How much cash was received from members in the year? A $45 870 B $50 000 C $52 130 D $56 130
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q385 · The equity of a limited company is as follows 9706/13 Oct/Nov 2014
15 The equity of a limited company is as follows. at 31 December 2012 at 31 December 2013 $ $ ordinary shares of $0.50 each 400 000 400 000 7% preference shares of $1 each 200 000 200 000 retained earnings 4 000 ? Profit for the year 2013 was $300 000. Dividends paid in 2013 were as follows: ordinary shares: $0.20 per share preference shares: half-year dividend What were the retained earnings at 31 December 2013? A $133 000 B $144 000 C $210 000 D $217 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2014
Q386 · A sole trader recovers a debt that had previously been written off as irrecoverable 9706/13 Oct/Nov 2014
16 A sole trader recovers a debt that had previously been written off as irrecoverable. How is this accounted for in his income statement? A credit in the profit and loss account B credit in the trading account C debit in the profit and loss account D debit in the trading account
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2014
Q387 · The following items appear in the books of a manufacturing company 9706/13 Oct/Nov 2014
17 The following items appear in the books of a manufacturing company. 1 factory wages 2 maintenance of factory machinery 3 direct materials 4 interest on debenture secured on factory machinery 5 factory cleaners’ wages Which items would be included in factory overheads? A 1 and 2 B 2 and 3 C 2 and 5 D 4 and 5
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q388 · A business values its inventory using the FIFO method 9706/13 Oct/Nov 2014
18 A business values its inventory using the FIFO method. The following transactions took place. month units $ April opening inventory 700 at 190 each May purchases 500 at 220 each June sales 400 at 400 each What is the value of the closing inventory at the end of June? A $152 000 B $162 000 C $167 000 D $176 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q389 · At the beginning of the financial year inventory was valued at $15 000 9706/13 Oct/Nov 2014
20 At the beginning of the financial year inventory was valued at $15 000. During the year, sales of $21 000 and purchases of $18 000 were made. Unfortunately, all inventory was stolen on the last day of the financial year. Goods are marked up by 50% to calculate selling price. What is the cost of the stolen inventory? A $7500 B $11 000 C $19 000 D $22 500
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q390 · The table shows equity and liabilities of a company at 31 December 2013 9706/13 Oct/Nov 2014
21 The table shows equity and liabilities of a company at 31 December 2013. $ ordinary share capital 750 000 8% non-redeemable preference shares 250 000 6% debentures (2020) 150 000 bank loan repayable (2019) 75 000 bank overdraft 110 000 mortgage on buildings (repayable 2014) 120 000 What is the total of non-current liabilities in the statement of financial position at 31 December 2013? A $195 000 B $225 000 C $345 000 D $595 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2014
Q391 · The table shows an extract from the statement of financial position of a limited company… 9706/13 Oct/Nov 2014
22 The table shows an extract from the statement of financial position of a limited company at 30 June 2014. $ 4% debenture (2018 – 2019) 30 000 5% preference share capital 20 000 ordinary shares of $1 each 80 000 The company declared a dividend of $0.05 per share. This was paid on 31 March 2014. What is the total amount of equity dividends paid for the year ended 30 June 2014? A $1000 B $4000 C $5000 D $6200
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2014
Q392 · A trader, whose year end was 31 December 2014, paid business rates of $3000 on 1 November… 9706/11 May/June 2015
2 A trader, whose year end was 31 December 2014, paid business rates of $3000 on 1 November 2014. The business rates were for the six months ending 31 March 2015, but no adjustment had been made for the prepayment. Which effect does this omission have on the profit for the year? A overstated $1500 B overstated $2000 C understated $1500 D understated $2000
1 marks
Answer: C
This question in 9706/11 May/June 2015
Q393 · Closing inventory of $5000 at 31 December 2014 has been incorrectly entered in the… 9706/11 May/June 2015
3 Closing inventory of $5000 at 31 December 2014 has been incorrectly entered in the financial statements as $3000. How does this affect the financial statements at 31 December 2014? profit for the year net assets A no effect understated B overstated overstated C understated no effect D understated understated
1 marks
Answer: D
This question in 9706/11 May/June 2015
Q394 · The following information is available at the end of the financial year 9706/11 May/June 2015
5 The following information is available at the end of the financial year. $ net assets 850 000 drawings 47 300 loss for the year 135 600 What is the value of capital at the start of the year? A $667 100 B $761 700 C $938 300 D $1 032 900
1 marks
Answer: D
This question in 9706/11 May/June 2015
Q395 · A company has two departments, X and Y 9706/11 May/June 2015
6 A company has two departments, X and Y. The following data is available for the year. Sales for the two departments are $25 000 and $35 000 respectively. Both departments apply the same mark up and total gross profit amounts to $24 000. Expenses are split 55% to X and 45% to Y. Total profit for the year amounts to $8000. What is department X’s profit for the year? A $1200 B $2800 C $5200 D $6800
1 marks
Answer: A
This question in 9706/11 May/June 2015
Q396 · An analysis of the cash account for a sole trader showed the following for the year 9706/11 May/June 2015
7 An analysis of the cash account for a sole trader showed the following for the year. $ capital introduced 300 cash takings banked 125 000 expenses paid 31 200 drawings 2 600 cash in hand at year-end 100 There were no credit sales. What was the revenue for the year? A $158 500 B $158 600 C $159 100 D $159 200
1 marks
Answer: B
This question in 9706/11 May/June 2015
Q397 · The following information has been taken from a summarised statement of financial position 9706/11 May/June 2015
11 The following information has been taken from a summarised statement of financial position. $ non-current assets 175 000 current assets 45 000 current liabilities ? 100 000 ordinary shares of $1 each 100 000 share premium 65 000 retained earnings 35 000 What is the value of the current liabilities? A $20 000 B $55 000 C $70 000 D $120 000
1 marks
Answer: A
This question in 9706/11 May/June 2015
Q398 · Which item appears as a credit entry in the appropriation account of a partnership? 9706/11 May/June 2015
13 Which item appears as a credit entry in the appropriation account of a partnership? A goodwill B interest on capital C partnership salaries D profit for the year
1 marks
Answer: D
This question in 9706/11 May/June 2015
Q399 · The following relates to subscriptions of a club for the year ended 31 March 2015 9706/11 May/June 2015
15 The following relates to subscriptions of a club for the year ended 31 March 2015. $ income credited to income and expenditure account 50 000 in arrears at the start of the year 400 in arrears at the end of the year 700 paid in advance at the start of the year 1 300 paid in advance at the end of the year 2 200 What is the amount of subscriptions received from members during the year? A $48 800 B $49 400 C $50 600 D $51 200
1 marks
Answer: C
This question in 9706/11 May/June 2015
Q400 · Rent is paid by a business monthly in advance on the first day of each month 9706/12 May/June 2015
3 Rent is paid by a business monthly in advance on the first day of each month. The payments during this financial year have been as follows. up to and including 1 June $500 per month from 1 July $600 per month Which amount(s) will appear in the financial statements for the year ended 31 October? income statement statement of financial expense position A $6400 $600 other receivables B $6400 $600 other payables C $6400 – D $7000 –
1 marks
Answer: C
This question in 9706/12 May/June 2015
Q401 · A business started on 1 January 2013 9706/12 May/June 2015
4 A business started on 1 January 2013. At 31 December 2014 the following information is available. 31 December 2013 31 December 2014 $ $ trade receivables 80 000 100 000 increase in provision for doubtful 4 000 2 000 debts in income statement What is the rate for provision for doubtful debts in 2014? A 2% B 3.33% C 5% D 6%
1 marks
Answer: D
This question in 9706/12 May/June 2015
Q402 · The table shows information for a business at 31 March in Year 1 9706/12 May/June 2015
7 The table shows information for a business at 31 March in Year 1. $ inventory 16 100 trade payables 5 200 other payables 2 000 The information excludes the purchase of $3700 of goods. These goods were delivered on 31 March Year 1, but the invoice states that legal title to the goods does not pass until payment is received. Which values should appear in the statement of financial position on 31 March Year 1? inventory trade payables other payables $ $ $ A 16 100 5200 2000 B 16 100 5200 5700 C 19 800 5200 5700 D 19 800 8900 2000
1 marks
Answer: D
This question in 9706/12 May/June 2015
Q403 · The following information is available 9706/12 May/June 2015
8 The following information is available. $ prime cost 400 000 factory overheads 220 000 inventories: opening closing $ $ raw materials 25 000 28 000 work-in-progress 46 000 52 000 finished goods 84 000 72 000 What is the cost of production? A $611 000 B $614 000 C $620 000 D $623 000
1 marks
Answer: B
This question in 9706/12 May/June 2015
Q404 · A business has extracted the following information from its books of account at 31… 9706/12 May/June 2015
9 A business has extracted the following information from its books of account at 31 December 2014, its first year of trading. $000 carriage inwards 12 carriage outwards 15 closing inventory 86 purchases 286 returns inwards 10 returns outwards 2 revenue 524 What is the gross profit for the year ended 31 December 2014? A $301 000 B $304 000 C $320 000 D $328 000
1 marks
Answer: B
This question in 9706/12 May/June 2015
Q405 · How are closing inventory and loss for the year treated? 9706/12 May/June 2015
11 How are closing inventory and loss for the year treated? closing inventory loss for the year A debit in statement of financial position debit in capital account credit in income statement credit in income statement B debit in statement of financial position debit in income statement credit in income statement credit in capital account C debit in income statement debit in capital account credit in statement of financial position credit in income statement D debit in income statement debit in income statement credit in statement of financial position credit in capital account
1 marks
Answer: A
This question in 9706/12 May/June 2015
Q406 · A cricket club provides the following information 9706/12 May/June 2015
14 A cricket club provides the following information. $ subscriptions owing at 1 January 2014 340 subscriptions paid in advance at 1 January 2014 580 subscriptions received in the year ended 31 December 2014 3600 subscriptions owing at 31 December 2014 410 subscriptions paid in advance at 31 December 2014 320 What is the value of subscriptions in the income and expenditure account for the year ended 31 December 2014? A $3450 B $3600 C $3750 D $3930
1 marks
Answer: D
This question in 9706/12 May/June 2015
Q407 · DEC Limited has produced the following information for the current financial year 9706/12 May/June 2015
15 DEC Limited has produced the following information for the current financial year. department X department Y $ $ revenue 54 000 26 000 cost of sales 23 700 16 600 gross profit 30 300 9 400 The rent and insurance of buildings total is $13 000. Heating and lighting total is $12 500. The floor area occupied by each department: X 60%, Y 40%. What is the profit or loss for the year for department Y? A $800 loss B $5900 loss C $15 000 profit D $20 100 profit
1 marks
Answer: A
This question in 9706/12 May/June 2015
Q408 · A business bought and sold the following items of inventory 9706/12 May/June 2015
16 A business bought and sold the following items of inventory. cost per unit month details units $ January purchased 30 2.00 February purchased 20 2.50 March sold 10 – It uses the AVCO method of inventory valuation. What was the value of inventory at the end of March? A $20 B $22 C $88 D $90
1 marks
Answer: C
This question in 9706/12 May/June 2015
Q409 · The profits of Bronte Limited are as follows 9706/12 May/June 2015
17 The profits of Bronte Limited are as follows. year ended 31 December 2013 nil year ended 31 December 2014 $60 000 Bronte Limited has in issue 200 000 5% preference shares of $1 each. What is the profit available for distribution to ordinary shareholders for the year ended 31 December 2014, if the preference shares are (i) cumulative or (ii) non-cumulative? cumulative non-cumulative $ $ A 40 000 40 000 B 40 000 50 000 C 50 000 40 000 D 50 000 50 000
1 marks
Answer: B
This question in 9706/12 May/June 2015
Q410 · A limited company issues 5000 ordinary shares of $2 each at a premium of $0.50 9706/12 May/June 2015
18 A limited company issues 5000 ordinary shares of $2 each at a premium of $0.50. What is the effect on share capital and liquidity? share capital liquidity $ A increase 10 000 improve B increase 10 000 no effect C increase 12 500 improve D increase 12 500 no effect
1 marks
Answer: A
This question in 9706/12 May/June 2015
Q411 · A new business was established with opening capital of $20 000 9706/12 May/June 2015
19 A new business was established with opening capital of $20 000. At the end of the first year, assets less liabilities were $26 000. The owner withdrew $7000 as drawings during the year and this resulted in a bank overdraft of $5000 at the end of the year. What was the profit during the first year? A $8000 B $12 000 C $13 000 D $18 000
1 marks
Answer: C
This question in 9706/12 May/June 2015
Q412 · A business provides the following information 9706/13 May/June 2015
4 A business provides the following information. trade provision for receivables doubtful debts $ $ 31 December 2013 46 200 1386 31 December 2014 43 100 1724 Which statement must be correct? A The rate of provision for doubtful debts has decreased. B The rate of provision for doubtful debts has increased. C The value of bad debts incurred has decreased. D The value of bad debts incurred has increased.
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q413 · The following information relates to a manufacturing business 9706/13 May/June 2015
5 The following information relates to a manufacturing business. $ factory overheads 590 000 prime cost 2 000 000 work in progress at start of year 83 000 work in progress at end of year 65 000 What was the cost of production? A $1 392 000 B $1 428 000 C $2 572 000 D $2 608 000
1 marks
Answer: D
This question in 9706/13 May/June 2015
Q414 · A summary of a trader’s bank statements for his first year of trading showed the… 9706/13 May/June 2015
6 A summary of a trader’s bank statements for his first year of trading showed the following amounts. $ receipts from credit customers 25 000 takings from cash sales banked 82 000 The trader took $2000 a month from takings as drawings before banking them. Trade receivables at the year end amounted to $9500. What was total revenue for the year? A $73 500 B $92 500 C $121 500 D $140 500
1 marks
Answer: D
This question in 9706/13 May/June 2015
Q415 · A business uses the AVCO method of inventory valuation 9706/13 May/June 2015
7 A business uses the AVCO method of inventory valuation. When is the average cost per unit calculated? A when the cost price decreases B when the cost price increases C when units are issued D when units are received
1 marks
Answer: D
This question in 9706/13 May/June 2015
Q416 · An electricity accrual of $375 was treated as a prepayment in preparing a trader’s income… 9706/13 May/June 2015
9 An electricity accrual of $375 was treated as a prepayment in preparing a trader’s income statement. What was the effect on profit? A overstated by $375 B overstated by $750 C understated by $375 D understated by $750
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q417 · The following information is taken from the rent account of a business 9706/13 May/June 2015
10 The following information is taken from the rent account of a business. $ rent prepaid at the beginning of the year 1 400 rent paid during the year 13 900 rent accrued at the end of the year 800 What is the rent expense for the year? A $11 700 B $13 300 C $14 500 D $16 100
1 marks
Answer: D
This question in 9706/13 May/June 2015
Q418 · A business has the following assets and liabilities at the start of the year 9706/13 May/June 2015
11 A business has the following assets and liabilities at the start of the year. a motor car valued at $2500 inventory which cost $4000 with a sale value of $5800 bank overdraft of $500 a loan to a friend from the business bank account $1000 What is the capital account balance at the start of the year? A $5000 B $7000 C $8000 D $8800
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q419 · A business buys a non-current asset and decides to apply the straight-line method of… 9706/13 May/June 2015
12 A business buys a non-current asset and decides to apply the straight-line method of depreciation. The accountant forgets to include an estimate of scrap value in the calculation. Which statements are correct? 1 The annual depreciation charge is too high. 2 The annual depreciation charge is too low. 3 There is likely to be a loss on disposal in the future. 4 There is likely to be a profit on disposal in the future. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q420 · What will increase profit? 9706/13 May/June 2015
13 What will increase profit? A increasing depreciation rates B increasing the general reserve C increasing the provision for doubtful debts D increasing the value of closing work-in-progress
1 marks
Answer: D
This question in 9706/13 May/June 2015
Q421 · Adil and Bashir are in partnership sharing profits and losses in the ratio 2 : 1 9706/13 May/June 2015
15 Adil and Bashir are in partnership sharing profits and losses in the ratio 2 : 1. Chandra joins the partnership and profits and losses are now to be shared between Adil, Bashir and Chandra in the ratio 3 : 2 : 1. The balances of the partners’ capital accounts prior to the introduction of Chandra are as shown. $ Adil 20 000 Bashir 10 000 Goodwill is to be valued at $36 000 and is not to be retained in the books of account. What is the balance on Adil’s capital account after the introduction of Chandra? A $20 000 B $26 000 C $38 000 D $44 000
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q422 · The table shows the assets and liabilities of a club 9706/13 May/June 2015
16 The table shows the assets and liabilities of a club. $ non-current assets 10 000 cash at bank 6 400 electricity owing 600 rent prepaid 900 subscriptions: in arrears 5 700 in advance 3 800 How much is the accumulated fund? A $14 200 B $14 800 C $18 000 D $18 600
1 marks
Answer: D
This question in 9706/13 May/June 2015
Q423 · A company issues 100 000 ordinary shares of $1 each at a premium of $2 9706/13 May/June 2015
17 A company issues 100 000 ordinary shares of $1 each at a premium of $2. The market value is $4 per share. Which statement is not correct? A Capital reserves increase by $200 000. B Funds available increase by $300 000. C Ordinary share capital increases by $100 000. D Revenue reserves increase by $400 000.
1 marks
Answer: D
This question in 9706/13 May/June 2015
Q424 · A trader provides the following information for the year 9706/13 May/June 2015
19 A trader provides the following information for the year. inventory 1 January $15 125 inventory 31 December $22 185 ordinary goods purchased $65 500 gross profit % on sales 25% What is the value of sales for the year? A $73 050 B $77 920 C $90 700 D $96 747
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q425 · The following forecasted data relates to the month of January 2015 9706/13 May/June 2015
30 The following forecasted data relates to the month of January 2015. $ bank on 1 January 2015 570 debit depreciation of non-current assets 820 payments to suppliers 39 400 revaluation of premises 50 000 provision for doubtful receivables 8 000 receipts from customers 148 250 What is the budgeted cash balance at end of January 2015? A $108 280 B $109 420 C $151 100 D $152 240
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q426 · A business prepared its draft financial statements 9706/11 Oct/Nov 2015
3 A business prepared its draft financial statements. It was later discovered that an adjustment for prepaid rent was required. What is the effect of this adjustment? expenses current assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q427 · A business had a draft loss for the year of $4650 9706/11 Oct/Nov 2015
5 A business had a draft loss for the year of $4650. Further adjustments were required. 1 a write off of $165 for bad debts 2 a reduction of $300 in the provision for doubtful debts What was the loss for the year after these adjustments? A $4185 B $4515 C $4785 D $5115
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q428 · A business provides the following information 9706/11 Oct/Nov 2015
11 A business provides the following information. $ cash received from customers 200 000 opening trade receivables 40 000 closing trade receivables 30 000 discounts allowed 5 000 provision for doubtful debts 4 000 How much are the credit sales? A $190 000 B $195 000 C $199 000 D $215 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q429 · A business has the following balances at the end of its financial period 9706/11 Oct/Nov 2015
13 A business has the following balances at the end of its financial period. $ trade receivables 10 620 bad debt not yet written off 260 provision for doubtful debts brought forward 460 What should the business do if it wishes to maintain the bad debt provision at 5% of trade receivables? A Decrease the existing provision by $58. B Increase the existing provision by $58. C Decrease the existing provision by $71. D Increase the existing provision by $71.
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q430 · At the year end a company discovers that some inventory is damaged 9706/11 Oct/Nov 2015
15 At the year end a company discovers that some inventory is damaged. This inventory originally cost $2000 and to replace it would now cost $1900. It would normally sell for $2400 but can now only be sold for $2200 if repairs costing $400 are undertaken. At what value should the damaged inventory be shown in the financial statements? A $1800 B $1900 C $2000 D $2200
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2015
Q431 · A fitness club operates a shop selling sports shoes 9706/11 Oct/Nov 2015
19 A fitness club operates a shop selling sports shoes. Which statement is correct? A The inventory of shoes appears in the receipts and payments account. B The payments to suppliers are adjusted for trade payables in the income and expenditure account. C The profit made appears in the trading account and the income and expenditure account. D The sales proceeds and payments to suppliers are netted off in the receipts and payments account.
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2015
Q432 · On 1 January a business had an inventory of 100 units at a cost of $10 each 9706/11 Oct/Nov 2015
20 On 1 January a business had an inventory of 100 units at a cost of $10 each. The following transactions then took place. units purchased units sold February 50 March 60 at $11 each April 70 at $12 each 100 May 30 All sales are made at $13 per unit. The business values its inventory on a FIFO basis. What is the value of the inventory at the end of May? A $390 B $550 C $600 D $650
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2015
Q433 · Information from a partnership’s accounts is shown 9706/11 Oct/Nov 2015
21 Information from a partnership’s accounts is shown. $ profit for the year before interest 15 000 interest on partner’s loan to the firm 1 000 interest on capital 2 000 drawings 10 000 Which profit figure is to be appropriated between the partners? A $3000 B $13 000 C $14 000 D $15 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2015
Q434 · The following information relates to the subscriptions of a club 9706/11 Oct/Nov 2015
22 The following information relates to the subscriptions of a club. in advance in arrears $ $ at the start of the year 50 75 at the end of the year 150 120 Cash for subscriptions received during the year was $3750. What was the subscription income for the year? A $3695 B $3750 C $3755 D $3805
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2015
Q435 · Which item will not be shown as part of the equity in the statement of financial position… 9706/11 Oct/Nov 2015
24 Which item will not be shown as part of the equity in the statement of financial position of a limited company? A debentures B ordinary share capital C retained earnings D share premium
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2015
Q436 · A trial balance at 30 June, before making end of year adjustments, showed the following 9706/12 Oct/Nov 2015
6 A trial balance at 30 June, before making end of year adjustments, showed the following. debit credit $ $ trade receivables 35 600 – provision for doubtful debts – 1 160 At 30 June, it was decided to write off a bad debt of $1600 and to make a provision for doubtful debts equal to 2% of trade receivables. What was the total decrease in the profit for the year ended 30 June arising from the bad and doubtful debts? A $680 B $1120 C $2080 D $2280
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2015
Q437 · Land and buildings are shown in the books of account at a cost price of $200 000 with… 9706/12 Oct/Nov 2015
7 Land and buildings are shown in the books of account at a cost price of $200 000 with accumulated depreciation of $40 000. The property is revalued at $340 000. Which entries record this transaction? debit credit account $ $ A land and buildings 140 000 income statement 140 000 B land and buildings 140 000 provision for depreciation 40 000 income statement 180 000 C land and buildings 140 000 revaluation reserve 140 000 D land and buildings 140 000 provision for depreciation 40 000 revaluation reserve 180 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2015
Q438 · A business depreciates its motor vehicles over four years using the straight-line method 9706/12 Oct/Nov 2015
13 A business depreciates its motor vehicles over four years using the straight-line method. A full year’s depreciation is charged in the year of purchase, but none in the year of sale. A vehicle purchased on 1 July 2011 for $18 000 had an estimated residual value of $4000. The vehicle was sold for $5000 on 31 December 2014. Which entry appeared in the income statement for the year ended 31 December 2014? A $1000 loss B $2500 loss C $2500 profit D $5000 profit
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2015
Q439 · Rachel’s trial balance did not agree and she placed the difference in a suspense account 9706/12 Oct/Nov 2015
14 Rachel’s trial balance did not agree and she placed the difference in a suspense account. The following shows how four errors have been corrected using the suspense account. suspense account $ $ difference in trial balance 200 discount received 310 discount allowed 160 sundry expenses 390 cash 340 700 700 The profit for the year before the errors were corrected was $35 400. What is the correct profit for the year? A $34 520 B $34 540 C $34 860 D $35 480
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2015
Q440 · Which item may appear in the manufacturing account of a business? 9706/12 Oct/Nov 2015
17 Which item may appear in the manufacturing account of a business? A carriage inwards B carriage outwards C discounts allowed D discounts received
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2015
Q441 · Inventory is valued at the lower of cost and net realisable value 9706/12 Oct/Nov 2015
18 Inventory is valued at the lower of cost and net realisable value. What is net realisable value? A selling price B selling price less cash discount C selling price less further cost to completion D selling price less trade discount
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2015
Q442 · A club provides the following information 9706/12 Oct/Nov 2015
20 A club provides the following information. $ opening subscriptions in advance 1 200 subscriptions received during the year 25 000 closing subscriptions in arrears 1 500 How much are subscriptions for the year in the income and expenditure account? A $22 300 B $24 700 C $25 300 D $27 700
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2015
Q443 · Which items increase when a company issues new shares? 9706/12 Oct/Nov 2015
21 Which items increase when a company issues new shares? 1 cash (and cash equivalents) 2 equity 3 non-current liabilities 4 retained earnings A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2015
Q444 · On 1 March a sales company has prepaid $3600 for 12 months’ travel costs 9706/13 Oct/Nov 2015
2 On 1 March a sales company has prepaid $3600 for 12 months’ travel costs. It also has an outstanding hotel bill of $180. During March it pays the outstanding hotel bill and a further $700 for airline tickets. At 31 March it has an outstanding hotel bill of $220. What is the correct cost of travel in the income statement for March? A $920 B $1220 C $1400 D $4520
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q445 · A book-keeper failed to record accrued rent payable of $12 000 at the year end 9706/13 Oct/Nov 2015
3 A book-keeper failed to record accrued rent payable of $12 000 at the year end. What is the effect of this on the financial statements? net assets profit for the year A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2015
Q446 · A business makes a provision for doubtful debts equal to 10% of trade receivables 9706/13 Oct/Nov 2015
8 A business makes a provision for doubtful debts equal to 10% of trade receivables. The provision at 31 March 2013 was $8300. The trade receivables after the provision on 31 March 2014 were $55 800. What is the change in provision over the 12 months? A $2100 decrease B $2100 increase C $2700 decrease D $2700 increase
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2015
Q447 · A trader’s closing inventory includes damaged items that originally cost $500 9706/13 Oct/Nov 2015
10 A trader’s closing inventory includes damaged items that originally cost $500. These items will cost $150 to repair and they will then be sold for $600. At which value will these items be recorded in the trader’s inventory? A $350 B $450 C $500 D $600
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q448 · The following financial information is available for a business 9706/13 Oct/Nov 2015
12 The following financial information is available for a business. $ draft profit for the year 12 650 closing capital 52 780 The following error has been discovered in the accounting system. Private fuel costs, $1930, had been charged in the business motor expenses account. What are the final figures for the year? profit for the year capital $ $ A 10 720 50 850 B 10 720 54 710 C 14 580 52 780 D 14 580 54 710
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2015
Q449 · Draft financial statements showed revenue of $106 000 and closing inventory of $2100 9706/13 Oct/Nov 2015
14 Draft financial statements showed revenue of $106 000 and closing inventory of $2100. There were 100 items which had cost $10 an item but which were for sale at $6 an item. At the year end these were with a customer on a sale or return basis. These items were treated as having been sold although no sale had been agreed. What were the values of revenue and inventory when the principle of prudence is applied? revenue inventory $ $ A 105 000 2700 B 105 000 3100 C 105 400 2700 D 105 400 3100
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2015
Q450 · A club charges each of its 100 members an annual subscription of $12 9706/13 Oct/Nov 2015
15 A club charges each of its 100 members an annual subscription of $12. At the end of a year four members had not paid their annual subscription. What will be the entries in the financial statements for subscriptions? income and statement of financial expenditure account position $ A 1152 current asset $48 B 1152 current liability $48 C 1200 current asset $48 D 1200 current liability $48
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2015
Q451 · Which items appear in a manufacturing account? 9706/13 Oct/Nov 2015
17 Which items appear in a manufacturing account? 1 depreciation of production machinery 2 marketing expenses 3 opening inventory of work in progress 4 opening inventory of finished goods A 1 and 2 B 1 and 3 C 2 and 3 D 3 and 4
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q452 · A company raises cash by issuing 8% debentures 9706/13 Oct/Nov 2015
19 A company raises cash by issuing 8% debentures. What is the effect on the company’s profits and equity in the year of issue? profits equity A decrease decrease B decrease no effect C increase decrease D increase no effect
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q453 · A business sells goods at a mark up of 33.3% 9706/13 Oct/Nov 2015
20 A business sells goods at a mark up of 33.3%. Information for a year is given. $ revenue 600 000 opening inventory 53 000 closing inventory 68 000 What are the total purchases for the year? A $415 000 B $435 000 C $450 000 D $465 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2015
Q454 · A business started on 1 January 2014 9706/13 Oct/Nov 2015
30 A business started on 1 January 2014. The following balances are available at 31 December 2014. $ total sales 150 000 cash purchases 72 000 cash expenses 32 000 depreciation 4 000 trade receivables 18 000 What is the cash surplus for the year? A $24 000 B $28 000 C $42 000 D $46 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q455 · A business maintains a provision for doubtful debts of 5% per annum 9706/12 Feb/March 2016
7 A business maintains a provision for doubtful debts of 5% per annum. It has trade receivables balances of $560 000 at the start and $468 000 at the end of the financial year. Which statements are correct? 1 Customers’ accounts have been credited with $4600. 2 $4600 is treated as income in the income statement. 3 $4600 is deducted from current assets in the statement of financial position. A 1, 2 and 3 B 1 only C 2 only D 2 and 3 only
1 marks
Answer: C
This question in 9706/12 Feb/March 2016
Q456 · The statement of the financial position of a company shows the following: $ tangible… 9706/12 Feb/March 2016
8 The statement of the financial position of a company shows the following: $ tangible non-current assets 20 600 intangible non-current assets 5 700 trade receivables 8 600 trade payables 3 200 loan repayable in three years 4 000 bank balance 5 200 credit inventory 6 900 What is total working capital? A $3100 B $7100 C $17 500 D $29 400
1 marks
Answer: B
This question in 9706/12 Feb/March 2016
Q457 · An inexperienced bookkeeper calculated a draft profit for the year ended 31 December 2015… 9706/12 Feb/March 2016
9 An inexperienced bookkeeper calculated a draft profit for the year ended 31 December 2015 of $578 500. He had not accounted for the following: 1 January 2015 31 December 2015 $ $ provision for doubtful debts 12 800 11 300 provision for depreciation 95 000 126 200 What was the revised profit for the year? A $441 000 B $463 600 C $545 800 D $548 800
1 marks
Answer: D
This question in 9706/12 Feb/March 2016
Q458 · The statements of financial position of Goh’s business showed the following: 30 June 2014… 9706/12 Feb/March 2016
12 The statements of financial position of Goh’s business showed the following: 30 June 2014 30 June 2015 net assets $152 000 $184 000 During the year ended 30 June 2015, Goh brought his own motor car into the business at the value of $14 000. The net book value of this motor car at 30 June 2015 was $13 200. He also withdrew $7900 cash from the business bank account. What was the profit for the year ended 30 June 2015? A $25 900 B $26 700 C $37 300 D $38 100
1 marks
Answer: A
This question in 9706/12 Feb/March 2016
Q459 · A business provides the following information 9706/12 Feb/March 2016
21 A business provides the following information. gross margin 20% $ sales 275 325 opening inventory 25 450 closing inventory 55 975 What are the purchases? A $189 735 B $220 260 C $250 785 D $259 963
1 marks
Answer: C
This question in 9706/12 Feb/March 2016
Q460 · A company provided the following information 9706/12 Feb/March 2016
22 A company provided the following information. material cost per unit units $ opening inventory 100 2.00 receipt of new inventory 400 2.10 issued to production 200 The company uses the first in first out (FIFO) method of valuing inventory. What is the cost of material issued to production? A $400 B $410 C $416 D $420
1 marks
Answer: B
This question in 9706/12 Feb/March 2016
Q461 · A company calculates a draft profit for the year of $88 000 9706/11 May/June 2016
8 A company calculates a draft profit for the year of $88 000. This includes the profit margin of $3000 on goods sold on credit but not yet paid for. It also includes $500 profit taken on goods sold to a customer on a sale or return basis. What is the correct gross profit? A $84 500 B $85 000 C $87 500 D $91 000
1 marks
Answer: C
This question in 9706/11 May/June 2016
Q462 · The draft profit for the year for a sole trader was $108 000 before the following were… 9706/11 May/June 2016
9 The draft profit for the year for a sole trader was $108 000 before the following were taken into account. 1 The provision brought forward for doubtful debts was $1850. The provision to carry forward should be $2250. 2 Depreciation of non-current assets had been undercharged by $2000. 3 An accrual of $600 for repairs had been treated as a prepayment. What was the correct profit for the year? A $104 400 B $105 200 C $109 000 D $111 600
1 marks
Answer: A
This question in 9706/11 May/June 2016
Q463 · The following balance appeared on a trial balance at 31 December 2015, after the… 9706/11 May/June 2016
10 The following balance appeared on a trial balance at 31 December 2015, after the preparation of the company’s financial statements. $ stationery 8000 debit What did this represent? A an amount due to the company’s stationery supplier for 2015 B a prepayment made to the stationery supplier at 31 December 2015 C inventory of stationery at 31 December 2014 D the annual stationery charge for 2015
1 marks
Answer: B
This question in 9706/11 May/June 2016
Q464 · At 31 December the following information was available 9706/11 May/June 2016
11 At 31 December the following information was available. $ non-current assets at net book value 10 000 current assets 5 000 provision for doubtful debts (1 500) current liabilities (3 000) It was decided to reduce the provision for doubtful debts to $800. Which effects will this adjustment have on the profit for the year and on net assets? profit for the year net assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: D
This question in 9706/11 May/June 2016
Q465 · The table shows information relating to closing inventory 9706/11 May/June 2016
12 The table shows information relating to closing inventory. $ cost 50 000 realisable value 45 000 costs of realisation 5 000 replacement cost 35 000 What is the value of the closing inventory? A $35 000 B $40 000 C $45 000 D $50 000
1 marks
Answer: B
This question in 9706/11 May/June 2016
Q466 · A business provides the following information 9706/11 May/June 2016
13 A business provides the following information. $ accrued expenses 9 350 accrued income 24 750 prepaid expenses 14 250 prepaid income 32 650 What is the total amount to be included in current liabilities? A $34 100 B $39 000 C $42 000 D $46 900
1 marks
Answer: C
This question in 9706/11 May/June 2016
Q467 · The statement of financial position showed the following balances at 31 December 2015 9706/11 May/June 2016
14 The statement of financial position showed the following balances at 31 December 2015. X Y $ $ capital accounts 20 000 10 000 current accounts 1 000 debit 2 500 credit Net assets at 1 January 2015 were $14 000. Property had been revalued upwards by $12 000 during the year ended 31 December 2015. No drawings had been made during the year. What was the profit for the year ended 31 December 2015? A $2500 B $5500 C $14 500 D $17 500
1 marks
Answer: B
This question in 9706/11 May/June 2016
Q468 · Smith and Jones are in partnership sharing profits and losses in the ratio 3 : 2… 9706/11 May/June 2016
15 Smith and Jones are in partnership sharing profits and losses in the ratio 3 : 2 respectively. Profit for the year was $152 000. Smith was charged interest on drawings of $1650. Jones had a partnership salary of $40 000. What was Smith’s share of residual profit? A $66 210 B $68 190 C $114 210 D $116 190
1 marks
Answer: B
This question in 9706/11 May/June 2016
Q469 · X, Y and Z have been in business sharing profits in the ratio 3 : 2 : 1 9706/11 May/June 2016
16 X, Y and Z have been in business sharing profits in the ratio 3 : 2 : 1. Y decided to retire at the end of the year when the balance on his capital account was $39 400. On that date the assets were revalued upwards by $57 000. The partnership does not account for goodwill. Y took a car valued at $4800 as part of the amount due to him. How much cash did Y receive? A $25 200 B $44 100 C $53 600 D $58 400
1 marks
Answer: C
This question in 9706/11 May/June 2016
Q470 · A company has a bank balance of $20 000 9706/11 May/June 2016
17 A company has a bank balance of $20 000. The company’s equity and reserves are shown. $ ordinary shares of $0.50 each 10 000 capital reserves 5 000 revenue reserves 3 000 The directors wish to pay the maximum dividend possible. How much of the bank balance will be used to pay the dividend? A $3000 B $5000 C $8000 D $20 000
1 marks
Answer: A
This question in 9706/11 May/June 2016
Q471 · A limited company's financial statements contain the following items 9706/11 May/June 2016
19 A limited company's financial statements contain the following items. 1 bonus issue of ordinary shares 2 debenture interest 3 profit for the year 4 profit on disposal of non-current assets Which items would be found in the statement of changes in equity? A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: B
This question in 9706/11 May/June 2016
Q472 · A company issued 25 000 ordinary shares of $0.50 each at a premium of 25% 9706/11 May/June 2016
20 A company issued 25 000 ordinary shares of $0.50 each at a premium of 25%. They had a market value of $1.50 each. What is the value of ordinary share capital in the statement of financial position? A $12 500 B $15 625 C $31 250 D $37 500
1 marks
Answer: A
This question in 9706/11 May/June 2016
Q473 · What might stop financial statements showing a true and fair view? 9706/12 May/June 2016
1 What might stop financial statements showing a true and fair view? A changes in depreciation methods from year to year B changes in dividend policy C creation of a general reserve D inclusion of purchased goodwill in a statement of financial position
1 marks
Answer: A
This question in 9706/12 May/June 2016
Q474 · In an income statement carriage outwards of $5000 has been treated as carriage inwards 9706/12 May/June 2016
8 In an income statement carriage outwards of $5000 has been treated as carriage inwards. Carriage inwards of $3000 has been treated as carriage outwards. What are the effect(s) of these errors on the profit? gross profit profit for the year A overstated by $2000 understated by $2000 B overstated by $8000 no effect C understated by $2000 no effect D understated by $8000 overstated by $8000
1 marks
Answer: C
This question in 9706/12 May/June 2016
Q475 · A company received interest of $8800 during the financial year 9706/12 May/June 2016
9 A company received interest of $8800 during the financial year. Interest of $700 was due at the beginning of the year and $850 at the end of the year. Which entry appeared in the interest received account to make the transfer to the income statement? A $8650 credit B $8650 debit C $8950 credit D $8950 debit
1 marks
Answer: D
This question in 9706/12 May/June 2016
Q476 · Katrina commenced business on 1 January 2015 9706/12 May/June 2016
10 Katrina commenced business on 1 January 2015. For the year ended 31 December 2015, the following information is available. $ drawings 53 500 profit for the year 62 700 revenue 1 500 000 expenses 875 000 What was the cost of sales for the year? A $562 300 B $571 500 C $678 000 D $687 700
1 marks
Answer: A
This question in 9706/12 May/June 2016
Q477 · The following information is available for rent and rates 9706/12 May/June 2016
11 The following information is available for rent and rates. $ prepaid rent at the start of the year 1250 accrued rates at the start of the year 1380 rent and rates income statement amount 8750 prepaid rent at the end of the year 1104 accrued rates at the end of the year 1000 What is the amount paid for rent and rates during the year? A $8516 B $8854 C $8880 D $8984
1 marks
Answer: D
This question in 9706/12 May/June 2016
Q478 · The directors of a company are completing the financial statements for the year ended 30… 9706/12 May/June 2016
12 The directors of a company are completing the financial statements for the year ended 30 April 2016. They discover that the inventory at 1 May 2015 was over-valued by $50 000. What are the effects of correcting this error? retained earnings profit for the year brought forward ended 30 April 2016 at 1 May 2015 A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: C
This question in 9706/12 May/June 2016
Q479 · A company has 1 000 000 ordinary shares of $1 issued at $2.50 9706/12 May/June 2016
16 A company has 1 000 000 ordinary shares of $1 issued at $2.50. It also has a 5% debenture of $300 000. Profit from operations for the year was $465 000. The directors paid an 8% ordinary share dividend during the year. By which amount did the retained earnings increase during the year? A $250 000 B $370 000 C $385 000 D $400 000
1 marks
Answer: B
This question in 9706/12 May/June 2016
Q480 · A company issues 100 000 new $1 ordinary shares at a premium of $0.20 each 9706/12 May/June 2016
17 A company issues 100 000 new $1 ordinary shares at a premium of $0.20 each. Which effect does this have on the statement of financial position? A Equity increases by the nominal value of the shares but decreases by the value of the premium. B Equity increases by the nominal value of the shares only. C Net assets increase by the nominal value of the shares plus the value of the premium. D Net assets increase by the nominal value of the shares but decrease by the value of the premium.
1 marks
Answer: C
This question in 9706/12 May/June 2016
Q481 · The trial balance on 31 December 2015 showed the following information 9706/12 May/June 2016
18 The trial balance on 31 December 2015 showed the following information. $ ordinary share capital ($1 shares) 500 000 retained earnings 300 000 On 1 January 2016 the directors created the general reserve of $70 000. At the same time 200 000 ordinary shares were issued for $300 000. By which amount did the total reserves increase on 1 January 2016? A $100 000 B $170 000 C $300 000 D $370 000
1 marks
Answer: A
This question in 9706/12 May/June 2016
Q482 · A company calculates a draft profit for the year of $88 000 9706/13 May/June 2016
8 A company calculates a draft profit for the year of $88 000. This includes the profit margin of $3000 on goods sold on credit but not yet paid for. It also includes $500 profit taken on goods sold to a customer on a sale or return basis. What is the correct gross profit? A $84 500 B $85 000 C $87 500 D $91 000
1 marks
Answer: C
This question in 9706/13 May/June 2016
Q483 · The draft profit for the year for a sole trader was $108 000 before the following were… 9706/13 May/June 2016
9 The draft profit for the year for a sole trader was $108 000 before the following were taken into account. 1 The provision brought forward for doubtful debts was $1850. The provision to carry forward should be $2250. 2 Depreciation of non-current assets had been undercharged by $2000. 3 An accrual of $600 for repairs had been treated as a prepayment. What was the correct profit for the year? A $104 400 B $105 200 C $109 000 D $111 600
1 marks
Answer: A
This question in 9706/13 May/June 2016
Q484 · The following balance appeared on a trial balance at 31 December 2015, after the… 9706/13 May/June 2016
10 The following balance appeared on a trial balance at 31 December 2015, after the preparation of the company’s financial statements. $ stationery 8000 debit What did this represent? A an amount due to the company’s stationery supplier for 2015 B a prepayment made to the stationery supplier at 31 December 2015 C inventory of stationery at 31 December 2014 D the annual stationery charge for 2015
1 marks
Answer: B
This question in 9706/13 May/June 2016
Q485 · At 31 December the following information was available 9706/13 May/June 2016
11 At 31 December the following information was available. $ non-current assets at net book value 10 000 current assets 5 000 provision for doubtful debts (1 500) current liabilities (3 000) It was decided to reduce the provision for doubtful debts to $800. Which effects will this adjustment have on the profit for the year and on net assets? profit for the year net assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: D
This question in 9706/13 May/June 2016
Q486 · The table shows information relating to closing inventory 9706/13 May/June 2016
12 The table shows information relating to closing inventory. $ cost 50 000 realisable value 45 000 costs of realisation 5 000 replacement cost 35 000 What is the value of the closing inventory? A $35 000 B $40 000 C $45 000 D $50 000
1 marks
Answer: B
This question in 9706/13 May/June 2016
Q487 · A business provides the following information 9706/13 May/June 2016
13 A business provides the following information. $ accrued expenses 9 350 accrued income 24 750 prepaid expenses 14 250 prepaid income 32 650 What is the total amount to be included in current liabilities? A $34 100 B $39 000 C $42 000 D $46 900
1 marks
Answer: C
This question in 9706/13 May/June 2016
Q488 · The statement of financial position showed the following balances at 31 December 2015 9706/13 May/June 2016
14 The statement of financial position showed the following balances at 31 December 2015. X Y $ $ capital accounts 20 000 10 000 current accounts 1 000 debit 2 500 credit Net assets at 1 January 2015 were $14 000. Property had been revalued upwards by $12 000 during the year ended 31 December 2015. No drawings had been made during the year. What was the profit for the year ended 31 December 2015? A $2500 B $5500 C $14 500 D $17 500
1 marks
Answer: B
This question in 9706/13 May/June 2016
Q489 · Smith and Jones are in partnership sharing profits and losses in the ratio 3 : 2… 9706/13 May/June 2016
15 Smith and Jones are in partnership sharing profits and losses in the ratio 3 : 2 respectively. Profit for the year was $152 000. Smith was charged interest on drawings of $1650. Jones had a partnership salary of $40 000. What was Smith’s share of residual profit? A $66 210 B $68 190 C $114 210 D $116 190
1 marks
Answer: B
This question in 9706/13 May/June 2016
Q490 · X, Y and Z have been in business sharing profits in the ratio 3 : 2 : 1 9706/13 May/June 2016
16 X, Y and Z have been in business sharing profits in the ratio 3 : 2 : 1. Y decided to retire at the end of the year when the balance on his capital account was $39 400. On that date the assets were revalued upwards by $57 000. The partnership does not account for goodwill. Y took a car valued at $4800 as part of the amount due to him. How much cash did Y receive? A $25 200 B $44 100 C $53 600 D $58 400
1 marks
Answer: C
This question in 9706/13 May/June 2016
Q491 · A company has a bank balance of $20 000 9706/13 May/June 2016
17 A company has a bank balance of $20 000. The company’s equity and reserves are shown. $ ordinary shares of $0.50 each 10 000 capital reserves 5 000 revenue reserves 3 000 The directors wish to pay the maximum dividend possible. How much of the bank balance will be used to pay the dividend? A $3000 B $5000 C $8000 D $20 000
1 marks
Answer: A
This question in 9706/13 May/June 2016
Q492 · A limited company's financial statements contain the following items 9706/13 May/June 2016
19 A limited company's financial statements contain the following items. 1 bonus issue of ordinary shares 2 debenture interest 3 profit for the year 4 profit on disposal of non-current assets Which items would be found in the statement of changes in equity? A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: B
This question in 9706/13 May/June 2016
Q493 · Inventory costing $1200 has been damaged 9706/11 Oct/Nov 2016
7 Inventory costing $1200 has been damaged. It would normally be sold for $1800. It can be sold for $1700 if repairs are undertaken at a cost of $600. To replace the inventory would cost $1000. At which value should the damaged inventory be shown in the financial statements? A $1000 B $1100 C $1200 D $1800
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2016
Q494 · A company’s trial balance showed trade receivables of $14 600 and an existing provision… 9706/11 Oct/Nov 2016
8 A company’s trial balance showed trade receivables of $14 600 and an existing provision for doubtful debts of $470. It was discovered that the trade receivables included an irrecoverable debt of $500. A contra entry of $400 was also to be made. The provision for doubtful debts is to be maintained at 5% of trade receivables. Which amount for doubtful debts was charged in the income statement? A $215 B $235 C $470 D $685
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q495 · A trader has prepared a draft income statement for the year showing a gross profit of $64… 9706/11 Oct/Nov 2016
10 A trader has prepared a draft income statement for the year showing a gross profit of $64 200. He discovers the following two errors. 1 Closing inventory has been overstated by $2500. 2 Sales returns of $400 have been treated as purchases returns. What is the correct gross profit? A $60 900 B $62 100 C $65 900 D $66 300
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q496 · A business paid $5750 during its trading year for advertising 9706/11 Oct/Nov 2016
11 A business paid $5750 during its trading year for advertising. This amount included $500 in respect of the next financial year. How would the correct treatment of the $500 affect the financial statements? profit for the year net current assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2016
Q497 · A statement of financial position at 31 December 2015 showed the following: $ non-current… 9706/11 Oct/Nov 2016
12 A statement of financial position at 31 December 2015 showed the following: $ non-current assets 18 000 trade receivables 3 000 inventory 1 800 trade payables 3 600 bank 350 credit capital (1 January 2015) 19 100 profit for the year 9 200 What were the owner’s drawings? A $8250 B $8750 C $8950 D $9450
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2016
Q498 · A trader received $15 000 from his credit customers in the first year of trading 9706/11 Oct/Nov 2016
13 A trader received $15 000 from his credit customers in the first year of trading. At the end of the year they still owed $600. Payments to credit suppliers was $3000 and $500 was owing to them at the end of the period. There was no closing inventory of unsold goods. What was the gross profit for the period? A $10 900 B $11 500 C $12 100 D $12 500
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2016
Q499 · Abdul and Omar are in partnership 9706/11 Oct/Nov 2016
14 Abdul and Omar are in partnership. The following information has been extracted from their current accounts. Abdul Omar $ $ balances at 1 January 2015 2 000 debit 3 000 credit drawings for the year 15 000 18 000 balances at 1 January 2016 1 000 credit 4 000 debit What was the total profit for the year ended 31 December 2015? A $29 000 B $33 000 C $37 000 D $39 000
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q500 · J, H and P are in partnership 9706/11 Oct/Nov 2016
15 J, H and P are in partnership. The profit for the year was $80 000. J is entitled to a partnership salary of $5000. They share profits in the ratio of 2 : 2 : 1 but P has guaranteed minimum earnings of $20 000. Which total profit share did J receive? A $27 500 B $32 000 C $32 500 D $35 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2016
Q501 · The issued ordinary share capital of a company at the beginning of a period was $240 000… 9706/11 Oct/Nov 2016
19 The issued ordinary share capital of a company at the beginning of a period was $240 000 (nominal value $0.60 per share). A rights issue of one share for every five held was made during the period at a price of $0.90 per share. At that time the market price was $1.10 per share. What was the issued ordinary share capital after the rights issue? A $288 000 B $292 800 C $312 000 D $328 000
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q502 · A potential investor looks at the financial statements of four companies 9706/11 Oct/Nov 2016
24 A potential investor looks at the financial statements of four companies. Their income statements all show the same level of revenue and profit from operations. The cost of purchasing inventory is increasing. company 1 uses AVCO to value inventory company 2 uses FIFO to value inventory company 3 uses absorption costing company 4 uses marginal costing The investor wishes to invest in companies with the best underlying profitability. Which companies should he select? A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2016
Q503 · An item of capital expenditure has been incorrectly treated as revenue expenditure in the… 9706/12 Oct/Nov 2016
8 An item of capital expenditure has been incorrectly treated as revenue expenditure in the financial statements of a business. What is the effect of this error on the financial statements of the business? assets profit A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2016
Q504 · A company pays or receives the following amounts on the last day of its financial year 9706/12 Oct/Nov 2016
9 A company pays or receives the following amounts on the last day of its financial year. $ deposit paid to a supplier 6500 rental income received in advance 8000 loan repayment 3000 payment for last month’s sales commission 900 Which of these amounts will be included as other receivables in the statement of financial position? A $6500 B $14 500 C $17 500 D $18 400
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2016
Q505 · A sole trader provides the following information 9706/12 Oct/Nov 2016
10 A sole trader provides the following information. start of year end of year $ $ total assets 100 000 135 000 total liabilities excluding owner’s capital (35 000) (40 000) During the year the owner took drawings of $18 000. What was the profit for the year? A $12 000 B $30 000 C $35 000 D $48 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2016
Q506 · How would a transfer to general reserve and the issue of shares at a premium affect the… 9706/12 Oct/Nov 2016
16 How would a transfer to general reserve and the issue of shares at a premium affect the revenue reserves of a limited company? transfer to issue of shares general reserve at a premium A decrease decrease B decrease increase C no effect increase D no effect no effect
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2016
Q507 · A company is formed with the issue of 100 000 6% non-cumulative preference shares of $1… 9706/12 Oct/Nov 2016
17 A company is formed with the issue of 100 000 6% non-cumulative preference shares of $1 each and 300 000 ordinary shares of $1 each issued at a premium of $0.20. It earned profits of $3000, $16 000 and $31 000 in the first three years of trading. The directors wish to pay an ordinary dividend of 5% each year when possible. What value of ordinary dividends does the company actually pay in years 2 and 3? year 2 year 3 $ $ A 7 000 15 000 B 7 000 18 000 C 10 000 15 000 D 10 000 18 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2016
Q508 · A company had an issued share capital of 400 000 ordinary shares of $1 each 9706/12 Oct/Nov 2016
18 A company had an issued share capital of 400 000 ordinary shares of $1 each. It then made a bonus issue of one share for every five held. This was later followed by a rights issue of one share for every three held. What was the balance on the share capital account after these transactions? A $480 000 B $533 333 C $613 333 D $640 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2016
Q509 · Which action will increase the equity of a limited company? 9706/12 Oct/Nov 2016
19 Which action will increase the equity of a limited company? A creating a general reserve B issuing bonus shares C issuing debentures D issuing non-redeemable preference shares
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2016
Q510 · A business uses the AVCO method of inventory valuation 9706/12 Oct/Nov 2016
22 A business uses the AVCO method of inventory valuation. The following transactions took place. 1 March purchased 1000 units at $65 per unit 2 March purchased 1200 units at $66 per unit 4 March sold 1850 units at $68 per unit What was the value of closing inventory? A $22 750 B $22 941 C $23 100 D $23 800
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2016
Q511 · A business had a profit for the year of $450 000 before correcting the following errors 9706/13 Oct/Nov 2016
8 A business had a profit for the year of $450 000 before correcting the following errors. 1 Closing inventory was undervalued by $15 000. 2 Sales returns of $5000 had been recorded as purchases returns. 3 The charge for depreciation was overstated by $20 000. What was the profit after correcting these errors? A $435 000 B $445 000 C $475 000 D $495 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2016
Q512 · A company pays rates annually in advance on 1 April each year 9706/13 Oct/Nov 2016
9 A company pays rates annually in advance on 1 April each year. $4000 is paid on 1 April 2014 and $4800 on 1 April 2015. The company’s accounting year end is 31 December. What is the charge for rates in the 2015 income statement? A $4000 B $4200 C $4600 D $4800
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2016
Q513 · A business has calculated inventory turnover ratio as 8 times 9706/13 Oct/Nov 2016
10 A business has calculated inventory turnover ratio as 8 times. Opening inventory was $25 000 and closing inventory was $28 000. What is the value of purchases? A $209 000 B $215 000 C $221 000 D $227 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2016
Q514 · The following information is available from the financial records of a trader 9706/13 Oct/Nov 2016
11 The following information is available from the financial records of a trader. $ capital at 1 January 2015 65 000 capital introduced on 30 June 2015 20 000 drawings for the year ended 31 December 2015 35 000 capital at 31 December 2015 90 000 What was the profit for the year ended 31 December 2015? A $10 000 B $30 000 C $35 000 D $40 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2016
Q515 · Draft financial statements showed the following: $ profit for the year 18 700 total… 9706/13 Oct/Nov 2016
12 Draft financial statements showed the following: $ profit for the year 18 700 total current assets 41 200 total current liabilities 36 050 It was then decided to create a provision for doubtful debts of $2100. Which figures were shown in the final financial statements? profit for the year current assets current liabilities $ $ $ A 16 600 39 100 36 050 B 16 600 41 200 33 950 C 20 800 41 200 38 150 D 20 800 43 300 36 050
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2016
Q516 · X and Y are in partnership sharing profits and losses in the ratio 3 : 2 respectively 9706/13 Oct/Nov 2016
15 X and Y are in partnership sharing profits and losses in the ratio 3 : 2 respectively. Z was introduced as a partner. Goodwill was valued at $75 000 but is not to be retained in the books of account. Non-current assets were revalued from $300 000 to $250 000. The new profit sharing ratio will be 5 : 3 : 2 respectively. What was the net adjustment in Y’s capital account? A $12 500 credit B $12 500 debit C $27 500 credit D $27 500 debit
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2016
Q517 · A and B are in partnership 9706/13 Oct/Nov 2016
16 A and B are in partnership. The following information relates to 2015. $ profit before appropriation 88 000 interest on drawings: A 1 000 B 1 000 interest on capital: A 3 000 B 1 000 The profit sharing ratio is in accordance with the proportion of the capital account. What is A’s share of the residual profit? A $41 000 B $43 000 C $61 500 D $64 500
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2016
Q518 · The following information is available for a limited company which has 280 000 ordinary… 9706/13 Oct/Nov 2016
19 The following information is available for a limited company which has 280 000 ordinary shares of $0.50 each. $ share premium 70 000 10% debentures 100 000 retained earnings 73 400 general reserve 62 700 What is the value of shareholders’ equity? A $346 100 B $446 100 C $486 100 D $586 100
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2016
Q519 · The following inventory transactions are available for a business 9706/13 Oct/Nov 2016
24 The following inventory transactions are available for a business. opening inventory on 1 January 16 items at $525 each receipts on 3 January 24 items at $675 each issues on 5 January 28 items The business uses the AVCO method to value inventory. What was the value of closing inventory on 7 January? A $6300 B $7200 C $7380 D $8100
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2016
Q520 · The following balances related to Ladha’s business 9706/12 Feb/March 2017
7 The following balances related to Ladha’s business. at 31 March 2016 at 31 March 2015 $ $ total assets 388 000 345 000 total liabilities 84 000 75 000 net assets 304 000 270 000 drawings during the year 22 000 20 000 What was Ladha’s profit for the year ended 31 March 2016? A $12 000 B $32 000 C $36 000 D $56 000
1 marks
Answer: D
This question in 9706/12 Feb/March 2017
Q521 · A trial balance showed a provision for doubtful debts as $1350 9706/12 Feb/March 2017
8 A trial balance showed a provision for doubtful debts as $1350. Trade receivables were $50 320 which included a debt of $500 which was irrecoverable. Which entry was required in the provision for doubtful debts account if the closing balance was to be 5% of trade receivables? A $1141 credit B $1141 debit C $1166 credit D $1166 debit
1 marks
Answer: A
This question in 9706/12 Feb/March 2017
Q522 · A business provides the following information 9706/12 Feb/March 2017
9 A business provides the following information. $ revenue 140 000 opening inventory 22 000 closing inventory 24 500 purchases 120 000 Goods are sold at cost plus 25%. The owner has taken goods for own use but has not recorded these as drawings. What is the value of the goods taken for own use? A $5500 B $10 500 C $12 500 D $17 500
1 marks
Answer: A
This question in 9706/12 Feb/March 2017
Q523 · The draft financial statements of a business show a profit for the year of $64 000 before… 9706/12 Feb/March 2017
10 The draft financial statements of a business show a profit for the year of $64 000 before taking account of the following: 1 the reduction of the provision for doubtful debts by $300 2 the purchase of office stationery costing $2400 which has not been entered in the books; only one-sixth of this stationery was used by the year end. What is the corrected profit for the year? A $61 900 B $63 900 C $64 100 D $64 300
1 marks
Answer: B
This question in 9706/12 Feb/March 2017
Q524 · The table shows transactions relating to a product during July 9706/12 Feb/March 2017
11 The table shows transactions relating to a product during July. There was no opening inventory. units $ (per unit) purchased 50 4 sold 30 10 Of the remaining units, 8 are damaged and therefore have no value. What is the profit for July? A $68 B $100 C $148 D $180
1 marks
Answer: C
This question in 9706/12 Feb/March 2017
Q525 · A trader provides the following financial information for the year ended 31 December 9706/12 Feb/March 2017
12 A trader provides the following financial information for the year ended 31 December. gross margin 20% cost of goods sold $220 000 drawings $7 000 profit for the year $28 000 How much are expenses? A $9000 B $16 000 C $20 000 D $27 000
1 marks
Answer: D
This question in 9706/12 Feb/March 2017
Q526 · The following information is given in the financial statements of a limited company 9706/12 Feb/March 2017
19 The following information is given in the financial statements of a limited company. $ ordinary shares 1 200 000 general reserve 120 000 retained earnings 710 000 8% debentures 400 000 What is the value of total equity? A $1 910 000 B $2 030 000 C $2 310 000 D $2 430 000
1 marks
Answer: B
This question in 9706/12 Feb/March 2017
Q527 · At the start of the year the provision for doubtful debts was $19 600 9706/11 May/June 2017
9 At the start of the year the provision for doubtful debts was $19 600. During the year irrecoverable debts of $12 300 were written off. The provision for doubtful debts at the year end was $15 500. What was the net effect of these items on the profit for the year? A $4100 decrease B $4100 increase C $8200 decrease D $8200 increase
1 marks
Answer: C
This question in 9706/11 May/June 2017
Q528 · The following financial information is available 9706/11 May/June 2017
10 The following financial information is available. $ inventory at 1 January 2016 800 inventory at 31 December 2016 1 010 purchases 9 260 carriage inwards 130 revenue 18 000 discount received 700 other costs 3 880 What are the values of gross profit and profit for the year? gross profit profit for the year $ $ A 8820 4240 B 8820 5640 C 9080 5900 D 9520 5640
1 marks
Answer: B
This question in 9706/11 May/June 2017
Q529 · The following information is extracted from the records of a business 9706/11 May/June 2017
11 The following information is extracted from the records of a business. $ at 1 January 2016 rent paid in advance 4 000 during the year ended 31 December 2016 rent paid 41 000 at 31 December 2016 rent paid in advance 7 000 How much will be charged for rent in the income statement for the year ended 31 December 2016? A $34 000 B $38 000 C $41 000 D $44 000
1 marks
Answer: B
This question in 9706/11 May/June 2017
Q530 · A company has the following: 12 000 ordinary shares of $1 each 10% debenture $10 000 It… 9706/11 May/June 2017
16 A company has the following: 12 000 ordinary shares of $1 each 10% debenture $10 000 It made a loss of $15 000 for the year ended 31 December 2016. An interim ordinary dividend of $0.20 per ordinary share was paid on 30 September 2016. An ordinary dividend of $0.40 per ordinary share was proposed at 31 December 2016. The retained earnings balance in the statement of changes in equity at 31 December 2016 was $20 000. What was the retained earnings balance at 1 January 2016? A $37 400 B $38 400 C $42 200 D $43 200
1 marks
Answer: A
This question in 9706/11 May/June 2017
Q531 · The following information is extracted from the statement of financial position of a… 9706/12 May/June 2017
7 The following information is extracted from the statement of financial position of a business at 31 December 2016. $ bank loan (repayable 2025) 16 200 other payables 1 880 bank overdraft 11 600 capital 20 710 drawings 19 100 inventory 14 610 other receivables 1 420 trade payables 14 110 trade receivables 9 050 What is the value of the net current liabilities? A $1590 B $2510 C $18 710 D $20 320
1 marks
Answer: B
This question in 9706/12 May/June 2017
Q532 · Finn provides the following information 9706/12 May/June 2017
9 Finn provides the following information. $ capital at the start of the year 19 800 profit for the year 24 000 drawings (cash) 19 500 drawings (goods for own use) 1 100 private vehicle transferred to business use 6 000 What was Finn’s capital at the end of the year? A $23 200 B $24 300 C $29 200 D $31 400
1 marks
Answer: C
This question in 9706/12 May/June 2017
Q533 · A business provides the following information 9706/12 May/June 2017
10 A business provides the following information. year 1 year 2 $ $ profit for the year 30 000 40 000 cost of goods sold 240 000 320 000 The owner then discovers that at the end of year 1 the value of inventory was overstated by $2000. What are the correct profits for the year and cost of goods sold figures? year 1 year 2 profit for cost of profit for cost of the year goods sold the year goods sold $ $ $ $ A 28 000 238 000 42 000 322 000 B 28 000 242 000 40 000 320 000 C 28 000 242 000 42 000 318 000 D 32 000 238 000 38 000 318 000
1 marks
Answer: C
This question in 9706/12 May/June 2017
Q534 · Sam was unable to conduct a physical count of inventory at 31 December 2016 9706/12 May/June 2017
11 Sam was unable to conduct a physical count of inventory at 31 December 2016. On 3 January 2017 inventory had been sold to Abdul for $11 950. The cost price of this inventory had been $9560. On 4 January 2017 inventory had been returned by Sita. It had been sold for $2390. The cost price of this inventory was $1912. Sam valued his inventory at 5 January 2017 at cost, $59 750. What was the value of inventory at 31 December 2016? A $50 190 B $52 012 C $67 398 D $69 310
1 marks
Answer: C
This question in 9706/12 May/June 2017
Q535 · A trader had the following transactions in March 2017 9706/13 May/June 2017
2 A trader had the following transactions in March 2017. $ cash sales for the month 6 900 credit sales invoiced in March 46 200 credit sales in March not yet invoiced 800 customer orders received on 31 March 1 200 goods sent to a customer on 1 March on sale or return 1 400 What is the amount of revenue to appear in the income statement for March 2017? A $53 100 B $53 900 C $54 500 D $55 700
1 marks
Answer: B
This question in 9706/13 May/June 2017
Q536 · A business maintains a mark-up of 40% 9706/13 May/June 2017
9 A business maintains a mark-up of 40%. The following information was available for the year. $ revenue 280 000 inventory at start 44 000 purchases 175 000 What was the value of closing inventory? A $19 000 B $37 000 C $51 000 D $69 000
1 marks
Answer: A
This question in 9706/13 May/June 2017
Q537 · A business does not include a prepayment for rent receivables in its financial statements… 9706/13 May/June 2017
10 A business does not include a prepayment for rent receivables in its financial statements at the end of the year. Which effects does this have? current assets current liabilities profit for the year A no effect overstated understated B no effect understated overstated C overstated no effect overstated D understated no effect overstated
1 marks
Answer: B
This question in 9706/13 May/June 2017
Q538 · The following is an extract from the trial balance of a business at 31 May 2017 9706/13 May/June 2017
11 The following is an extract from the trial balance of a business at 31 May 2017. $ trade receivables 72 000 provision for doubtful debts 3 250 A customer owing $5000 has been declared bankrupt. The provision for doubtful debts is to be maintained at 5% of trade receivables. Which amount should be included in the financial statements at 31 May 2017? income statement statement of financial position (expense) (current assets) $ $ A 3 350 expense 63 650 B 3 350 expense 66 900 C 5 100 expense 63 650 D 5 100 expense 66 900
1 marks
Answer: C
This question in 9706/13 May/June 2017
Q539 · L and M are in partnership 9706/13 May/June 2017
13 L and M are in partnership. Their profit and loss appropriation account shows the following. L M total $ $ $ interest on capital 1 600 1 800 3 400 interest charged on drawings 500 400 900 partners’ salaries 2 000 3 000 5 000 share of profit 8 000 12 000 20 000 What is the profit for the year before appropriations? A $17 500 B $22 500 C $27 500 D $29 300
1 marks
Answer: C
This question in 9706/13 May/June 2017
Q540 · A company has a debenture (2020) 9706/13 May/June 2017
15 A company has a debenture (2020). Which description of this is correct at 31 December 2016? A a current liability with a fixed rate of interest B a current liability with a variable rate of interest C a non-current liability with a fixed rate of interest D a non-current liability with a variable rate of interest
1 marks
Answer: C
This question in 9706/13 May/June 2017
Q541 · A limited company made the following issues of shares 9706/13 May/June 2017
16 A limited company made the following issues of shares. bonus issue of 20 000 ordinary shares of $0.50 each rights issue of 10 000 ordinary shares of $0.50 each at a price of $0.75 each By how much did the issues increase the equity of the company? A $5000 B $7500 C $15 000 D $17 500
1 marks
Answer: B
This question in 9706/13 May/June 2017
Q542 · What would not be included in a statement of changes in equity for a limited company? 9706/13 May/June 2017
17 What would not be included in a statement of changes in equity for a limited company? A dividends paid B issue of ordinary share capital C profit for the year D repayment of a debenture
1 marks
Answer: D
This question in 9706/13 May/June 2017
Q543 · A business values inventory using the AVCO method 9706/13 May/June 2017
21 A business values inventory using the AVCO method. The following information is available. August 1 inventory of 6 units at $14.40 each 4 purchased 9 units at $18.40 each 6 sold 5 units at $20.20 each What was the cost of the goods sold? A $72 B $84 C $92 D $101
1 marks
Answer: B
This question in 9706/13 May/June 2017
Q544 · The owner of a transport business purchased a motor vehicle 9706/11 Oct/Nov 2017
5 The owner of a transport business purchased a motor vehicle. This was charged to the motor expenses account. What were the effects of this on the end-of-year statement of financial position? non-current assets current assets capital account A overstated no effect overstated B overstated overstated no effect C understated no effect understated D understated understated no effect
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2017
Q545 · X sent goods to Y on a sale or return basis but treated them as a sale of $1200 9706/11 Oct/Nov 2017
7 X sent goods to Y on a sale or return basis but treated them as a sale of $1200. The goods had a cost price of $750. A trial balance was extracted from the ledger and the following balances were included. account $ revenue 31 250 trade receivables 14 100 Inventory had been valued at $2300. What should have been the correct values? revenue trade receivables inventory $ $ $ A 30 050 12 900 3050 B 30 050 13 650 3050 C 30 800 13 650 3500 D 30 800 14 850 3500
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2017
Q546 · A business prepares its financial statements on 31 December 9706/11 Oct/Nov 2017
10 A business prepares its financial statements on 31 December. Insurance premiums paid were as follows. date paid period covered $ January 2015 1 July 2014 to 31 December 2014 940 July 2015 1 January 2015 to 30 June 2015 1120 January 2016 1 July 2015 to 31 December 2015 1245 March 2016 1 January 2016 to 30 June 2016 1880 Which amount should be shown in the income statement for the year ended 31 December 2015? A $1120 B $2060 C $2365 D $3305
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2017
Q547 · Closing inventory has been overvalued 9706/11 Oct/Nov 2017
12 Closing inventory has been overvalued. What is the effect on the financial statements? net current assets profit from operations A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2017
Q548 · The following information is available for a partnership at 31 December 2016 9706/11 Oct/Nov 2017
13 The following information is available for a partnership at 31 December 2016. $ residual loss 3 000 total salaries to partners 5 000 total interest on capital 27 000 total drawings 14 000 total interest on drawings 700 How much is the profit for the year? A $14 300 B $20 300 C $28 300 D $34 300
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2017
Q549 · A company’s capital employed consists of ordinary shares of $1 each and retained earnings… 9706/11 Oct/Nov 2017
15 A company’s capital employed consists of ordinary shares of $1 each and retained earnings of $50 000. The following information is available for the year ended 31 December. $ profit from operations 47 000 finance costs 3 000 profit for the year 44 000 Return on capital employed was 10%. How many ordinary shares had been issued? A 390 000 B 420 000 C 440 000 D 470 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2017
Q550 · When is a share premium account opened? 9706/11 Oct/Nov 2017
16 When is a share premium account opened? A when shares are issued at a price above nominal value B when a bonus issue is made C when shares are sold at a premium by shareholders D when shares have a market value above cost at the year end
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2017
Q551 · A company has ordinary share capital of $80 000 9706/11 Oct/Nov 2017
17 A company has ordinary share capital of $80 000. Each share has a nominal value of $0.25. A dividend of $0.06 per share is paid. What is the total dividend paid? A $1200 B $4800 C $15 200 D $19 200
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2017
Q552 · On 1 January 2016, a company’s total equity was $56 000 9706/11 Oct/Nov 2017
18 On 1 January 2016, a company’s total equity was $56 000. The company made a profit for the year of $13 000, and paid a dividend of $2000. At the year end, $5000 was transferred to the general reserve and the directors proposed a final dividend of $4000. What was the total equity on 31 December 2016? A $58 000 B $62 000 C $67 000 D $68 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2017
Q553 · The following information is available for the inventory of a business 9706/11 Oct/Nov 2017
21 The following information is available for the inventory of a business. July 1 opening inventory 60 units at $4.50 per unit 15 issued 40 units 23 purchased 120 units at $5.20 per unit 29 issued 65 units What is the value of the inventory on 31 July based on AVCO? A $337.50 B $363.75 C $382.50 D $390.00
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2017
Q554 · The following information is available 9706/12 Oct/Nov 2017
7 The following information is available. $ provision for doubtful debts at the beginning of the year 6 250 trade receivables at the end of the year 93 750 Provision for doubtful debts is to be maintained at 6% of trade receivables. Which effect will the provision for doubtful debts have on profit for the year in the income statement? A decrease by $625 B decrease by $5625 C increase by $625 D increase by $5625
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2017
Q555 · Hedley has 100 items of inventory in his warehouse and five more with a customer on a… 9706/12 Oct/Nov 2017
9 Hedley has 100 items of inventory in his warehouse and five more with a customer on a sale or return basis. He provides the following information. $ per unit historic cost paid 60 selling price 85 current replacement cost 65 Which value should appear in the statement of financial position for inventory? A $6000 B $6300 C $6825 D $8500
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2017
Q556 · A business does not keep complete accounting records 9706/12 Oct/Nov 2017
10 A business does not keep complete accounting records. The following information is known for the year. $ capital at start 52 000 capital at end 55 000 drawings 13 000 capital introduced 25 000 What is the profit or loss for the year? A loss $9000 B profit $9000 C loss $15 000 D profit $15 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2017
Q557 · A business has 500 items of inventory at a cost price of $3 each 9706/12 Oct/Nov 2017
11 A business has 500 items of inventory at a cost price of $3 each. The selling price per unit is based on a mark-up of 20%. Before sale, the items need to be repaired at a total cost of $400. What is the net realisable value of the inventory? A $1400 B $1475 C $2200 D $2275
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2017
Q558 · The following information is available for the year ended 31 December 2016 9706/12 Oct/Nov 2017
12 The following information is available for the year ended 31 December 2016. $ revenue 75 000 purchases 32 000 carriage inwards 5 400 carriage outwards 4 500 inventory at 1 January 2016 6 300 inventory at 31 December 2016 7 600 What was the gross profit for the year ended 31 December 2016? A $36 300 B $37 200 C $38 900 D $39 800
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2017
Q559 · A partnership maintains capital accounts and current accounts 9706/12 Oct/Nov 2017
13 A partnership maintains capital accounts and current accounts. Which statements are correct? 1 The capital accounts show the total amount owed to each partner. 2 The capital accounts represent the retained earnings of the business. 3 The capital and current accounts equal the net assets. A 1 and 2 B 1 and 3 C 2 only D 3 only
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2017
Q560 · A partnership provides the following financial information for the year ended 30 June 2017 9706/12 Oct/Nov 2017
16 A partnership provides the following financial information for the year ended 30 June 2017. $ profit from operations 240 000 bank interest payable 21 000 interest on capital 15 000 drawings 50 000 partnership salaries 45 000 What is the residual balance of profits to be appropriated between the partners? A $109 000 B $154 000 C $159 000 D $204 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2017
Q561 · From which accounts can a company pay dividends? 9706/12 Oct/Nov 2017
18 From which accounts can a company pay dividends? 1 general reserve 2 retained earnings 3 revaluation reserve 4 share capital A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2017
Q562 · A company provides the following data on 1 January 2016 9706/12 Oct/Nov 2017
19 A company provides the following data on 1 January 2016. $ 10% debentures (2020) 200 000 bank loan (2017) 130 000 bank loan (2018) 10 000 bank overdraft 24 000 What is the total value of non-current liabilities at 31 December 2016? A $154 000 B $210 000 C $340 000 D $364 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2017
Q563 · Bradshaw does not keep proper books of account 9706/12 Oct/Nov 2017
21 Bradshaw does not keep proper books of account. The following information is available for the year. cost of sales $750 000 mark-up 20% cash sales $300 000 trade receivables $46 000 What are total sales and trade receivables turnover? trade total sales receivables $ turnover (days) A 900 000 19 B 900 000 28 C 937 500 18 D 937 500 27
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2017
Q564 · The financial statements of a company showed the following 9706/12 Oct/Nov 2017
22 The financial statements of a company showed the following. $ current liabilities 15 000 non-current liabilities 40 000 ordinary shares 120 000 general reserve 10 000 retained earnings 46 000 interest paid 11 000 Profit for the year was $23 000. What was the return on capital employed? A 10.65% B 13.07% C 15.74% D 19.32%
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2017
Q565 · A trader’s accounts showed a gross profit for the year of $32 500 9706/13 Oct/Nov 2017
8 A trader’s accounts showed a gross profit for the year of $32 500. After the draft financial statements were prepared, it was found that the opening inventory had been overstated by $2400 and the closing inventory had been understated by $3400. What is the corrected gross profit for the year? A $26 700 B $31 500 C $33 500 D $38 300
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2017
Q566 · At 1 January 2016 a company had the trade receivables totalling $45 000 9706/13 Oct/Nov 2017
9 At 1 January 2016 a company had the trade receivables totalling $45 000. At 31 December 2016 the trade receivables totalled $32 800 after writing off irrecoverable debts. The company policy is to maintain a provision for doubtful debts of 5%. On 1 March 2016 the company was owed $7750 by a customer. The customer could only pay 40% of the debt. The balance was written off as irrecoverable. What was the net expense in the income statement for the year ended 31 December 2016 for irrecoverable and doubtful debts? A $3010 B $4040 C $5260 D $6290
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2017
Q567 · A sole trader withdraws goods for his own use 9706/12 Feb/March 2018
6 A sole trader withdraws goods for his own use. How does this affect his financial statements? income statement statement of financial position A decrease closing inventories decrease drawings B decrease cost of goods sold increase drawings C increase cost of goods sold decrease drawings D increase sales revenue increase drawings
1 marks
Answer: B
This question in 9706/12 Feb/March 2018
Q568 · A company has a year-end of 31 December 9706/12 Feb/March 2018
9 A company has a year-end of 31 December. Its inventory records on that date showed an inventory of 600 units with a cost of $10 each. A fire on 31 December had totally destroyed 100 units and caused a further 50 units to be damaged. These would cost $7 each to be repaired. The inventory records had not been adjusted for the fire. The selling price is $15 per unit. What is the value of the inventory to be used in the financial statements at 31 December? A $4500 B $4850 C $4900 D $5400
1 marks
Answer: C
This question in 9706/12 Feb/March 2018
Q569 · A business has a draft profit for the year of $182 750 9706/12 Feb/March 2018
10 A business has a draft profit for the year of $182 750. The following adjustments have not yet been made. 1 a decrease of $2800 in the provision for doubtful debts 2 a prepayment of rent by the tenant of $3900 at the year-end What is the actual profit for the year? A $176 050 B $181 650 C $183 850 D $189 450
1 marks
Answer: B
This question in 9706/12 Feb/March 2018
Q570 · Opening inventory is found to be overstated by $8000 and closing inventory is overstated… 9706/11 May/June 2018
4 Opening inventory is found to be overstated by $8000 and closing inventory is overstated by $6500. What is the effect of the correction of these errors on profit for the year? A decrease of $1500 B decrease of $14 500 C increase of $1500 D increase of $14 500
1 marks
Answer: C
This question in 9706/11 May/June 2018
Q571 · During the past month, a business lost some inventory because of theft 9706/11 May/June 2018
11 During the past month, a business lost some inventory because of theft. The table shows the trading results for the month. $ opening inventory, at cost 50 000 purchases 220 000 sales 300 000 closing inventory, at cost 16 000 The mark-up was 25%. What was the cost price of the stolen inventory? A $13 000 B $14 000 C $29 000 D $34 000
1 marks
Answer: B
This question in 9706/11 May/June 2018
Q572 · At the beginning of the financial year inventory was valued at $15 000 9706/12 May/June 2018
11 At the beginning of the financial year inventory was valued at $15 000. During the year, sales of $21 000 and purchases of $18 000 were made. Unfortunately, all inventory was stolen on the last day of the financial year. Goods are marked up by 50% to calculate selling price. What is the cost of the stolen inventory? A $7500 B $11 000 C $19 000 D $22 500
1 marks
Answer: C
This question in 9706/12 May/June 2018
Q573 · The following summarised information has been taken from the statement of financial… 9706/12 May/June 2018
13 The following summarised information has been taken from the statement of financial position of a partnership. $ non-current assets 42 000 capital accounts 36 000 current accounts (debit) 6 000 current liabilities 8 000 non-current liabilities 15 000 What is the value of current assets? A $5000 B $6000 C $11 000 D $23 000
1 marks
Answer: C
This question in 9706/12 May/June 2018
Q574 · X and Y had been in partnership for some years when Z was admitted as a partner 9706/12 May/June 2018
14 X and Y had been in partnership for some years when Z was admitted as a partner. On that date the premises account was debited with $120 000 following a revaluation. Profits were shared equally both before and after Z’s admission. What were the credit entries recording the revaluation? A capital accounts X $40 000, Y $40 000, Z $40 000 B capital accounts X $60 000, Y $60 000 C current accounts X $40 000, Y $40 000, Z $40 000 D current accounts X $60 000, Y $60 000
1 marks
Answer: B
This question in 9706/12 May/June 2018
Q575 · How should inventory be valued according to the prudence concept? 9706/13 May/June 2018
1 How should inventory be valued according to the prudence concept? A cost price only B lower of cost and net realisable value C replacement cost only D lower of replacement cost and revaluation cost
1 marks
Answer: B
This question in 9706/13 May/June 2018
Q576 · How is a decrease in the provision for doubtful debts recorded? 9706/13 May/June 2018
6 How is a decrease in the provision for doubtful debts recorded? in the provision for in the income statement doubtful debts account A added to gross profit credit B added to gross profit debit C subtracted from gross profit credit D subtracted from gross profit debit
1 marks
Answer: B
This question in 9706/13 May/June 2018
Q577 · A company’s year-end is 30 June, but the inventory could not be counted until 6 July 9706/13 May/June 2018
7 A company’s year-end is 30 June, but the inventory could not be counted until 6 July. The inventory valuation at this date was $86 500. The table shows the inventory movements between 30 June and 6 July. $ sales (at cost) 1750 purchases 1550 returns inwards at cost 310 returns outwards 190 What was the value of inventory at 30 June? A $86 180 B $86 420 C $86 580 D $86 820
1 marks
Answer: C
This question in 9706/13 May/June 2018
Q578 · During the month a company lost a quantity of inventory in a burglary 9706/13 May/June 2018
10 During the month a company lost a quantity of inventory in a burglary. The table shows the company’s results for the month. $ opening inventory, at cost 30 000 purchases 210 000 revenue 330 000 closing inventory, at cost 4 000 A gross profit on all sales of 30% had been achieved. What was the cost of the inventory lost in the burglary? A $4000 B $5000 C $9000 D $13 000
1 marks
Answer: B
This question in 9706/13 May/June 2018
Q579 · A company paid an ordinary share dividend of $15 000 in the year 9706/13 May/June 2018
14 A company paid an ordinary share dividend of $15 000 in the year. Where would it appear in the financial statements? A as a finance cost in the income statement B as an administrative expense in the income statement C under retained earnings in the statement of changes in equity D under share capital in the statement of changes in equity
1 marks
Answer: C
This question in 9706/13 May/June 2018
Q580 · What would result in cash coming into a business? 9706/11 Oct/Nov 2018
7 What would result in cash coming into a business? A a transfer to general reserve B an issue of bonus shares C proceeds from the sale of a non-current asset D the revaluation of an asset
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2018
Q581 · A sole trader has the following information available for rent and rates for a year 9706/11 Oct/Nov 2018
8 A sole trader has the following information available for rent and rates for a year. $ opening accrual 750 bank payments during the year 2650 closing prepayment 850 What is the rent and rates expense to be included in the income statement for the year? A $1050 B $2550 C $2750 D $4250
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2018
Q582 · A company sells goods at a mark-up of 25% 9706/11 Oct/Nov 2018
9 A company sells goods at a mark-up of 25%. The following information was available at the end of the financial year. goods in warehouse $300 000 (cost) goods sent on sale or return $200 000 (at invoice price) What was the value of closing inventory in the financial statements? A $300 000 B $450 000 C $460 000 D $500 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2018
Q583 · X started a business 3 years ago and now has a capital of $175 000 9706/11 Oct/Nov 2018
10 X started a business 3 years ago and now has a capital of $175 000. Over that period his profits have been $73 000 and his drawings $52 000. In year 2 he introduced cash of $35 000 and in year 3 he took out of the business, for his own use, a non-current asset with a net book value of $4000. How much capital did he start the business with? A $67 000 B $115 000 C $123 000 D $158 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2018
Q584 · P and Q are in partnership sharing profits and losses equally 9706/11 Oct/Nov 2018
12 P and Q are in partnership sharing profits and losses equally. The following information is available in respect of P. $ current account credit balance at start of the year 20 150 share of asset revaluation 10 000 drawings 10 200 The total partnership profit for the year was $130 000. Partnership salaries were P $20 000, Q $30 000. What was the balance on the current account of P at the end of the year? A $10 350 B $69 950 C $79 950 D $90 350
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2018
Q585 · Dele and Iyabo are partners in a business and share profits in the ratio of 3 : 1 9706/11 Oct/Nov 2018
13 Dele and Iyabo are partners in a business and share profits in the ratio of 3 : 1. Their profit for the year is $80 000. The following information is available. Dele Iyabo $ $ interest on capital 3000 2500 interest on drawings 500 1000 How will the residual profit be shared? Dele Iyabo $ $ A 57 000 19 000 B 57 500 18 500 C 62 500 21 500 D 63 000 21 000
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2018
Q586 · A business values its inventory using the FIFO method 9706/11 Oct/Nov 2018
23 A business values its inventory using the FIFO method. The following transactions took place. month units April opening inventory 700 at $190 each May purchases 500 at $220 each June sales 400 at $400 each What was the value of the closing inventory at the end of June? A $152 000 B $162 000 C $167 000 D $176 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2018
Q587 · A company has the following balances 9706/12 Oct/Nov 2018
9 A company has the following balances. $ trade receivables at 31 December 2017 125 400 provision for doubtful debts at 1 January 2017 1 800 During the year ended 31 December 2017 debts of $20 500 had been written off. The company provides for doubtful debts at a rate of 5% of trade receivables at each year end. Which expense for doubtful debts was included in the income statement for the year ended 31 December 2017? A $3445 B $4470 C $5245 D $6270
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2018
Q588 · How are purchases calculated when proper accounting records have not been kept? 9706/12 Oct/Nov 2018
10 How are purchases calculated when proper accounting records have not been kept? A sales × (1 – margin) – closing inventory + opening inventory B sales × (1 – margin) + closing inventory – opening inventory C sales × (1 – mark-up) – closing inventory + opening inventory D sales × (1 – mark-up) + closing inventory – opening inventory
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2018
Q589 · The draft financial statements for a business included an inventory valued at $550 000 9706/12 Oct/Nov 2018
11 The draft financial statements for a business included an inventory valued at $550 000. This valuation included damaged items which originally cost $50 000. These could be sold for $15 000 provided that $5000 is spent on repairs. What is the correct inventory valuation? A $490 000 B $500 000 C $510 000 D $515 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2018
Q590 · A trader took out a 6% bank loan of $30 000 on 1 November 2017, to be repaid in full in… 9706/12 Oct/Nov 2018
12 A trader took out a 6% bank loan of $30 000 on 1 November 2017, to be repaid in full in 10 years’ time. Interest is to be paid annually. No interest had been paid by 30 April 2018. How should this be recorded in the statement of financial position at 30 April 2018? current non-current liabilities liabilities $ $ A 0 30 000 B 900 30 000 C 1 800 30 000 D 30 900 0
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2018
Q591 · A business has trade receivables of $52 000 at the year-end 9706/13 Oct/Nov 2018
9 A business has trade receivables of $52 000 at the year-end. The existing provision for doubtful debts is $3000. The provision for doubtful debts is to be maintained at 5% of trade receivables. What is the effect of adjusting the provision? on profit on current assets A decrease by $2600 decrease by $400 B decrease by $2600 decrease by $2600 C increase by $400 decrease by $400 D increase by $400 increase by $400
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2018
Q592 · A business provided the following information for two years 9706/13 Oct/Nov 2018
11 A business provided the following information for two years. year 1 year 2 $ $ non-current assets 9 000 12 000 net current assets 1 000 2 000 There were no non-current liabilities. The drawings in year 1 were $5000 and in year 2 were $3000. What was the profit for year 2? A $1000 B $4000 C $5000 D $7000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2018
Q593 · A limited company provided the following information 9706/13 Oct/Nov 2018
16 A limited company provided the following information. $ retained earnings at the start of the year 244 000 retained earnings at the end of the year 286 000 finance costs 12 000 dividend paid 80 000 dividend proposed 50 000 What is the profit or loss from operations? A $122 000 B $134 000 C $172 000 D $184 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2018
Q594 · A business paid an annual rent of $24 000 9706/12 Feb/March 2019
9 A business paid an annual rent of $24 000. At 1 January 2018 there was accrued rent of $4000. Rental payments were as follows. $ 1 January 2018 12 000 1 July 2018 10 000 1 September 2018 13 000 How was rent recorded in the financial statements at 31 December 2018? income statement other receivables other payables $ $ $ A 24 000 7 000 nil B 24 000 nil 7 000 C 35 000 11 000 nil D 35 000 nil 11 000
1 marks
Answer: A
This question in 9706/12 Feb/March 2019
Q595 · At the year-end, a business has some damaged goods in inventory 9706/12 Feb/March 2019
10 At the year-end, a business has some damaged goods in inventory. The following information is available. 1 The goods were purchased for $8500. 2 If the goods are repaired, they can be sold for $10 400. The business will have to pay $2000 repairing cost and pay $300 to a salesman. 3 The same quantity of damaged goods can be purchased from the supplier for $8200. What is the value of the damaged goods at the year-end? A $8100 B $8200 C $8400 D $8500
1 marks
Answer: A
This question in 9706/12 Feb/March 2019
Q596 · A company undervalued the closing inventory for its current accounting period 9706/12 Feb/March 2019
11 A company undervalued the closing inventory for its current accounting period. How did this affect gross profit? current period following period A no effect no effect B understated overstated C understated no effect D understated understated
1 marks
Answer: B
This question in 9706/12 Feb/March 2019
Q597 · For the year ended 31 December 2018, Sim’s net assets increased by $1210 9706/12 Feb/March 2019
12 For the year ended 31 December 2018, Sim’s net assets increased by $1210. The following transactions took place during 2018. 1 Payments out of Sim’s personal bank account: rent for business office $3600, rent for personal residence $2000. 2 Drawing of goods: with a cost $6200 and sales value $7700. 3 Drawing of cash: $9750. What was the profit for the year ended 31 December 2018? A $11 560 B $13 560 C $15 060 D $15 160
1 marks
Answer: B
This question in 9706/12 Feb/March 2019
Q598 · Meena was a sole trader 9706/12 Feb/March 2019
13 Meena was a sole trader. On 1 July 2018, Hanna entered into a partnership with her sharing profits equally. Profit for the year ended 31 December 2018 was $168 000 accruing evenly over the year. An irrecoverable debt of $8000 was incurred during March 2018 and it was agreed that this would be paid for by Meena. What is Hanna’s share of profit? A $40 000 B $42 000 C $44 000 D $46 000
1 marks
Answer: C
This question in 9706/12 Feb/March 2019
Q599 · Z is admitted as a new partner in the partnership of X and Y 9706/12 Feb/March 2019
14 Z is admitted as a new partner in the partnership of X and Y. He brings the following into the business. $ cash 20 000 inventory 6 000 vehicle 11 000 Interest on capital is calculated at 10% per annum. There is no goodwill on Z’s admission. What is Z’s interest on capital per annum? A $1700 B $2000 C $3100 D $3700
1 marks
Answer: D
This question in 9706/12 Feb/March 2019
Q600 · L and M are in partnership sharing the profits equally 9706/12 Feb/March 2019
15 L and M are in partnership sharing the profits equally. No goodwill account is maintained in the accounts. N joins the partnership and pays $30 000 cash for his share of the goodwill. Profits are to be shared equally between L, M and N. What are the increases in the capital accounts on the admission of N into the partnership? capital accounts L M N $ $ $ A 10 000 10 000 10 000 B – – 30 000 C 15 000 15 000 – D – – –
1 marks
Answer: C
This question in 9706/12 Feb/March 2019
Q601 · Brian sent goods to Ravi on a sale or return basis at a selling price of $5000 9706/11 May/June 2019
9 Brian sent goods to Ravi on a sale or return basis at a selling price of $5000. His selling price is based on a mark-up of 25%. Ravi returned goods with a selling price of $1000 and purchased the remainder. What was the net effect on Brian’s inventory value? A $800 increase B $1000 increase C $3200 decrease D $4000 decrease
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q602 · A business has provided the following information about its inventory 9706/11 May/June 2019
10 A business has provided the following information about its inventory. $ cost price 18 750 cost of repairs required to bring 3 750 the inventory to a saleable condition selling price after the repairs 21 000 Which valuation should be used for inventory in the financial statements? A $15 000 B $17 250 C $22 500 D $24 750
1 marks
Answer: B
This question in 9706/11 May/June 2019
Q603 · A business provided the following information about telephone expenses for the year ended… 9706/11 May/June 2019
11 A business provided the following information about telephone expenses for the year ended 31 December 2018. $ prepaid at 1 January 2018 975 accrued at 1 January 2018 650 bank payments during the year 4875 prepaid at 31 December 2018 1175 accrued at 31 December 2018 545 What was the telephone expense to be included in the income statement for the year ended 31 December 2018? A $3920 B $4570 C $5180 D $5830
1 marks
Answer: B
This question in 9706/11 May/June 2019
Q604 · L and M are in partnership 9706/11 May/June 2019
12 L and M are in partnership. Which item should appear in the partnership appropriation account? A additional capital contributed by M B cash drawings of L and M during the year C salary due to L D salary paid to M’s sister
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q605 · X and Y had been in partnership sharing profits and losses equally 9706/11 May/June 2019
13 X and Y had been in partnership sharing profits and losses equally. On 1 July 2018, Z was admitted as partner and the three partners shared profits and losses equally. On that date assets were revalued and there was a profit on revaluation, $36 000. What were the accounting entries to record the profit on revaluation? A credit X current account $18 000, credit Y current account $18 000 B credit X current account $12 000, credit Y current account $12 000, credit Z current account $12 000 C credit X capital account $18 000, credit Y capital account $18 000 D credit X capital account $12 000, credit Y capital account $12 000, credit Z capital account $12 000
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q606 · P, Q and R are in partnership 9706/11 May/June 2019
14 P, Q and R are in partnership. Q is retiring and the following terms have been agreed. Goodwill is valued at $35 000 but will not be retained in the books of account. Net assets are revalued downwards. Which entries in the capital account of Q record these adjustments? revaluation goodwill of assets A credit credit B credit debit C debit credit D debit debit
1 marks
Answer: B
This question in 9706/11 May/June 2019
Q607 · The provision for doubtful debts at 1 January 2018 was $1580 9706/12 May/June 2019
7 The provision for doubtful debts at 1 January 2018 was $1580. Trade receivables at 31 December 2018 were $44 750. This included a debt of $12 500, considered irrecoverable. The provision for doubtful debts was to be maintained at a rate of 5%. Which entry for doubtful debts was included in the income statement for the year ended 31 December 2018? A $32.50 expense B $32.50 income C $657.50 expense D $657.50 income
1 marks
Answer: A
This question in 9706/12 May/June 2019
Q608 · Which statements about valuing inventory are correct? 9706/12 May/June 2019
8 Which statements about valuing inventory are correct? 1 Any charges for carriage inwards should be included in its cost. 2 Cost should always be compared with the net realisable value. 3 Cost should always be compared with replacement price. A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: B
This question in 9706/12 May/June 2019
Q609 · A sole trader calculated a draft profit for the year of $56 750 9706/12 May/June 2019
9 A sole trader calculated a draft profit for the year of $56 750. He then discovered that discounts received of $580 and discounts allowed of $665 had been recorded on the wrong sides of their respective accounts. What is the correct profit for the year? A $56 580 B $56 665 C $56 835 D $56 920
1 marks
Answer: A
This question in 9706/12 May/June 2019
Q610 · Which item will not appear in the income statement of a sole trader? 9706/12 May/June 2019
10 Which item will not appear in the income statement of a sole trader? A accounting charges B bank loan interest C director’s fee D rental charge for machinery
1 marks
Answer: C
This question in 9706/12 May/June 2019
Q611 · At the end of its financial year a business had trade receivables of $16 000 and a… 9706/13 May/June 2019
8 At the end of its financial year a business had trade receivables of $16 000 and a provision for doubtful debts of $640. The provision is to be maintained at 5%. Which amount is shown in the income statement? A $160 expense B $160 income C $800 expense D $800 income
1 marks
Answer: A
This question in 9706/13 May/June 2019
Q612 · A business provided the following information about general expenses for the year ended… 9706/13 May/June 2019
9 A business provided the following information about general expenses for the year ended 31 March 2019. $ accrued at 1 April 2018 3 975 prepaid at 1 April 2018 2 450 payments made for the year ended 31 March 2019 47 700 accrued at 31 March 2019 6 360 prepaid at 31 March 2019 5 825 What was the amount for general expenses to be included in the income statement for the year ended 31 March 2019? A $45 640 B $46 710 C $48 690 D $49 760
1 marks
Answer: B
This question in 9706/13 May/June 2019
Q613 · A business provides the following information 9706/13 May/June 2019
10 A business provides the following information. debit credit $ $ prepaid expenses 4 620 accrued expenses 8 125 bank balances 14 920 3 612 trade payables 18 148 loan (10 years) 15 000 What is the total for current liabilities? A $26 273 B $26 380 C $29 885 D $44 885
1 marks
Answer: C
This question in 9706/13 May/June 2019
Q614 · A company provided the following information about an item of inventory 9706/13 May/June 2019
11 A company provided the following information about an item of inventory. $ production cost 103 000 delivery cost to be incurred 1 000 expected selling cost 500 expected selling price 102 000 What is the correct inventory valuation? A $100 500 B $102 000 C $103 000 D $104 500
1 marks
Answer: A
This question in 9706/13 May/June 2019
Q615 · A depreciated non-current asset is revalued upwards 9706/11 Oct/Nov 2019
2 A depreciated non-current asset is revalued upwards. What is the effect of this? capital reserve revenue reserve A decrease no effect B increase no effect C no effect decrease D no effect increase
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2019
Q616 · The following information is available for a business 9706/11 Oct/Nov 2019
7 The following information is available for a business. $ trade receivables at 1 January 2018 63 000 provision for doubtful debts at 1 January 2018 1 890 total credit sales for the year 327 000 cash received from credit customers during the year 324 000 after 4% cash discount A provision for doubtful debts of 2% is to be made. Which amount is recorded in the income statement for the year ended 31 December 2018? A $570 expense B $570 income C $840 expense D $840 income
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2019
Q617 · Which items will not appear on an income statement? 9706/11 Oct/Nov 2019
8 Which items will not appear on an income statement? 1 deposit received from a customer for a future delivery 2 interest paid to a supplier on an overdue account 3 inventory at the end of the financial period A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2019
Q618 · The following information is available at the end of the financial year of a sole trader 9706/11 Oct/Nov 2019
9 The following information is available at the end of the financial year of a sole trader. $ non-current assets 41 000 trade receivables 12 500 trade payables 4 500 bank 3 900 credit long-term bank loan (due 2025) 6 000 drawings 2 500 profit for the year 4 200 What was the closing balance on the capital account? A $37 400 B $39 100 C $40 800 D $46 900
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2019
Q619 · The following information about the financial statements of a partnership is given 9706/11 Oct/Nov 2019
13 The following information about the financial statements of a partnership is given. $ profit from operations 160 000 interest on bank loan 14 000 interest credited to capital accounts 15 000 drawings 70 000 partnership salaries 24 000 What is the remaining balance of profits to be appropriated amongst the partners? A $66 000 B $107 000 C $121 000 D $137 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2019
Q620 · A business bought the following units of inventory in May 9706/11 Oct/Nov 2019
22 A business bought the following units of inventory in May. date quantity unit cost 4 May 1000 units $12.00 20 May 1000 units $14.00 28 May 800 units $14.75 1200 units were sold on 22 May for $20 each. The inventory’s net realisable value at 31 May was $24 per unit. There was no opening inventory. What was the value of closing inventory using the AVCO method of valuing inventory? A $21 600 B $21 773 C $22 200 D $38 400
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2019
Q621 · The table shows information for a business at 31 March 2019 9706/12 Oct/Nov 2019
7 The table shows information for a business at 31 March 2019. $ inventory 16 100 trade payables 5 200 other payables 2 000 The information excludes the purchase of $3700 of goods. These goods were delivered on 31 March 2019, but the invoice states that legal title to the goods does not pass until payment is received. Which values should appear in the statement of financial position on 31 March 2019? inventory trade payables other payables $ $ $ A 16 100 5200 2000 B 16 100 5200 5700 C 19 800 5200 5700 D 19 800 8900 2000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2019
Q622 · A business has valued some of its closing inventories at cost 9706/12 Oct/Nov 2019
8 A business has valued some of its closing inventories at cost. Their net realisable value is lower than cost. What is the effect of this error on financial statements? profit for the year current assets A no effect no effect B overstated overstated C understated understated D no effect overstated
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2019
Q623 · The following balances were extracted from a trial balance at 31 March 2019 9706/12 Oct/Nov 2019
9 The following balances were extracted from a trial balance at 31 March 2019. $ total trade receivables 84 600 provision for doubtful debts at 1 April 2018 2 835 irrecoverable debt 1 600 There was a decrease in the provision for doubtful debts, $280, for the year ended 31 March 2019. What was the amount of net trade receivables at 31 March 2019? A $79 885 B $80 445 C $81 485 D $82 045
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2019
Q624 · A business had the following assets and liabilities at the start of the year 9706/12 Oct/Nov 2019
10 A business had the following assets and liabilities at the start of the year. a motor car valued at $2500 inventory which cost $4000 with a sales value of $5800 bank overdraft of $500 a loan to a friend from the business bank account of $1000 What was the capital account balance at the start of the year? A $5000 B $7000 C $8000 D $8800
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2019
Q625 · A sole trader had the following transactions 9706/12 Oct/Nov 2019
11 A sole trader had the following transactions. $ returns outwards 2750 carriage inwards 4820 goods for own use 1460 What was the total effect of these transactions on the cost of sales? A $610 increase B $3530 increase C $6110 decrease D $9030 decrease
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2019
Q626 · A sole trader’s personal expenses had been paid out of the business bank account and… 9706/12 Oct/Nov 2019
12 A sole trader’s personal expenses had been paid out of the business bank account and included in his income statement. What was the effect of this on the profit and capital? profit capital A no effect no effect B no effect overstated C understated no effect D understated understated
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2019
Q627 · A warehouse was damaged by fire on 31 March and some of the inventory was destroyed 9706/12 Oct/Nov 2019
13 A warehouse was damaged by fire on 31 March and some of the inventory was destroyed. The following information is available. $ inventory at cost on 1 January 6 000 inventory at cost on 31 March after fire 3 200 sales during the period 14 700 purchases during the period 9 500 The business uses a mark-up of 33.33%. What was the value of the inventory destroyed? A $1275 B $1800 C $2000 D $2500
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2019
Q628 · P and Q are in partnership 9706/12 Oct/Nov 2019
14 P and Q are in partnership. R was admitted as a partner on 1 July 2018, and the profit and loss sharing ratio among P, Q and R was 2 : 2 : 1 respectively. For the purpose of R’s admission, the partners agreed: goodwill would be valued at $20 000, but not retained in the books of account R would introduce cash, $40 000, and motor vehicle, $10 000 R would be entitled to an annual salary, $5000. What was R’s capital account balance immediately after his admission? A $36 000 B $46 000 C $51 000 D $54 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2019
Q629 · Hilary and Lee commenced in partnership on 1 January 2018 9706/12 Oct/Nov 2019
15 Hilary and Lee commenced in partnership on 1 January 2018. There was no partnership agreement. They provided the following information. Hilary Lee $ $ capital contributions 5000 6000 loan to partnership – 1000 Profit for the year ended 31 December 2018 before the loan interest was $8850. What was Lee’s share of the profit? A $4400 B $4425 C $4800 D $4827
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2019
Q630 · L, M and N are in partnership sharing profits and losses equally 9706/12 Oct/Nov 2019
16 L, M and N are in partnership sharing profits and losses equally. L retired when the credit balances on her capital and current accounts were $100 000 and $40 000. Partnership assets were revalued upwards by $60 000. L took half of the amount due to her on retirement. The other half was left as a loan to the business. How much was L paid from the partnership bank account on her retirement? A $20 000 B $40 000 C $60 000 D $80 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2019
Q631 · What is the effect on the financial statements if closing inventory is overvalued? 9706/13 Oct/Nov 2019
7 What is the effect on the financial statements if closing inventory is overvalued? profit for the year total assets A understated overstated B overstated overstated C understated understated D overstated understated
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2019
Q632 · A company had the following assets and liabilities at 31 December 2018 9706/13 Oct/Nov 2019
8 A company had the following assets and liabilities at 31 December 2018. $ trade receivables 30 000 trade payables 12 600 short-term bank deposit 8 800 bank loan repayable on 1 May 2019 20 000 bank loan interest unpaid 500 motor vehicle 9 400 What was the working capital? A $5700 B $6200 C $15 100 D $25 700
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2019
Q633 · Why does a trader account for accrued income? 9706/13 Oct/Nov 2019
9 Why does a trader account for accrued income? A so that current liabilities are not overstated B so that current liabilities are not understated C so that profit is not overstated D so that profit is not understated
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2019
Q634 · A sole trader provided the following financial information for the year ended 31 December… 9706/13 Oct/Nov 2019
10 A sole trader provided the following financial information for the year ended 31 December 2018. $ purchases 95 000 returns inwards 3 300 returns outwards 2 100 inventory withdrawn for personal use 5 000 Inventory on 31 December 2018 was valued at $1000 more than on 1 January 2018. What was the cost of sales? A $85 700 B $86 900 C $89 000 D $97 100
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2019
Q635 · A trader has suffered inventory losses due to theft during the year 9706/13 Oct/Nov 2019
11 A trader has suffered inventory losses due to theft during the year. What is necessary to calculate the value of the inventory stolen? 1 amounts banked for sales and spent on purchases 2 amounts spent for business expenses 3 inventory at the beginning and end of the year 4 percentage of mark-up on purchase price A 1, 2 and 3 B 1, 2 and 4 C 1, 3 and 4 D 2, 3 and 4
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2019
Q636 · A business has extracted the following information from its books of account at 31… 9706/13 Oct/Nov 2019
12 A business has extracted the following information from its books of account at 31 December 2018, its first year of trading. $000 carriage inwards 12 carriage outwards 15 closing inventory 86 purchases 286 returns inwards 10 returns outwards 2 revenue 524 What is the gross profit for the year ended 31 December 2018? A $301 000 B $304 000 C $320 000 D $328 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2019
Q637 · Alice and Bharti have been in partnership sharing profits and losses in the ratio of 3 : 2 9706/13 Oct/Nov 2019
13 Alice and Bharti have been in partnership sharing profits and losses in the ratio of 3 : 2. The balances on the partners’ capital accounts at 31 December 2018 are shown. $ Alice 32 000 Bharti 18 000 The partners decided to share profits and losses equally with effect from 1 January 2019. There was no goodwill account in the books. Goodwill is valued at $30 000 and is not to be retained in the books of account. What is the balance on Alice’s capital account after the adjustment for goodwill? A $15 000 B $18 000 C $35 000 D $50 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2019
Q638 · X, Y and Z are in partnership 9706/13 Oct/Nov 2019
14 X, Y and Z are in partnership. What would be shown in the partnership appropriation account? 1 goods taken for personal use of X 2 interest on a loan made by Y 3 interest on drawings made by Z A 1 and 2 B 1 and 3 C 2 only D 3 only
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2019
Q639 · A business makes a provision for doubtful debts equal to 10% of trade receivables 9706/12 Feb/March 2020
8 A business makes a provision for doubtful debts equal to 10% of trade receivables. The provision at 31 March 2018 was $8300. The trade receivables after the provision on 31 March 2019 were $55 800. What is the change in the provision over the year? A $2100 decrease B $2100 increase C $2720 decrease D $2720 increase
1 marks
Answer: A
This question in 9706/12 Feb/March 2020
Q640 · A trader sent goods to a customer on a sale or return basis 9706/12 Feb/March 2020
9 A trader sent goods to a customer on a sale or return basis. At the trader’s year end he had not heard if the customer had accepted the goods. Where should the value of goods be included in the trader’s books of account at the year end? A inventory and sales revenue B inventory only C sales revenue and trade receivables D sales revenue only
1 marks
Answer: B
This question in 9706/12 Feb/March 2020
Q641 · On 1 May 2018 Trevor had a debit balance of $3000 on his rent receivable account 9706/12 Feb/March 2020
10 On 1 May 2018 Trevor had a debit balance of $3000 on his rent receivable account. Rent received during the year was as follows. $ 28 May 2018 18 000 30 November 2018 16 000 On 30 April 2019, $4000 was owing to Trevor for rent for the period ended 30 April 2019. Which entry should be made in the income statement for rent receivable for the year ended 30 April 2019? A $33 000 B $35 000 C $38 000 D $41 000
1 marks
Answer: B
This question in 9706/12 Feb/March 2020
Q642 · A sole trader makes a profit for the year of $31 000, after taking the following items… 9706/12 Feb/March 2020
11 A sole trader makes a profit for the year of $31 000, after taking the following items into account. $ carriage inwards 2 600 decrease in provision for doubtful debts 1 500 discount received 2 000 other expenses 28 000 profit on disposal of non-current asset 300 What was the gross profit for the year? A $55 200 B $55 500 C $56 700 D $57 800
1 marks
Answer: A
This question in 9706/12 Feb/March 2020
Q643 · X and Y are in partnership sharing profit and losses equally 9706/12 Feb/March 2020
12 X and Y are in partnership sharing profit and losses equally. Y’s opening current account balance was $1350 debit. The residual profit for the year was $23 500. Y was entitled to the following. $ interest on capital 1 200 salary 14 500 Y’s drawings during the year were $25 000. What is the closing balance of Y’s current account at the year end? A $1100 credit B $1100 debit C $3800 credit D $3800 debit
1 marks
Answer: A
This question in 9706/12 Feb/March 2020
Q644 · L and M are in partnership, sharing profits and losses in proportion to their capital… 9706/12 Feb/March 2020
14 L and M are in partnership, sharing profits and losses in proportion to their capital invested. The following information is available: $ capital: L 68 000 M 102 000 profit for the year before appropriation 28 900 drawings: L 8 000 M 12 000 No interest is charged on drawings up to $10 000 for each partner. Interest at a rate of 5% is charged on any drawings in excess of $10 000. What was L’s share of residual profit? A $11 520 B $11 600 C $11 800 D $11 960
1 marks
Answer: B
This question in 9706/12 Feb/March 2020
Q645 · What is a purpose of financial statements? 9706/11 May/June 2020
8 What is a purpose of financial statements? A to aid managers to manage the business B to allow the owner to take drawings C to ensure a profit is made D to ensure accuracy of the double entry
1 marks
Answer: A
This question in 9706/11 May/June 2020
Q646 · An electricity accrual of $375 was treated as a prepayment when preparing a trader’s… 9706/11 May/June 2020
9 An electricity accrual of $375 was treated as a prepayment when preparing a trader’s income statement. What was the effect of this on the profit for the year? A overstated by $375 B overstated by $750 C understated by $375 D understated by $750
1 marks
Answer: B
This question in 9706/11 May/June 2020
Q647 · The draft financial statements of a business show a profit for the year of $64 000 before… 9706/11 May/June 2020
10 The draft financial statements of a business show a profit for the year of $64 000 before taking account of the following: 1 the reduction of the provision for doubtful debts by $300 2 the purchase of office stationery costing $2400 which has not been entered in the books; only one-sixth of this stationery was used by the year end. What is the corrected profit for the year? A $61 900 B $63 900 C $64 100 D $64 300
1 marks
Answer: B
This question in 9706/11 May/June 2020
Q648 · A company receives rental income from letting out two properties 9706/11 May/June 2020
11 A company receives rental income from letting out two properties. Total rental income received from these two properties for the year ended 31 December 2019 was $55 000. Further information relating to these two properties was as follows. property 1 property 2 $ $ rent received in advance 1 January 2019 1840 31 December 2019 720 rent receivable in arrears 1 January 2019 2120 31 December 2019 1100 What was the total amount of rental income shown in the income statement for the year ended 31 December 2019? A $54 340 B $54 900 C $55 100 D $55 660
1 marks
Answer: C
This question in 9706/11 May/June 2020
Q649 · Finn provided the following information 9706/11 May/June 2020
12 Finn provided the following information. $ capital at the start of the year 19 800 profit for the year 24 000 drawings (cash) 19 500 drawings (goods for own use) 1 100 private vehicle transferred to business use 6 000 What was Finn’s capital at the end of the year? A $23 200 B $24 300 C $29 200 D $31 400
1 marks
Answer: C
This question in 9706/11 May/June 2020
Q650 · The following financial information is available for a business 9706/12 May/June 2020
6 The following financial information is available for a business. $ draft profit for the year 12 650 closing capital 52 780 The following error has been discovered. Private fuel costs, $1930, had been charged in the business motor expenses account. What are the correct figures for the year? profit for the year closing capital $ $ A 10 720 50 850 B 10 720 54 710 C 14 580 52 780 D 14 580 54 710
1 marks
Answer: C
This question in 9706/12 May/June 2020
Q651 · A business provides the following information 9706/12 May/June 2020
9 A business provides the following information. trade provision for receivables doubtful debts $ $ 31 December 2018 46 200 1386 31 December 2019 48 100 1924 Which statement must be correct? A The rate of provision for doubtful debts has decreased. B The rate of provision for doubtful debts has increased. C The value of irrecoverable debts incurred has decreased. D The value of irrecoverable debts incurred has increased.
1 marks
Answer: B
This question in 9706/12 May/June 2020
Q652 · On 1 March a company has prepaid $3600 for 12 months’ travel costs 9706/12 May/June 2020
10 On 1 March a company has prepaid $3600 for 12 months’ travel costs. It also has an outstanding hotel bill of $180. During March it pays the outstanding hotel bill and a further $700 for airline tickets for the month. At 31 March it has an outstanding hotel bill of $220. What is the correct cost of travel in the income statement for March? A $920 B $1220 C $1400 D $4520
1 marks
Answer: B
This question in 9706/12 May/June 2020
Q653 · A business owner provided the following information at the end of his first year of… 9706/12 May/June 2020
11 A business owner provided the following information at the end of his first year of trading. $ closing inventory 15 000 total payments to suppliers 60 000 amount owing to suppliers 5 000 total receipts from customers 85 000 amount owed by customers 10 000 What was the gross profit for the year? A $10 000 B $15 000 C $25 000 D $45 000
1 marks
Answer: D
This question in 9706/12 May/June 2020
Q654 · A business sells goods at a uniform mark-up of 25% 9706/12 May/June 2020
17 A business sells goods at a uniform mark-up of 25%. The following information is available. $ sales revenue 120 000 opening inventory 18 000 purchases 95 000 returns outwards 2 000 What is the value of closing inventory? A $15 000 B $19 000 C $21 000 D $25 000
1 marks
Answer: A
This question in 9706/12 May/June 2020
Q655 · What is a purpose of financial statements? 9706/13 May/June 2020
8 What is a purpose of financial statements? A to aid managers to manage the business B to allow the owner to take drawings C to ensure a profit is made D to ensure accuracy of the double entry
1 marks
Answer: A
This question in 9706/13 May/June 2020
Q656 · An electricity accrual of $375 was treated as a prepayment when preparing a trader’s… 9706/13 May/June 2020
9 An electricity accrual of $375 was treated as a prepayment when preparing a trader’s income statement. What was the effect of this on the profit for the year? A overstated by $375 B overstated by $750 C understated by $375 D understated by $750
1 marks
Answer: B
This question in 9706/13 May/June 2020
Q657 · The draft financial statements of a business show a profit for the year of $64 000 before… 9706/13 May/June 2020
10 The draft financial statements of a business show a profit for the year of $64 000 before taking account of the following: 1 the reduction of the provision for doubtful debts by $300 2 the purchase of office stationery costing $2400 which has not been entered in the books; only one-sixth of this stationery was used by the year end. What is the corrected profit for the year? A $61 900 B $63 900 C $64 100 D $64 300
1 marks
Answer: B
This question in 9706/13 May/June 2020
Q658 · A company receives rental income from letting out two properties 9706/13 May/June 2020
11 A company receives rental income from letting out two properties. Total rental income received from these two properties for the year ended 31 December 2019 was $55 000. Further information relating to these two properties was as follows. property 1 property 2 $ $ rent received in advance 1 January 2019 1840 31 December 2019 720 rent receivable in arrears 1 January 2019 2120 31 December 2019 1100 What was the total amount of rental income shown in the income statement for the year ended 31 December 2019? A $54 340 B $54 900 C $55 100 D $55 660
1 marks
Answer: C
This question in 9706/13 May/June 2020
Q659 · Finn provided the following information 9706/13 May/June 2020
12 Finn provided the following information. $ capital at the start of the year 19 800 profit for the year 24 000 drawings (cash) 19 500 drawings (goods for own use) 1 100 private vehicle transferred to business use 6 000 What was Finn’s capital at the end of the year? A $23 200 B $24 300 C $29 200 D $31 400
1 marks
Answer: C
This question in 9706/13 May/June 2020
Q660 · A company purchased a new delivery vehicle 9706/11 Oct/Nov 2020
2 A company purchased a new delivery vehicle. Which items would appear in the income statement? 1 delivery cost of the delivery vehicle 2 insurance for the delivery vehicle 3 painting of the company name on the delivery vehicle 4 purchase cost of the delivery vehicle A 1 and 2 B 1 only C 2 and 3 D 2 only
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2020
Q661 · When preparing the financial statements for the year the following errors are discovered 9706/11 Oct/Nov 2020
6 When preparing the financial statements for the year the following errors are discovered. 1 No provision had been made for accrued wages of $250. 2 No account had been taken of prepaid rent of $400. 3 The sales journal was undercast by $300. The draft profit for the year is $8050. What will be the profit when the errors are corrected? A $8100 B $8500 C $8750 D $9000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2020
Q662 · A business valued its inventory at the year end at cost, $24 650 9706/11 Oct/Nov 2020
9 A business valued its inventory at the year end at cost, $24 650. This did not take account of the following. 1 Goods had been invoiced to a customer at $3000 and included in sales. They should have been treated as goods on sale or return as the customer had not indicated they would buy them. 2 Goods purchased for $6400 and included in the inventory have been damaged and now have a sales value of $5700. 3 Returns inwards which had been sold for $800 had not been included in the inventory. The business has a mark-up of 25%. What was the correct value of the inventory? A $26 350 B $26 990 C $27 590 D $27 750
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2020
Q663 · At 1 April 2019 a business had a provision for doubtful debts of $3400 9706/11 Oct/Nov 2020
11 At 1 April 2019 a business had a provision for doubtful debts of $3400. An analysis of trade receivables at 31 March 2020 was as follows. amount provision $ required 50 000 nil 40 000 5% 1 600 20% During the year an irrecoverable debt of $3000 had been written off in the customer’s account, but no entry made in the income statement. No entry had been made for the increase or the decrease in the provision for doubtful debts. The income statement for the year ended 31 March 2020 showed a draft profit for the year of $90 000. What was the effect on the draft profit for the year of these omissions? A $680 overstated B $680 understated C $1920 overstated D $1920 understated
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2020
Q664 · Rent is paid by a business monthly in advance on the first day of each month 9706/12 Oct/Nov 2020
9 Rent is paid by a business monthly in advance on the first day of each month. The payments during a financial year were as follows. up to and including 1 June $500 per month from 1 July $600 per month Which amounts will appear in the financial statements for the year ended 31 October? statement of financial income statement position A $6300 $600 other receivables B $6300 $600 other payables C $6400 – D $6500 –
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2020
Q665 · What is the effect on profit for the year and net assets when accrued expenses are… 9706/12 Oct/Nov 2020
10 What is the effect on profit for the year and net assets when accrued expenses are understated? profit for the year net assets A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2020
Q666 · Ali’s trade receivables at 31 December 2019 were $26 500 9706/12 Oct/Nov 2020
11 Ali’s trade receivables at 31 December 2019 were $26 500. He knew that $400 of these were irrecoverable. He wished to maintain a provision for doubtful debts equal to 5% of the trade receivables. At 1 January 2019 the balance of the provision for doubtful debts was $1200. Which entry does Ali make in the provision for doubtful debts account at 31 December 2019? A $105 credit B $105 debit C $125 credit D $125 debit
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2020
Q667 · At the year end a company discovers that some of its inventory is damaged 9706/13 Oct/Nov 2020
9 At the year end a company discovers that some of its inventory is damaged. This inventory originally cost $2000 and to replace it would now cost $1900. It would normally sell for $2400 but can now only be sold for $2200 if repairs costing $400 are undertaken. What value of the damaged inventory should be shown in the financial statements? A $1800 B $1900 C $2000 D $2200
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2020
Q668 · The following information relates to rent receivable for the year ended 31 March 2020 9706/13 Oct/Nov 2020
10 The following information relates to rent receivable for the year ended 31 March 2020. $ 1 April 2019 rent owed by the tenants 700 1 April 2019 rent prepaid by the tenants 1200 rent received during the year 7800 31 March 2020 rent owed by the tenants 1000 How much is the rental income entered in the income statement for the year ended 31 March 2020? A $6300 B $7300 C $8300 D $9300
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2020
Q669 · A business has provided the following information 9706/13 Oct/Nov 2020
11 A business has provided the following information. A provision for doubtful debts has been calculated as $1750. It is based on 5% of trade receivables after an irrecoverable debt of $4200 had been written off. What was the original amount of trade receivables before making these adjustments? A $29 050 B $30 800 C $37 450 D $39 200
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2020
Q670 · A sole trader provides the following information 9706/13 Oct/Nov 2020
12 A sole trader provides the following information. start of year end of year $ $ total assets 100 000 135 000 total liabilities excluding owner’s capital 35 000 40 000 During the year the owner took drawings of $18 000. What was the profit for the year? A $12 000 B $30 000 C $35 000 D $48 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2020
Q671 · A business has calculated its draft profit for the year as $15 000 9706/12 Feb/March 2021
9 A business has calculated its draft profit for the year as $15 000. The following were then discovered. 1 General expenses were understated by $600. 2 The sales journal total of $55 690 had been posted to the sales account as $56 590. 3 Repairs to vehicles of $1100 had been entered in the vehicles (at cost) account. 4 The salaries account included travelling expenses of $2400 paid to the salesmen. What was the correct profit for the year? A $12 400 B $13 600 C $14 200 D $14 800
1 marks
Answer: A
This question in 9706/12 Feb/March 2021
Q672 · A sole trader maintains a provision for doubtful debts at 5% of trade receivables 9706/12 Feb/March 2021
10 A sole trader maintains a provision for doubtful debts at 5% of trade receivables. Provision for doubtful debts at the start of the year was $2750. The following information is available at the end of the year. $ trade receivables 37 500 irrecoverable debts written off during the year 500 What is the effect on the profit for the year due to the change in the provision for doubtful debts? A decrease by $875 B decrease by $900 C increase by $875 D increase by $900
1 marks
Answer: C
This question in 9706/12 Feb/March 2021
Q673 · Esarba has a financial year end of 31 December 9706/12 Feb/March 2021
11 Esarba has a financial year end of 31 December. On 31 March 2020, she transferred her private vehicle to the business at a value of $12 000. Her profit for the year ended 31 December 2020 was $7800 and her cash drawings amounted to $8000. Depreciation of $900 had been provided on the vehicle. She also took goods for her own use with a cost price of $1000 and a selling price of $2000. What was the increase in Esarba’s capital account balance in the year ended 31 December 2020? A $8900 B $9800 C $9900 D $10 800
1 marks
Answer: D
This question in 9706/12 Feb/March 2021
Q674 · On 1 January 2020, Marek bought some machinery 9706/11 May/June 2021
2 On 1 January 2020, Marek bought some machinery. He paid a total of $50 000. Of this, $6000 was for maintenance of the machinery until 31 December 2022. Marek depreciates his machinery at the rate of 10% per annum. How was the expenditure recorded in Marek’s financial statements for the year ended 31 December 2020? non-current current income assets assets statement $ $ $ A 39 600 nil 10 400 B 39 600 4 000 6 400 C 41 600 4 000 4 400 D 45 000 nil 5 000
1 marks
Answer: B
This question in 9706/11 May/June 2021
Q675 · An item of revenue expenditure is wrongly treated as capital expenditure 9706/11 May/June 2021
4 An item of revenue expenditure is wrongly treated as capital expenditure. What is the effect of this error? non-current profit for the assets year A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/11 May/June 2021
Q676 · A businessman suspects some of his inventory has been stolen 9706/11 May/June 2021
7 A businessman suspects some of his inventory has been stolen. The following information is available. $ sales revenue 45 600 purchases 33 600 inventory at 1 May 2020 8 300 inventory at 30 April 2021 4 500 All goods are marked up at a rate of 33 %. 1 3 What was the value of inventory stolen? A $600 B $3200 C $4400 D $7000
1 marks
Answer: B
This question in 9706/11 May/June 2021
Q677 · At the end of the year, Barack’s draft accounts showed a capital account balance of $4300 9706/11 May/June 2021
8 At the end of the year, Barack’s draft accounts showed a capital account balance of $4300. His drawings account included a debit entry of $150 for goods taken for his own use. Barack realised that this entry had been recorded in error at selling price rather than cost price. He sells goods with a mark-up of 50%. What is the correct closing capital account balance? A $4225 B $4250 C $4300 D $4350
1 marks
Answer: C
This question in 9706/11 May/June 2021
Q678 · The following information is available for a sole trader at 31 December 2020 9706/11 May/June 2021
9 The following information is available for a sole trader at 31 December 2020. $ goods taken by owner for own use 1 000 inventories 1 January 2020 10 000 31 December 2020 12 000 purchases 75 000 returns debit balance 3 000 credit balance 4 000 What was the cost of sales? A $68 000 B $69 000 C $70 000 D $71 000
1 marks
Answer: A
This question in 9706/11 May/June 2021
Q679 · Which items only appear on the credit side of a partner’s capital account? 9706/11 May/June 2021
10 Which items only appear on the credit side of a partner’s capital account? 1 goodwill in an agreed ratio split 2 opening balances 3 profit on revaluation of assets 4 transfers from current accounts A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/11 May/June 2021
Q680 · A sole trader has a draft profit for the year of $47 500 9706/11 May/June 2021
11 A sole trader has a draft profit for the year of $47 500. No entries have been made in respect of the following. 1 At the end of the year trade receivables were $5600 more than the previous year. However, an irrecoverable debt of $360 had not been written off. The trader maintains a provision of doubtful debts of 5%. 2 A machine had been sold for $4000. It had a net book value of $3500. What will be the correct profit for the year? A $46 360 B $47 378 C $47 902 D $47 920
1 marks
Answer: B
This question in 9706/11 May/June 2021
Q681 · A sole trader had trade receivables of $21 650 at the start of the year 9706/11 May/June 2021
12 A sole trader had trade receivables of $21 650 at the start of the year. During the year there were irrecoverable debts of $450 written off. Cash received from customers was $42 670. At the year end, the statement of financial position showed trade receivables of $25 745 after deducting a provision for doubtful debts of 5%. What were the sales for the year? A $46 765 B $47 215 C $47 670 D $48 570
1 marks
Answer: D
This question in 9706/11 May/June 2021
Q682 · A business had a draft profit for the year of $200 000 9706/12 May/June 2021
8 A business had a draft profit for the year of $200 000. The following items were then discovered. 1 Depreciation charges had been overstated by $20 000. 2 The value of closing inventory was overstated by $15 000. 3 A year-end accrual for wages was needed, $8000. 4 A year-end adjustment for prepaid insurance, $2500, was required. What was the corrected profit for the year? A $159 500 B $199 500 C $240 500 D $245 500
1 marks
Answer: B
This question in 9706/12 May/June 2021
Q683 · A sole trader provided the following information 9706/12 May/June 2021
10 A sole trader provided the following information. $ sales 200 000 opening inventory 50 000 closing inventory 75 000 gross margin 25% What were the purchases for the year? A $125 000 B $150 000 C $175 000 D $185 000
1 marks
Answer: C
This question in 9706/12 May/June 2021
Q684 · Which item would not appear in the financial statements of a sole trader? 9706/12 May/June 2021
11 Which item would not appear in the financial statements of a sole trader? A bank overdraft B dividends paid C interest received D loss on disposal of machinery
1 marks
Answer: B
This question in 9706/12 May/June 2021
Q685 · L and M are partners sharing profits and losses equally 9706/12 May/June 2021
12 L and M are partners sharing profits and losses equally. This year M’s share of the profit is $18 000. Next year they plan to change the partnership agreement so that L has an annual salary of $10 000 and a one-third share of any profits or losses. What does the total partnership profit for next year need to be for M to receive the same amount of profit as this year? A $22 000 B $34 000 C $37 000 D $42 000
1 marks
Answer: C
This question in 9706/12 May/June 2021
Q686 · V and E are in partnership, sharing profits and losses equally 9706/12 May/June 2021
13 V and E are in partnership, sharing profits and losses equally. Their capital accounts showed the following credit balances at 31 March 2021. $ V 80 000 E 40 000 Z was admitted as a partner on 1 April 2021. At that date the following items were taken into account. 1 Non-current assets were revalued downwards by $20 000. 2 Goodwill was valued at $80 000, but will not remain in the books of account after Z is admitted. The new profit-sharing ratio will be V 40%, E 30% and Z 30%. What was the balance on E’s capital account after the admission of Z? A $30 000 B $46 000 C $56 000 D $70 000
1 marks
Answer: B
This question in 9706/12 May/June 2021
Q687 · Which account is used to calculate the profit or loss on the dissolution of a partnership? 9706/12 May/June 2021
14 Which account is used to calculate the profit or loss on the dissolution of a partnership? A appropriation account B capital account C realisation account D revaluation account
1 marks
Answer: C
This question in 9706/12 May/June 2021
Q688 · Some items of closing inventory have been incorrectly included in the financial… 9706/13 May/June 2021
9 Some items of closing inventory have been incorrectly included in the financial statements at their cost prices rather than their net realisable values. What was the effect of this error? profit for the year current assets A higher higher B lower lower C higher lower D lower higher
1 marks
Answer: A
This question in 9706/13 May/June 2021
Q689 · Marianna rents part of her premises to Paul 9706/13 May/June 2021
10 Marianna rents part of her premises to Paul. On 1 April 2020, the rent receivable account showed a balance of $800 as Paul owed rent for the last month of the financial year ended 31 March 2020. From 1 April 2020 there was a 5% increase in the annual rent. Marianna received payments from Paul during the year ended 31 March 2021 totalling $10 040. Which figures should be included in Marianna’s financial statements for the year ended 31 March 2021? income statement current assets $ $ A 10 040 800 B 10 040 840 C 10 080 800 D 10 080 840
1 marks
Answer: D
This question in 9706/13 May/June 2021
Q690 · A business had calculated a draft profit for the year 9706/11 Oct/Nov 2021
9 A business had calculated a draft profit for the year. The following items have been discovered. 1 A customer has been declared bankrupt and is unable to pay the amount they owe. 2 Unsold goods on sale or return basis have been included in inventory. 3 Rent paid in advance has not been included. 4 The owner's cash drawings have been entered into the owner’s capital account. Which of these need to be adjusted to calculate the correct profit for the period? A 1 and 2 B 1 and 3 only C 1, 3 and 4 D 2 and 3
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2021
Q691 · The following information has been extracted from the statement of financial position of… 9706/11 Oct/Nov 2021
10 The following information has been extracted from the statement of financial position of a sole trader at 31 March 2021. $ non-current assets 130 000 current assets 32 000 current liabilities 18 000 non-current liabilities 25 000 profit for the year ended 31 March 2021 20 000 drawings 15 000 What was the balance on the capital account at 31 March 2021? A $114 000 B $119 000 C $124 000 D $167 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2021
Q692 · At the start of the year the balance on a sole trader’s capital account was $183 000 9706/11 Oct/Nov 2021
11 At the start of the year the balance on a sole trader’s capital account was $183 000. During the year the following took place. 1 The owner introduced a motor vehicle into the business. This had a cost of $90 000 and had a market value of $74 000. 2 The owner took cash drawings of $15 000. 3 The owner took inventory for personal use. This had a cost of $24 000 and a selling price of $32 000. After recording these and the profit for the year, the closing balance on the capital account was $265 000. What was the profit for the year? A $31 000 B $39 000 C $47 000 D $55 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2021
Q693 · X and Y are in partnership 9706/11 Oct/Nov 2021
13 X and Y are in partnership. The following information relates to the partnership. start of the year end of the year current account $ $ X 12 000 credit 17 500 credit Y 6 000 credit 4 000 debit The following transactions took place during the year. drawings $ X 13 000 Y 19 000 X received a salary of $5000. What was the profit for the year before appropriation? A $22 500 B $27 500 C $30 500 D $32 500
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2021
Q694 · L, M and N were partners sharing profits and losses equally 9706/11 Oct/Nov 2021
14 L, M and N were partners sharing profits and losses equally. N’s capital account was as follows. $ $ motor vehicle 7 000 balance 14 000 bank 8 000 current account 1 000 15 000 15 000 What explained the entries in the capital account? A N bought a motor vehicle from the business paying $1000 more than its book value. B N’s capital account includes his share of the loss on the disposal of a motor vehicle. C N increased his capital by introducing a motor vehicle and paying cash into the bank. D N retired and took the amount due to him in the form of a motor vehicle and money from the bank.
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2021
Q695 · On which basis will non-current assets be valued if the business is not a going concern? 9706/12 Oct/Nov 2021
2 On which basis will non-current assets be valued if the business is not a going concern? A net book value B original cost C the amount they could be sold for D the value placed on them by the owner
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2021
Q696 · Brian had a service business which held no inventory 9706/12 Oct/Nov 2021
9 Brian had a service business which held no inventory. His current assets and current liabilities at 1 April were as follows. $ trade receivables 10 000 trade payables 6 100 bank overdraft 1 900 On that date he set off a sales ledger balance, $600, against a purchases ledger balance and then created a provision for doubtful debts of 5%. What was the value of his working capital after these adjustments? A $1470 B $1500 C $1530 D $1900
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2021
Q697 · Frieda’s provision for the doubtful debts account for the year included a debit entry… 9706/12 Oct/Nov 2021
10 Frieda’s provision for the doubtful debts account for the year included a debit entry representing the change in the amount provided. The rate of provision for doubtful debts has not changed. What might have happened during the year to make this entry necessary? 1 Credit control procedures had been improved. 2 Credit control procedures had been reduced. 3 Total trade receivables had decreased. 4 Total trade receivables had increased. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2021
Q698 · A trader’s income statement recorded sales, $10 000, and cost of sales, $7070 9706/12 Oct/Nov 2021
11 A trader’s income statement recorded sales, $10 000, and cost of sales, $7070. The trader had taken goods for his own use during the year, cost $280, selling price $410, but had omitted to record this. What effect did the omission have on the gross margin? A 2.8% overstated B 2.8% understated C 4.1% overstated D 4.1% understated
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2021
Q699 · William buys radios for $10 each and sells them for $15 each 9706/12 Oct/Nov 2021
12 William buys radios for $10 each and sells them for $15 each. His draft statement of financial position included a value of $1500 for inventory. His method of calculation of inventory was correct. He then found that 12 radios could only be sold for $8 each and 4 radios had been stolen. By how much should William reduce his inventory valuation? A $64 B $84 C $124 D $144
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2021
Q700 · A sole trader has not kept a full set of double-entry records 9706/12 Oct/Nov 2021
13 A sole trader has not kept a full set of double-entry records. The following information relates to the business for the year ended 31 March 2021. $ sales 210 000 inventory at 1 April 2020 17 600 inventory at 31 March 2021 18 700 prepaid expense at 1 April 2020 630 expenses paid by cheque 11 900 All goods are marked up by 25%. What were the purchases and profit for the year? profit for the purchases year $ $ A 158 600 40 150 B 168 000 29 470 C 168 000 30 730 D 169 100 29 470
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2021
Q701 · A trader calculated his draft profit for the year as $16 000 9706/13 Oct/Nov 2021
9 A trader calculated his draft profit for the year as $16 000. The following items had not been adjusted. 1 decrease in prepaid insurance, $400 2 increase in closing inventory, $1200 3 decrease in provision for doubtful debts, $120 4 increase in accrued rent receivable, $300 What was the profit for the year after adjusting for these items? A $16 620 B $16 980 C $17 220 D $17 780
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2021
Q702 · An item of capital expenditure has been incorrectly treated as revenue expenditure in the… 9706/13 Oct/Nov 2021
10 An item of capital expenditure has been incorrectly treated as revenue expenditure in the financial statements of a business. What is the effect of this error on the financial statements? assets profit for the year A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2021
Q703 · The following information is available for a business 9706/13 Oct/Nov 2021
11 The following information is available for a business. $ at the start of the year non-current assets 45 000 current assets 17 800 current liabilities 11 300 for the year drawings 5 000 profit for the year 6 950 What is the closing balance on the capital account at the year end? A $49 550 B $53 450 C $72 150 D $76 050
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2021
Q704 · On 1 July 2021, Tim bought a delivery van for $10 000 9706/12 Feb/March 2022
3 On 1 July 2021, Tim bought a delivery van for $10 000. He paid an additional $900 to have racks fitted inside, and $800 for a year’s insurance. Tim provides for depreciation at the rate of 10% per annum. A full year’s depreciation is charged in the year of acquisition. What was the total for expenses recorded in Tim’s income statement in respect of the van for the year ended 30 September 2021? A $1290 B $1690 C $2100 D $2500
1 marks
Answer: A
This question in 9706/12 Feb/March 2022
Q705 · Which statement is correct? 9706/12 Feb/March 2022
7 Which statement is correct? A The balance on the irrecoverable debts account is carried down to the next accounting period. B The balance on the irrecoverable debts account is treated as an expense in the income statement. C The balance on the provision for doubtful debts account is calculated before the deduction of irrecoverable debts. D The balance on the provision for doubtful debts account is not included in a trial balance.
1 marks
Answer: B
This question in 9706/12 Feb/March 2022
Q706 · The following information is available for a business at 31 December 2021 9706/12 Feb/March 2022
8 The following information is available for a business at 31 December 2021. $ general expenses in arrears 1 January 420 general expenses in advance 1 January 240 general expenses in arrears 31 December 720 general expenses in advance 31 December 120 Total amount paid during the year ended 31 December 2021 is $11 500. What is the amount to be included in the income statement for general expenses for the year ended 31 December 2021? A $10 240 B $10 720 C $11 080 D $11 920
1 marks
Answer: D
This question in 9706/12 Feb/March 2022
Q707 · When would the year end value of inventory need to be adjusted? 9706/12 Feb/March 2022
9 When would the year end value of inventory need to be adjusted? 1 when inventory has not yet been paid for 2 when selling price has fallen below cost 3 when the owner has recorded taking goods for his own use during the year A 1 and 2 B 2 and 3 C 2 only D 3 only
1 marks
Answer: C
This question in 9706/12 Feb/March 2022
Q708 · A business had a draft profit for the year of $250 000 9706/12 Feb/March 2022
10 A business had a draft profit for the year of $250 000. The following errors were then discovered. 1 Depreciation charged was $25 000. The figure should have been $40 000. 2 Closing inventory for the period was undervalued by $10 000. What was the correct profit for the year? A $225 000 B $245 000 C $255 000 D $275 000
1 marks
Answer: B
This question in 9706/12 Feb/March 2022
Q709 · A capital account for a sole trader contained three entries, in addition to the opening… 9706/12 Feb/March 2022
11 A capital account for a sole trader contained three entries, in addition to the opening and closing balances. What did these entries represent? debit side credit side A capital introduced drawings, loss for the year B capital introduced, drawings profit for the year C drawings, loss for the year capital introduced D profit for the year capital introduced, drawings
1 marks
Answer: C
This question in 9706/12 Feb/March 2022
Q710 · The year end of a business is 31 December 2021 9706/12 Feb/March 2022
12 The year end of a business is 31 December 2021. On 5 January 2022, inventory was counted and valued at cost, $30 000. The following was then discovered. 1 Goods purchased and received after the year end, costing $1500, had been included in the valuation. 2 It included goods returned by a customer after the year end. They had a selling price of $900 which included a mark-up of 25% during the year. 3 Some goods included in the inventory, costing $500, were damaged. They can be sold for $300 after repairs costing $100. Which value of inventory should be included in the financial statements at 31 December 2021? A $27 480 B $27 525 C $28 275 D $29 270
1 marks
Answer: A
This question in 9706/12 Feb/March 2022
Q711 · A sole trader provided the following information for the year ended 31 December 9706/12 Feb/March 2022
13 A sole trader provided the following information for the year ended 31 December. $ non-current assets increased by 25 000 current assets increased by 10 000 current liabilities increased by 12 500 additional capital introduced during the year 20 000 drawings for the year 13 000 What was the profit for the year ended 31 December? A $10 500 B $14 500 C $15 500 D $29 500
1 marks
Answer: C
This question in 9706/12 Feb/March 2022
Q712 · At the beginning of the financial year, inventory was valued at $15 000 9706/11 May/June 2022
8 At the beginning of the financial year, inventory was valued at $15 000. During the year, sales of $21 000 and purchases of $18 000 were made. Unfortunately, all inventory was stolen on the last day of the financial year. Goods are marked up by 50% to calculate selling price. What is the cost of the stolen inventory? A $7500 B $11 000 C $19 000 D $22 500
1 marks
Answer: C
This question in 9706/11 May/June 2022
Q713 · What will be used to calculate the general provision for doubtful debts? 9706/11 May/June 2022
9 What will be used to calculate the general provision for doubtful debts? A total trade receivables only B total trade receivables less irrecoverable debts only C total trade receivables less provision for specific doubtful debts only D total trade receivables less irrecoverable debts and provision for specific doubtful debts
1 marks
Answer: D
This question in 9706/11 May/June 2022
Q714 · At 31 December 2021, a business had calculated the draft profit for the year of $57 500 9706/11 May/June 2022
10 At 31 December 2021, a business had calculated the draft profit for the year of $57 500. It was then discovered that the following adjustments were necessary. 1 Inventory valued at $2400 was damaged and now had a resale value of $1660. 2 Rent receivable included $400 prepaid for 2022. 3 The provision for doubtful debts needed to be increased by $890. What is the correct profit for the year? A $55 470 B $56 270 C $58 050 D $58 730
1 marks
Answer: A
This question in 9706/11 May/June 2022
Q715 · Closing inventory has been undervalued 9706/11 May/June 2022
11 Closing inventory has been undervalued. What is the effect on the financial statements? total current assets profit for the year A no effect understated B overstated overstated C understated no effect D understated understated
1 marks
Answer: D
This question in 9706/11 May/June 2022
Q716 · A sole trader has provided the following information 9706/11 May/June 2022
12 A sole trader has provided the following information. $ net assets at 1 January 2021 10 000 net assets at 31 December 2021 24 000 during the year ended 31 December 2021 drawings for the year 3 200 cash introduced by owner 6 000 motor vehicle introduced by owner 2 500 What was the trader’s profit for the year ended 31 December 2021? A $8000 B $8700 C $14 700 D $19 300
1 marks
Answer: B
This question in 9706/11 May/June 2022
Q717 · A sole trader has changed the method of depreciating his machinery from the reducing… 9706/12 May/June 2022
2 A sole trader has changed the method of depreciating his machinery from the reducing balance method in the year 1 to the straight-line method in the year 2 of trading. The same percentage rate of depreciation is used in both cases. What is the effect on the net book value of machinery and profit for the year 2? net book value profit for the year 2 A higher higher B higher lower C lower higher D lower lower
1 marks
Answer: D
This question in 9706/12 May/June 2022
Q718 · Paul has a year end of 31 December 9706/12 May/June 2022
3 Paul has a year end of 31 December. On 1 January 2020, he bought a non-current asset for $10 000. He sold it on 1 January 2021 for $8500. Paul usually provides depreciation at the rate of 10% per annum. A full year’s depreciation is charged in the year of acquisition and none in the year of disposal. He forgot to provide for any depreciation on this non-current asset. What was the effect of this error on Paul’s profit for the year ended 31 December 2021? A $1000 higher B $1000 lower C $1500 higher D $1500 lower
1 marks
Answer: B
This question in 9706/12 May/June 2022
Q719 · At the year-end, Victor had 100 units of inventory which had cost $12 per unit 9706/12 May/June 2022
8 At the year-end, Victor had 100 units of inventory which had cost $12 per unit. Of these, eight units had been received on the last day of the year and had not yet been paid for. An additional six units were damaged and would be sold for $10 each once repairs to them totalling $20 were made. What was the value of inventory in Victor’s financial statements at the year-end? A $1072 B $1092 C $1168 D $1188
1 marks
Answer: C
This question in 9706/12 May/June 2022
Q720 · Which items are treated as expenses in the income statement? 9706/12 May/June 2022
9 Which items are treated as expenses in the income statement?
accrued wages _| prepaid telephone increase in
at the end of charges at the provision for
the year end of the year doubtful debts
00 WwW D>
<x \ x
«x «KX
\ \ NX
1 marks
Answer: C
This question in 9706/12 May/June 2022
Q721 · At 31 December 2021, the draft statement of financial position for a business showed… 9706/12 May/June 2022
10 At 31 December 2021, the draft statement of financial position for a business showed total assets of $1 000 000. The following was then discovered. 1 An increase in the provision for doubtful debts, $5000, had not been recorded. 2 Closing inventory had been overvalued by $20 000. 3 Depreciation, $10 000, had not been recorded. What was the corrected total assets value? A $965 000 B $985 000 C $1 005 000 D $1 015 000
1 marks
Answer: A
This question in 9706/12 May/June 2022
Q722 · On what basis does a trading business produce an income statement? 9706/12 May/June 2022
11 On what basis does a trading business produce an income statement? 1 cash received and paid out by the business in the year 2 income earned less costs incurred by the business during the year 3 revenue received less any cash paid out by the business during the year A 1 and 2 B 1 and 3 C 2 and 3 D 2 only
1 marks
Answer: D
This question in 9706/12 May/June 2022
Q723 · A business provides the following information 9706/12 May/June 2022
12 A business provides the following information. $ revenue 140 000 opening inventory 22 000 closing inventory 24 500 purchases 120 000 Goods are sold at cost plus 25%. The owner has taken goods for own use but has not recorded these as drawings. What is the value of the goods taken for own use? A $5500 B $10 500 C $12 500 D $17 500
1 marks
Answer: A
This question in 9706/12 May/June 2022
Q724 · A business owner does not maintain a full set of accounting records 9706/12 May/June 2022
13 A business owner does not maintain a full set of accounting records. At the end of the financial year the following information is available. $ trade payables opening balance 22 500 closing balance 27 400 returns outwards 1 000 payments to trade payables 110 600 There were no cash purchases. The opening and closing inventory has remained at the same amount. What was the amount of the cost of sales? A $105 700 B $106 700 C $115 500 D $116 500
1 marks
Answer: C
This question in 9706/12 May/June 2022
Q725 · The cost of direct materials is increasing 9706/12 May/June 2022
22 The cost of direct materials is increasing. What is the effect if a business uses first-in-first-out (FIFO) instead of average cost (AVCO) for inventory valuation in this situation? closing inventory cost of sales profit for the year value A increases decreases increases B increases decreases decreases C decreases increases decreases D decreases increases increases
1 marks
Answer: D
This question in 9706/12 May/June 2022
Q726 · Which statements regarding the financial statements of a sole trader are correct? 9706/13 May/June 2022
9 Which statements regarding the financial statements of a sole trader are correct? 1 Cash drawings for the year are recorded in the income statement. 2 Gross profit for the year is shown in the statement of financial position. 3 Prepayments only appear in the income statement. 4 Trade receivables appear in the statement of financial position. A 1 and 2 B 2 and 3 C 3 and 4 D 4 only
1 marks
Answer: D
This question in 9706/13 May/June 2022
Q727 · A business provided the following information regarding its first year of trading 9706/13 May/June 2022
10 A business provided the following information regarding its first year of trading. $ credit sales 93 730 receipts from credit customers 76 500 irrecoverable debt written off 150 contra recorded between purchases ledger and sales ledger 80 The net trade receivables recorded in the statement of financial position at the end of the year were $16 660. What was the balance on the provision for doubtful debts account at the end of the year? A $340 B $490 C $500 D $650
1 marks
Answer: A
This question in 9706/13 May/June 2022
Q728 · Which items are recorded in the income statement of a sole trader? 9706/13 May/June 2022
11 Which items are recorded in the income statement of a sole trader? 1 interest payable on bank loan 2 interest on capital 3 transfer to general reserve A 1 and 2 B 1 and 3 C 1 only D 2 and 3
1 marks
Answer: C
This question in 9706/13 May/June 2022
Q729 · A summary of a trader’s bank statements for his first year of trading showed the… 9706/13 May/June 2022
12 A summary of a trader’s bank statements for his first year of trading showed the following amounts. $ receipts from credit customers 25 000 cash sales takings banked 82 000 The trader took $2000 every month from takings as drawings before banking the remaining takings. Trade receivables at the year end amounted to $9500. What was total revenue for the year? A $73 500 B $92 500 C $121 500 D $140 500
1 marks
Answer: D
This question in 9706/13 May/June 2022
Q730 · Jane provided the following information about her business 9706/13 May/June 2022
13 Jane provided the following information about her business. 1 January 2021 31 December 2021 $ $ total assets 108 000 119 000 current liabilities 7 500 11 500 During the year, the business took a long-term loan of $10 000 and Jane’s drawings totalled $12 000. What was Jane’s profit for the year ended 31 December 2021? A $7000 B $9000 C $19 000 D $29 000
1 marks
Answer: B
This question in 9706/13 May/June 2022
Q731 · How are closing inventory and loss for the year treated in the financial statements of a… 9706/11 Oct/Nov 2022
10 How are closing inventory and loss for the year treated in the financial statements of a sole trader? closing inventory loss for the year A asset in statement of financial position debit in capital account credit in income statement credit in income statement B asset in statement of financial position debit in income statement credit in income statement credit in capital account C debit in income statement debit in capital account liability in statement of financial position credit in income statement D debit in income statement debit in income statement liability in statement of financial position credit in capital account
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2022
Q732 · A trader had the following closing trade receivables 9706/11 Oct/Nov 2022
11 A trader had the following closing trade receivables. year $ 1 64 000 2 80 000 3 90 000 He usually provides for doubtful debts at the rate of 5%. At the end of year 2 he forgot to adjust the provision. What was the effect on profit in year 3 of forgetting to adjust the provision in year 2? A $800 decrease B $800 increase C $1300 decrease D $1300 increase
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2022
Q733 · The following information is available for the year ended 31 December 2021 9706/11 Oct/Nov 2022
12 The following information is available for the year ended 31 December 2021. $ revenue 1 400 000 inventory as at 1 January 2021 140 000 inventory as at 31 December 2021 148 000 The trader uses a mark-up of 60% on all purchases. What was the value of purchases for the year? A $848 000 B $867 000 C $875 000 D $883 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2022
Q734 · The following information is available for a business for the year ended 31 March 2022 9706/11 Oct/Nov 2022
13 The following information is available for a business for the year ended 31 March 2022. $ non-current assets at cost at 1 April 2021 62 000 provision for depreciation on non-current assets at 1 April 2021 12 000 expenses paid by cash and cheques during the year 42 200 expenses prepaid at 31 March 2022 4 600 trade receivables at 31 March 2022 25 000 A provision for doubtful debts is to be created at 2% of trade receivables. Depreciation on non-current assets is to be provided at 20% using the reducing balance method. What was the total of expenses for the year? A $47 600 B $48 100 C $50 500 D $57 300
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2022
Q735 · A draft statement of financial position for a business showed total net assets of $600 000 9706/12 Oct/Nov 2022
8 A draft statement of financial position for a business showed total net assets of $600 000. The following items were then discovered. 1 A long-term loan for $10 000 had not been recorded. This was taken out on the last day of the financial year. 2 Closing inventory had been overstated by $20 000. 3 Depreciation had been understated by $15 000. What is the correct total net assets value? A $555 000 B $565 000 C $595 000 D $605 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2022
Q736 · A company has produced draft financial statements for the year 9706/12 Oct/Nov 2022
9 A company has produced draft financial statements for the year. It is then discovered that some inventory is damaged and the value must be reduced. What will be the effect? profit for the year current assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2022
Q737 · A trader took out a 6% bank loan of $30 000 on 1 November 2021, to be repaid in full in… 9706/12 Oct/Nov 2022
10 A trader took out a 6% bank loan of $30 000 on 1 November 2021, to be repaid in full in 10 years’ time. Interest is to be paid annually. No interest had been paid by 30 April 2022. How should this be recorded in the statement of financial position at 30 April 2022? current non-current liabilities liabilities $ $ A 0 30 000 B 900 30 000 C 1 800 30 000 D 30 900 0
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2022
Q738 · In preparing the financial statements, an accrual for rent payable was treated as a… 9706/12 Oct/Nov 2022
11 In preparing the financial statements, an accrual for rent payable was treated as a prepayment. What effect does this have on the profit and the current liabilities? profit current liabilities A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2022
Q739 · A sole trader is preparing his income statement for the year ended 31 December 2021, his… 9706/12 Oct/Nov 2022
12 A sole trader is preparing his income statement for the year ended 31 December 2021, his first year of trading. The following information is available. $ takings banked 16 400 payments to trade payables 8 500 expenses for the year 2 900 balance of trade payables 1 200 balance of trade receivables 700 He took goods for his own use, $1000, during the year. There was no closing inventory. What was his profit for the year? A $4500 B $5500 C $7400 D $7900
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2022
Q740 · What is recorded in both the appropriation account and the current accounts of a… 9706/12 Oct/Nov 2022
14 What is recorded in both the appropriation account and the current accounts of a partnership? 1 drawings 2 interest on drawings 3 interest on capital A 1, 2 and 3 B 1 only C 2 and 3 only D 3 only
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2022
Q741 · R, S and T were in partnership, sharing profits equally 9706/12 Oct/Nov 2022
15 R, S and T were in partnership, sharing profits equally. T retired as a partner. At that time, the balance on his capital and current accounts totalled $320 000. Goodwill was valued at $60 000. The partnership assets were revalued upwards by $30 000. T agreed to leave $90 000 in the partnership as a loan on retirement. The balance due to him was paid from the partnership bank account. How much was paid to T on his retirement? A $230 000 B $240 000 C $250 000 D $260 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2022
Q742 · A business has calculated its draft profit for the year 9706/13 Oct/Nov 2022
9 A business has calculated its draft profit for the year. The following information was then discovered. 1 Closing inventory had been overvalued. 2 Irrecoverable debts needed to be written off. 3 Depreciation of non-current assets needed to be reduced. What is the effect on the profit for the year when these items are adjusted? closing trade depreciation inventory receivables reduction A decreased decreased increased B decreased increased decreased C increased decreased decreased D increased decreased increased
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2022
Q743 · A business makes a provision for doubtful debts of 4% 9706/13 Oct/Nov 2022
10 A business makes a provision for doubtful debts of 4%. At 31 March 2021 the value of trade receivables after deducting the provision was $153 600. For the year ended 31 March 2022, there was an increase of $960 in the provision for doubtful debts. What was the value of trade receivables at 31 March 2022 after deducting the provision for doubtful debts? A $161 000 B $170 496 C $176 640 D $177 600
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2022
Q744 · When preparing a sole trader’s financial statements, no adjustment was made for a… 9706/13 Oct/Nov 2022
11 When preparing a sole trader’s financial statements, no adjustment was made for a prepayment at the end of the year. What is the effect of this omission? A current assets overstated and owner’s capital overstated B current assets understated and owner’s capital understated C profit for the year overstated and trade payables understated D profit for the year understated and trade payables understated
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2022
Q745 · A sole trader has not kept proper accounting records for his first year of trading 9706/13 Oct/Nov 2022
12 A sole trader has not kept proper accounting records for his first year of trading. The following information is available. $ cash from customers 70 000 trade receivables 4 000 cash paid to suppliers 65 000 trade payables 2 000 closing inventory 20 000 expenses paid 3 000 What was the profit for the year? A $24 000 B $26 000 C $27 000 D $28 000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2022
Q746 · On 1 January 2022 a sole trader’s inventory was valued at $4500 9706/13 Oct/Nov 2022
13 On 1 January 2022 a sole trader’s inventory was valued at $4500. On 14 April 2022 there was a fire in his business premises. Up to 14 April 2022 his sales were $24 600 and his purchases were $16 700. He worked on a mark-up of 33 %. 1 3 Goods which had cost $1485 were saved from the fire. This included some goods which had cost $800 but as a result of the fire damage can now only be sold for $650. What was the total inventory loss for the business? A $1115 B $1265 C $1415 D $2750
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2022
Q747 · At the start of a financial period, the owner’s capital account of a business showed a… 9706/12 Feb/March 2023
4 At the start of a financial period, the owner’s capital account of a business showed a balance of $85 000. During the period, the owner introduced to the business a private vehicle worth $30 000. In addition, the owner made cash drawings of $15 000. The business made a net loss for the period of $22 000. What is the balance on the capital account at the end of the period? A $18 000 B $48 000 C $78 000 D $100 000
1 marks
Answer: C
This question in 9706/12 Feb/March 2023
Q748 · A business has incorrectly recorded a vehicle purchase as a vehicle repair 9706/12 Feb/March 2023
5 A business has incorrectly recorded a vehicle purchase as a vehicle repair. The business does not charge depreciation on assets in the year of purchase. What is the effect of this error on the financial statements? statement of statement of profit or loss financial position A profit overstated assets overstated B profit overstated assets understated C profit understated assets overstated D profit understated assets understated
1 marks
Answer: D
This question in 9706/12 Feb/March 2023
Q749 · At the start of the year on 1 January, a business had an inventory of stationery which… 9706/12 Feb/March 2023
13 At the start of the year on 1 January, a business had an inventory of stationery which had cost $3740. On that date, $1200 was owed to suppliers for stationery. During the financial year ended 31 December, a total of $38 800 was paid for stationery. Some old stationery was sold to staff for $240. At the end of the year on 31 December, the business had an inventory of stationery valued at cost, $4200. On that date, $1800 was owed to suppliers for stationery. Which figure should be included in the statement of profit or loss for the year ended 31 December for stationery? A $34 960 B $36 160 C $38 700 D $38 940
1 marks
Answer: C
This question in 9706/12 Feb/March 2023
Q750 · The following information is extracted from the records of a business for a financial year 9706/12 Feb/March 2023
14 The following information is extracted from the records of a business for a financial year. $ at 1 January rent paid in advance 4 000 during the year ended 31 December rent paid 41 000 at 31 December rent paid in advance 7 000 How much will be charged for rent in the statement of profit or loss for the year ended 31 December? A $34 000 B $38 000 C $41 000 D $44 000
1 marks
Answer: B
This question in 9706/12 Feb/March 2023
Q751 · Which items would affect a sole trader’s gross profit? 9706/12 Feb/March 2023
15 Which items would affect a sole trader’s gross profit? 1 carriage inwards 2 cash discounts allowed 3 commission received 4 trade discounts received A 1 and 4 B 1 only C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/12 Feb/March 2023
Q752 · John and Mary are in partnership 9706/12 Feb/March 2023
16 John and Mary are in partnership. After the first year of operation, the current accounts of both partners had a debit balance. What might have caused the debit balances? 1 drawings 2 loss for the year 3 salaries they are entitled to A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 only
1 marks
Answer: B
This question in 9706/12 Feb/March 2023
Q753 · The following information is available for a partnership at the end of the financial year 9706/12 Feb/March 2023
17 The following information is available for a partnership at the end of the financial year. $ residual loss 3 000 total salaries to partners 5 000 total interest on capital 27 000 total drawings 14 000 total interest on drawings 700 How much was the profit for the year? A $14 300 B $20 300 C $28 300 D $34 300
1 marks
Answer: C
This question in 9706/12 Feb/March 2023
Q754 · Phil purchased new premises and made the following payments 9706/11 May/June 2023
2 Phil purchased new premises and made the following payments. $ premises 60 000 legal fees relating to purchase 2 000 insurance for the financial year 700 When recording the purchase of the premises, the legal fees and insurance were both treated incorrectly. Phil’s accounting policy is not to charge depreciation on non-current assets in the year of purchase. What was the effect of the errors on the profit for the year? A $1300 overstated B $1300 understated C $2700 overstated D $2700 understated
1 marks
Answer: B
This question in 9706/11 May/June 2023
Q755 · The delivery cost of a machine purchased for business use has been included in carriage… 9706/11 May/June 2023
3 The delivery cost of a machine purchased for business use has been included in carriage inwards. What is the effect on the profit for the year and on total assets? profit for total assets the year A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: D
This question in 9706/11 May/June 2023
Q756 · A company undervalued the closing inventory for its current accounting period 9706/11 May/June 2023
12 A company undervalued the closing inventory for its current accounting period. How did this affect gross profit? current period following period A no effect no effect B understated overstated C understated no effect D understated understated
1 marks
Answer: B
This question in 9706/11 May/June 2023
Q757 · Draft financial statements for a business showed a profit for the year of $62 000 9706/11 May/June 2023
13 Draft financial statements for a business showed a profit for the year of $62 000. The following errors were discovered. 1 Accrued loan interest payable of $3900 had not been accounted for. 2 Allowance for irrecoverable debts had been overstated by $4800. 3 Depreciation was found to be understated by $7500. 4 Prepaid rent expense of $2600 had not been accounted for. What was the corrected profit for the year? A $43 200 B $48 400 C $58 000 D $60 600
1 marks
Answer: C
This question in 9706/11 May/June 2023
Q758 · The owner of a business does not keep a full set of accounting records for his business 9706/11 May/June 2023
15 The owner of a business does not keep a full set of accounting records for his business. The following information is available about assets and liabilities. current year end previous year end $ $ inventory 19 200 17 500 trade receivables 31 200 22 400 trade payables 14 300 16 600 All purchases and sales are on credit. During the current year: 1 The business received $168 000 from customers after allowing them a discount of $3400. 2 The business paid $74 000 to suppliers for inventory. No discounts were received. 3 The owner took inventory of $3200 for personal use. What was the gross profit for the current year? A $110 000 B $110 200 C $111 700 D $113 400
1 marks
Answer: D
This question in 9706/11 May/June 2023
Q759 · A partnership agreement includes the following provisions 9706/11 May/June 2023
16 A partnership agreement includes the following provisions. 1 interest on capital 2 interest on drawings 3 interest on partners’ loans Which provisions will result in entries in the partnership’s appropriation account? A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: B
This question in 9706/11 May/June 2023
Q760 · The partnership agreement of X and Y stated that interest on capital should be calculated… 9706/11 May/June 2023
17 The partnership agreement of X and Y stated that interest on capital should be calculated at the rate of 10% per annum. At the beginning of the year on 1 January, the balances on X’s accounts were: capital $50 000, current $2000 debit. On 1 July, X contributed additional capital of $20 000. On 31 December, the balance on X’s current account was $20 500 credit. He had made no drawings. What was X’s share of the residual profit for the year? A $12 500 B $15 500 C $16 500 D $17 500
1 marks
Answer: C
This question in 9706/11 May/June 2023
Q761 · The financial year of a business ends on 31 December 9706/12 May/June 2023
4 The financial year of a business ends on 31 December. At the beginning of the financial year, the following payments were made in respect of a new machine. $ purchase cost 60 000 installation cost 10 000 It was discovered that the installation cost had been incorrectly treated as an expense. It is the policy of the business to depreciate machinery at 20% per annum using the straight-line method. What was the effect of this error on the profit for the year ended 31 December? A $8000 overstated B $8000 understated C $12 000 overstated D $12 000 understated
1 marks
Answer: B
This question in 9706/12 May/June 2023
Q762 · Which statement contains the correct accounting treatment for accrued income? 9706/12 May/June 2023
11 Which statement contains the correct accounting treatment for accrued income? A added to income and shown as a current asset B added to income and shown as a current liability C deducted from income and shown as a current asset D deducted from income and shown as a current liability
1 marks
Answer: A
This question in 9706/12 May/June 2023
Q763 · A business receives rent from letting part of its premises 9706/12 May/June 2023
12 A business receives rent from letting part of its premises. On 1 January 2022, there was a balance brought forward of $1000 in the rent receivable account in respect of one month’s rent received in advance. During the year ended 31 December 2022, the business received further amounts totalling $13 000 to cover the period from 1 February 2022 to 31 January 2023. A rent increase of 10% was introduced from 1 April 2022. The statement of profit or loss for the year ended 31 December 2022 incorrectly included an amount of $13 000 for rent receivable. What was the effect of this error on the profit for the year? A $100 overstated B $100 understated C $1100 overstated D $1100 understated
1 marks
Answer: A
This question in 9706/12 May/June 2023
Q764 · A sole trader’s personal expenses had been paid out of the business bank account and… 9706/12 May/June 2023
13 A sole trader’s personal expenses had been paid out of the business bank account and included in the statement of profit or loss. What was the effect of this on the profit for the year and on capital? profit for the year capital A no effect no effect B no effect overstated C understated no effect D understated understated
1 marks
Answer: C
This question in 9706/12 May/June 2023
Q765 · A business has a gross profit margin of 25% 9706/12 May/June 2023
14 A business has a gross profit margin of 25%. The following information is available for the year. $ sales revenue 200 000 opening inventory 10 000 closing inventory 5 000 What were the purchases for the year? A $135 000 B $145 000 C $155 000 D $165 000
1 marks
Answer: B
This question in 9706/12 May/June 2023
Q766 · A partnership maintains separate capital accounts and current accounts 9706/12 May/June 2023
15 A partnership maintains separate capital accounts and current accounts. Which statements are correct? 1 The capital accounts represent the retained earnings of the business. 2 The capital accounts show the total amount owed to each partner. 3 The capital accounts and current accounts equal the net assets. A 1 and 2 B 1 and 3 C 2 only D 3 only
1 marks
Answer: D
This question in 9706/12 May/June 2023
Q767 · X, Y and Z are in partnership, sharing profits and losses in the ratio 2 : 2 : 1 9706/12 May/June 2023
16 X, Y and Z are in partnership, sharing profits and losses in the ratio 2 : 2 : 1. X is allowed an annual salary of $10 000. Y has made a loan to the partnership on which the partnership pays interest of $5000 each year. Profit for the year before appropriation was $150 000. What was Z’s total share of profit for the year? A $27 000 B $28 000 C $29 000 D $30 000
1 marks
Answer: B
This question in 9706/12 May/June 2023
Q768 · On 1 January, the owner of a business purchased a new machine 9706/13 May/June 2023
5 On 1 January, the owner of a business purchased a new machine. All non-current assets are depreciated by 25% per annum. During the year, the following payments were made in respect of the machine. $ cost of machine 16 000 delivery 400 installation 600 one year’s insurance 100 A charge of $5100 for these items was included in the draft statement of profit or loss for the year ended 31 December. By how much was the draft profit for the year understated? A $300 B $450 C $750 D $850
1 marks
Answer: C
This question in 9706/13 May/June 2023
Q769 · A statement of financial position at the end of the financial year showed the following… 9706/13 May/June 2023
14 A statement of financial position at the end of the financial year showed the following information. $ non-current assets 18 000 trade receivables 3 000 inventory 1 800 trade payables 3 600 bank 350 credit Capital at the start of the financial year was $19 100. The profit for the year was $9200. What were the owner’s drawings for the year? A $8250 B $8750 C $8950 D $9450
1 marks
Answer: D
This question in 9706/13 May/June 2023
Q770 · Victor and Wasim are in partnership 9706/13 May/June 2023
16 Victor and Wasim are in partnership. At the start of the financial year, the balances on the partners’ current accounts were Victor, $22 500 credit, and Wasim, $3700 debit. The following information is available for the financial year. Victor Wasim $ $ interest on capital 1 500 1 700 share of profits 65 000 97 500 drawings 22 000 17 500 interest on drawings 660 525 capital introduced – 5 000 What was the balance on Wasim’s current account at the end of the financial year? A $72 475 B $77 475 C $78 525 D $82 475
1 marks
Answer: B
This question in 9706/13 May/June 2023
Q771 · A business has trade receivables of $52 000 at the year-end 9706/11 Oct/Nov 2023
12 A business has trade receivables of $52 000 at the year-end. The allowance for irrecoverable debts in the draft statement of financial position is $3000. The allowance for irrecoverable debts is to be changed to 5% of trade receivables. What is the effect of changing the allowance? on profit on current assets A decrease by $2600 decrease by $400 B decrease by $2600 decrease by $2600 C increase by $400 decrease by $400 D increase by $400 increase by $400
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2023
Q772 · A trader prepared her financial statements but made no adjustments for accrued rent… 9706/11 Oct/Nov 2023
13 A trader prepared her financial statements but made no adjustments for accrued rent receivable at the end of the year. What is the effect of this omission? current assets current liabilities profit for the year A no effect overstated overstated B overstated no effect understated C understated overstated no effect D understated no effect understated
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2023
Q773 · A sole trader calculated her draft profit for the year as $50 000 9706/11 Oct/Nov 2023
14 A sole trader calculated her draft profit for the year as $50 000. She asked her accountant for advice regarding four issues which she thought might affect the draft profit. 1 A customer debt of $2000 needs to be written off as irrecoverable. 2 She accounted for her drawings of $10 000 as if they were staff salaries. 3 She wants to increase the value of a non-current asset by $20 000. 4 The existing charge for depreciation is overstated by $5000. What was the profit for the year? A $43 000 B $57 000 C $63 000 D $73 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2023
Q774 · Which items in the books of a partnership would increase the profit available for… 9706/11 Oct/Nov 2023
15 Which items in the books of a partnership would increase the profit available for distribution to the partners? 1 discount received 2 interest on capital 3 interest on drawings 4 partnership salary A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2023
Q775 · L and M are in partnership, sharing profits and losses in proportion to their capital… 9706/11 Oct/Nov 2023
16 L and M are in partnership, sharing profits and losses in proportion to their capital invested. The following information is available. $ capital: L 68 000 M 102 000 profit for the year before appropriation 28 900 drawings: L 8 000 M 12 000 No interest is charged on drawings up to $10 000 for each partner. Interest at a rate of 5% is charged on any drawings in excess of $10 000. What was L’s share of residual profit? A $11 520 B $11 600 C $11 800 D $11 960
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2023
Q776 · The following information is available for a limited company’s financial year ended 31… 9706/11 Oct/Nov 2023
18 The following information is available for a limited company’s financial year ended 31 December. 1 At 1 January the total equity was $350 000. This included 100 000 ordinary shares of $1 each. 2 On 30 June there was a rights issue of 10 000 ordinary shares for $1.50 each. This was fully subscribed. 3 On 1 October the company paid a dividend of $0.10 per ordinary share. 4 On 1 December a dividend was proposed totalling $20 000. 5 Profit for the year was $26 500. What was the total equity on 31 December? A $360 500 B $375 500 C $380 500 D $391 500
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2023
Q777 · A business prepared its statement of profit or loss for the year ended 31 December 9706/12 Oct/Nov 2023
14 A business prepared its statement of profit or loss for the year ended 31 December. During that year, on 30 April, a non-current asset had been sold. The following information is available in respect of this item. cost $130 000 sale proceeds $53 500 residual value $10 000 carrying value at 1 January $52 500 expected life 8 years Non-current assets are depreciated using the straight-line method, with depreciation being charged for each month of ownership. No accounting entries had been made in respect of this non-current asset for the year ended 31 December. What was the effect of this omission on the profit for the year? A $1000 understated B $5000 overstated C $6000 understated D $9000 overstated
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2023
Q778 · The owner of a trading business prepared draft financial statements for the year ended 31… 9706/12 Oct/Nov 2023
15 The owner of a trading business prepared draft financial statements for the year ended 31 December. It was then discovered that the following transactions occurring during the year had not been recorded. 1 A cheque for $500 had been received for commission earned. 2 Cash amounting to $2900 was received for a sale of goods which had cost $3000. 3 Inventory costing $5000 had been taken from the business by the owner for personal use. 4 Non-current assets with a carrying value of $6500 had been sold for $7000 cash. Which transactions will affect both the gross profit for the year and the total value of net assets on the statement of financial position? A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2023
Q779 · A business sells some inventory for $80 on credit 9706/12 Oct/Nov 2023
16 A business sells some inventory for $80 on credit. This originally cost $50. How does this affect the statement of financial position? current assets owner’s capital A decrease by $30 decreases by $30 B decrease by $30 increases by $30 C increase by $30 decreases by $30 D increase by $30 increases by $30
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2023
Q780 · Which entries are made to record interest on capital in partnership accounts? 9706/12 Oct/Nov 2023
17 Which entries are made to record interest on capital in partnership accounts? debit credit A appropriation account capital account B appropriation account current account C capital account appropriation account D current account appropriation account
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2023
Q781 · L and M are in partnership, sharing profits and losses in the ratio of 3 : 2 respectively 9706/12 Oct/Nov 2023
18 L and M are in partnership, sharing profits and losses in the ratio of 3 : 2 respectively. For the year ended 31 March, their statement of profit or loss showed a profit for the year of $68 000. The following information relates to the partnership for the same period. $ interest on loan from L 400 total for both partners: interest on capital 2 600 interest charged on drawings 1 200 salaries 20 000 How much of the residual profit will L receive? A $26 520 B $27 720 C $27 960 D $28 200
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2023
Q782 · A business commenced trading on 1 January 9706/12 Oct/Nov 2023
23 A business commenced trading on 1 January. The purchases and sales of inventory for January were as follows: date purchases sales January 4 3 at $200 each – 13 – 2 at $400 each 26 3 at $250 each – 28 – 2 at $400 each The business used the first in first out (FIFO) method of inventory valuation. What was the gross profit for January? A $250 B $650 C $700 D $750
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2023
Q783 · An improvement to business premises has been incorrectly treated as an expense in the… 9706/13 Oct/Nov 2023
4 An improvement to business premises has been incorrectly treated as an expense in the financial statements. What is the effect on the financial statements after this error has been corrected? assets profit for the year A decreased decreased B decreased increased C increased decreased D increased increased
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2023
Q784 · Which statements are correct? 9706/13 Oct/Nov 2023
14 Which statements are correct? 1 An increase in the allowance for irrecoverable debts increases profit for the year. 2 Irrecoverable debts decrease profit for the year. 3 Rental income received in advance at the end of the period will increase profit for the year. 4 Revenue which has been earned but not yet received will increase profit for the year. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2023
Q785 · A business paid an annual rent of $24 000 9706/13 Oct/Nov 2023
15 A business paid an annual rent of $24 000. At the beginning of the year, on 1 January, there was accrued rent of $4000. Rental payments during the year were as follows: $ 1 January 12 000 1 July 10 000 1 September 13 000 How was rent recorded in the financial statements at 31 December? statement of other other profit or loss receivables payables $ $ $ A 24 000 7 000 nil B 24 000 nil 7 000 C 35 000 11 000 nil D 35 000 nil 11 000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2023
Q786 · A business adds a mark-up of 25% to all goods sold 9706/13 Oct/Nov 2023
16 A business adds a mark-up of 25% to all goods sold. The following information is available for the year ended 30 June. $ receipts from credit customers 284 300 opening trade receivables 22 100 closing trade receivables 26 500 cash used for business expenses and drawings 52 400 discount allowed to credit customers 1 200 closing cash balance 500 Receipts from cash sales were used to pay business expenses and drawings. Any remaining cash was placed in the cash account. The opening cash balance was nil. What was the value of total sales for the year? A $340 400 B $341 600 C $342 800 D $428 500
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2023
Q787 · At the beginning of the financial year on 1 January, a business acquired a new motor… 9706/12 Feb/March 2024
6 At the beginning of the financial year on 1 January, a business acquired a new motor vehicle for $34 000. In error, this was recorded in the account for motor expenses. Motor vehicles are depreciated using the reducing balance method at the rate of 30% per annum. It is estimated that the motor vehicle will have a residual value of $4000 at the end of its life. If the error is not corrected, what will be the effect on the profit for the year ended 31 December? A $10 200 overstated B $23 800 understated C $25 000 understated D $34 000 understated
1 marks
Answer: B
This question in 9706/12 Feb/March 2024
Q788 · A business prepared a trial balance that included a suspense account 9706/12 Feb/March 2024
9 A business prepared a trial balance that included a suspense account. Draft financial statements were prepared which showed a profit for the year of $85 000. The following errors were then discovered. 1 Discounts allowed of $1000 had been debited to the discounts received account. 2 Motoring expenses of $4000 had been debited to the purchases account. 3 A payment for purchases of $5000 had been correctly entered in the cash book but credited to the drawings account. After correcting these errors the balance on the suspense account was eliminated. What was the revised profit for the year? A $76 000 B $78 000 C $80 000 D $82 000 Amit compared his bank statement with his cash book.
1 marks
Answer: C
This question in 9706/12 Feb/March 2024
Q789 · Deepak provided the following information 9706/12 Feb/March 2024
14 Deepak provided the following information. end of year 1 end of year 2 allowance for irrecoverable debts $600 $800 rate of allowance 3% 5% By how much did the total of trade receivables change from the end of year 1 to the end of year 2? A $4000 decrease B $4000 increase C $10 000 decrease D $10 000 increase
1 marks
Answer: A
This question in 9706/12 Feb/March 2024
Q790 · A sole trader began a business on 1 January with $50 000 capital 9706/12 Feb/March 2024
15 A sole trader began a business on 1 January with $50 000 capital. During the year she introduced to the business her own private vehicle which had cost $22 000 but which was valued at $16 000 when she added it to the business. Drawings for the year were $20 000. At the end of the financial year on 31 December the closing balance on the capital account was $105 000. What was the profit for the year? A $39 000 B $53 000 C $59 000 D $75 000
1 marks
Answer: C
This question in 9706/12 Feb/March 2024
Q791 · A partnership provided the following information for the year 9706/12 Feb/March 2024
17 A partnership provided the following information for the year. $ gross profit 76 000 operating costs 30 000 bank interest 1 300 interest on partner’s loan 600 interest on capital 5 600 interest on drawings 2 000 What were the profit for the year and the residual profit shared by the partners? profit for the year residual profit $ $ A 44 100 40 500 B 44 100 47 700 C 44 700 40 500 D 44 700 47 700
1 marks
Answer: A
This question in 9706/12 Feb/March 2024
Q792 · The following information relates to the non-current assets of a business that was formed… 9706/11 May/June 2024
4 The following information relates to the non-current assets of a business that was formed three years ago. $ cost at start of year 1 10 000 accumulated depreciation at end of year 3 6 000 draft profit for year 3 18 000 In calculating the draft profit for year 3, depreciation has been consistently charged using the straight-line method. Prior to finalising the accounts, the business decided to change the method of depreciation for year 3 to the reducing balance method at a rate of 25% per annum. What was the revised profit for year 3? A $16 000 B $17 500 C $18 500 D $19 000
1 marks
Answer: C
This question in 9706/11 May/June 2024
Q793 · A business maintains an allowance for irrecoverable debts of 5% of trade receivables 9706/11 May/June 2024
11 A business maintains an allowance for irrecoverable debts of 5% of trade receivables. At the end of the current financial year, trade receivables totalled $8000 which was 20% less than the year before. How will the profit for the current financial year be affected by the change in the allowance for irrecoverable debts? A decrease by $100 B decrease by $400 C increase by $100 D increase by $400
1 marks
Answer: C
This question in 9706/11 May/June 2024
Q794 · A trader does not keep full records but supplies the following information 9706/11 May/June 2024
12 A trader does not keep full records but supplies the following information. 1 January 31 December $ $ bank (debit) 4240 6320 cash balance 264 271 Cheques issued during the year were $19 950. All takings from sales were banked except that cash of $5400 was used for drawings and $7200 was paid for wages. In addition, $3000 was paid to bank from the sale of a motor vehicle. What was the total amount of sales during the year? A $22 037 B $31 630 C $31 637 D $34 637
1 marks
Answer: C
This question in 9706/11 May/June 2024
Q795 · Which statement(s) are true of drawings? 9706/11 May/June 2024
13 Which statement(s) are true of drawings? 1 They are a reduction in the owner’s investment. 2 They have to be less than the profit for the year. 3 They represent the salary paid to the owner. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: B
This question in 9706/11 May/June 2024
Q796 · Vikram is a partner in a business 9706/11 May/June 2024
14 Vikram is a partner in a business. Partners do not receive salaries or interest on capital, but they are charged 5% interest on the balance of their drawings account. Vikram made drawings of $40 000 during the year and his share of profits was $47 500. His current account showed a credit balance of $4500 after the relevant entries were made at the end of the financial year. What was the debit balance on Vikram’s current account at the beginning of the financial year? A $1000 B $3000 C $5000 D $5500
1 marks
Answer: A
This question in 9706/11 May/June 2024
Q797 · A partnership operates without having a partnership agreement 9706/11 May/June 2024
15 A partnership operates without having a partnership agreement. Which rules will apply to the partnership? 1 Partners will be entitled to interest on any loans made to the business at a rate of 10% per annum. 2 Partners will be entitled to interest on their capital at a rate of 5% per annum. 3 Partners will not be charged interest on their drawings. 4 Partners will not be entitled to a salary. A 1 and 3 B 1 and 4 C 2 and 3 D 3 and 4 L and M are in partnership, sharing profits and losses in the ratio of 3 : 2 respectively.
1 marks
Answer: D
This question in 9706/11 May/June 2024
Q798 · The following information was available at year end 9706/11 May/June 2024
16 The following information was available at year end. L M $ $ capital 200 000 150 000 interest on capital 8% drawings 30 000 20 000 interest on drawings 5% partners’ salaries 22 000 17 000 The residual profit shared by L was $24 000. What was the profit for the year before appropriation? A $48 500 B $88 500 C $104 500 D $109 500
1 marks
Answer: C
This question in 9706/11 May/June 2024
Q799 · Non-current assets, and depreciation at 10% of cost was charged to the draft statement of… 9706/13 May/June 2024
4 non-current assets, and depreciation at 10% of cost was charged to the draft statement of profit or loss for the period. In addition the business paid $14 000 for installation of the machinery and $6000 for insuring the machine. These amounts were treated as revenue expenditure for the period. The draft statement of profit or loss for the period showed a profit of $50 000. What is the revised profit for the period? A $48 600 B $50 000 C $62 600 D $68 000
1 marks
Answer: C
This question in 9706/13 May/June 2024
Q800 · Jake sold a non-current asset which was not fully depreciated 9706/13 May/June 2024
5 Jake sold a non-current asset which was not fully depreciated. He mistakenly recorded this by debiting the bank account and crediting the sales account with the proceeds. What was the effect of this error? 1 Assets were overstated. 2 Assets were understated. 3 Profit was overstated. 4 Profit was understated. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/13 May/June 2024
Q801 · Sara bought a non-current asset 9706/13 May/June 2024
6 Sara bought a non-current asset. Depreciation was provided at the rate of 10% per annum in years 1 and 2. It was sold at a profit in year 3. The policy of the business is not to charge depreciation in the year of disposal. How would profits be affected if the rate had been 15% per annum? profit in profit in years 1 and 2 year 3 A higher higher B higher lower C lower higher D lower lower
1 marks
Answer: C
This question in 9706/13 May/June 2024
Q802 · In a draft statement of profit or loss, two errors were discovered 9706/13 May/June 2024
13 In a draft statement of profit or loss, two errors were discovered. 1 A profit of $6000 on the disposal of equipment had been treated as a loss. 2 A charge of $18 000 for the depreciation of a motor vehicle had been omitted. What was the effect of these errors on the draft profit for the year? A overstated $6000 B overstated $12 000 C understated $6000 D understated $12 000
1 marks
Answer: A
This question in 9706/13 May/June 2024
Q803 · At the beginning of the financial year on 1 July, a business shows an accrual on the rent… 9706/13 May/June 2024
14 At the beginning of the financial year on 1 July, a business shows an accrual on the rent account of $600. During the financial year, payments were made for rent as detailed below. $ 26 July paid 3 months' rent to 31 July 900 11 November paid 4 months' rent to 30 November 1 200 15 March paid 4 months' rent to 31 March 1 200 Which amount is to be shown as a prepayment or accrual for rent at the end of the financial year on 30 June? A $600 accrual B $600 prepayment C $900 accrual D $900 prepayment
1 marks
Answer: C
This question in 9706/13 May/June 2024
Q804 · A sole trader sold goods at a mark-up of 50% 9706/13 May/June 2024
15 A sole trader sold goods at a mark-up of 50%. During the year, he withdrew goods for his own use. The drawings account was debited and the sales account was credited with goods at the selling price of $5400. What was the effect of these errors on the profit for the year? A $1800 overstated B $1800 understated C $2700 overstated D $2700 understated
1 marks
Answer: A
This question in 9706/13 May/June 2024
Q805 · Yasmin and Zara are in partnership, sharing profits and losses in the ratio 3 : 2… 9706/13 May/June 2024
17 Yasmin and Zara are in partnership, sharing profits and losses in the ratio 3 : 2 respectively after providing Zara with a partnership salary of $8000 per annum. During the partnership’s first year of trading, Yasmin’s drawings totalled $11 500 and the partnership made a profit of $7000 before appropriation. What was the closing debit balance on Yasmin’s current account? A $7300 B $10 900 C $11 900 D $12 100
1 marks
Answer: D
This question in 9706/13 May/June 2024
Q806 · A depreciated non-current asset is revalued upwards 9706/11 Oct/Nov 2024
6 A depreciated non-current asset is revalued upwards. What is the effect of this? capital reserve revenue reserve A decrease no effect B increase no effect C no effect decrease D no effect increase
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2024
Q807 · What is a purpose of financial statements? 9706/11 Oct/Nov 2024
12 What is a purpose of financial statements? A to aid the managers in running the business B to allow the owner to take drawings C to ensure a profit is made D to ensure accuracy of the double entry
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2024
Q808 · A business owner provided the following information at the end of his first year of… 9706/11 Oct/Nov 2024
13 A business owner provided the following information at the end of his first year of trading. $ closing inventory 15000 total payments to suppliers 60000 amount owing to suppliers 5000 total receipts from customers 85000 amount owed by customers 10000 What was the gross profit for the year? A $10000 B $15000 C $25000 D $45000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2024
Q809 · Lu had the following capital account balances 9706/11 Oct/Nov 2024
14 Lu had the following capital account balances. End of year 1 End of year 2 $45700 $63400 During year 2 the following took place: 1 cash drawings $33000 2 personal motor vehicle introduced to the business at a value of $24500. Expenses for the year include a payment for rent of $10000, of which 40% was for Lu’s personal use. What was his profit for year 2? A $5200 B $13200 C $22200 D $30200
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2024
Q810 · A business maintains an allowance for irrecoverable debts of 2% of trade receivables 9706/11 Oct/Nov 2024
15 A business maintains an allowance for irrecoverable debts of 2% of trade receivables. At the beginning of the financial year on 1 January the trade receivables total was $48000. At the end of the financial year on 31 December the trade receivables total was $37000. When the business owner prepared the statement of profit or loss for the year ended 31 December, an irrecoverable debt of $1600 which had occurred during the year had not been written off. No adjustment had been made to deal with the allowance for irrecoverable debts at 31 December. By which amount was the profit for the year overstated? A $892 B $1348 C $1852 D $2308
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2024
Q811 · P and Q are in partnership sharing profits and losses equally 9706/11 Oct/Nov 2024
17 P and Q are in partnership sharing profits and losses equally. The following information is available in respect of P. $ current account credit balance at start of the year 20150 share of asset revaluation 10000 drawings 10200 The total partnership profit for the year was $130000. Partnership salaries were P $20000, Q $30000. What was the balance on the current account of P at the end of the year? A $10350 B $69950 C $79950 D $90350
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2024
Q812 · Which statements are correct? 9706/11 Oct/Nov 2024
18 Which statements are correct? 1 capital reserves arise from normal trading activities 2 capital reserves can be used to pay dividends 3 revenue reserves may be used when bonus shares are issued 4 revenue reserves represent profits which have been realised A 1 and 2 B 2 and 3 C 3 and 4 D 4 only
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2024
Q813 · The following information is provided for a company for the financial year ended 31 March 9706/11 Oct/Nov 2024
19 The following information is provided for a company for the financial year ended 31 March. $ revenue 7200000 administrative expenses 320000 finance costs 150000 distribution costs 250000 dividend paid 60000 There were no other expenses for this period. The company adds a uniform mark-up of 25% on all goods sold. What was the profit from operations for the year ended 31 March? A $720000 B $870000 C $1080000 D $1170000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2024
Q814 · Which item is capital income? 9706/12 Oct/Nov 2024
4 Which item is capital income? A bank interest received B proceeds from sale of business premises C rental income from property D sale of inventory to a customer
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2024
Q815 · The draft profit for the year of a business is $53000 9706/12 Oct/Nov 2024
5 The draft profit for the year of a business is $53000. During the year, the business acquired new premises and included the following costs in the cost of the premises. $ legal fees 1500 insurance 4500 The business does not charge any depreciation on premises. What is the revised profit for the year? A $47000 B $48500 C $51500 D $59000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2024
Q816 · The current assets of a company include the balances on both the rent payable and rent… 9706/12 Oct/Nov 2024
14 The current assets of a company include the balances on both the rent payable and rent receivable accounts. What do these balances represent? rent payable rent receivable A accrued accrued B accrued prepaid C prepaid accrued D prepaid prepaid
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2024
Q817 · The following information is available for a sole trader 9706/12 Oct/Nov 2024
15 The following information is available for a sole trader. $ allowance for irrecoverable debts at the start of the year 1400 total trade receivables at the end of the year 36000 At the end of the year it was decided to write off $1000 as irrecoverable debts and maintain the allowance for irrecoverable debts at 3% of trade receivables. What is the entry in the allowance for irrecoverable debts account? A $320 debit B $320 credit C $350 debit D $350 credit
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2024
Q818 · A sole trader’s statement of profit or loss shows the following information 9706/12 Oct/Nov 2024
16 A sole trader’s statement of profit or loss shows the following information. $ opening inventory 5000 operating expenses 3000 profit for the year 5400 Closing inventory is 10% less than opening inventory. All goods sold are marked up by 50%. What were the purchases for the year? A $10300 B $15700 C $16300 D $17300
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2024
Q819 · L and M are in partnership, sharing profits and losses in the ratio of 3:2 9706/12 Oct/Nov 2024
17 L and M are in partnership, sharing profits and losses in the ratio of 3:2. They have the following current account balances. L M $ $ 31 March 2023 3000 credit 4500 debit 31 March 2024 14200 credit 6200 debit The balances at 31 March 2024 are after taking into account the following: L M $ $ interest on drawings 1000 1500 interest on capital 3000 2000 drawings 10000 15000 What was the residual profit to be shared between L and M for the year ended 31 March 2024? A $24000 B $27000 C $29000 D $32000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2024
Q820 · A business recorded expenditure on improving a non-current asset as revenue expenditure 9706/13 Oct/Nov 2024
4 A business recorded expenditure on improving a non-current asset as revenue expenditure. What is the effect of this error on the carrying value of non-current assets and profit for the year? carrying value of profit for non-current the year assets A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2024
Q821 · A book-keeper makes the following adjustments to ledger accounts before making transfers… 9706/13 Oct/Nov 2024
13 A book-keeper makes the following adjustments to ledger accounts before making transfers to the statement of profit or loss for the period. 1 The insurance expense account is debited for a prepaid amount. 2 The account for rent received is debited for an amount received in advance. 3 The allowance for irrecoverable debts account is debited for the reduction in the allowance. 4 The provision for depreciation on machinery account is debited for the annual depreciation charge. Which entries are correct? A 1, 2 and 3 B 1, 3 and 4 C 2 and 3 only D 2 and 4
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2024
Q822 · At the end of a financial year, the following took place in a business: 1 Trade… 9706/13 Oct/Nov 2024
14 At the end of a financial year, the following took place in a business: 1 Trade receivables with a value of $10000 were written off as irrecoverable. 2 A bank loan of $20000 was received. What was the effect of the two transactions on the net assets of the business? A $10000 decrease B $20000 decrease C $10000 increase D $20000 increase
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2024
Q823 · A trader started business on 1 January with capital of $120 000 9706/13 Oct/Nov 2024
15 A trader started business on 1 January with capital of $120 000. At the end of the financial year on 31 December, the balance on the capital account was $150 000 after entering the profit for the year of $70 000 and an amount for drawings. During the year, the trader had introduced a motor vehicle which had previously been for private use. This had cost $30 000 but was valued at $20 000 when it was brought into the business. The trader had also introduced a further $25000 in cash. What was the drawings figure for the year? A $40000 B $60000 C $85000 D £95000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2024
Q824 · Annie and Benny were in partnership 9706/13 Oct/Nov 2024
16 Annie and Benny were in partnership. They maintained both capital and current accounts. On 1 January Annie’s capital was $20000. On 1 April she transferred her private motor vehicle to the business at a valuation of $12000. On 1 July she took goods with a cost price of $2000 for personal use. Interest on capital was calculated at the rate of 10% per annum. What was Annie’s interest on capital for the year ended 31 December? A $2800 B $2900 C $3000 D $3200
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2024
Q825 · X and Y are in partnership 9706/13 Oct/Nov 2024
17 X and Y are in partnership. The following information is available at the end of the year. X Y total $ $ $ interest on loan – 2000 2000 interest on drawings 600 750 1350 interest on capital 12000 10800 22800 share of profit 36330 24220 60550 What is the profit for the year before appropriation? A $80000 B $82000 C $84000 D $84700
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2024
Q826 · A business has the following balances at the end of a financial period 9706/11 May/June 2025
2 A business has the following balances at the end of a financial period. $ non-current assets 102000 trade receivables 39000 trade payables 27000 profit for the period 65000 drawings 32000 long-term loan 50000 What is the closing balance on the owner’s capital account at the end of the financial period? A $32000 B $64000 C $97000 D $141000
1 marks
Answer: B
This question in 9706/11 May/June 2025
Q827 · The draft profit for the year of a business was $84000 9706/11 May/June 2025
12 The draft profit for the year of a business was $84000. The following errors were then discovered. 1 Discounts received of $2500 had been debited to the discounts allowed account. 2 Wages of $9000 had been completely omitted. 3 Sales returns of $8000 had been debited to the purchases returns account. What is the corrected profit for the year? A $64000 B $72000 C $77500 D $80000
1 marks
Answer: D
This question in 9706/11 May/June 2025
Q828 · Which items would increase the profit for the year? 9706/11 May/June 2025
13 Which items would increase the profit for the year? 1 increase in allowance for irrecoverable debts 2 decrease in allowance for irrecoverable debts 3 increase in prepaid rent expense 4 decrease in prepaid rent expense A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/11 May/June 2025
Q829 · Sam was unable to conduct a physical count of inventory at 31 December 2024 9706/11 May/June 2025
14 Sam was unable to conduct a physical count of inventory at 31 December 2024. On 3 January 2025, inventory was sold to Abdul for $11950. The cost price of this inventory was $9560. On 4 January 2025, inventory had been returned by Sita. It had been sold on 21 December 2024 for $2390. The cost price of this inventory was $1912. Sam valued his inventory on 5 January 2025 at a cost of $59750. What was the value of inventory at 31 December 2024? A $50190 B $52012 C $67398 D $69310
1 marks
Answer: C
This question in 9706/11 May/June 2025
Q830 · Why does a sole trader account for accrued income? 9706/11 May/June 2025
15 Why does a sole trader account for accrued income? A so that current liabilities are not overstated B so that current liabilities are not understated C so that profit is not overstated D so that profit is not understated
1 marks
Answer: D
This question in 9706/11 May/June 2025
Q831 · The following information is available for a sole trader’s business at the end of the… 9706/11 May/June 2025
16 The following information is available for a sole trader’s business at the end of the financial year. $ cost of sales 540000 expenses 325000 profit for the year 63000 sales returns 30000 What was the total sales figure for the year? A $865000 B $895000 C $928000 D $958000
1 marks
Answer: D
This question in 9706/11 May/June 2025
Q832 · A partnership maintains both capital and current accounts for its partners 9706/11 May/June 2025
17 A partnership maintains both capital and current accounts for its partners. What is the correct accounting entry for recording interest on capital for partner X? account to account to be debited be credited A appropriation X’s capital B appropriation X’s current C X’s capital appropriation D X’s current appropriation
1 marks
Answer: B
This question in 9706/11 May/June 2025
Q833 · Arnold is in a partnership with Bradley 9706/11 May/June 2025
18 Arnold is in a partnership with Bradley. Their financial period ends on 31 December. One of the terms of their partnership agreement is that interest is charged on drawings on a monthly basis at the rate of 5% per annum. Arnold made the following drawings during the year on the dates specified. $ 31 March 6000 30 June 10000 30 September 12000 31 December 8000 What is the correct treatment for interest on drawings in the appropriation account for the partnership? A $625 added to profit for the year B $625 deducted from profit for the year C $775 added to profit for the year D $775 deducted from profit for the year
1 marks
Answer: A
This question in 9706/11 May/June 2025
Q834 · A business paid $5750 during its trading year for advertising 9706/12 May/June 2025
14 A business paid $5750 during its trading year for advertising. This amount included $500 in respect of the next financial year. How would the correct treatment of the $500 affect the financial statements? profit for the year net current assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: D
This question in 9706/12 May/June 2025
Q835 · The books of a business showed the following balances at the end of the financial year on… 9706/12 May/June 2025
15 The books of a business showed the following balances at the end of the financial year on 31 December. $ trade receivables 18820 allowance for irrecoverable debts 760 The following adjustments need to be made. 1 An irrecoverable debt of $470, which was written off in the previous year, has been recovered. No entries for this have been made in the financial statements. 2 Irrecoverable debts of $680 need to be written off. 3 The allowance for irrecoverable debts is to be 5% of trade receivables. How will the total of these adjustments be recorded in the statement of profit or loss for the year ended 31 December? A $63 expense B $63 income C $357 expense D $357 income
1 marks
Answer: C
This question in 9706/12 May/June 2025
Q836 · After preparing the financial statements of a sole trader, the following items were… 9706/12 May/June 2025
16 After preparing the financial statements of a sole trader, the following items were discovered. 1 Drawings consisted of goods taken for own use at their sales value of $12000. The owner applies a mark-up of 50% on all goods sold. 2 Profit for the year included an insurance expense of $7500. One-third was for the owner’s health insurance. What is the effect on the profit for the year after correcting these items? A $1500 decrease B $3500 decrease C $6500 increase D $8500 increase
1 marks
Answer: A
This question in 9706/12 May/June 2025
Q837 · L and M are in partnership 9706/12 May/June 2025
17 L and M are in partnership. Which item should appear in the partnership appropriation account? A additional capital contributed by M B cash drawings of L and M during the year C salary due to L D salary paid to M’s sister
1 marks
Answer: C
This question in 9706/12 May/June 2025
Q838 · Valerie and Paul are in partnership, sharing profits and losses in the ratio of 5:3… 9706/12 May/June 2025
18 Valerie and Paul are in partnership, sharing profits and losses in the ratio of 5:3 respectively. The partnership profit for the year was $250000. The appropriation account of the partnership for the year included the following information. $ total interest on partners’ drawings 12000 total interest on partners’ capital contributions 18000 What was Paul’s share of the residual profits? A $82500 B $91500 C $93750 D $96000
1 marks
Answer: B
This question in 9706/12 May/June 2025
Q839 · A business has the following balances at the end of a financial period 9706/13 May/June 2025
2 A business has the following balances at the end of a financial period. $ non-current assets 102000 trade receivables 39000 trade payables 27000 profit for the period 65000 drawings 32000 long-term loan 50000 What is the closing balance on the owner’s capital account at the end of the financial period? A $32000 B $64000 C $97000 D $141000
1 marks
Answer: B
This question in 9706/13 May/June 2025
Q840 · The draft profit for the year of a business was $84000 9706/13 May/June 2025
12 The draft profit for the year of a business was $84000. The following errors were then discovered. 1 Discounts received of $2500 had been debited to the discounts allowed account. 2 Wages of $9000 had been completely omitted. 3 Sales returns of $8000 had been debited to the purchases returns account. What is the corrected profit for the year? A $64000 B $72000 C $77500 D $80000
1 marks
Answer: D
This question in 9706/13 May/June 2025
Q841 · Which items would increase the profit for the year? 9706/13 May/June 2025
13 Which items would increase the profit for the year? 1 increase in allowance for irrecoverable debts 2 decrease in allowance for irrecoverable debts 3 increase in prepaid rent expense 4 decrease in prepaid rent expense A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: C
This question in 9706/13 May/June 2025
Q842 · Sam was unable to conduct a physical count of inventory at 31 December 2024 9706/13 May/June 2025
14 Sam was unable to conduct a physical count of inventory at 31 December 2024. On 3 January 2025, inventory was sold to Abdul for $11950. The cost price of this inventory was $9560. On 4 January 2025, inventory had been returned by Sita. It had been sold on 21 December 2024 for $2390. The cost price of this inventory was $1912. Sam valued his inventory on 5 January 2025 at a cost of $59750. What was the value of inventory at 31 December 2024? A $50190 B $52012 C $67398 D $69310
1 marks
Answer: C
This question in 9706/13 May/June 2025
Q843 · Why does a sole trader account for accrued income? 9706/13 May/June 2025
15 Why does a sole trader account for accrued income? A so that current liabilities are not overstated B so that current liabilities are not understated C so that profit is not overstated D so that profit is not understated
1 marks
Answer: D
This question in 9706/13 May/June 2025
Q844 · The following information is available for a sole trader’s business at the end of the… 9706/13 May/June 2025
16 The following information is available for a sole trader’s business at the end of the financial year. $ cost of sales 540000 expenses 325000 profit for the year 63000 sales returns 30000 What was the total sales figure for the year? A $865000 B $895000 C $928000 D $958000
1 marks
Answer: D
This question in 9706/13 May/June 2025
Q845 · A partnership maintains both capital and current accounts for its partners 9706/13 May/June 2025
17 A partnership maintains both capital and current accounts for its partners. What is the correct accounting entry for recording interest on capital for partner X? account to account to be debited be credited A appropriation X’s capital B appropriation X’s current C X’s capital appropriation D X’s current appropriation
1 marks
Answer: B
This question in 9706/13 May/June 2025
Q846 · Arnold is in a partnership with Bradley 9706/13 May/June 2025
18 Arnold is in a partnership with Bradley. Their financial period ends on 31 December. One of the terms of their partnership agreement is that interest is charged on drawings on a monthly basis at the rate of 5% per annum. Arnold made the following drawings during the year on the dates specified. $ 31 March 6000 30 June 10000 30 September 12000 31 December 8000 What is the correct treatment for interest on drawings in the appropriation account for the partnership? A $625 added to profit for the year B $625 deducted from profit for the year C $775 added to profit for the year D $775 deducted from profit for the year
1 marks
Answer: A
This question in 9706/13 May/June 2025
Q847 · At the end of a financial period, a business had the following assets and liabilities 9706/11 Oct/Nov 2025
2 At the end of a financial period, a business had the following assets and liabilities. 1 non-current assets at carrying value 2 current assets 3 non-current liabilities 4 current liabilities How is the capital of the business calculated? A 1 + 2 + 3 + 4 B 1 – 2 – 3 + 4 C 1 + 2 – 3 – 4 D 1 – 2 + 3 – 4
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2025
Q848 · A business makes an allowance for irrecoverable debts at the year end 9706/11 Oct/Nov 2025
4 A business makes an allowance for irrecoverable debts at the year end. Which accounting concepts have been applied? 1 matching / accruals 2 materiality 3 prudence 4 substance over form A 1 and 2 B 1 and 3 C 2, 3 and 4 D 3 and 4 only
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2025
Q849 · 1 Revenue income includes the amounts received from renting out part of the business… 9706/11 Oct/Nov 2025
6 1 Revenue income includes the amounts received from renting out part of the business premises. 2 Capital income includes amounts received from the sale of non-current assets. 3 Capital income includes loans taken by a business. A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2025
Q850 · A business paid $5750 for advertising during its trading year 9706/11 Oct/Nov 2025
13 A business paid $5750 for advertising during its trading year. This amount included $500 in respect of the next financial year. How would the correct treatment of the $500 affect the financial statements? profit for the year current assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2025
Q851 · A trader has calculated a draft loss for the year of $320 9706/11 Oct/Nov 2025
14 A trader has calculated a draft loss for the year of $320. However, the following adjustments have still to be made. 1 Irrecoverable debts of $930 were recovered. 2 The allowance for irrecoverable debts had been $520. The required allowance is to be 5% of trade receivables. Trade receivables totalled $9600. What is the revised profit or loss for the year? A loss of $1210 B loss of $1730 C profit of $130 D profit of $650
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2025
Q852 · Jaime provided the following information 9706/11 Oct/Nov 2025
15 Jaime provided the following information. $ capital at the beginning of the year 14000 capital at the end of the year 12300 loan received during the year 4000 cash drawings 17200 private phone charges paid by the business 300 What was the profit for the year? A $11800 B $15500 C $15800 D $19200
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2025
Q853 · An item of capital expenditure has been treated as revenue expenditure 9706/12 Oct/Nov 2025
4 An item of capital expenditure has been treated as revenue expenditure. What is the effect on the non-current assets and on the loss for the year? non-current assets loss for the year A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2025
Q854 · Y Limited purchased a motor van and incurred the following expenditure at the beginning… 9706/12 Oct/Nov 2025
5 Y Limited purchased a motor van and incurred the following expenditure at the beginning of the year. $ motor van 50000 delivery of motor van 4500 upgrading the engine 6000 2-year maintenance 4000 contract annual licence fee 1200 The motor van is to be depreciated at 20% using the straight-line method. What is the total amount of expenses to be included in the statement of profit or loss for the year? A $14340 B $15300 C $17300 D $20100
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2025
Q855 · Which item would result in a credit entry in a statement of profit or loss? 9706/12 Oct/Nov 2025
13 Which item would result in a credit entry in a statement of profit or loss? A a reduction in the allowance for irrecoverable debts B an increase in the allowance for irrecoverable debts C the creation of an allowance for irrecoverable debts D the writing off of a trade receivable
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2025
Q856 · A sole trader rented out part of his business office on 1 January 2024 at $500 per month… 9706/12 Oct/Nov 2025
14 A sole trader rented out part of his business office on 1 January 2024 at $500 per month for 24 months. During the year ended 31 December 2024, he received the following amounts: • rent of $5500 • rent deposit of $500 refundable at the end of month 24. Which amounts should be shown in the statement of financial position at 31 December 2024? current assets current liabilities A nil $500 B $500 nil C $500 $500 D $1000 nil
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2025
Q857 · What will have the effect of increasing the profits when entered in the statement of… 9706/12 Oct/Nov 2025
15 What will have the effect of increasing the profits when entered in the statement of profit or loss for a sole trader? A carriage inwards B discounts allowed C goods taken for own use D sales returns
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2025
Q858 · A partnership maintains both capital and current accounts for its partners 9706/12 Oct/Nov 2025
16 A partnership maintains both capital and current accounts for its partners. What is the correct accounting entry for recording interest on capital for partner X? account to account to be debited be credited A appropriation X’s capital B appropriation X’s current C X’s capital appropriation D X’s current appropriation
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2025
Q859 · Lee and Mia are in partnership sharing profits and losses in the ratio 4 : 3 respectively 9706/12 Oct/Nov 2025
17 Lee and Mia are in partnership sharing profits and losses in the ratio 4 : 3 respectively. An error was made when their appropriation account for the year was prepared. Interest on drawings was omitted: Lee $90 and Mia $50. By what amount will the balance of Lee’s current account decrease when this error is corrected? A $10 B $30 C $150 D $170
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2025
Q860 · The following information is extracted from the draft statement of financial position of… 9706/12 Oct/Nov 2025
18 The following information is extracted from the draft statement of financial position of a limited company at 31 December. $ ordinary share capital 900000 share premium 80000 general reserve 96000 retained earnings (opening) 230000 profit for the year 145000 What is the maximum amount of dividend that the limited company can declare? A $145000 B $375000 C $471000 D $551000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2025
Q861 · Closing inventory of $5000 at the end of the year on 31 December has been incorrectly… 9706/13 Oct/Nov 2025
9 Closing inventory of $5000 at the end of the year on 31 December has been incorrectly entered in the financial statements as $3000. How does this affect the financial statements for the year? profit for the year total assets A no effect understated B overstated overstated C understated no effect D understated understated
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2025
Q862 · A statement of profit or loss shows a draft loss for the year of $9450 9706/13 Oct/Nov 2025
14 A statement of profit or loss shows a draft loss for the year of $9450. However, the following errors have been discovered. 1 Depreciation of $10 000 on non-current assets has been incorrectly charged using the straight-line method at 25% per annum. The correct depreciation rate is 20% per annum. 2 No record has been made of goods taken for own use by the owner, $720. What is the corrected draft loss? A $6730 B $8170 C $8230 D $9670
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2025
Q863 · The amount of trade receivables at the year end of Year 2, before deducting the allowance… 9706/13 Oct/Nov 2025
15 The amount of trade receivables at the year end of Year 2, before deducting the allowance for irrecoverable debts, was the same as at the end of Year 1. There were no irrecoverable debts in either year. The sole trader reduced the rate of allowance for irrecoverable debts in Year 2. What is the effect of this action on profit for the year and on current assets? profit for the year current assets A increased increased B increased decreased C decreased increased D decreased decreased
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2025
Q864 · Jane has just completed her first year in business as a sole trader 9706/13 Oct/Nov 2025
16 Jane has just completed her first year in business as a sole trader. The following details are available for the year ended 31 December. $ profit for the year 89200 bank loan at 31 December 10000 drawings for the year 46500 capital at 31 December 202000 capital introduced during the year 20000 How much capital did Jane begin the business with? A $92800 B $129300 C $139300 D $159300
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2025
Q865 · How is a partnership appropriation account prepared? 9706/13 Oct/Nov 2025
17 How is a partnership appropriation account prepared? added to profit for the subtracted from profit year for the year A interest on capital interest on drawings, partners’ salaries B interest on capital, interest on drawings, partners’ salaries drawings C interest on drawings, interest on capital, drawings partners’ salaries D interest on drawings interest on capital, partners’ salaries
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2025
Q866 · Tom had a credit balance on his current account 9706/13 Oct/Nov 2025
18 Tom had a credit balance on his current account. He had a partner’s salary of $5000 and interest on drawings of $800. These were both posted to the wrong side of his current account. What was the effect of these errors on the balance on his current account? A $8400 overstated B $8400 understated C $11600 overstated D $11600 understated
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2025
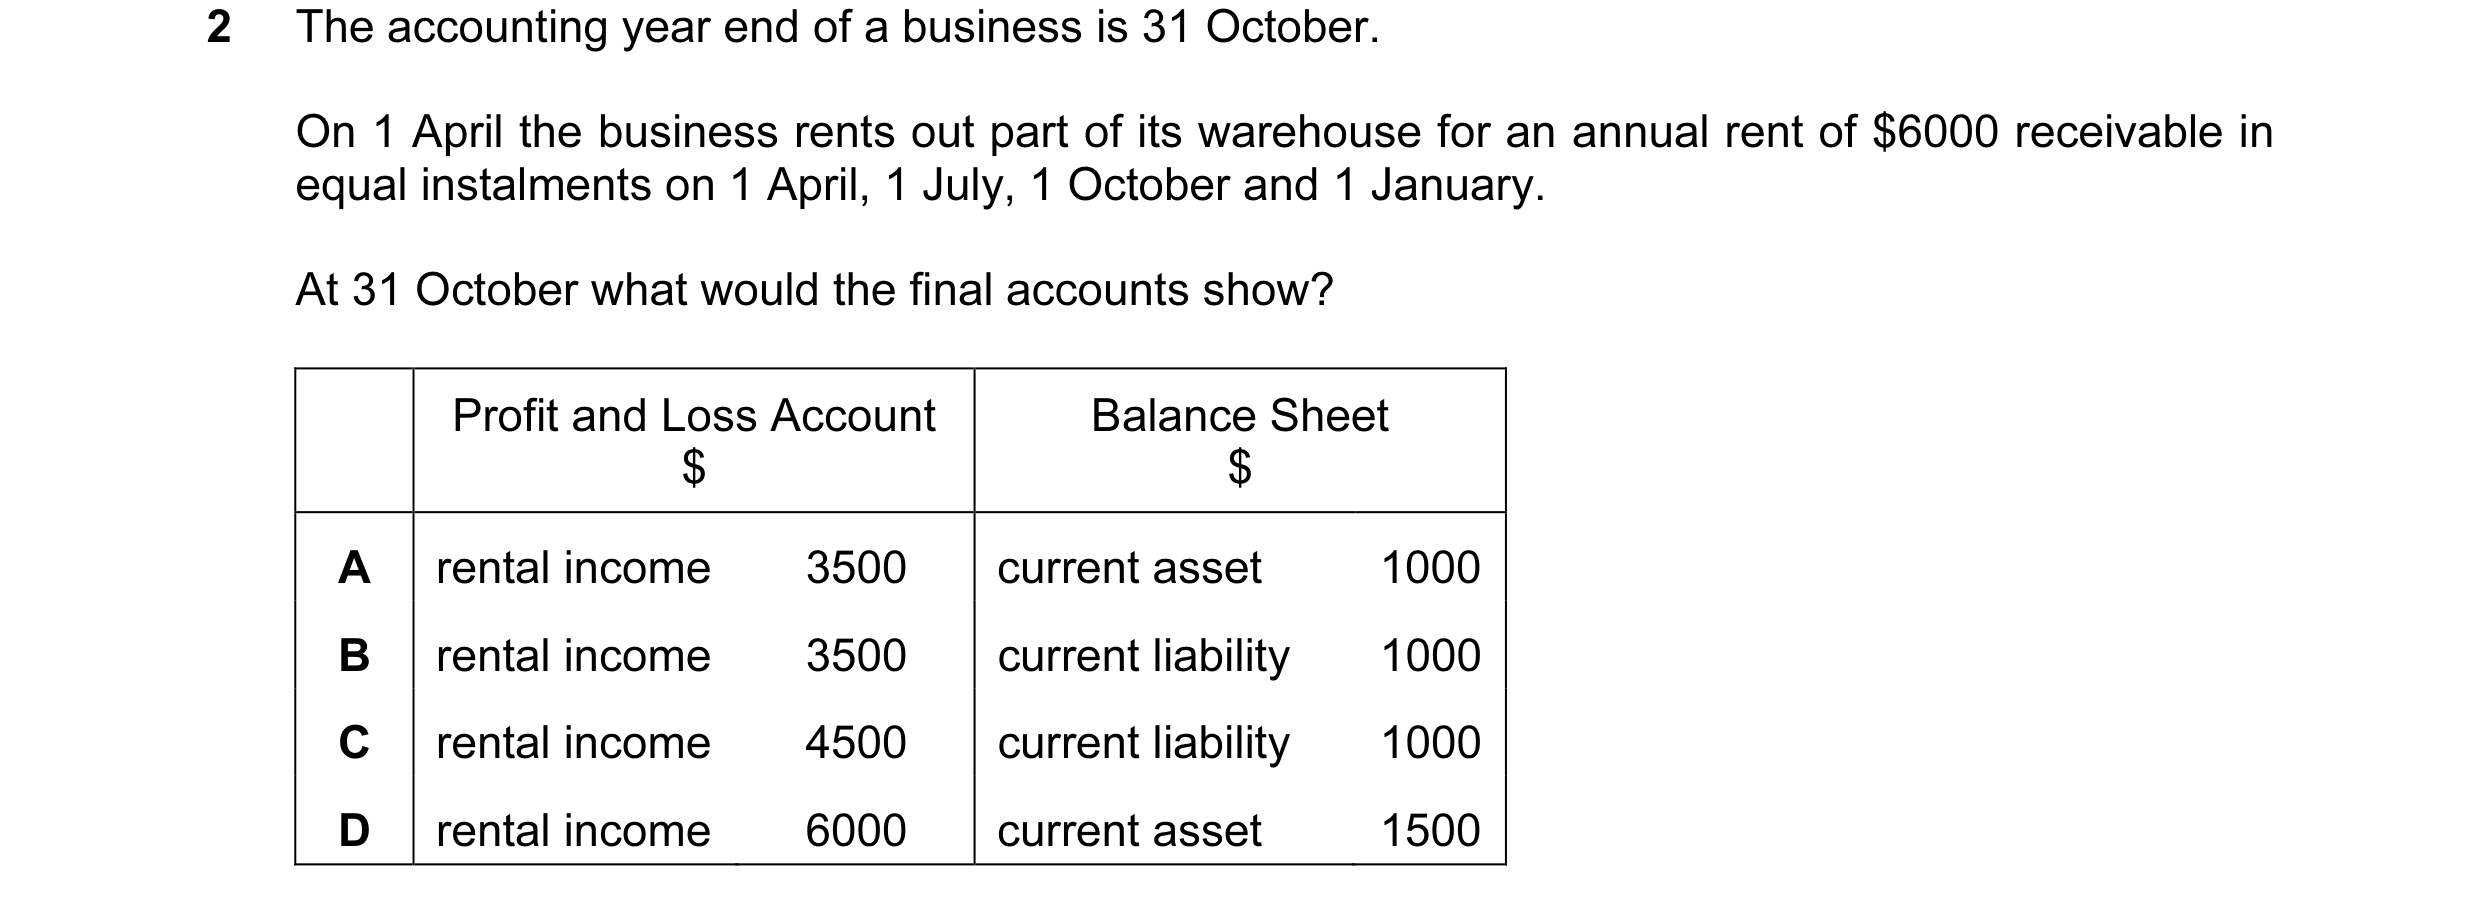
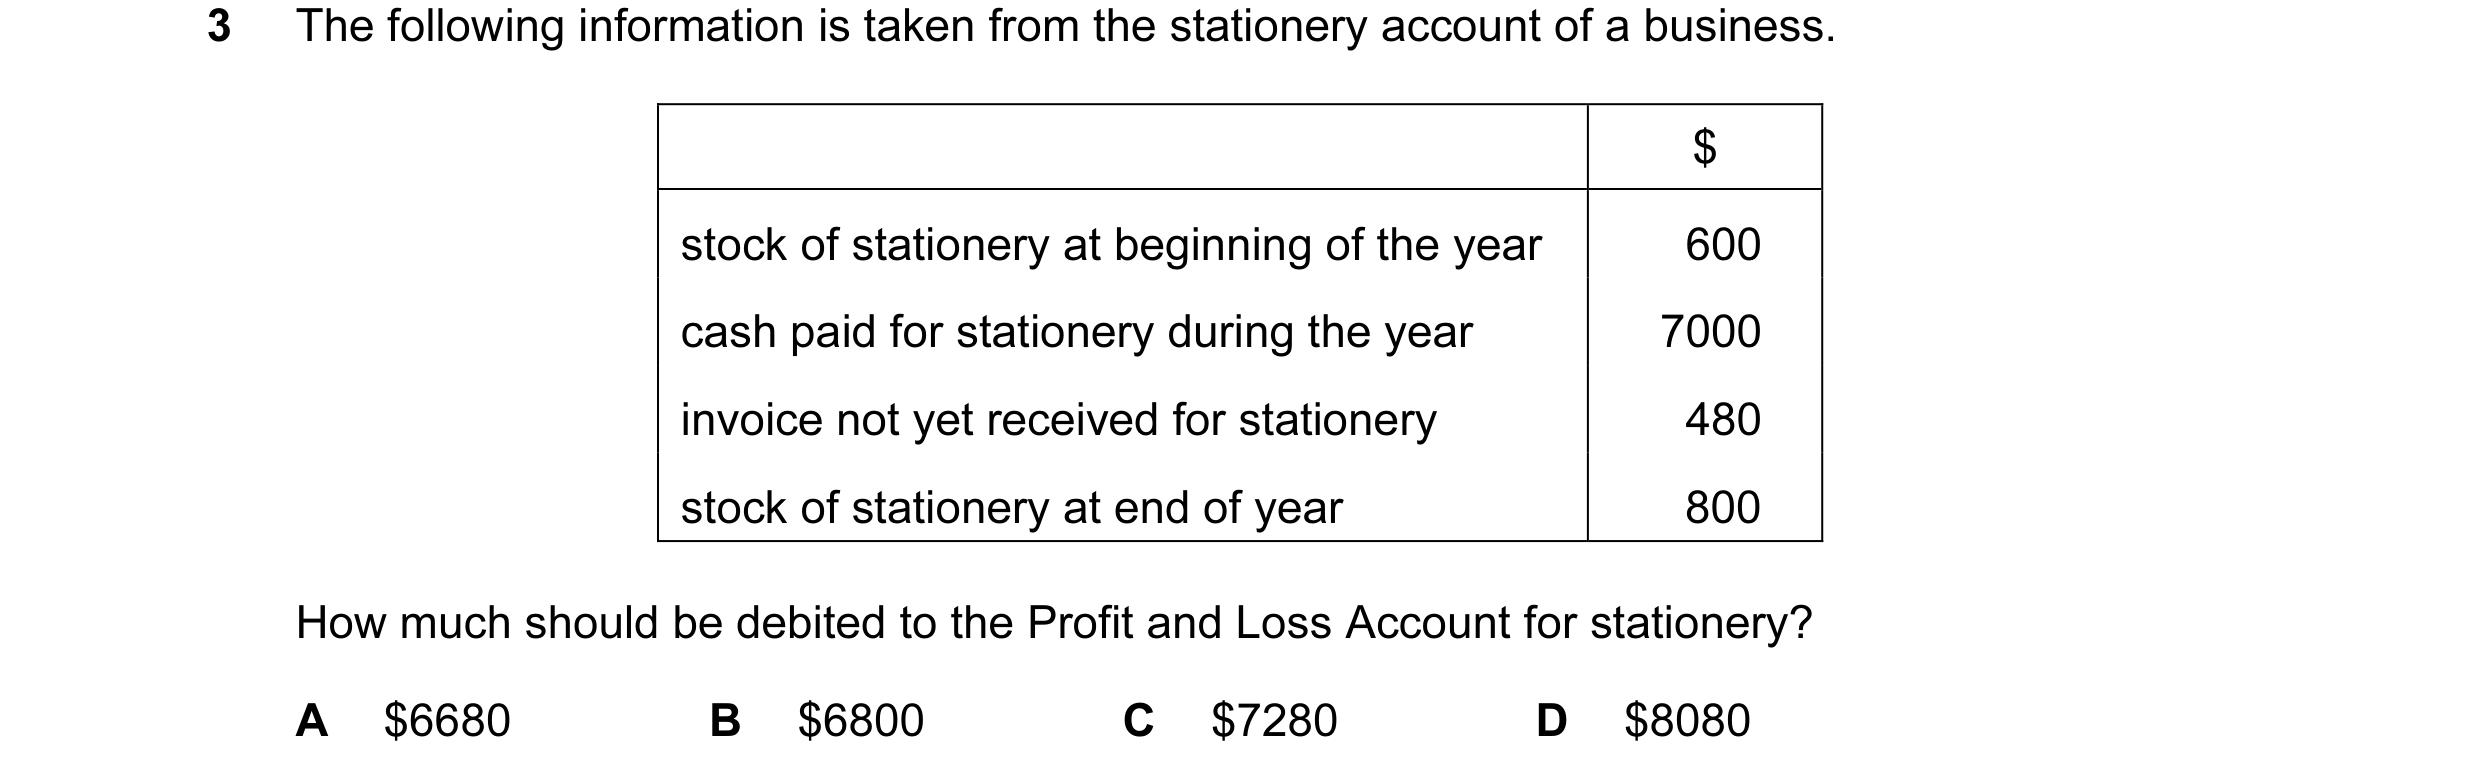
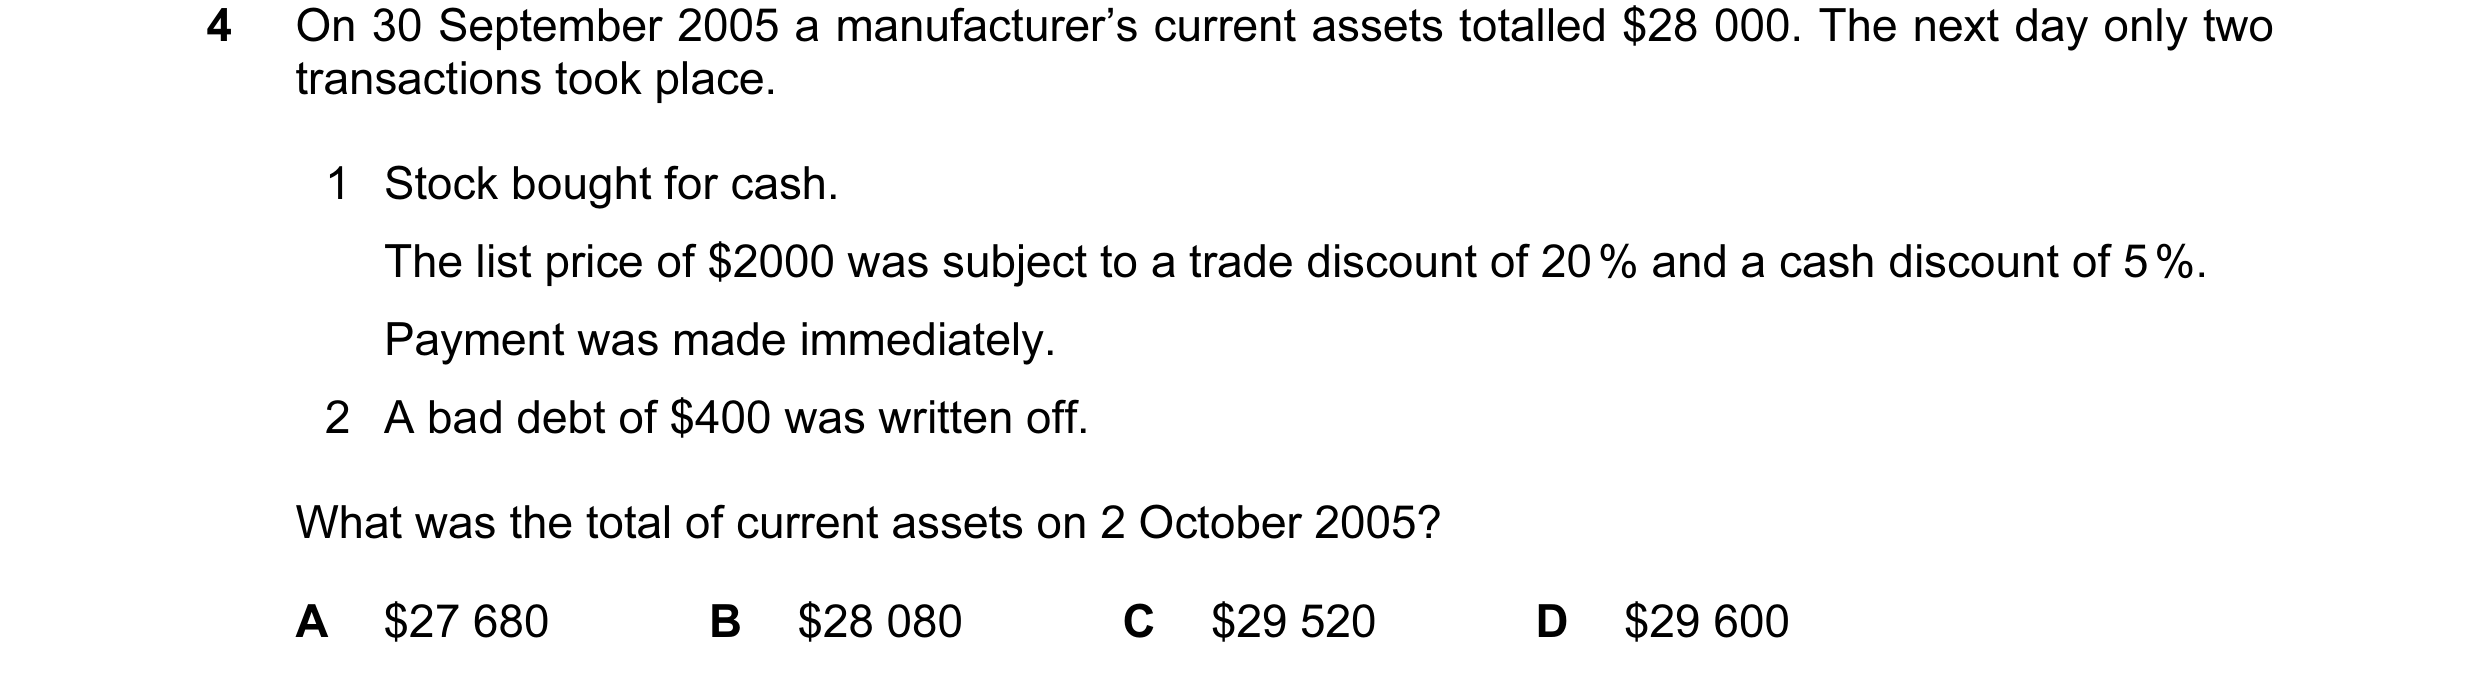
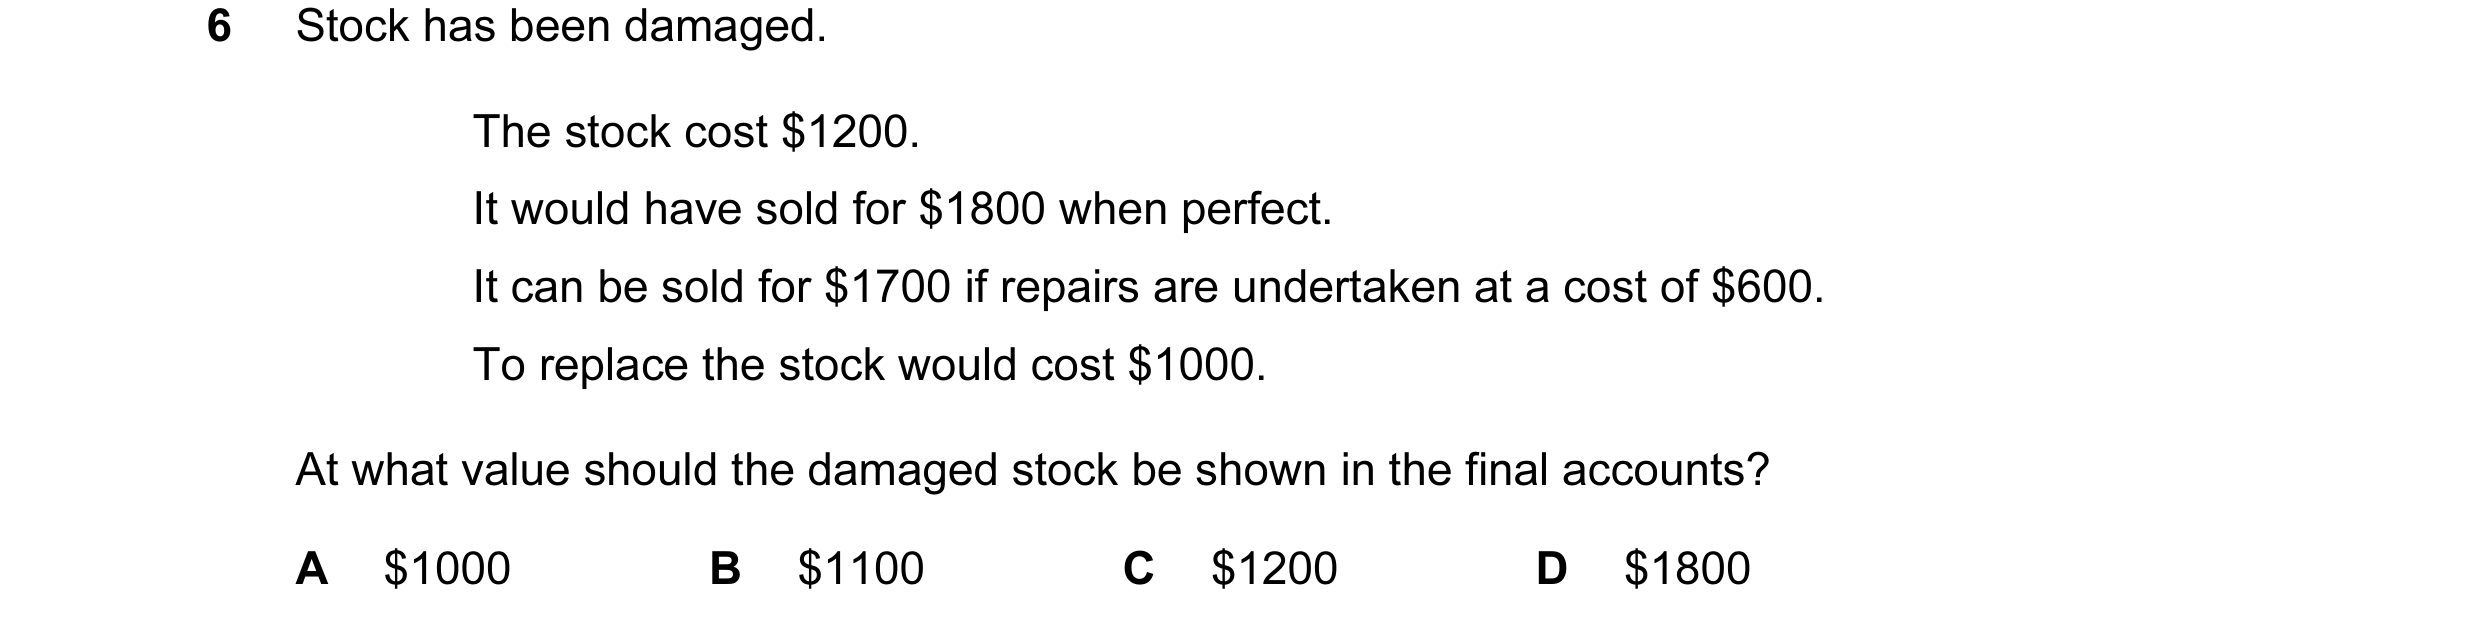 1 / 233
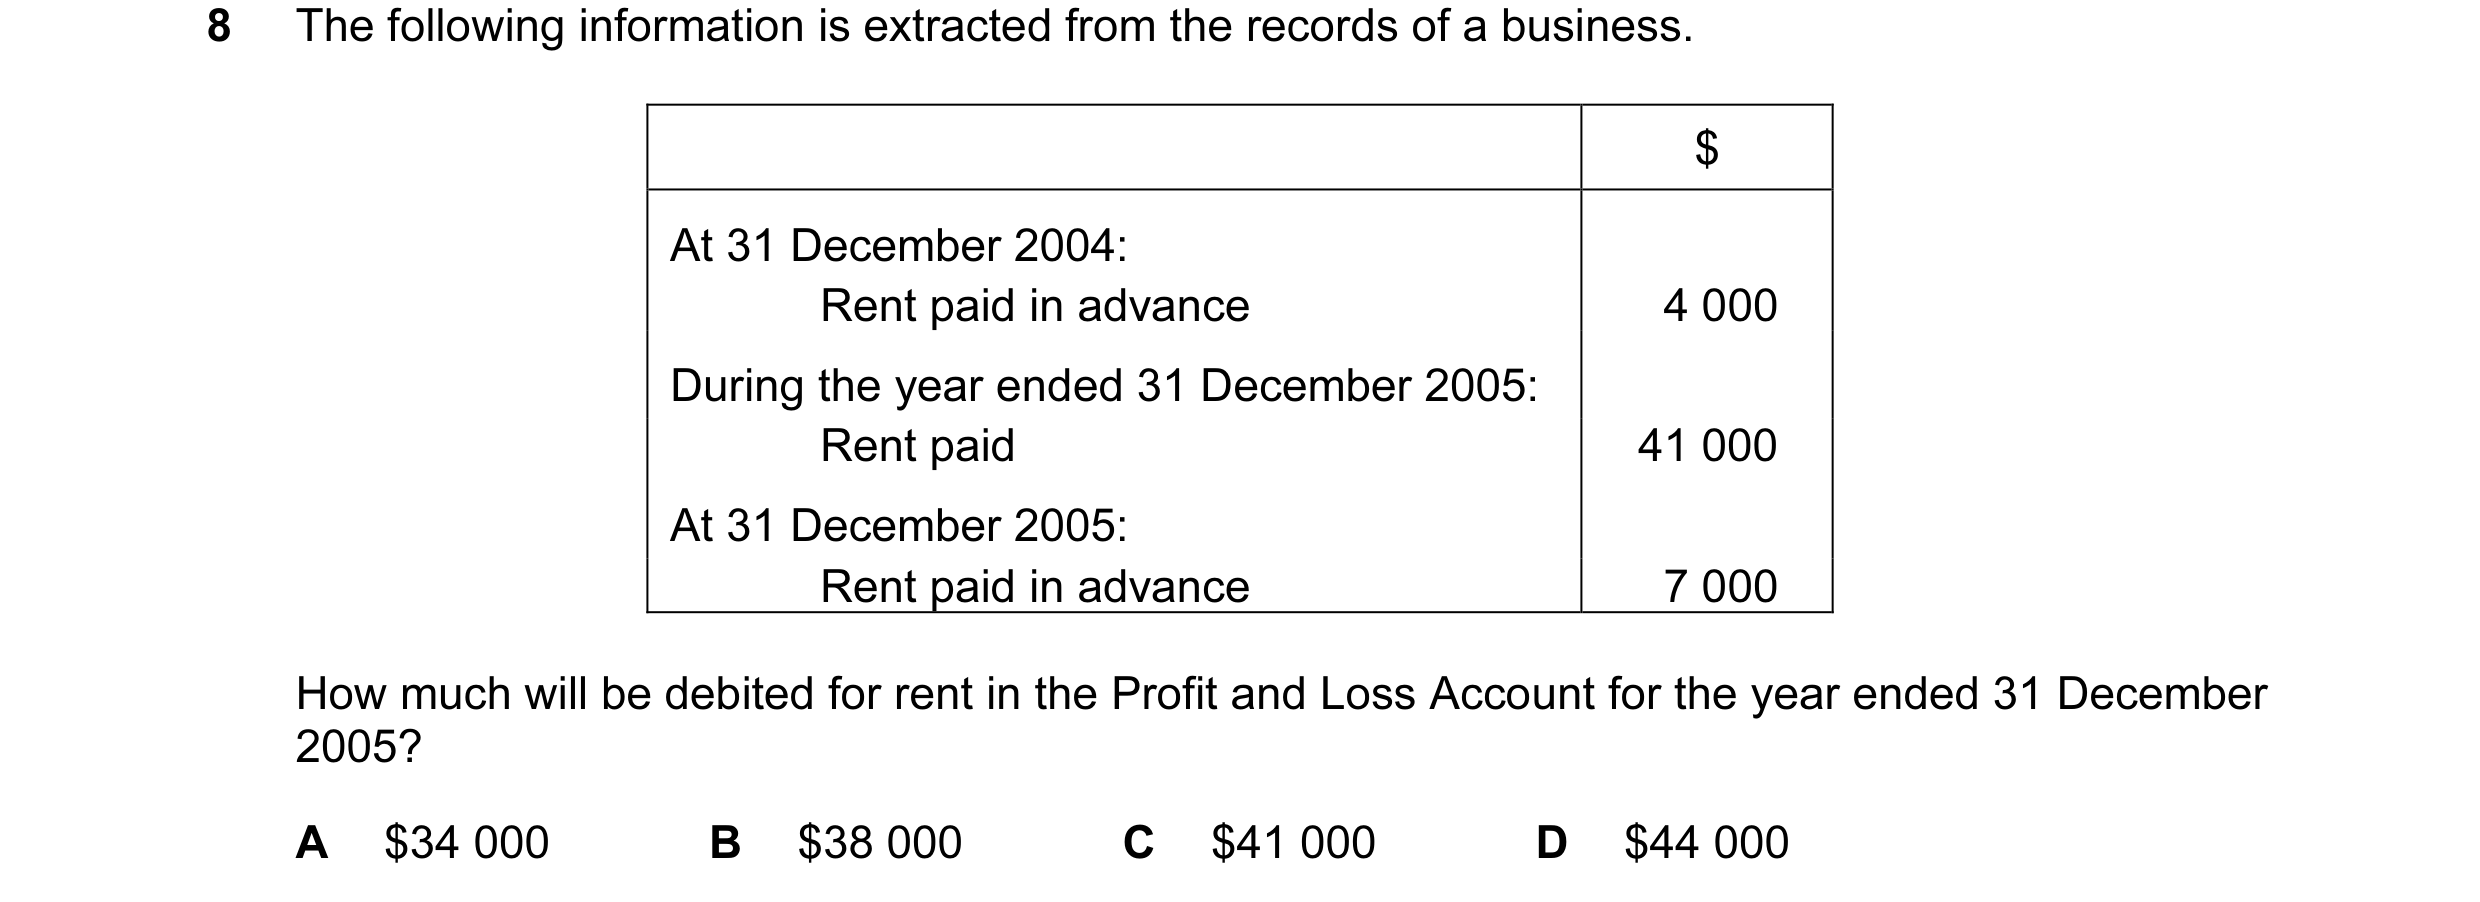
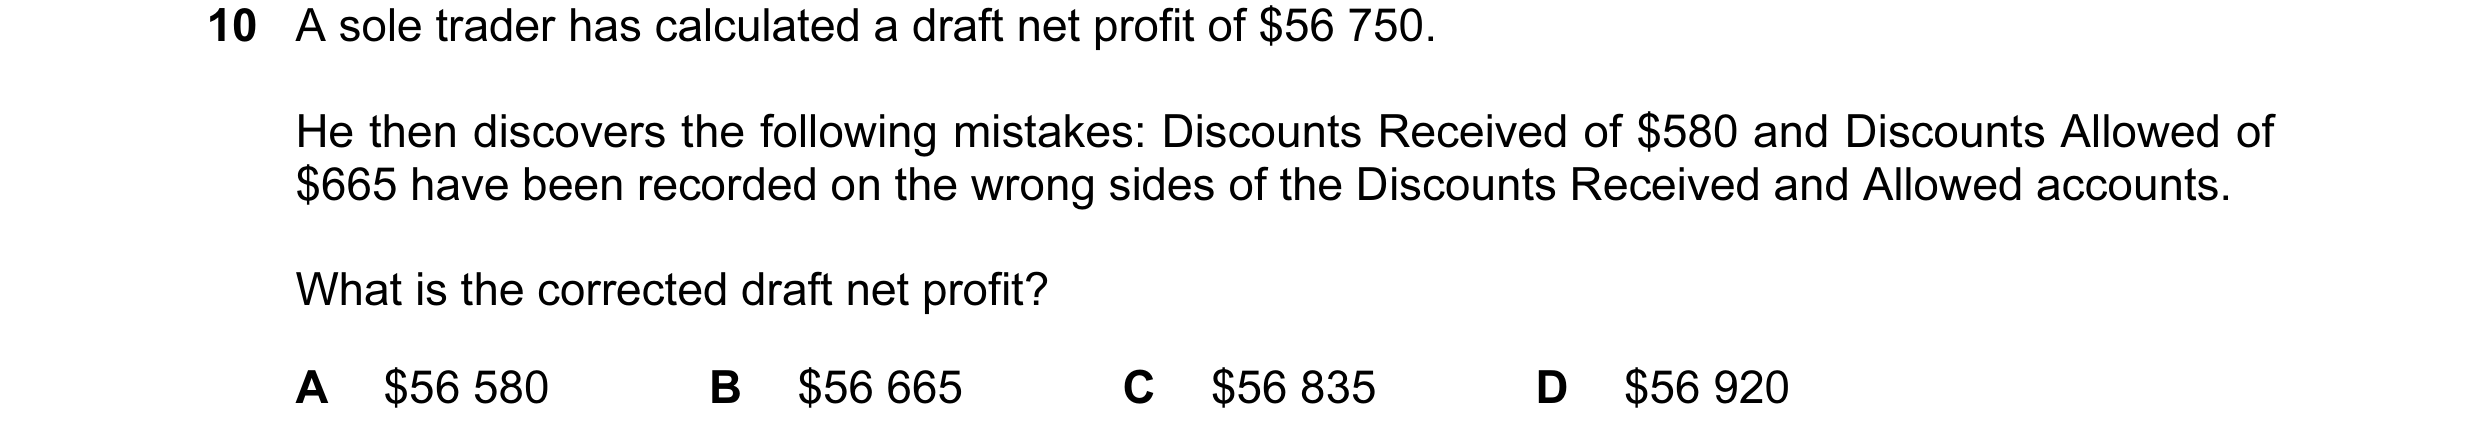
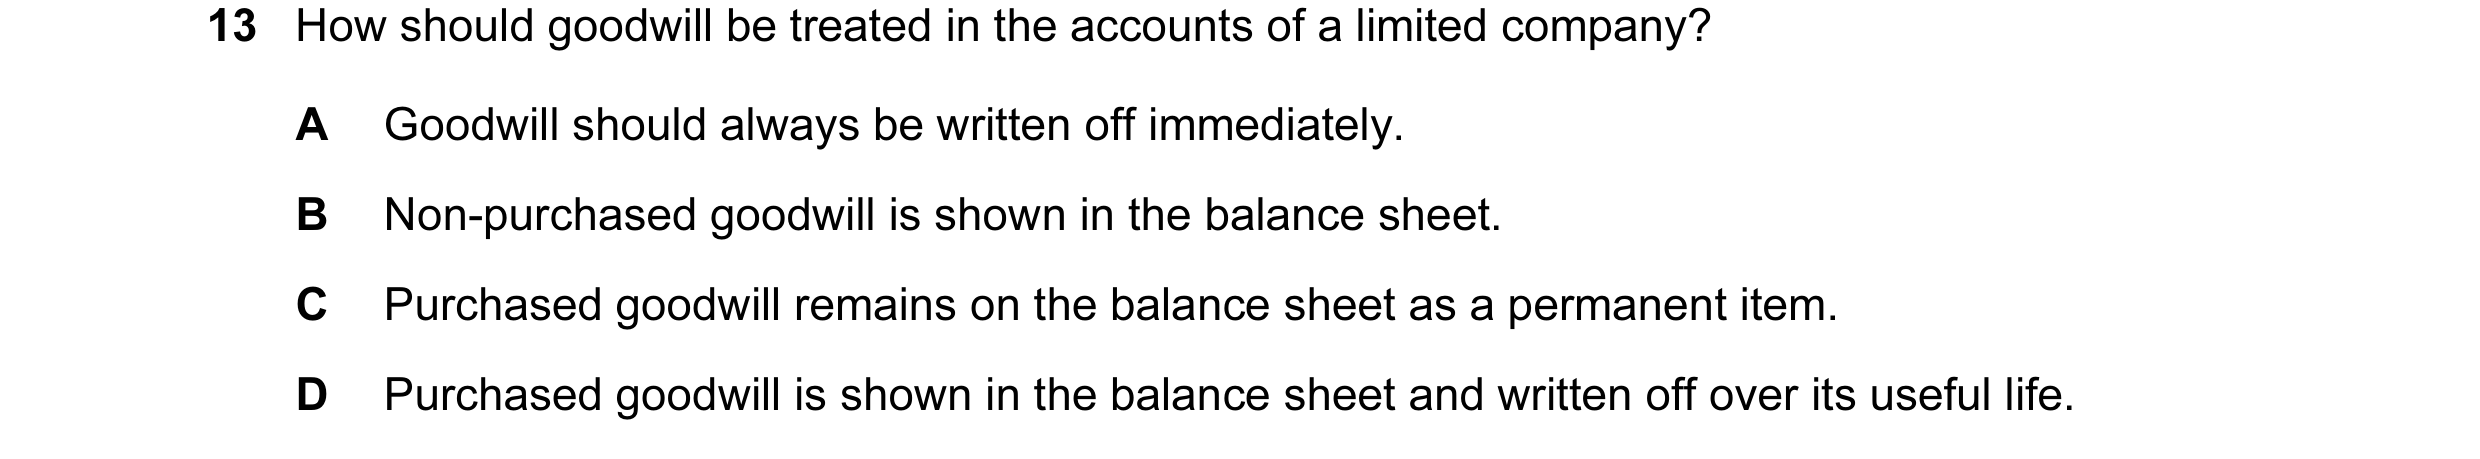
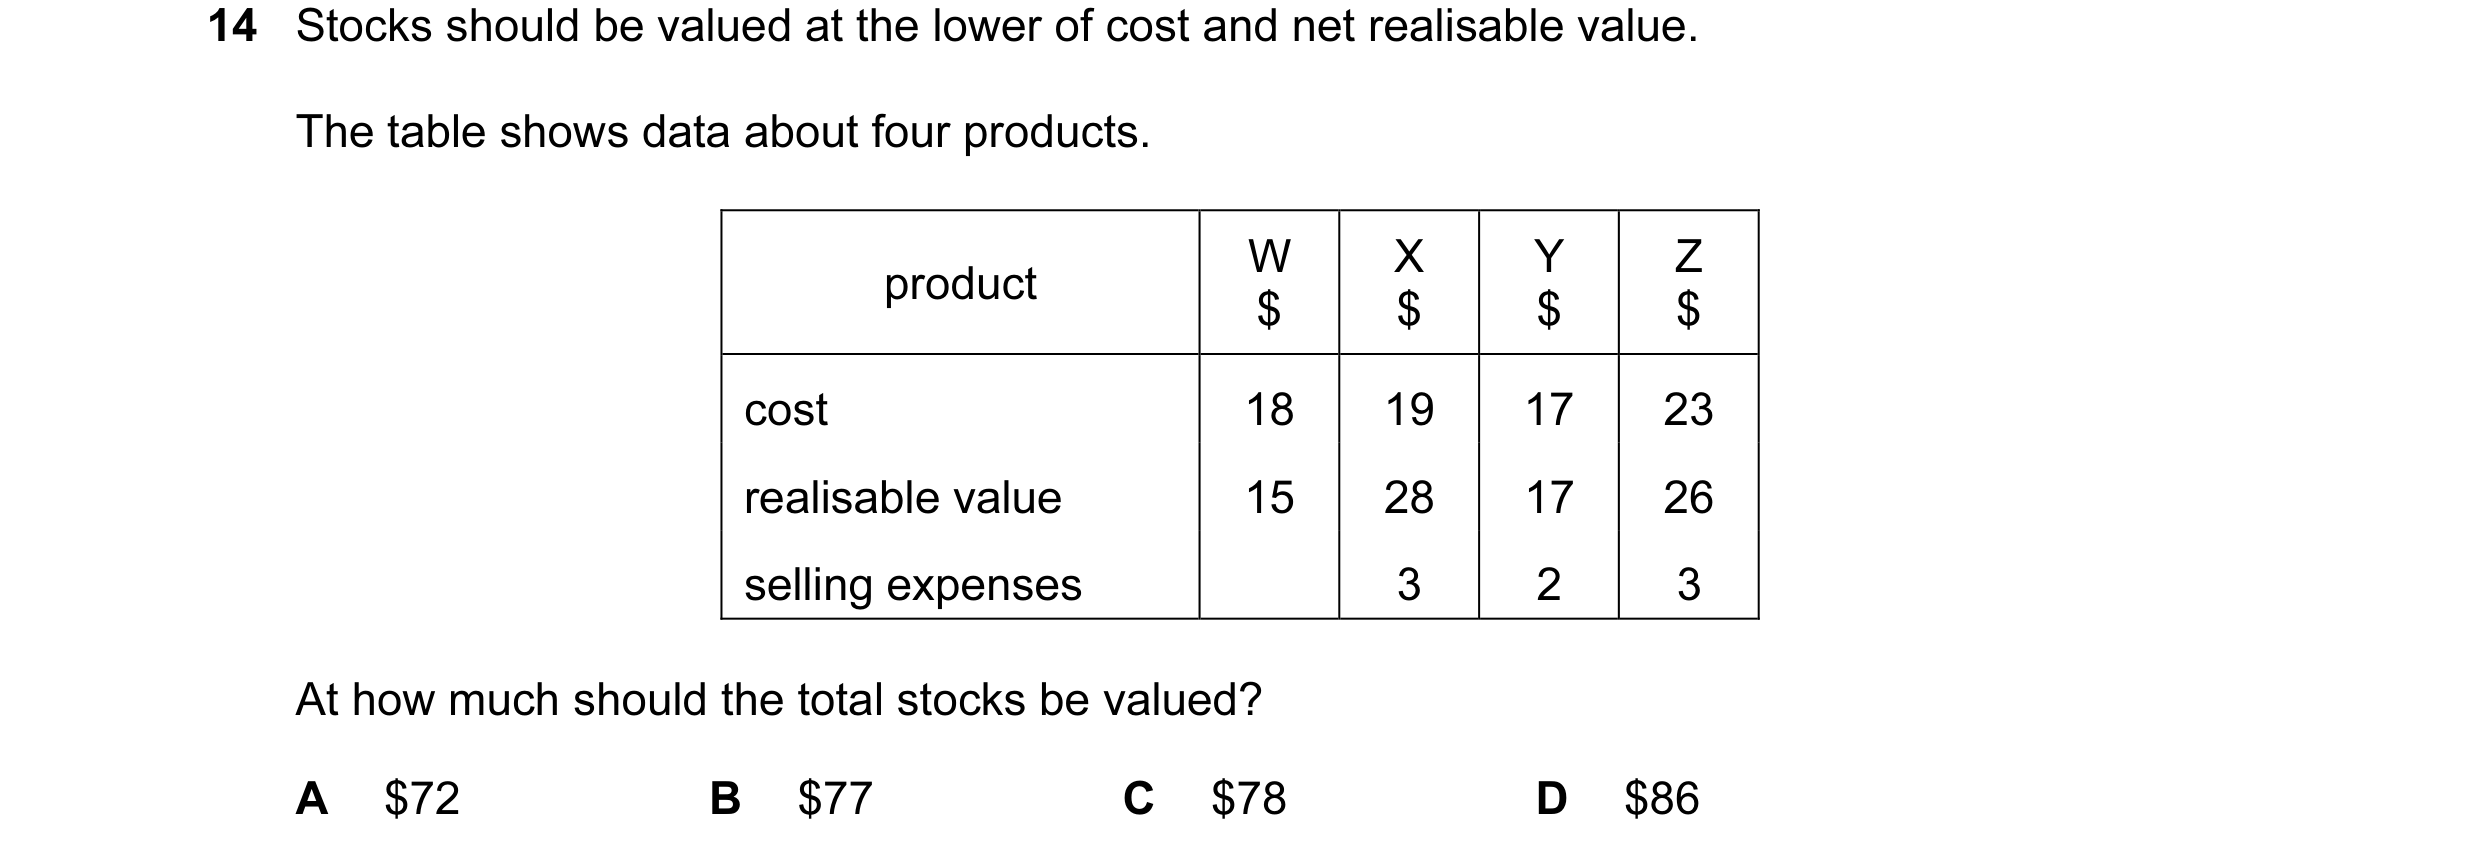 2 / 233
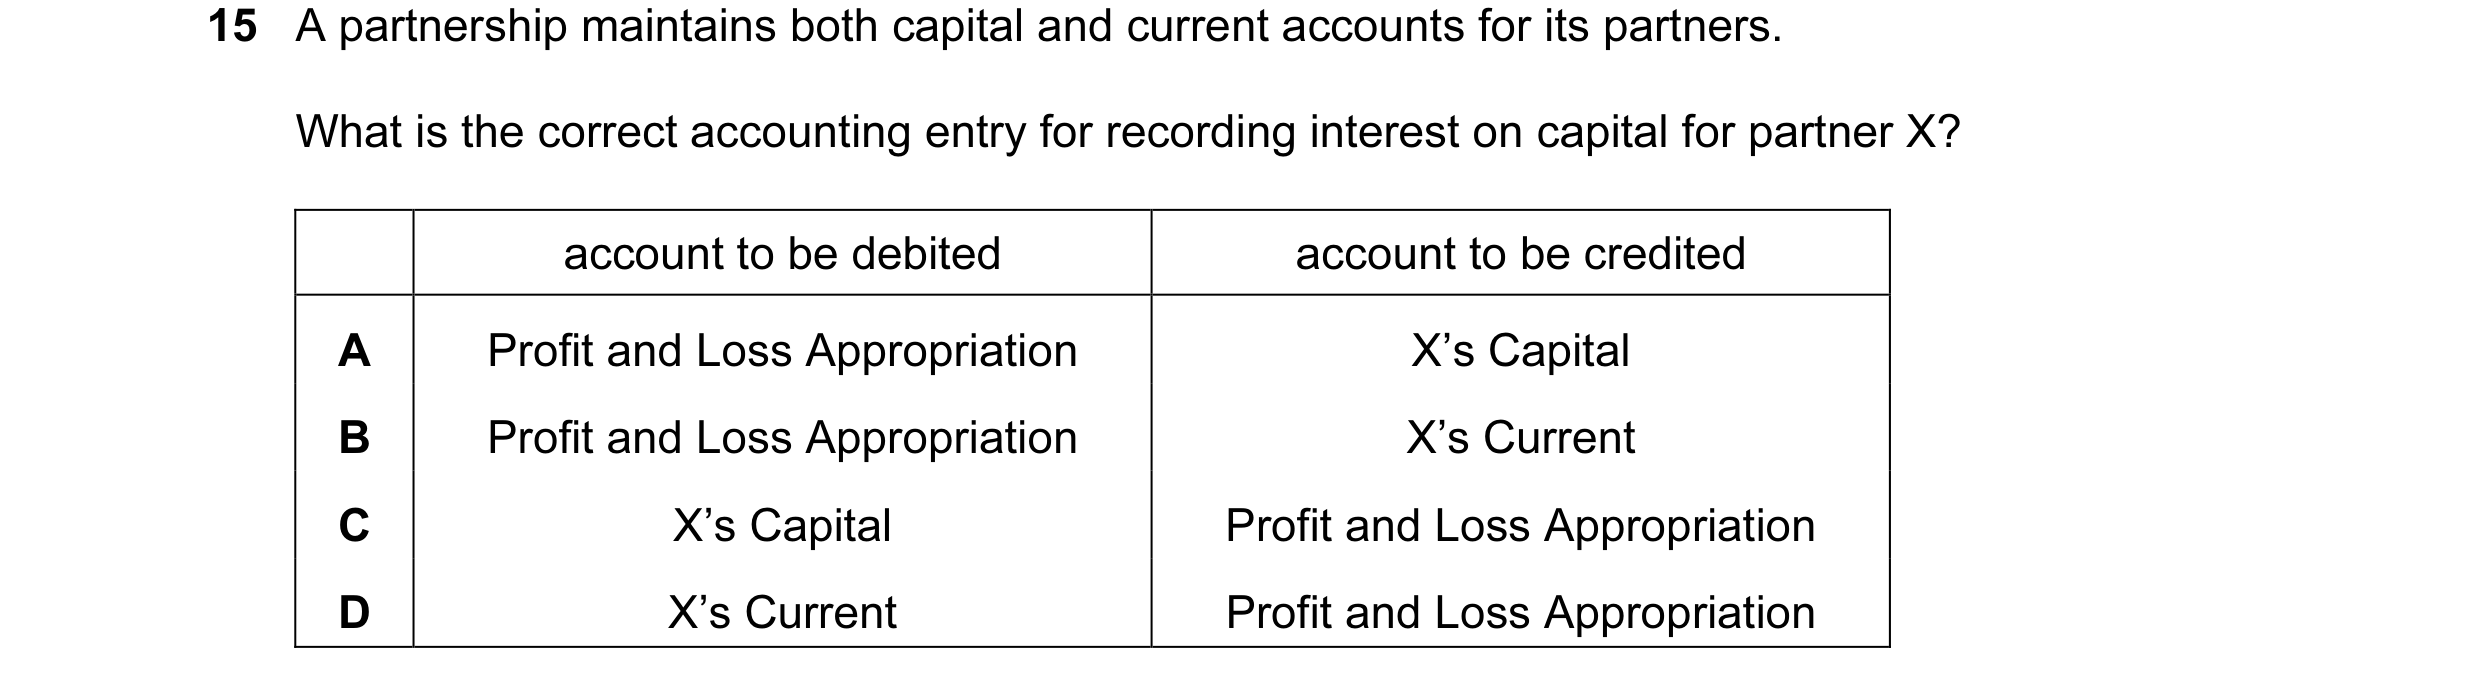
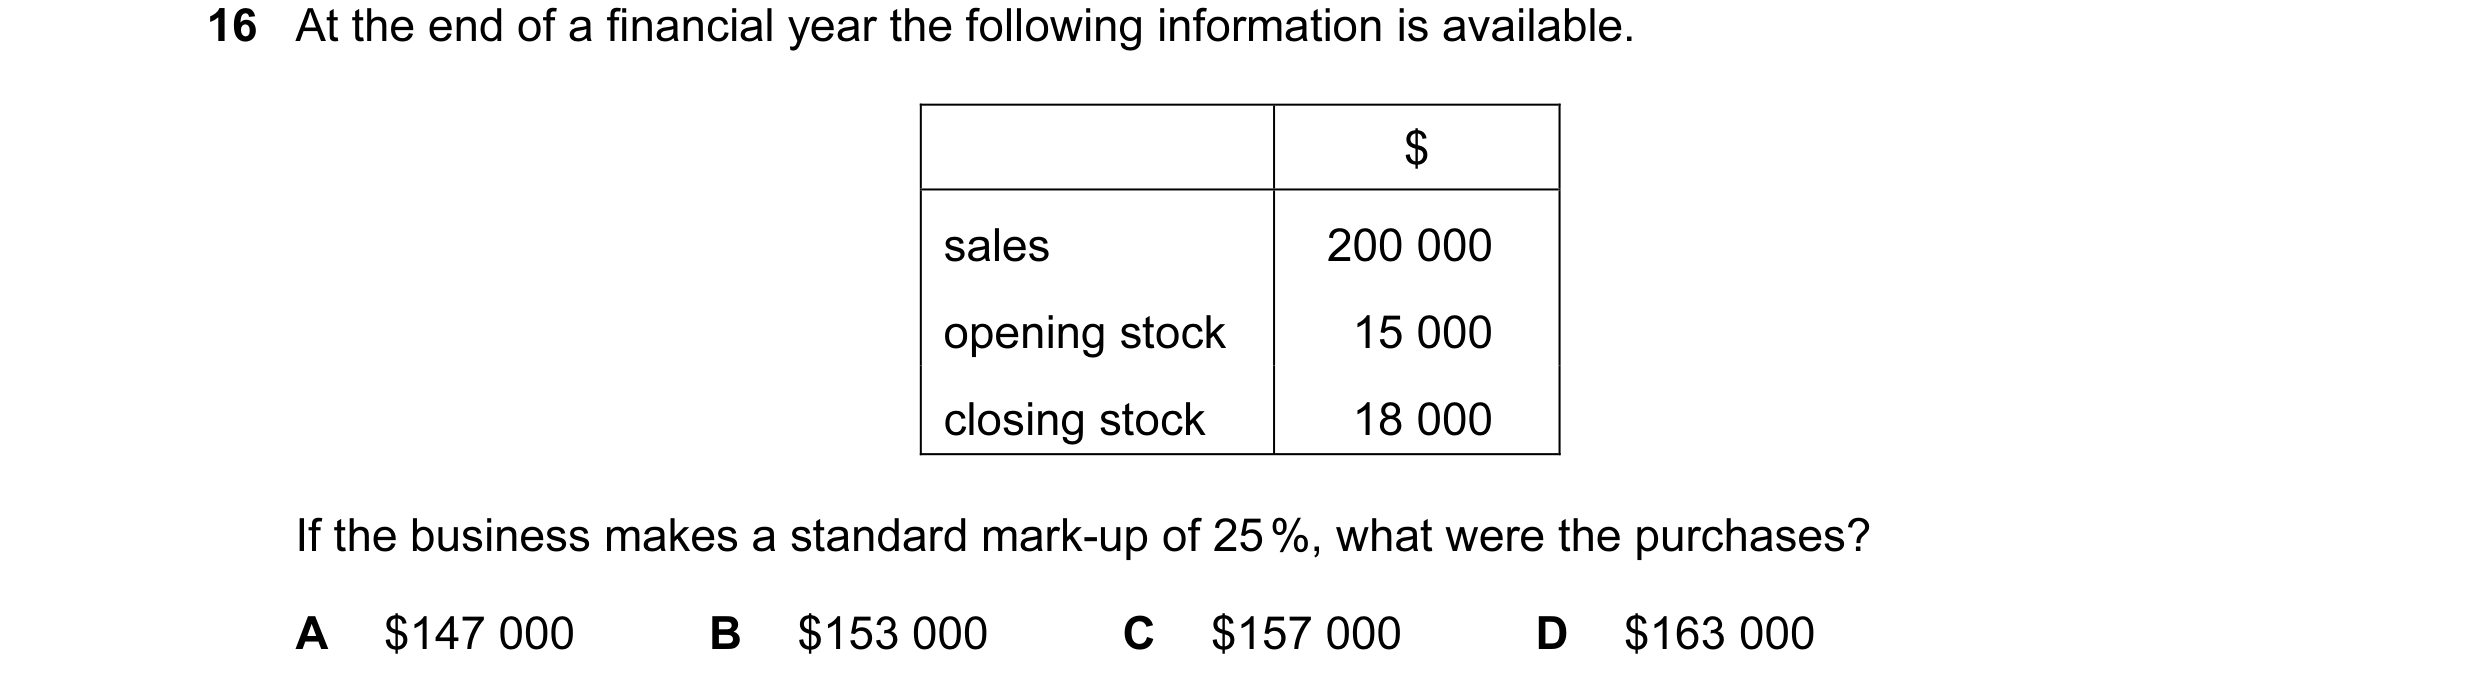
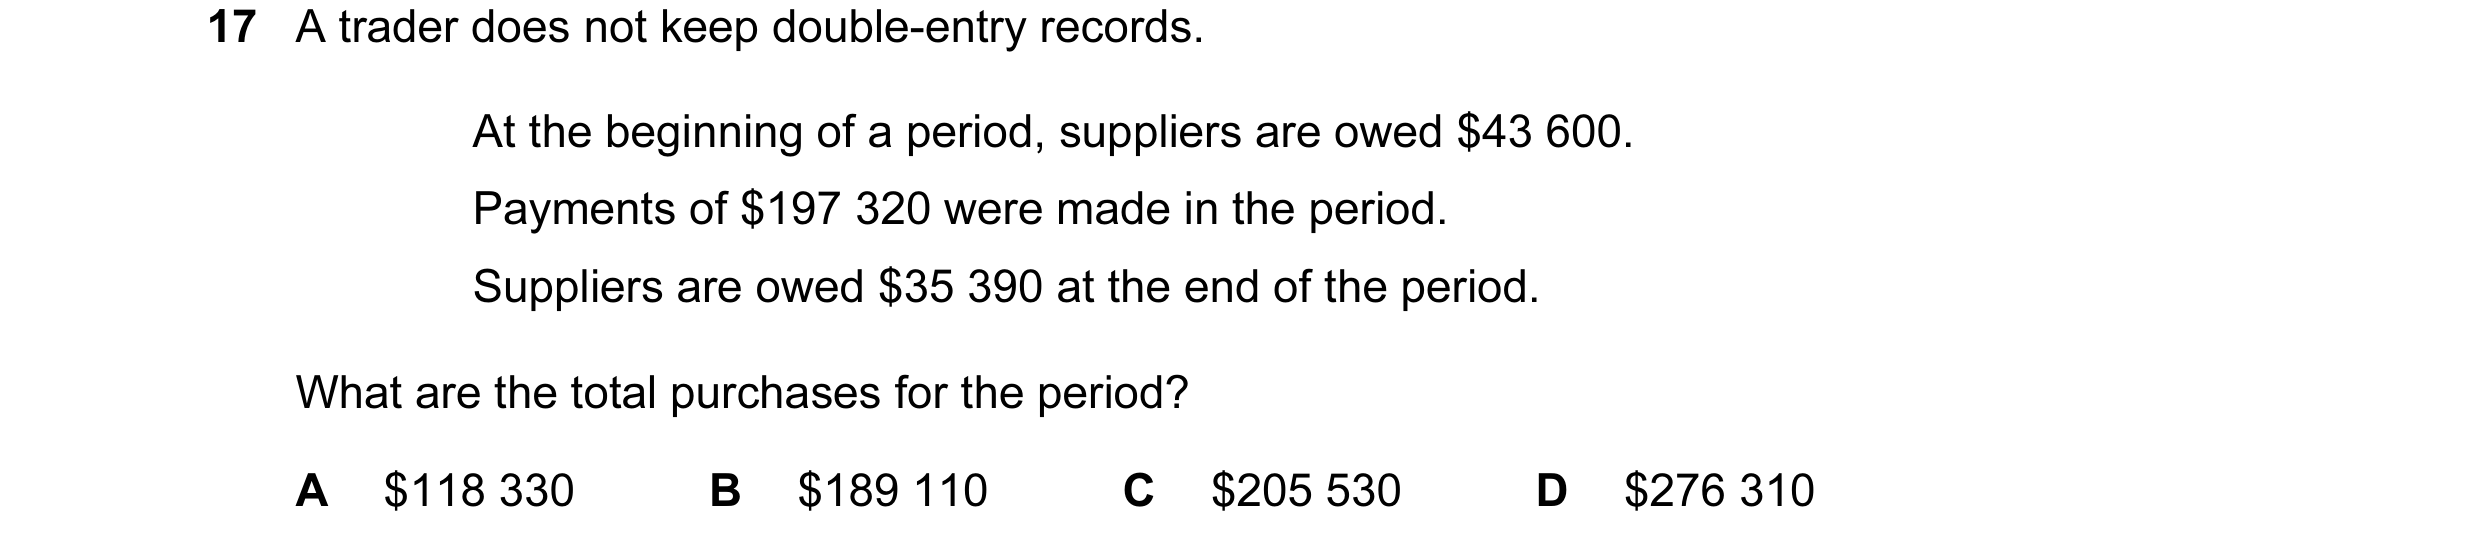
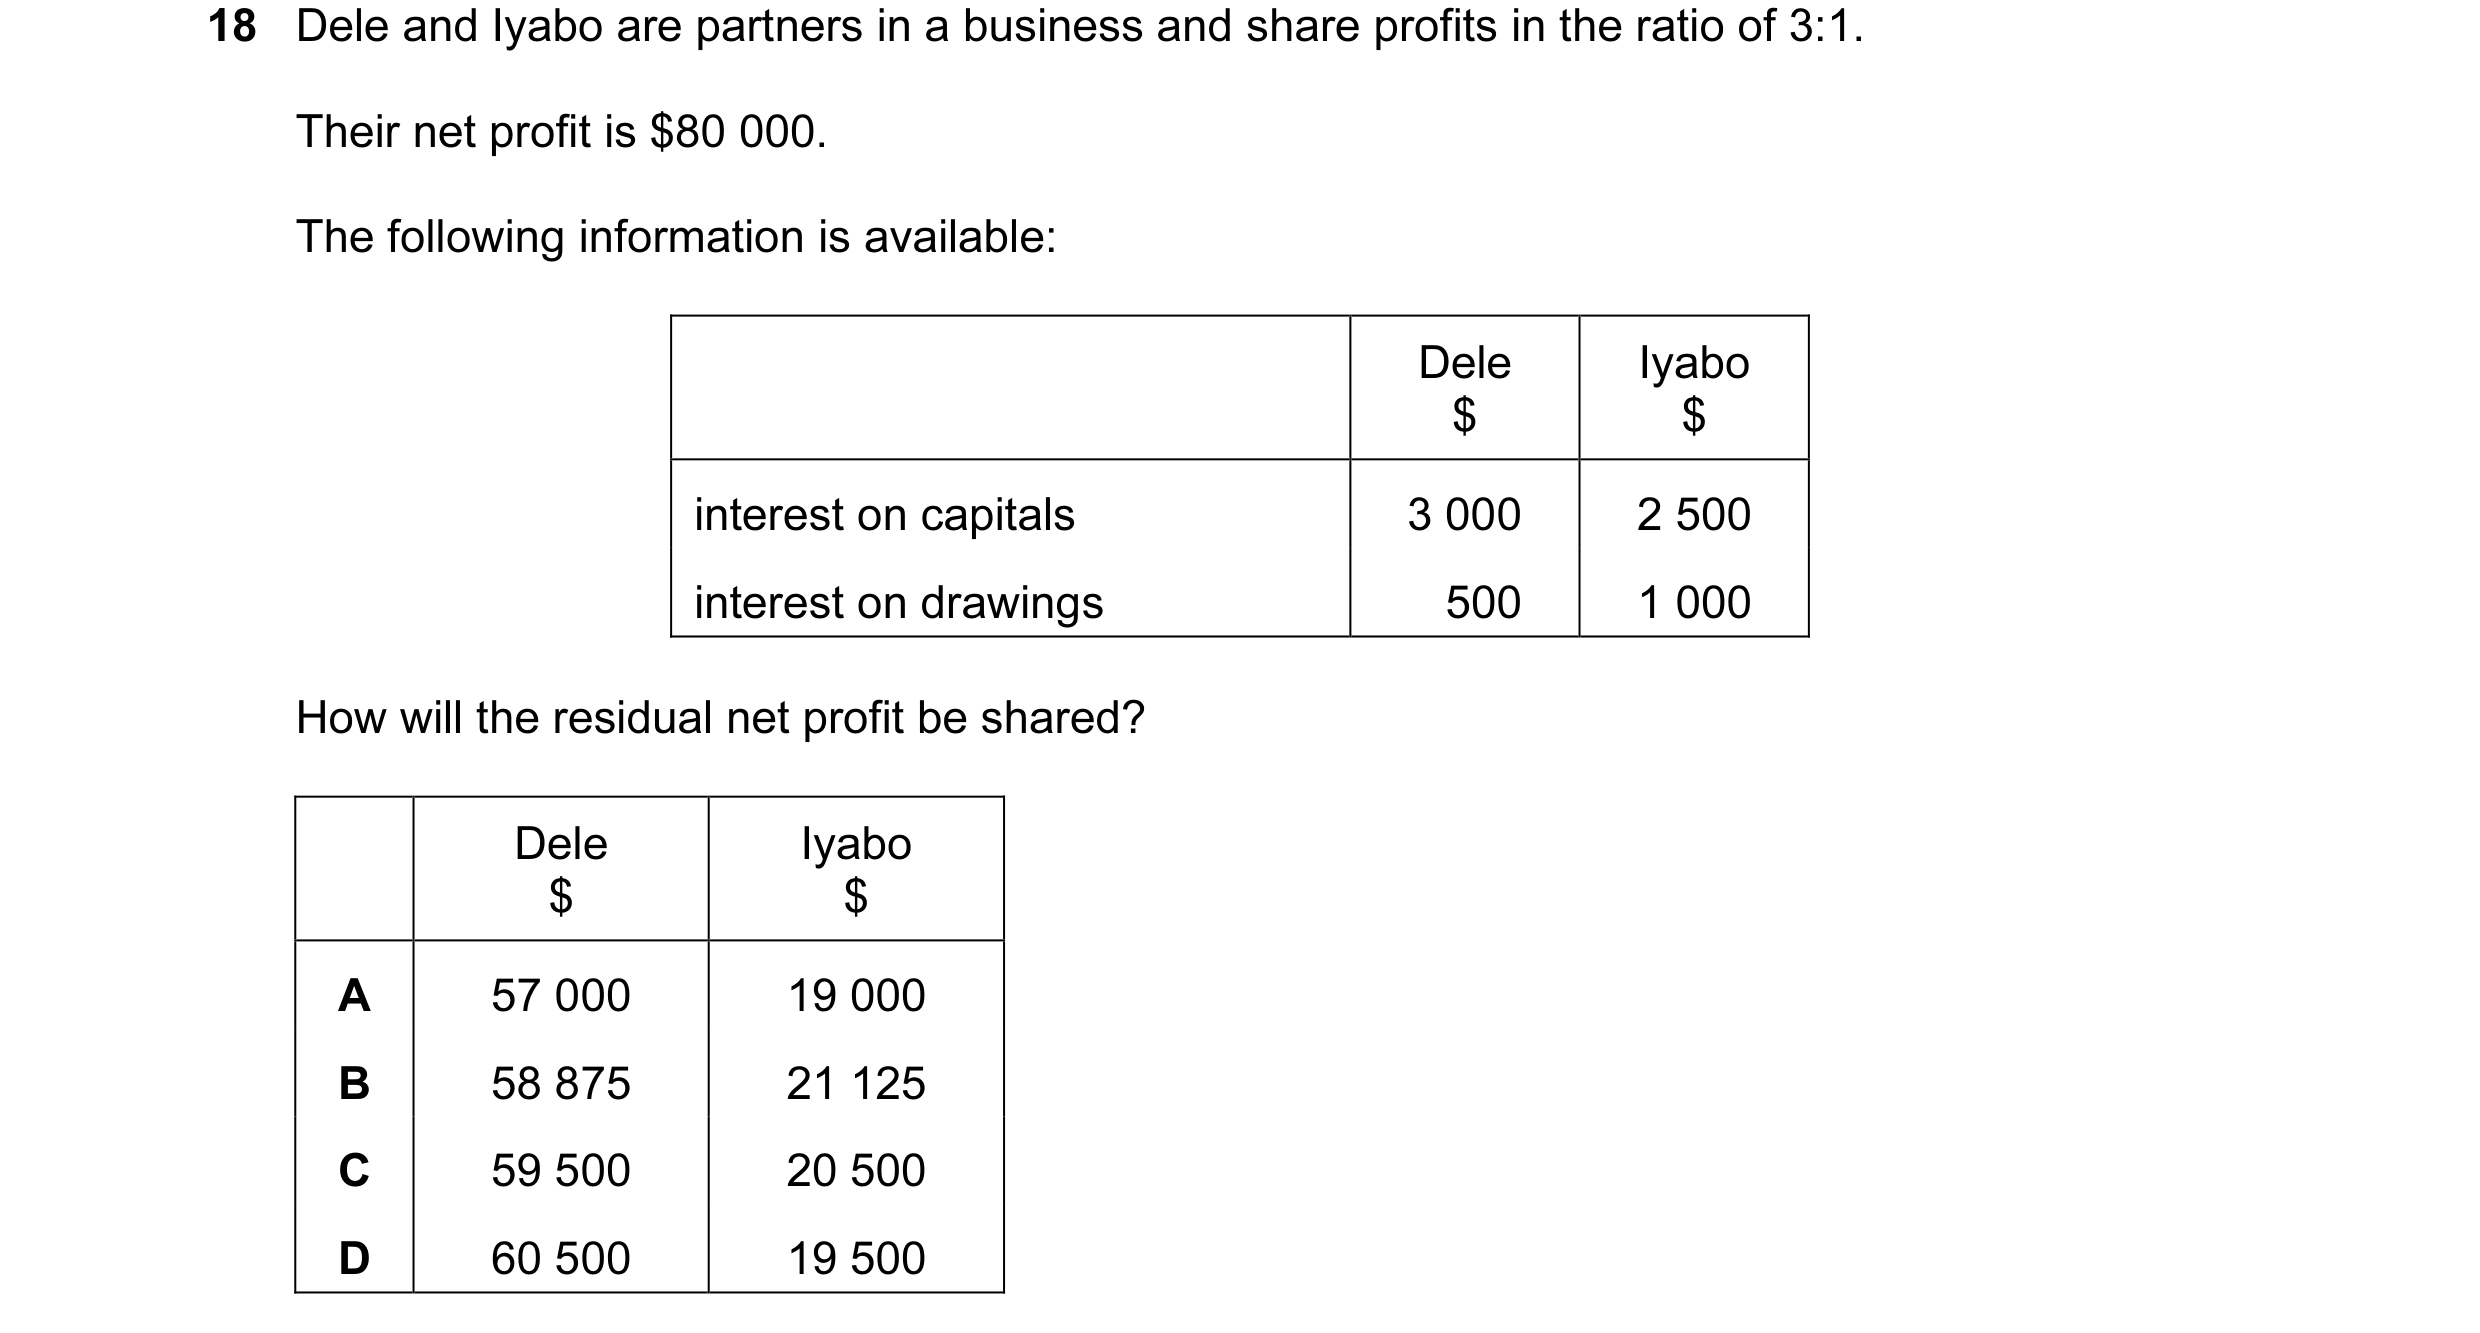 3 / 233
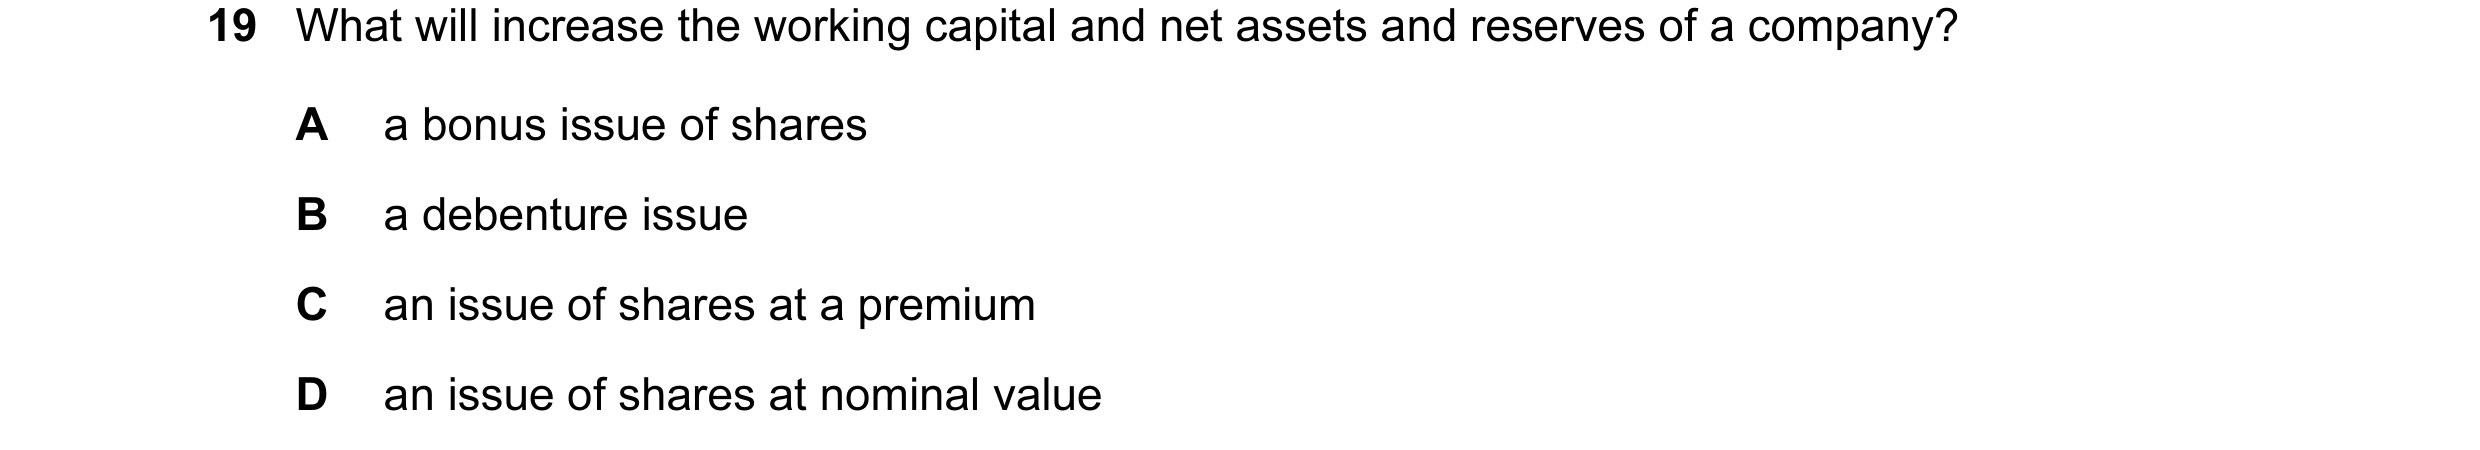
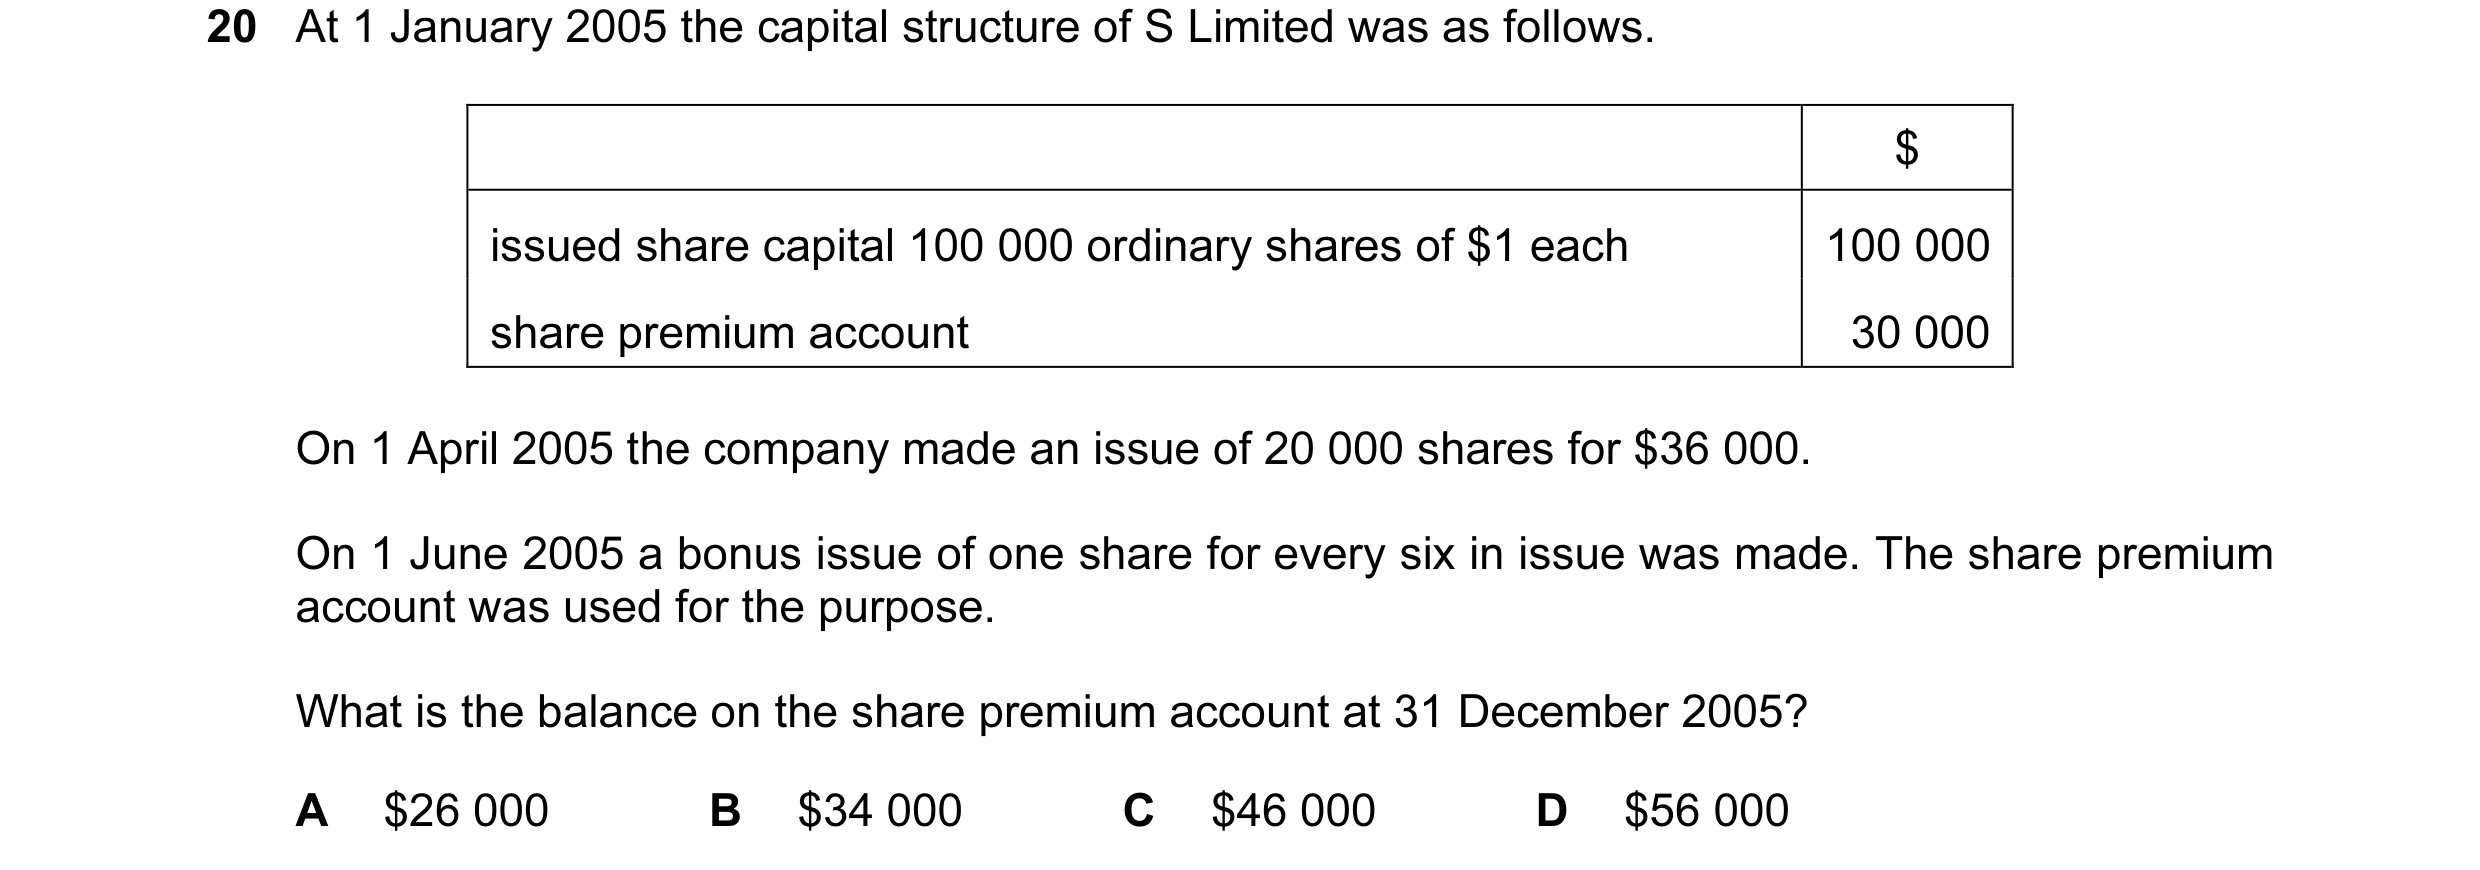
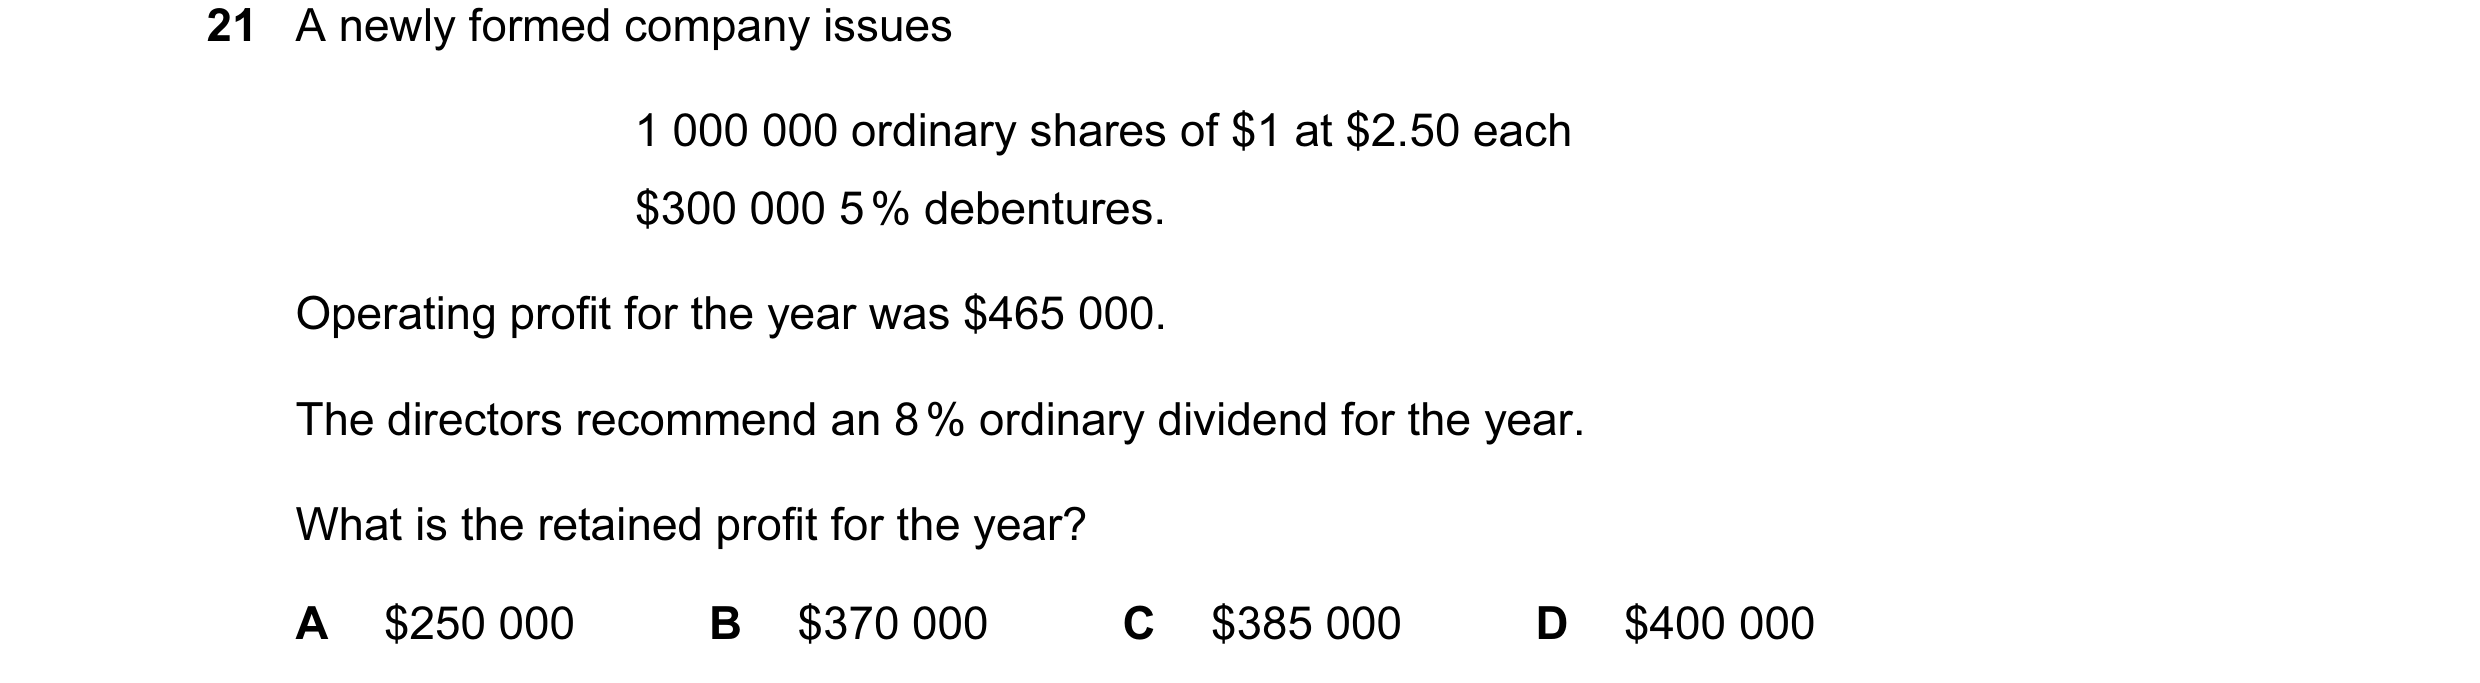
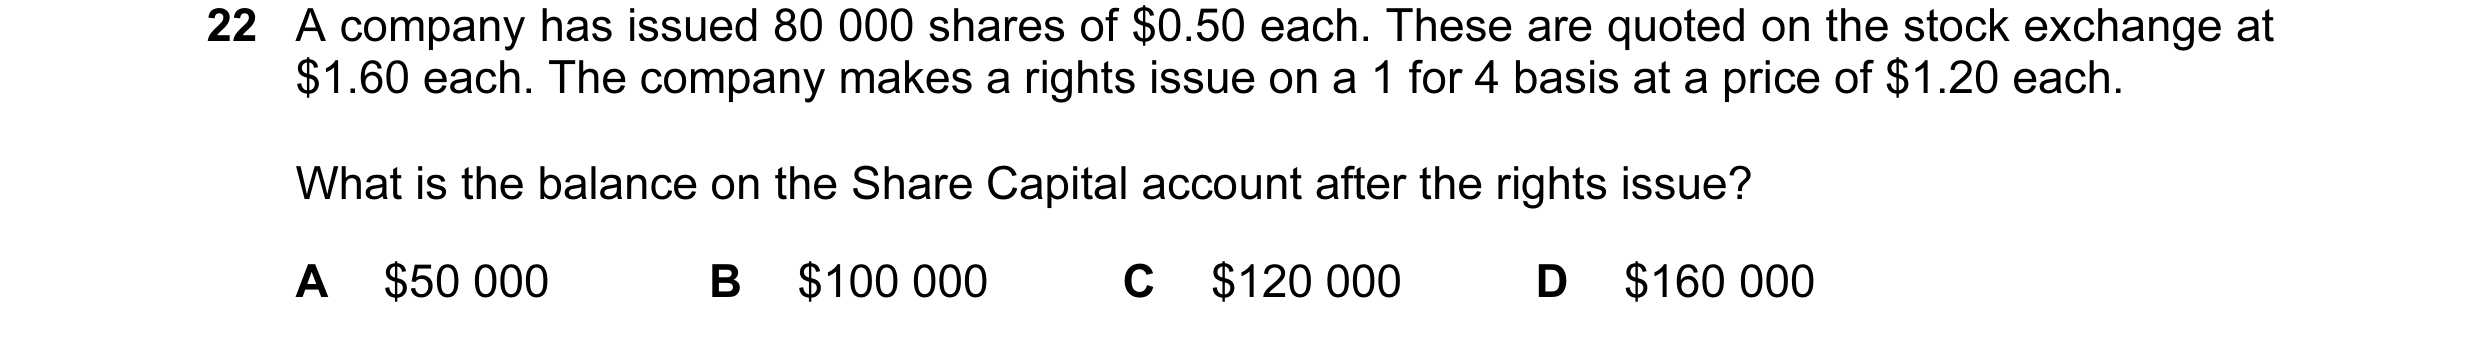
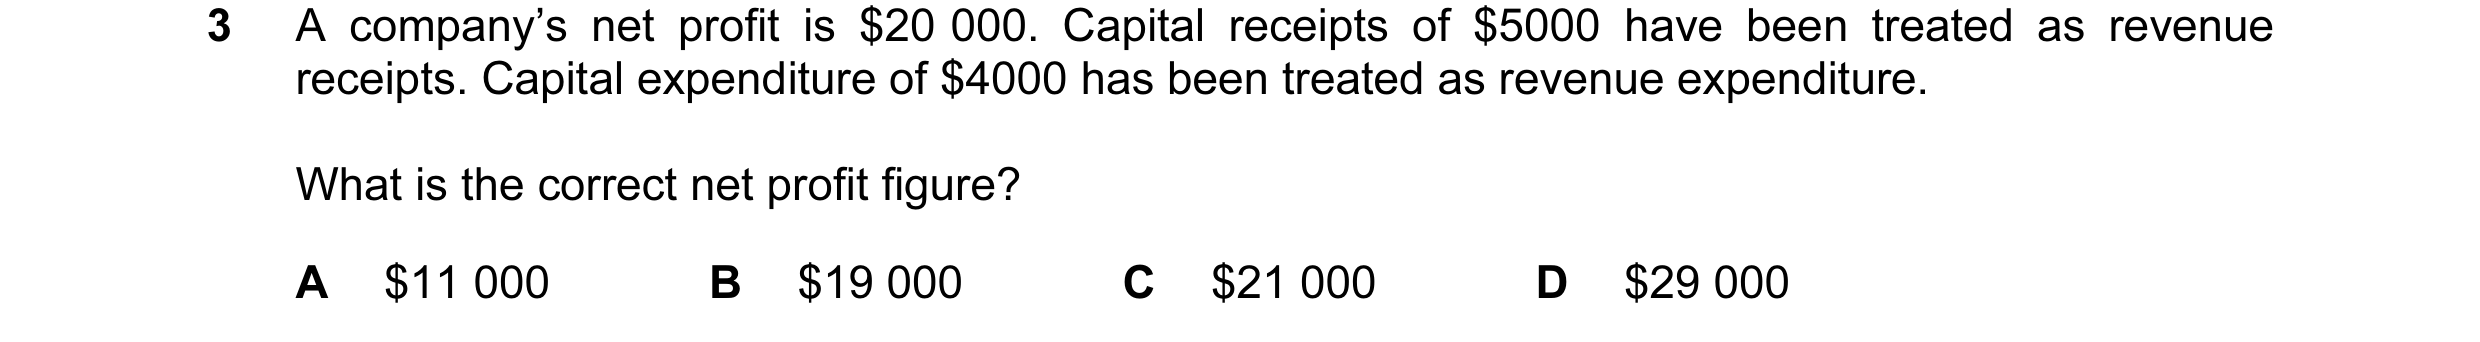 4 / 233
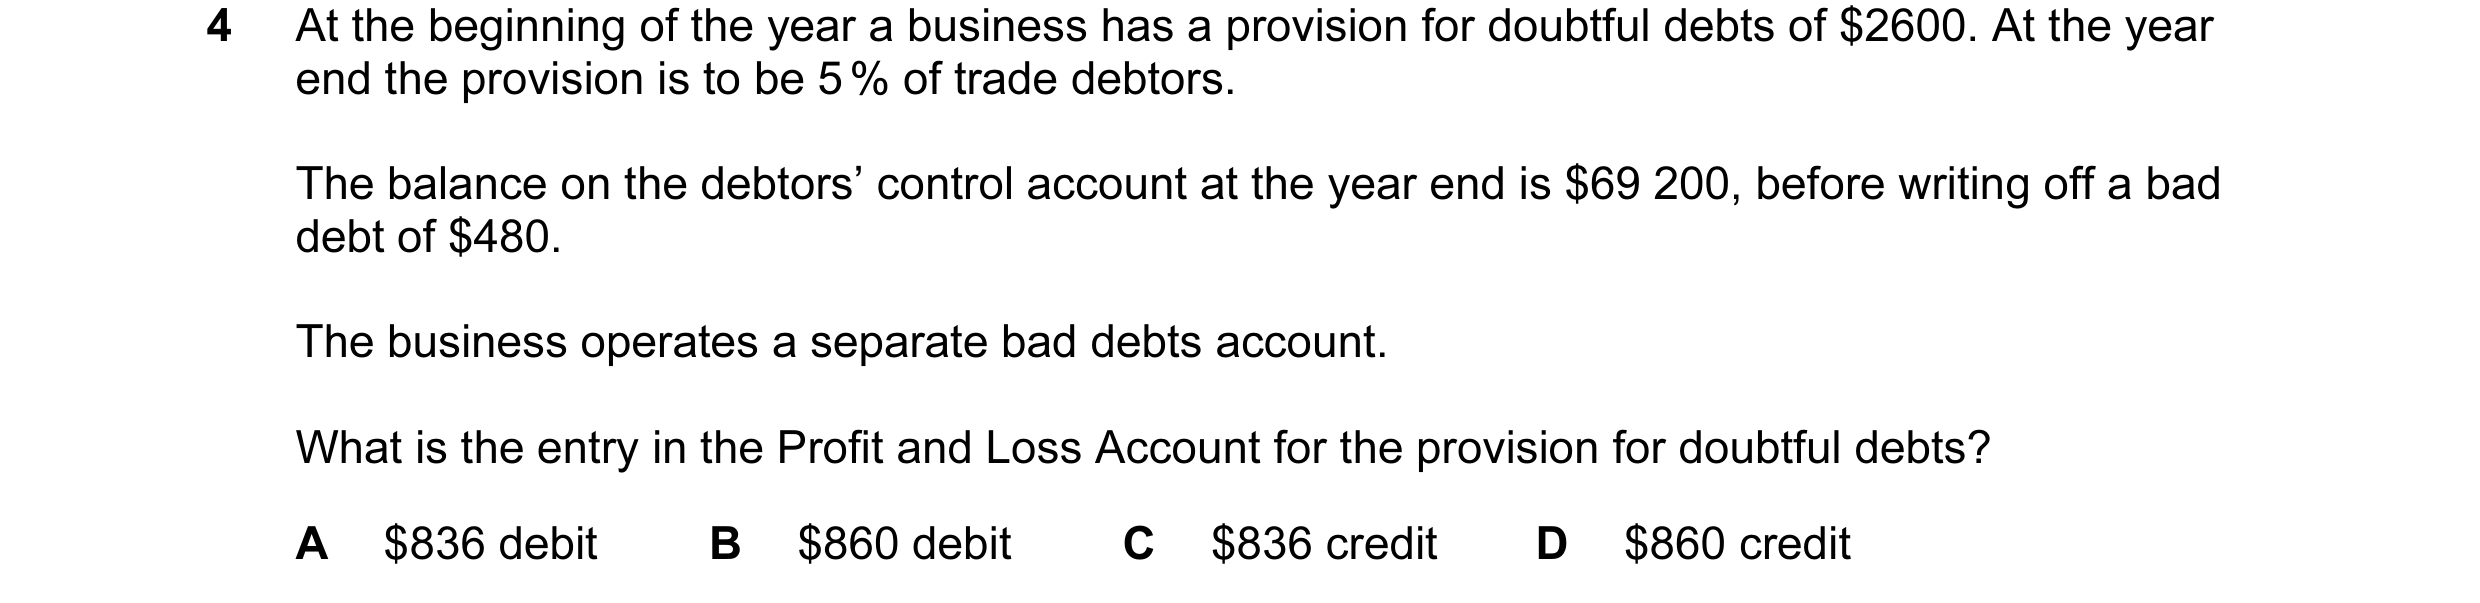
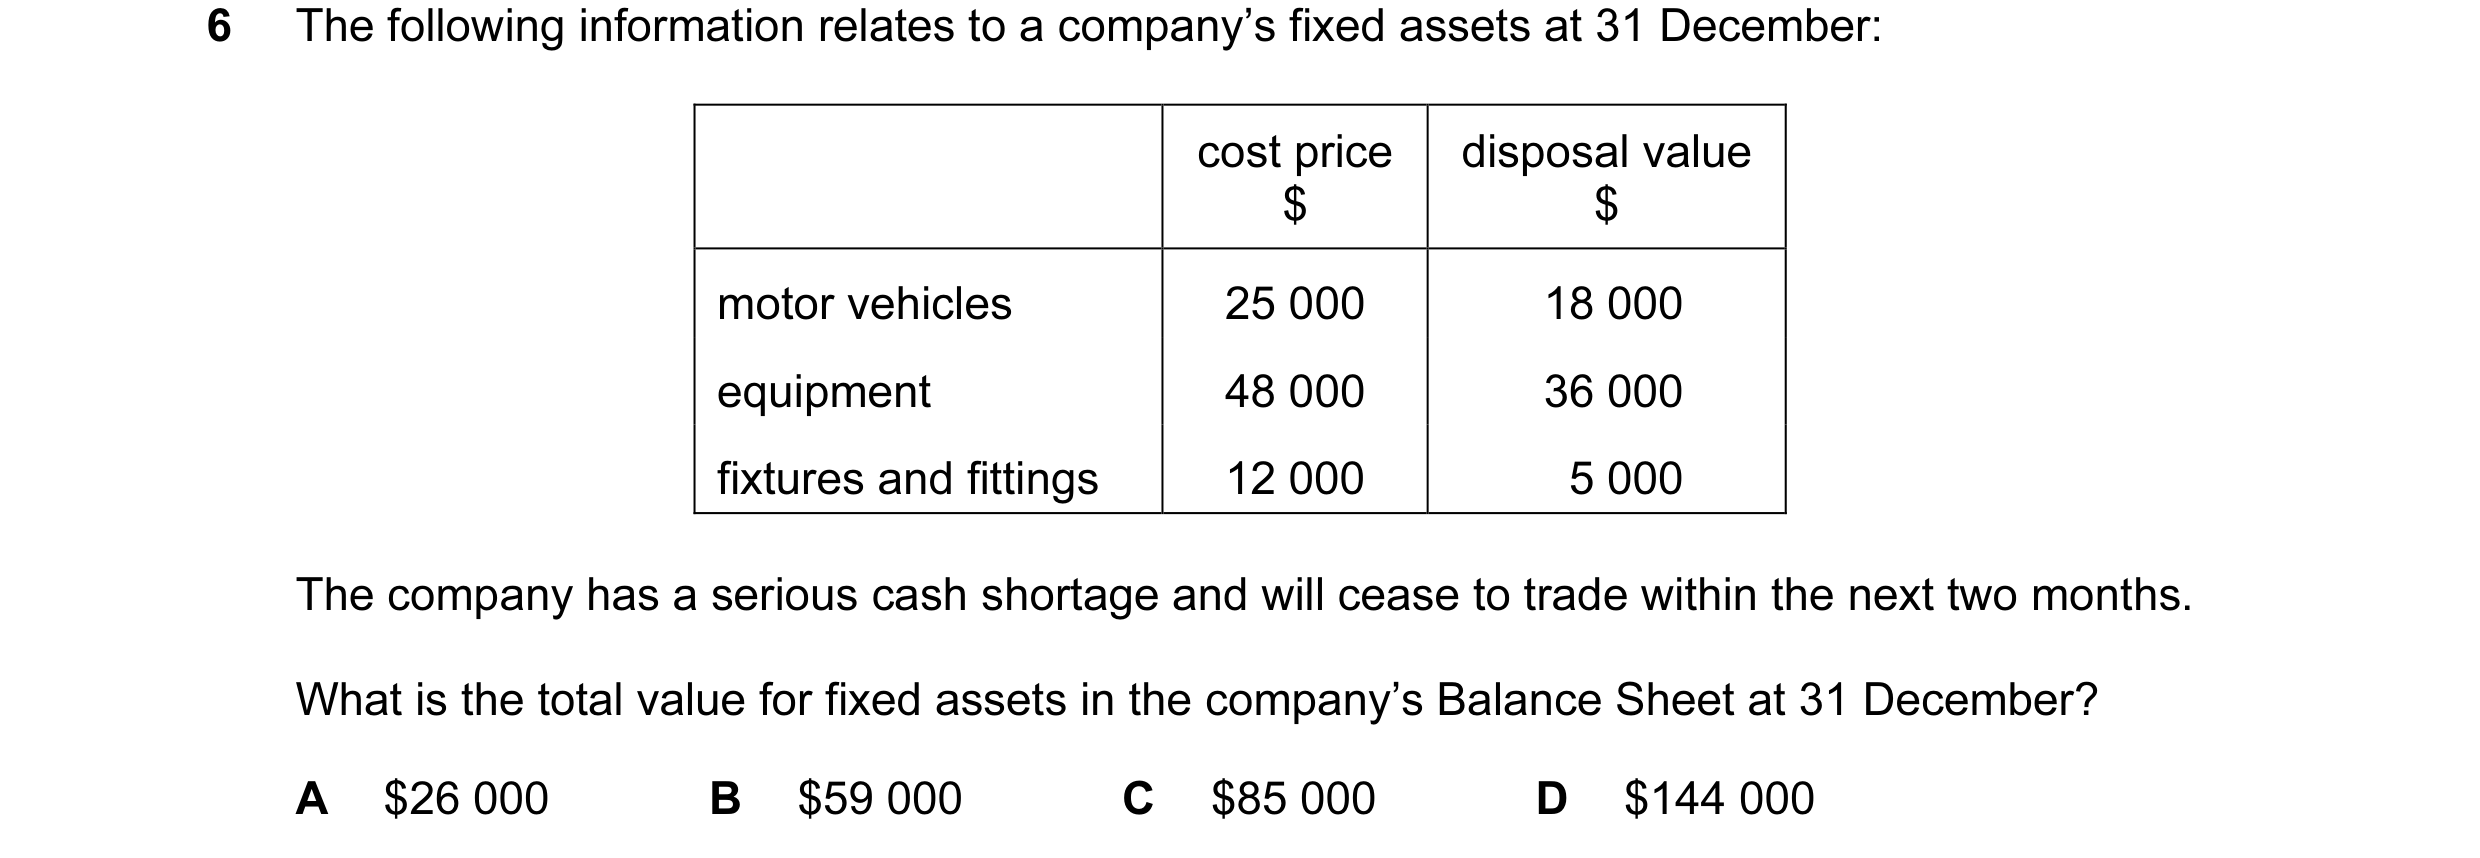
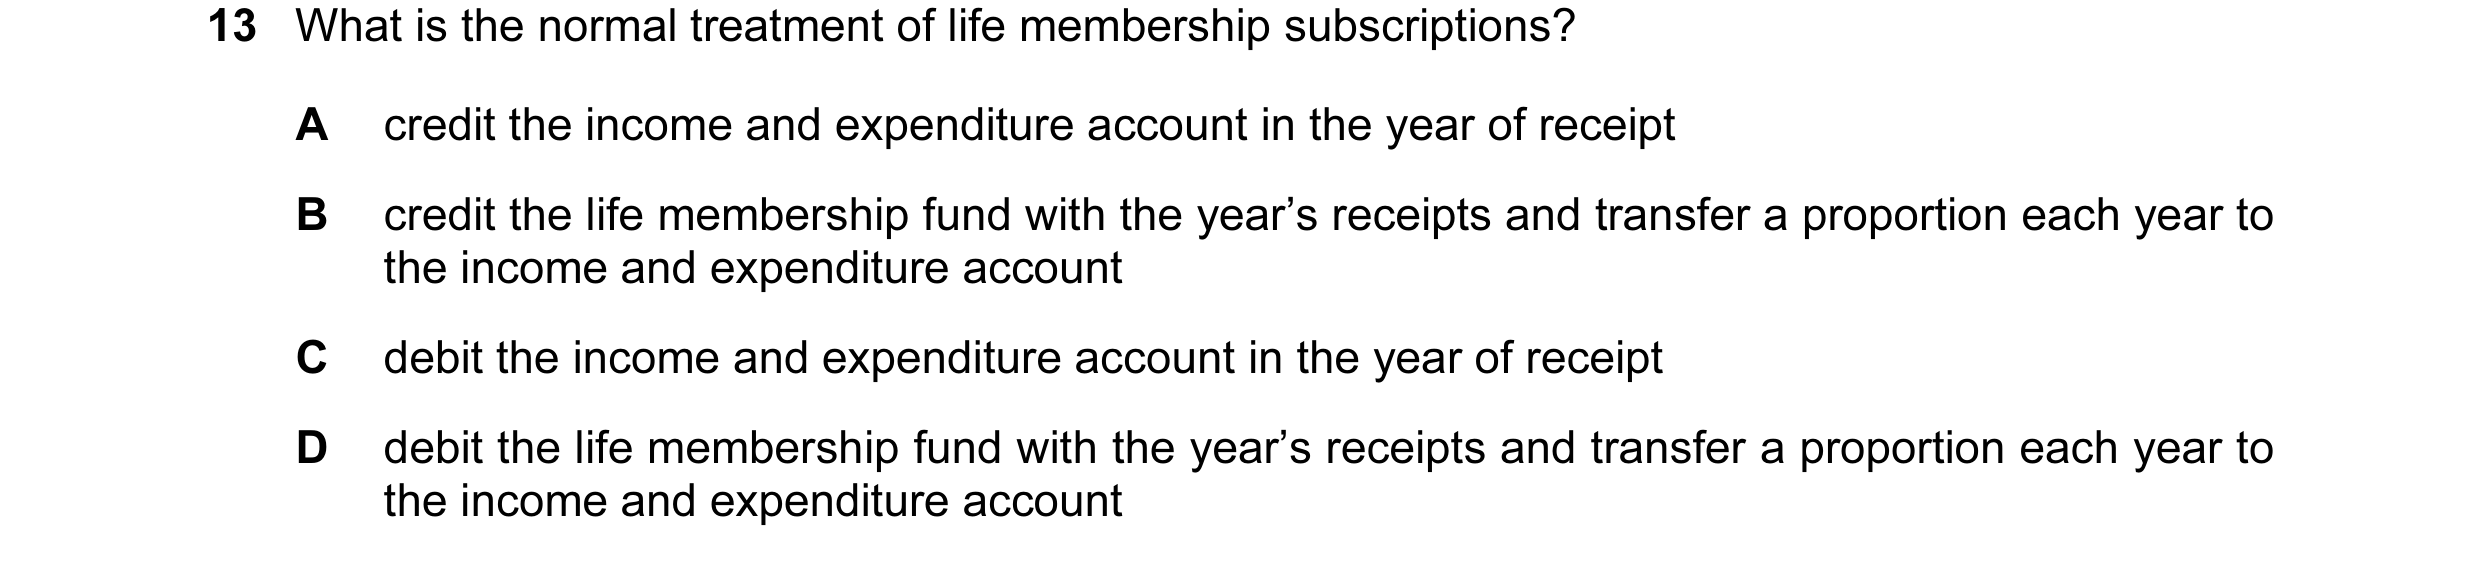
 5 / 233
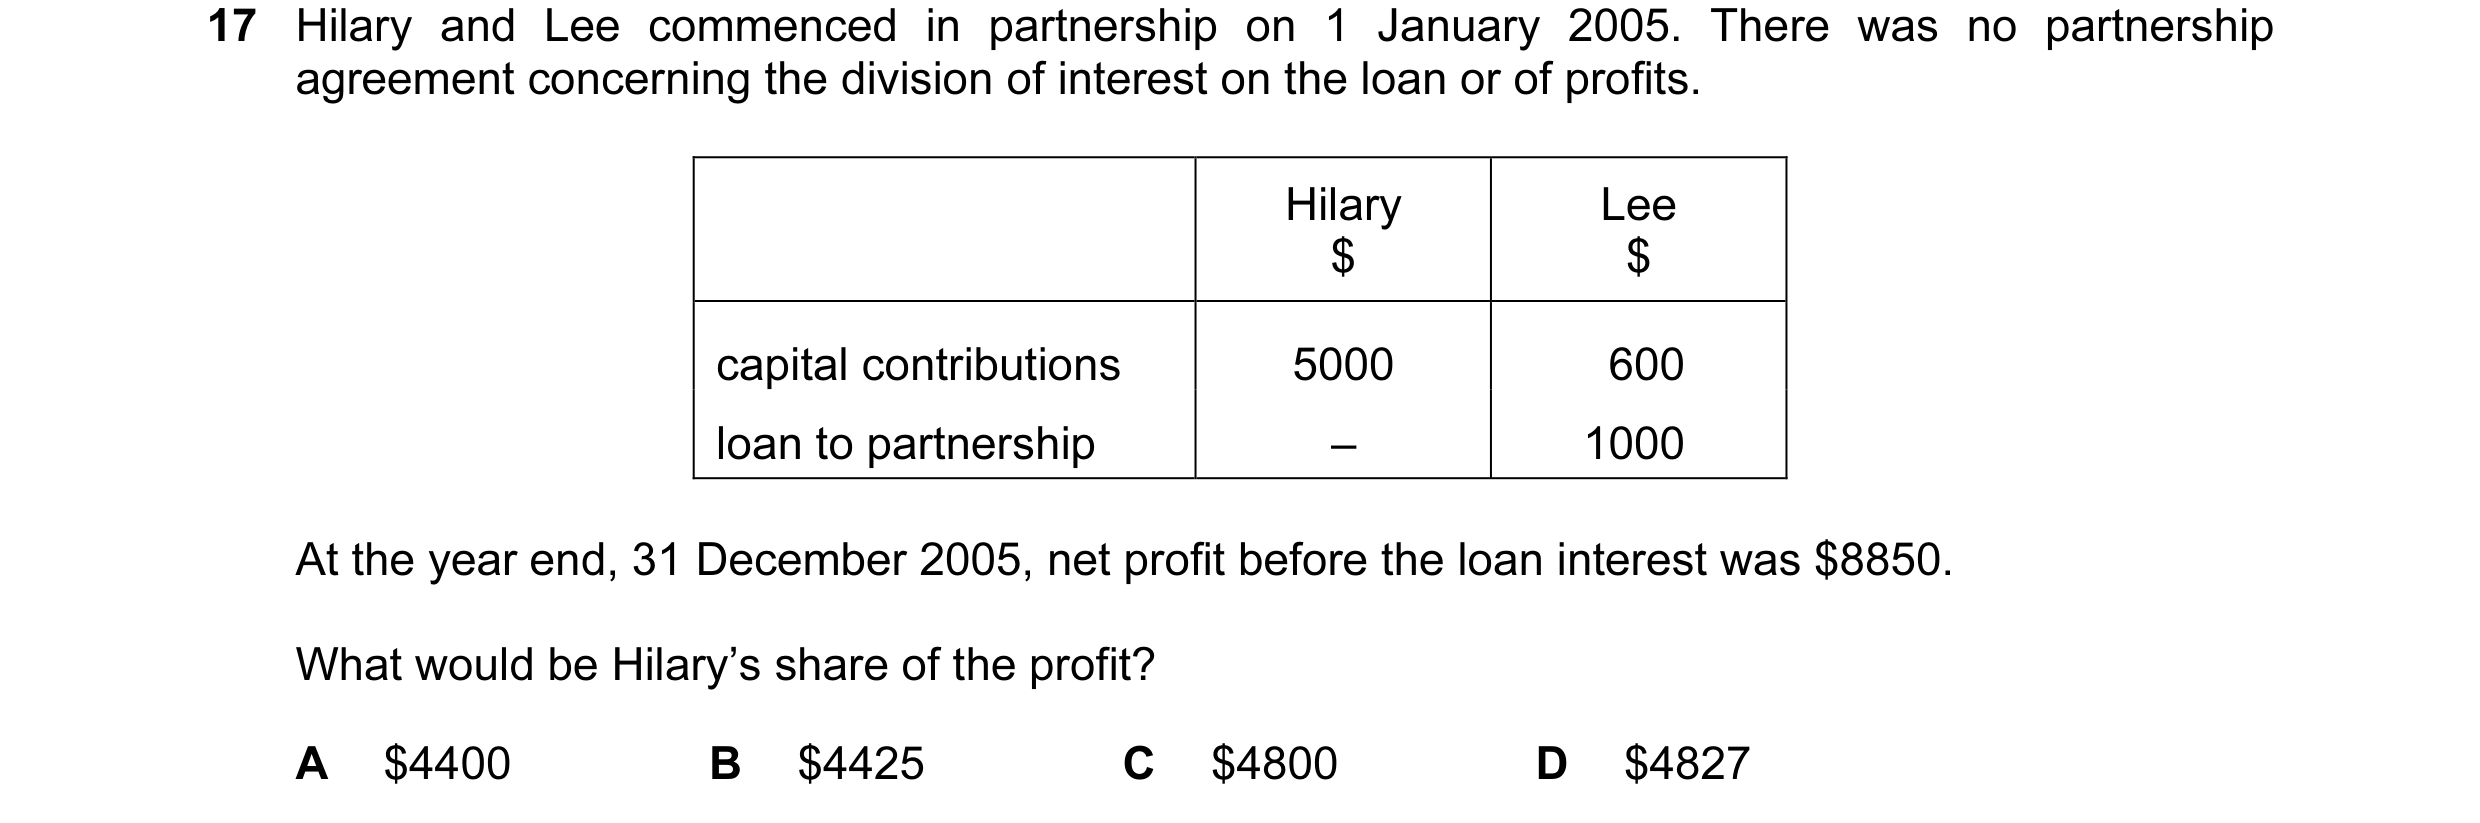
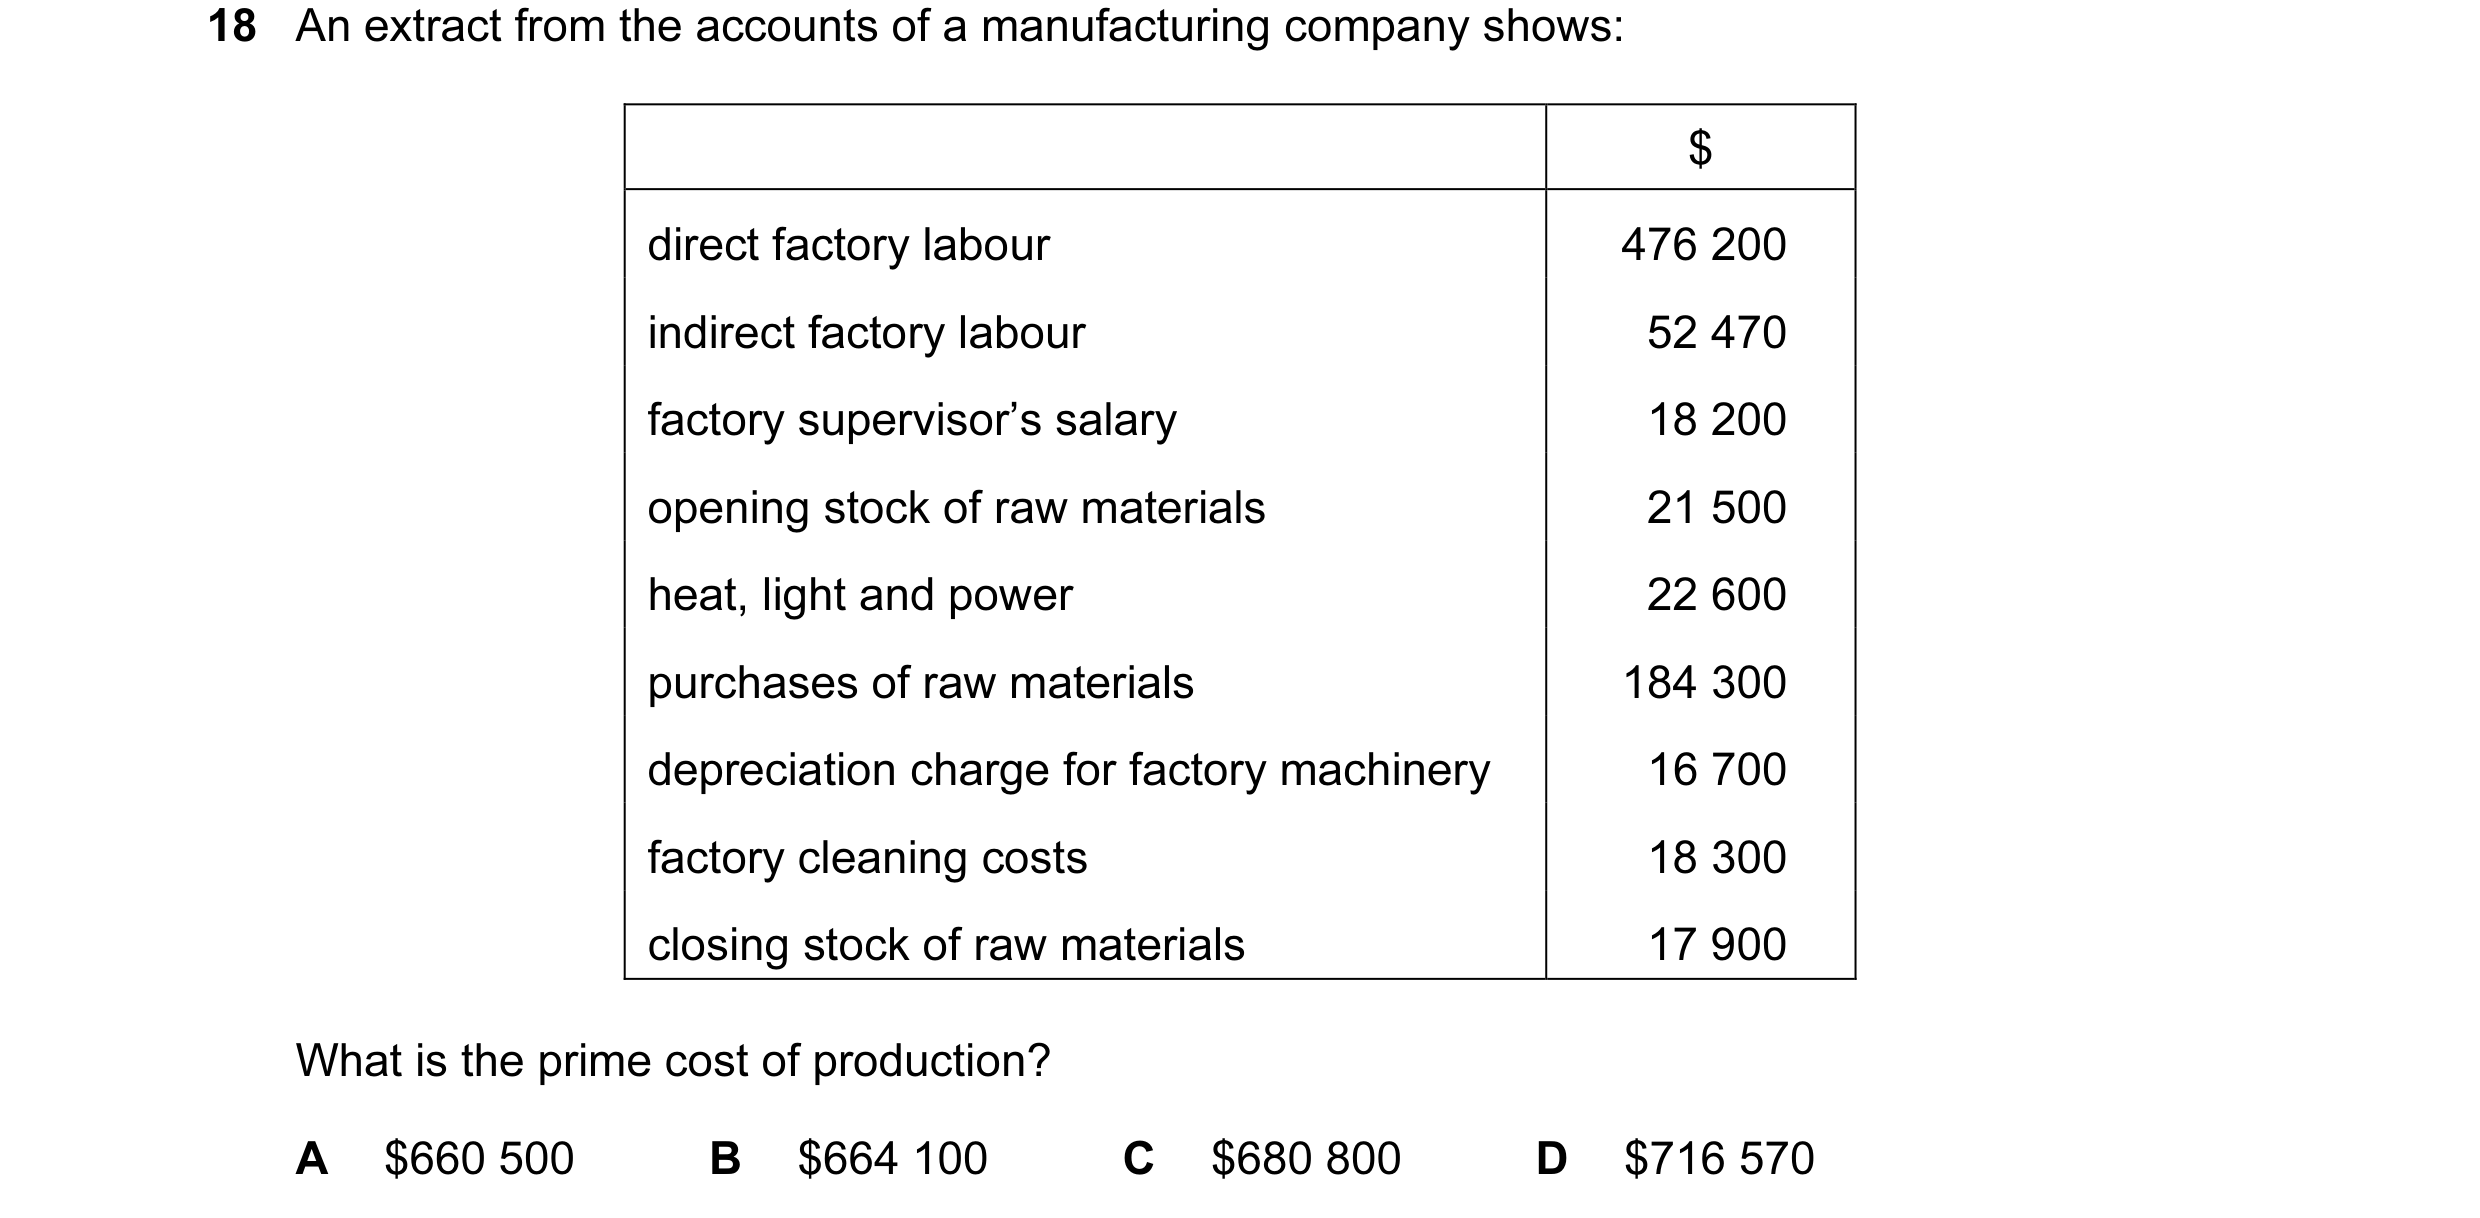
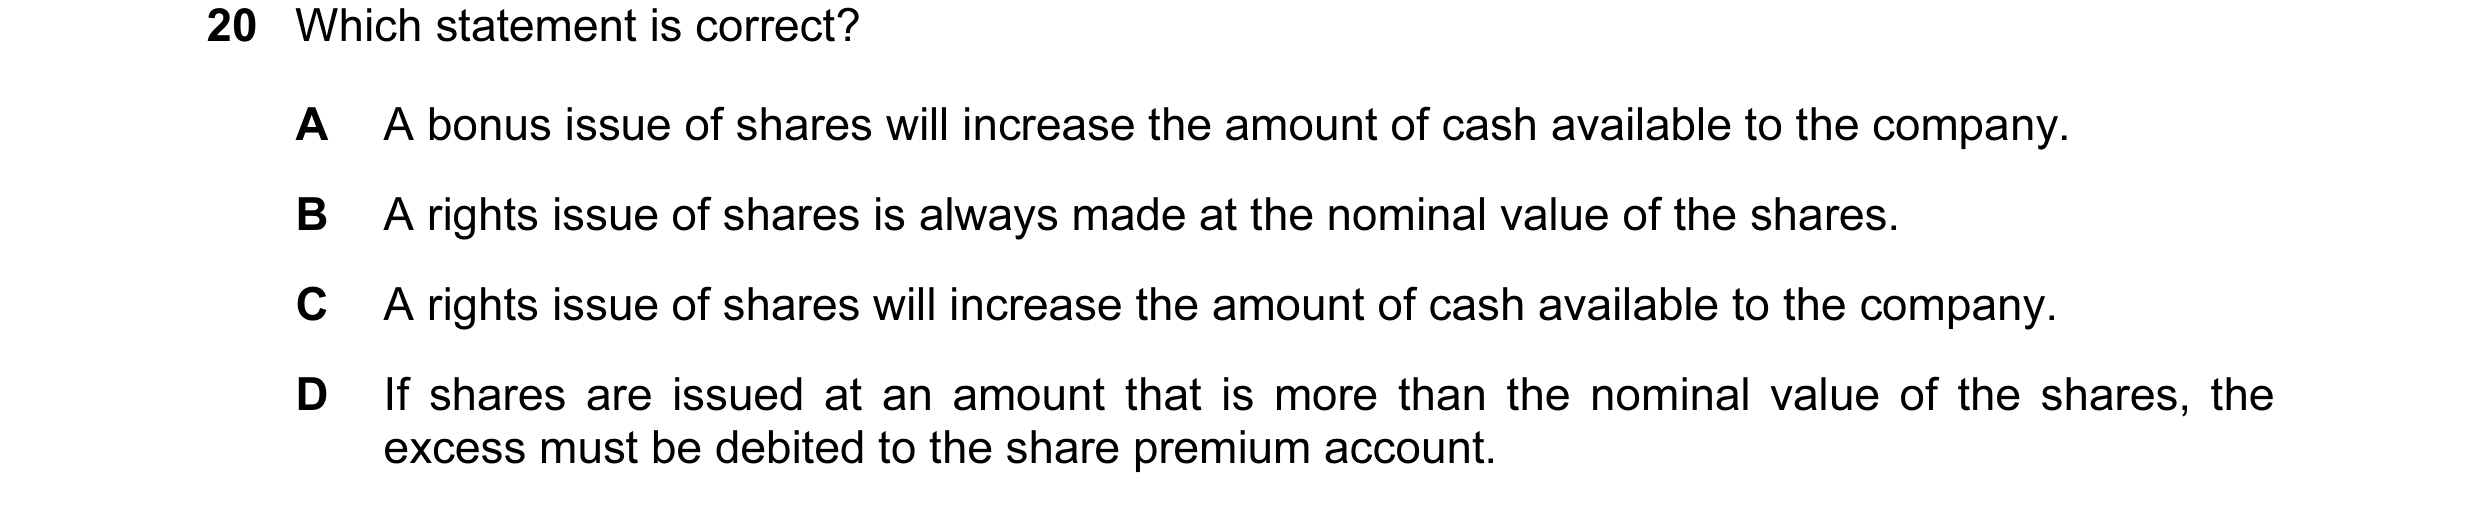 6 / 233
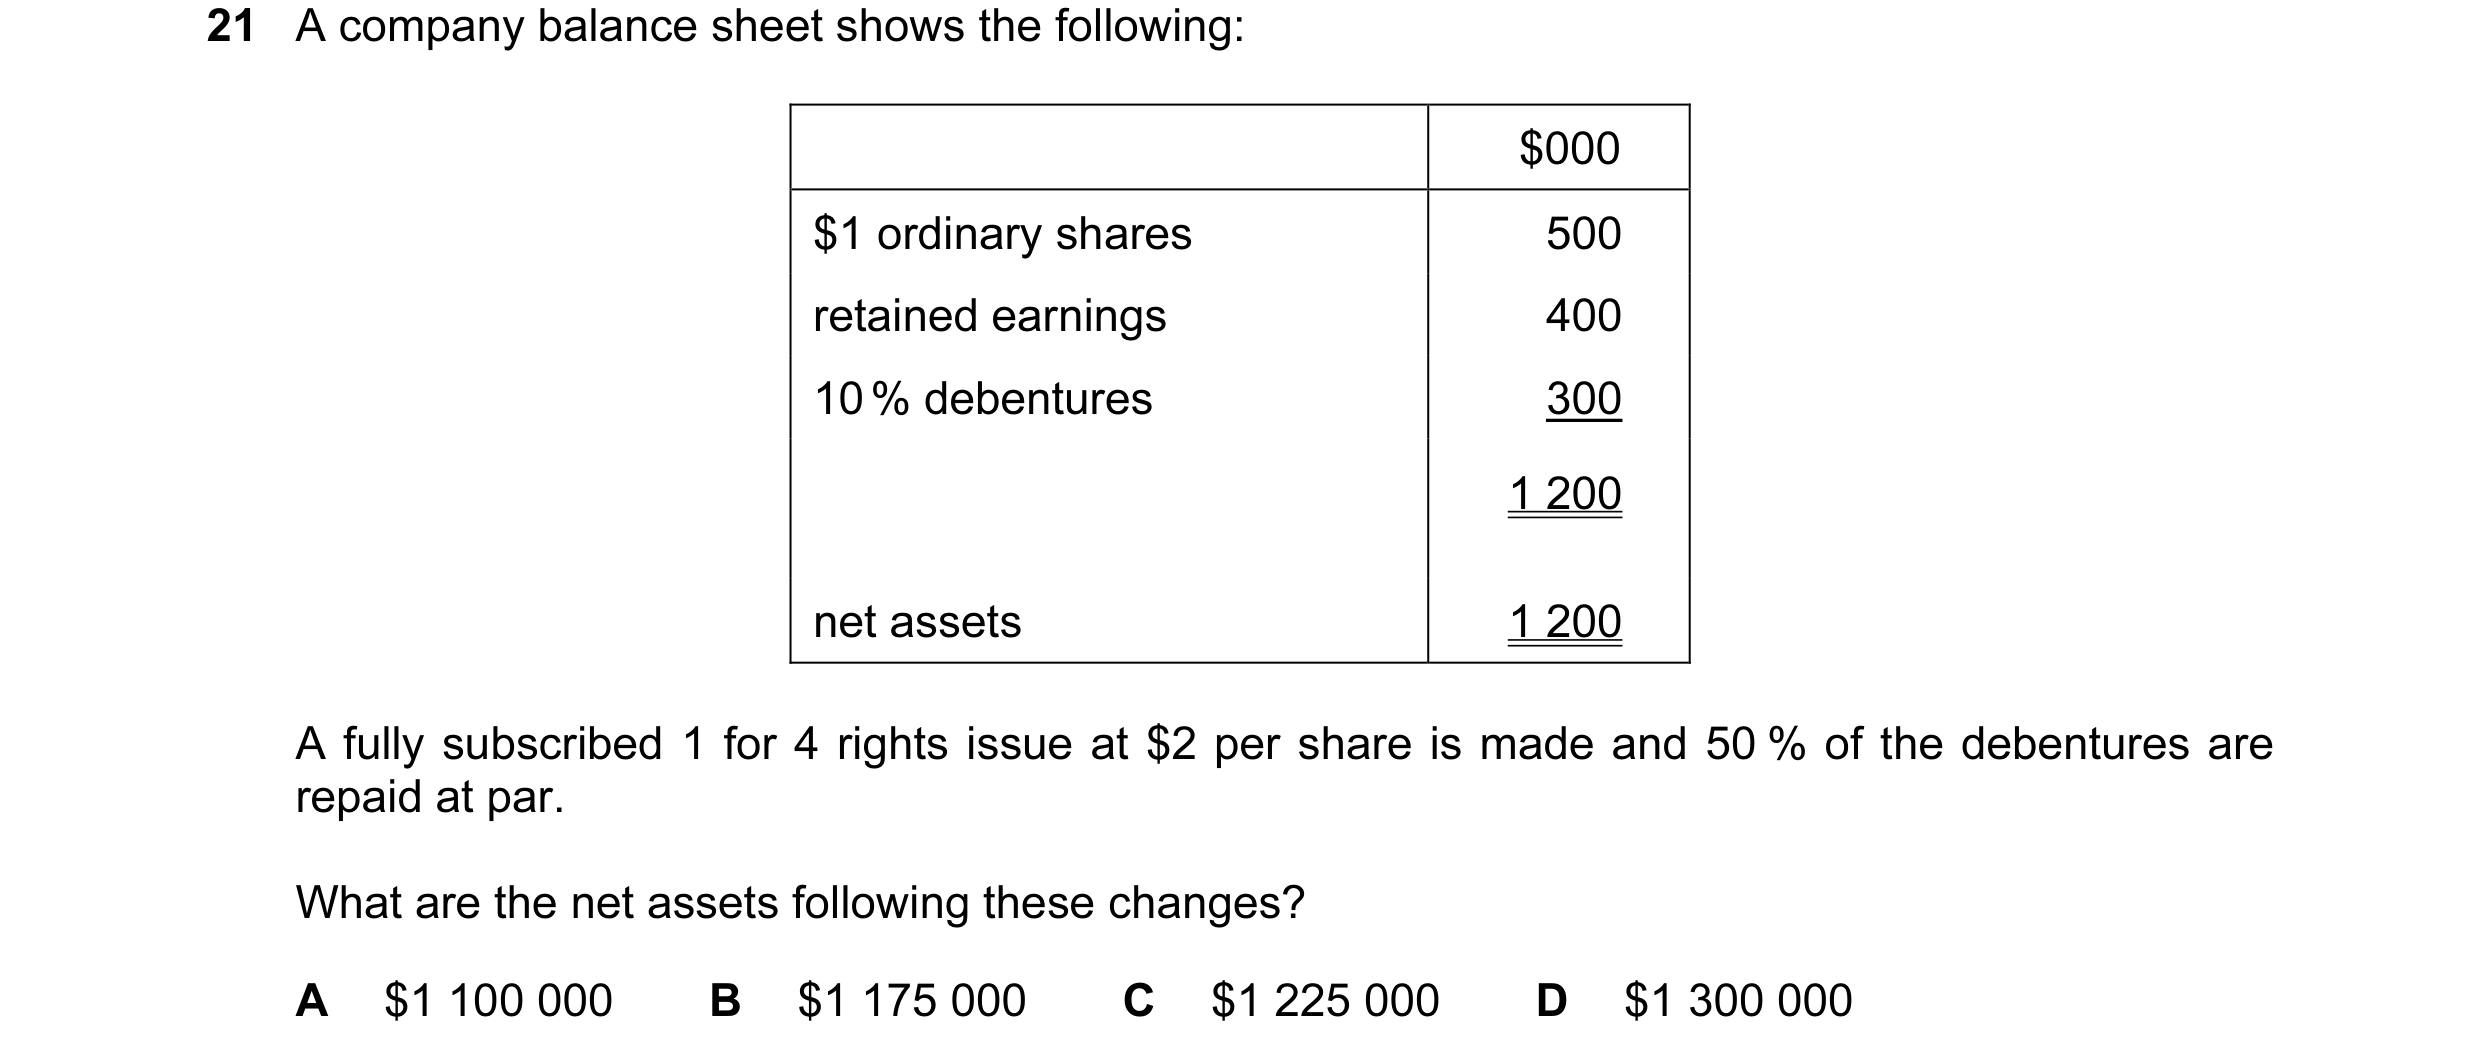
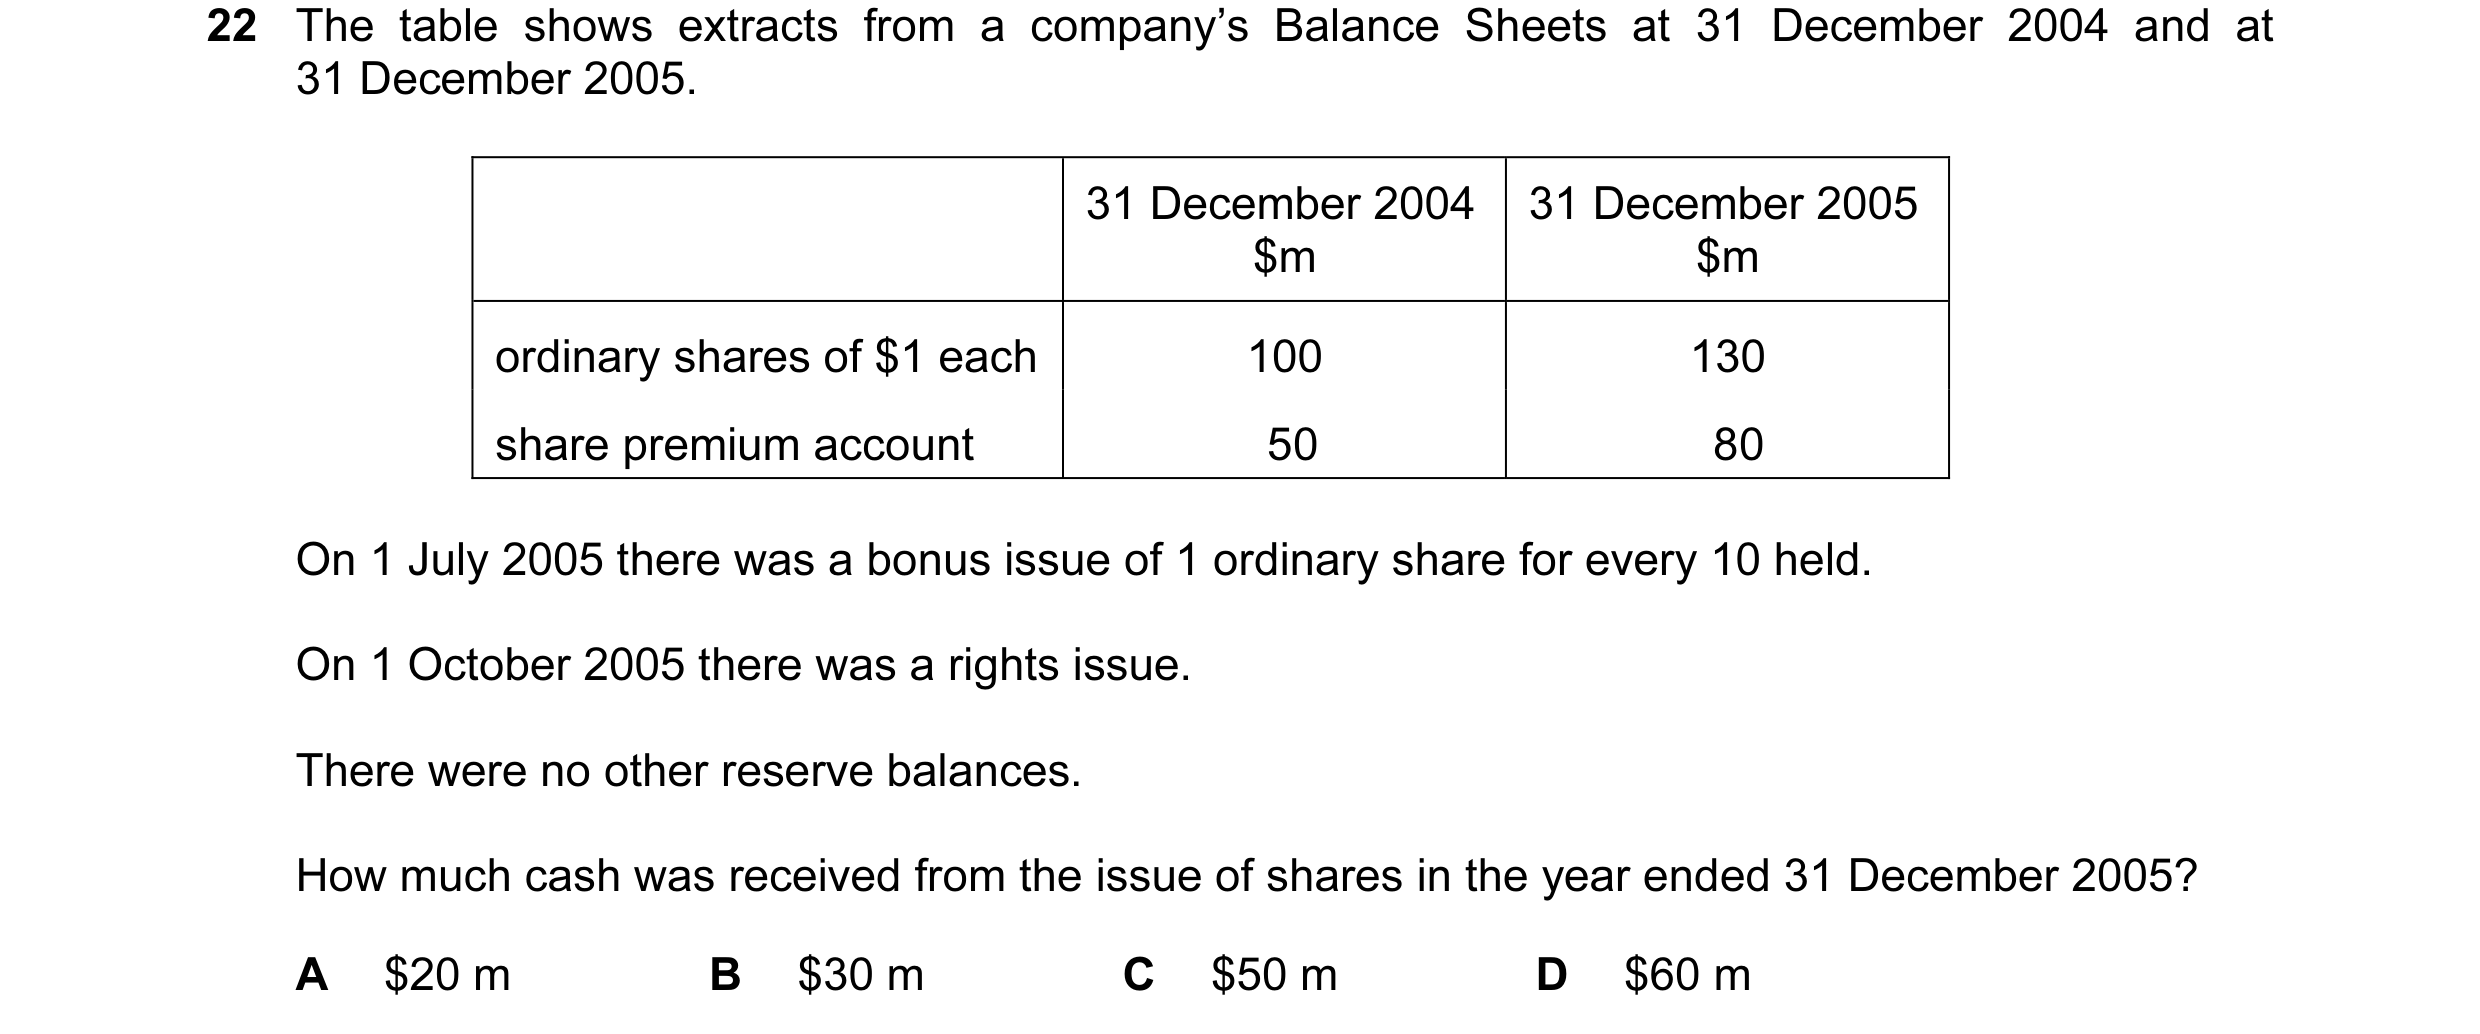
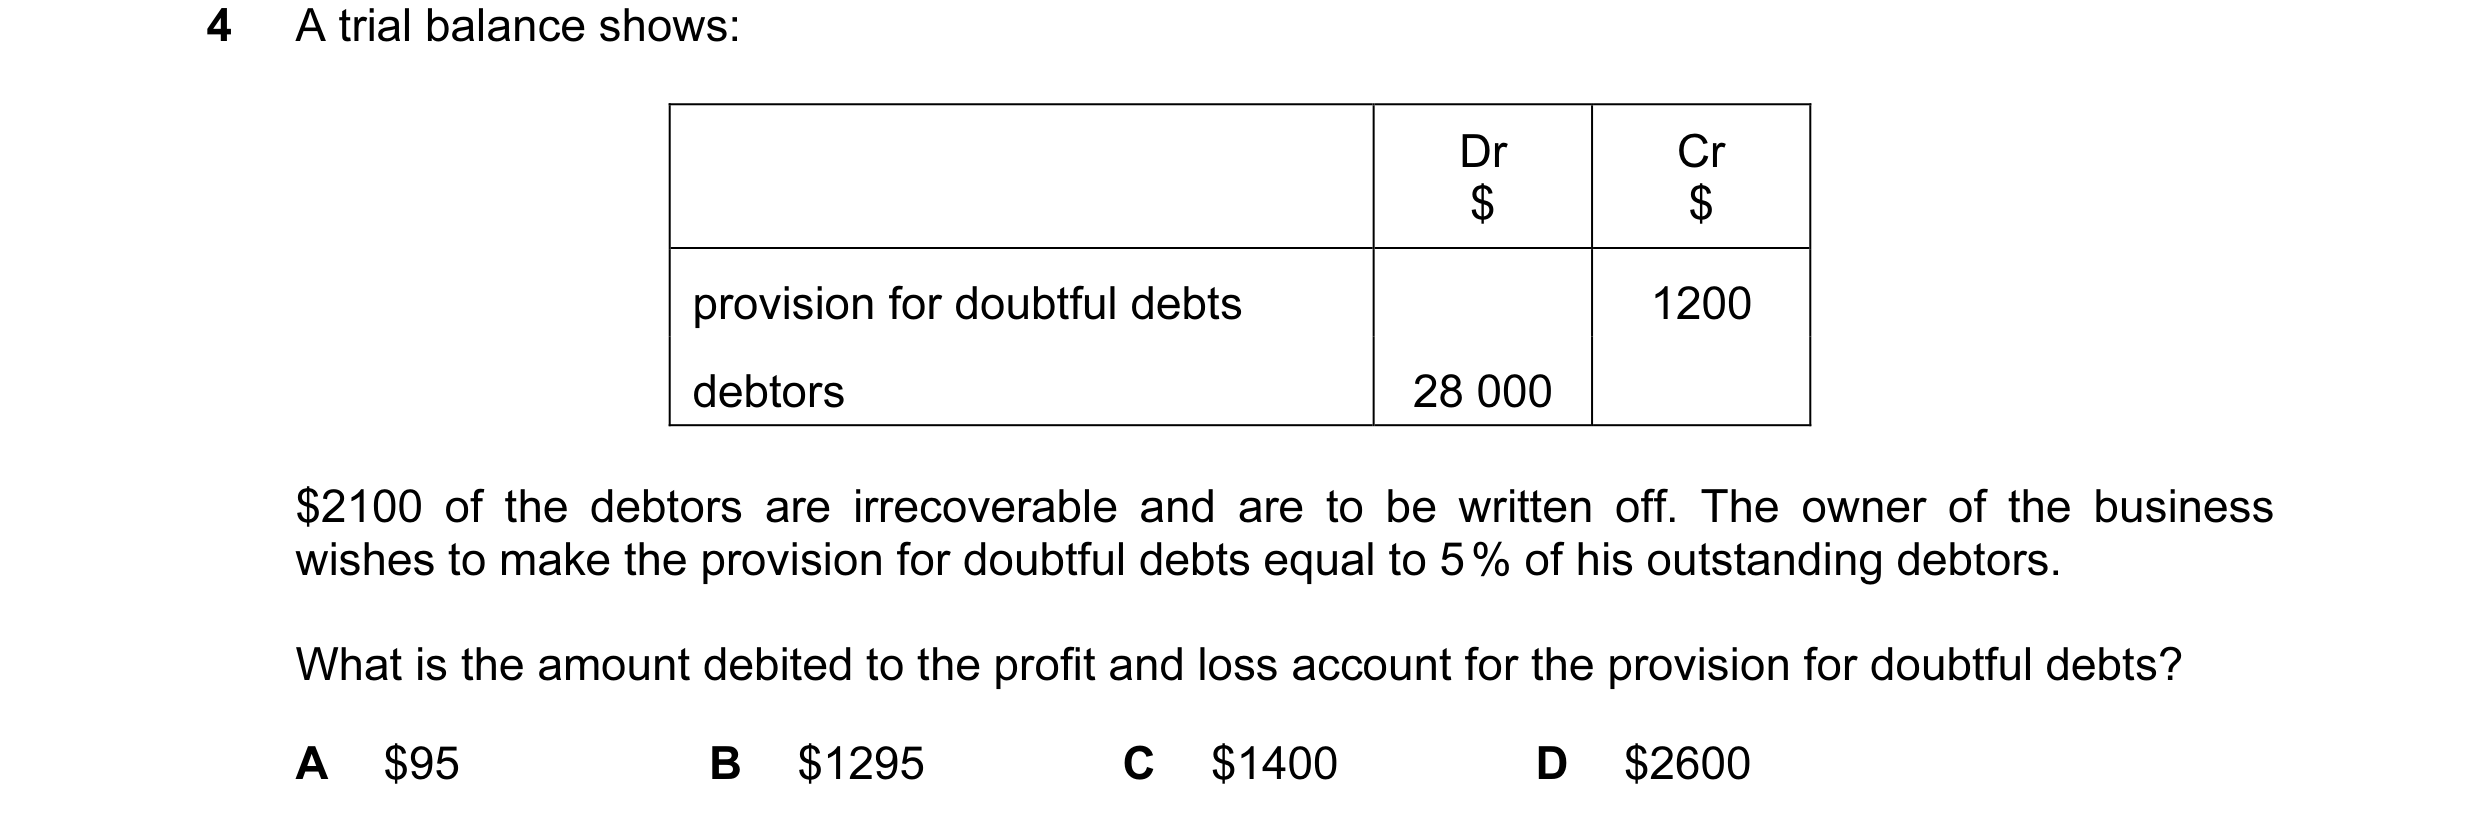 7 / 233
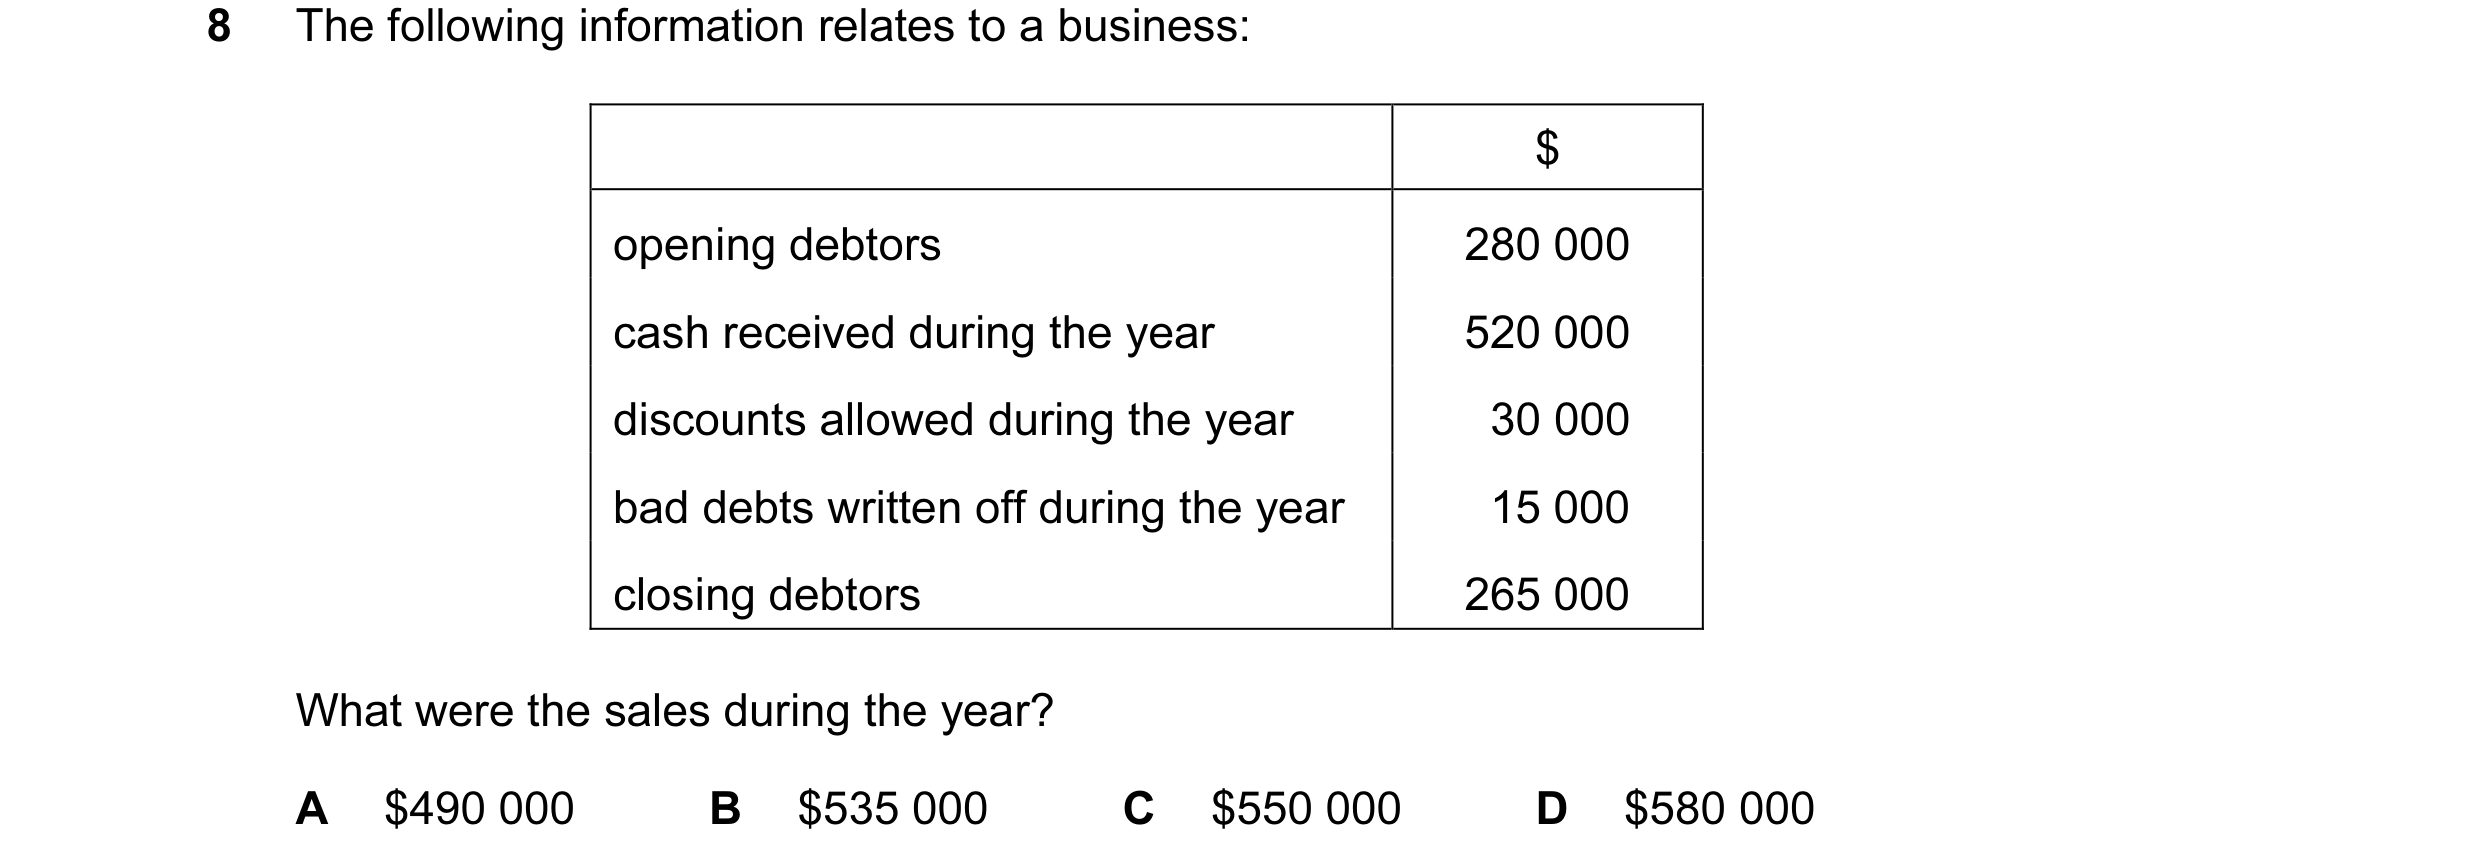
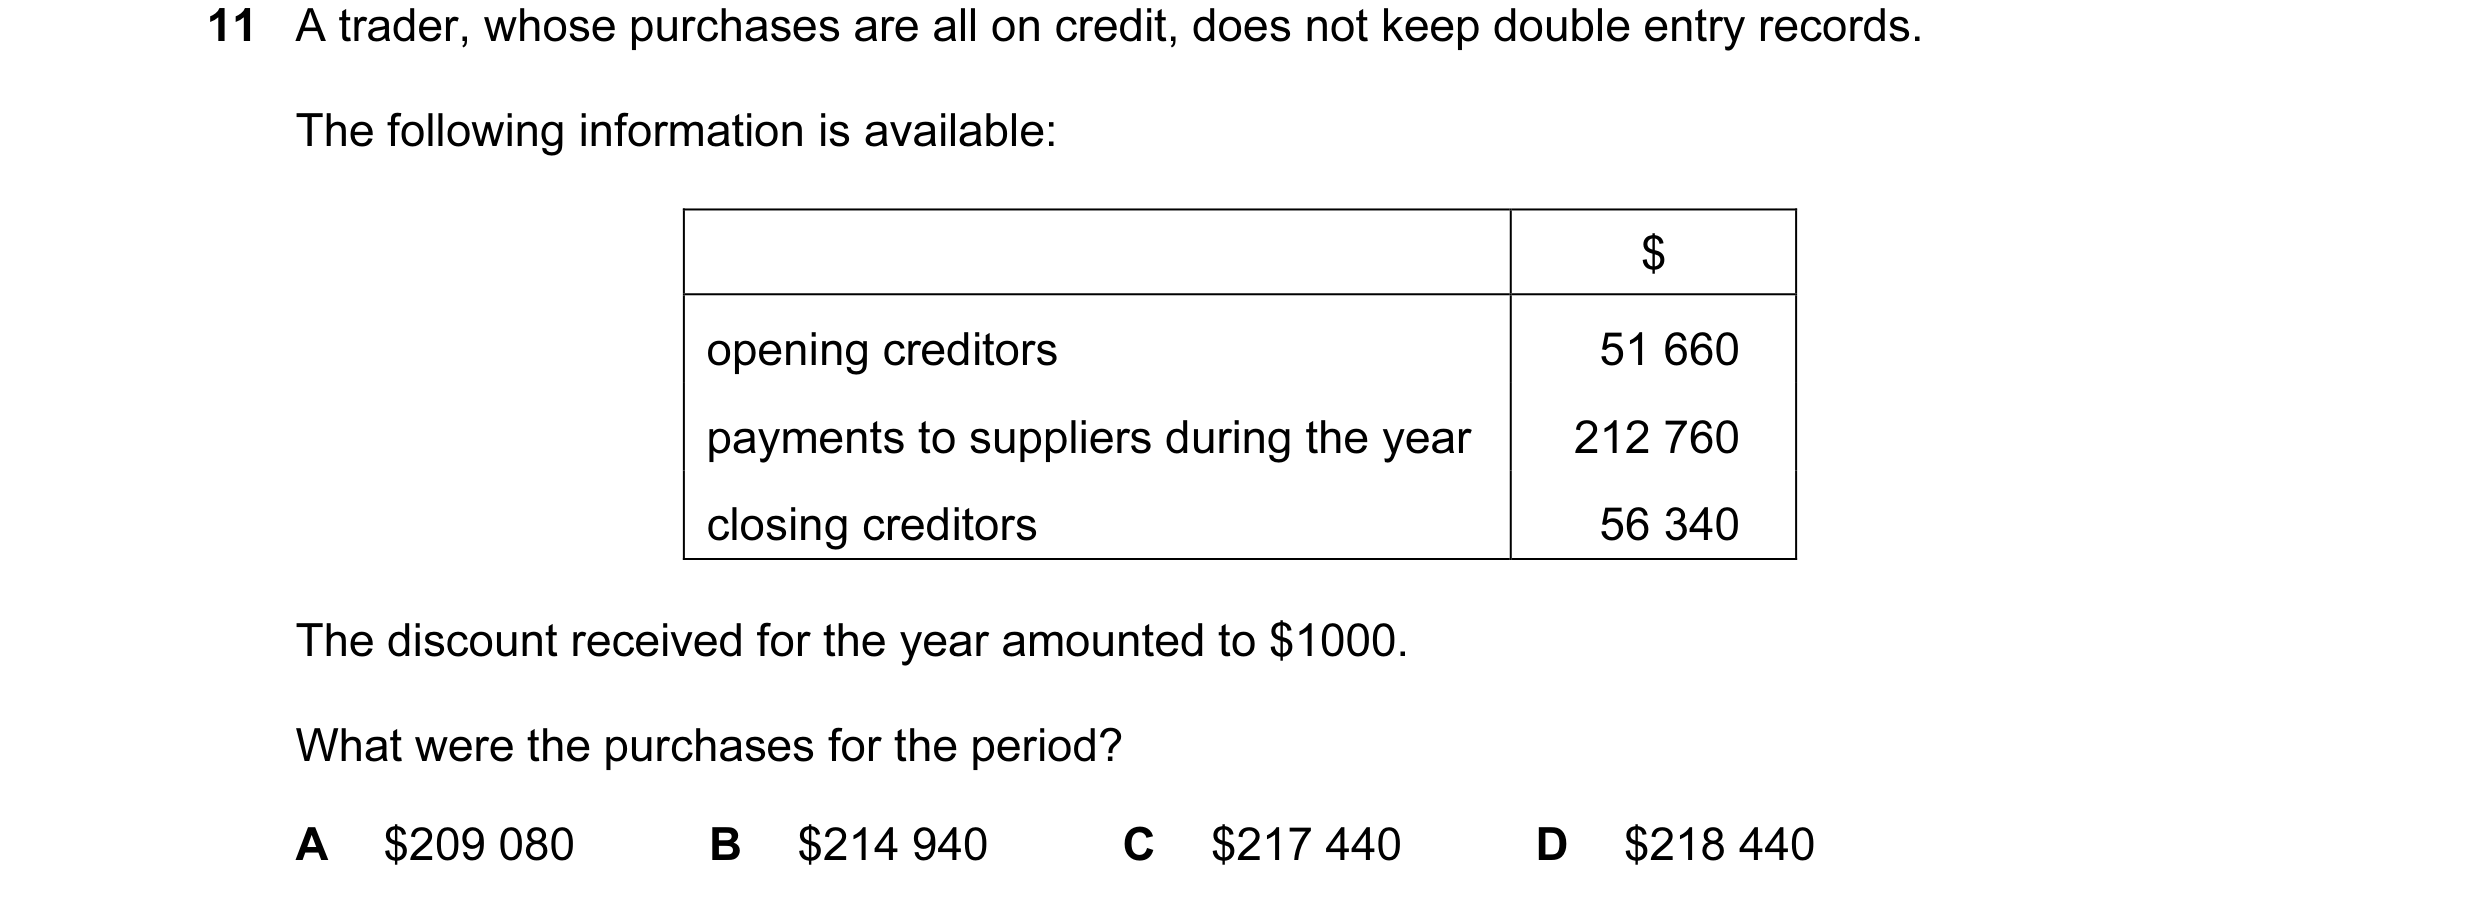 8 / 233
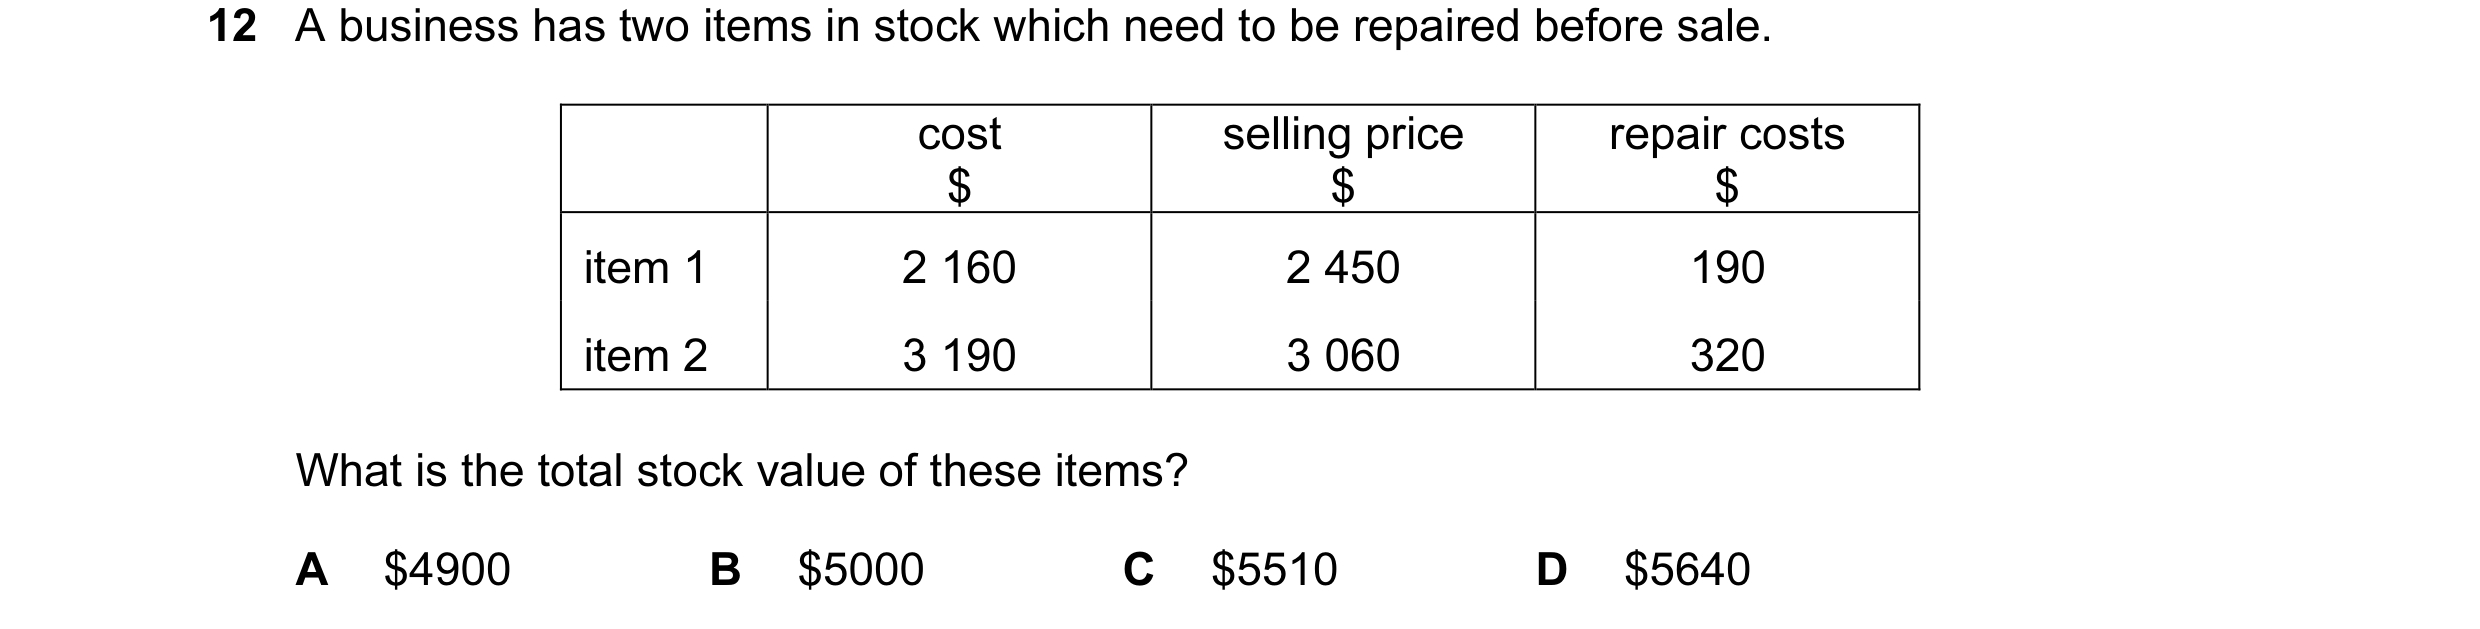
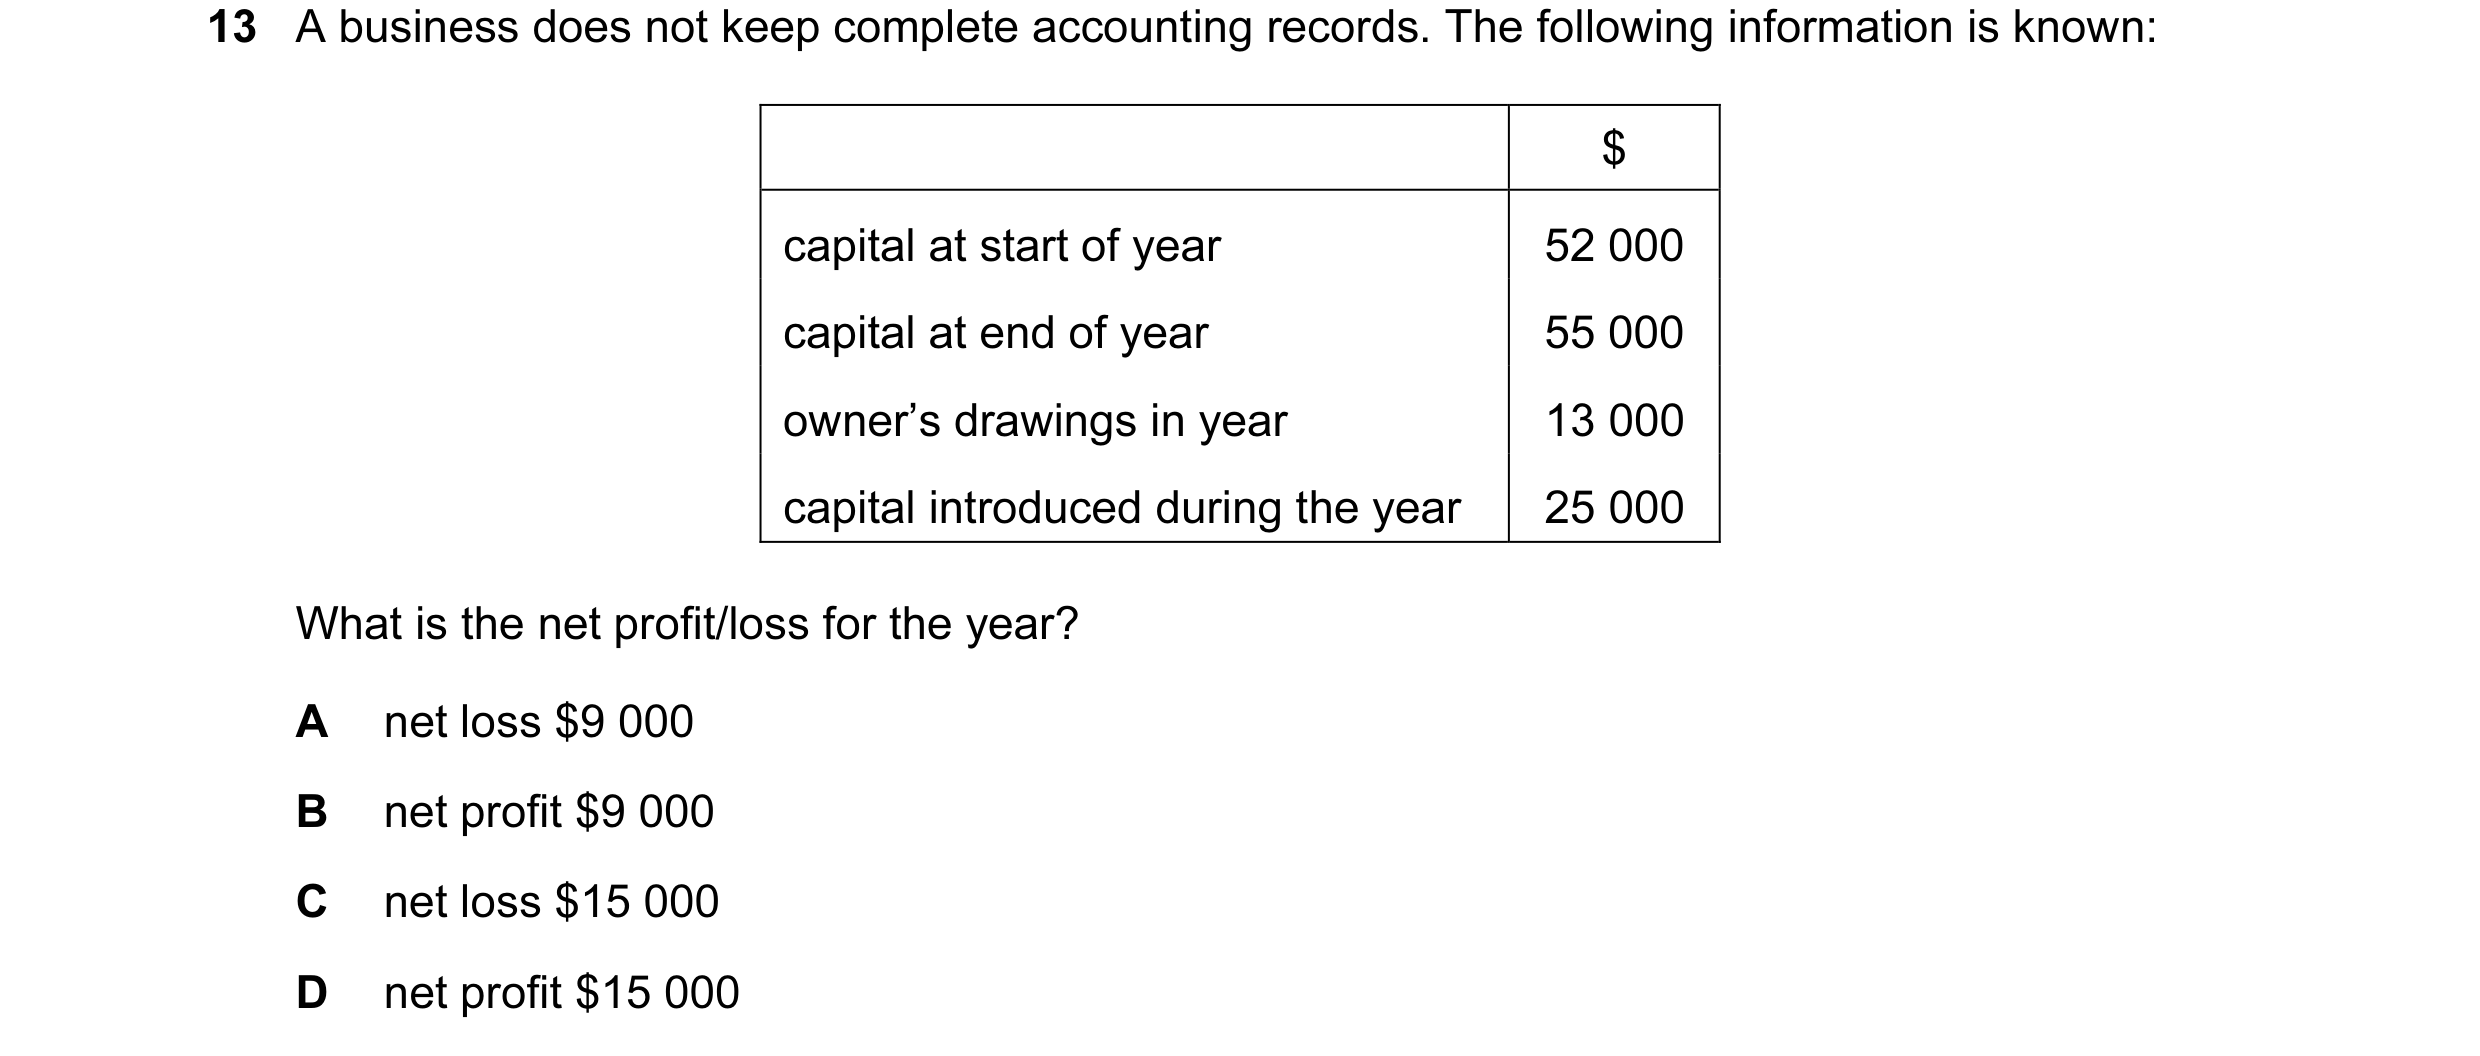
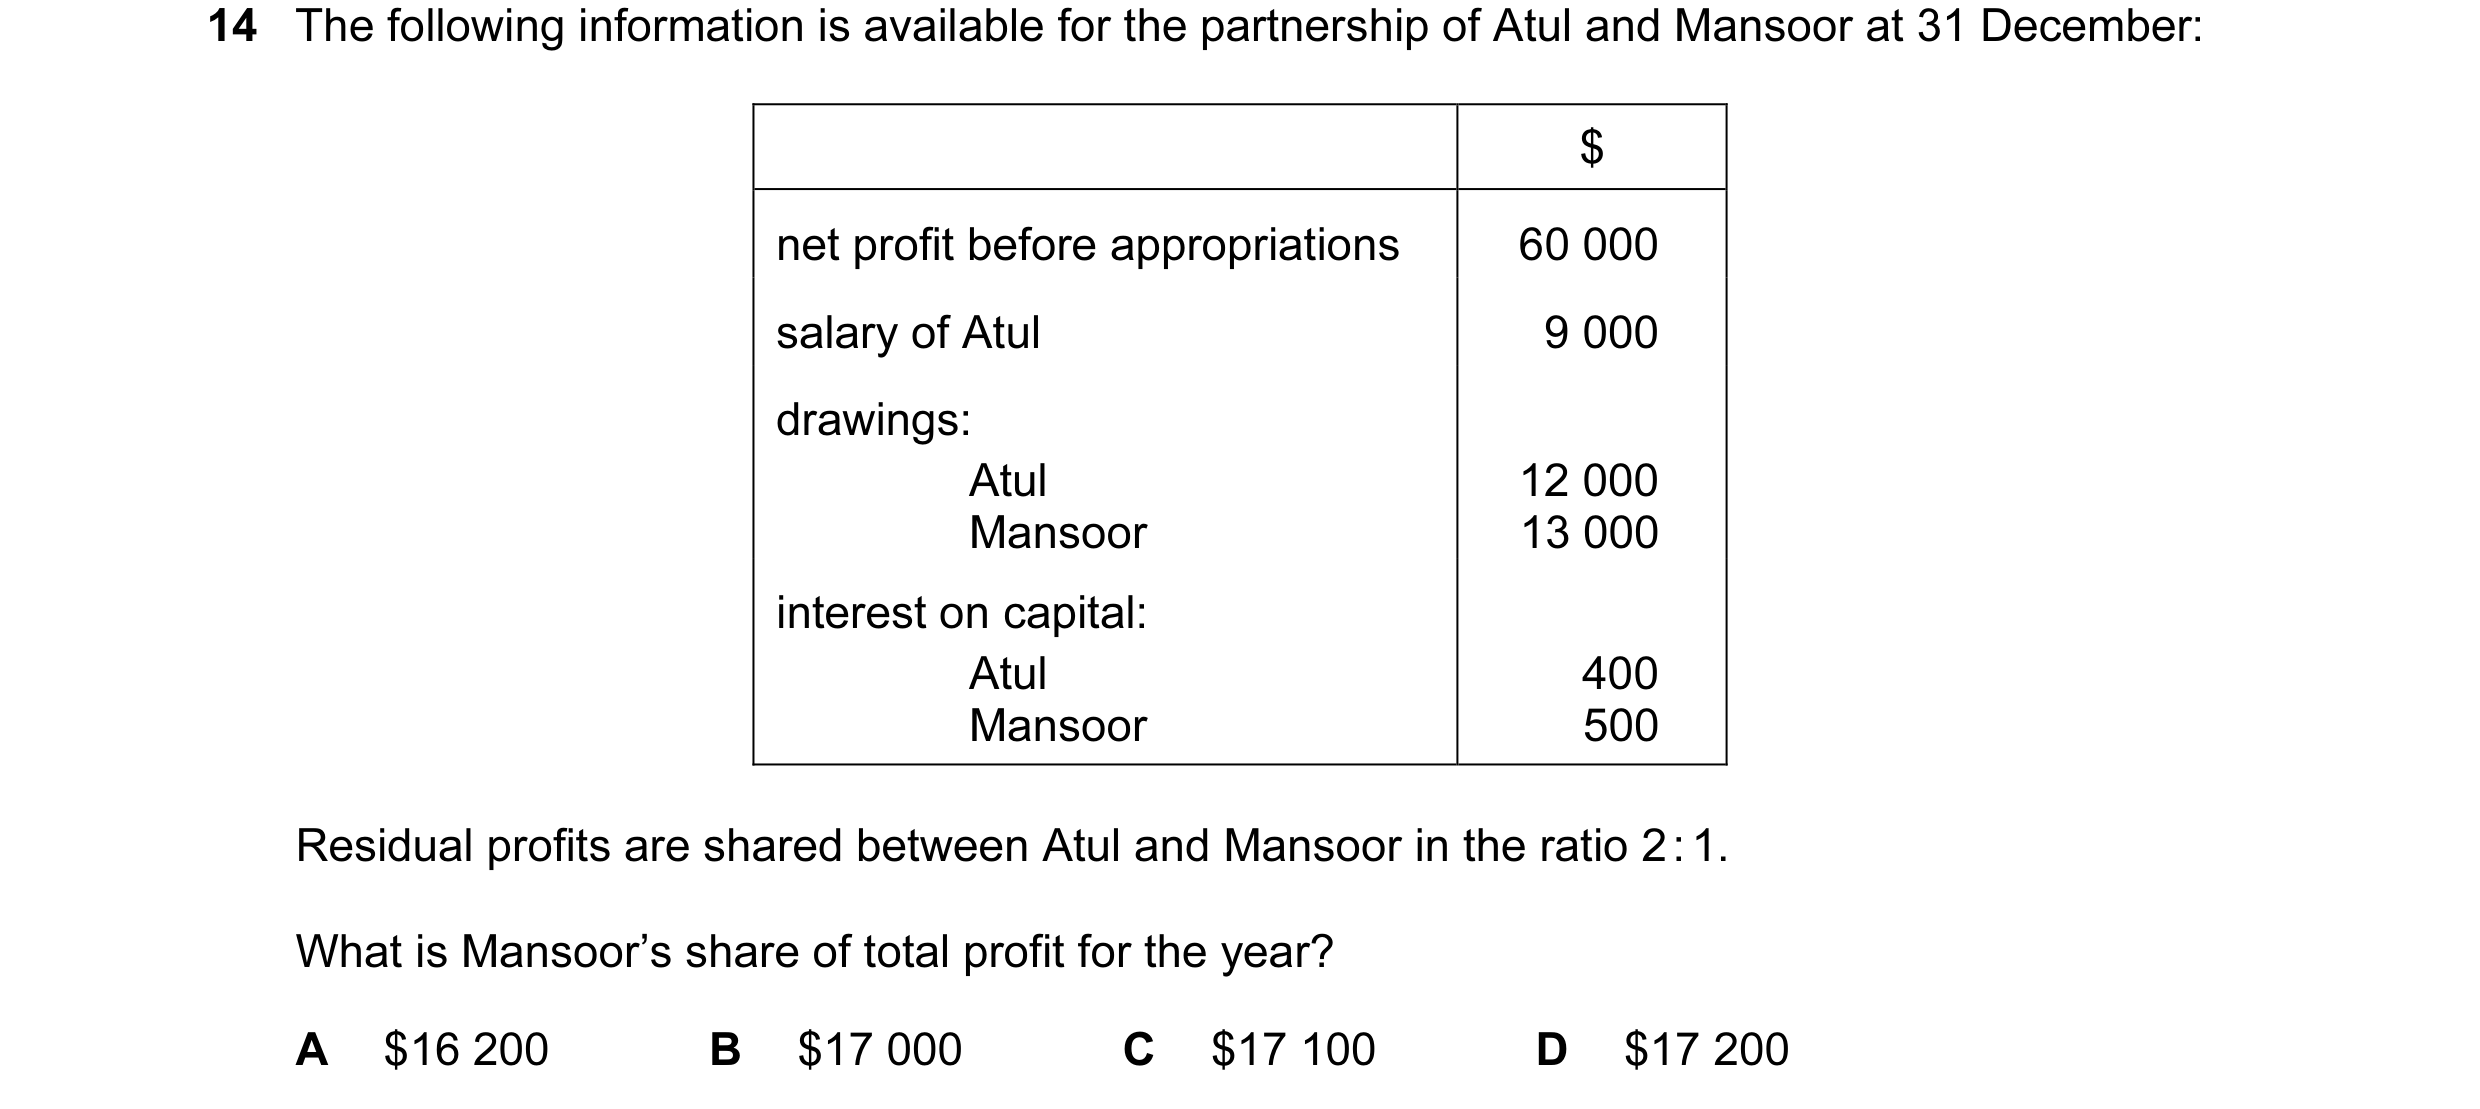
 9 / 233
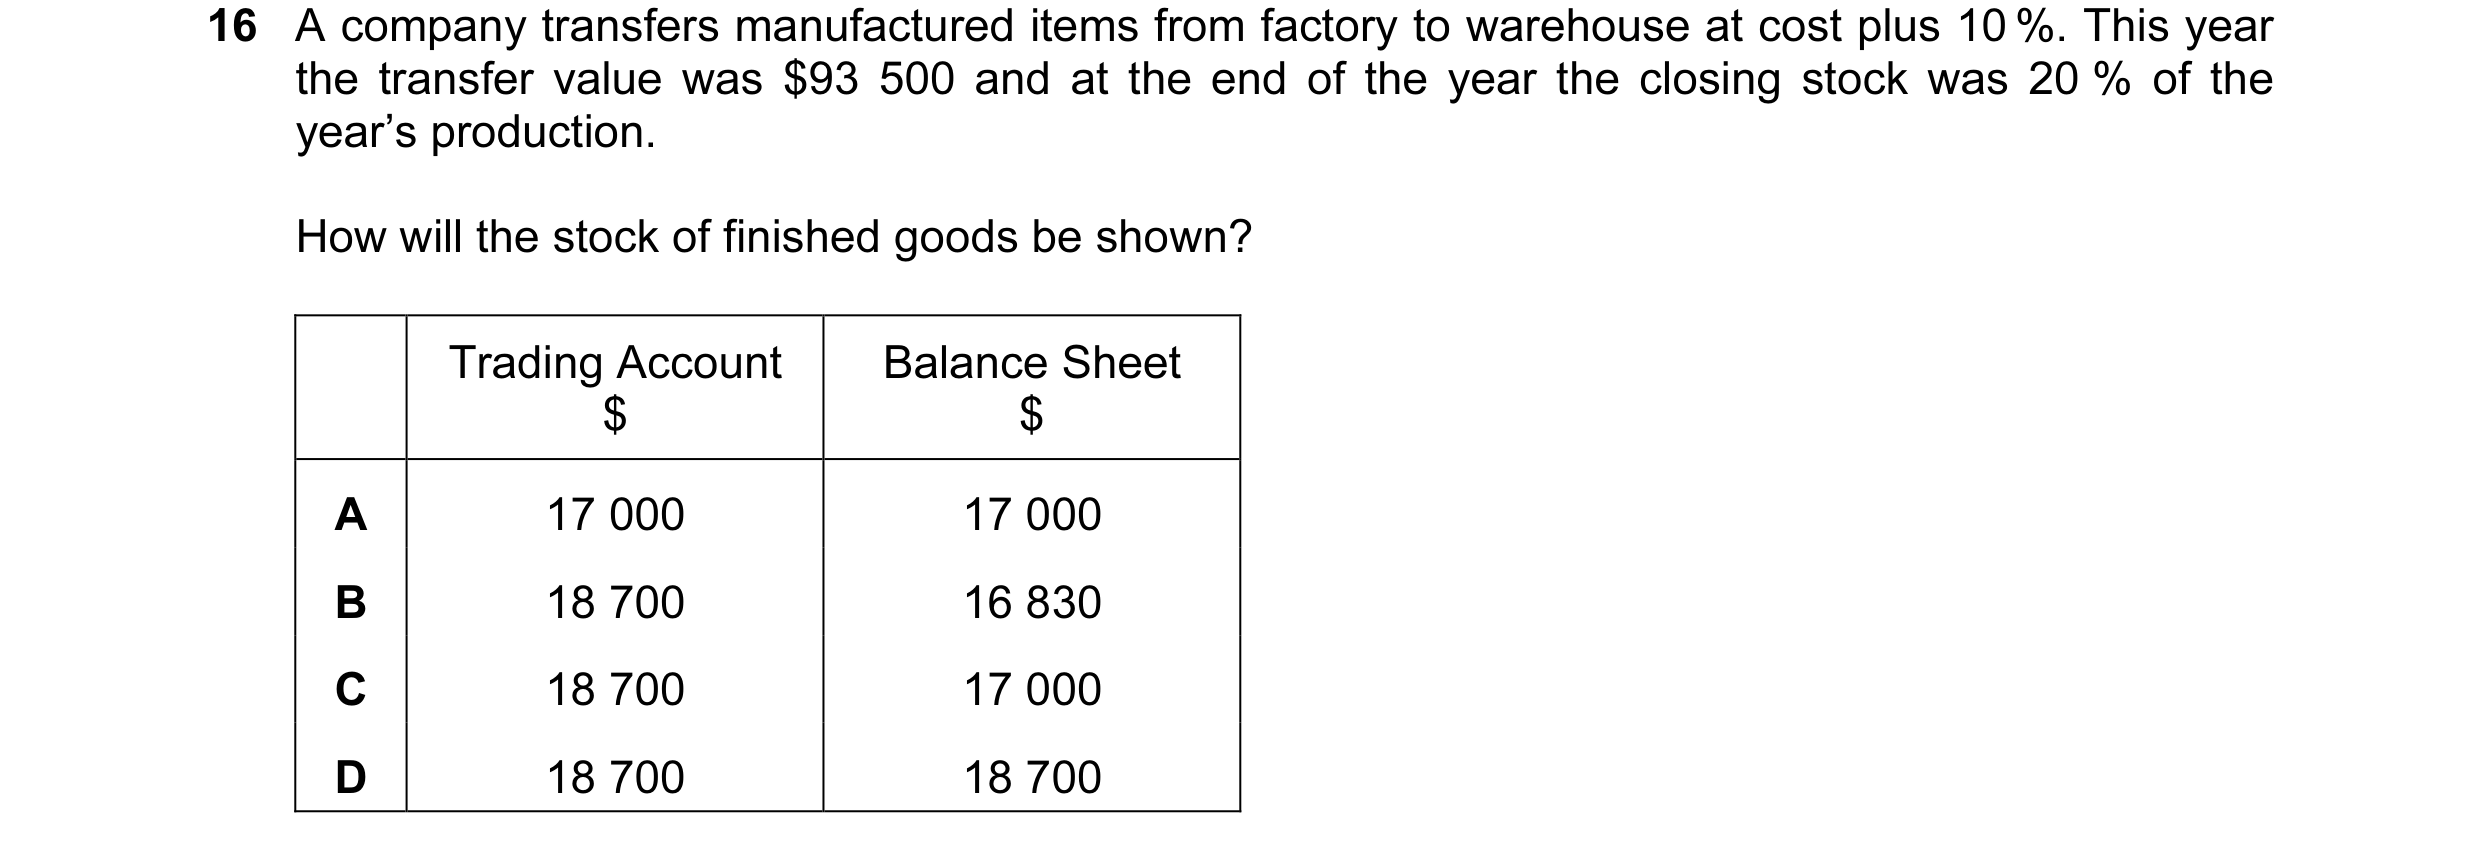
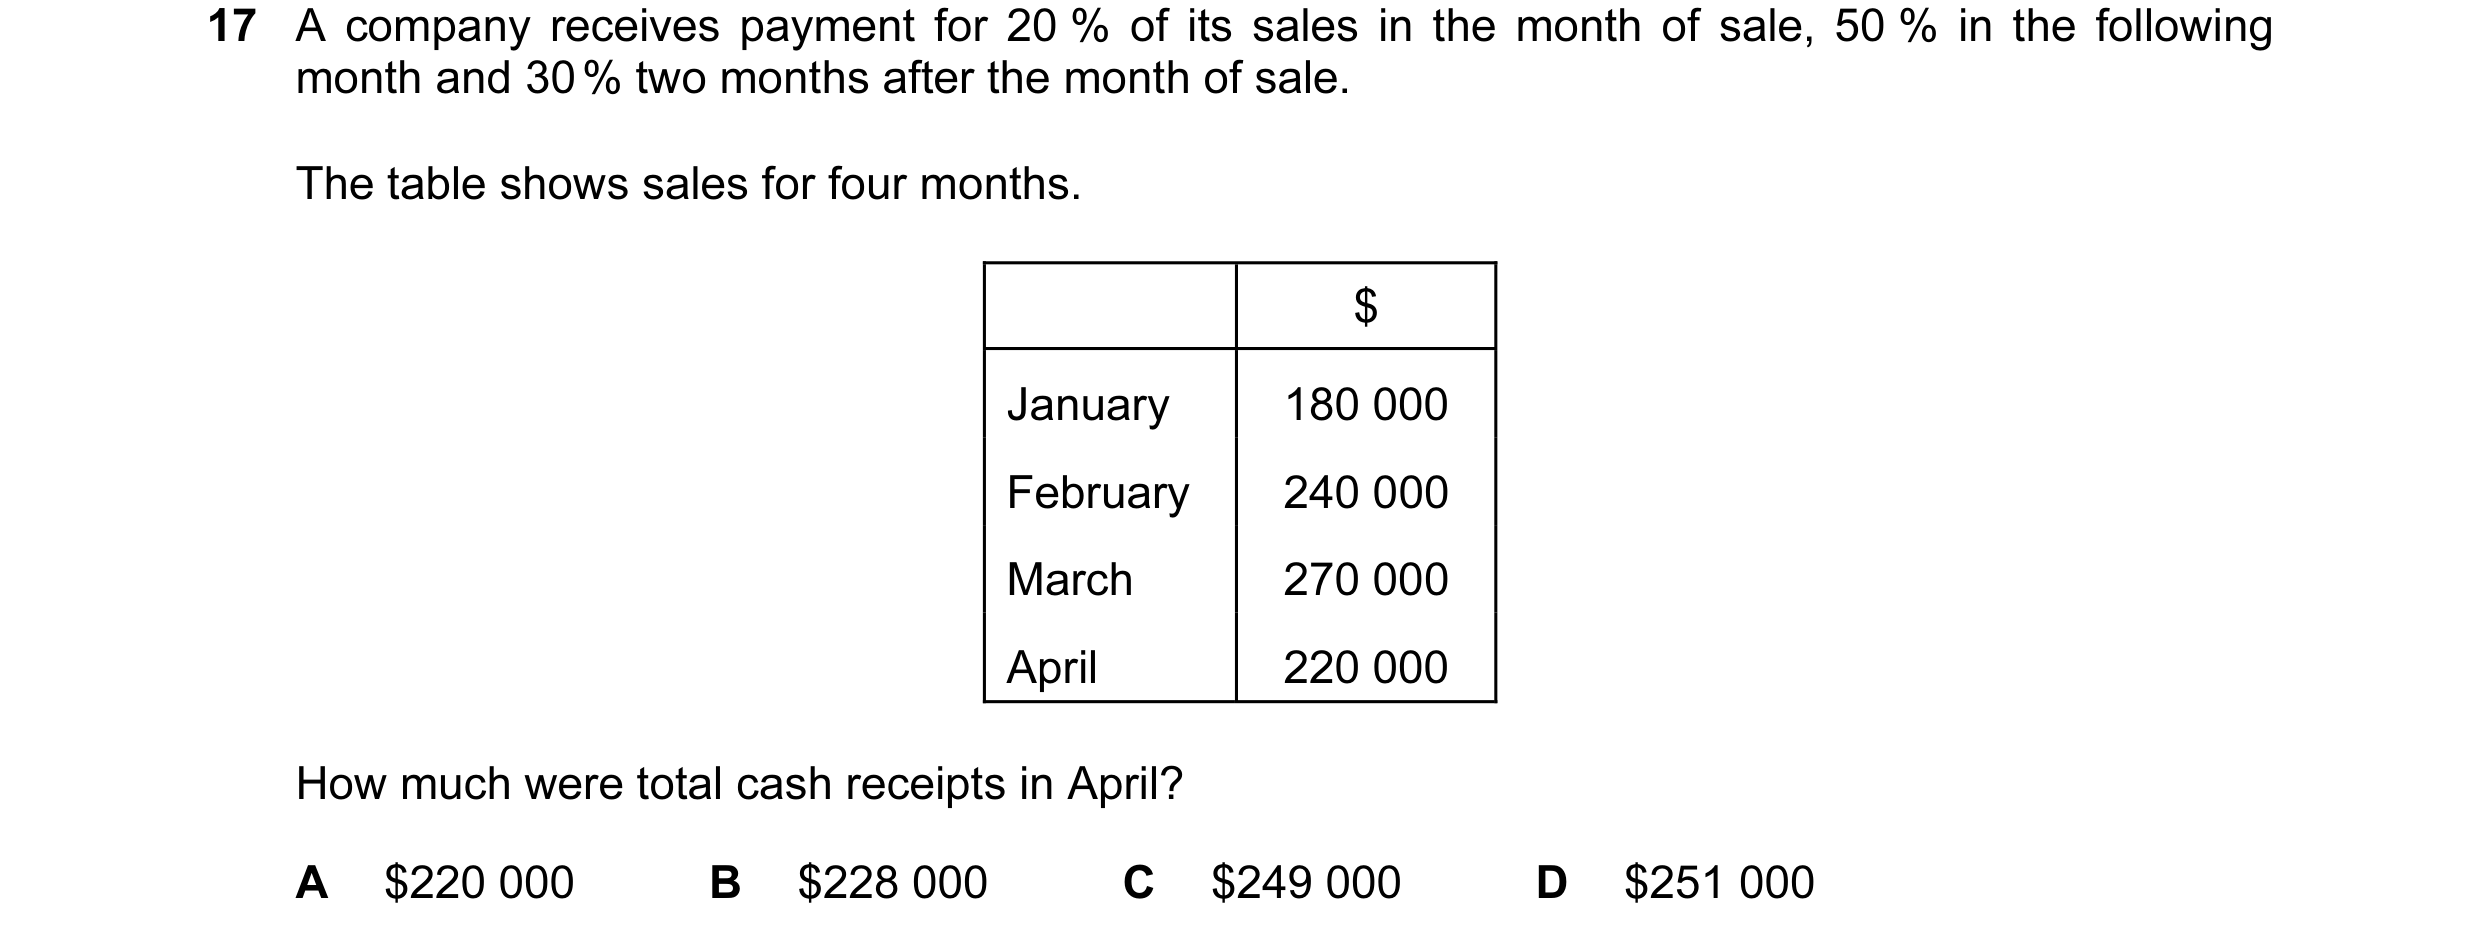
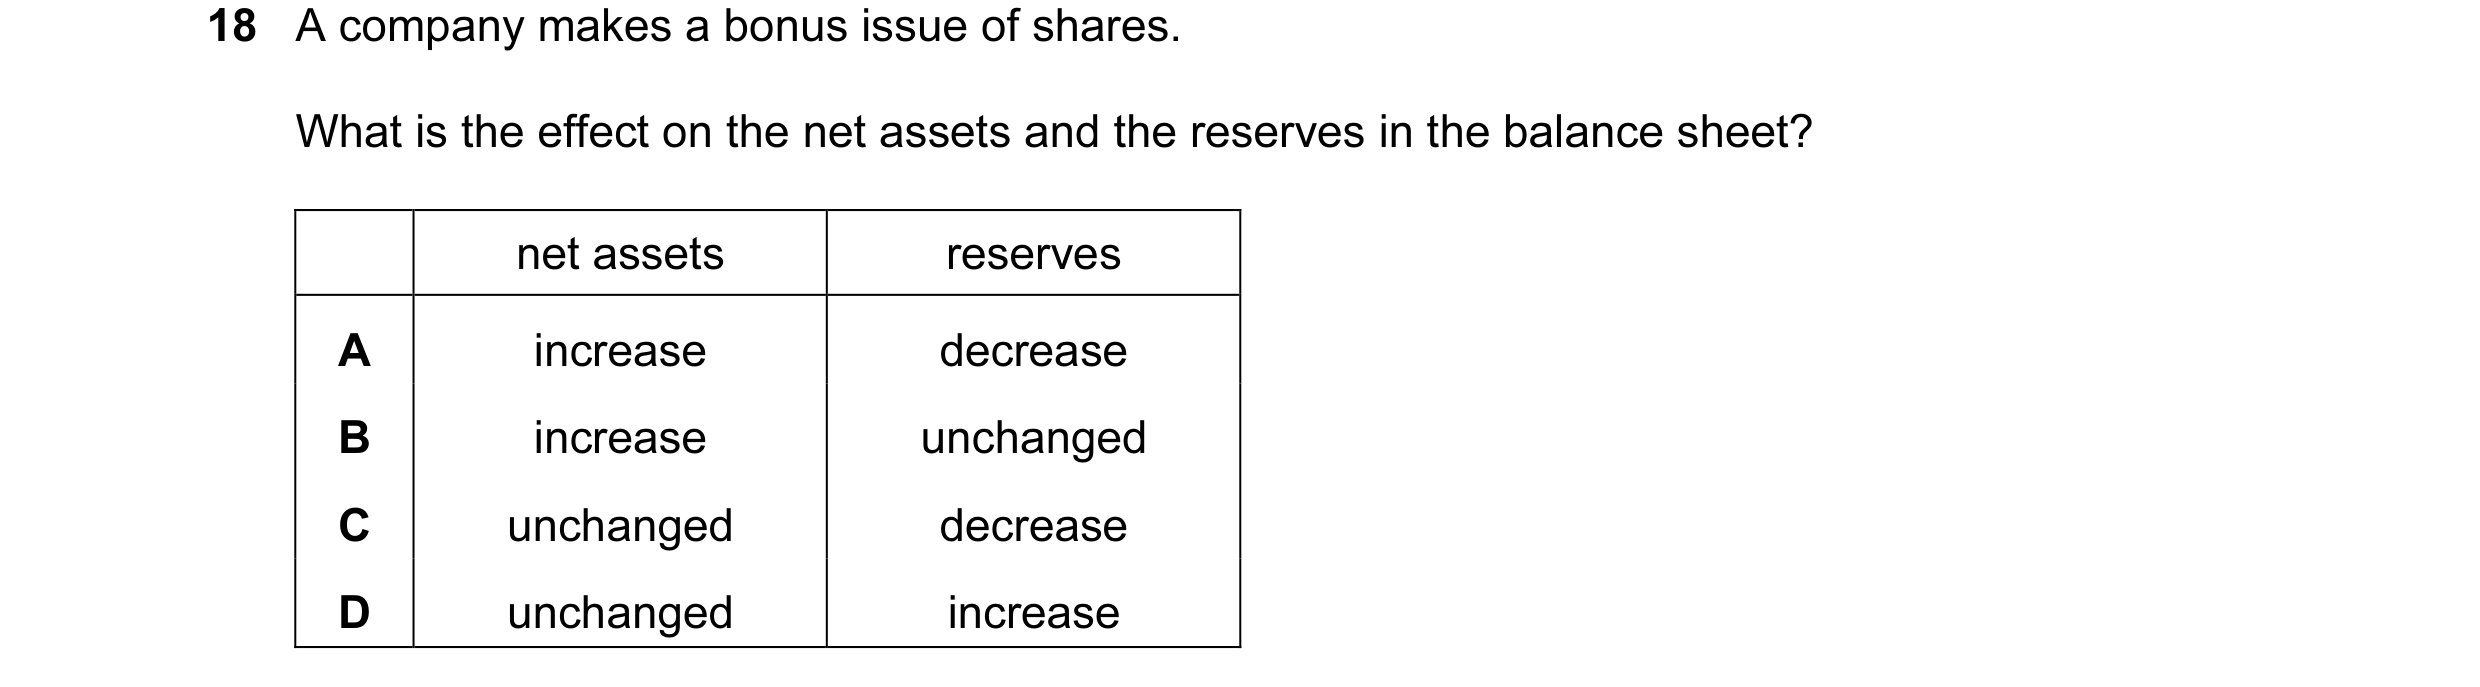
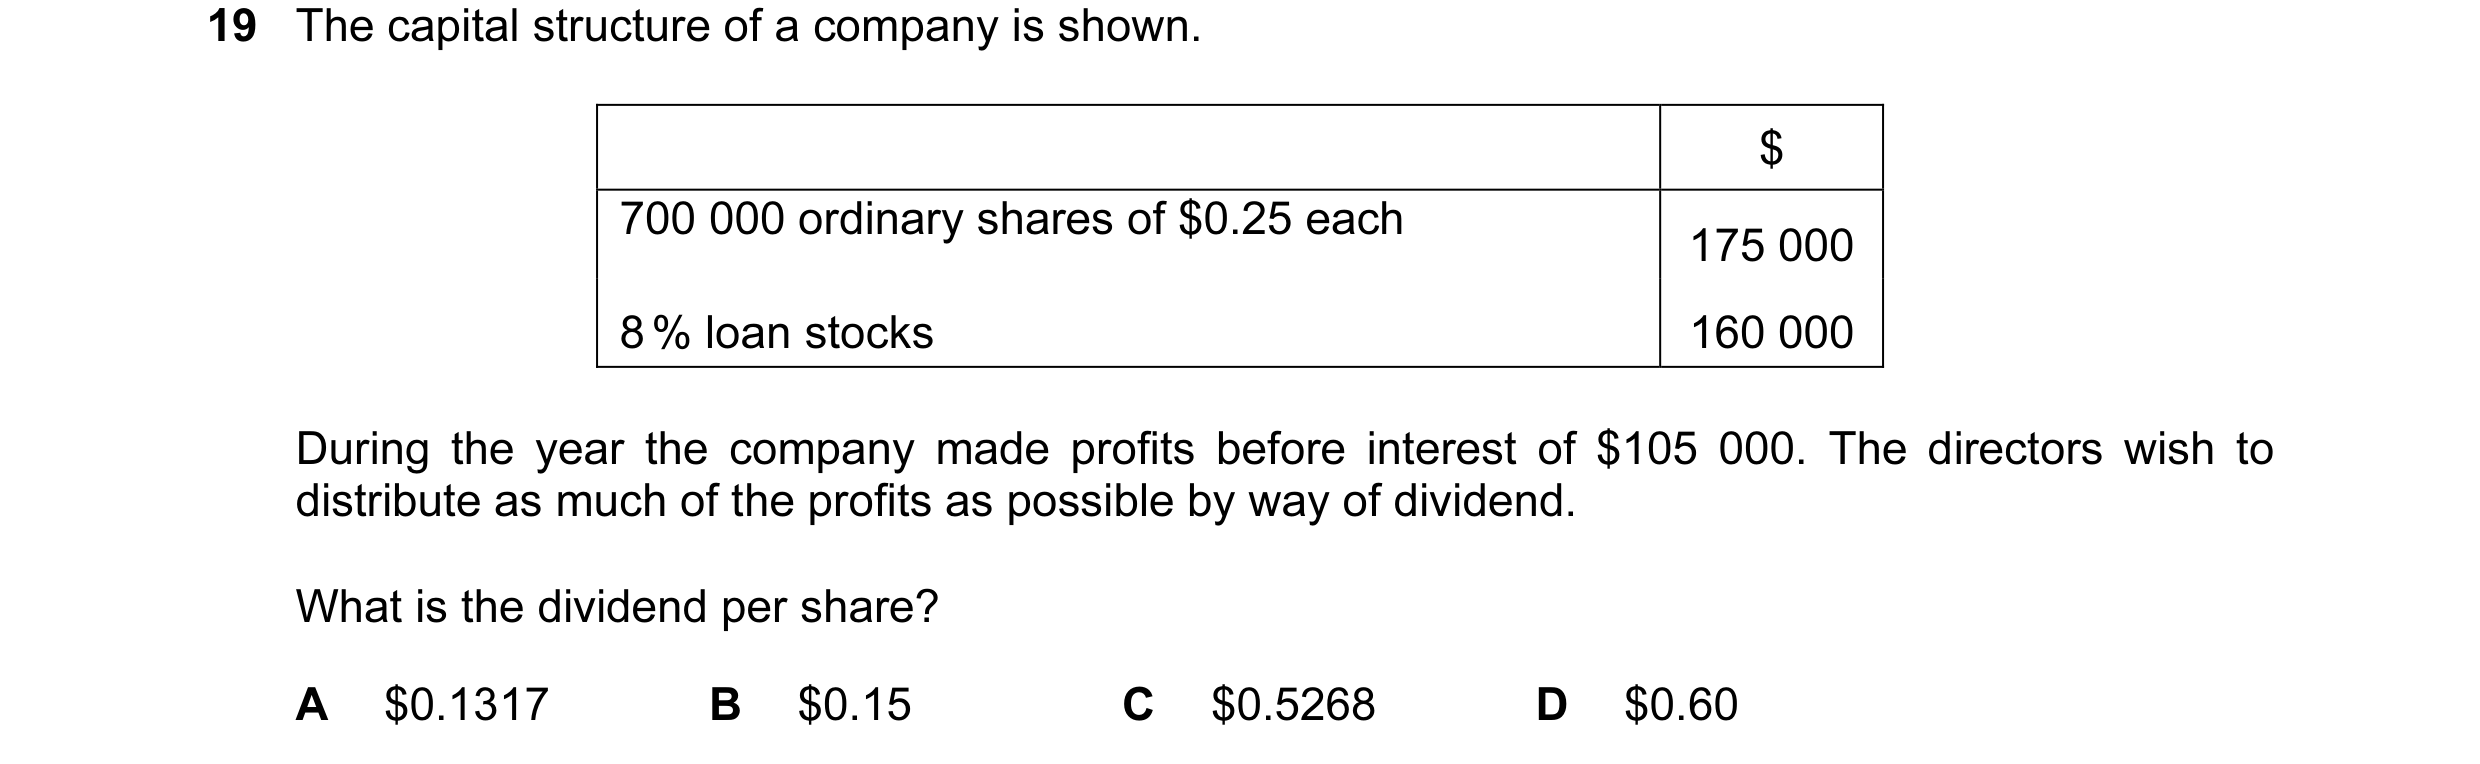 10 / 233
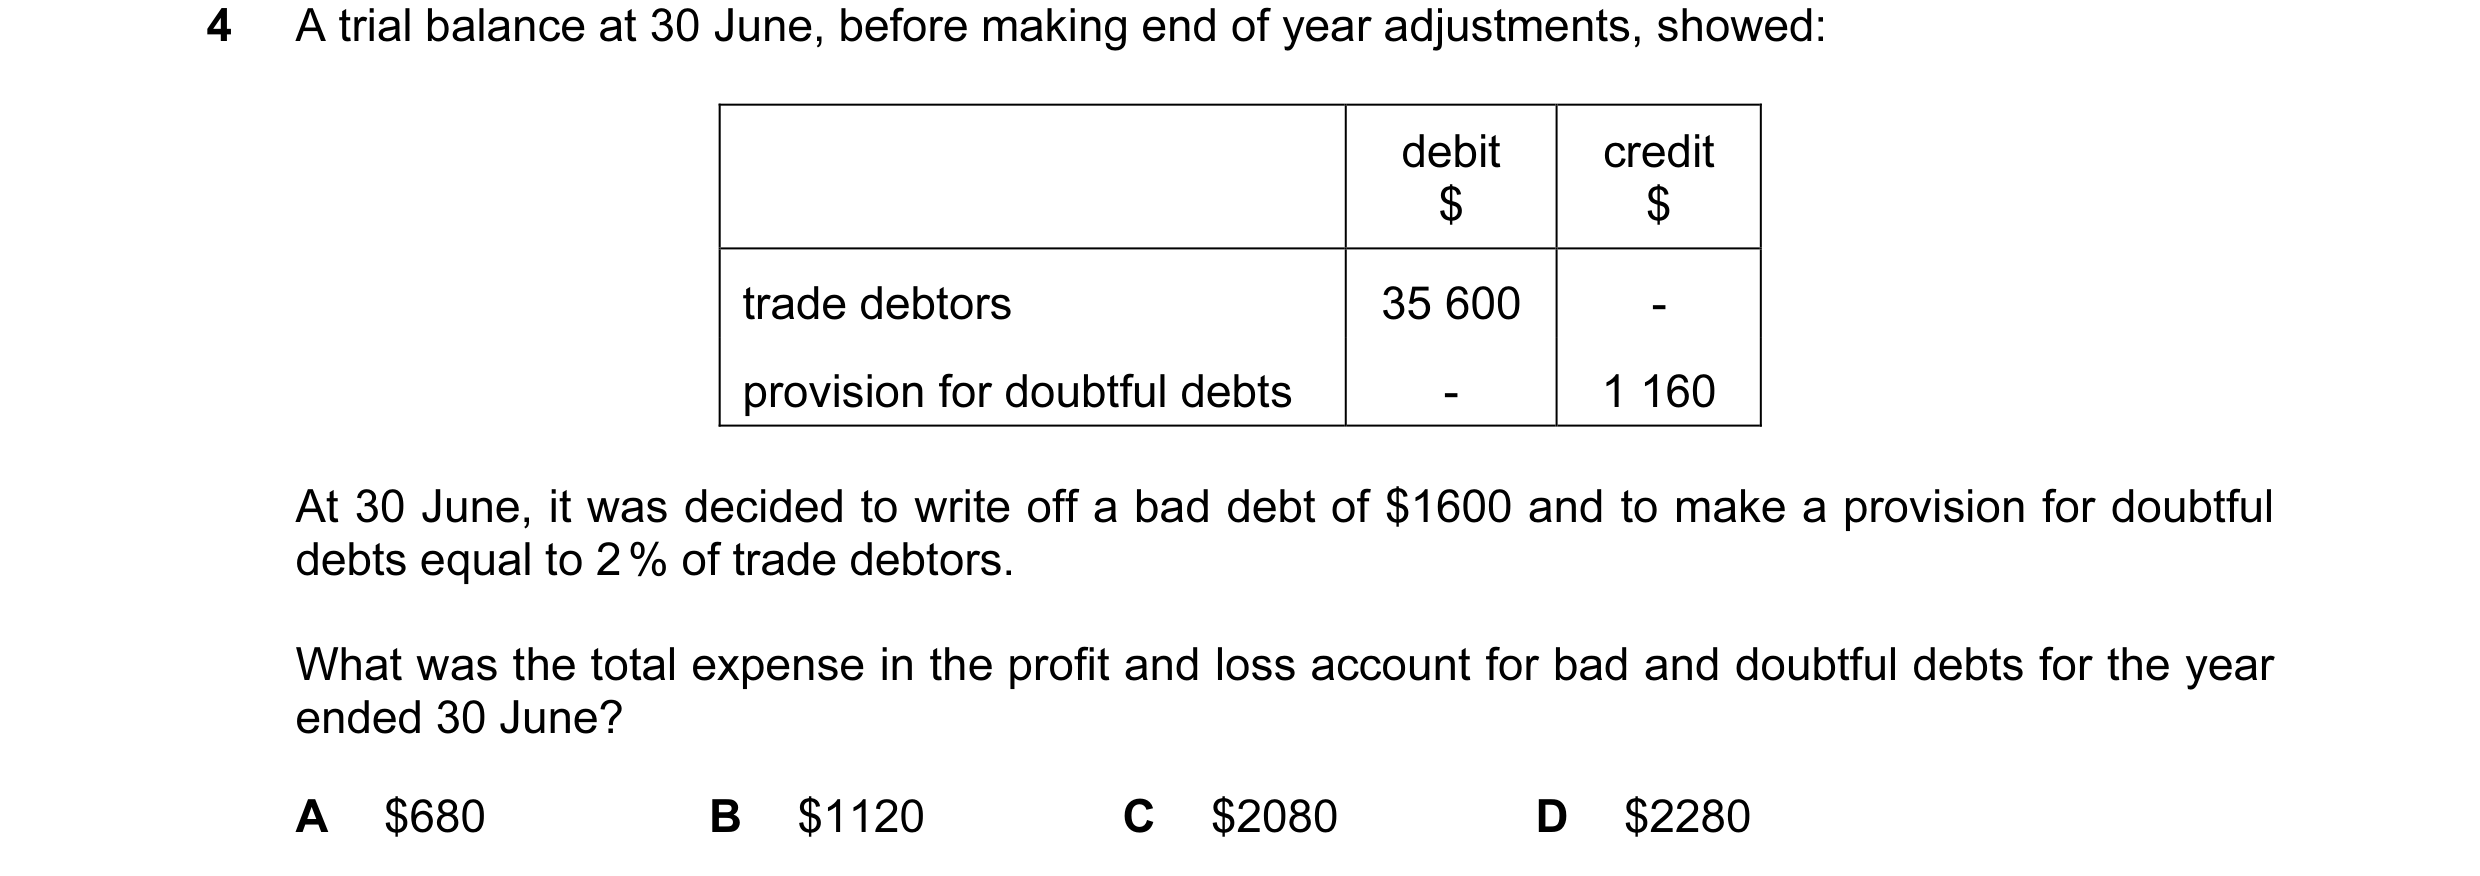
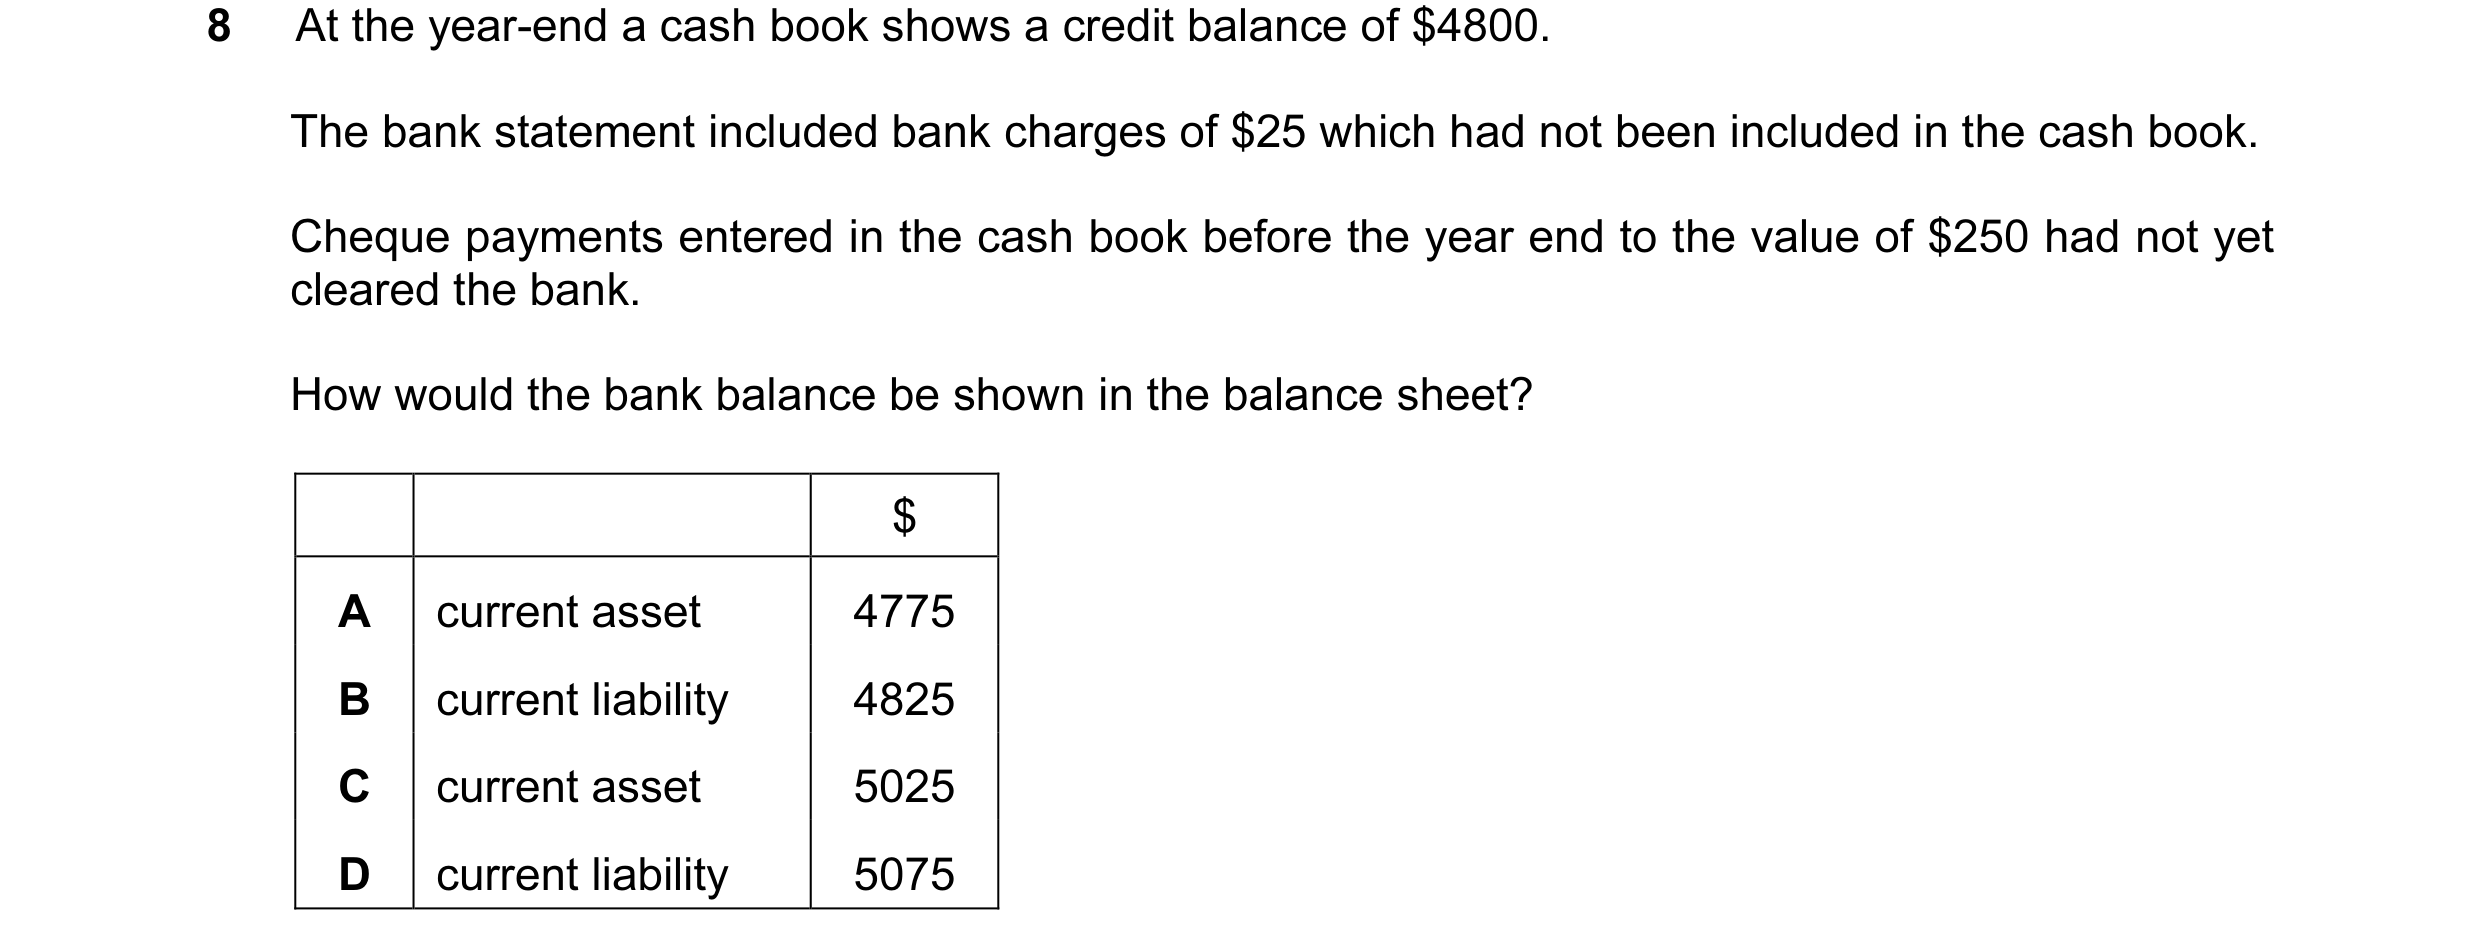 11 / 233
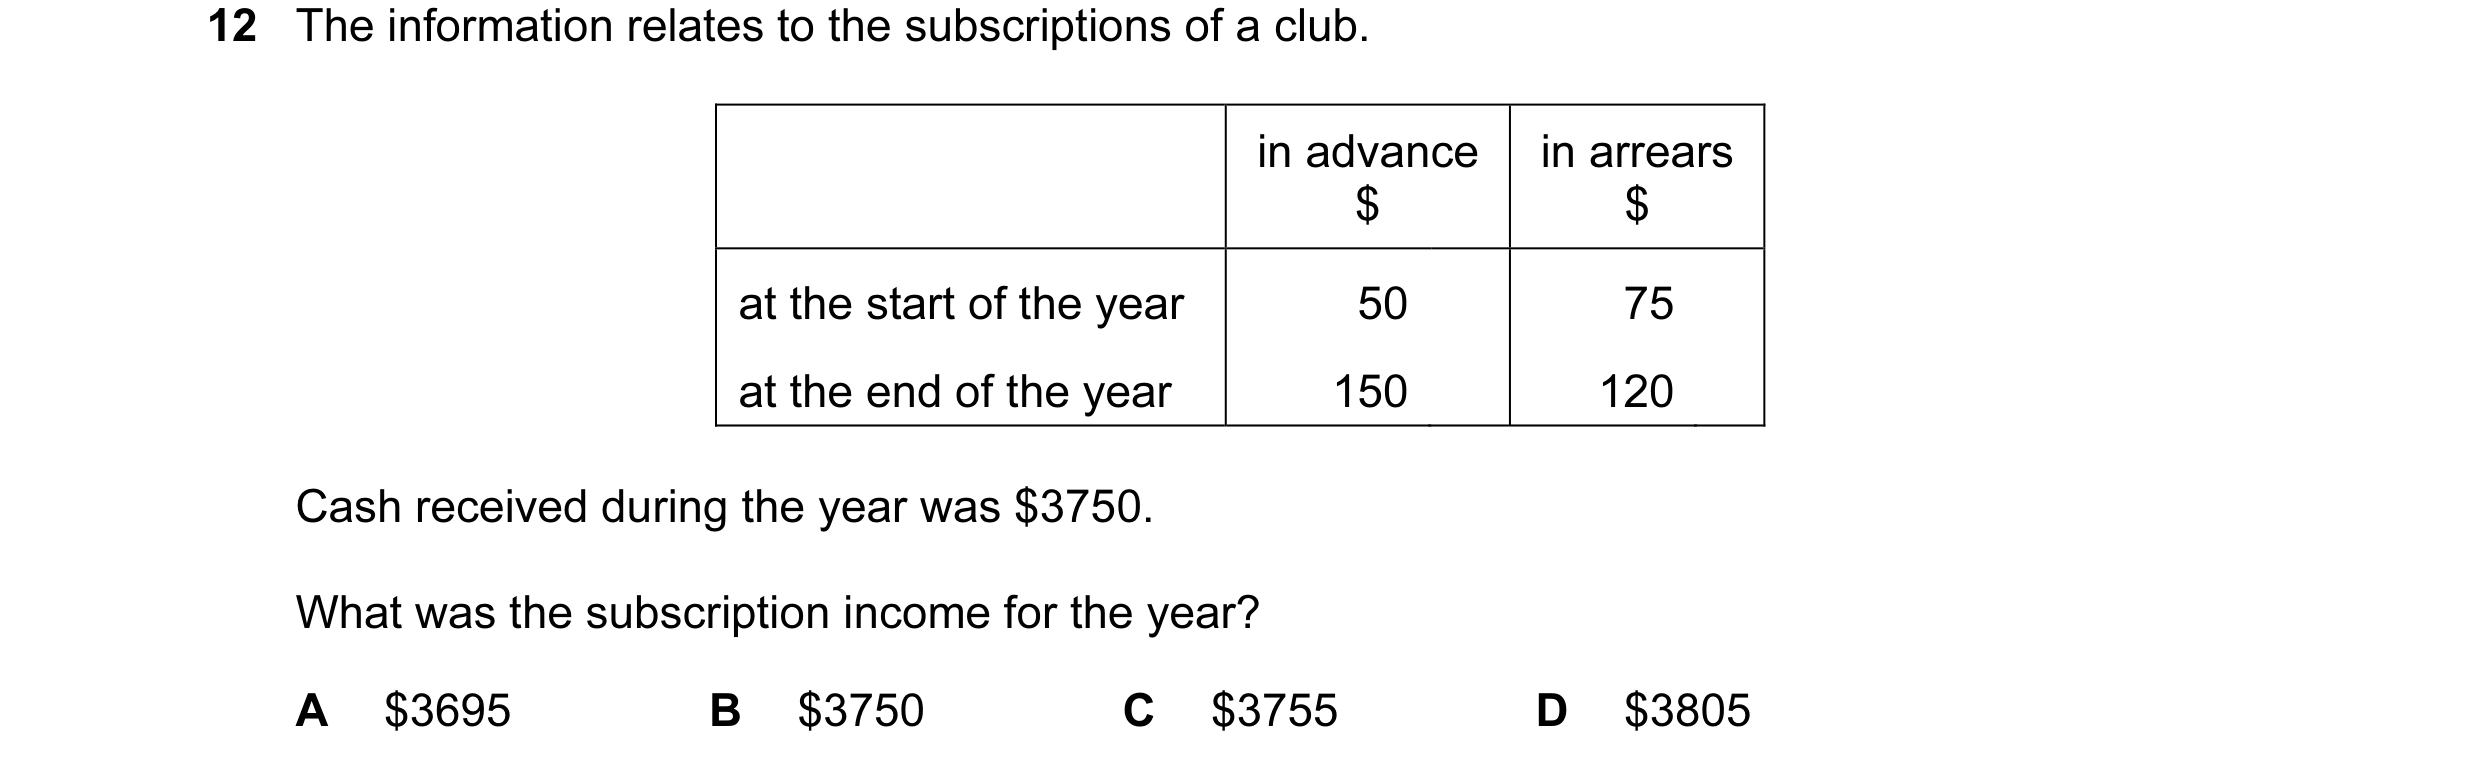
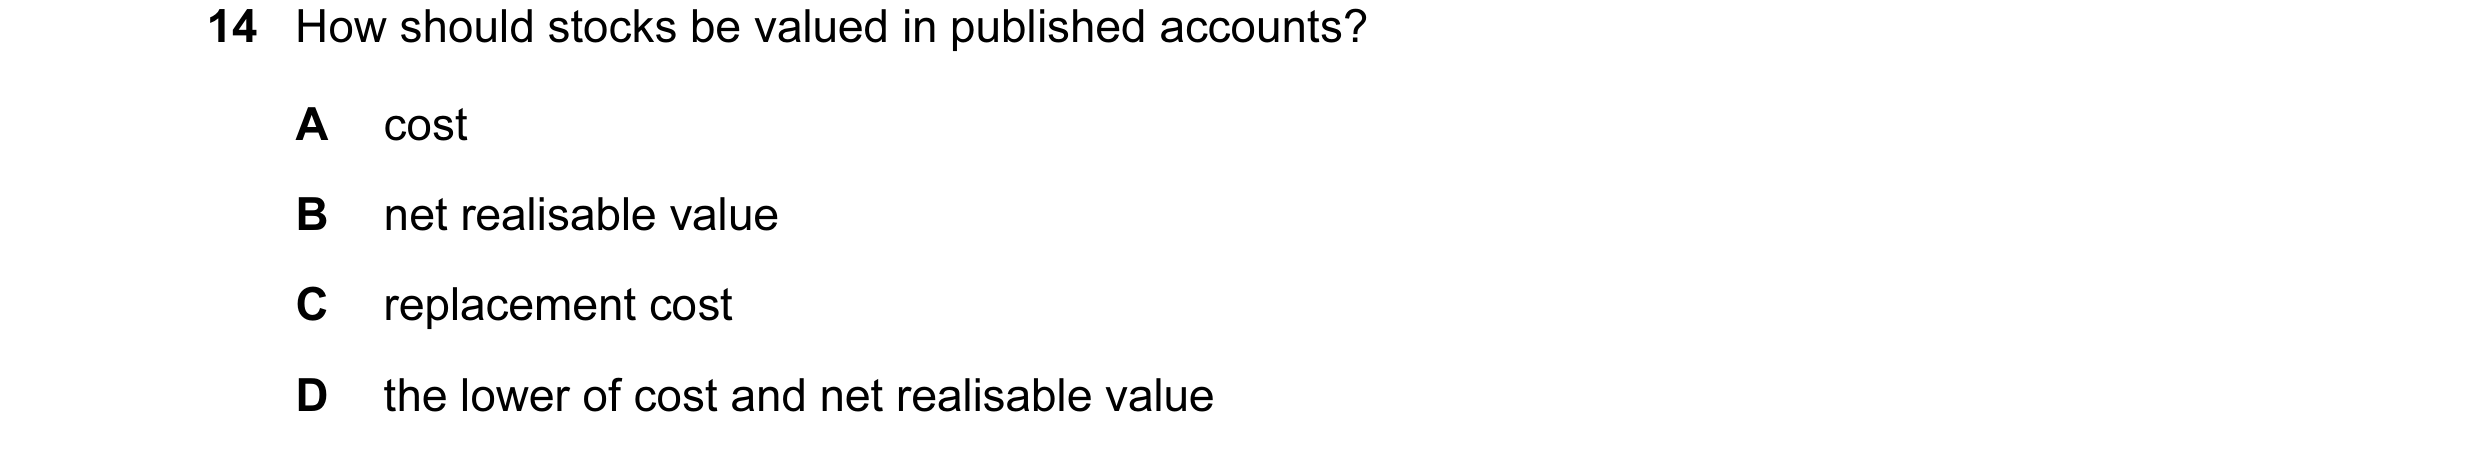
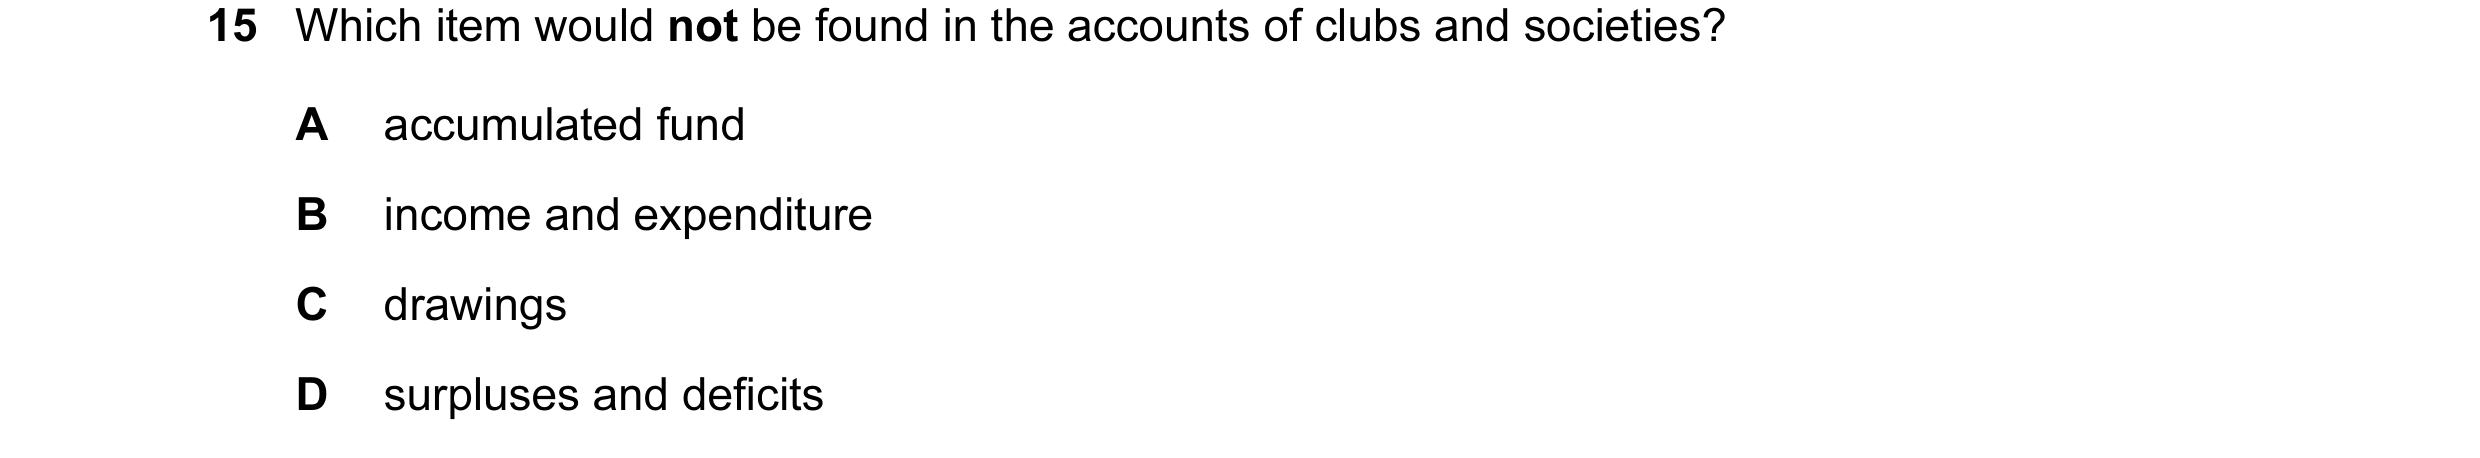
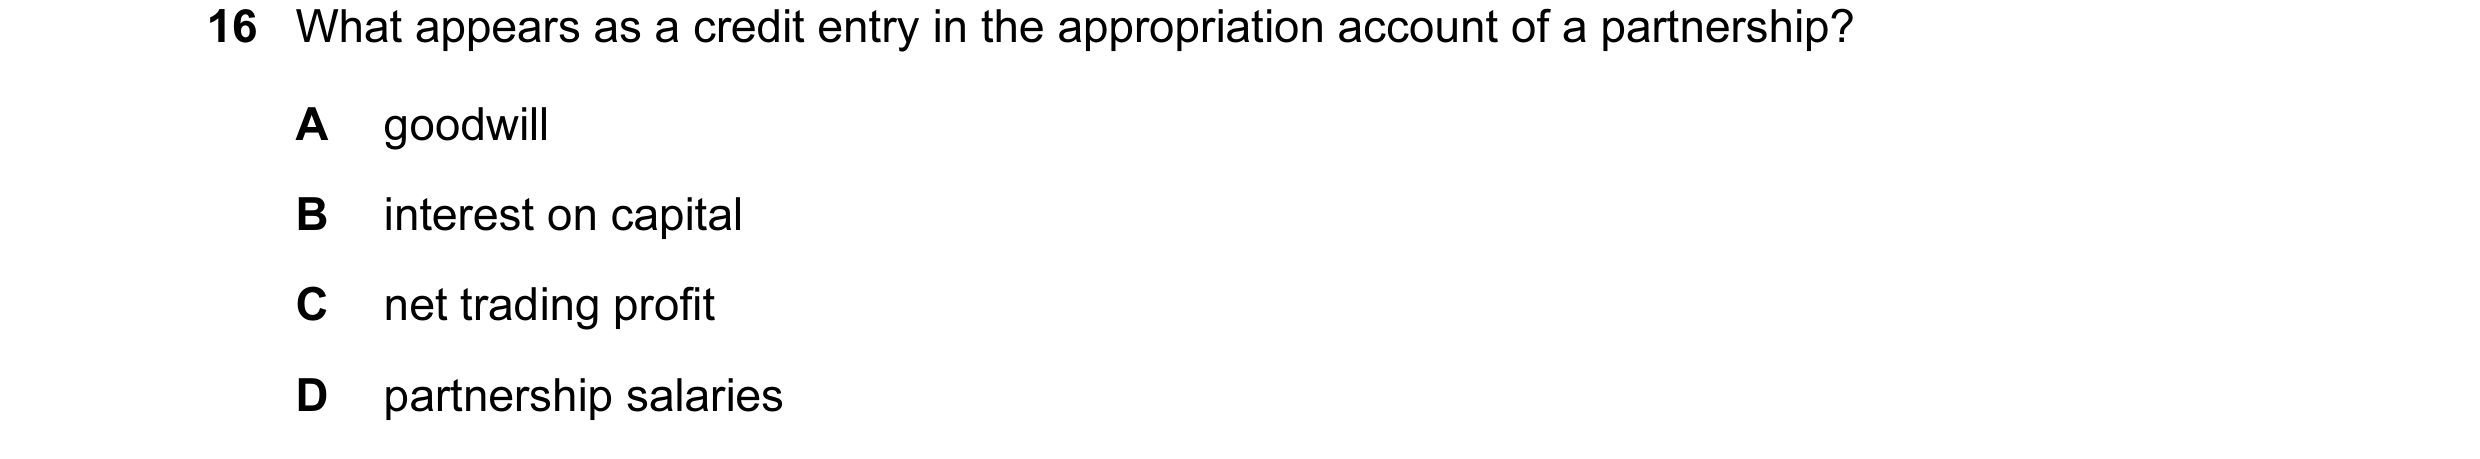
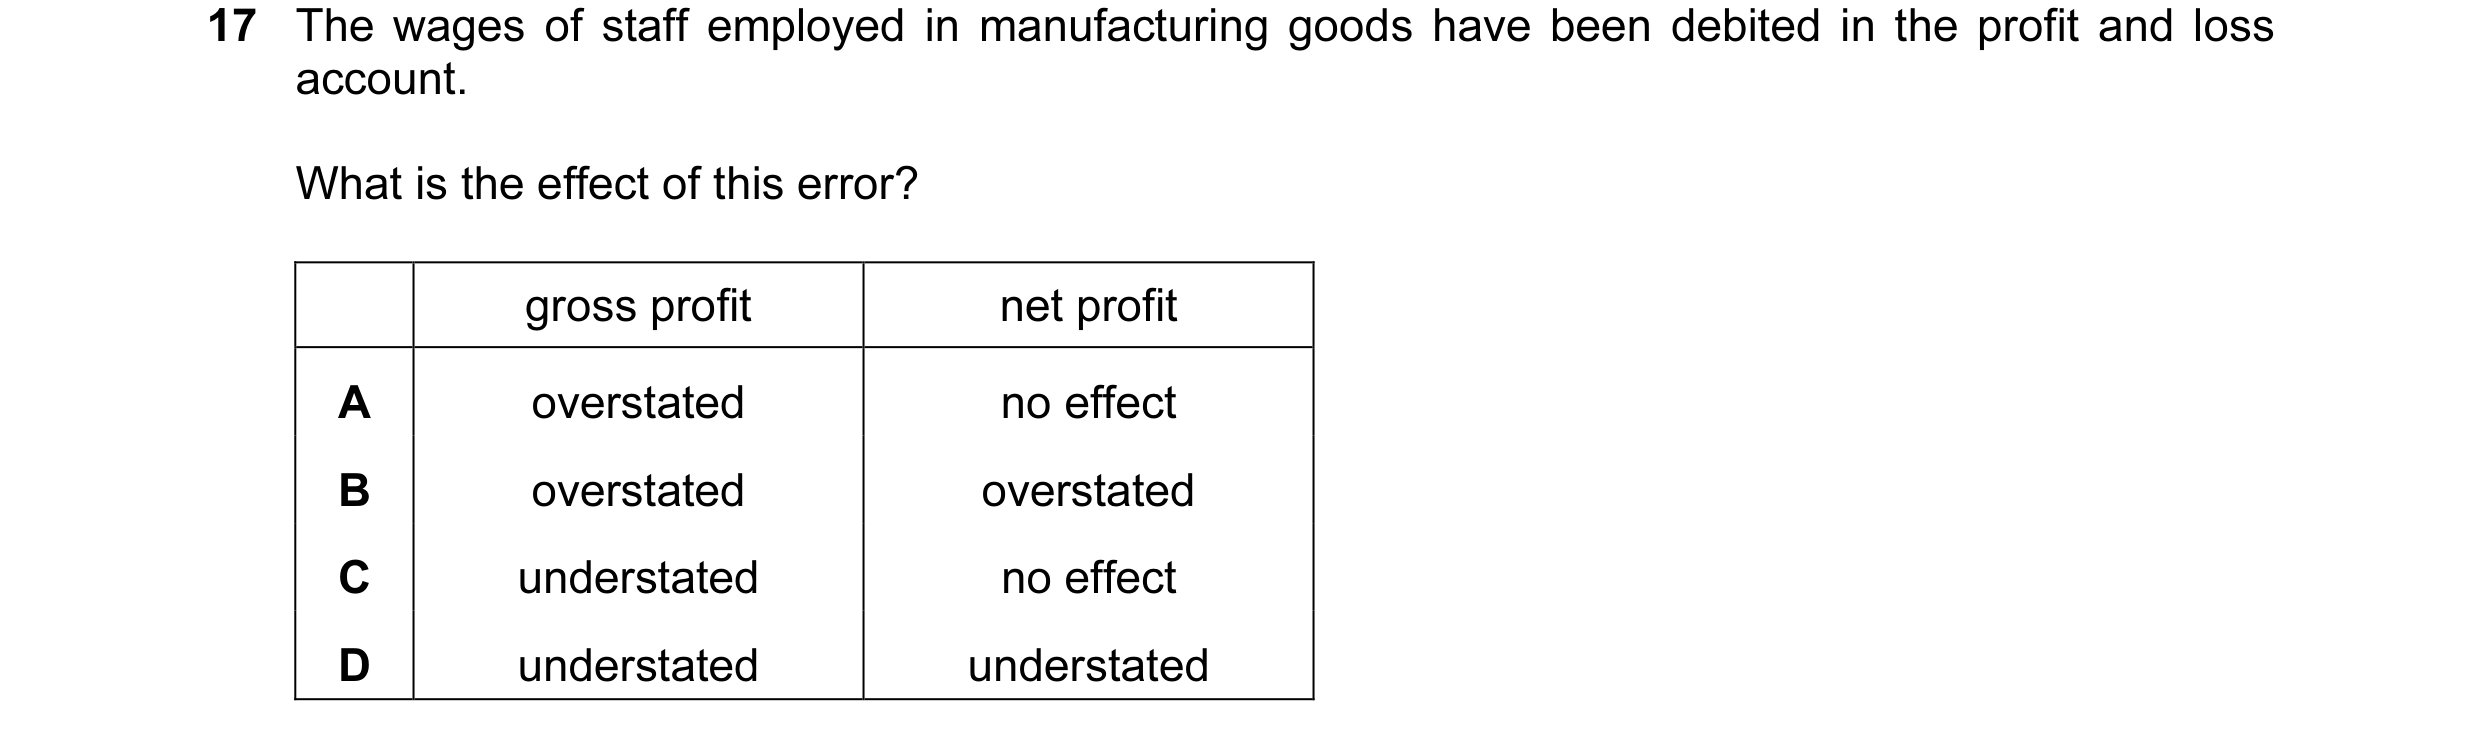 12 / 233
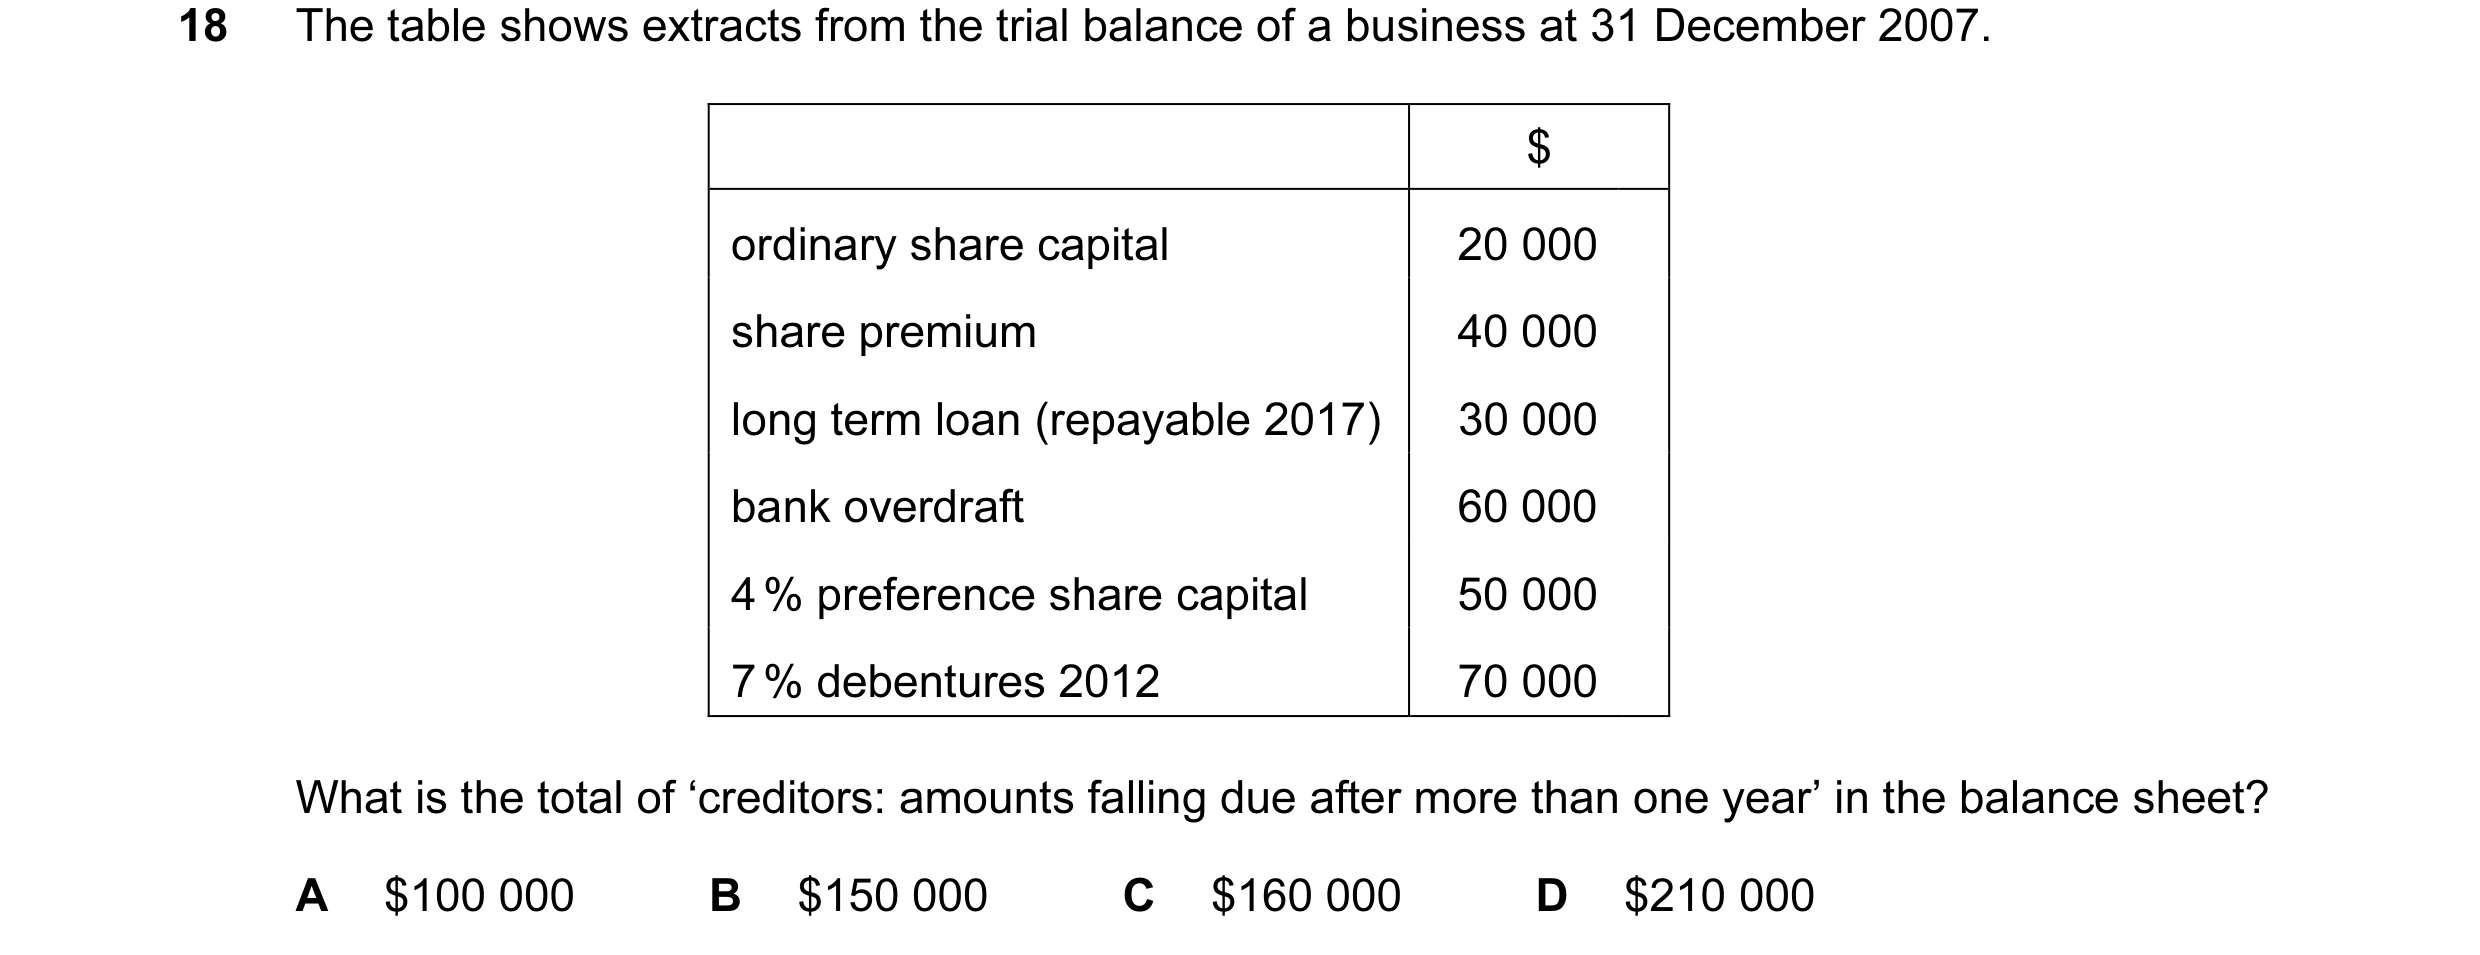
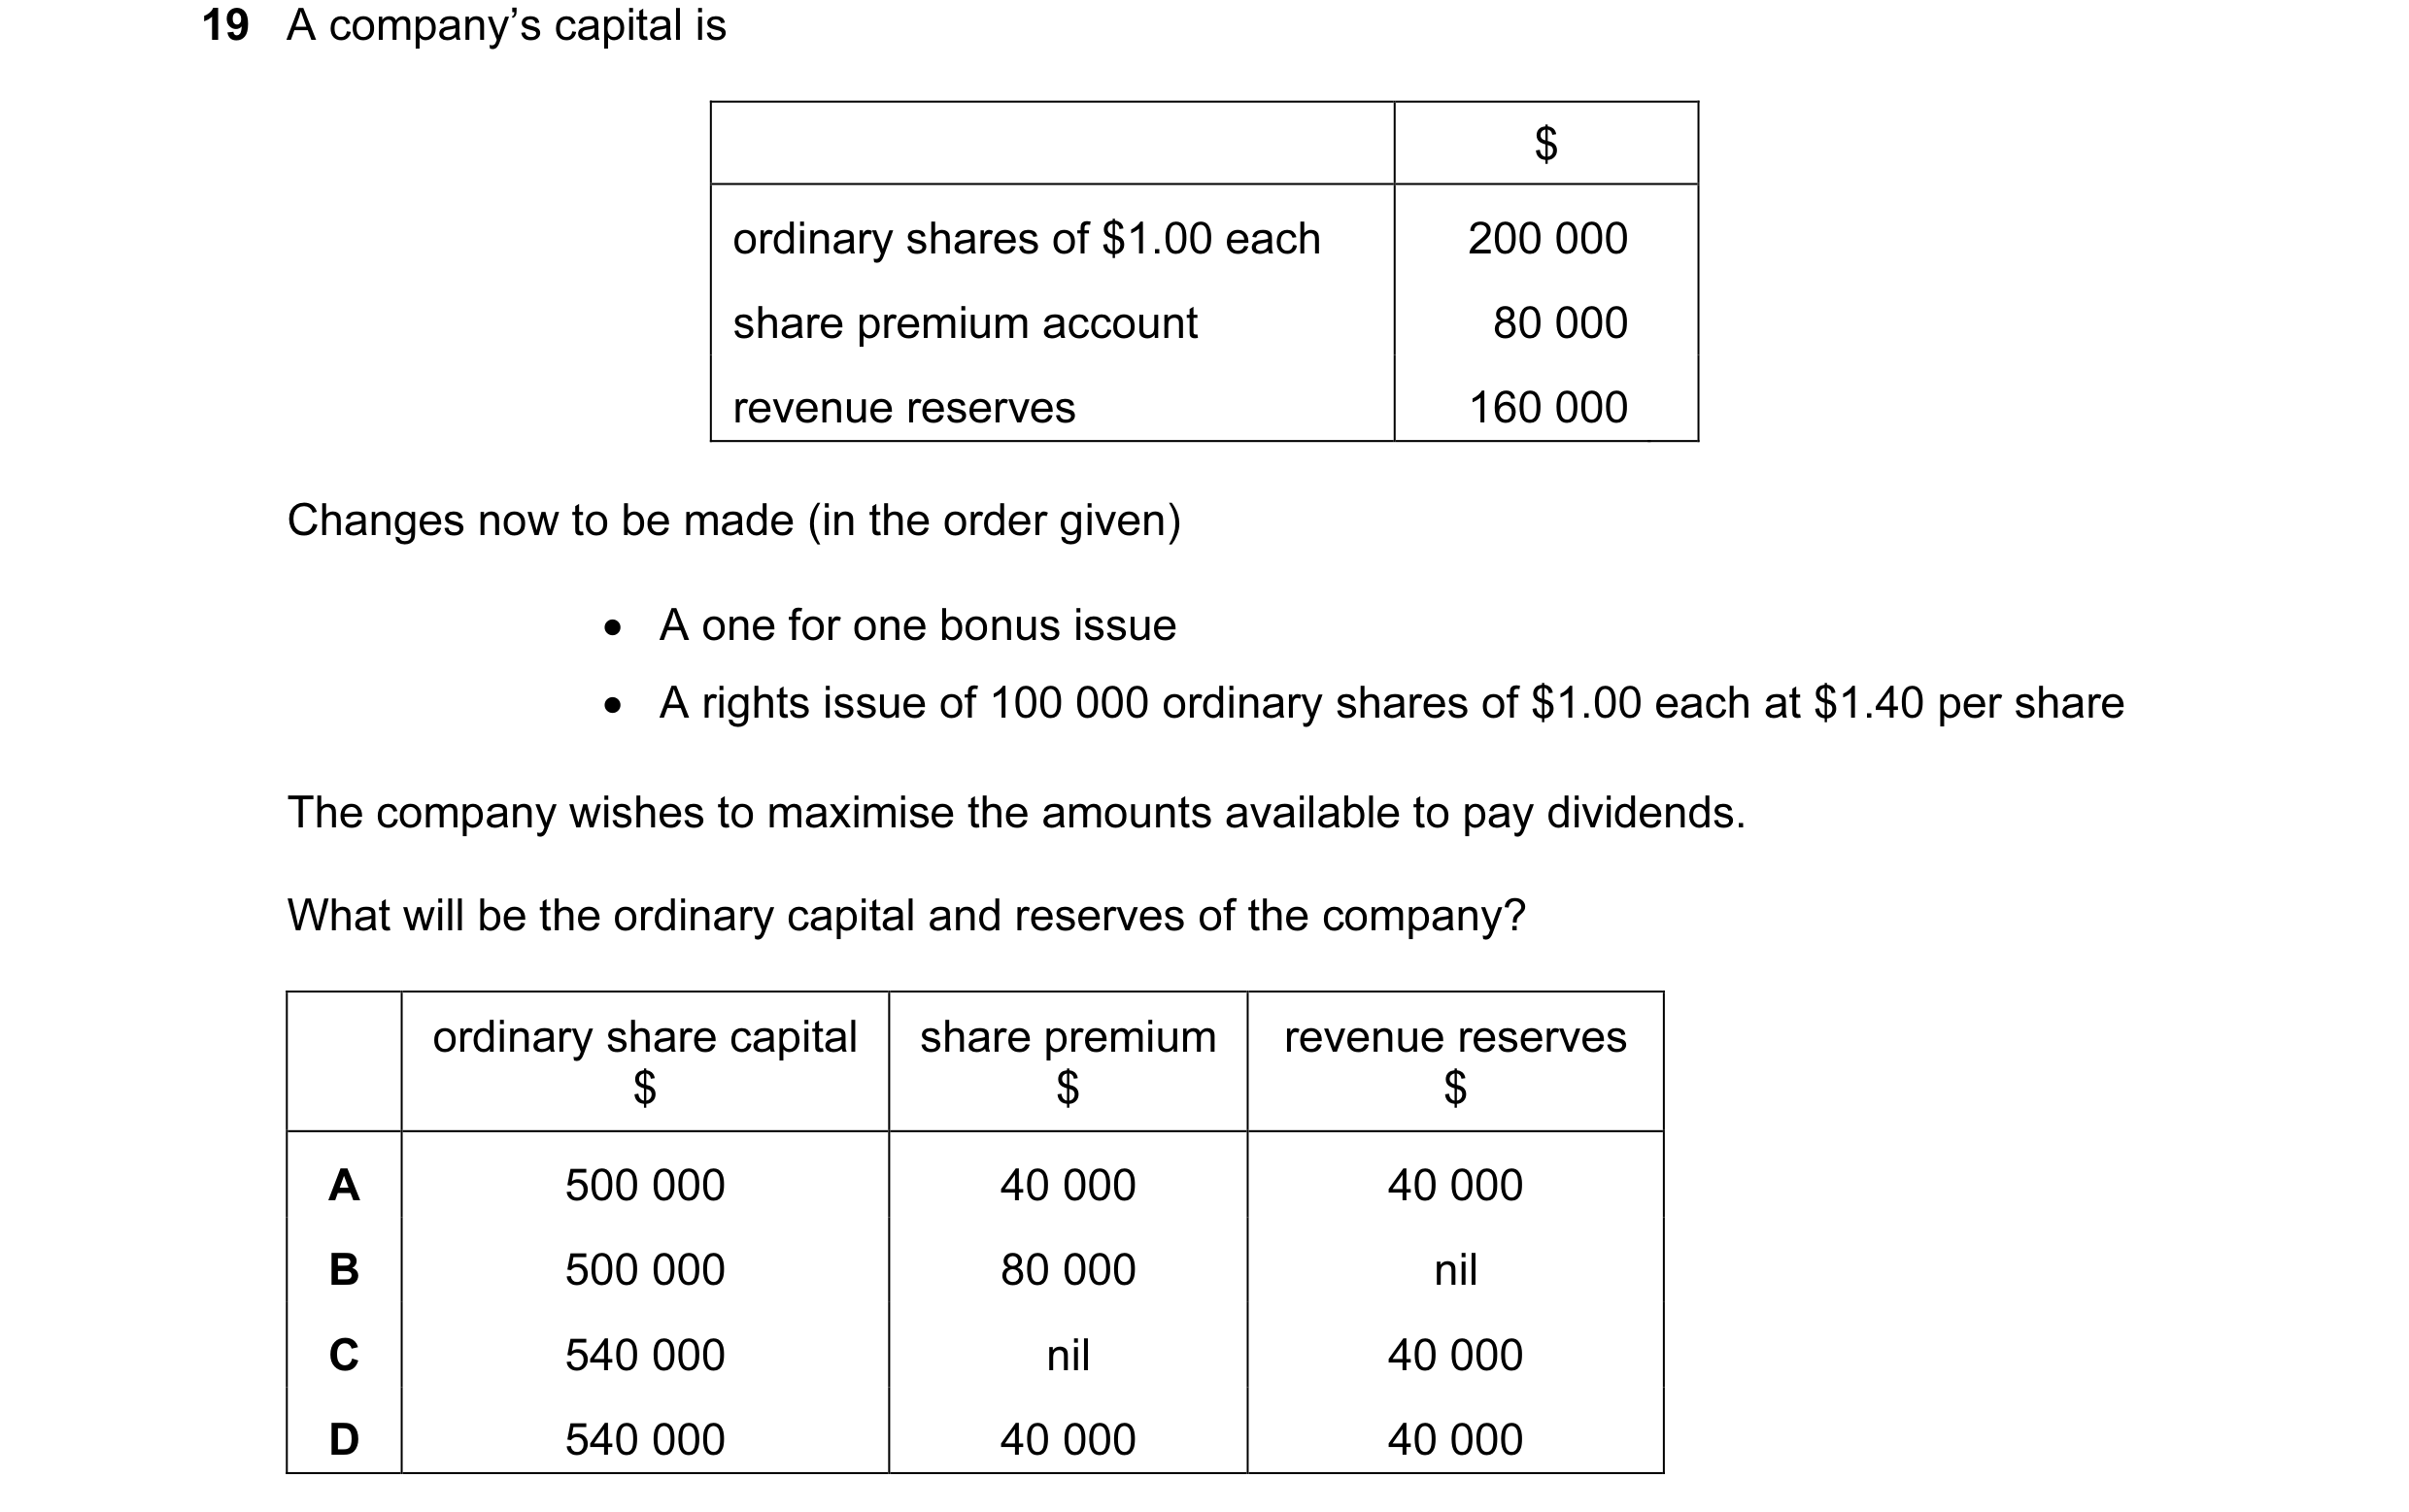
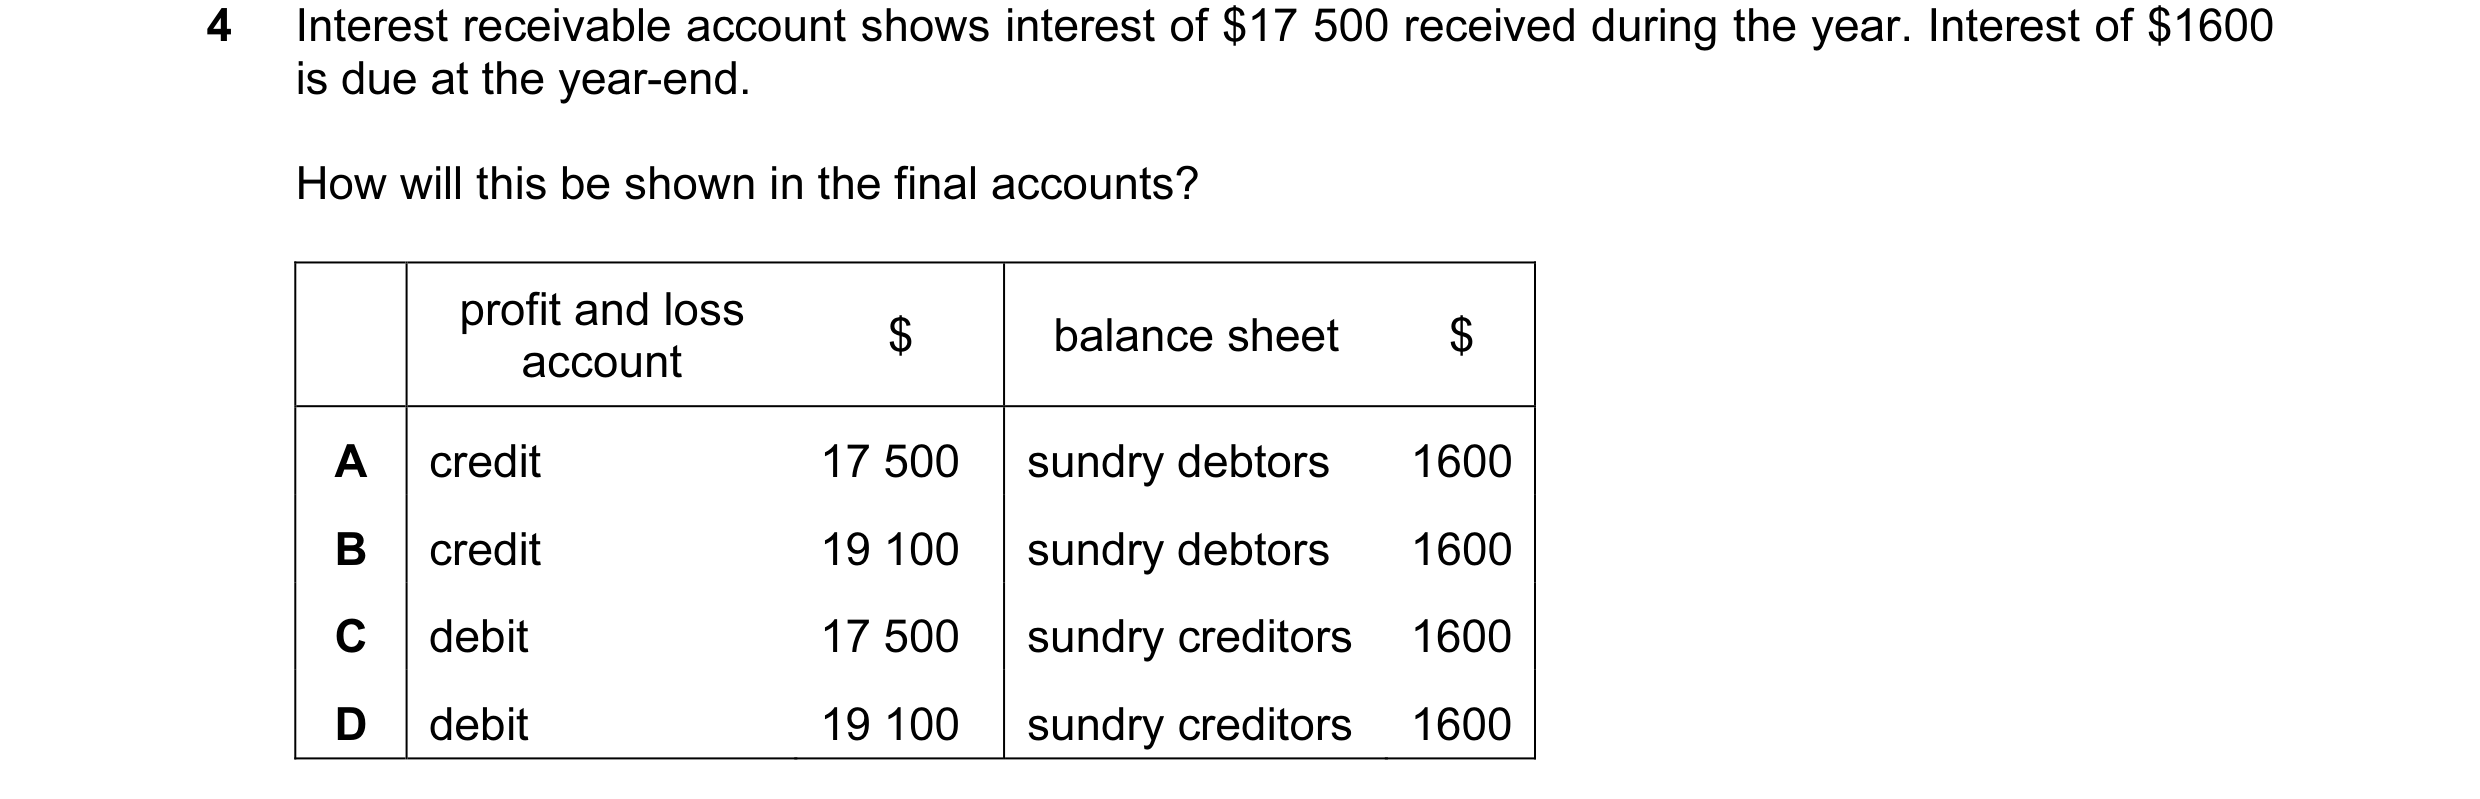 13 / 233
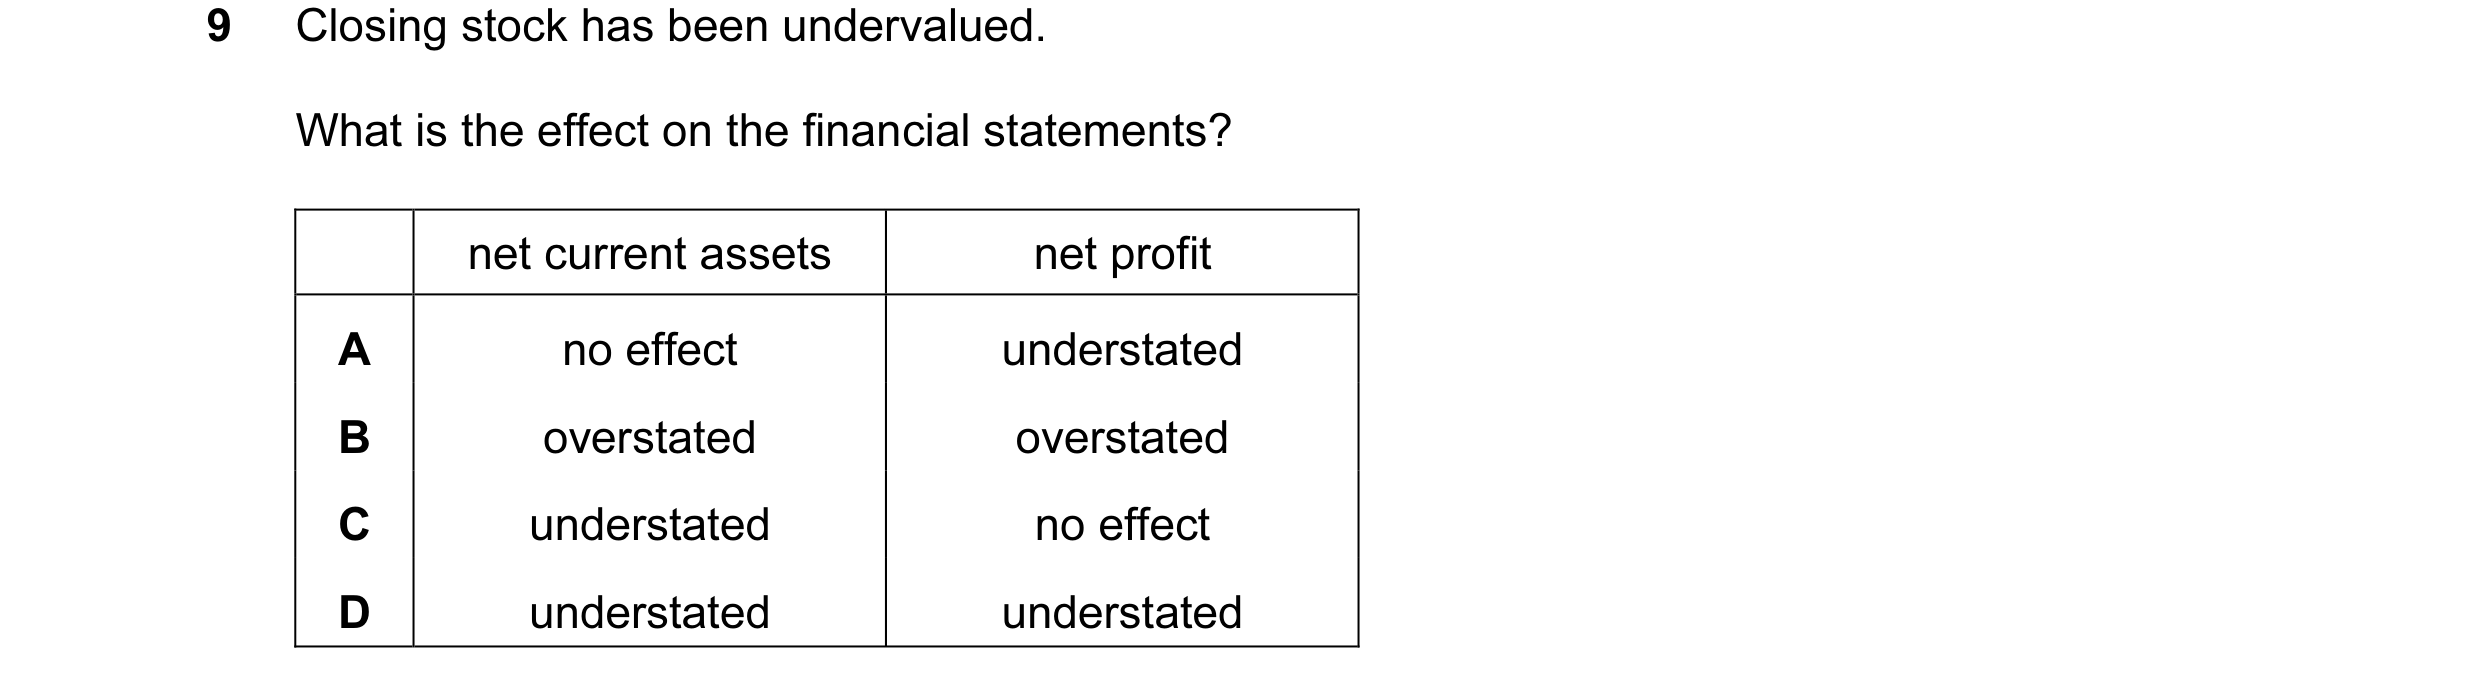
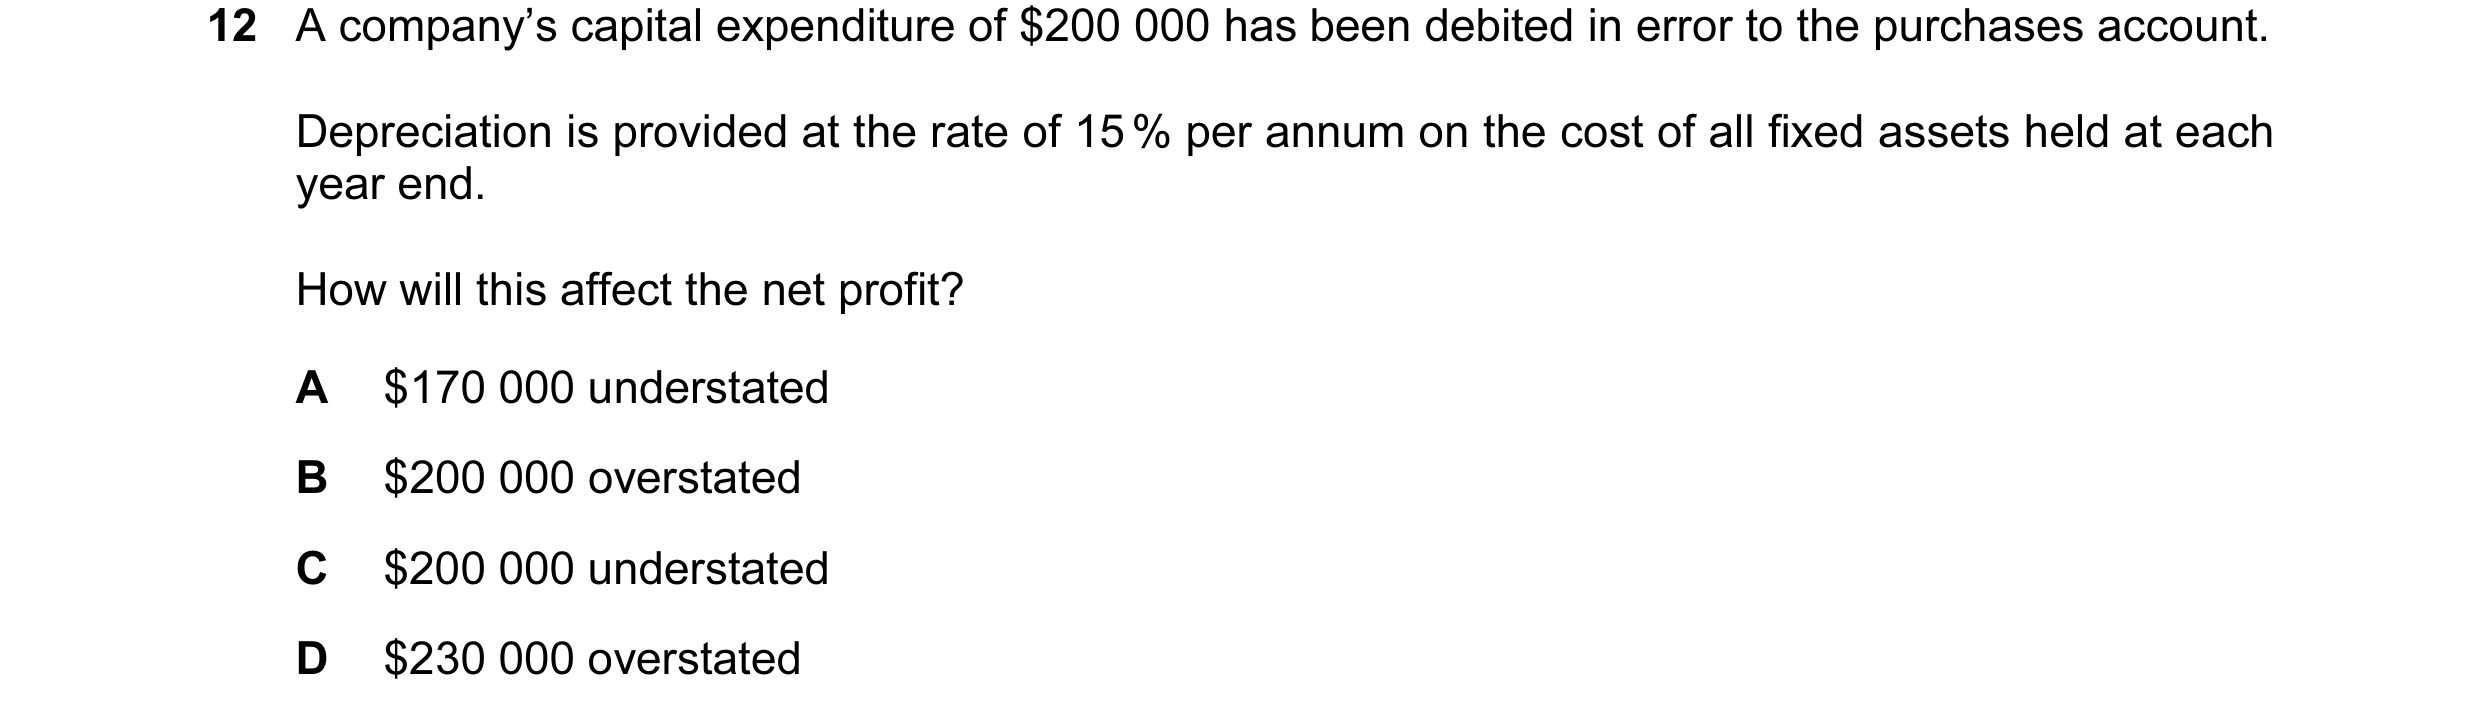
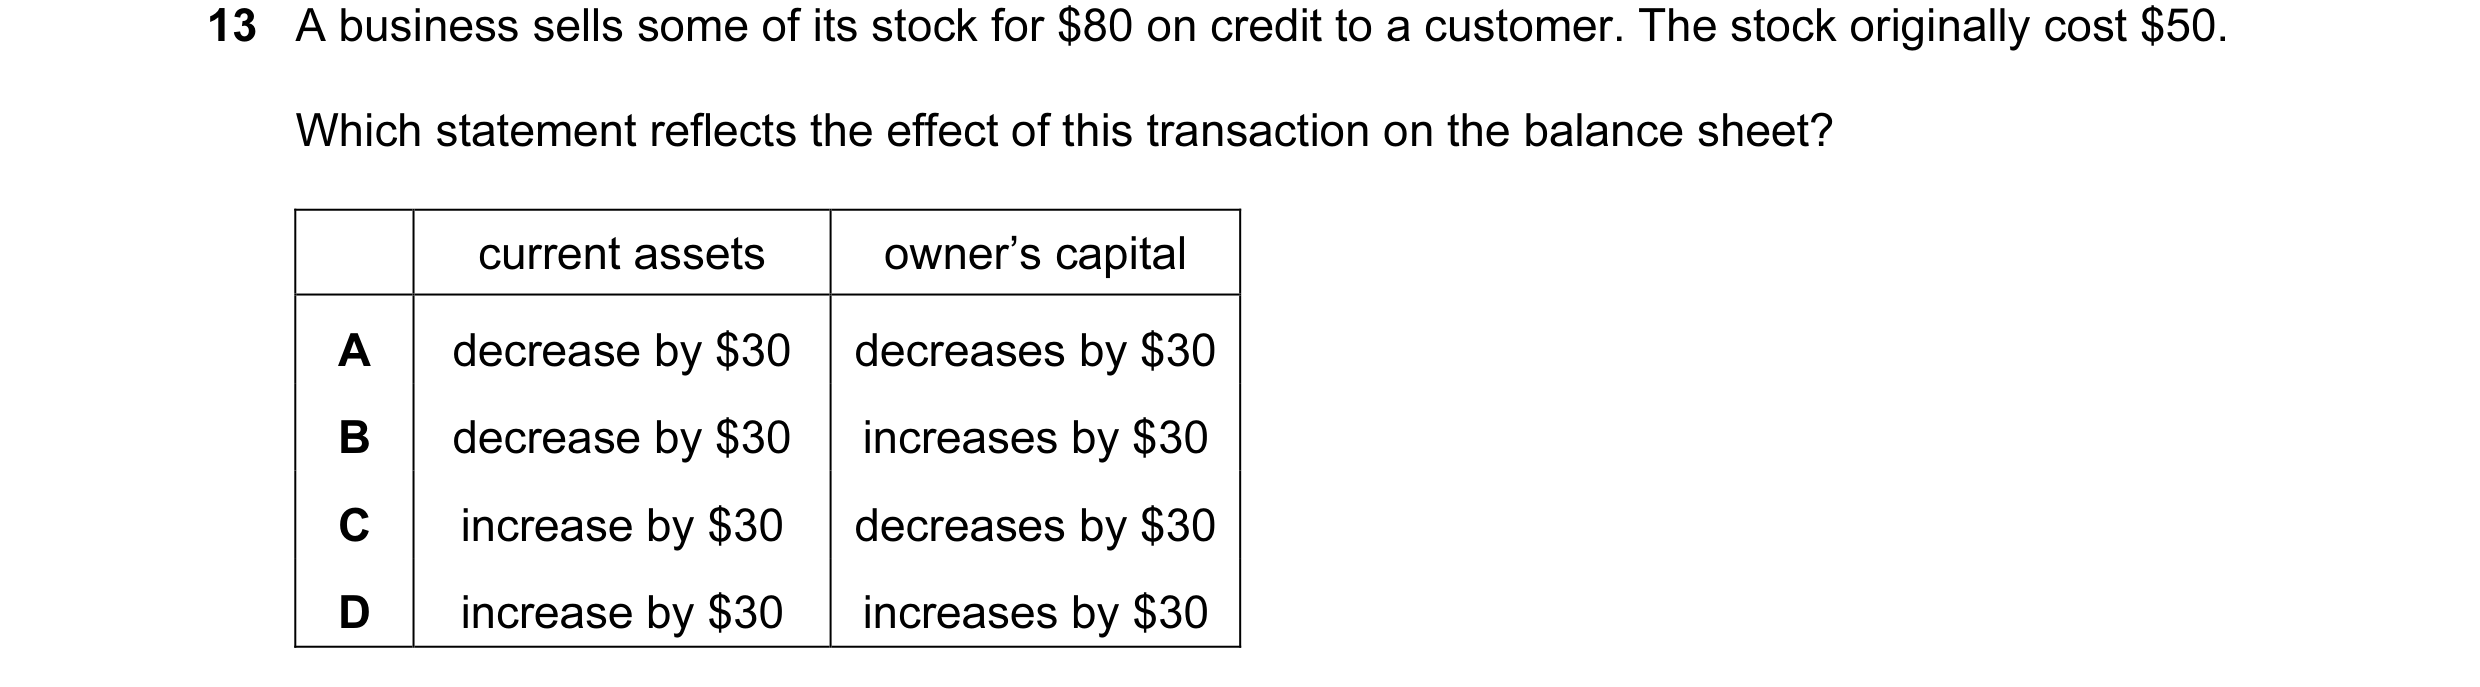
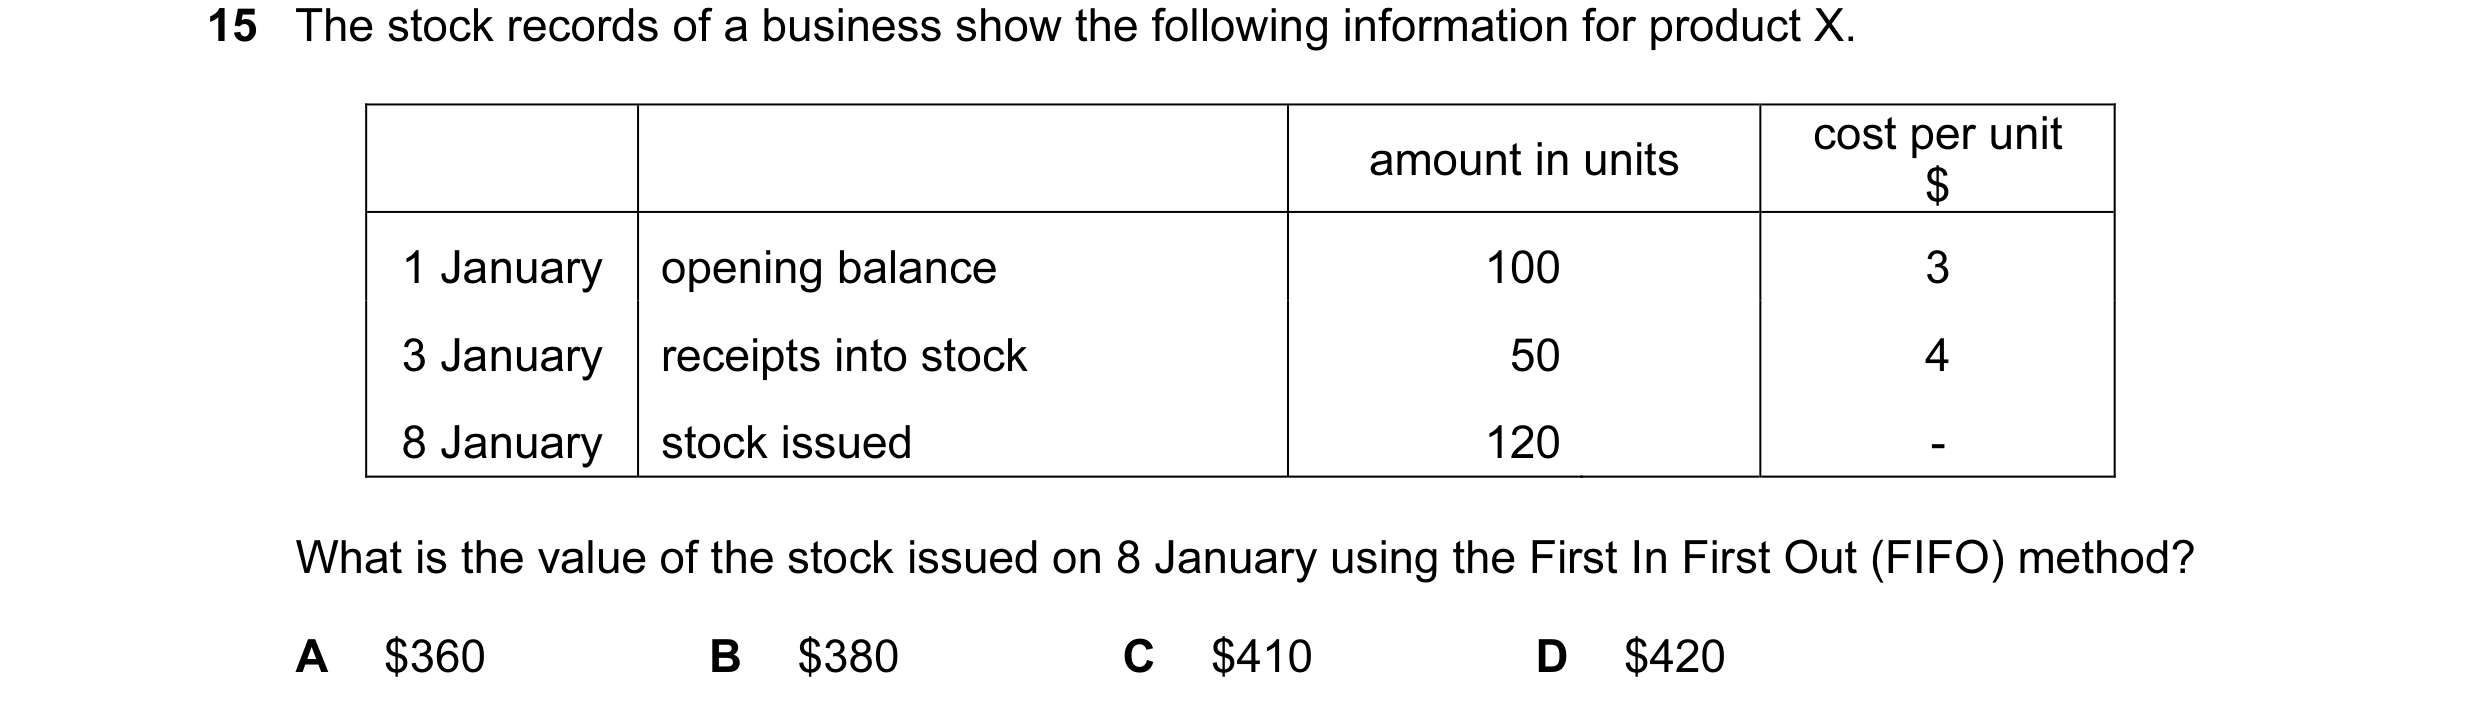 14 / 233
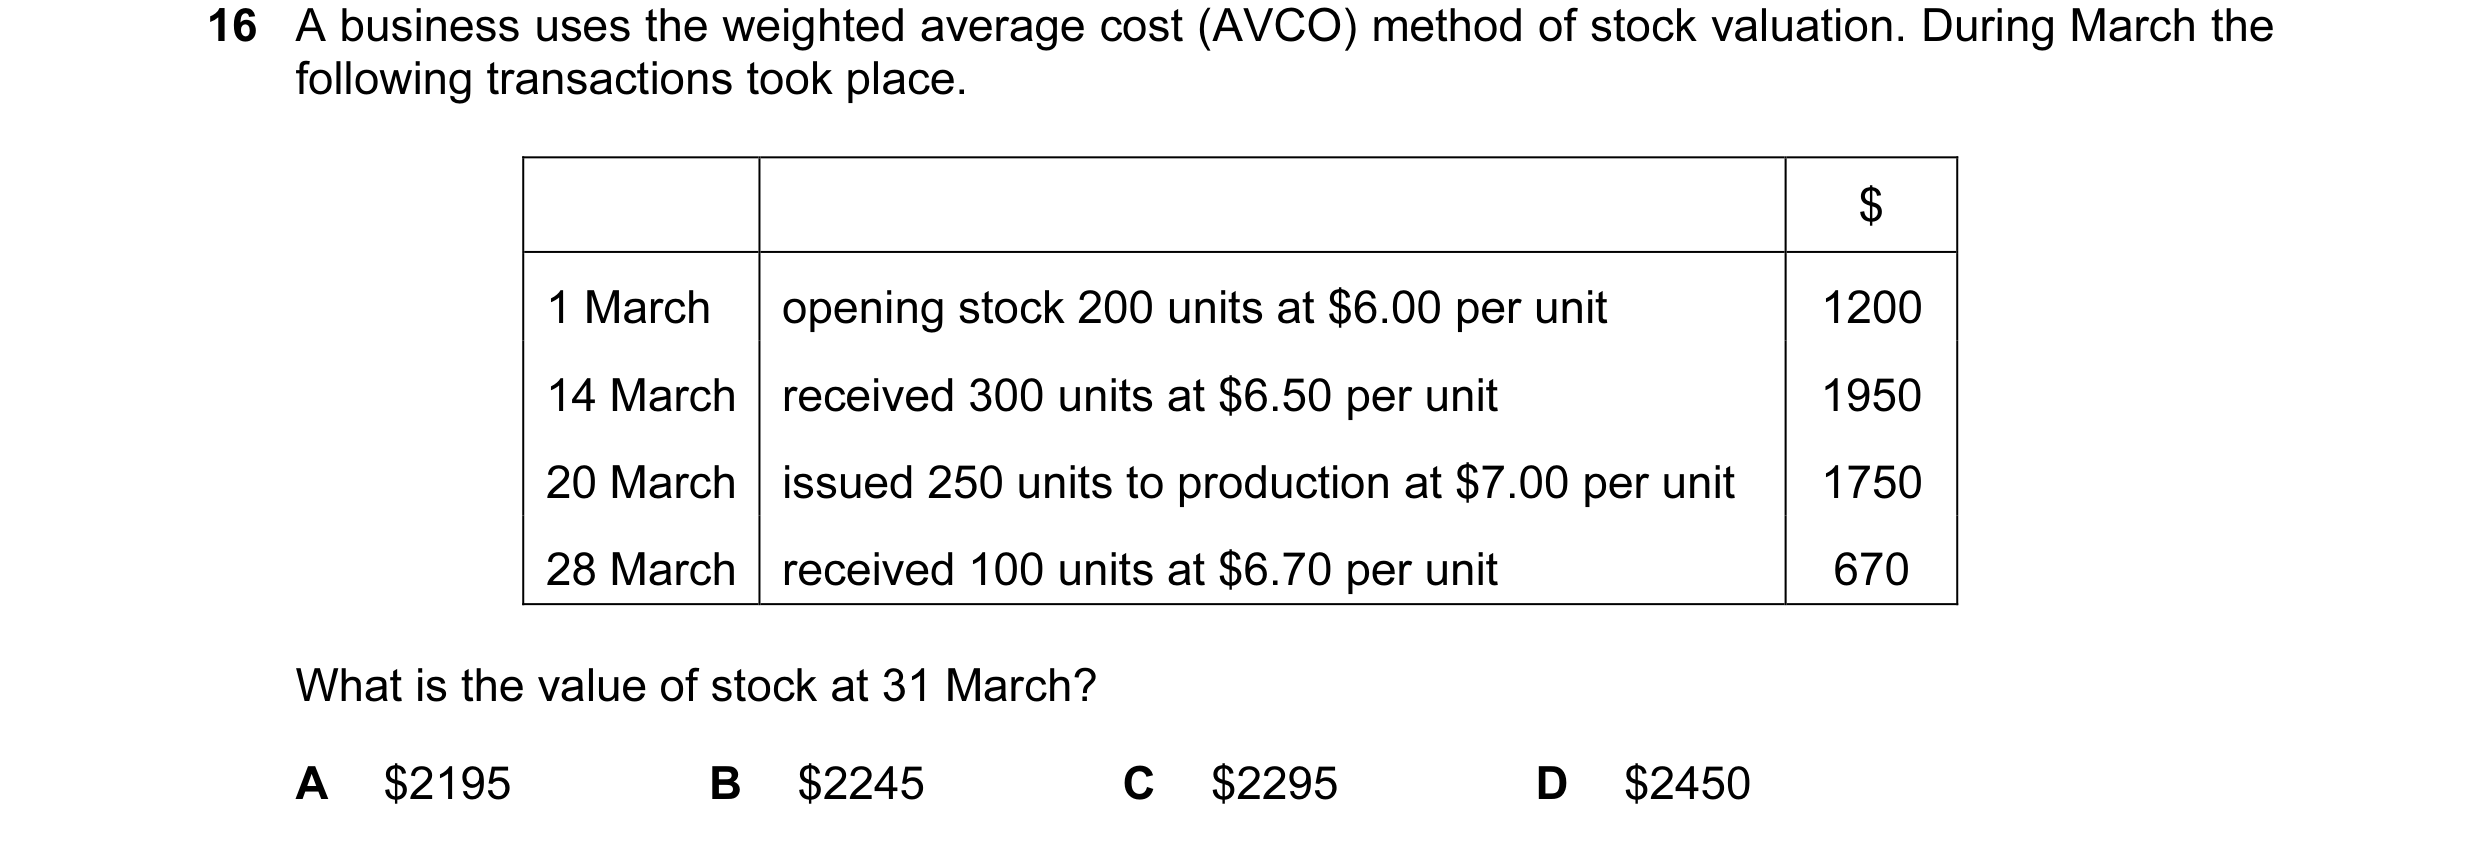
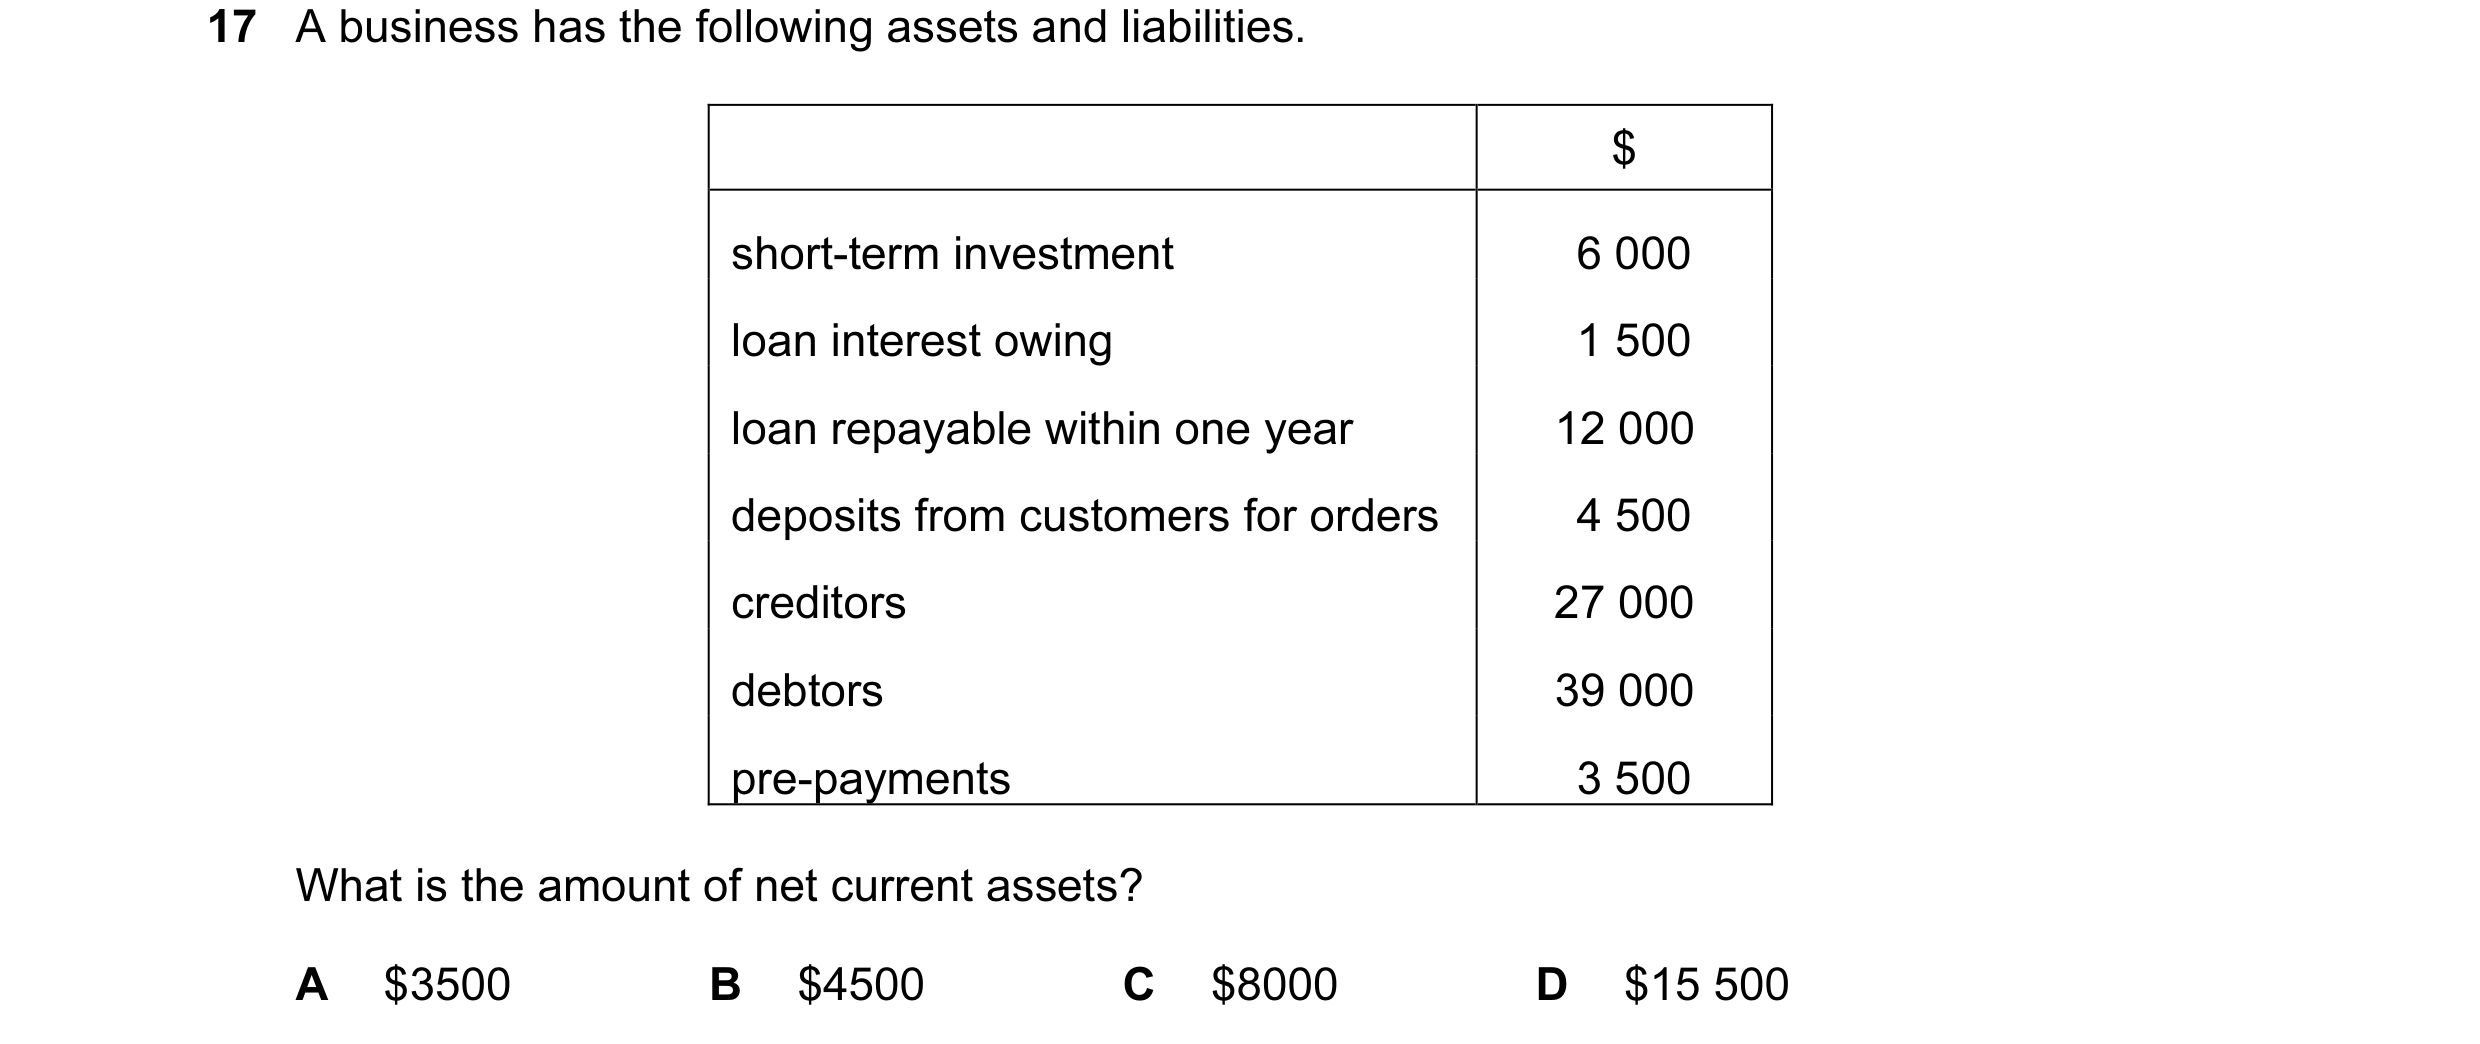
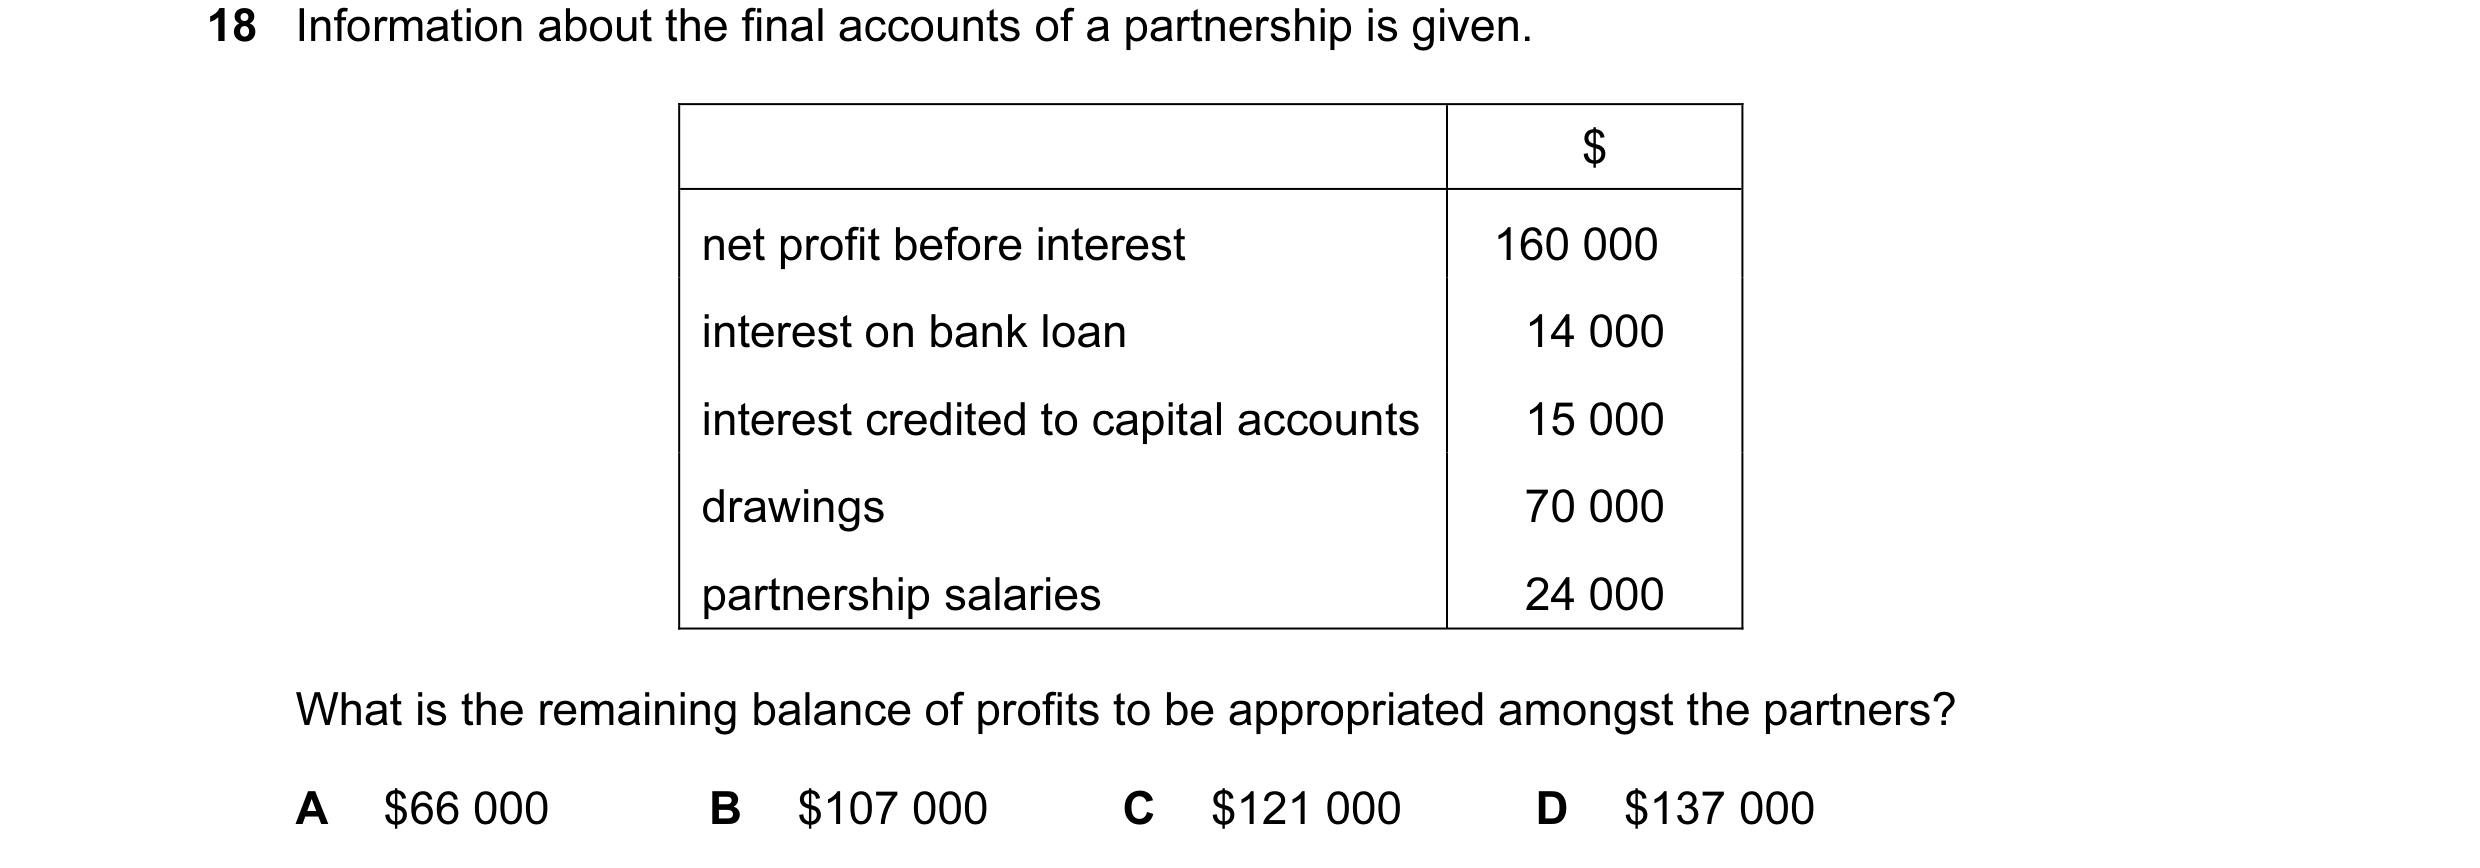 15 / 233
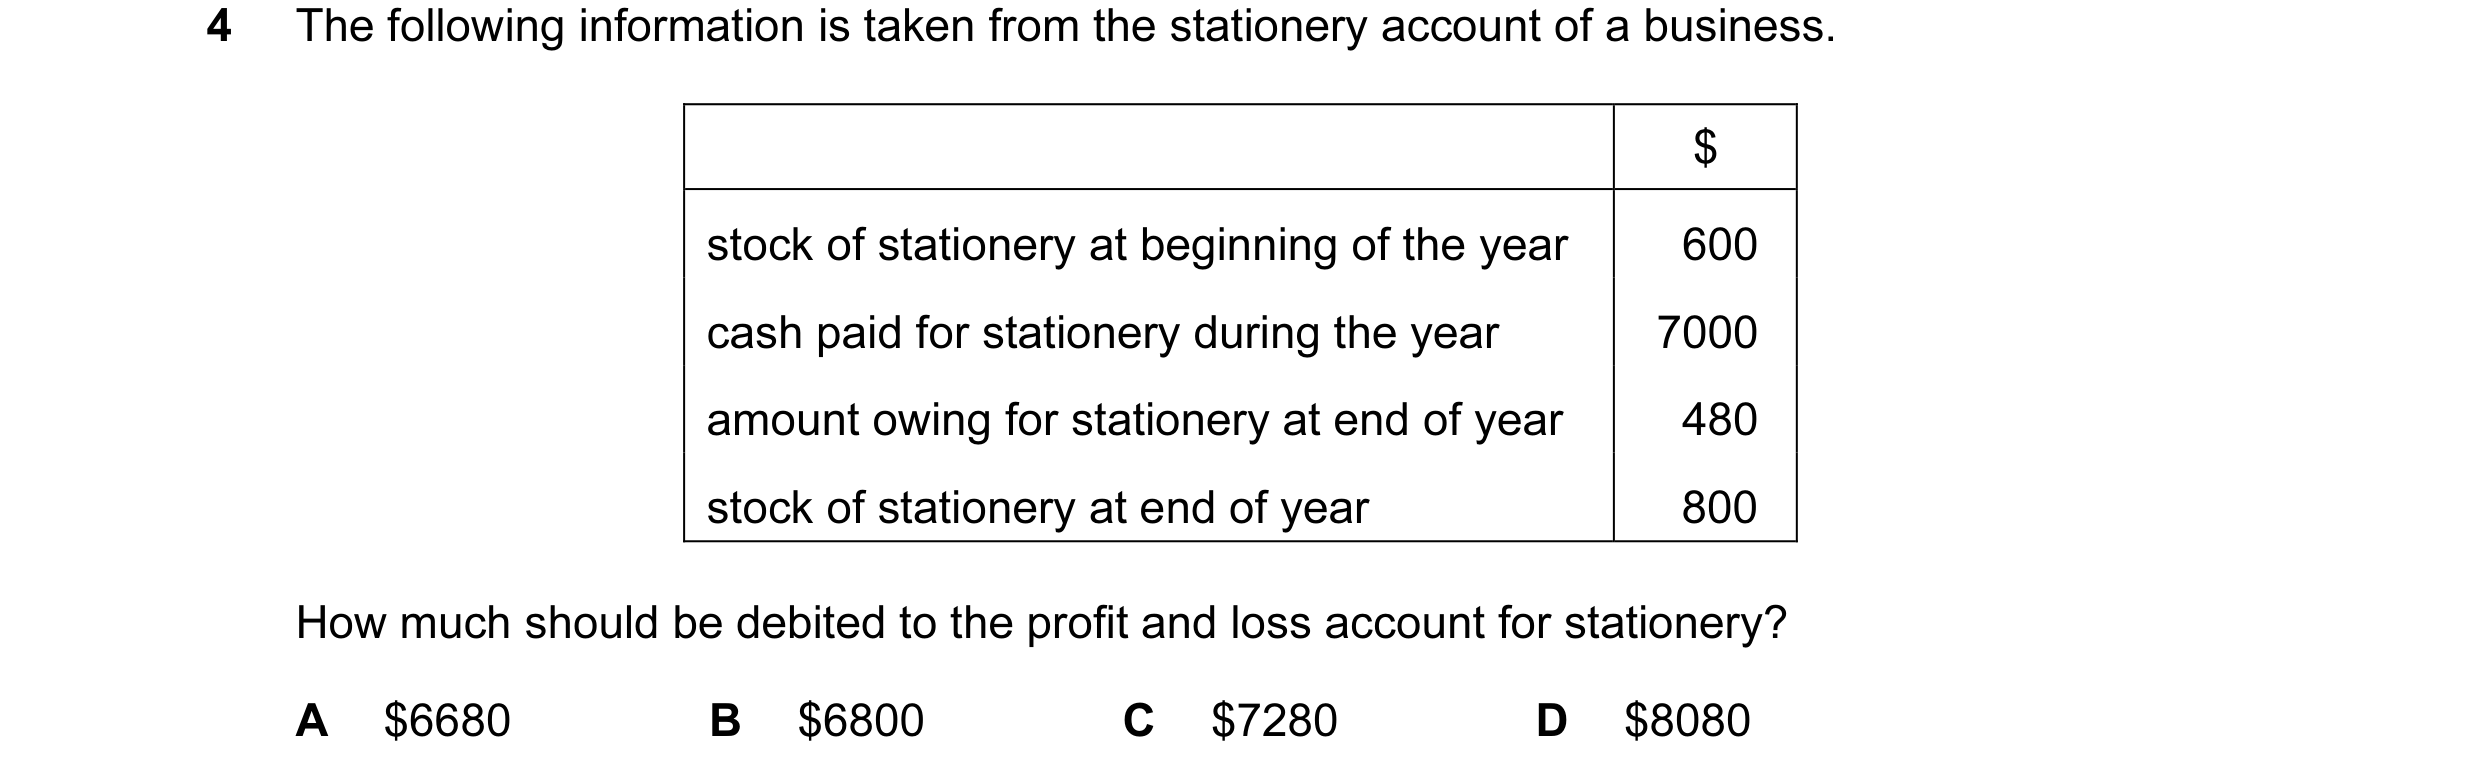
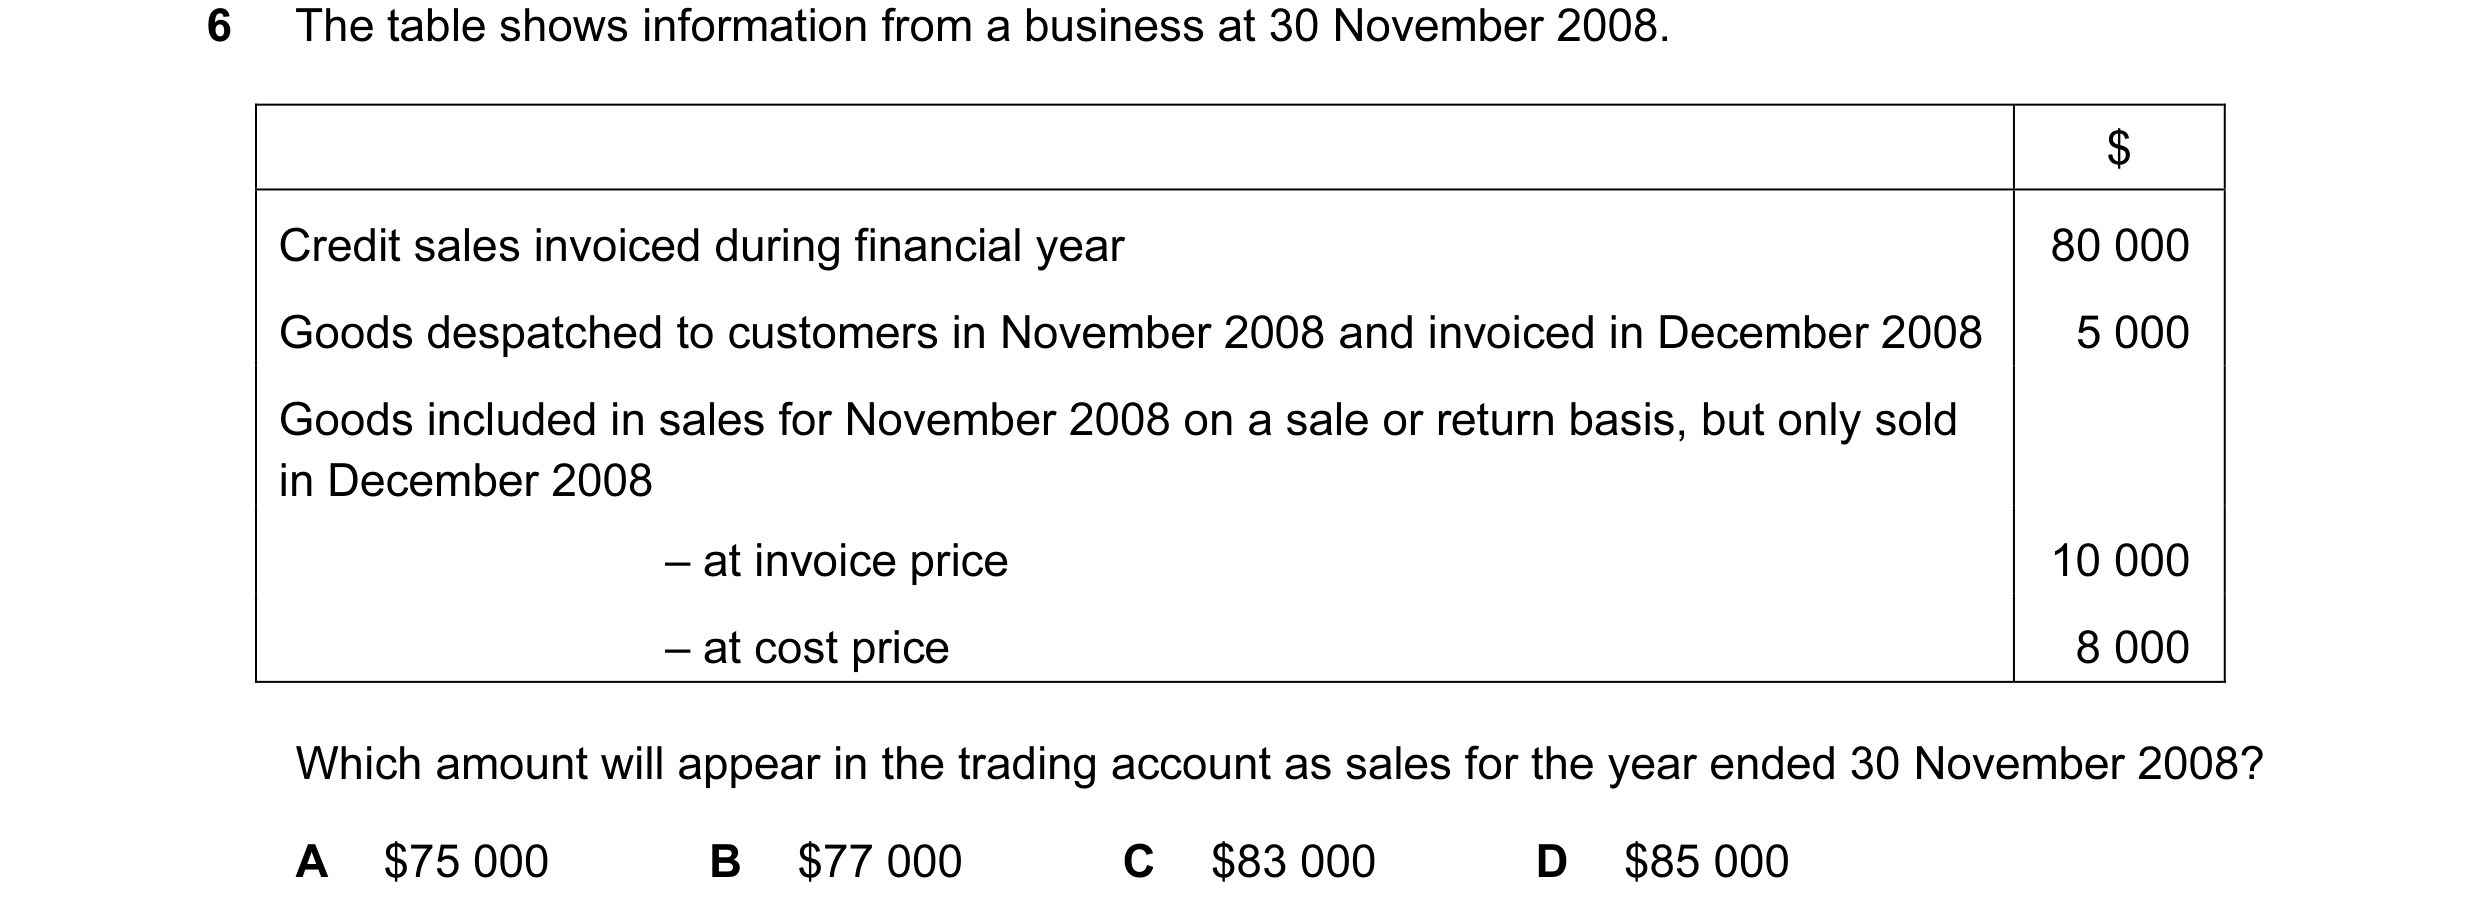
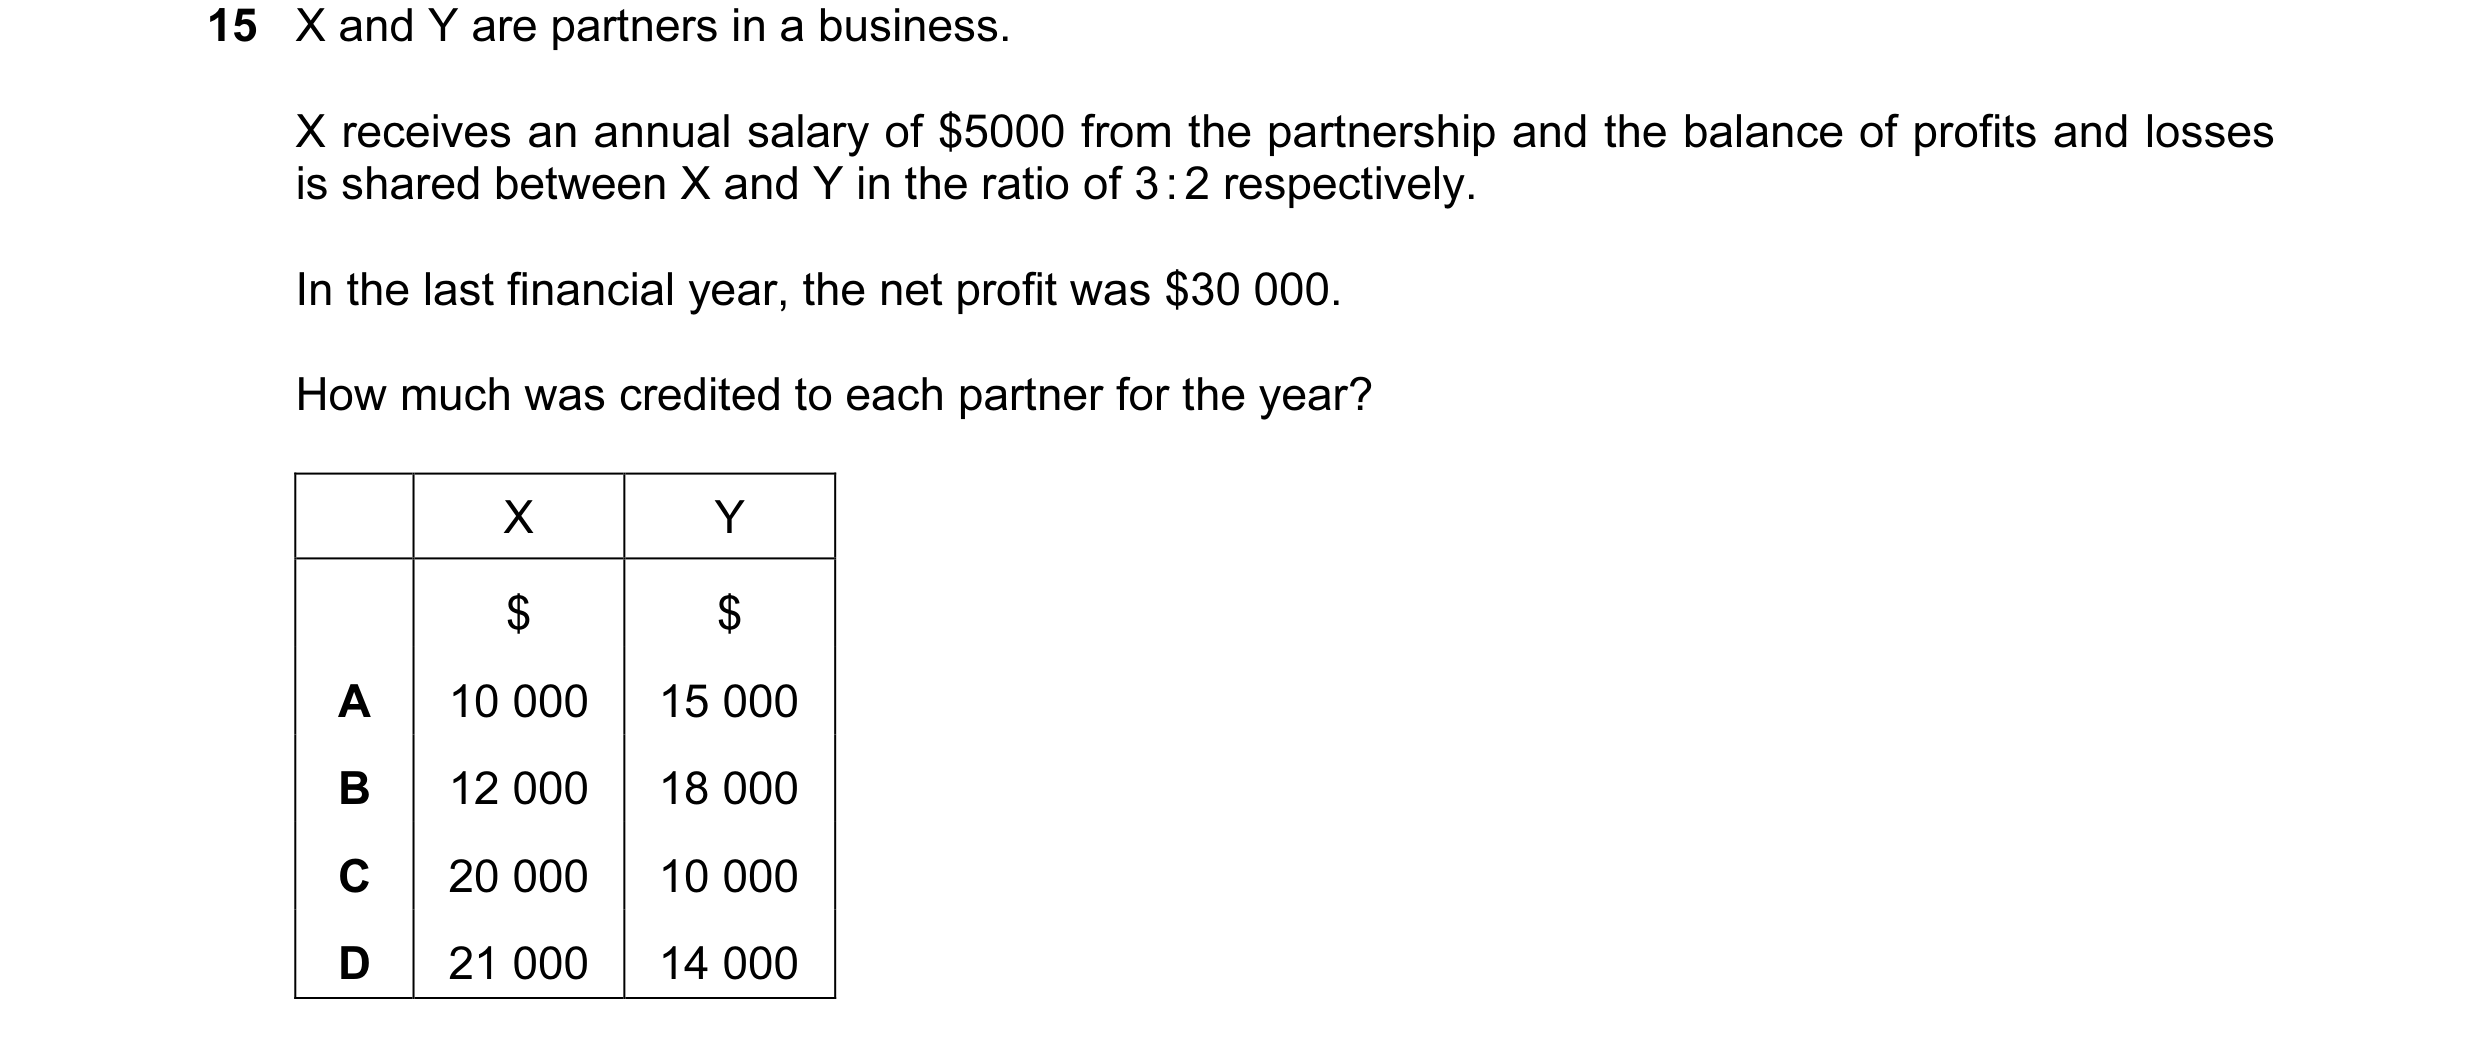 16 / 233
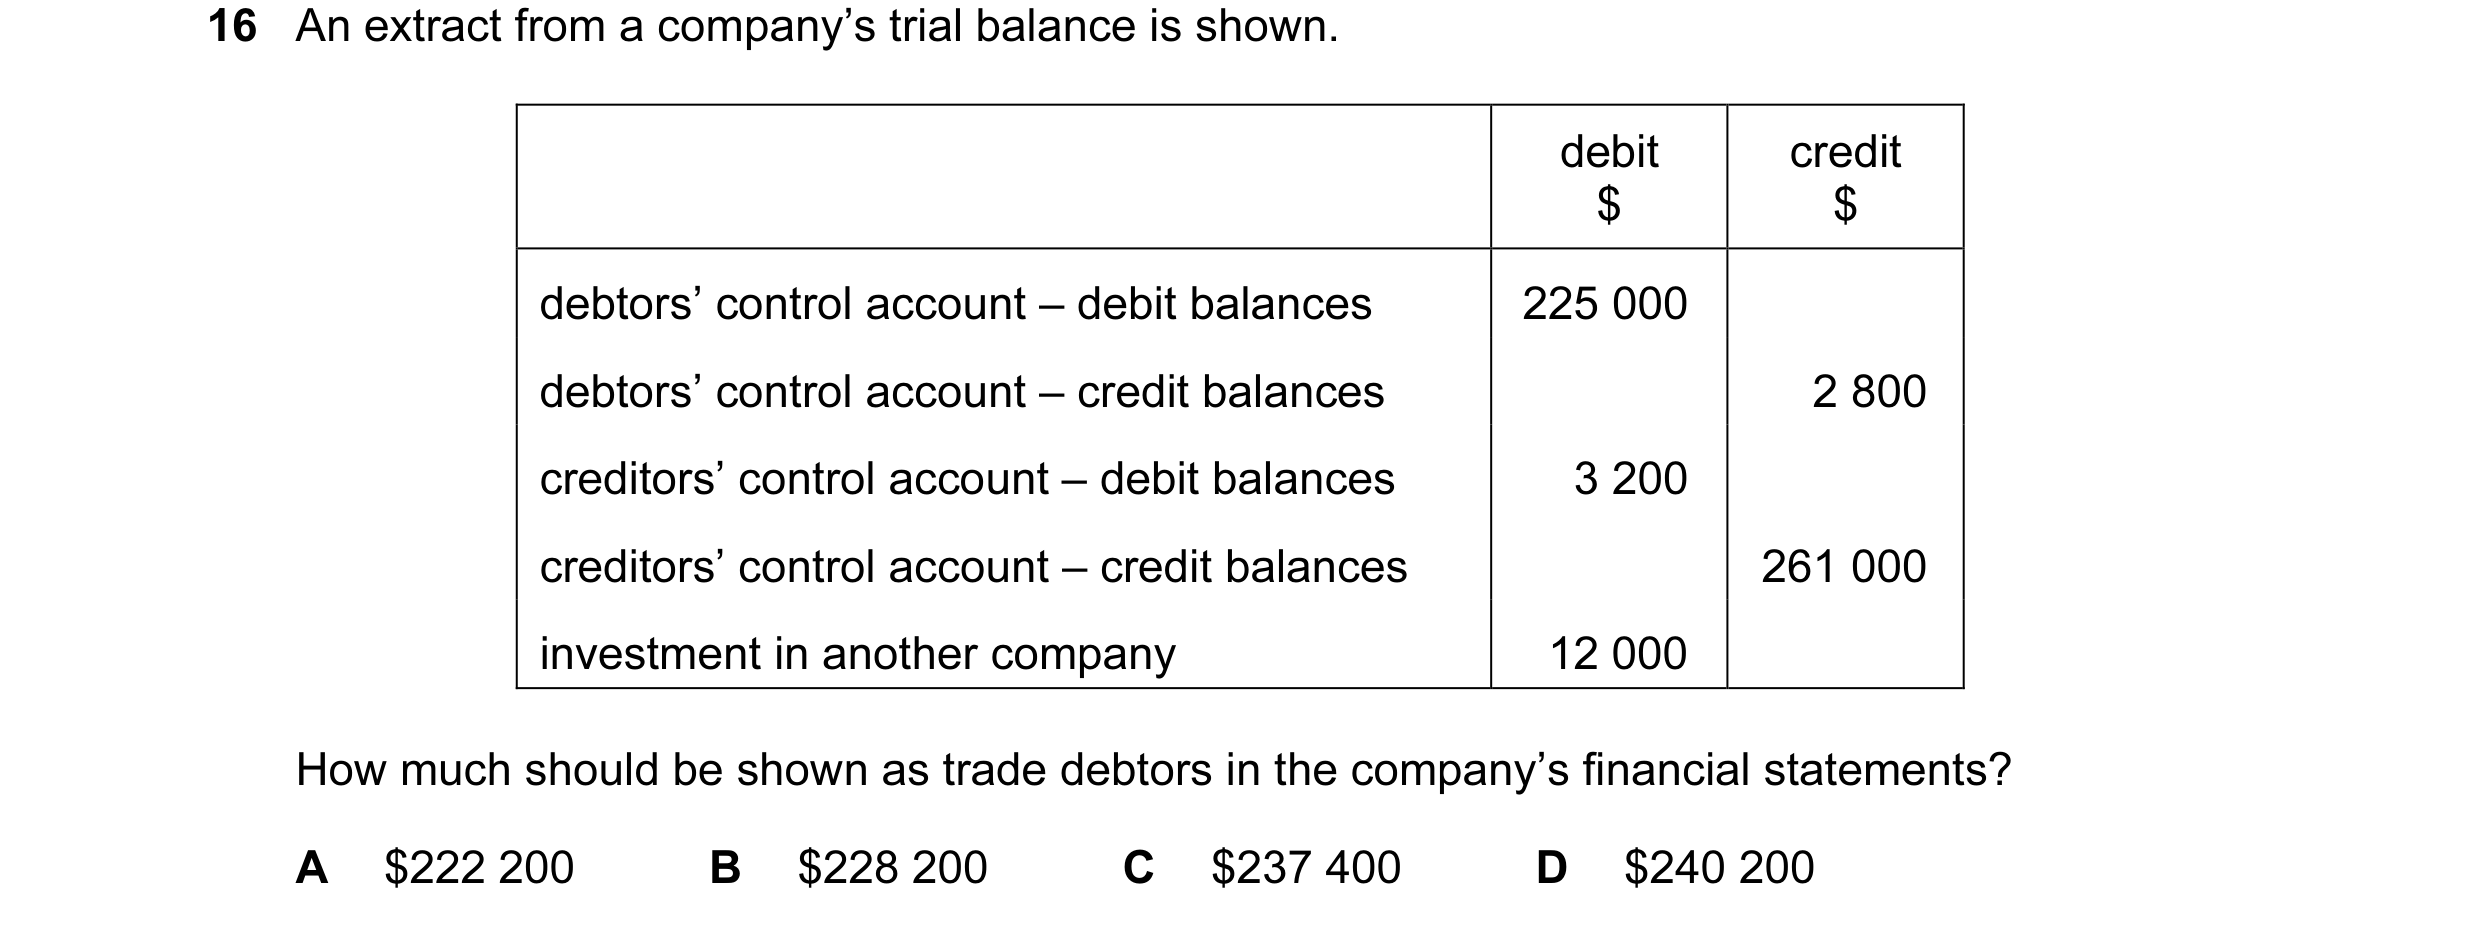
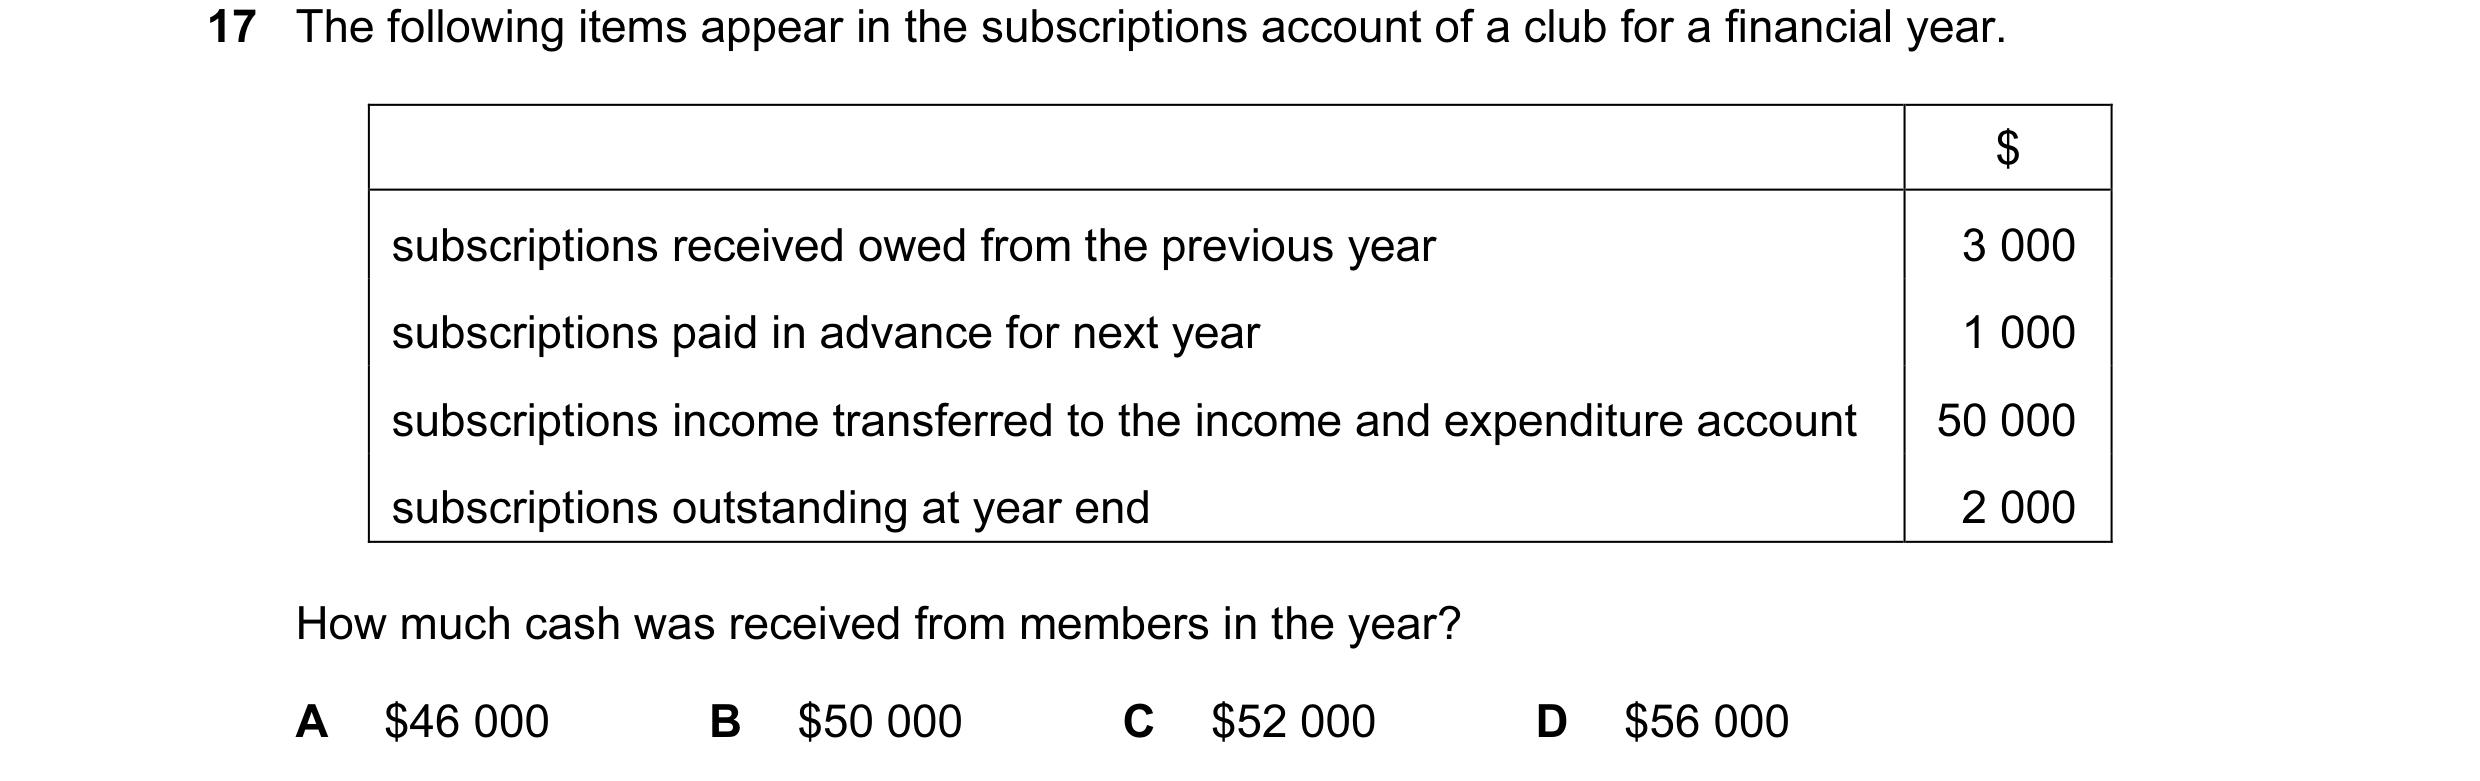
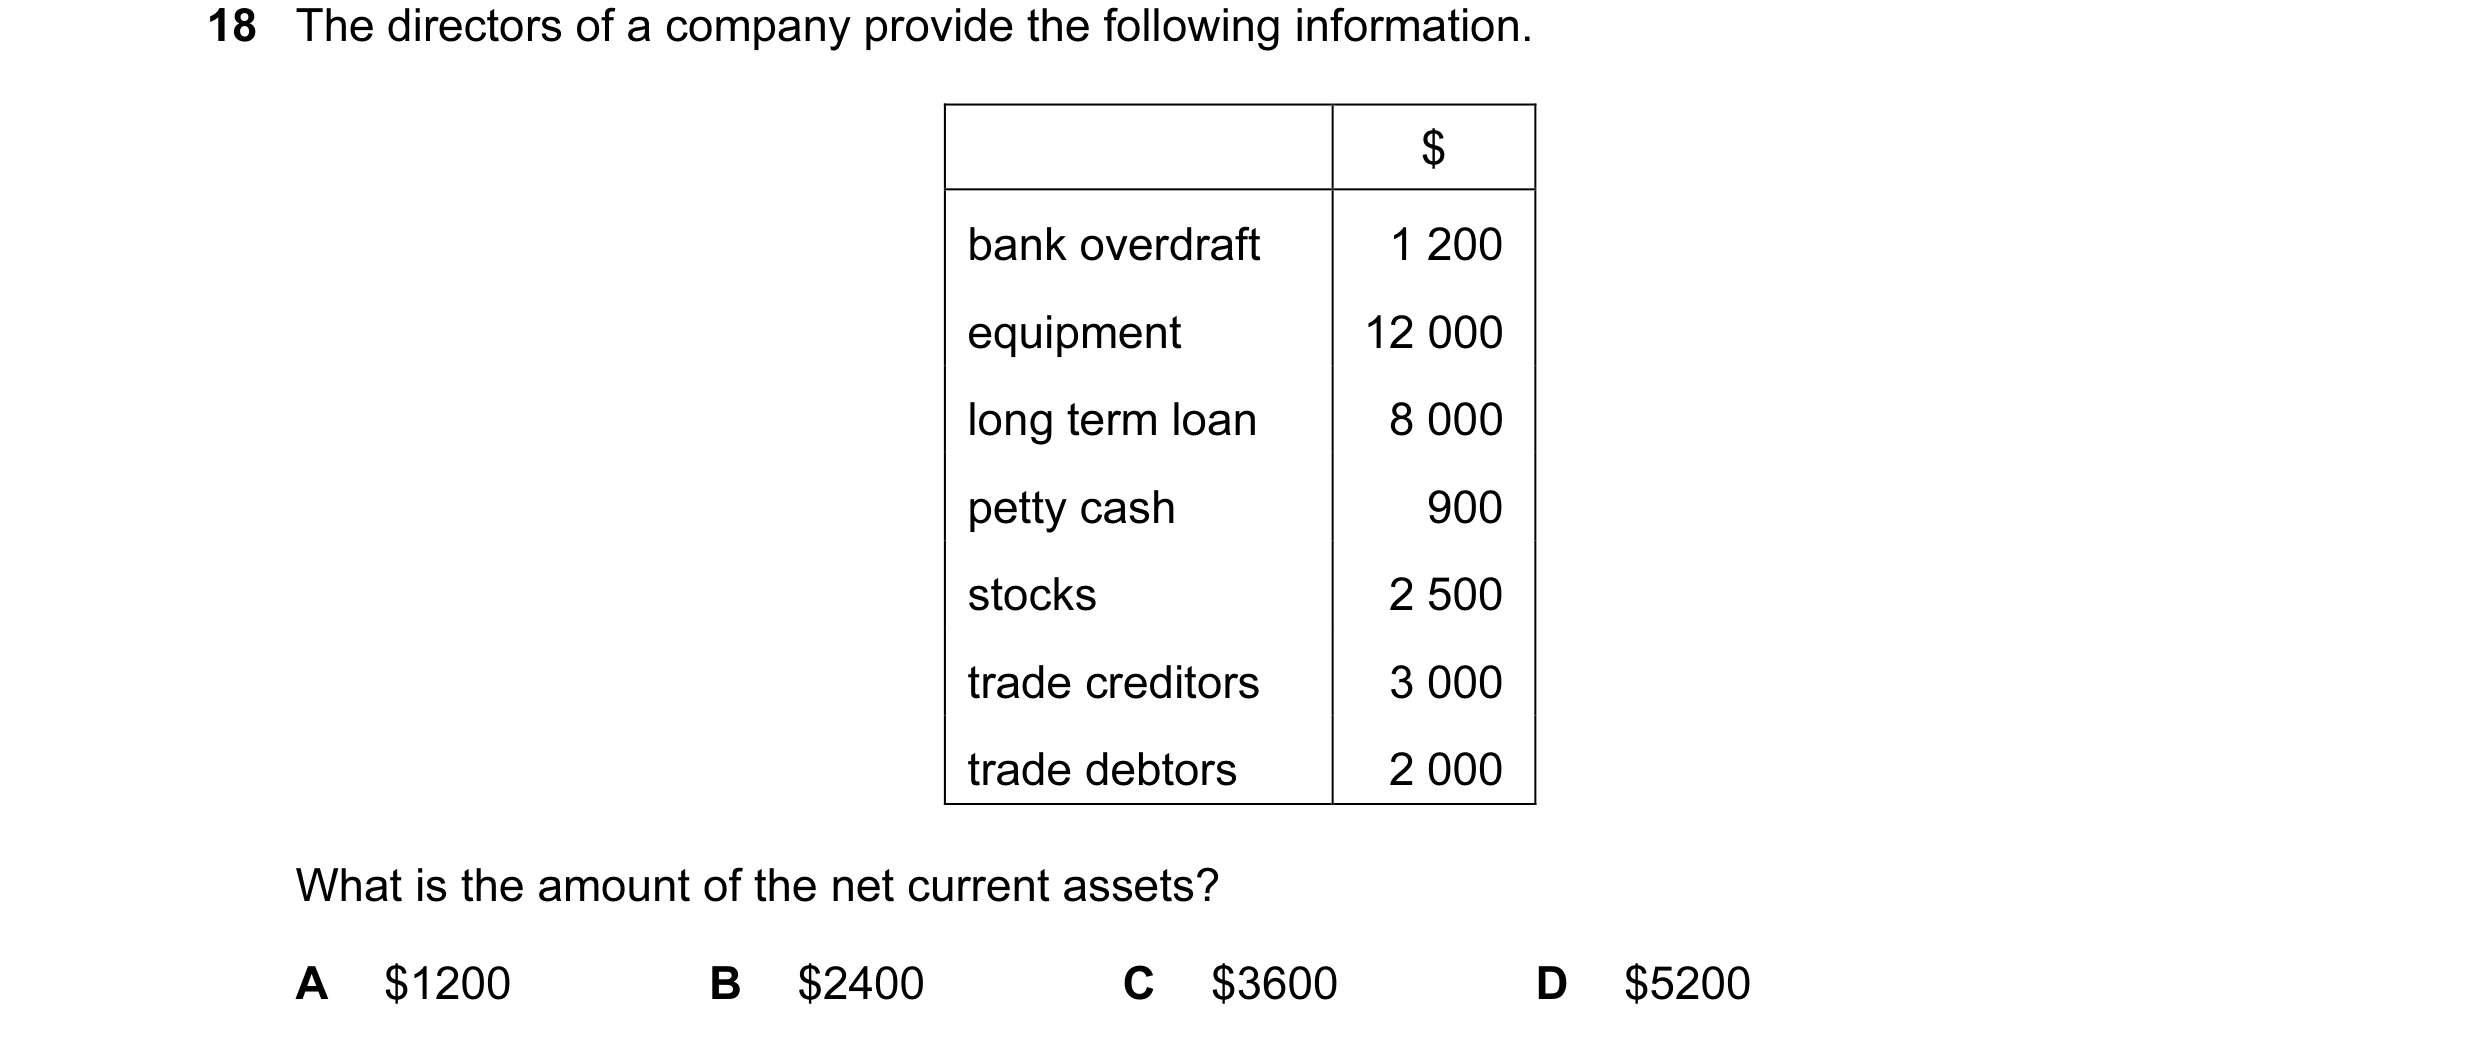 17 / 233
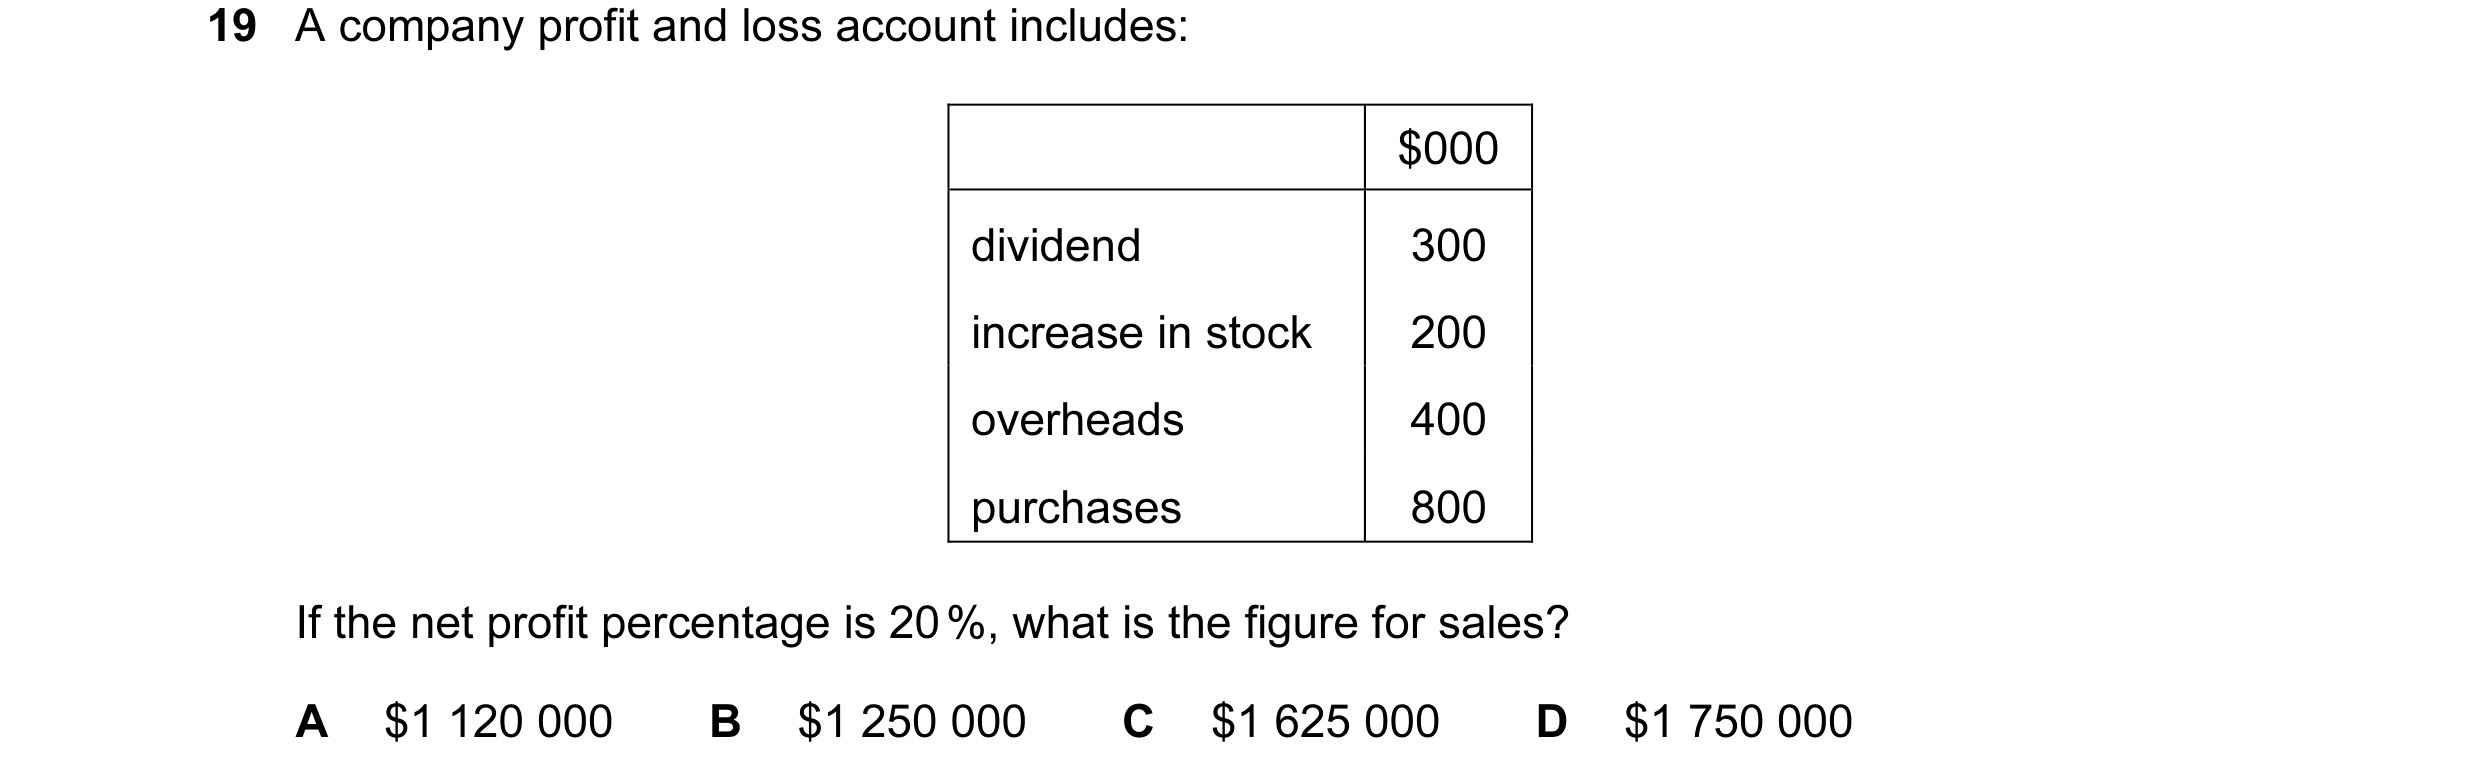
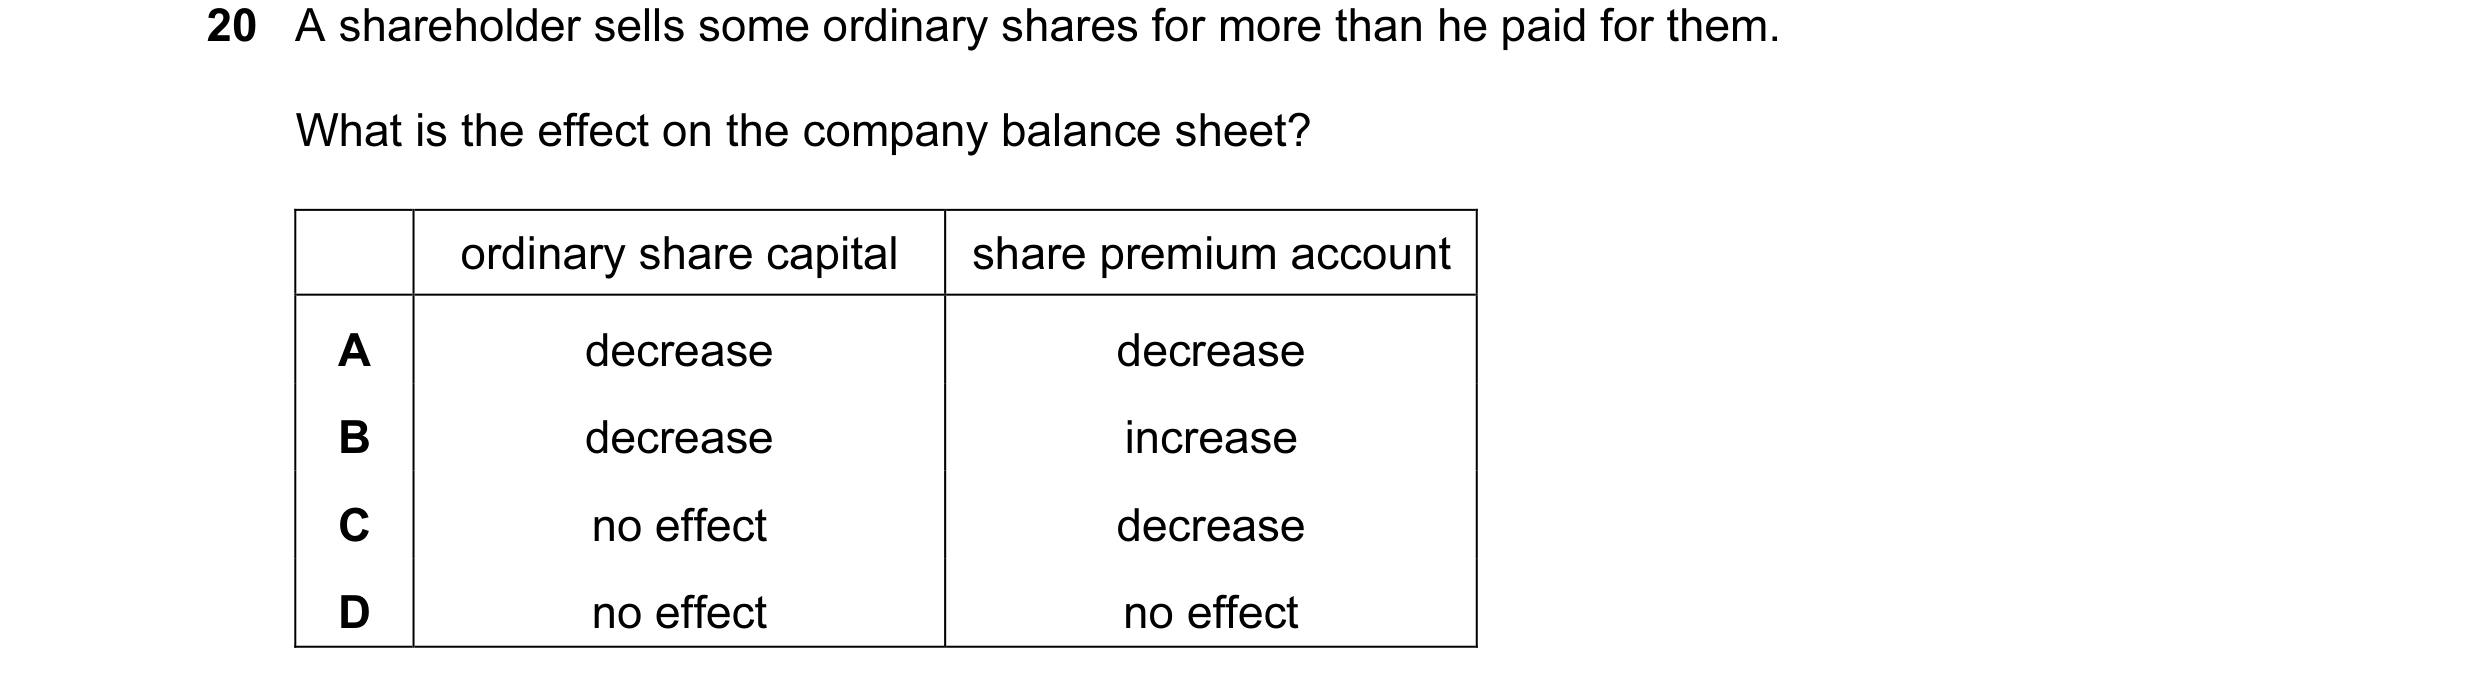
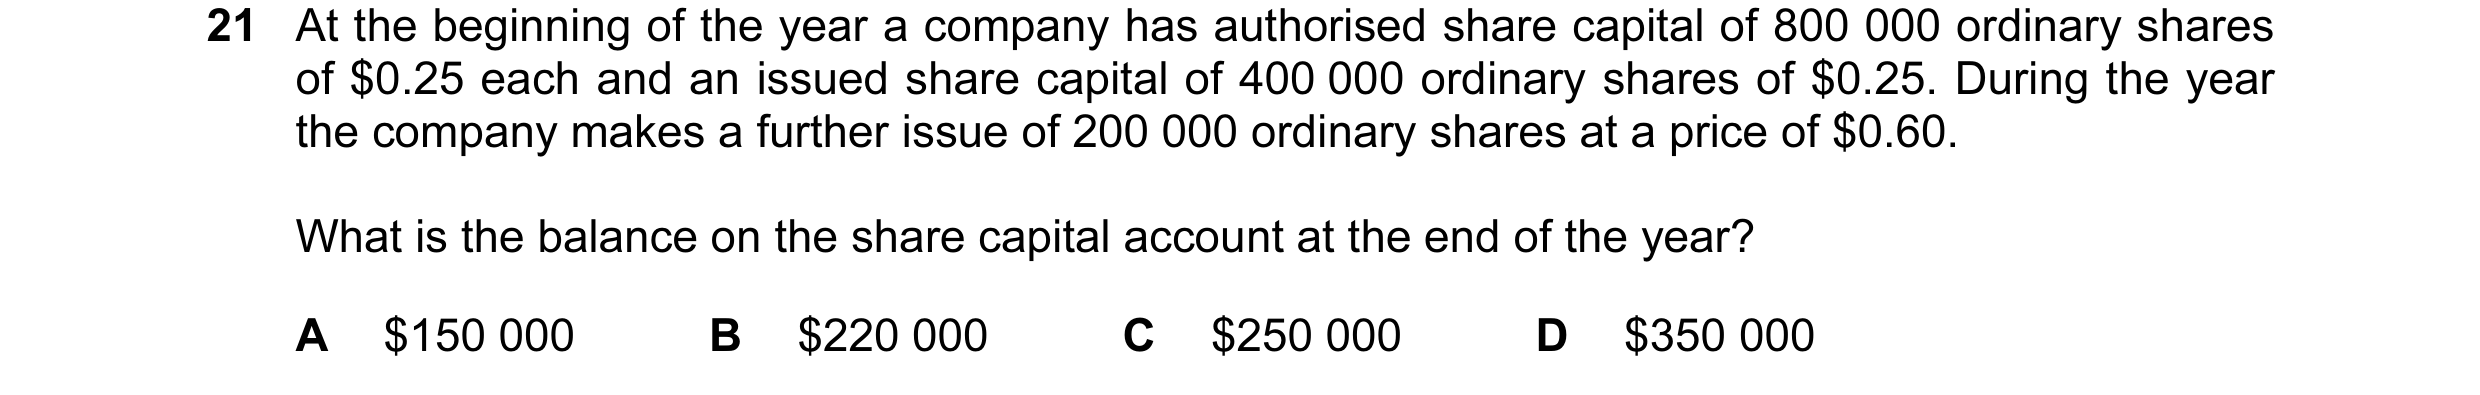
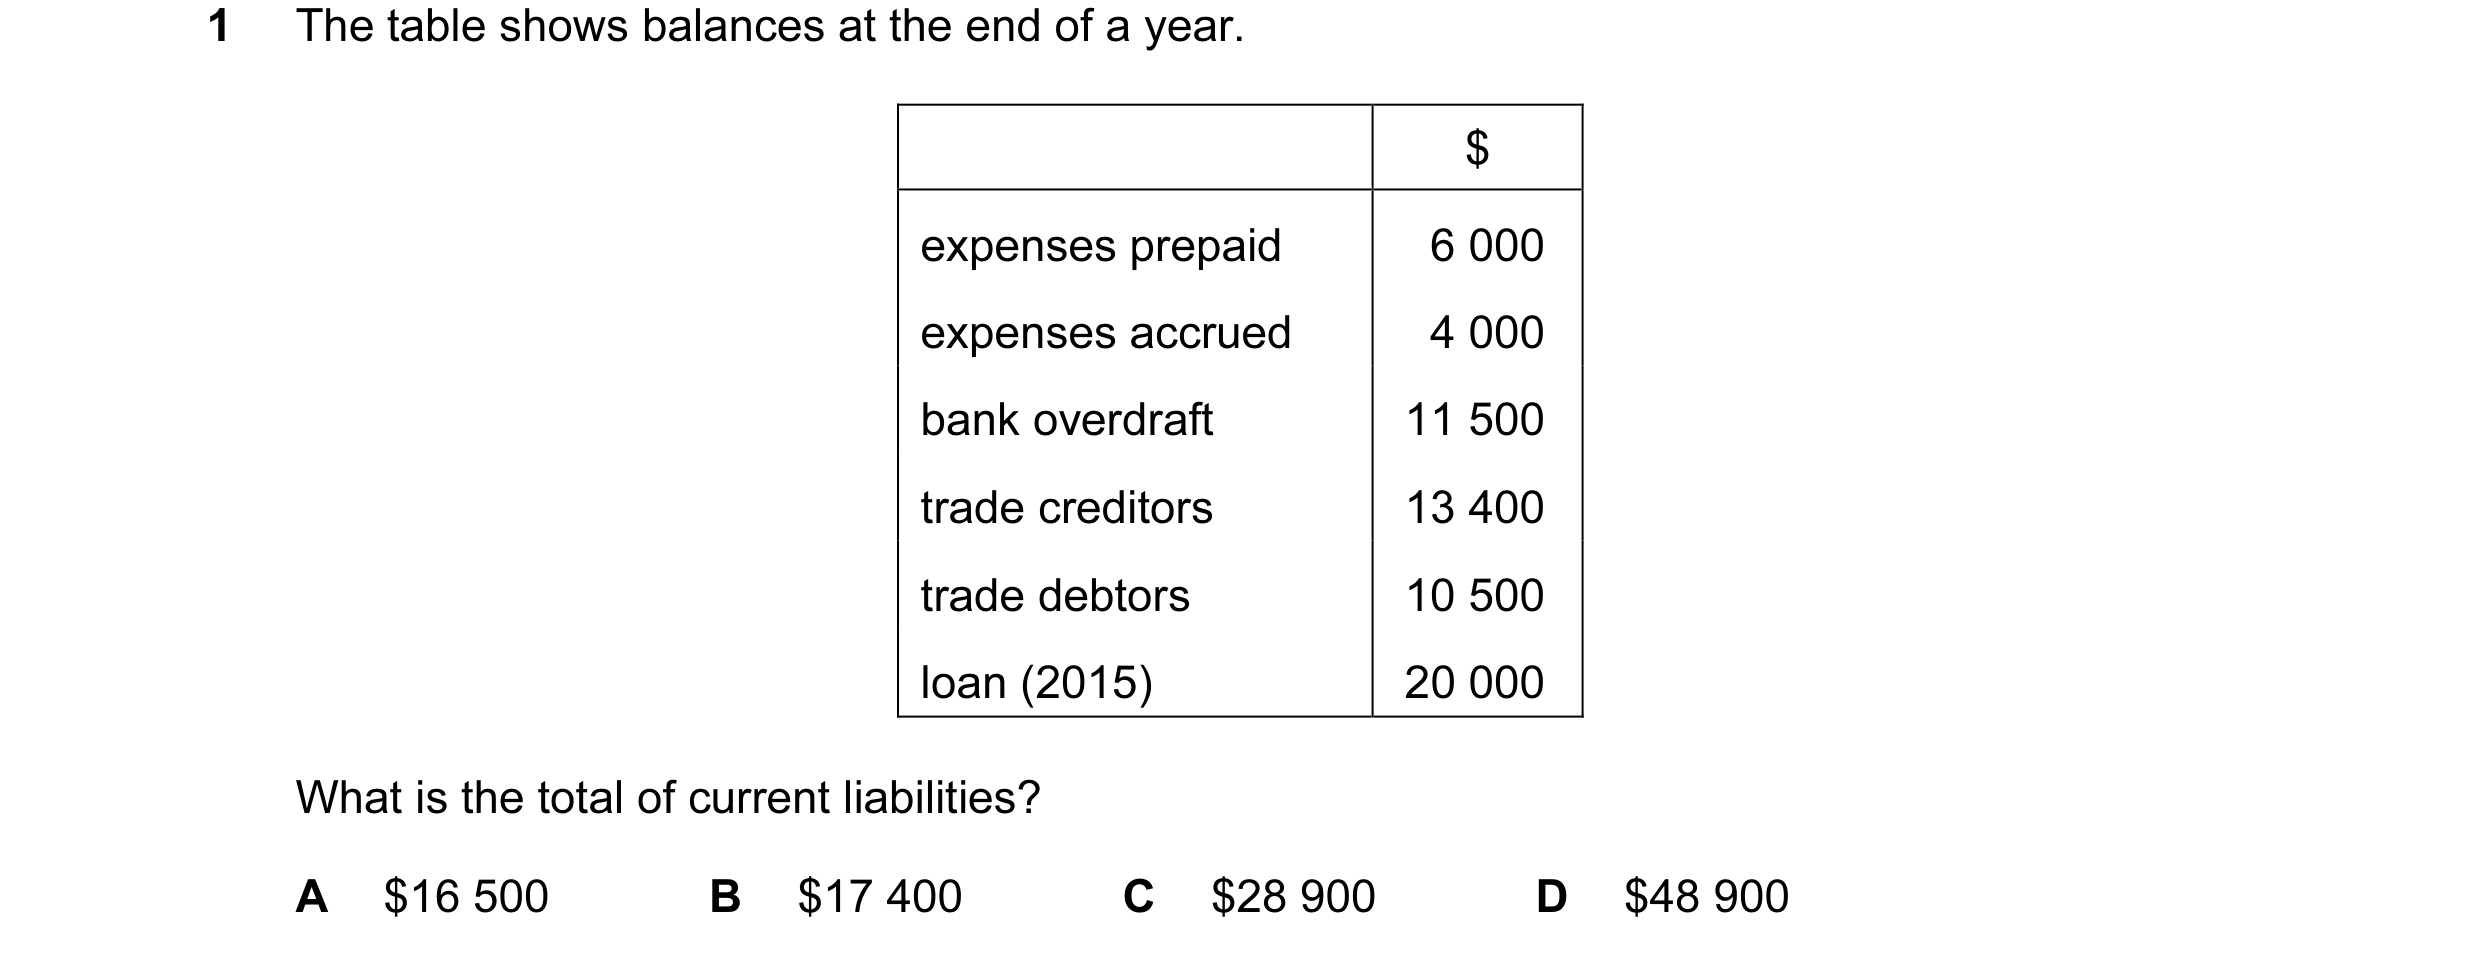 18 / 233
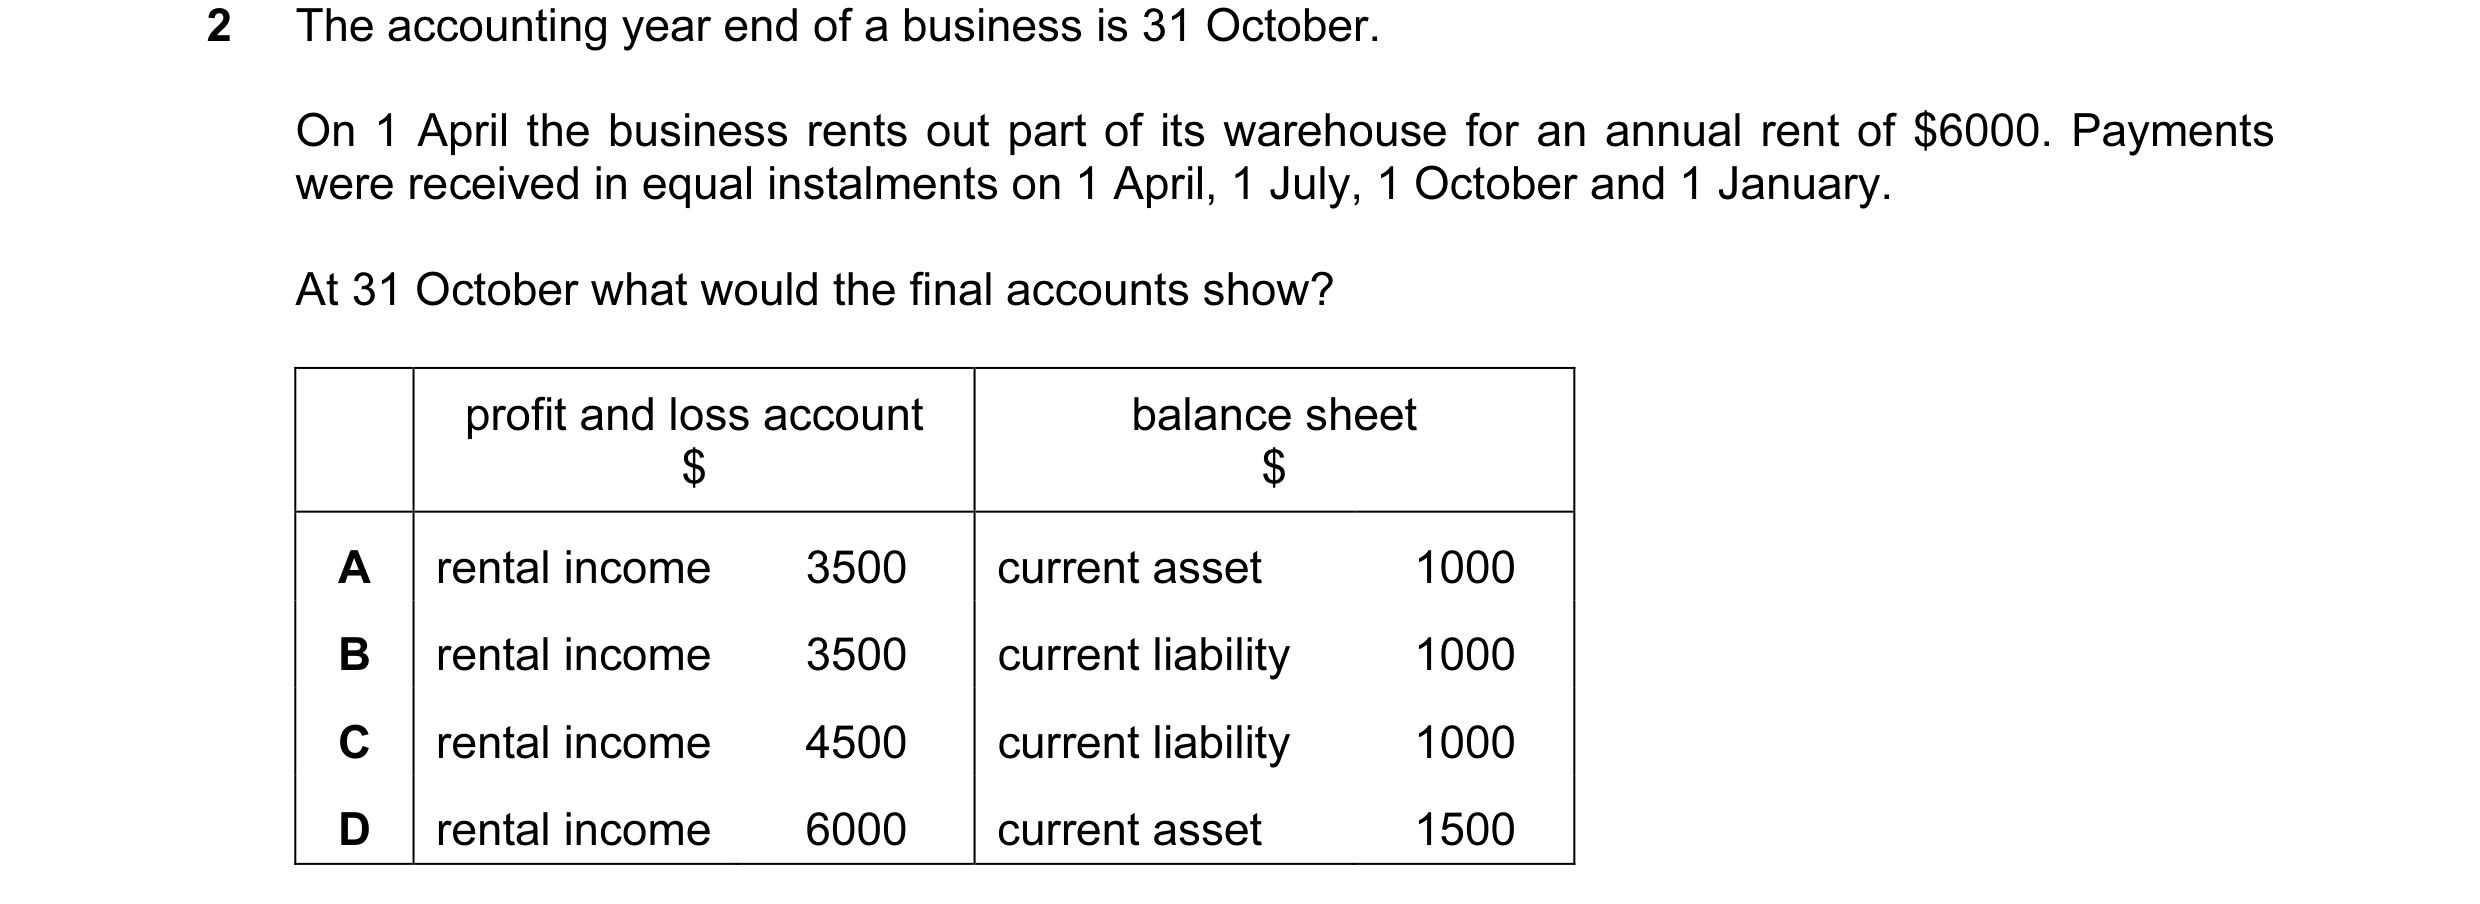
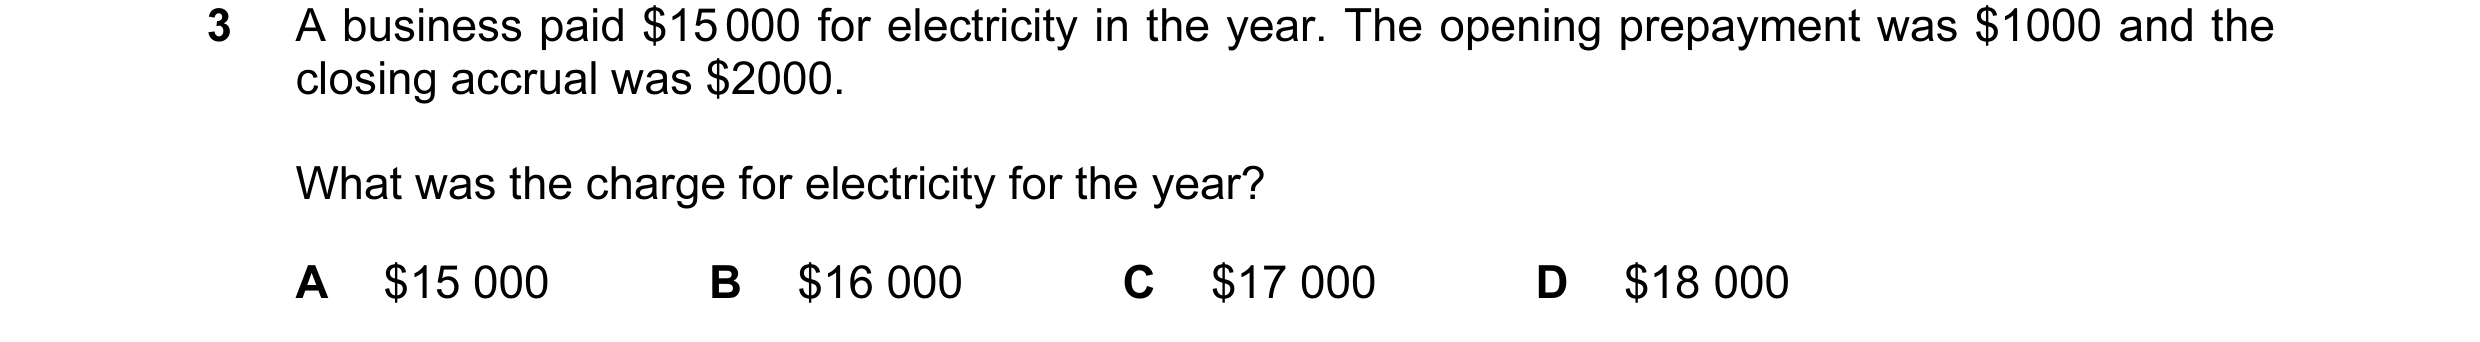
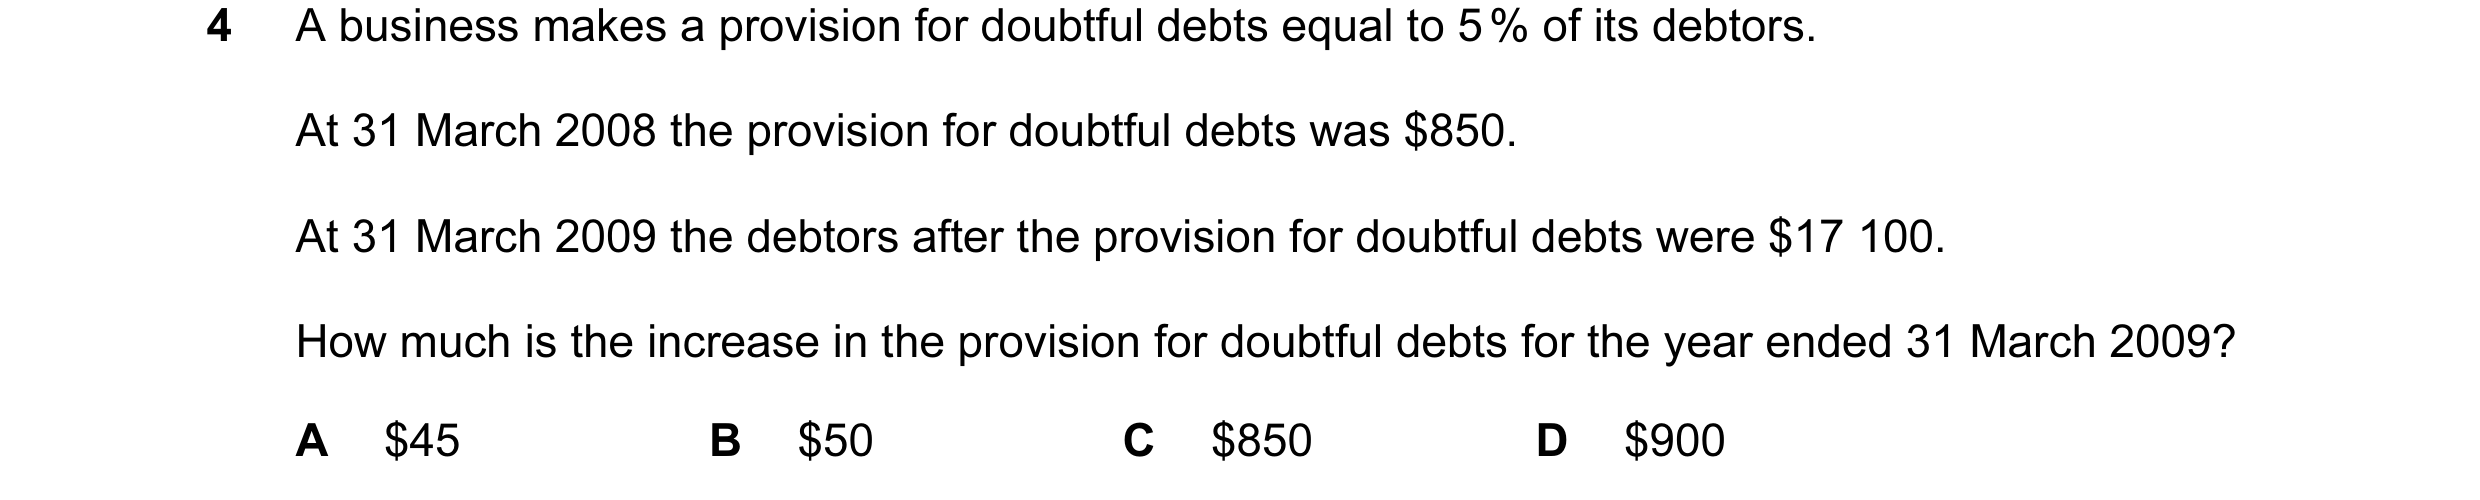
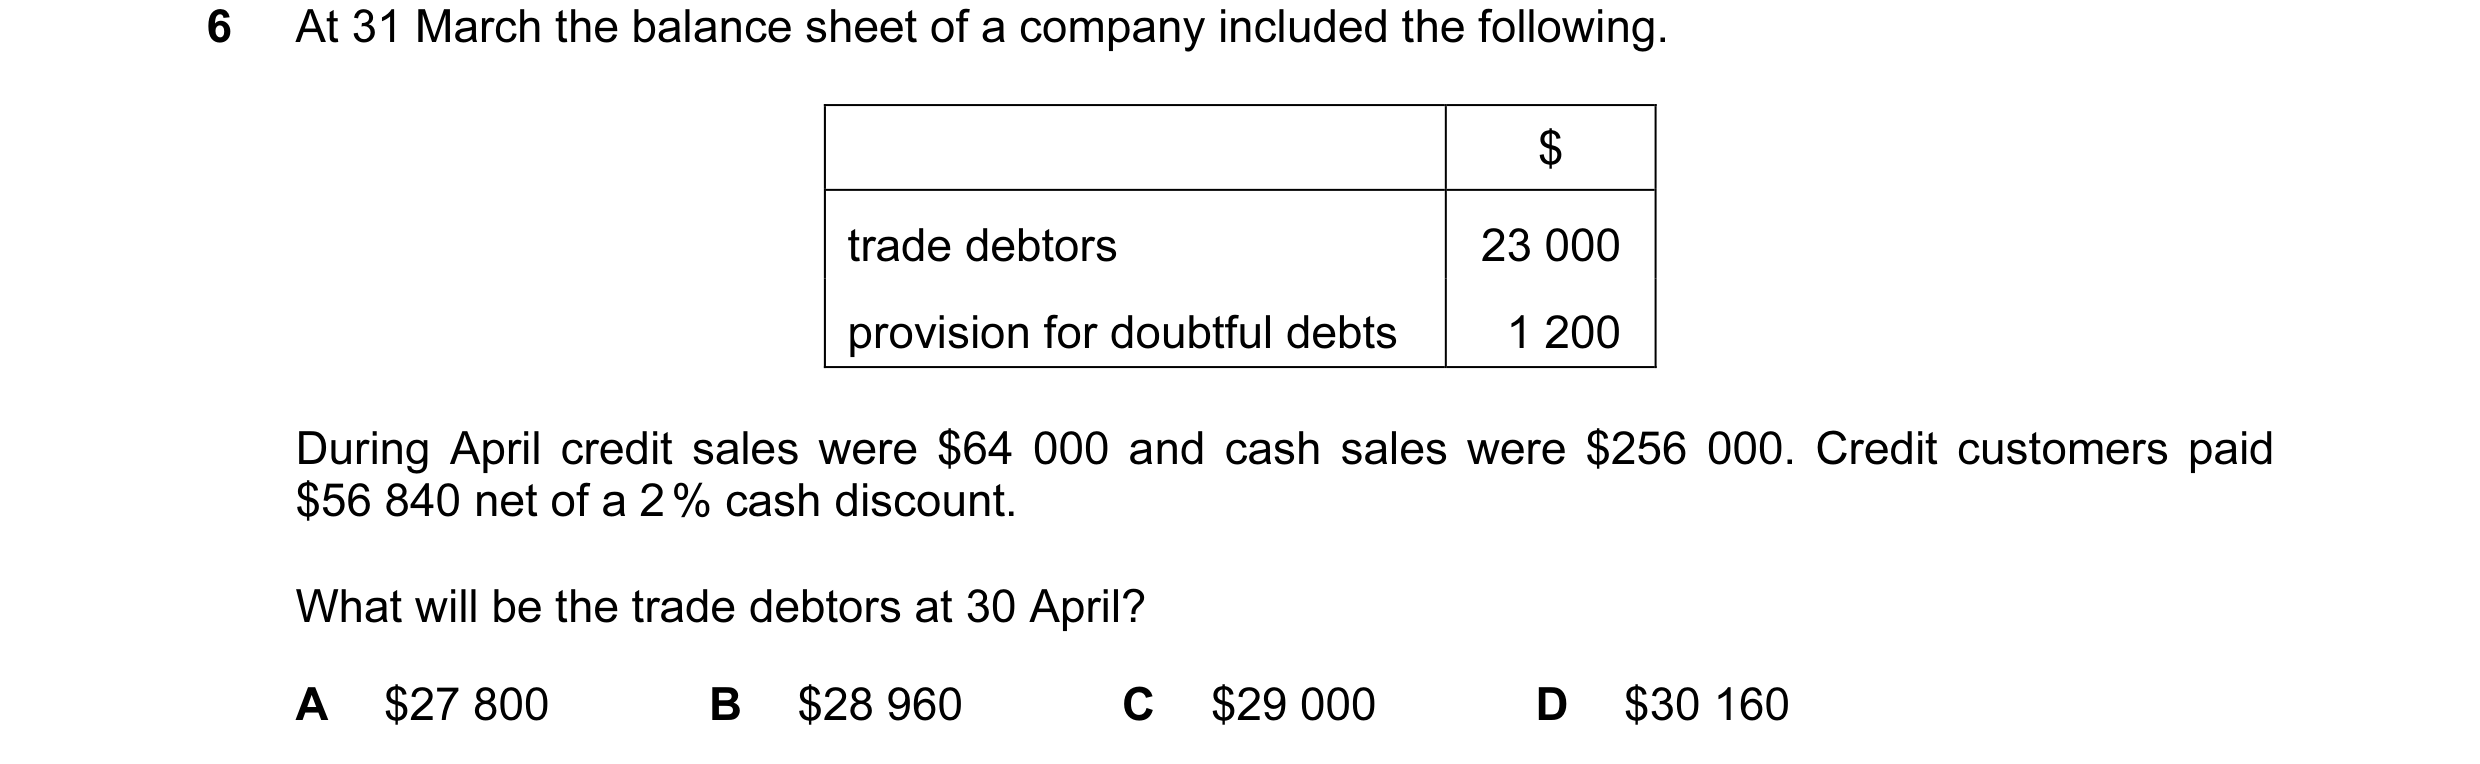
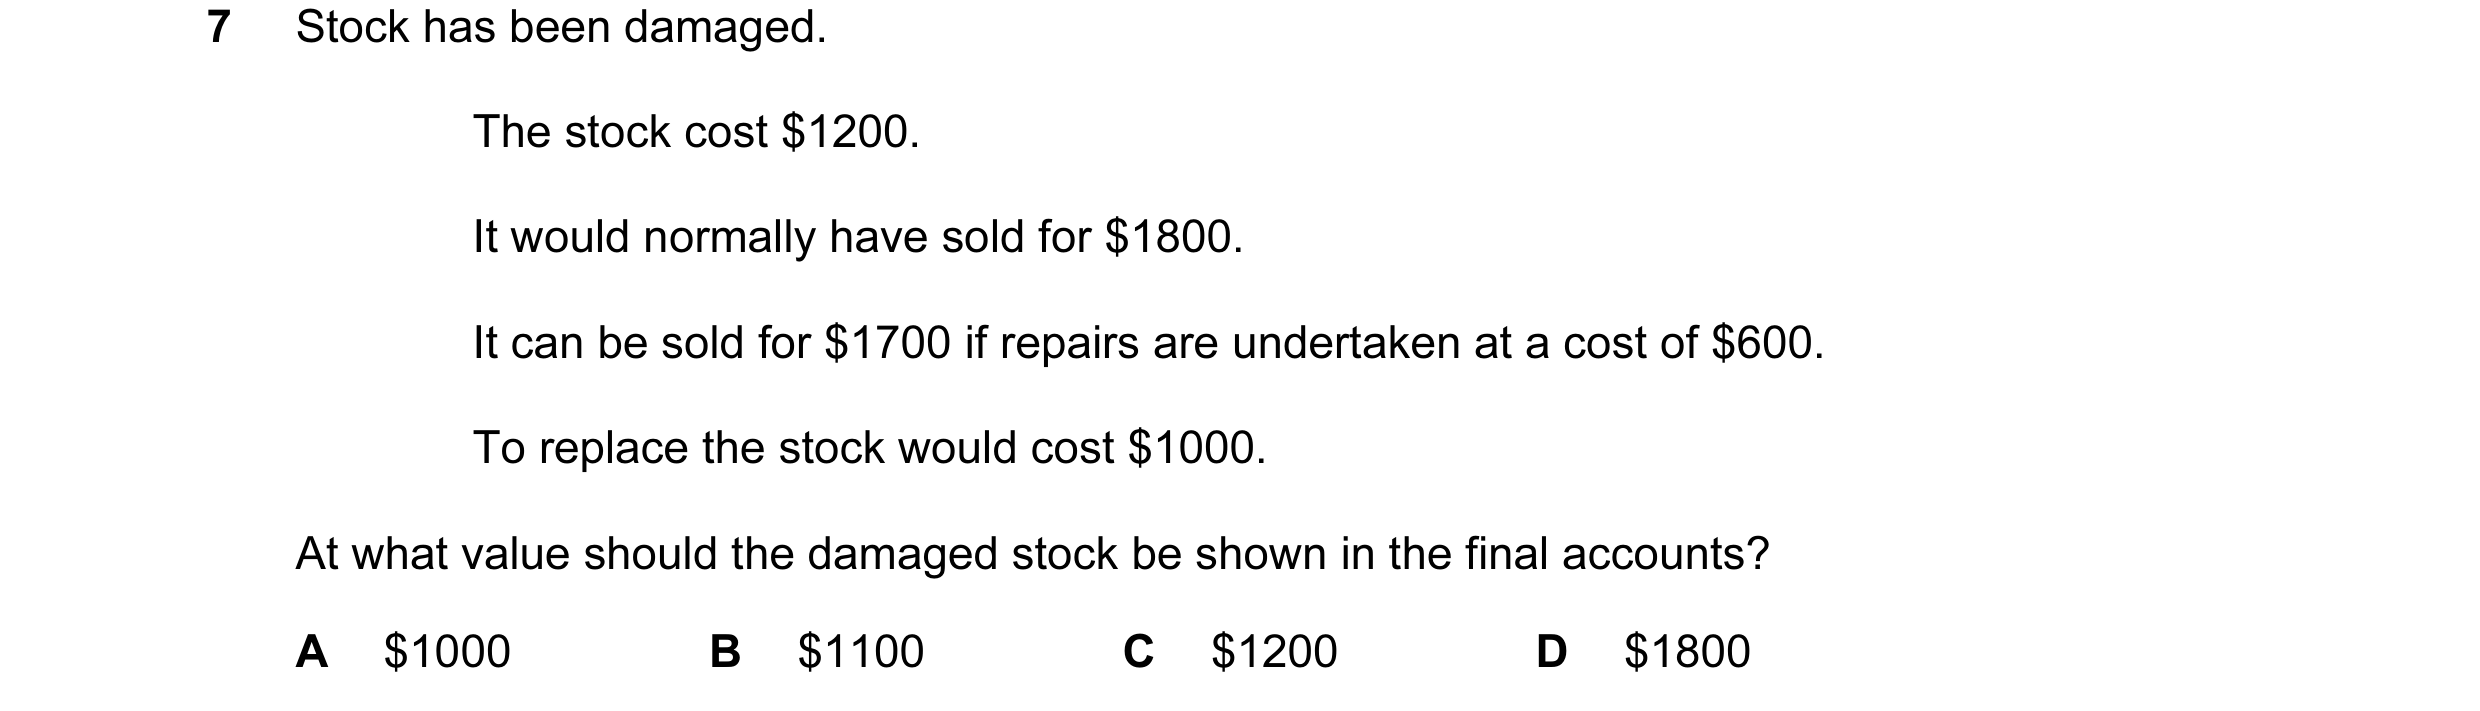 19 / 233
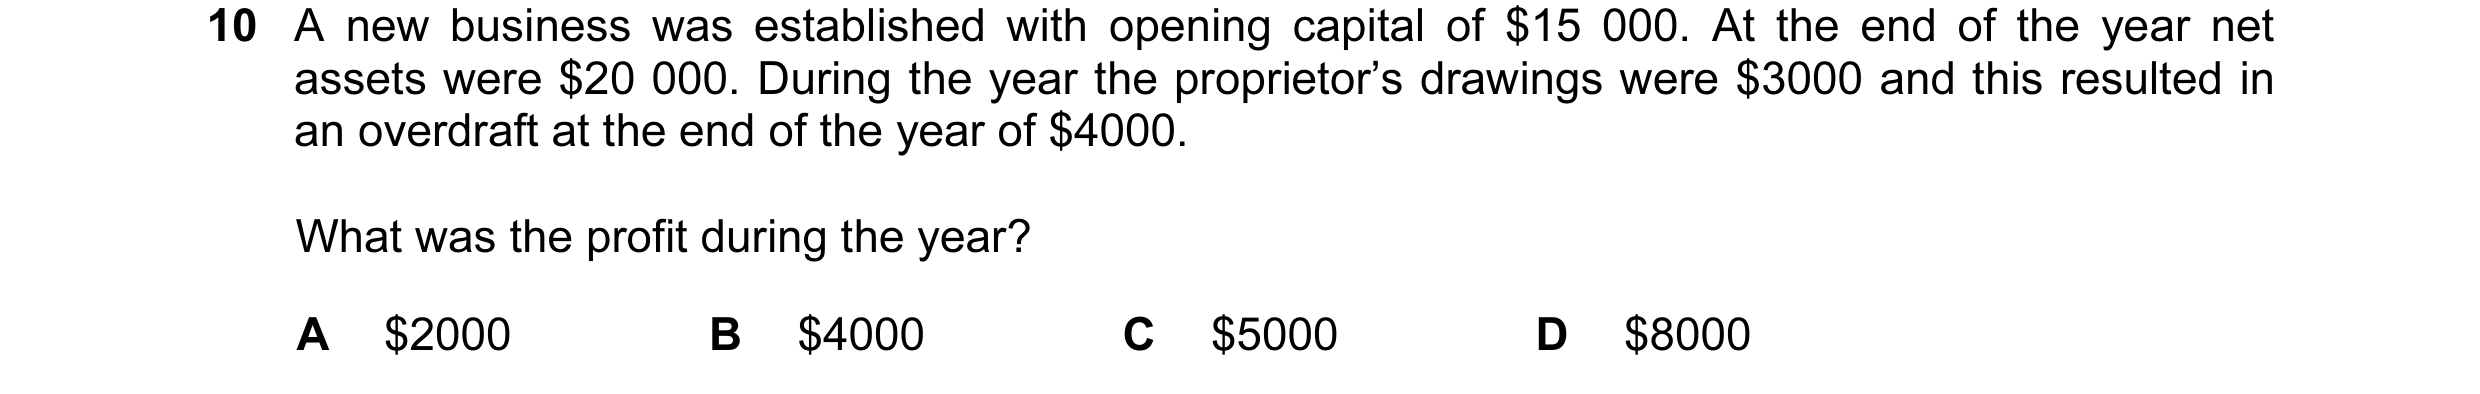
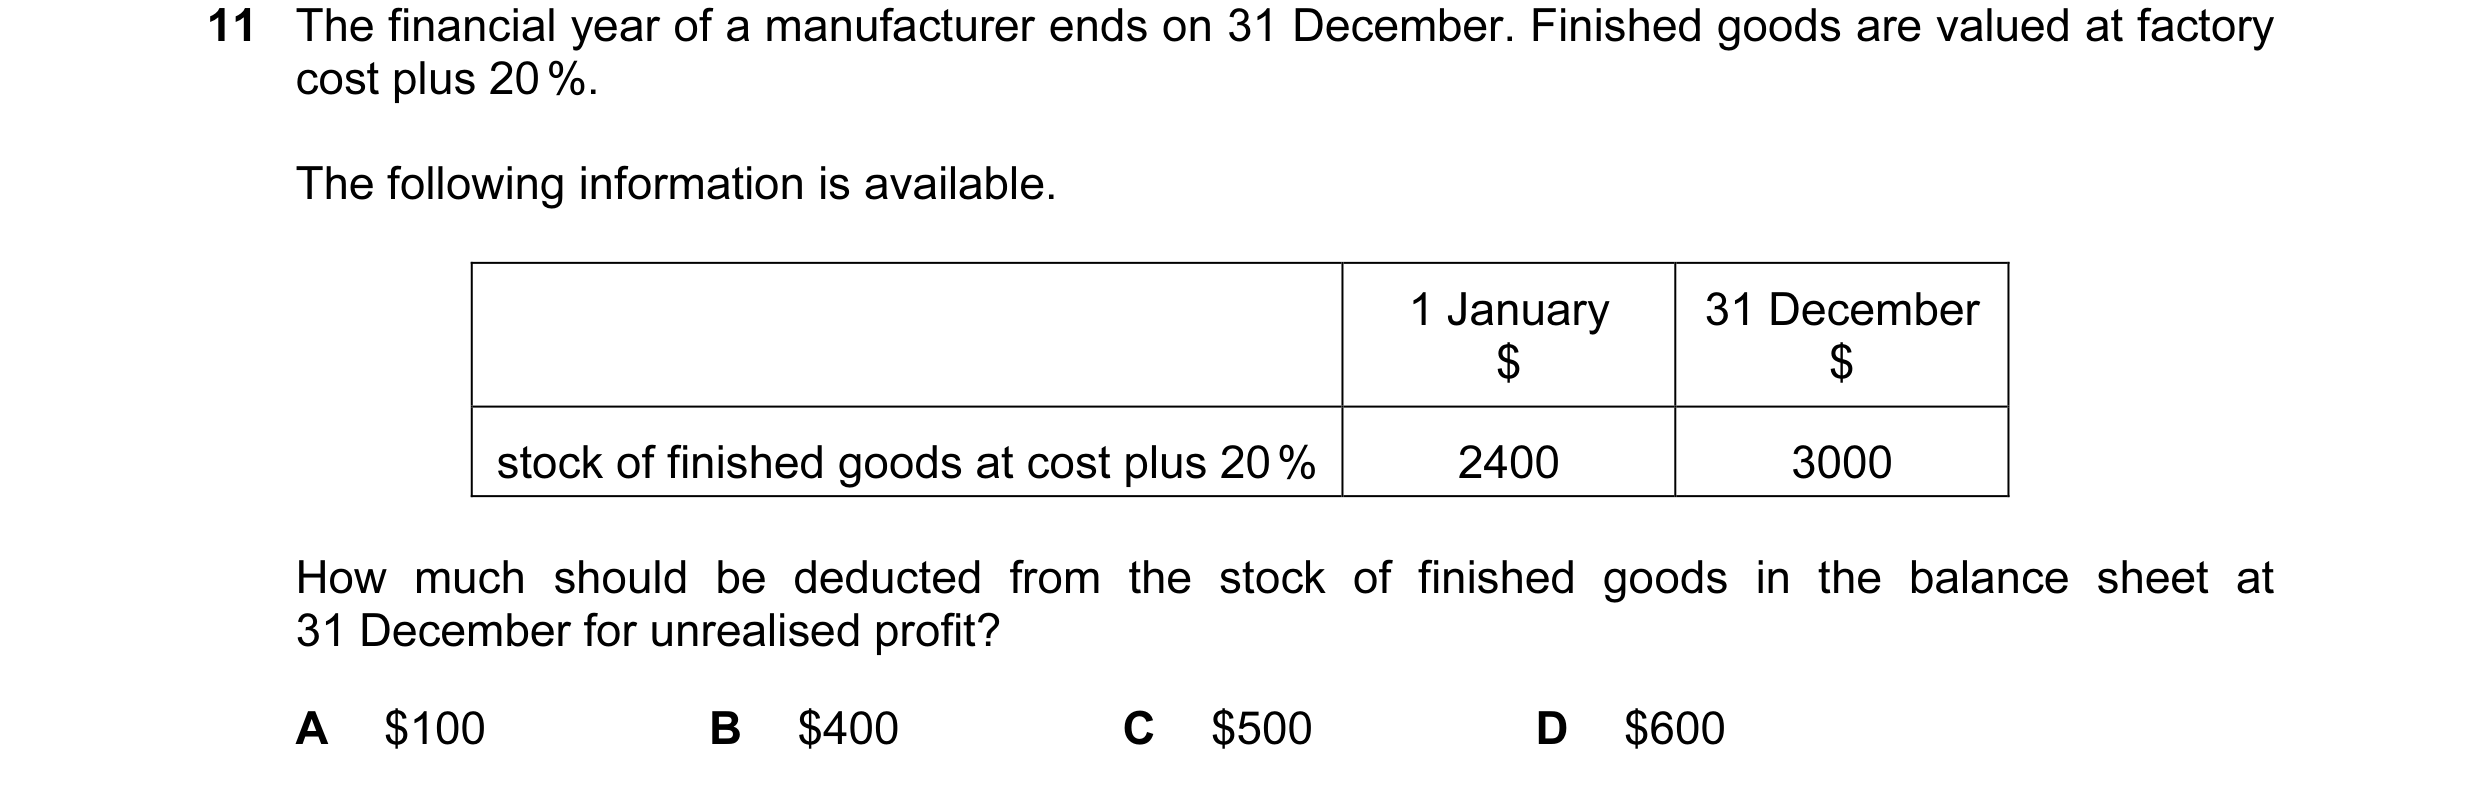
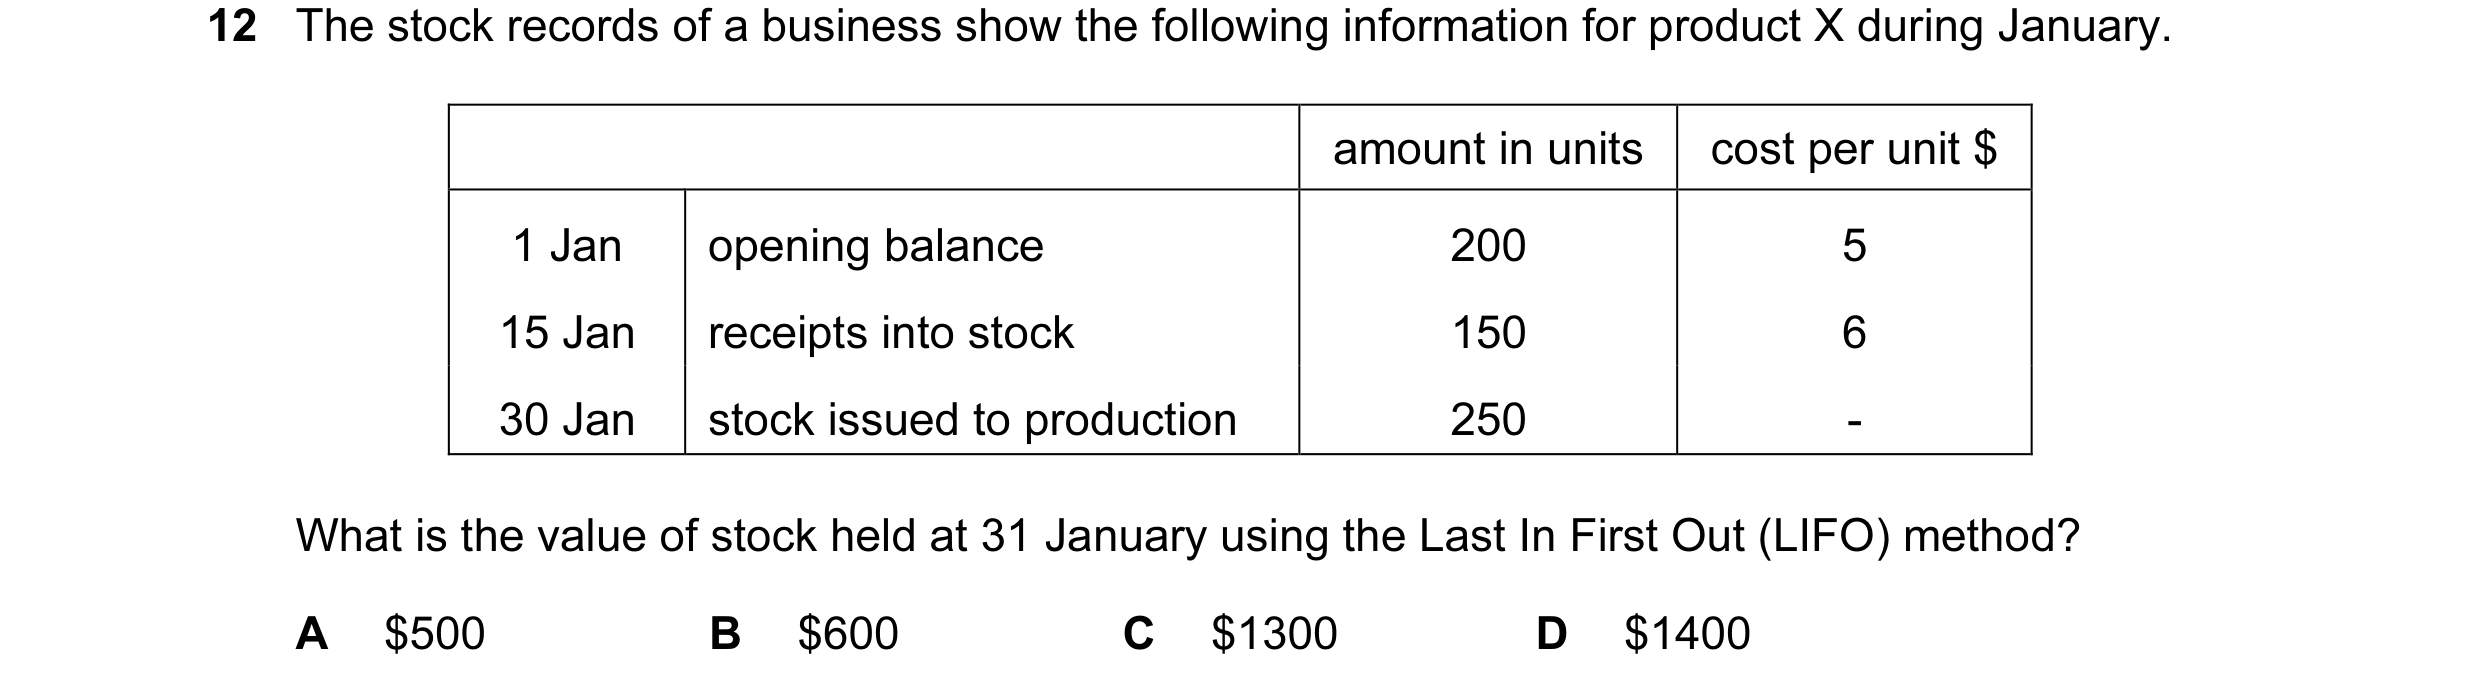
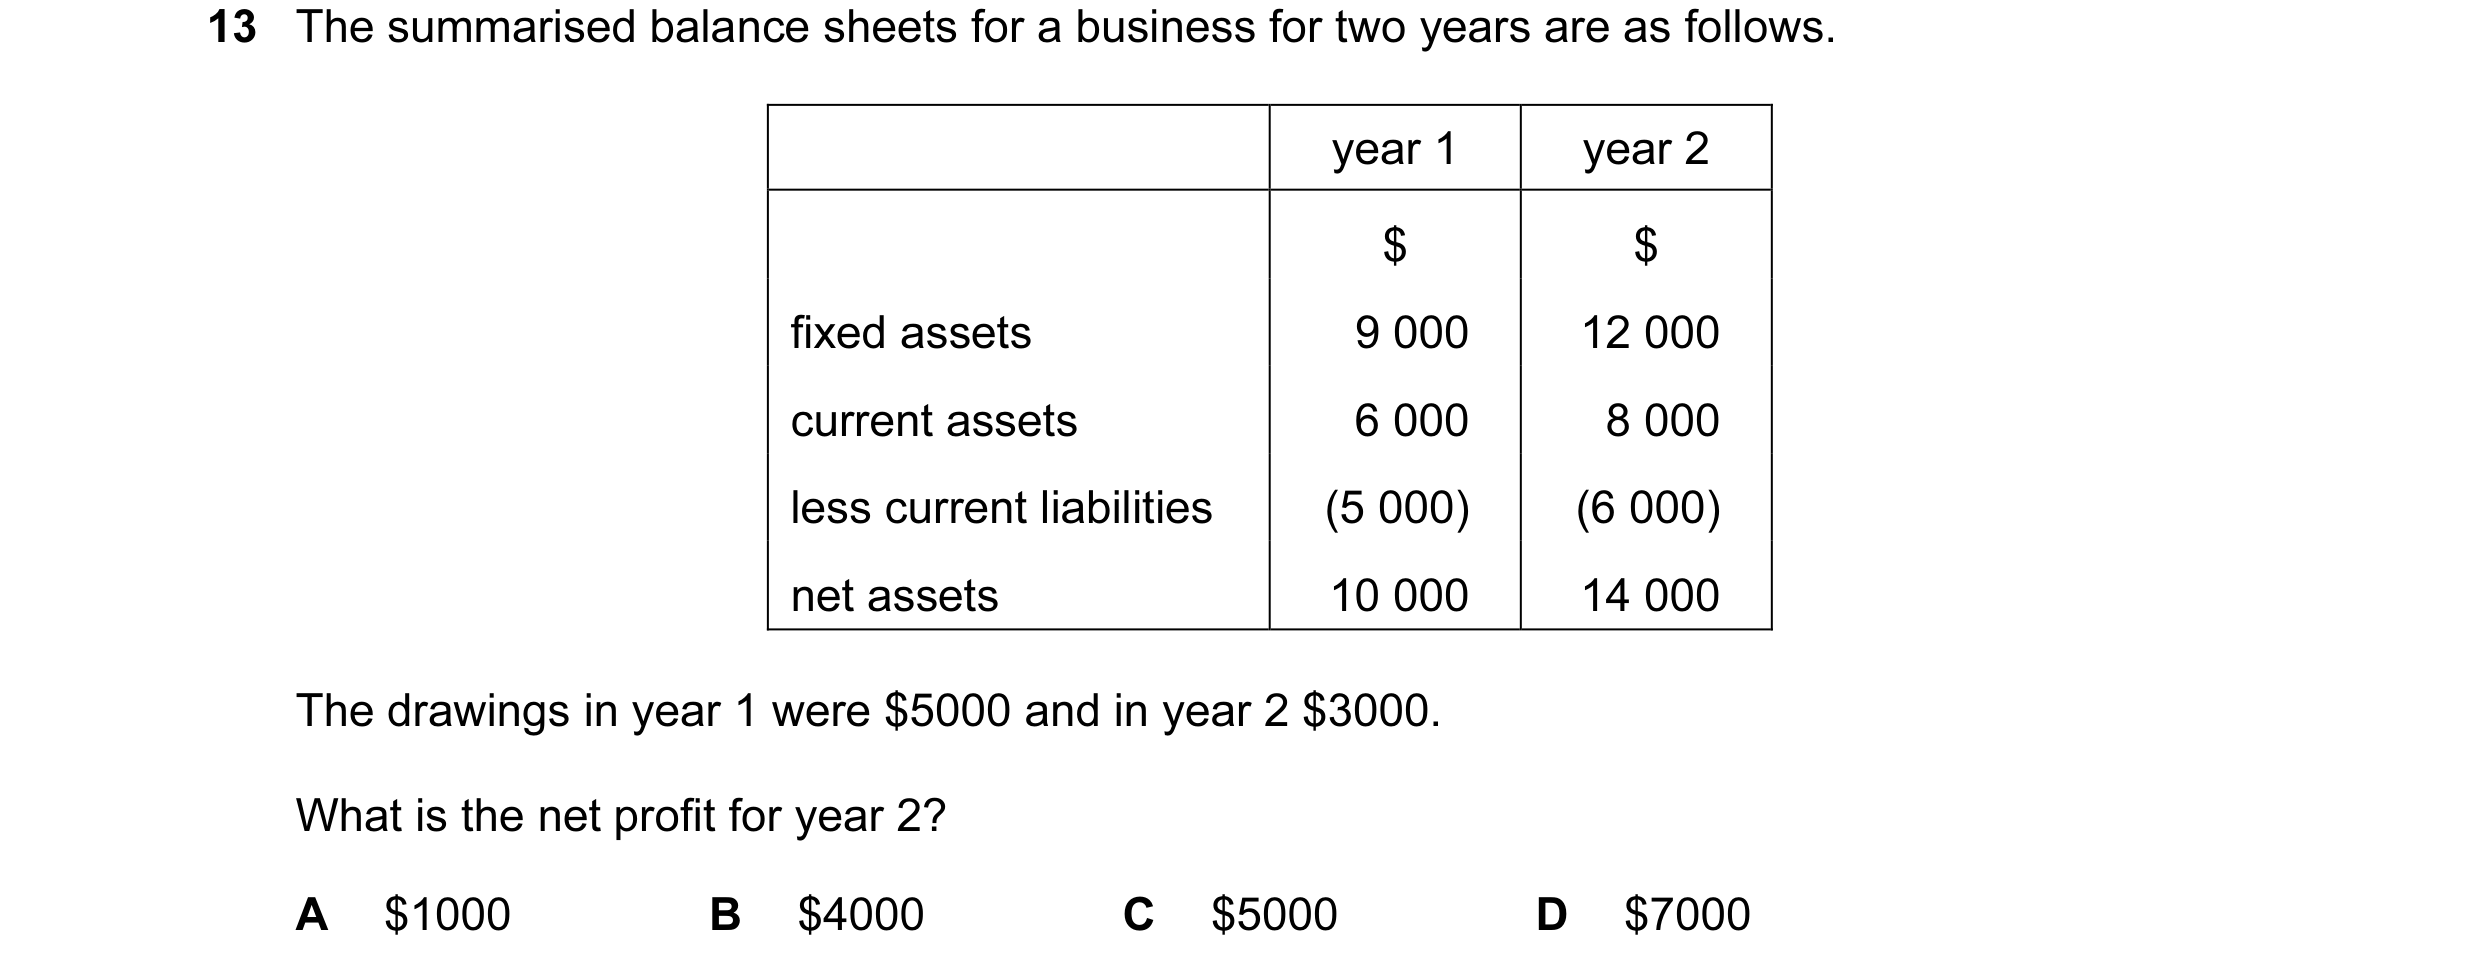 20 / 233
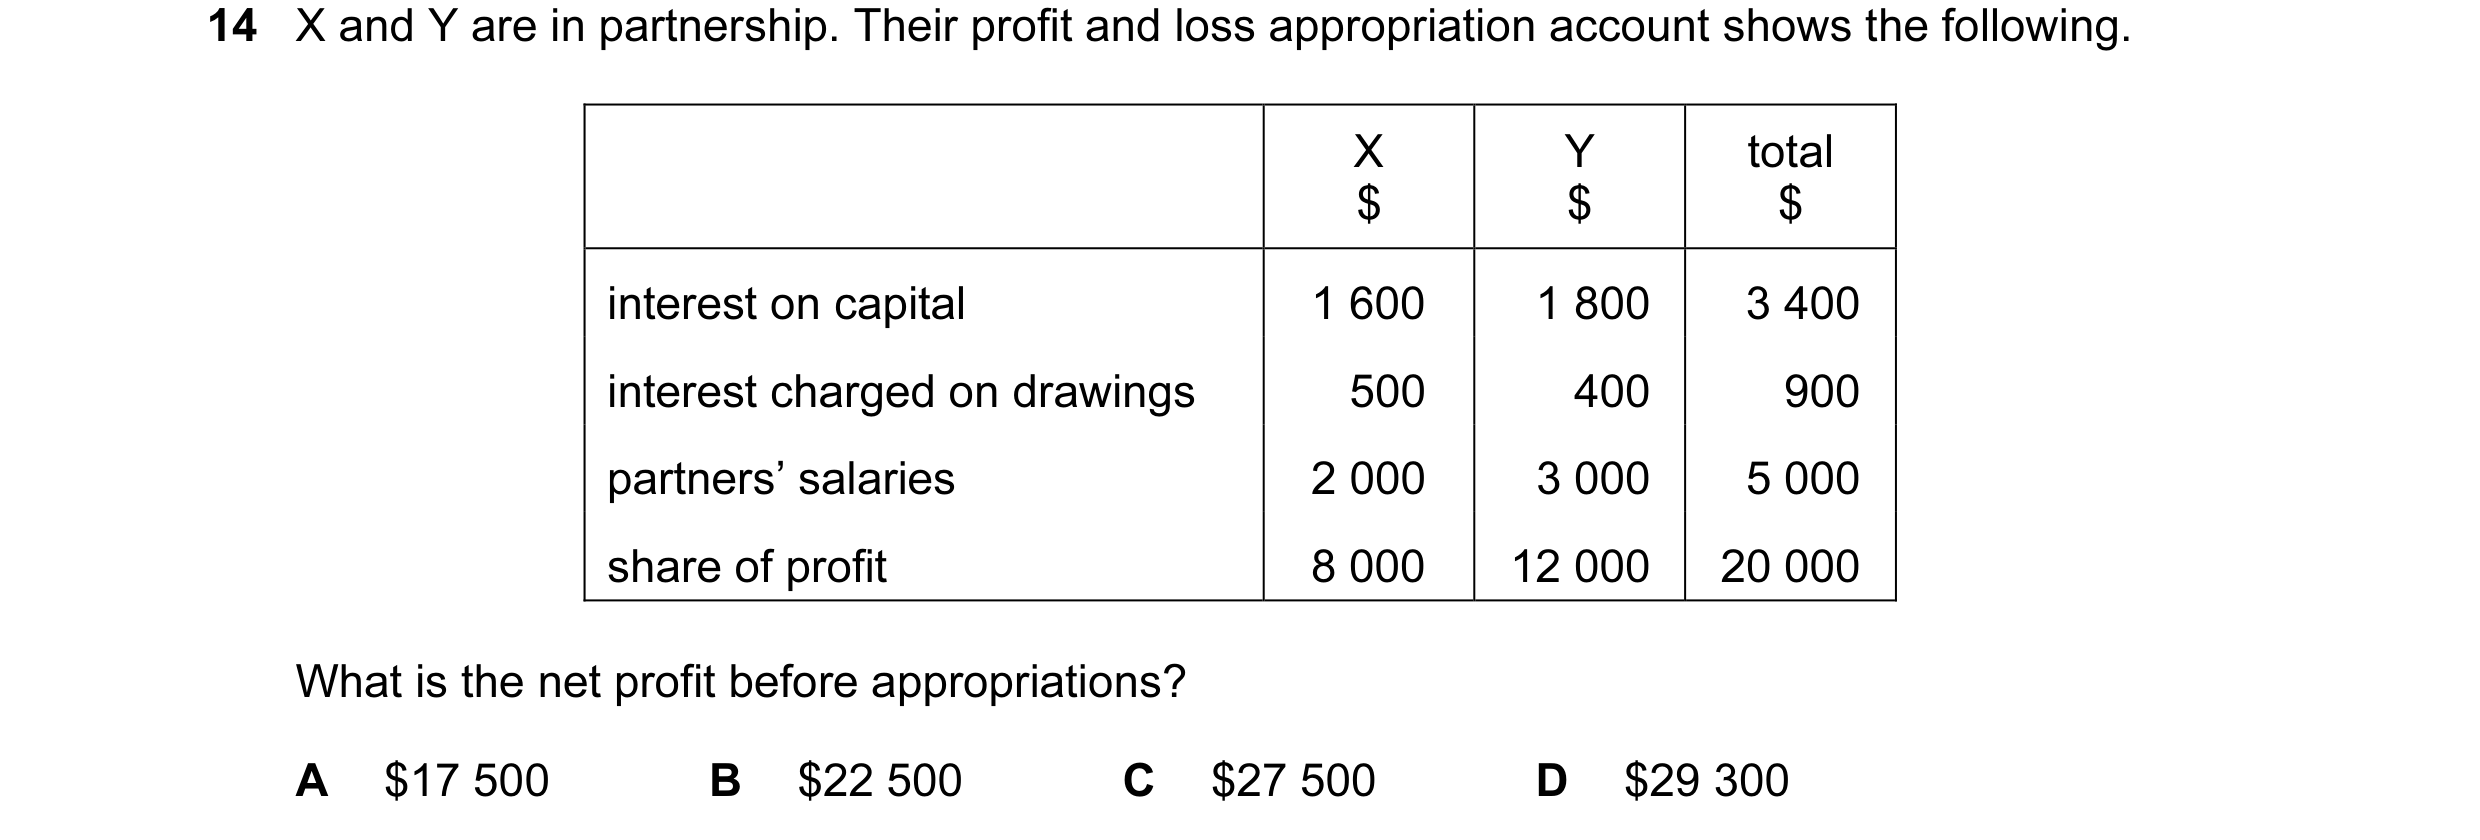
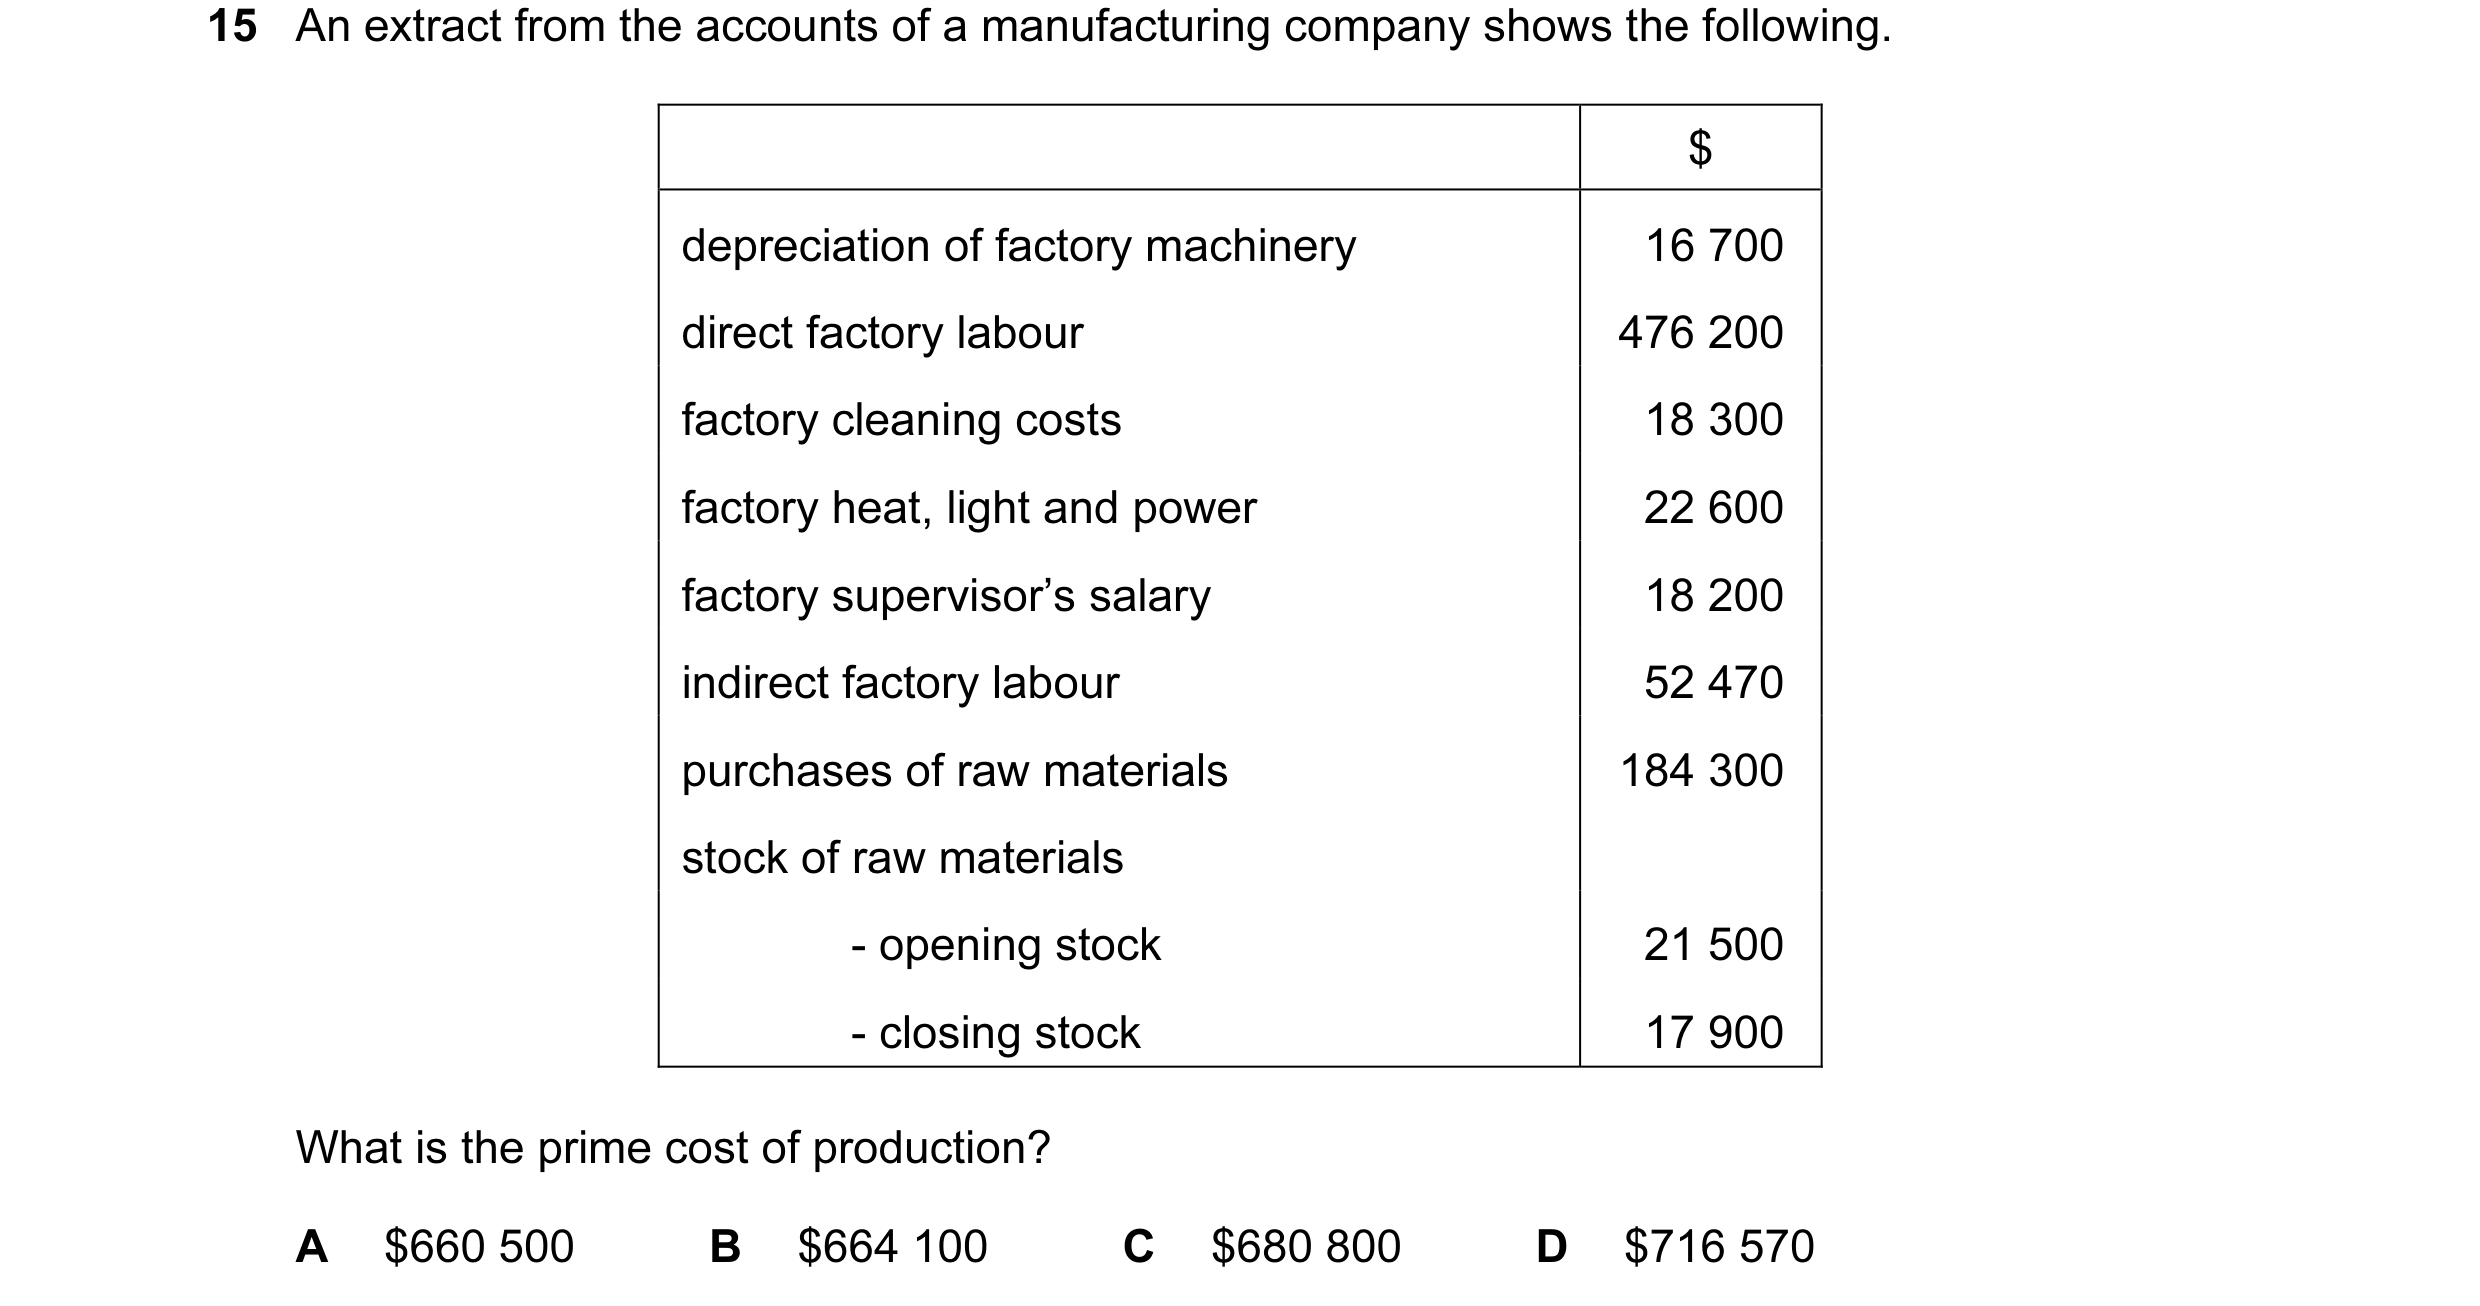
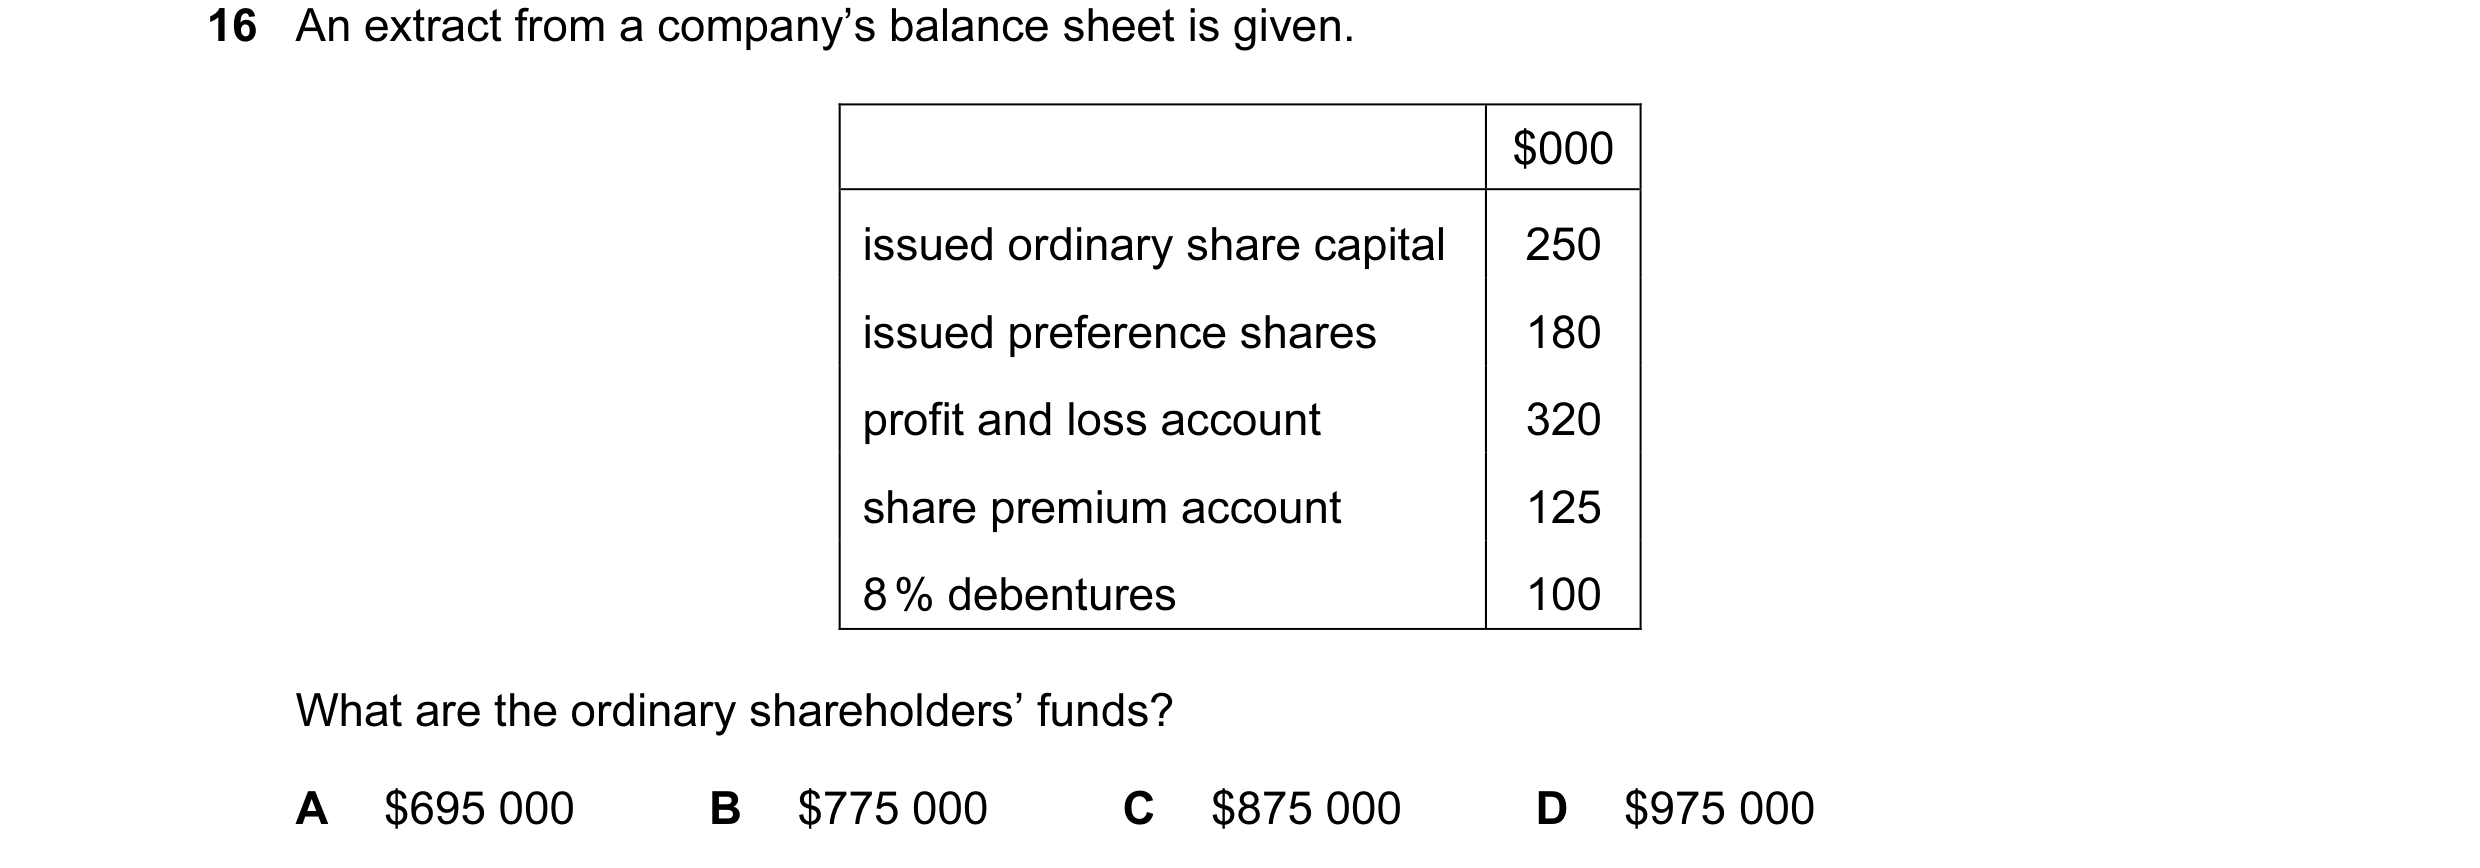 21 / 233
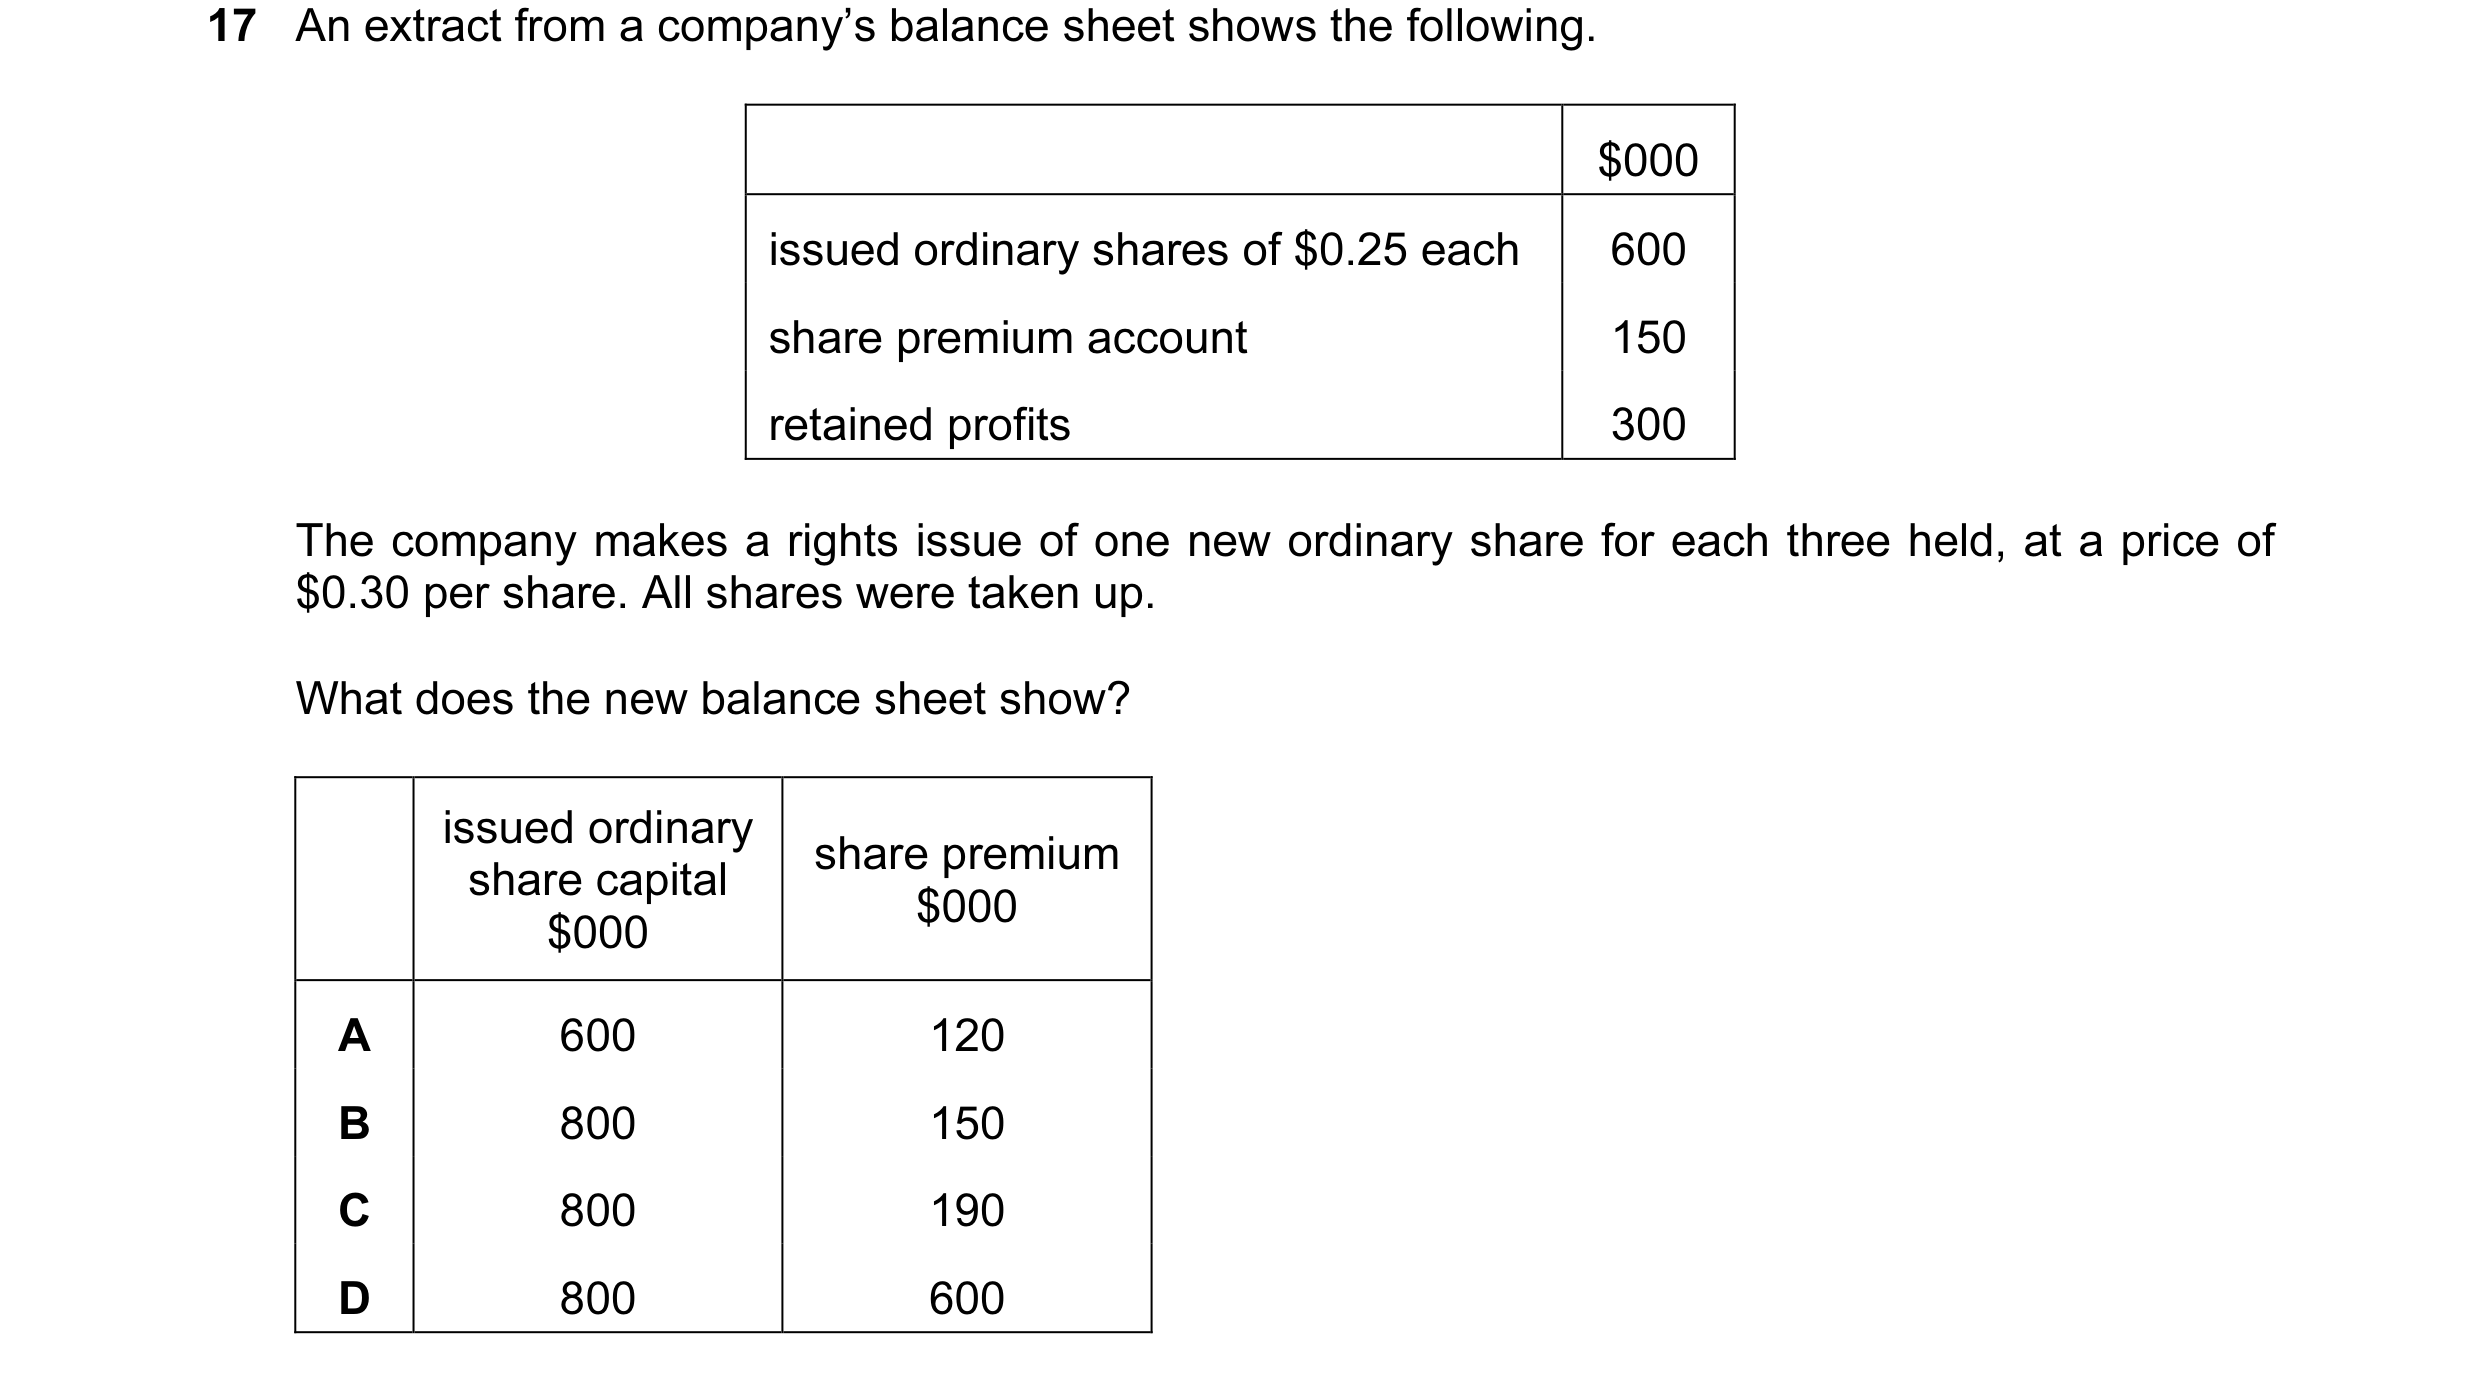
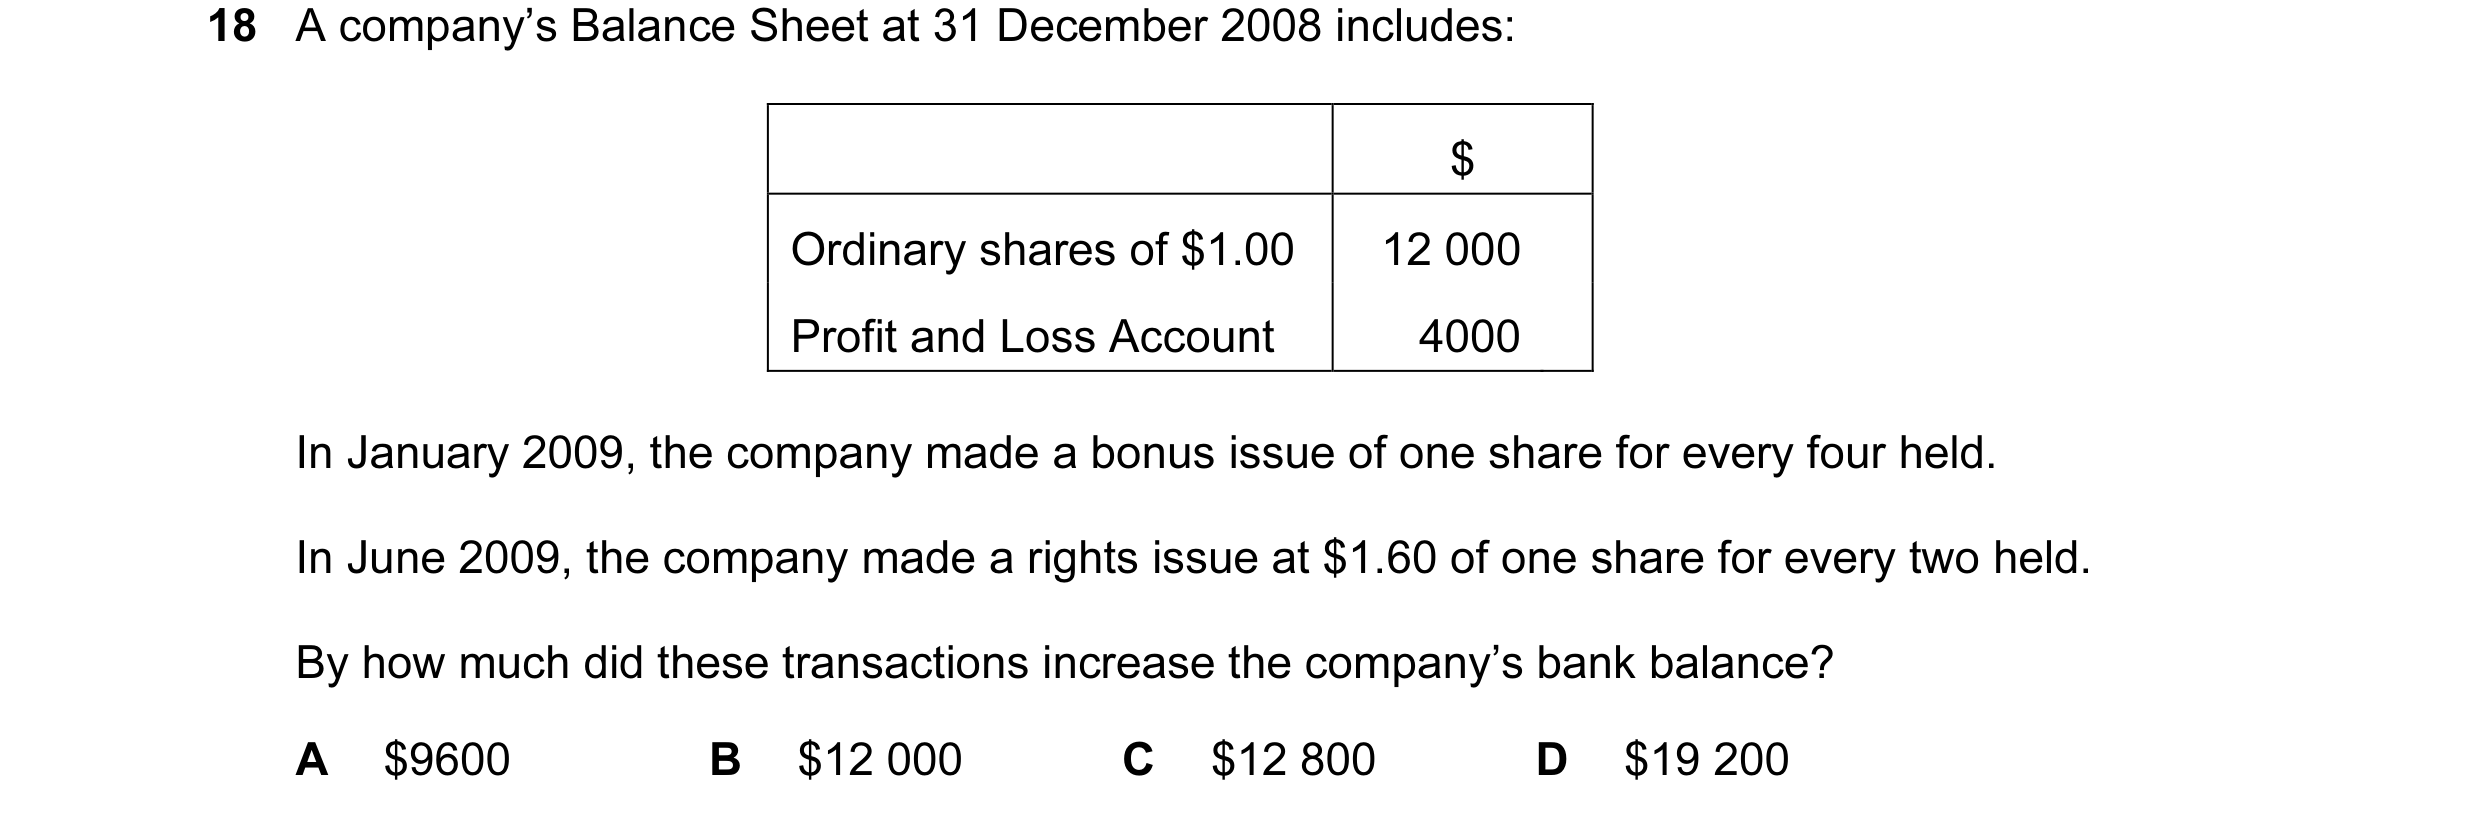
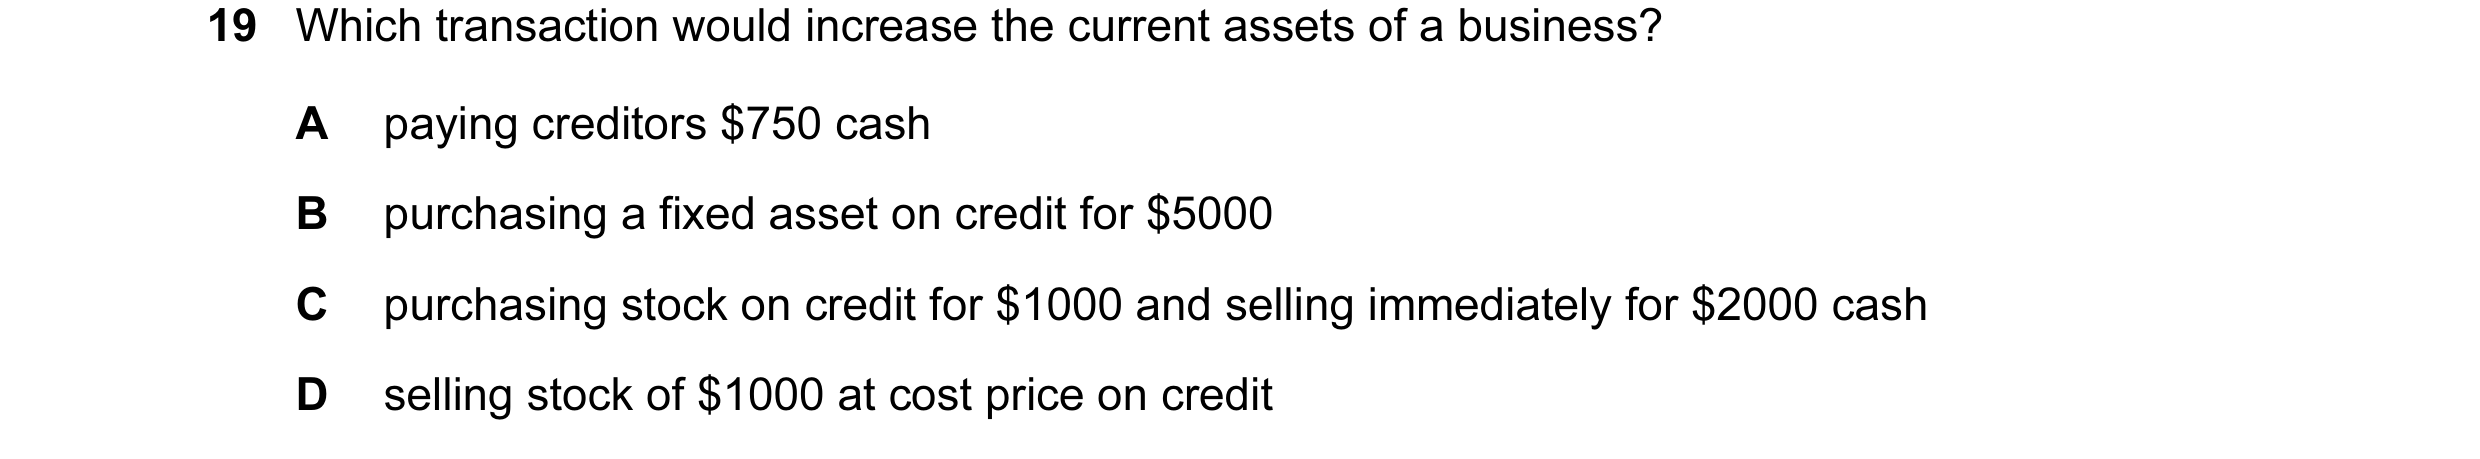 22 / 233
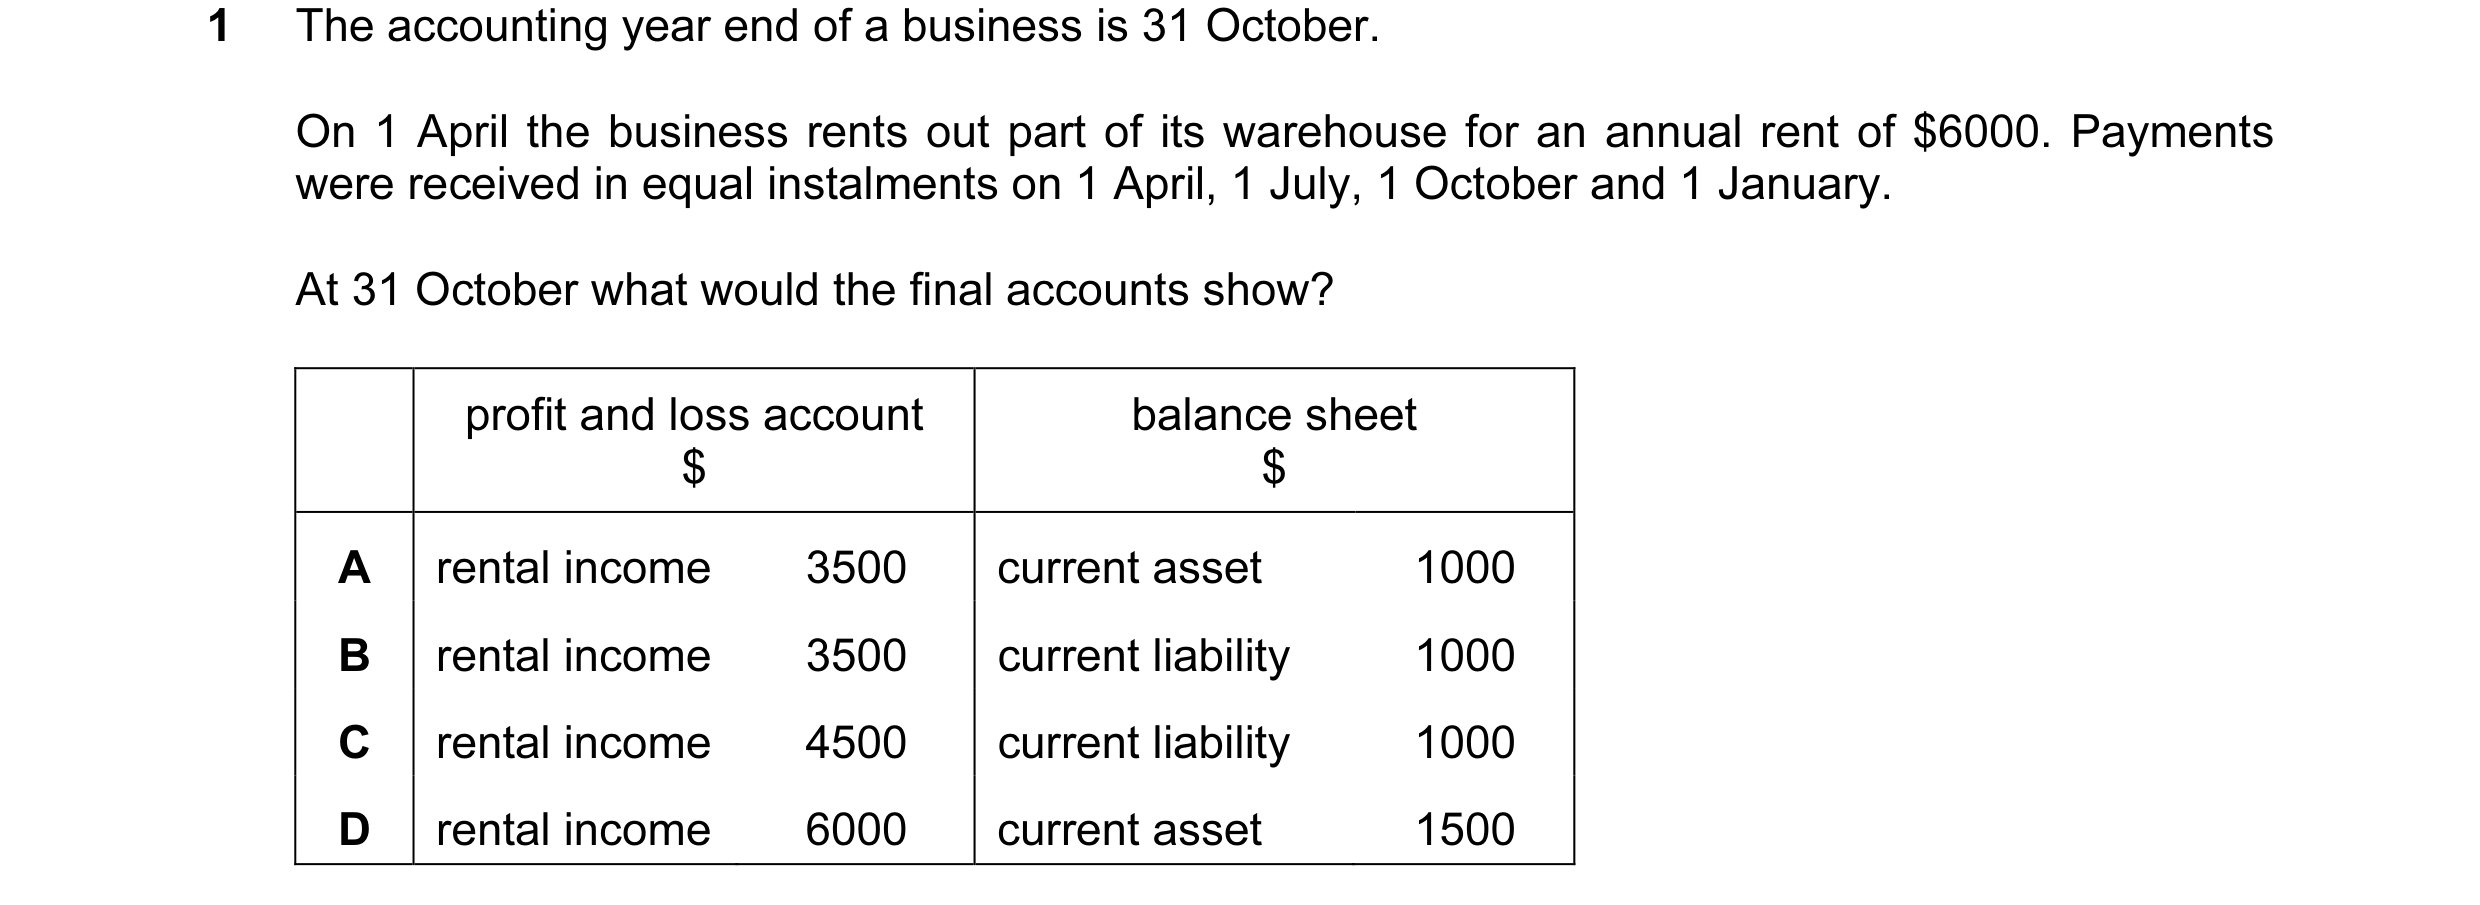
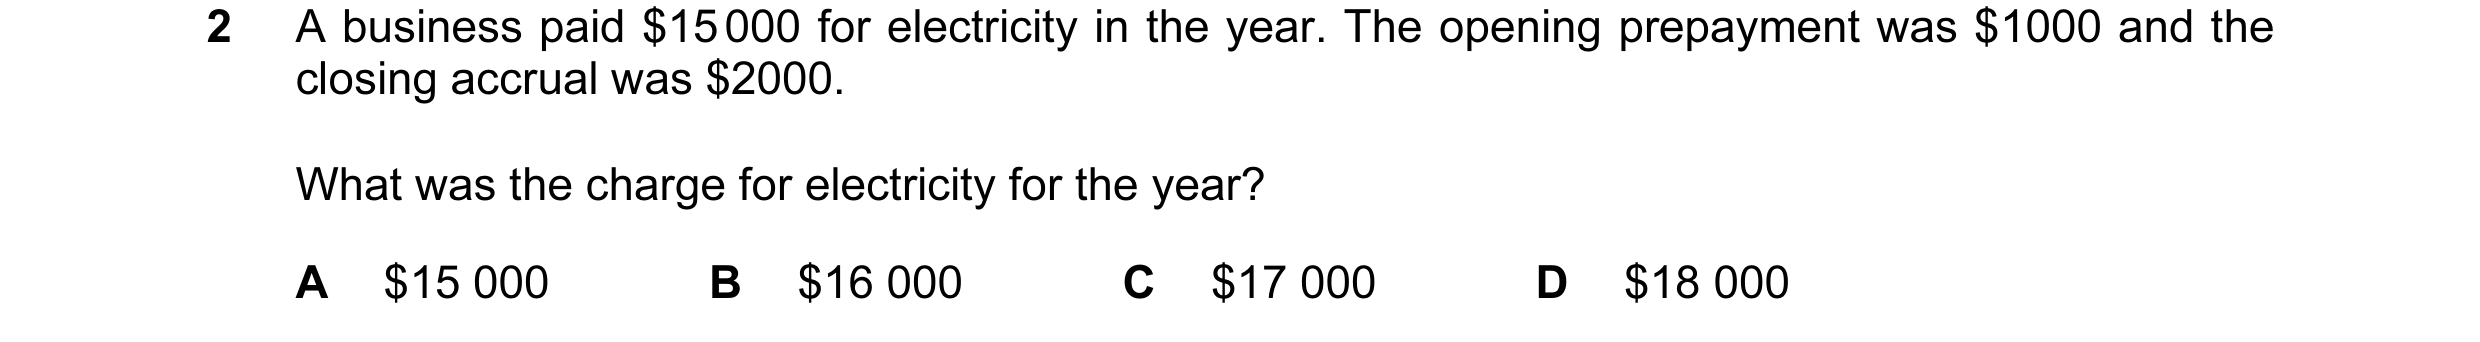
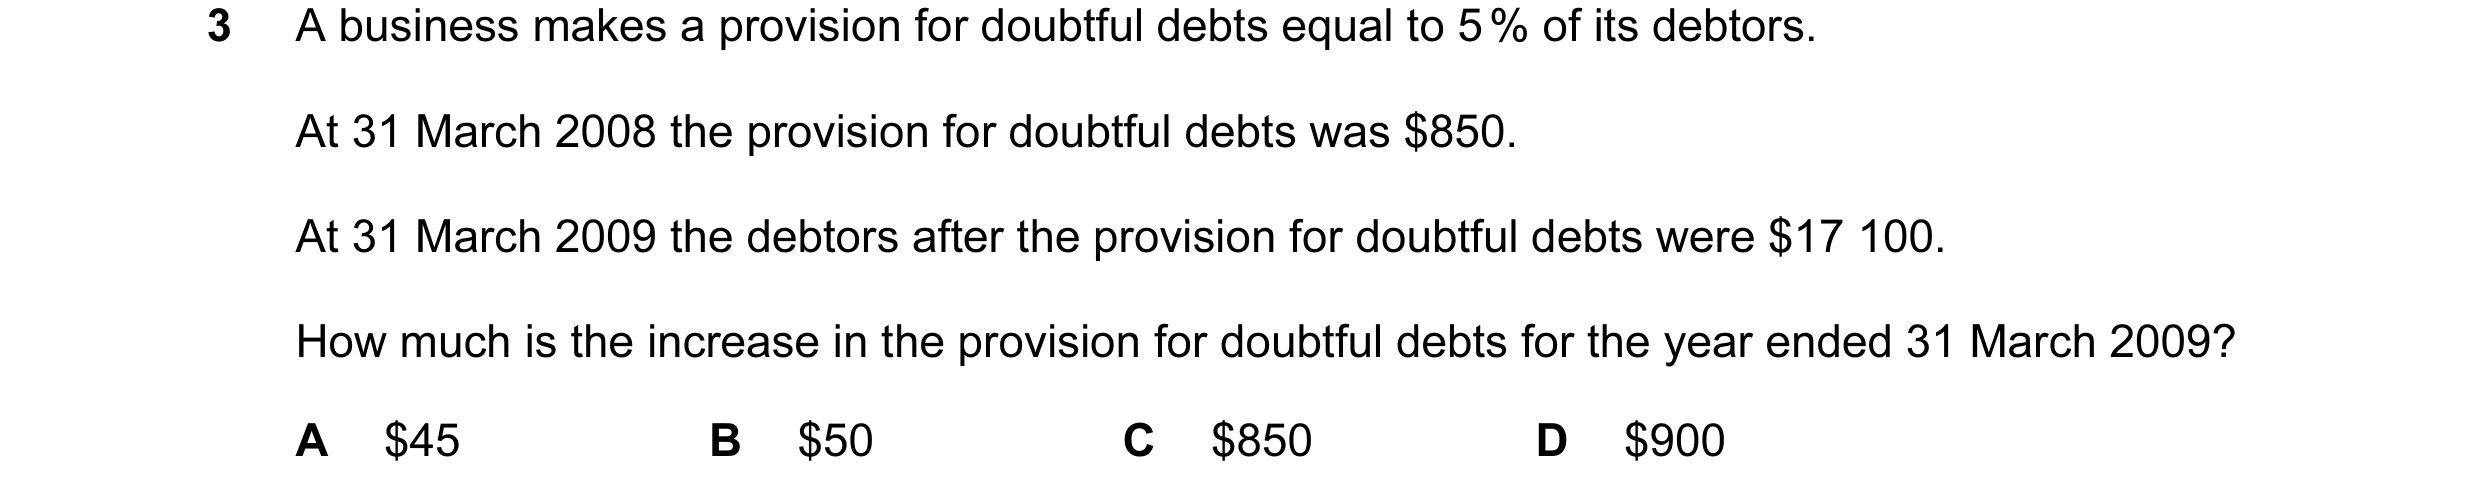
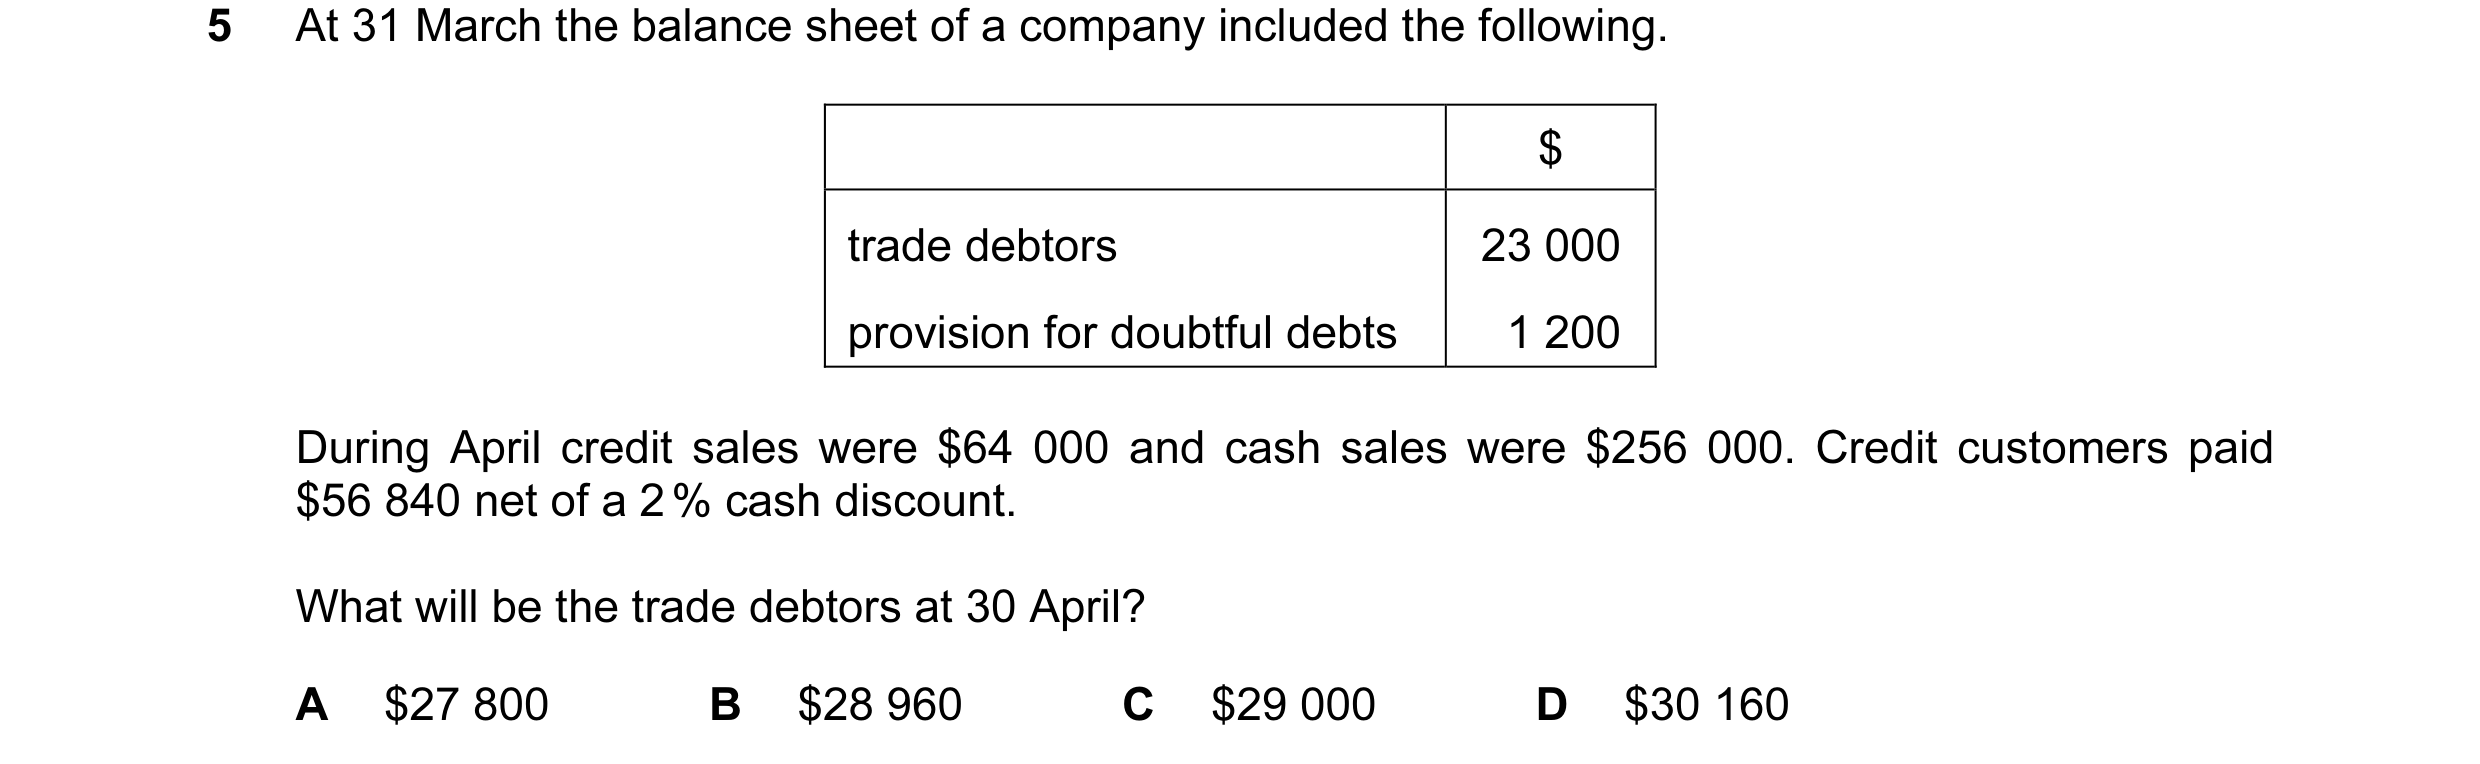
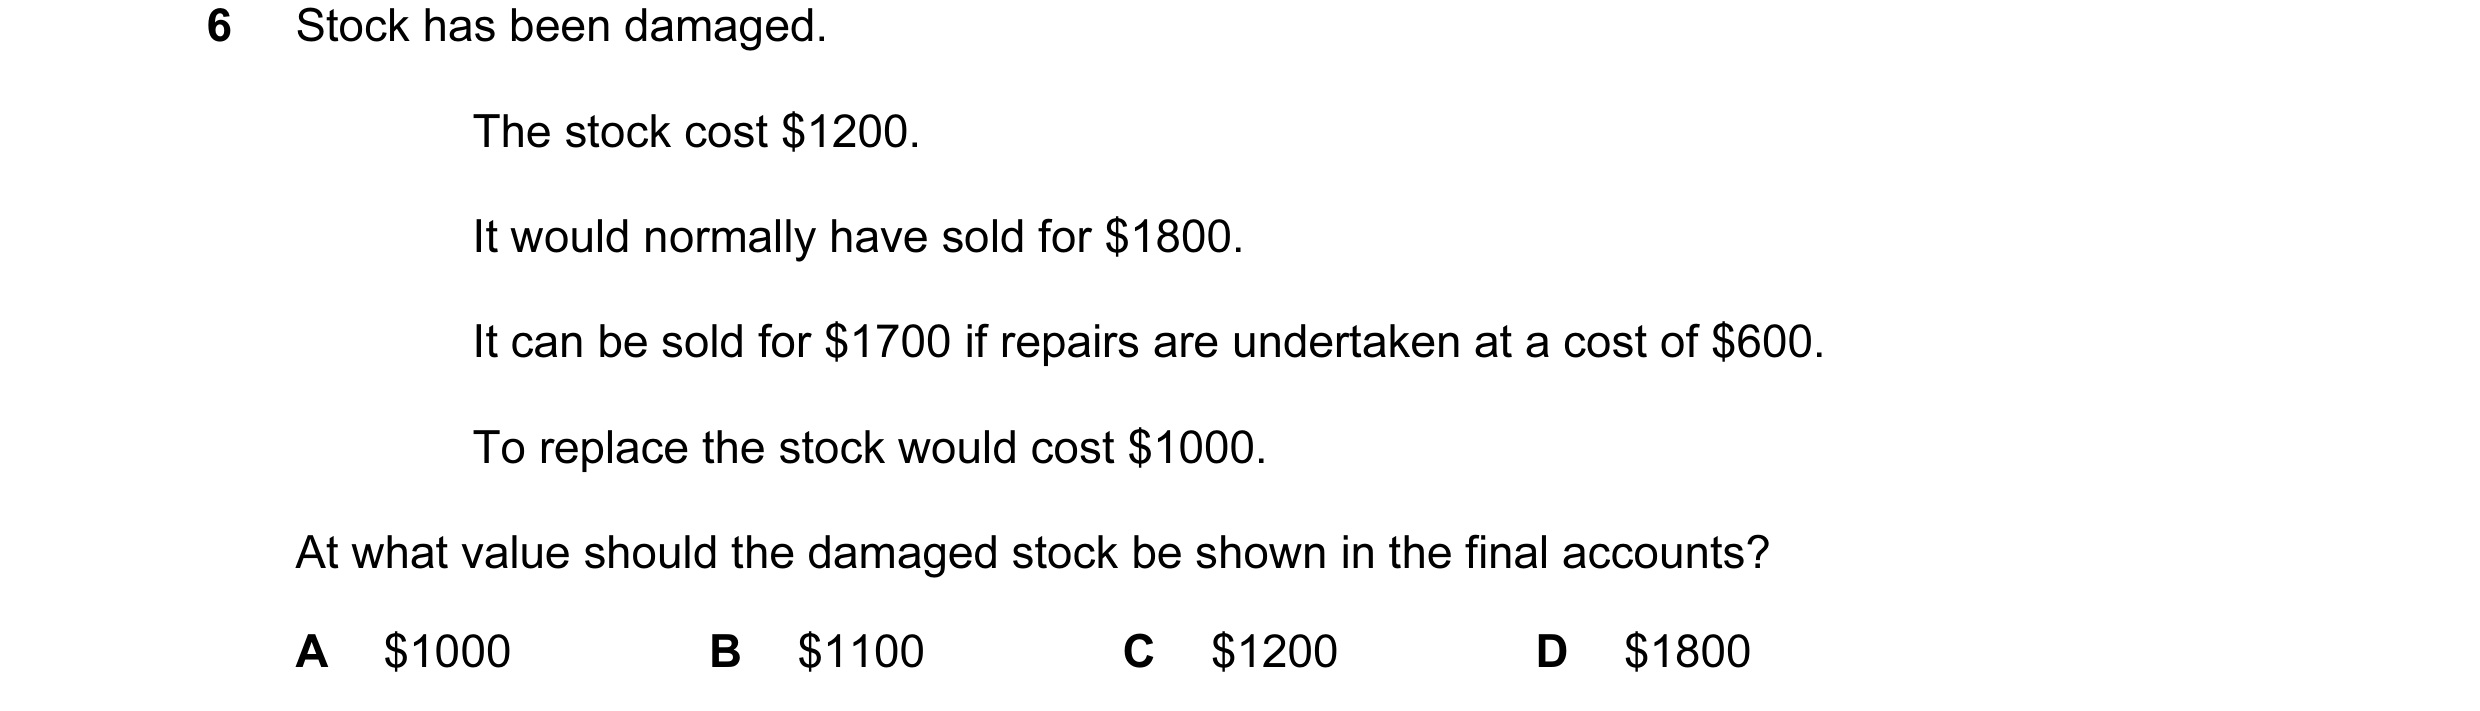 23 / 233
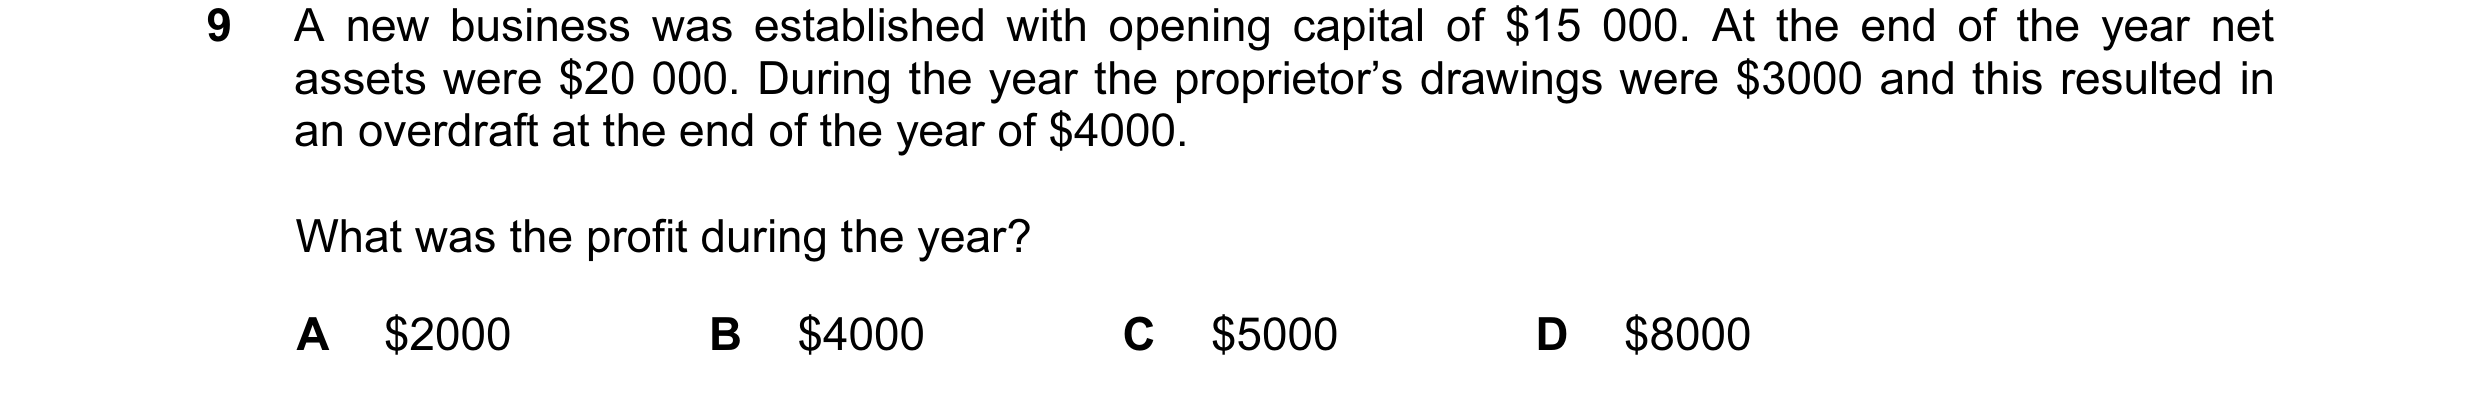
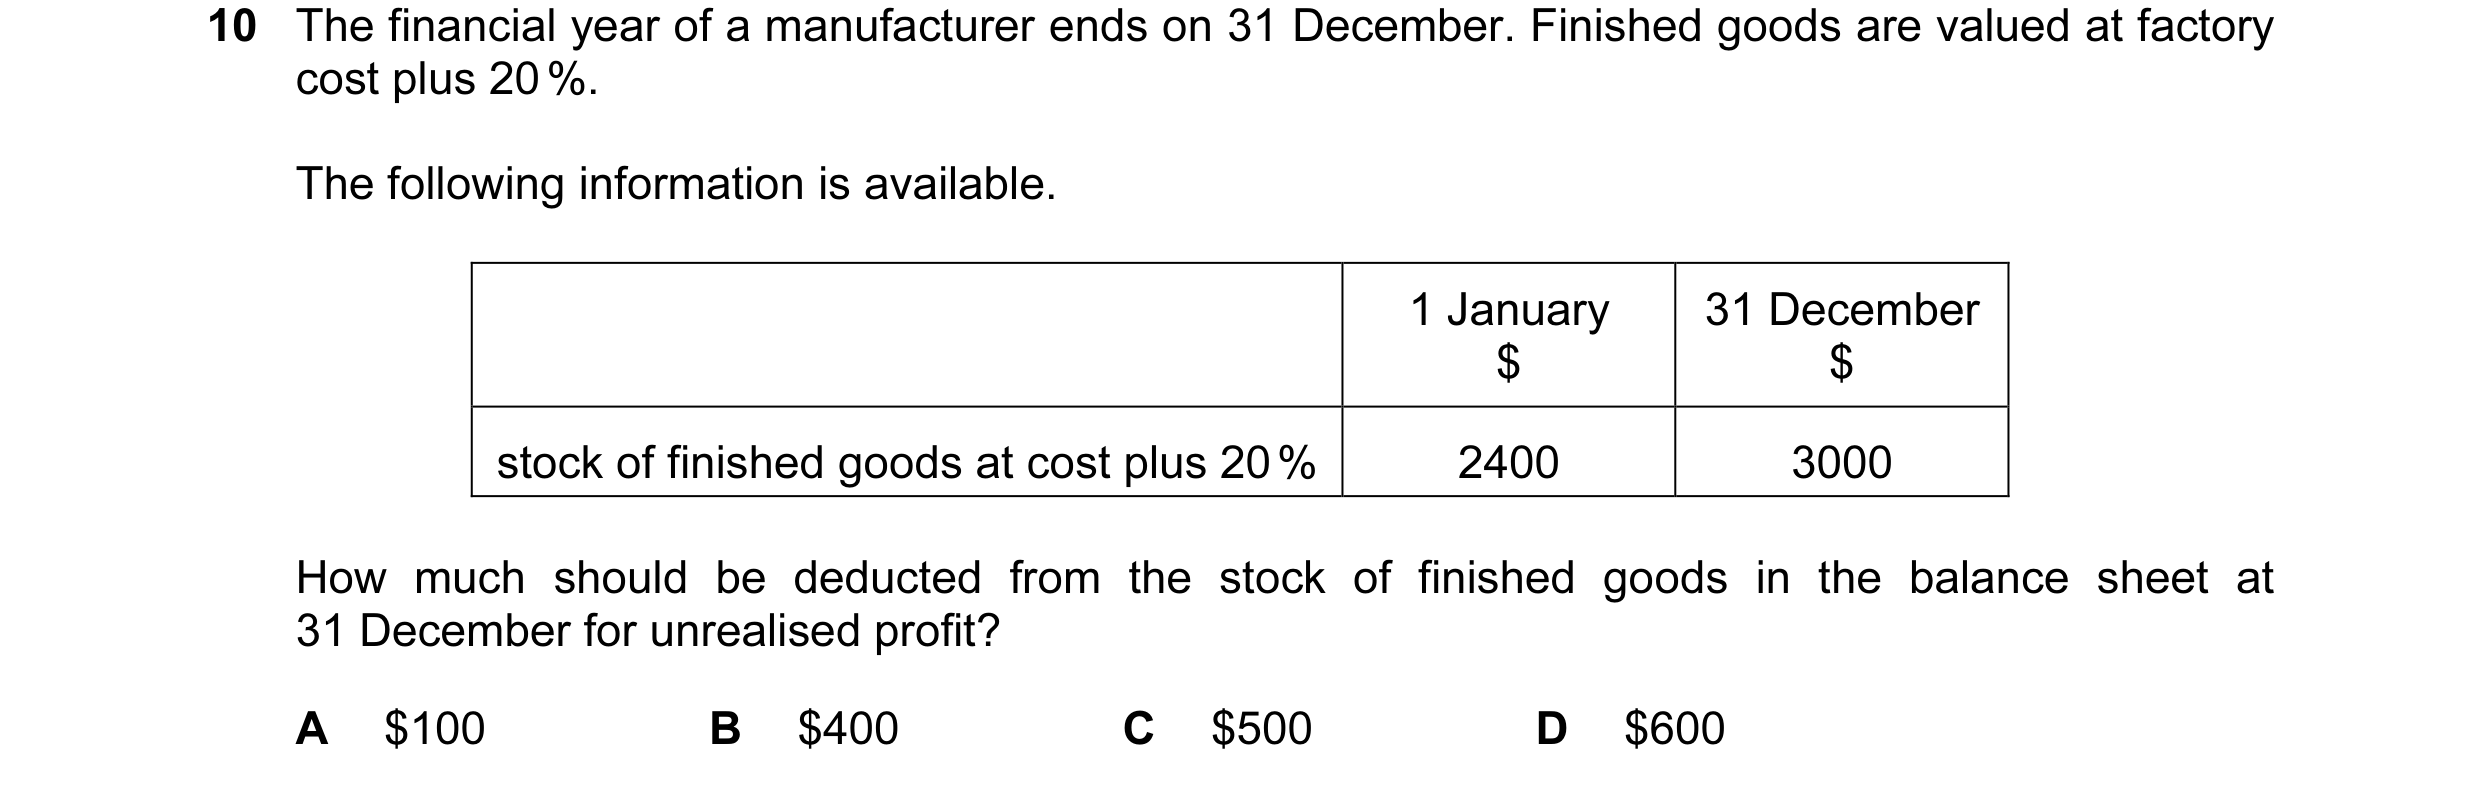
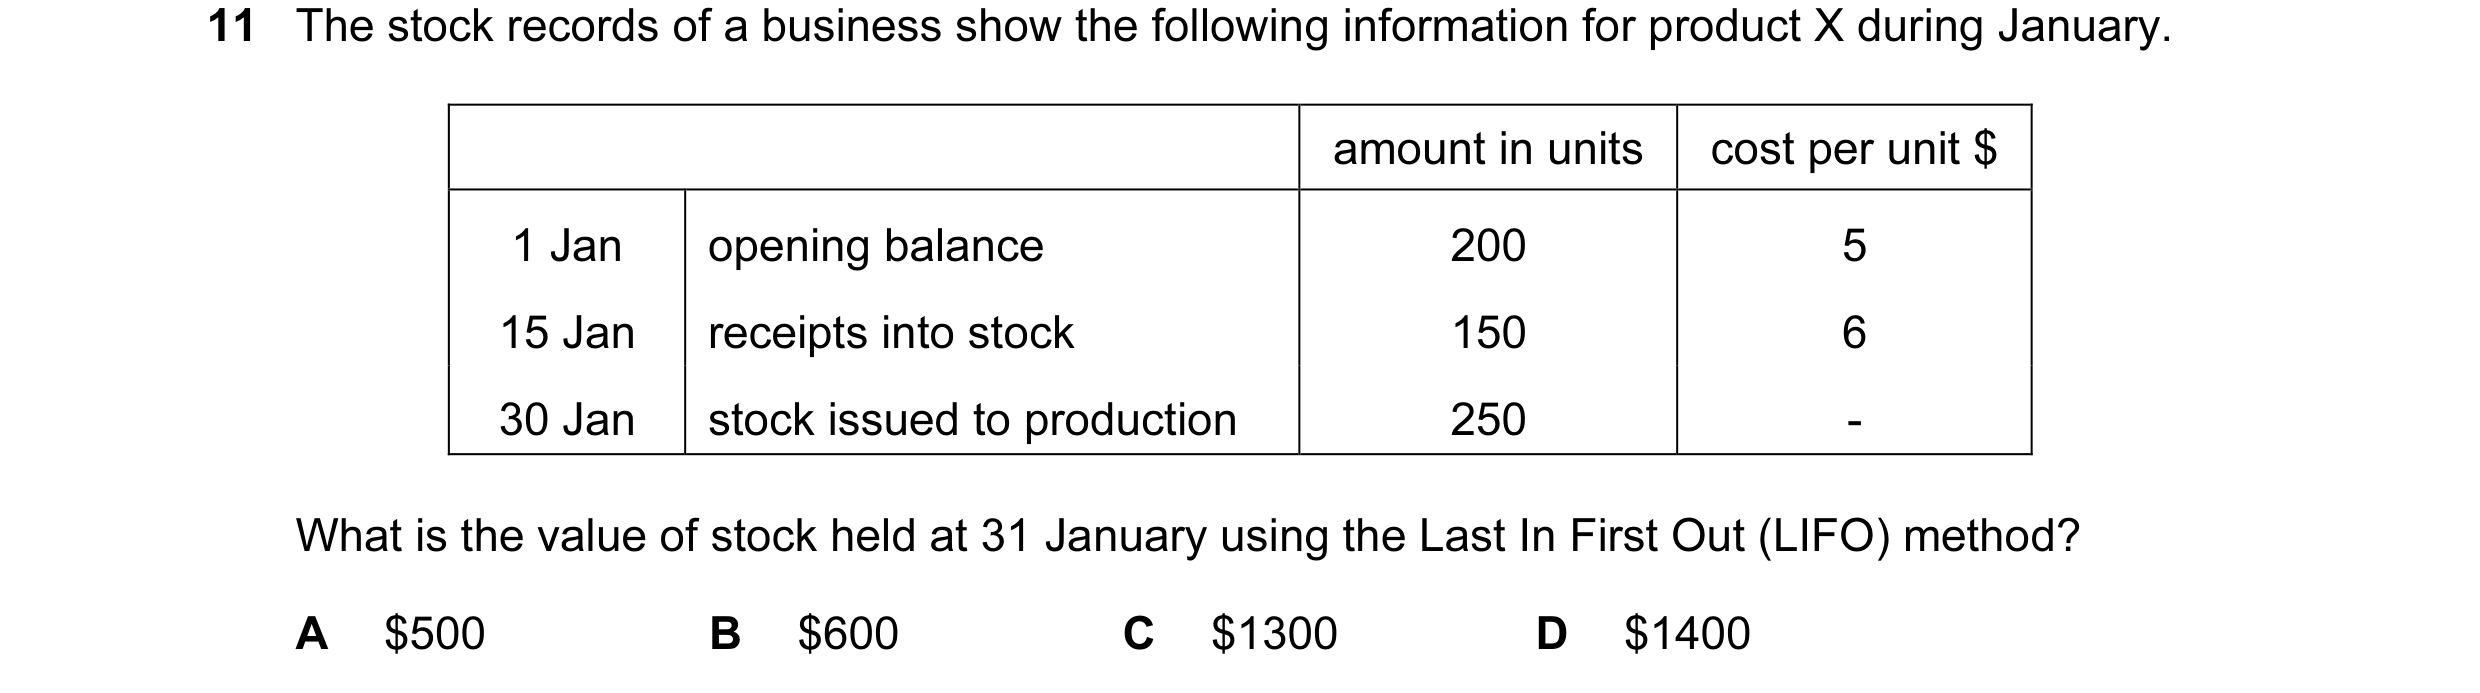
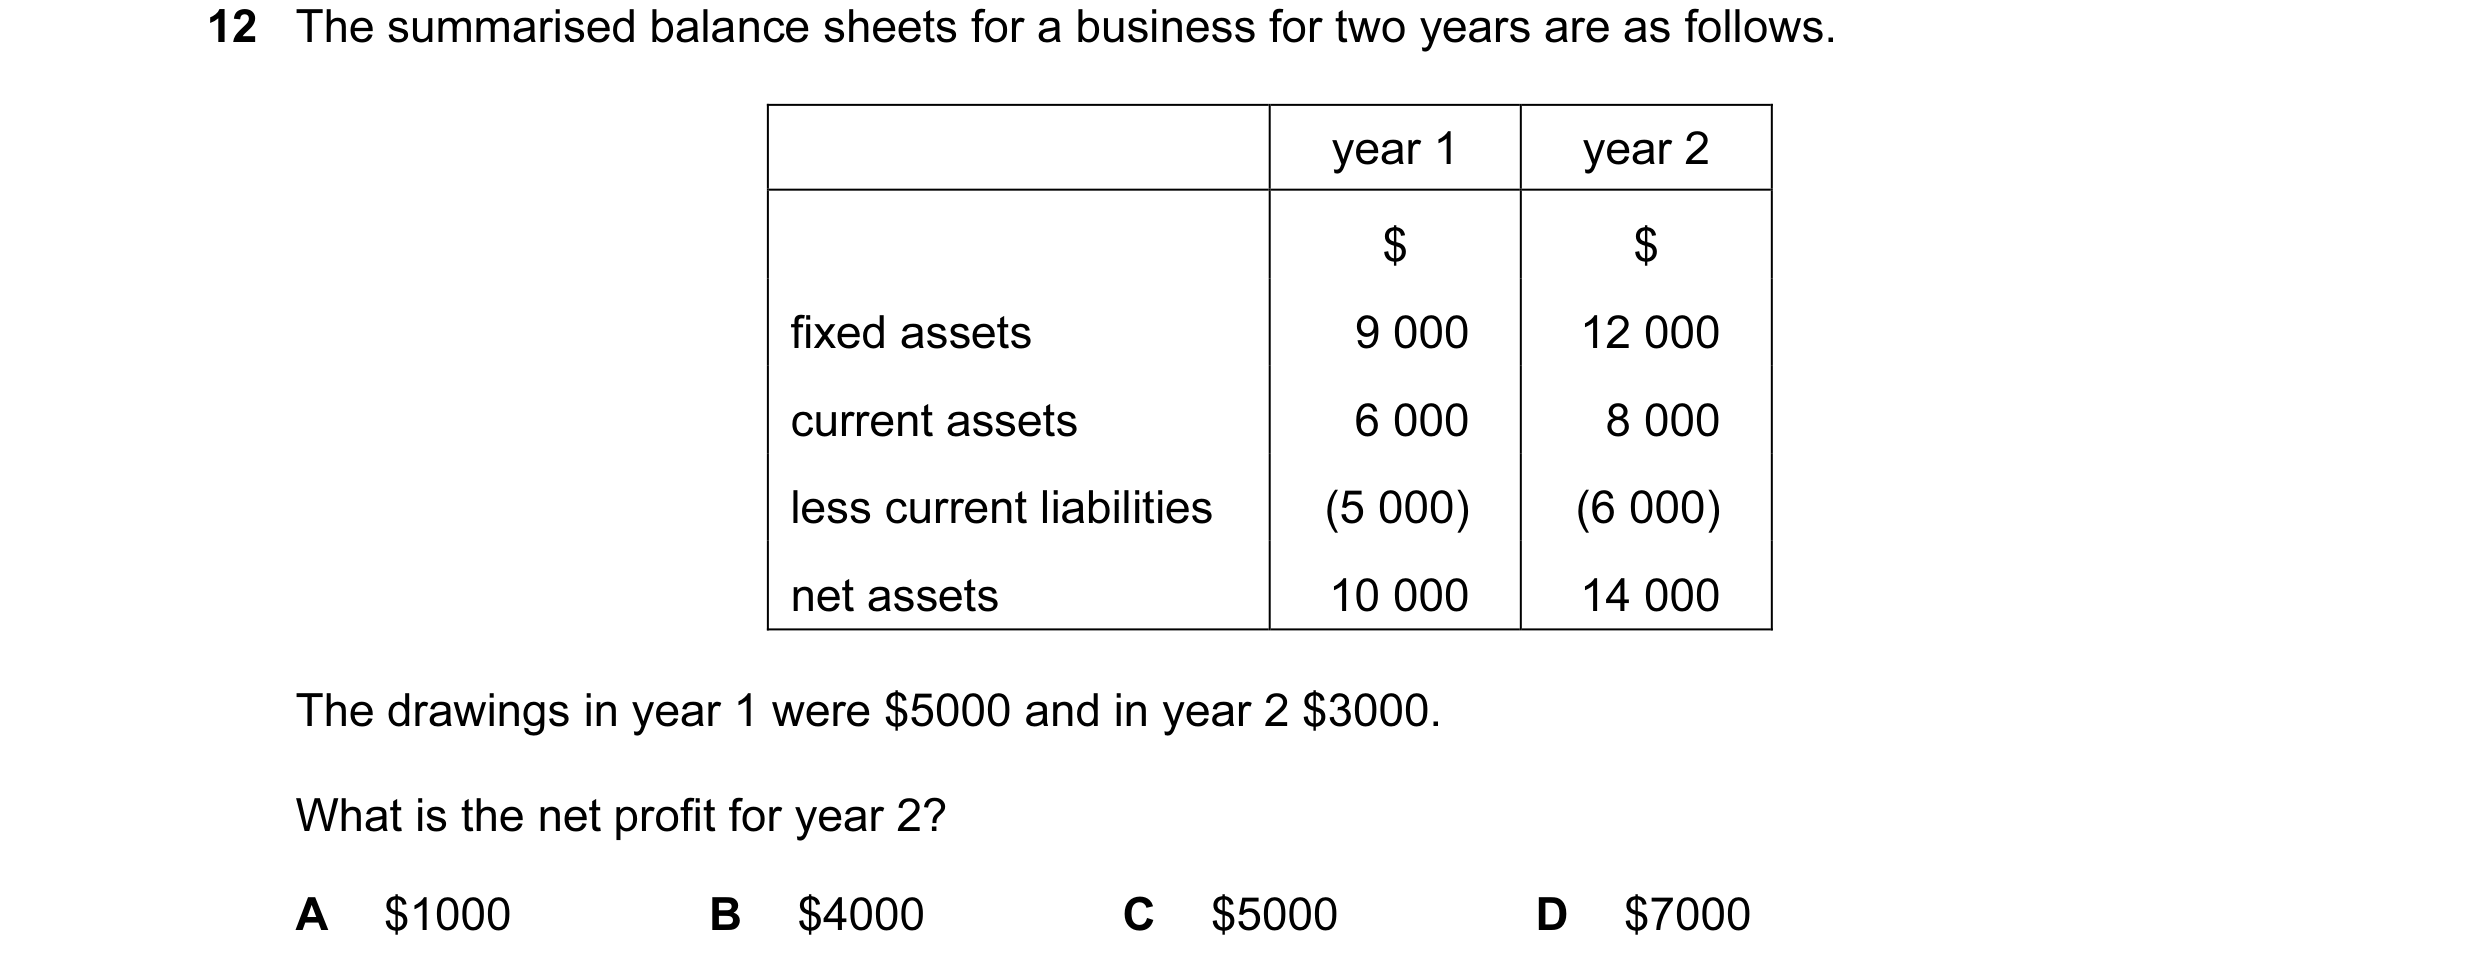 24 / 233
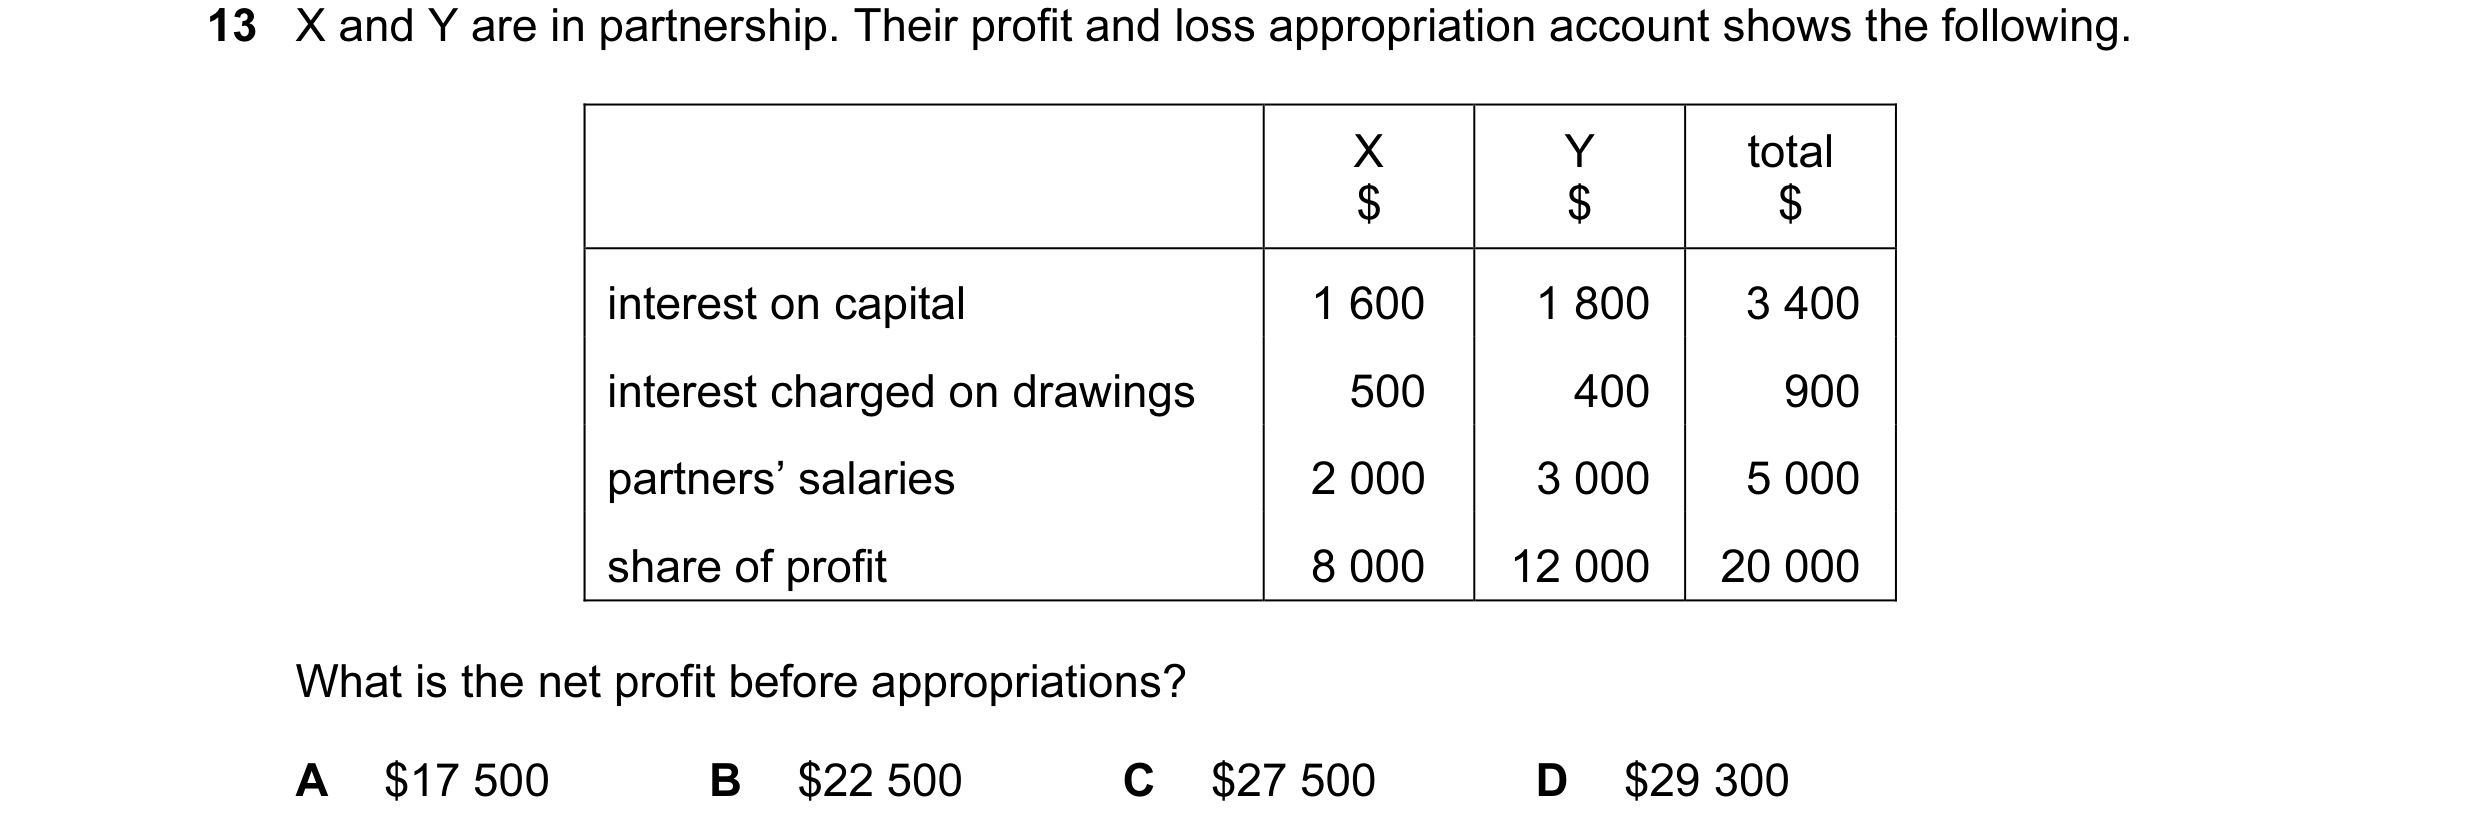
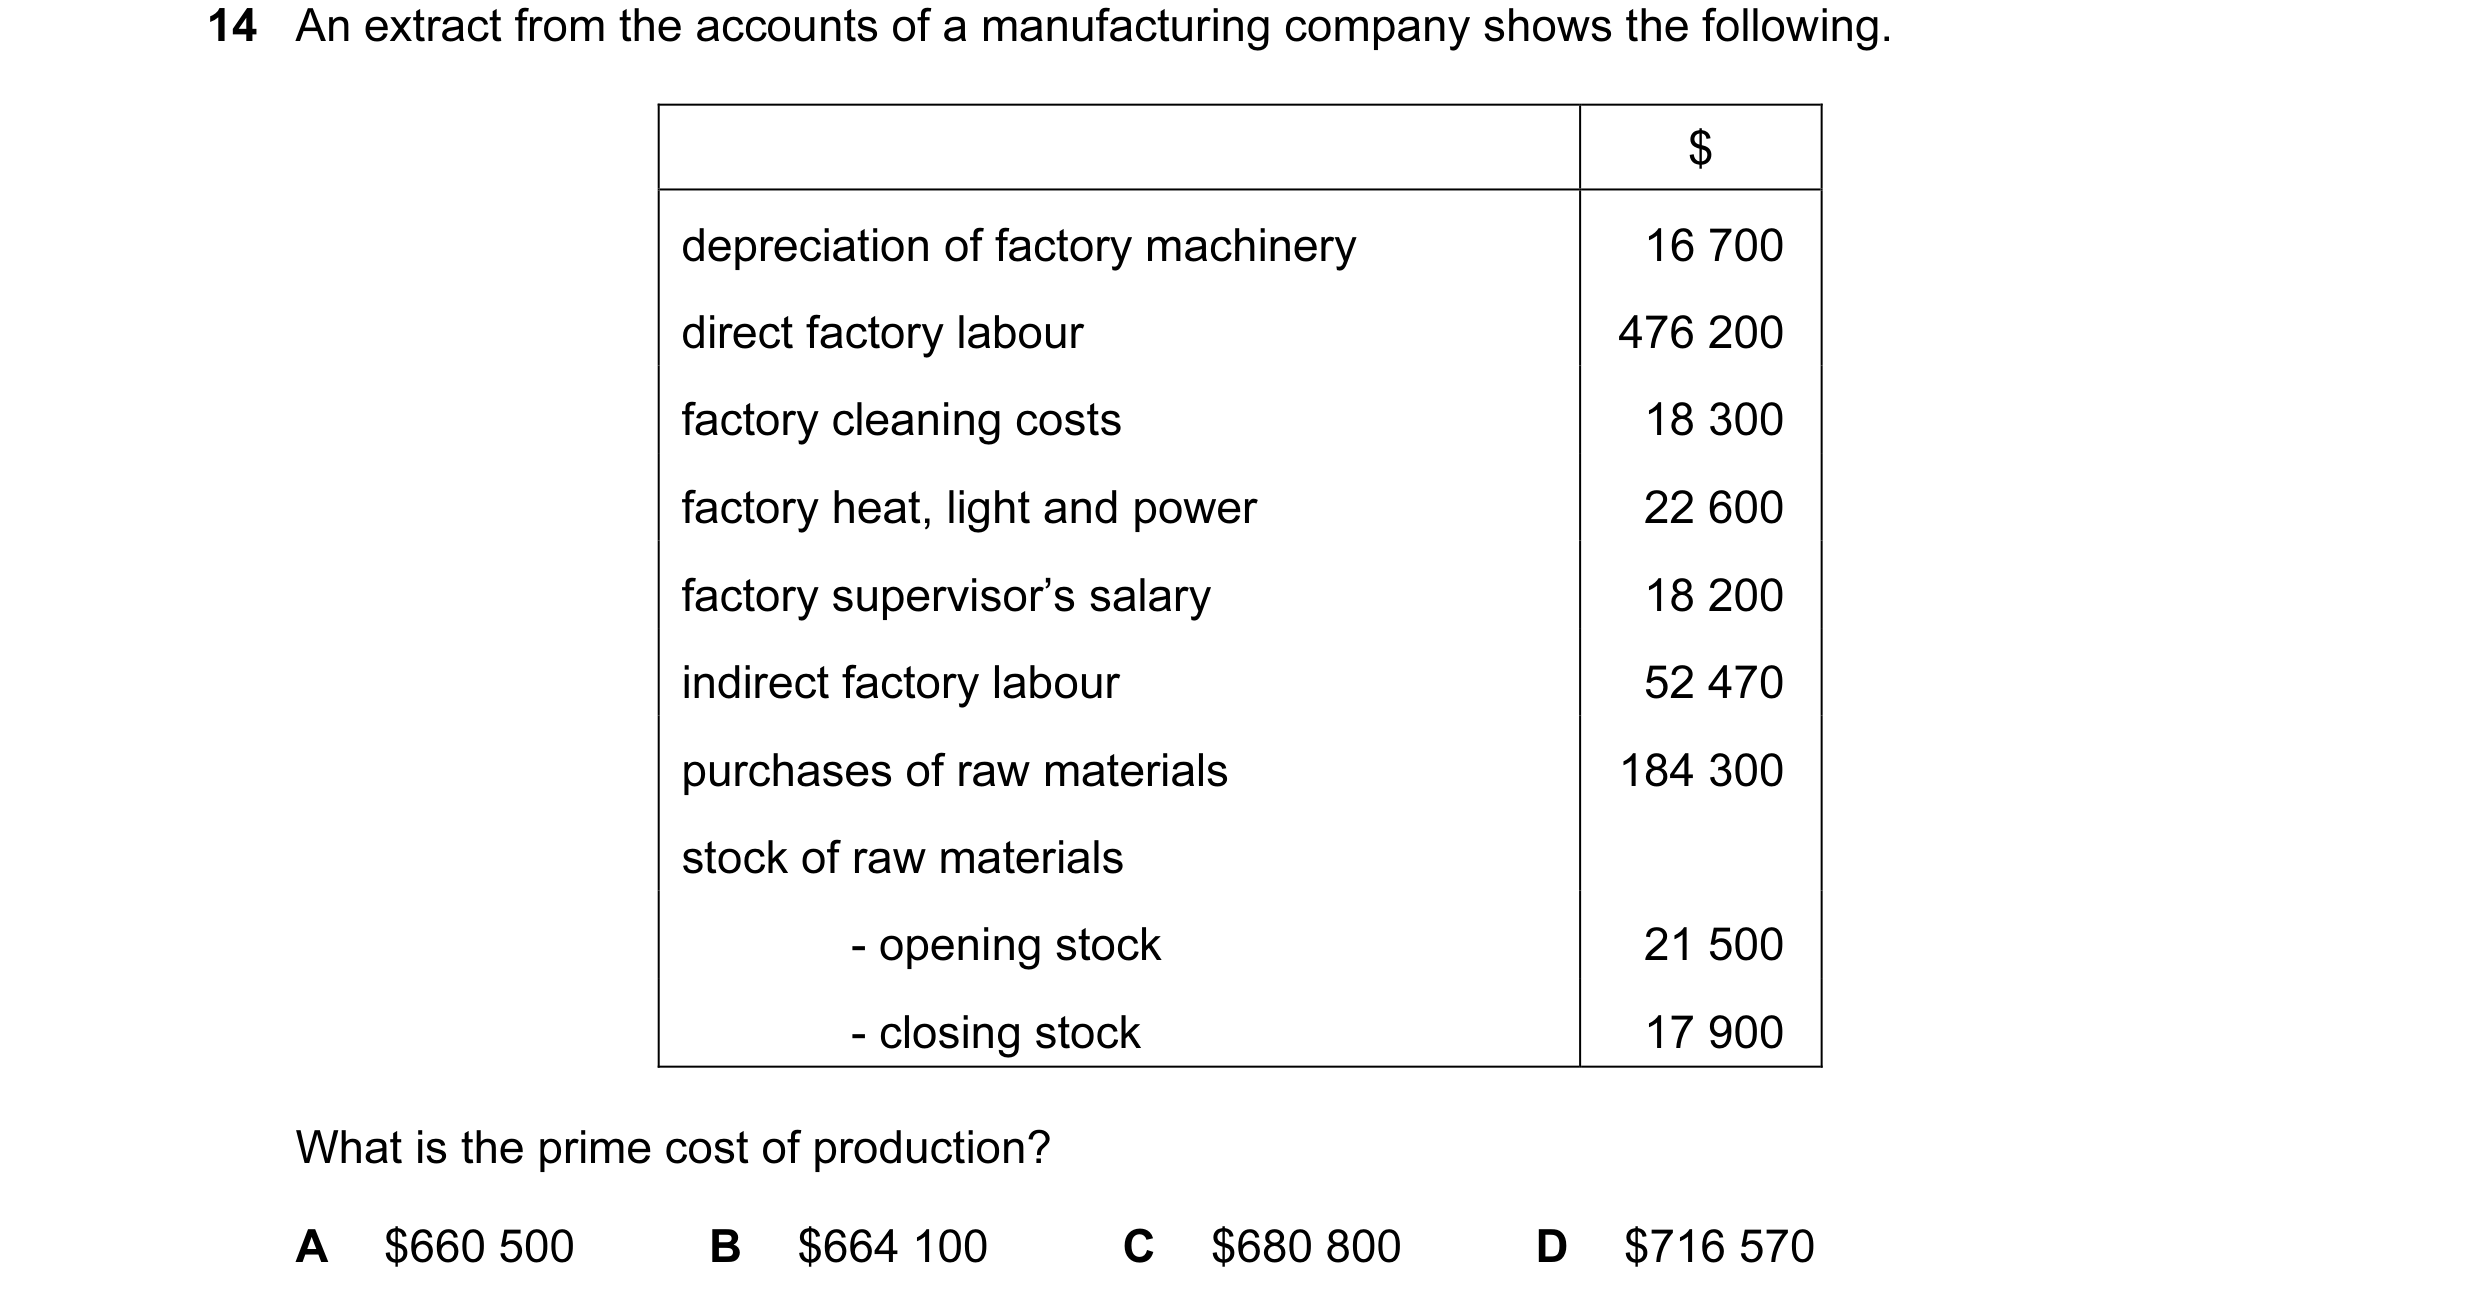
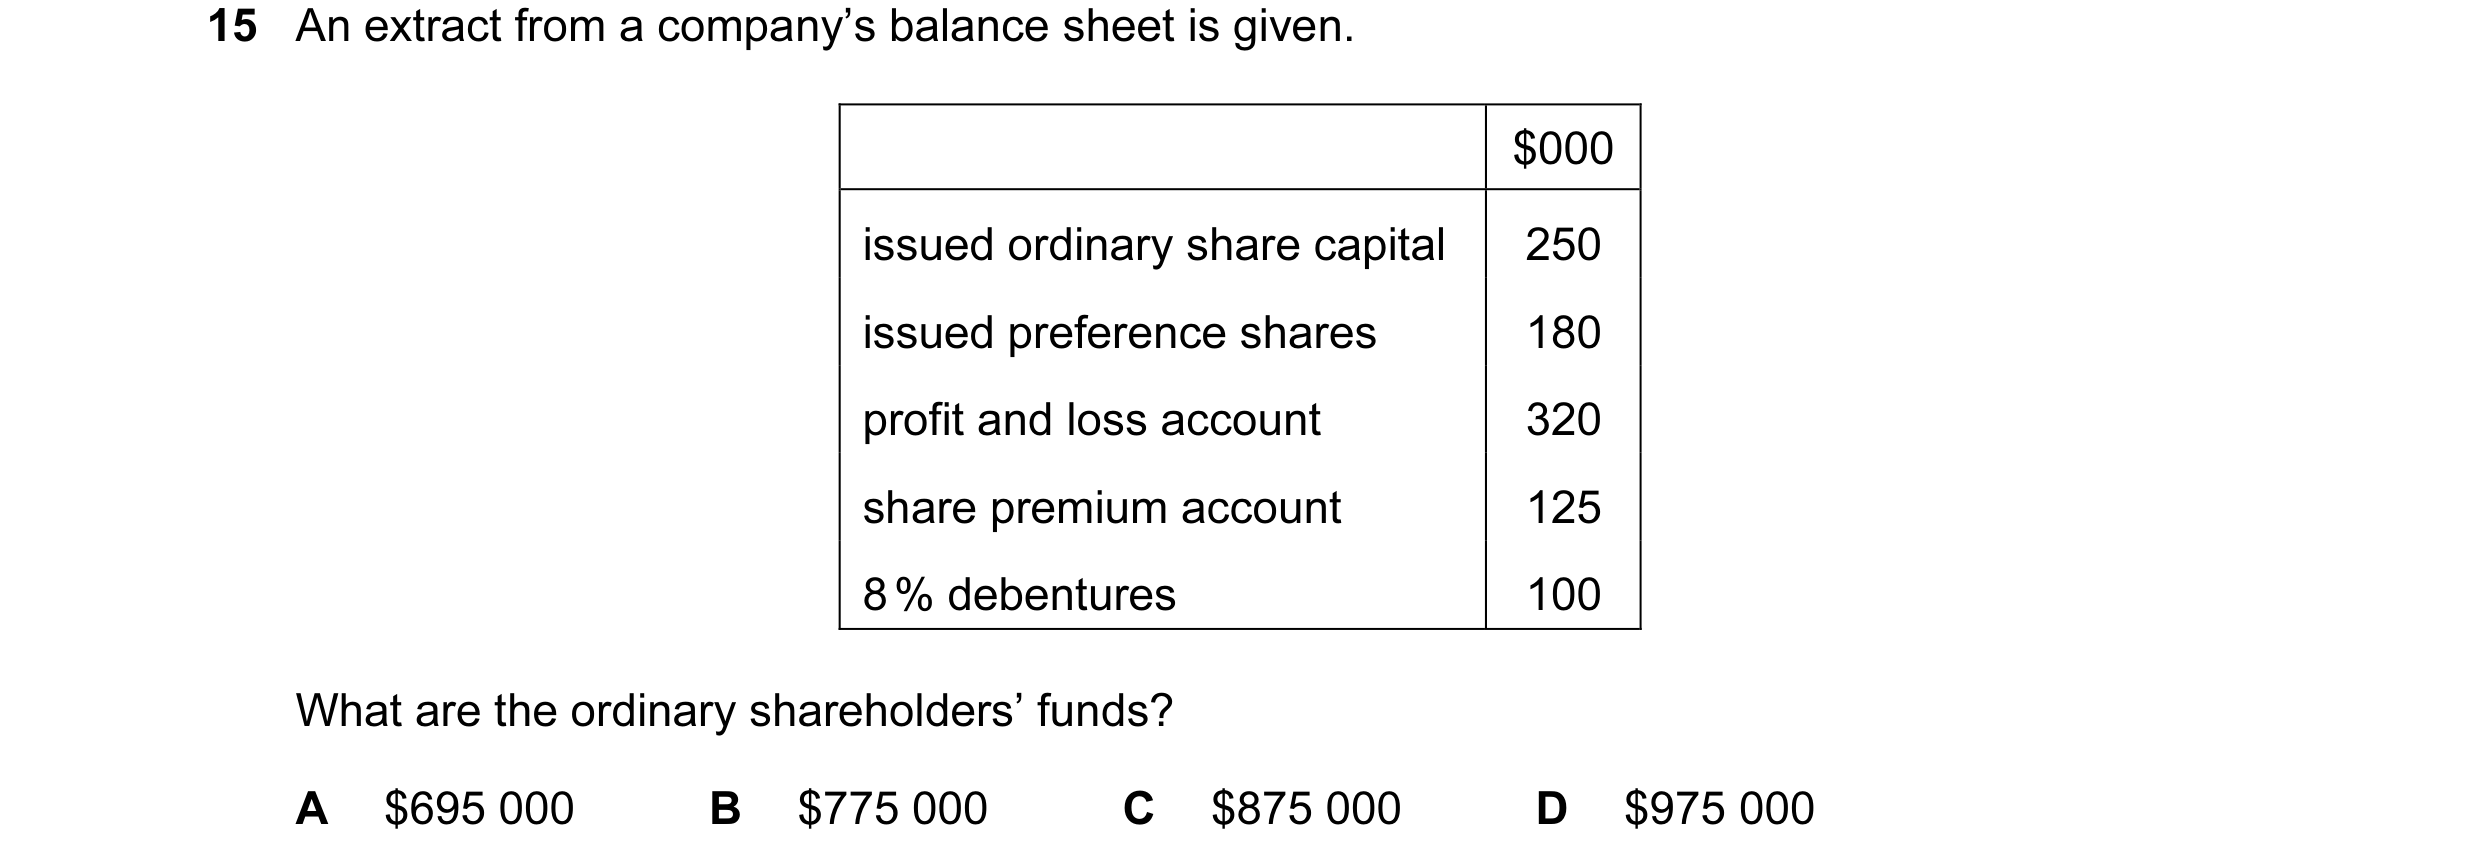 25 / 233
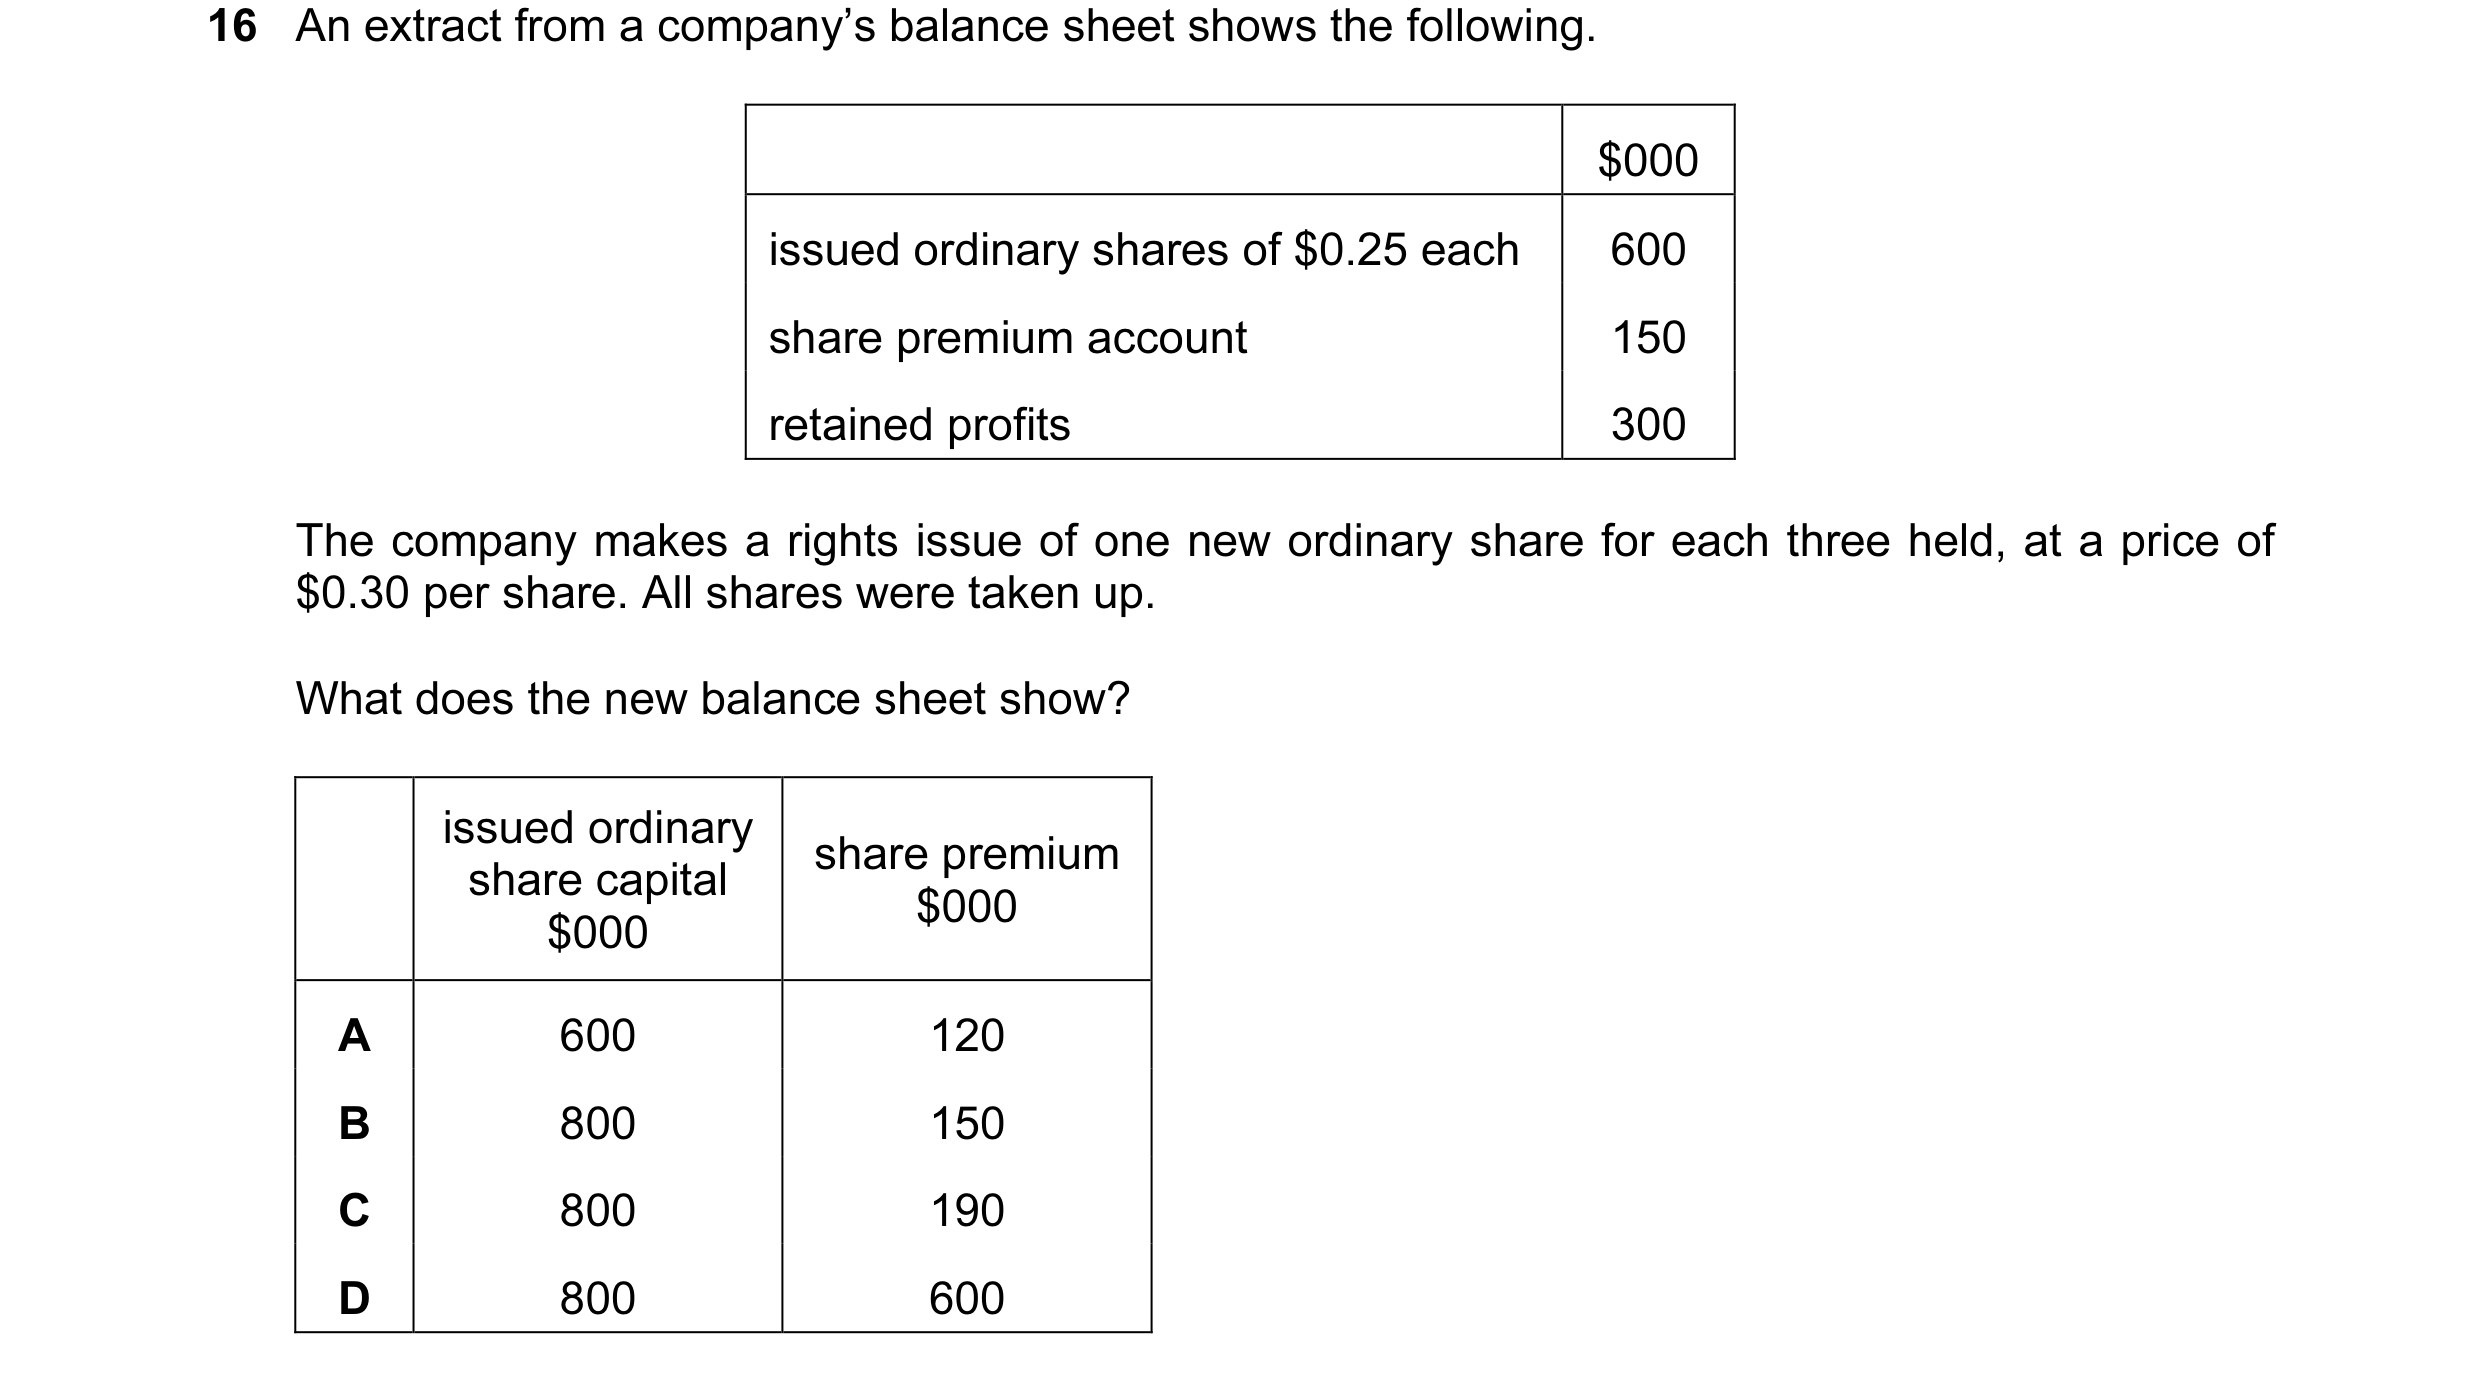
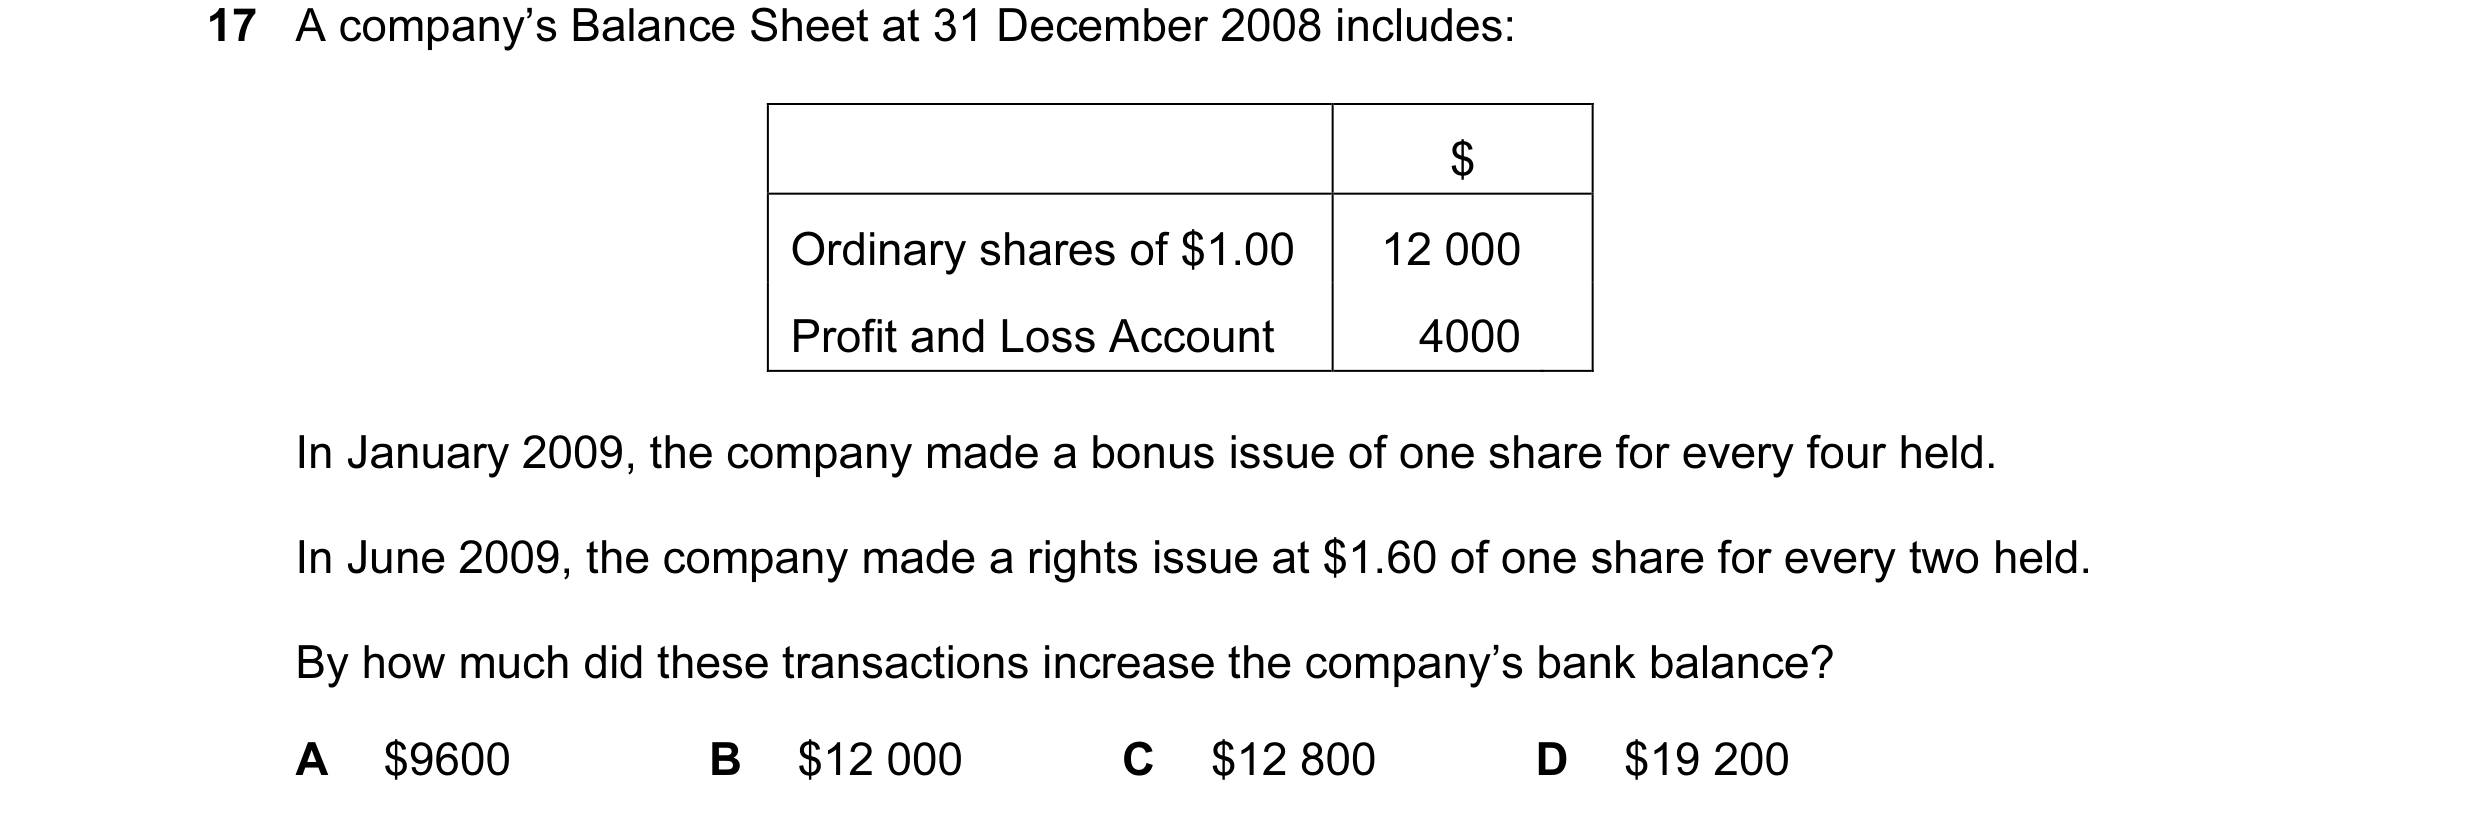
 26 / 233
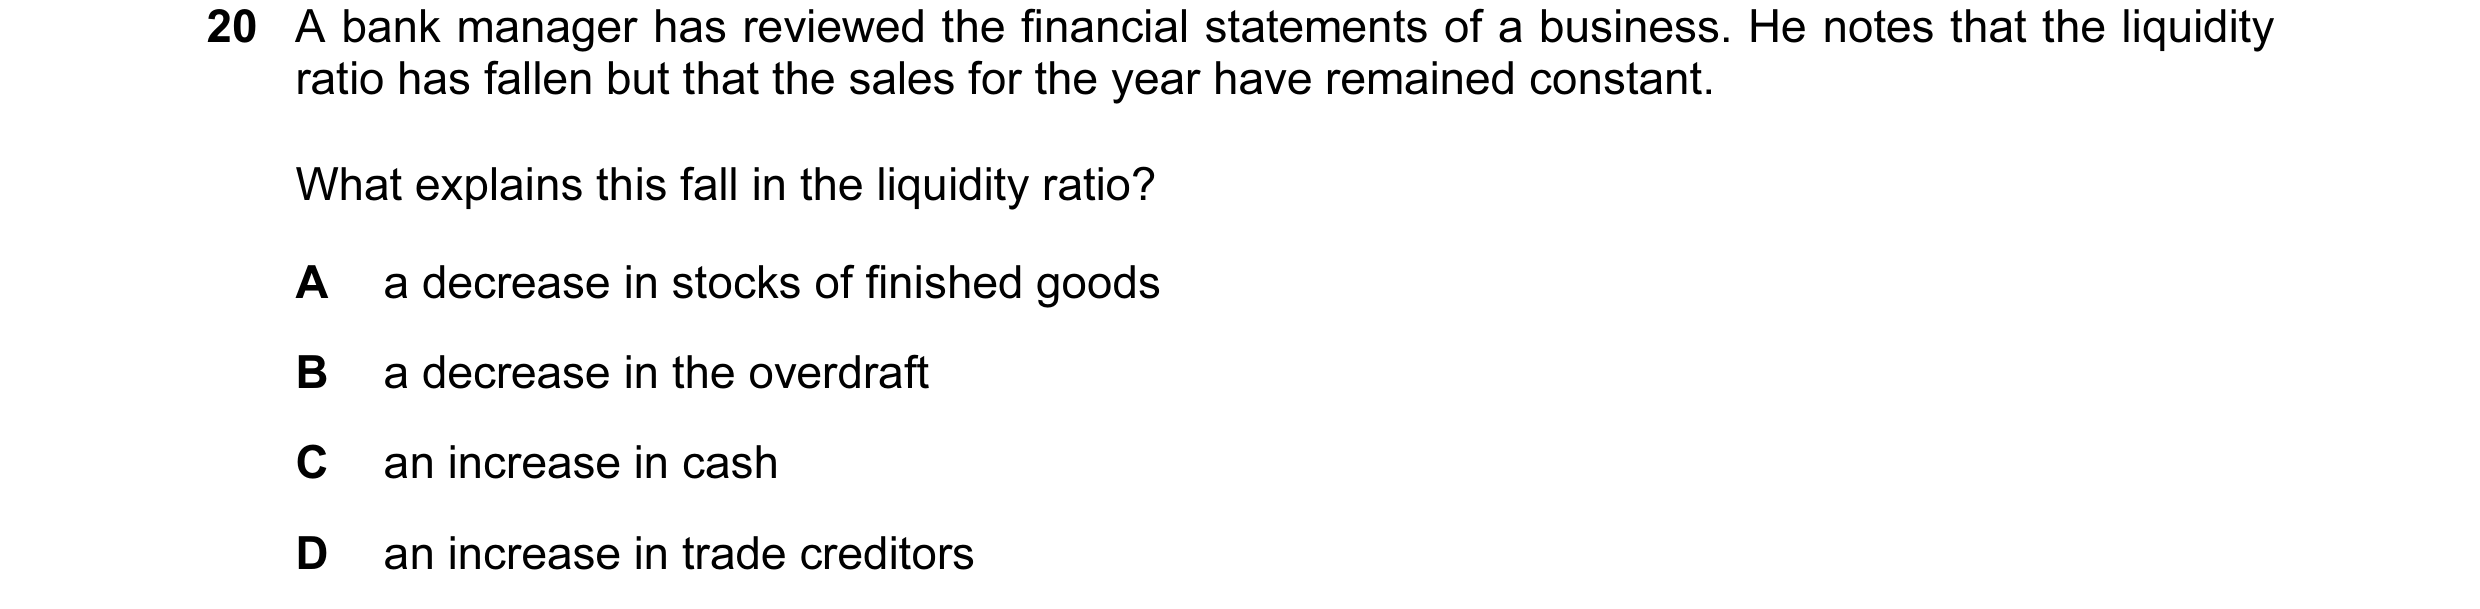
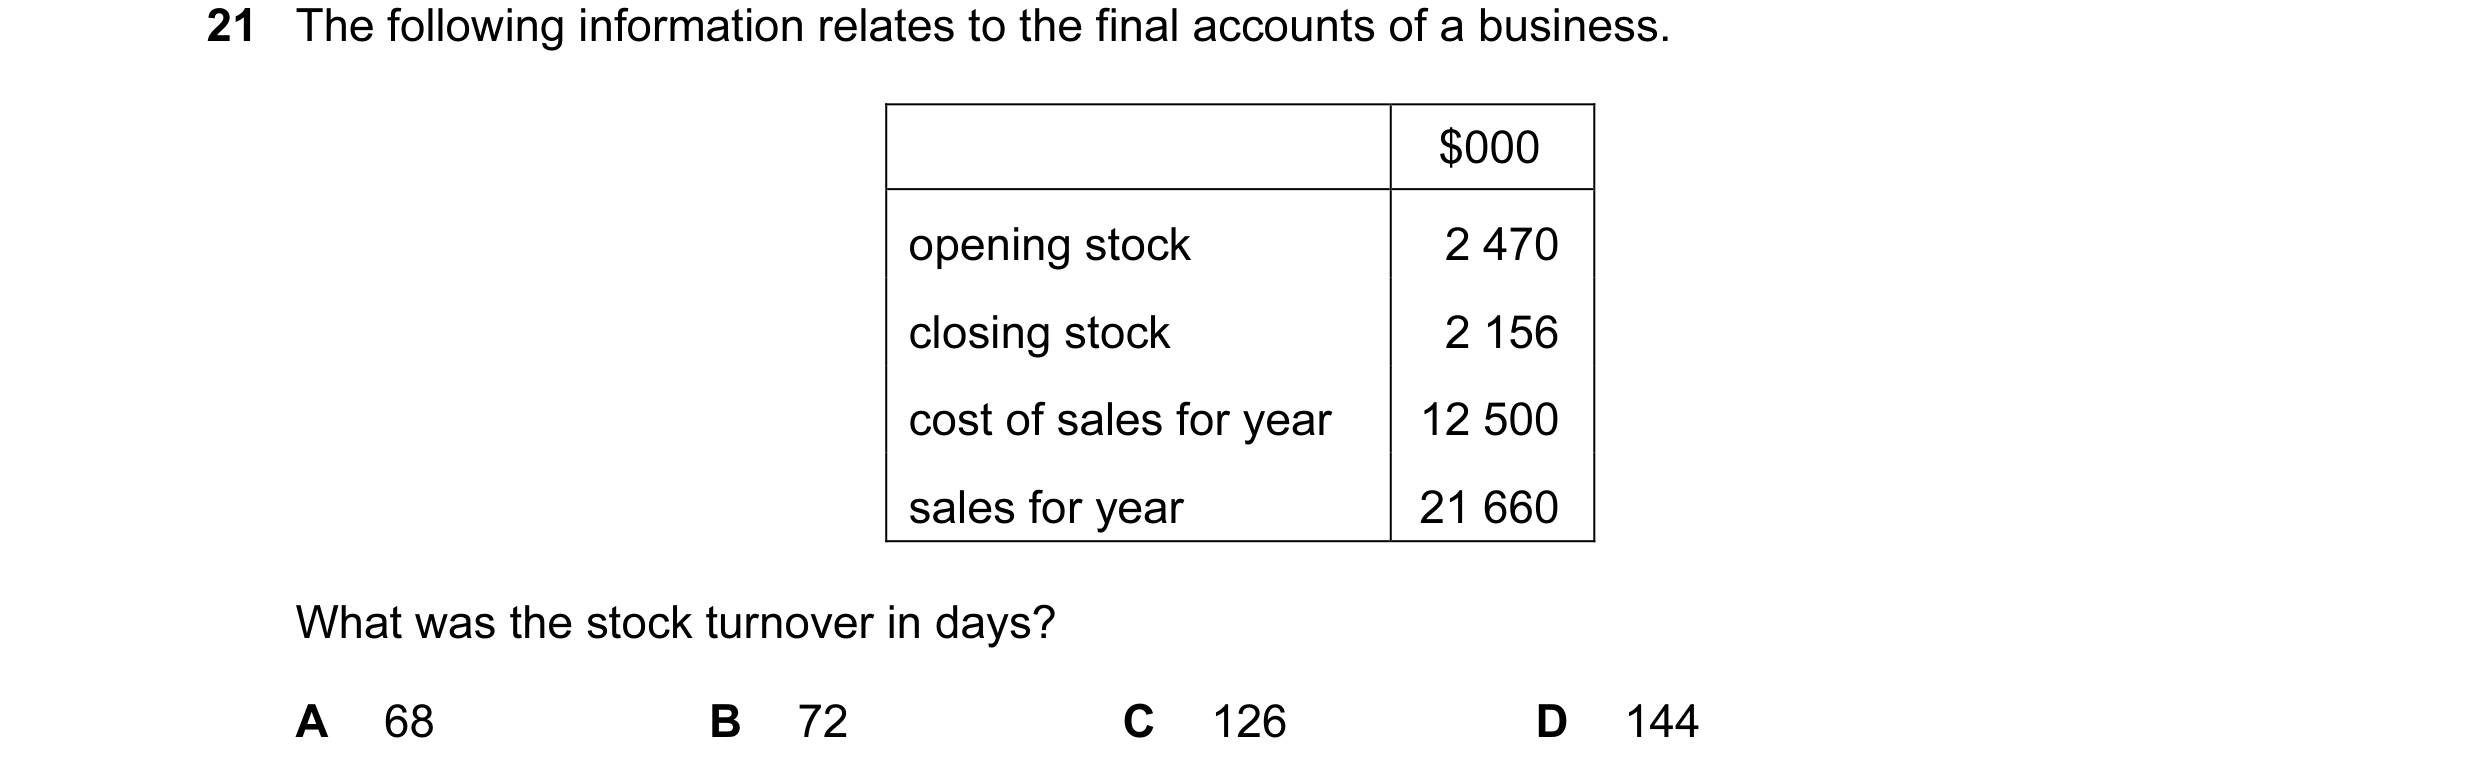
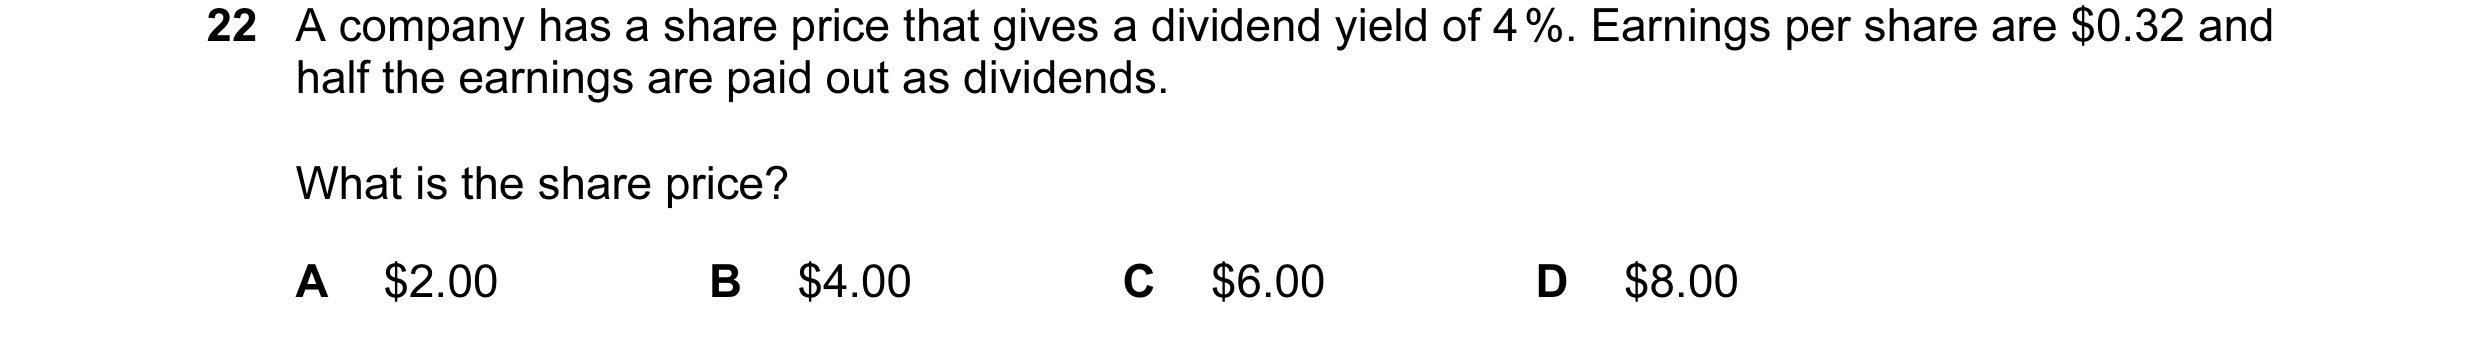
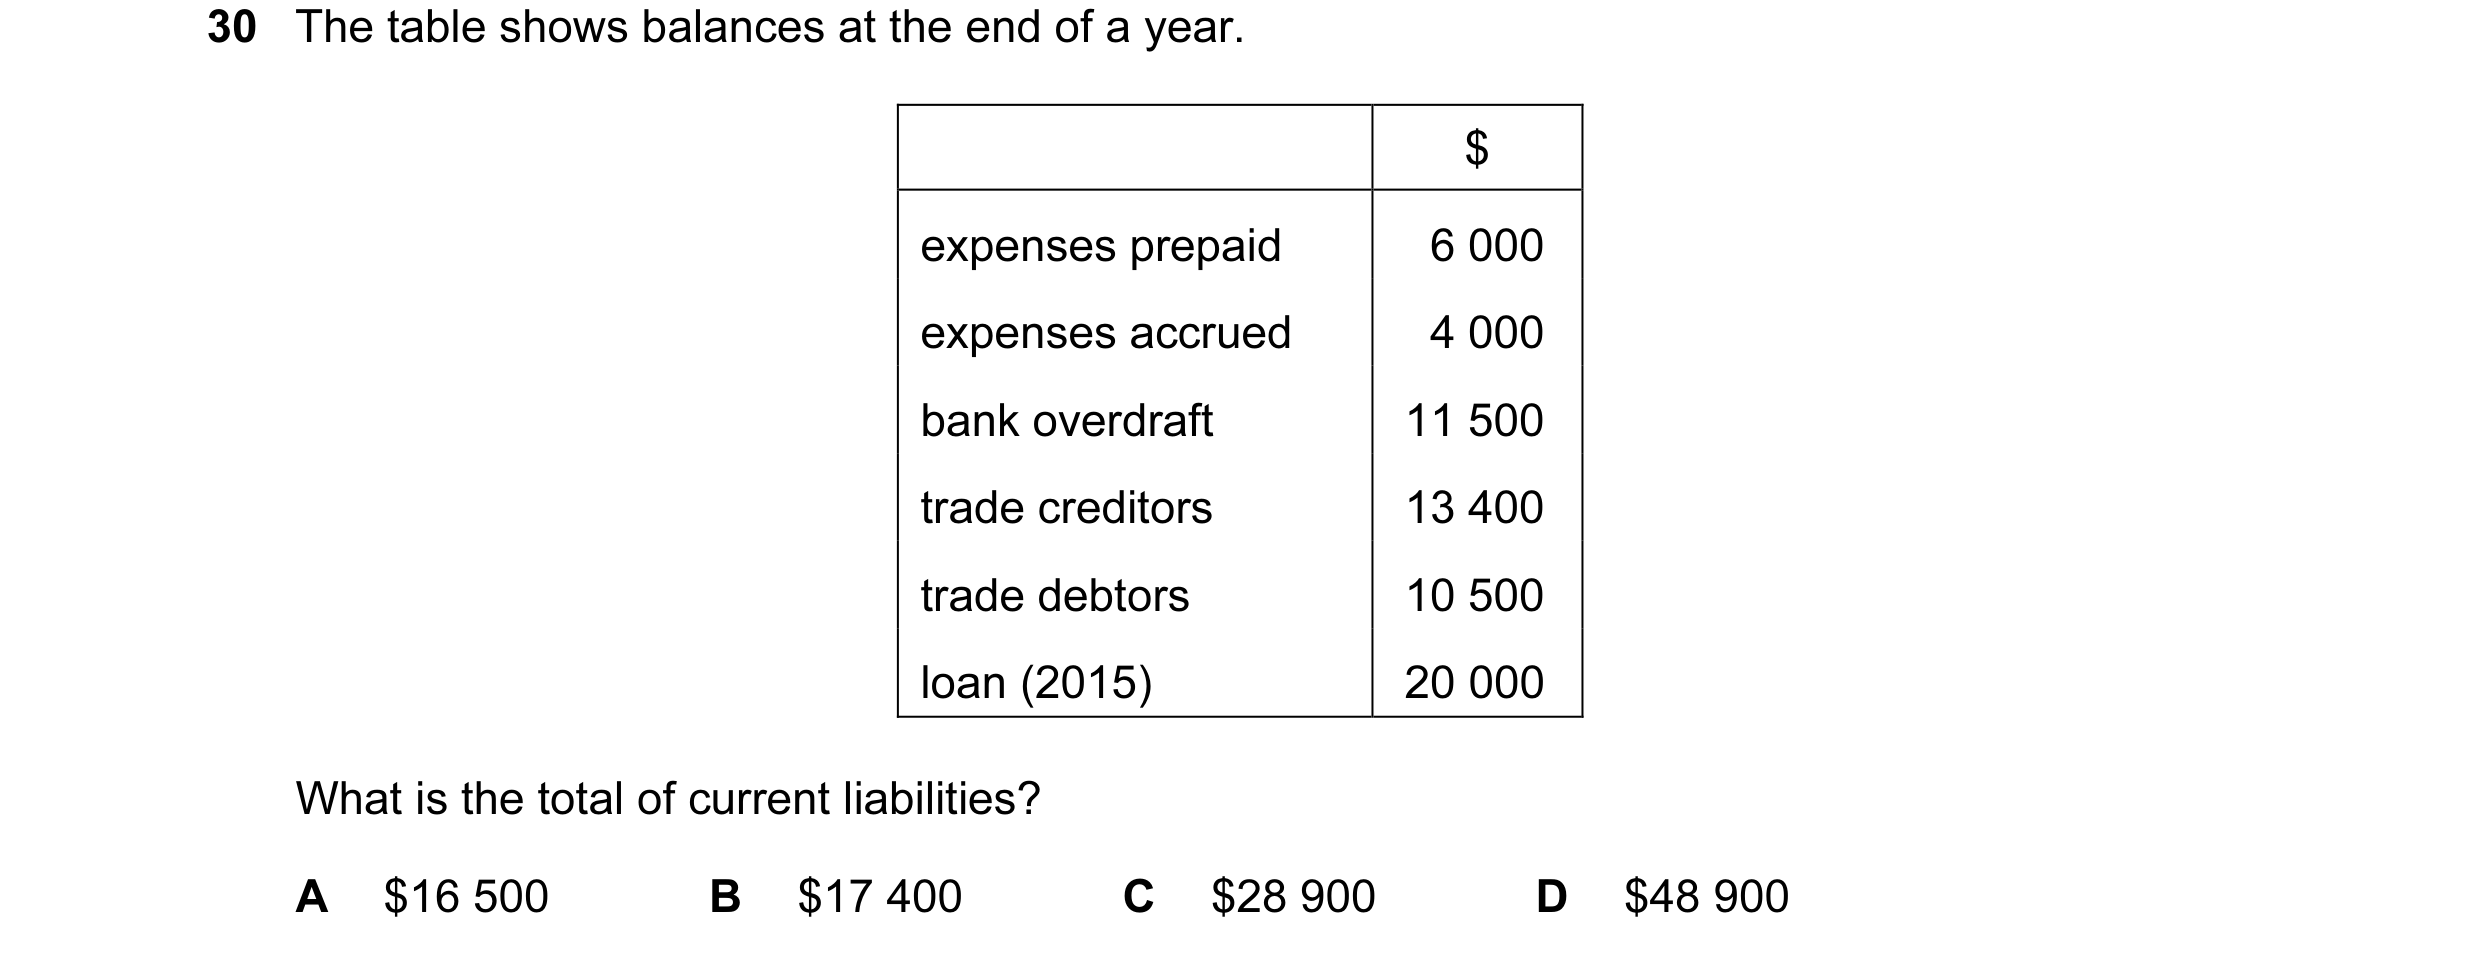 27 / 233
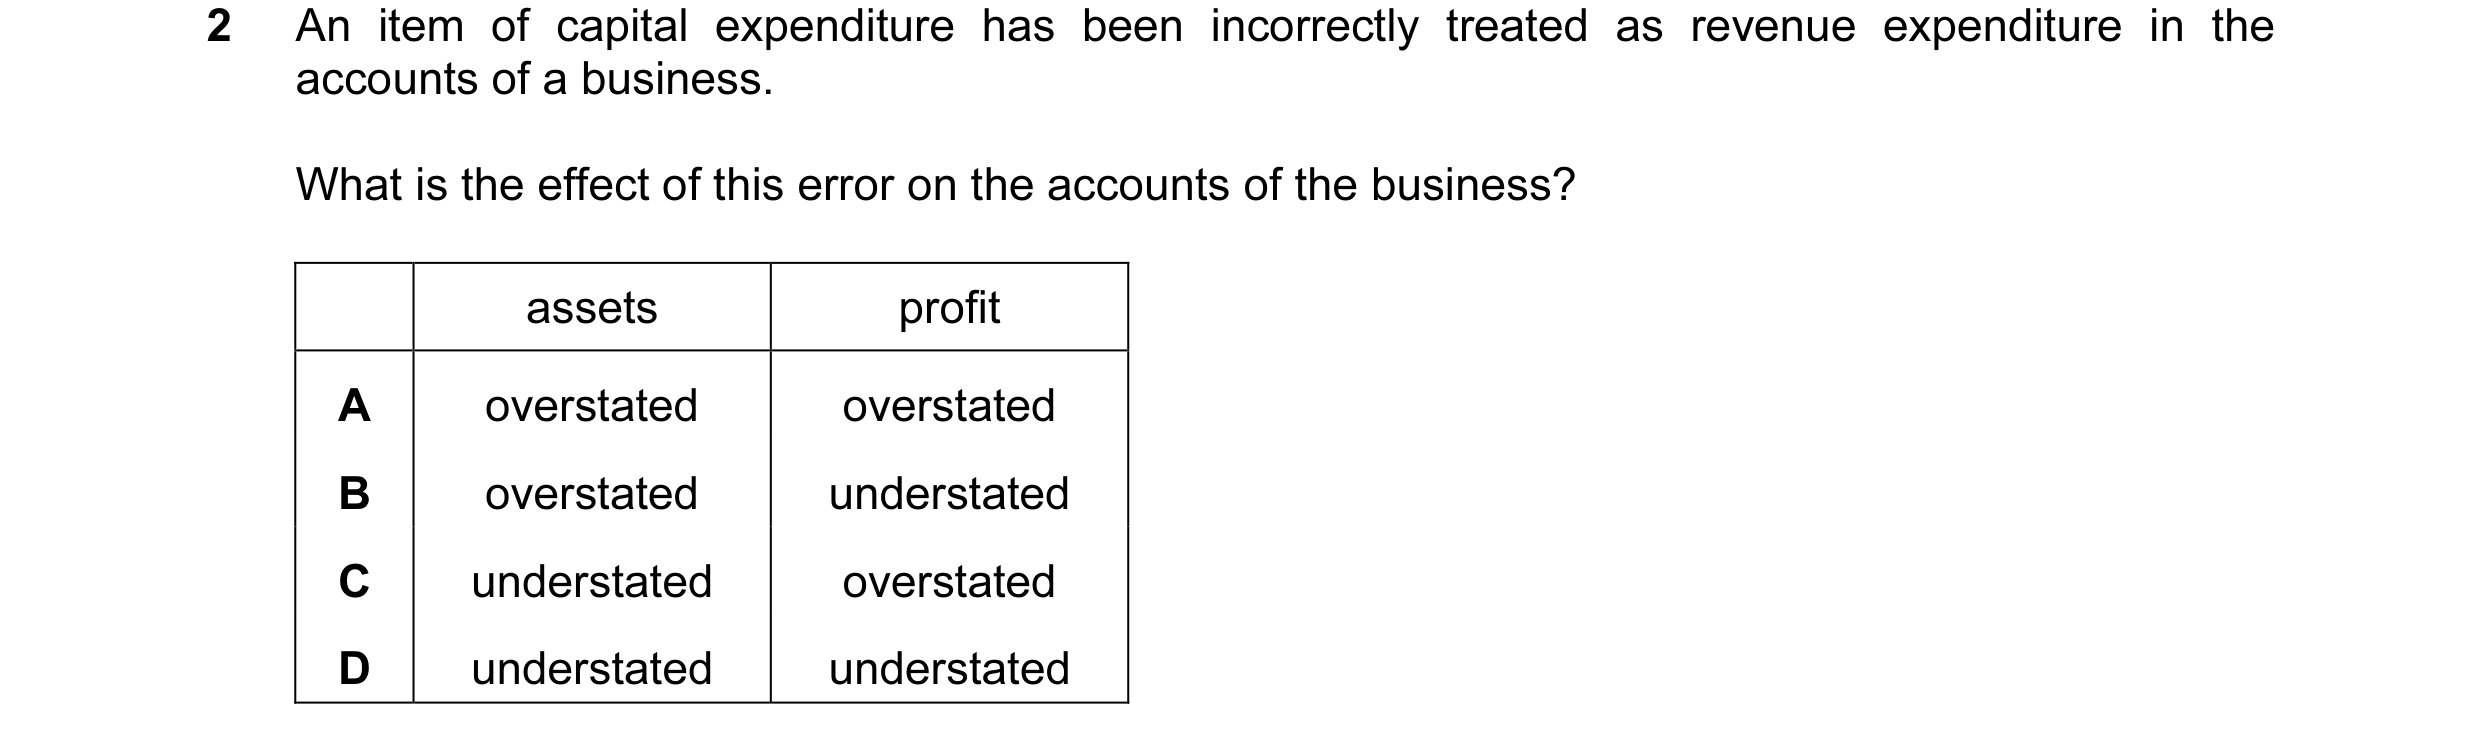
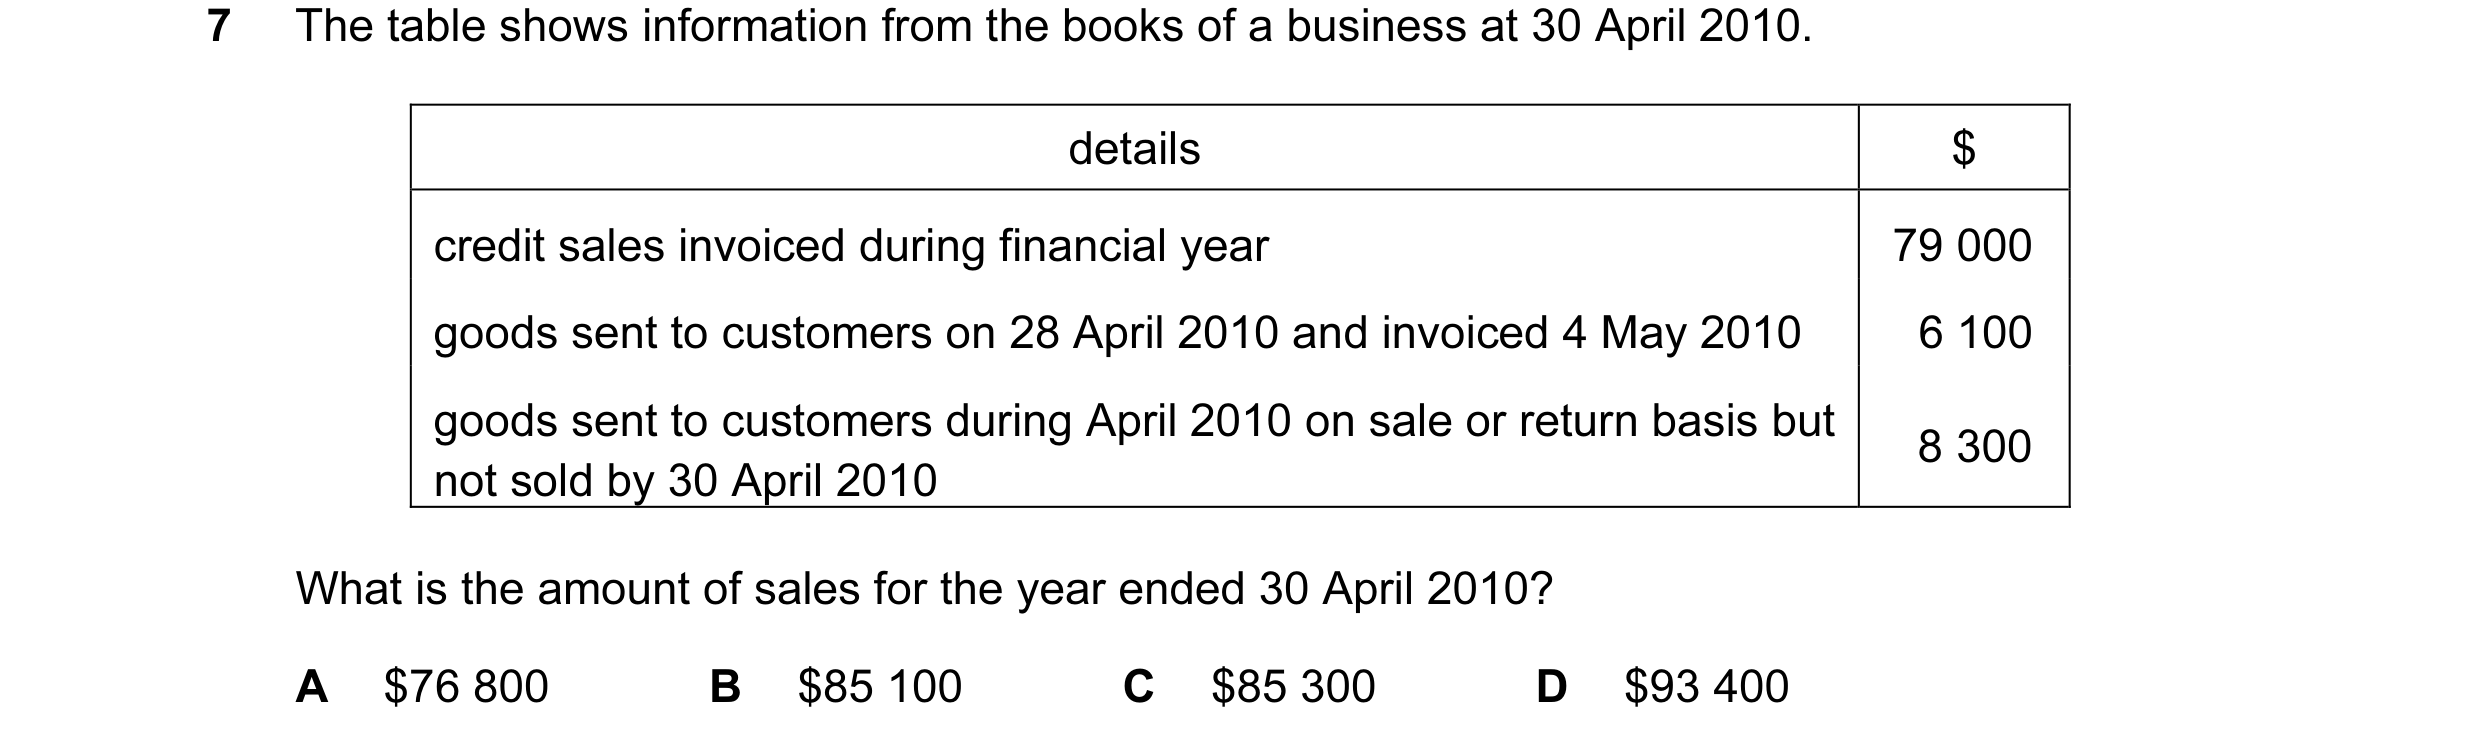
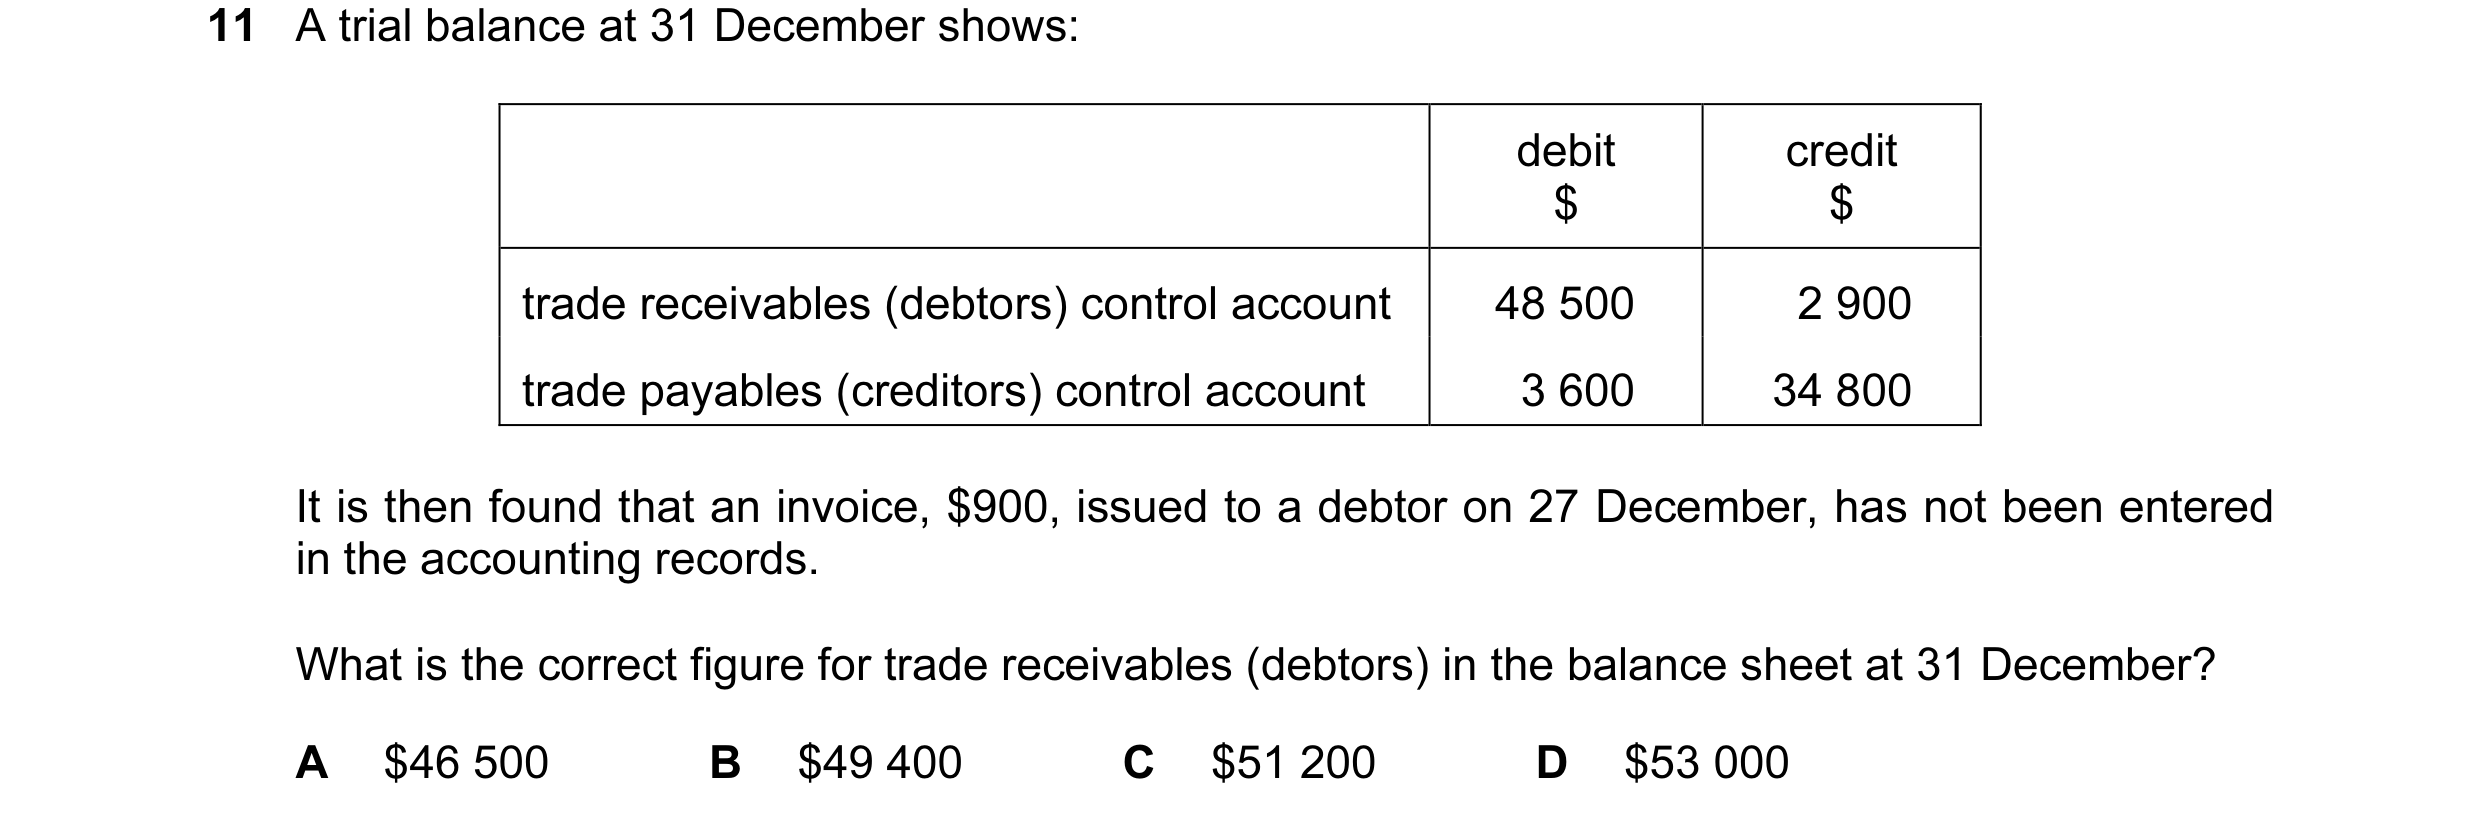
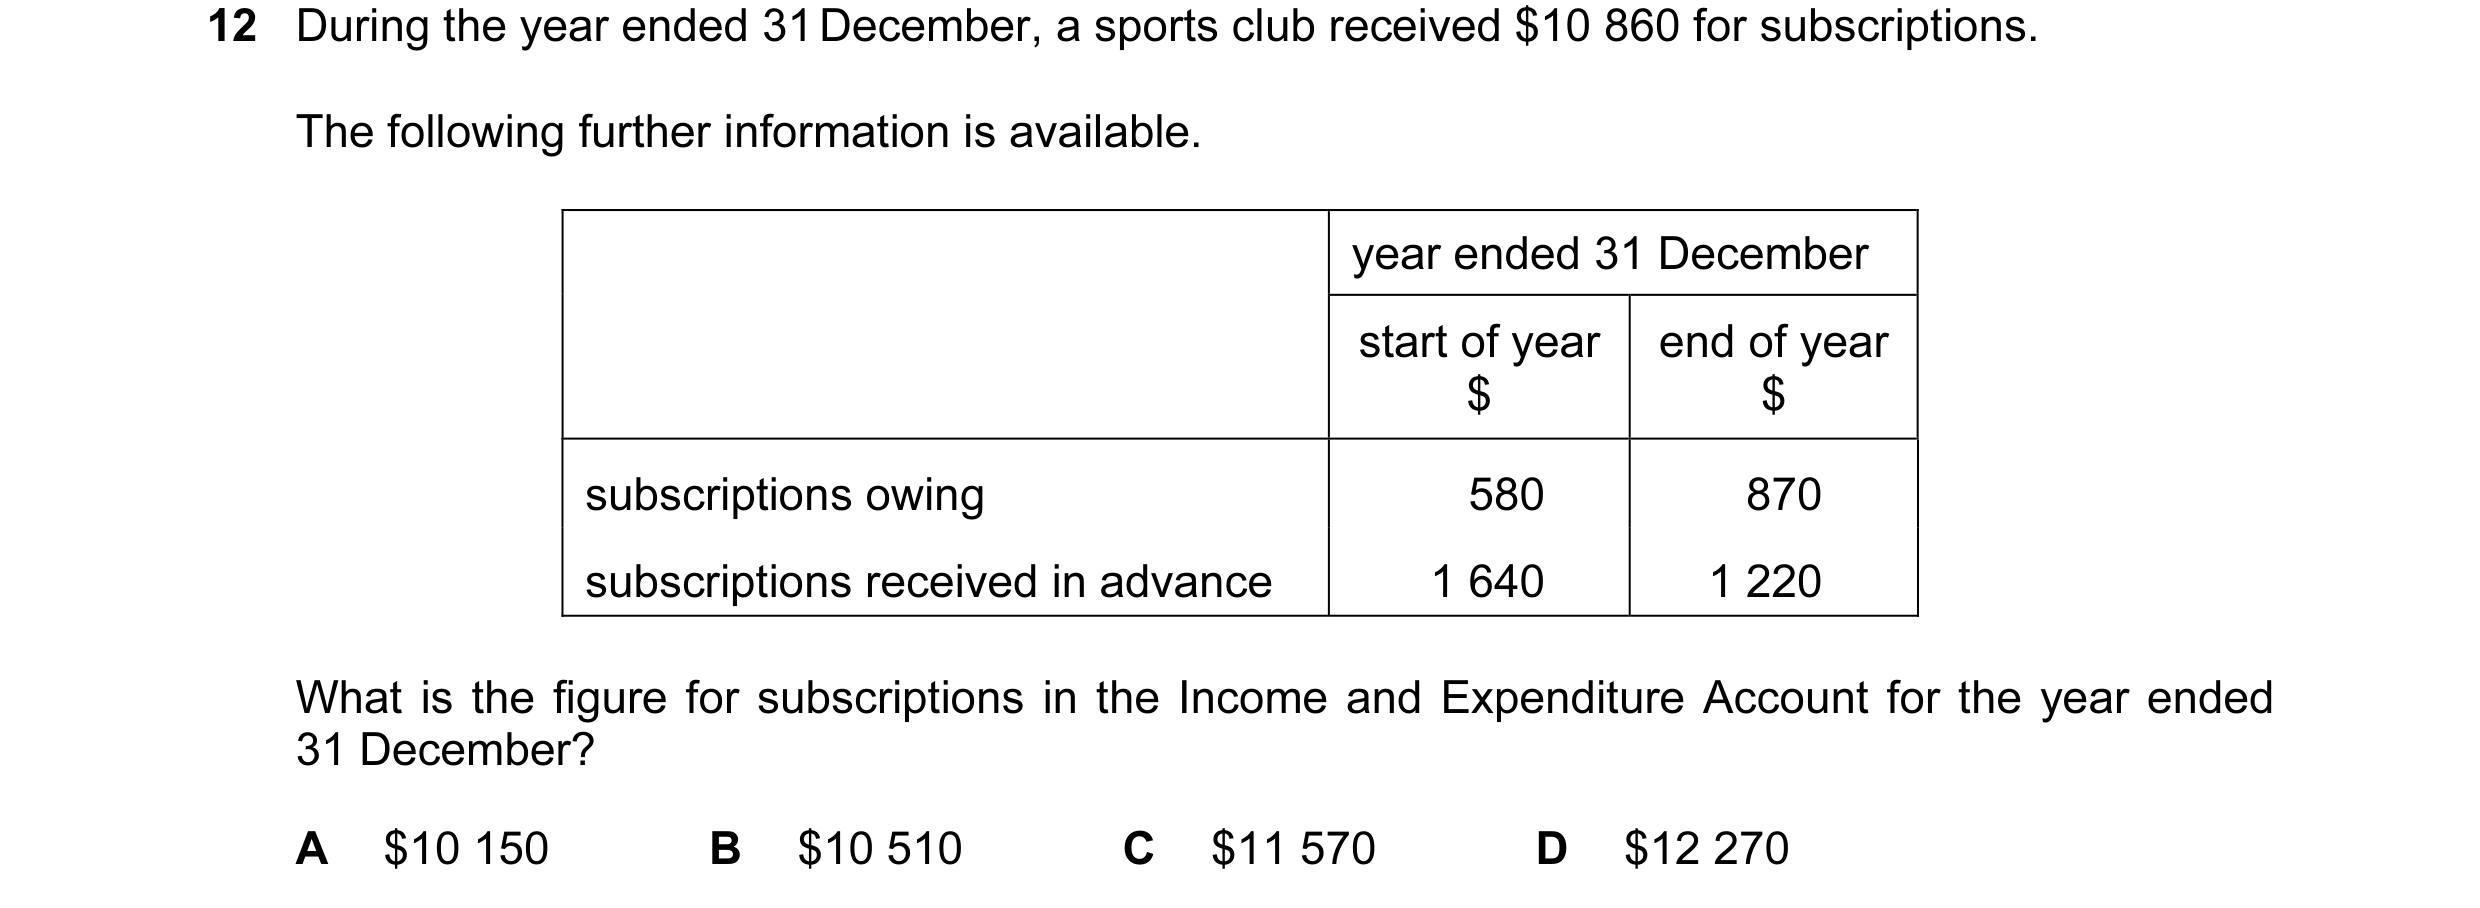 28 / 233
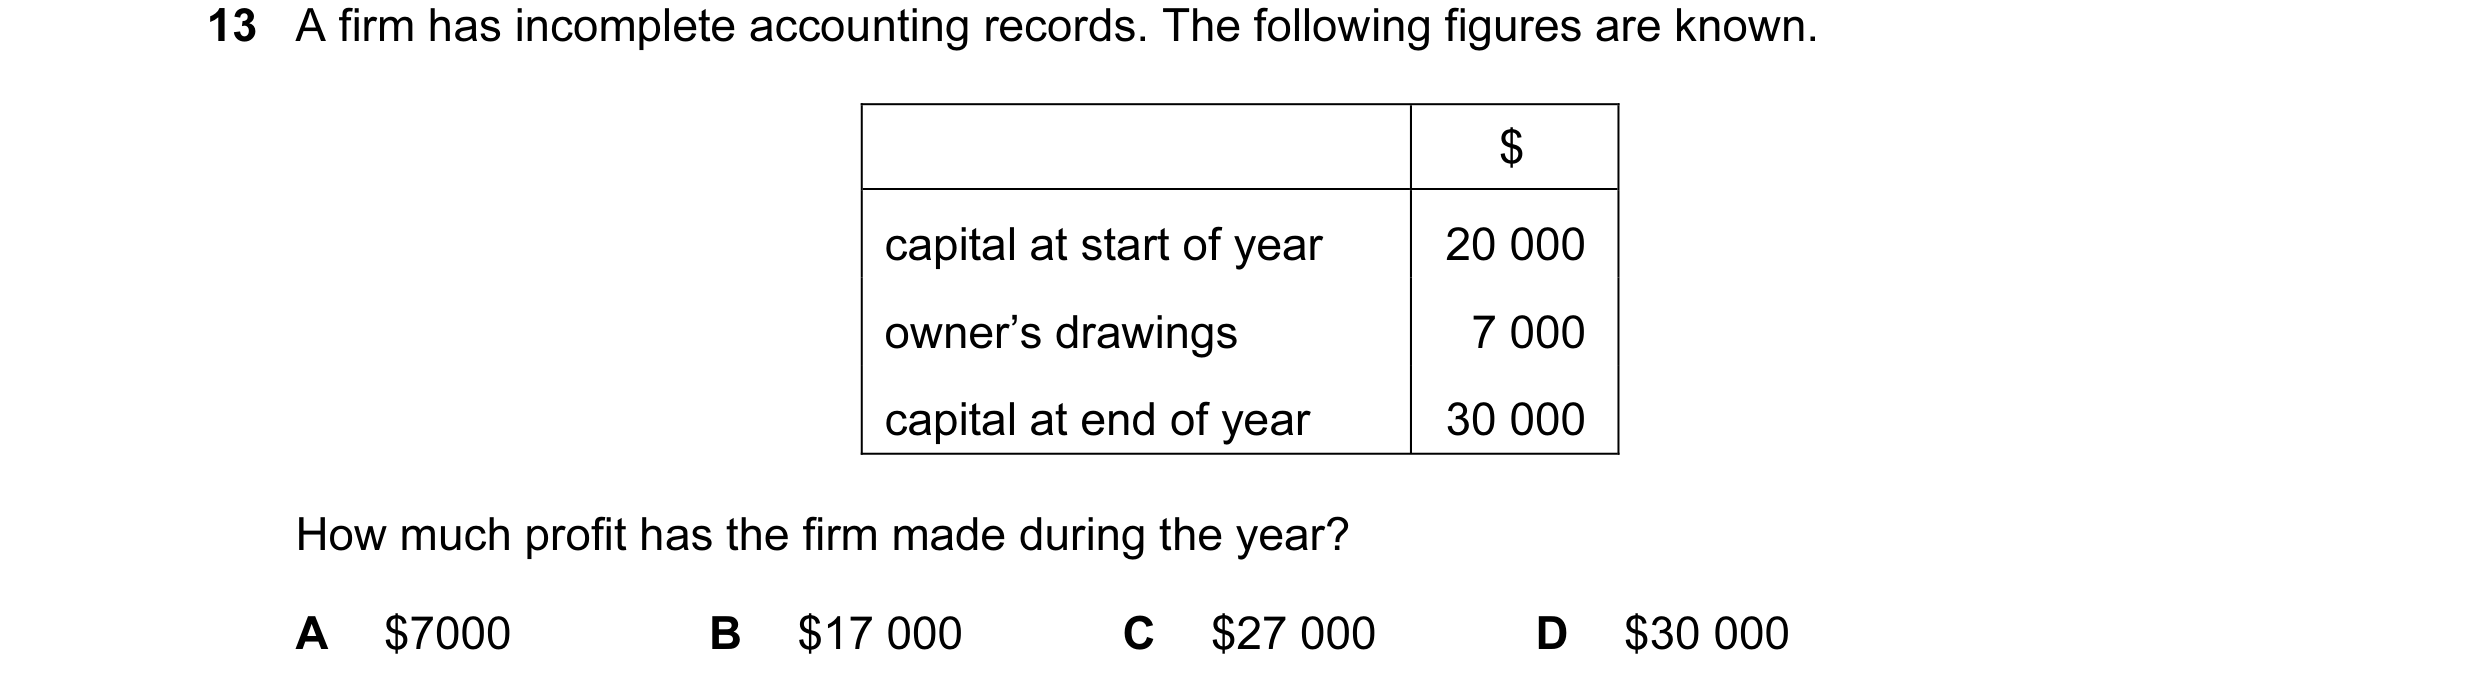
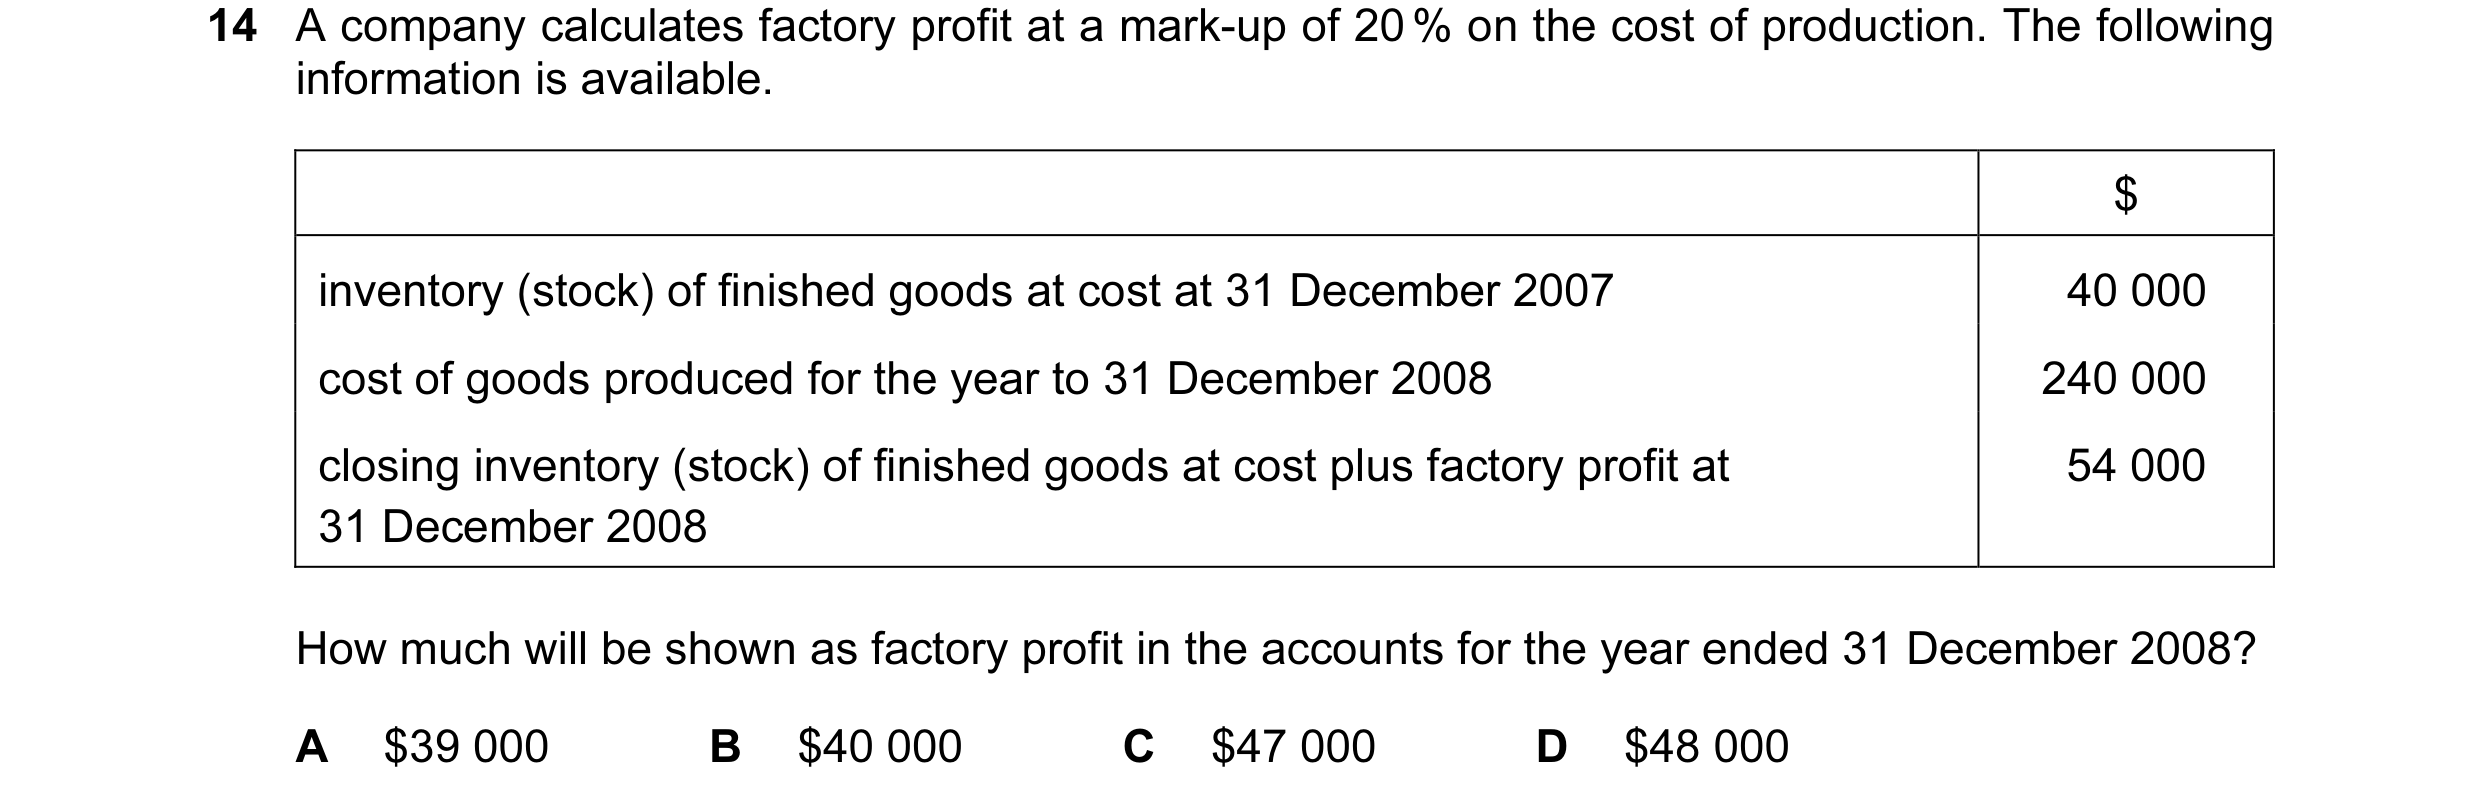
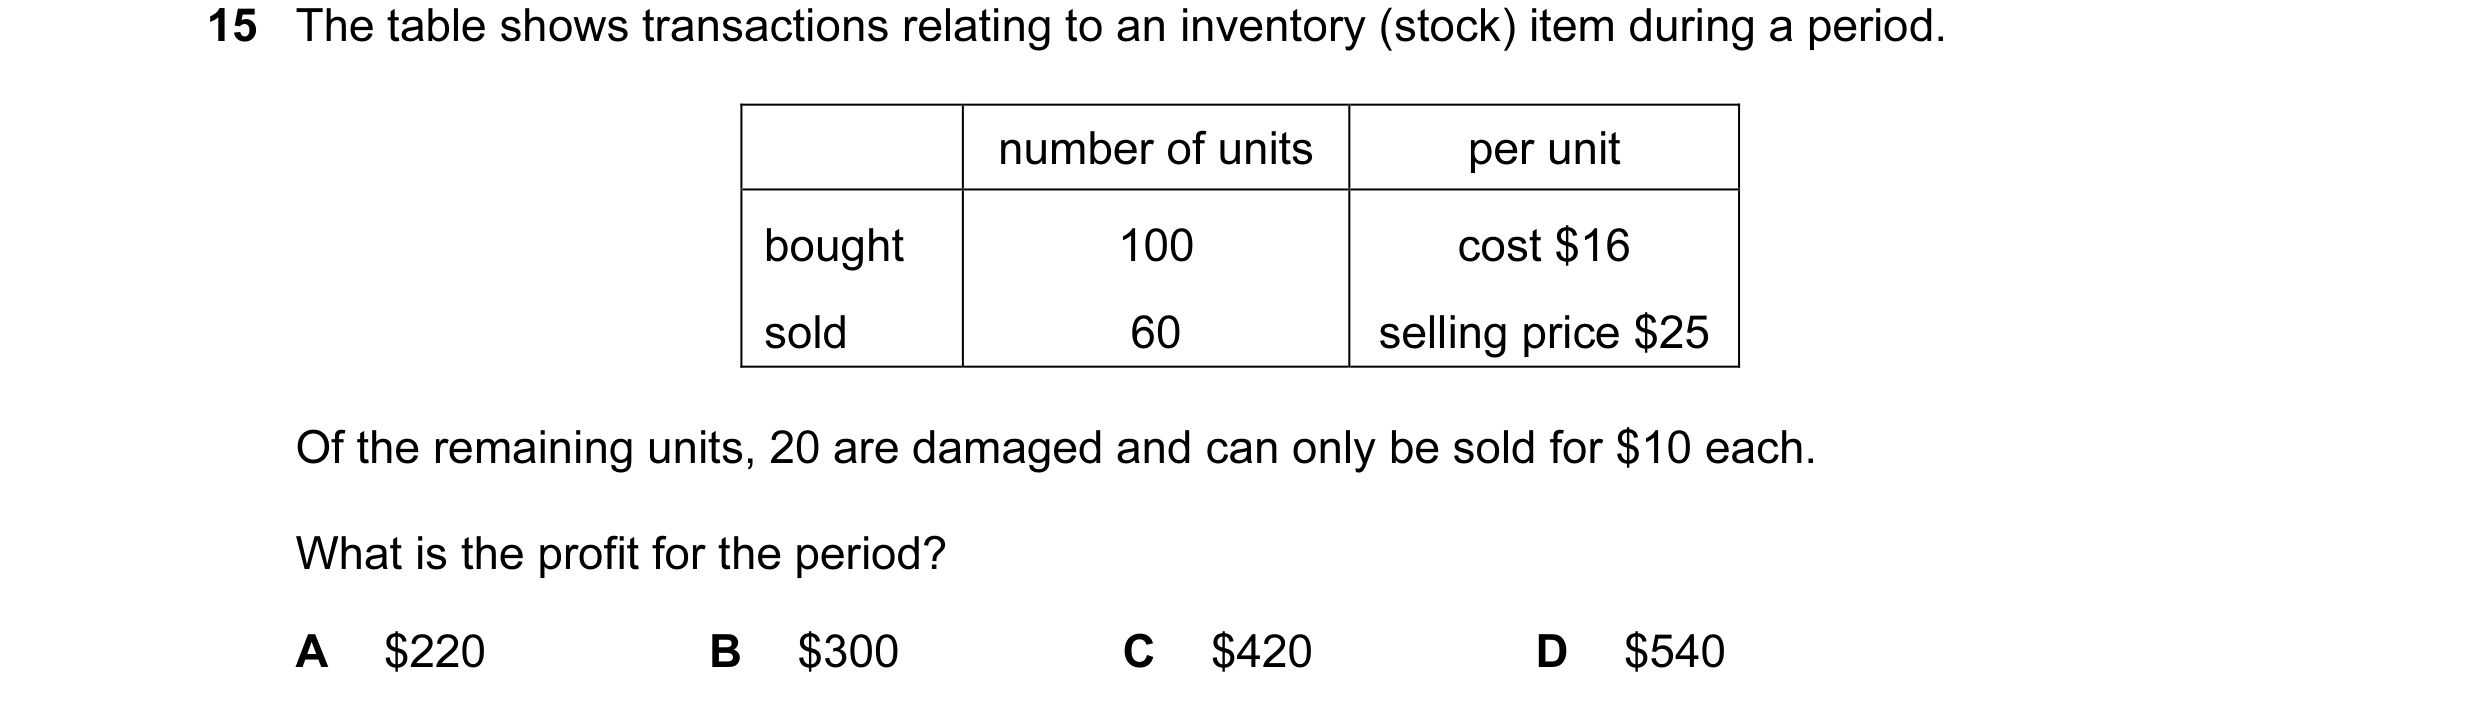
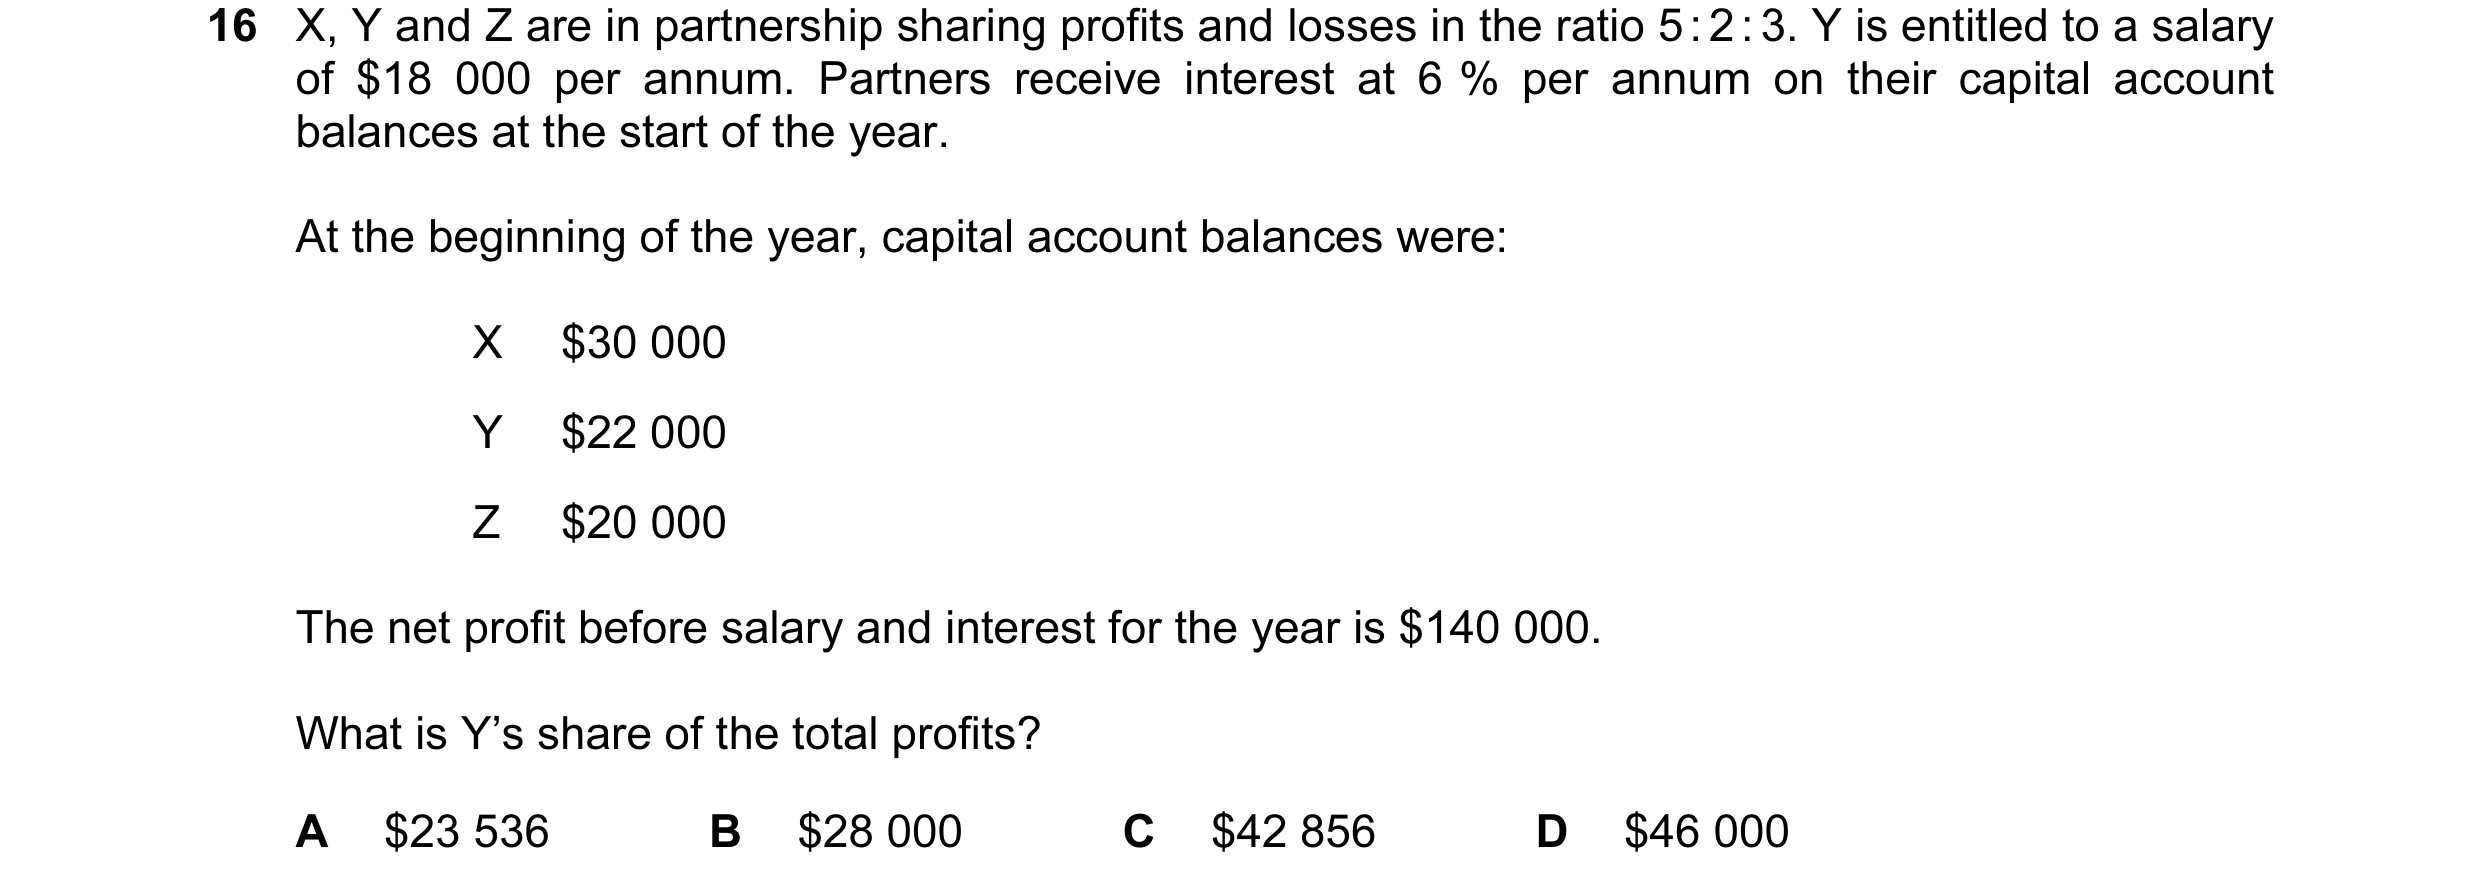 29 / 233
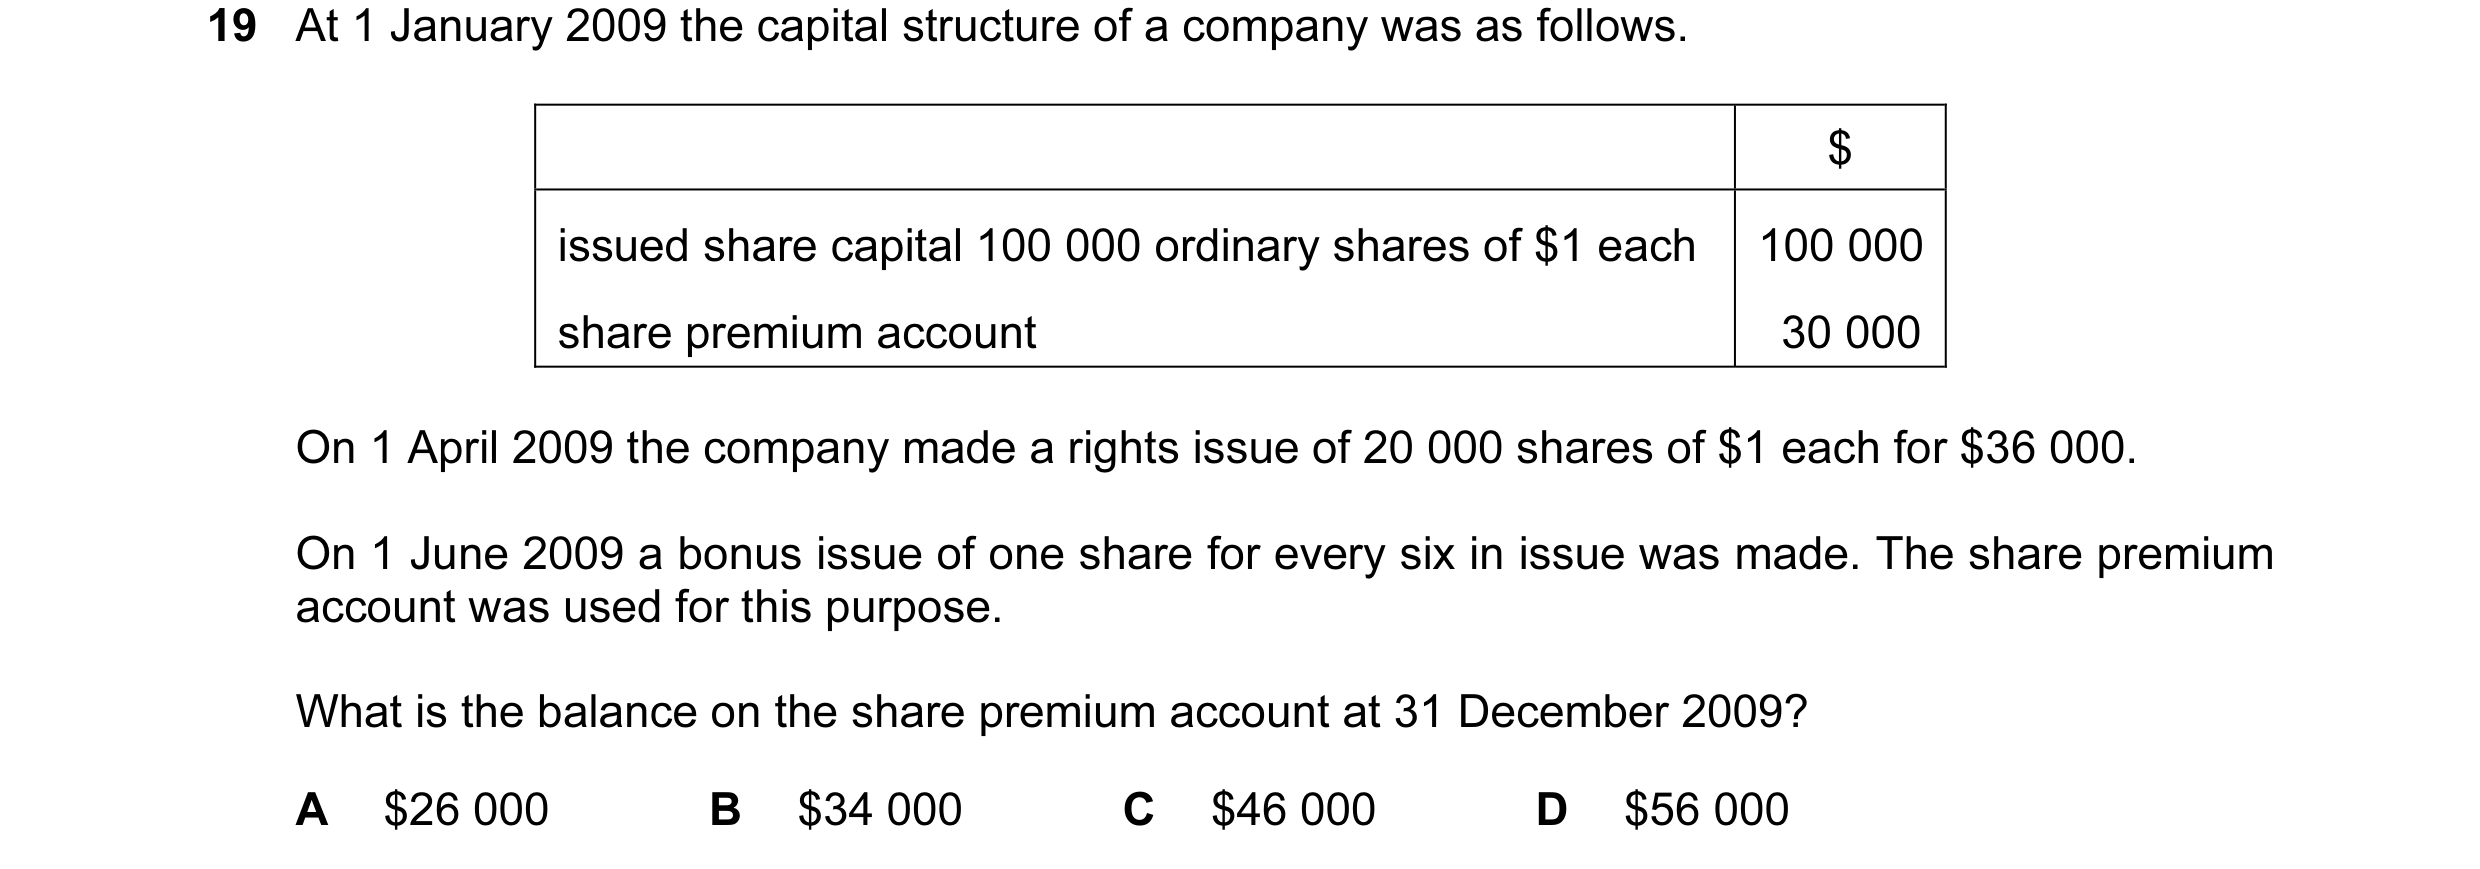
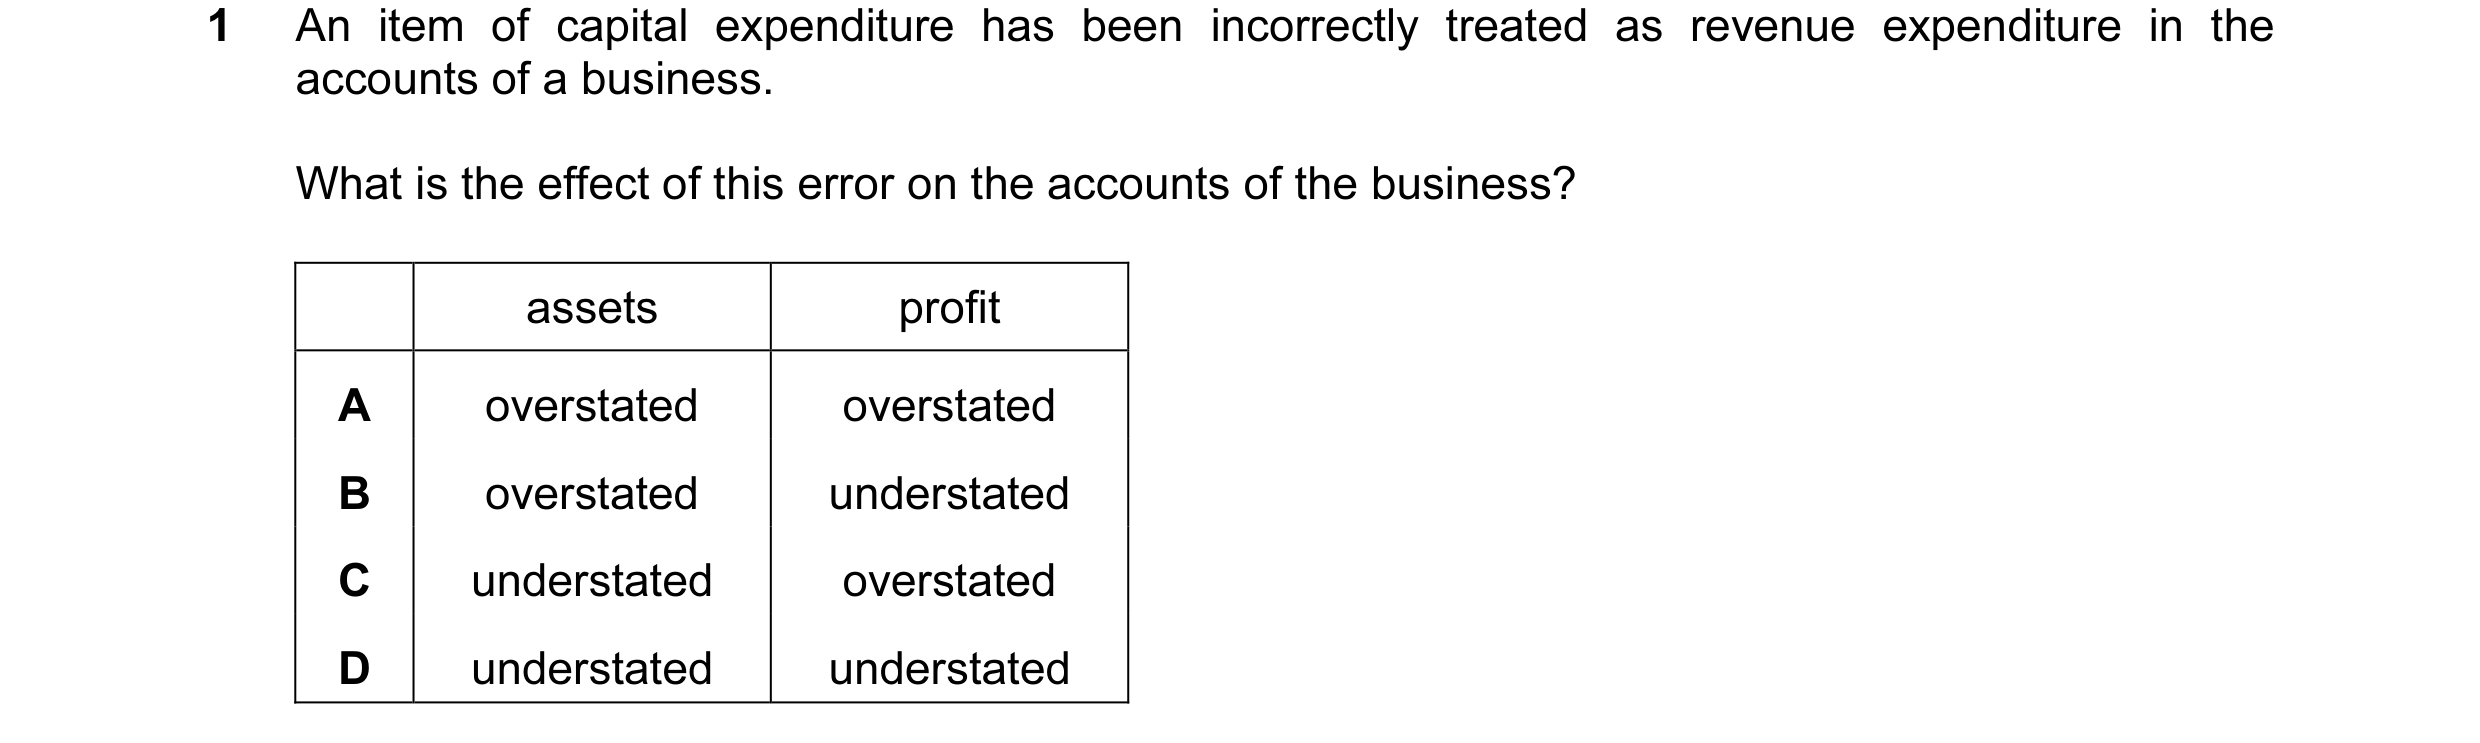 30 / 233
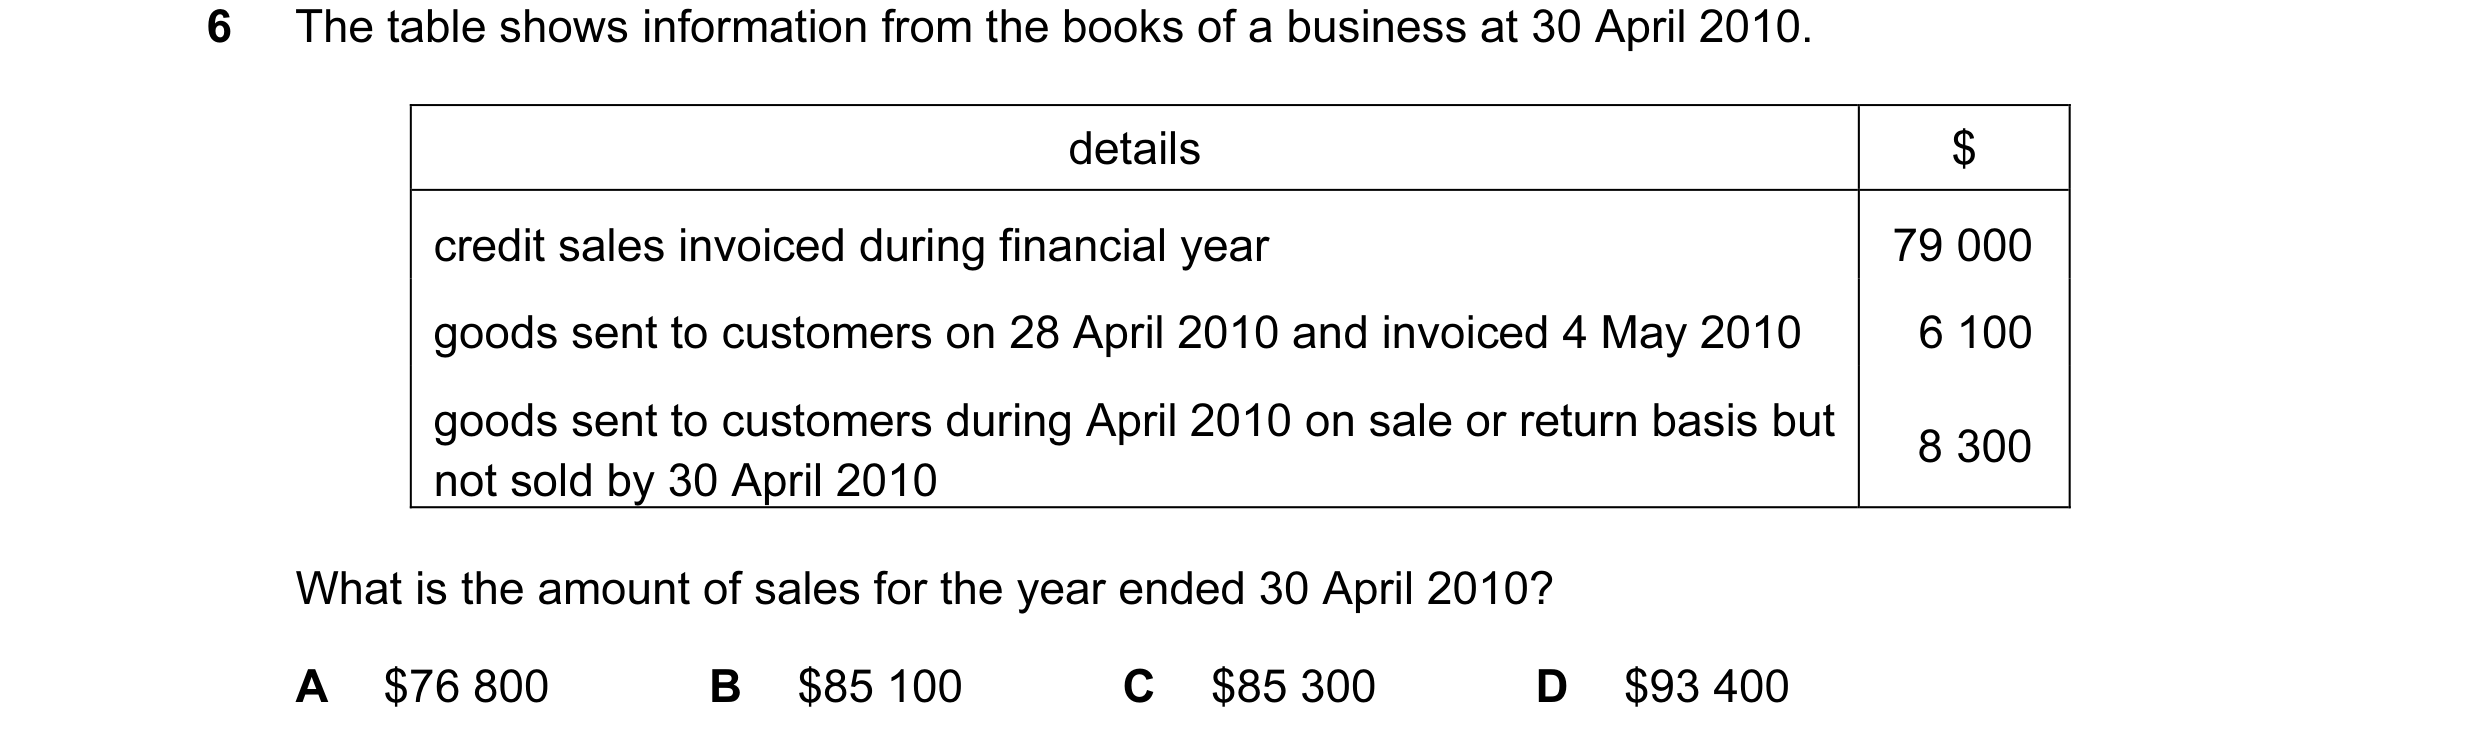
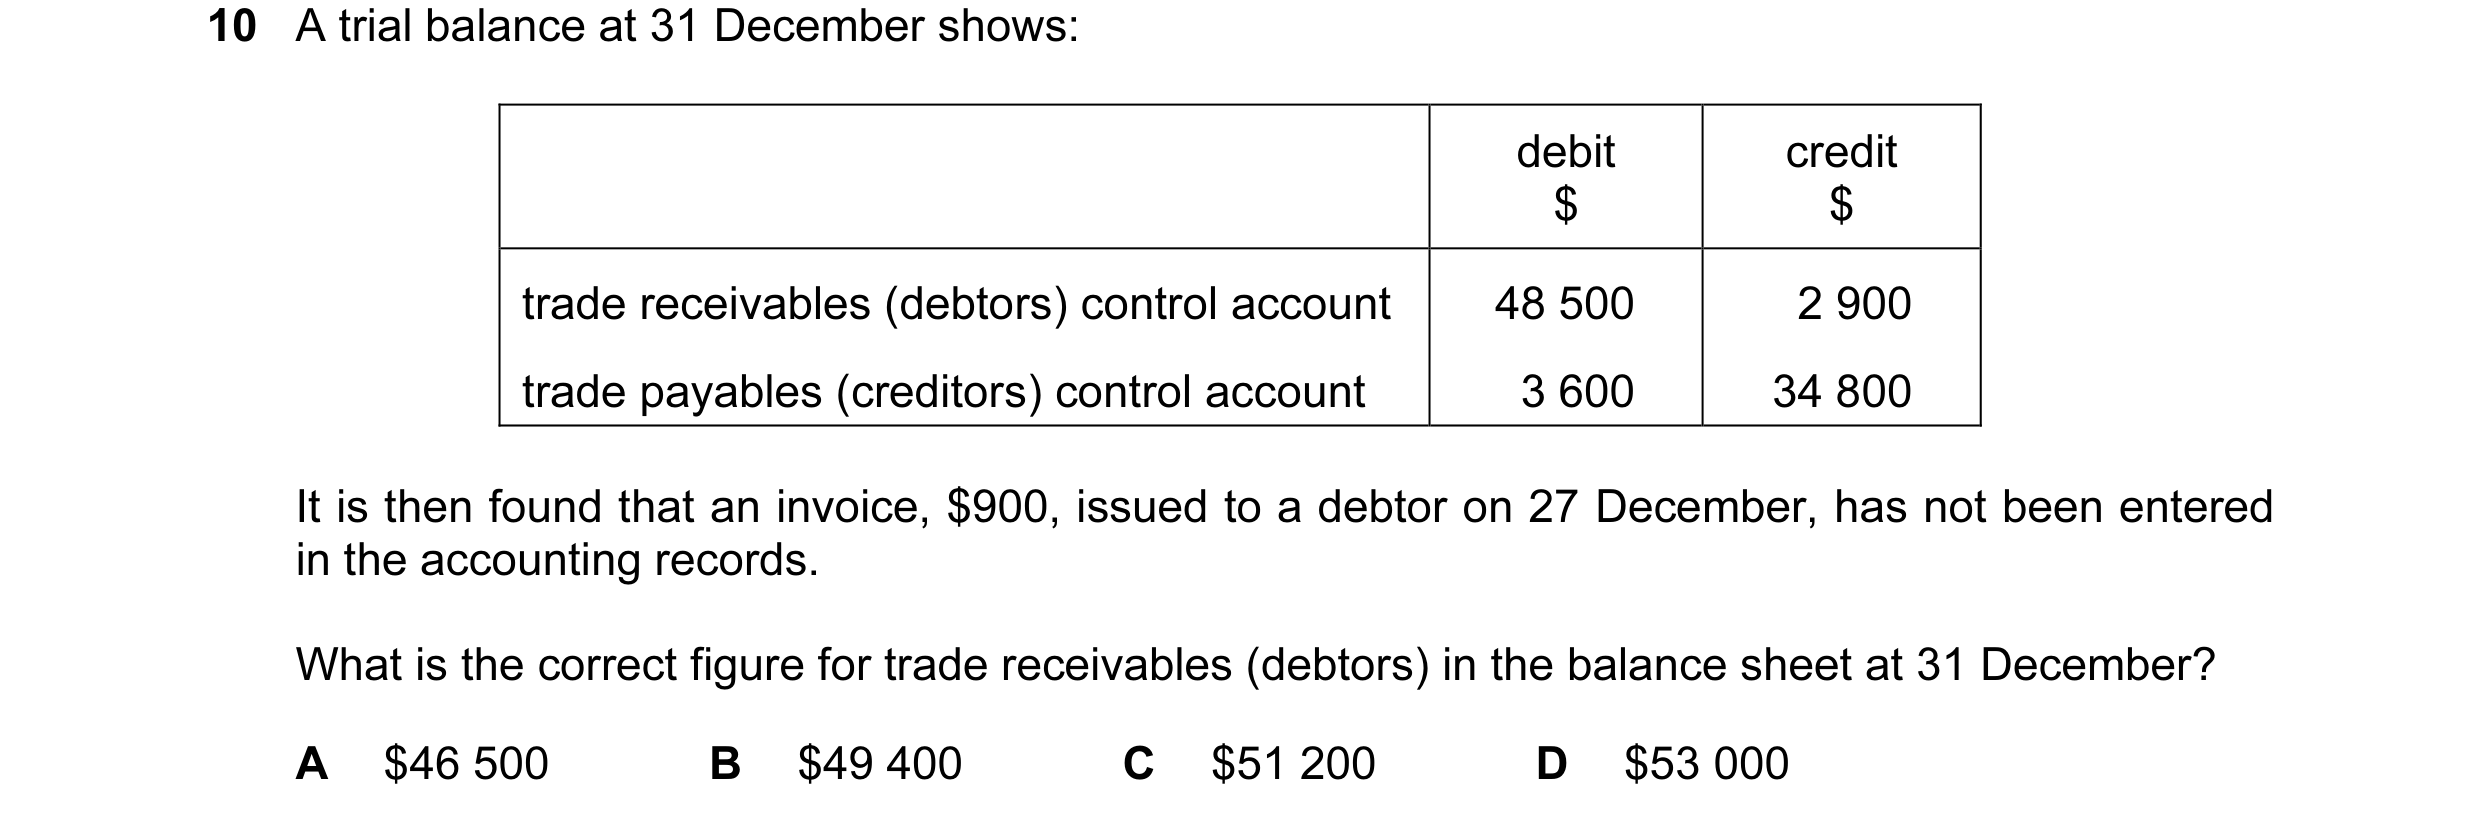
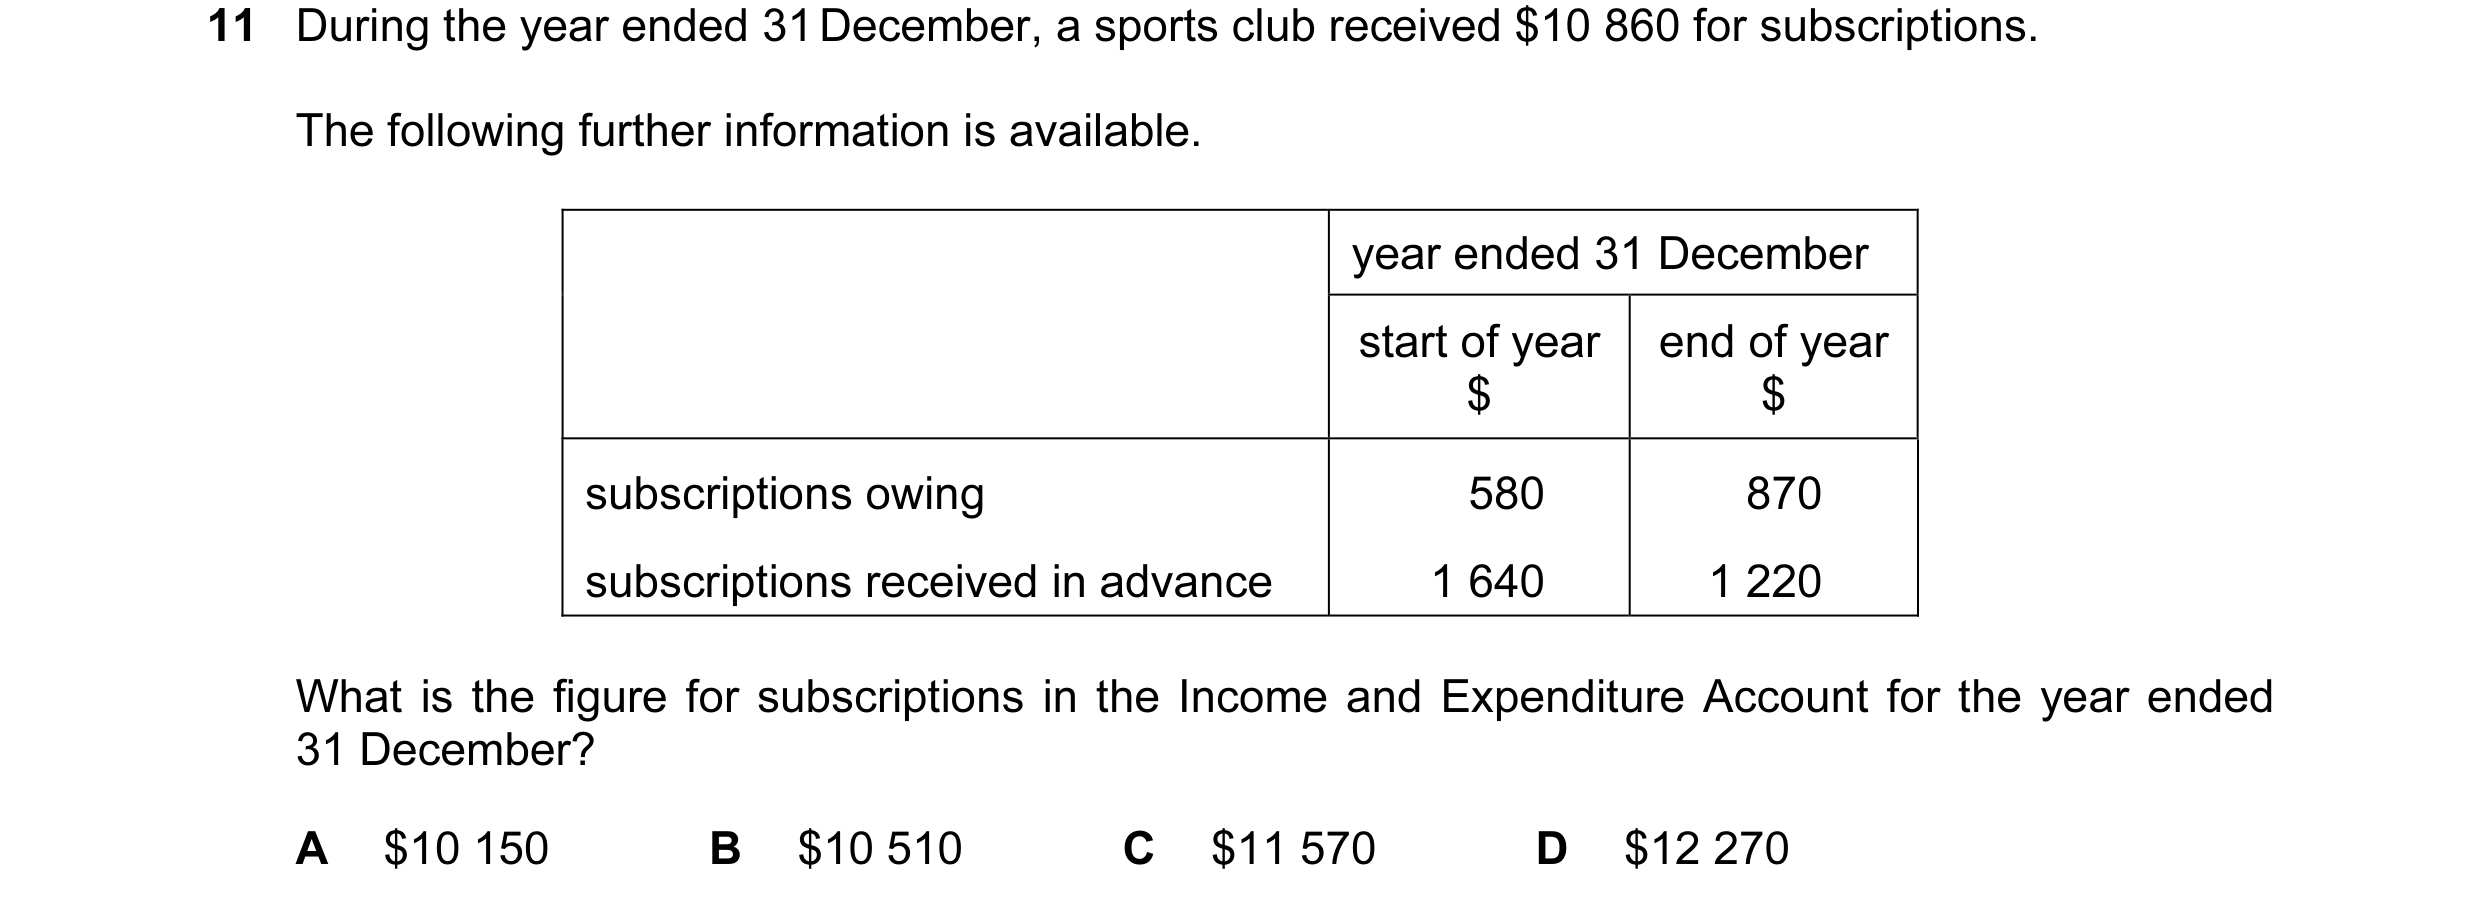
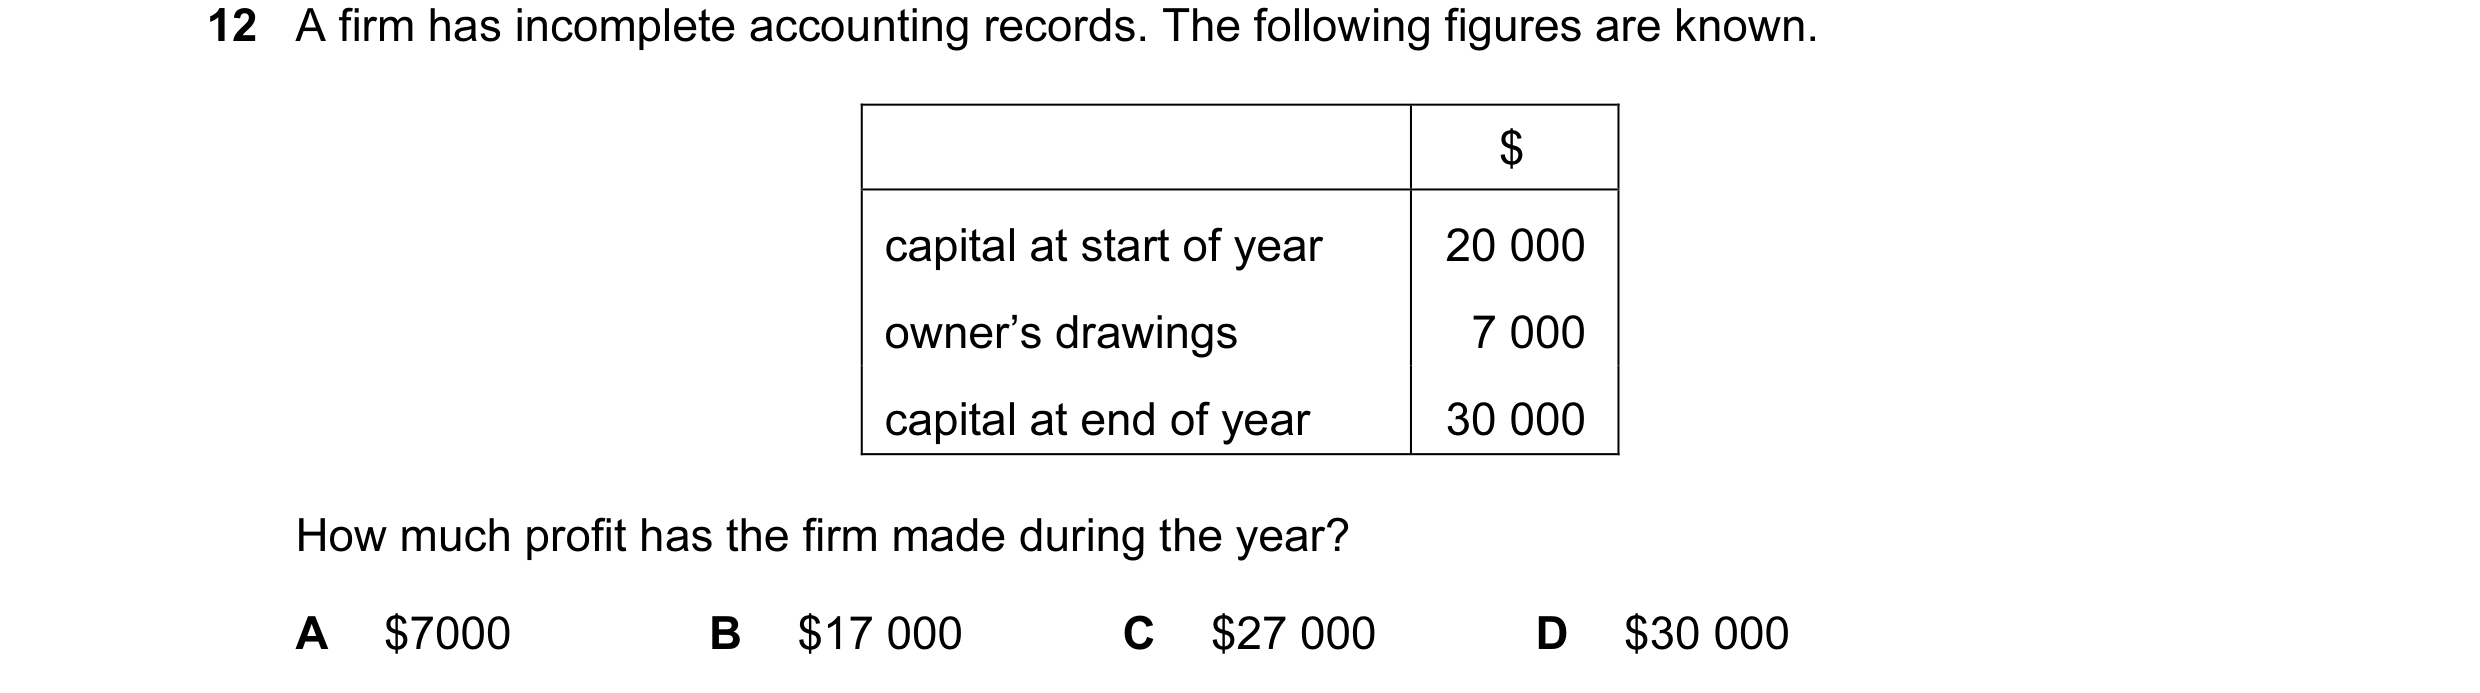 31 / 233
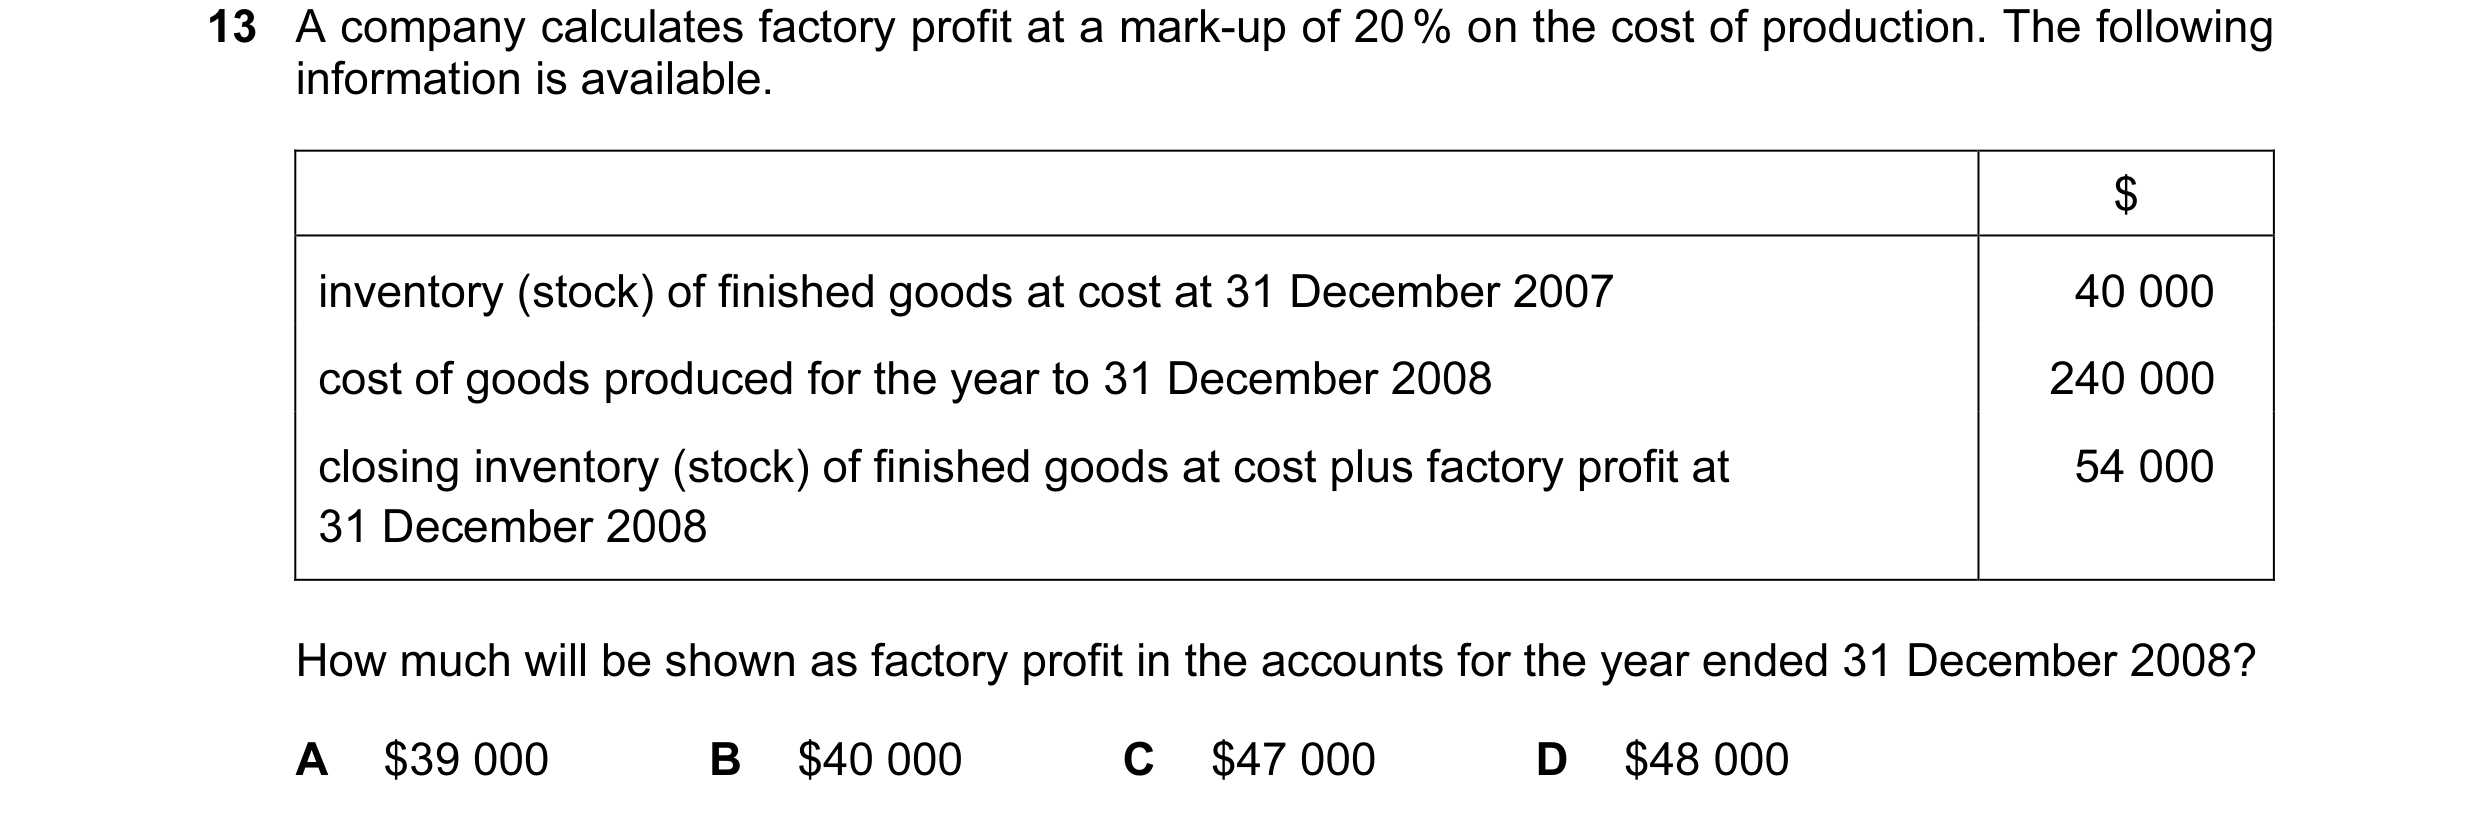
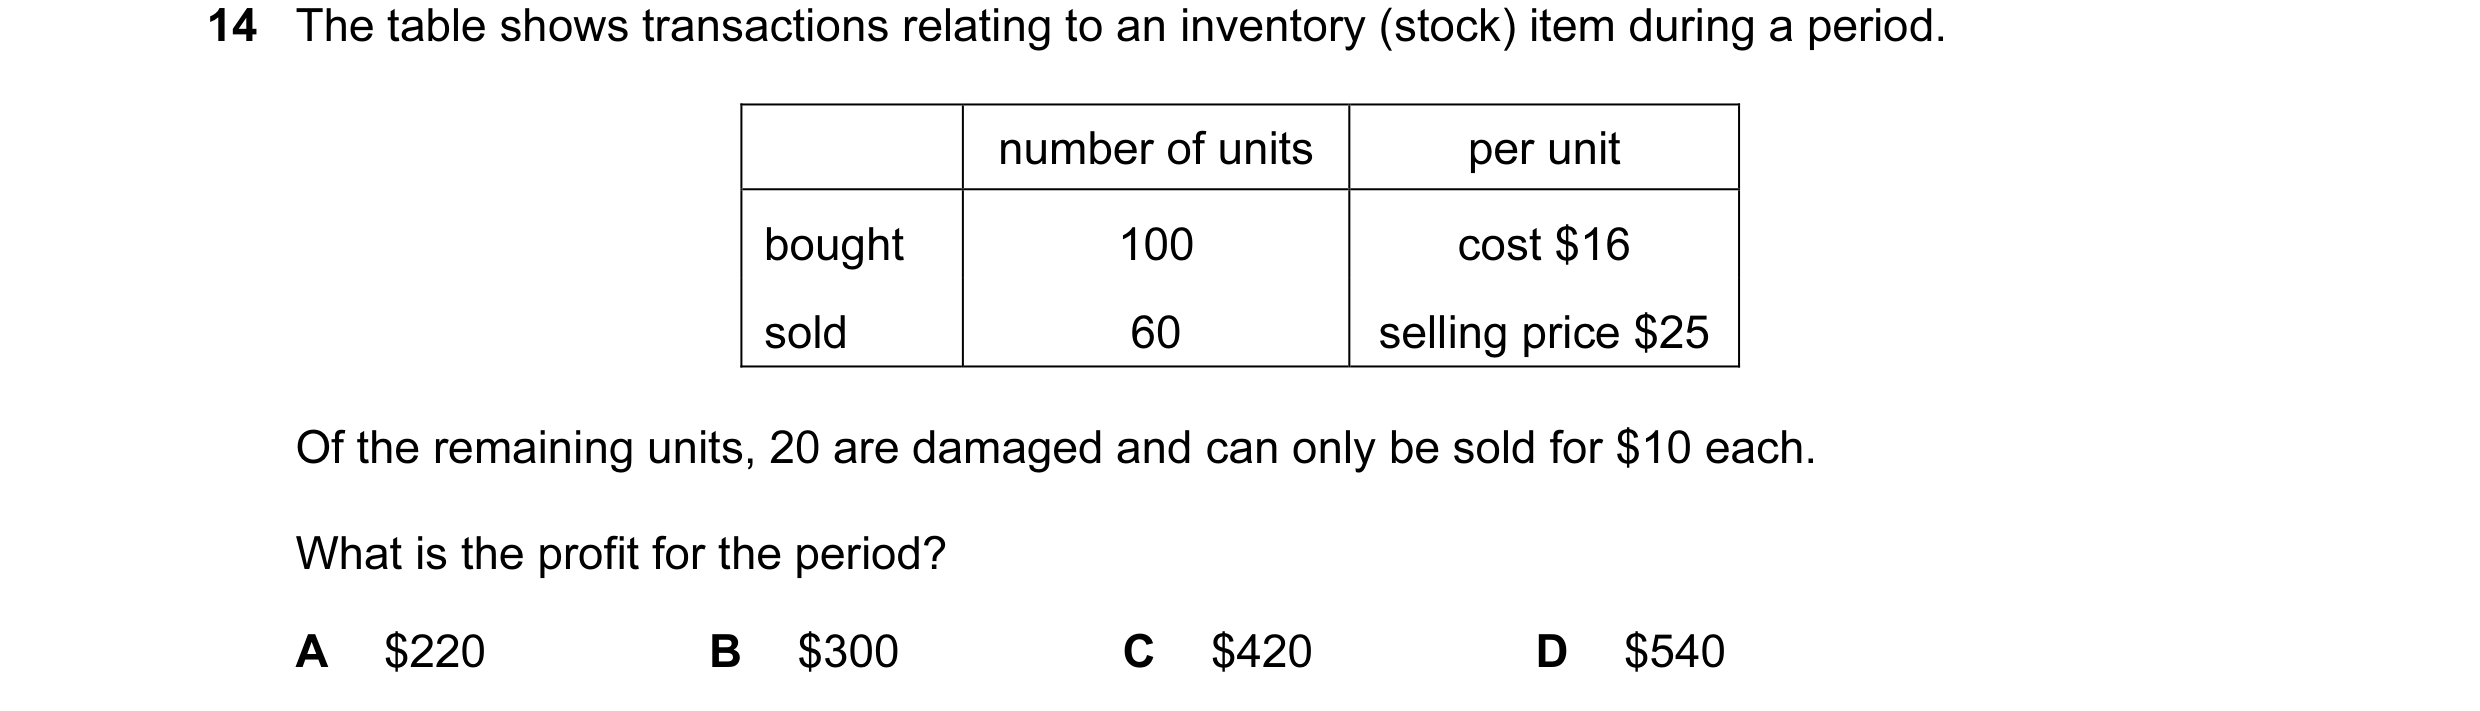
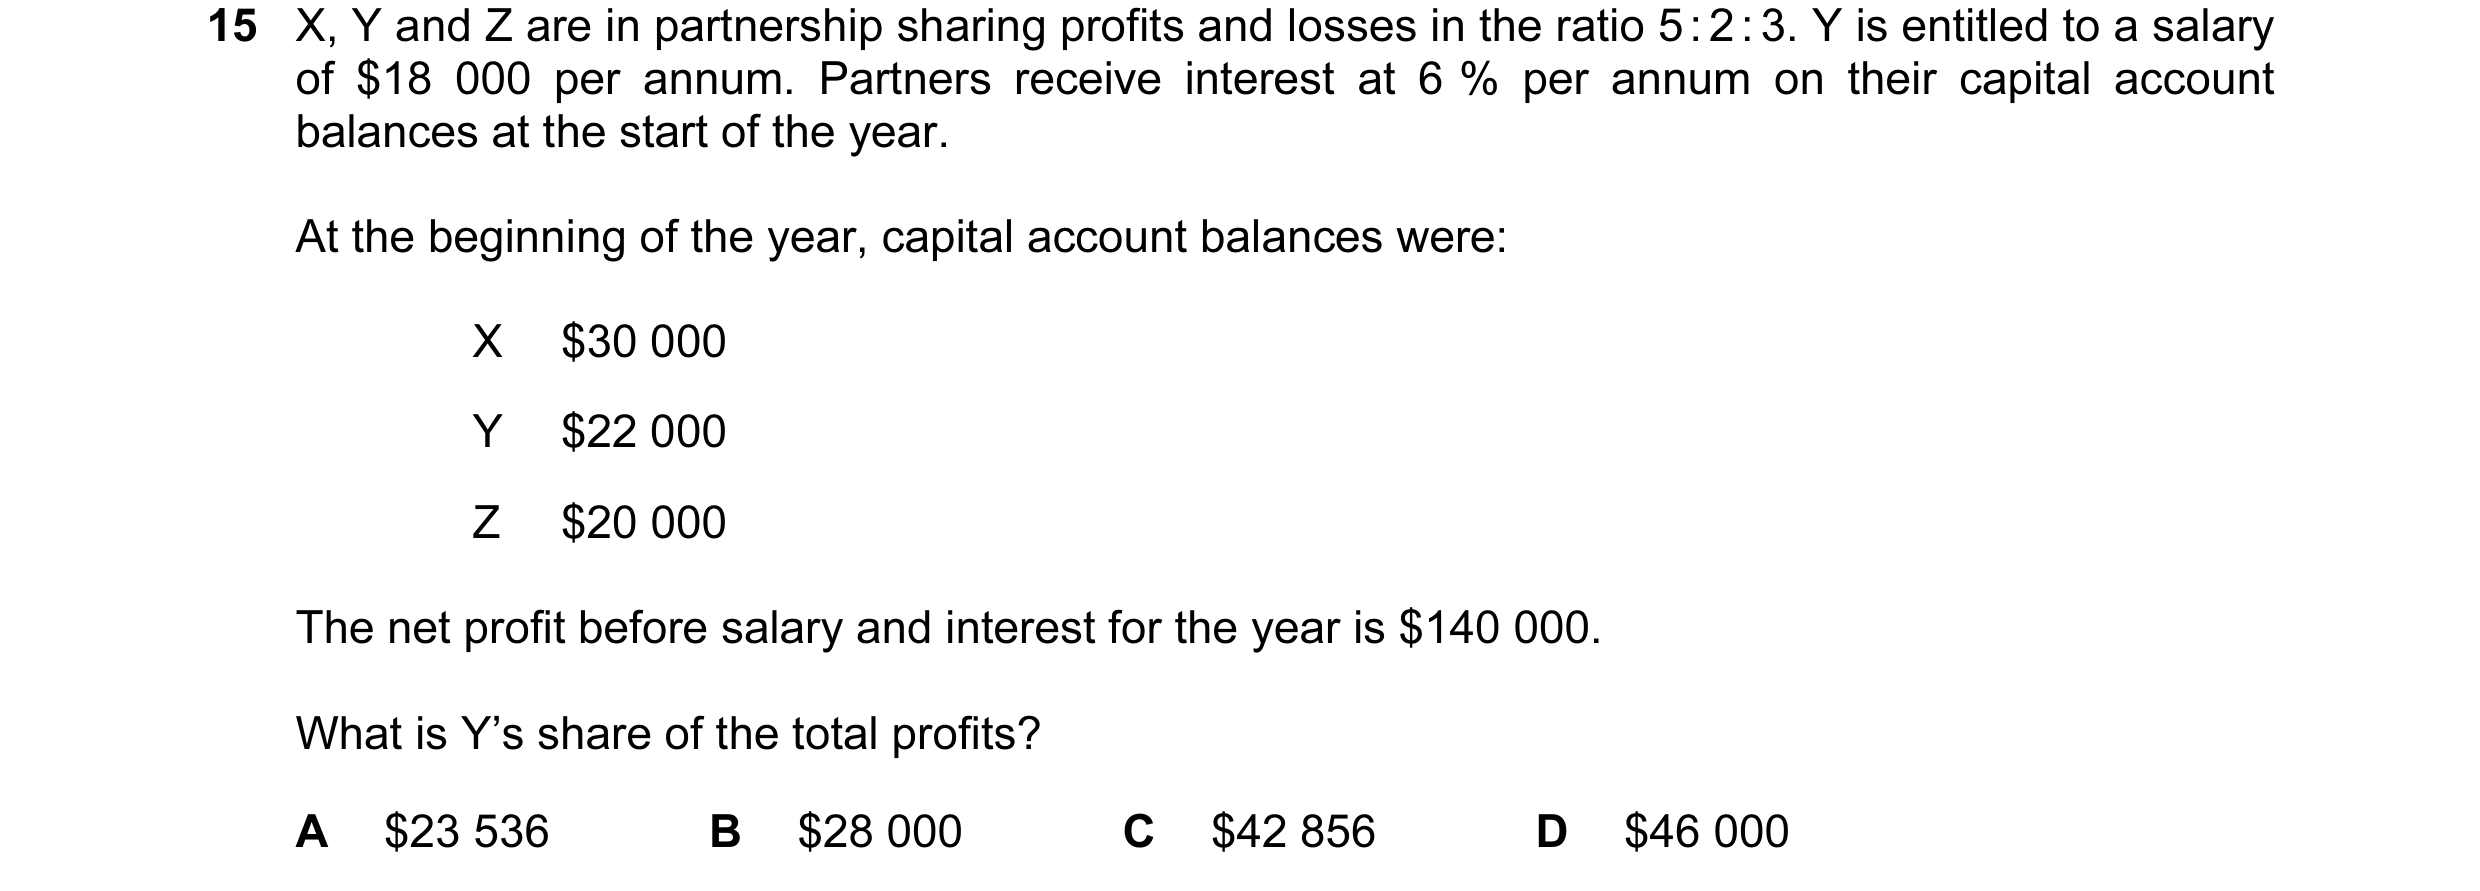
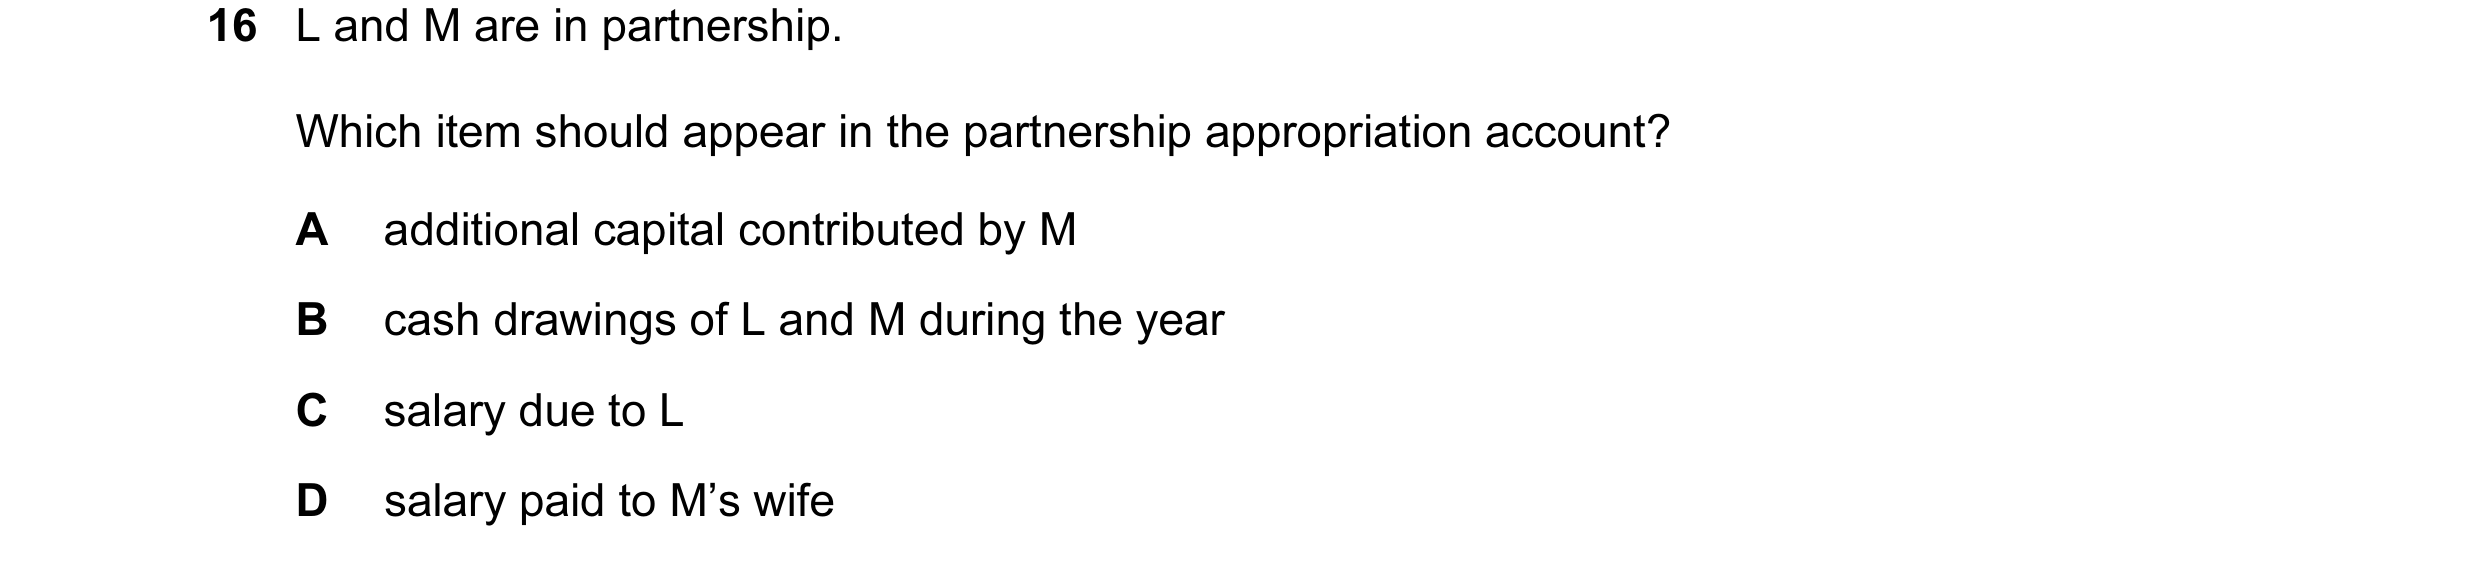 32 / 233
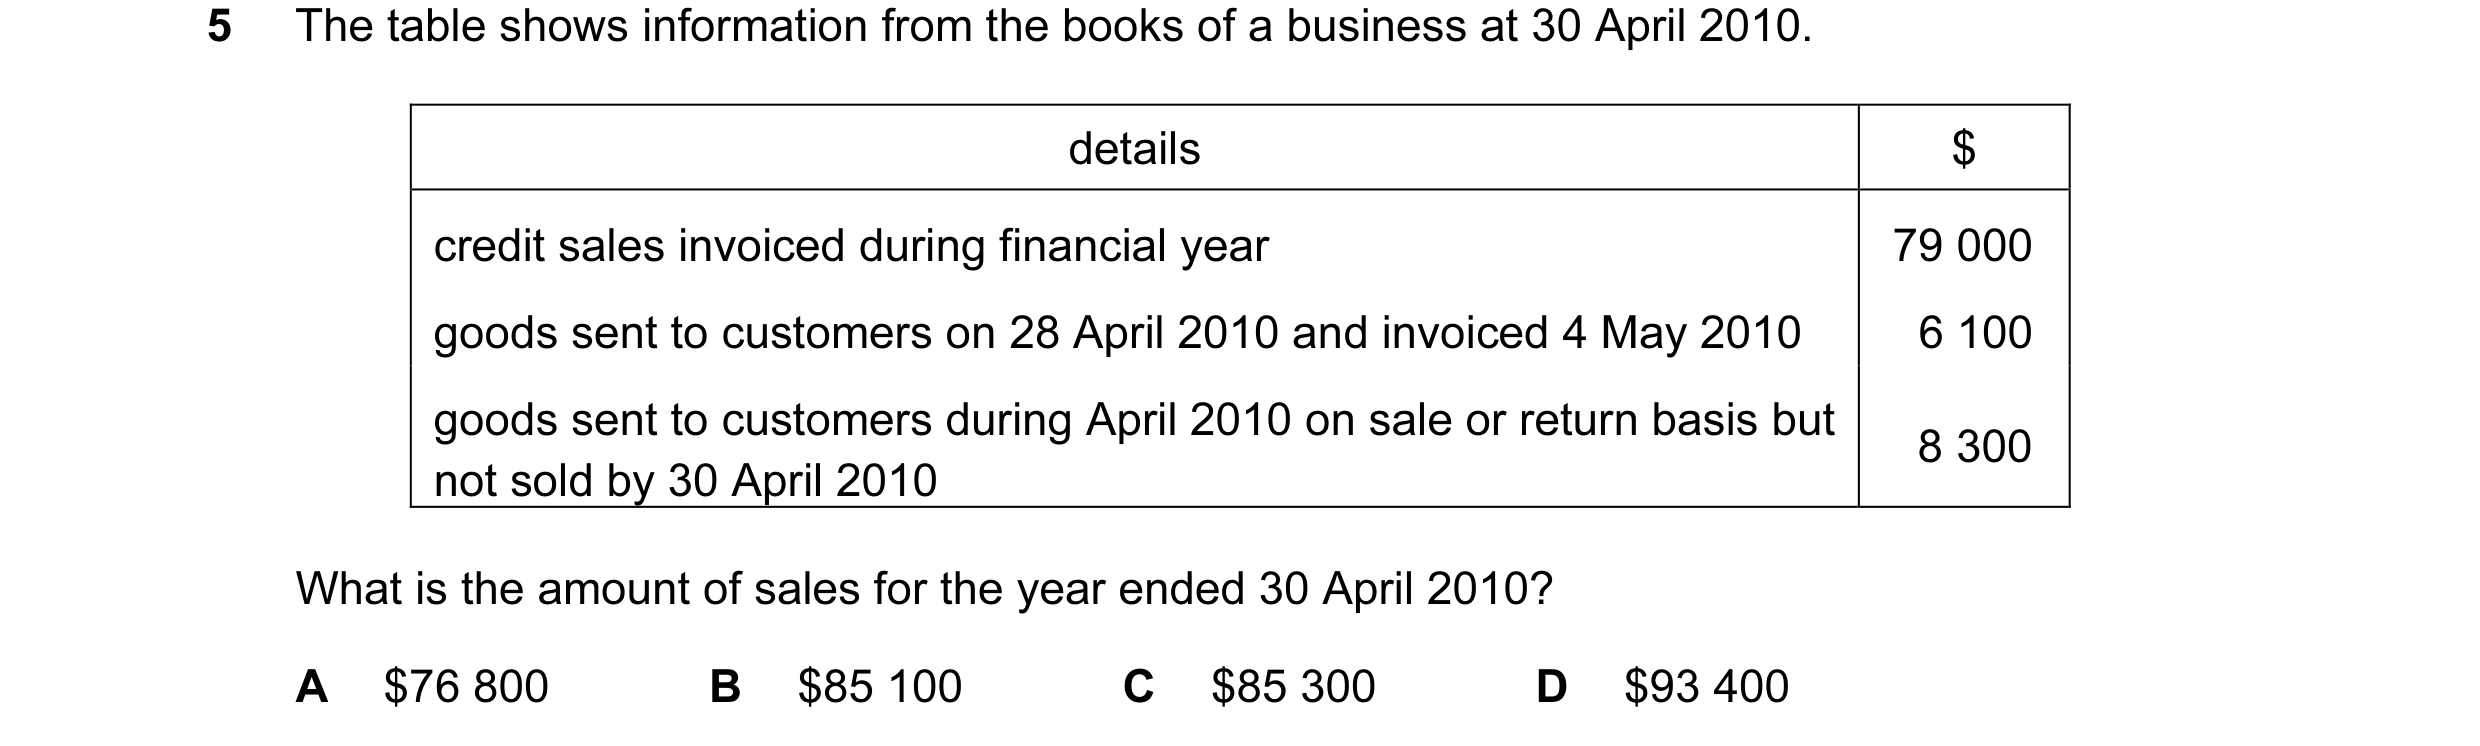
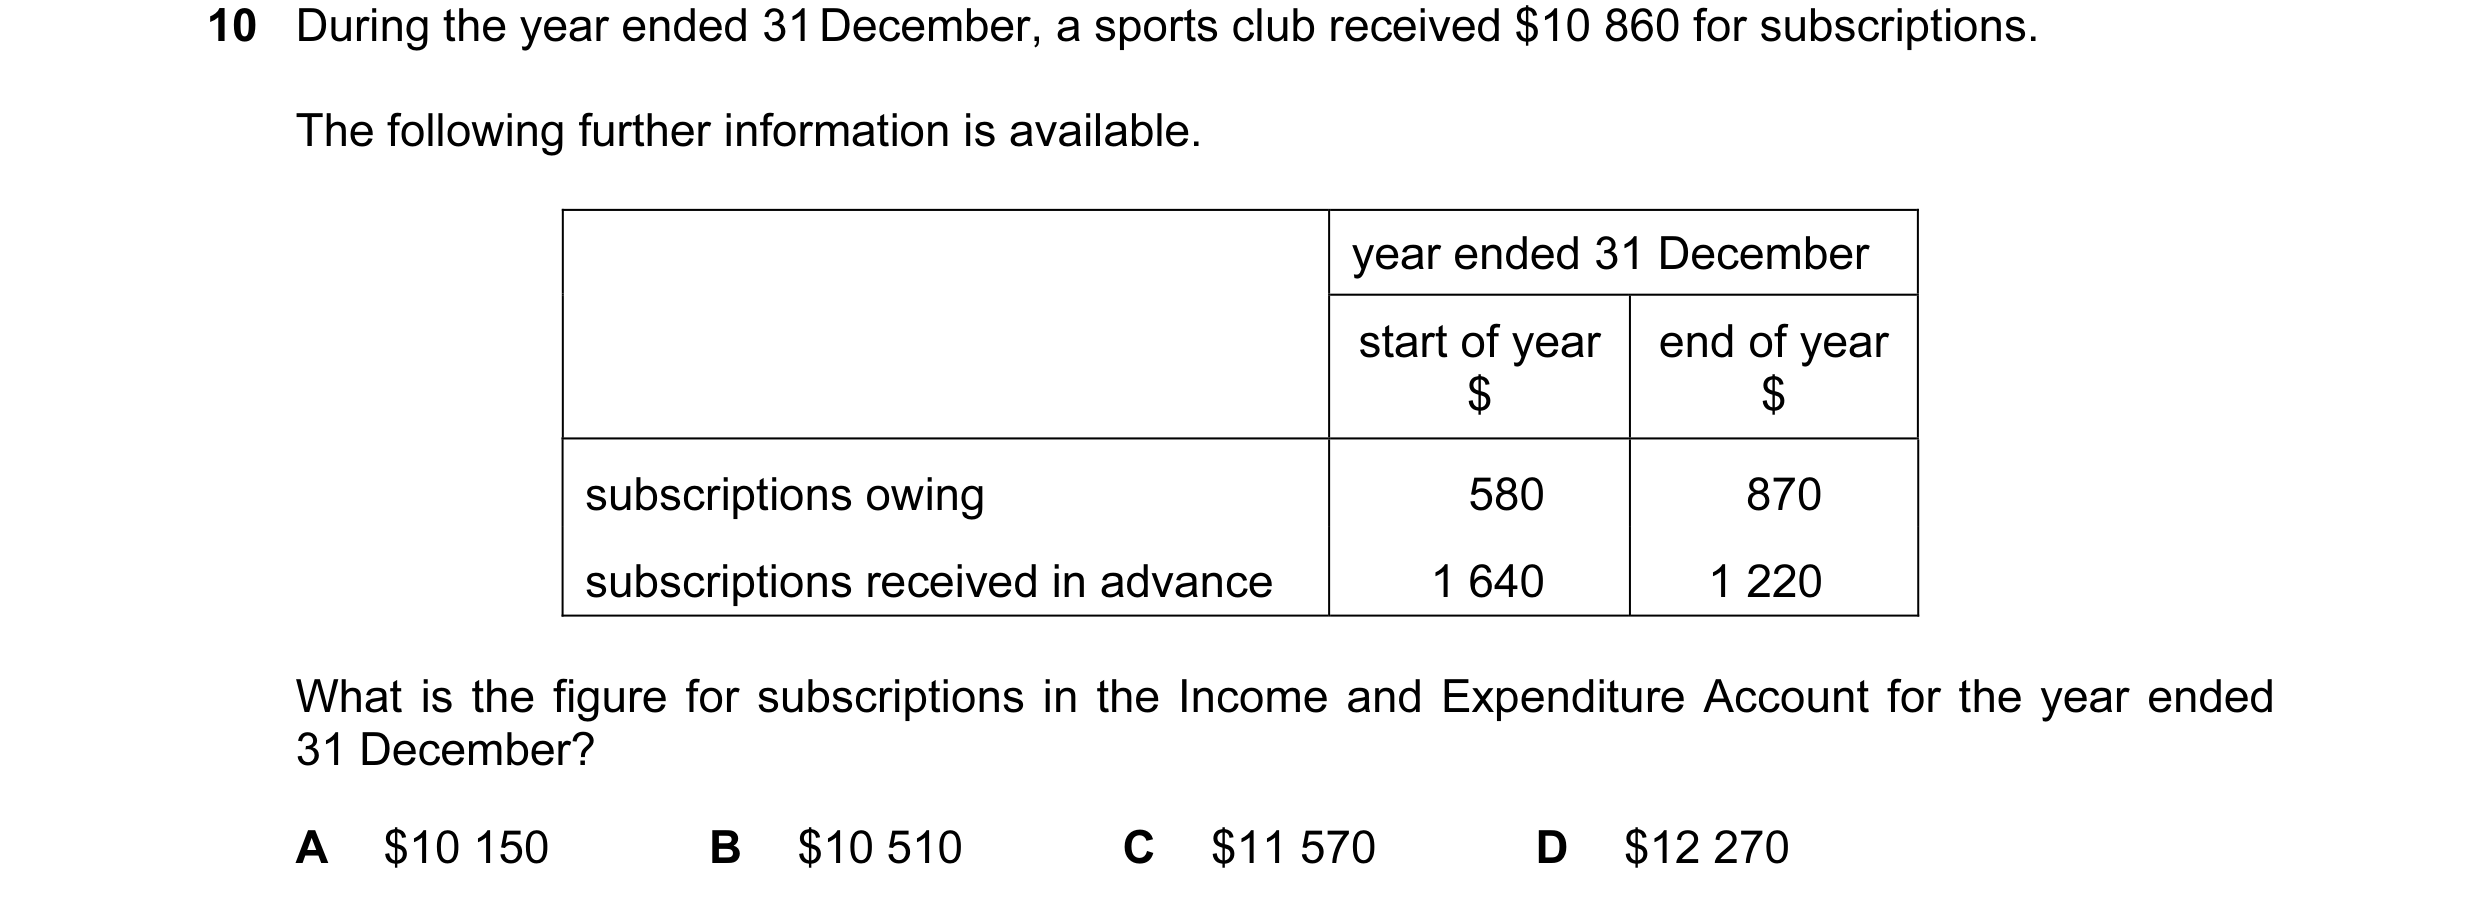
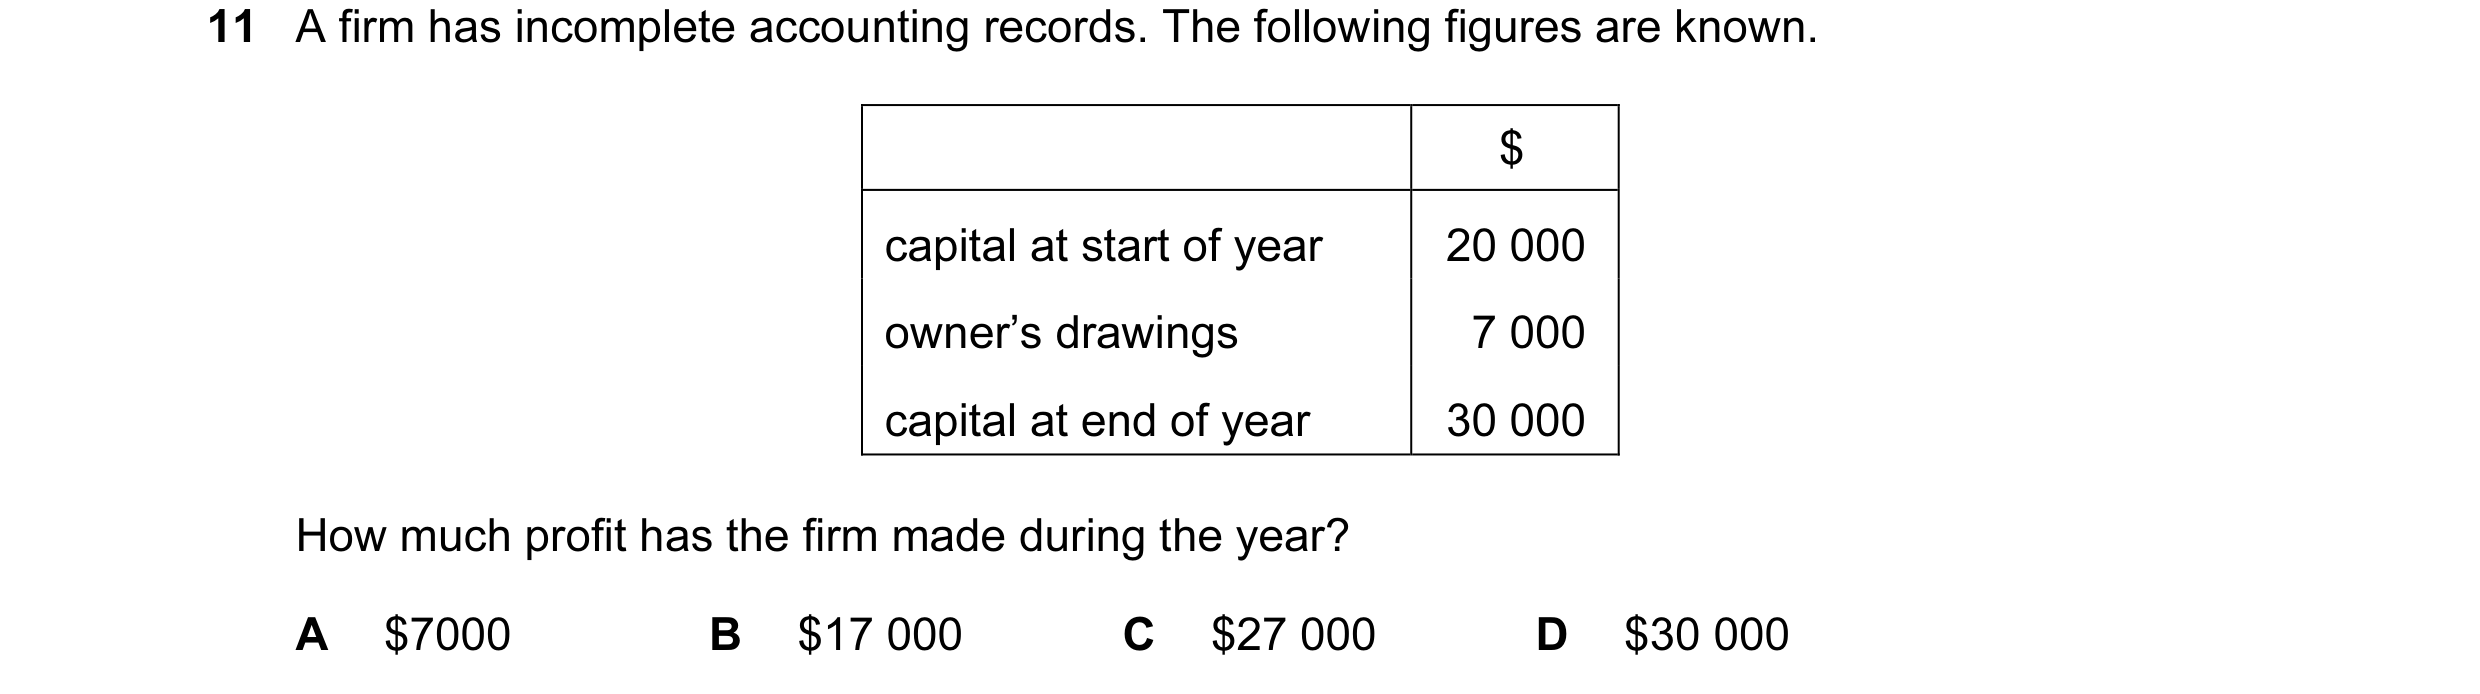
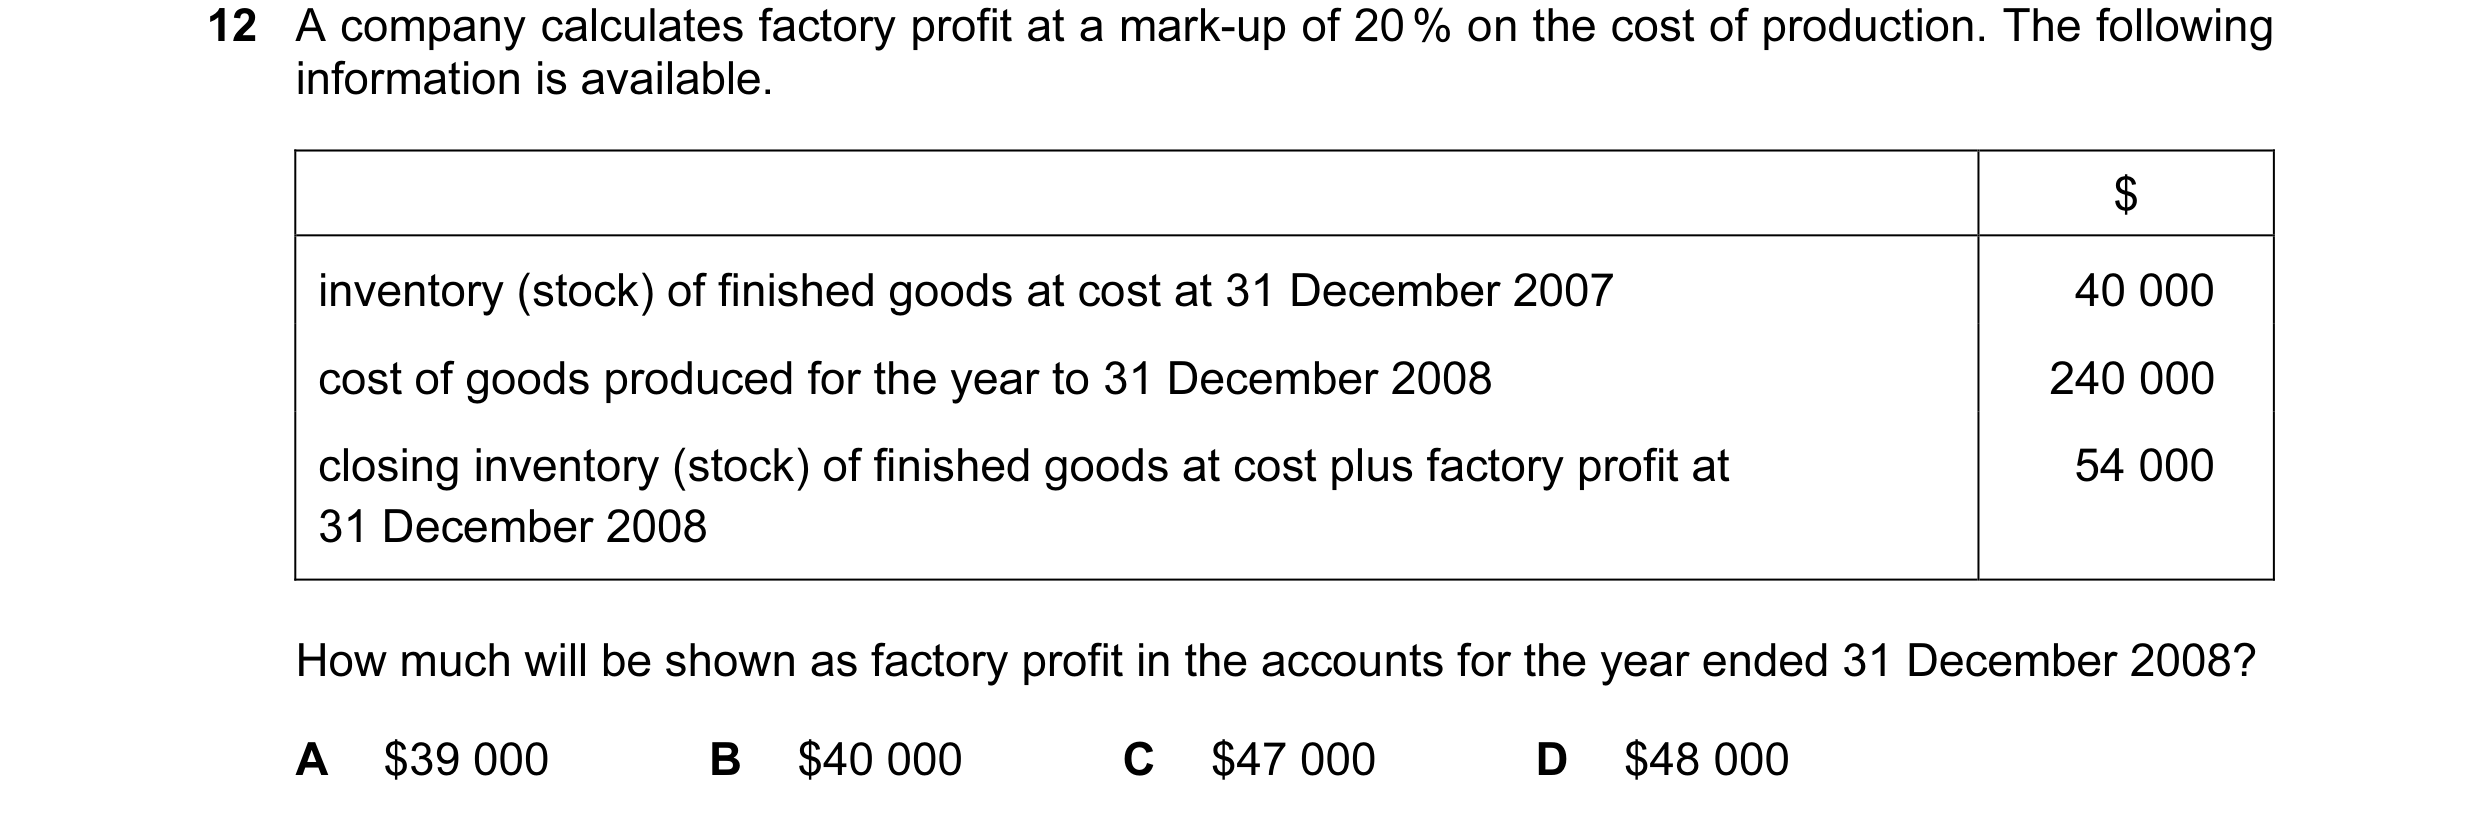 33 / 233
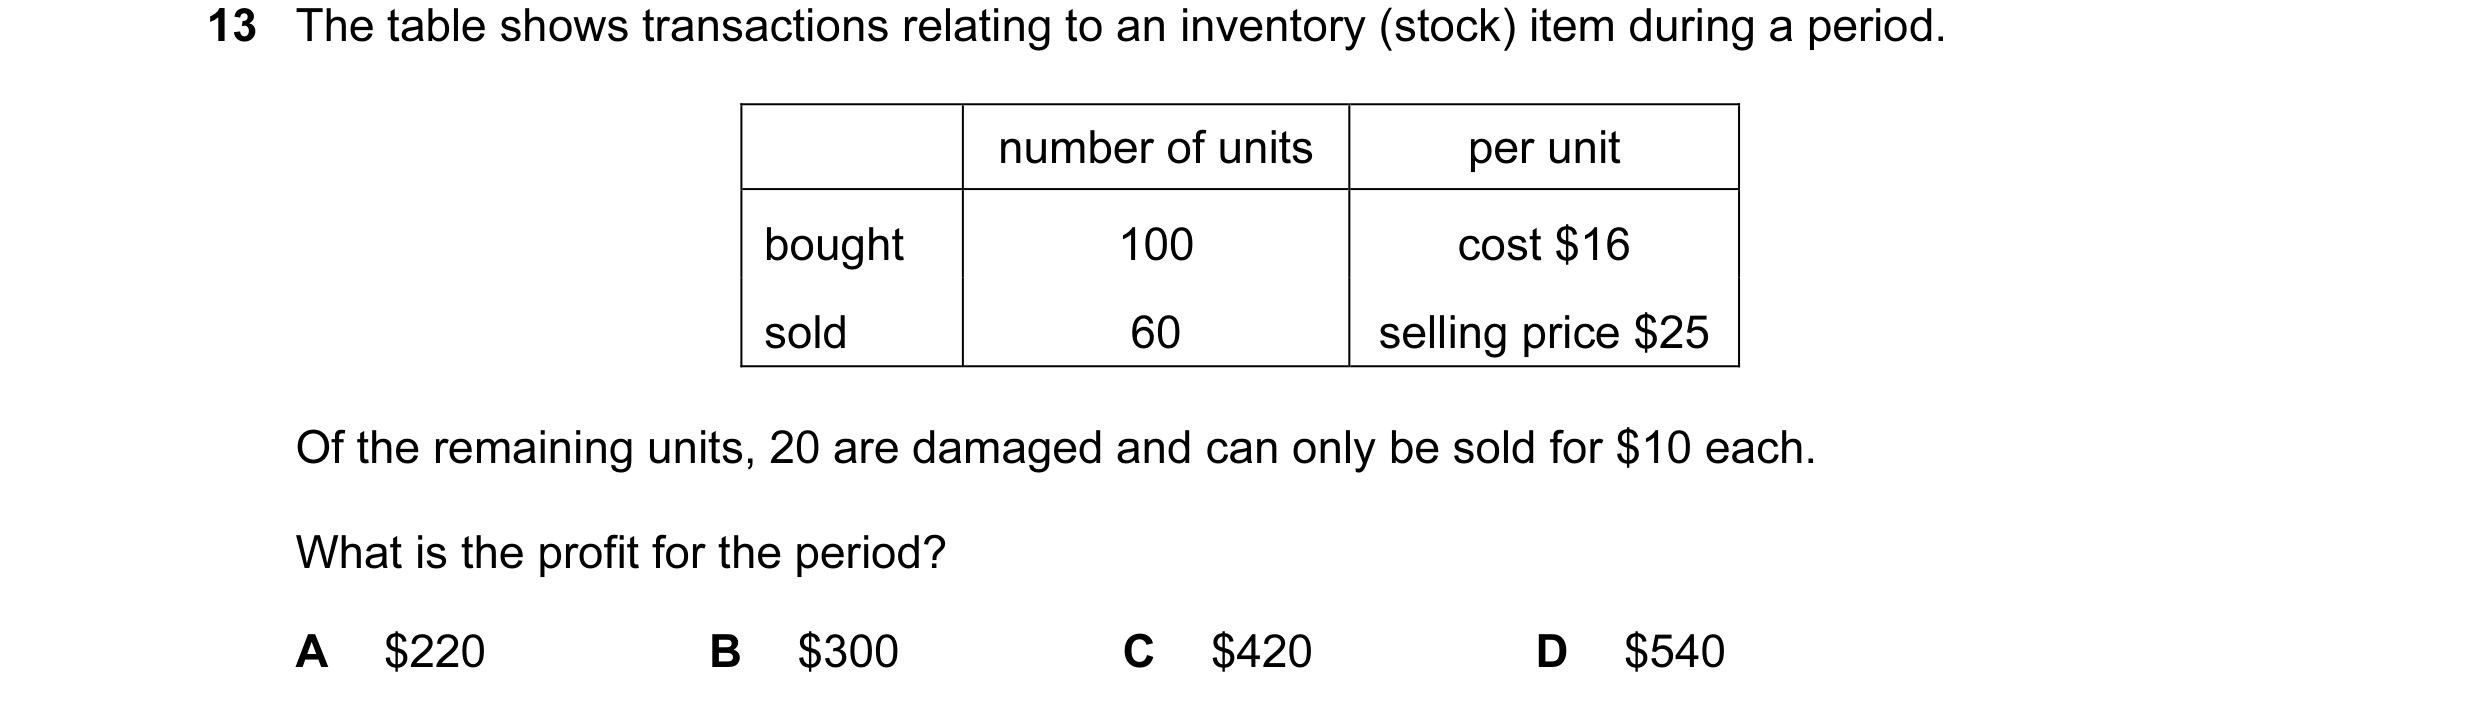
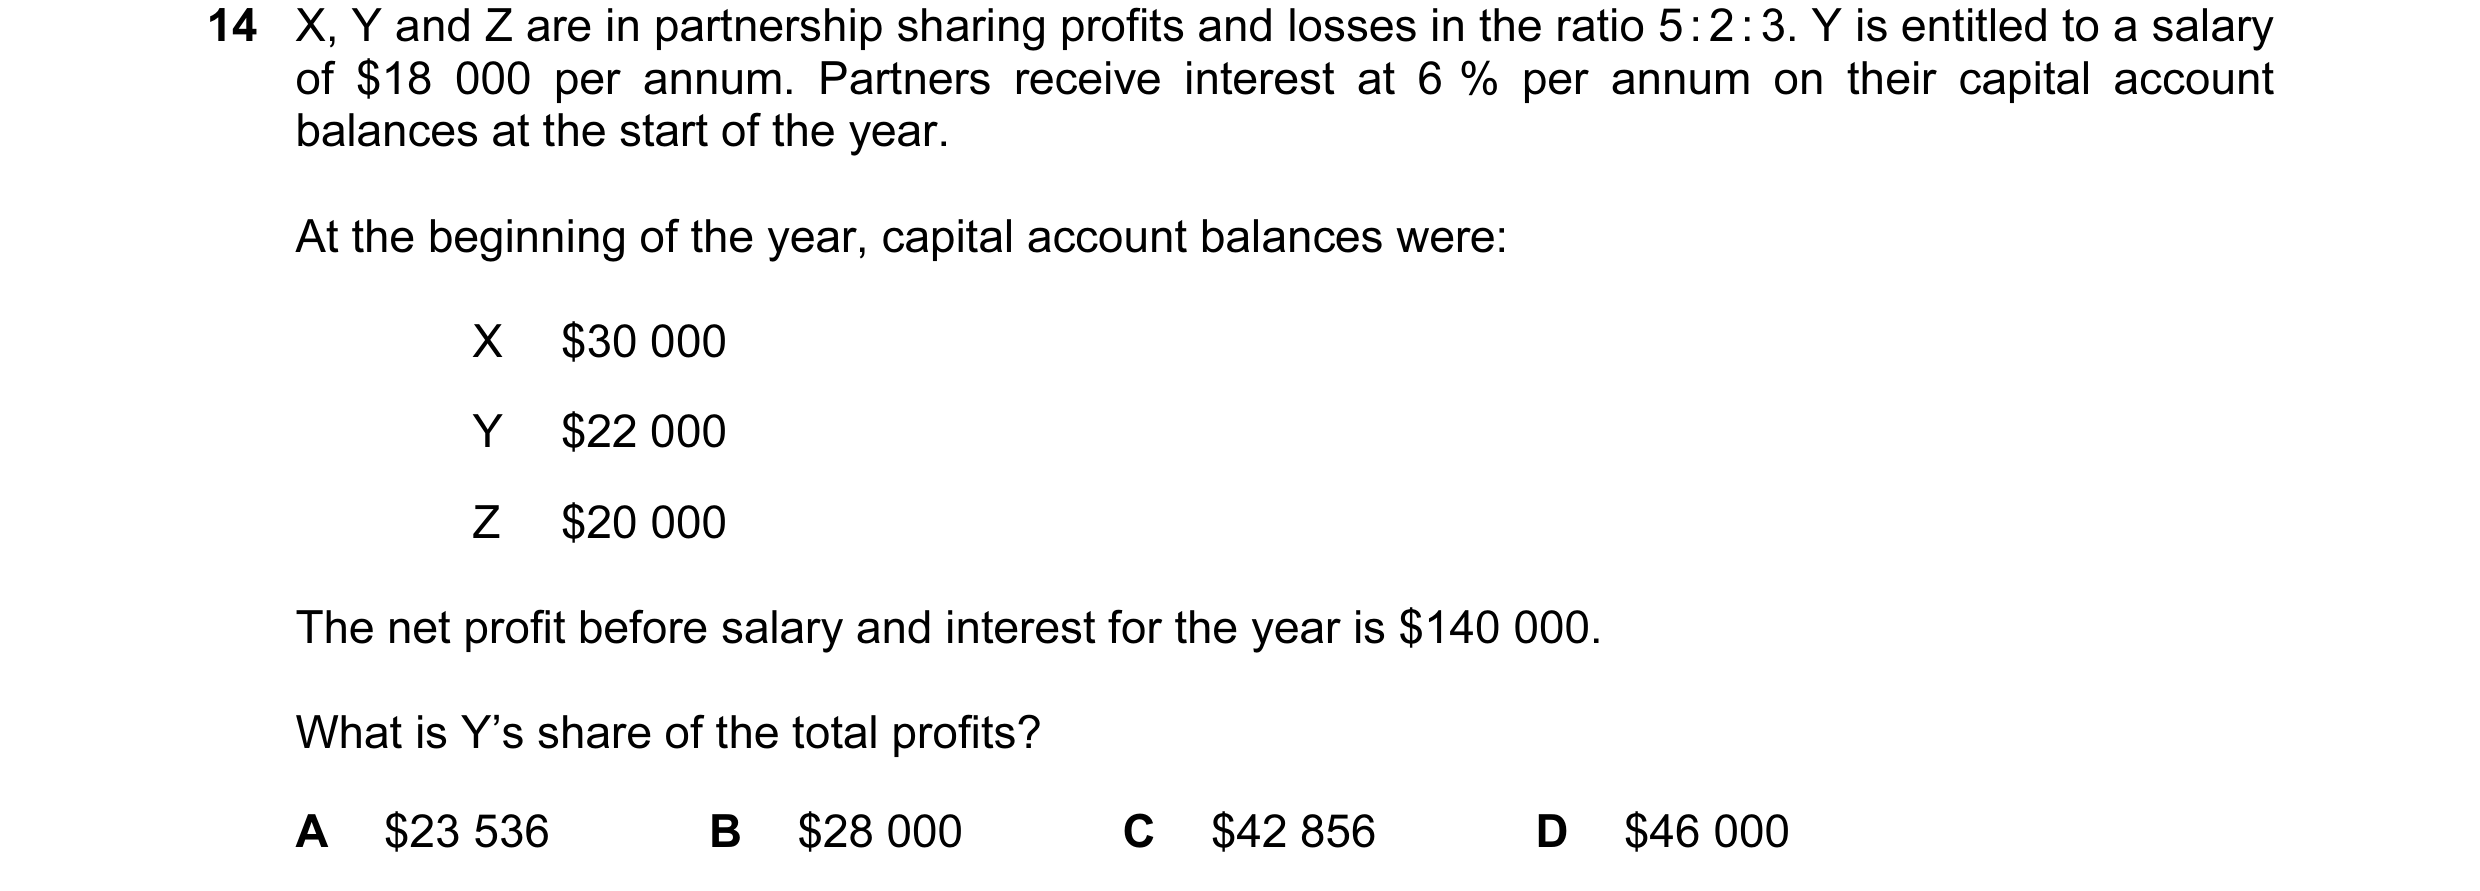
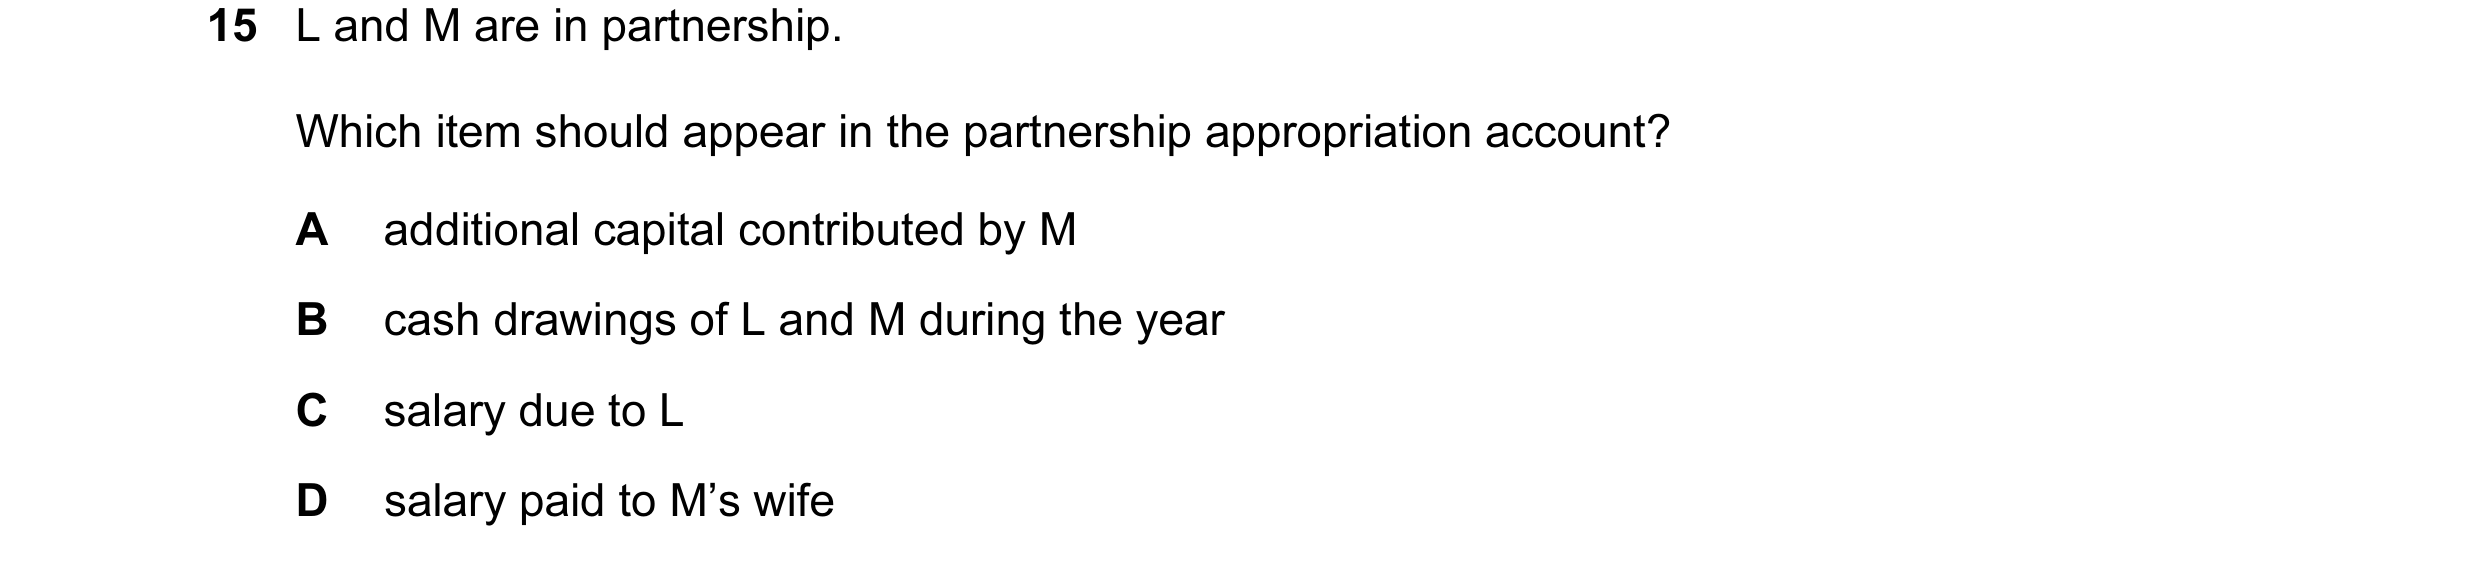
 34 / 233
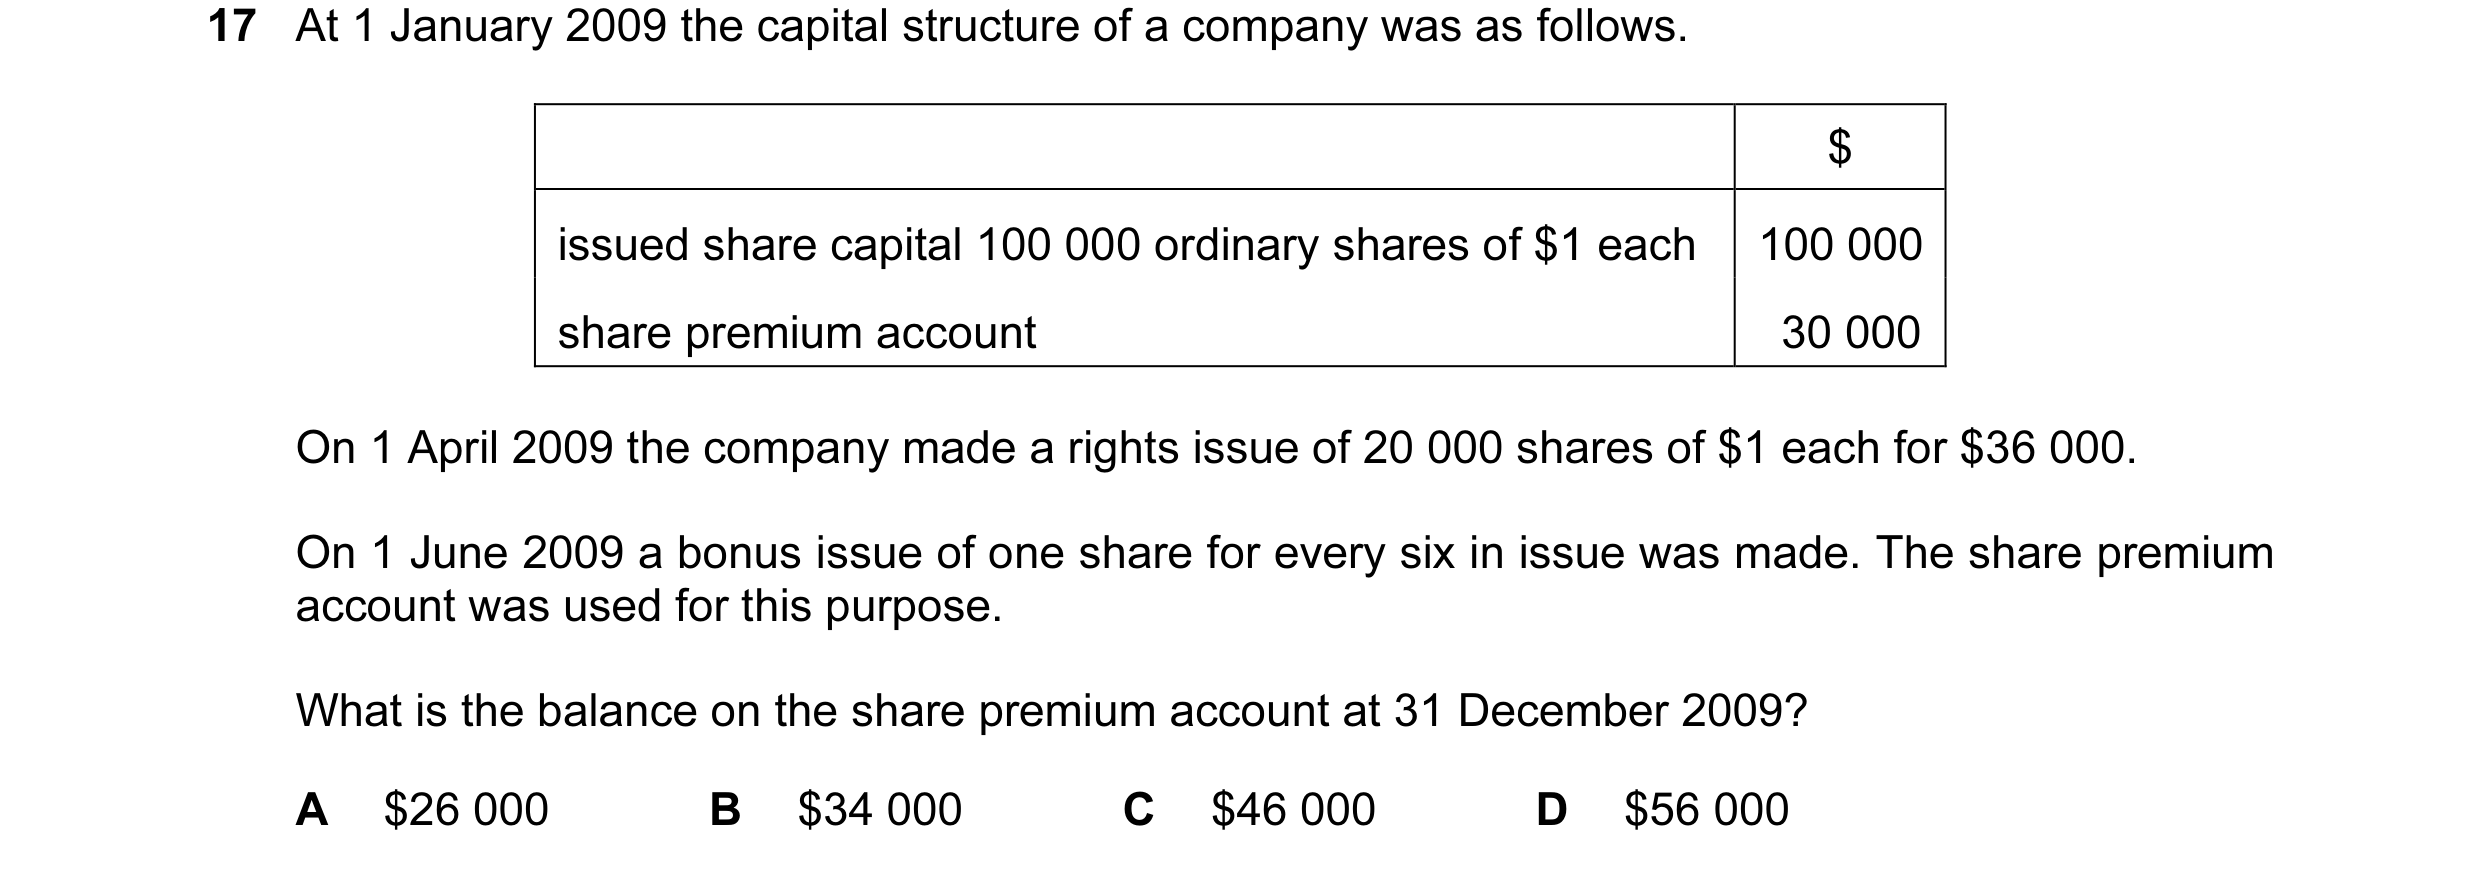
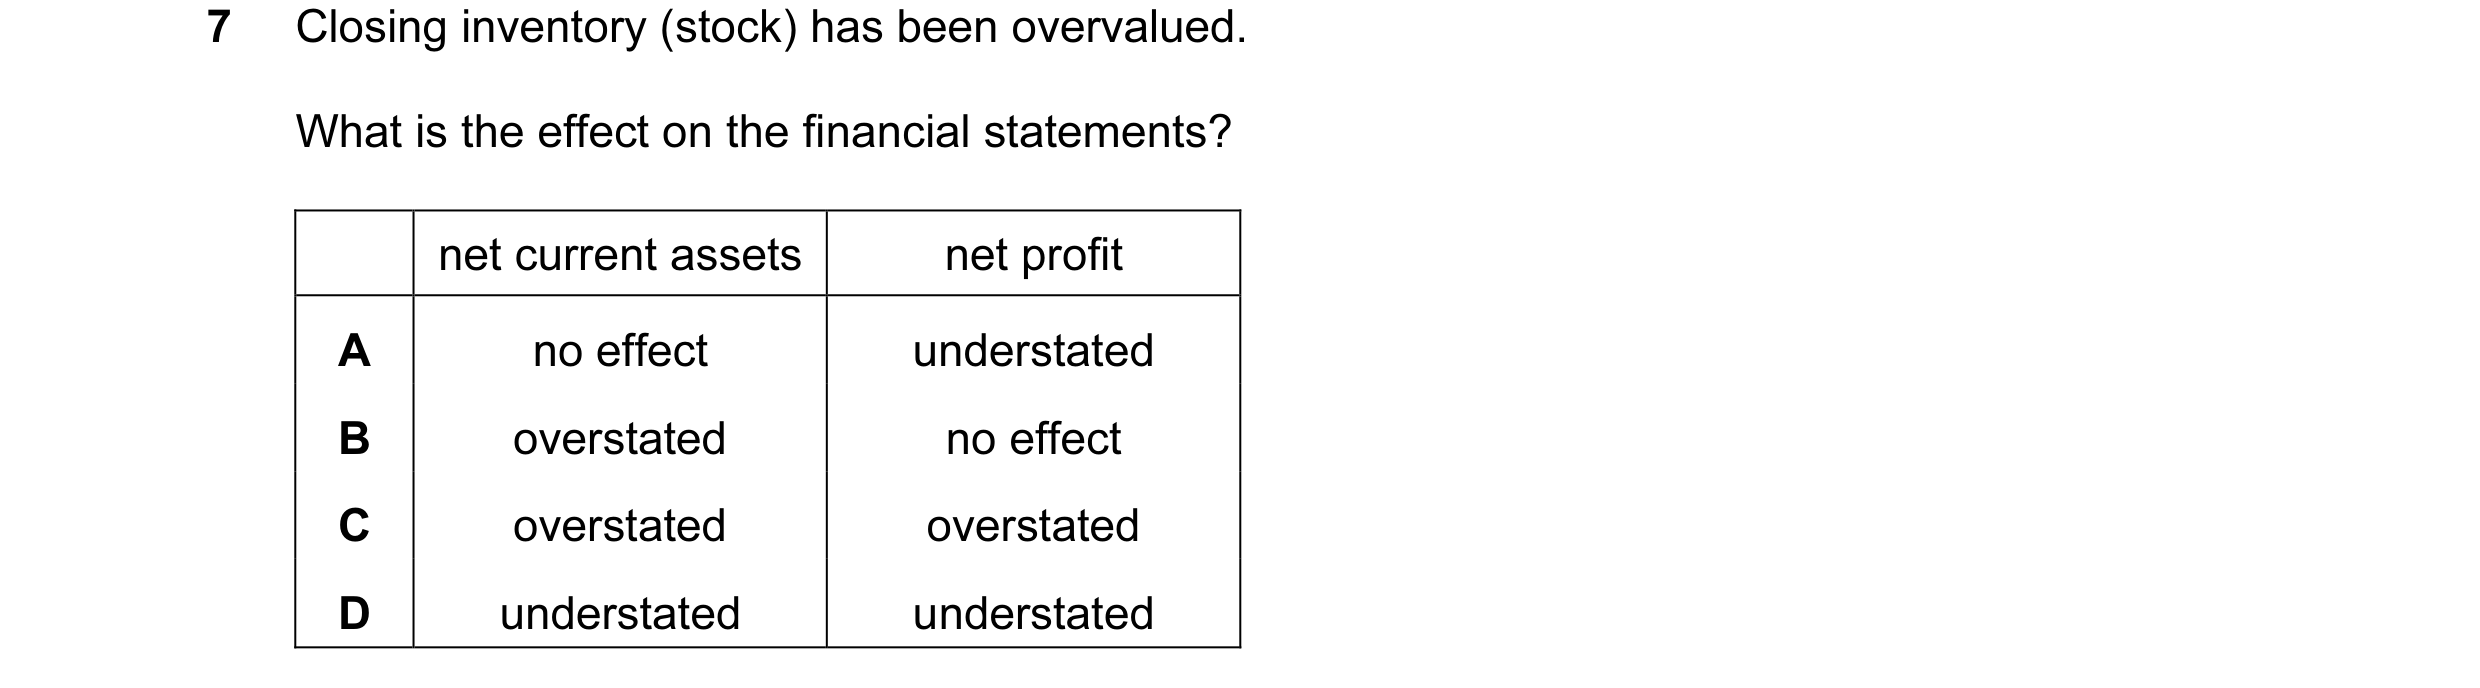
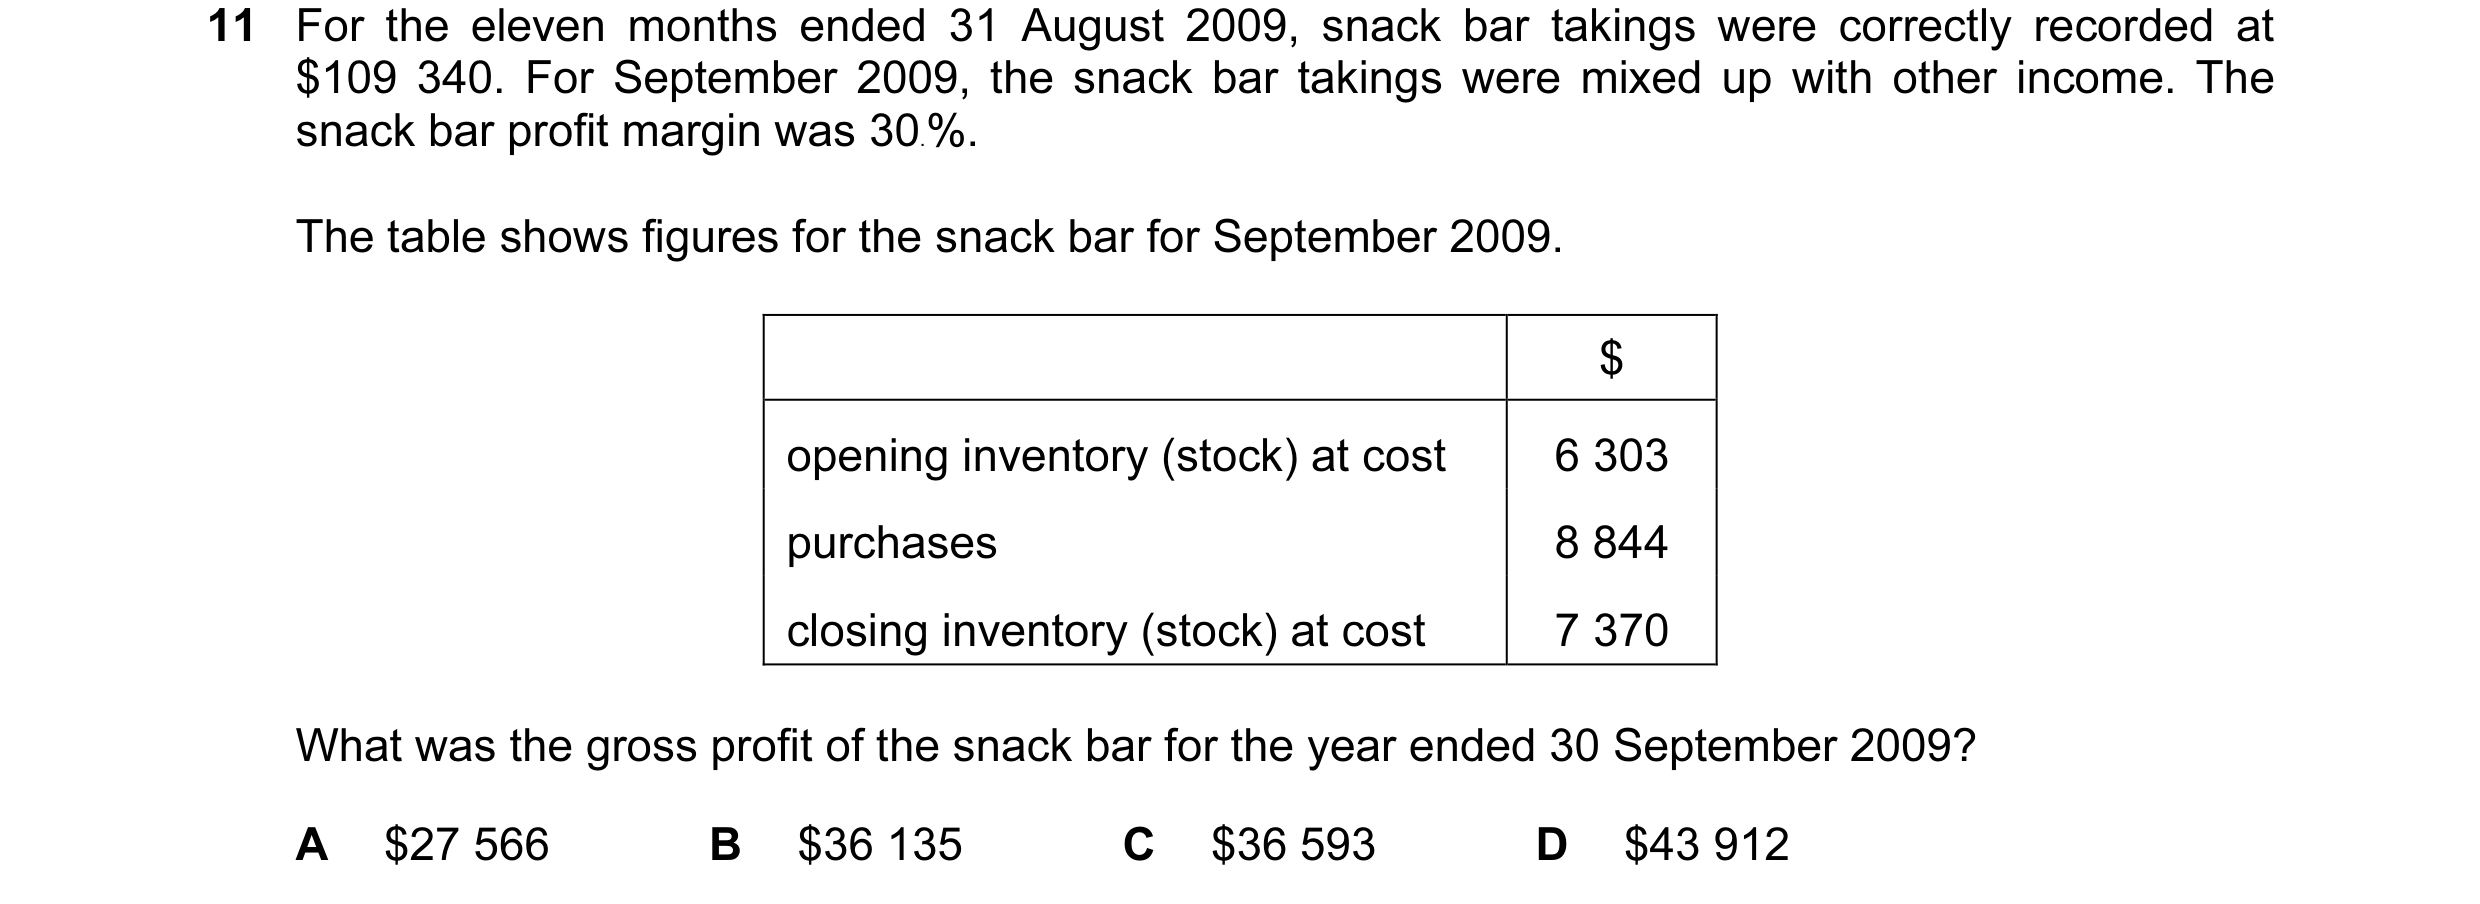 35 / 233
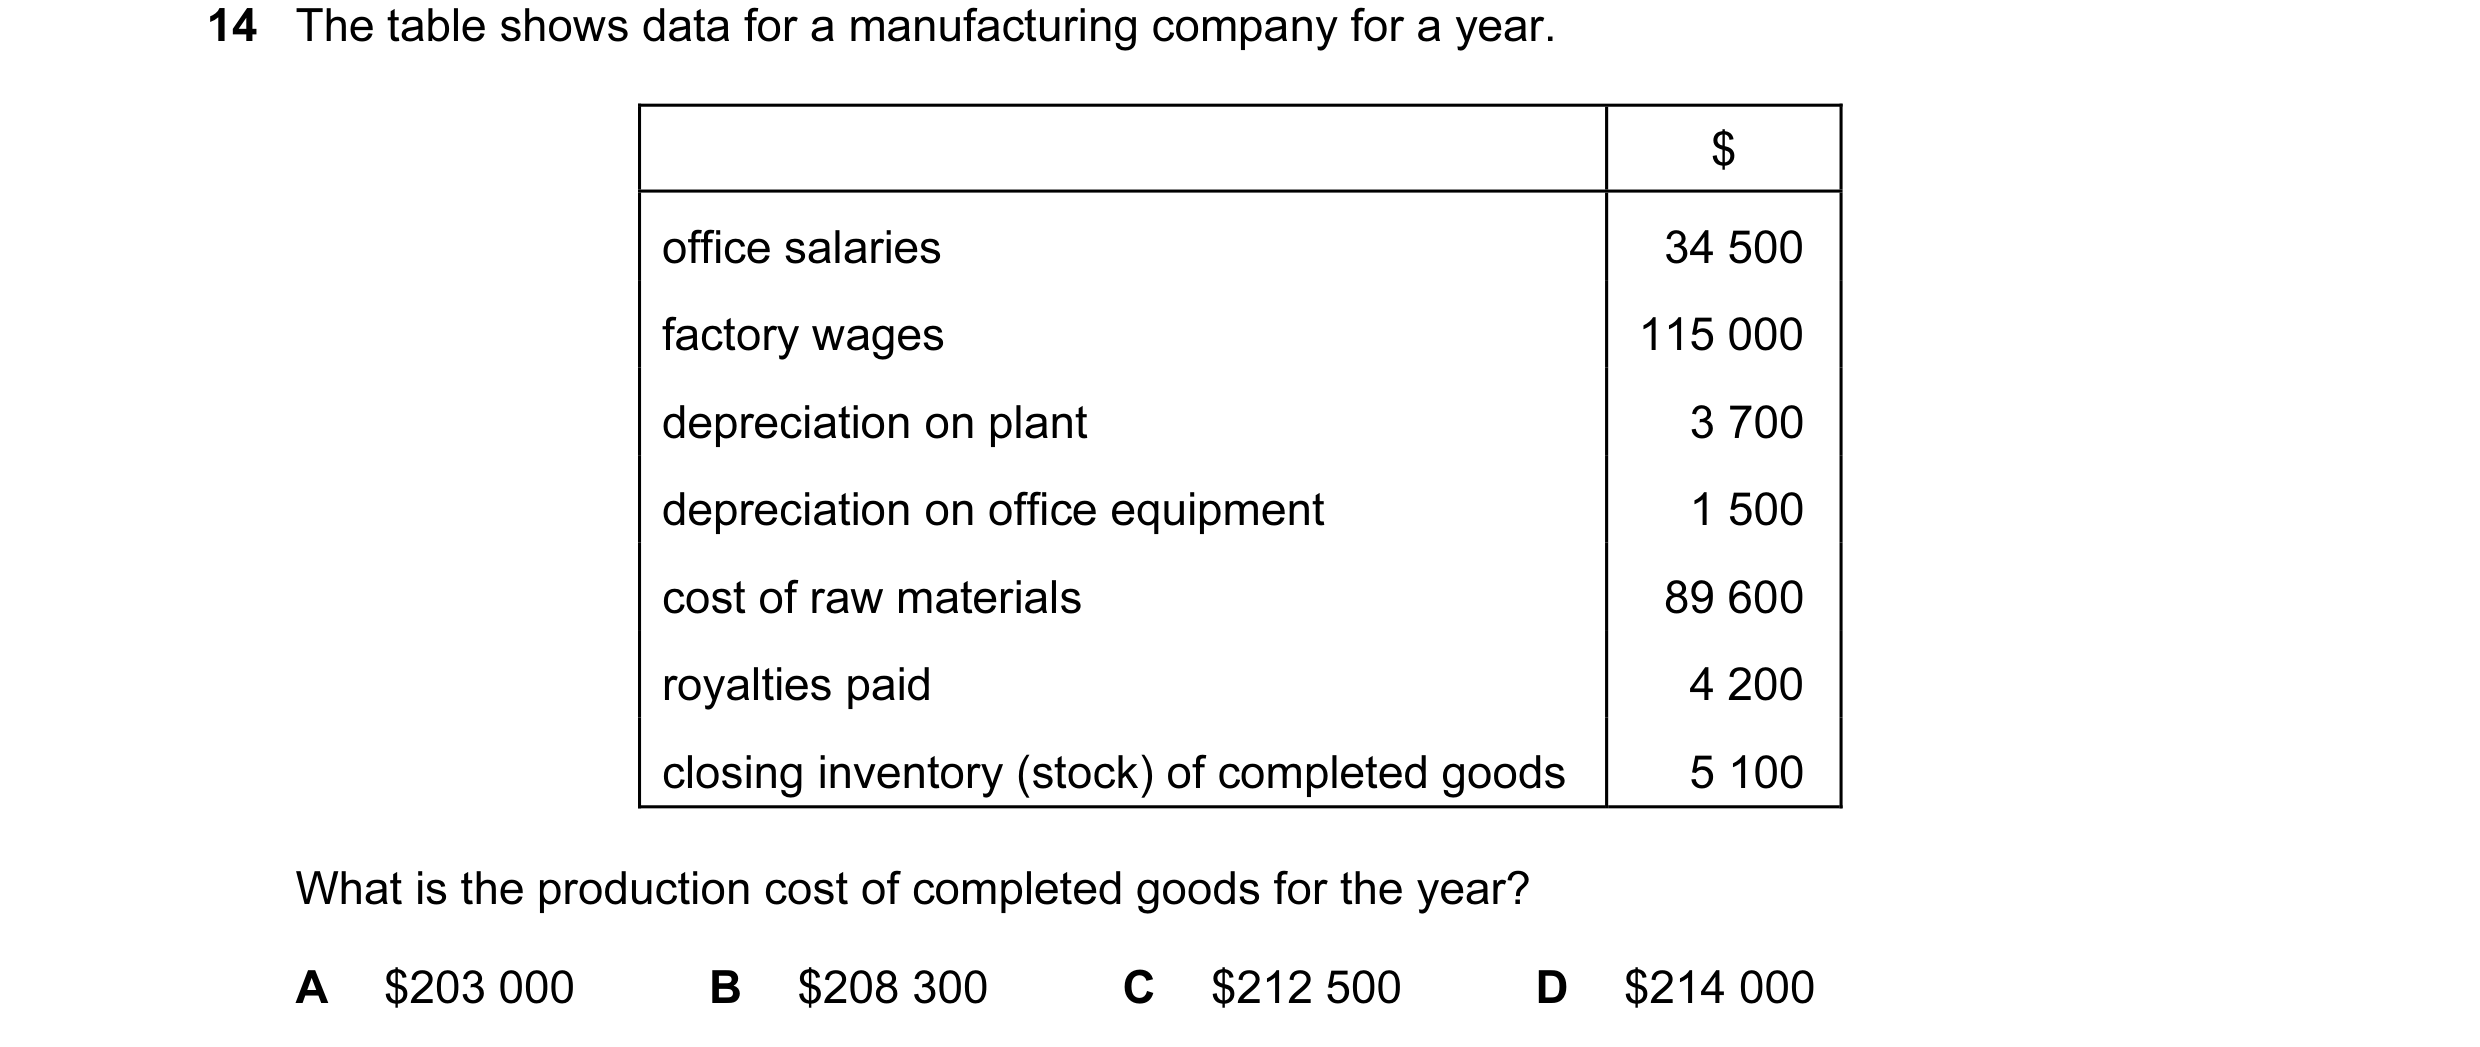
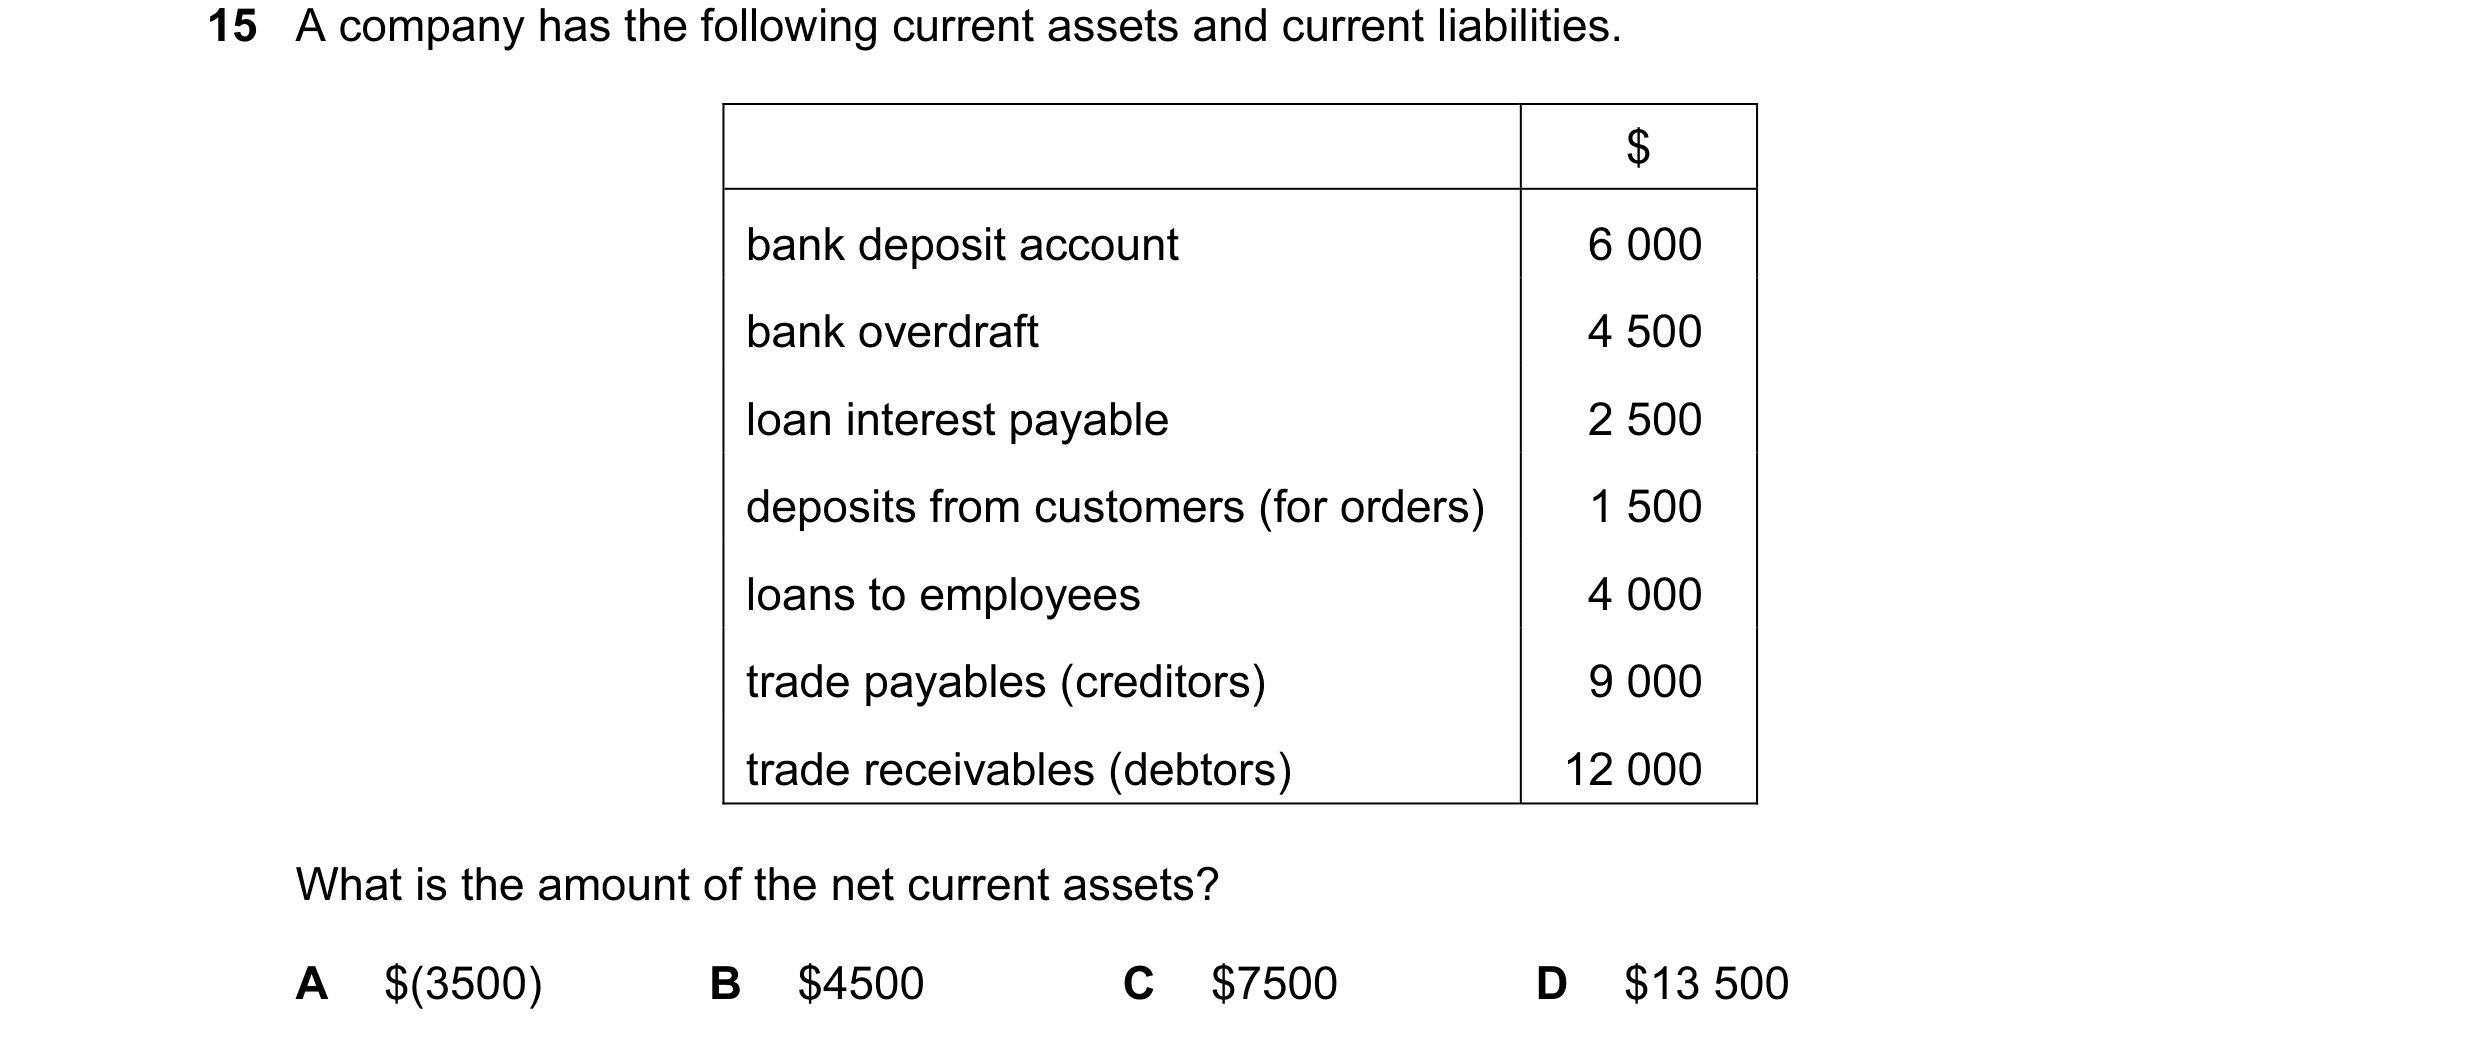
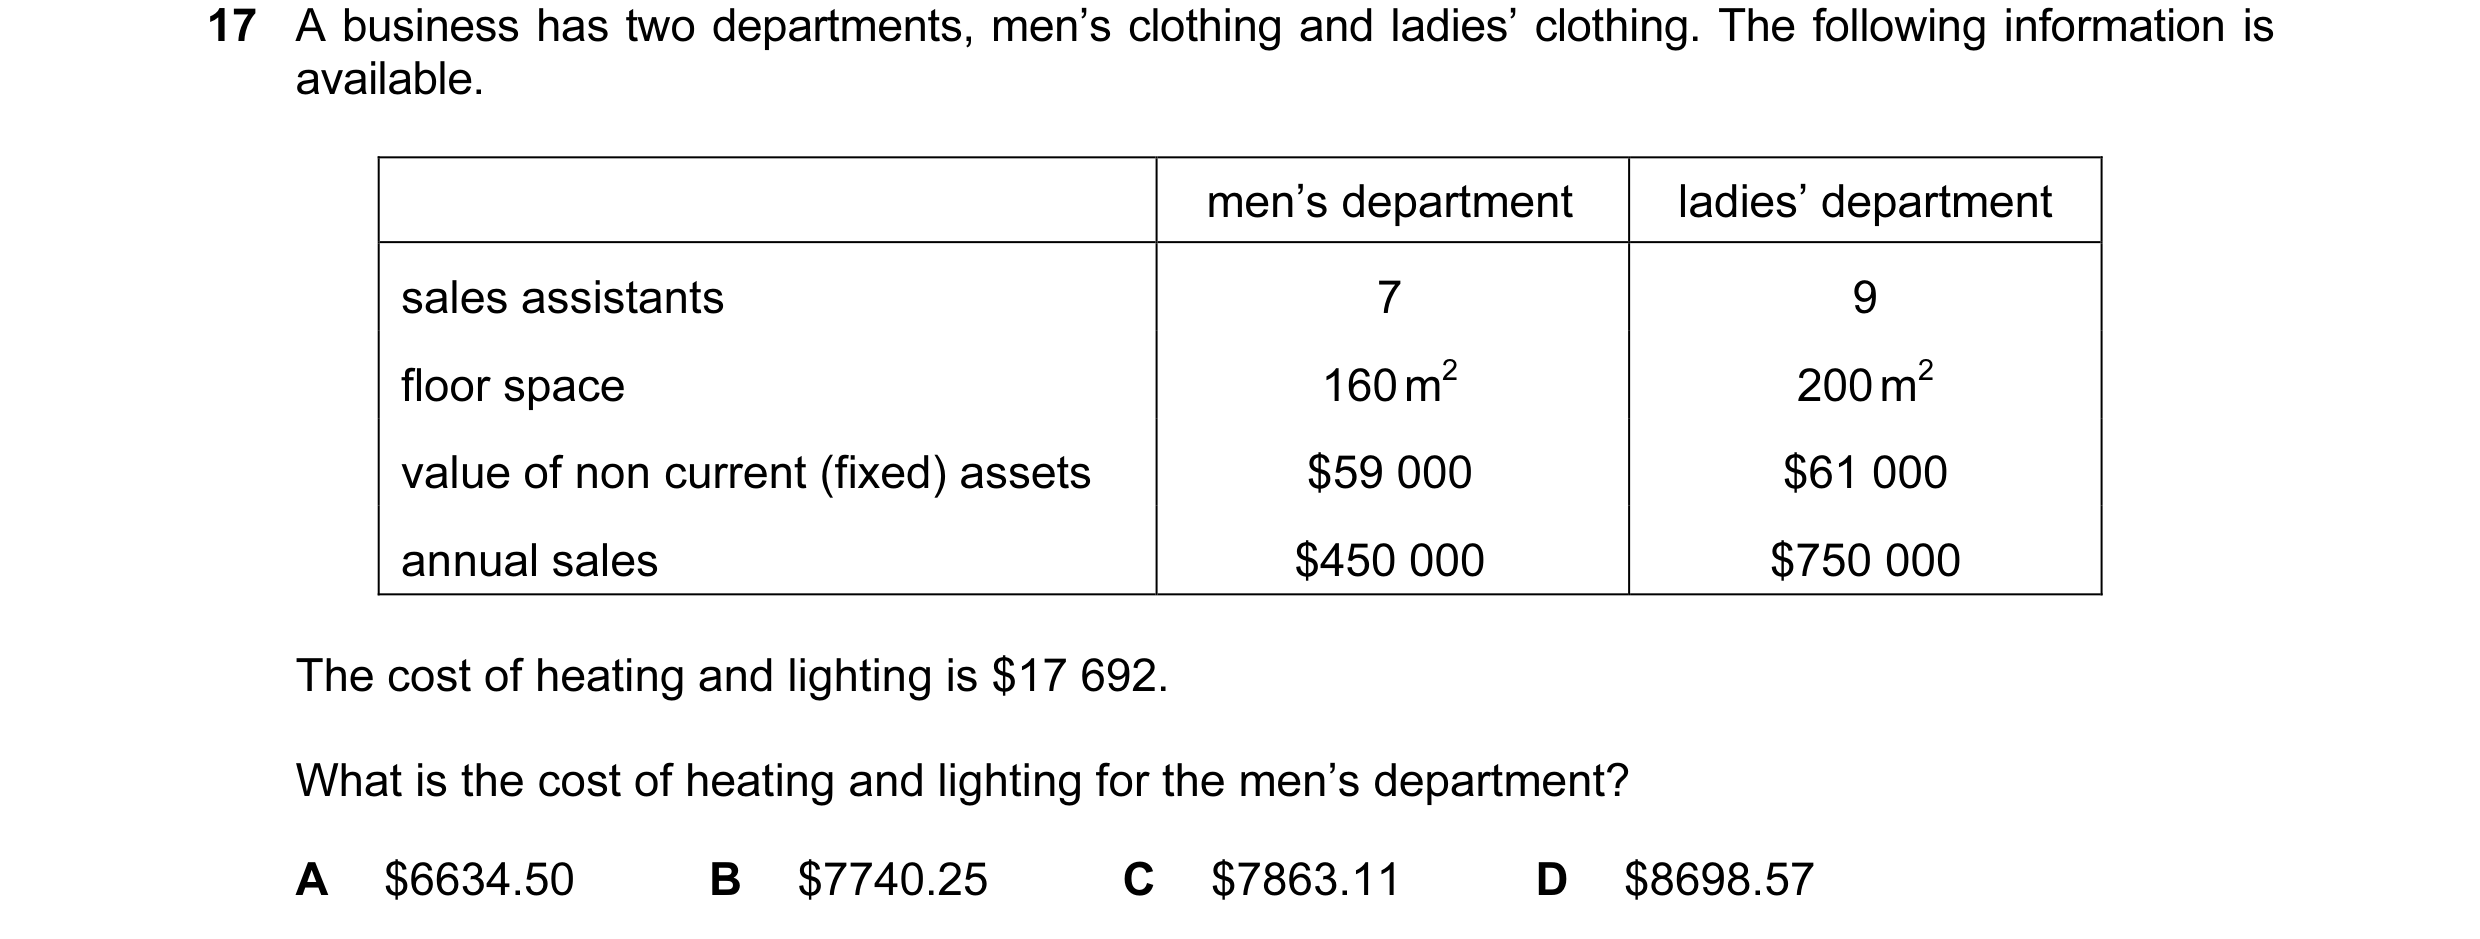 36 / 233
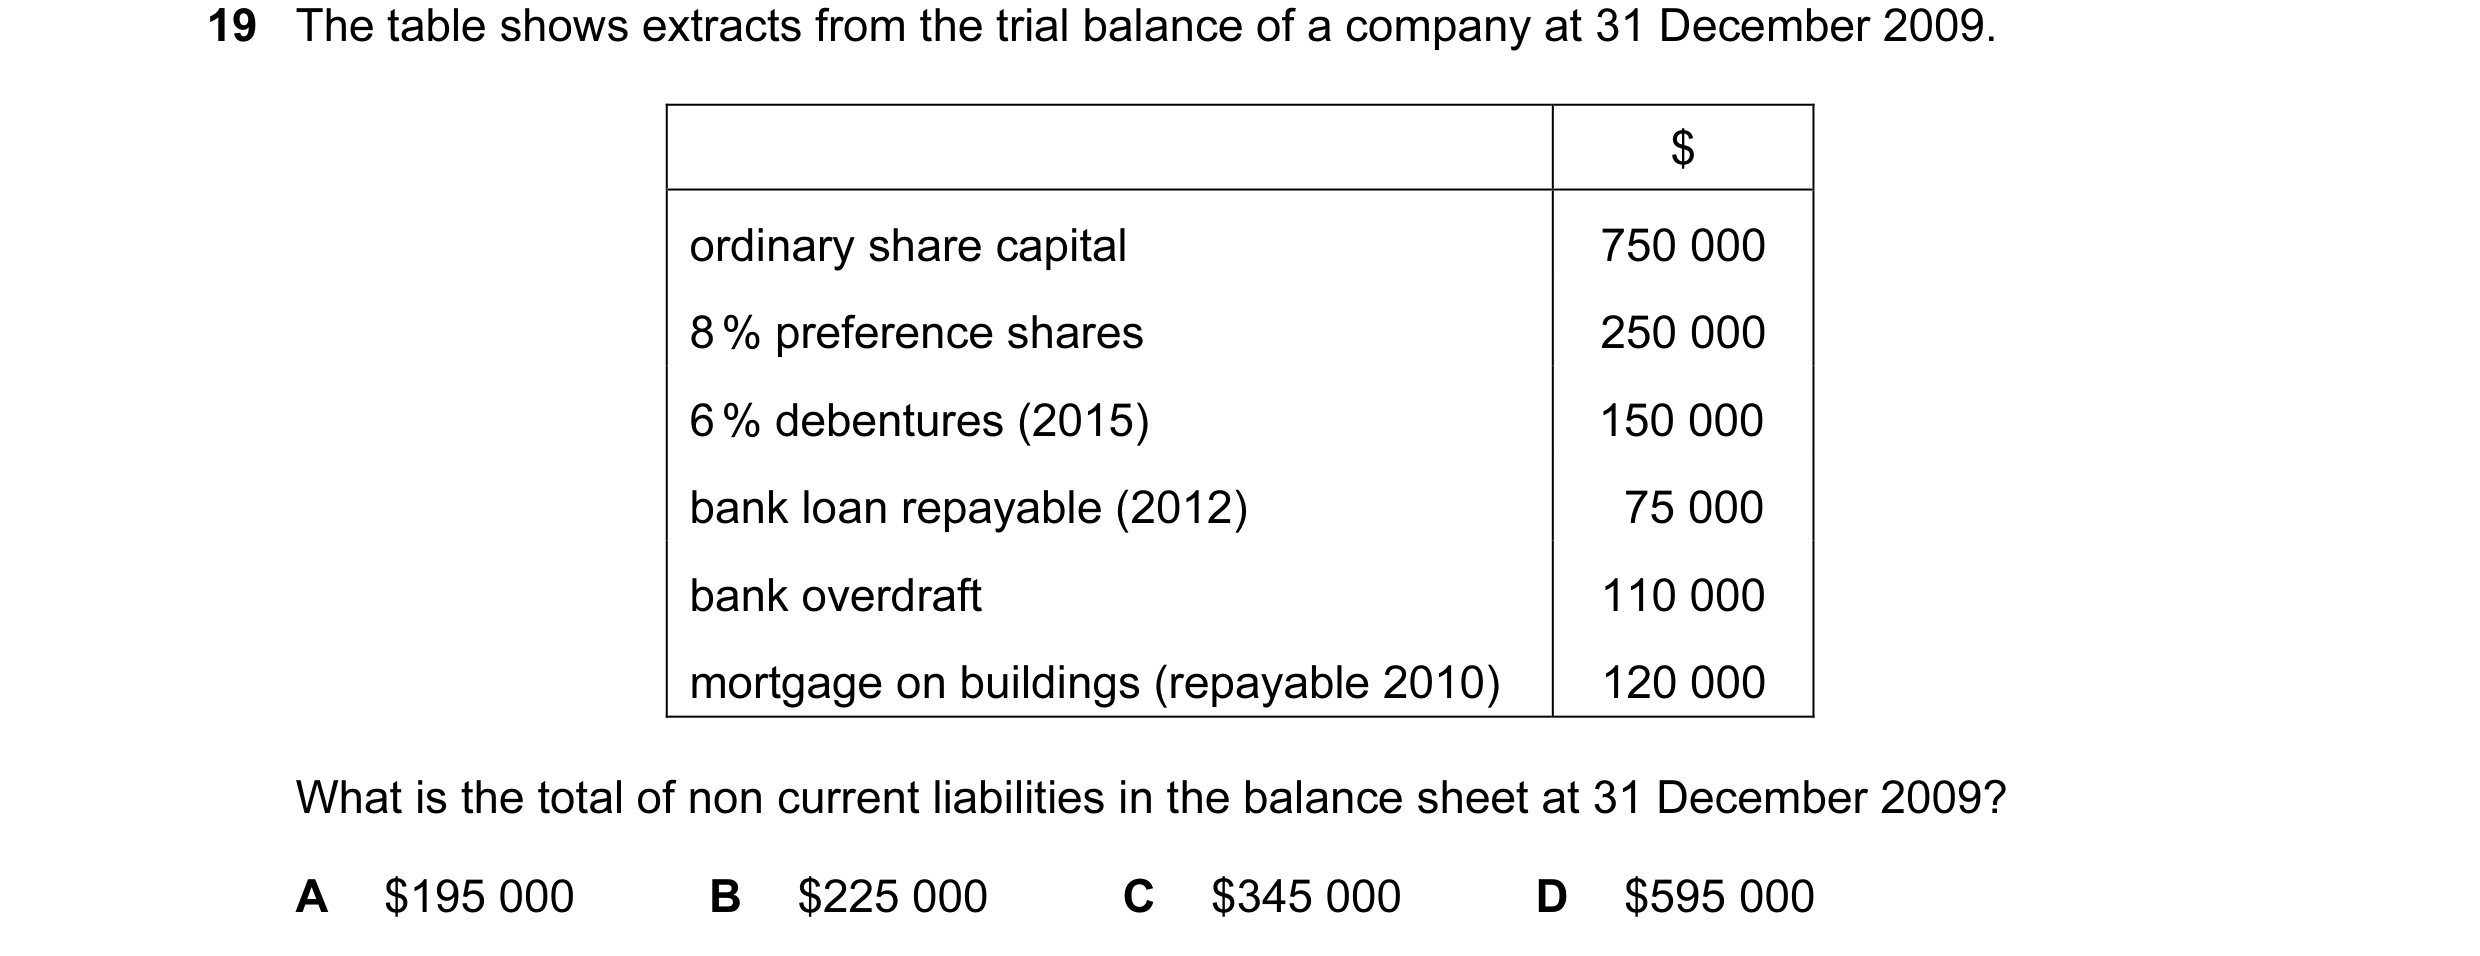
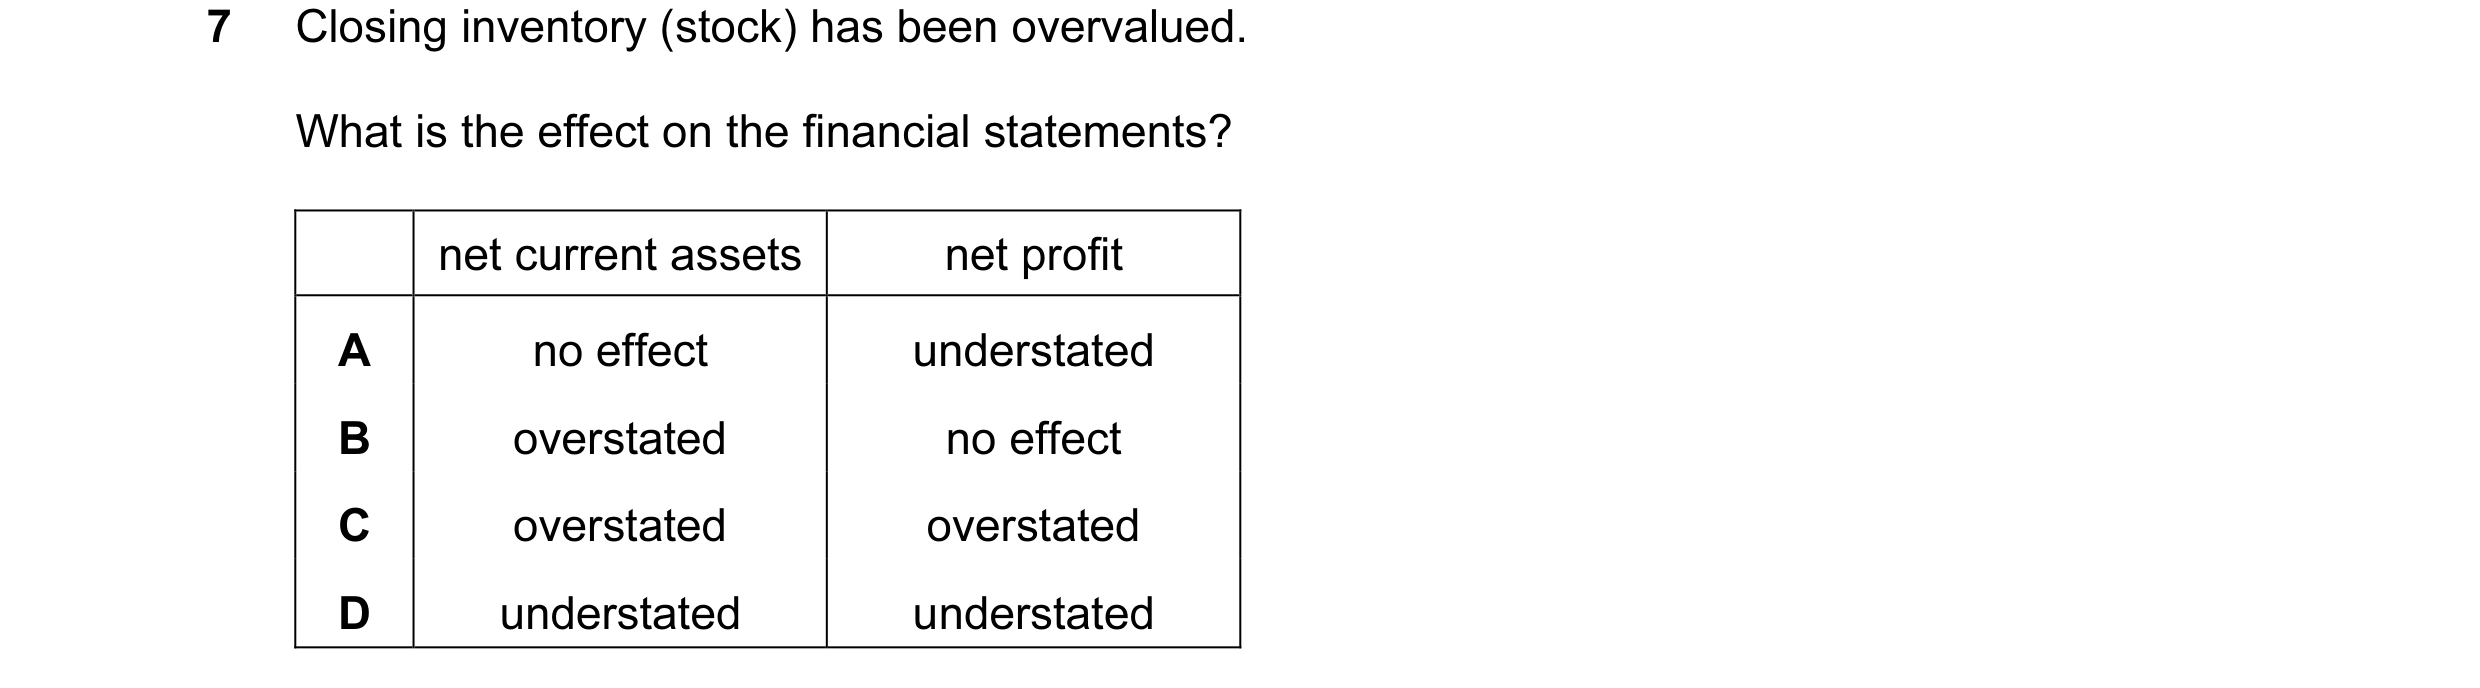
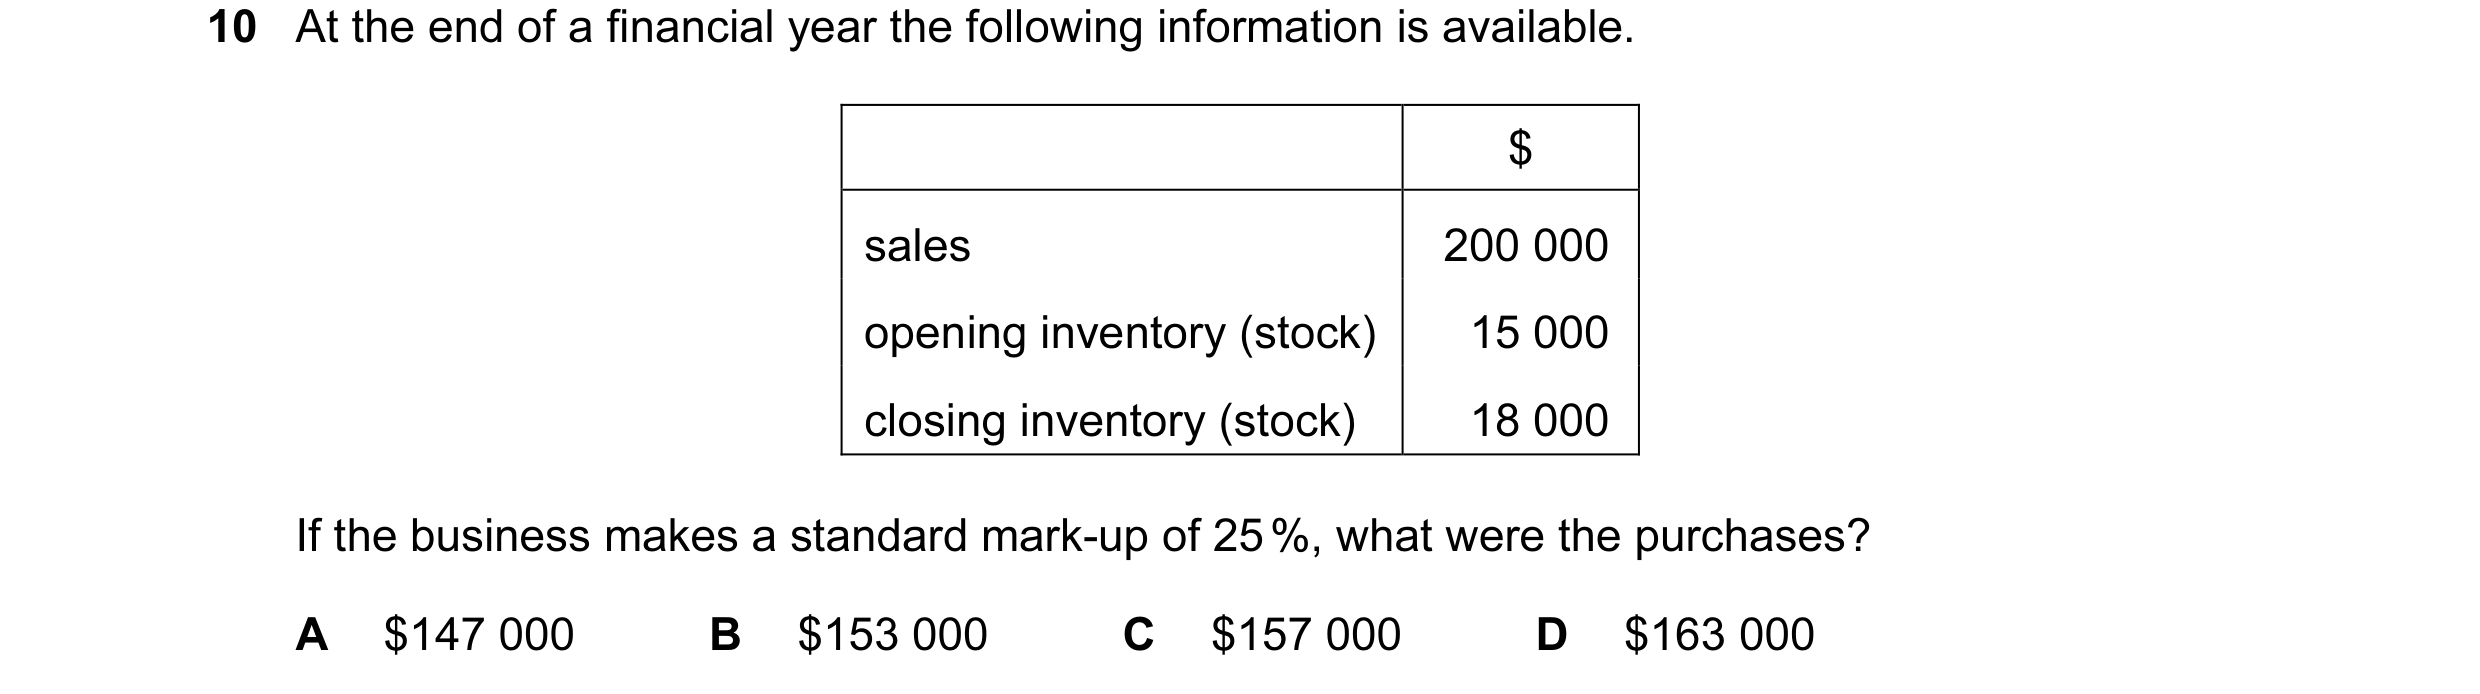
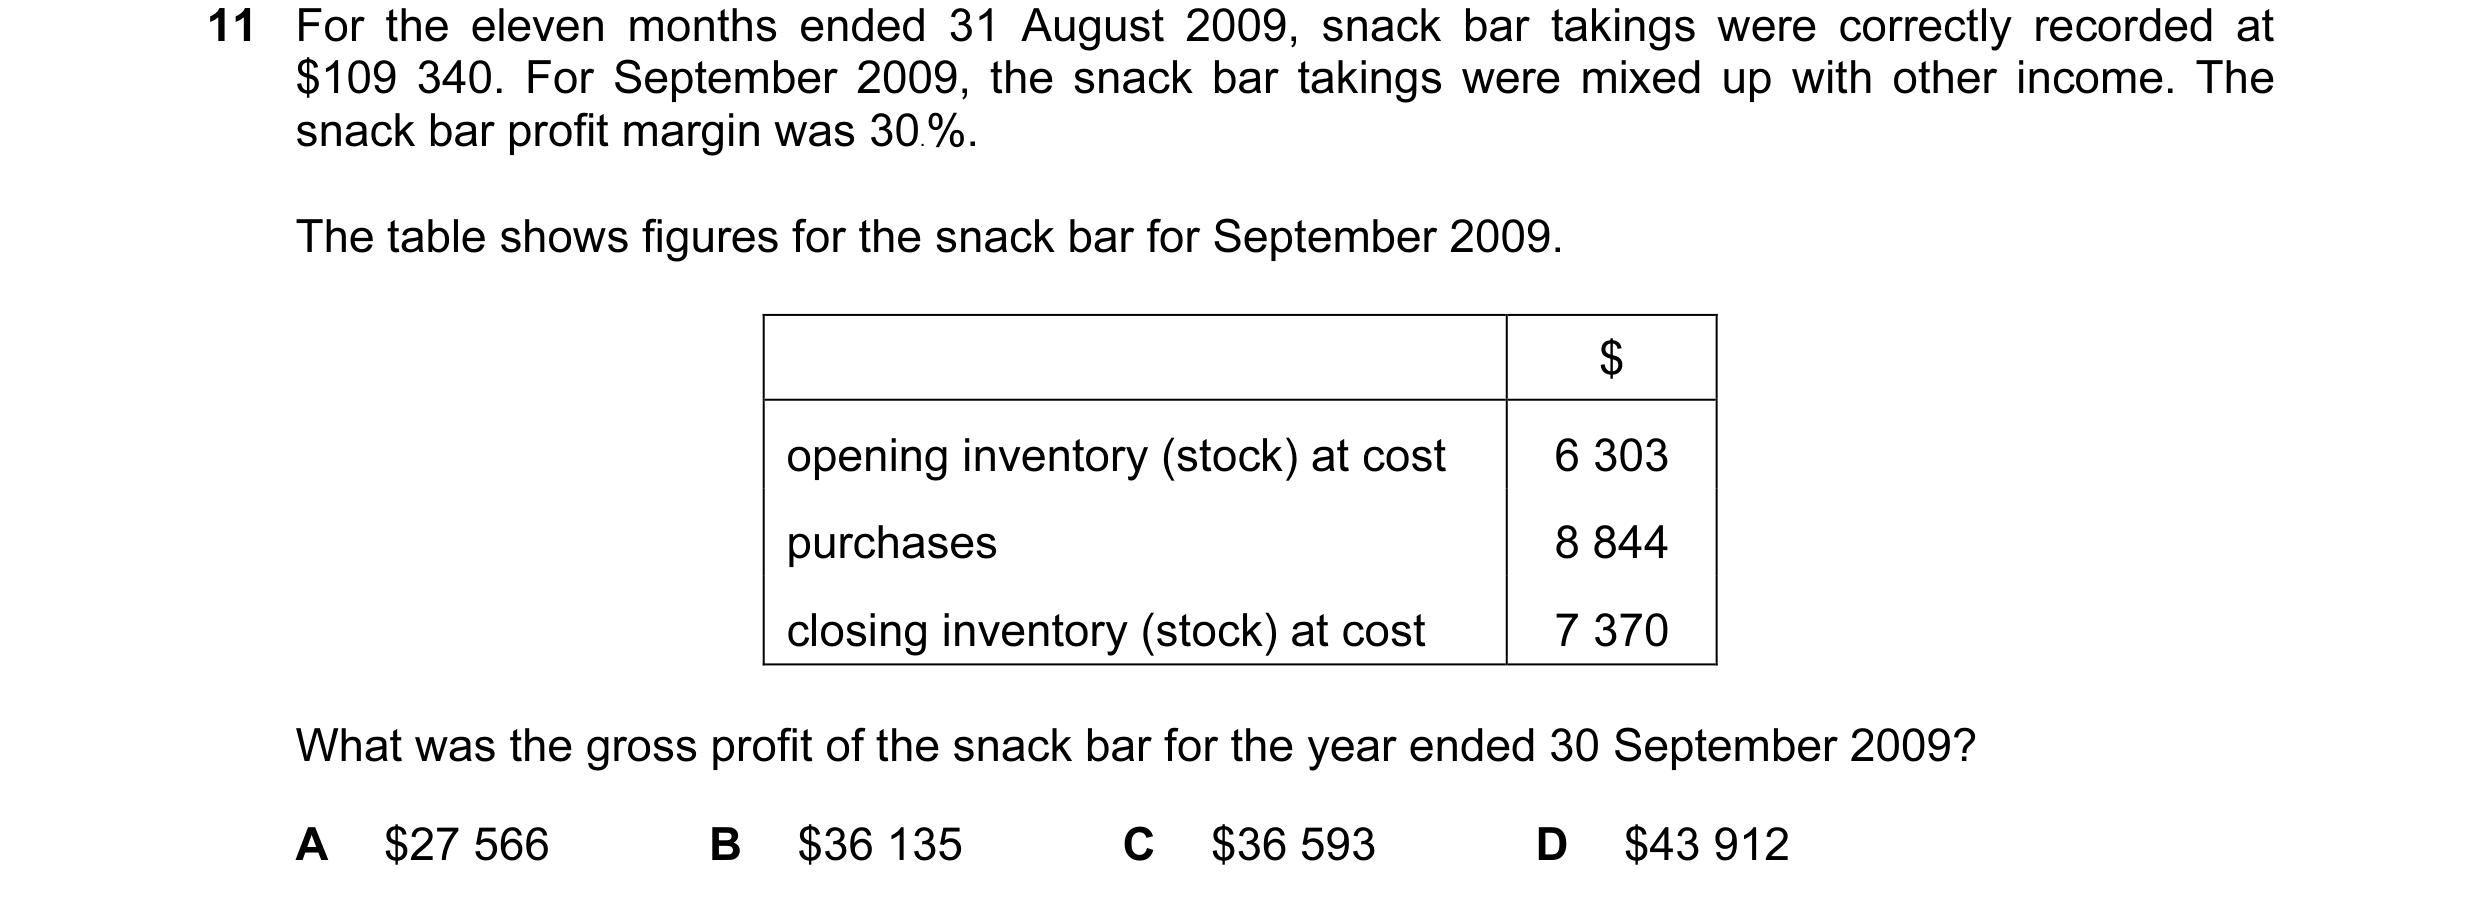 37 / 233
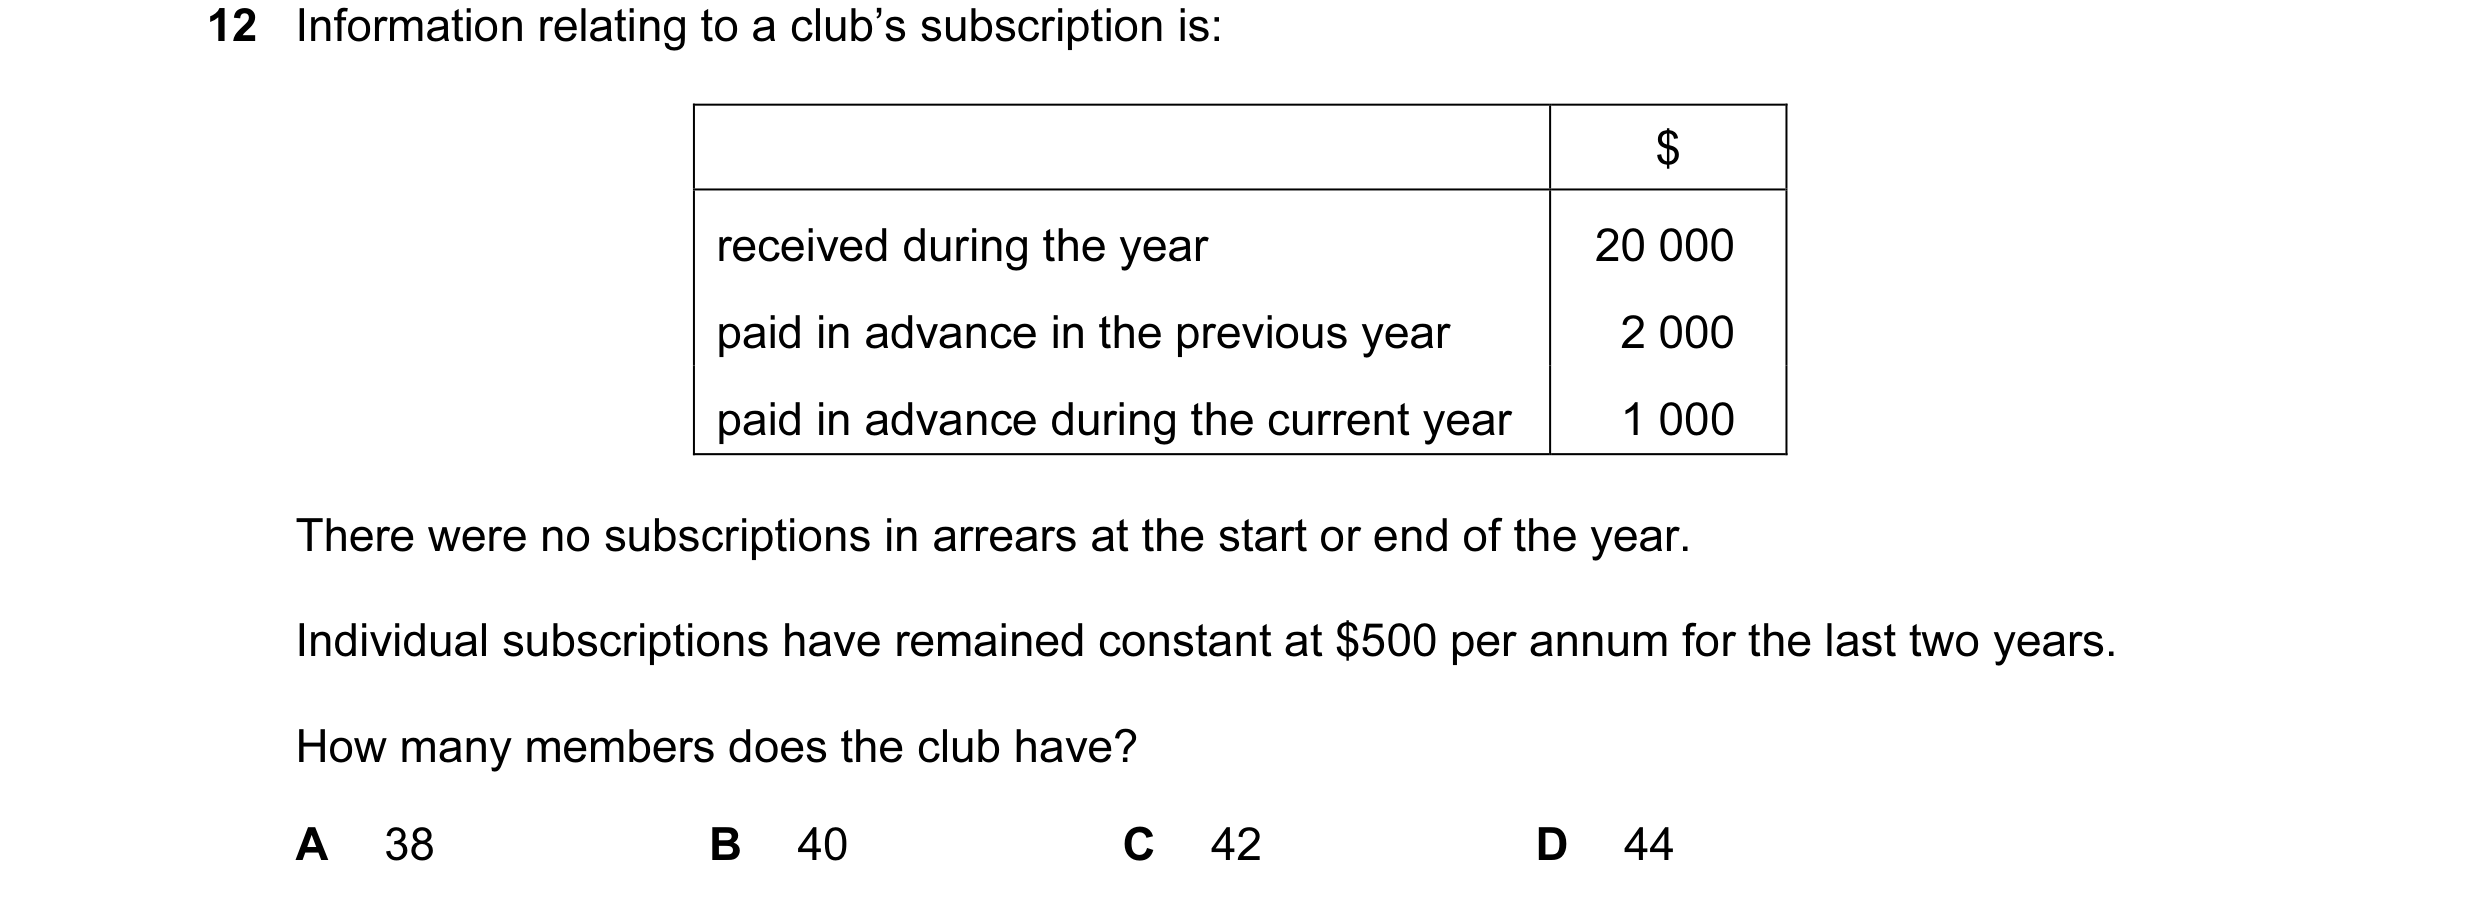
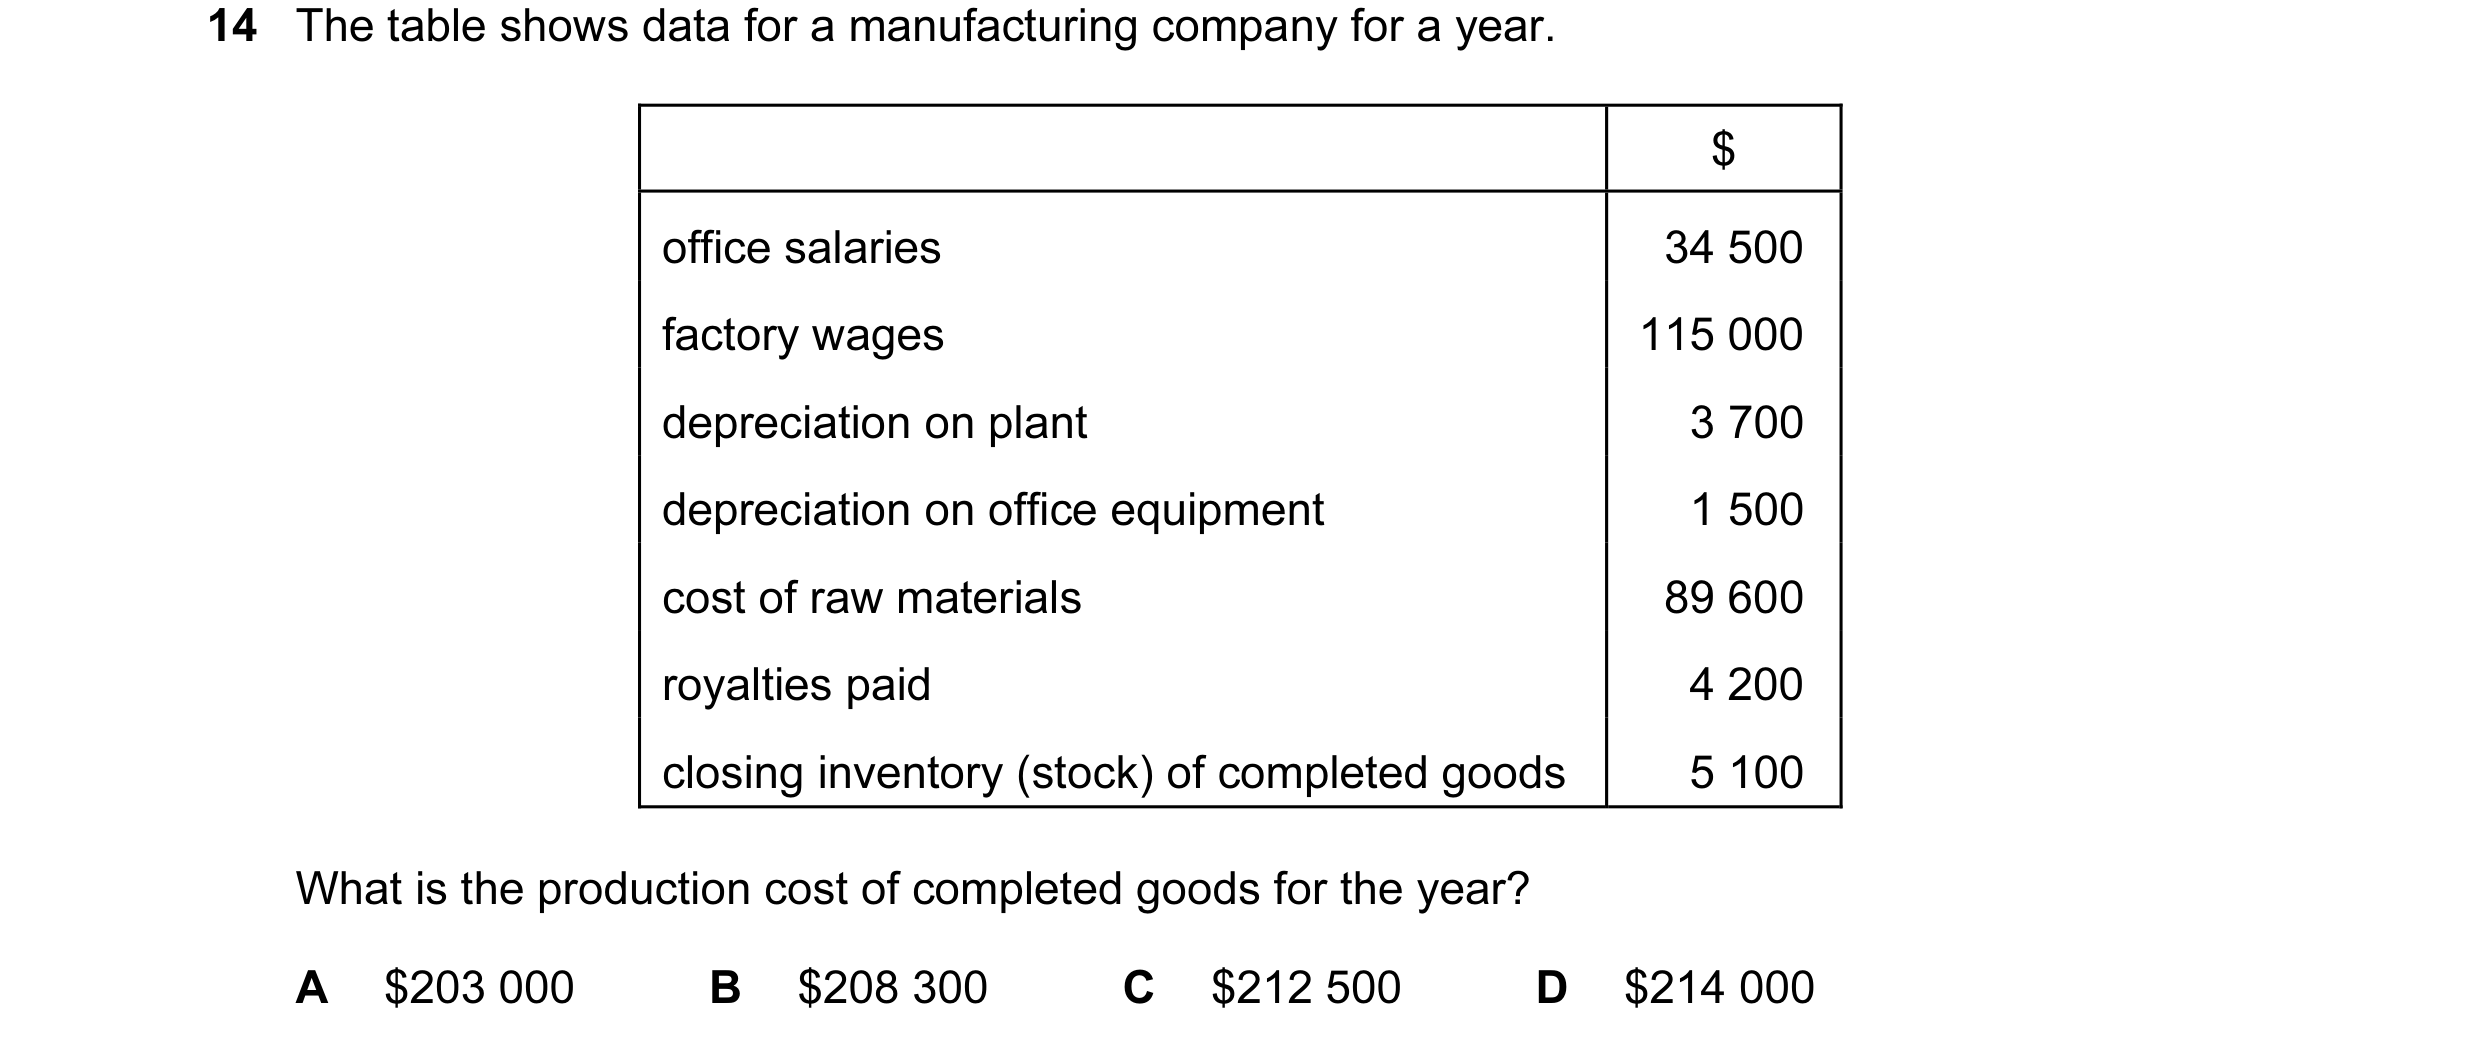
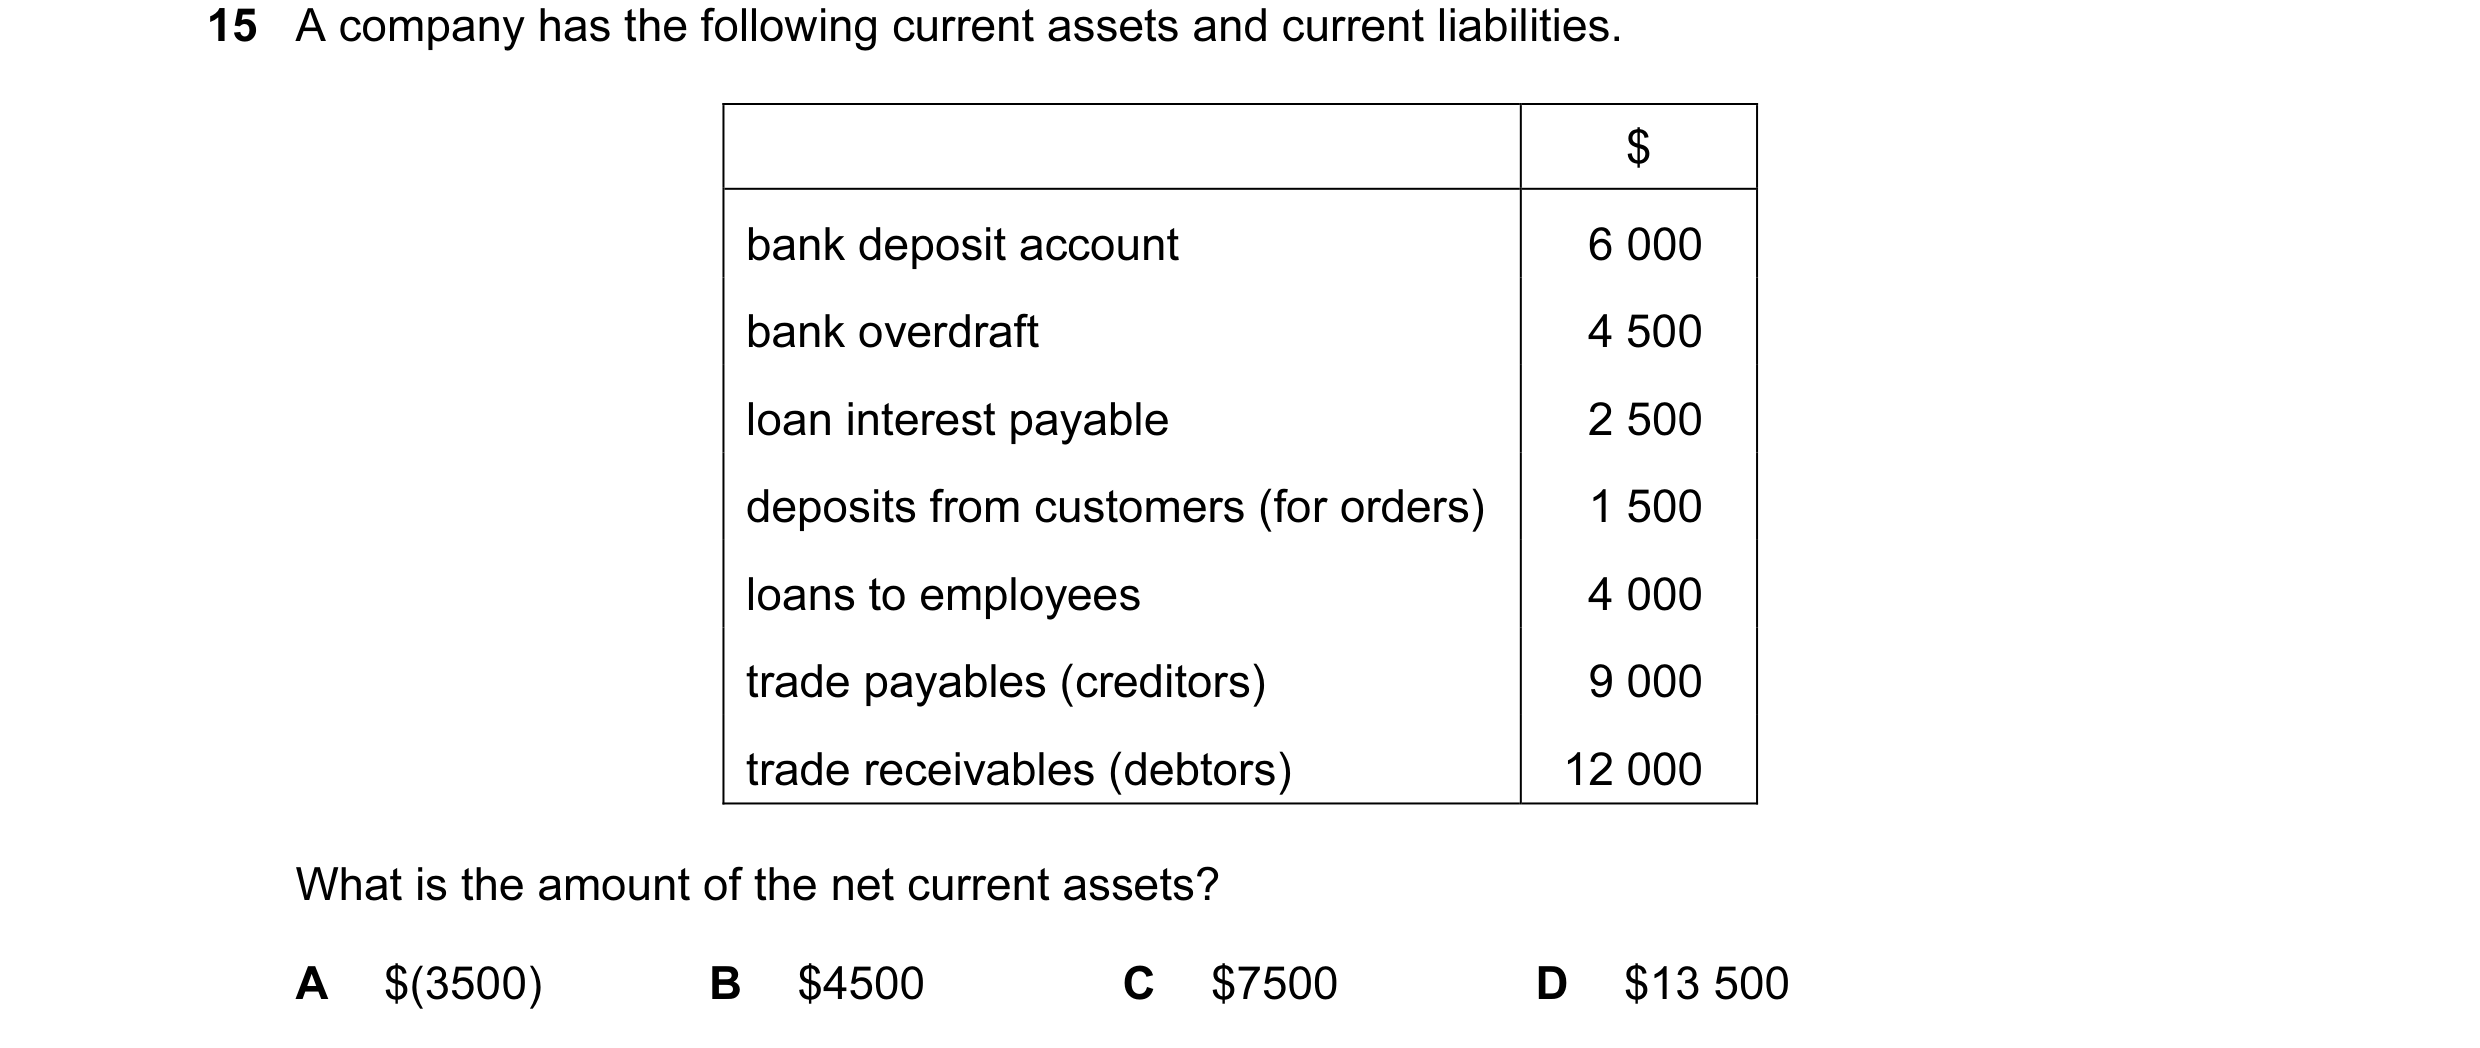 38 / 233
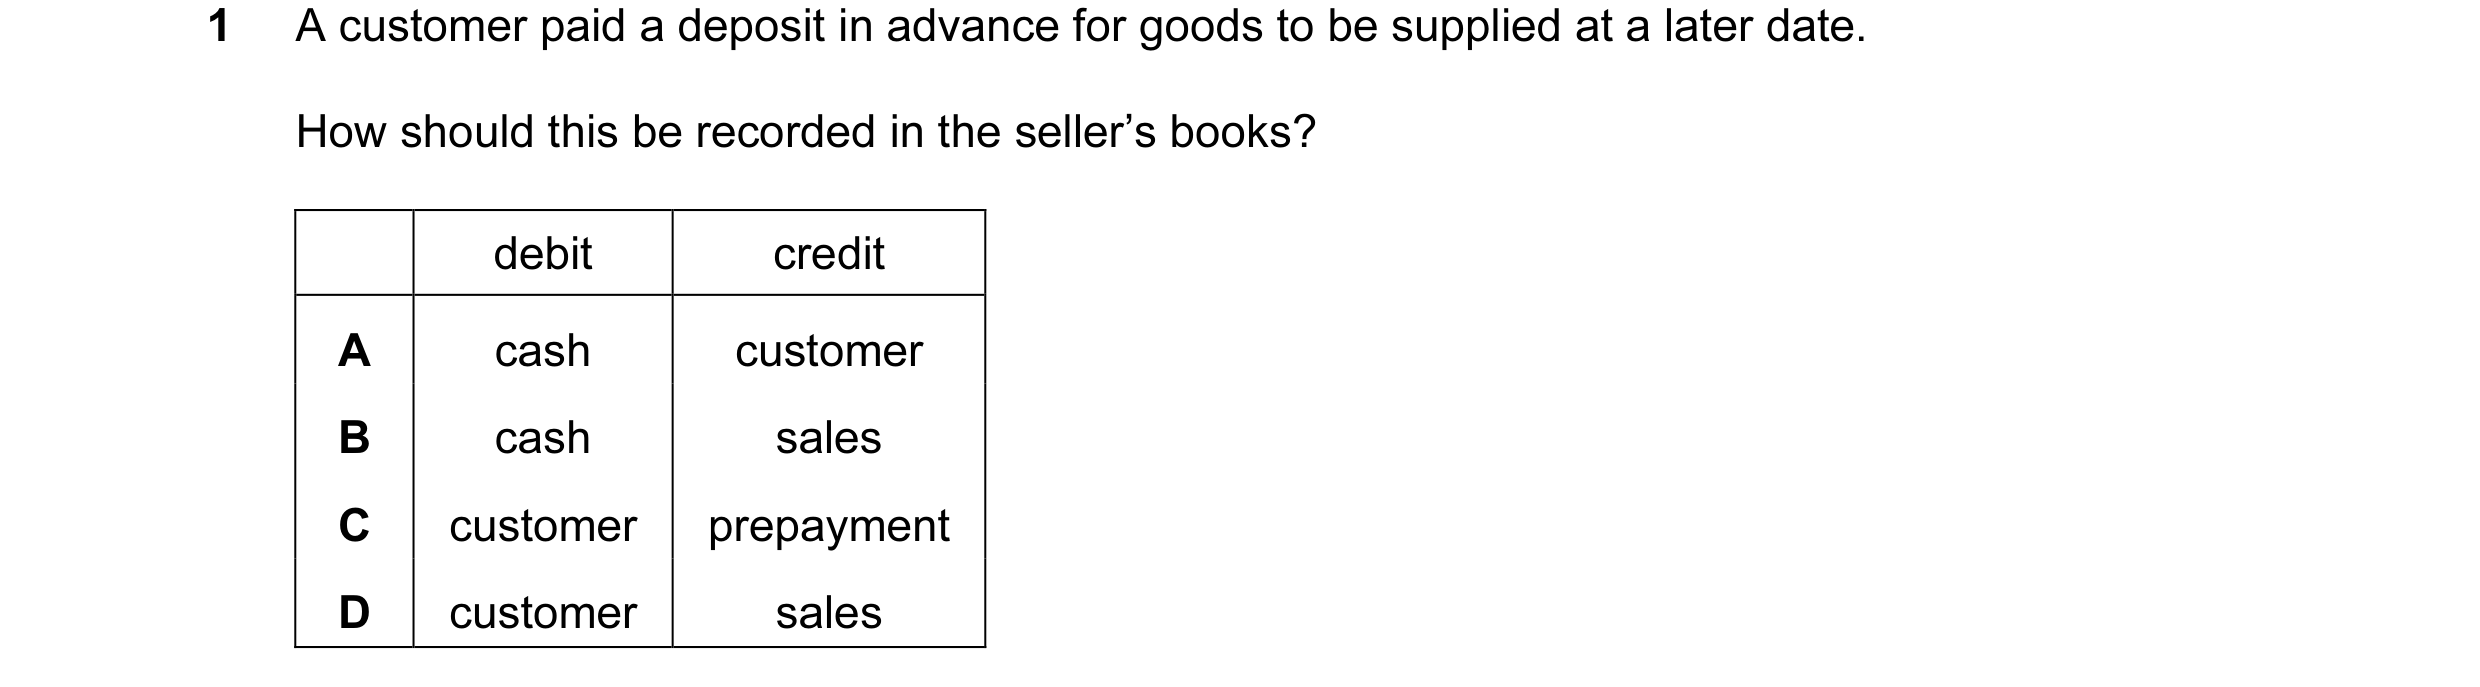
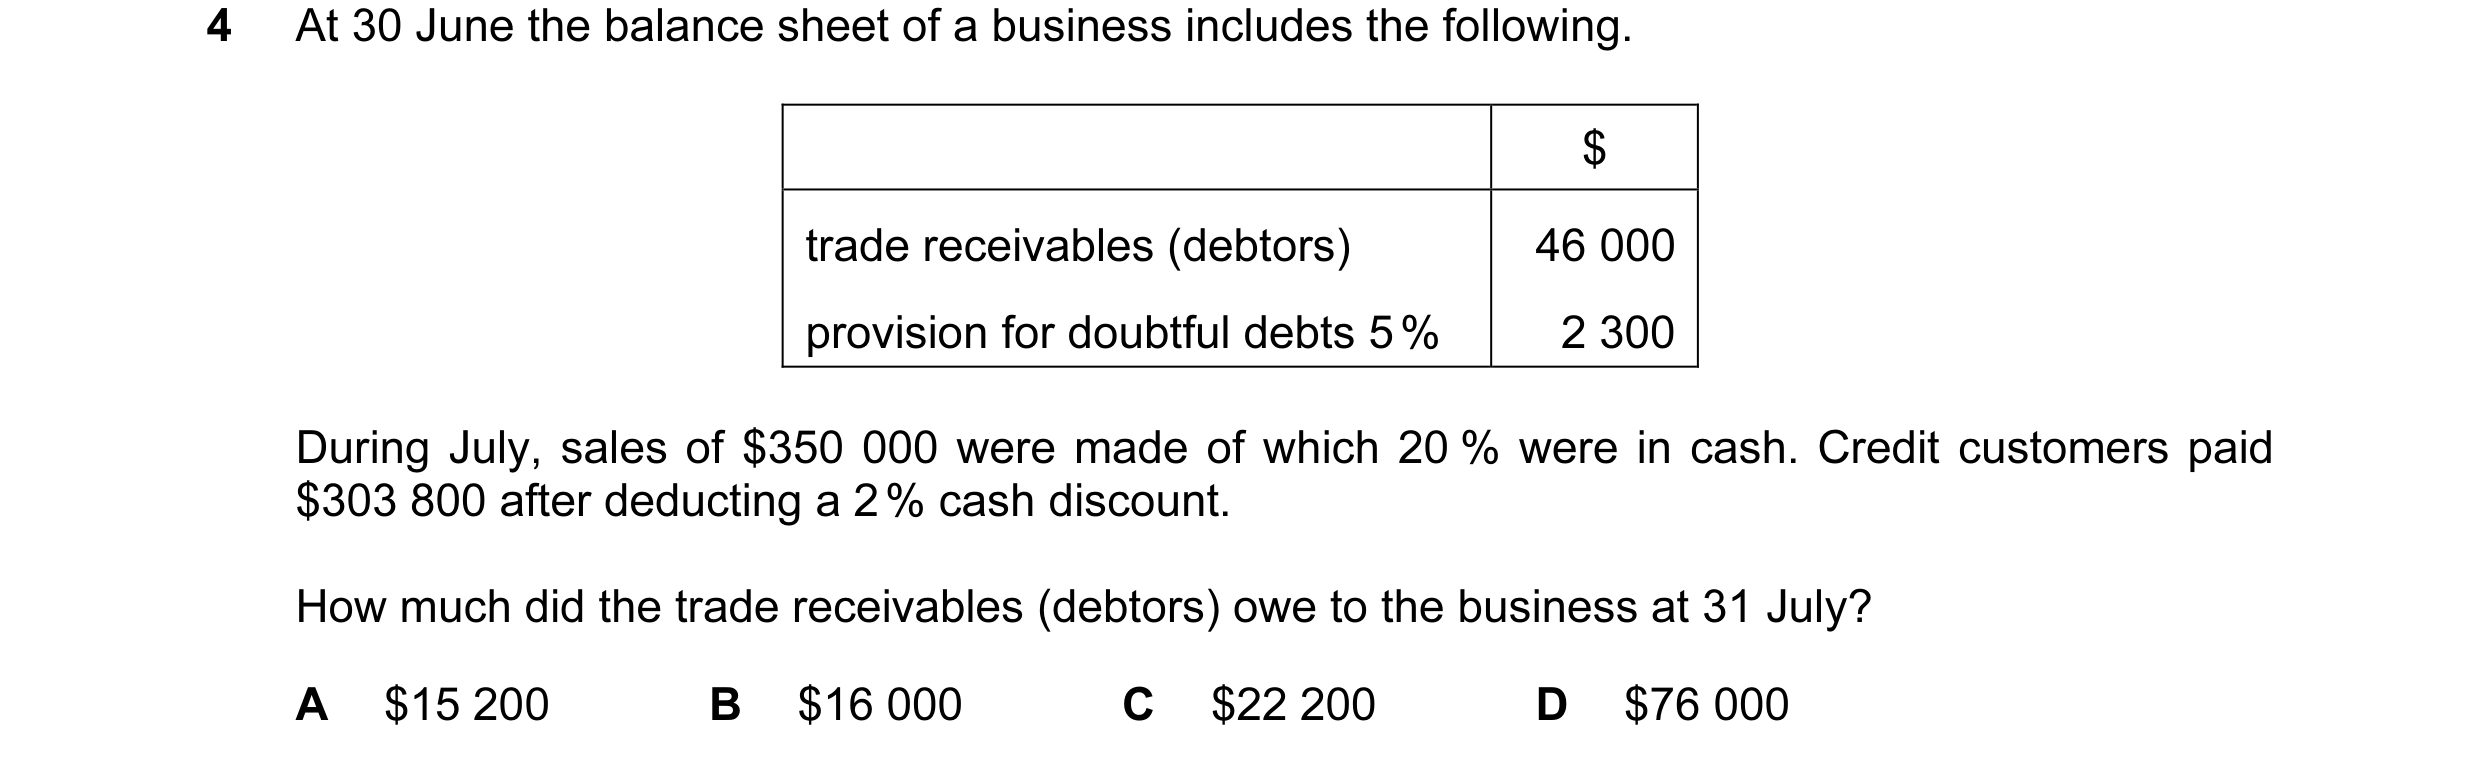
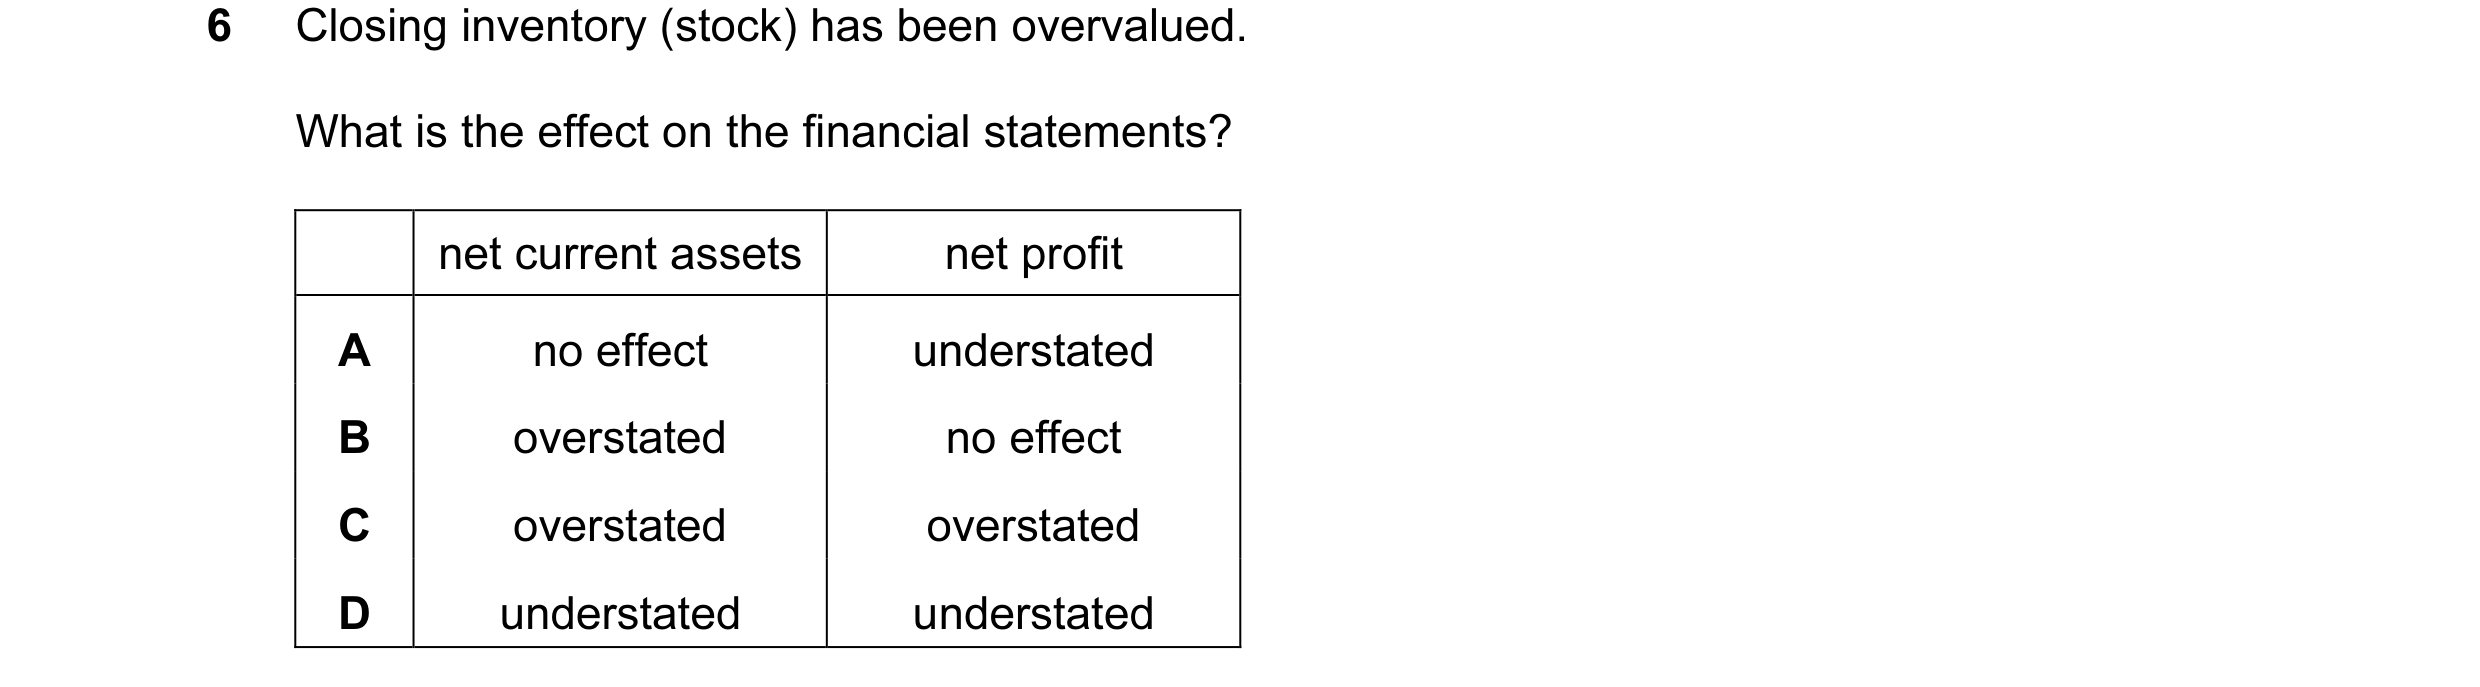
 39 / 233
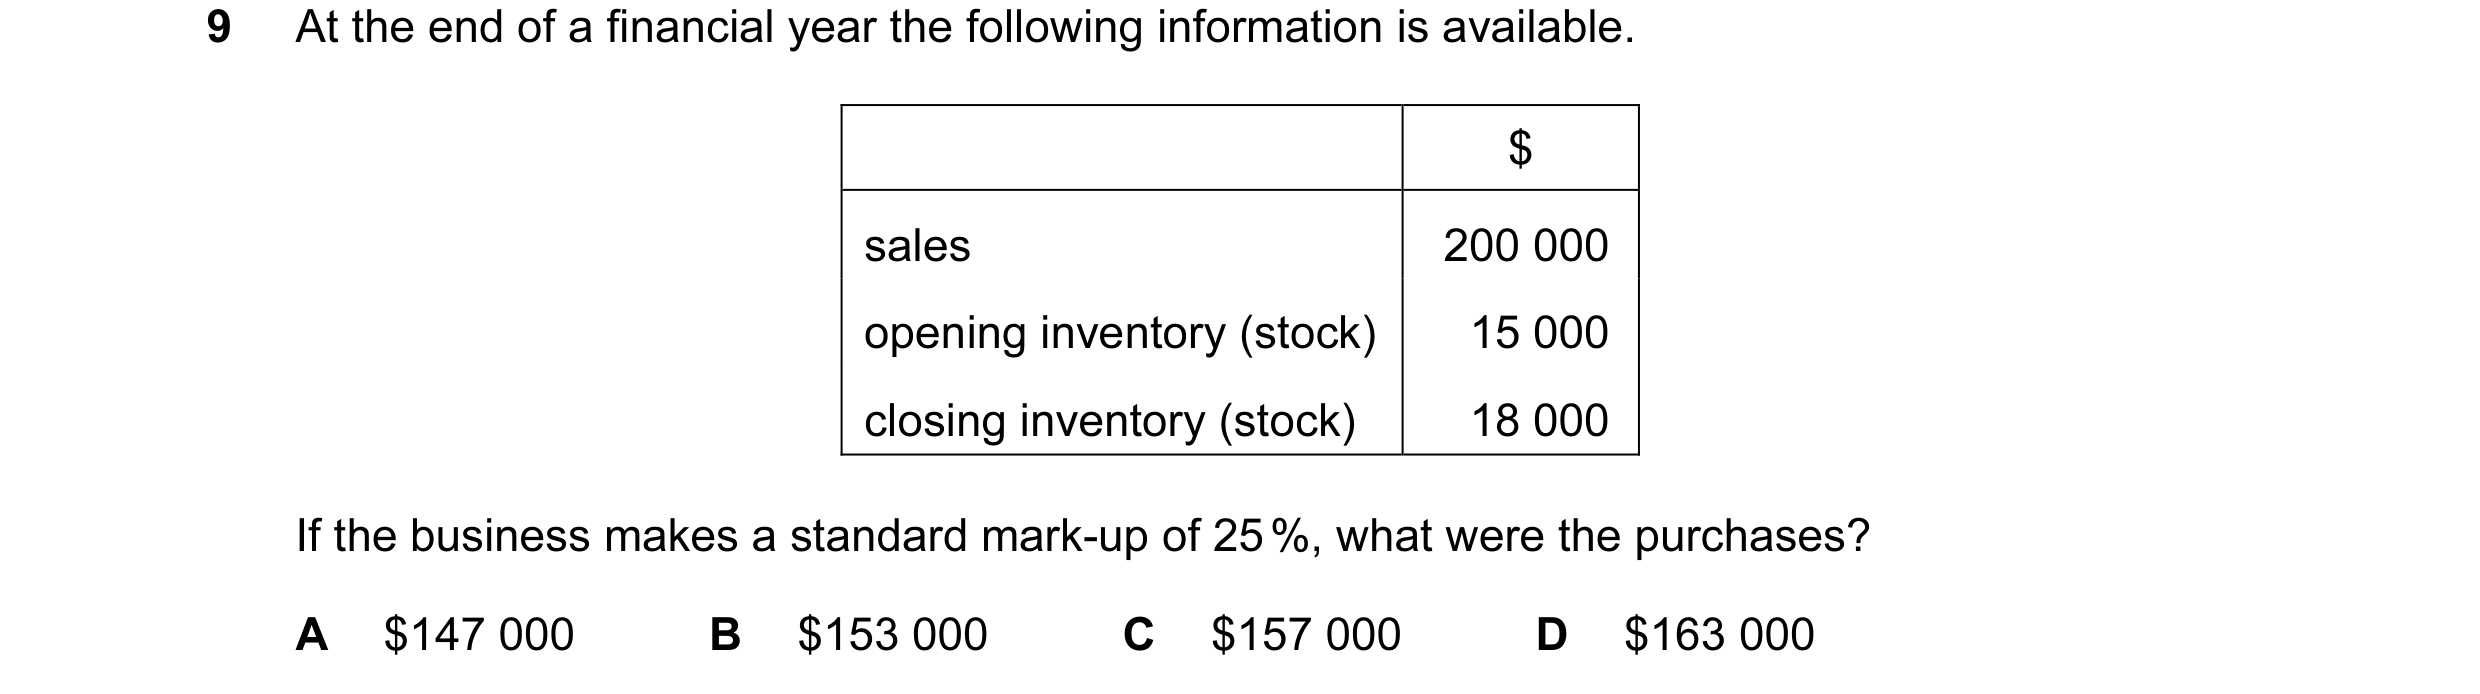
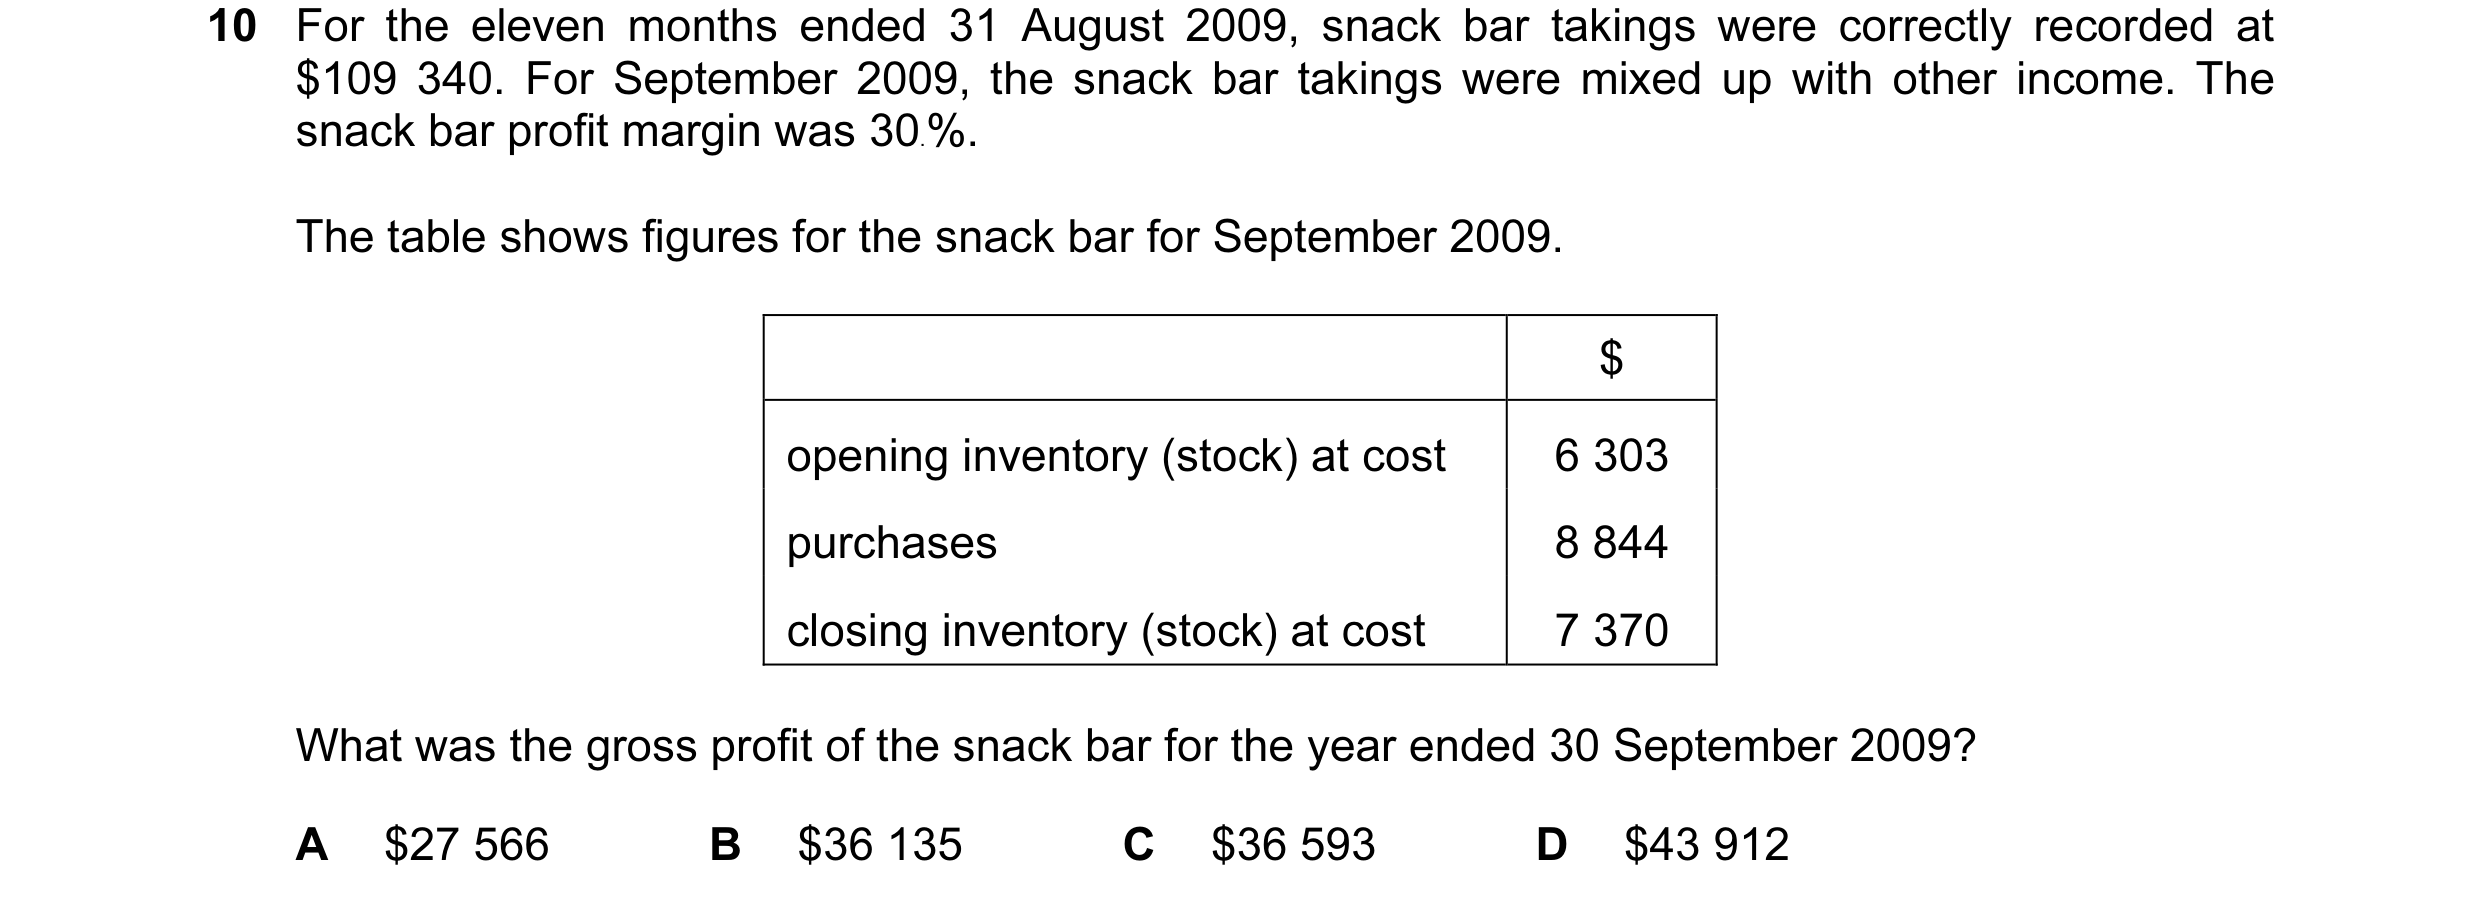
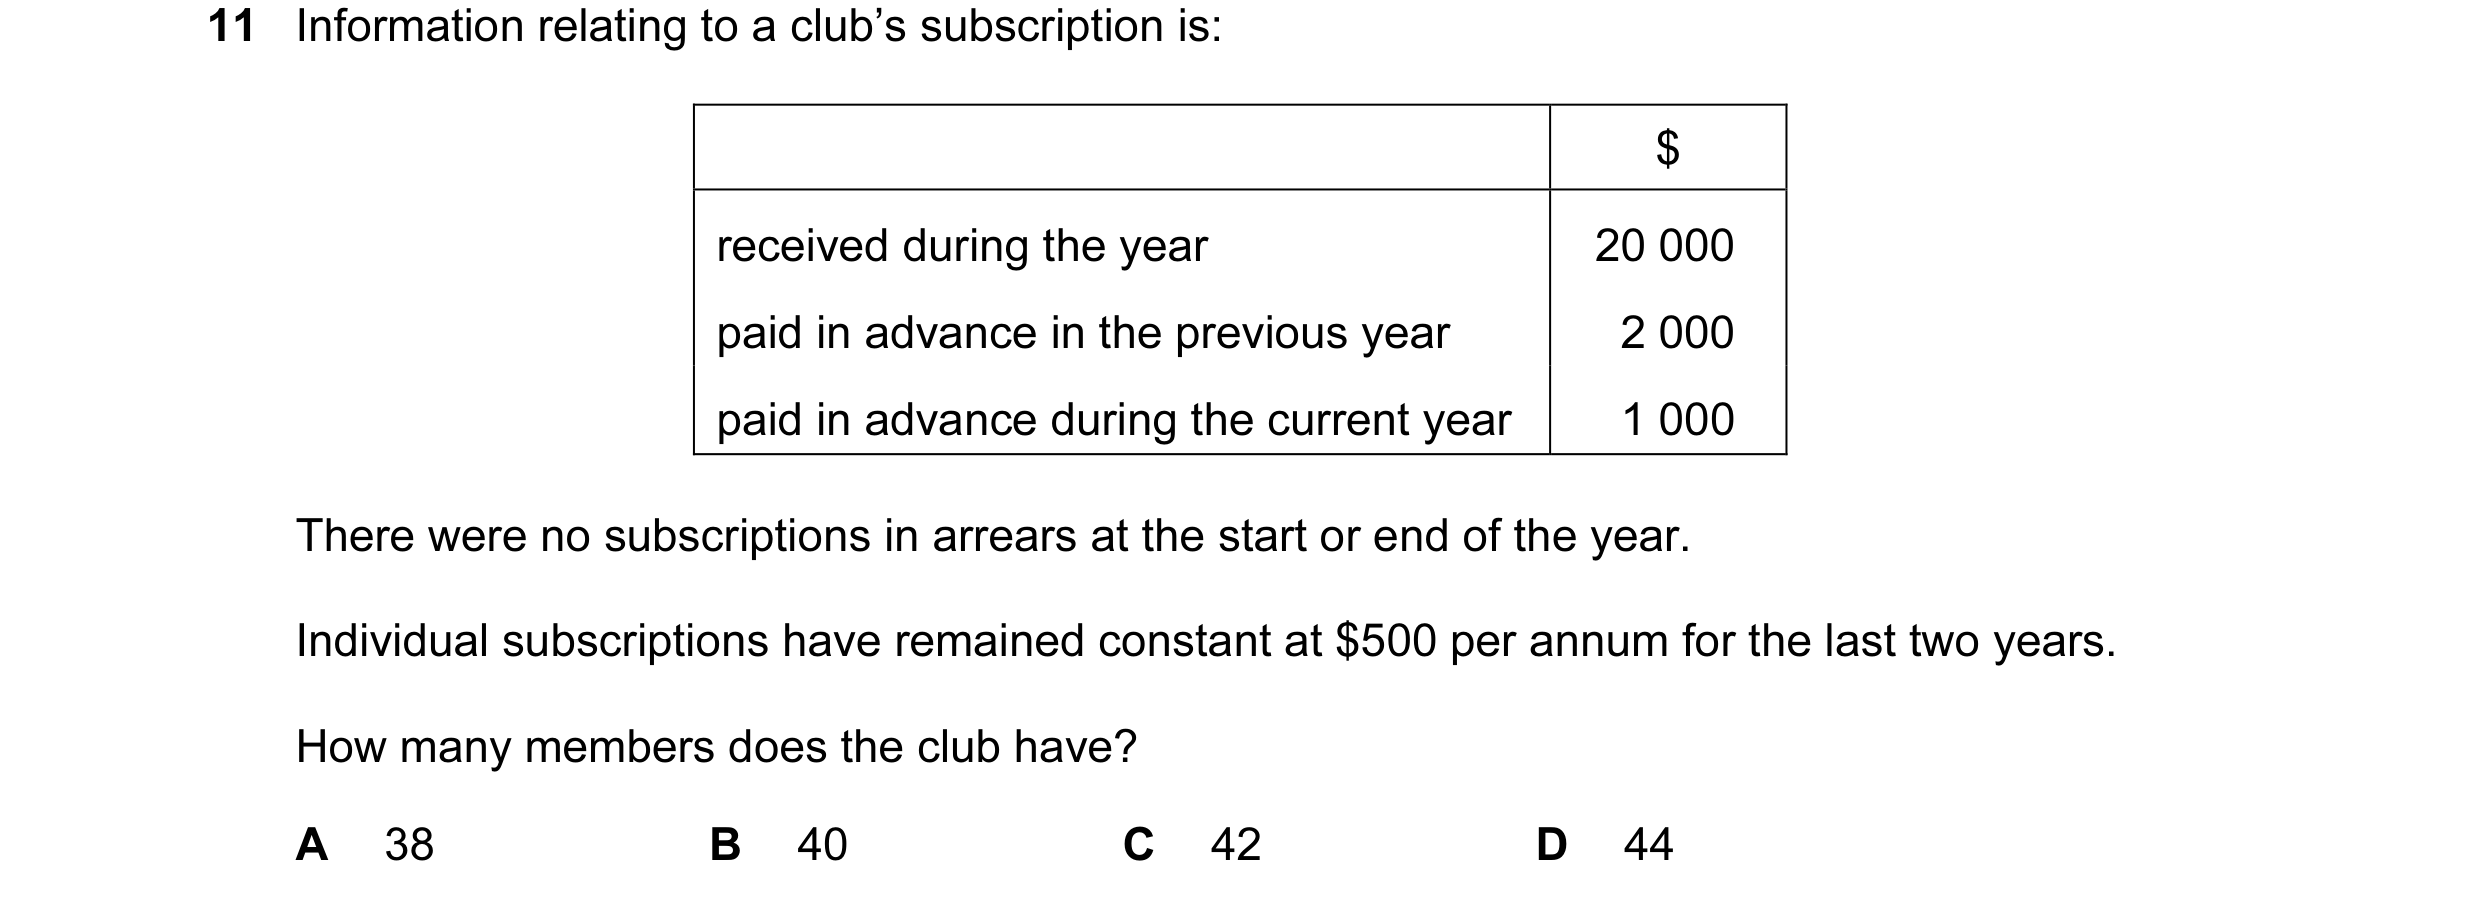 40 / 233
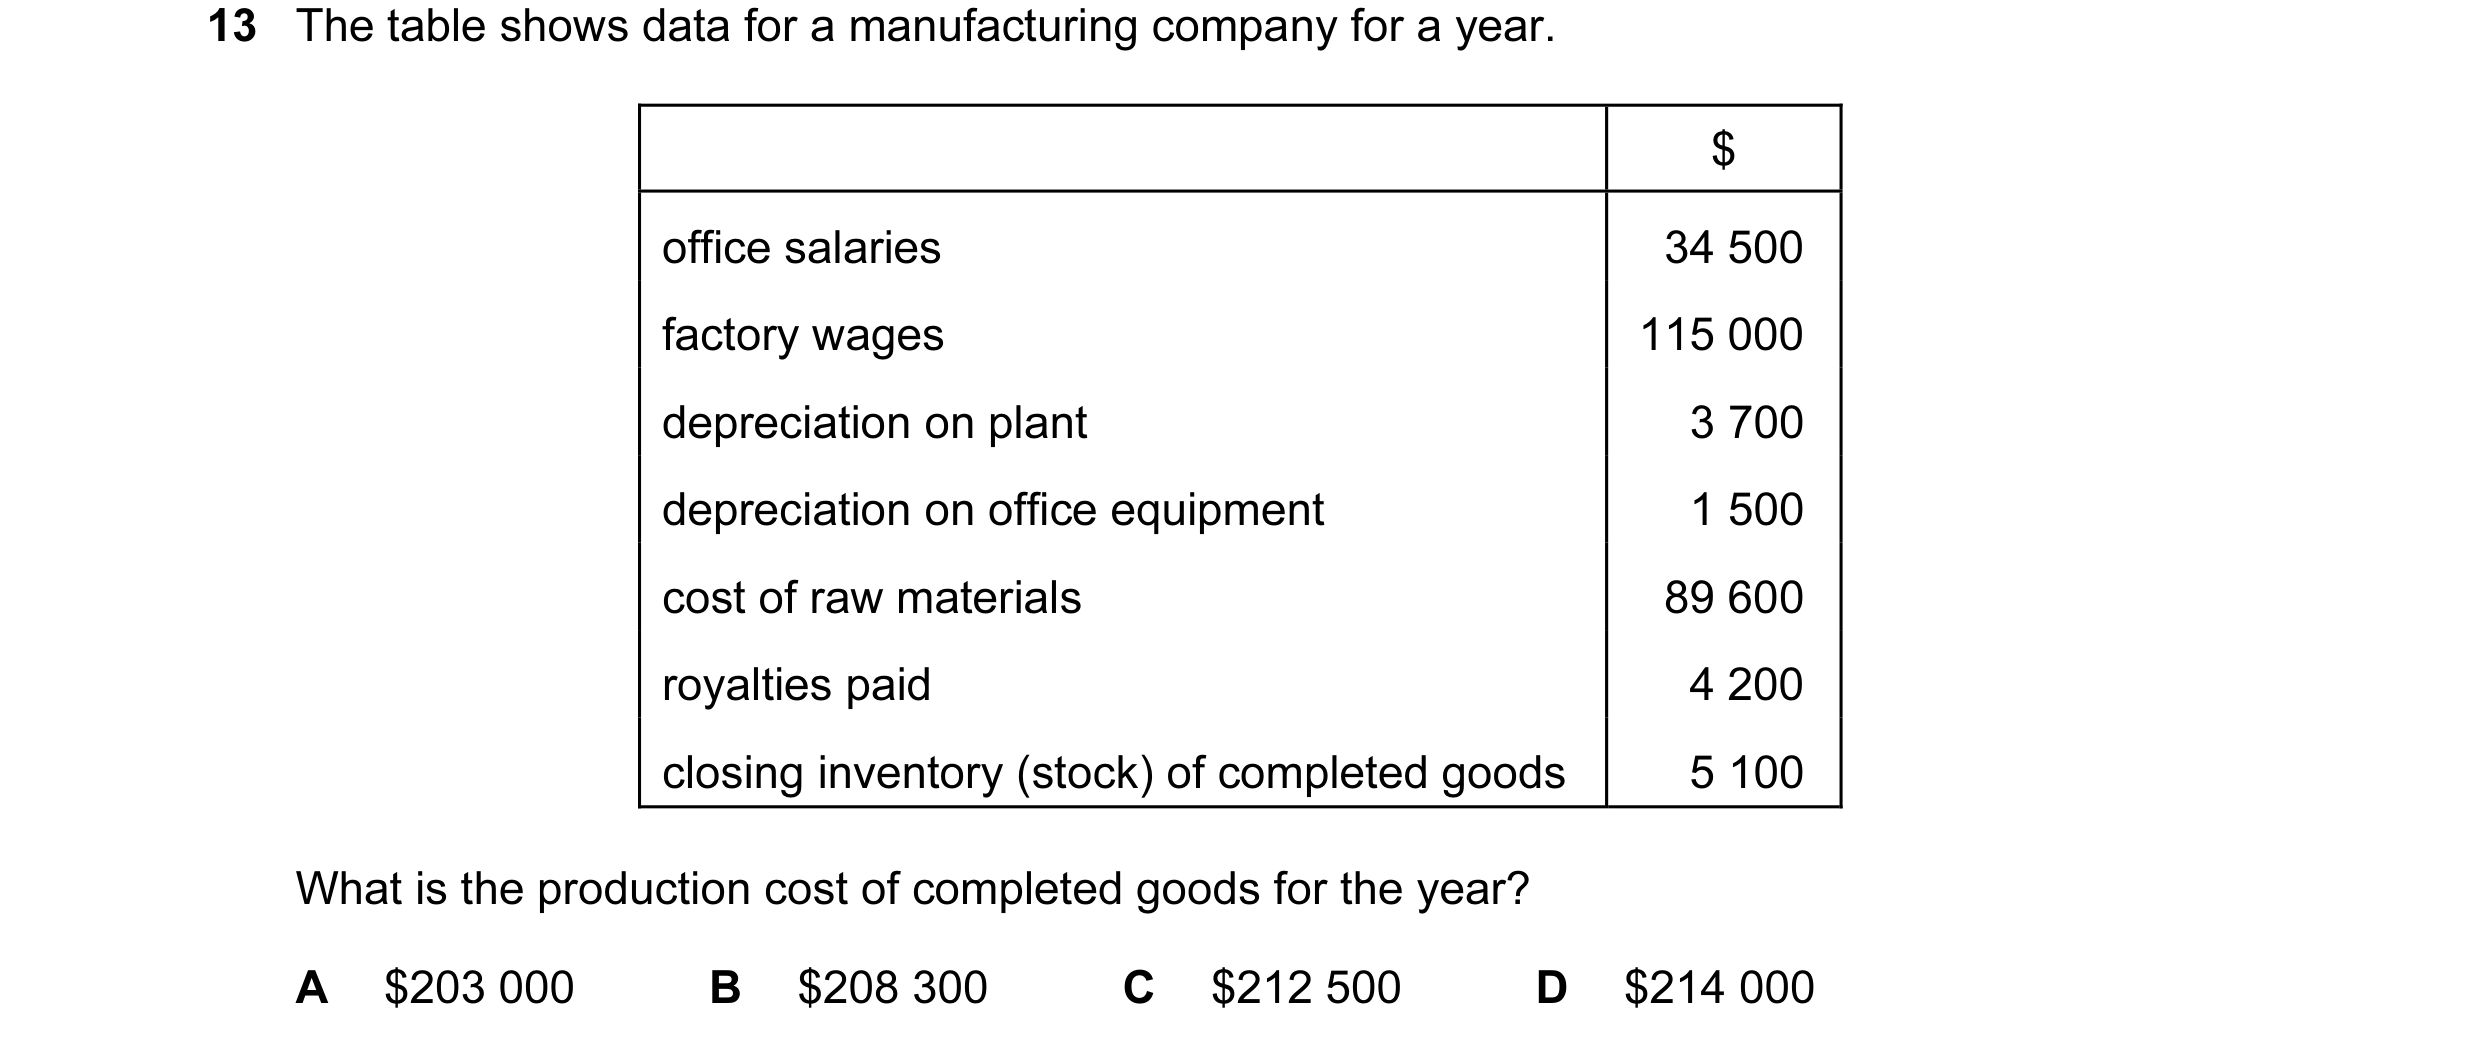
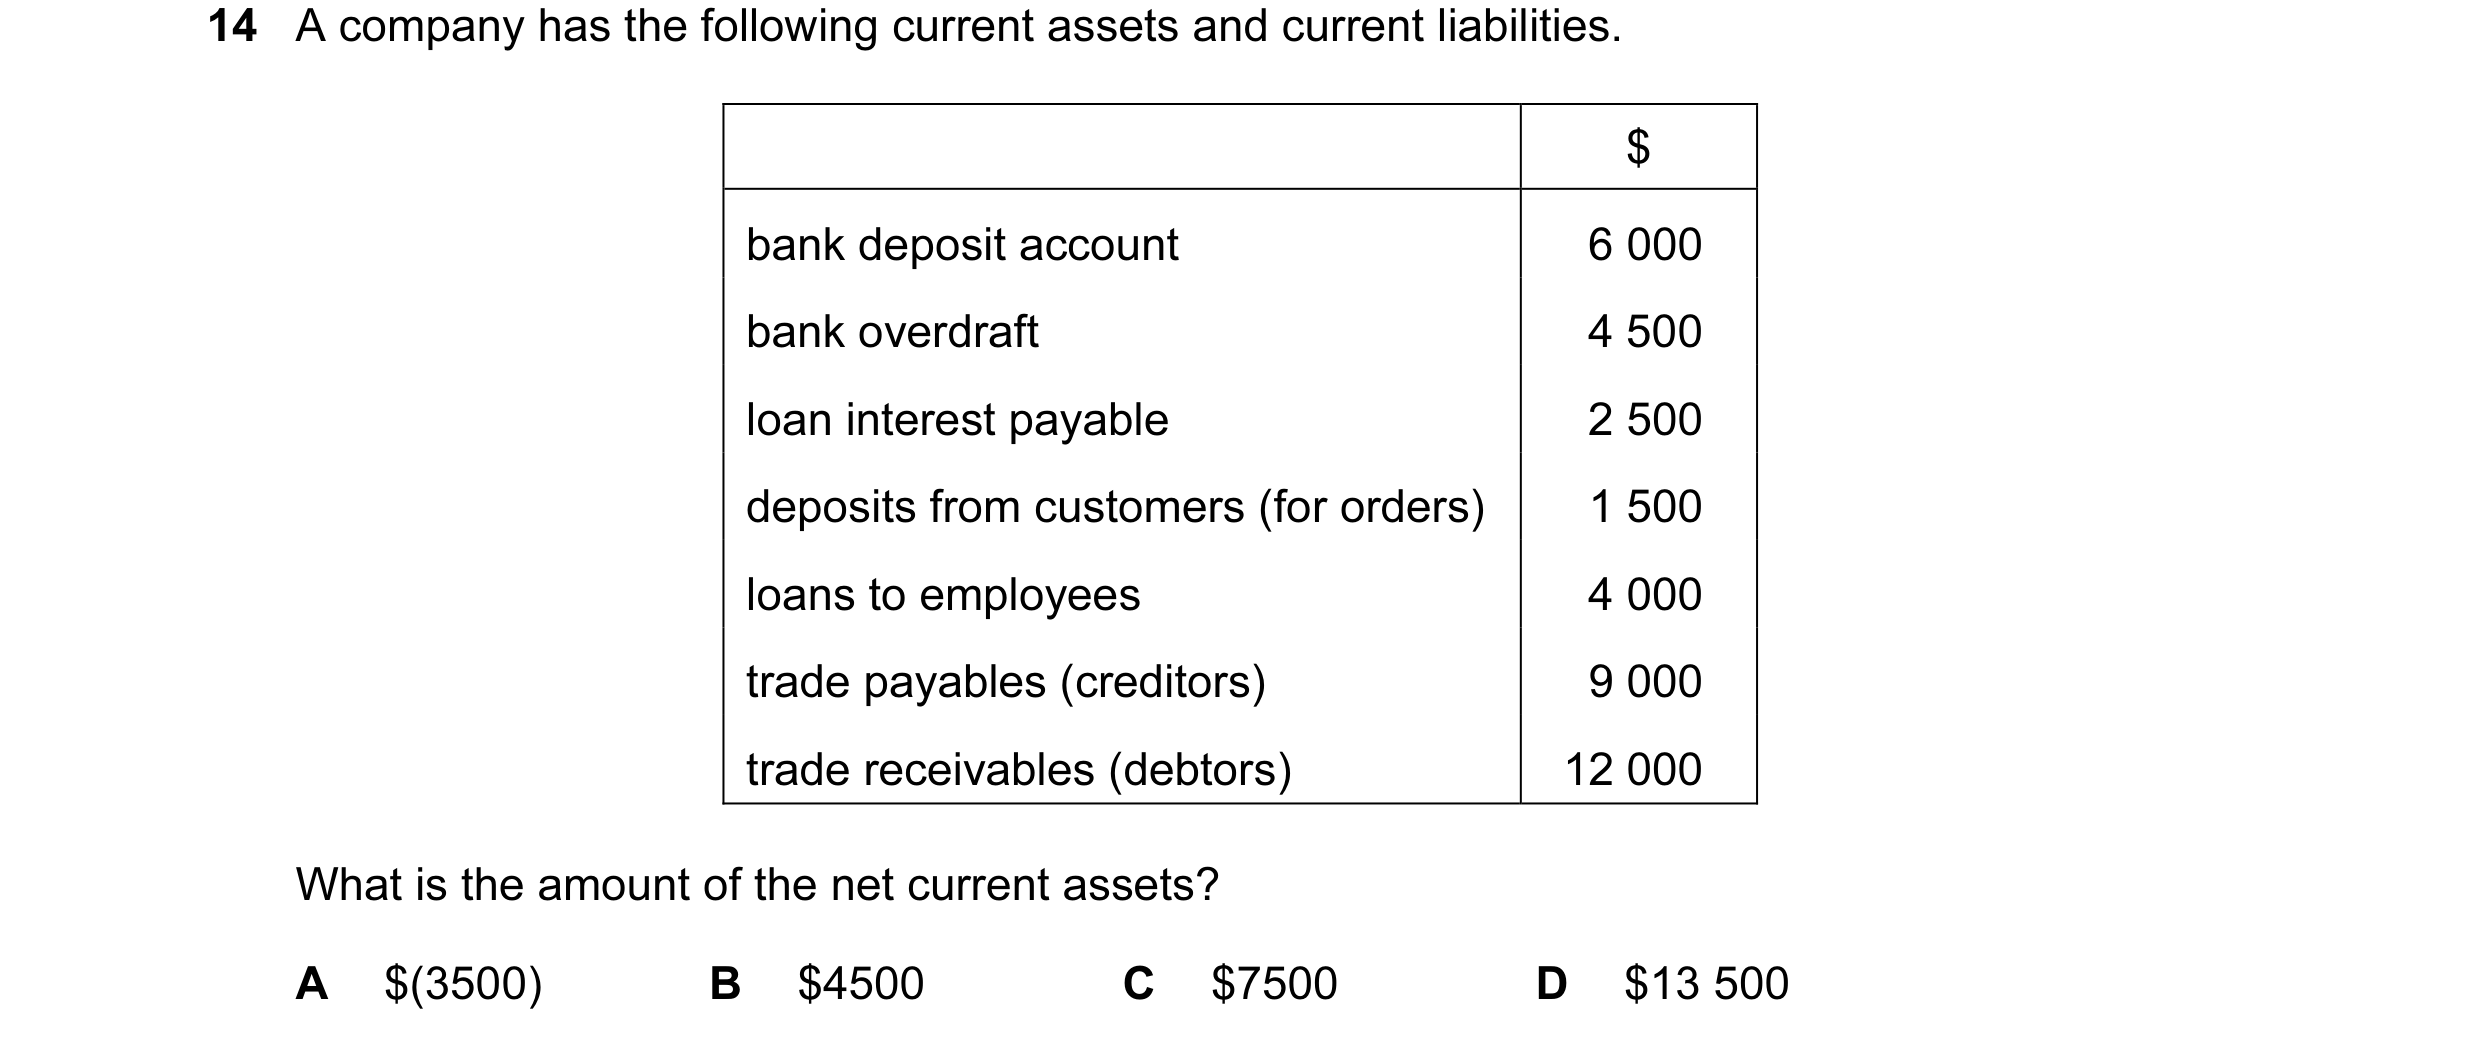 41 / 233
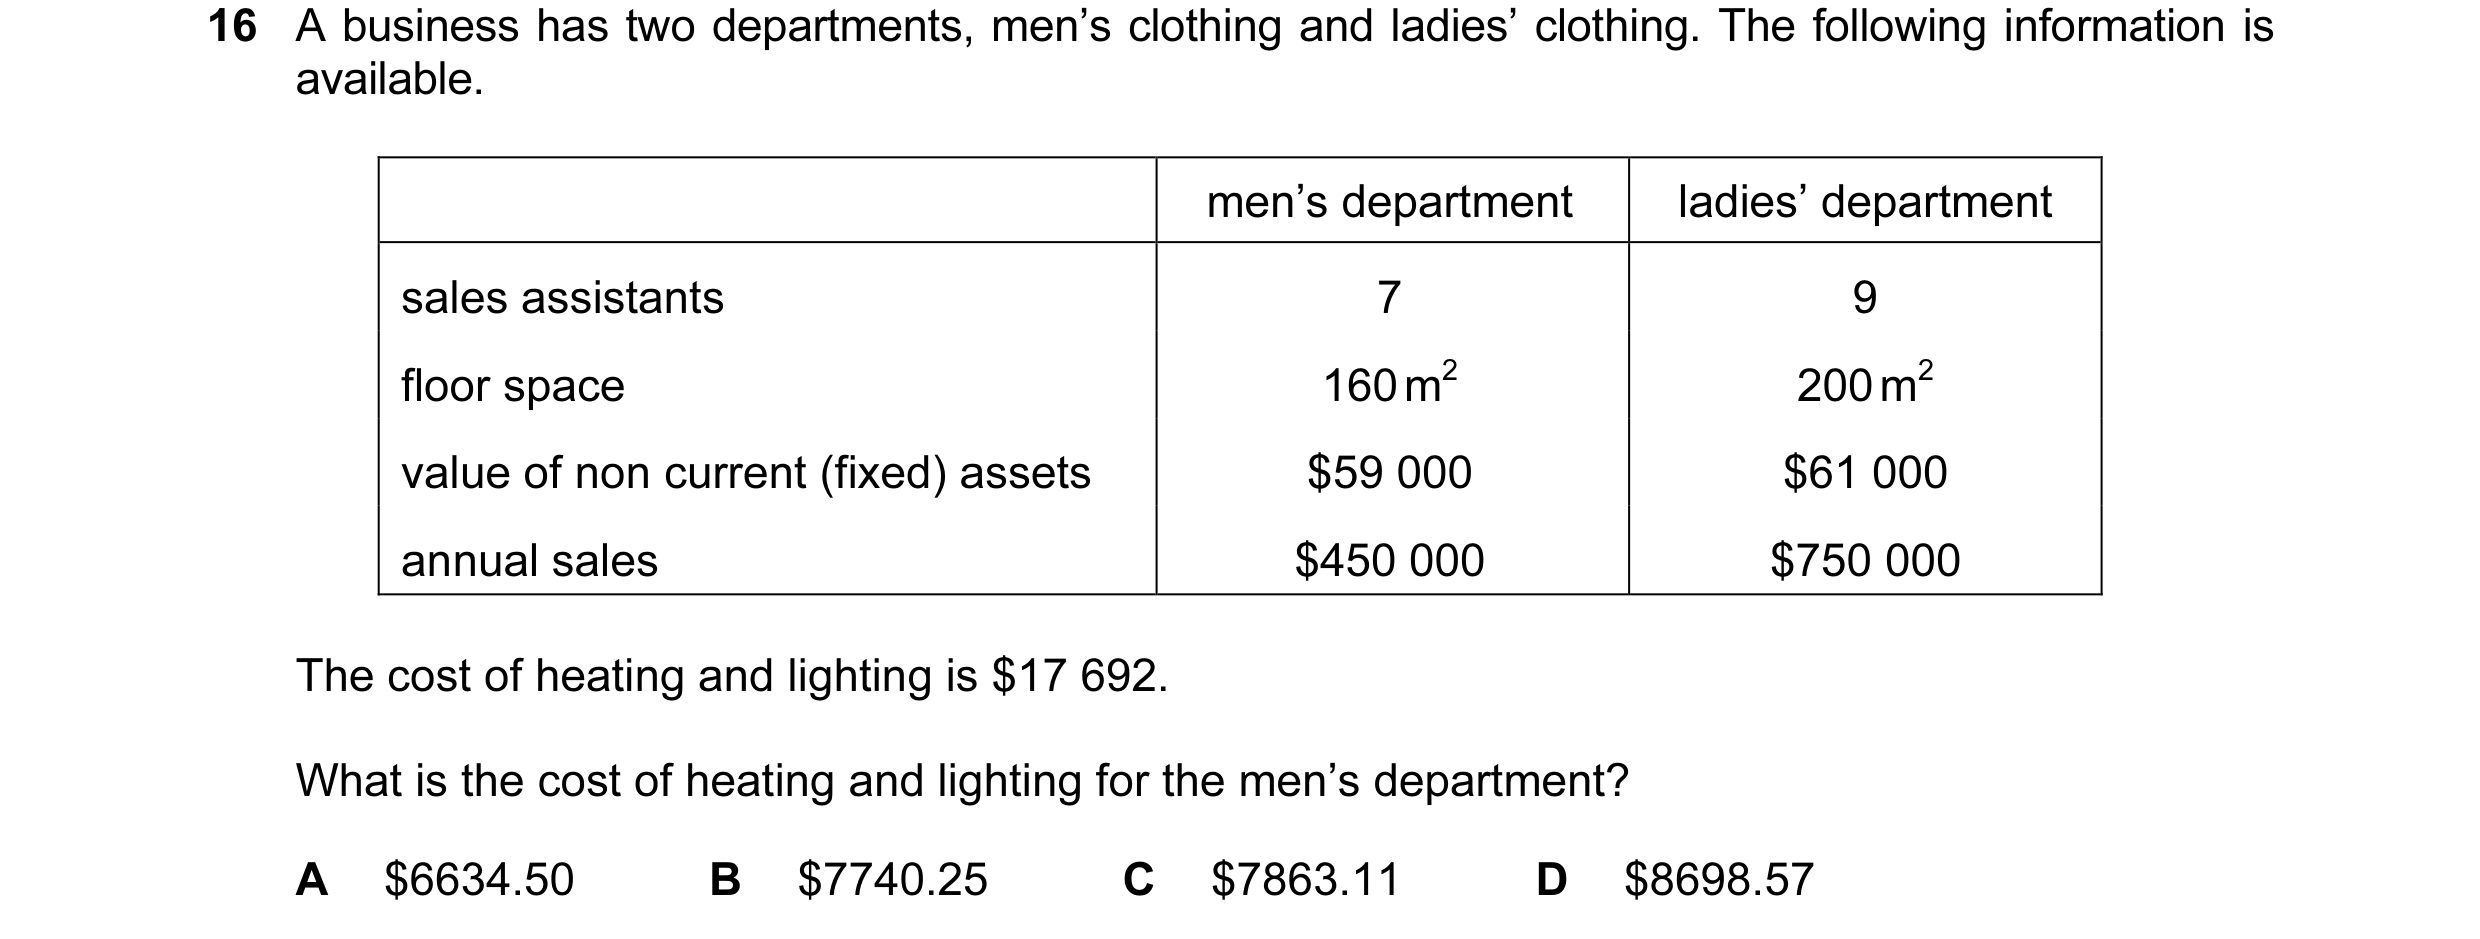
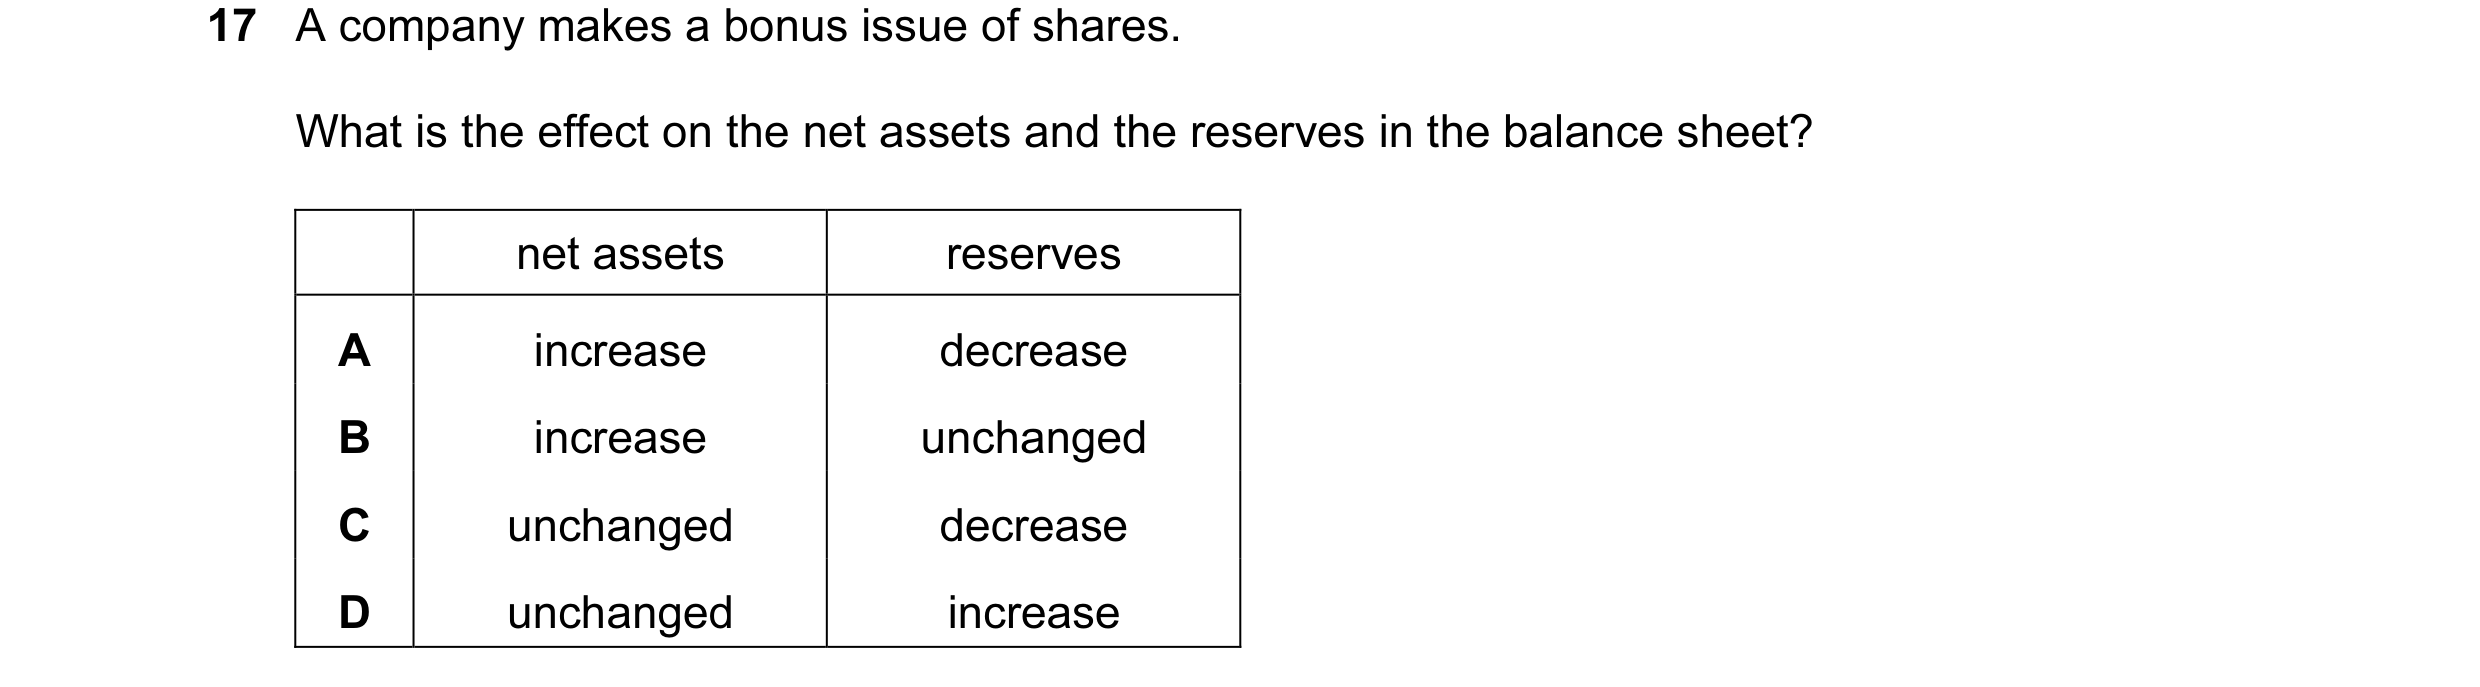
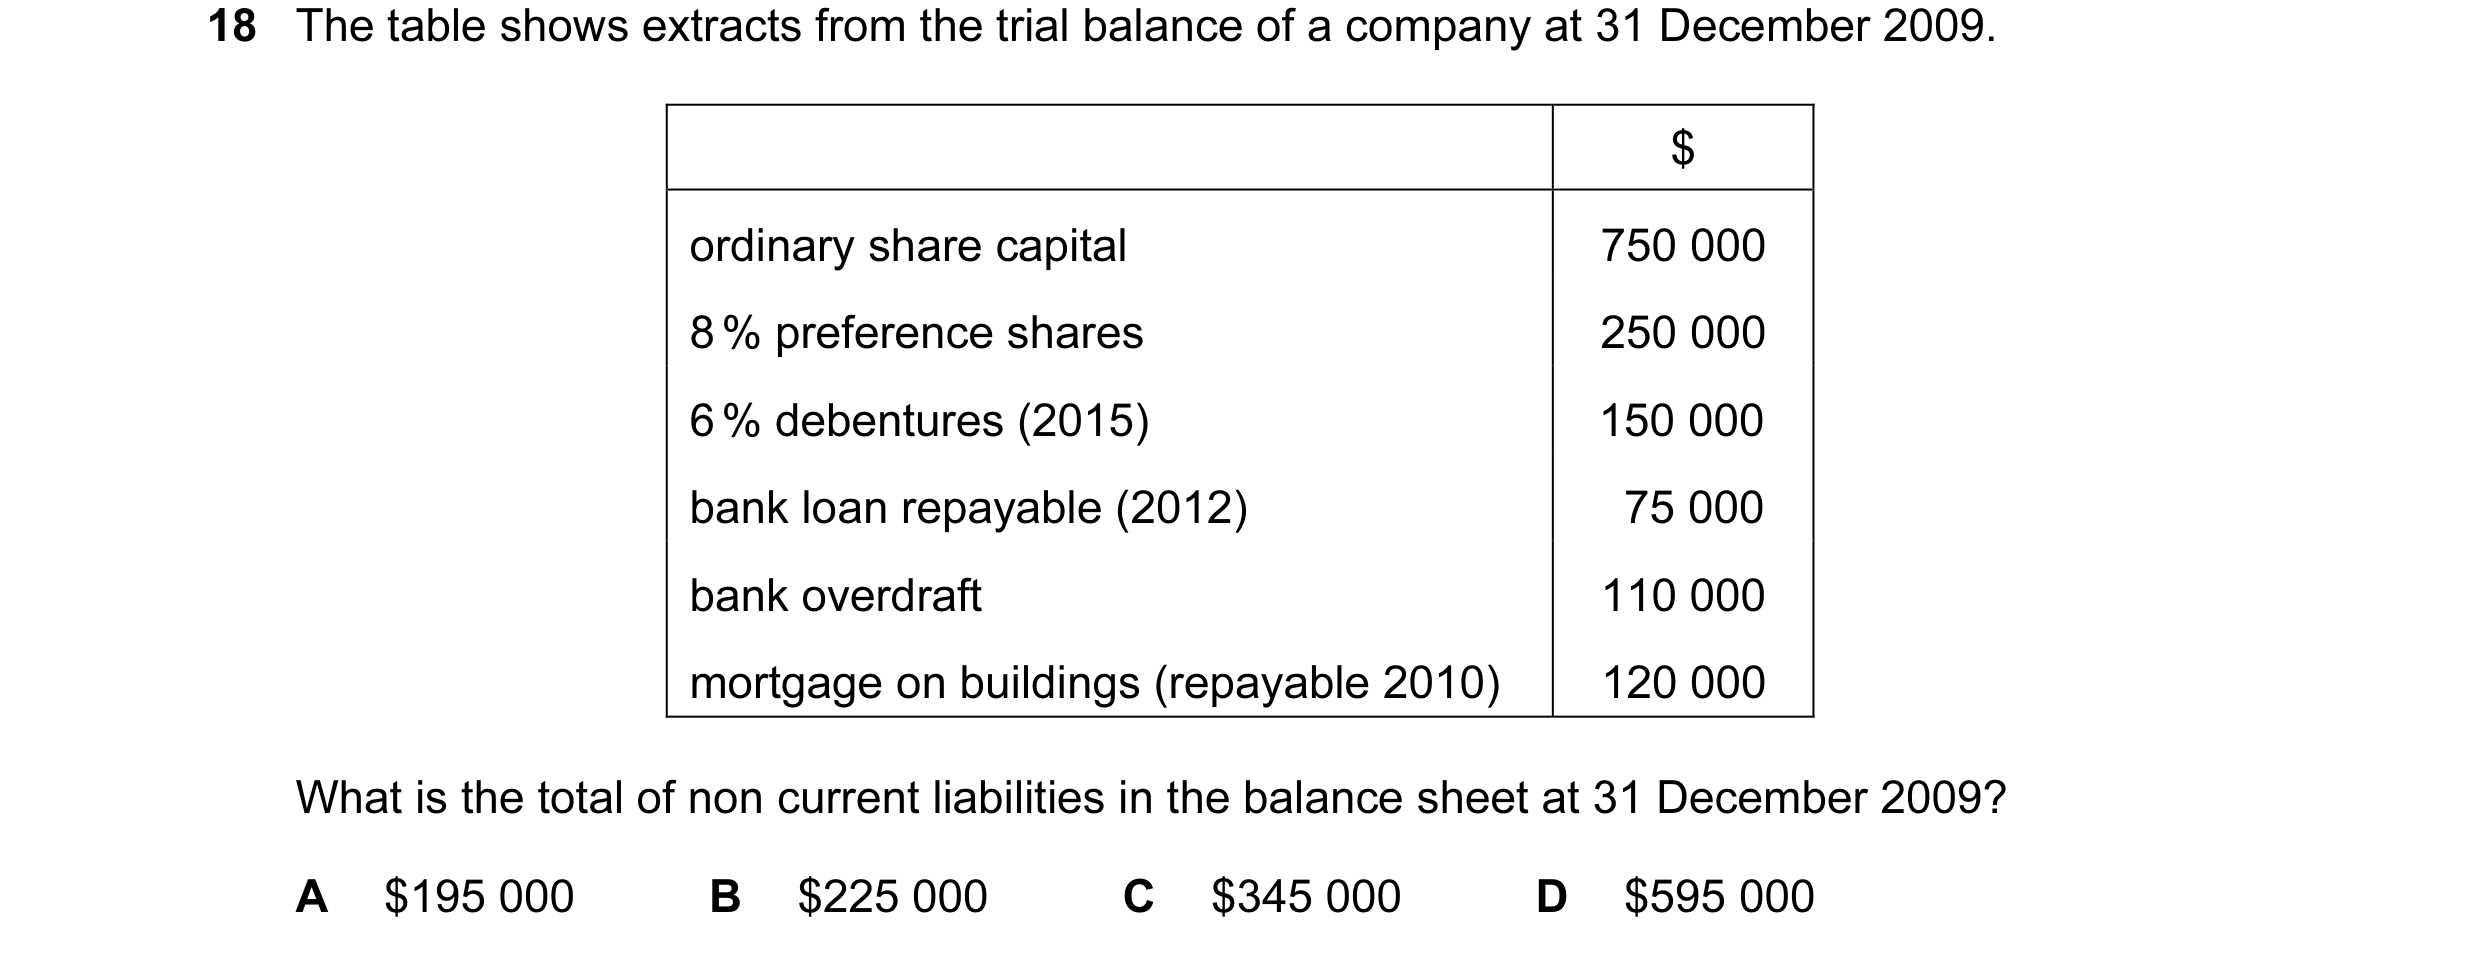 42 / 233
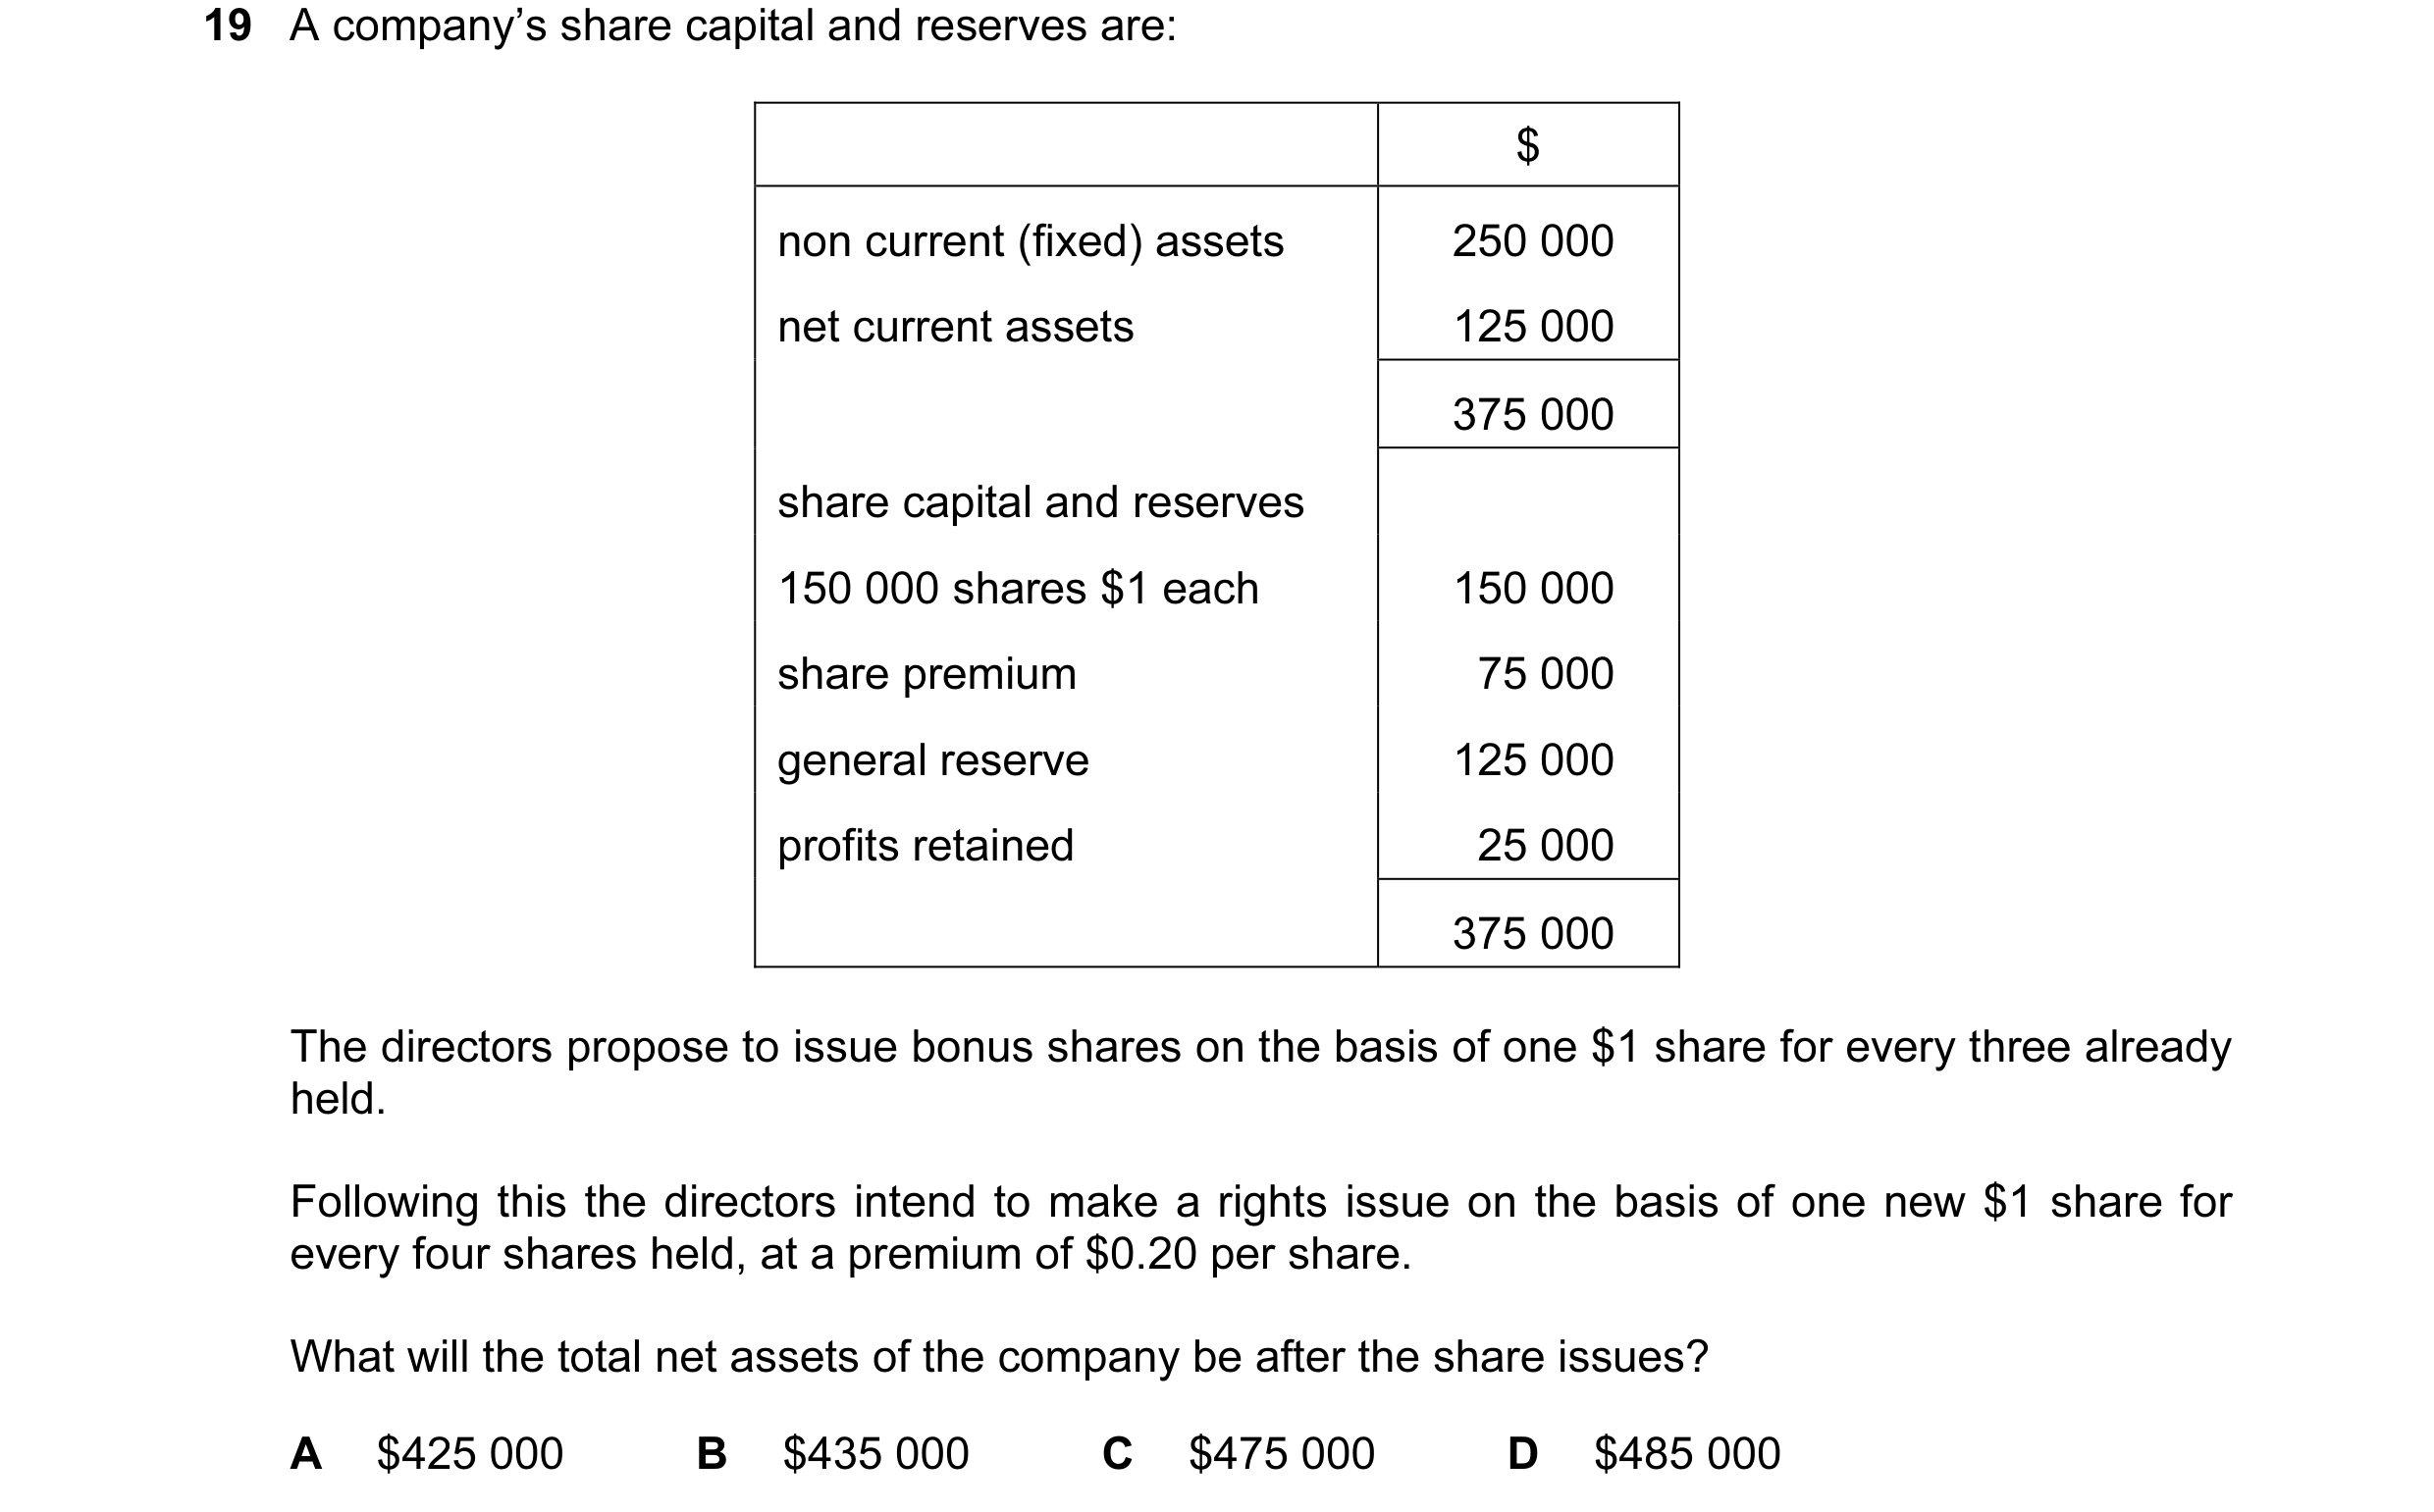
 43 / 233
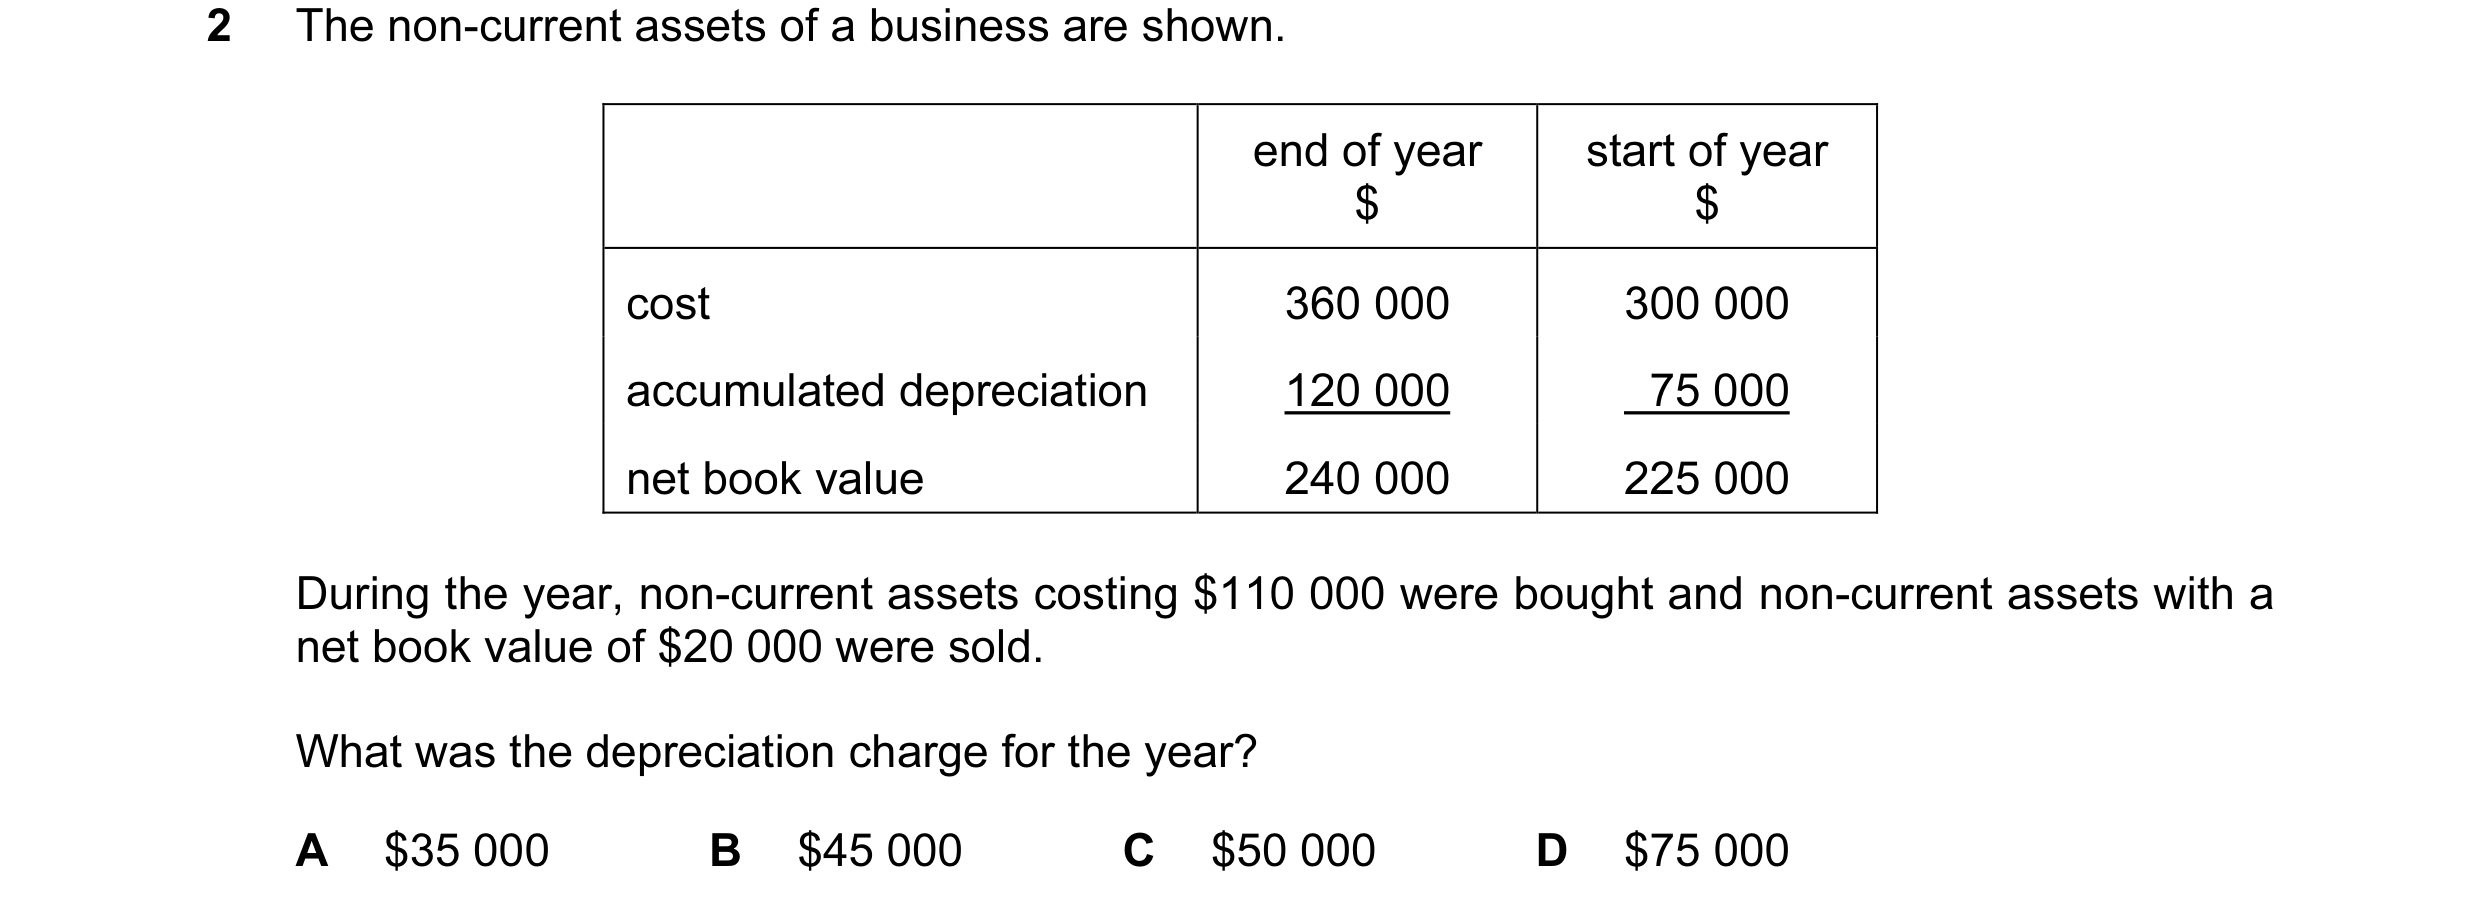
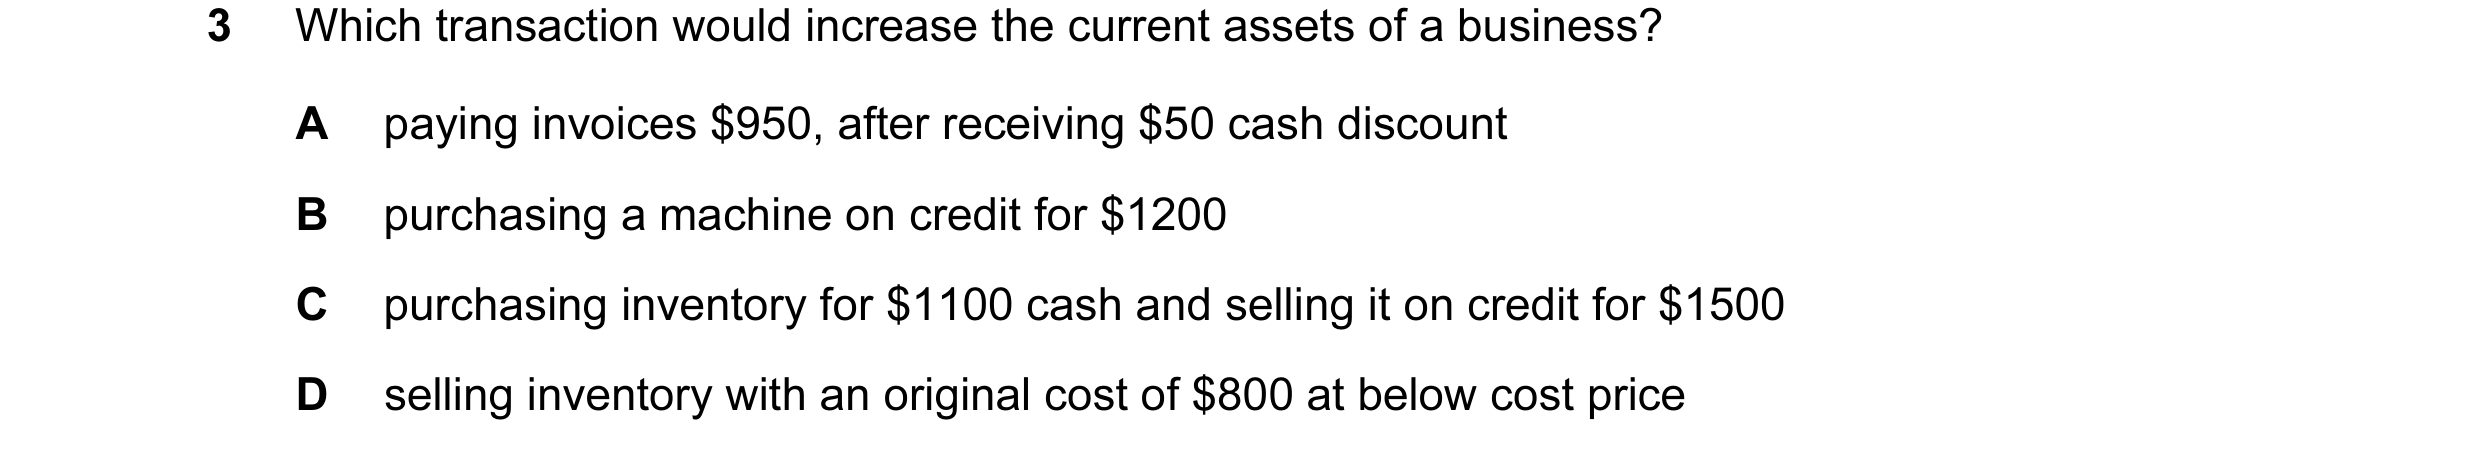
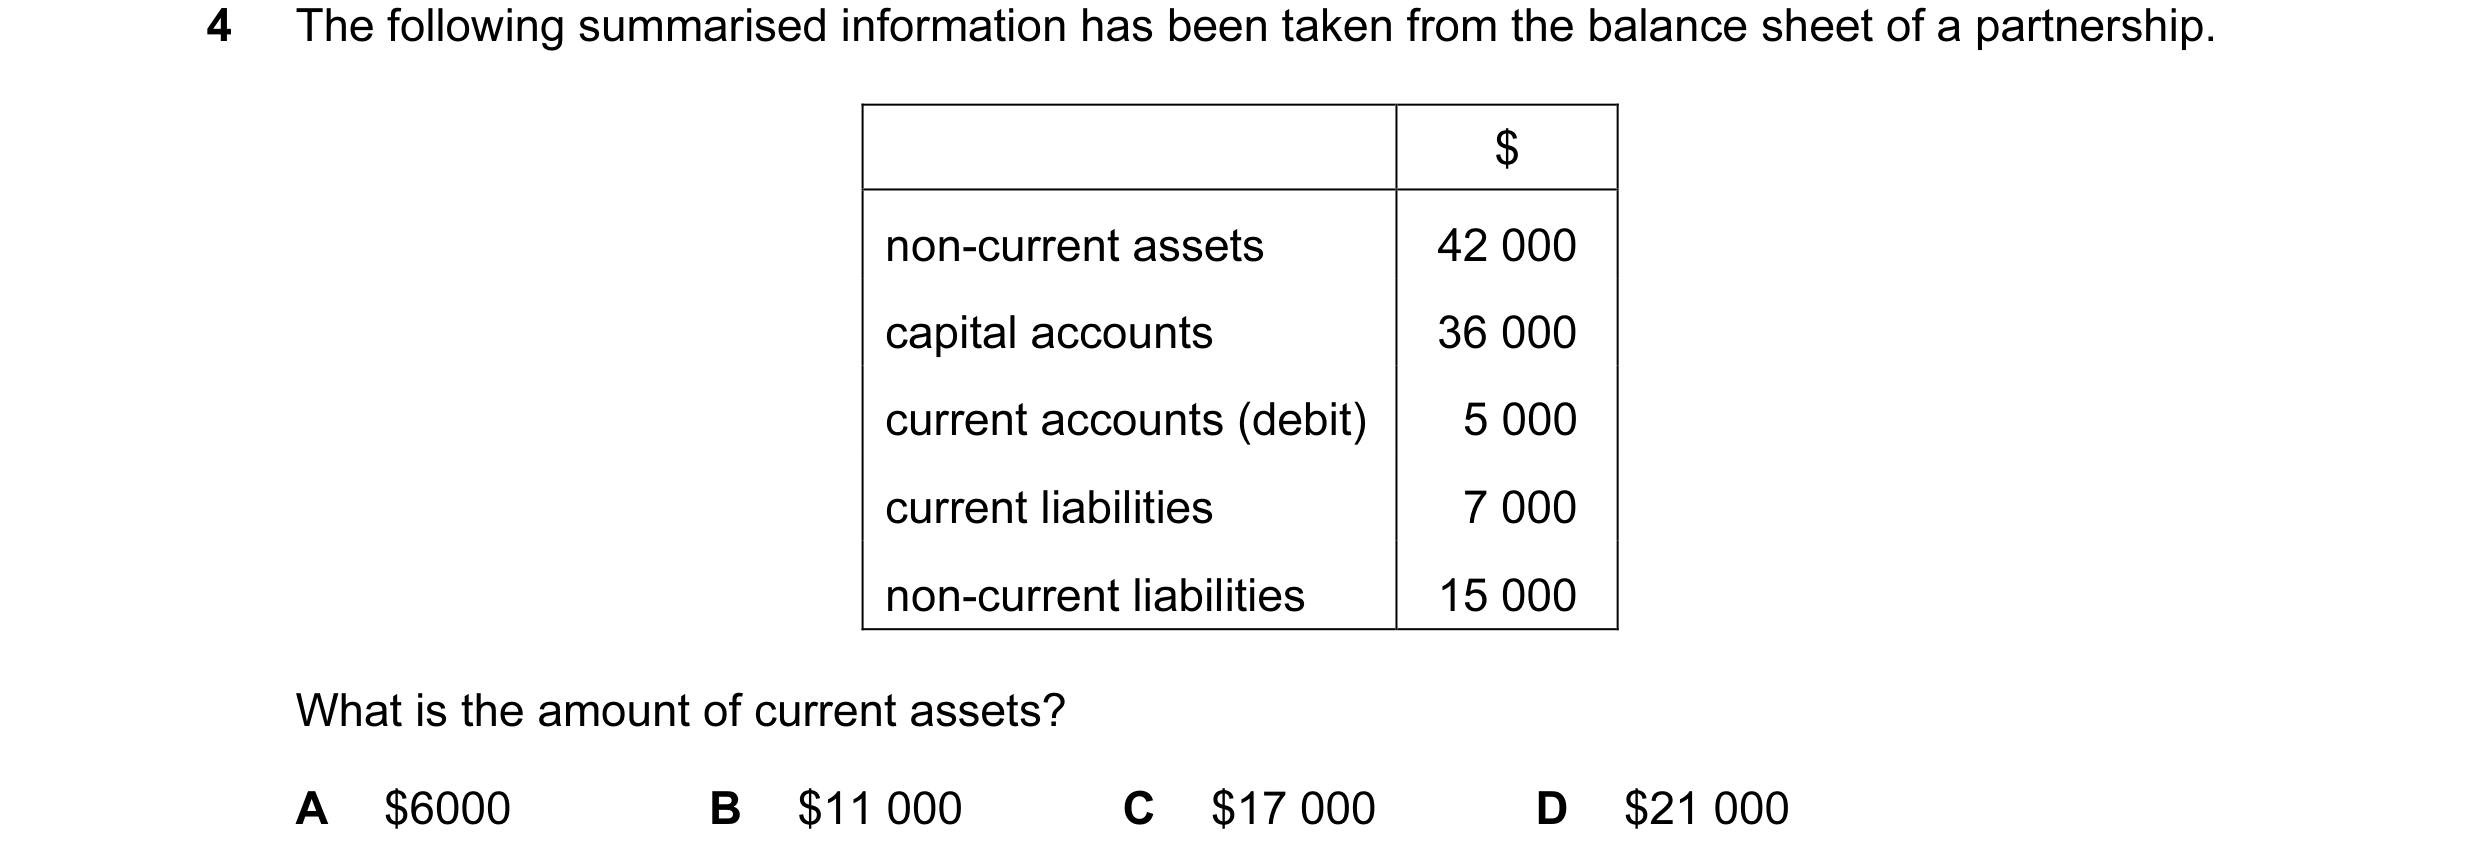
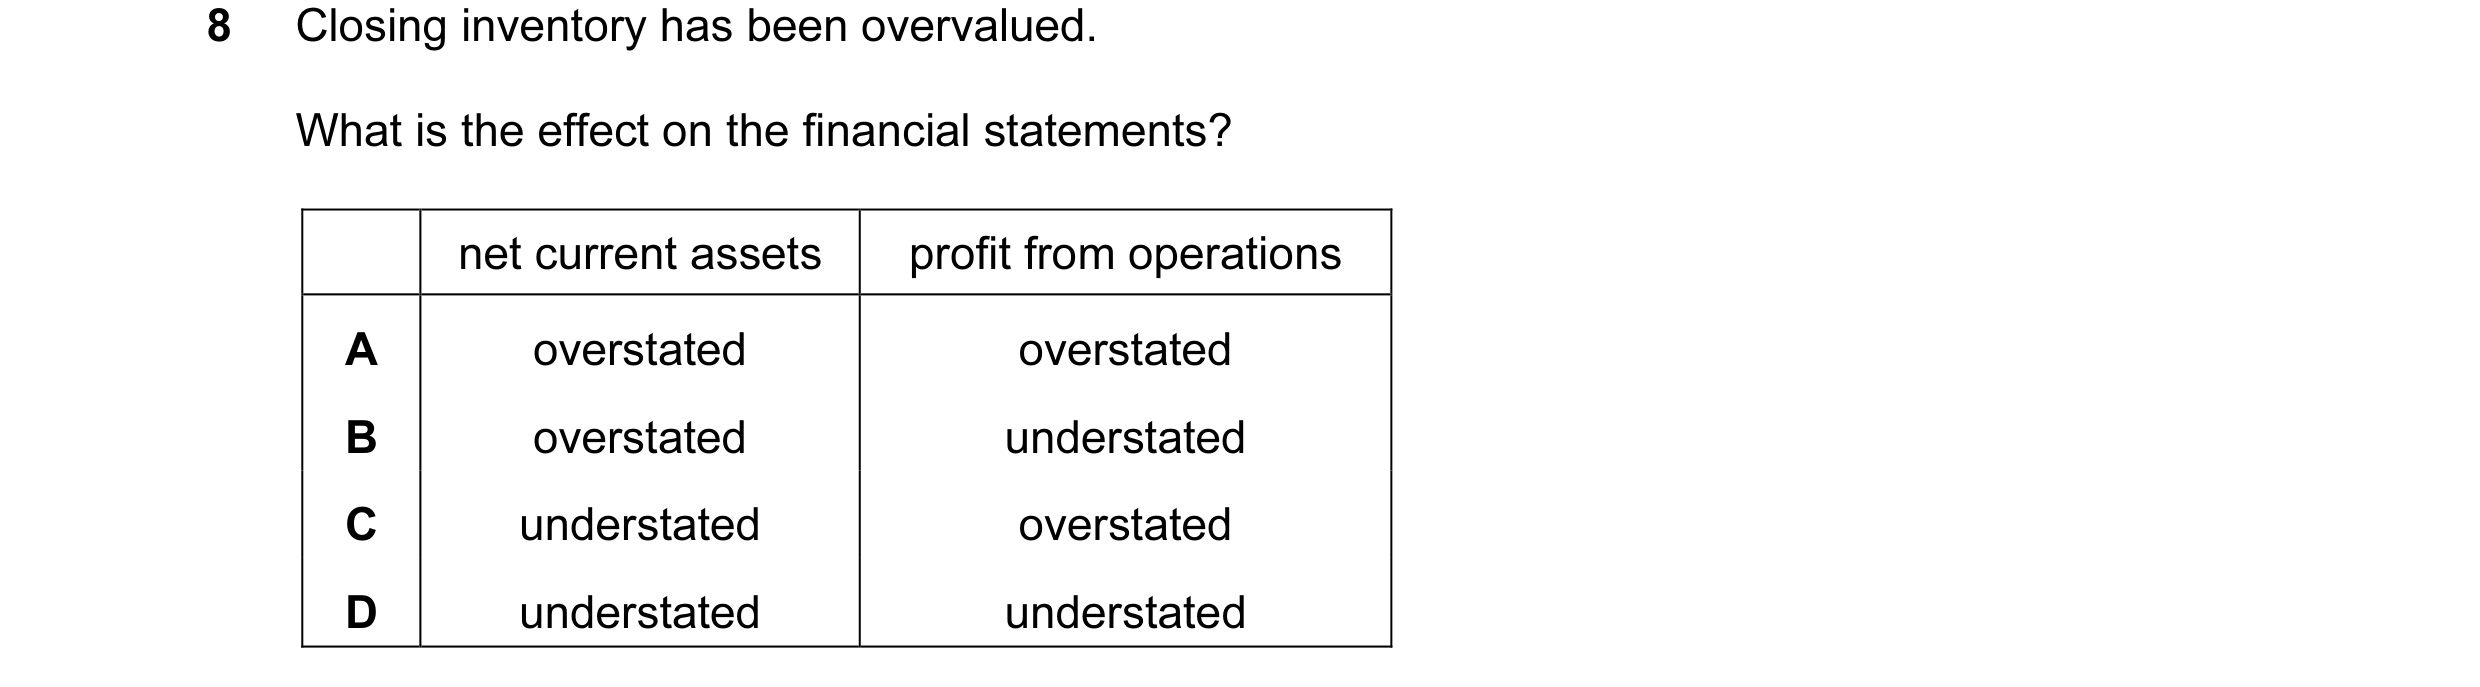 44 / 233
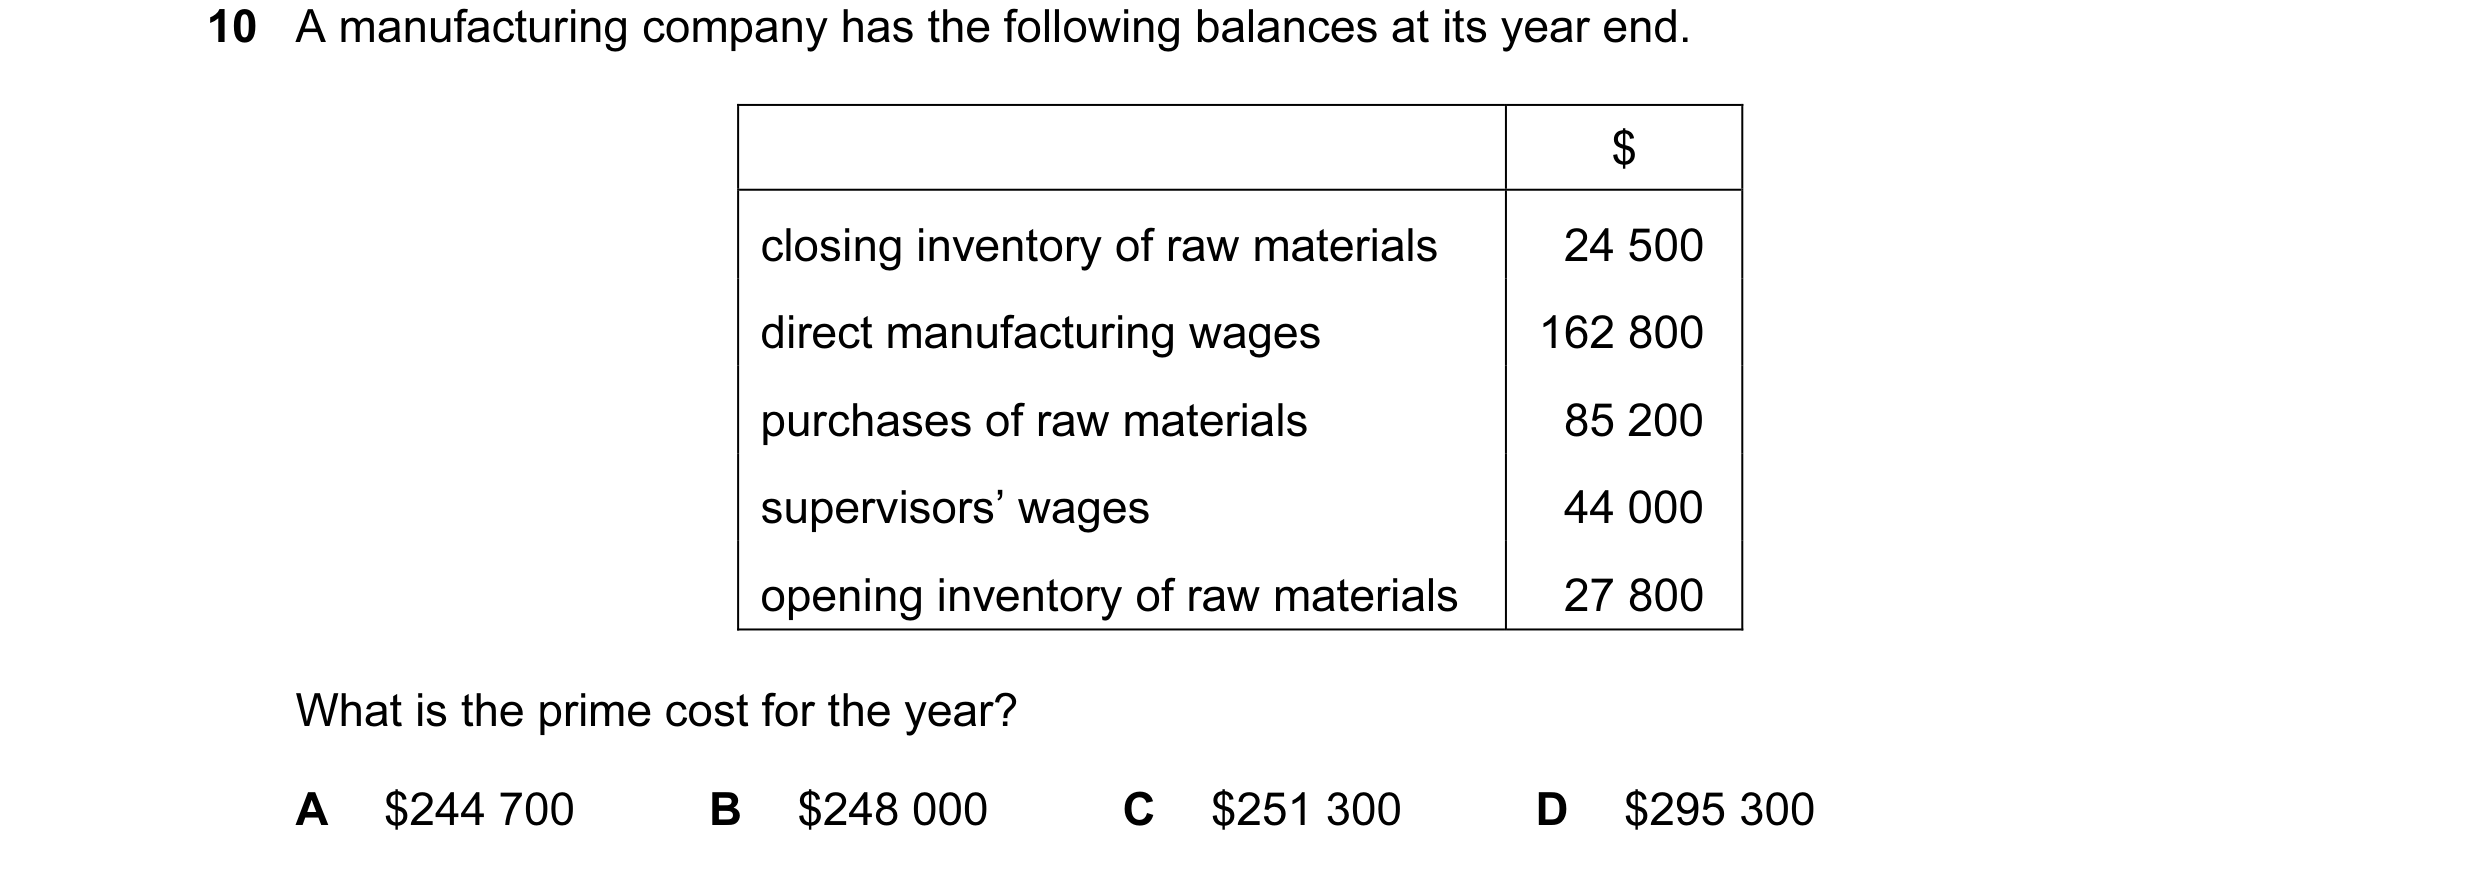
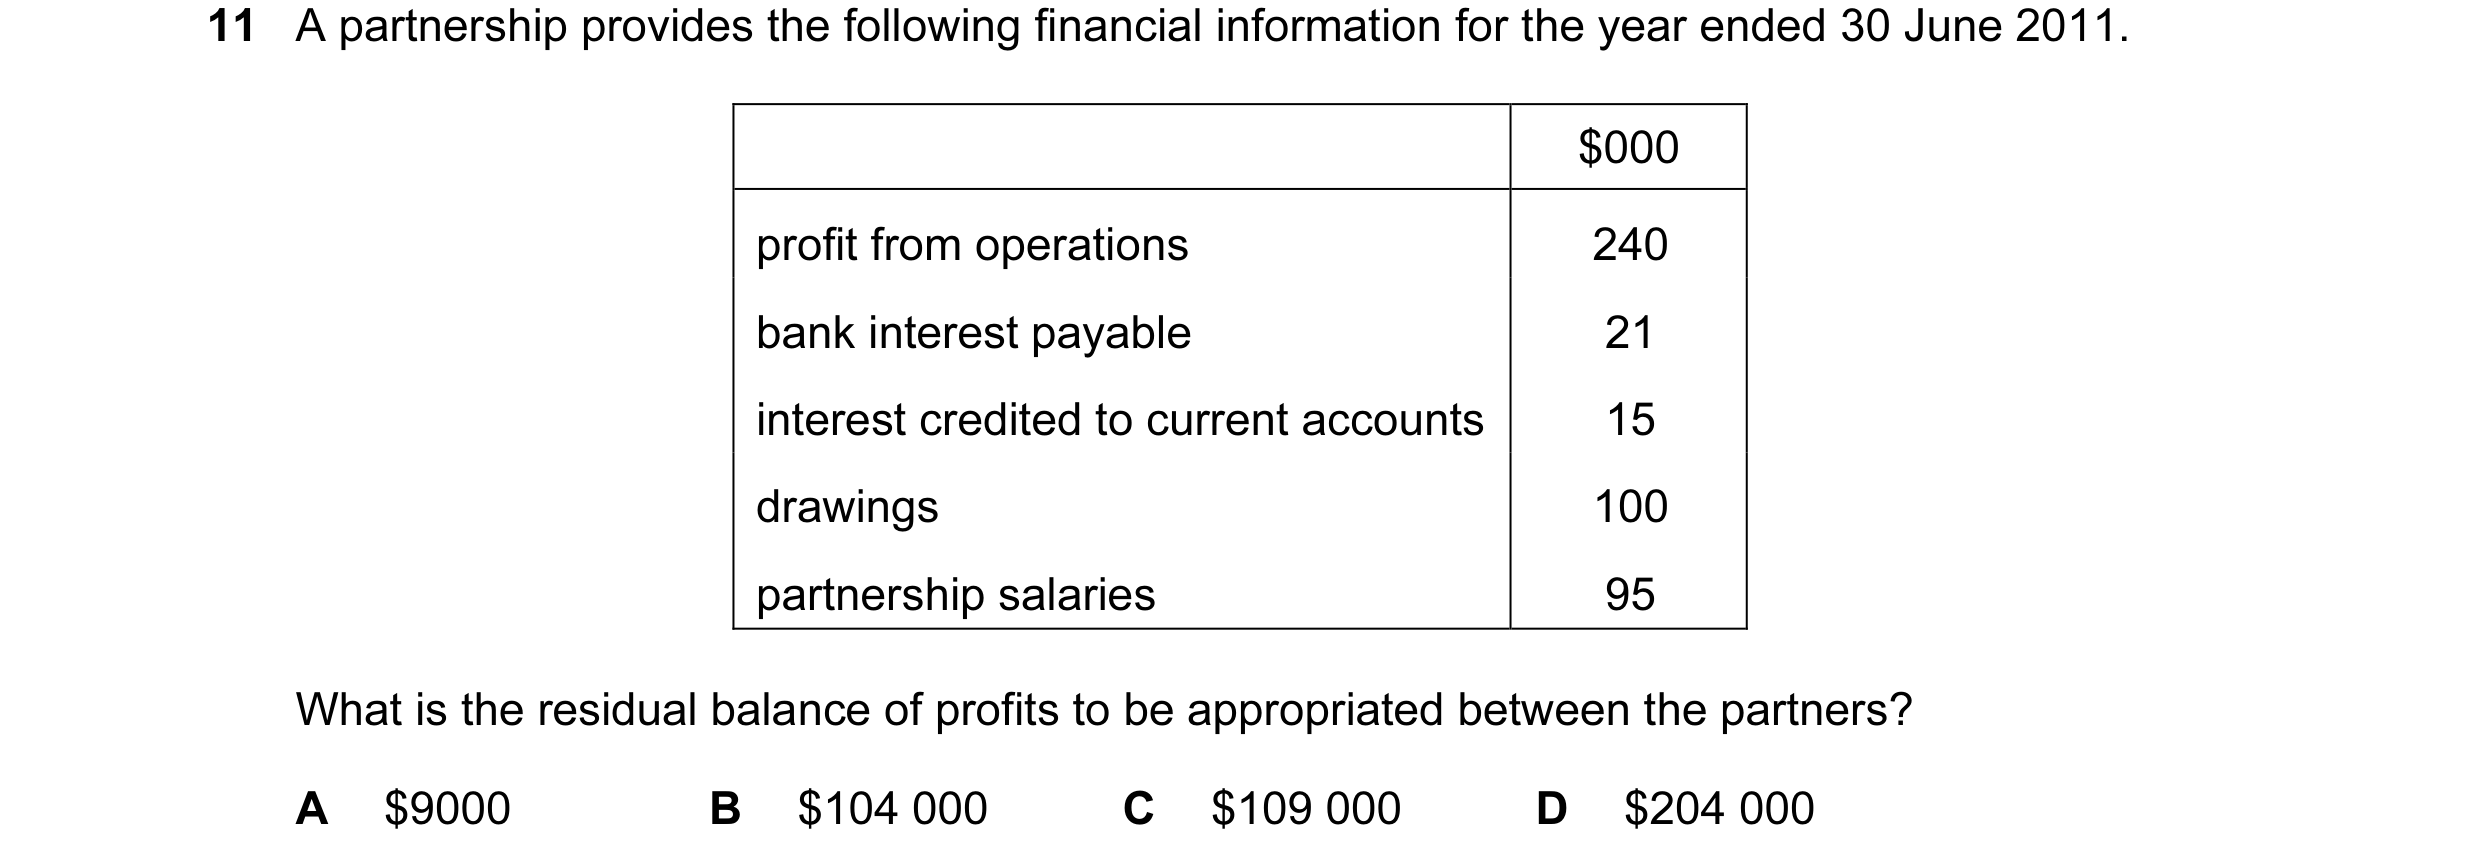
 45 / 233
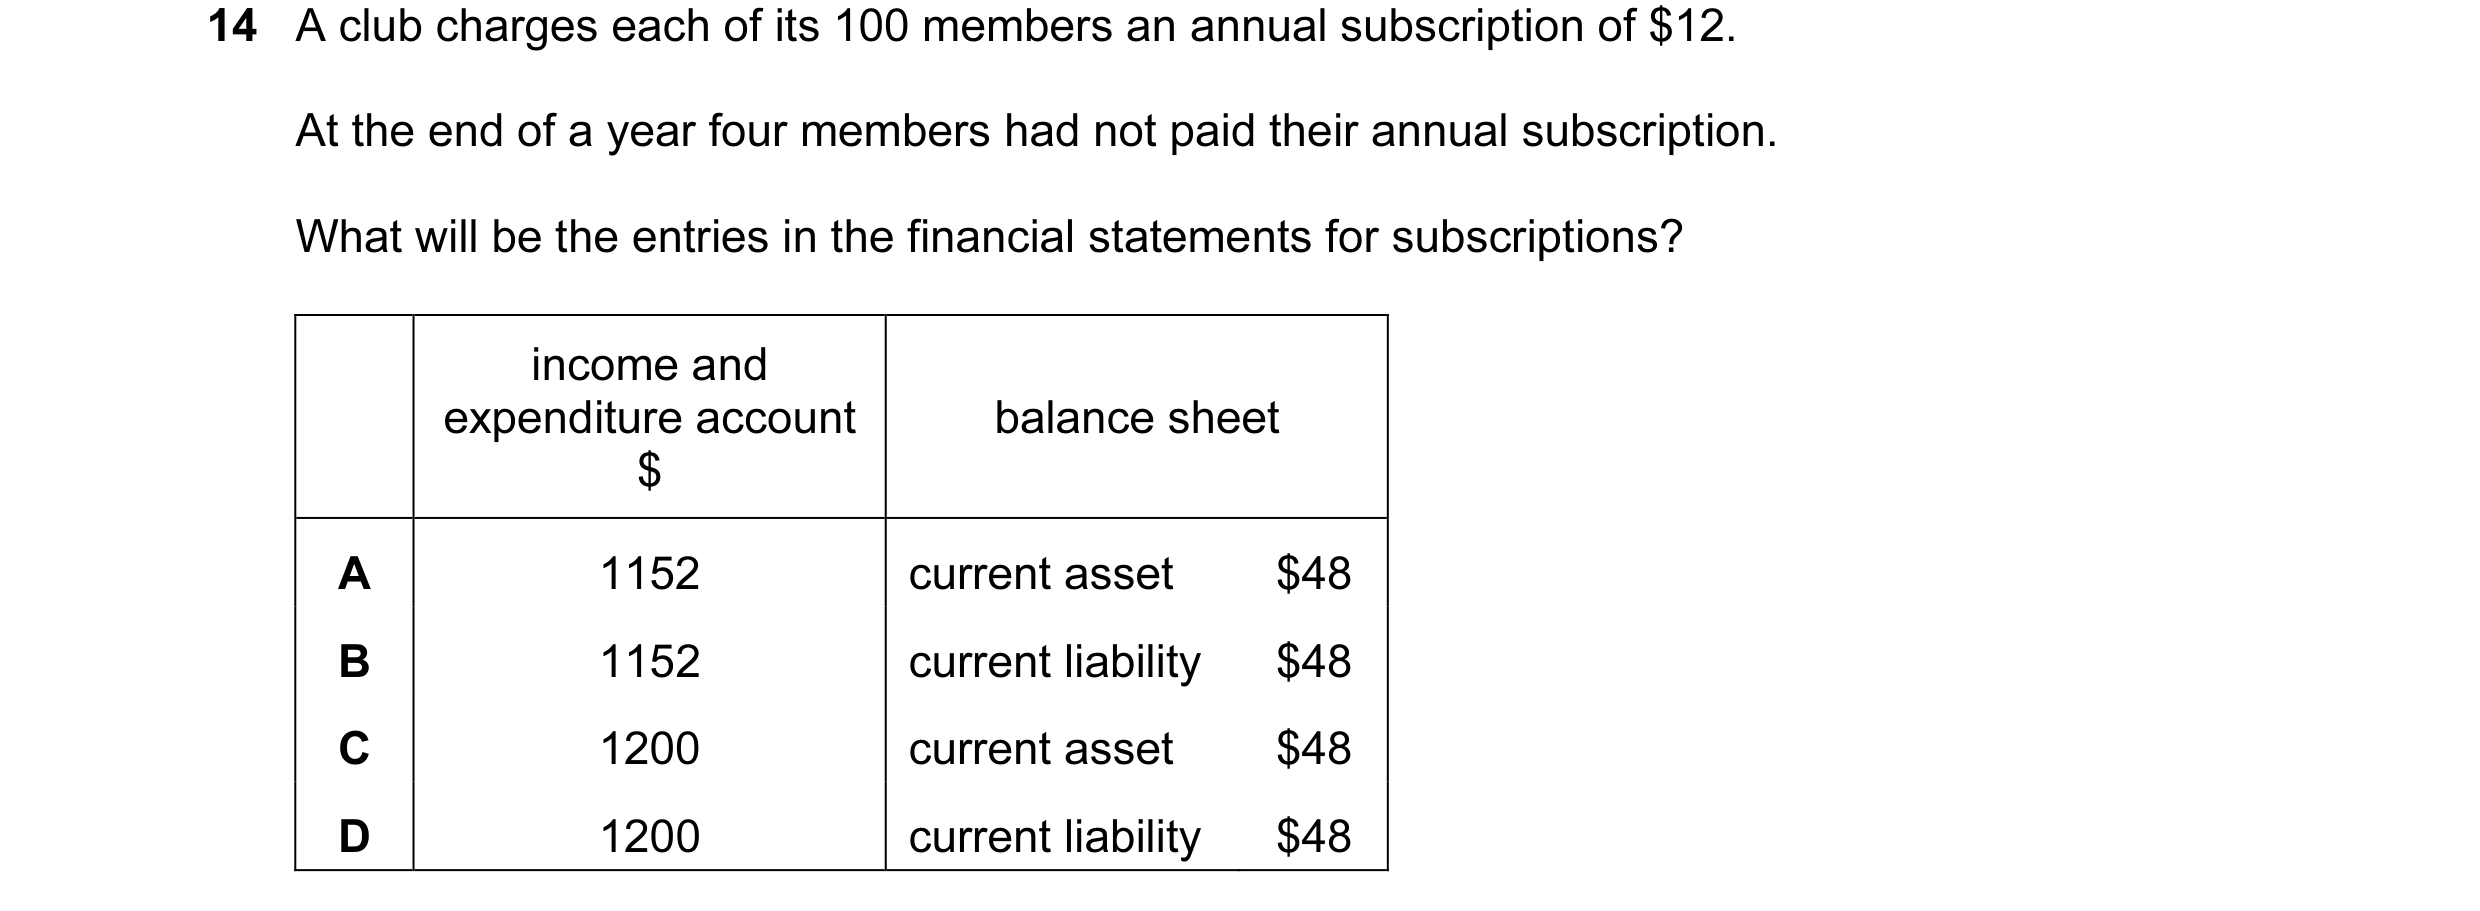
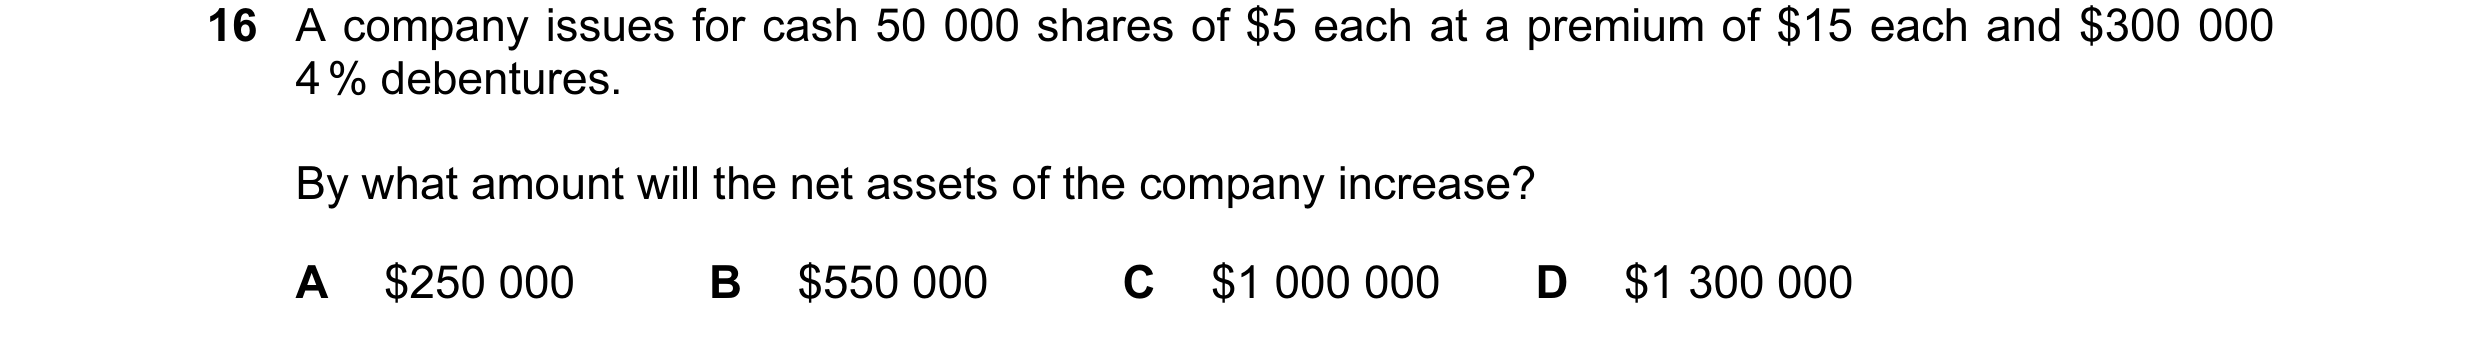
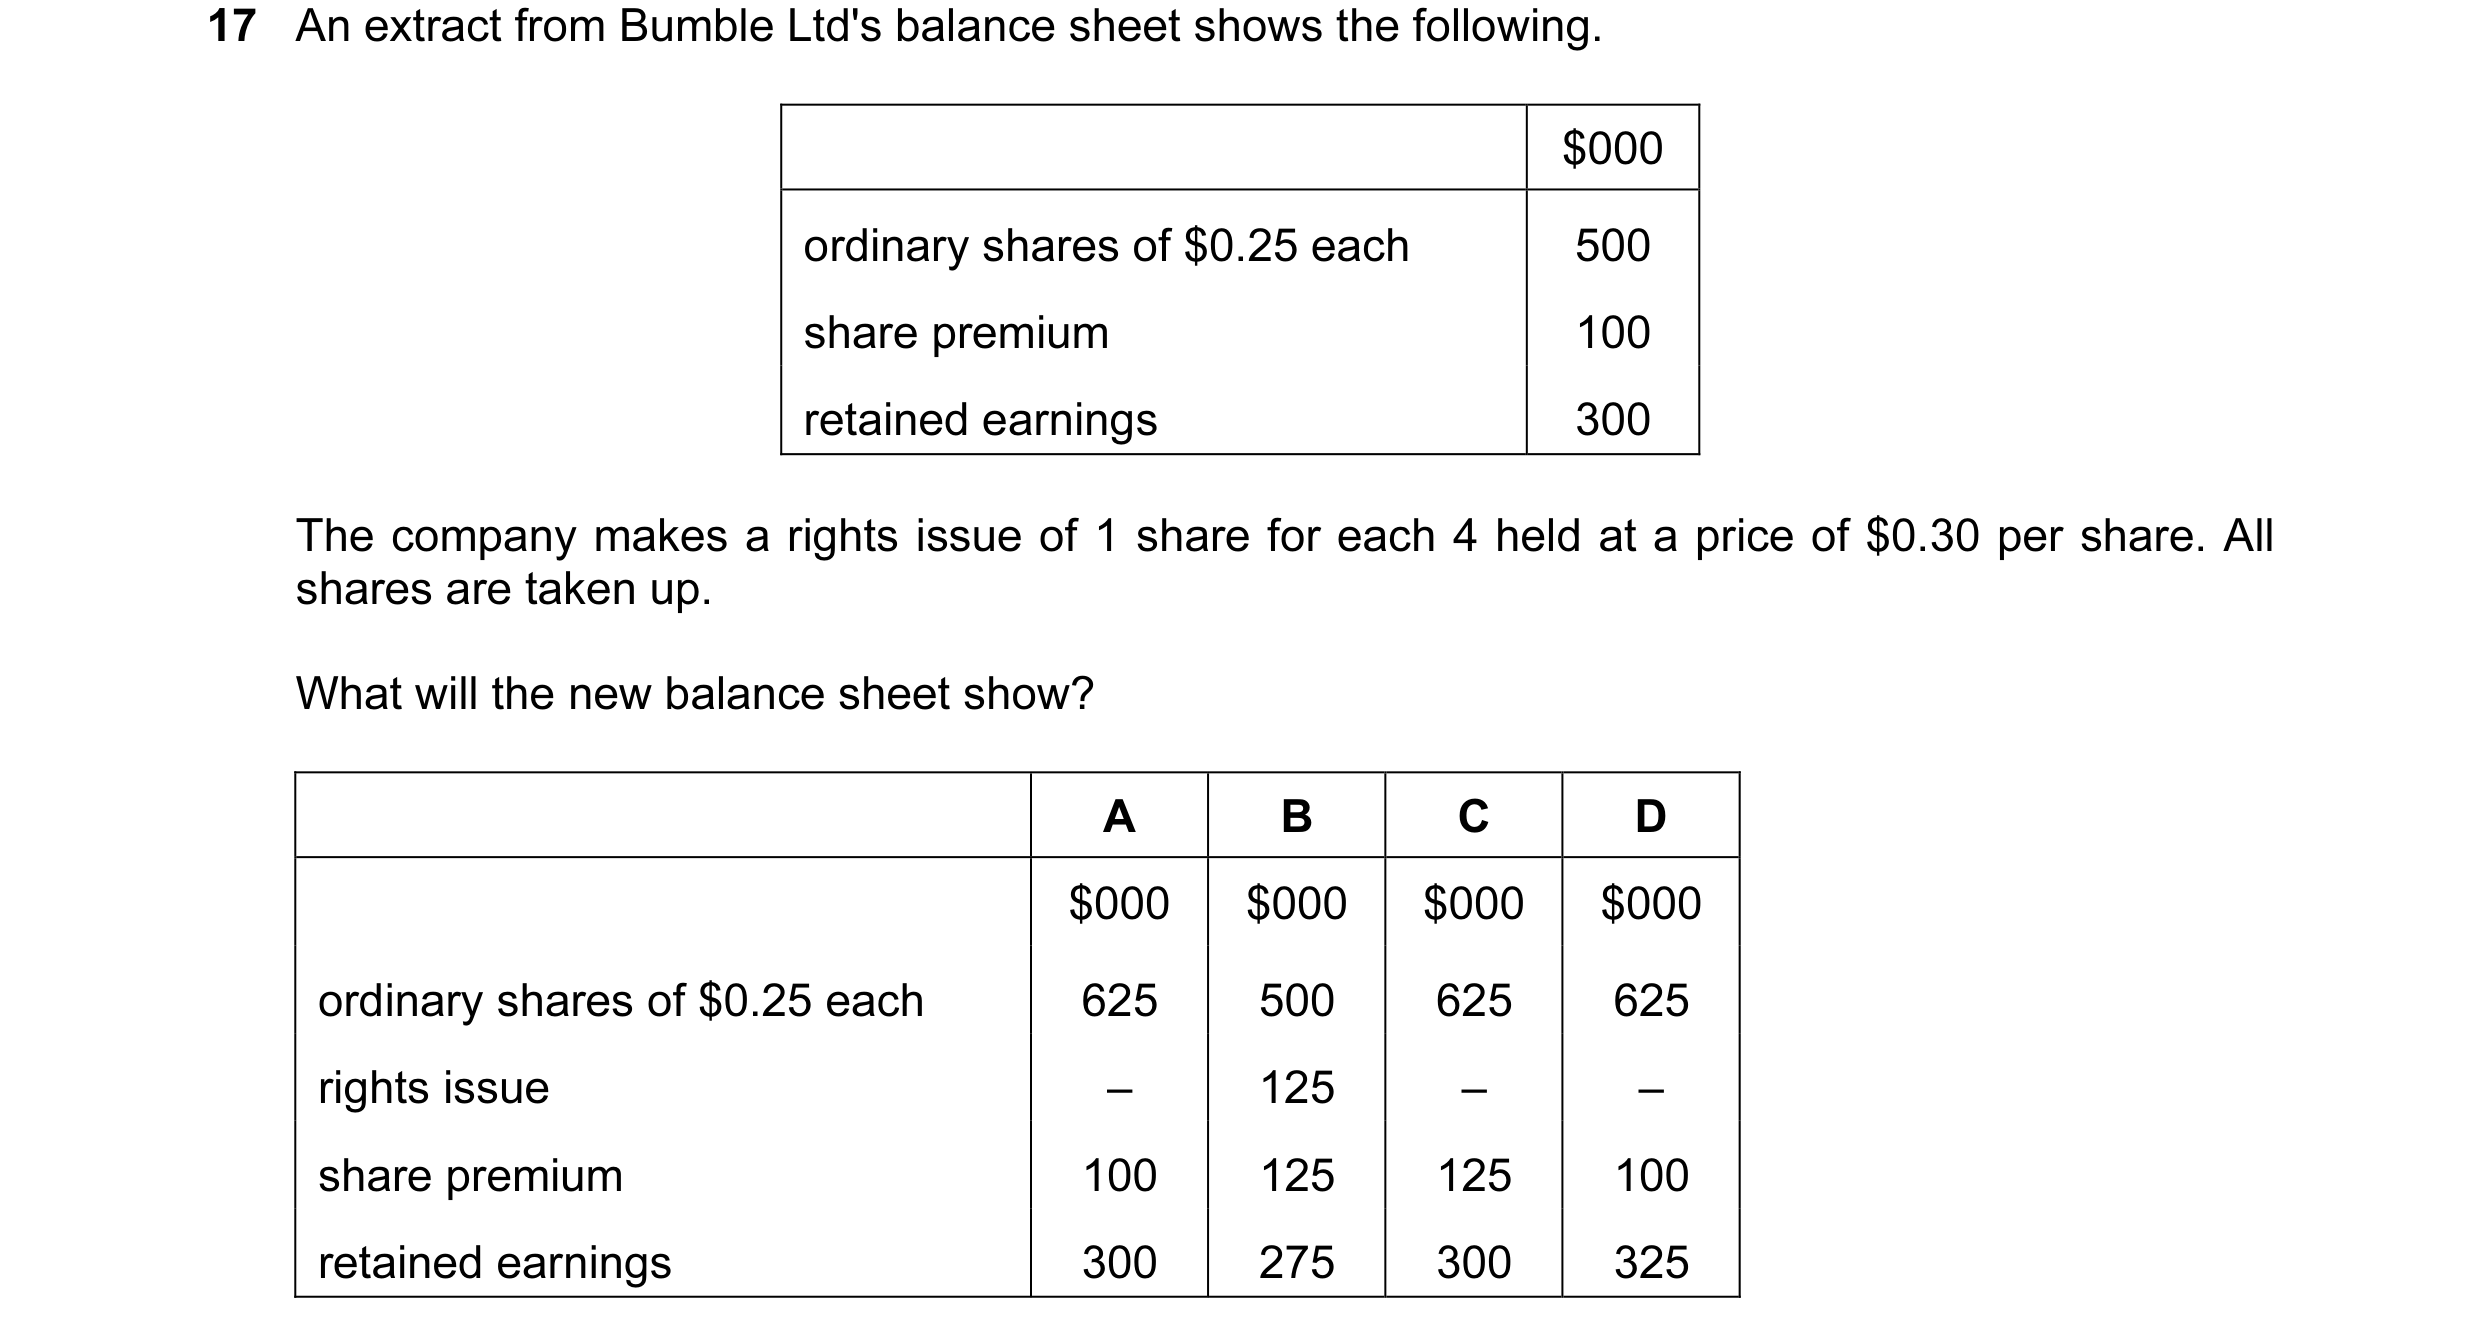 46 / 233
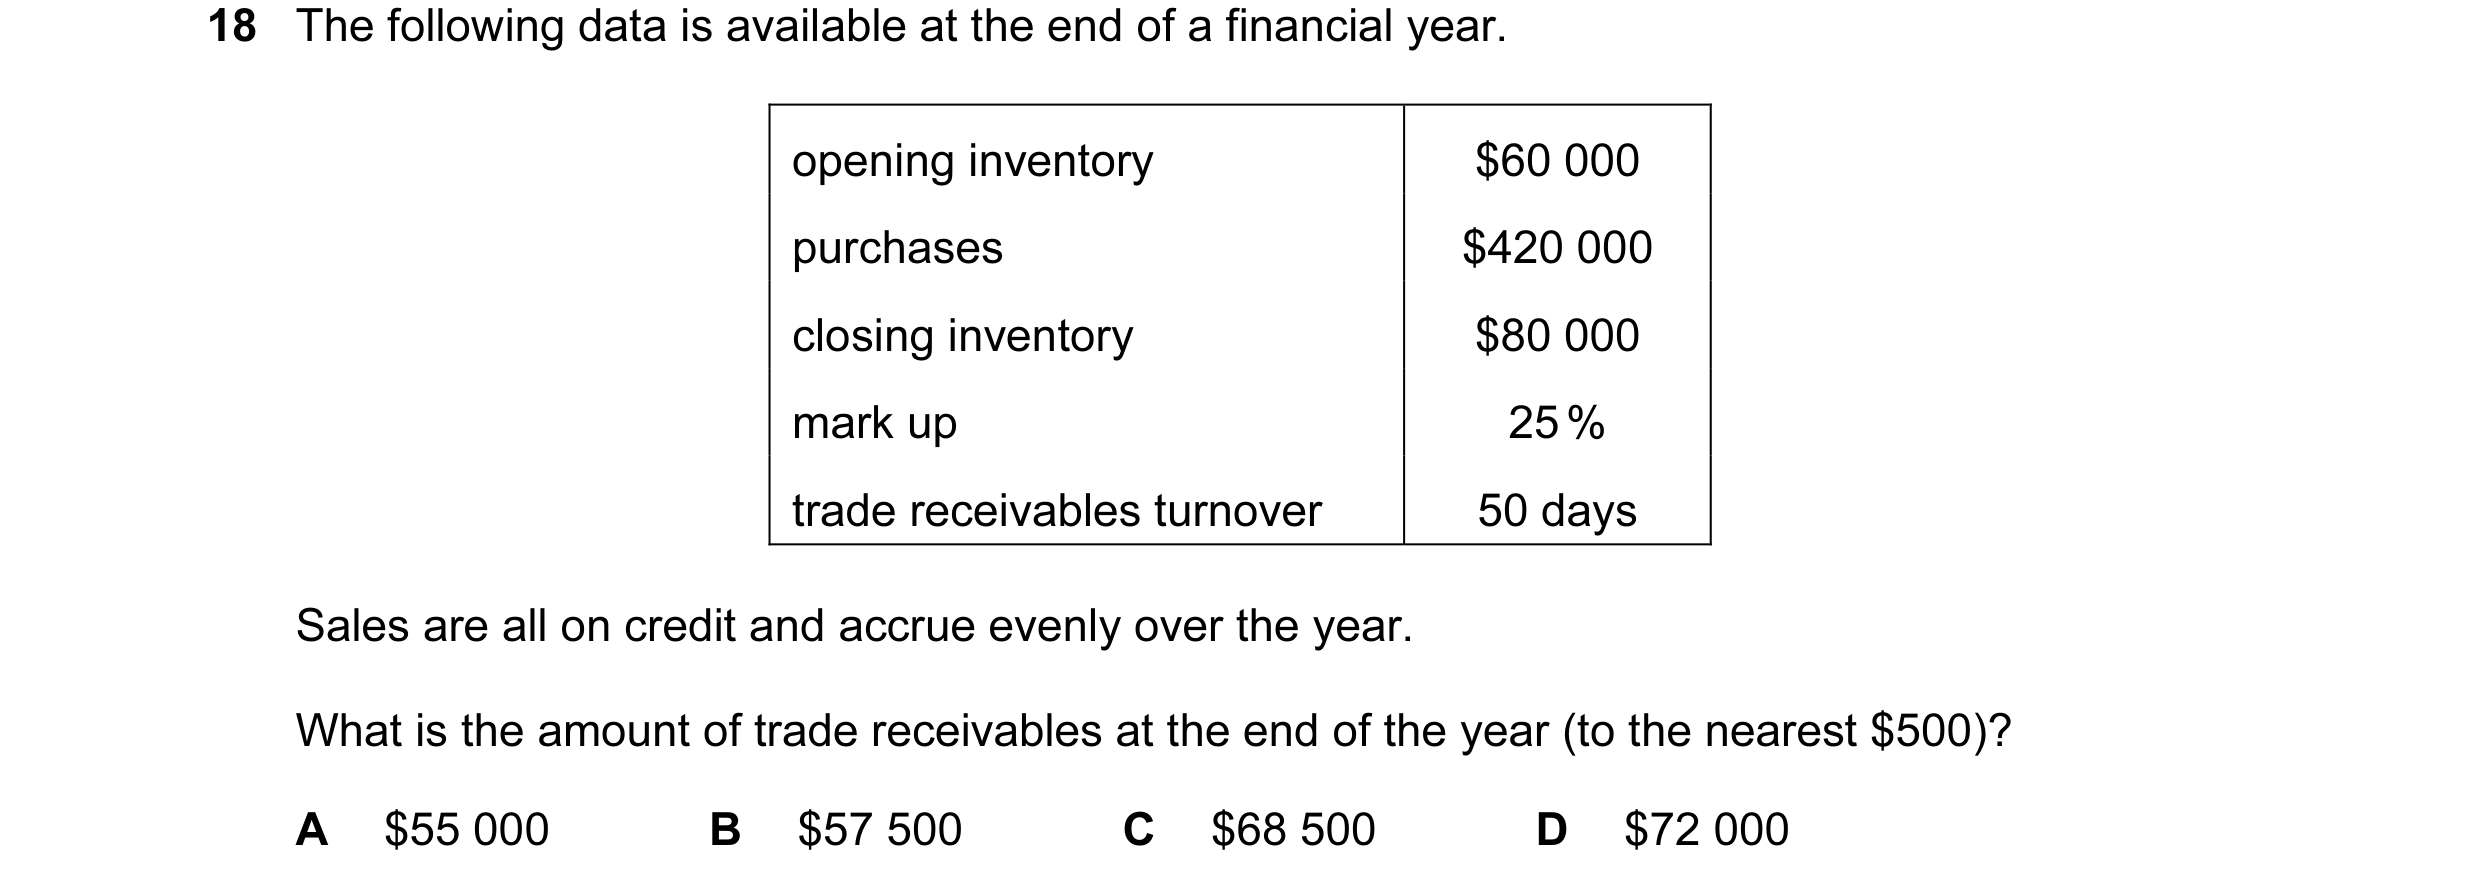
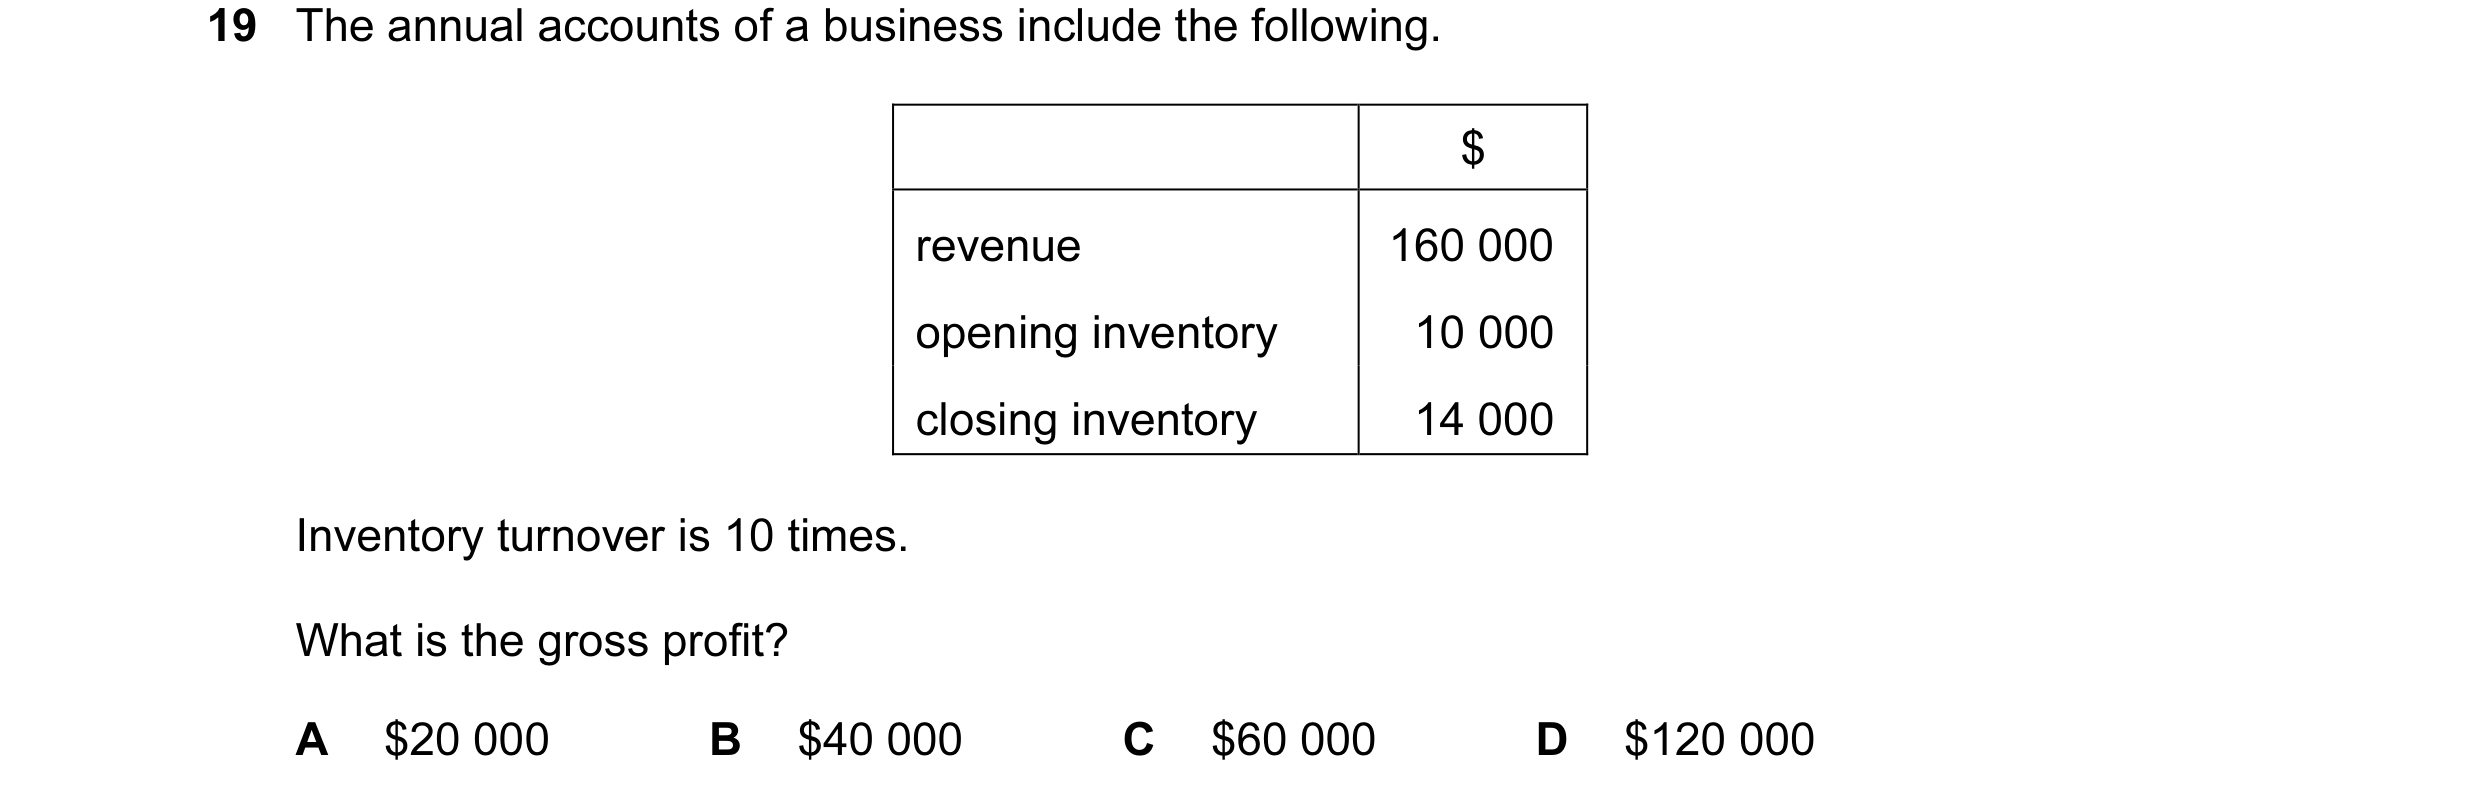
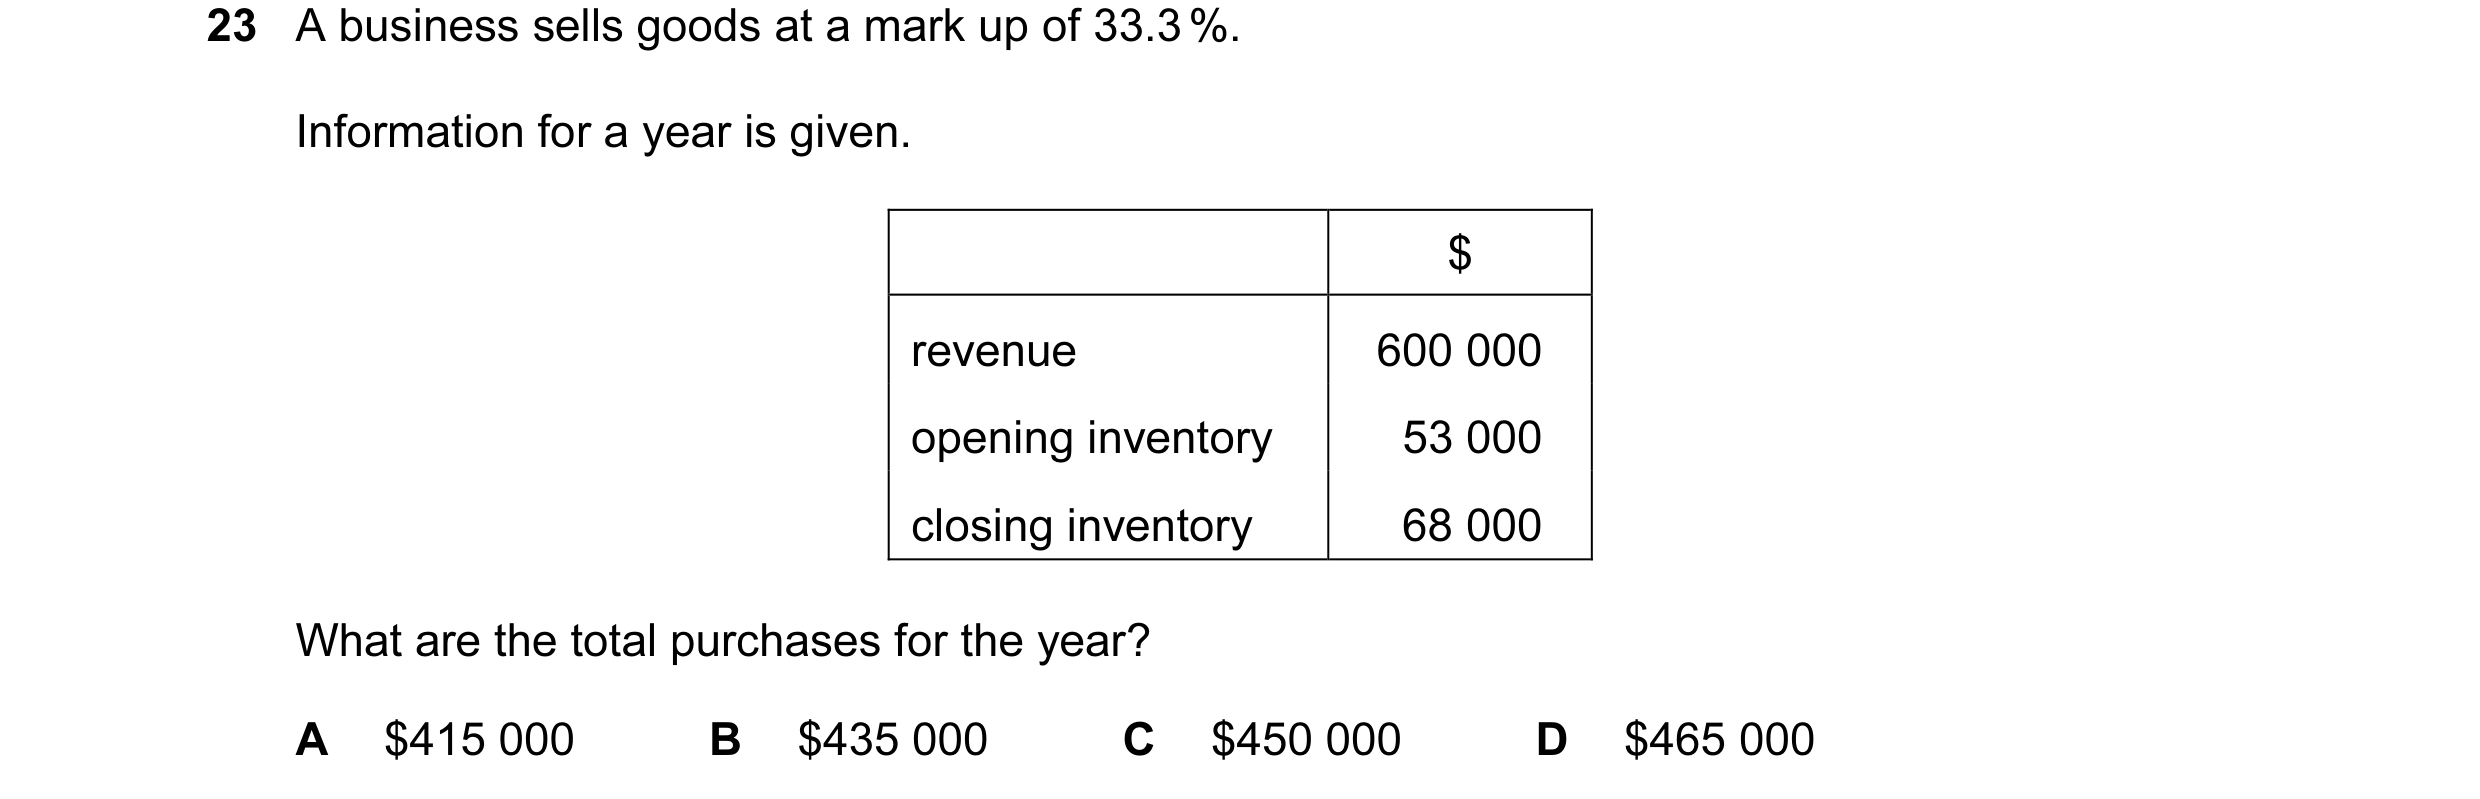
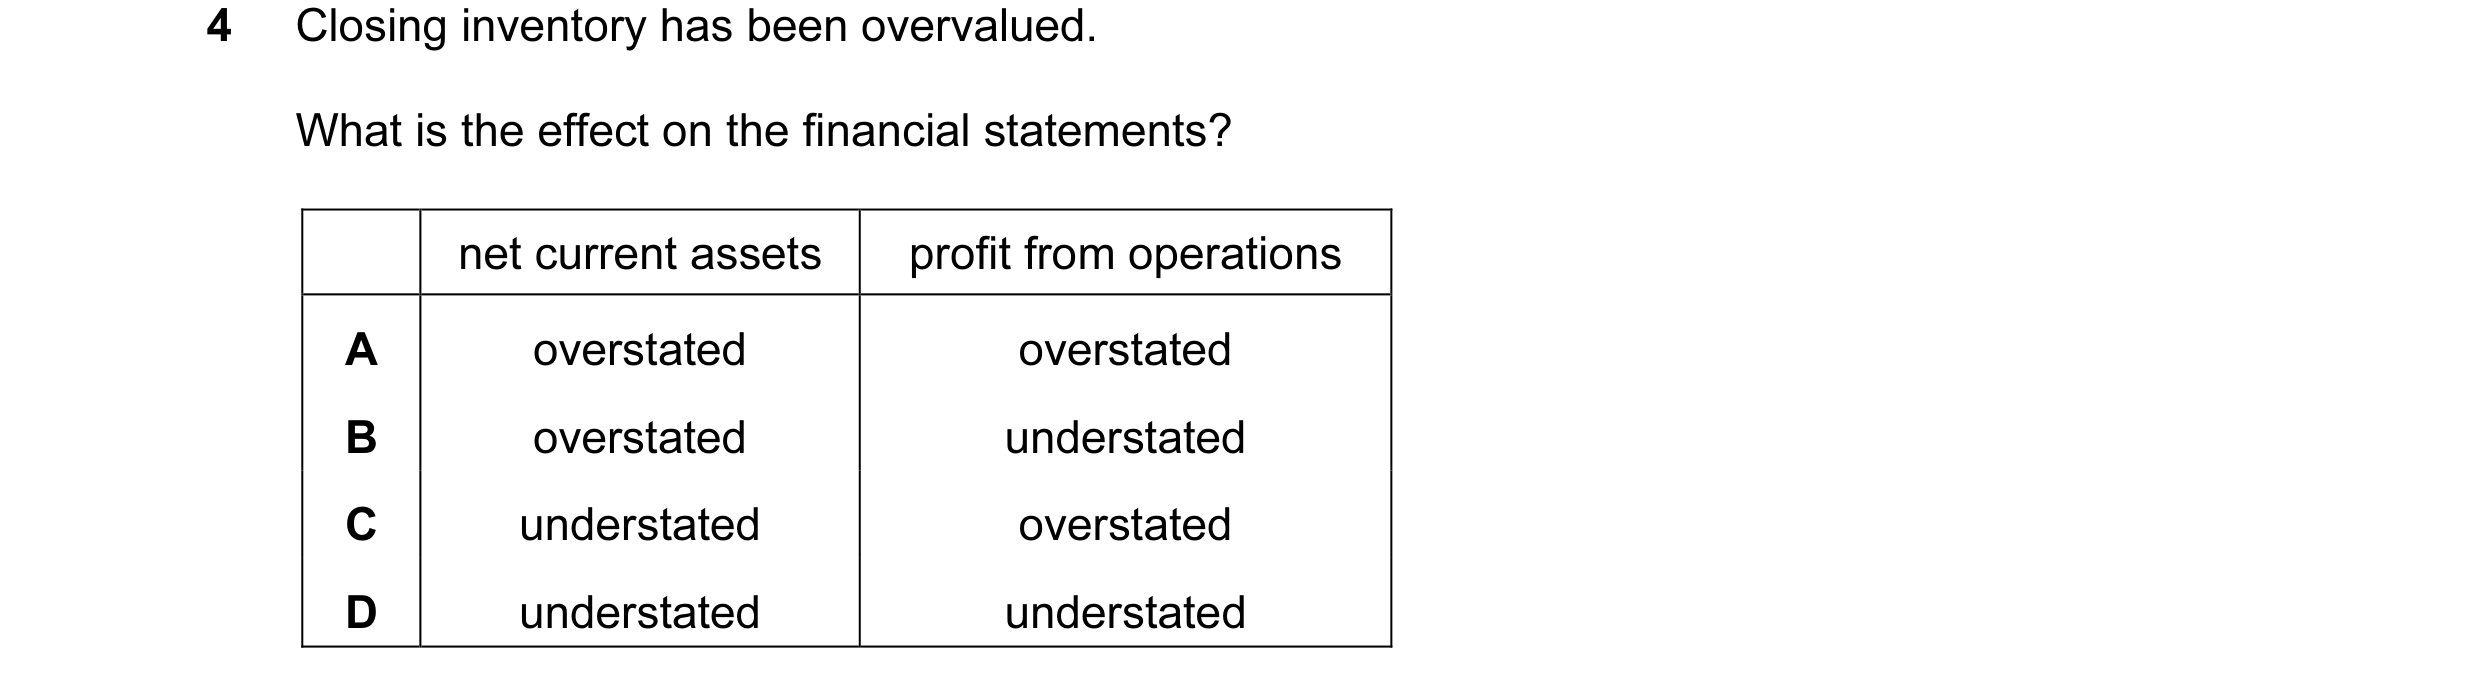 47 / 233
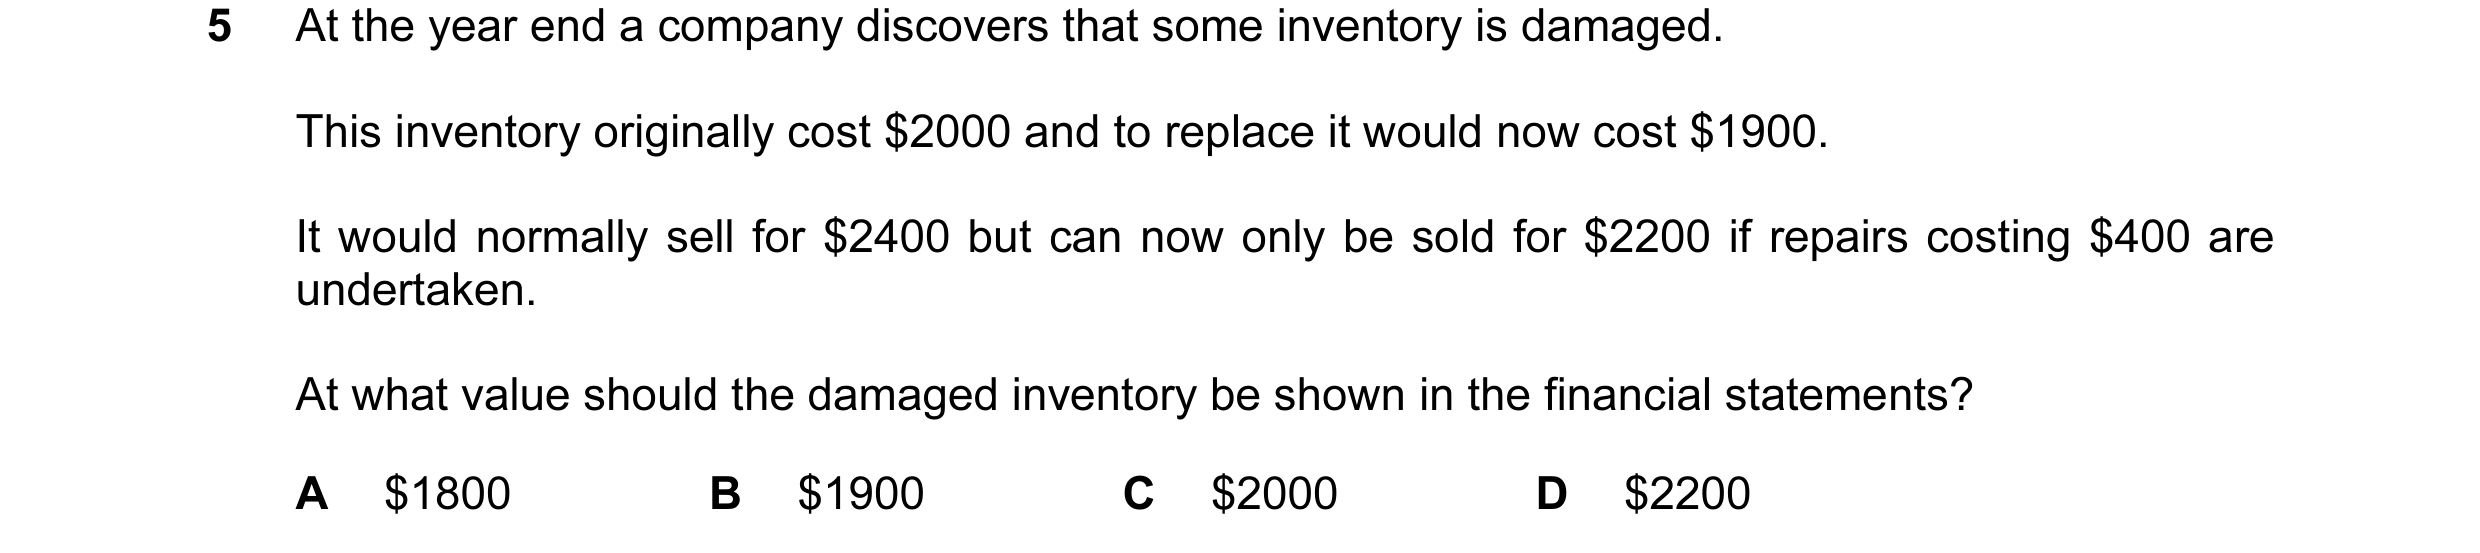
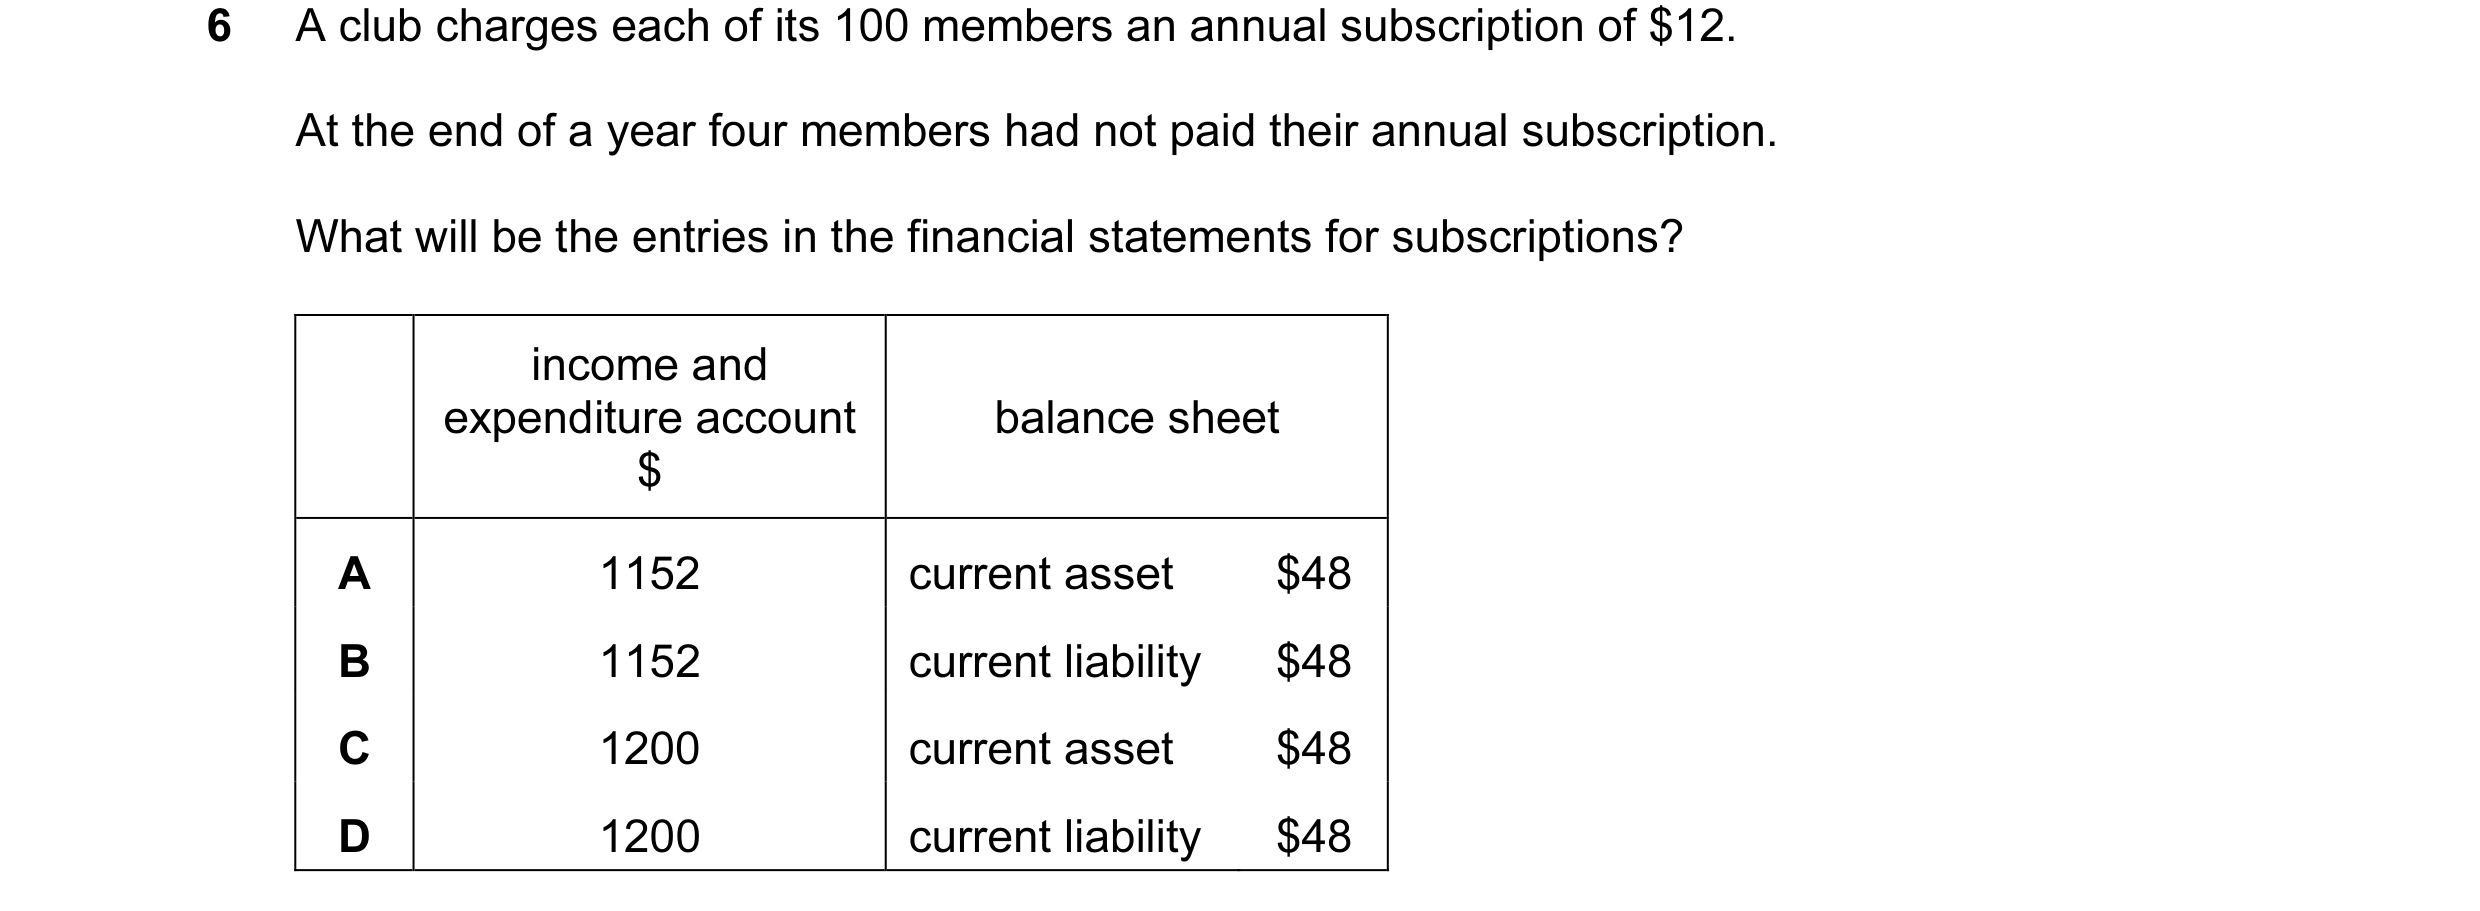
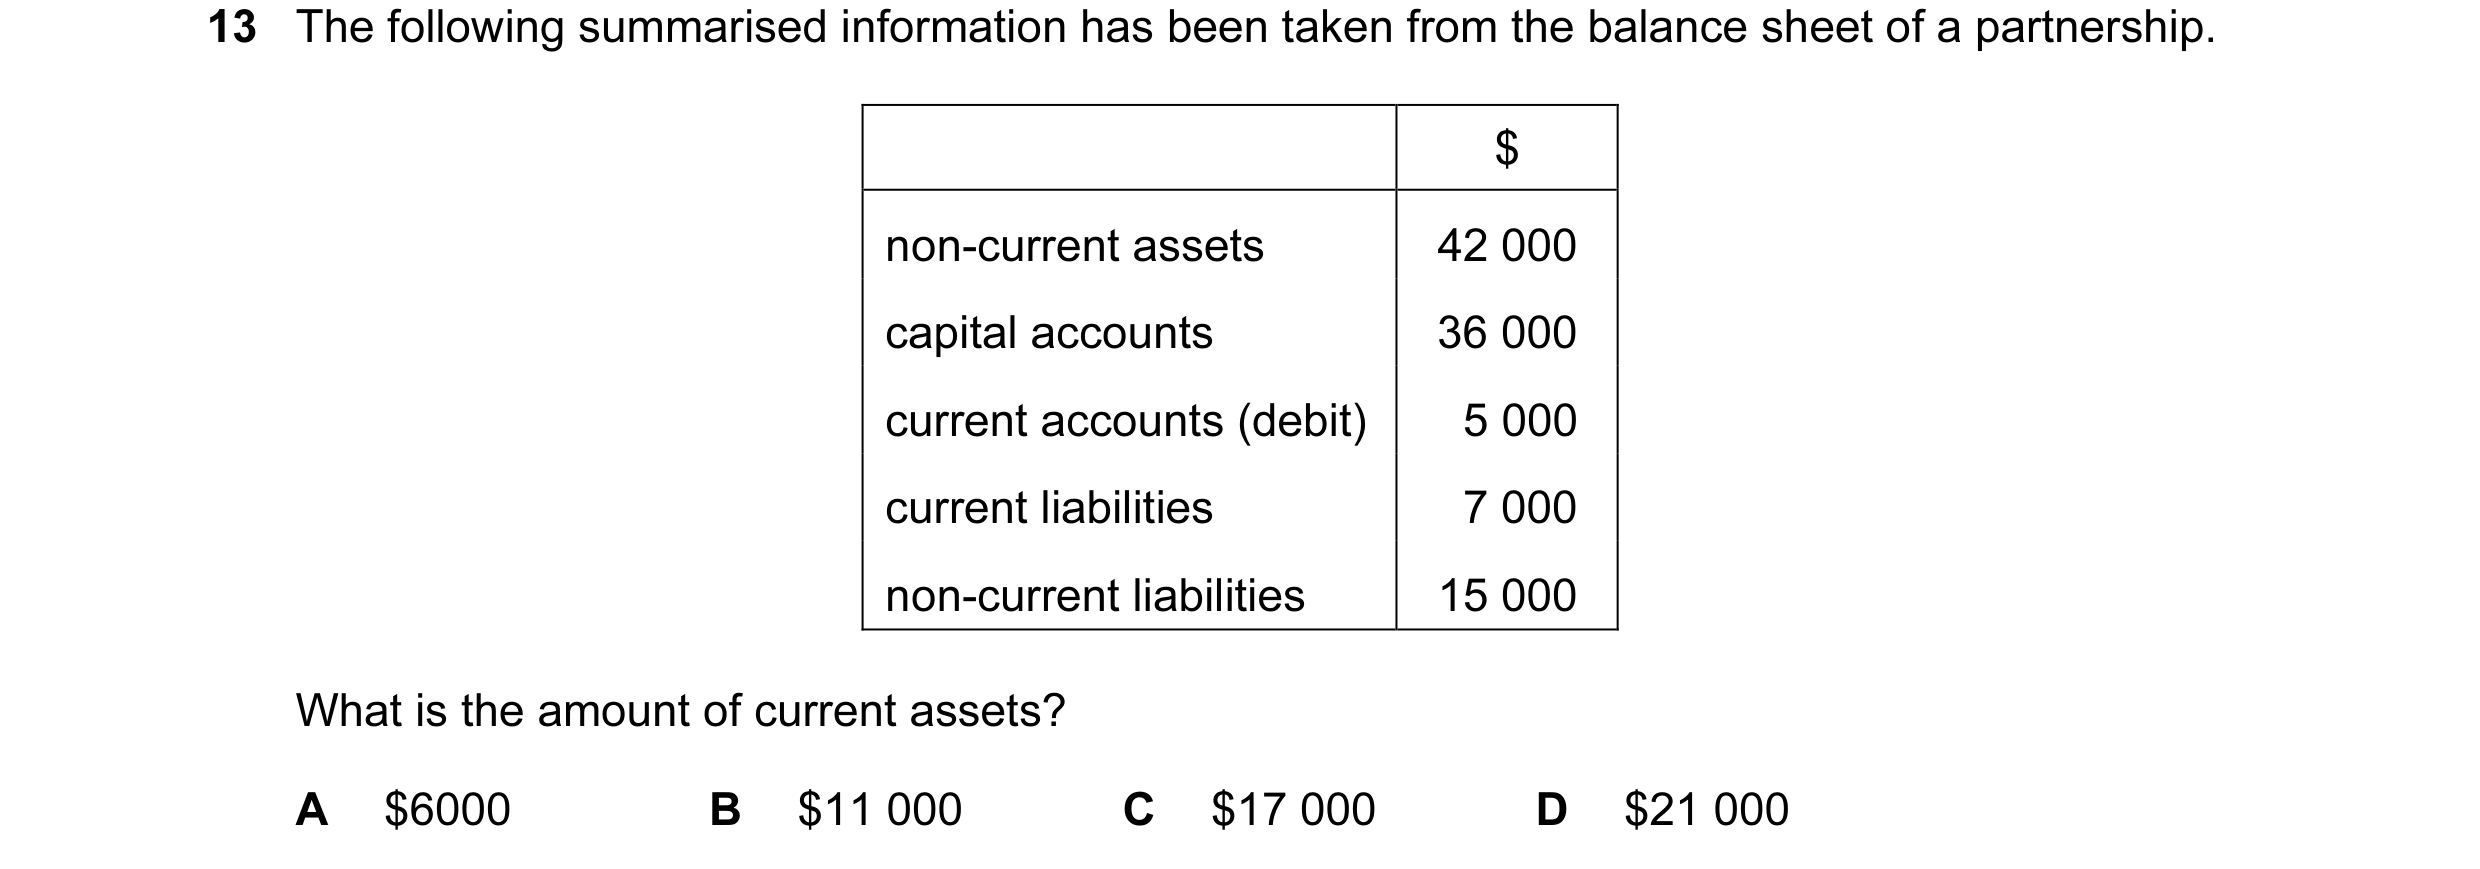
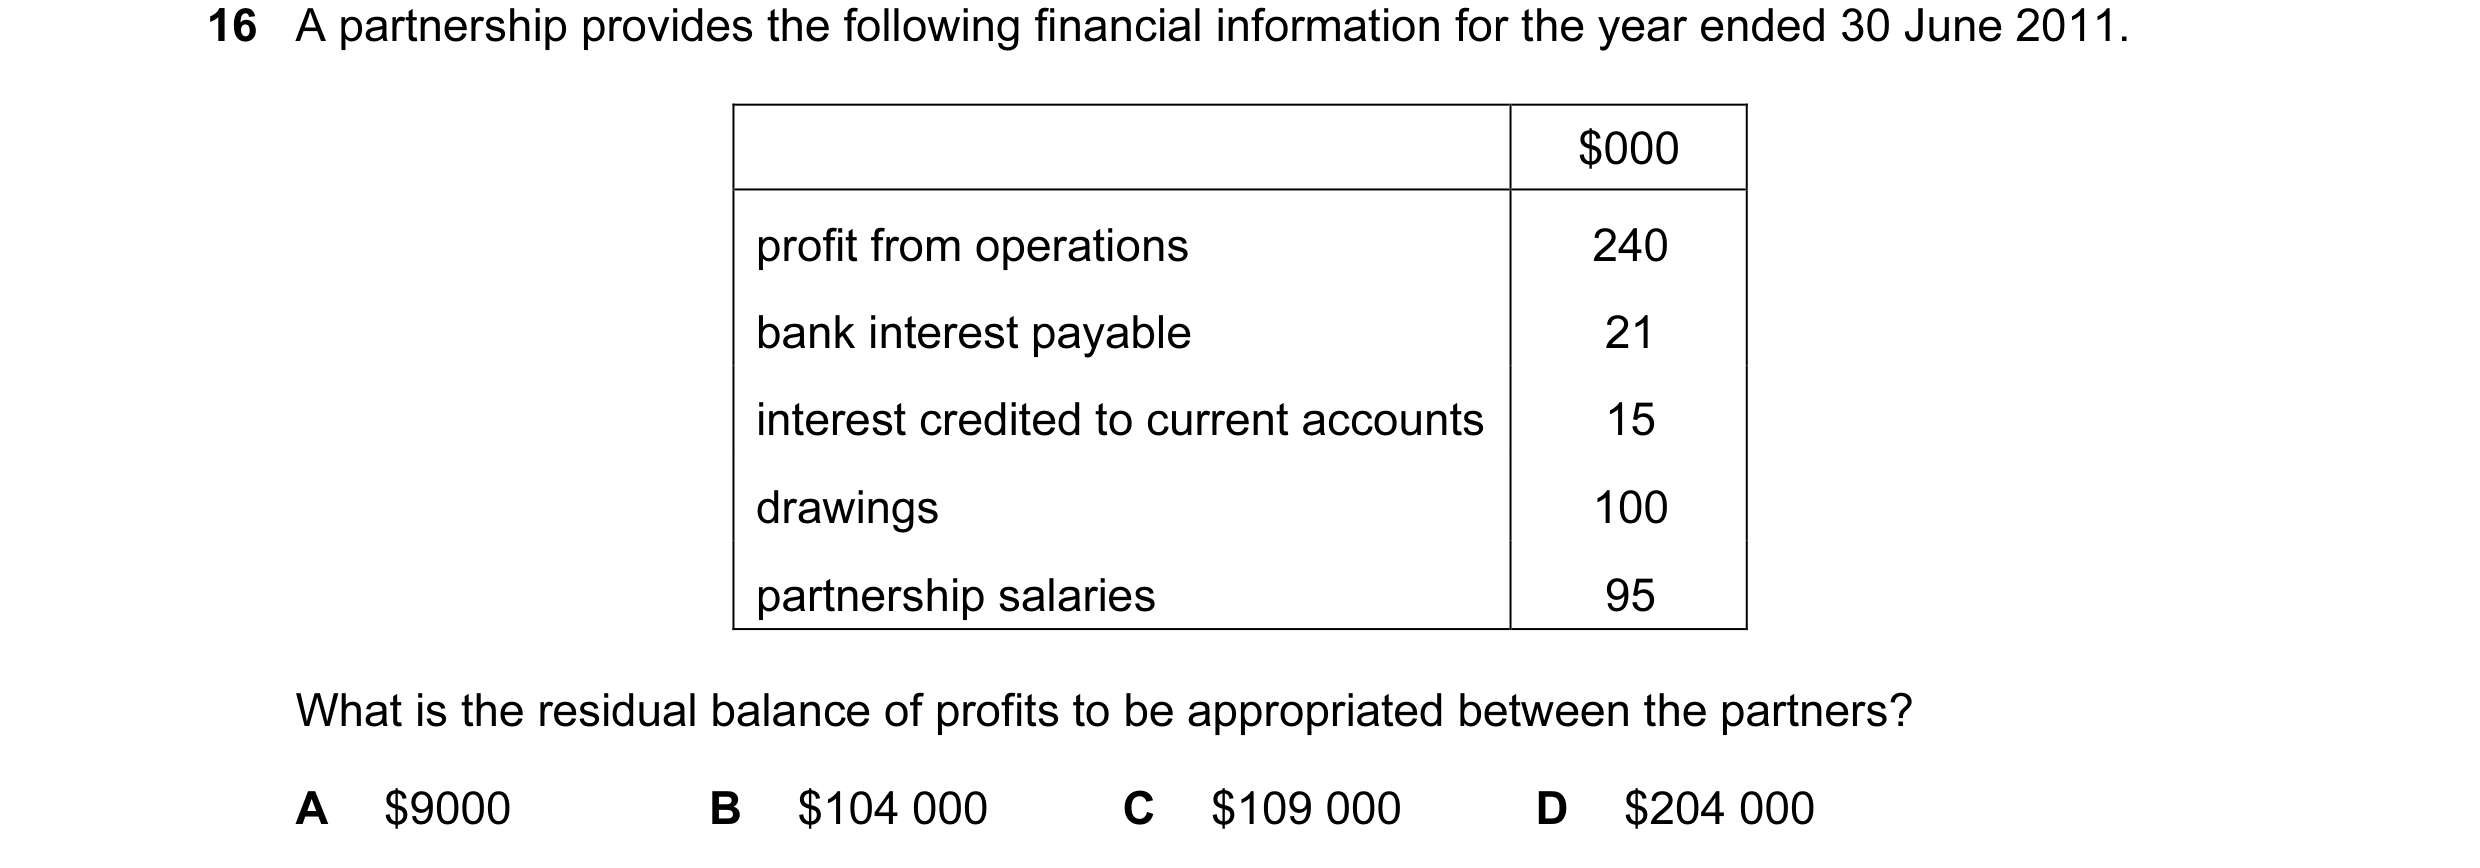 48 / 233
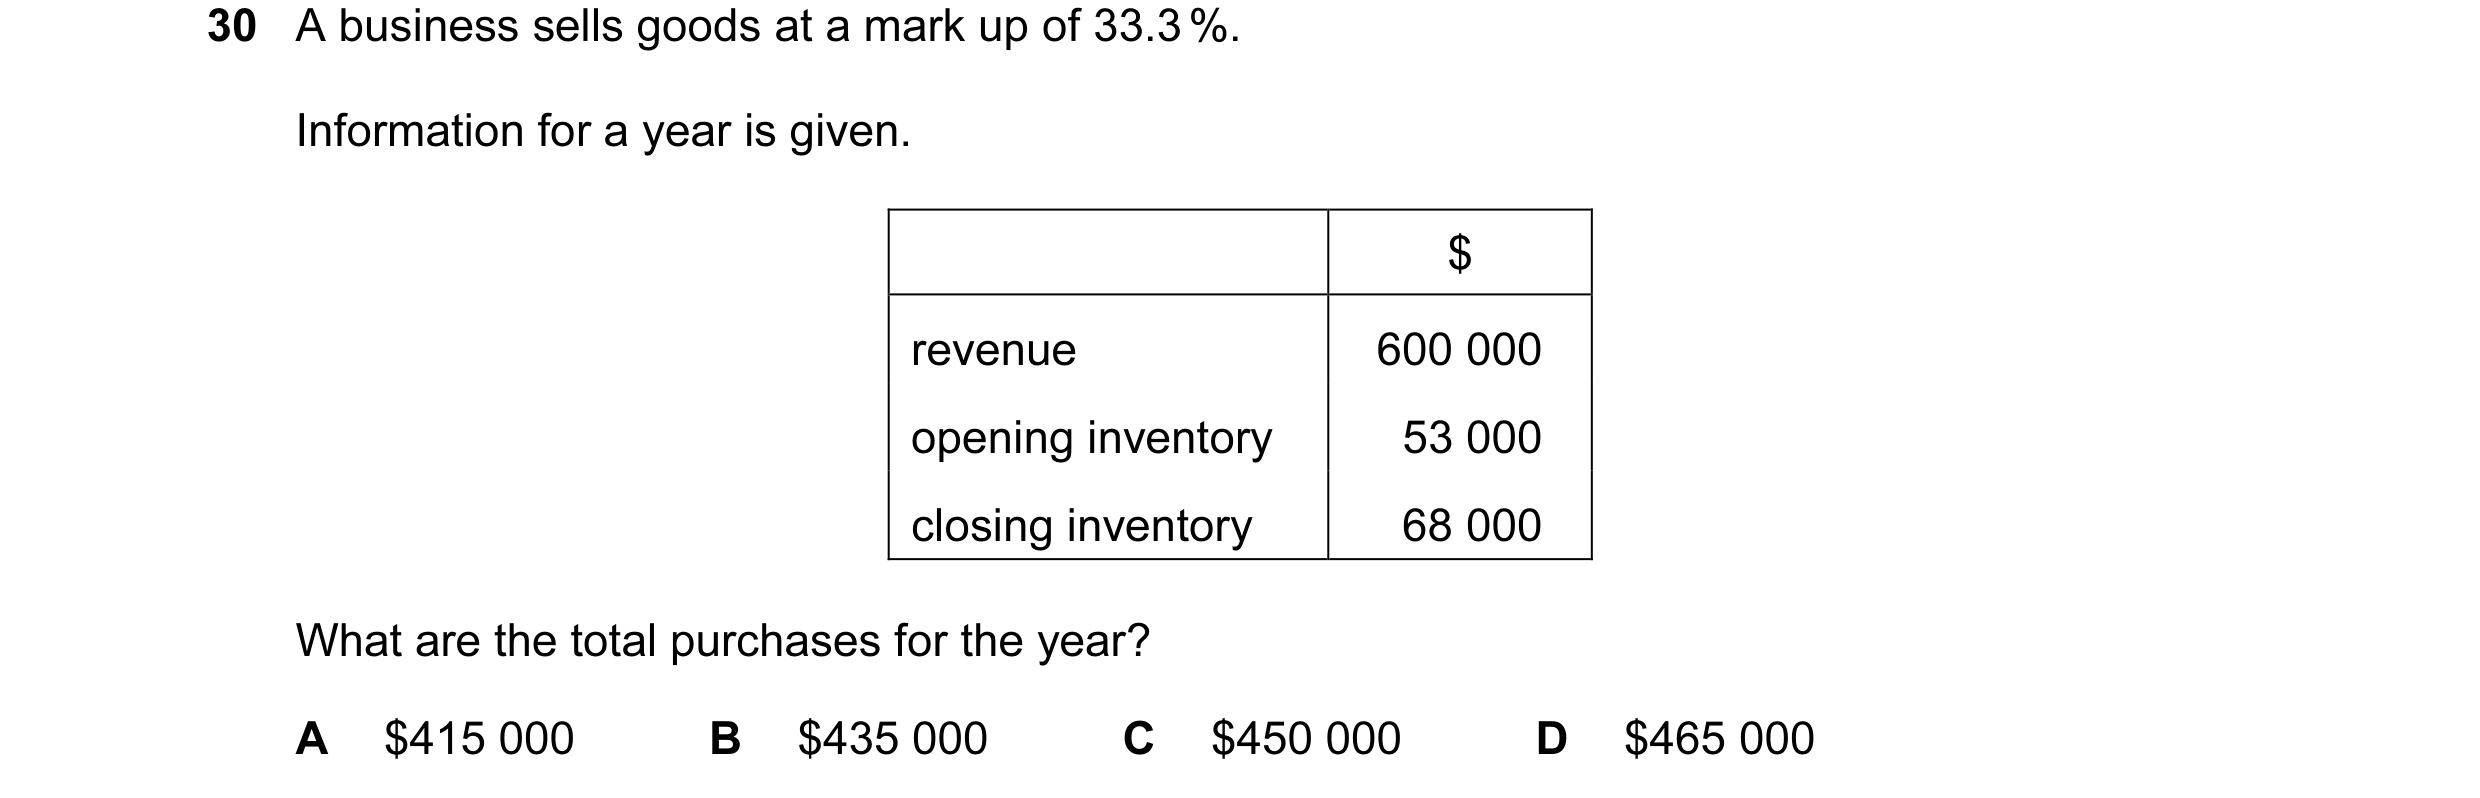
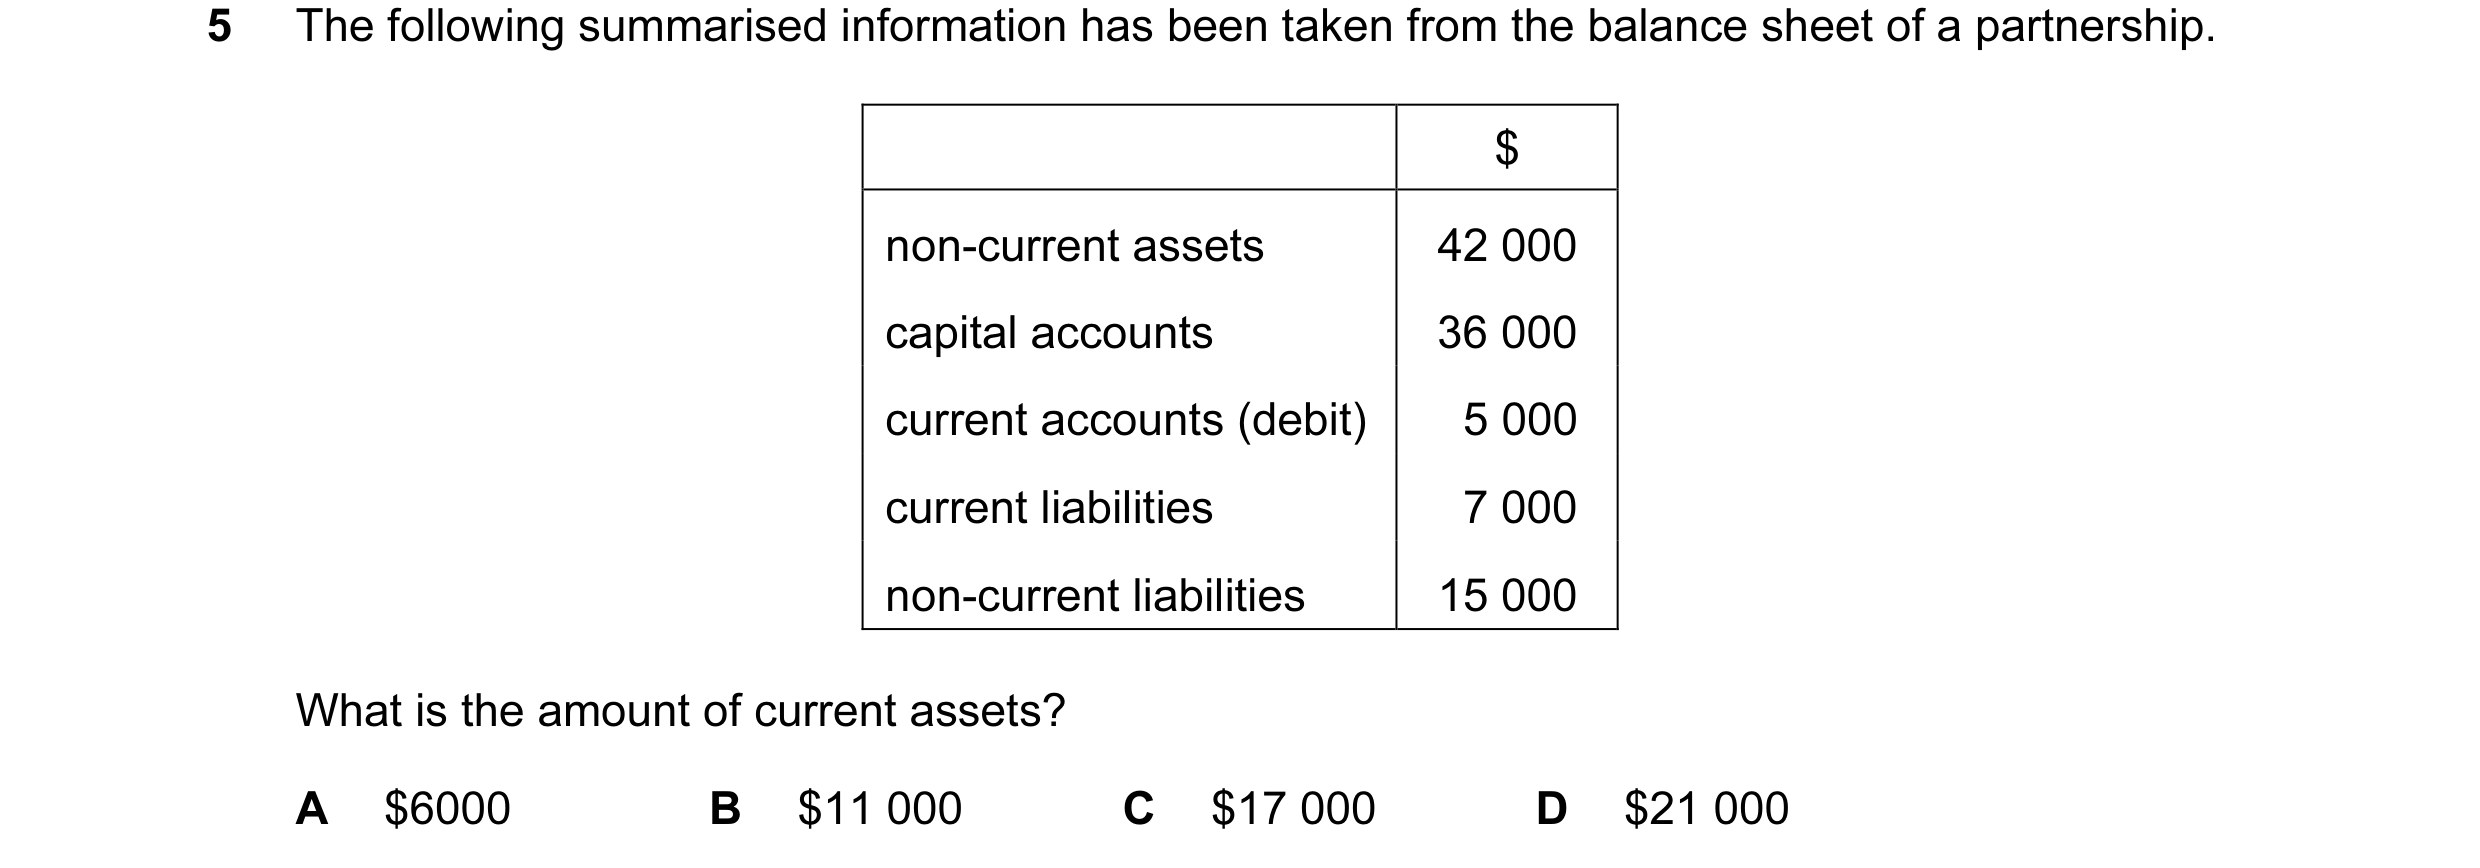
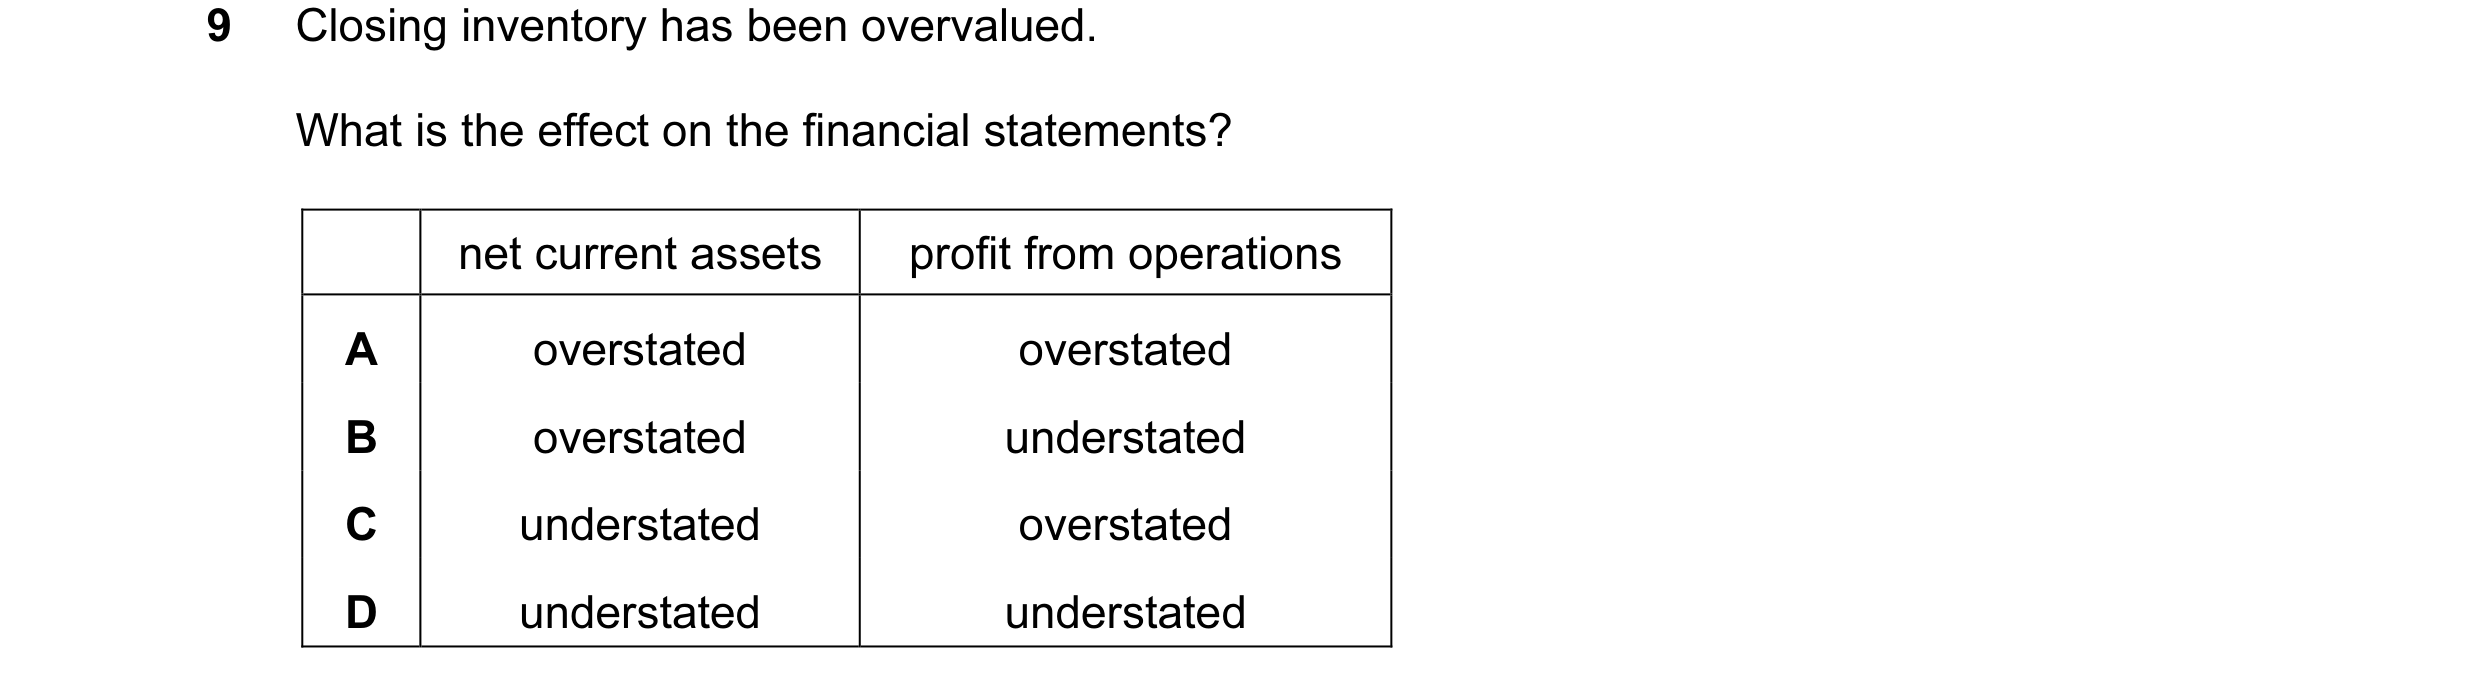 49 / 233
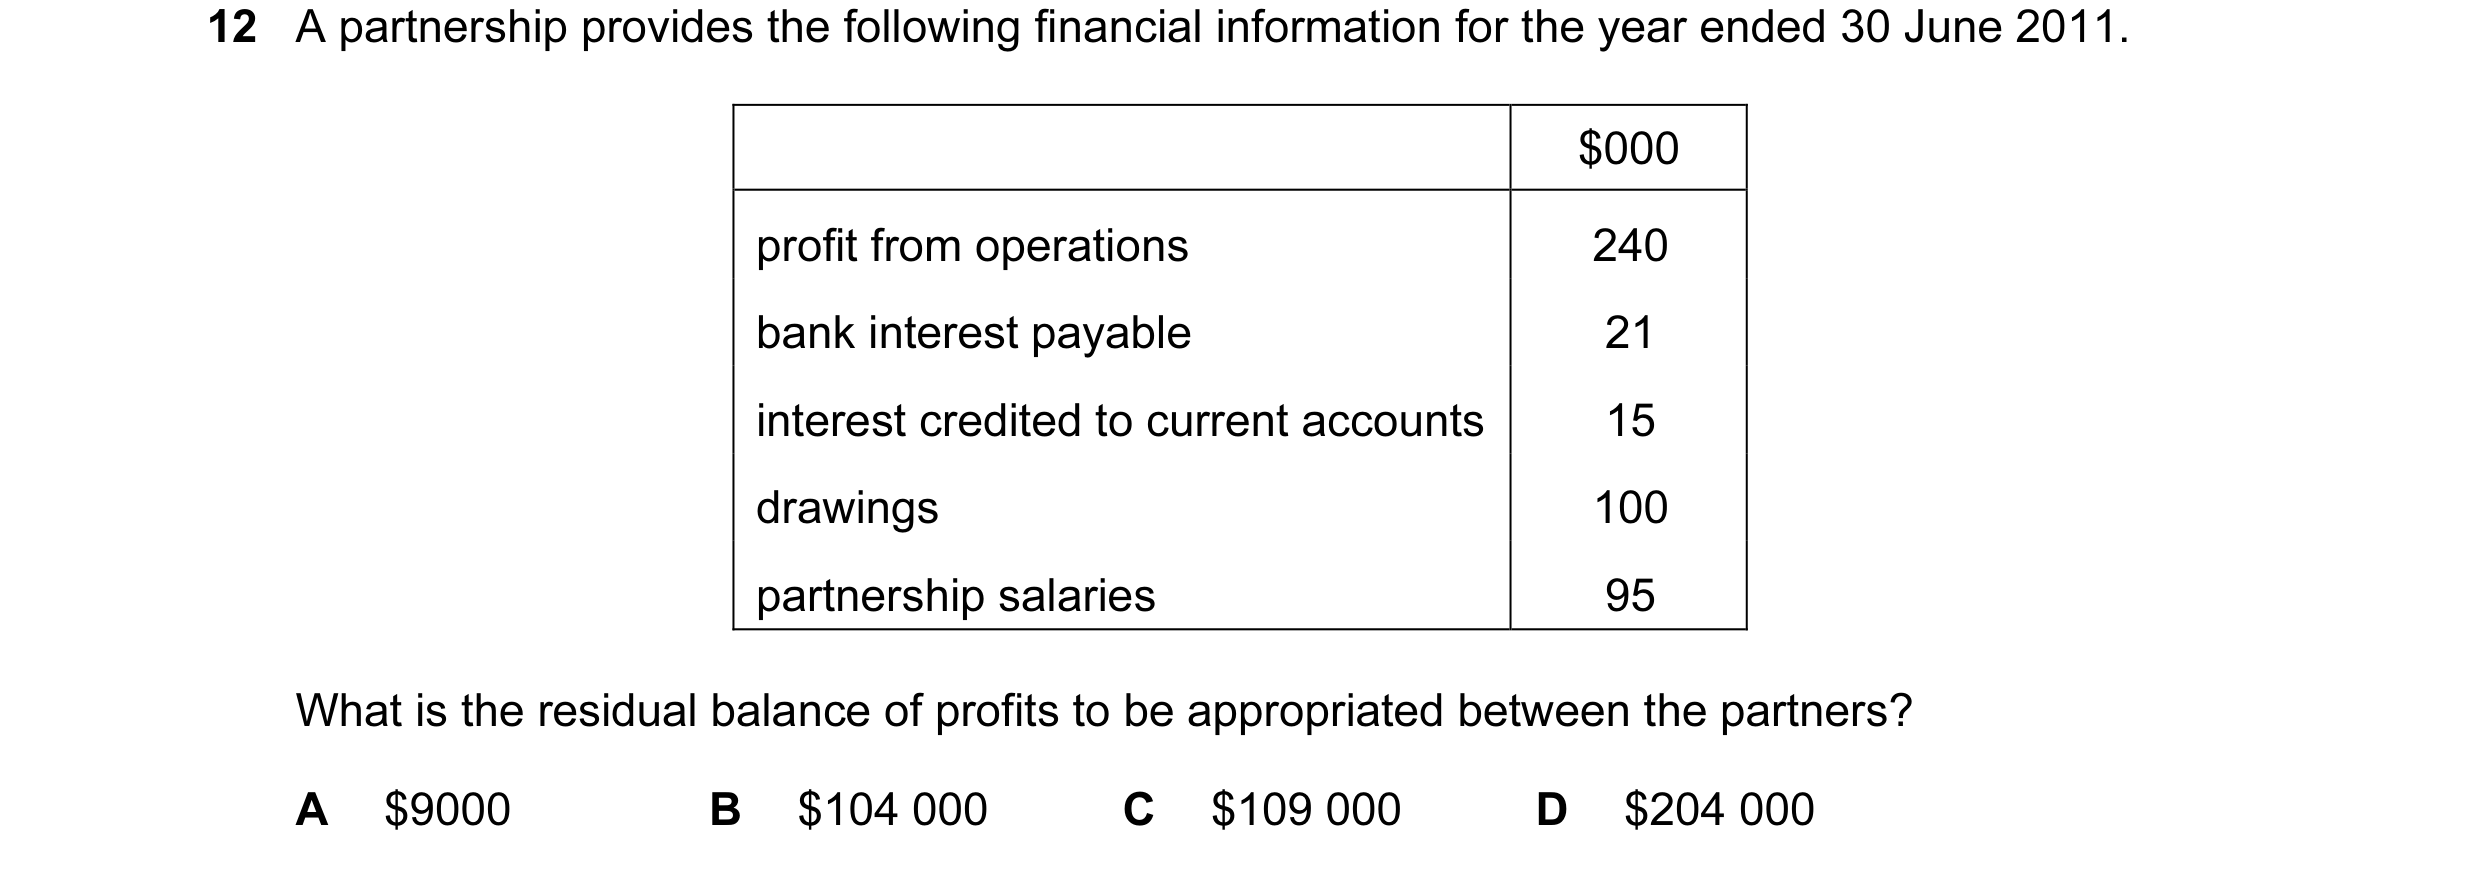
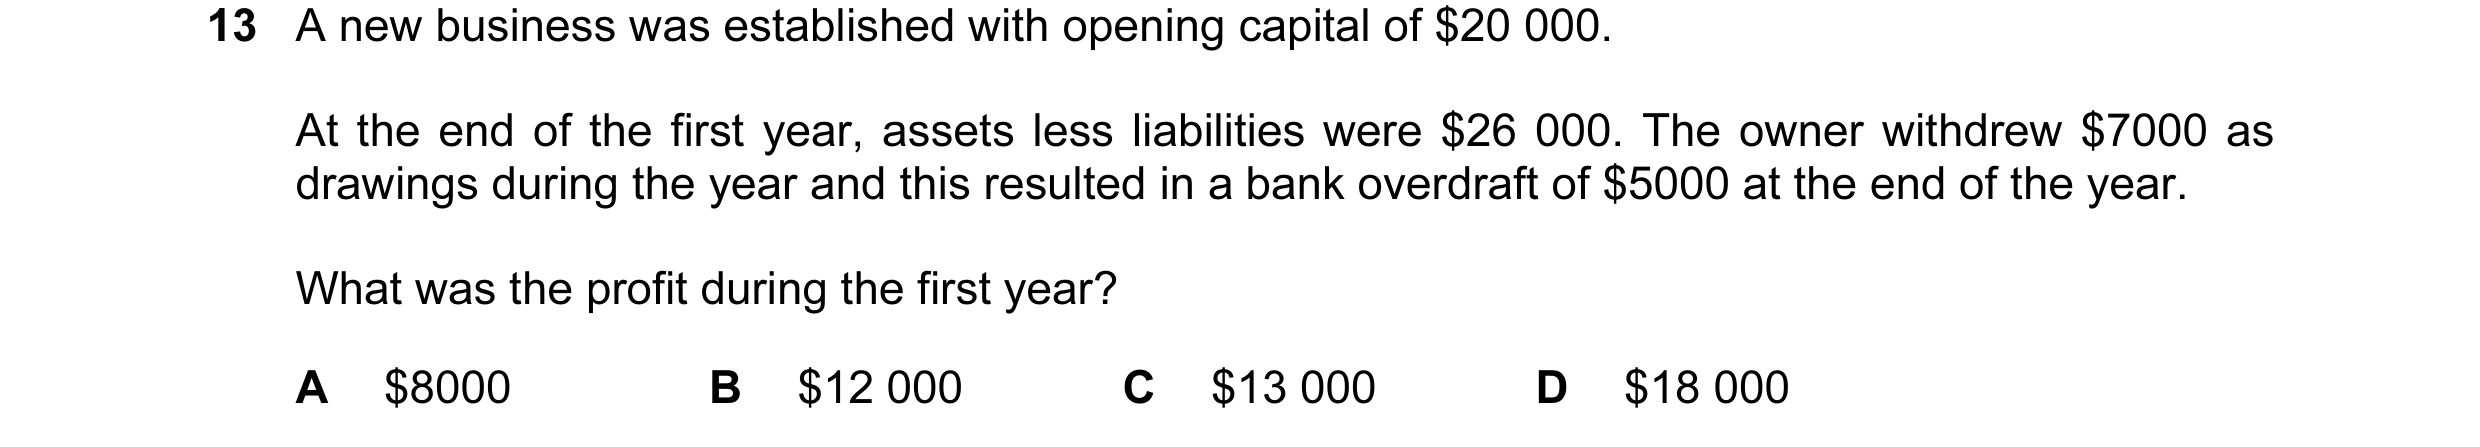
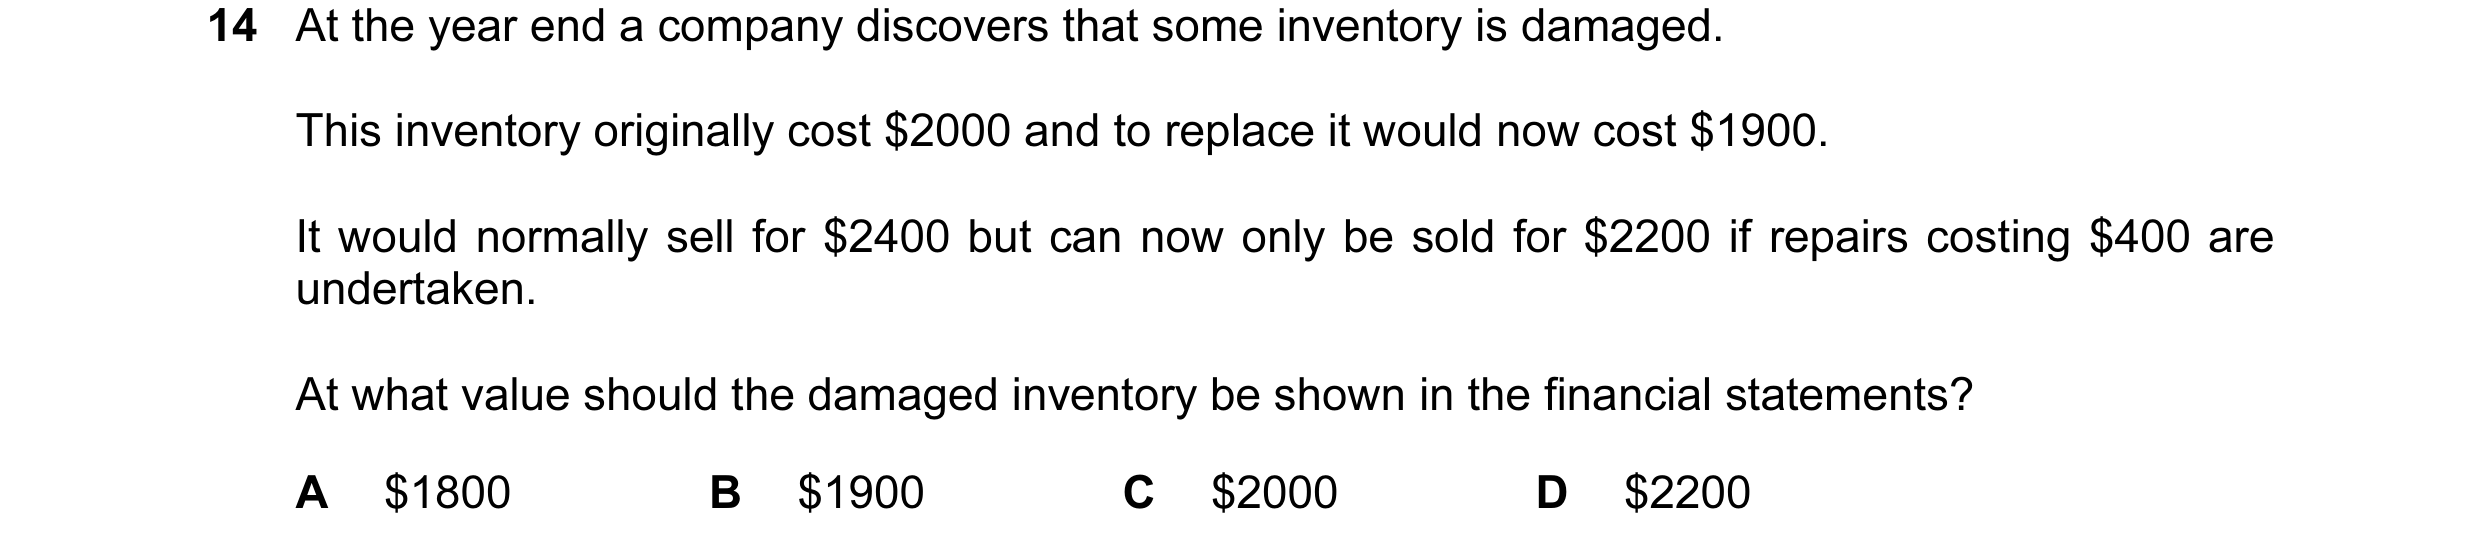
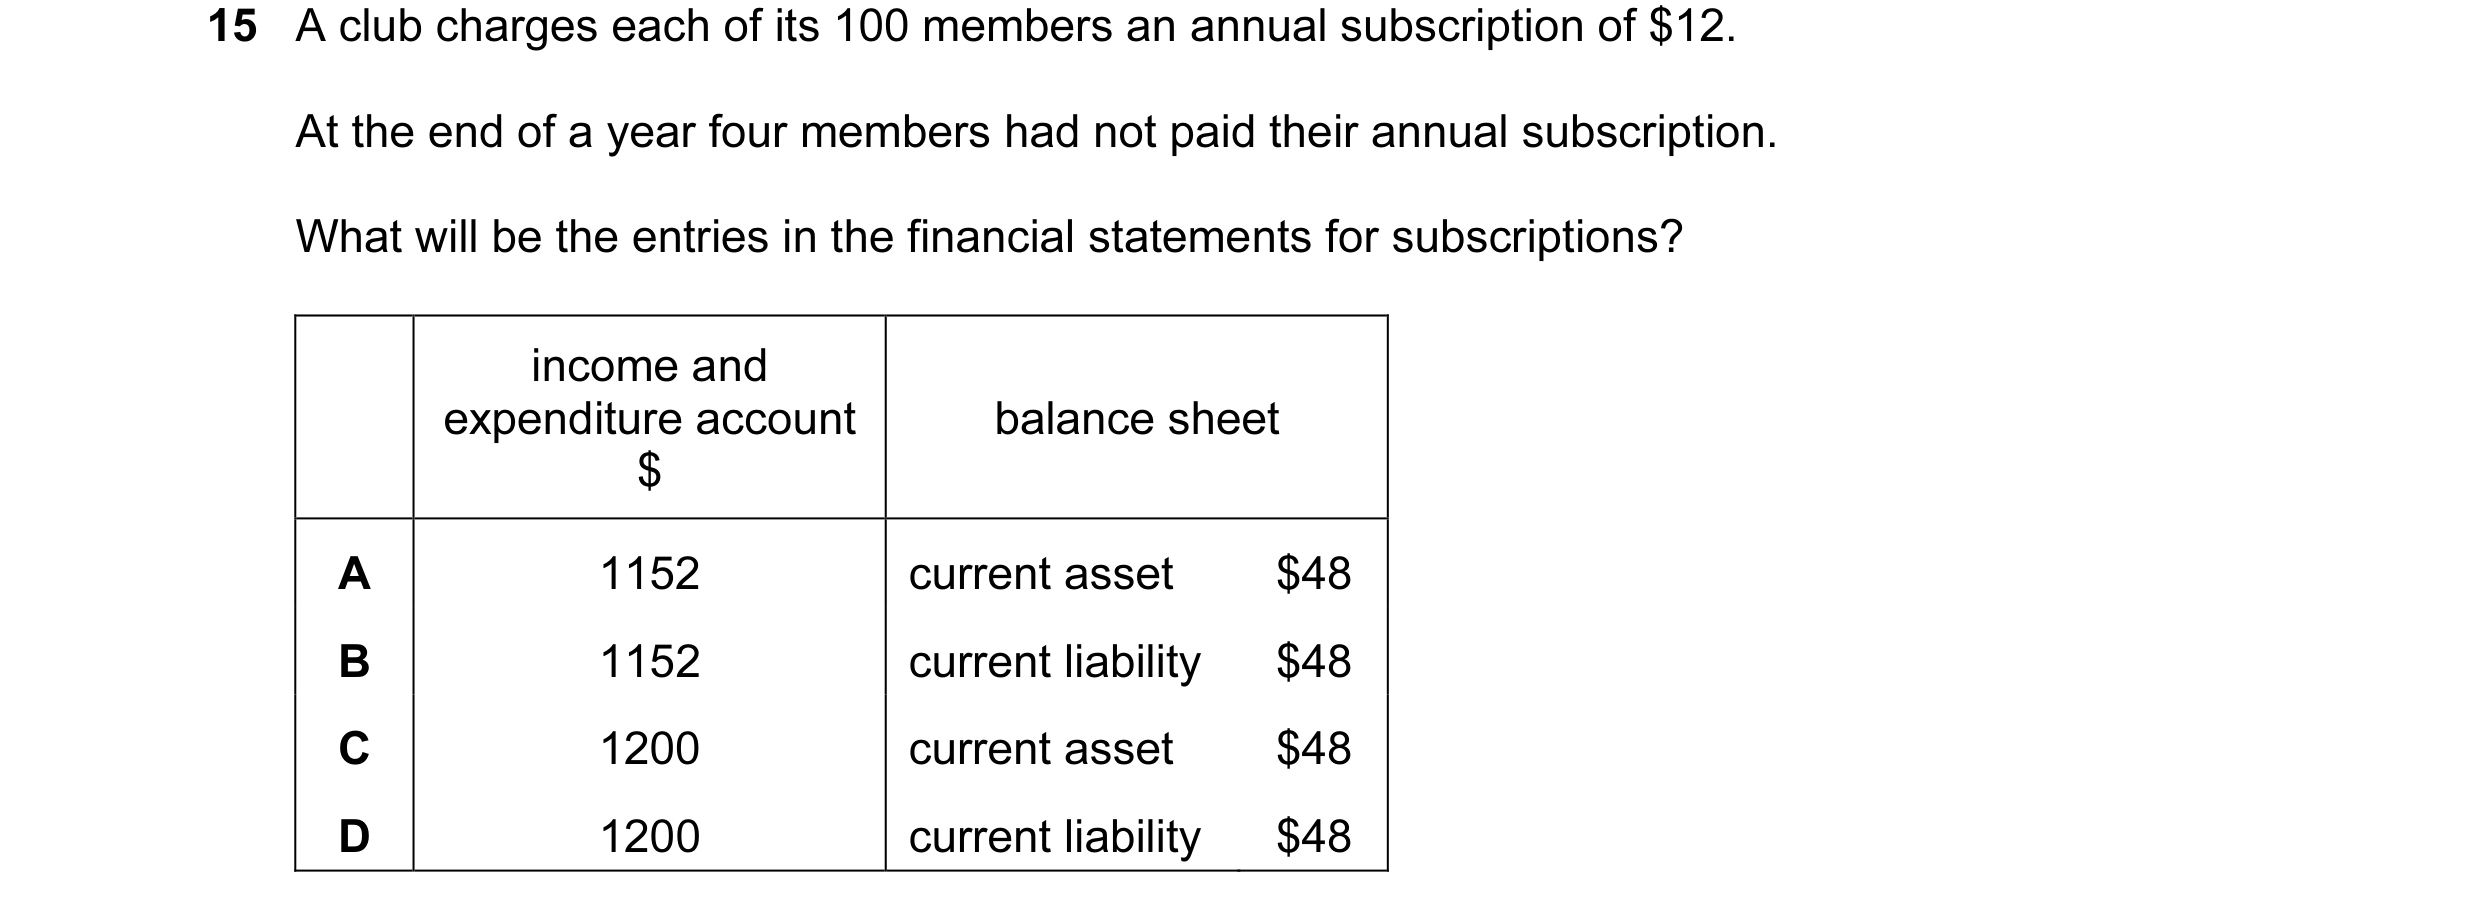
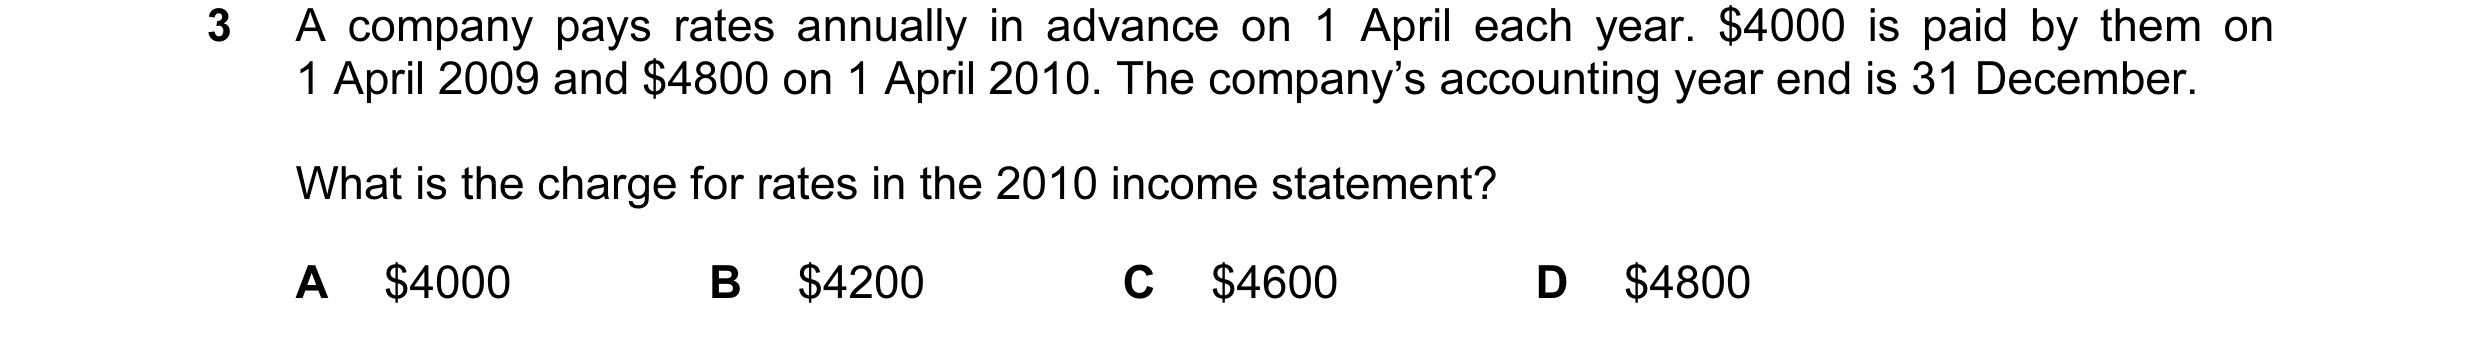 50 / 233
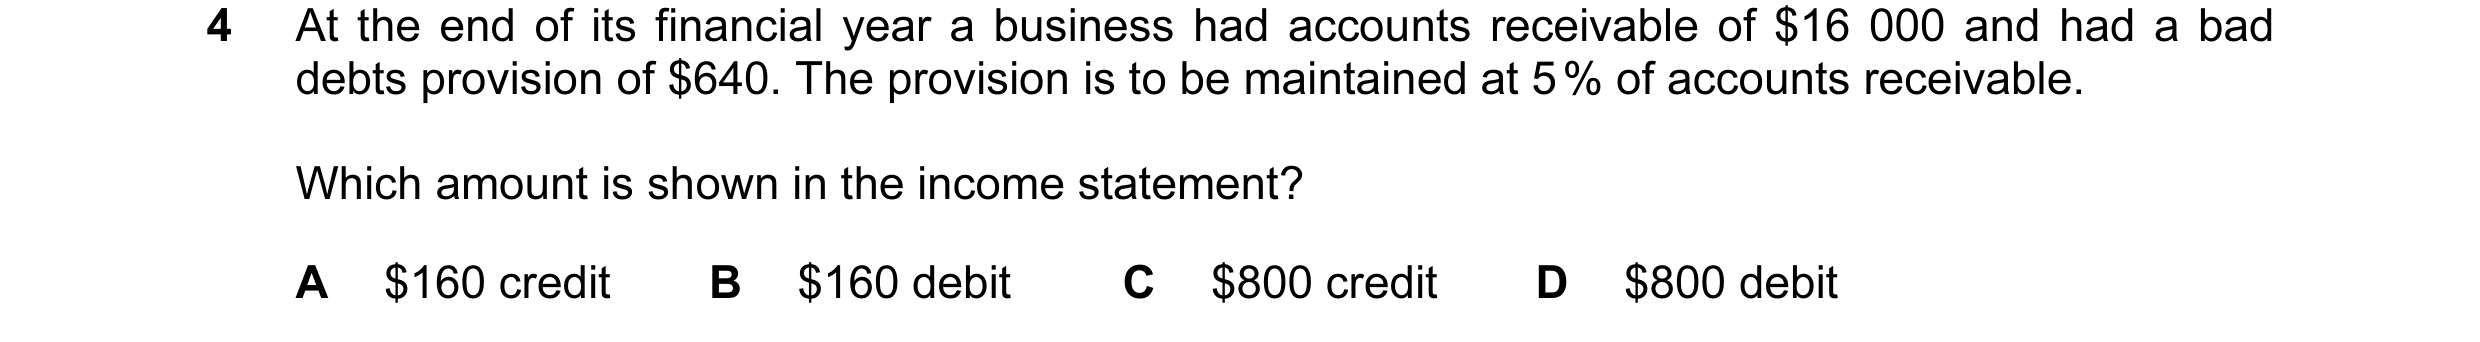
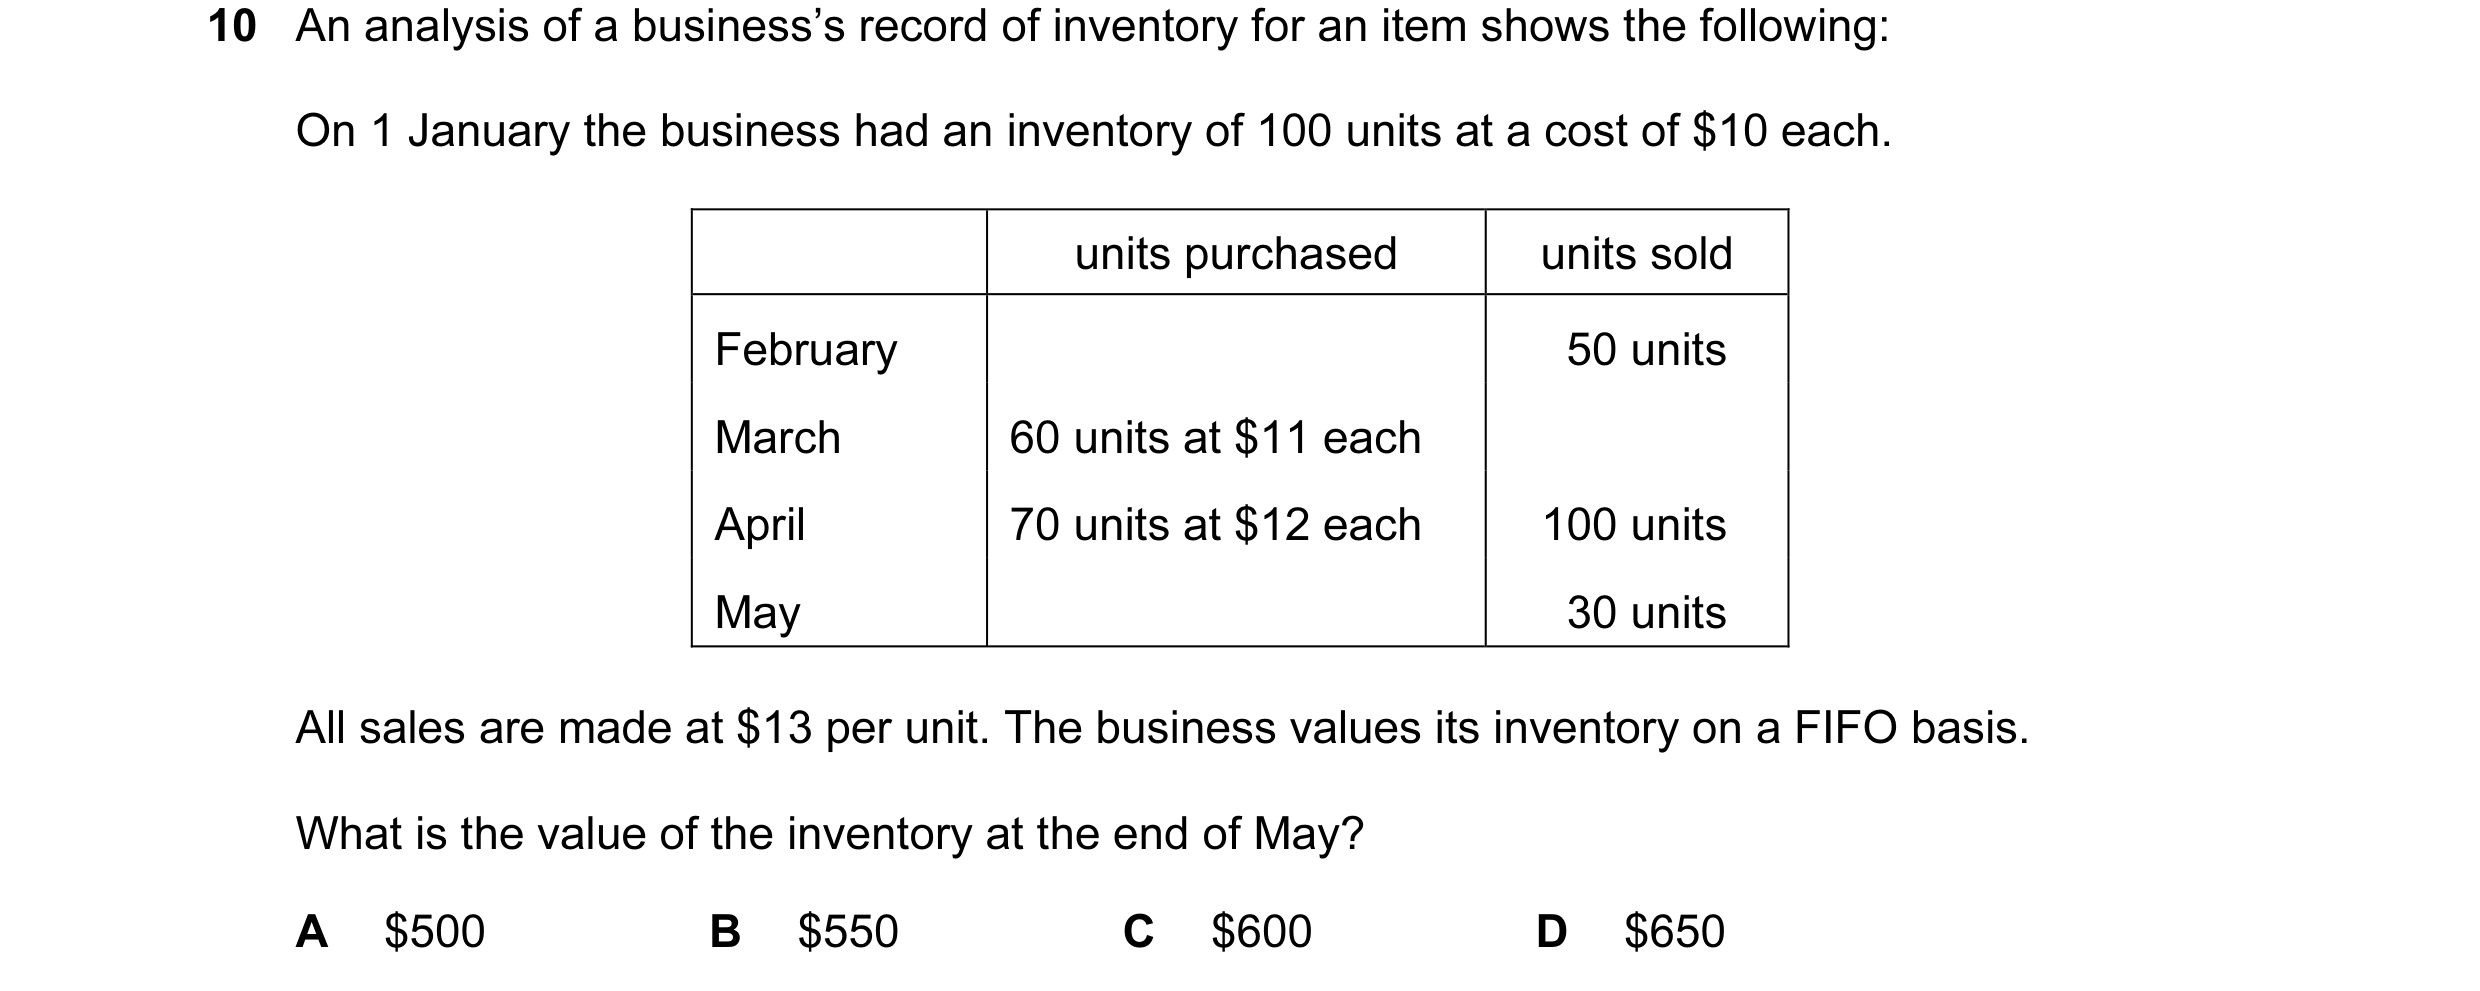
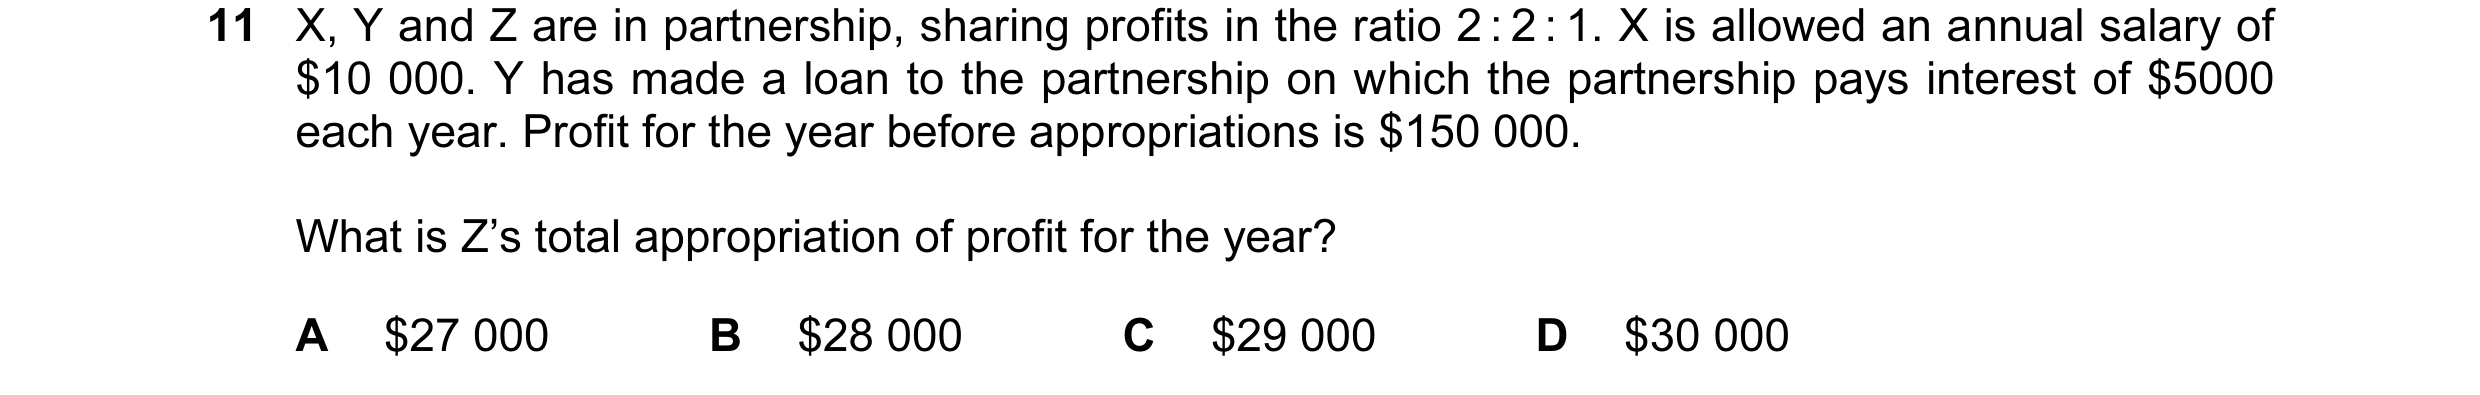
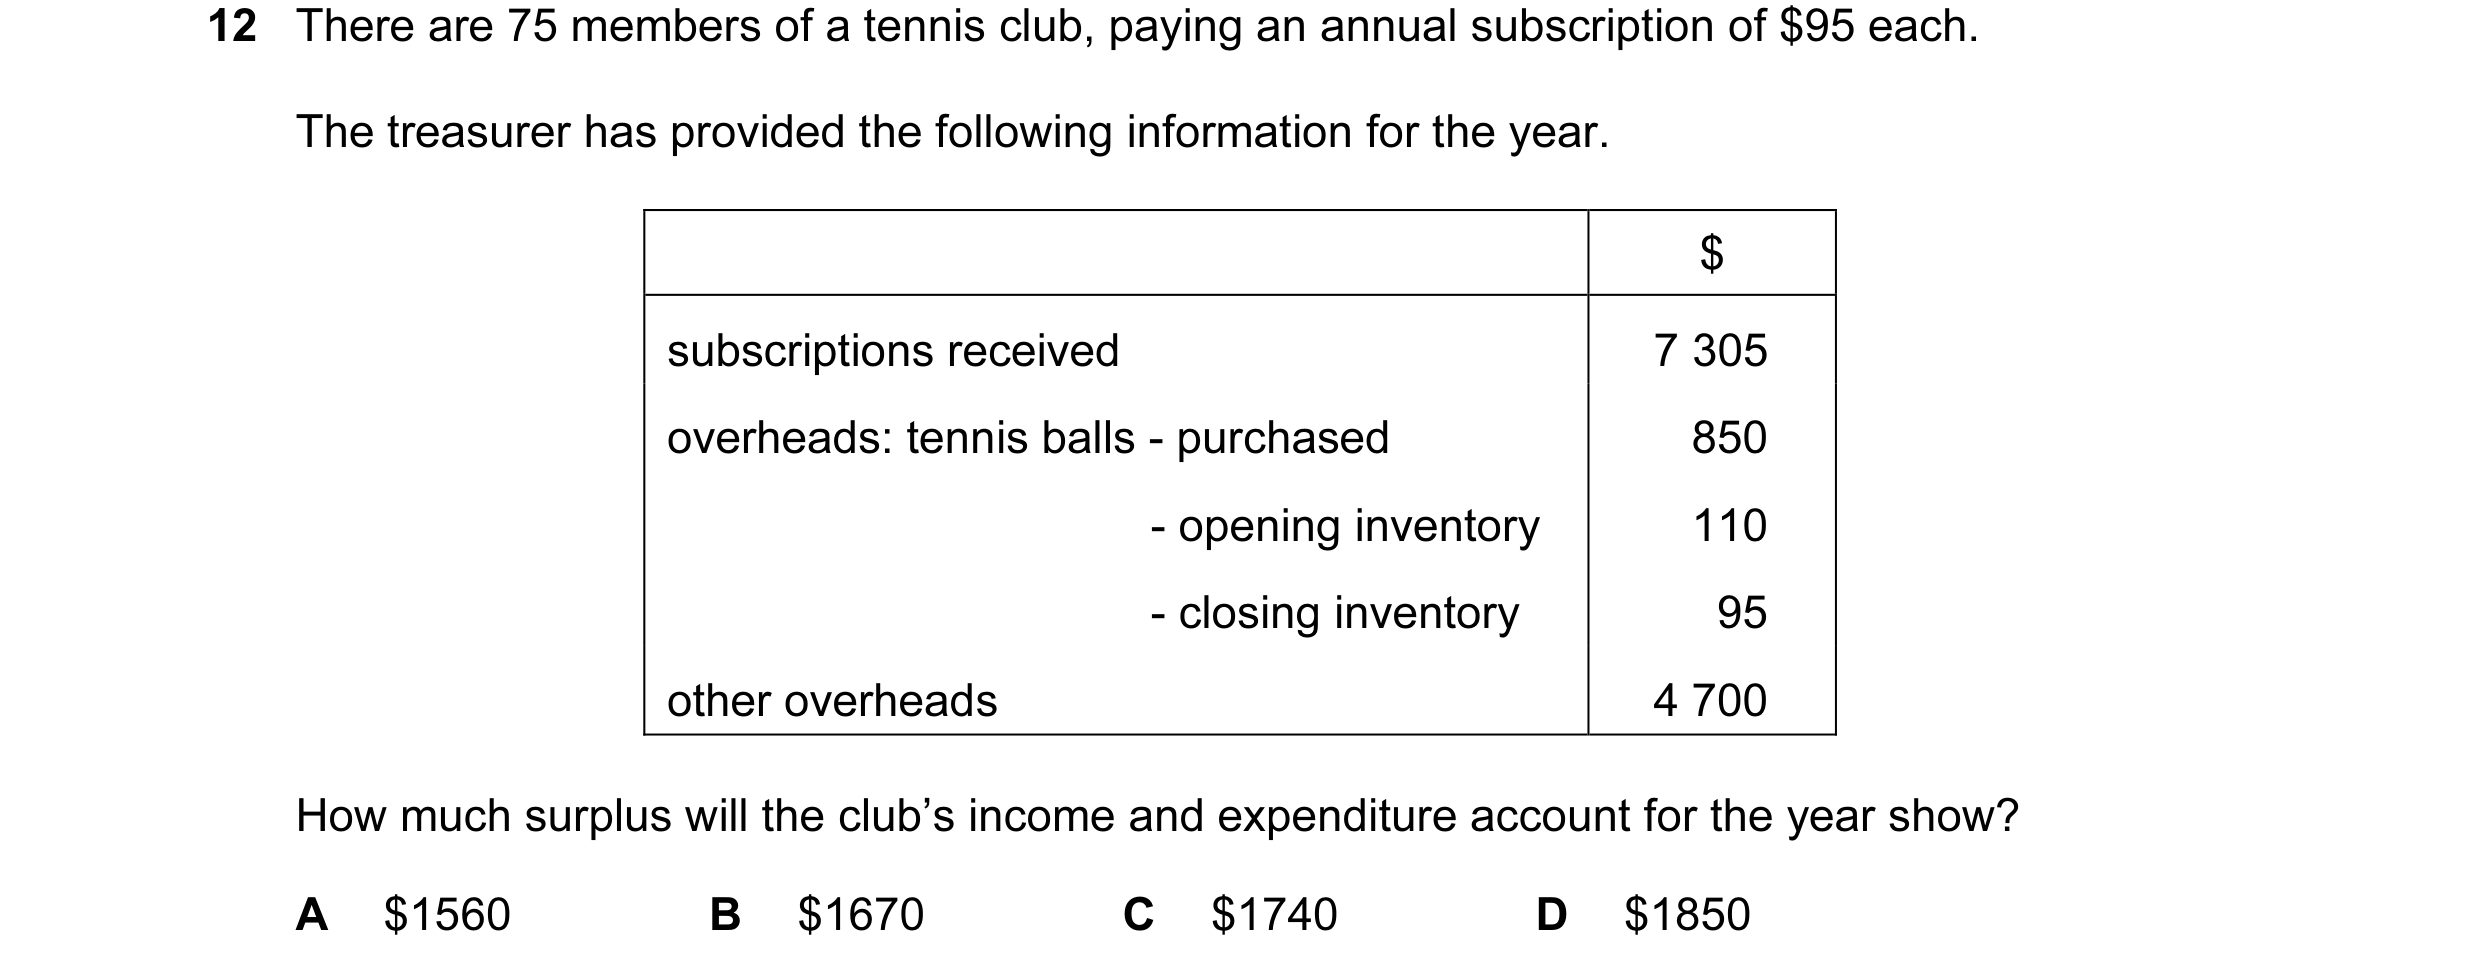 51 / 233
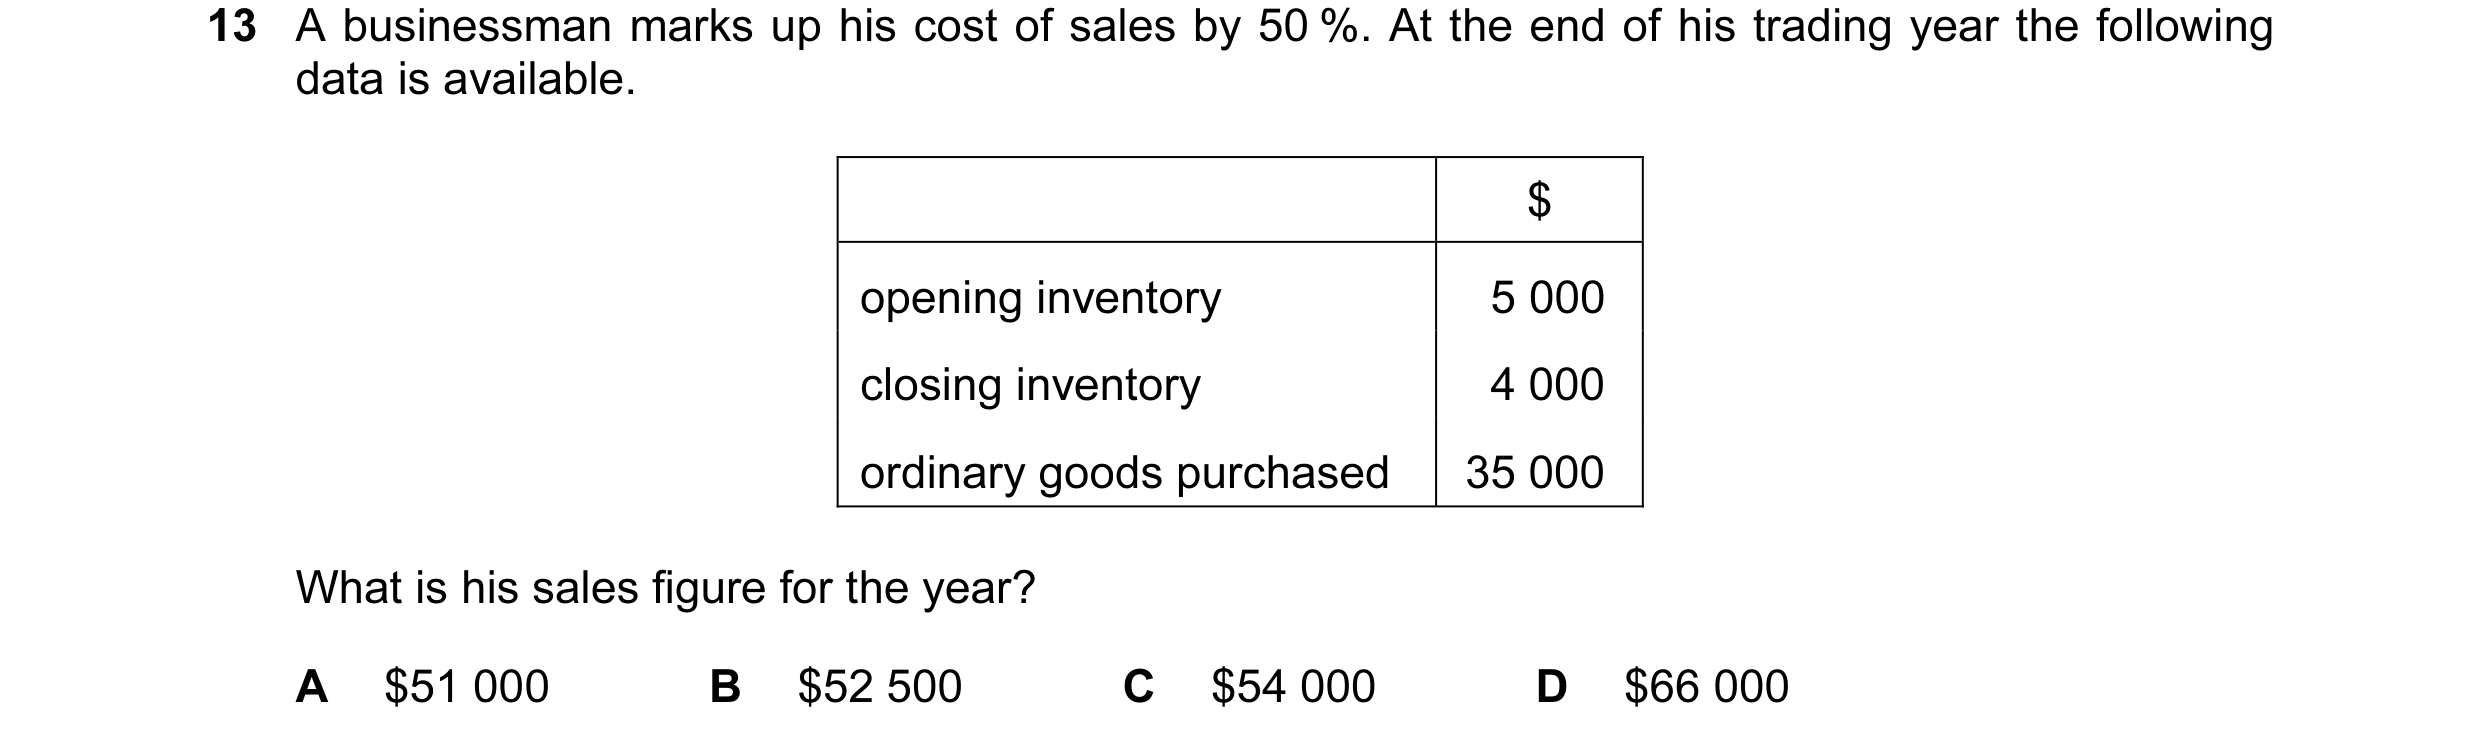
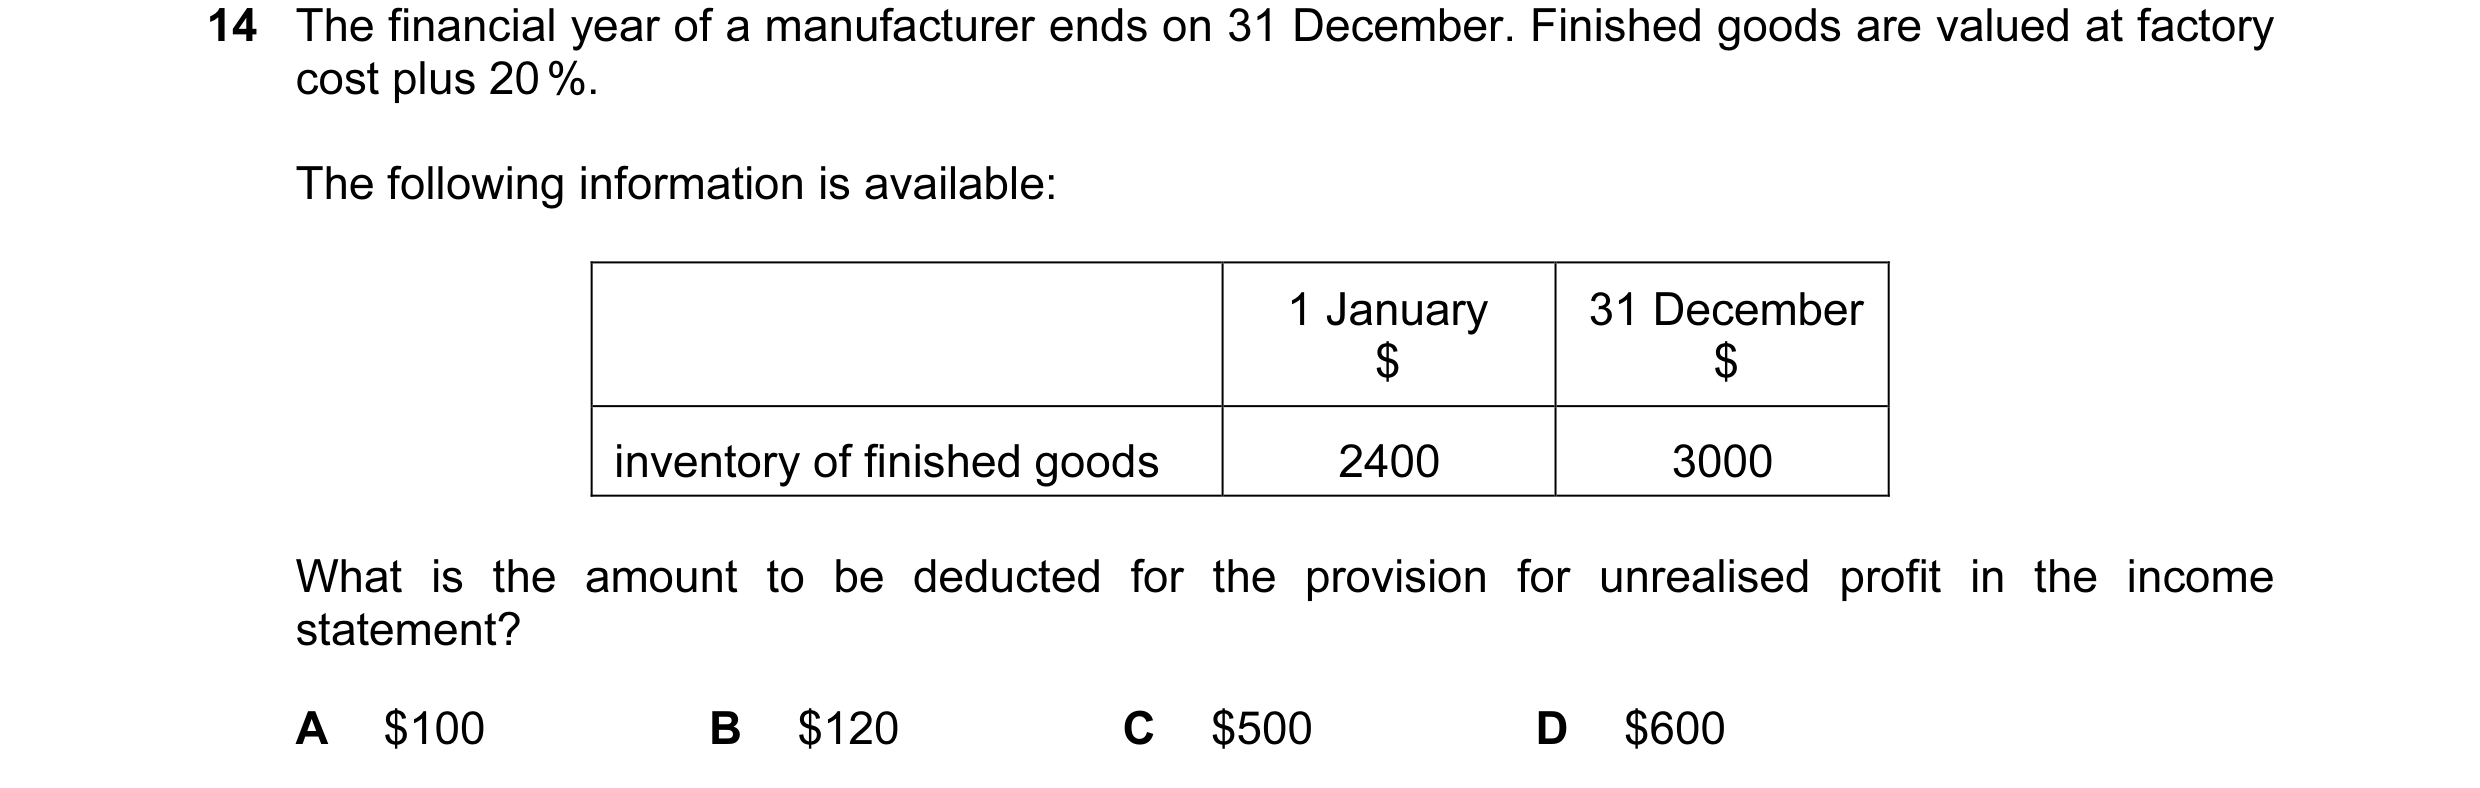
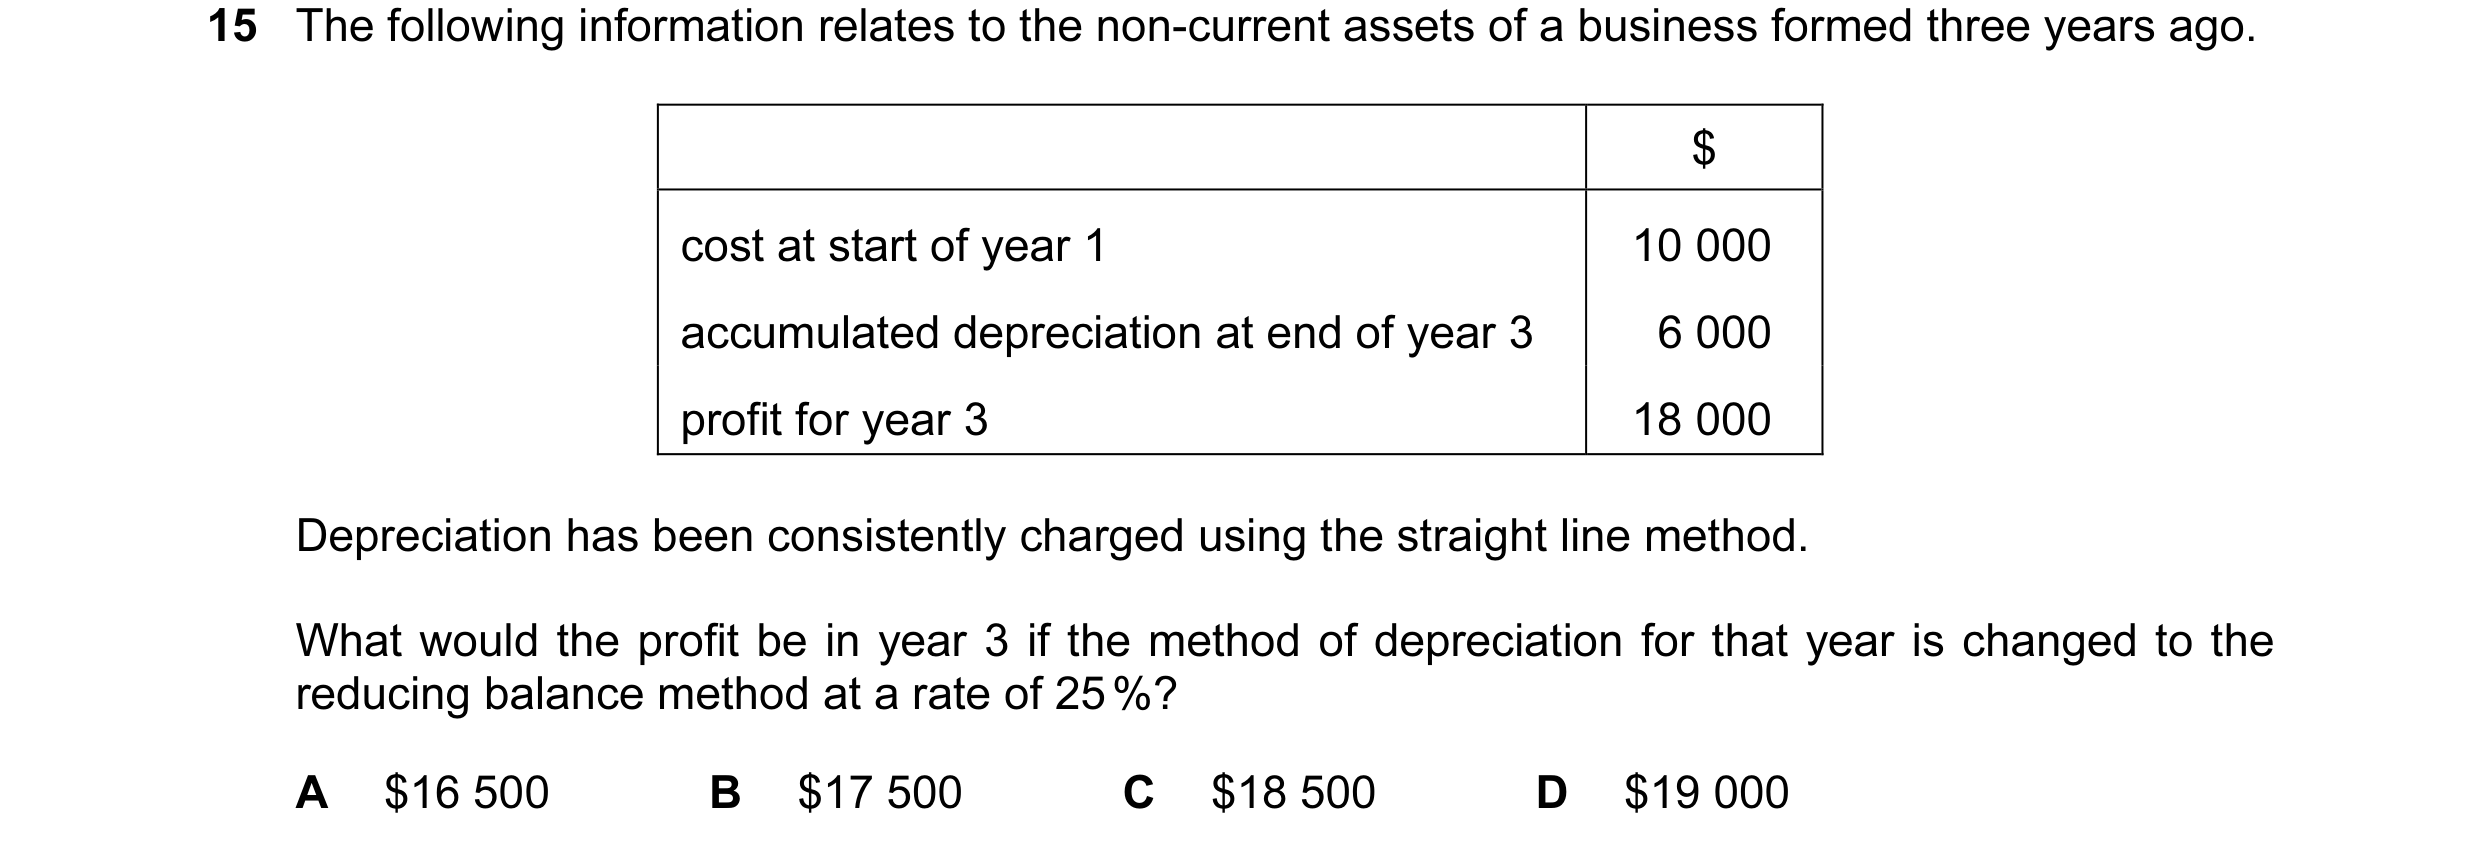 52 / 233
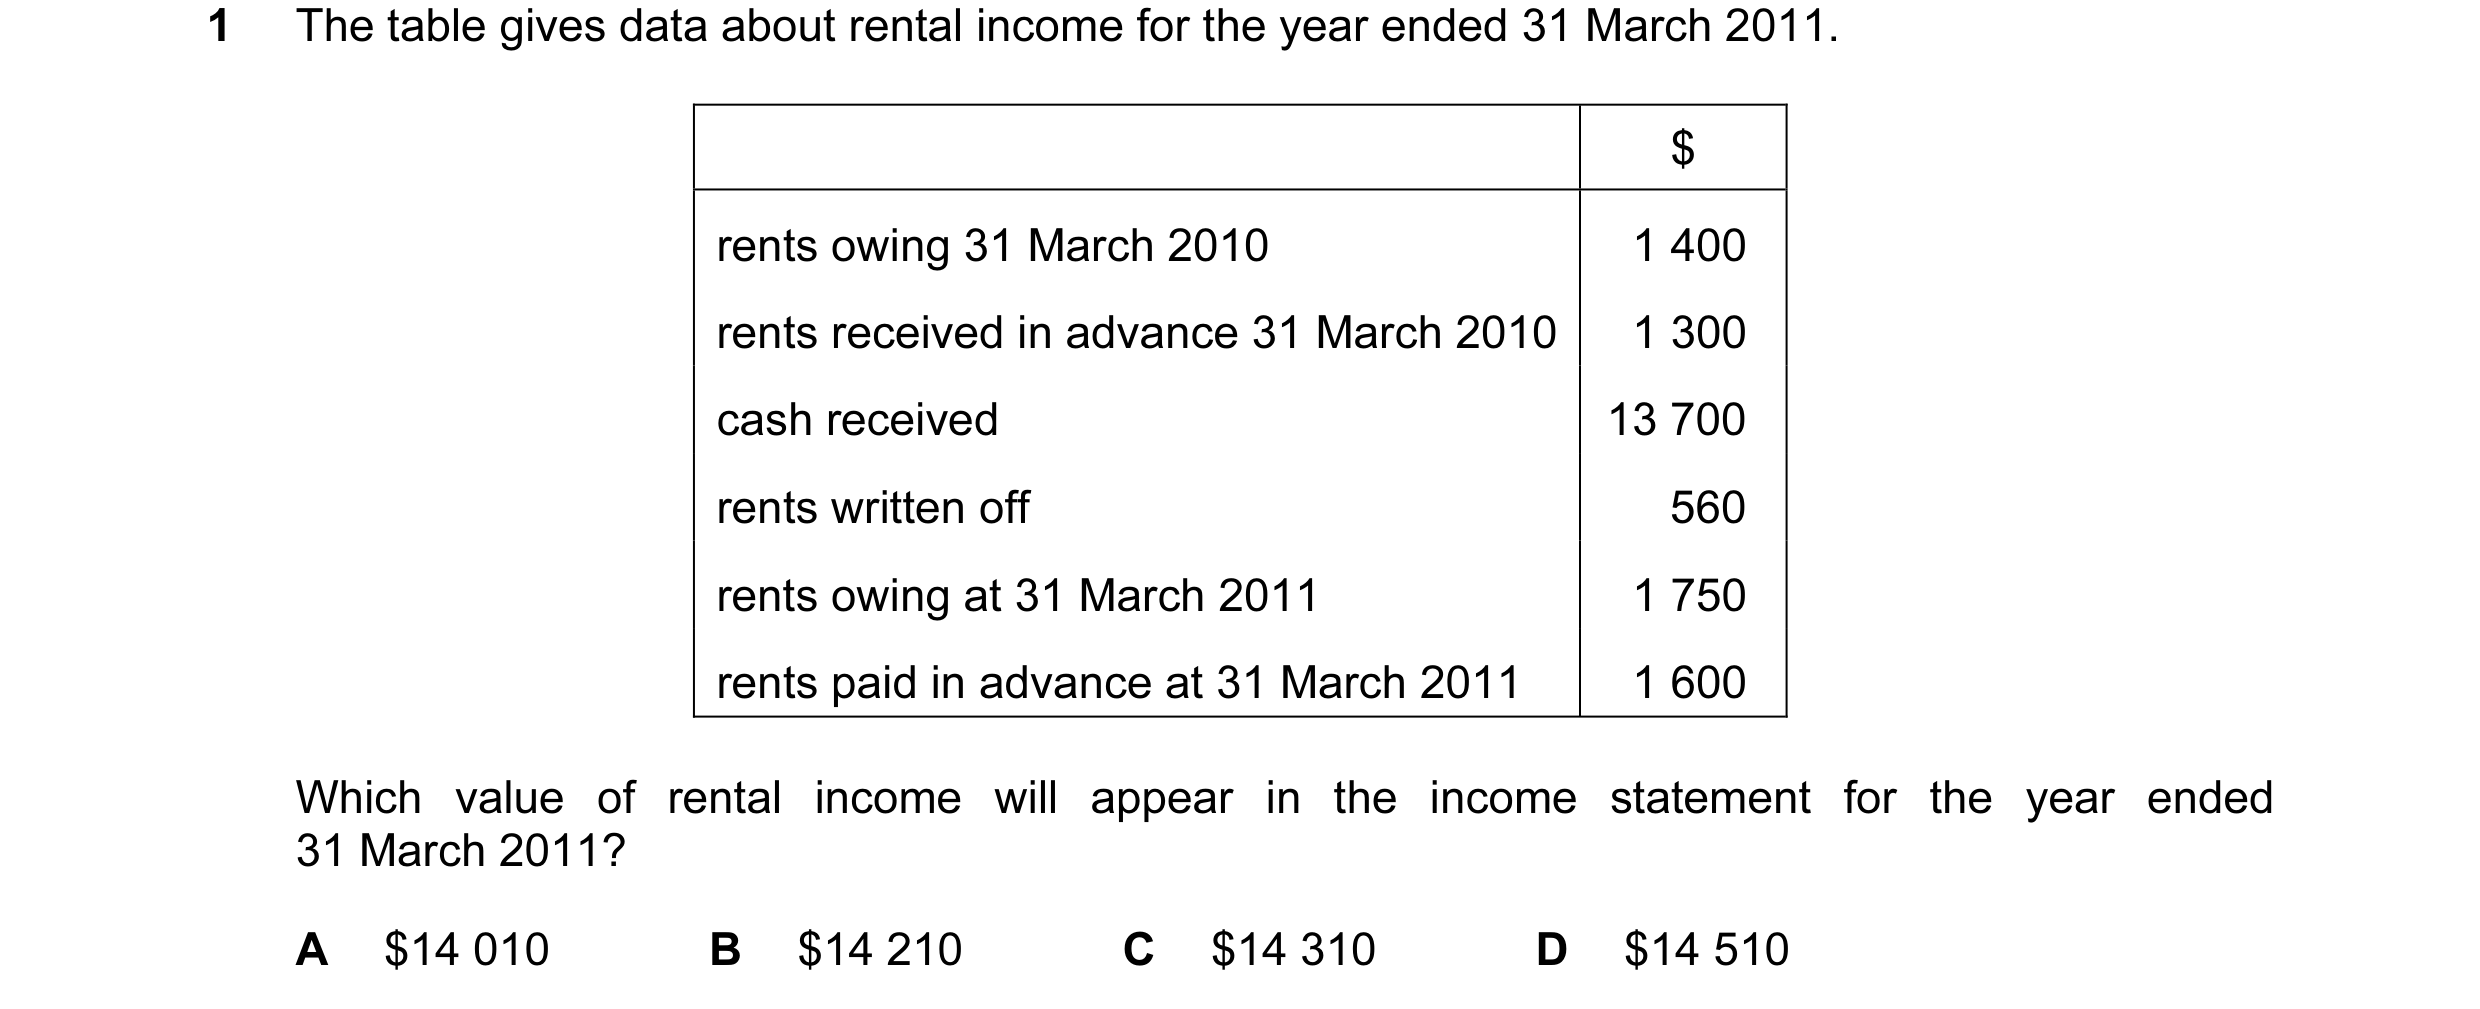
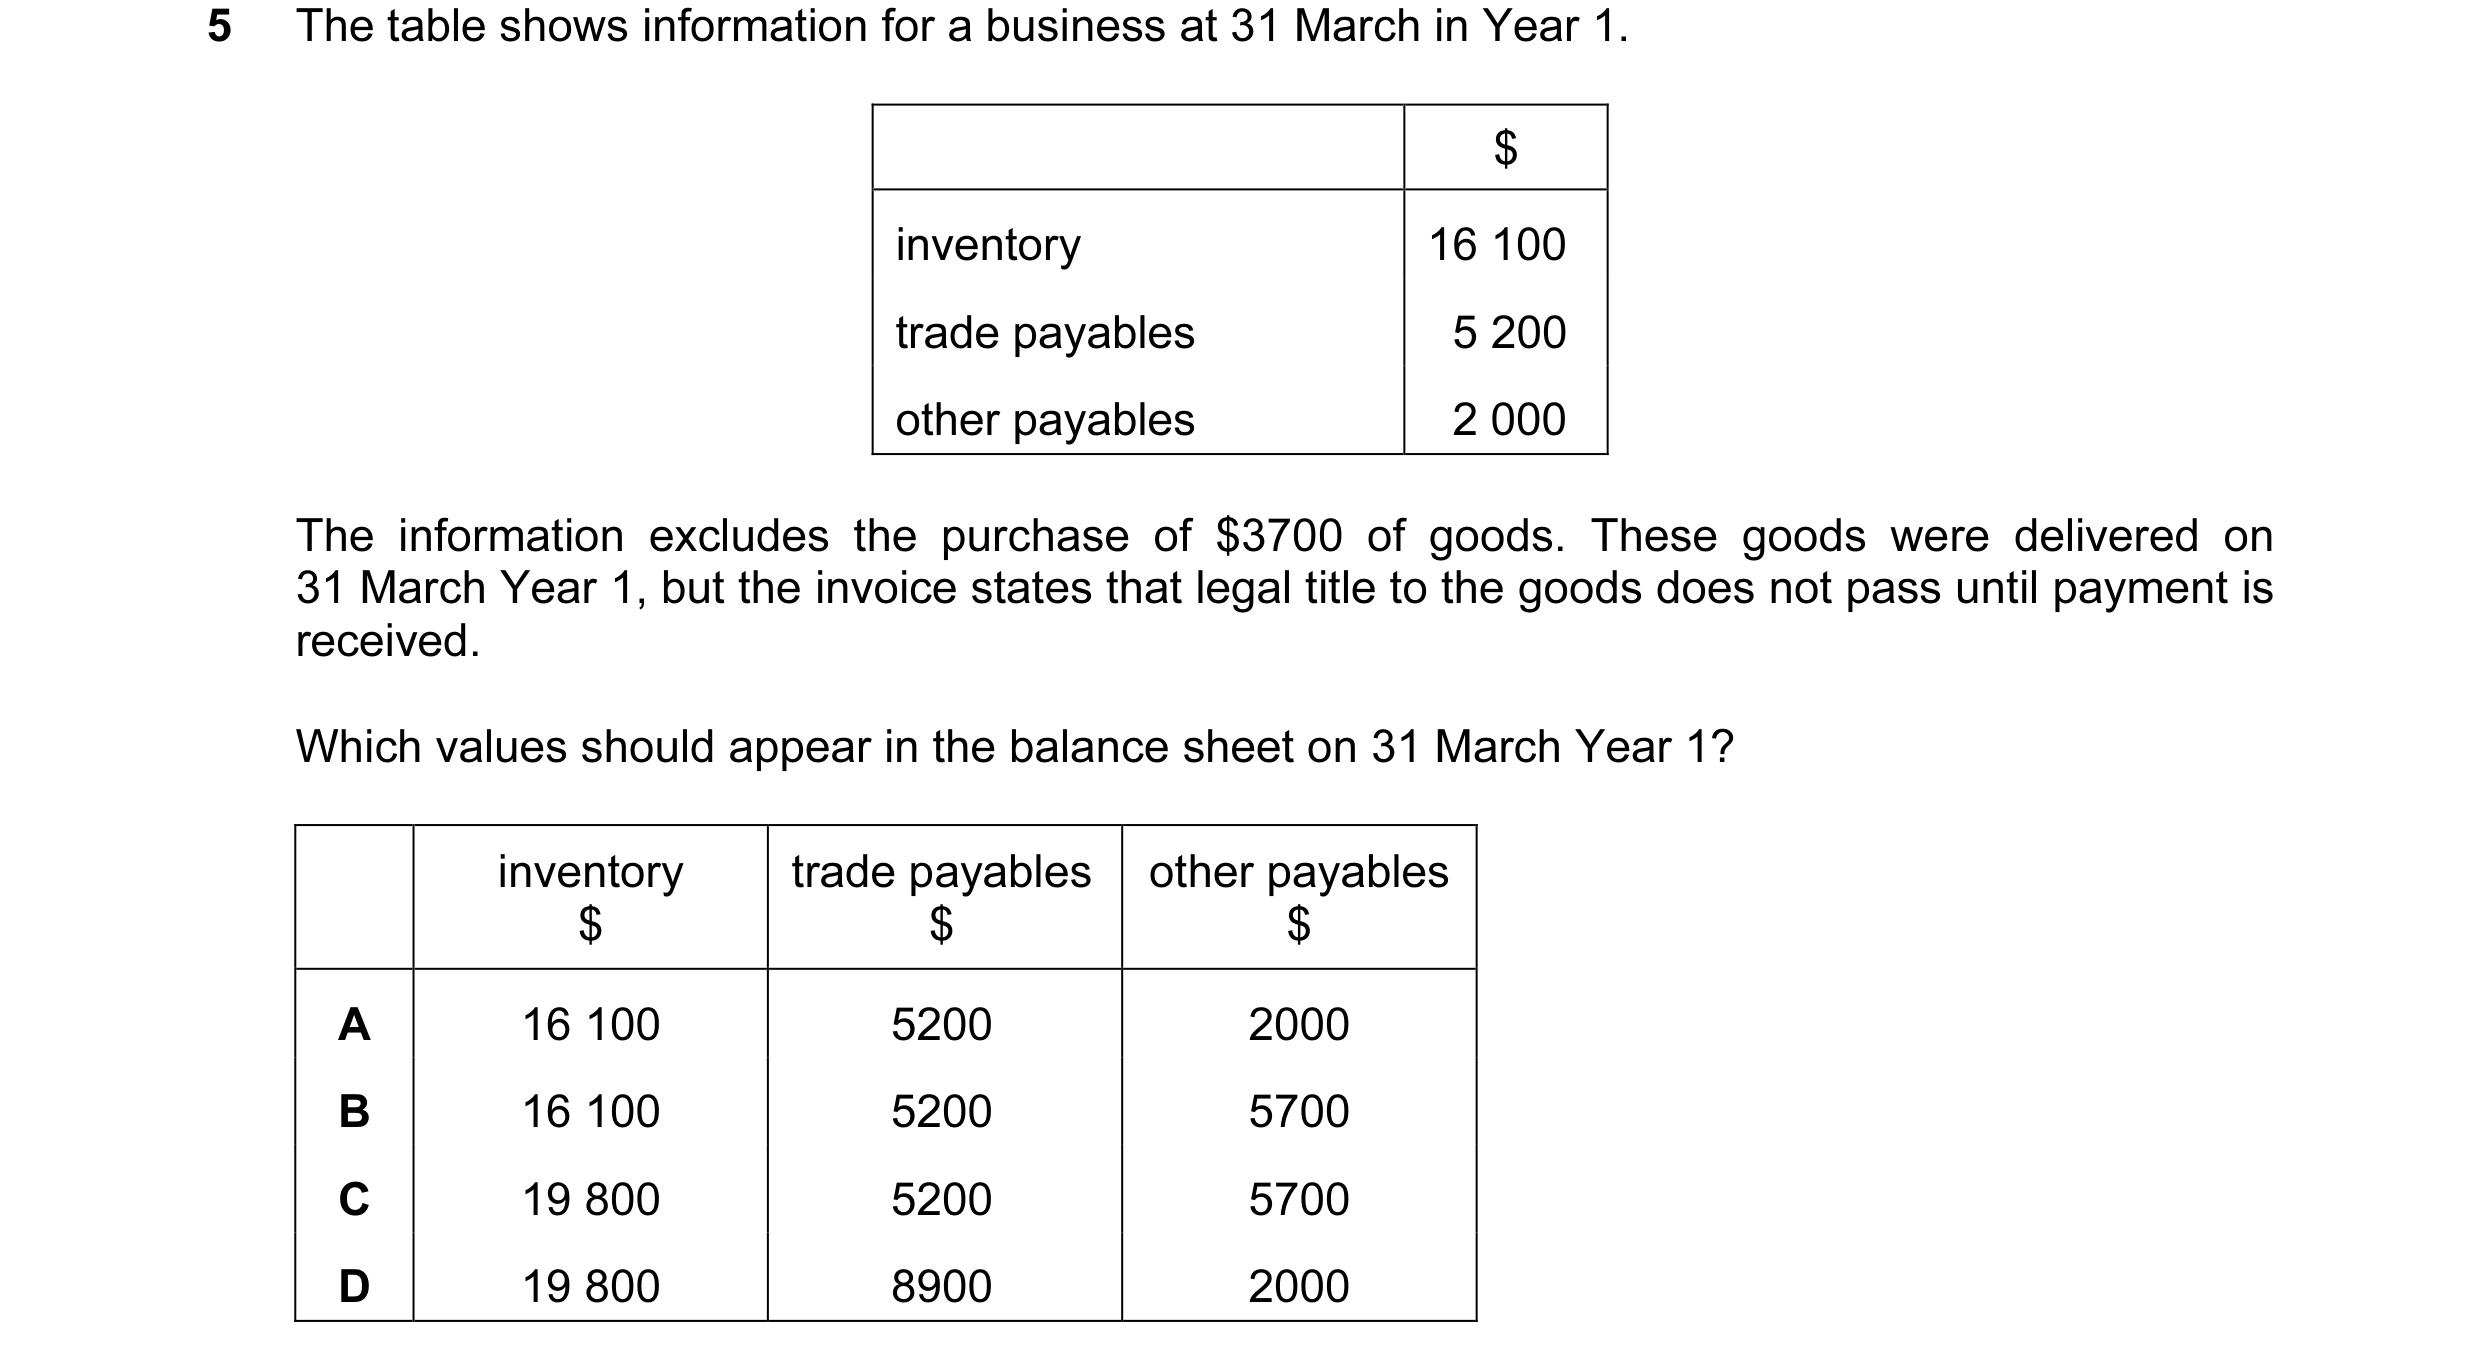 53 / 233
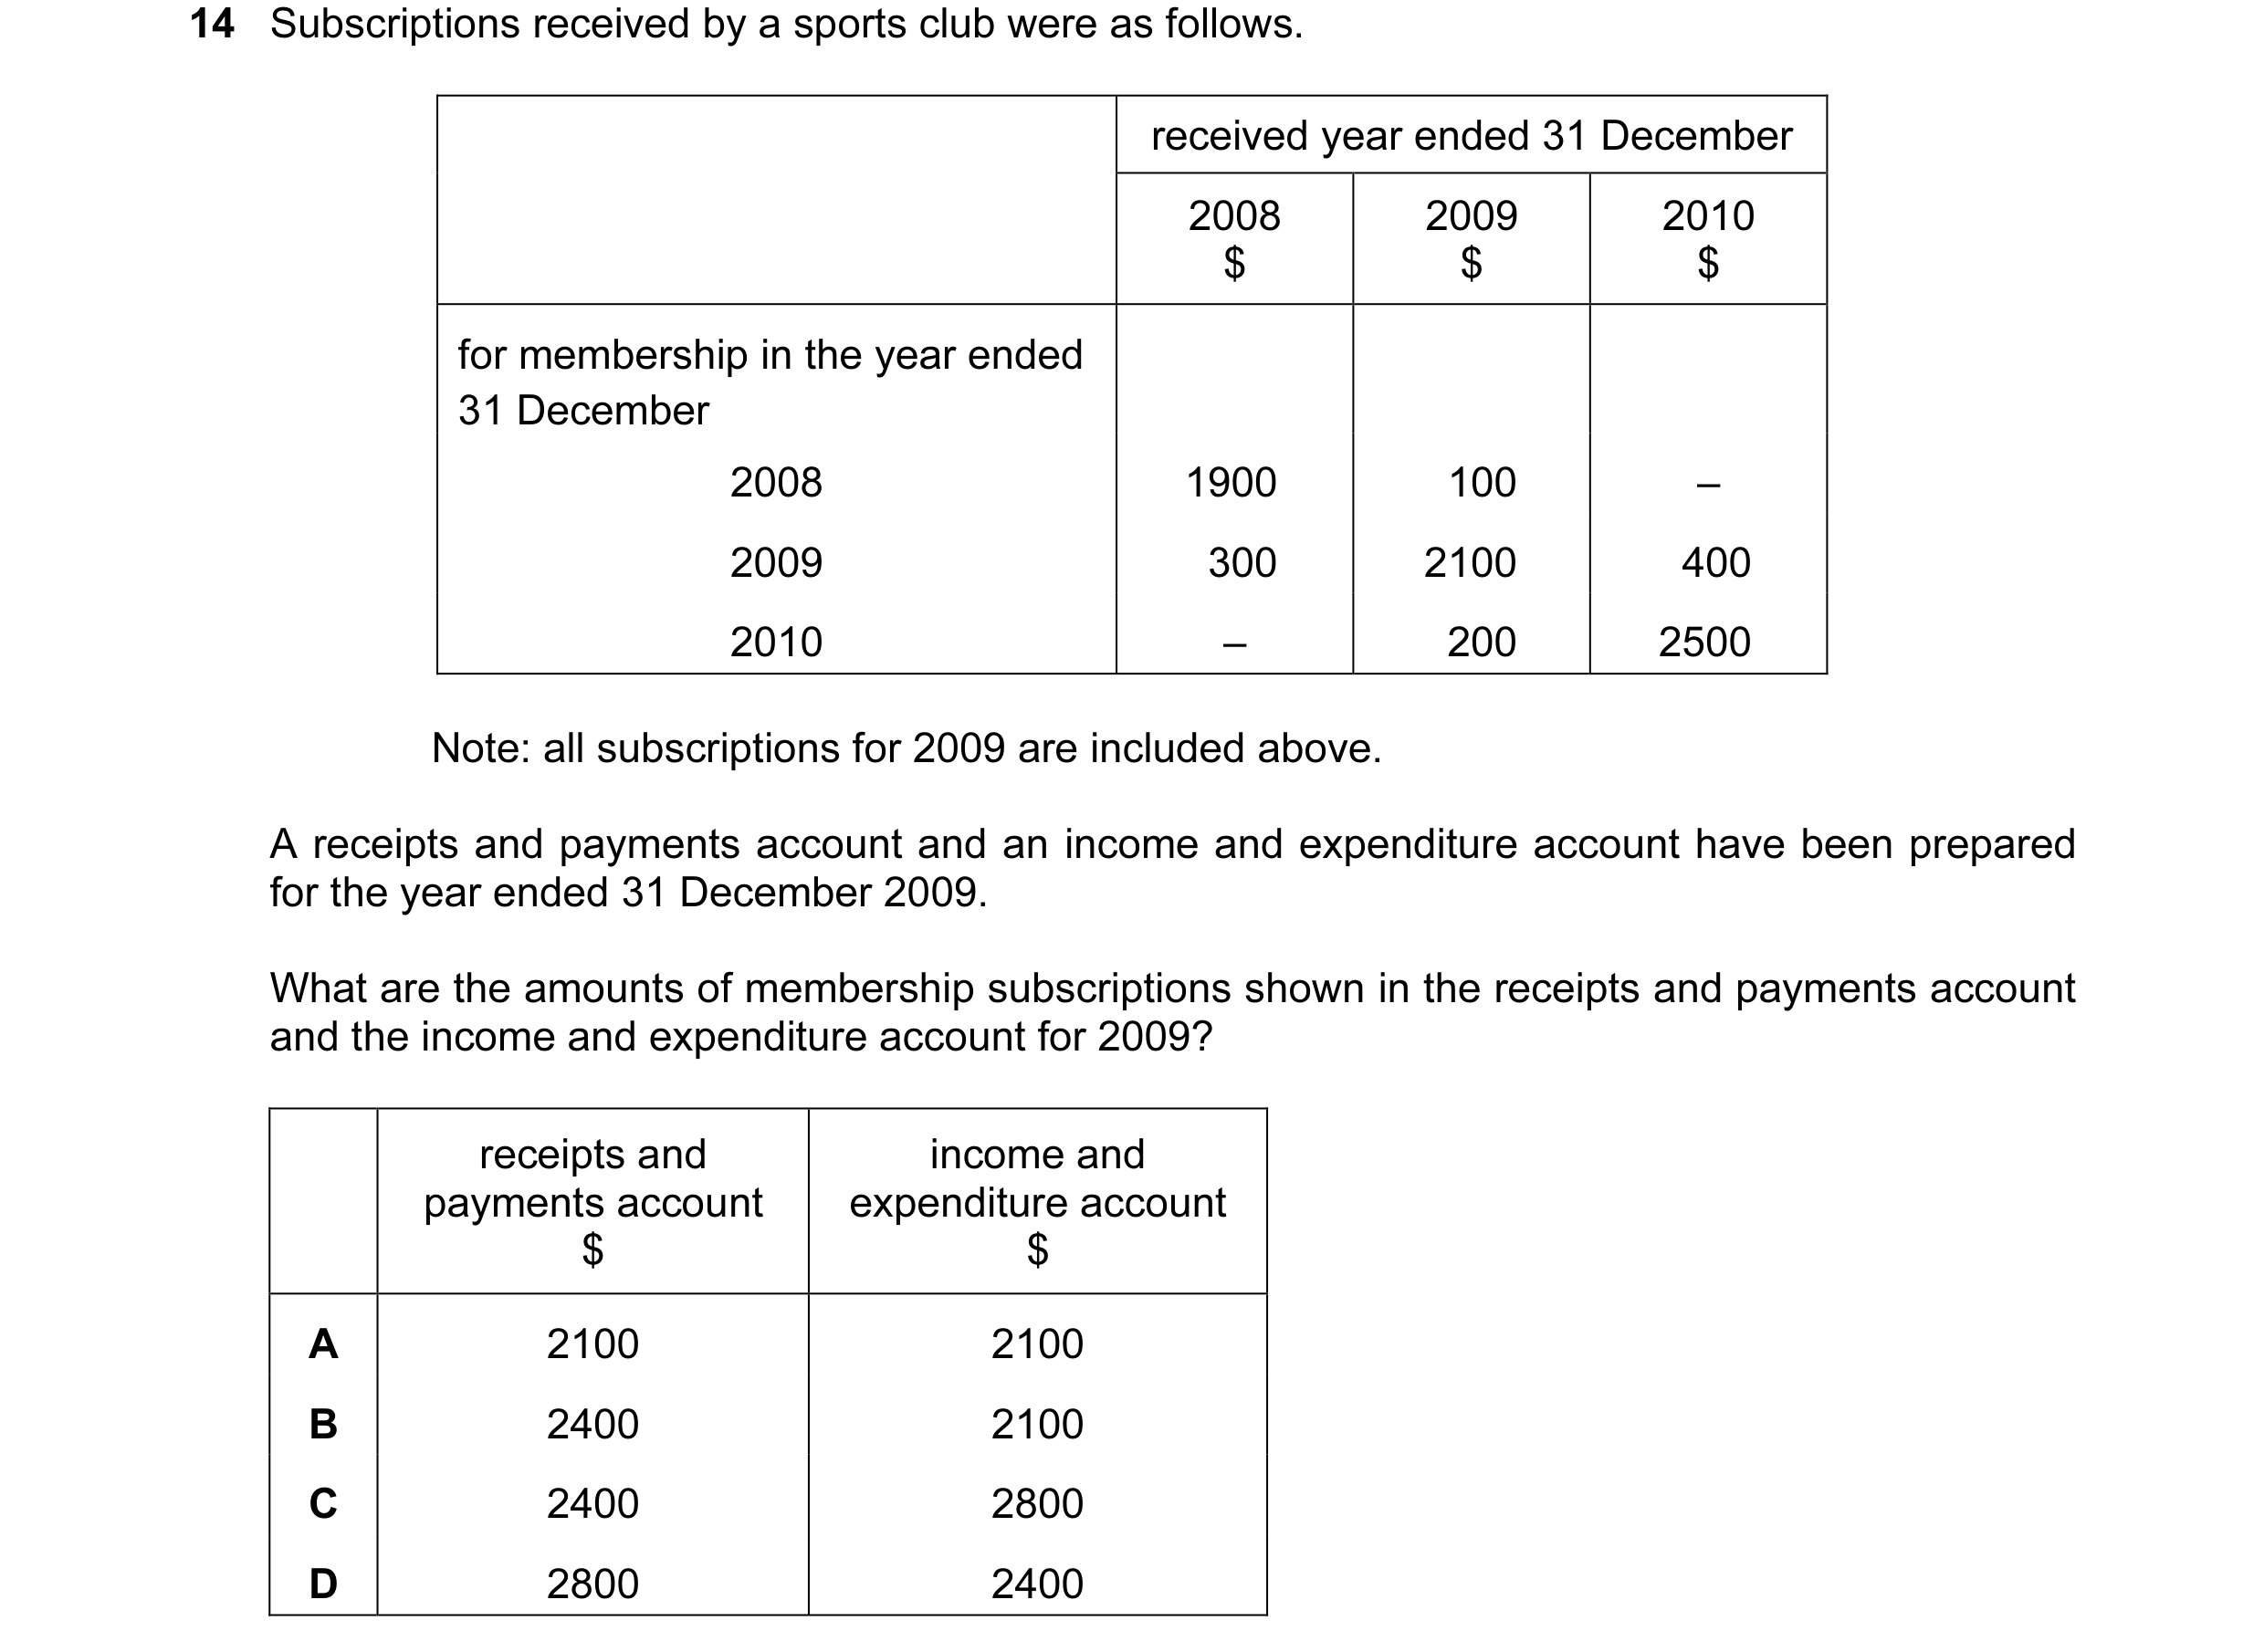
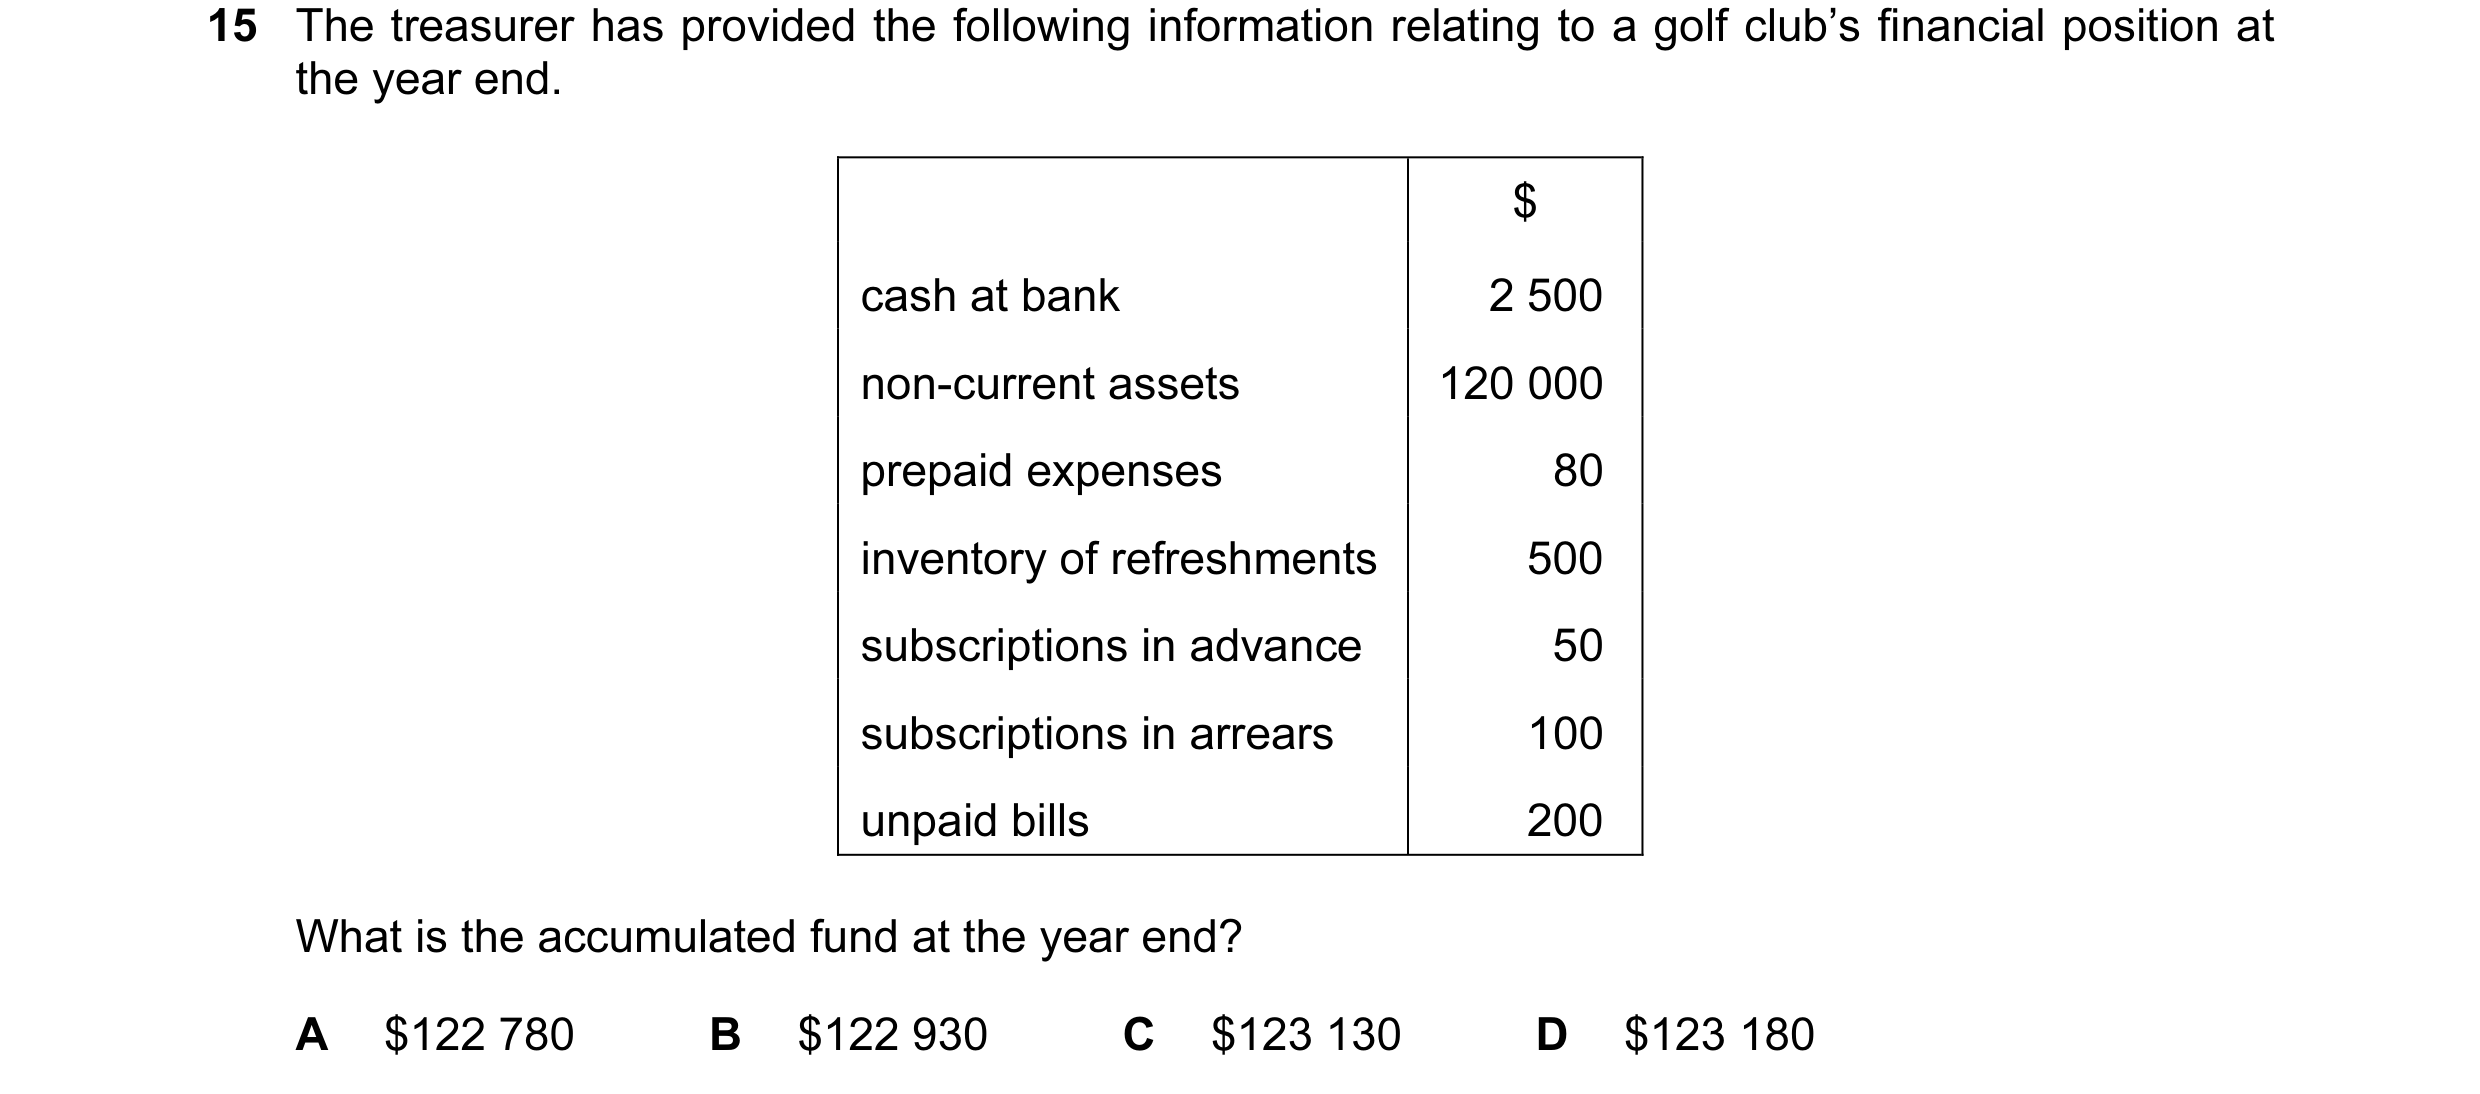 54 / 233
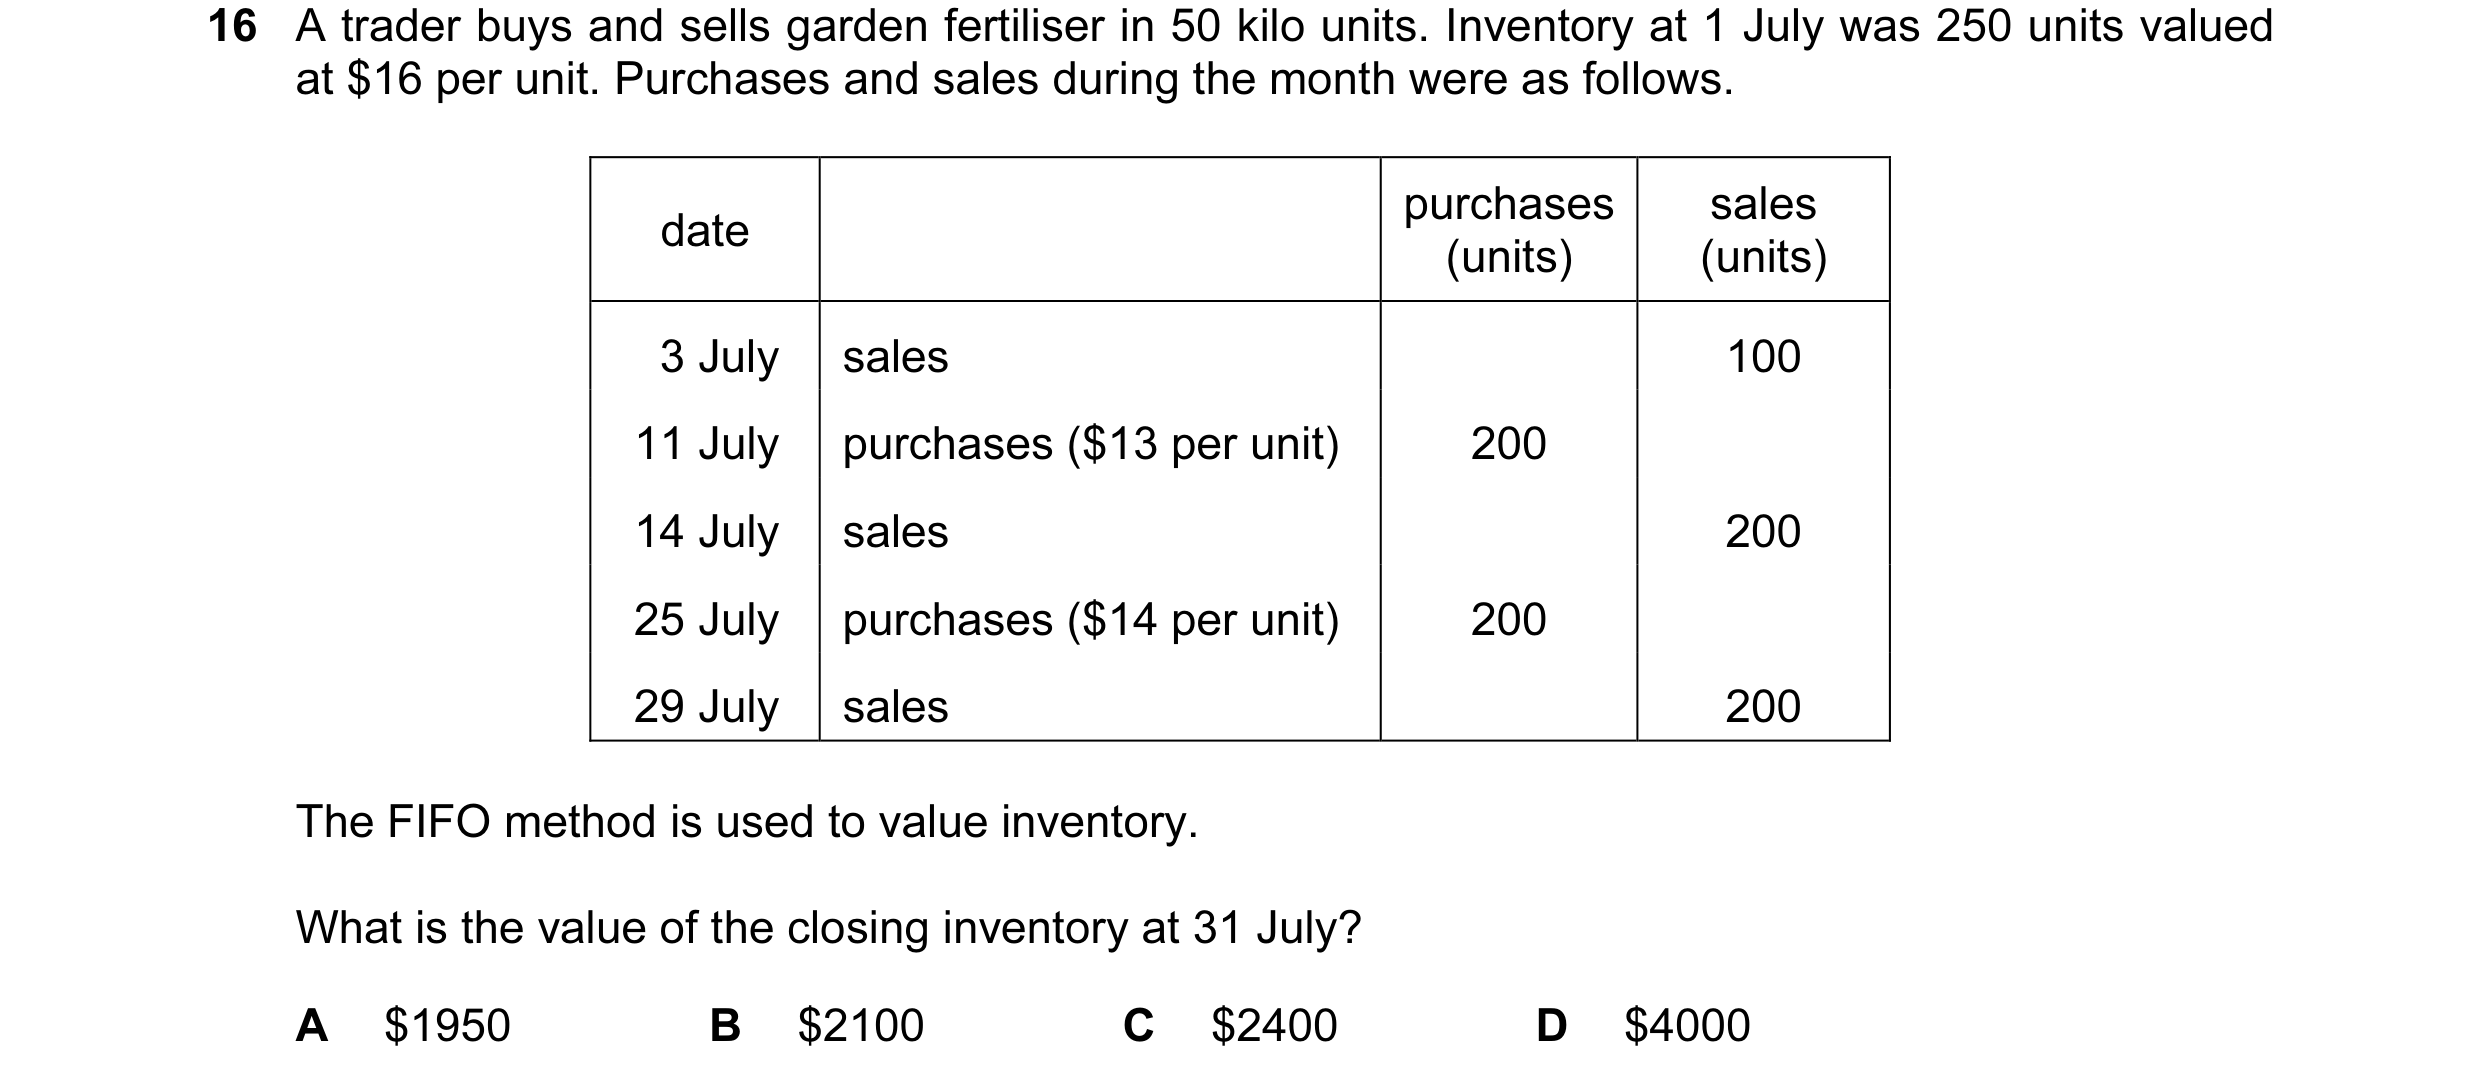
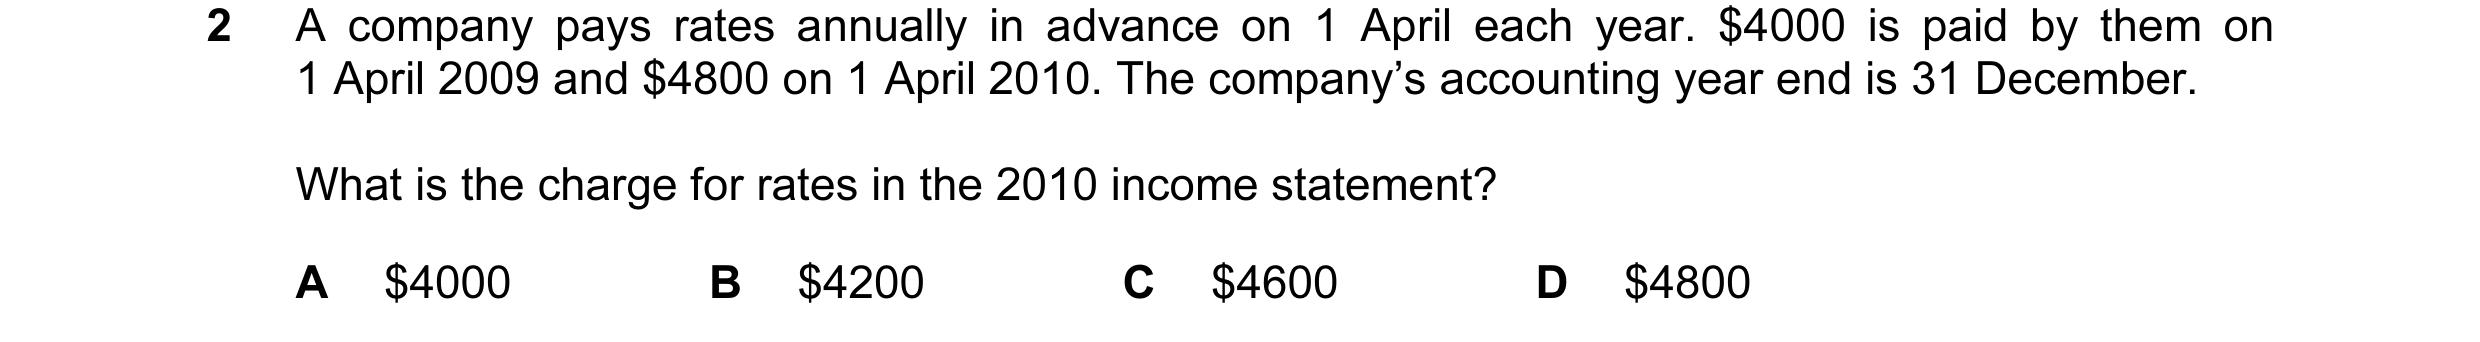
 55 / 233
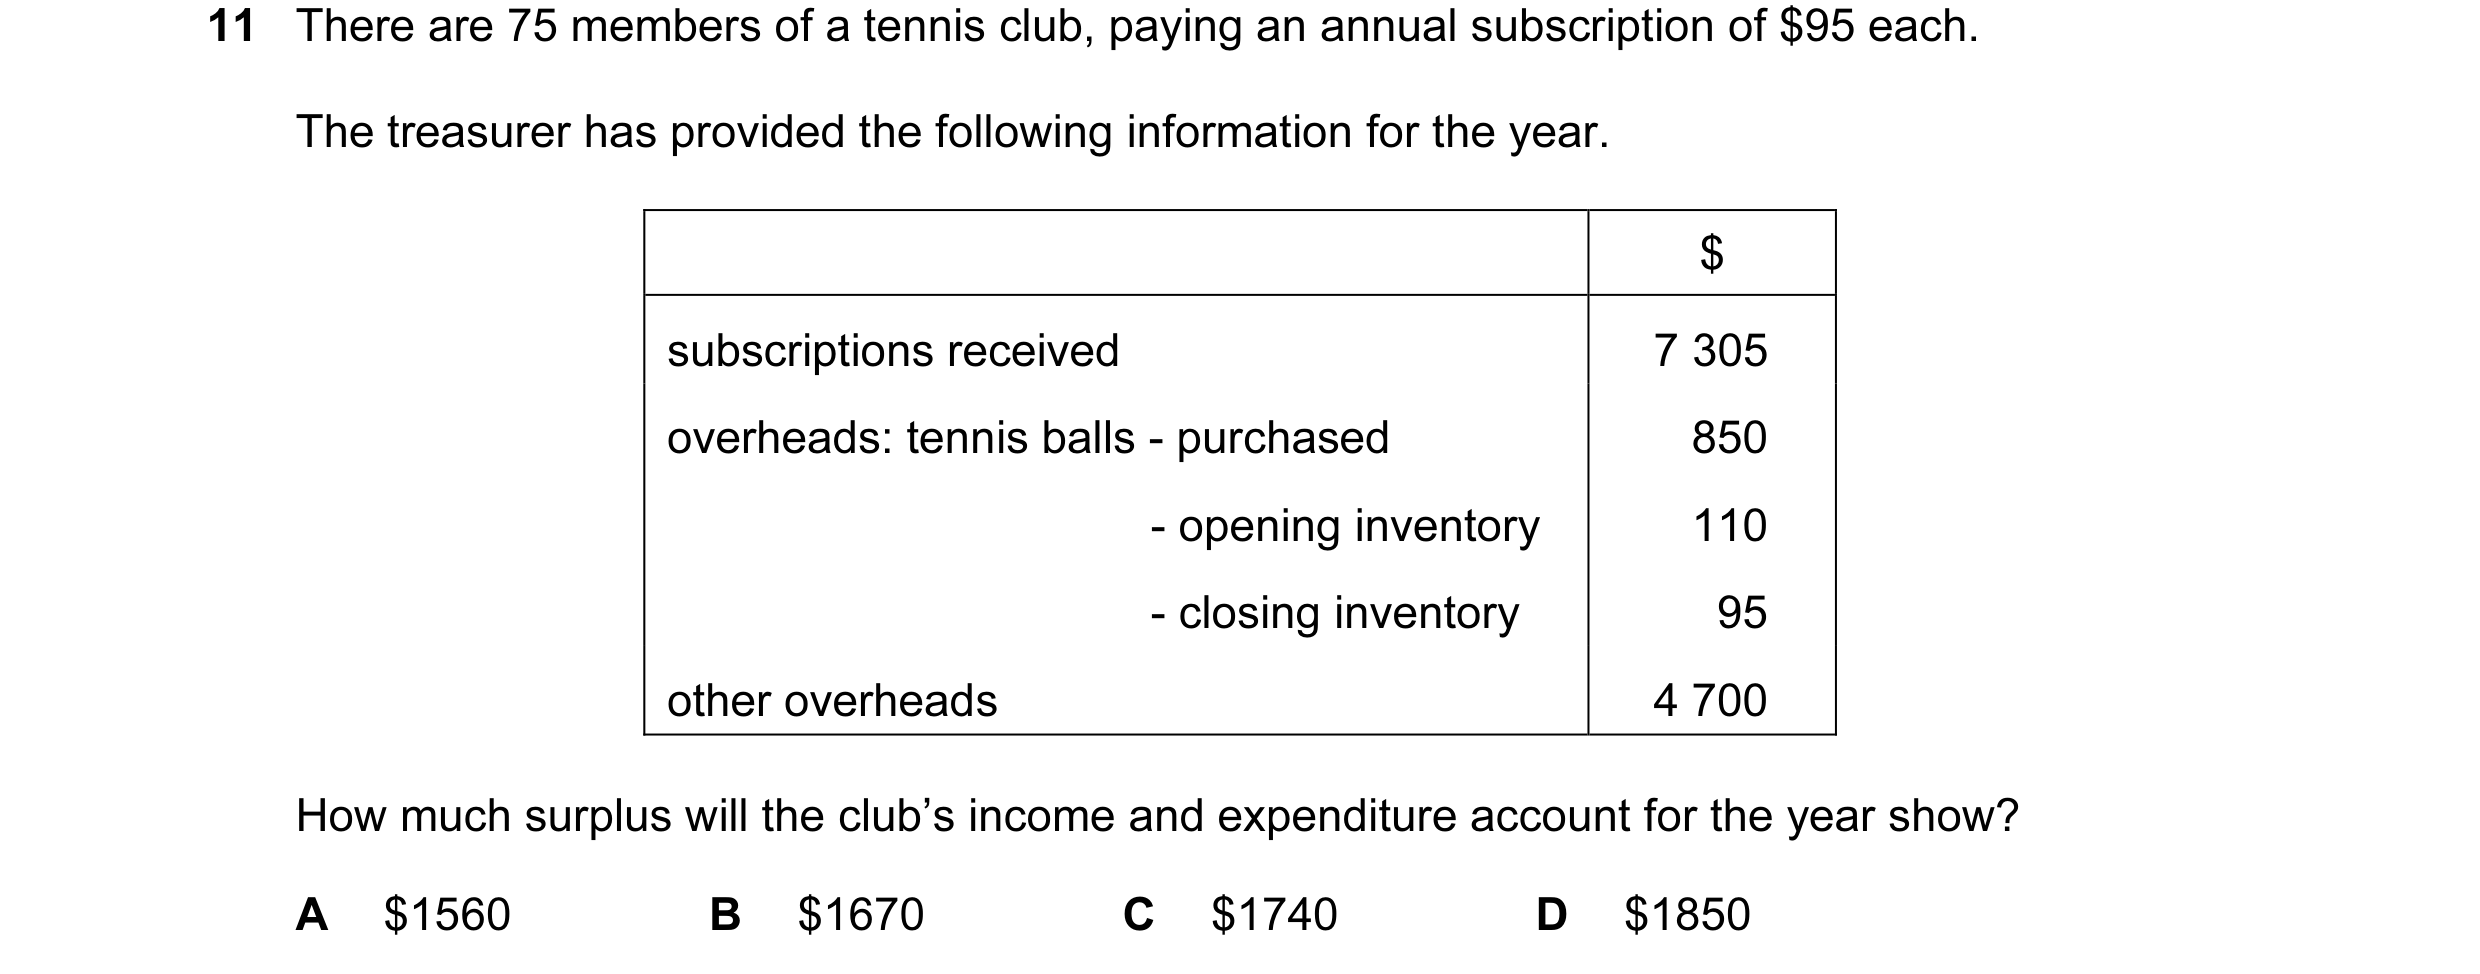
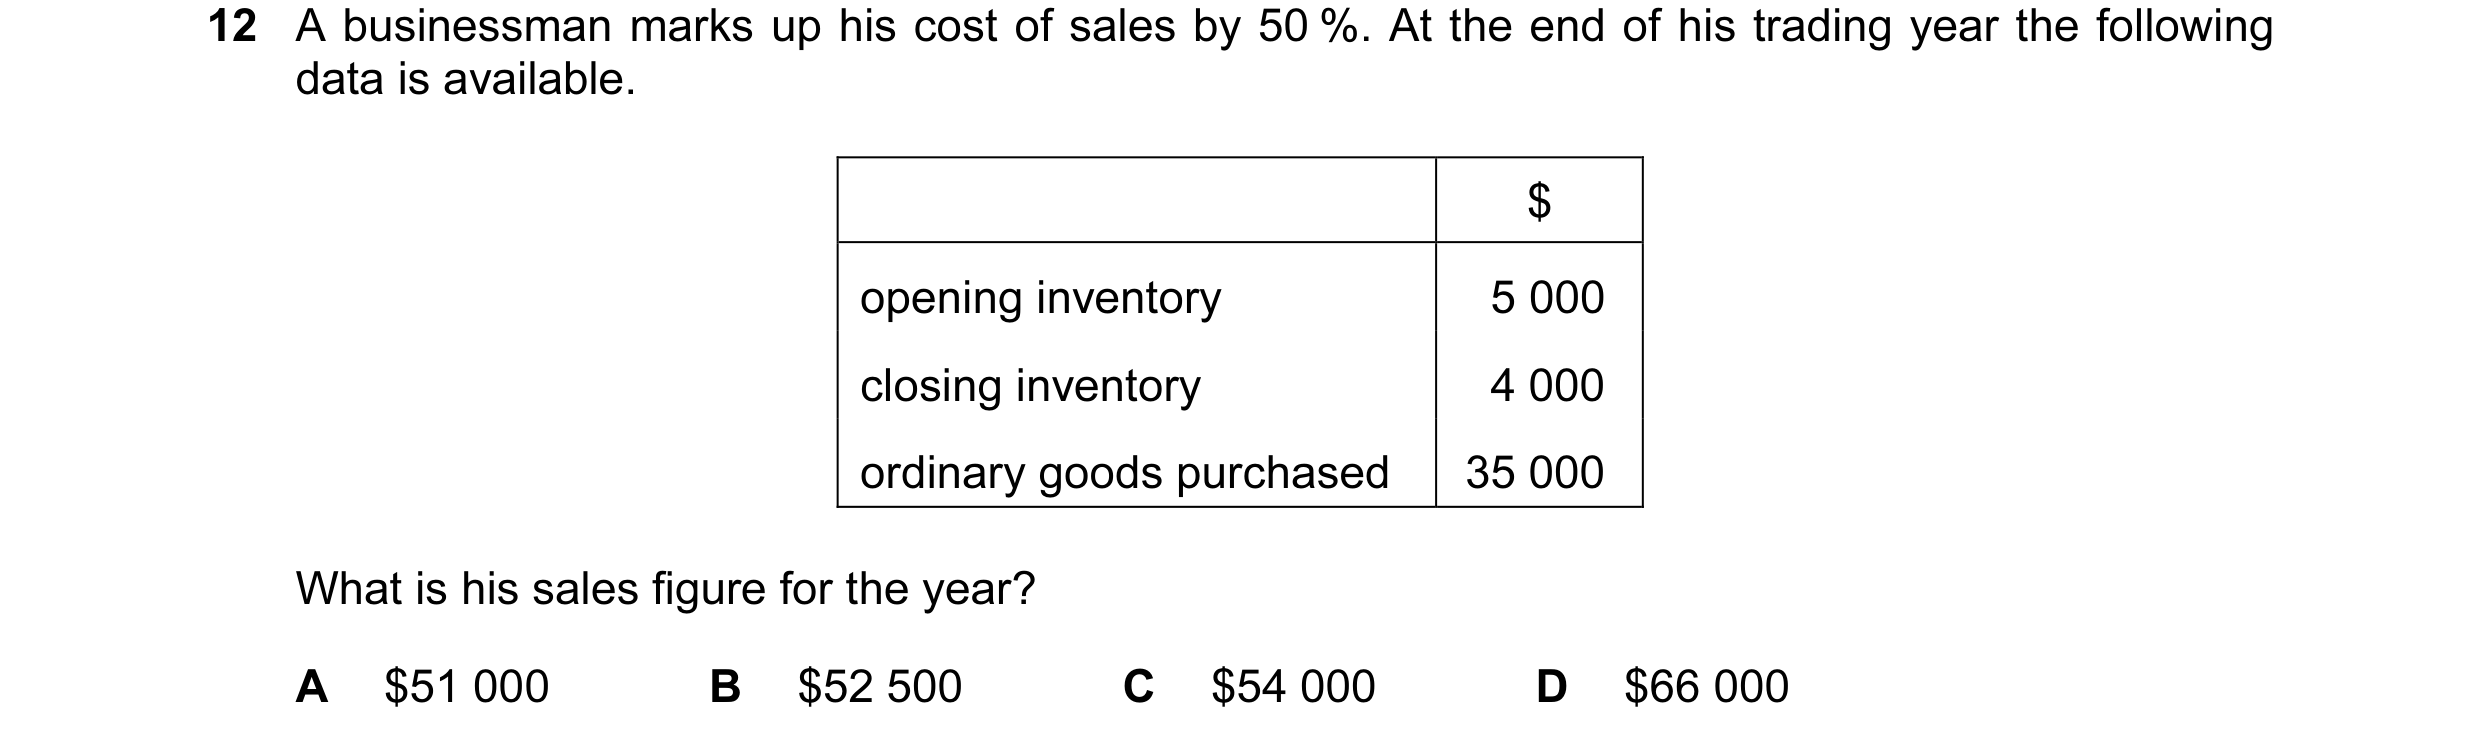
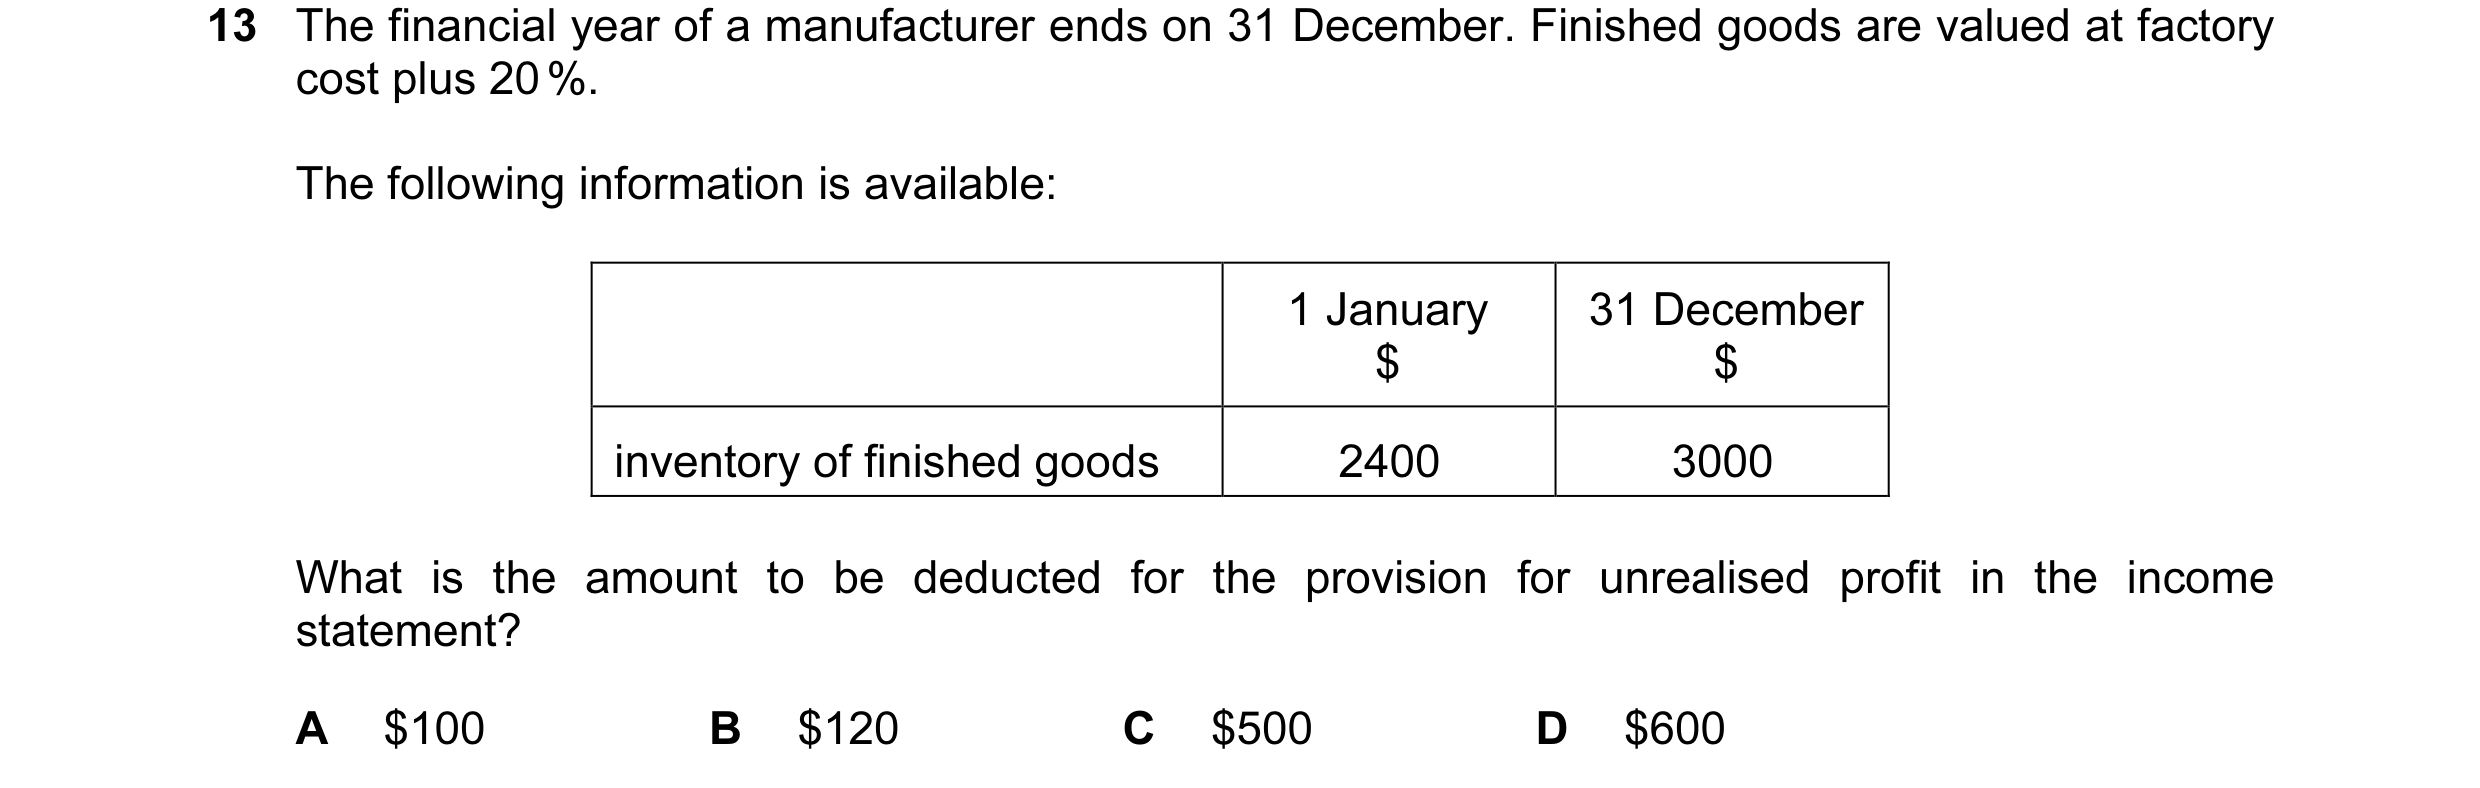 56 / 233
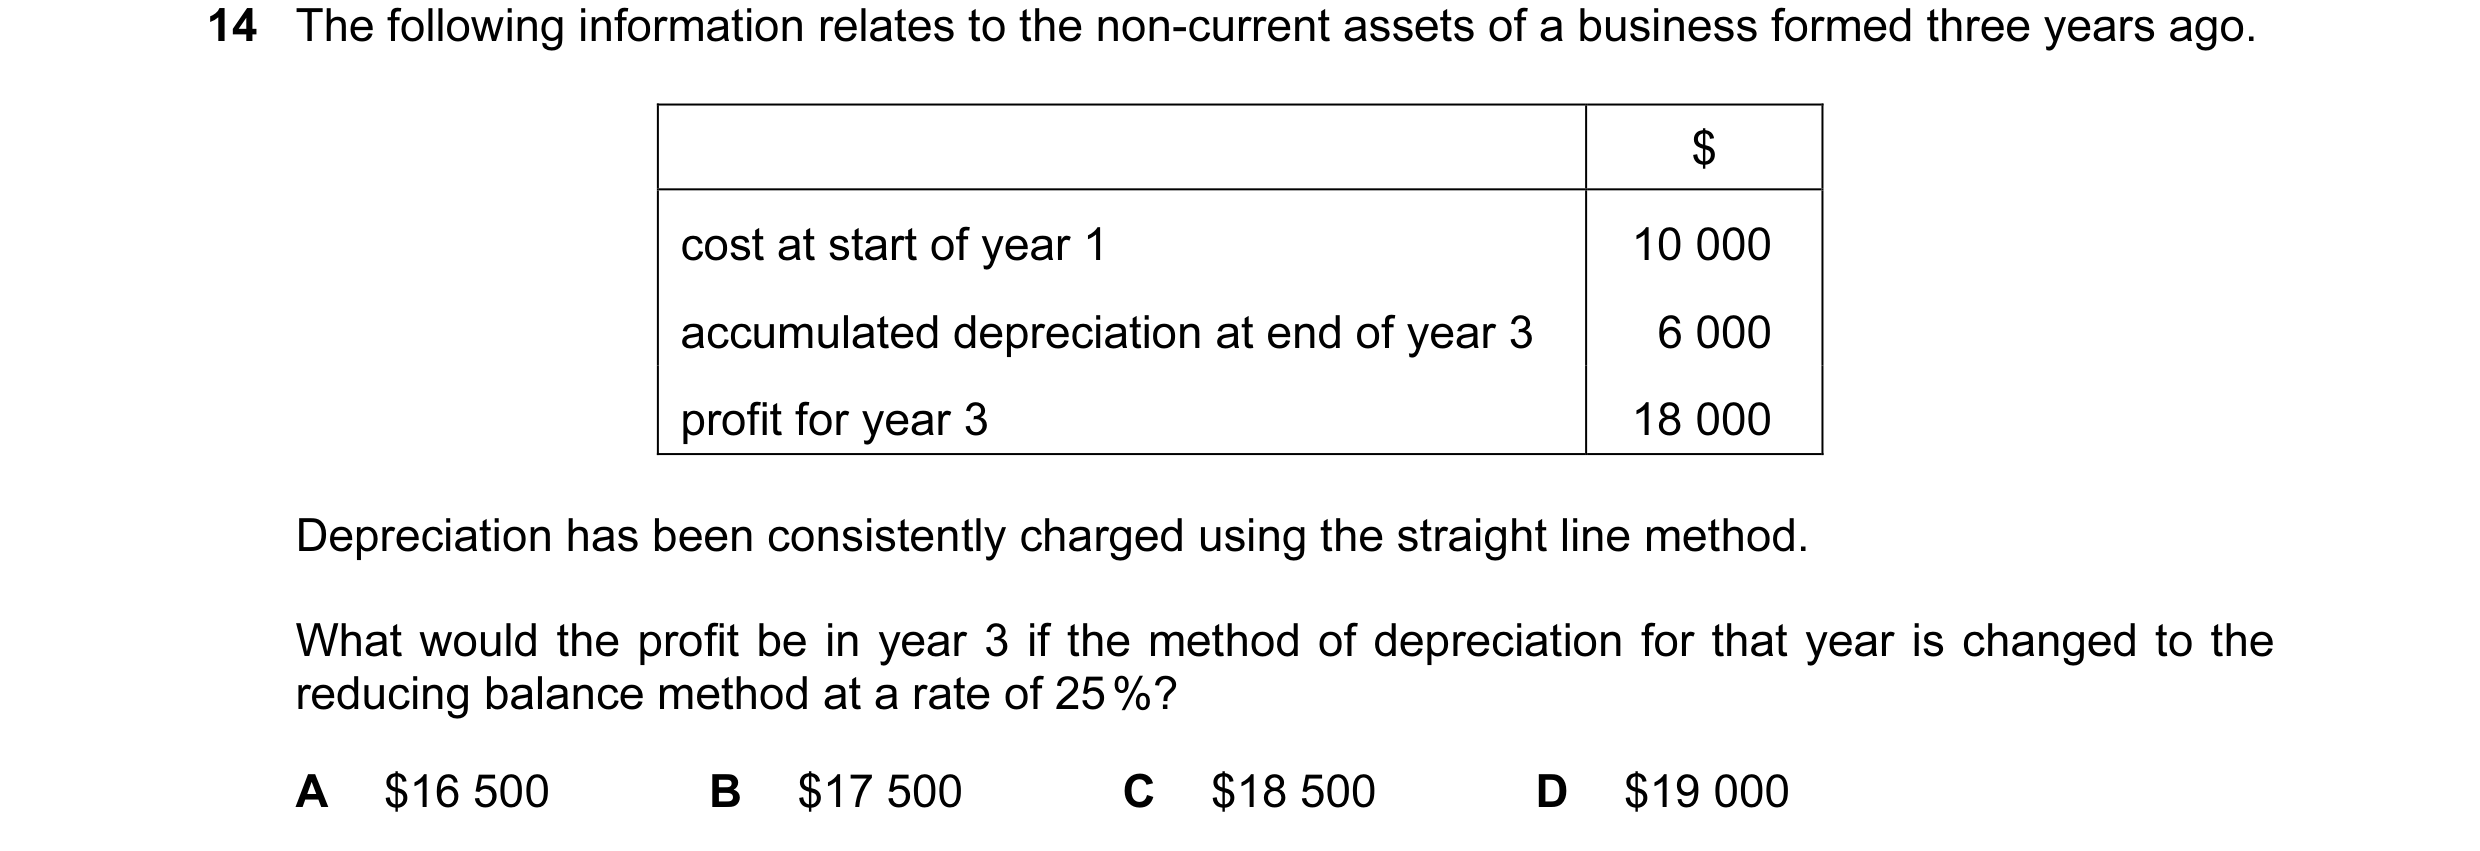
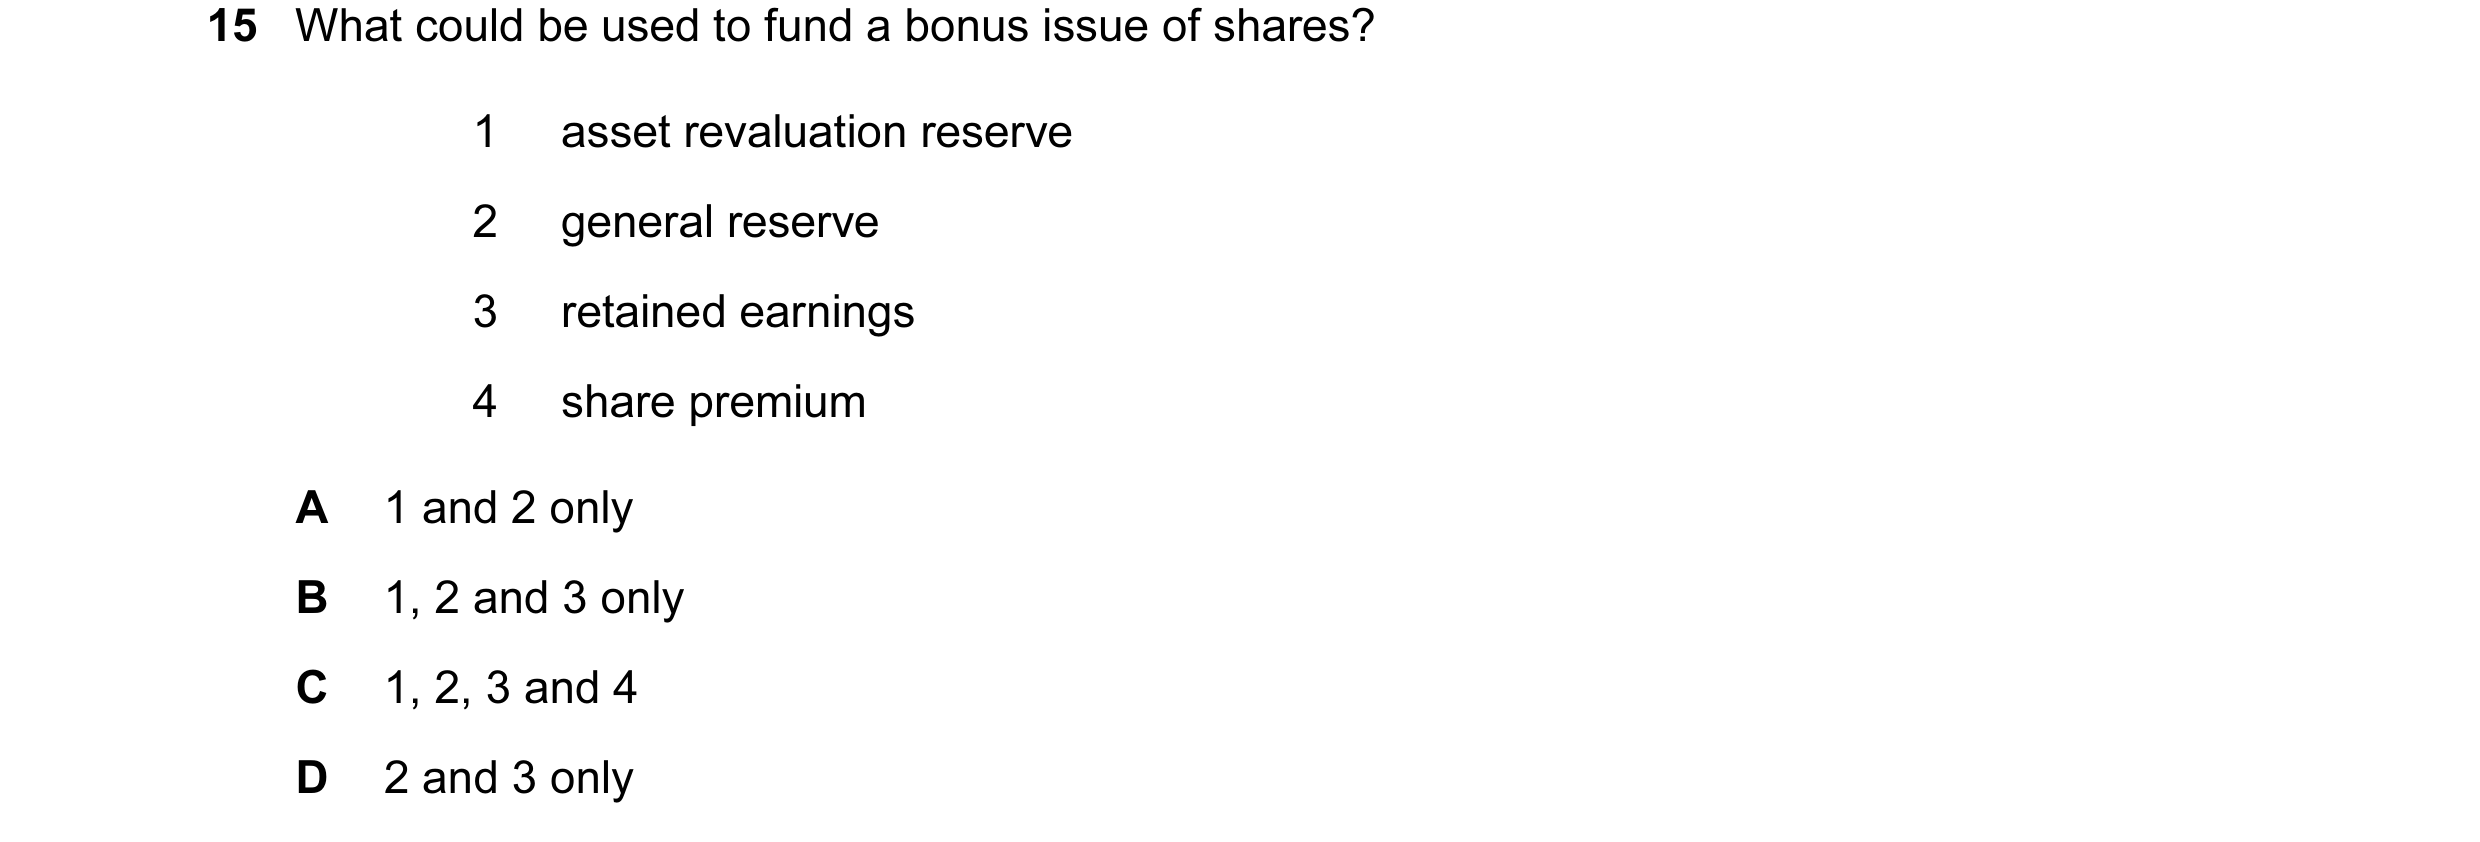
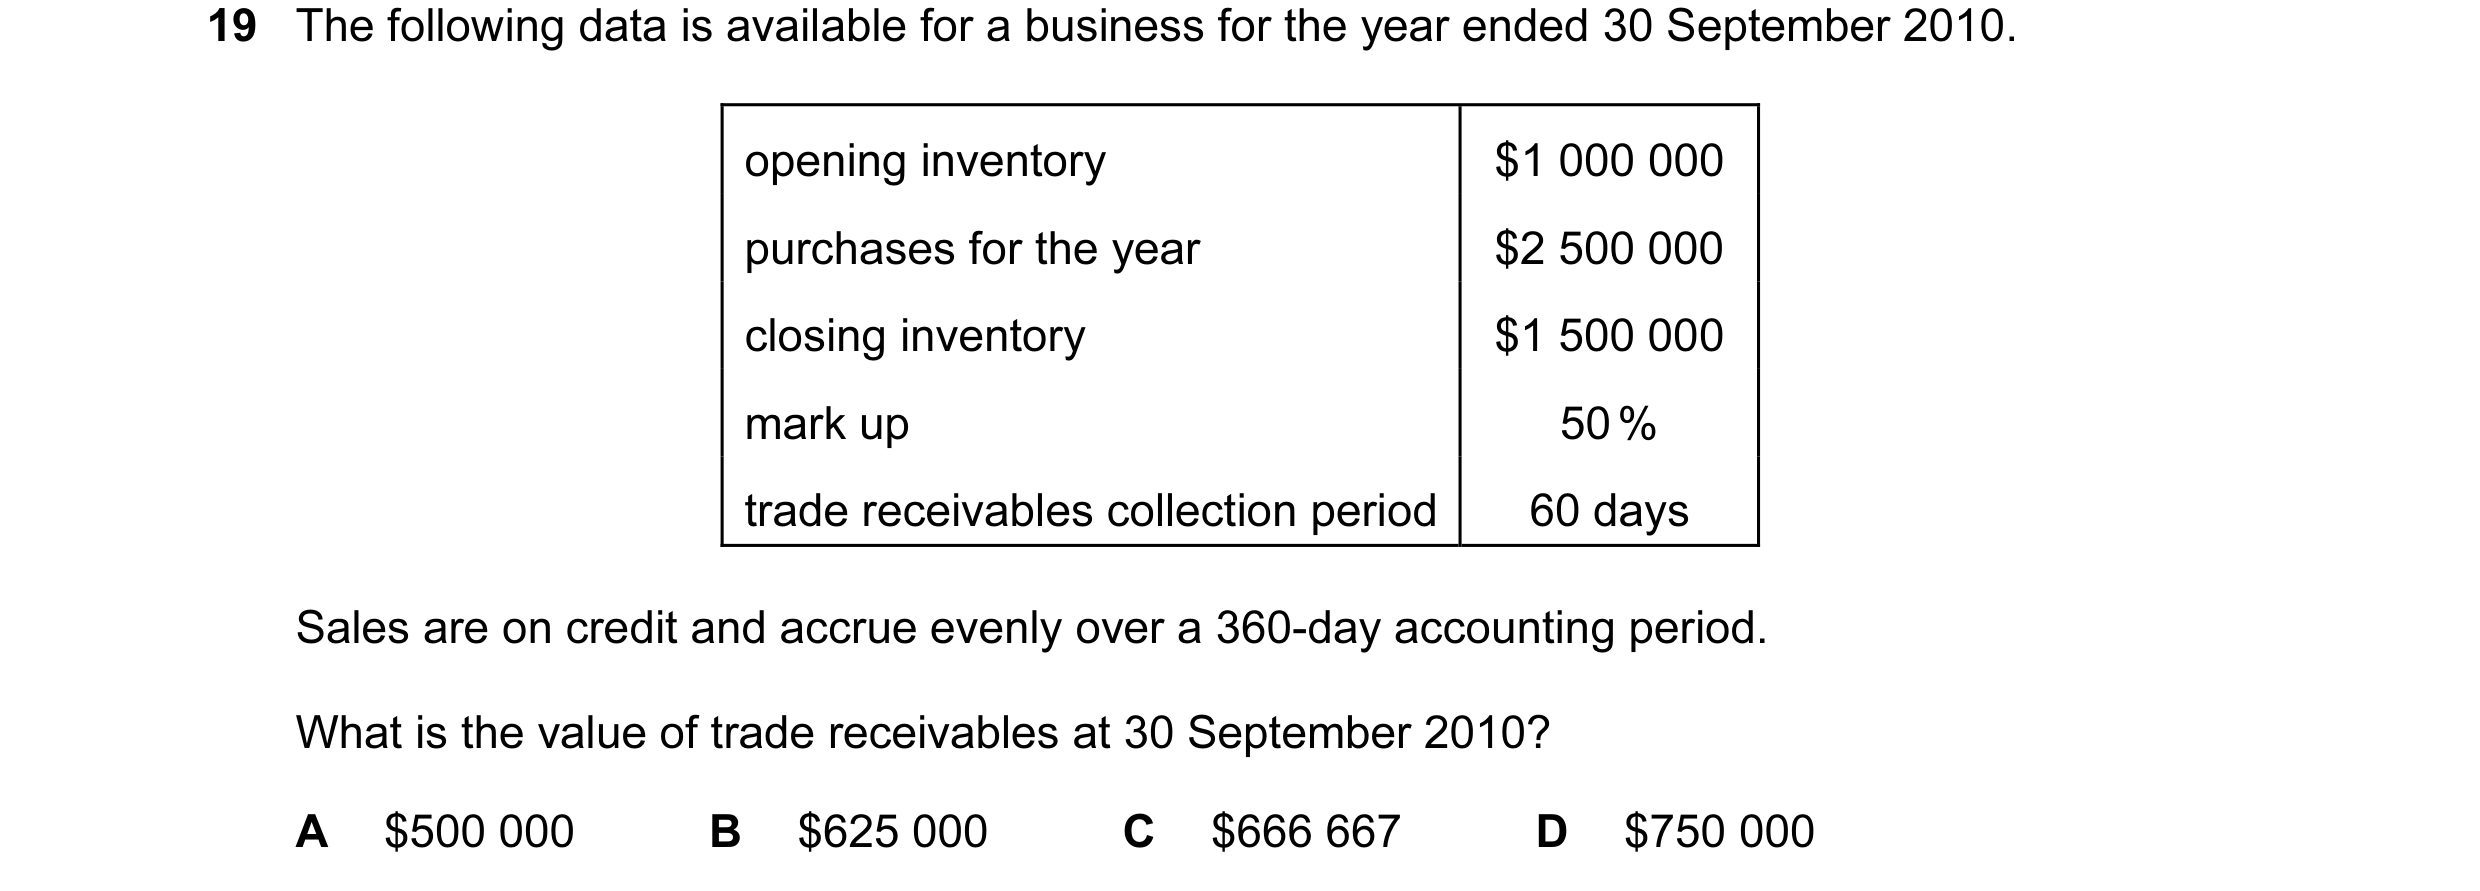
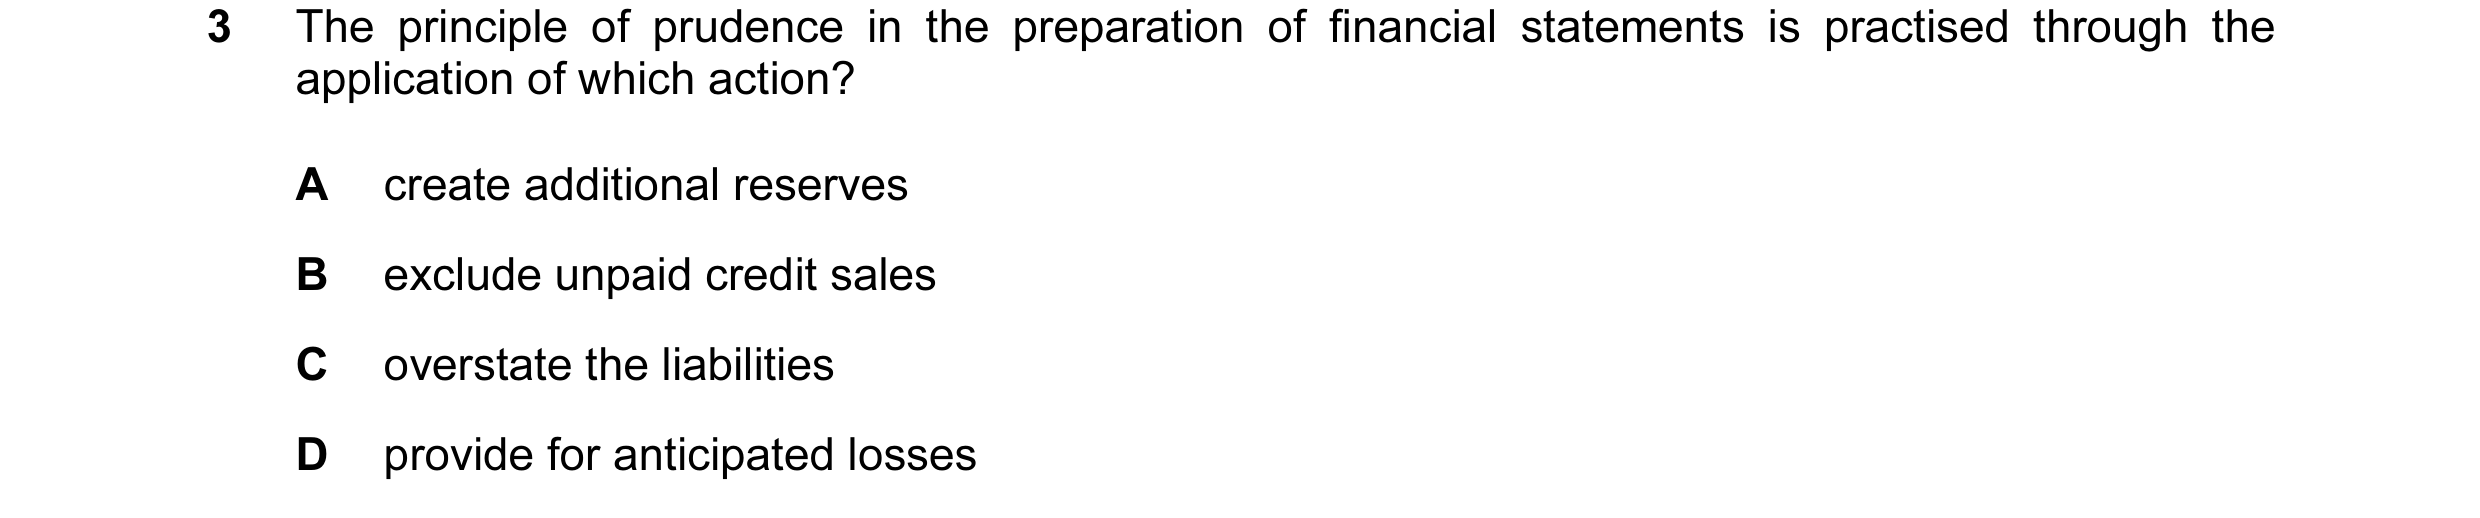 57 / 233
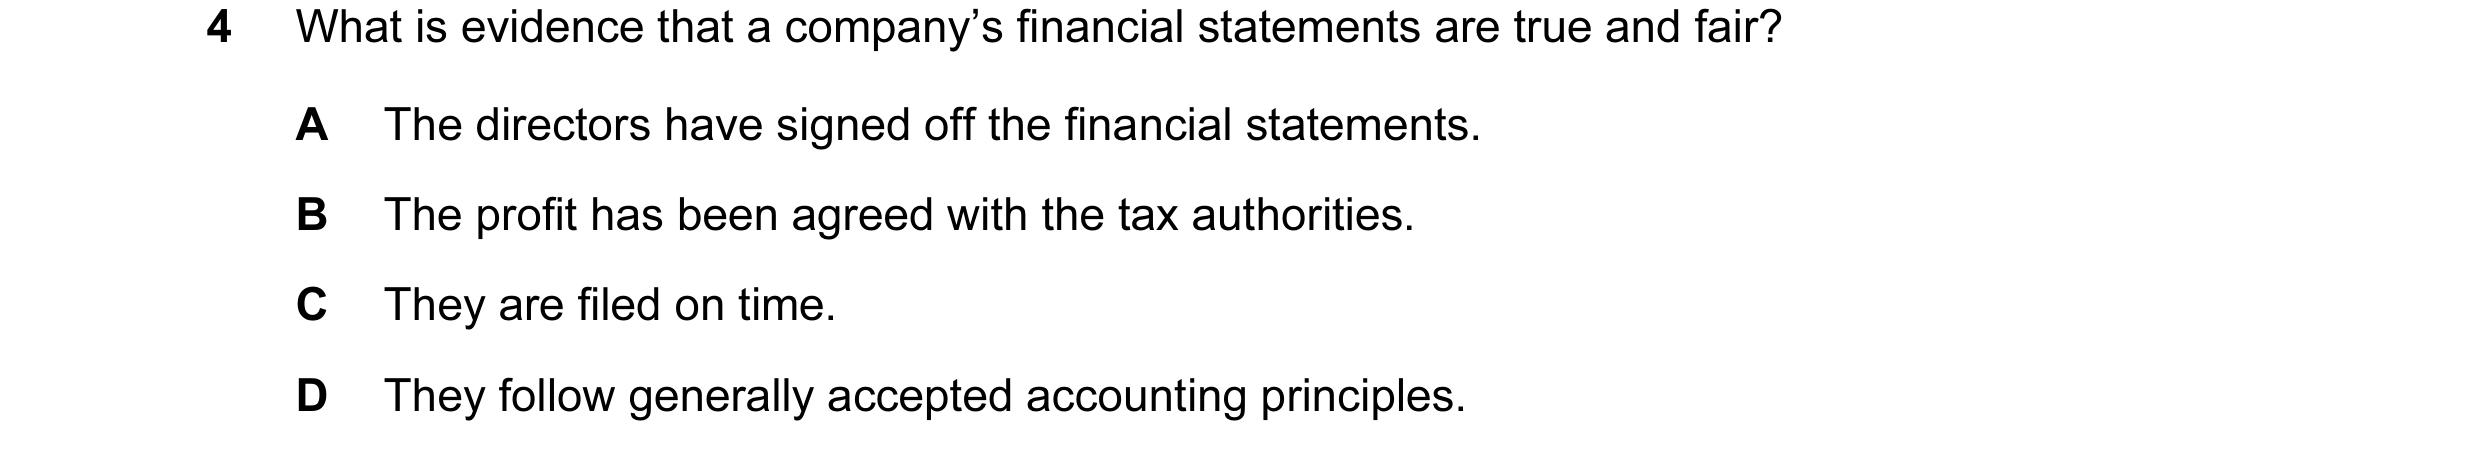
 58 / 233
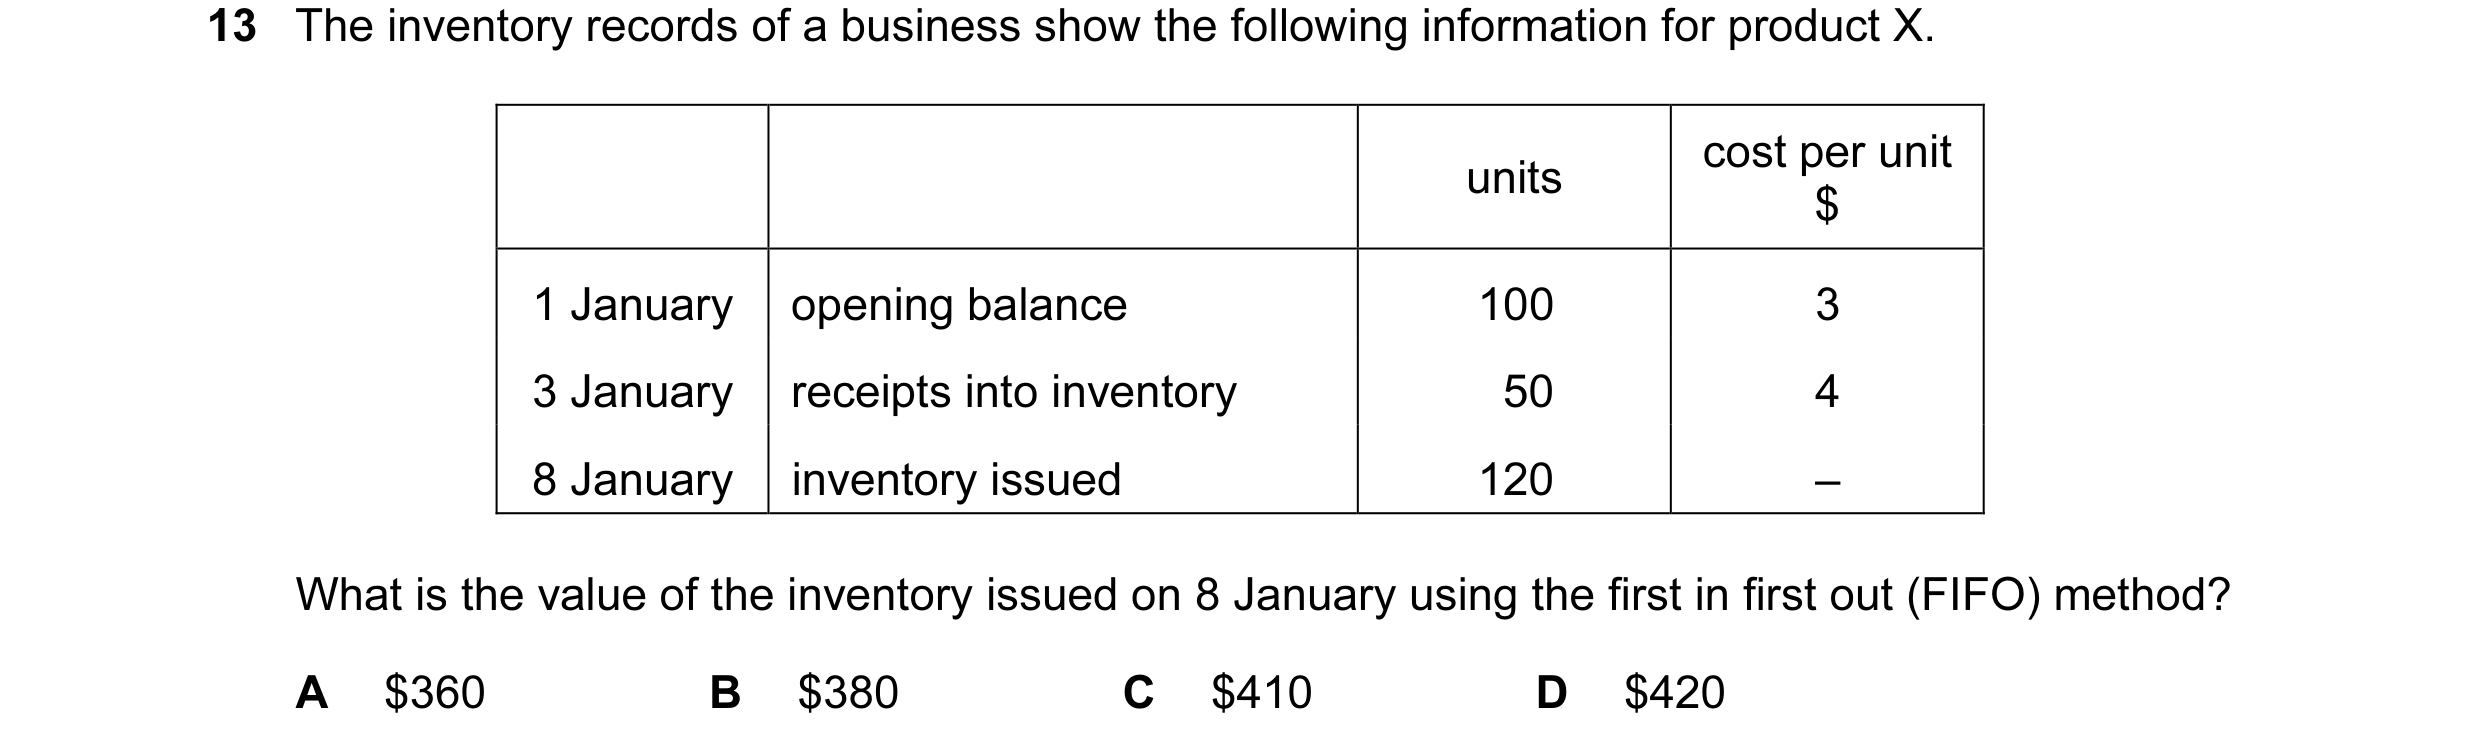
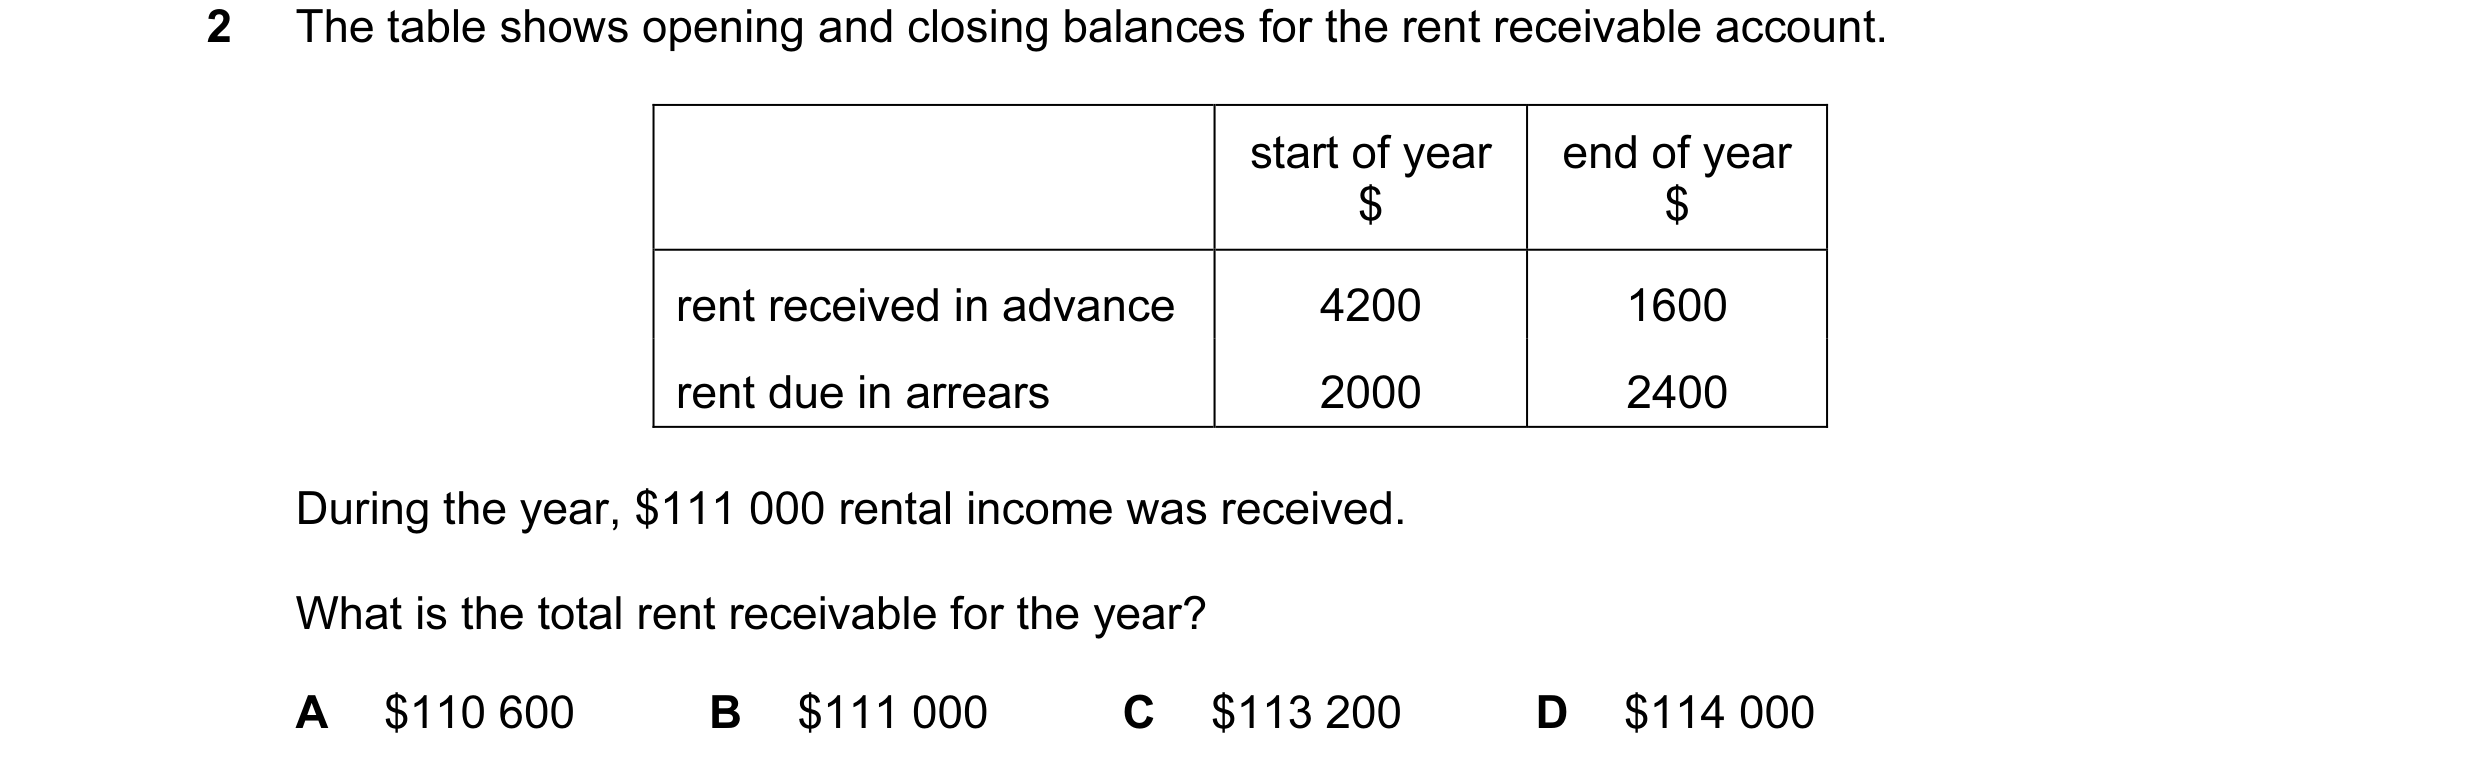
 59 / 233
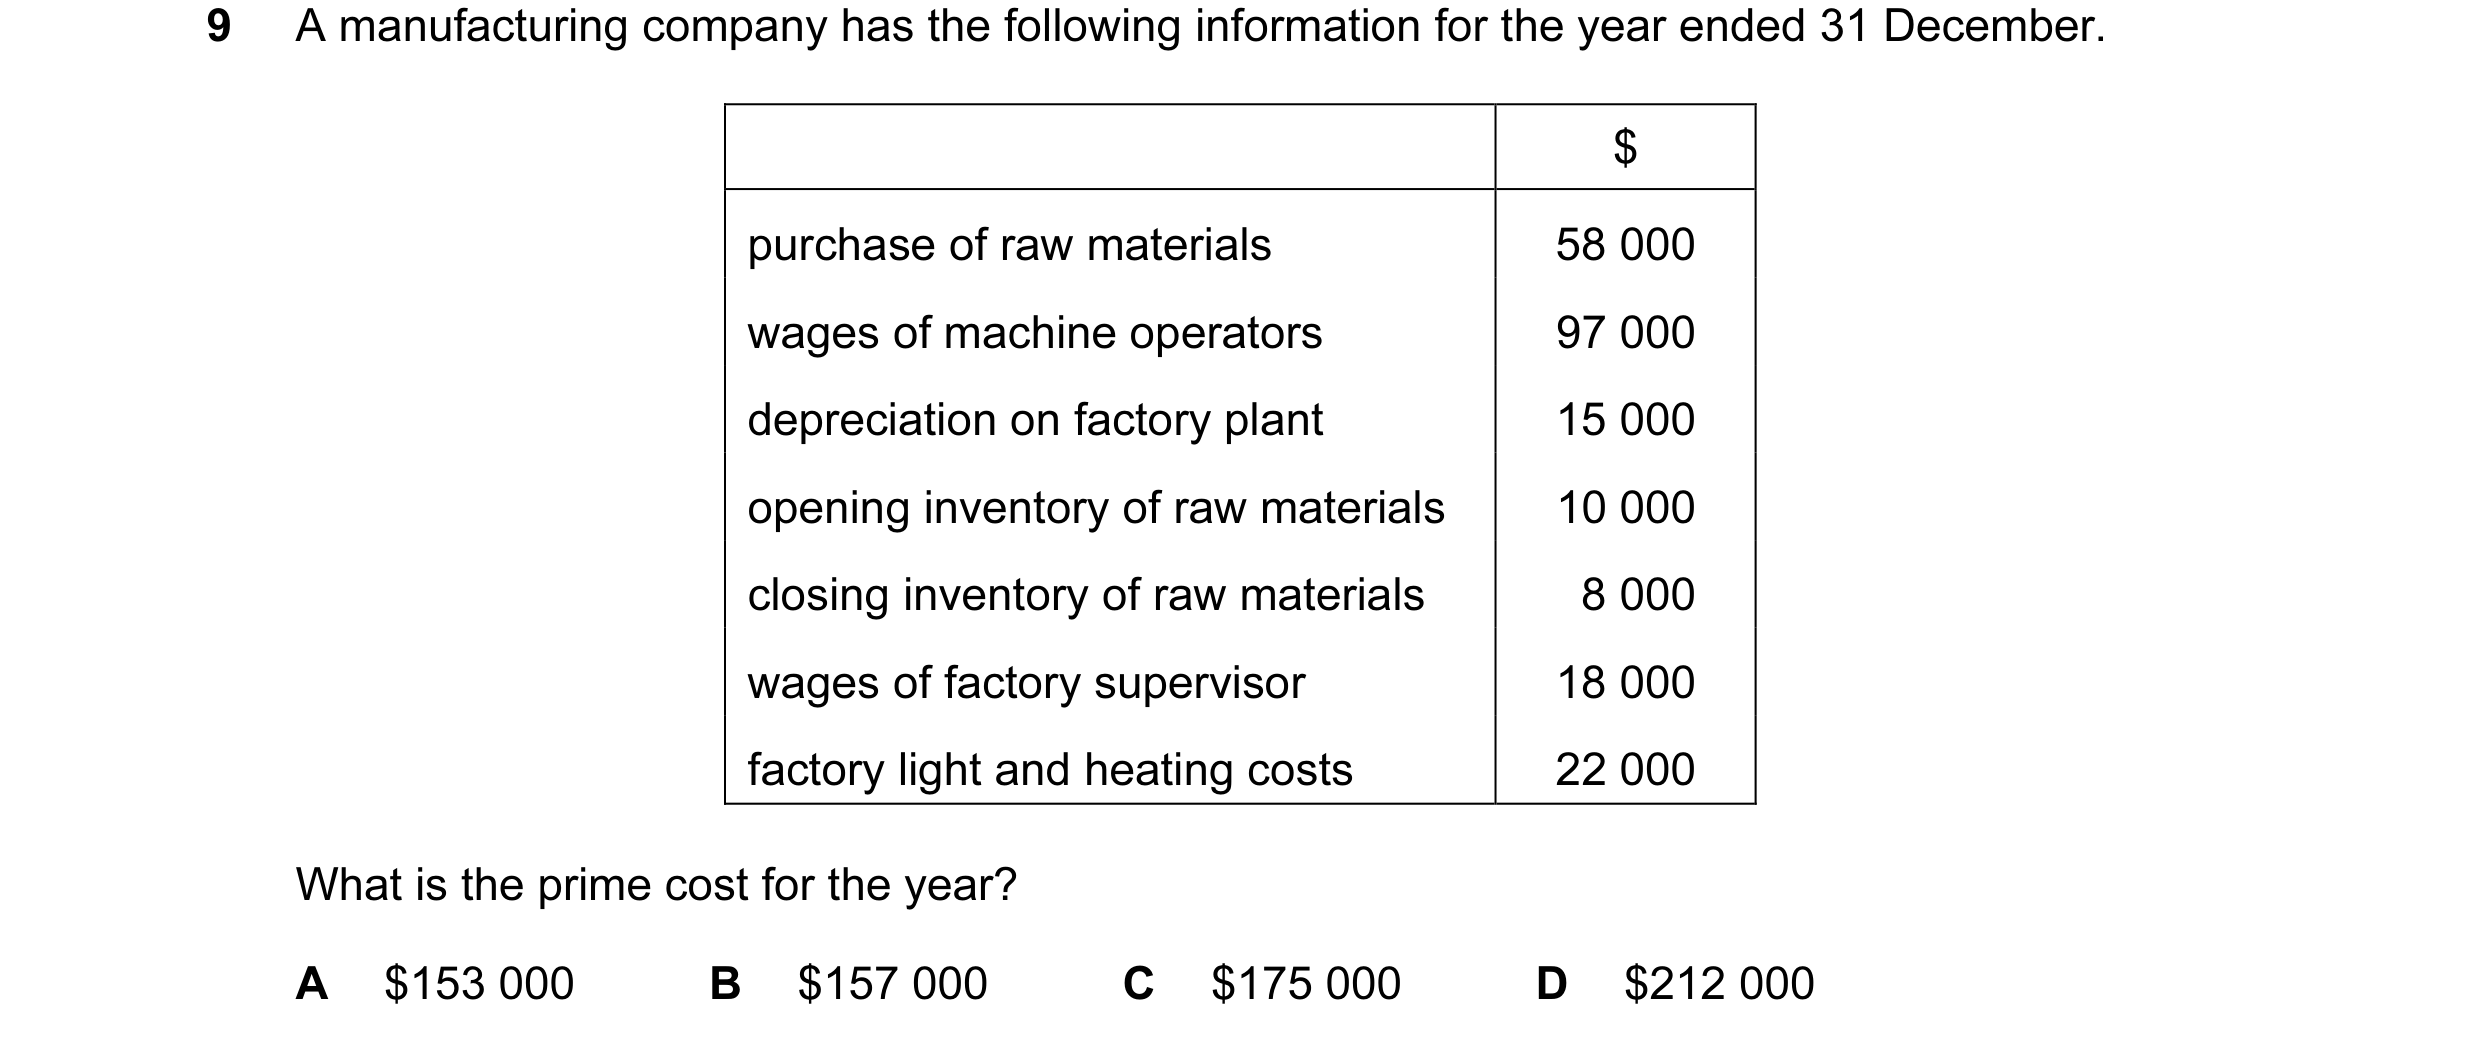
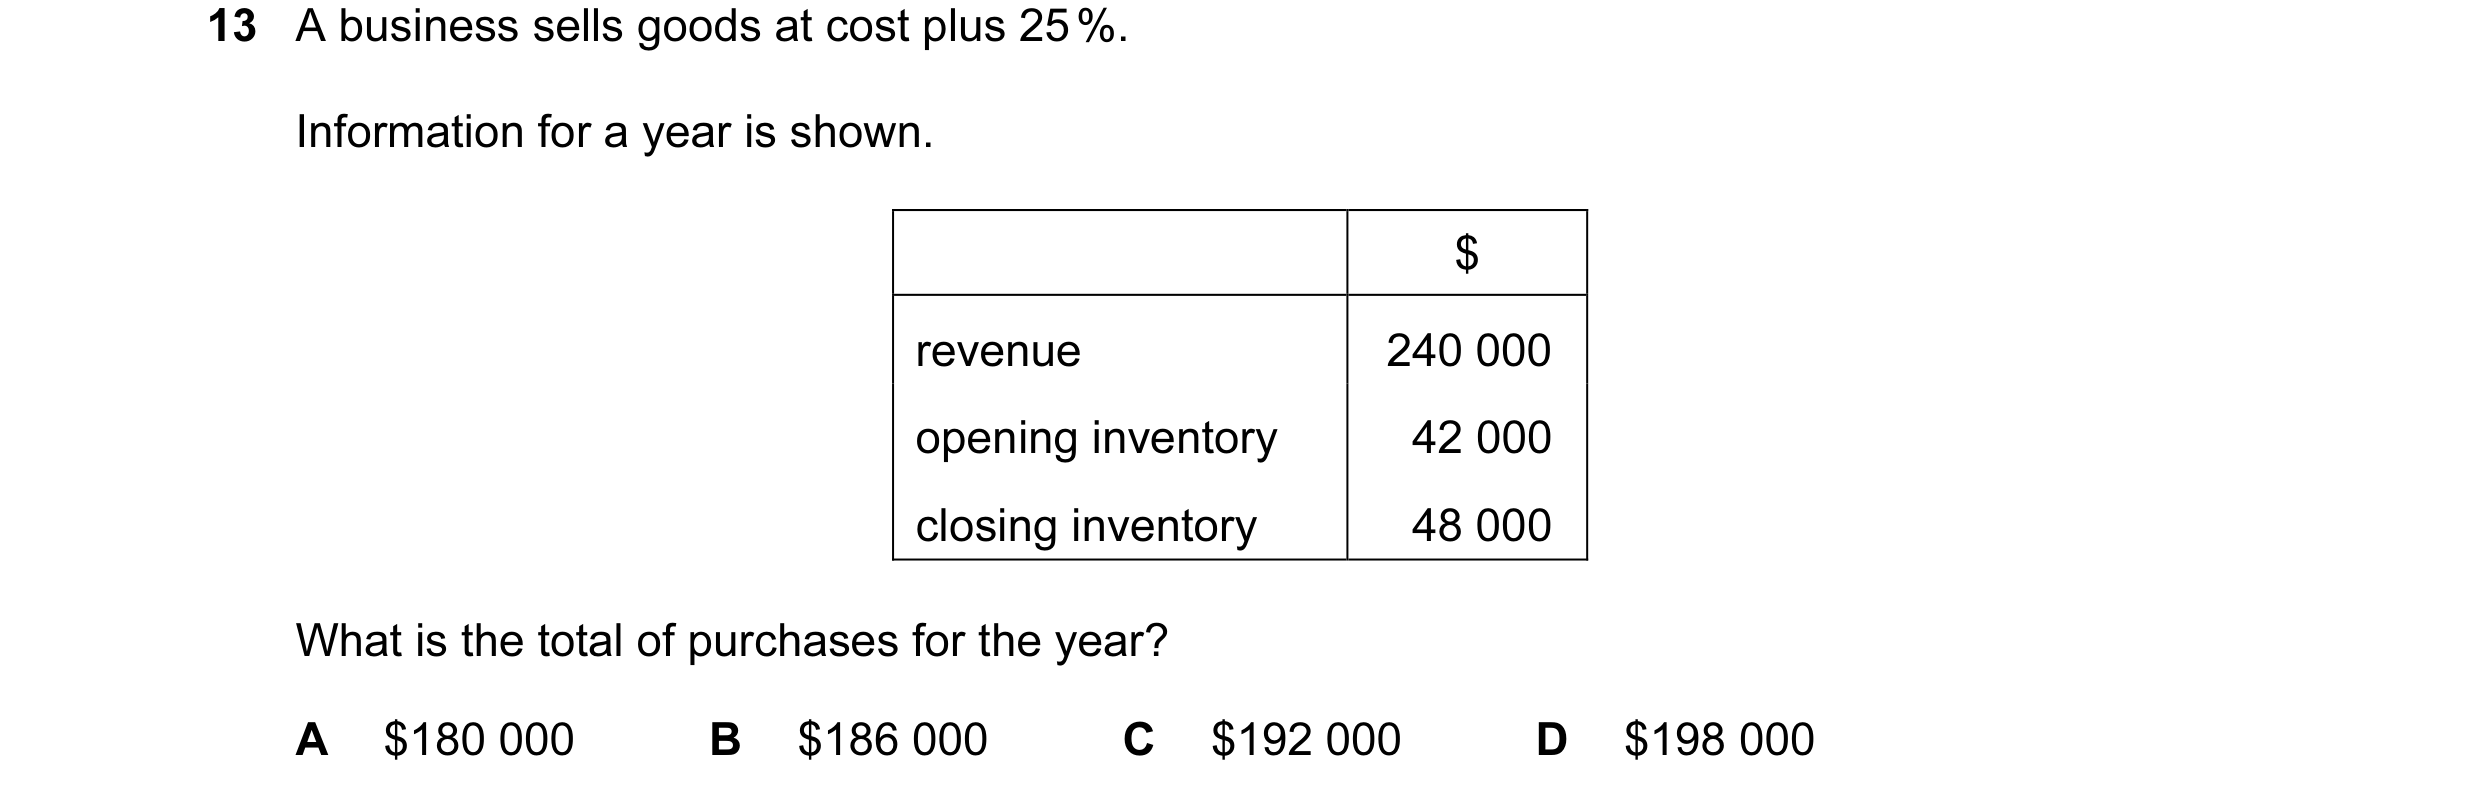
 60 / 233
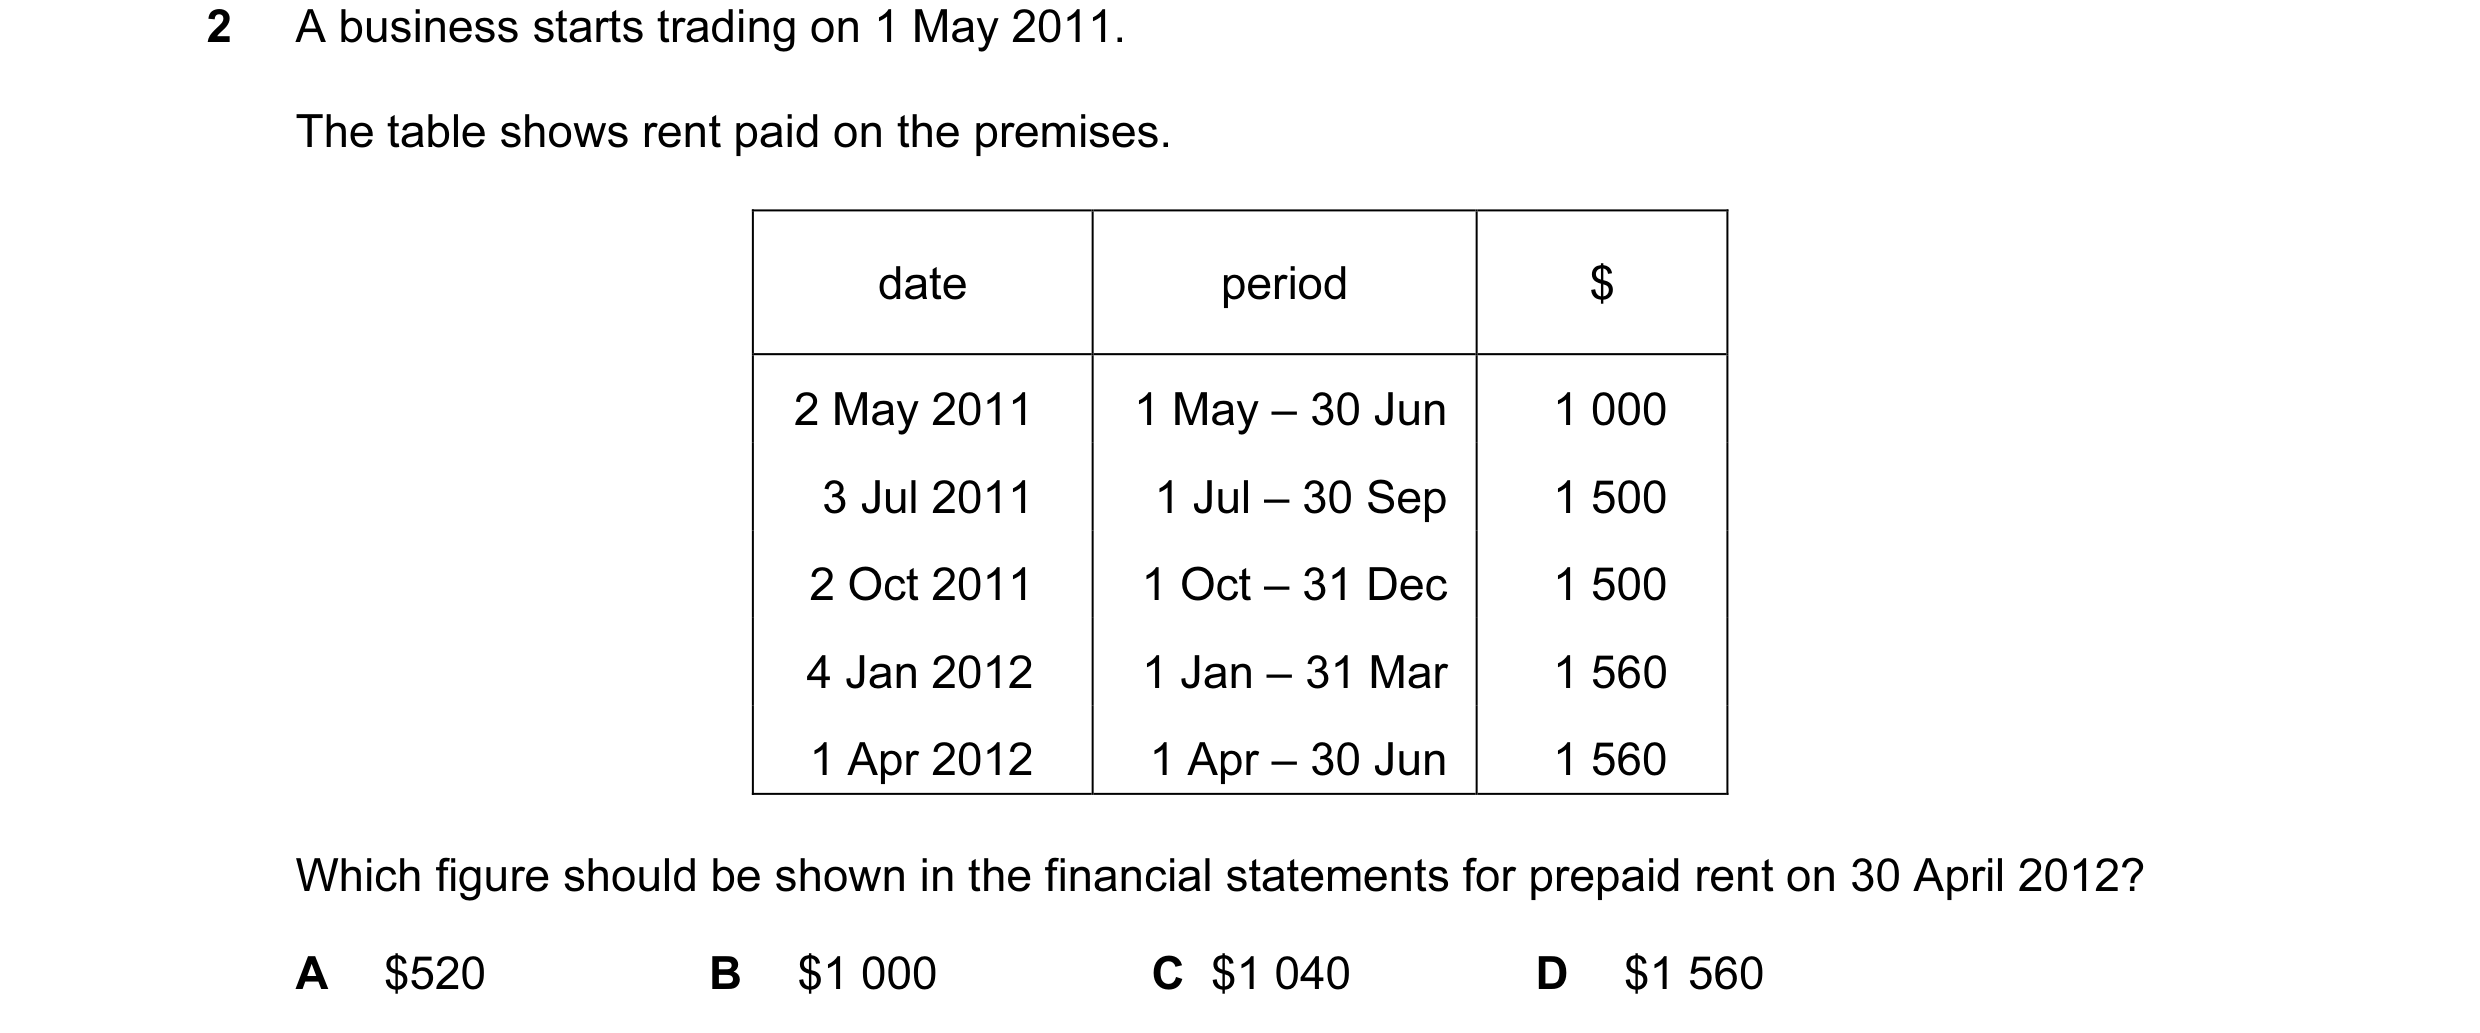
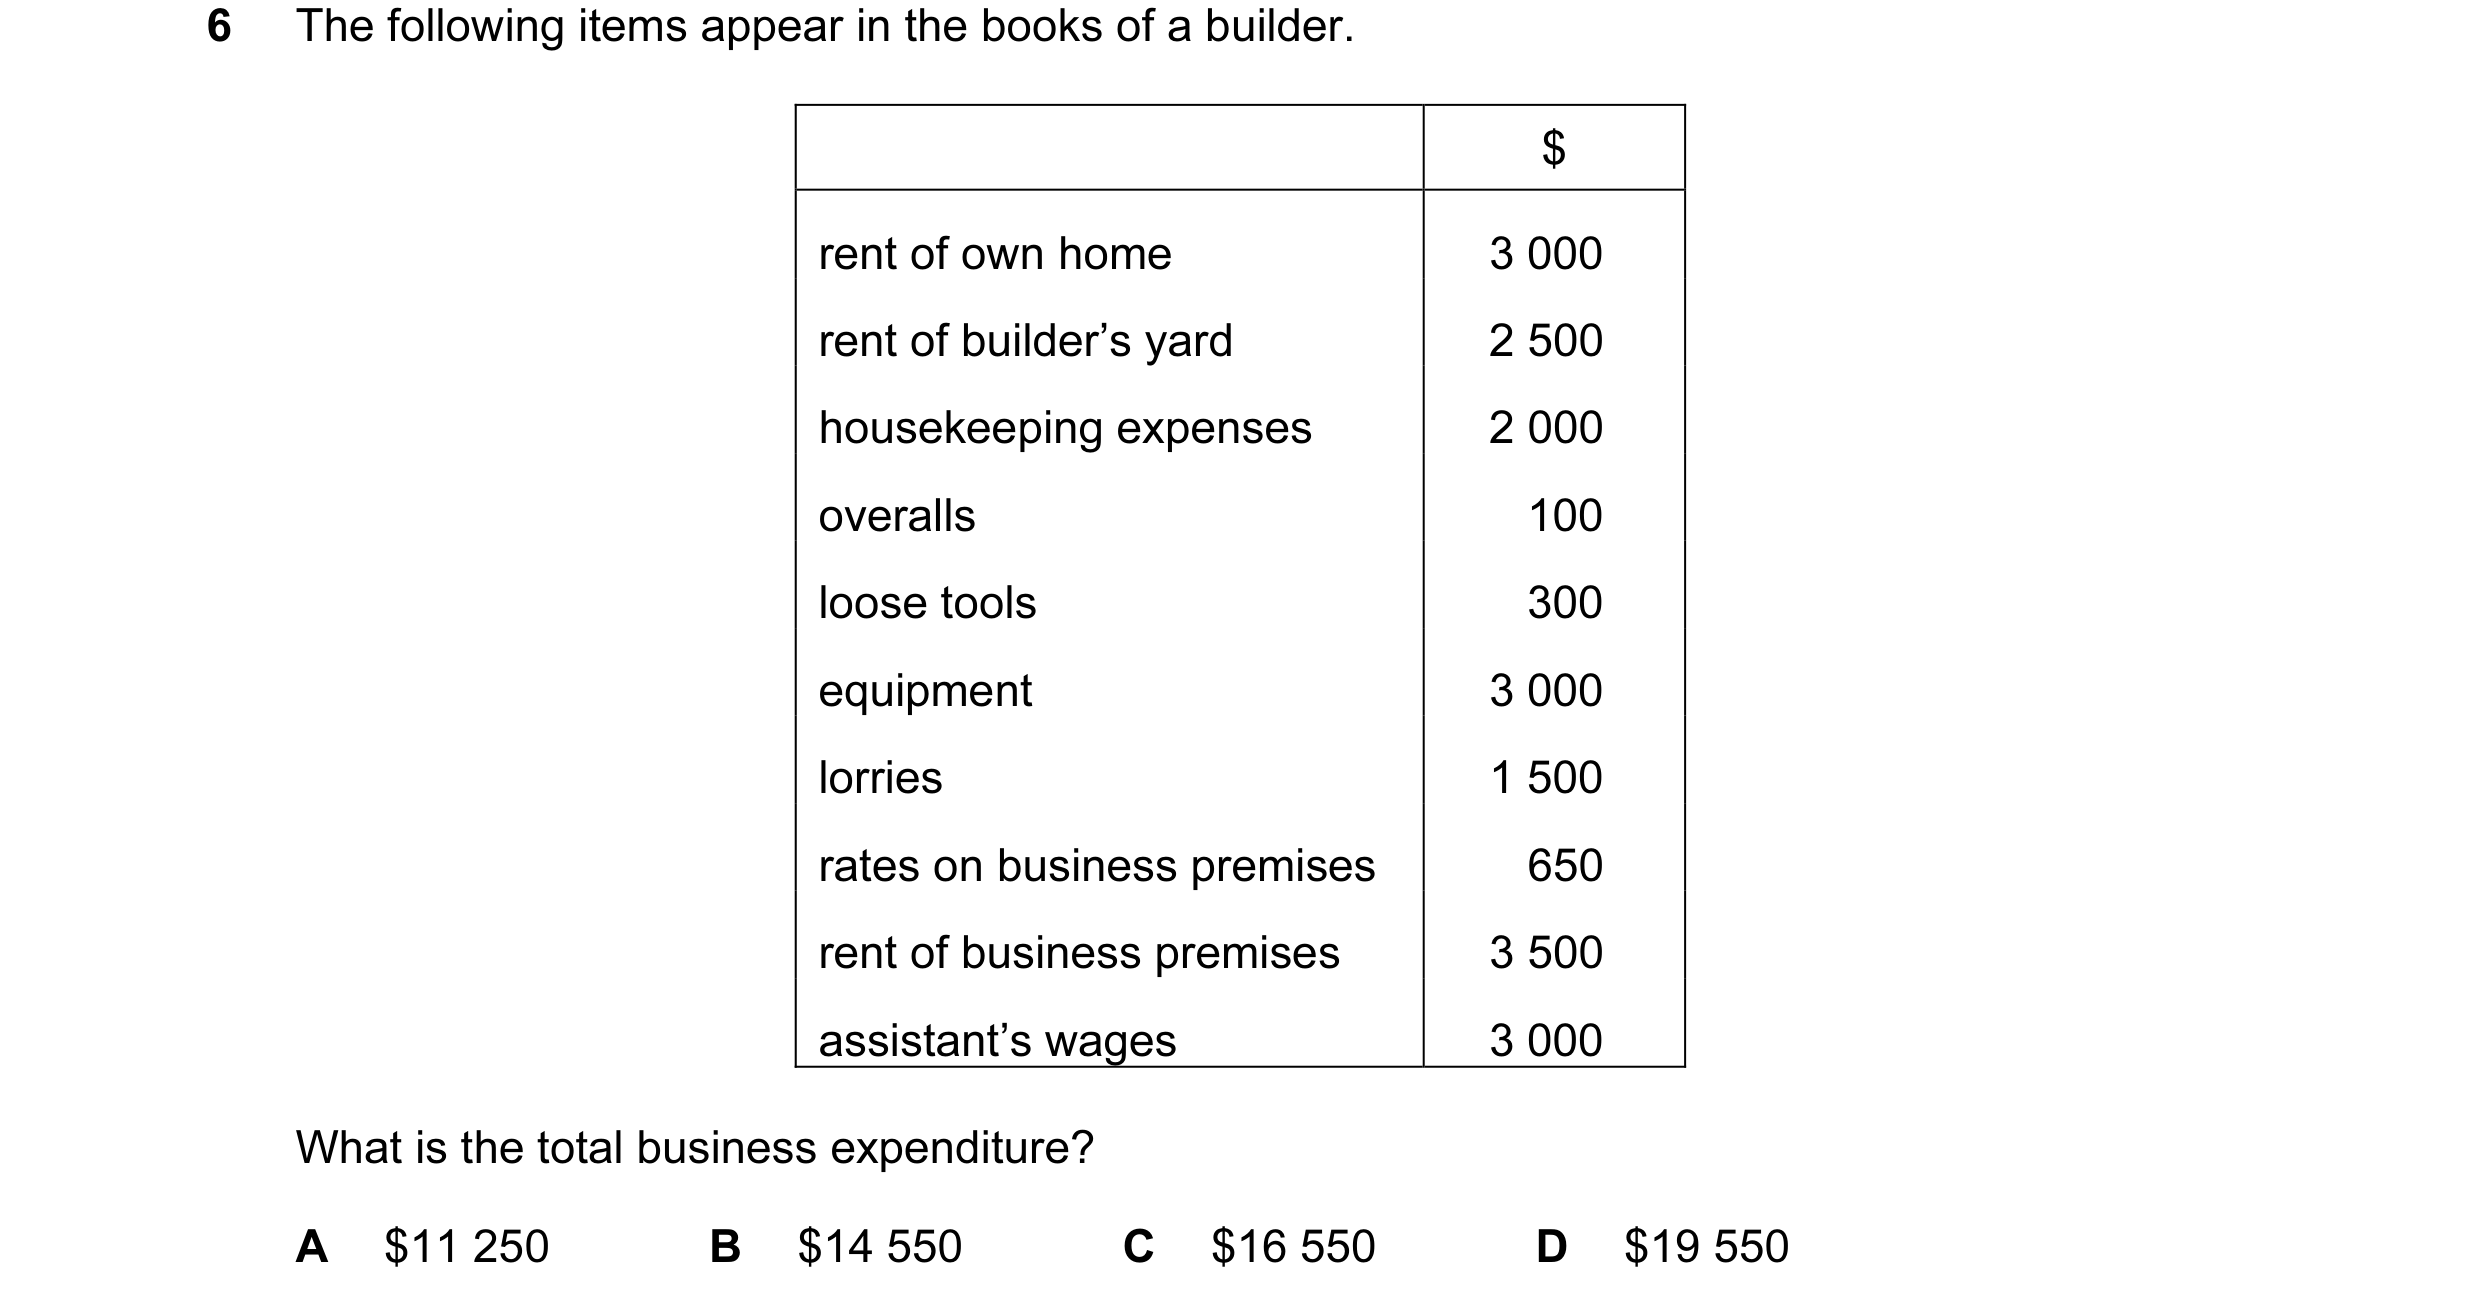
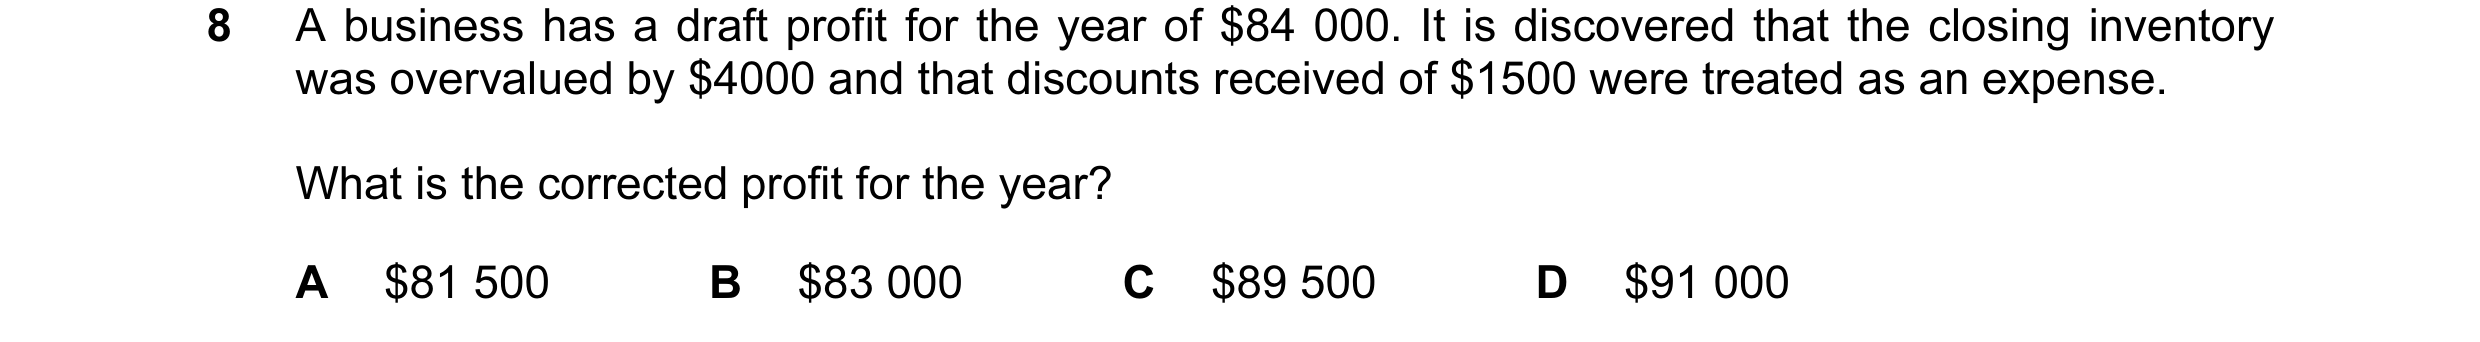 61 / 233
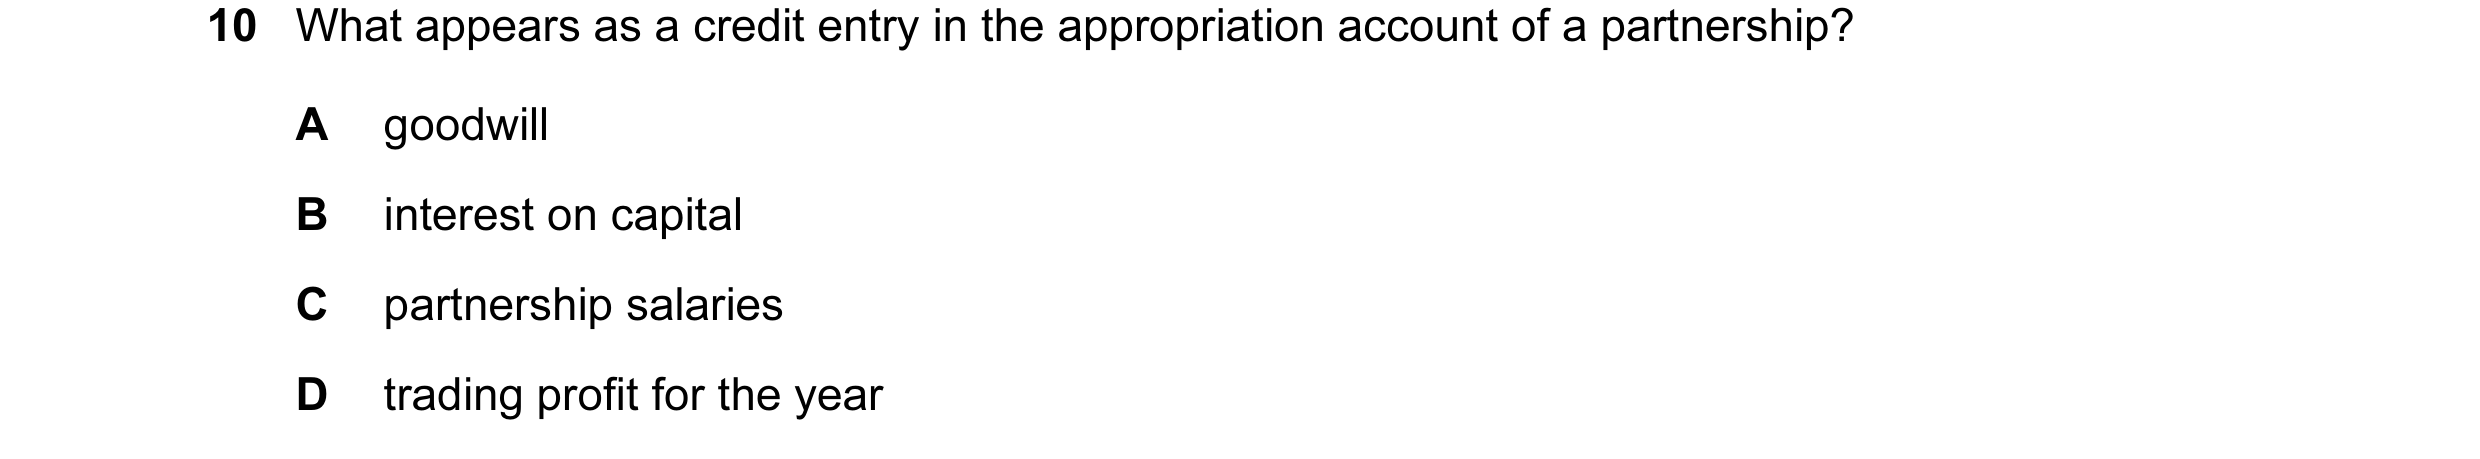
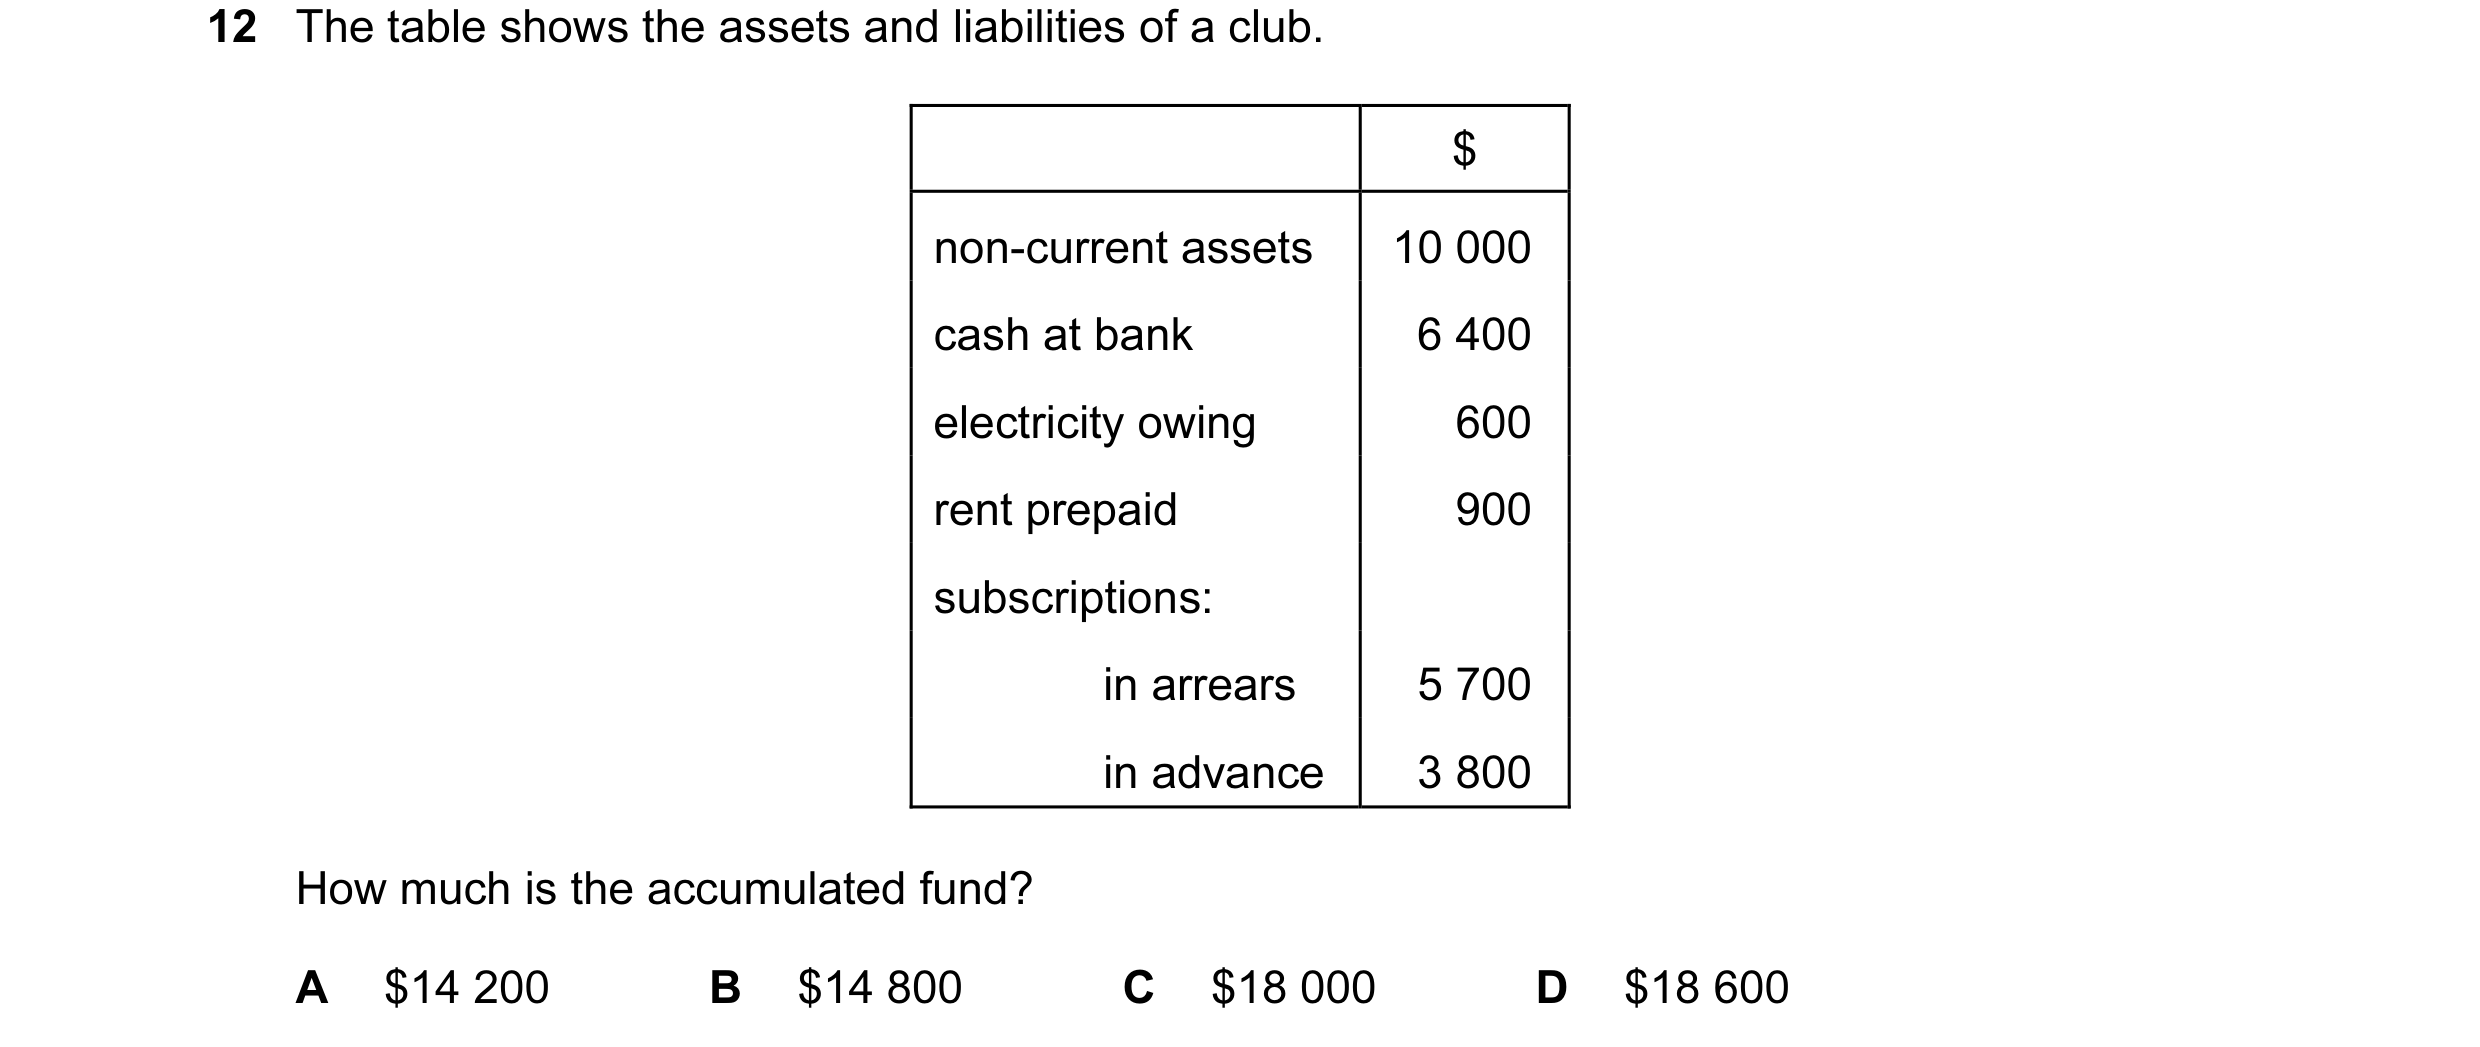
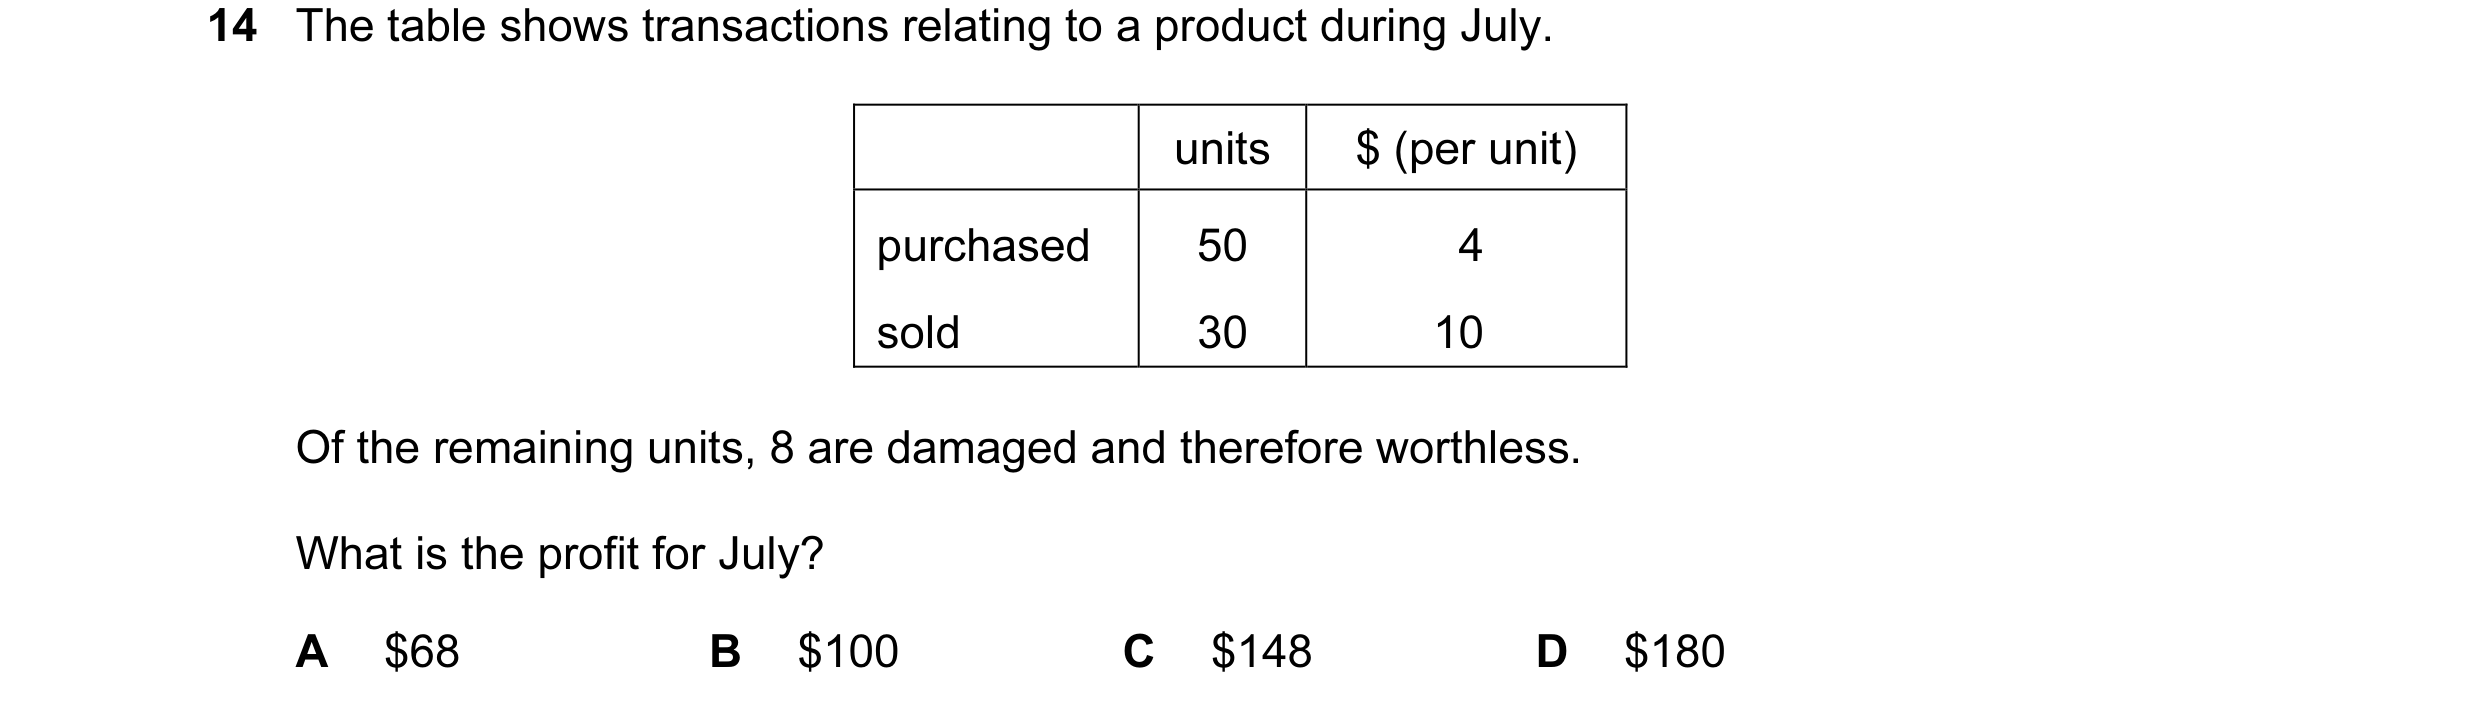
 62 / 233
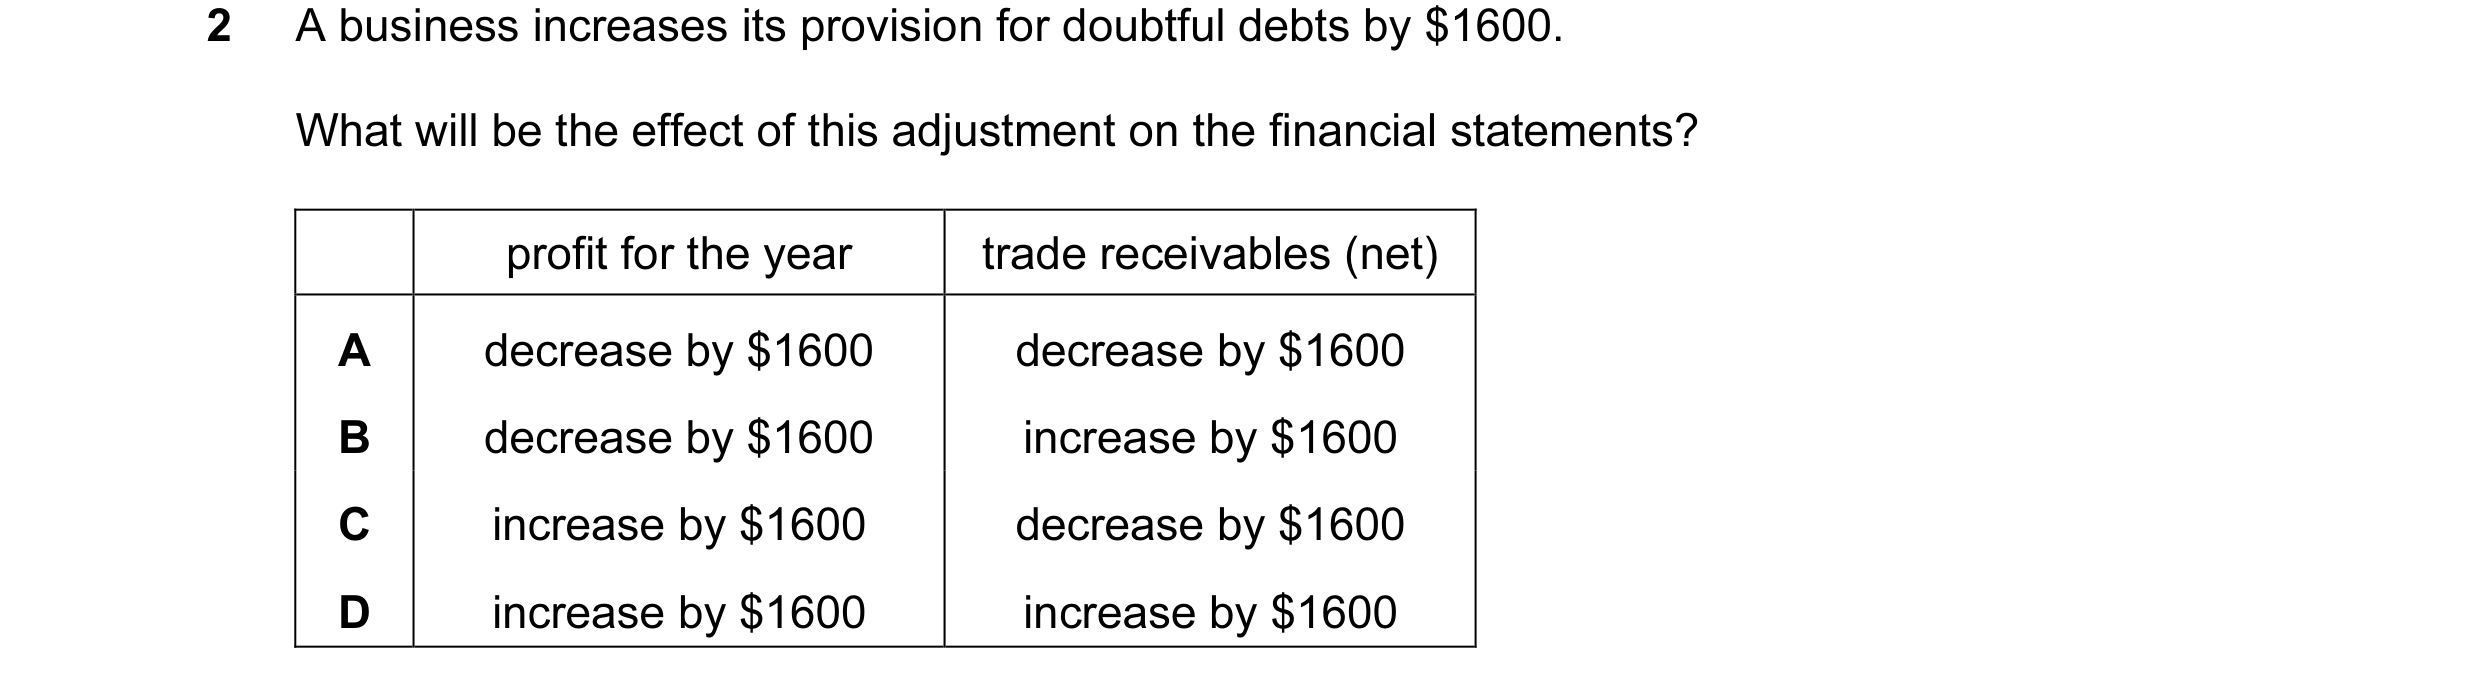
 63 / 233
 64 / 233
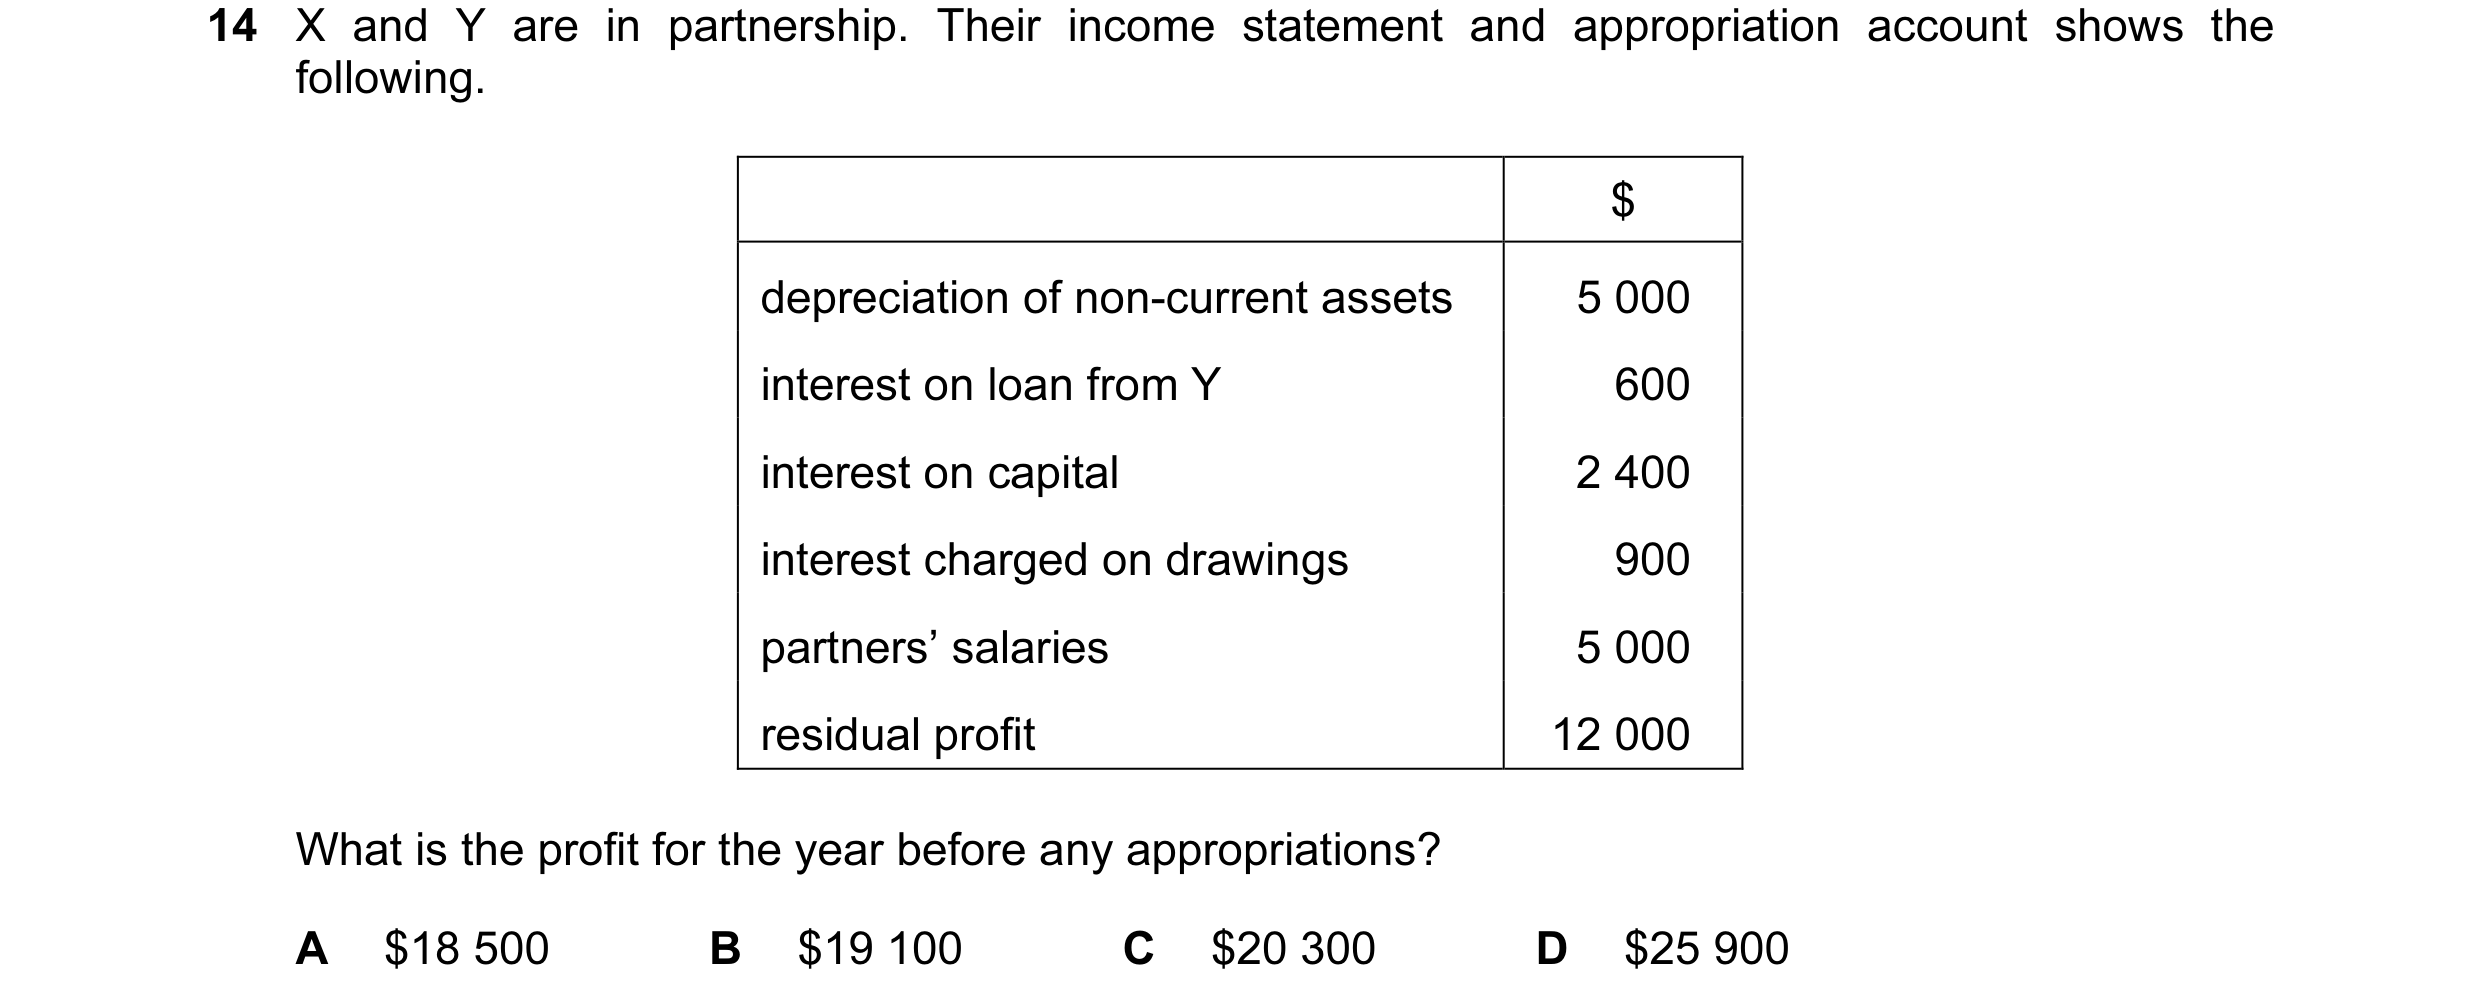
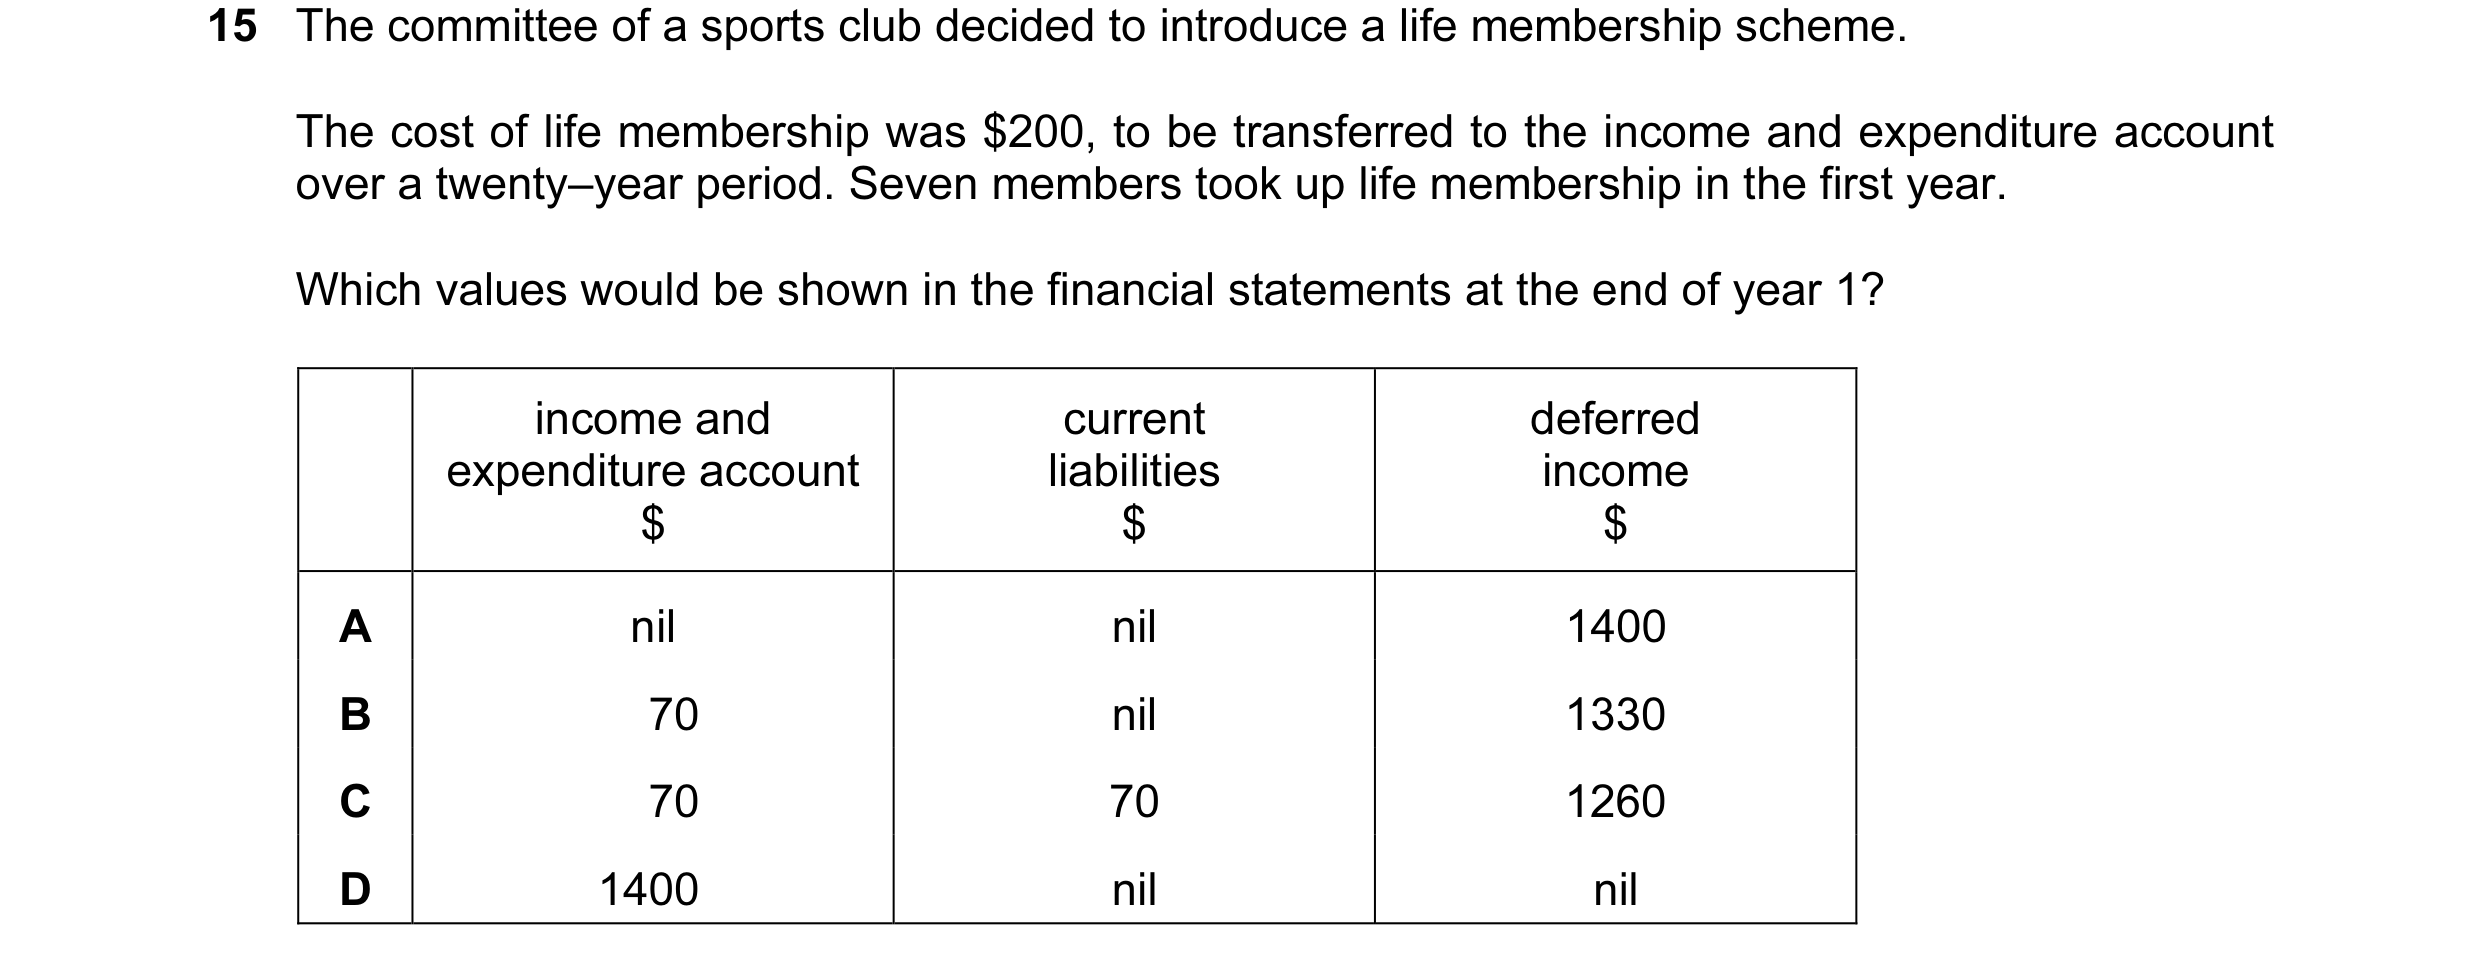
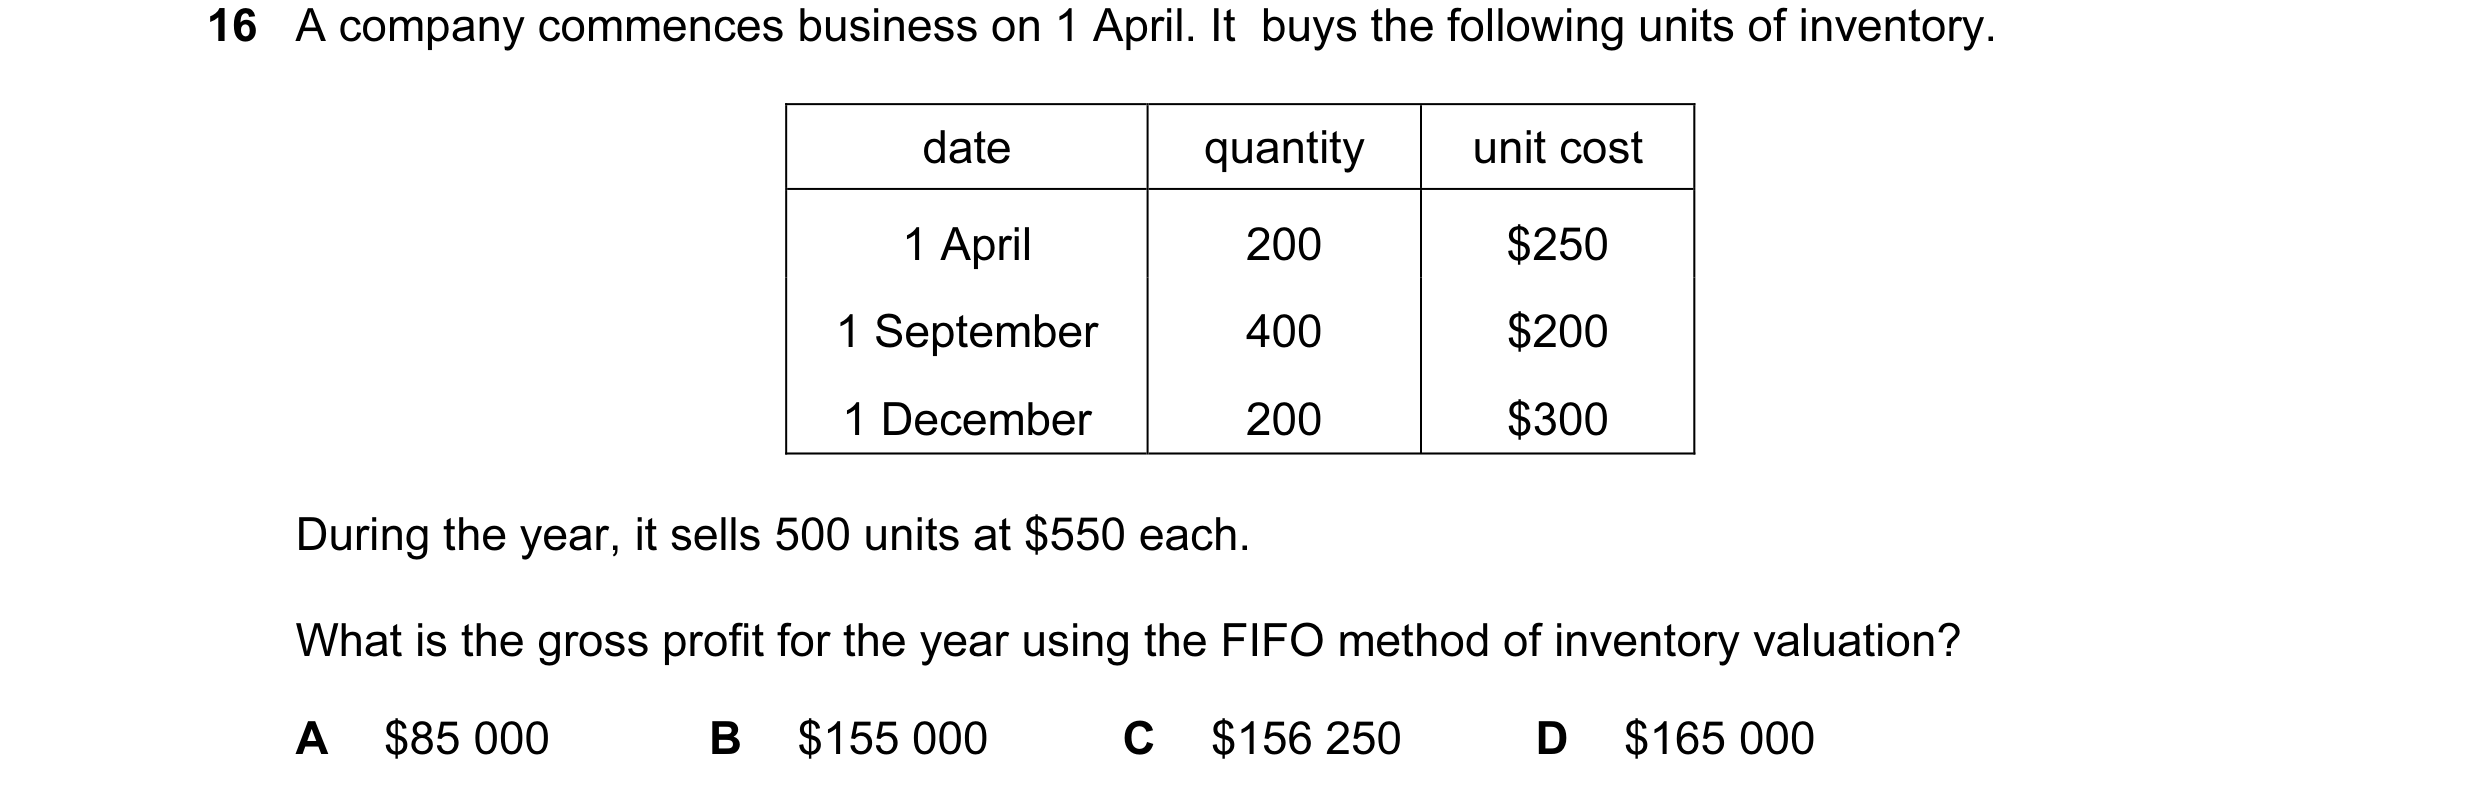 65 / 233
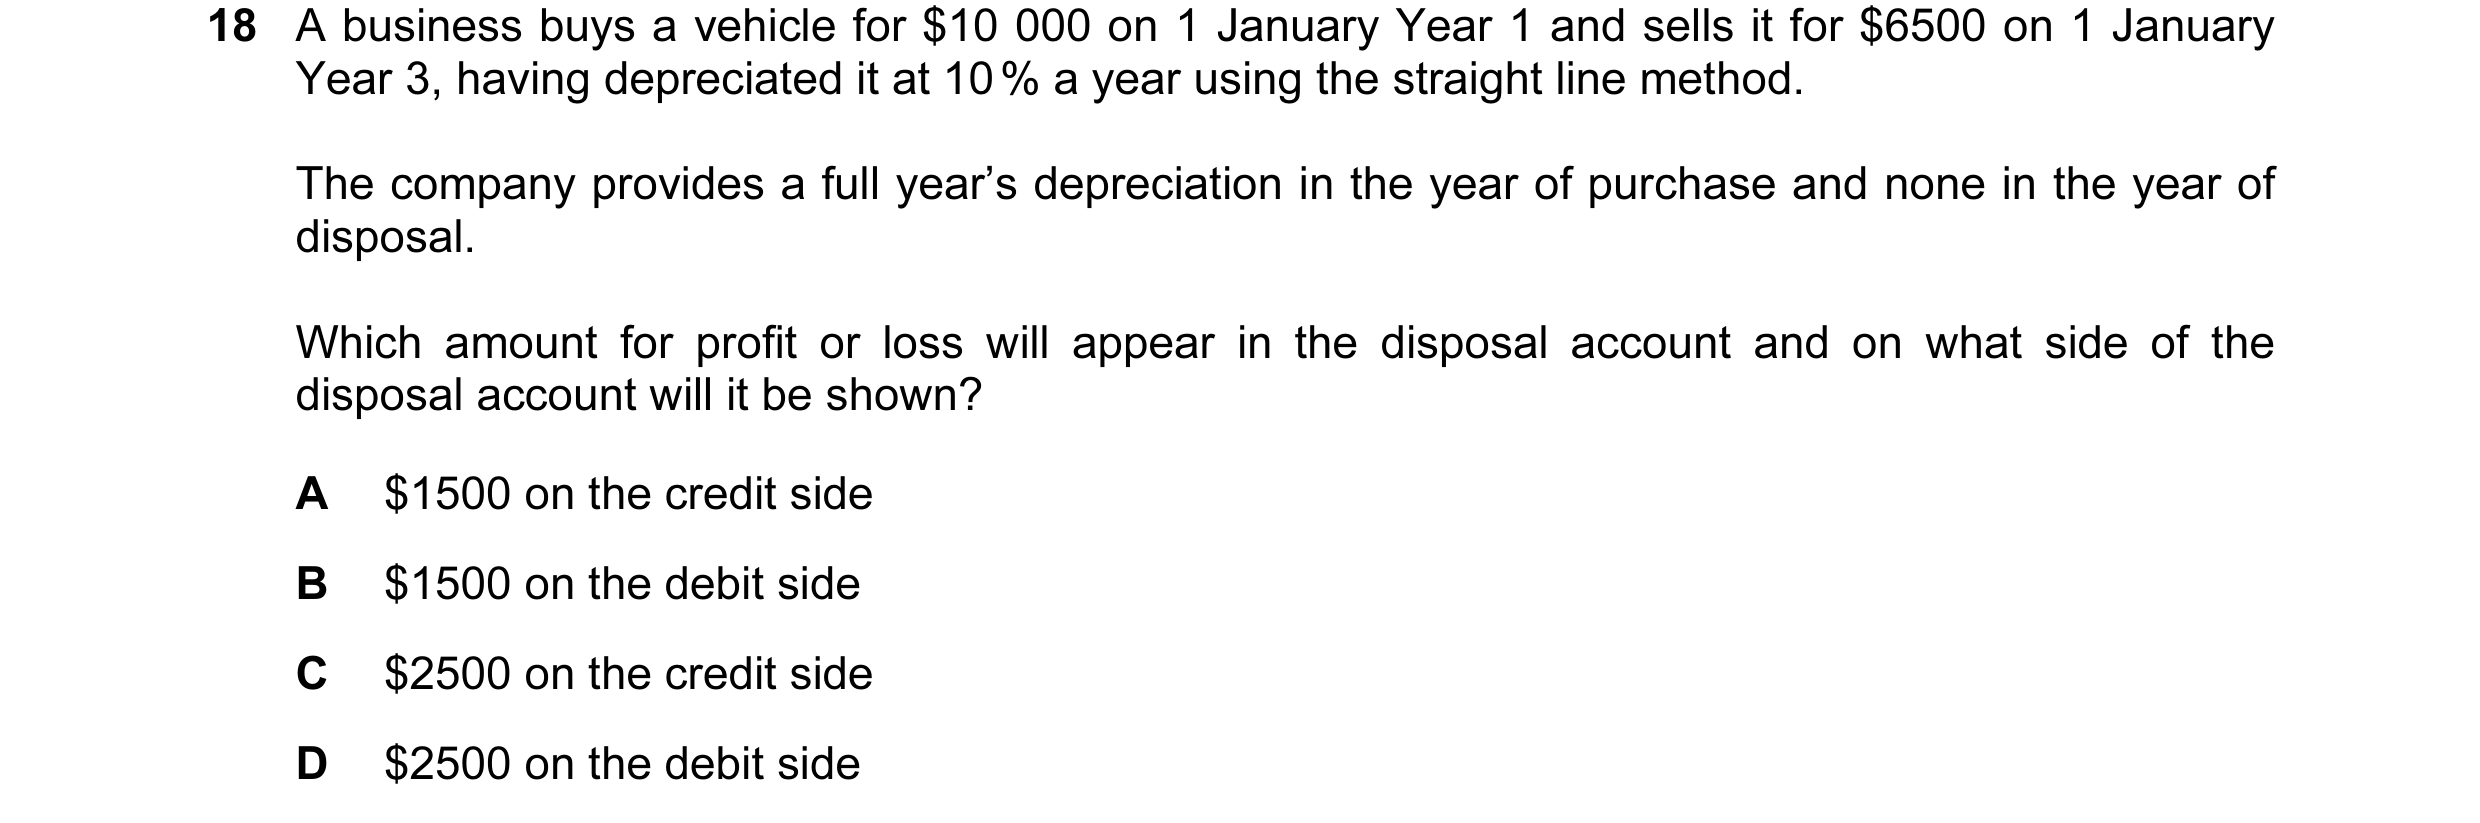
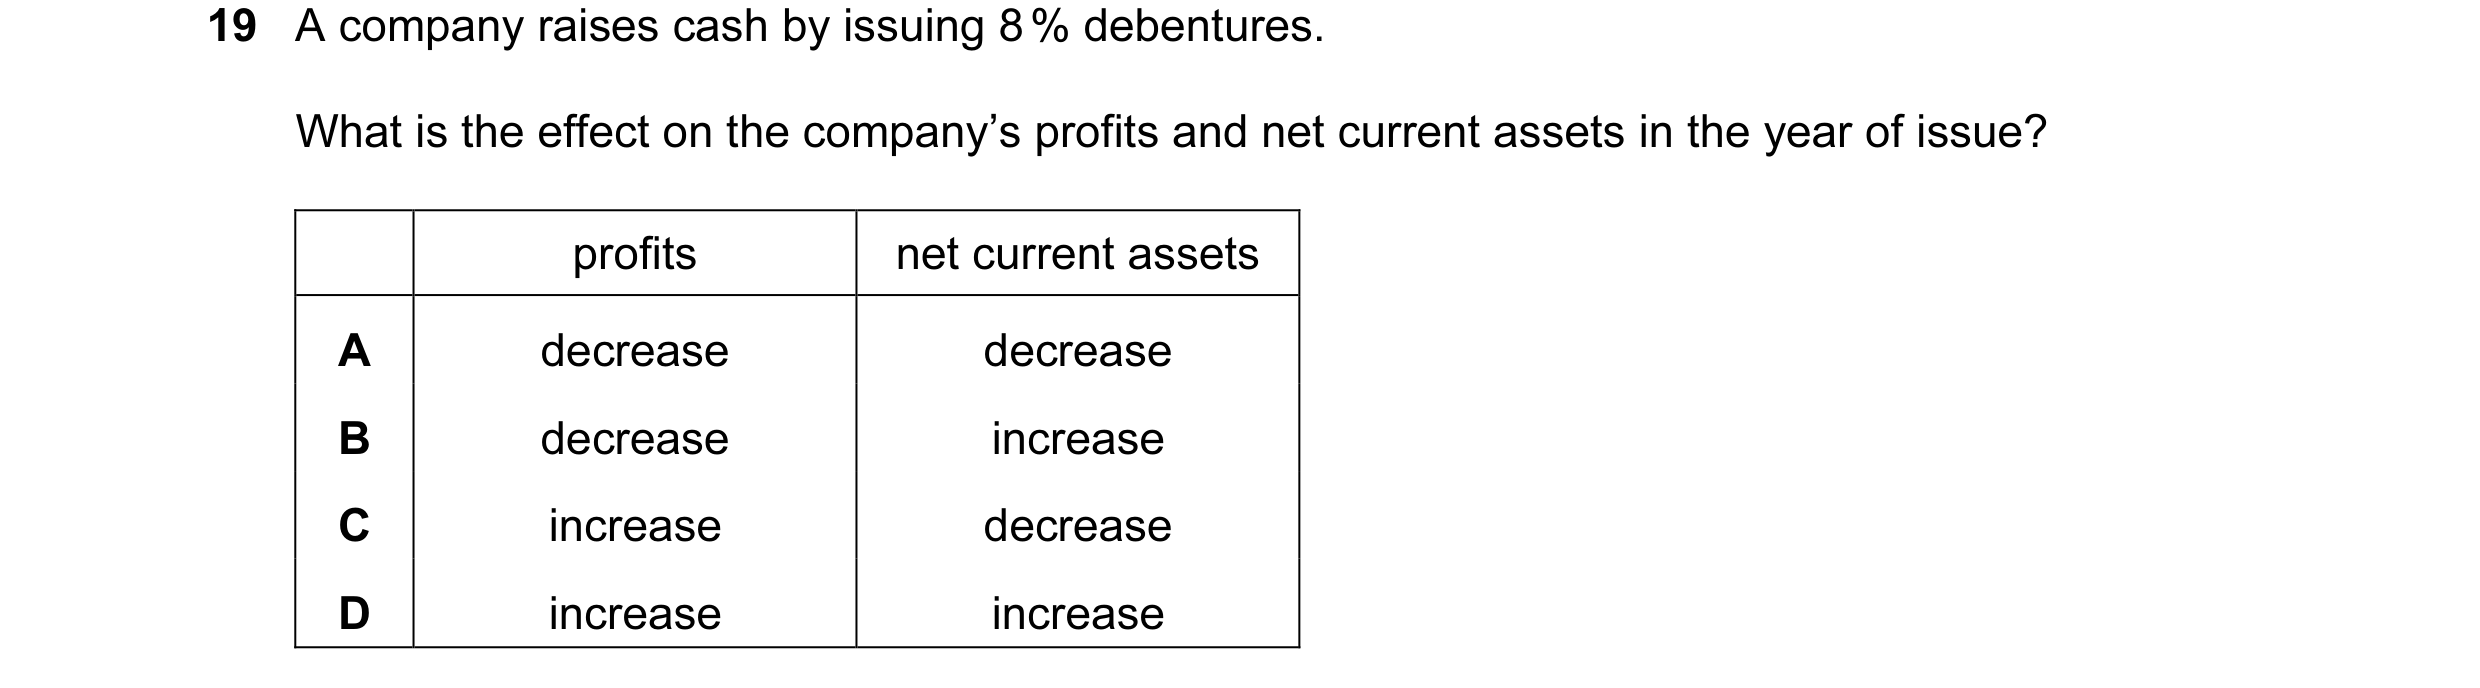
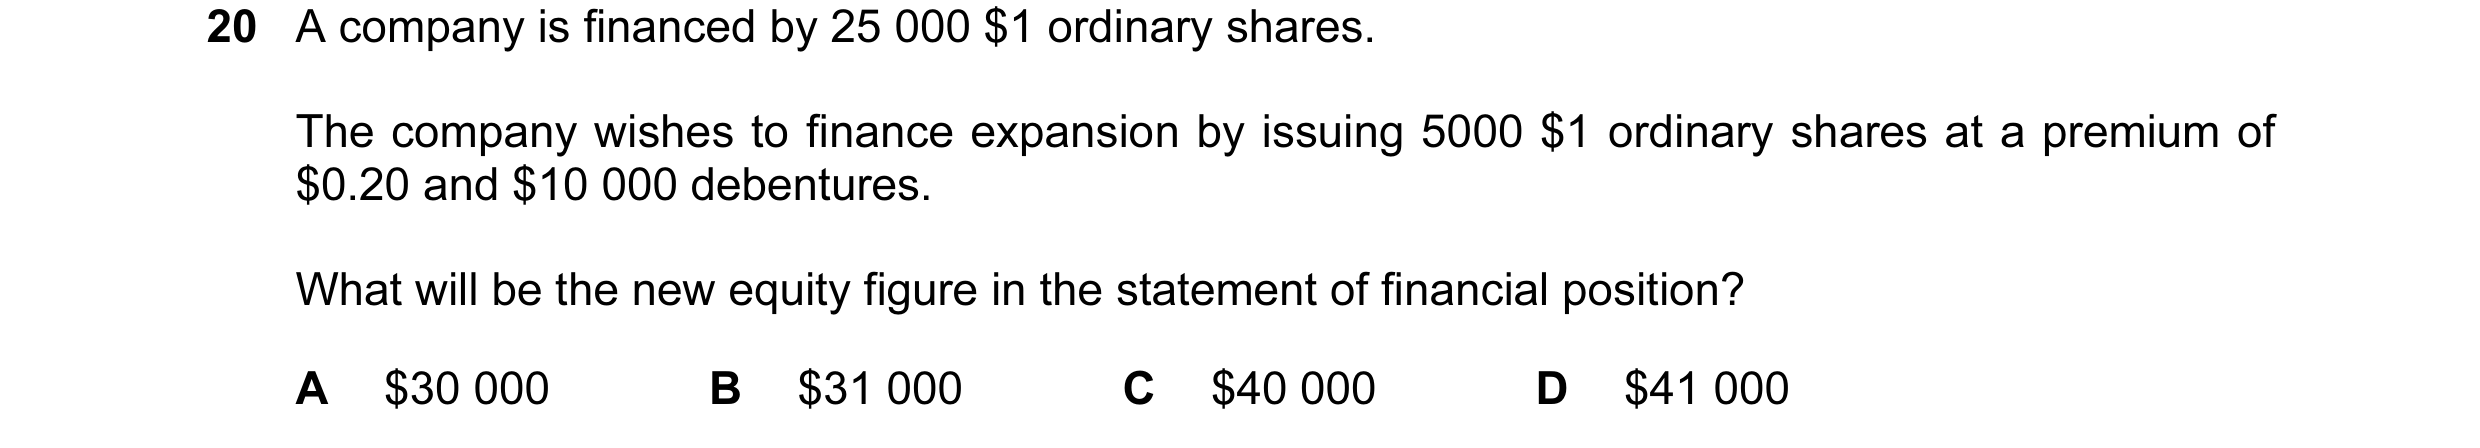
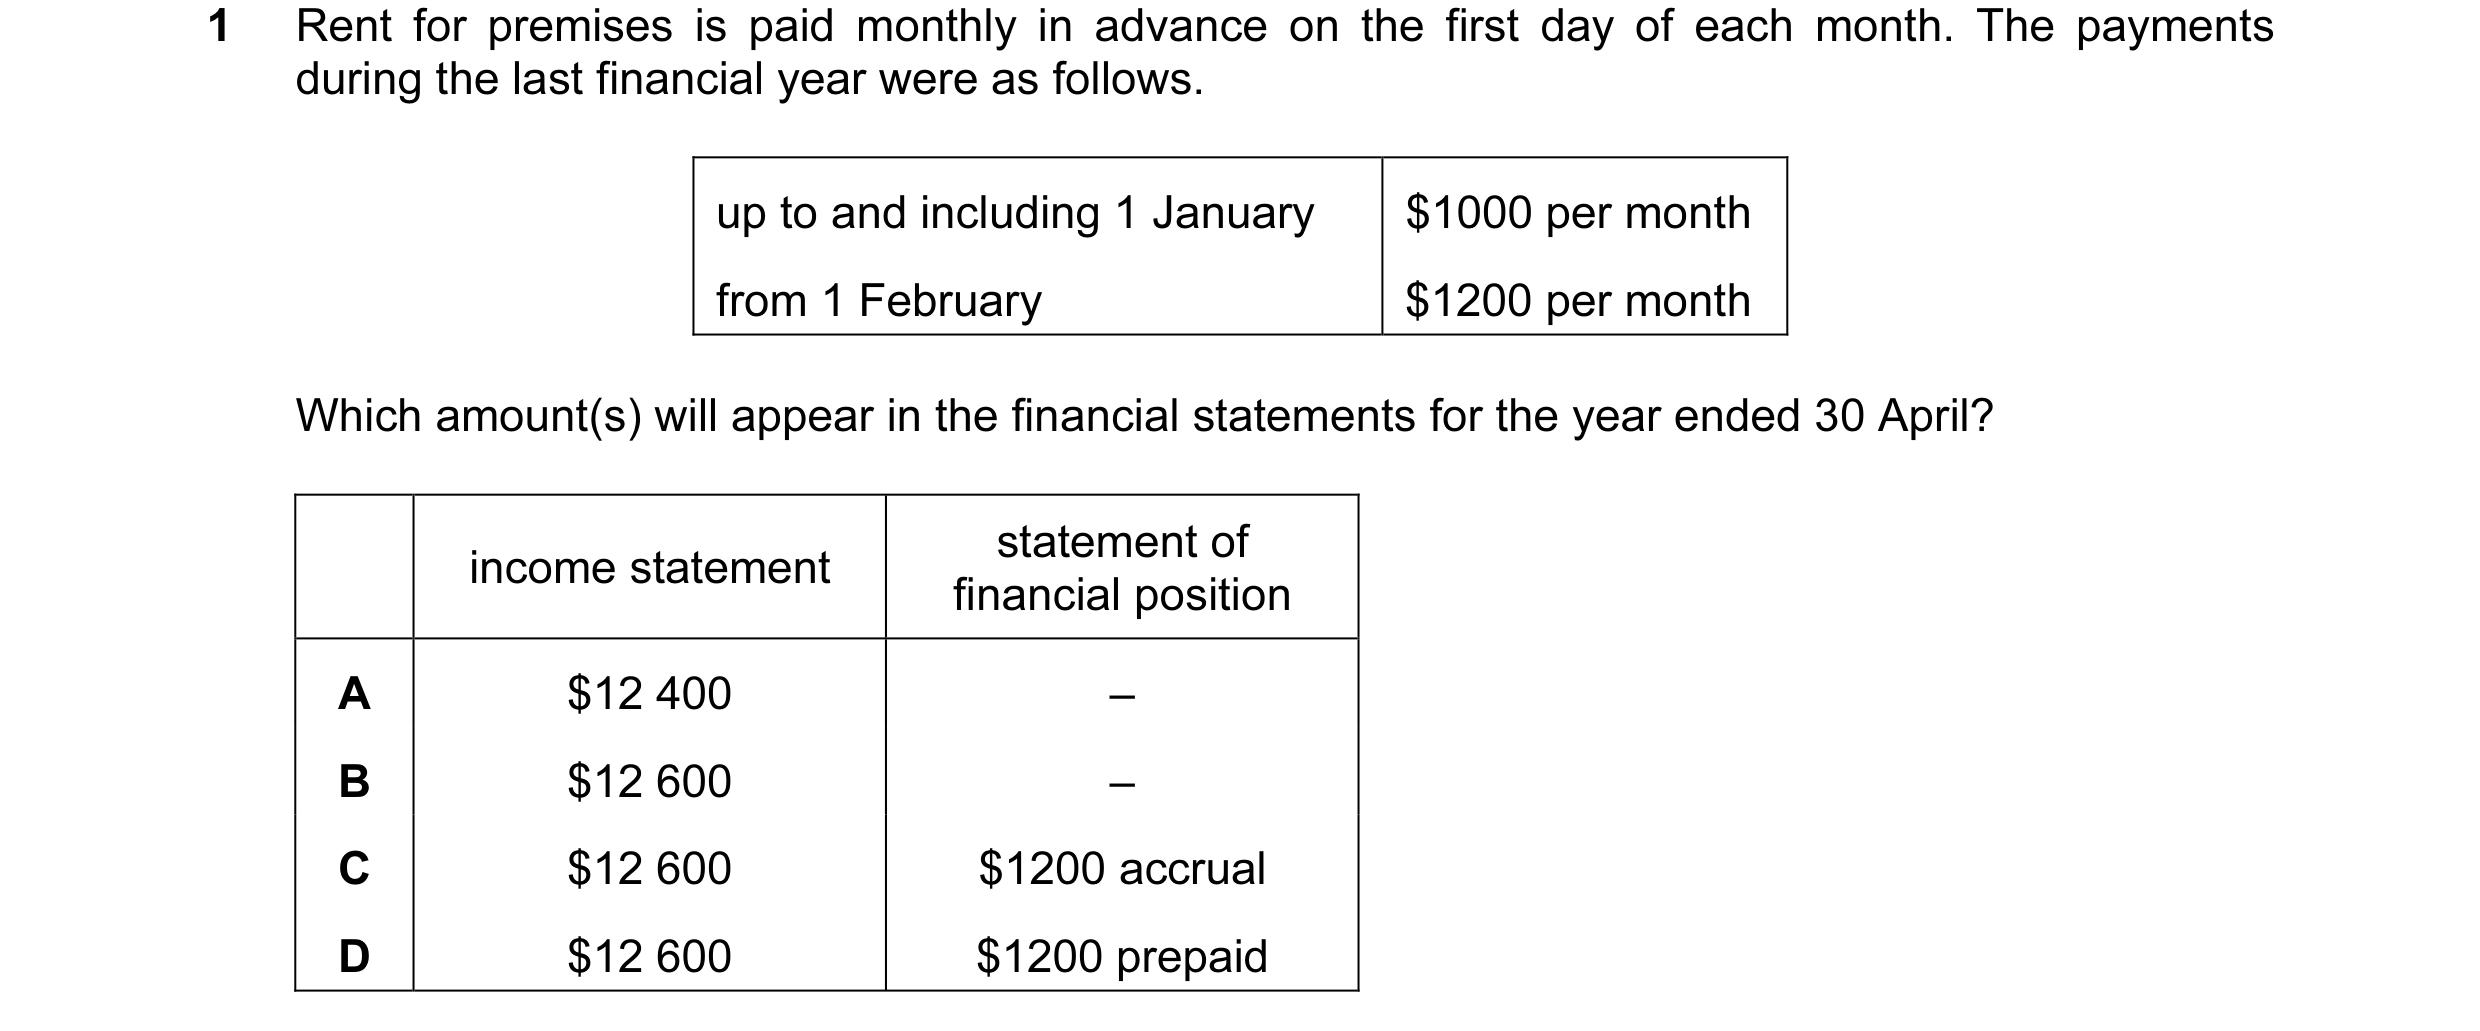 66 / 233
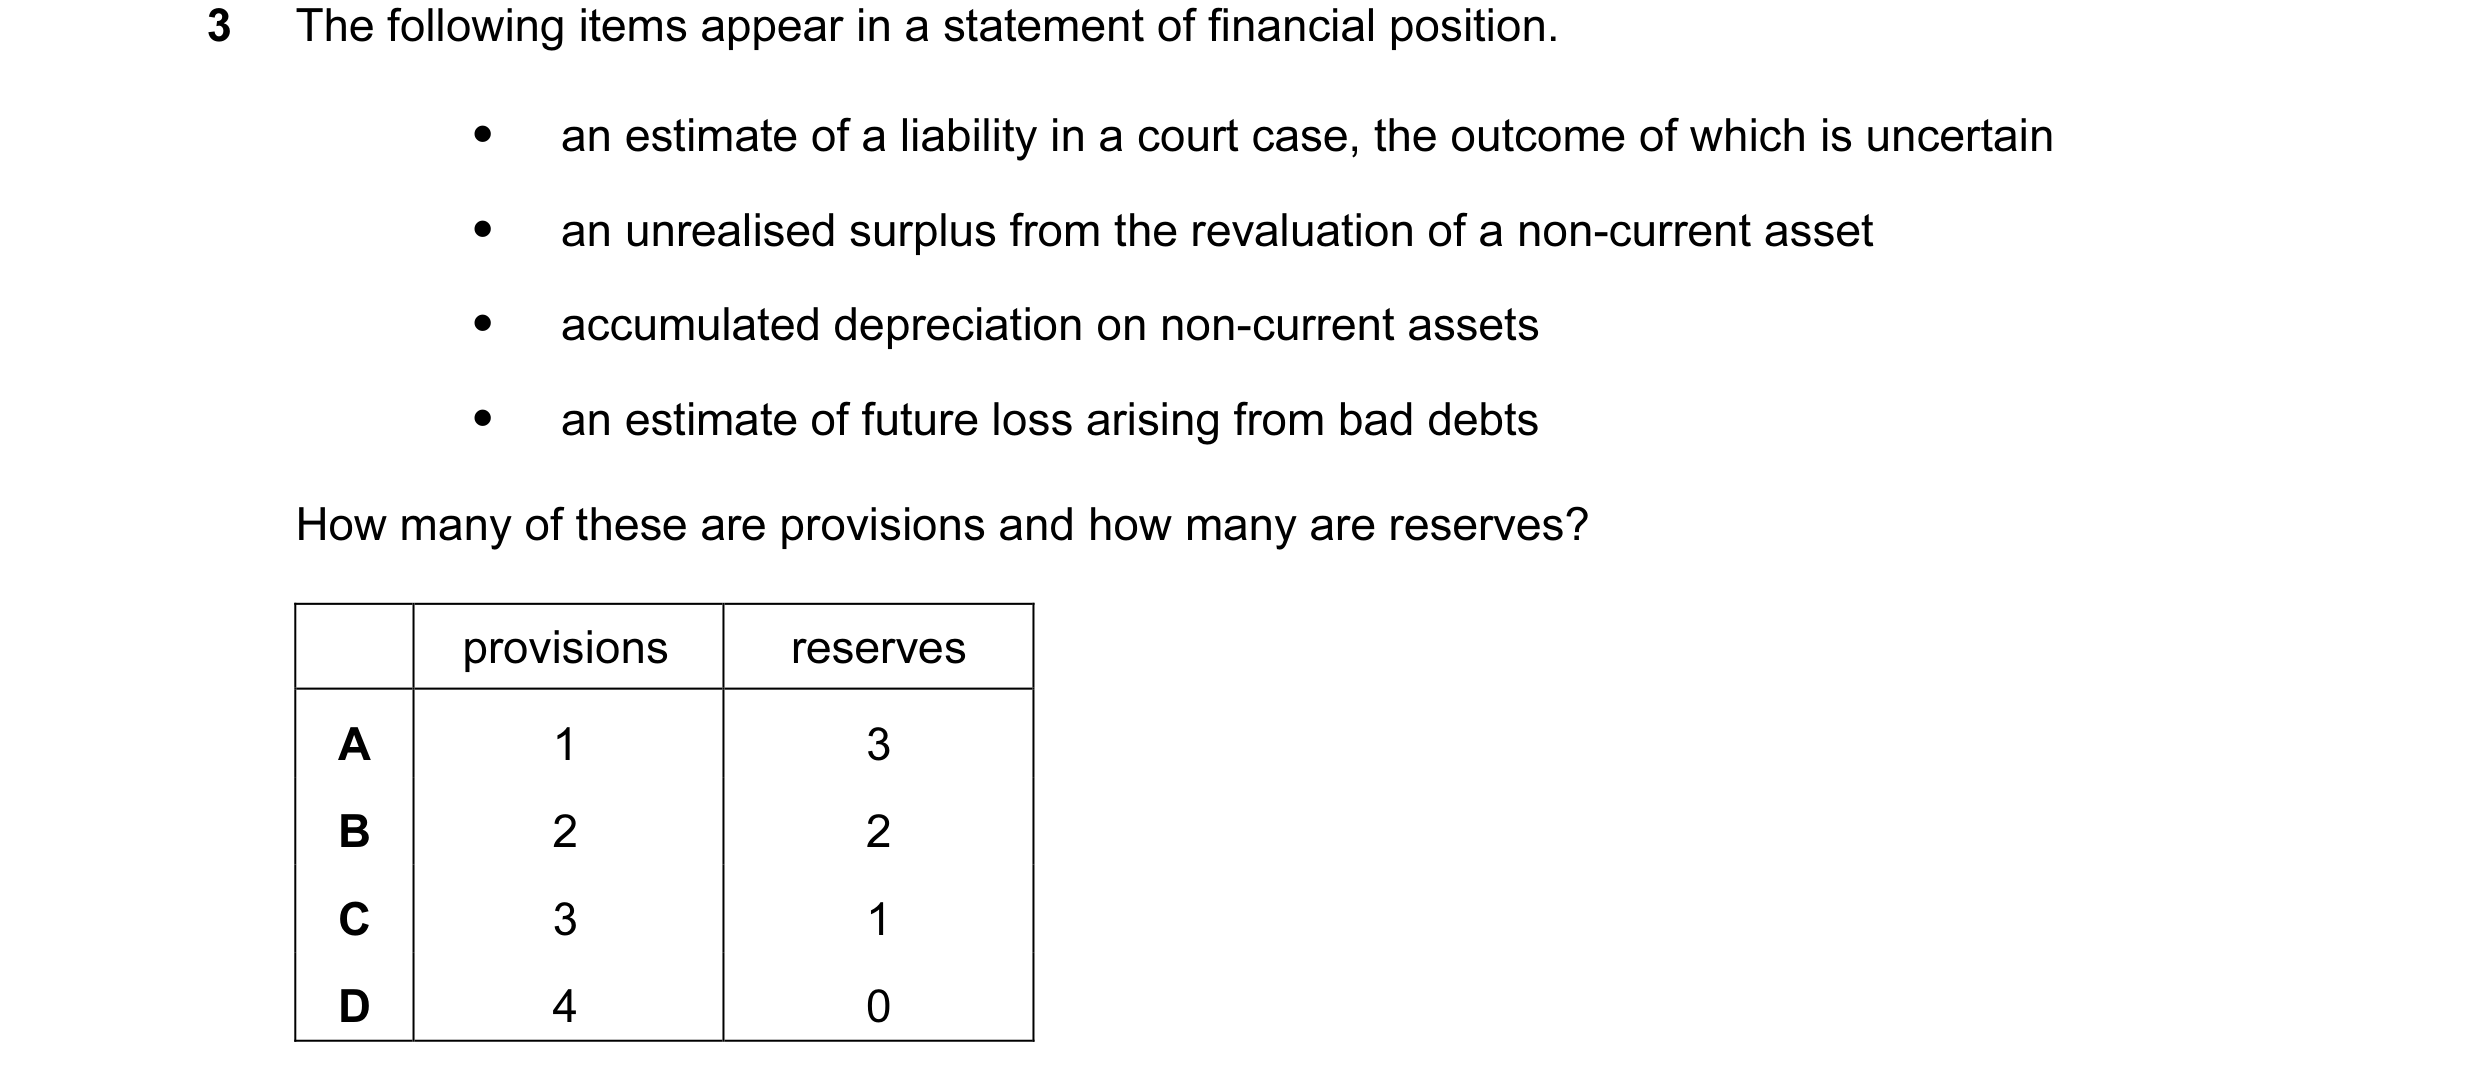
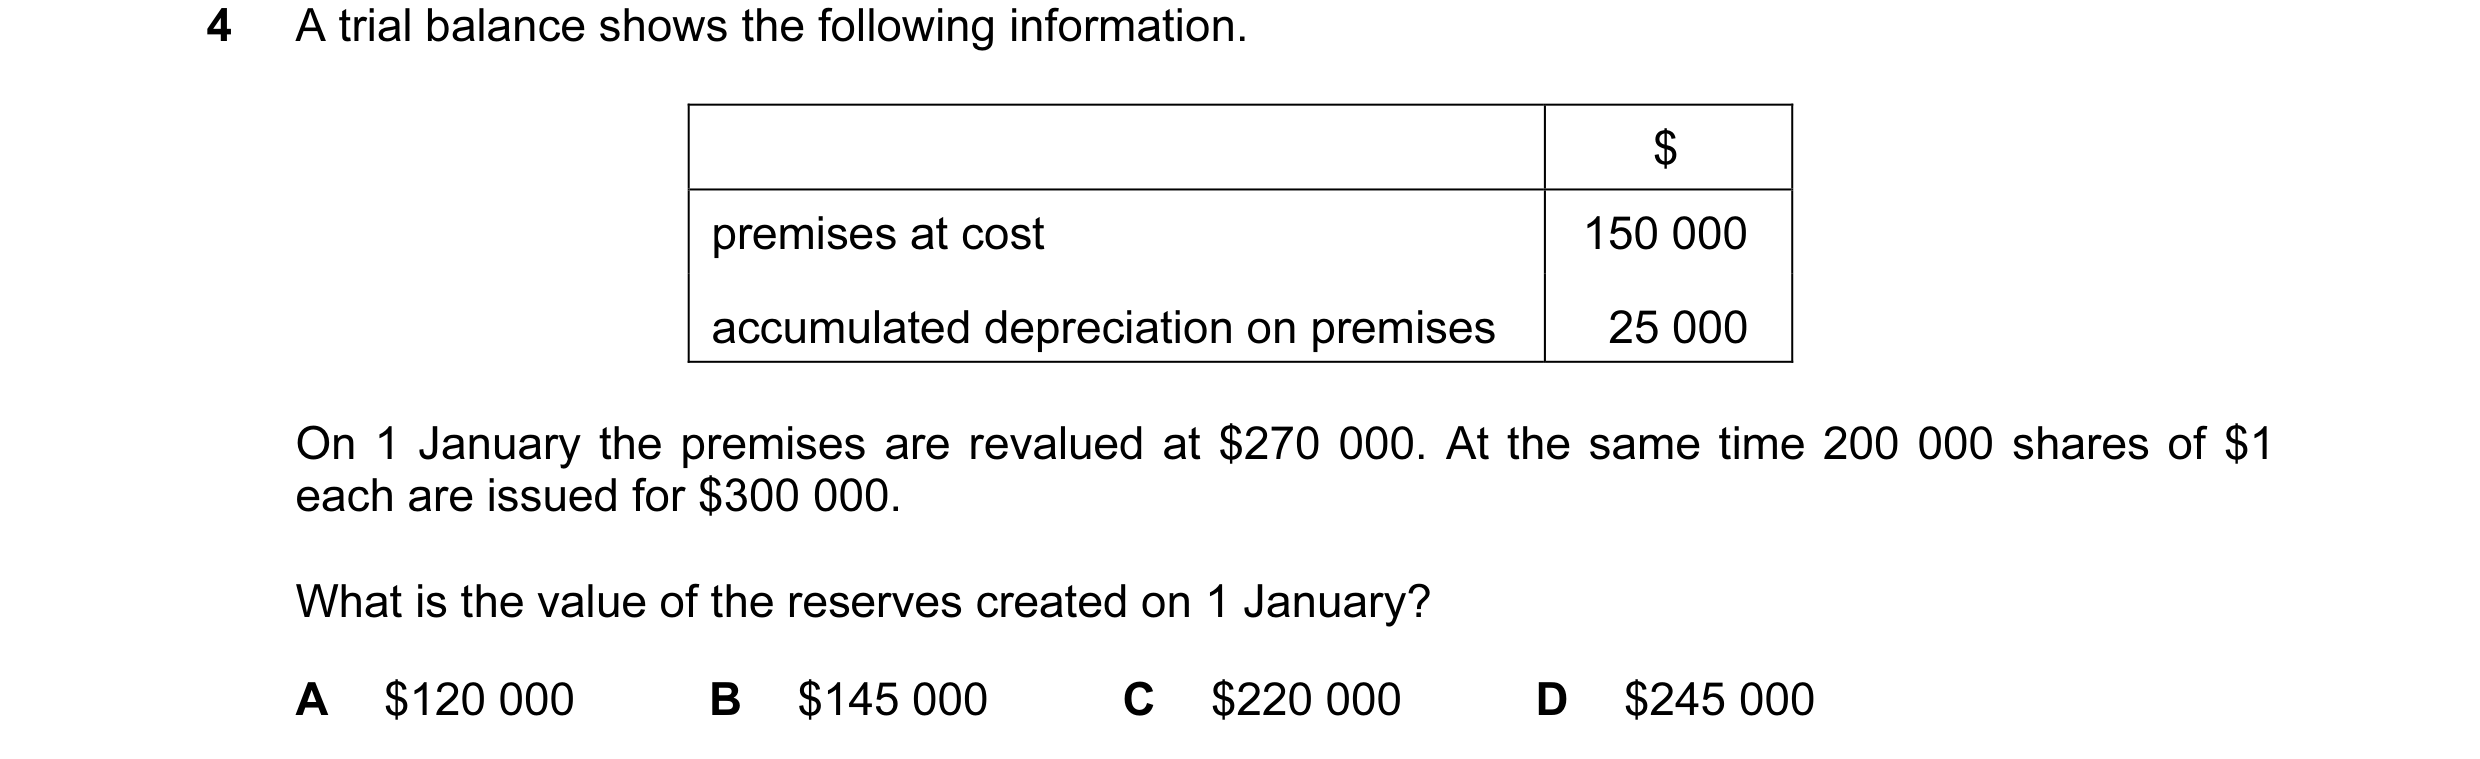
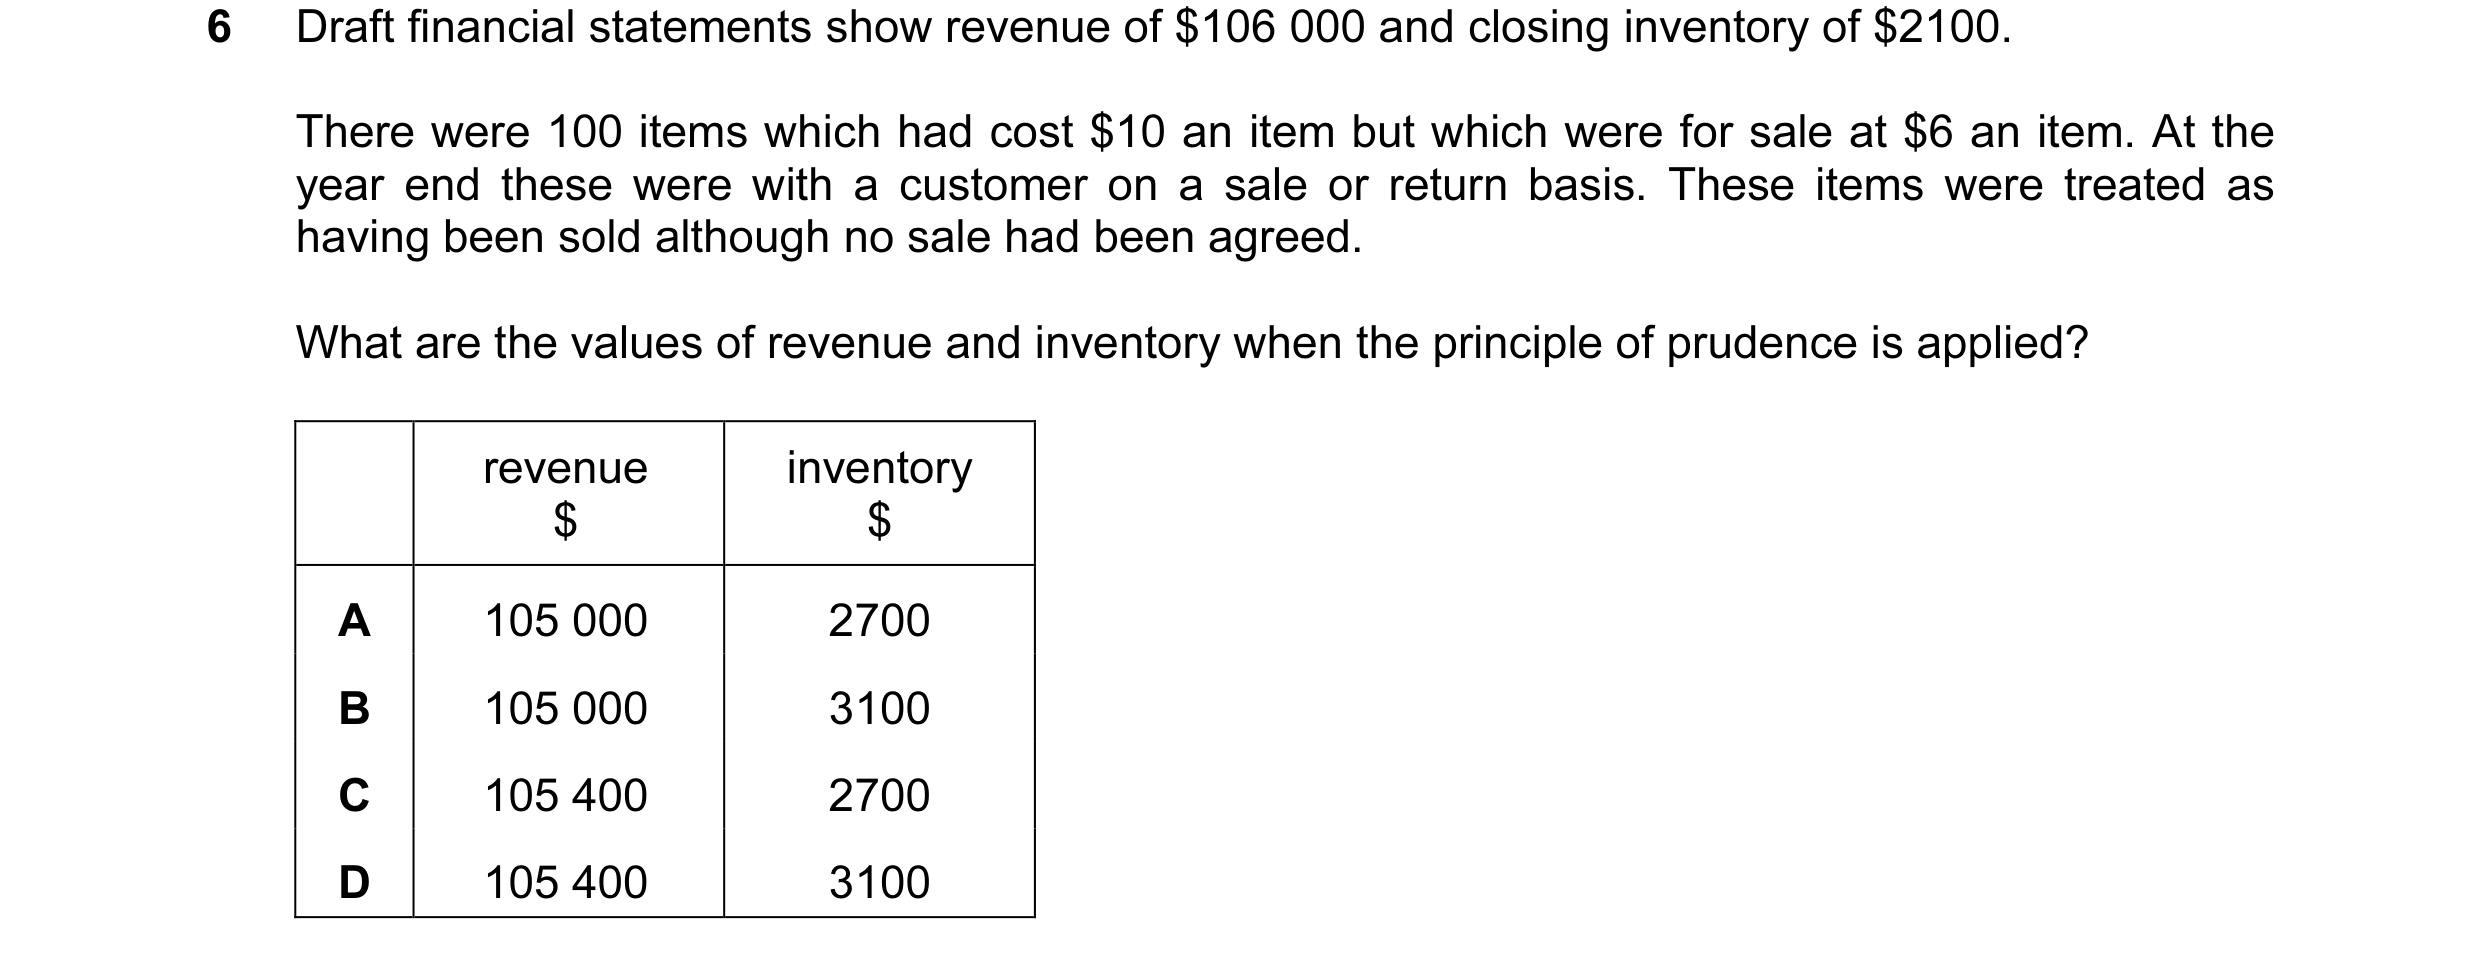
 67 / 233
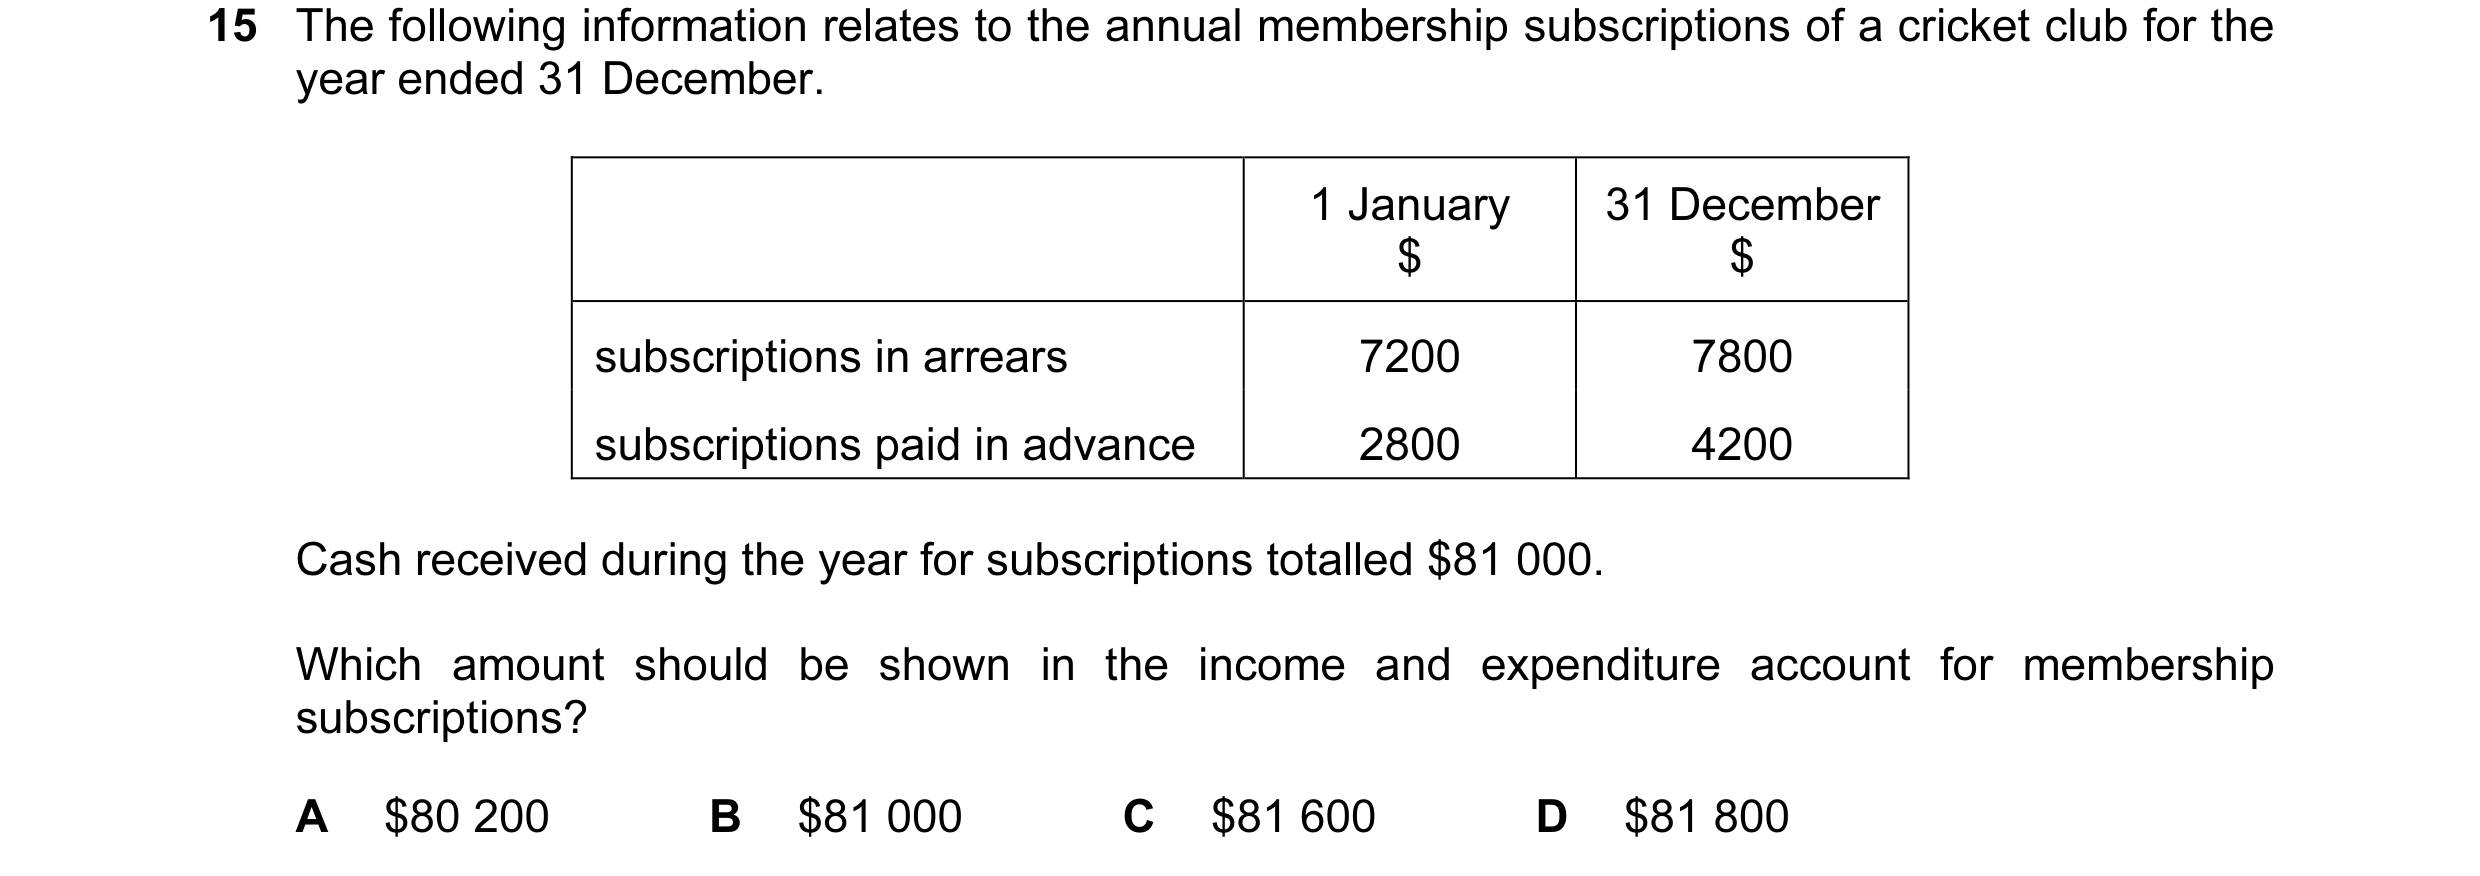
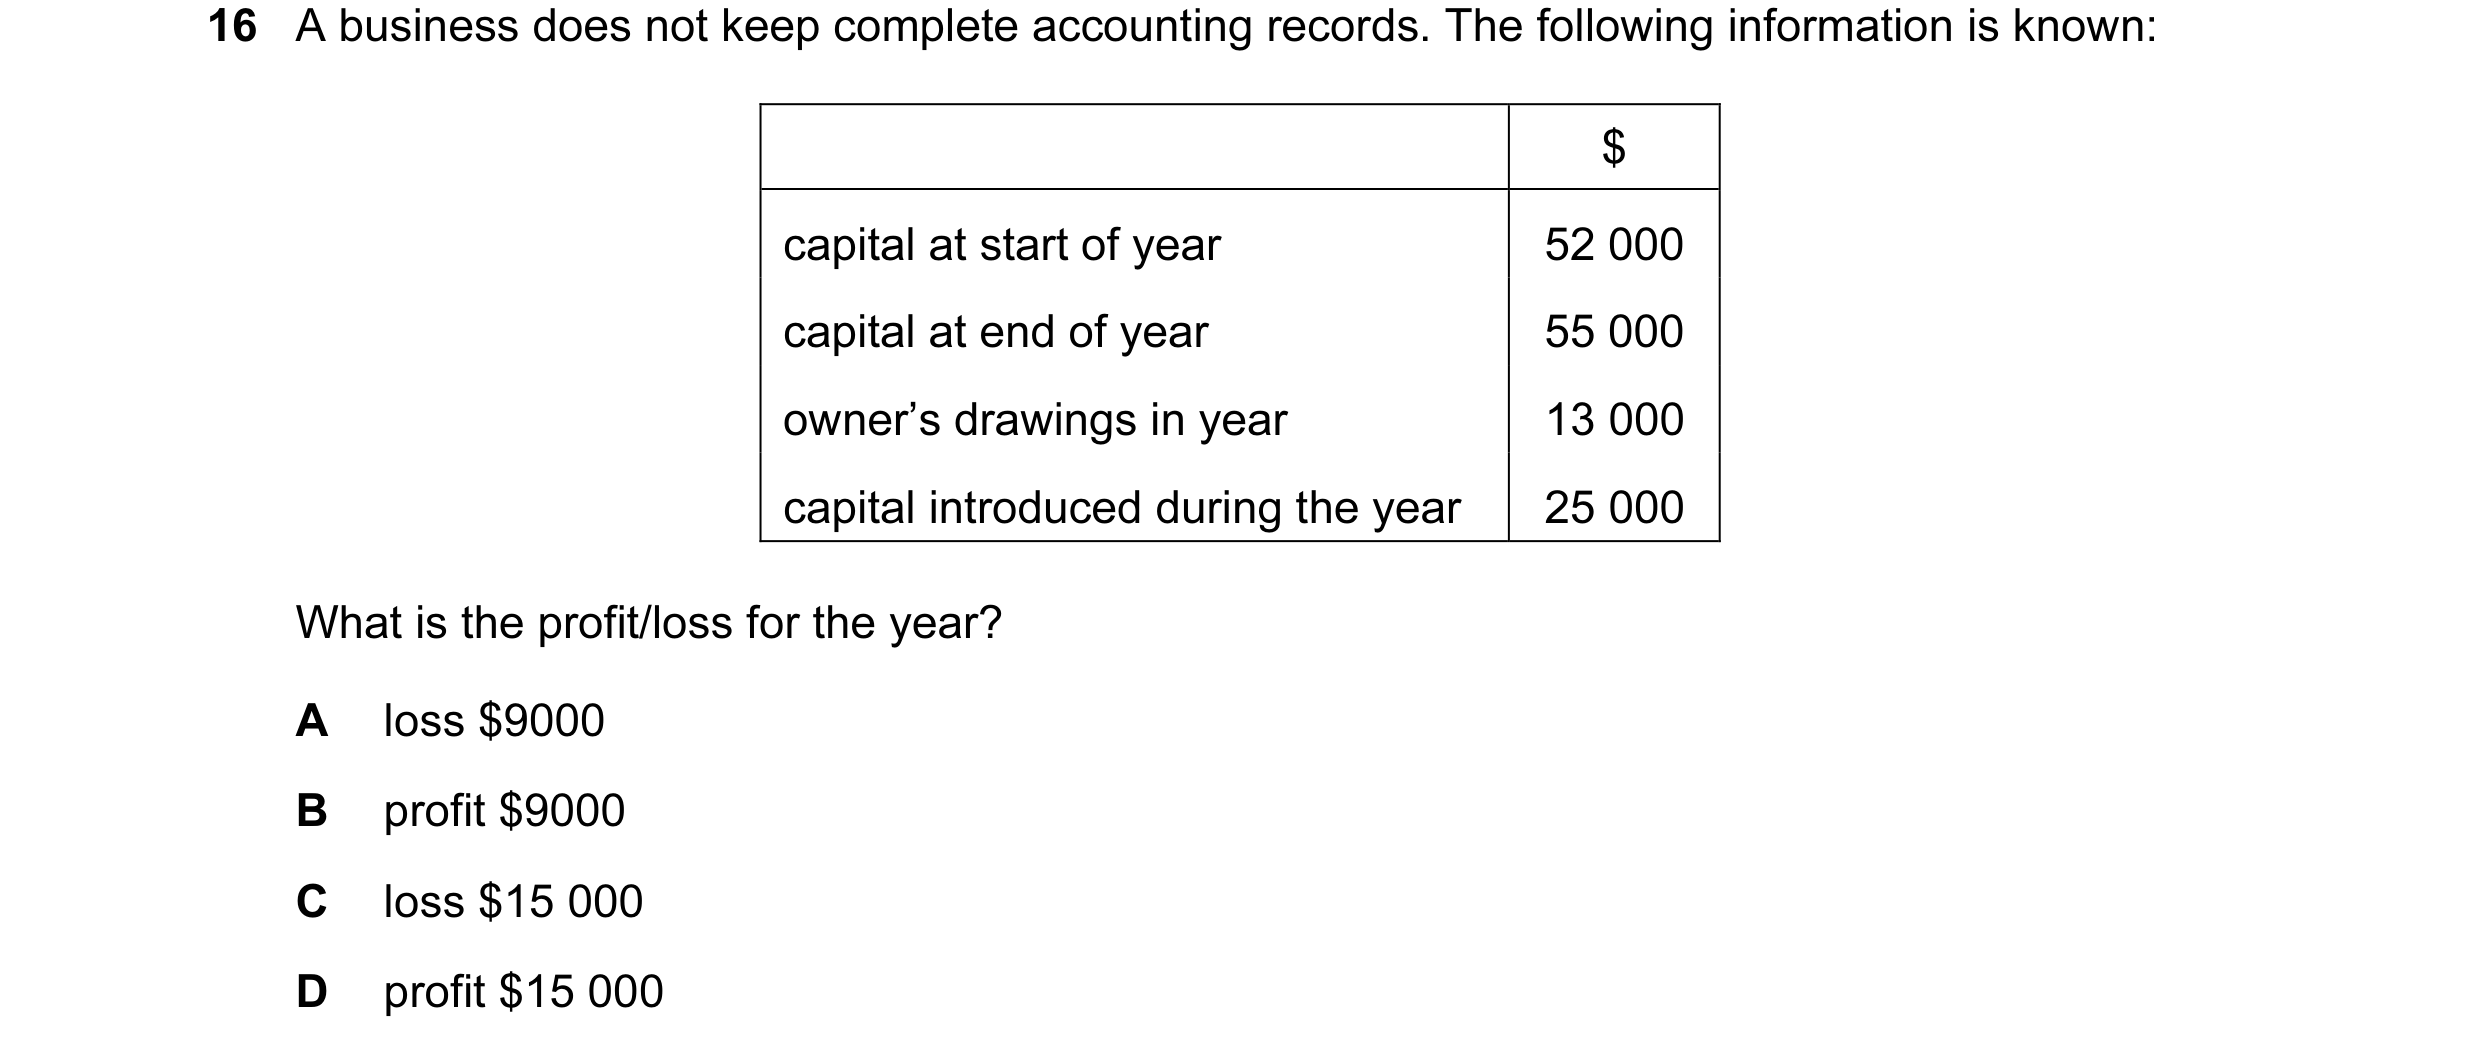 68 / 233
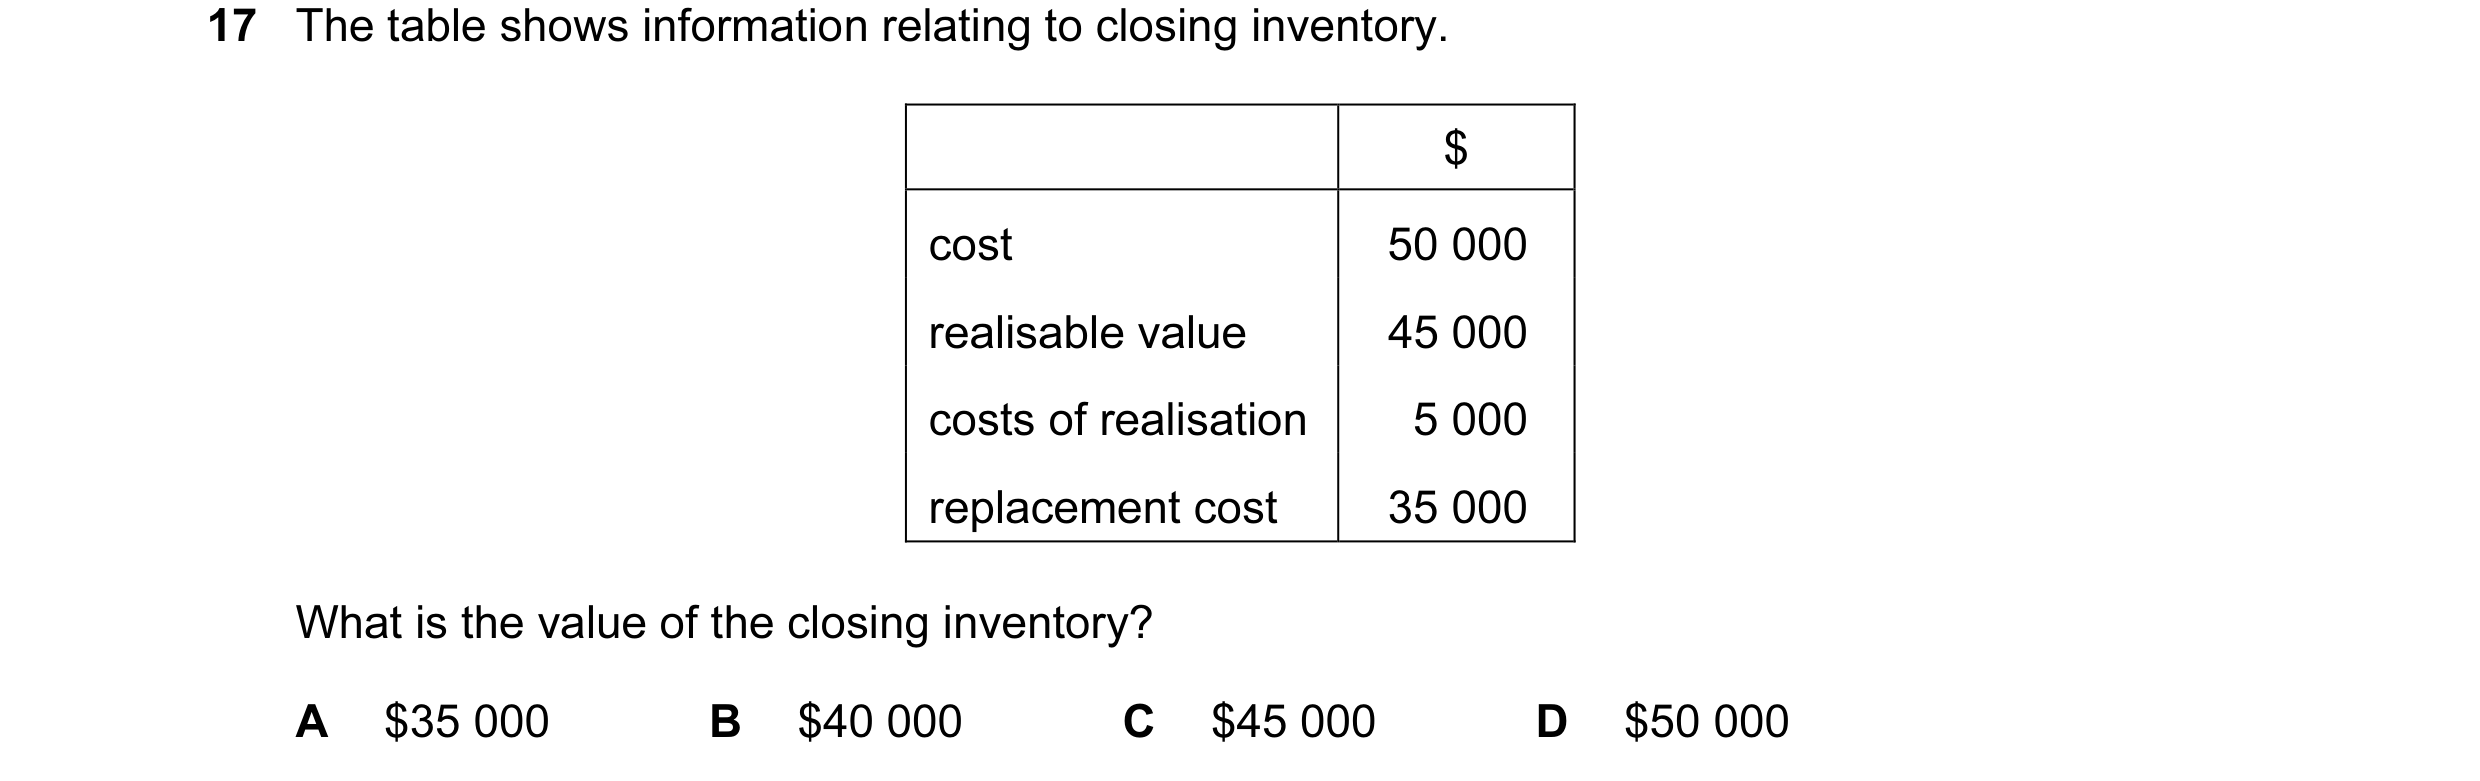
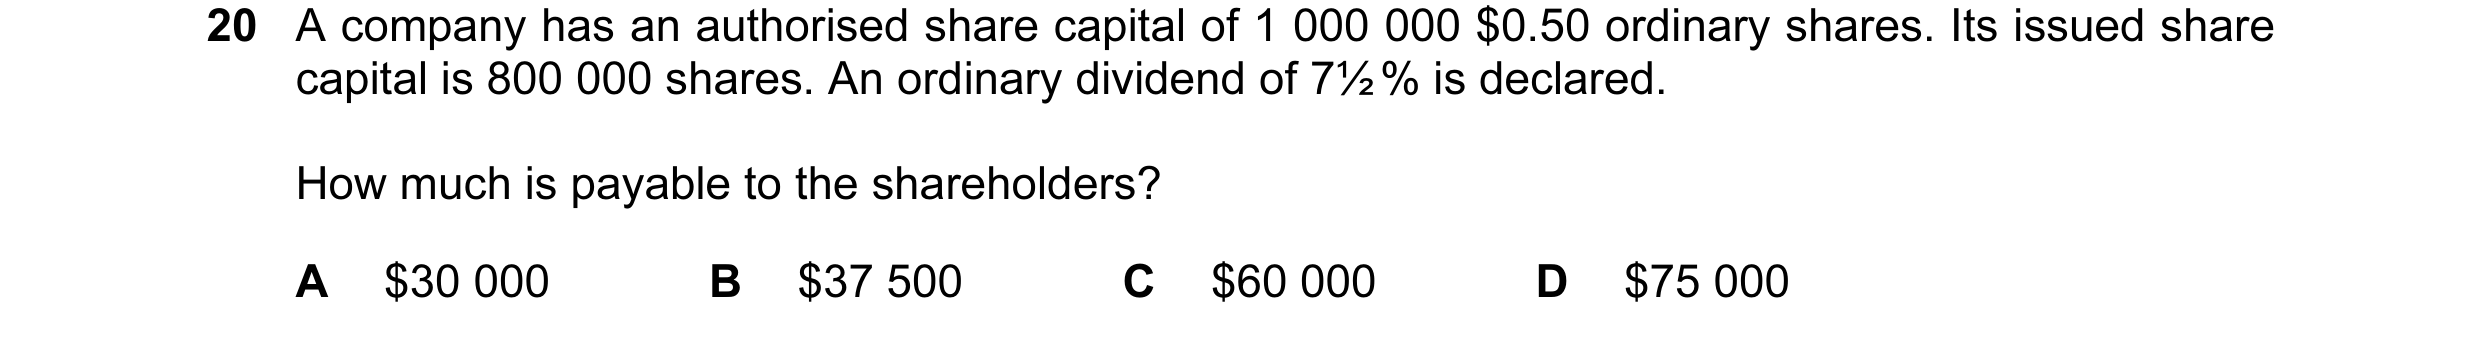
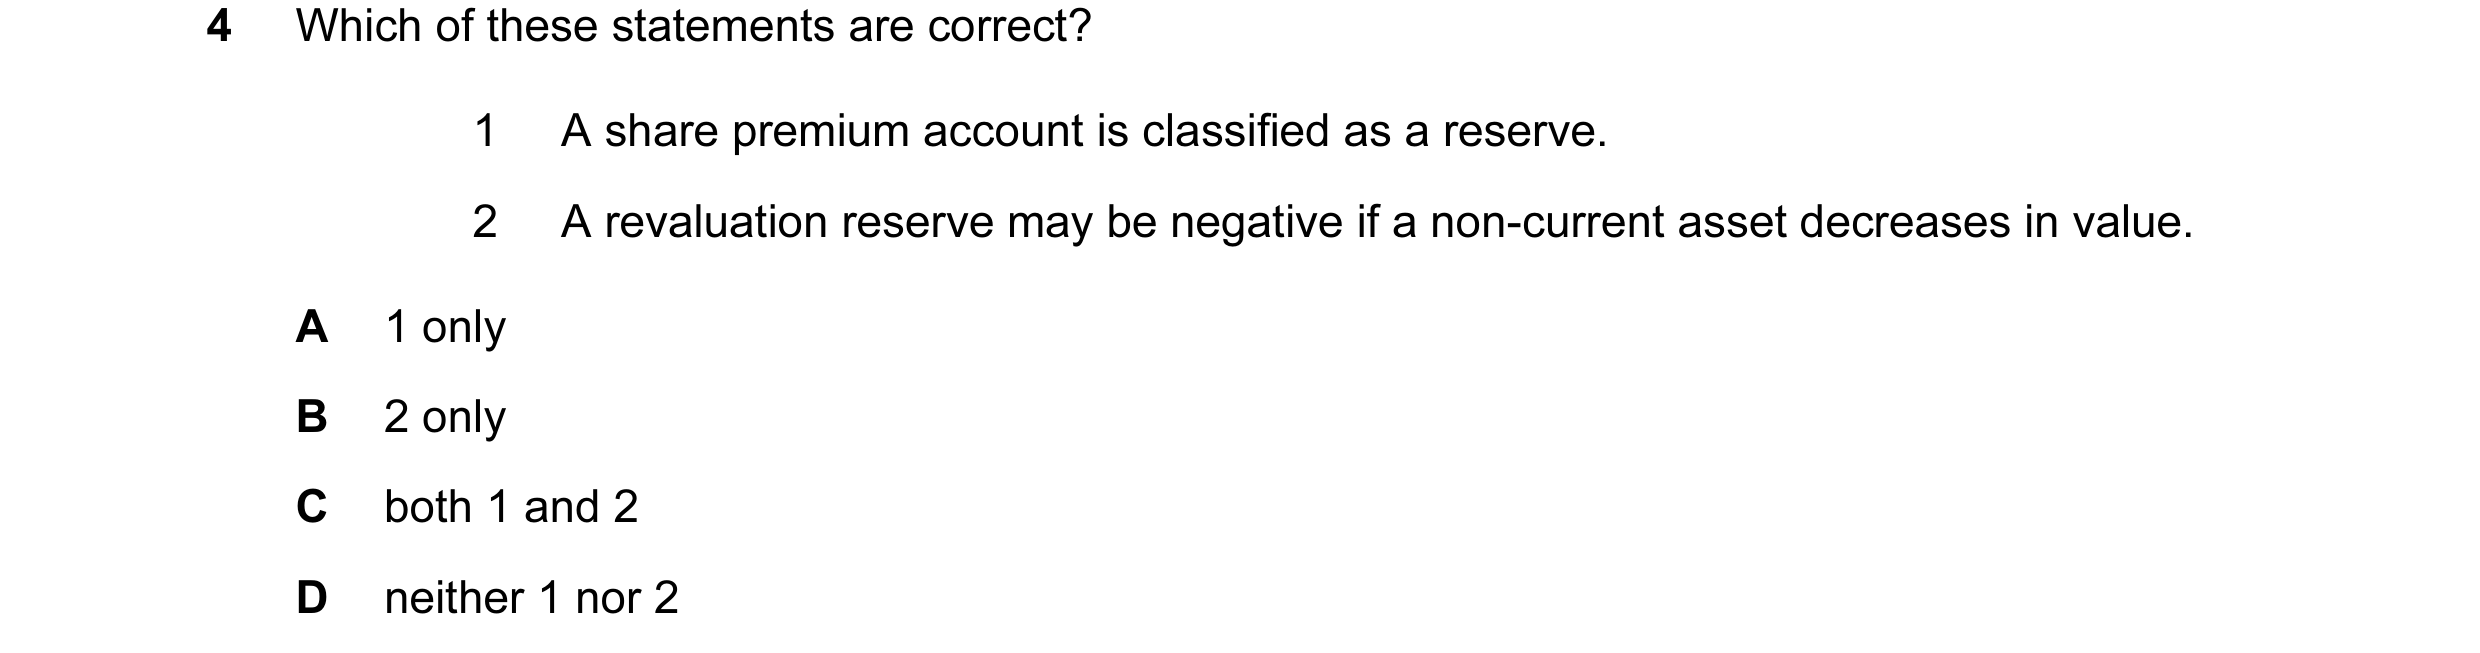
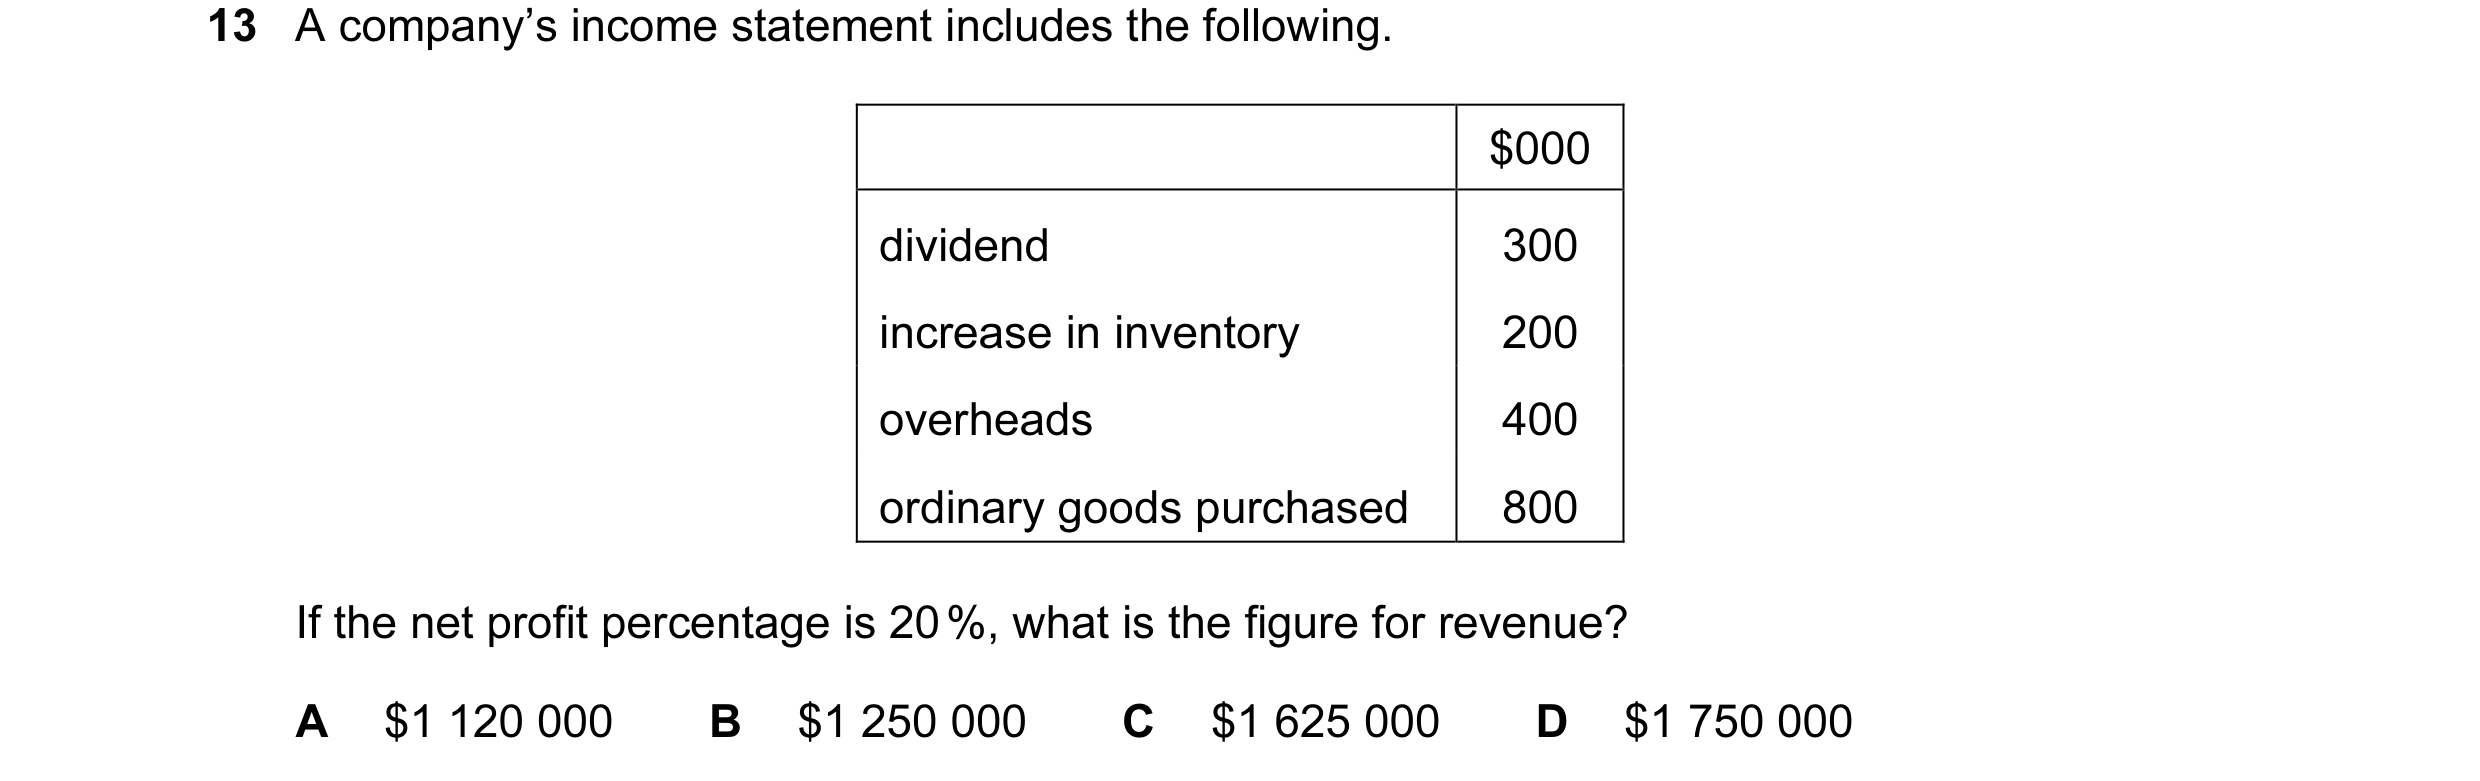 69 / 233
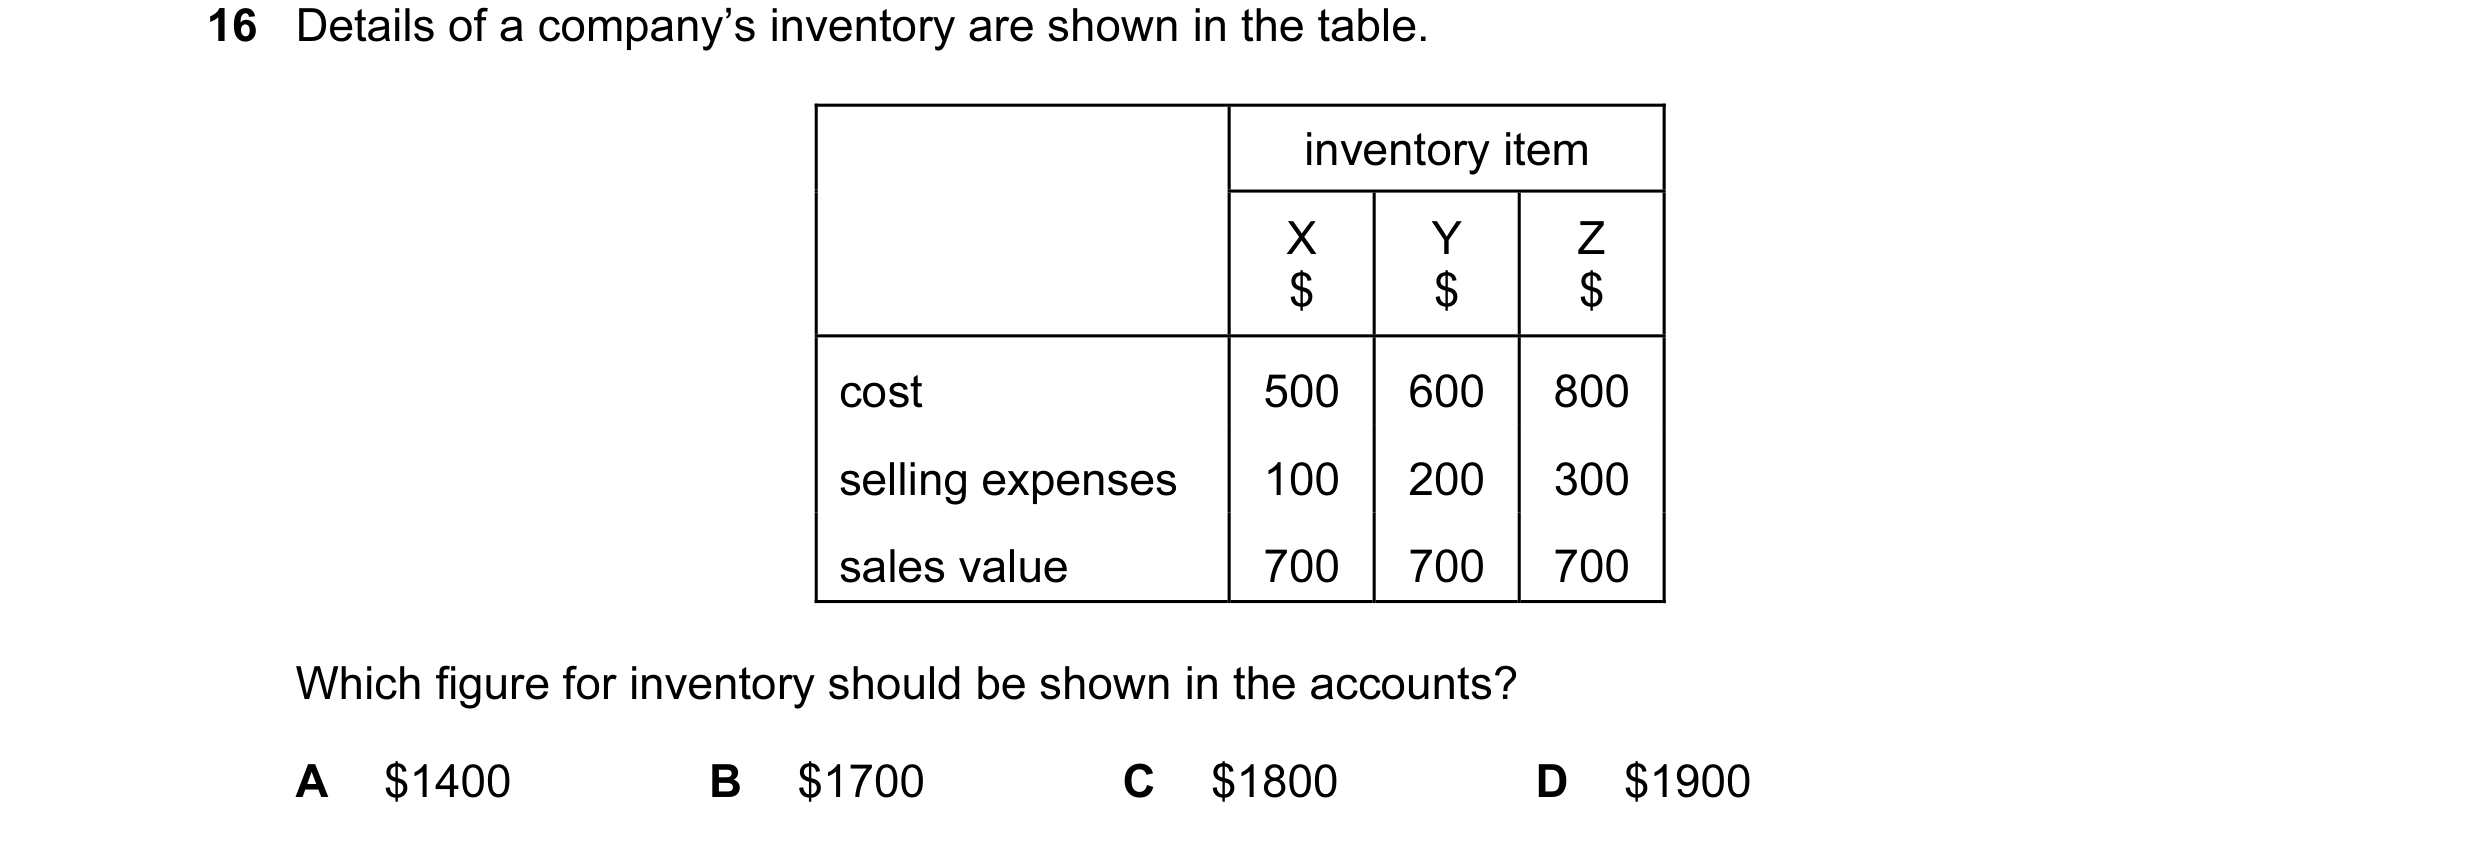
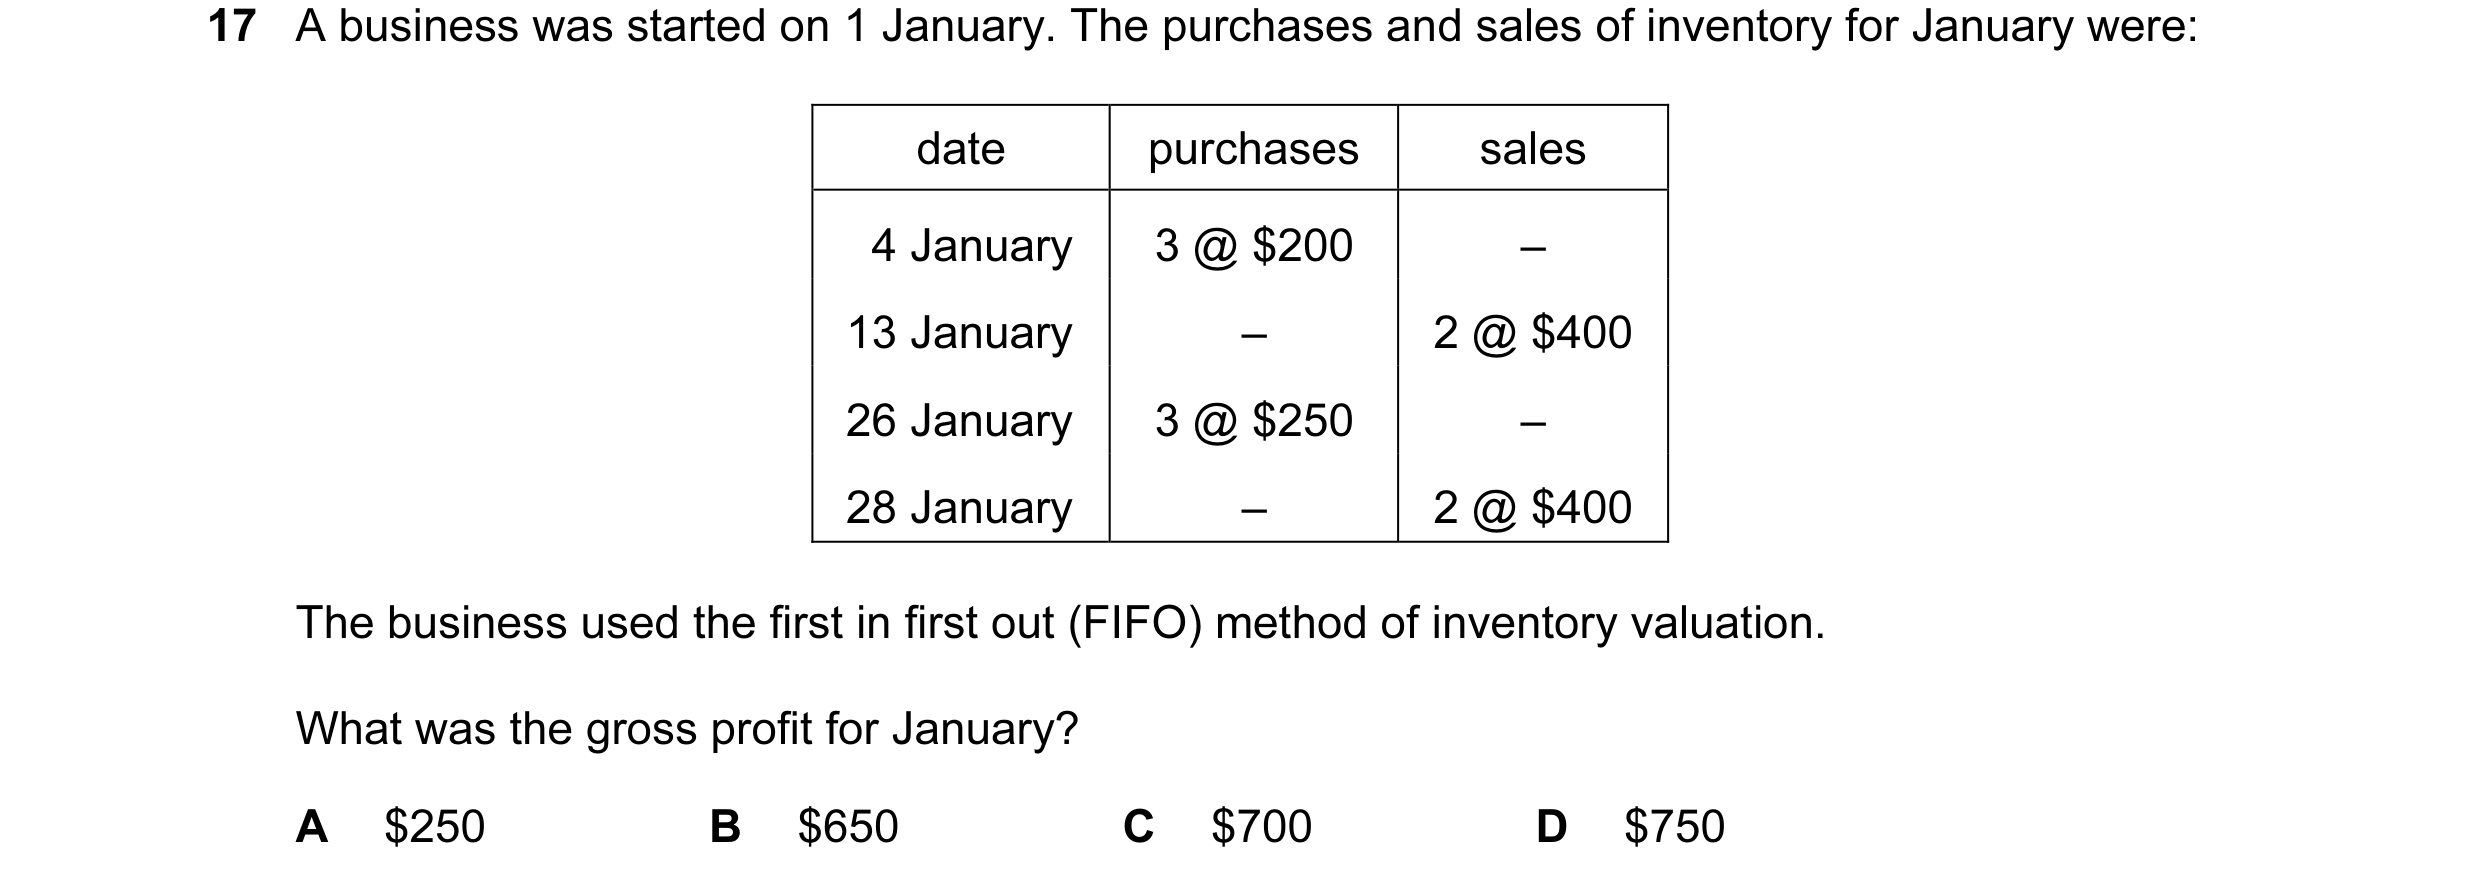
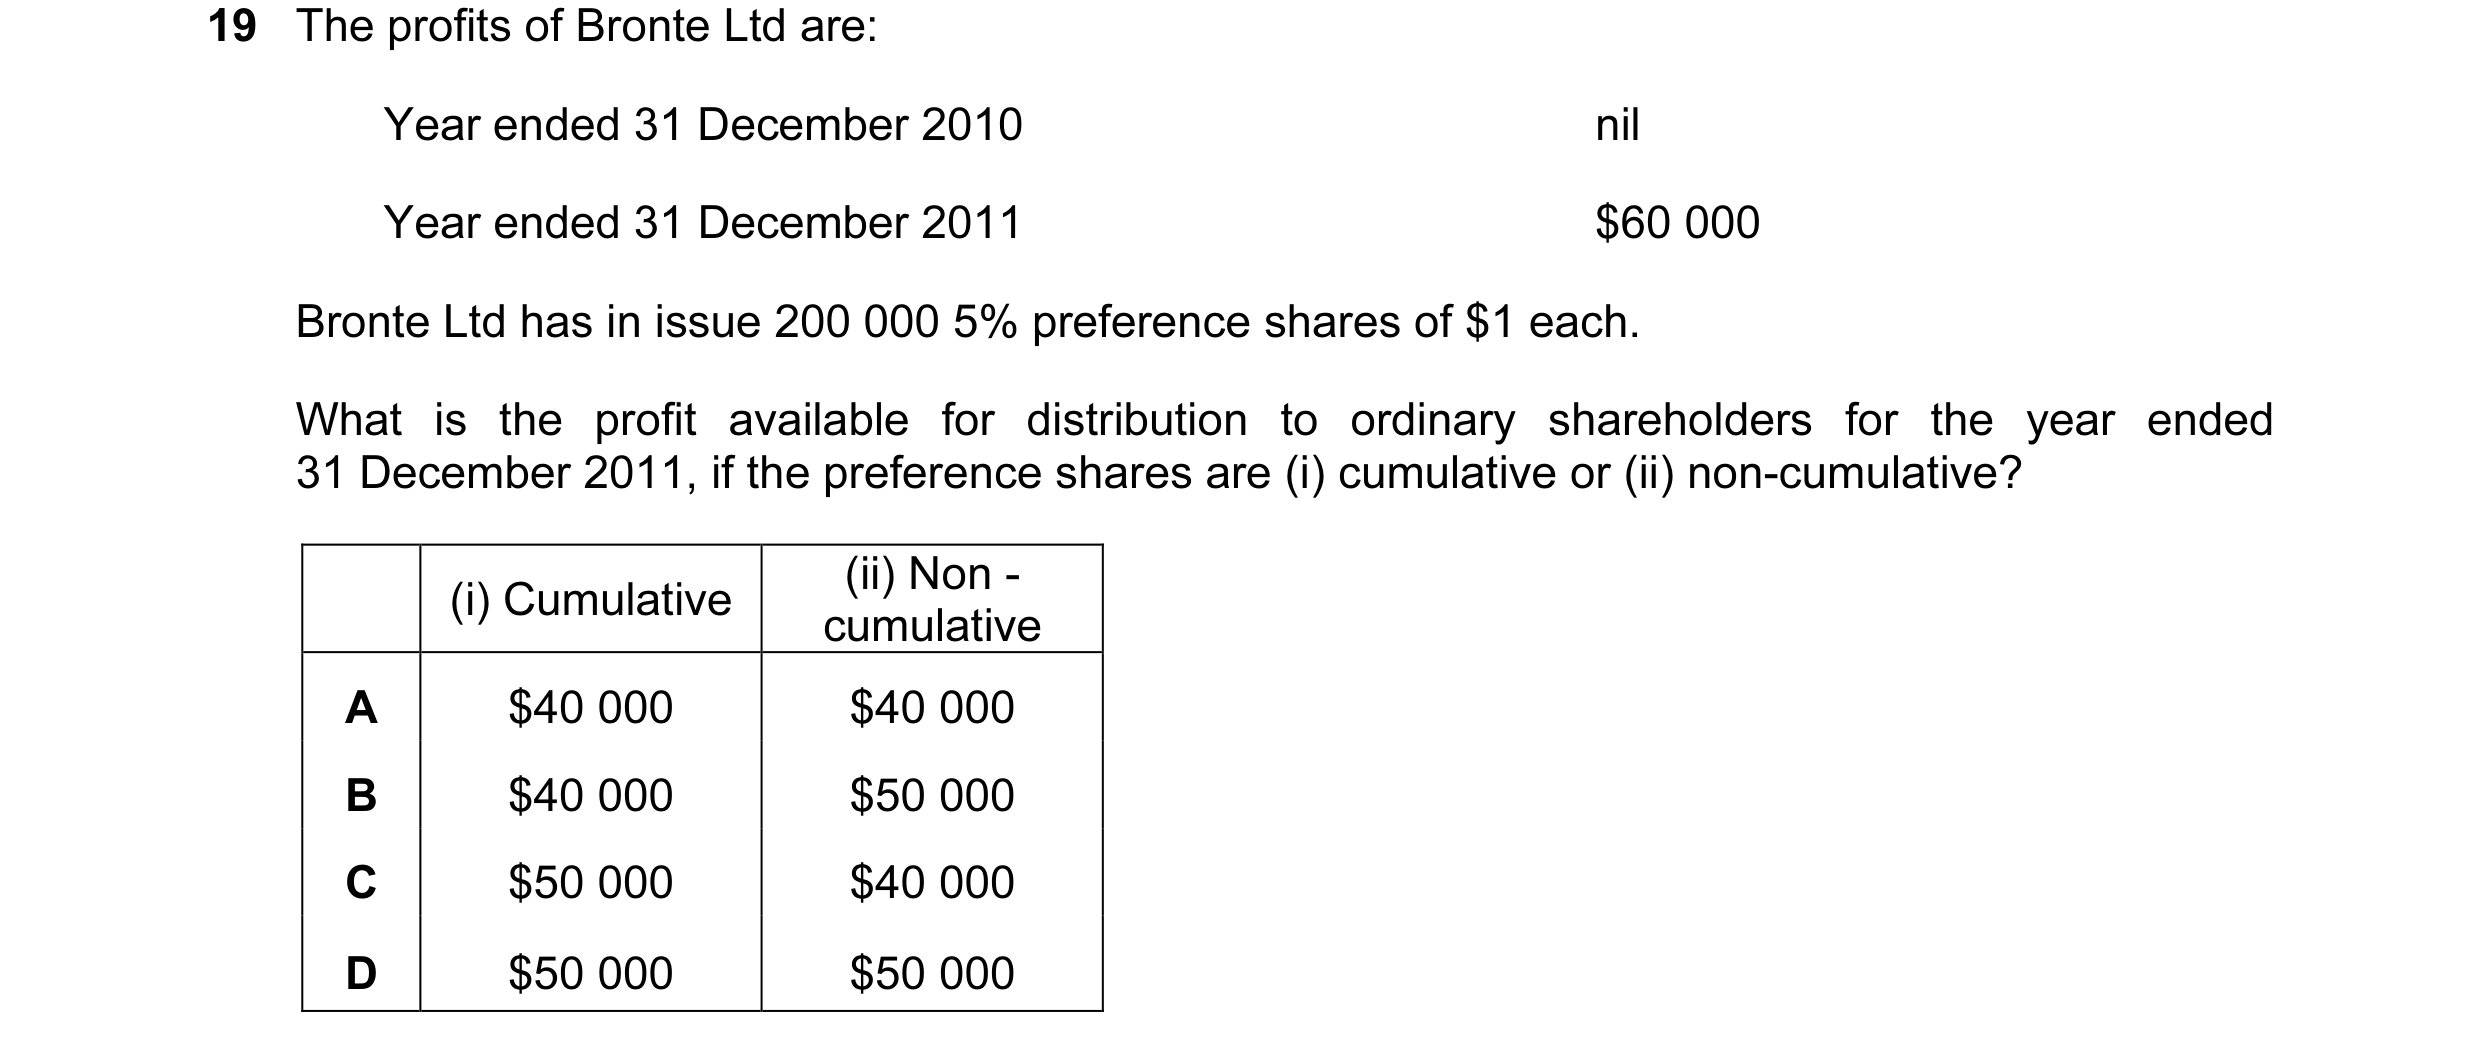
 70 / 233
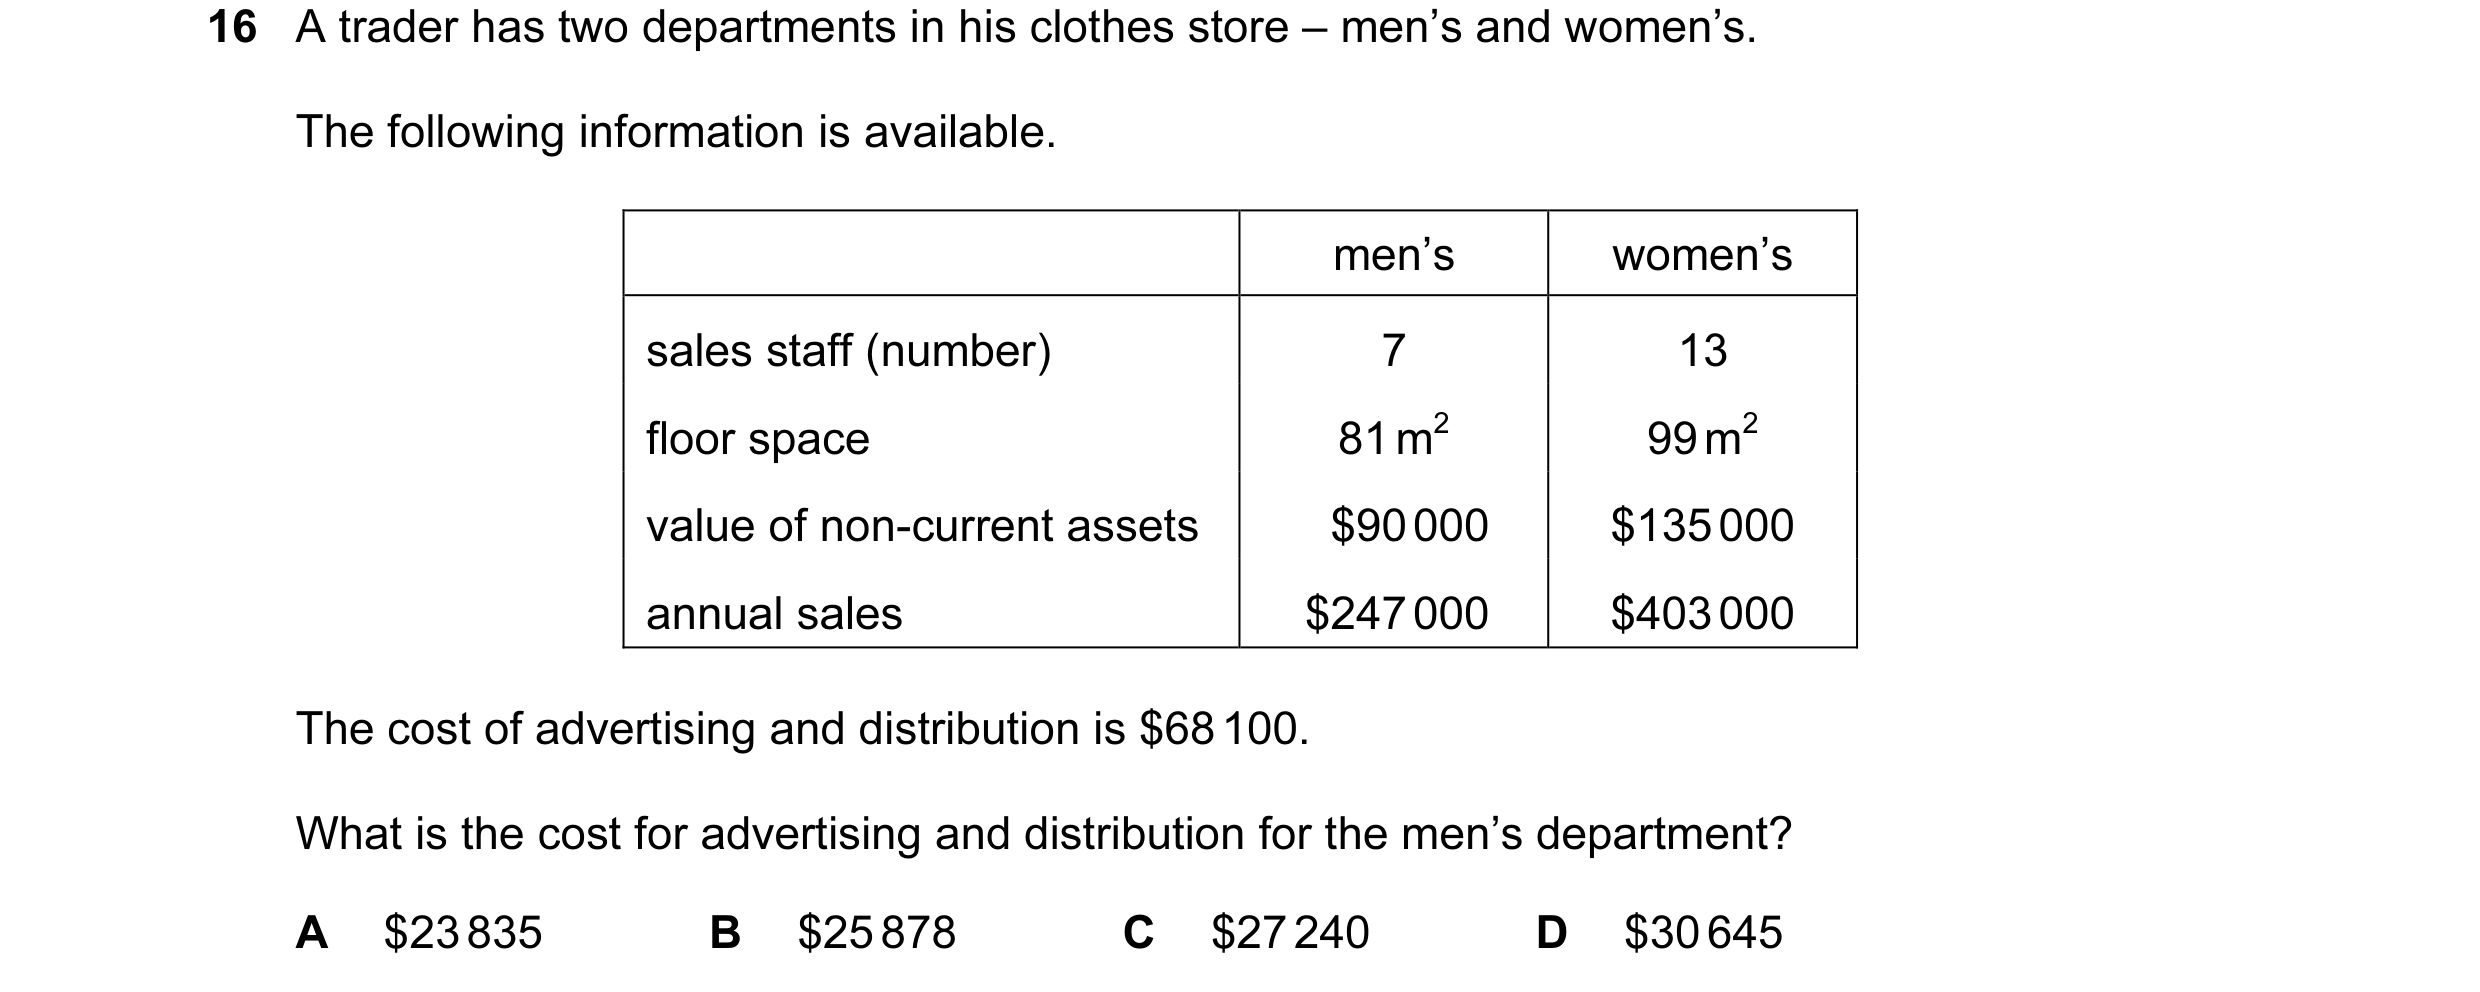
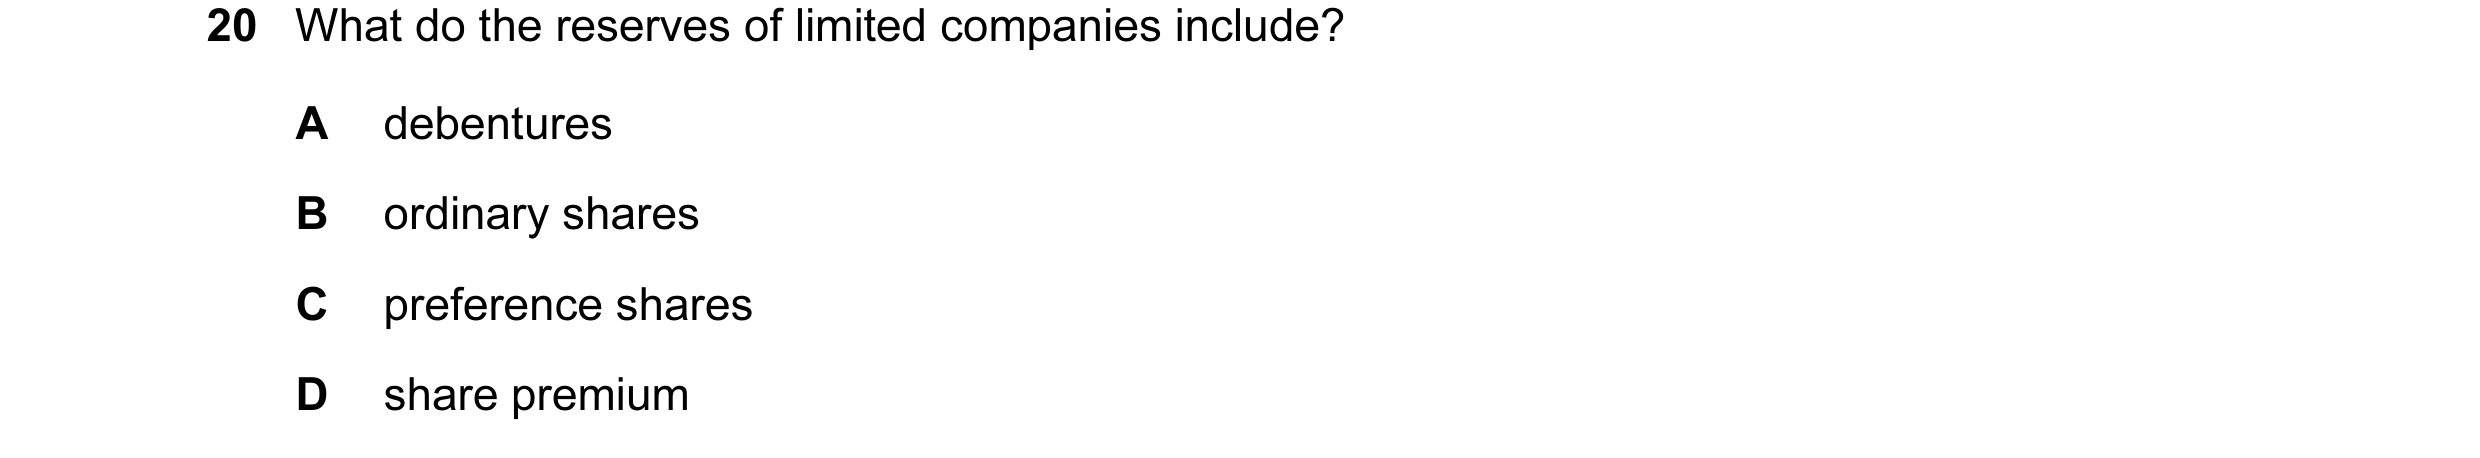
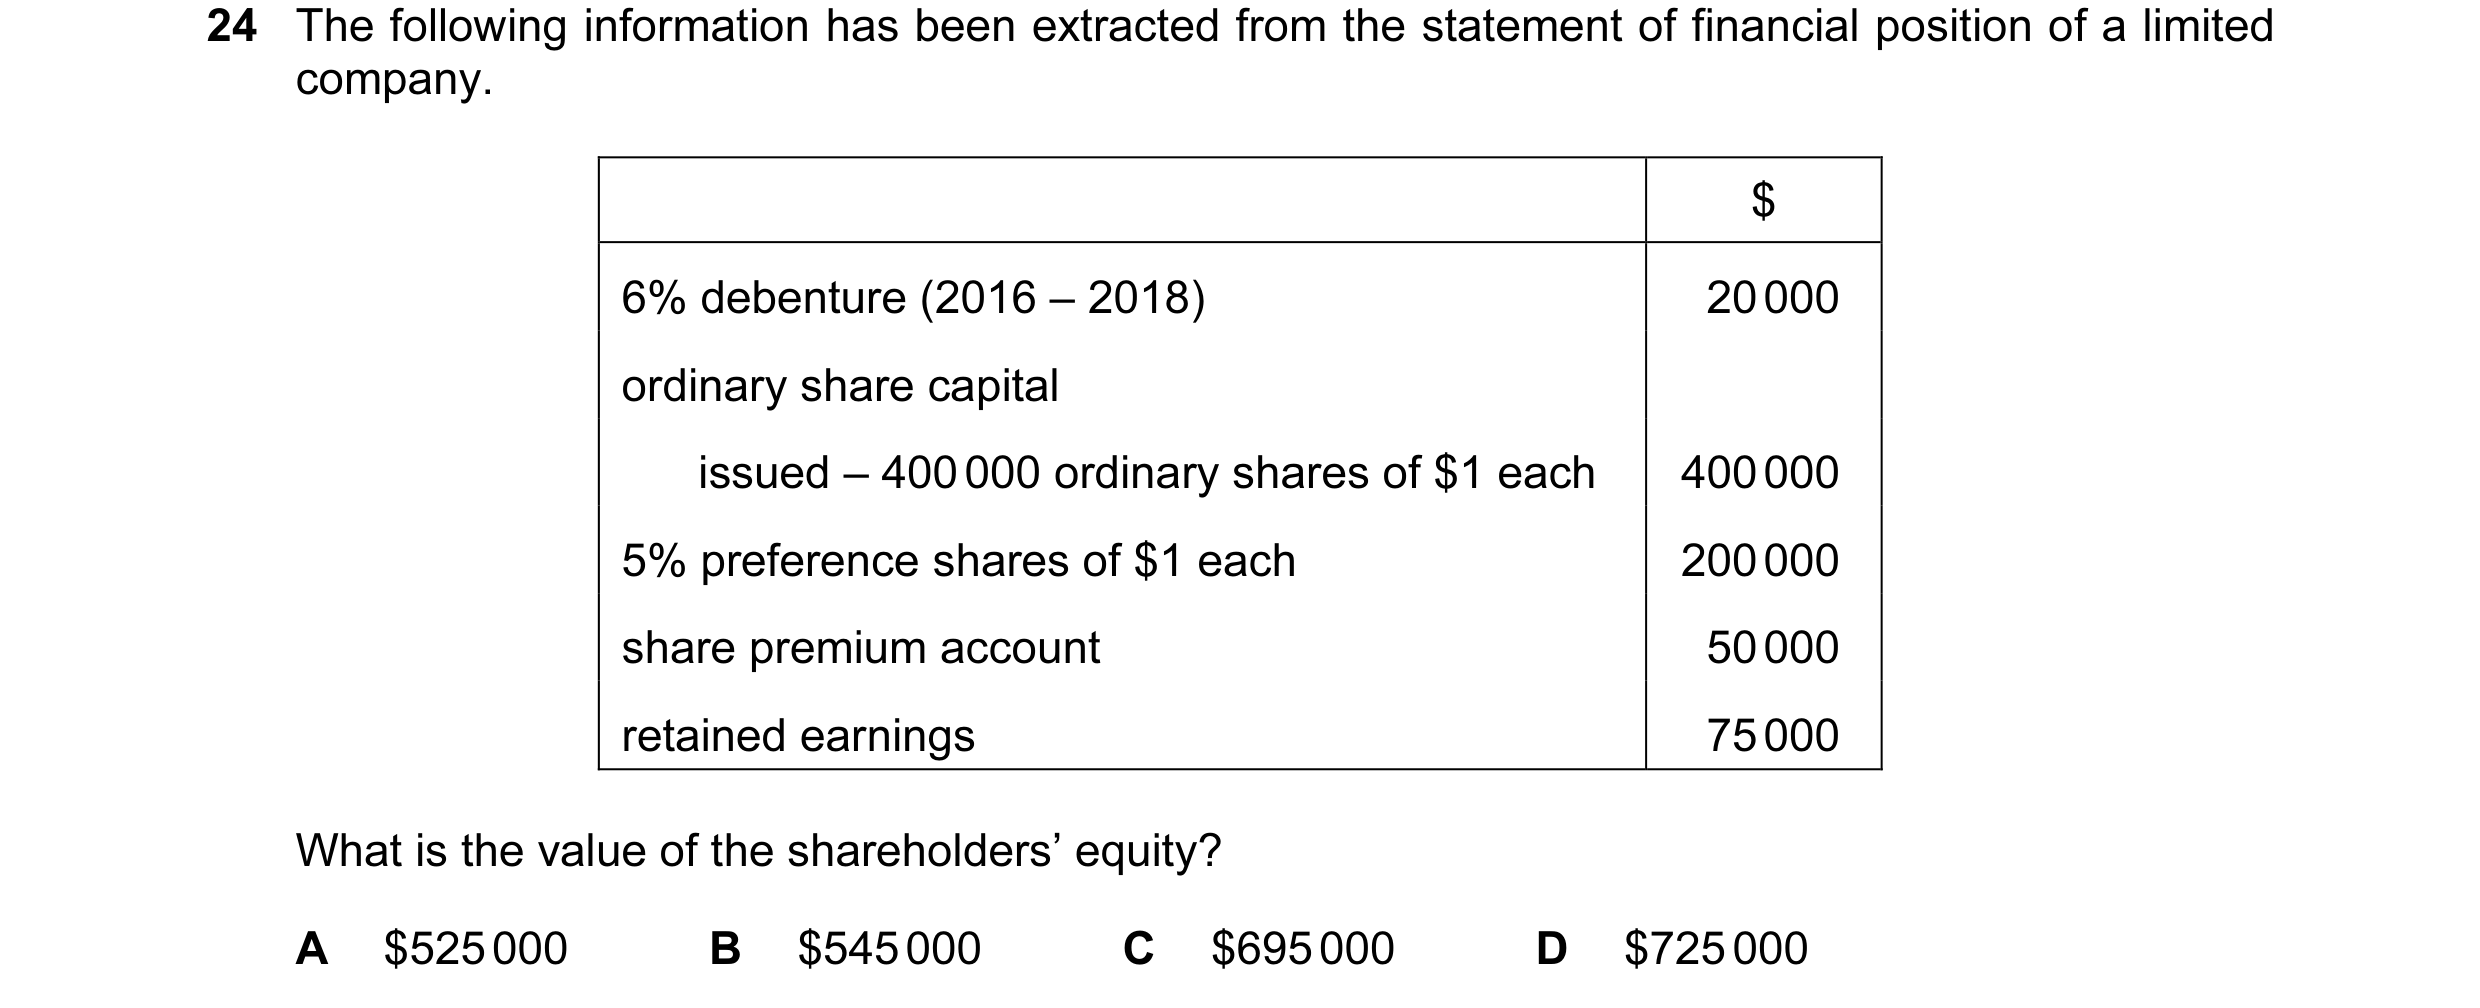 71 / 233
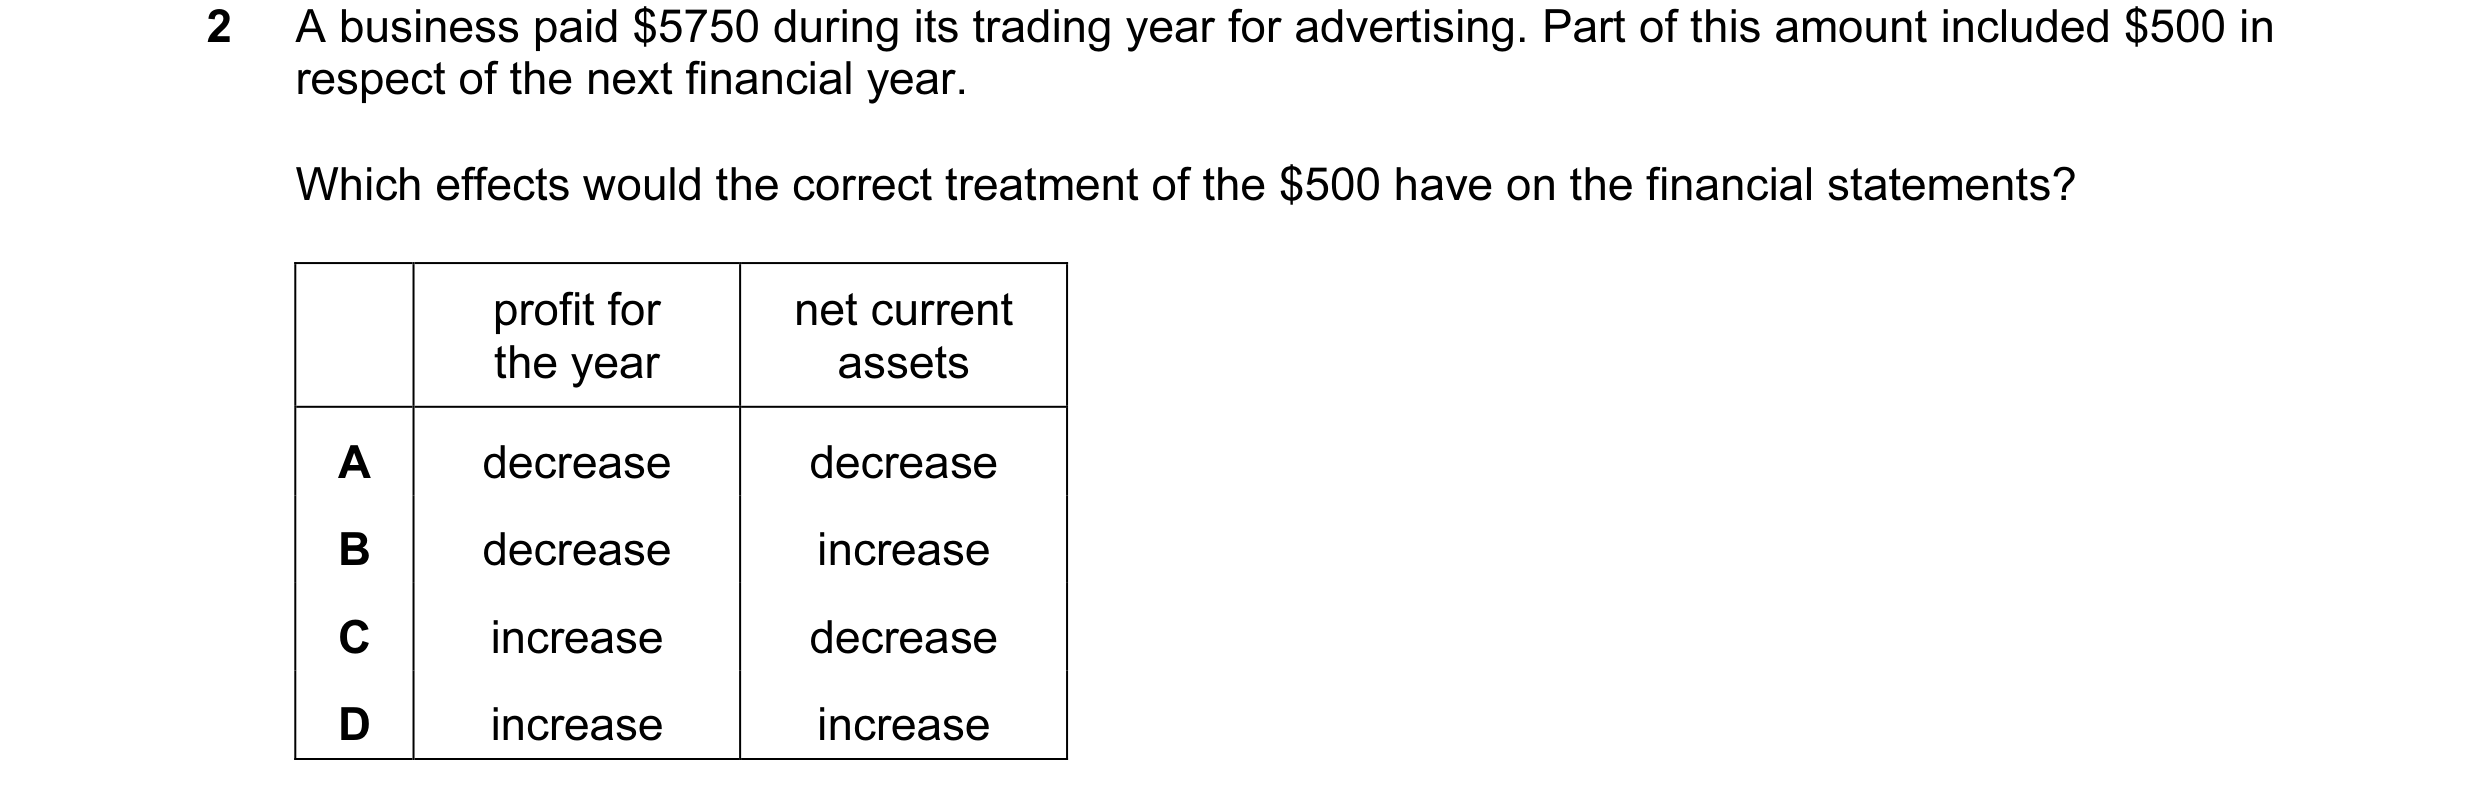
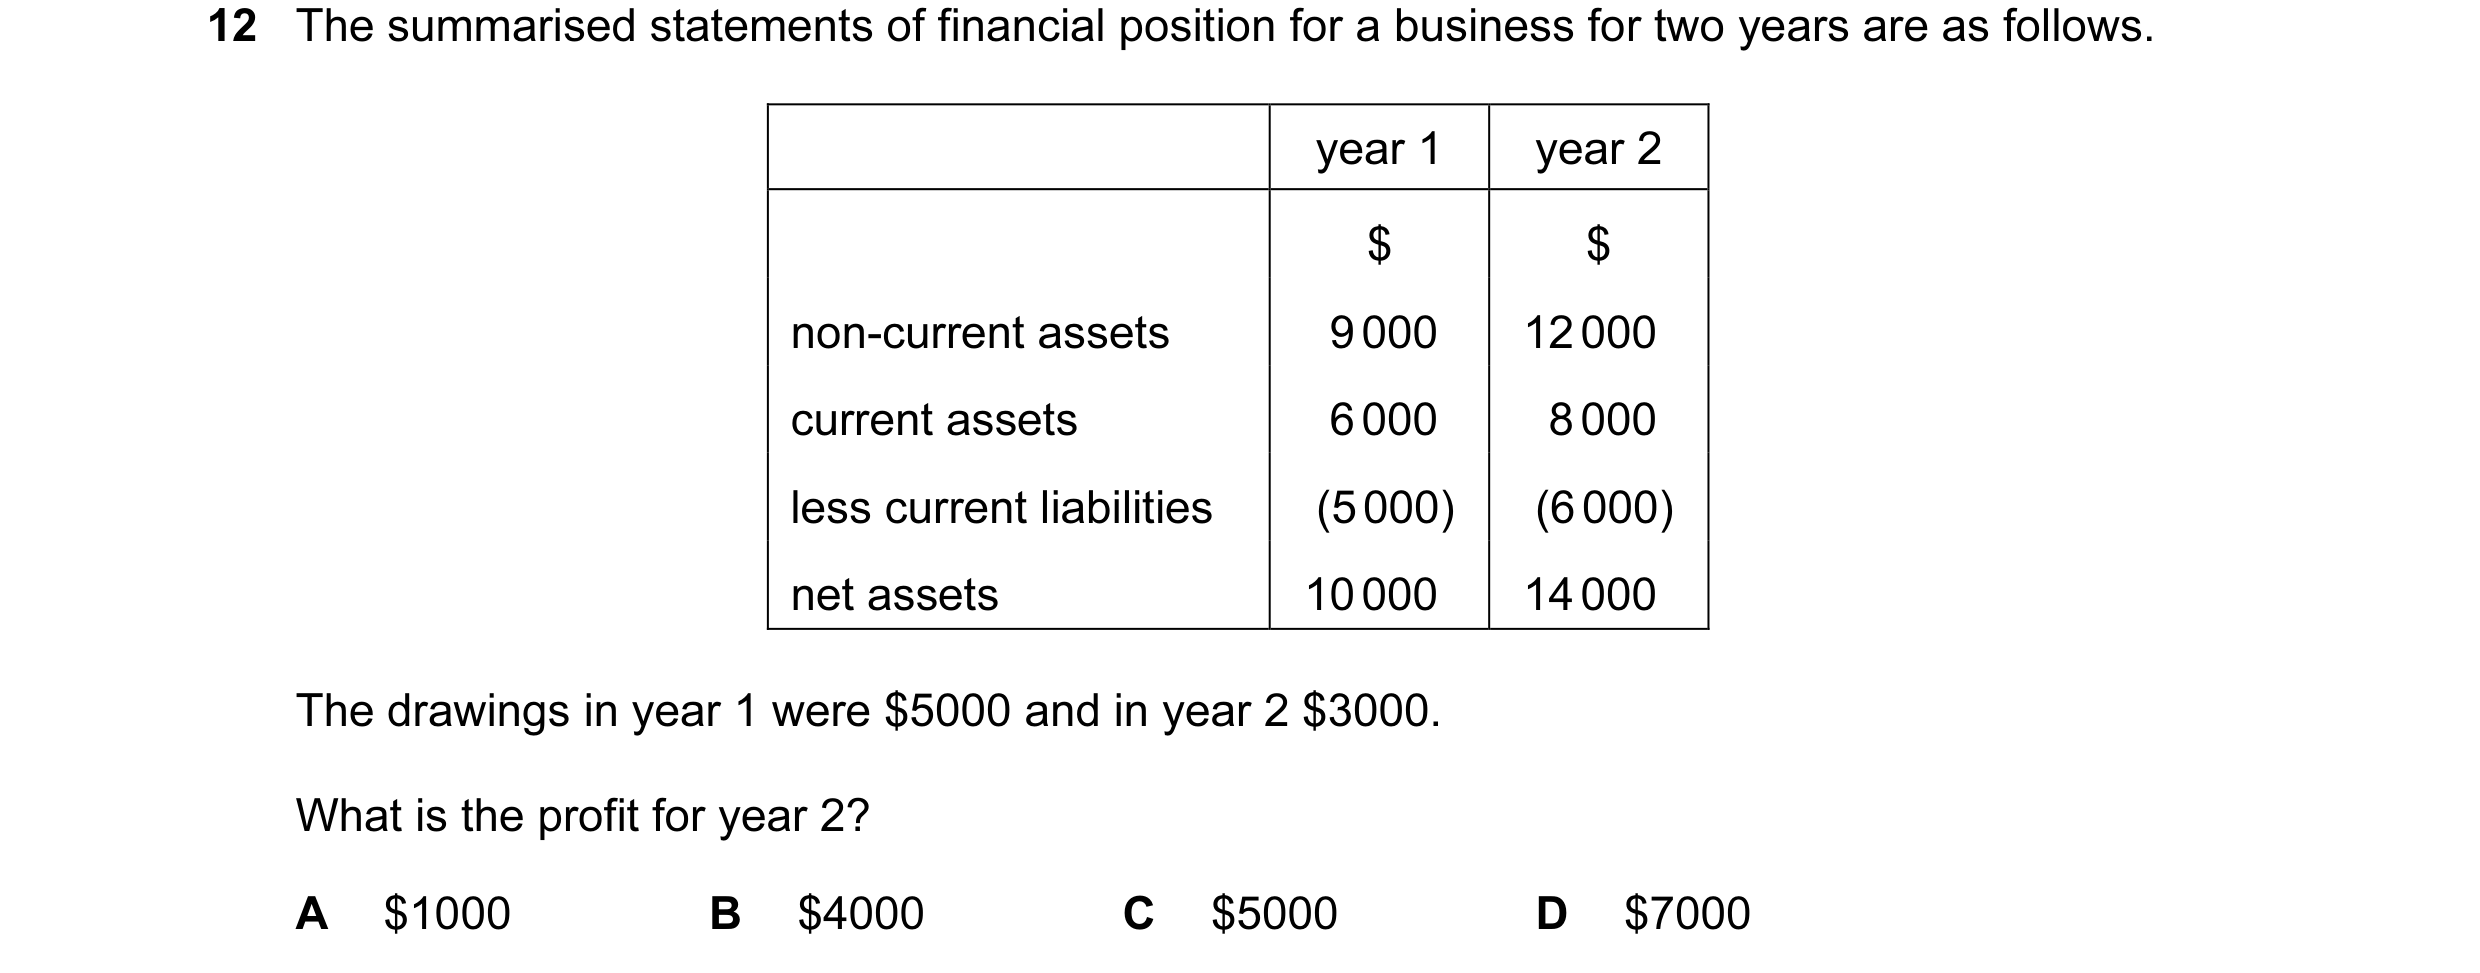 72 / 233
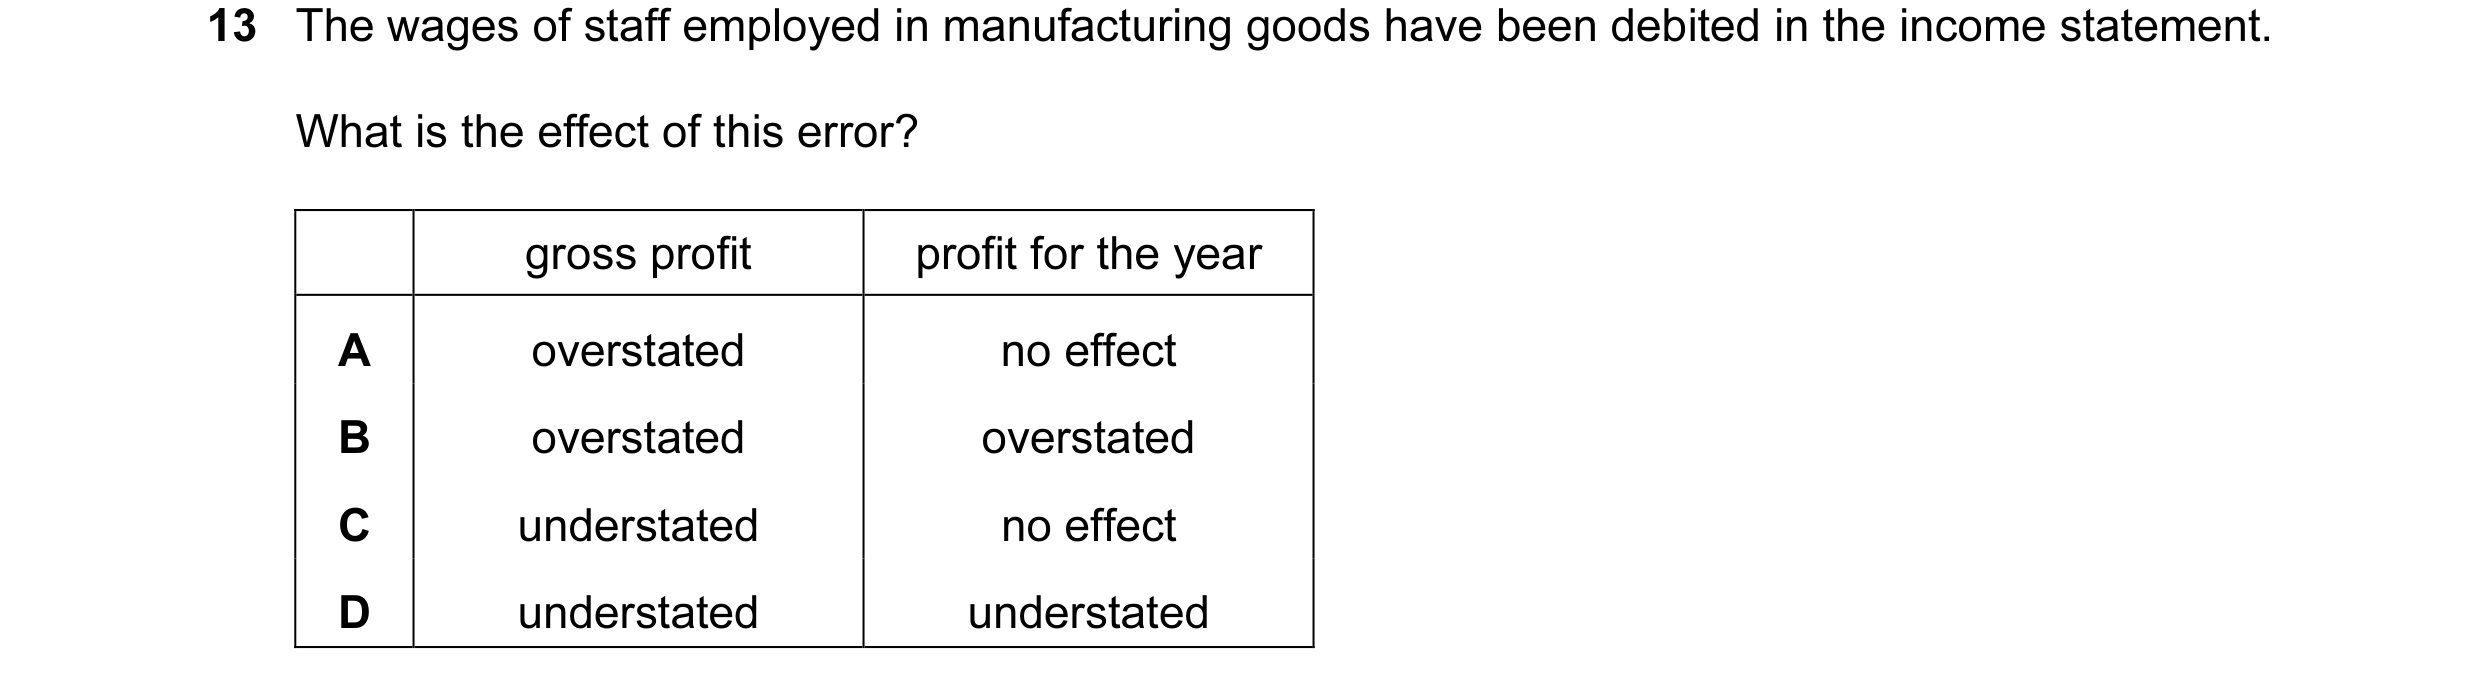
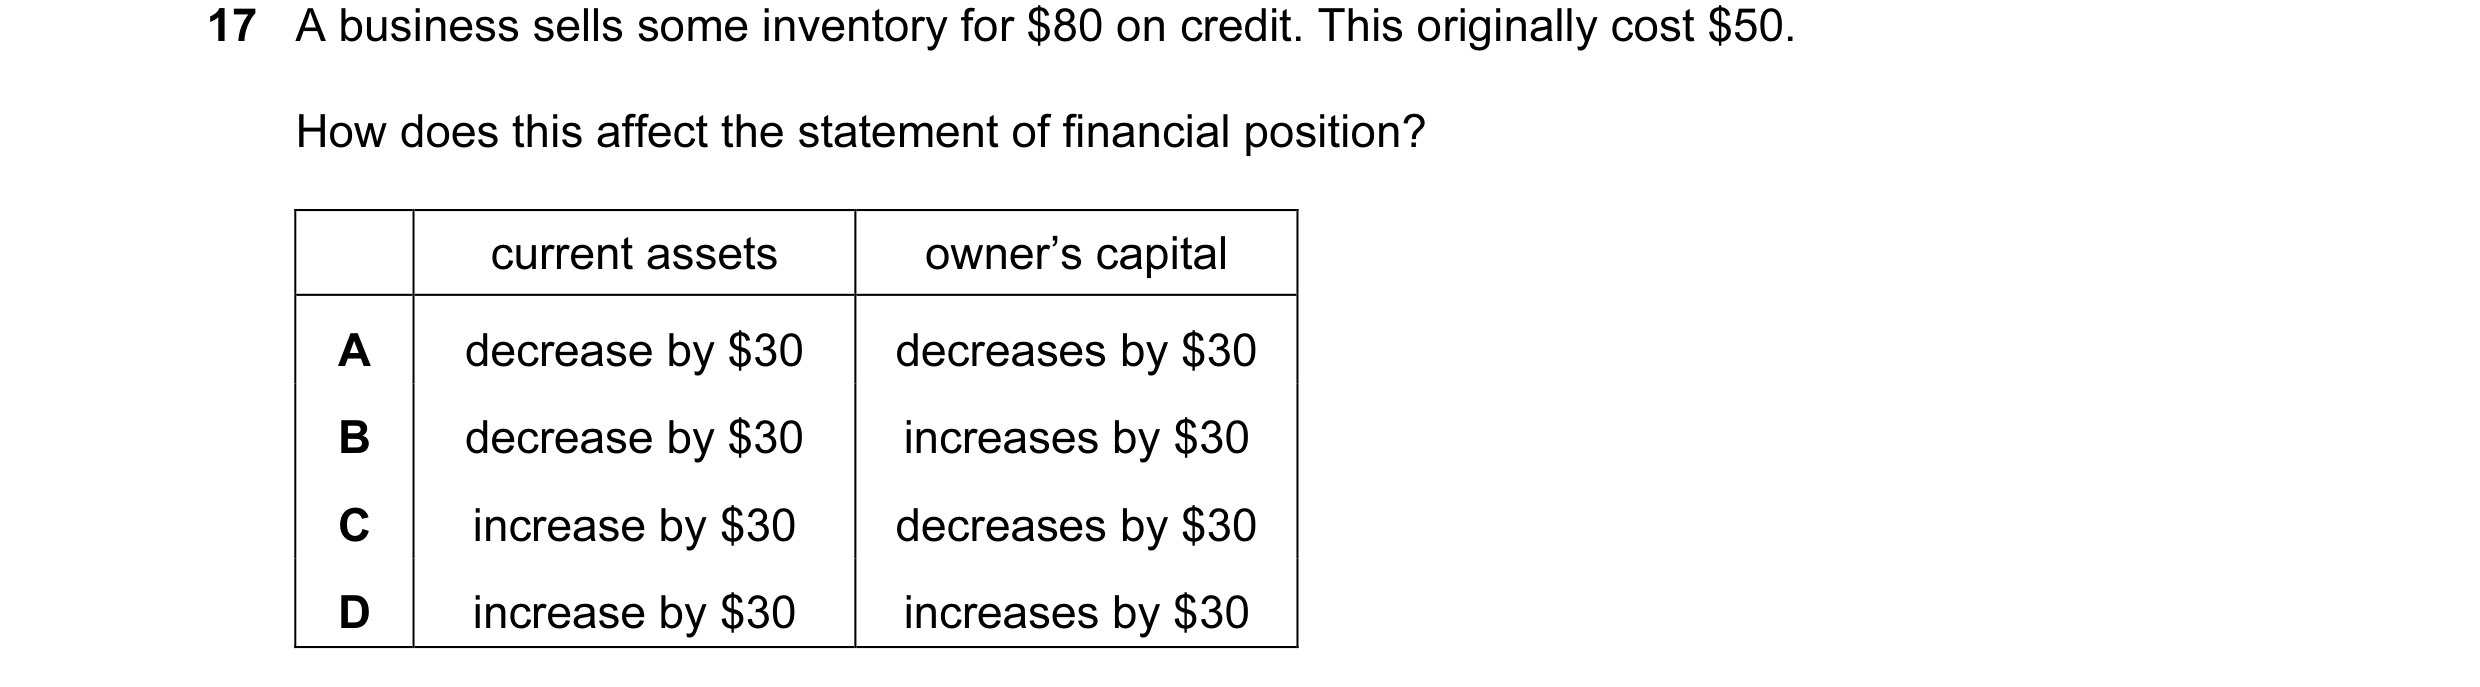
 73 / 233
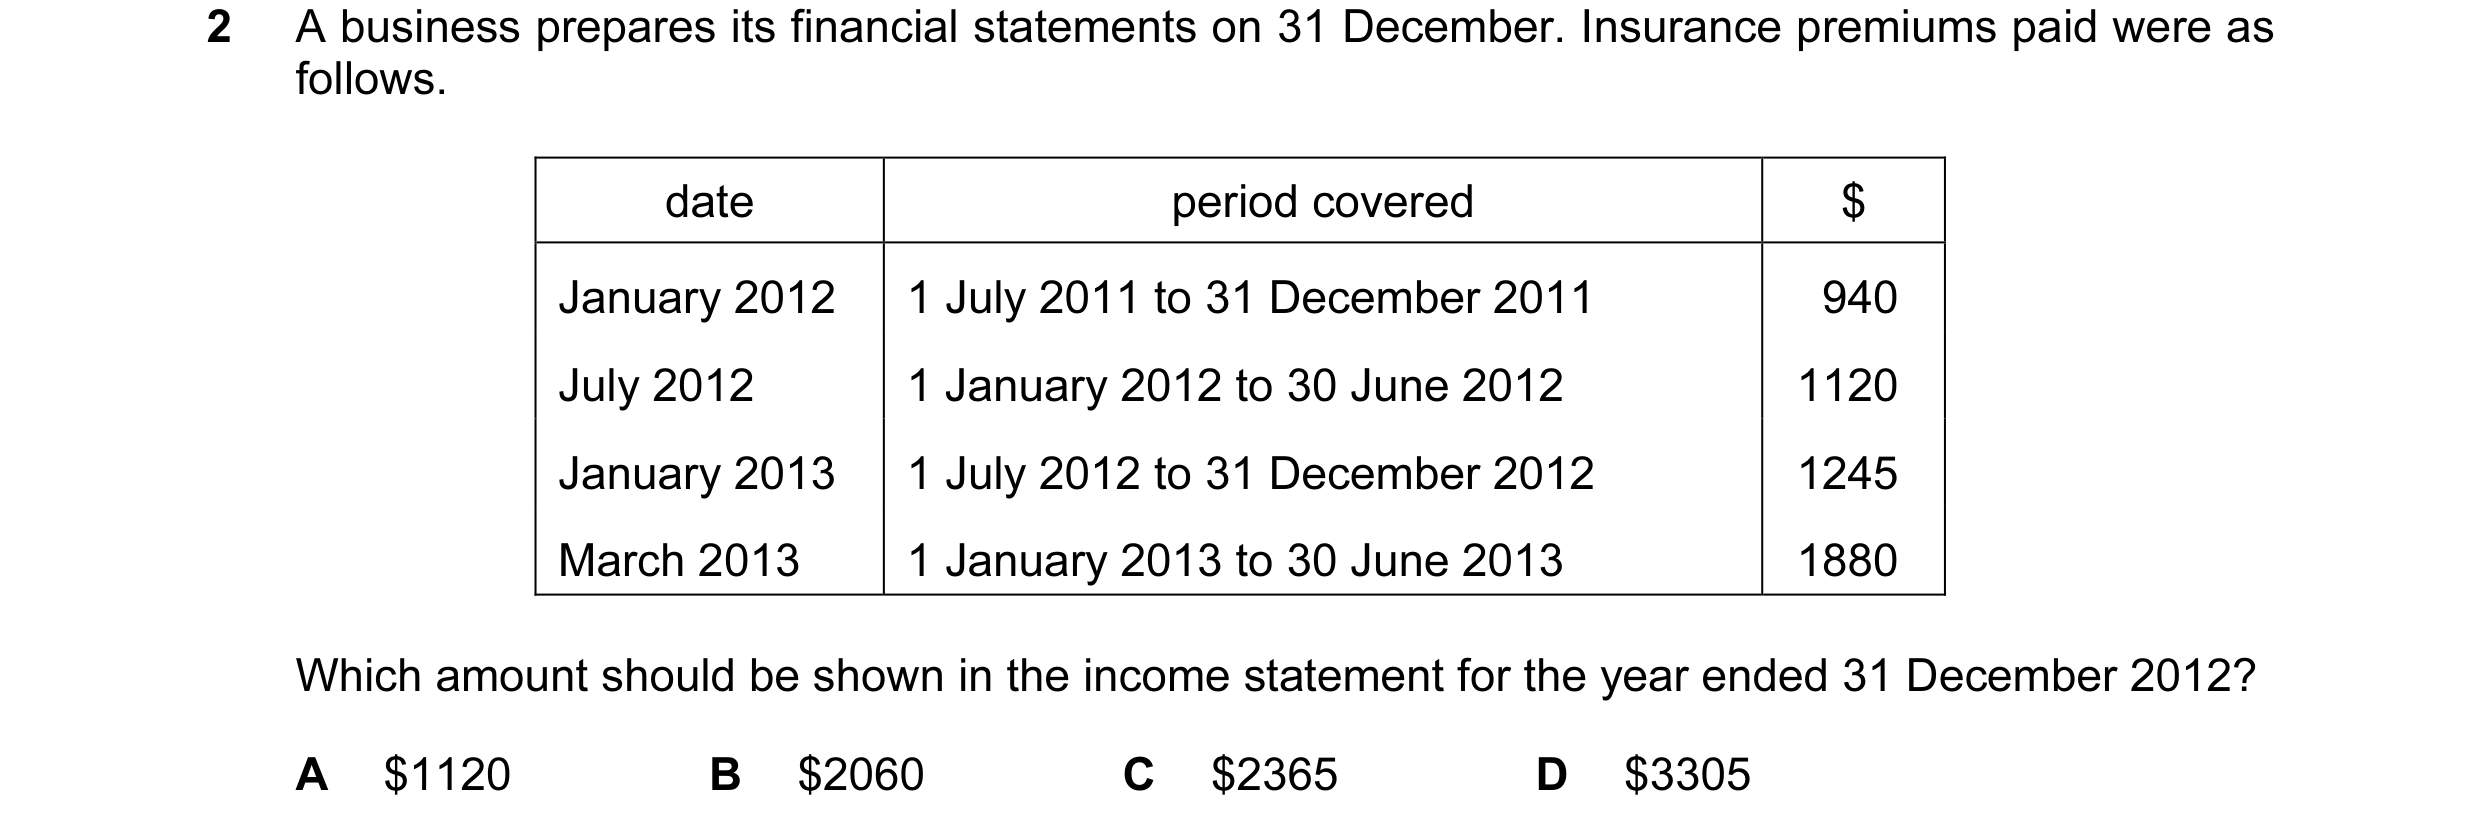
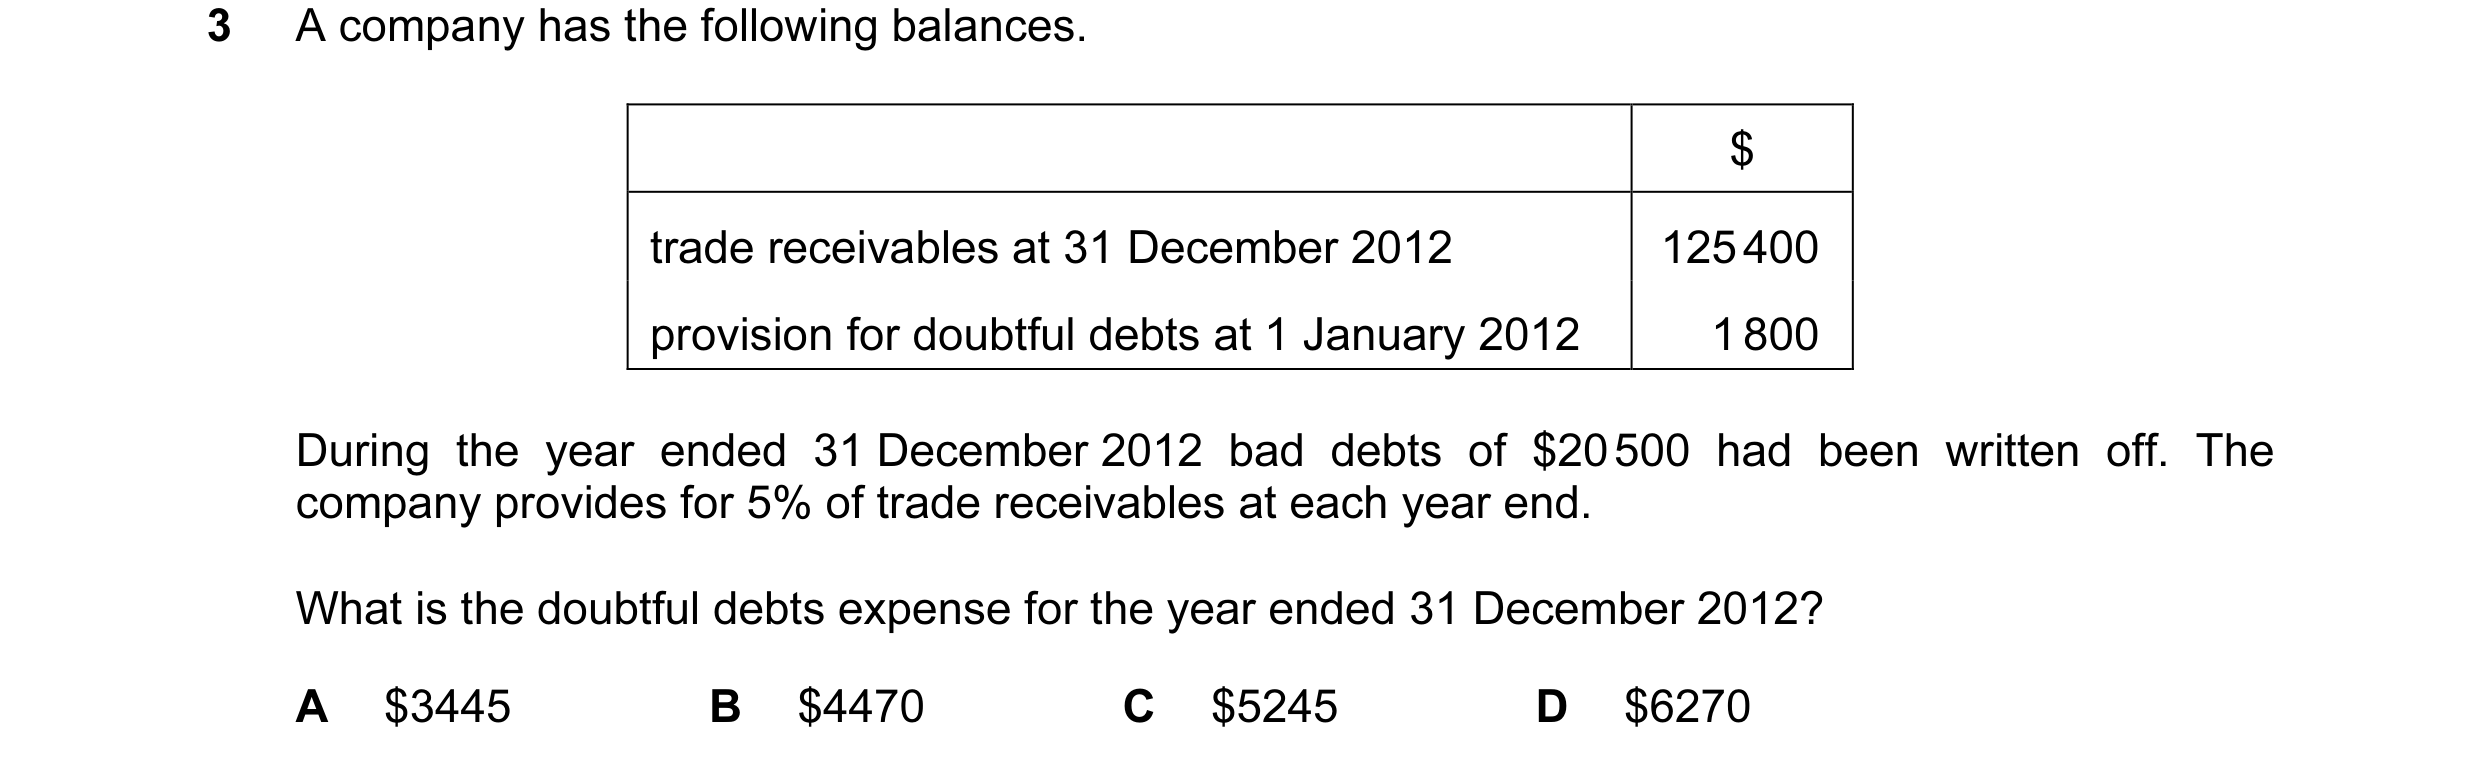
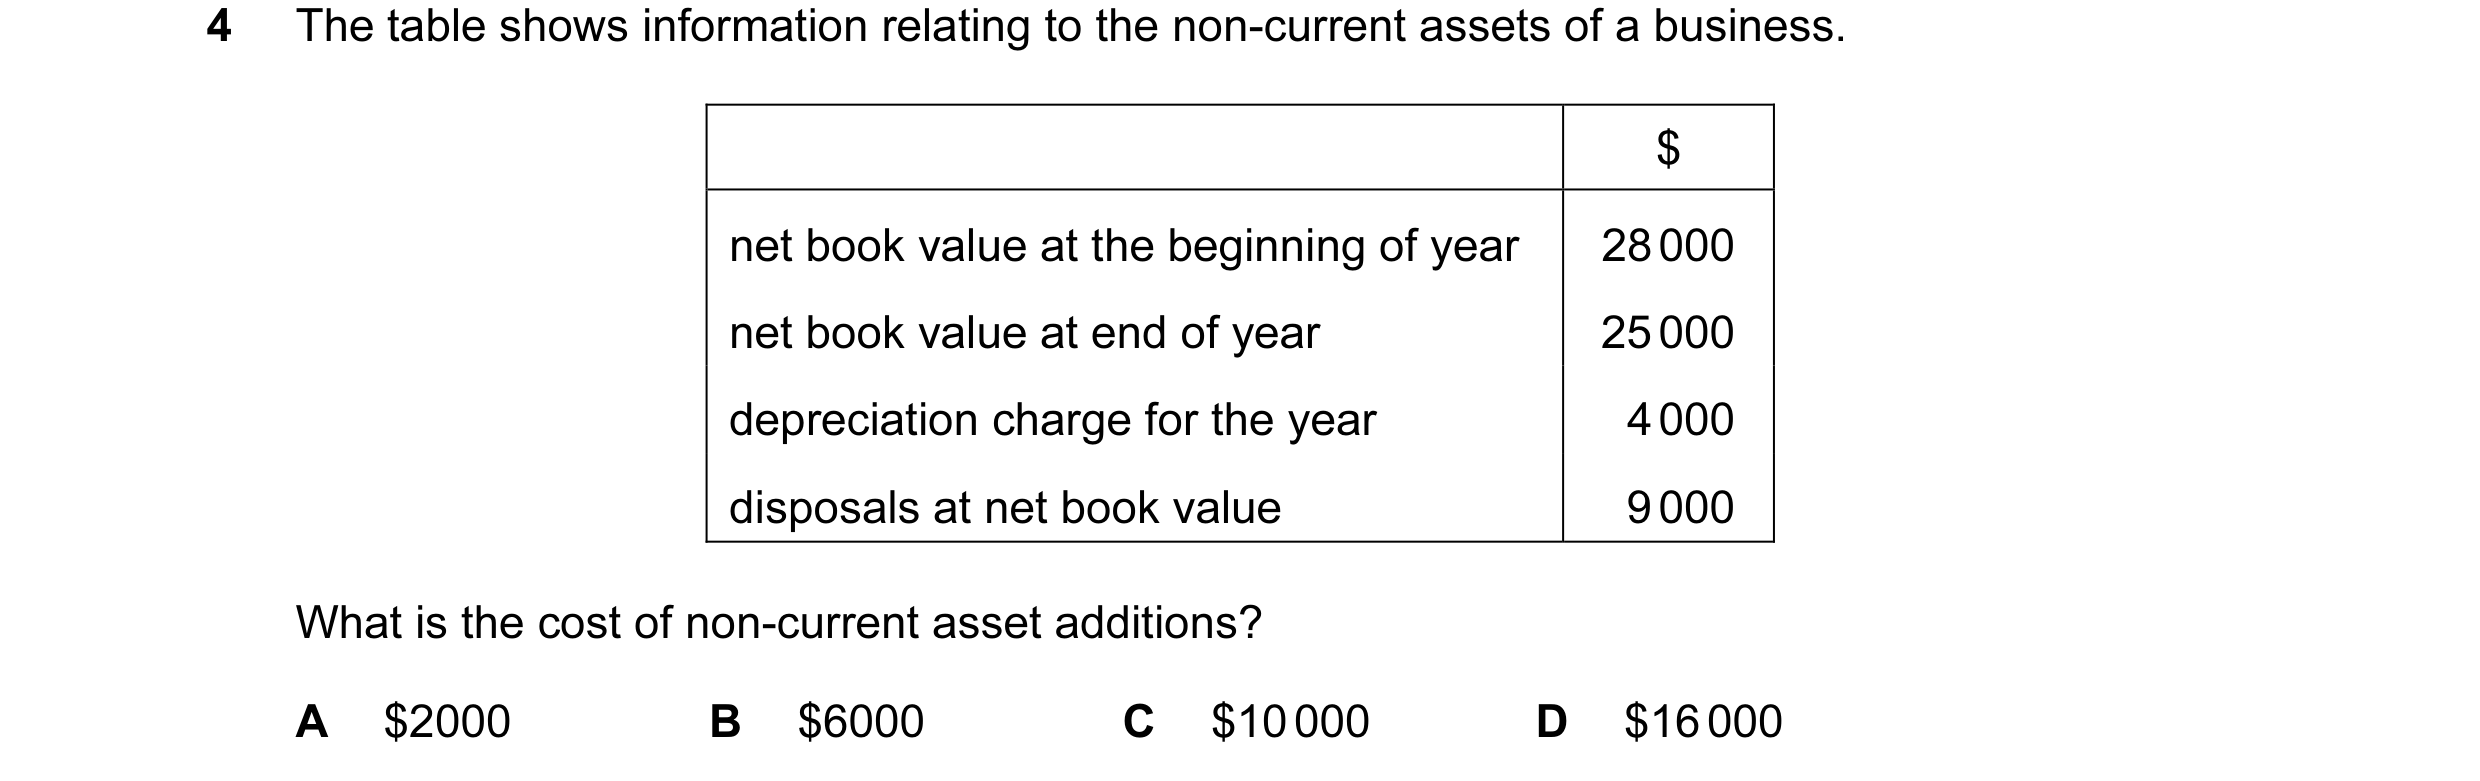
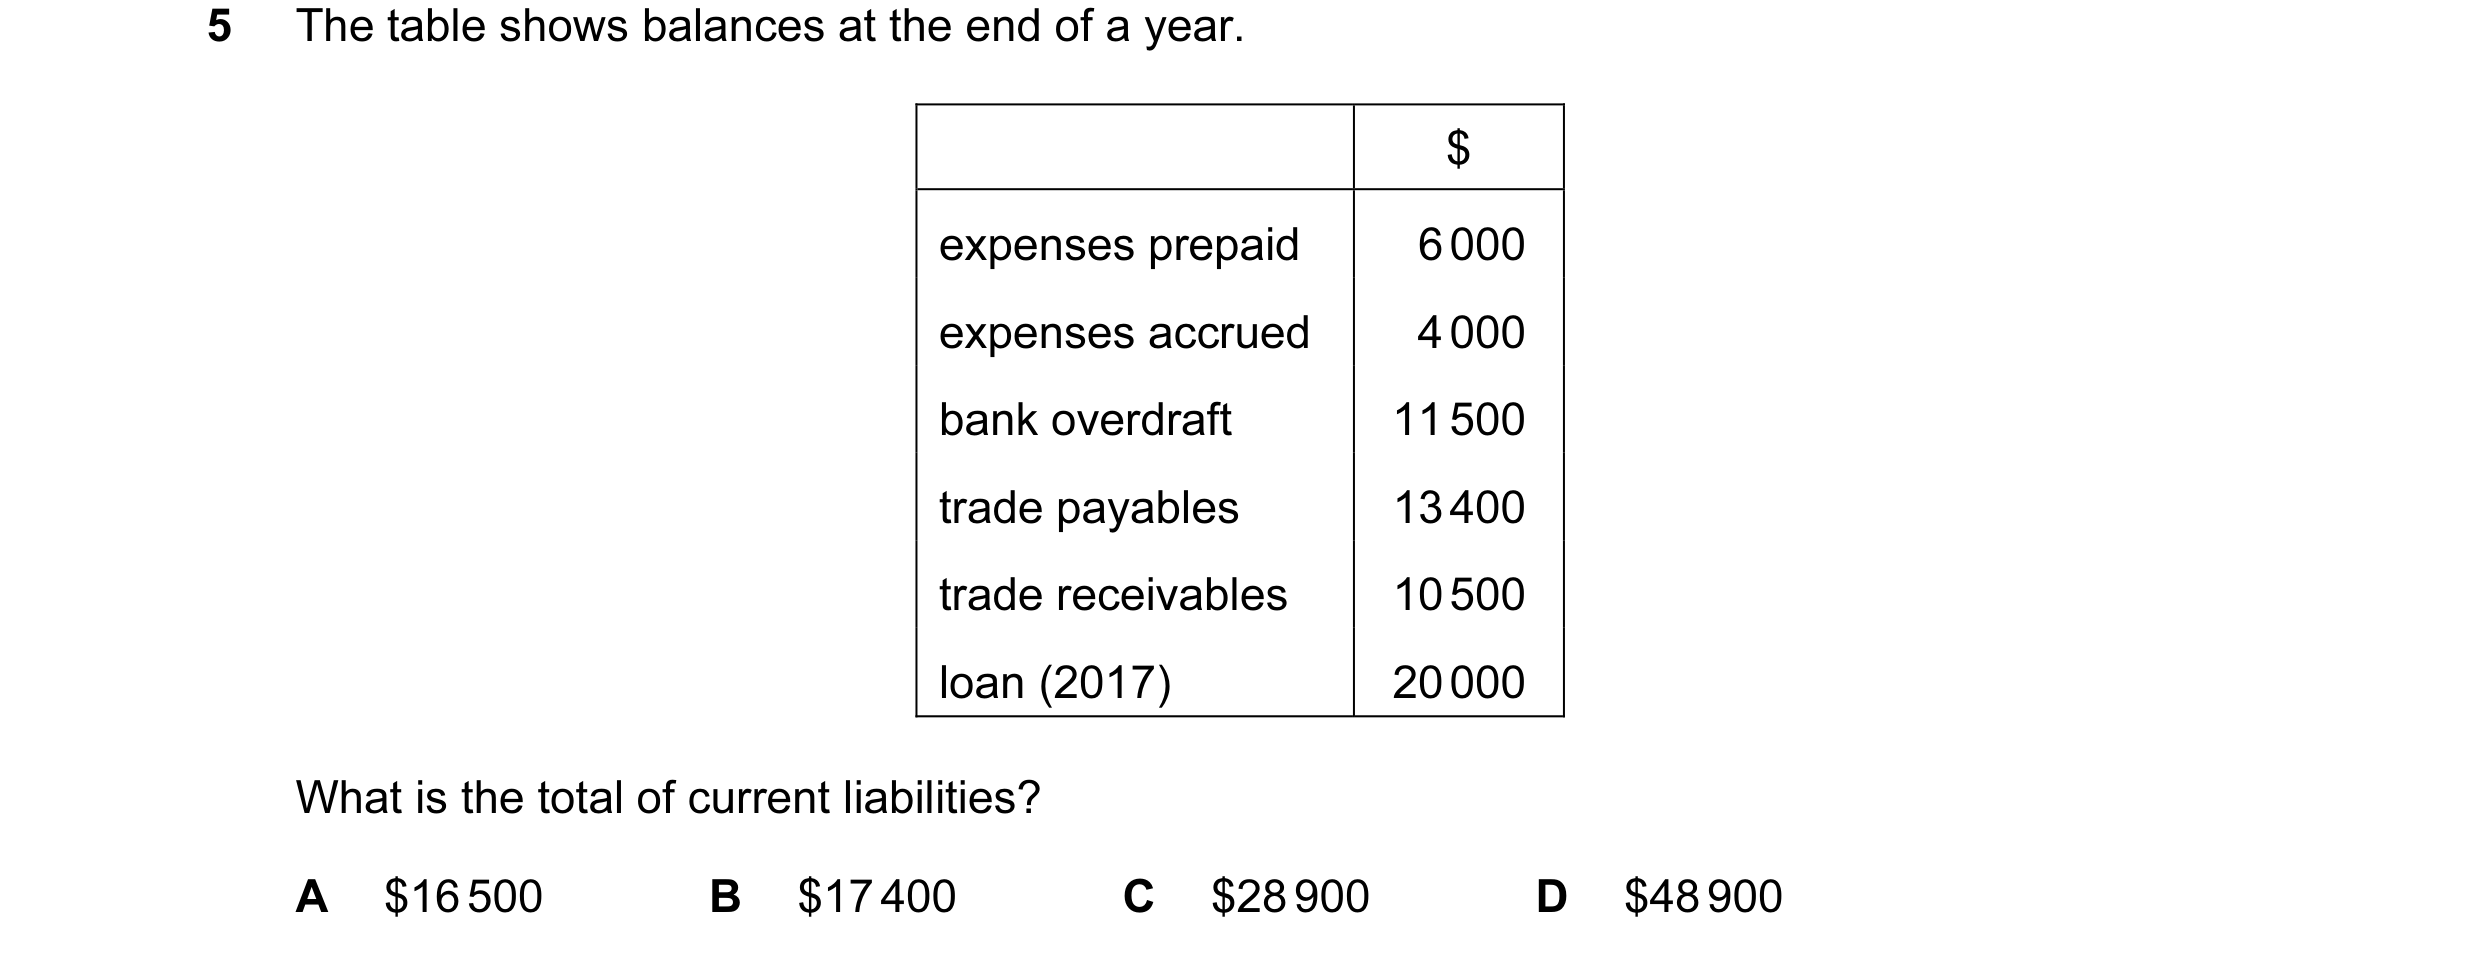 74 / 233
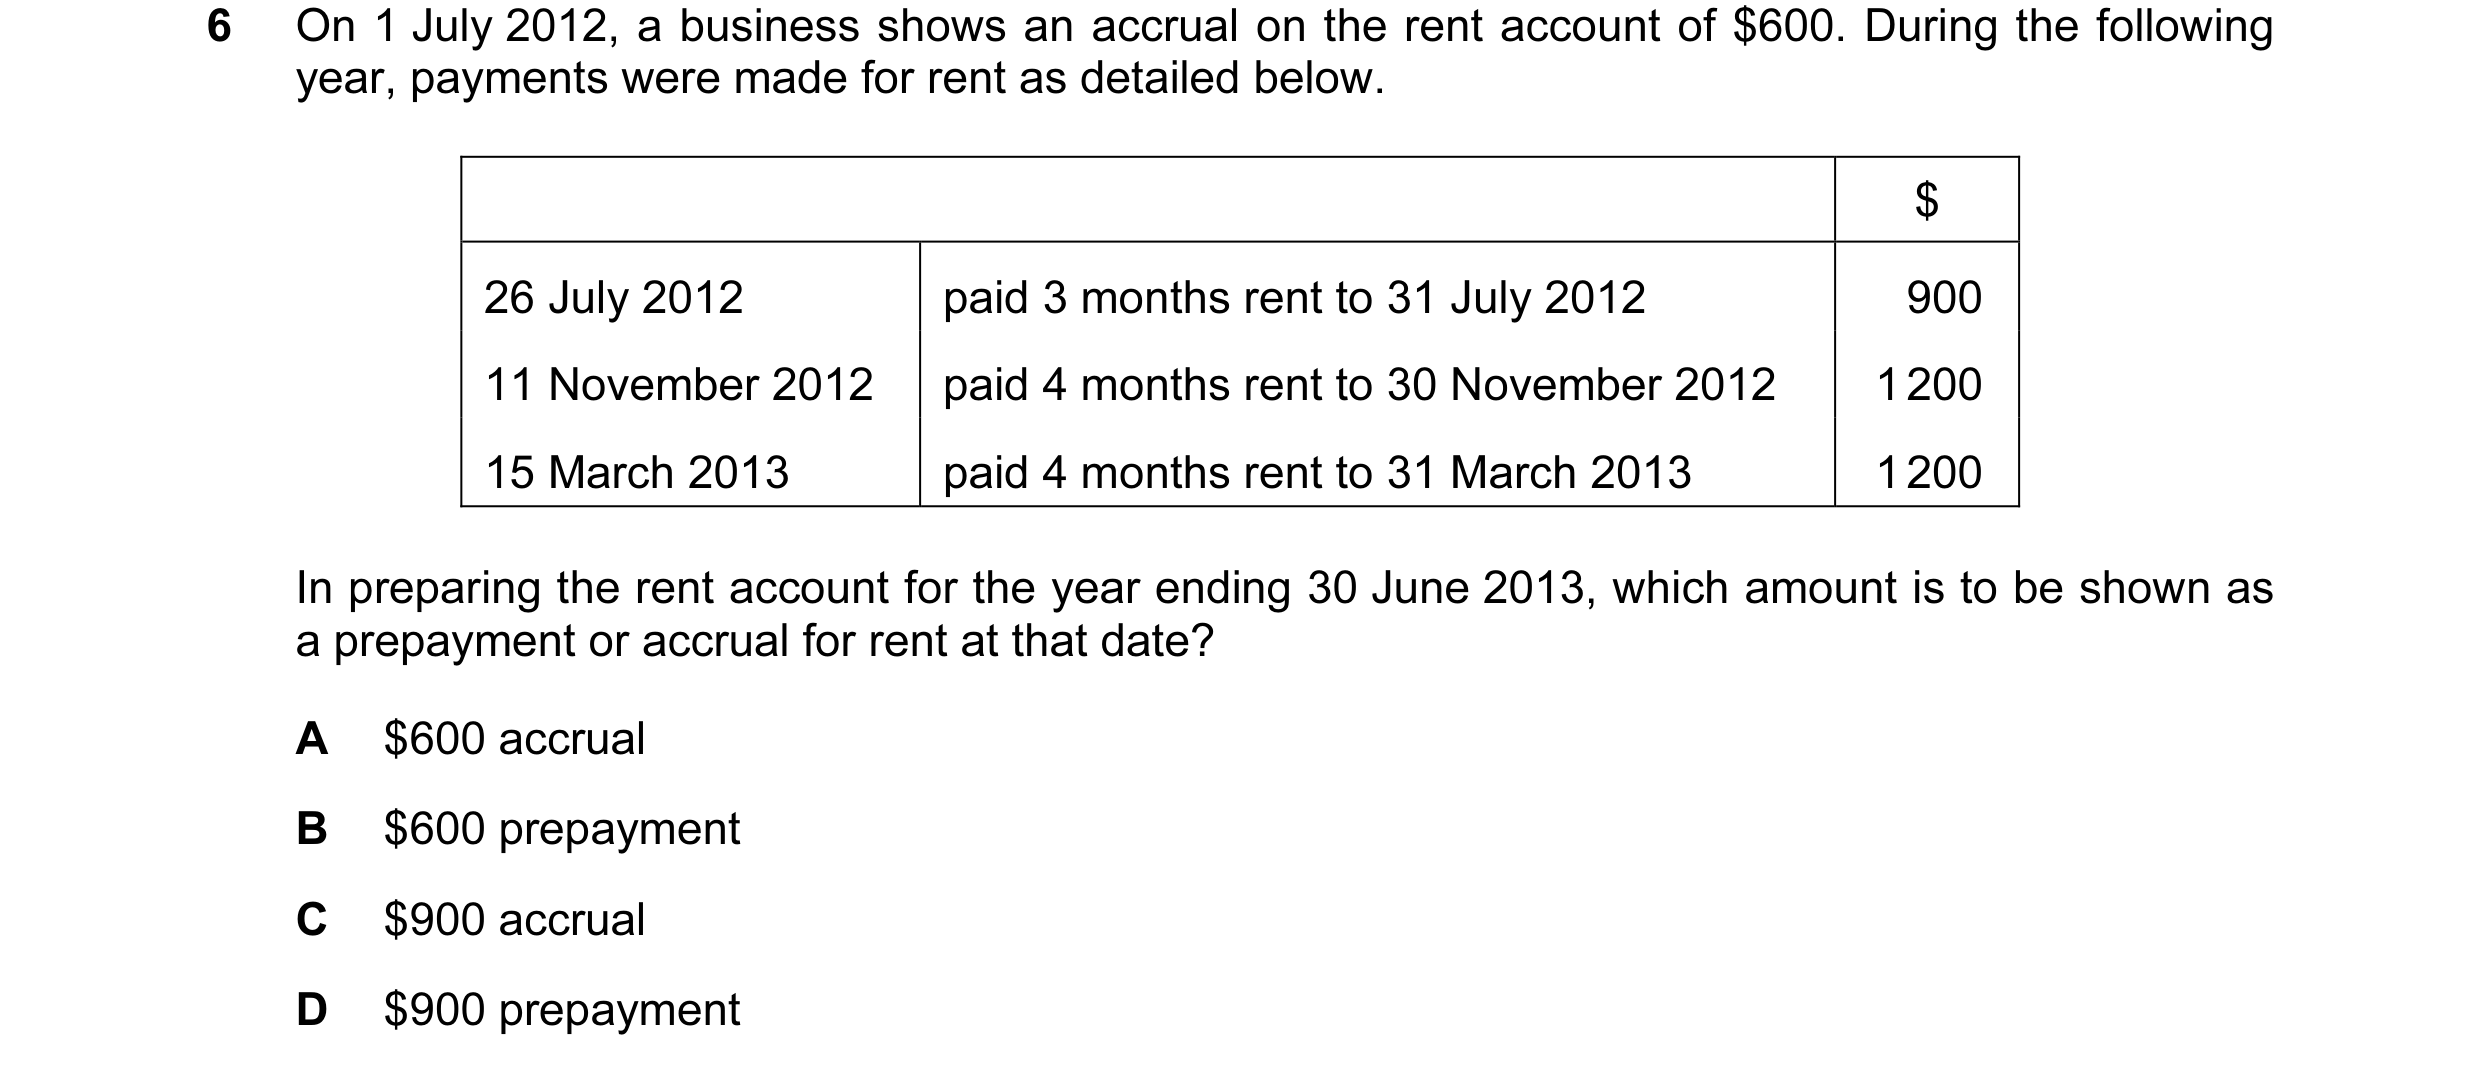
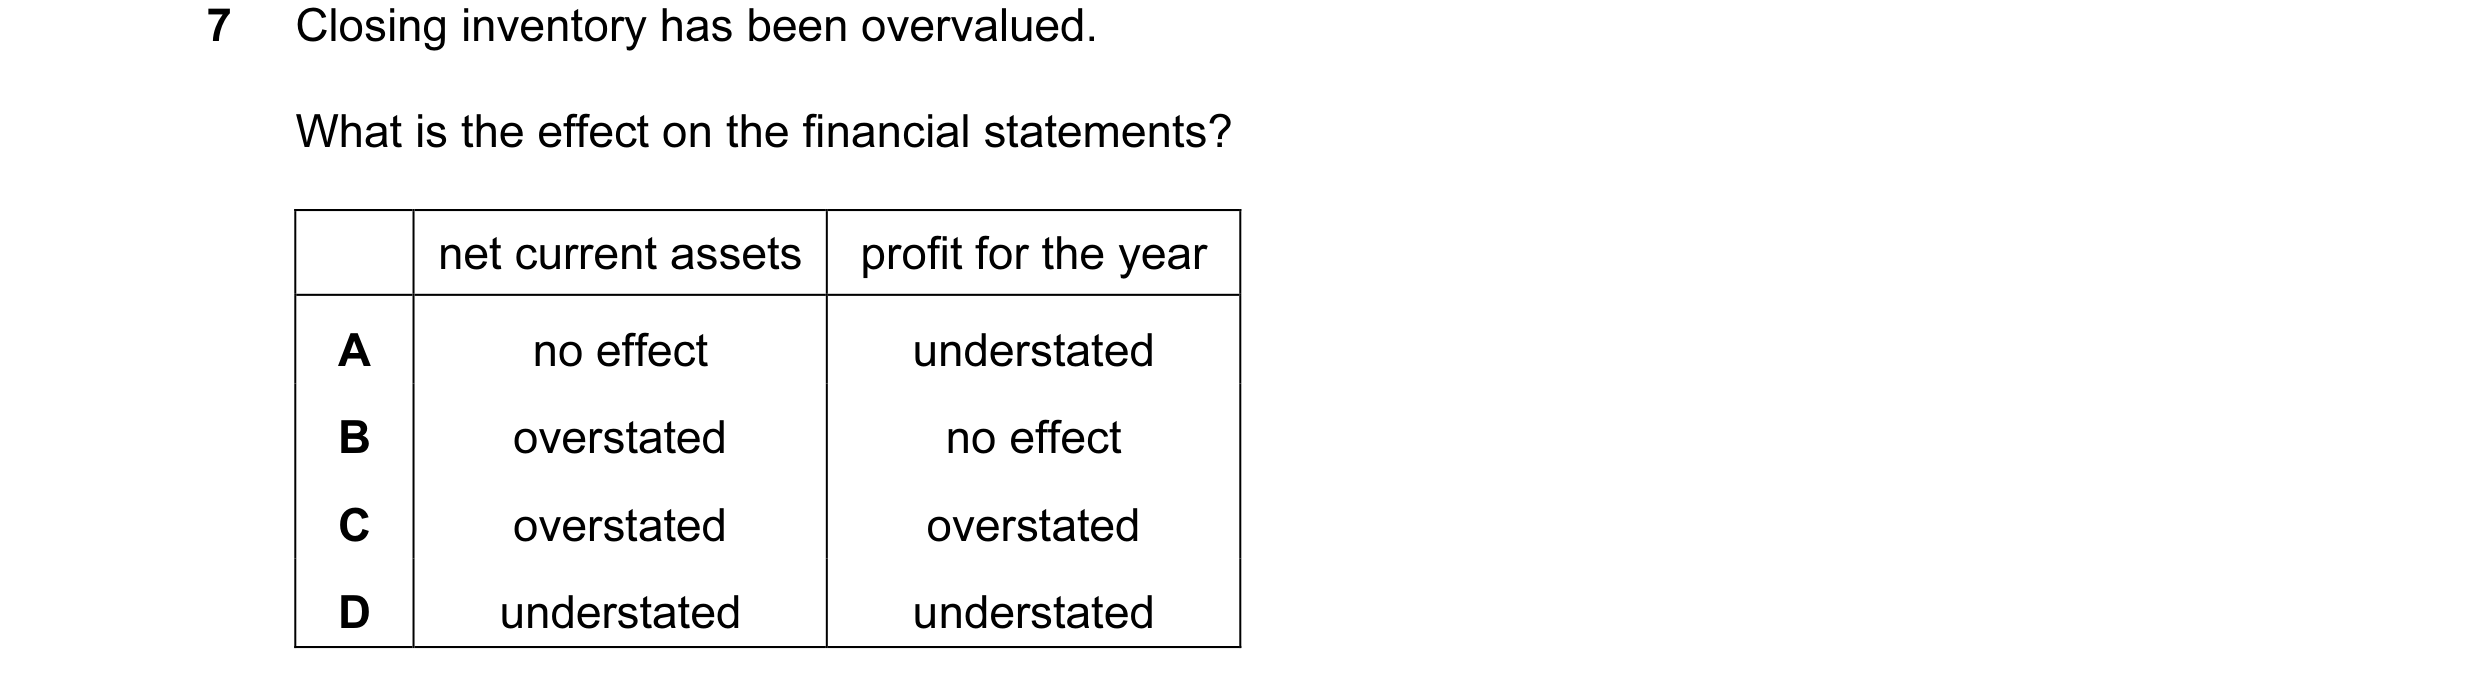
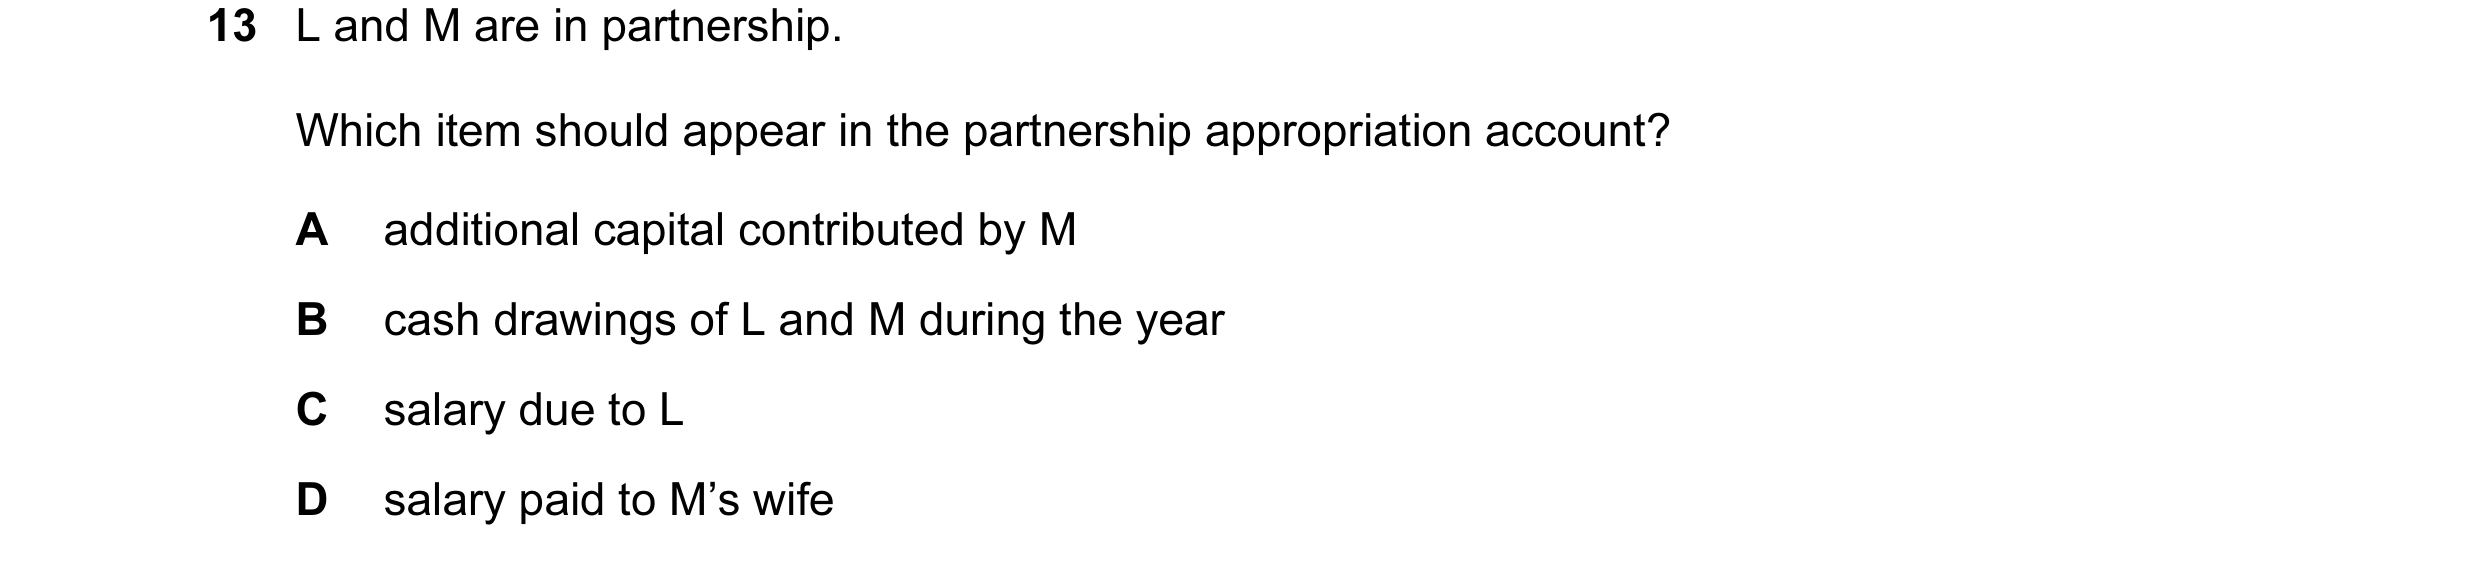
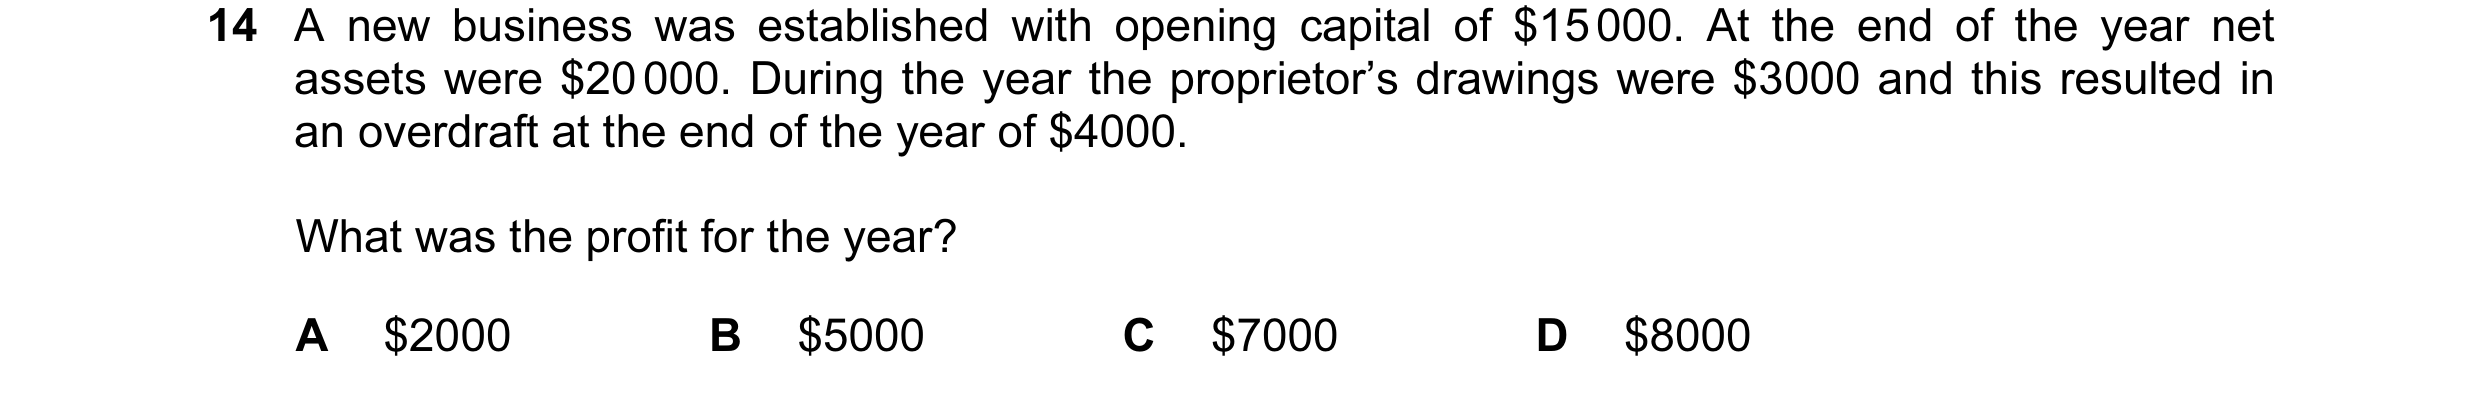 75 / 233
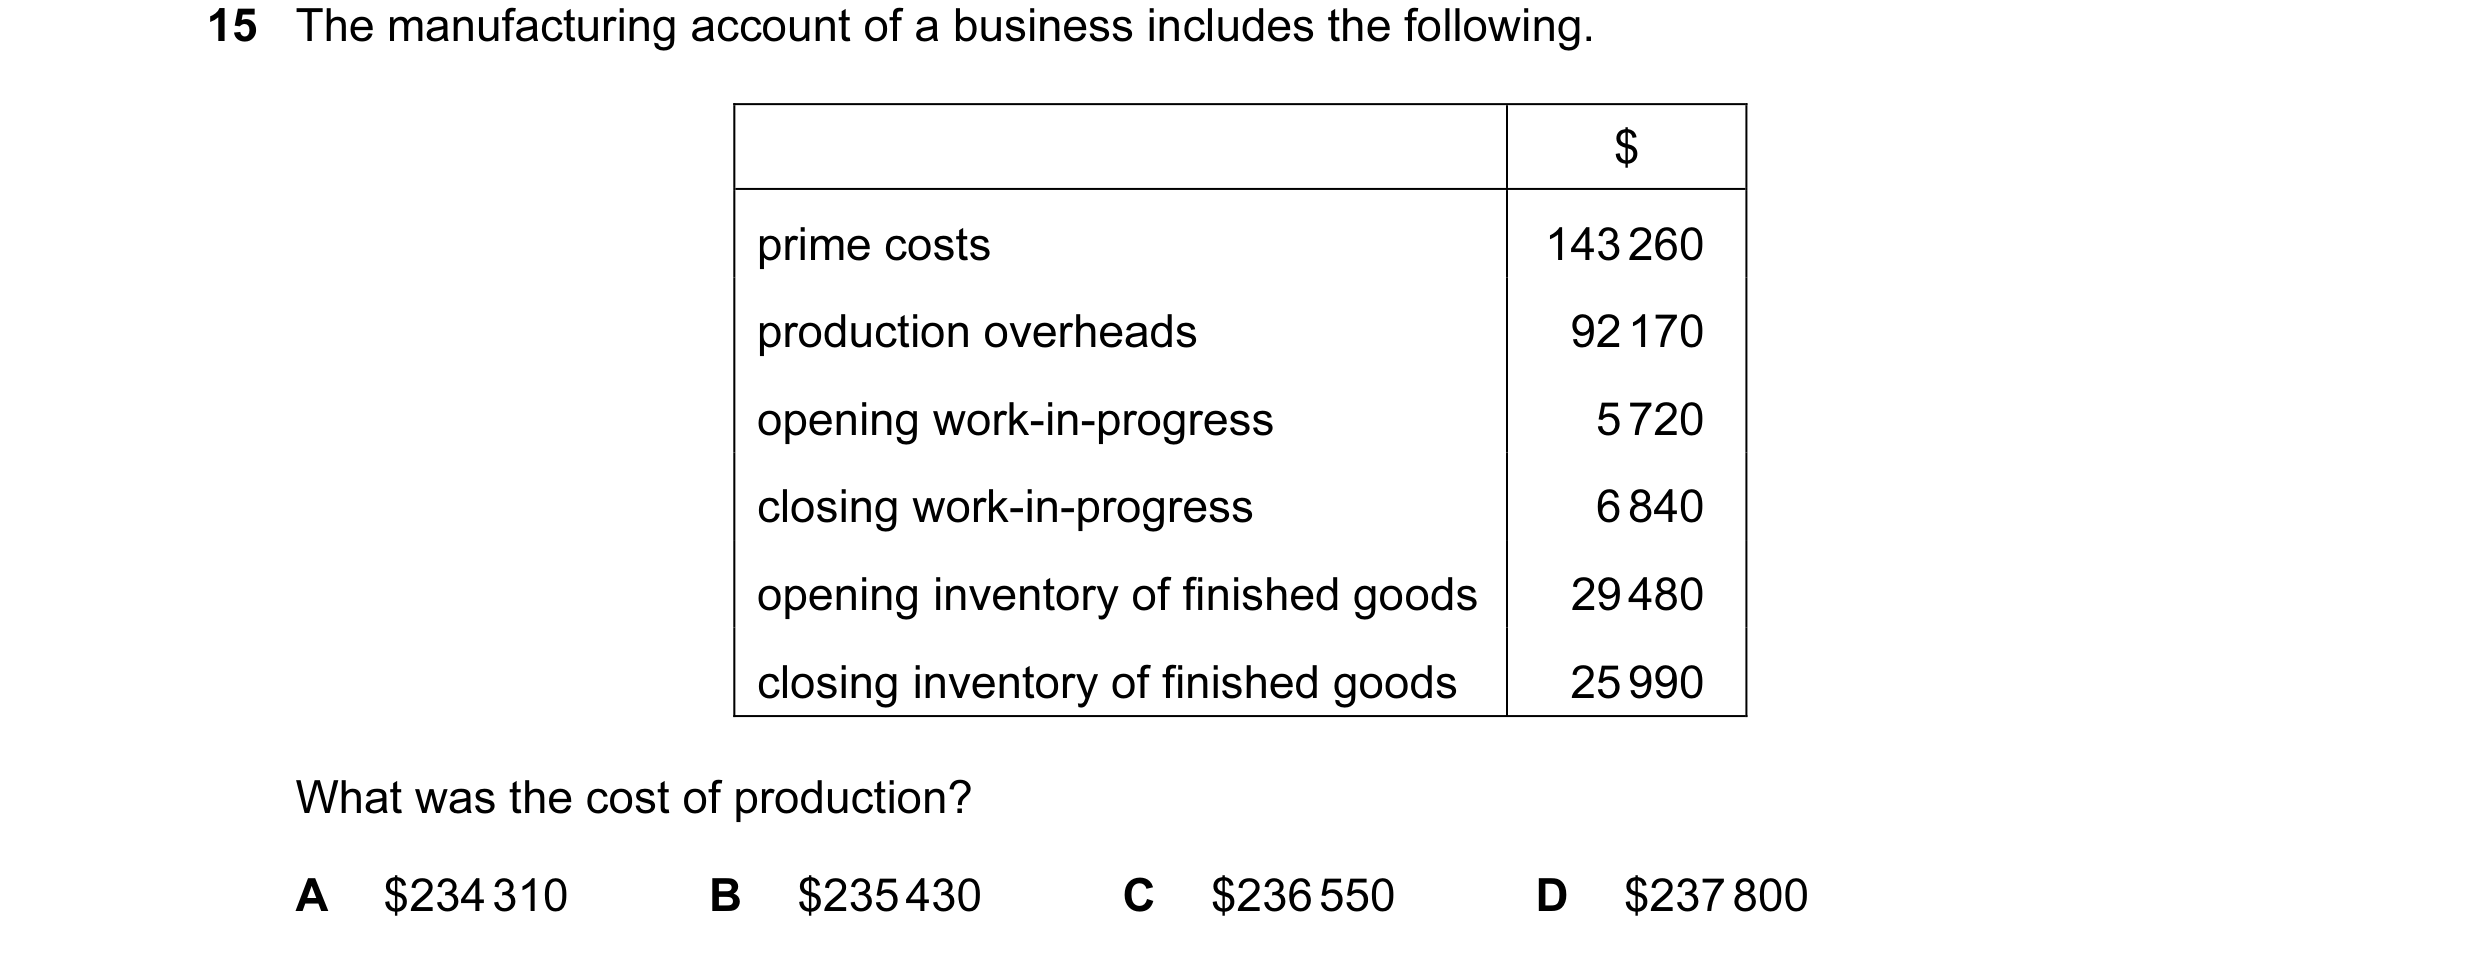
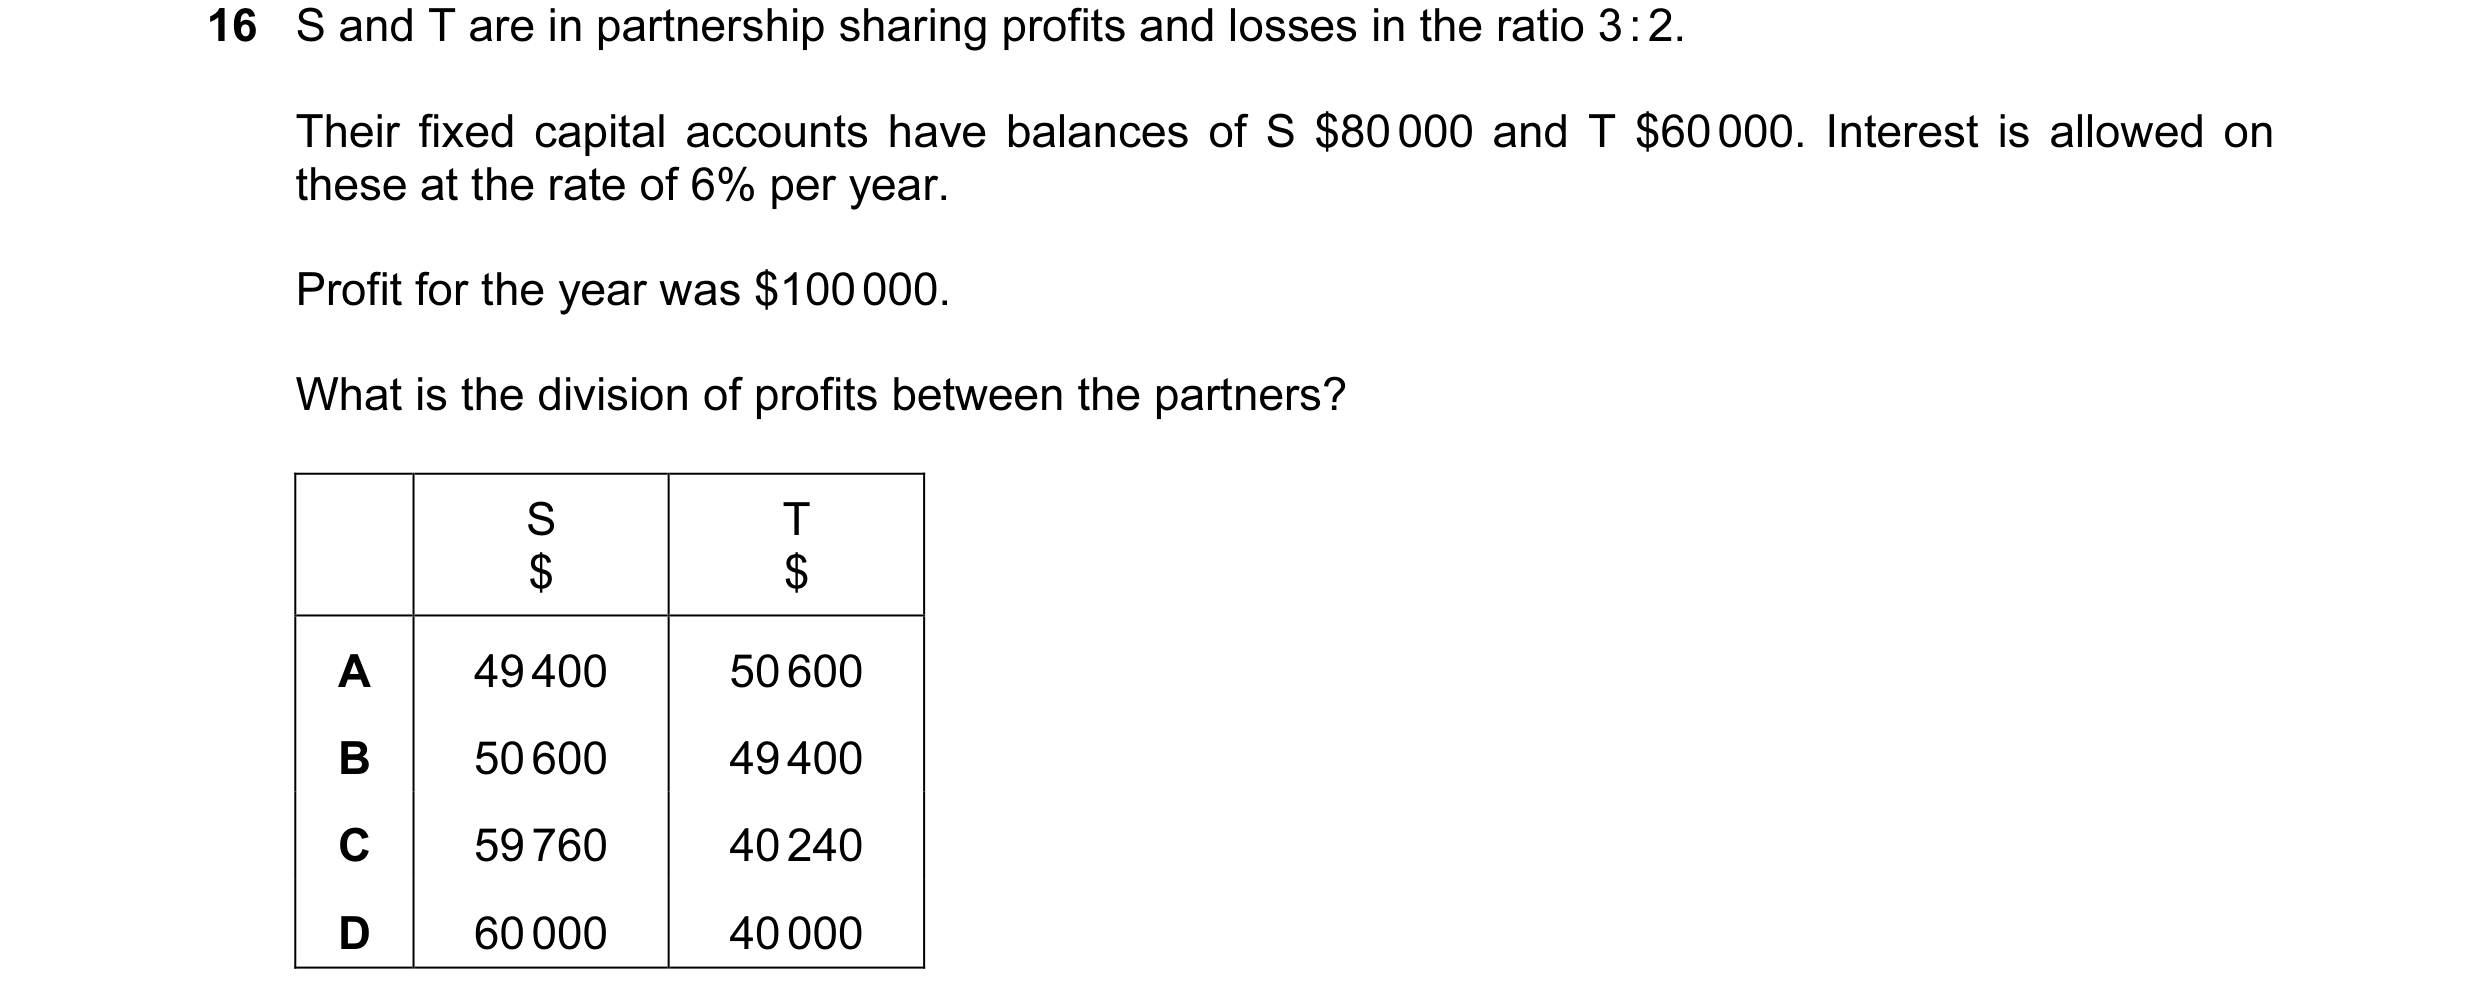
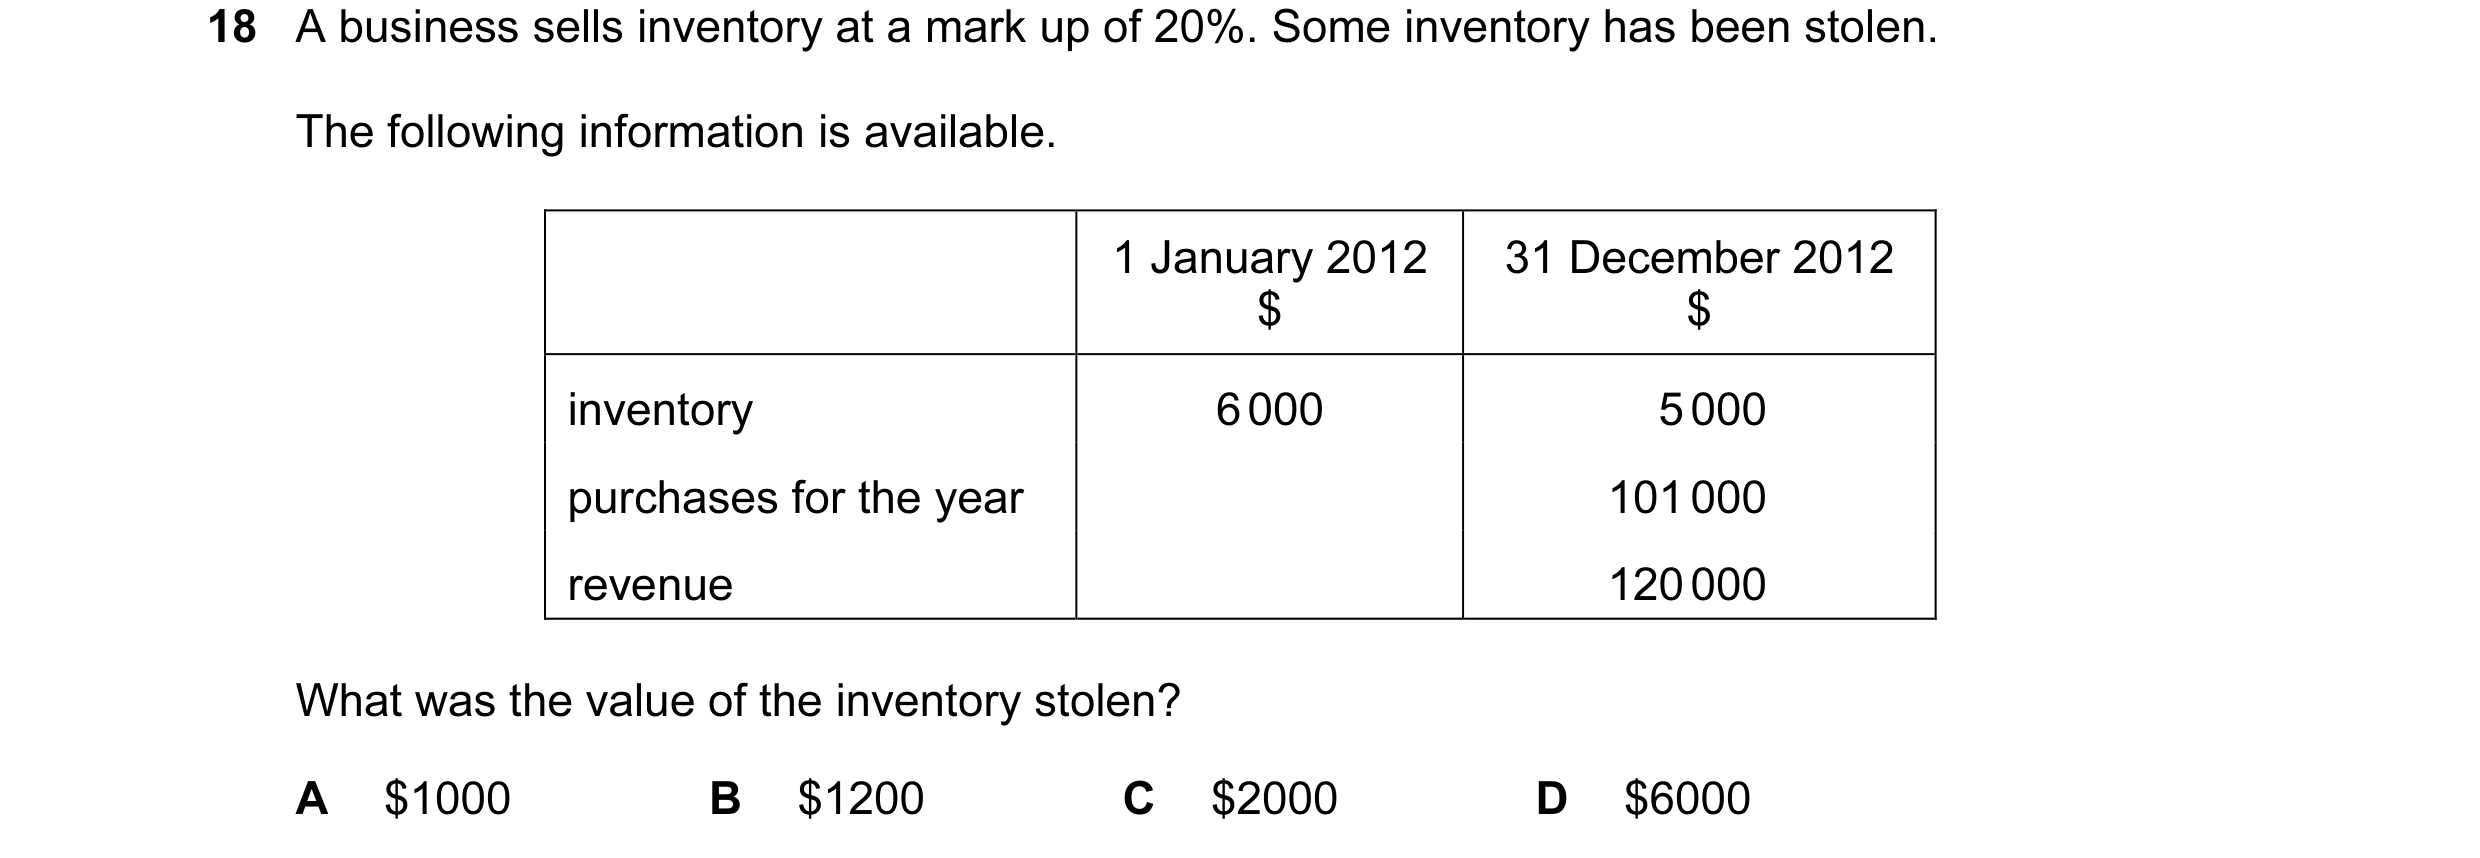 76 / 233
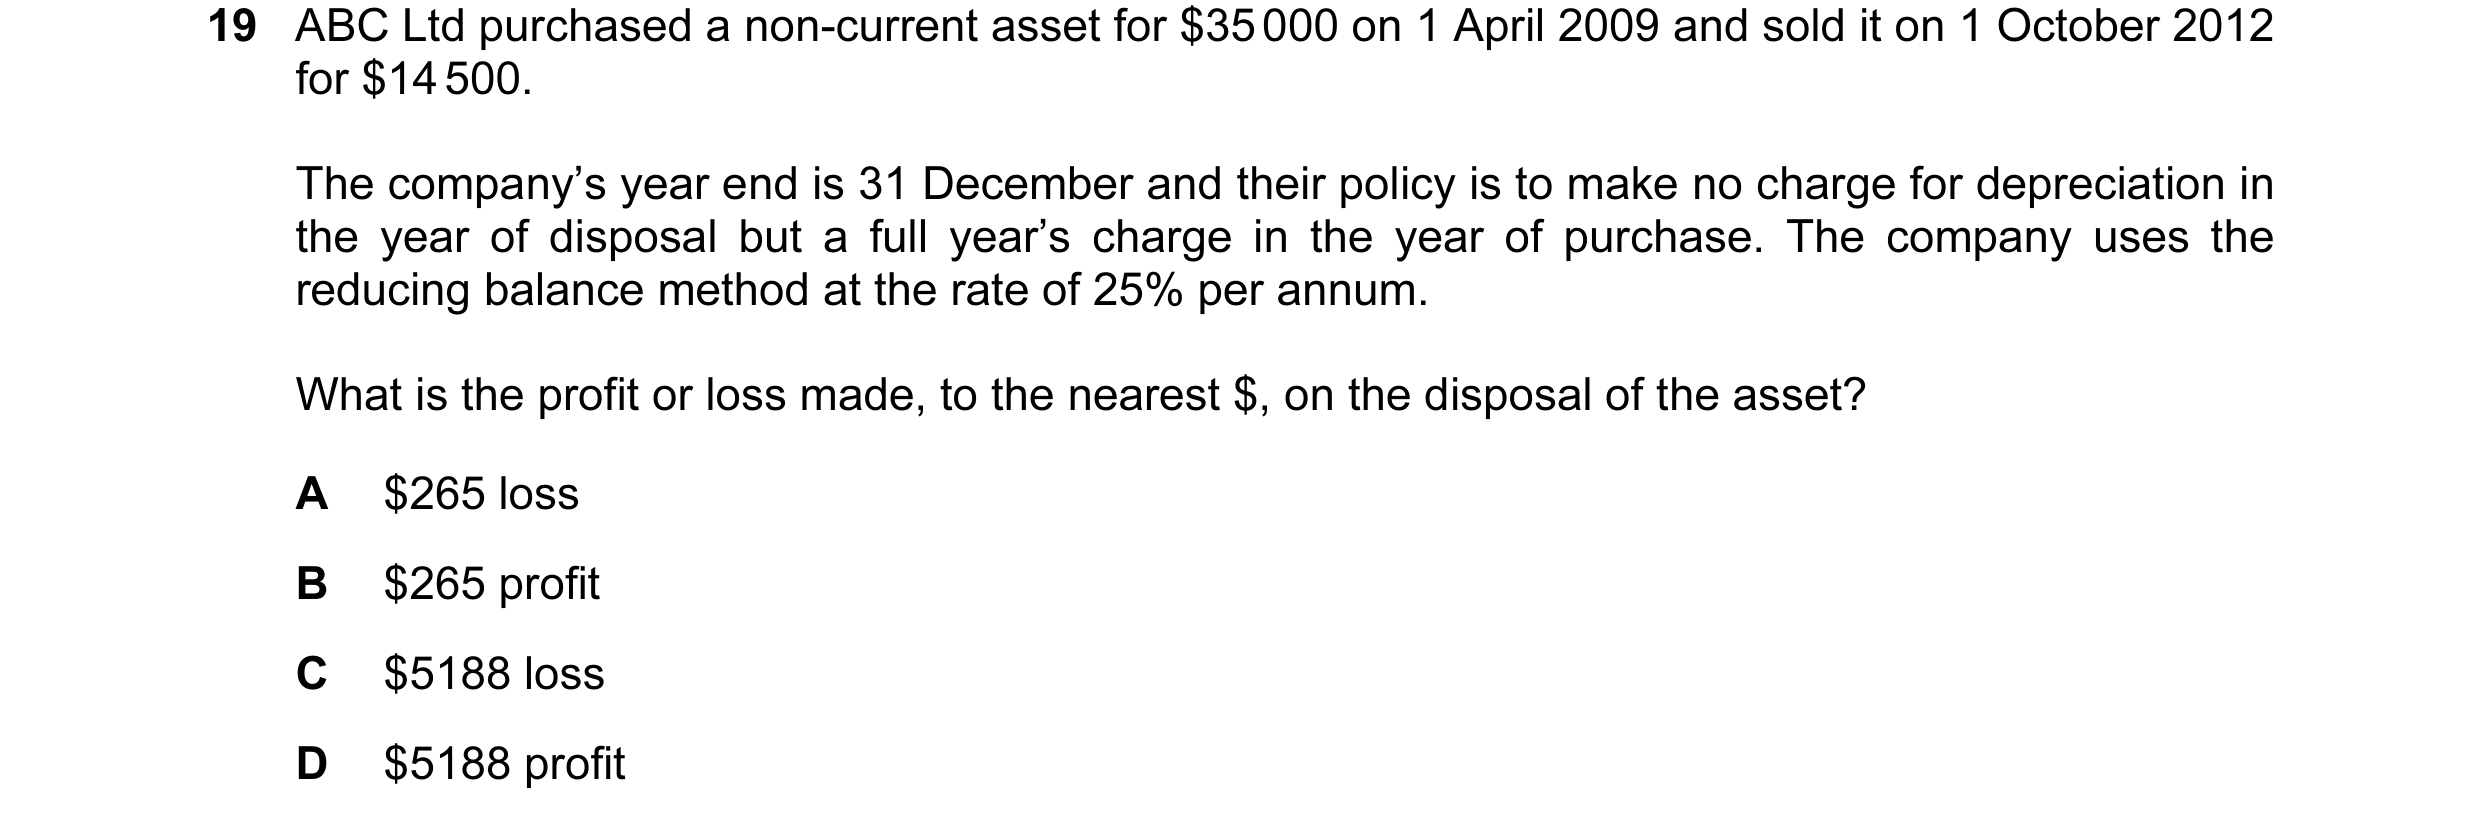
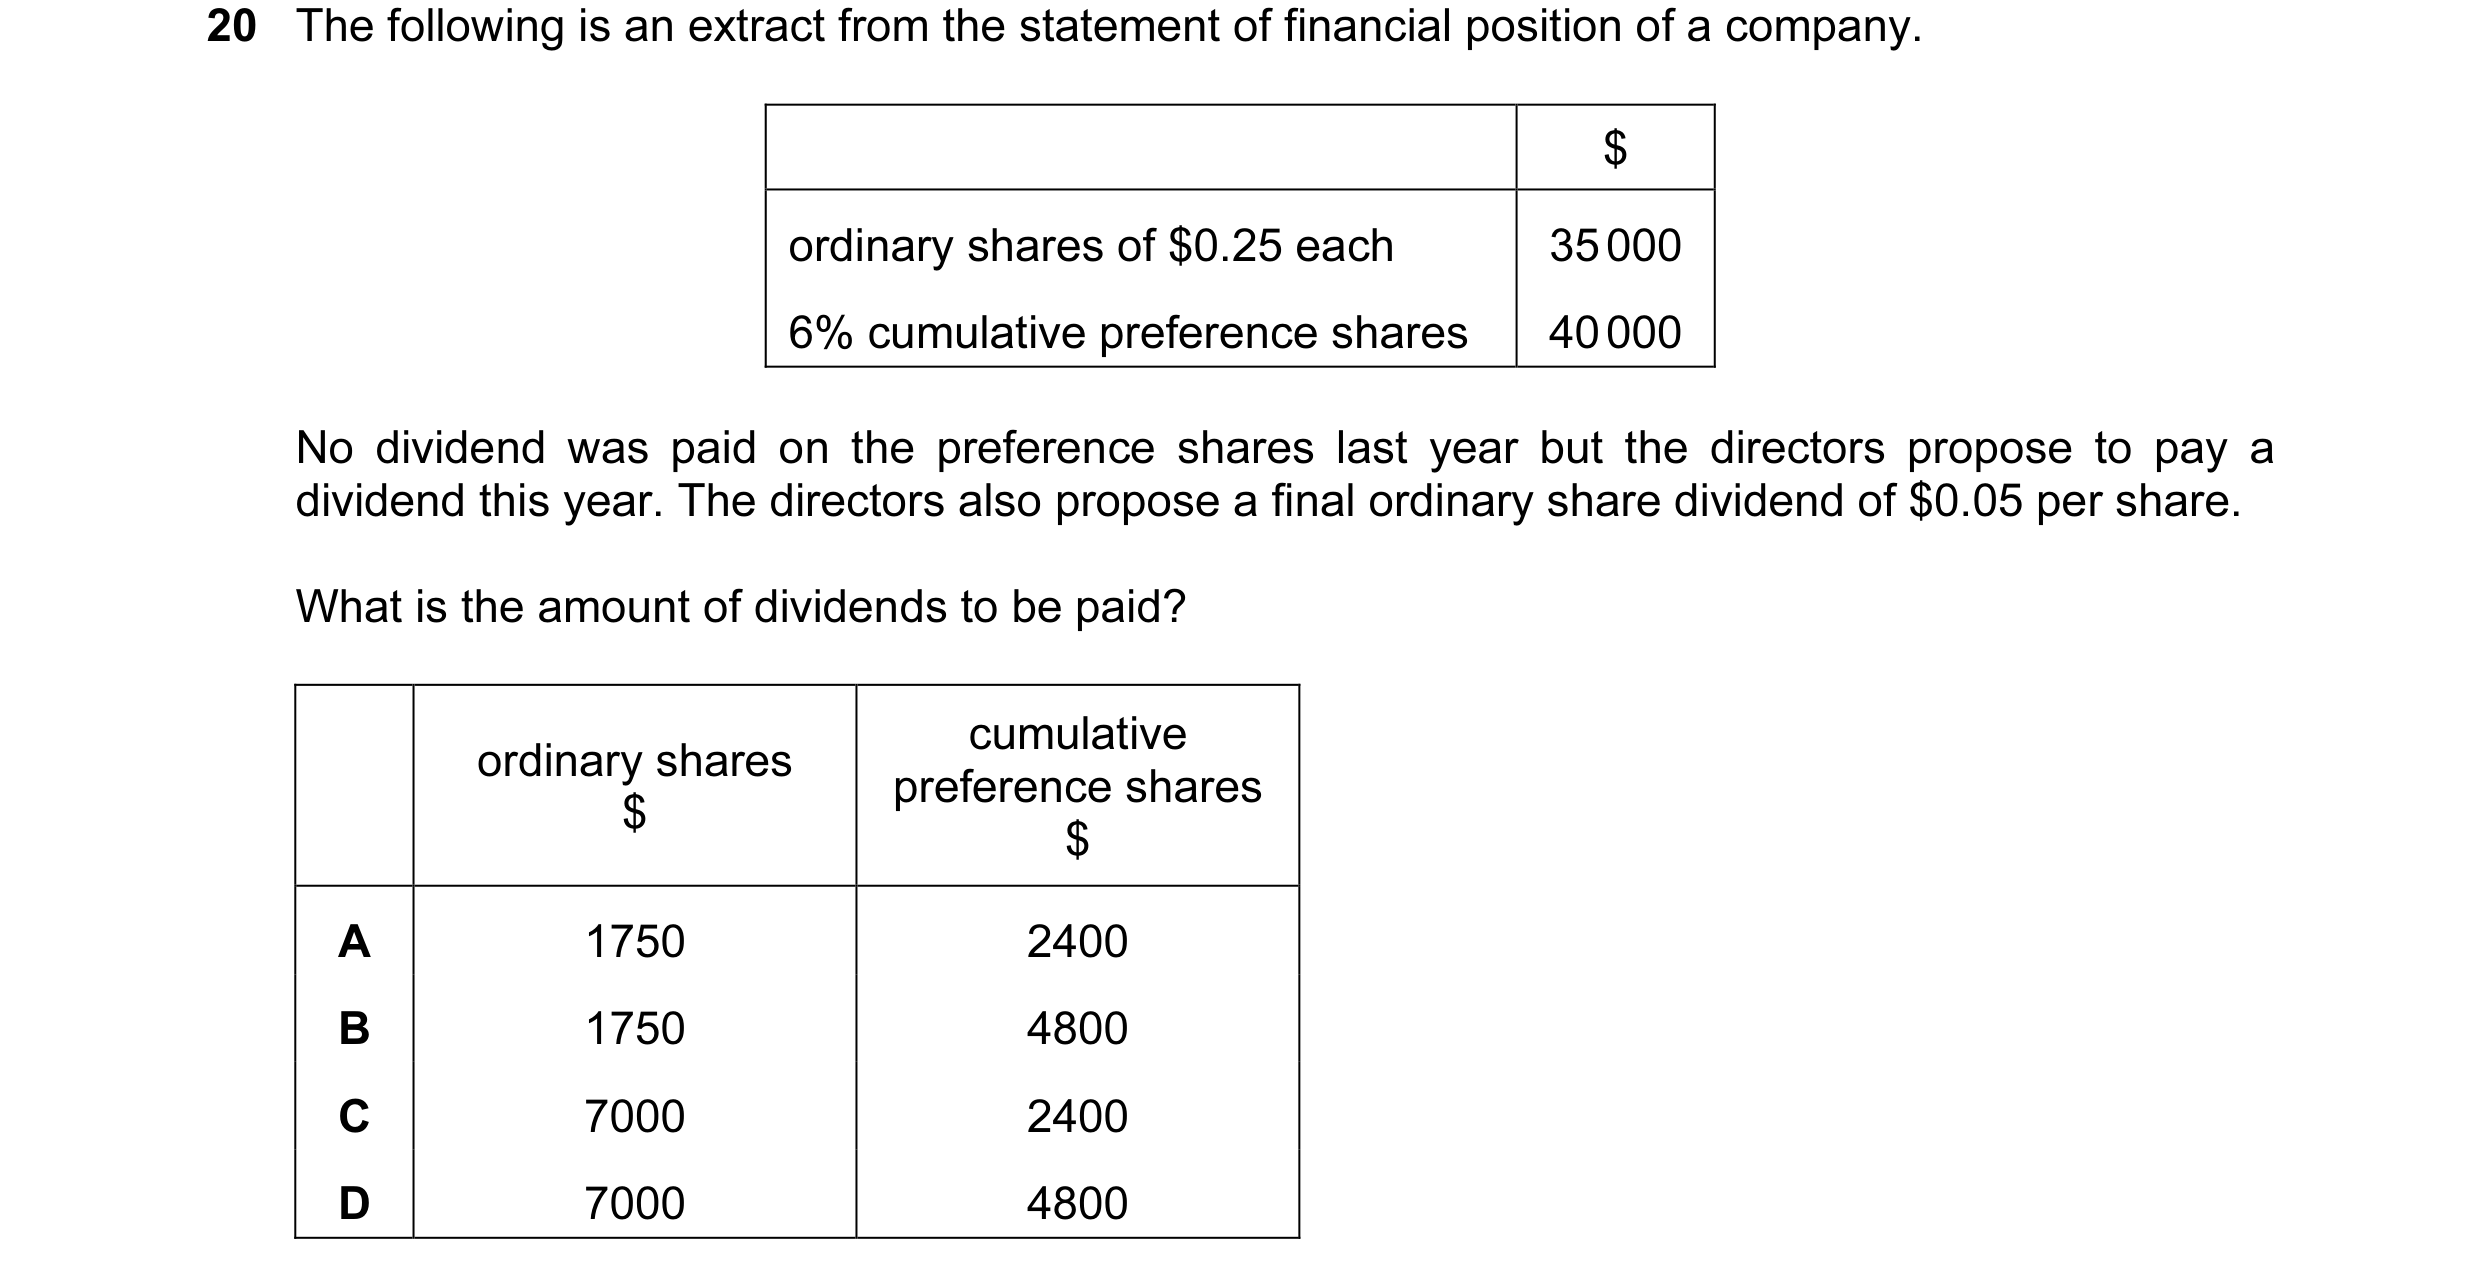
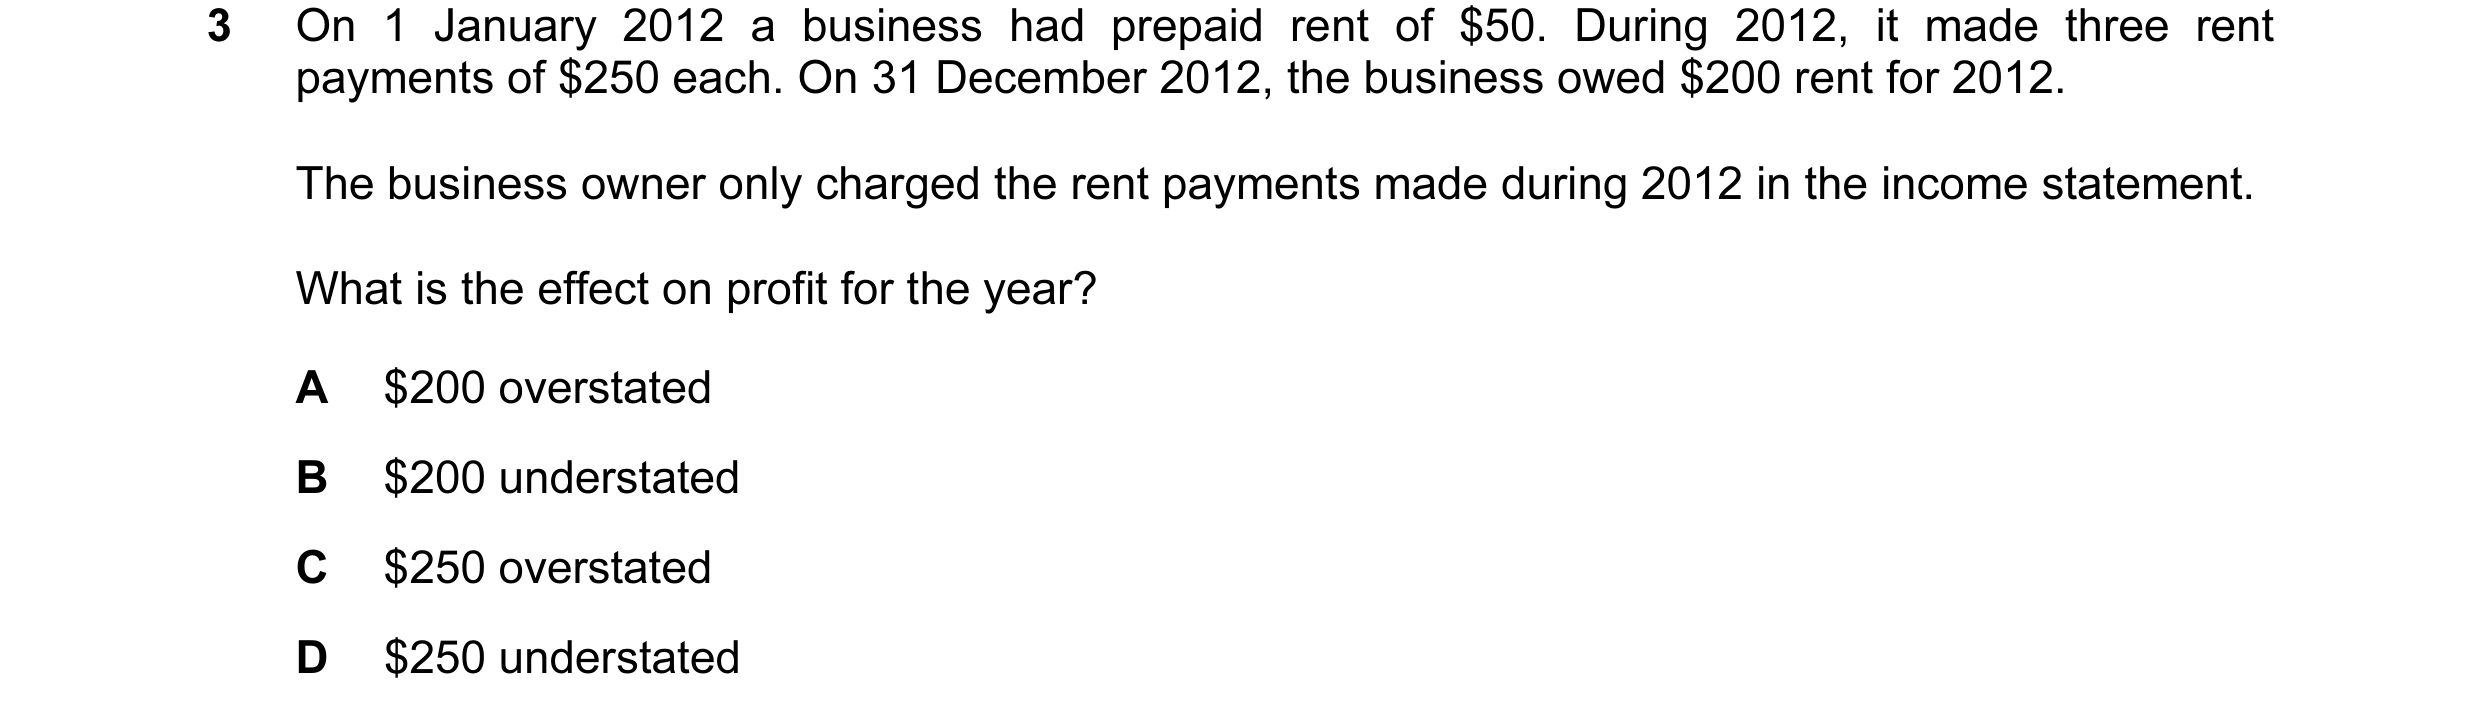 77 / 233
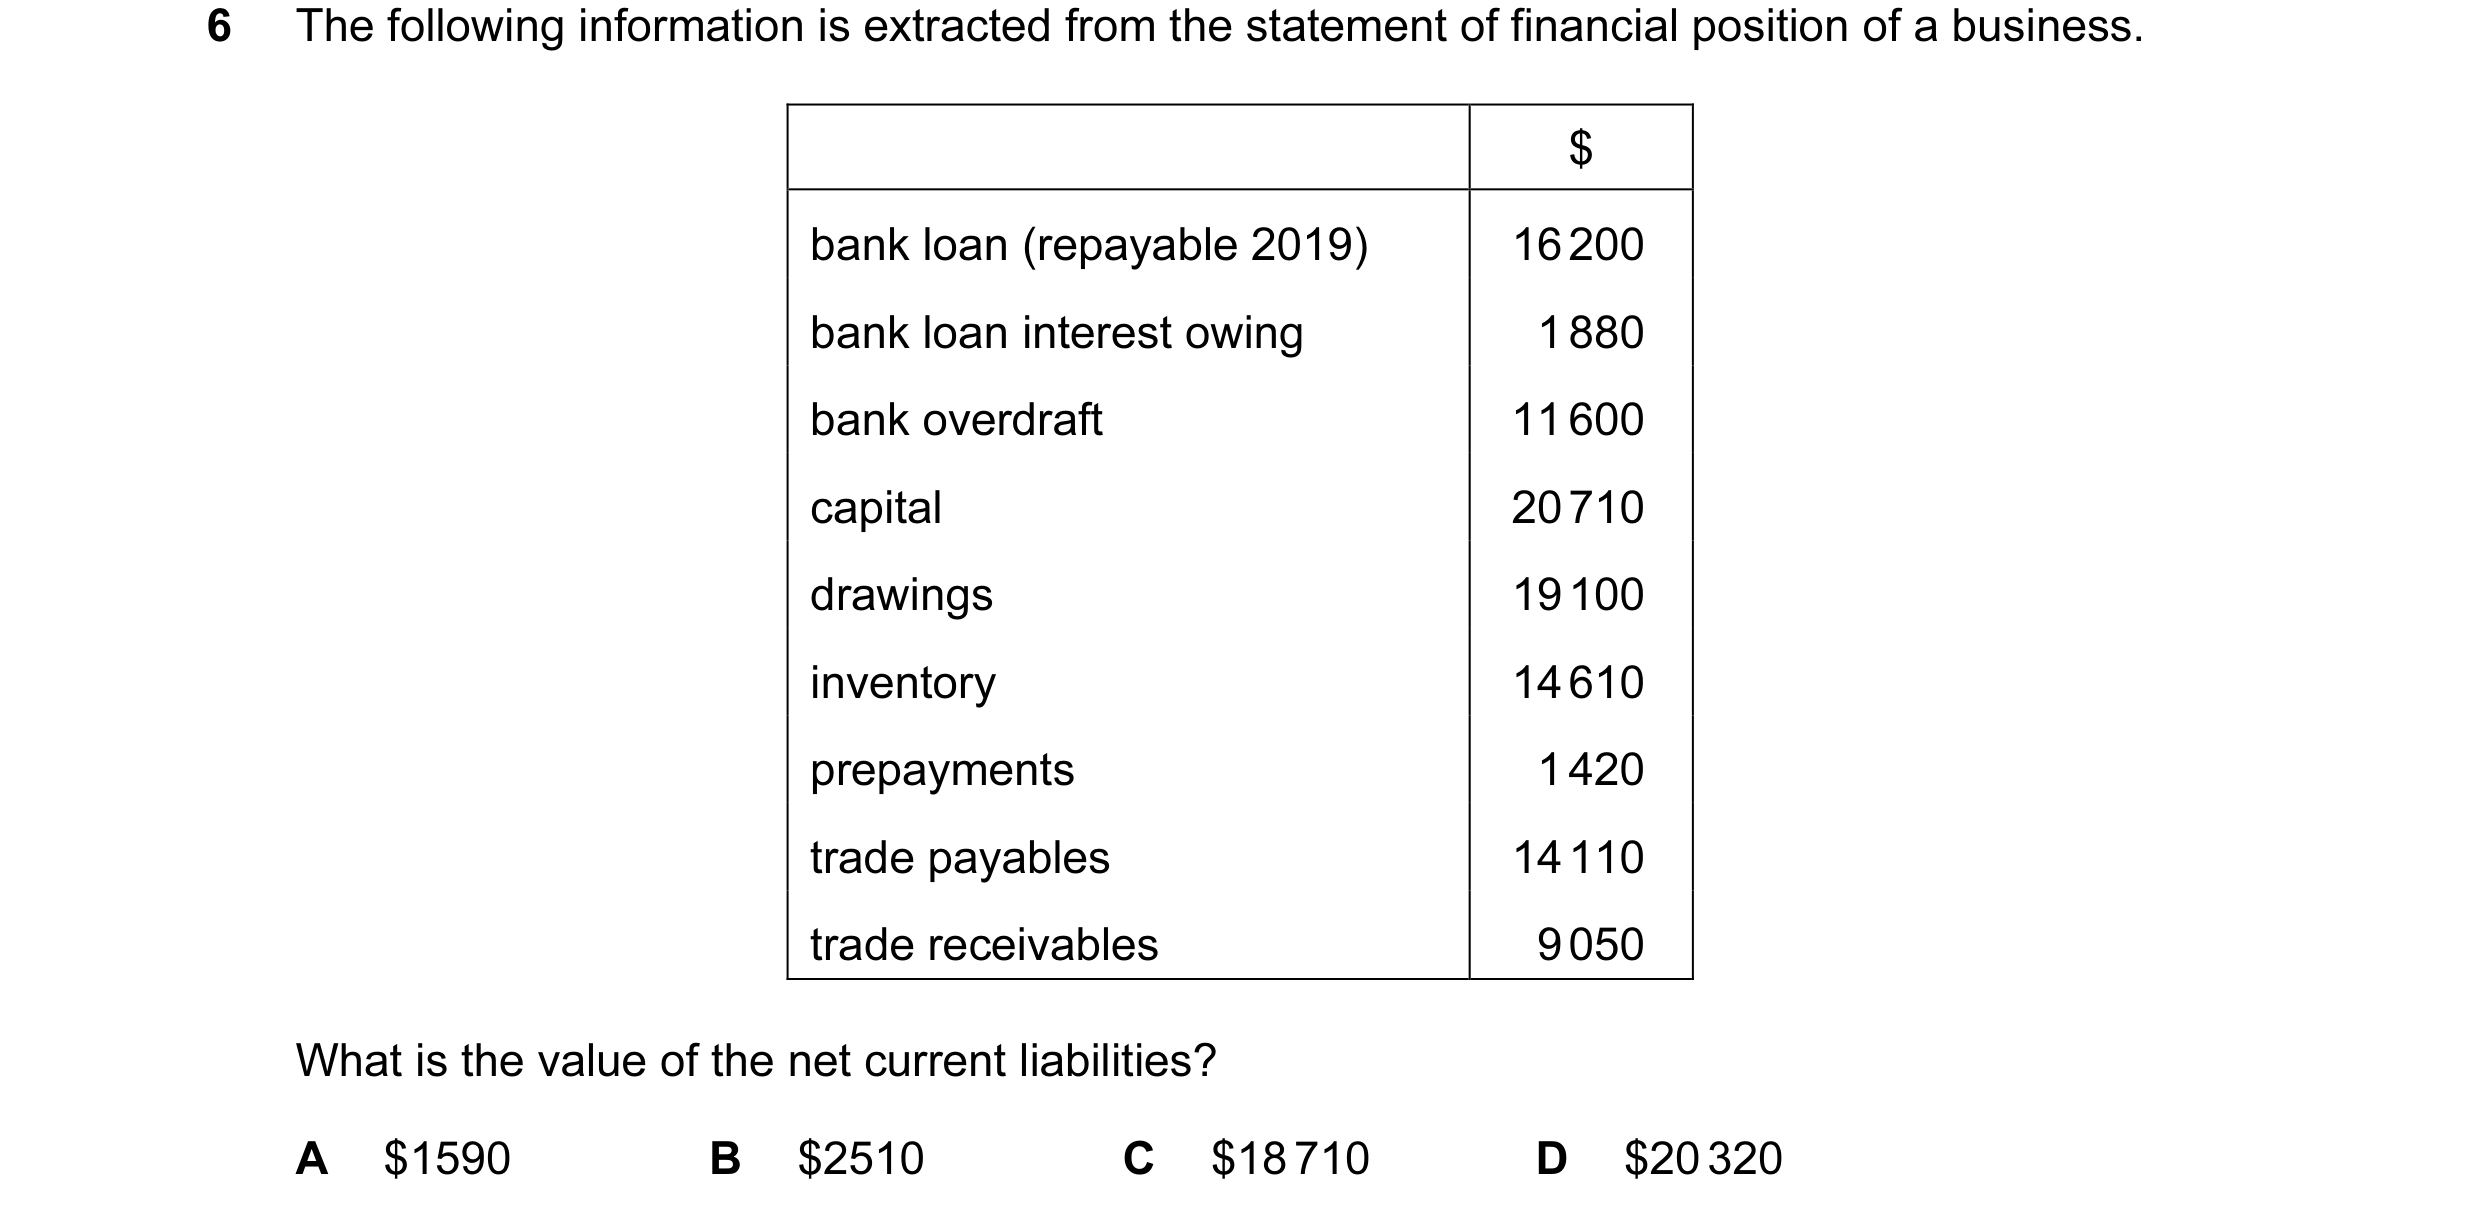
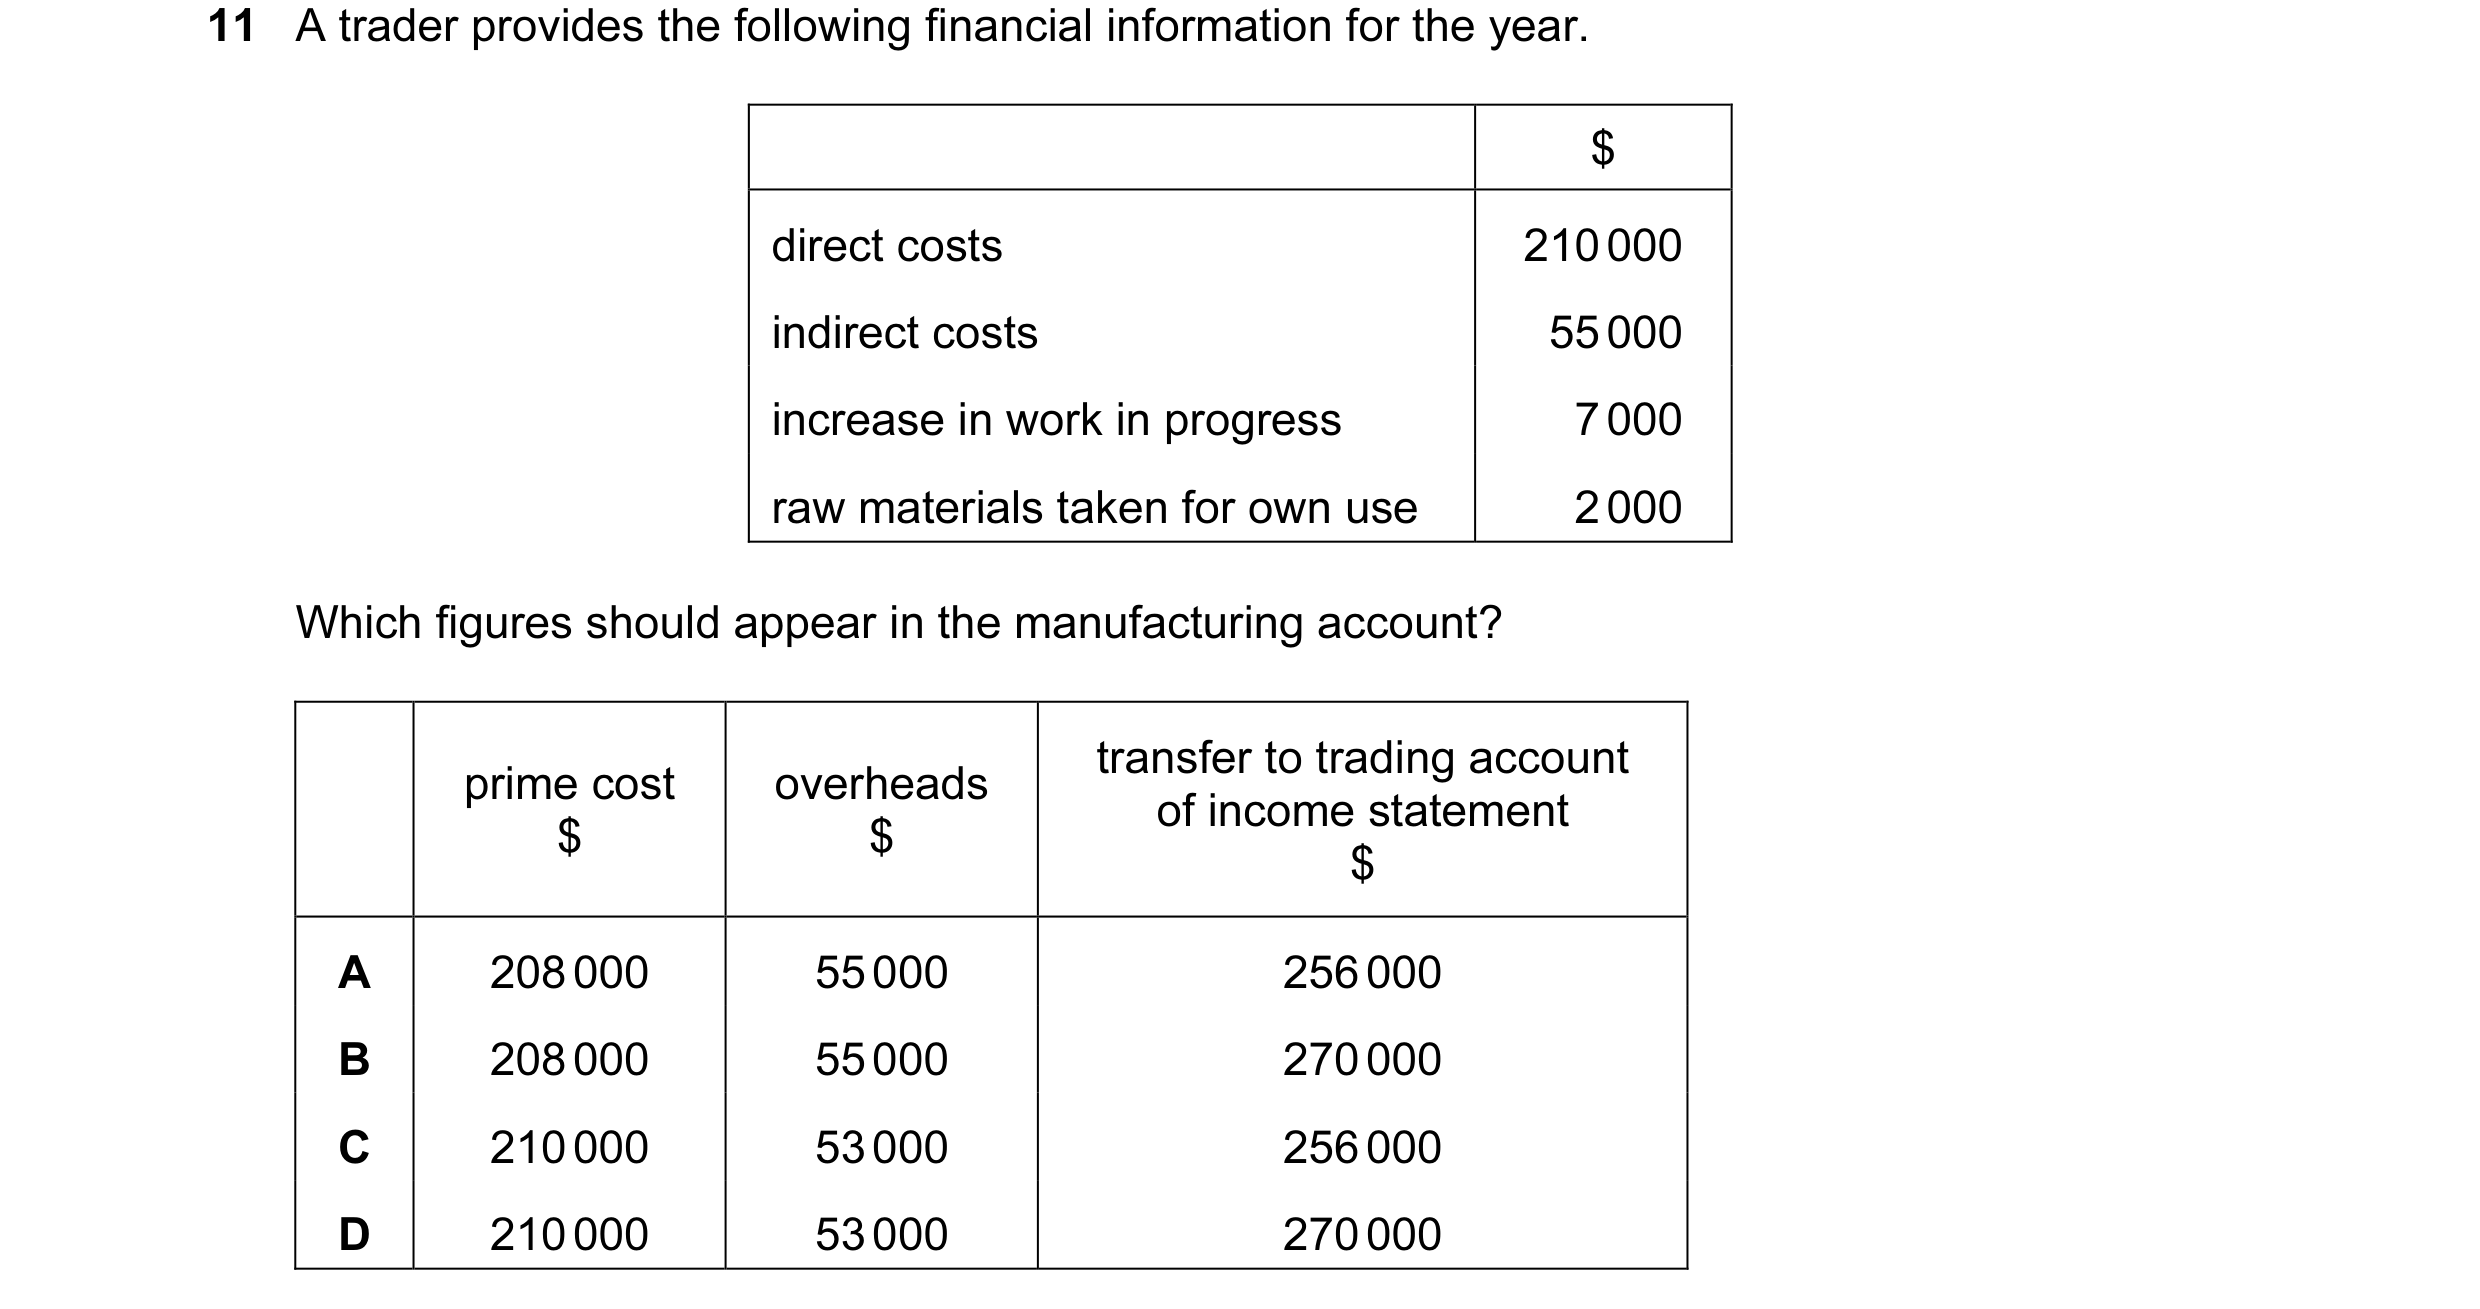
 78 / 233
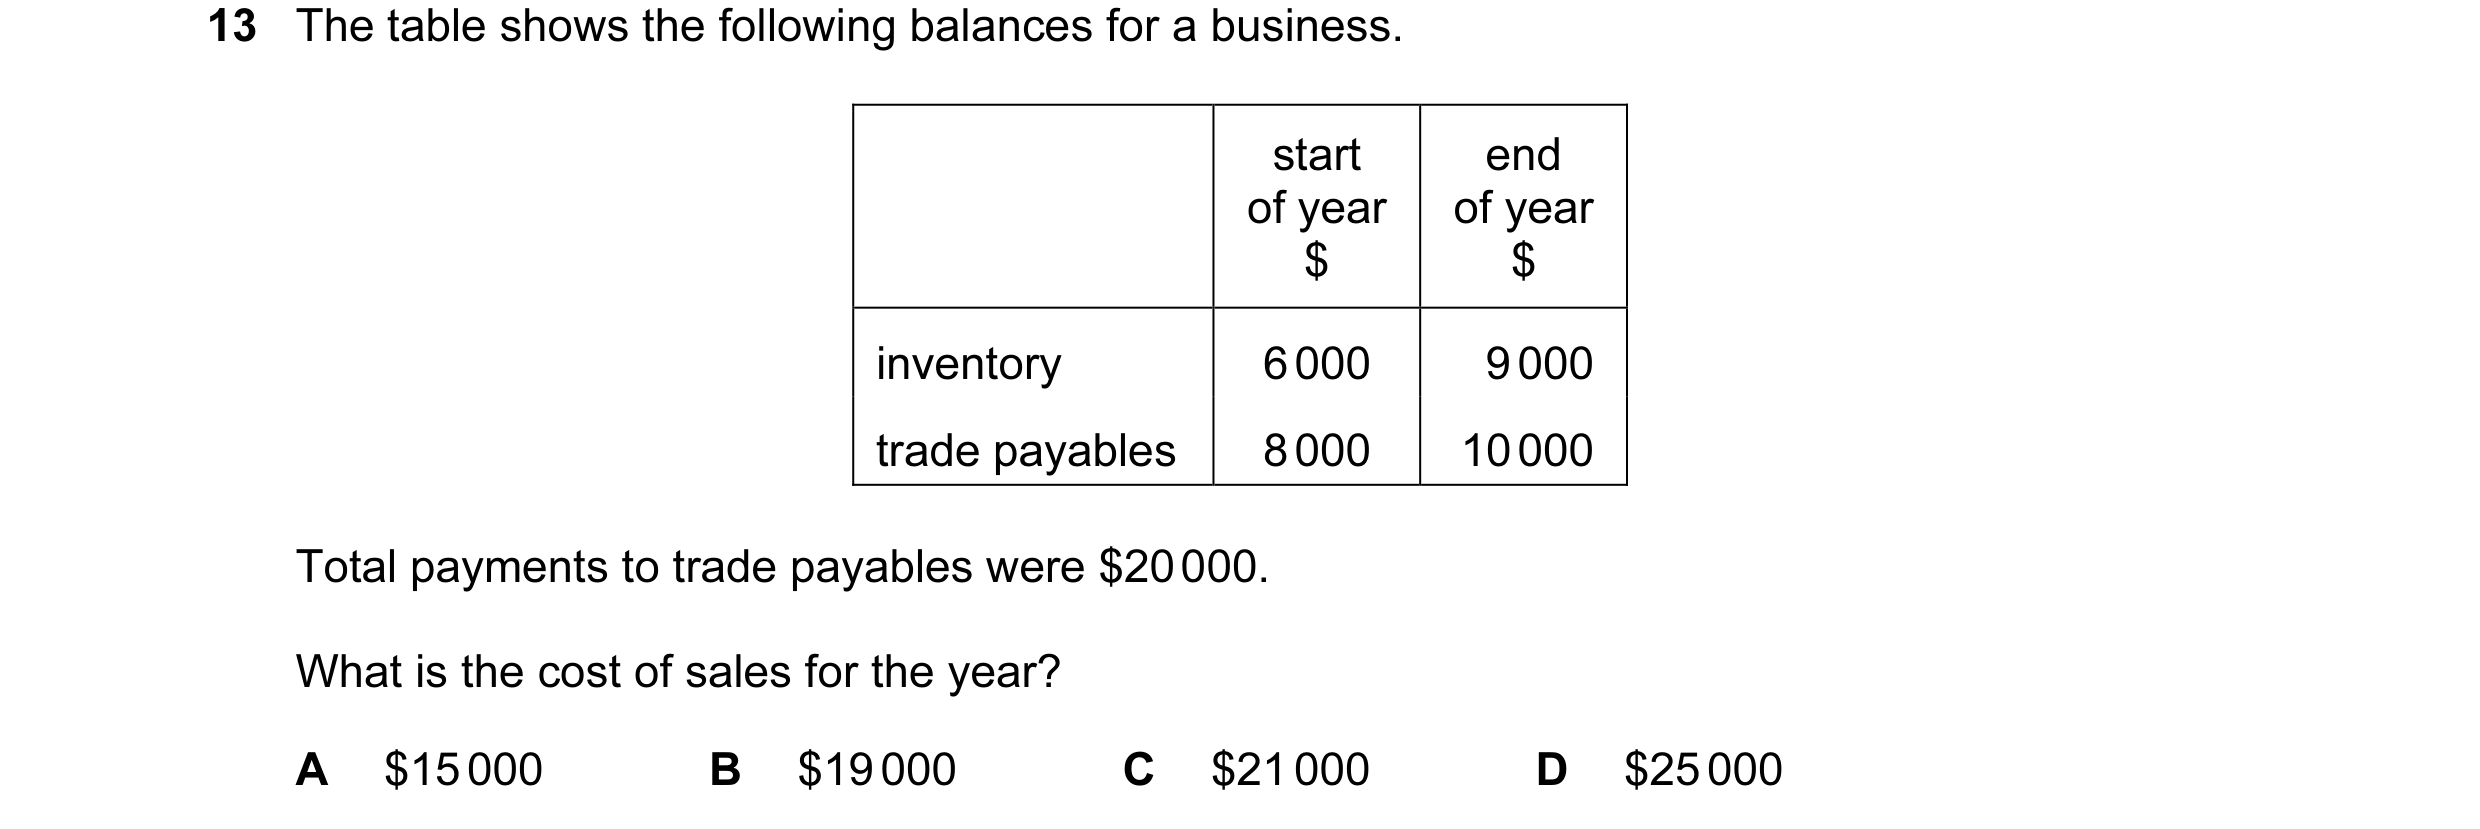
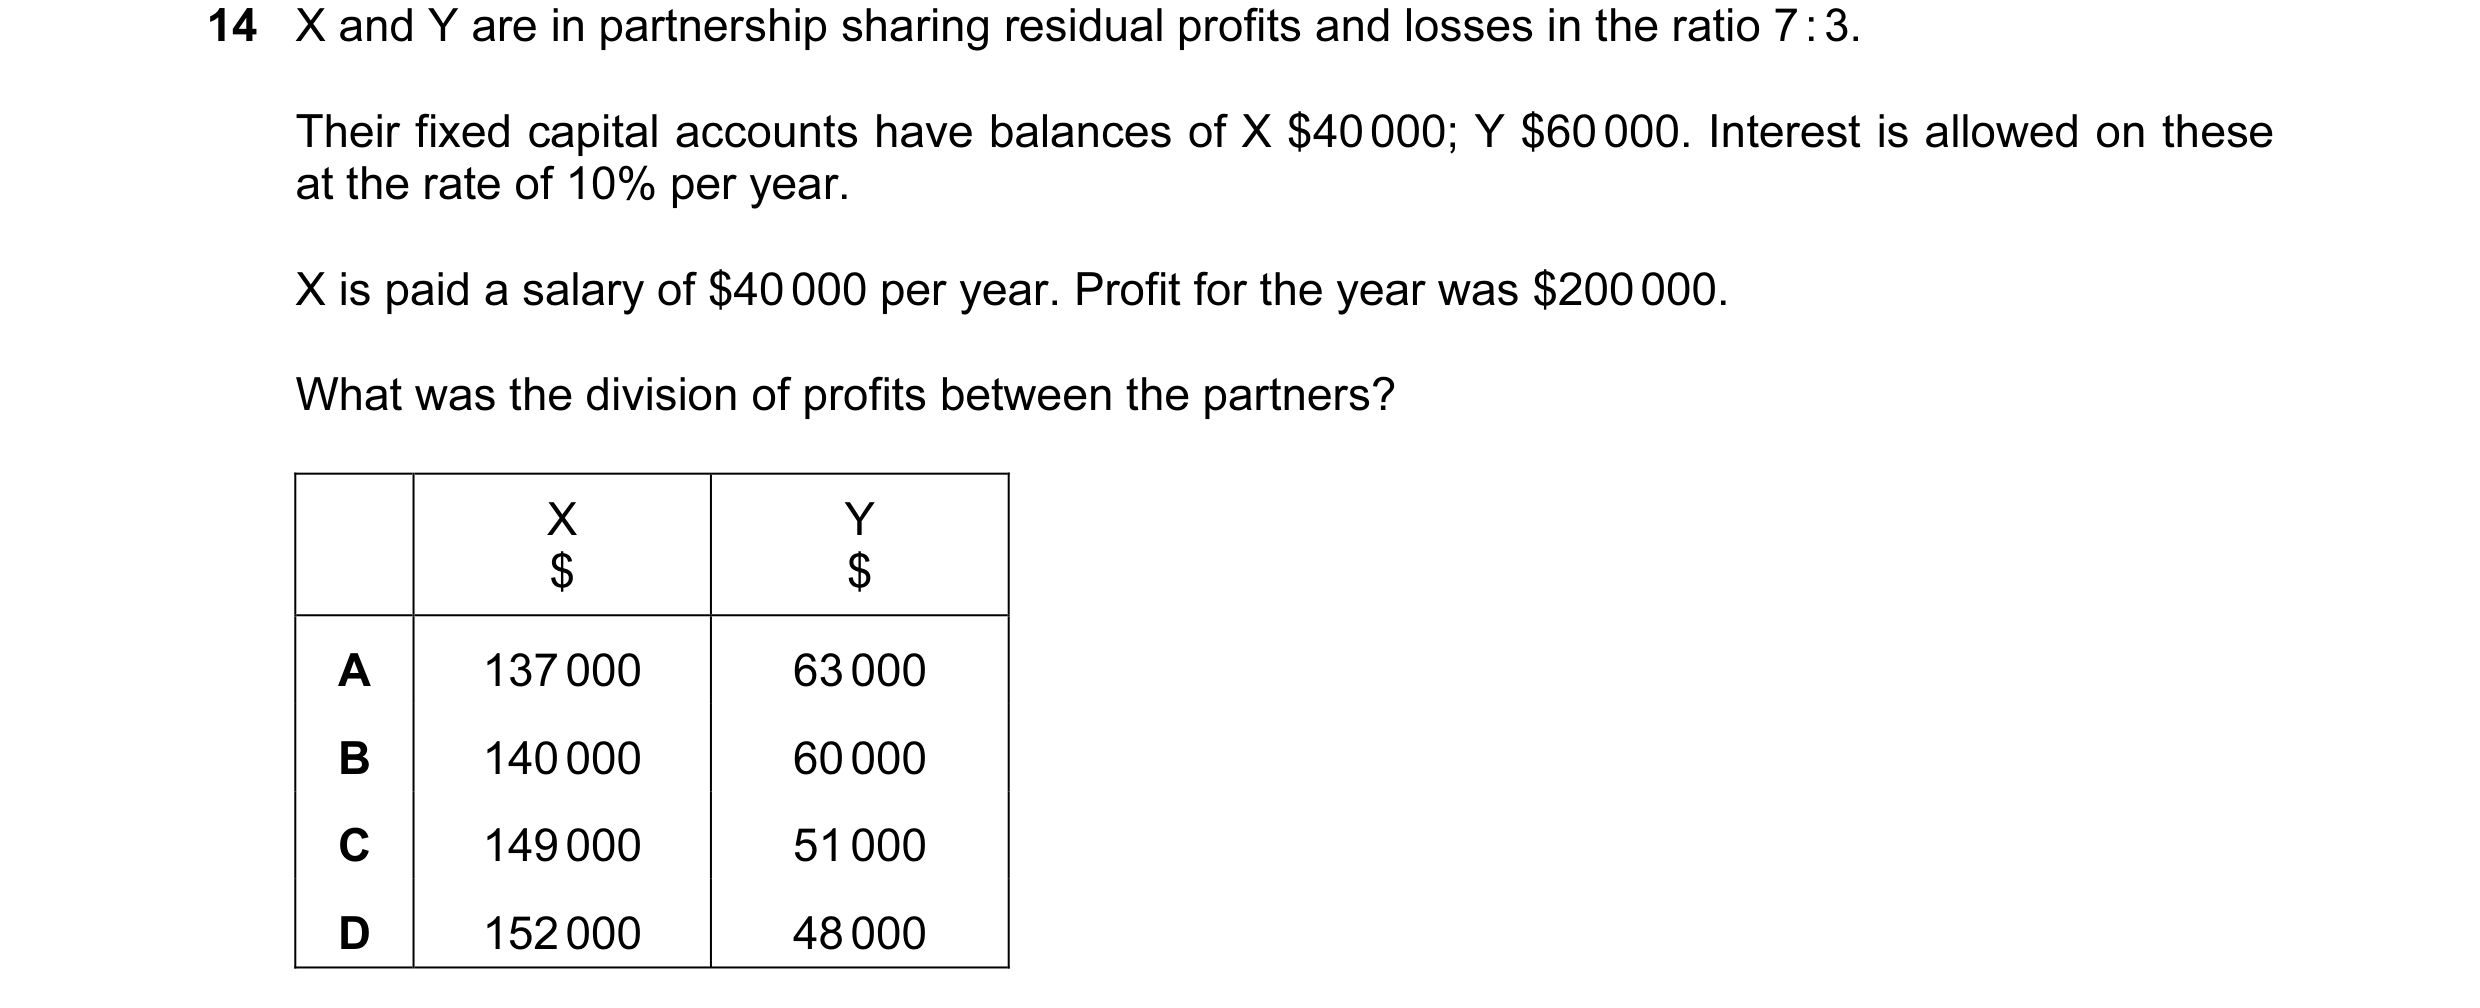
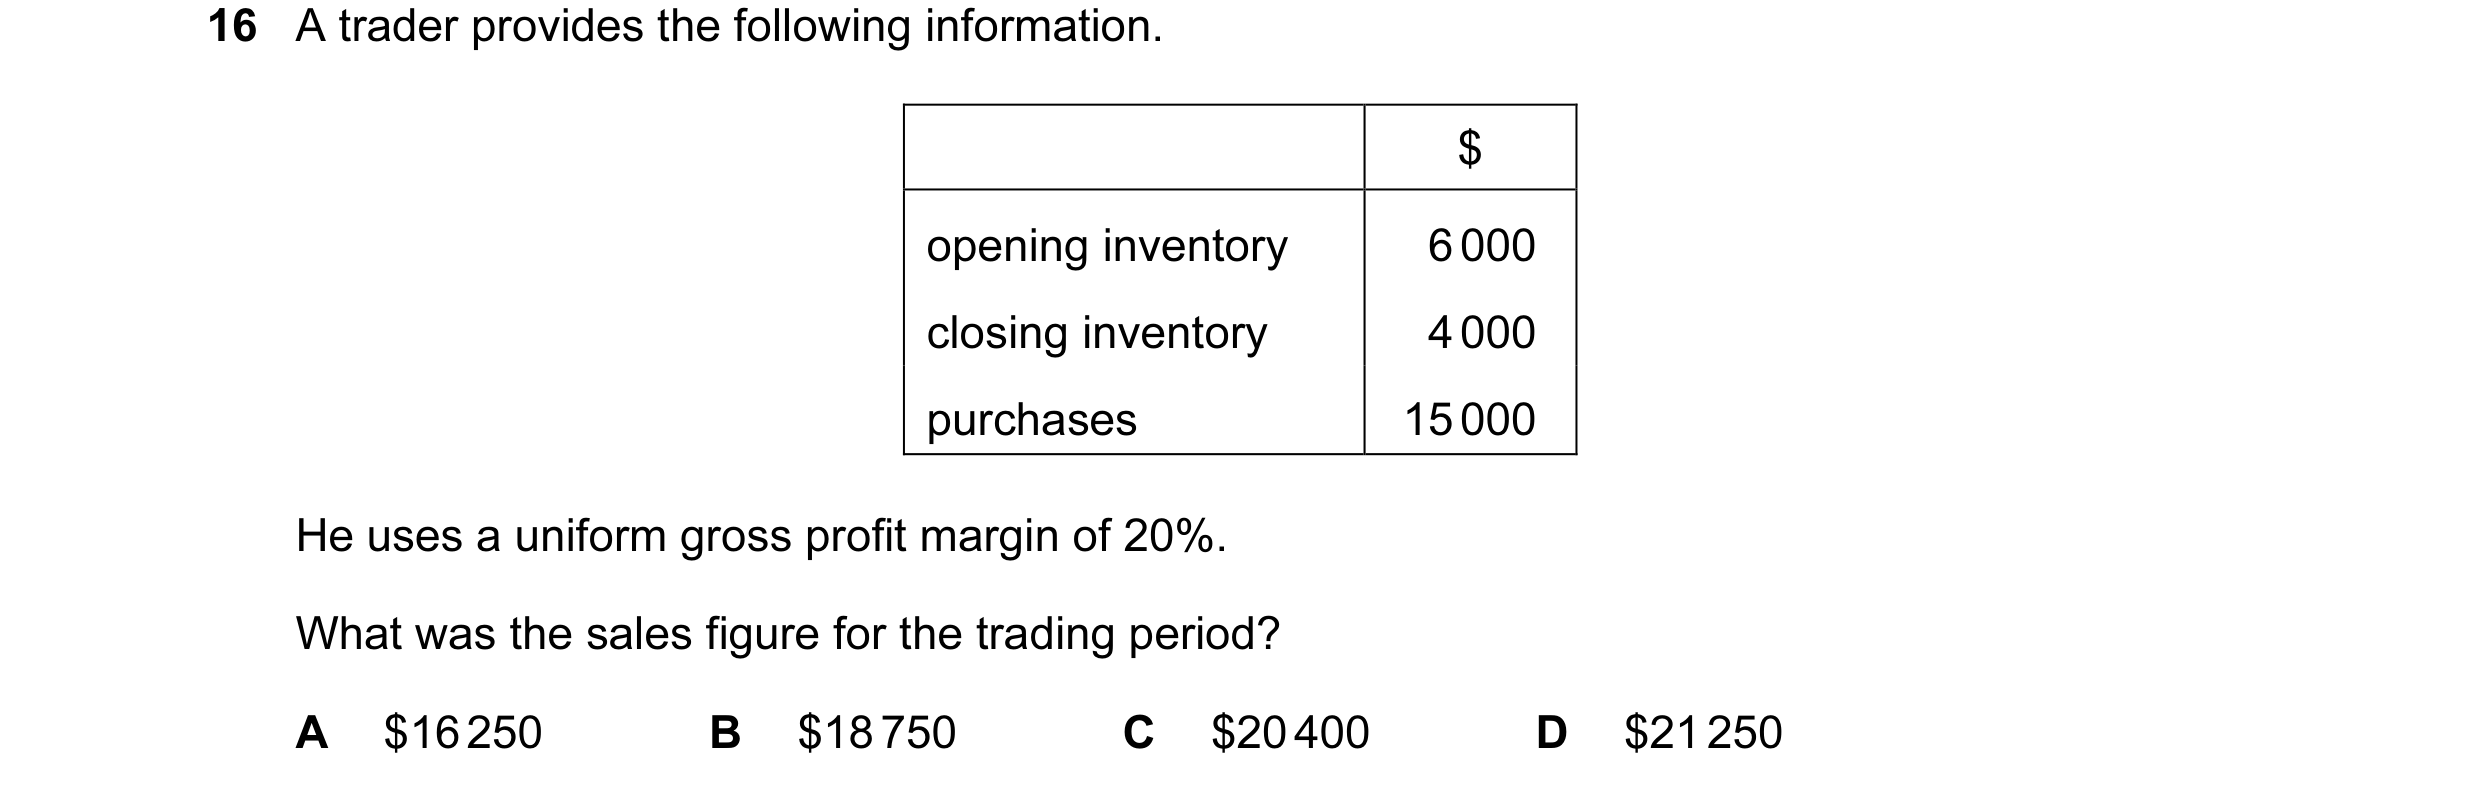 79 / 233
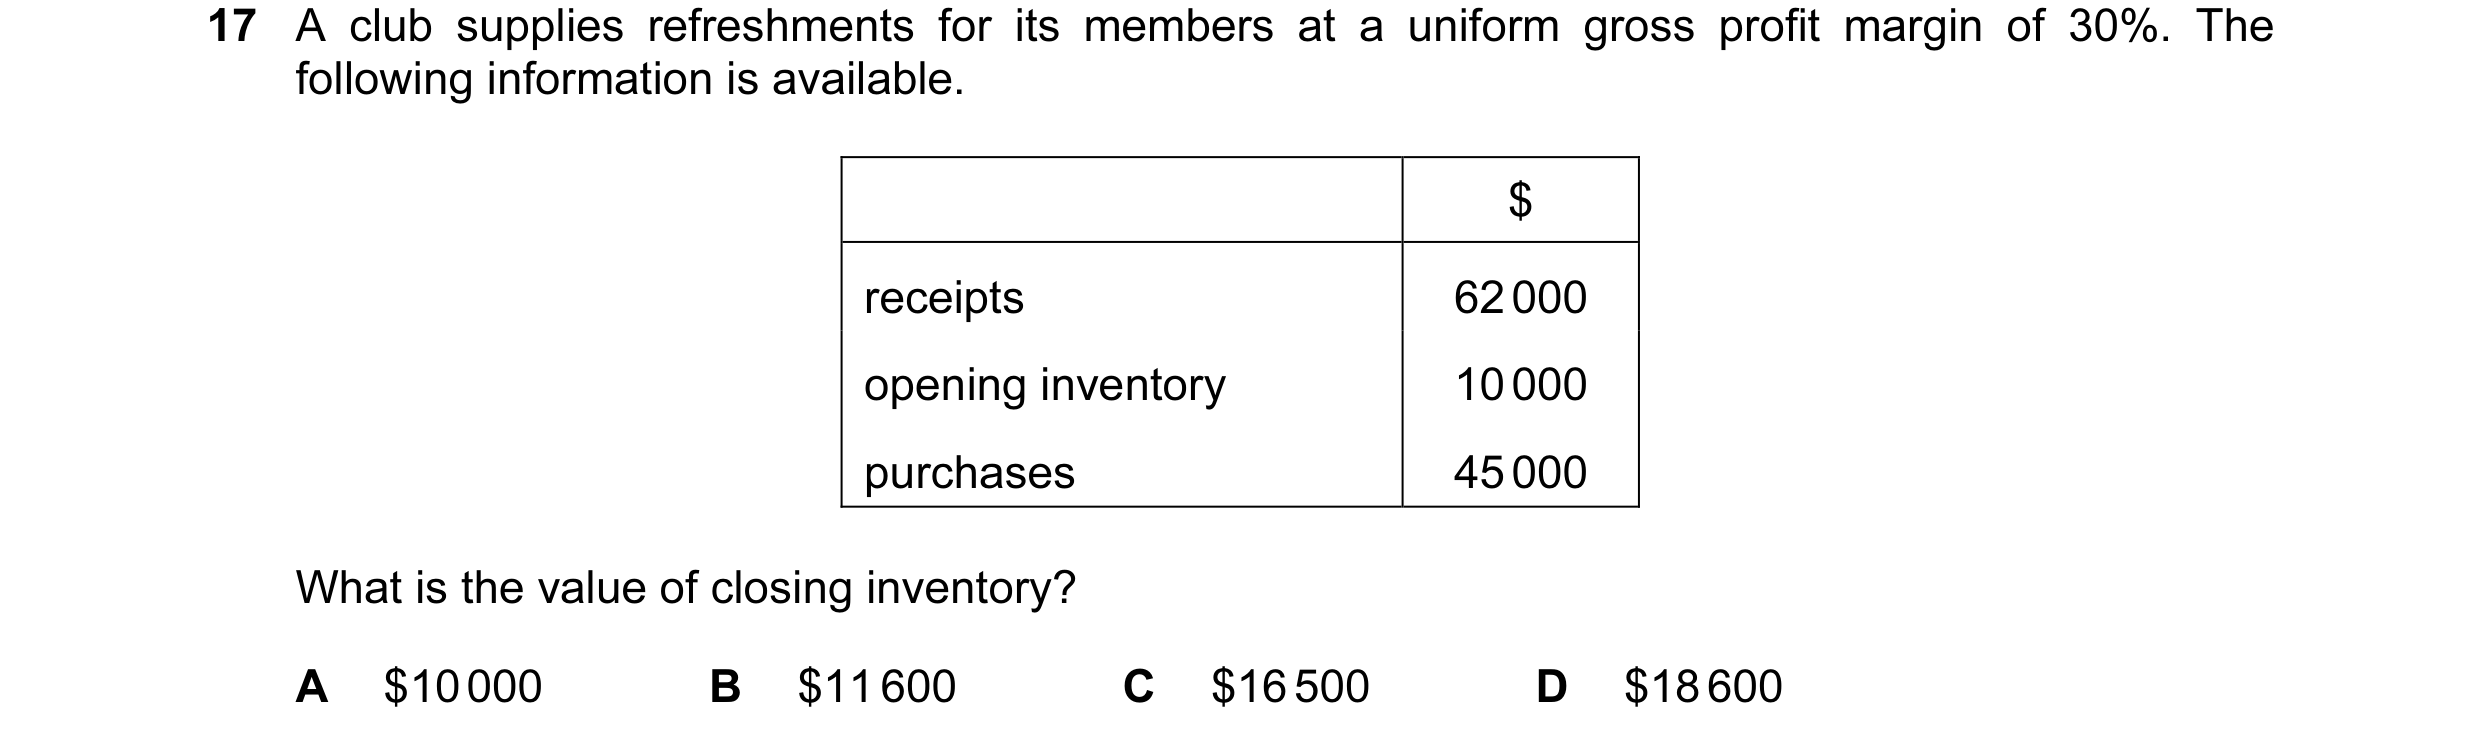
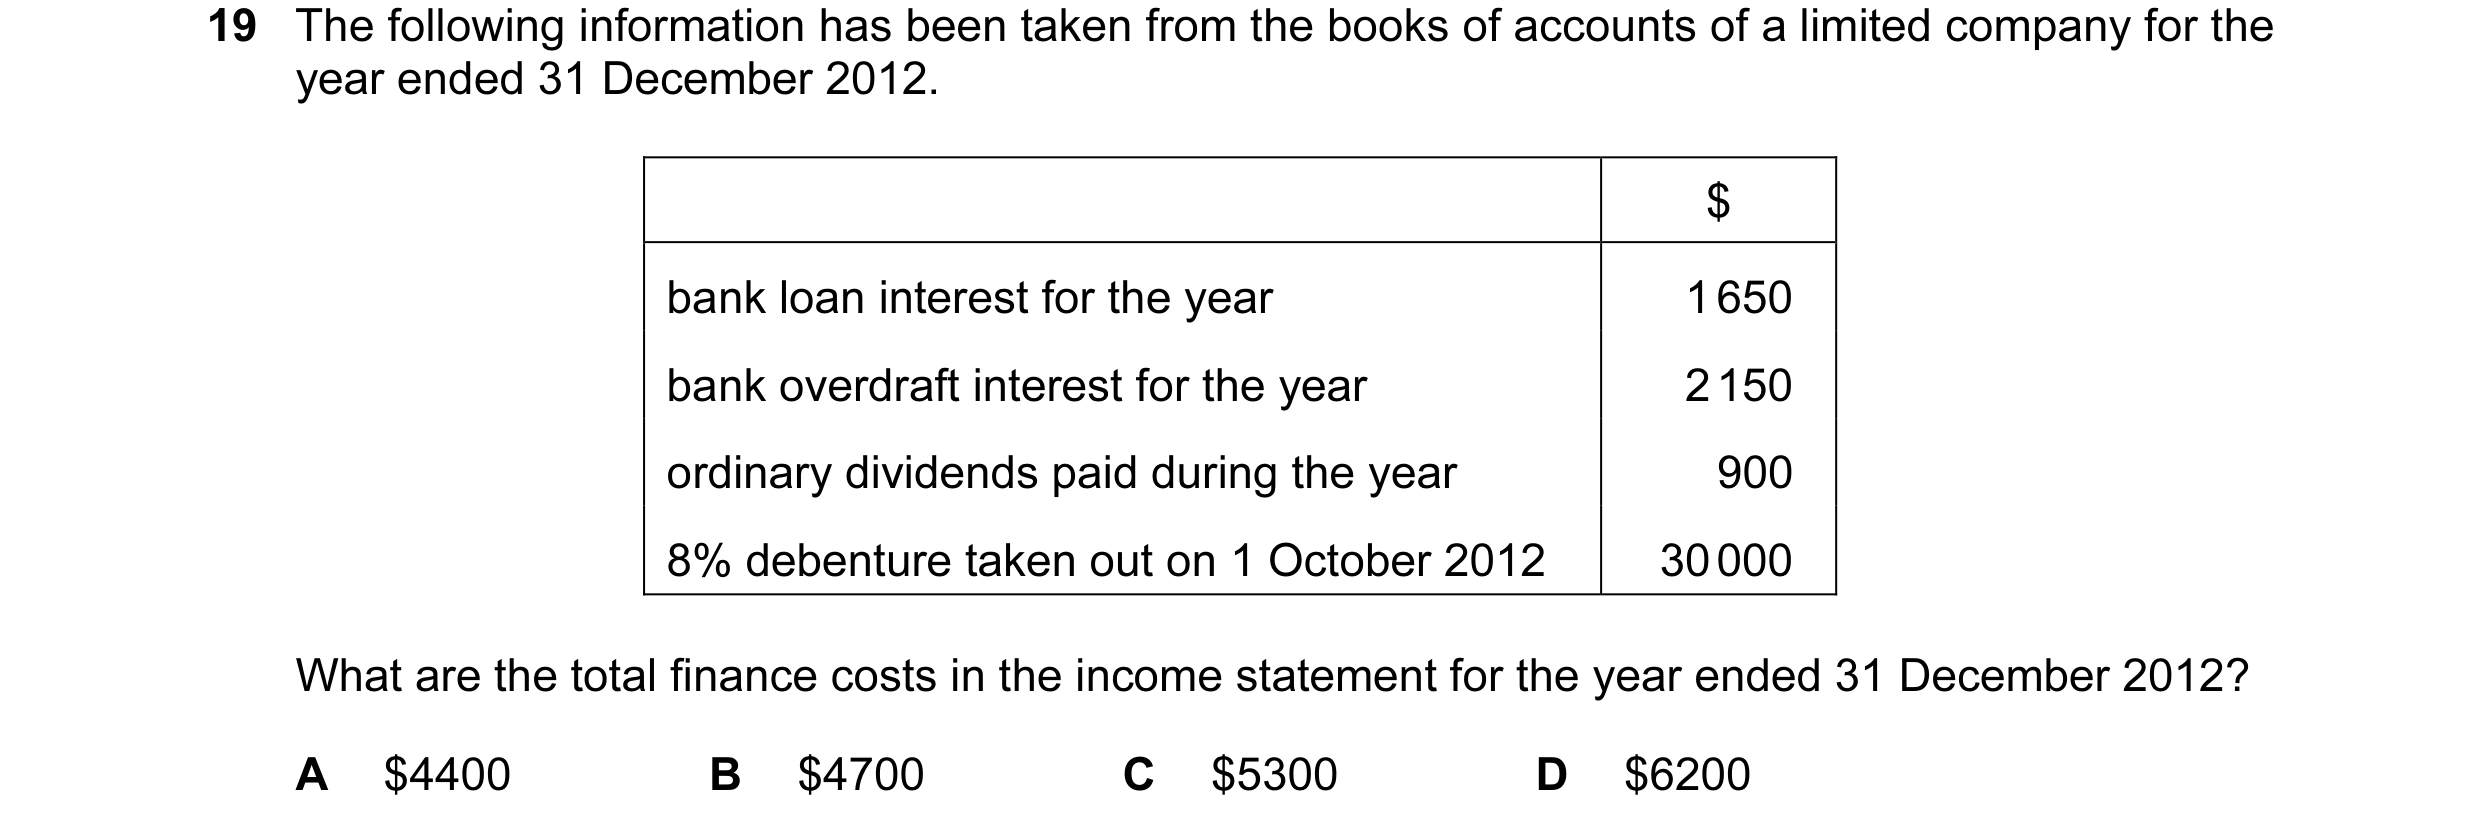
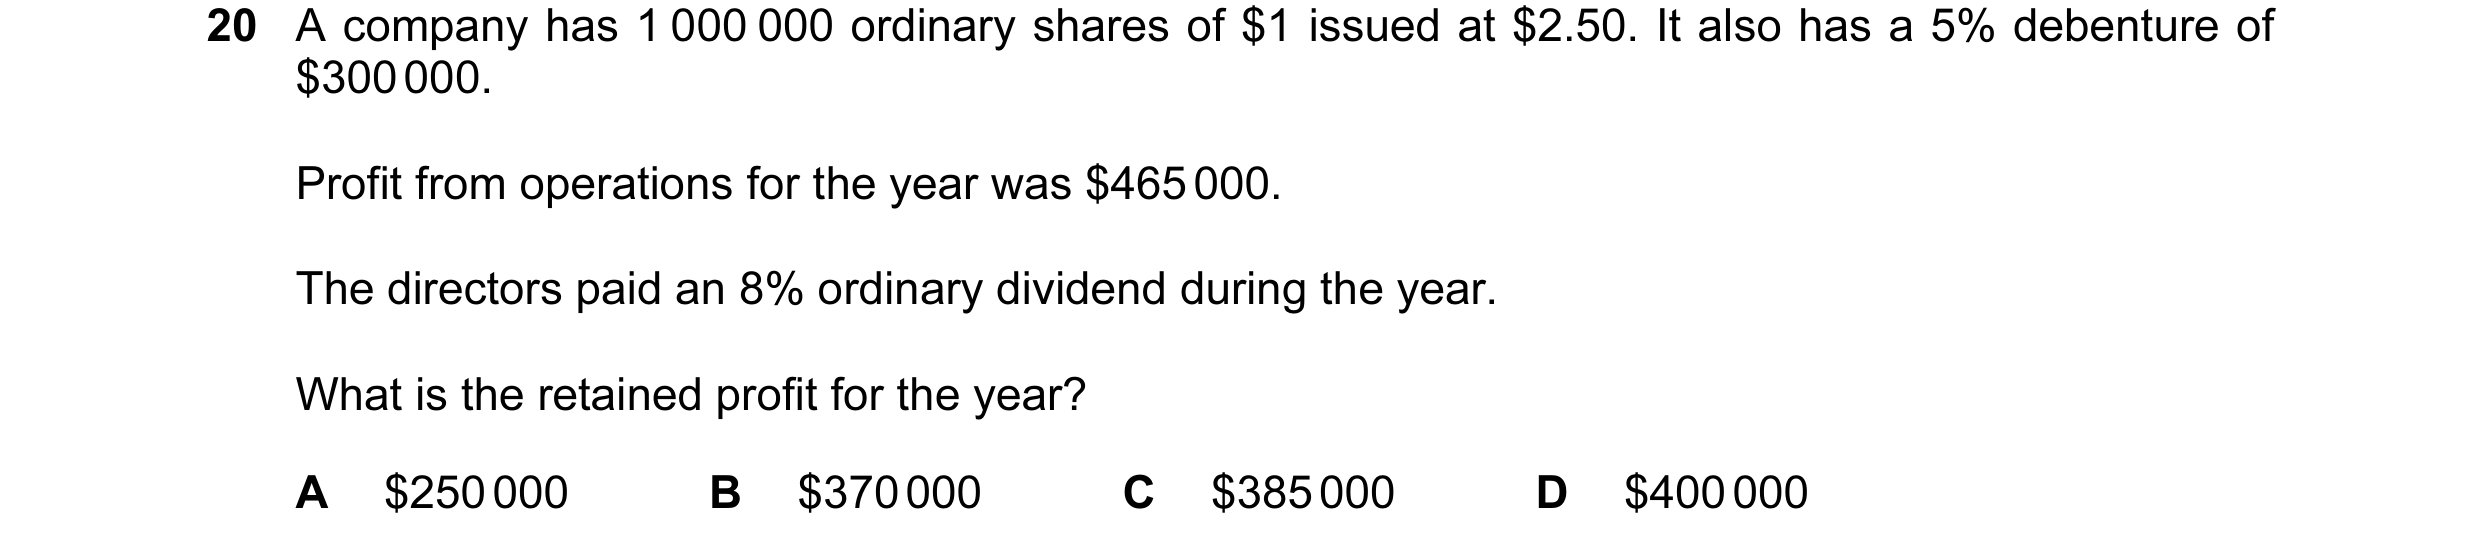
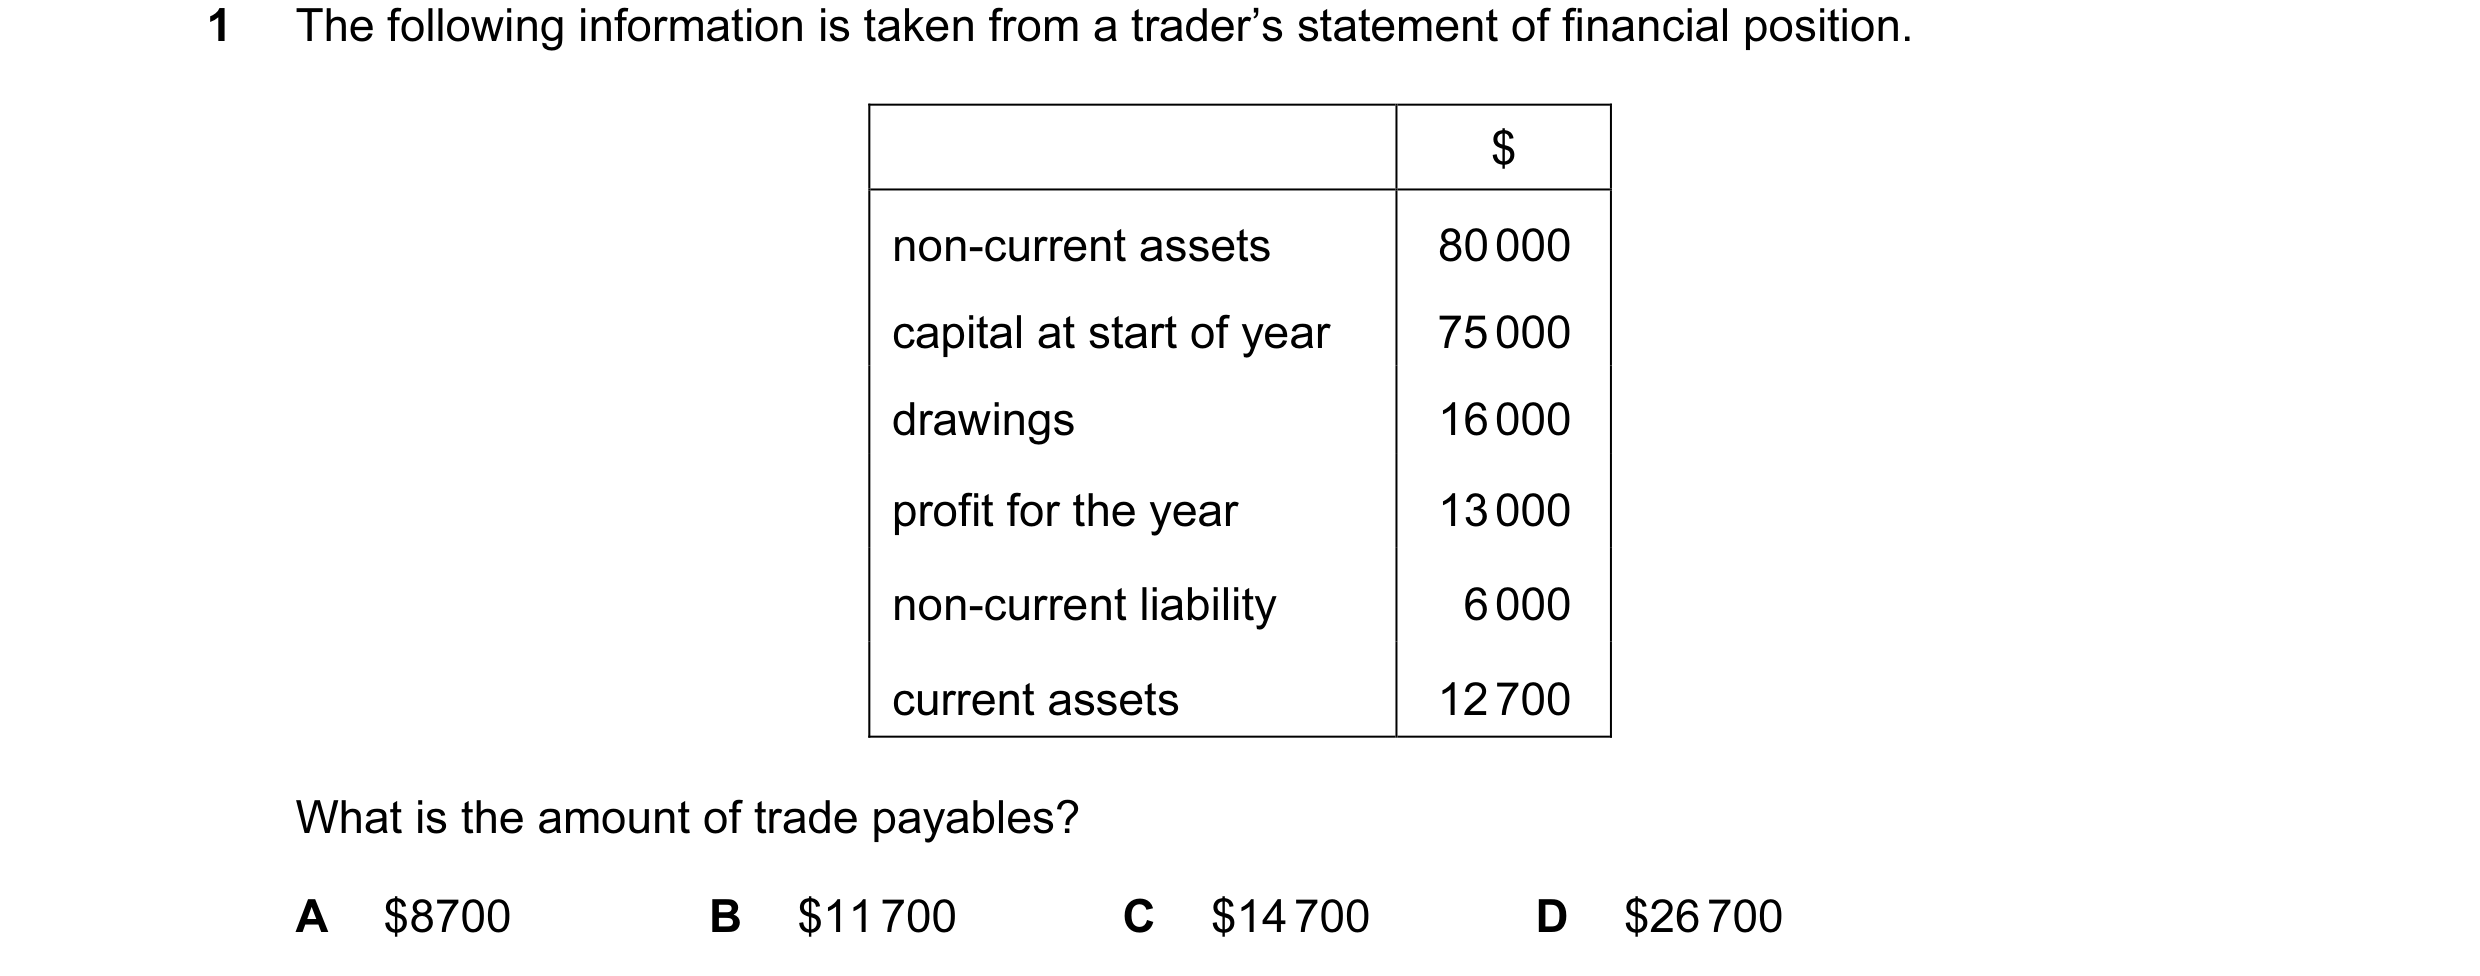 80 / 233
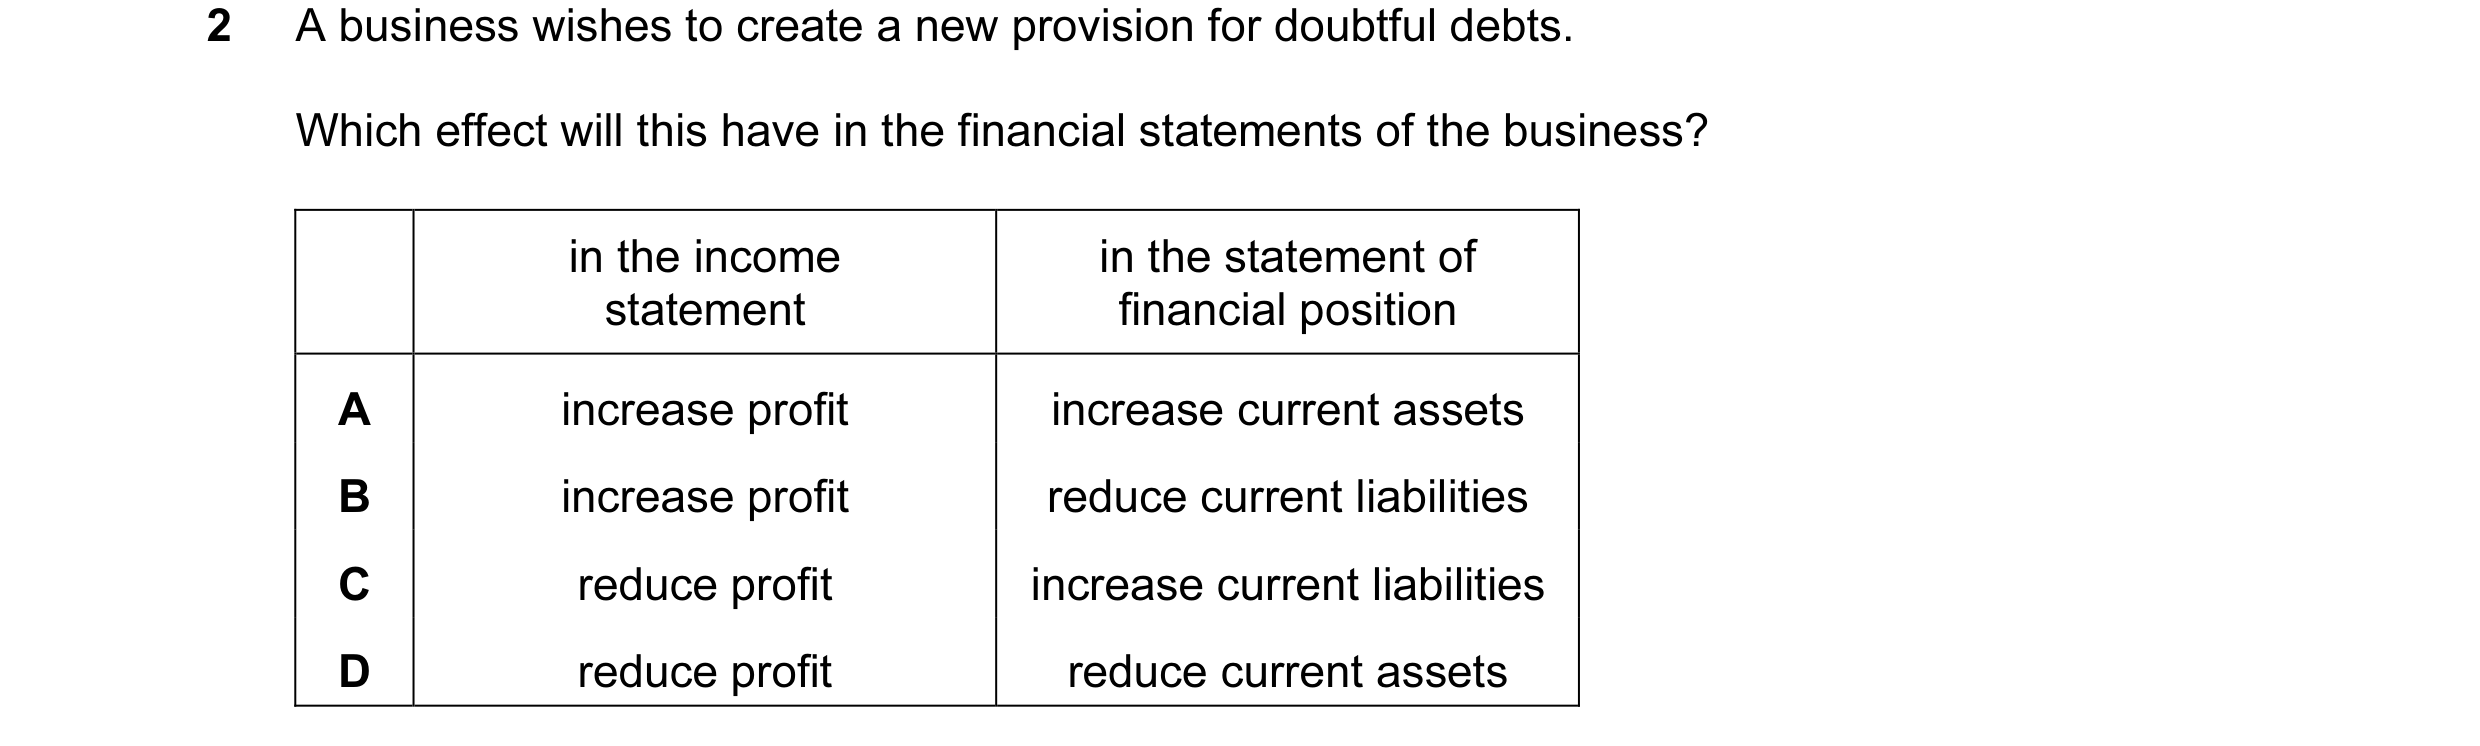
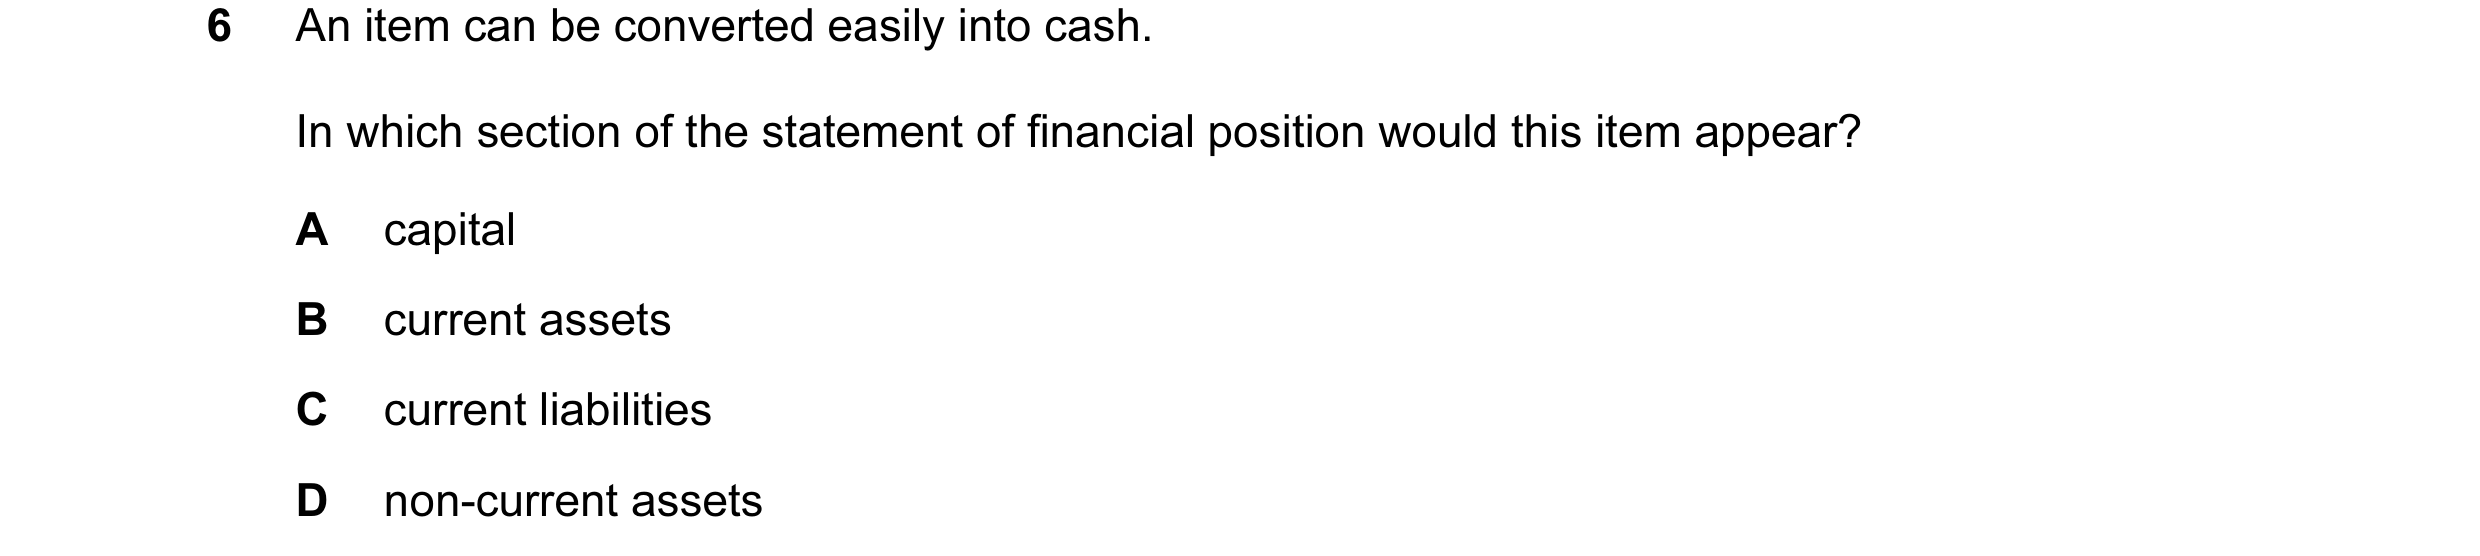
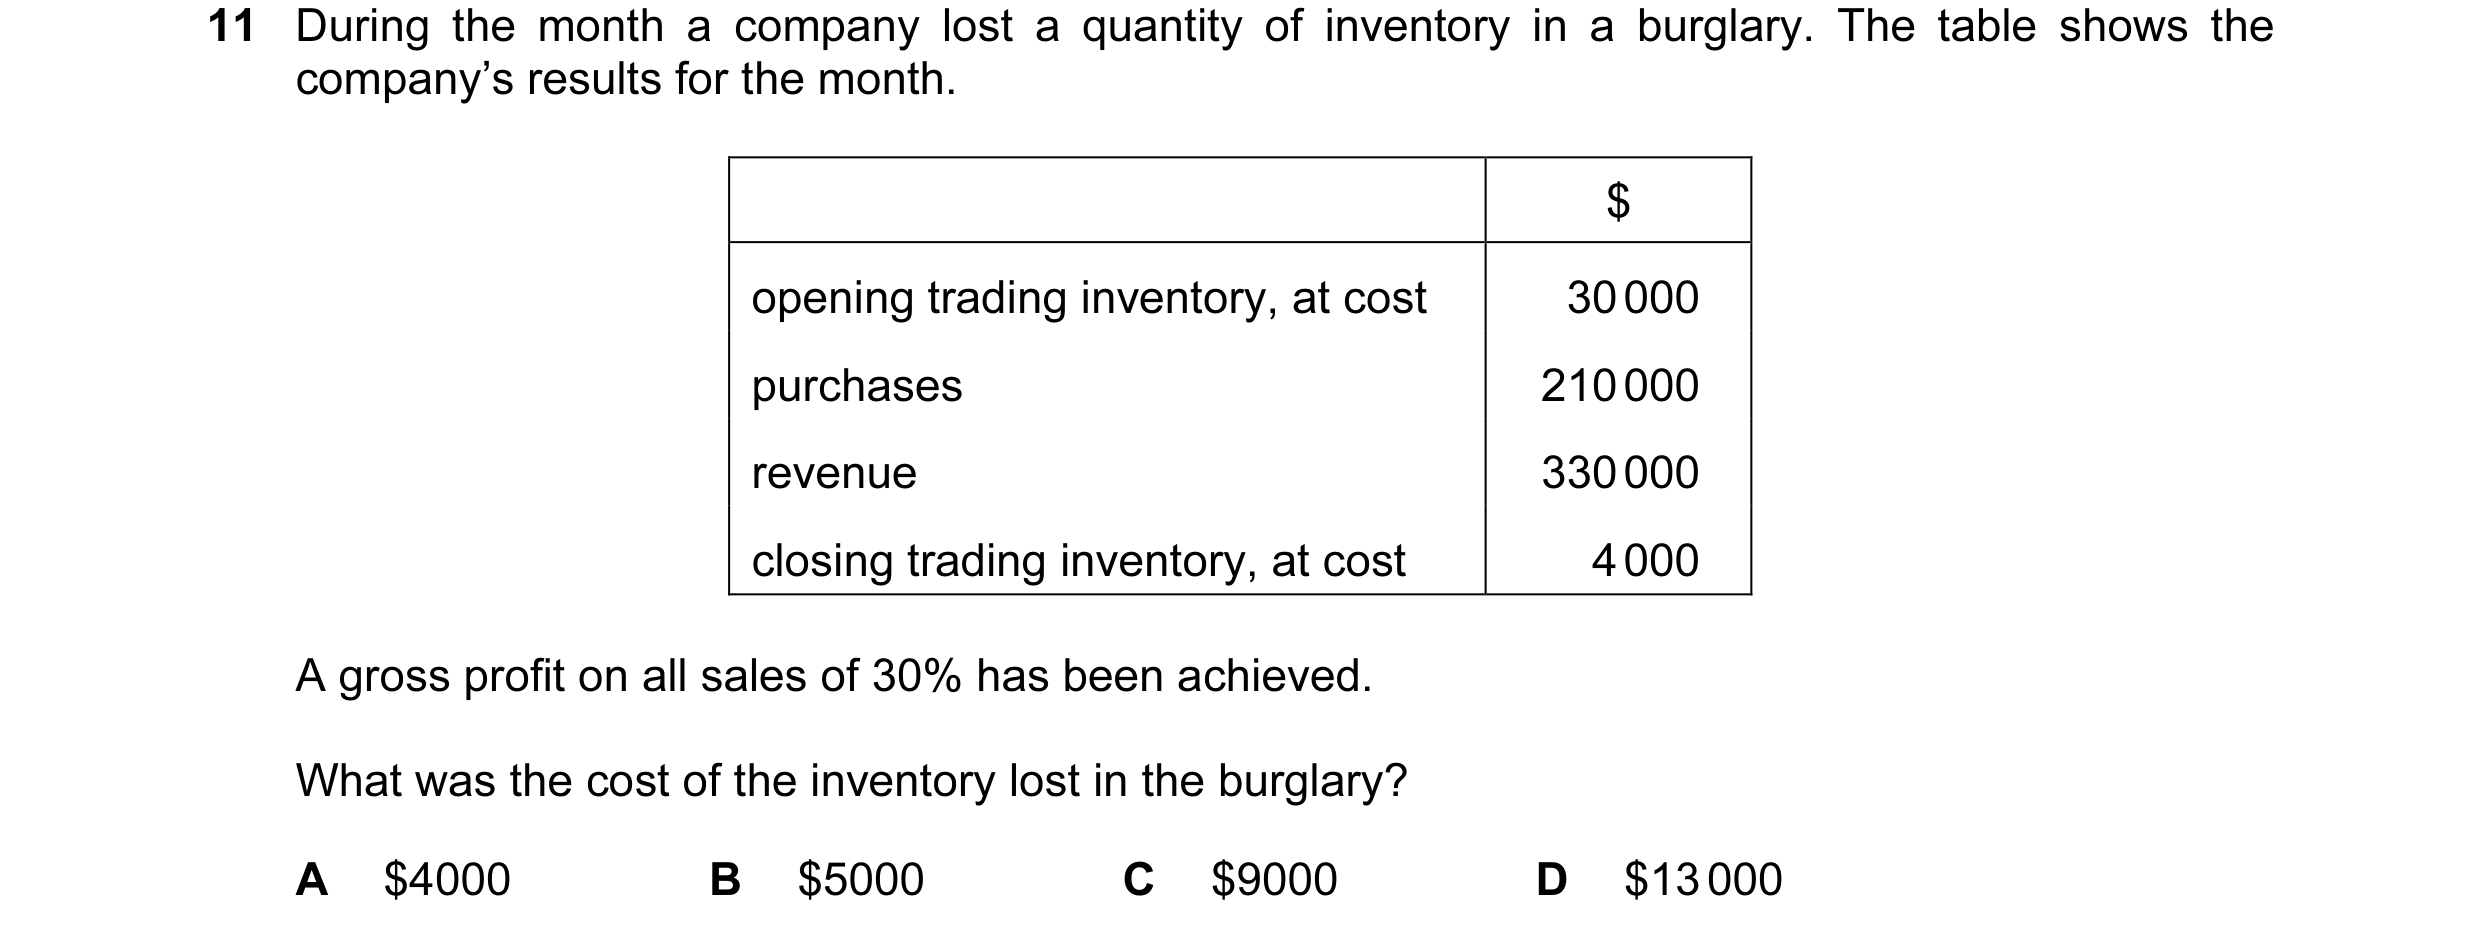
 81 / 233
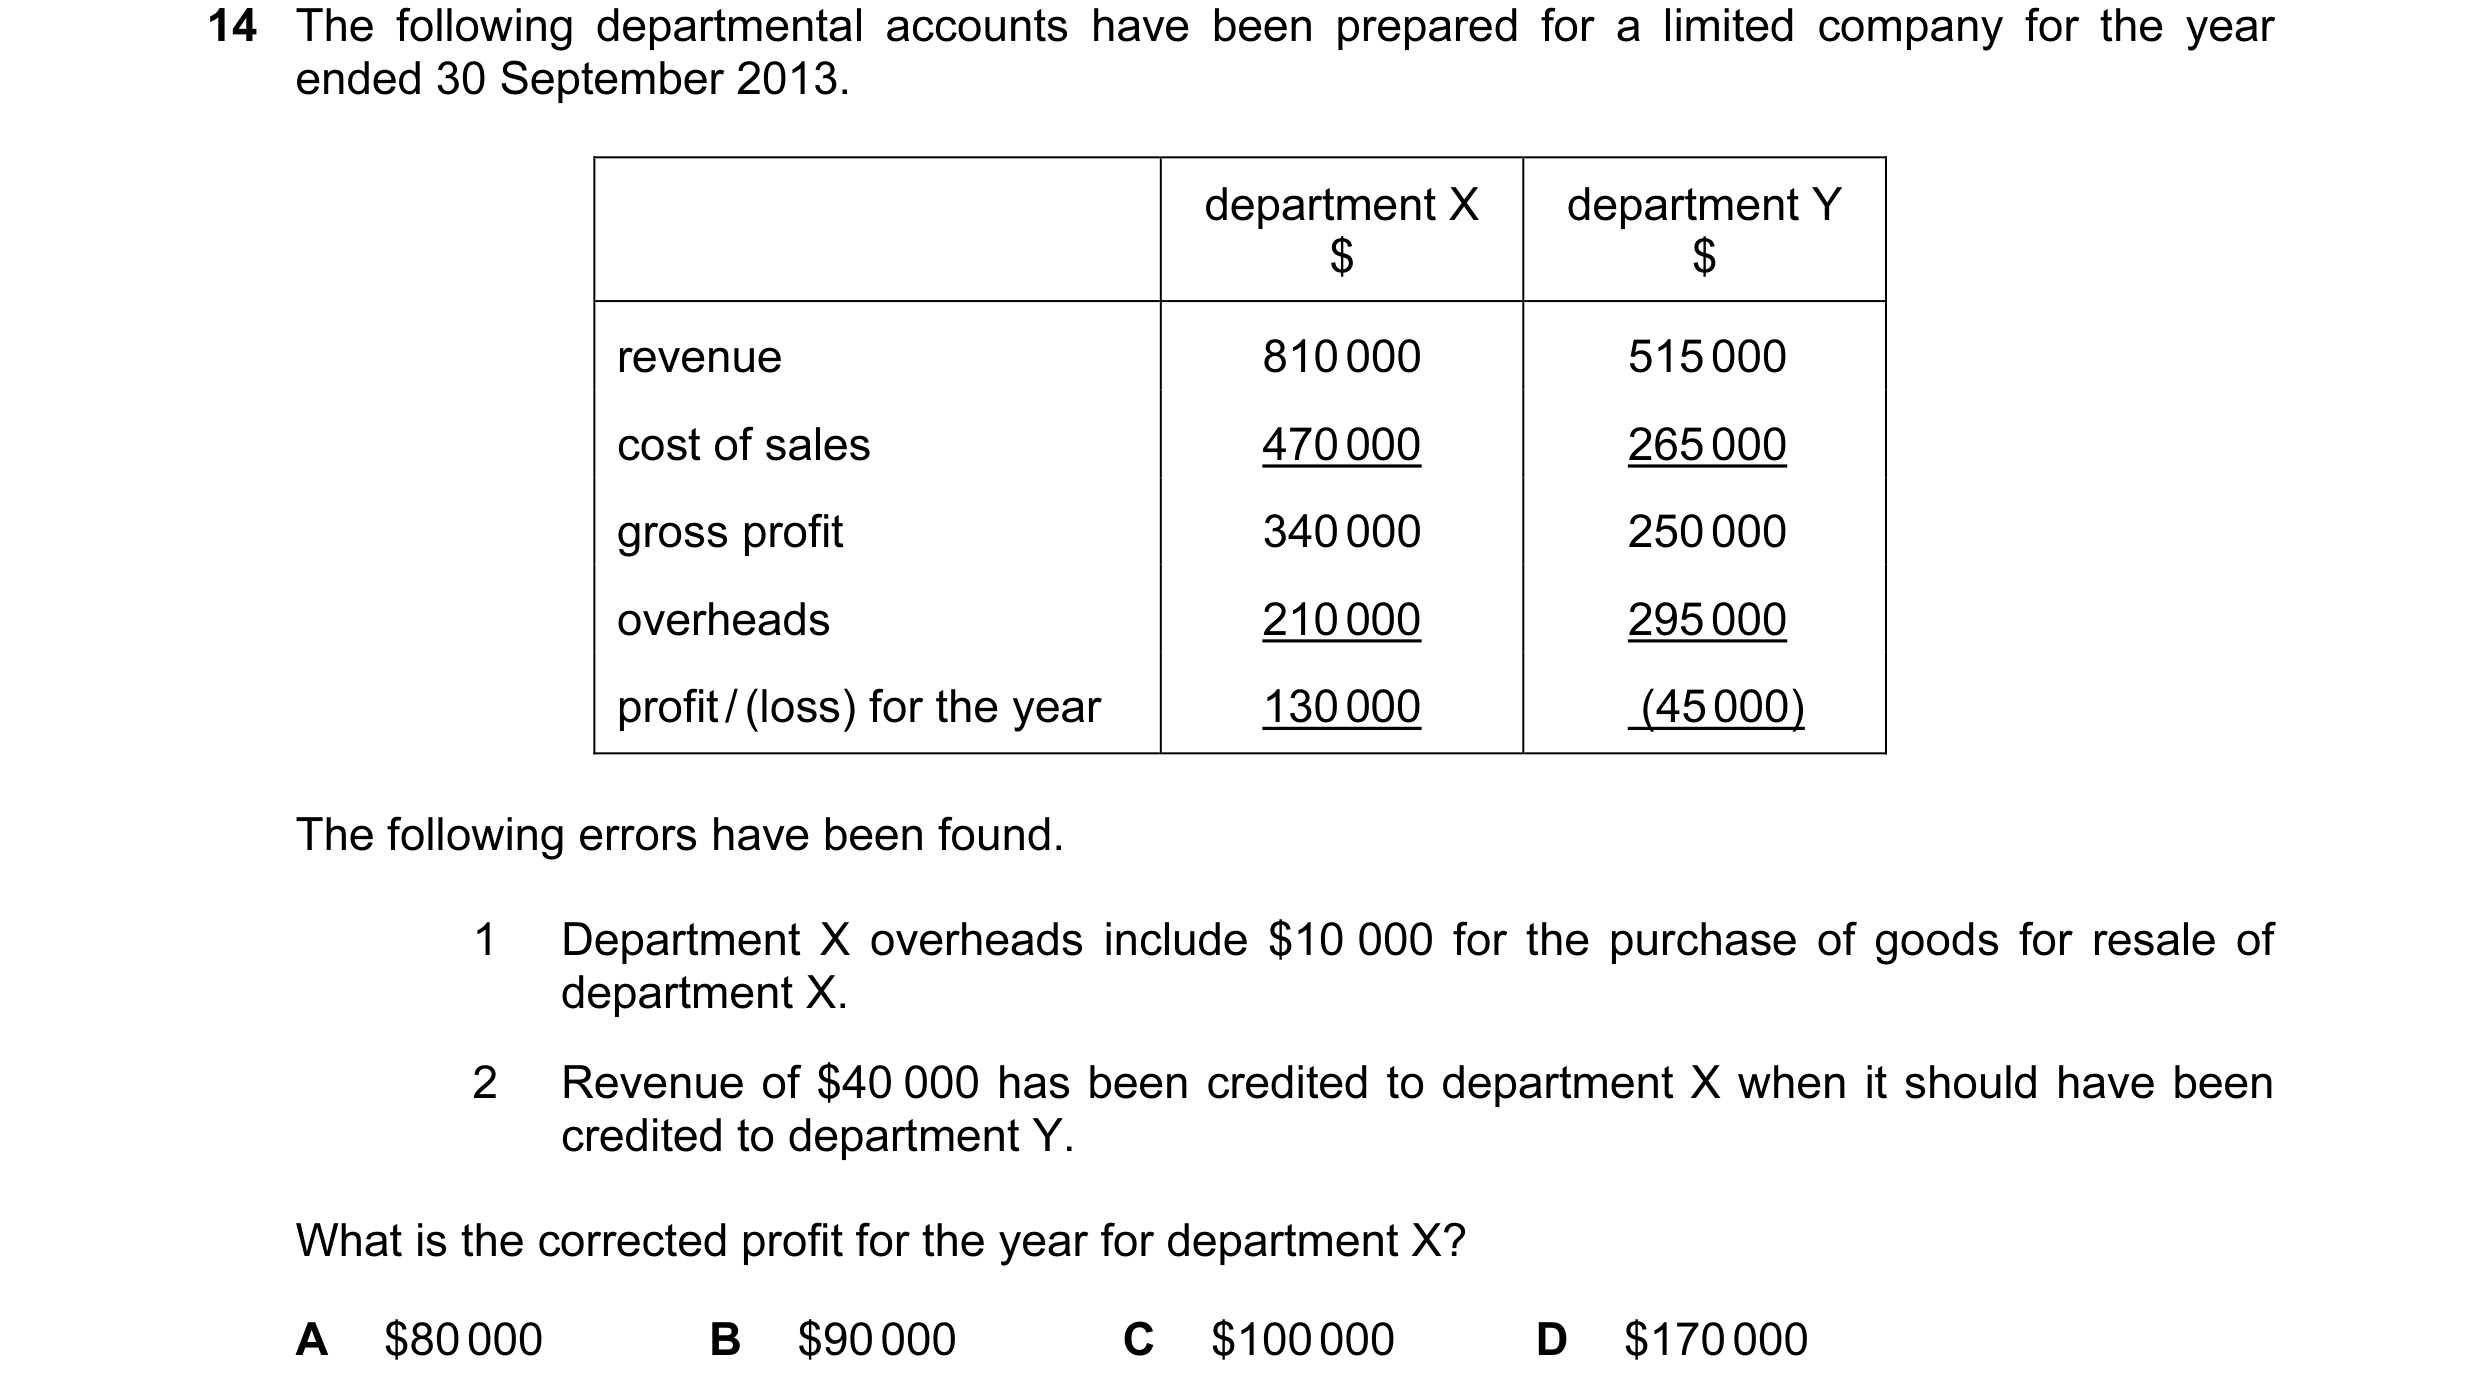
 82 / 233
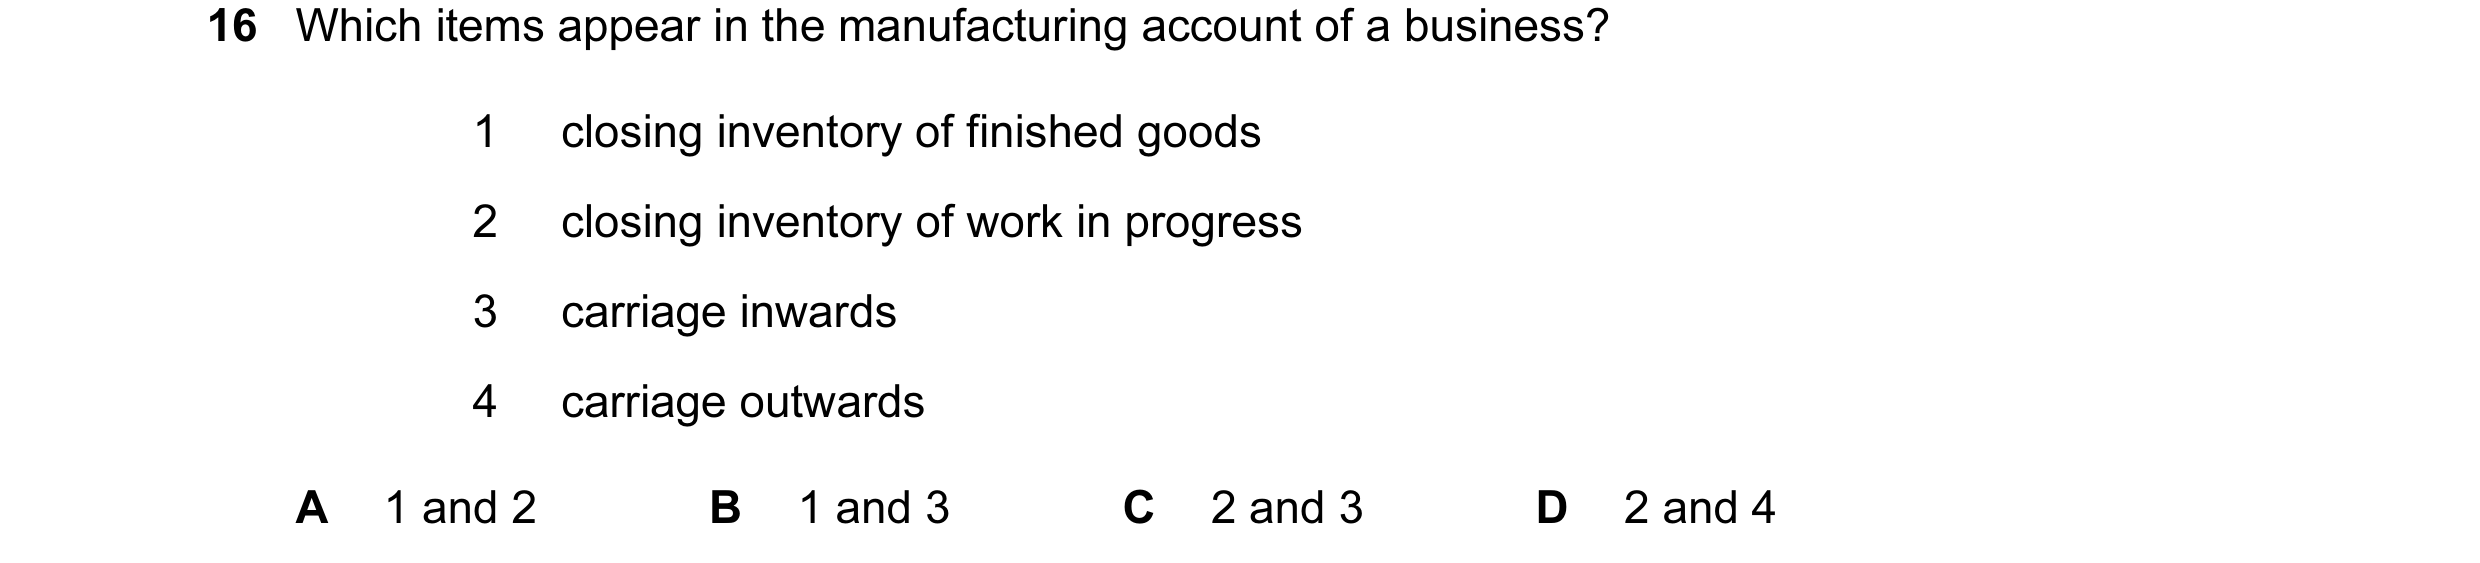
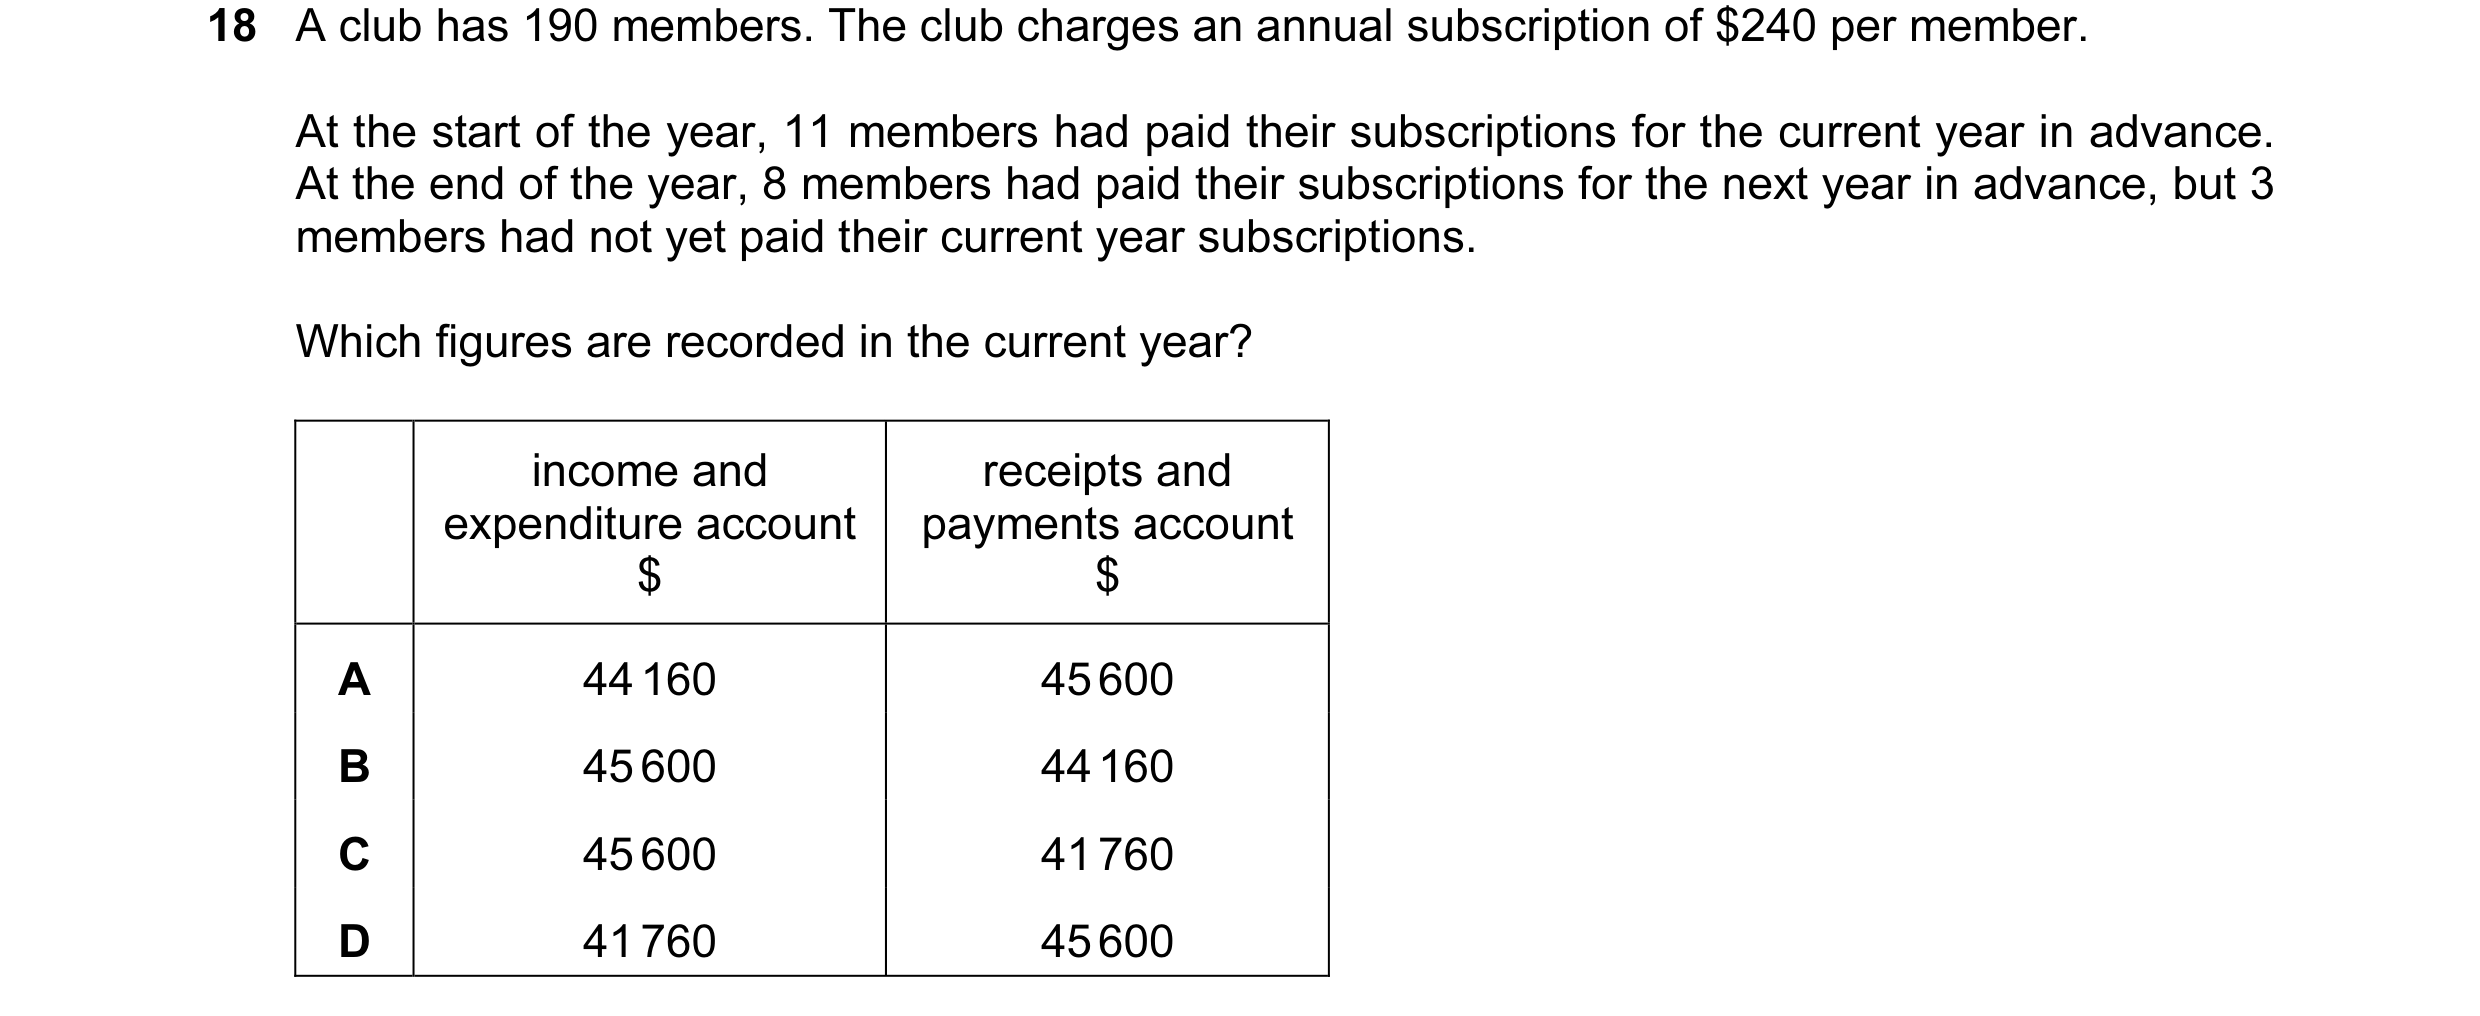
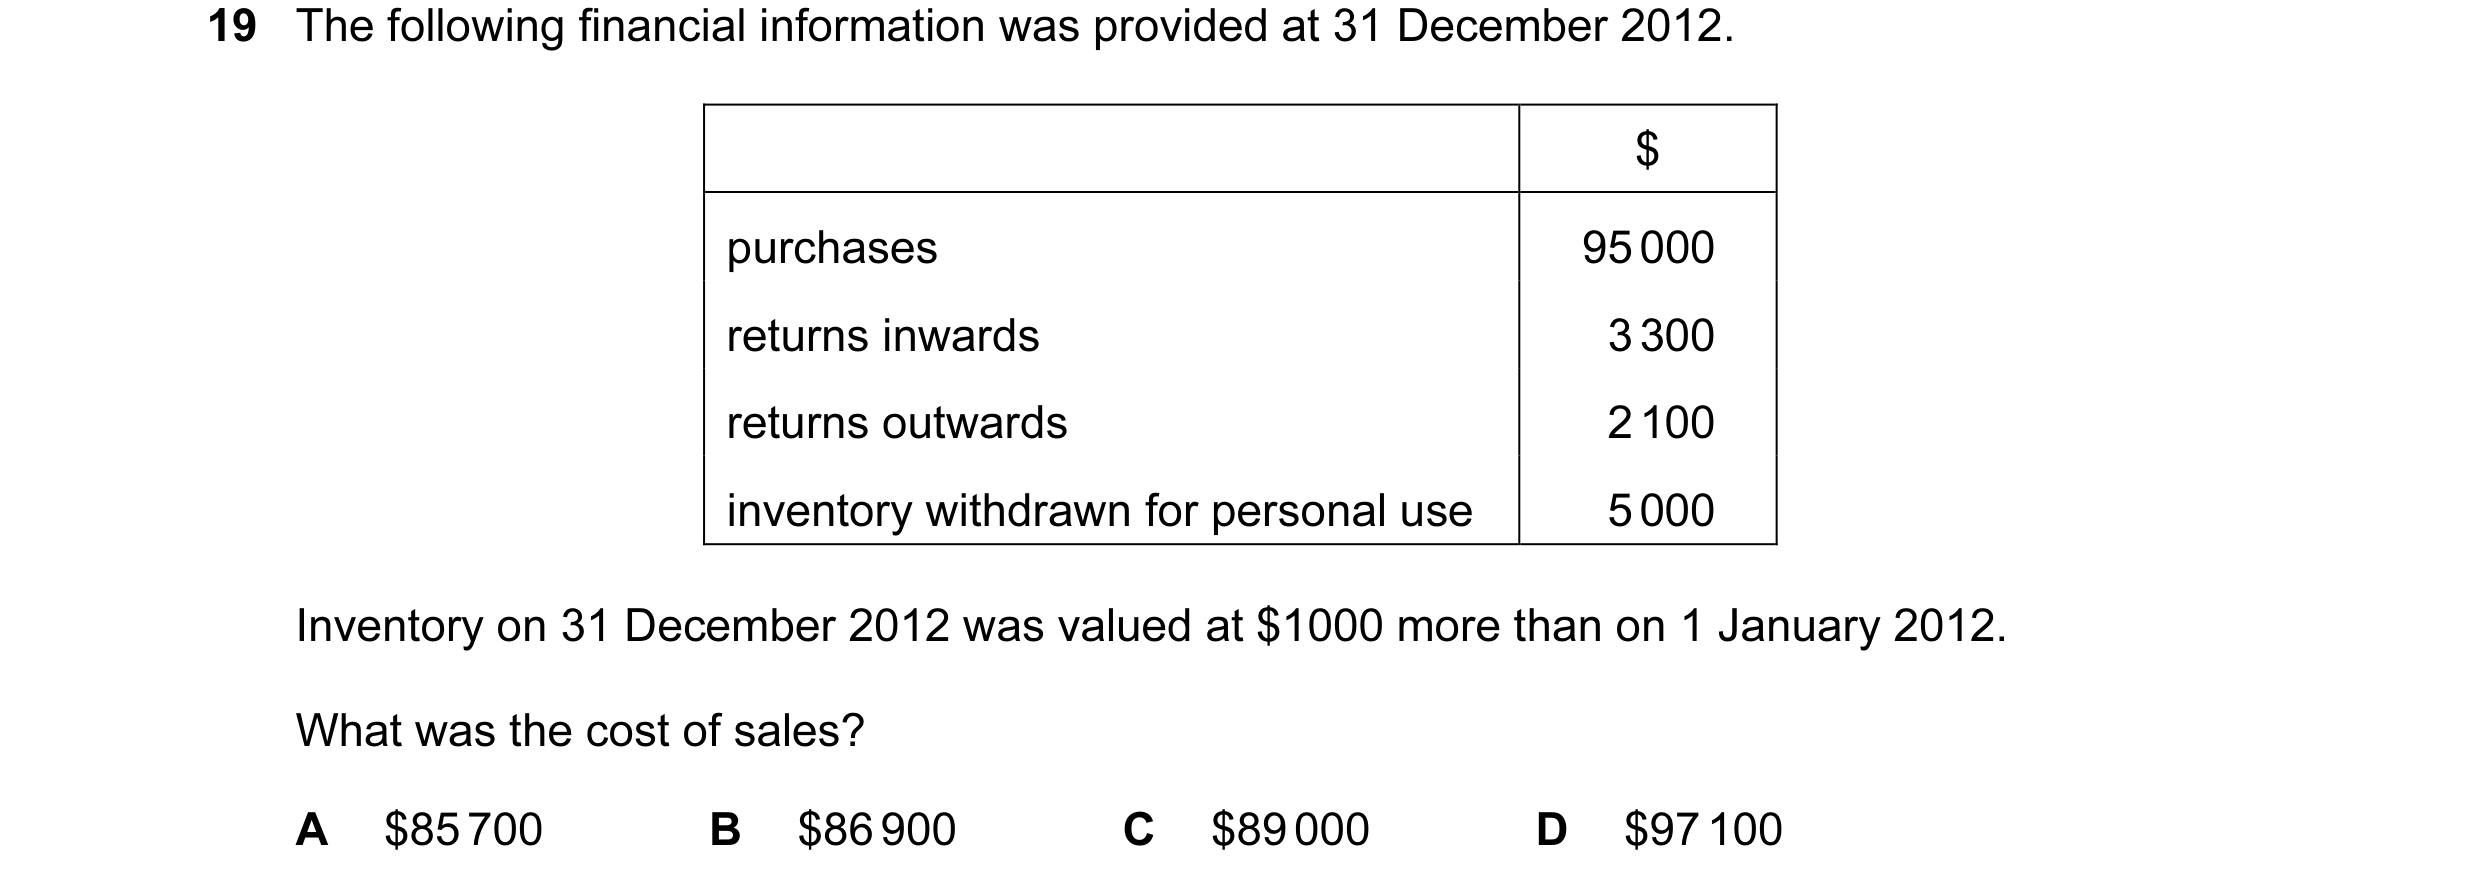 83 / 233
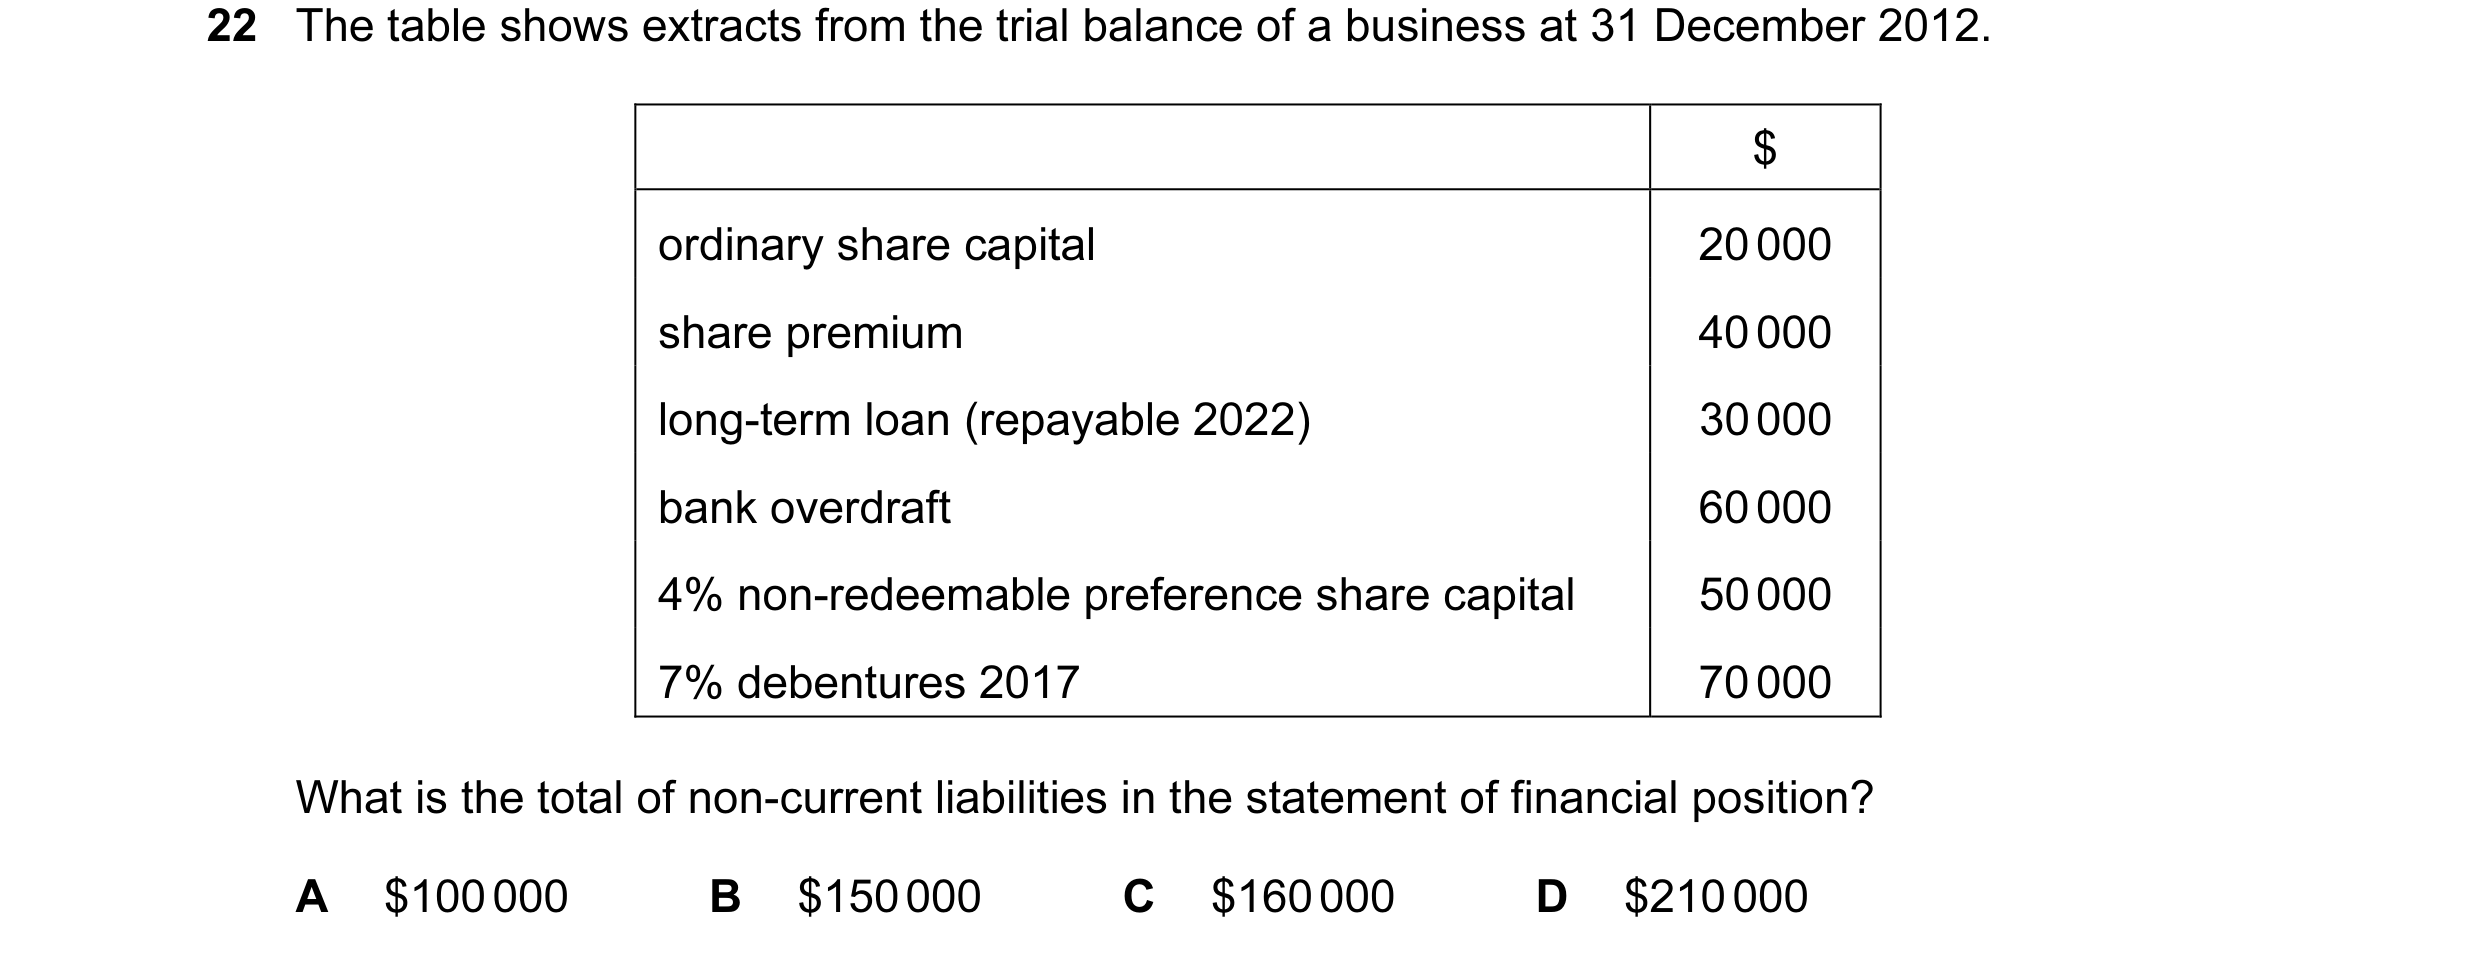
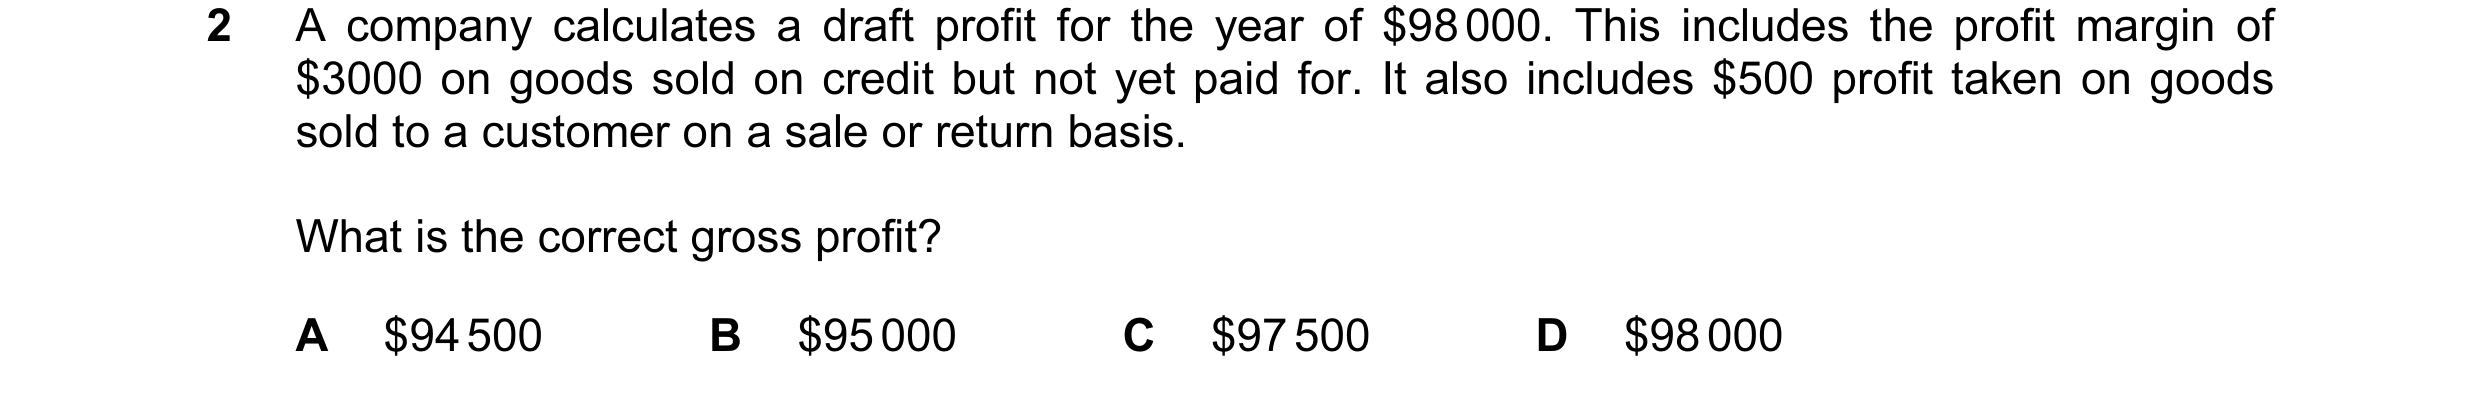
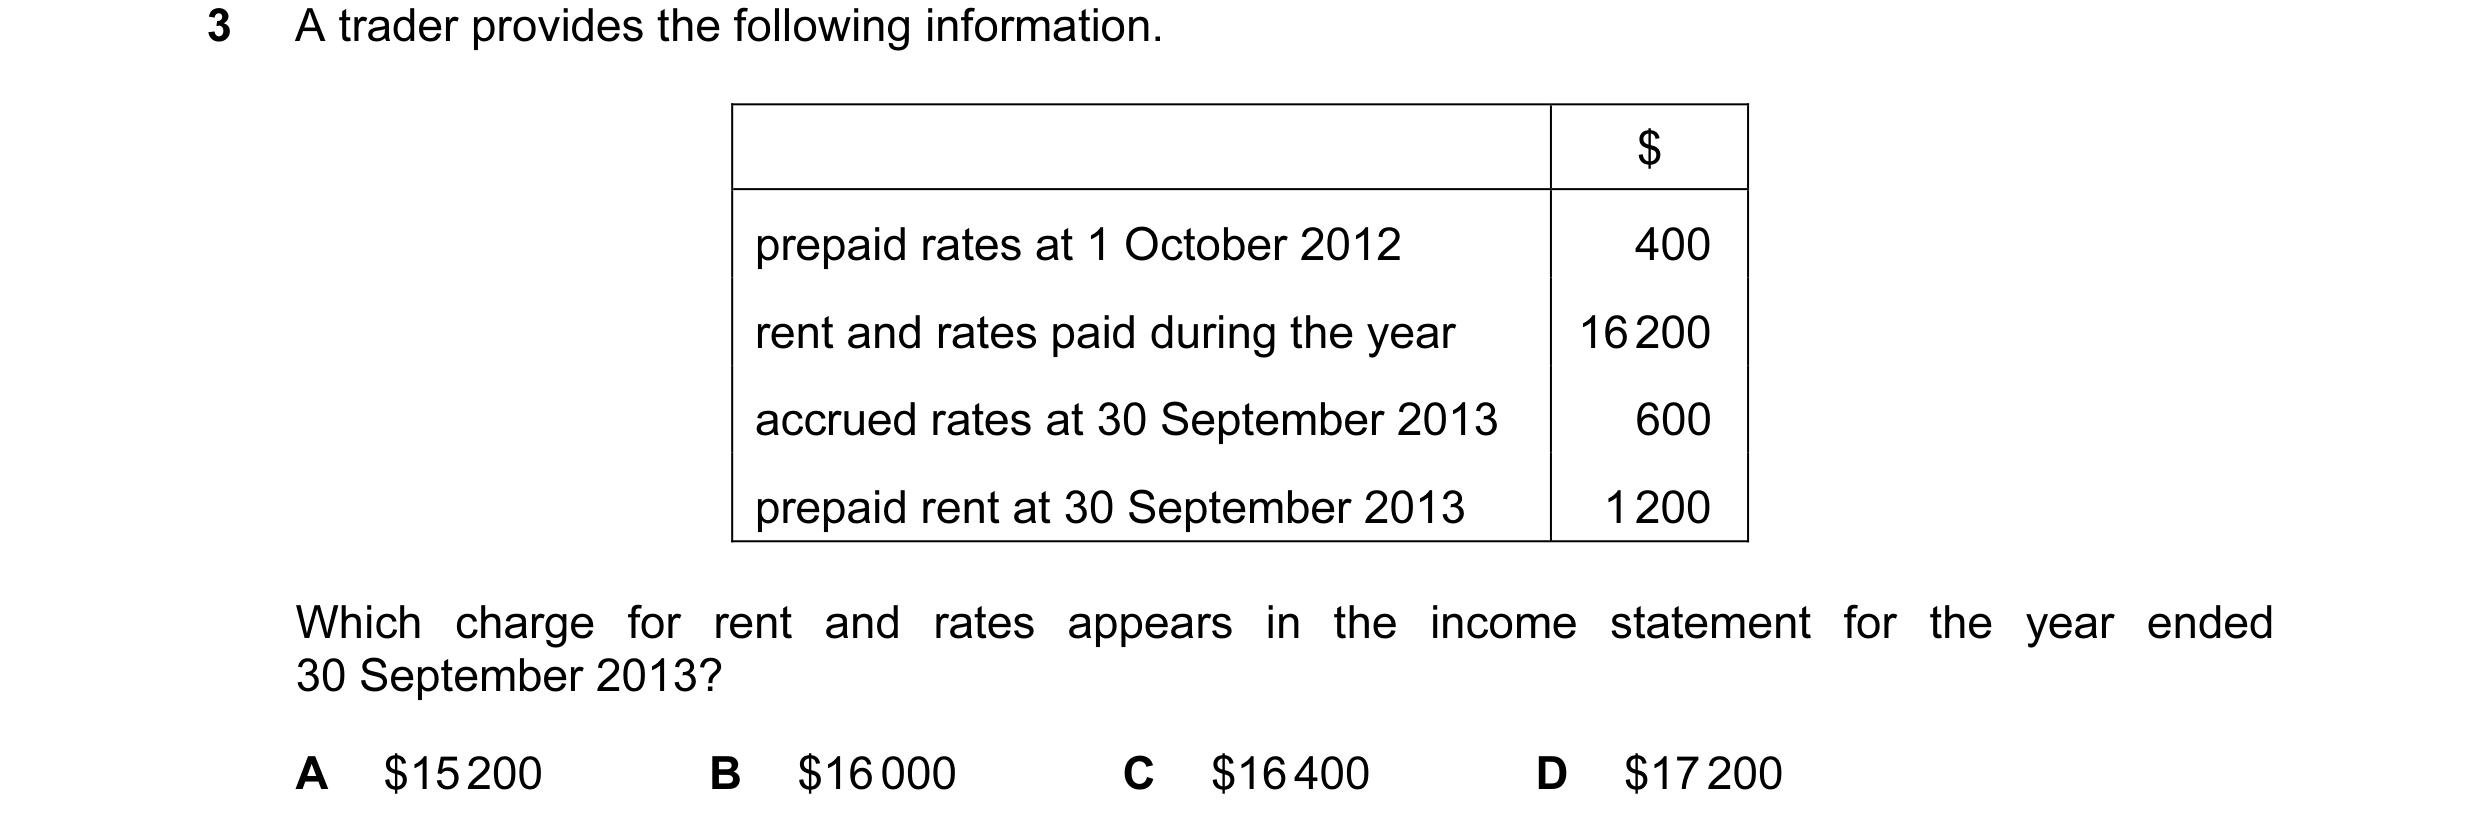
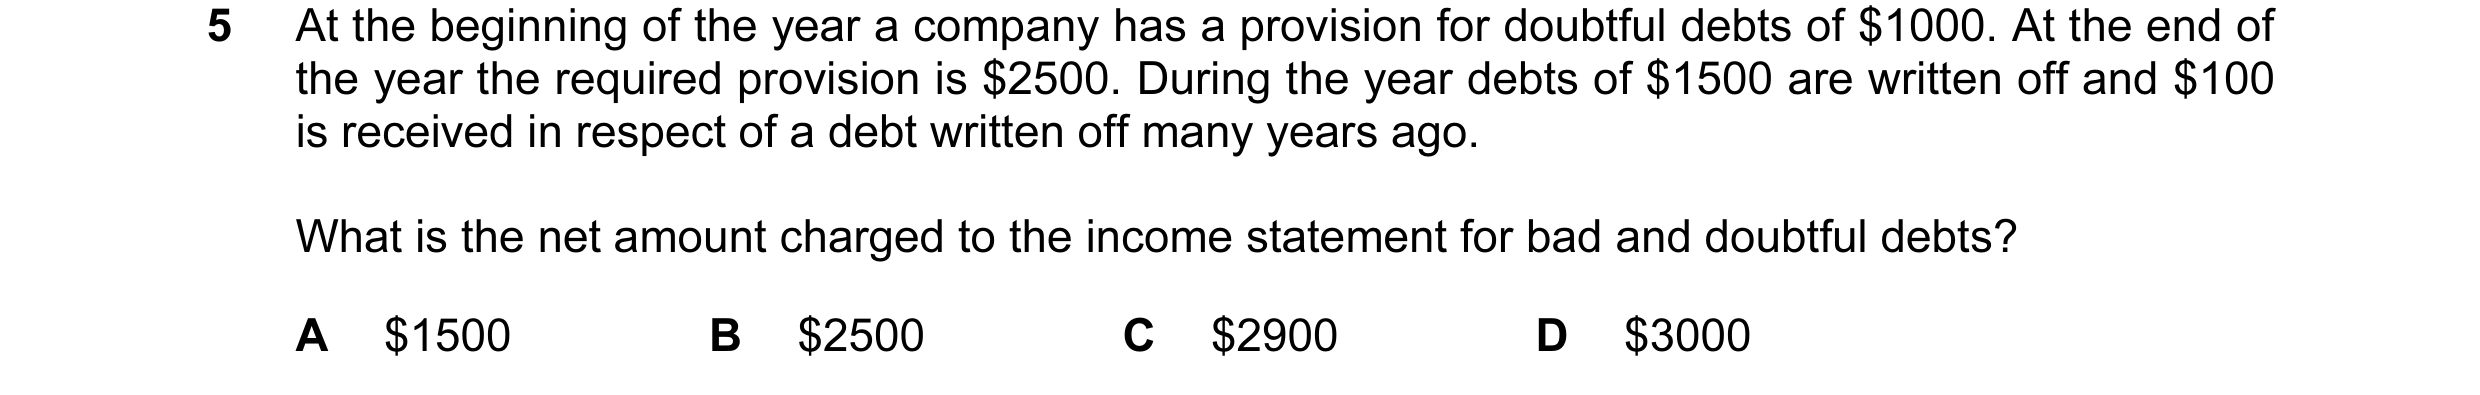
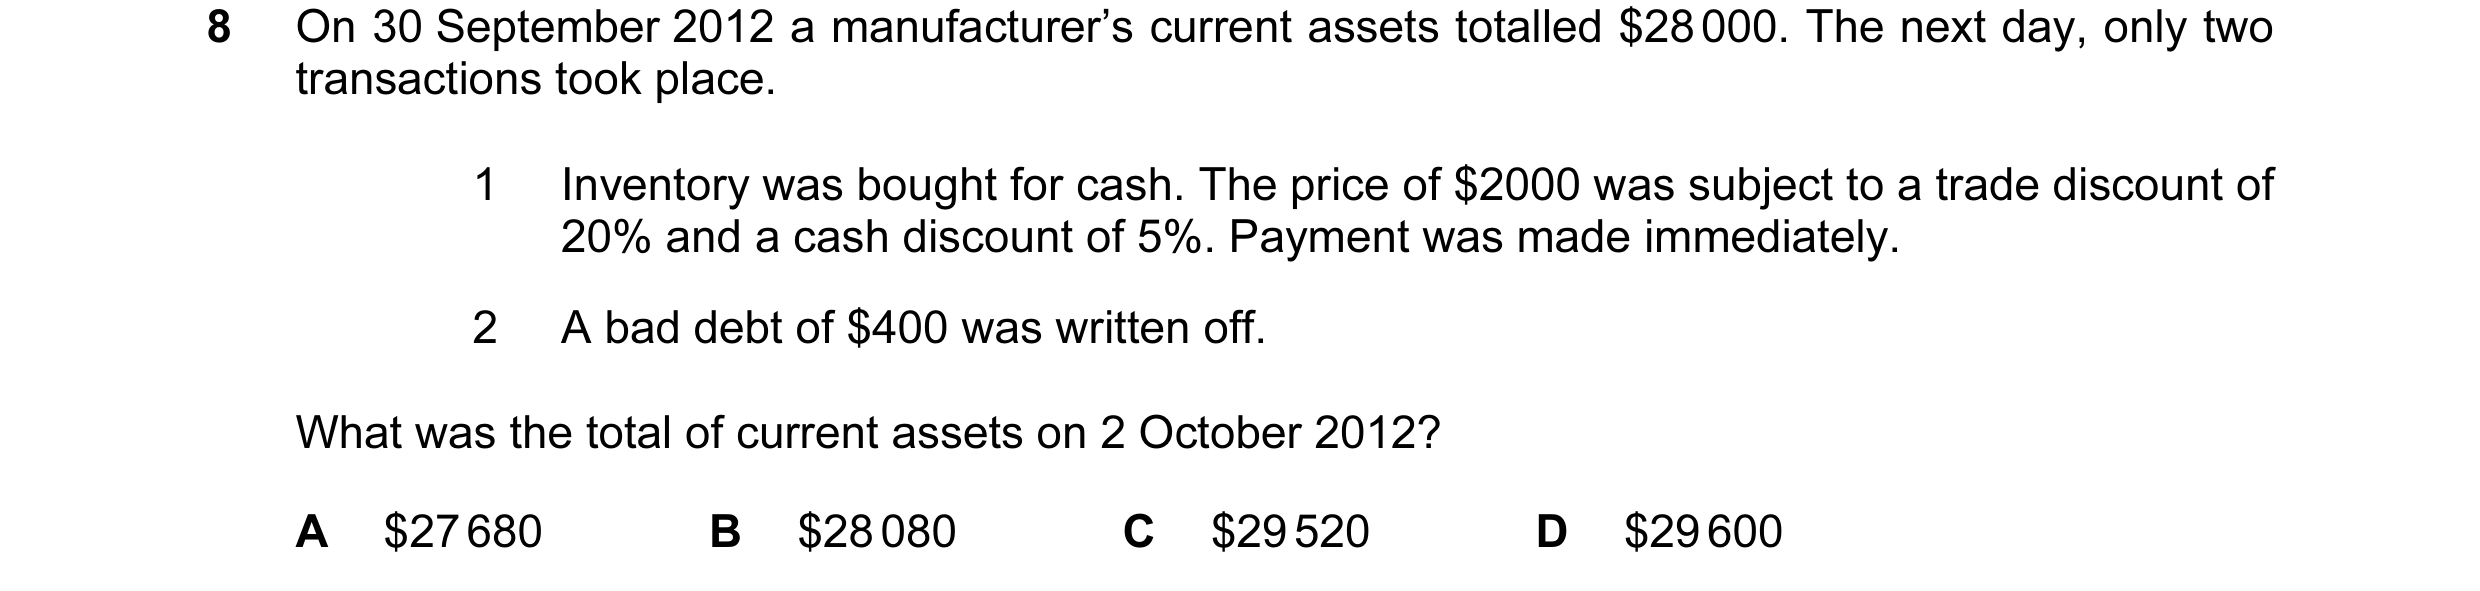 84 / 233
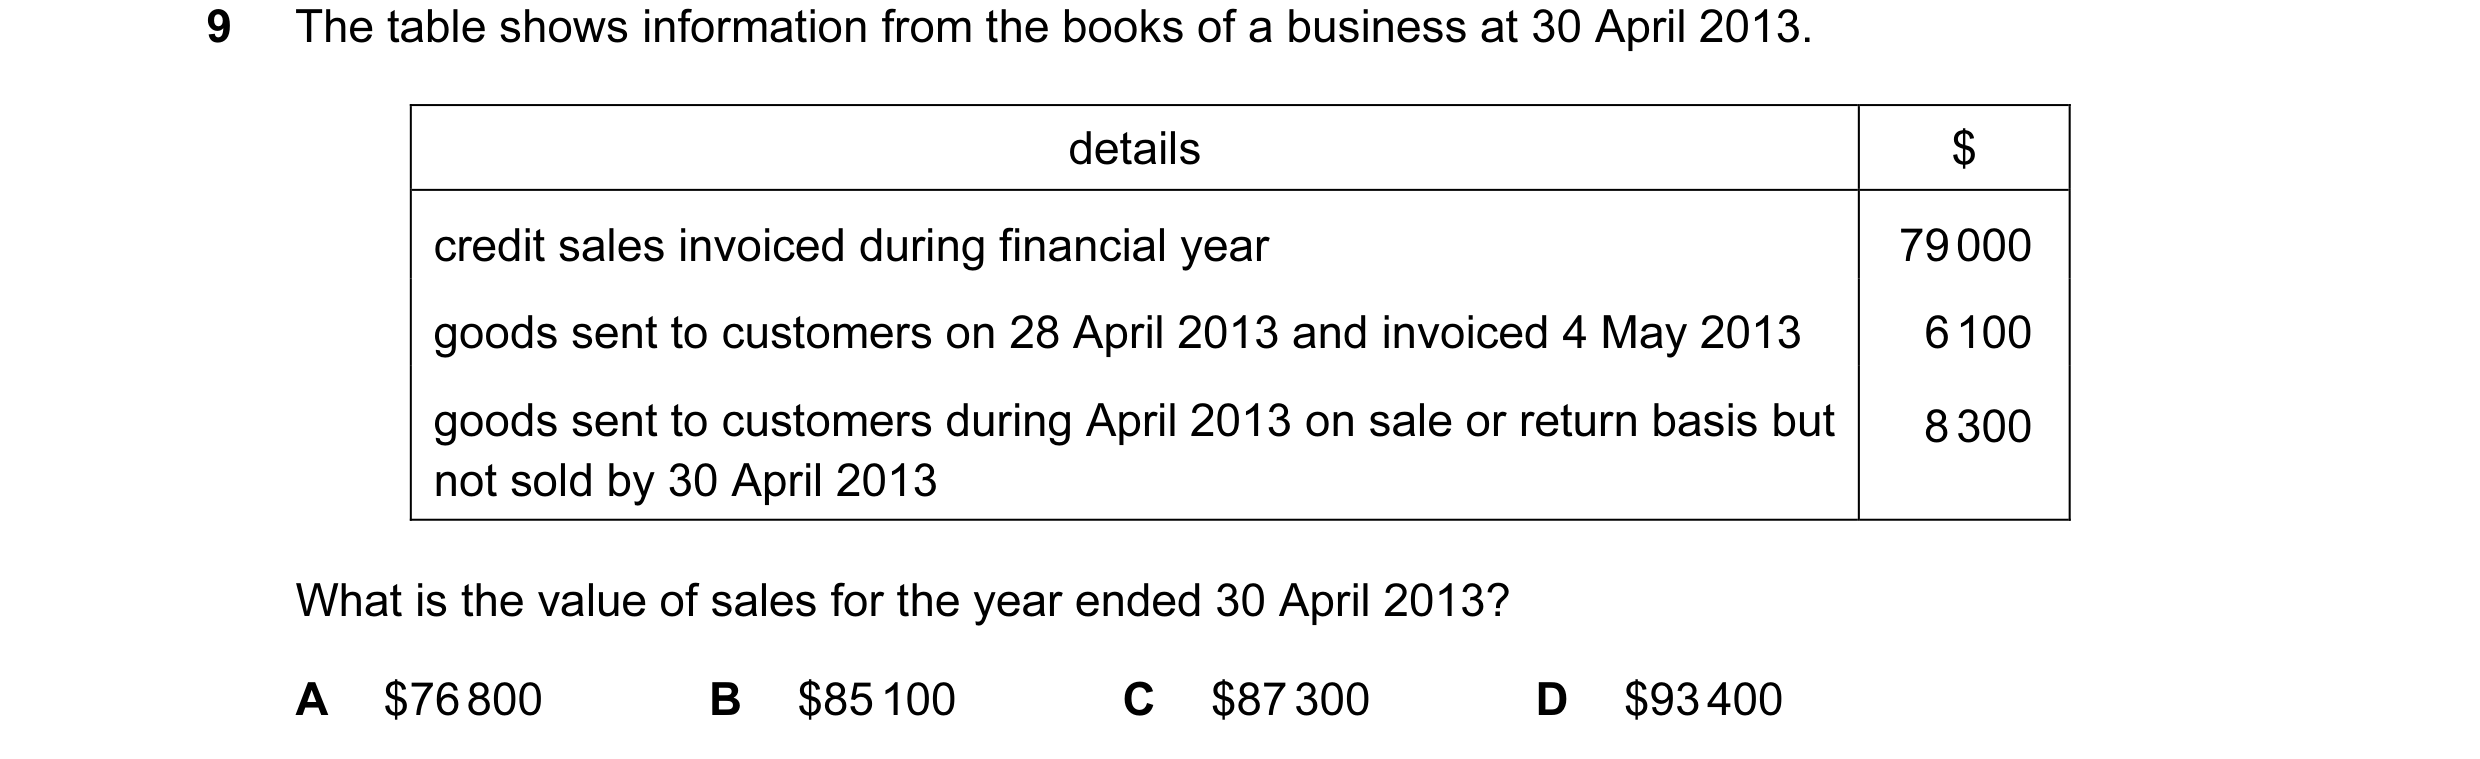
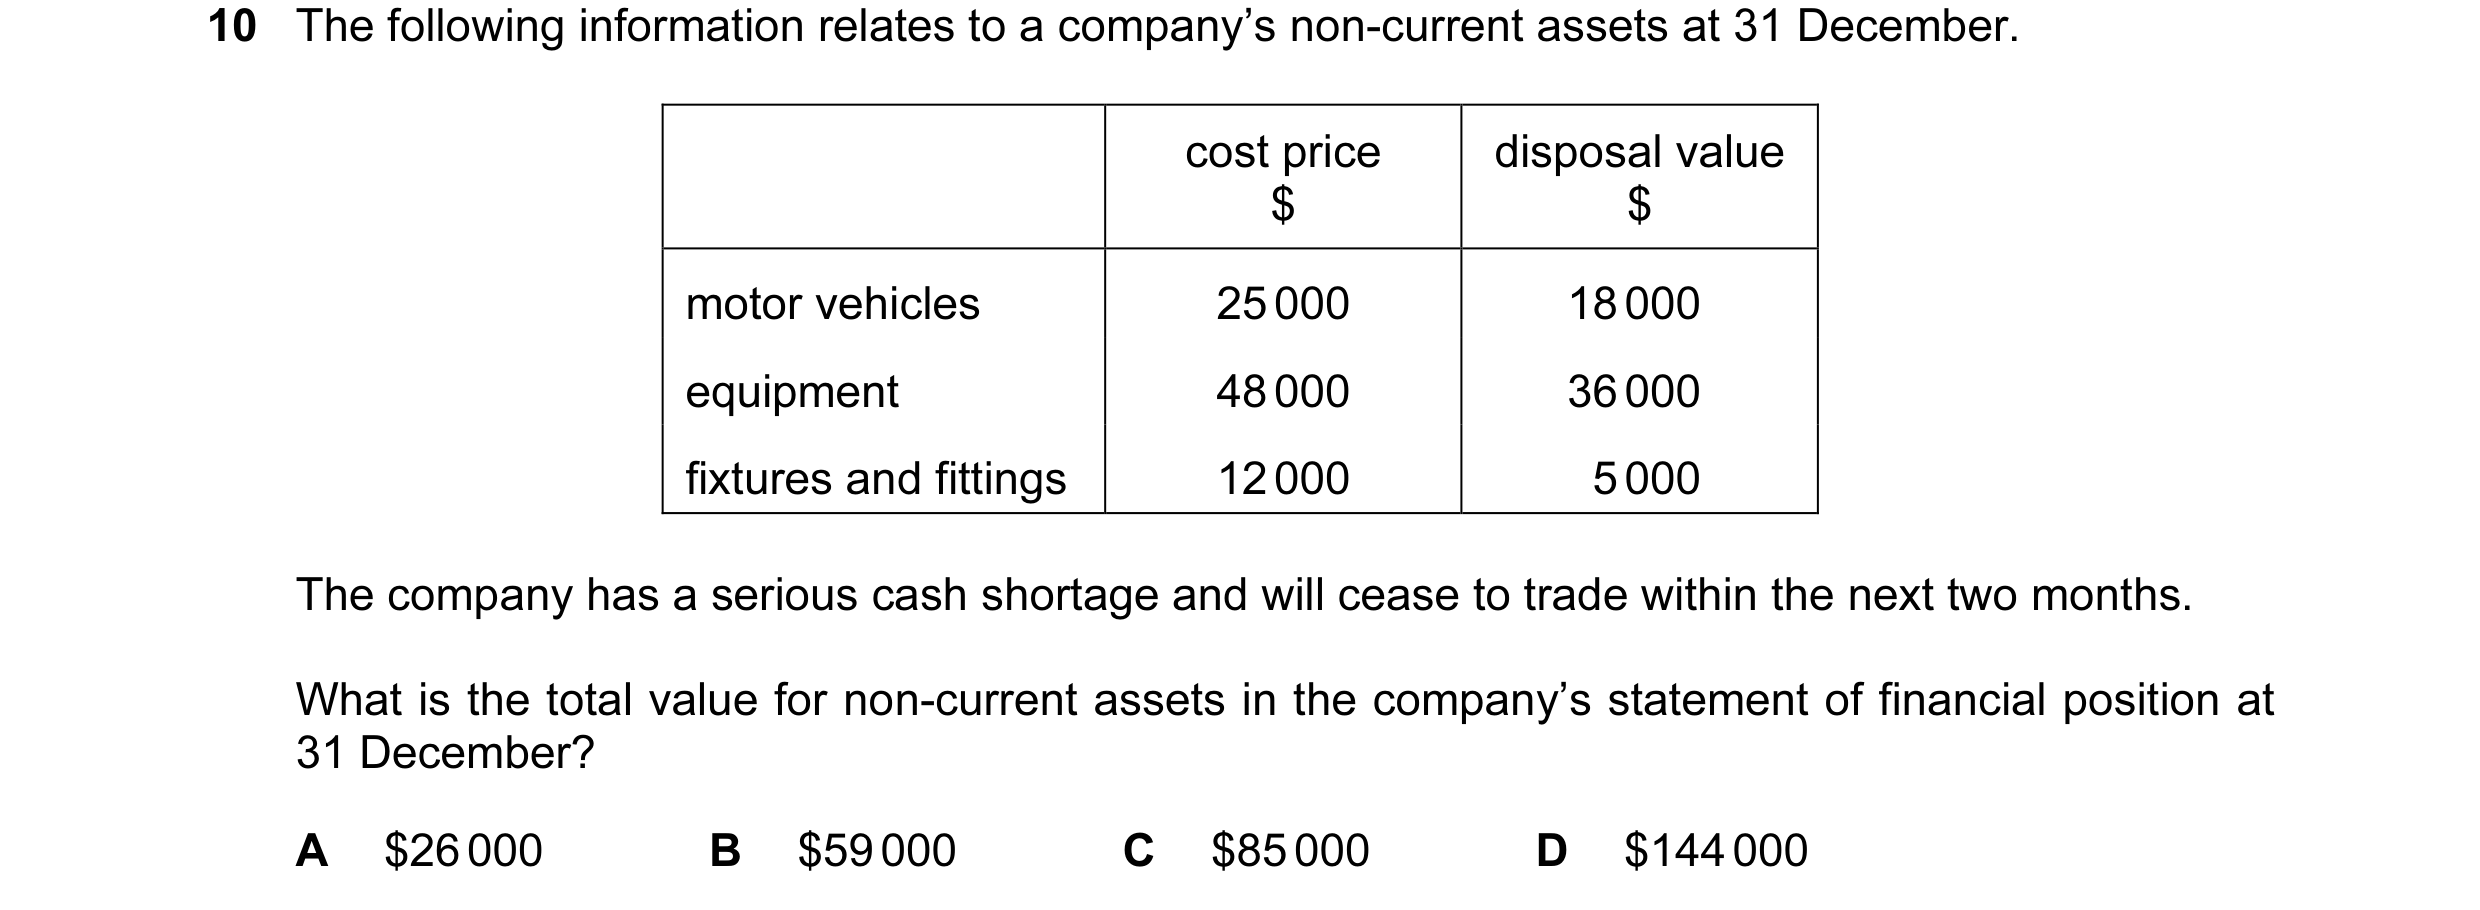
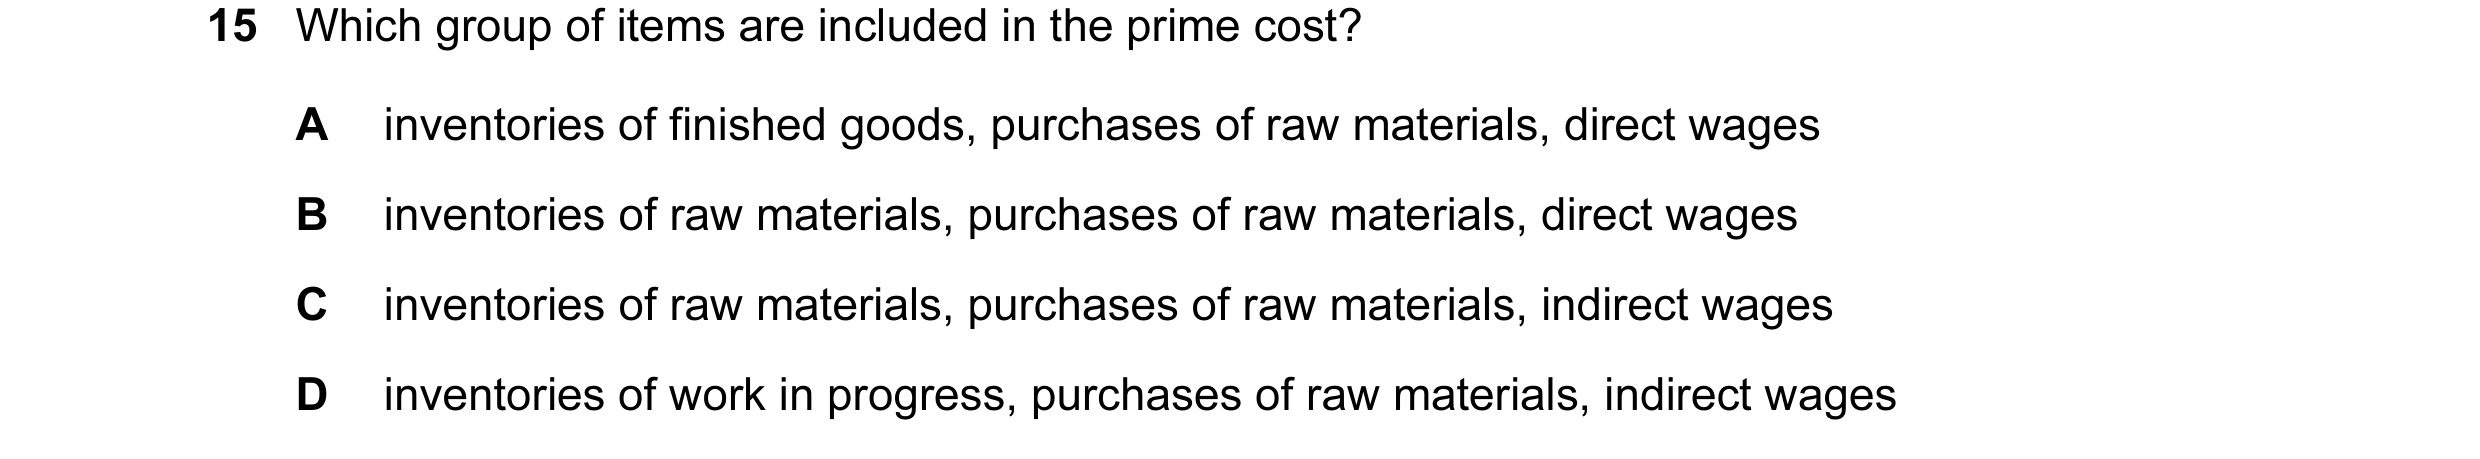
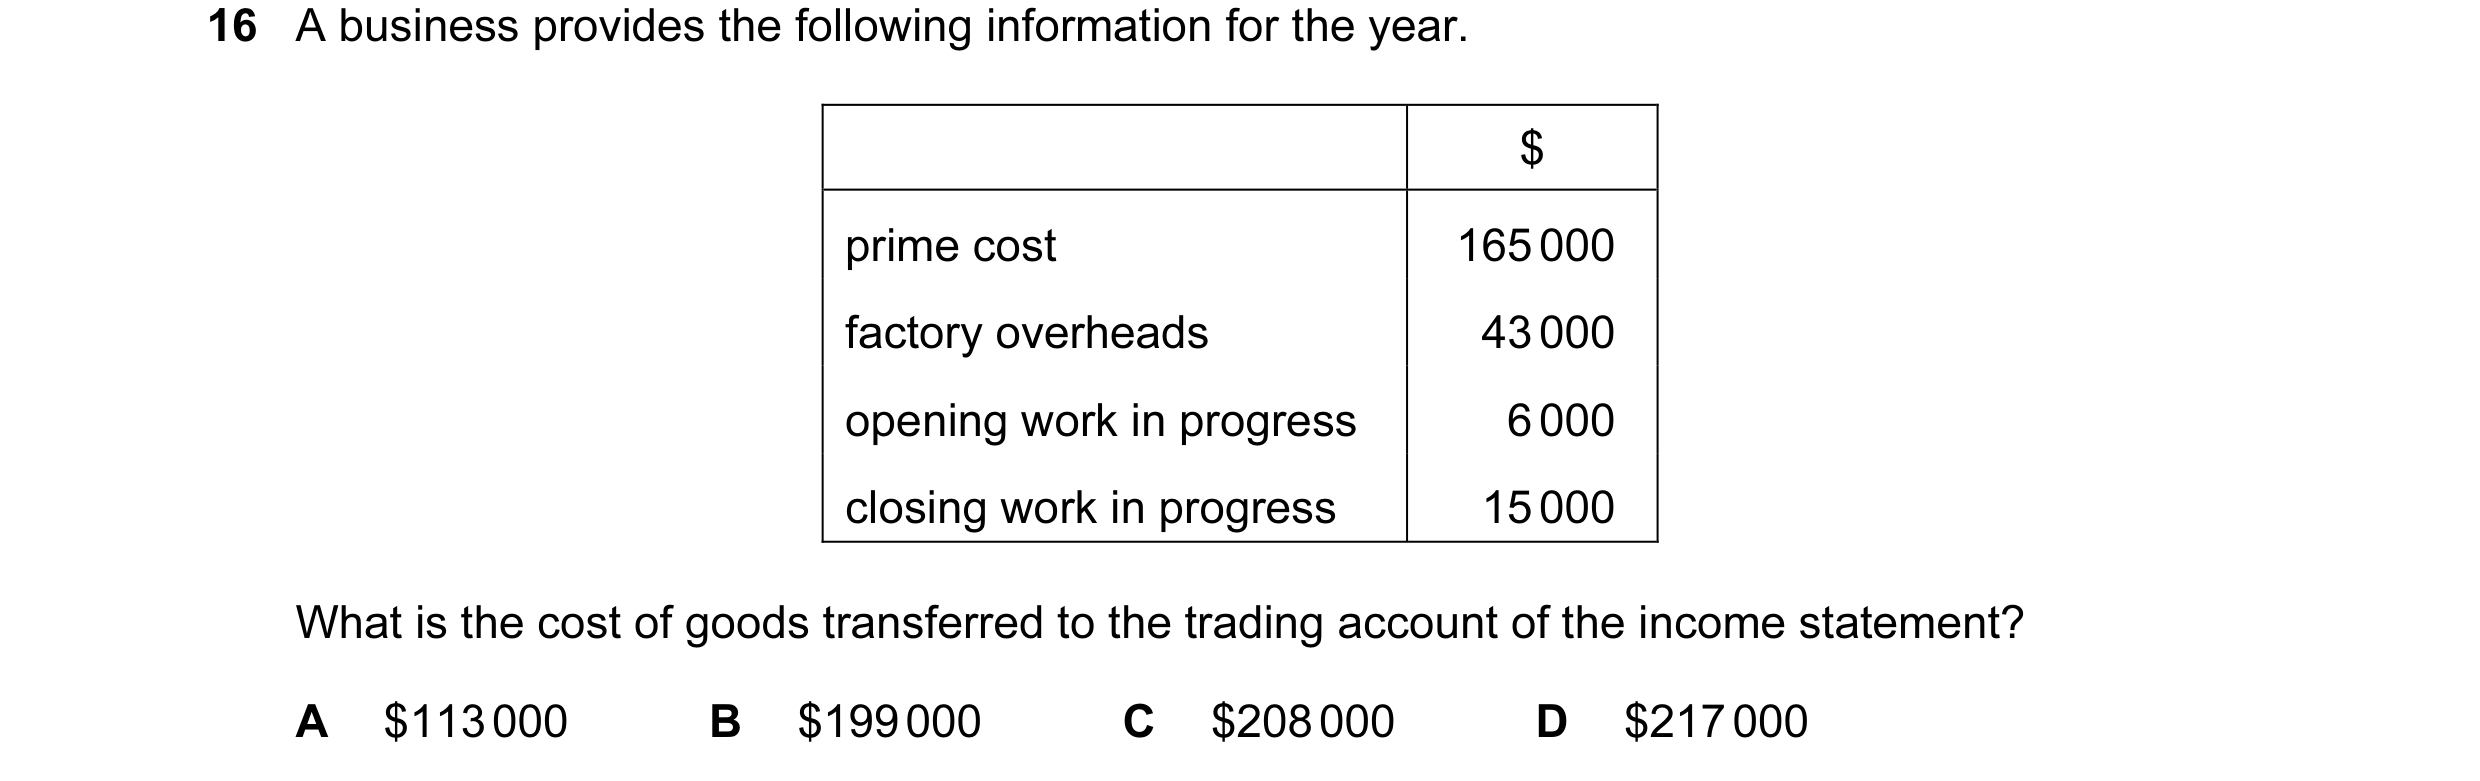 85 / 233
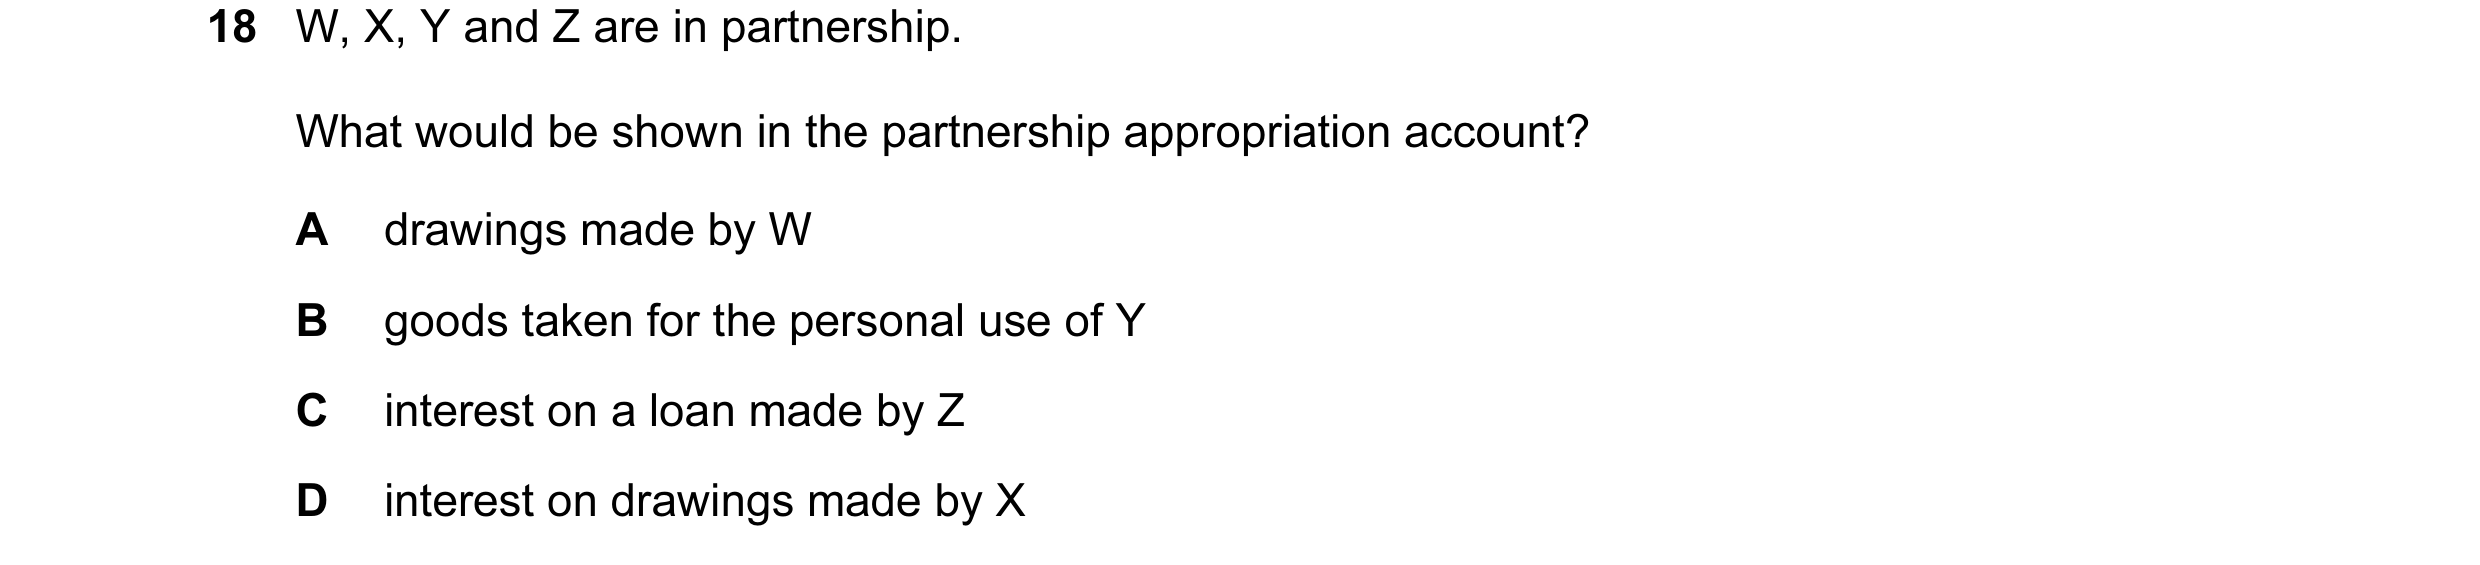
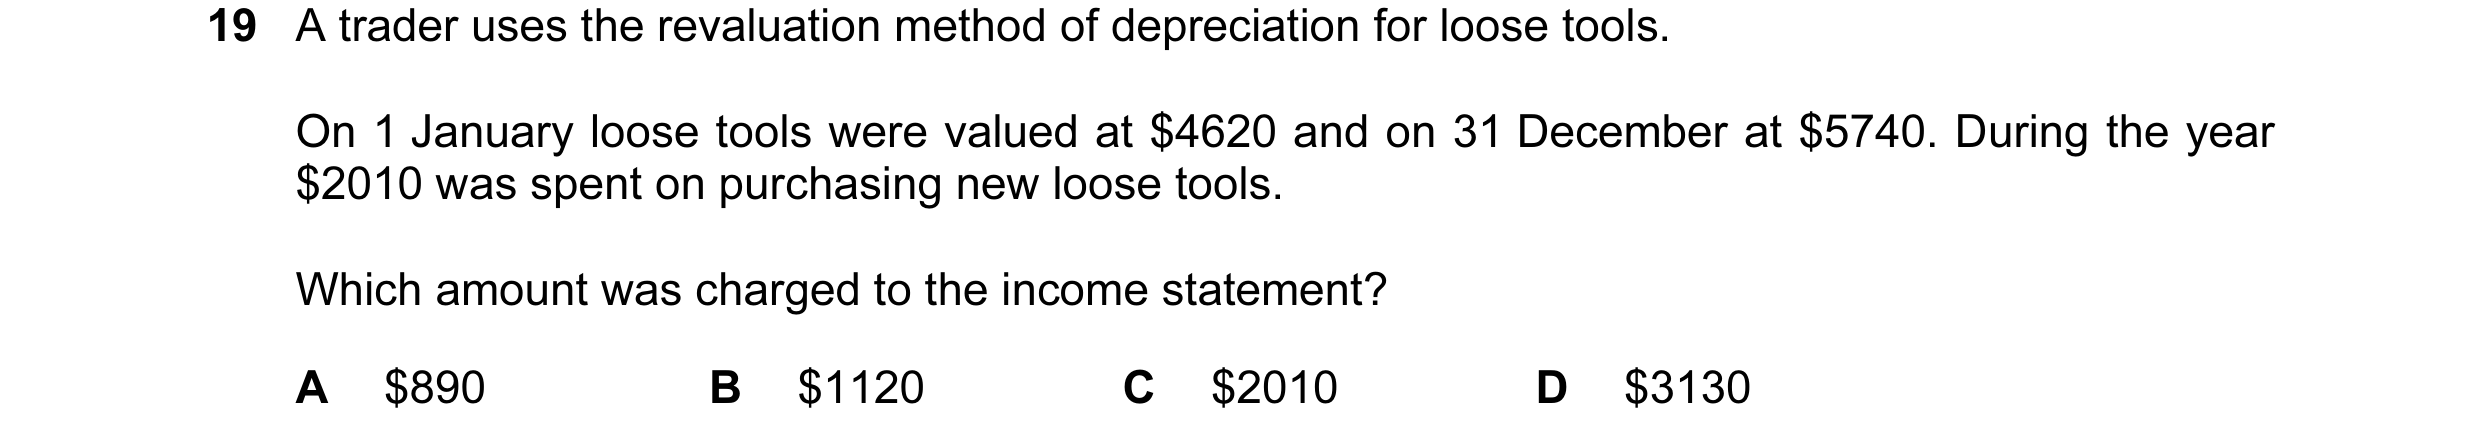
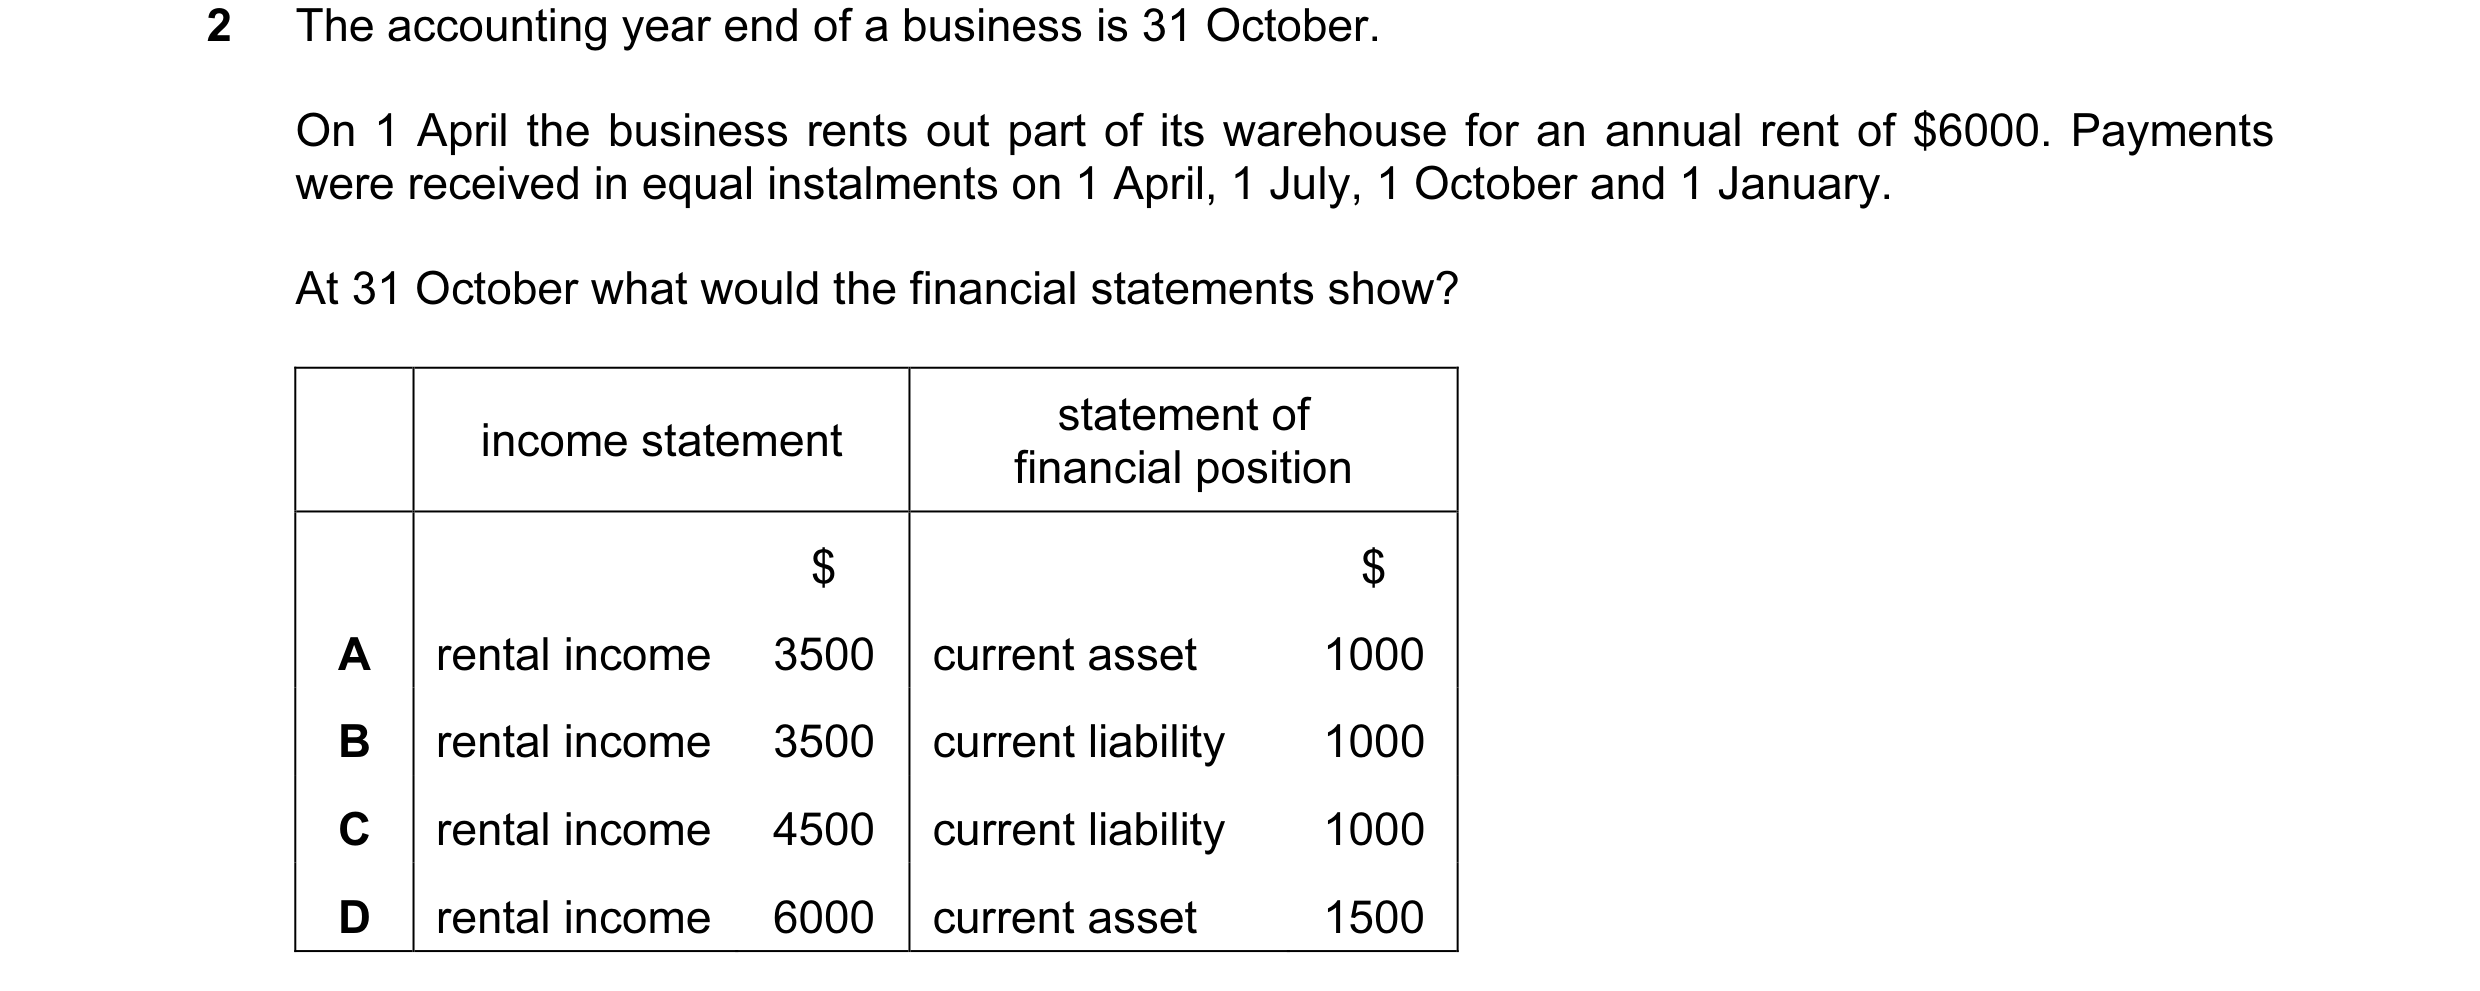
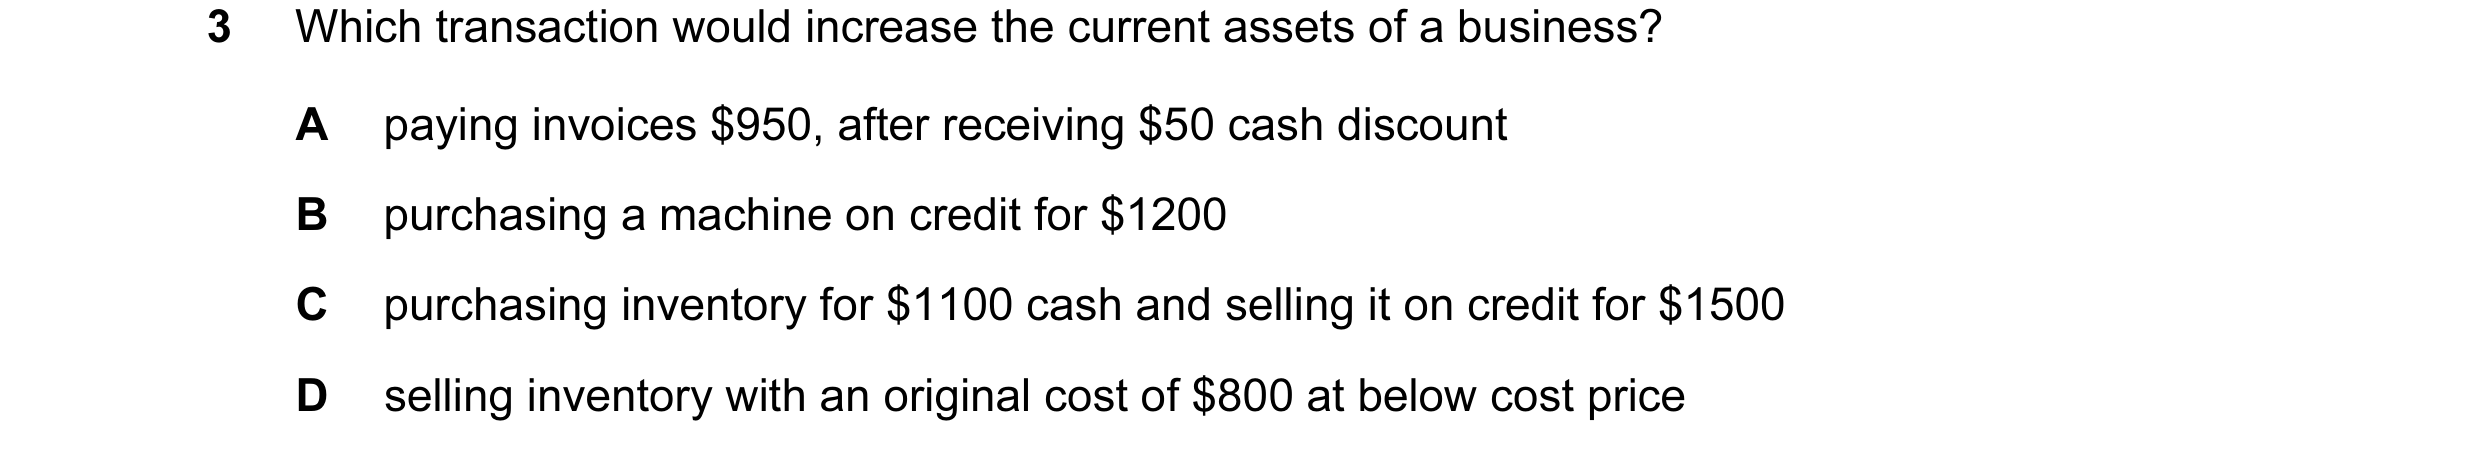
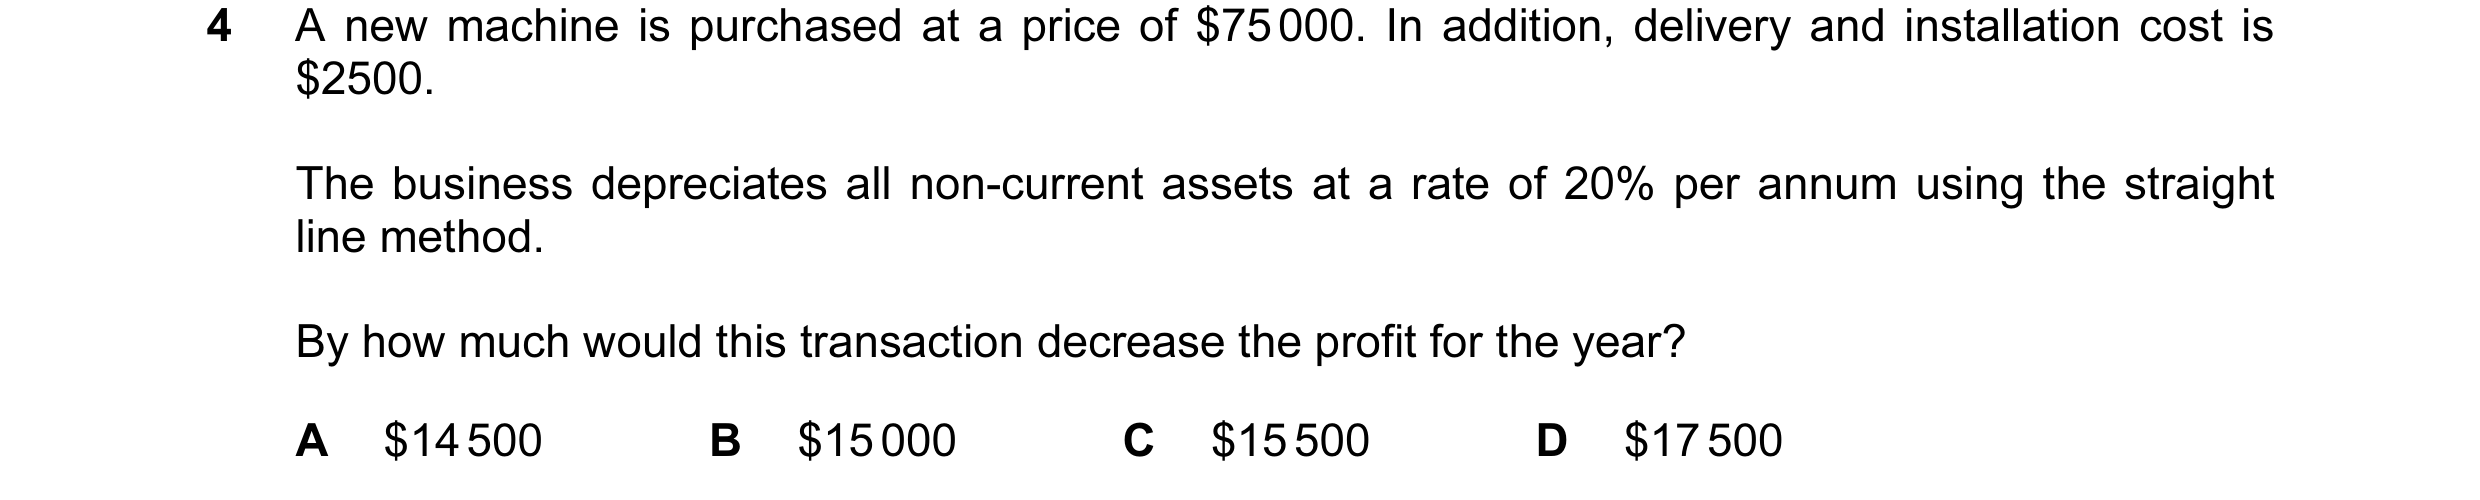 86 / 233
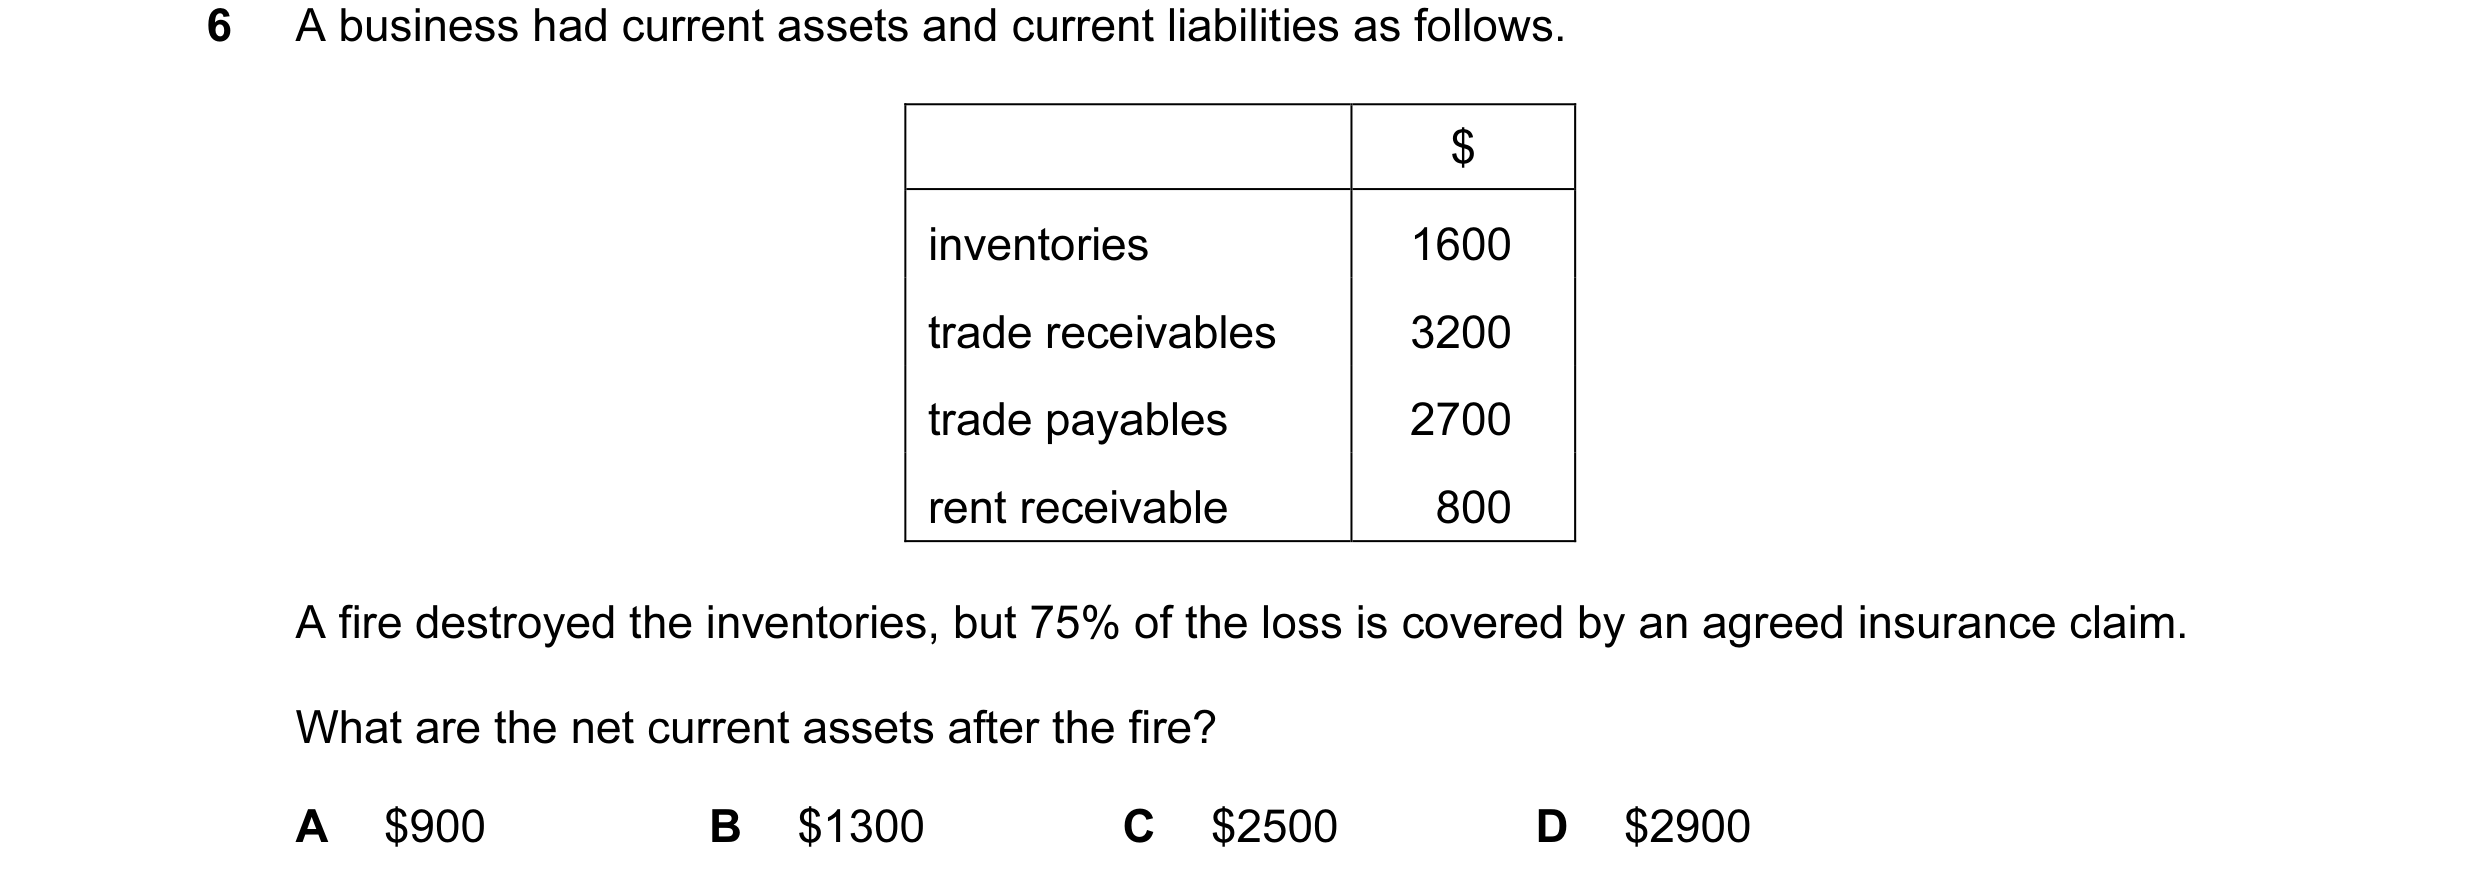
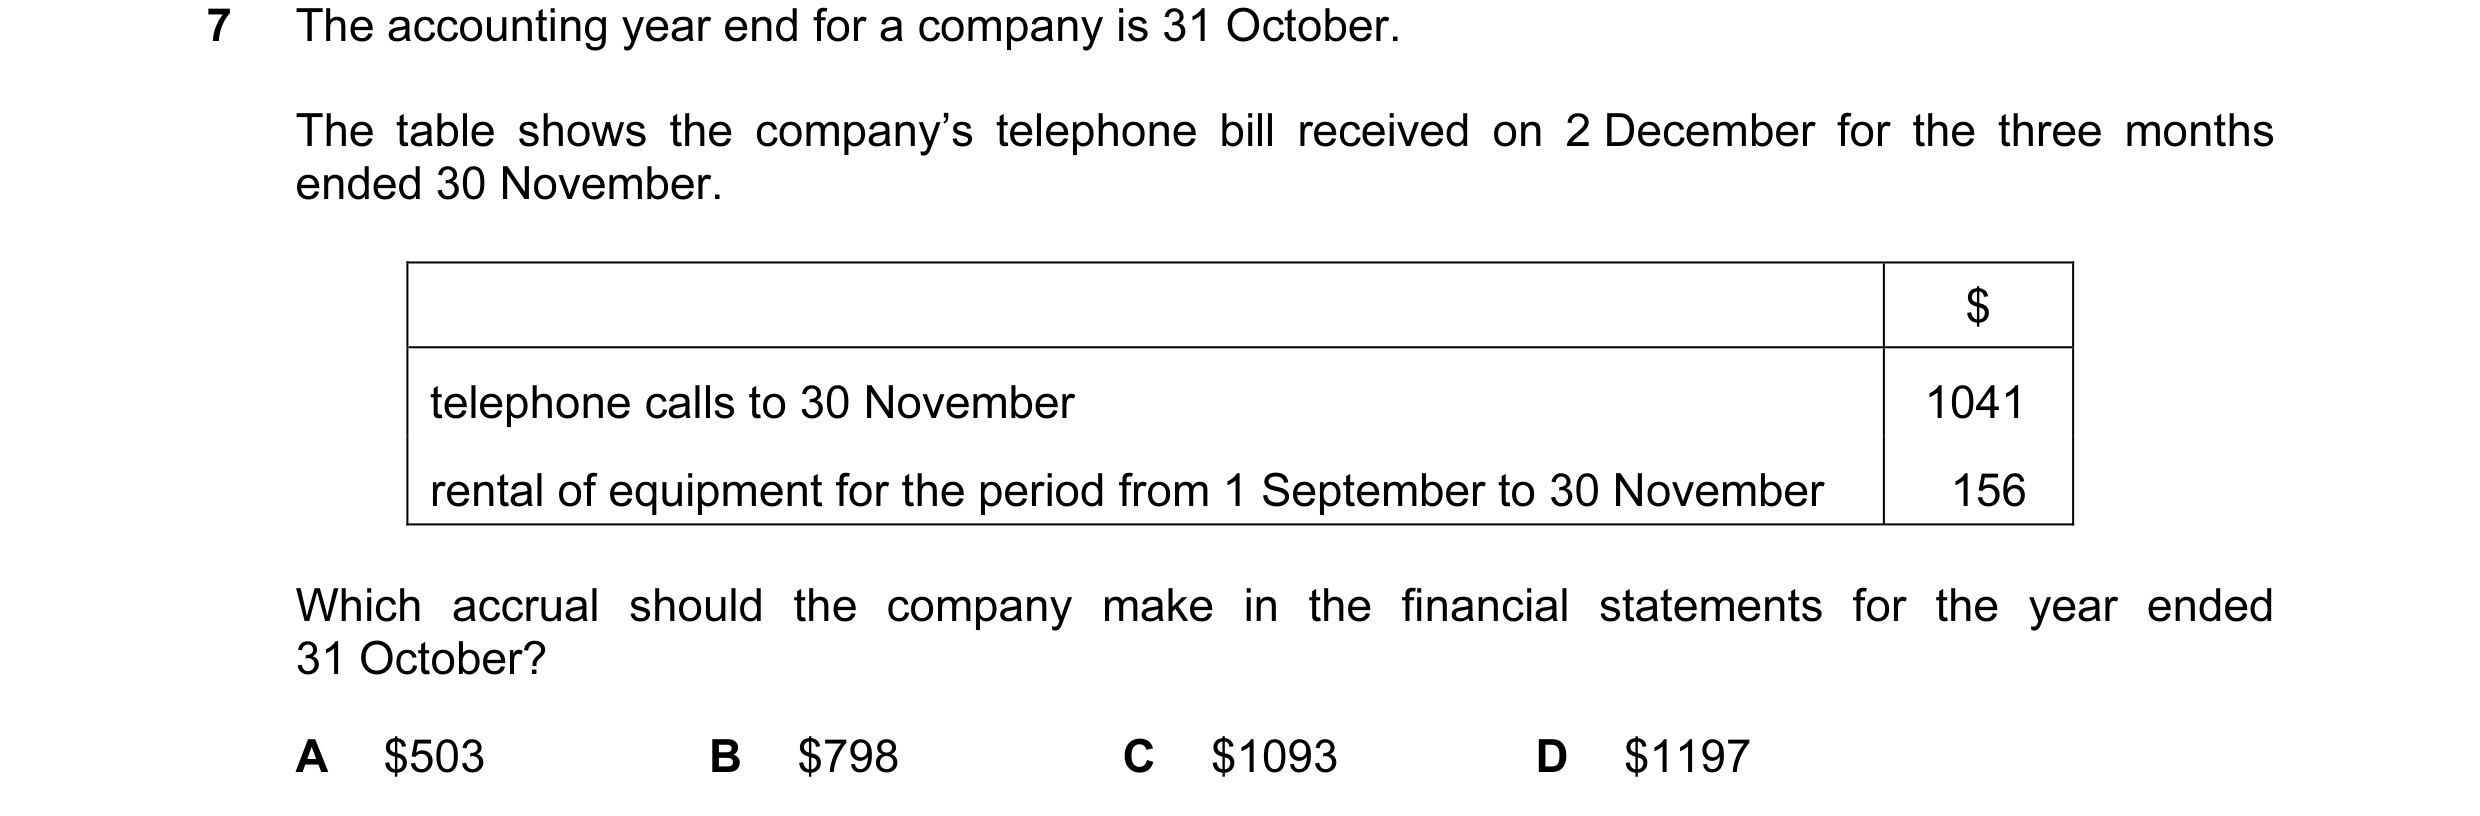
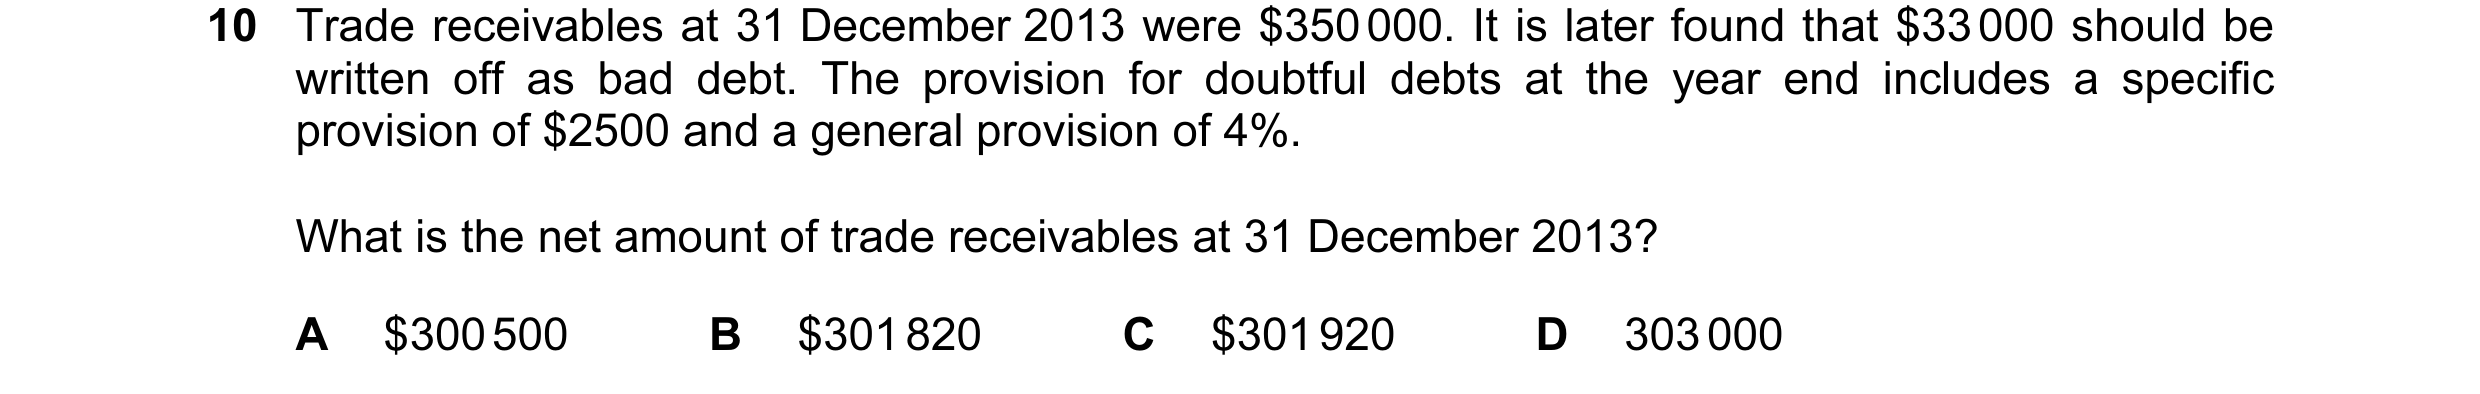
 87 / 233
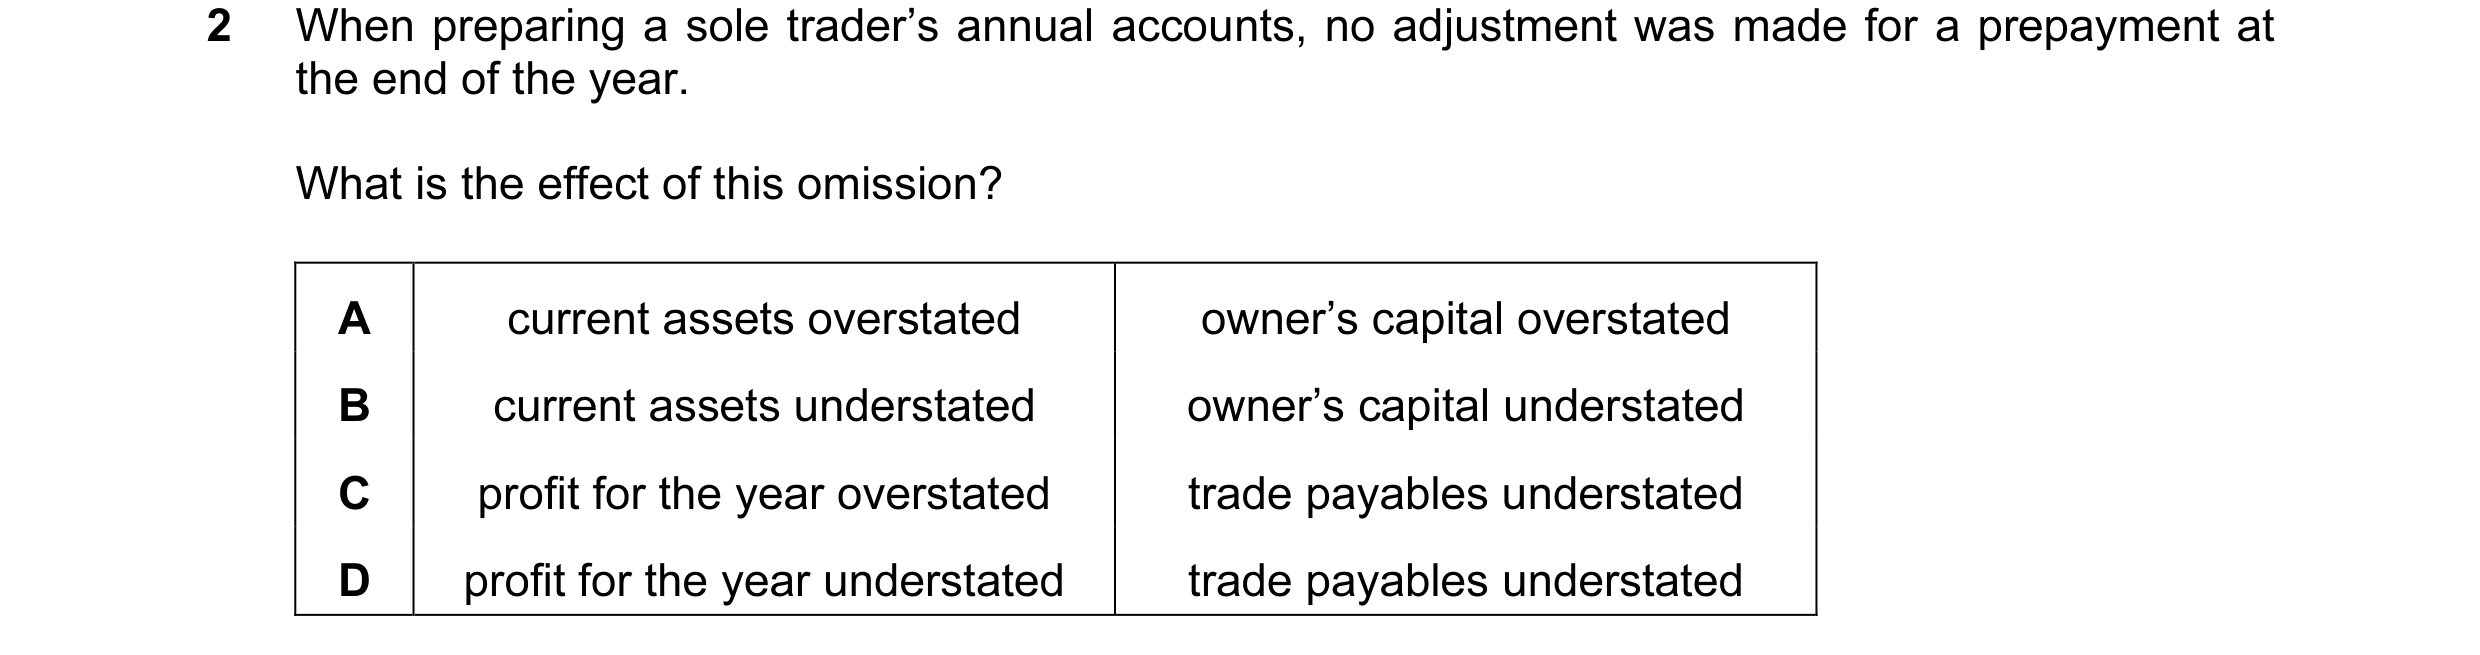 88 / 233
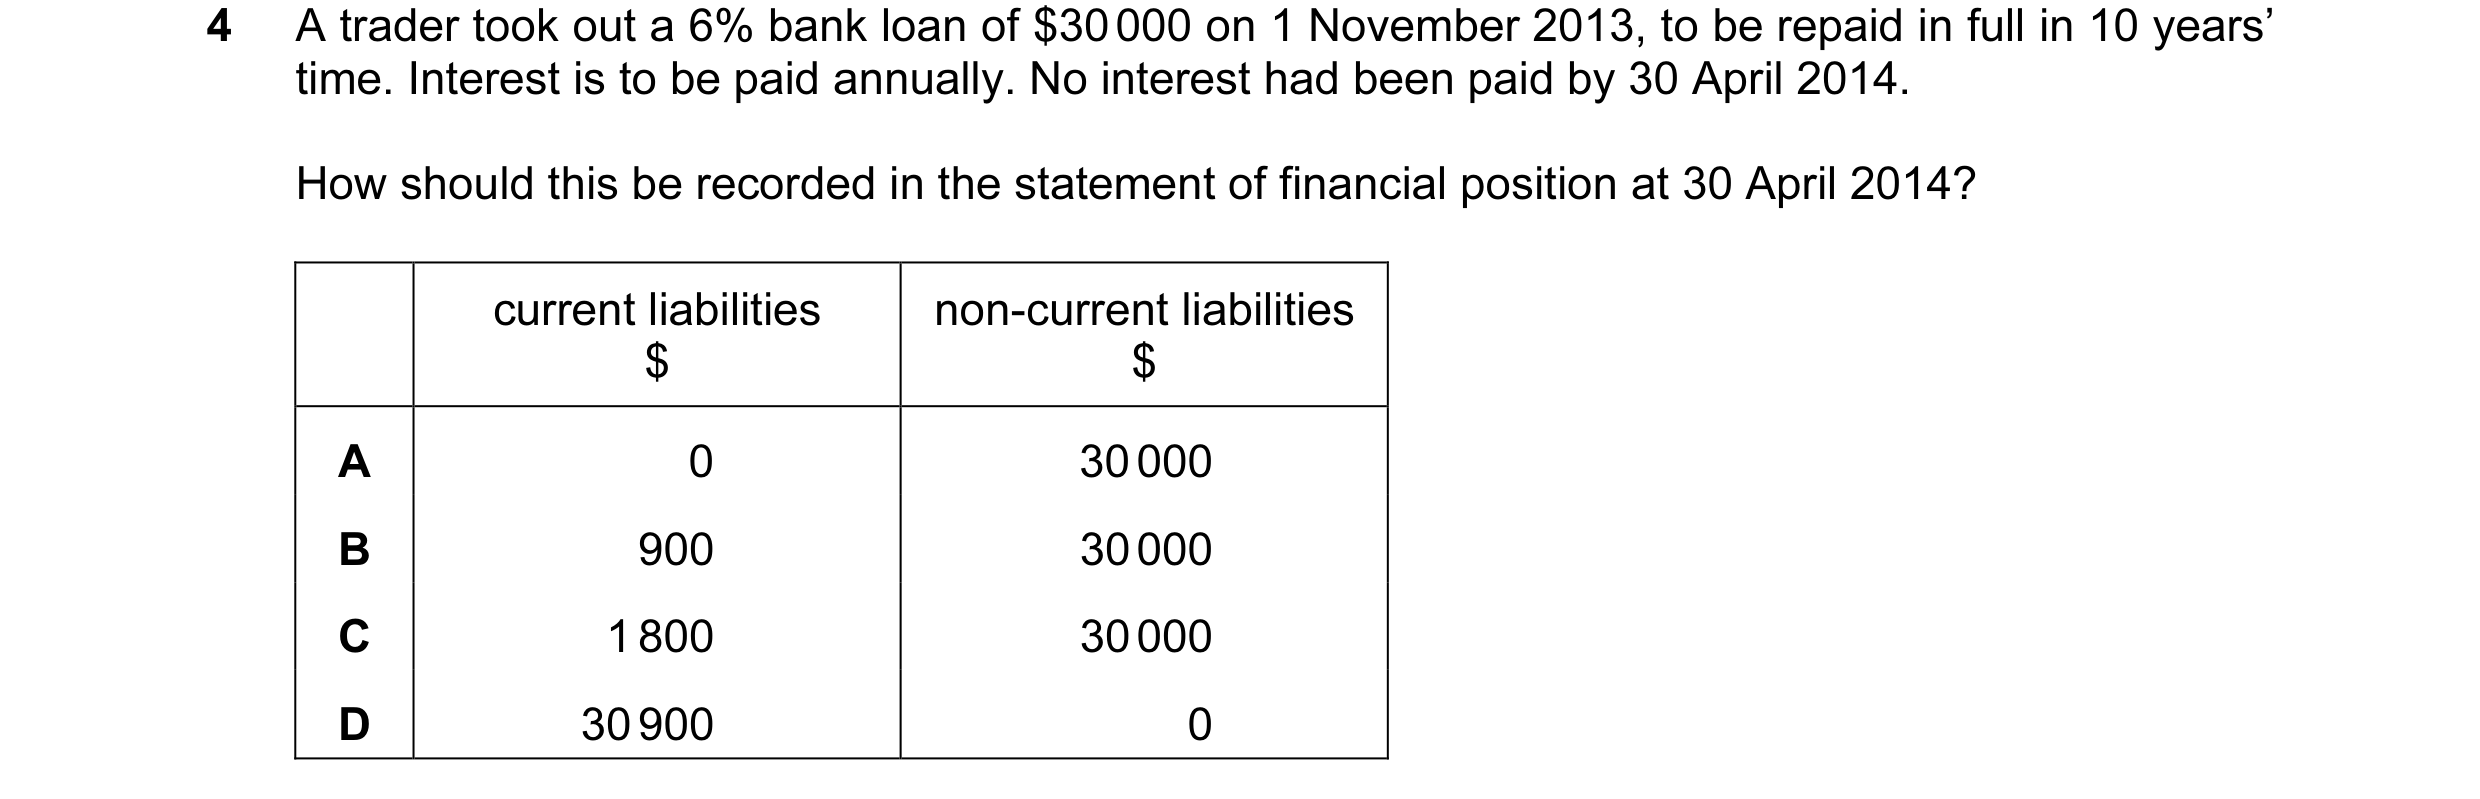
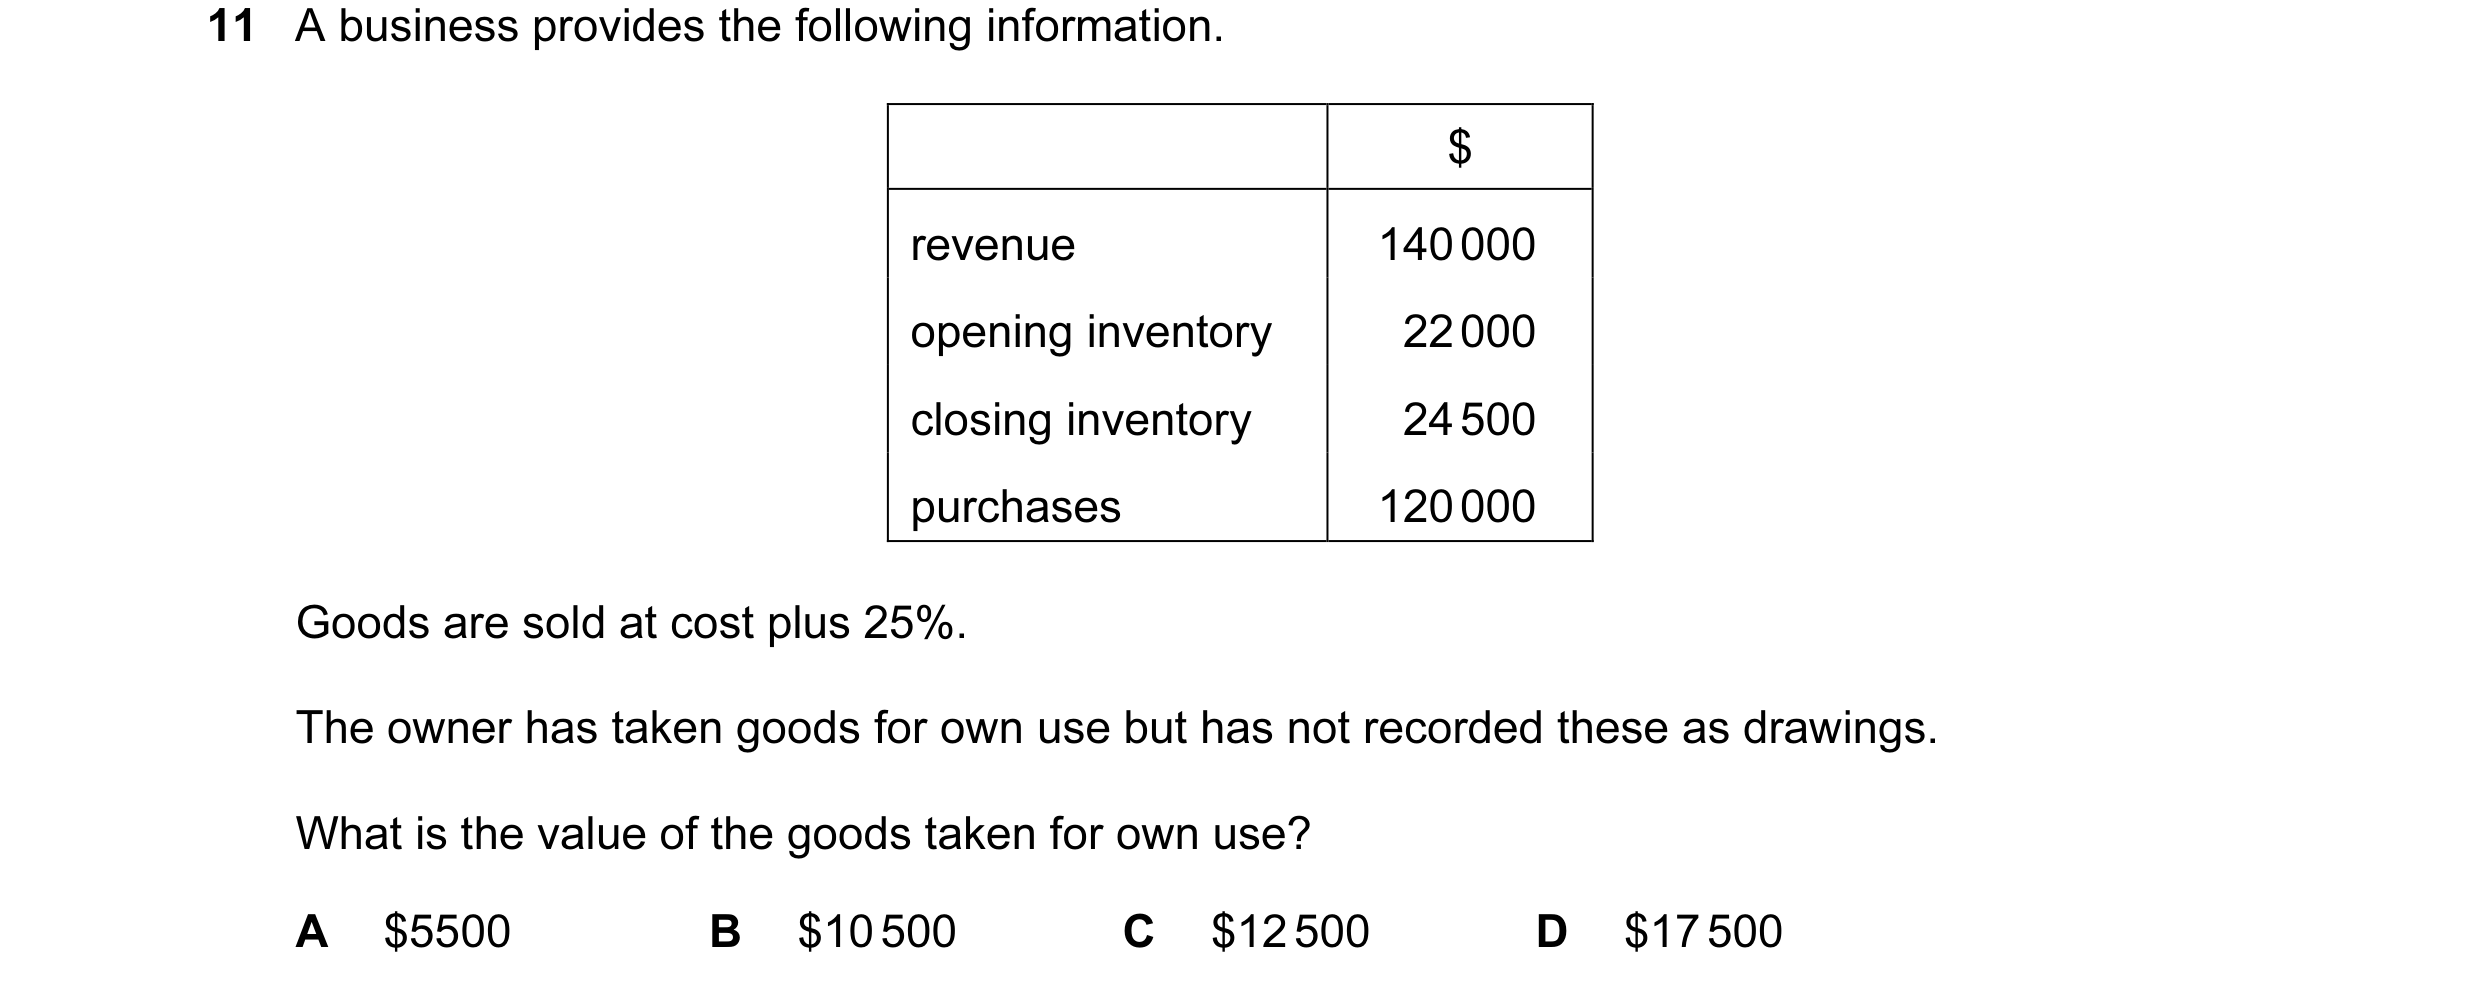
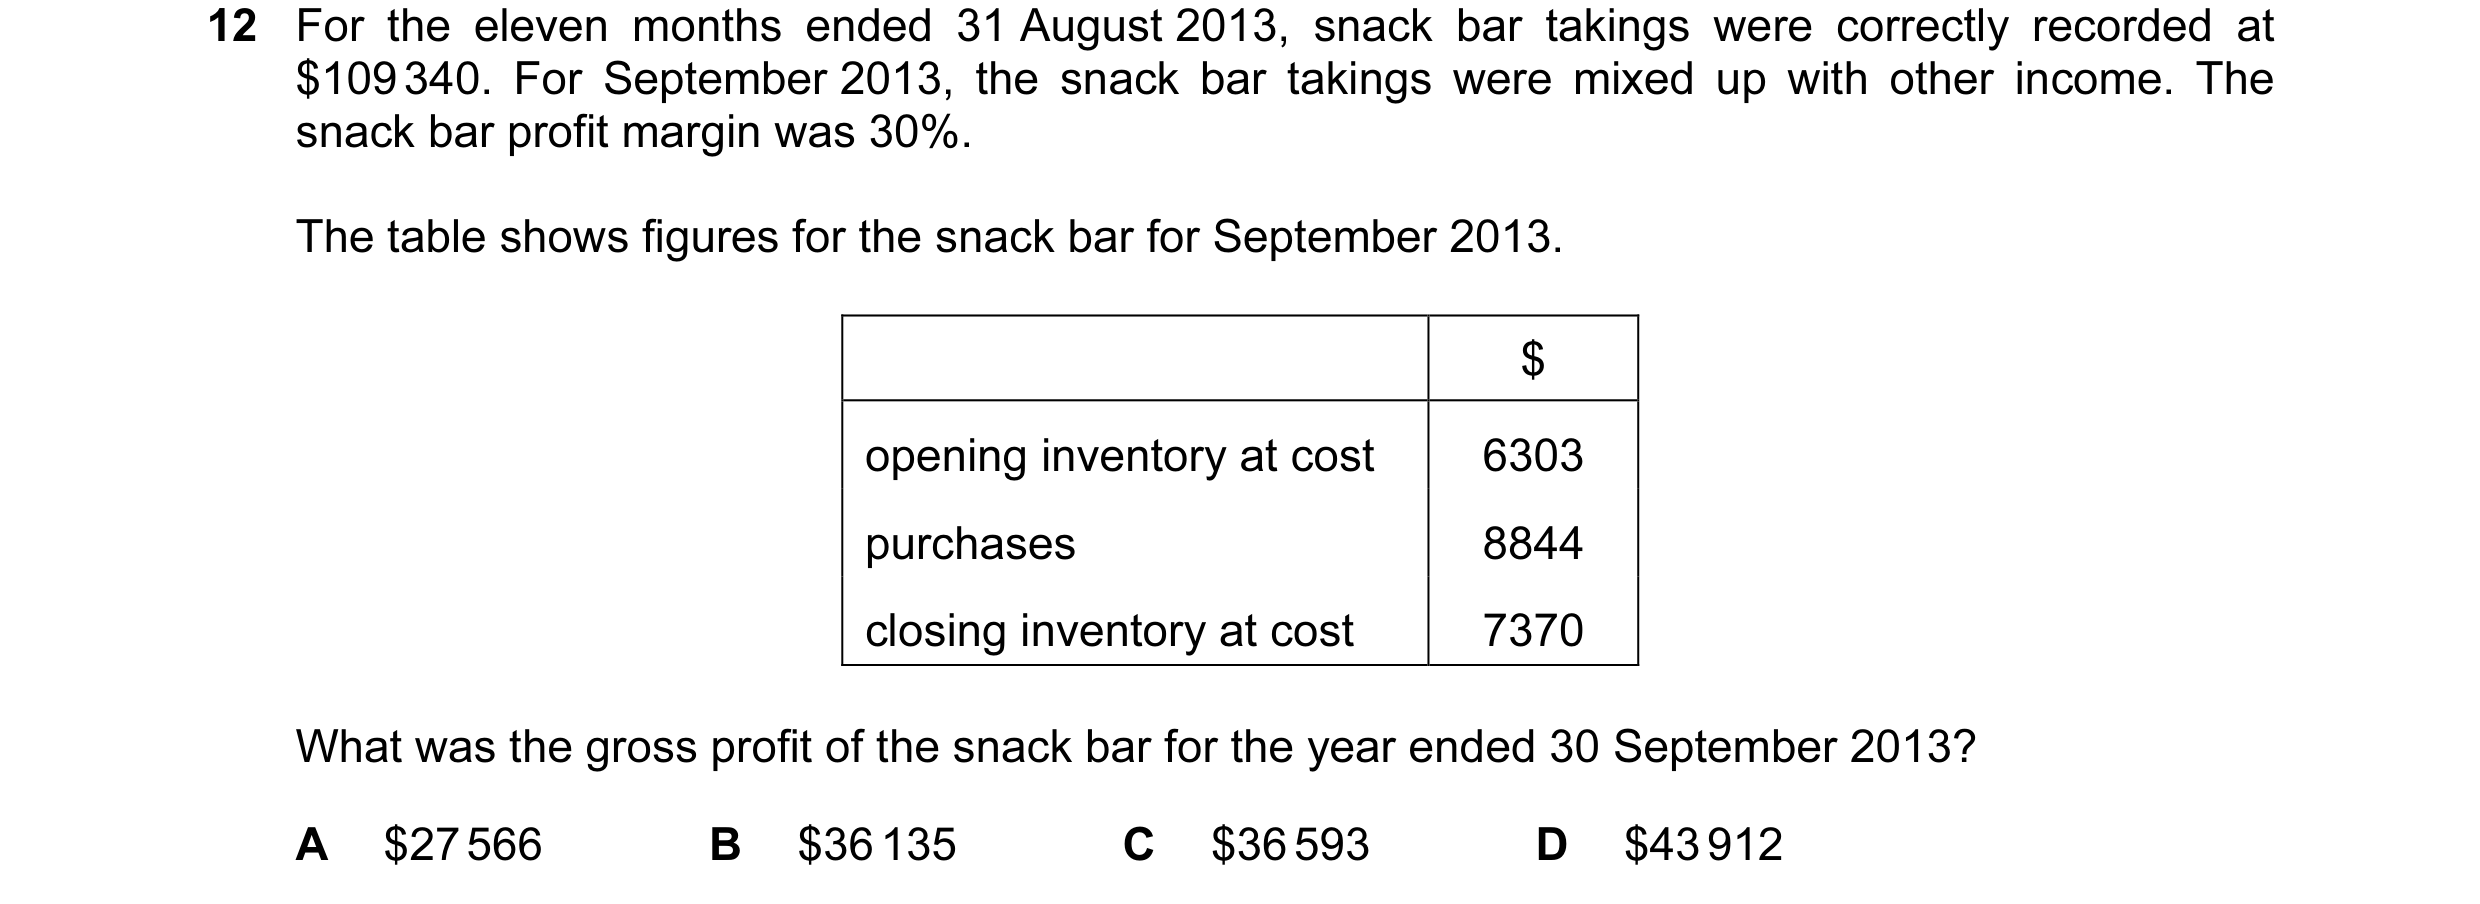
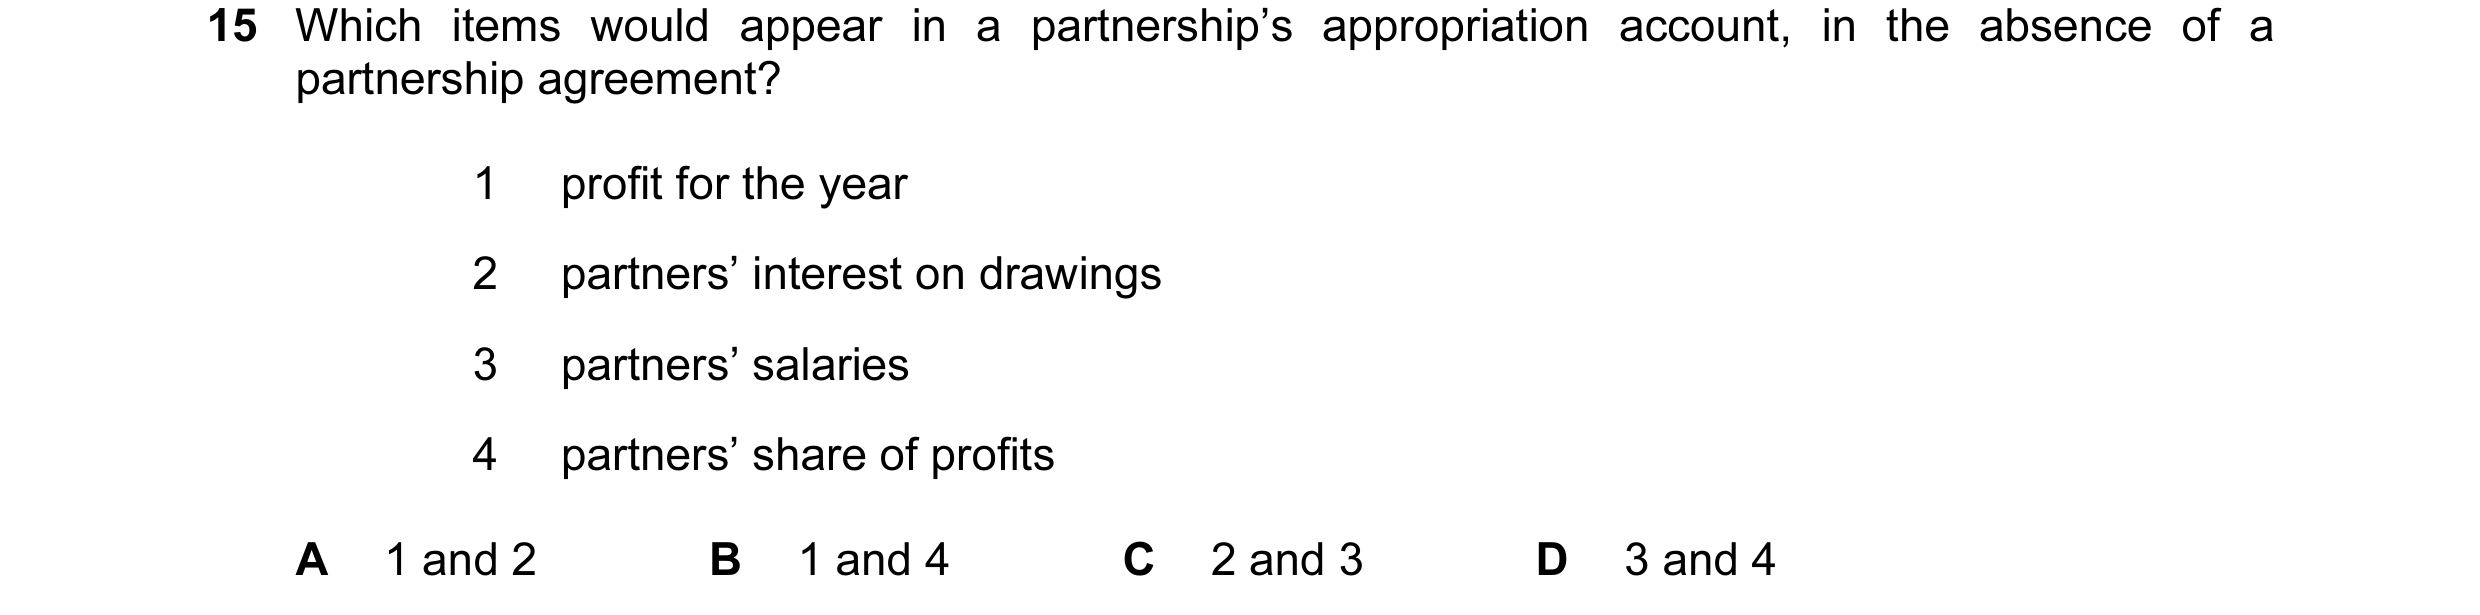 89 / 233
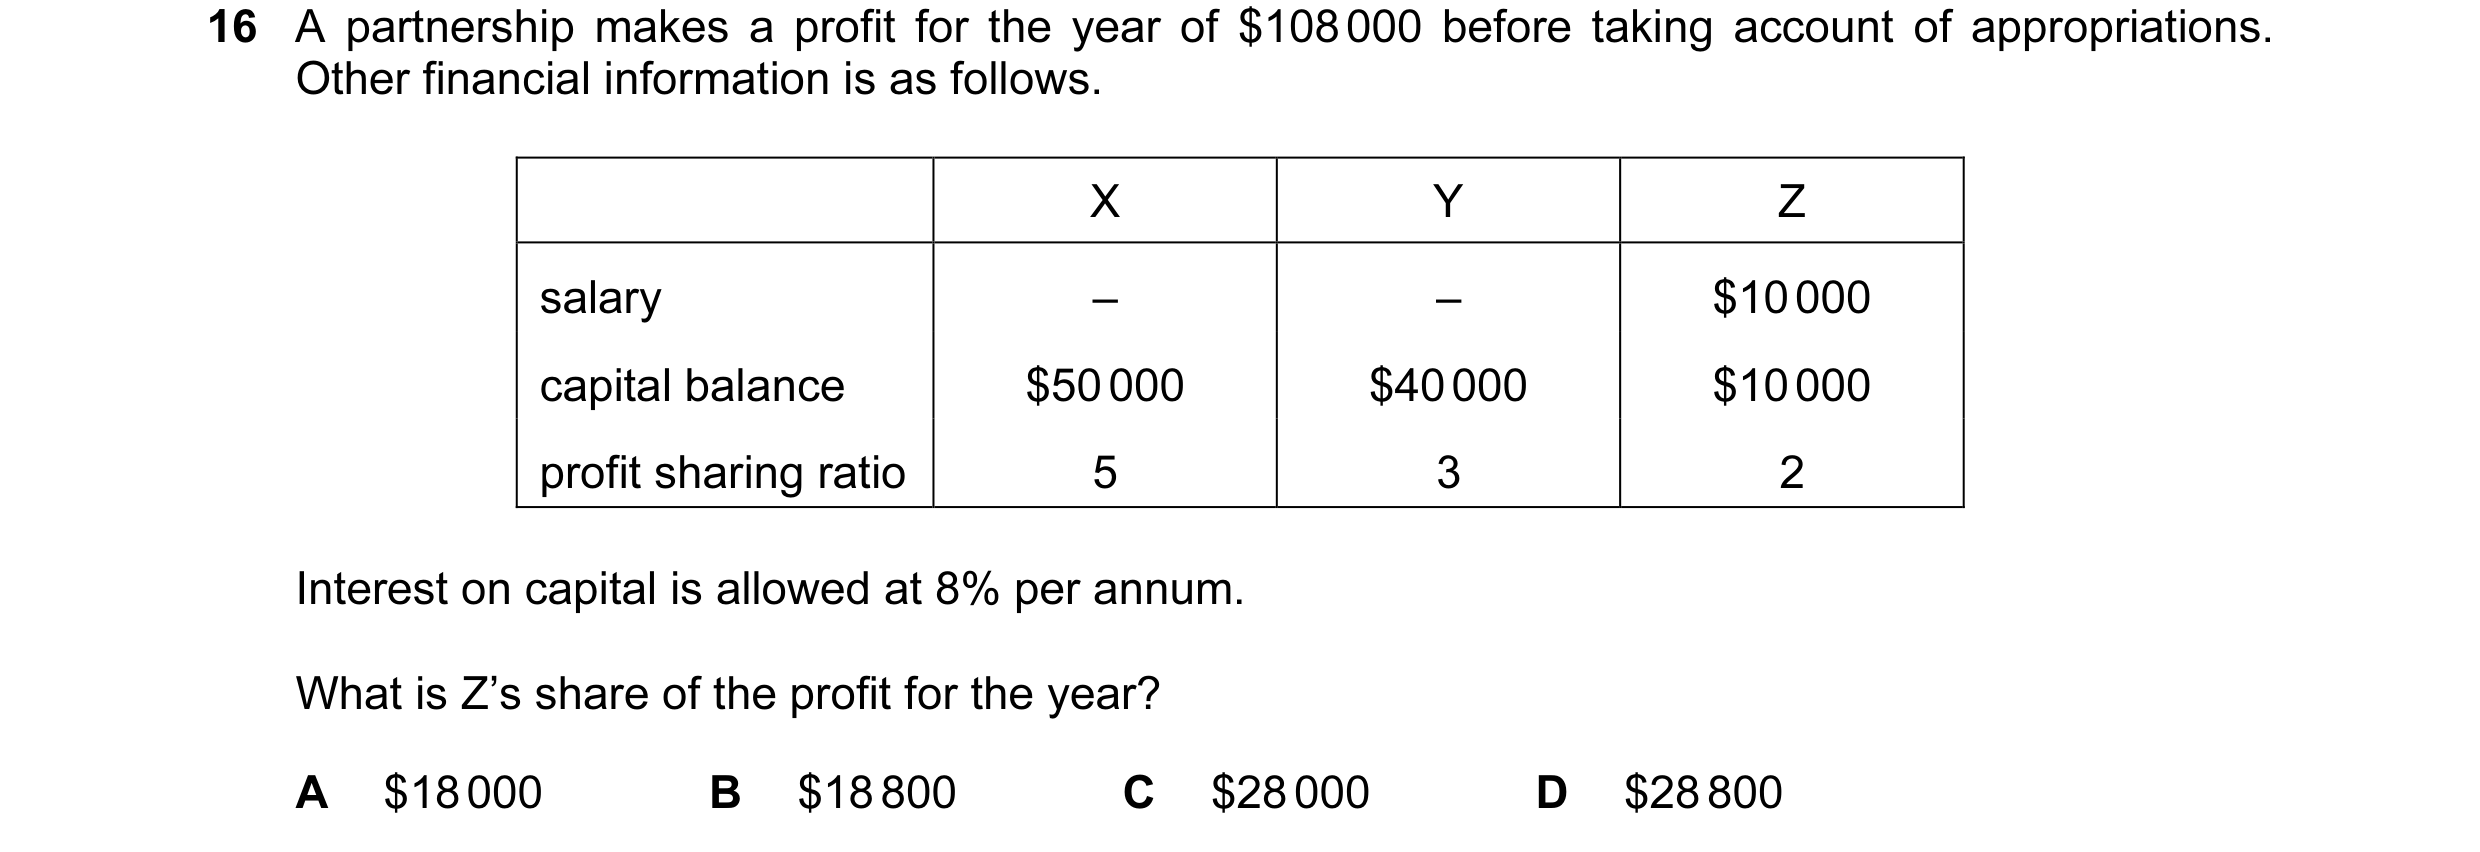
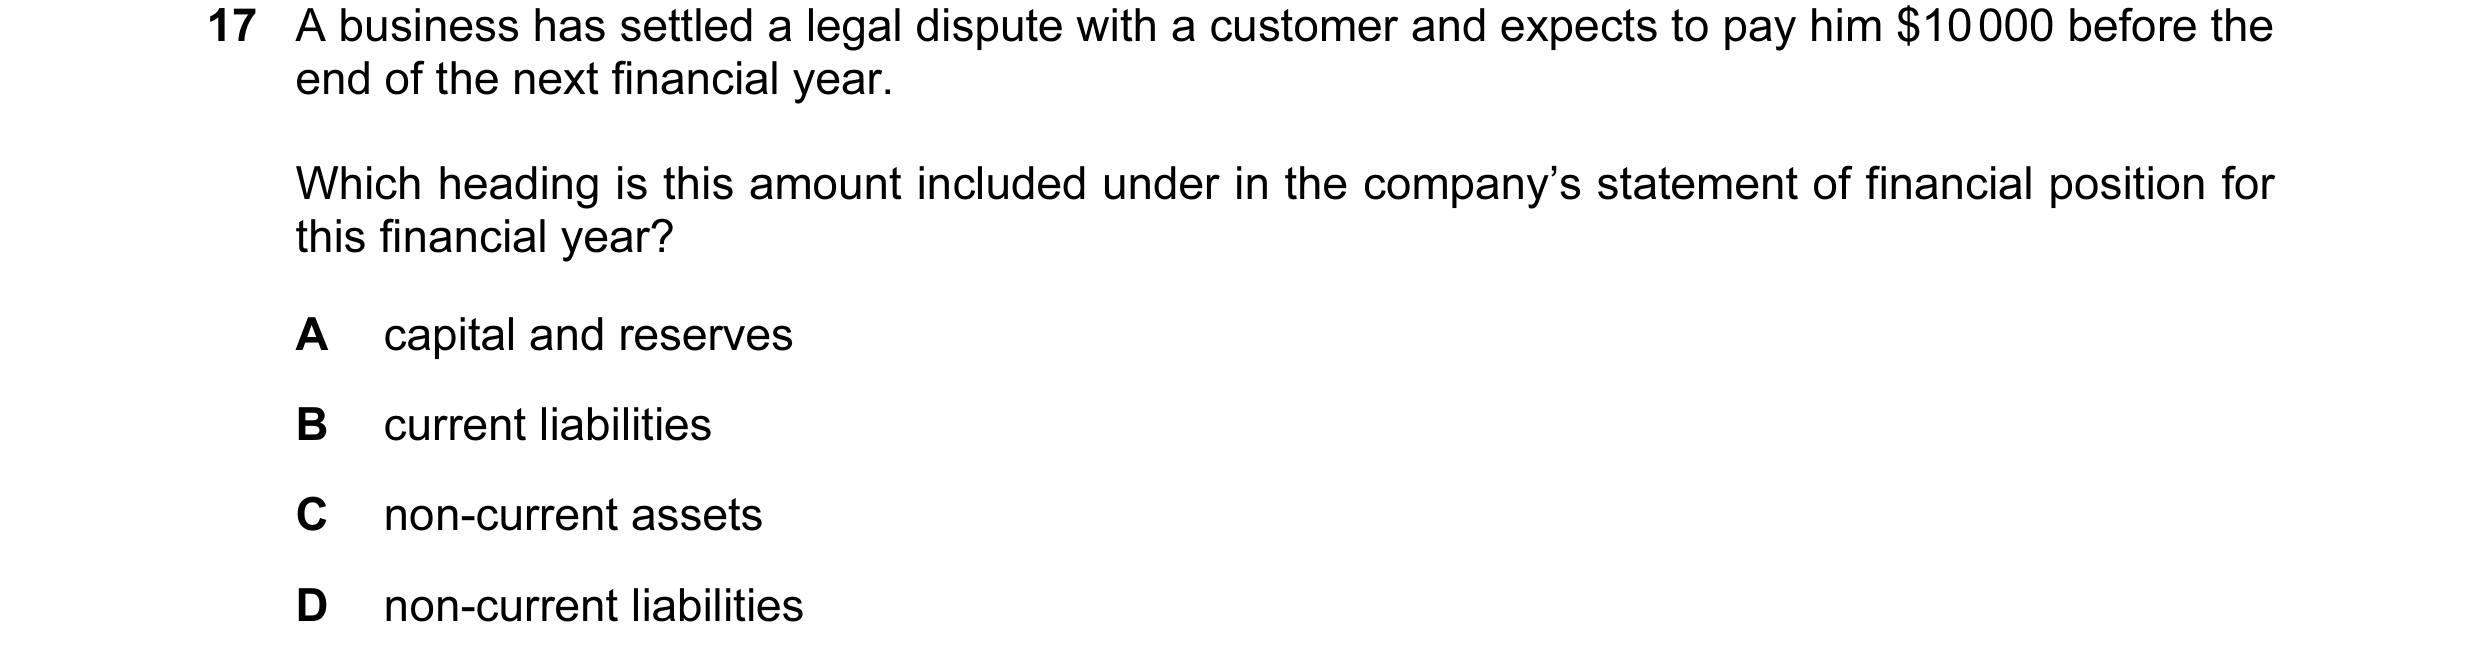
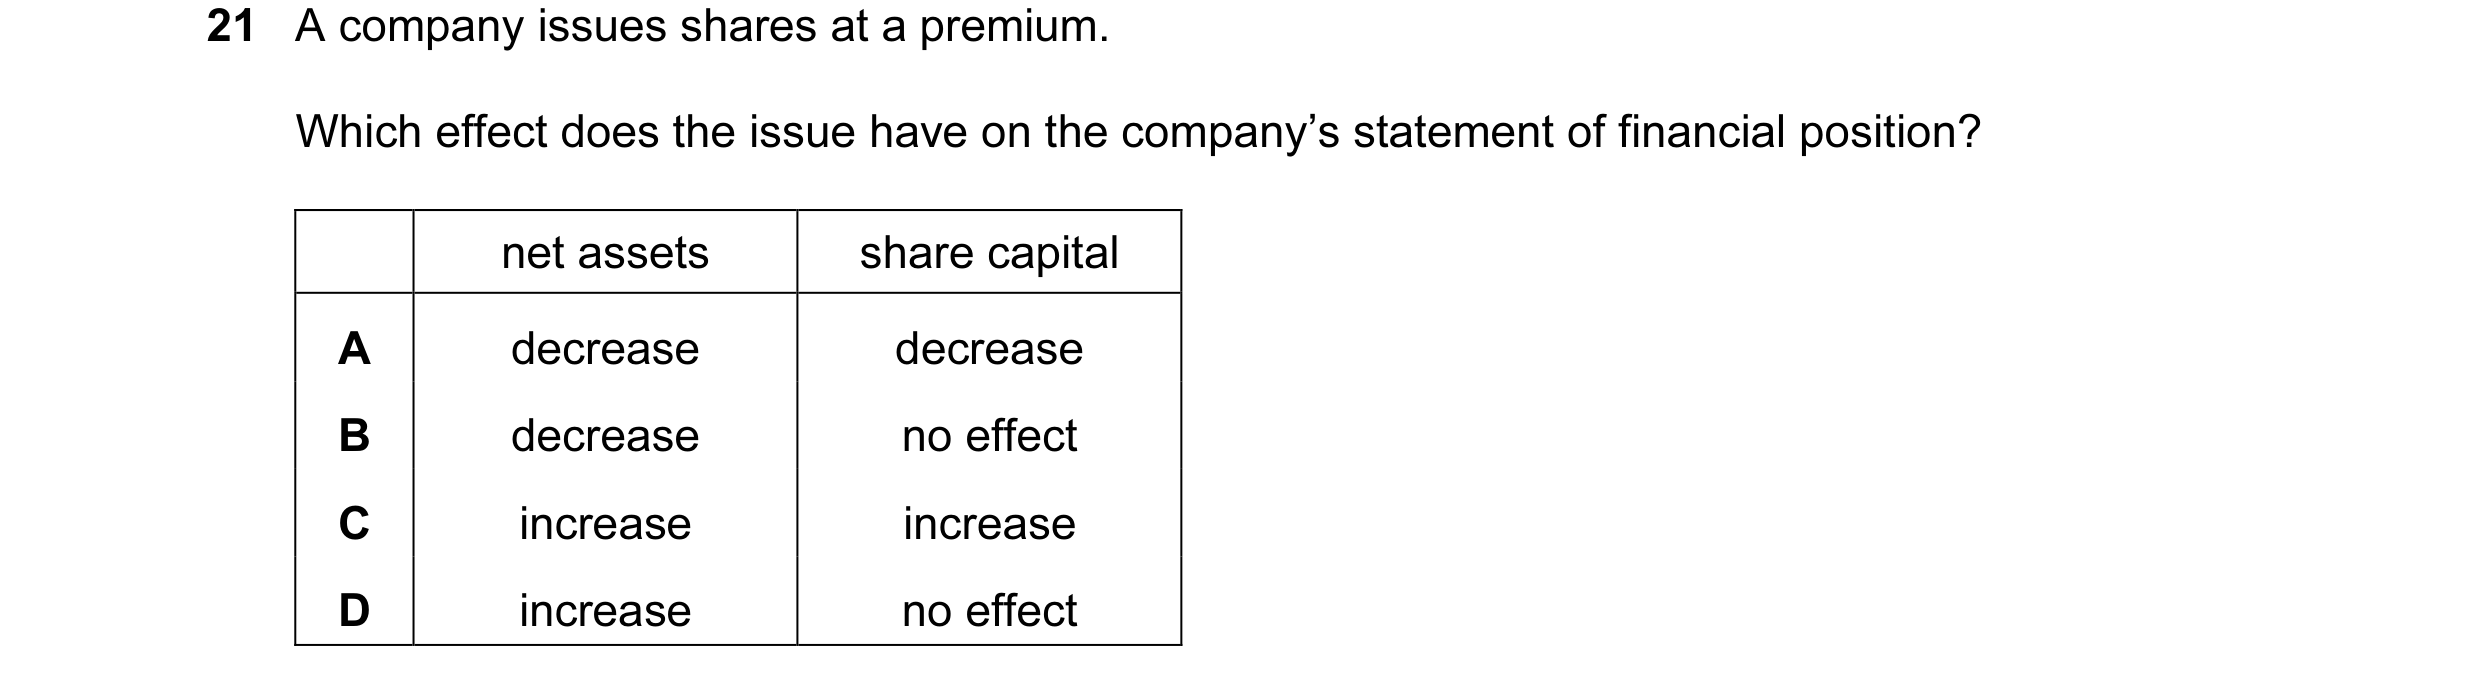
 90 / 233
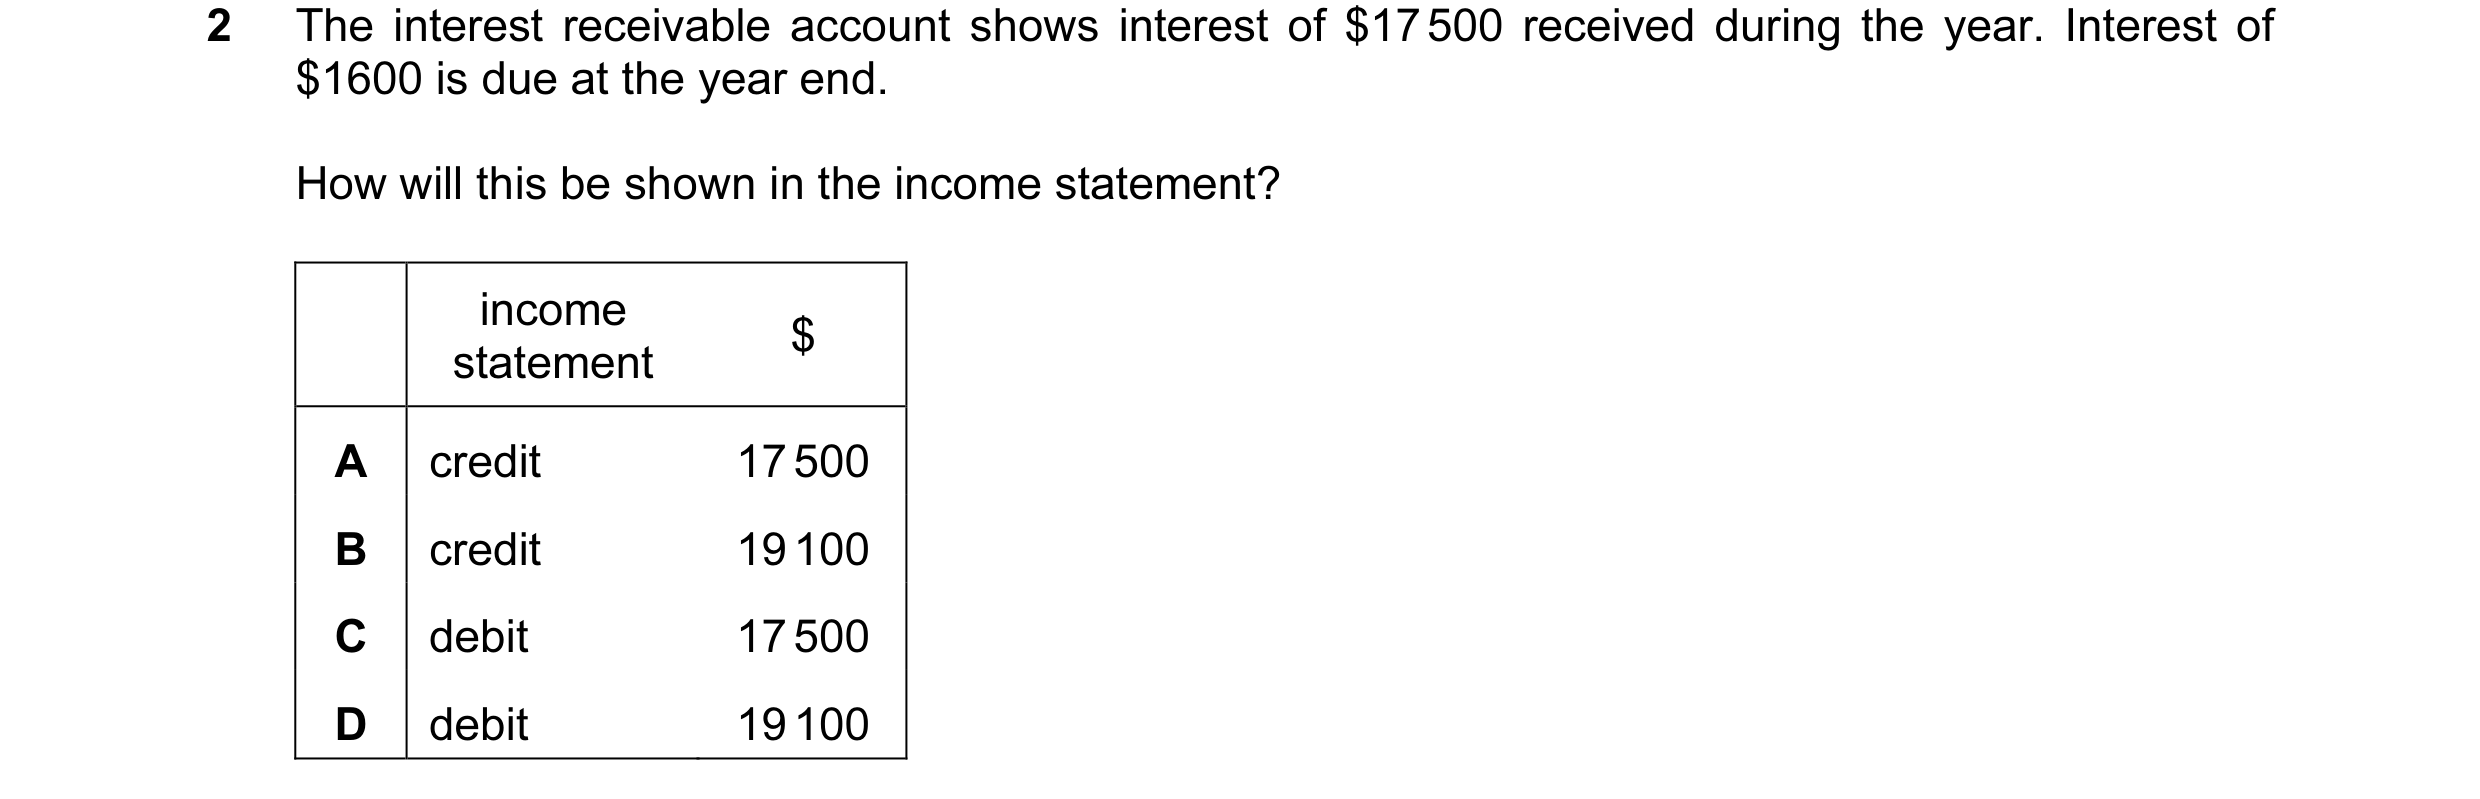
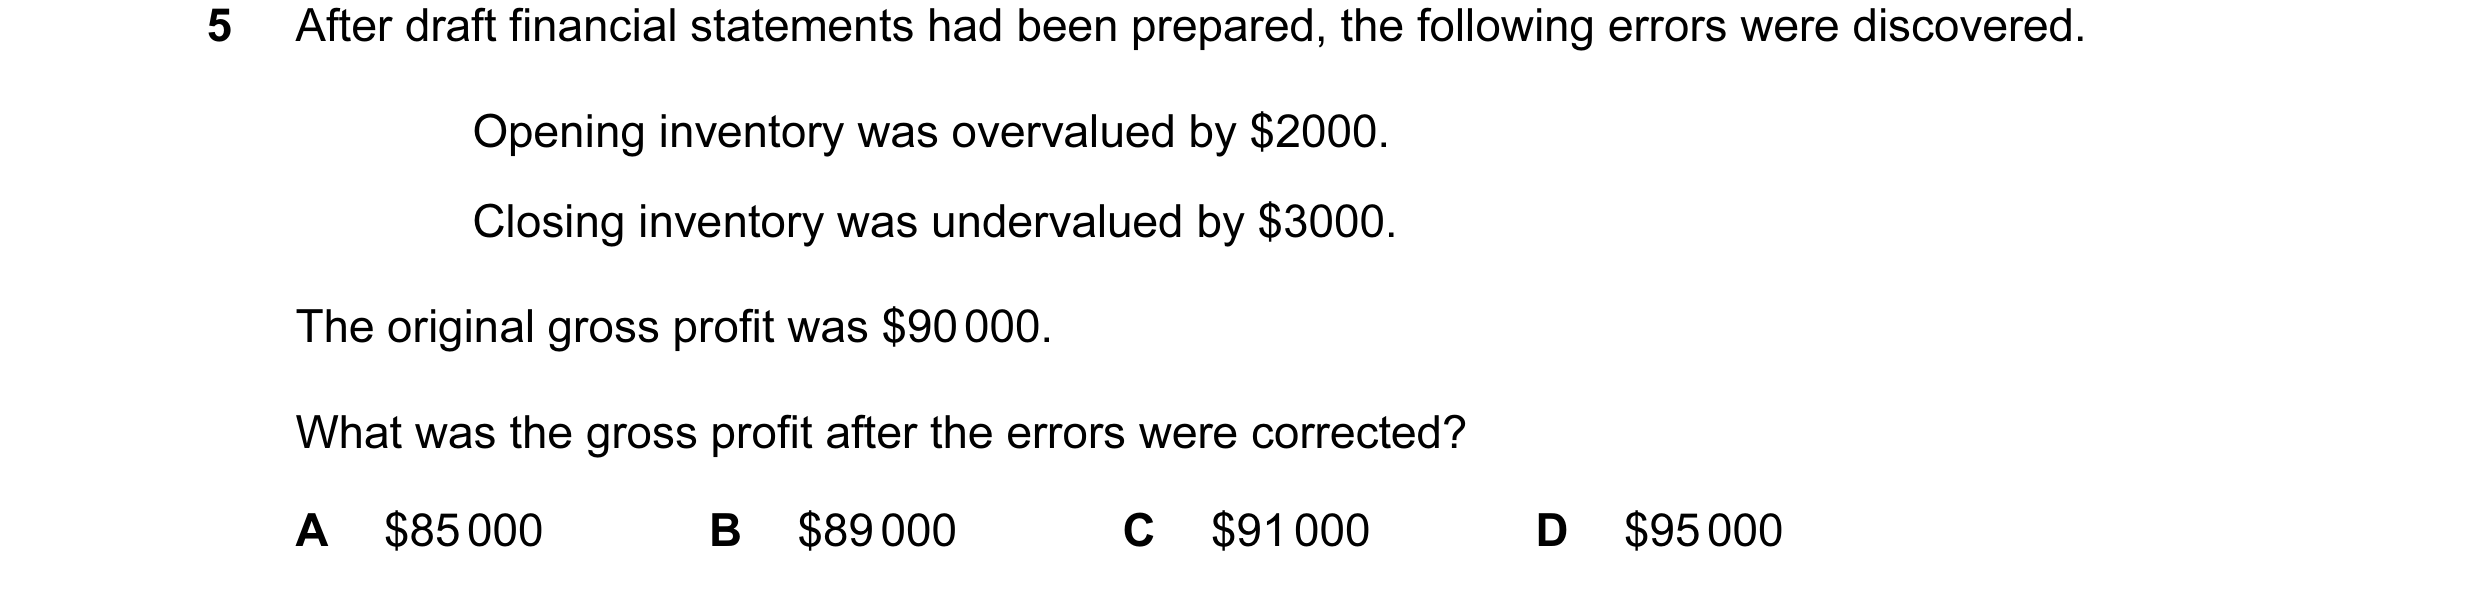 91 / 233
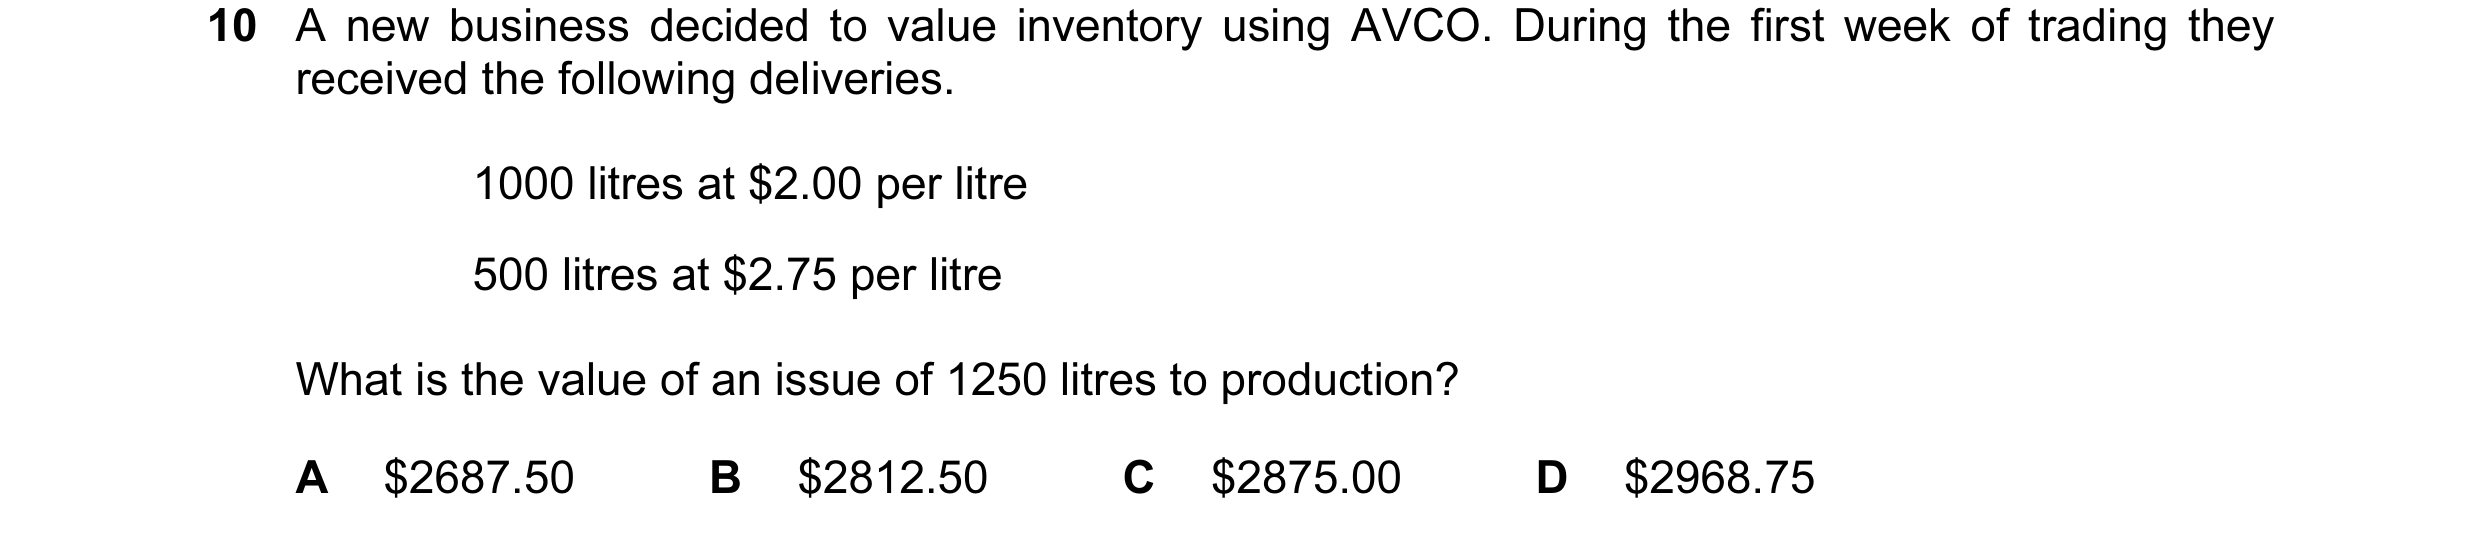
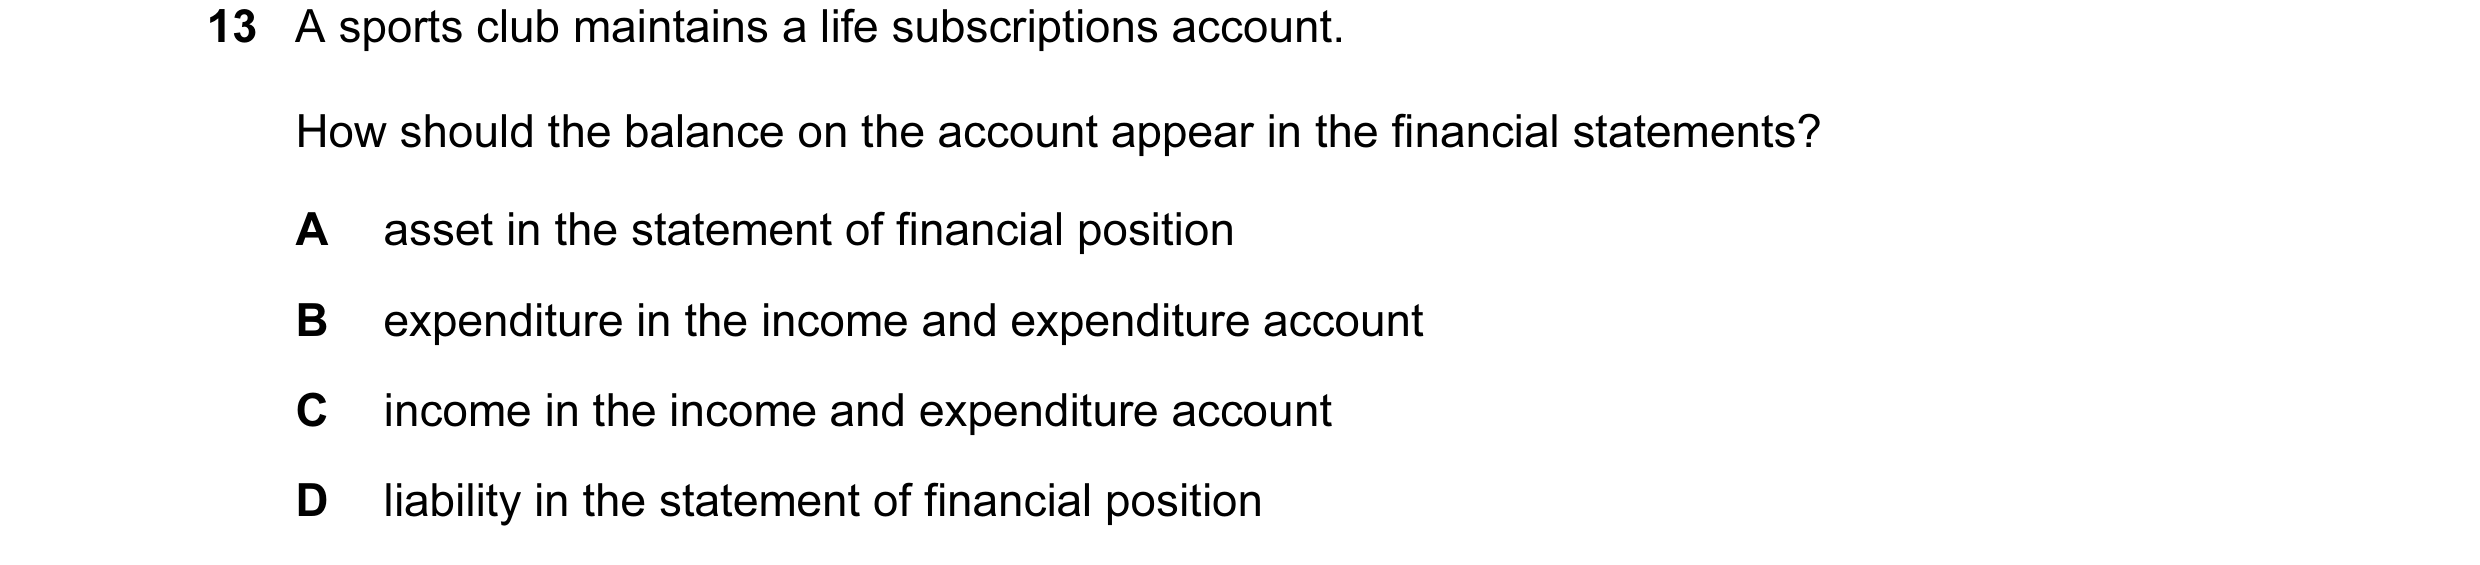
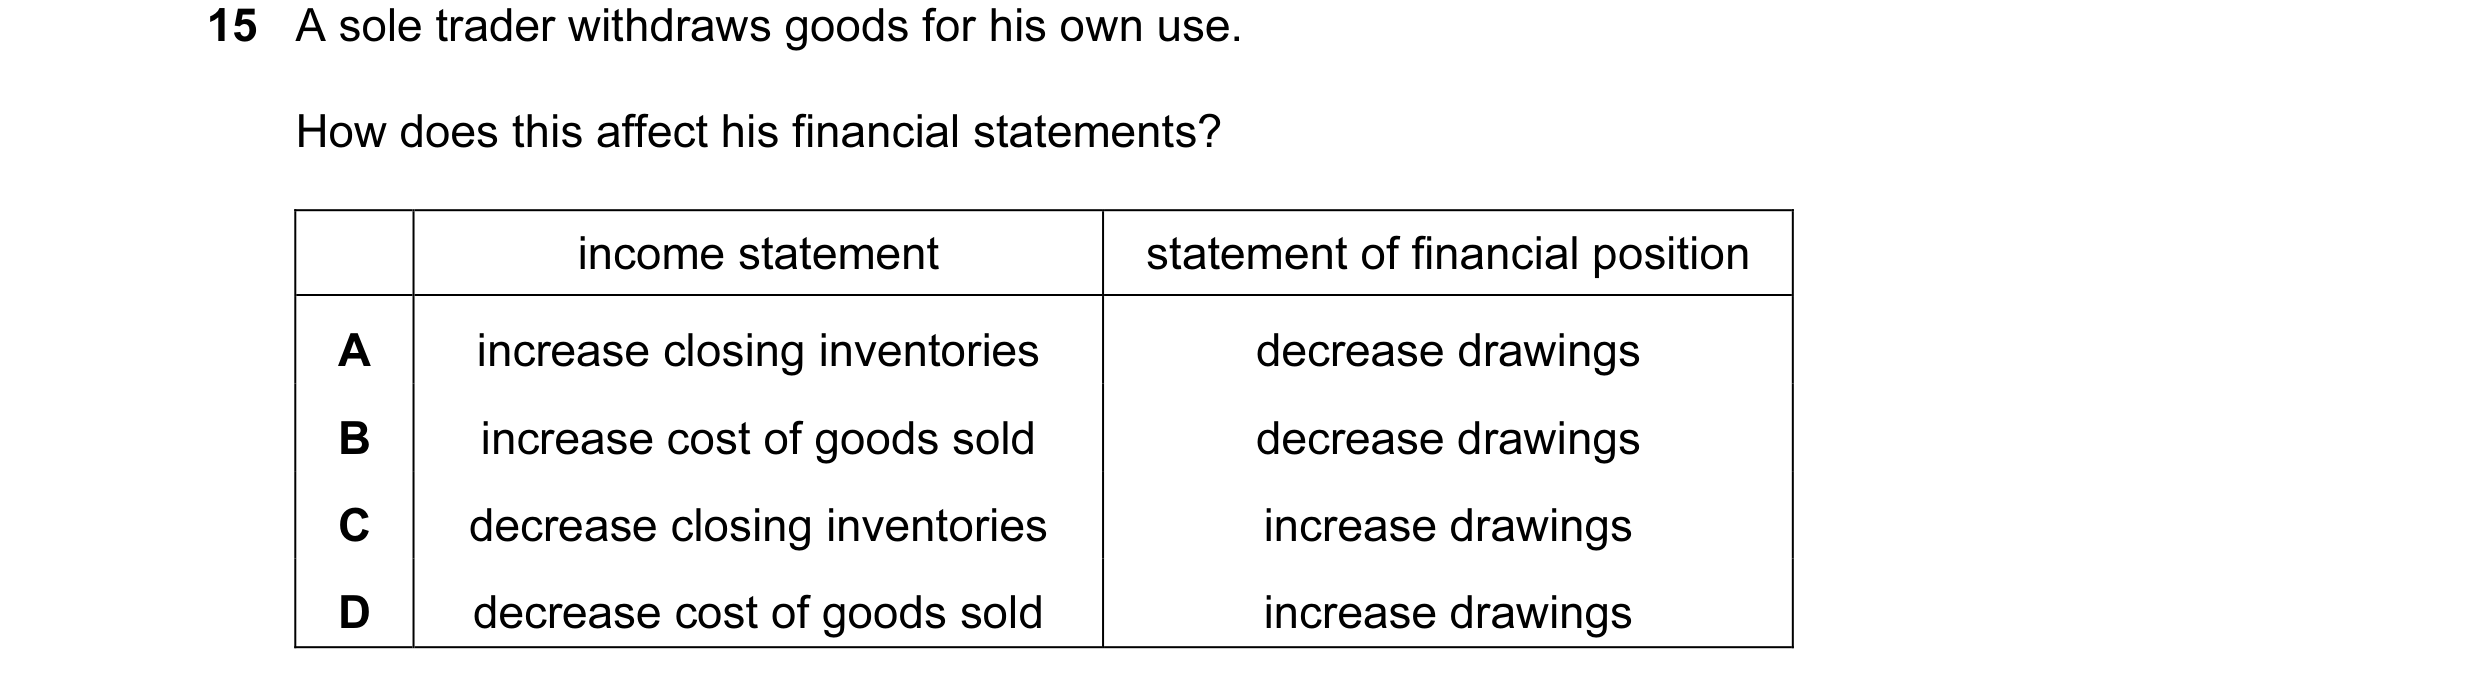
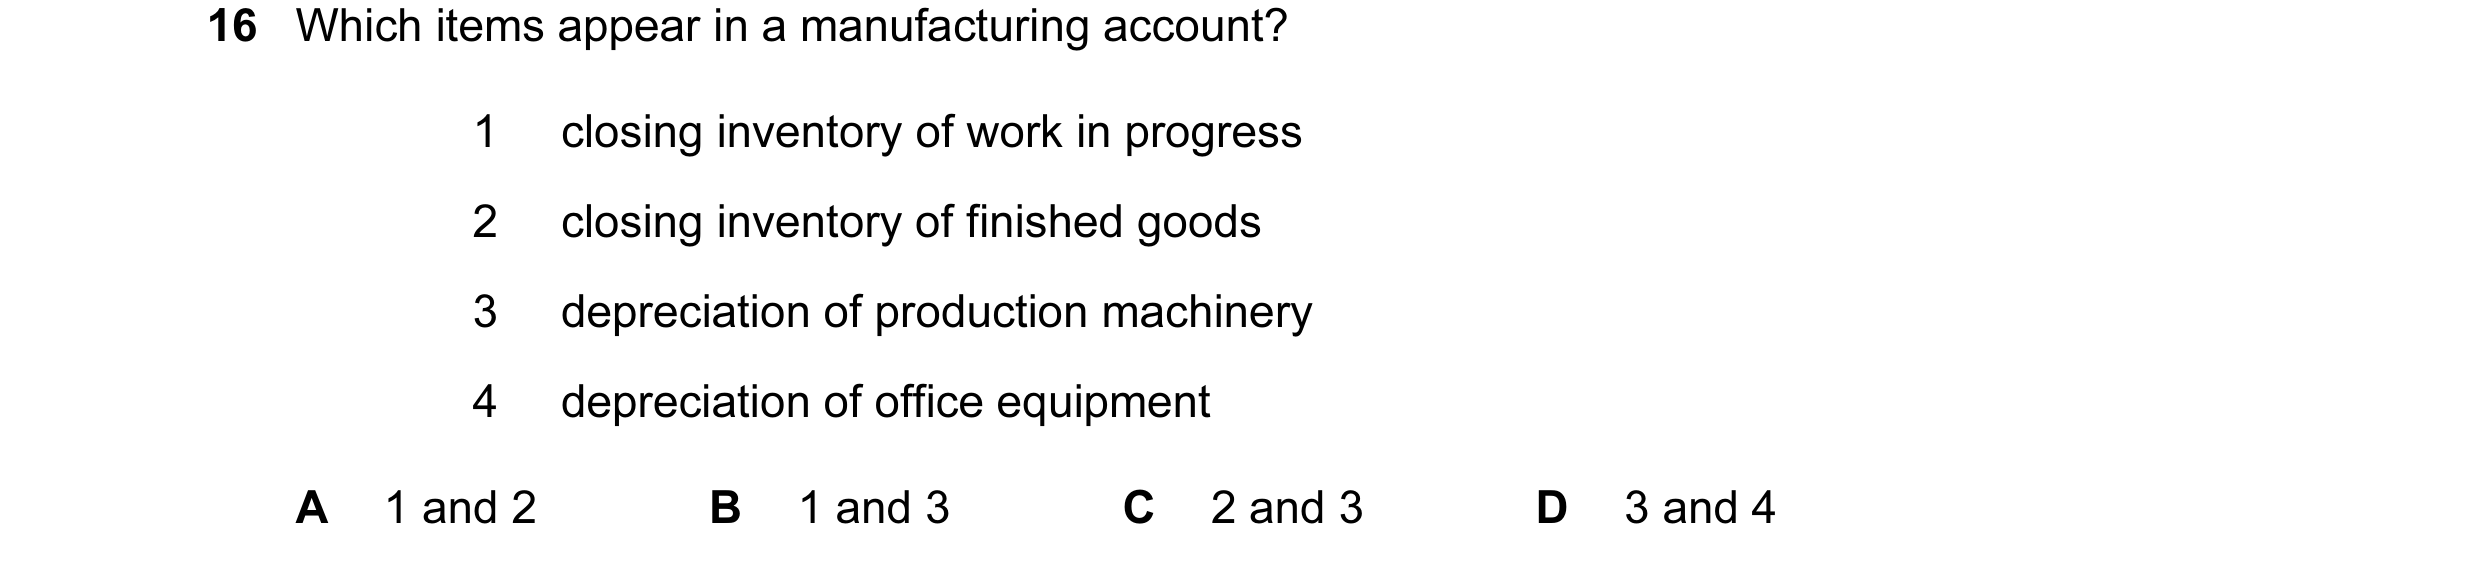
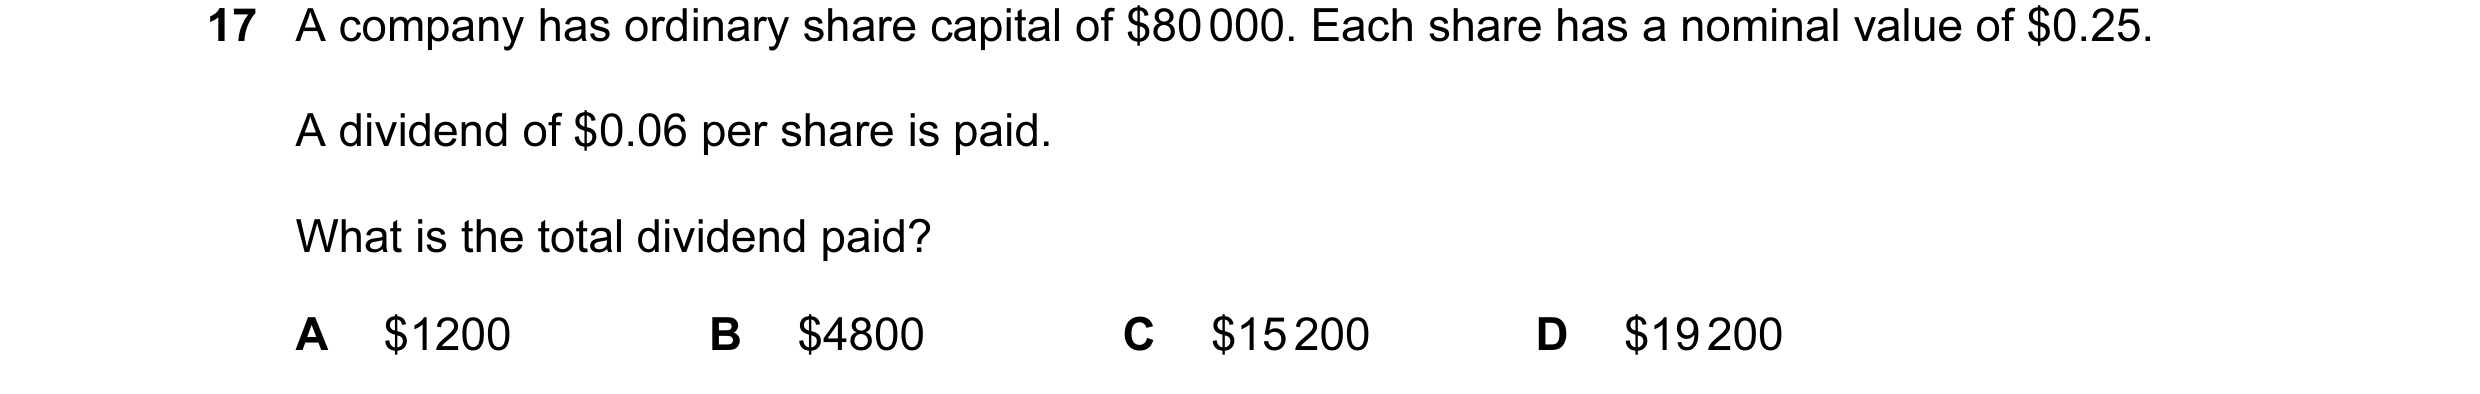 92 / 233
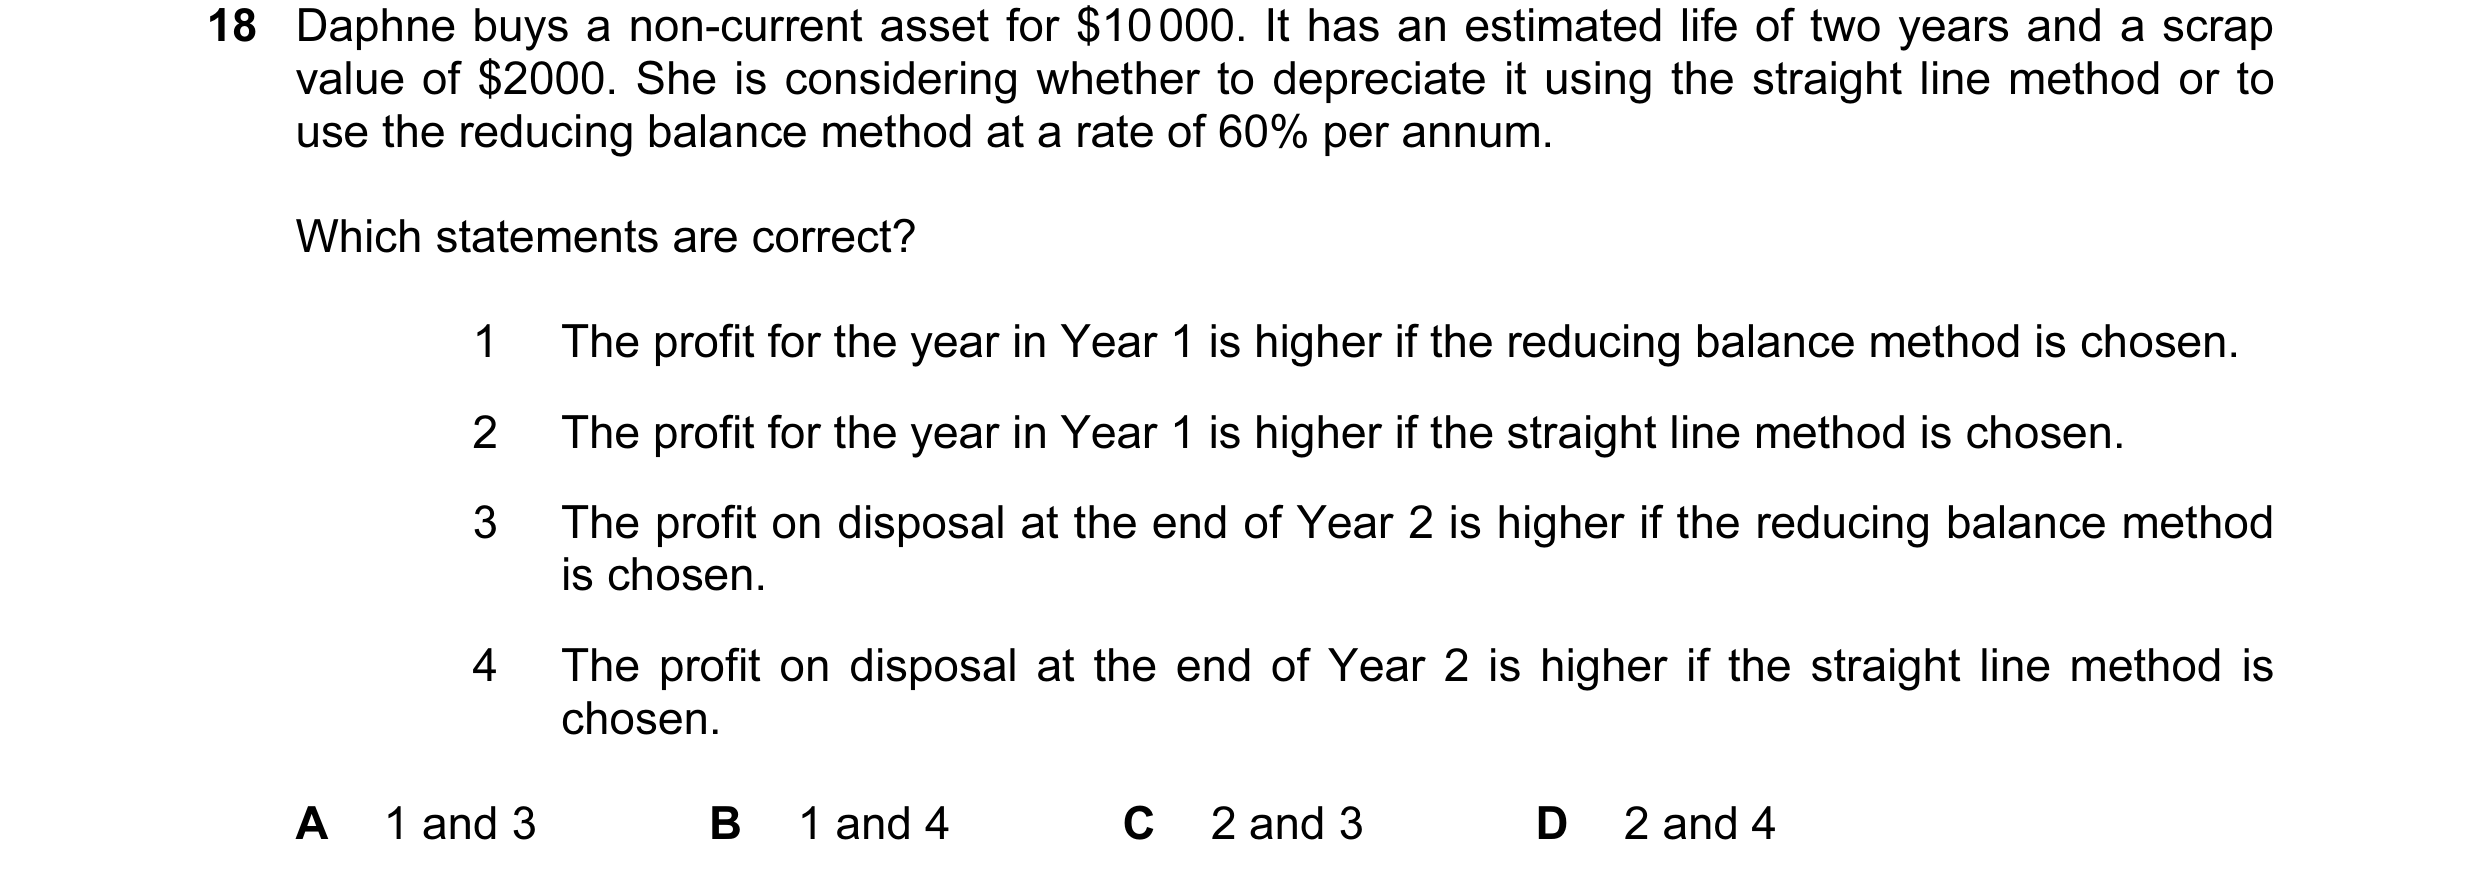
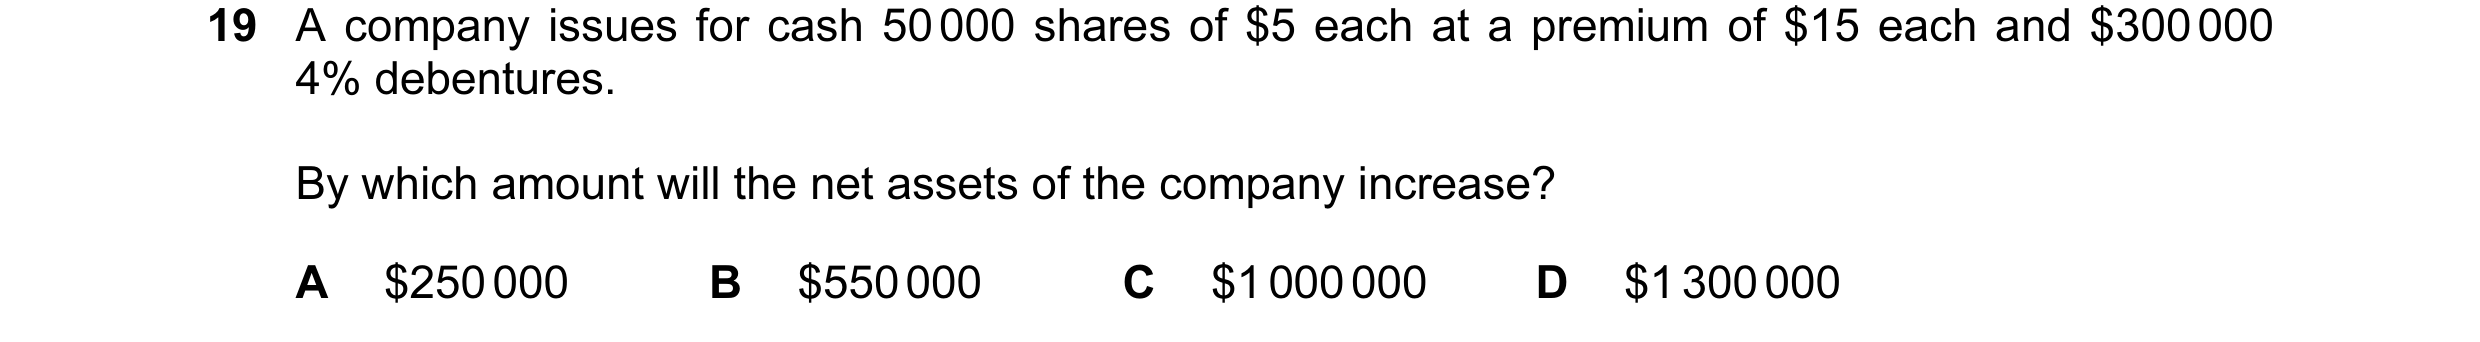
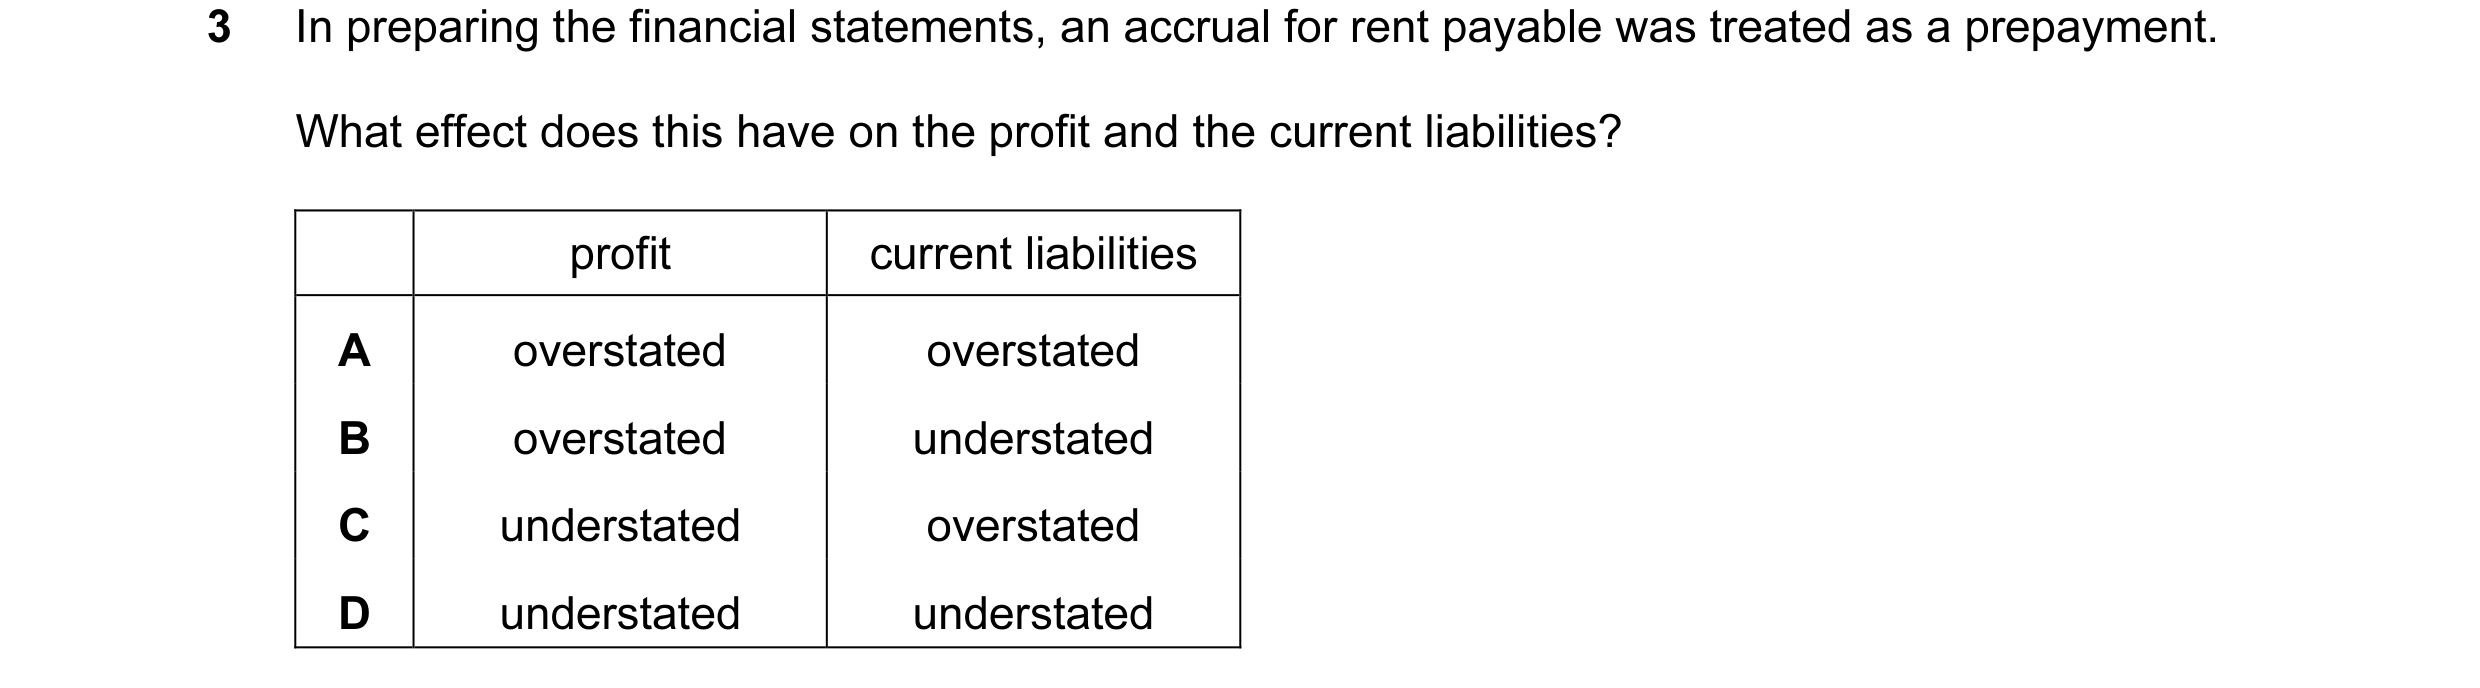
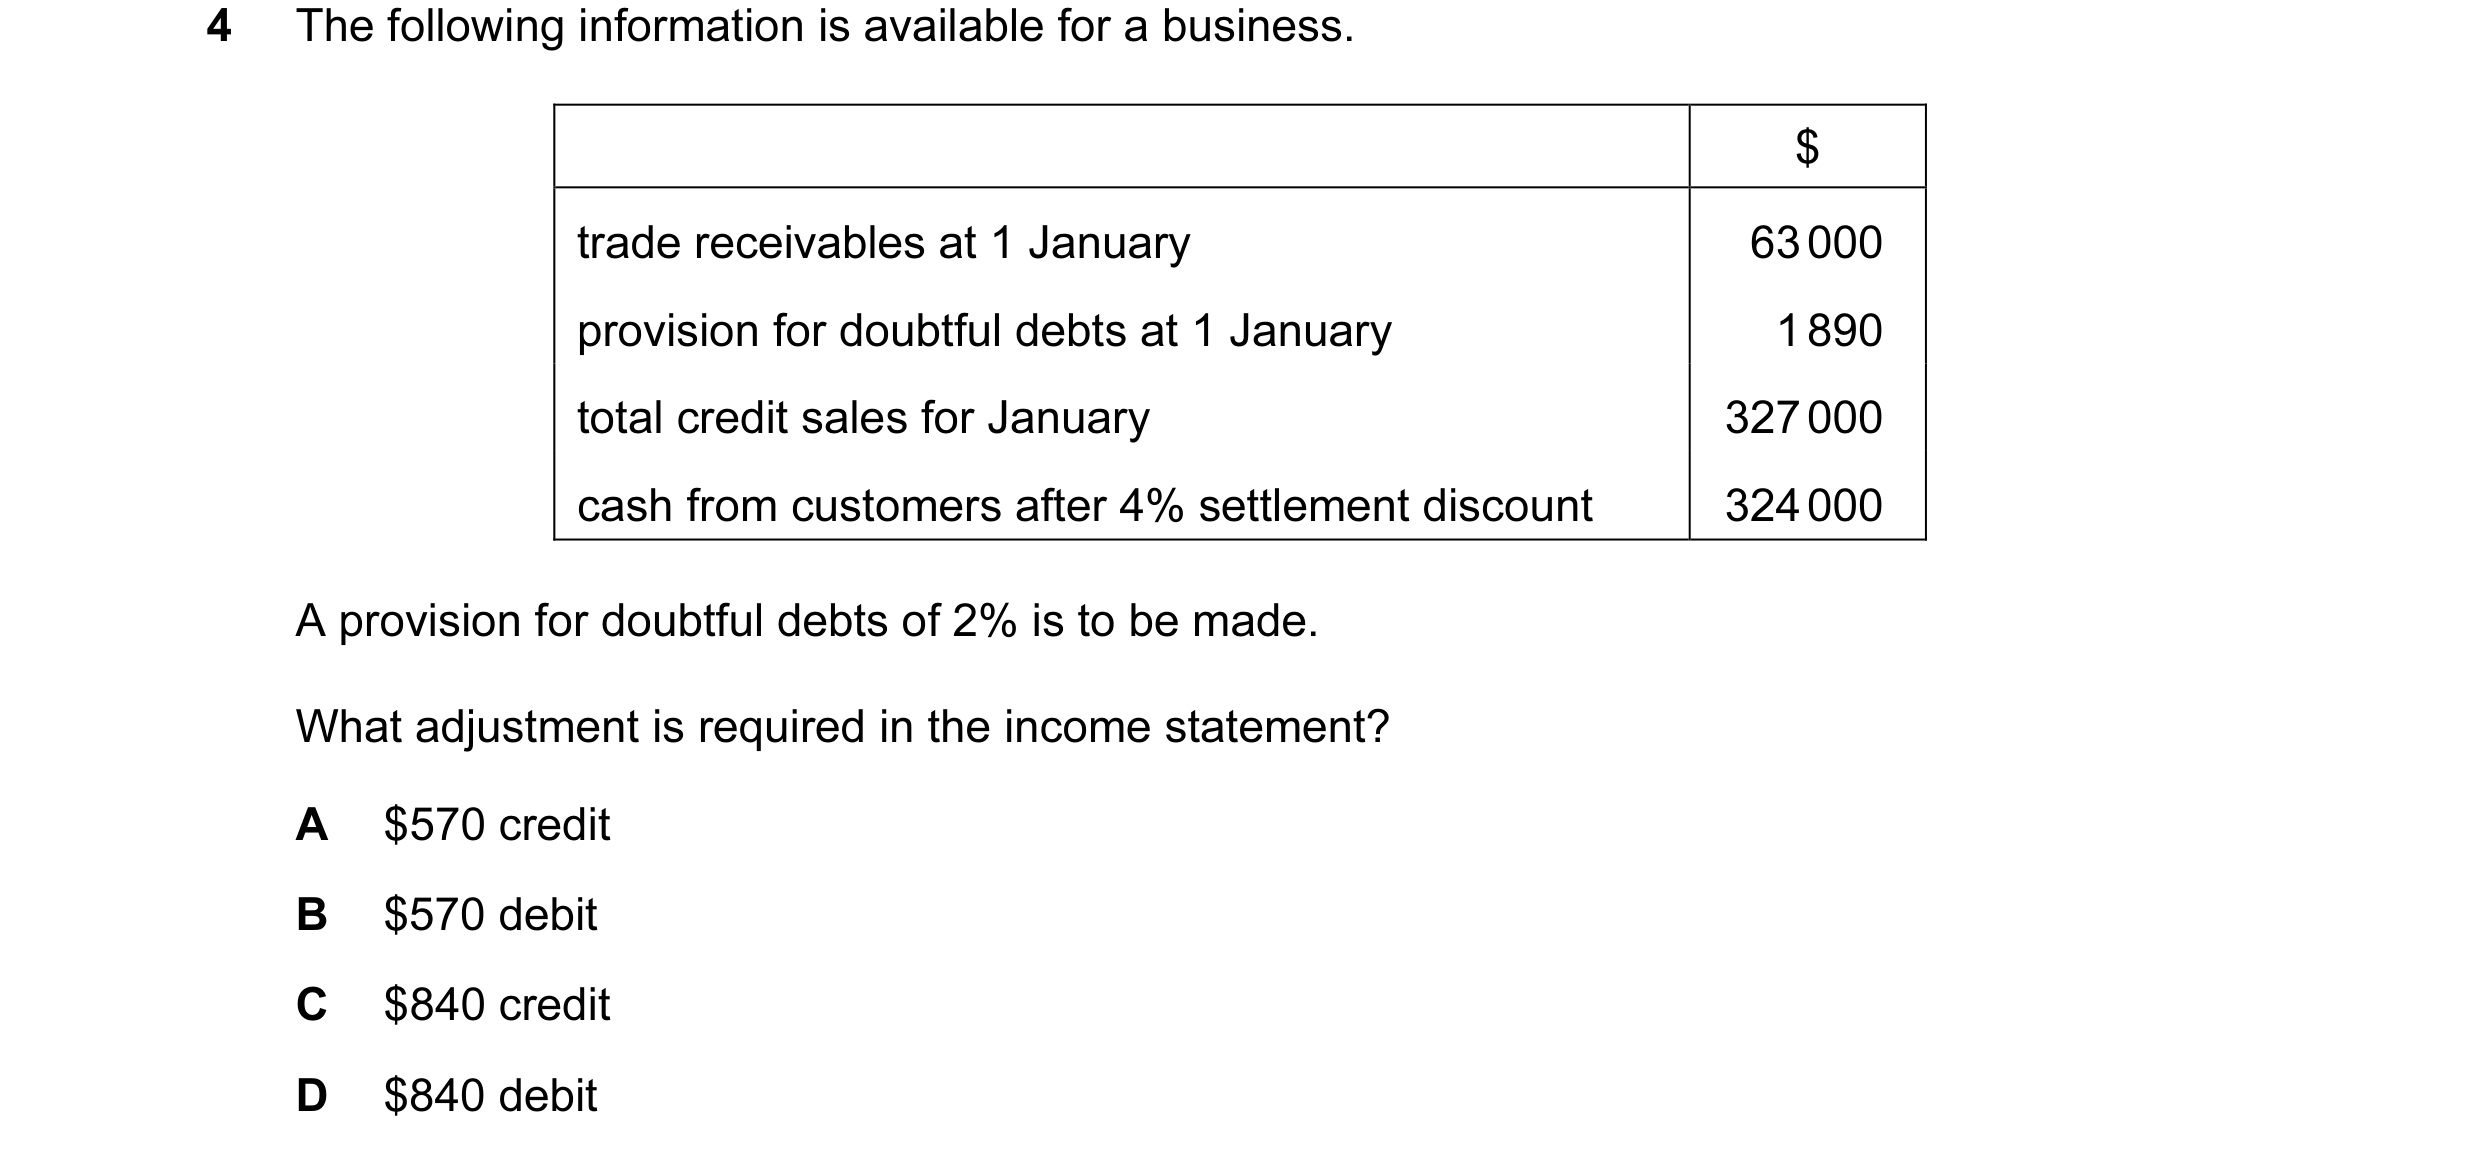 93 / 233
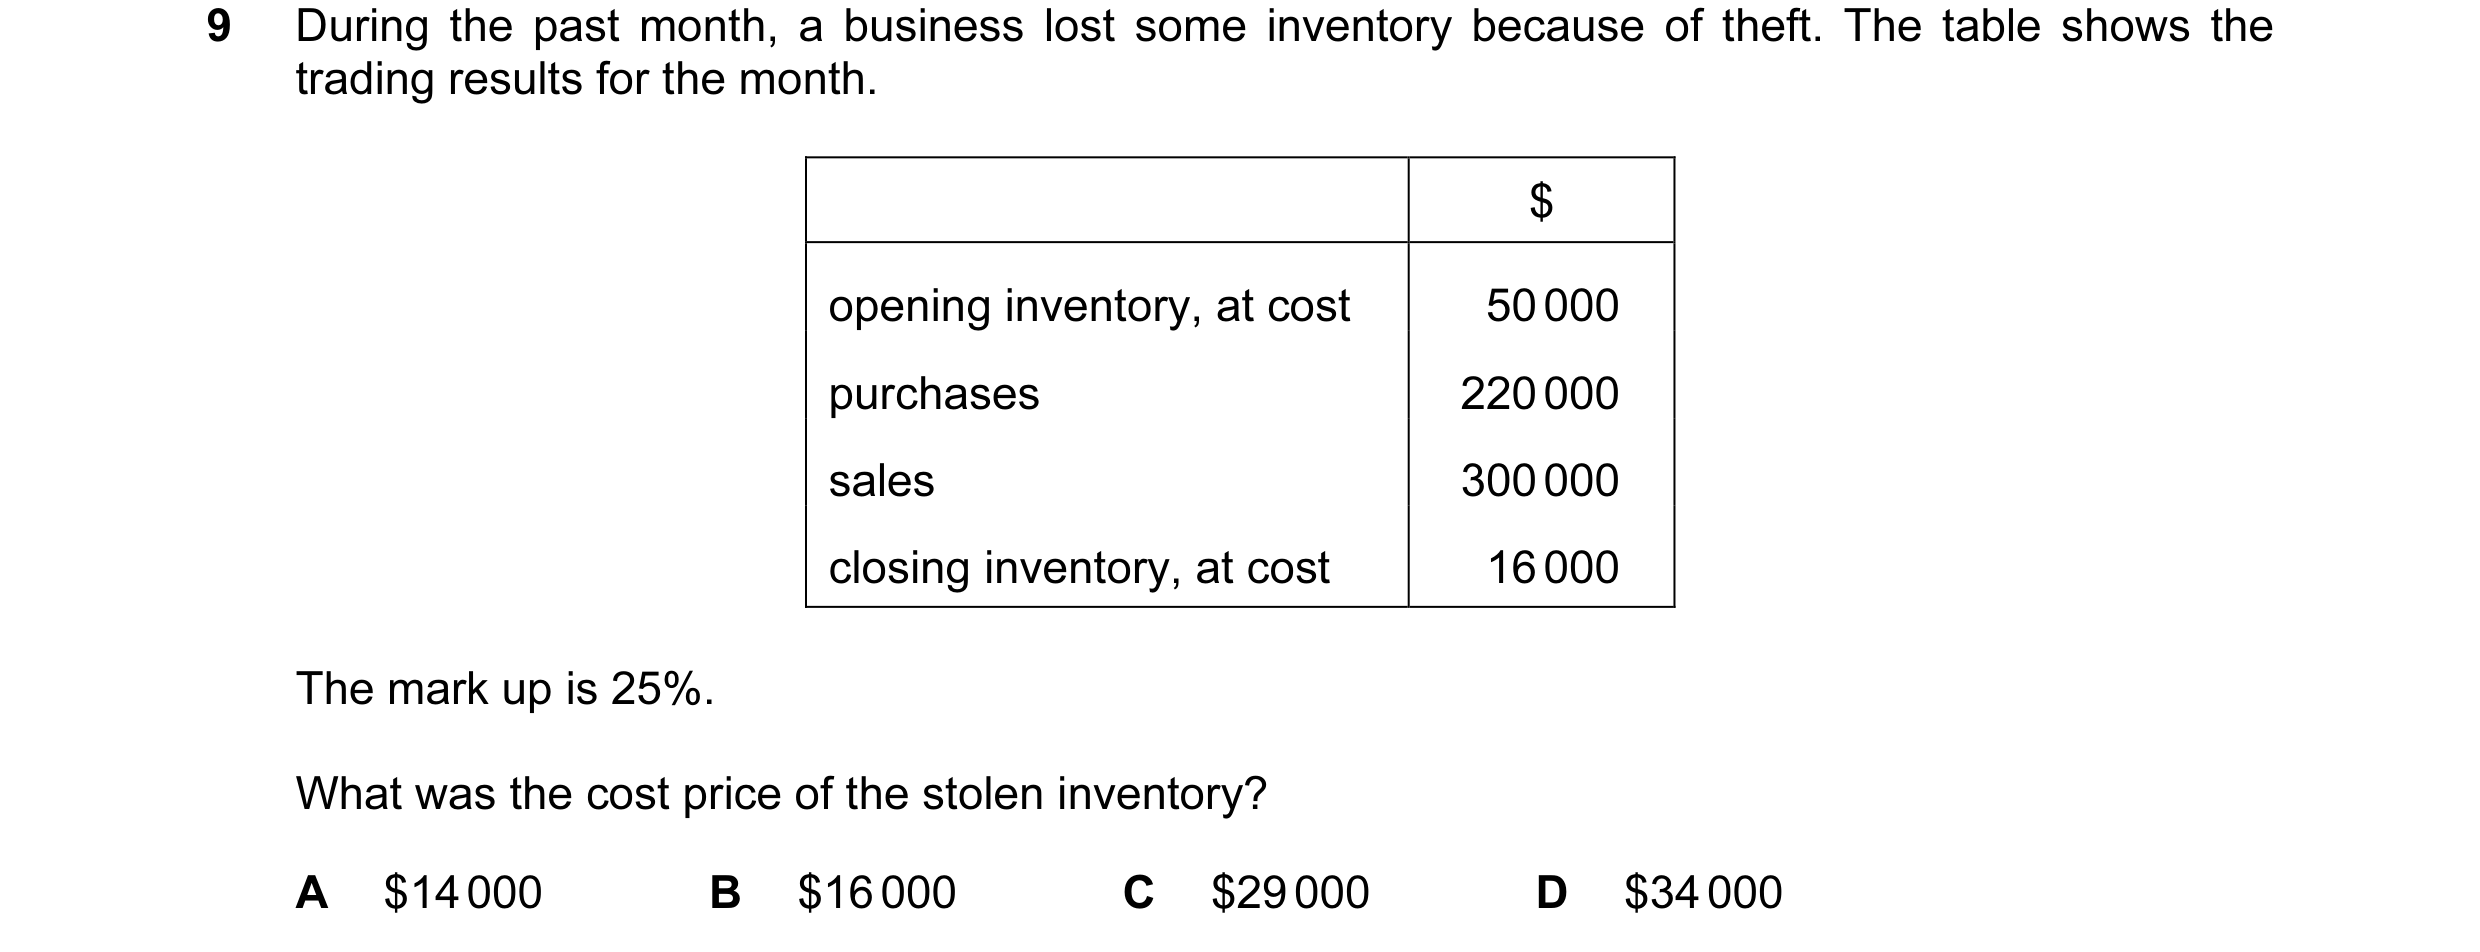
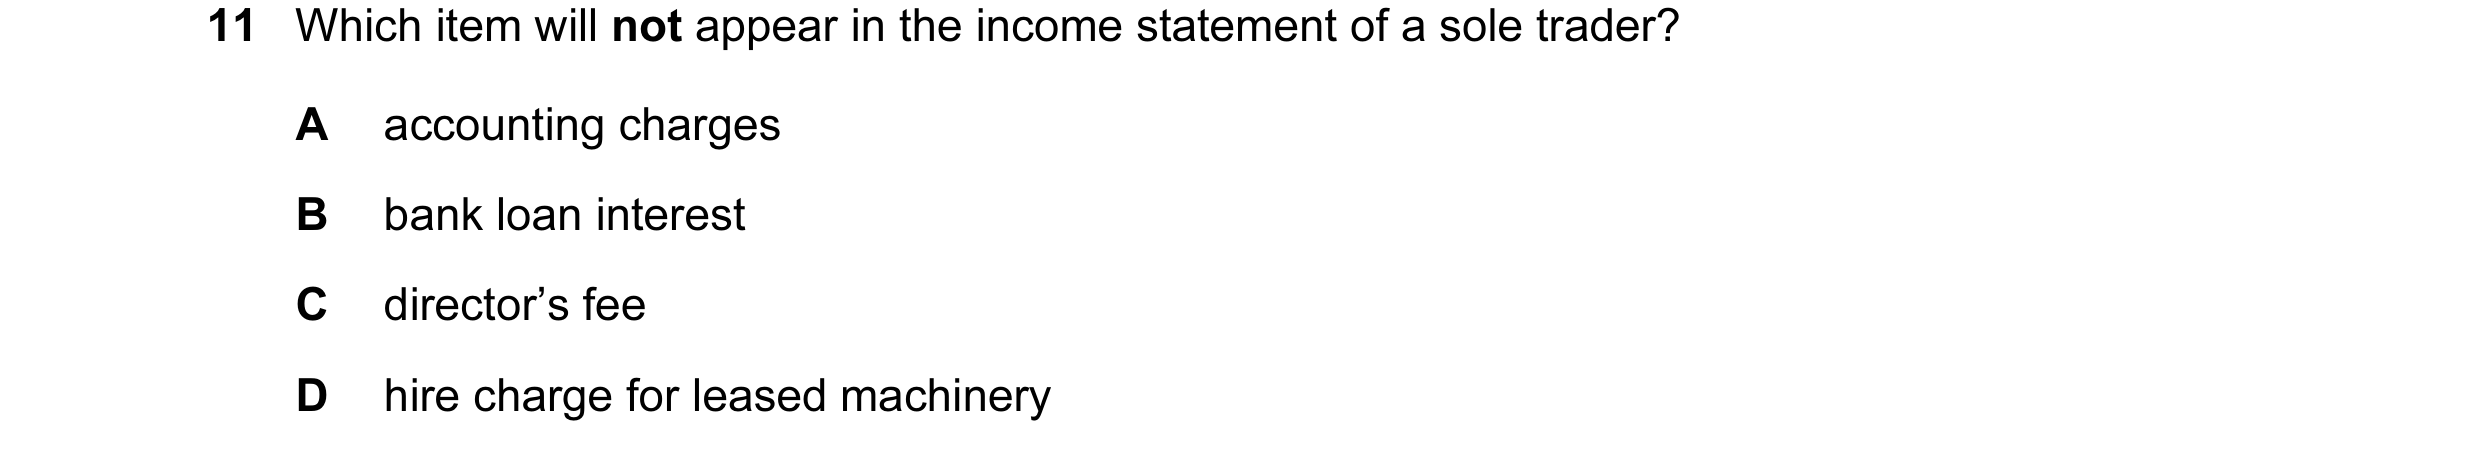
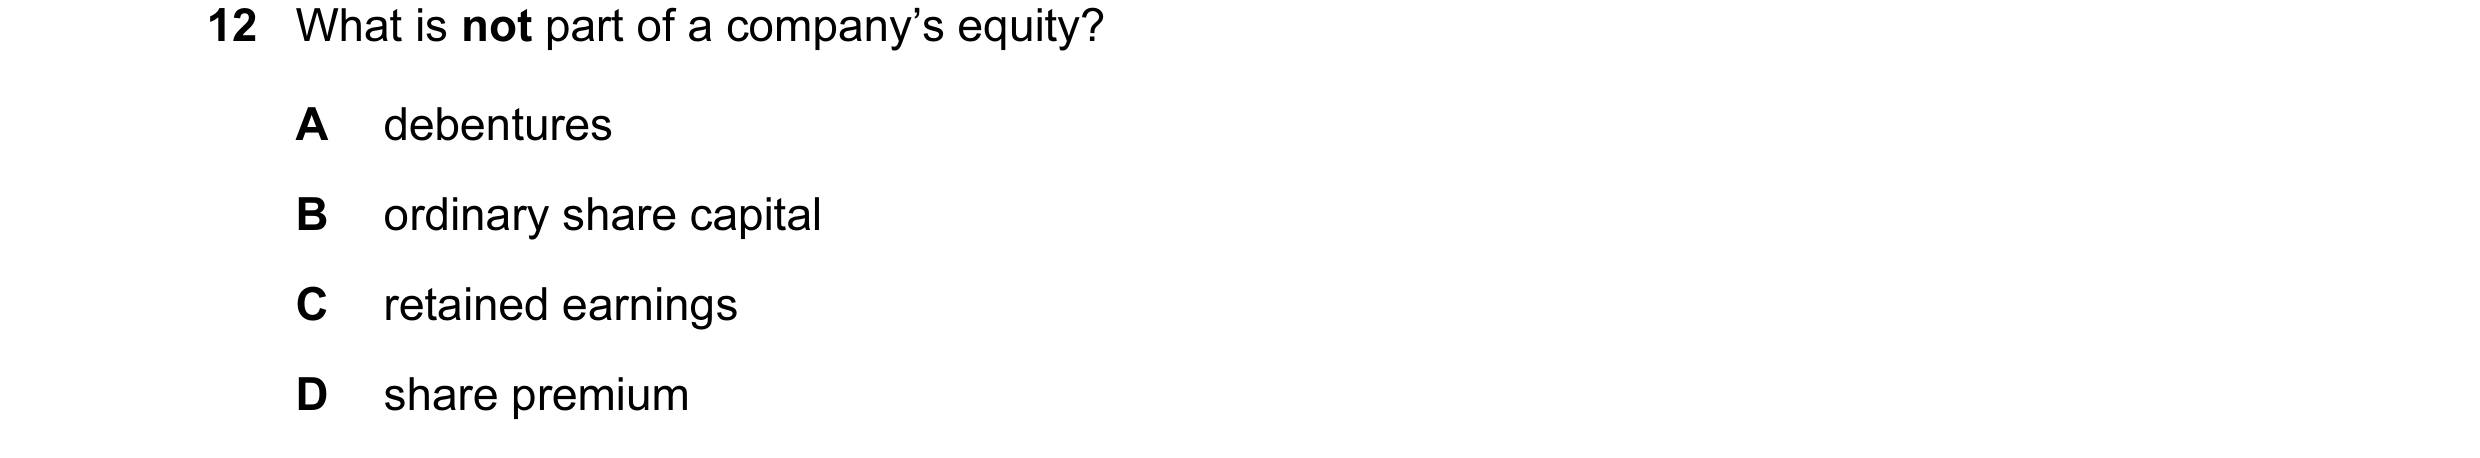
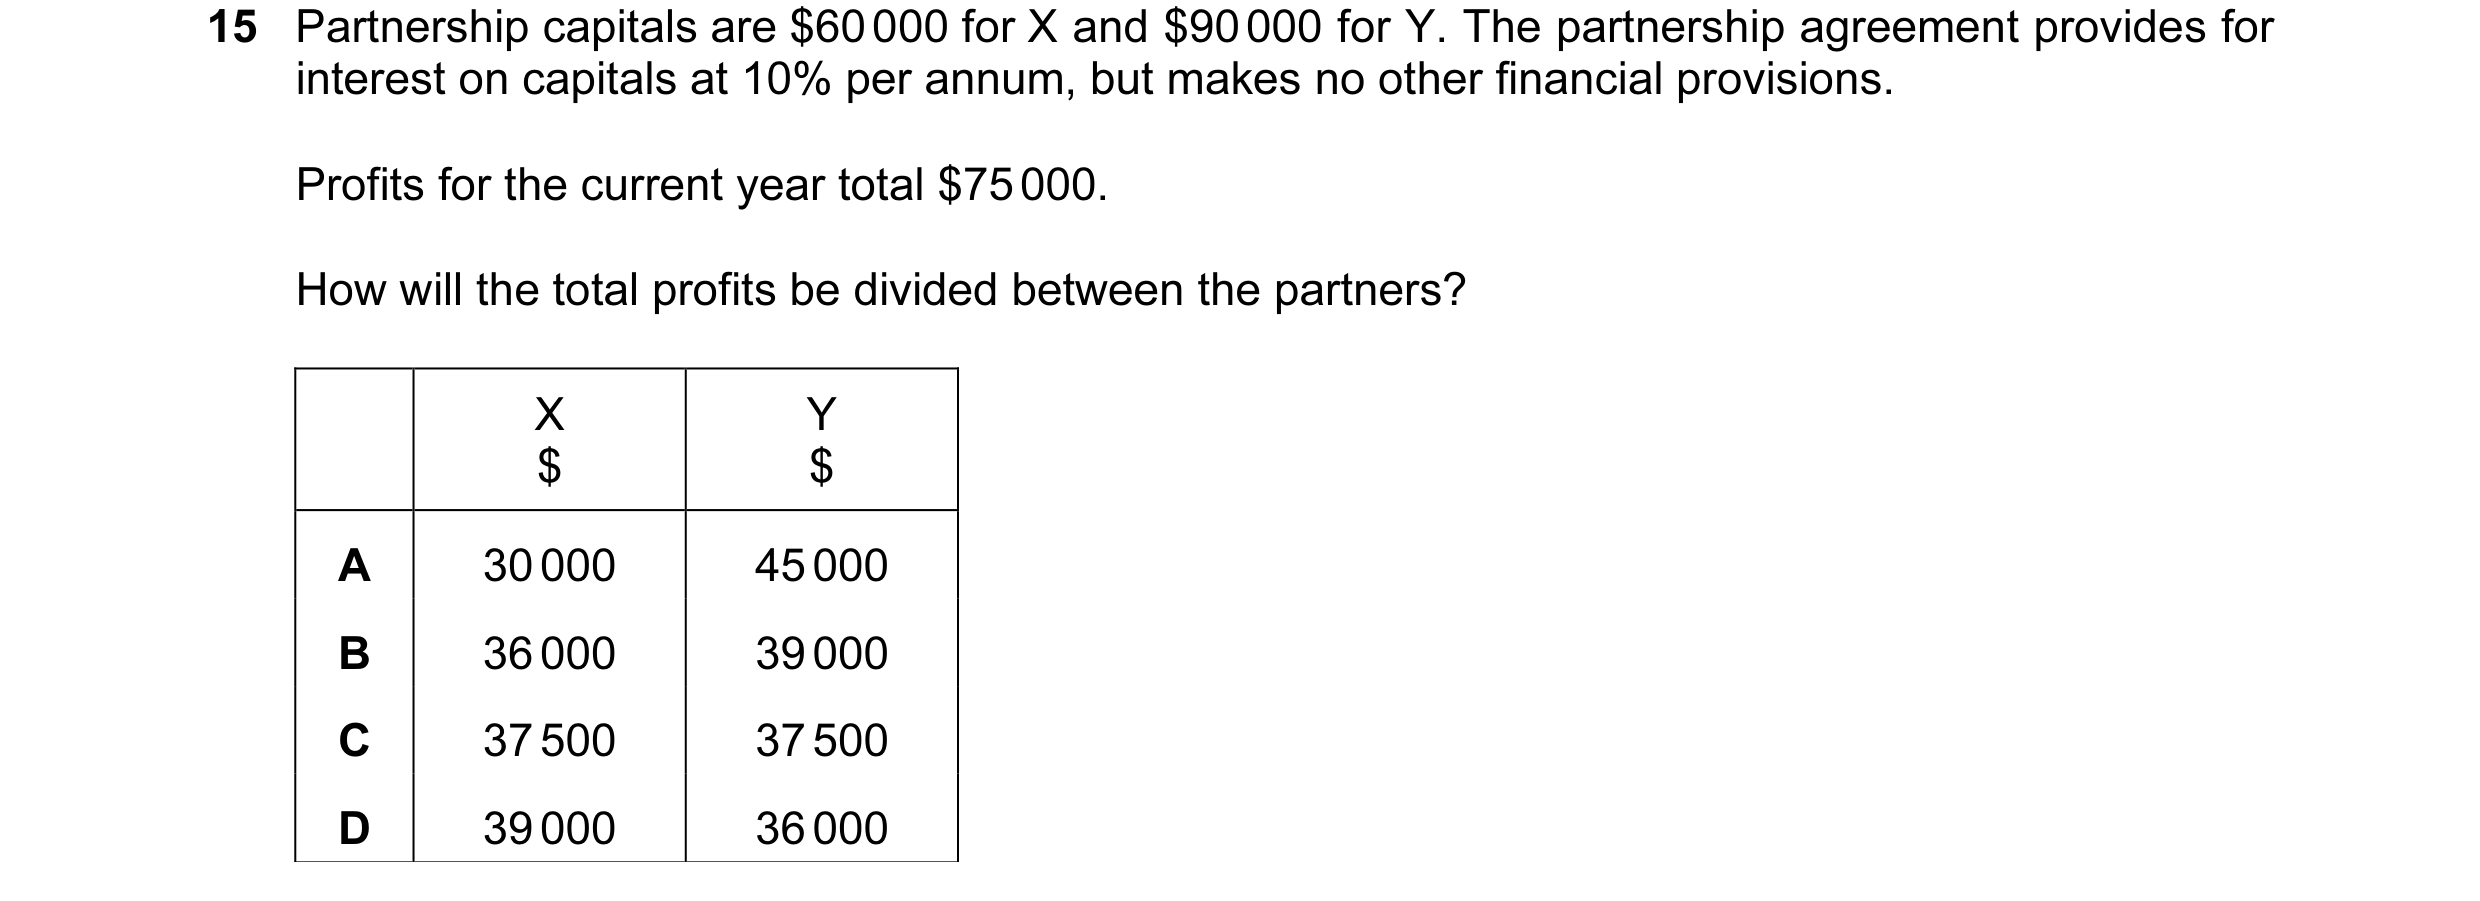 94 / 233
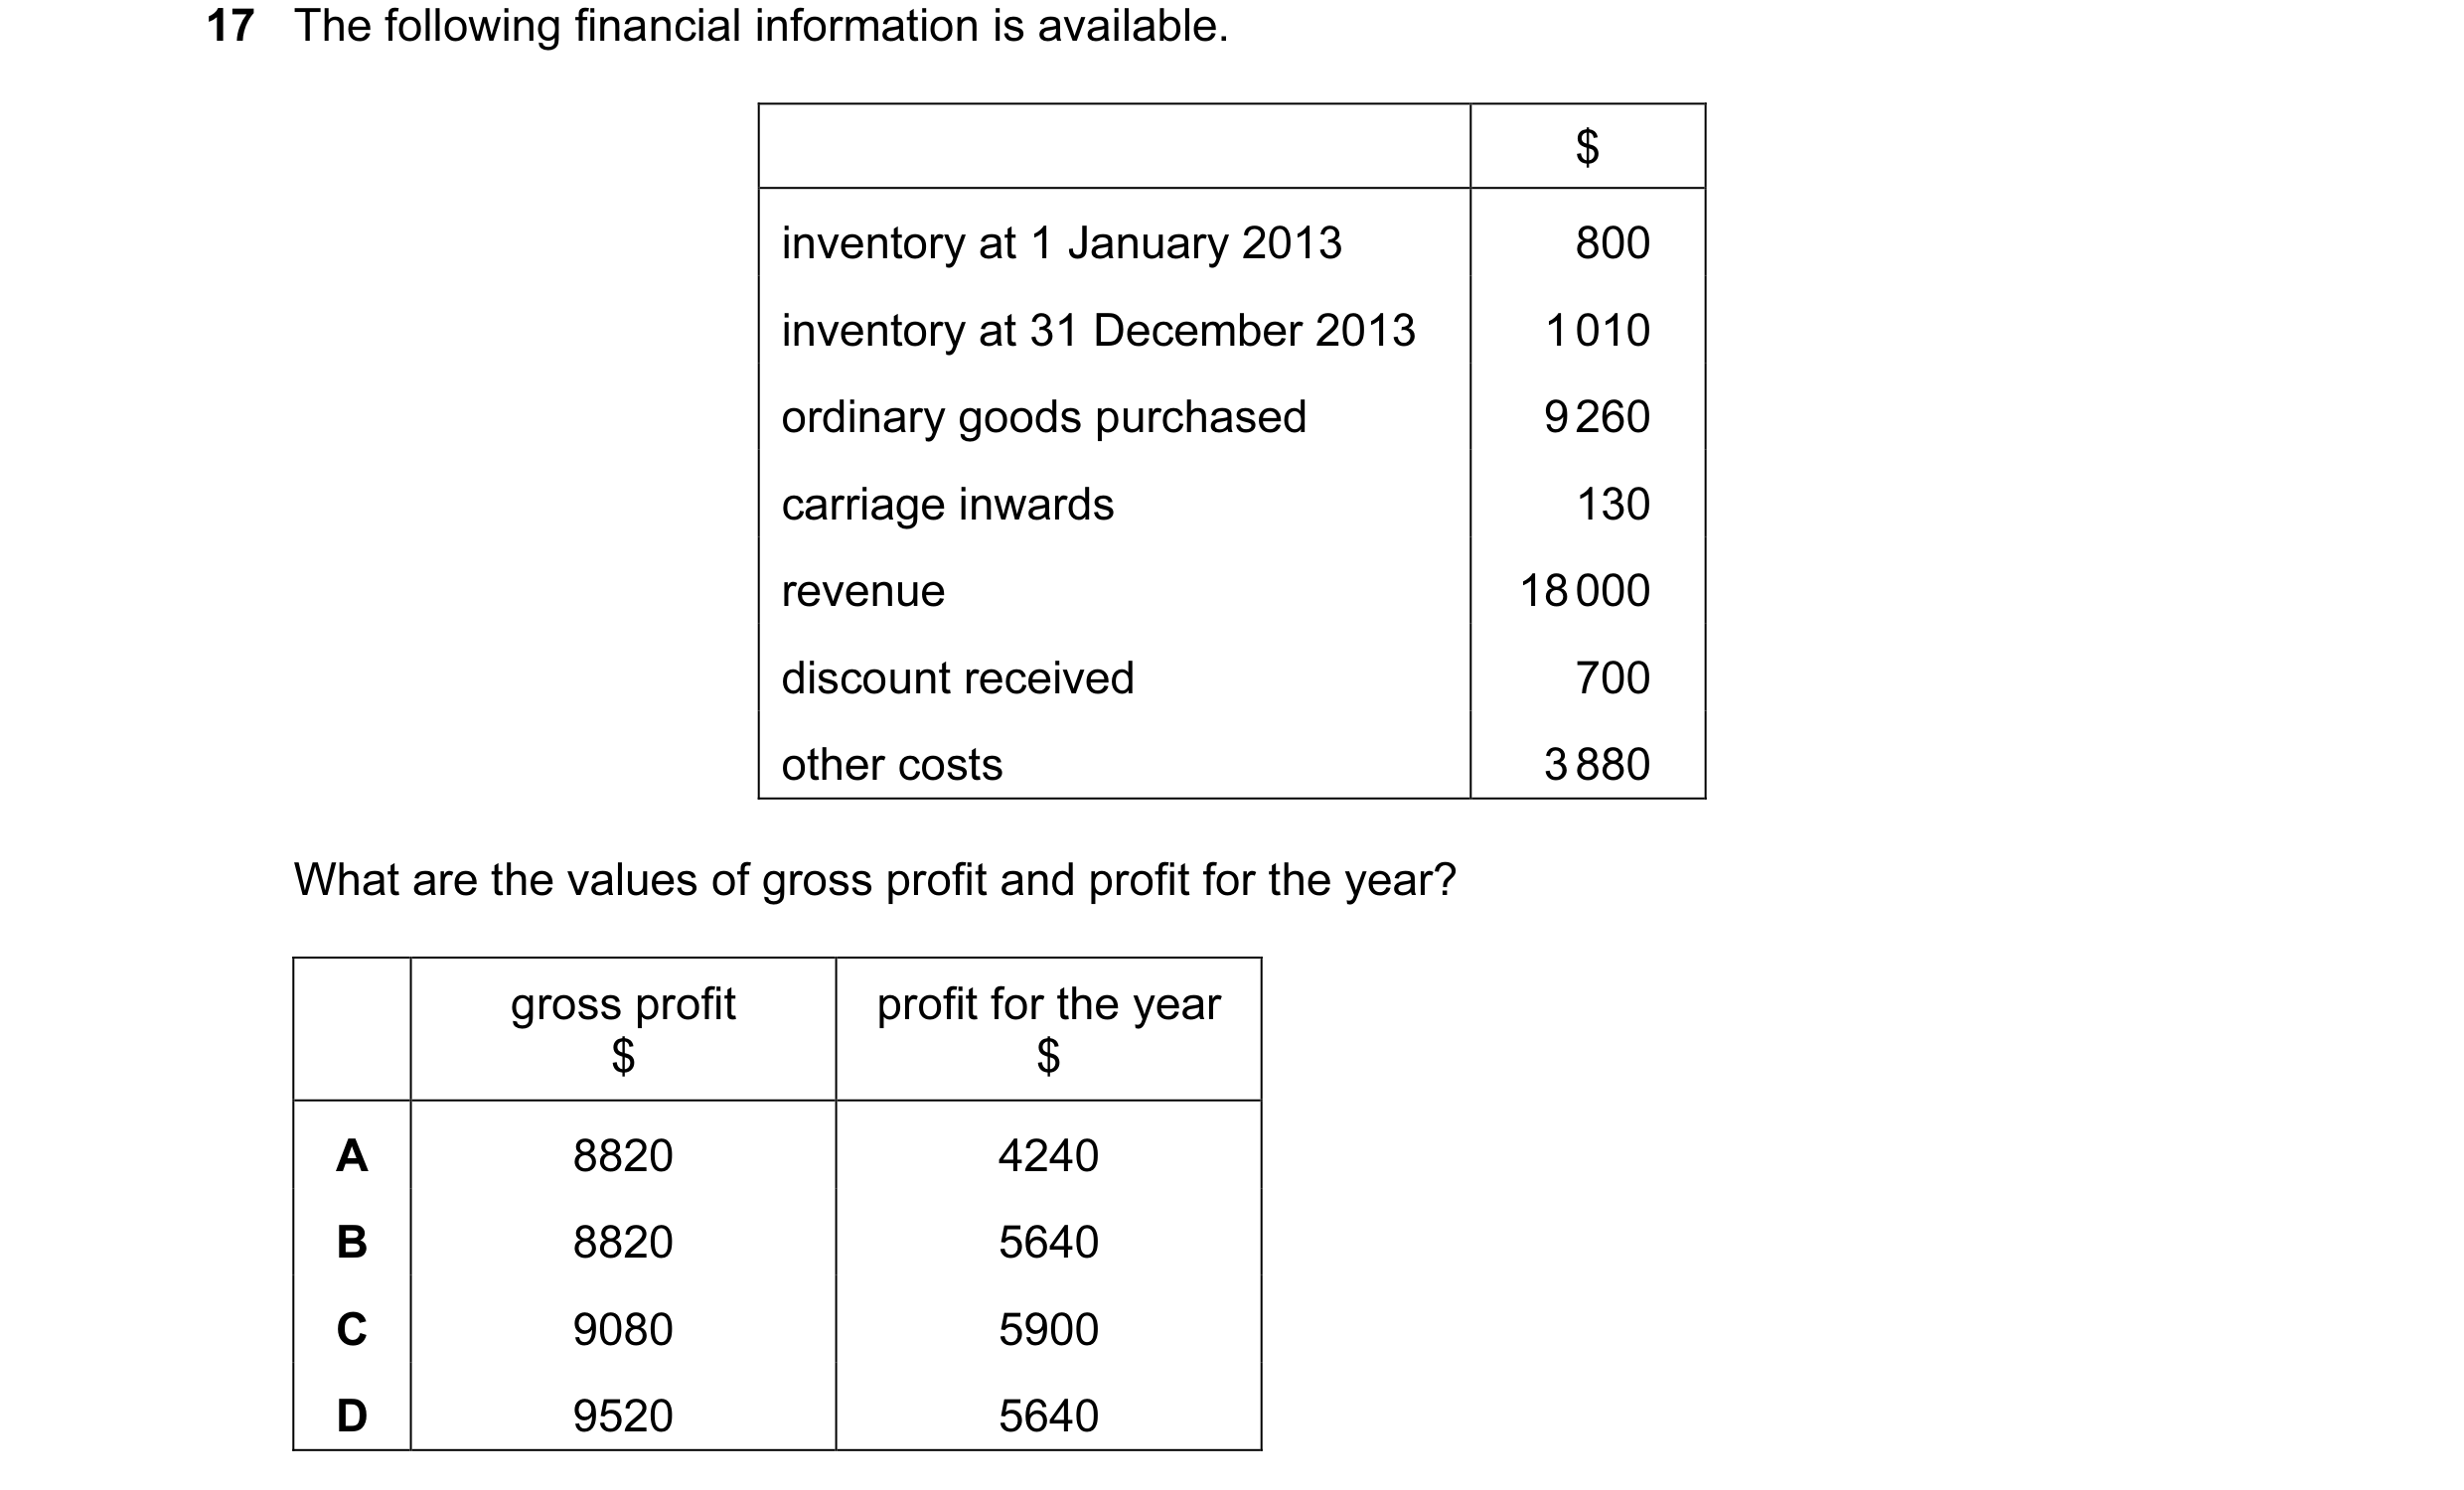
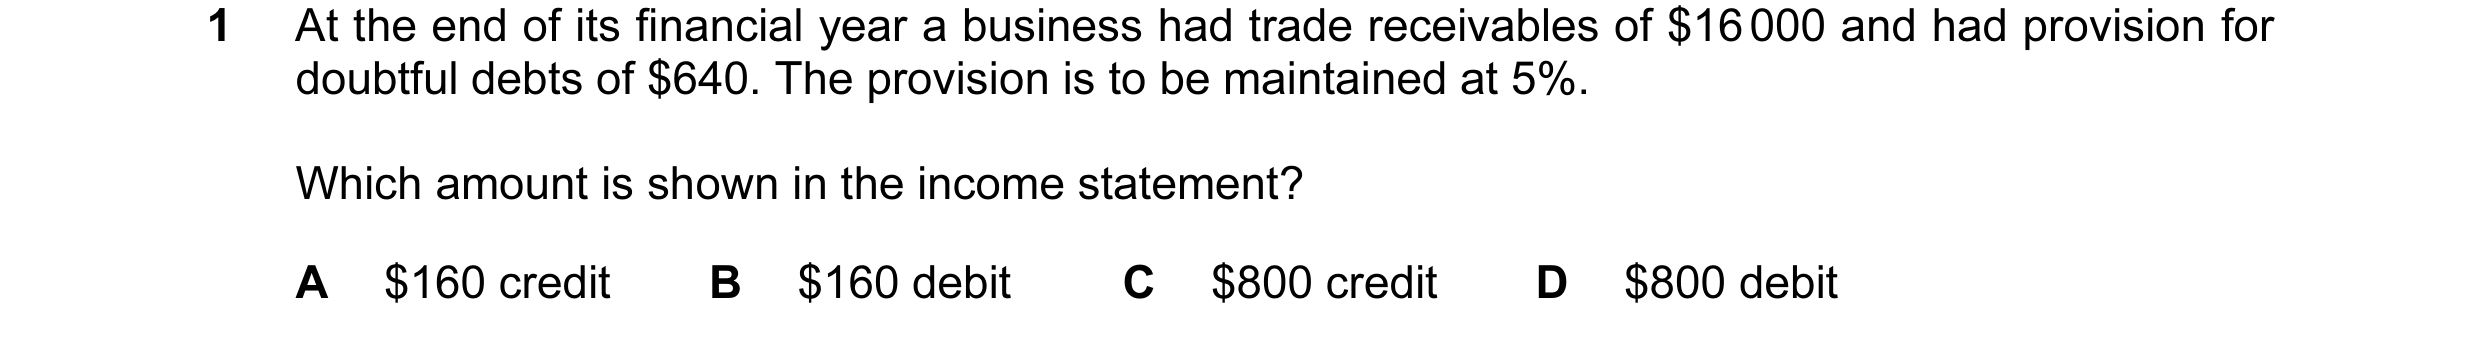
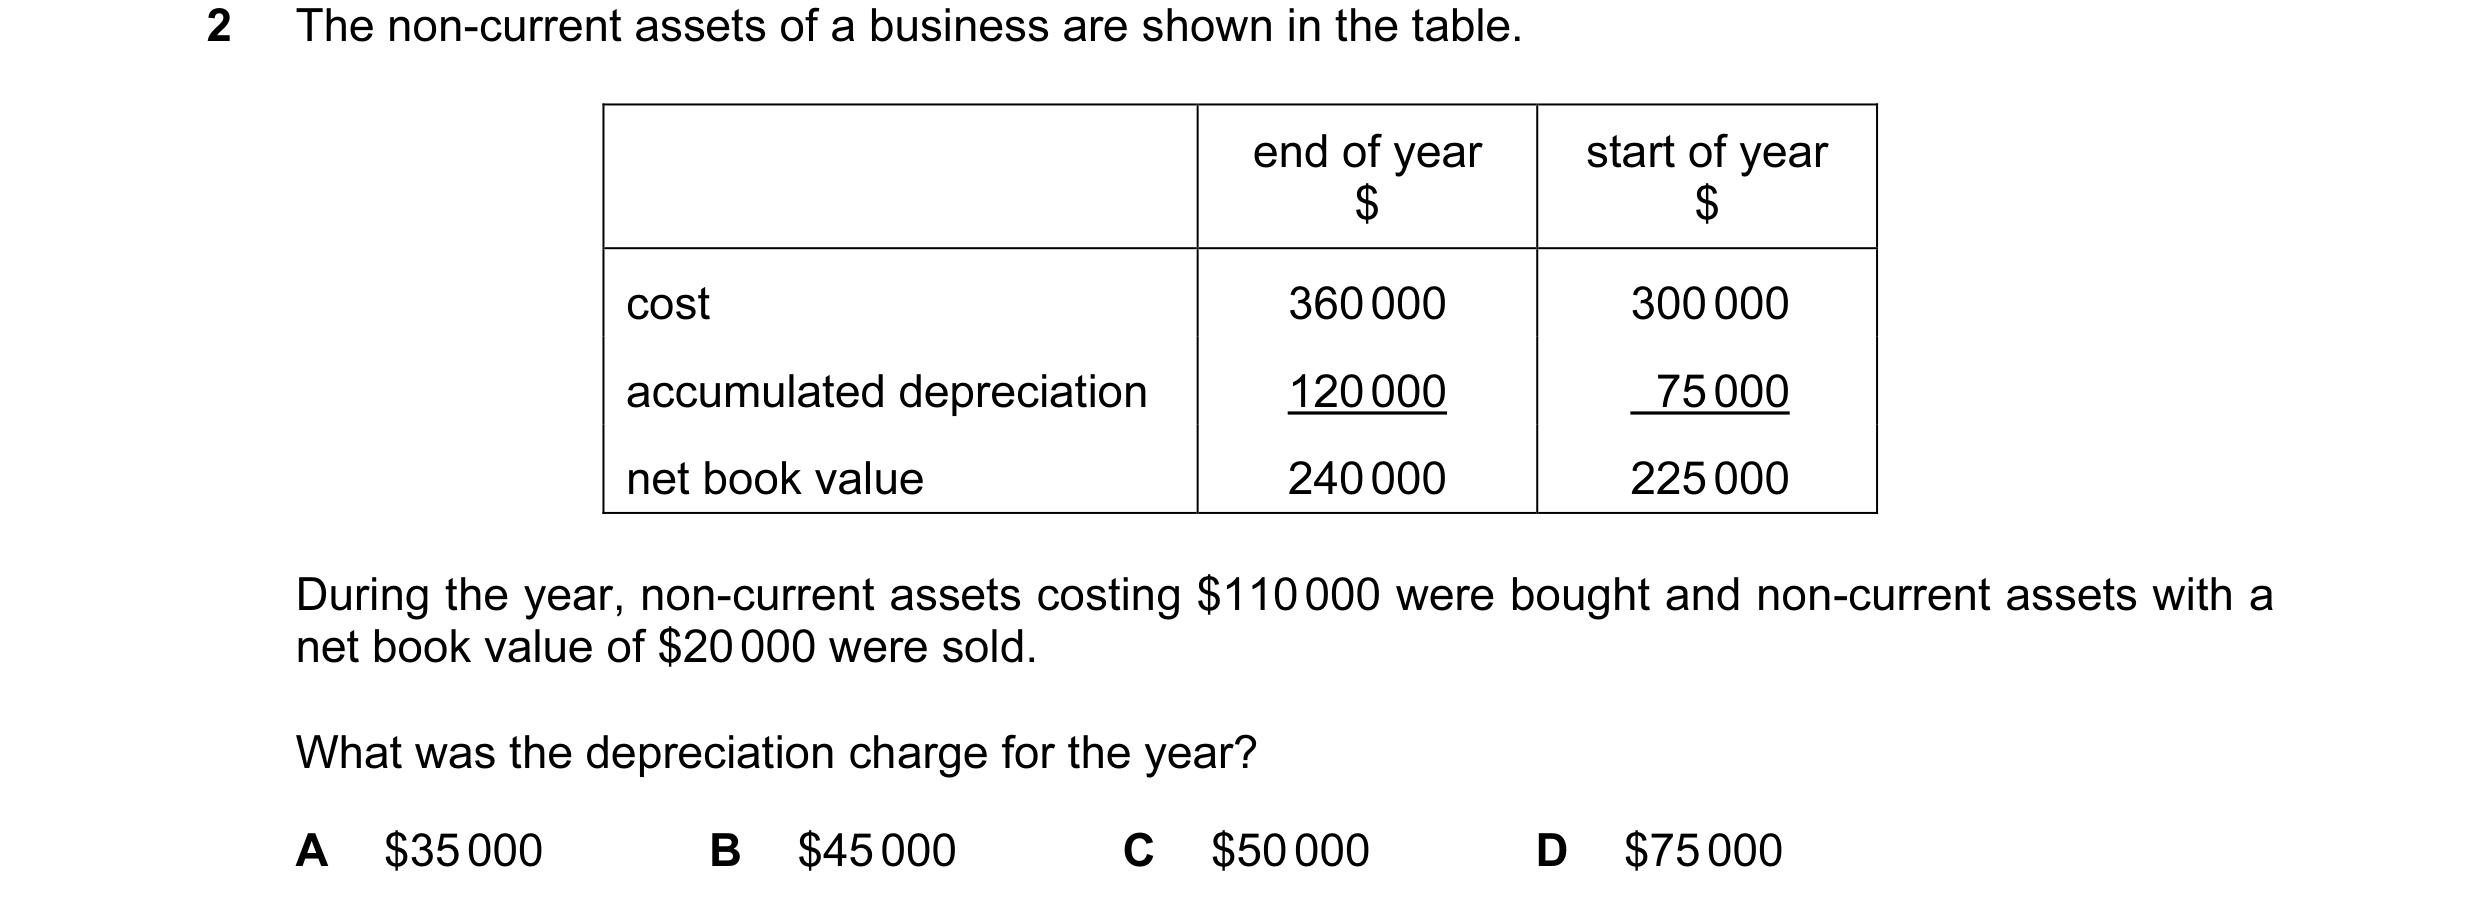
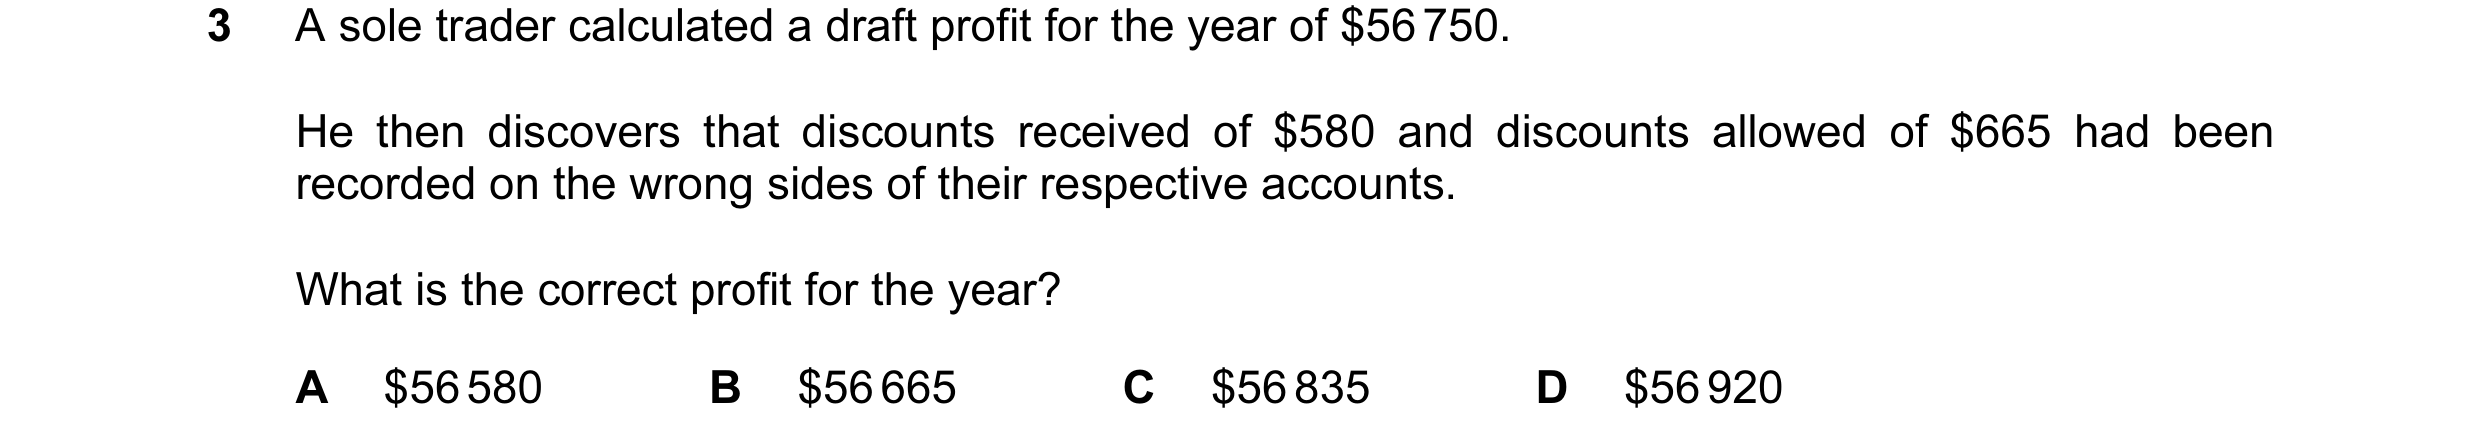 95 / 233
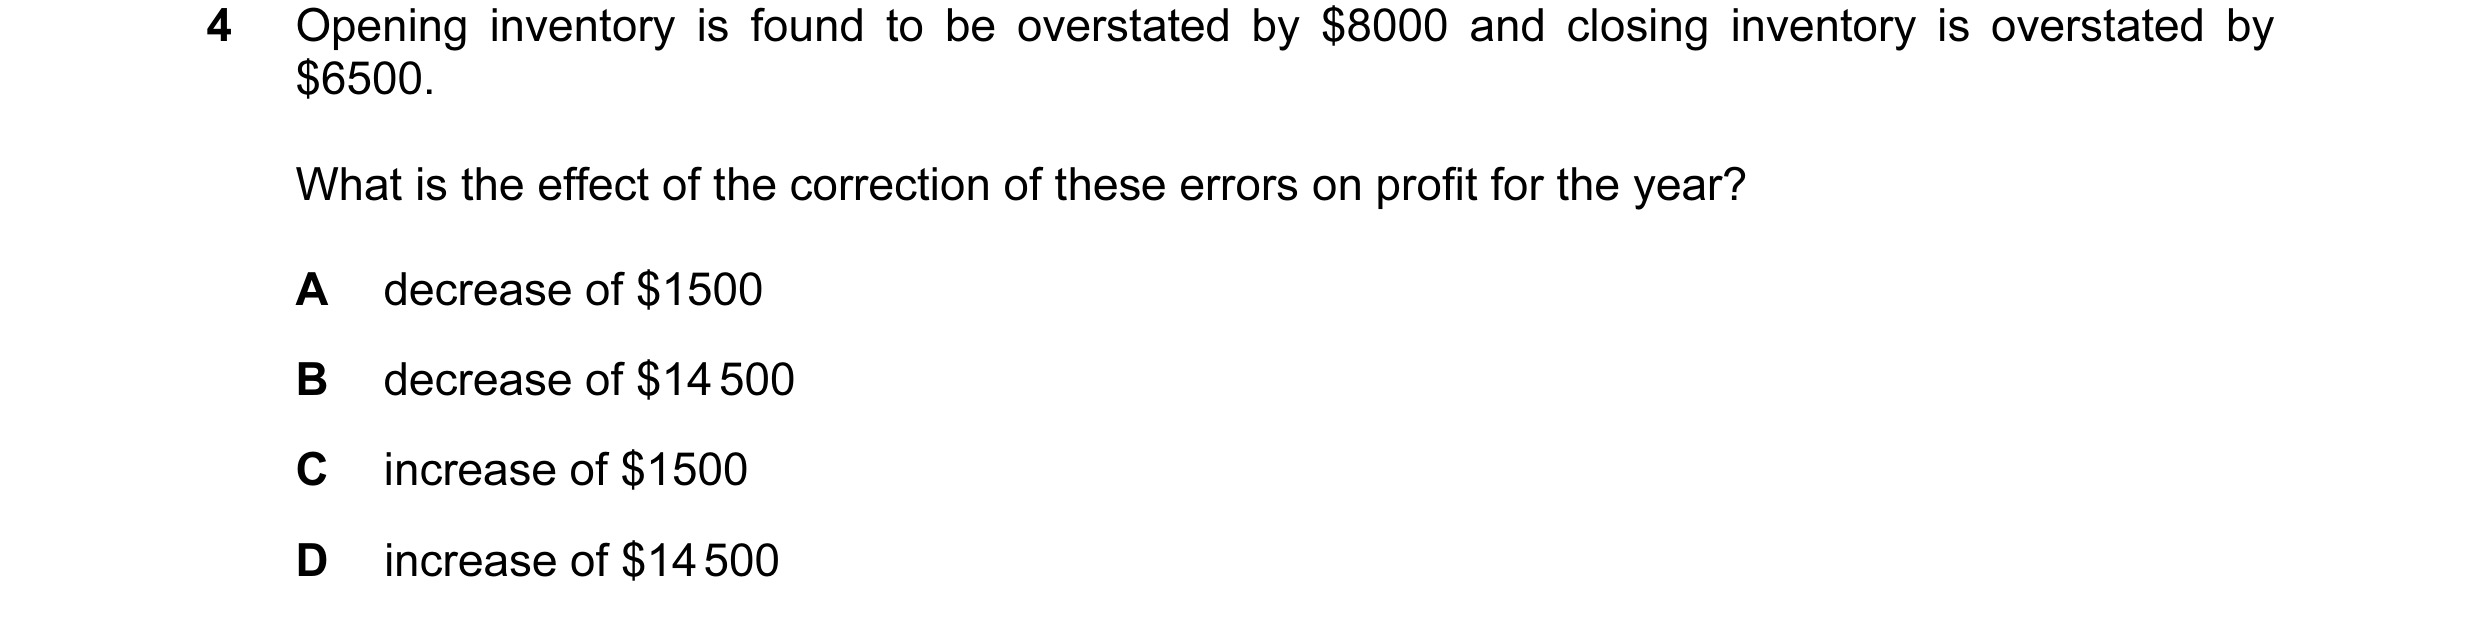
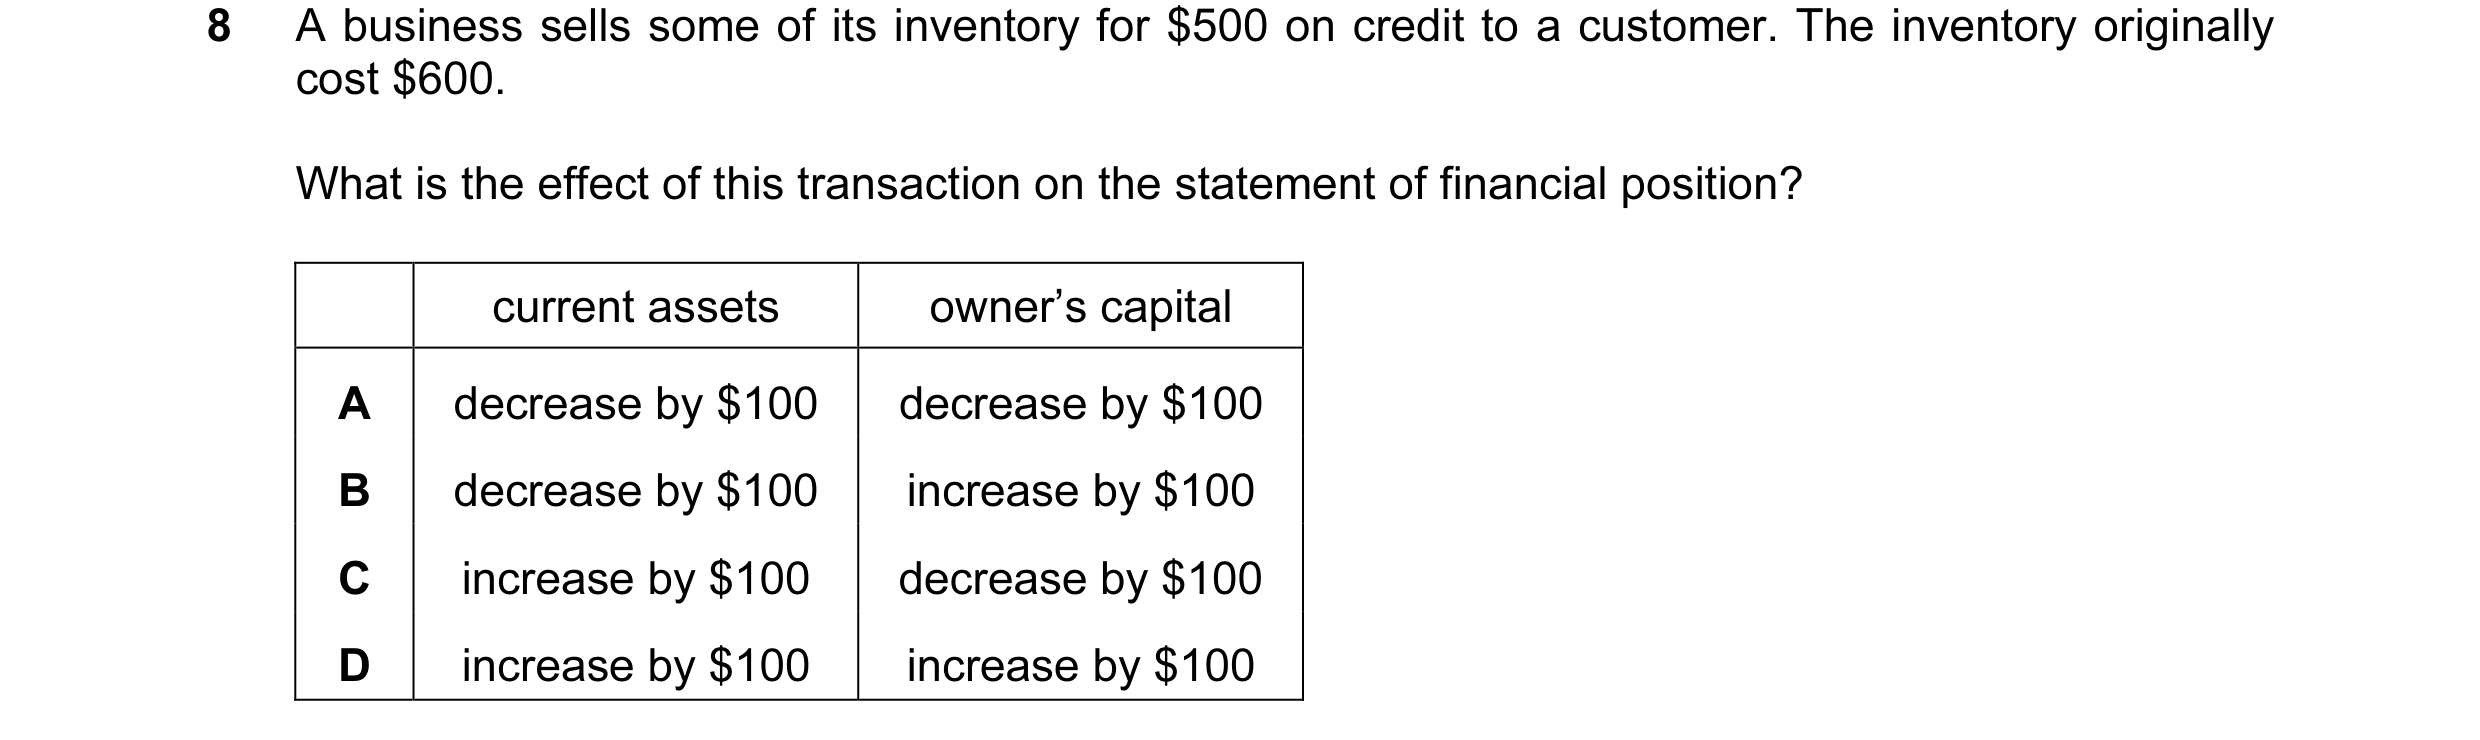
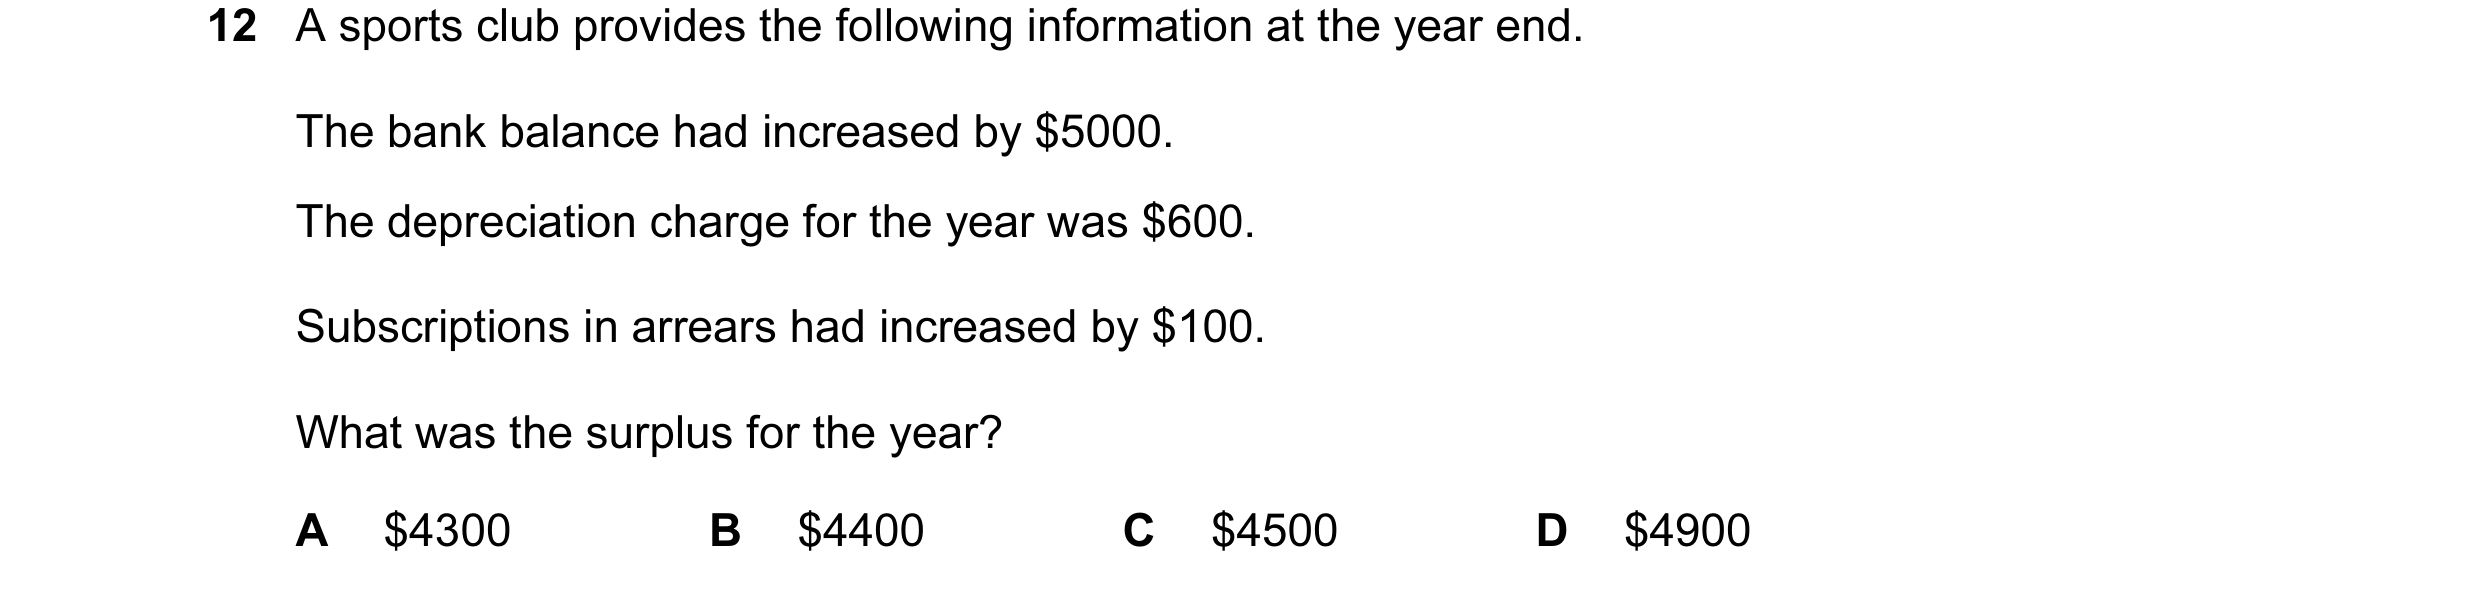 96 / 233
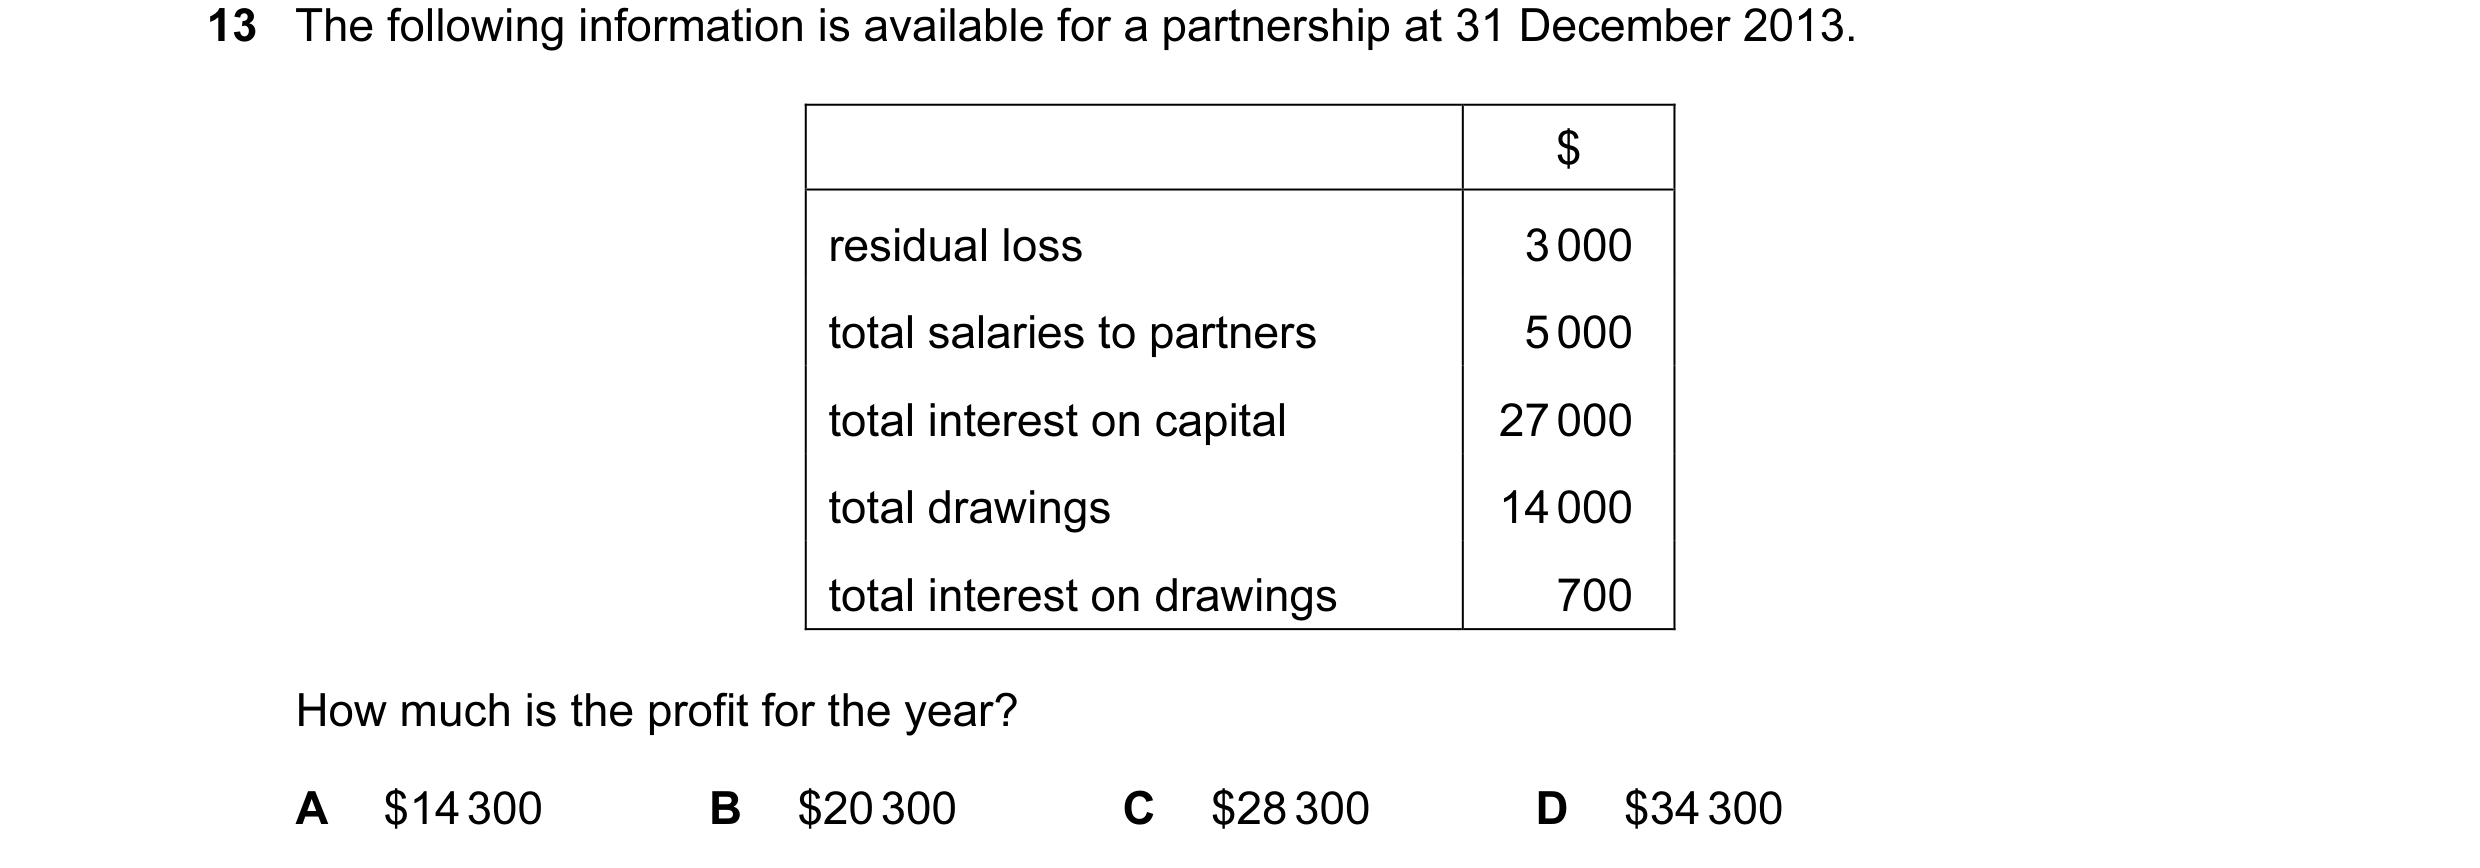
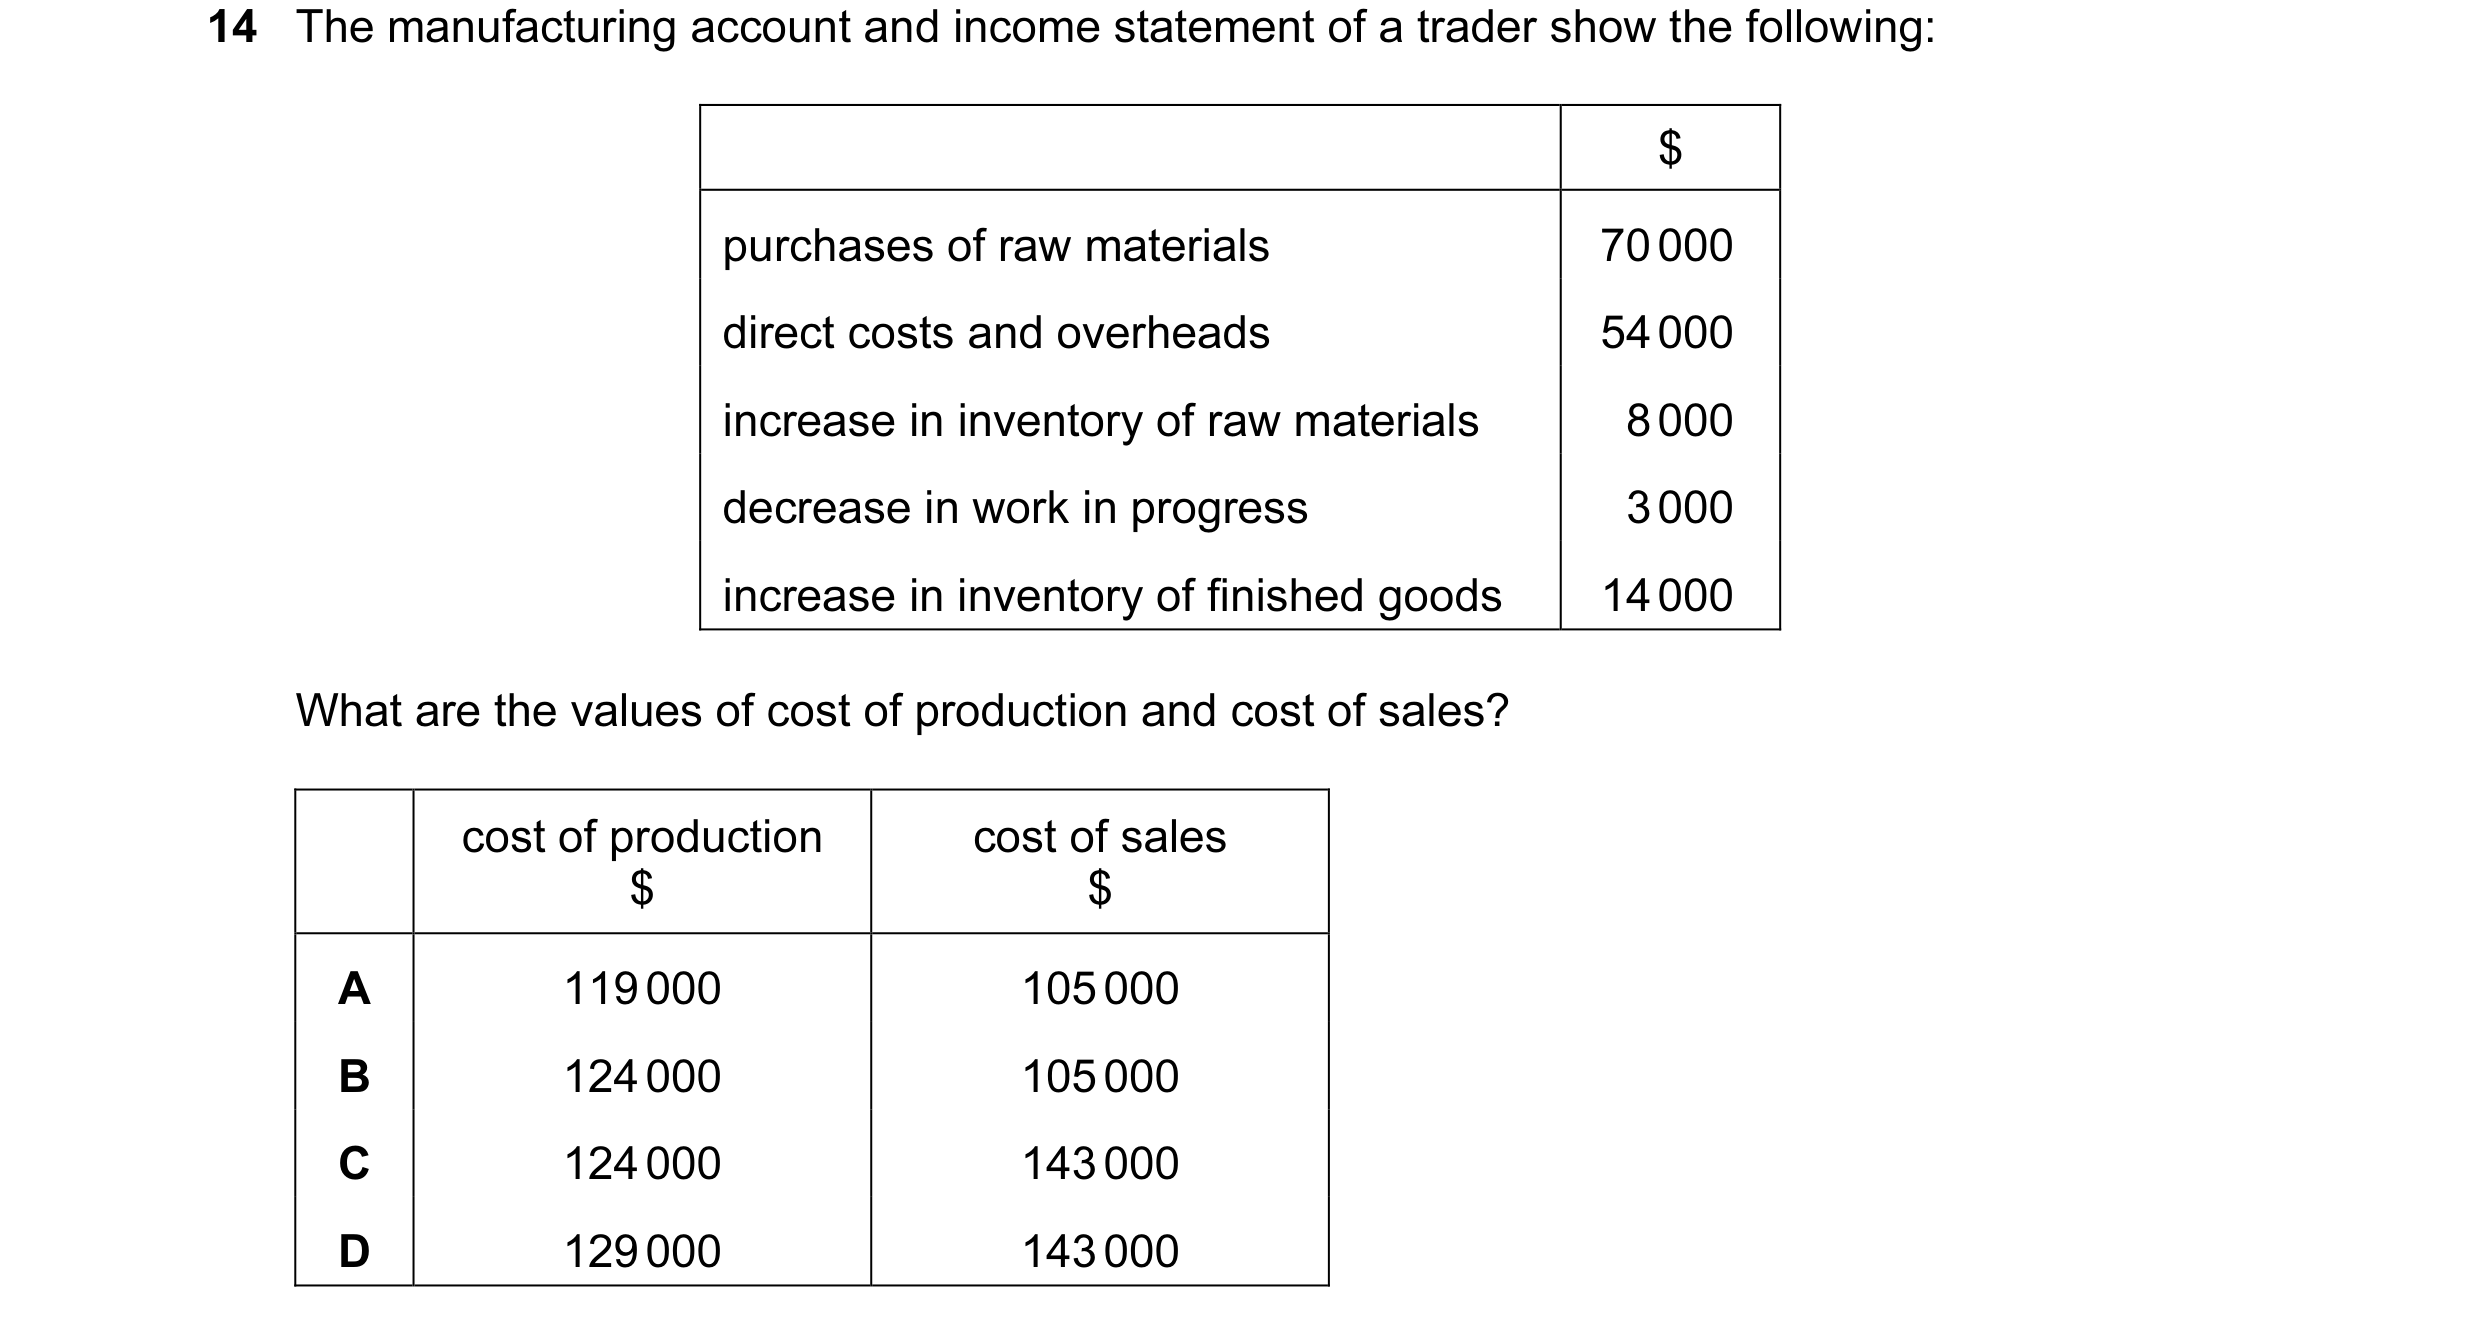
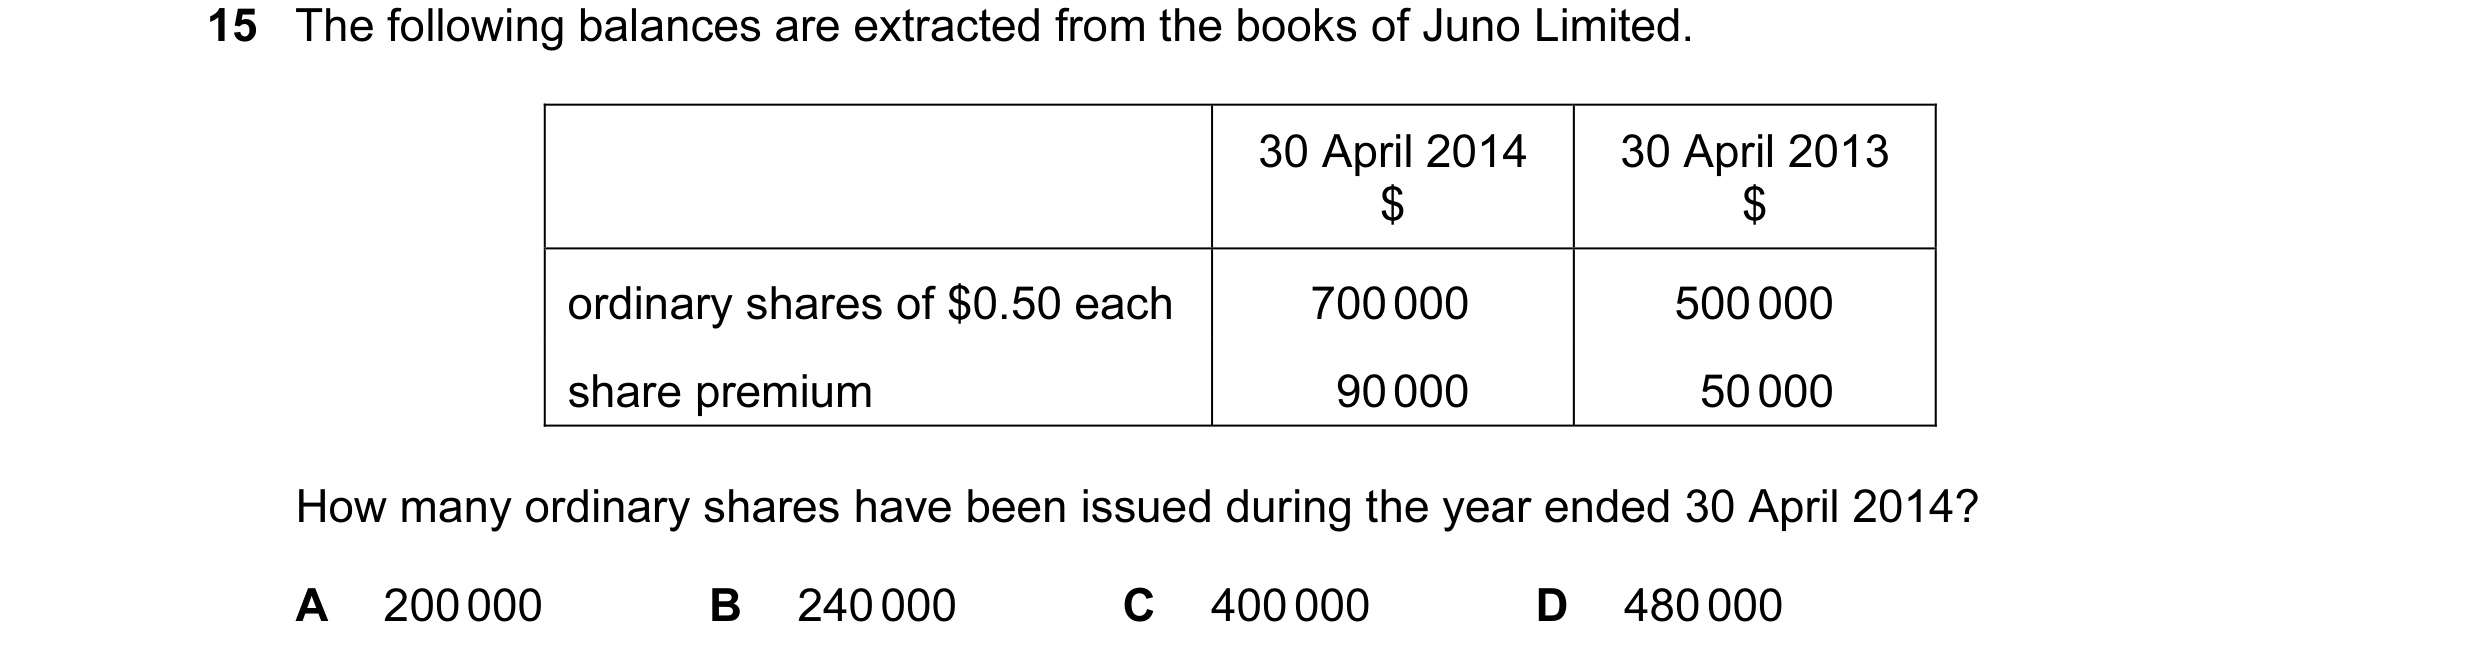
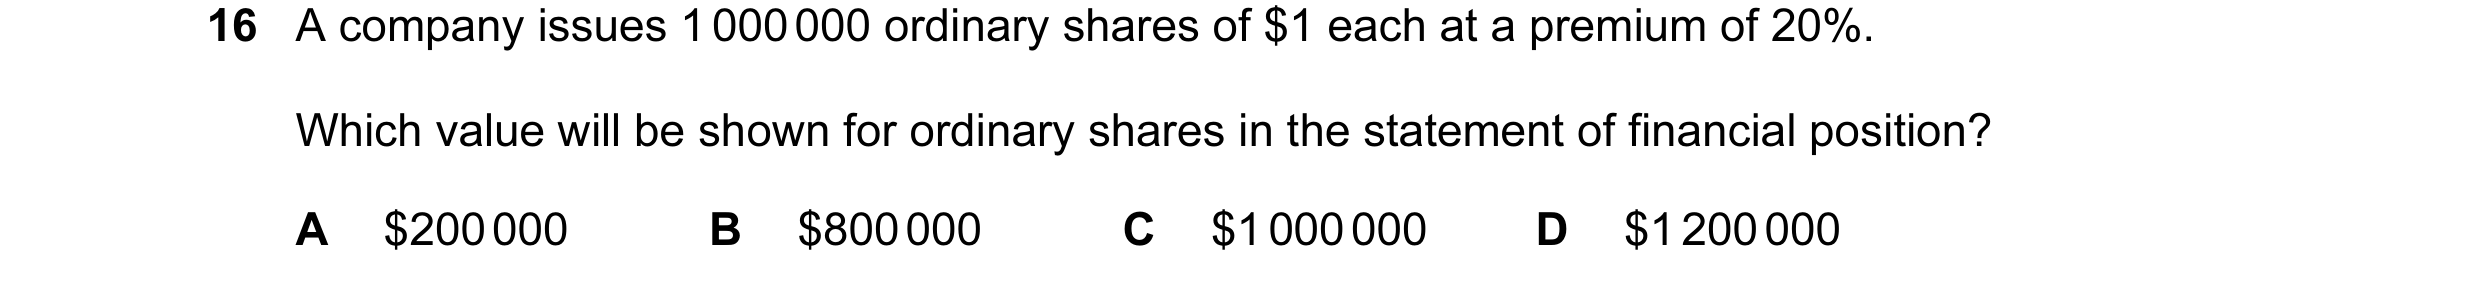 97 / 233
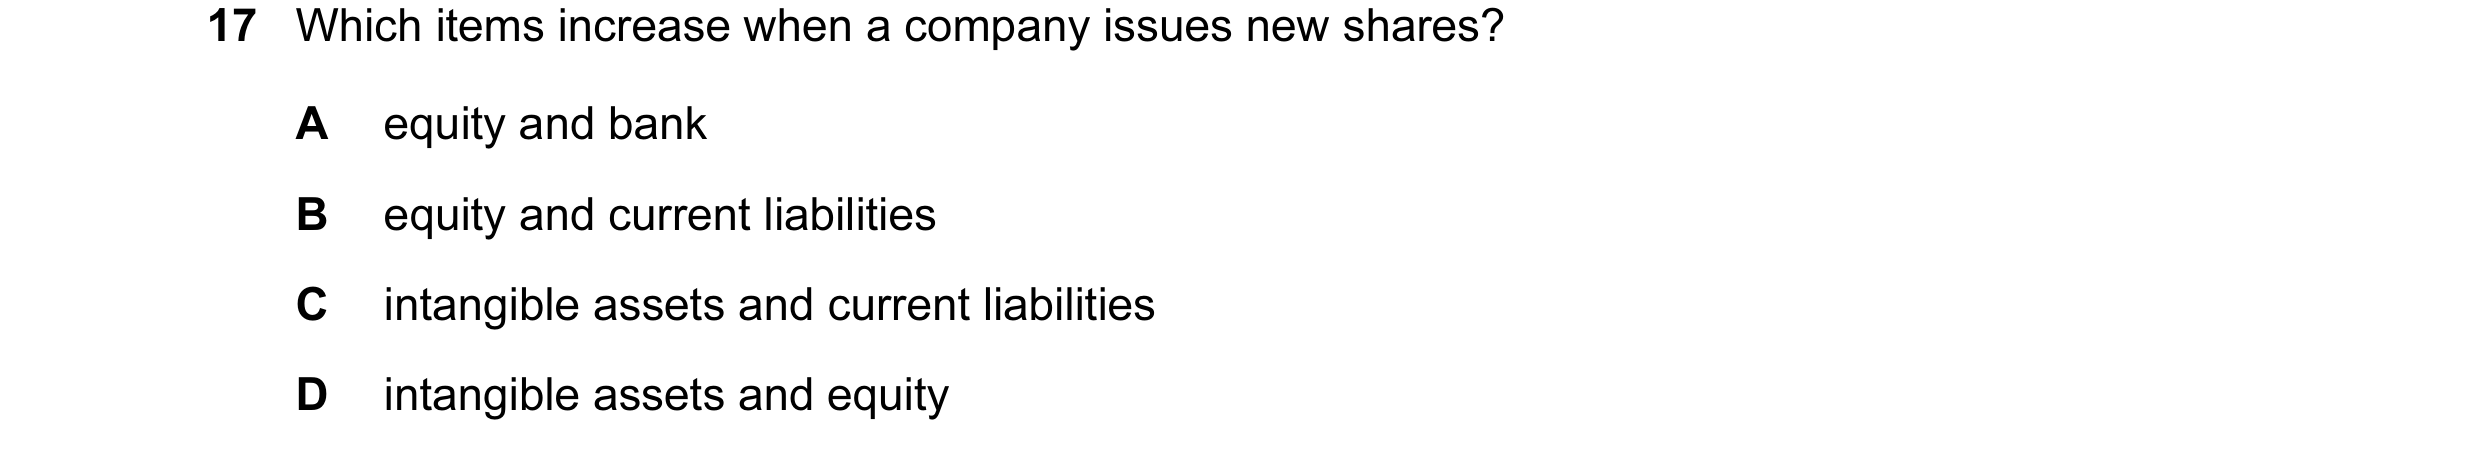
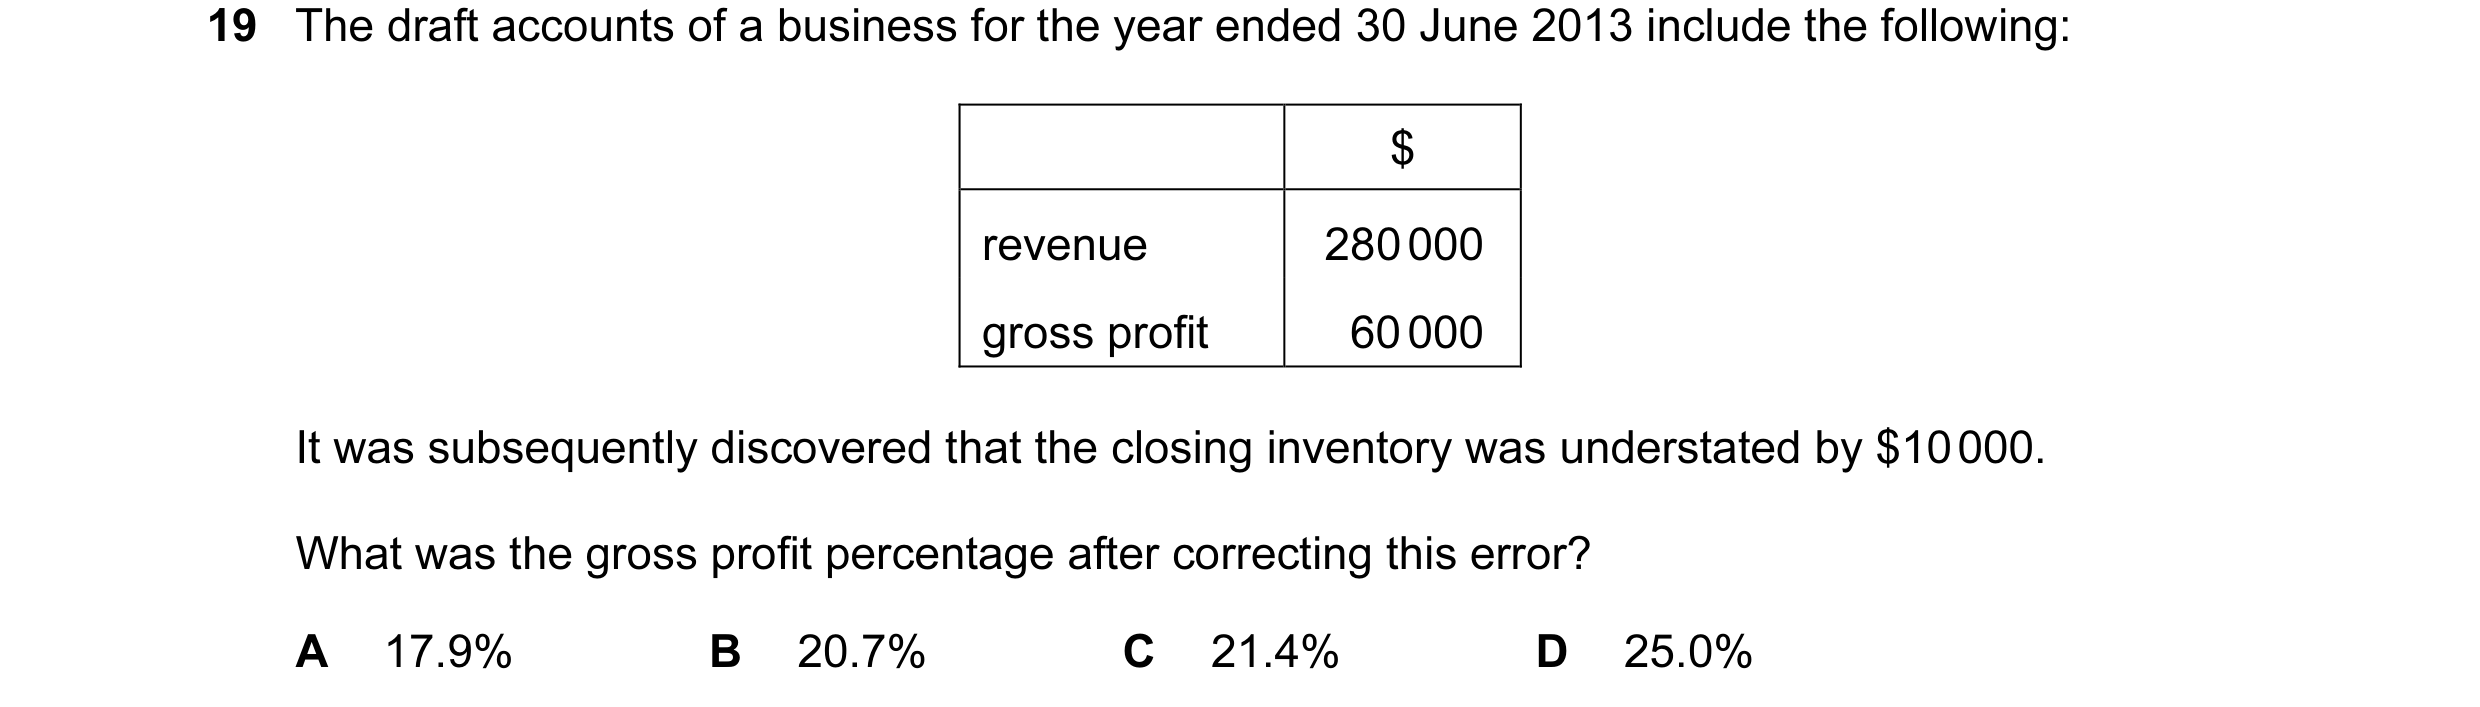
 98 / 233
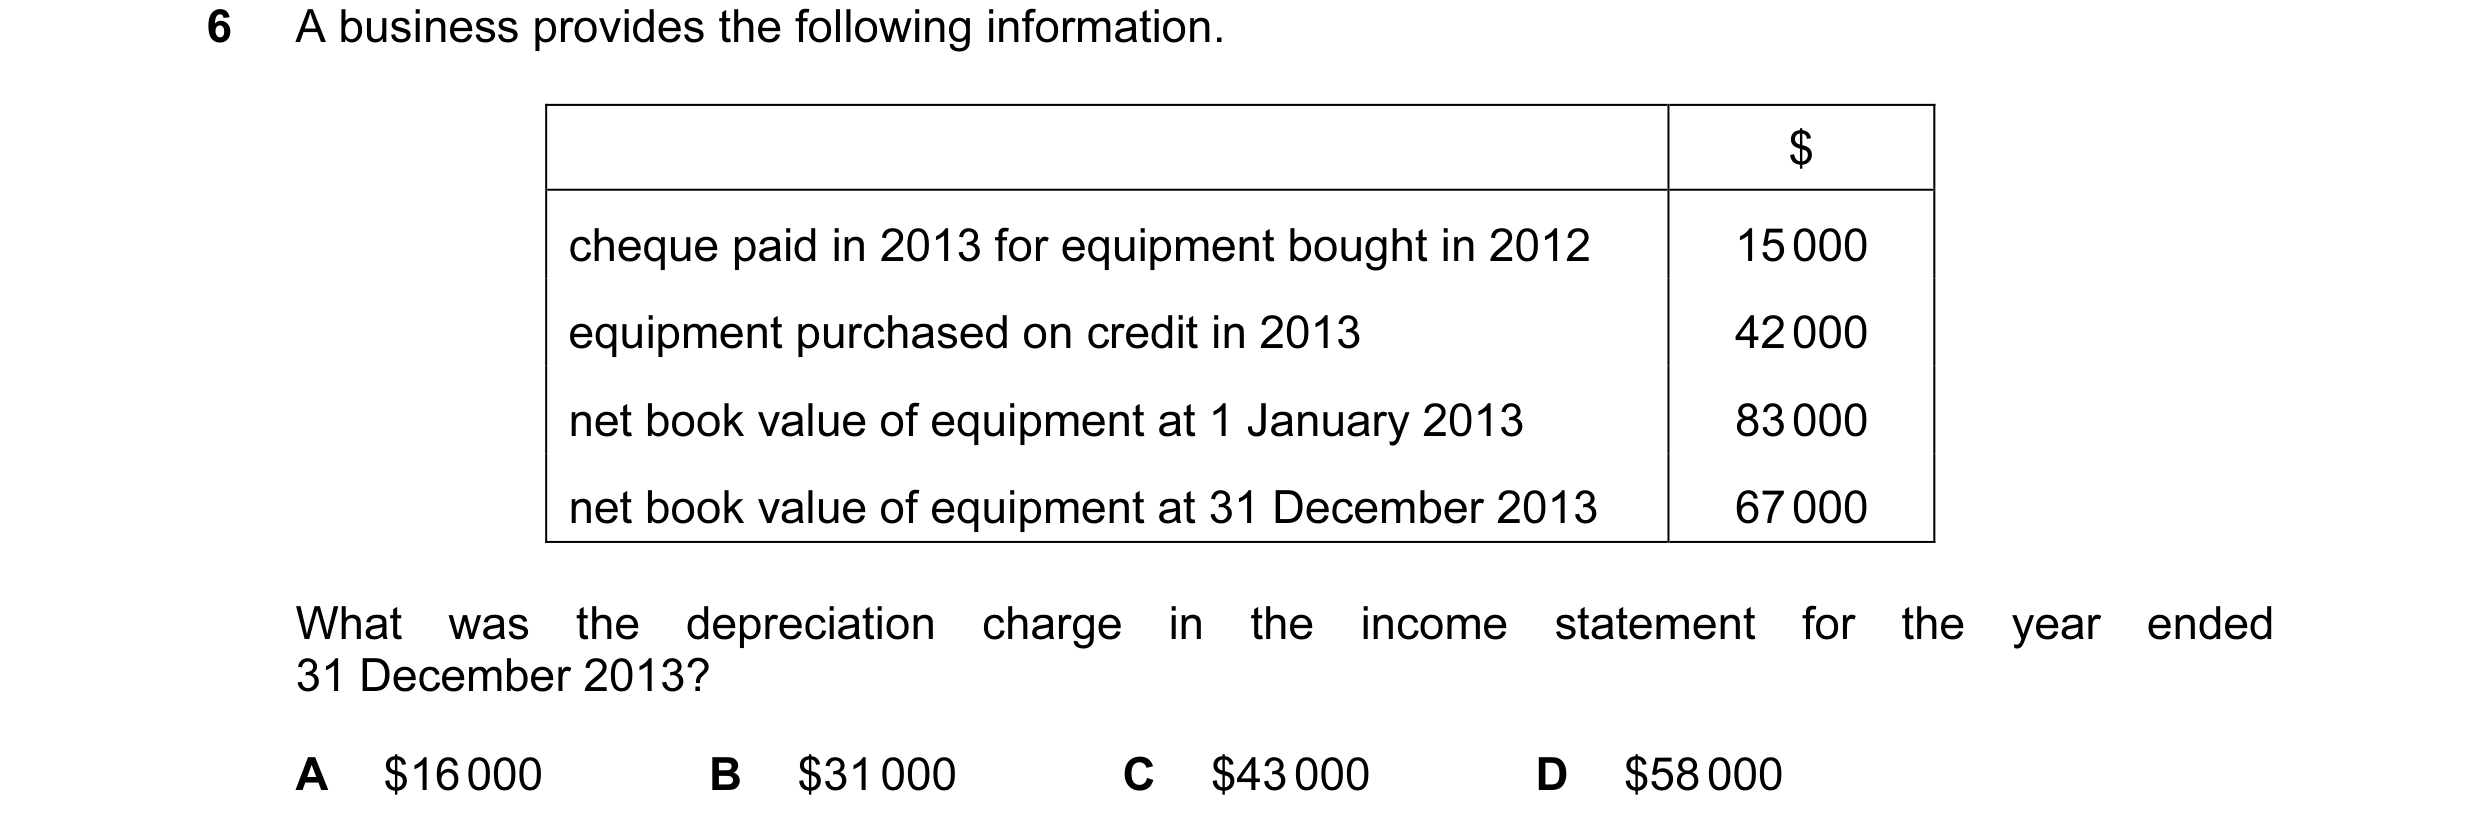
 99 / 233
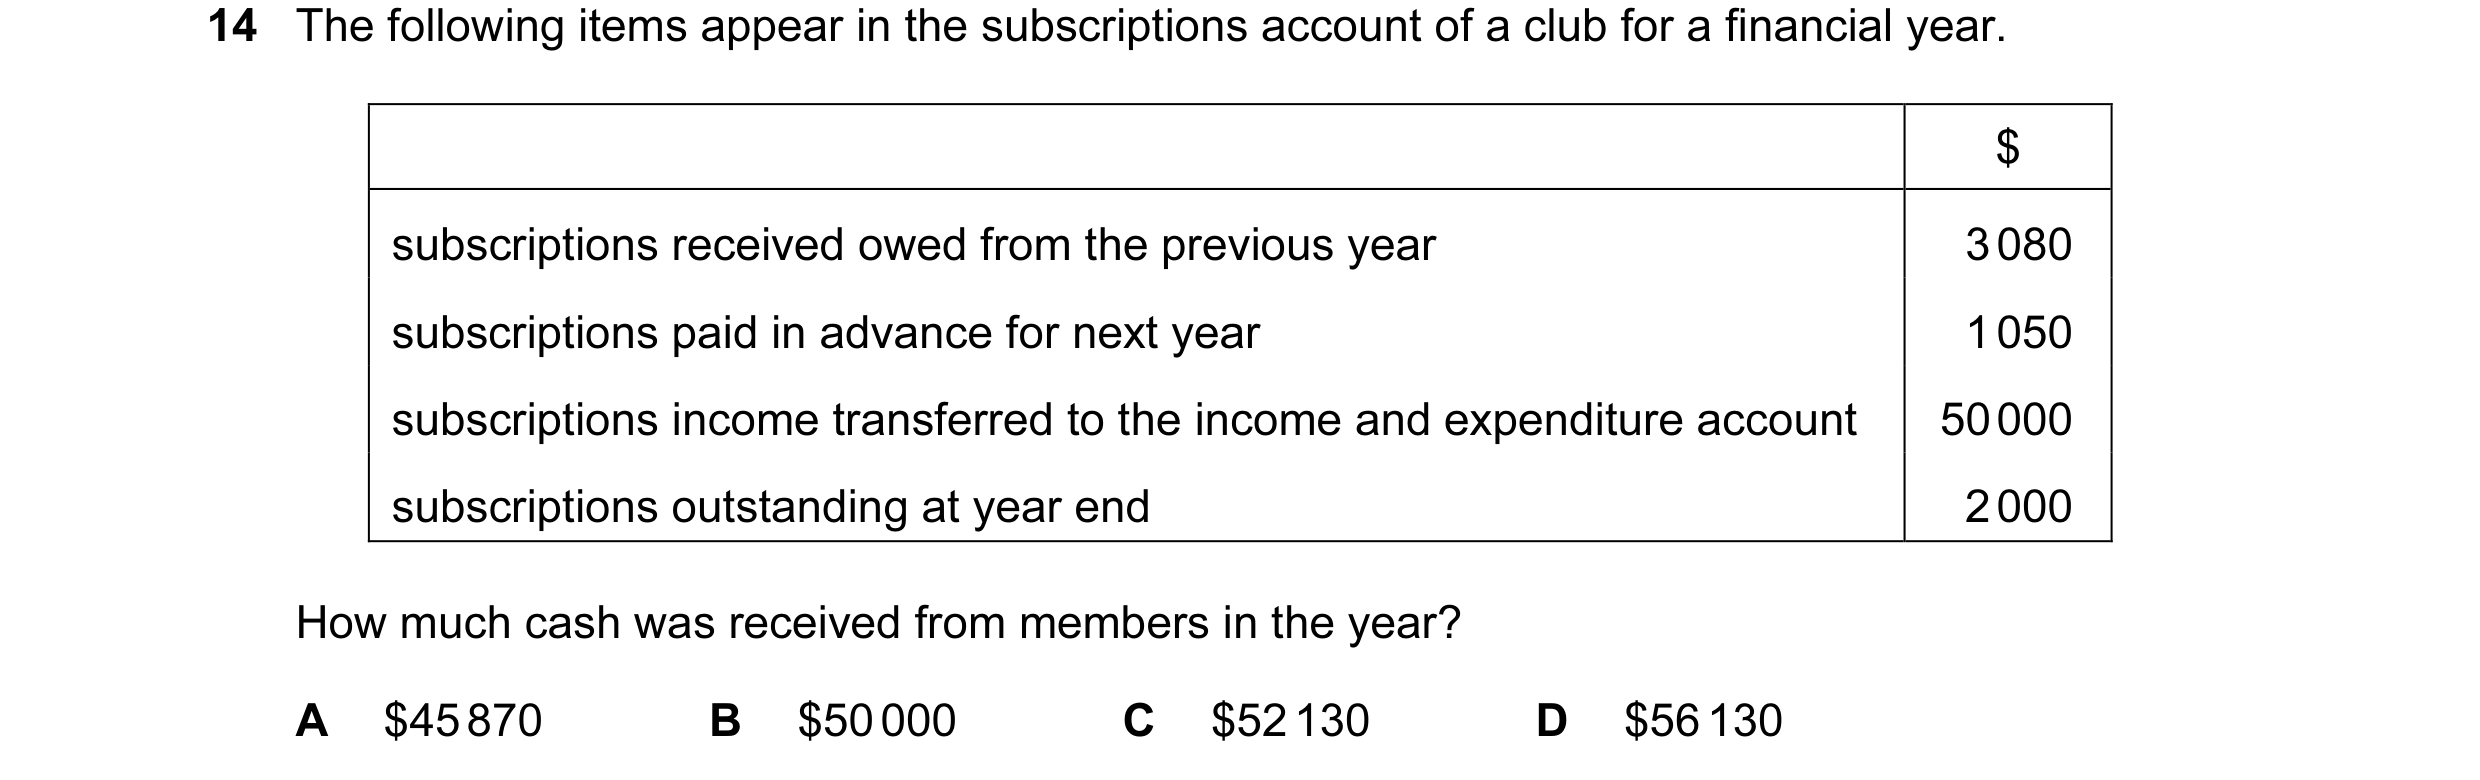
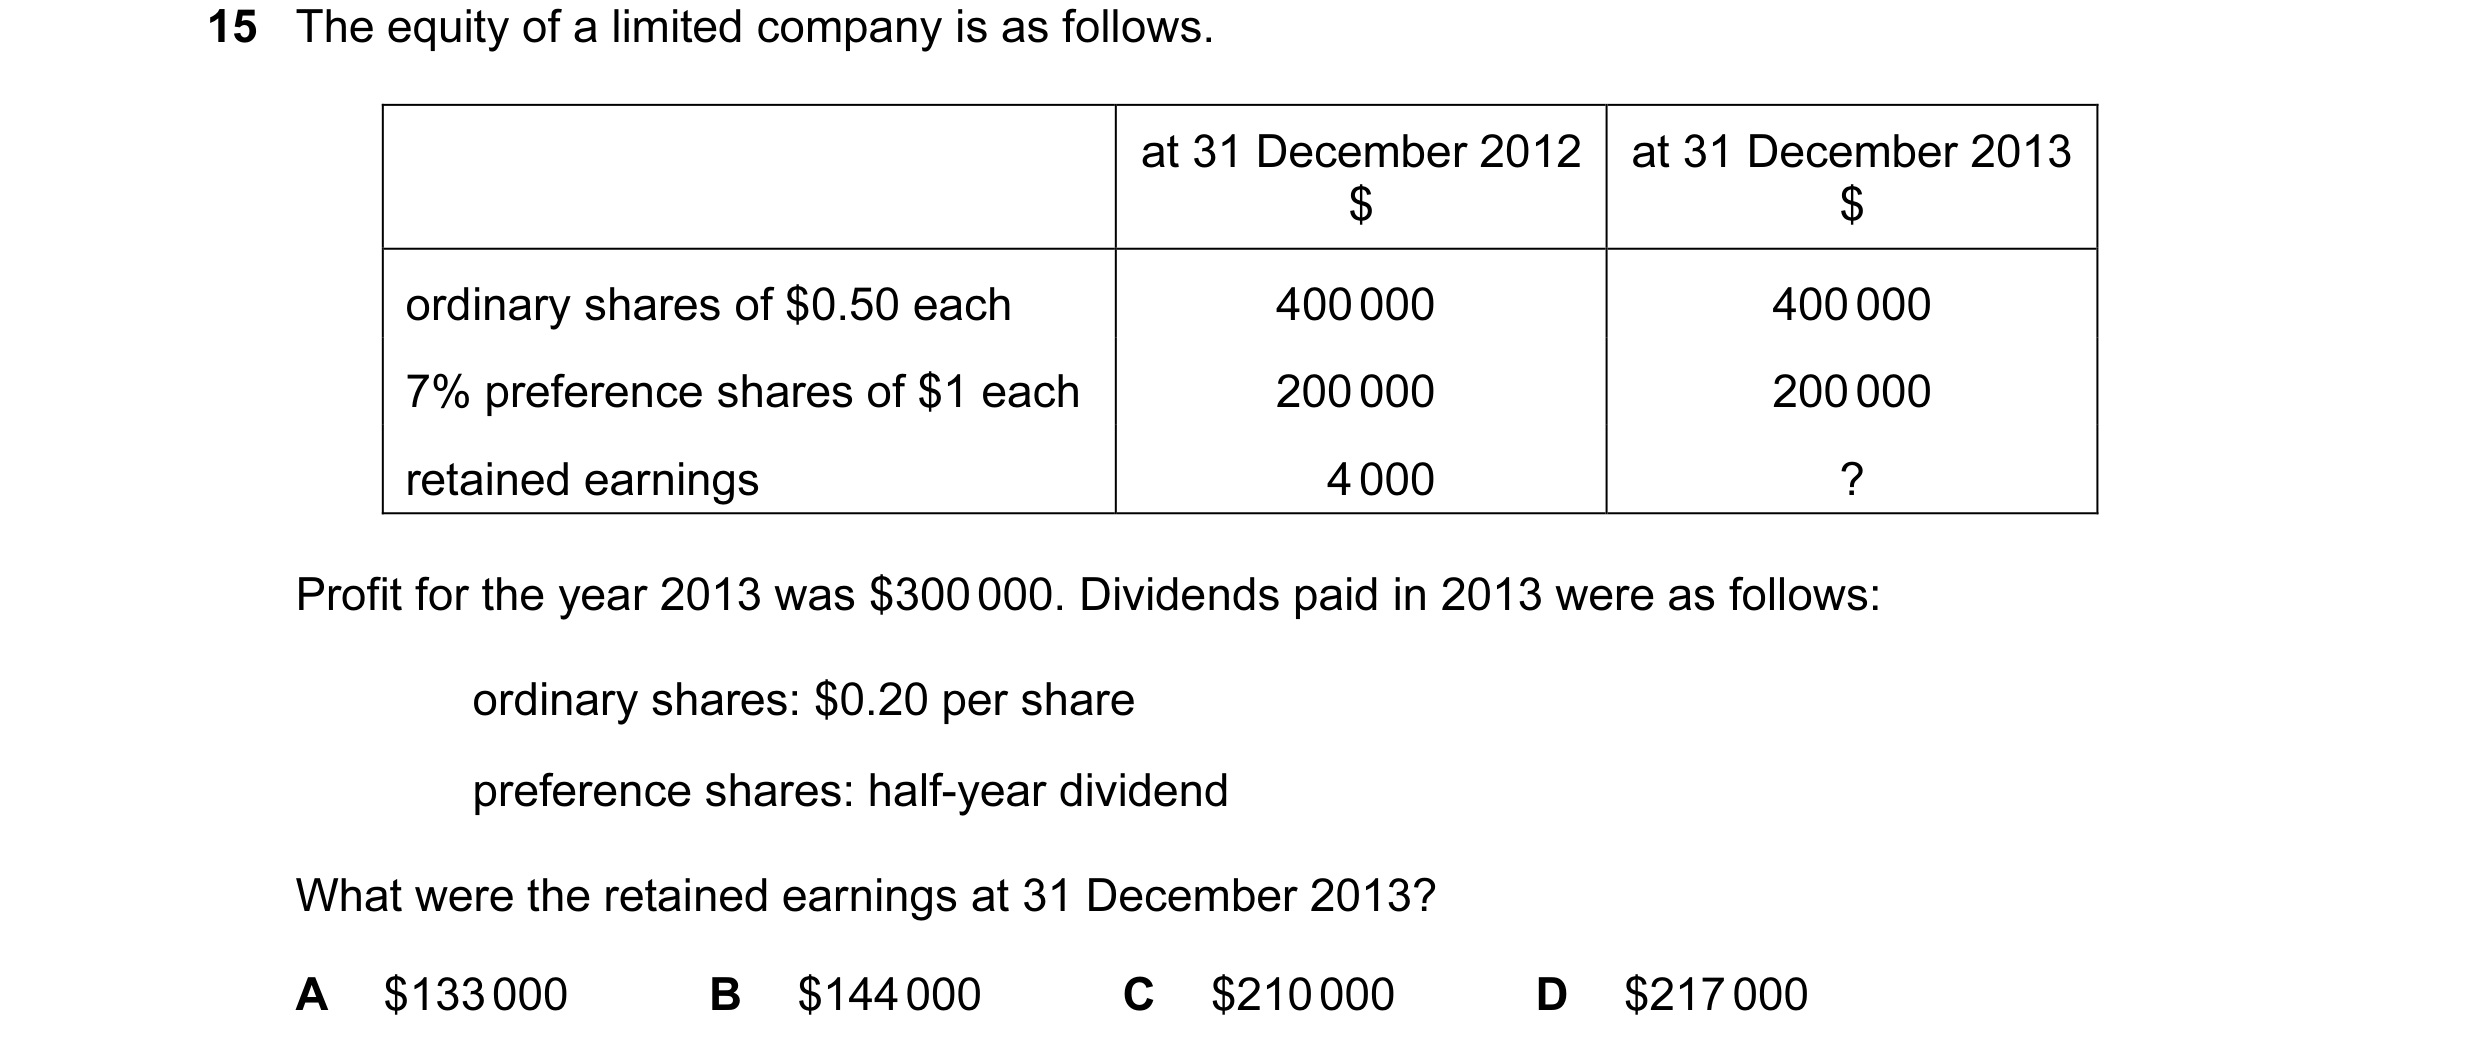
 100 / 233
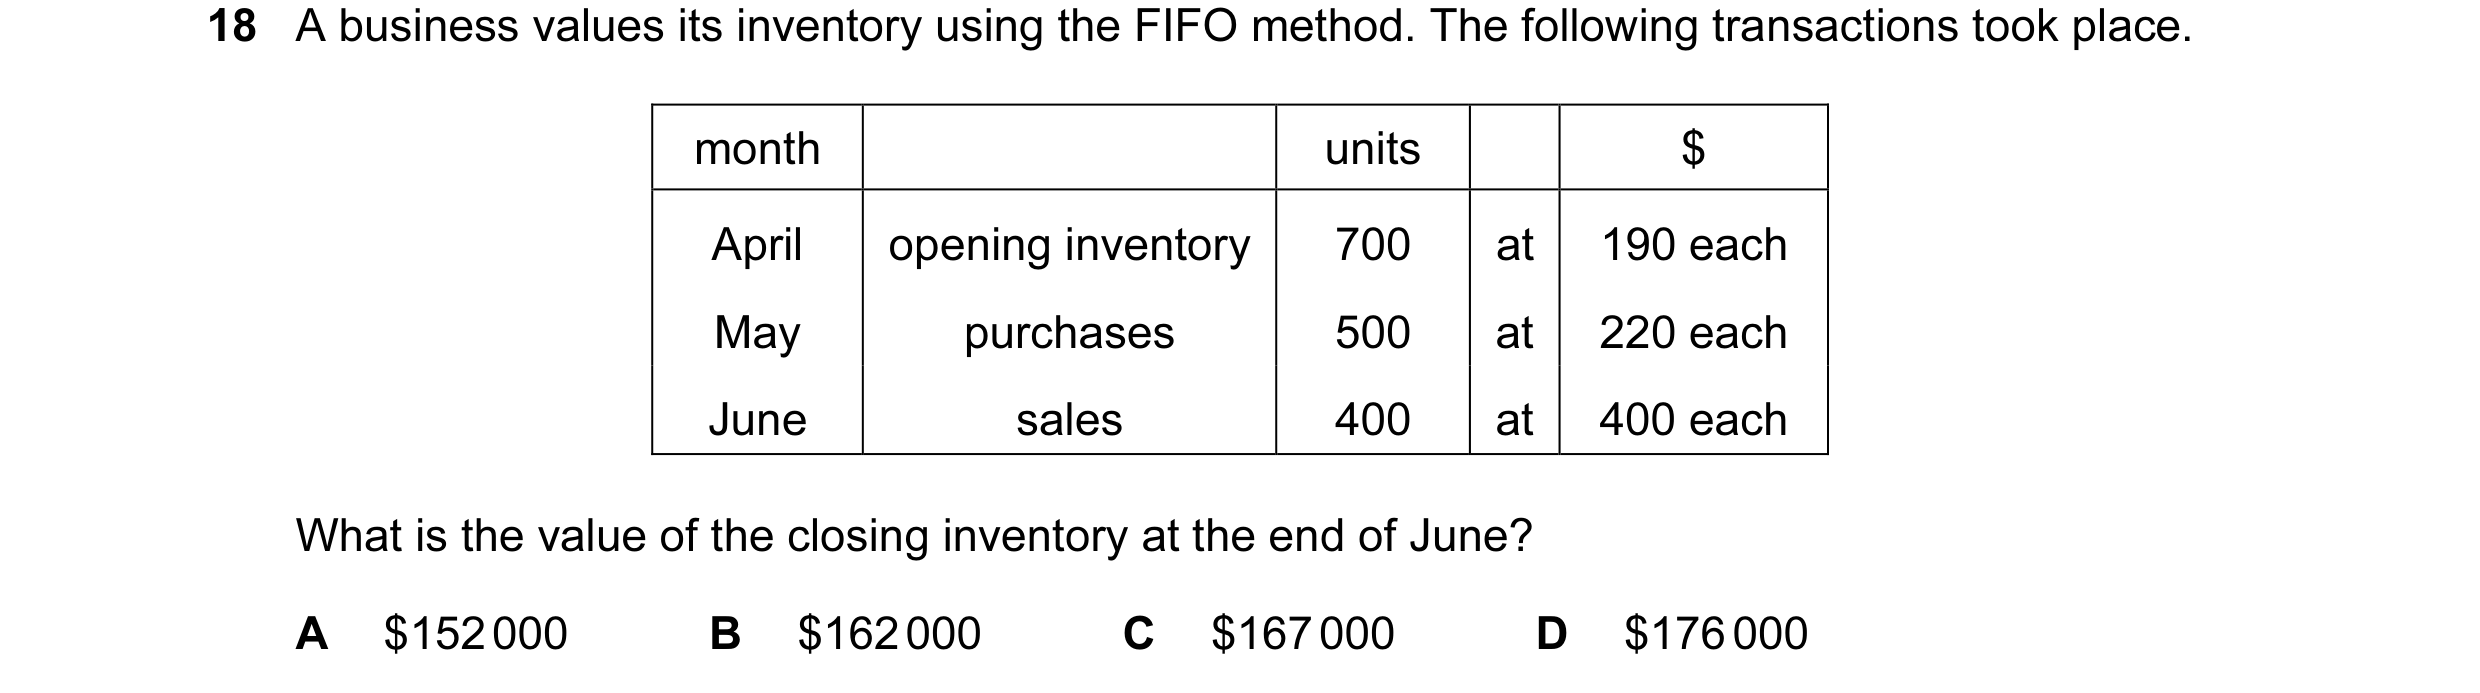
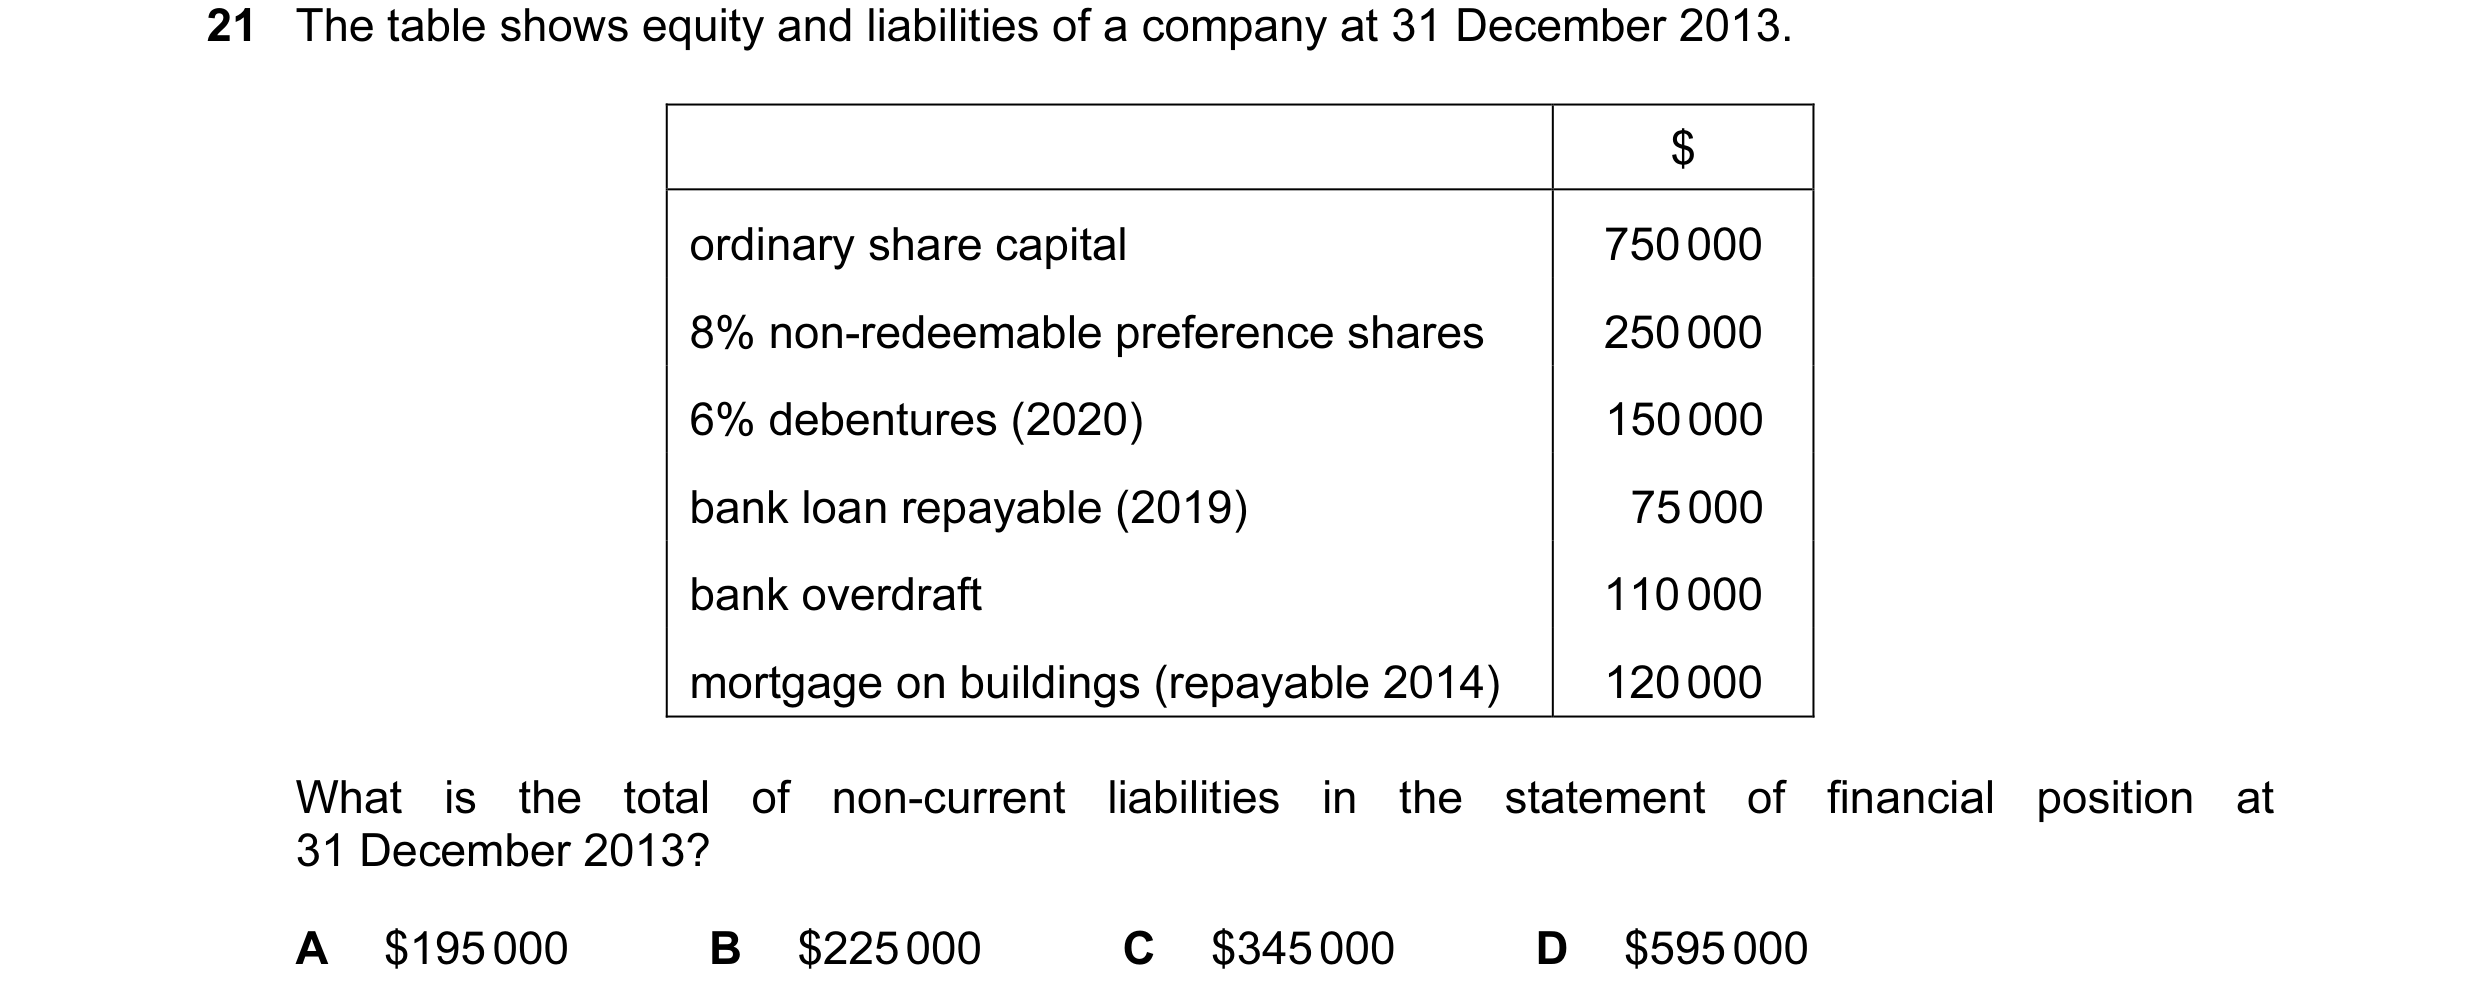 101 / 233
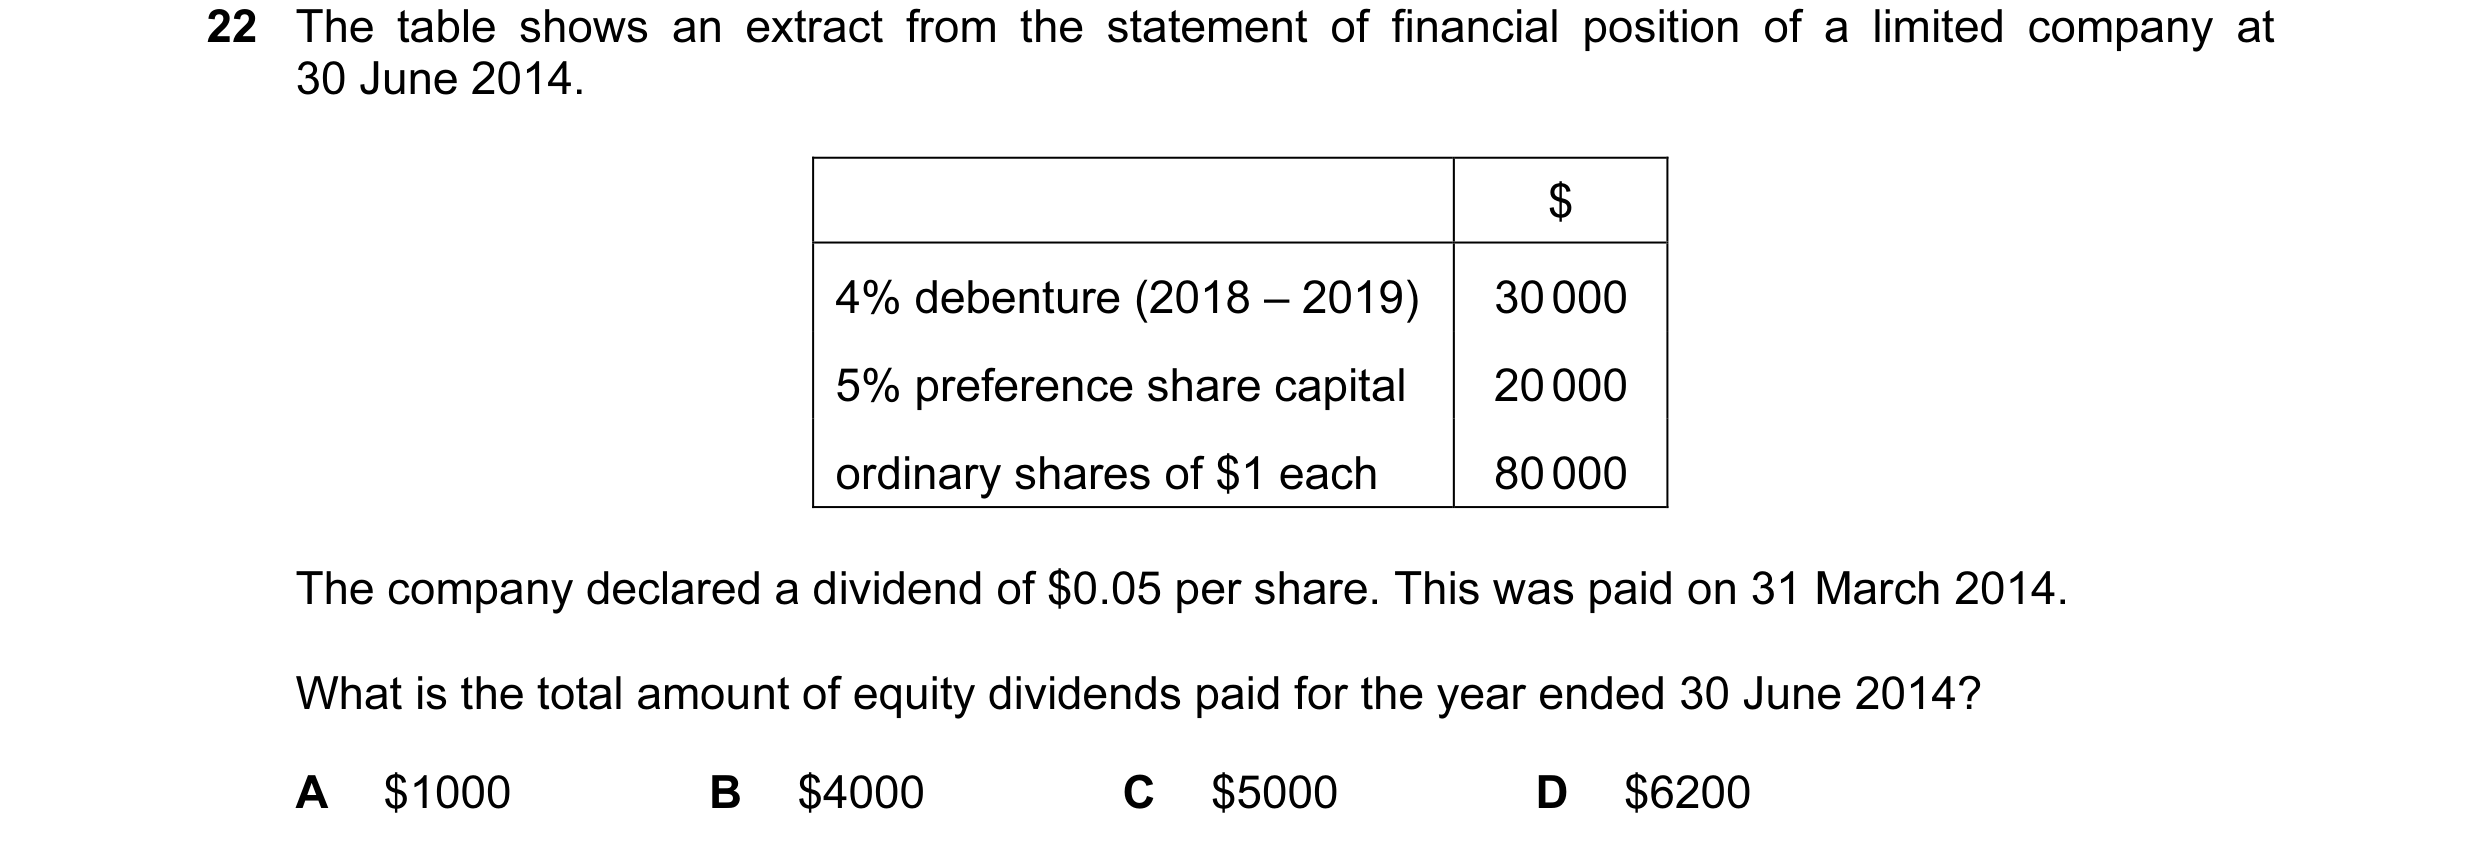
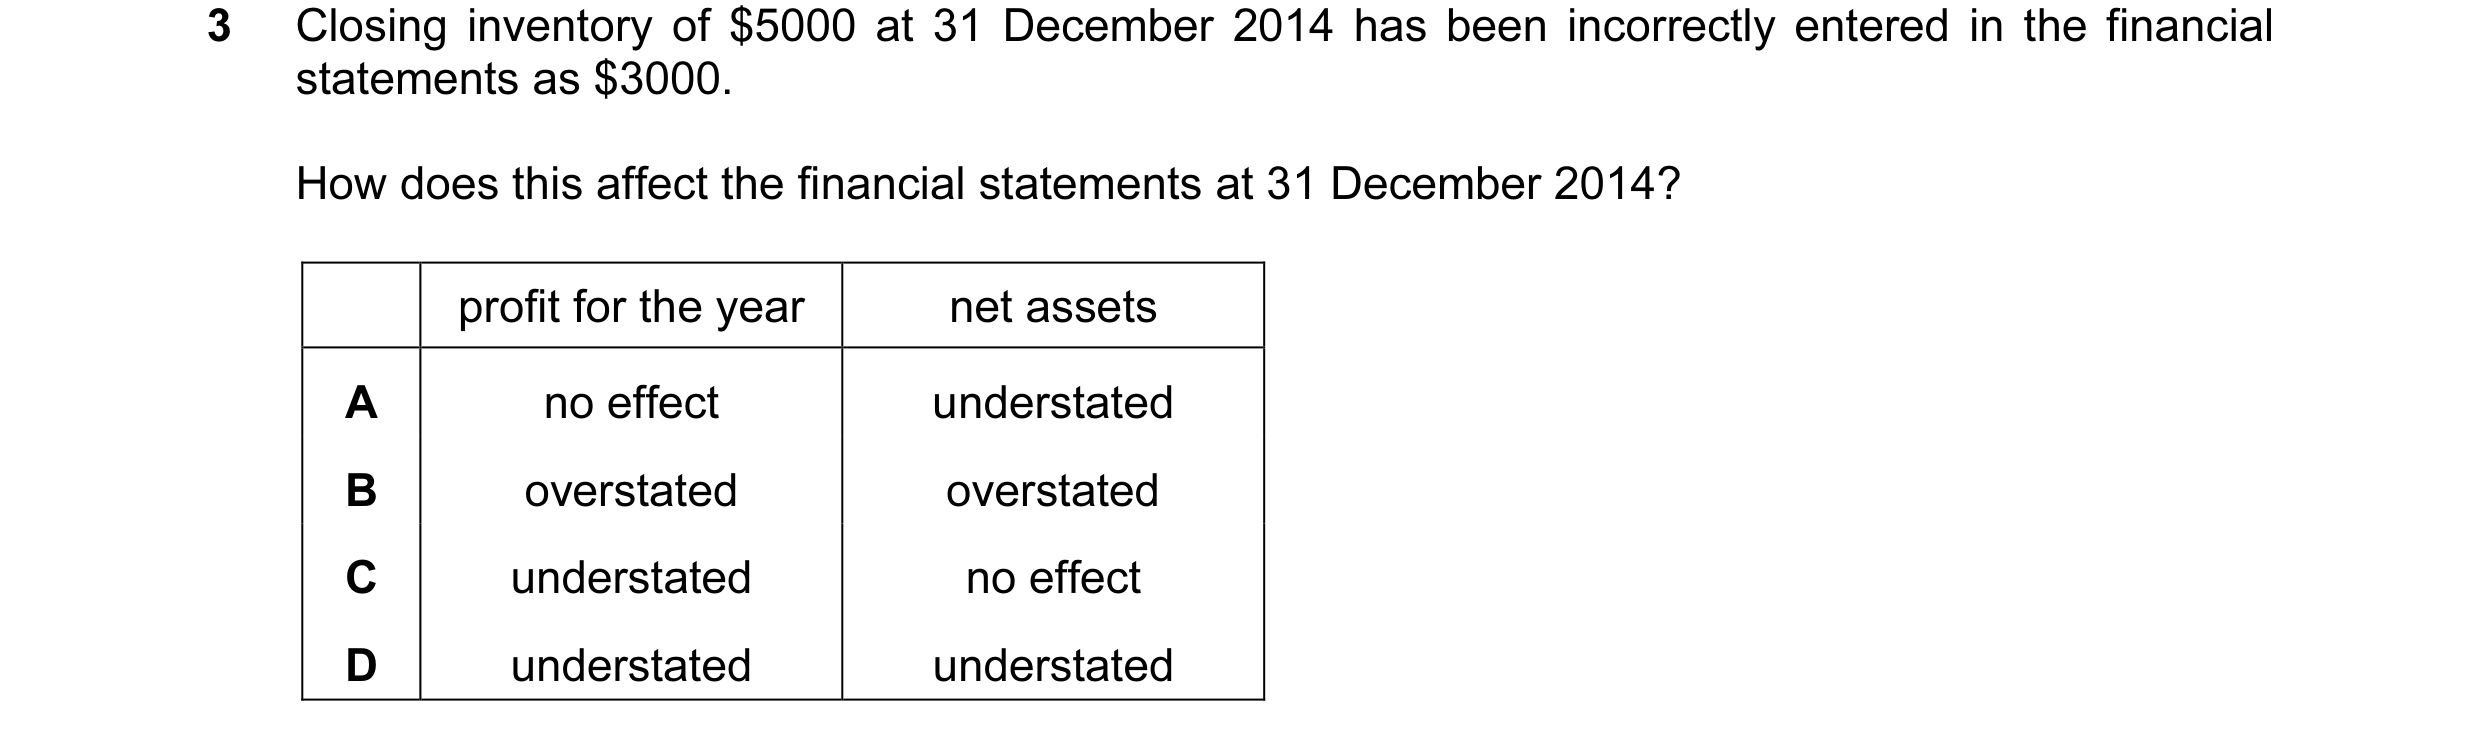
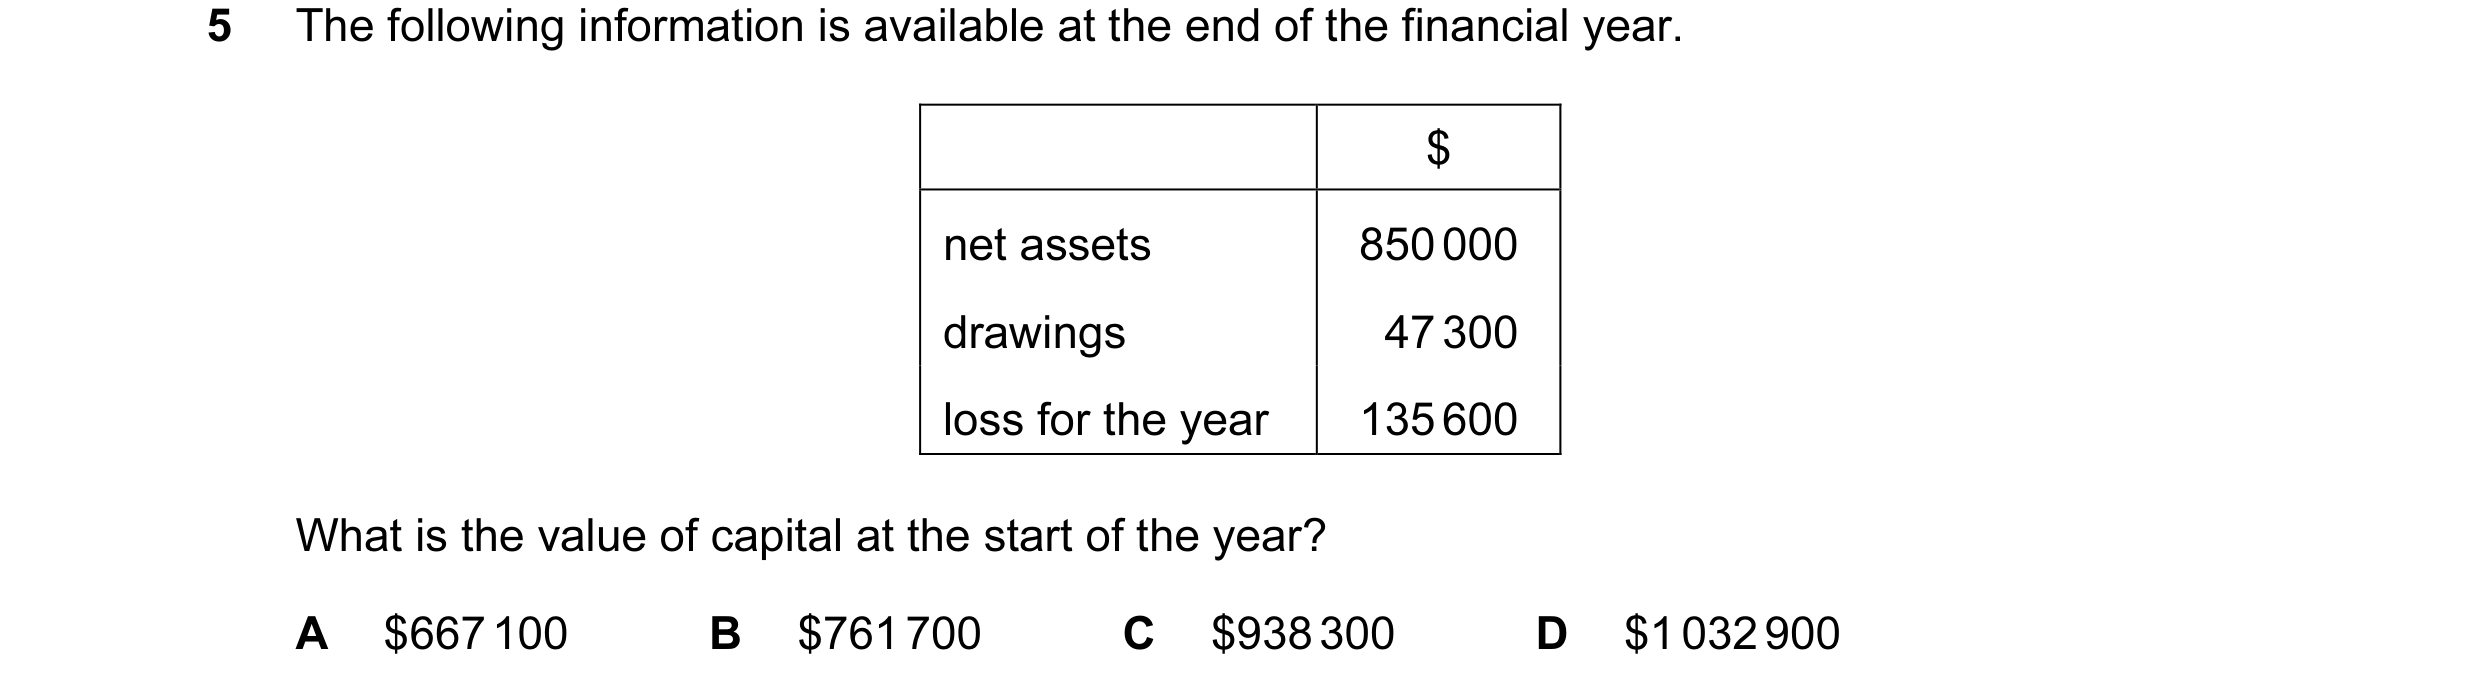 102 / 233
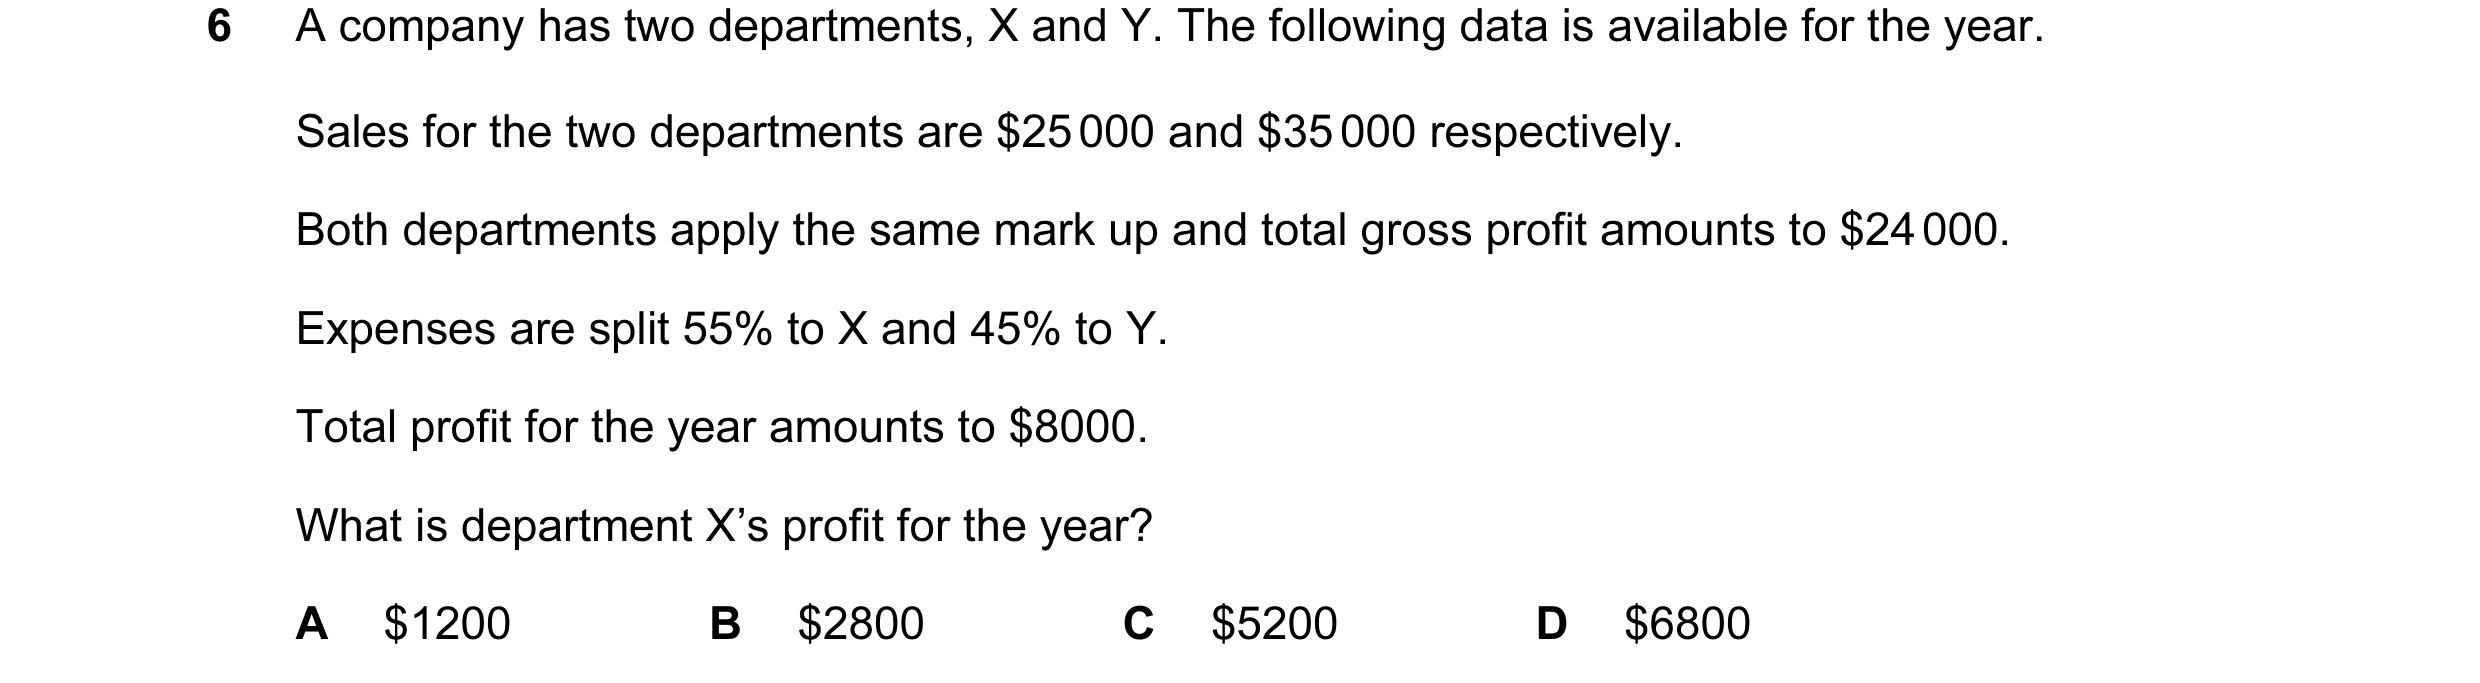
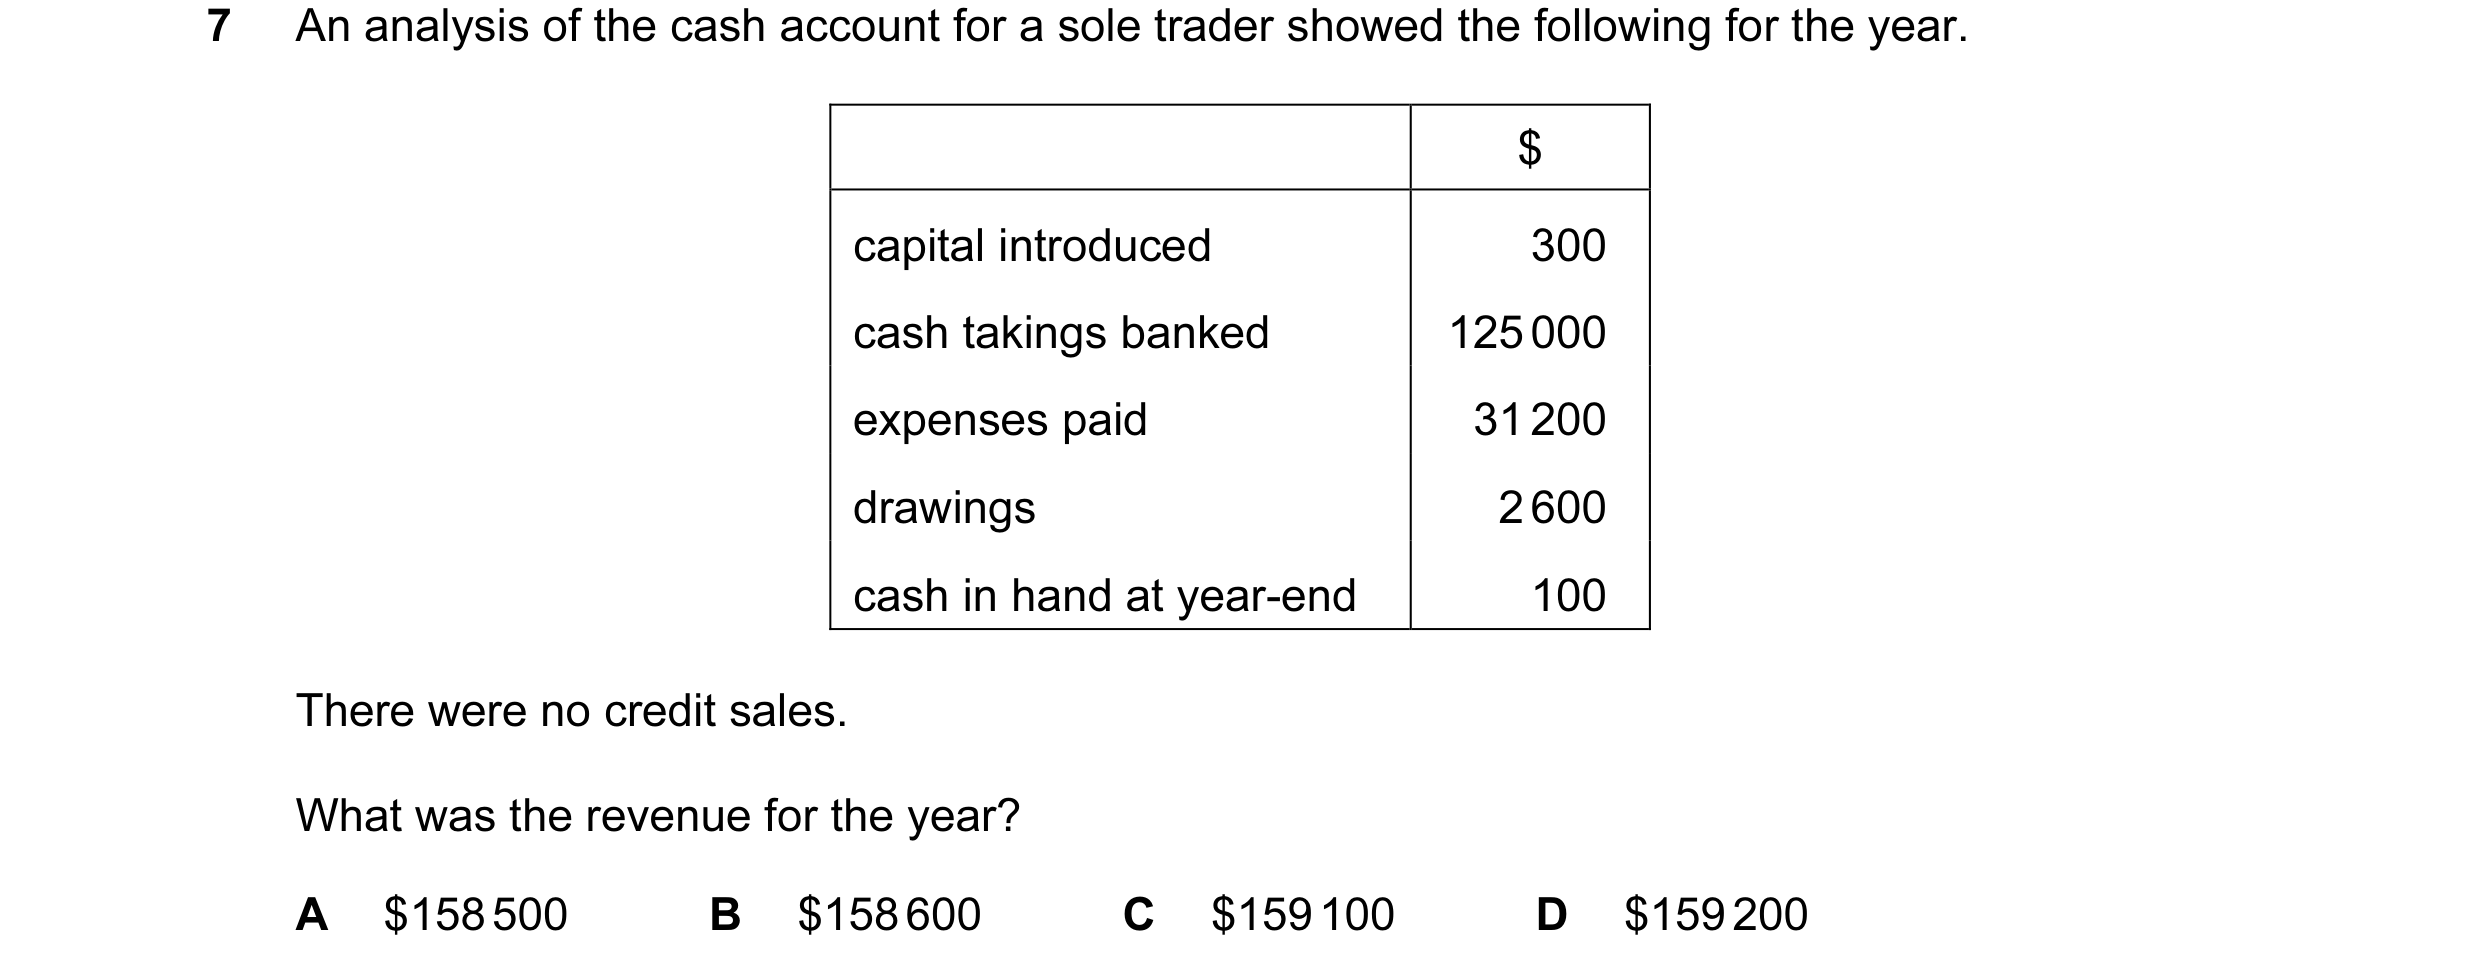
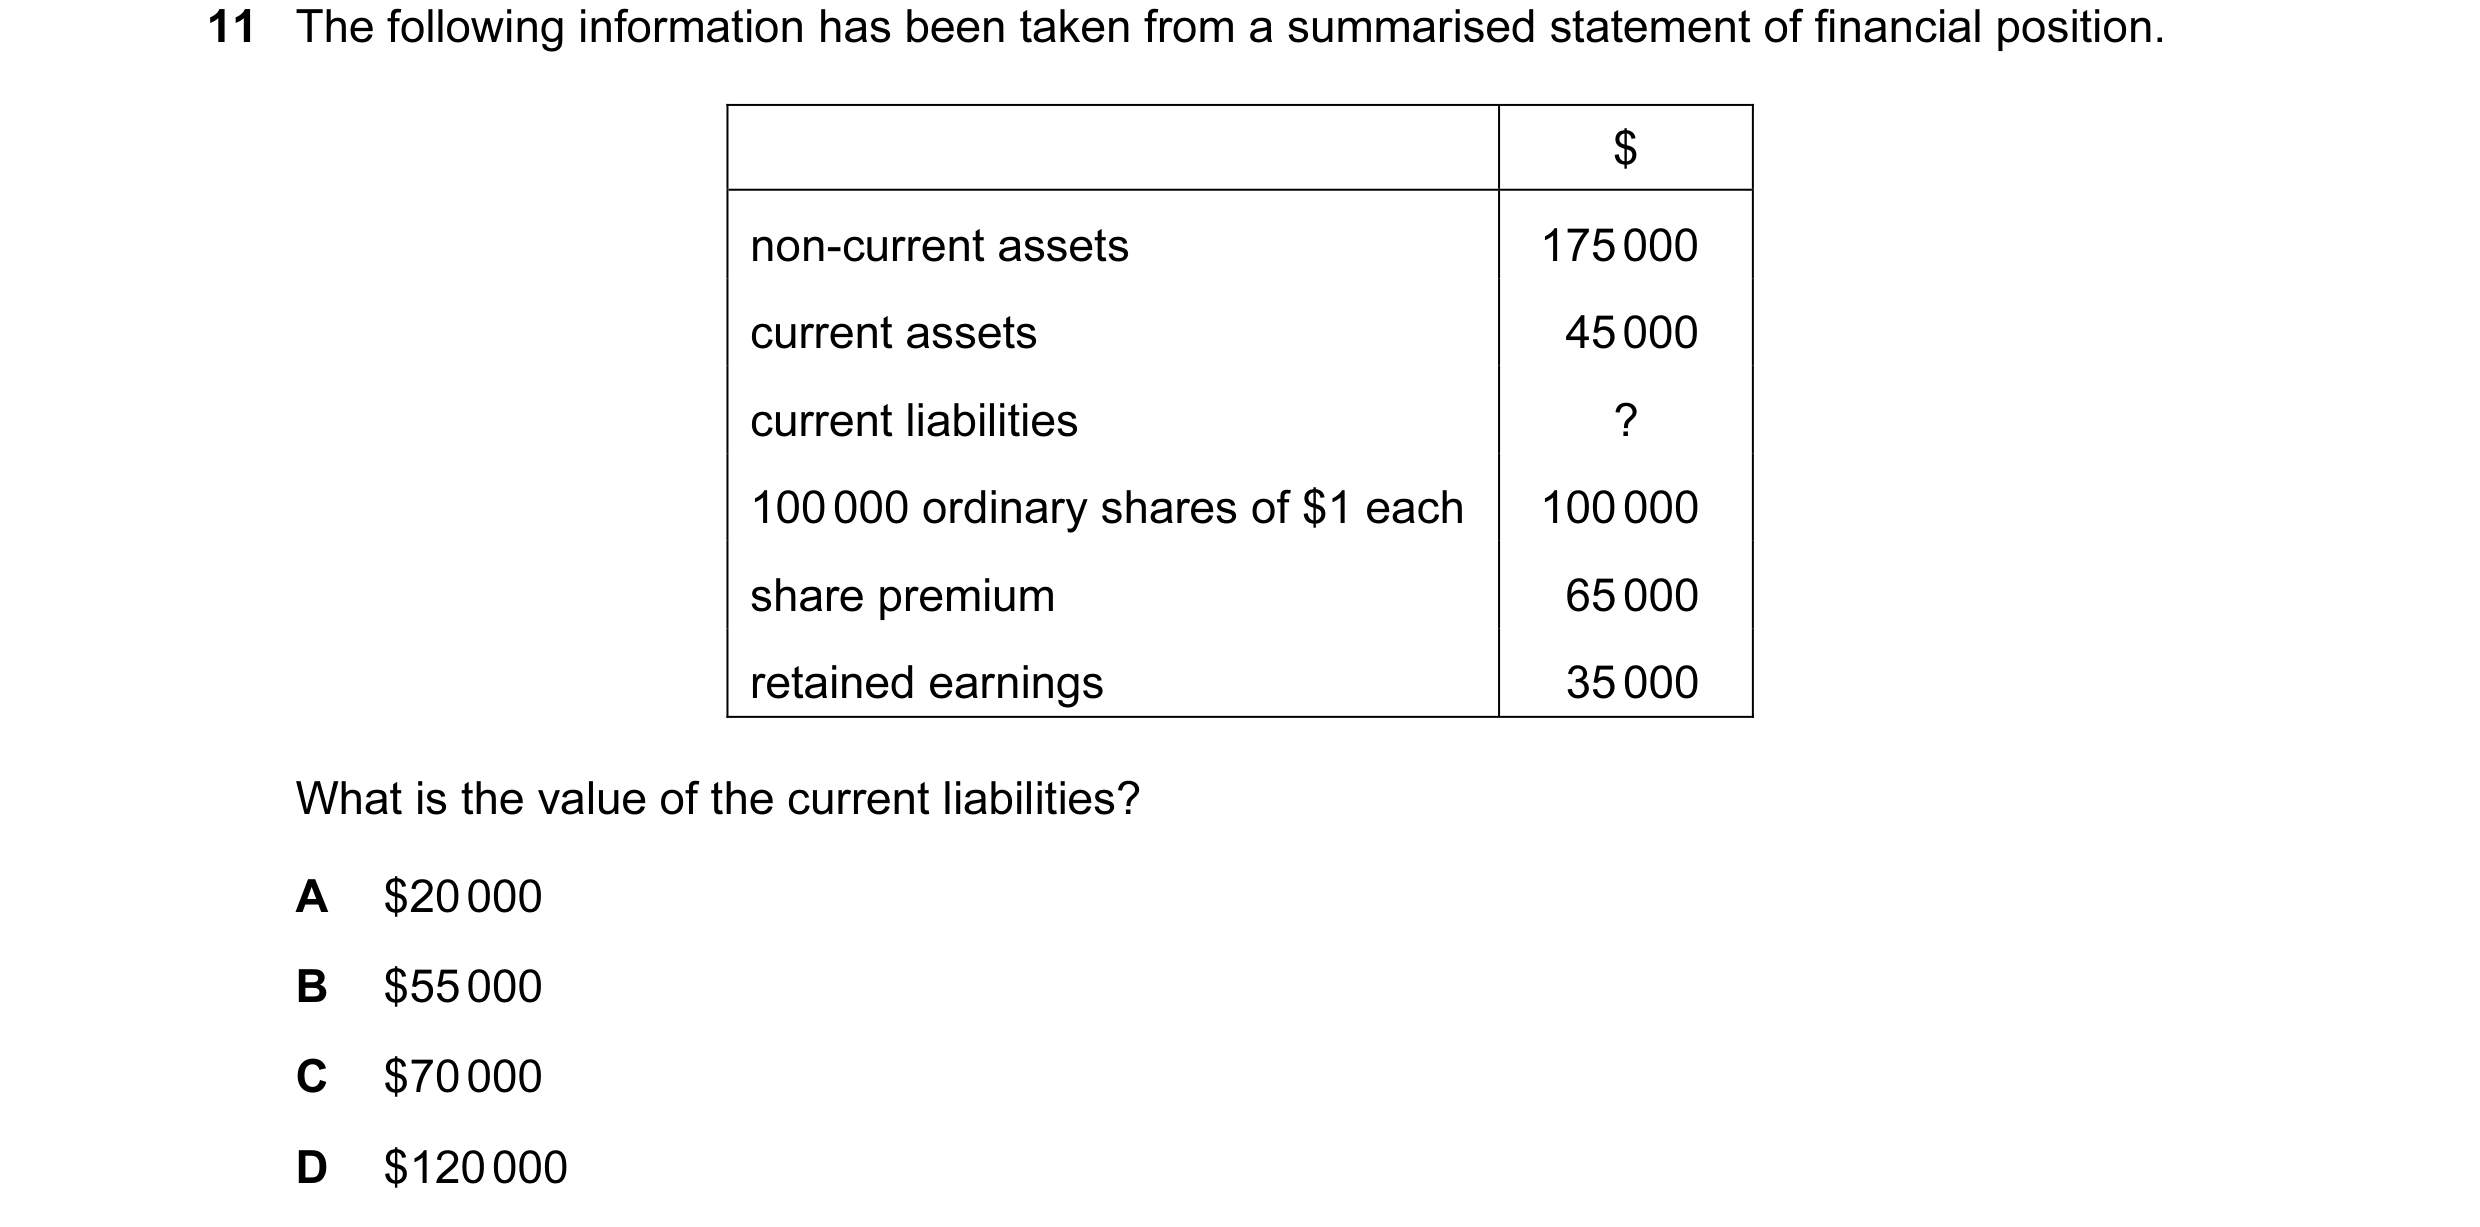
 103 / 233
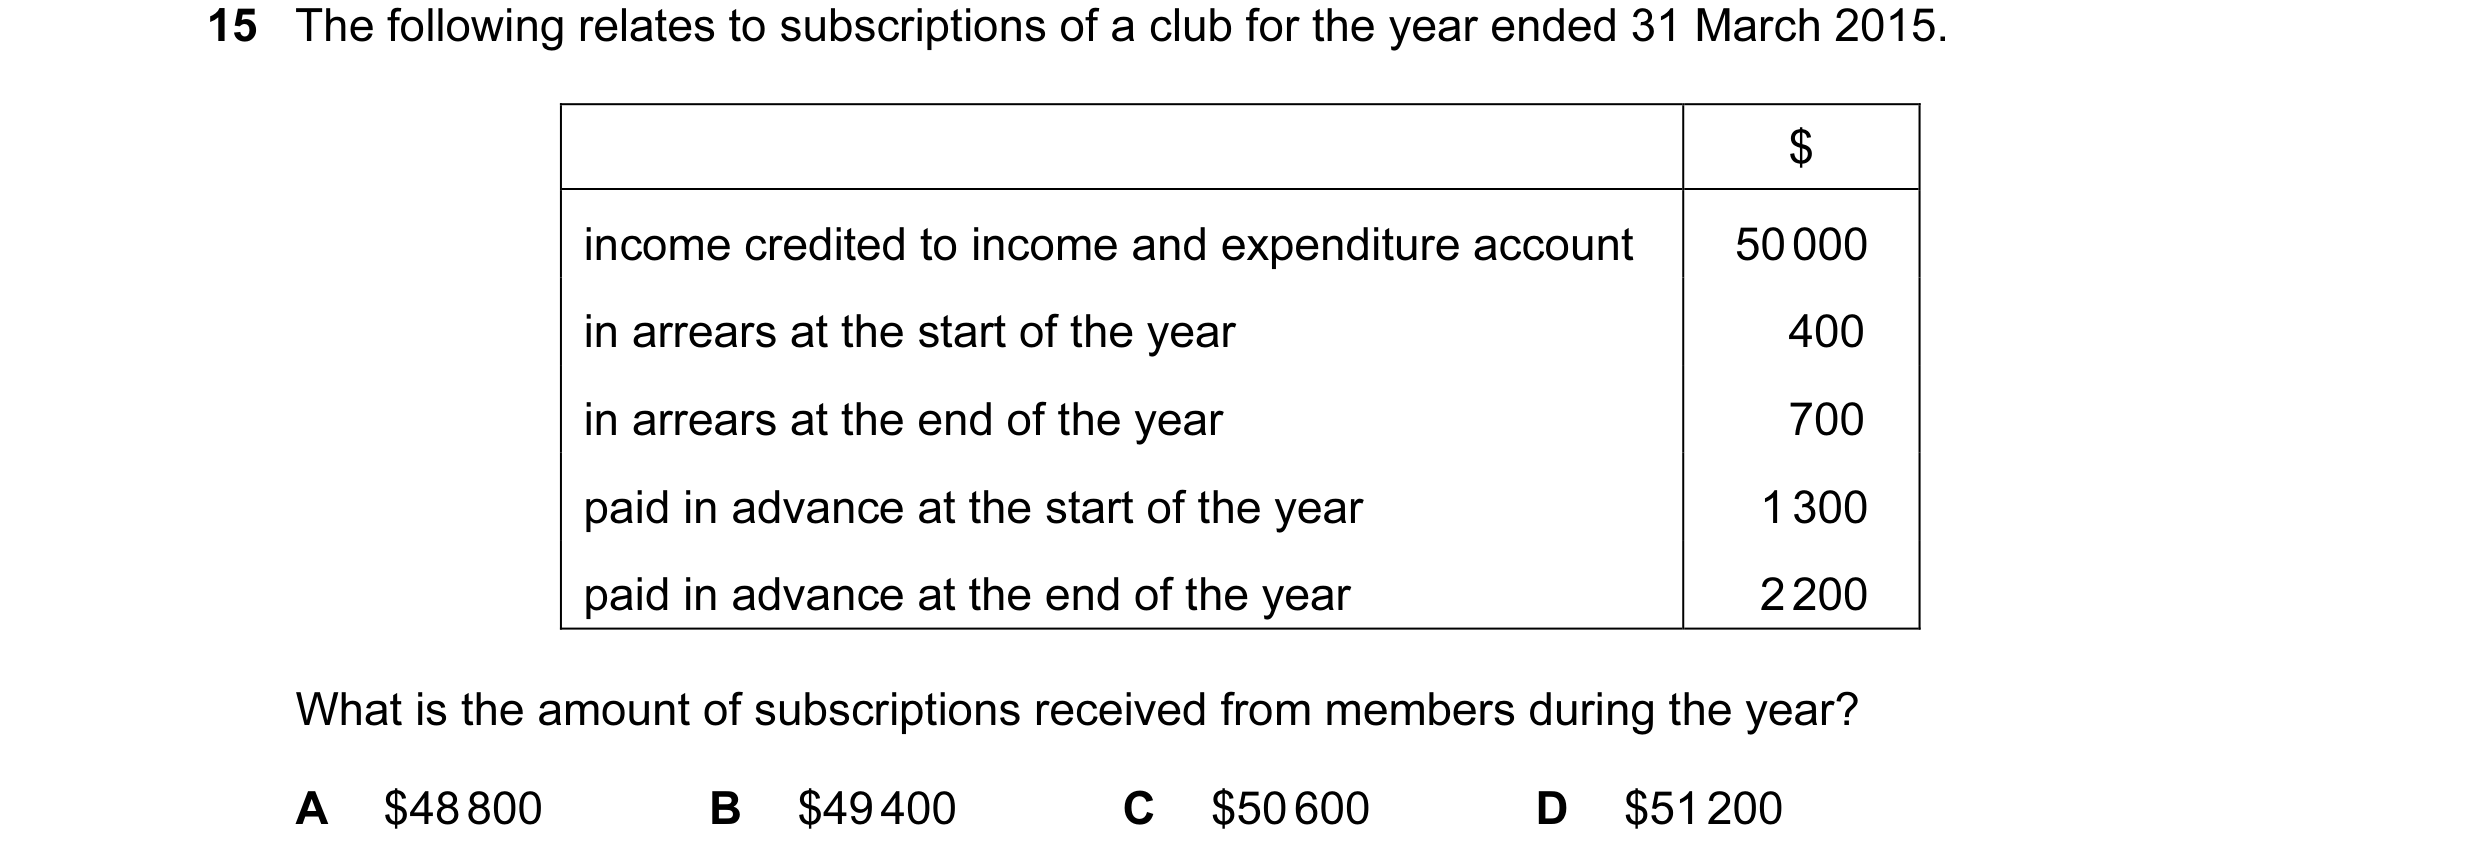
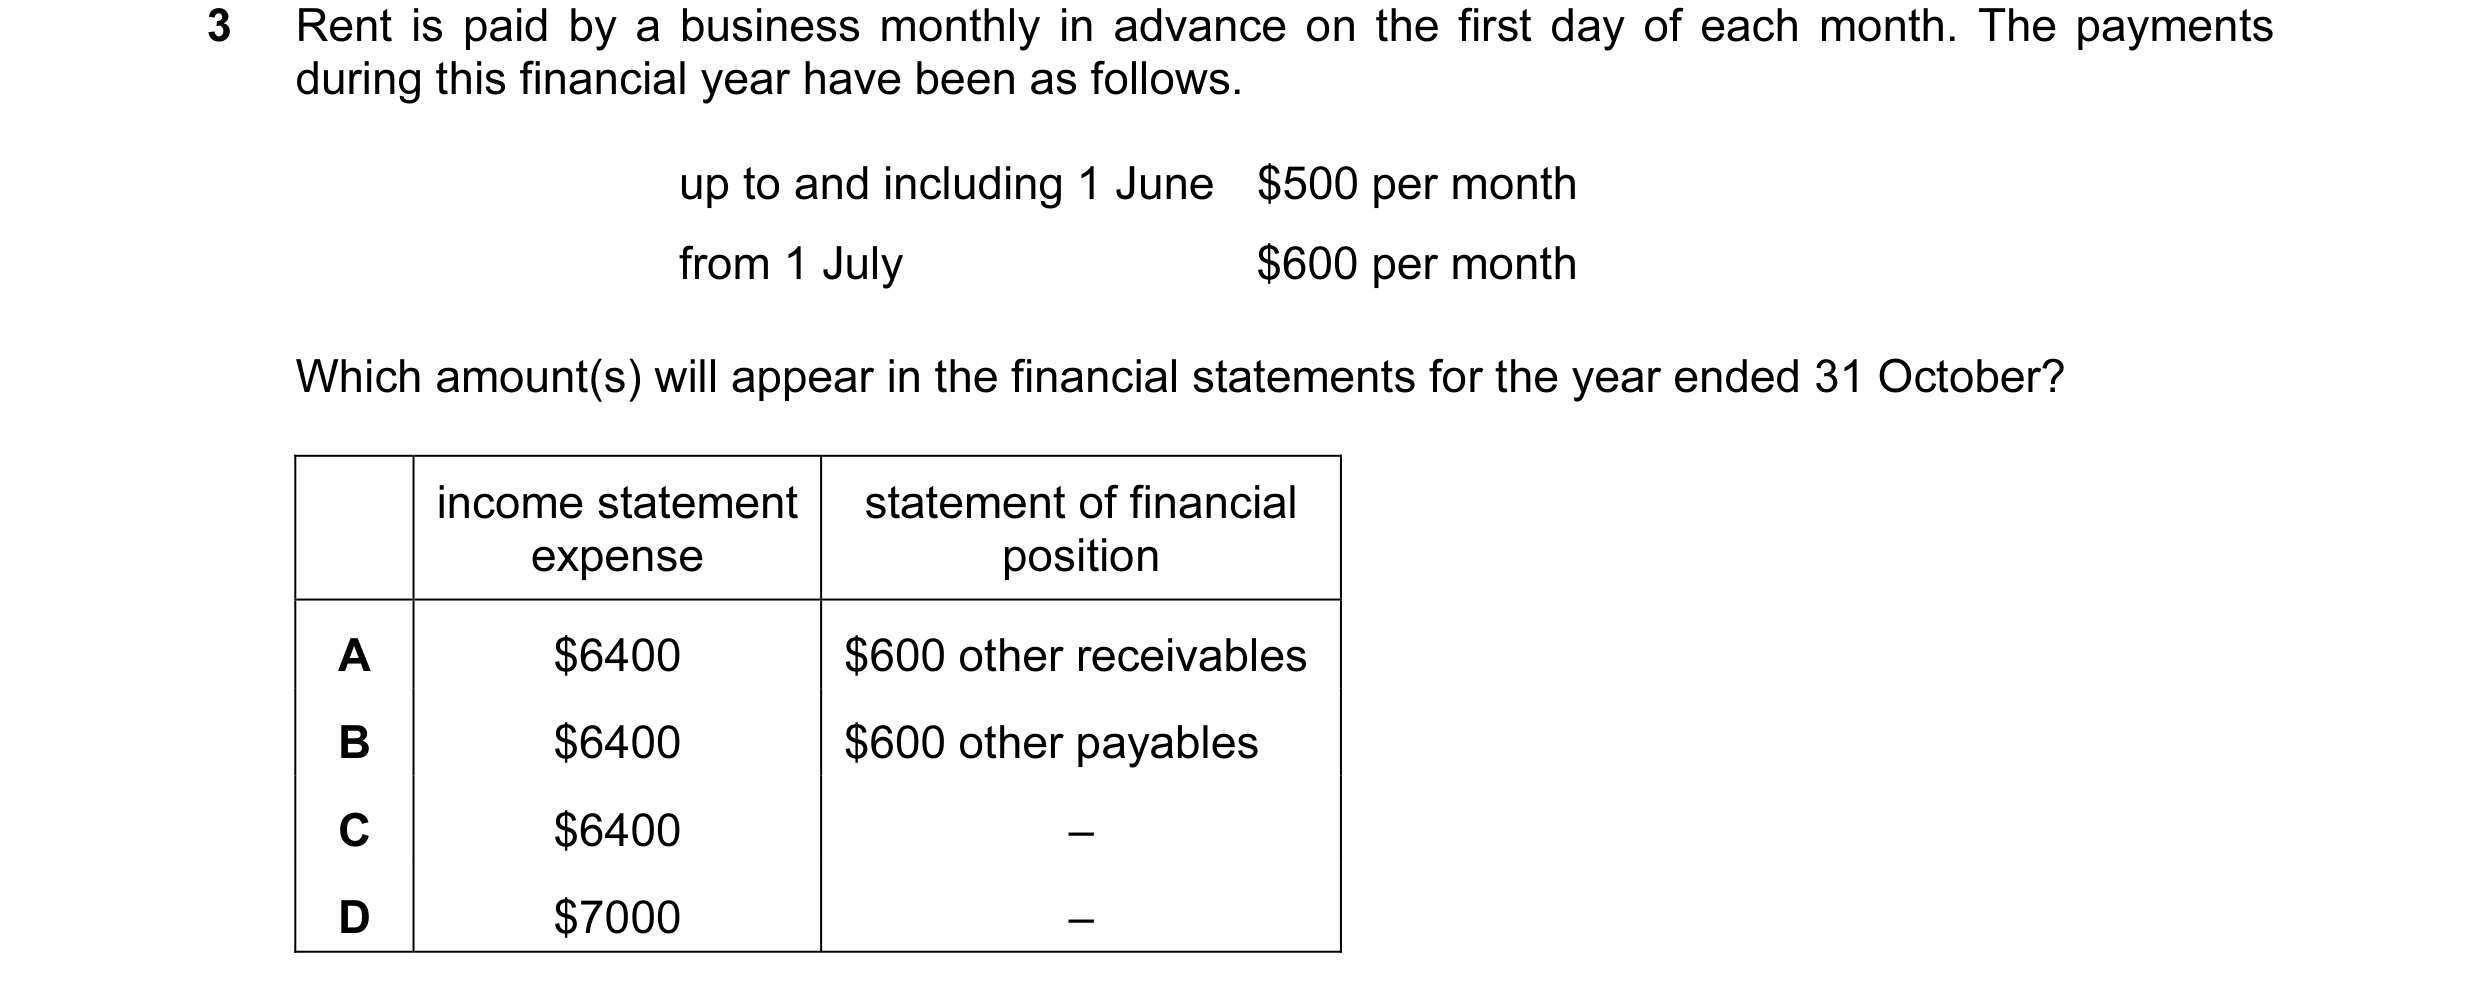
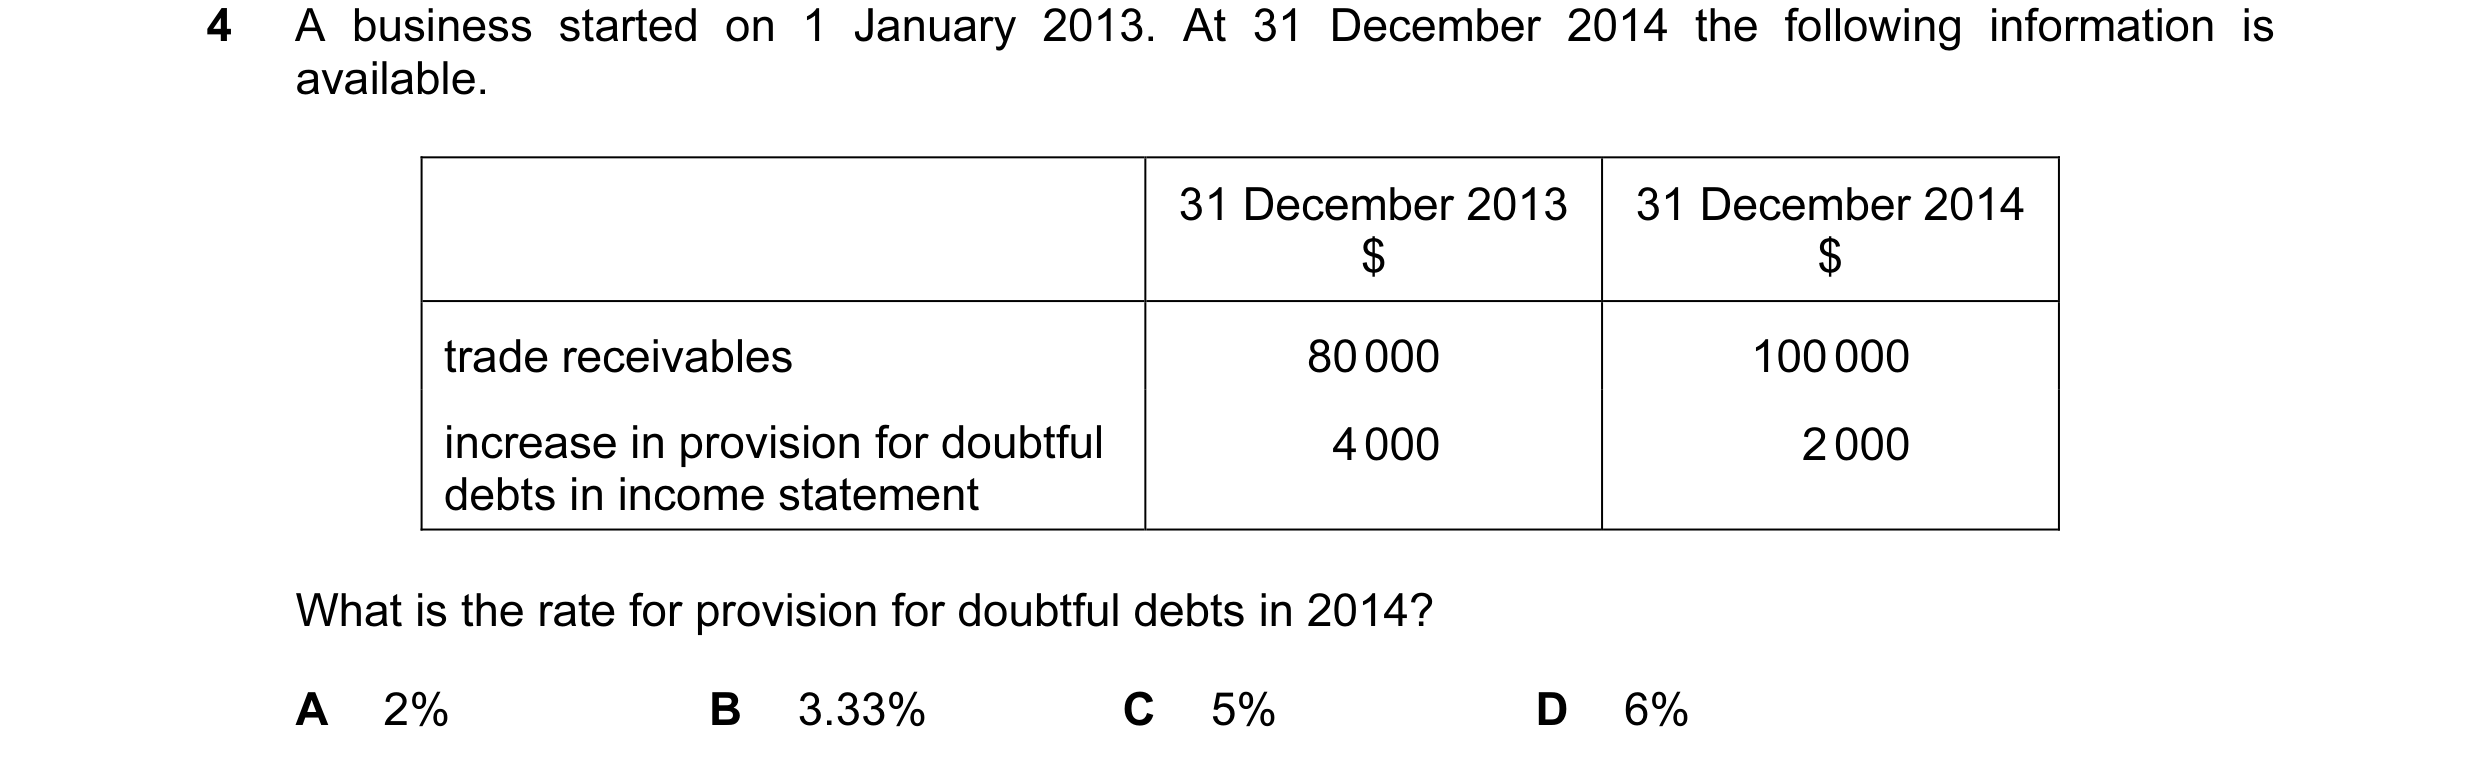 104 / 233
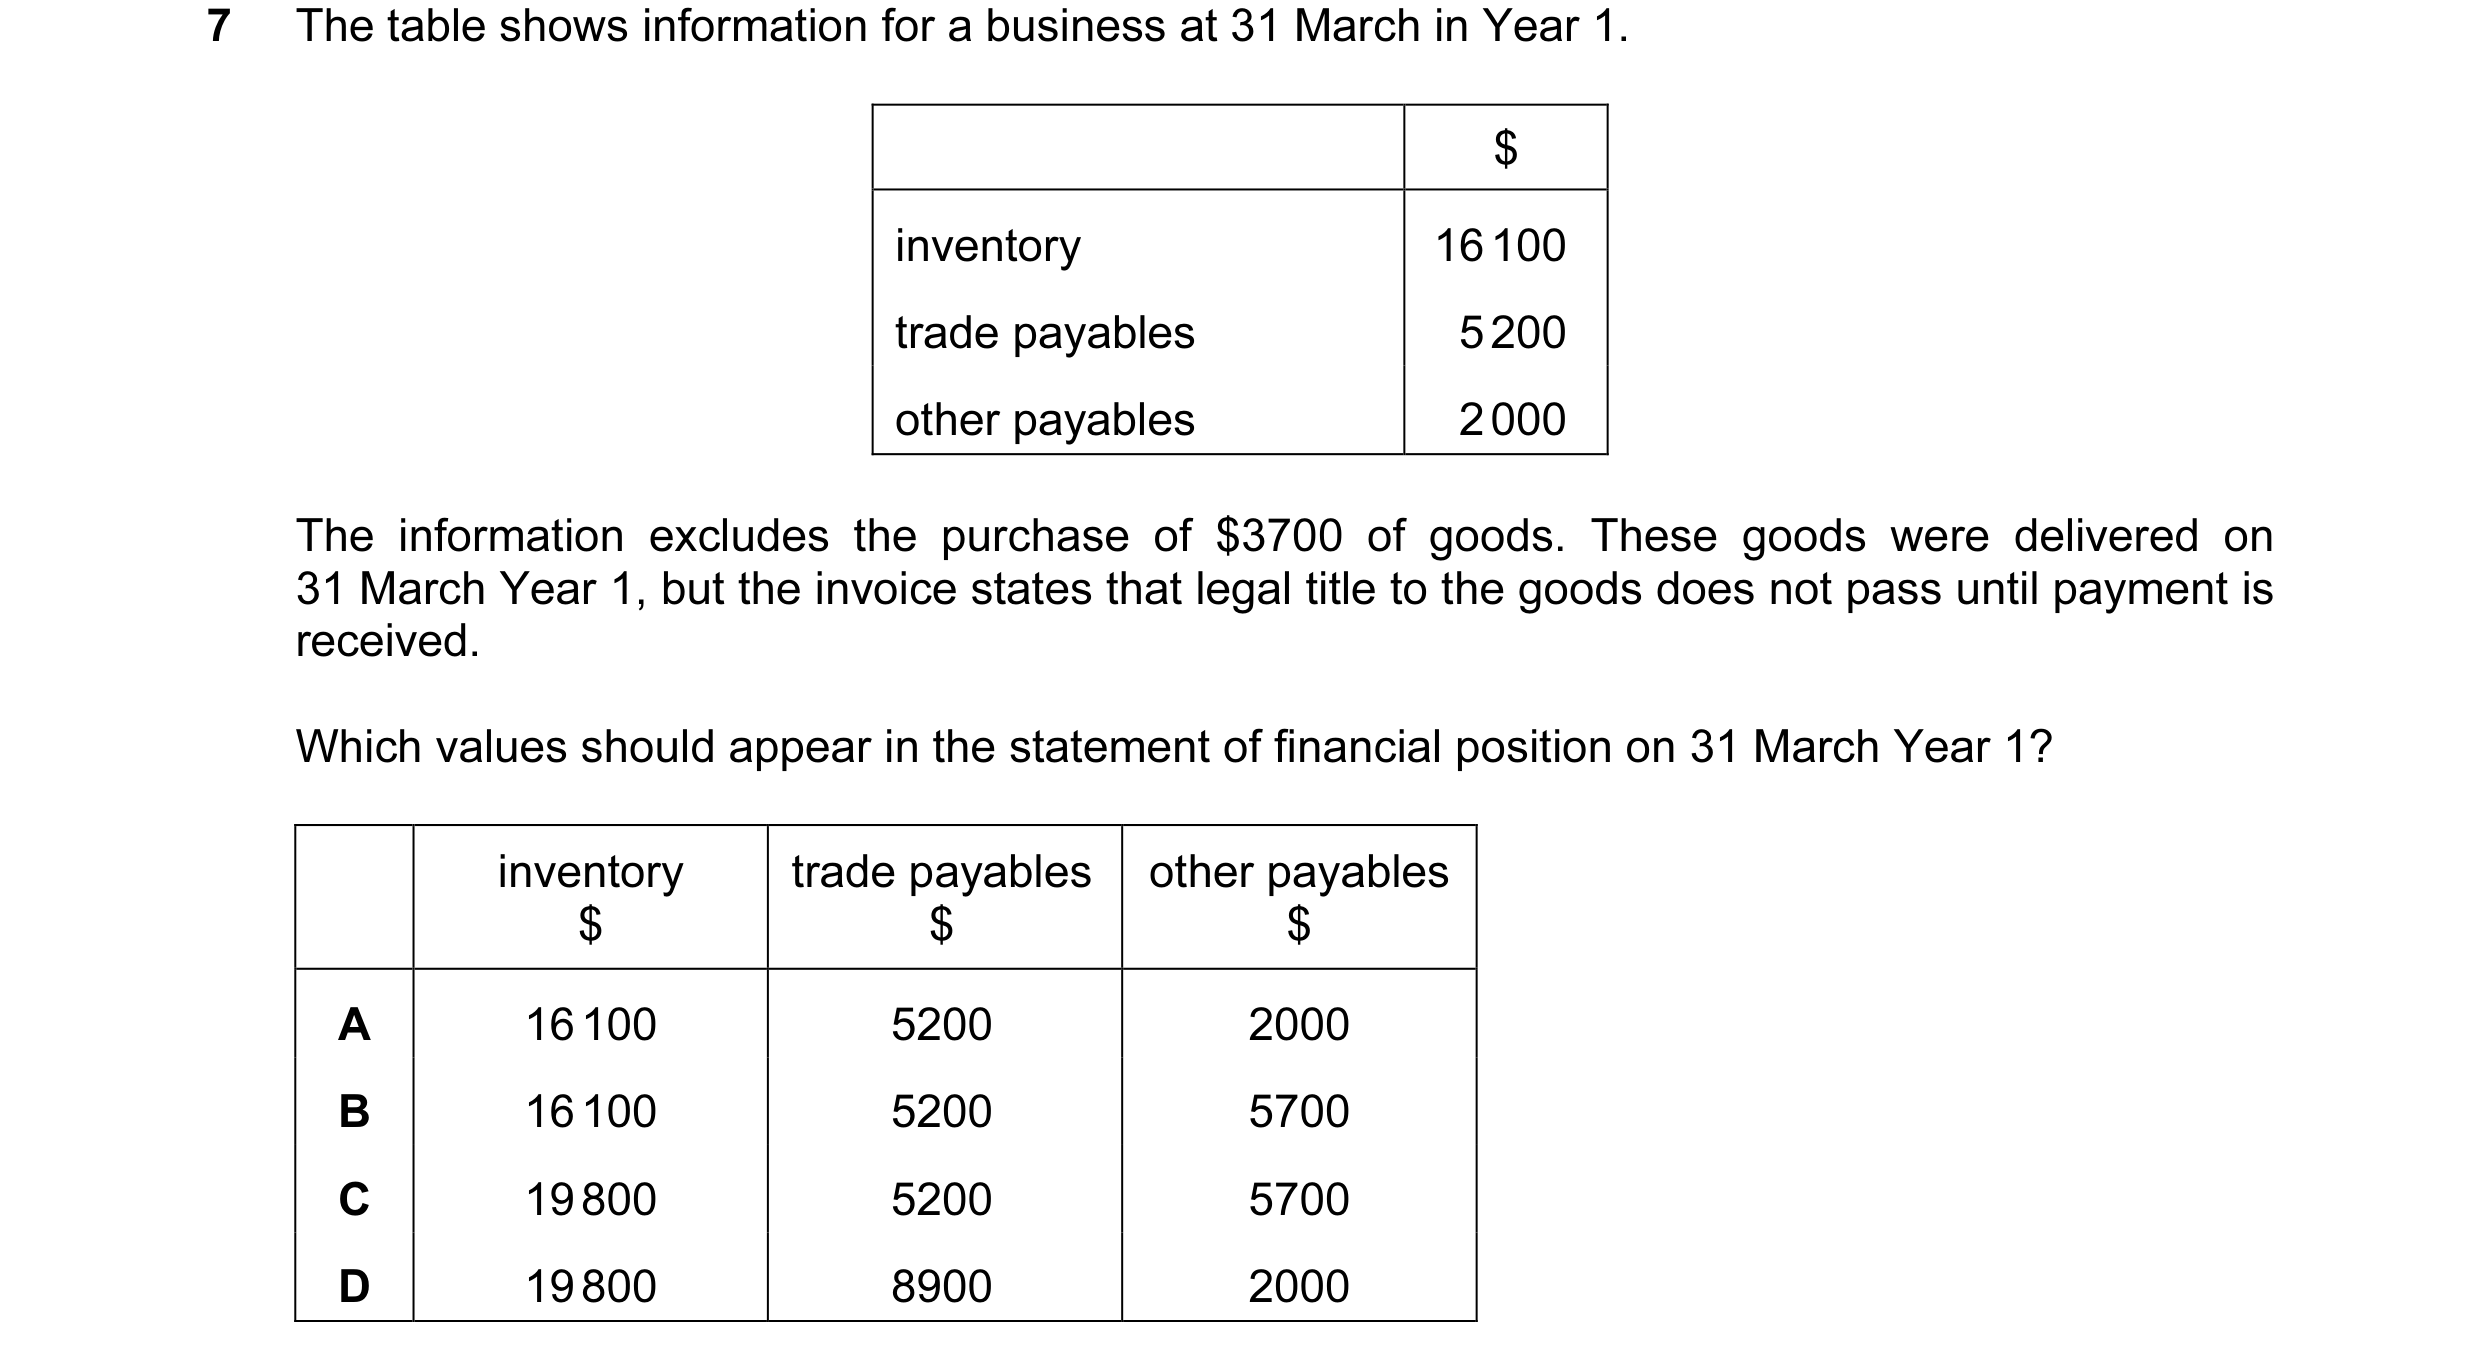
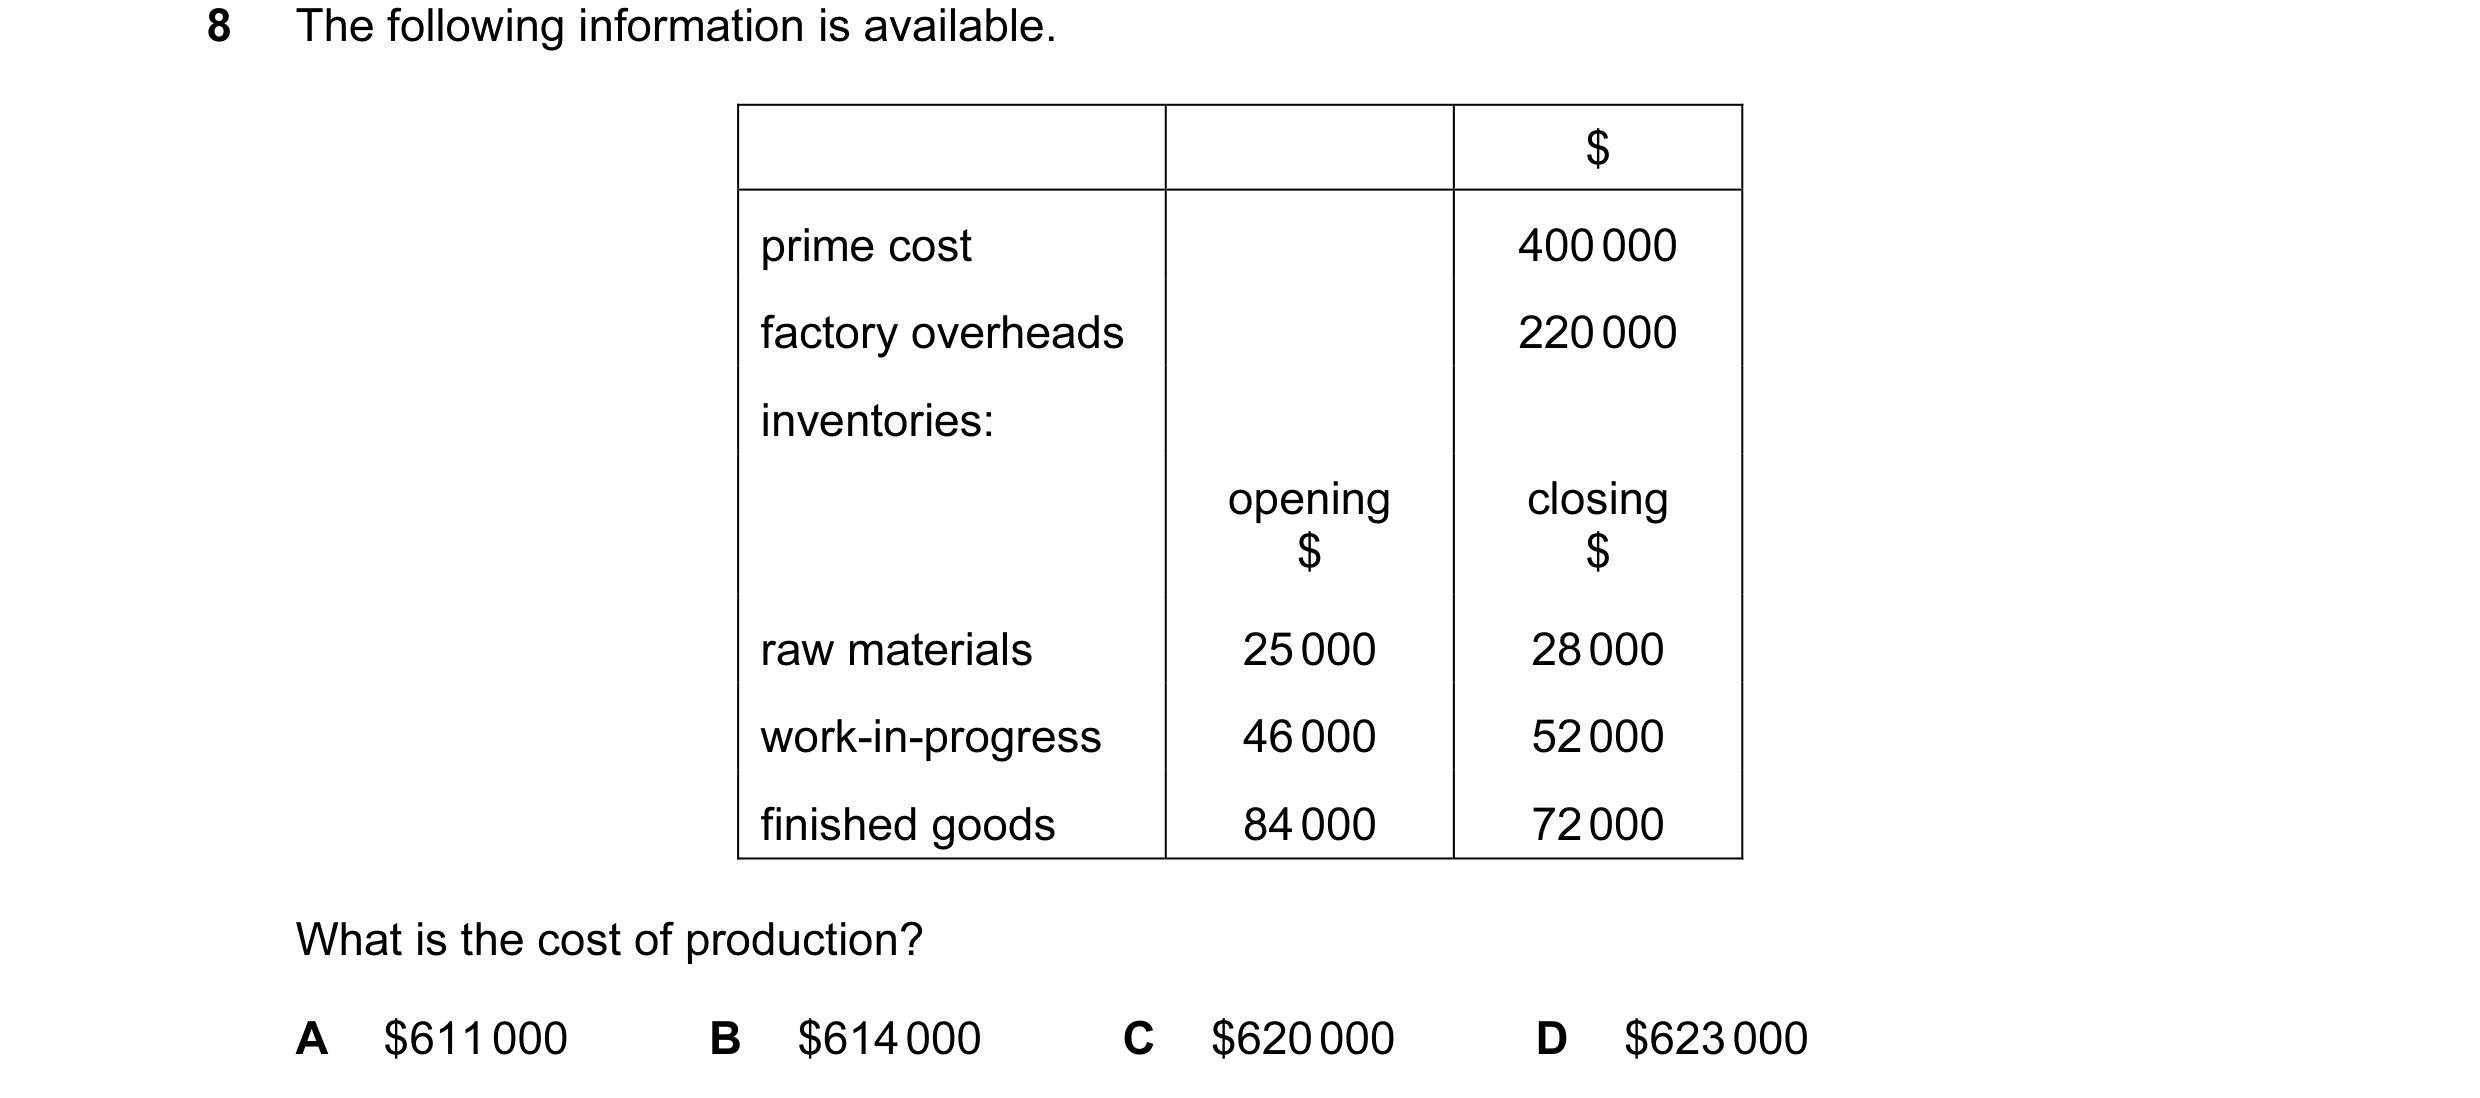 105 / 233
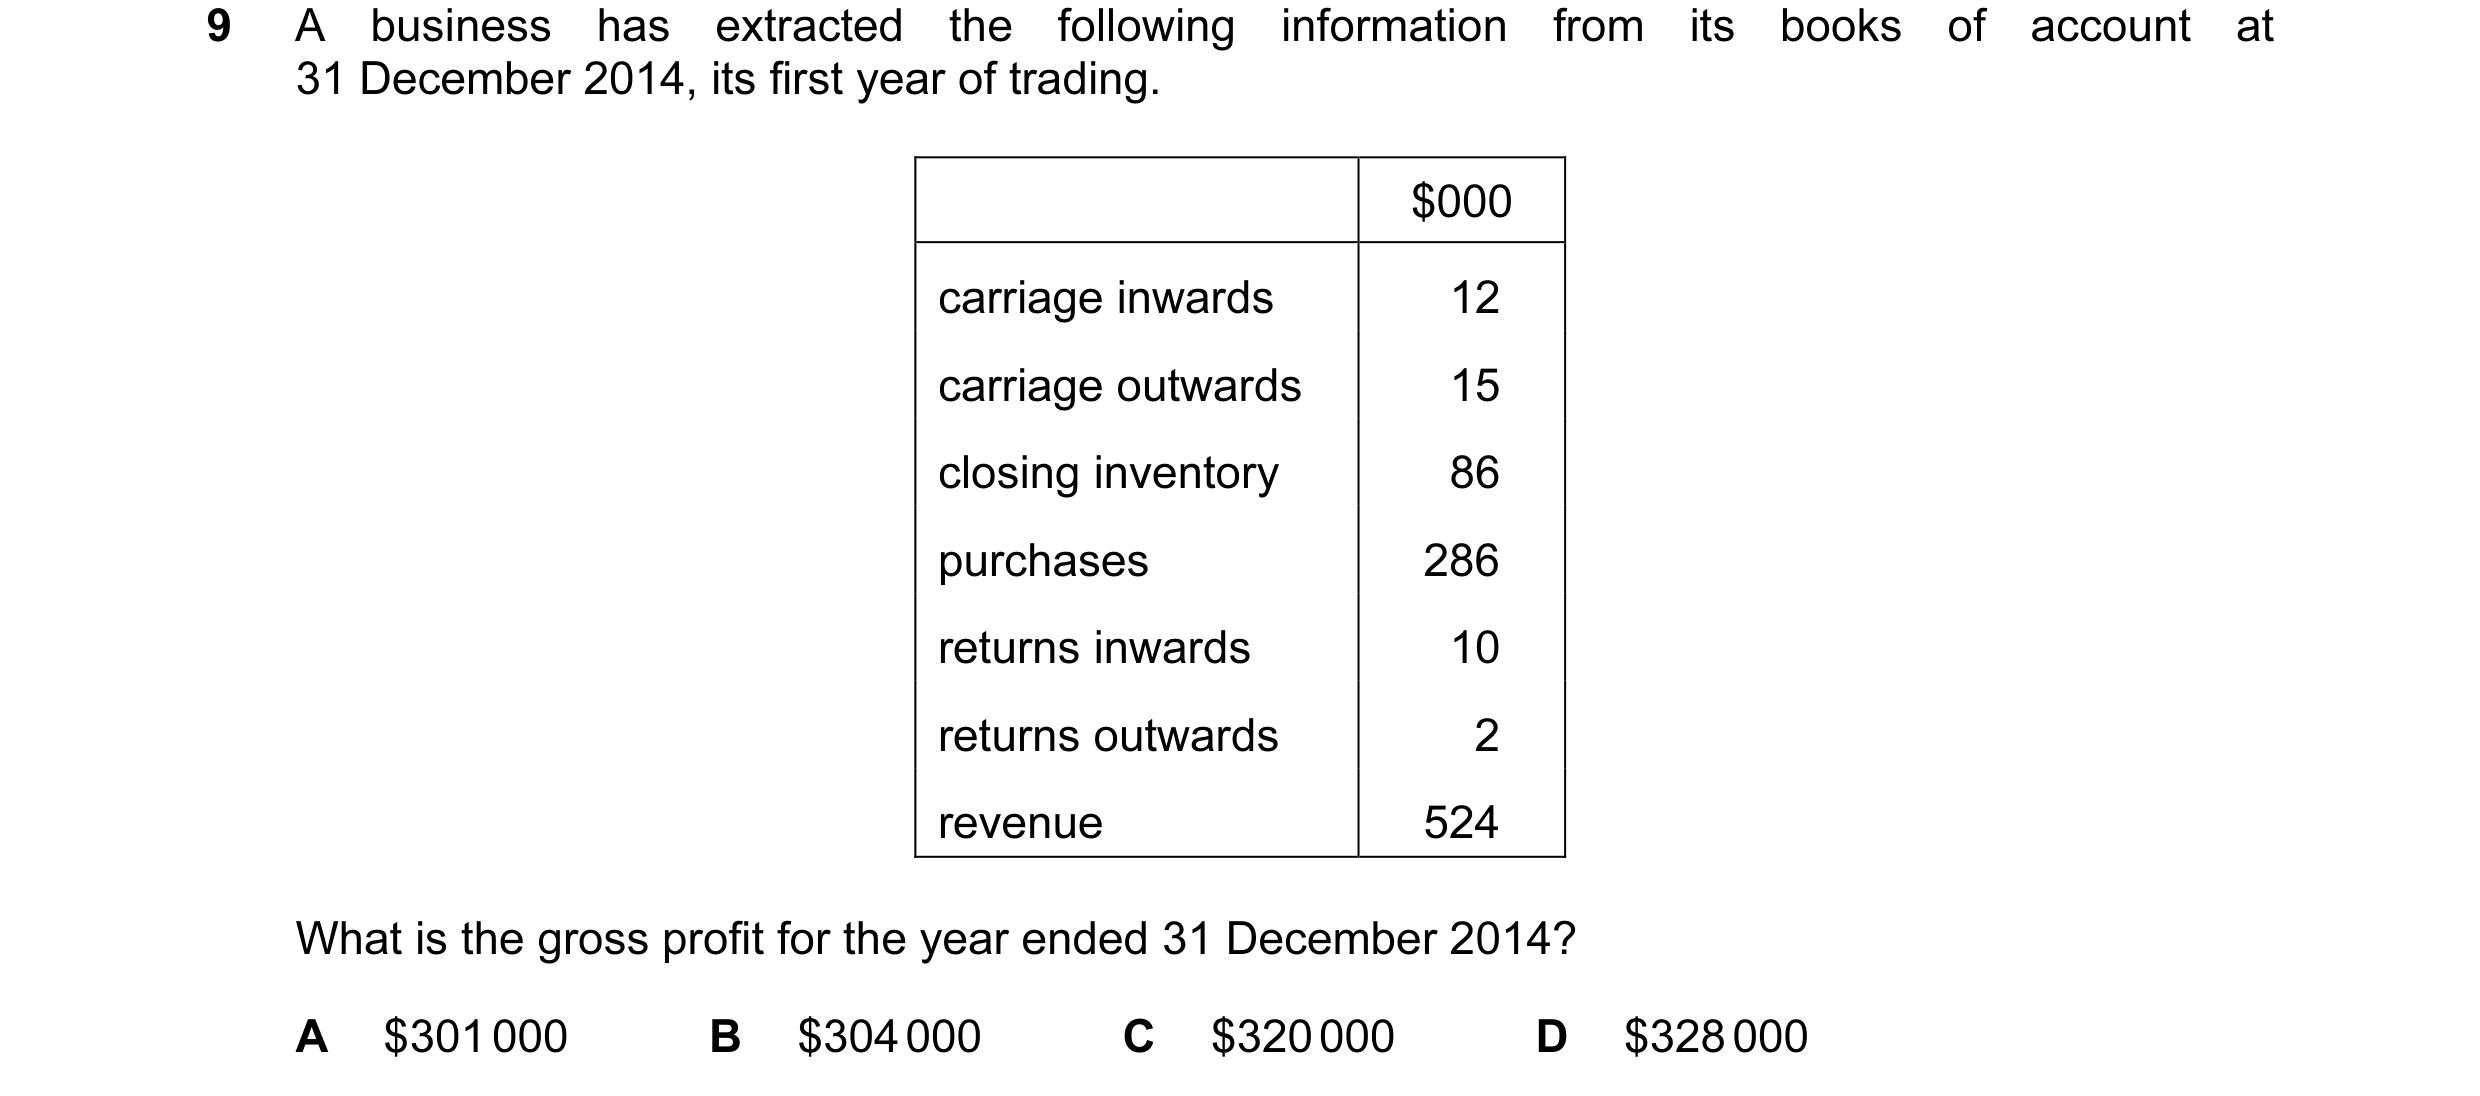
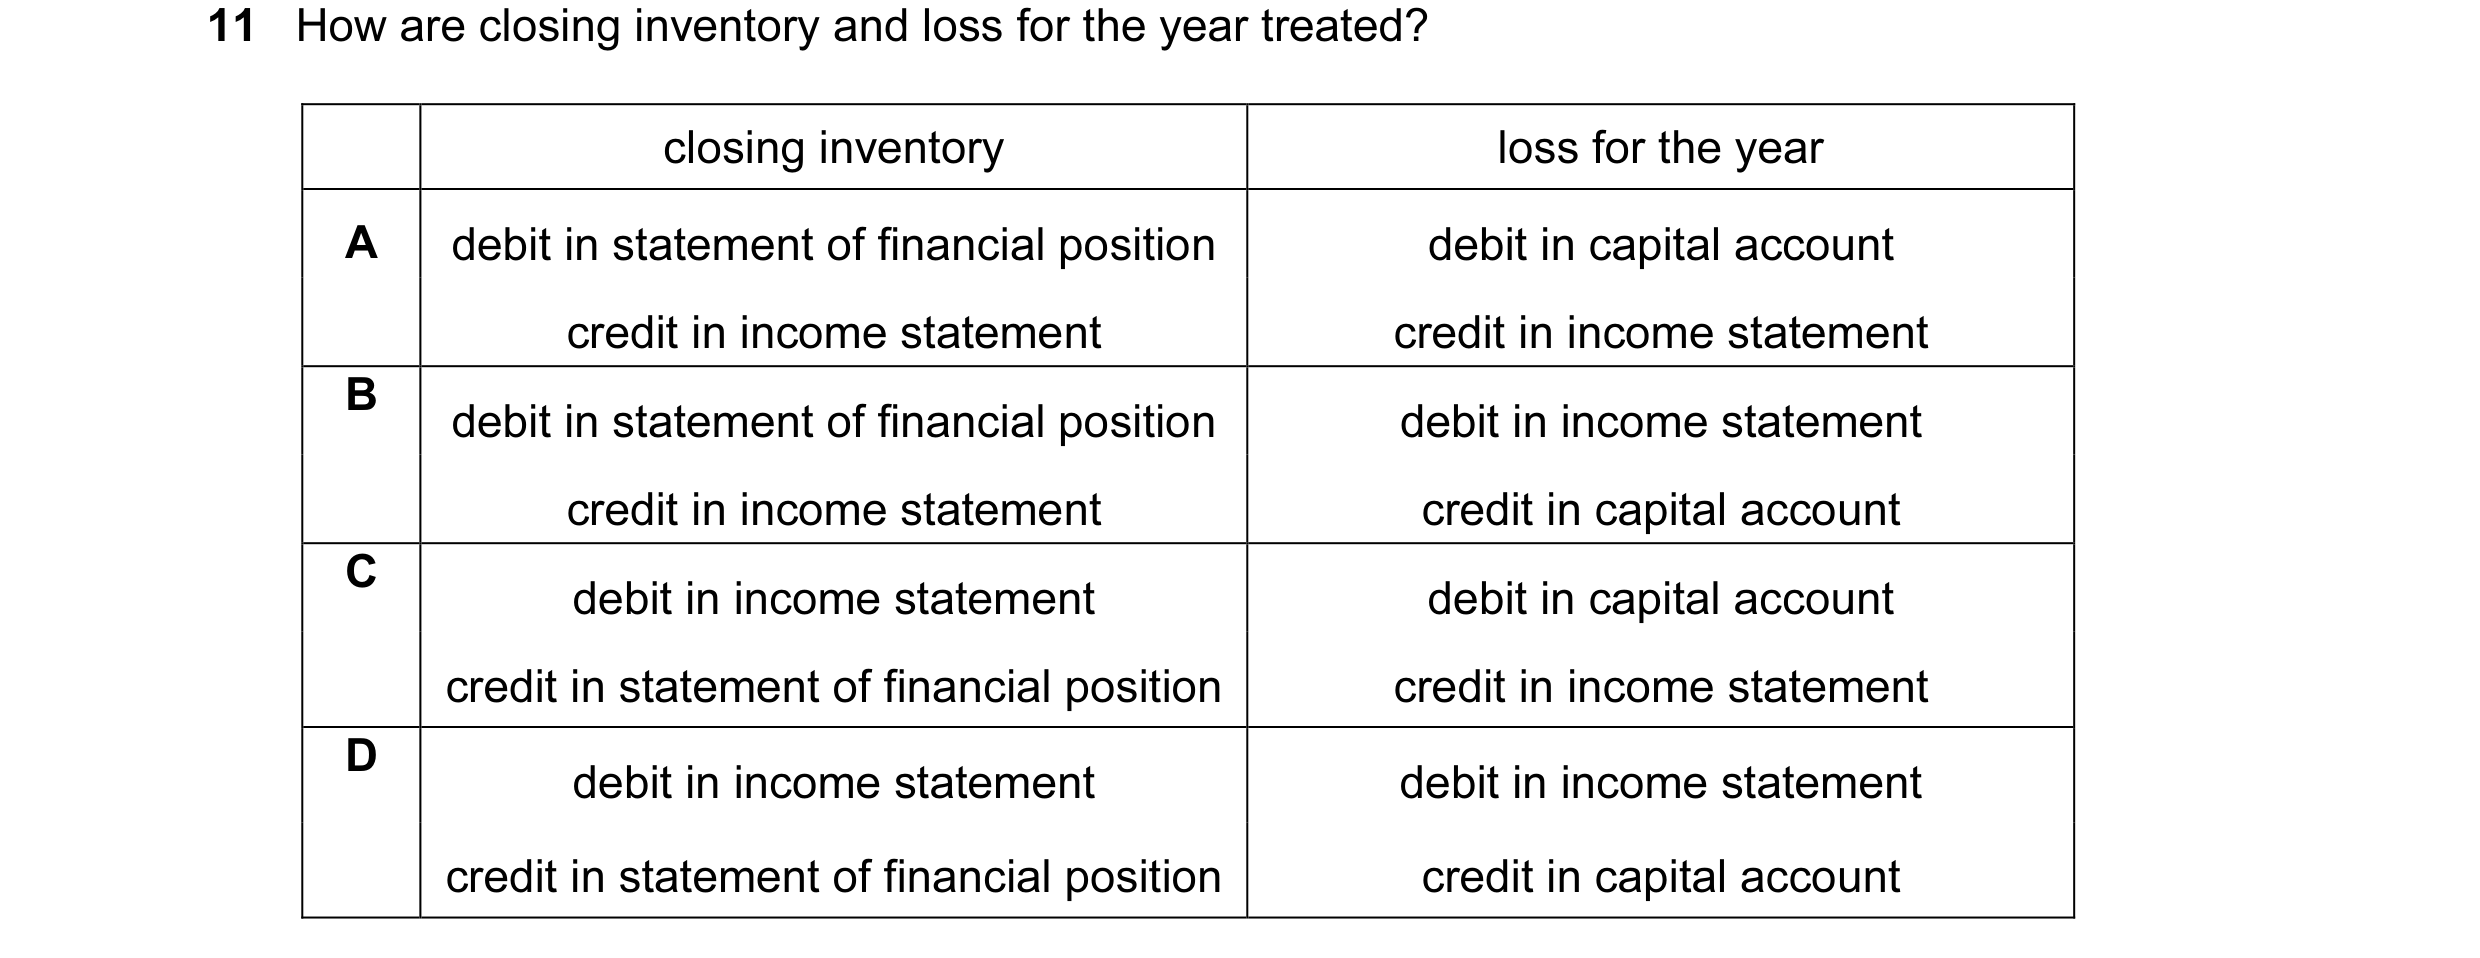
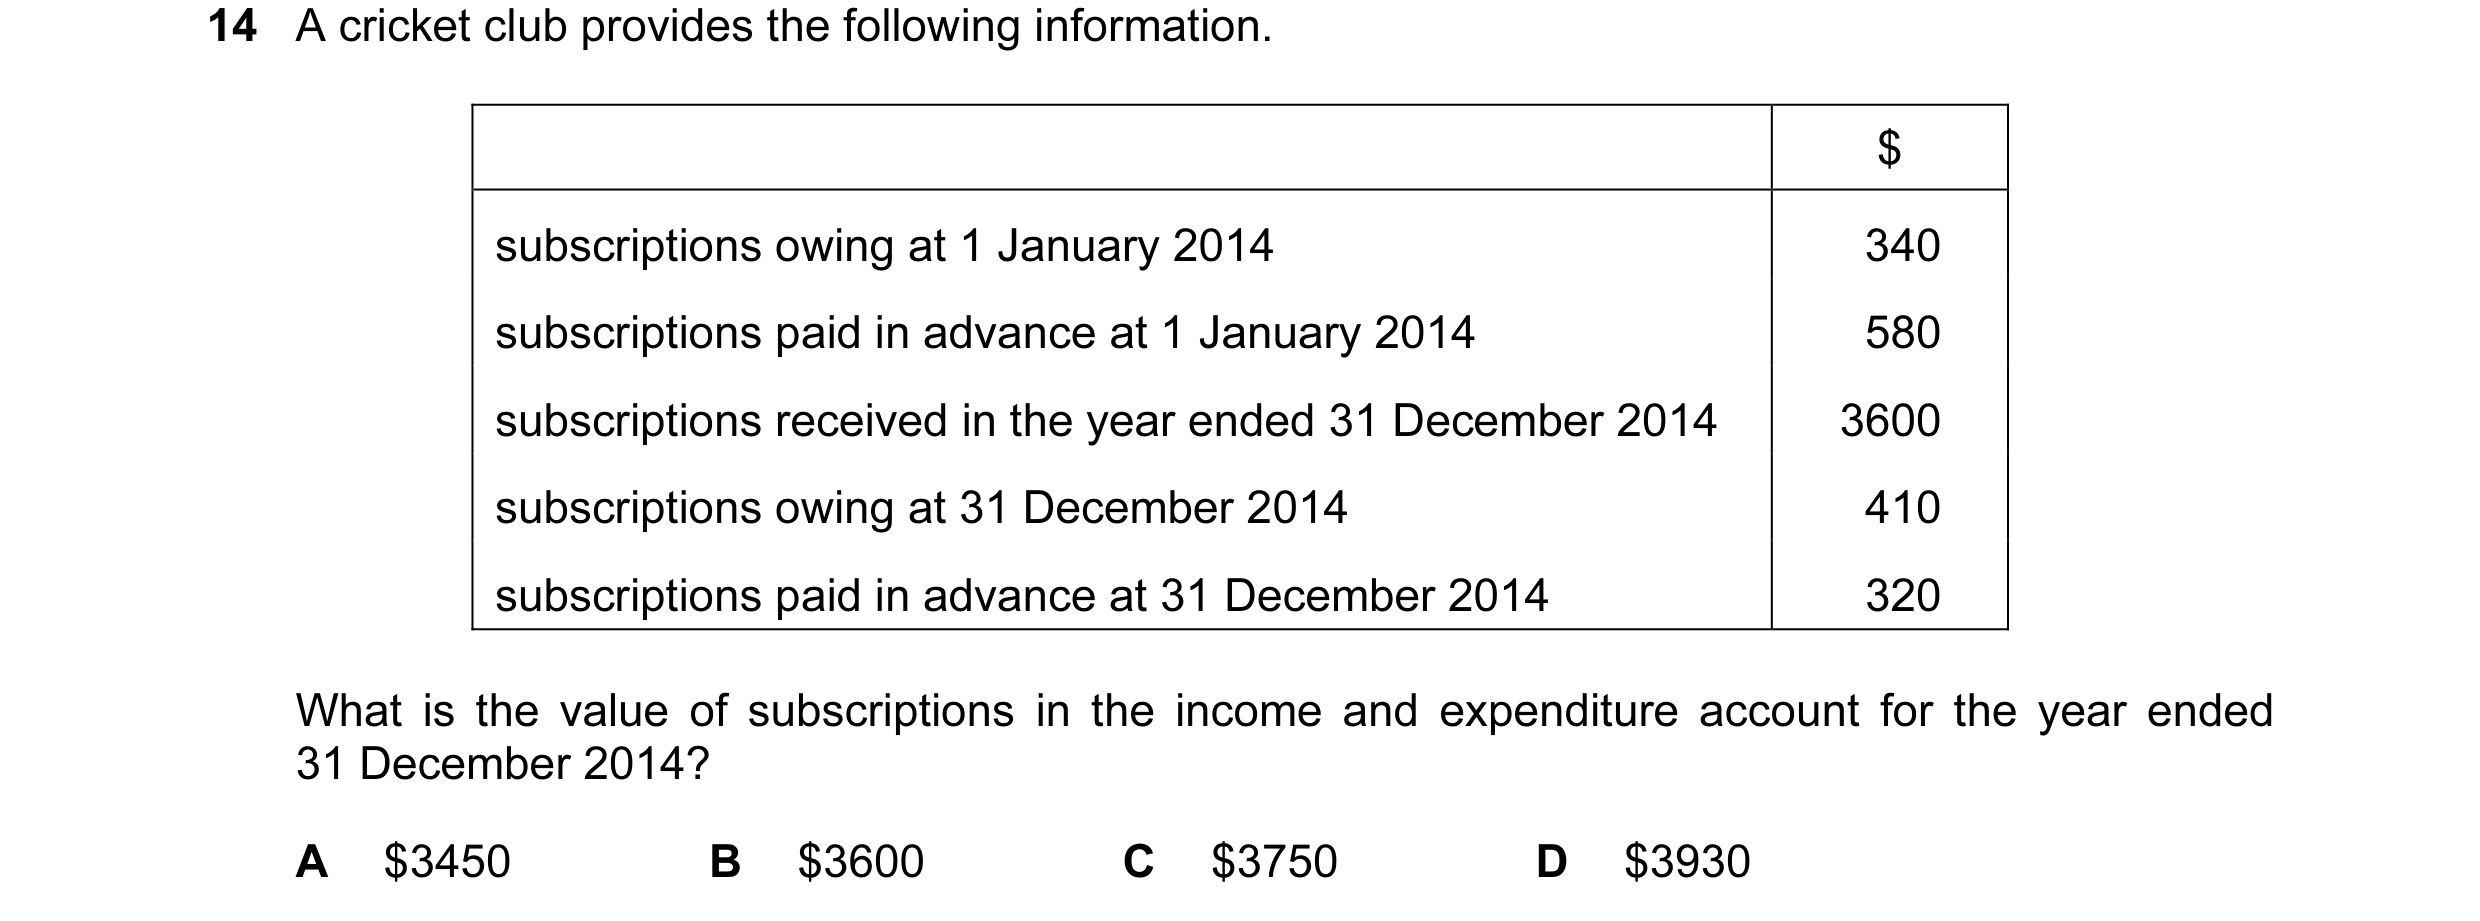 106 / 233
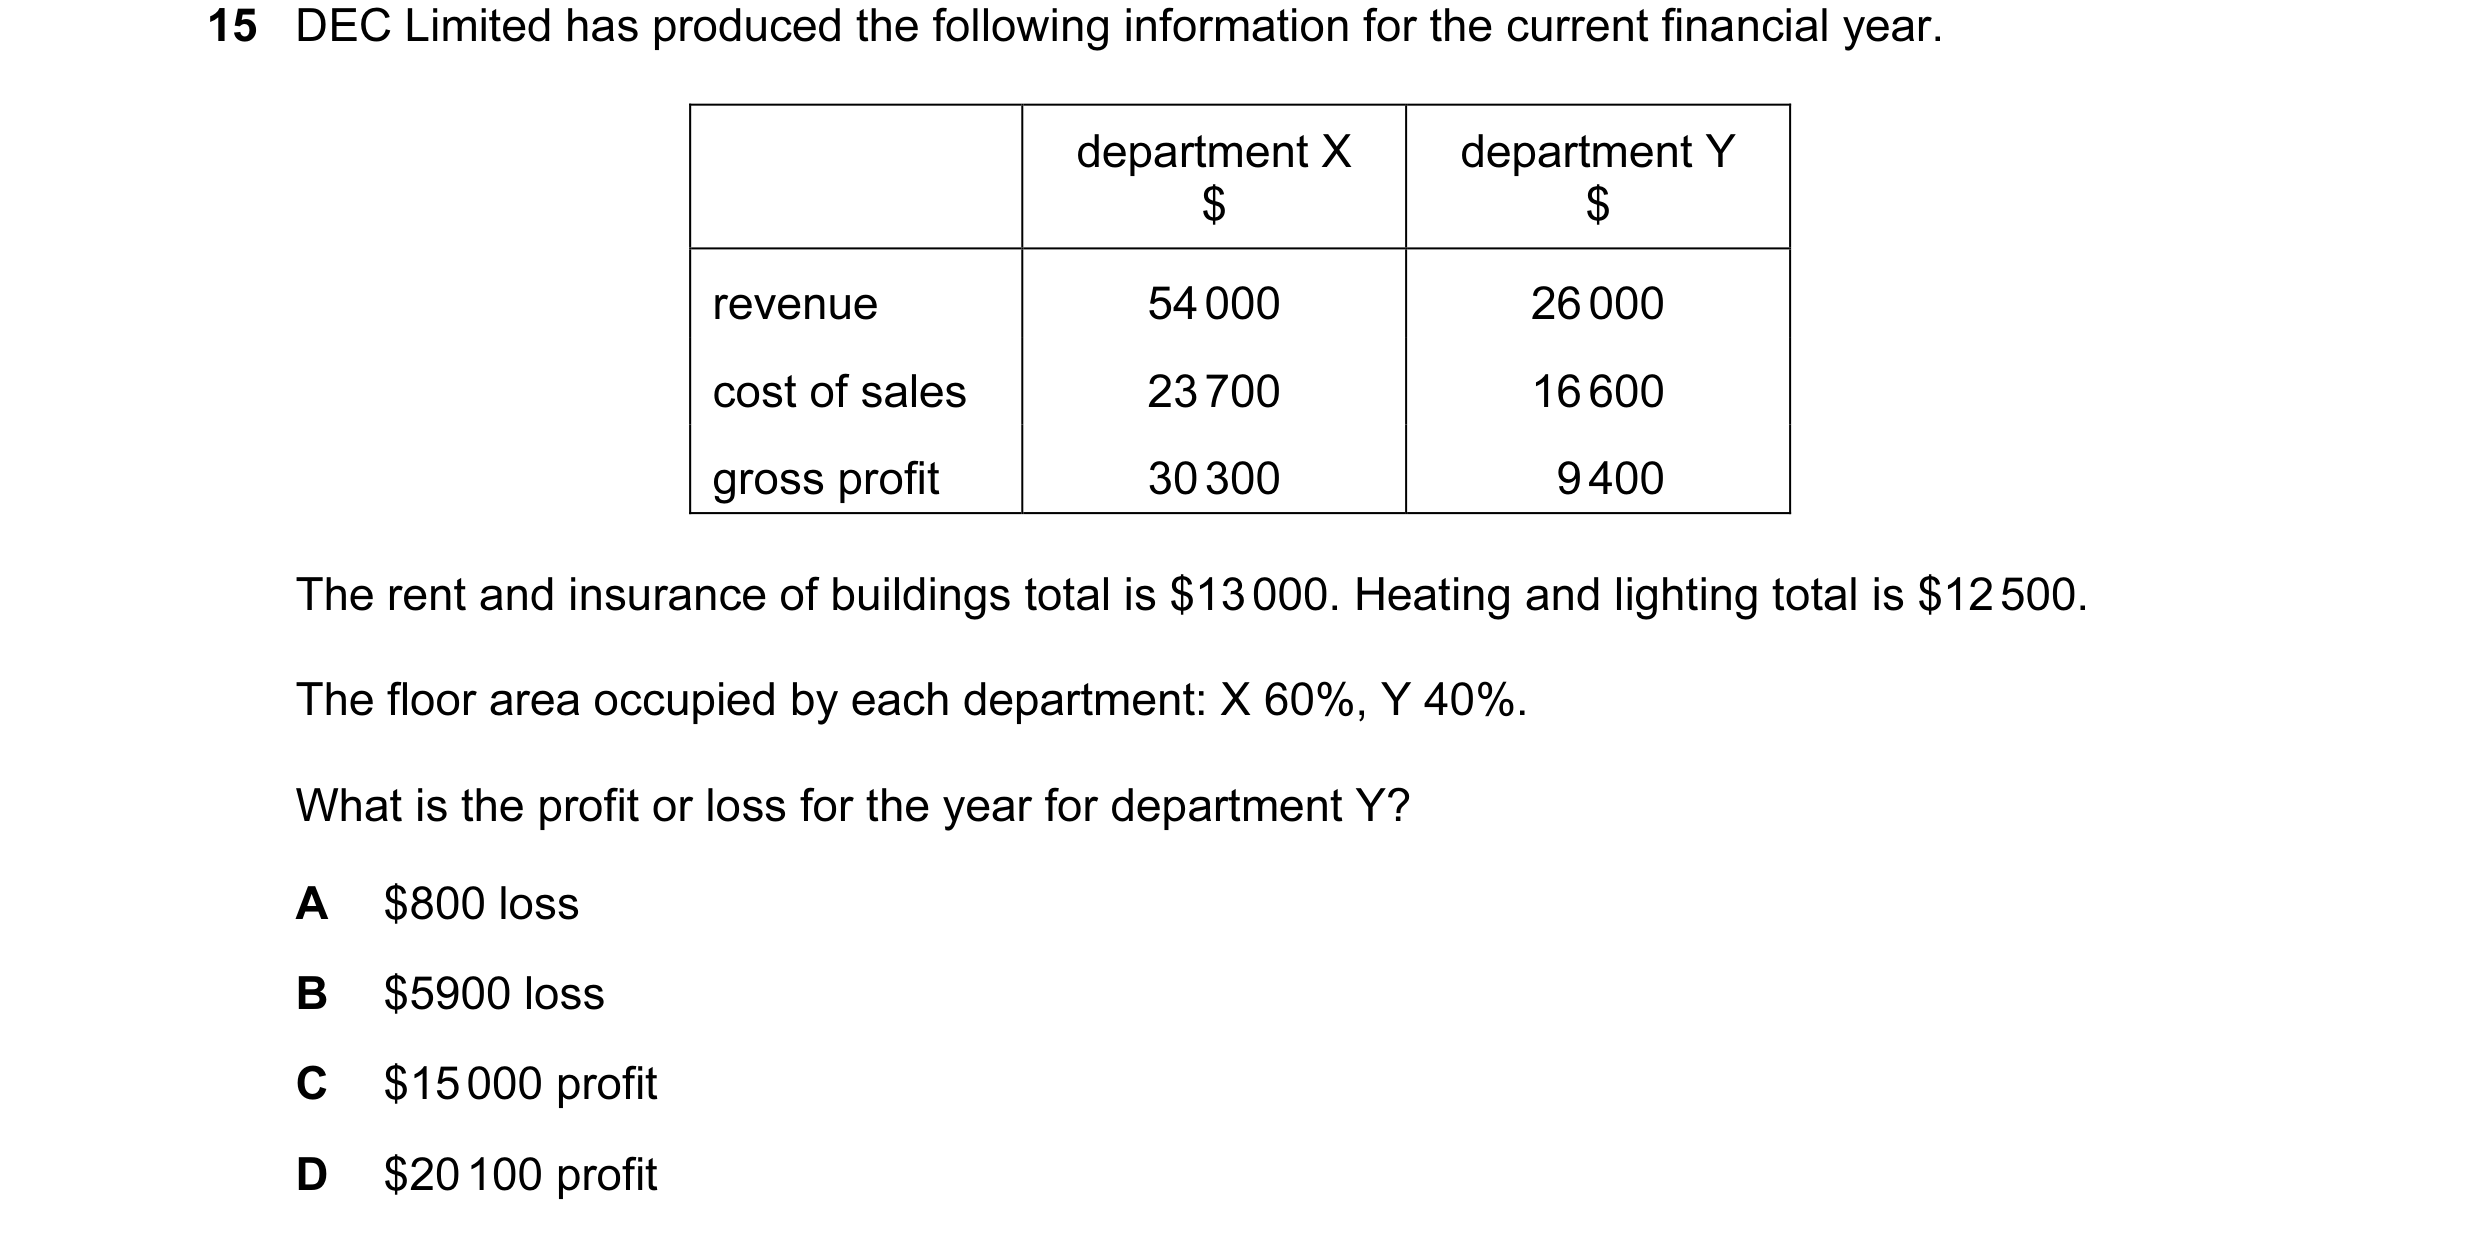
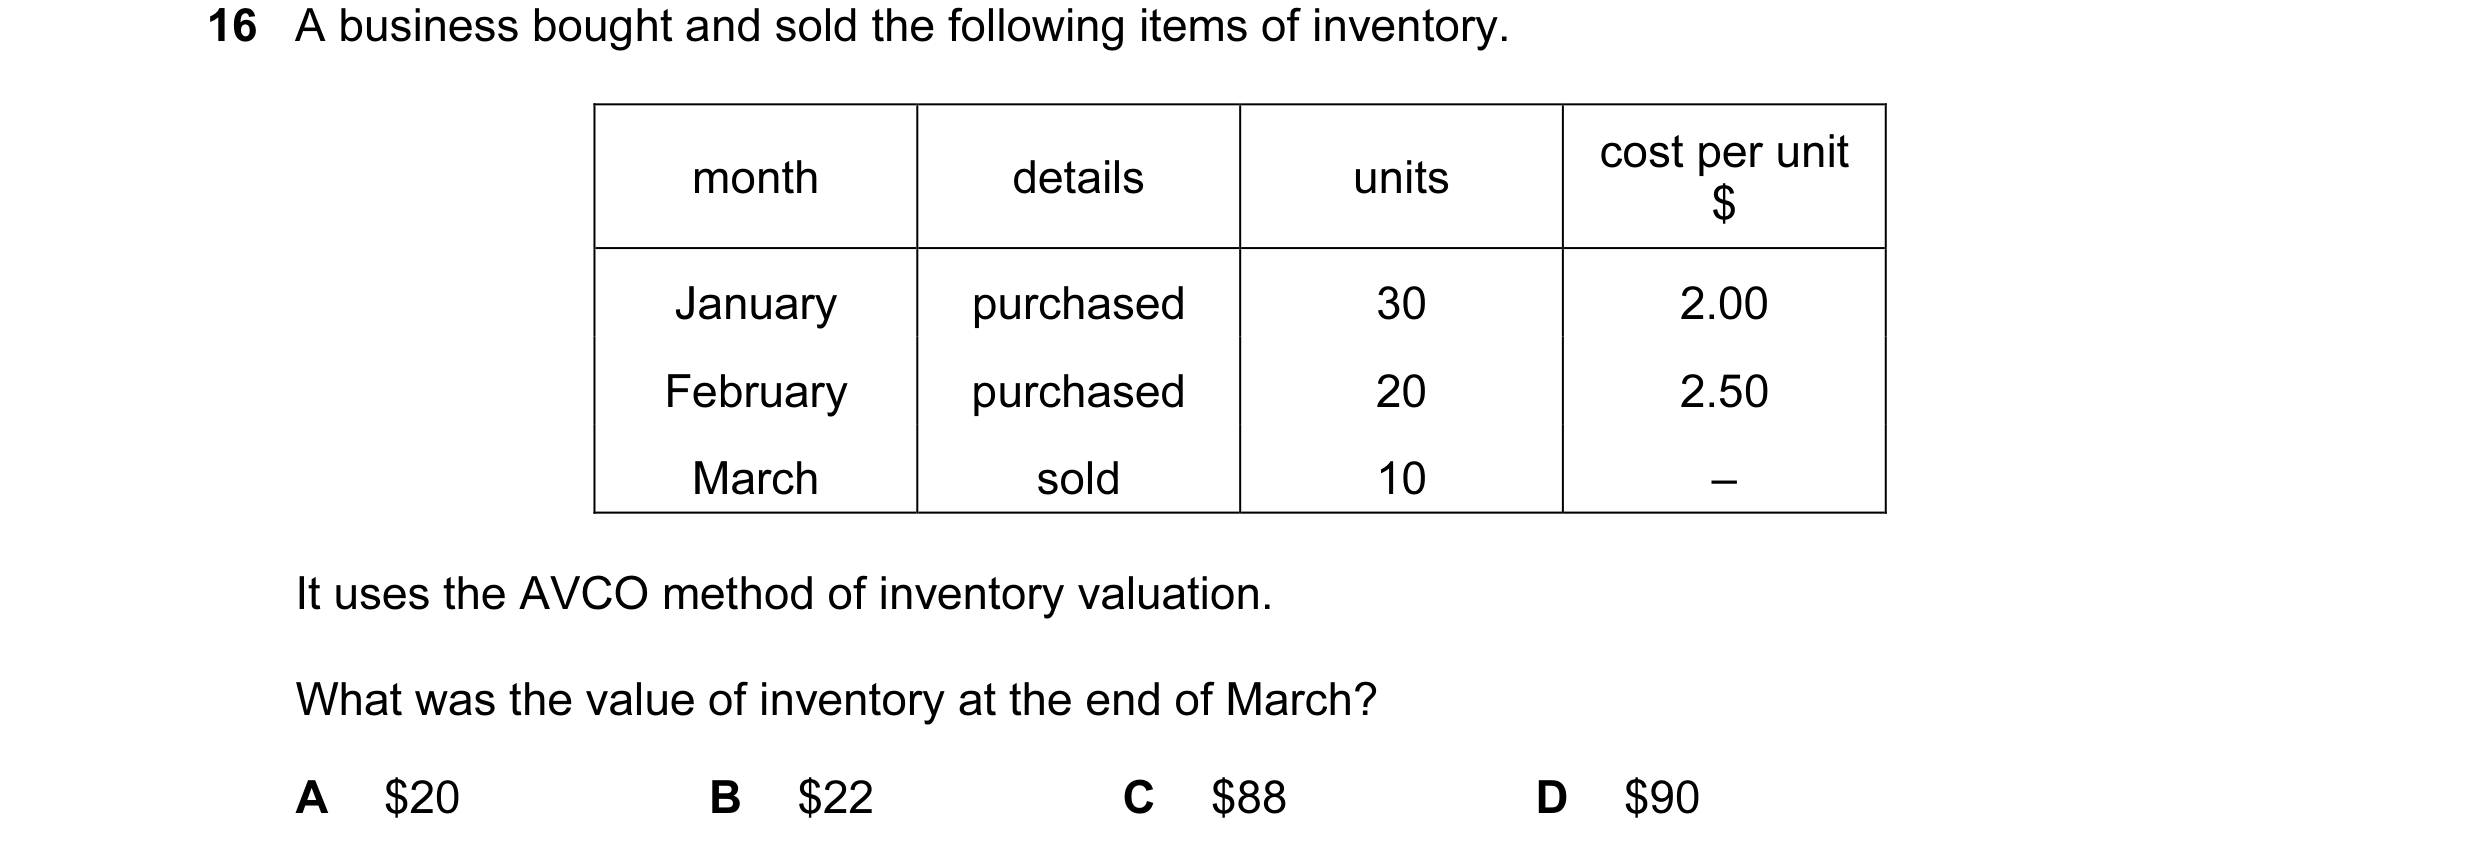
 107 / 233
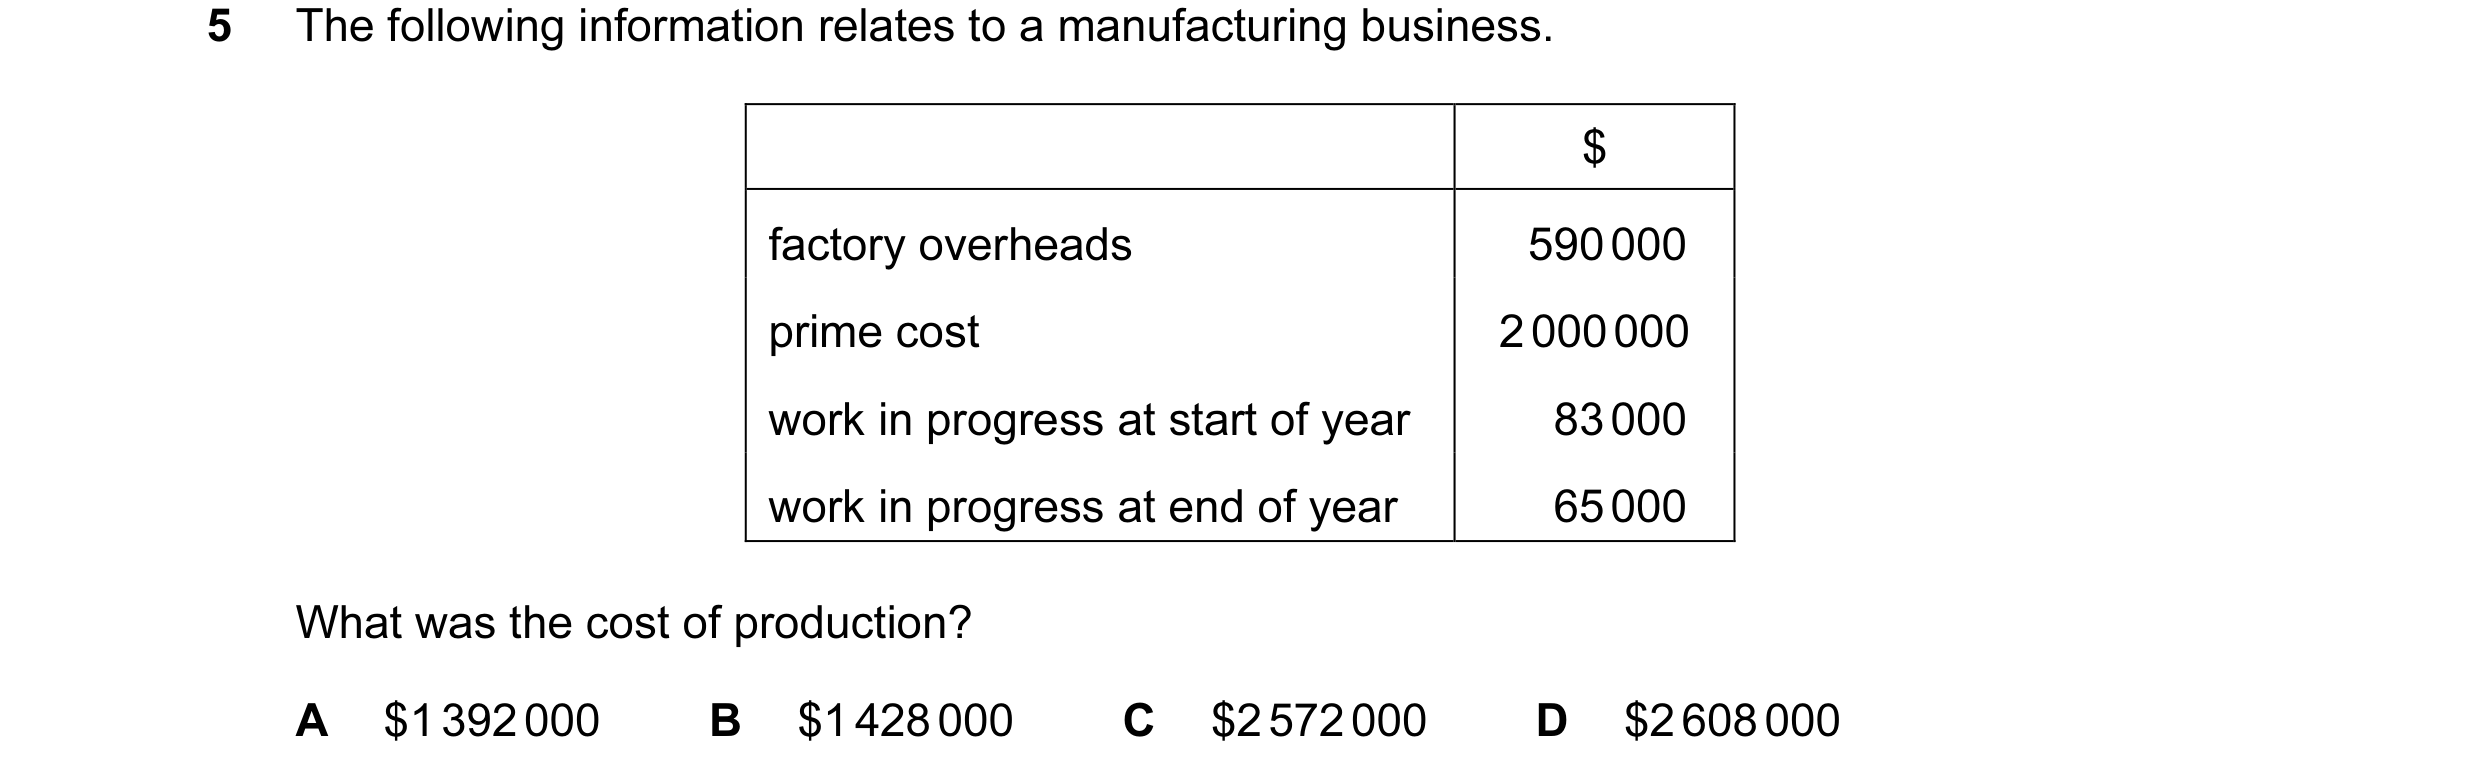 108 / 233
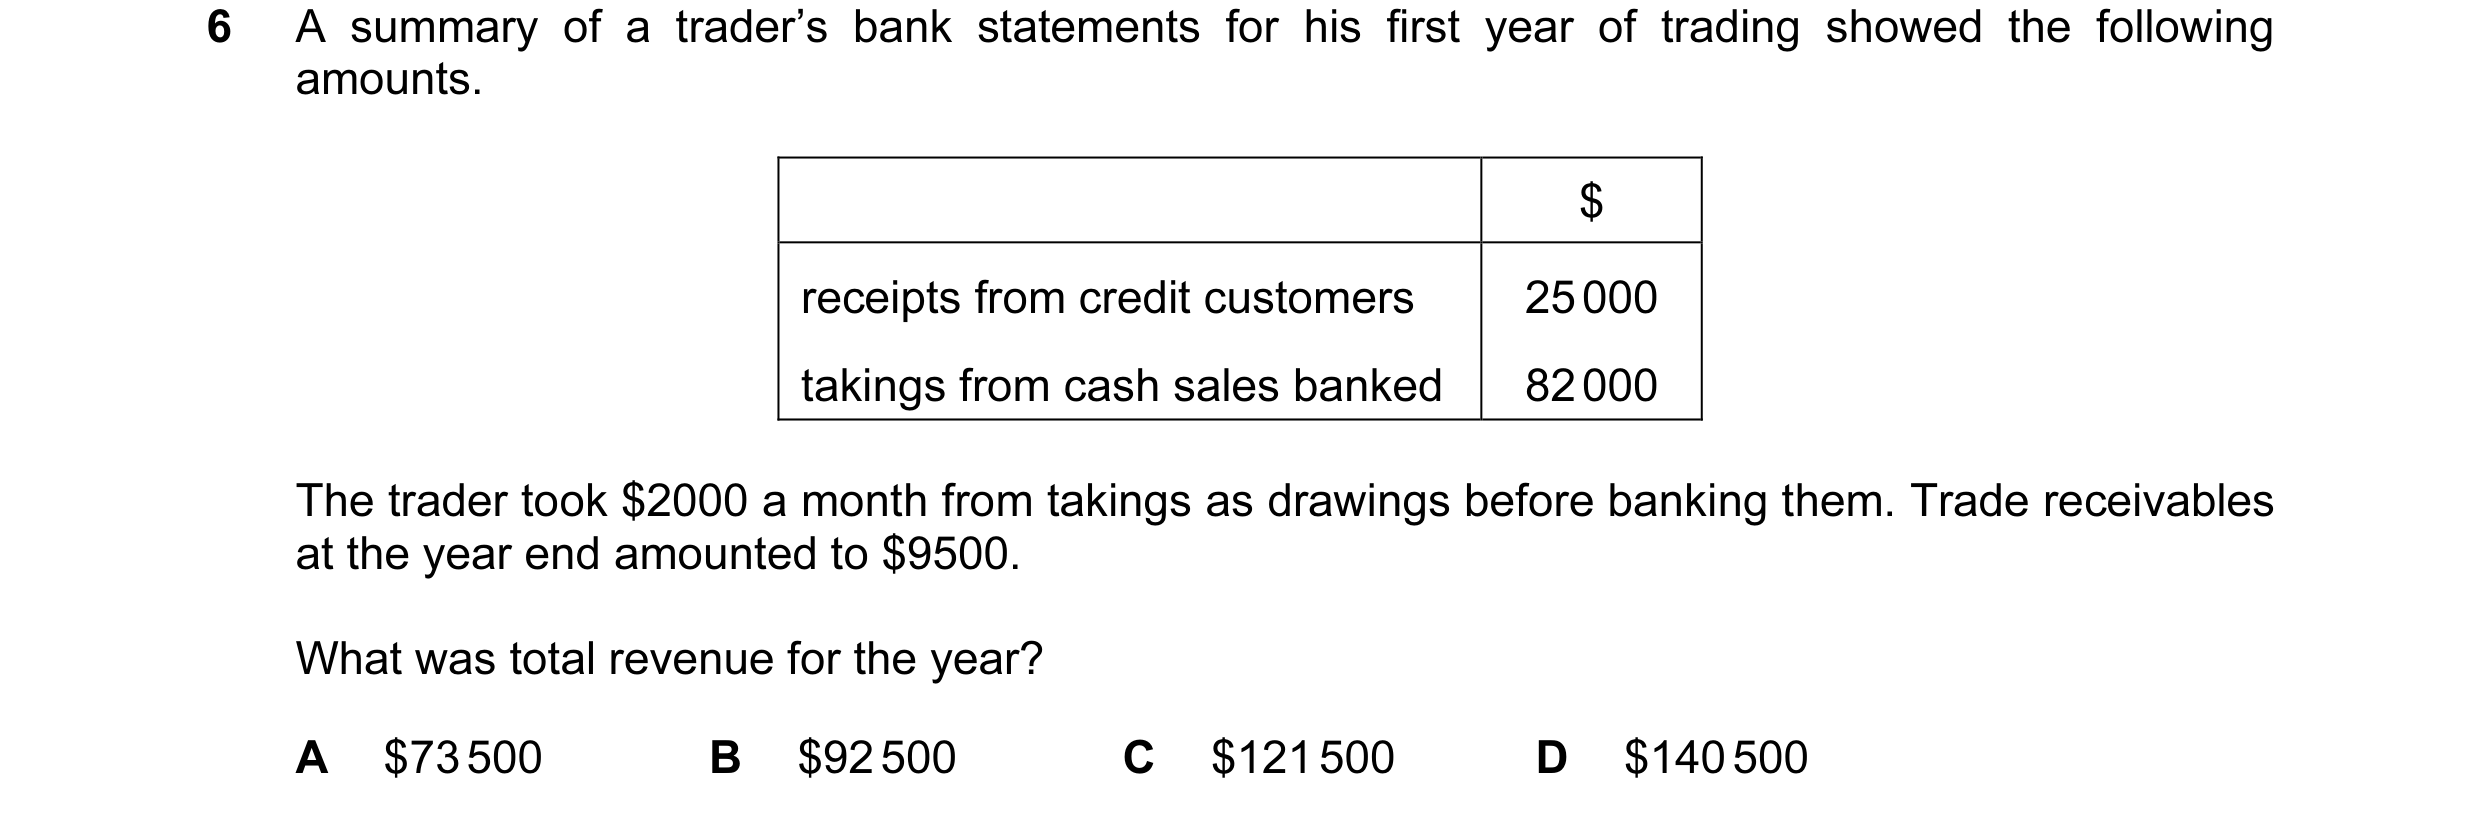
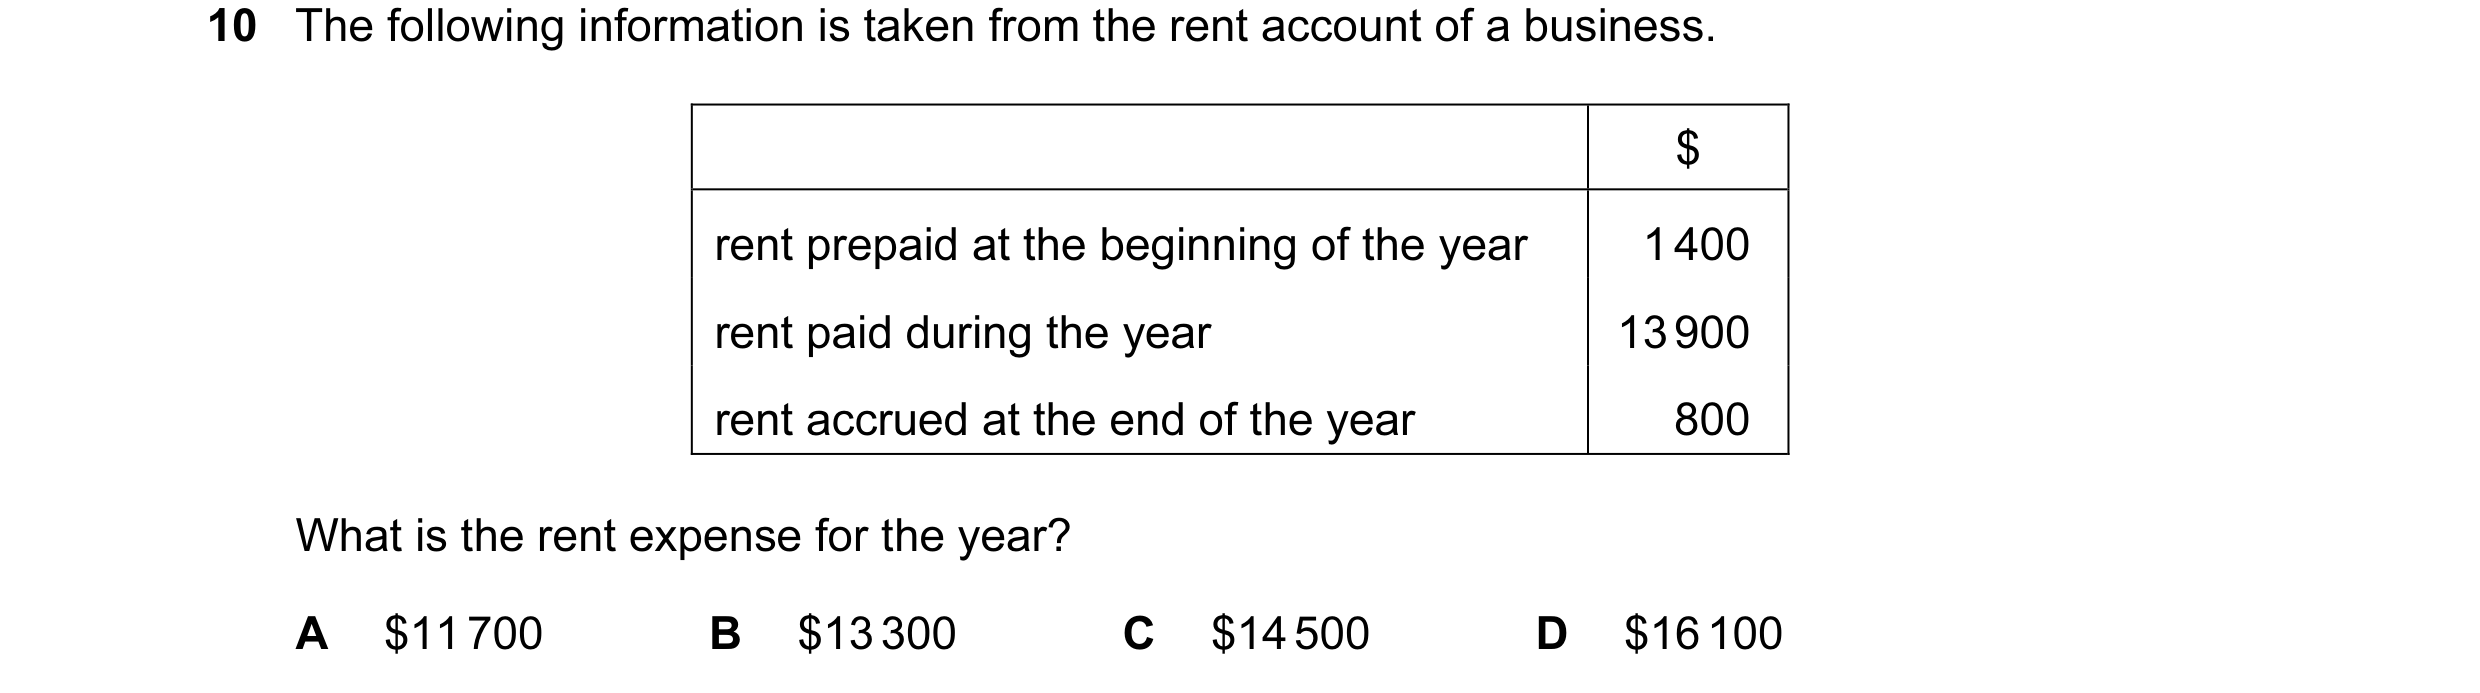 109 / 233
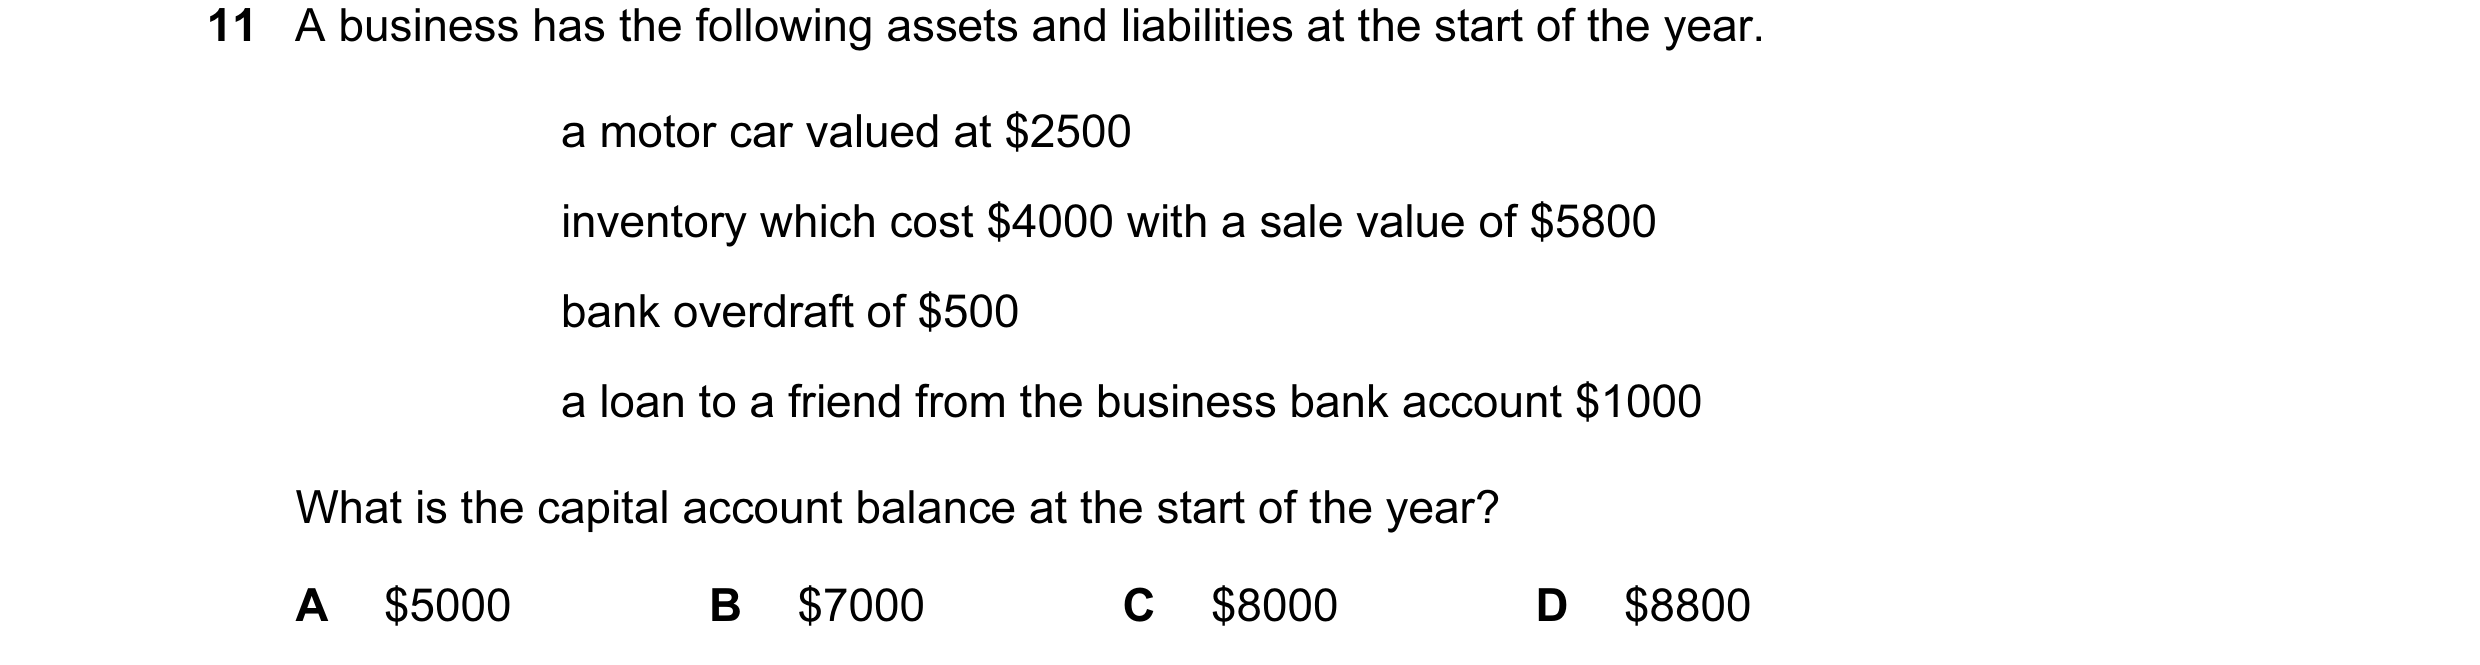
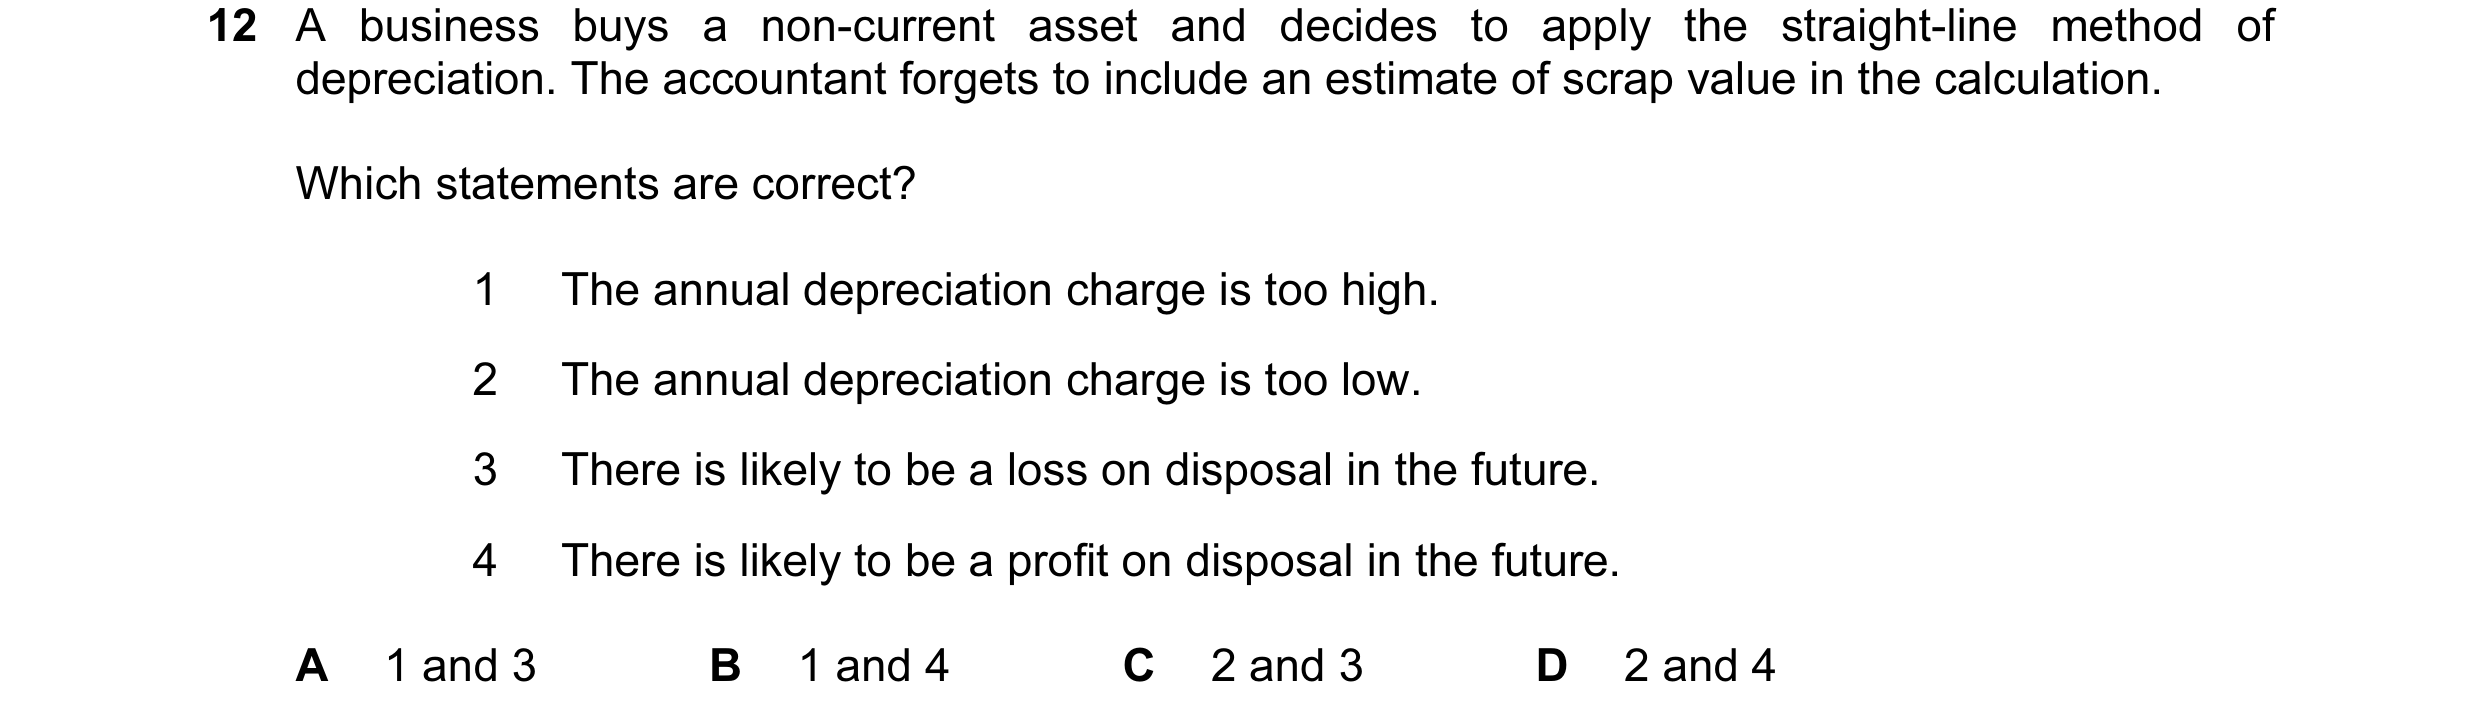
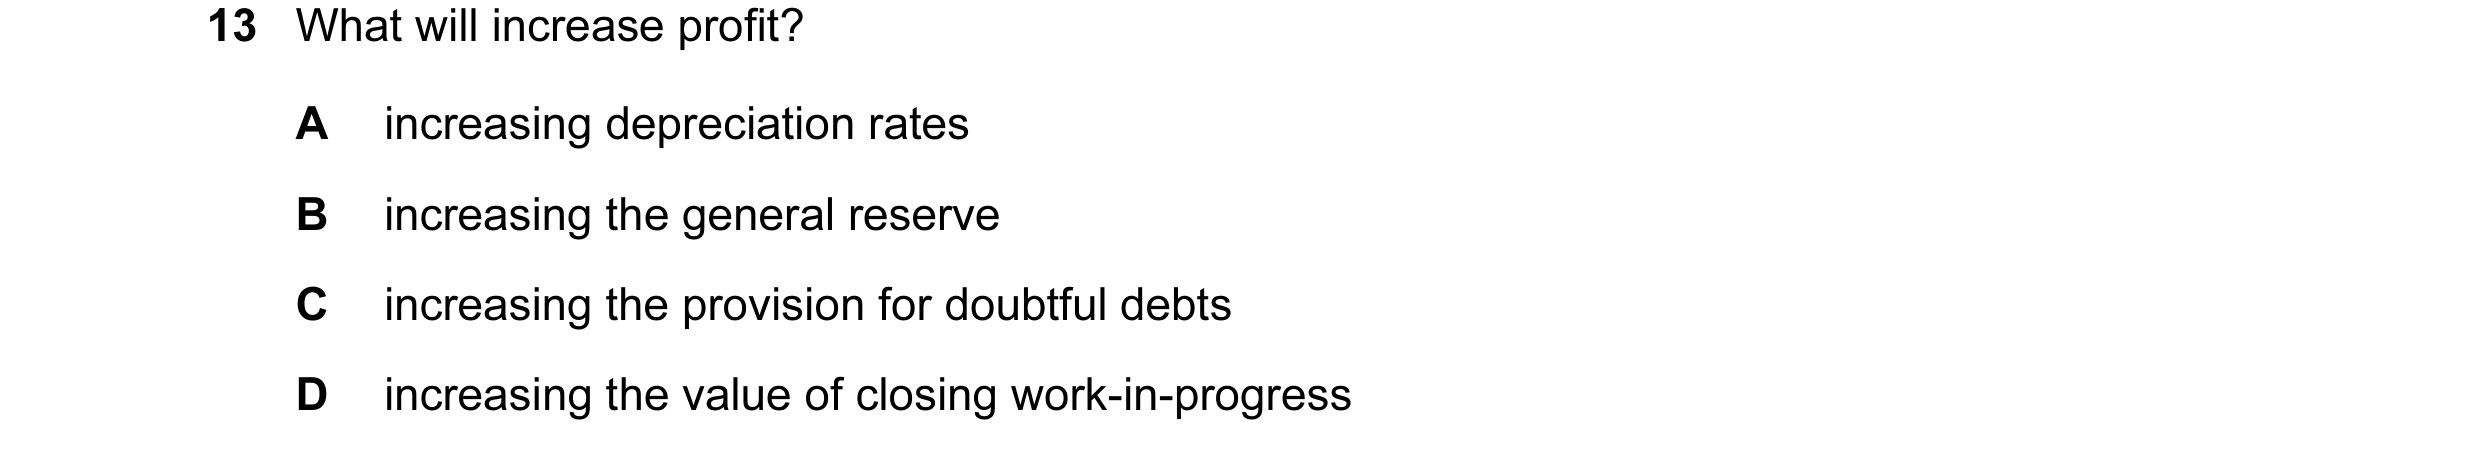
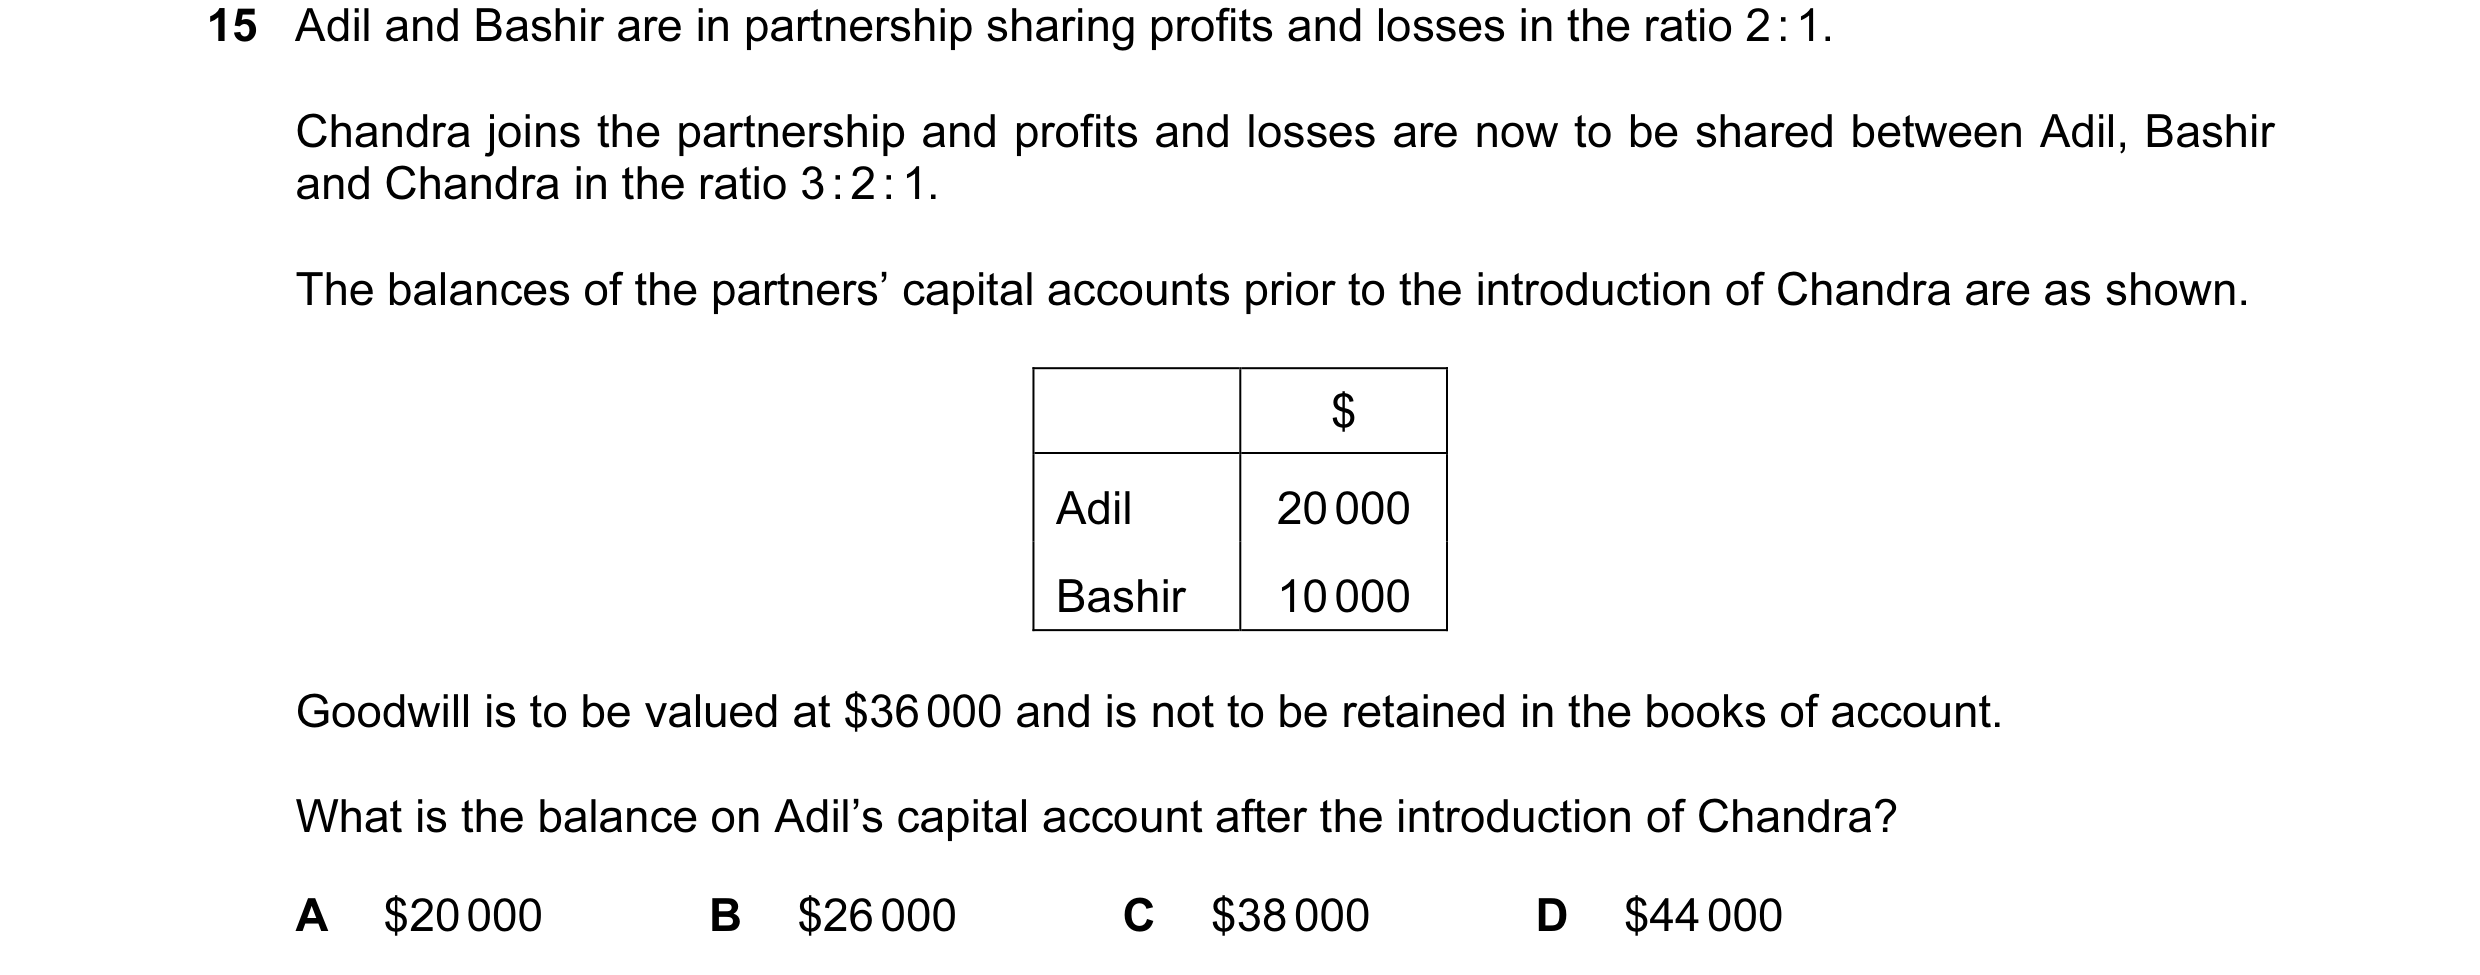 110 / 233
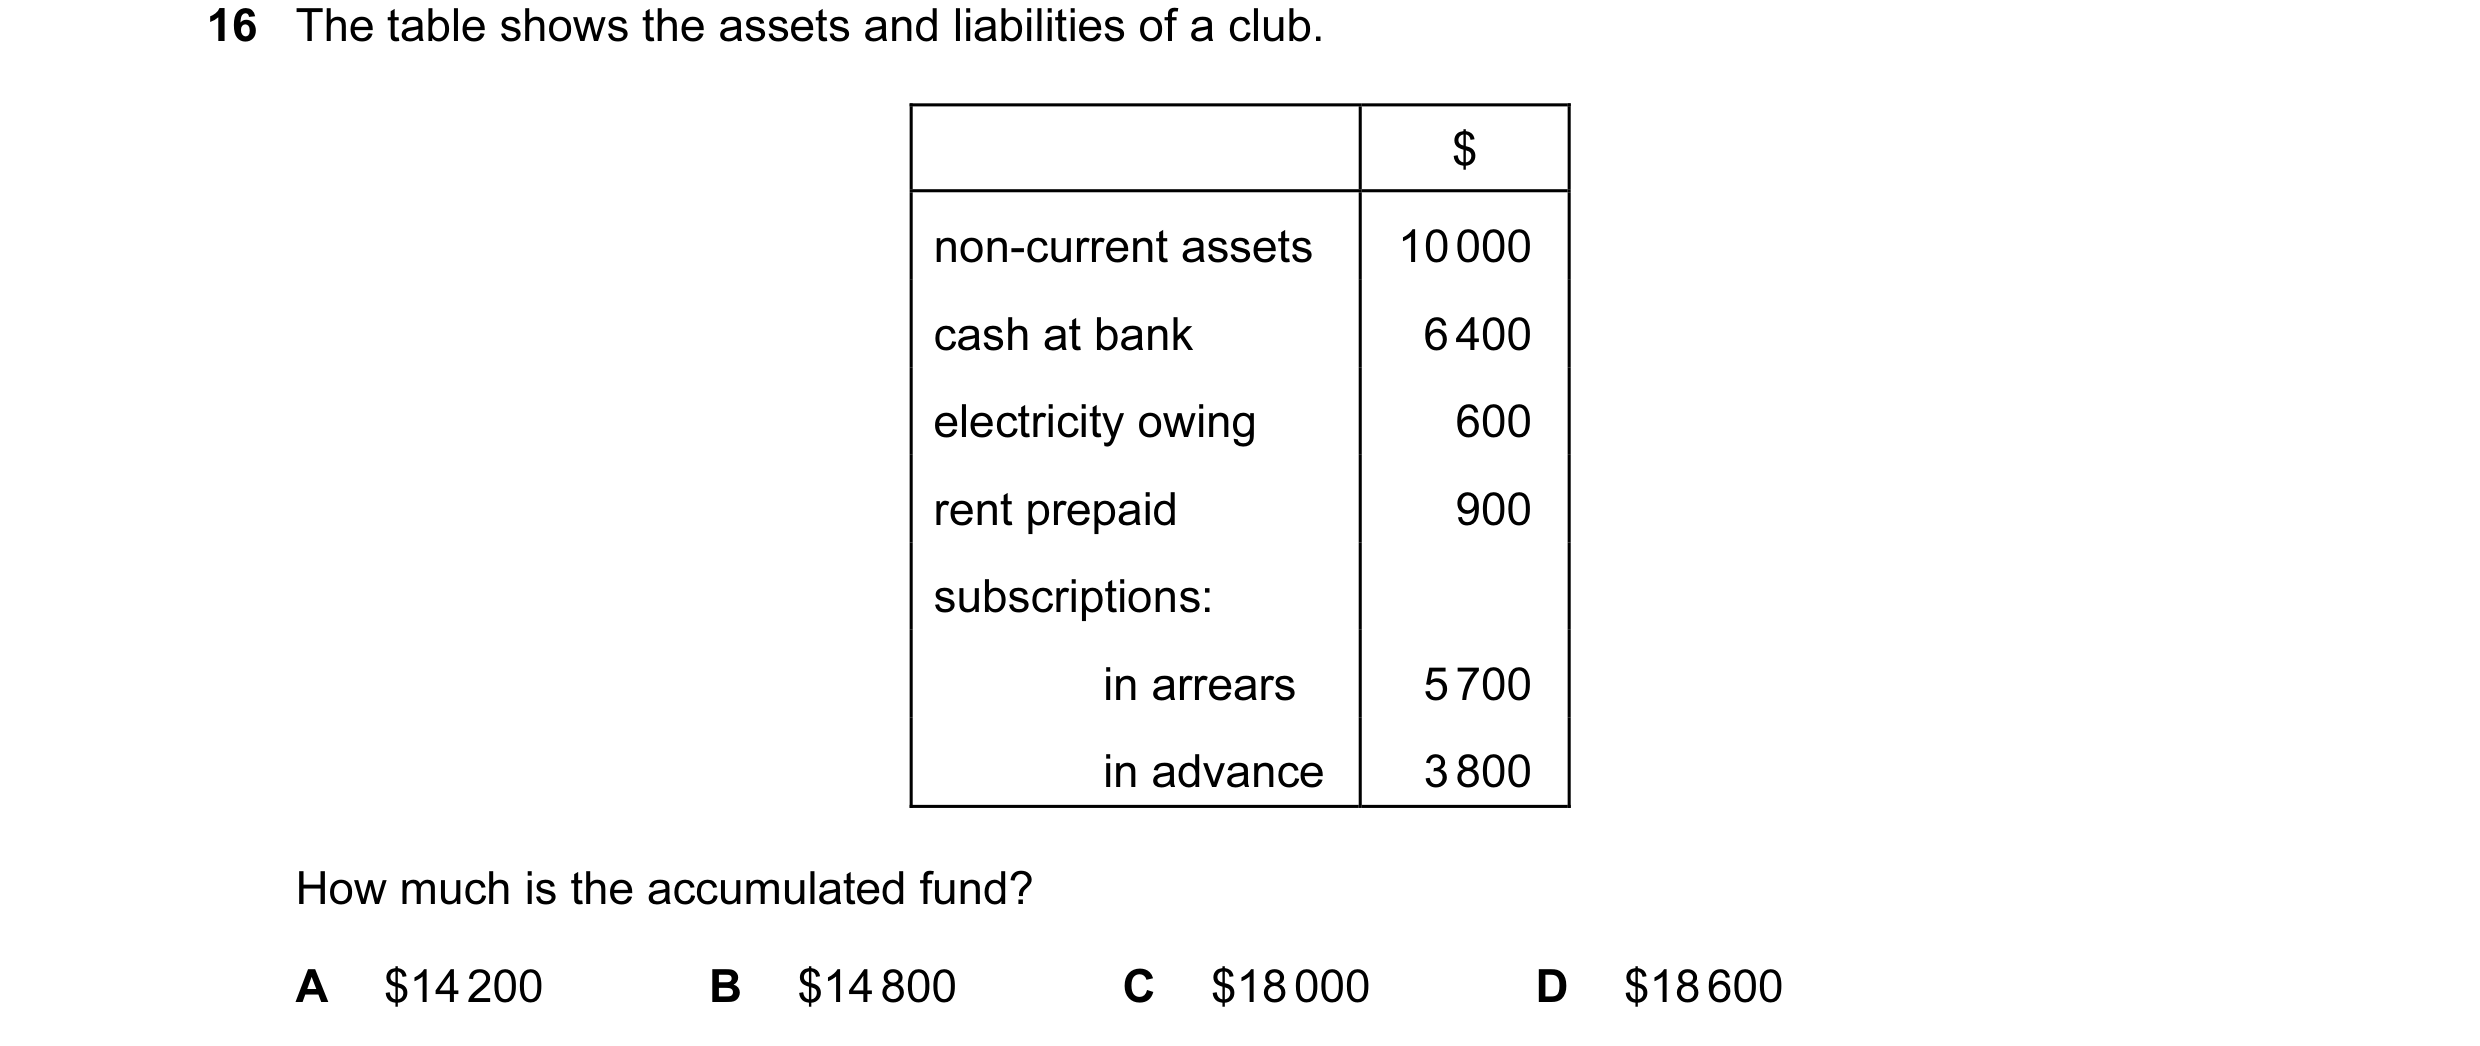
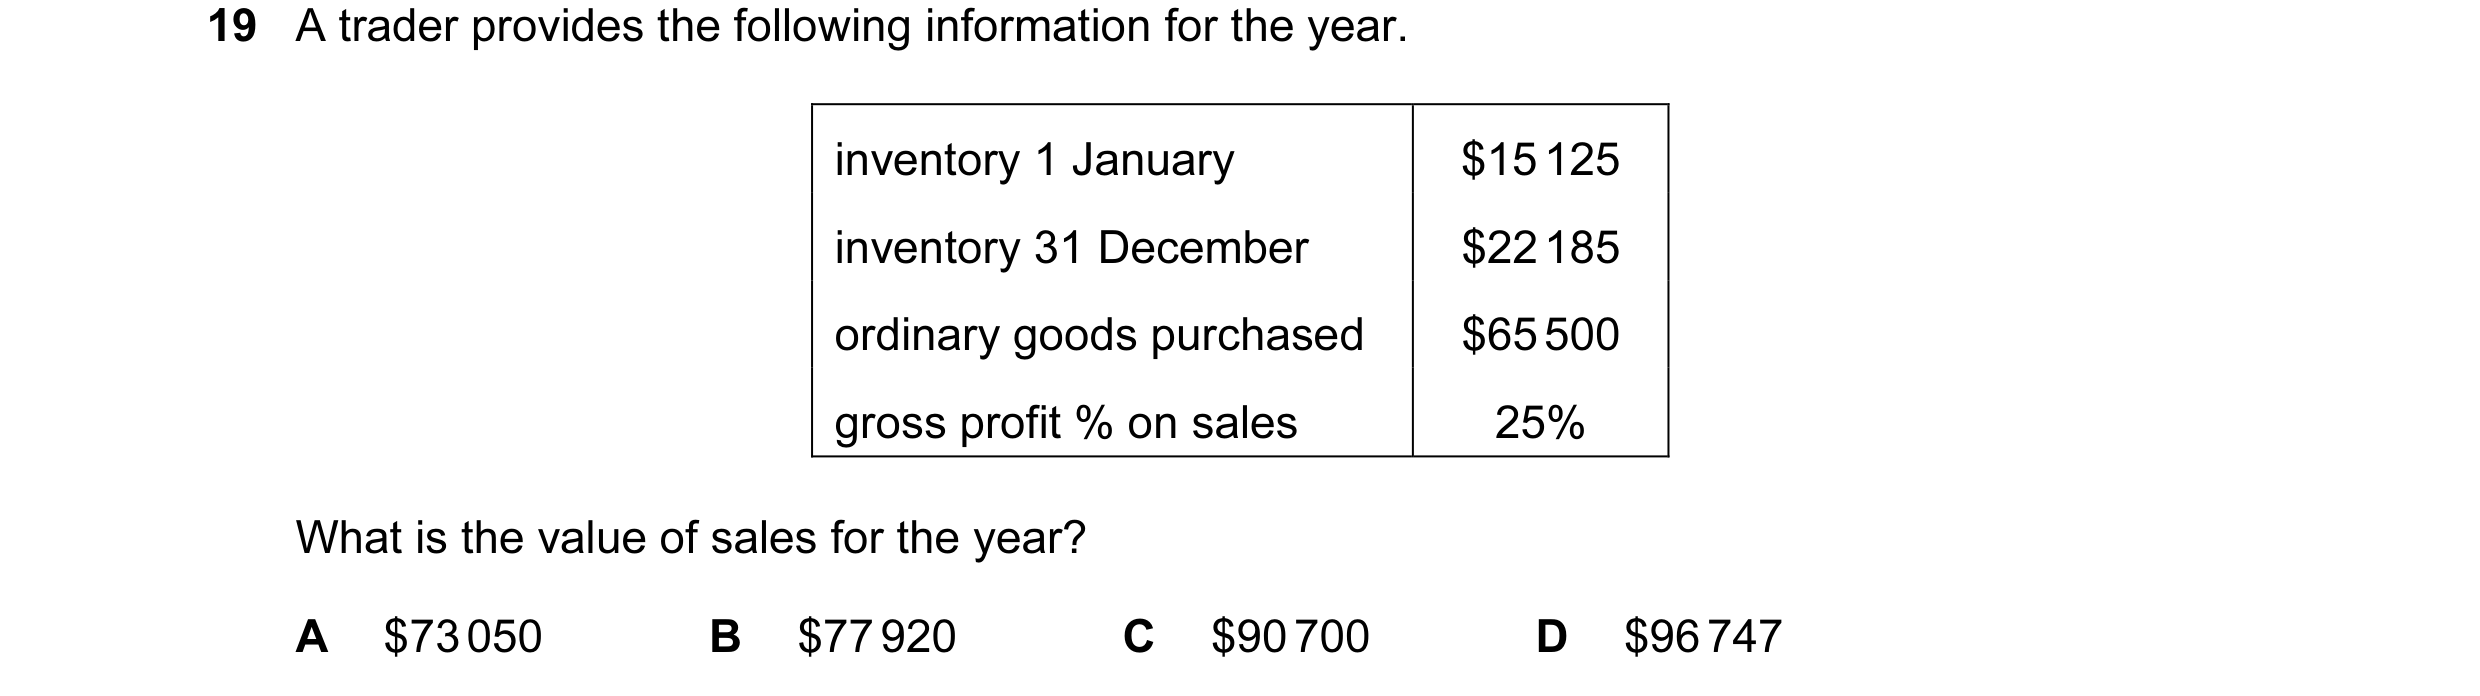
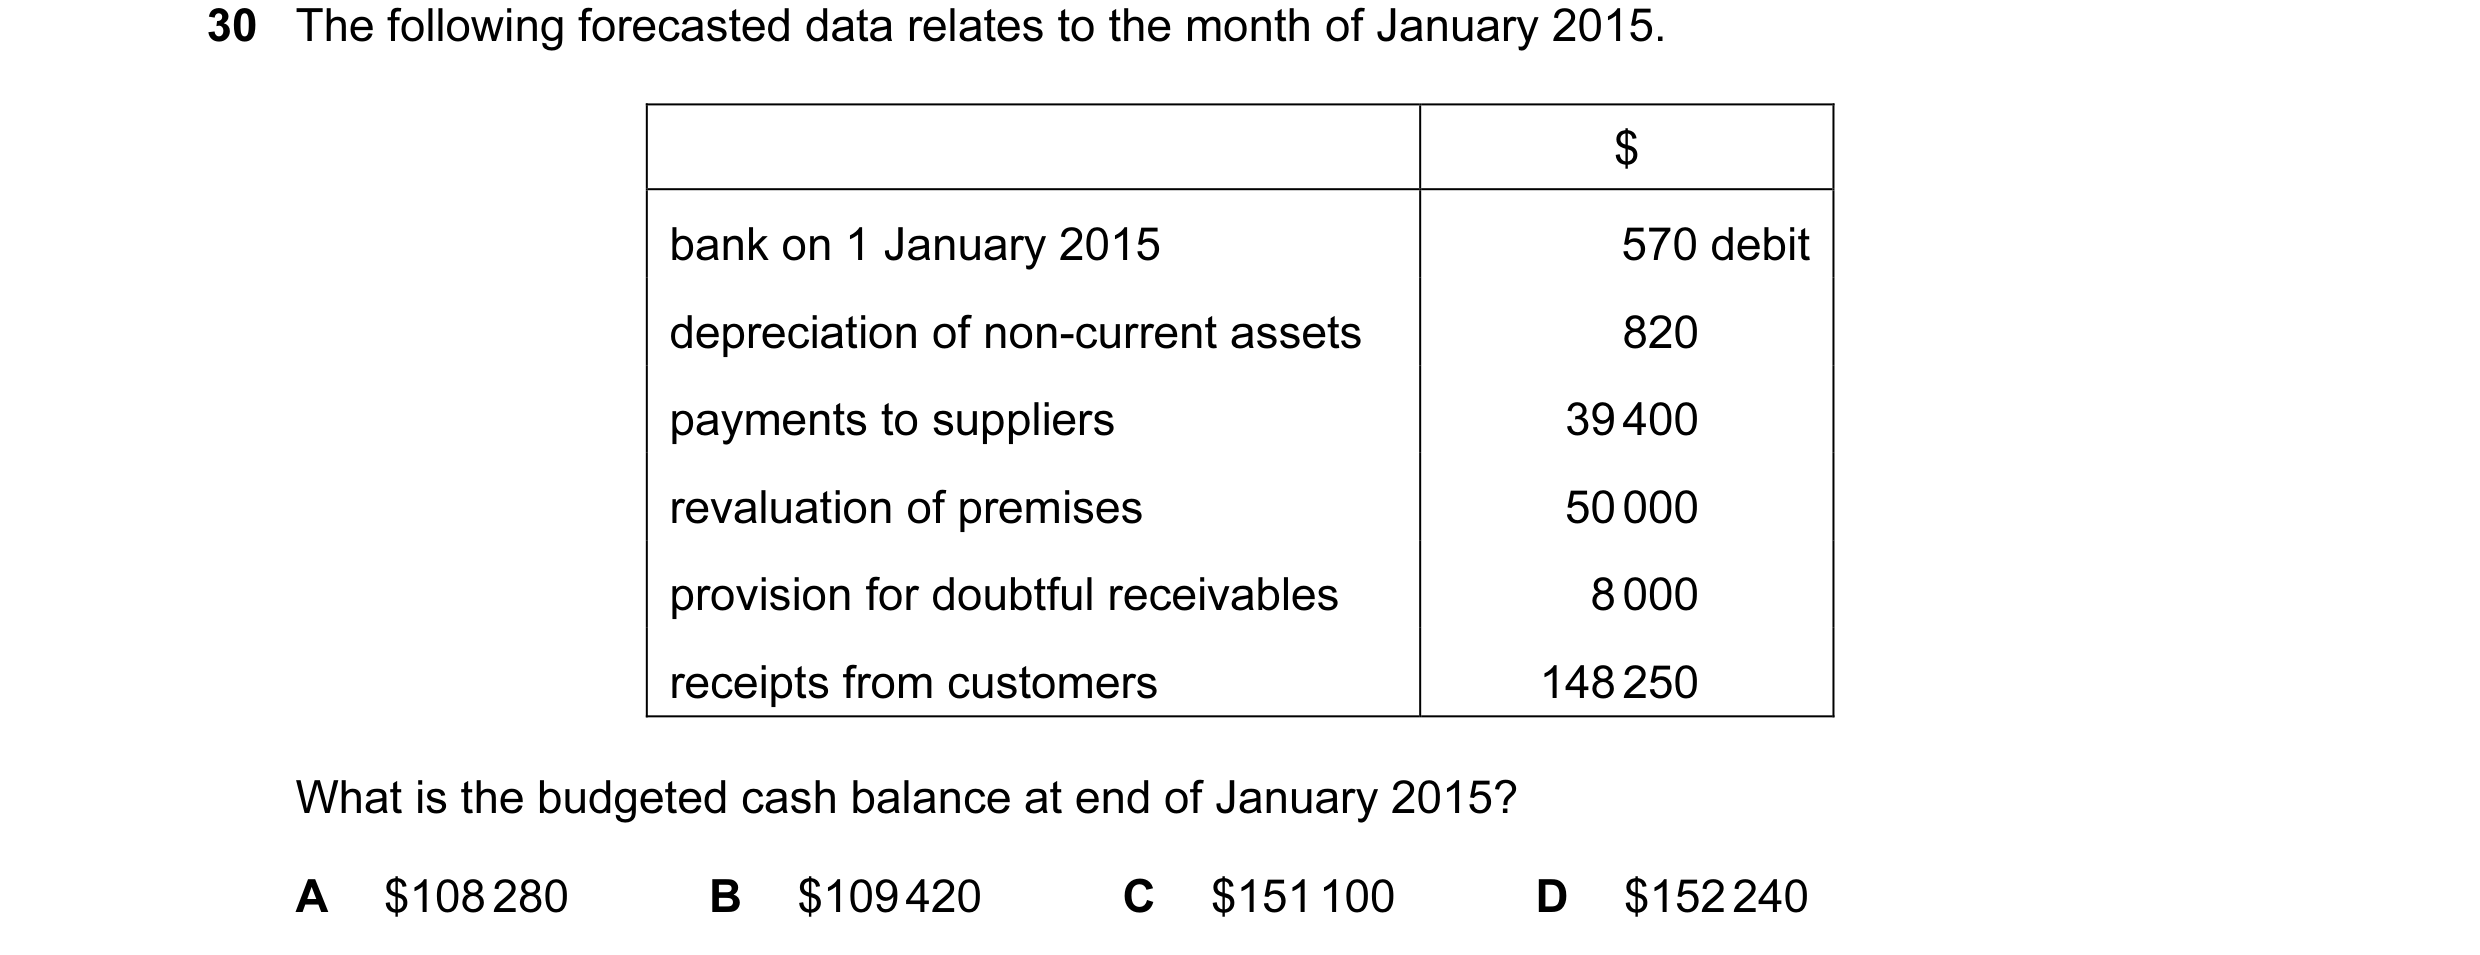 111 / 233
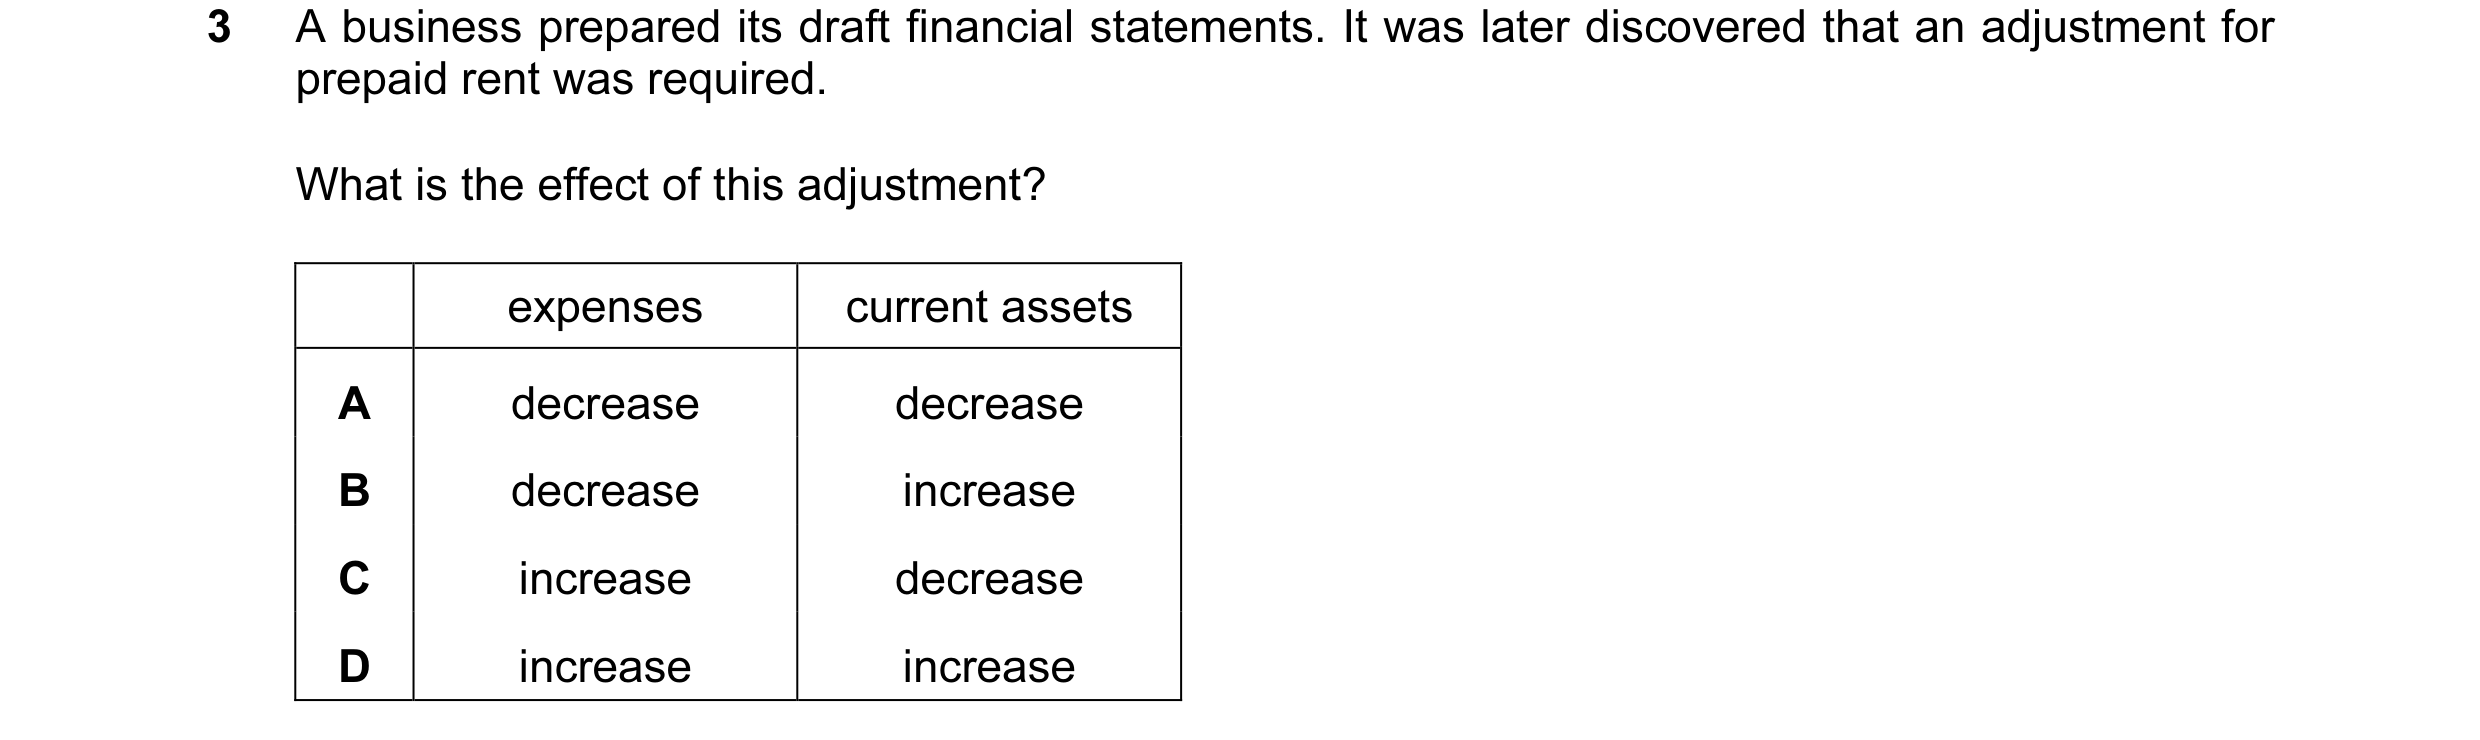
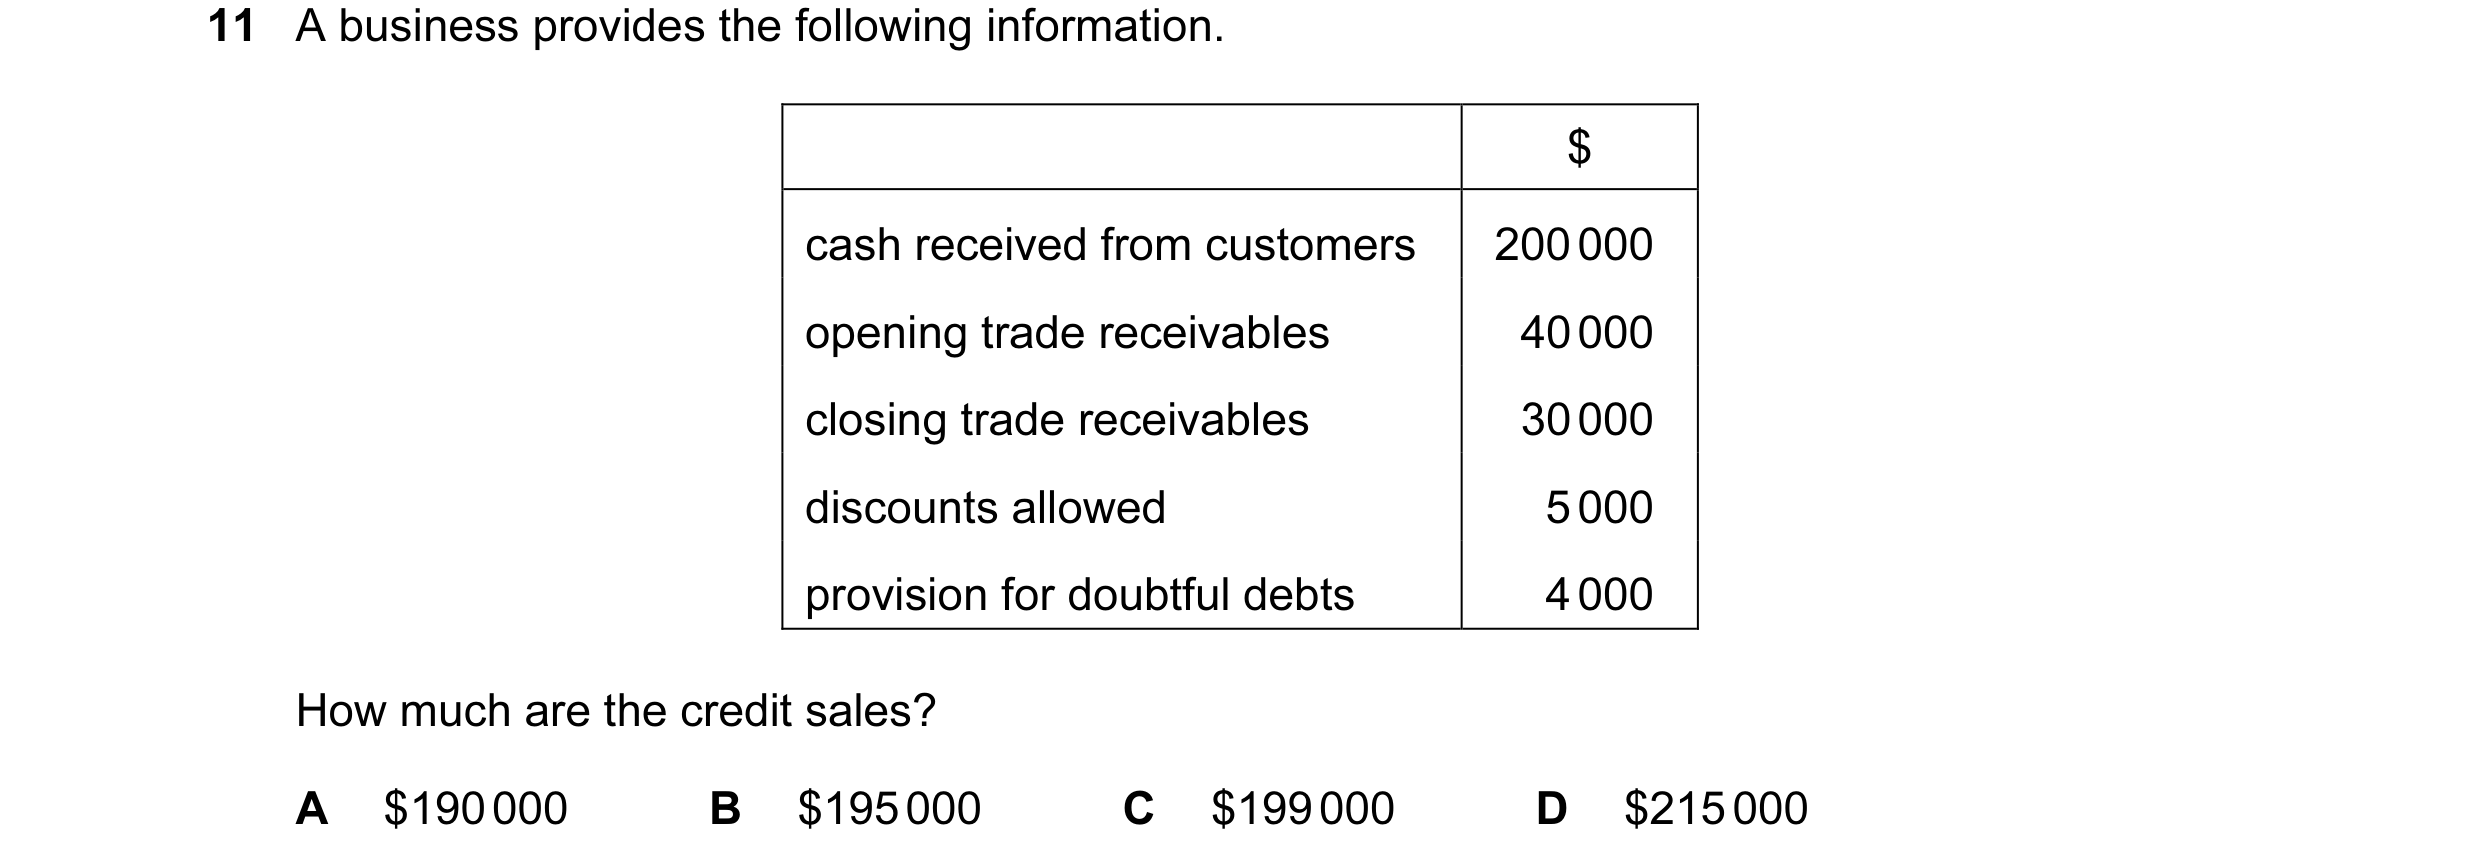
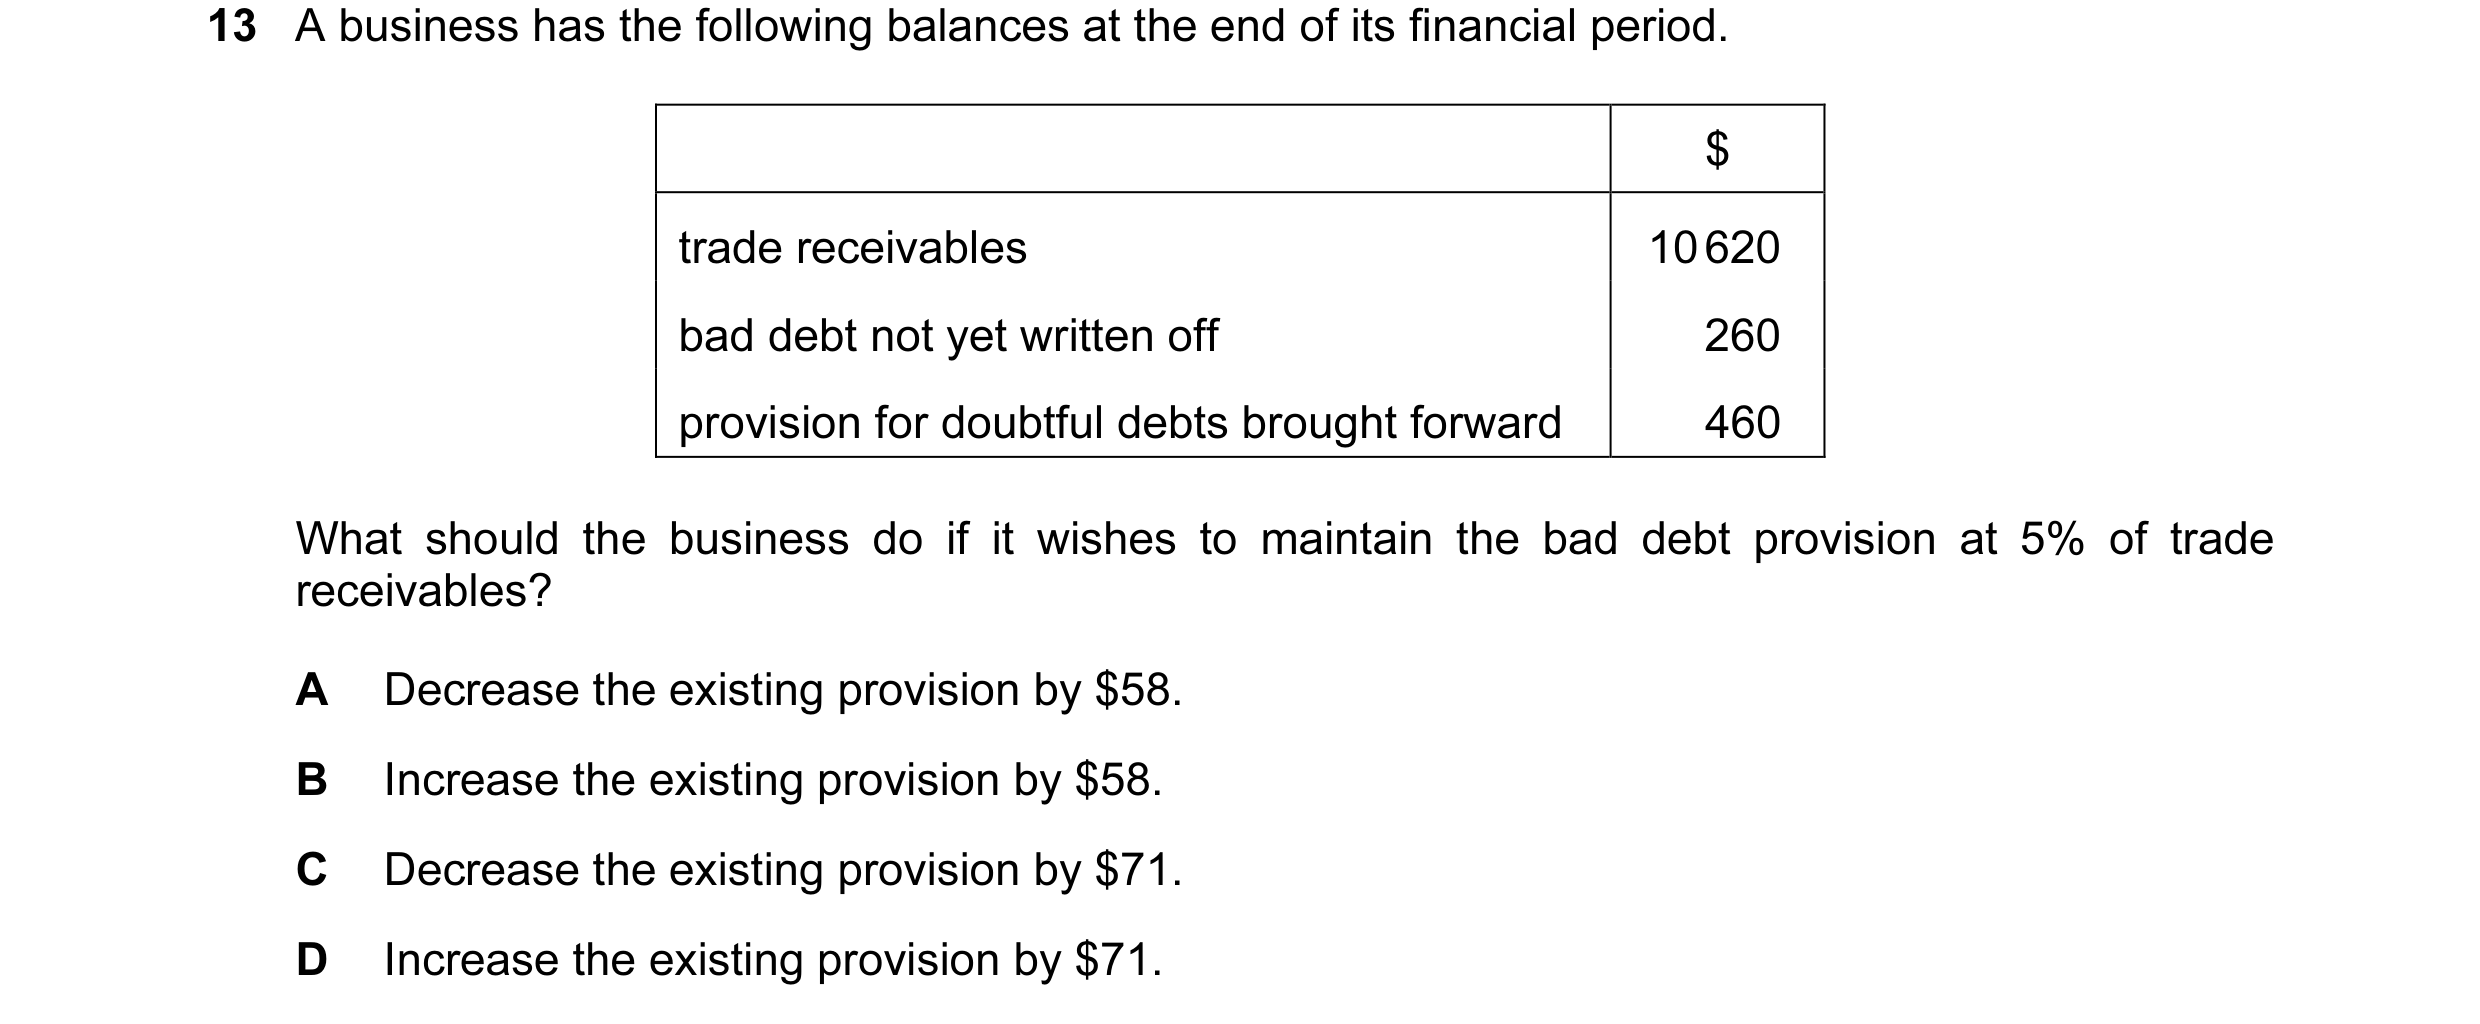 112 / 233
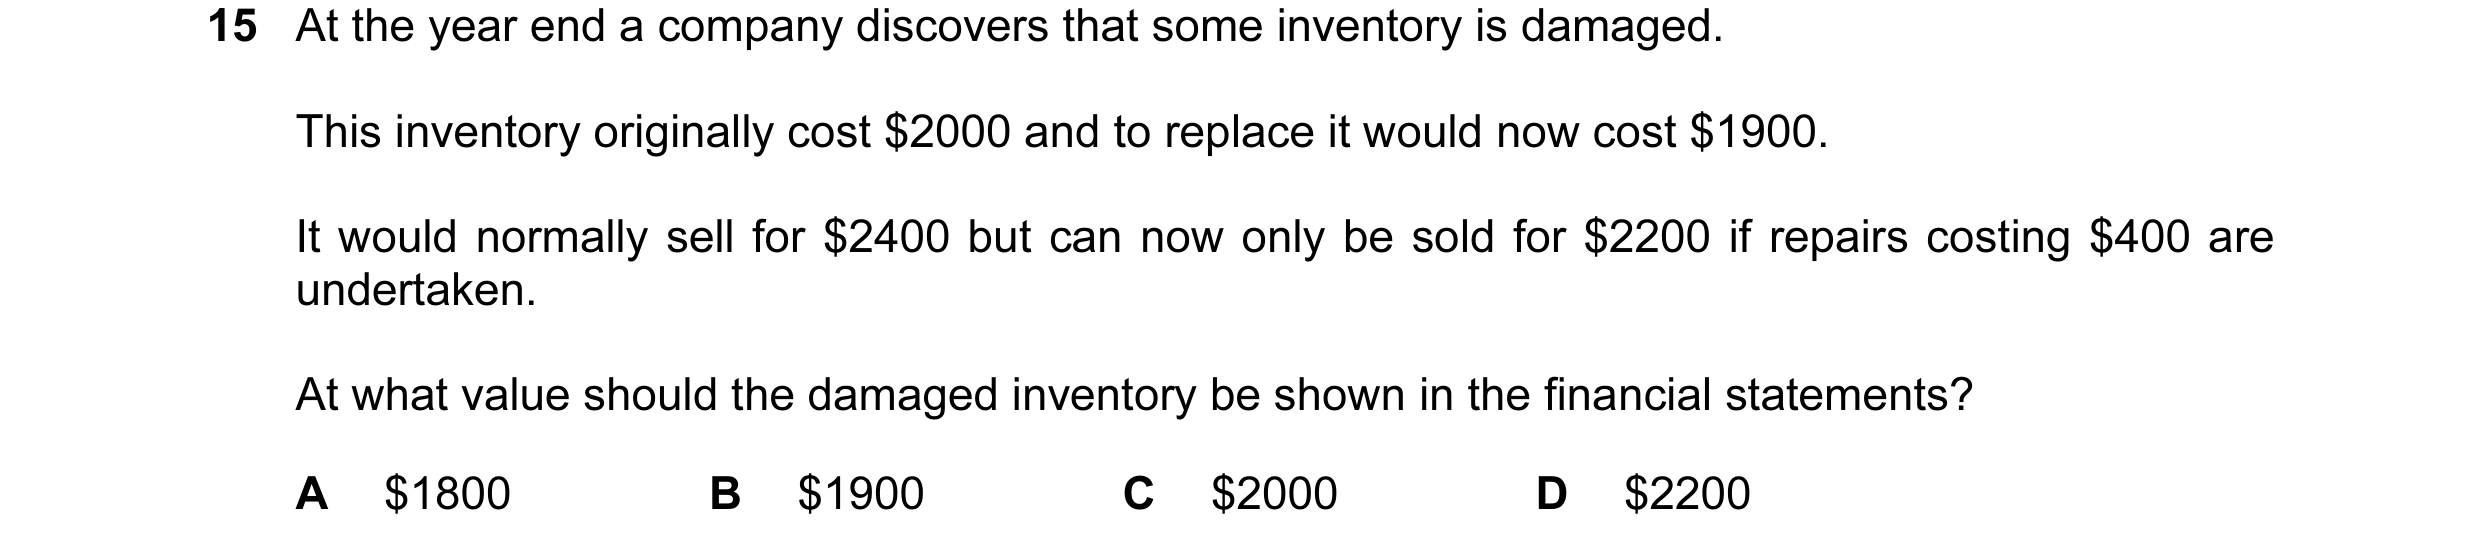
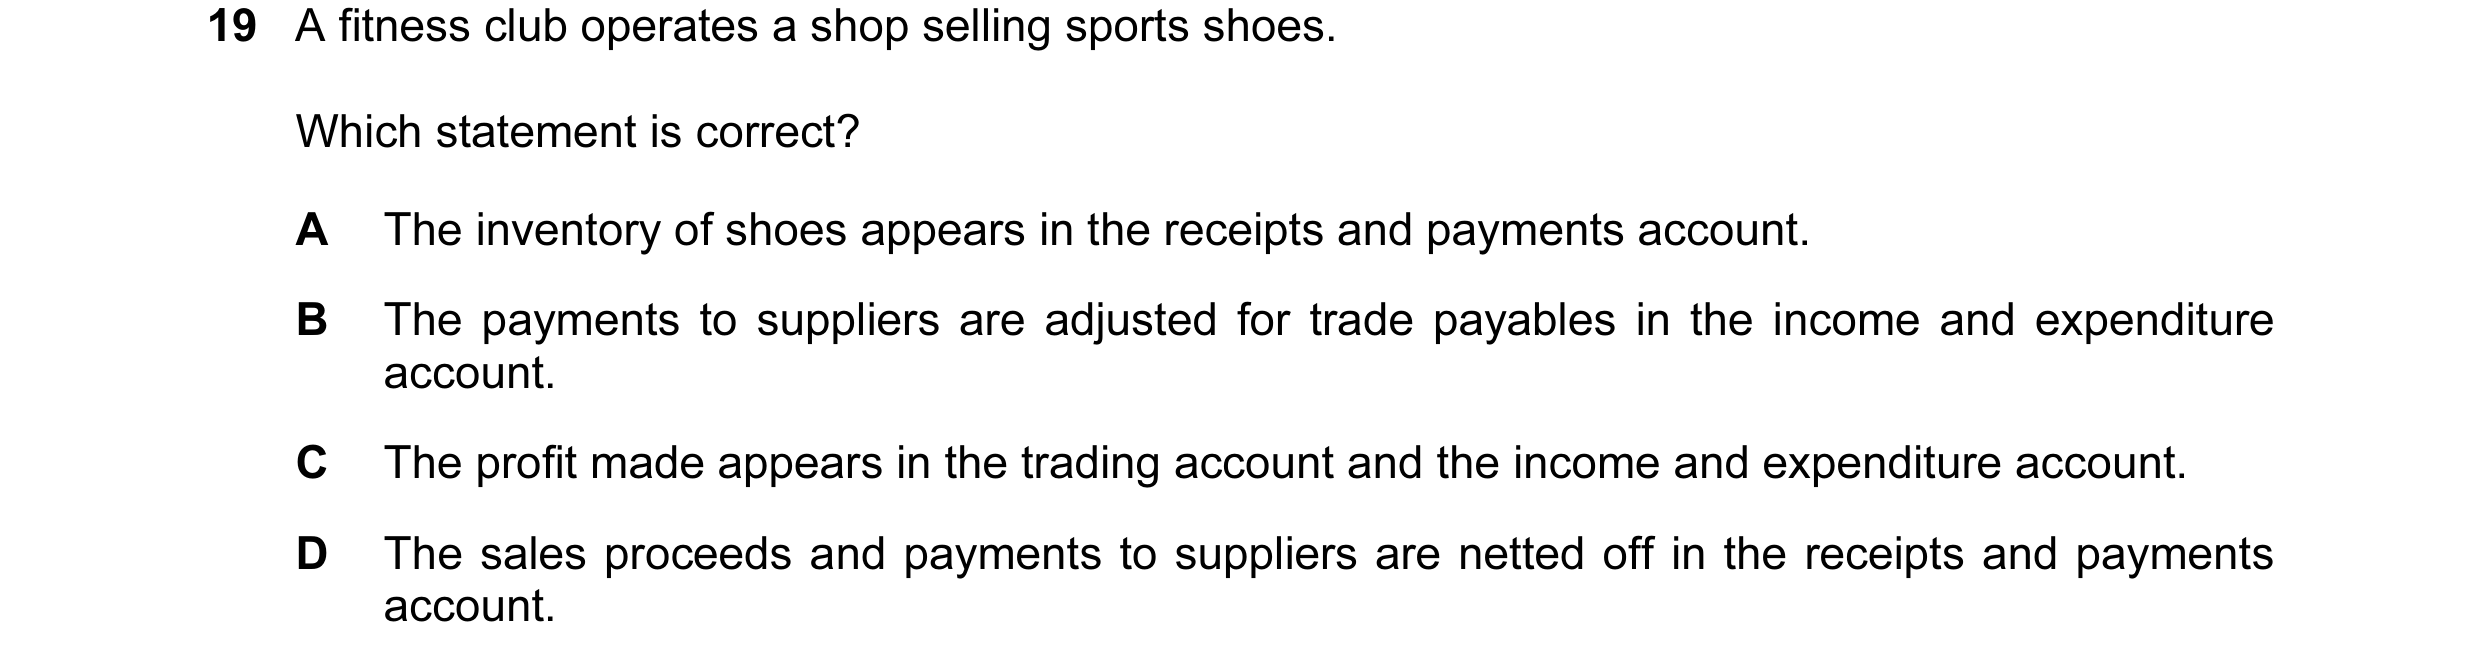
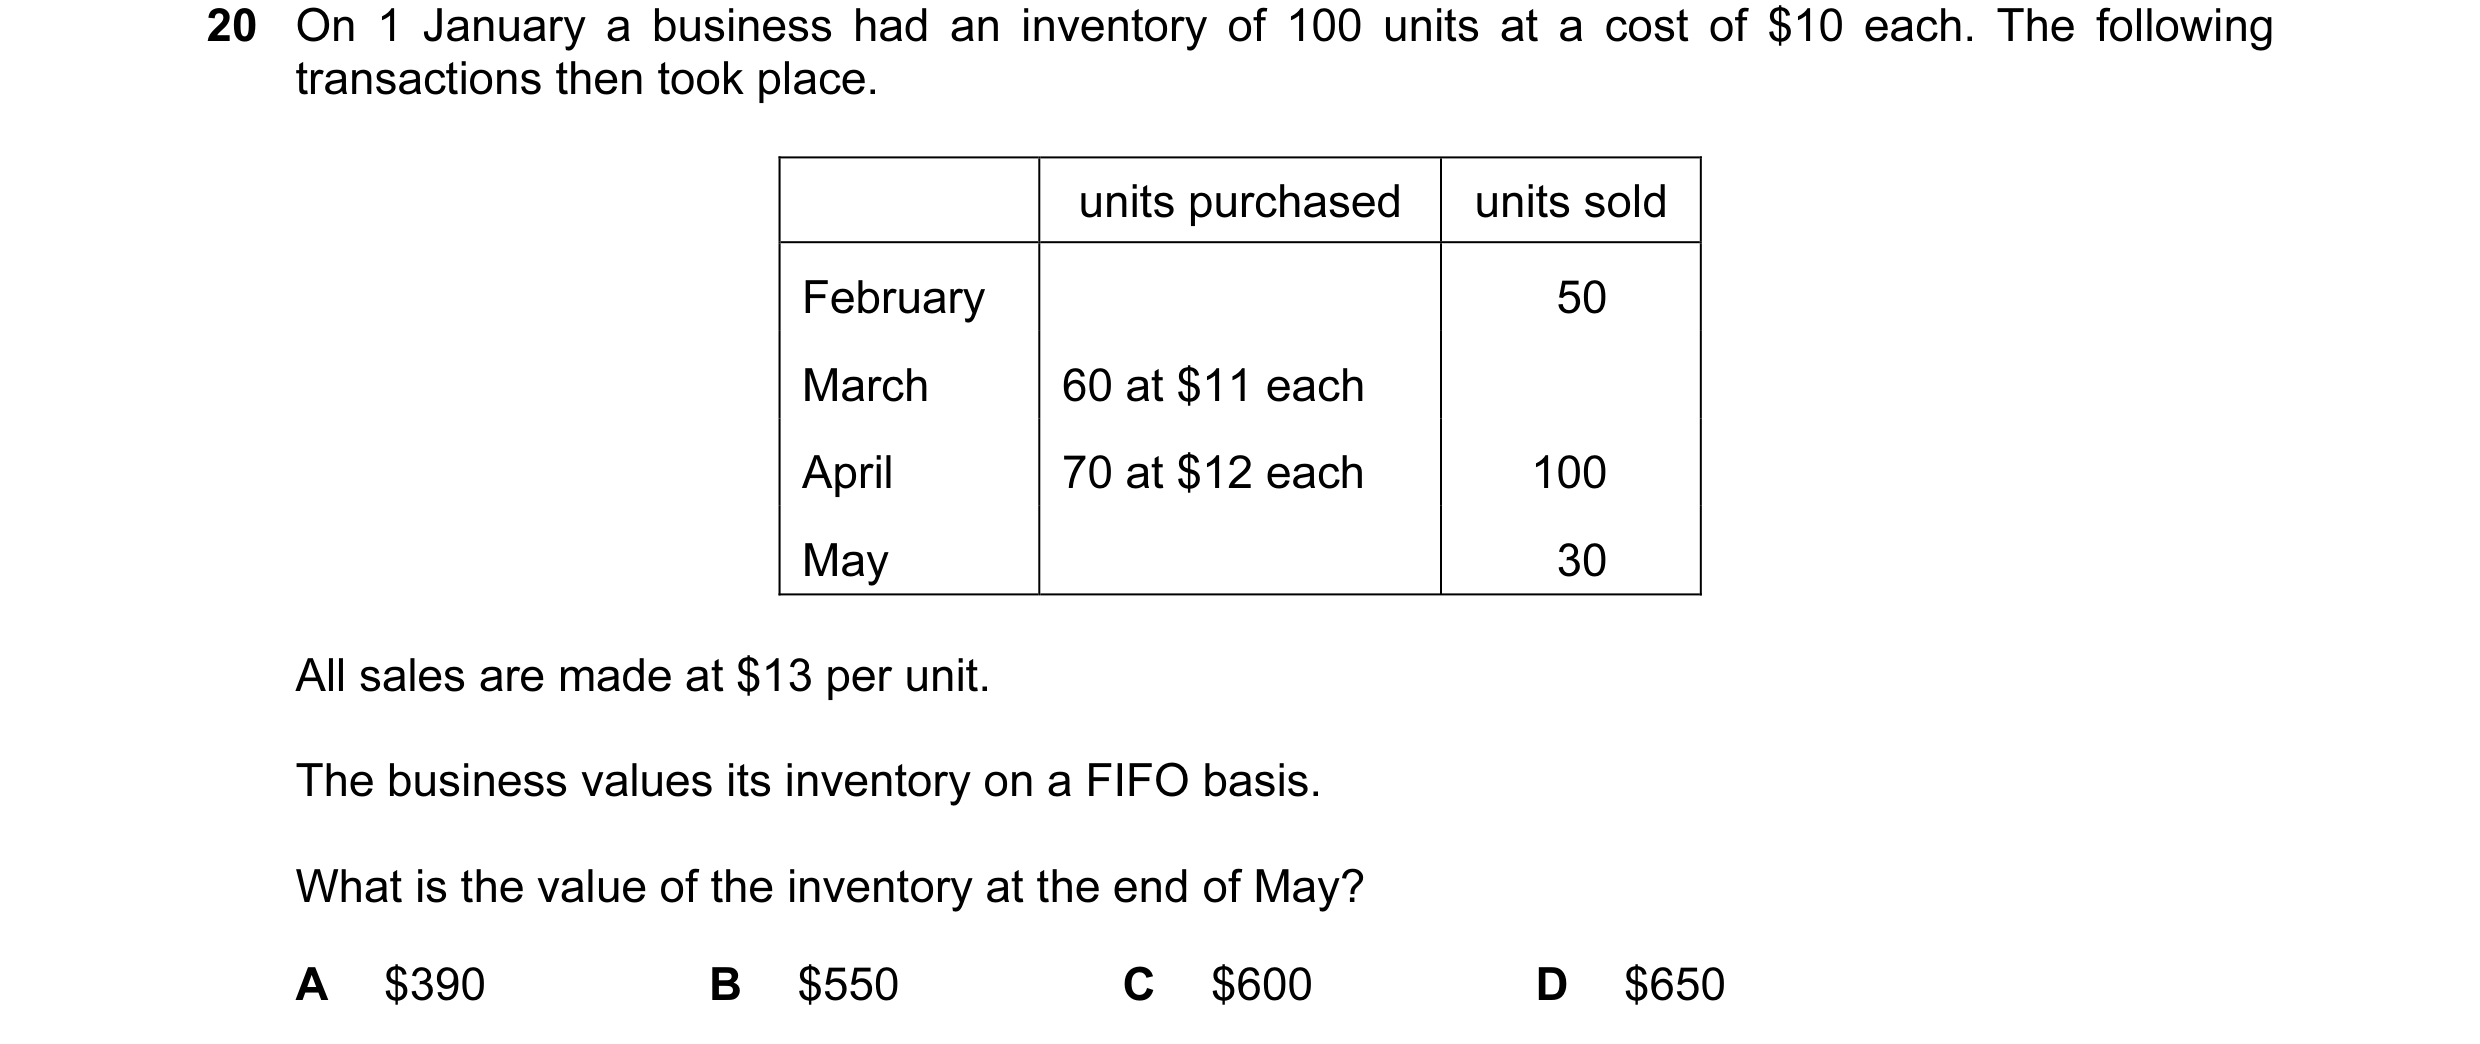
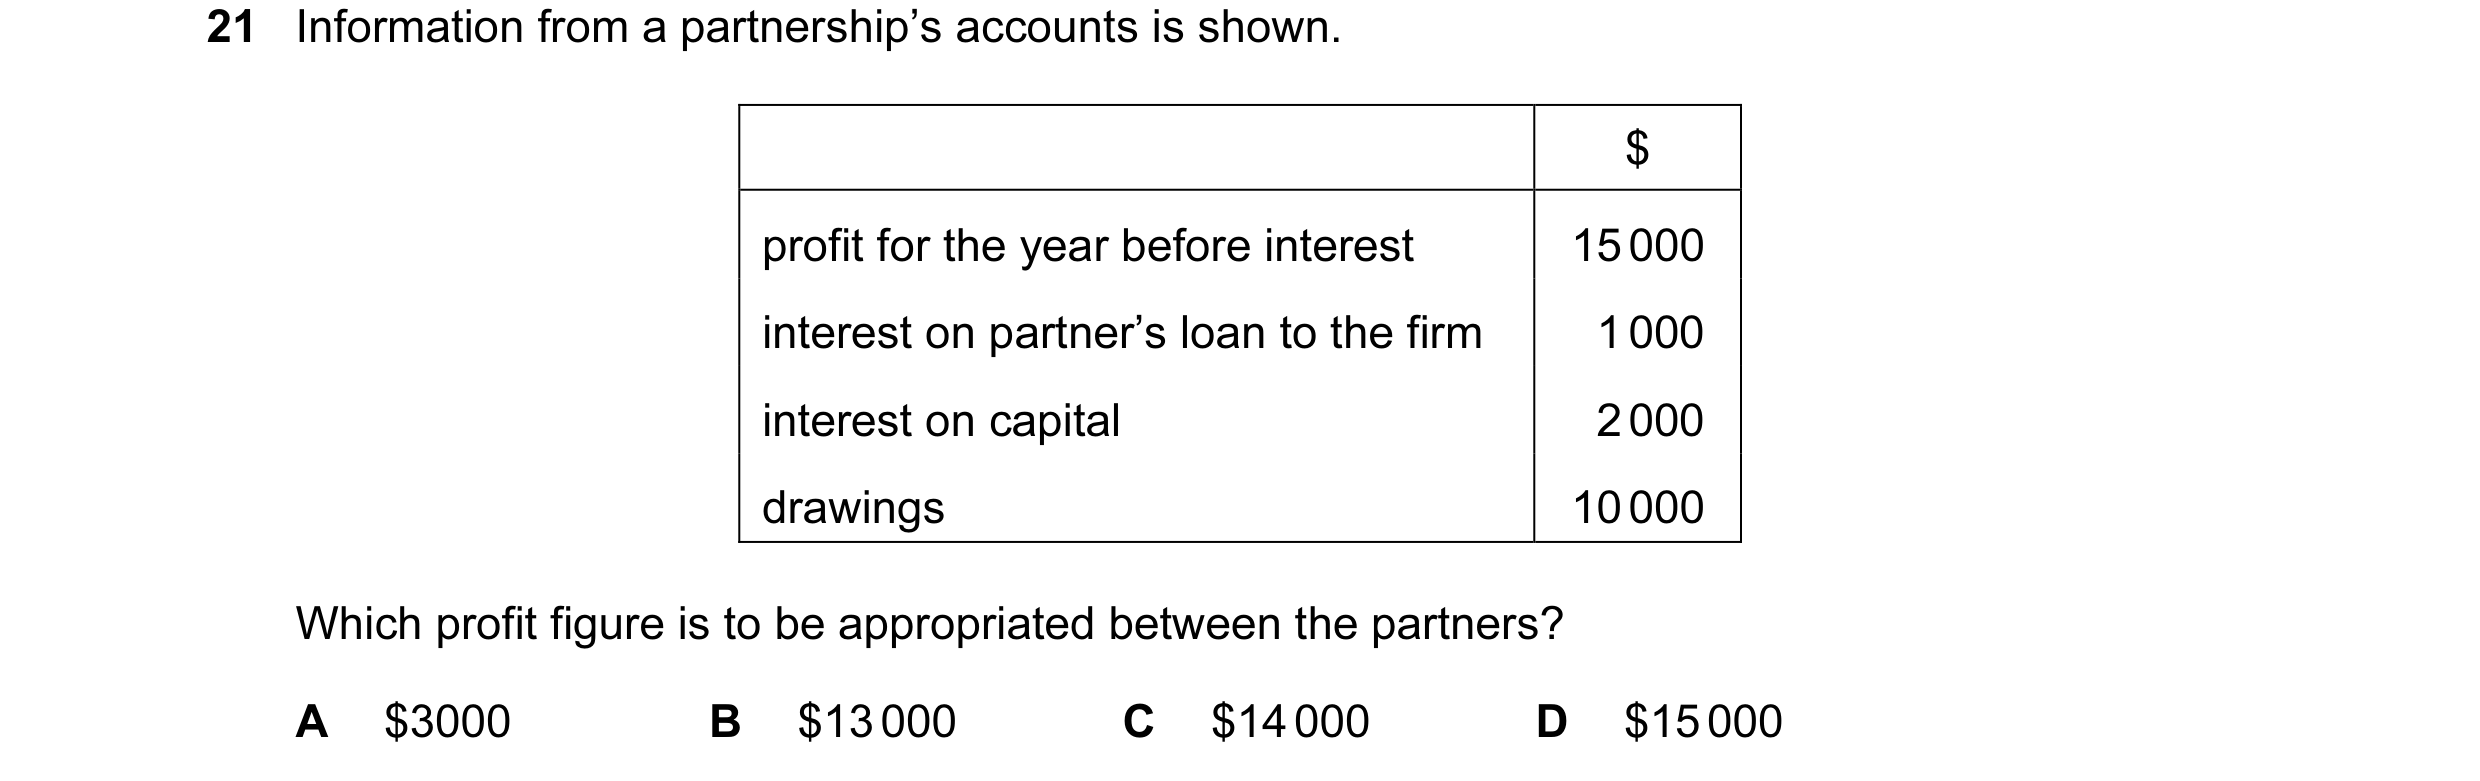 113 / 233
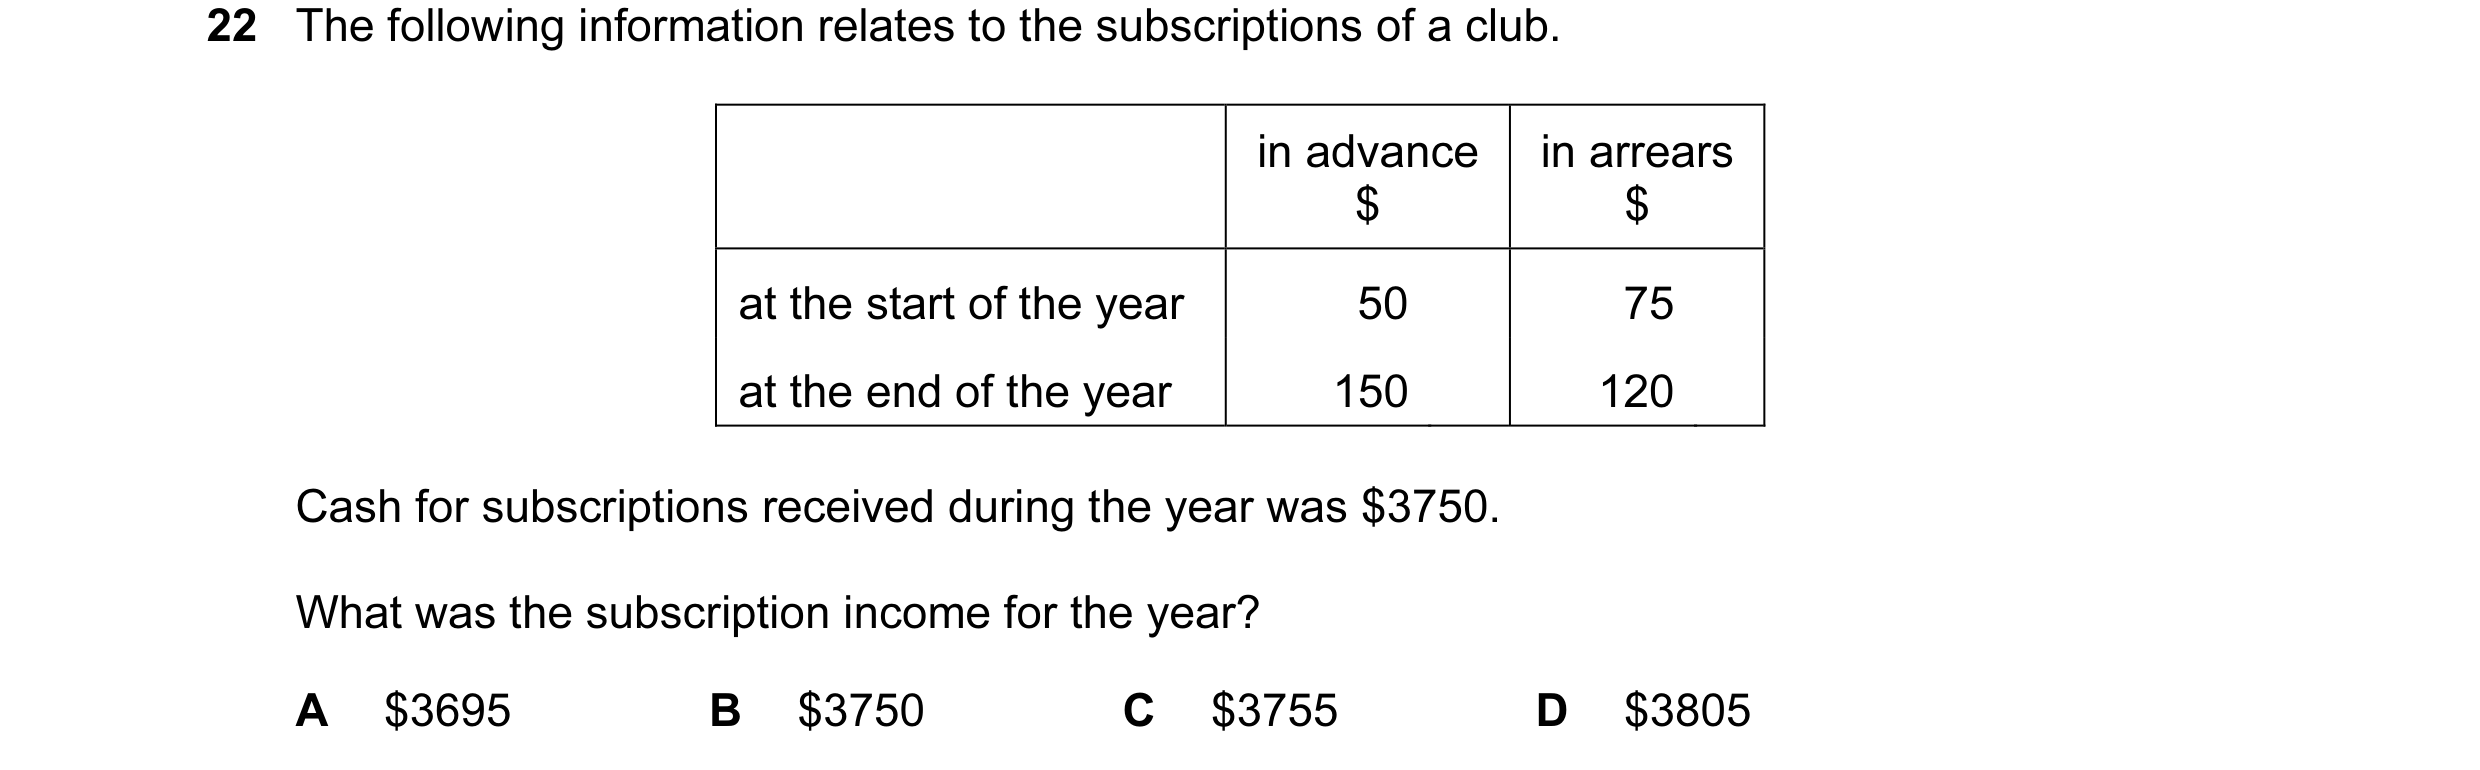
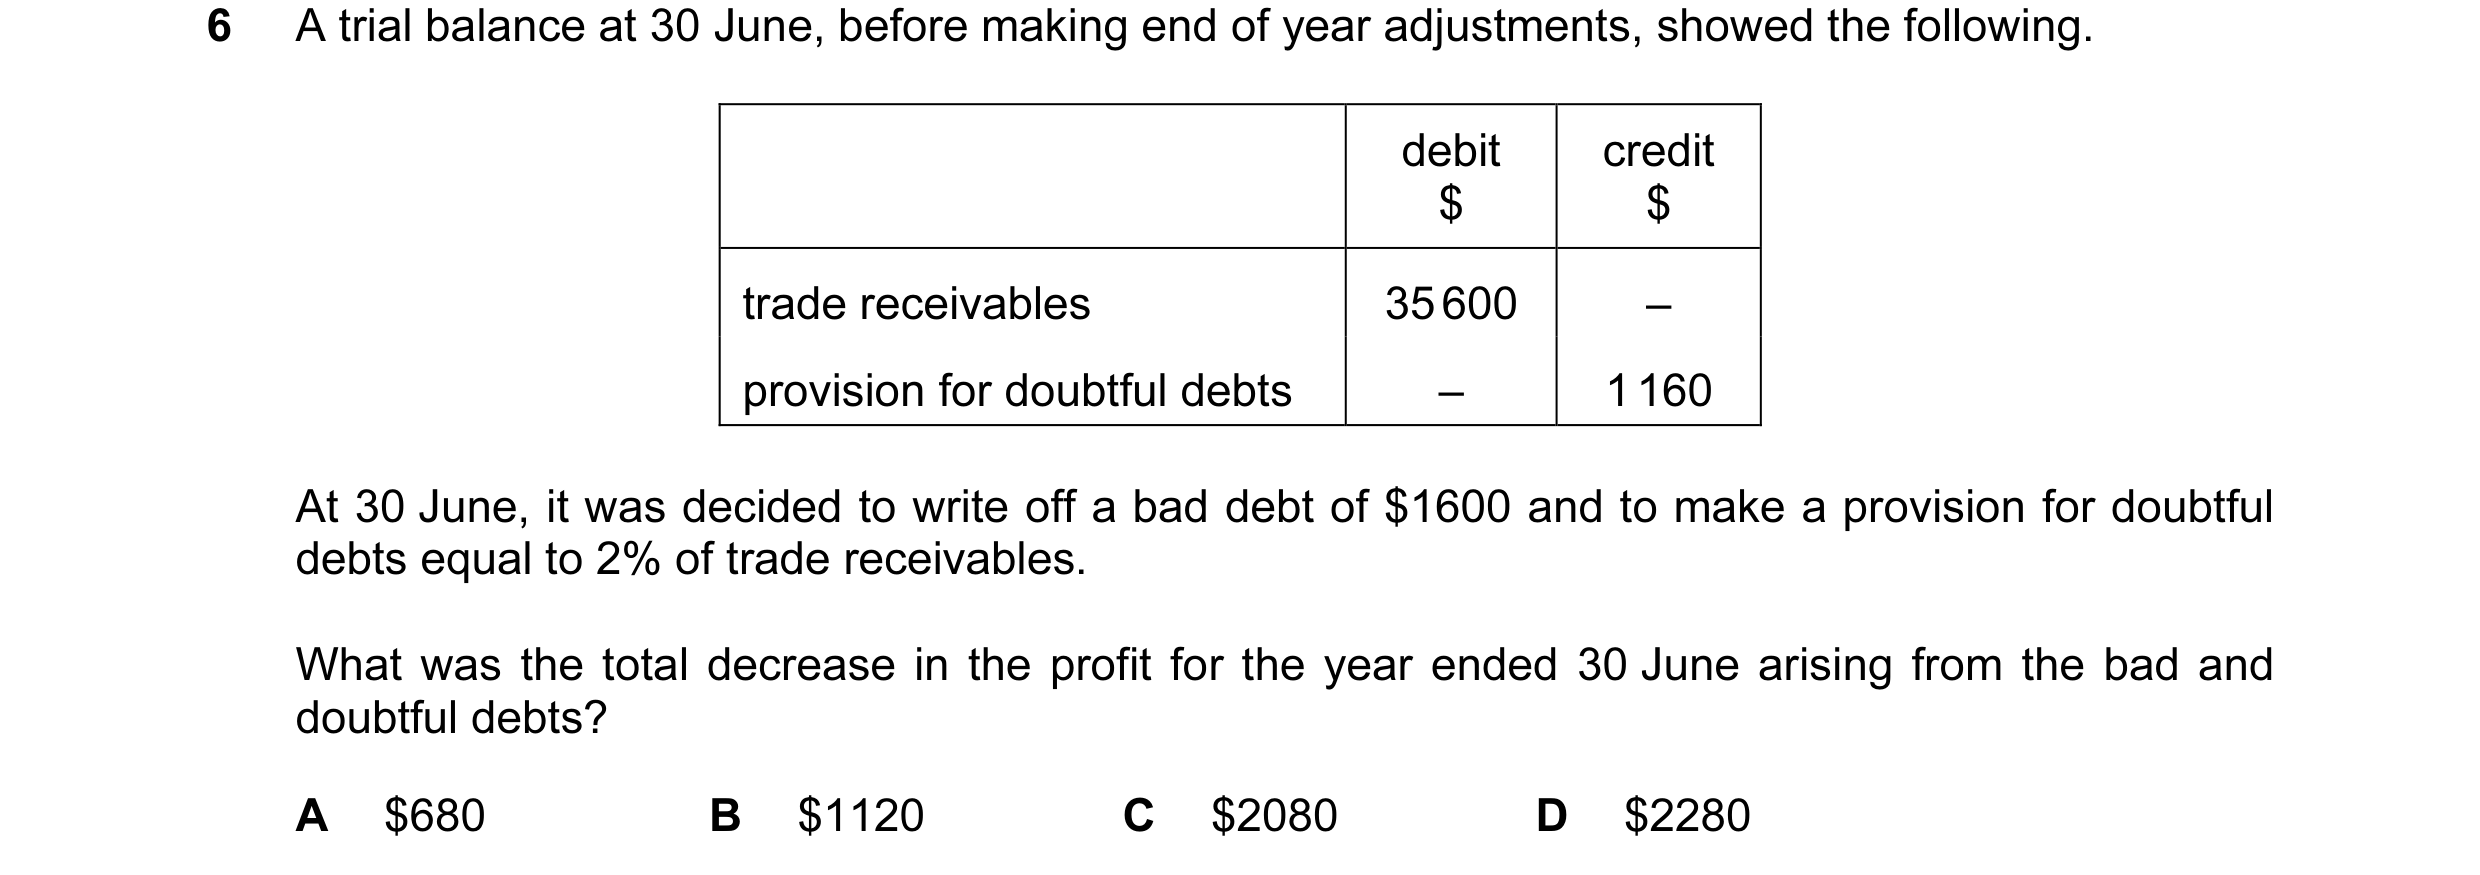 114 / 233
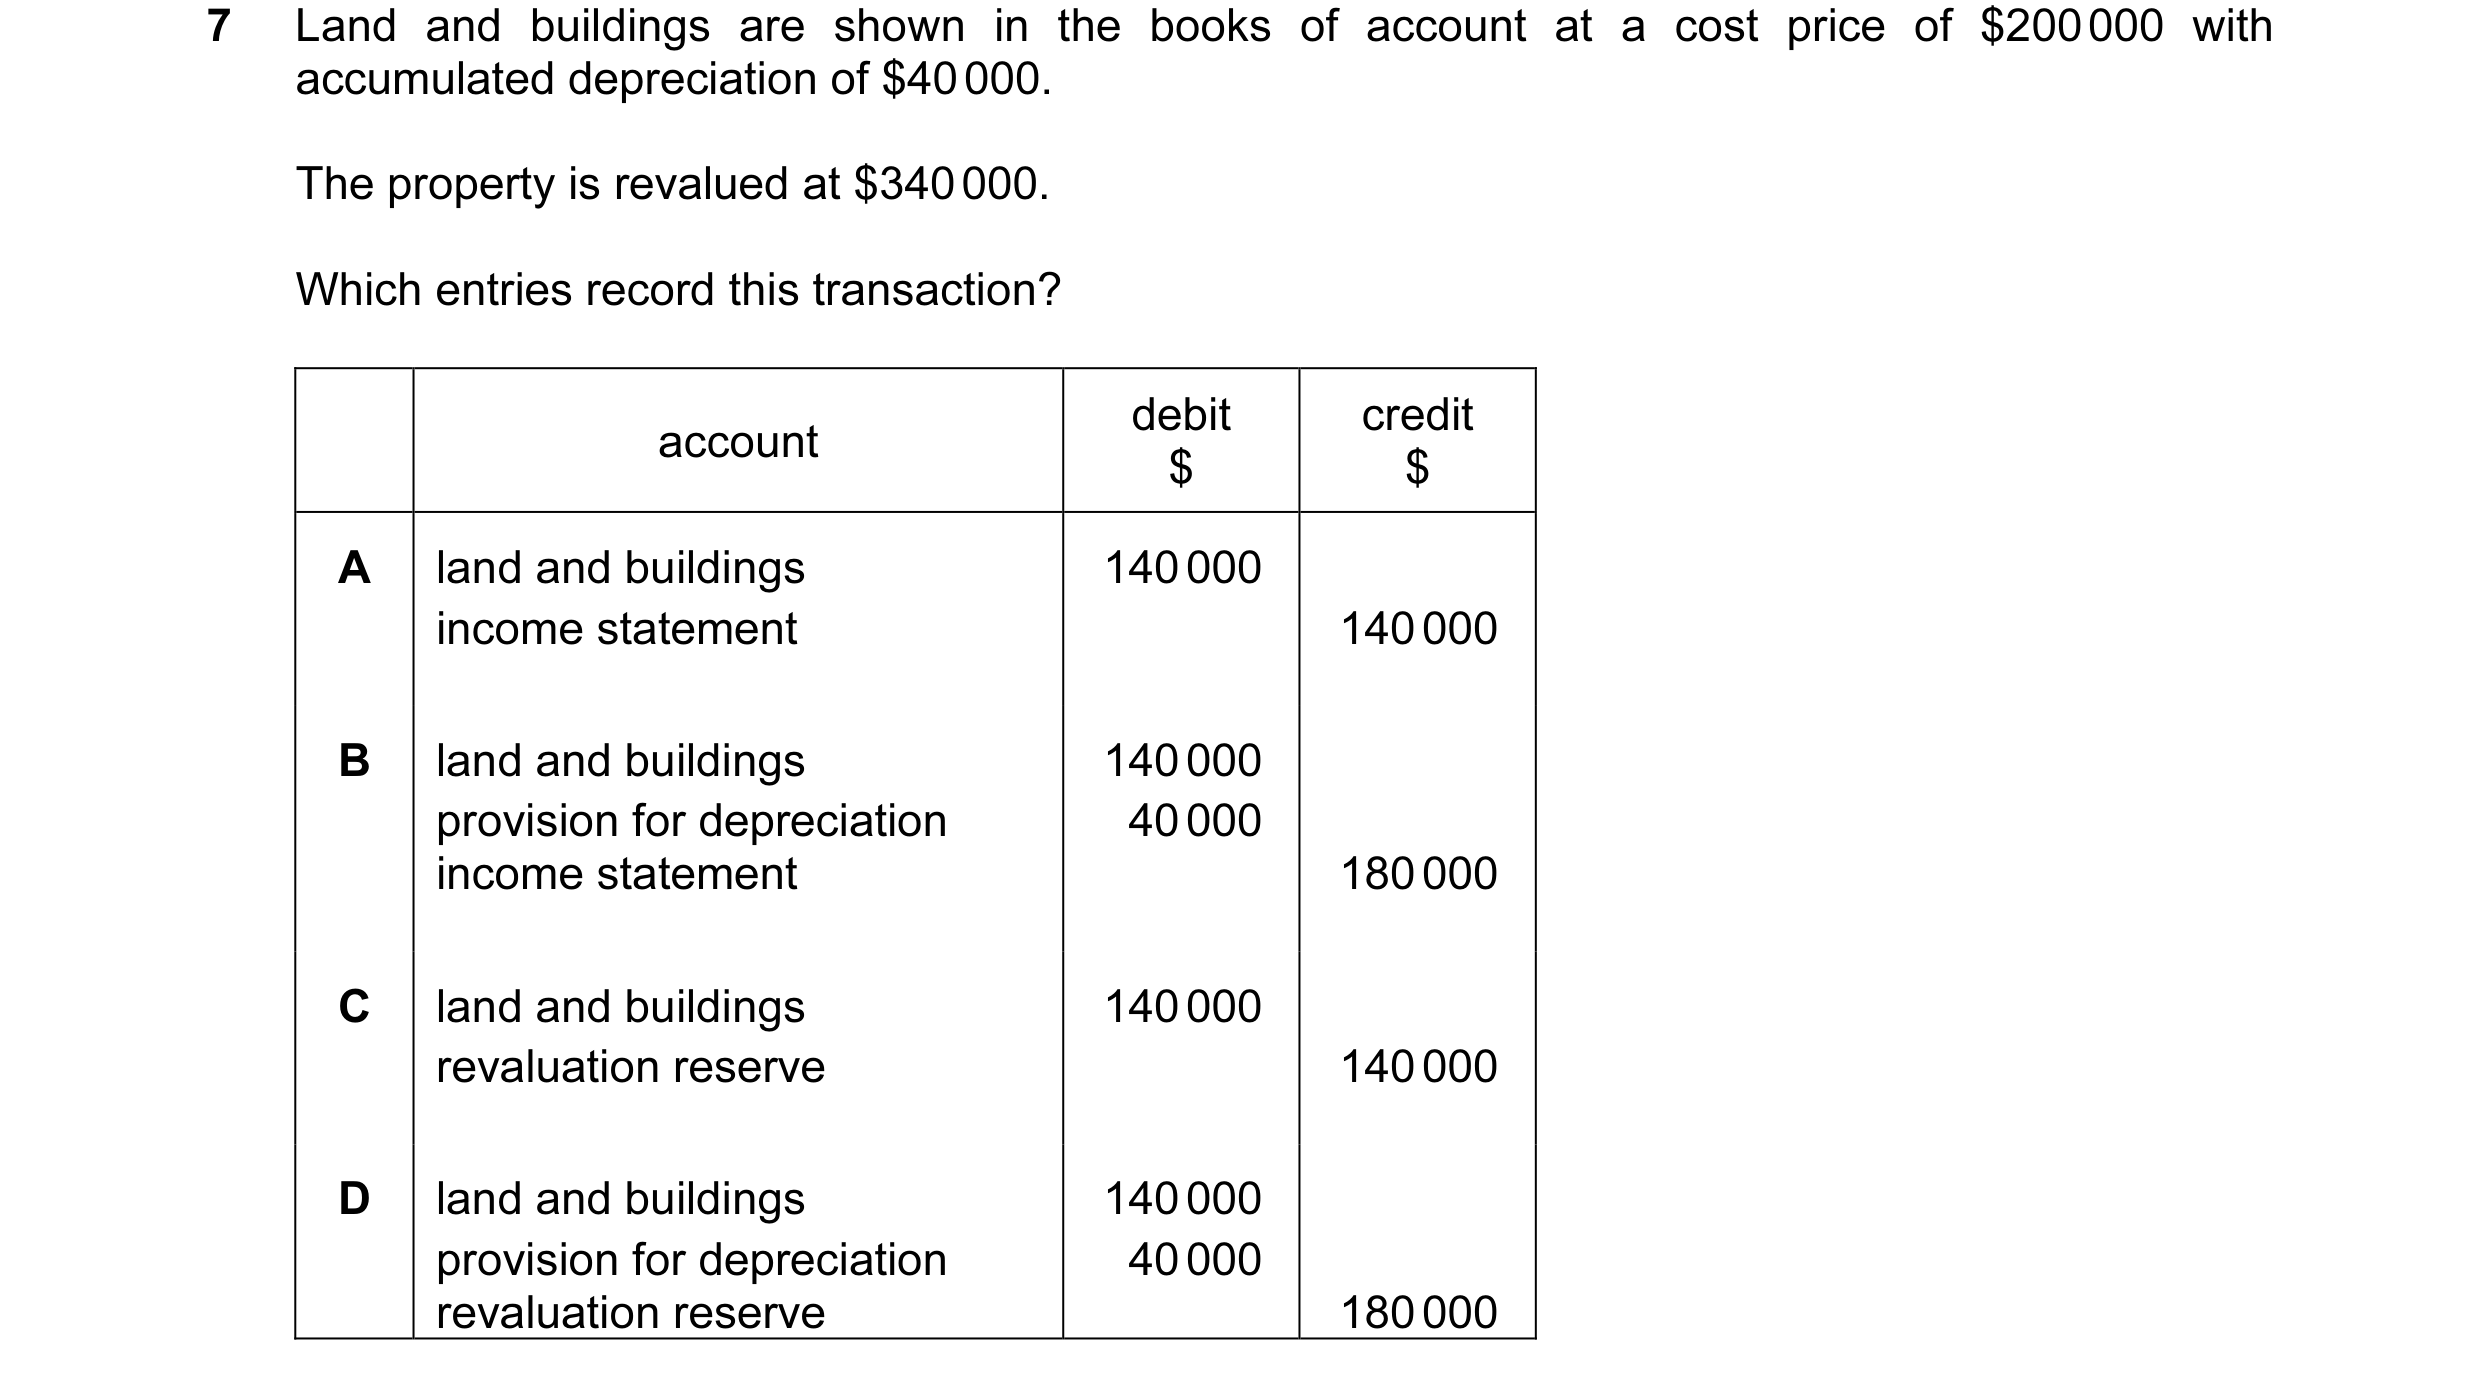
 115 / 233
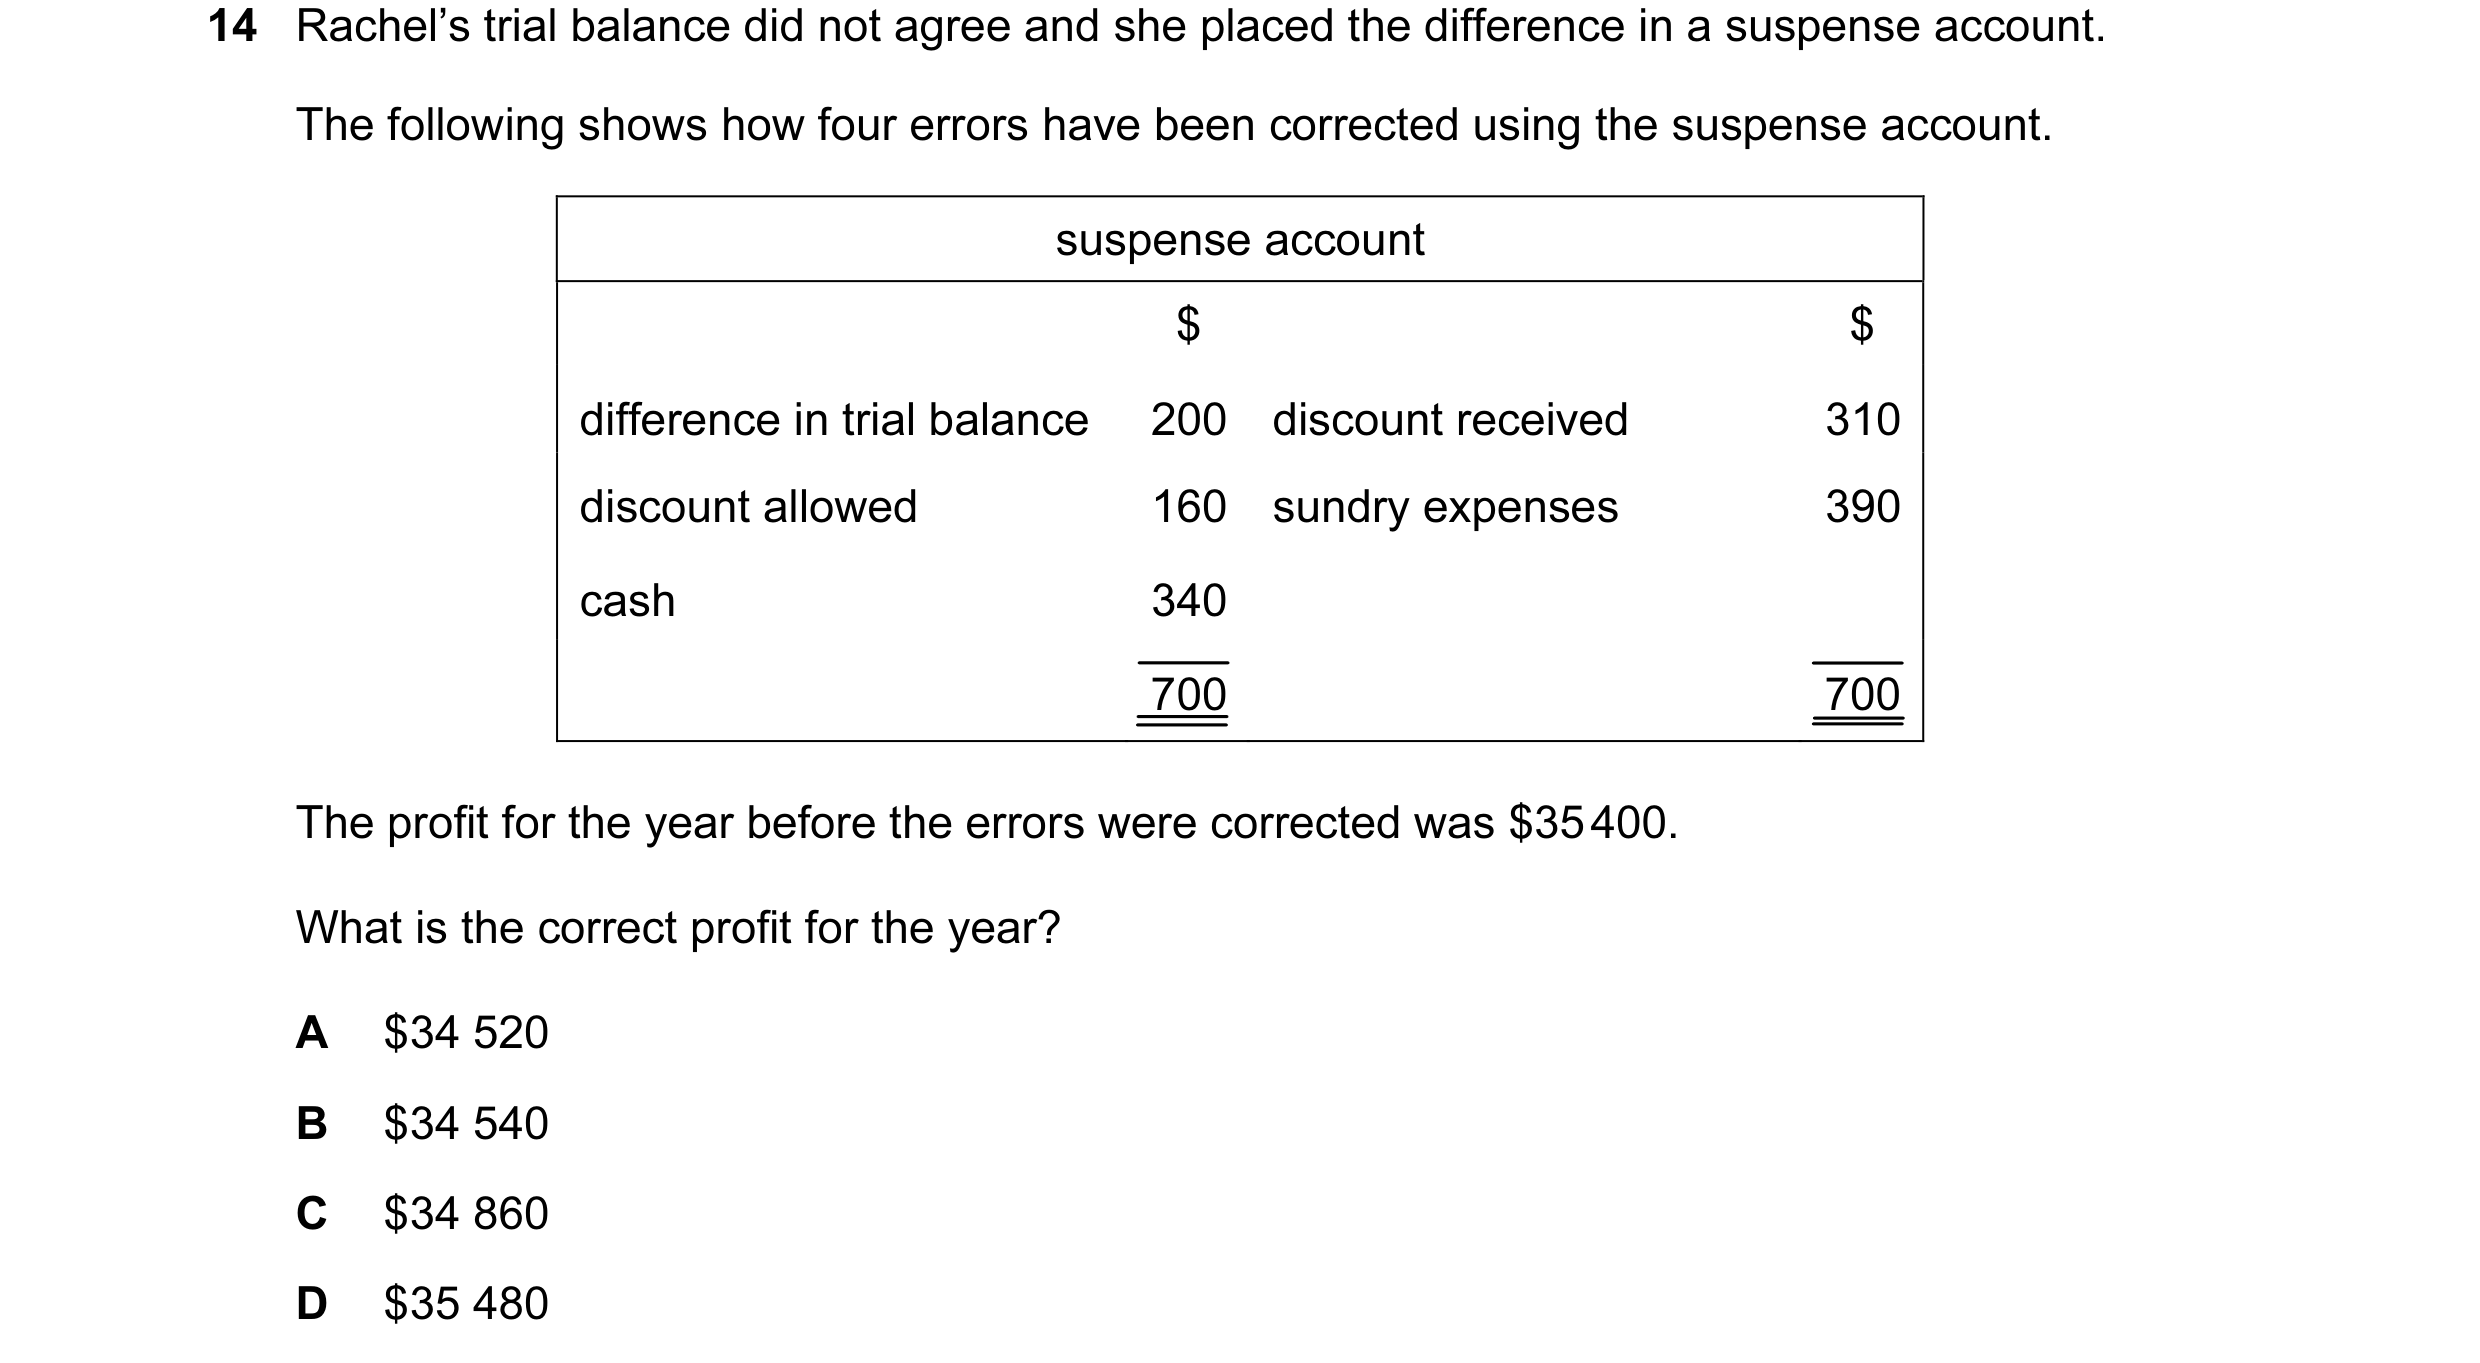
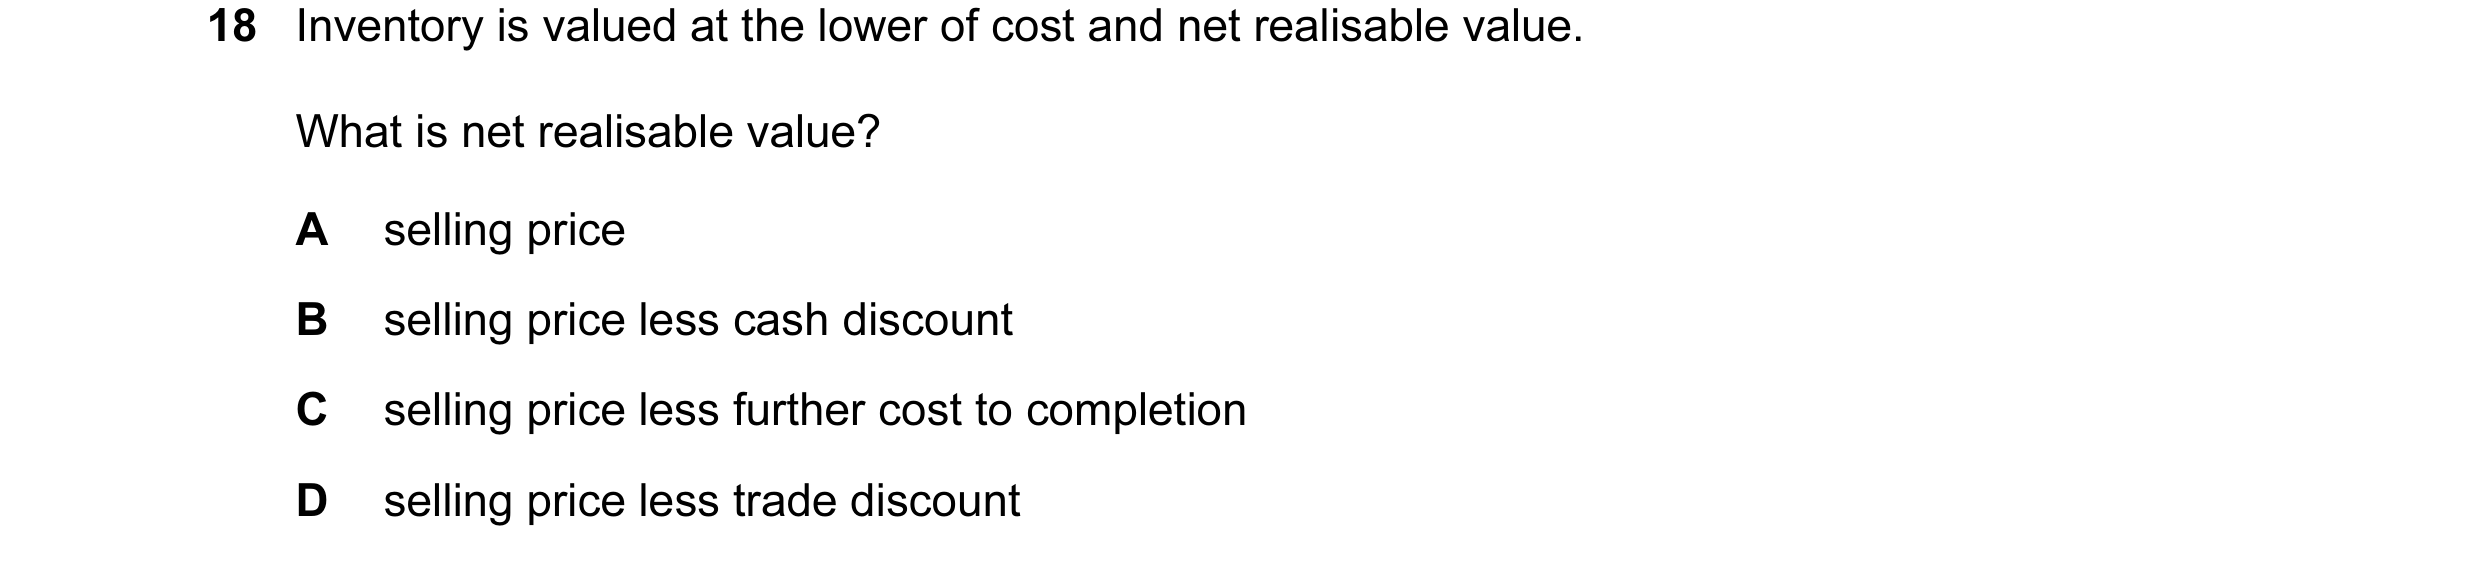
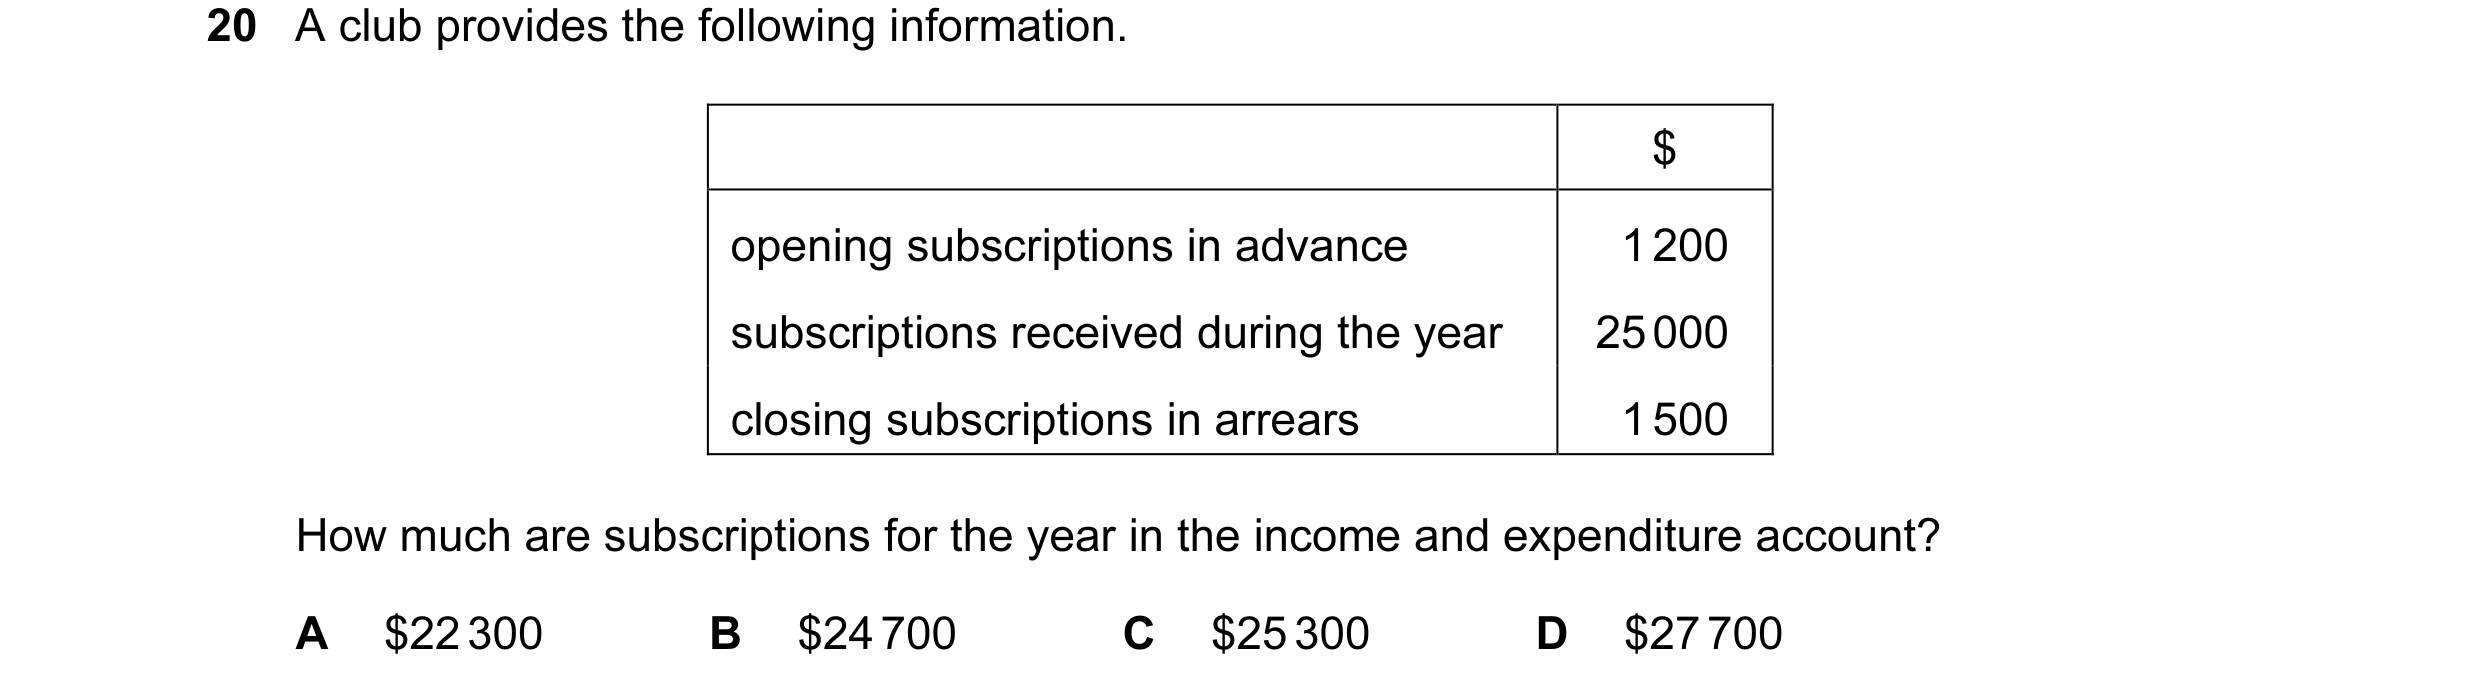 116 / 233
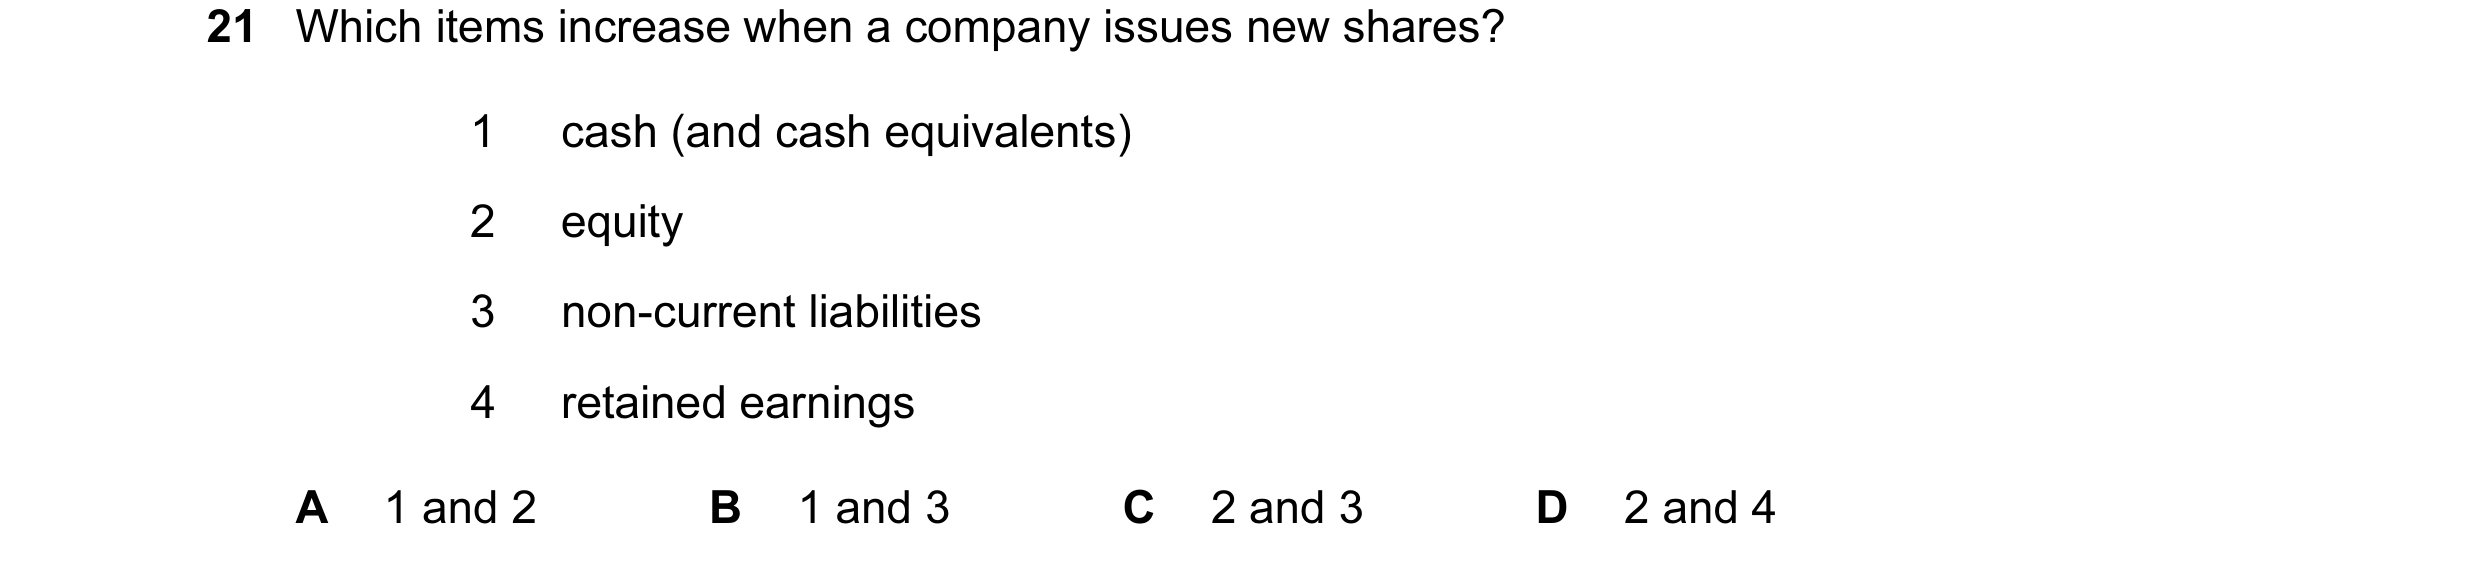
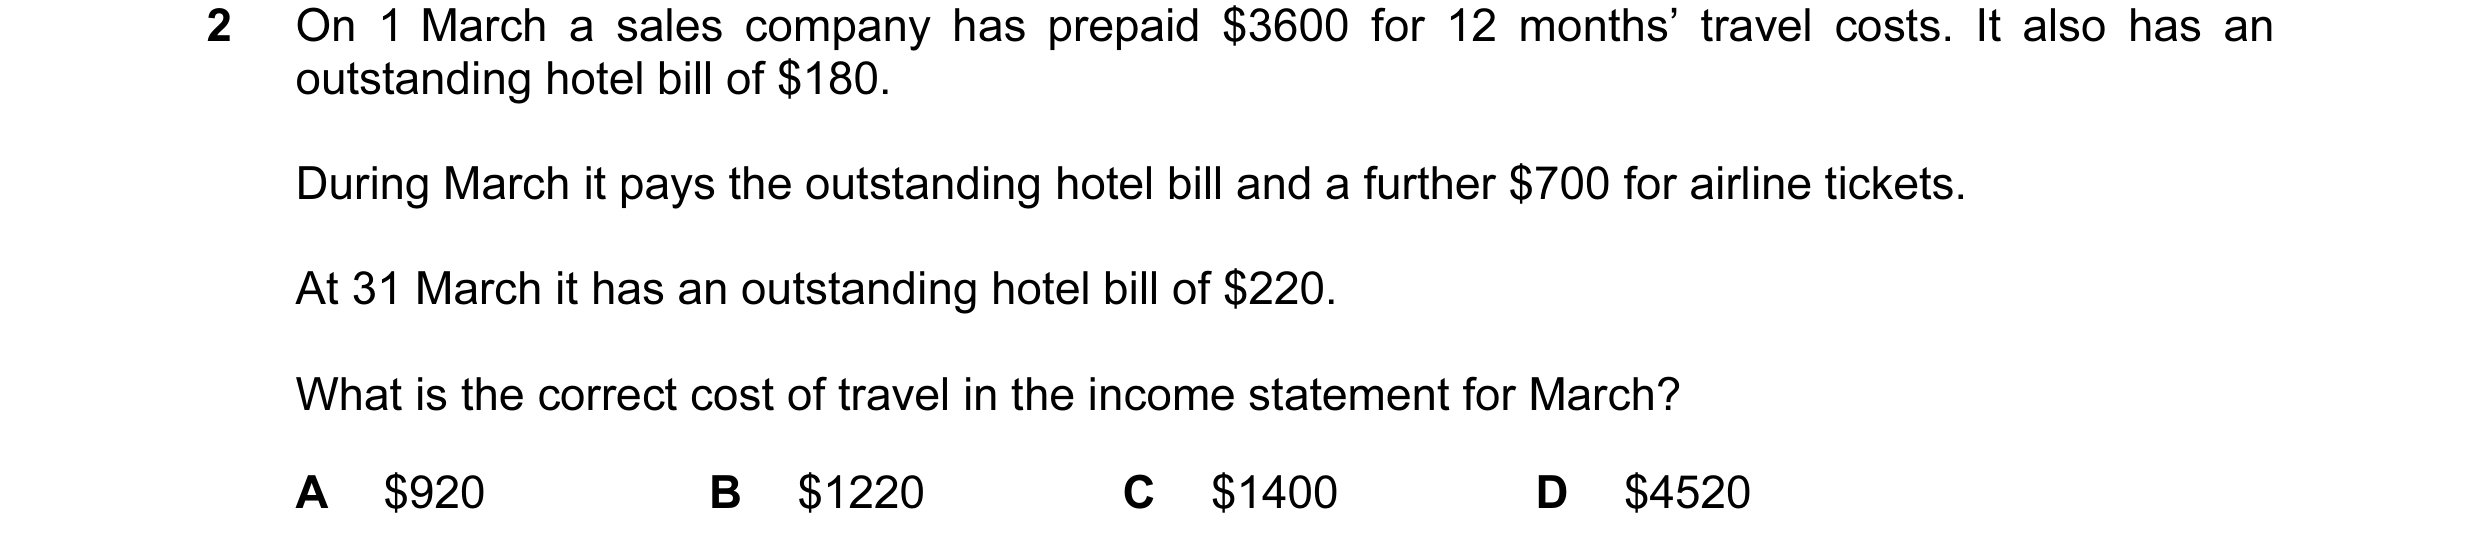
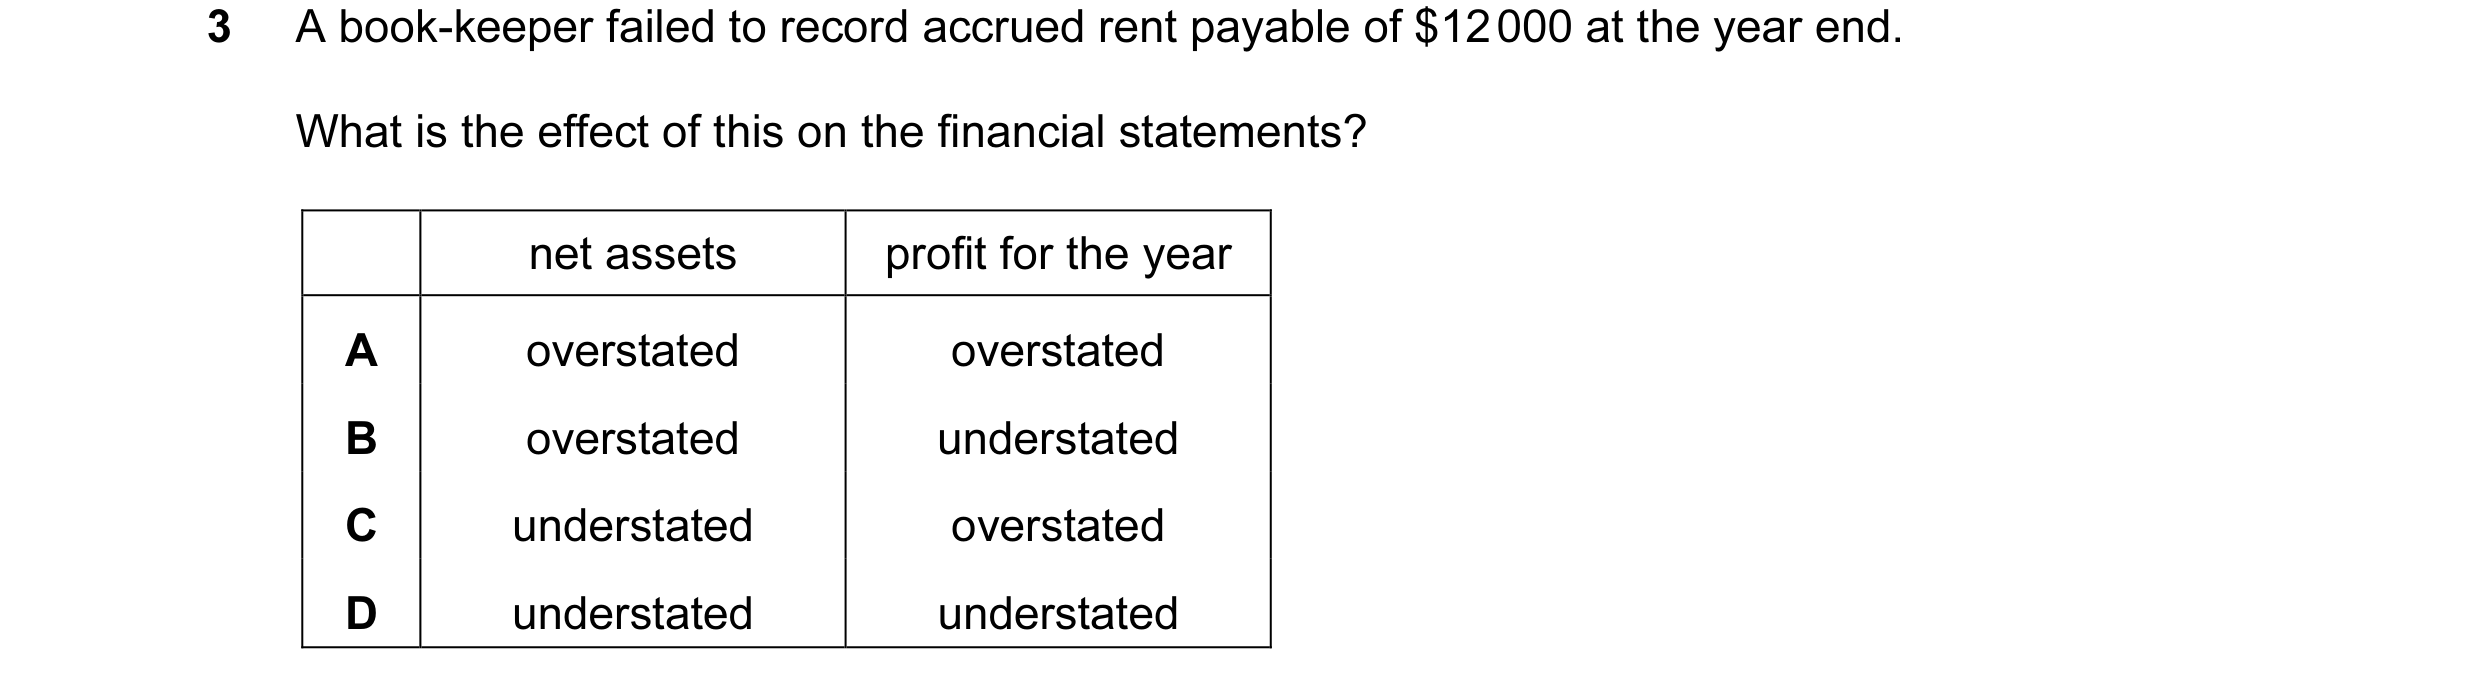
 117 / 233
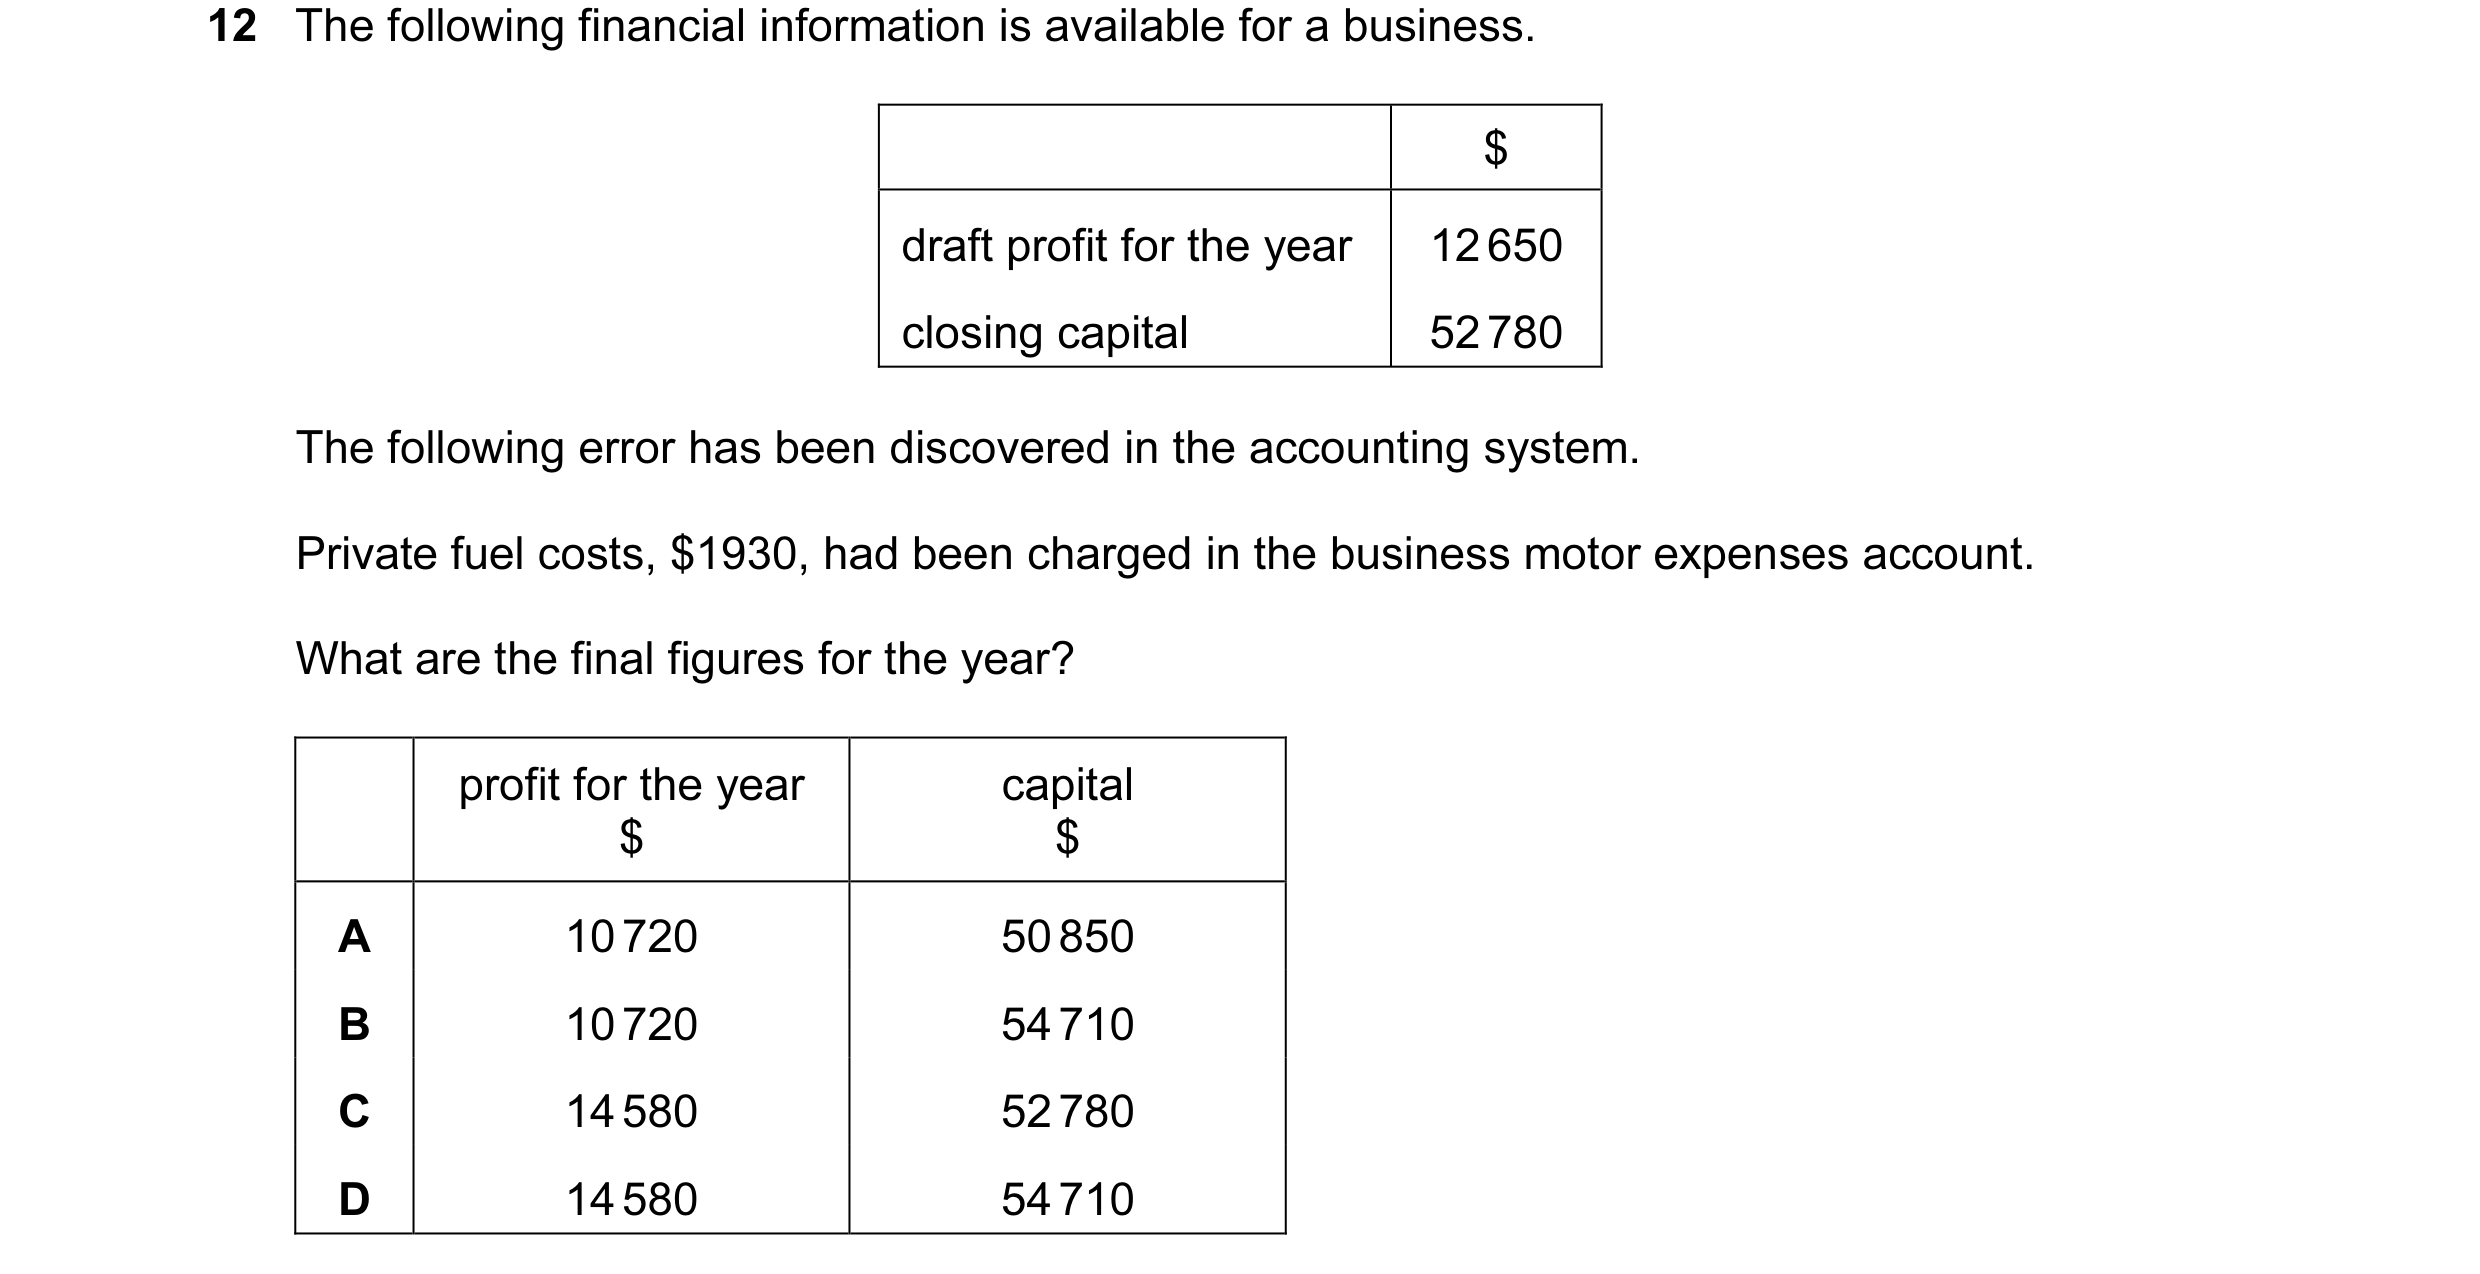
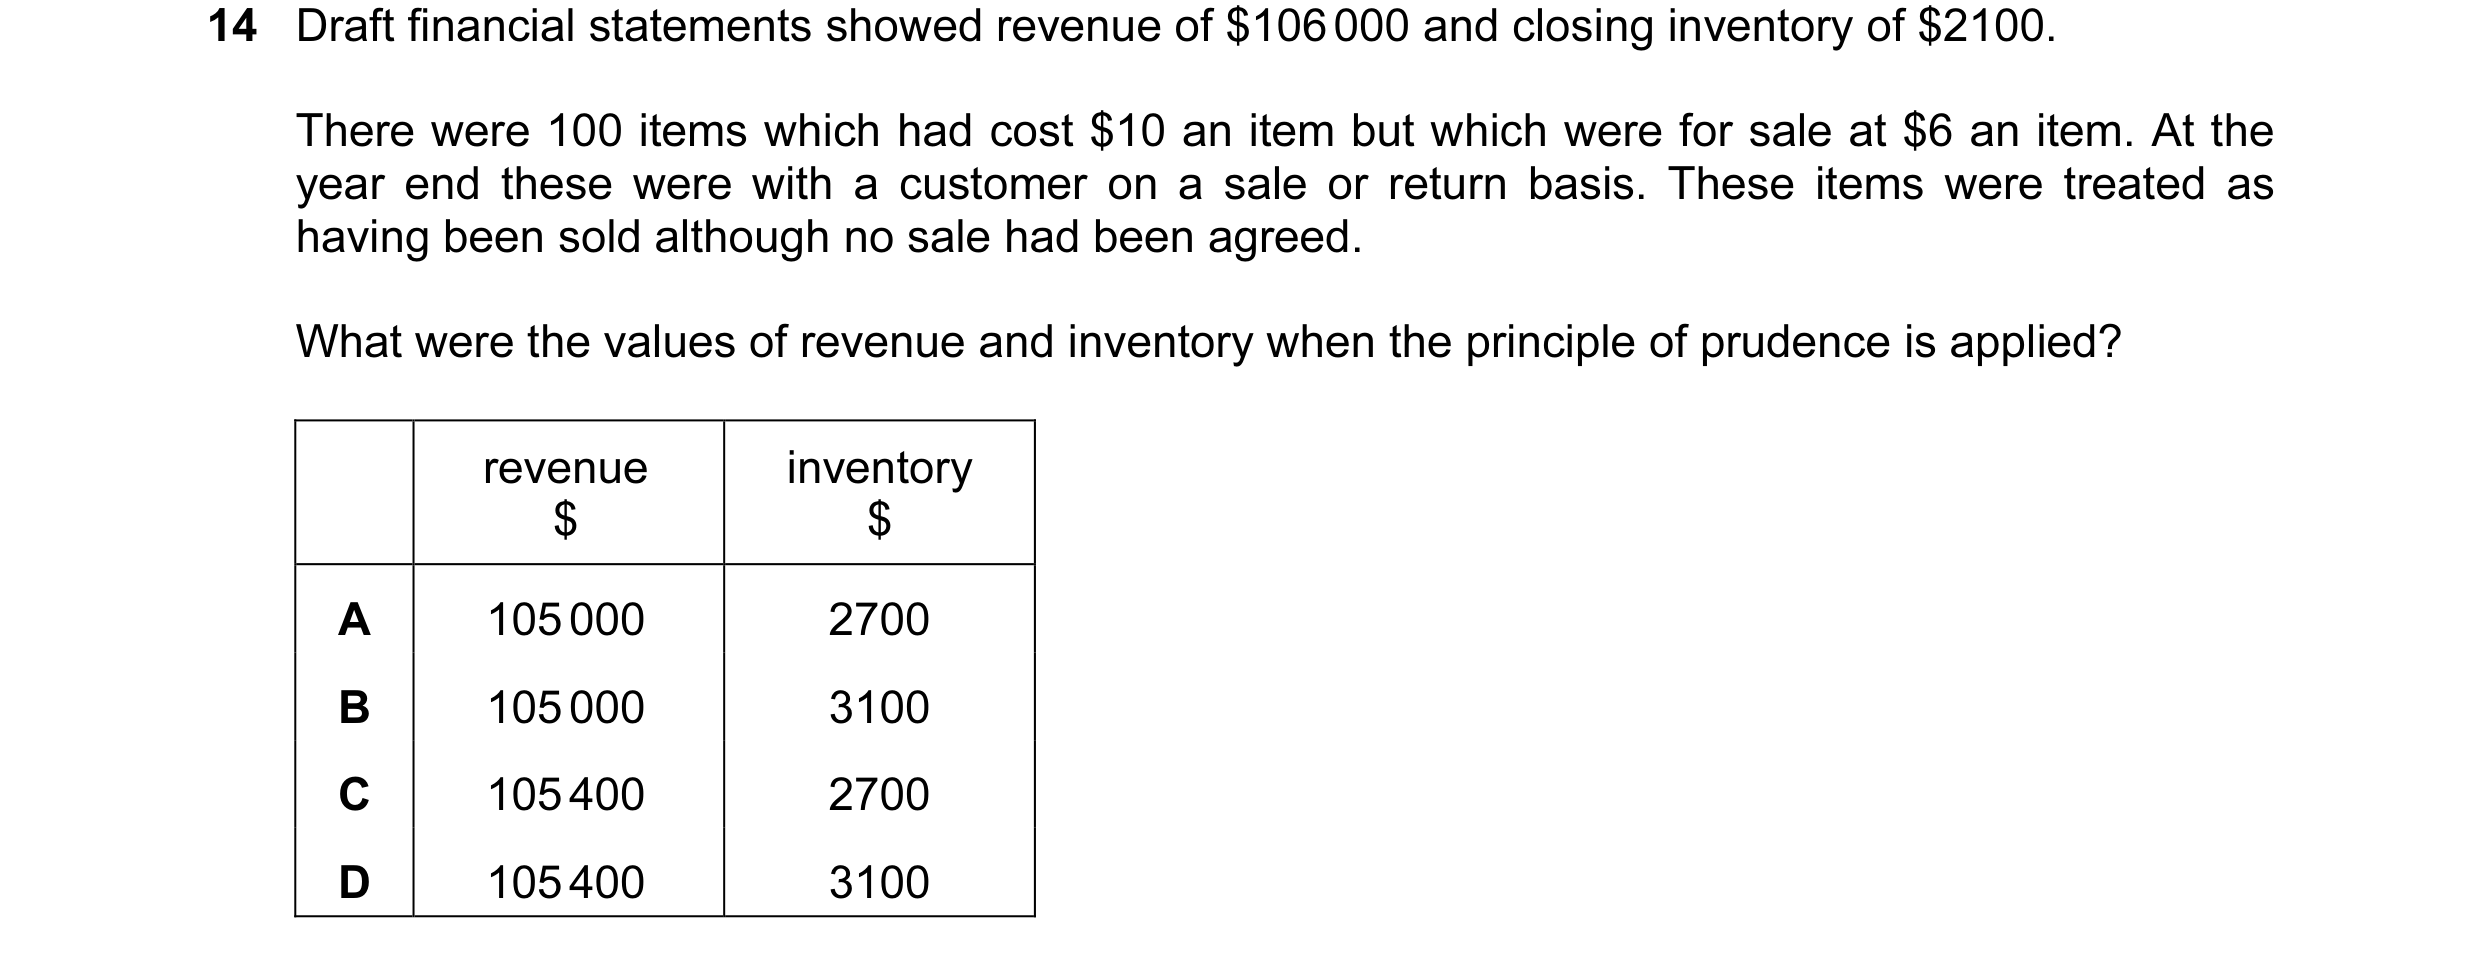
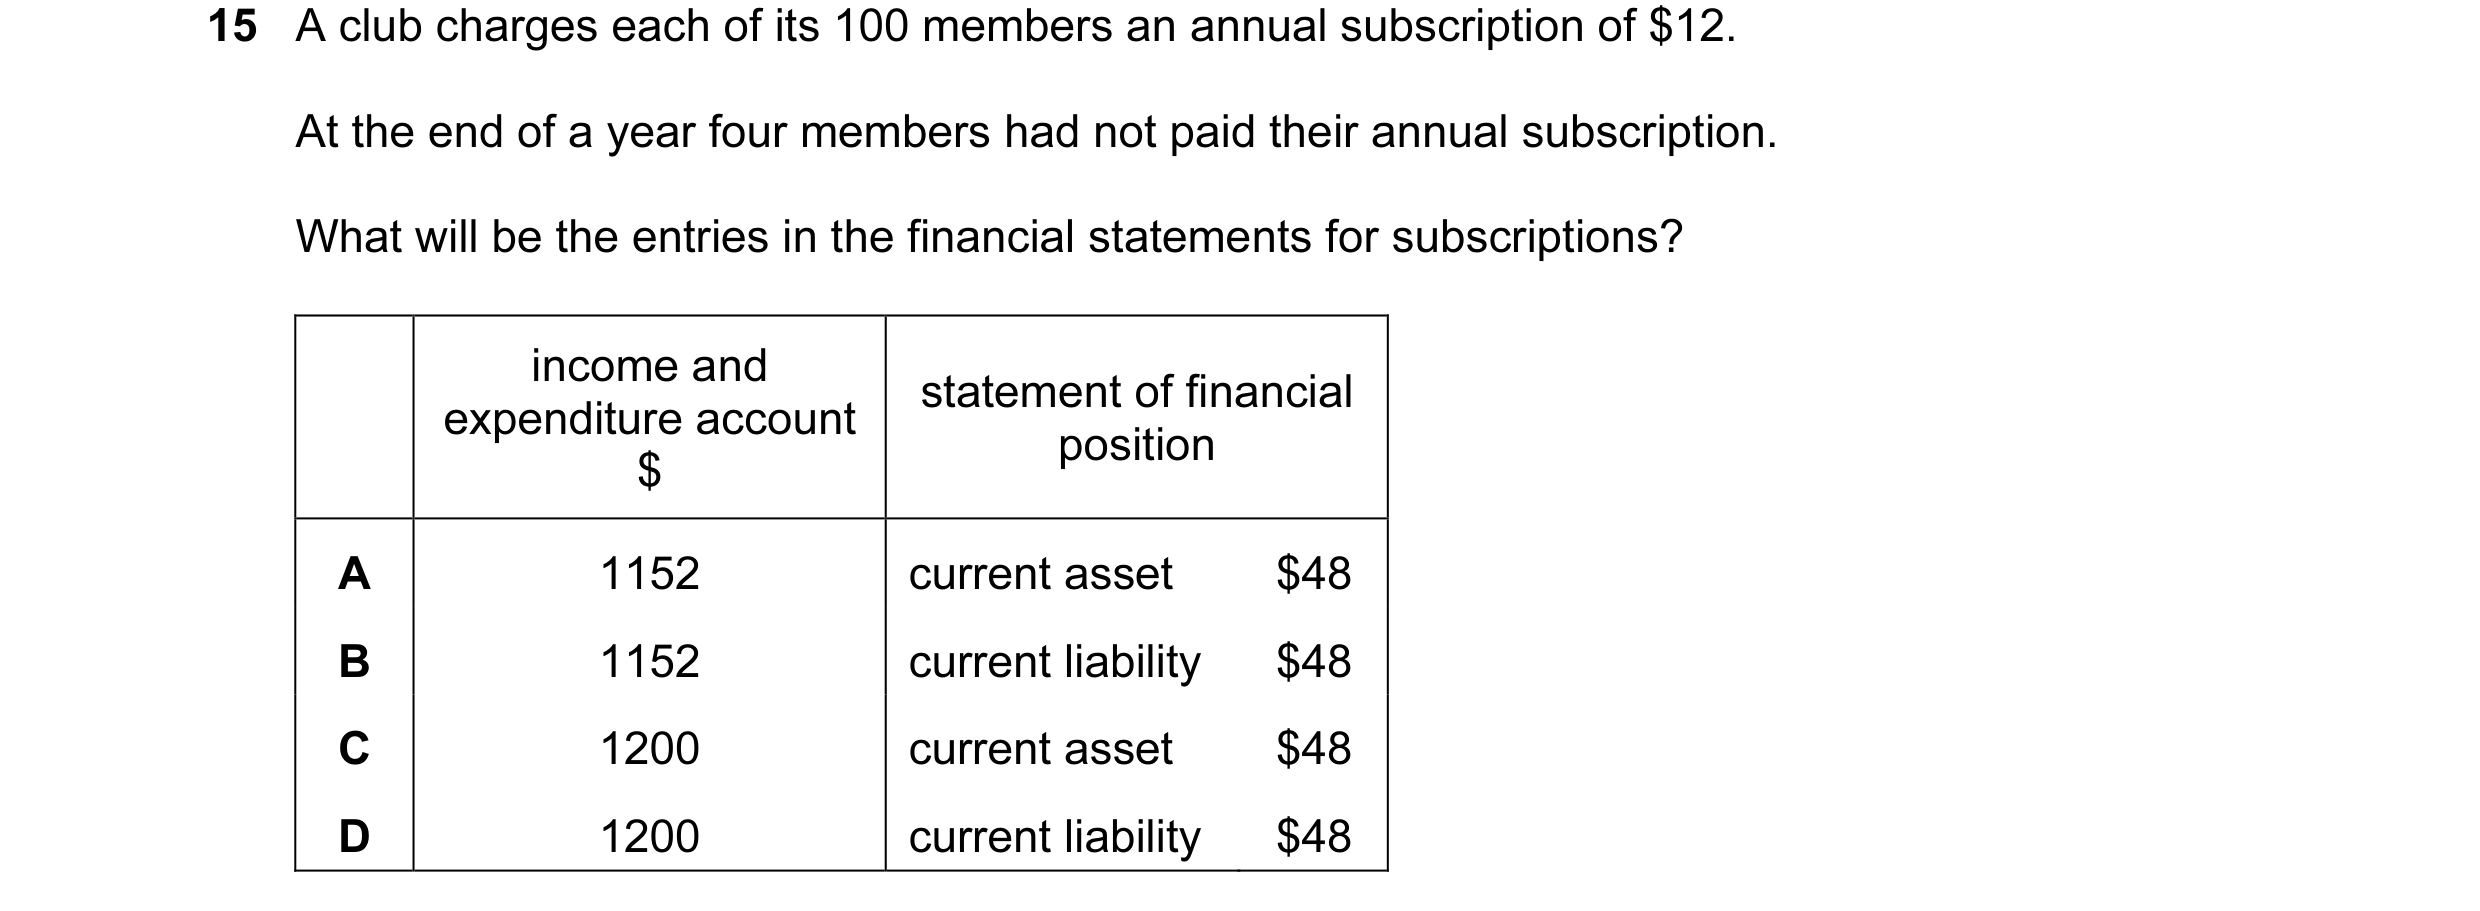 118 / 233
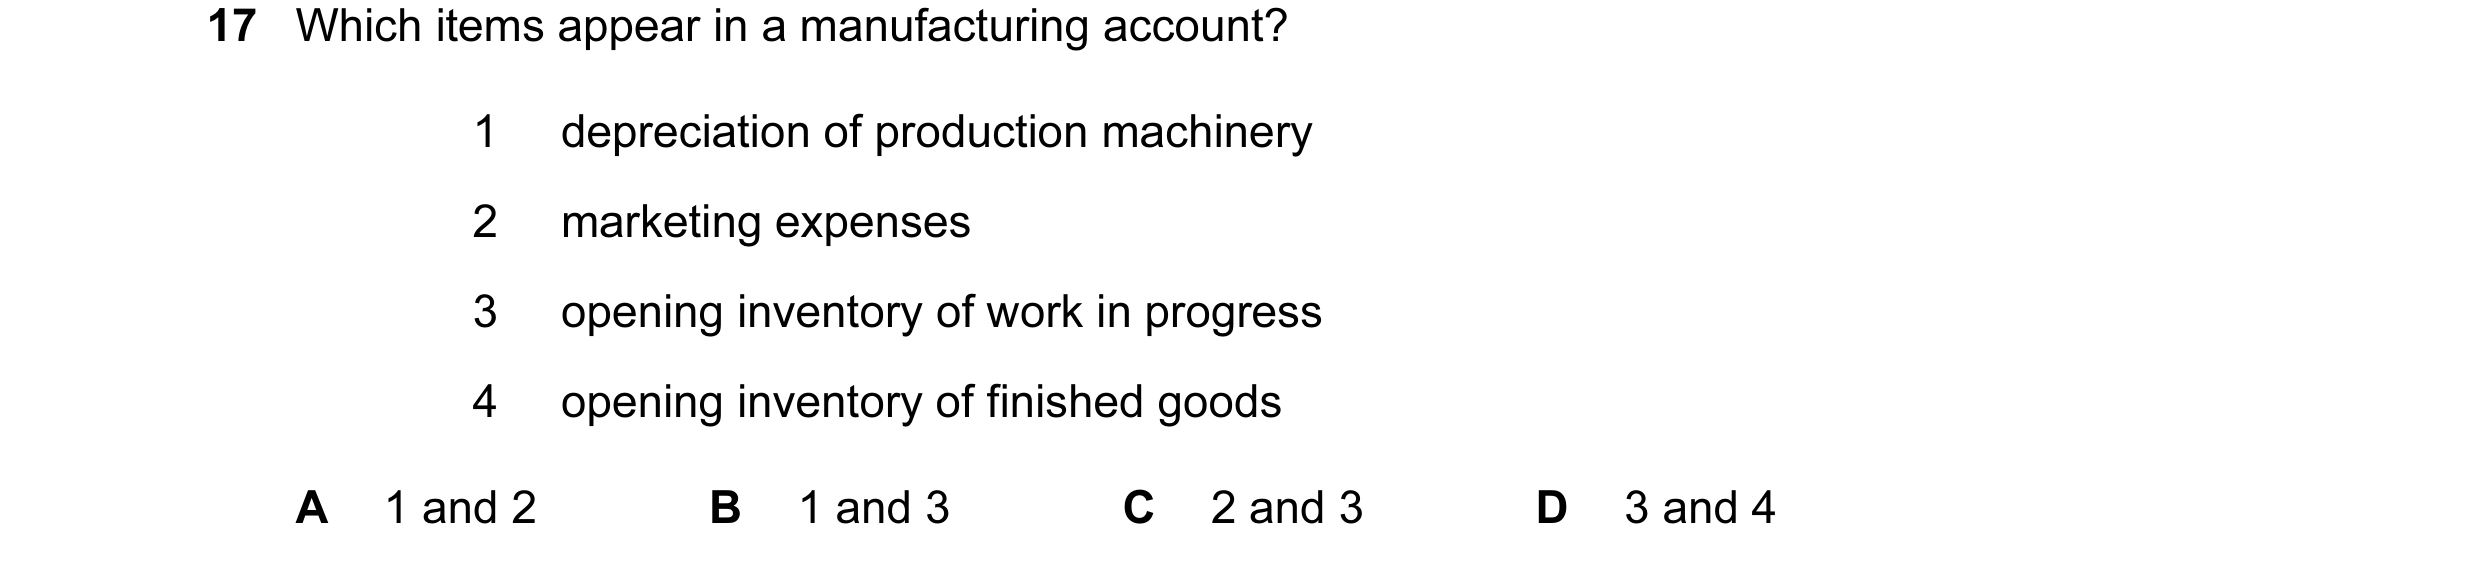
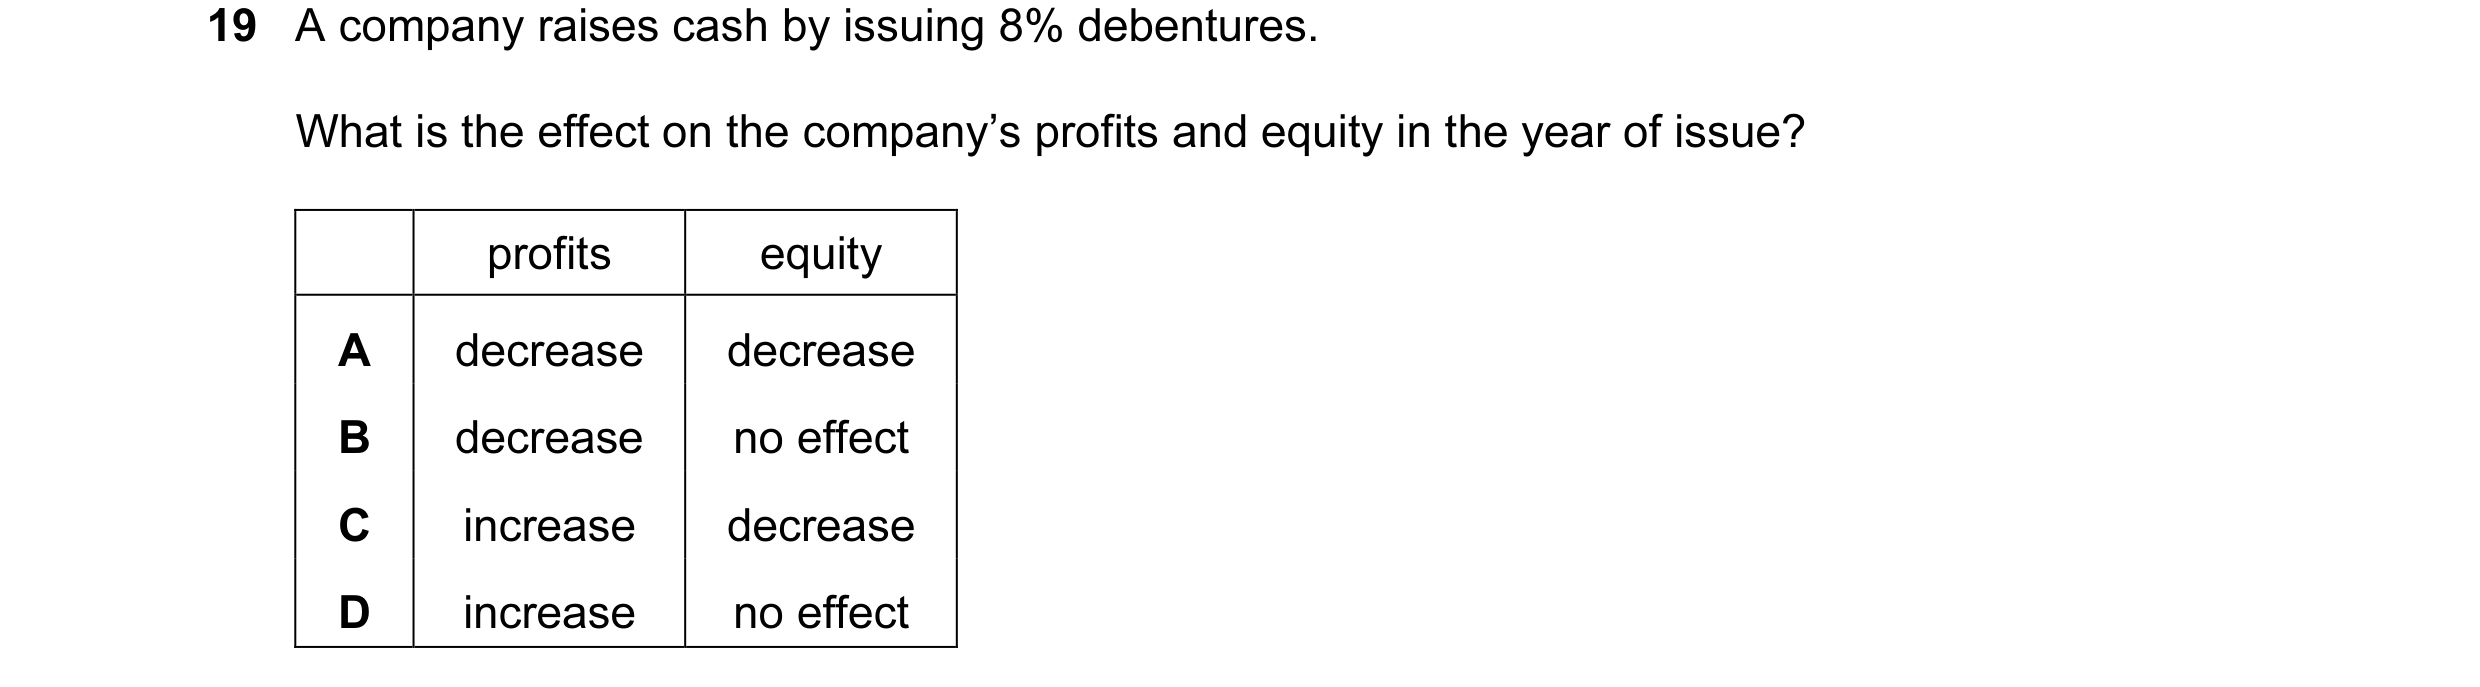
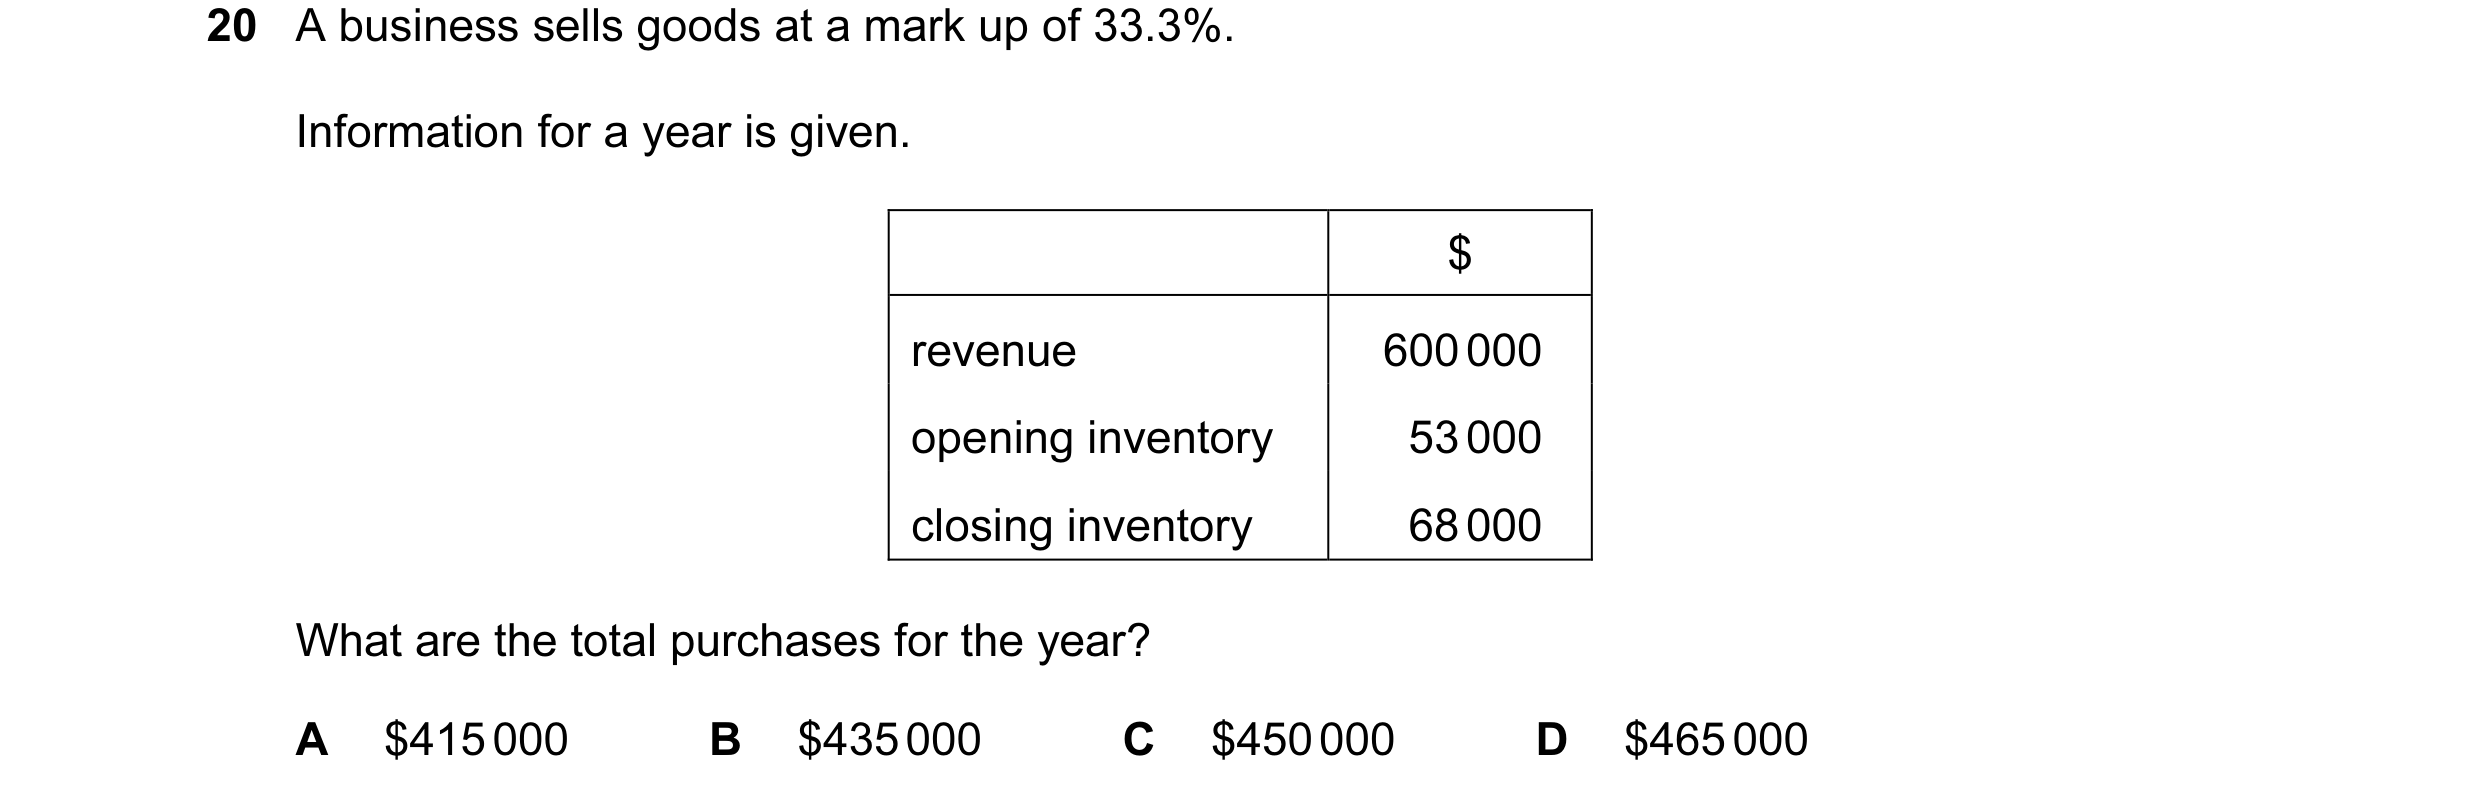
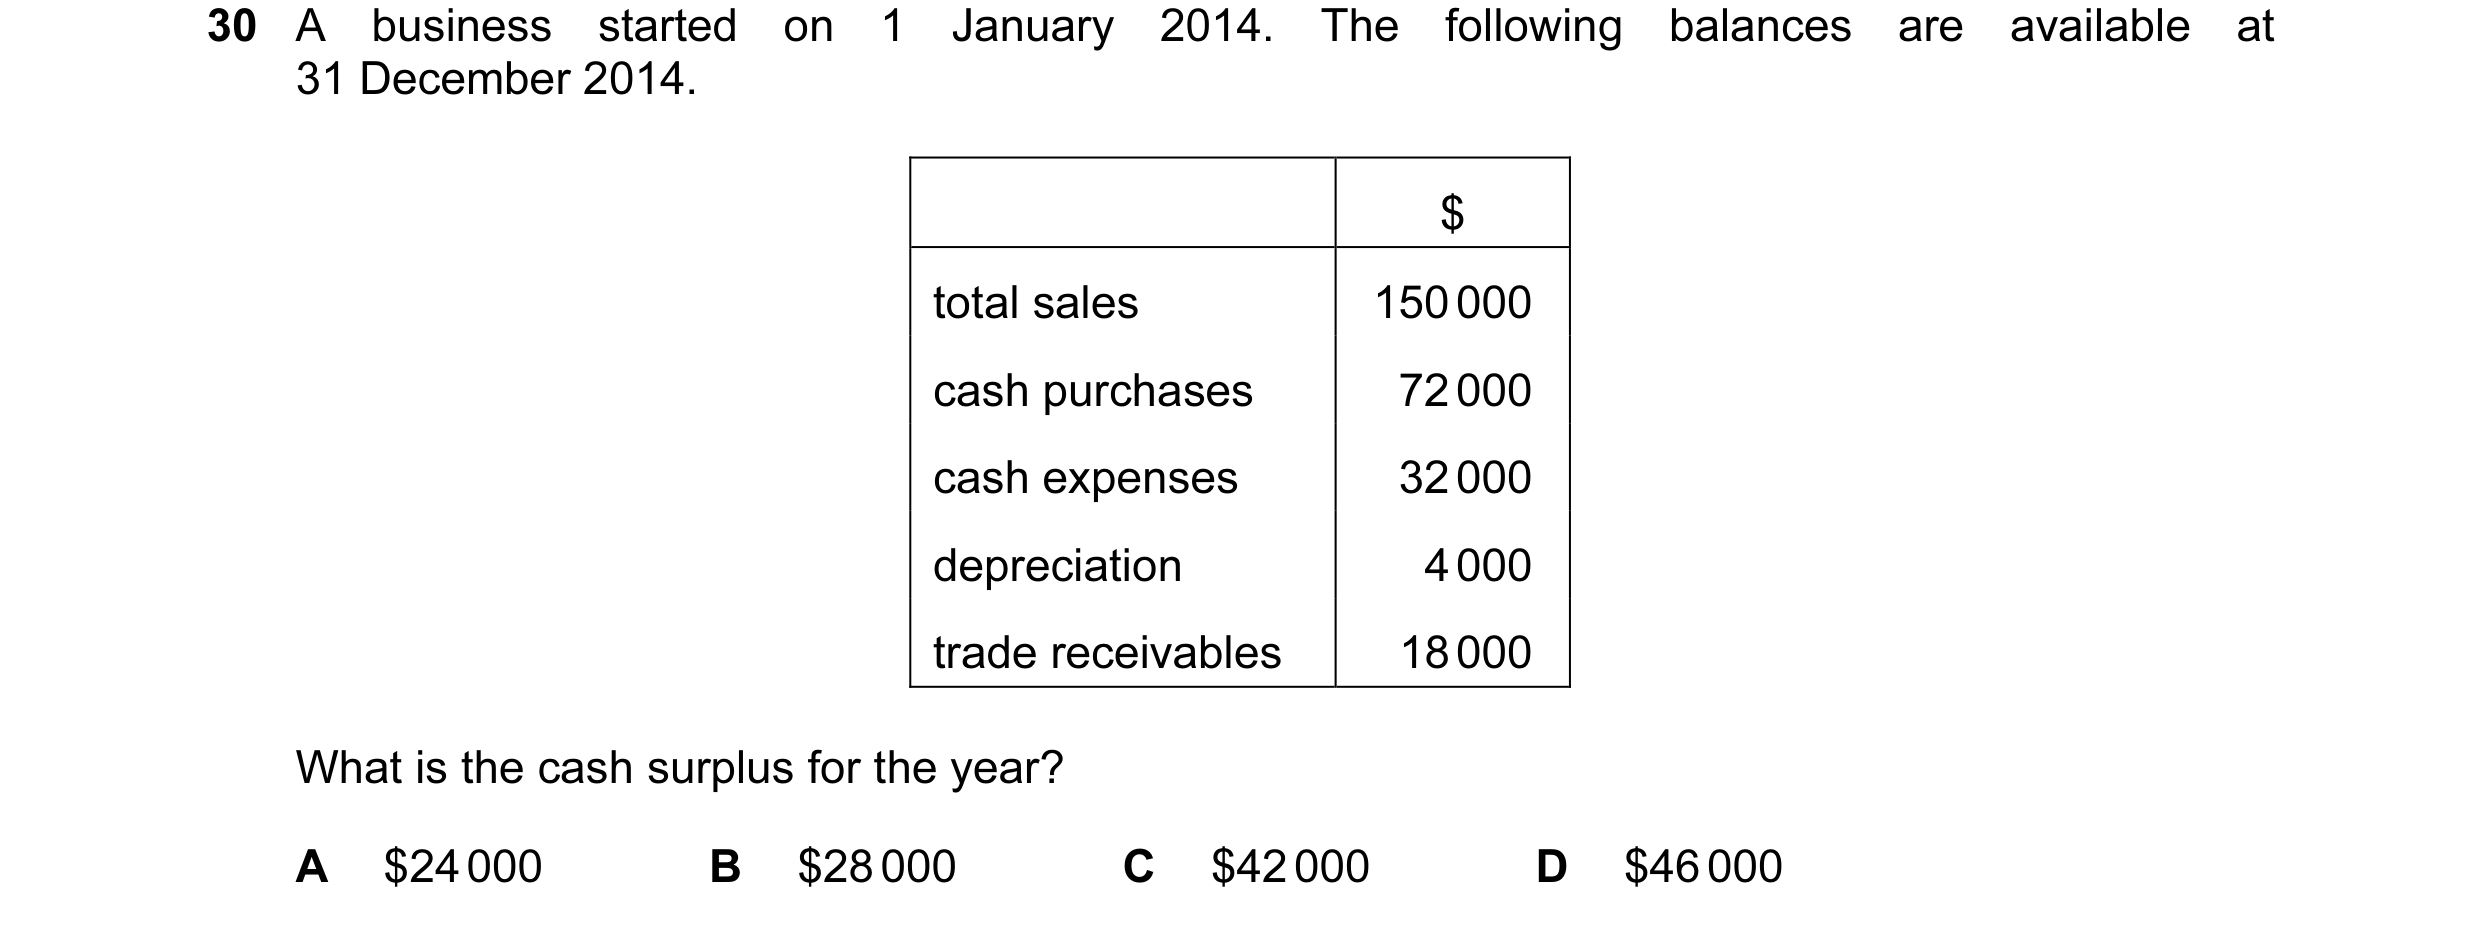 119 / 233
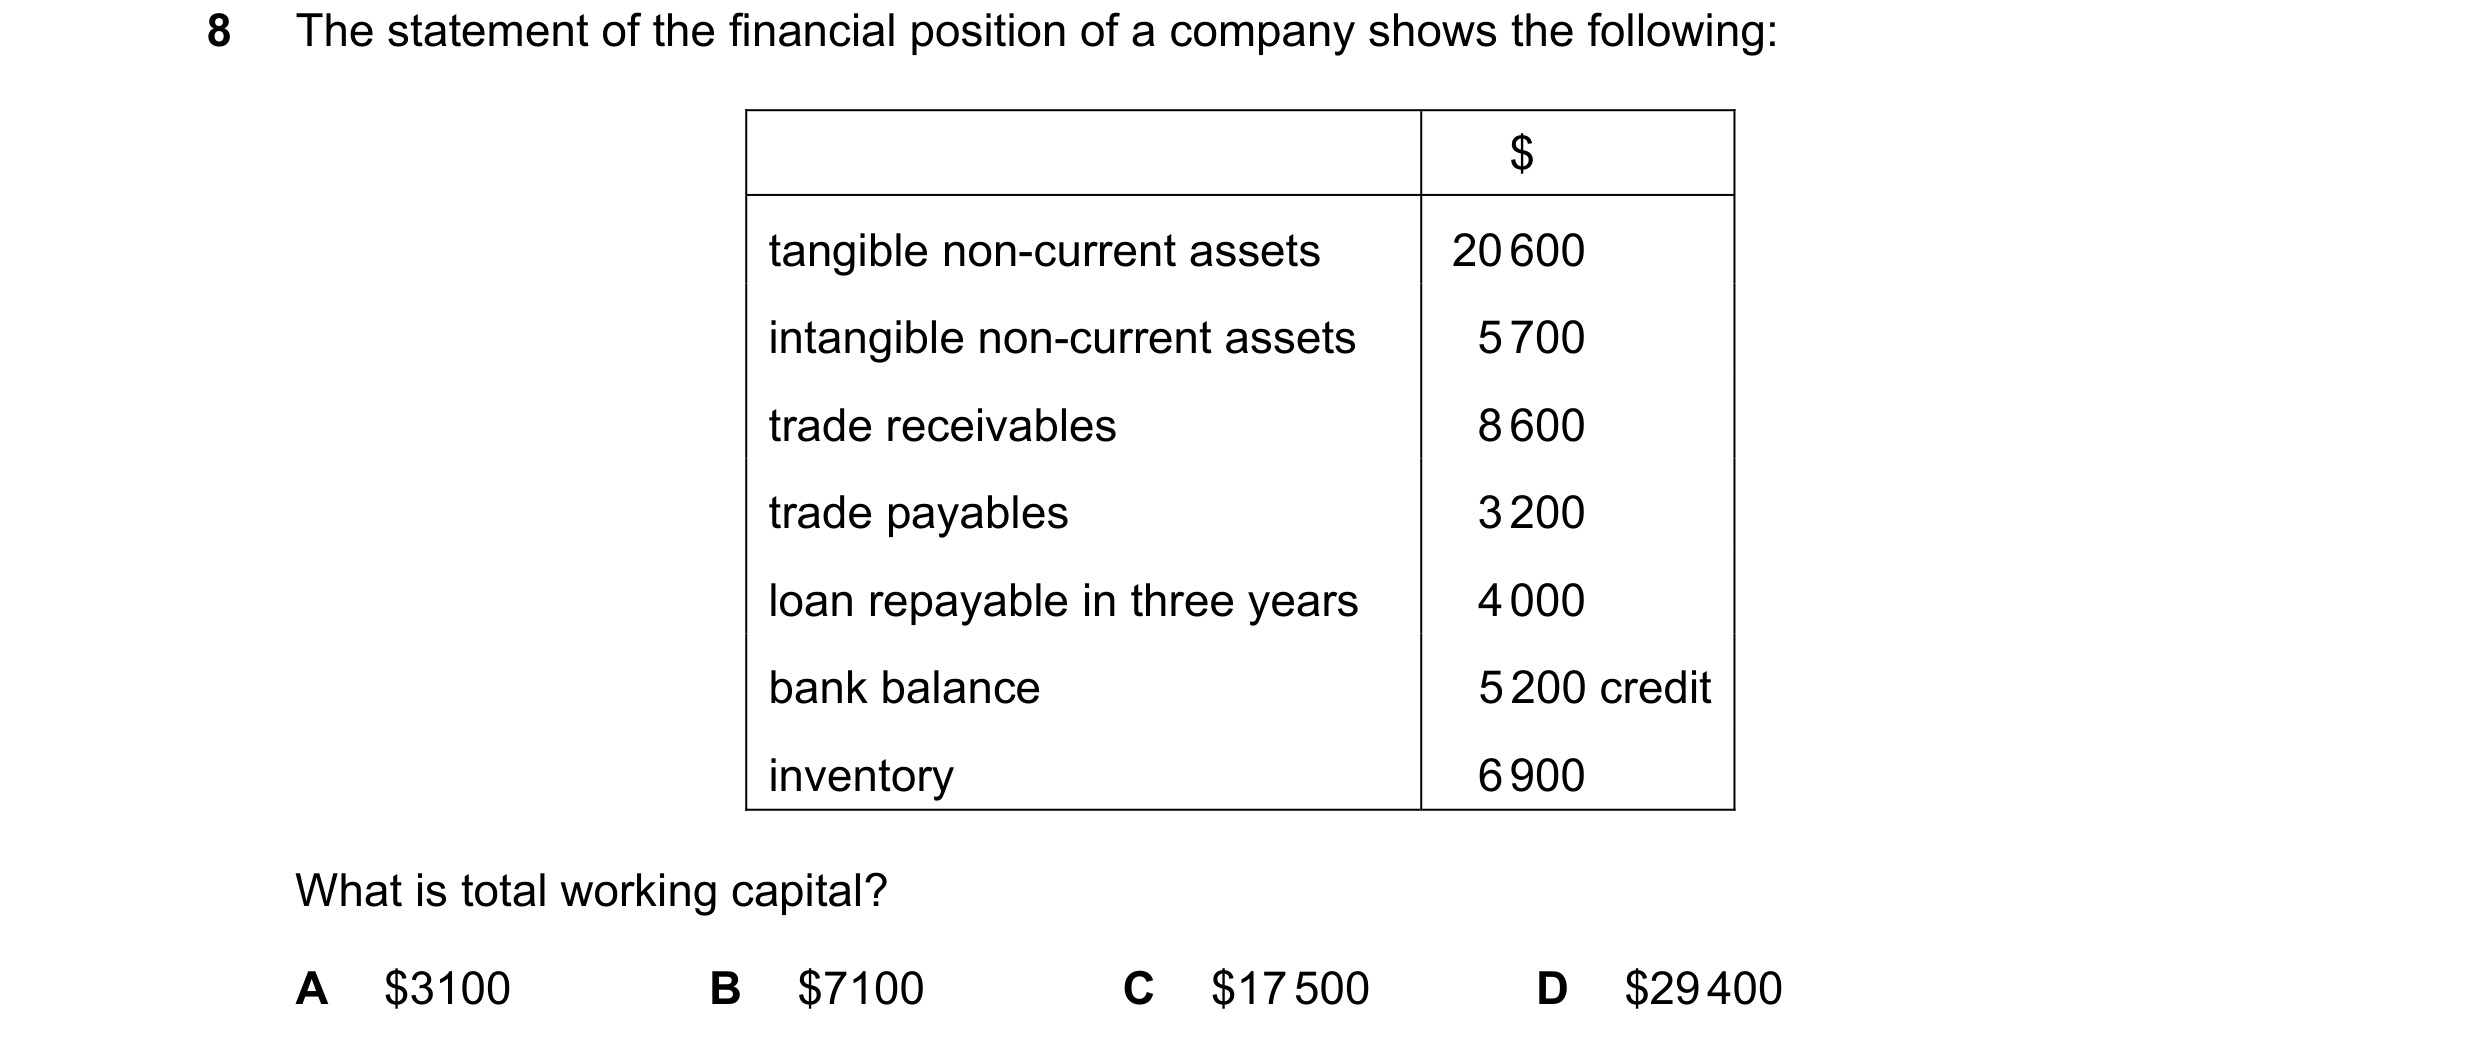
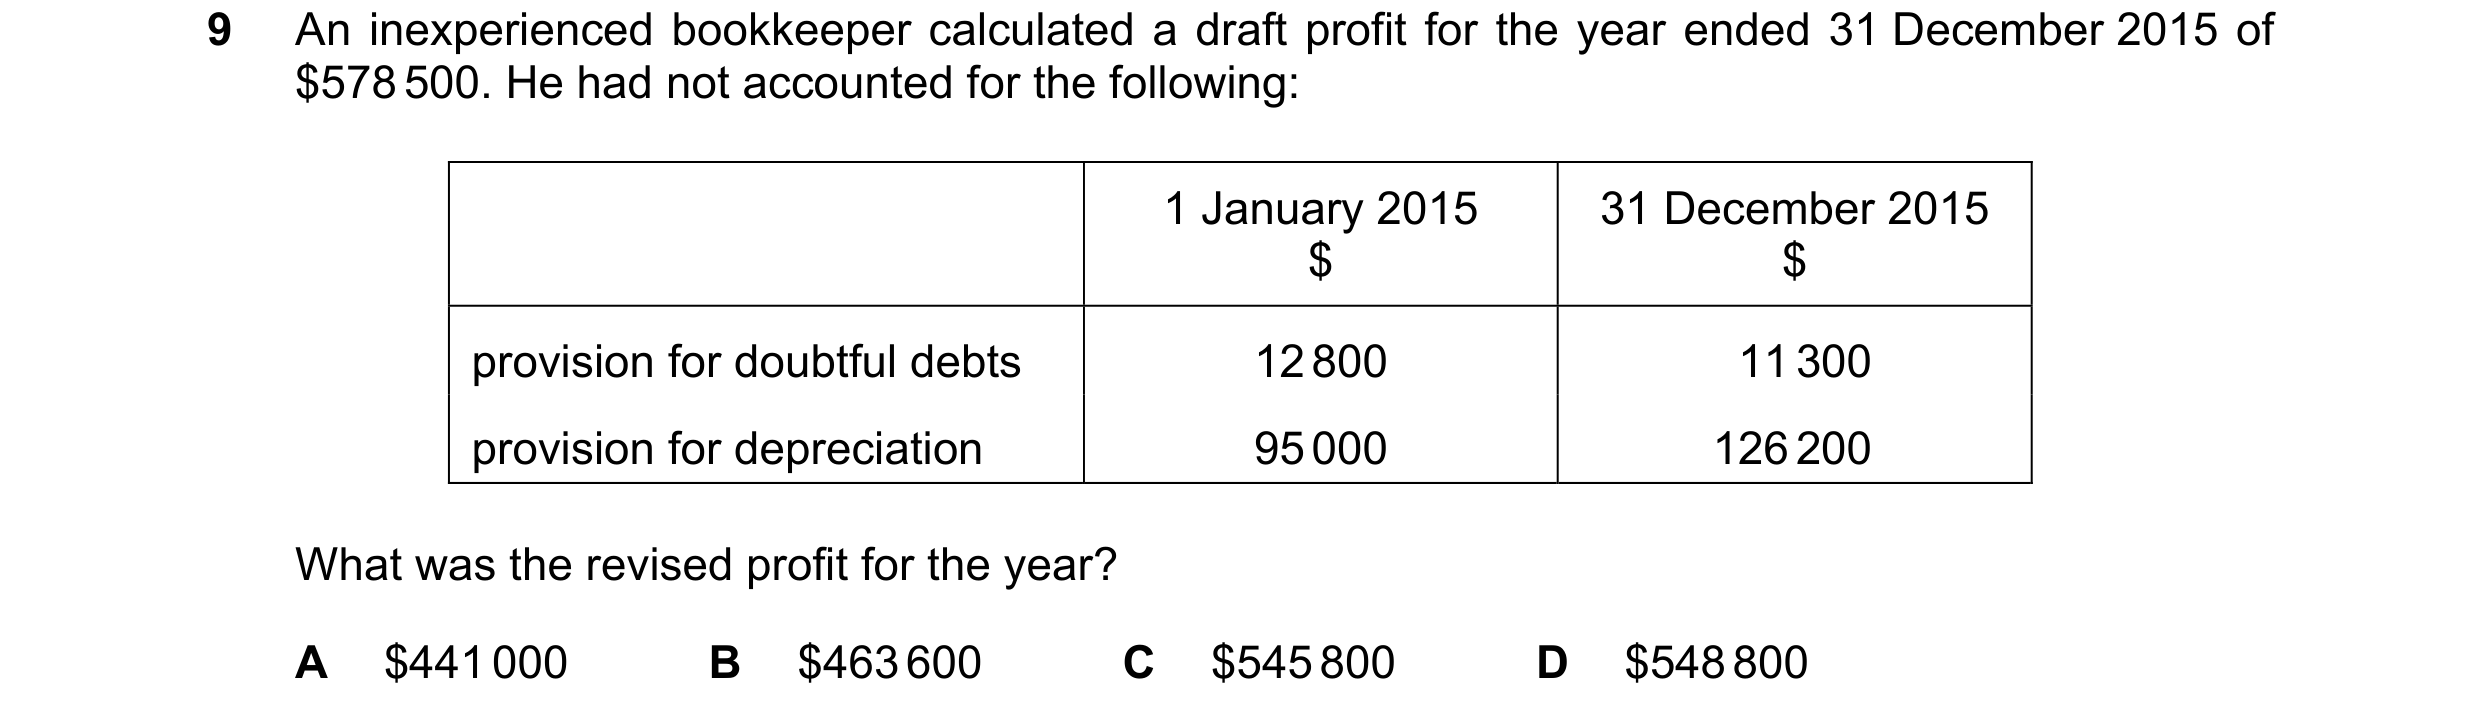
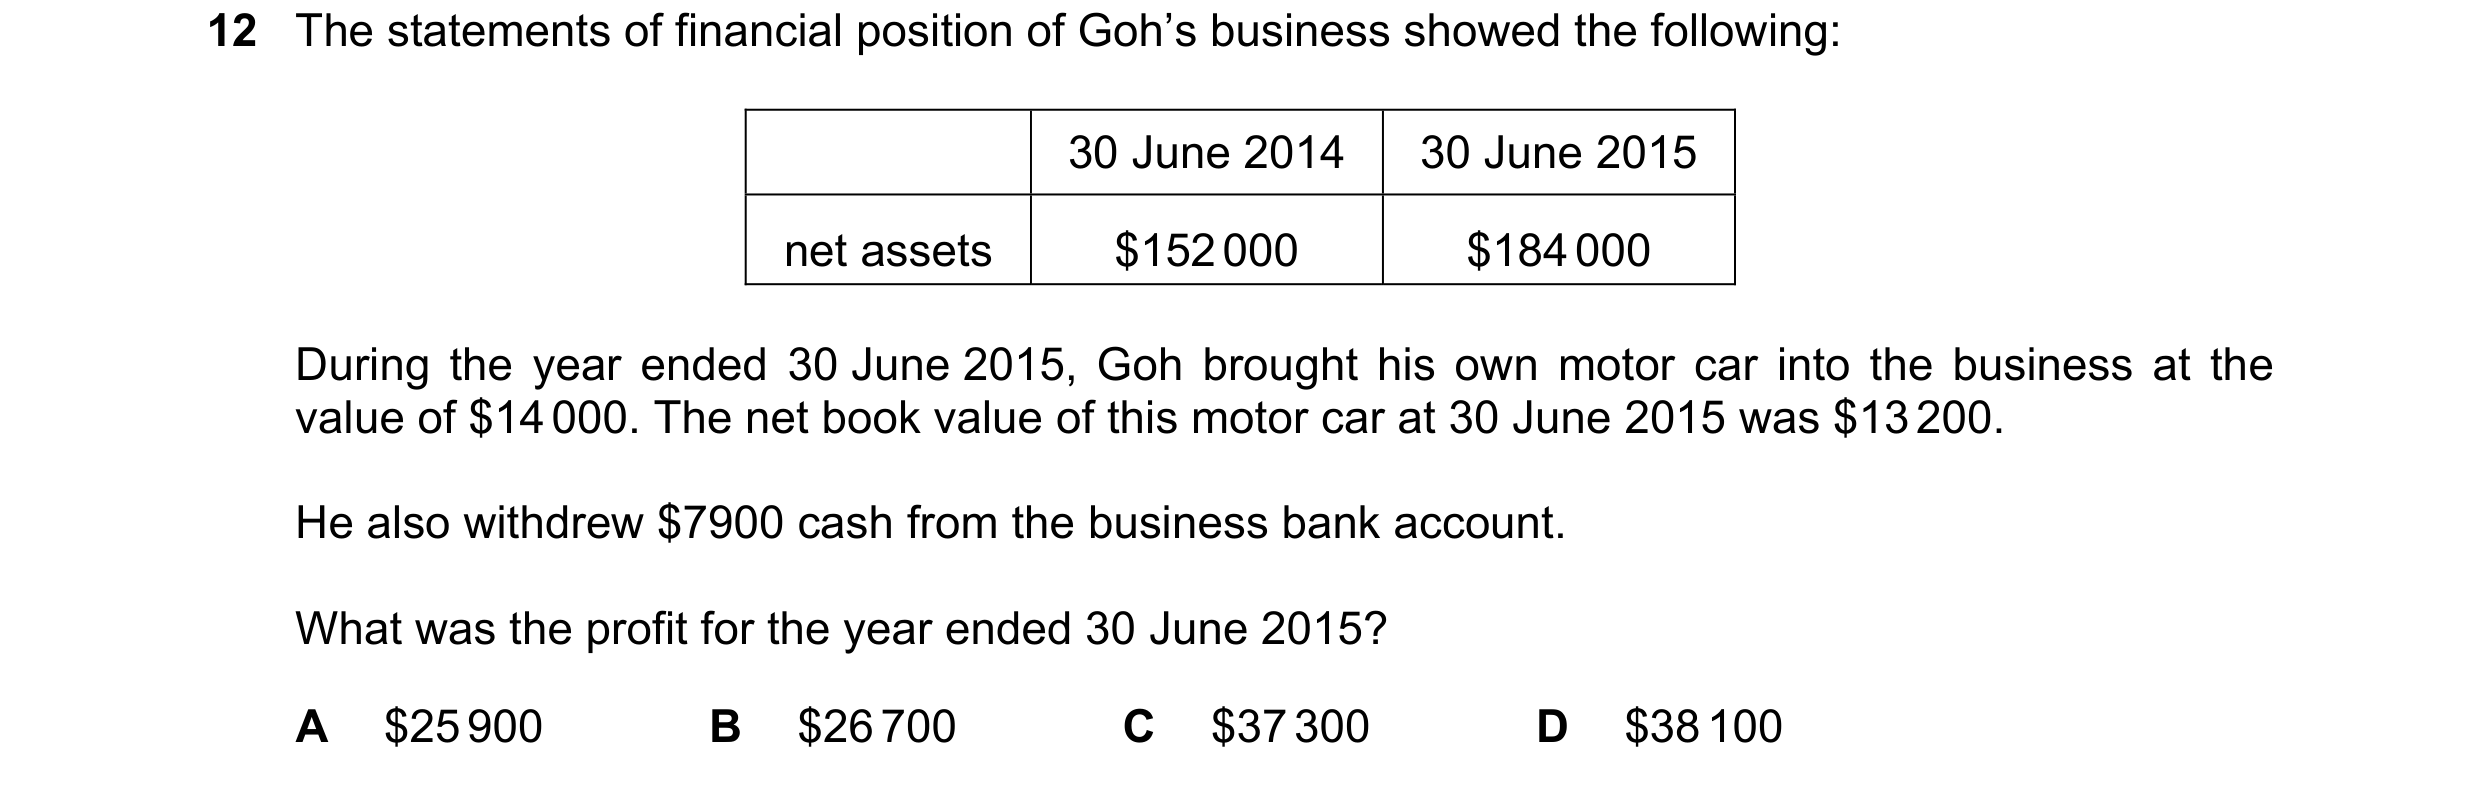 120 / 233
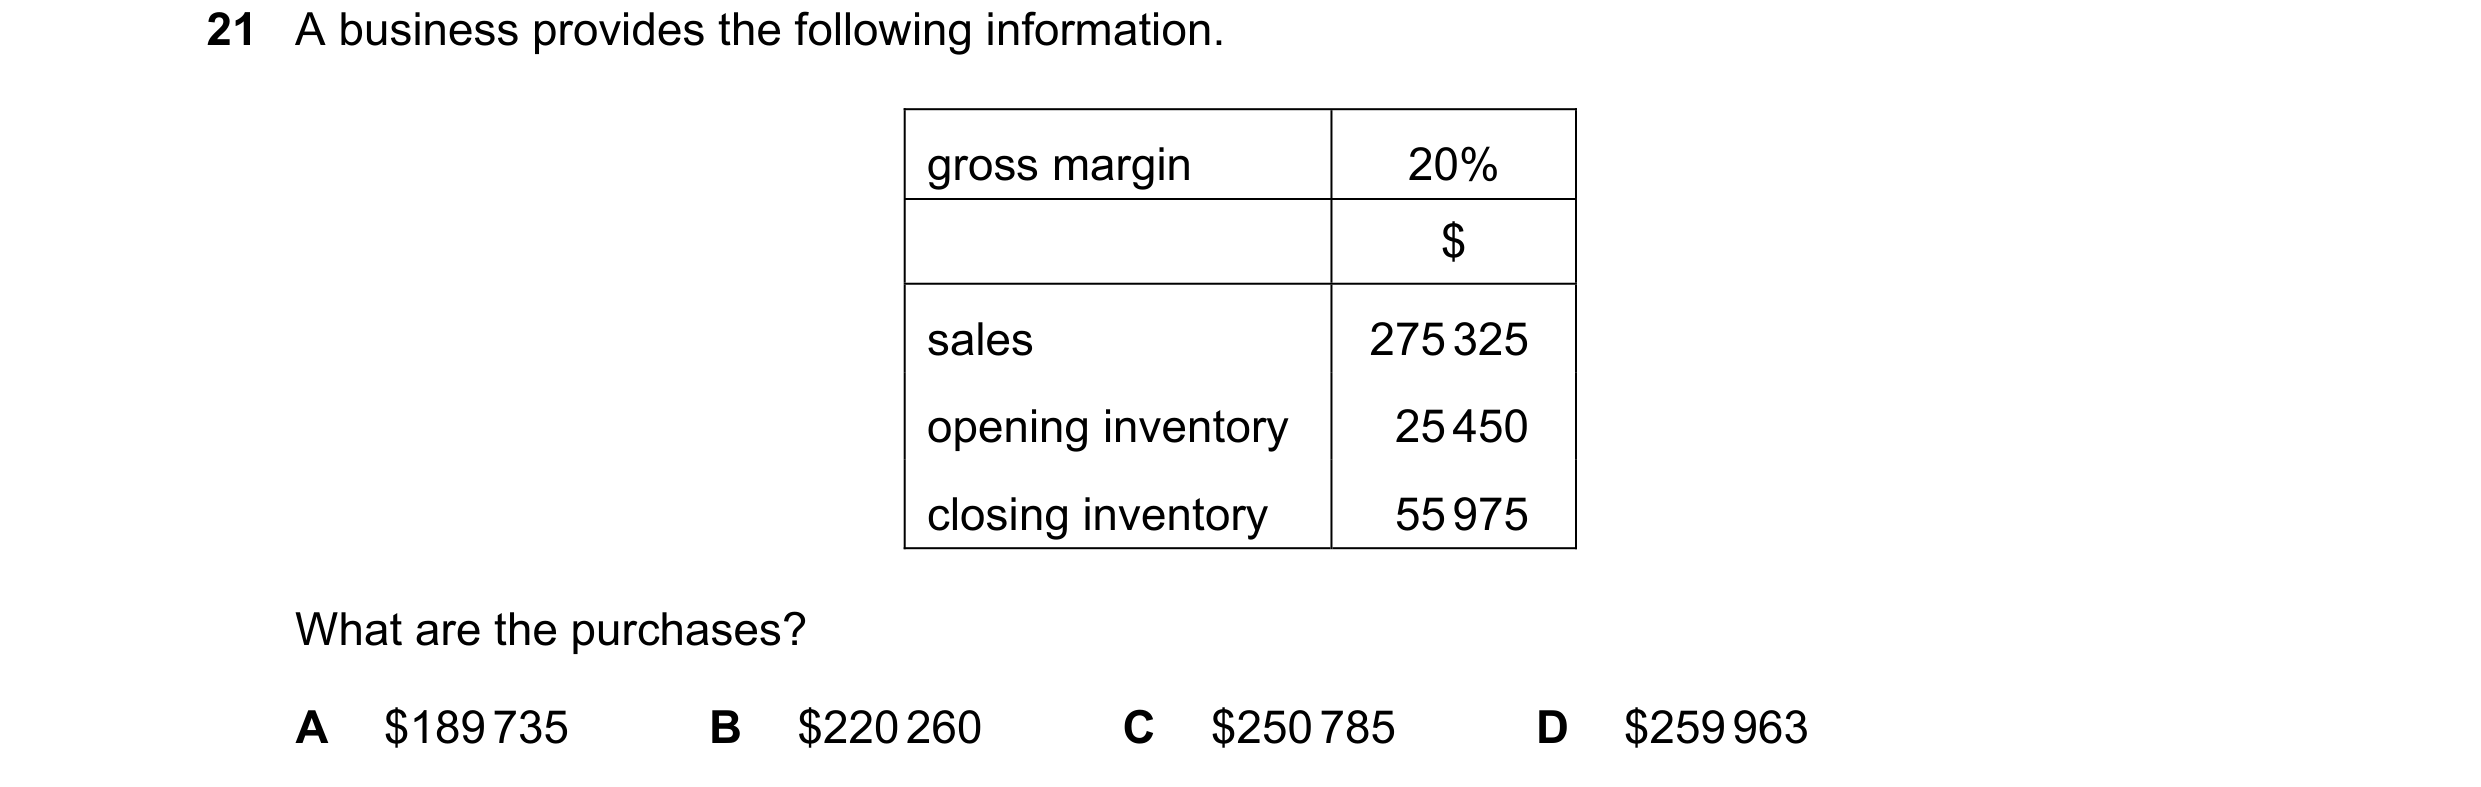
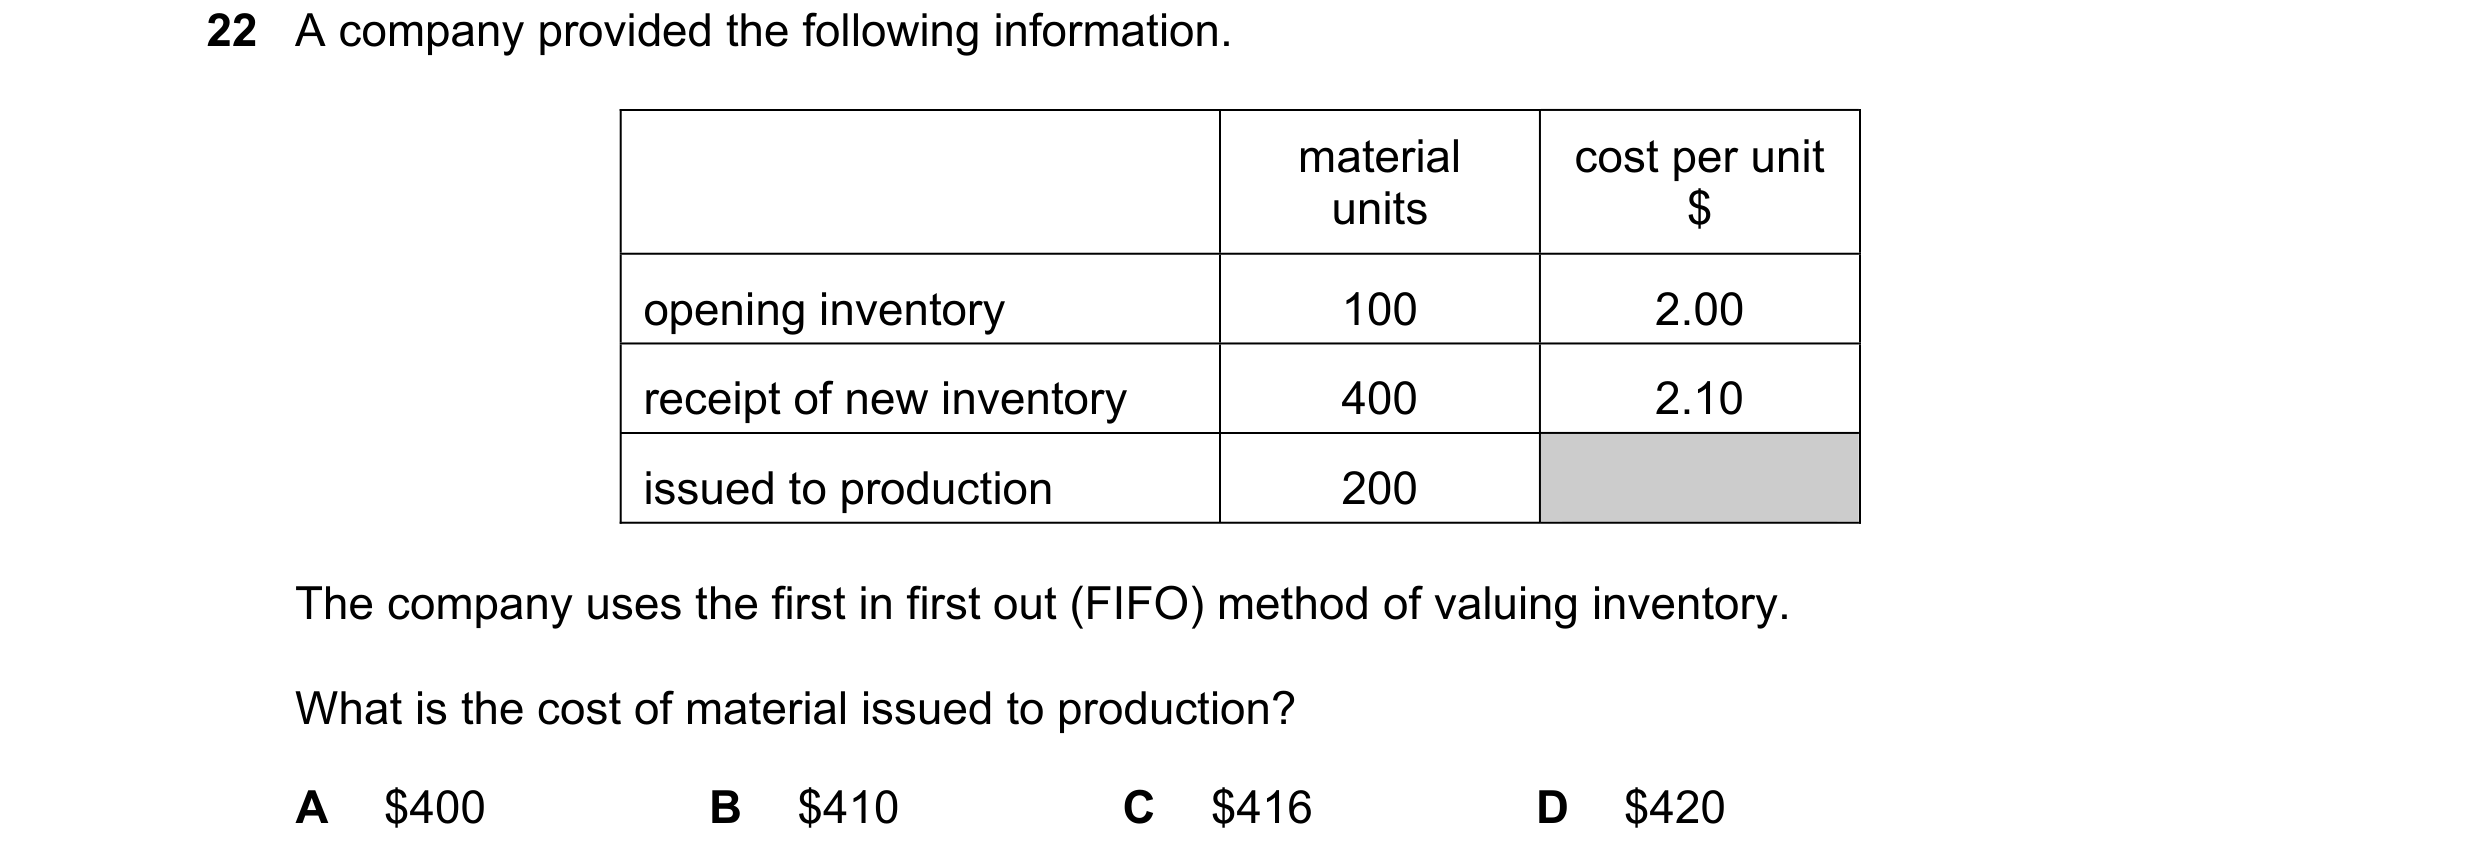
 121 / 233
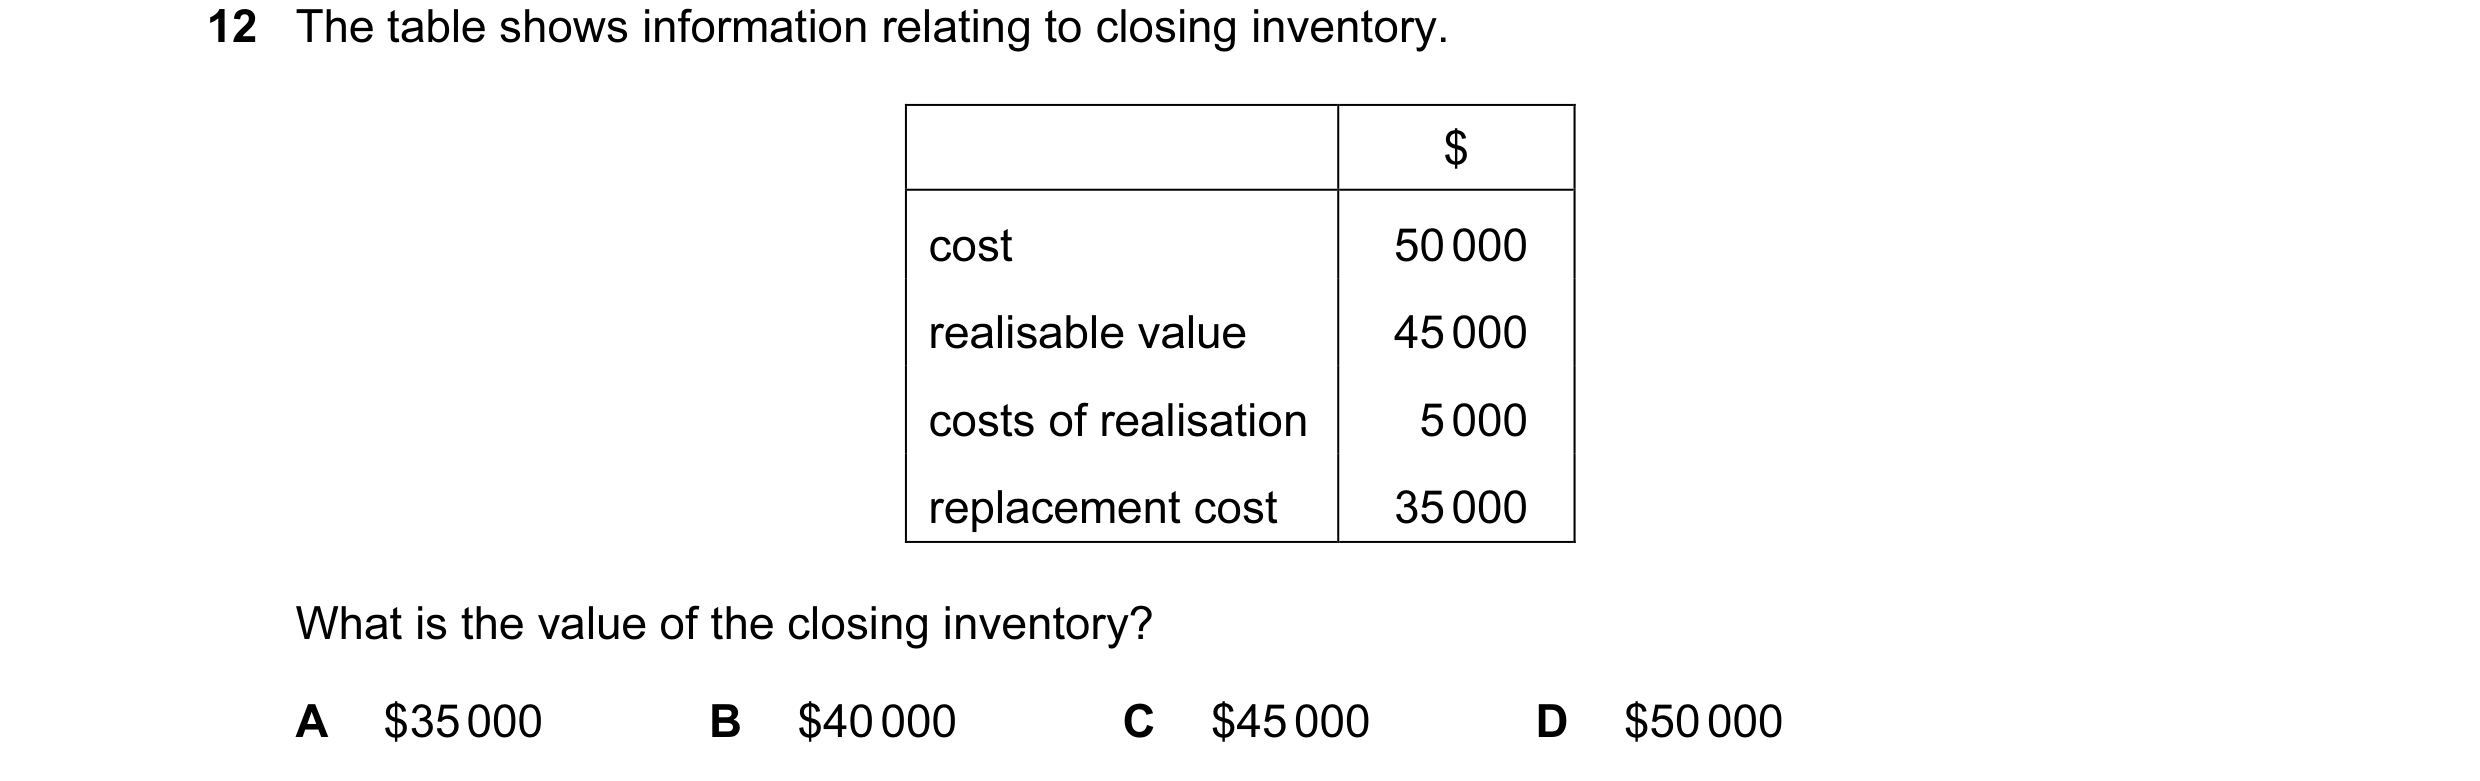 122 / 233
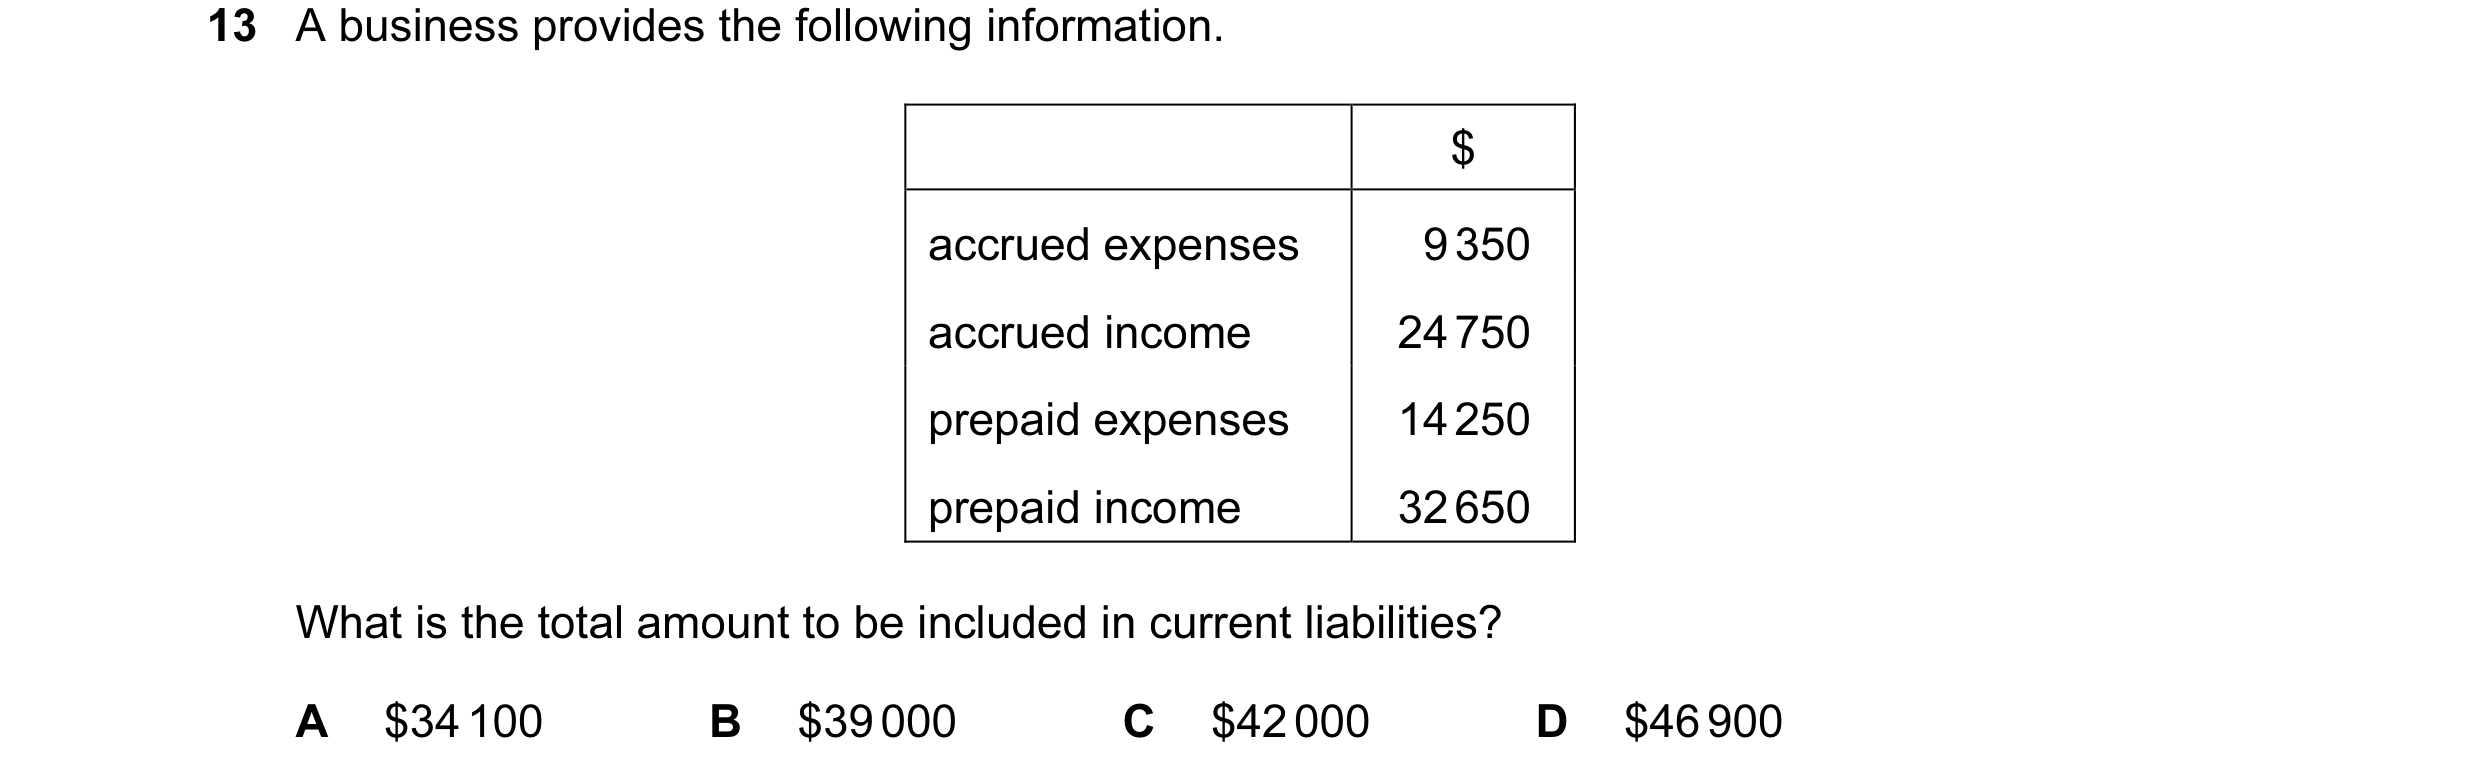
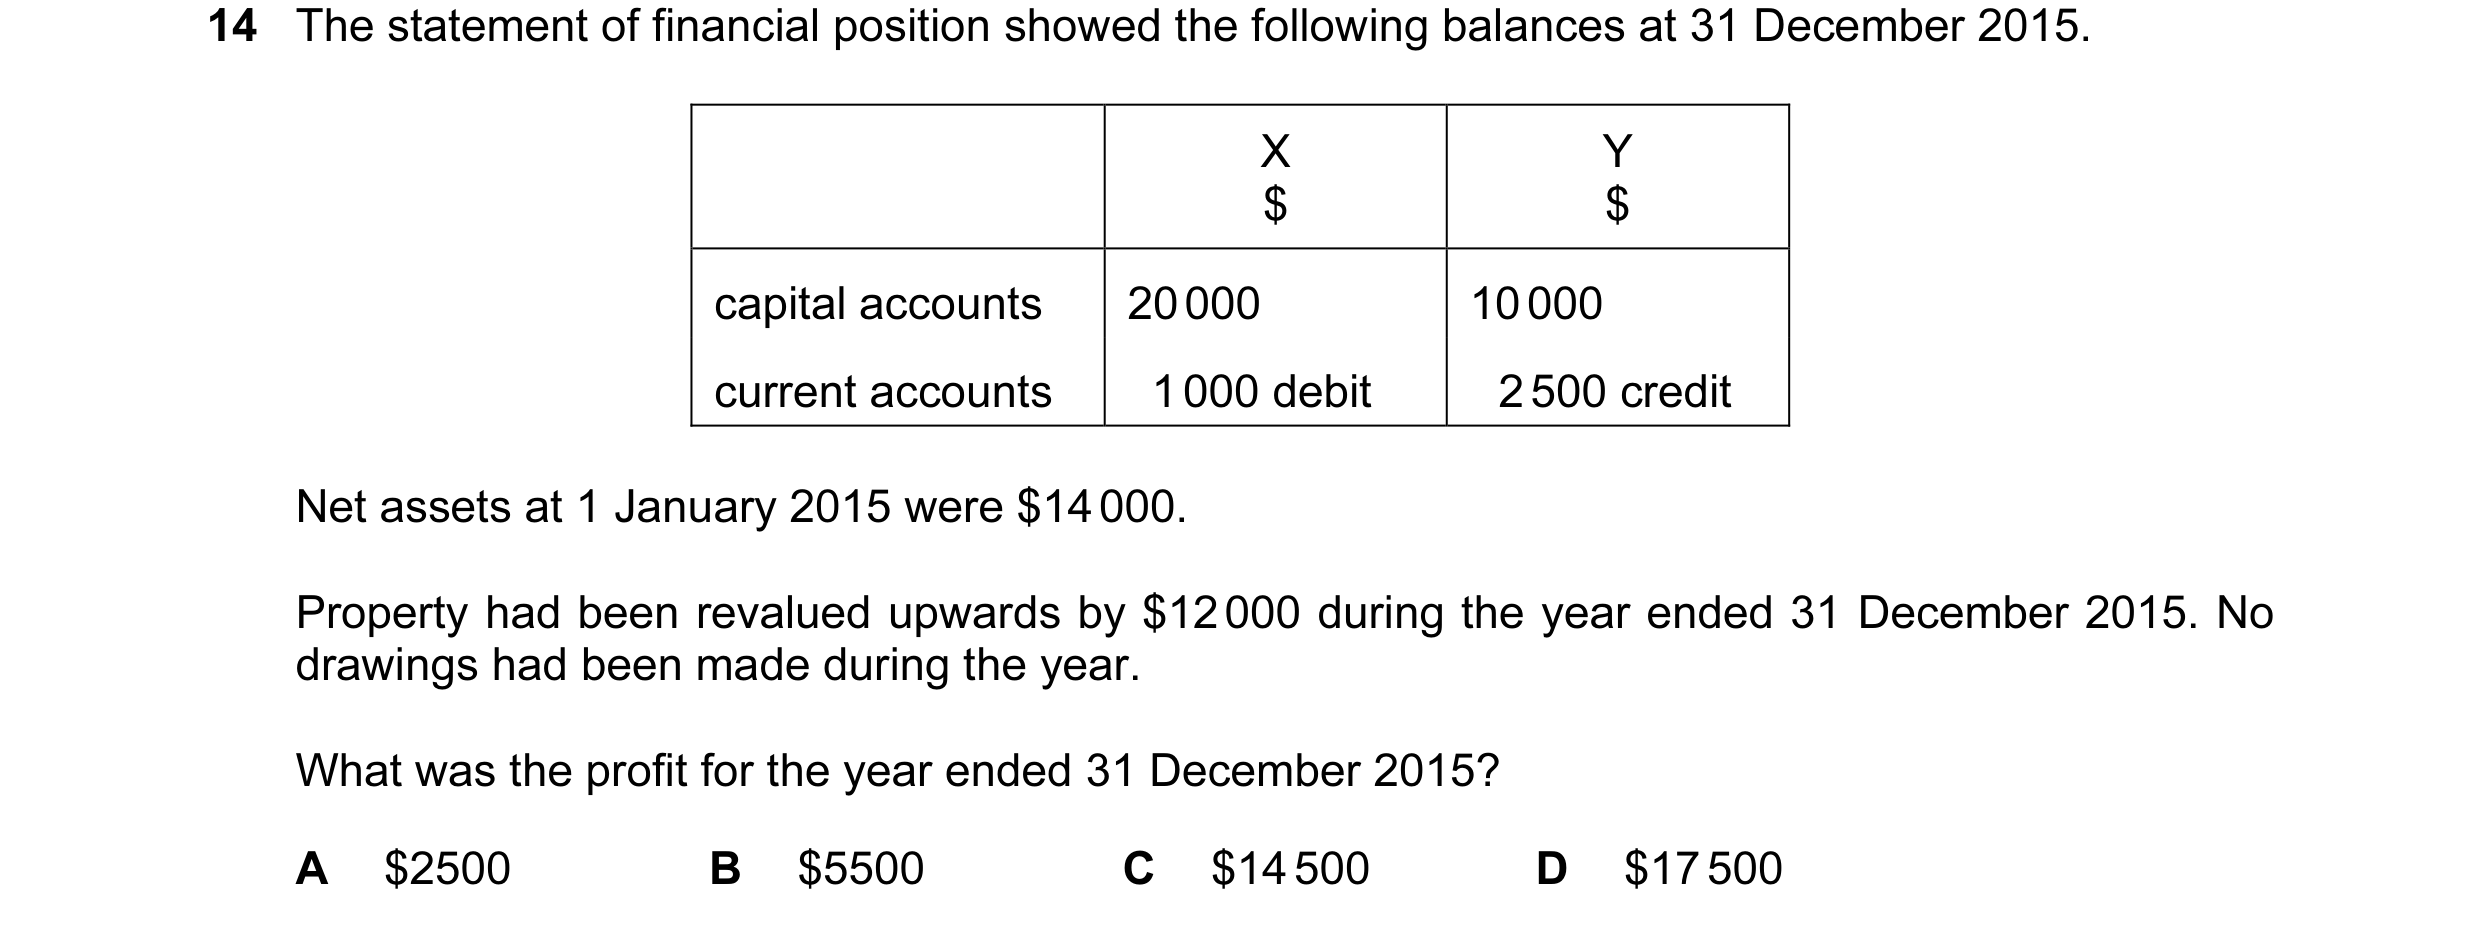
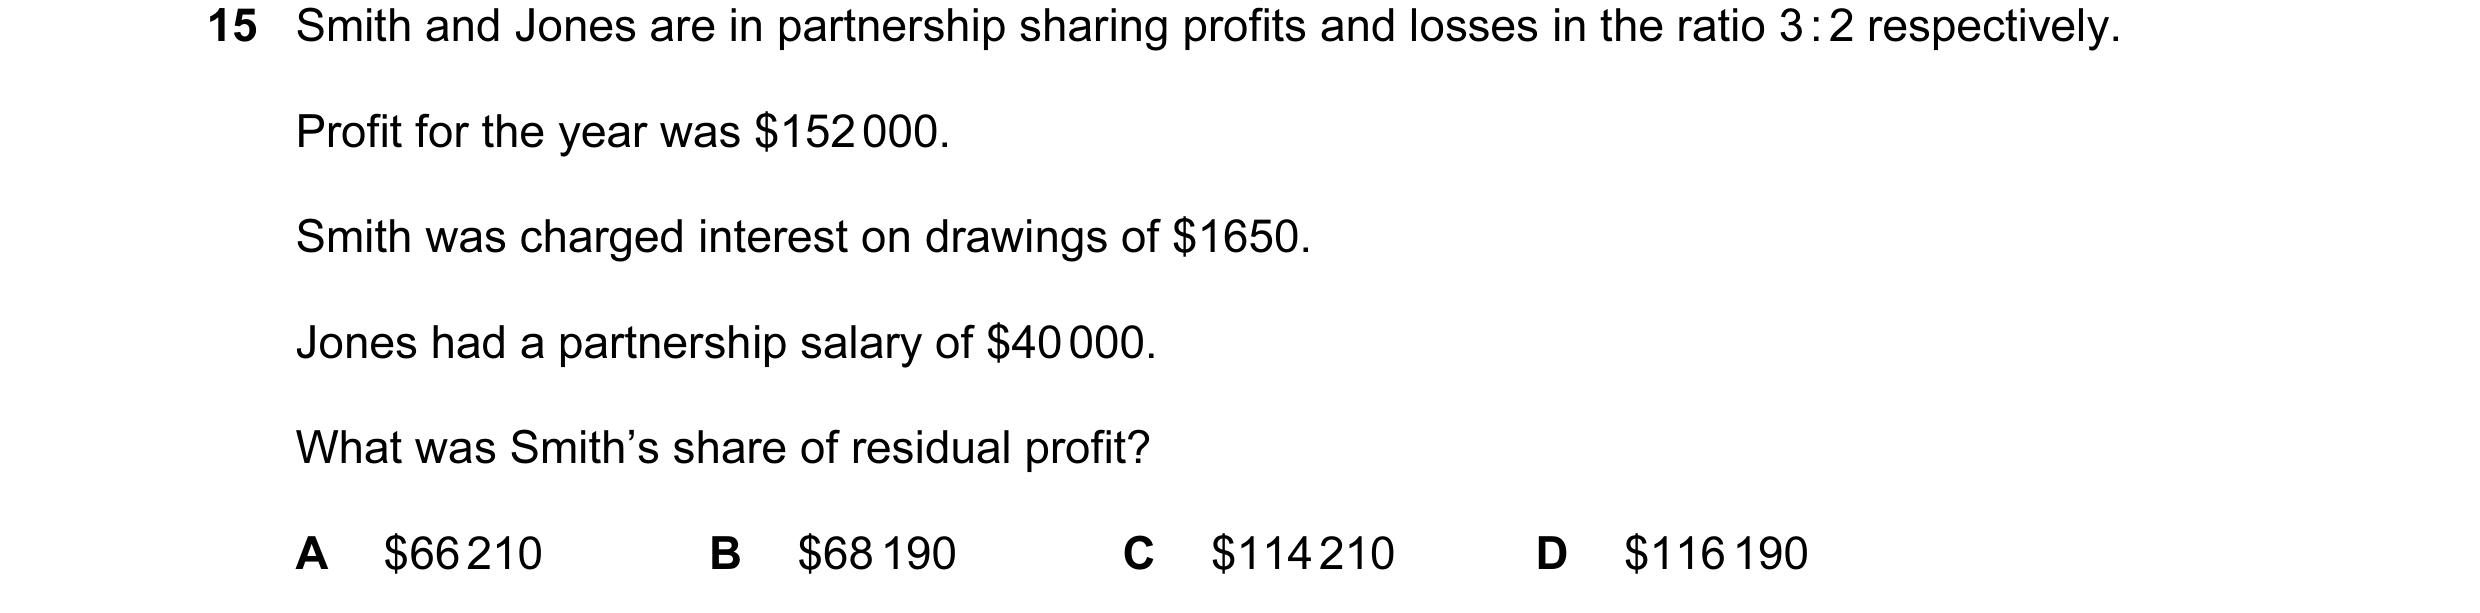
 123 / 233
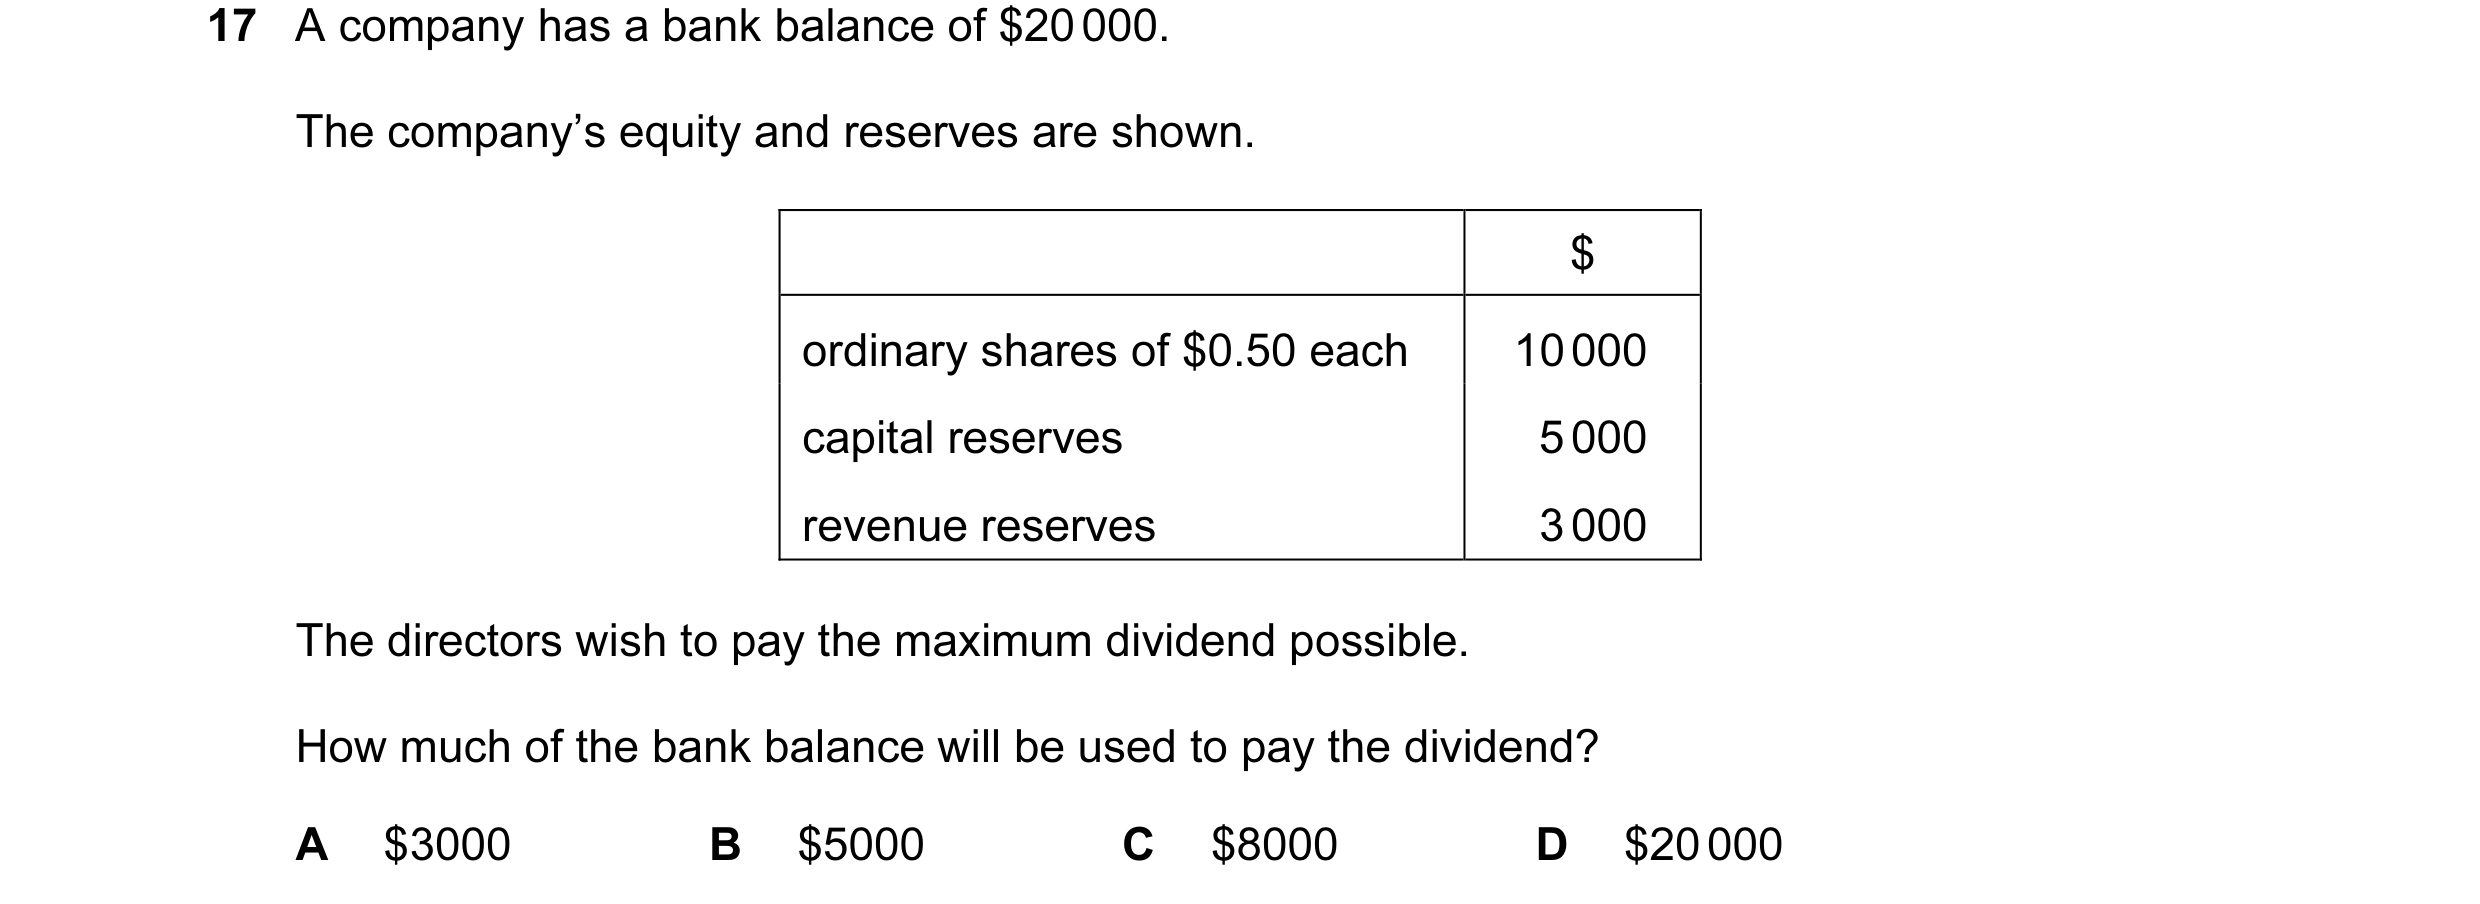
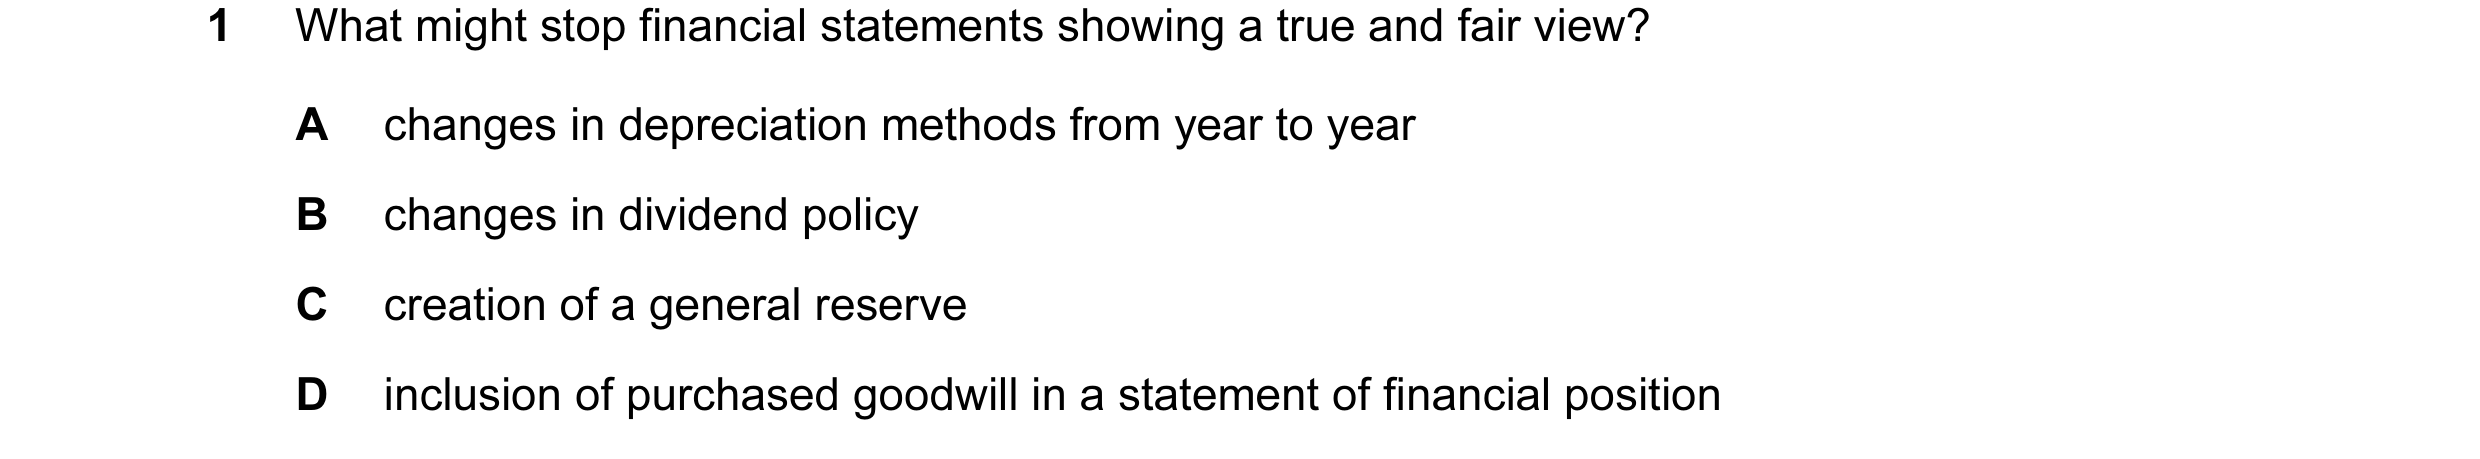
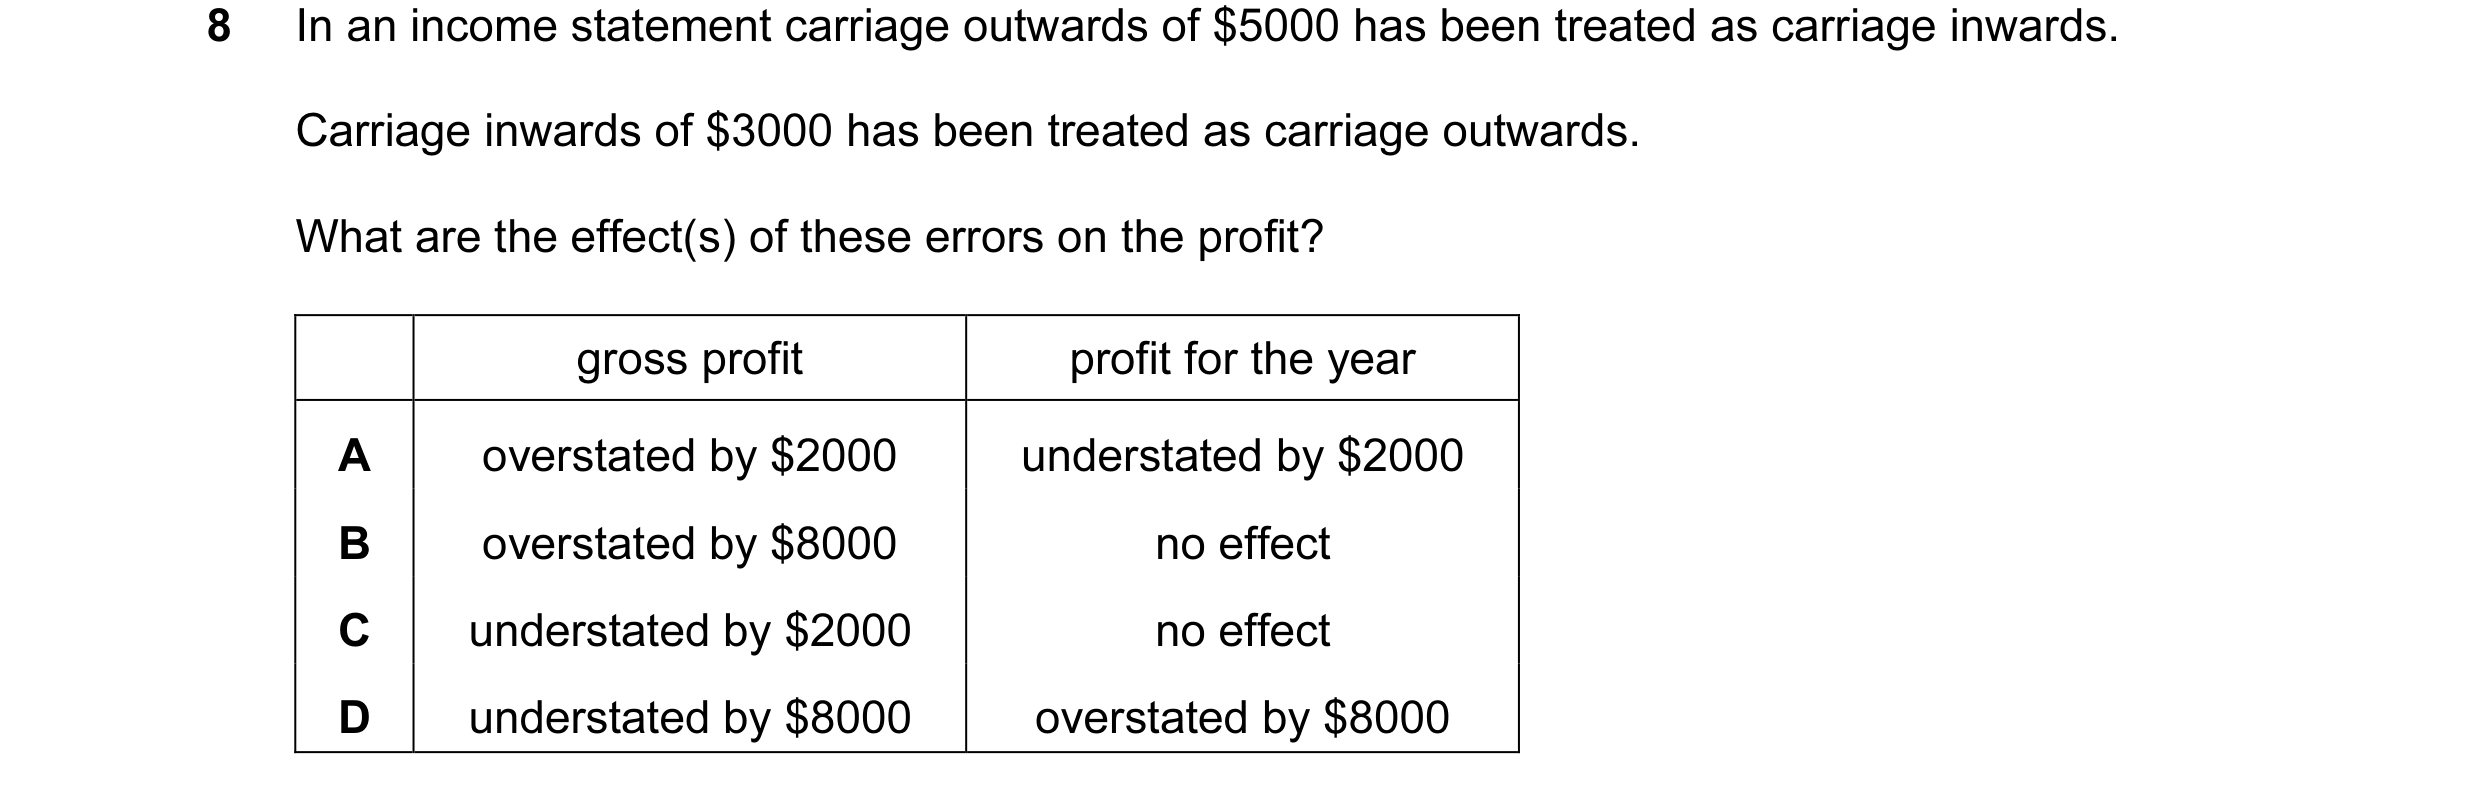 124 / 233
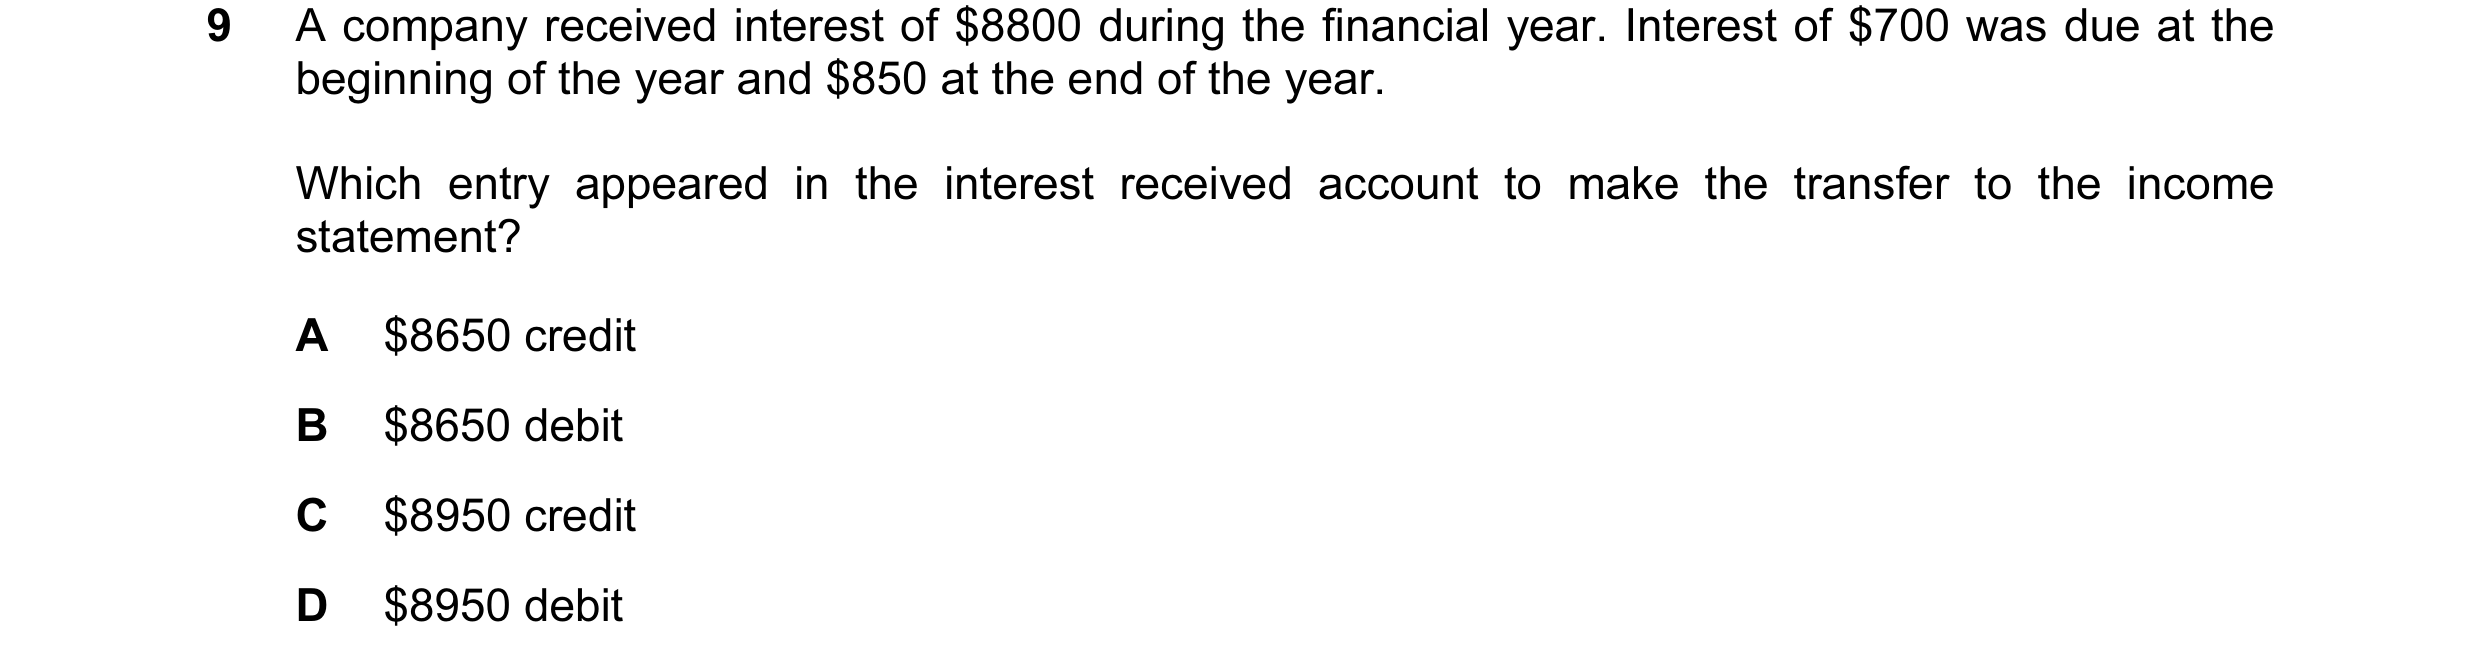
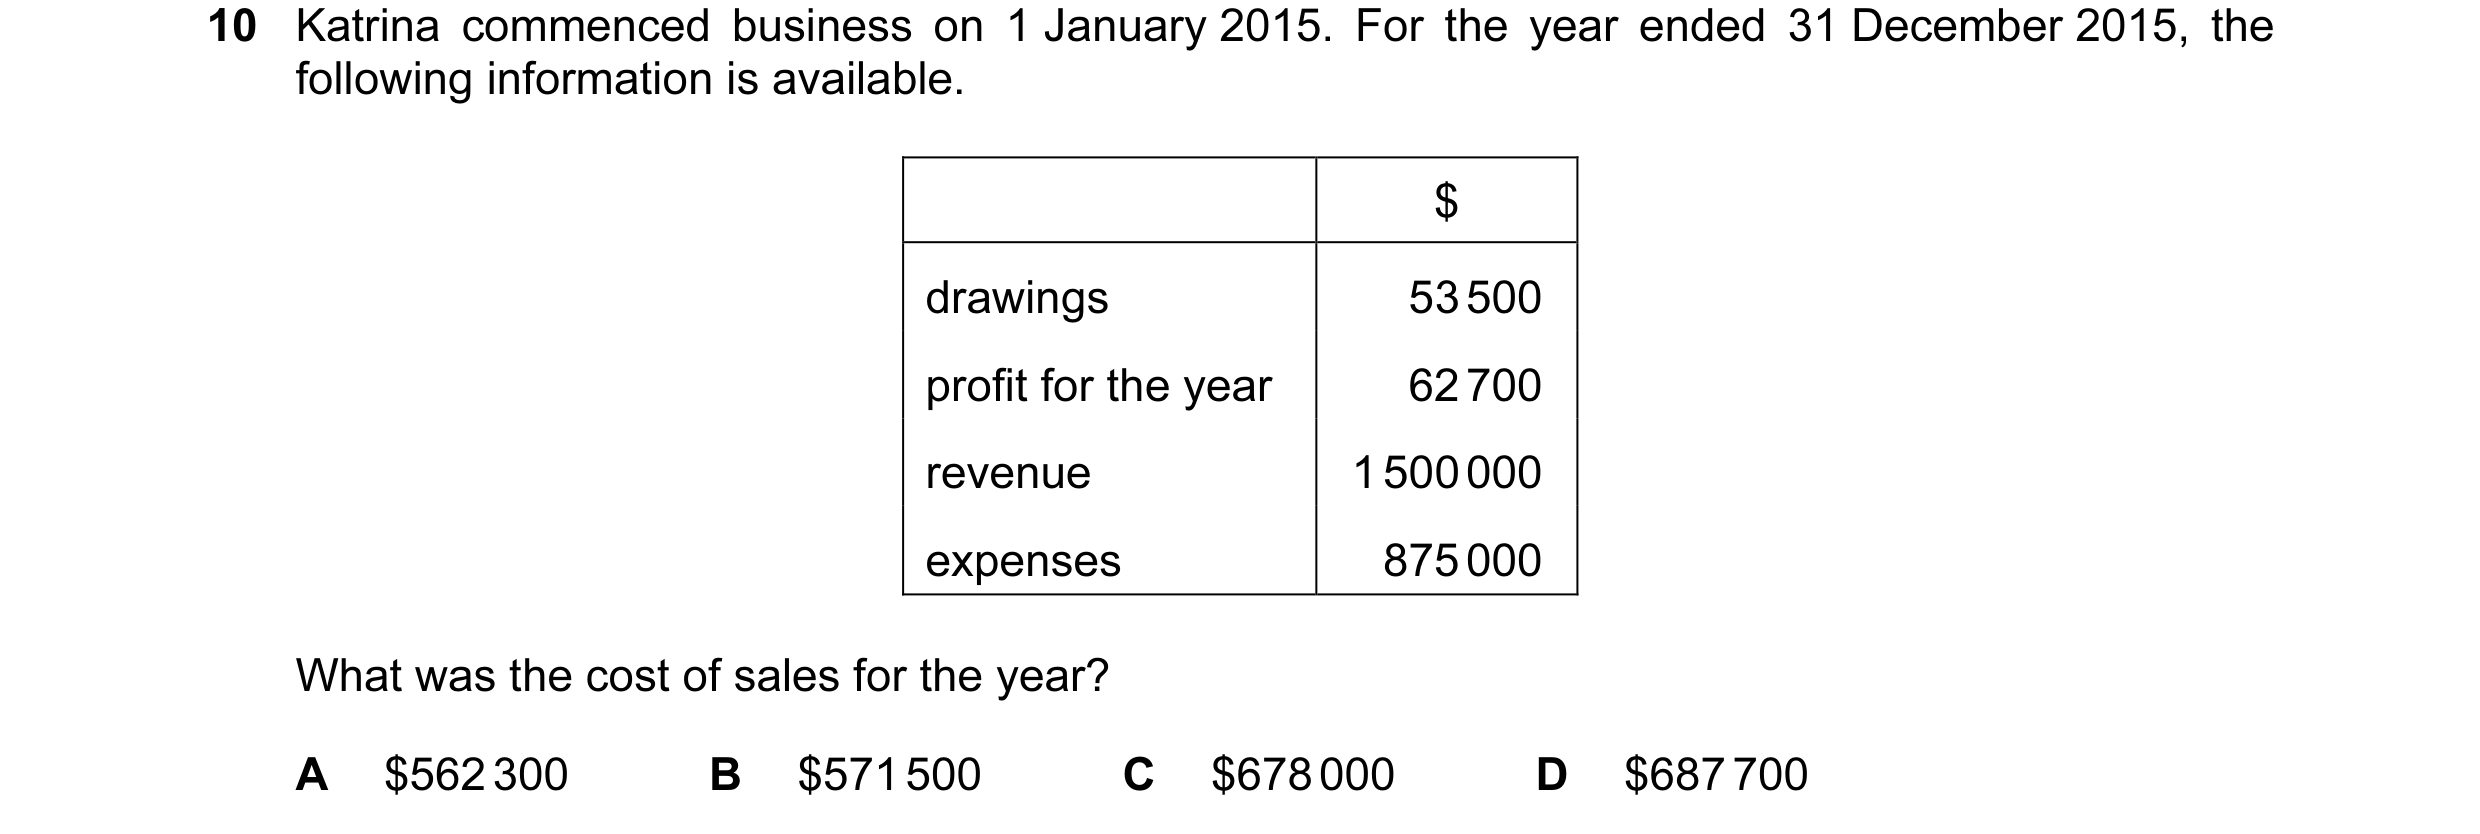
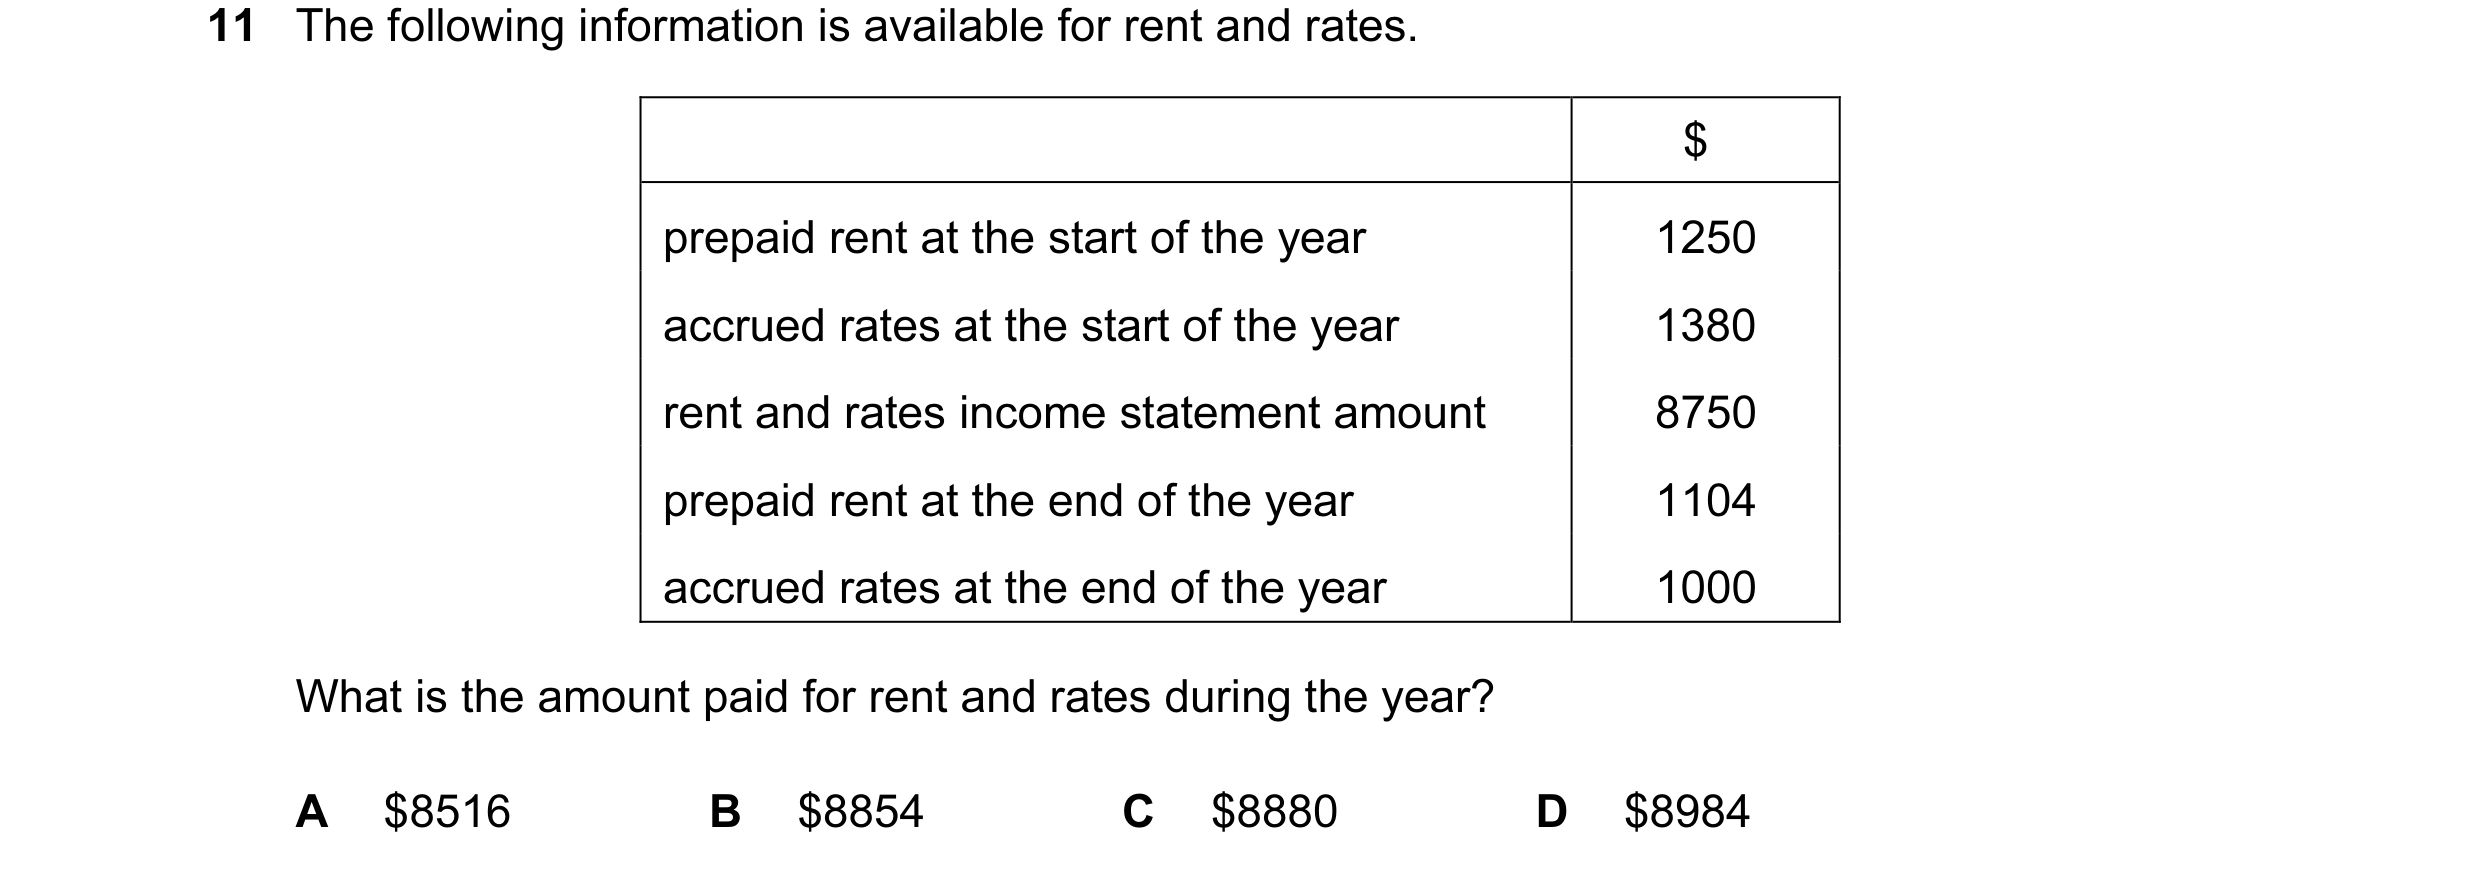
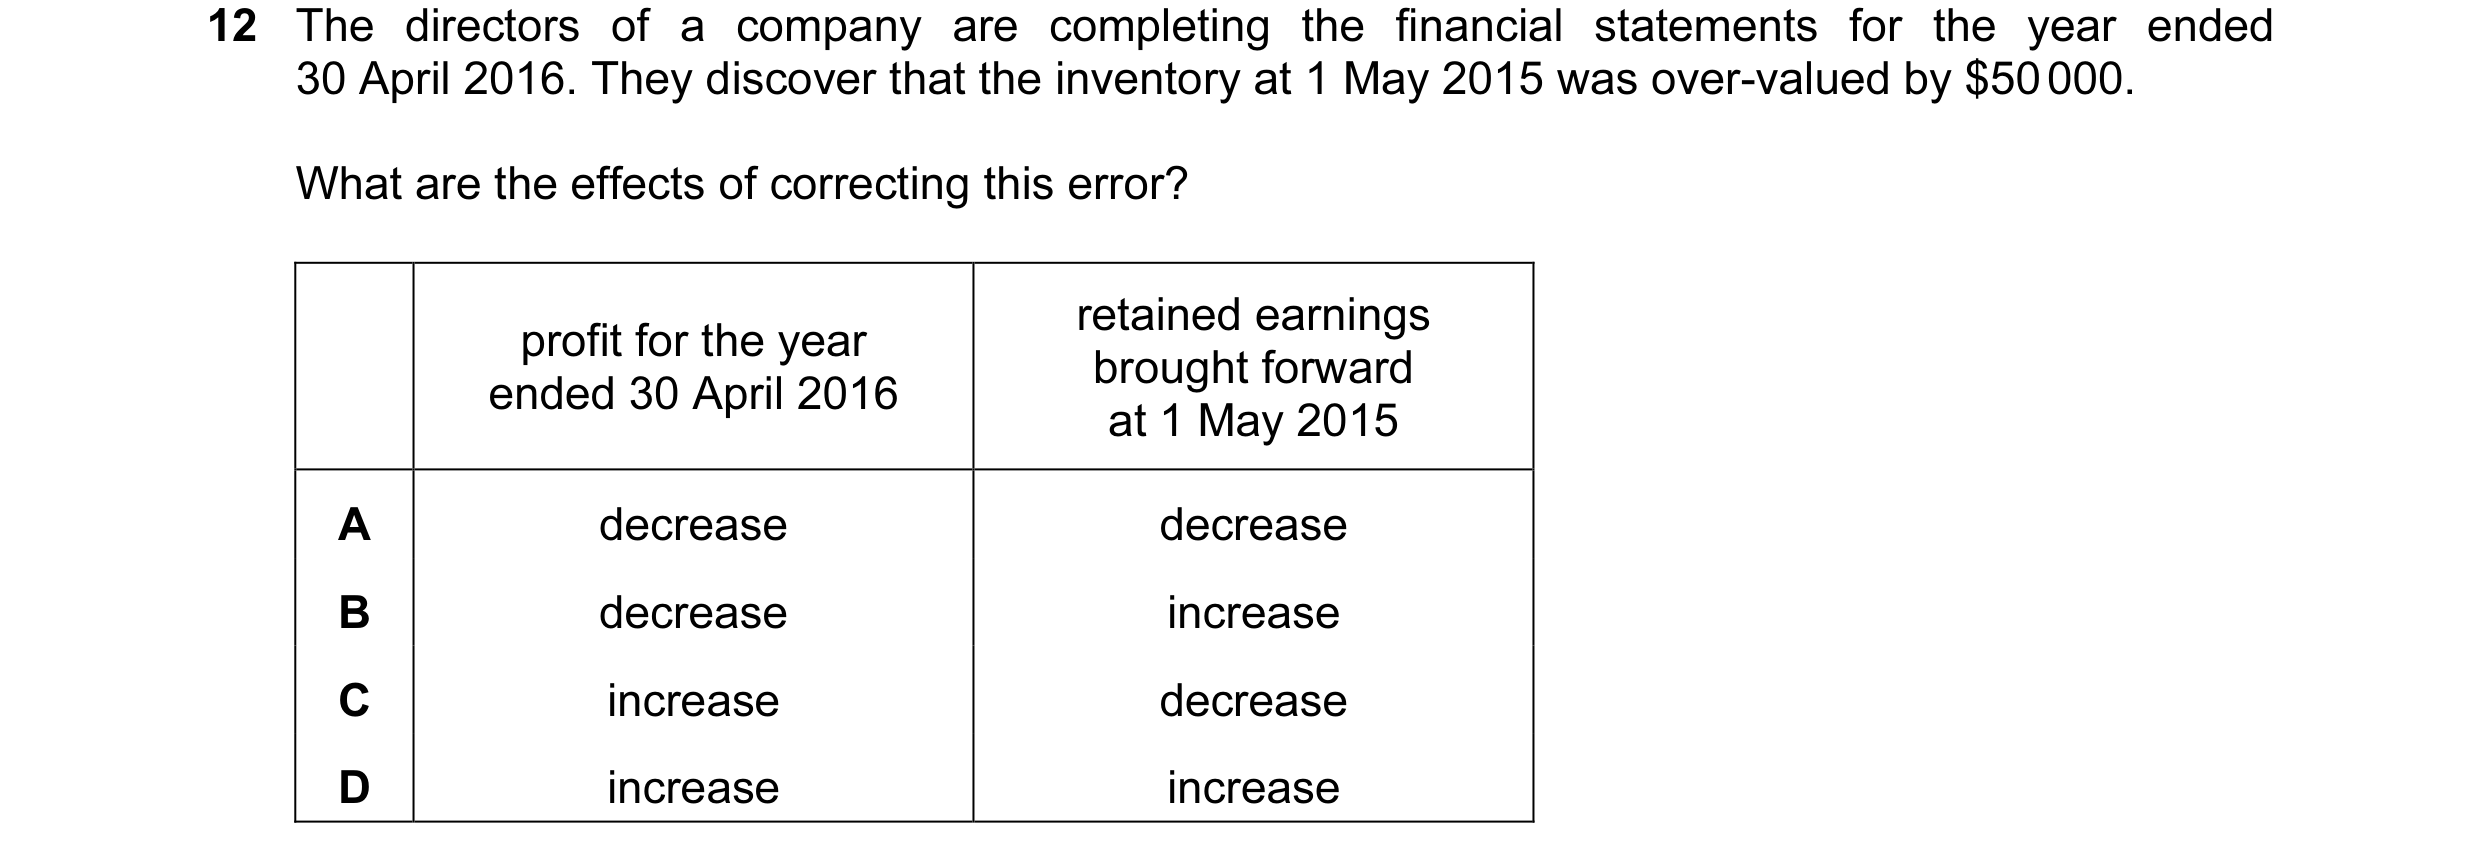 125 / 233
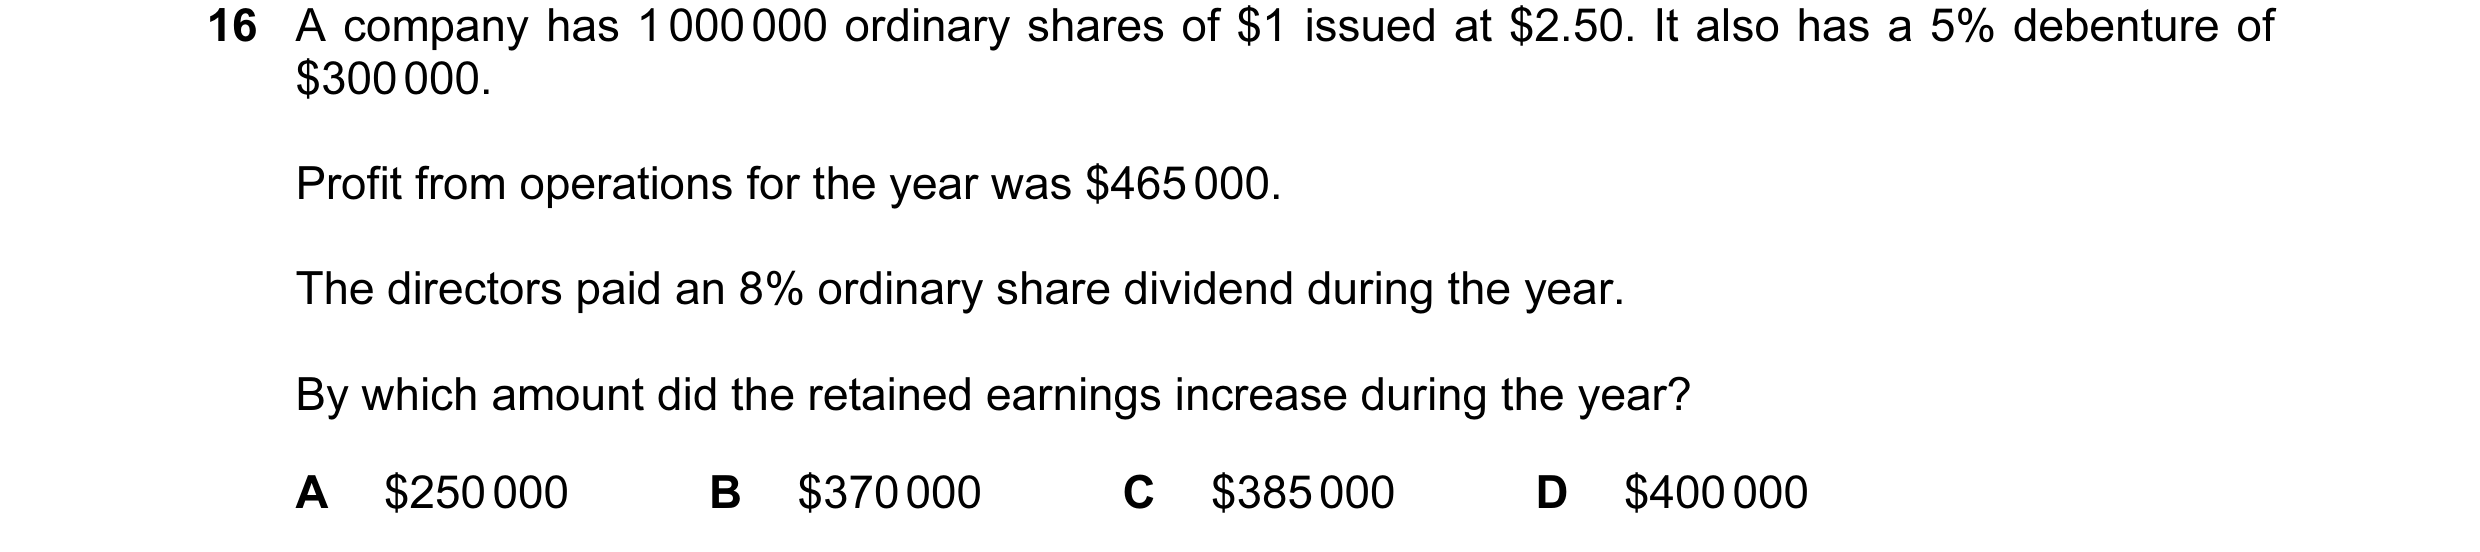
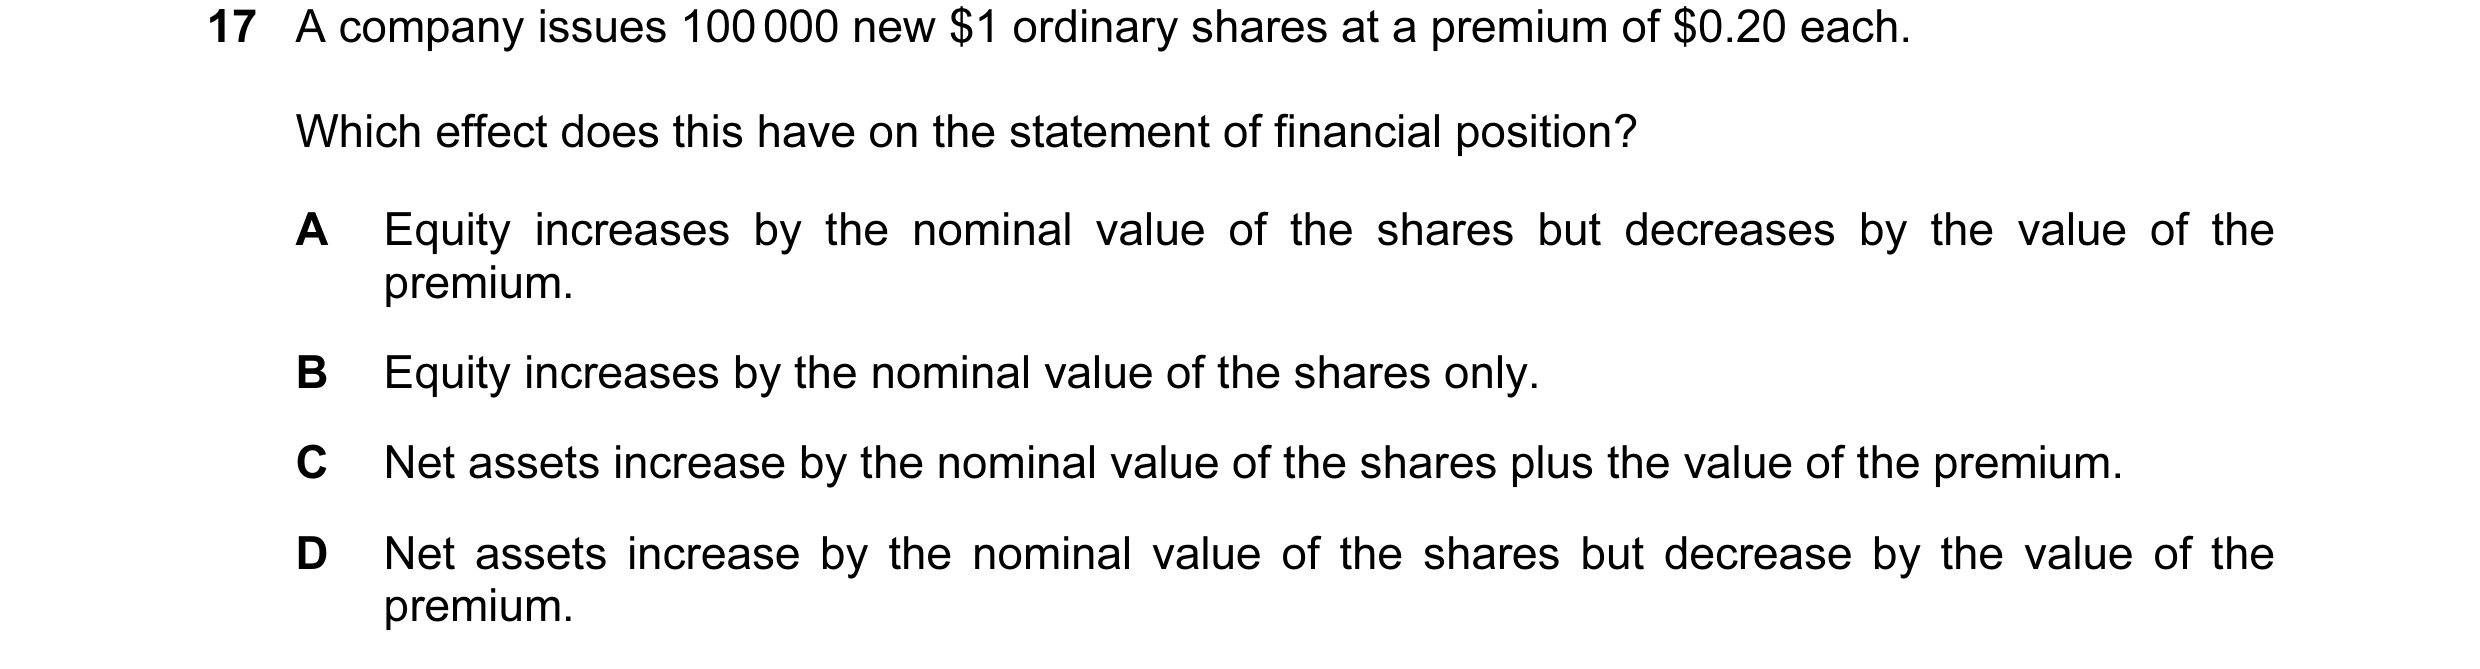
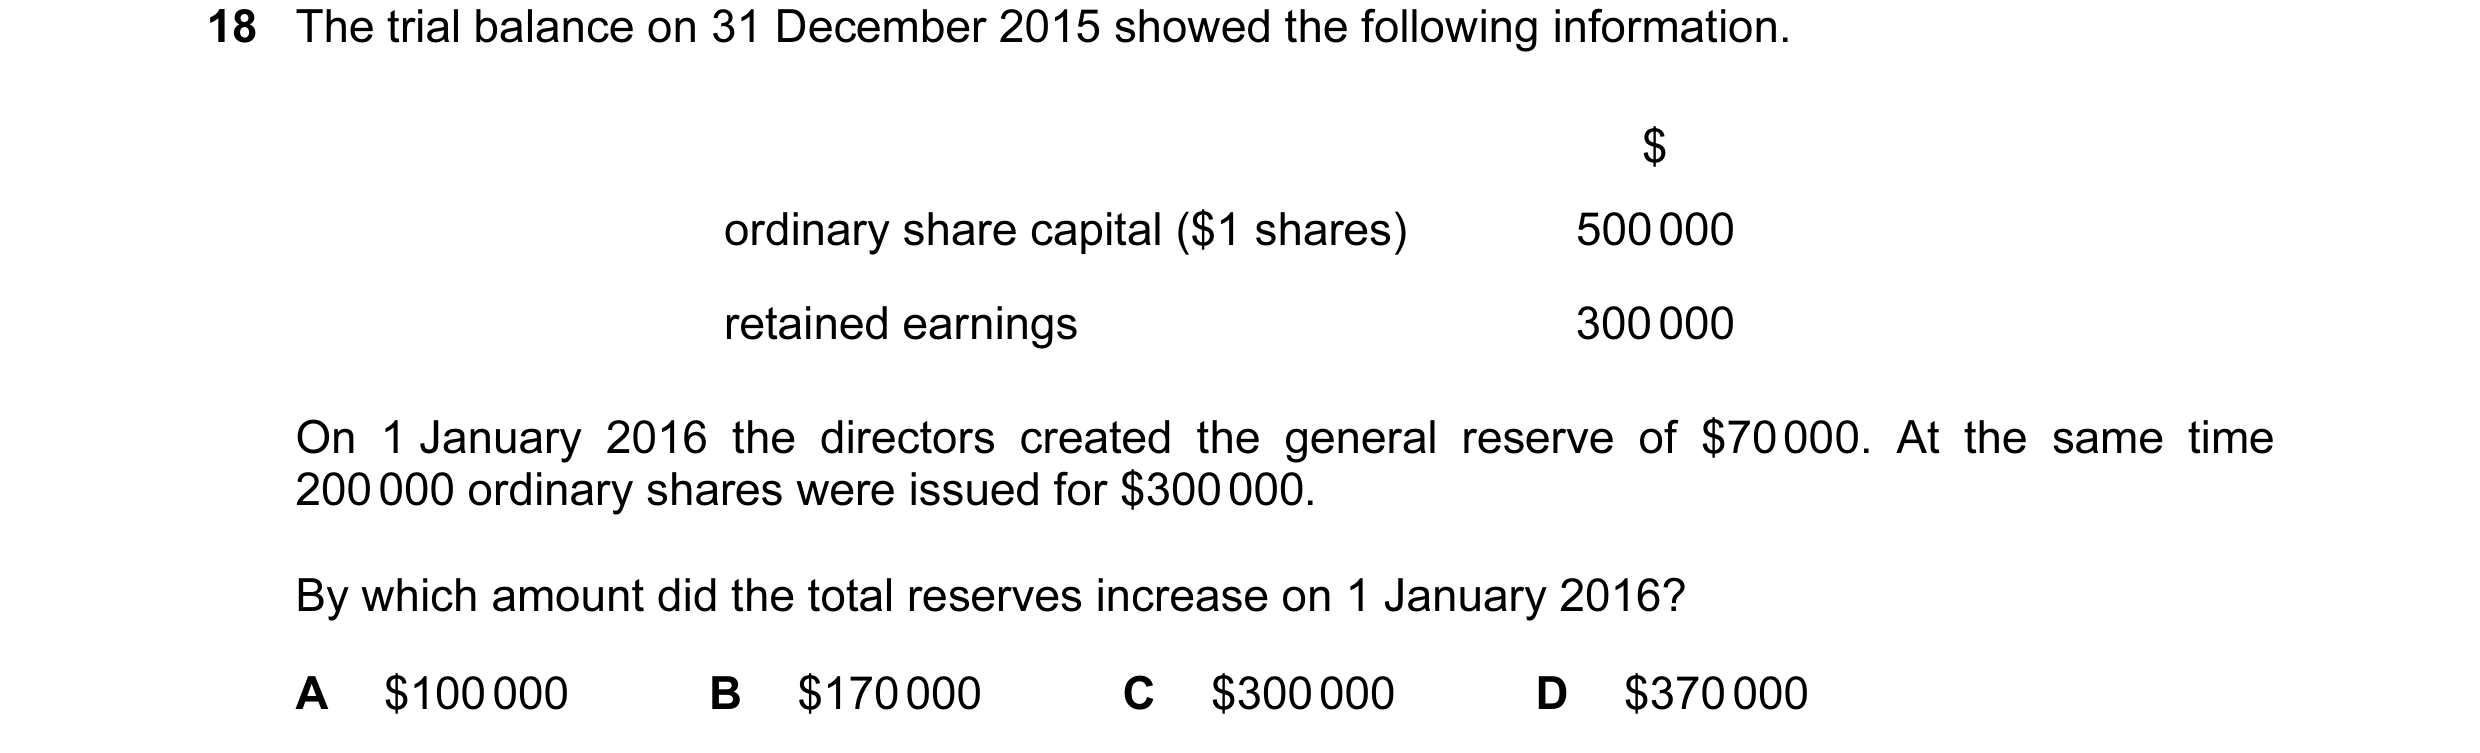
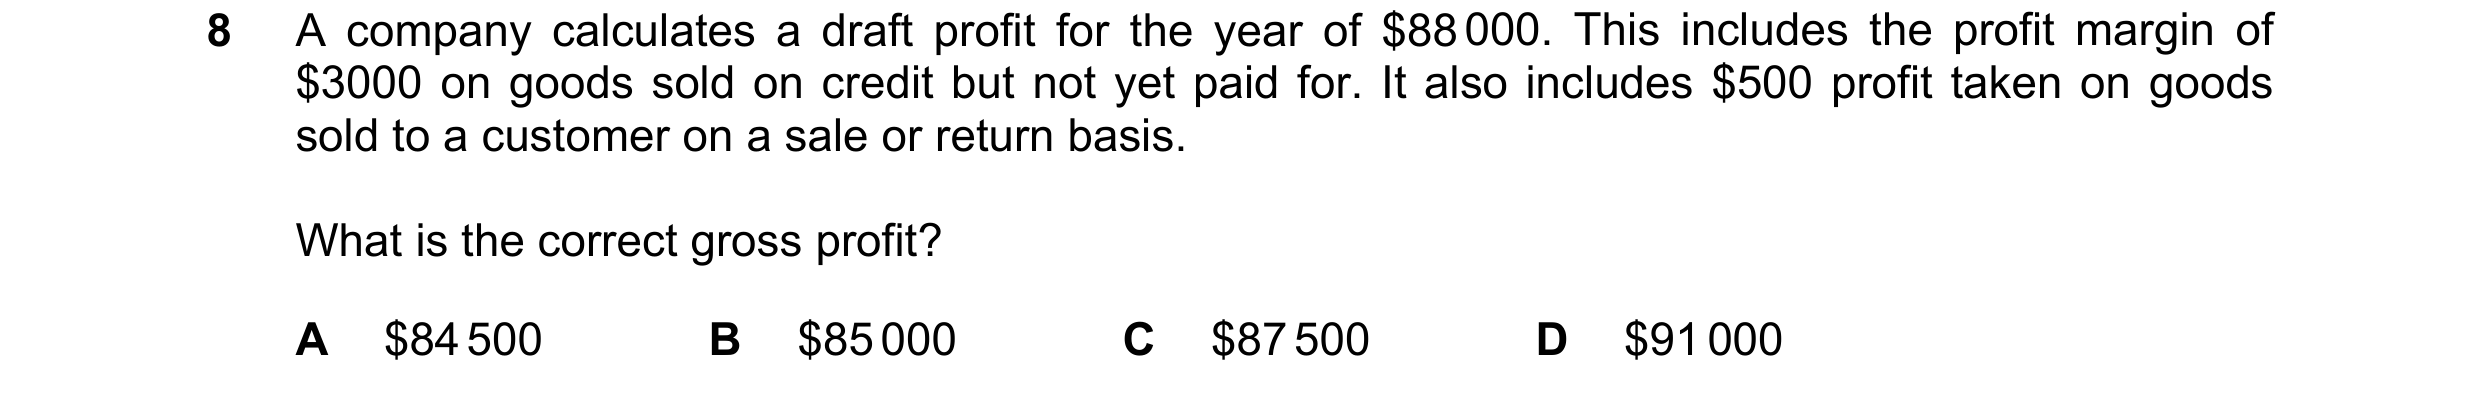
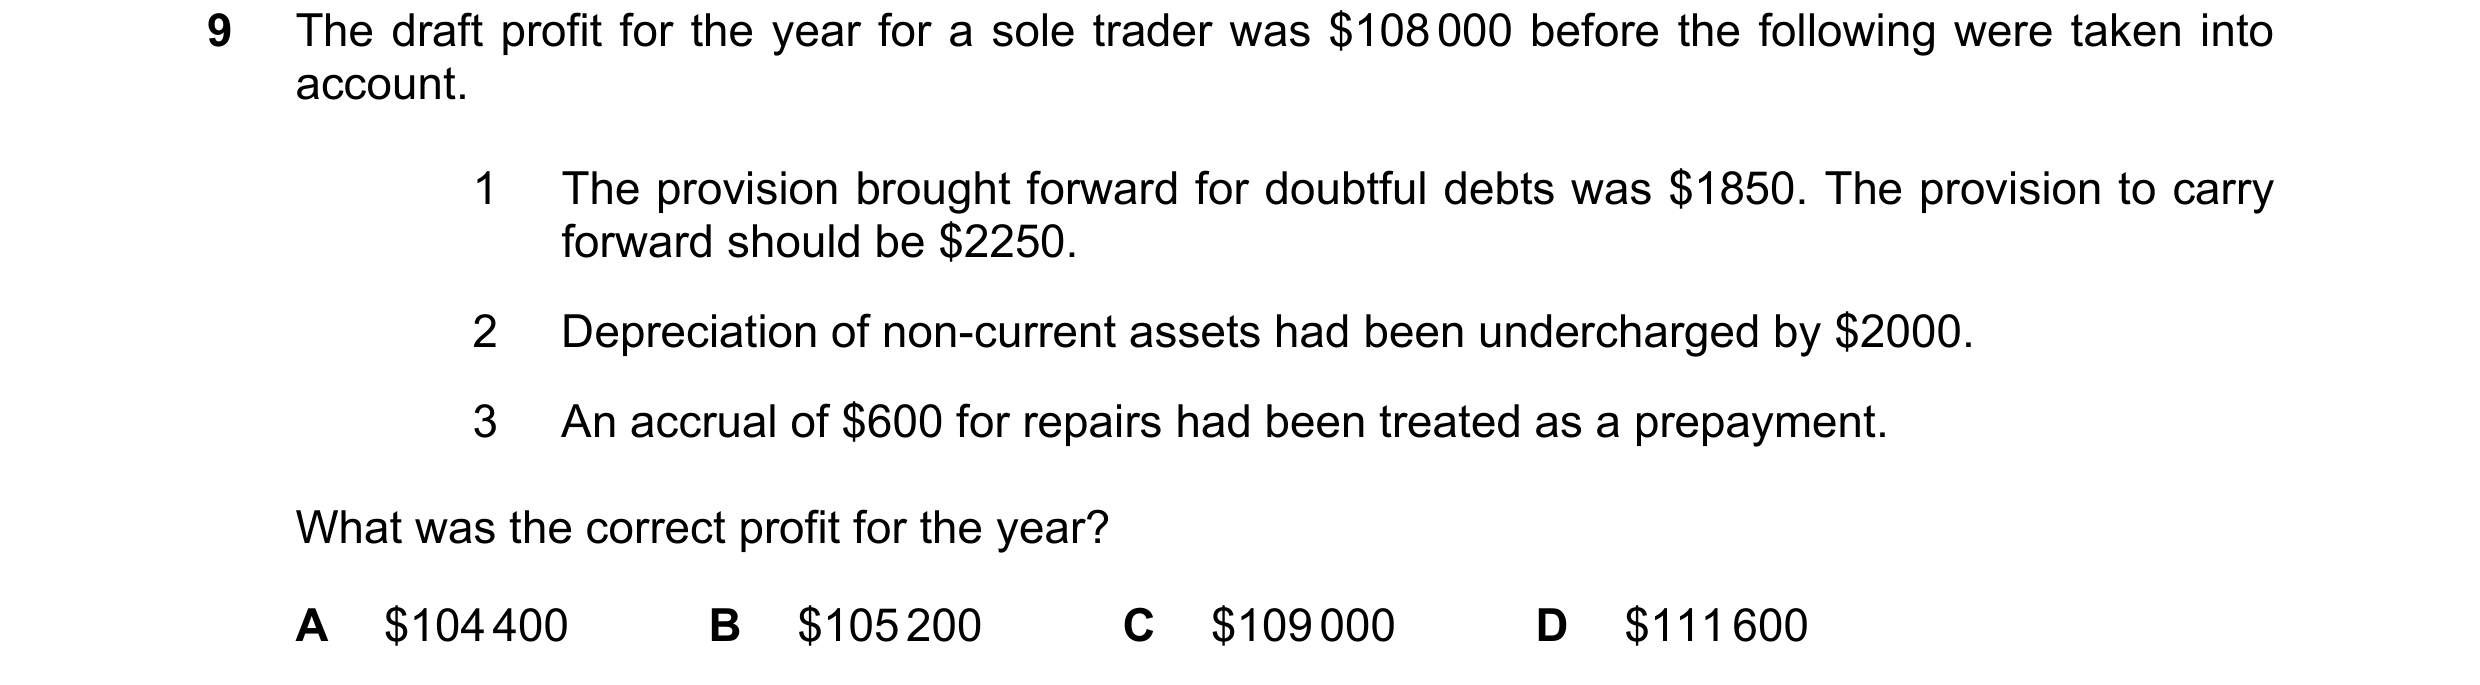 126 / 233
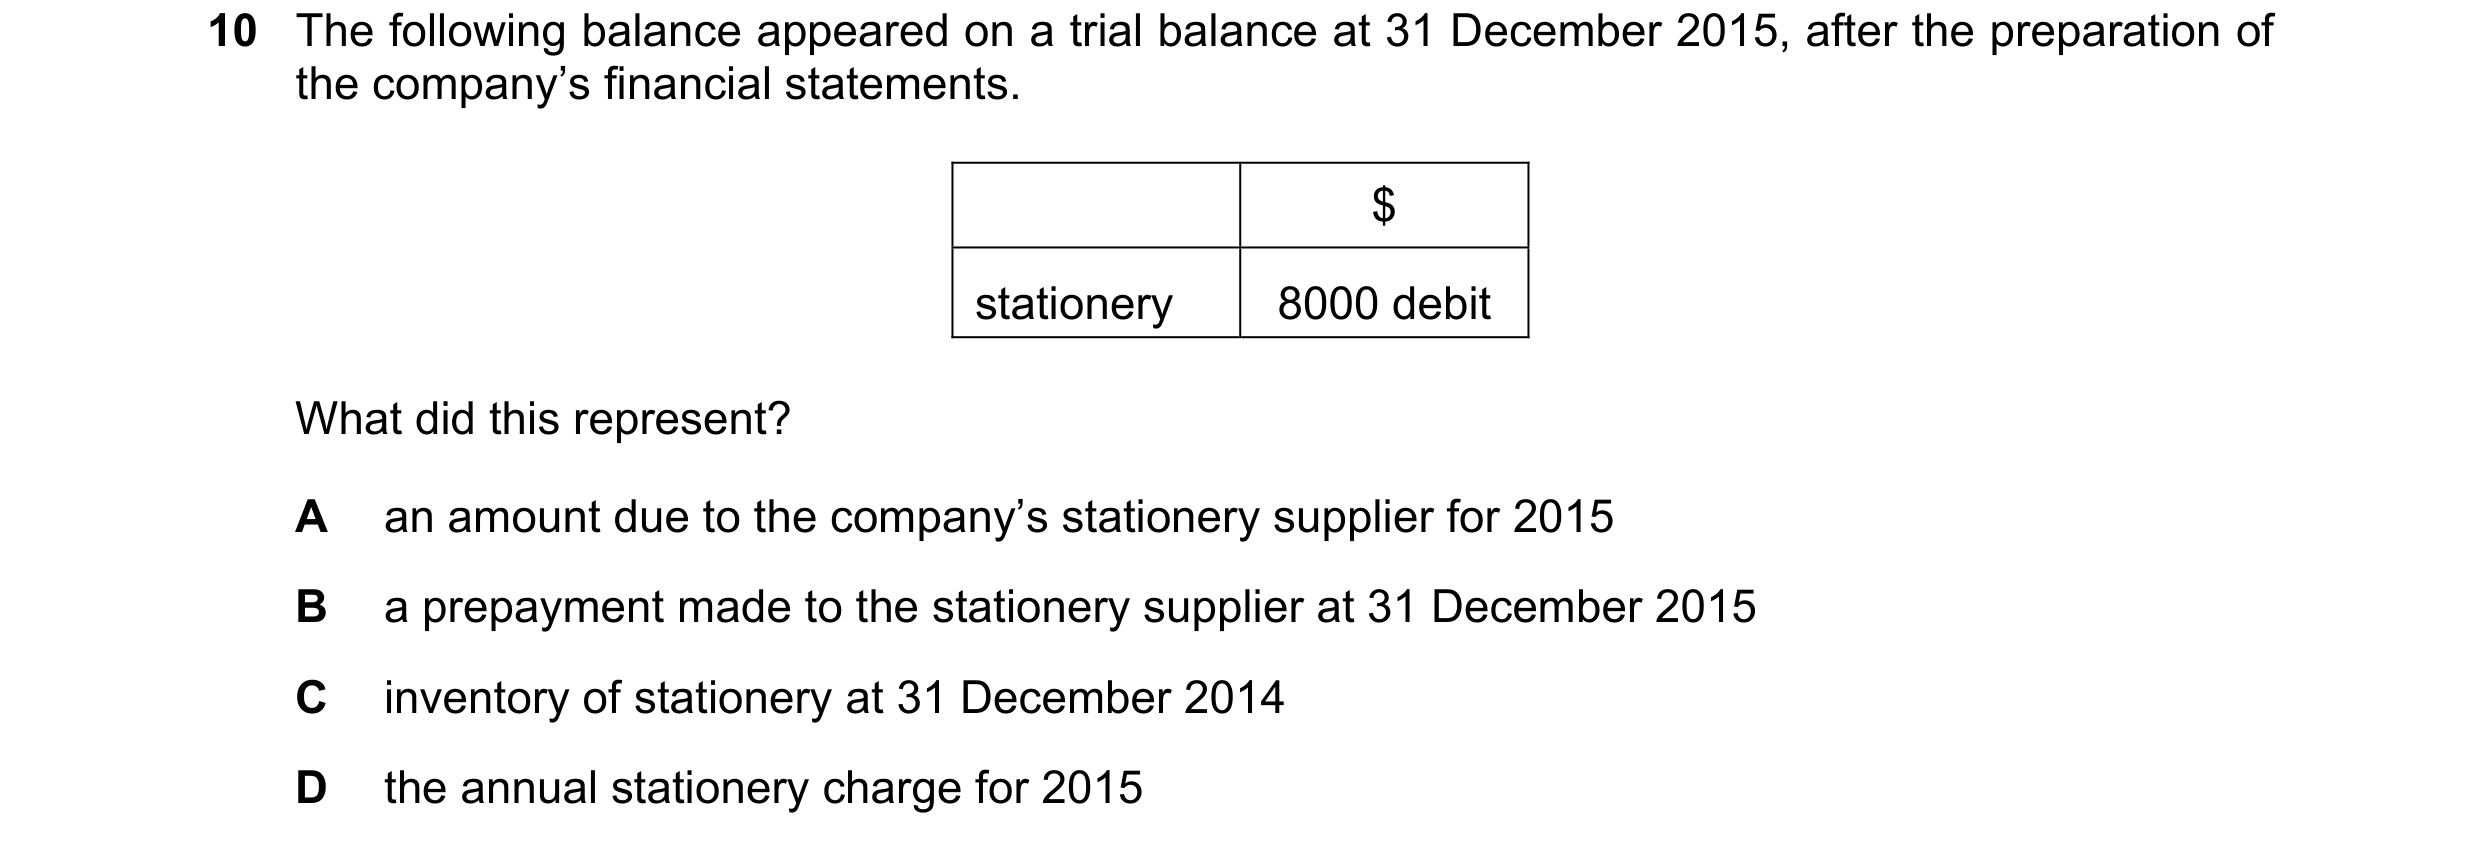
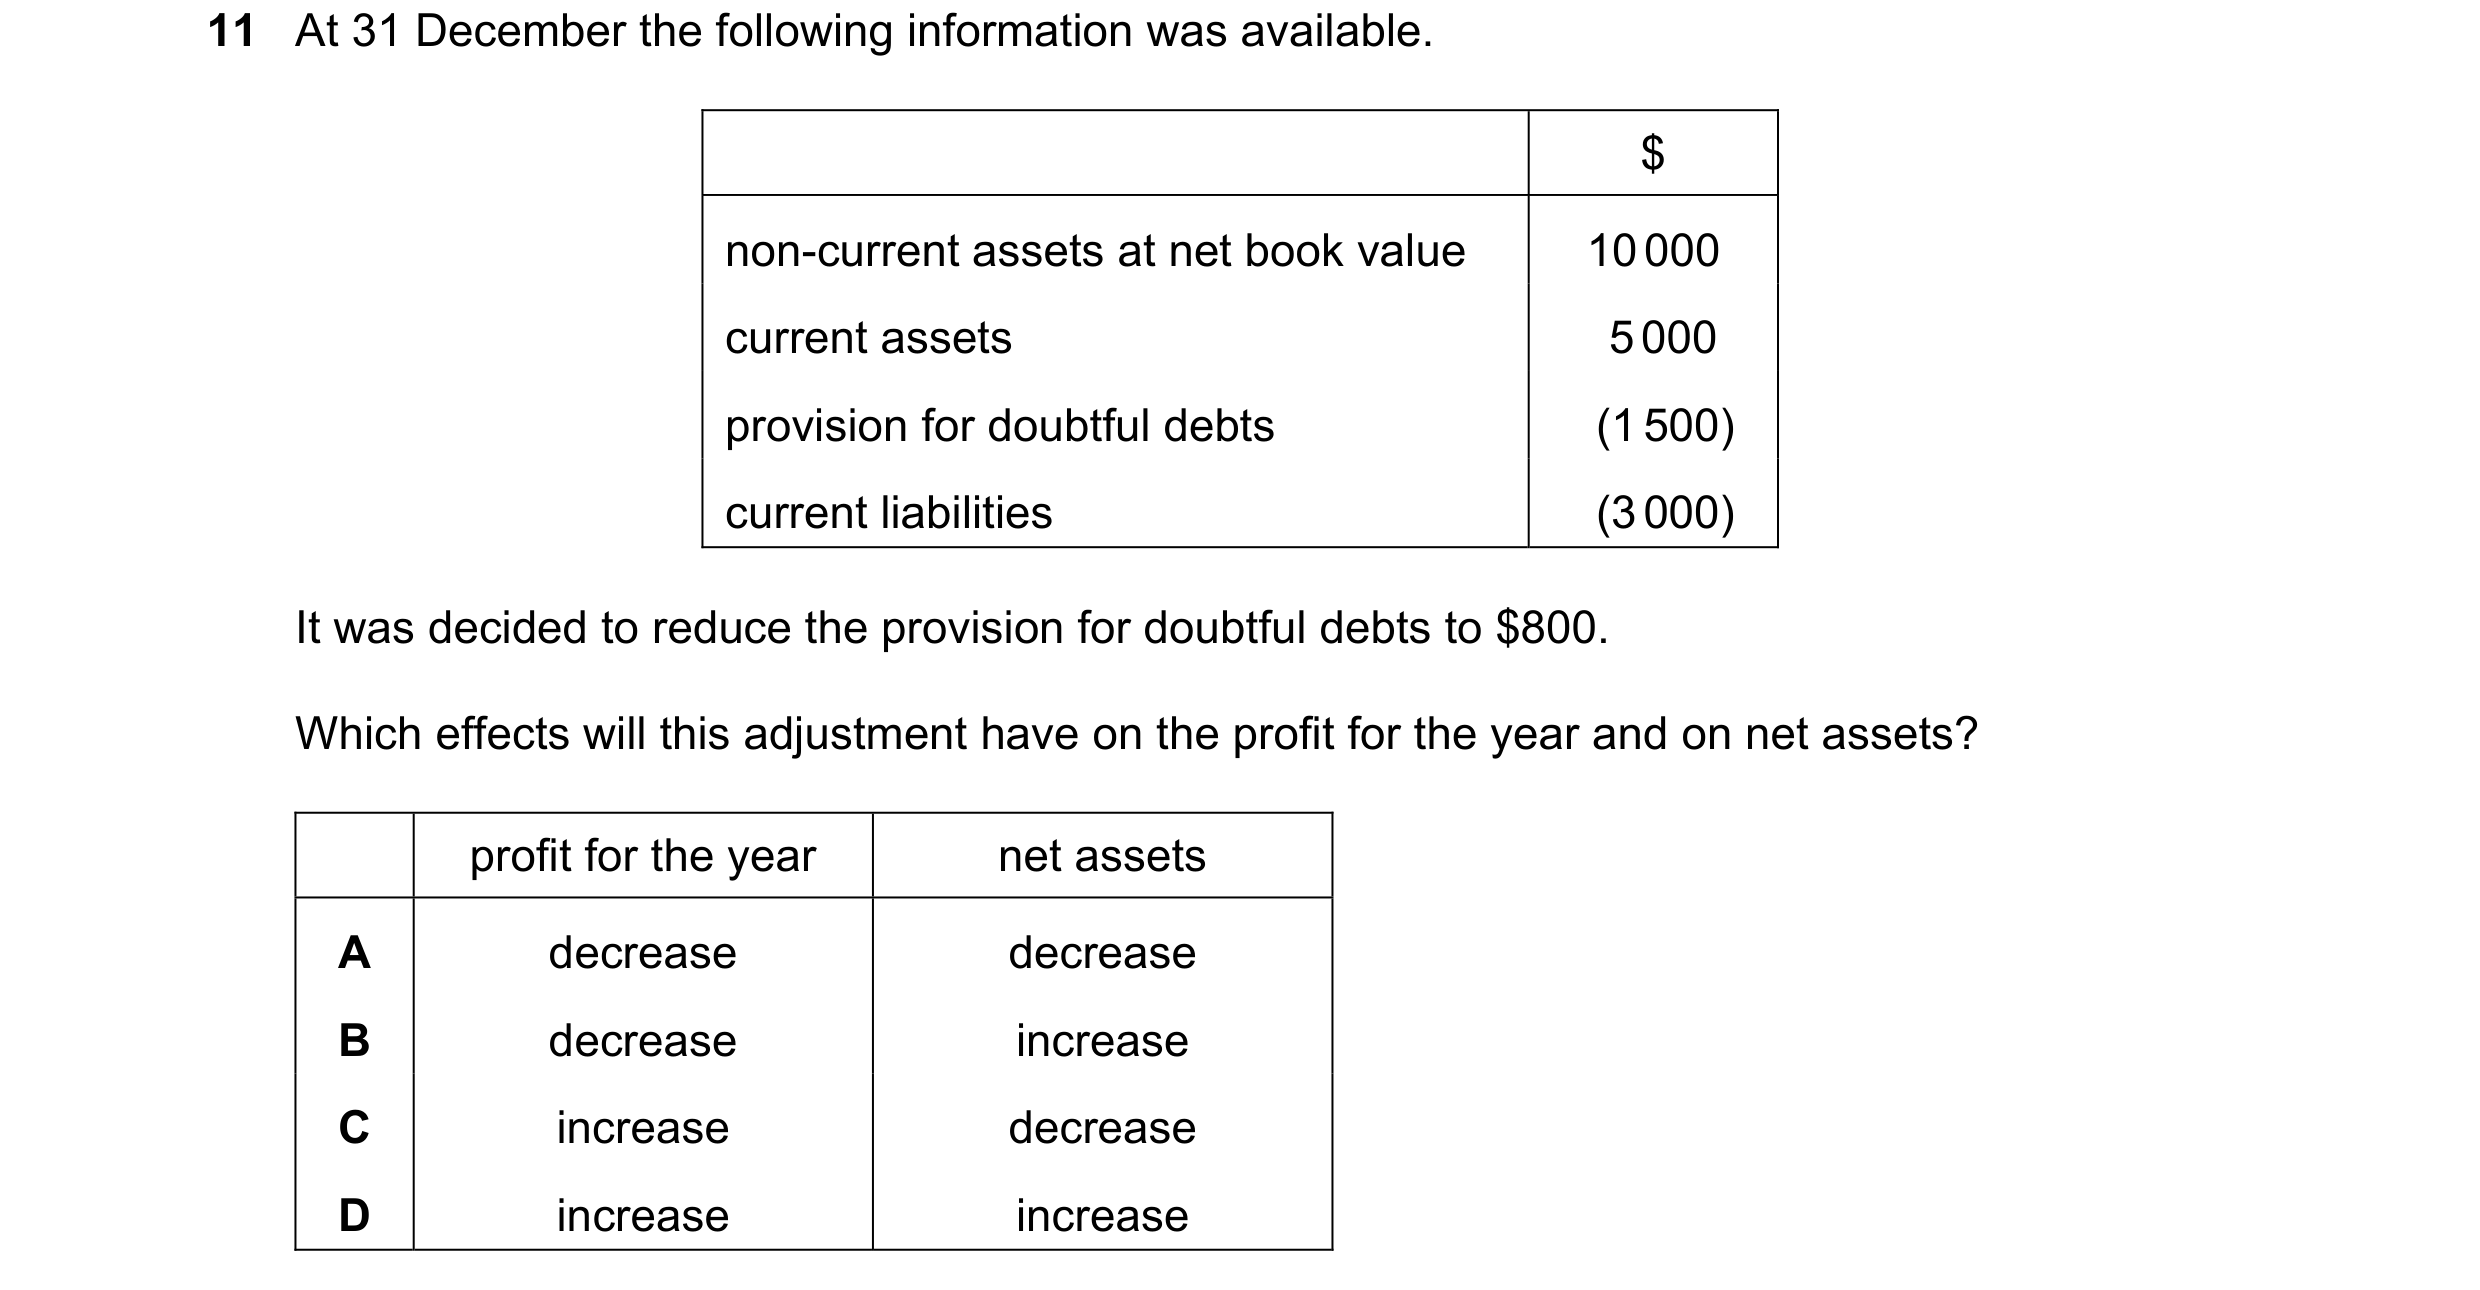
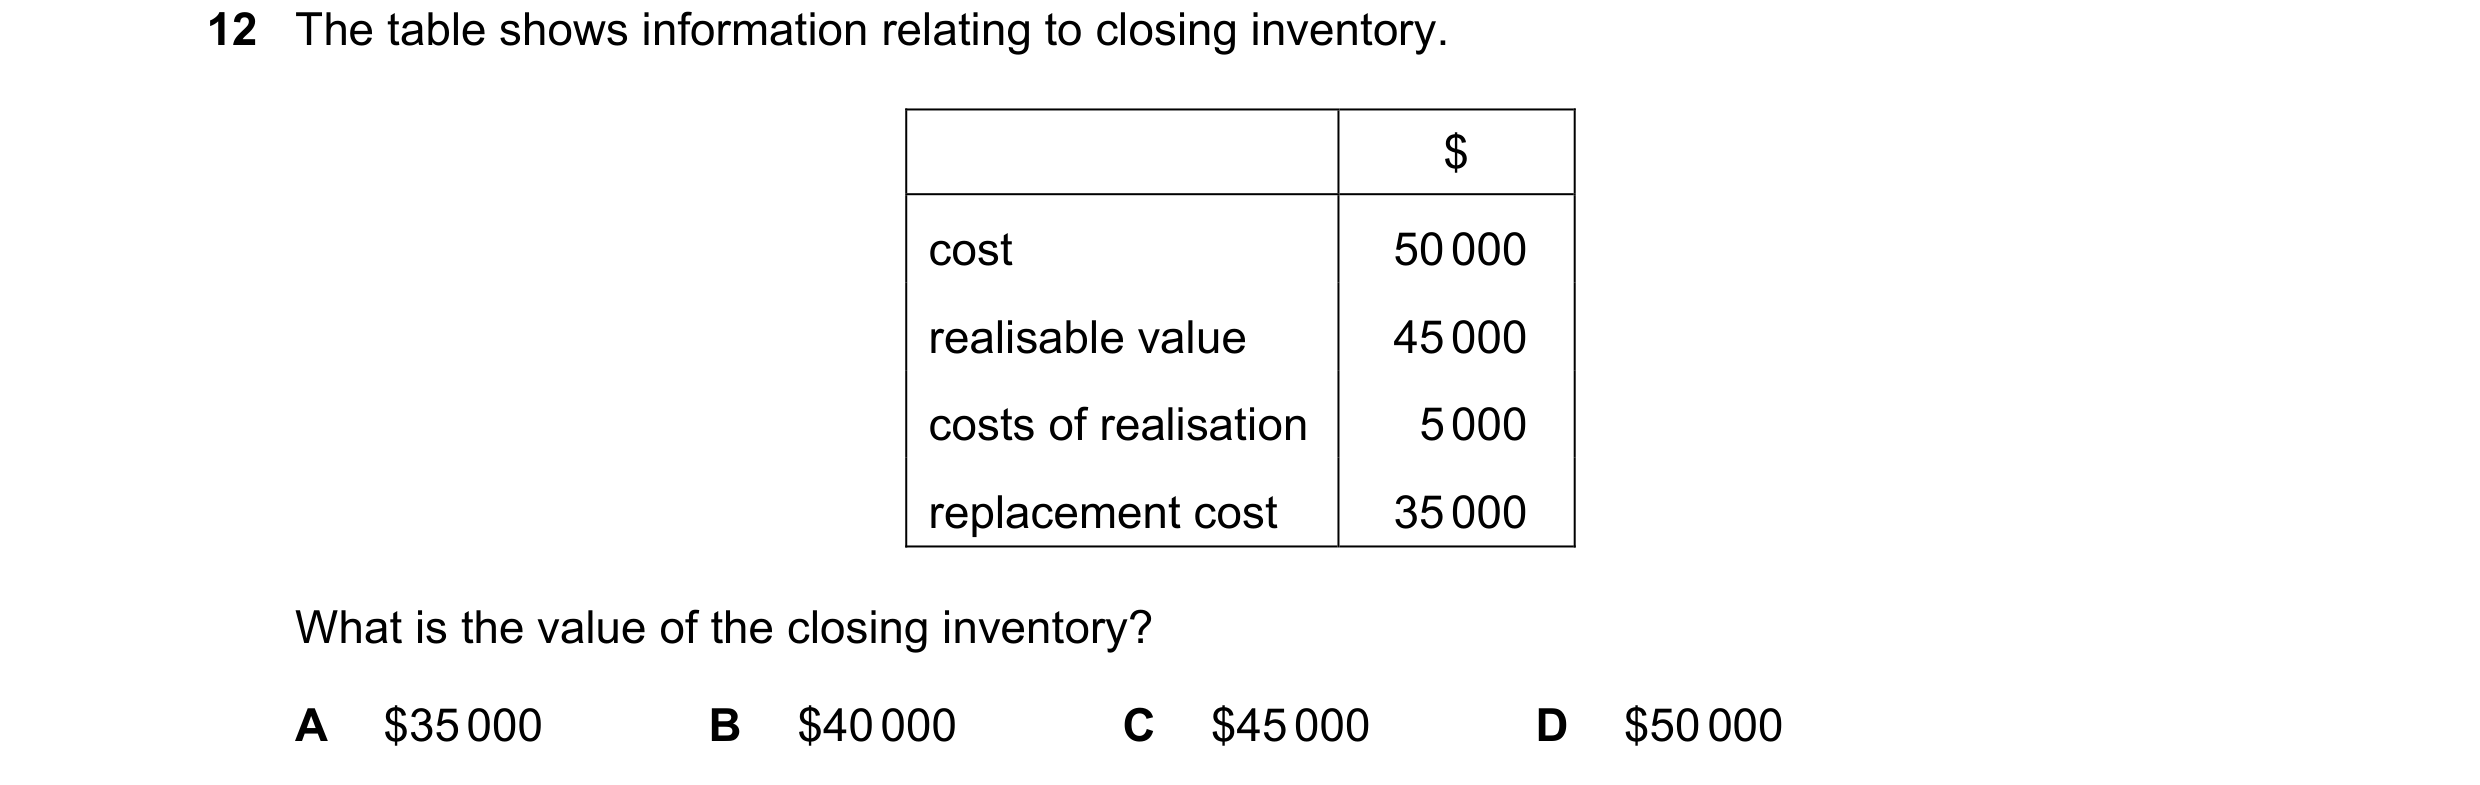 127 / 233
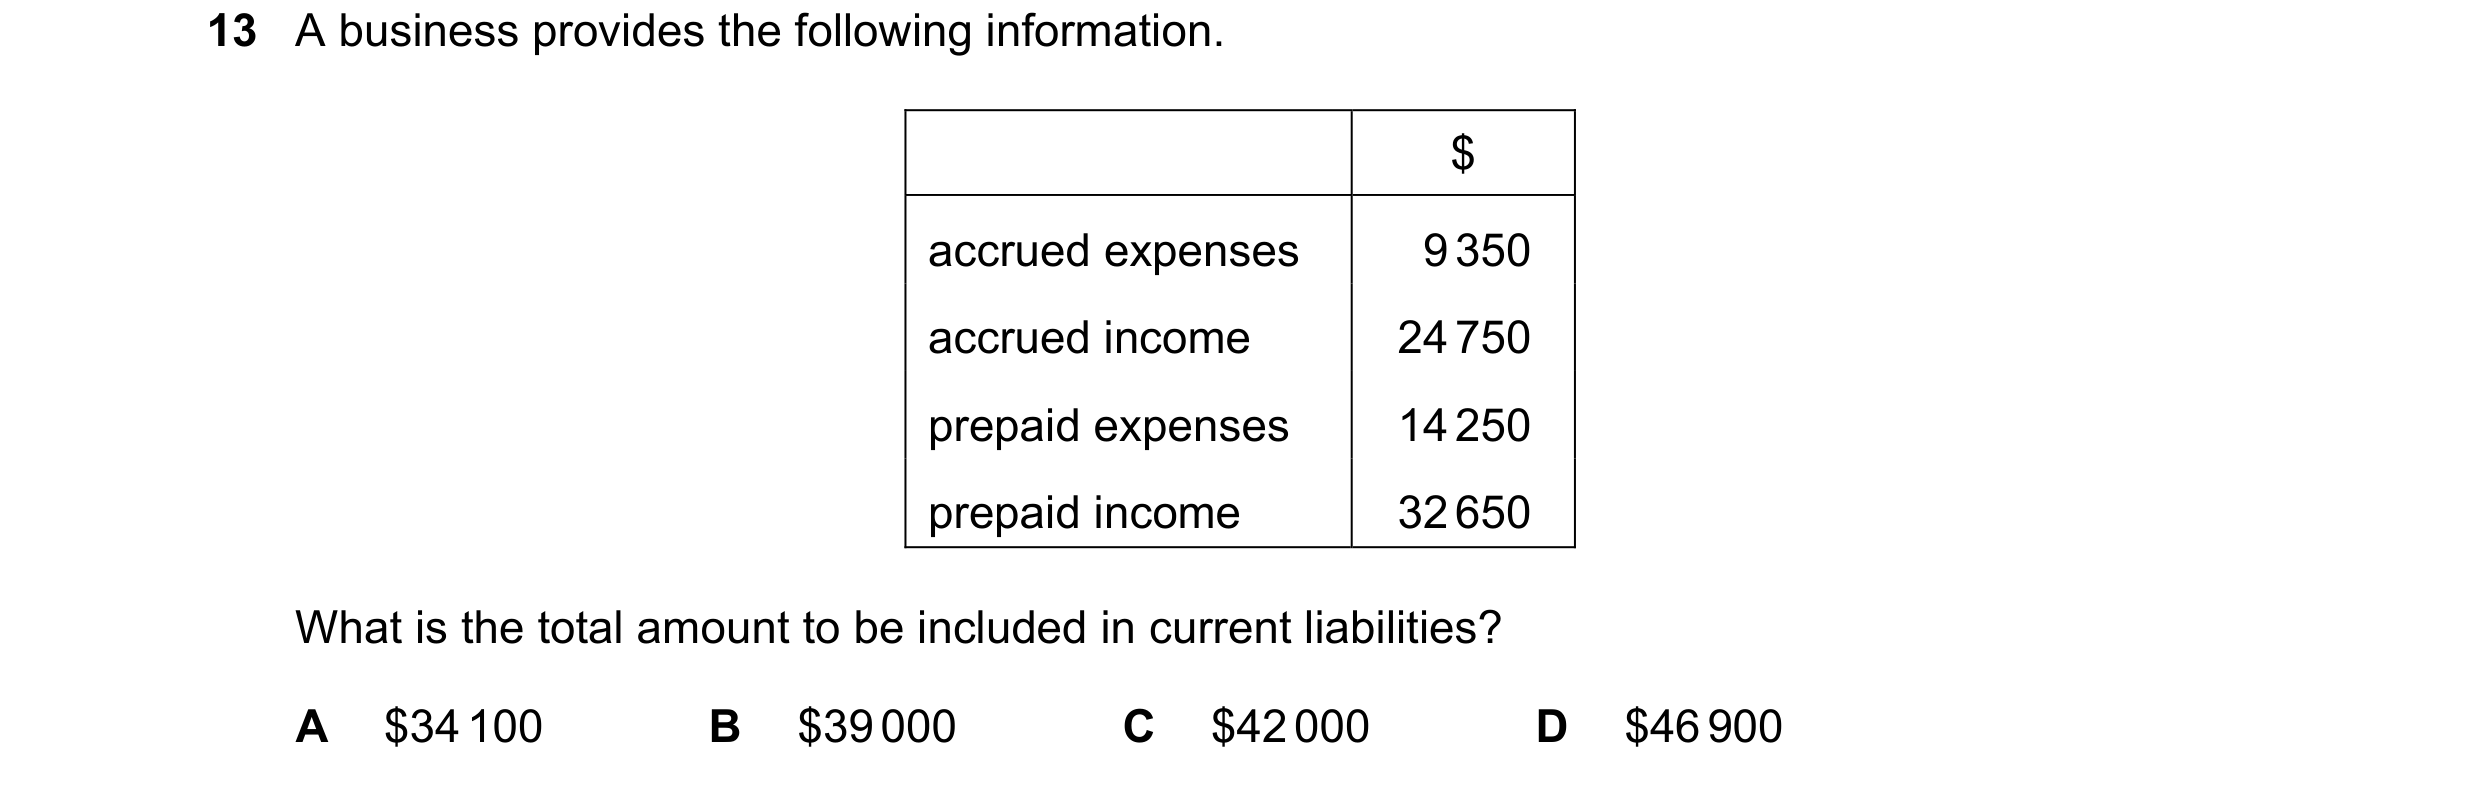
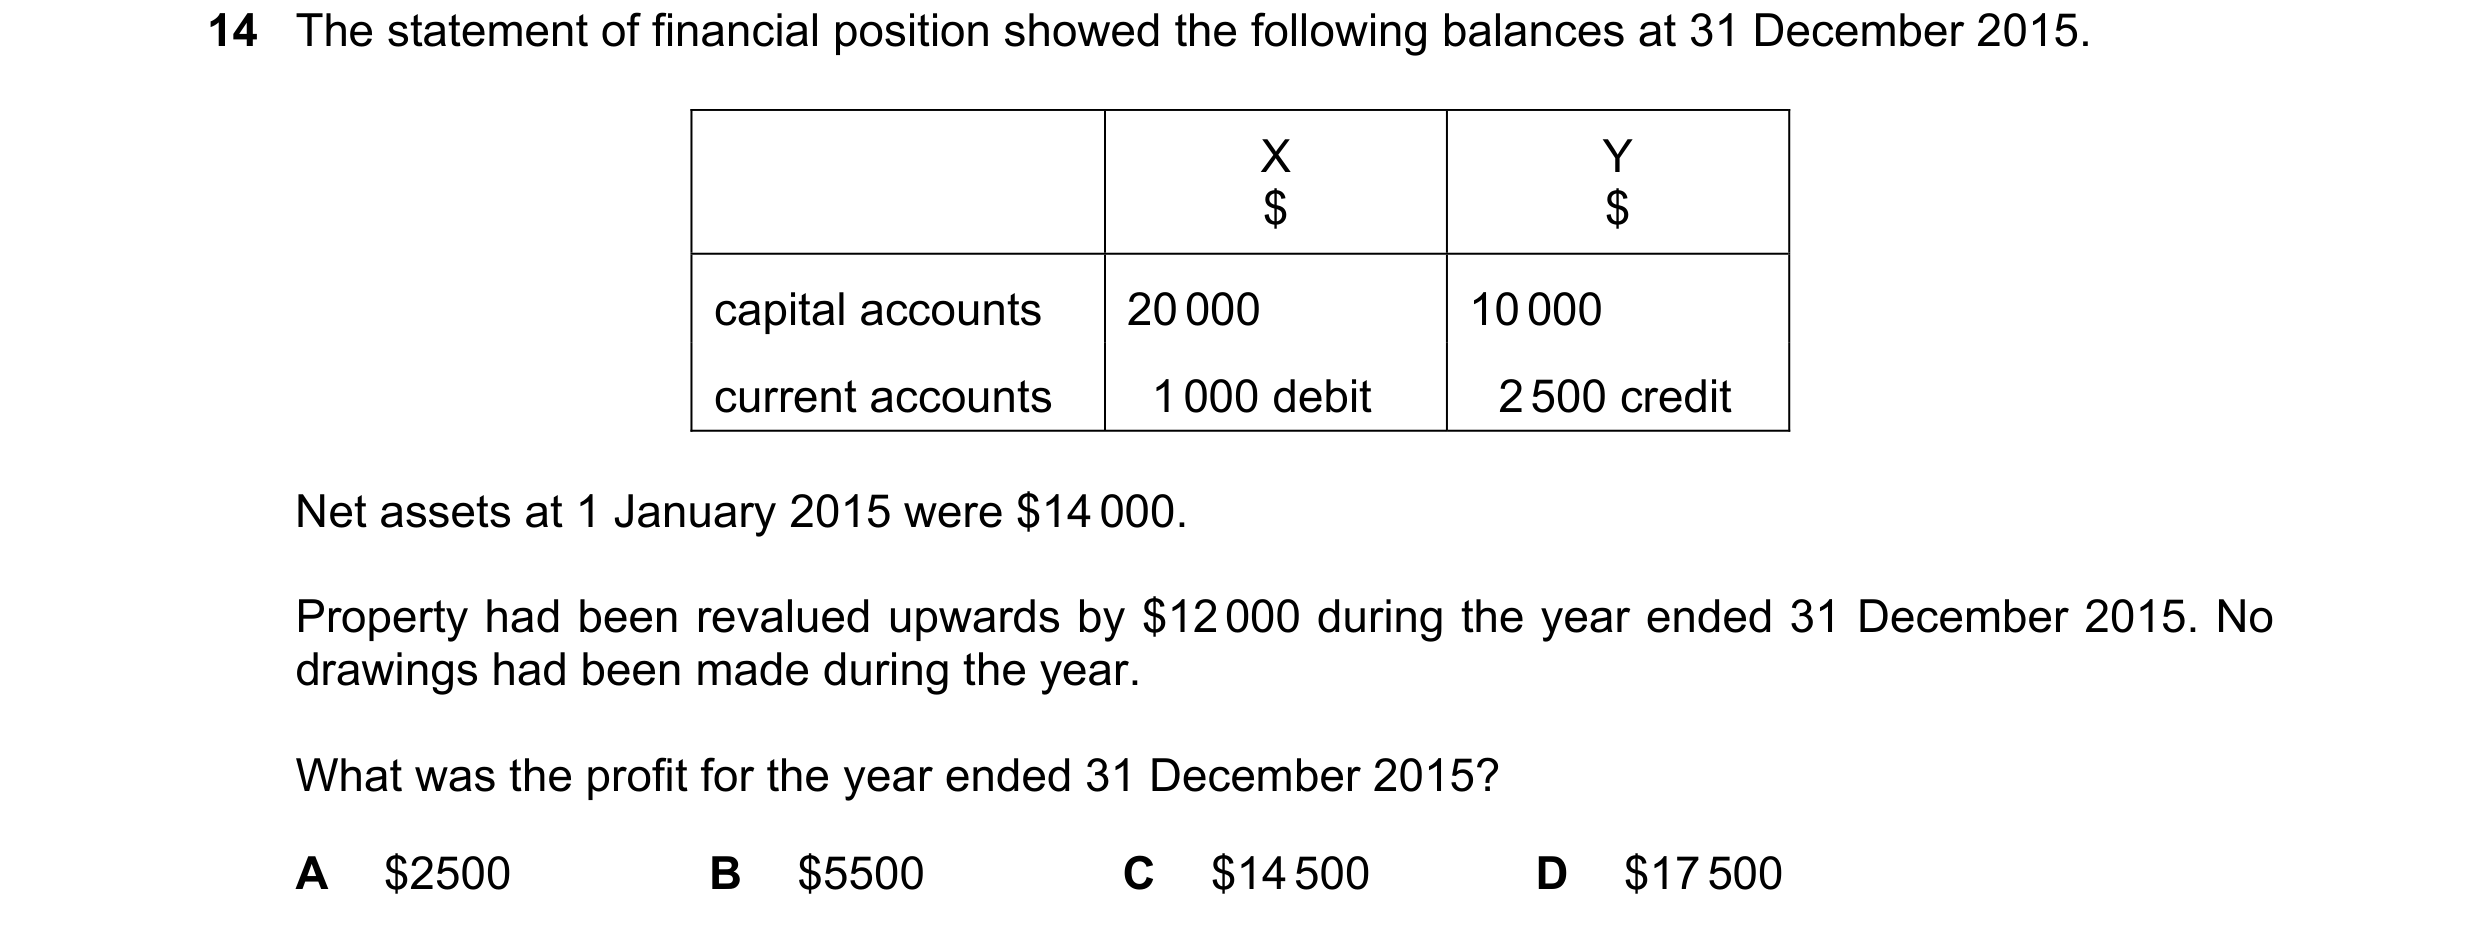
 128 / 233
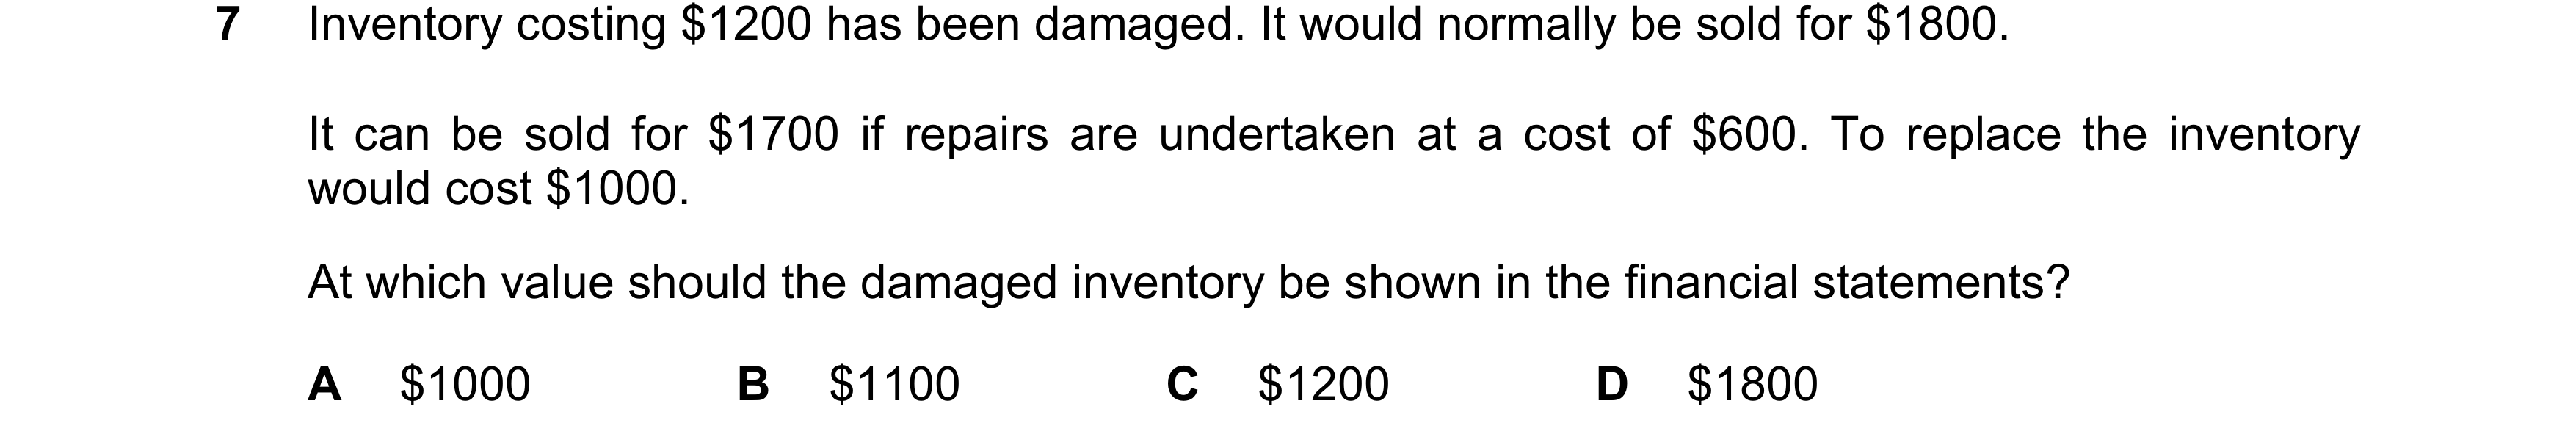
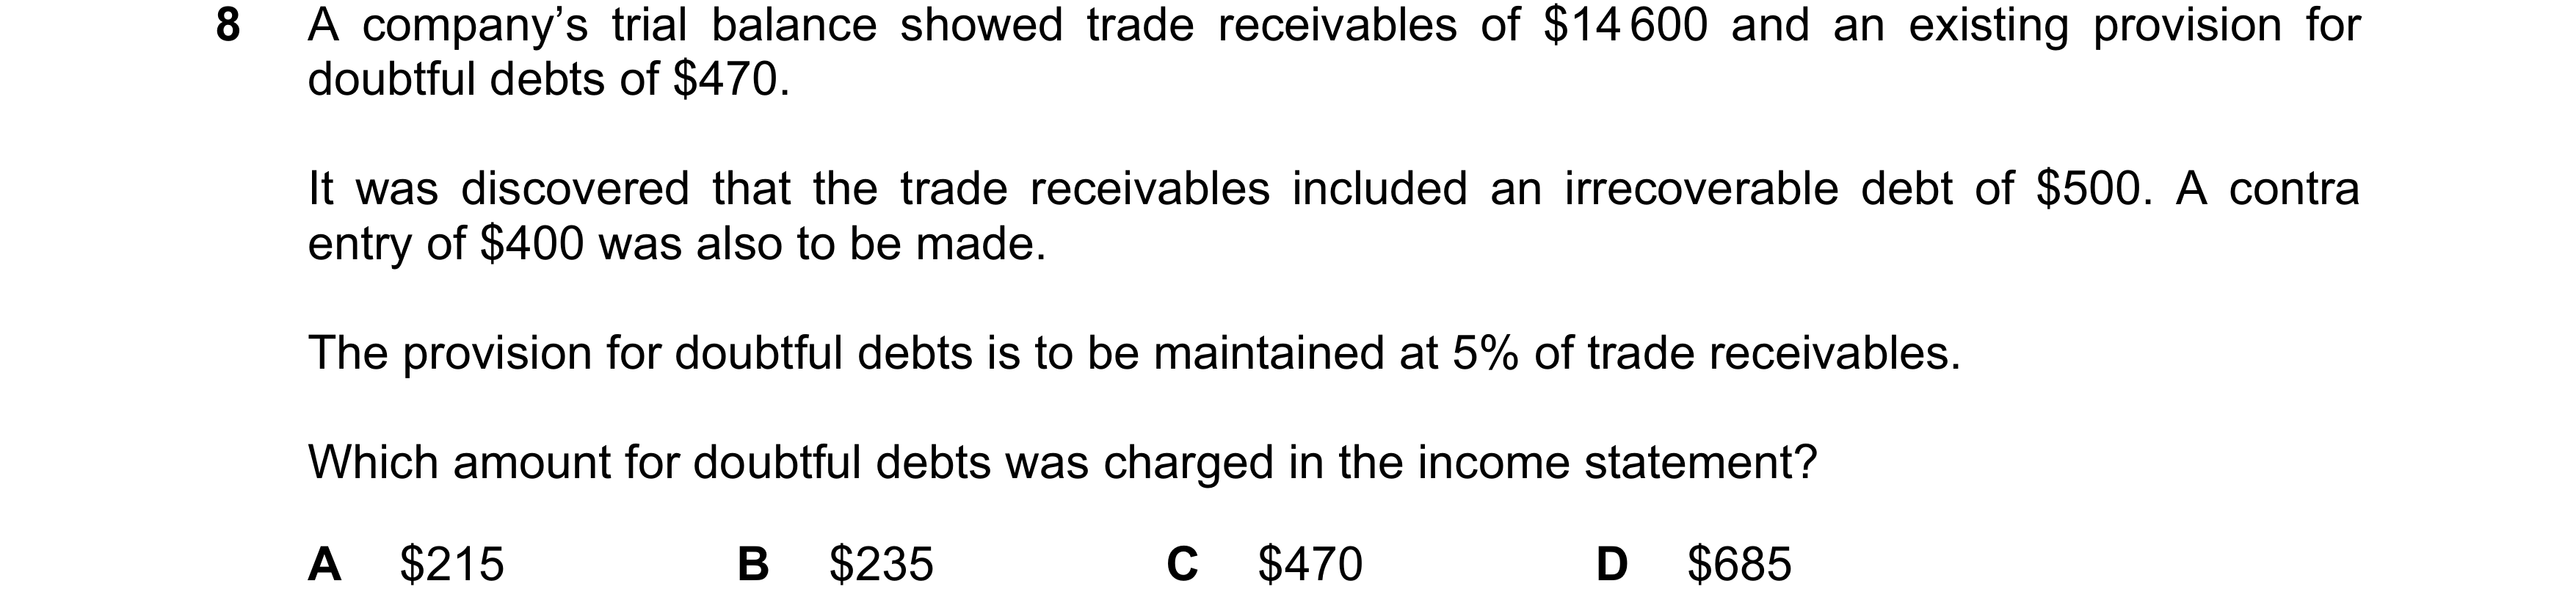
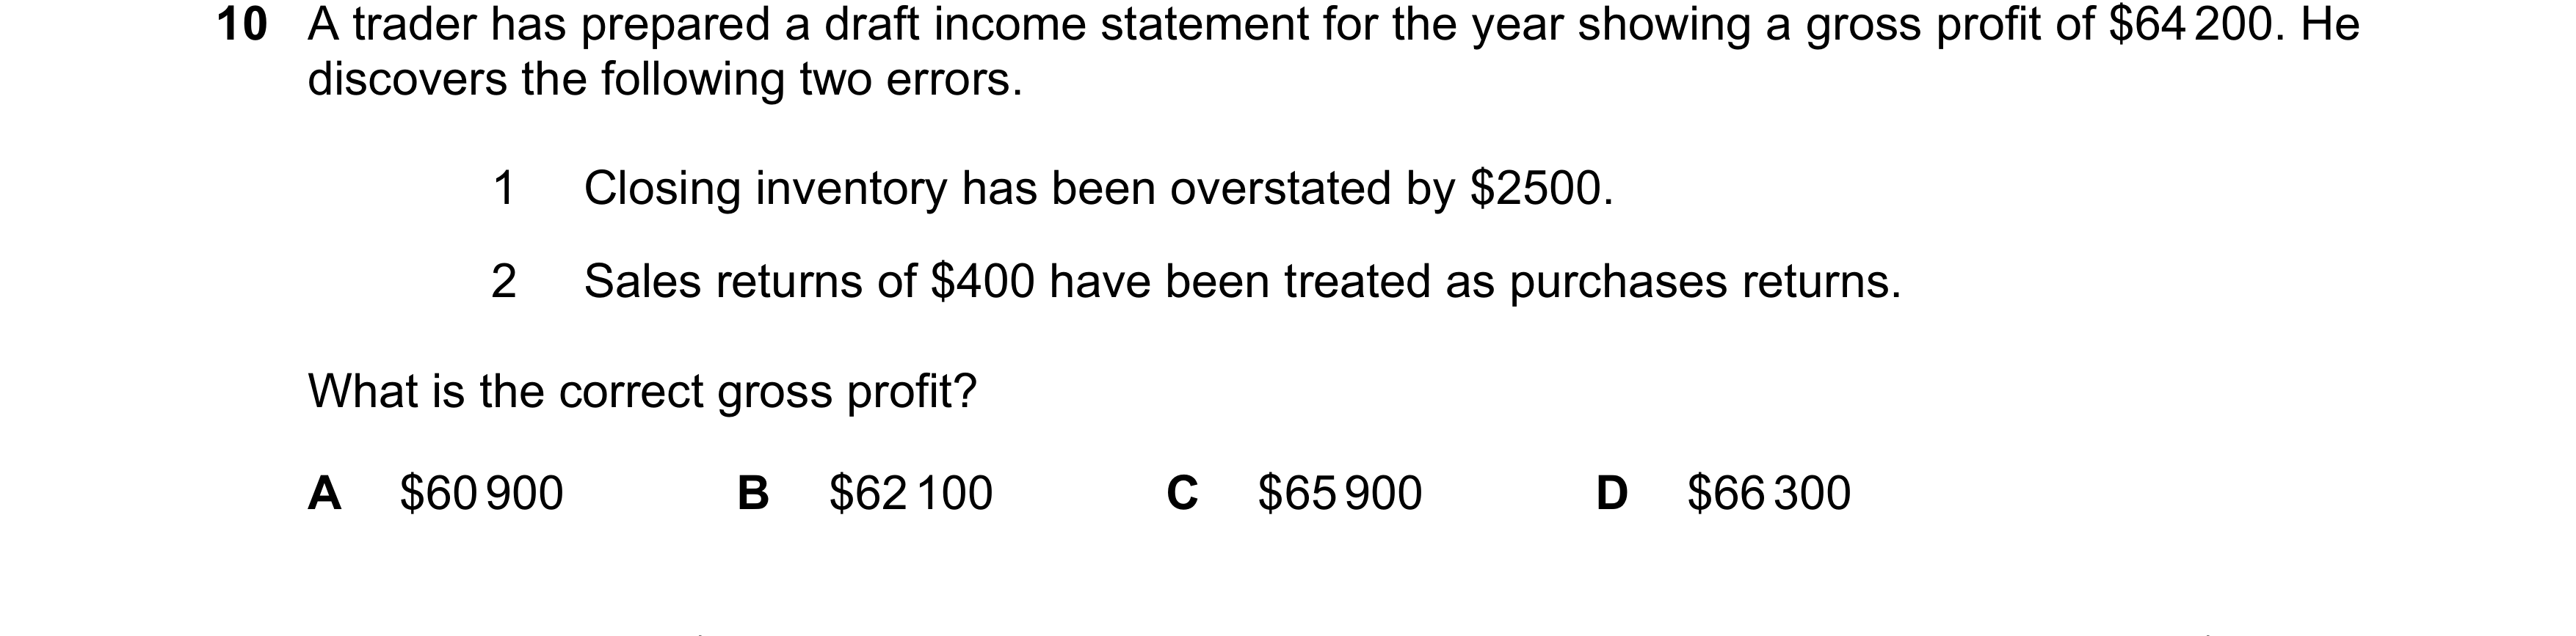 129 / 233
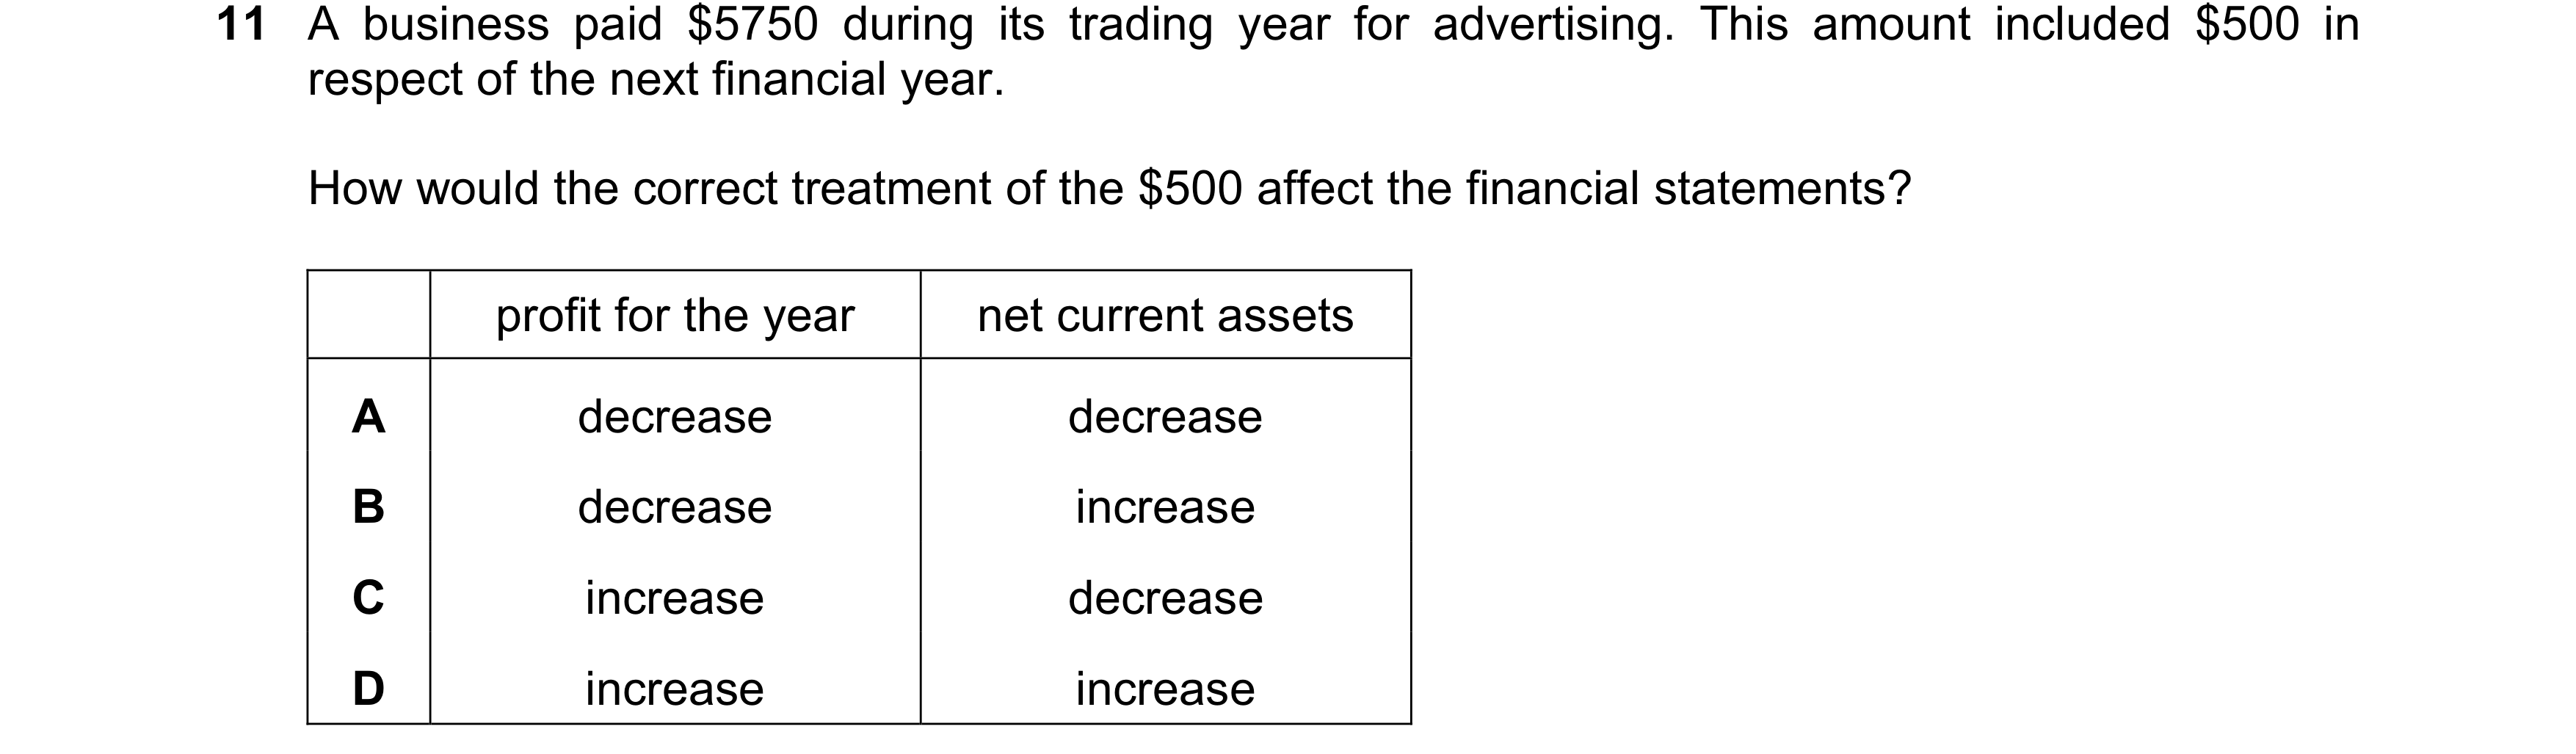
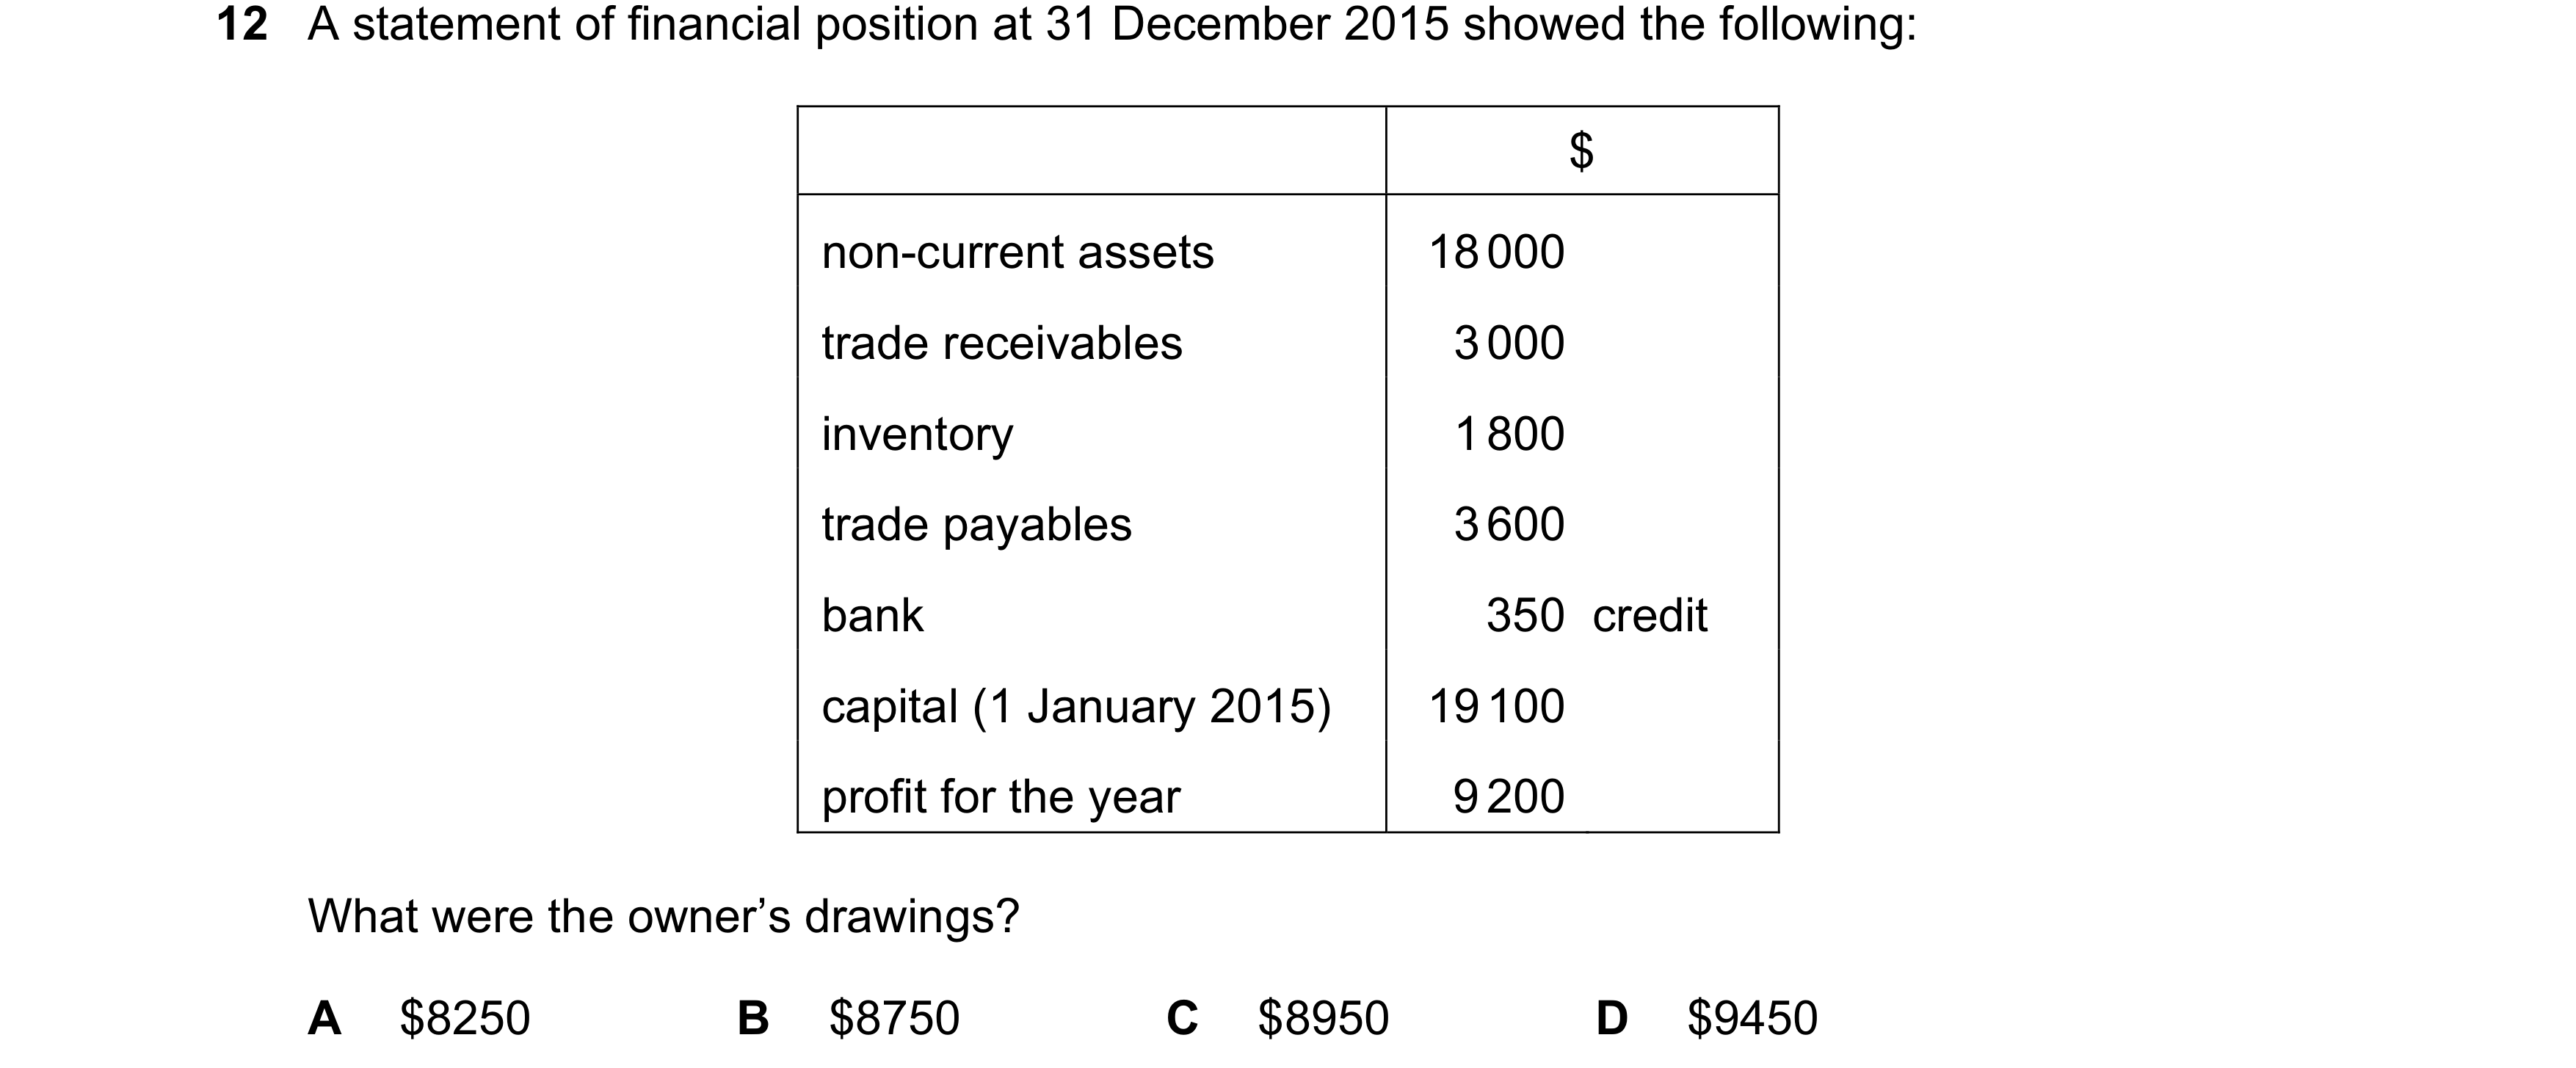
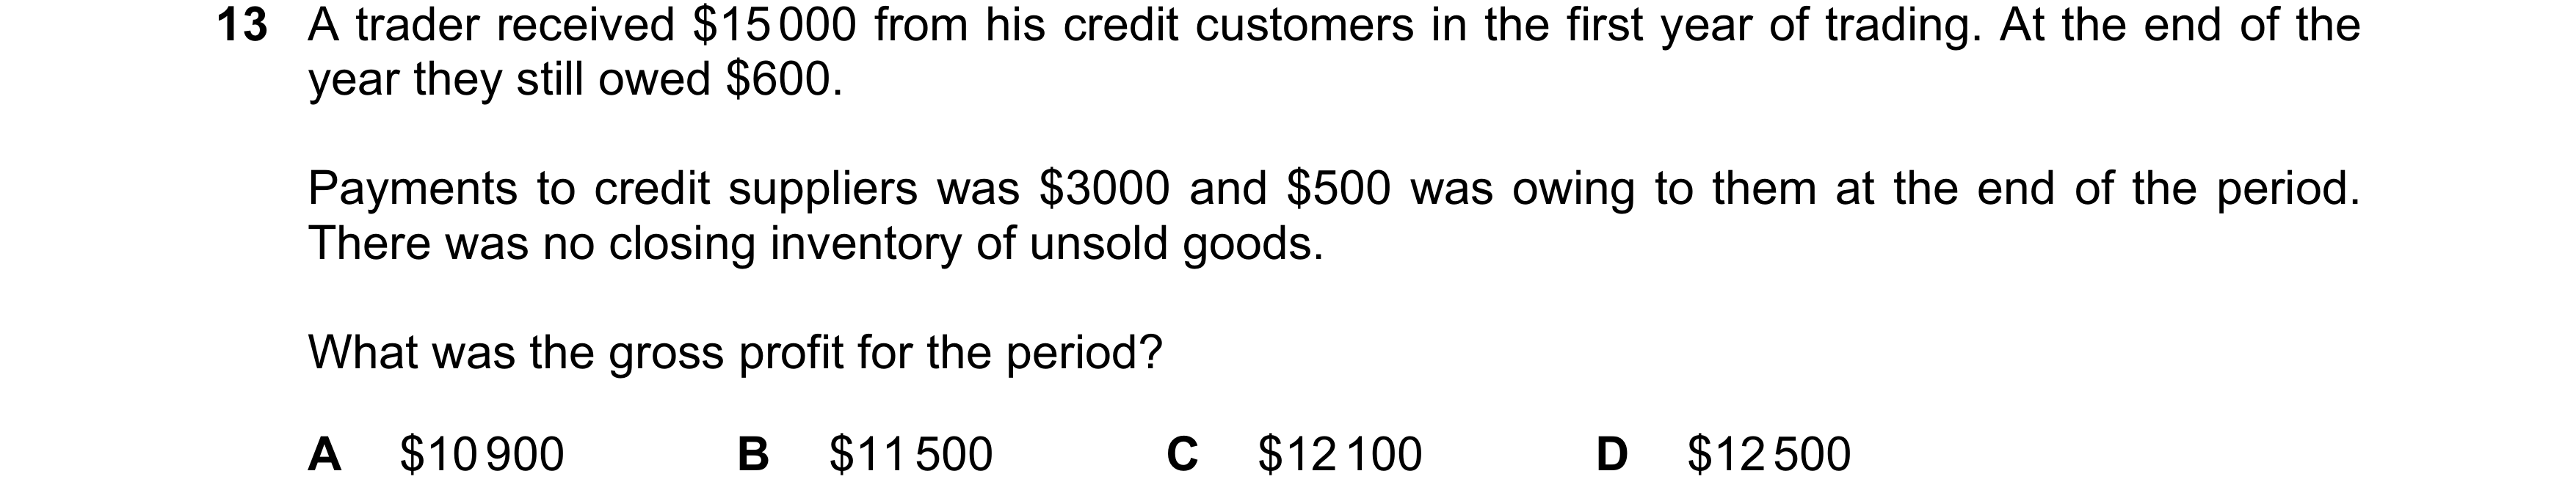 130 / 233
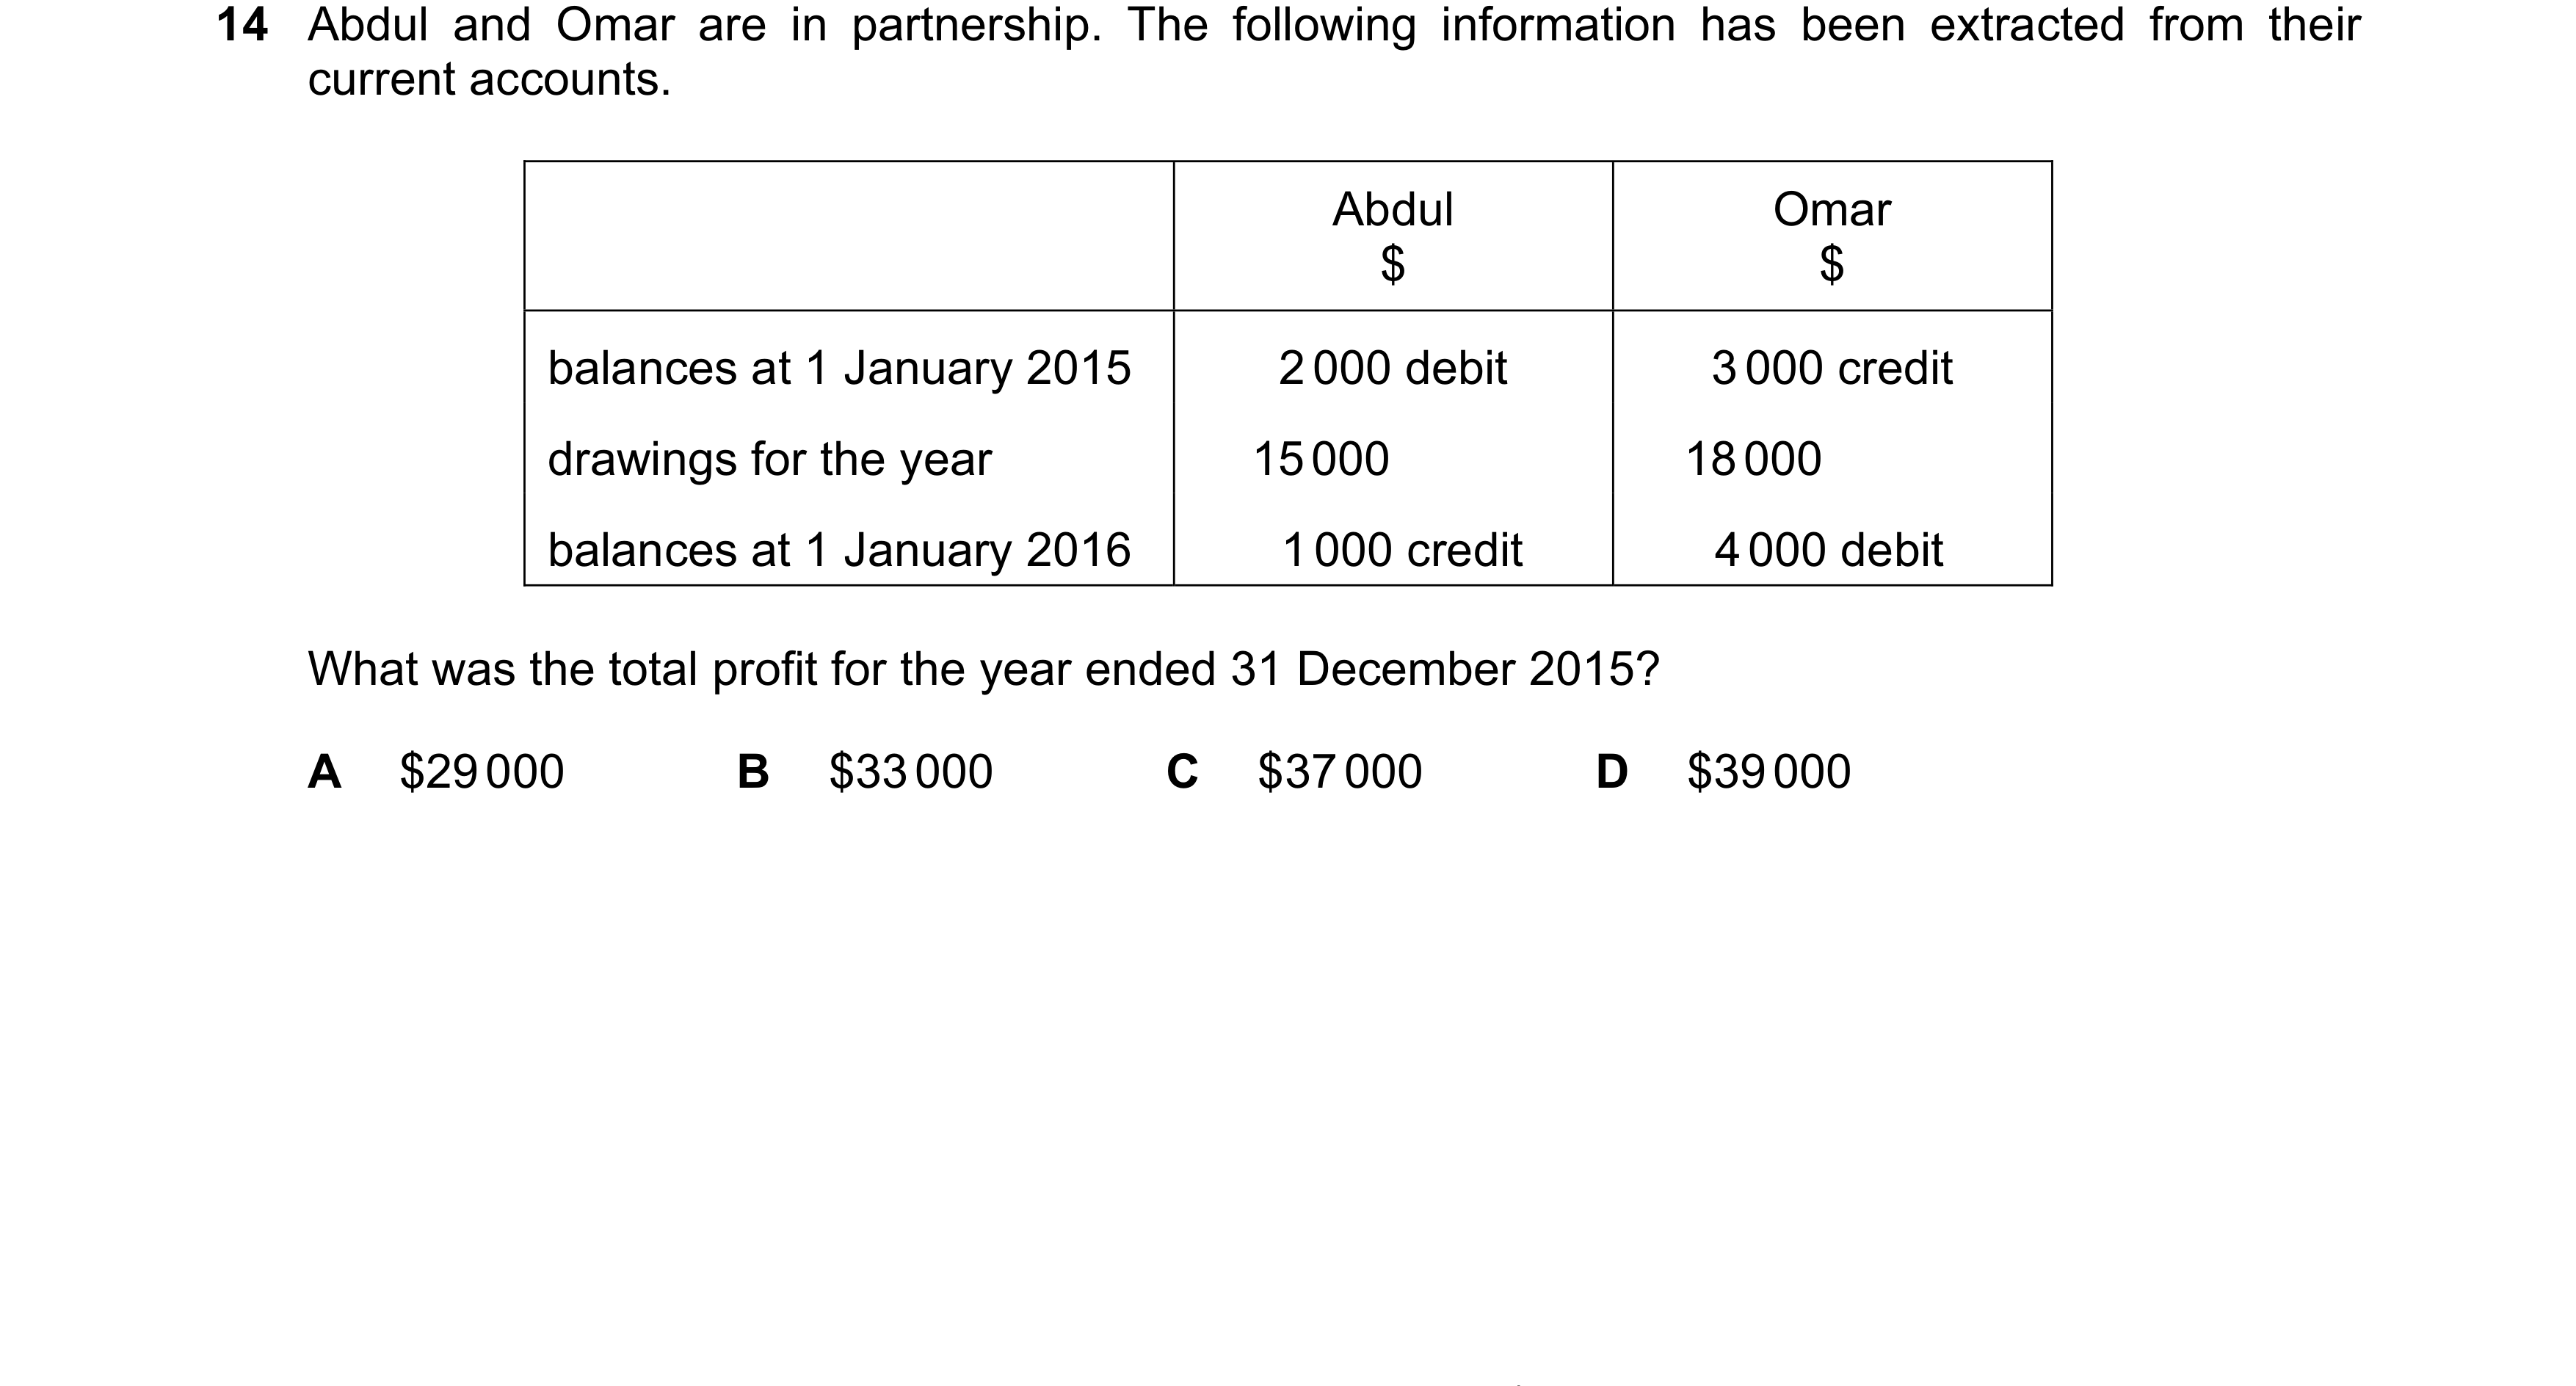
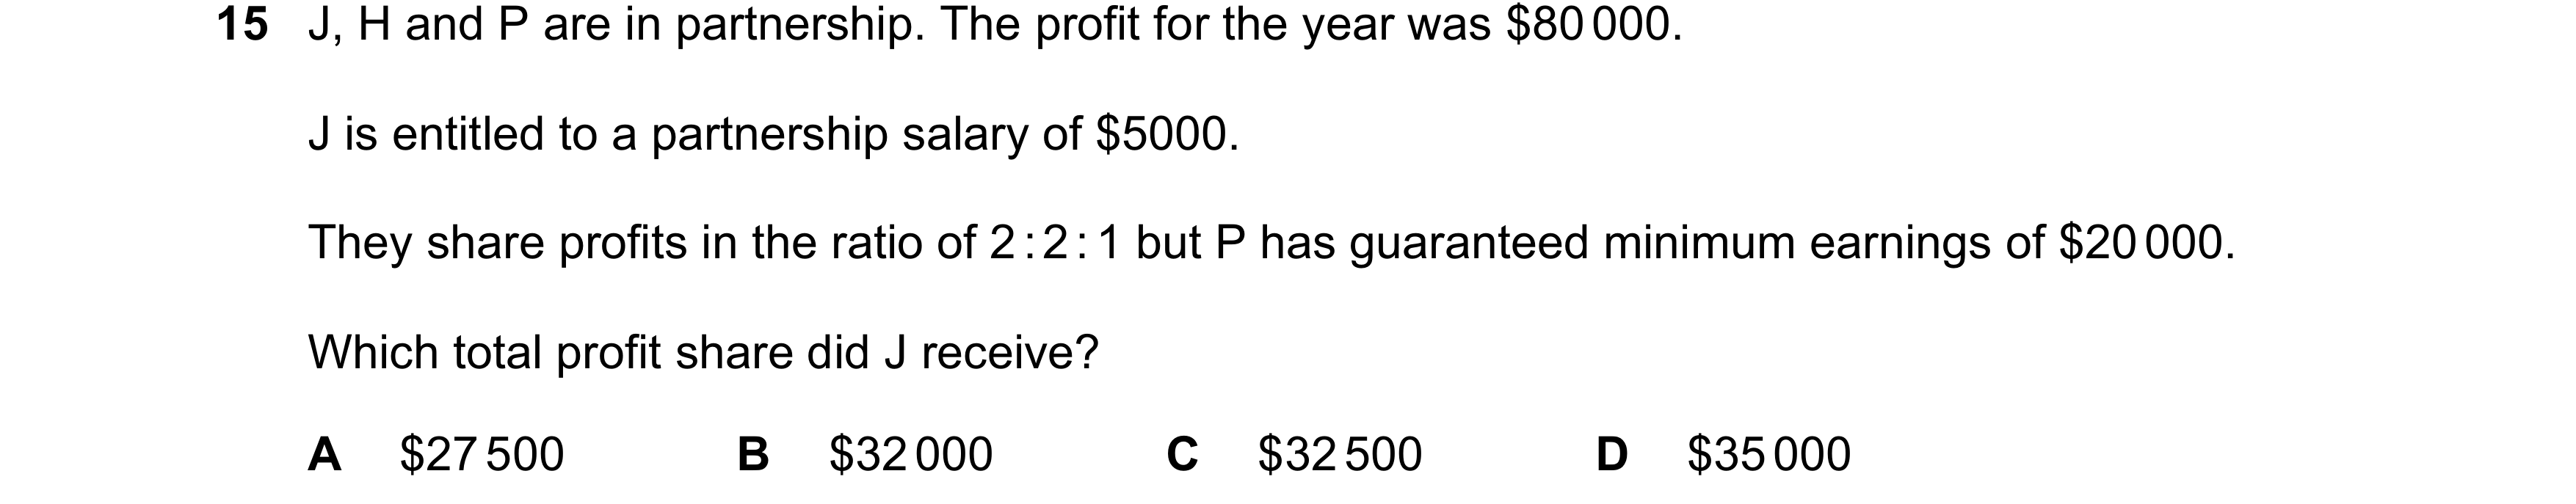
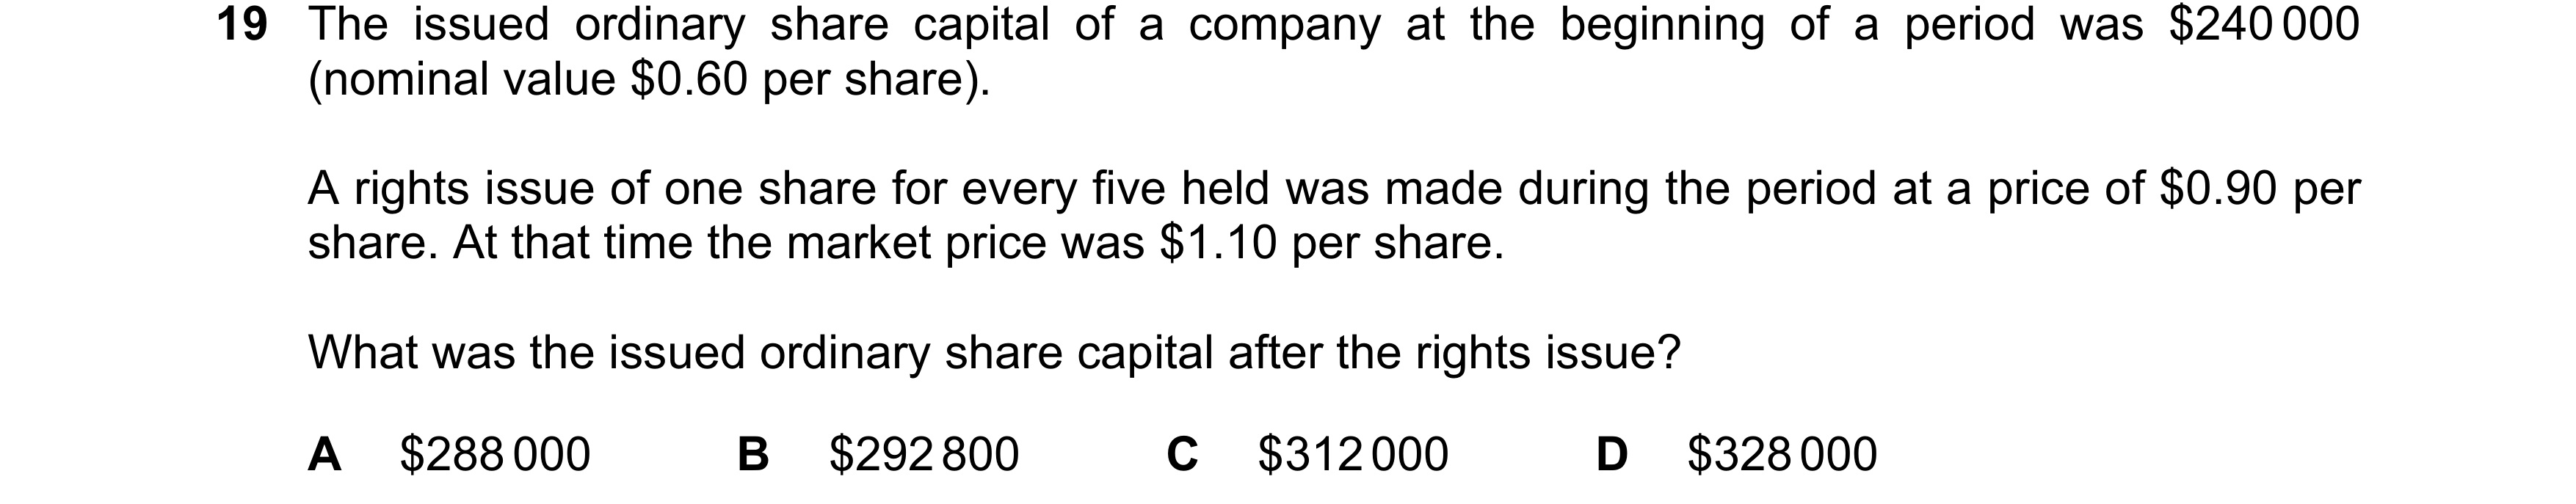
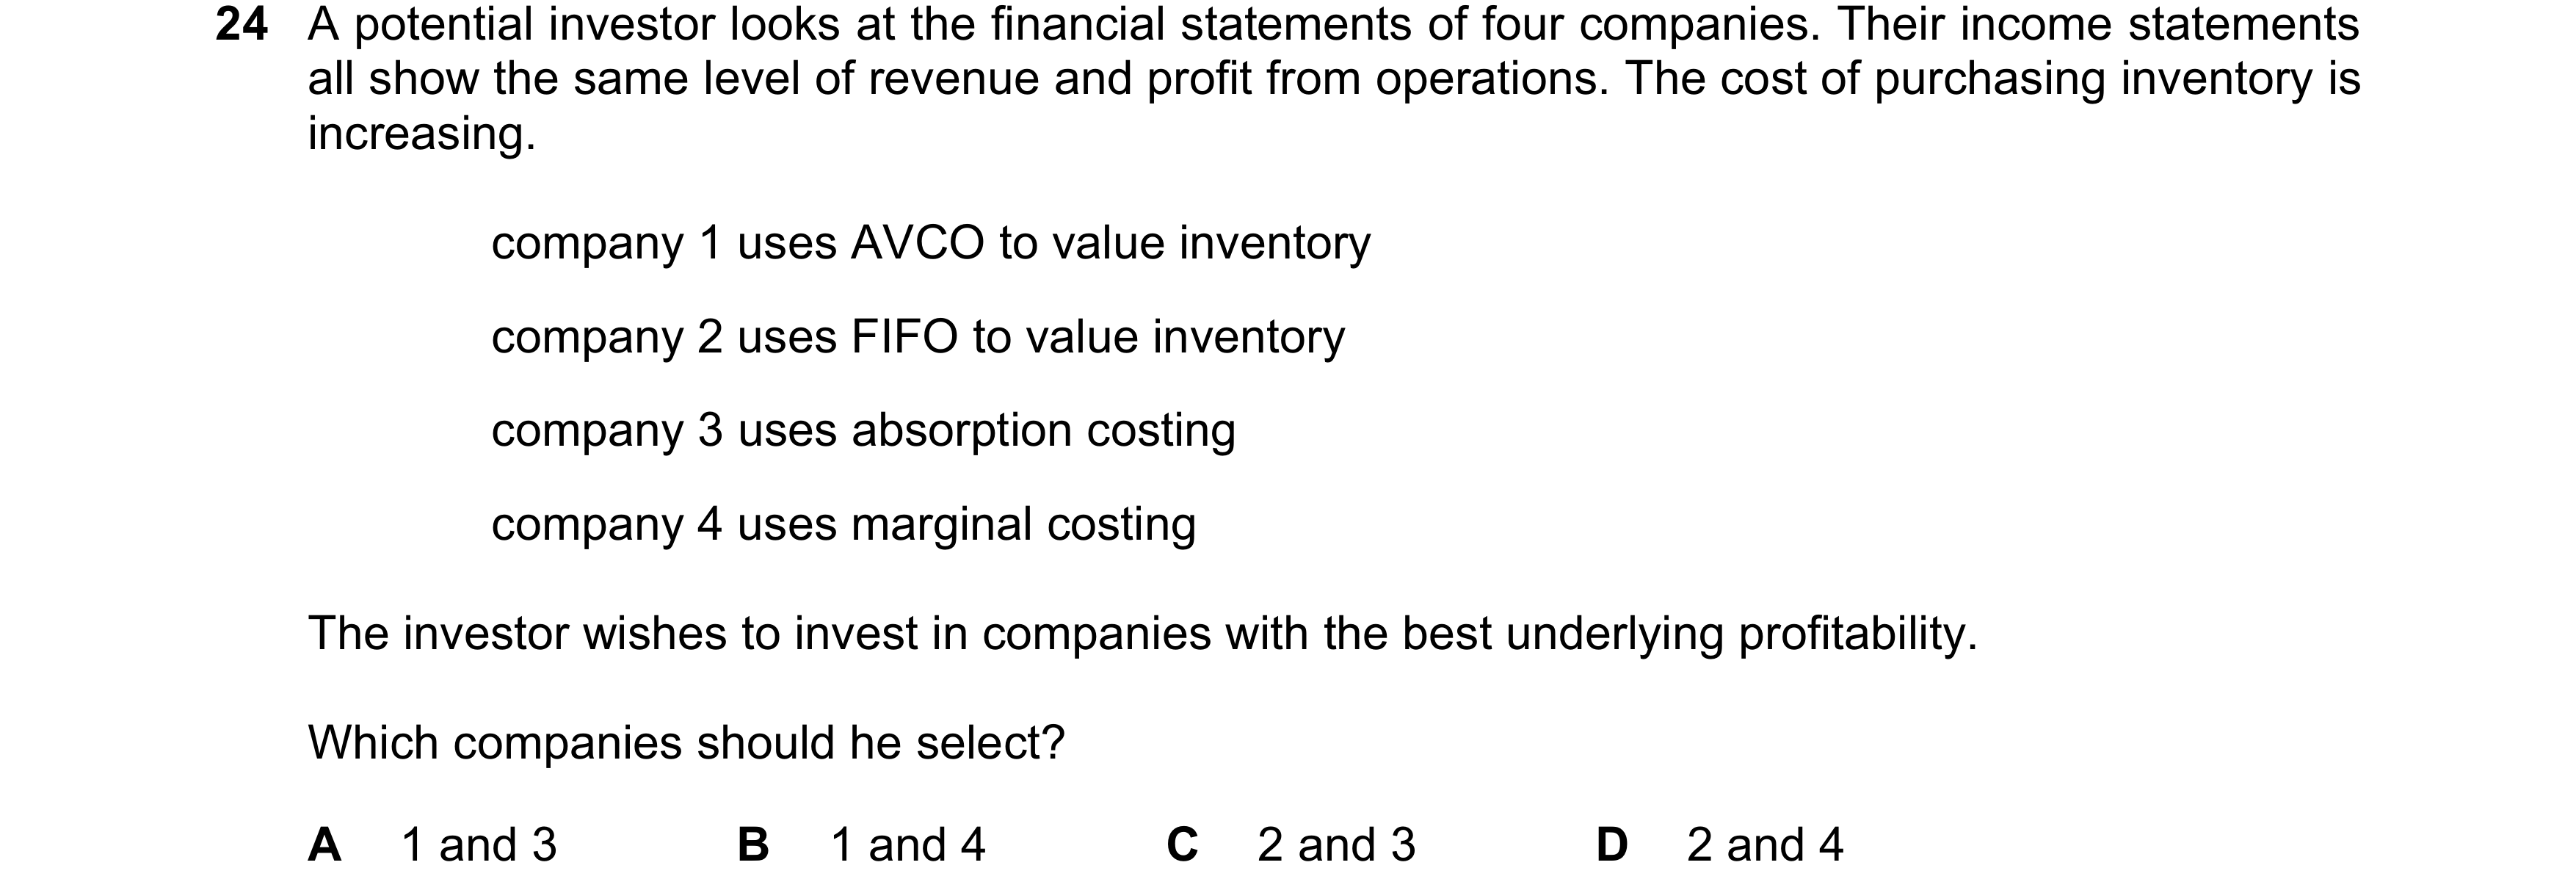 131 / 233
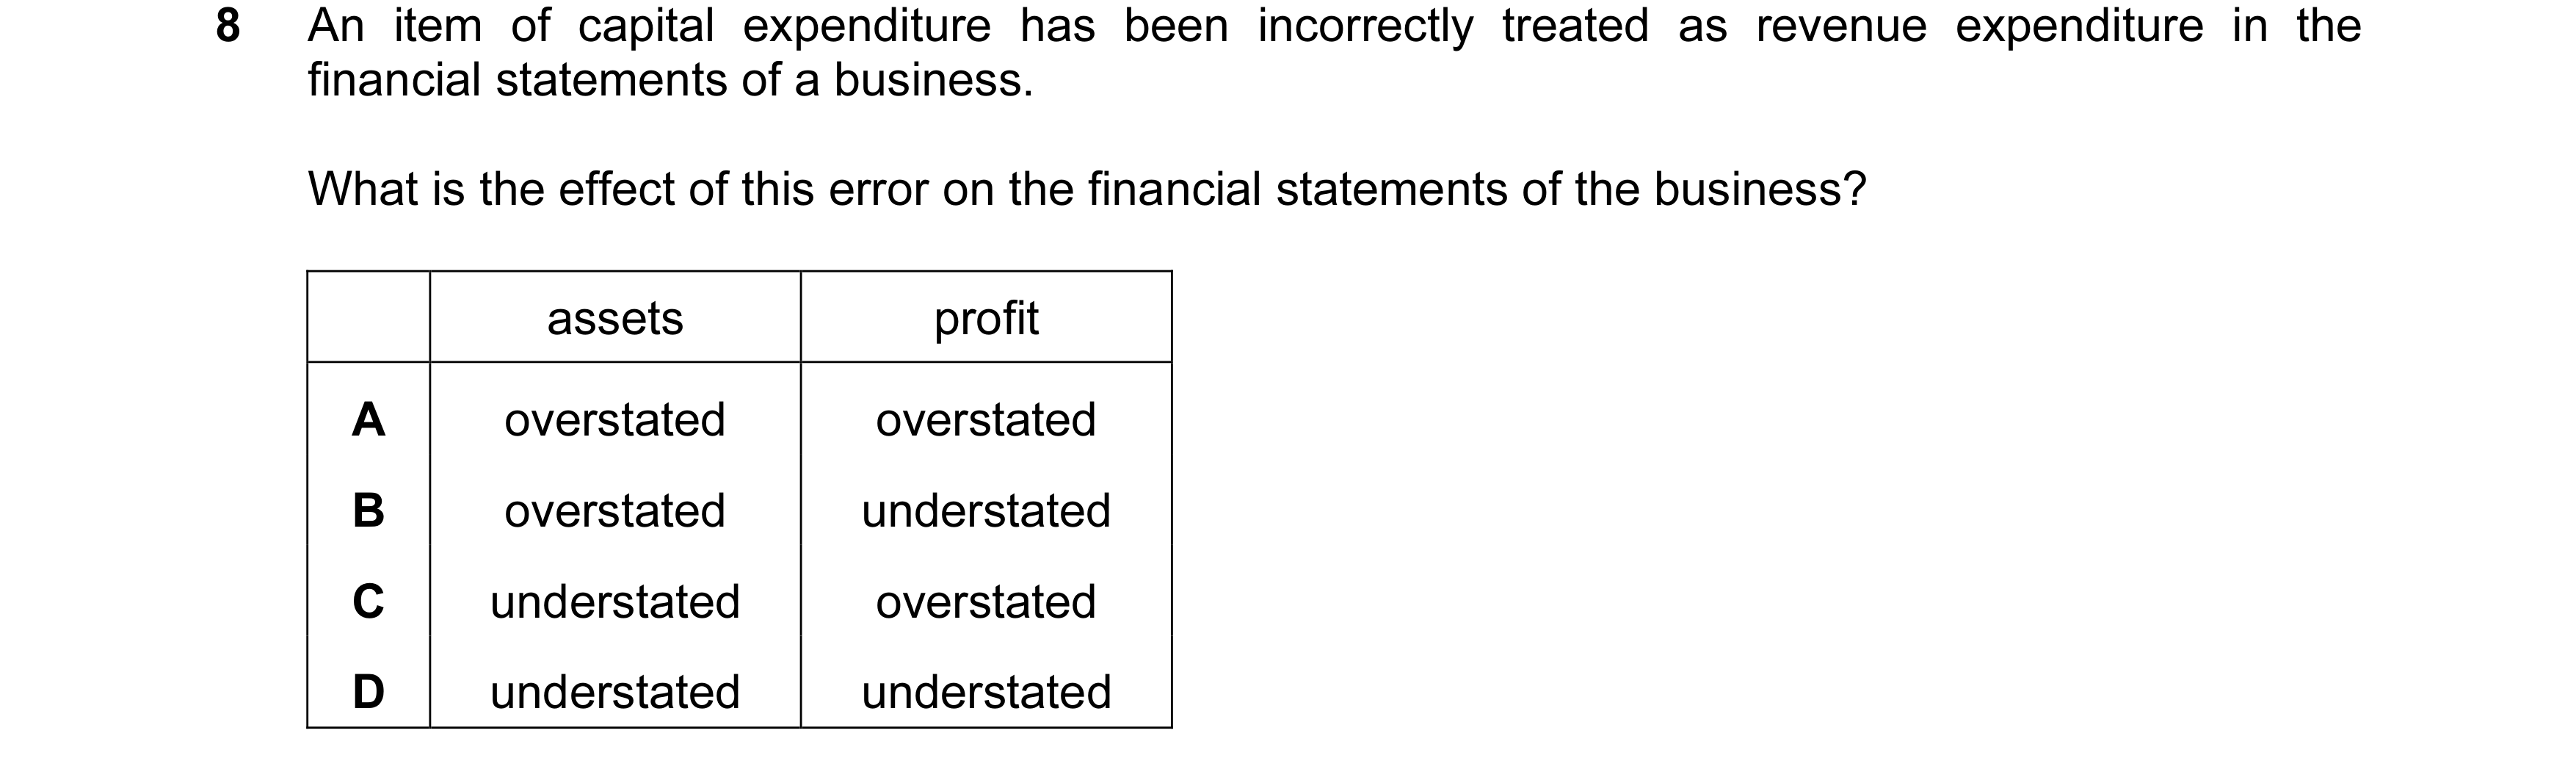
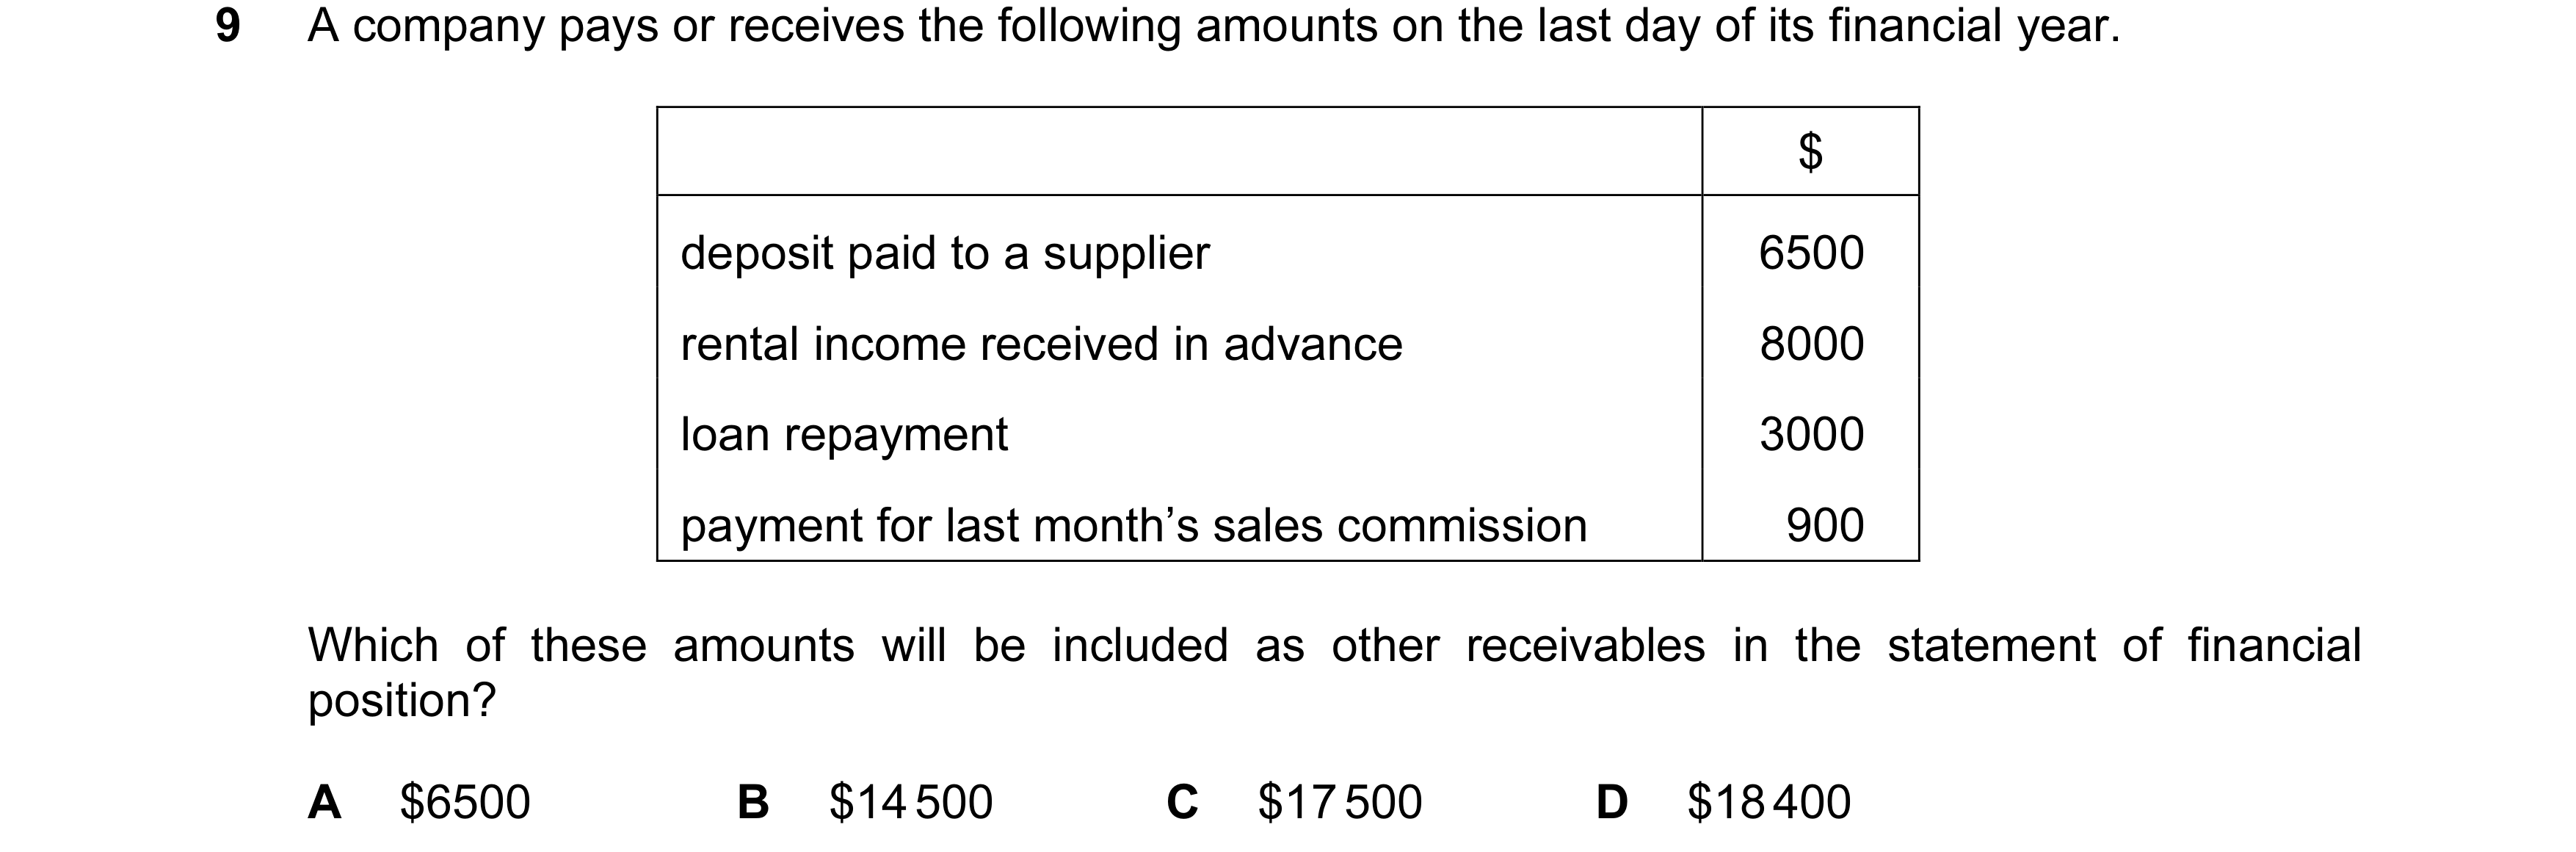
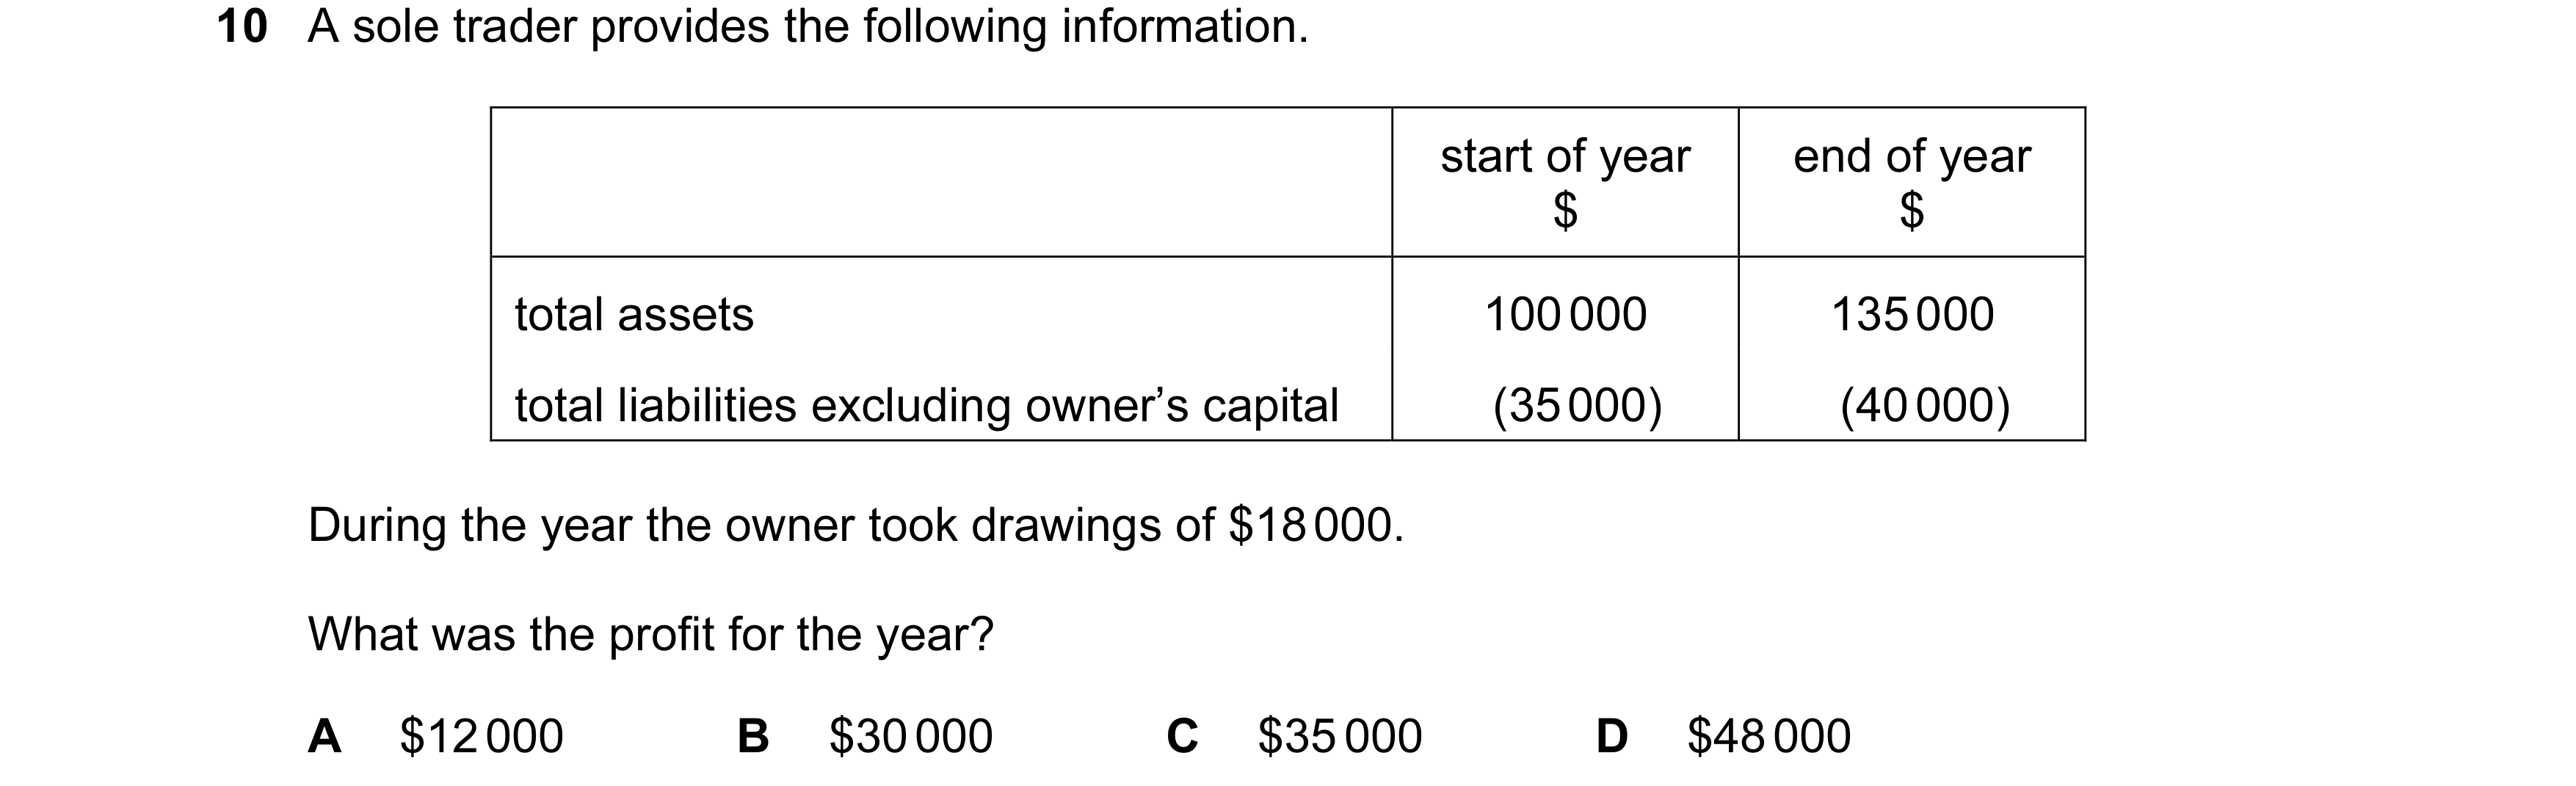
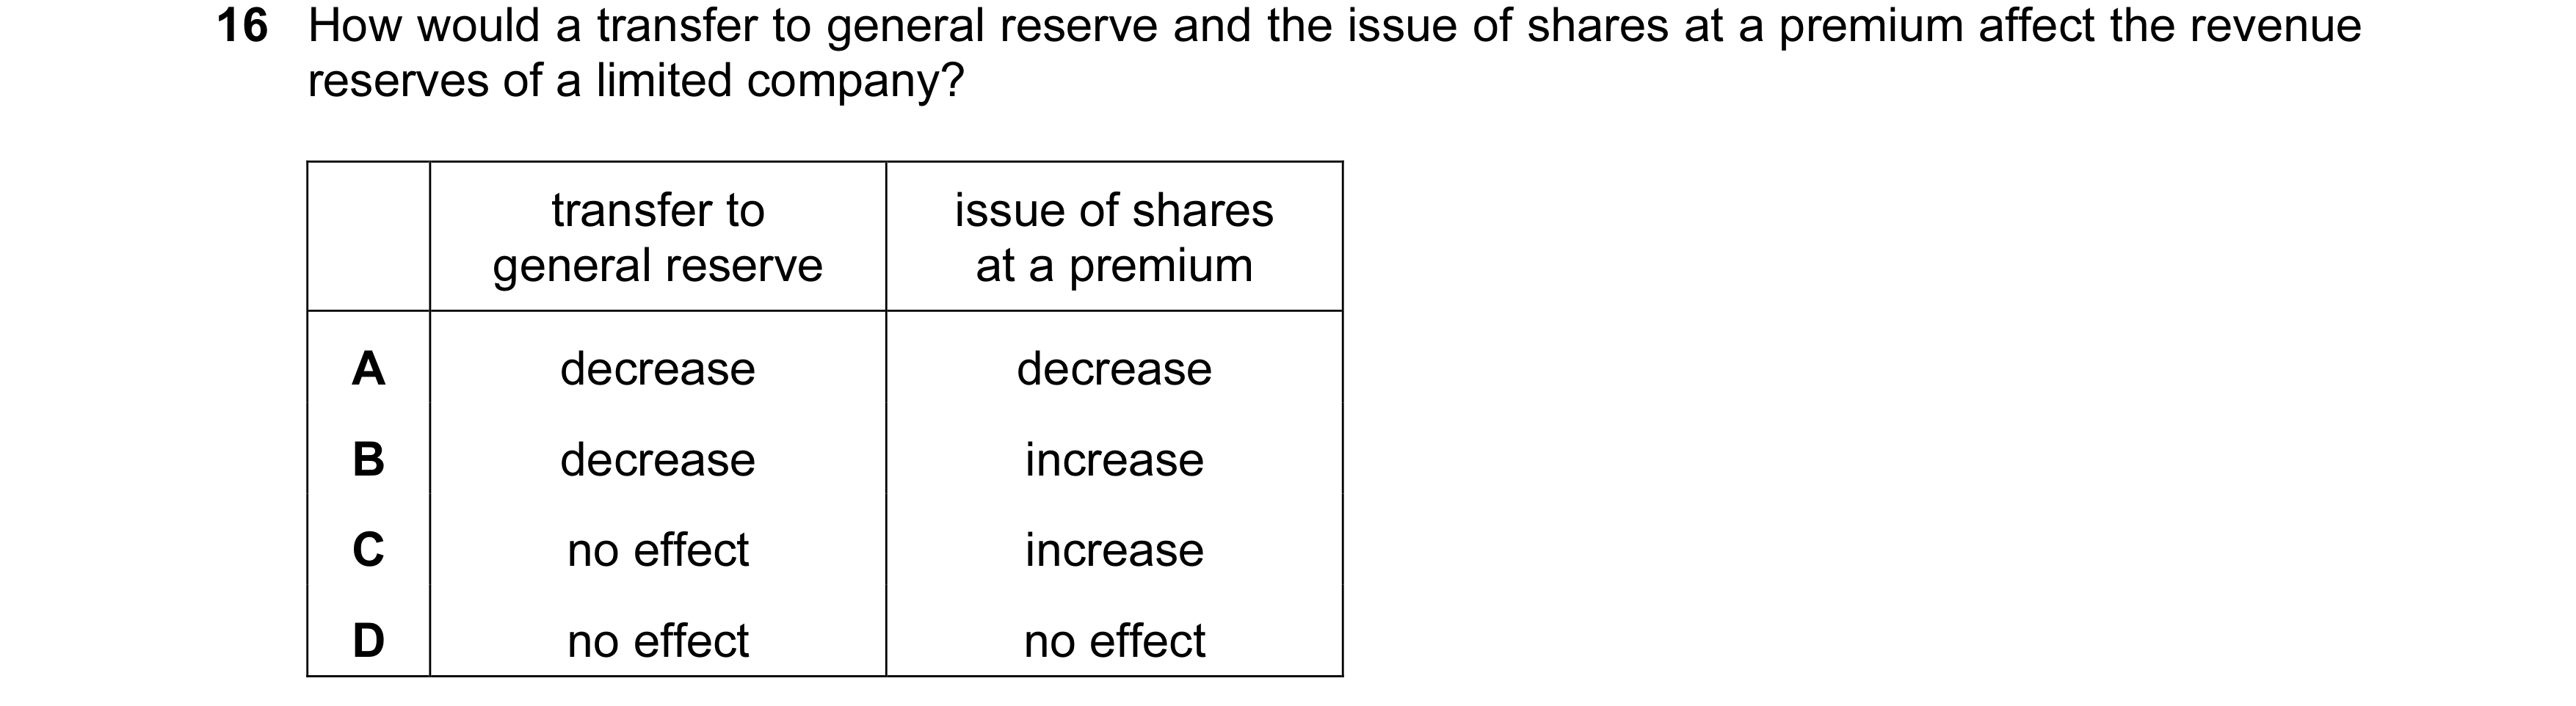 132 / 233
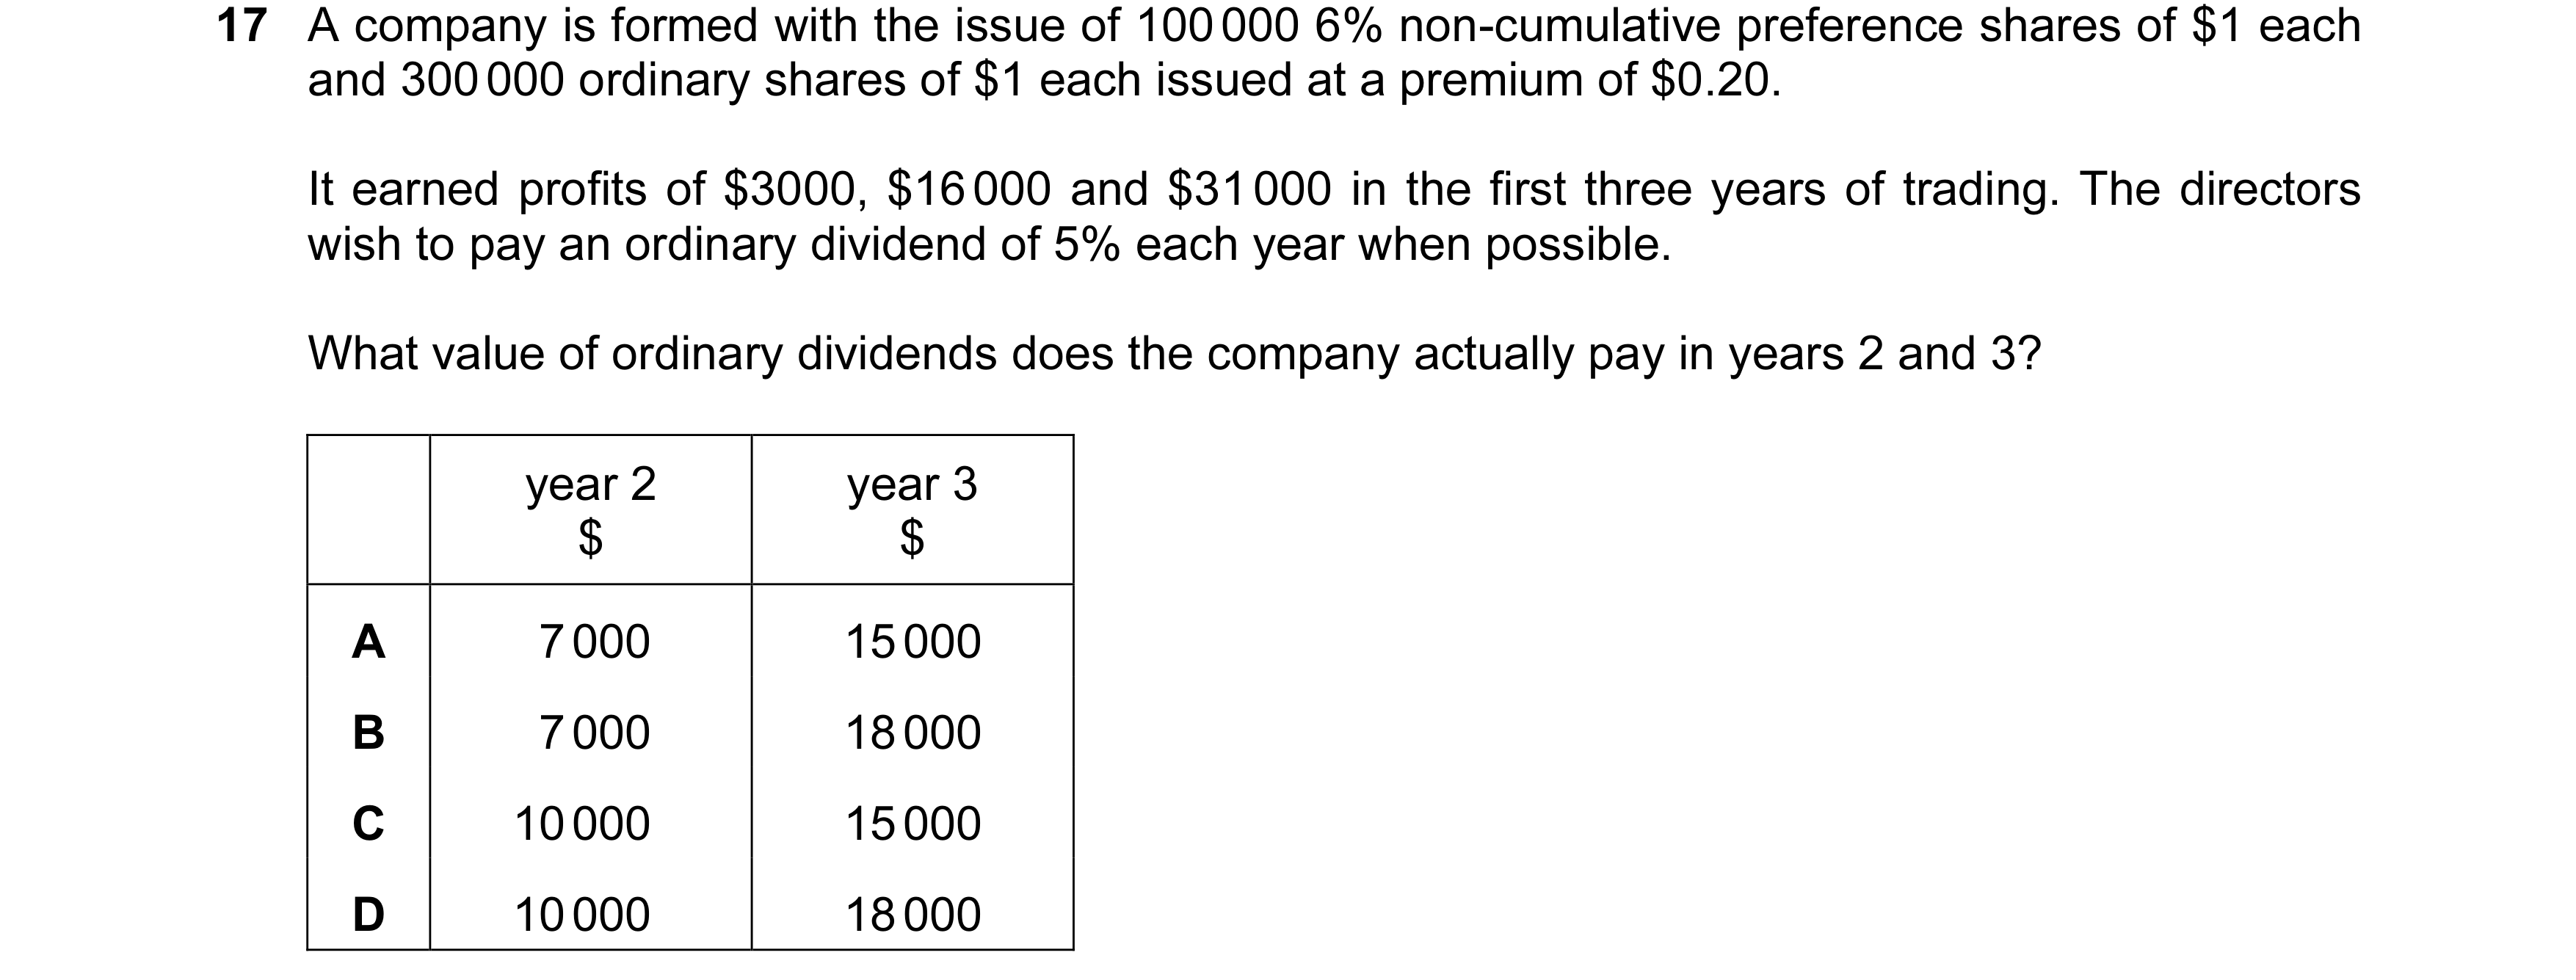
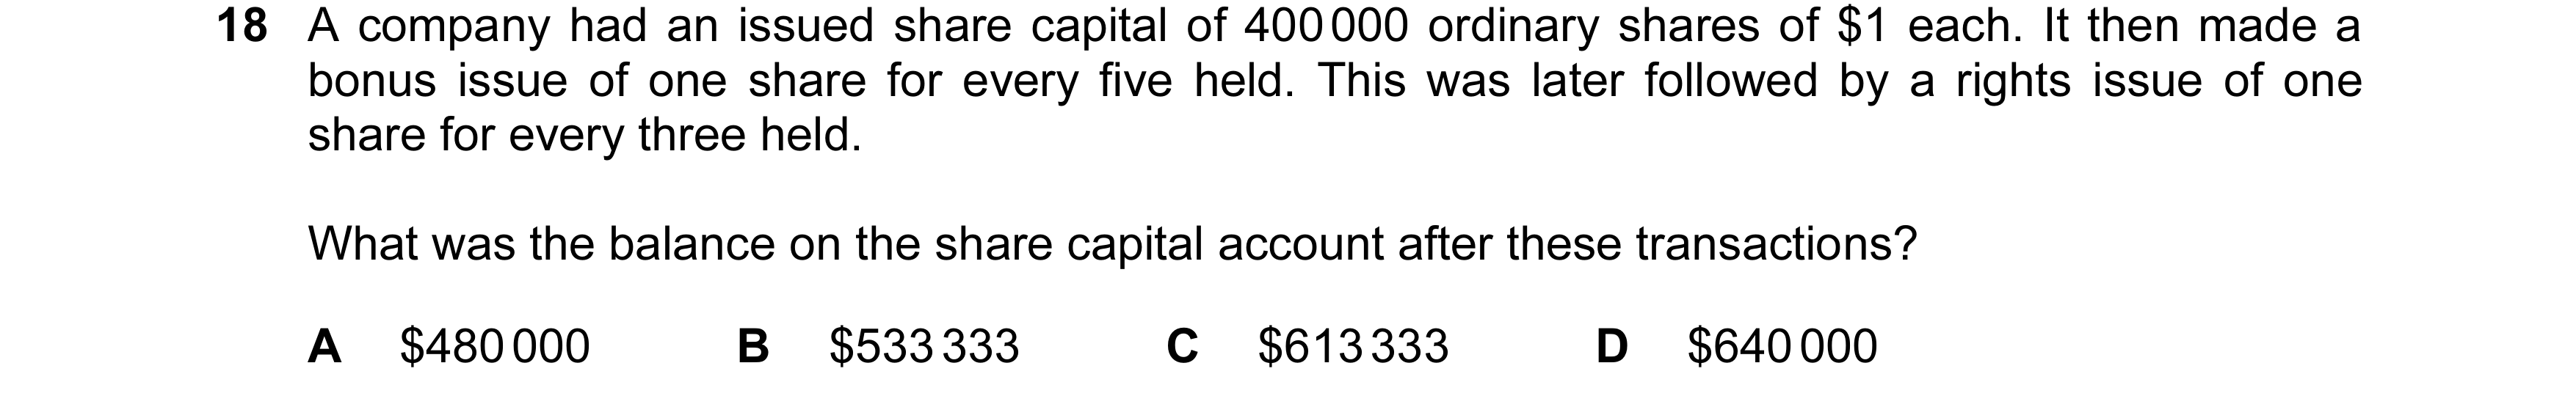
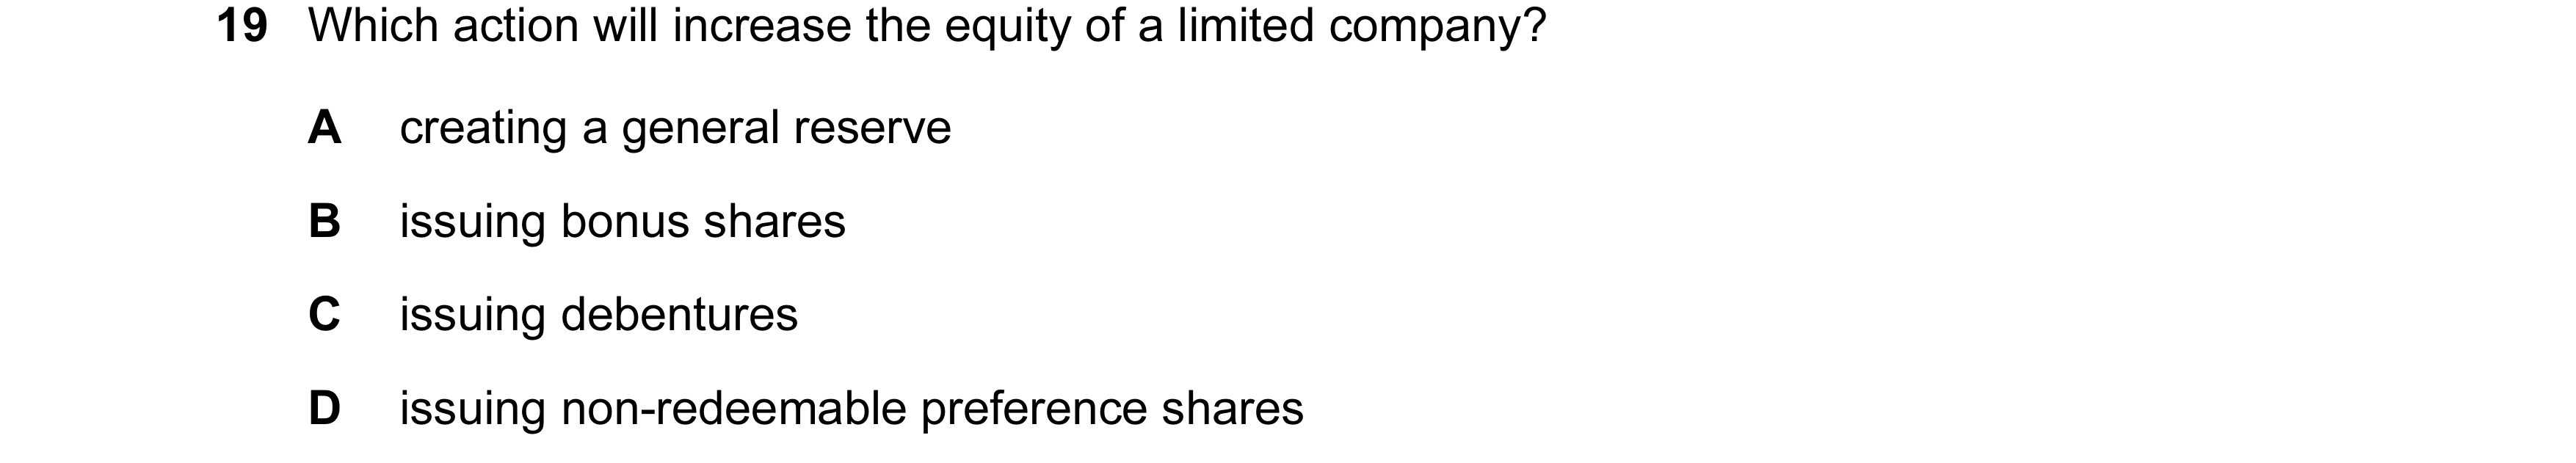
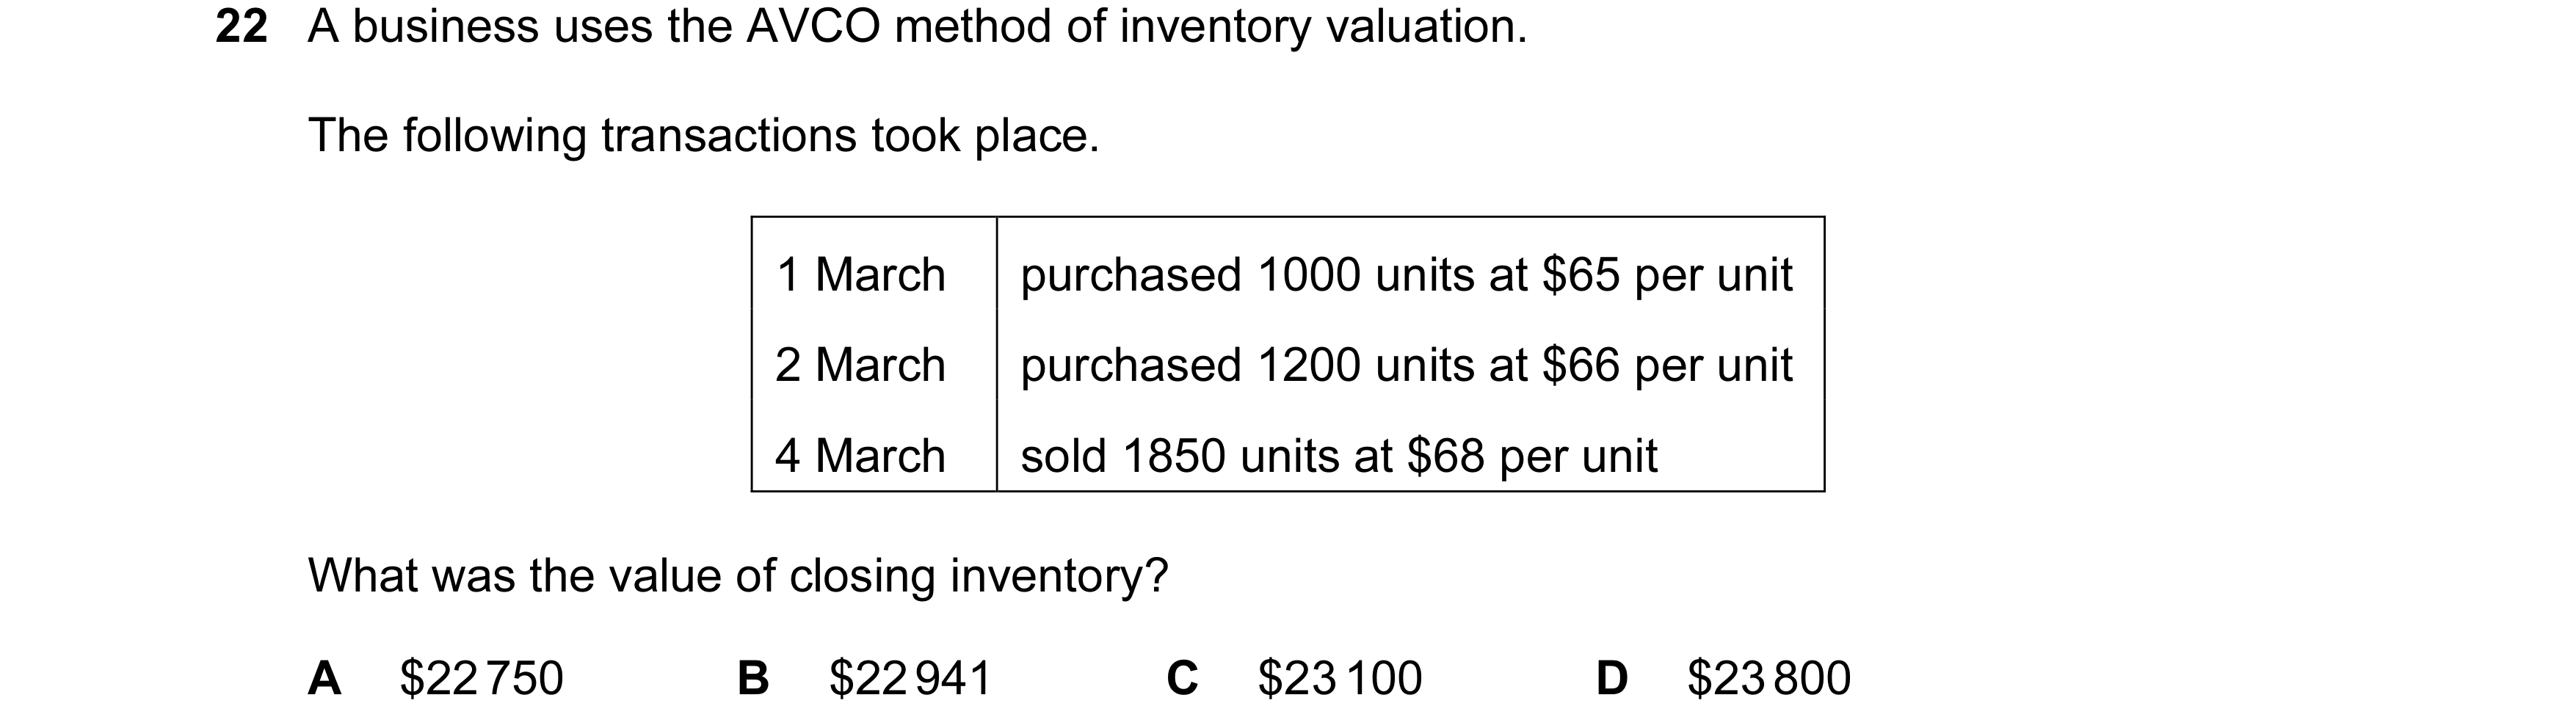
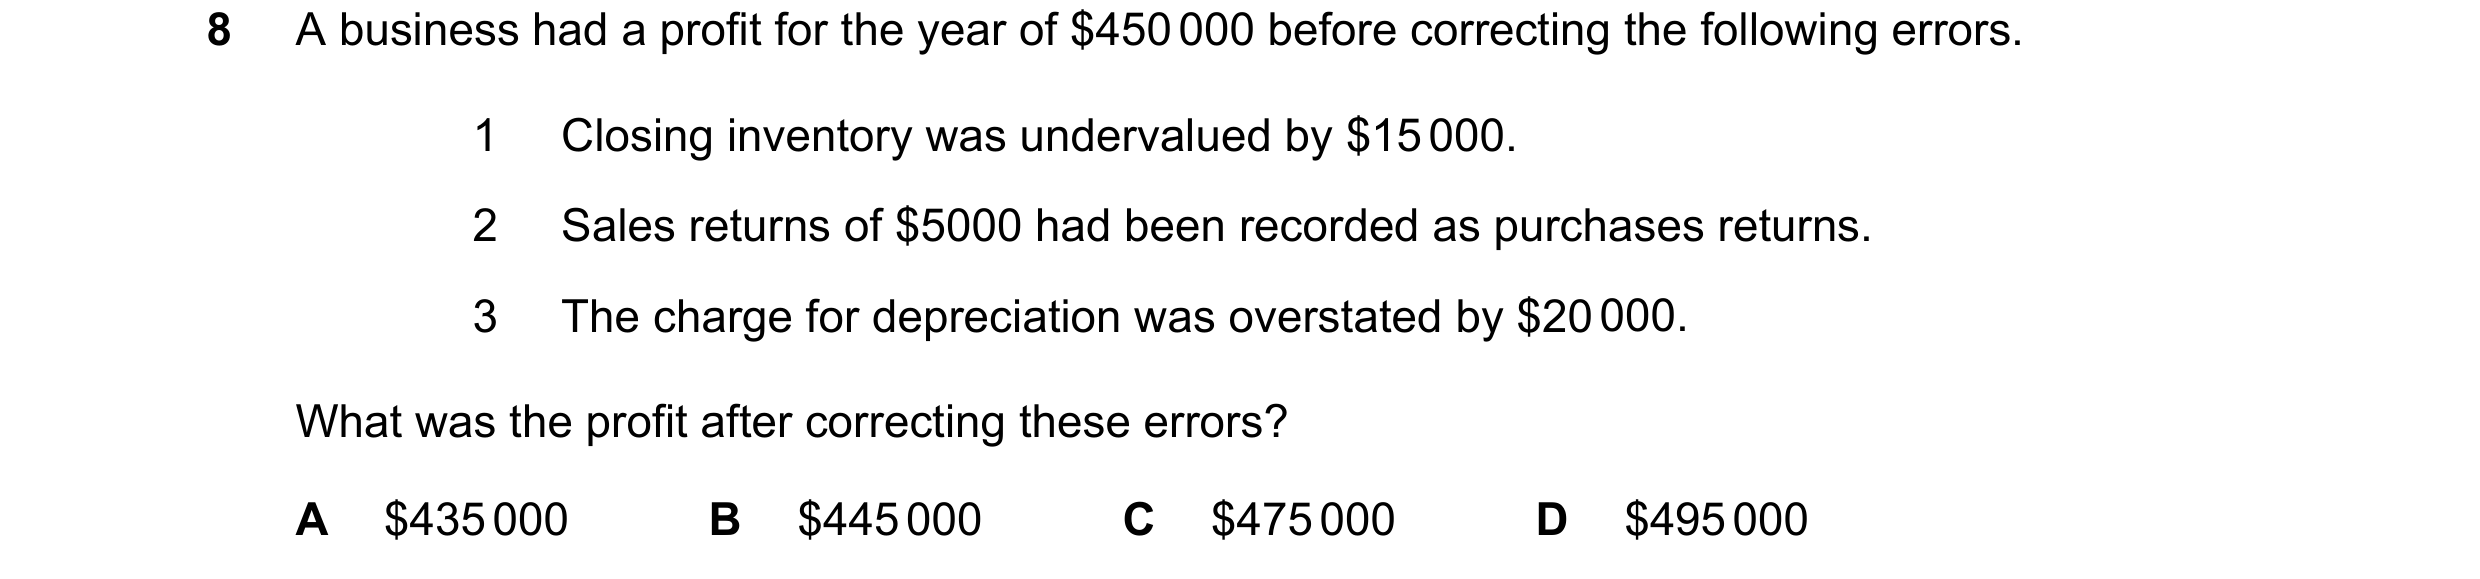 133 / 233
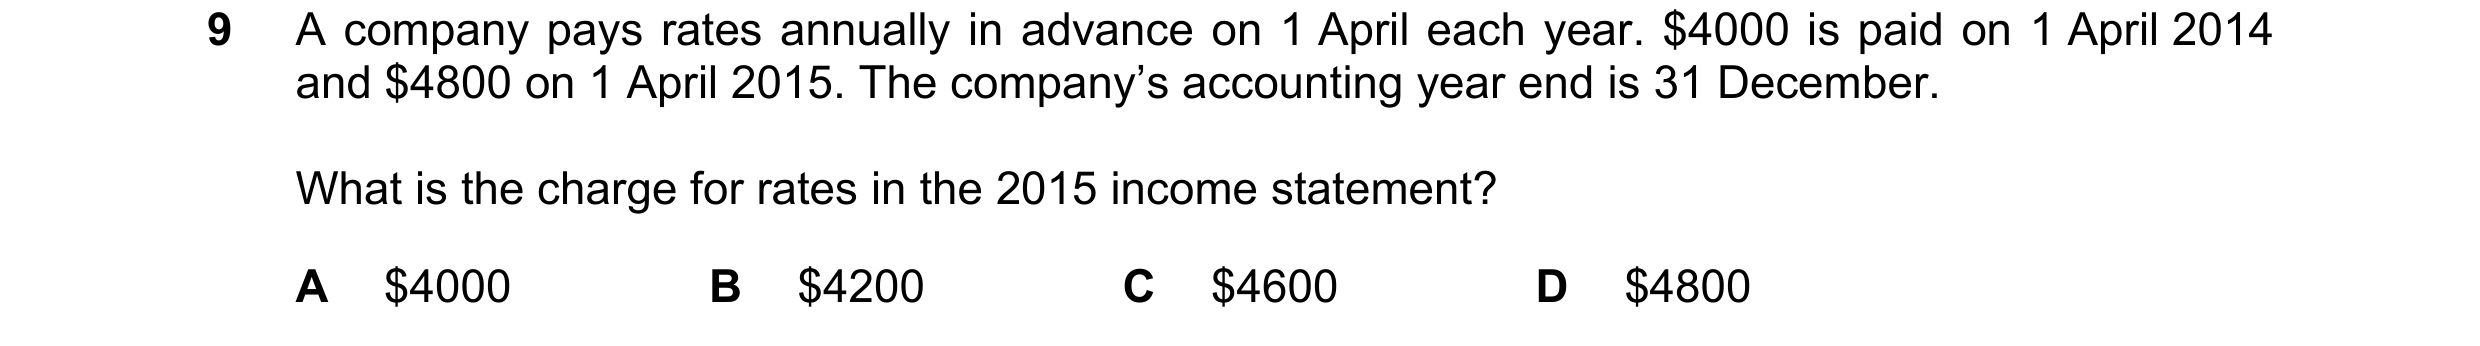
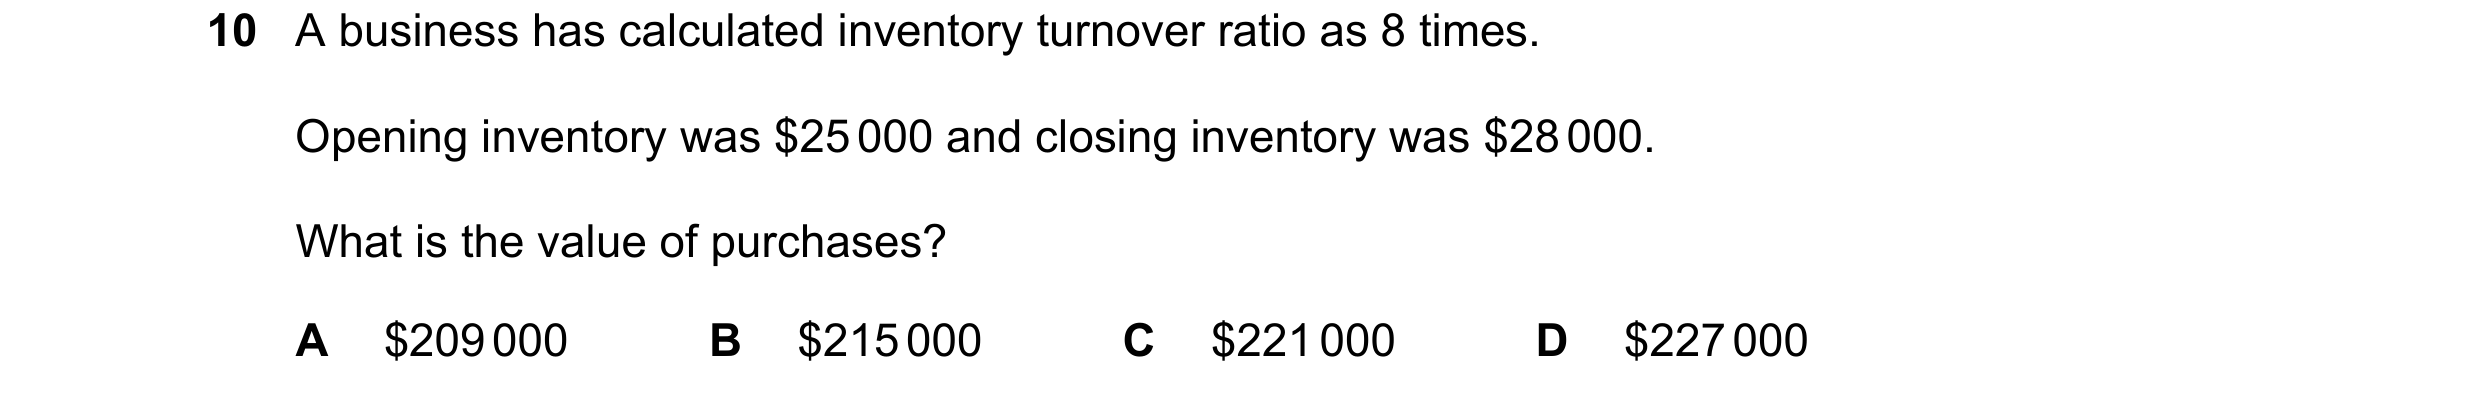
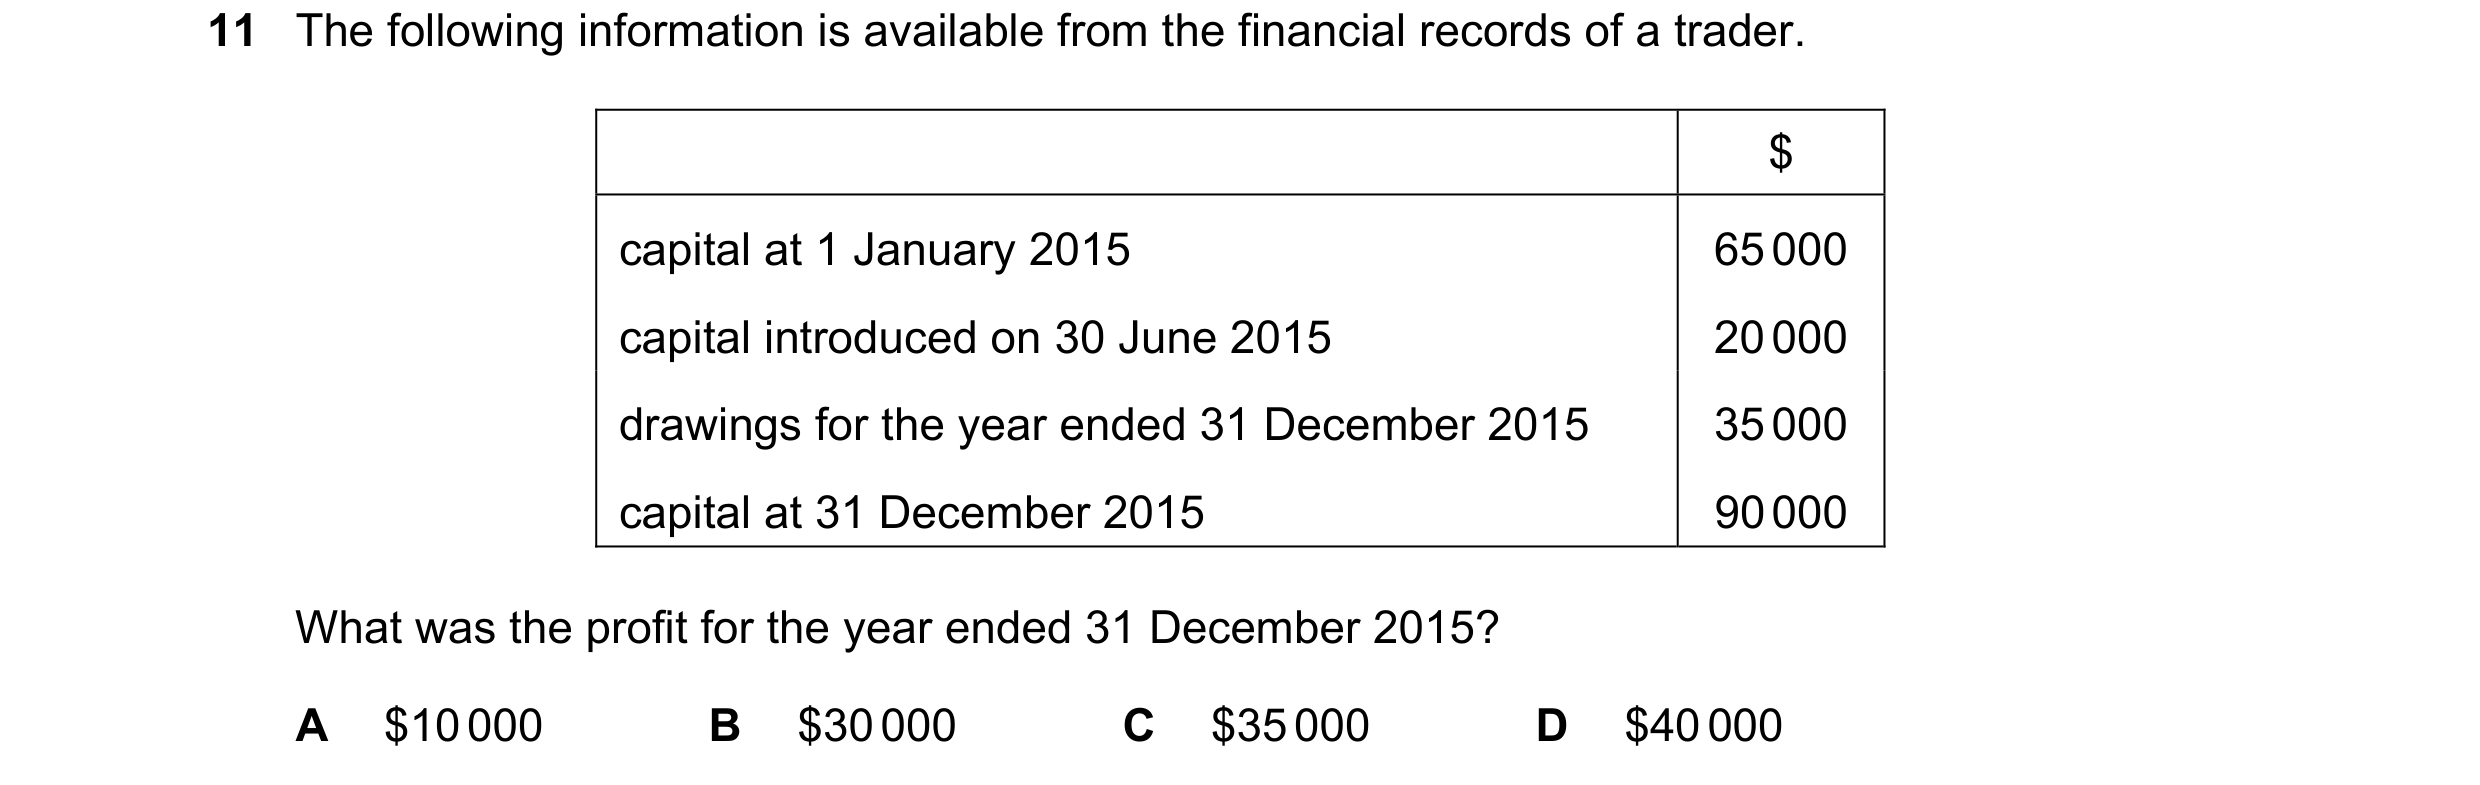
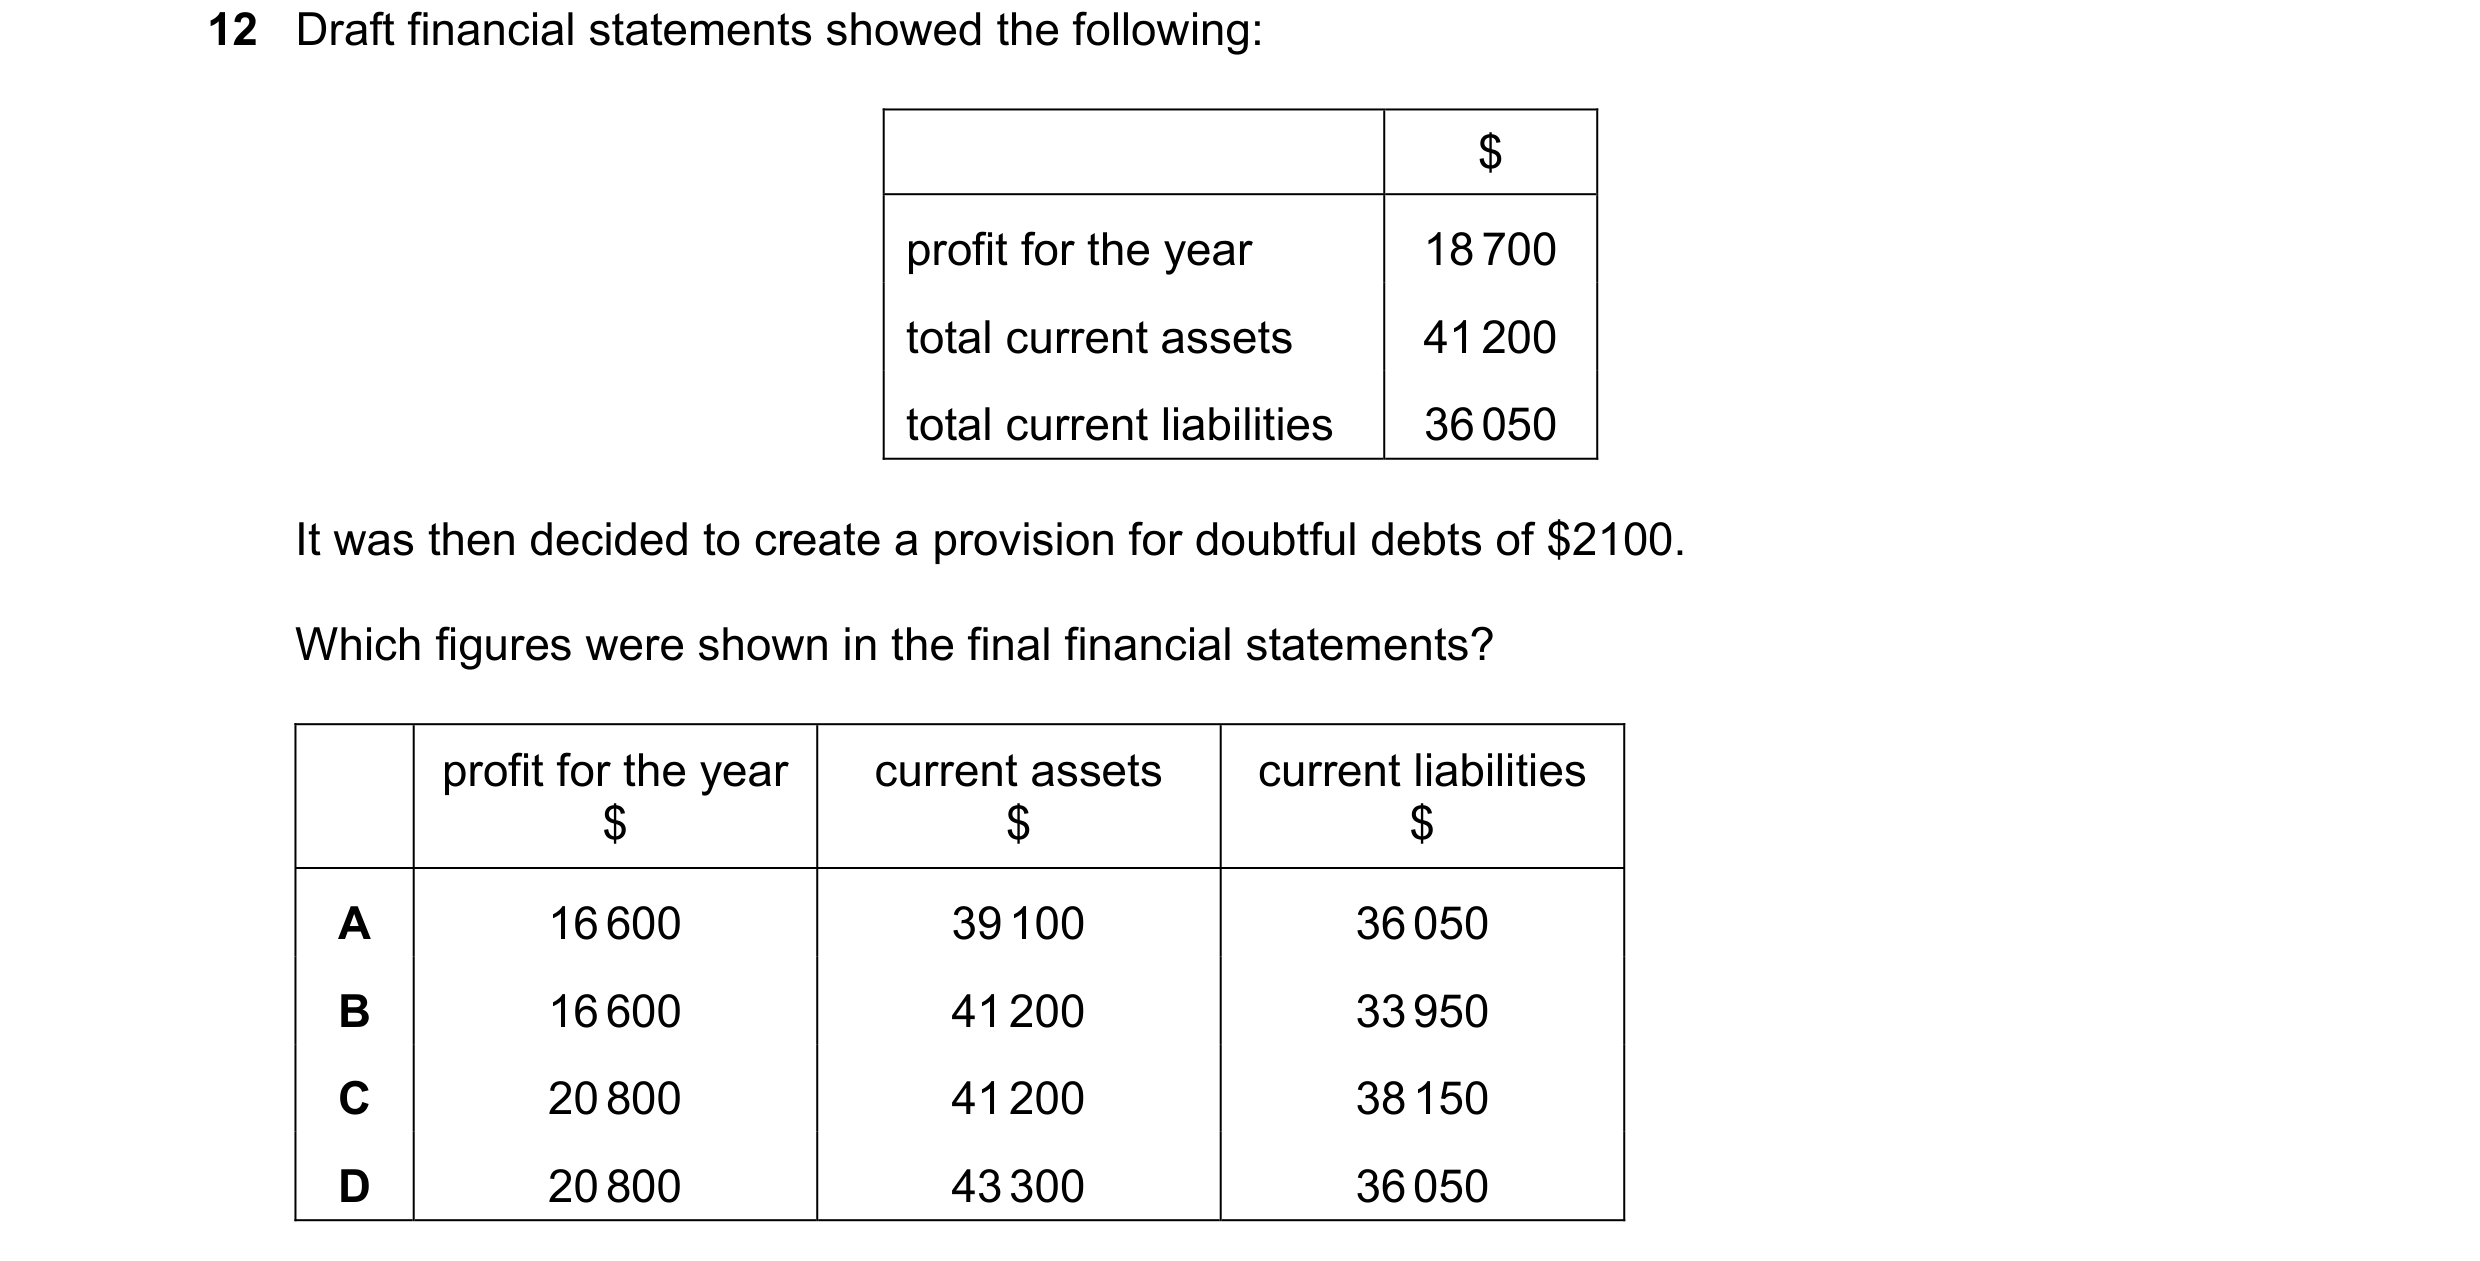 134 / 233
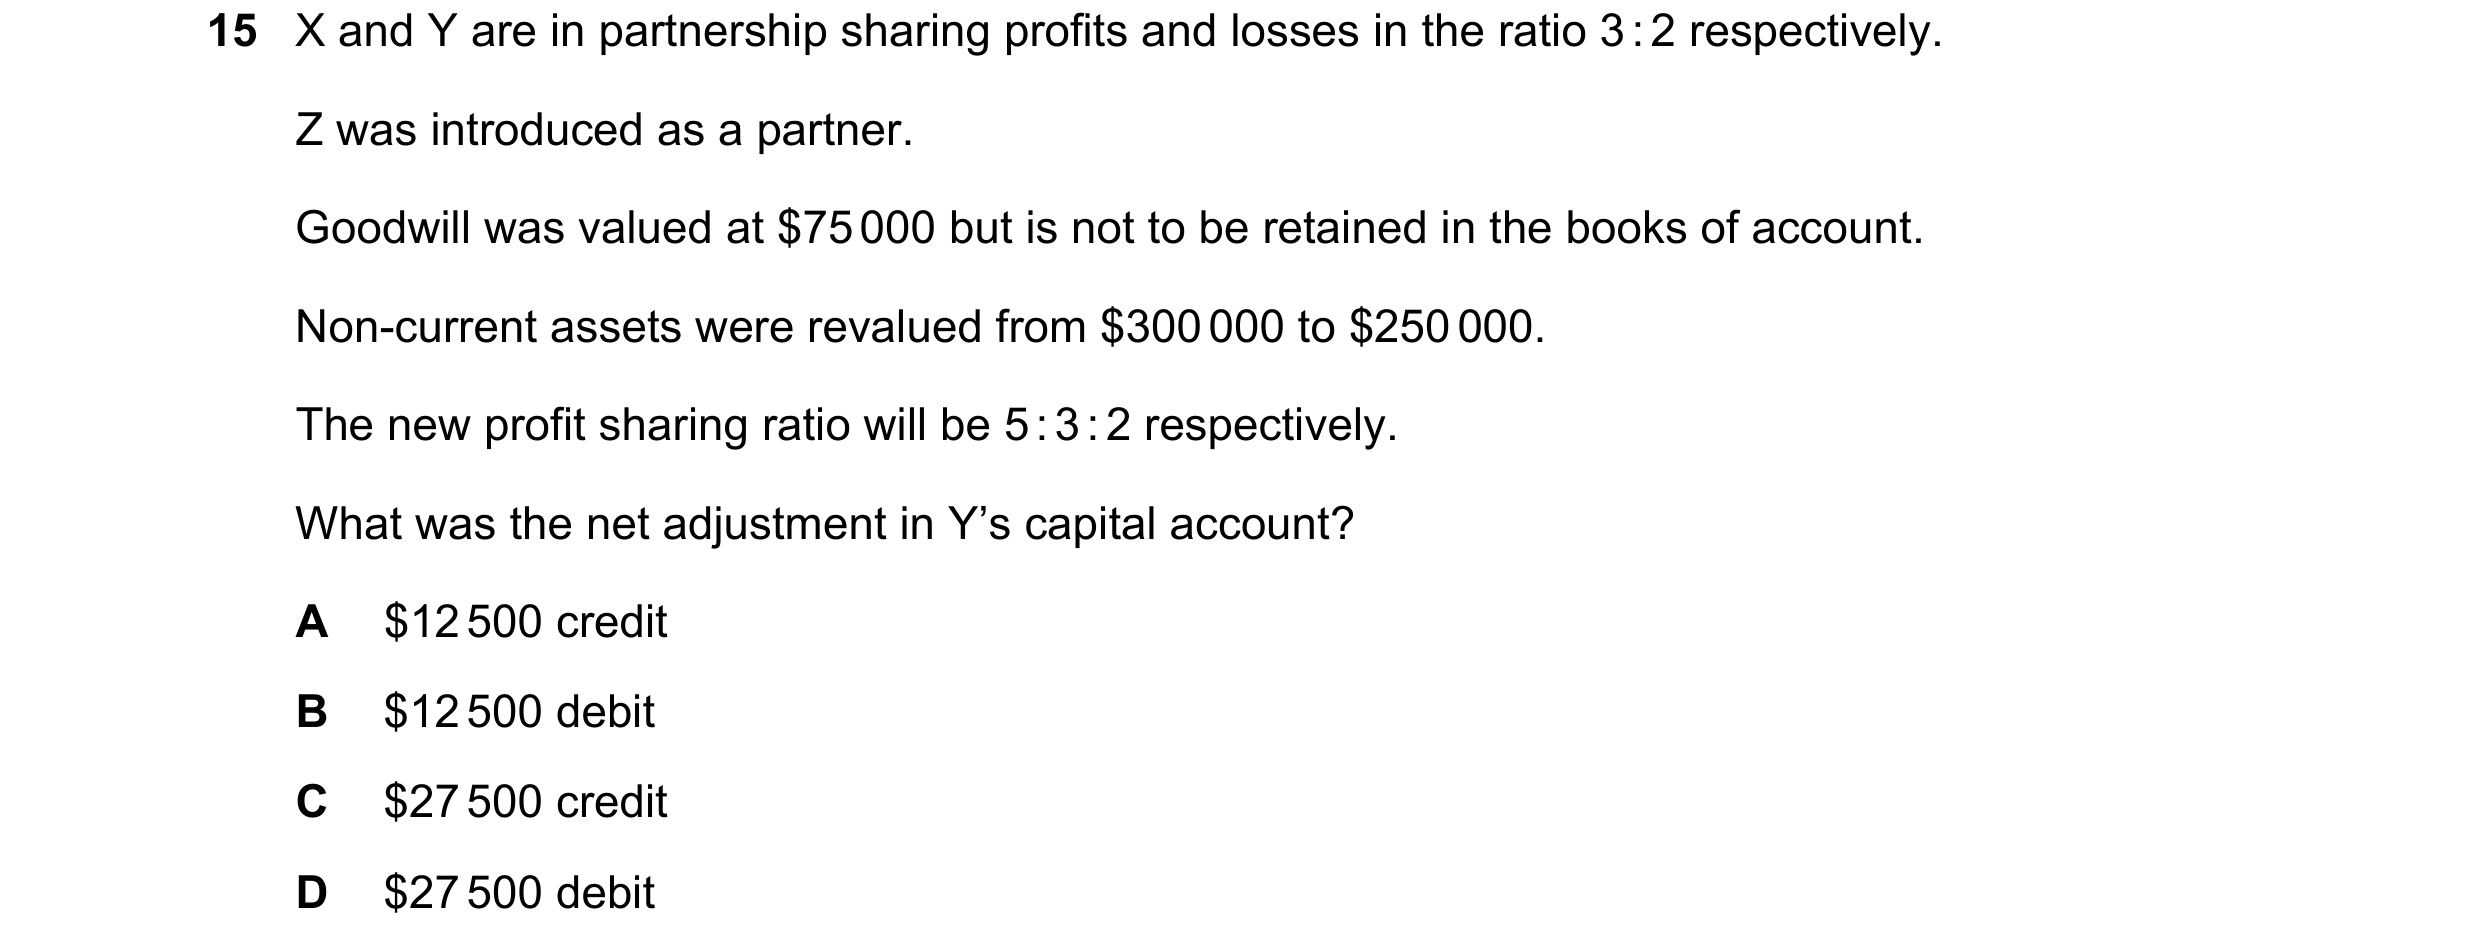
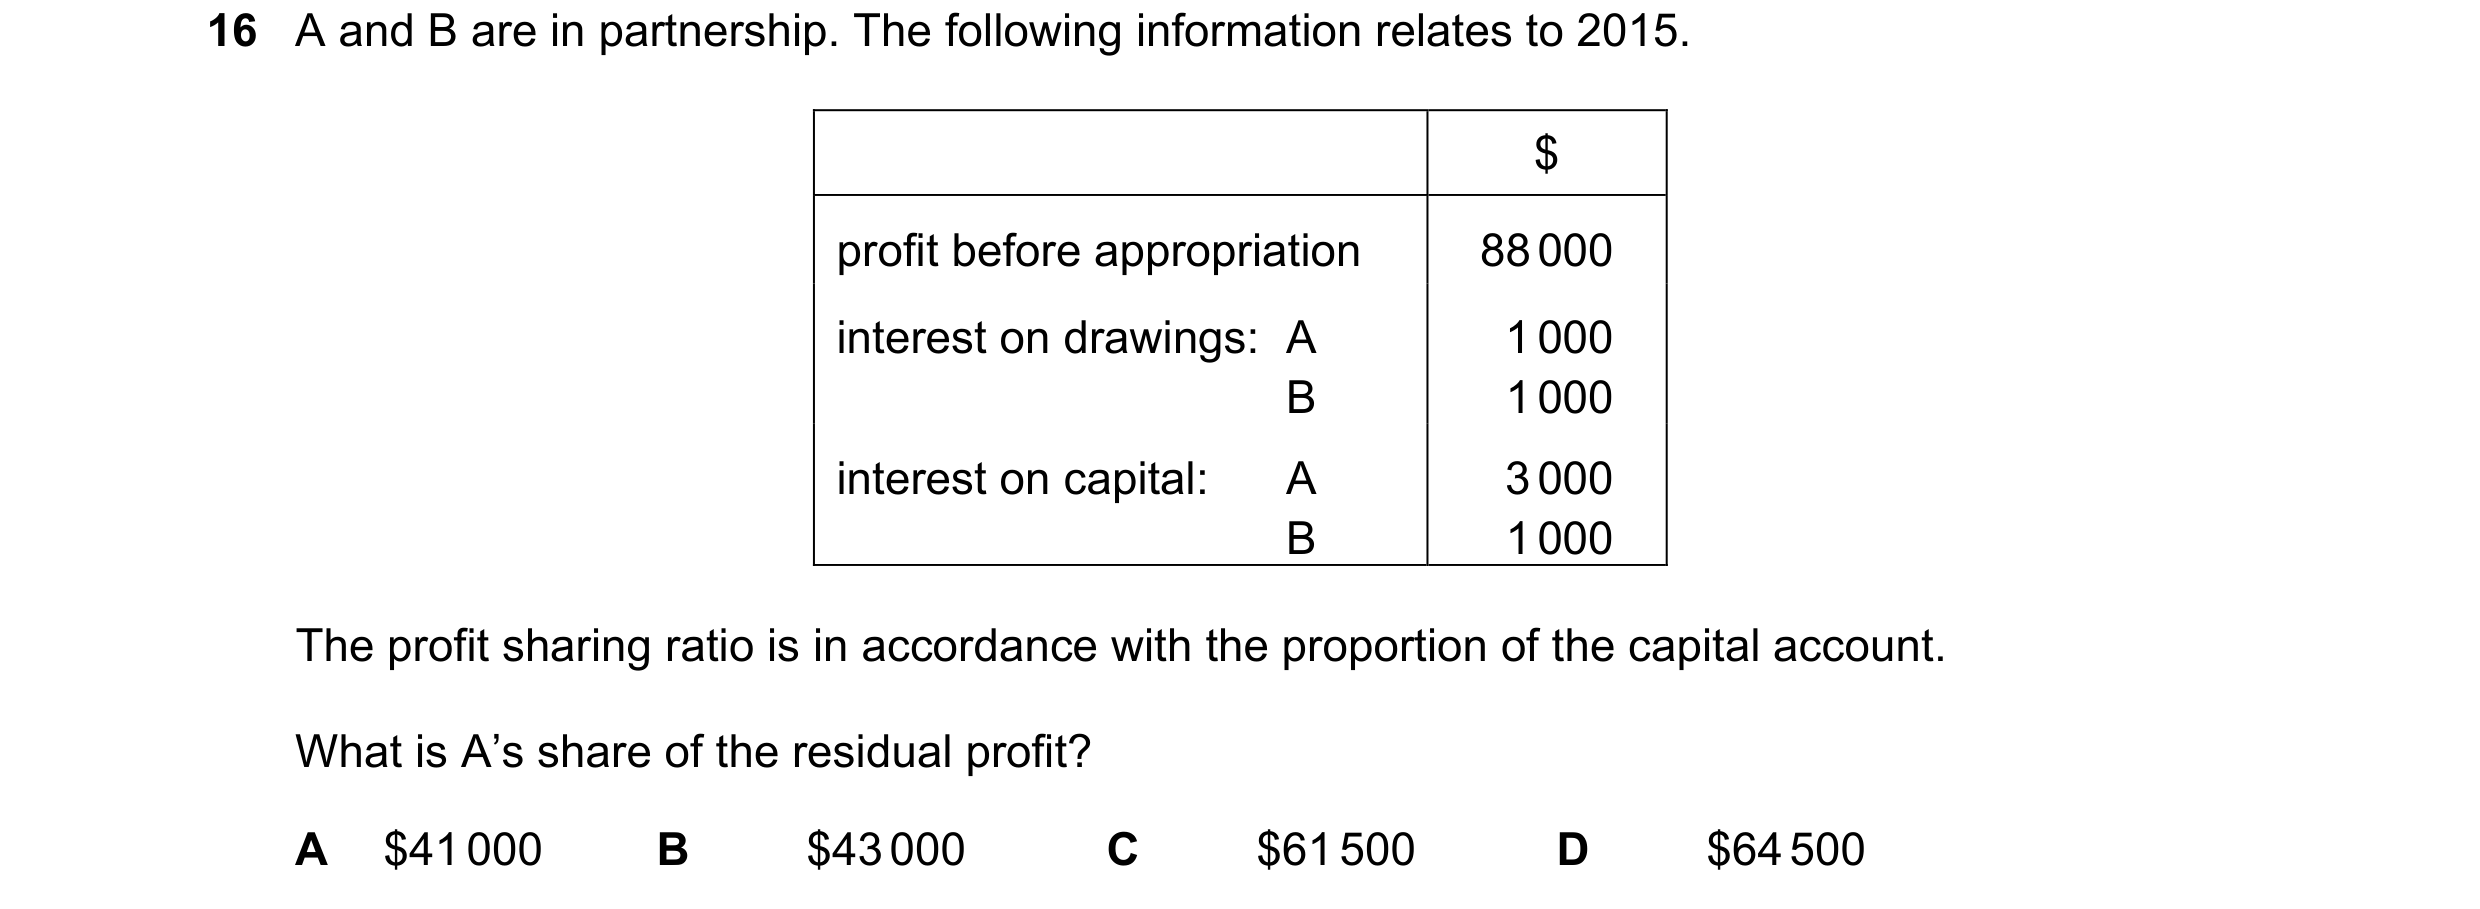
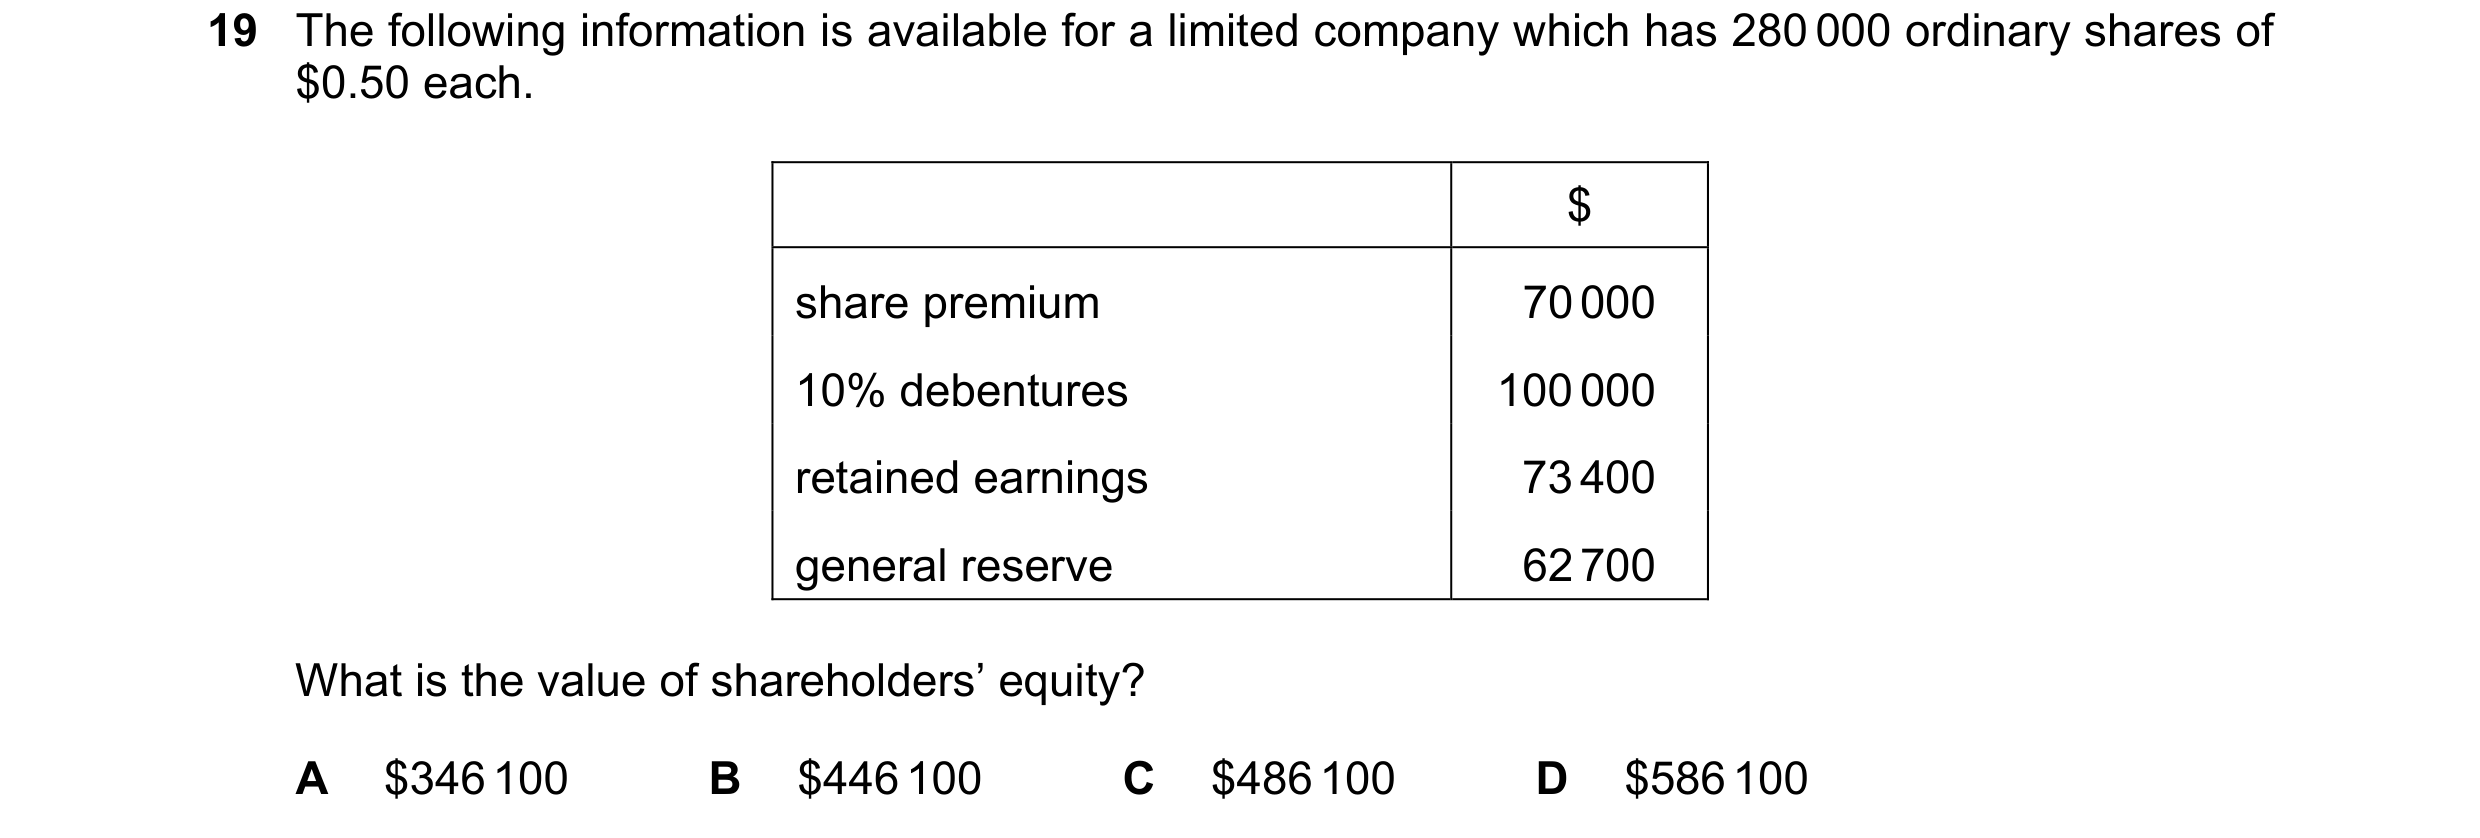 135 / 233
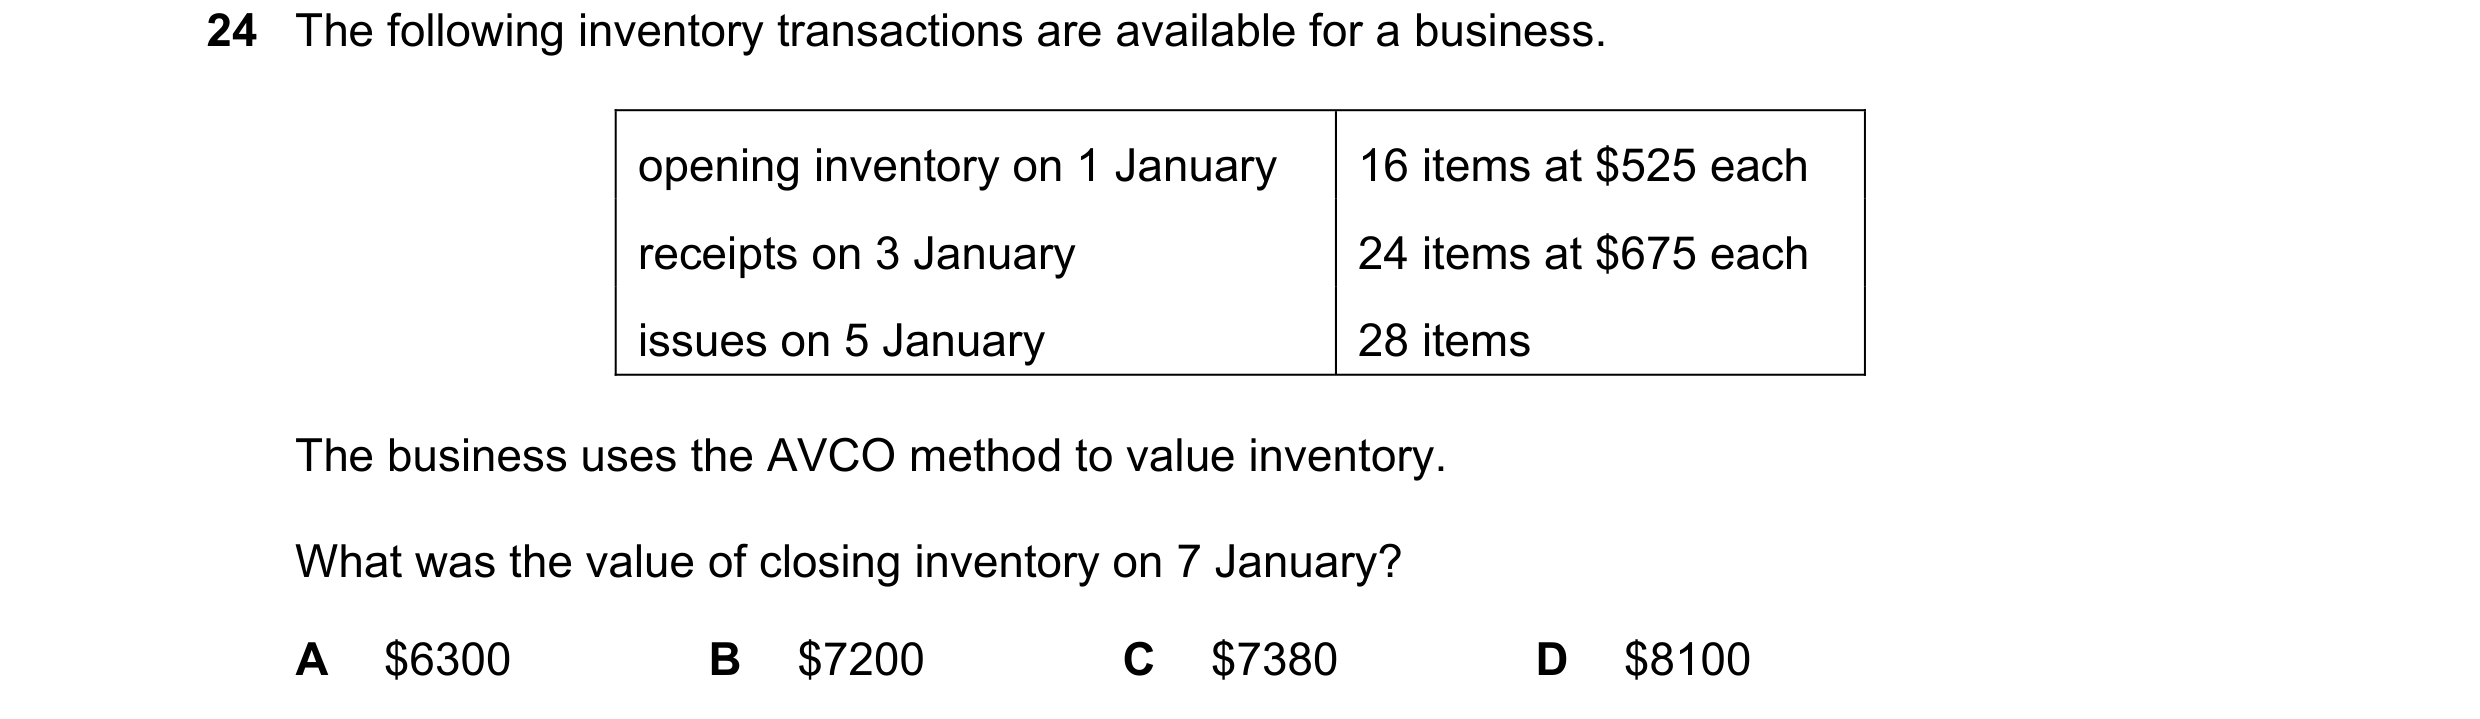
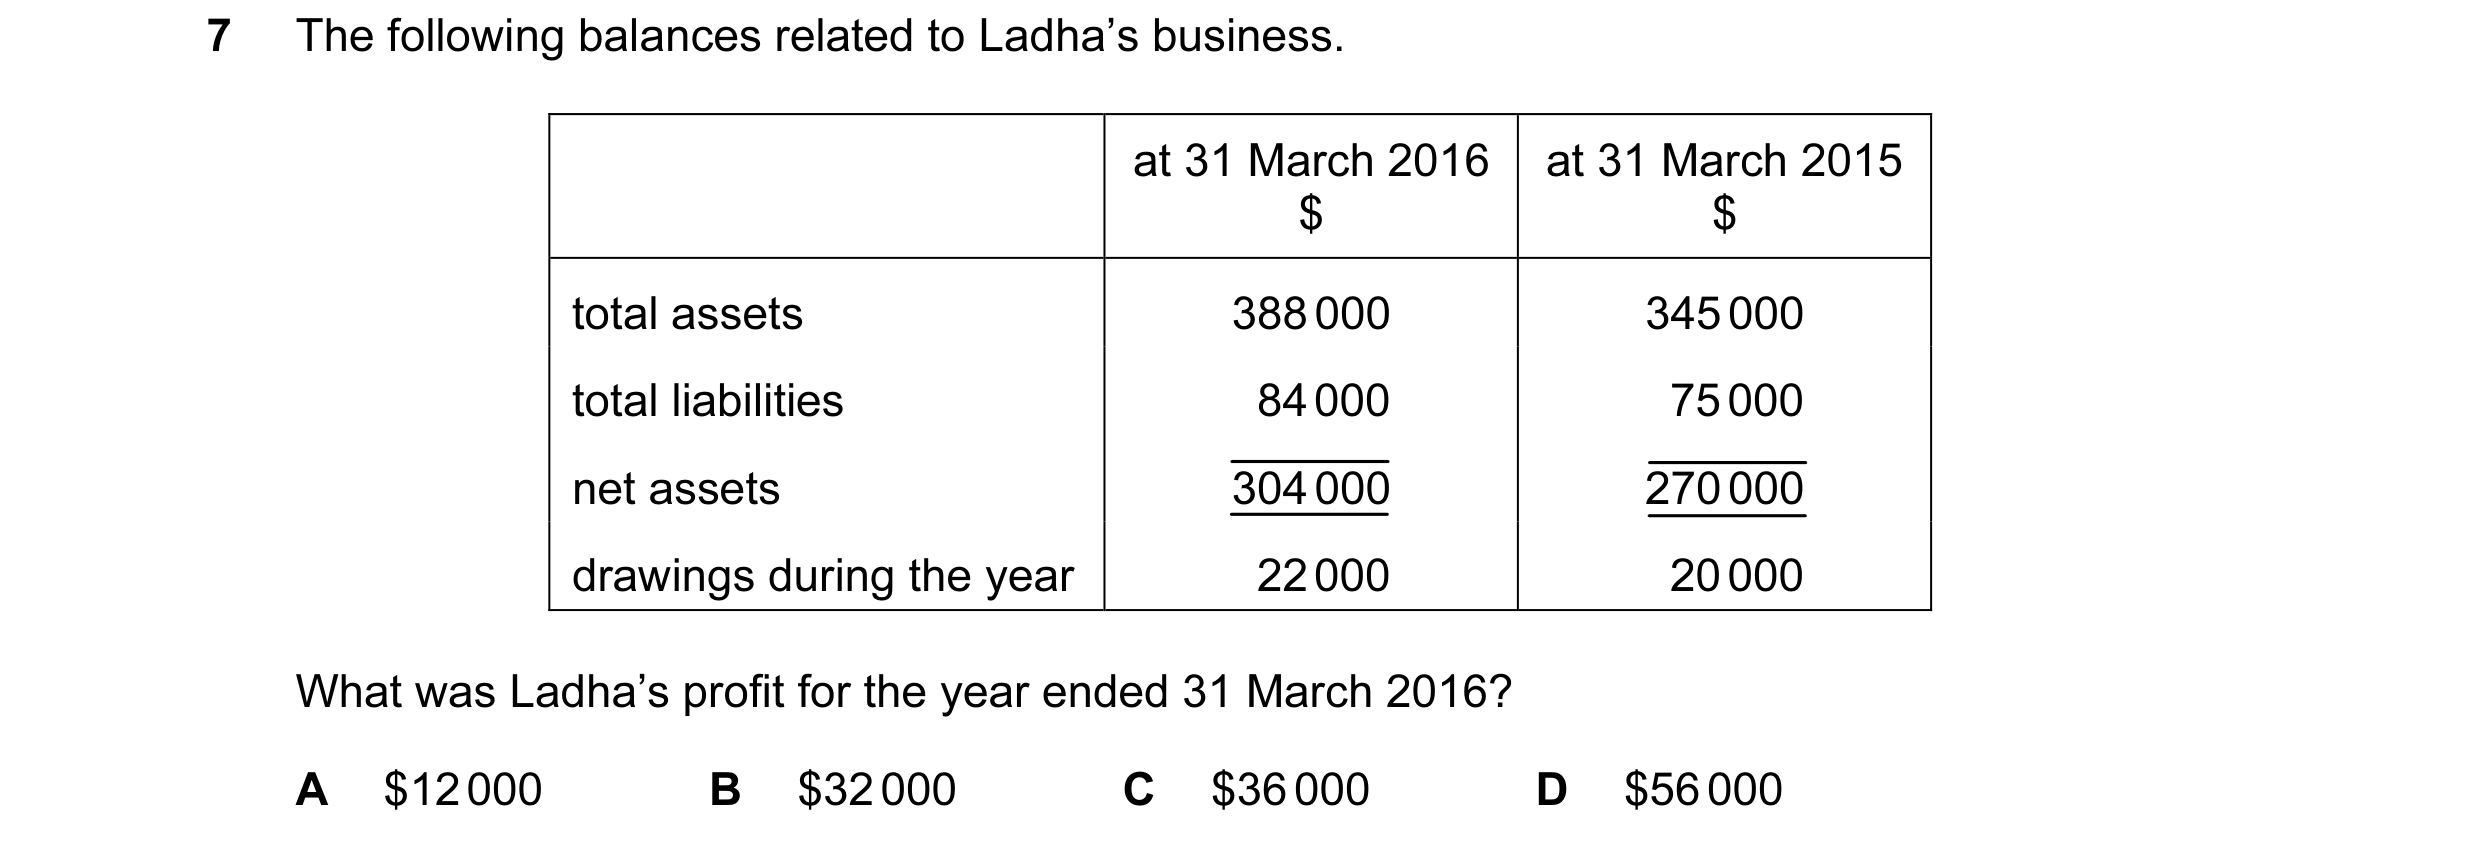
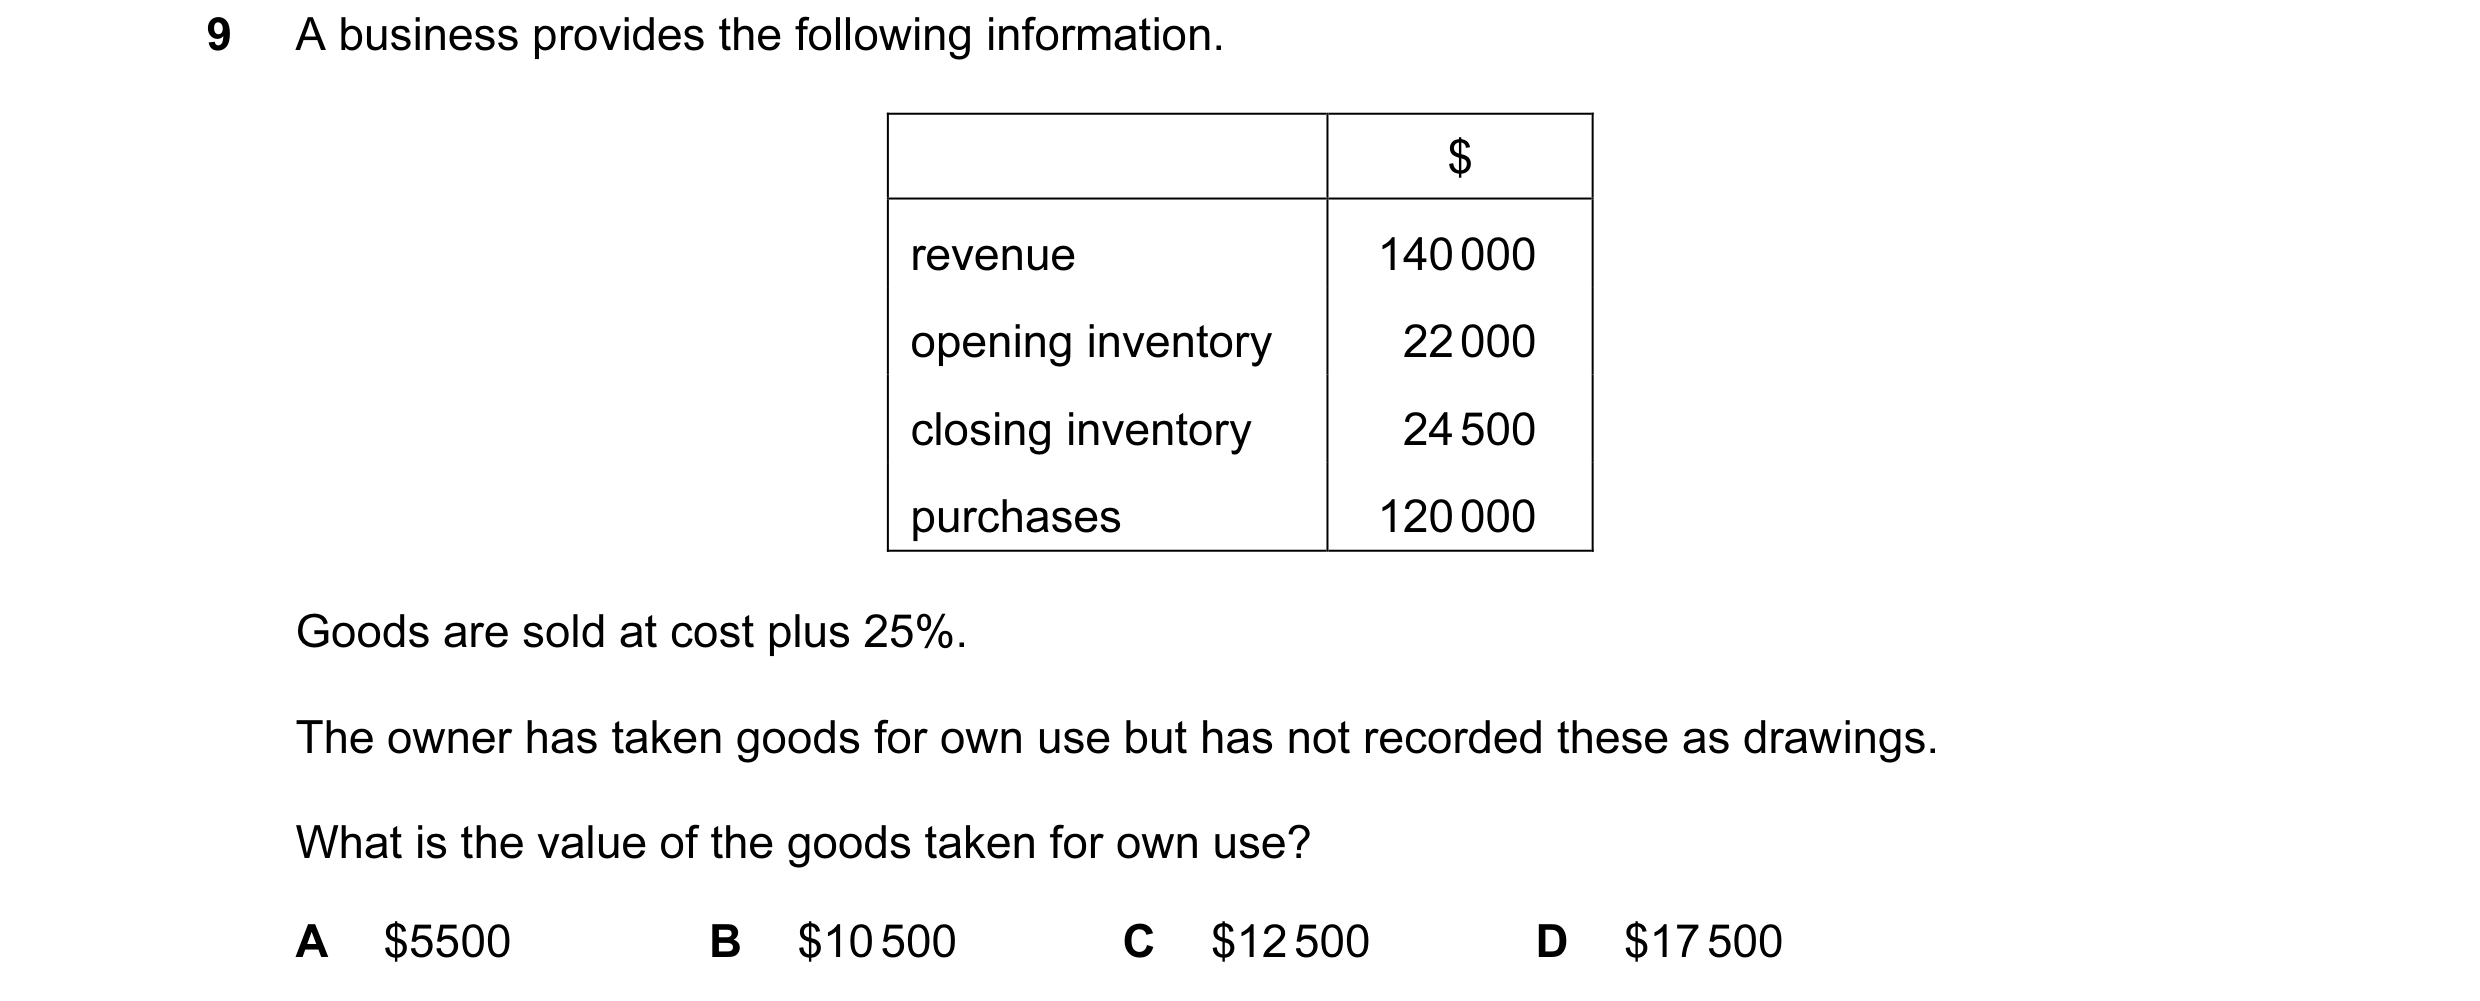 136 / 233
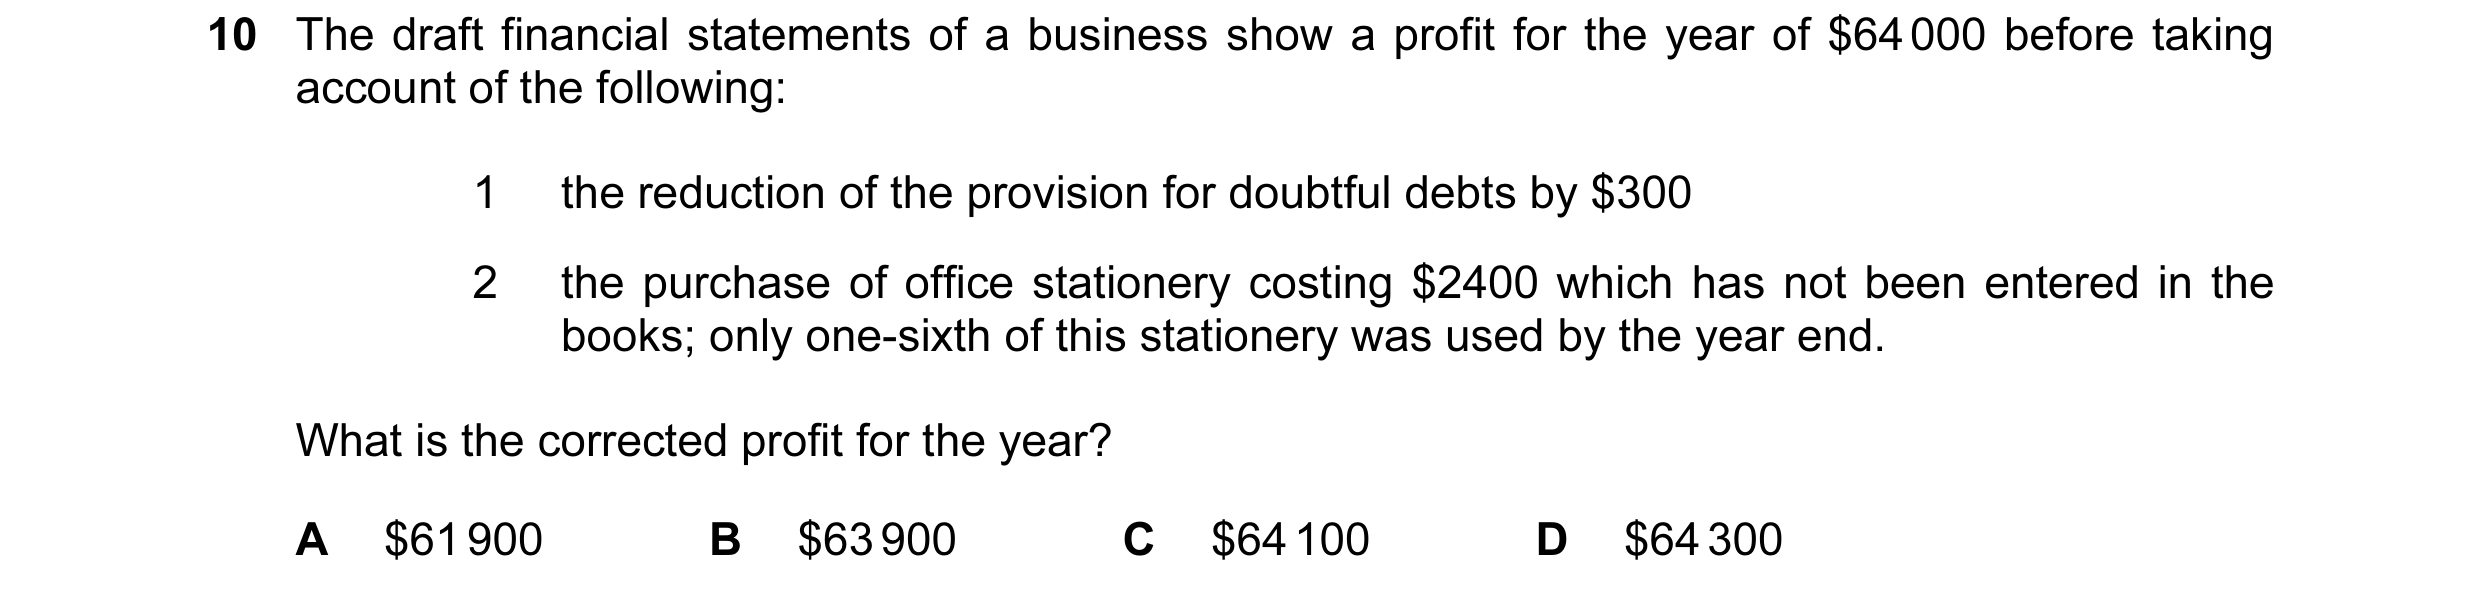
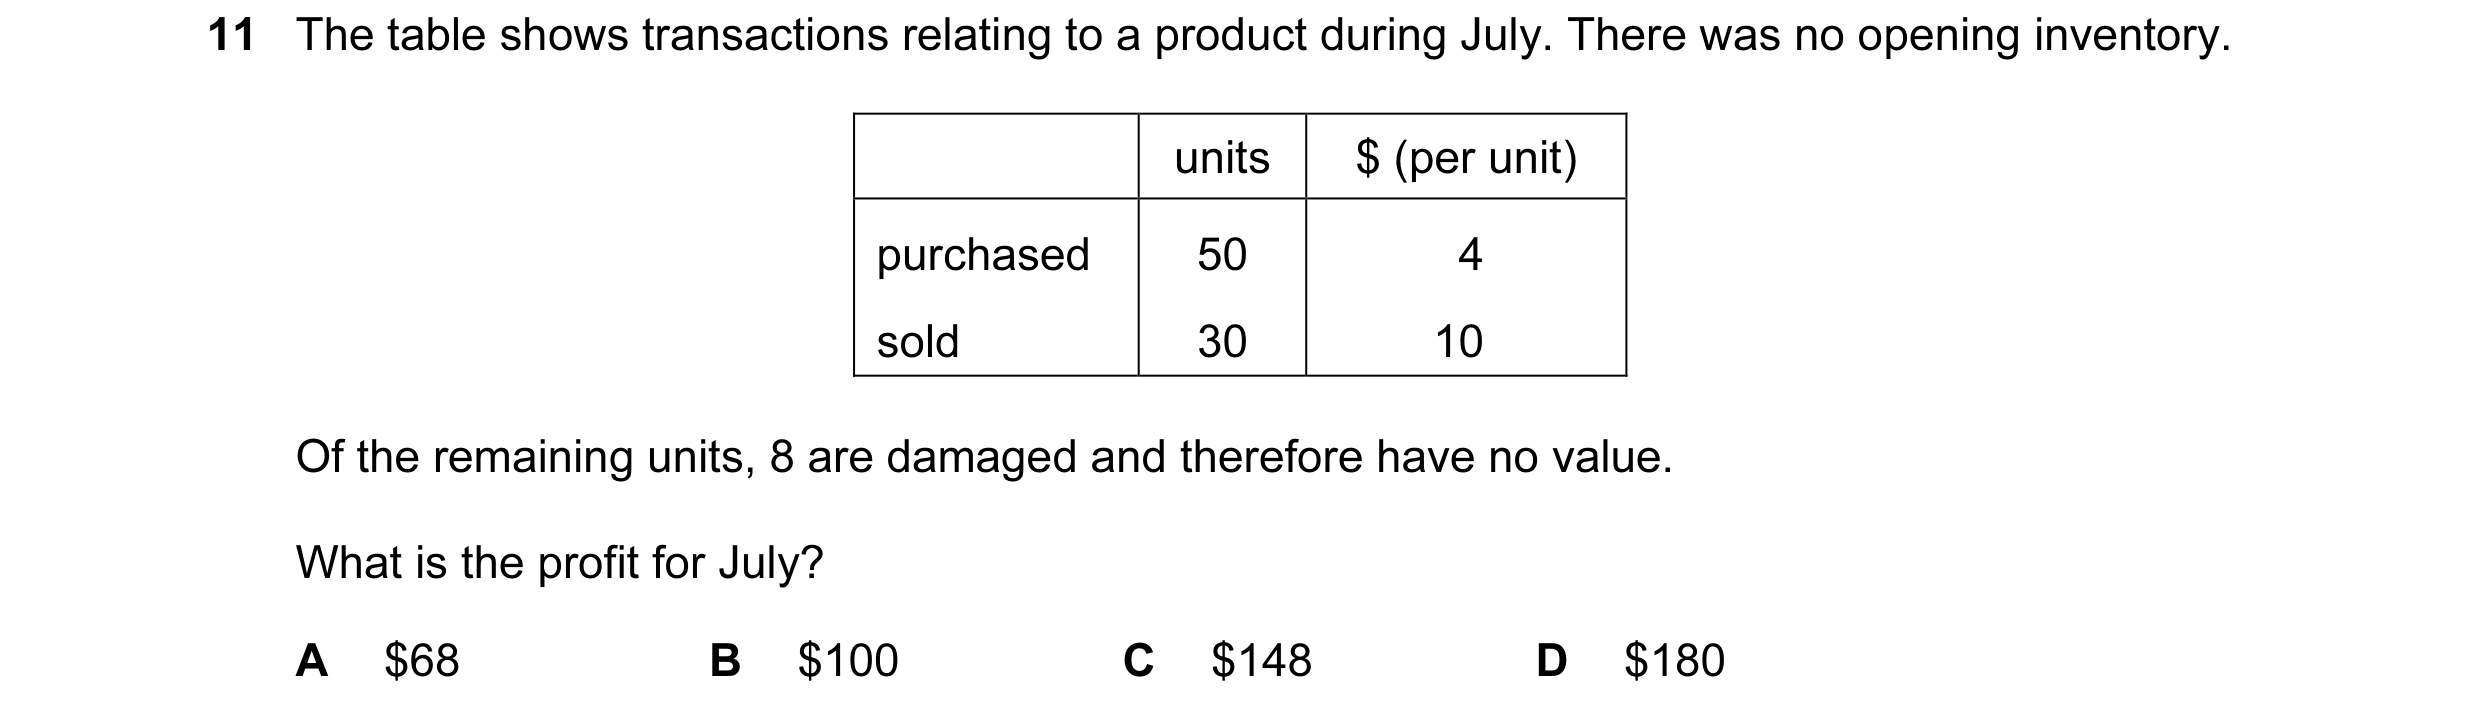
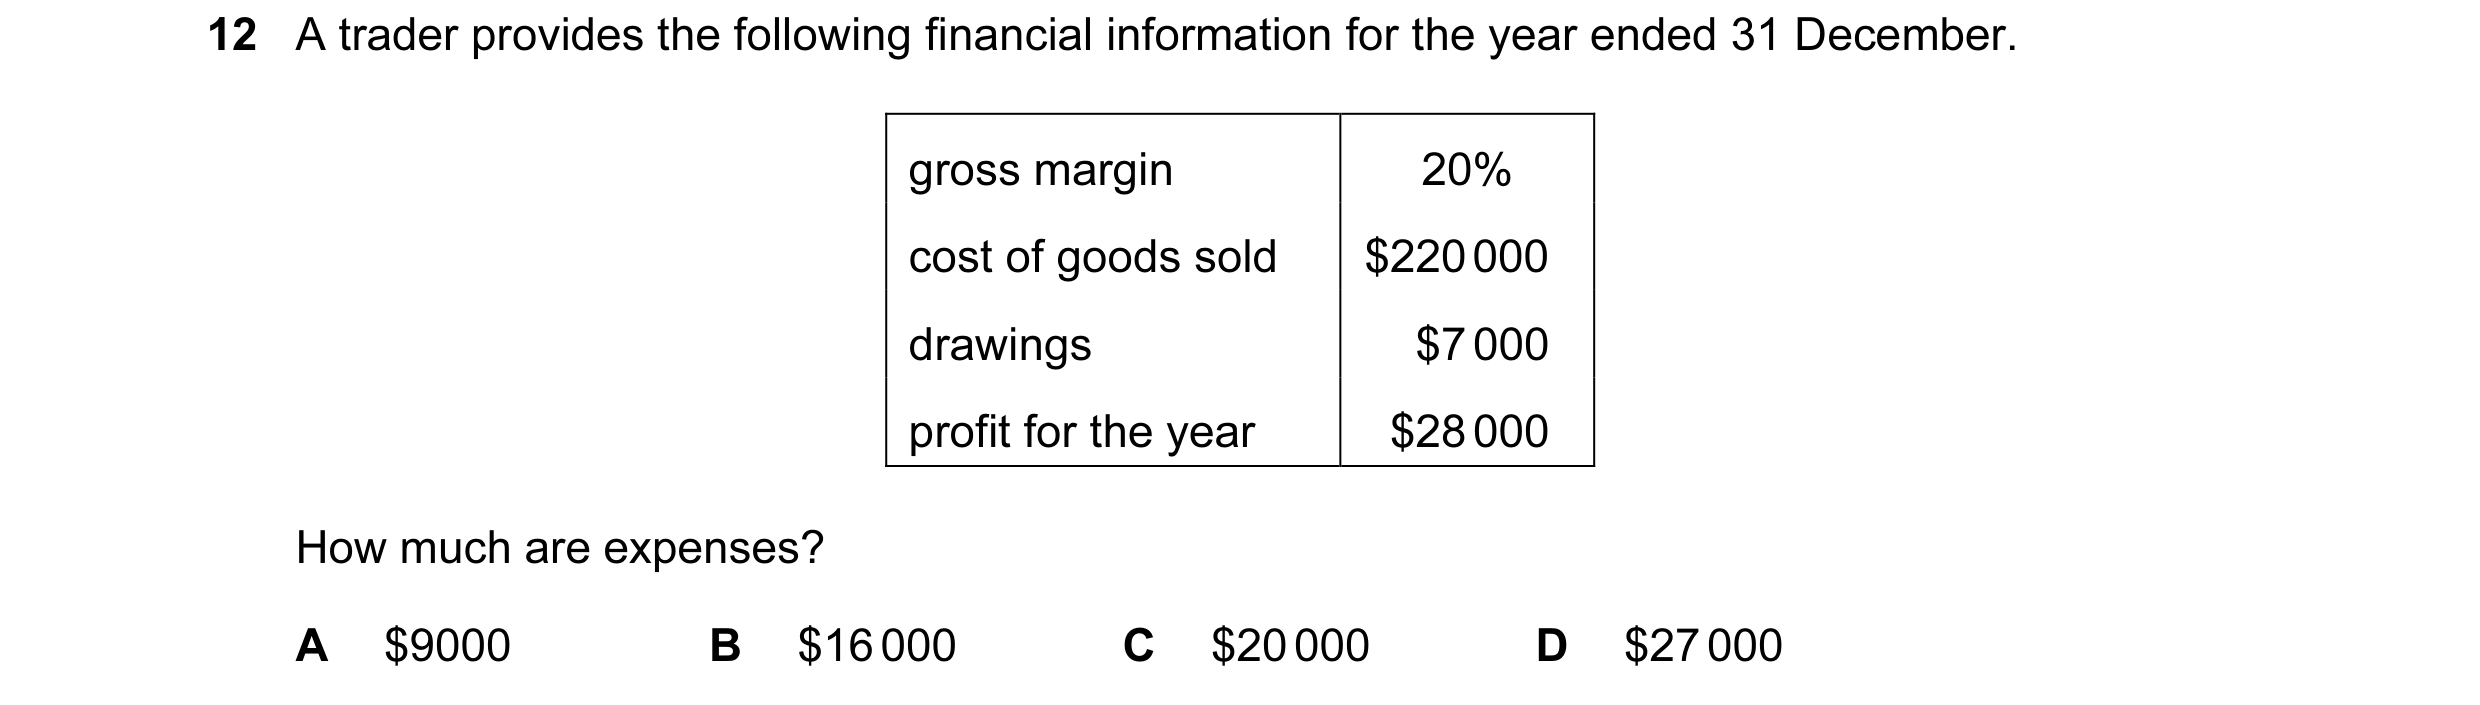
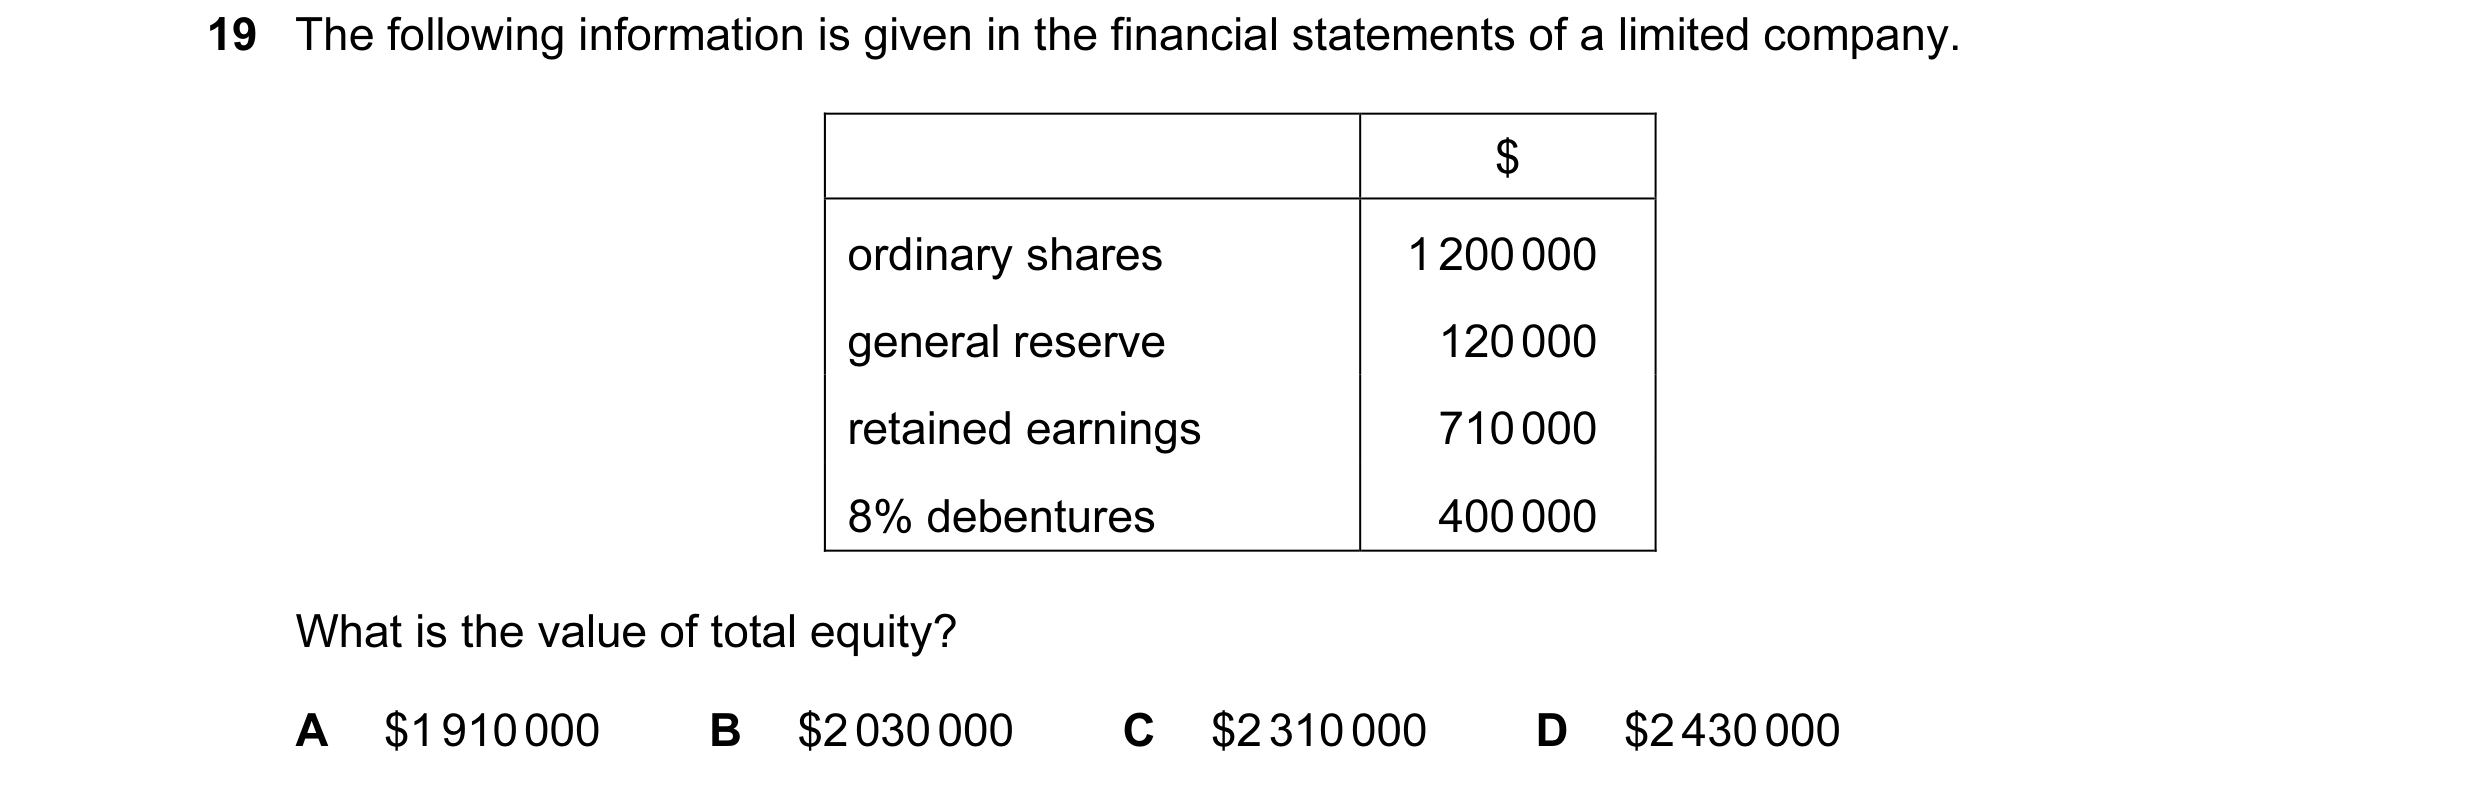 137 / 233
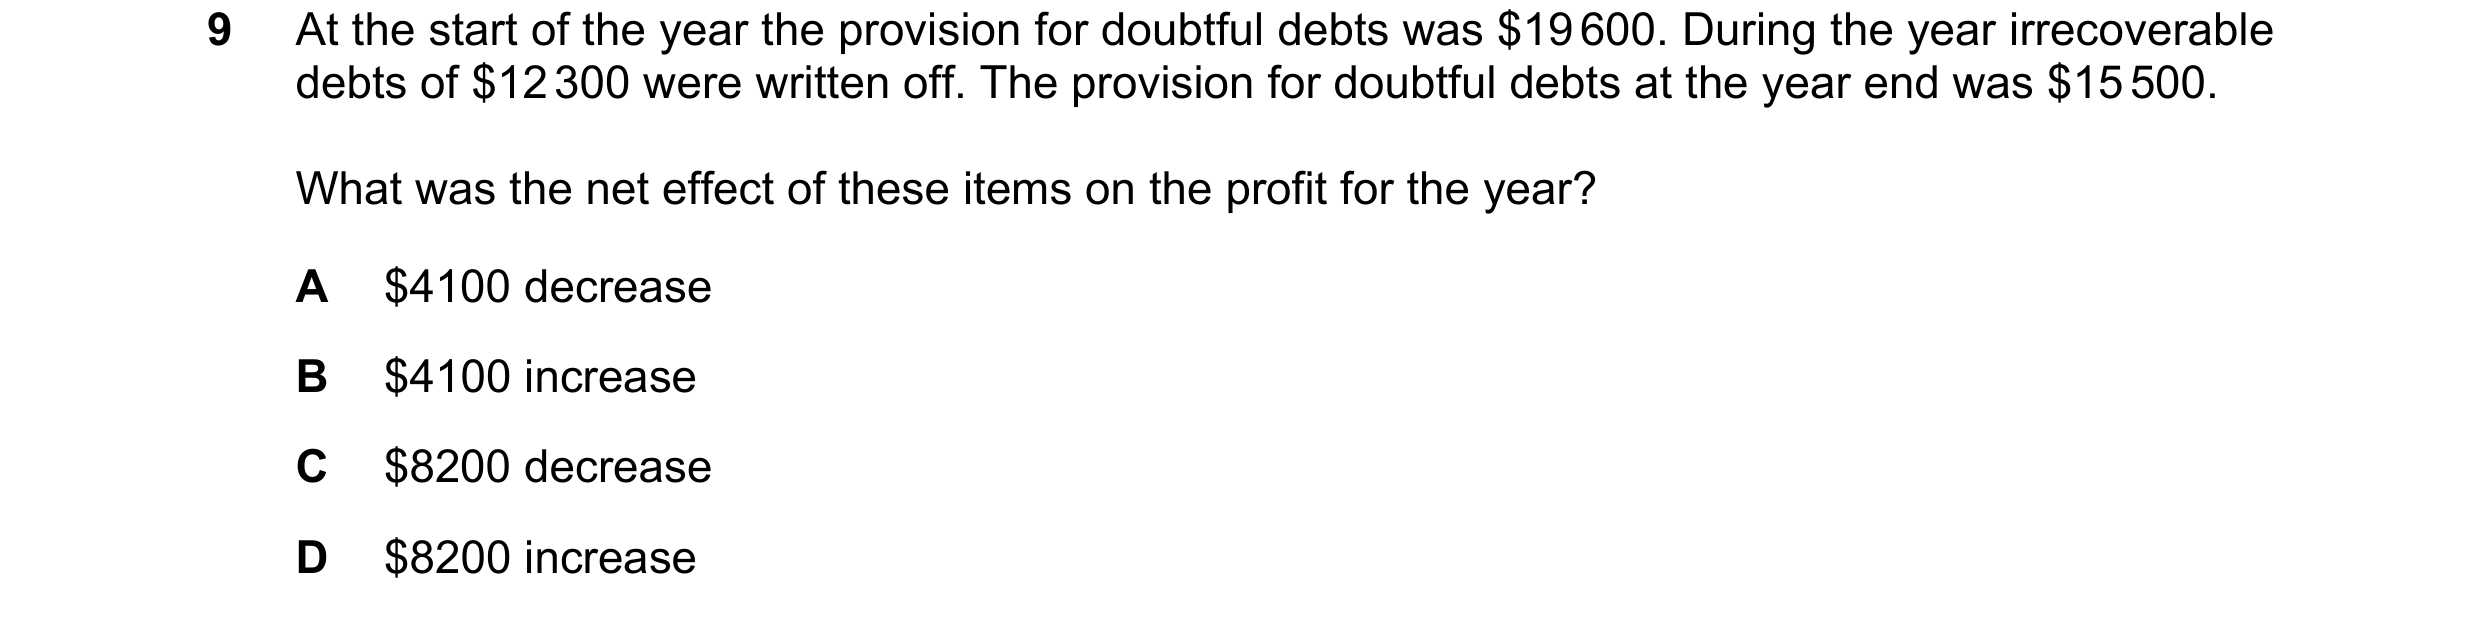
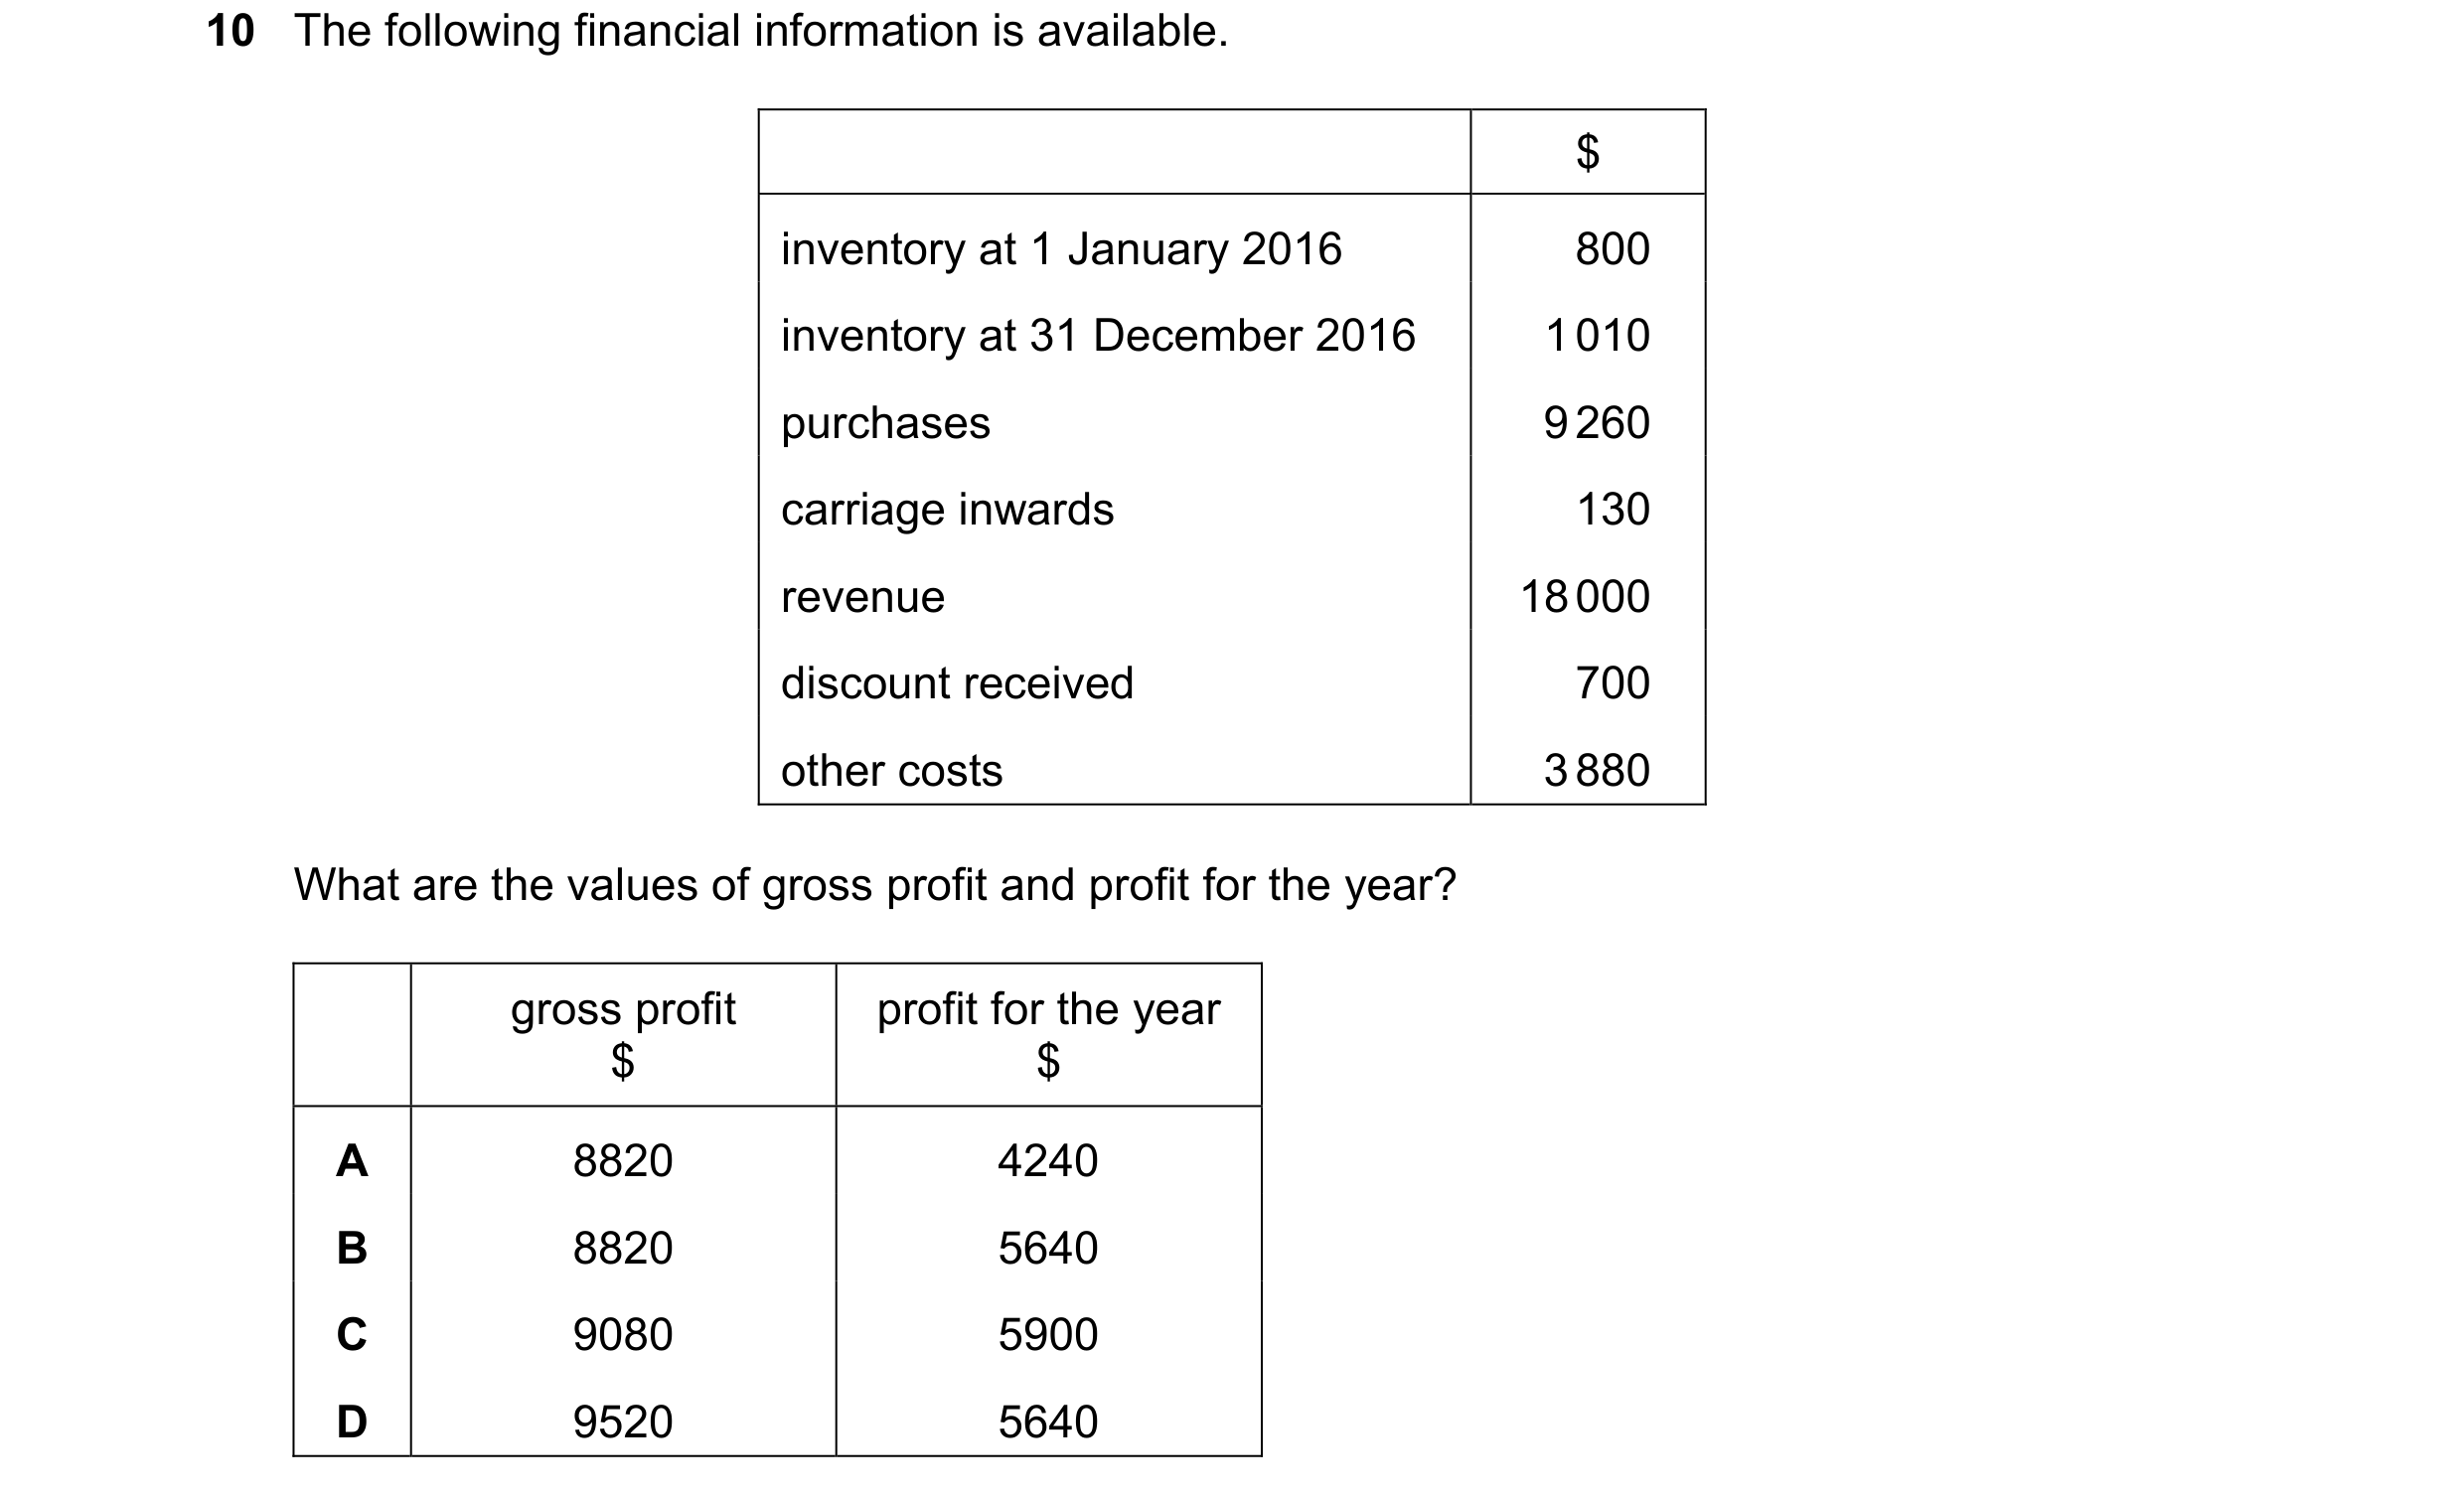
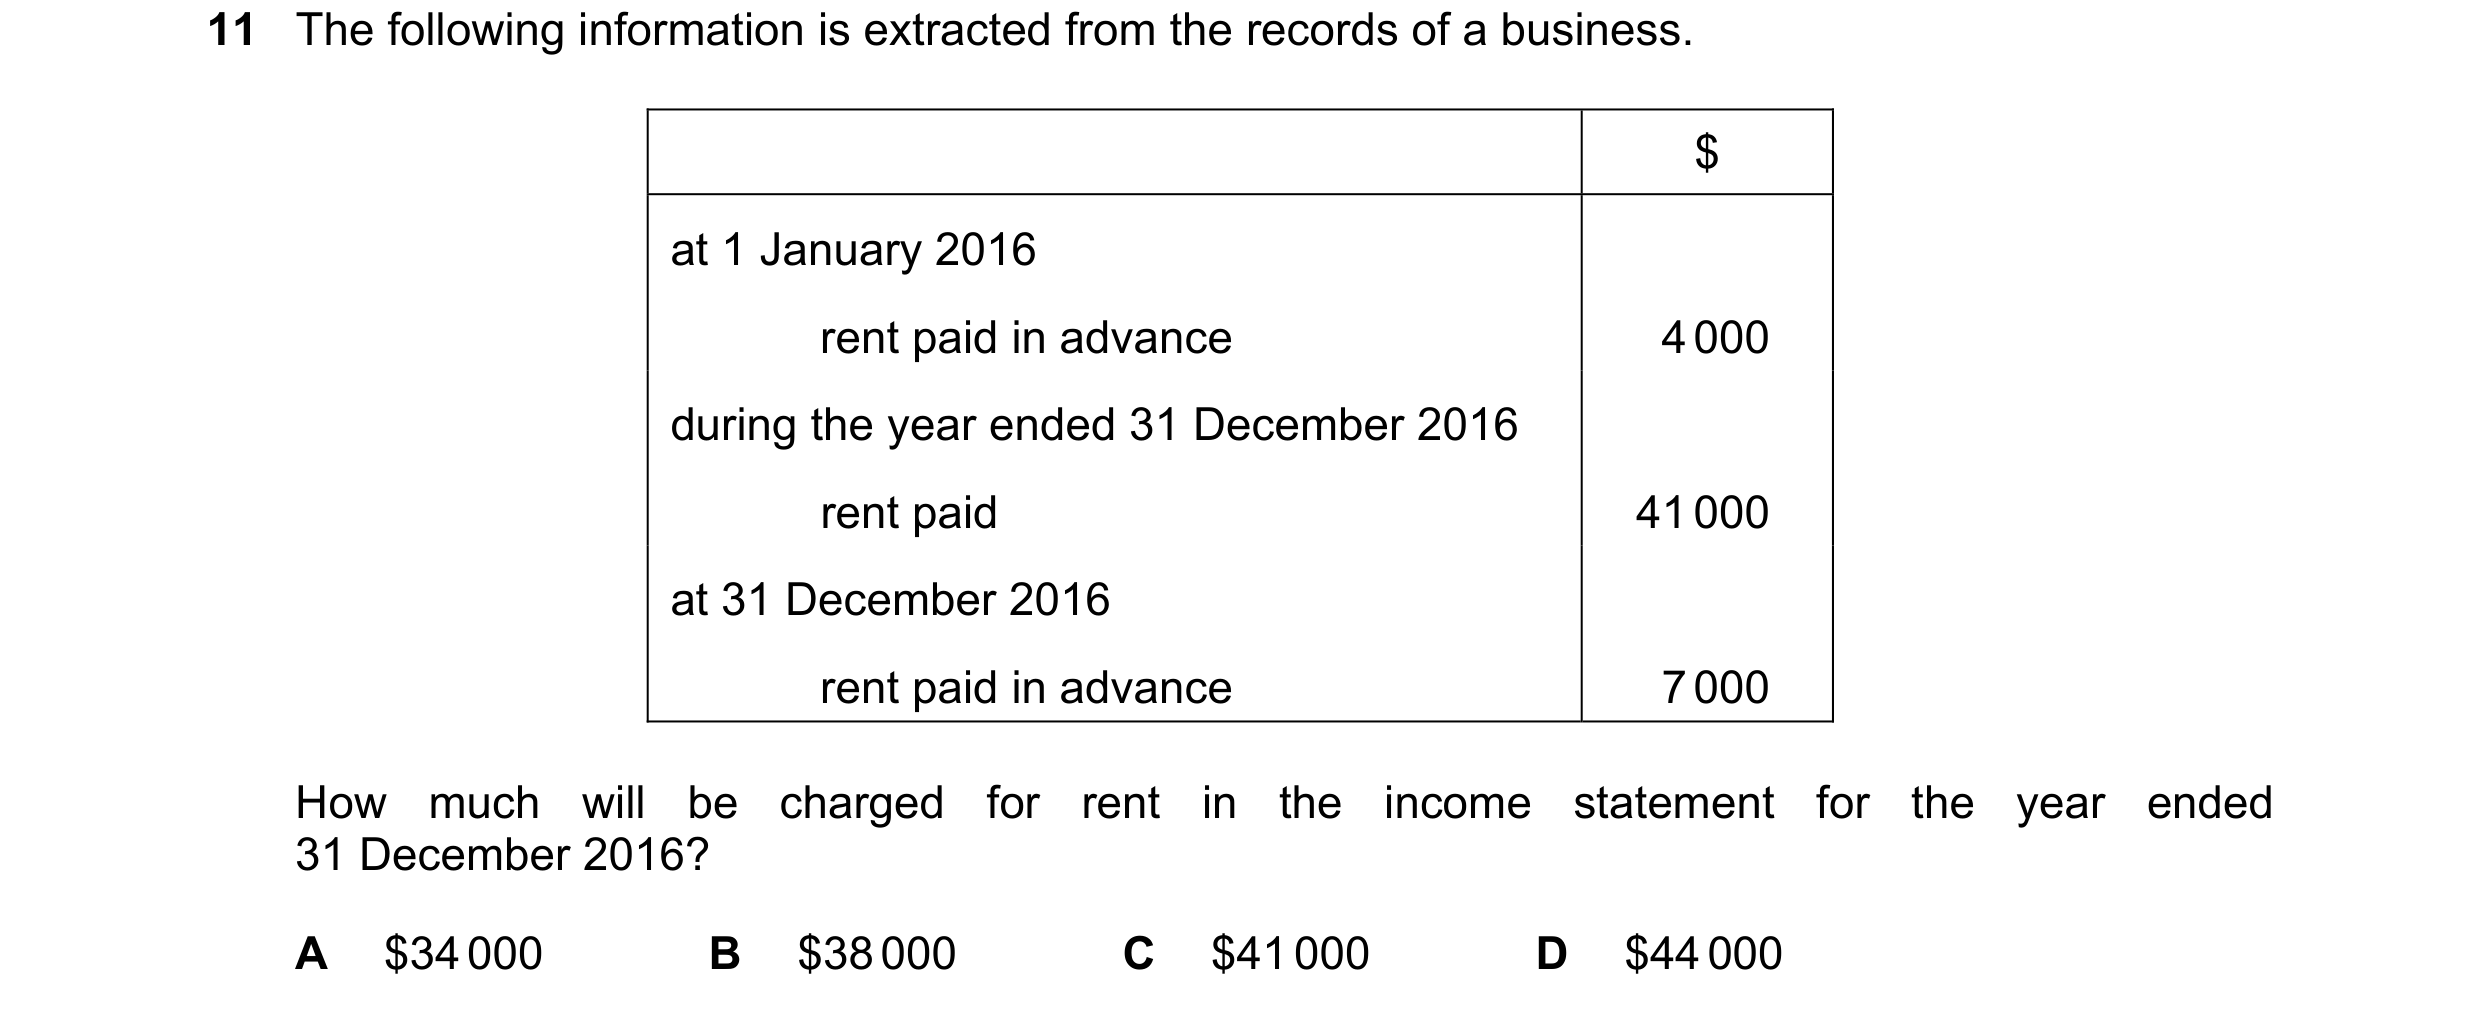 138 / 233
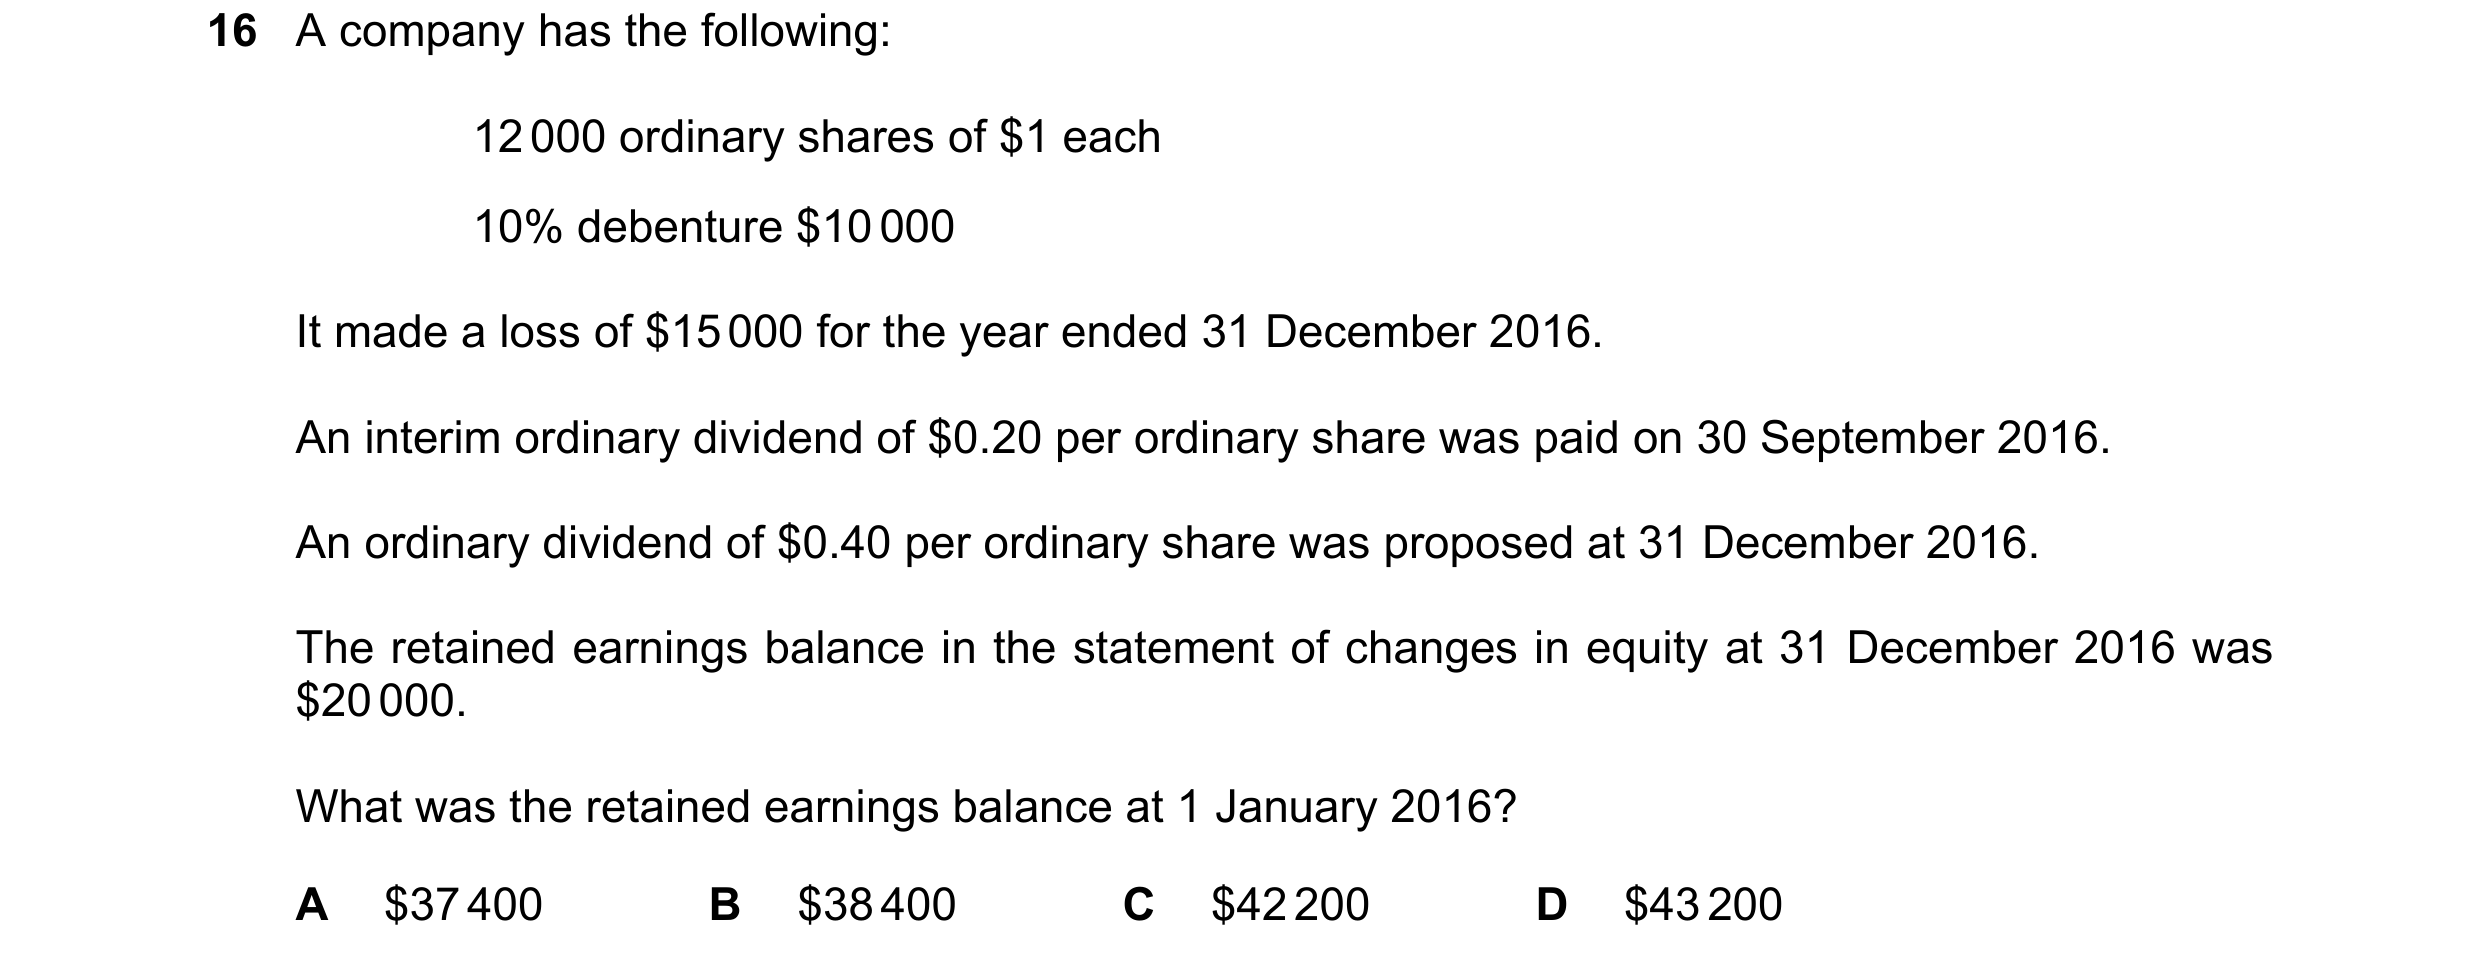
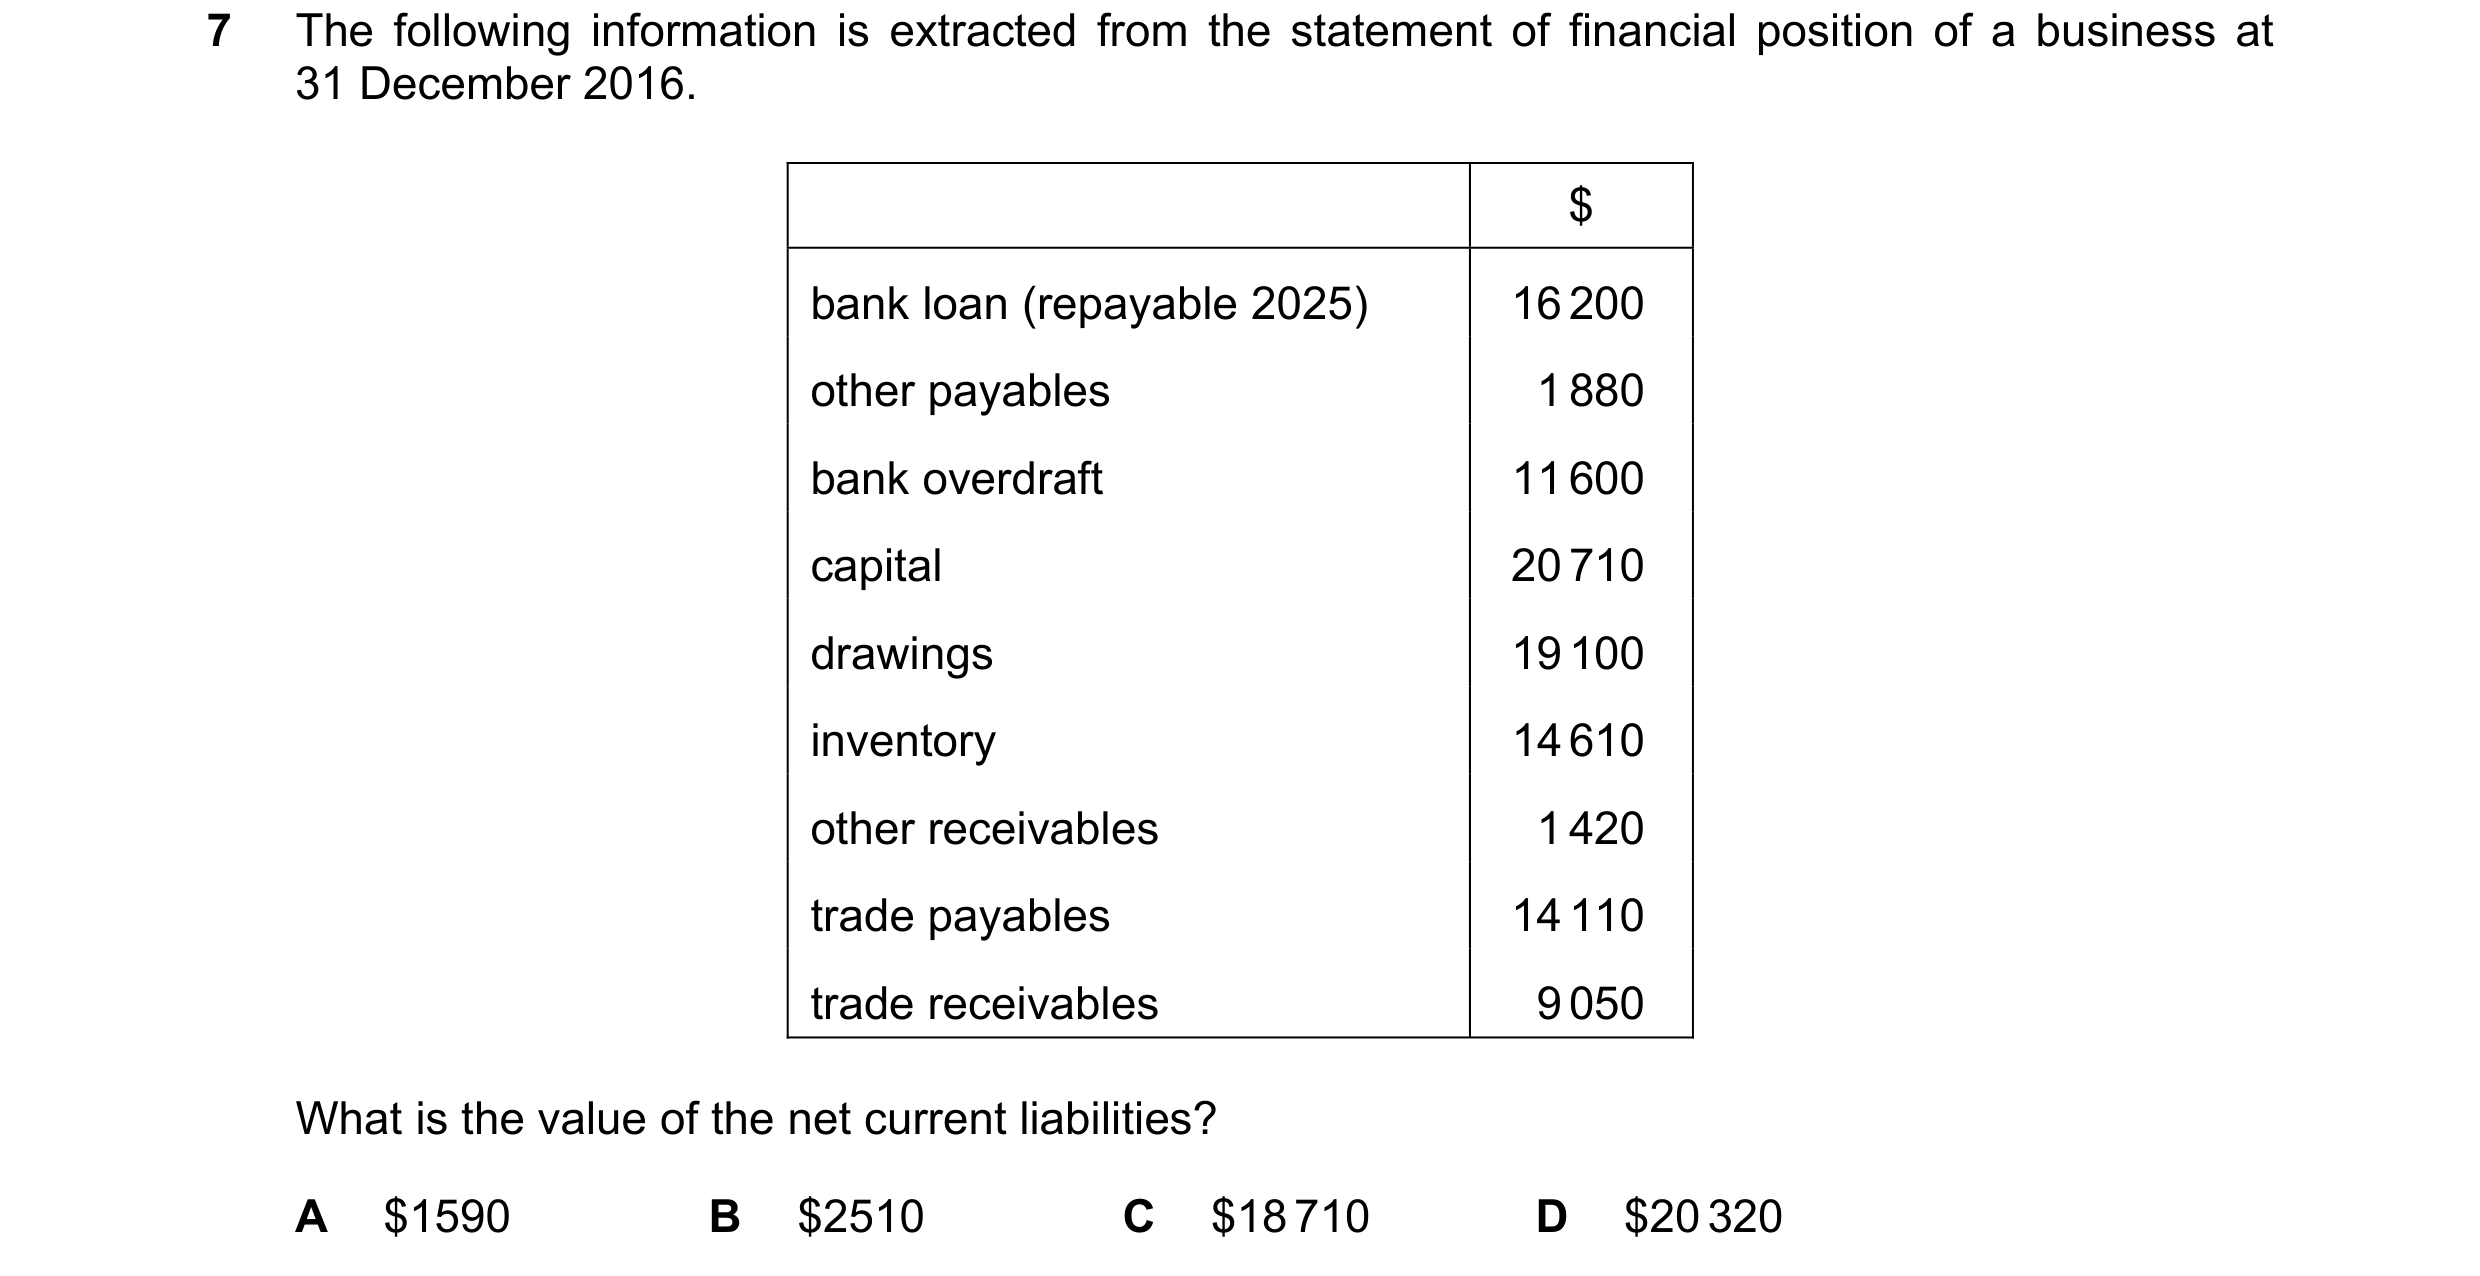
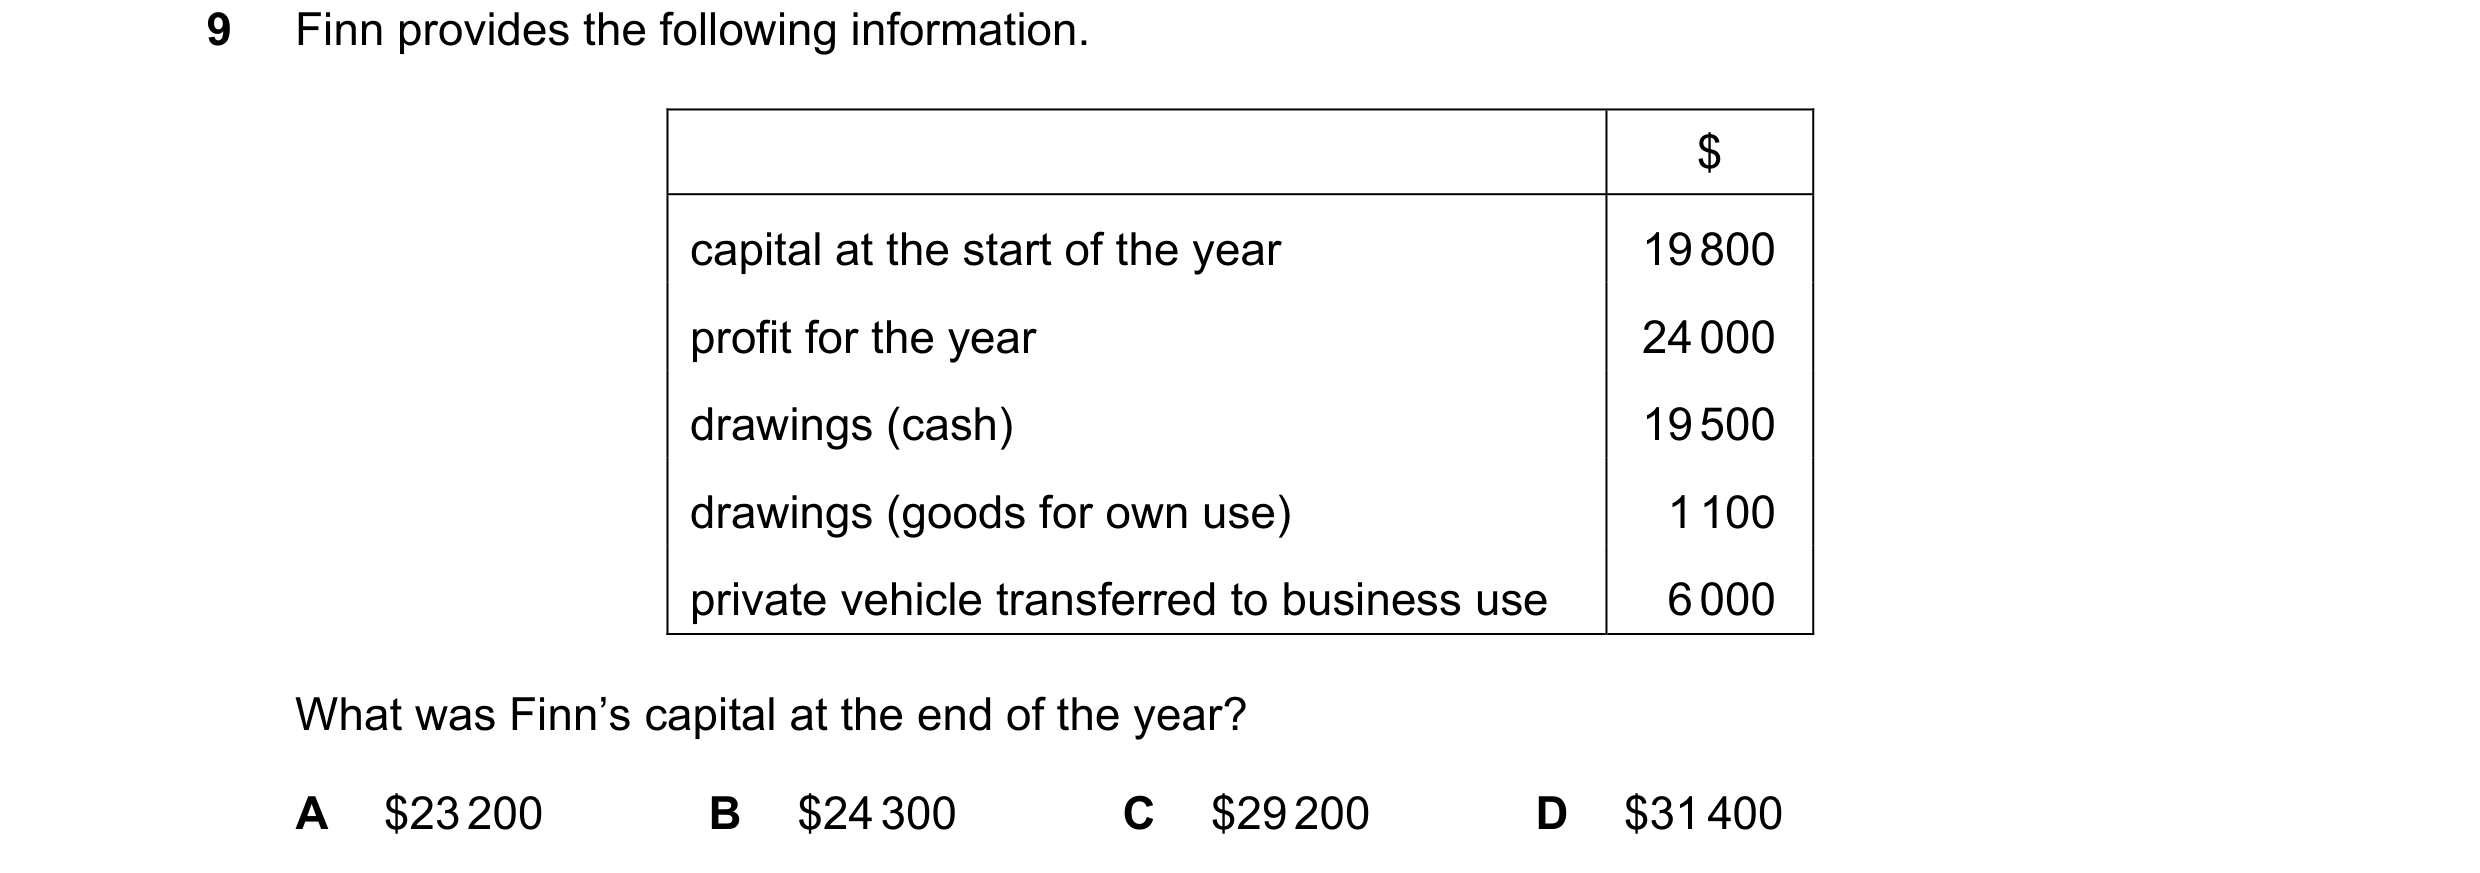 139 / 233
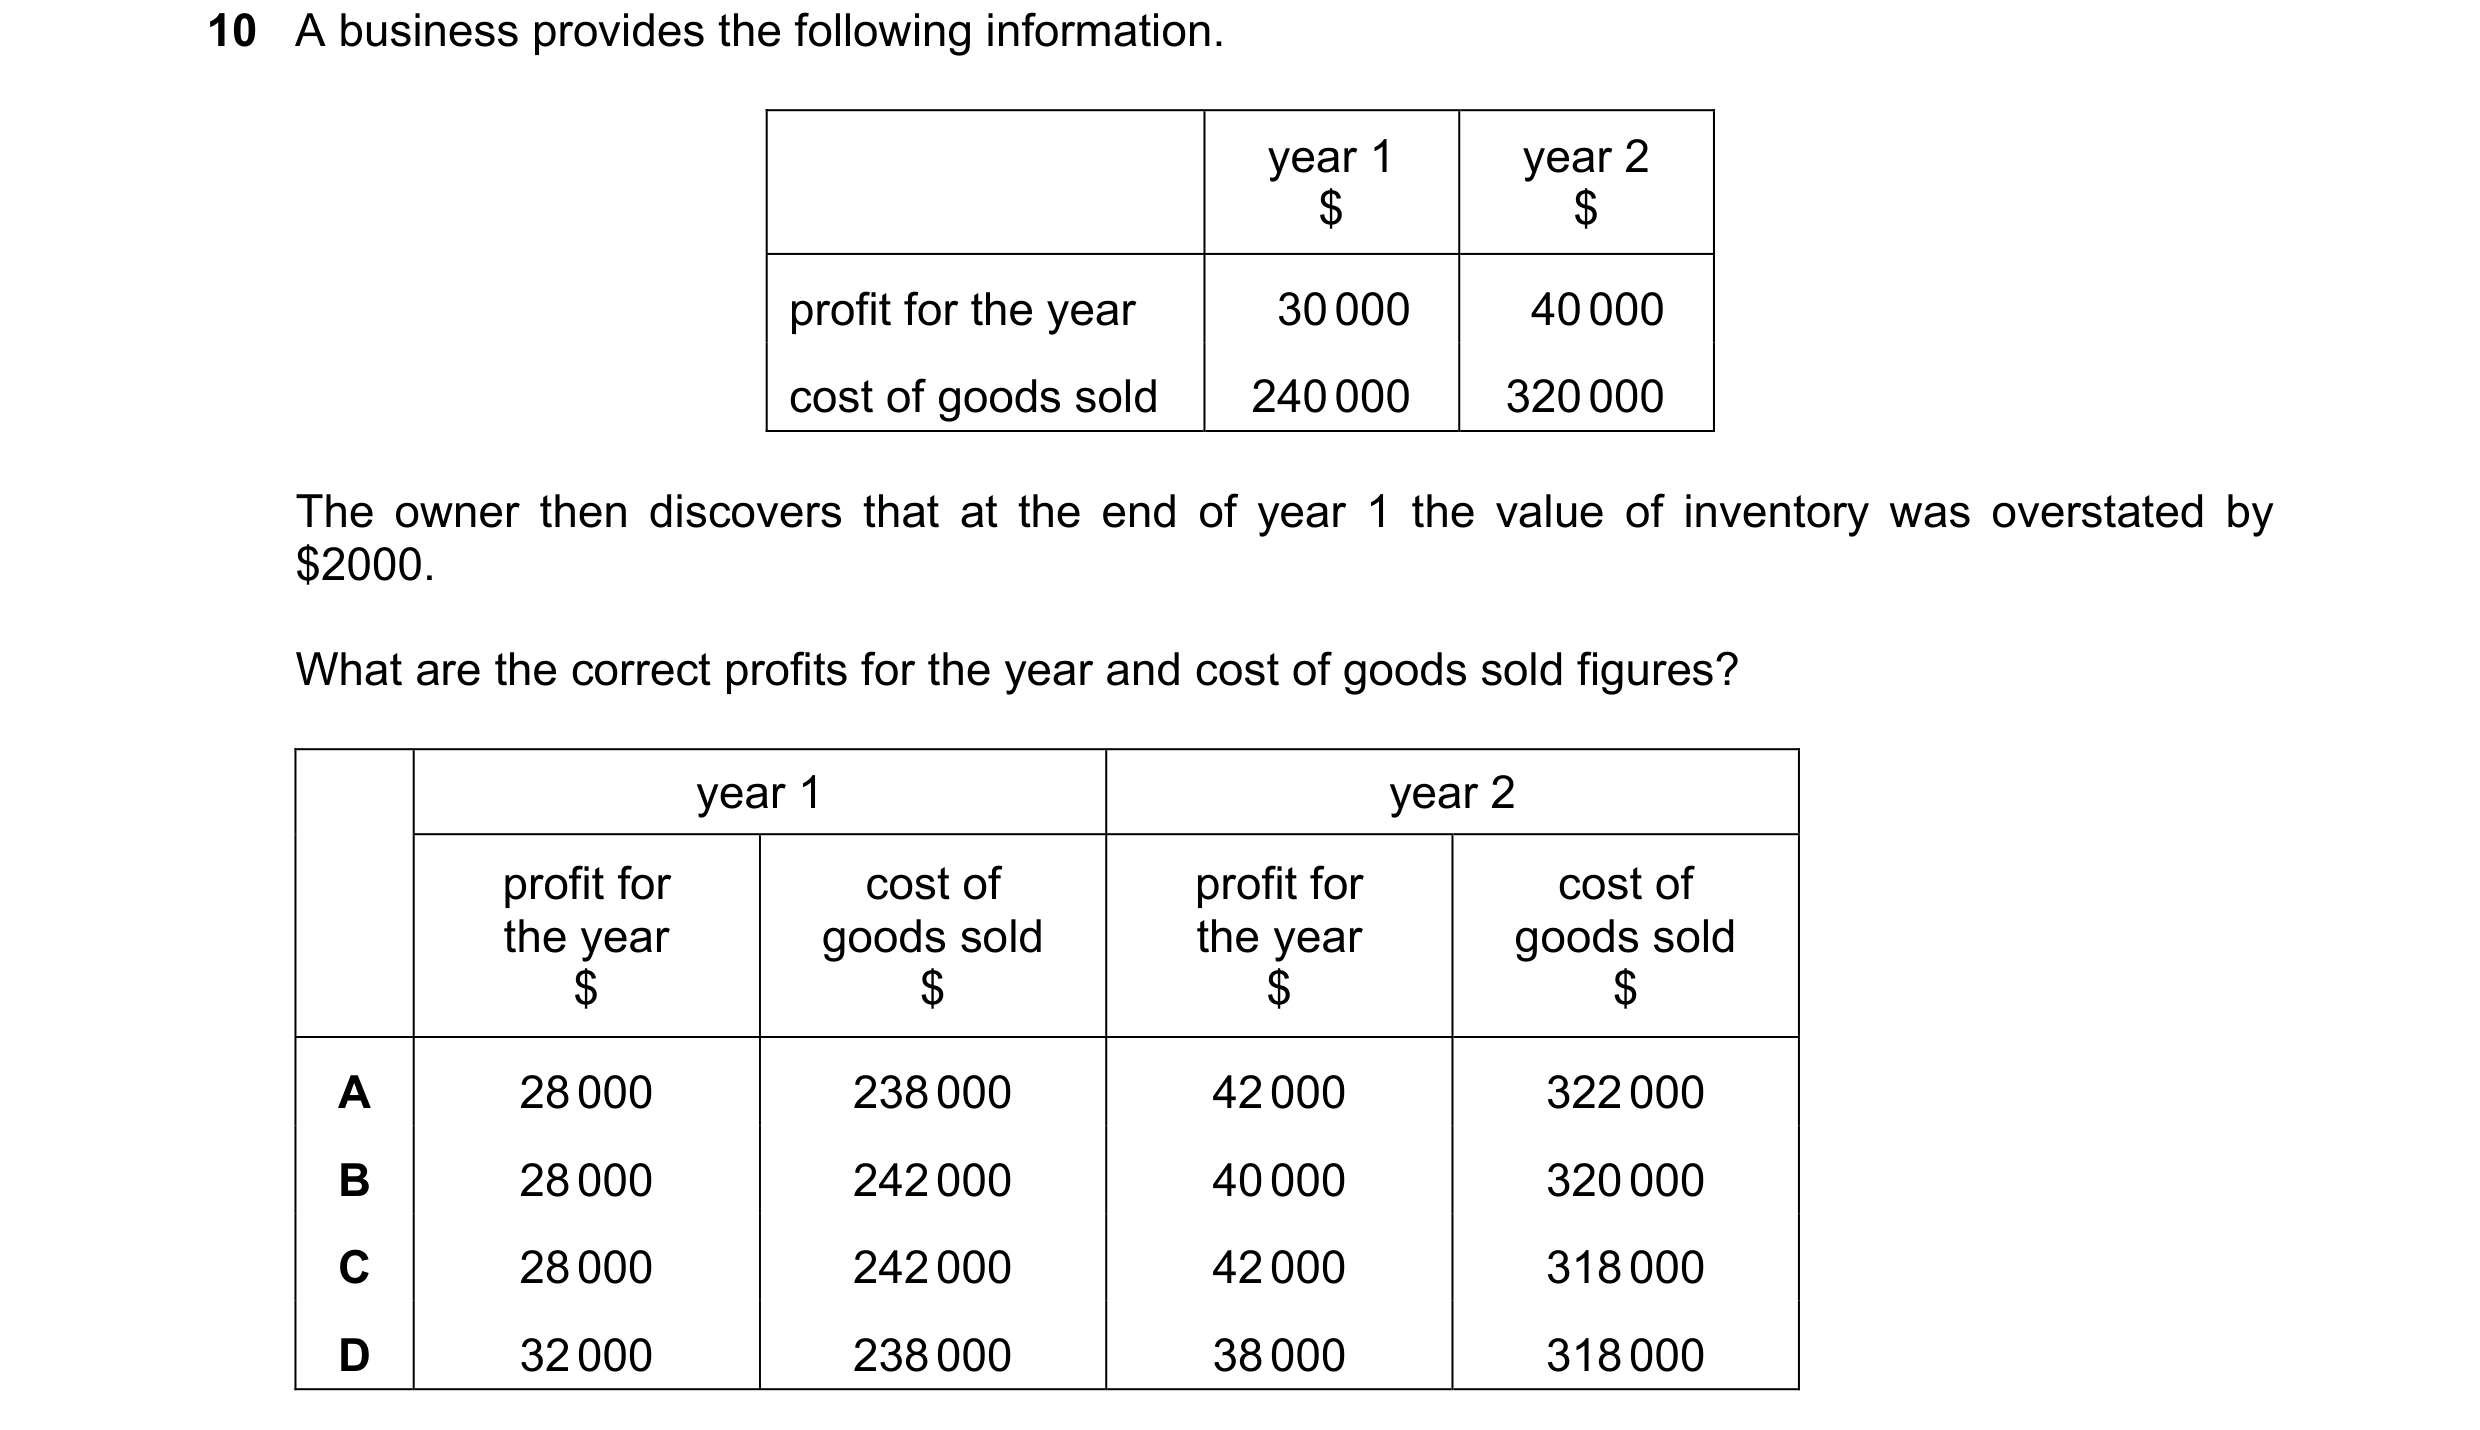
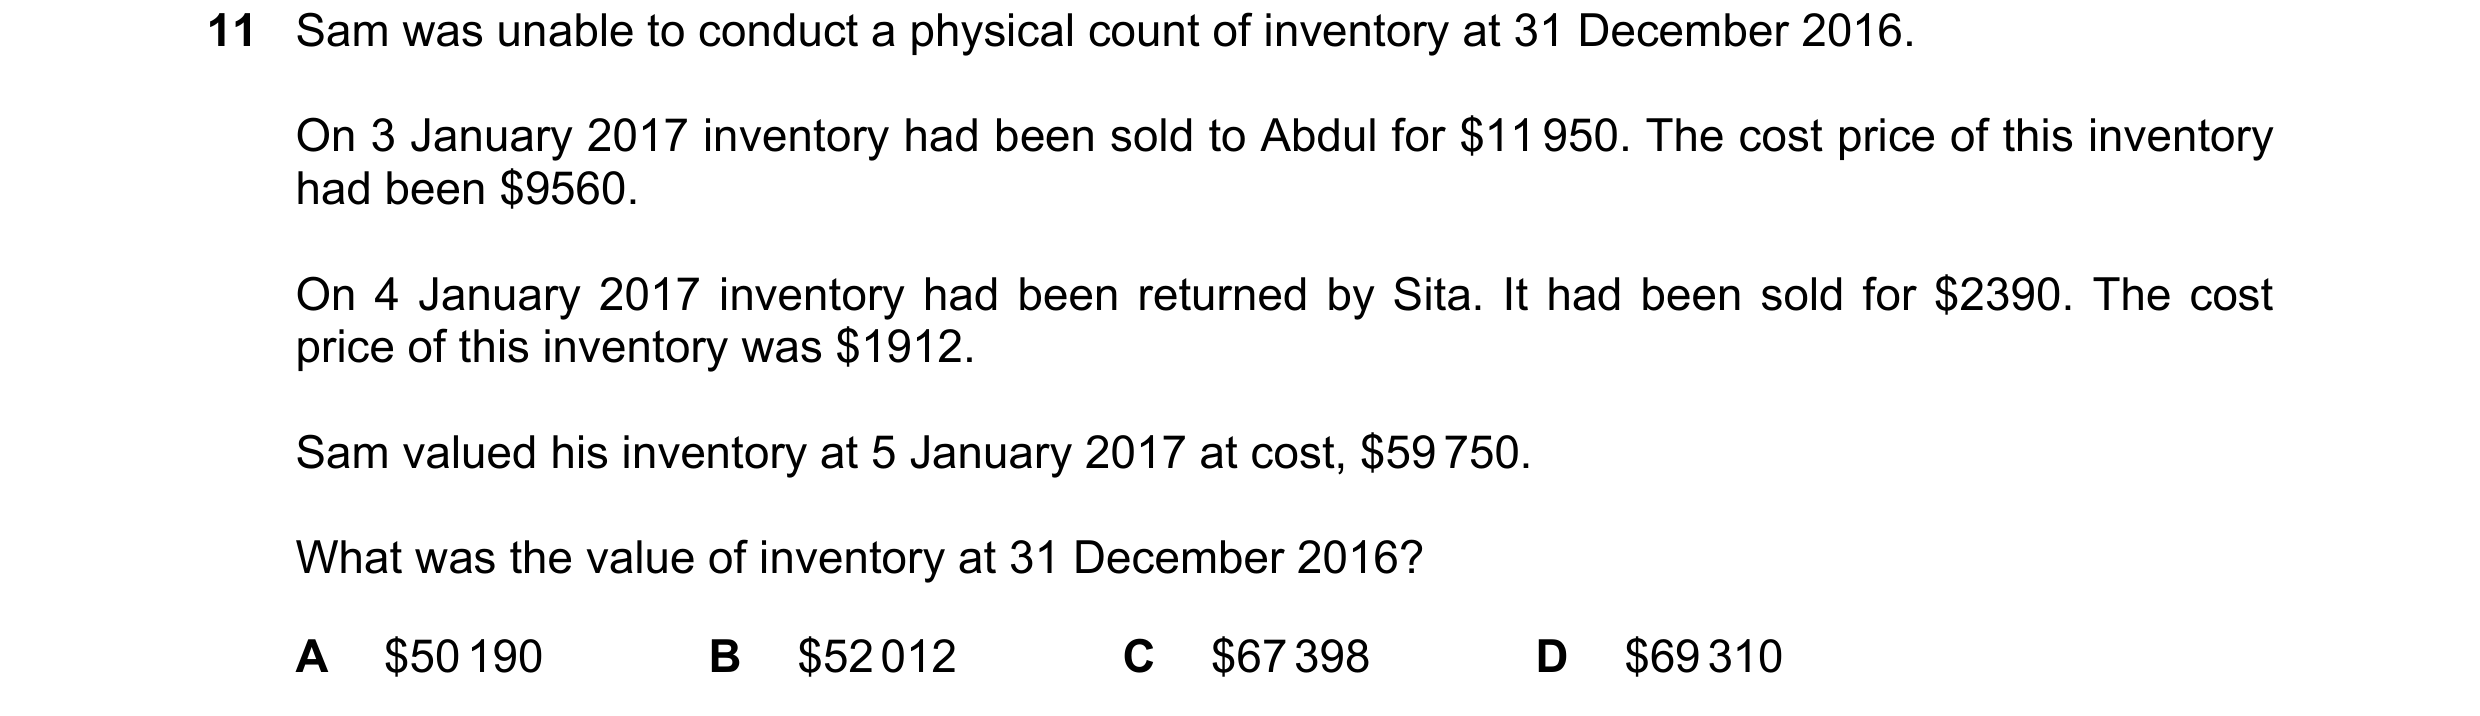
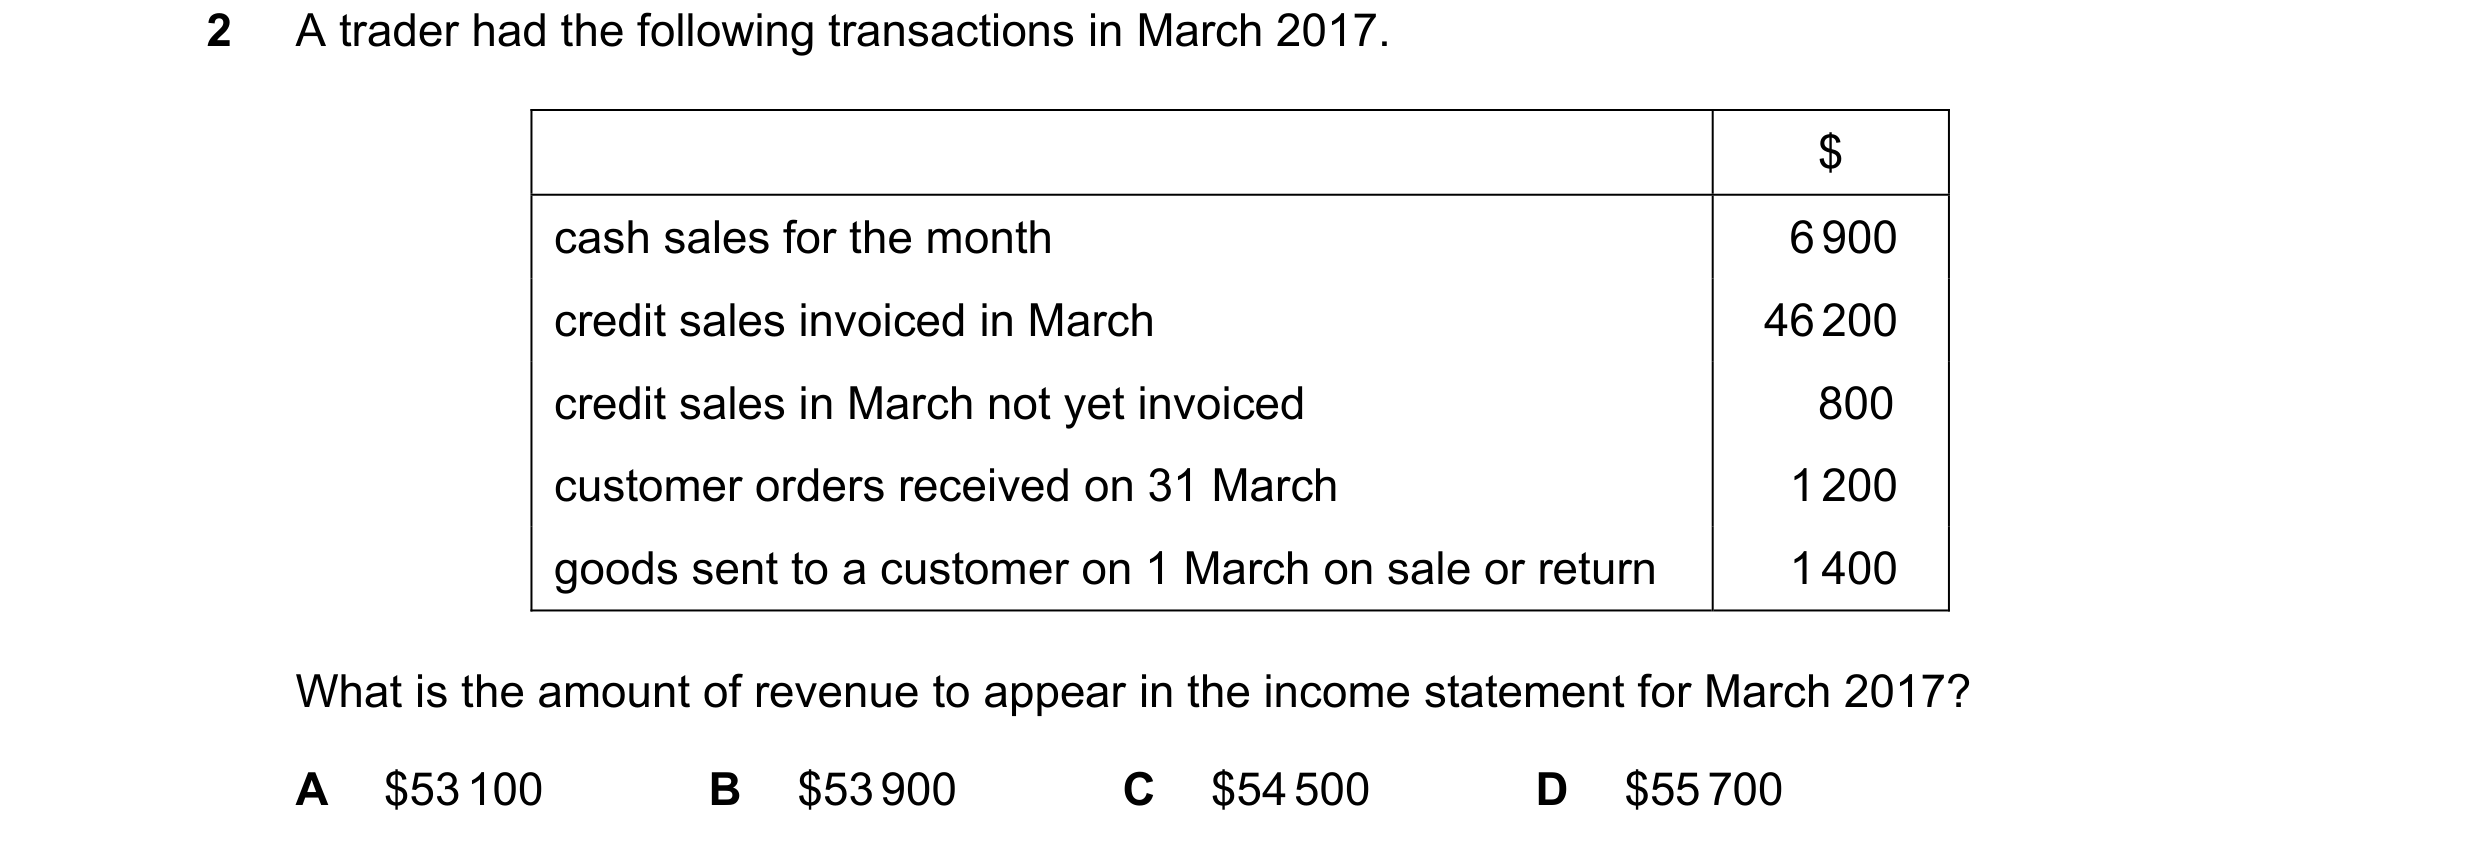 140 / 233
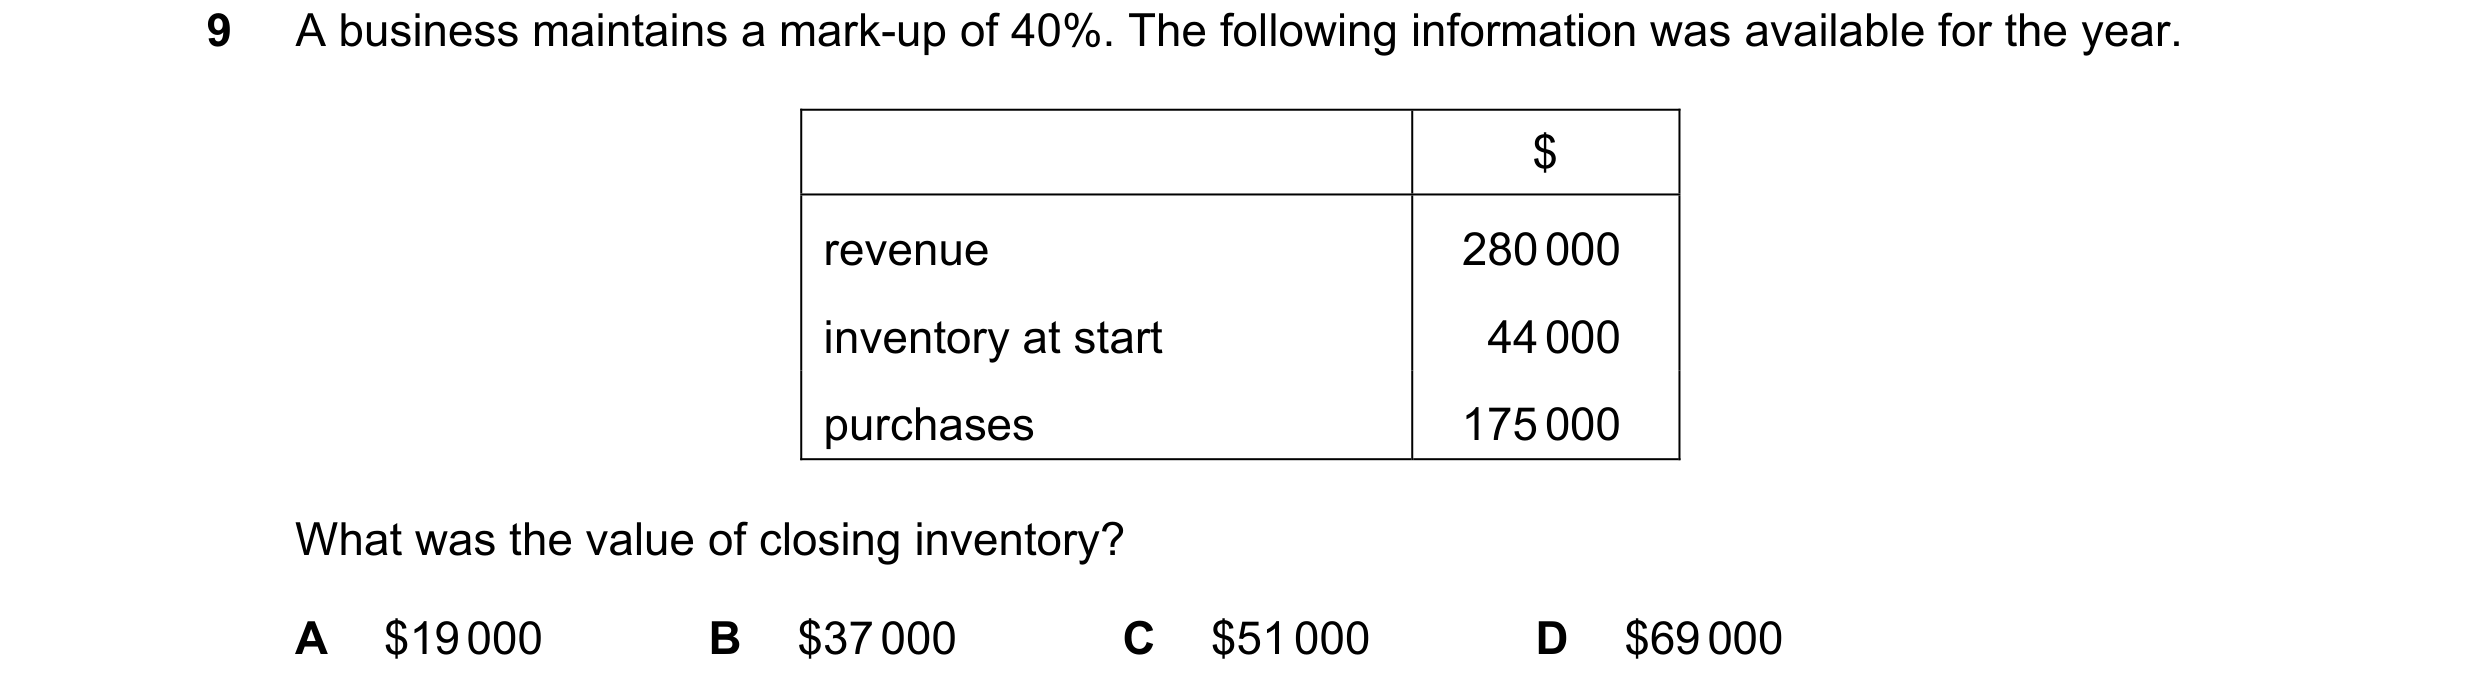
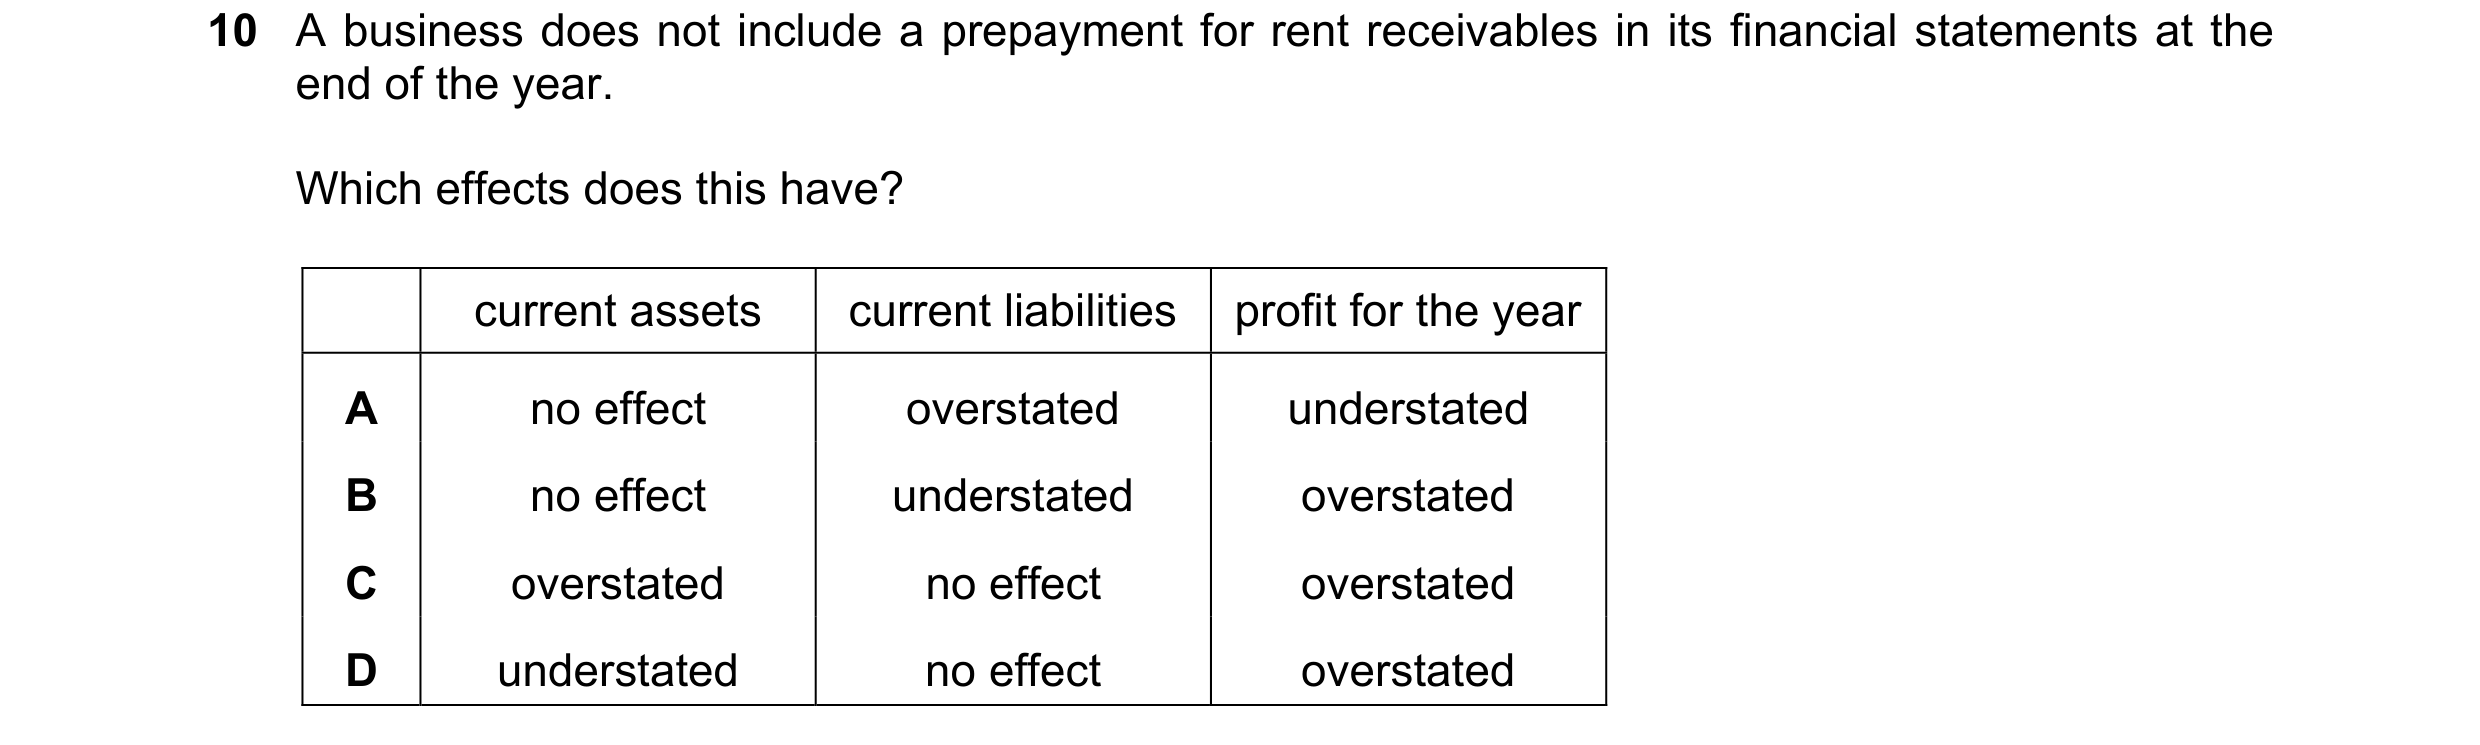
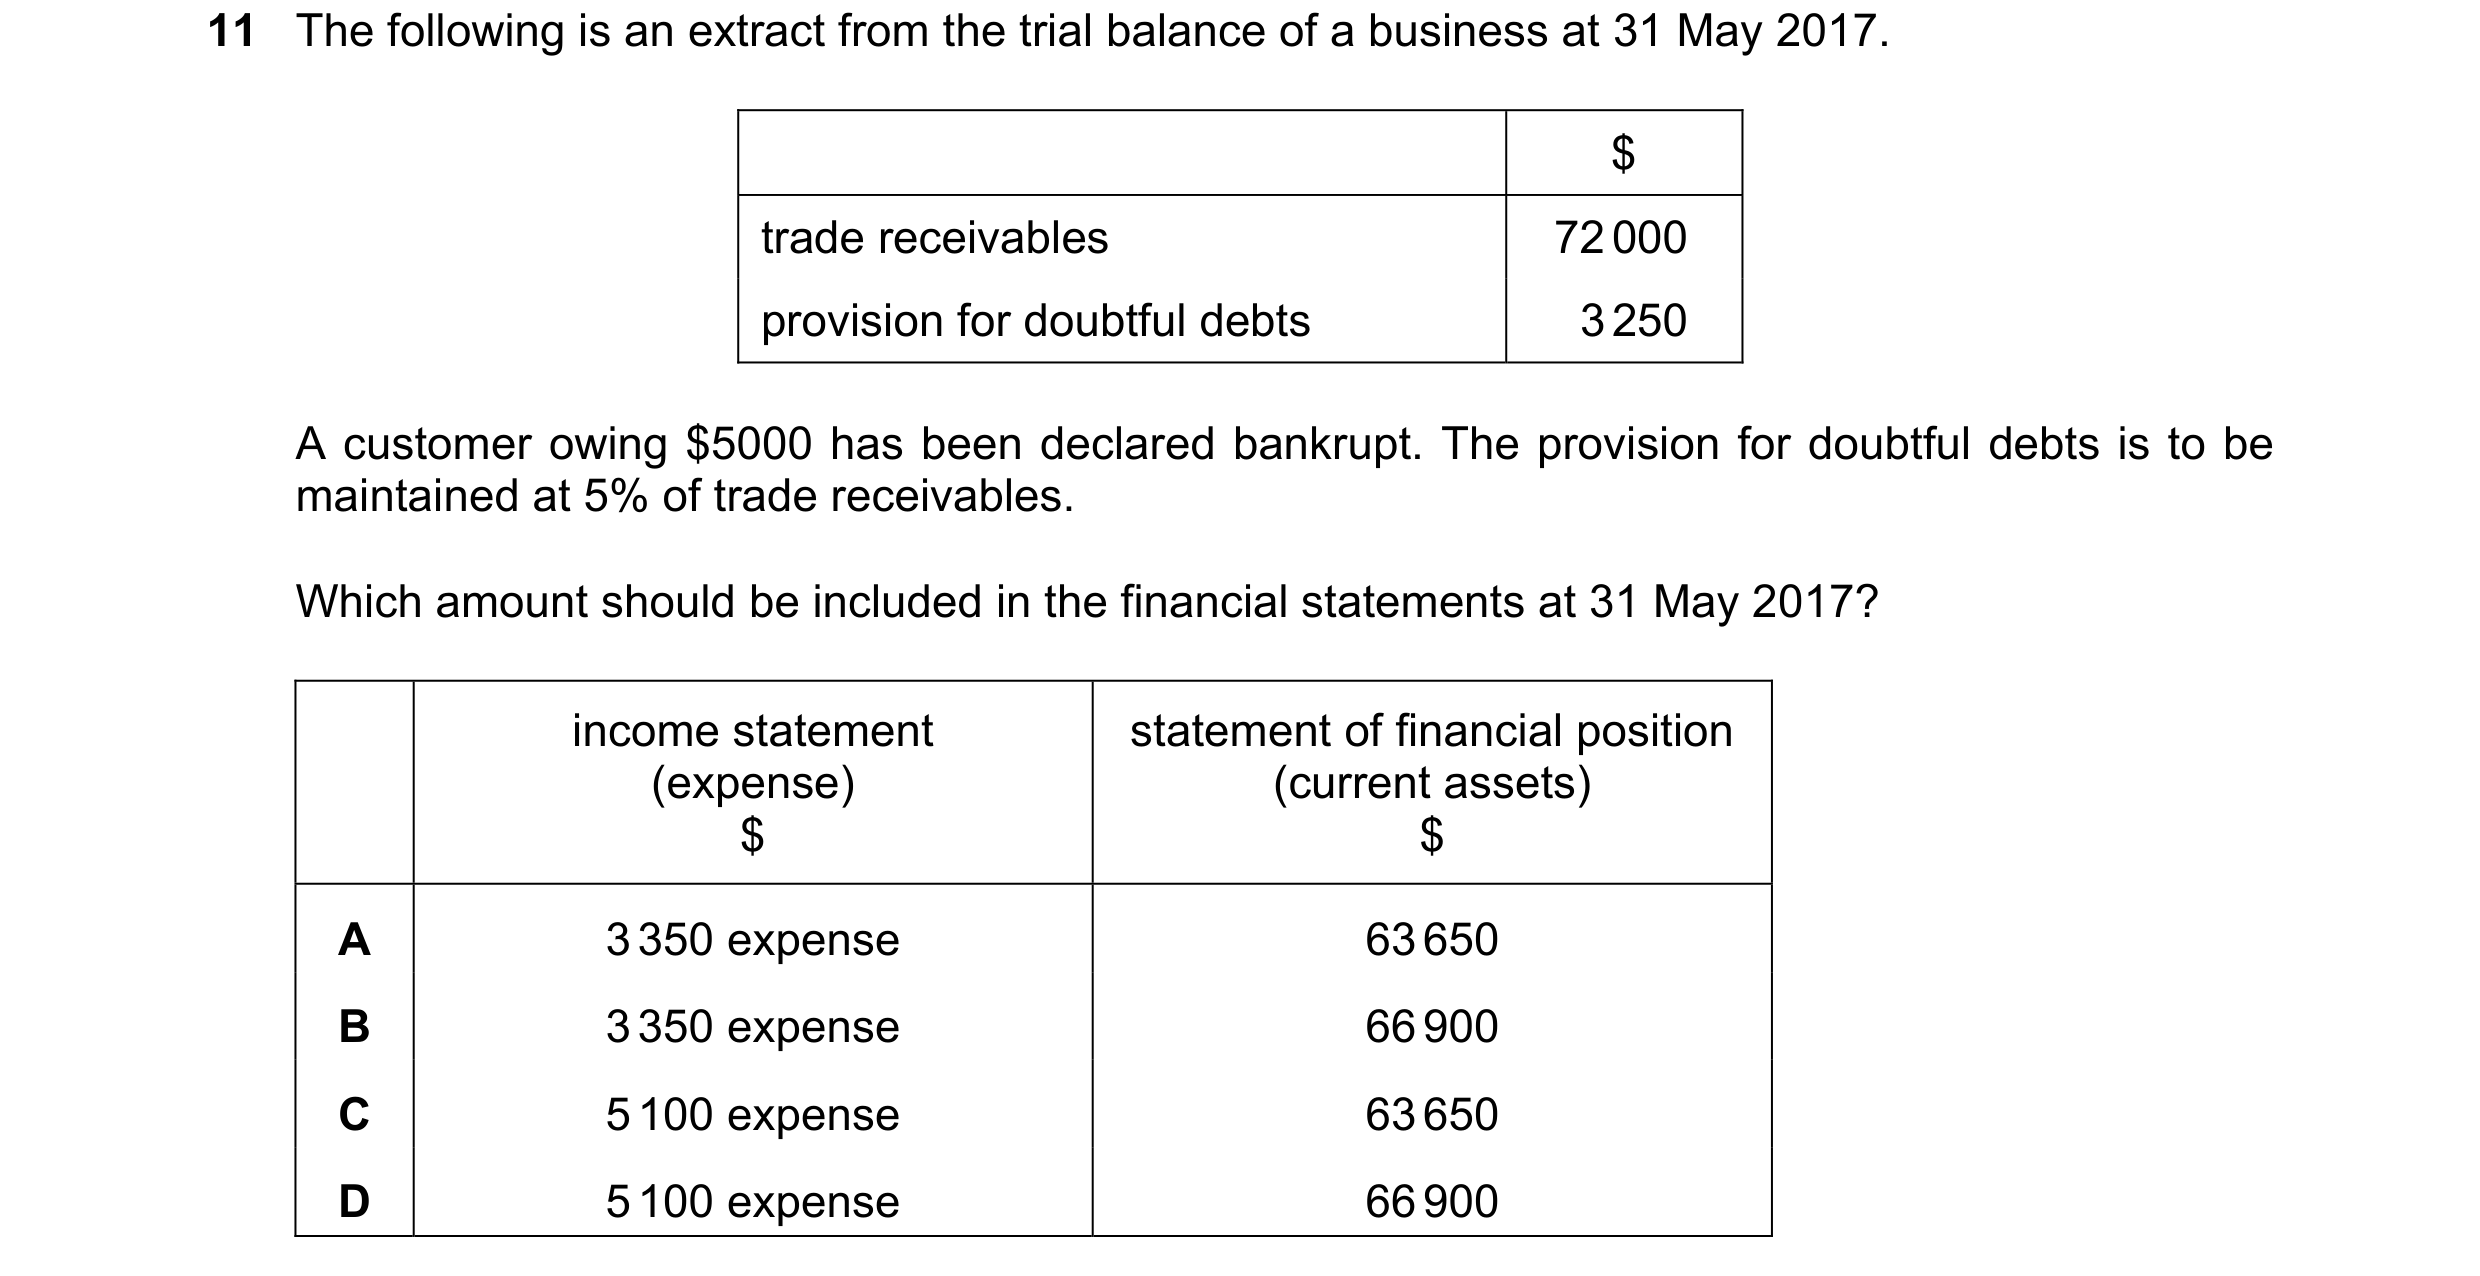 141 / 233
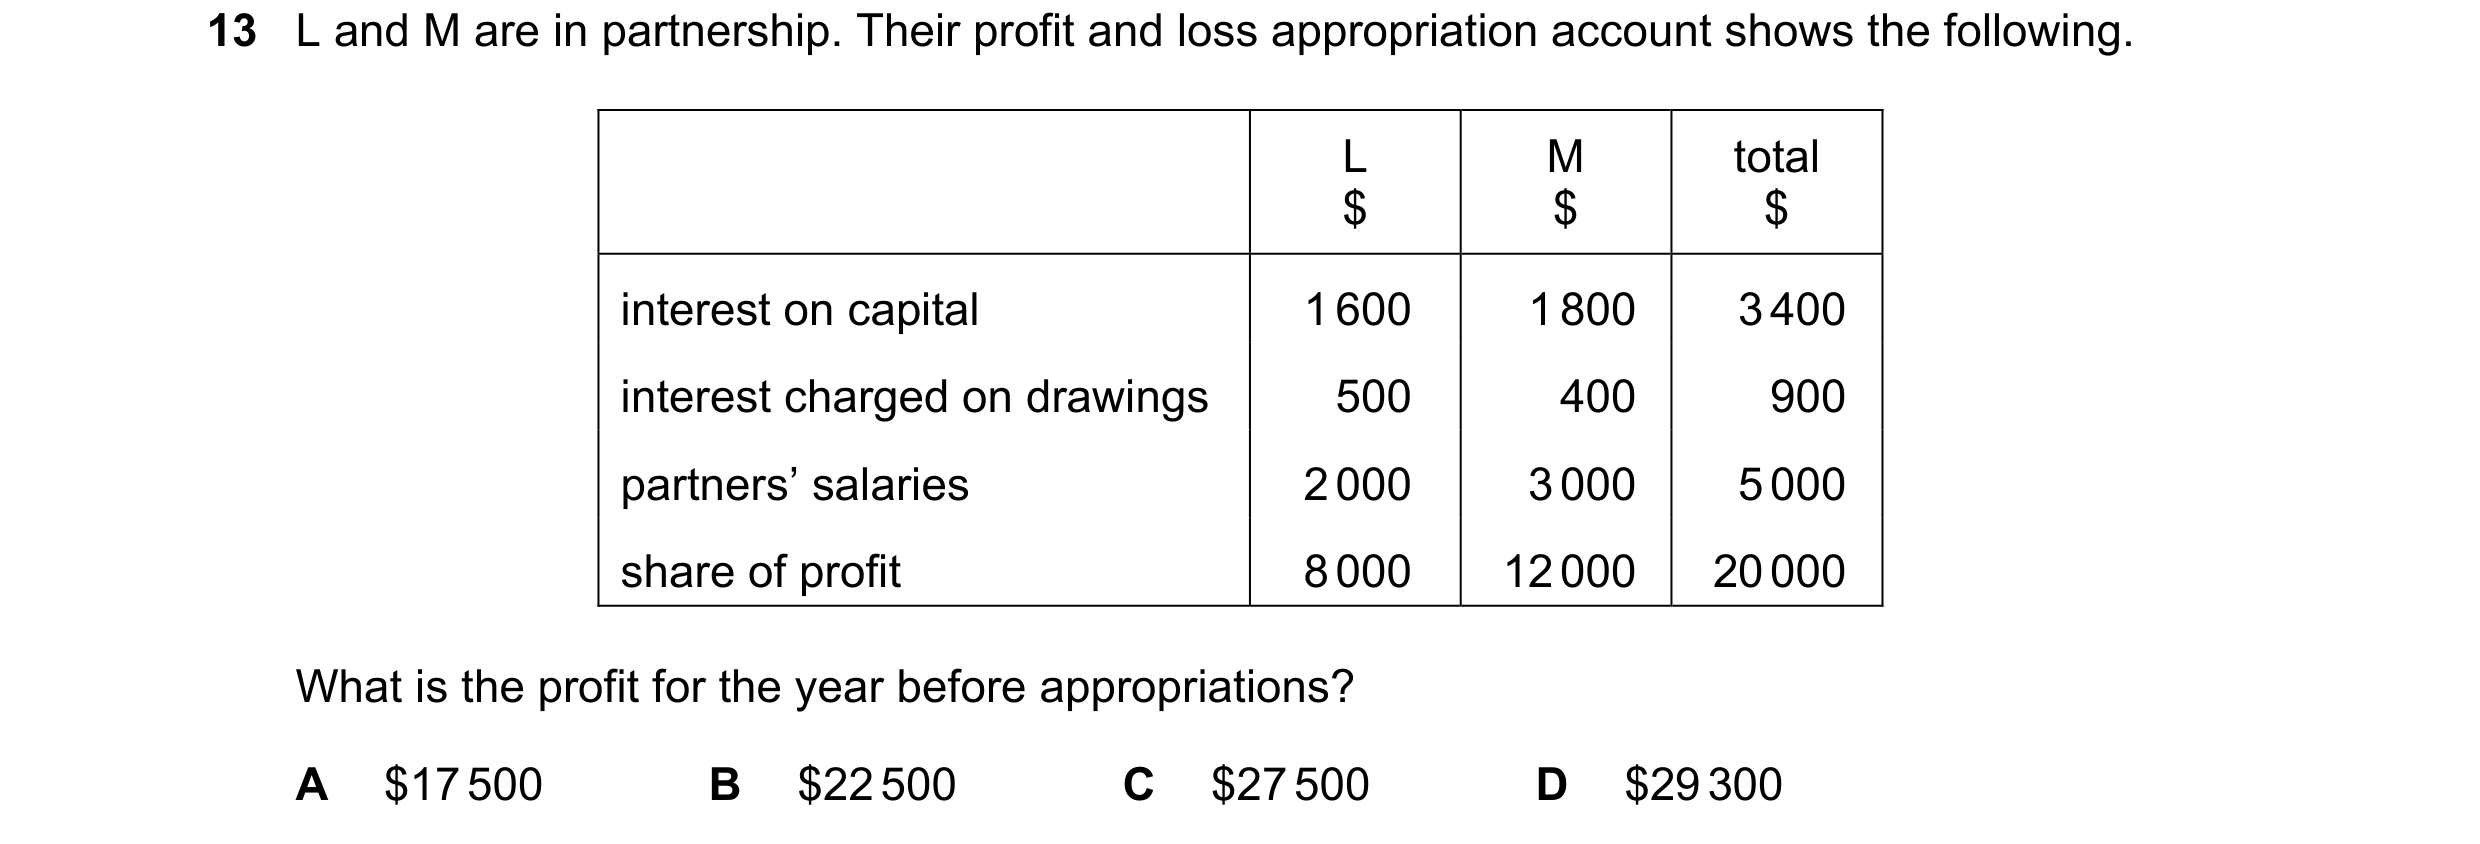
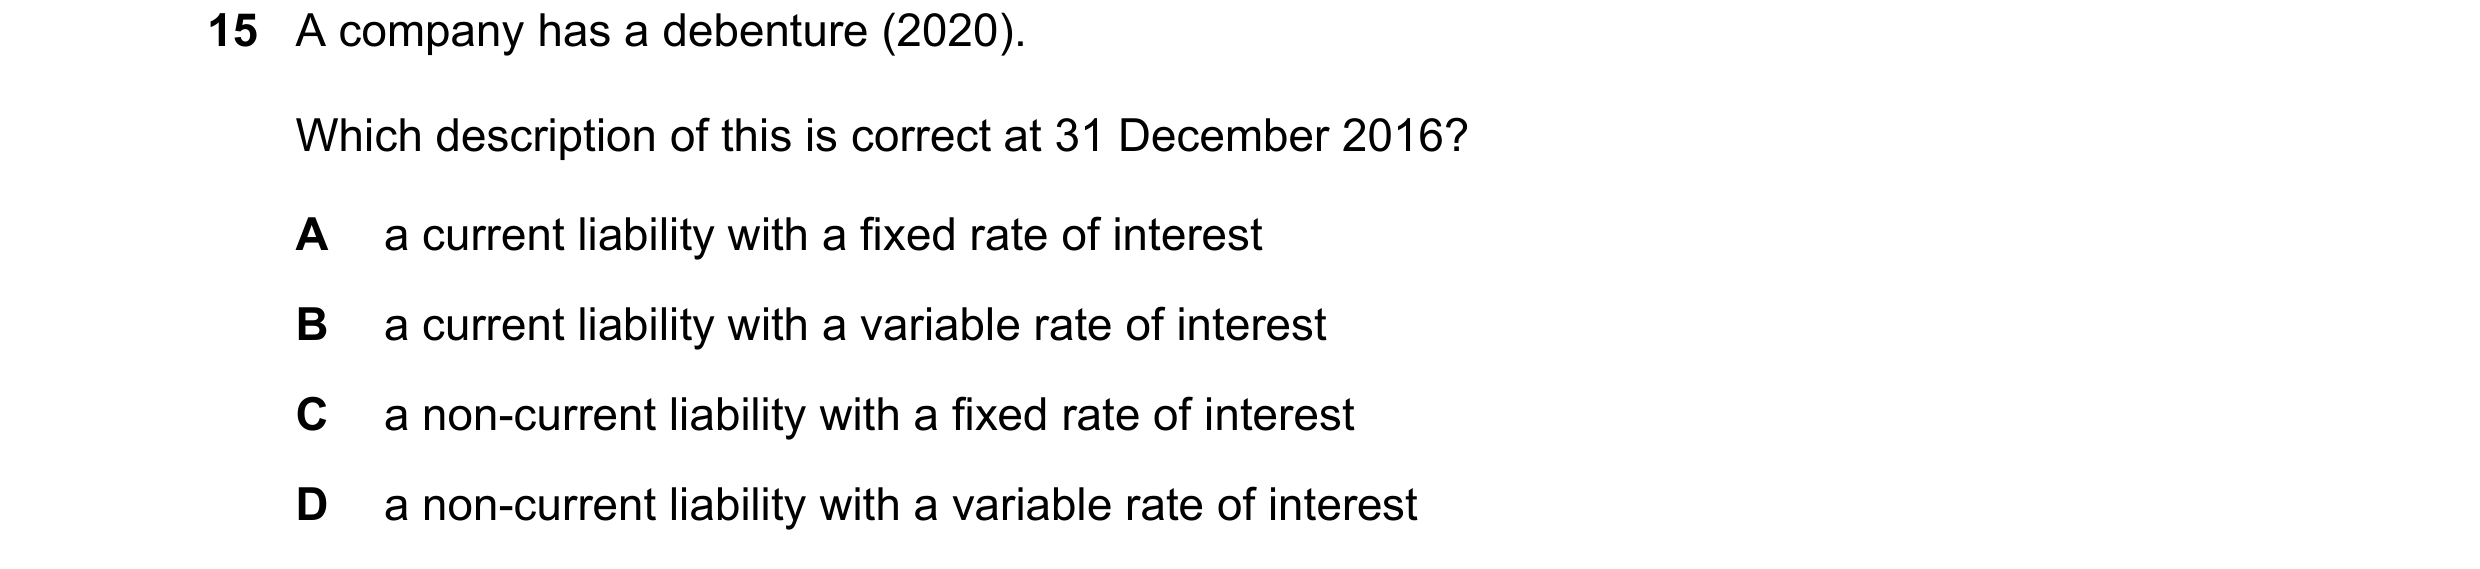
 142 / 233
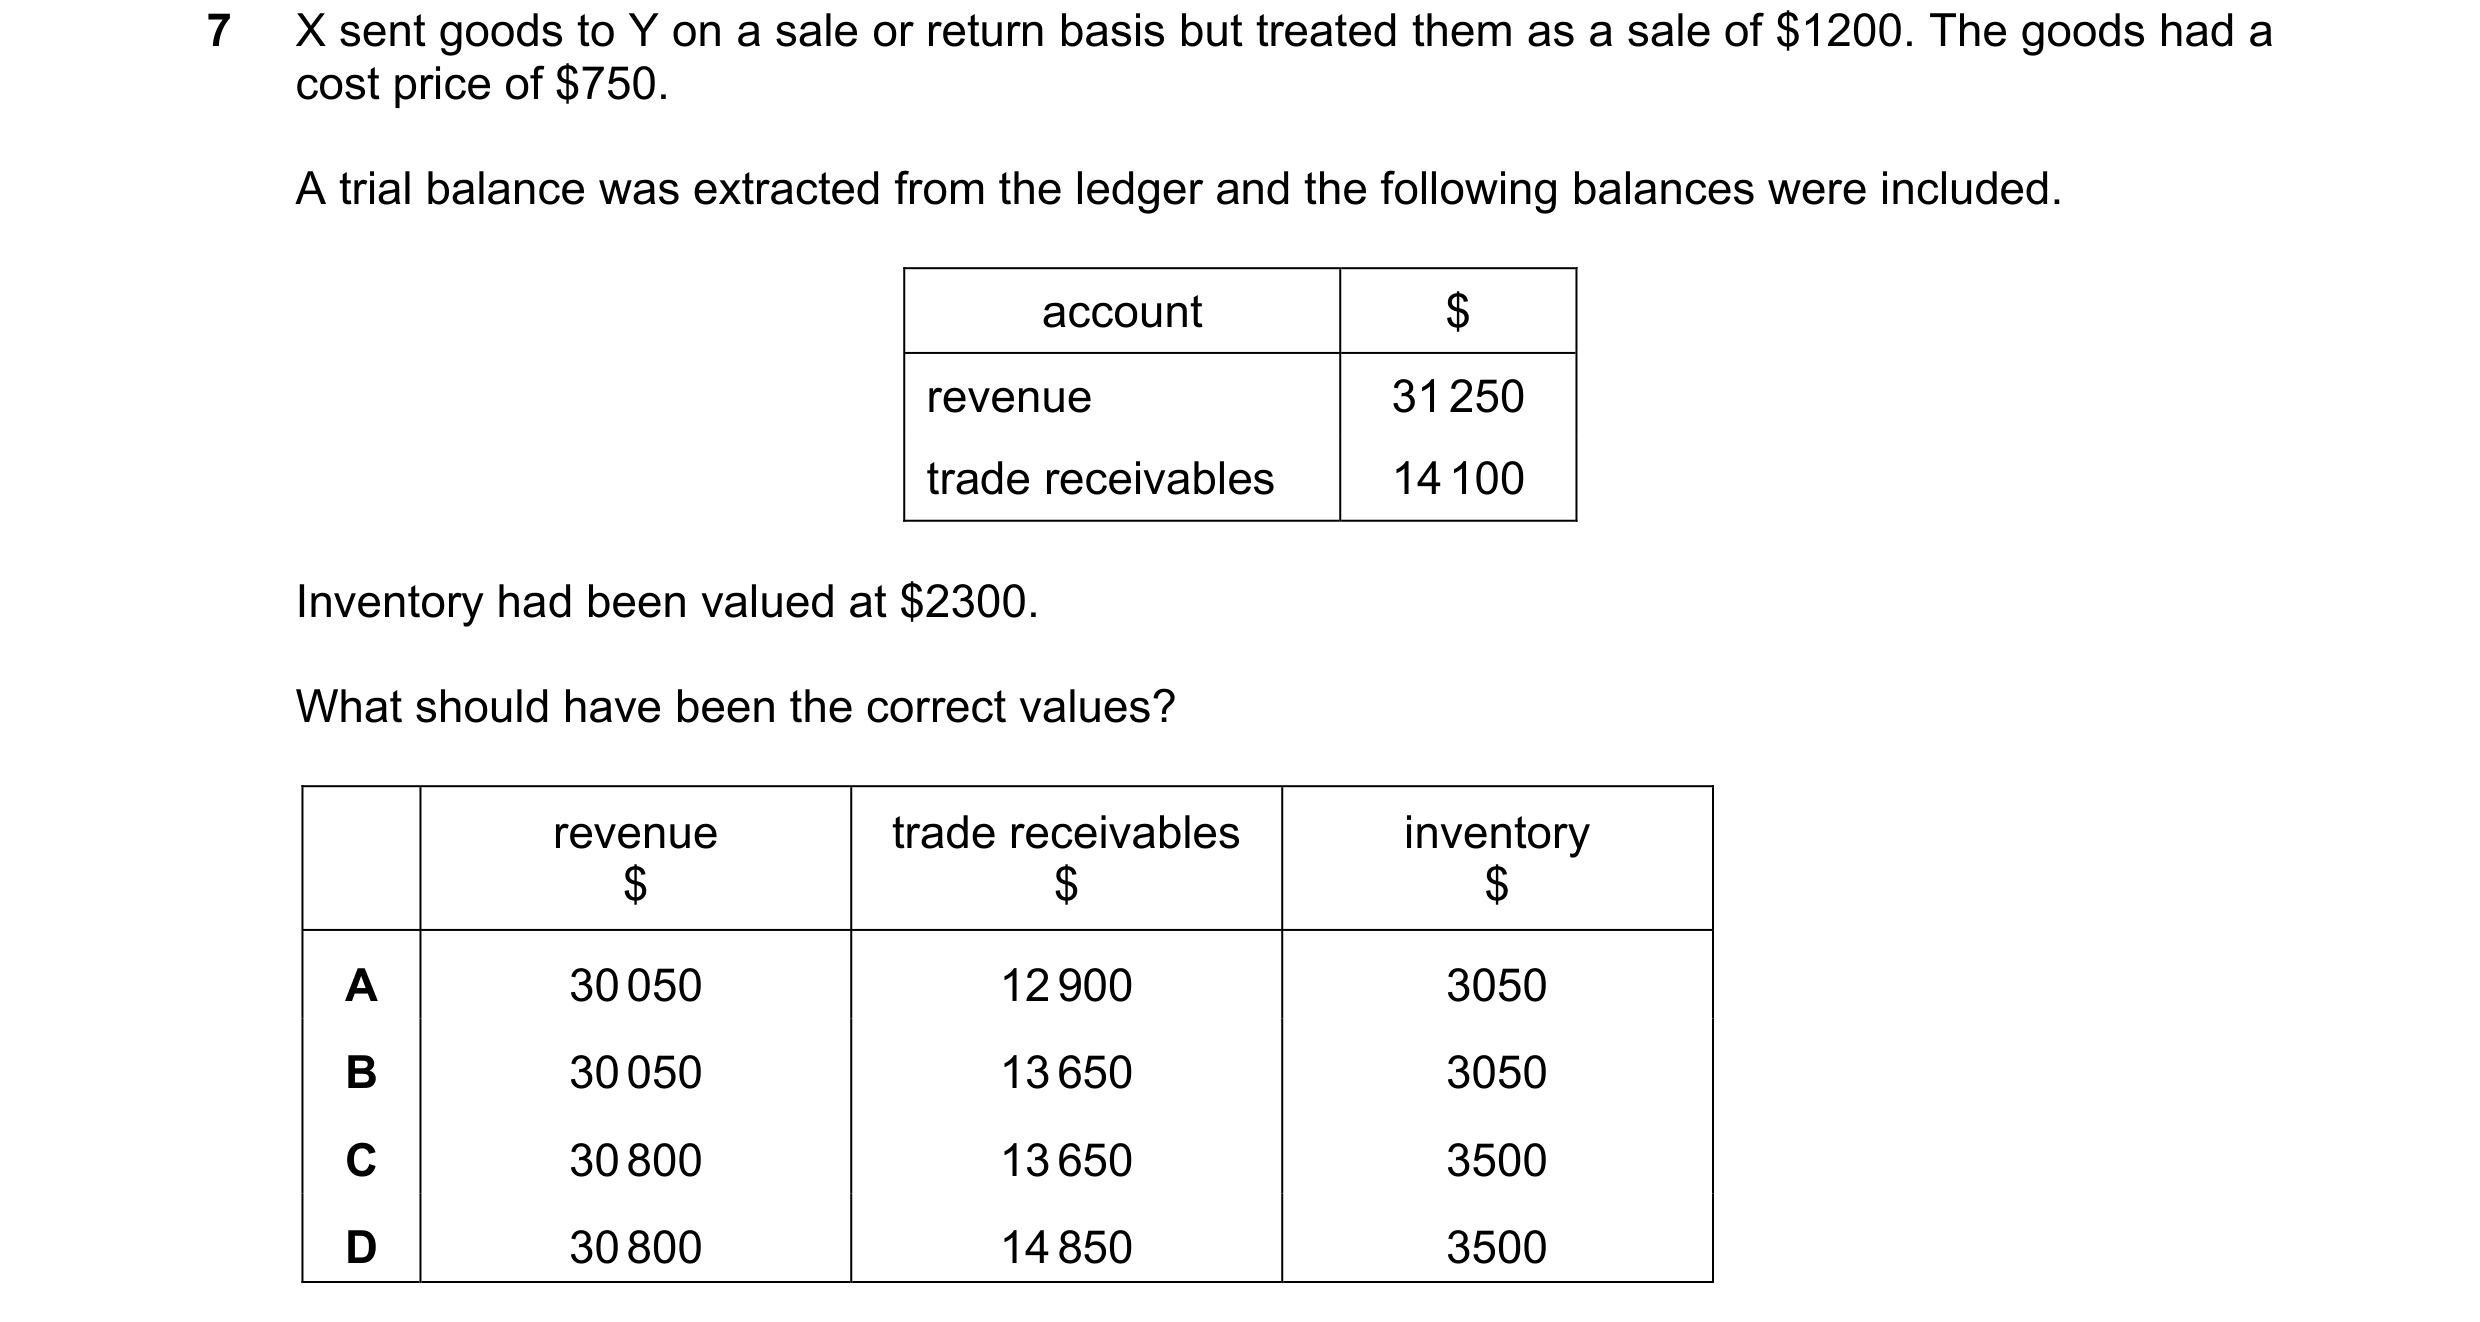
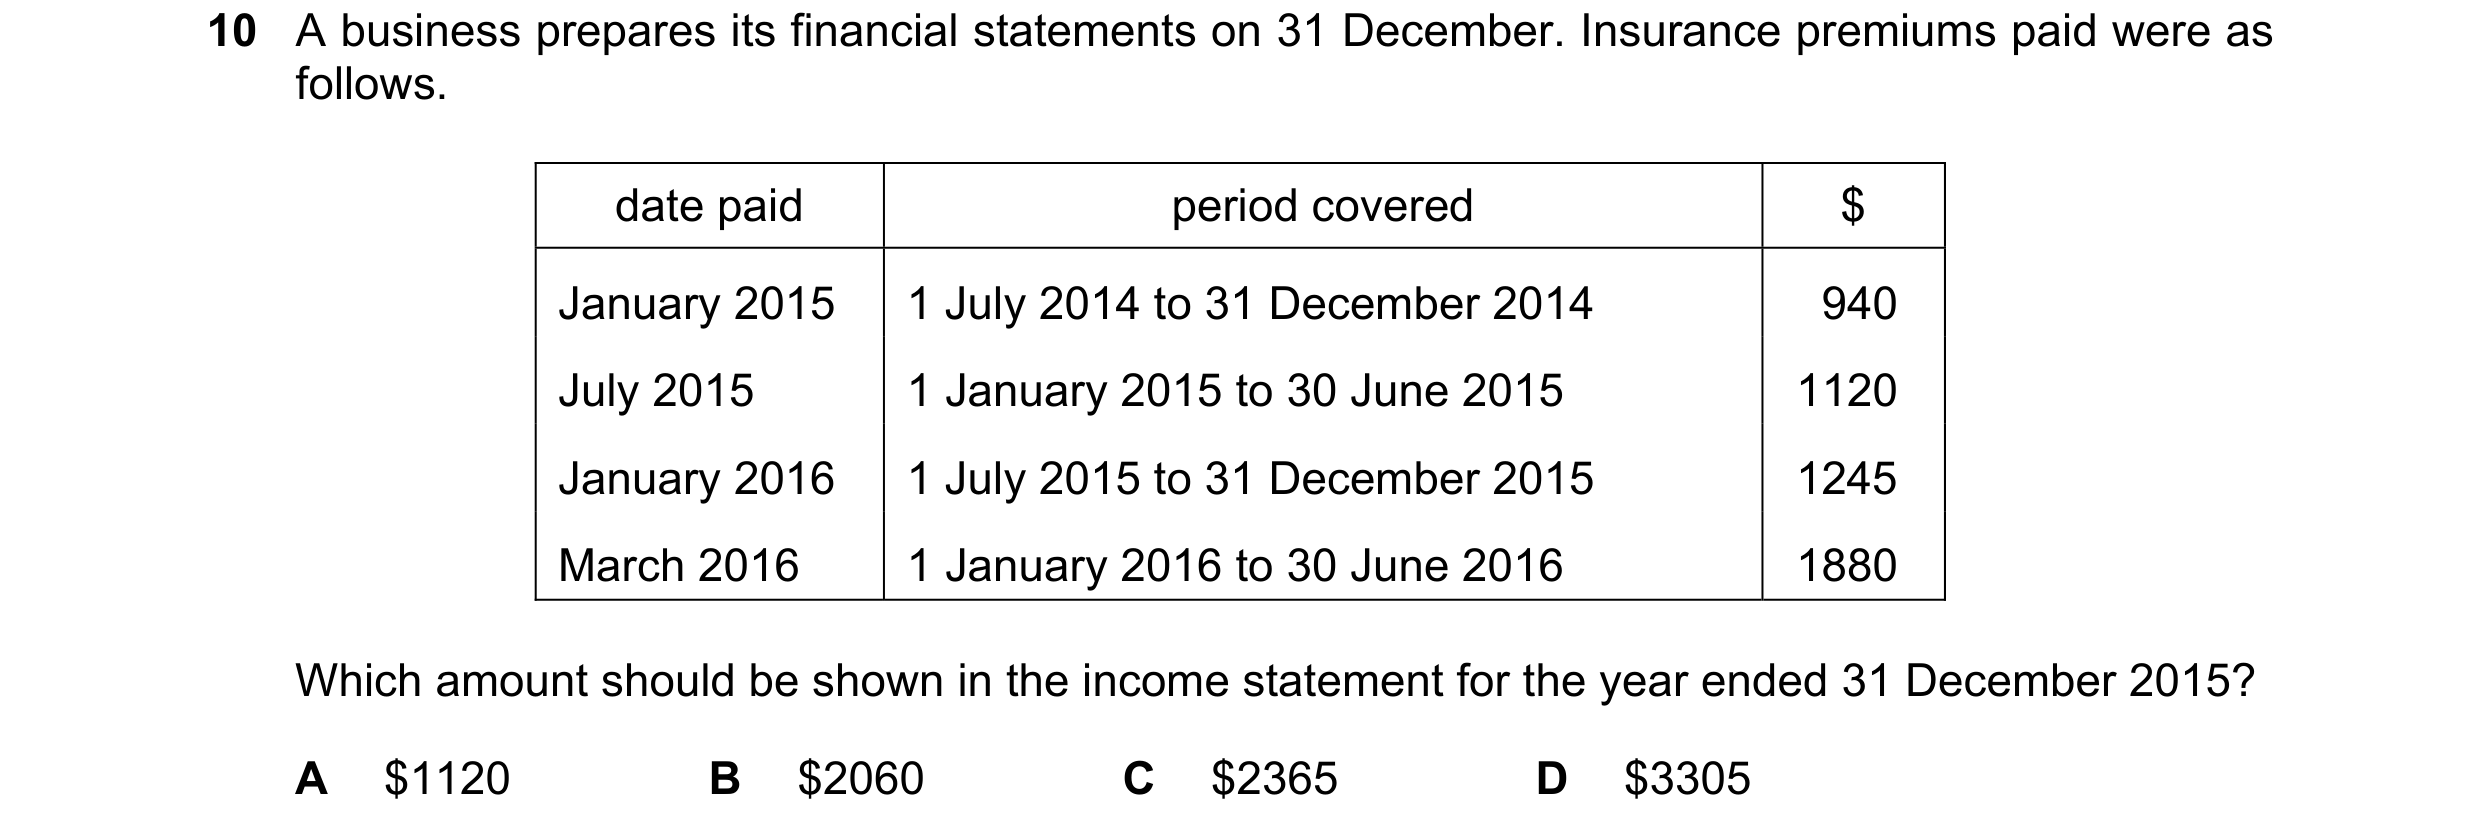 143 / 233
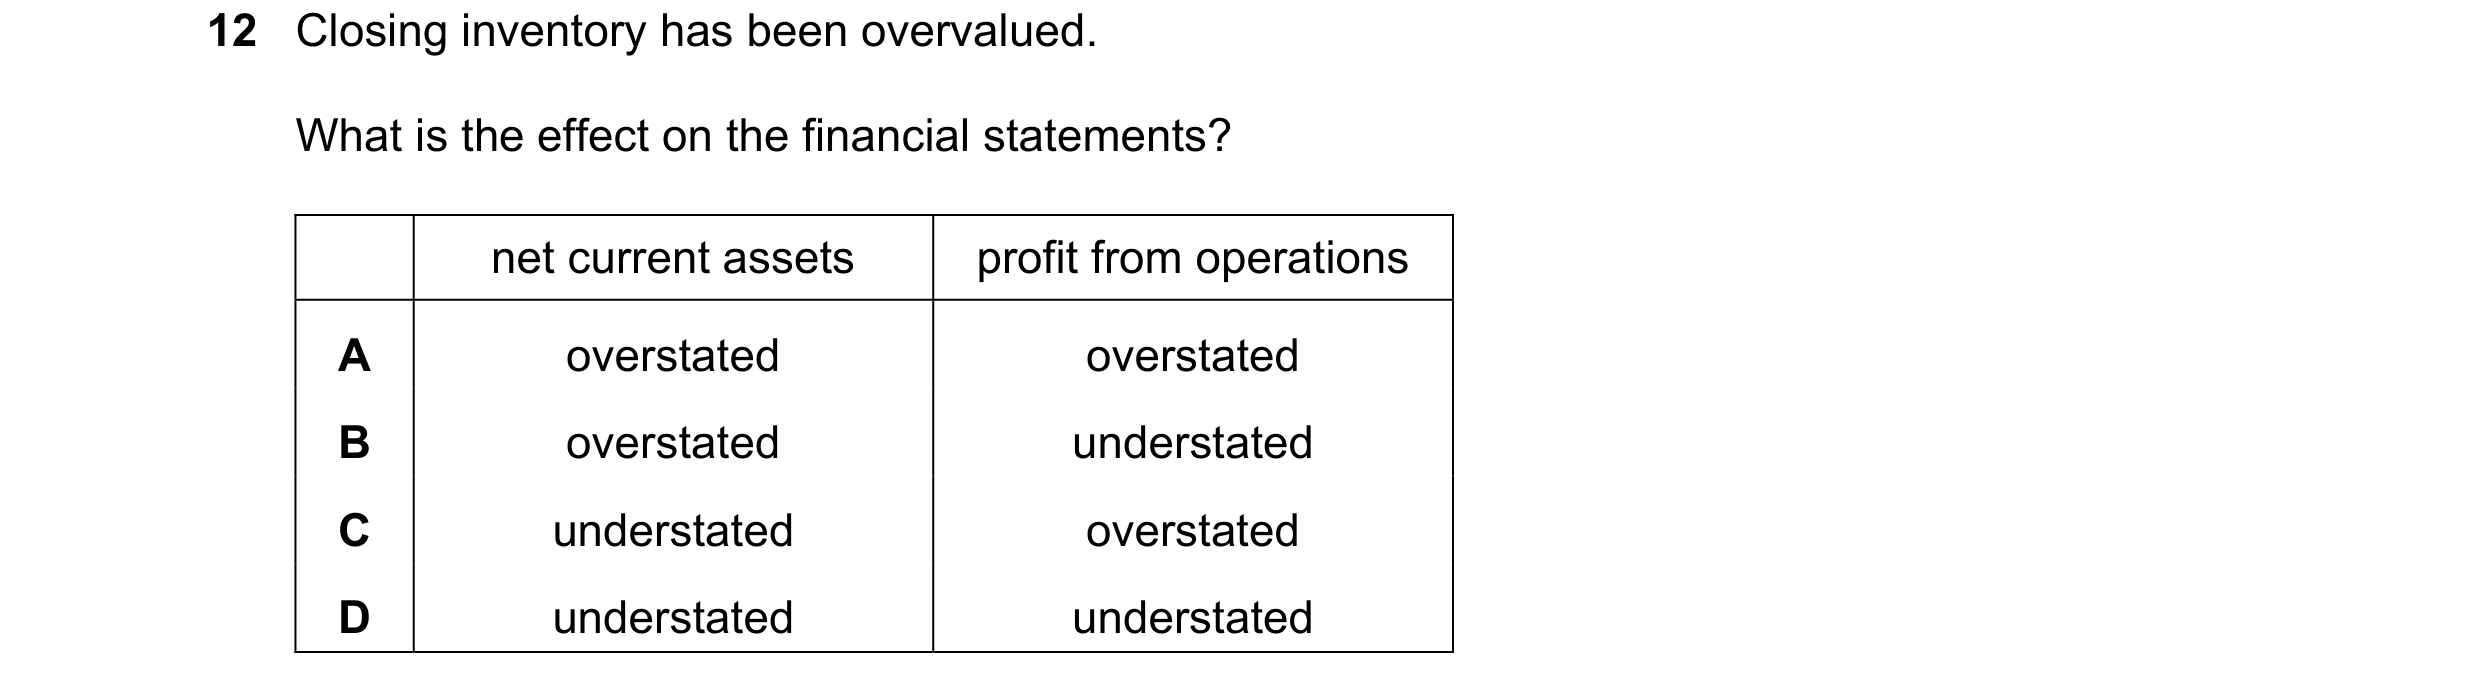
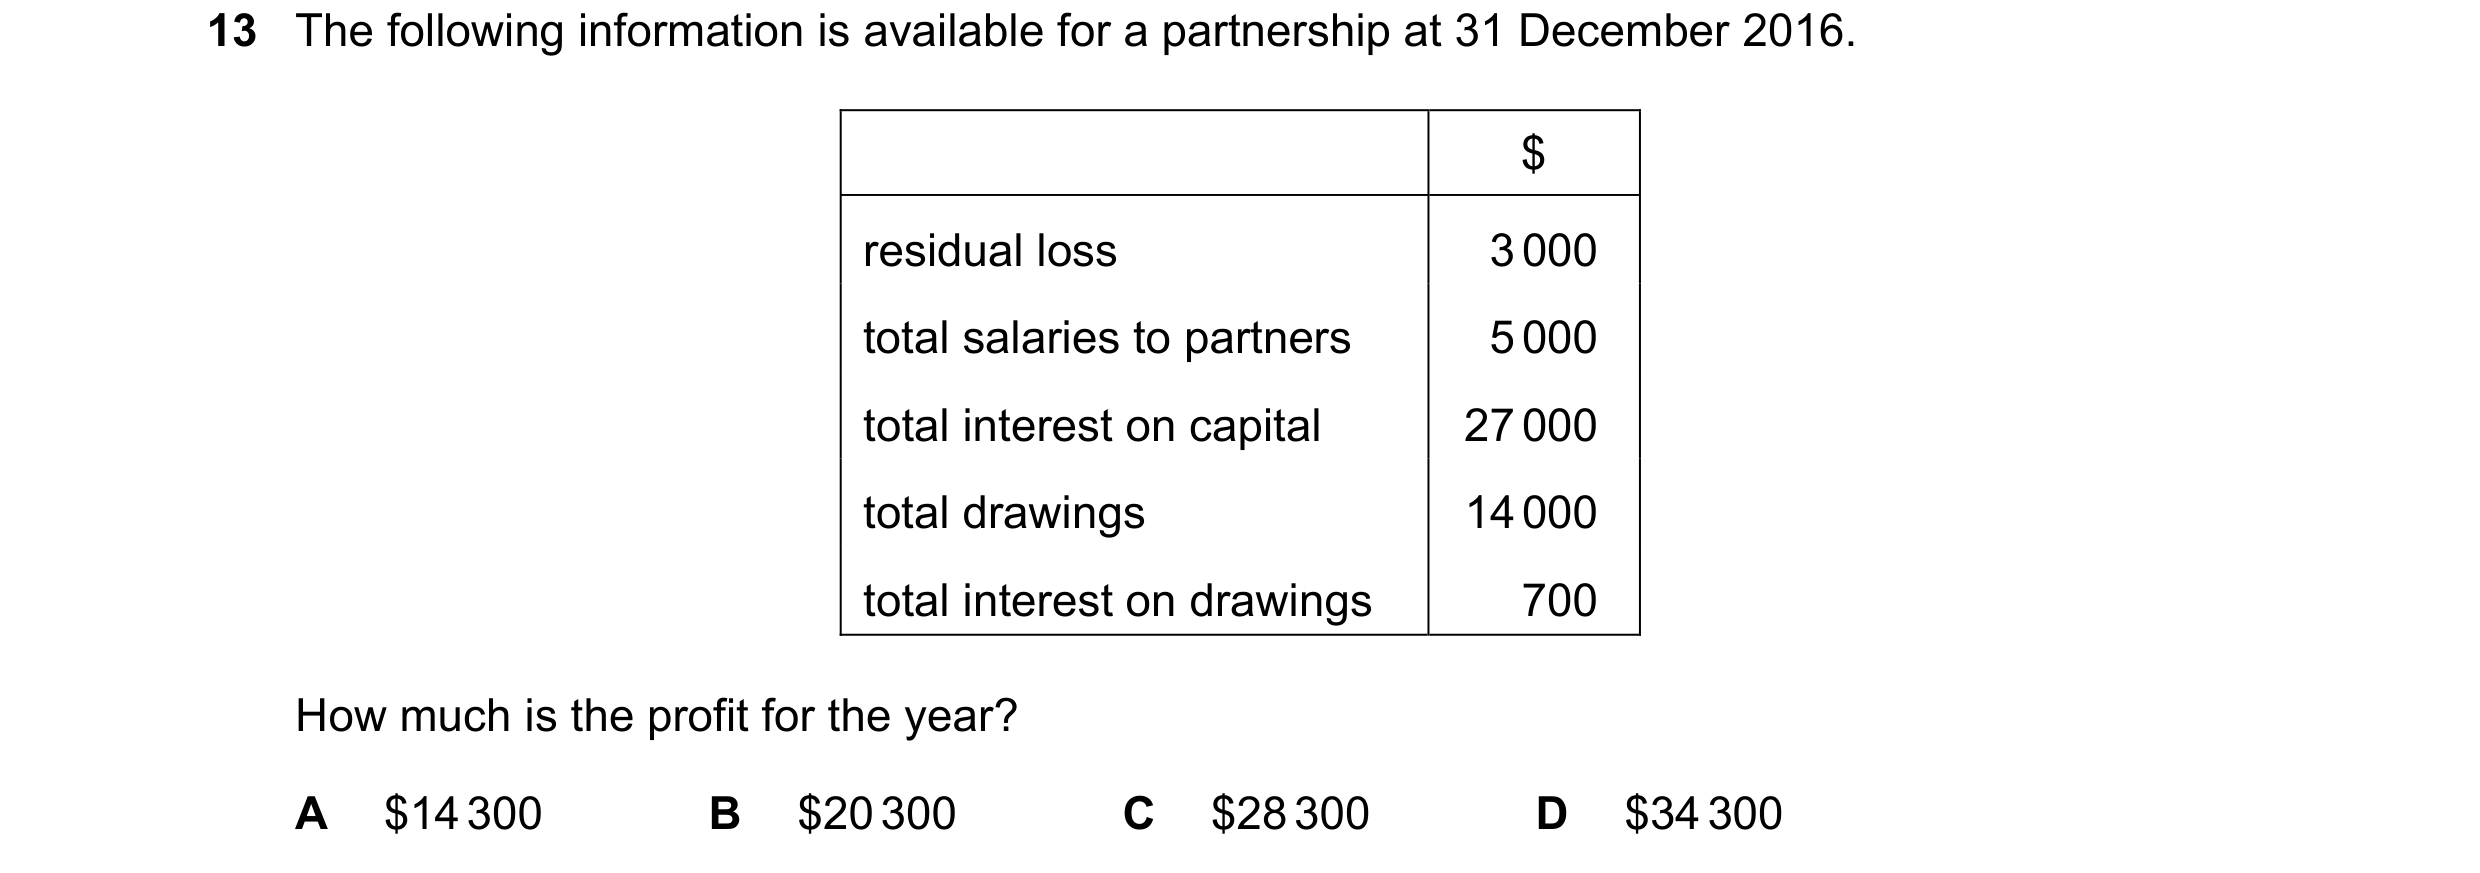
 144 / 233
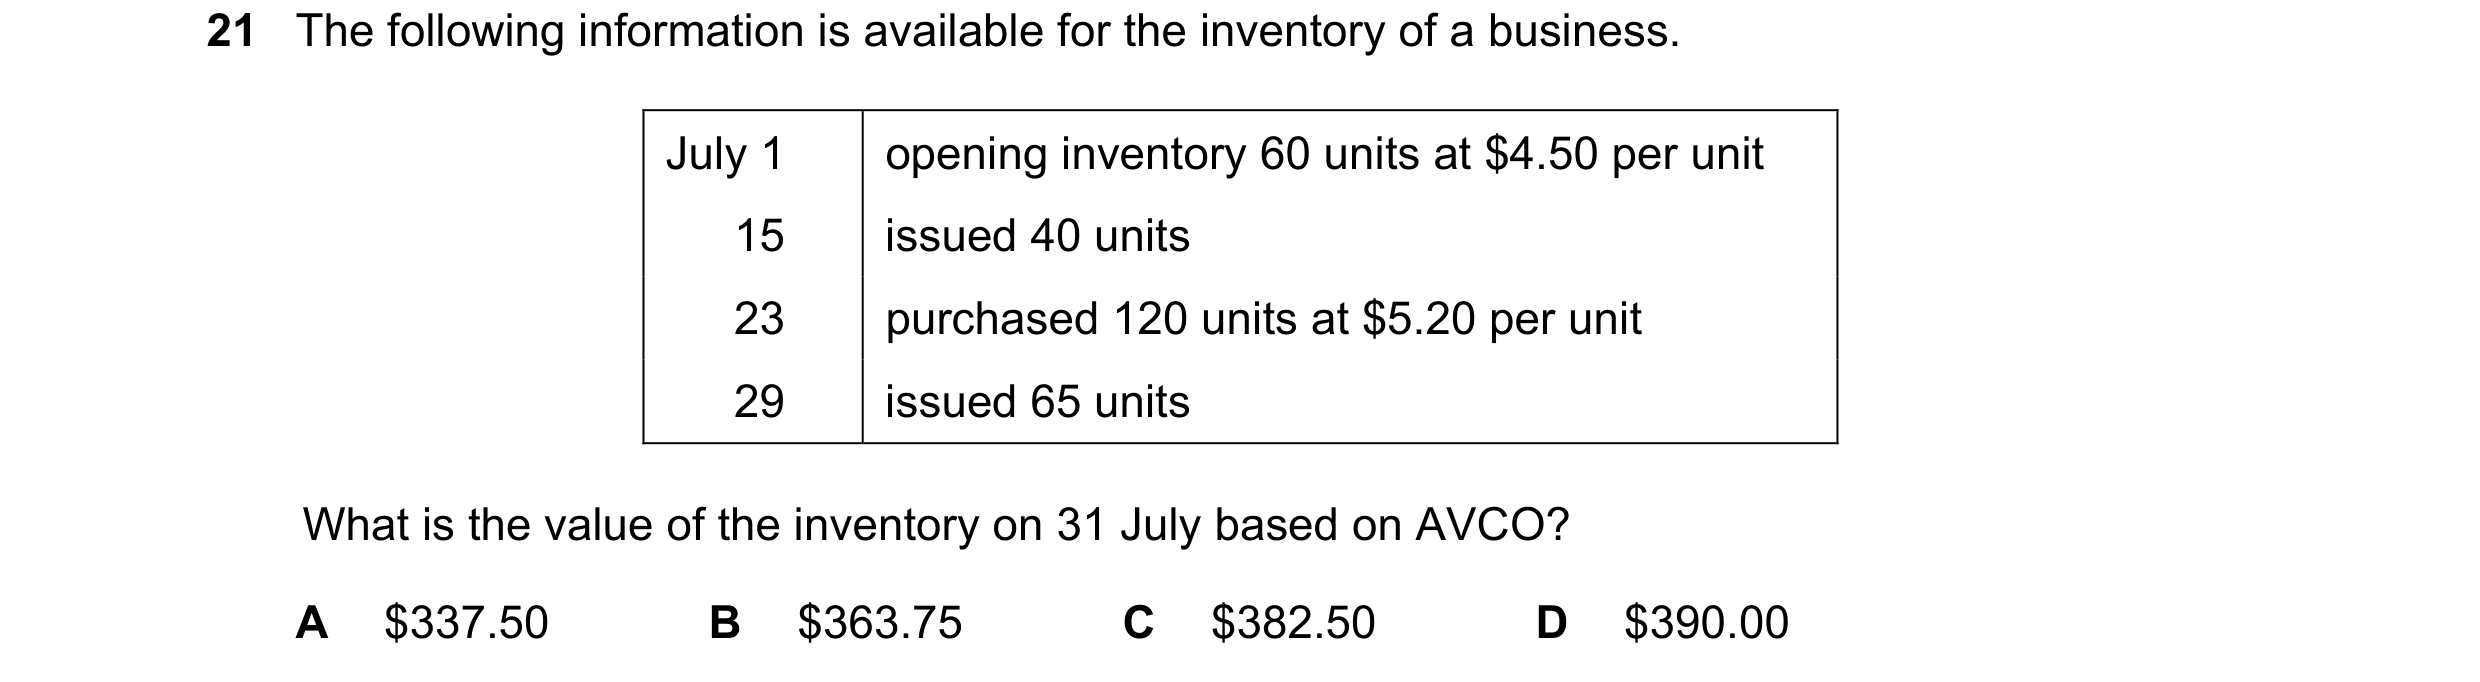
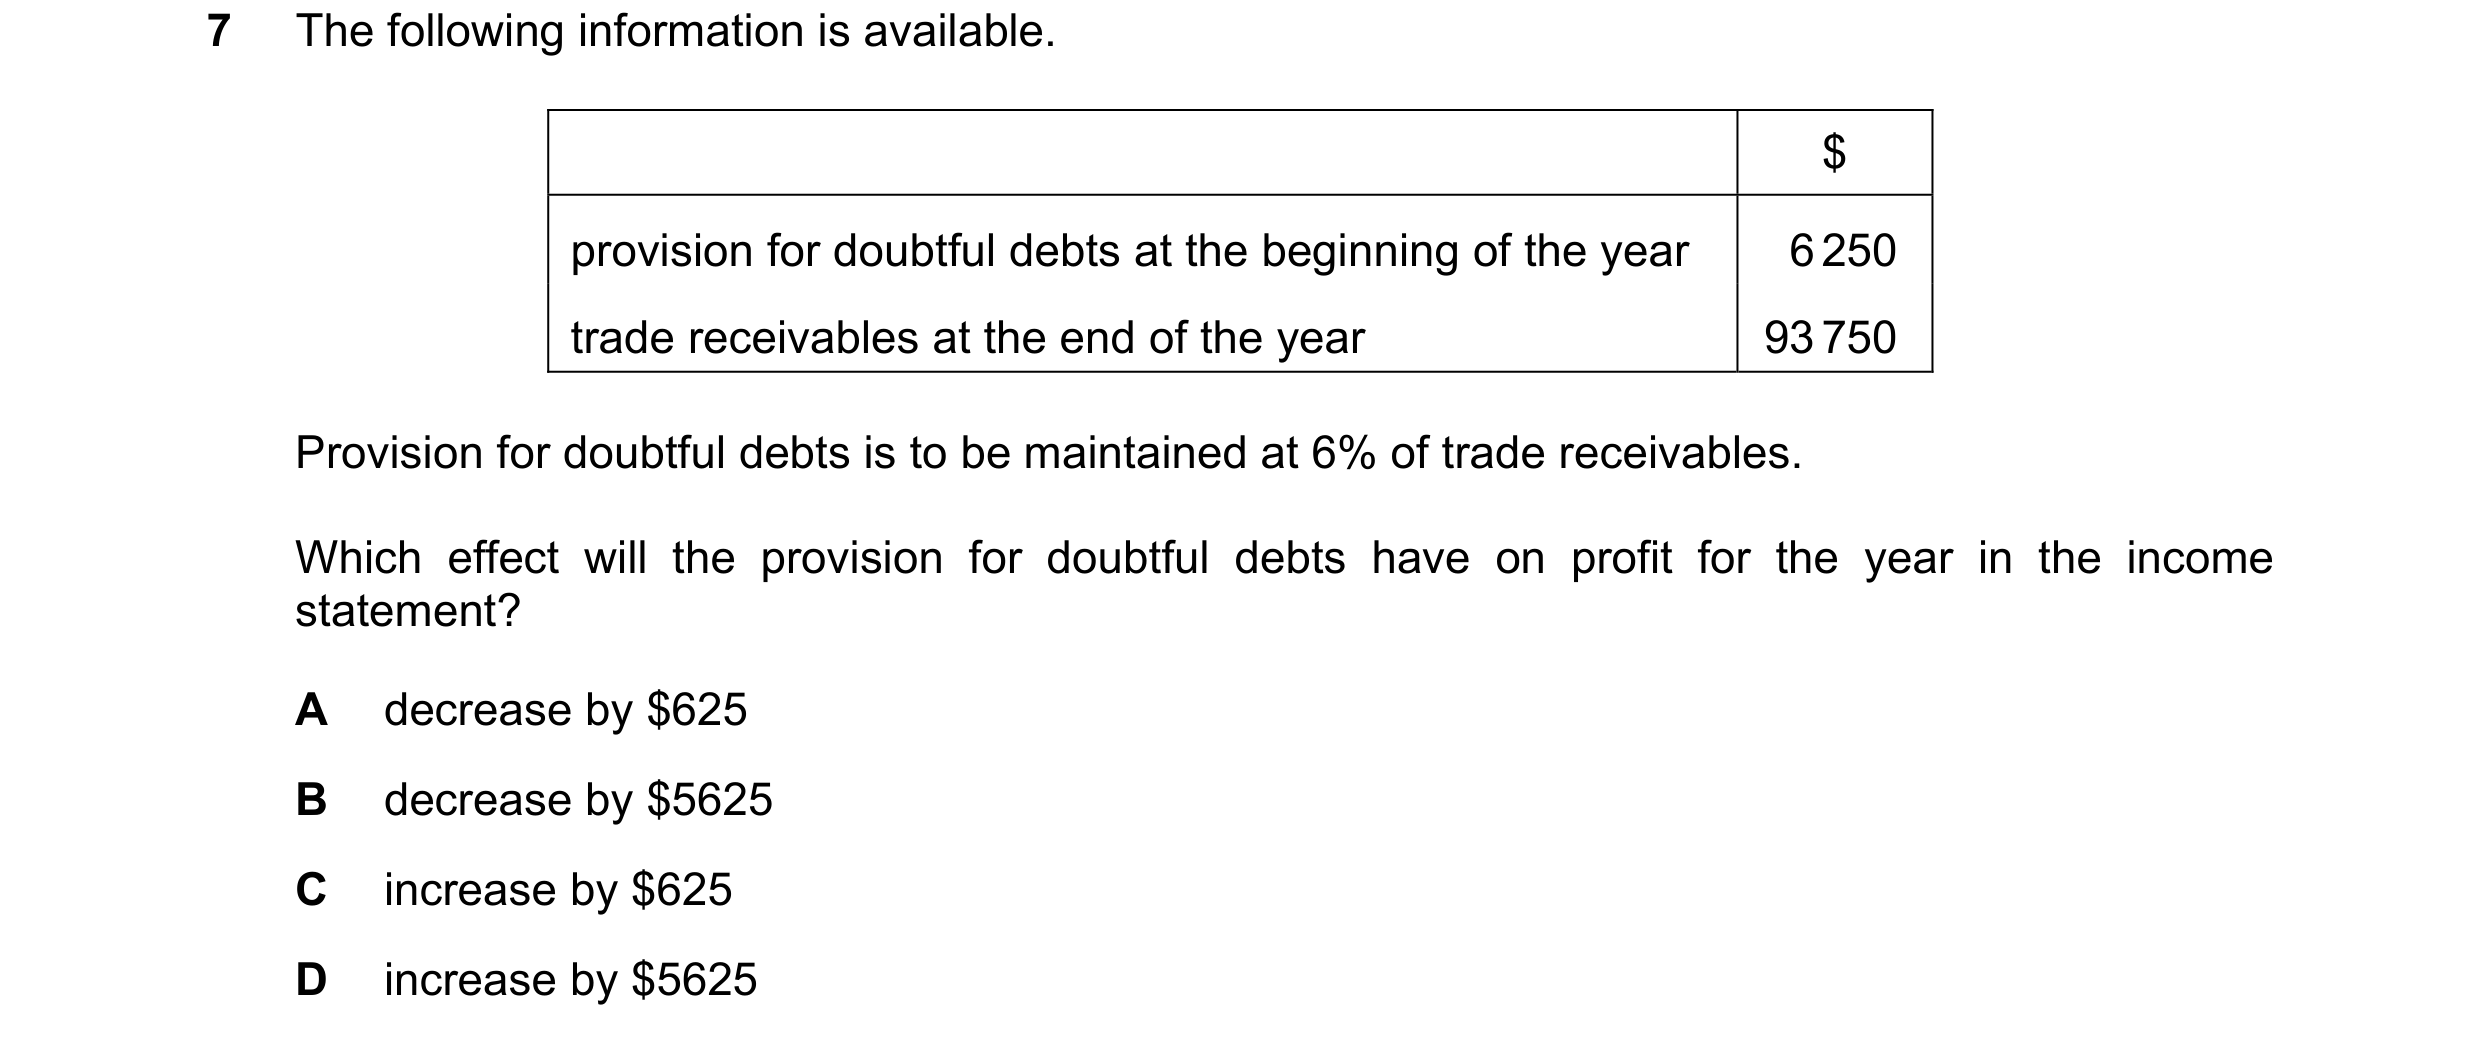
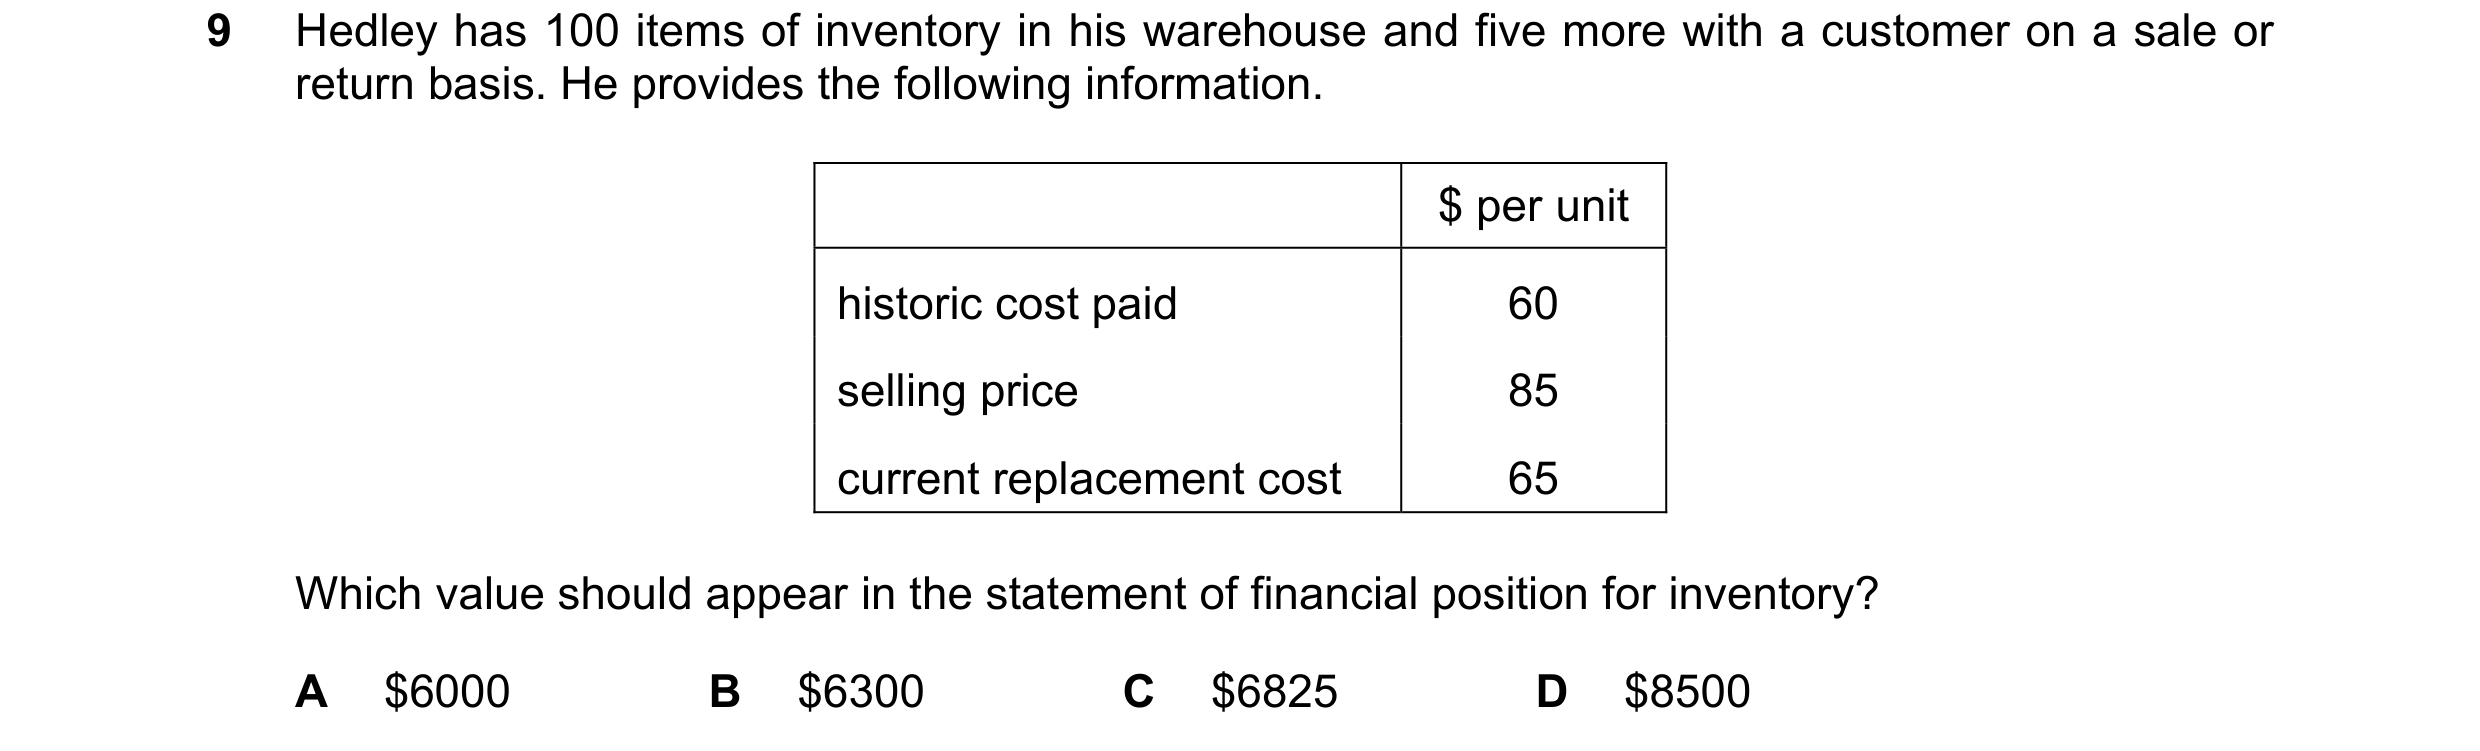 145 / 233
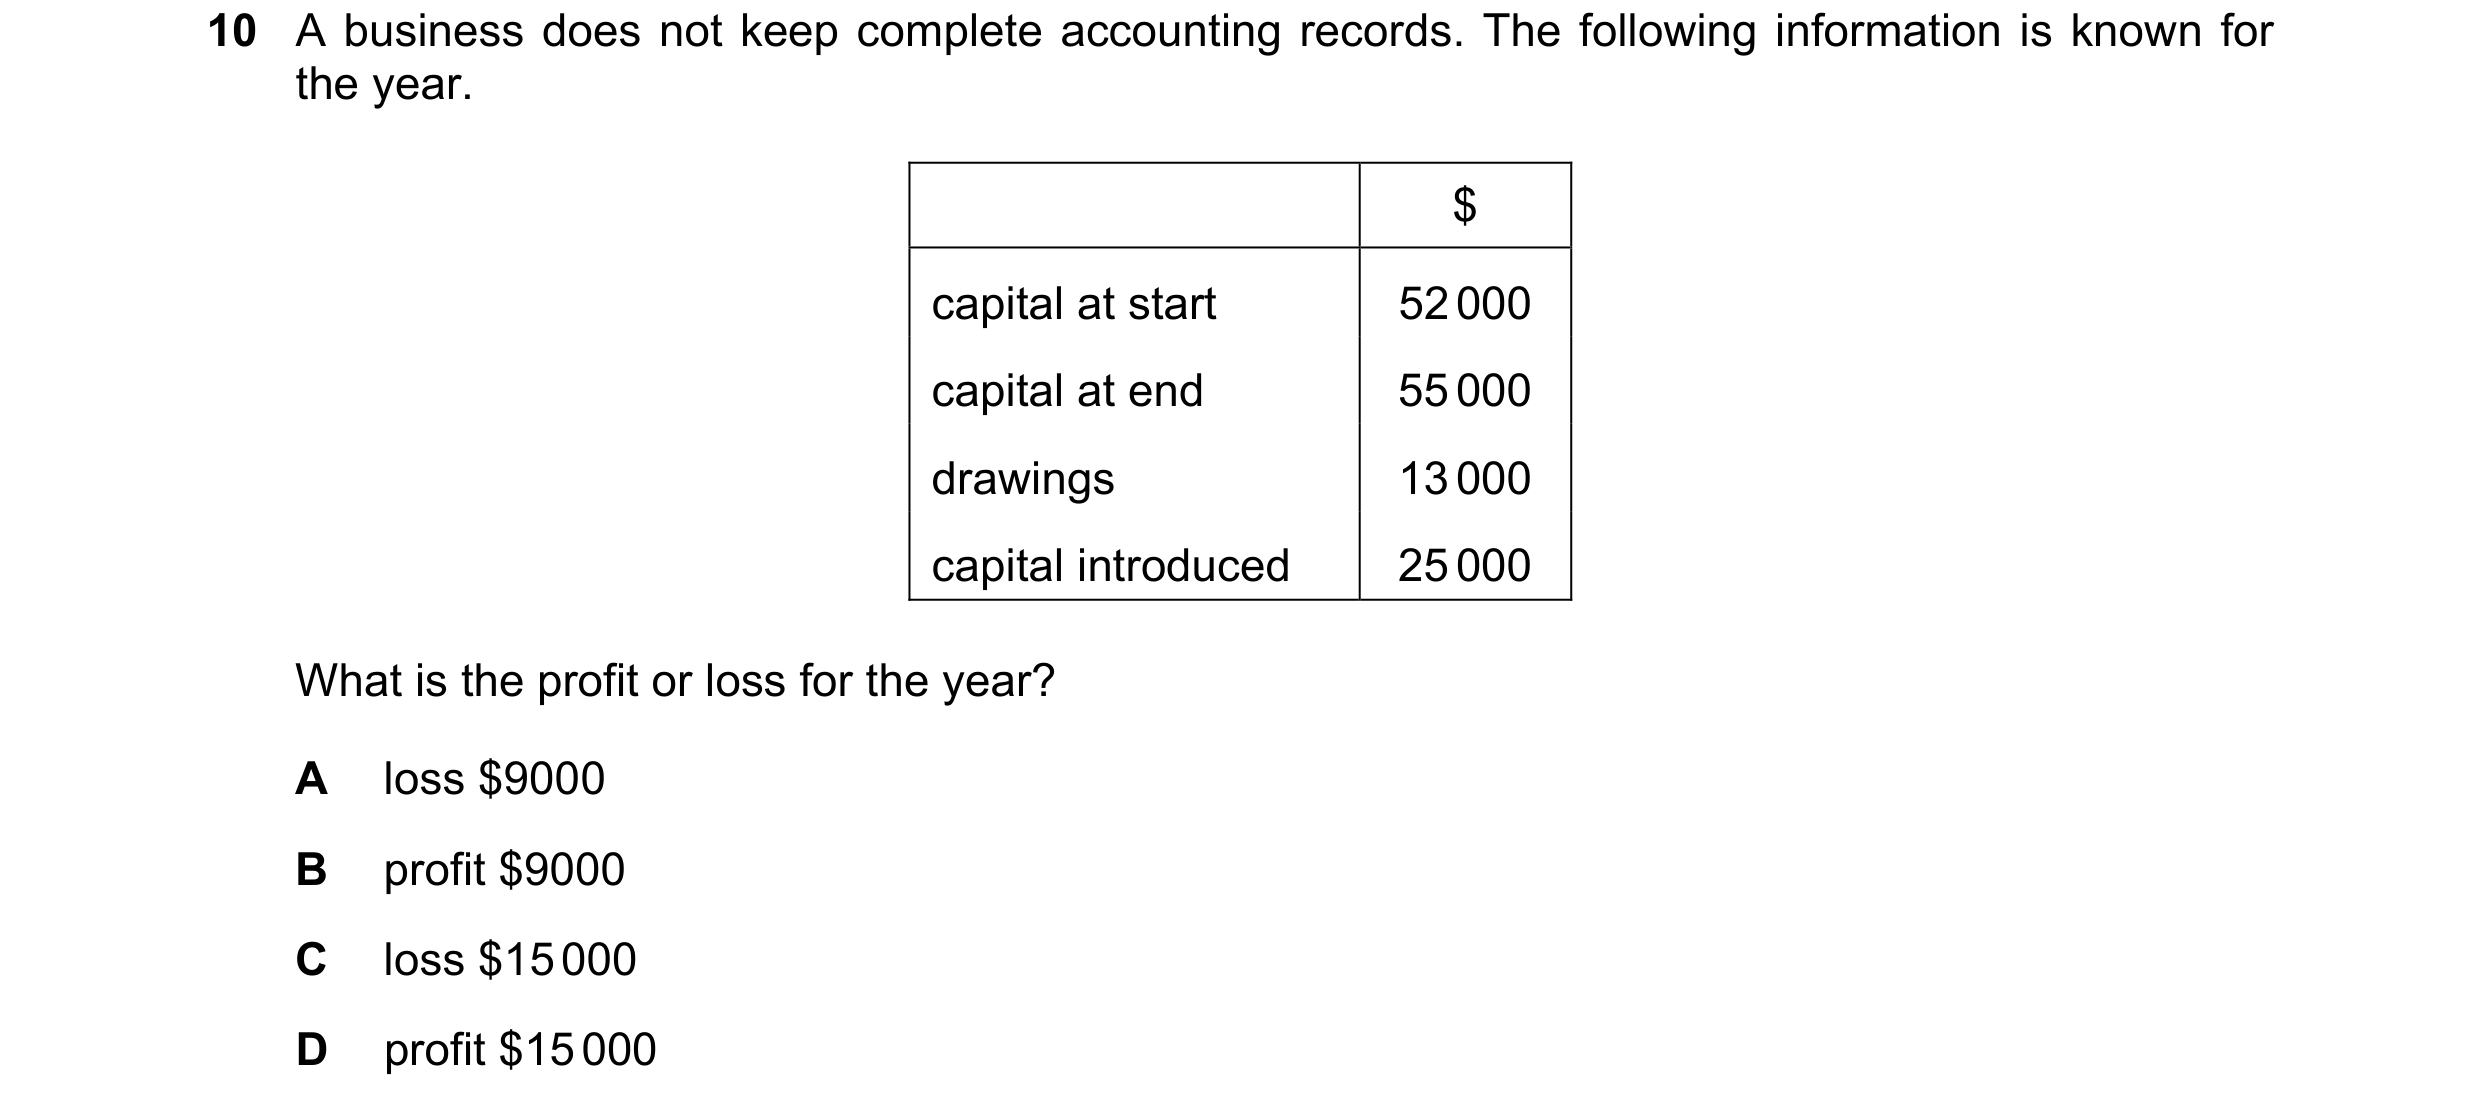
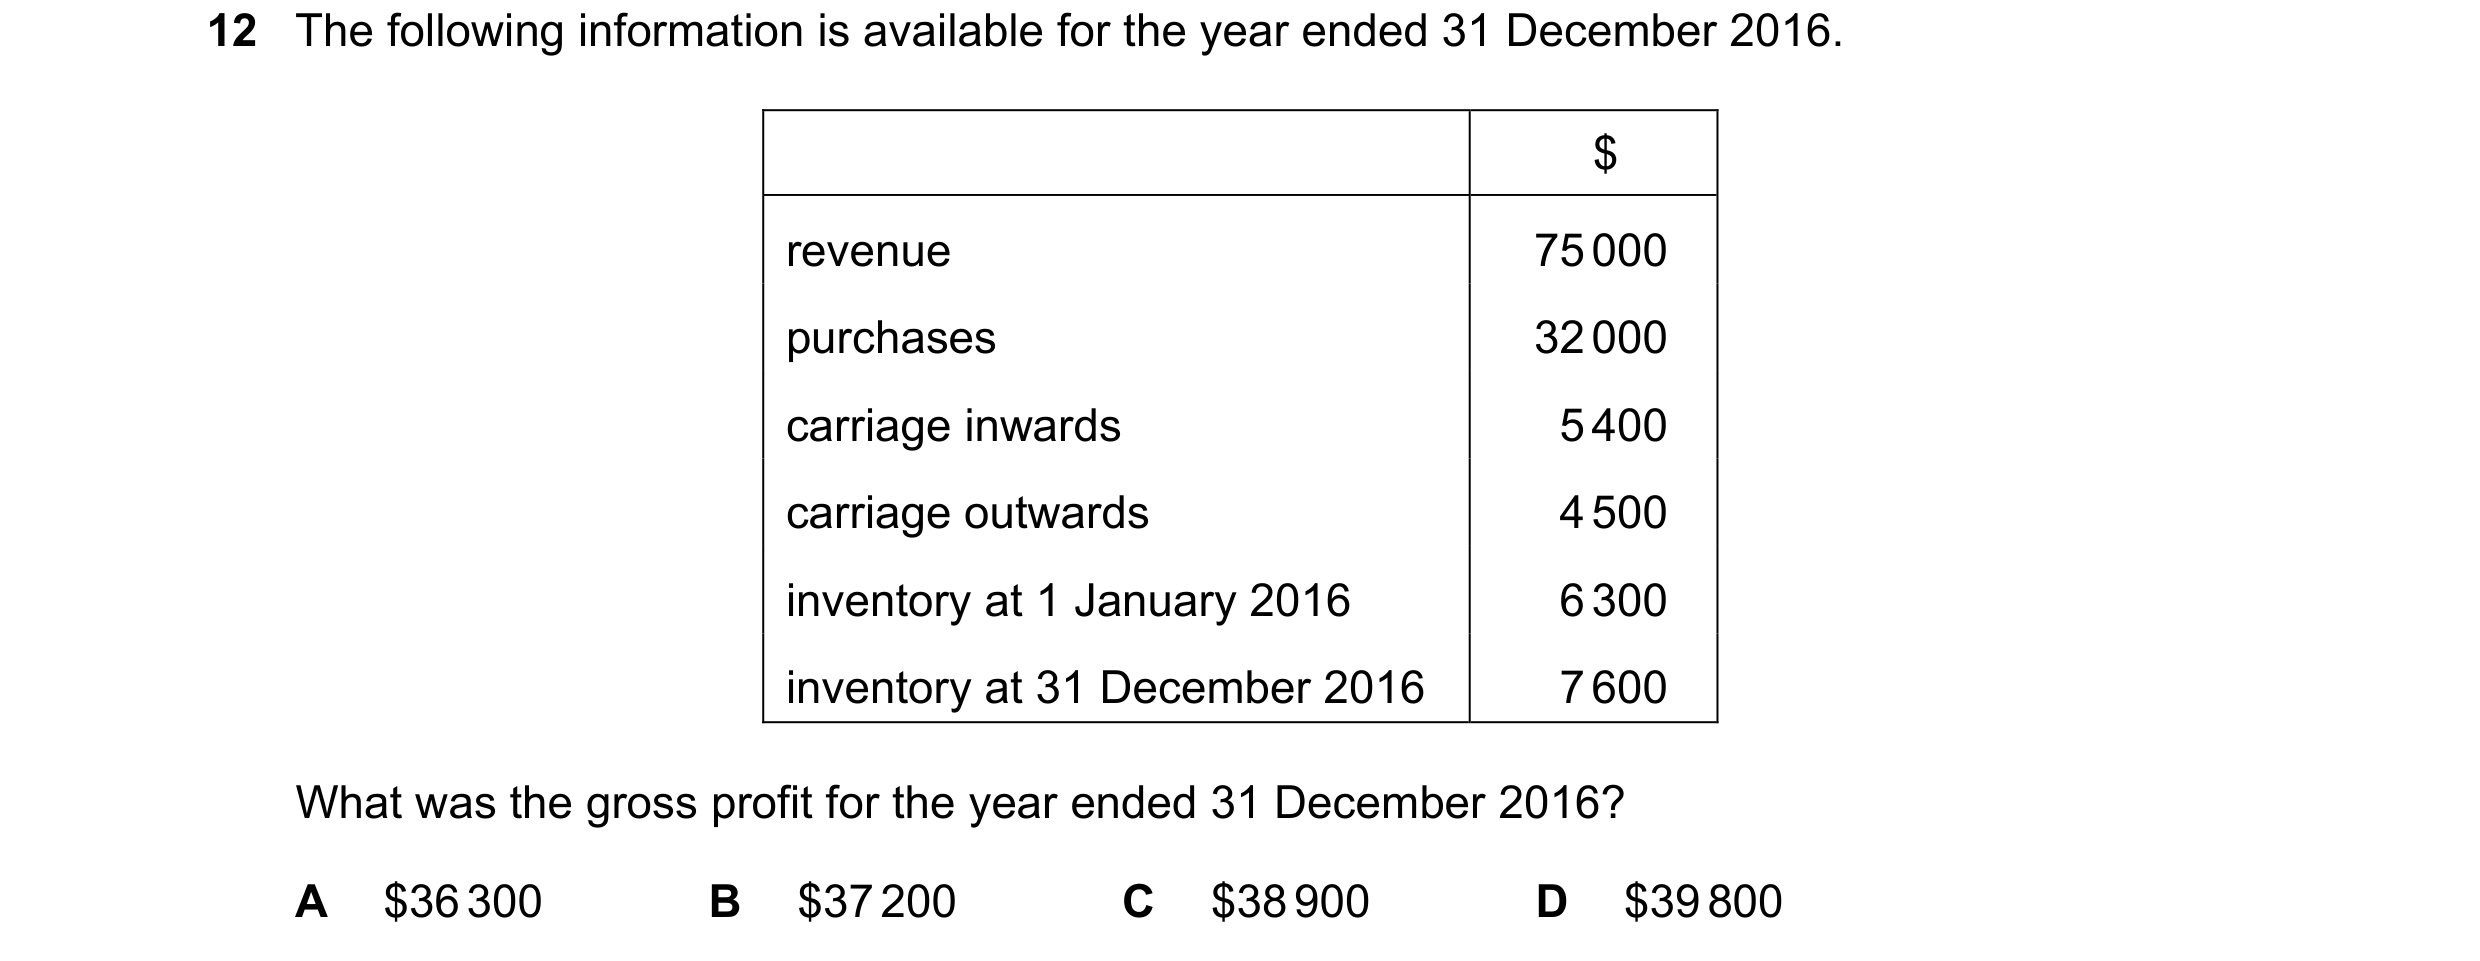
 146 / 233
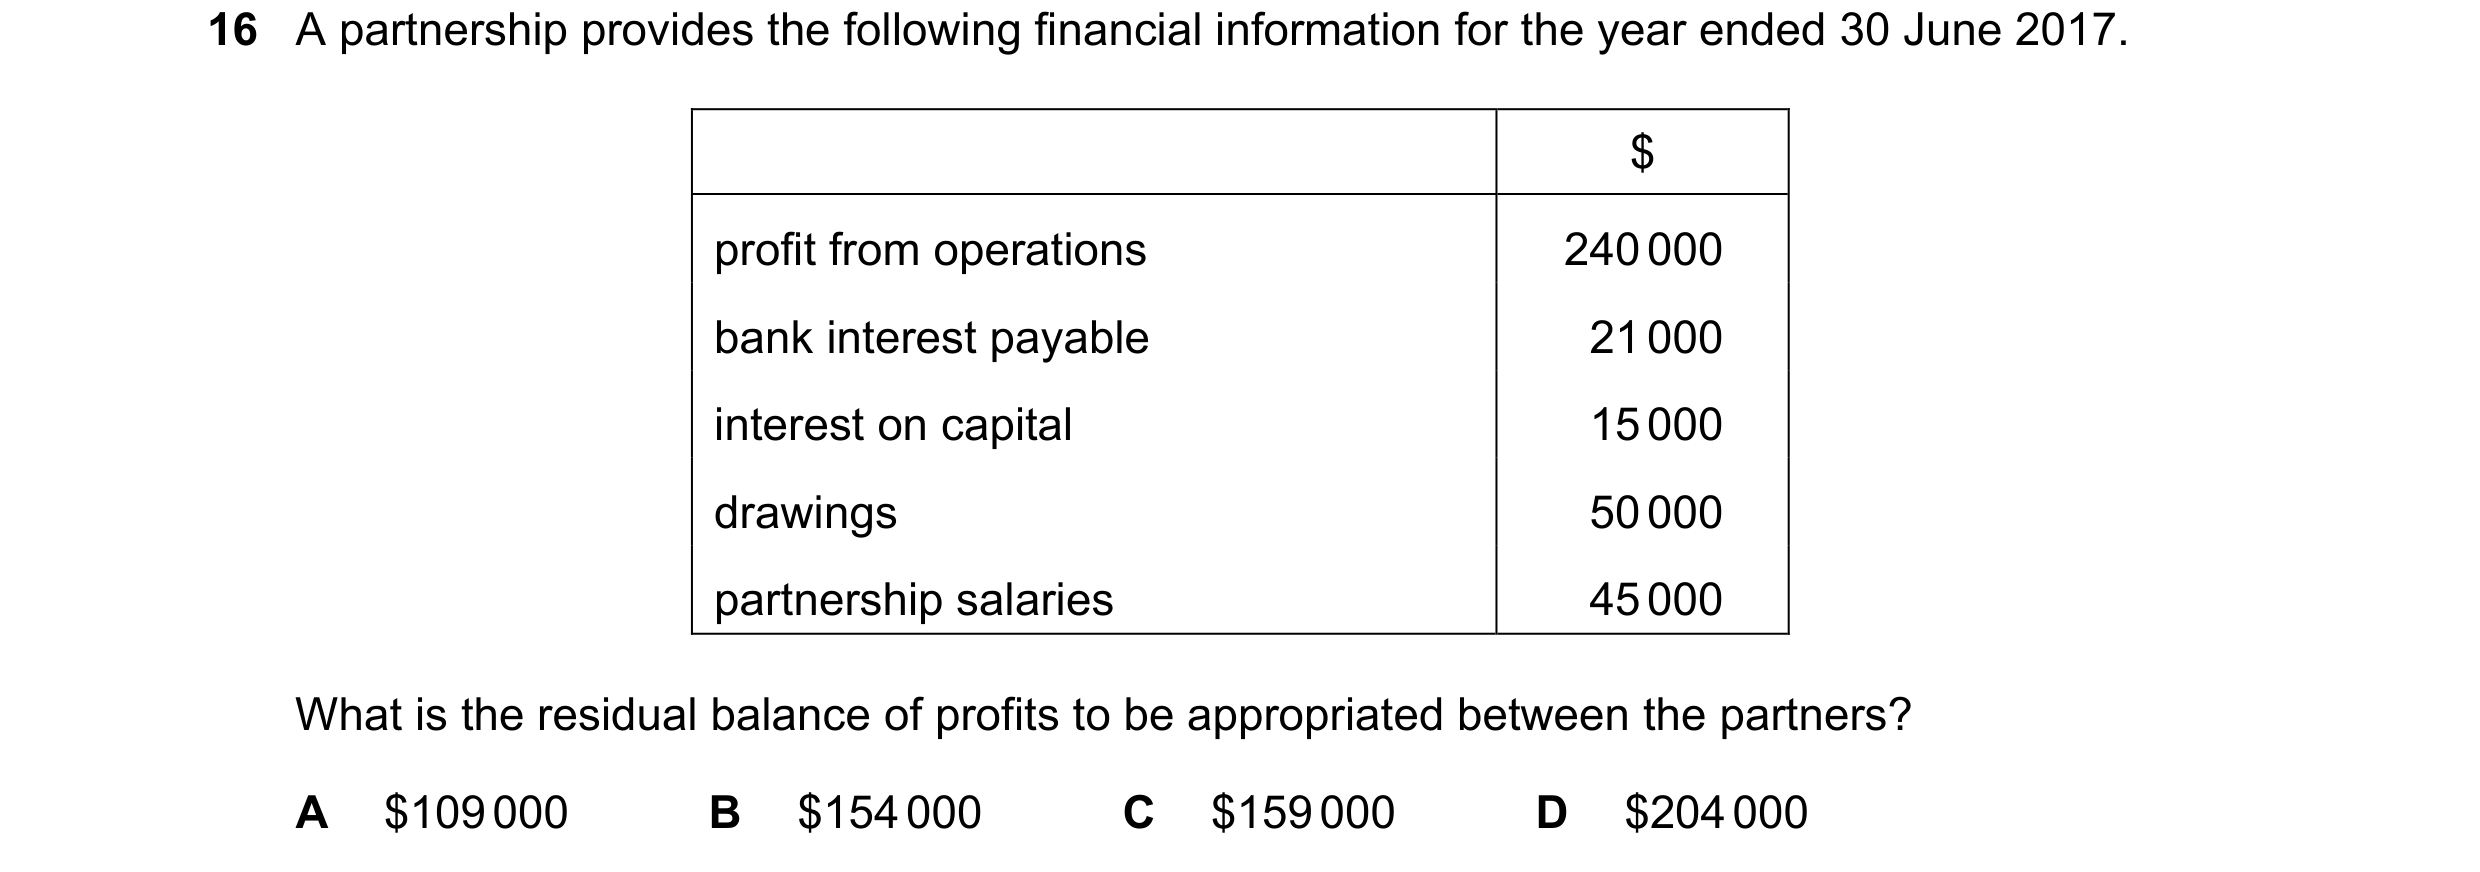
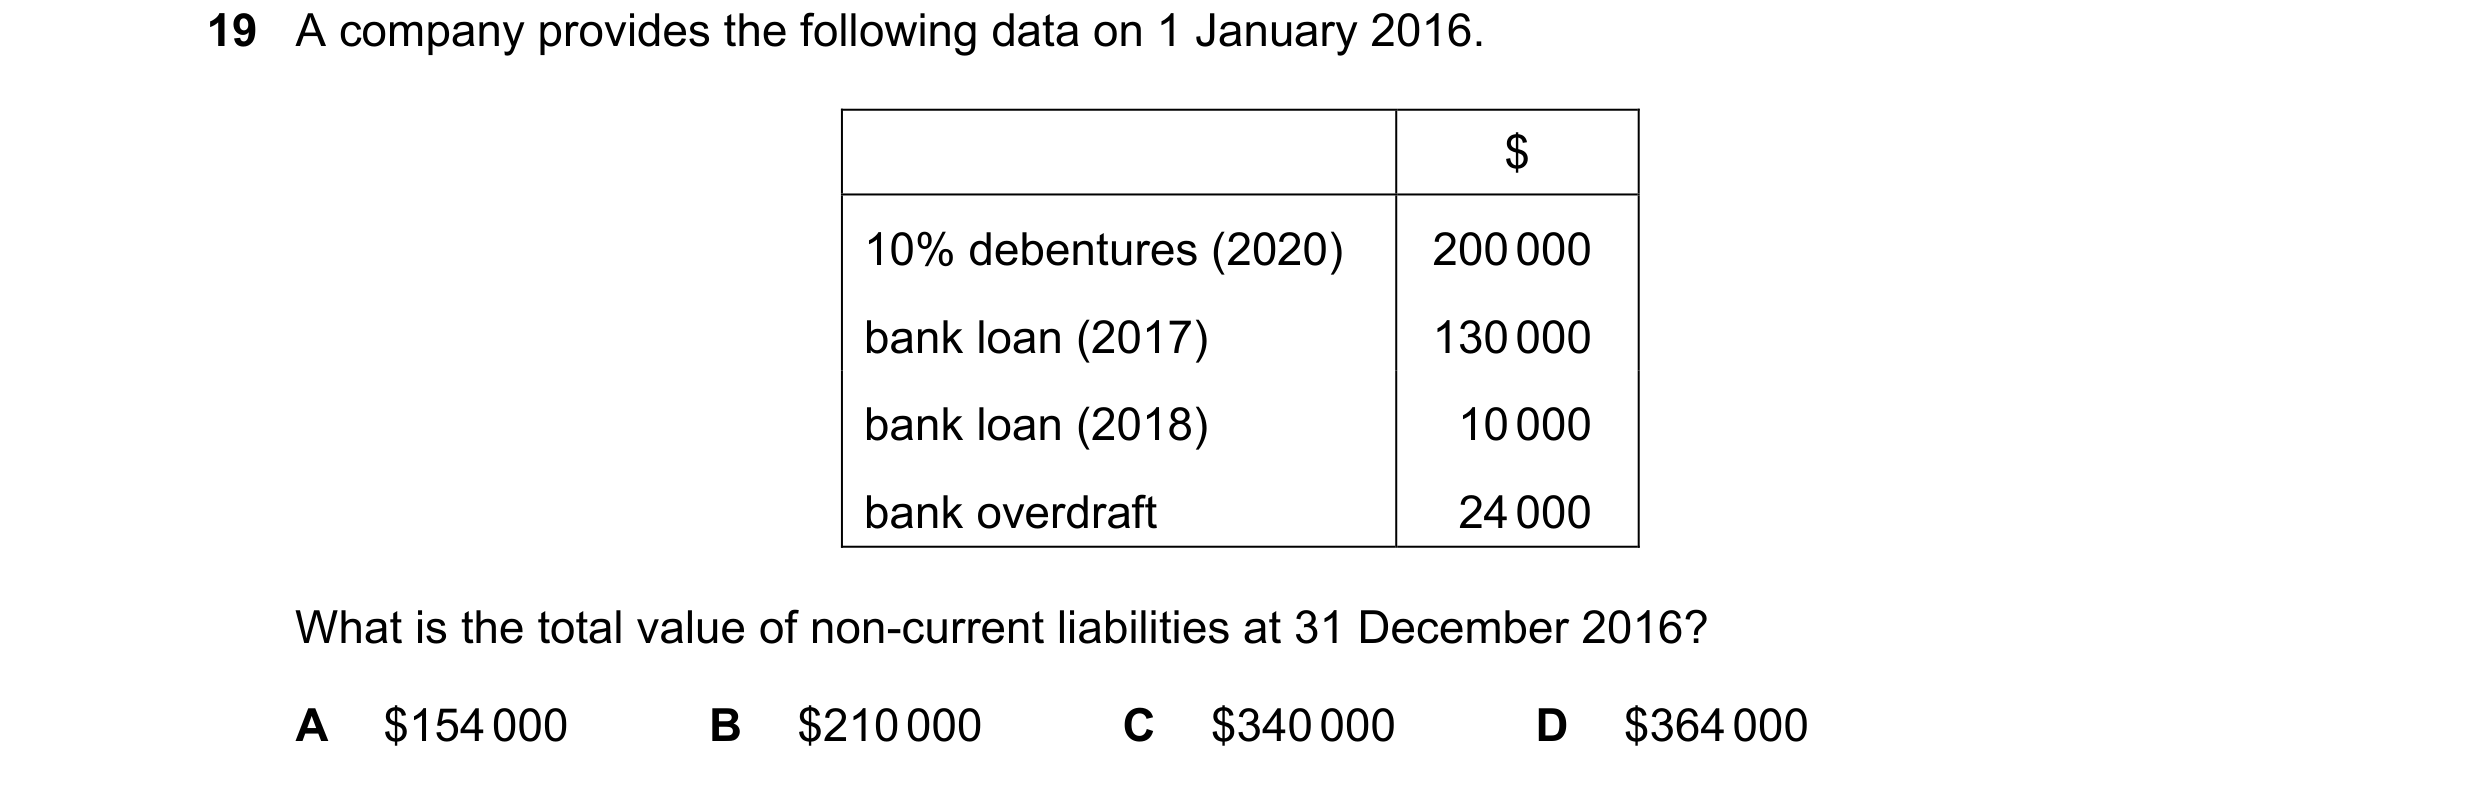 147 / 233
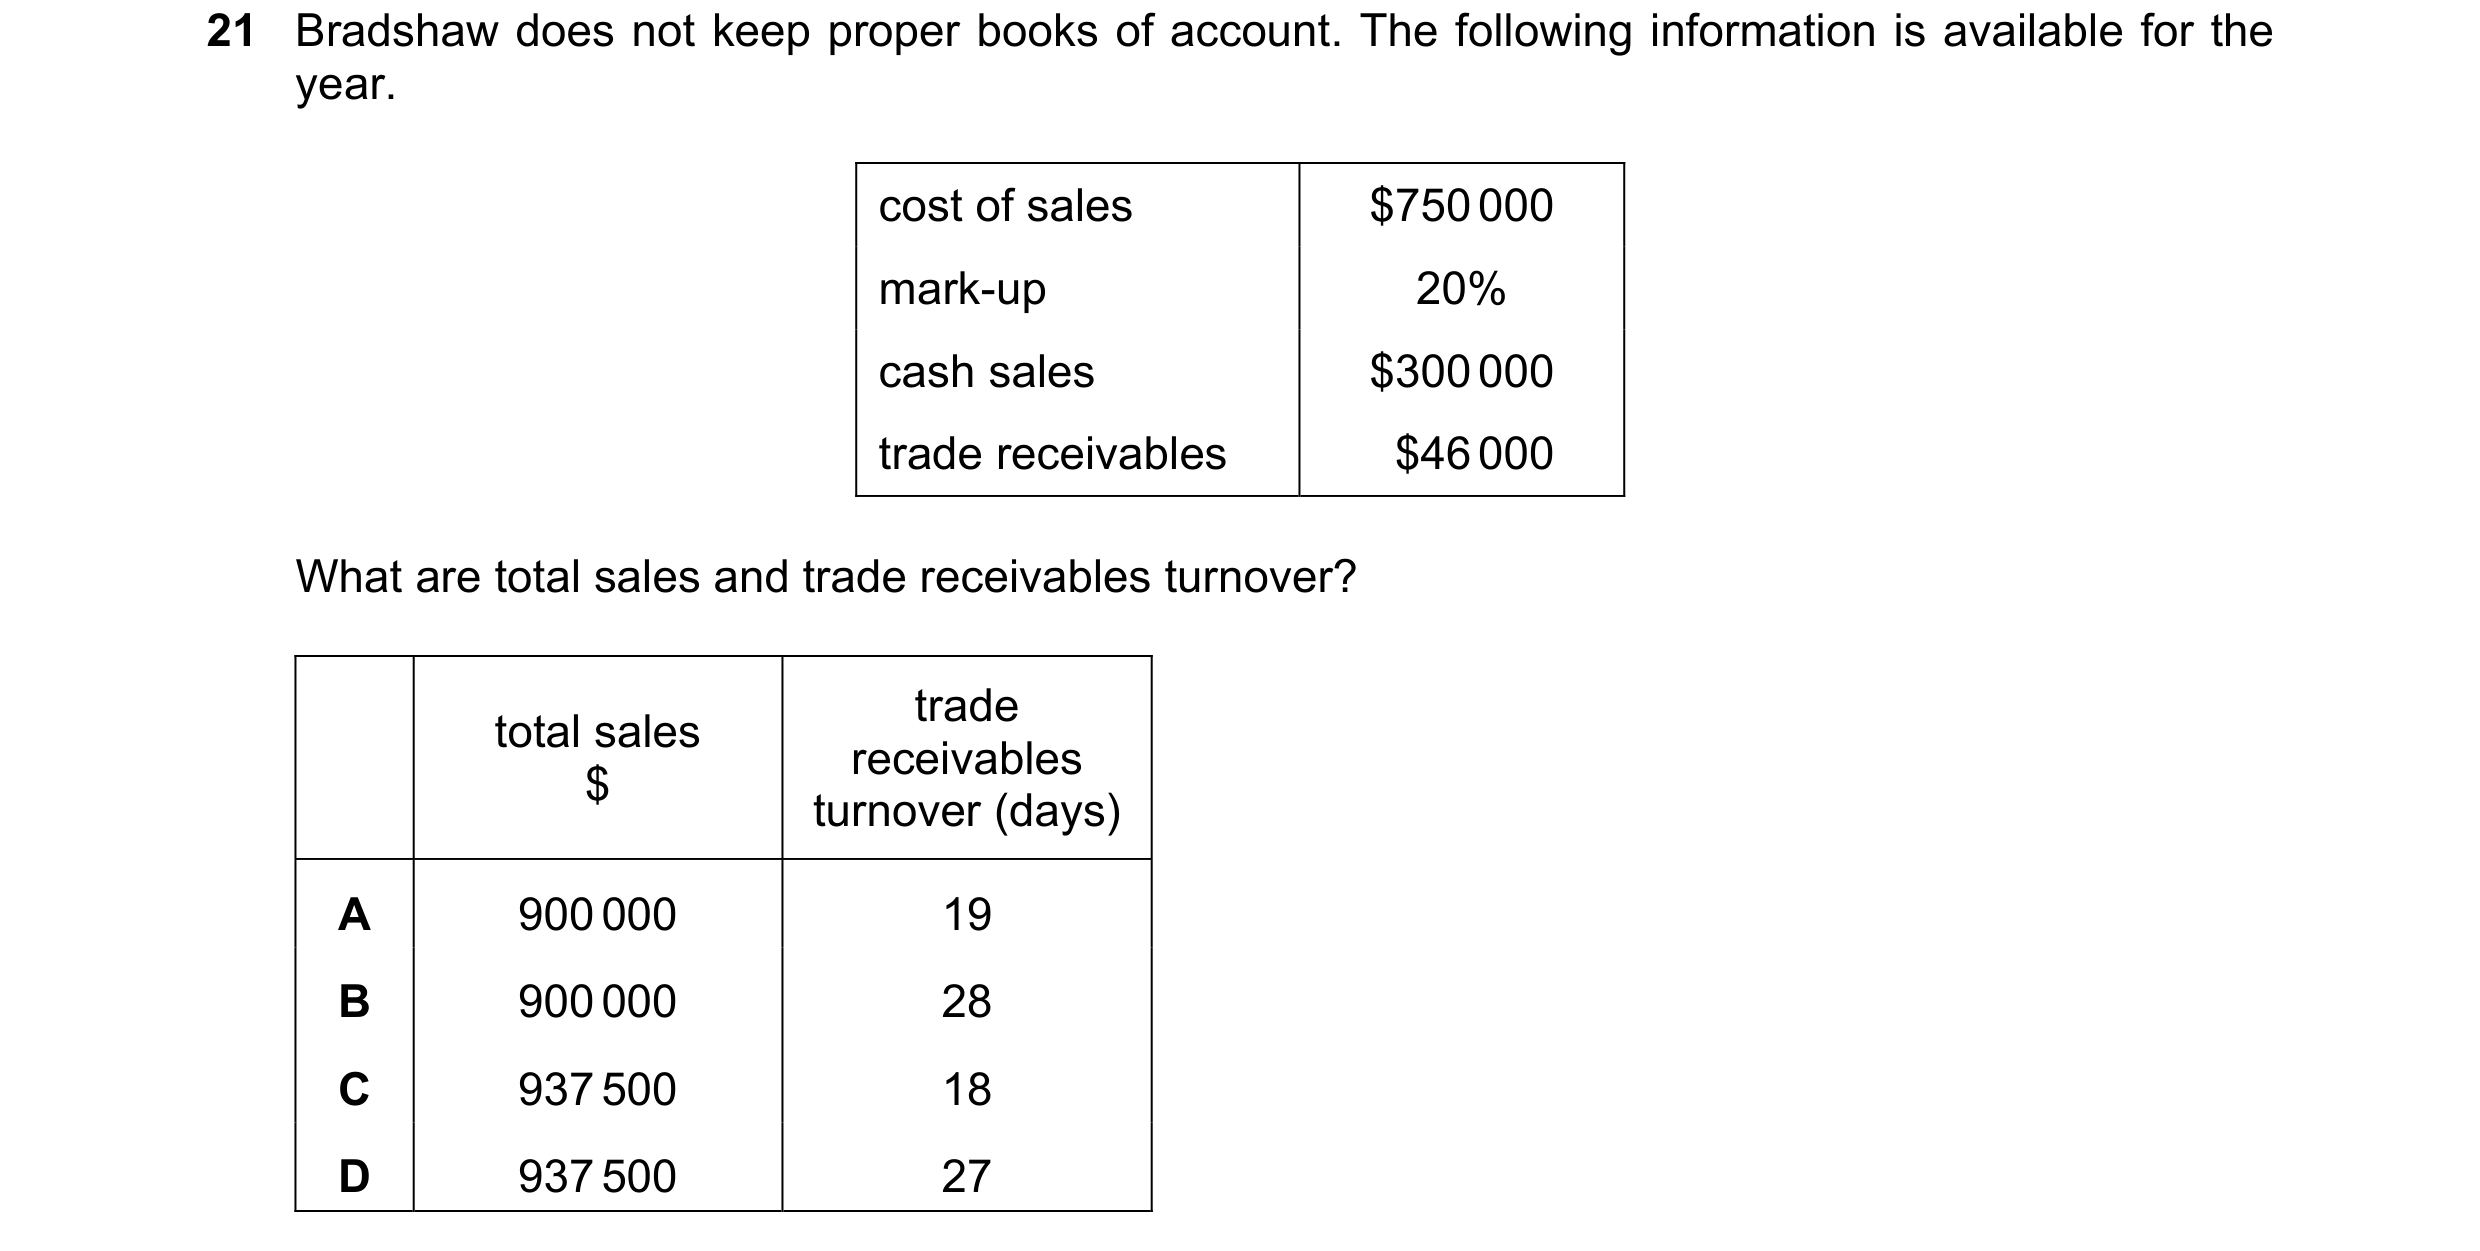
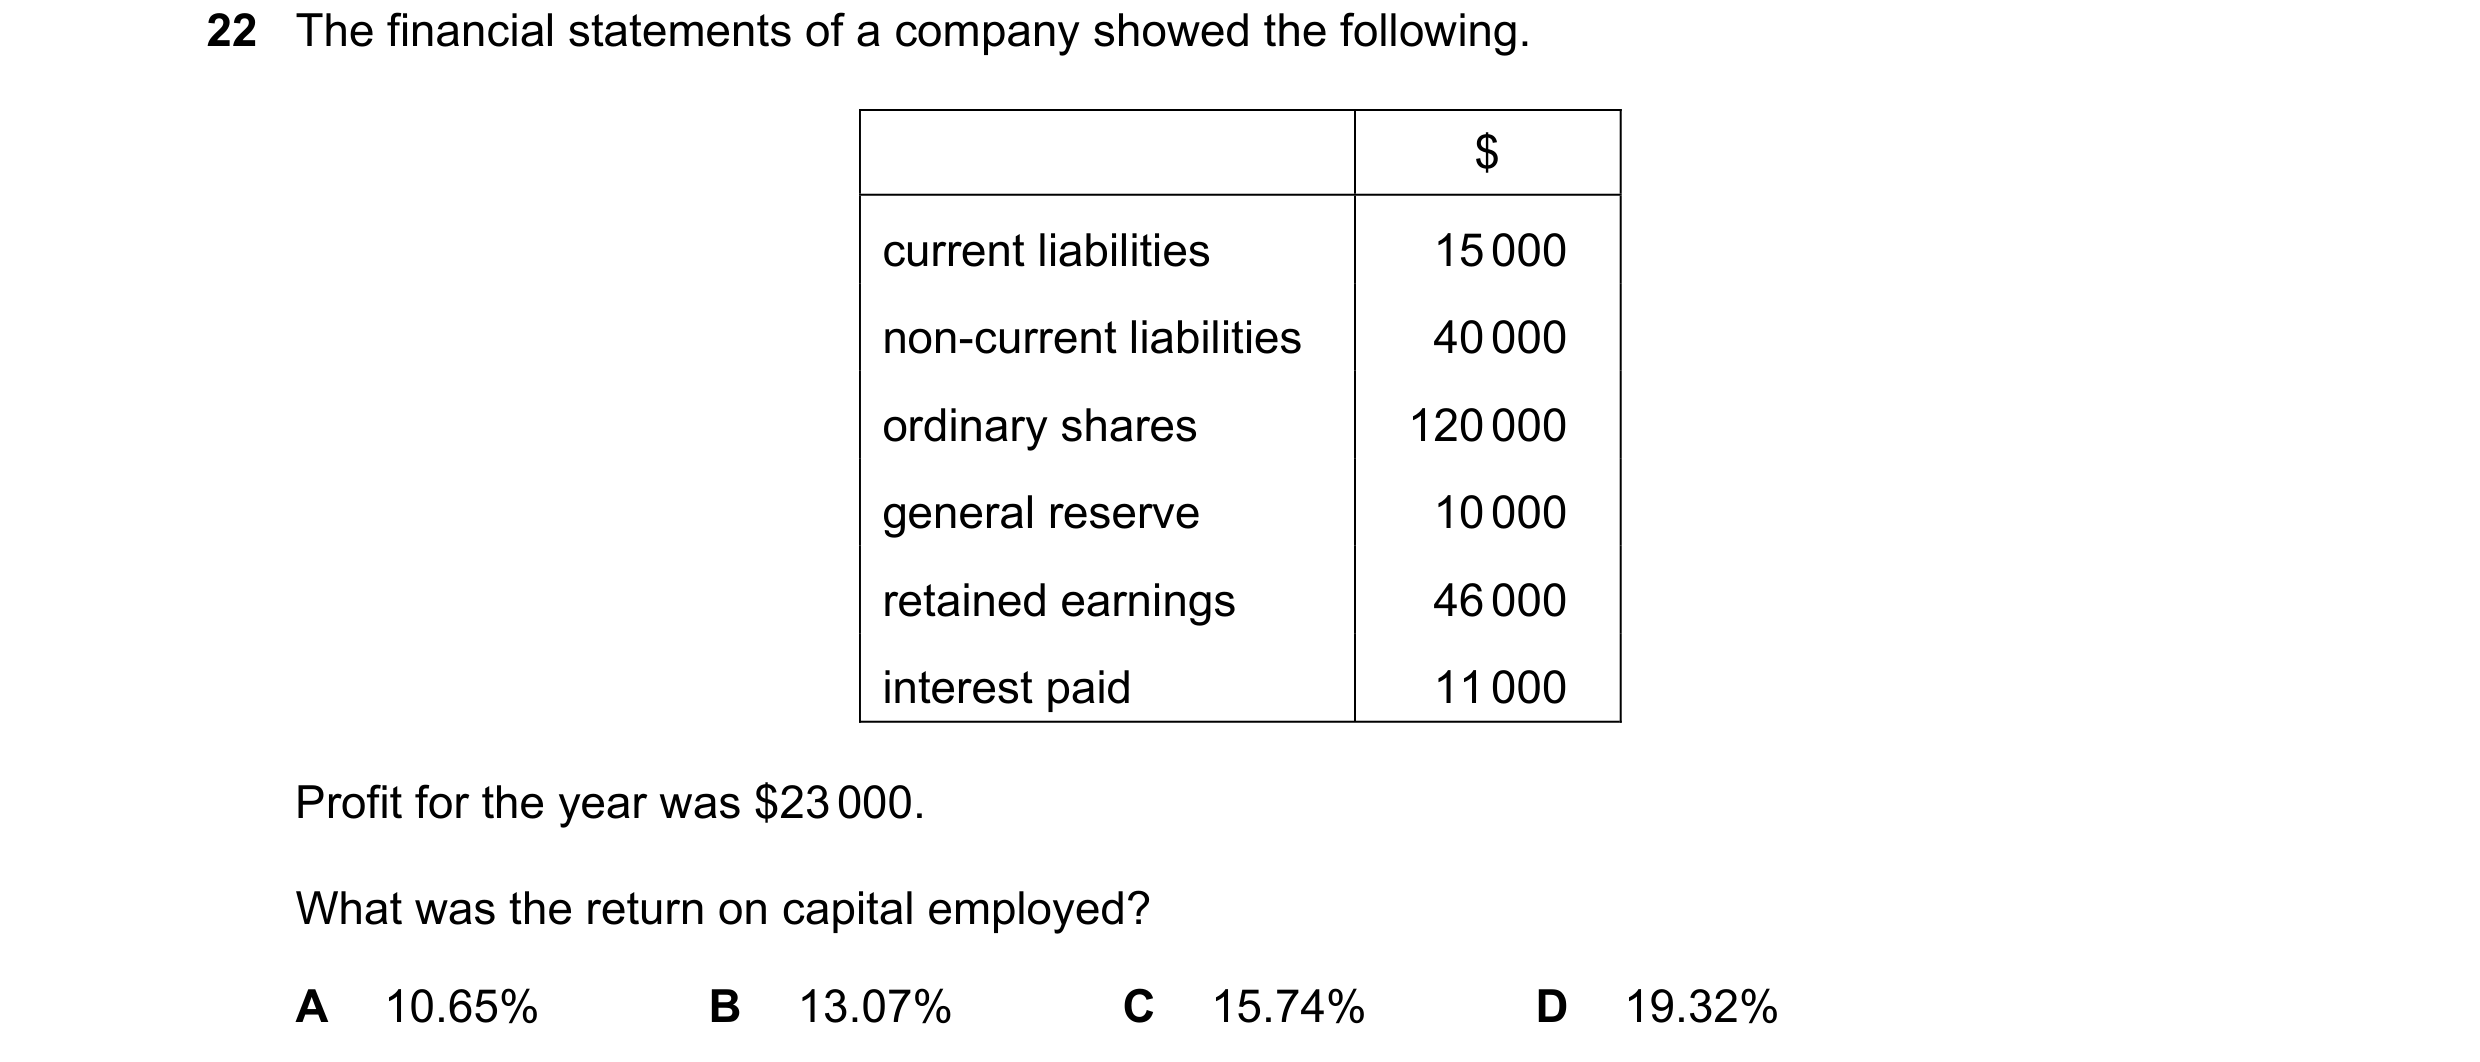
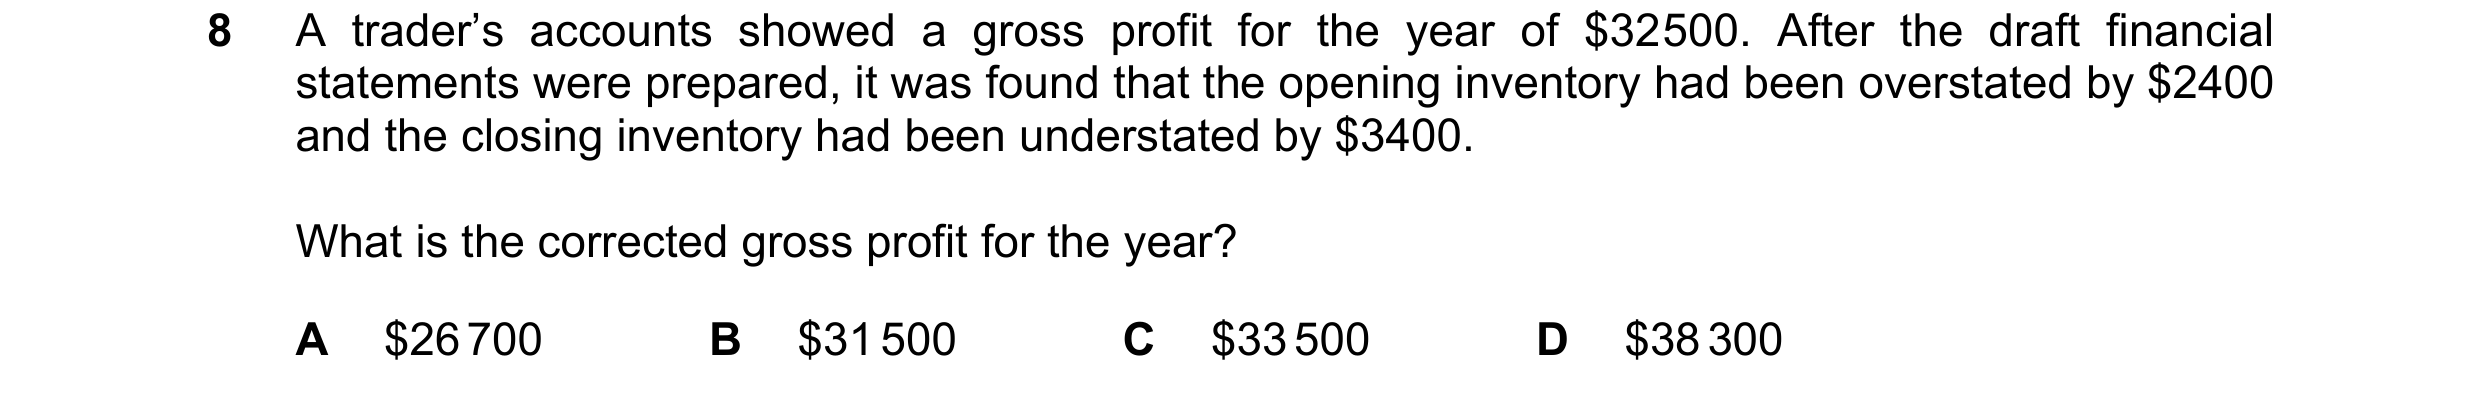
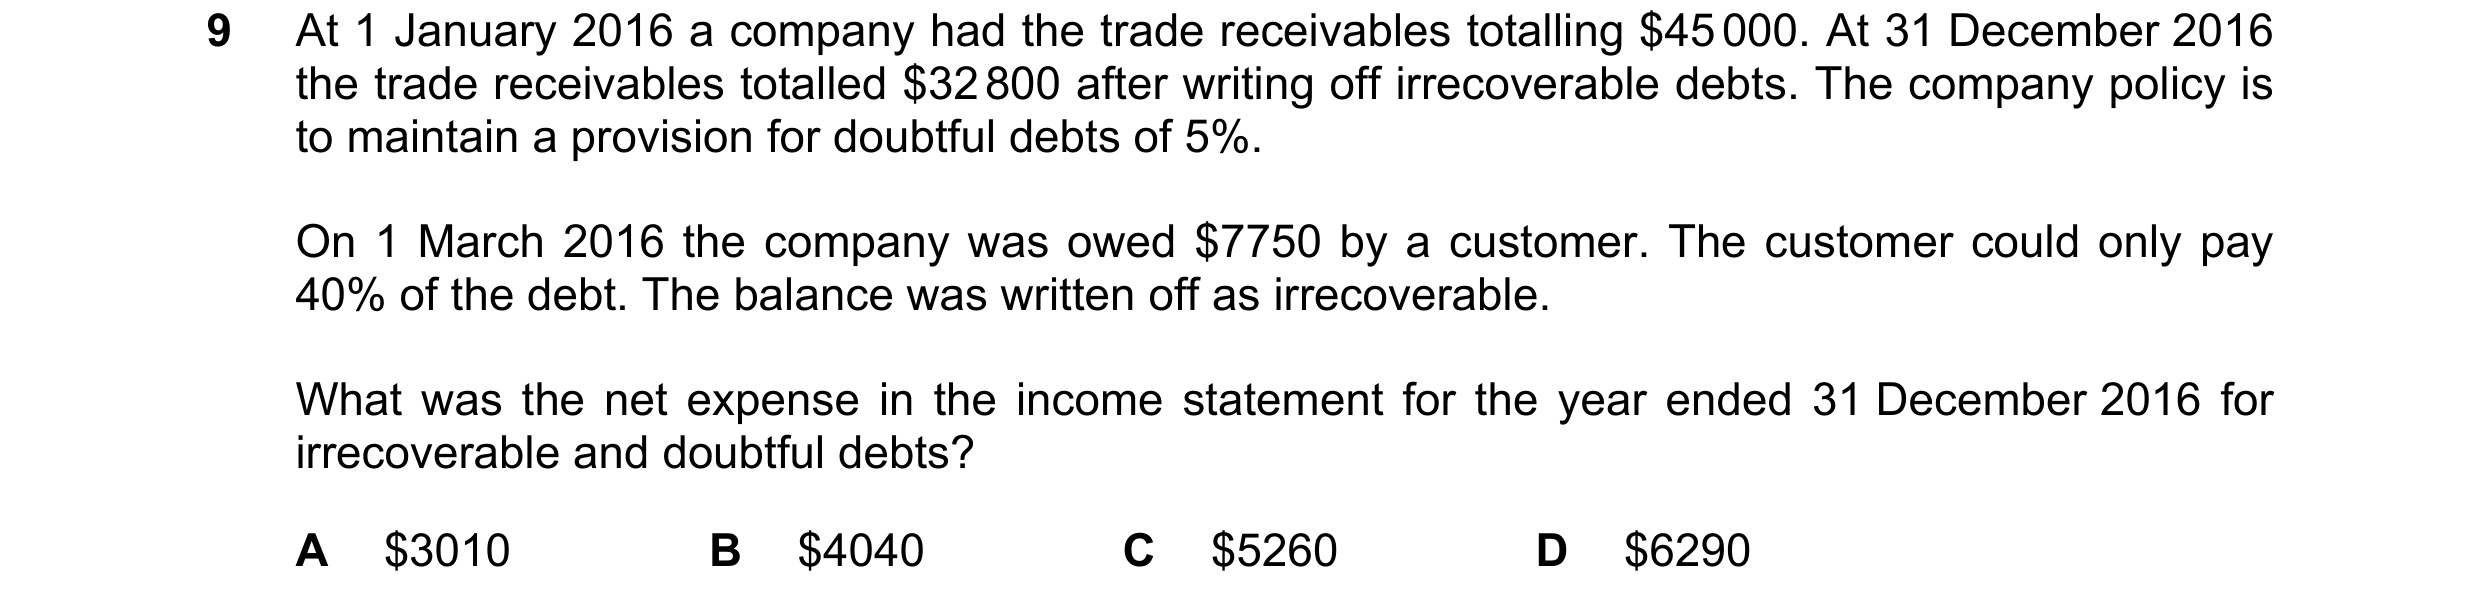 148 / 233
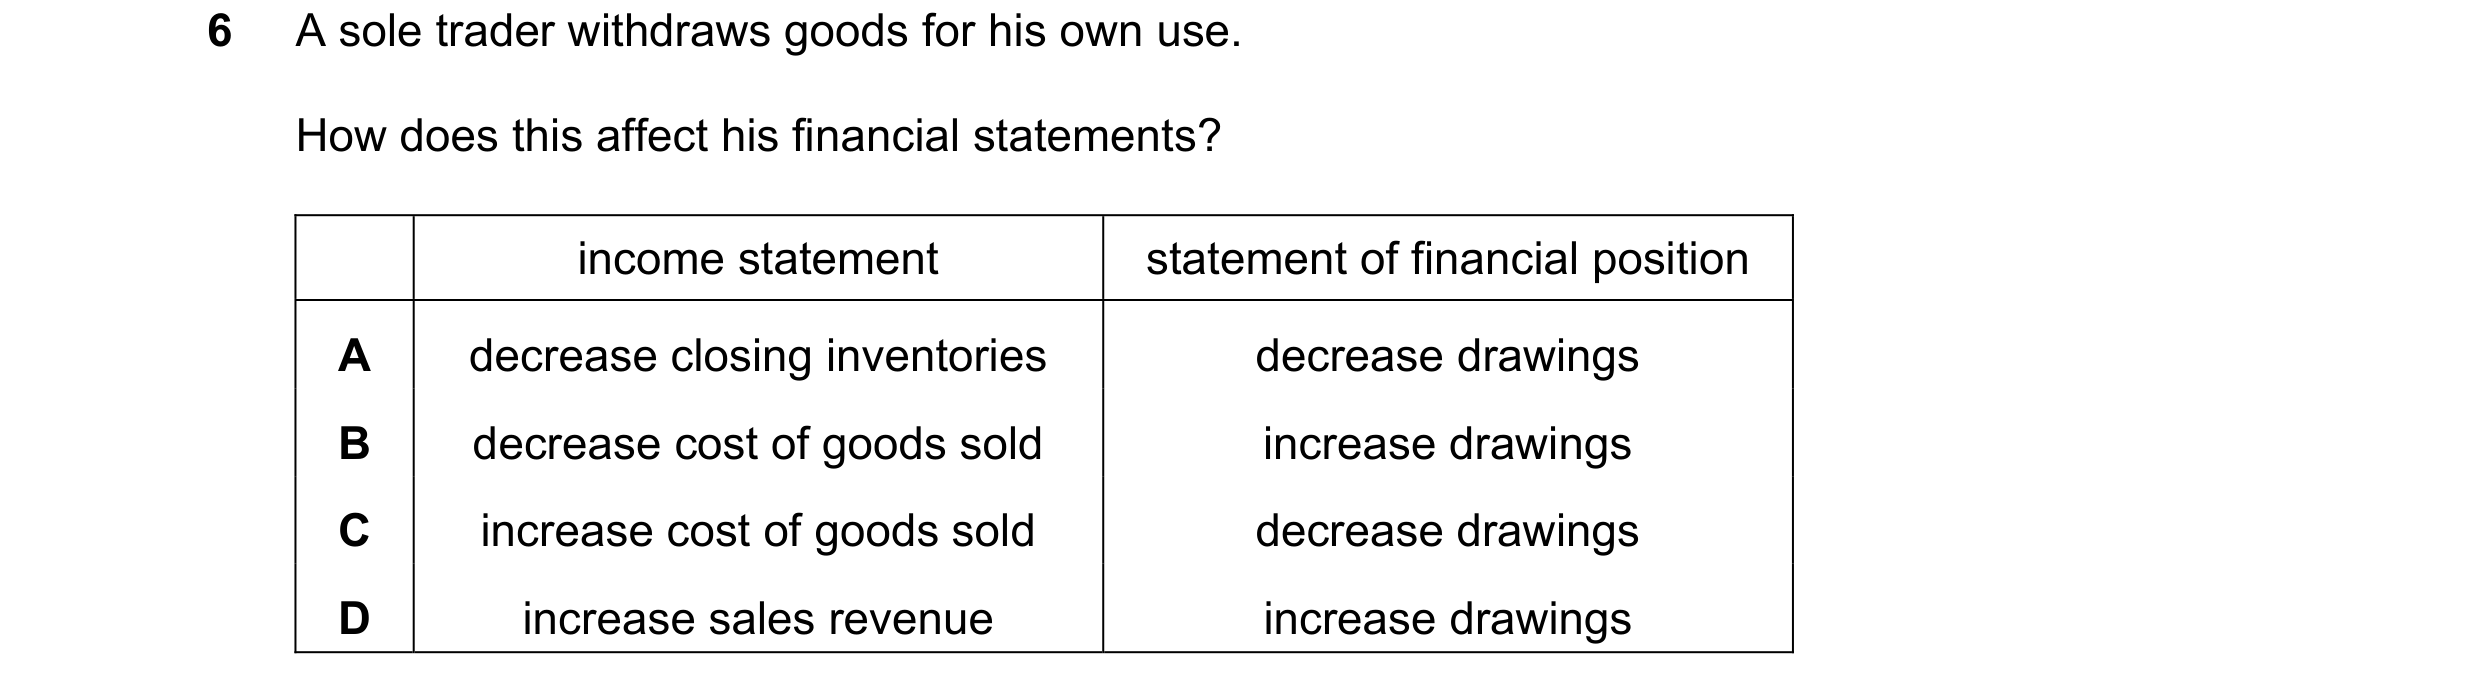
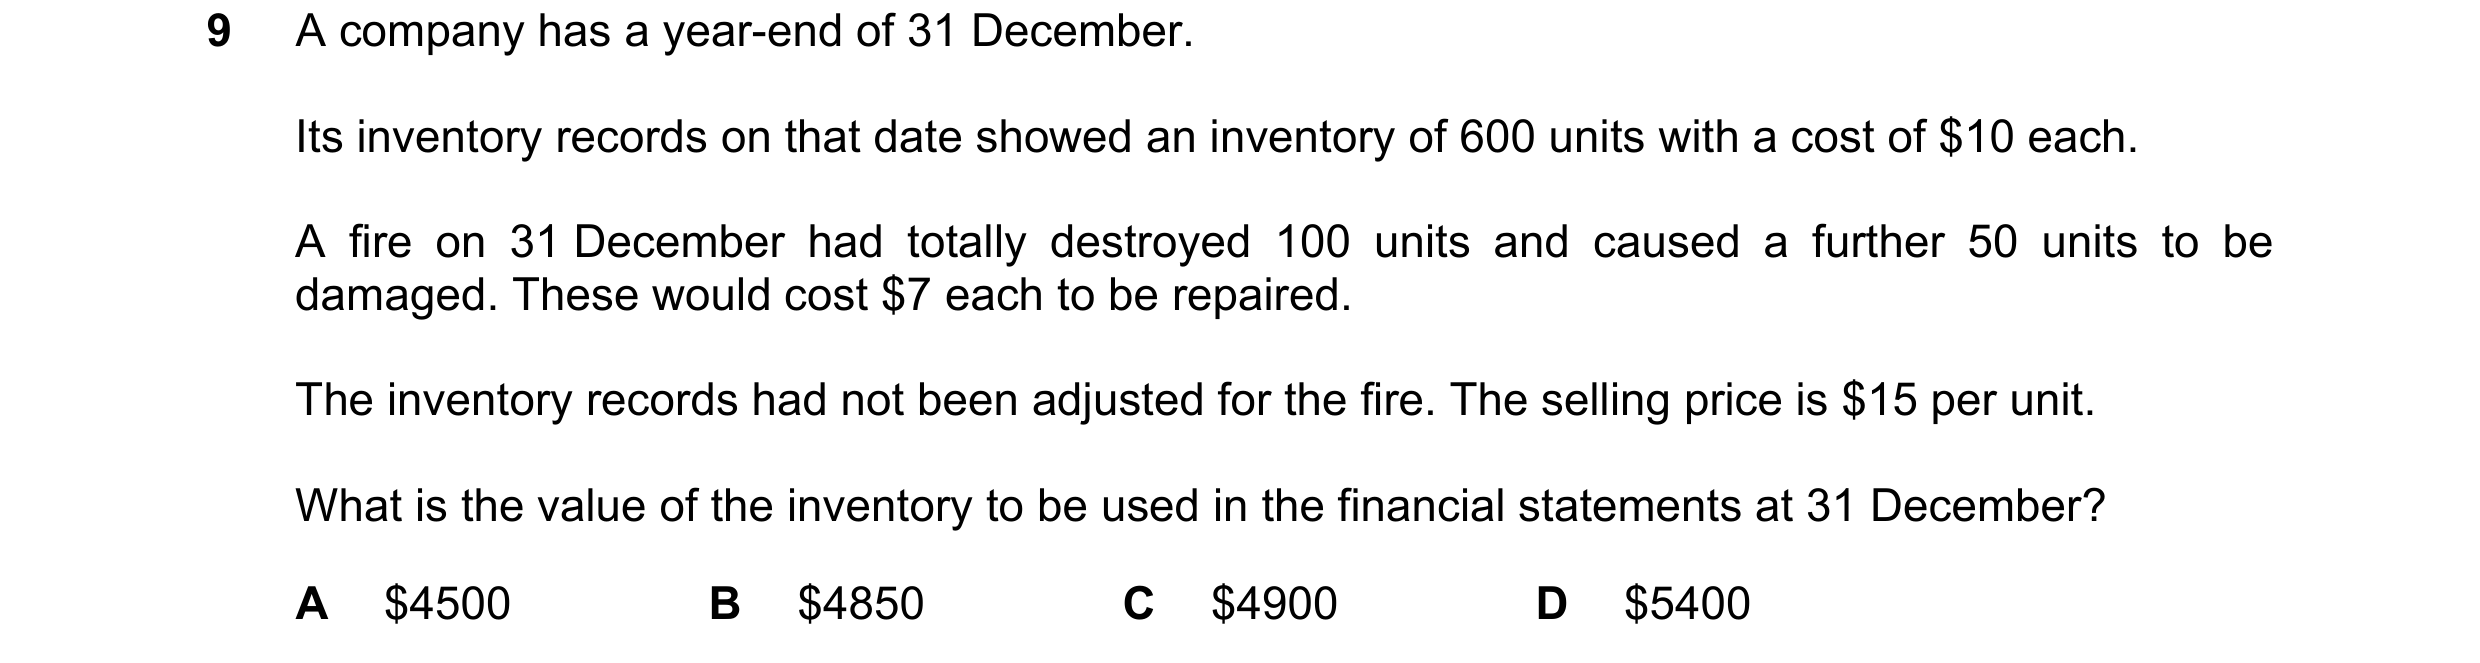
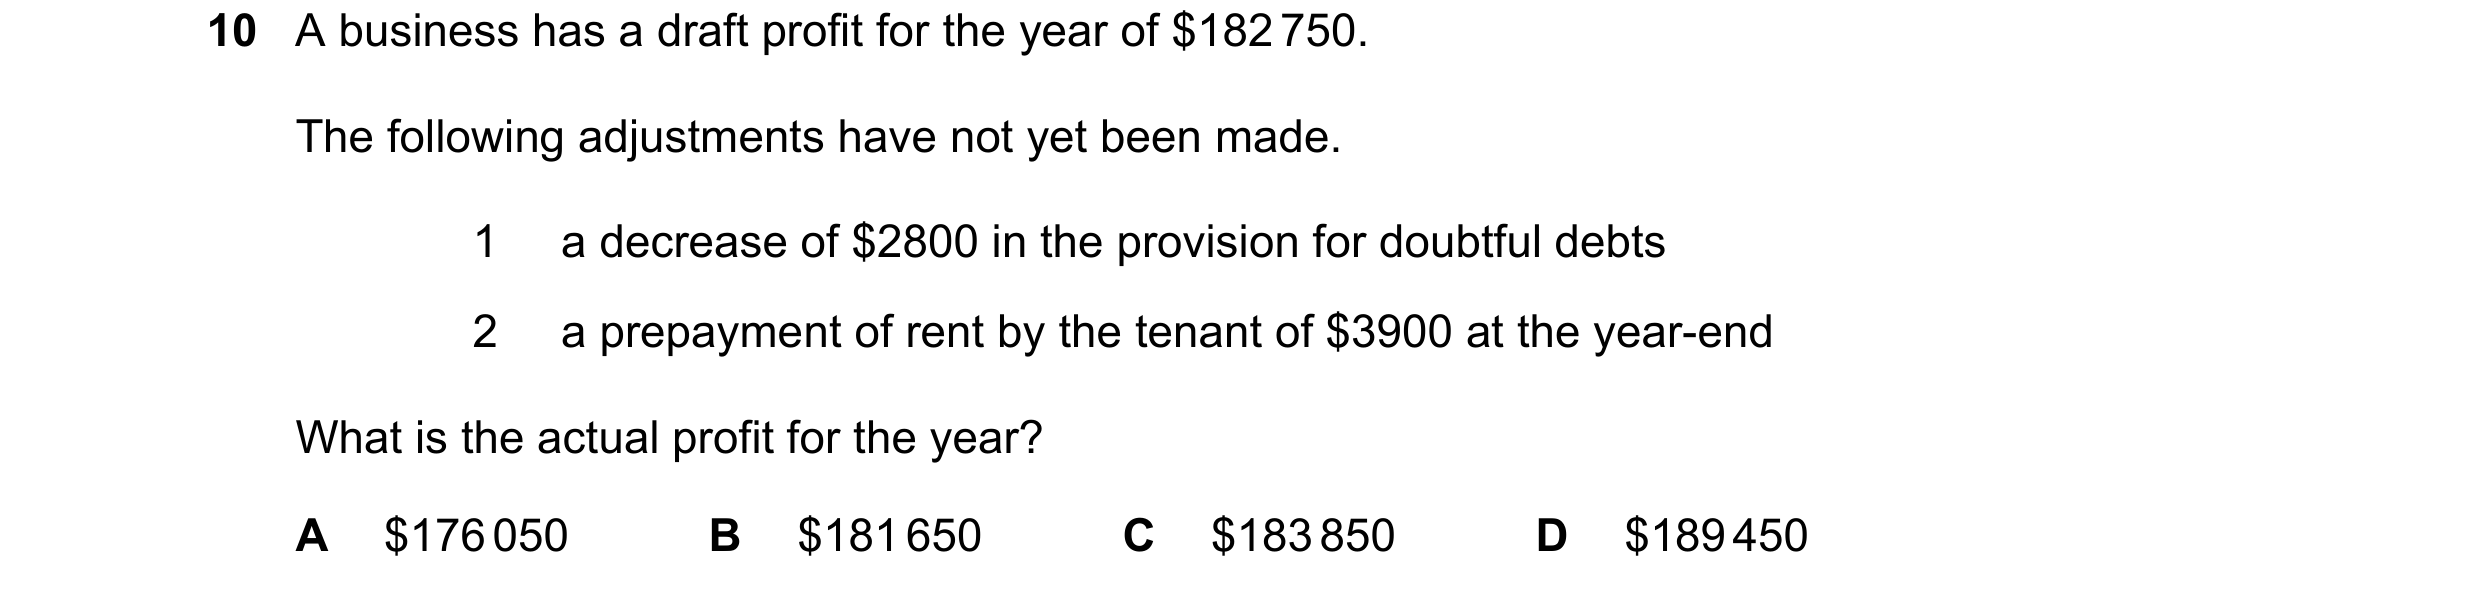
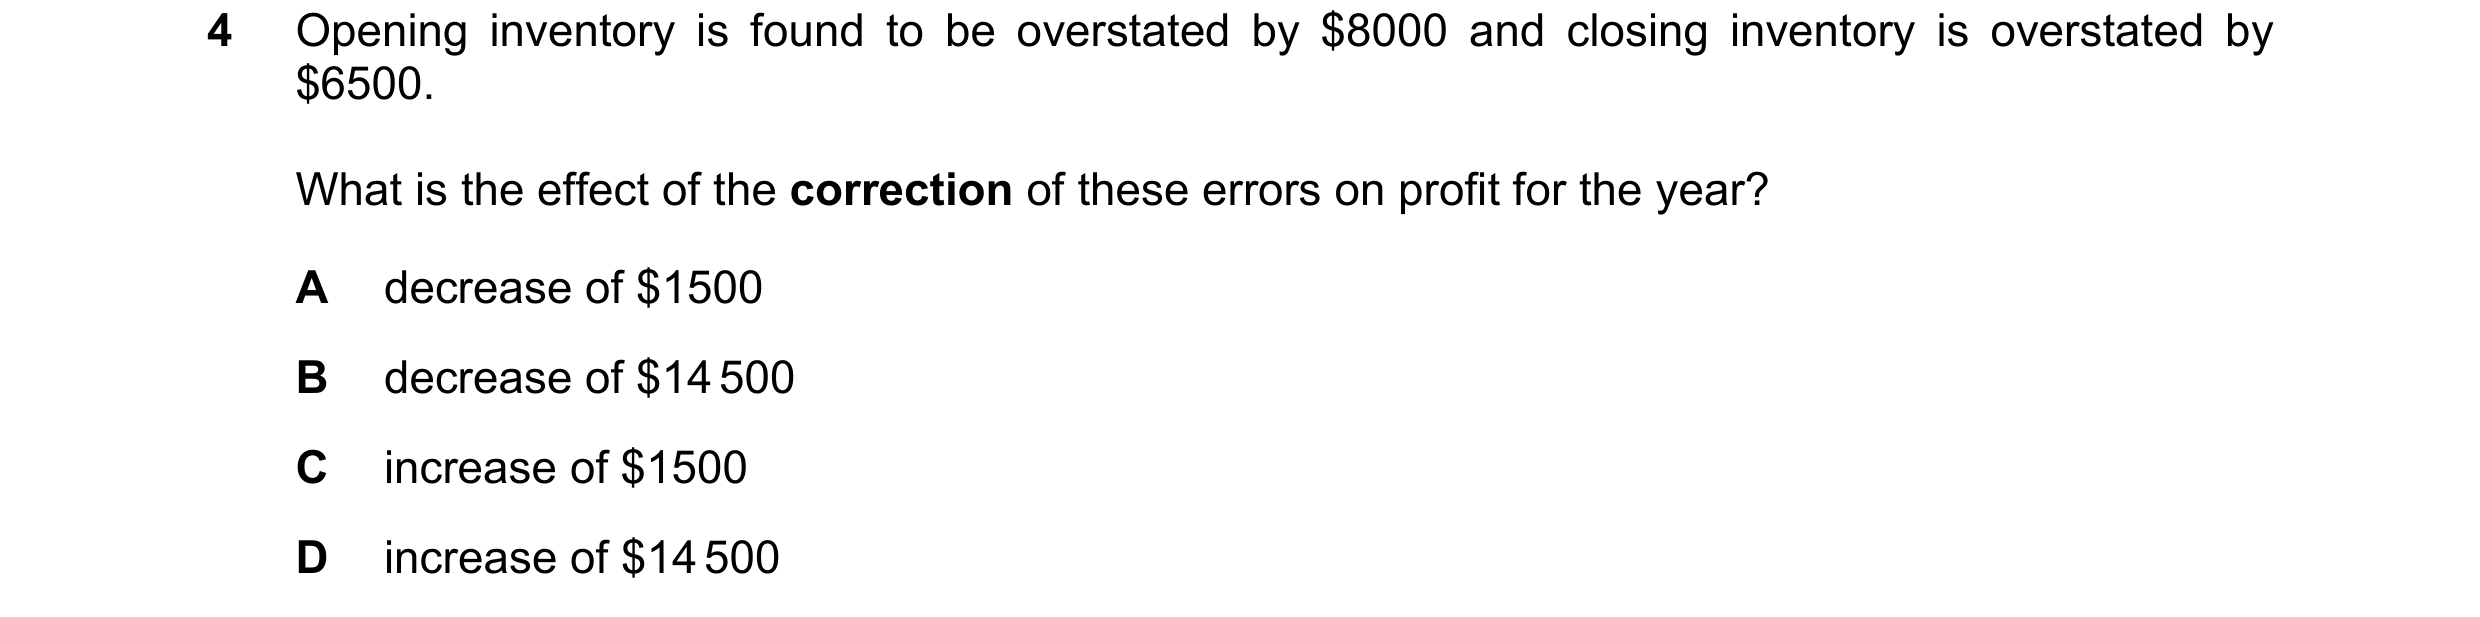 149 / 233
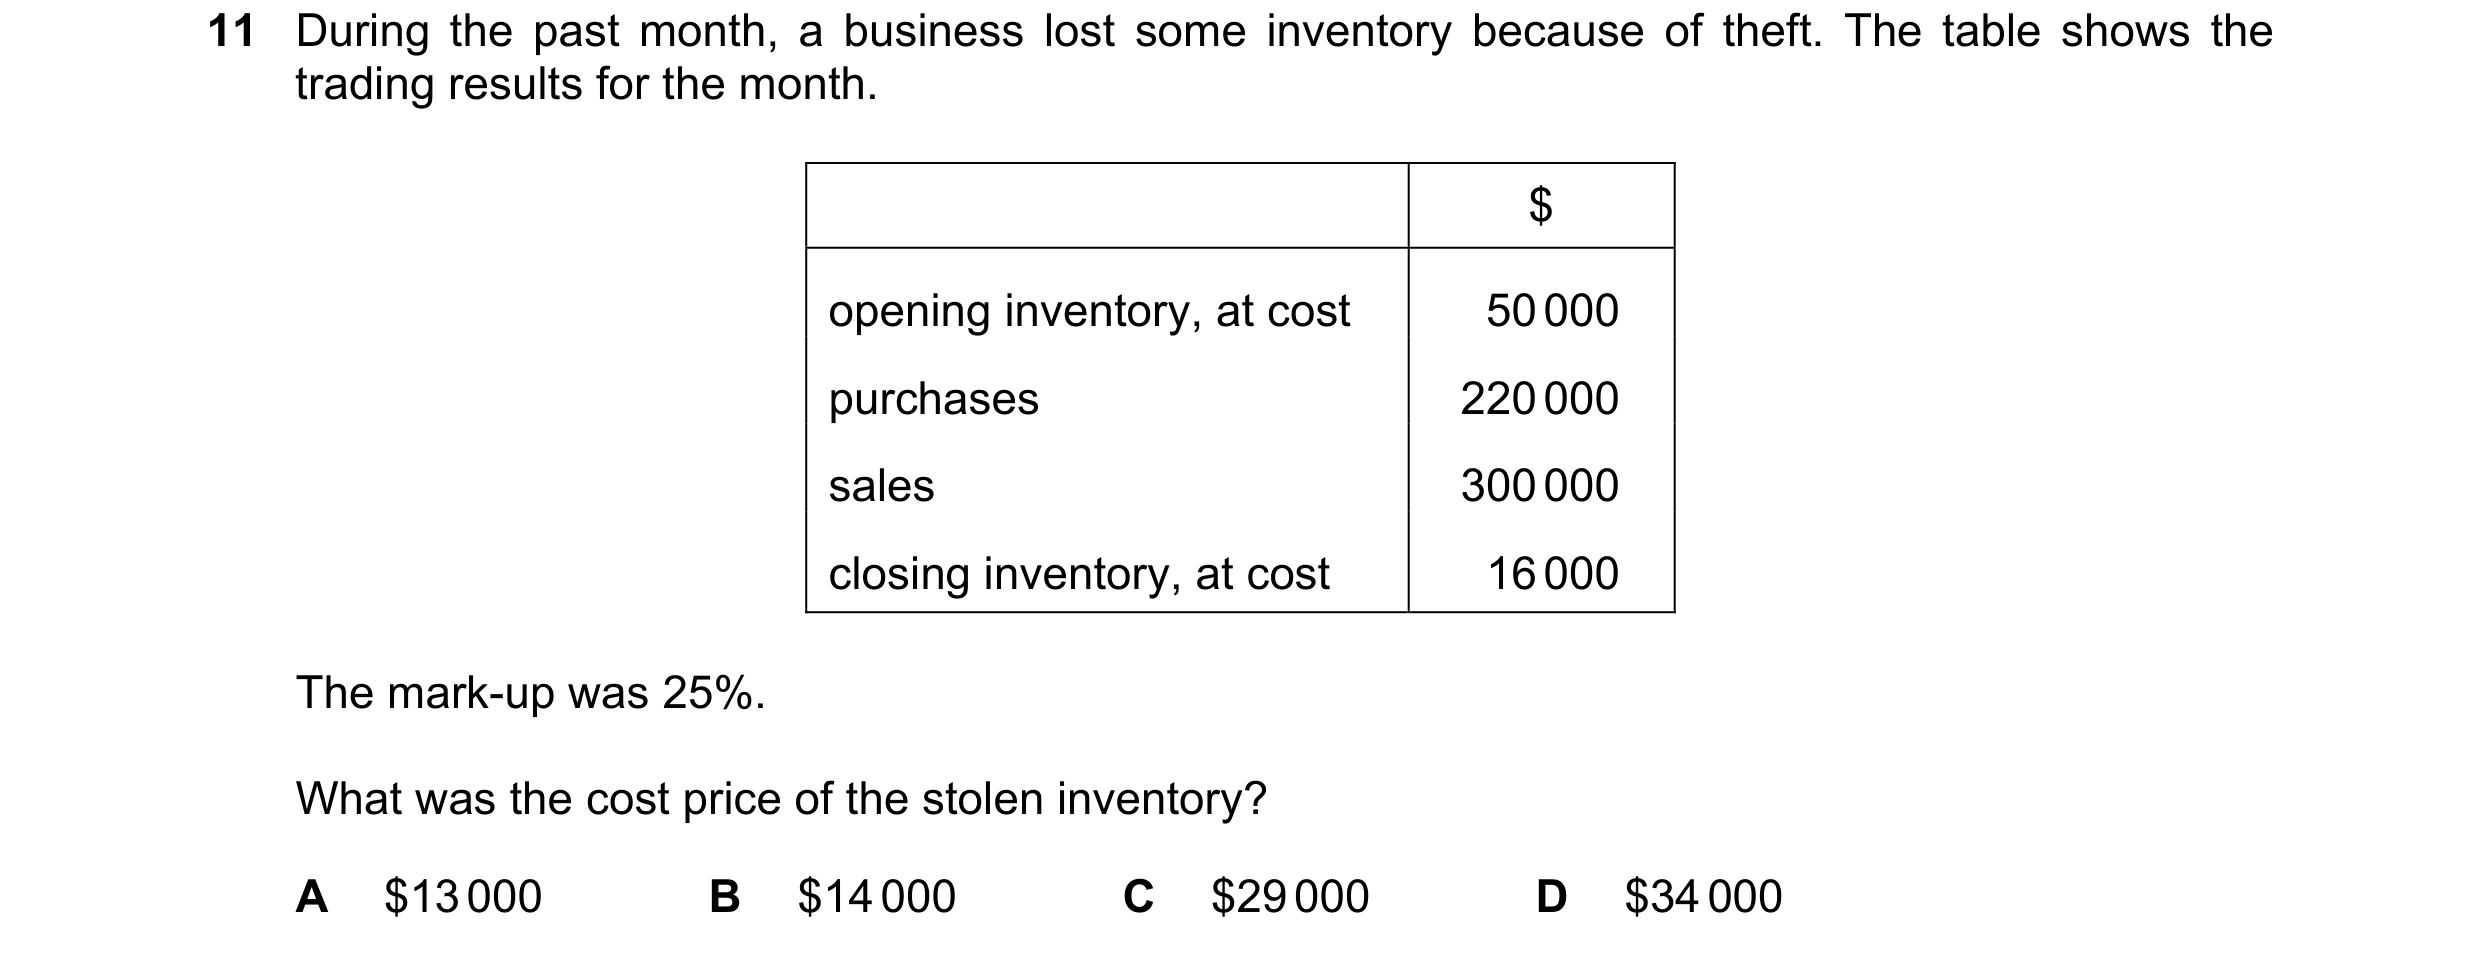
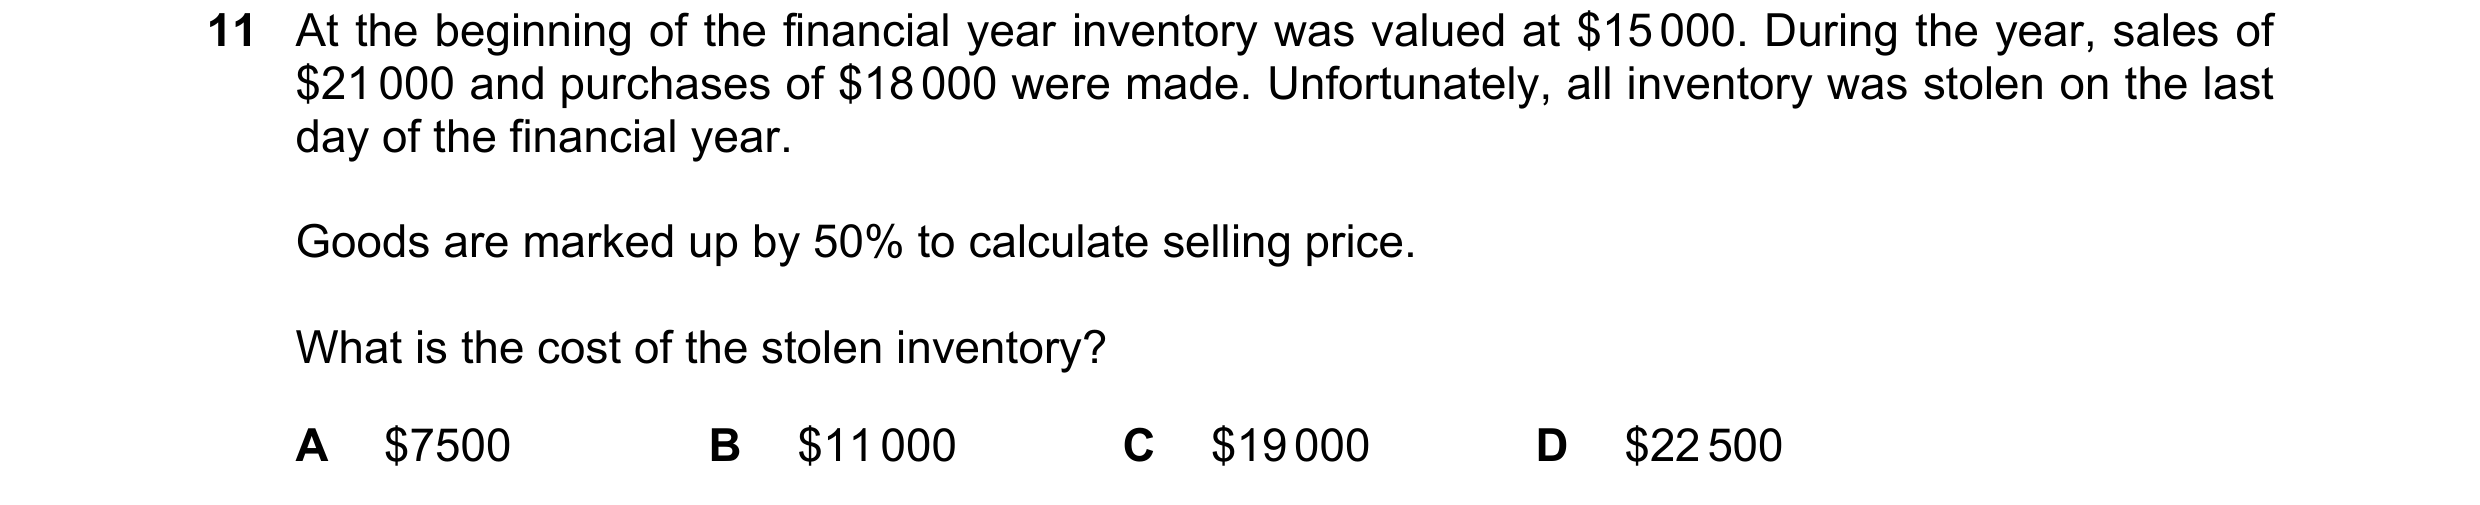
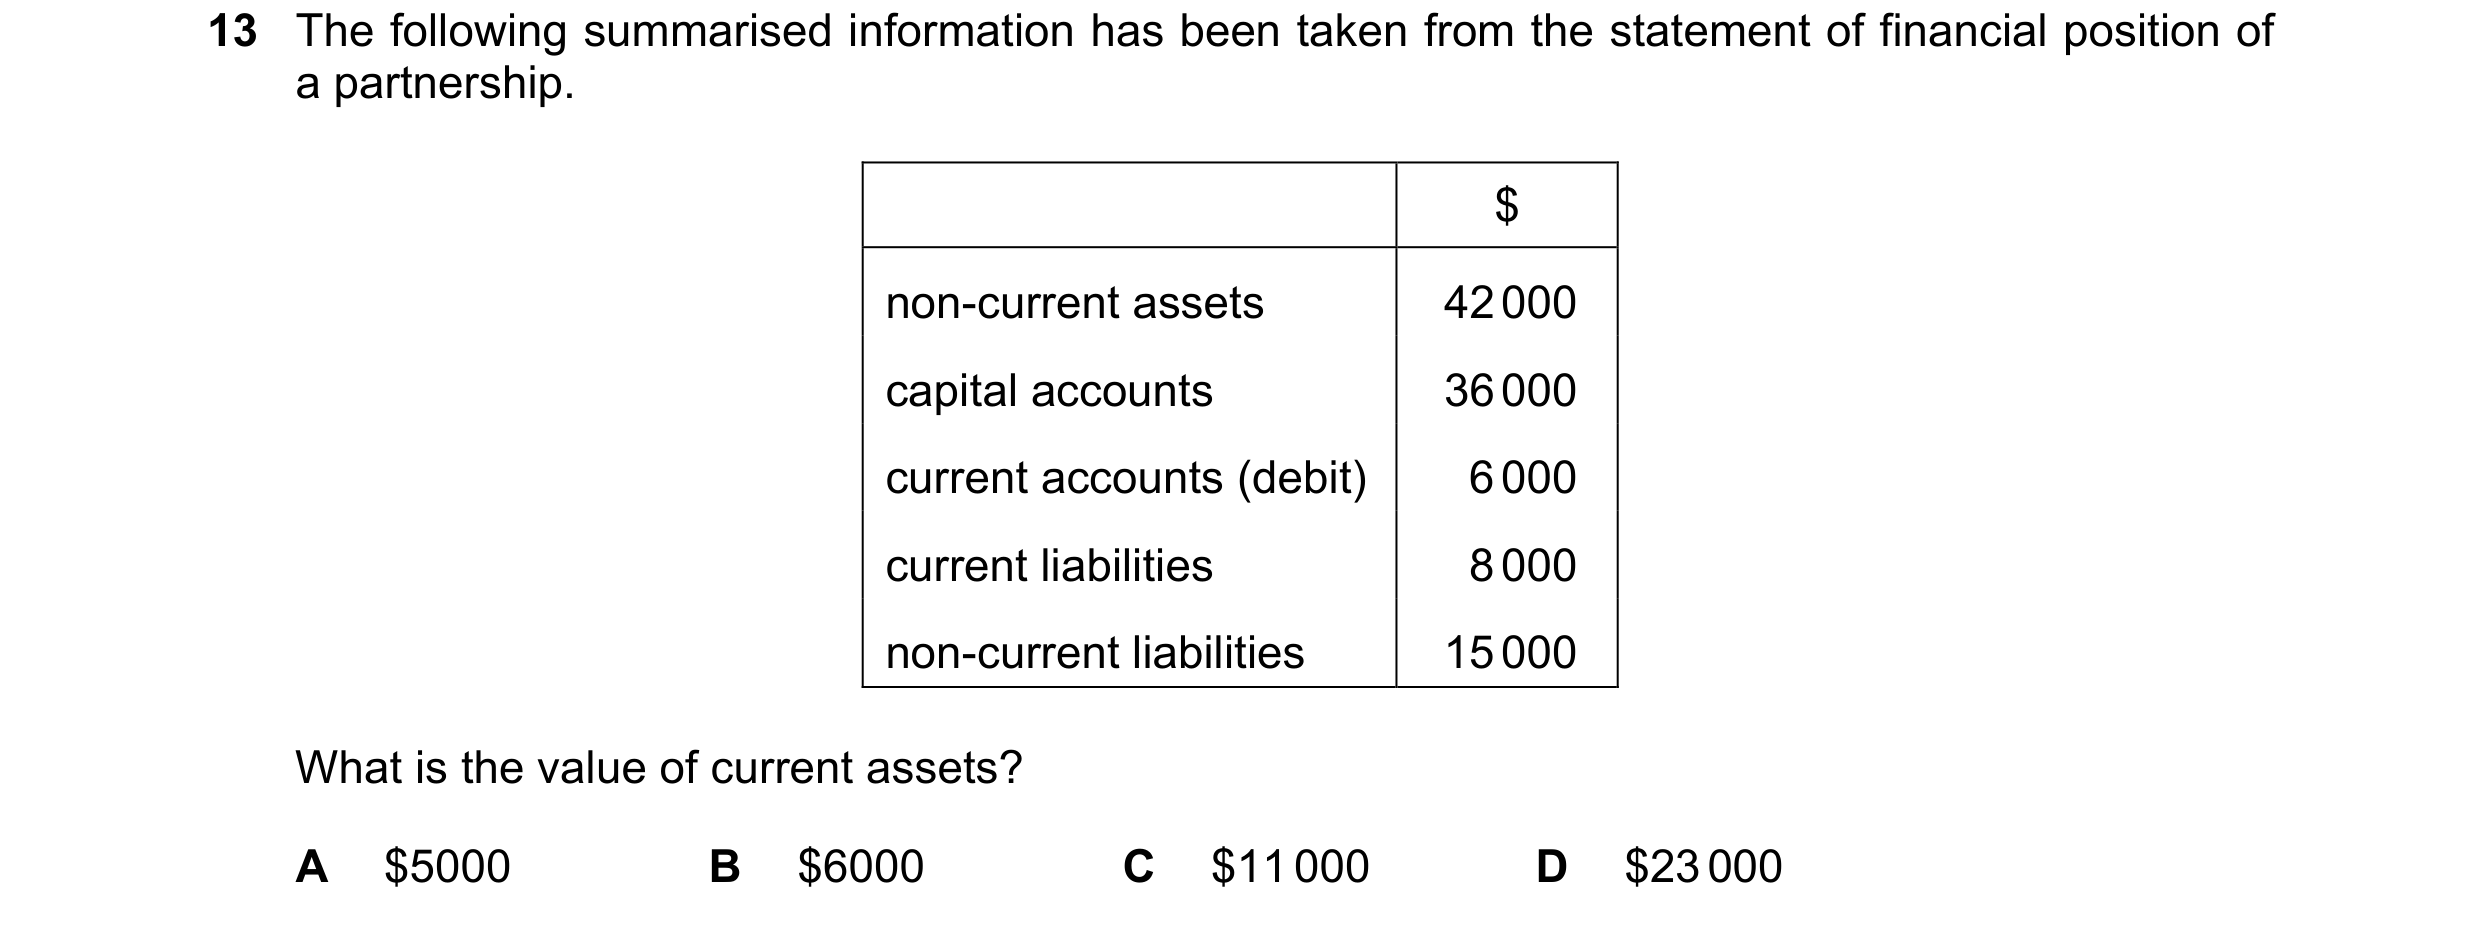
 150 / 233
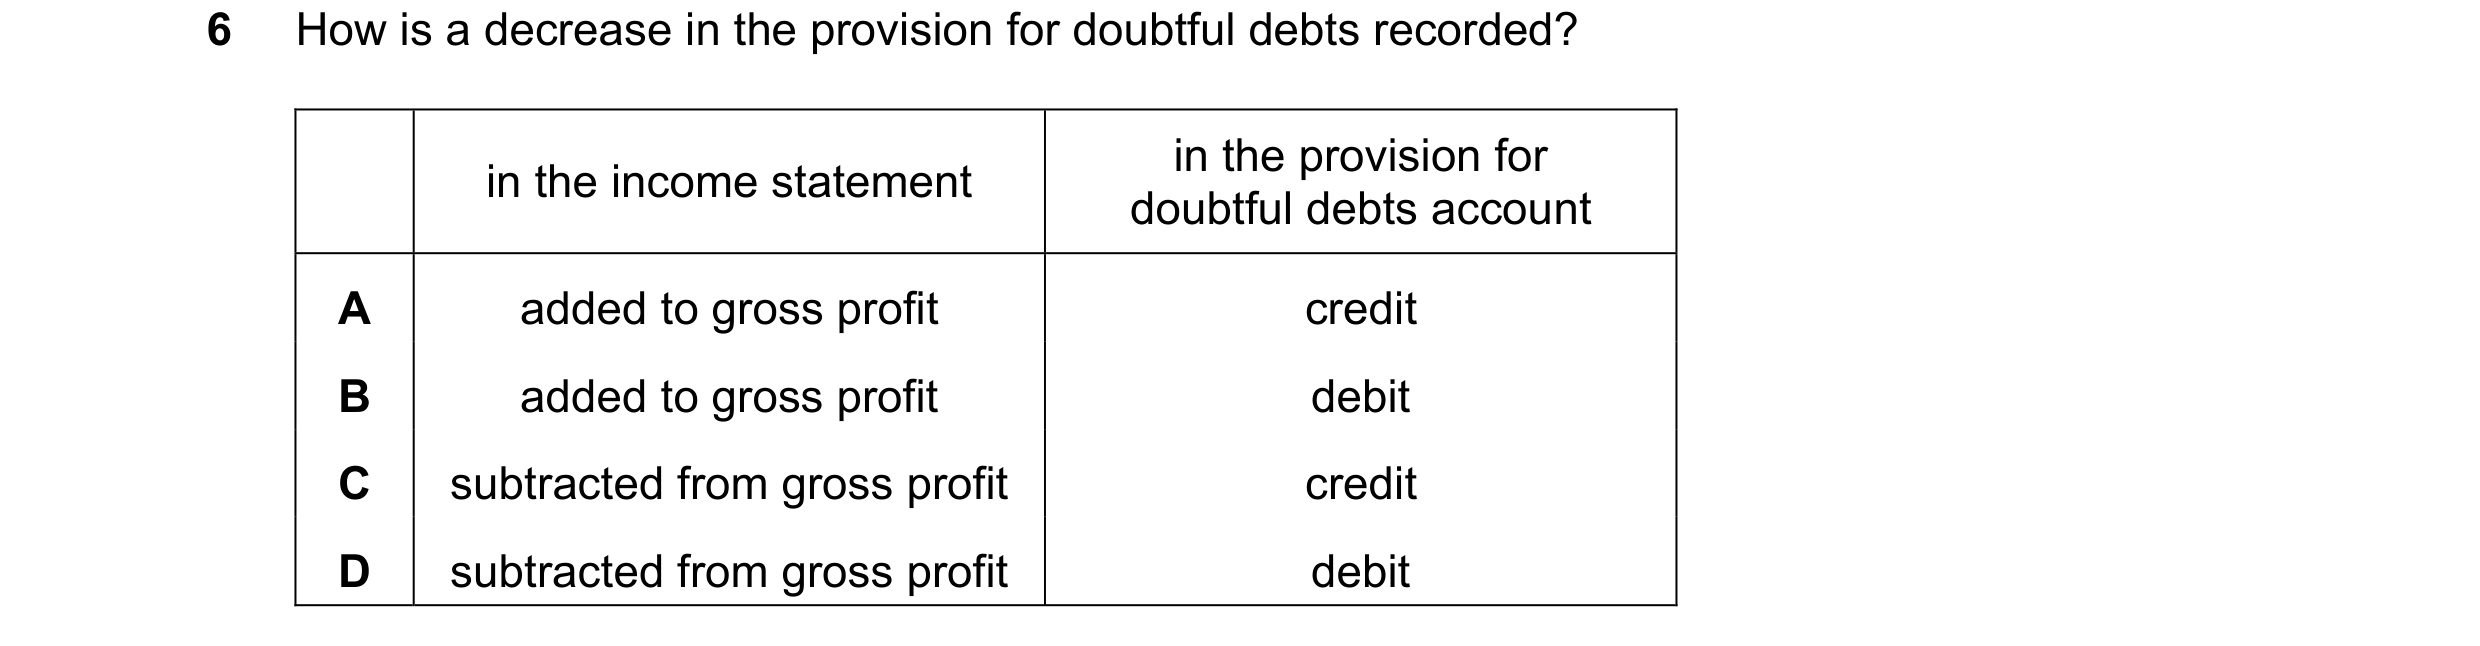
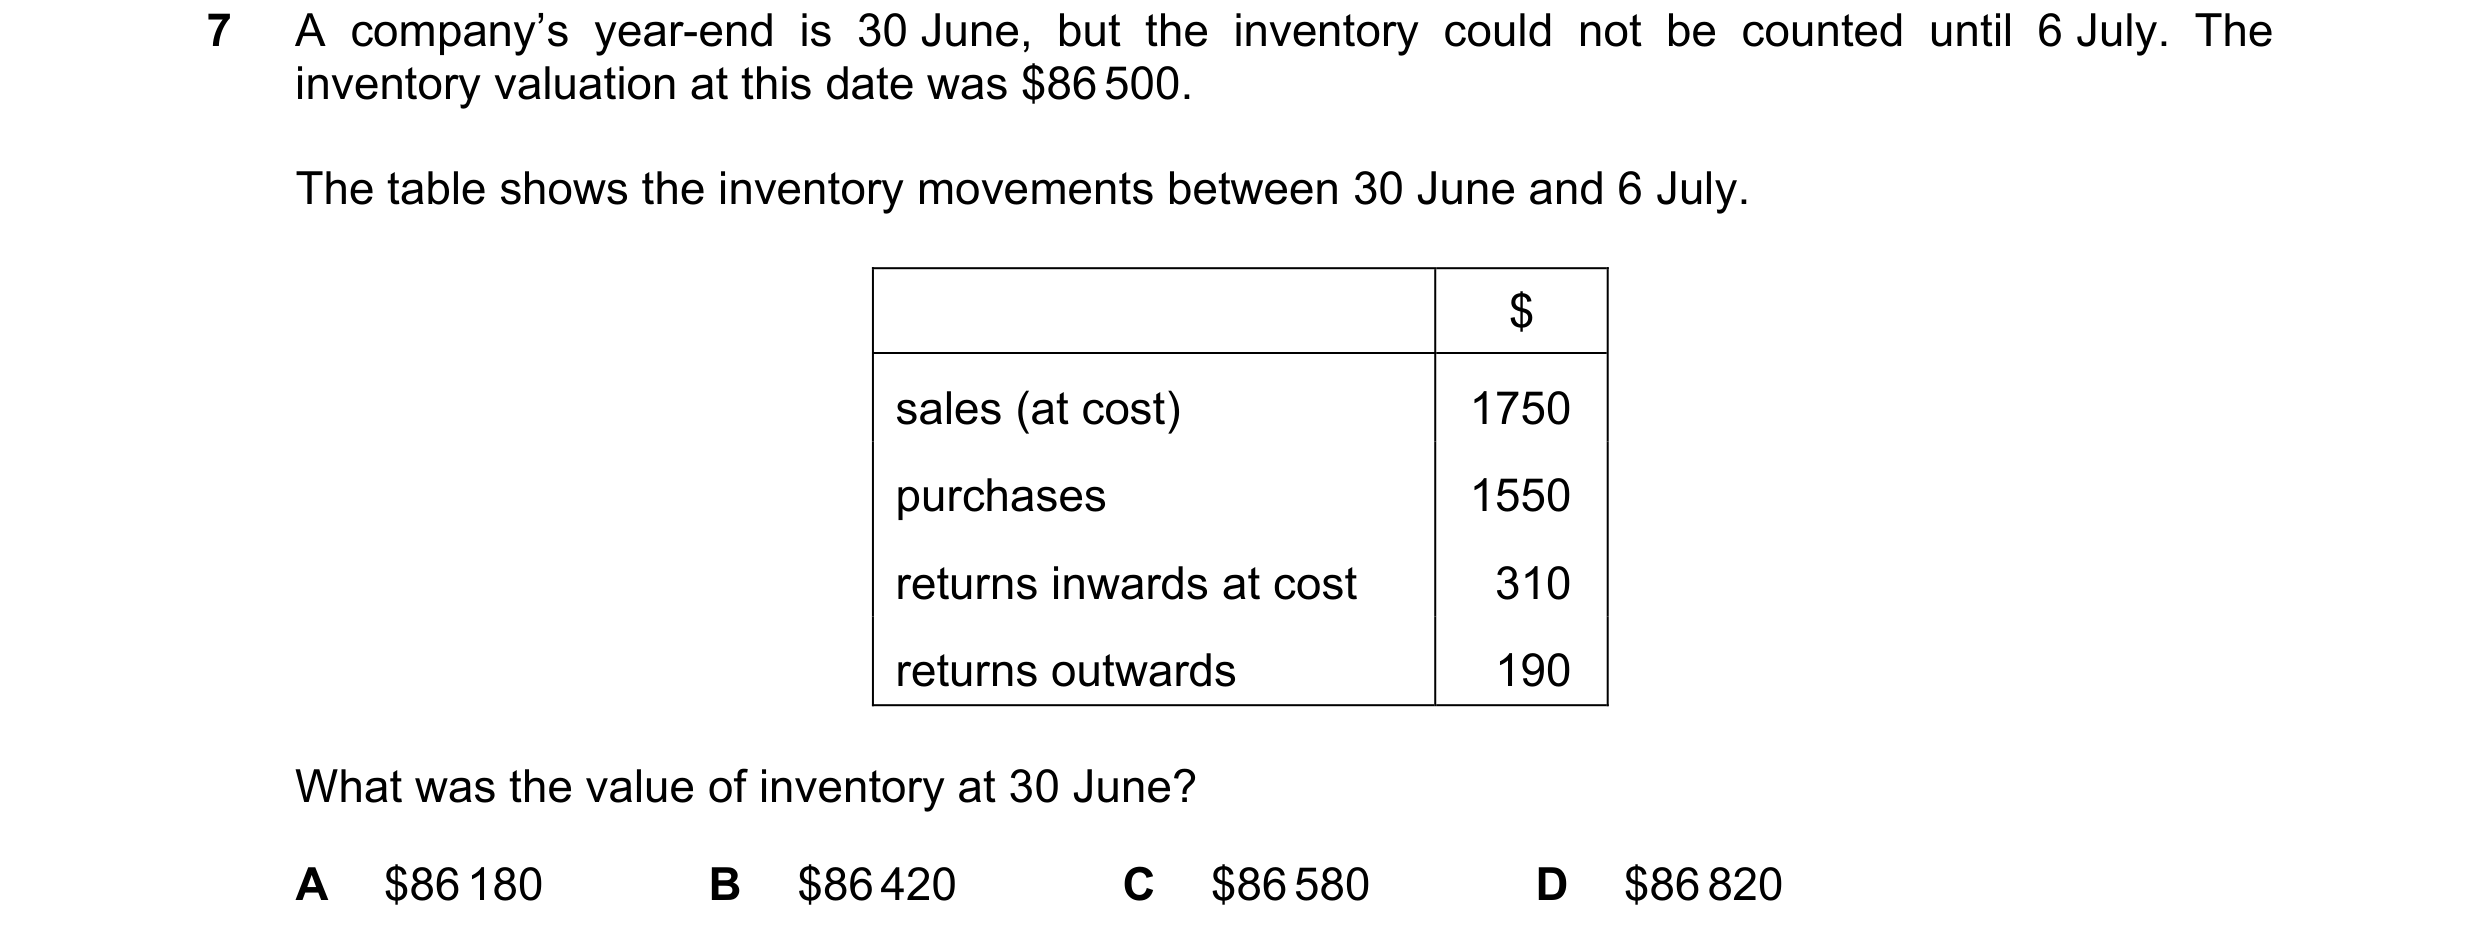
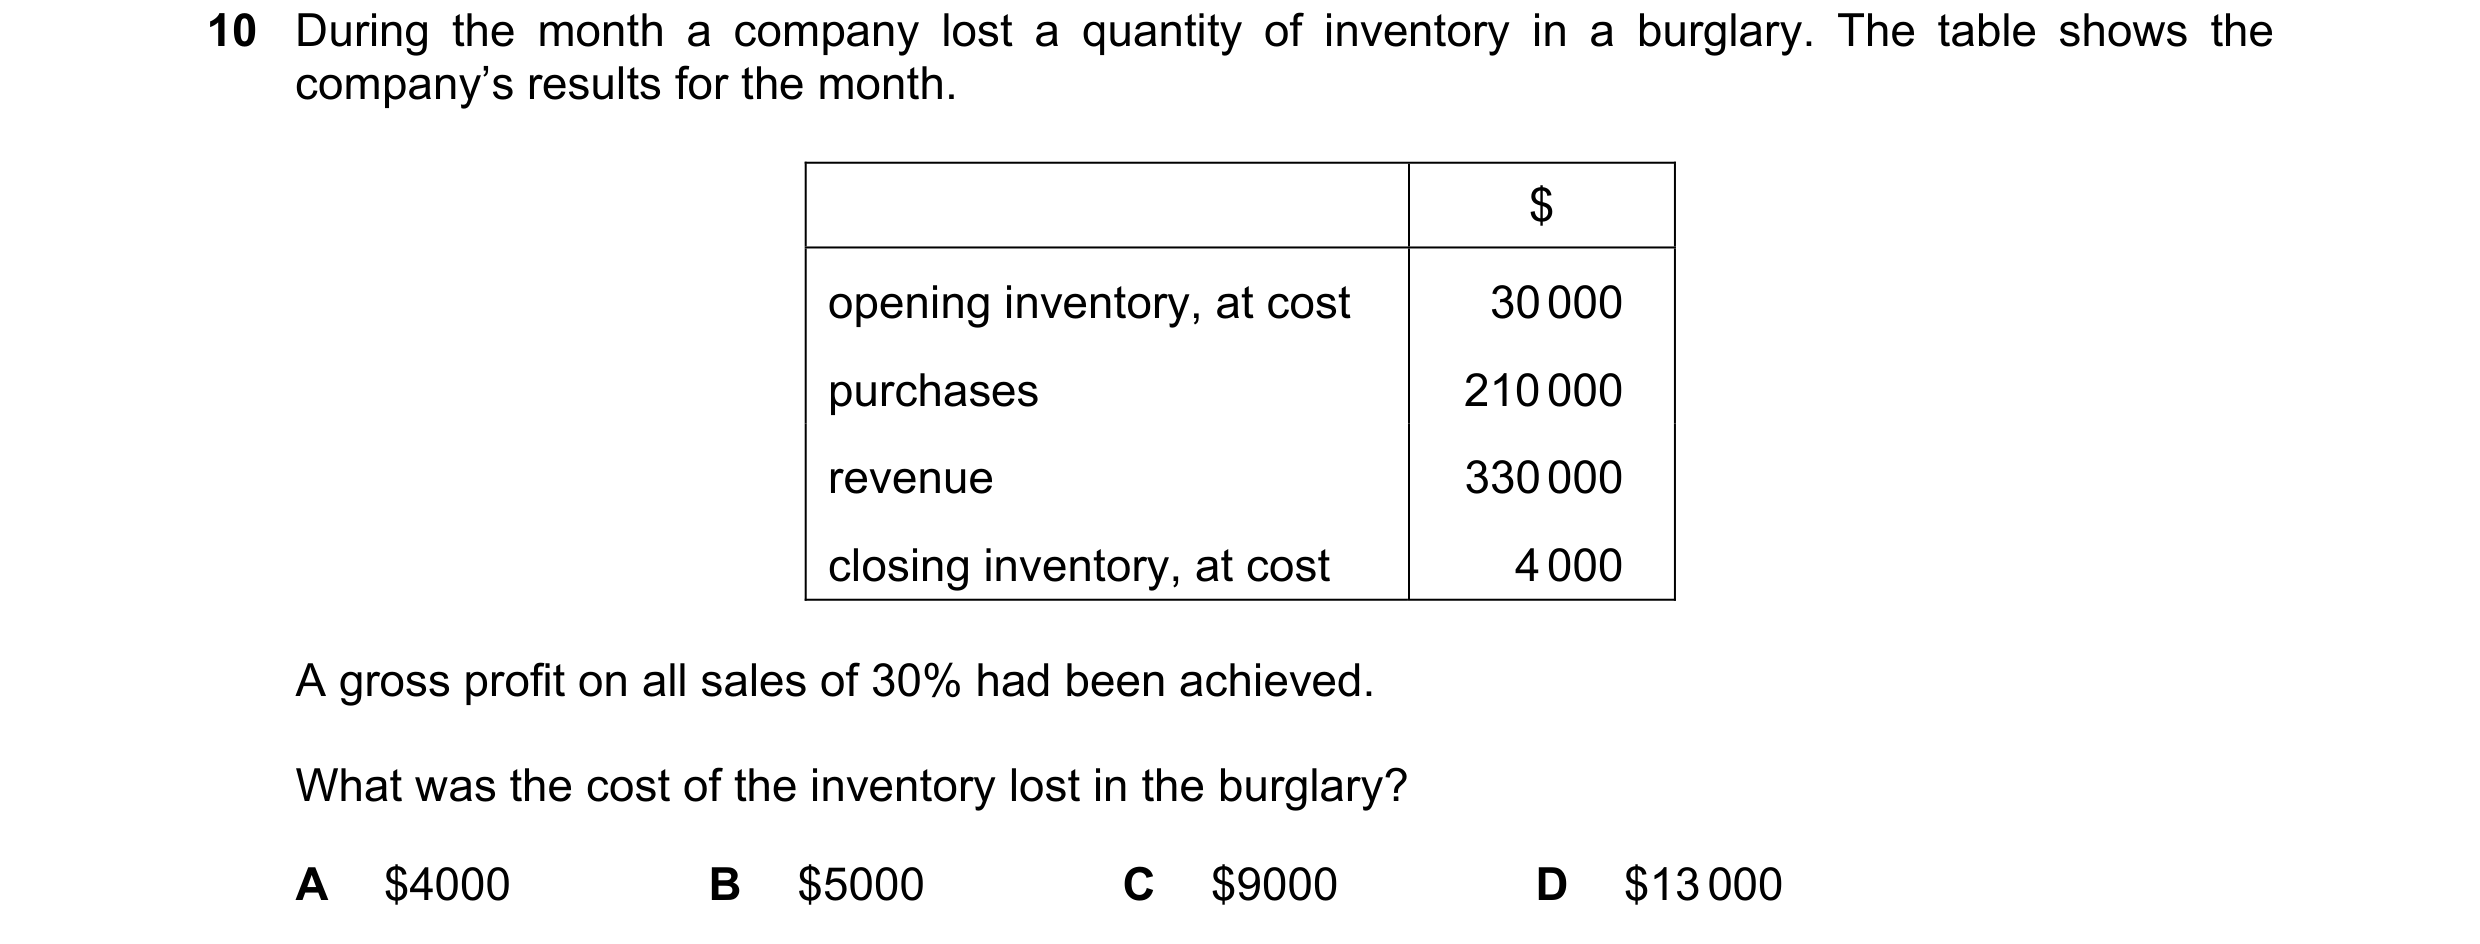 151 / 233
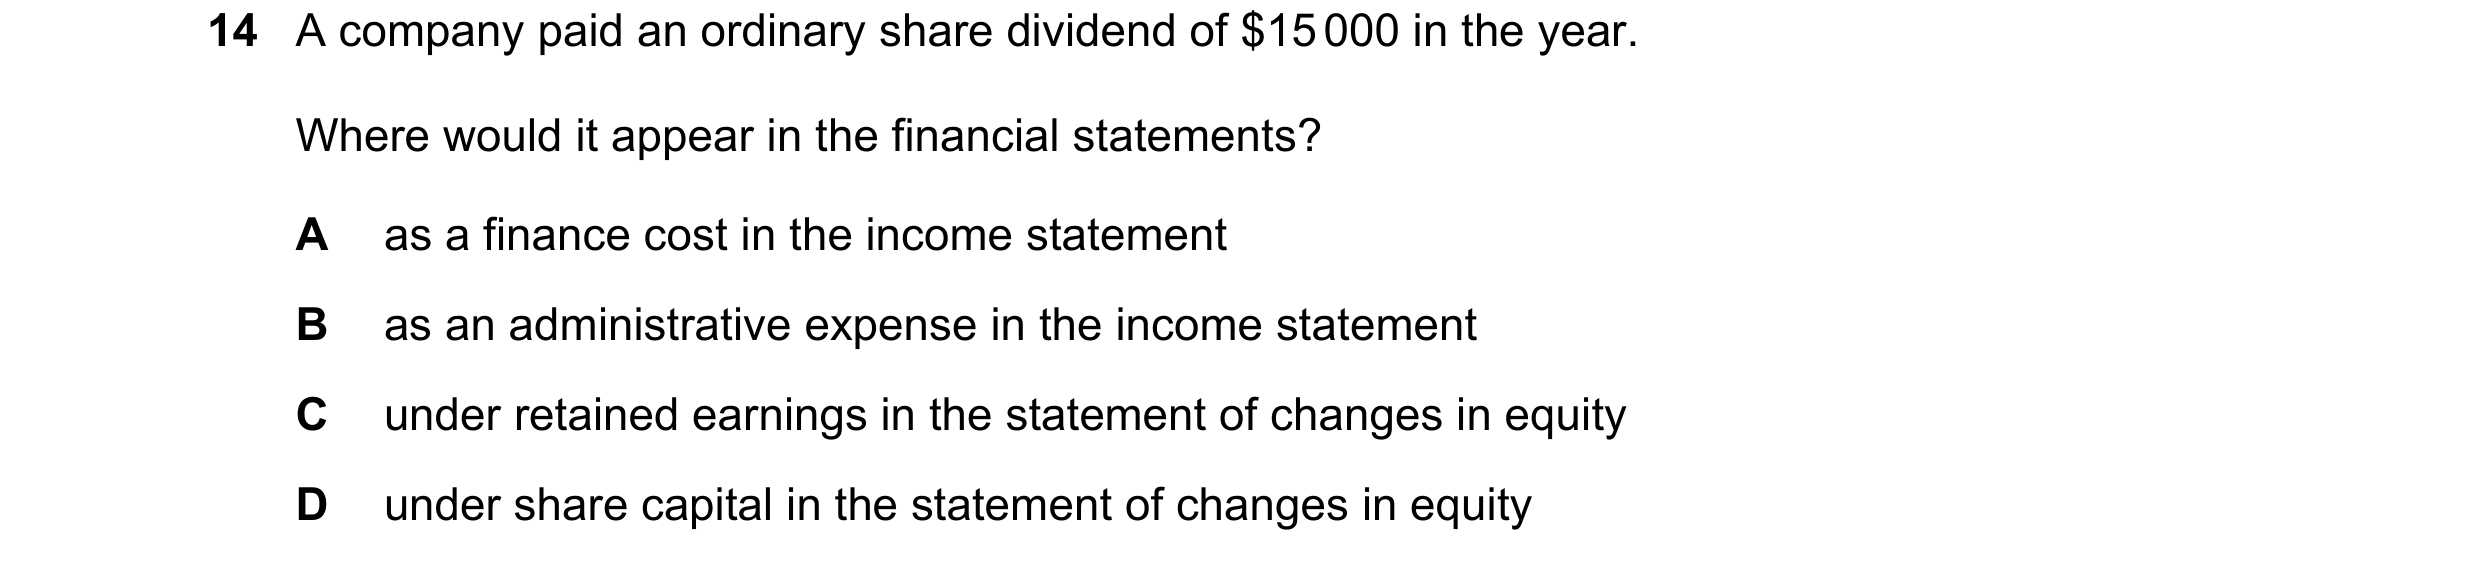
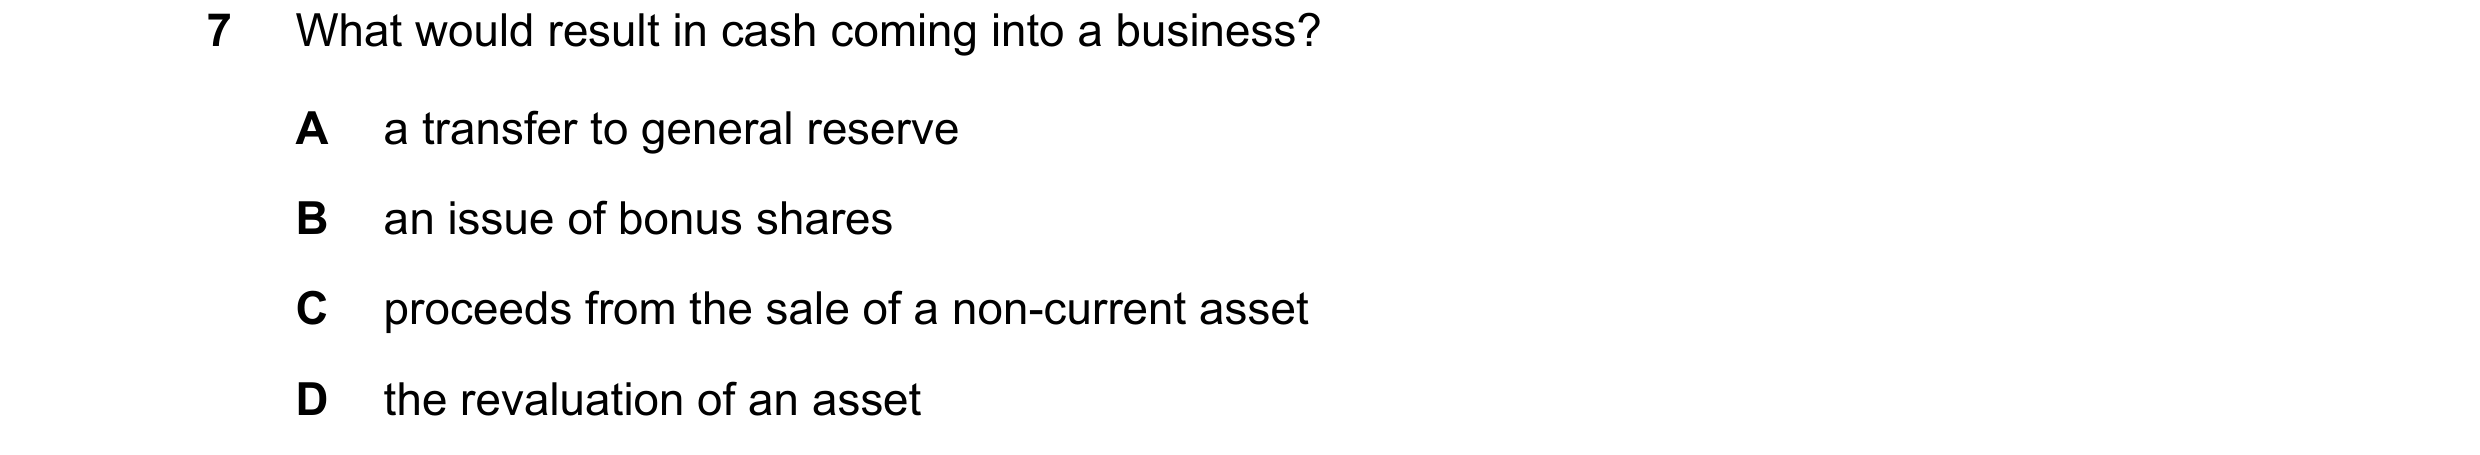
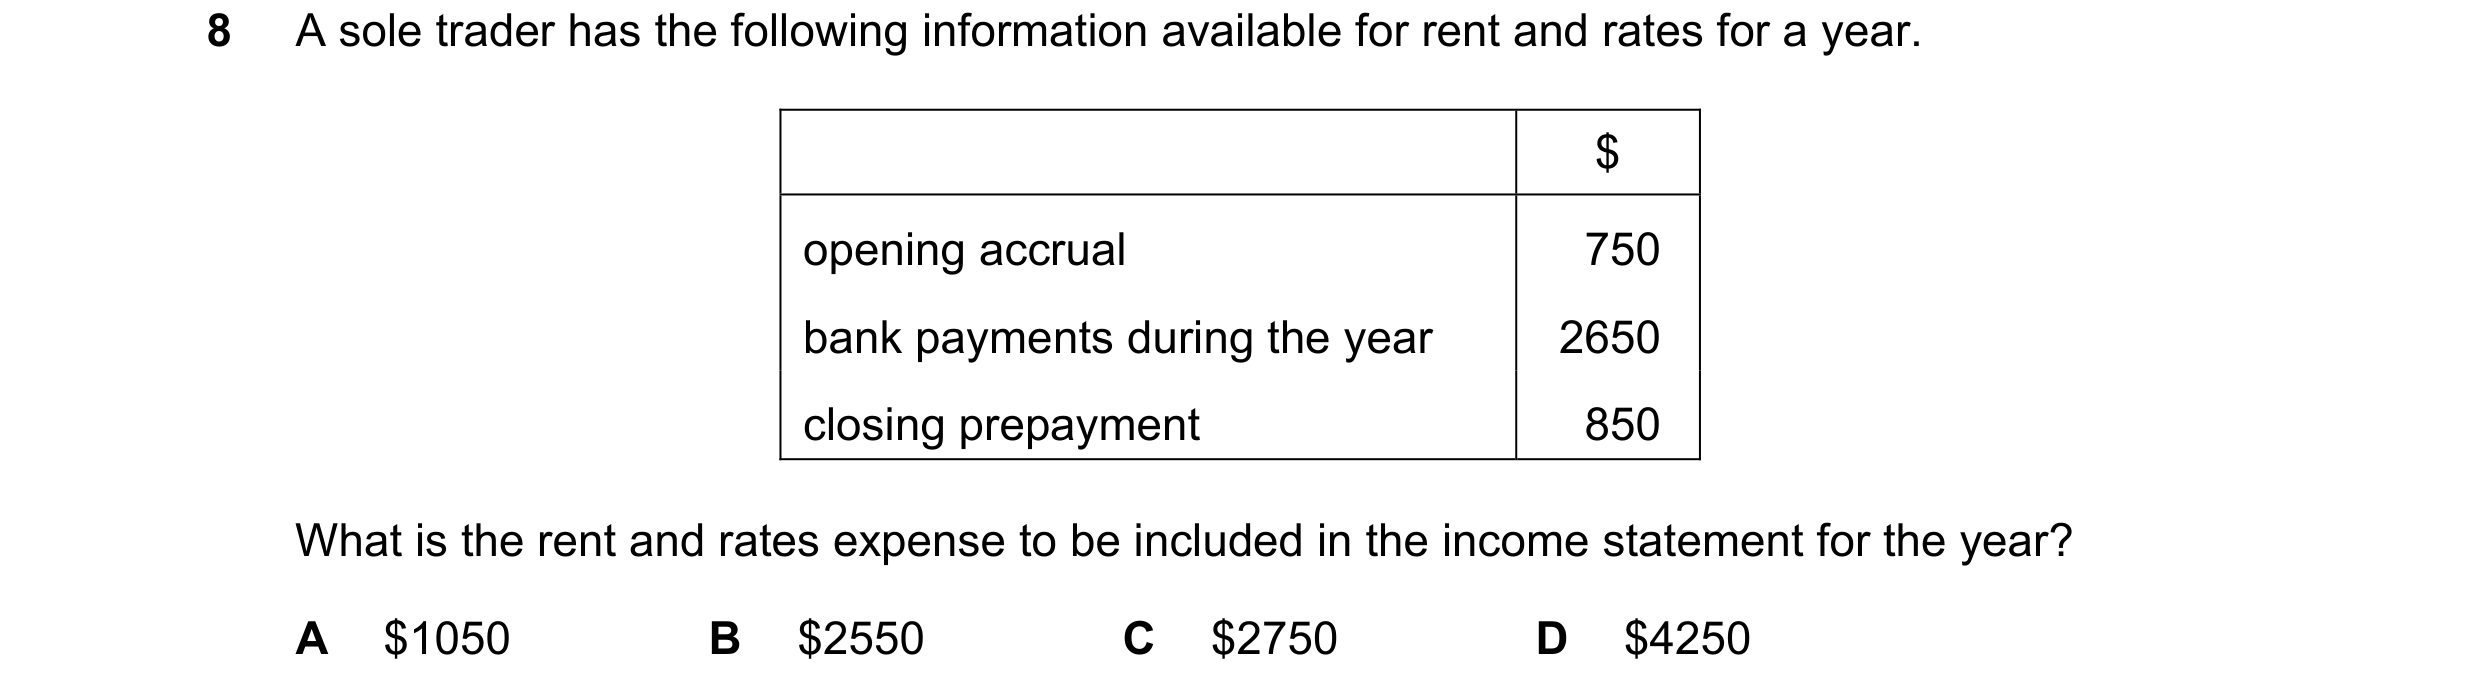
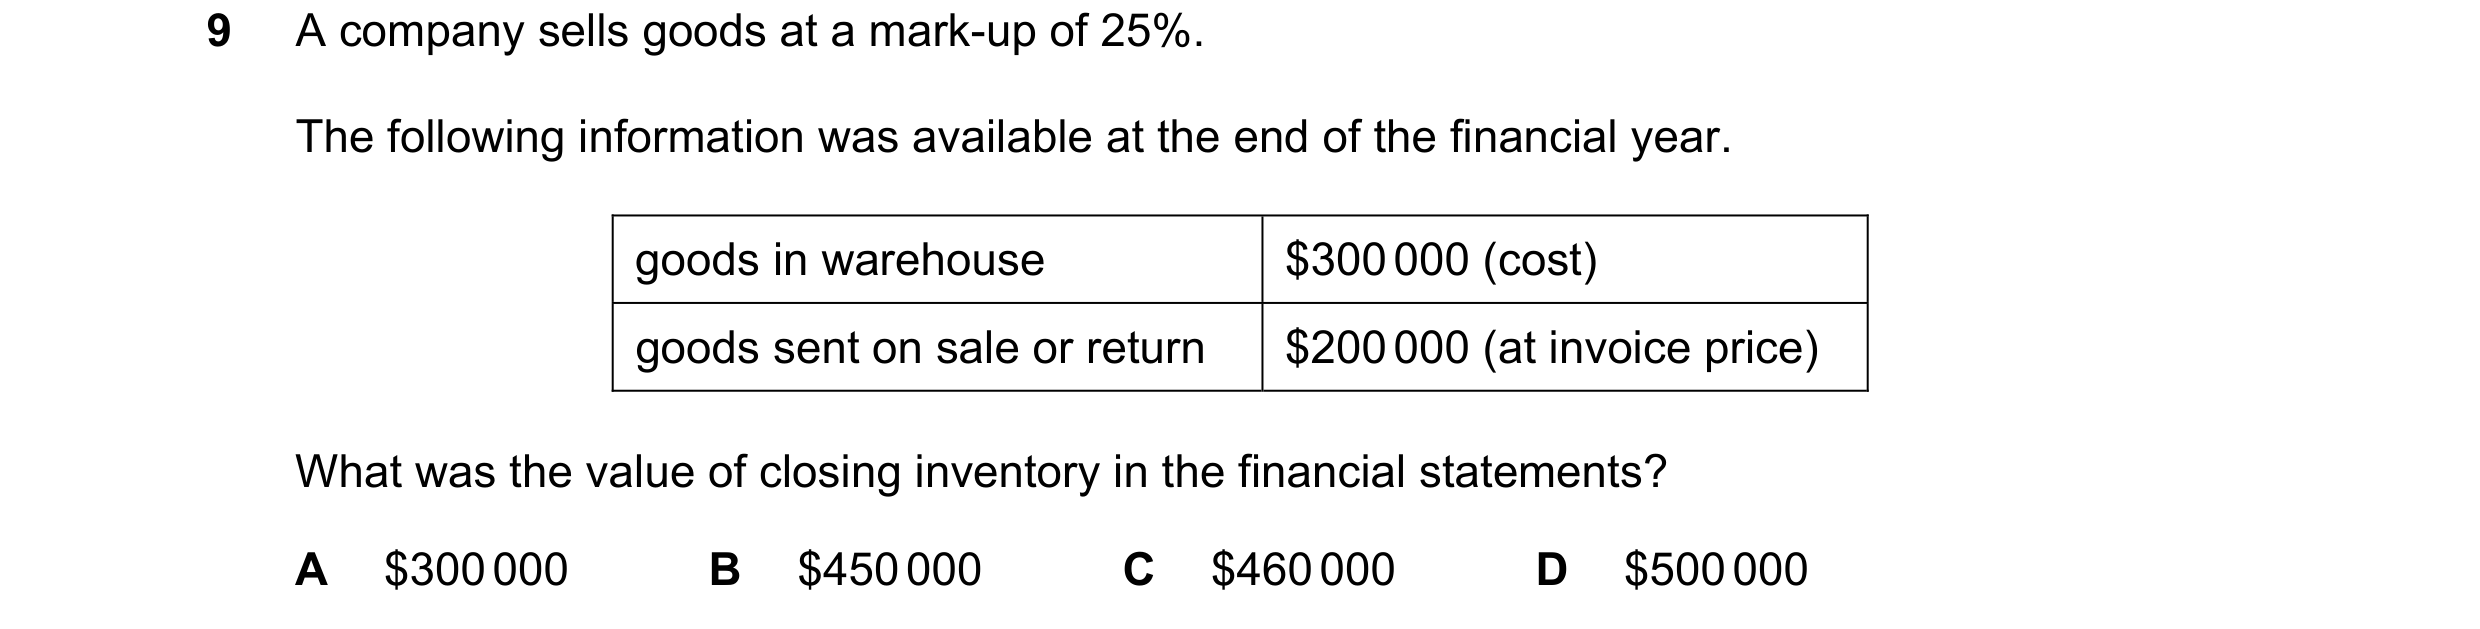
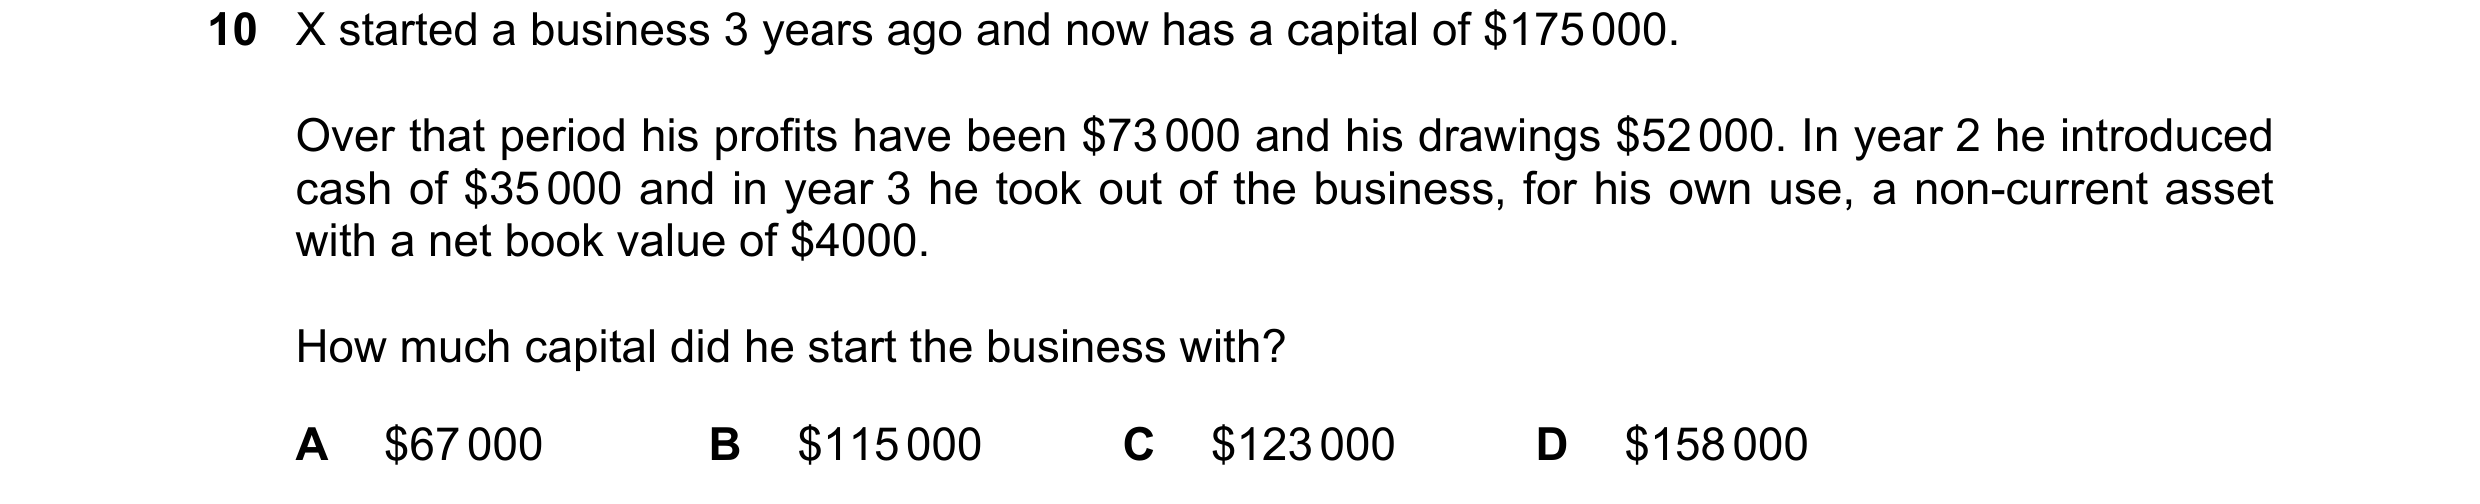 152 / 233
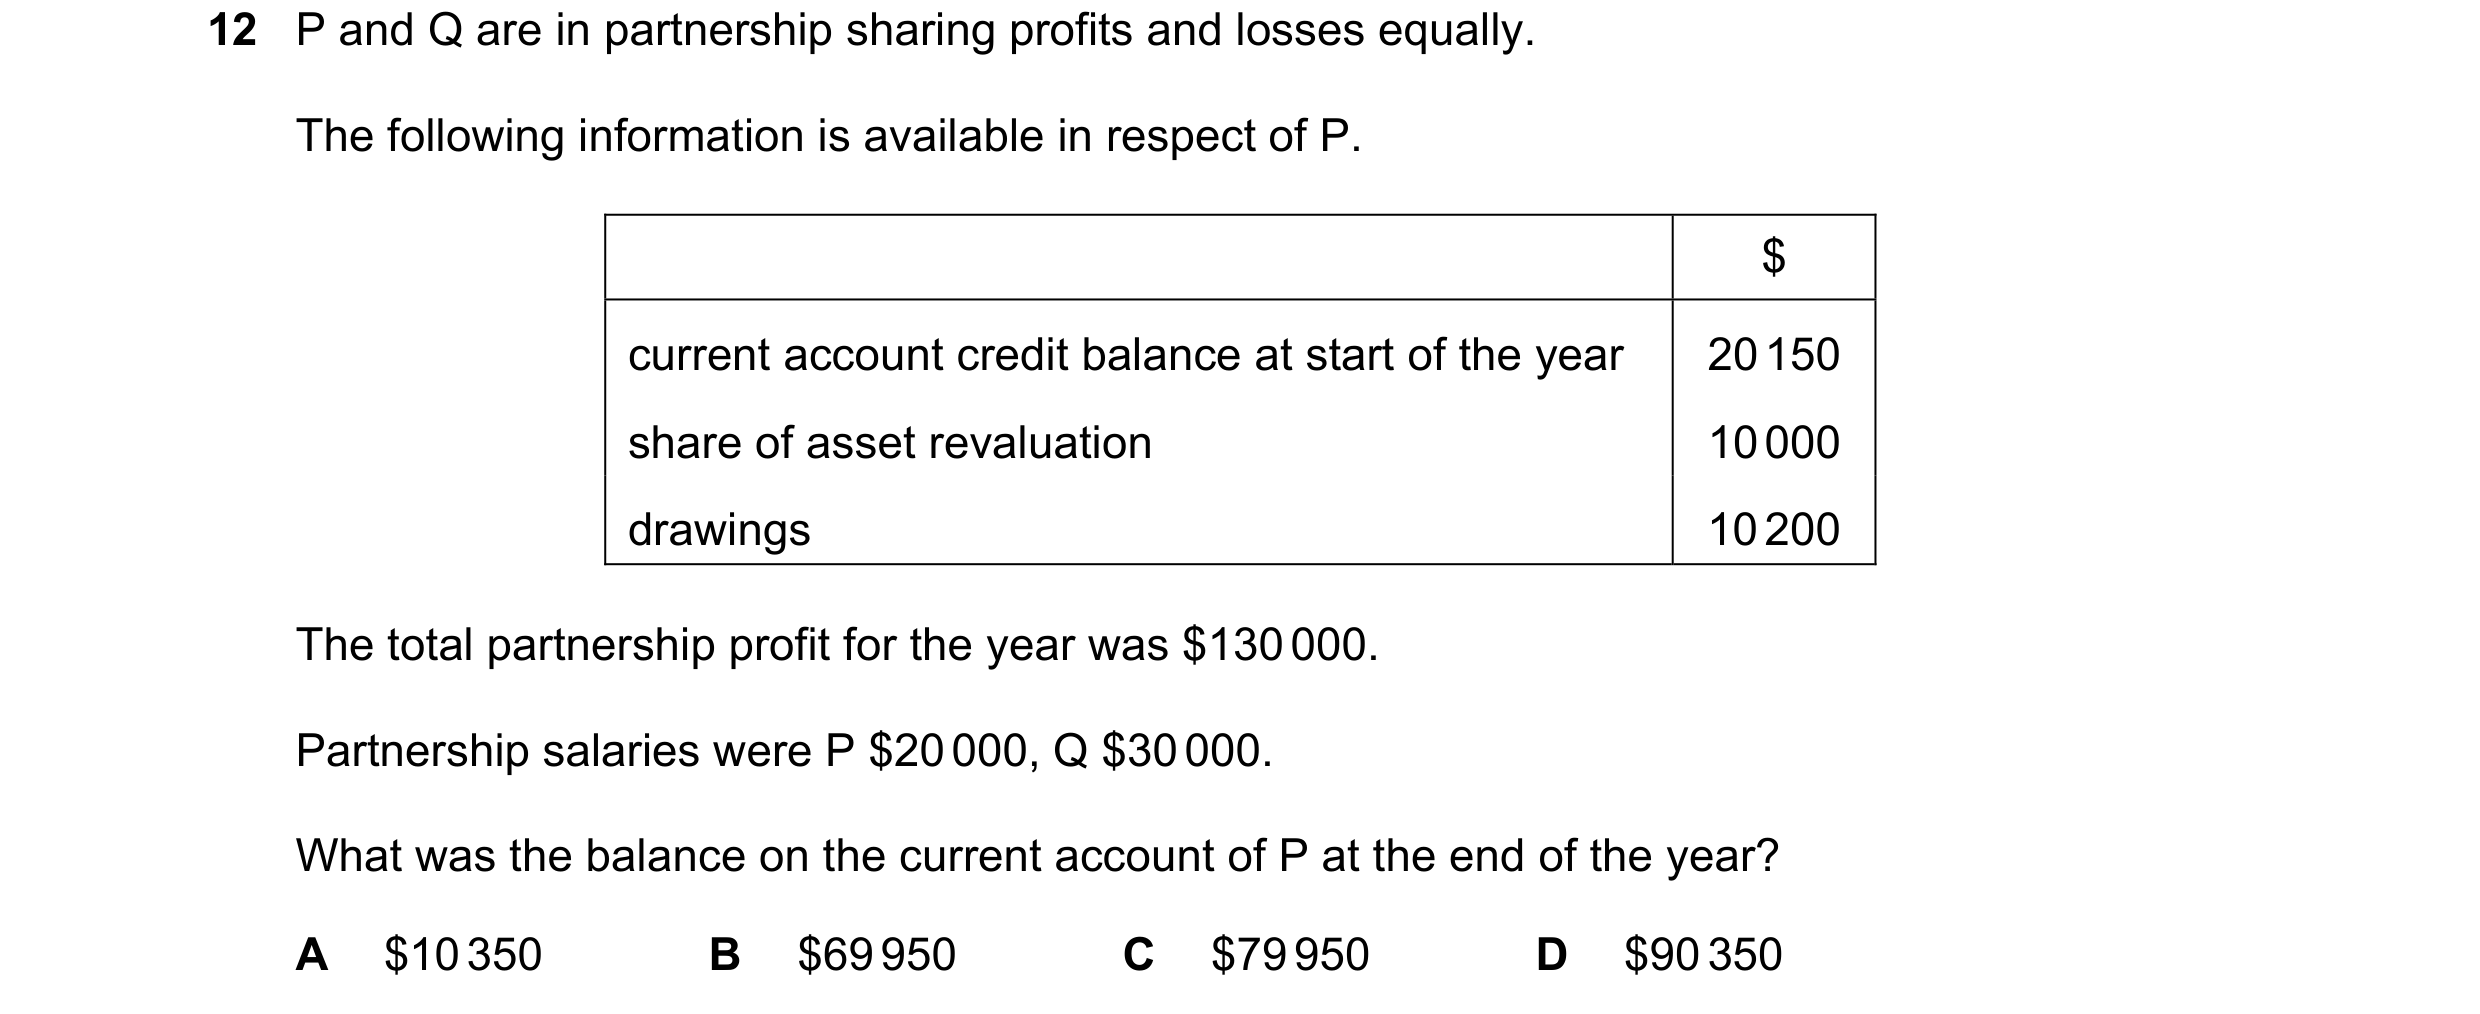
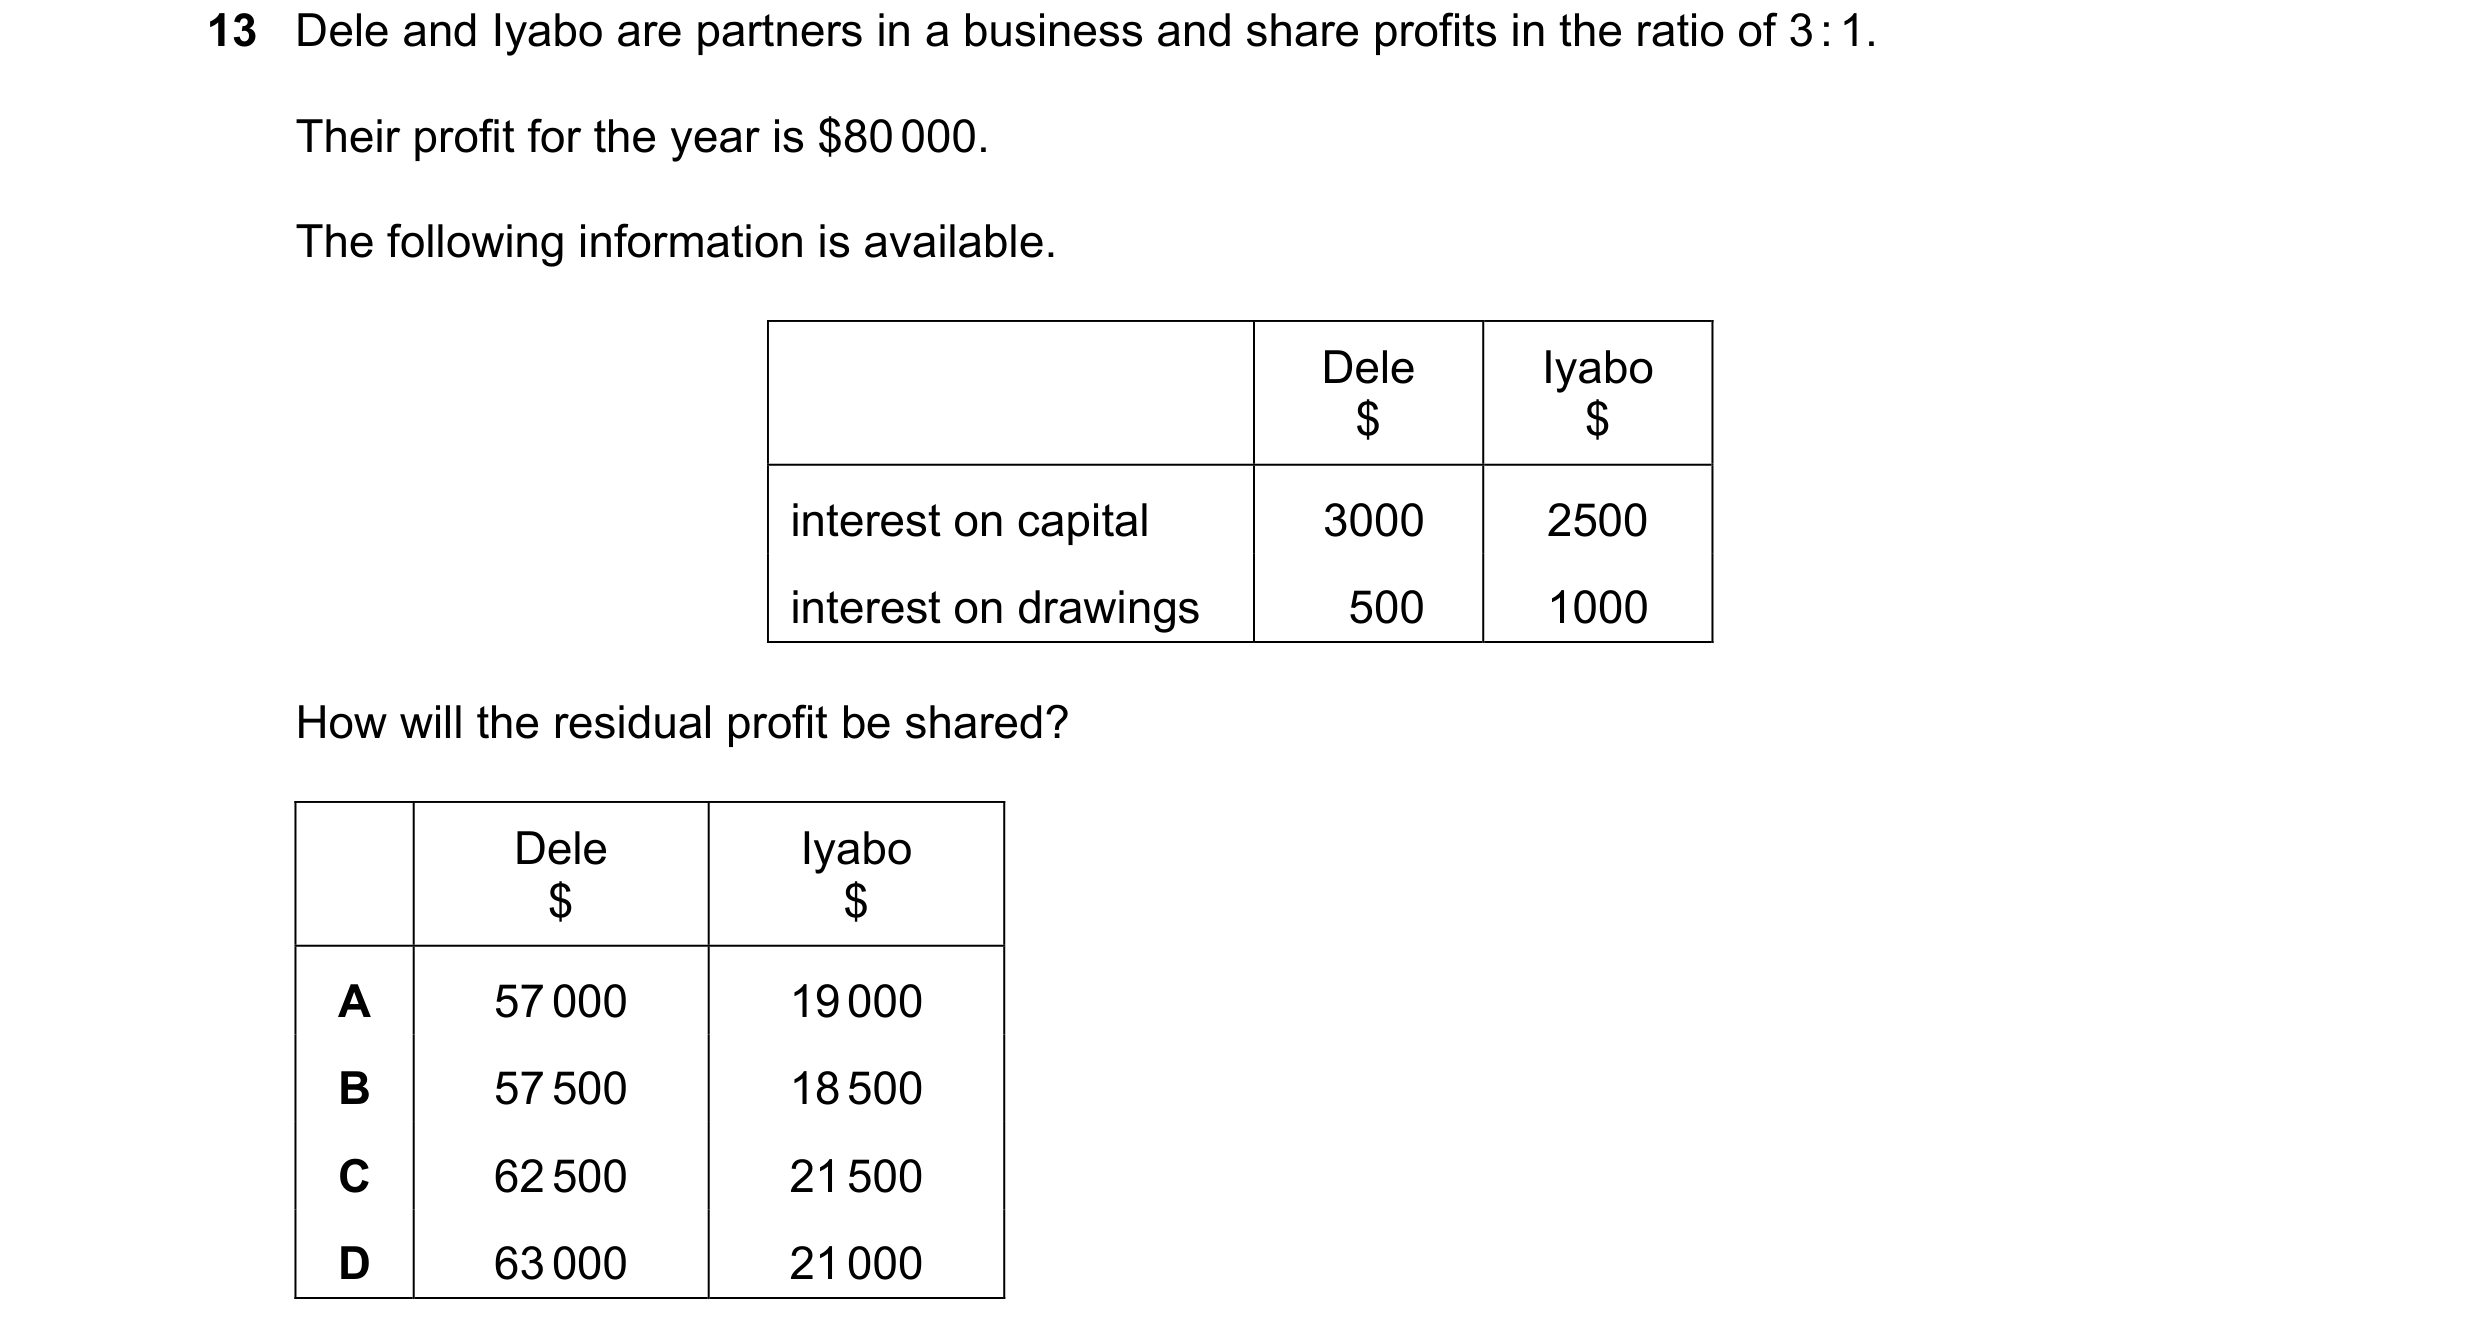
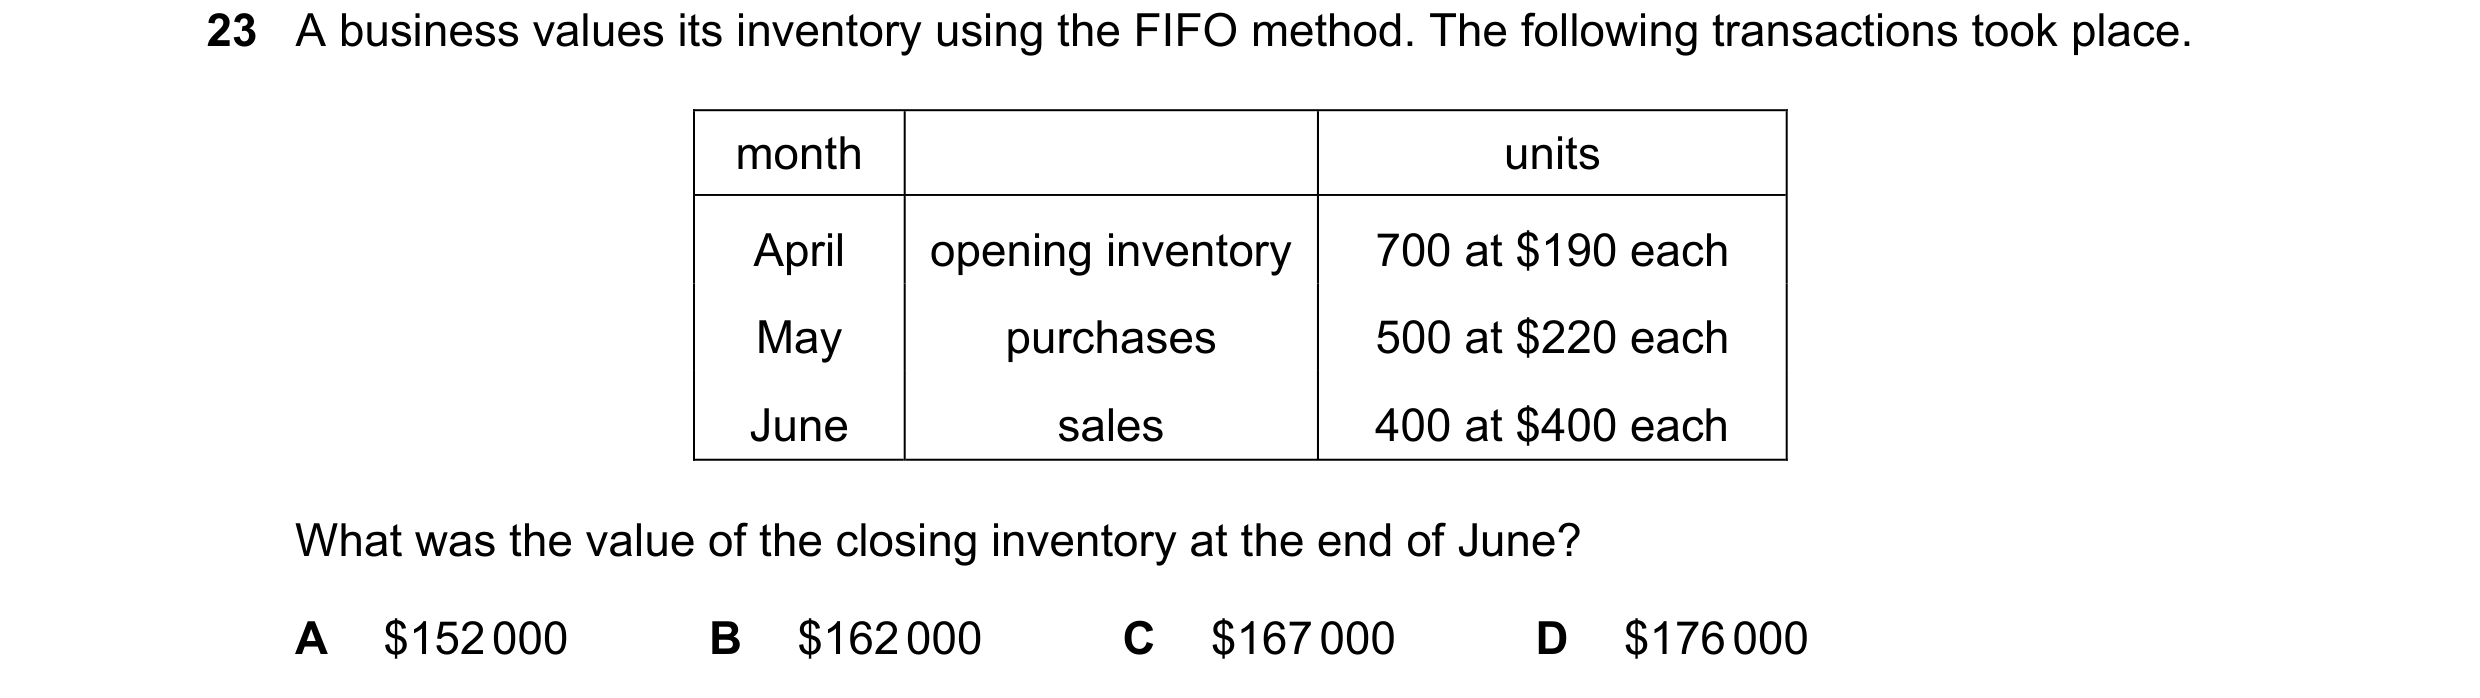 153 / 233
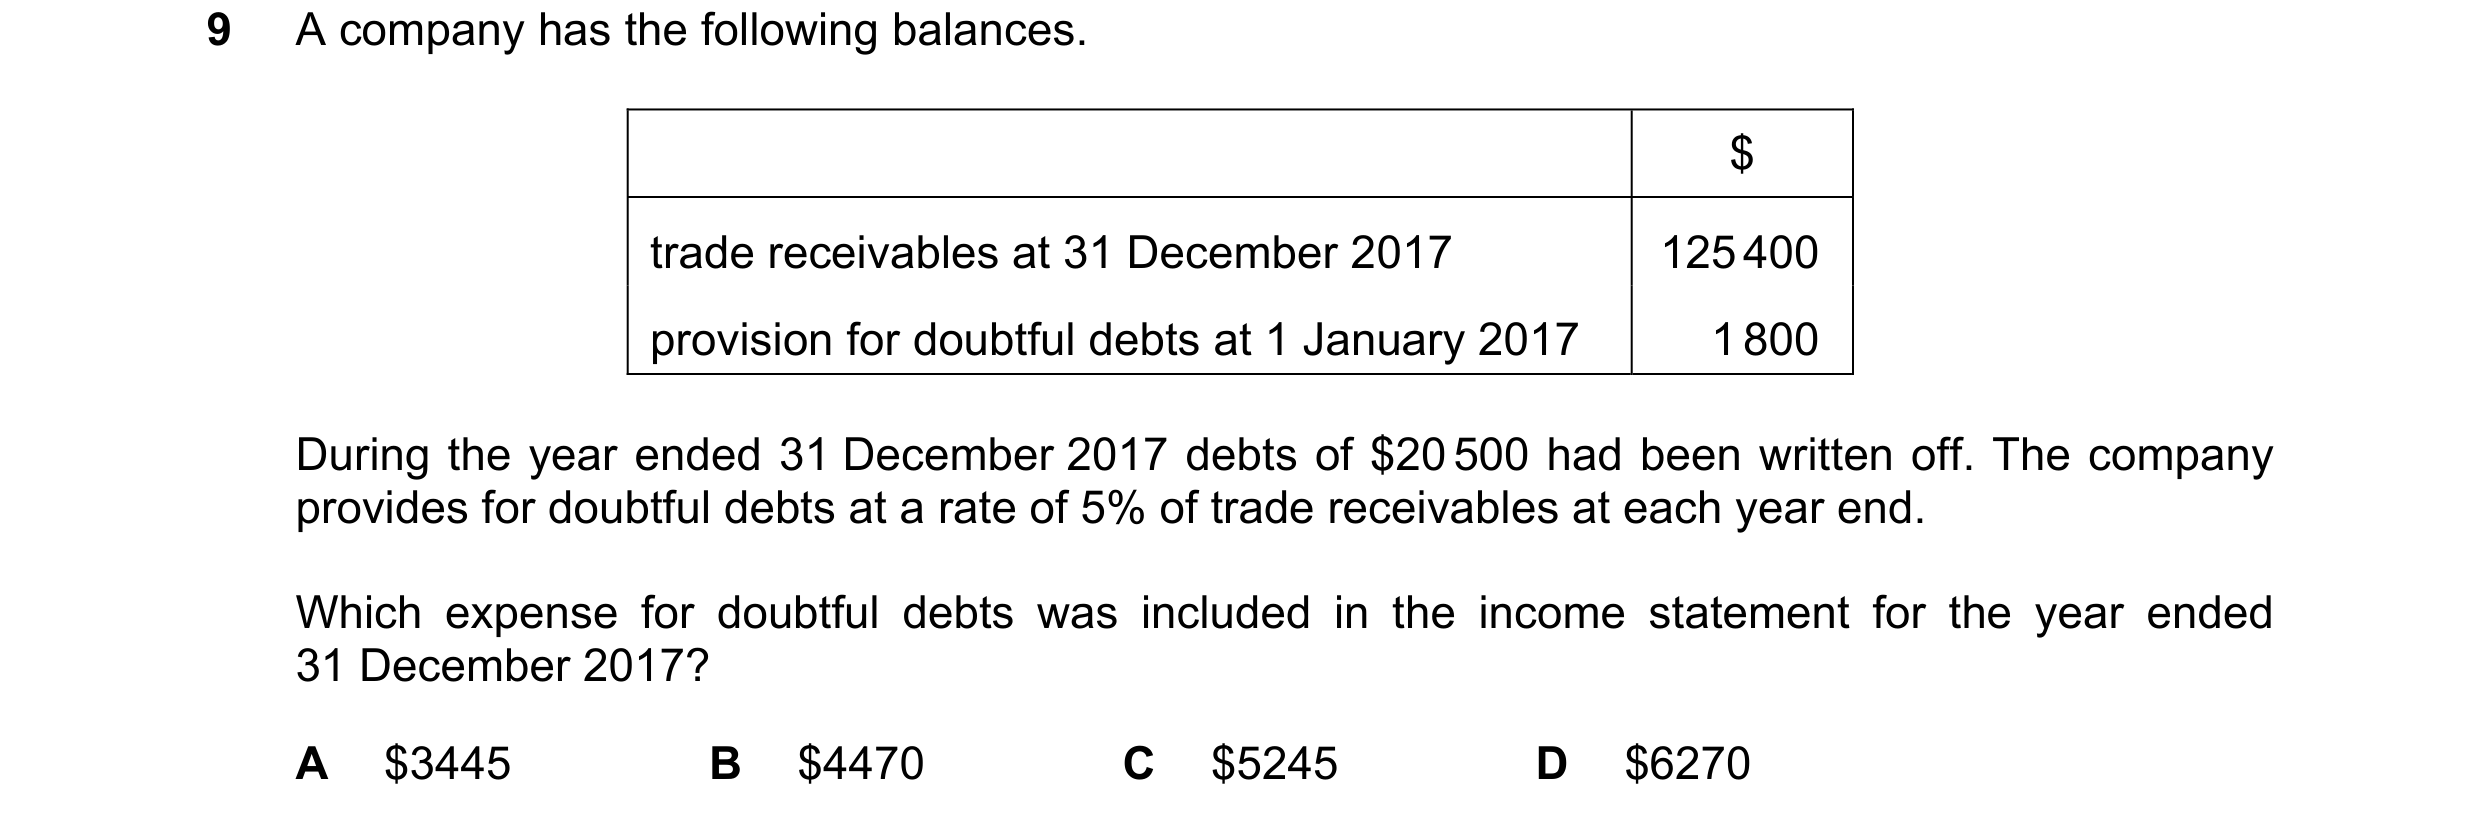
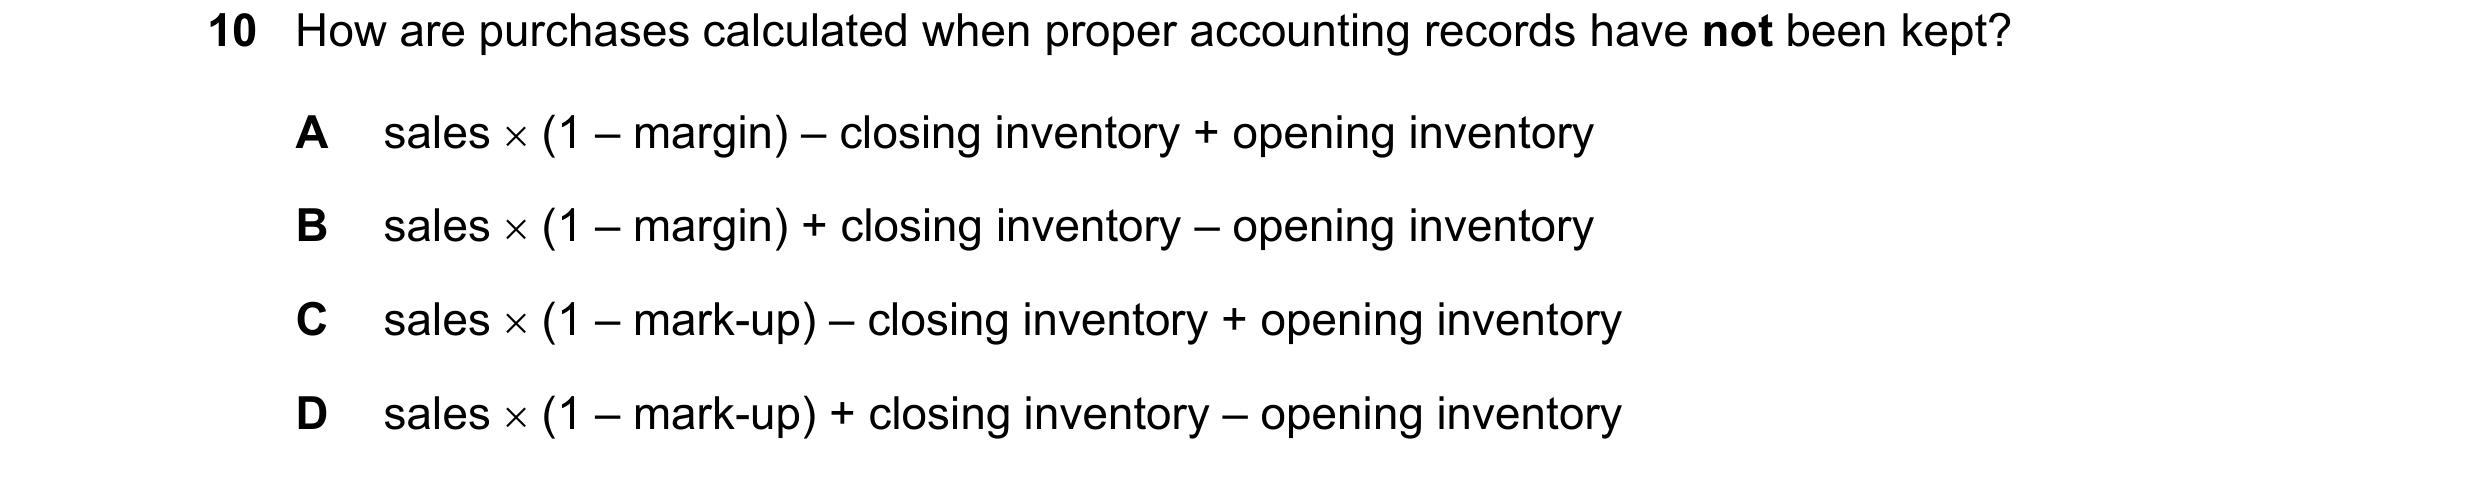
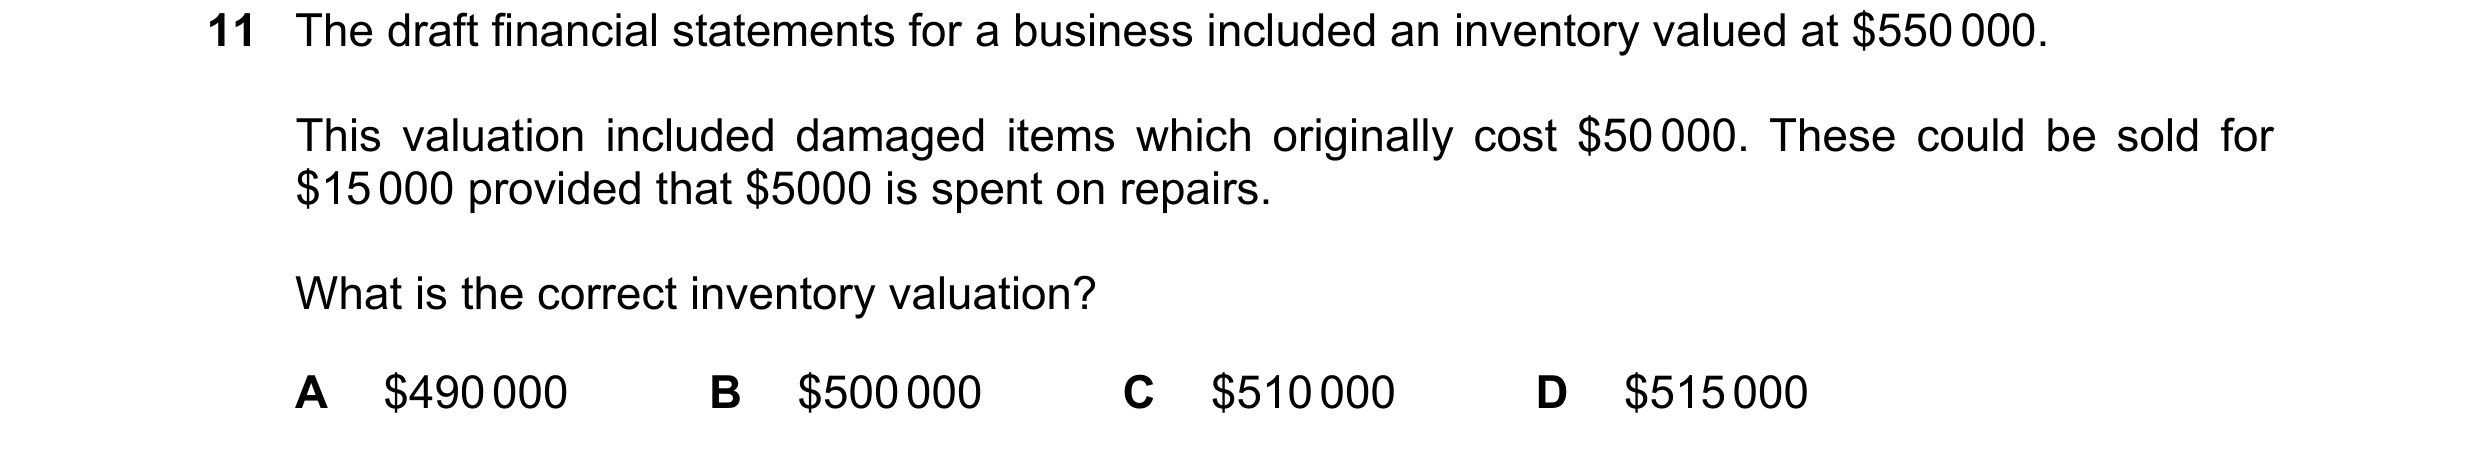
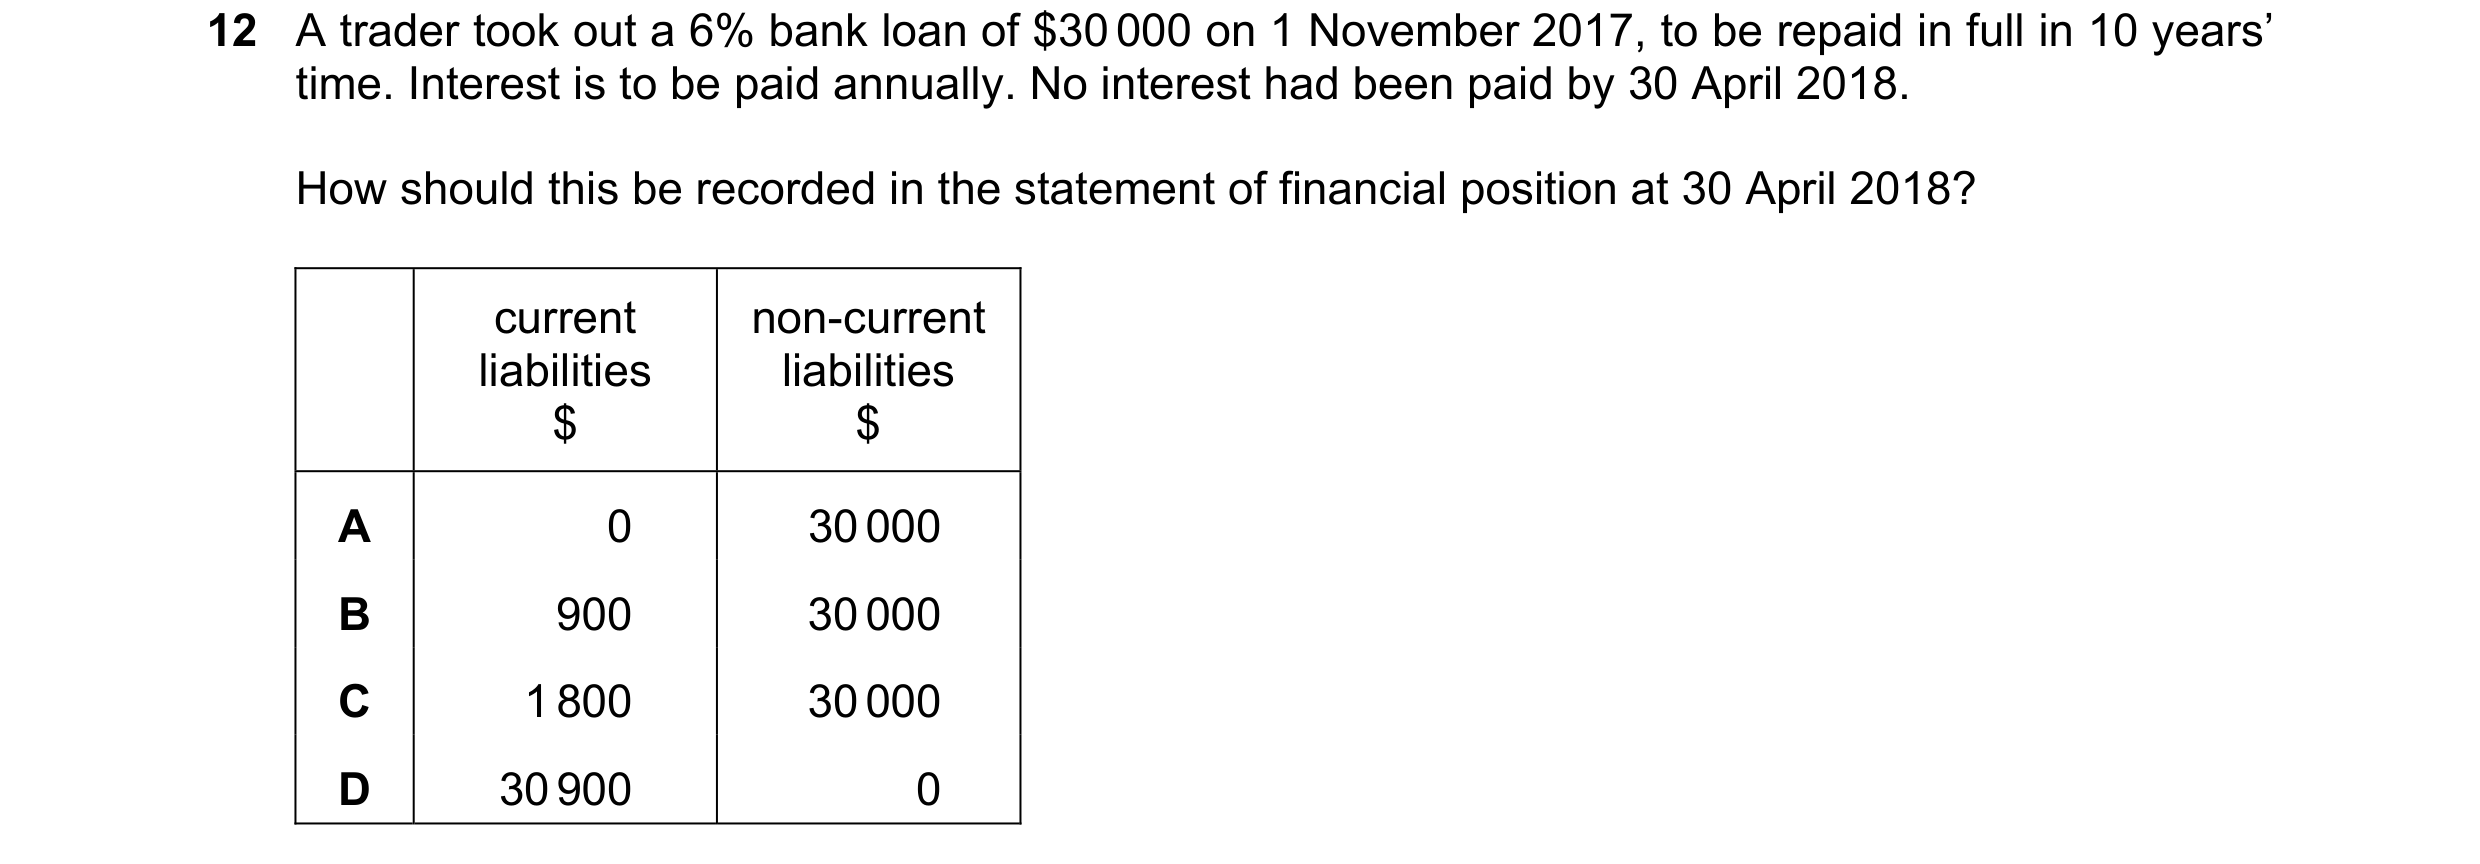 154 / 233
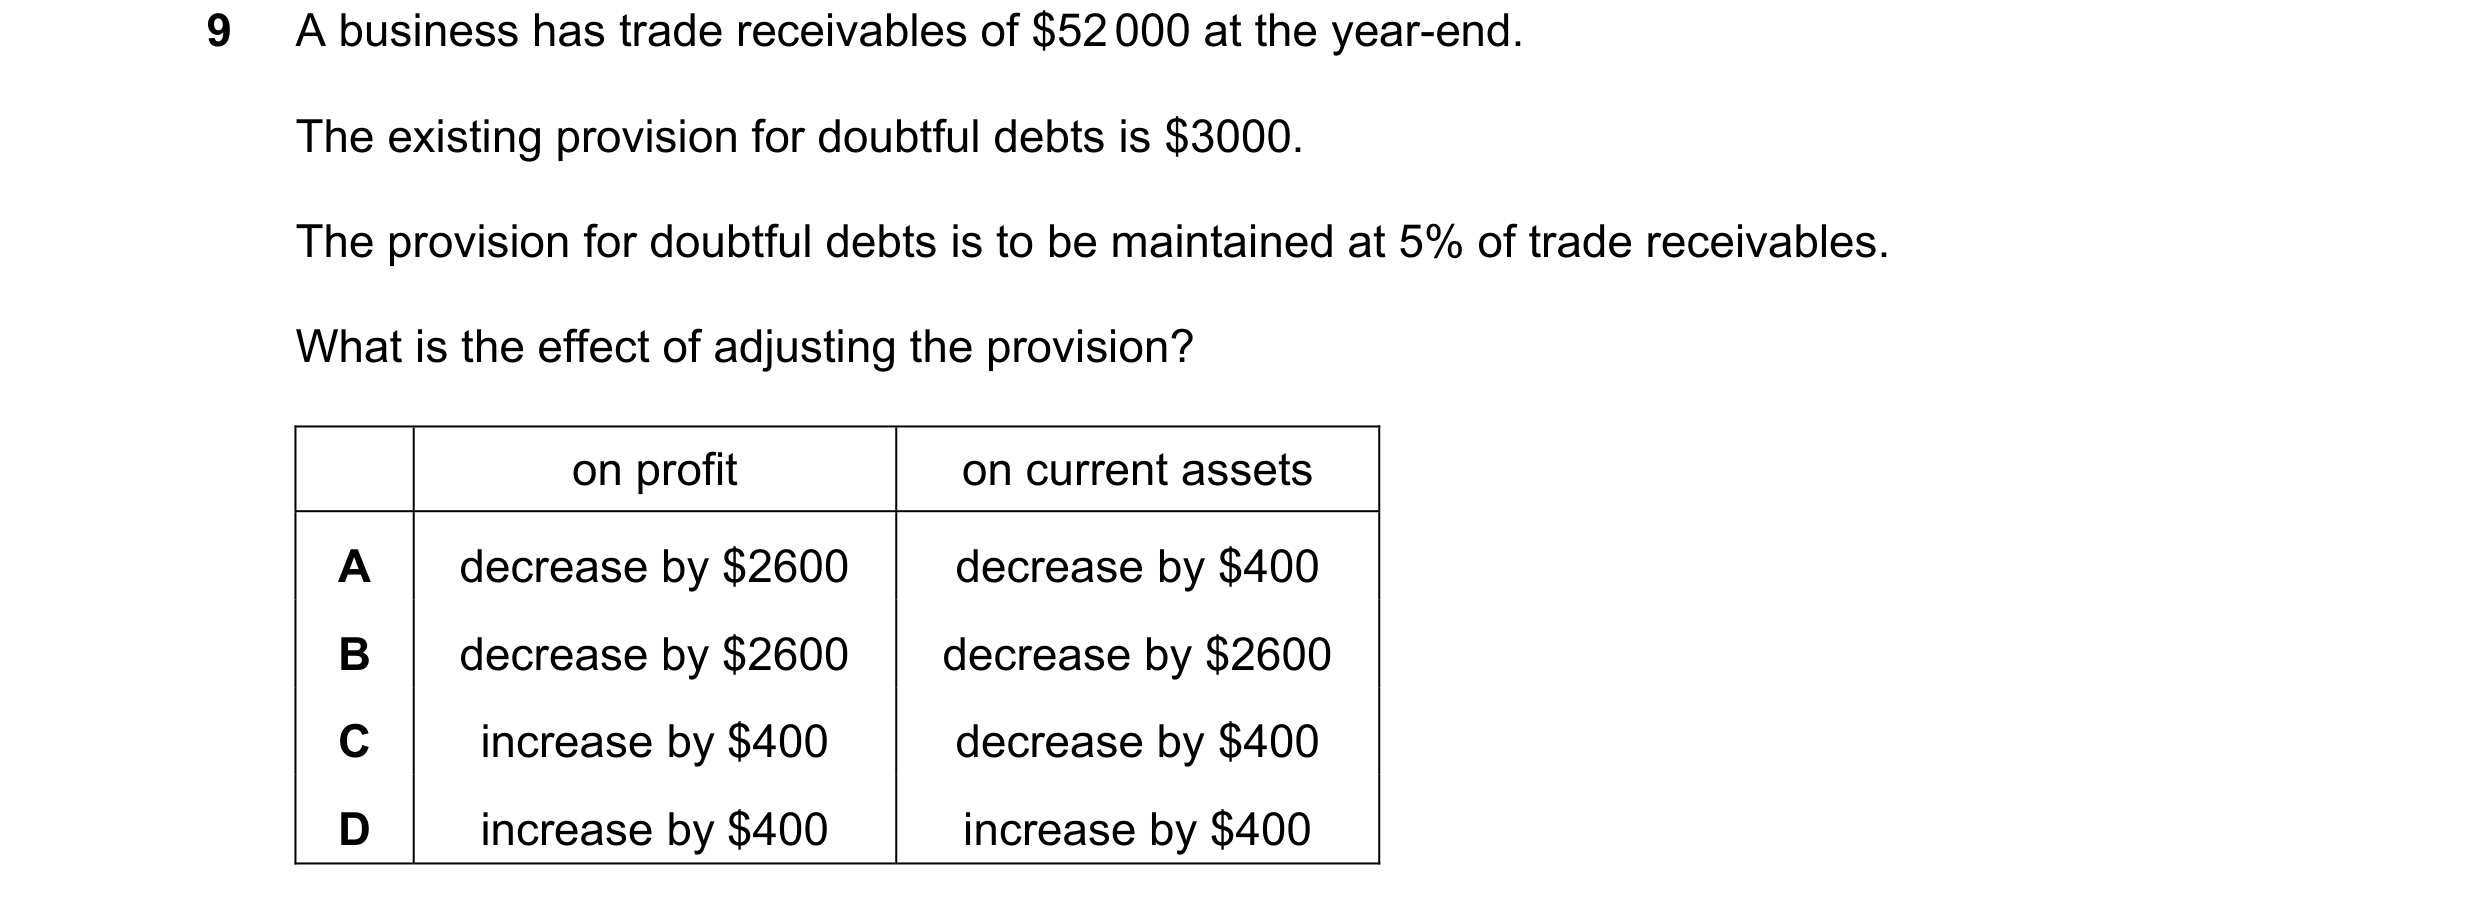
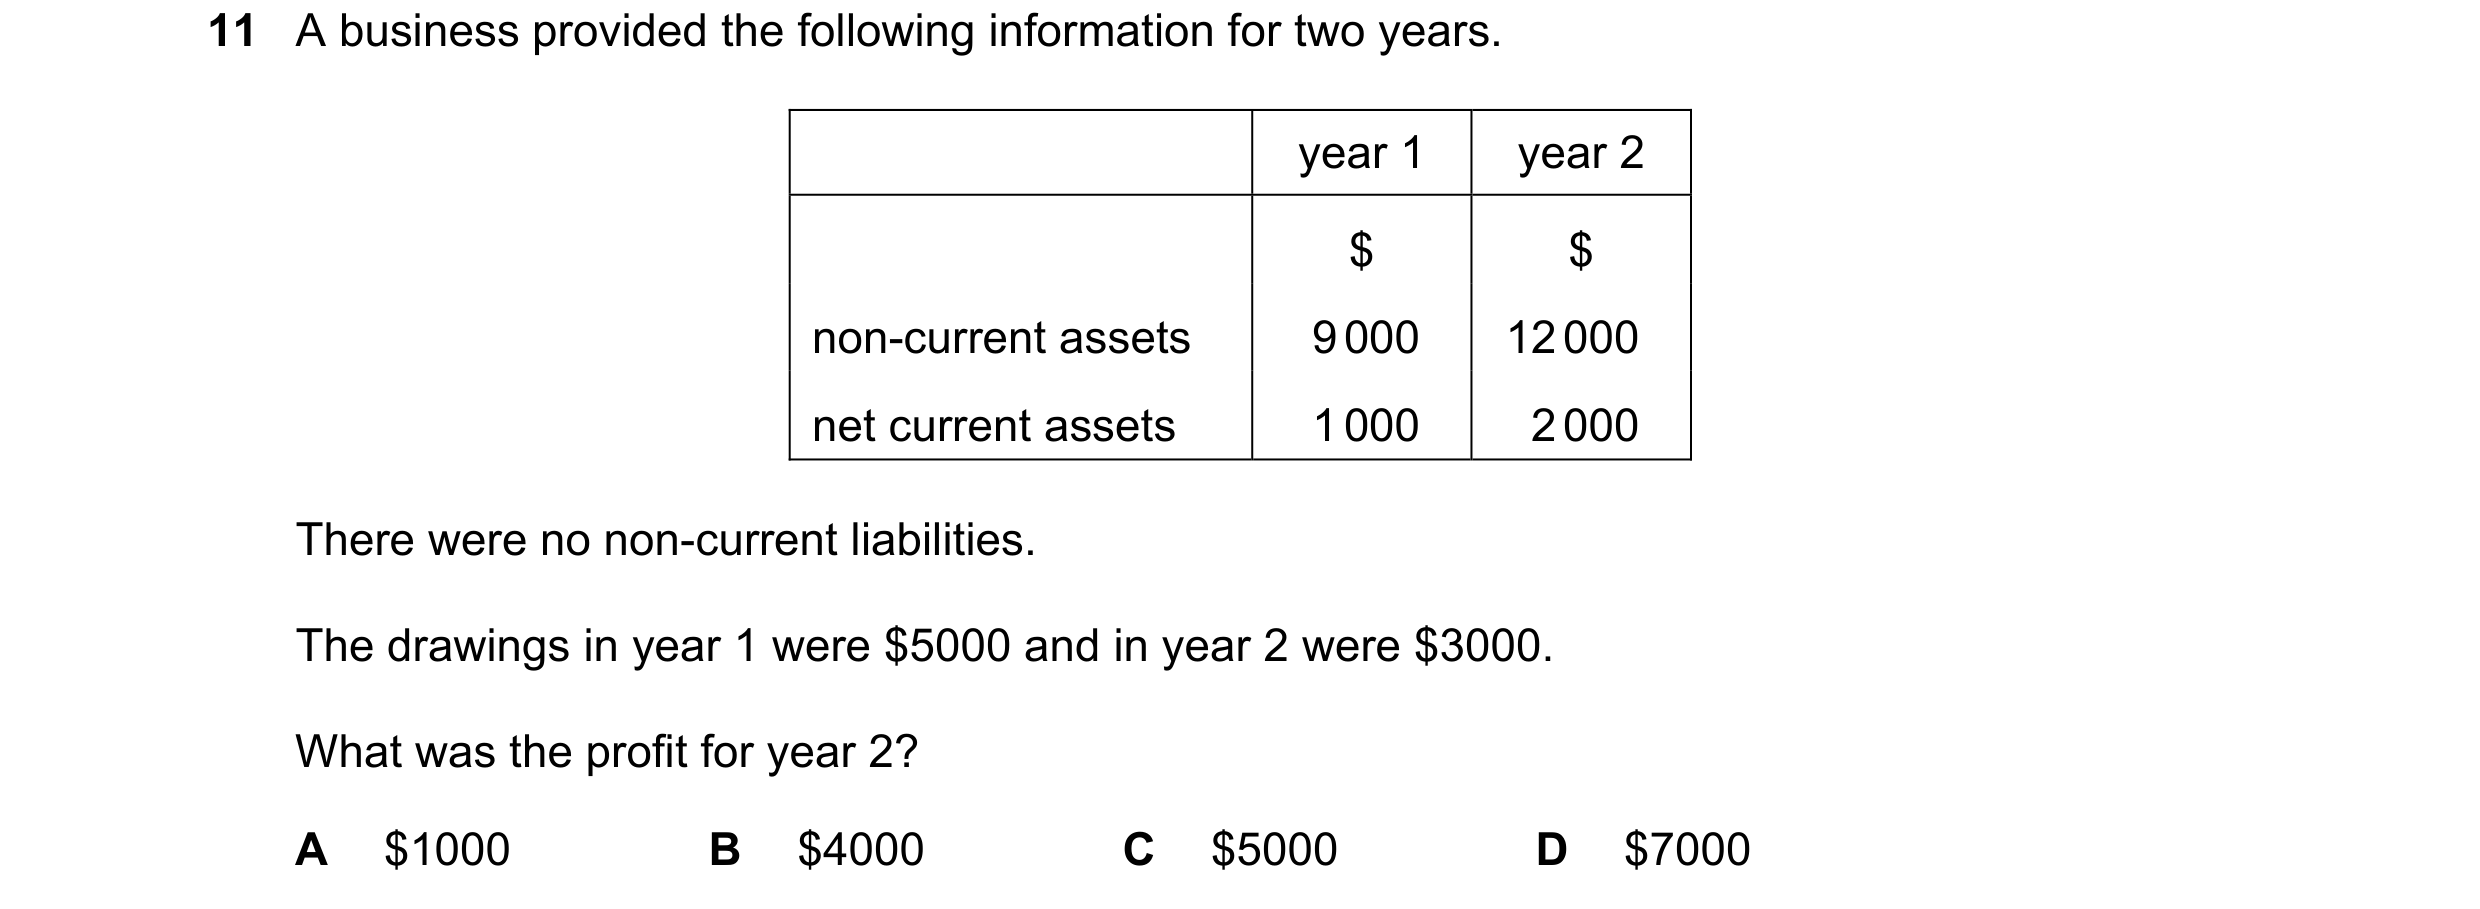
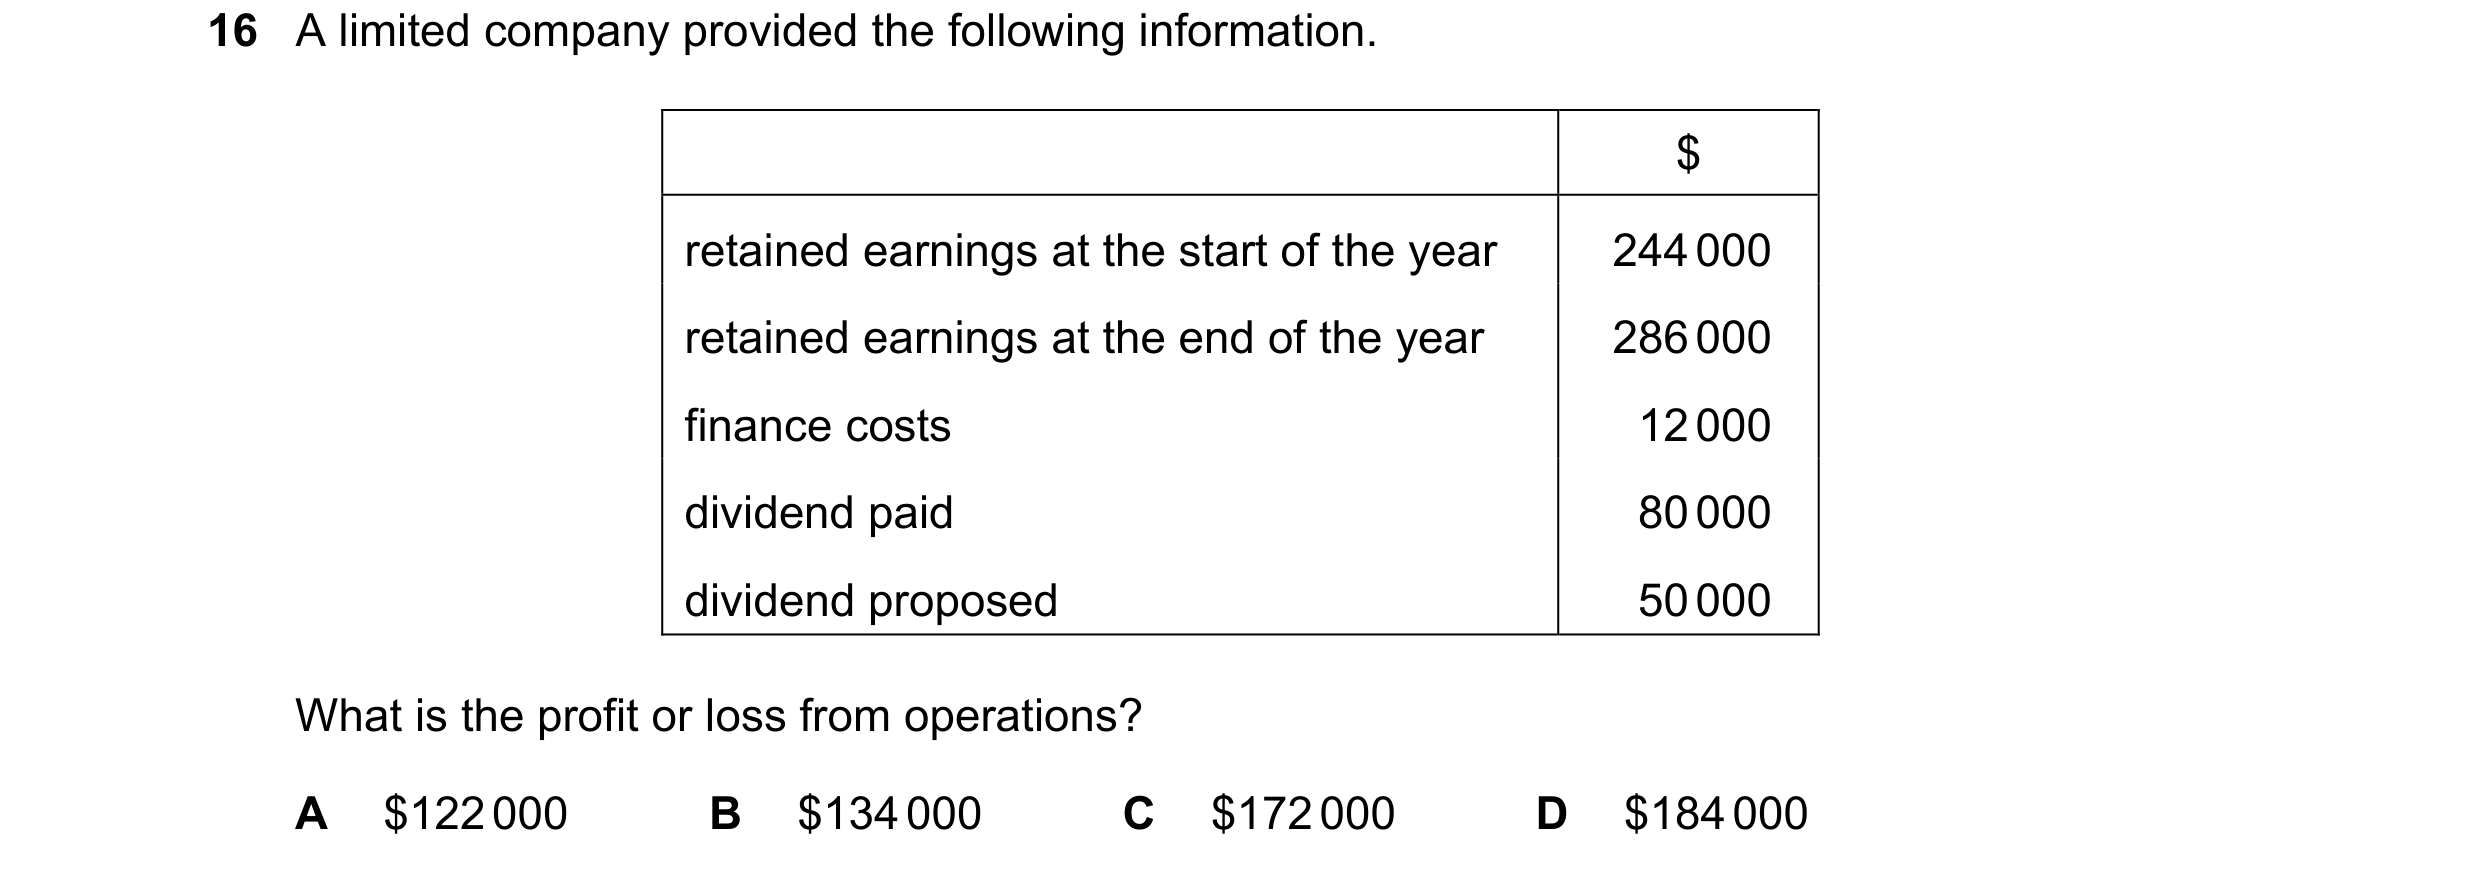 155 / 233
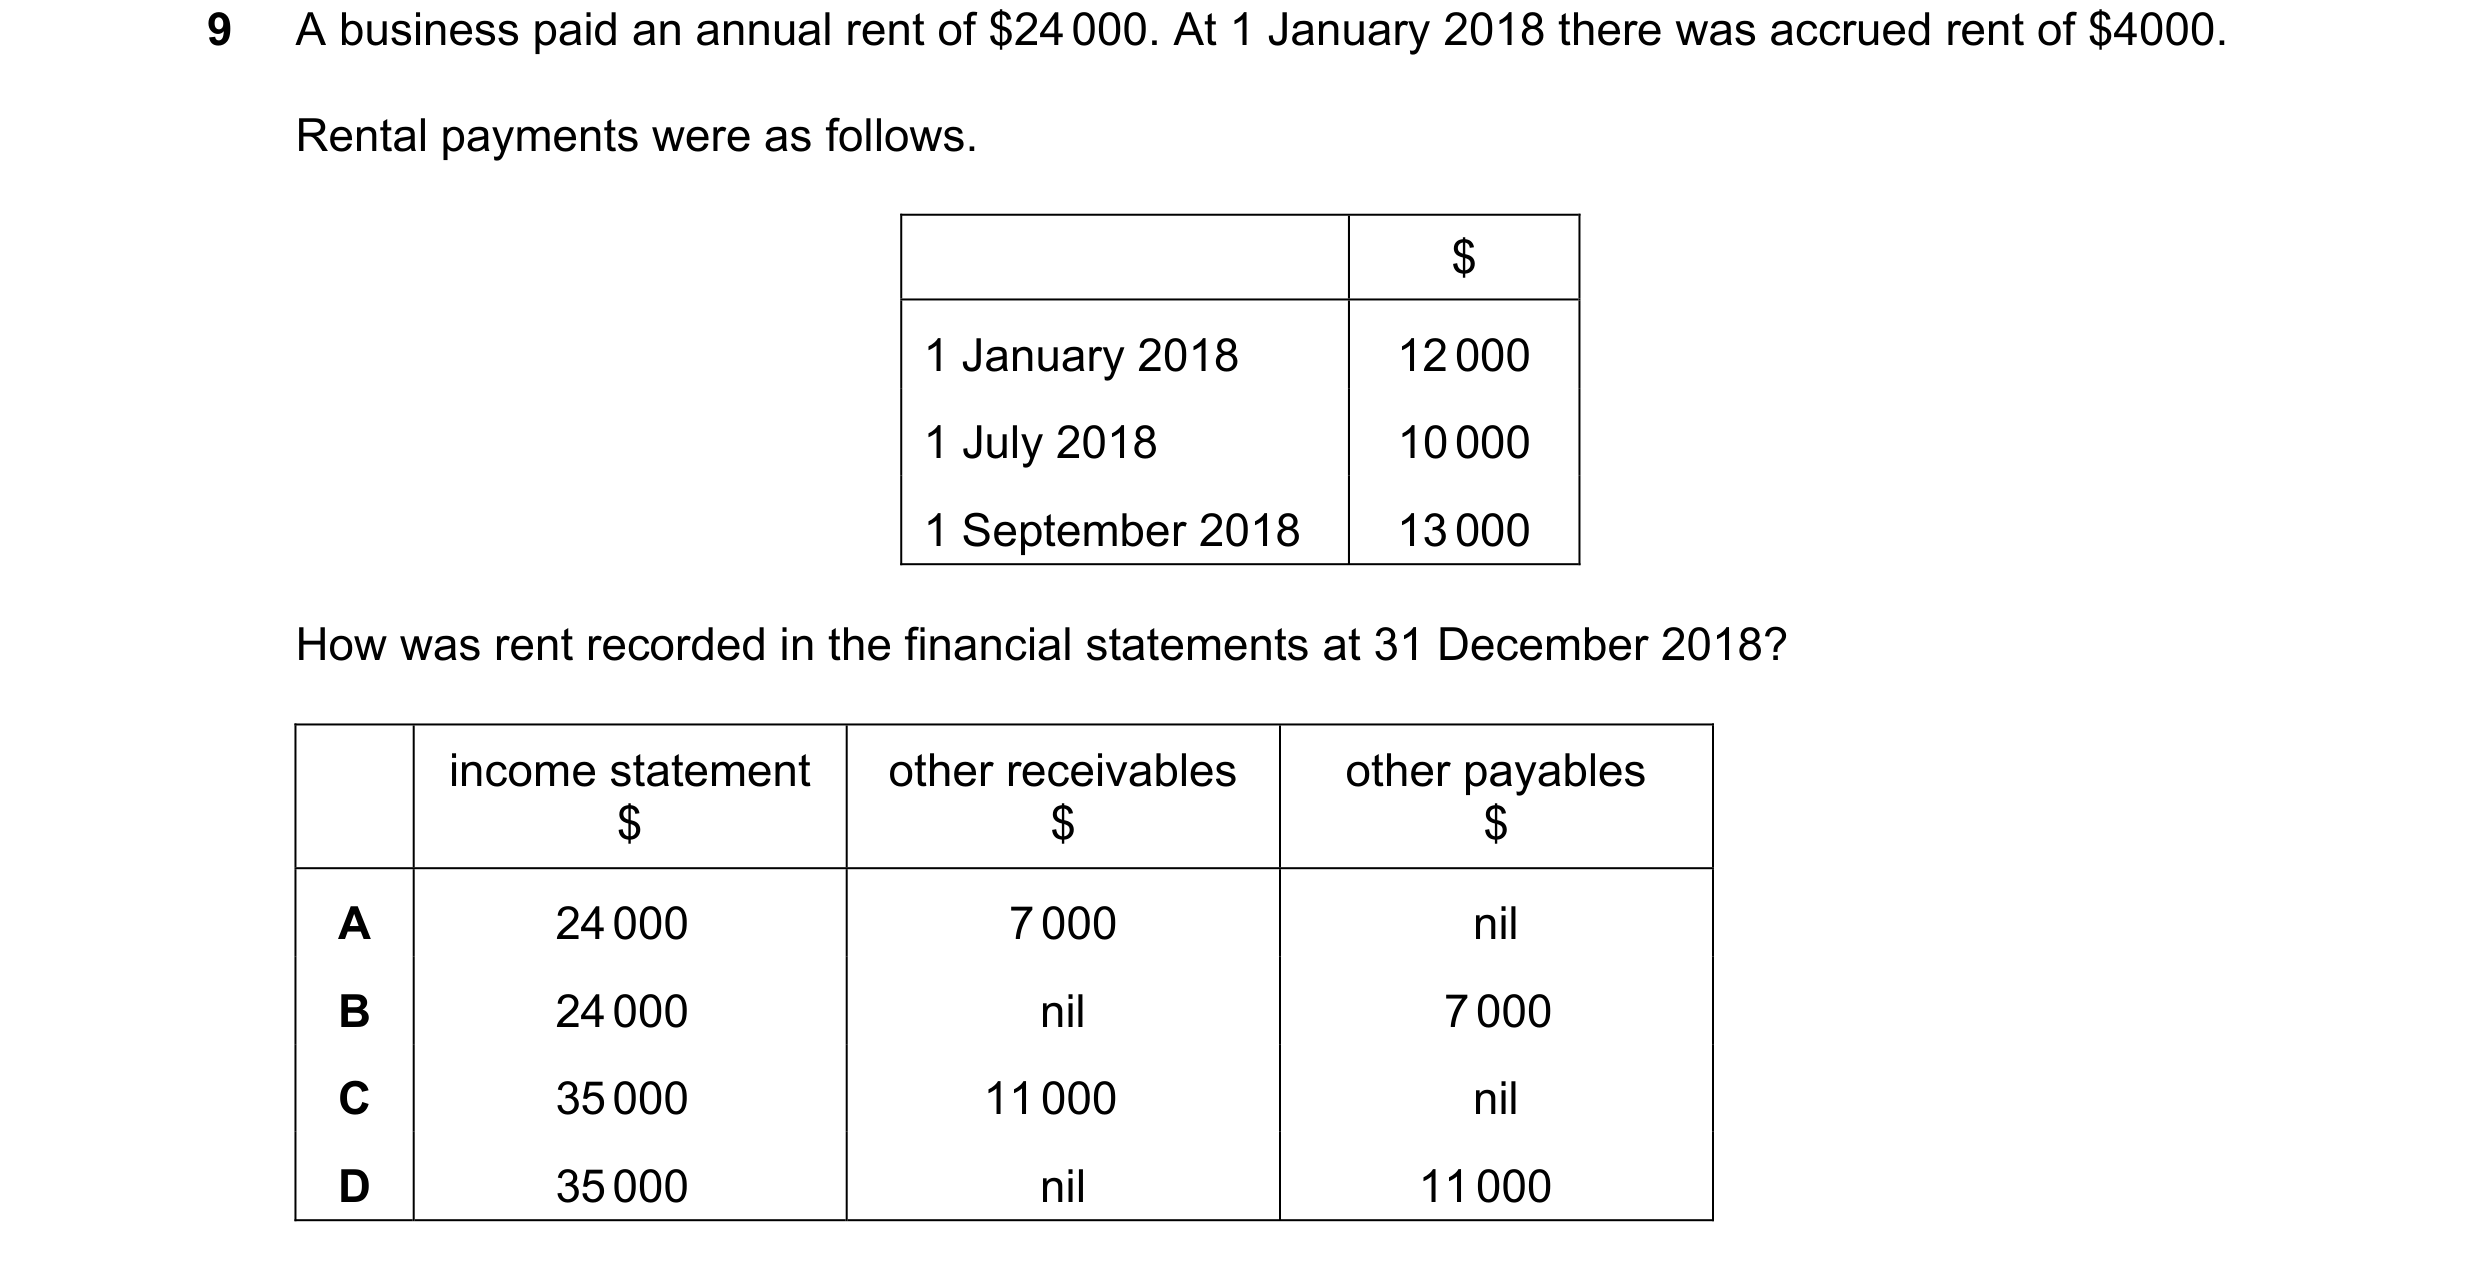
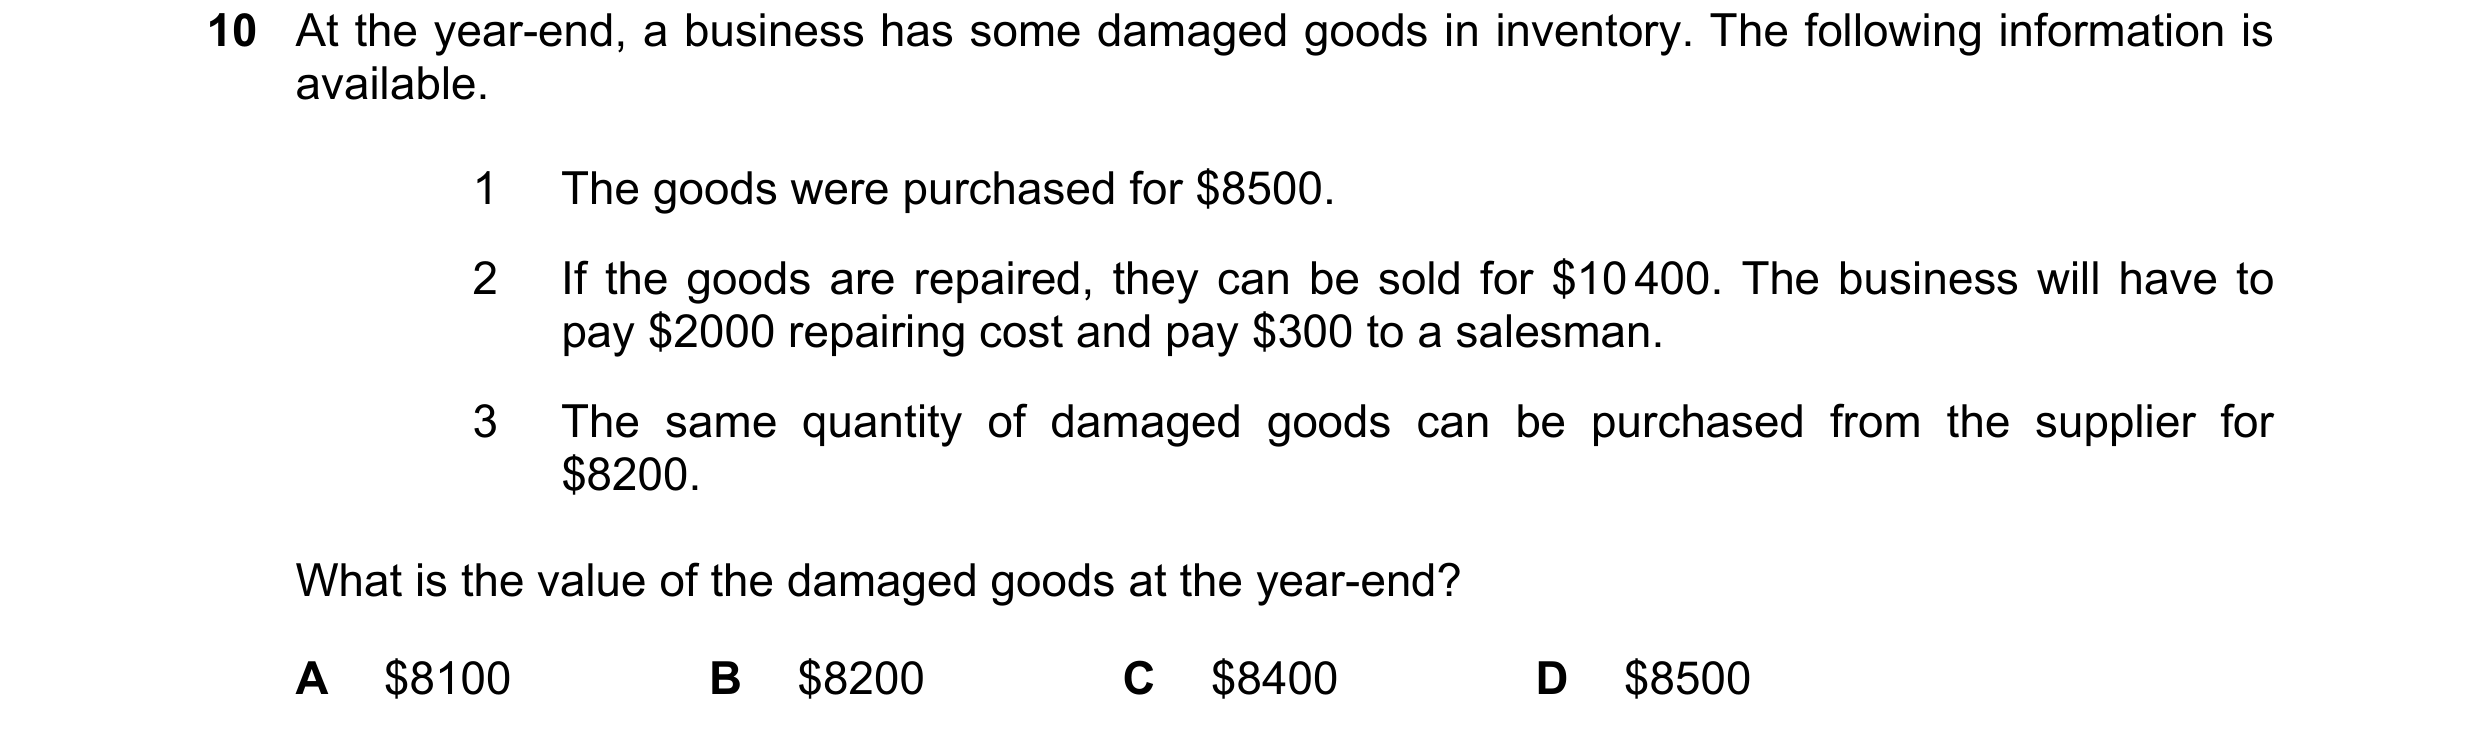
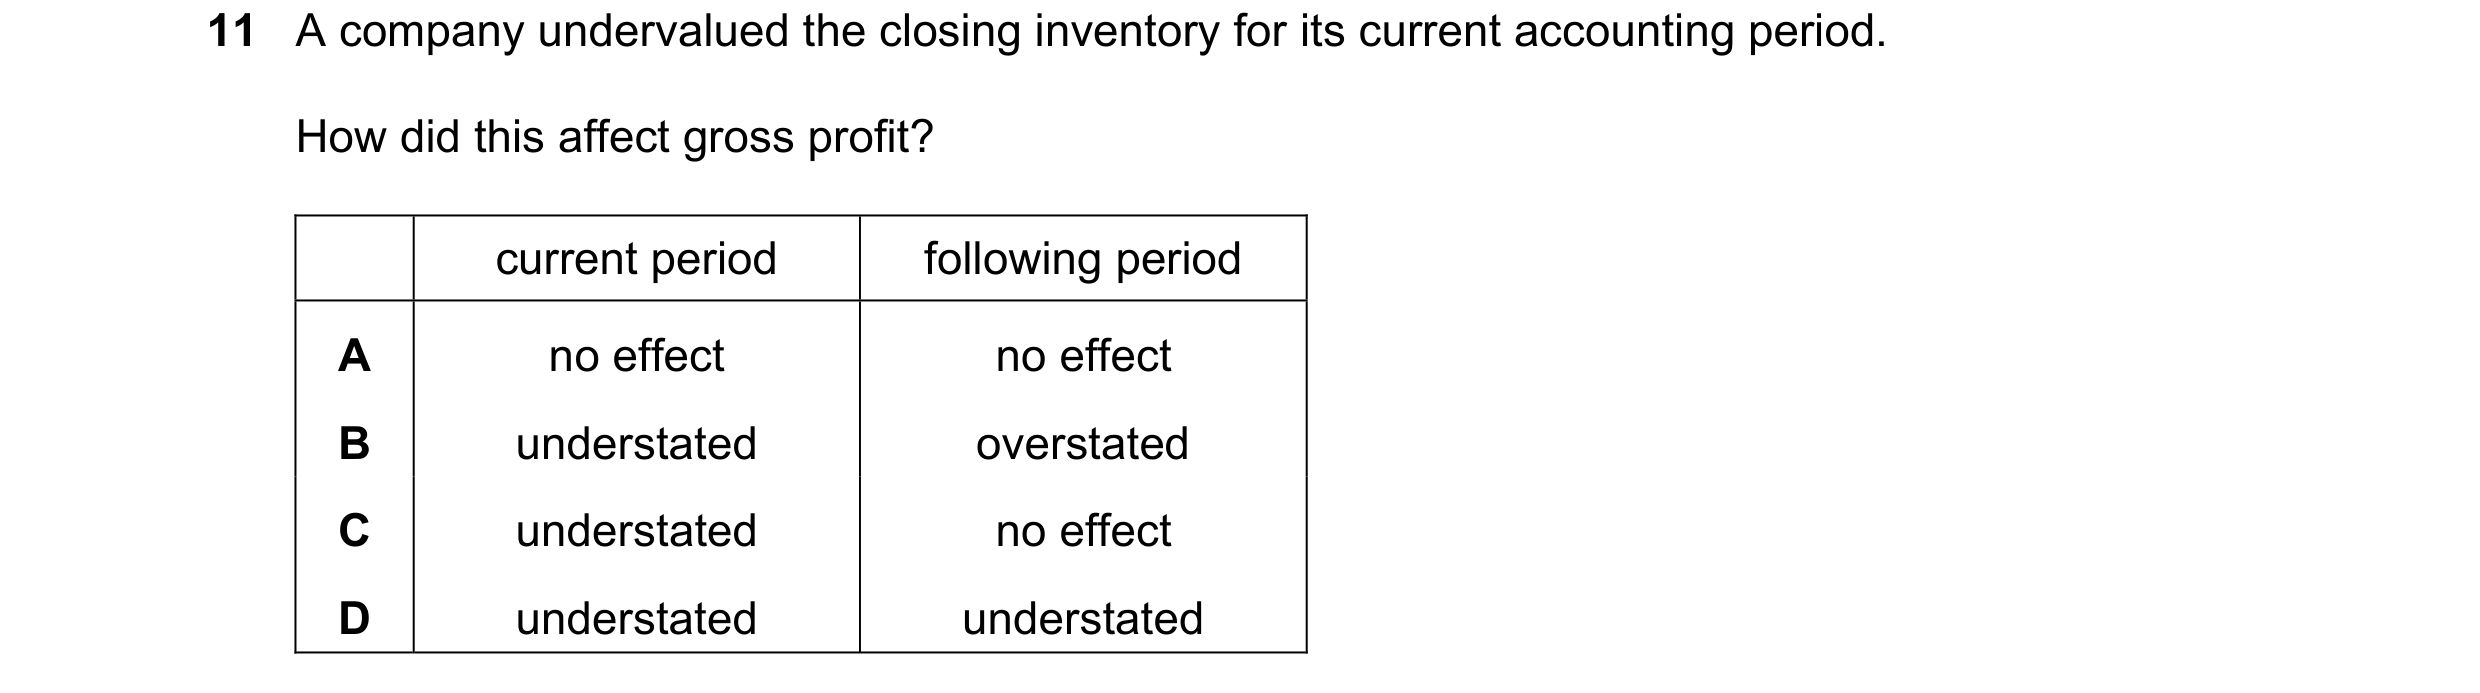 156 / 233
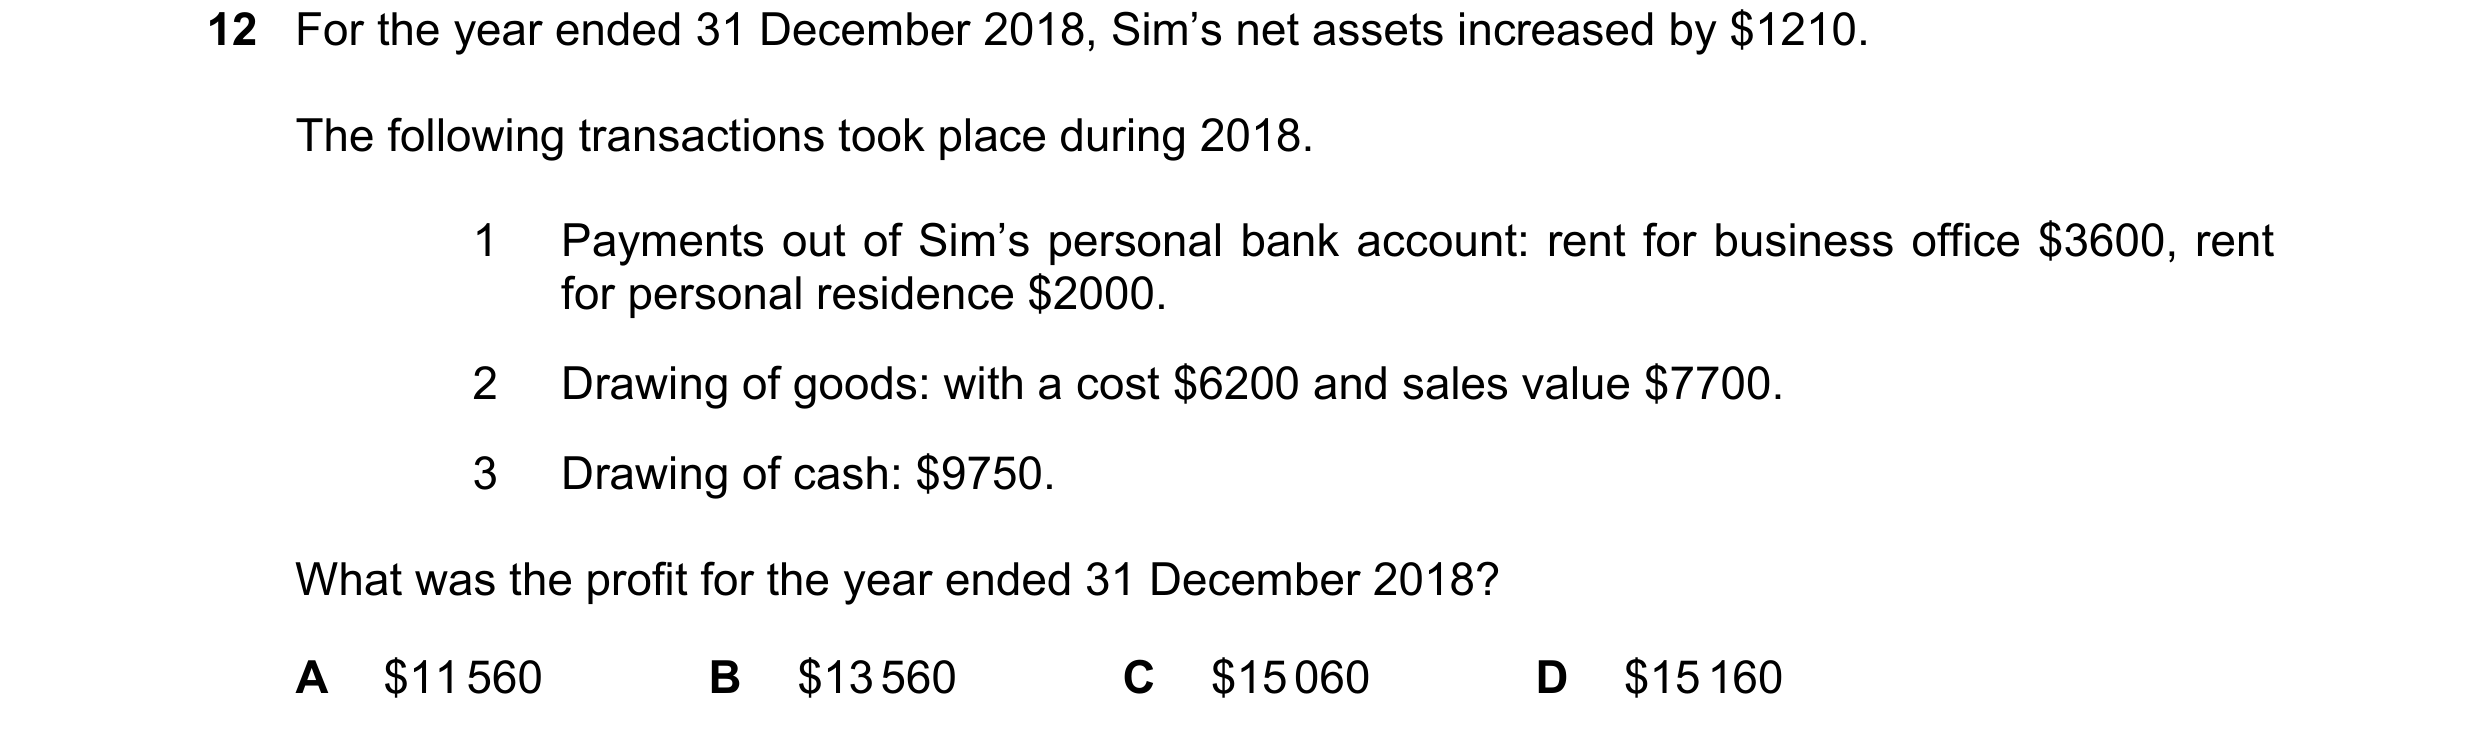
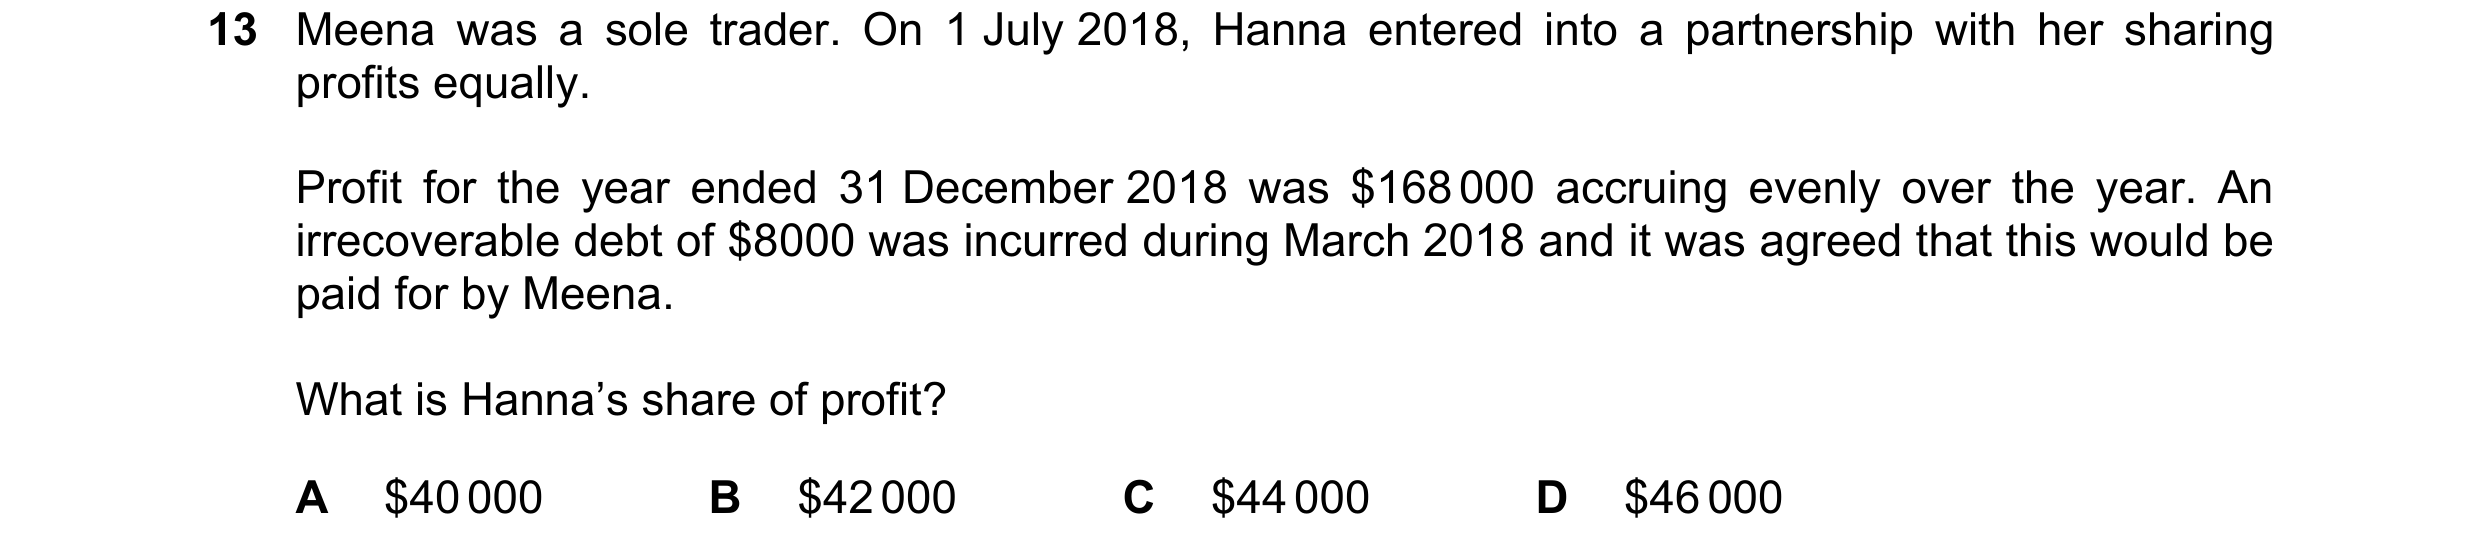
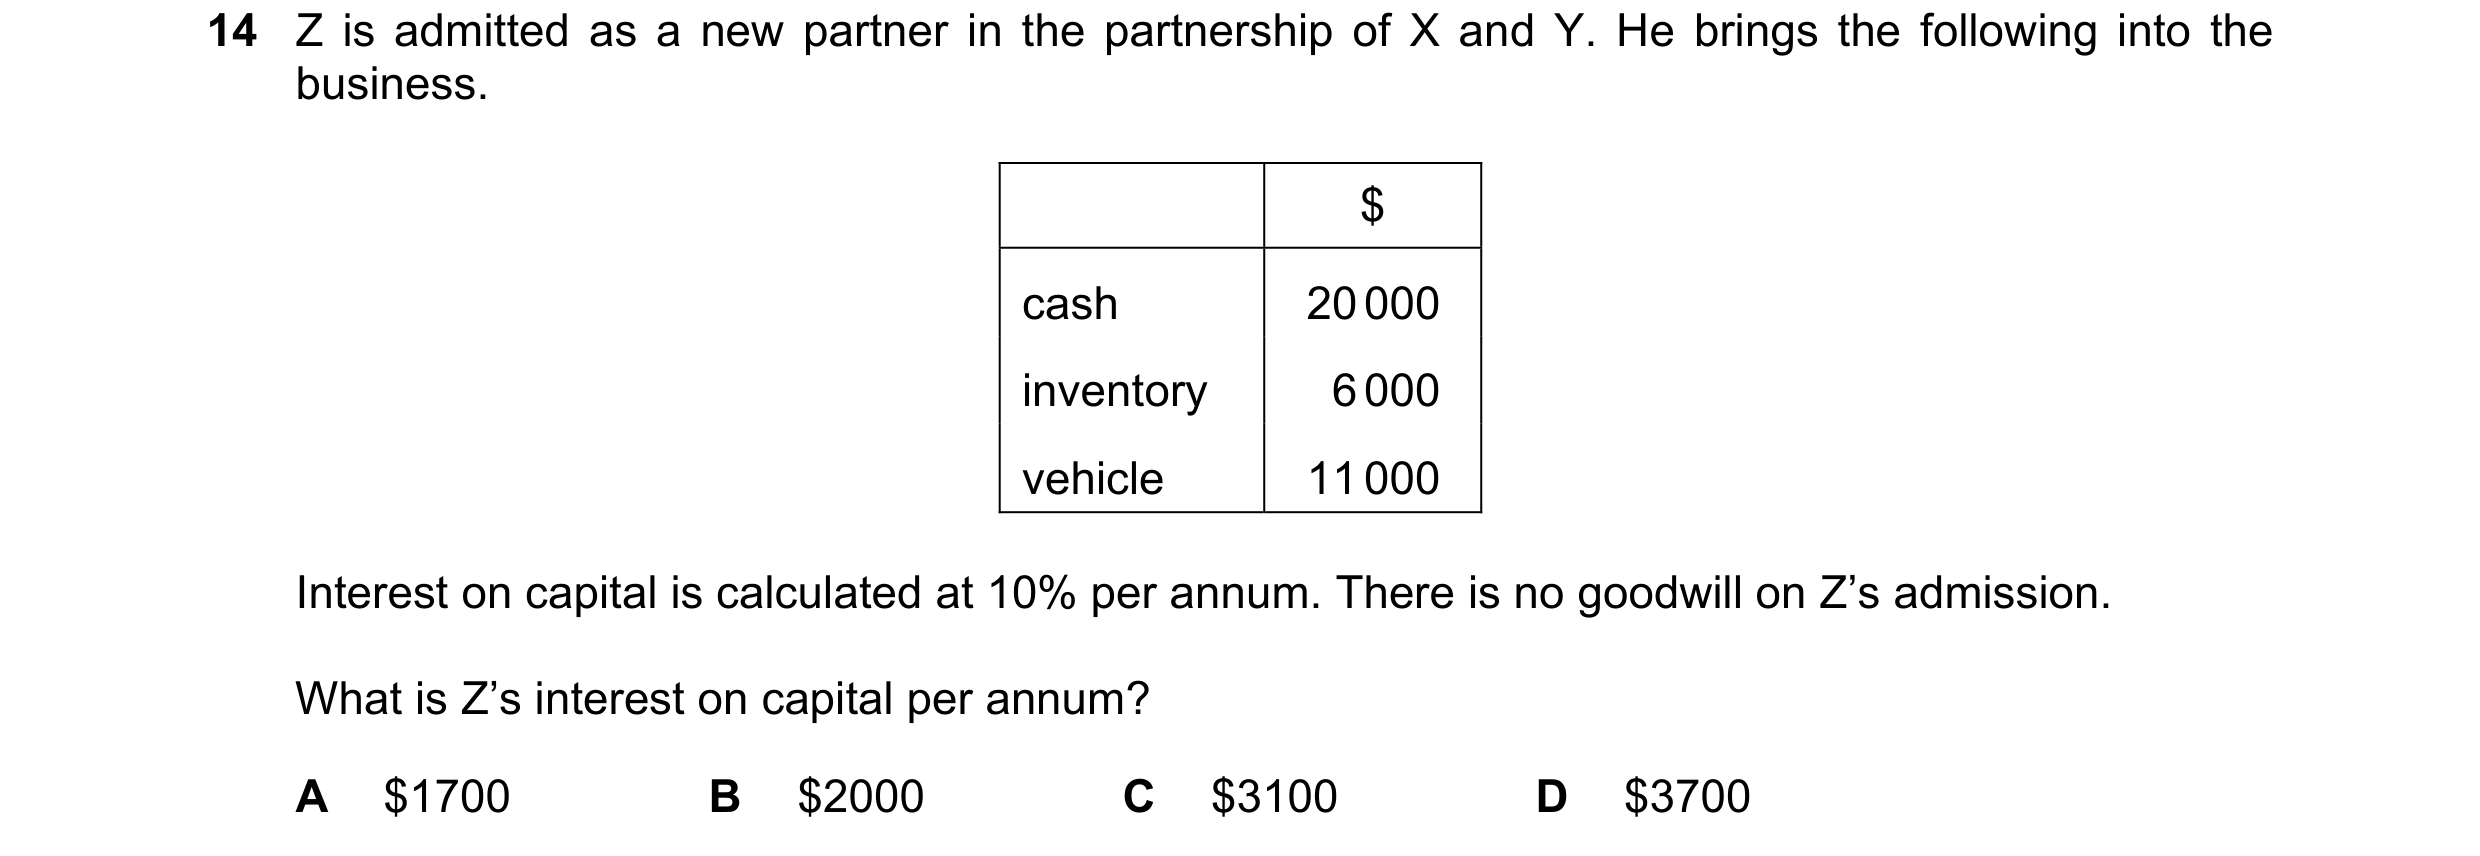
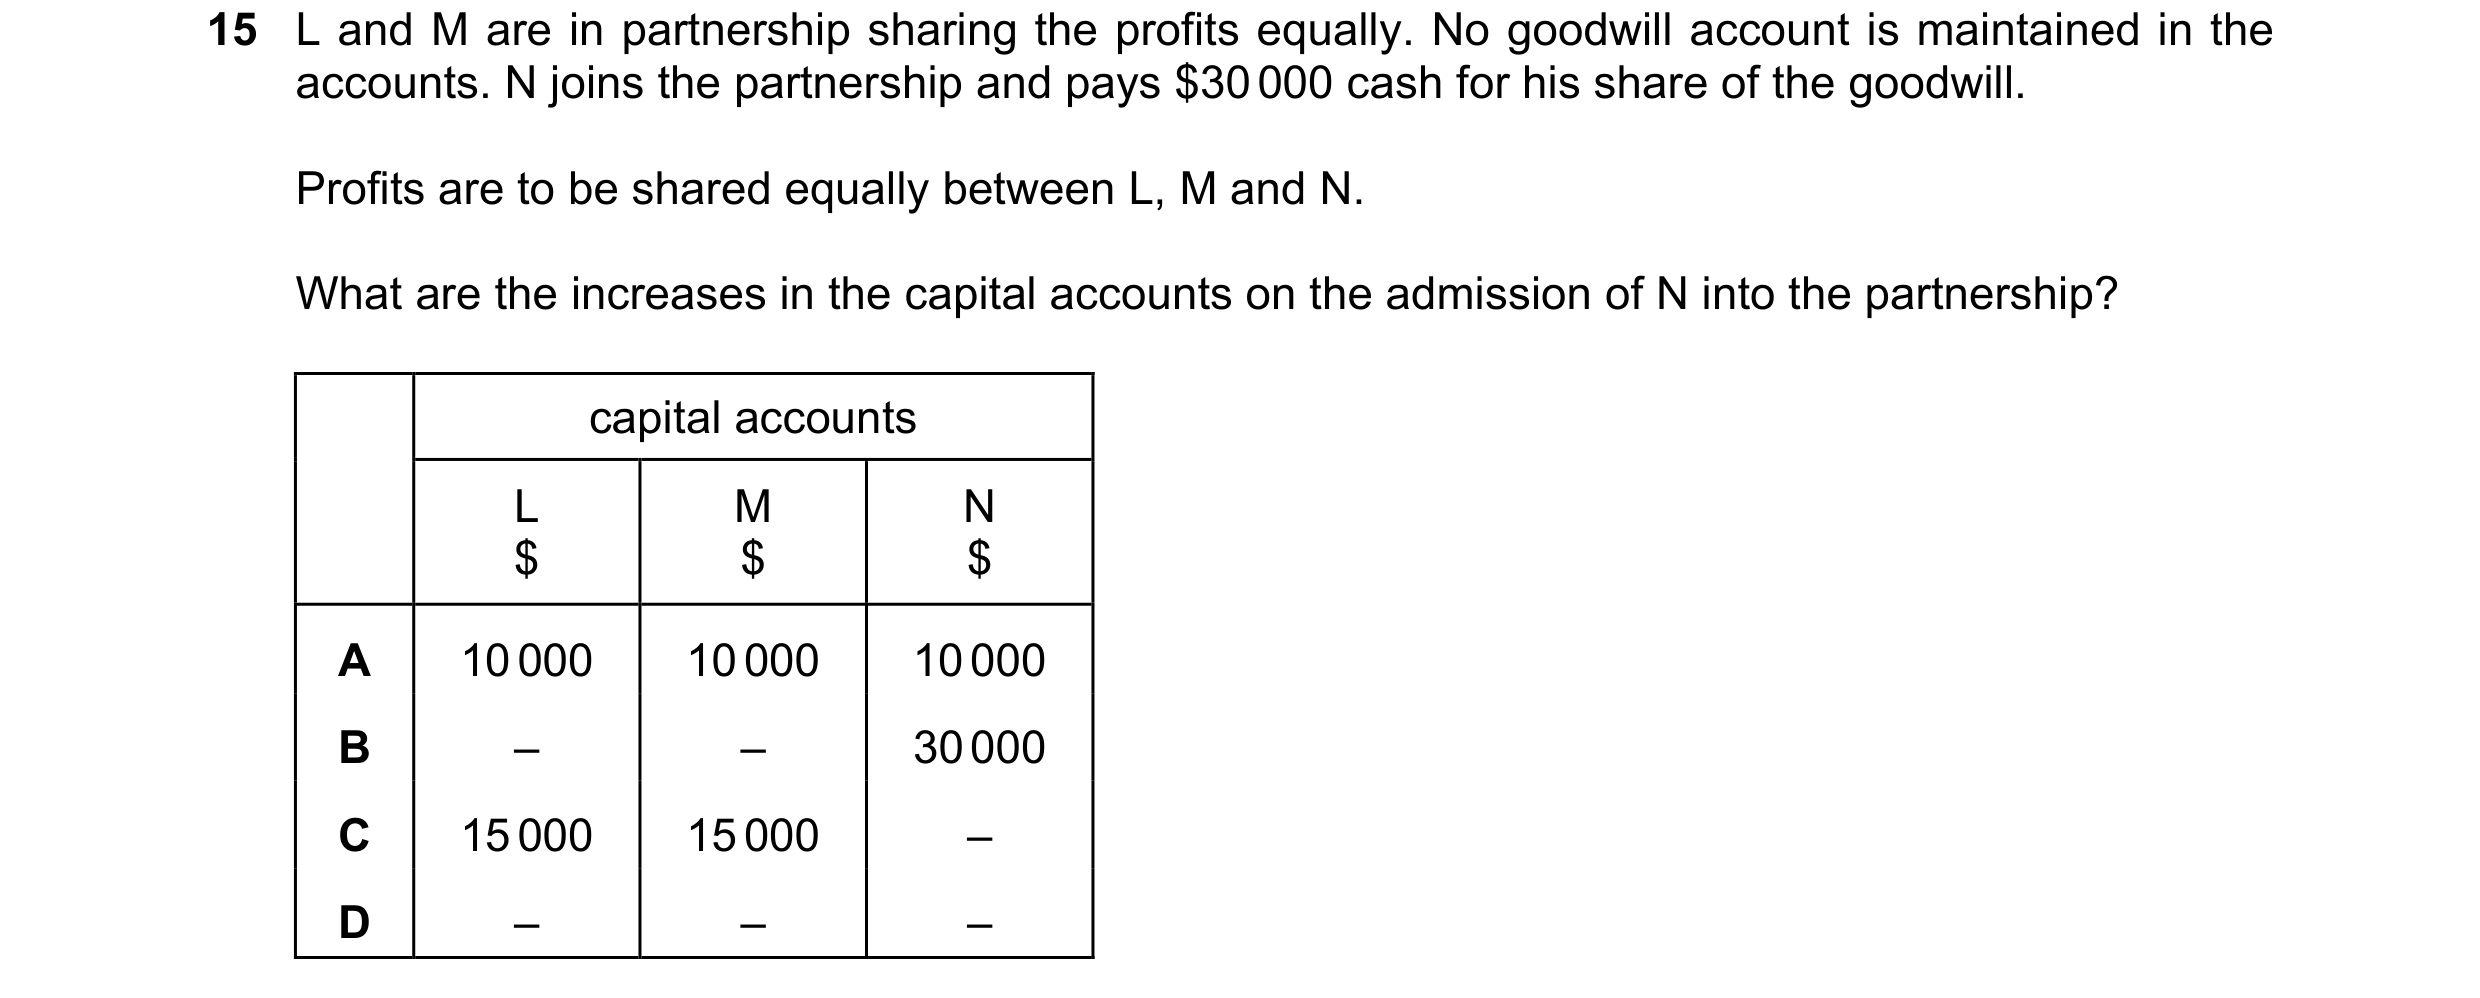 157 / 233
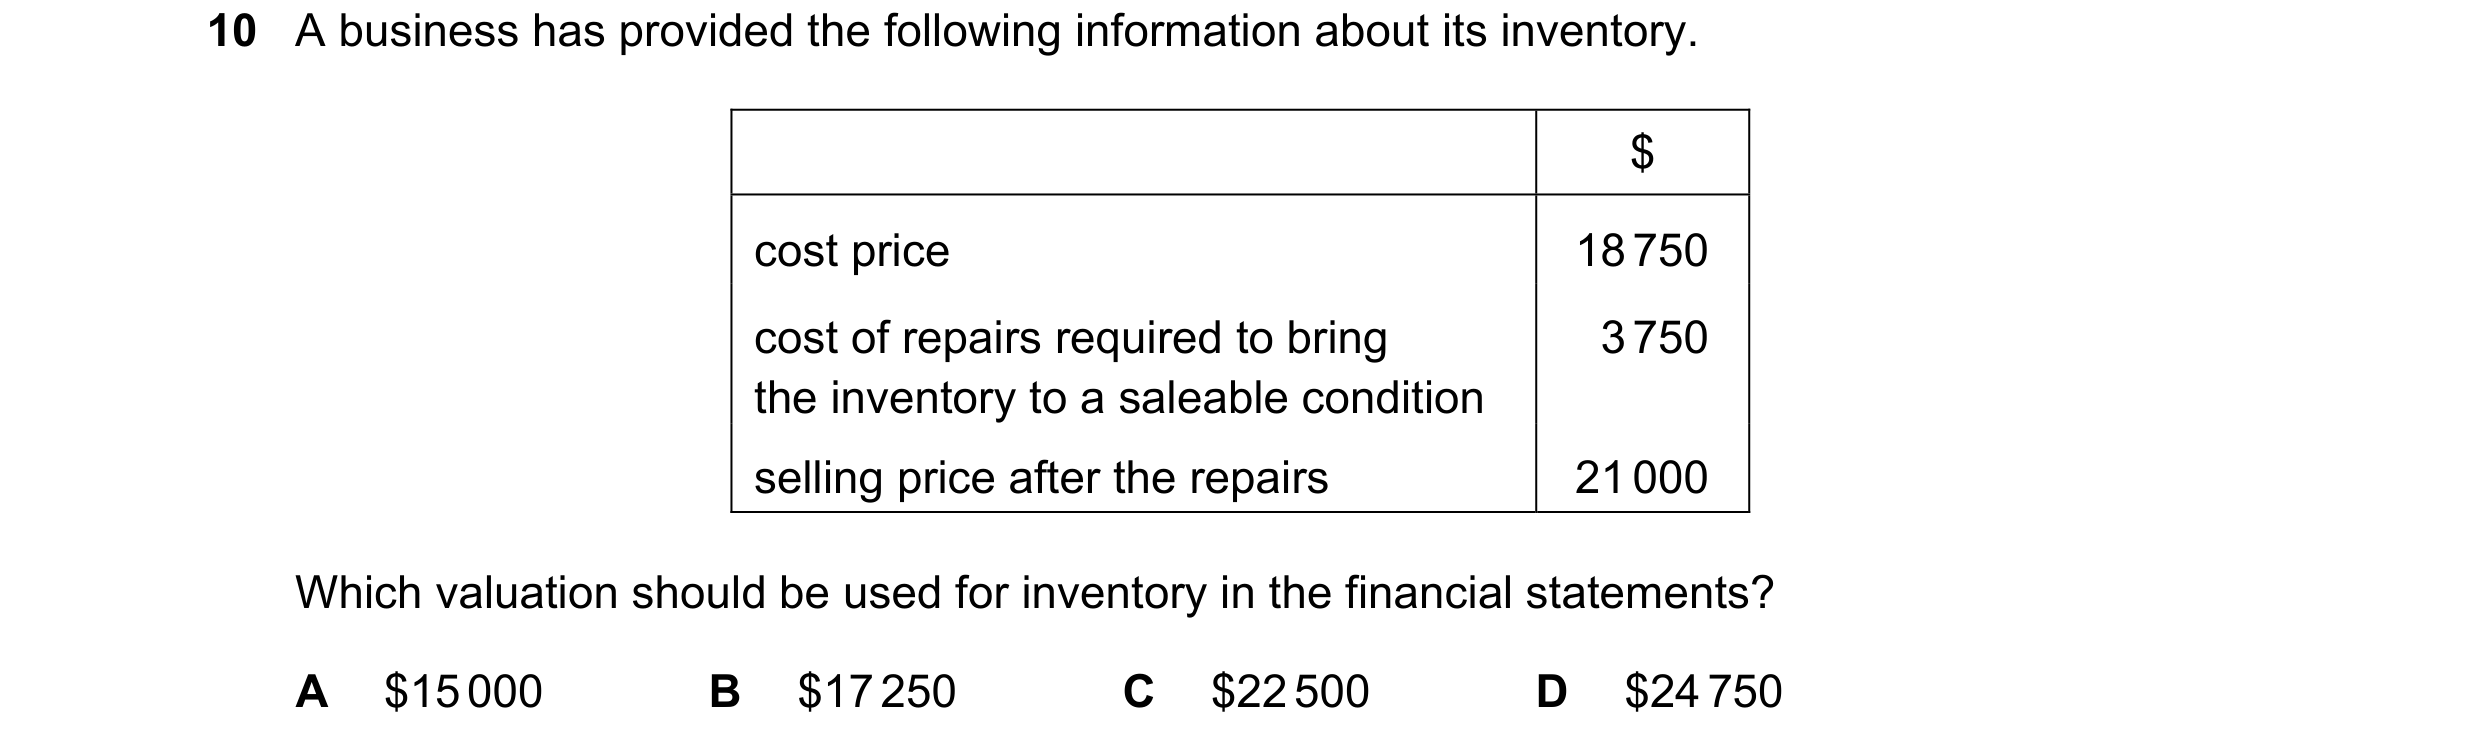
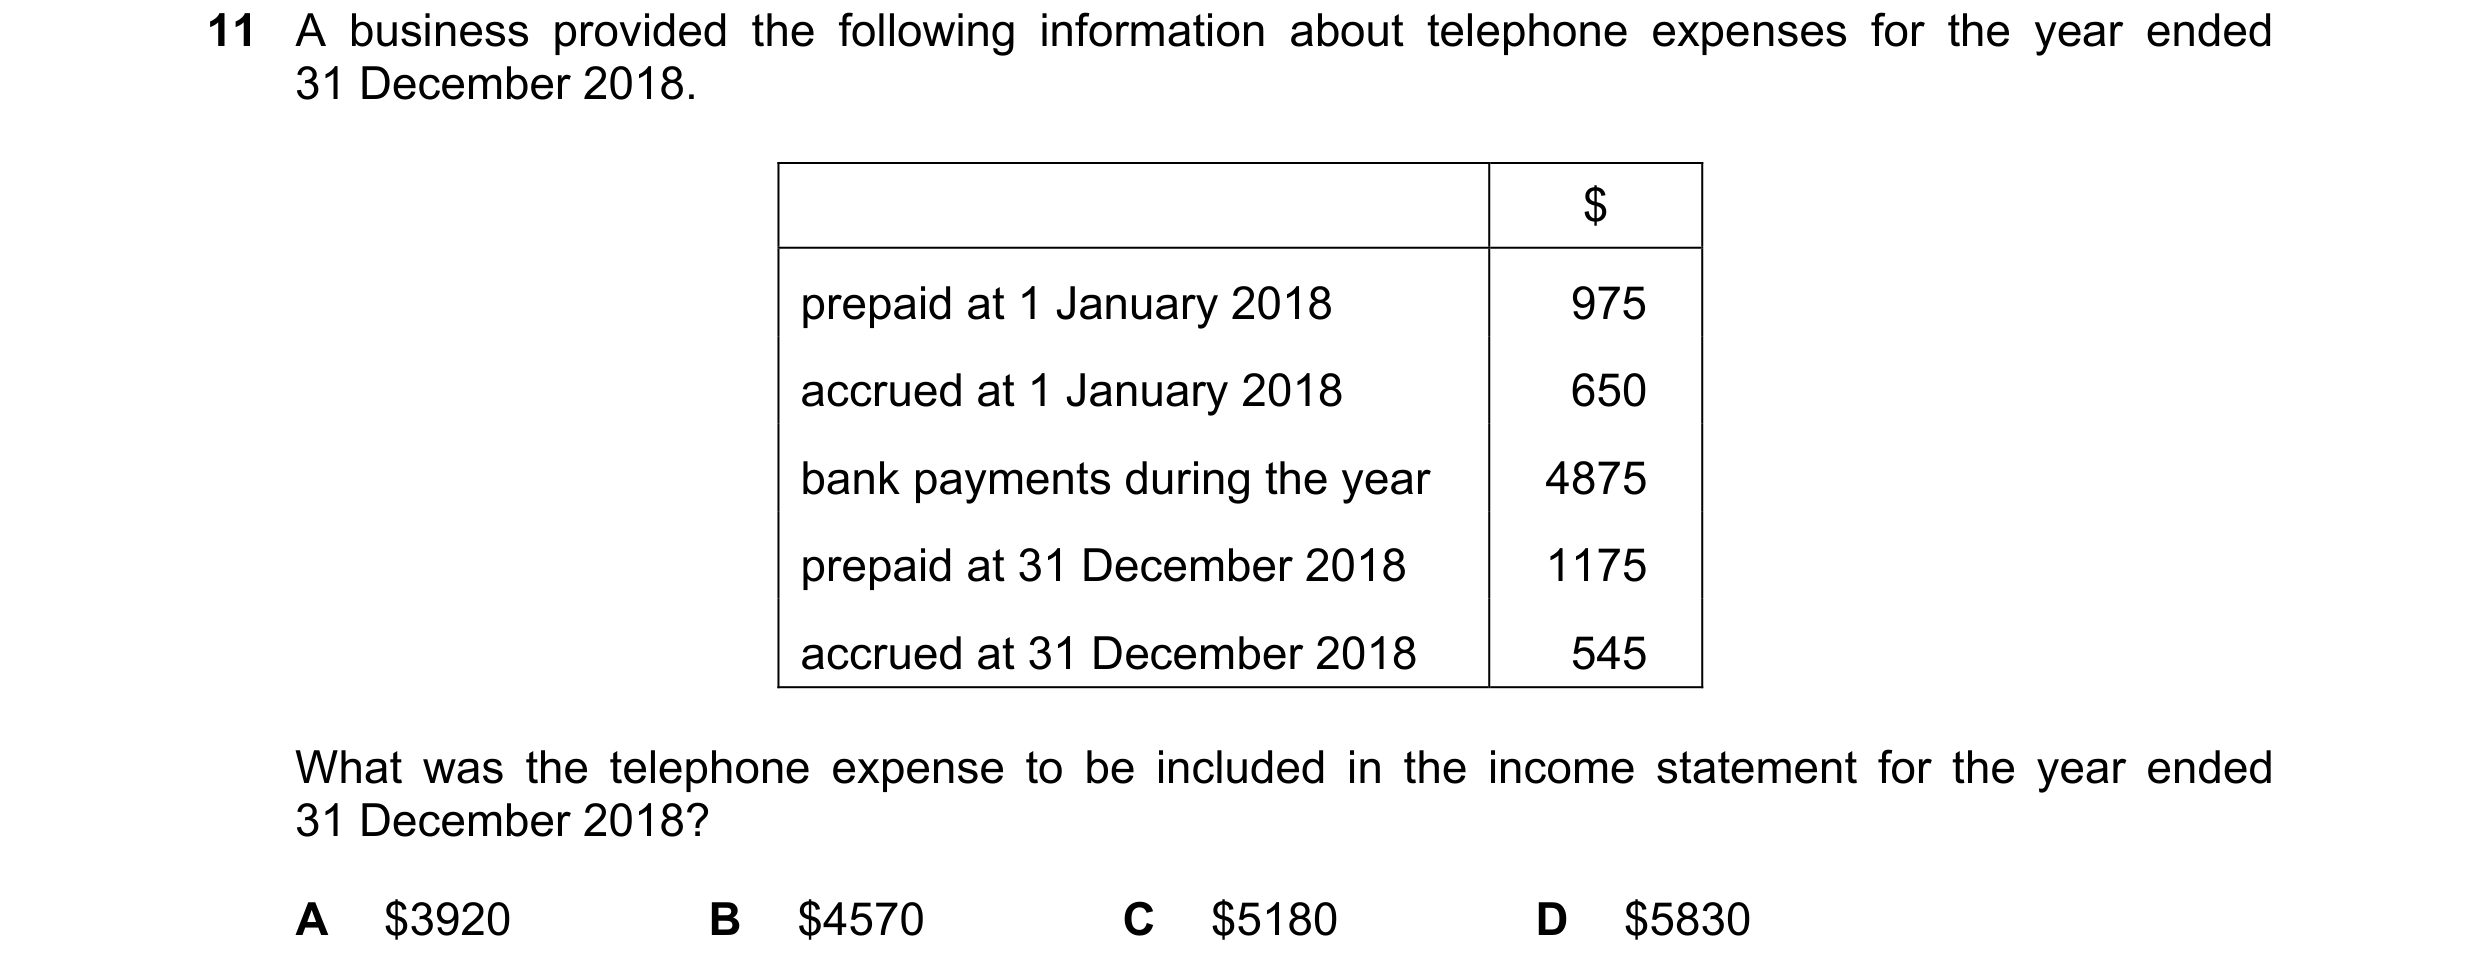
 158 / 233
 159 / 233
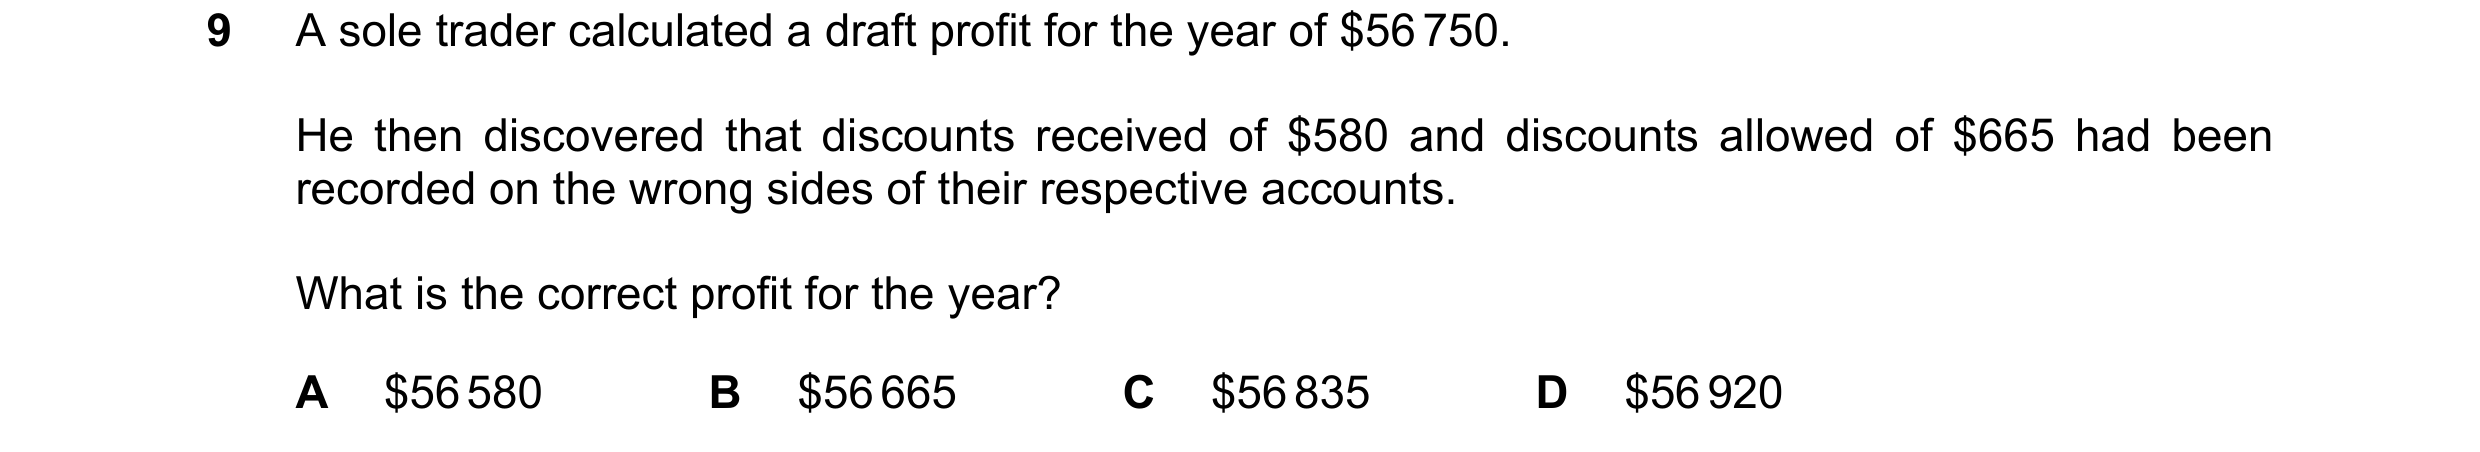
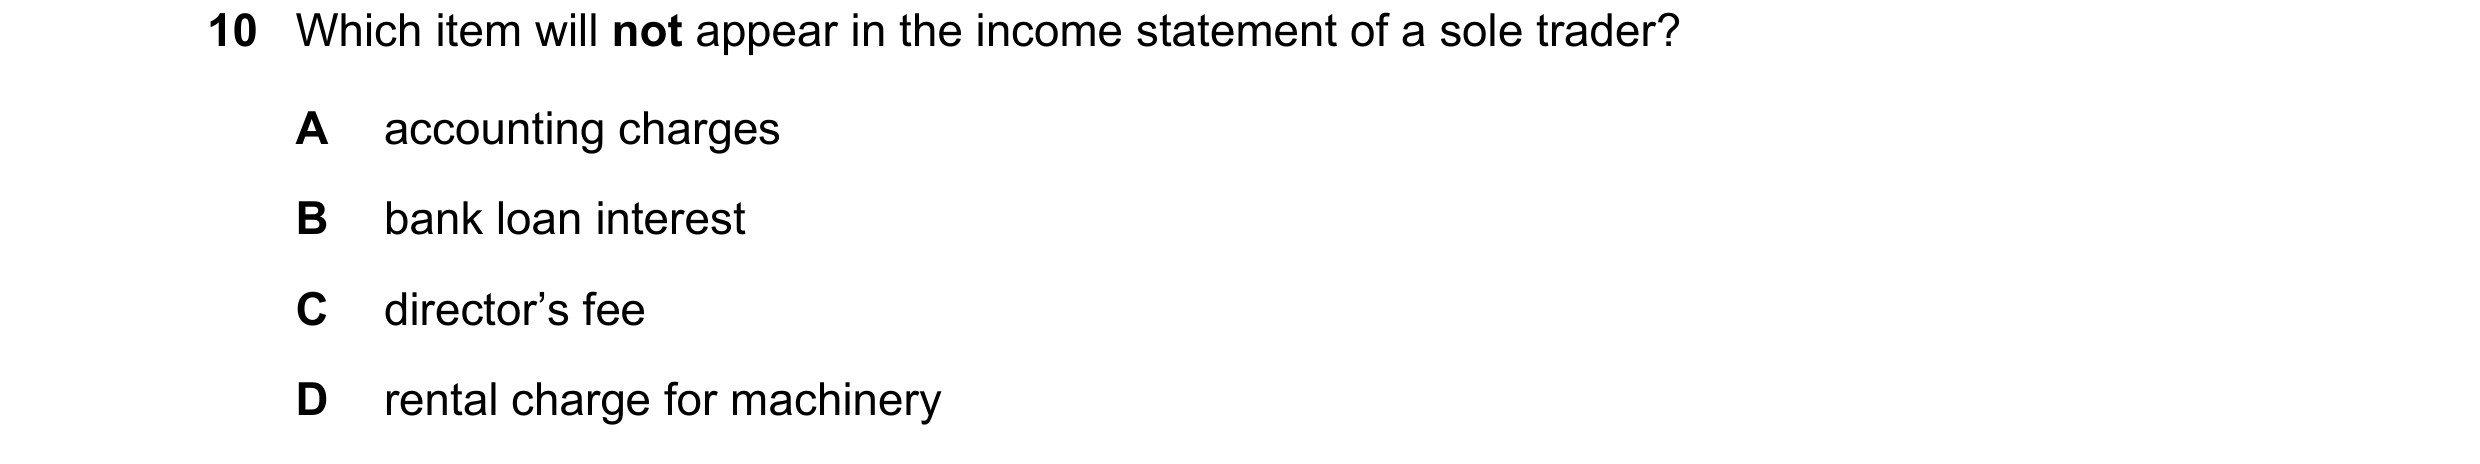
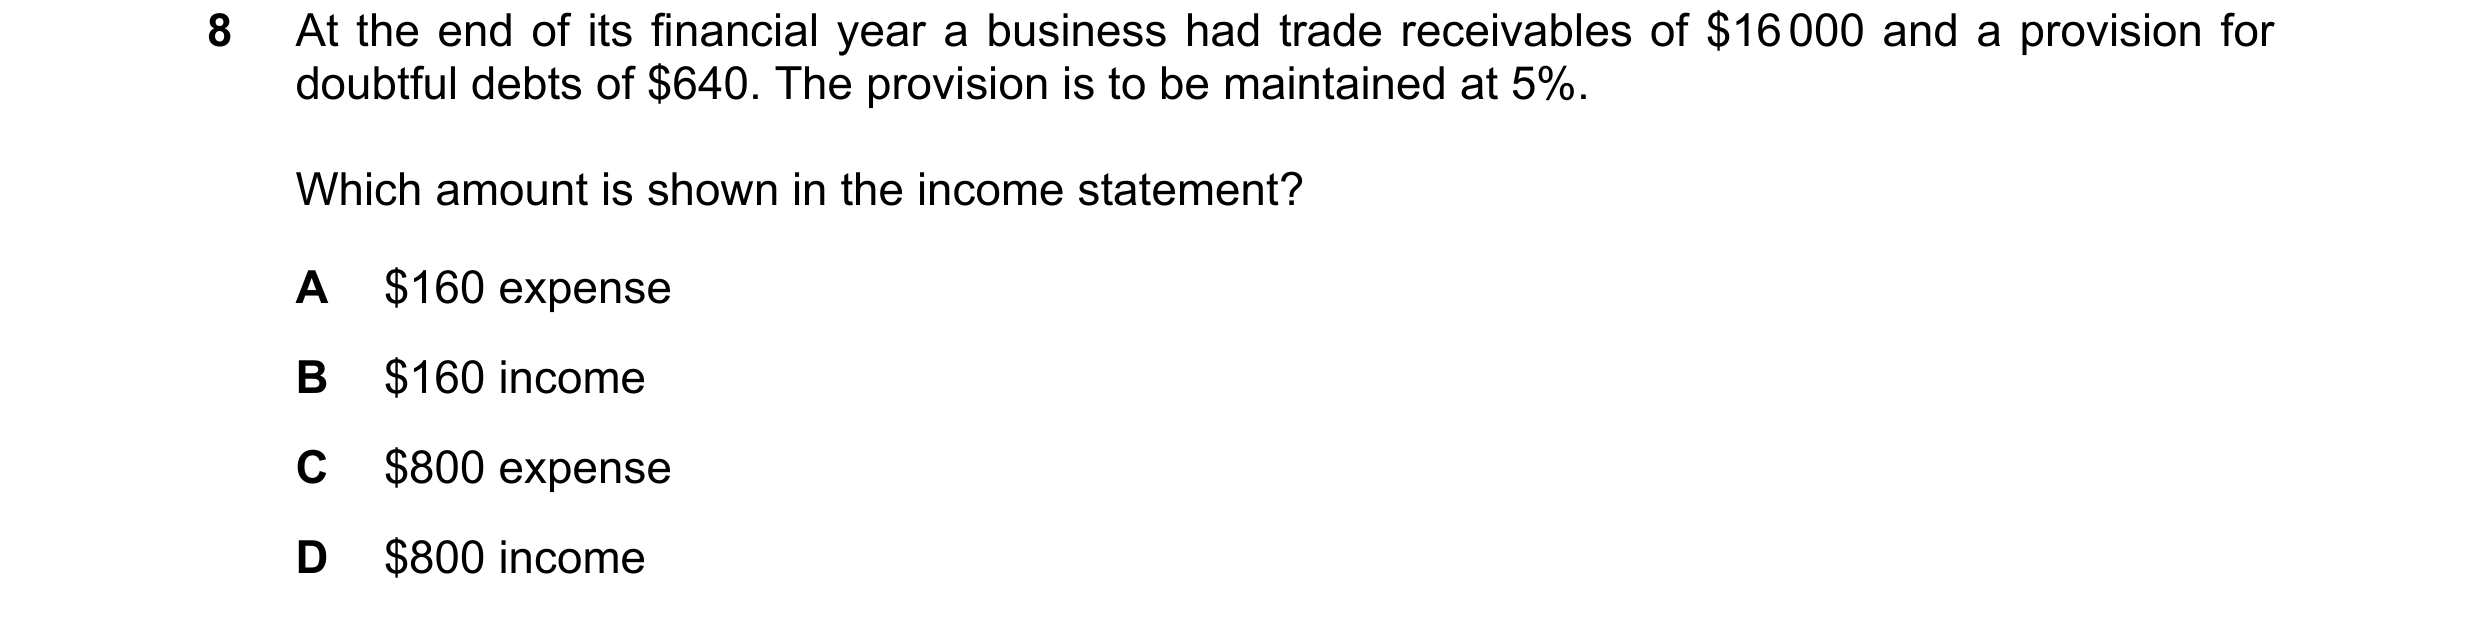
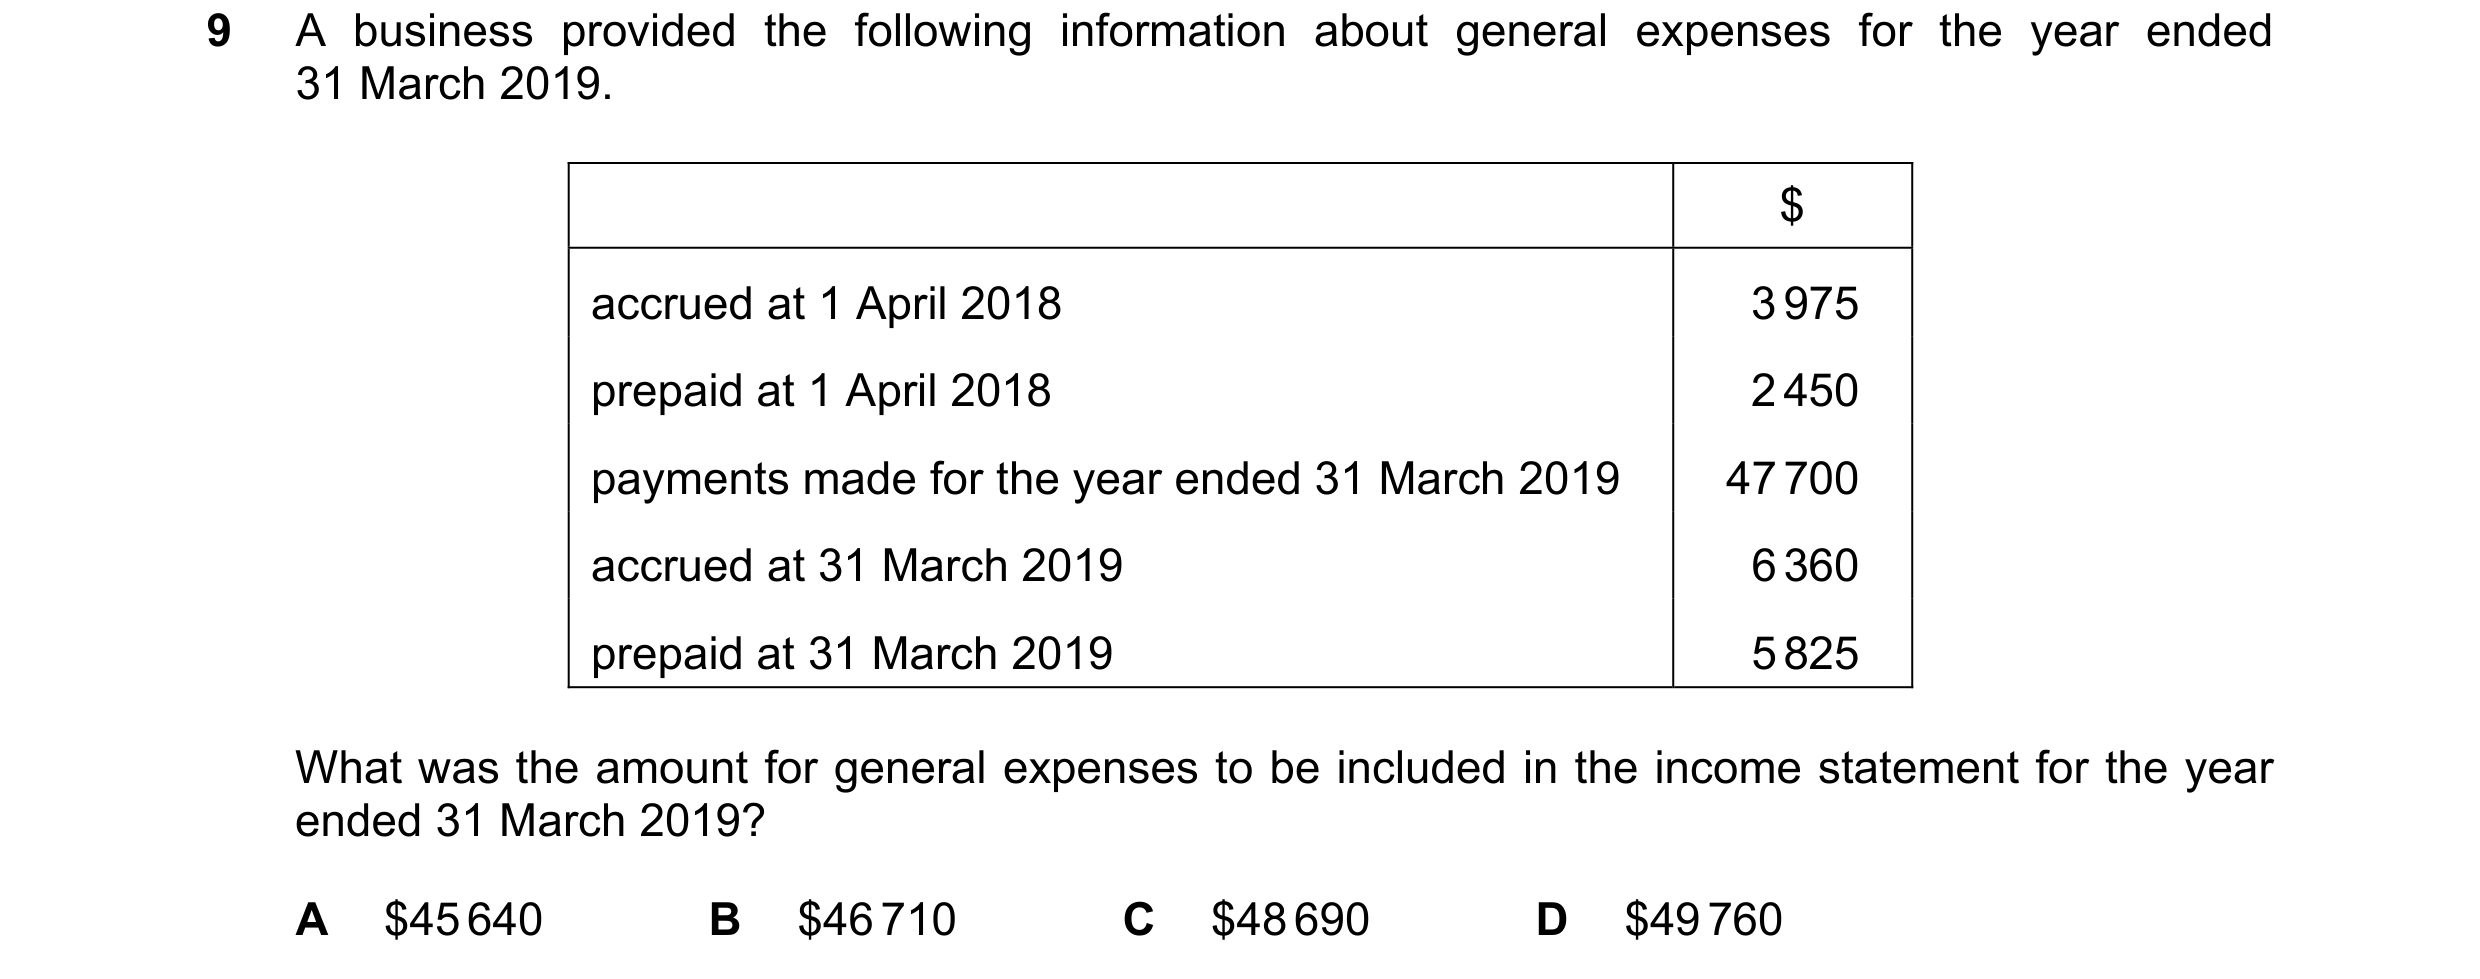 160 / 233
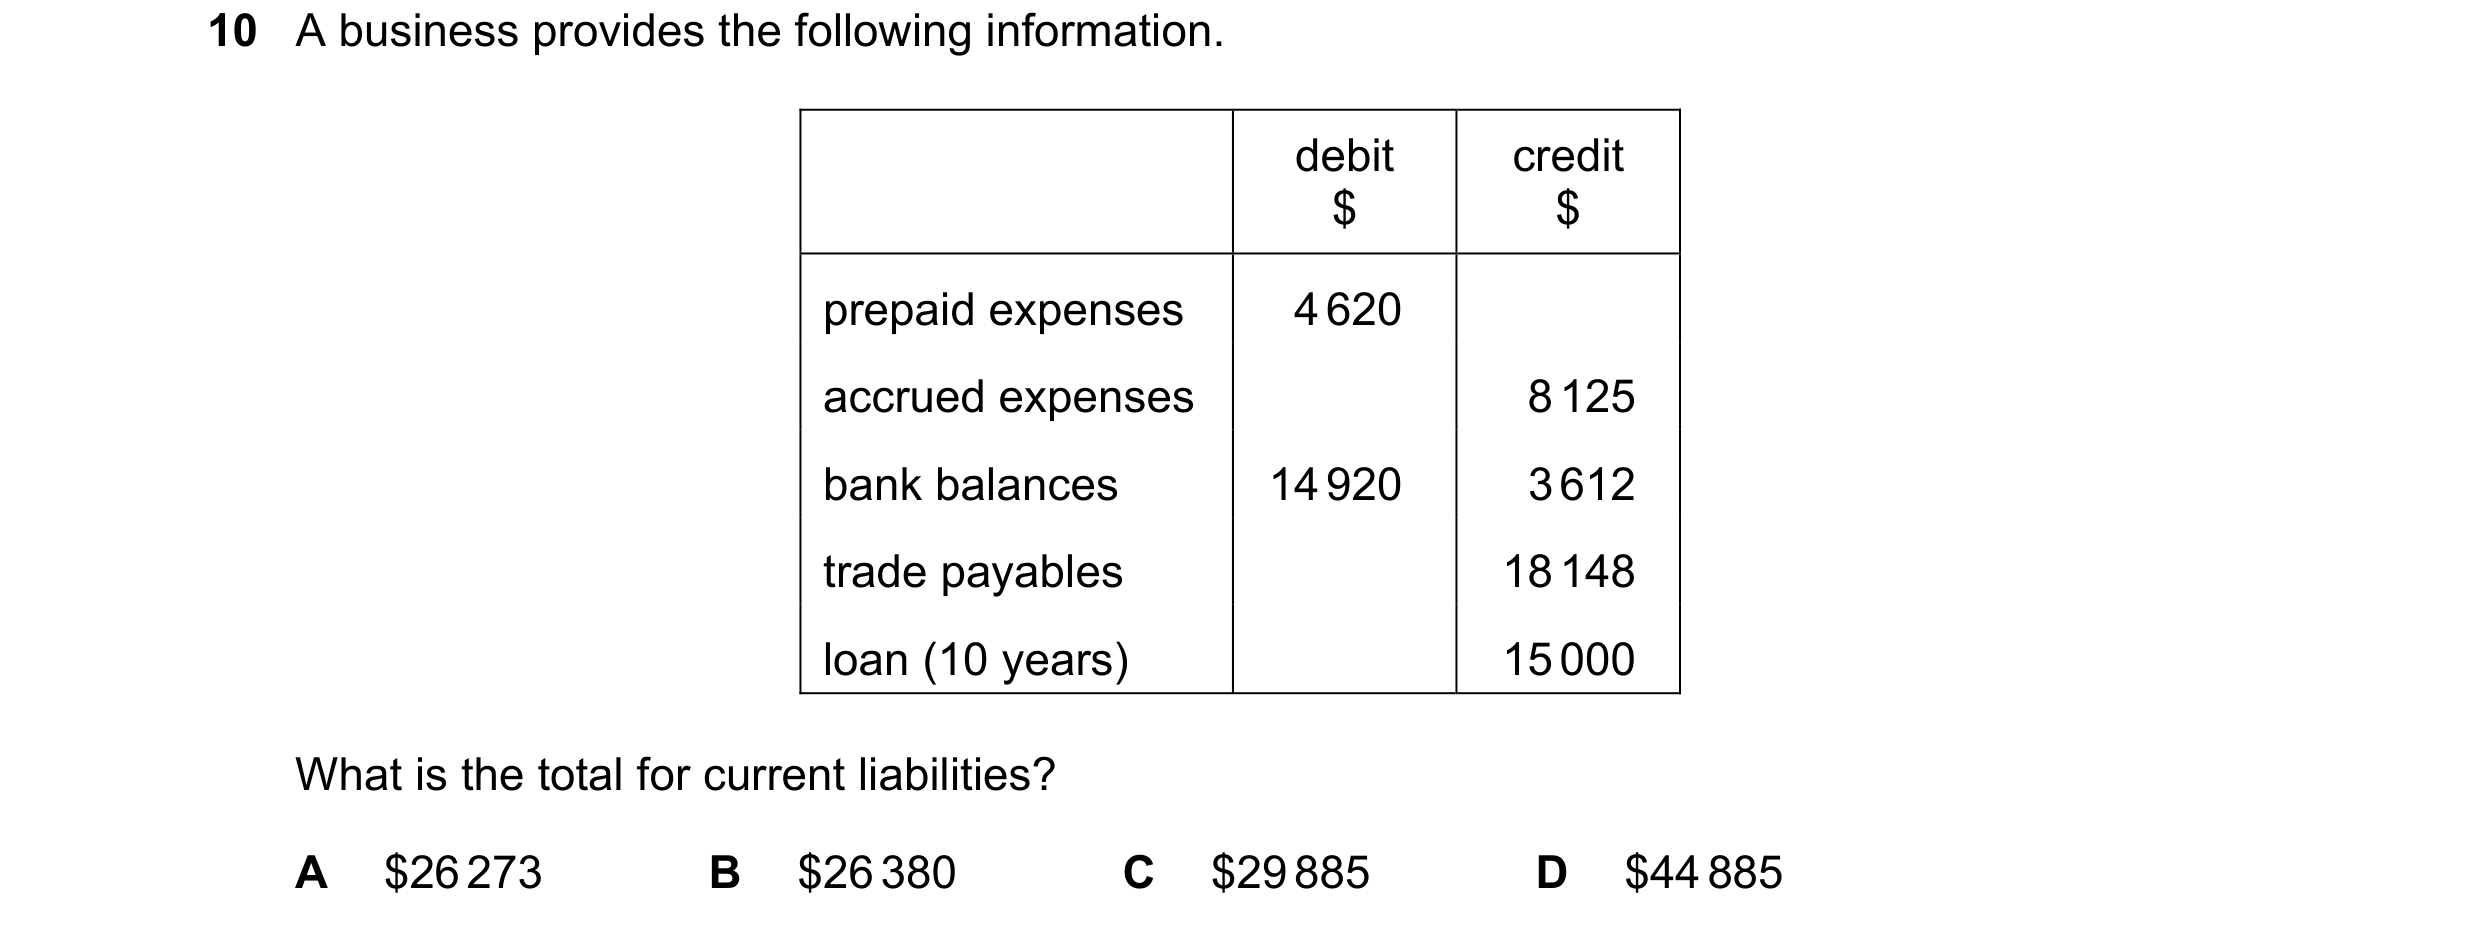
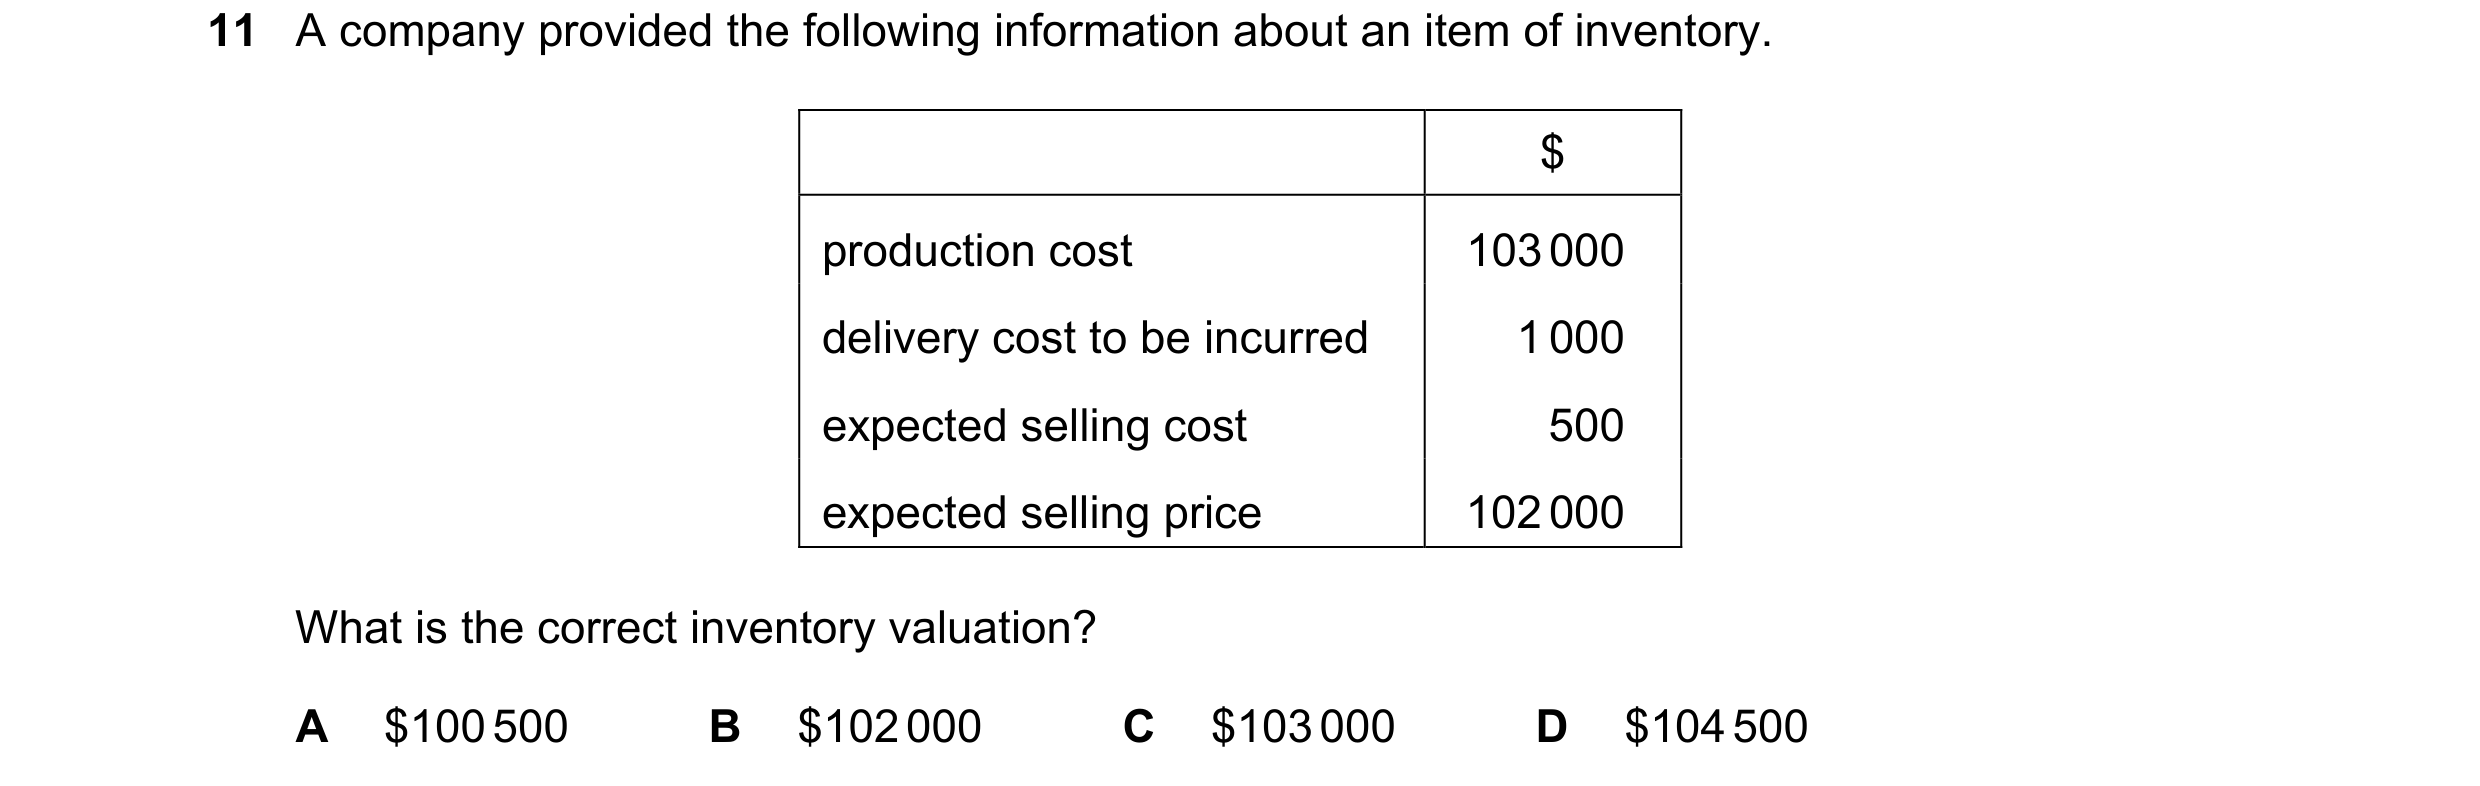
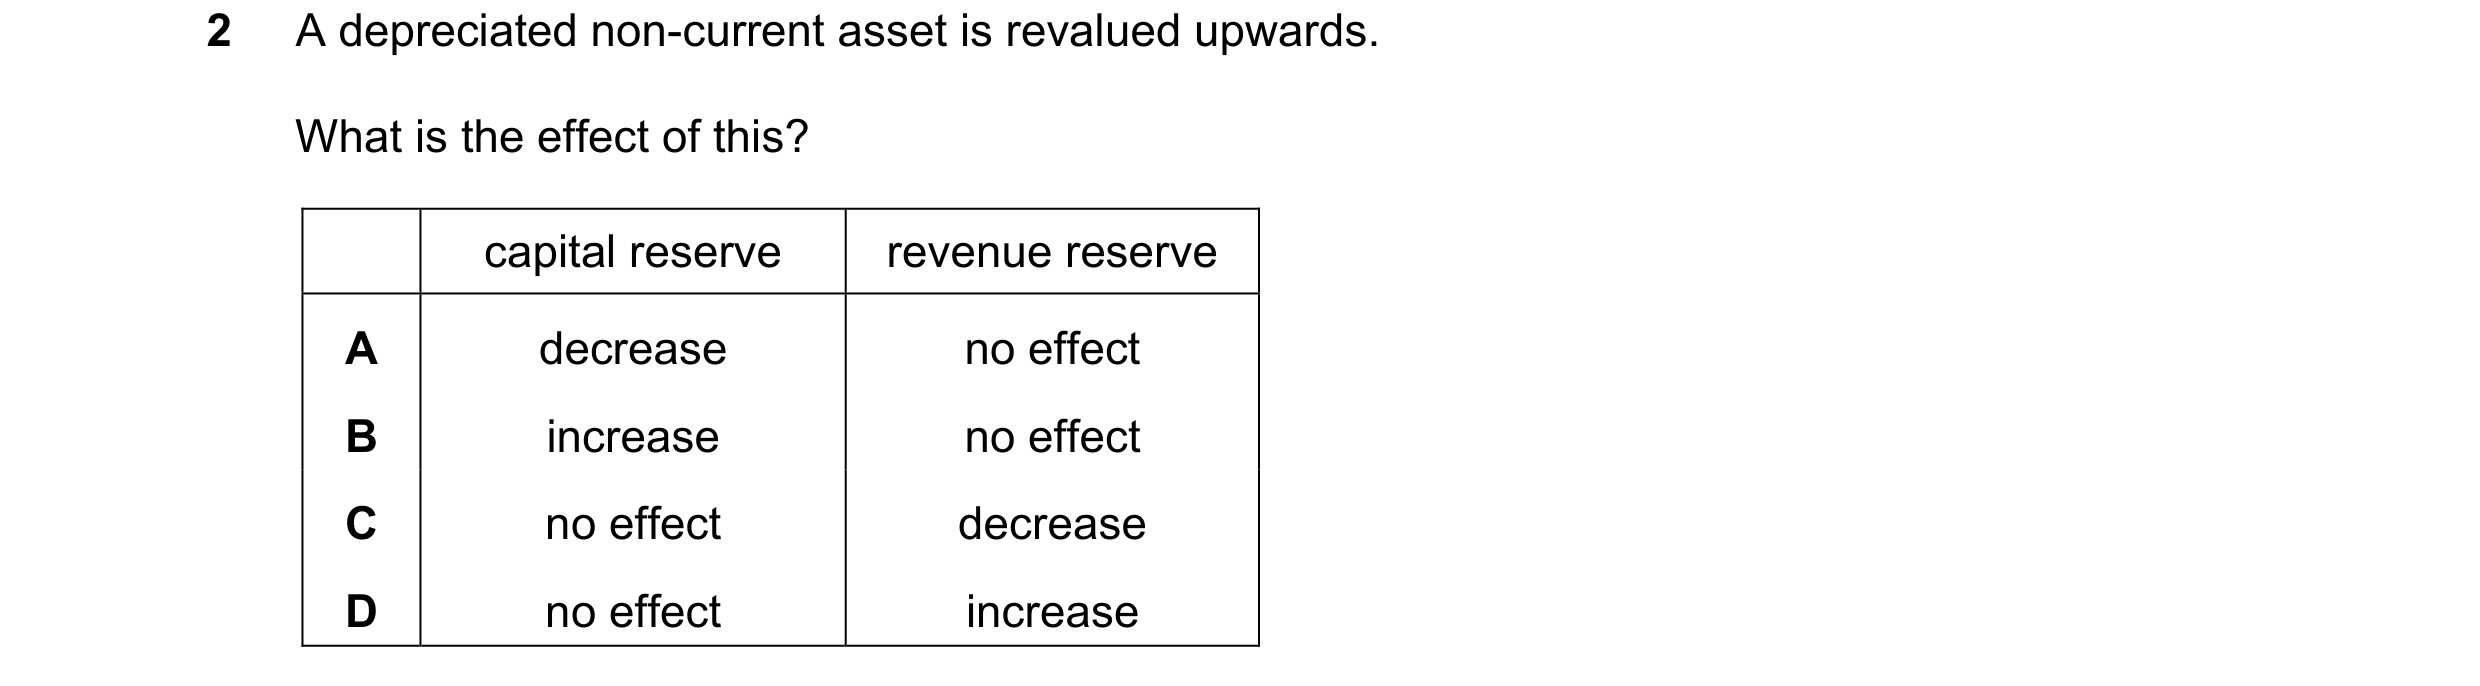 161 / 233
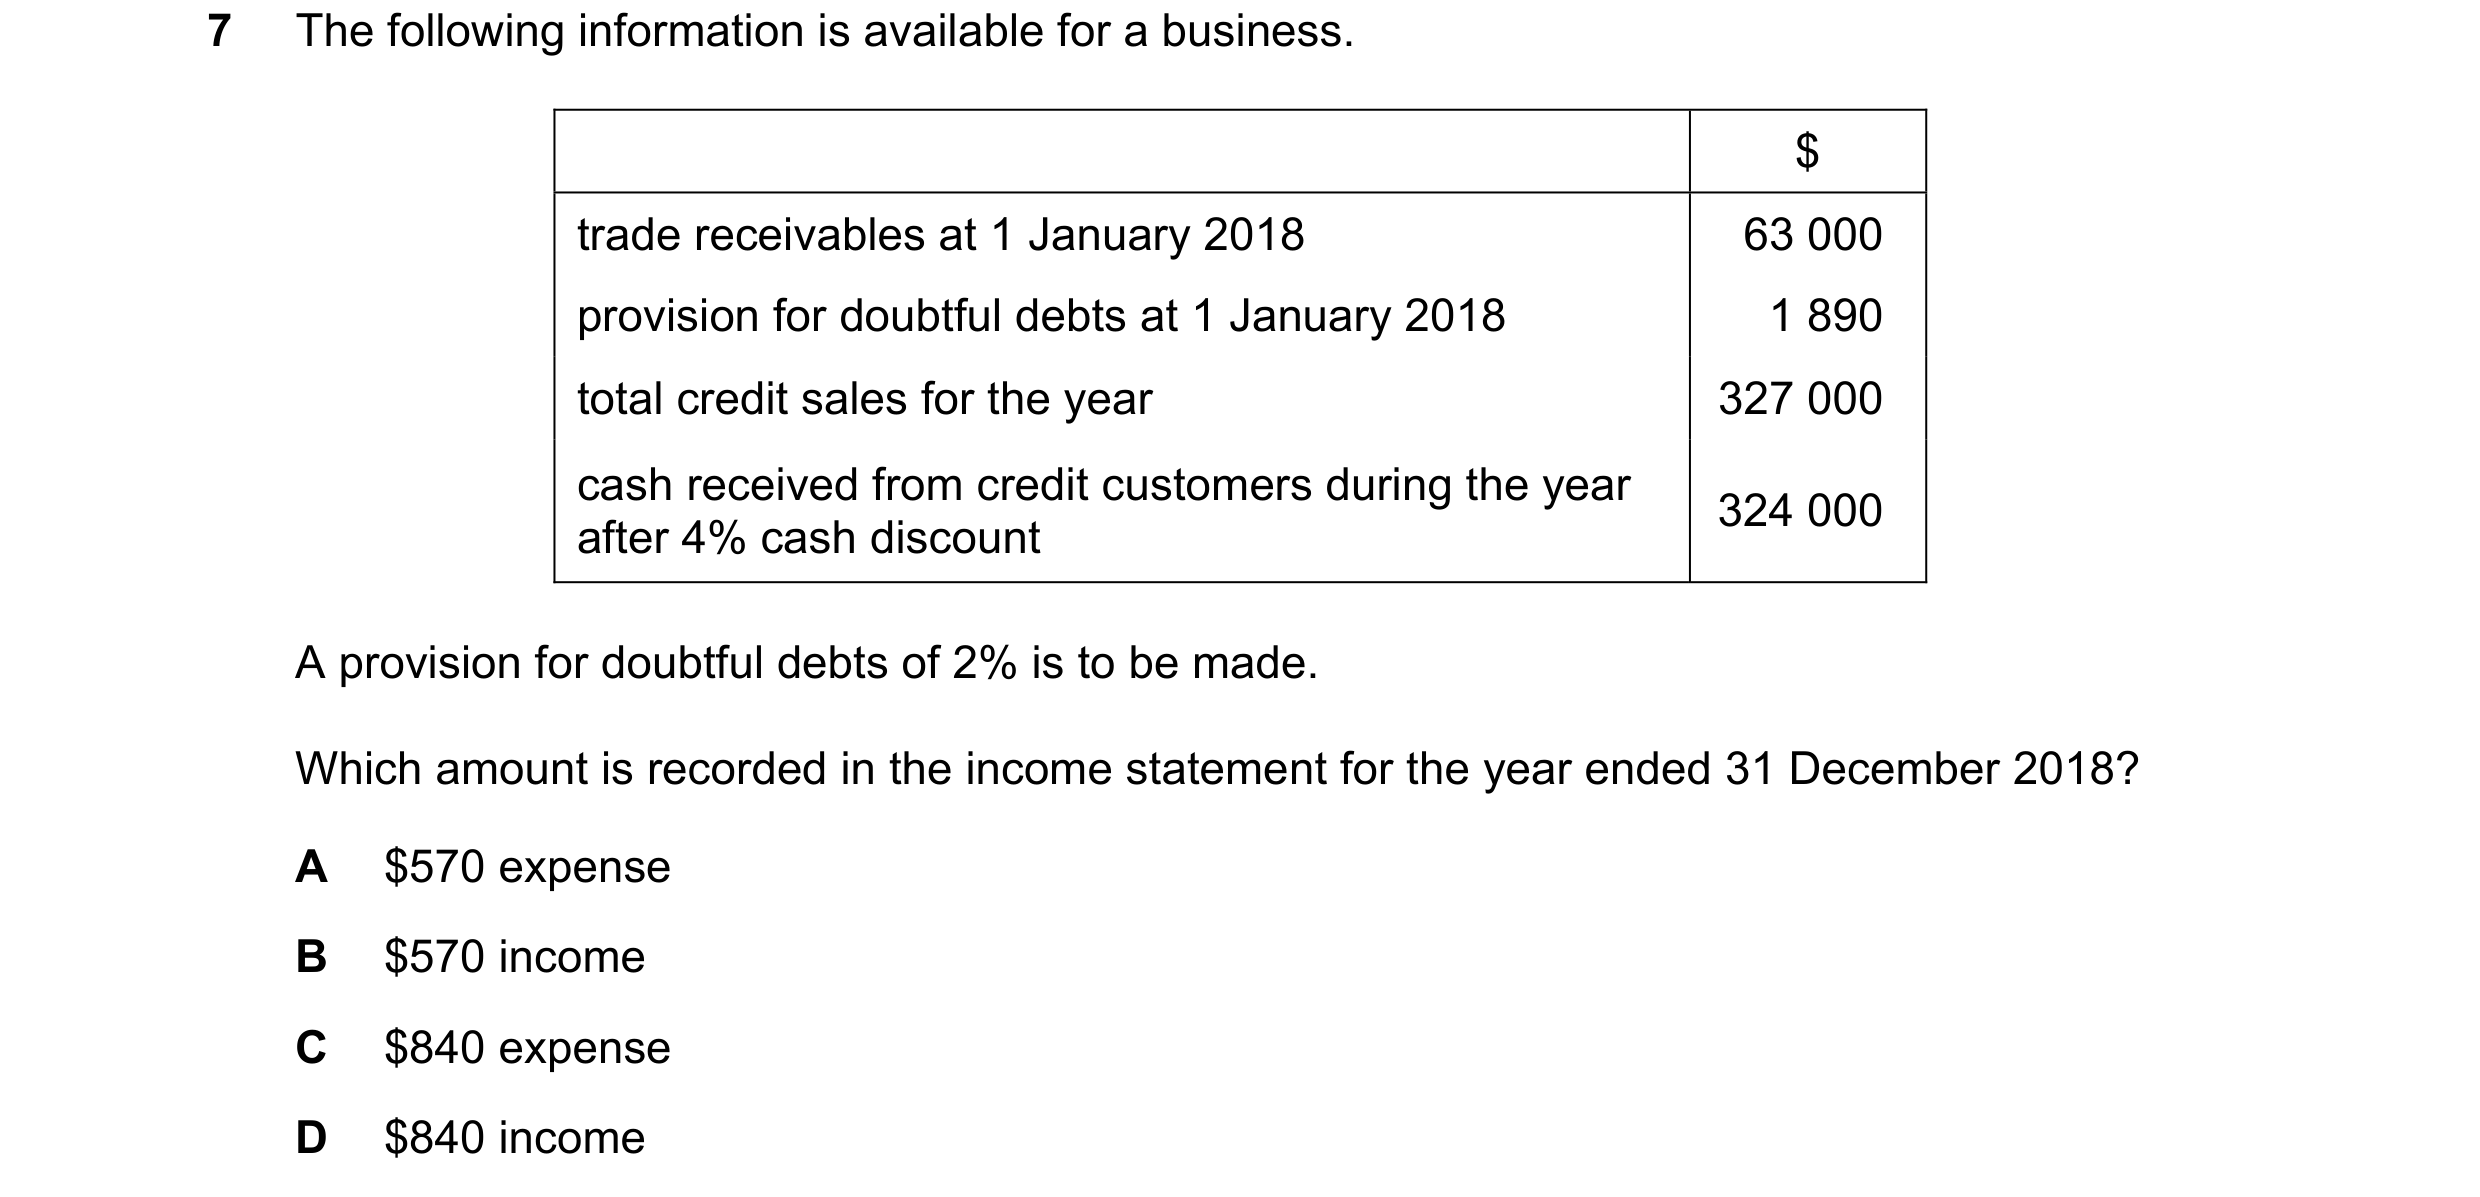
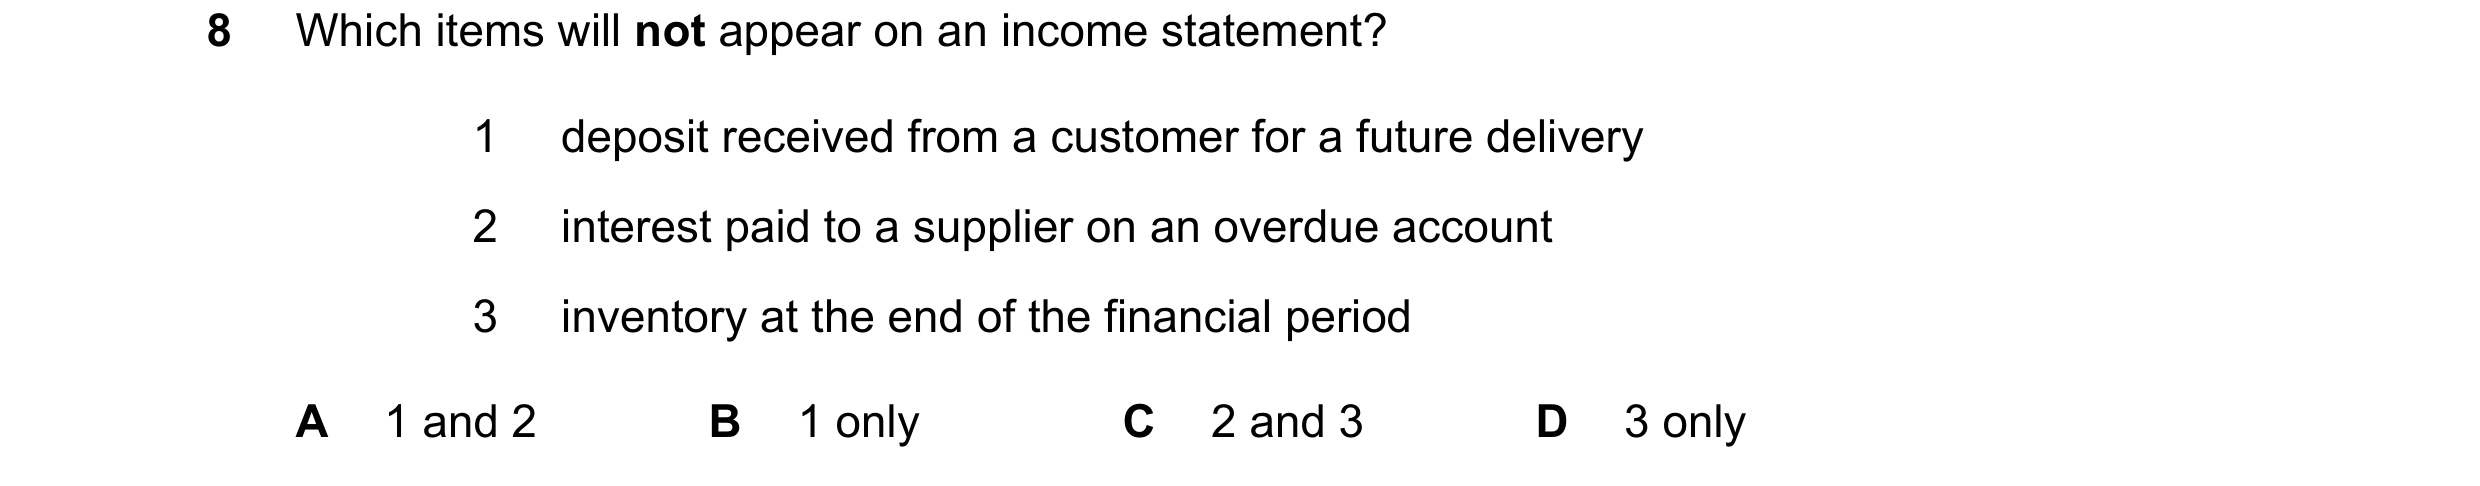
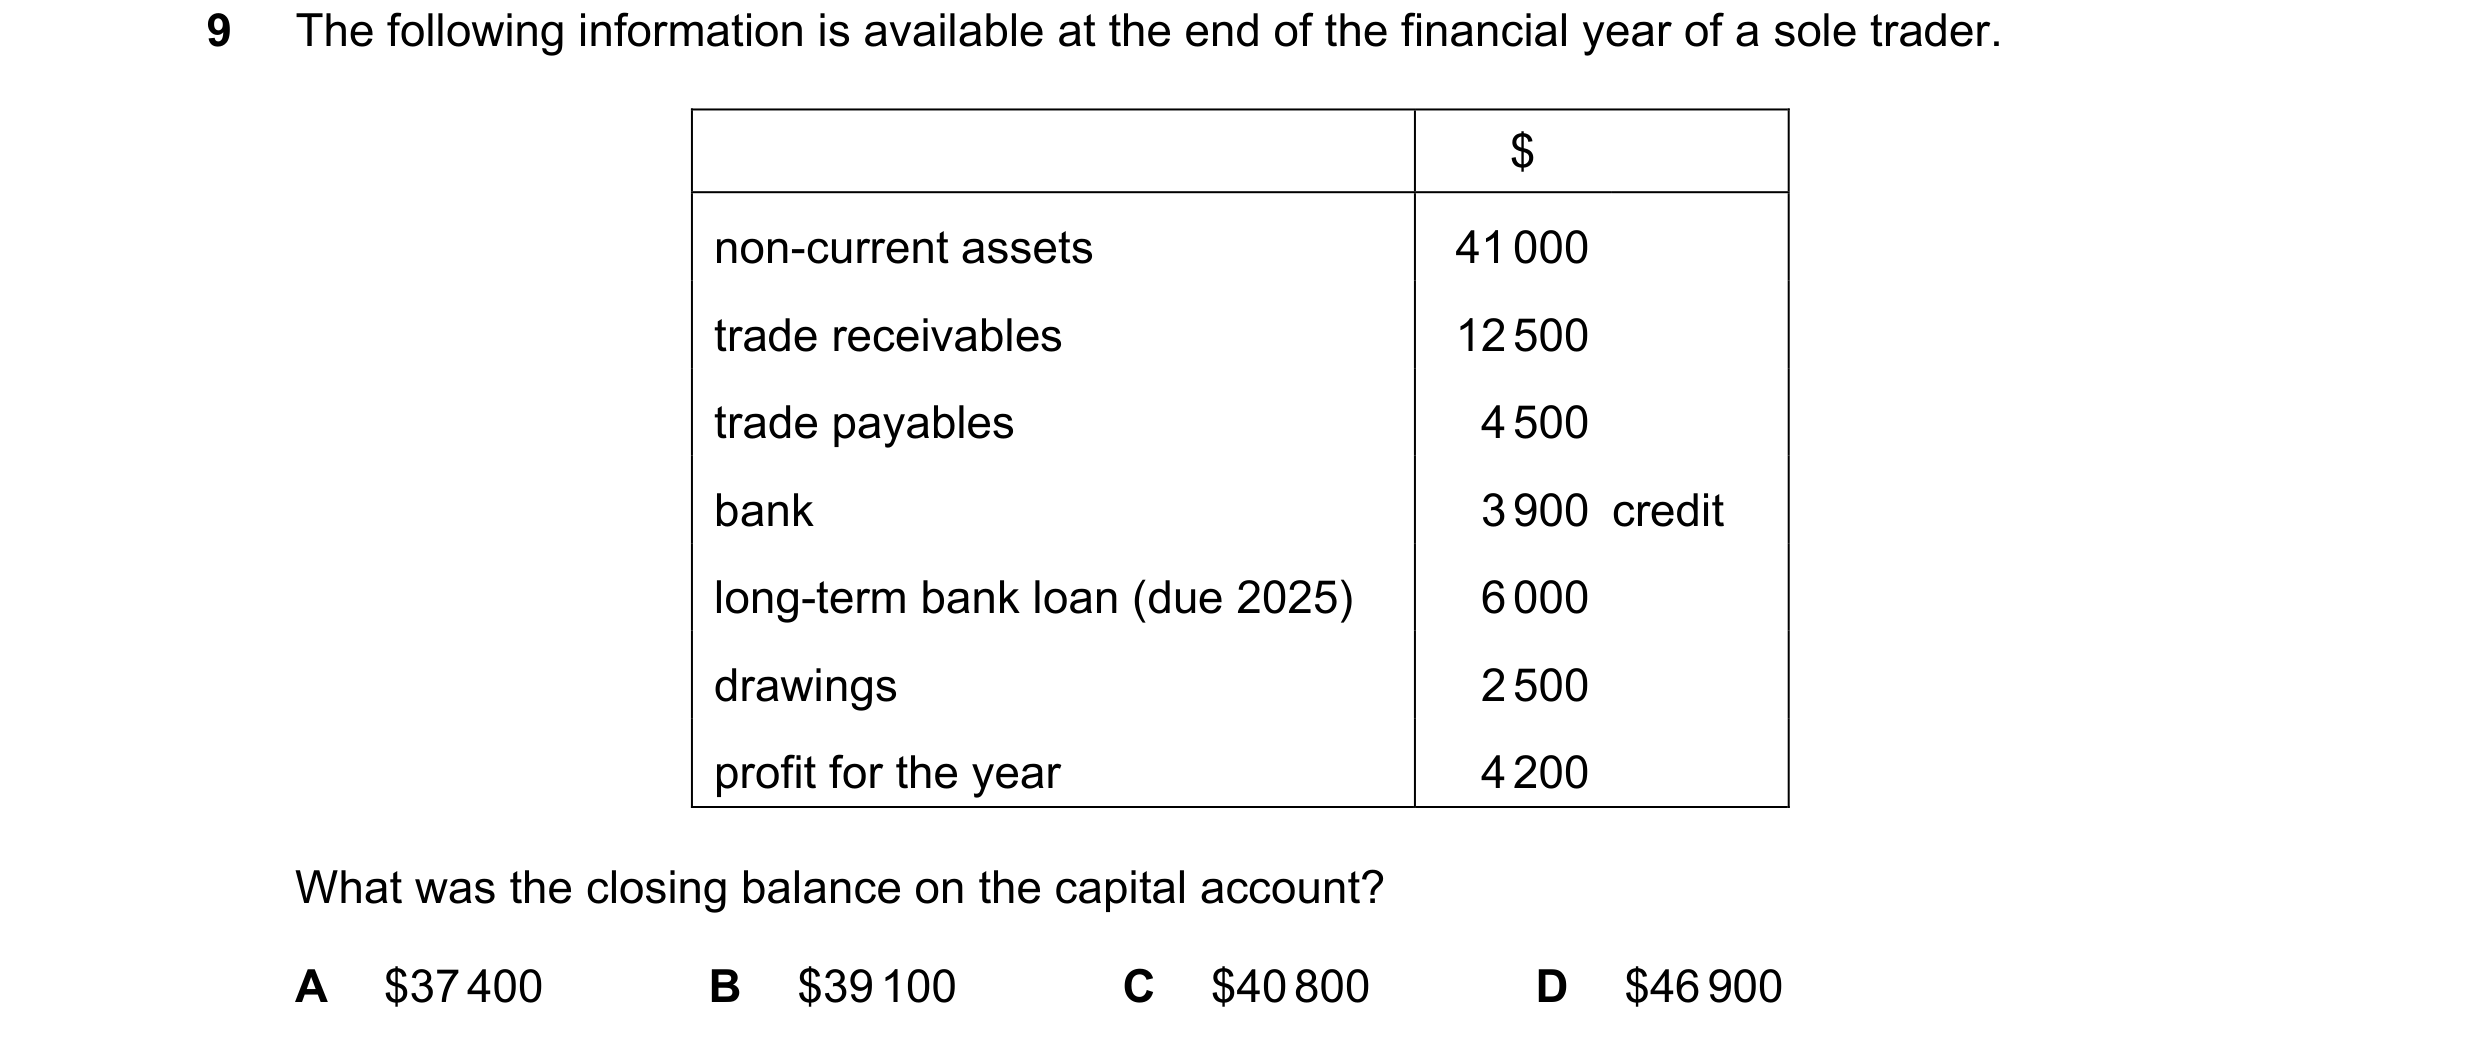 162 / 233
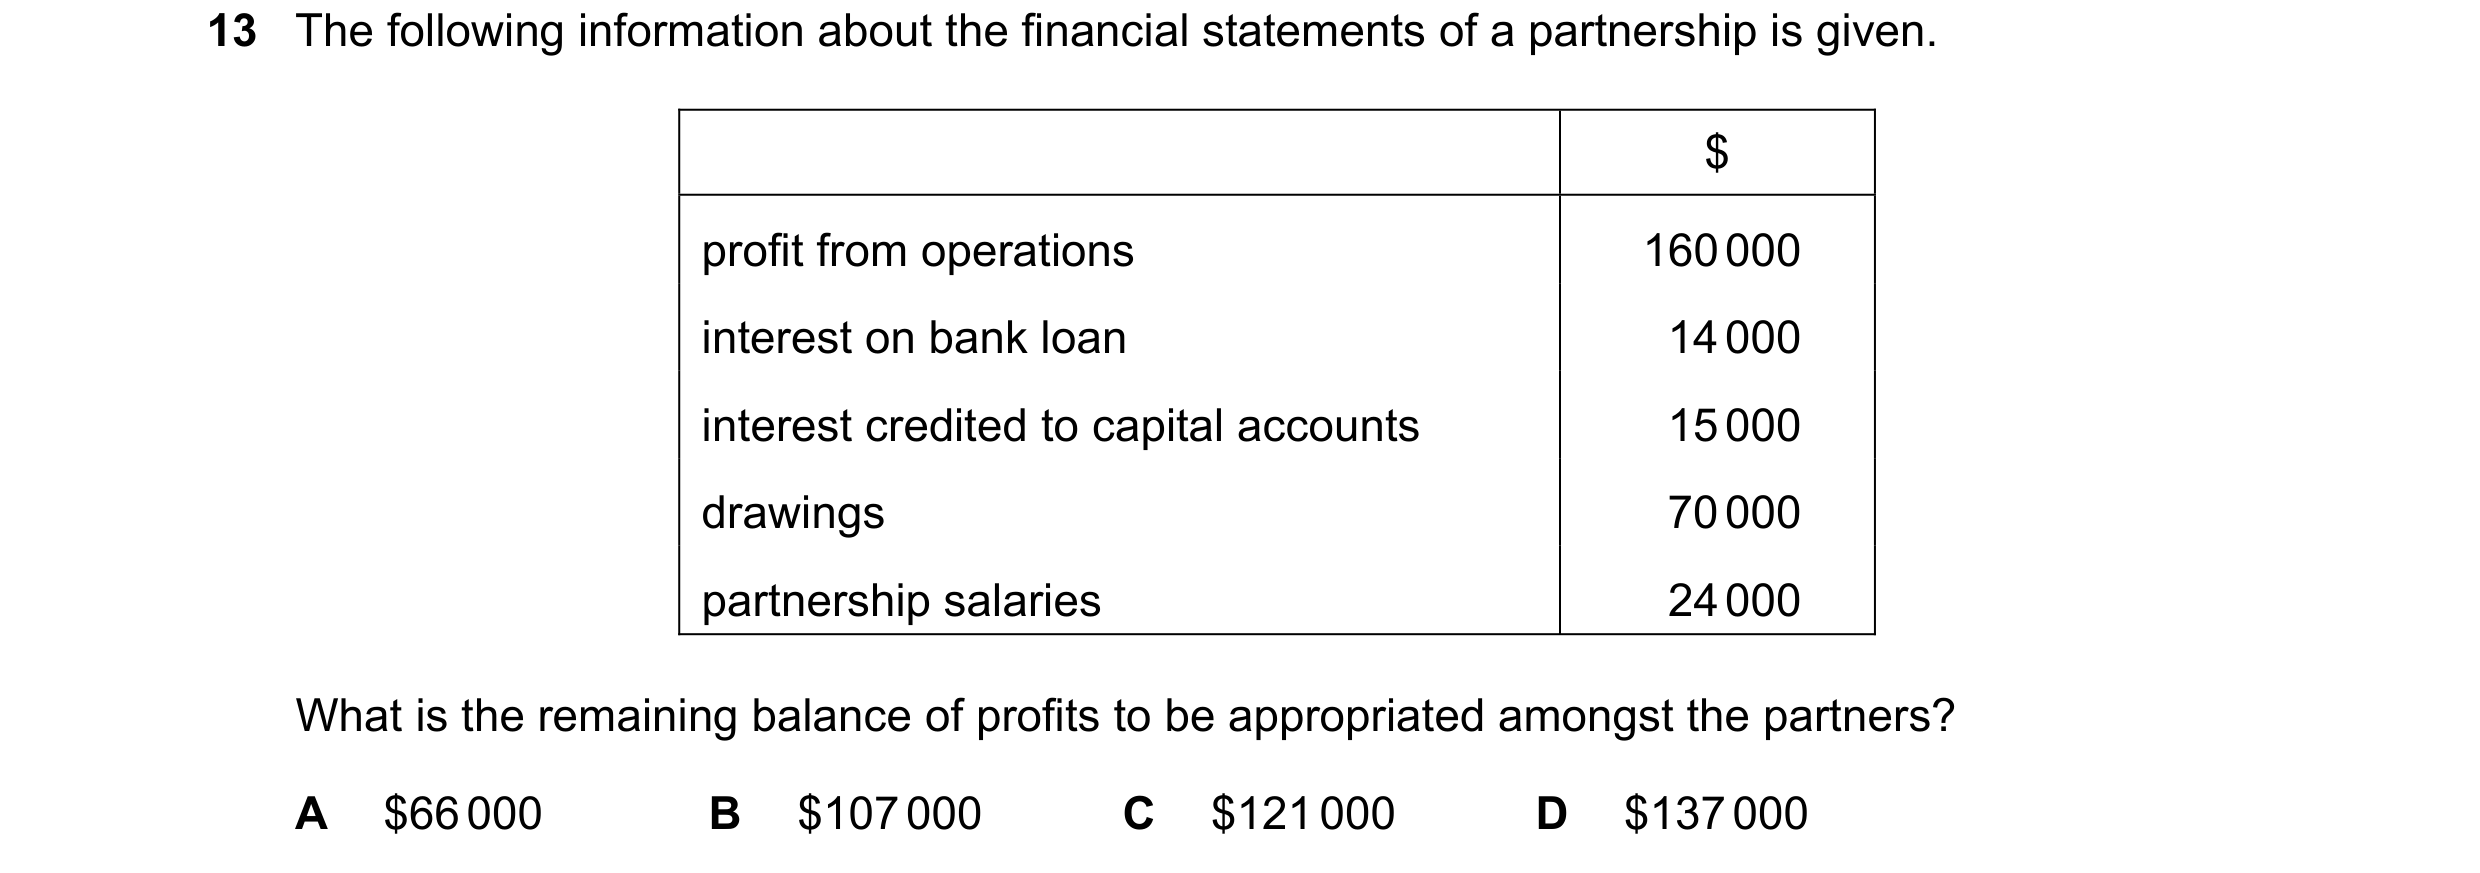
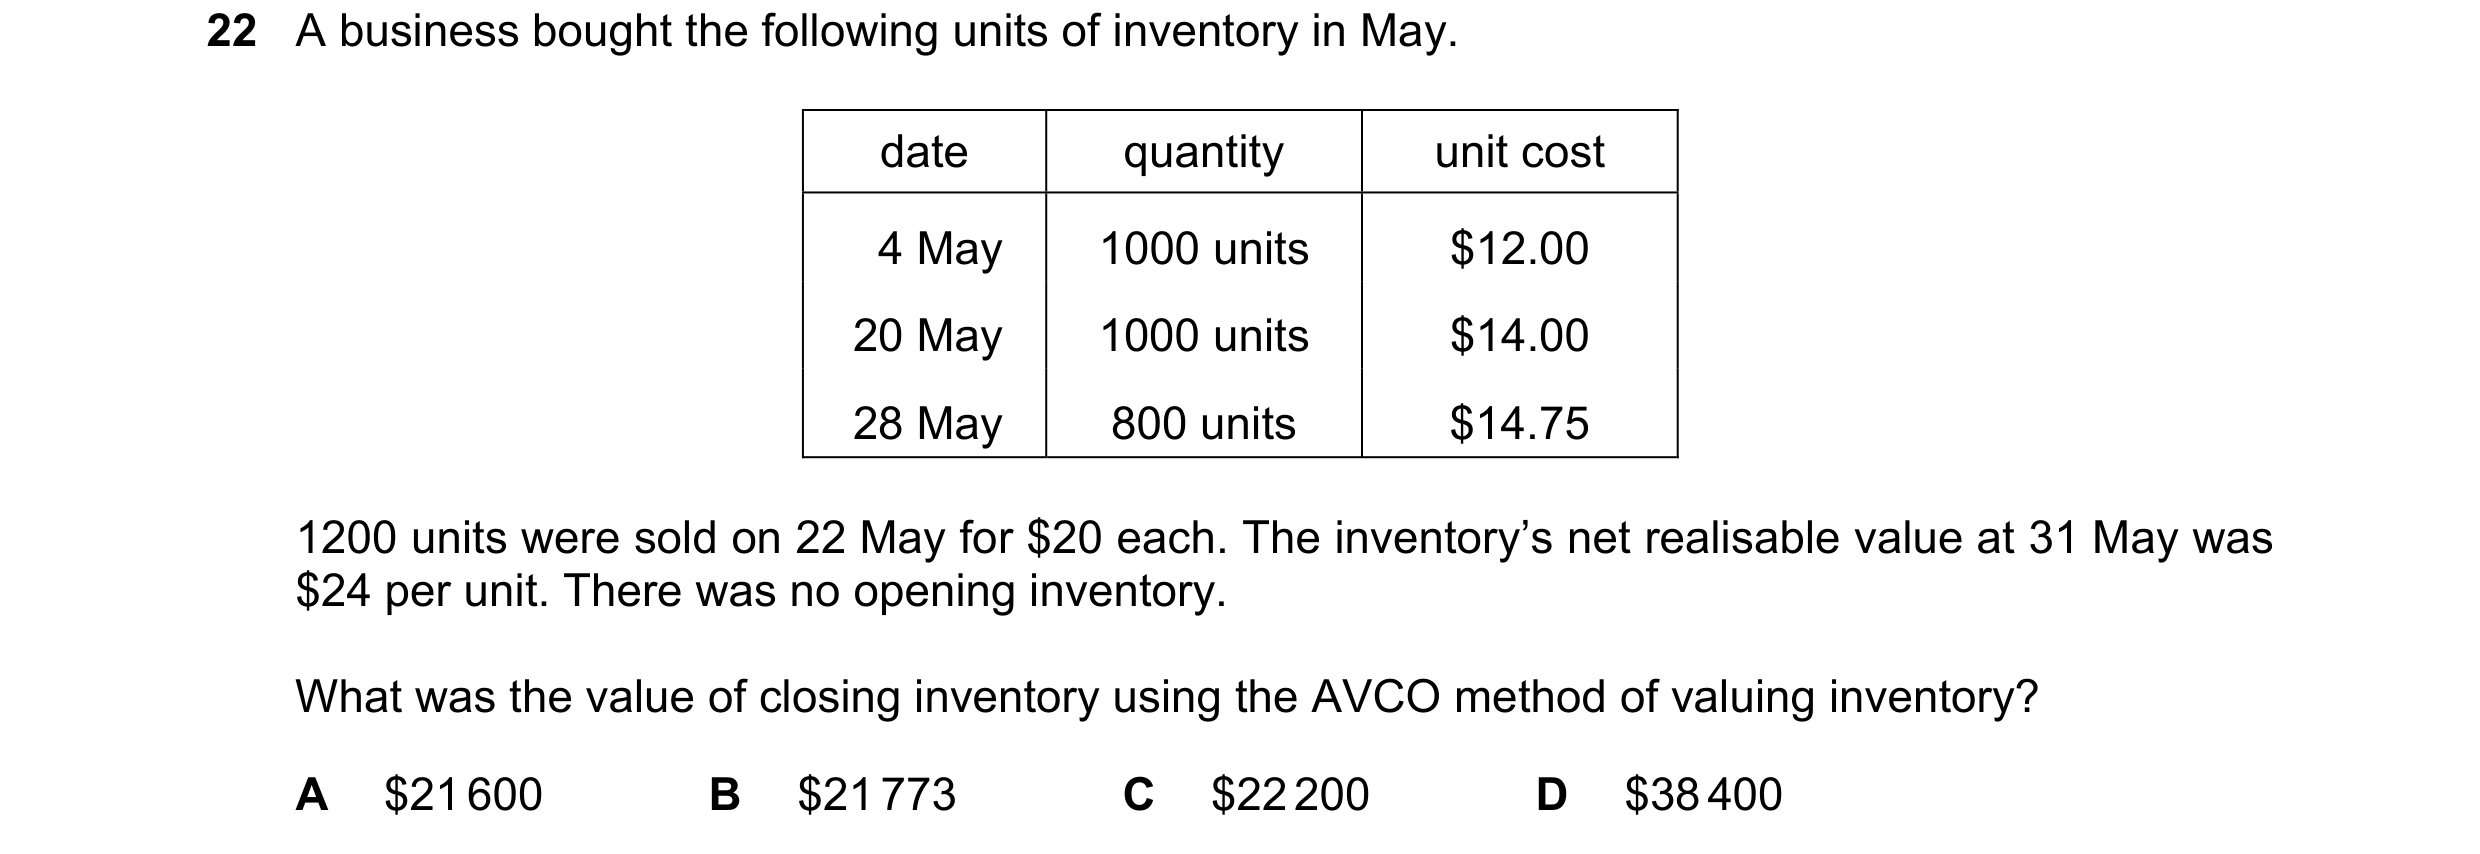
 163 / 233
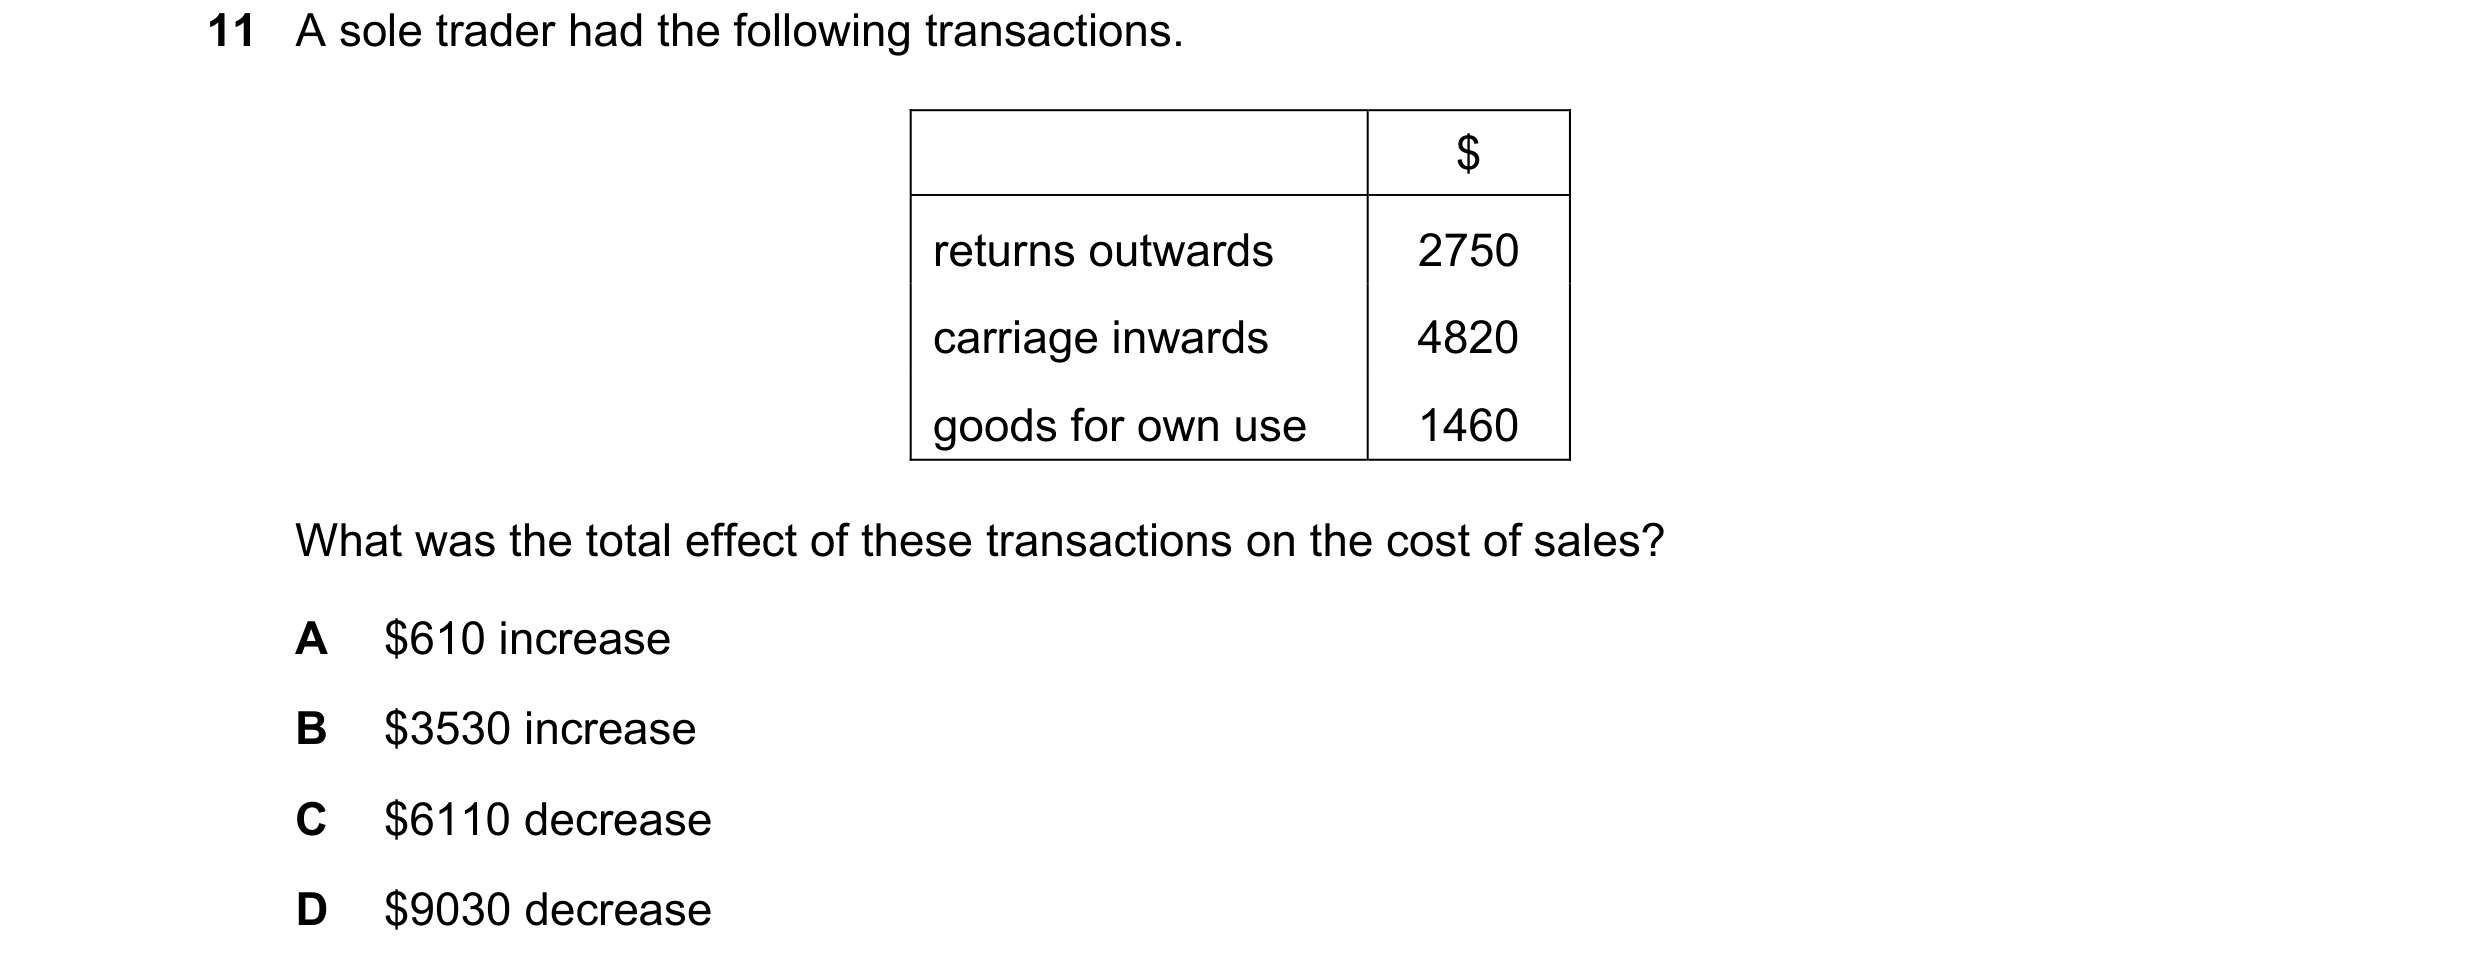 164 / 233
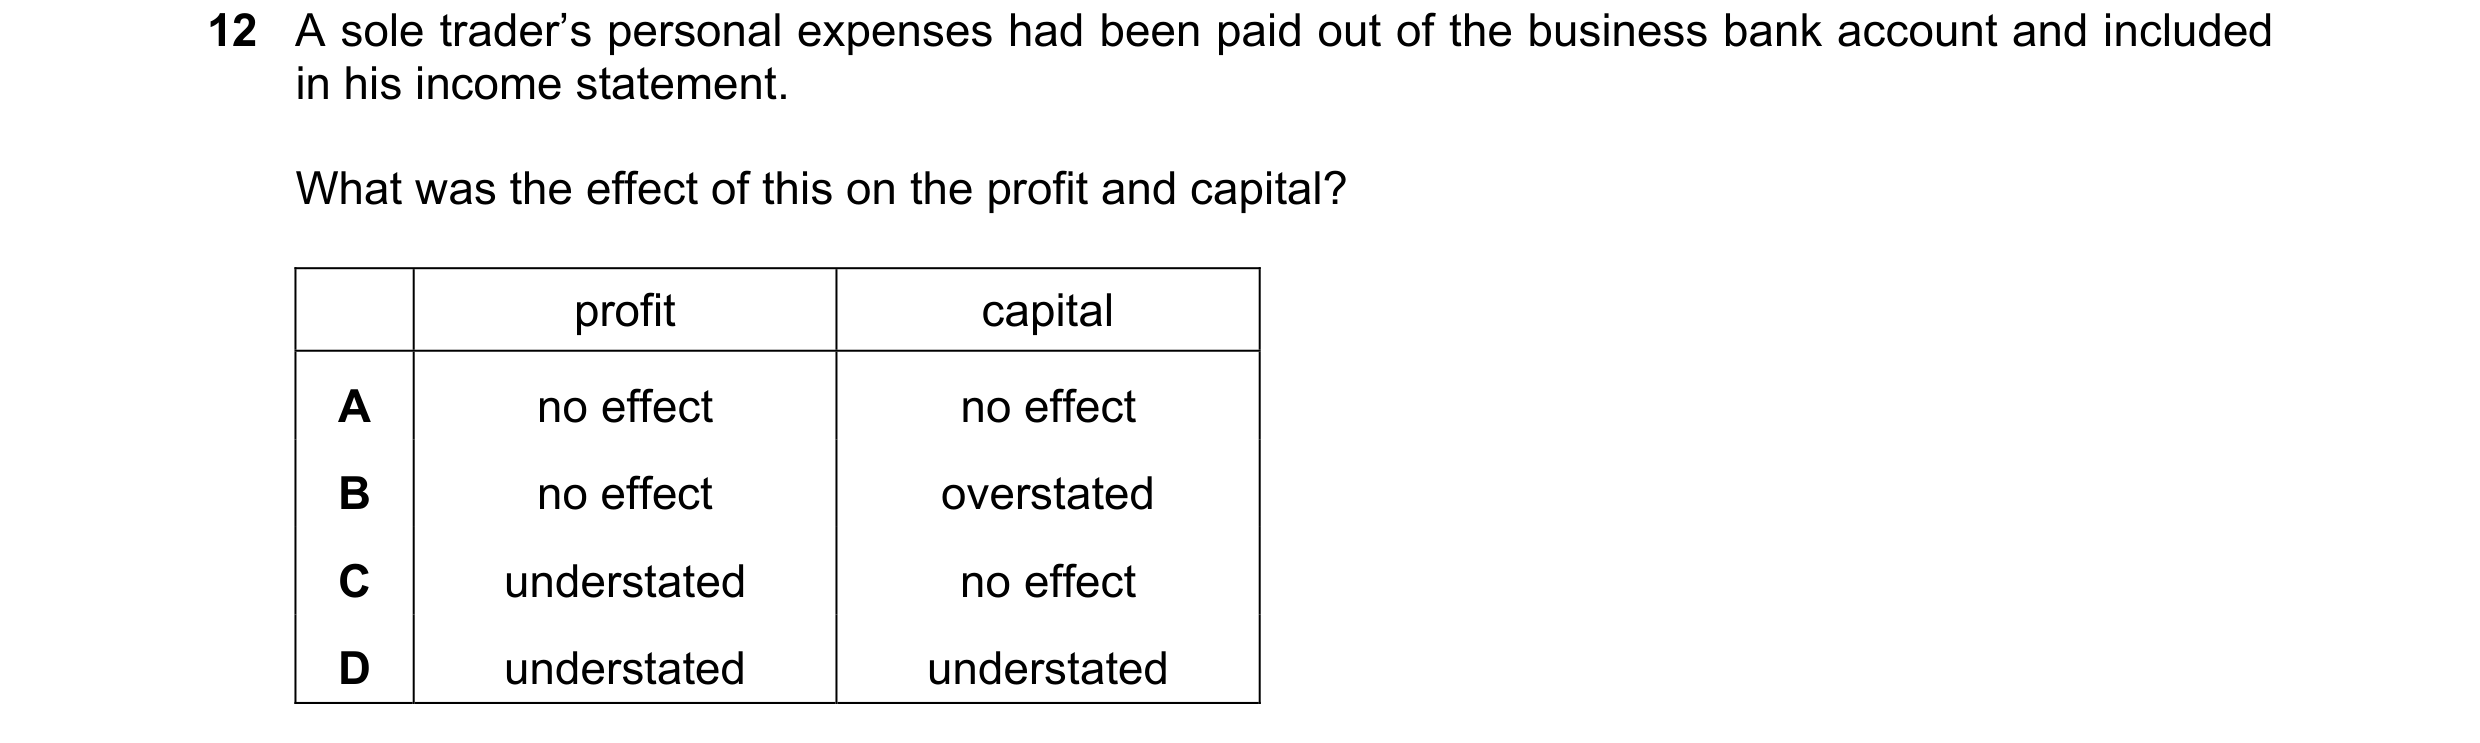
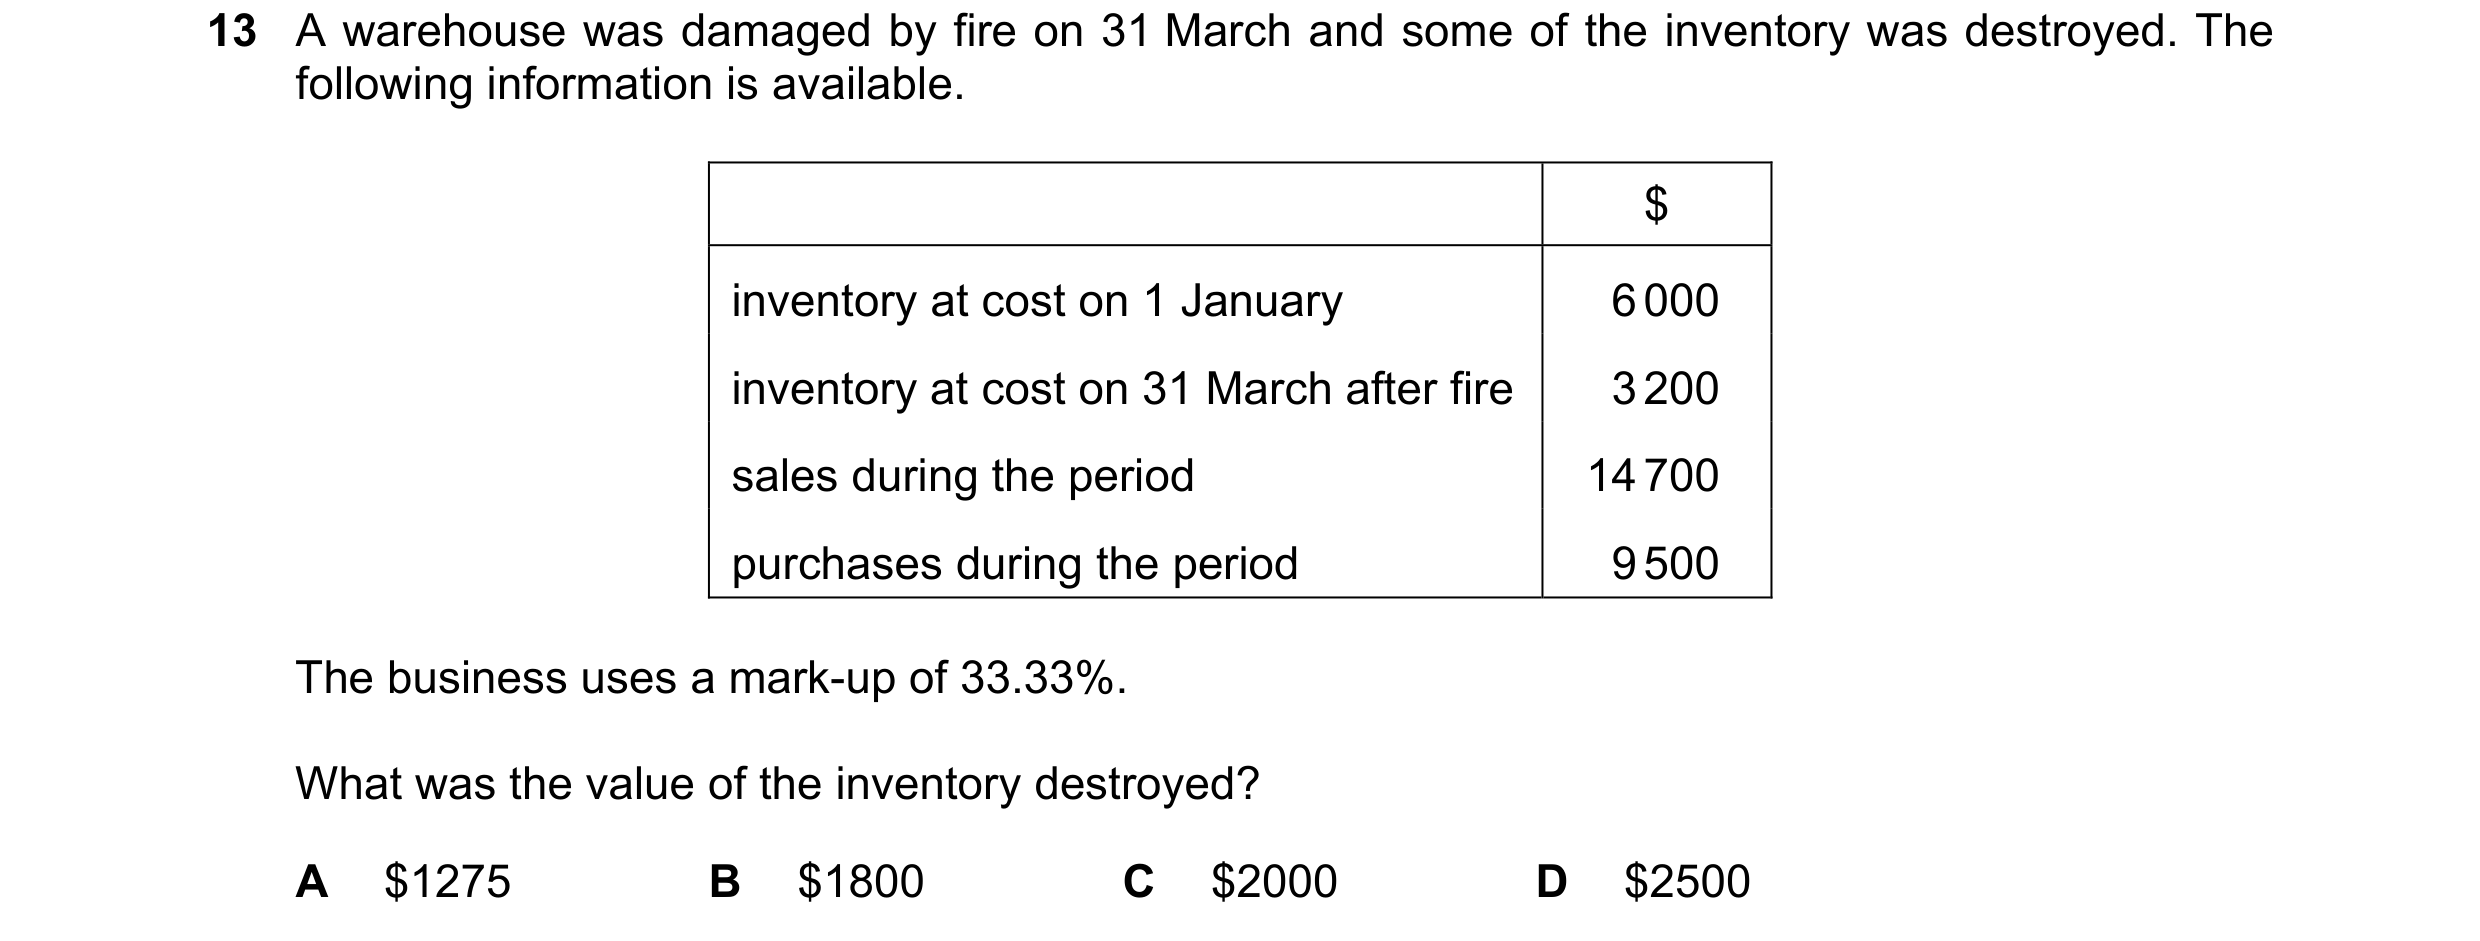
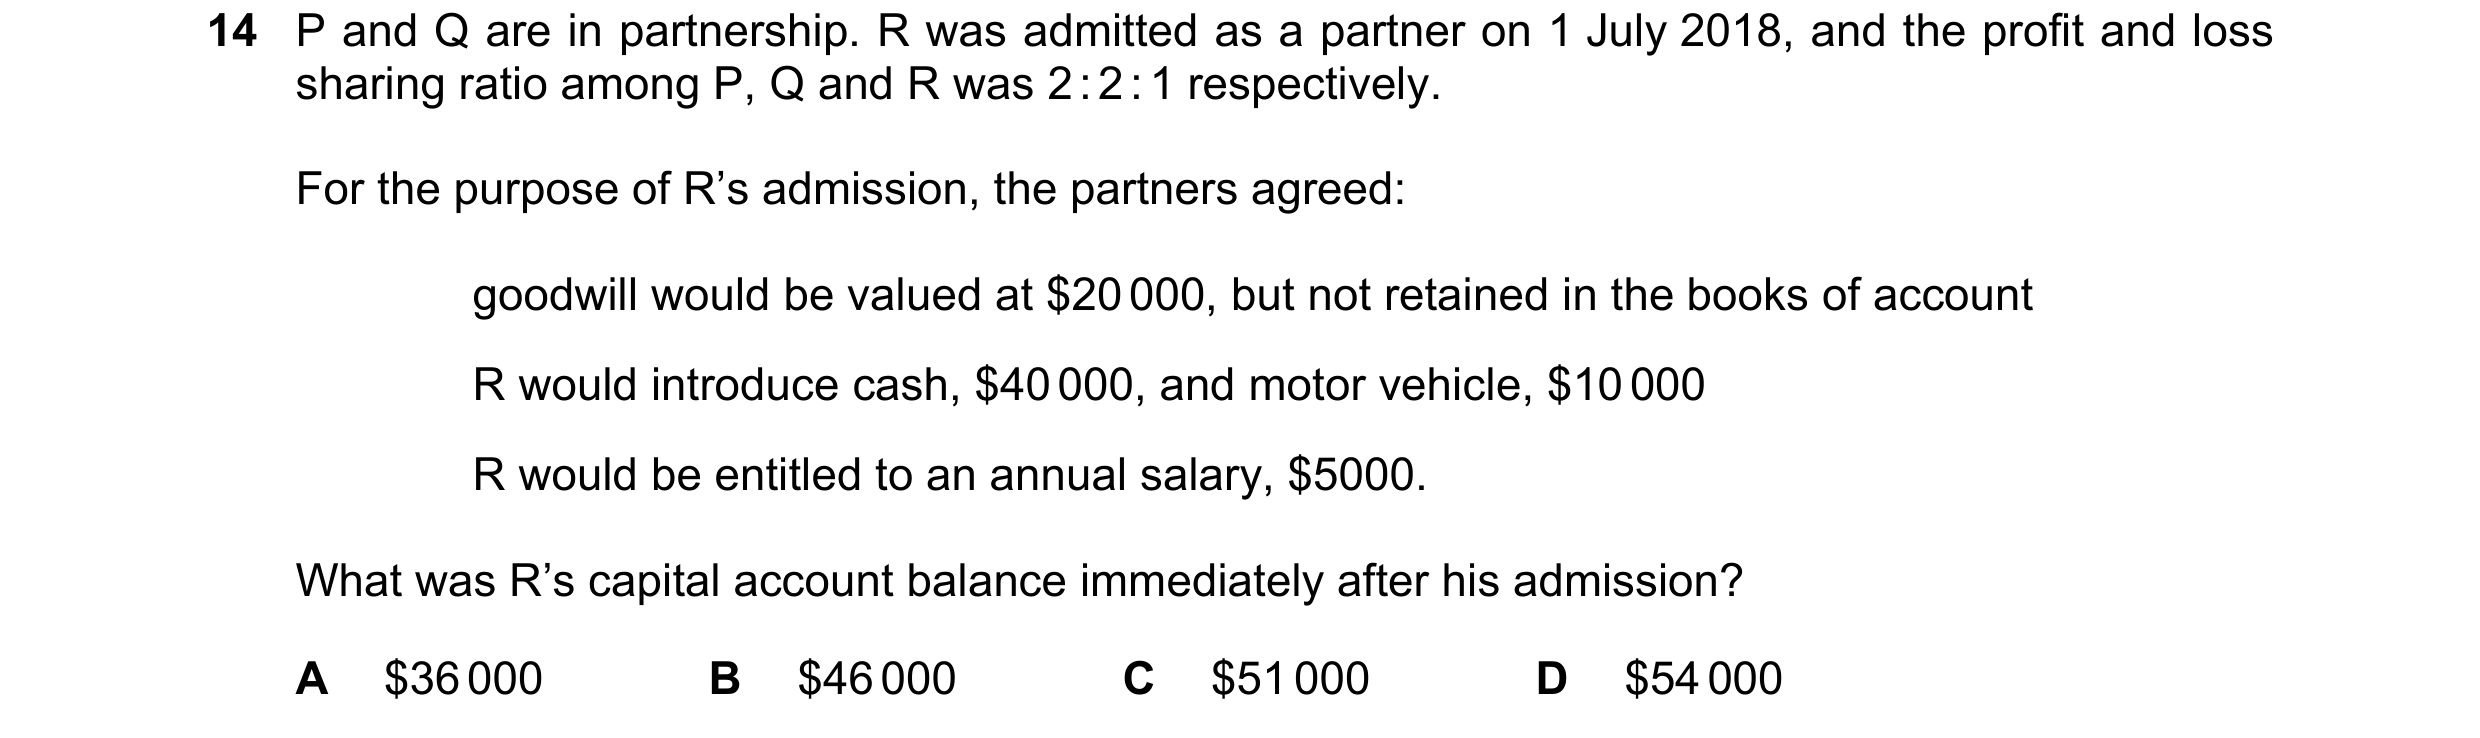
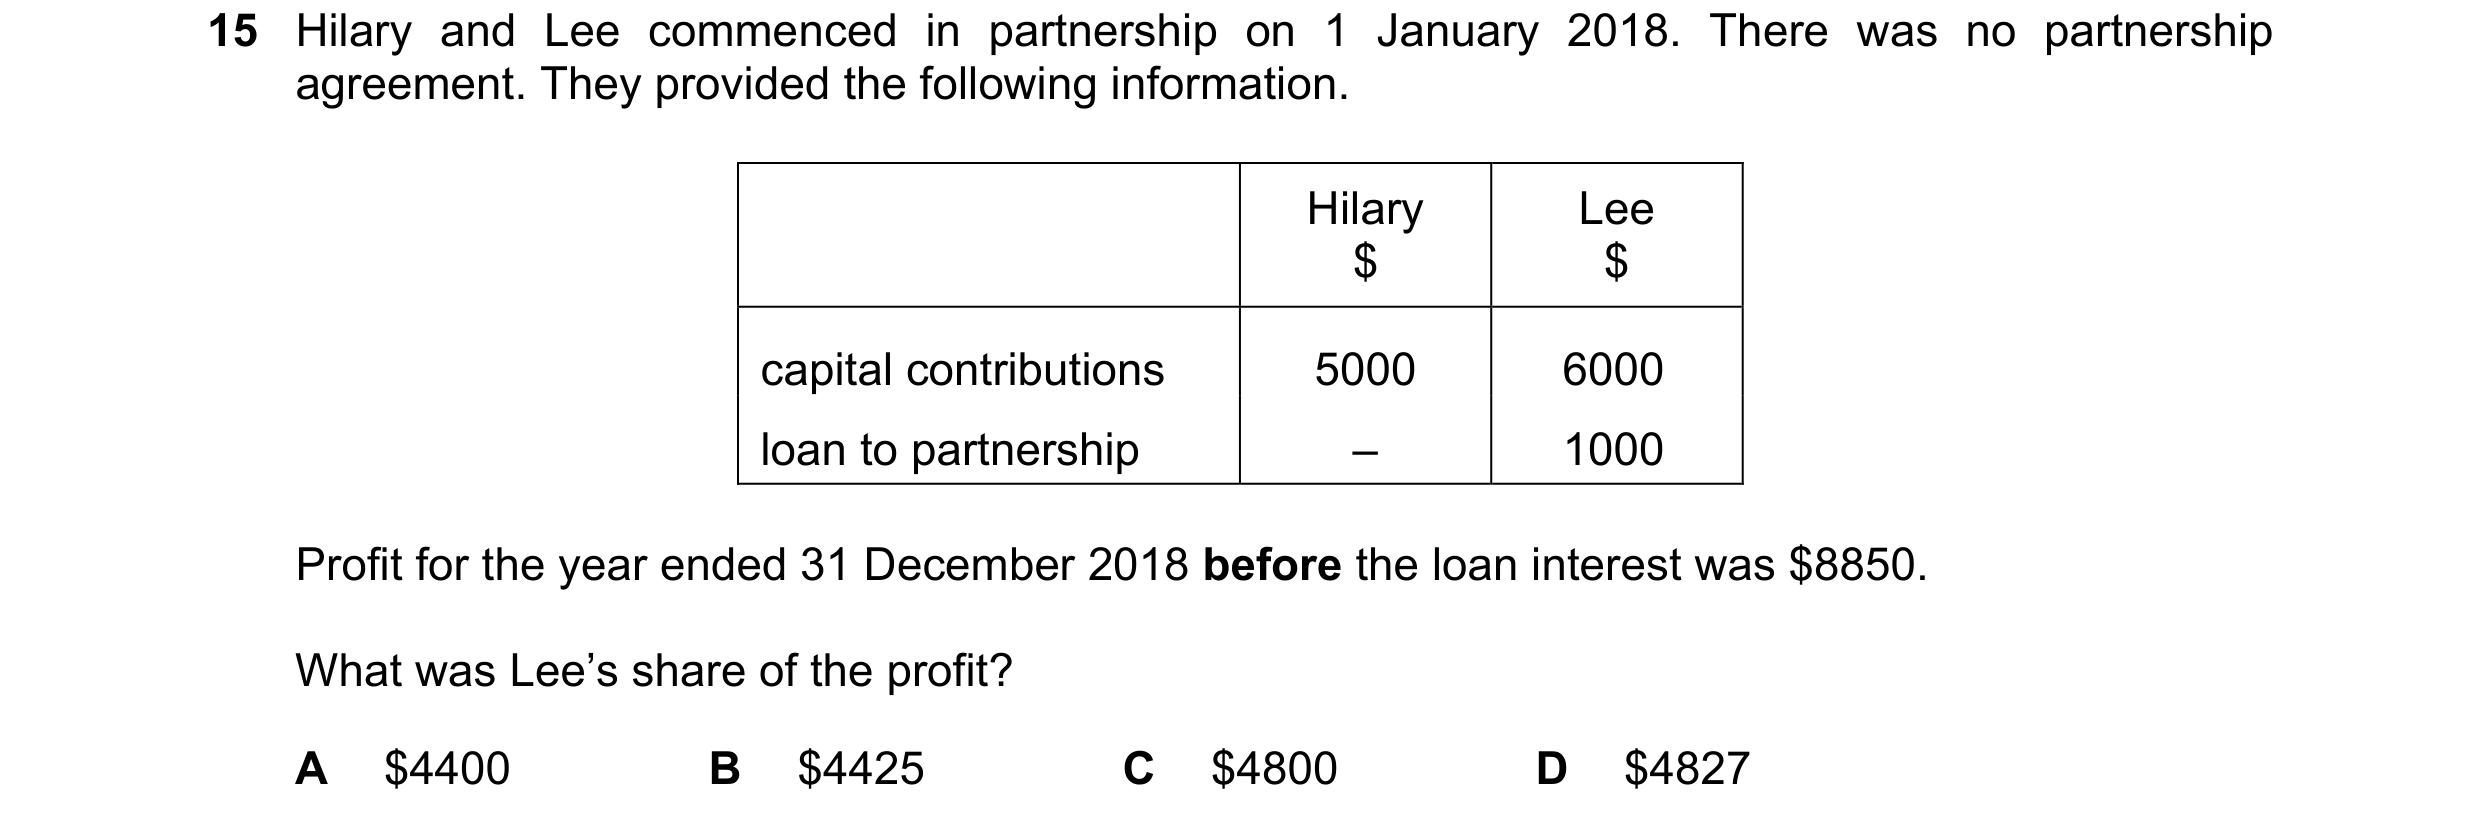 165 / 233
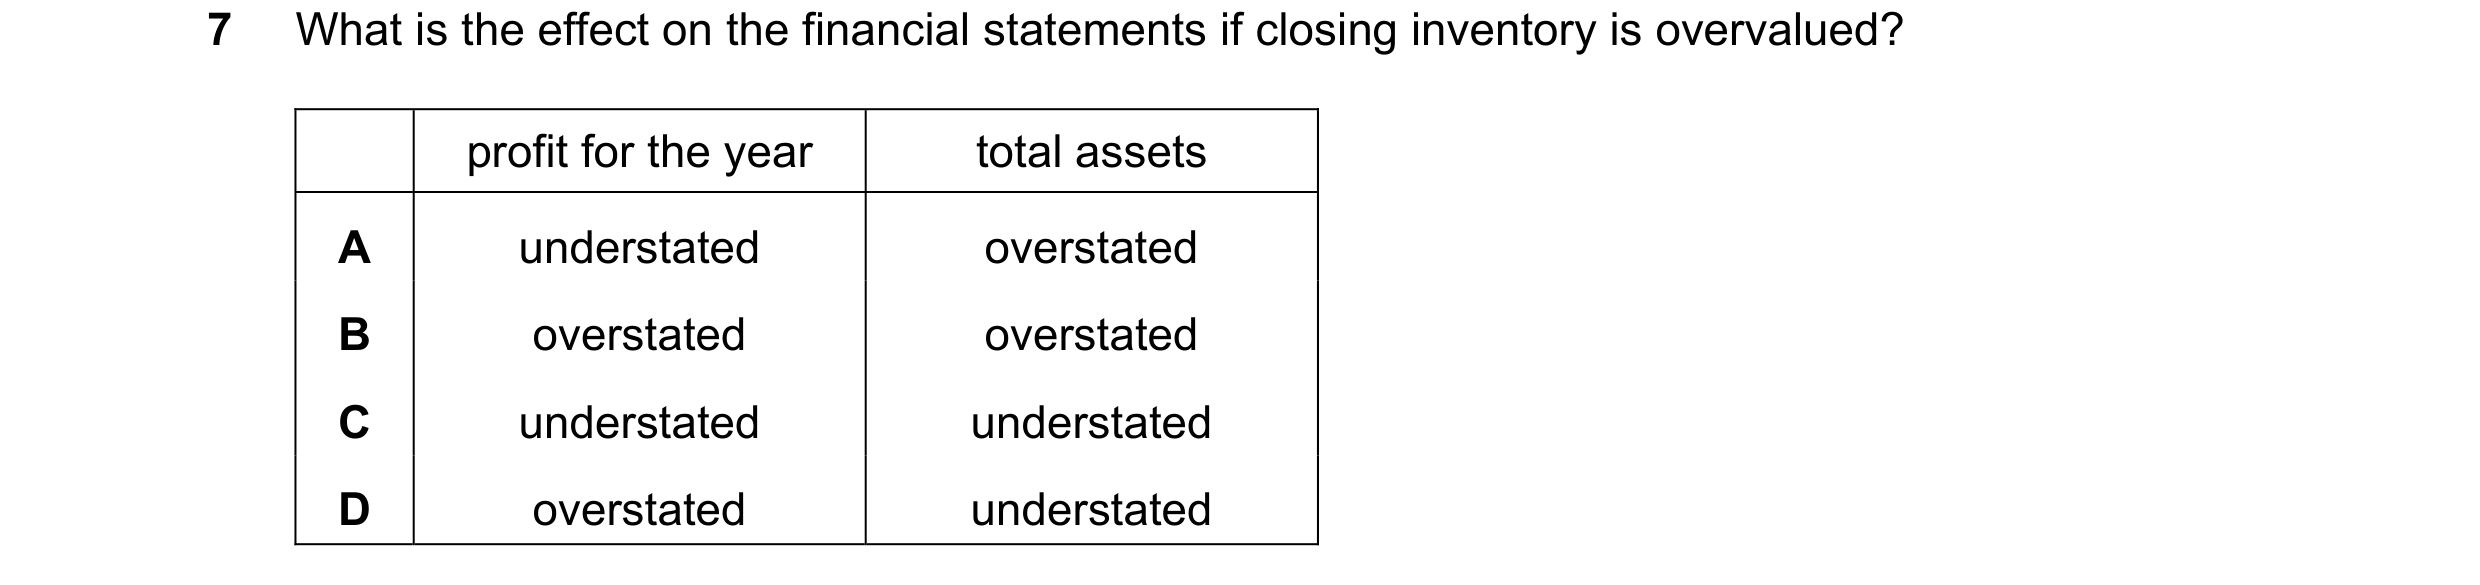
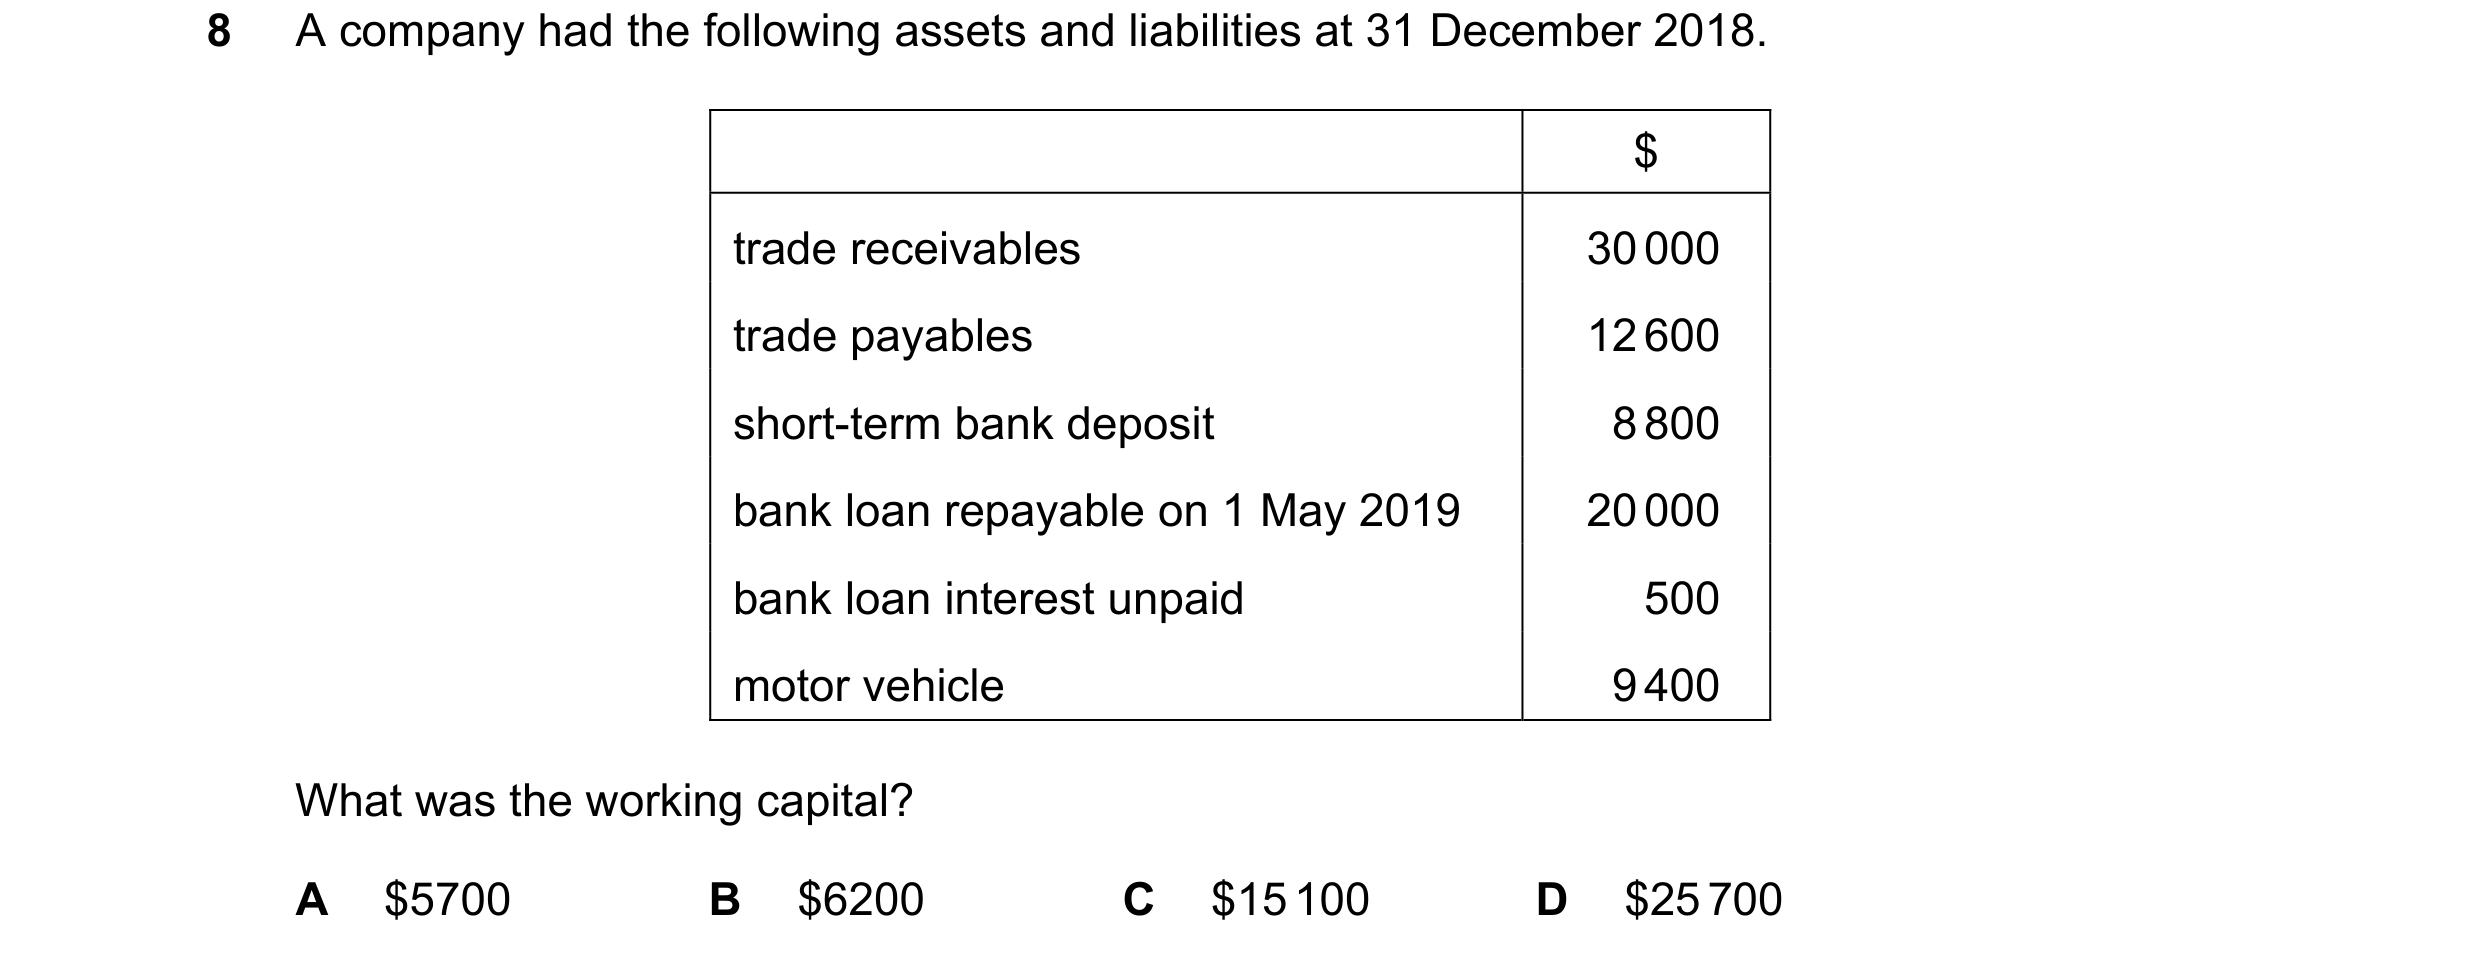
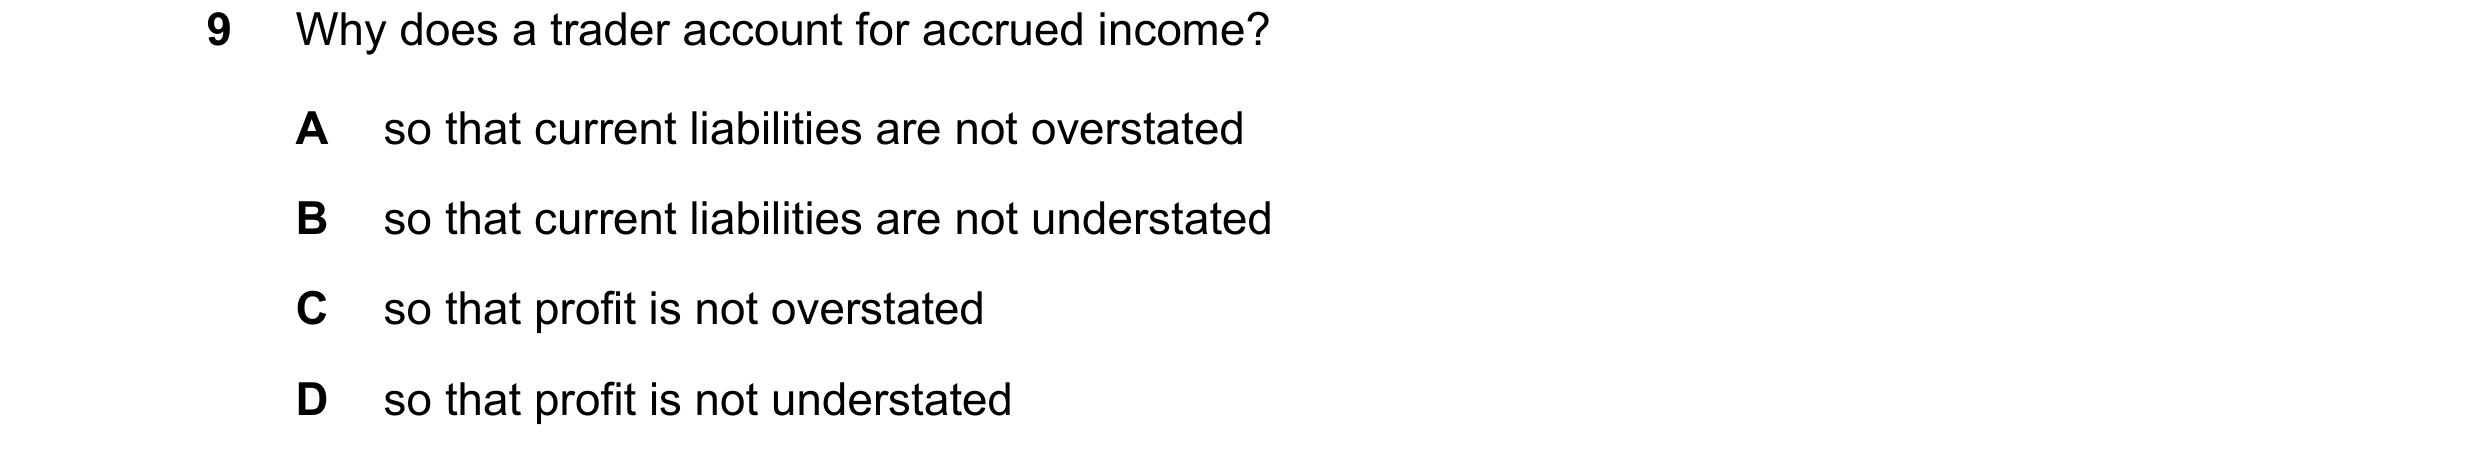 166 / 233
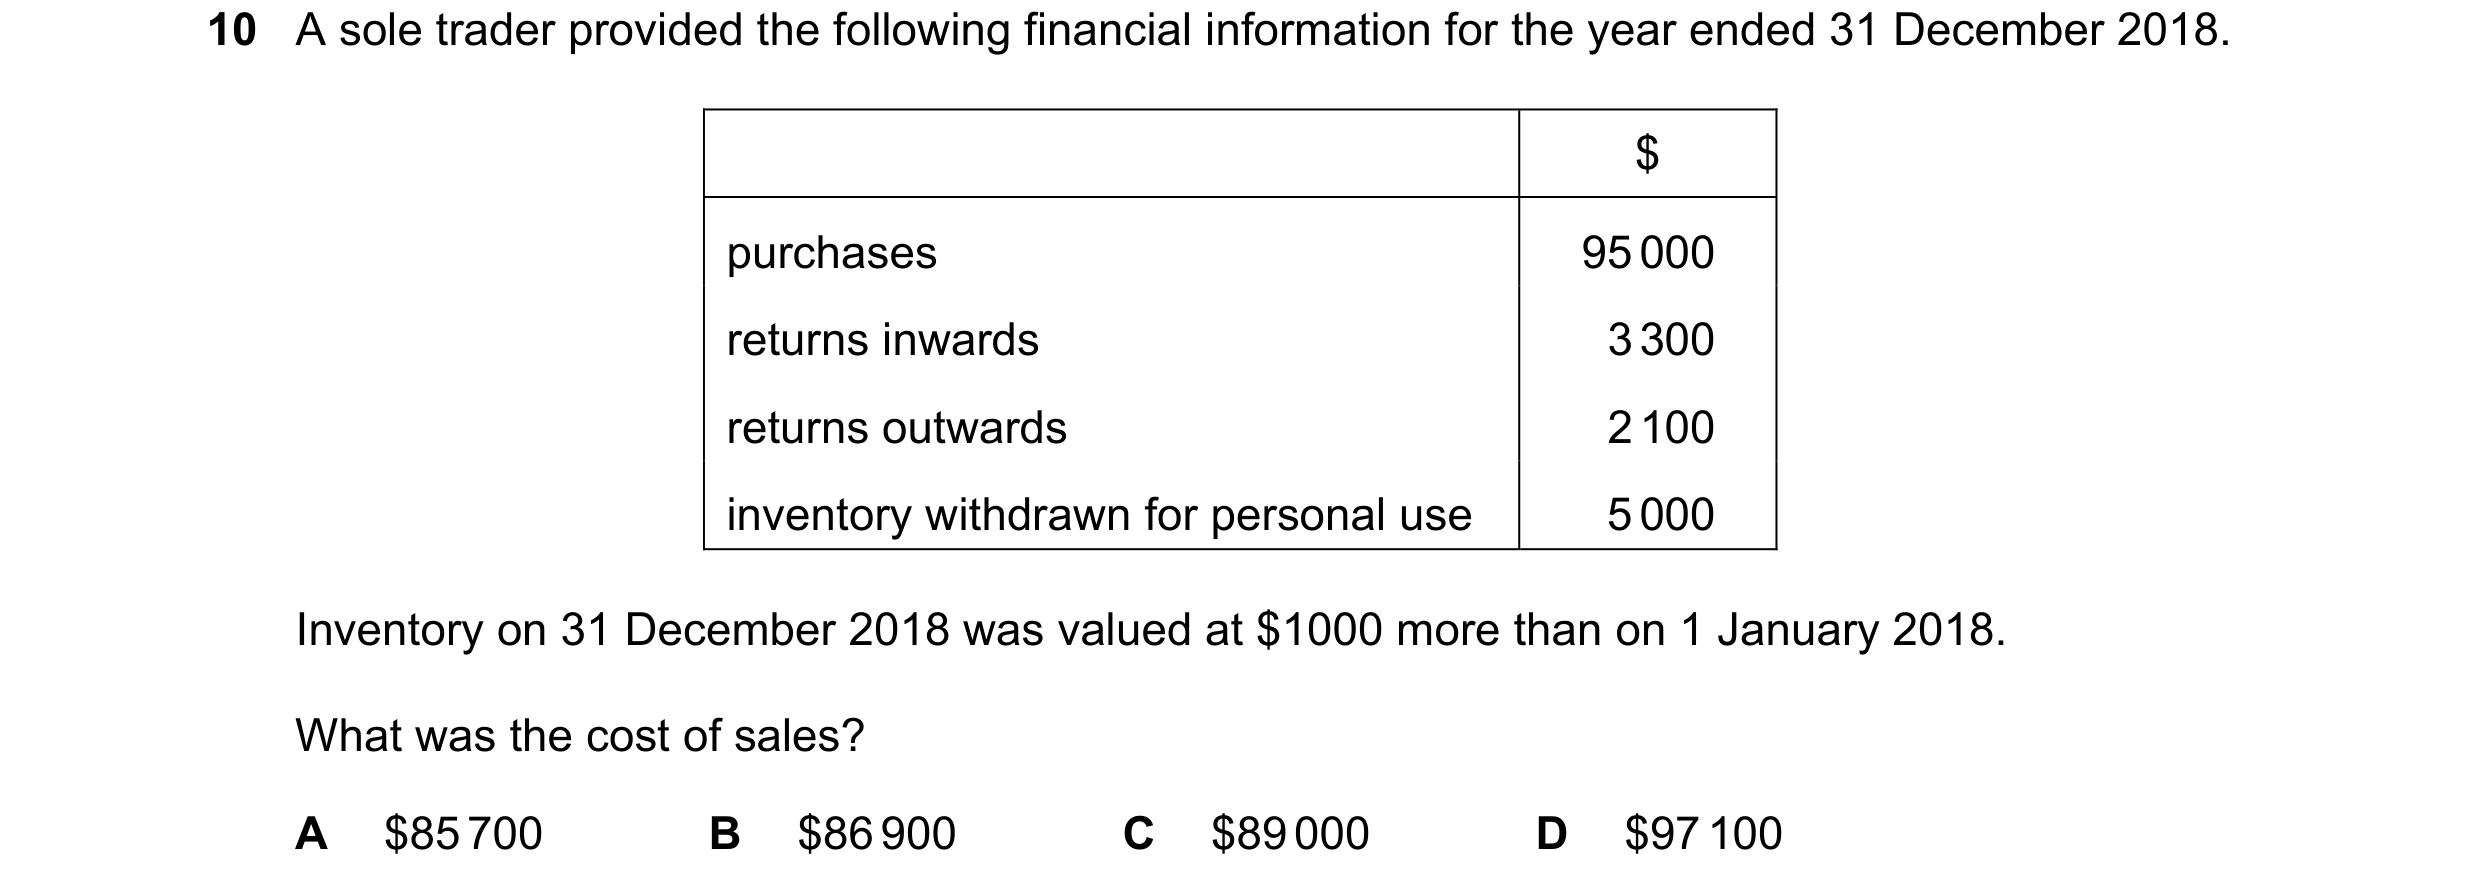
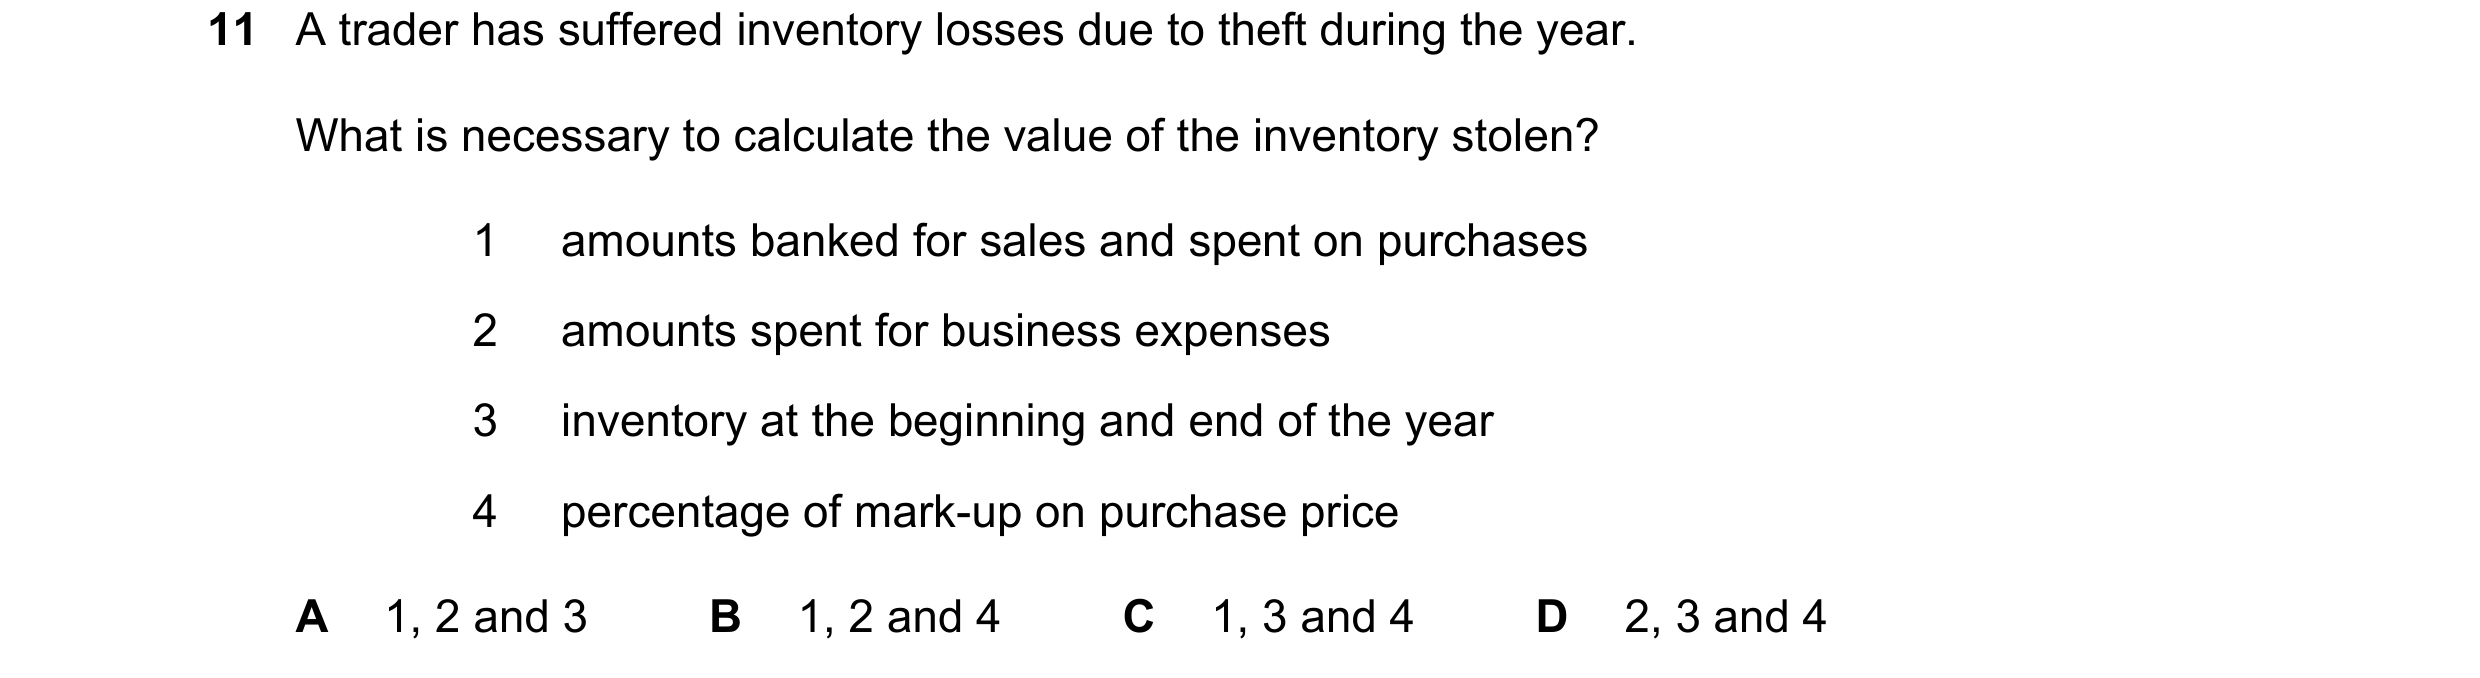
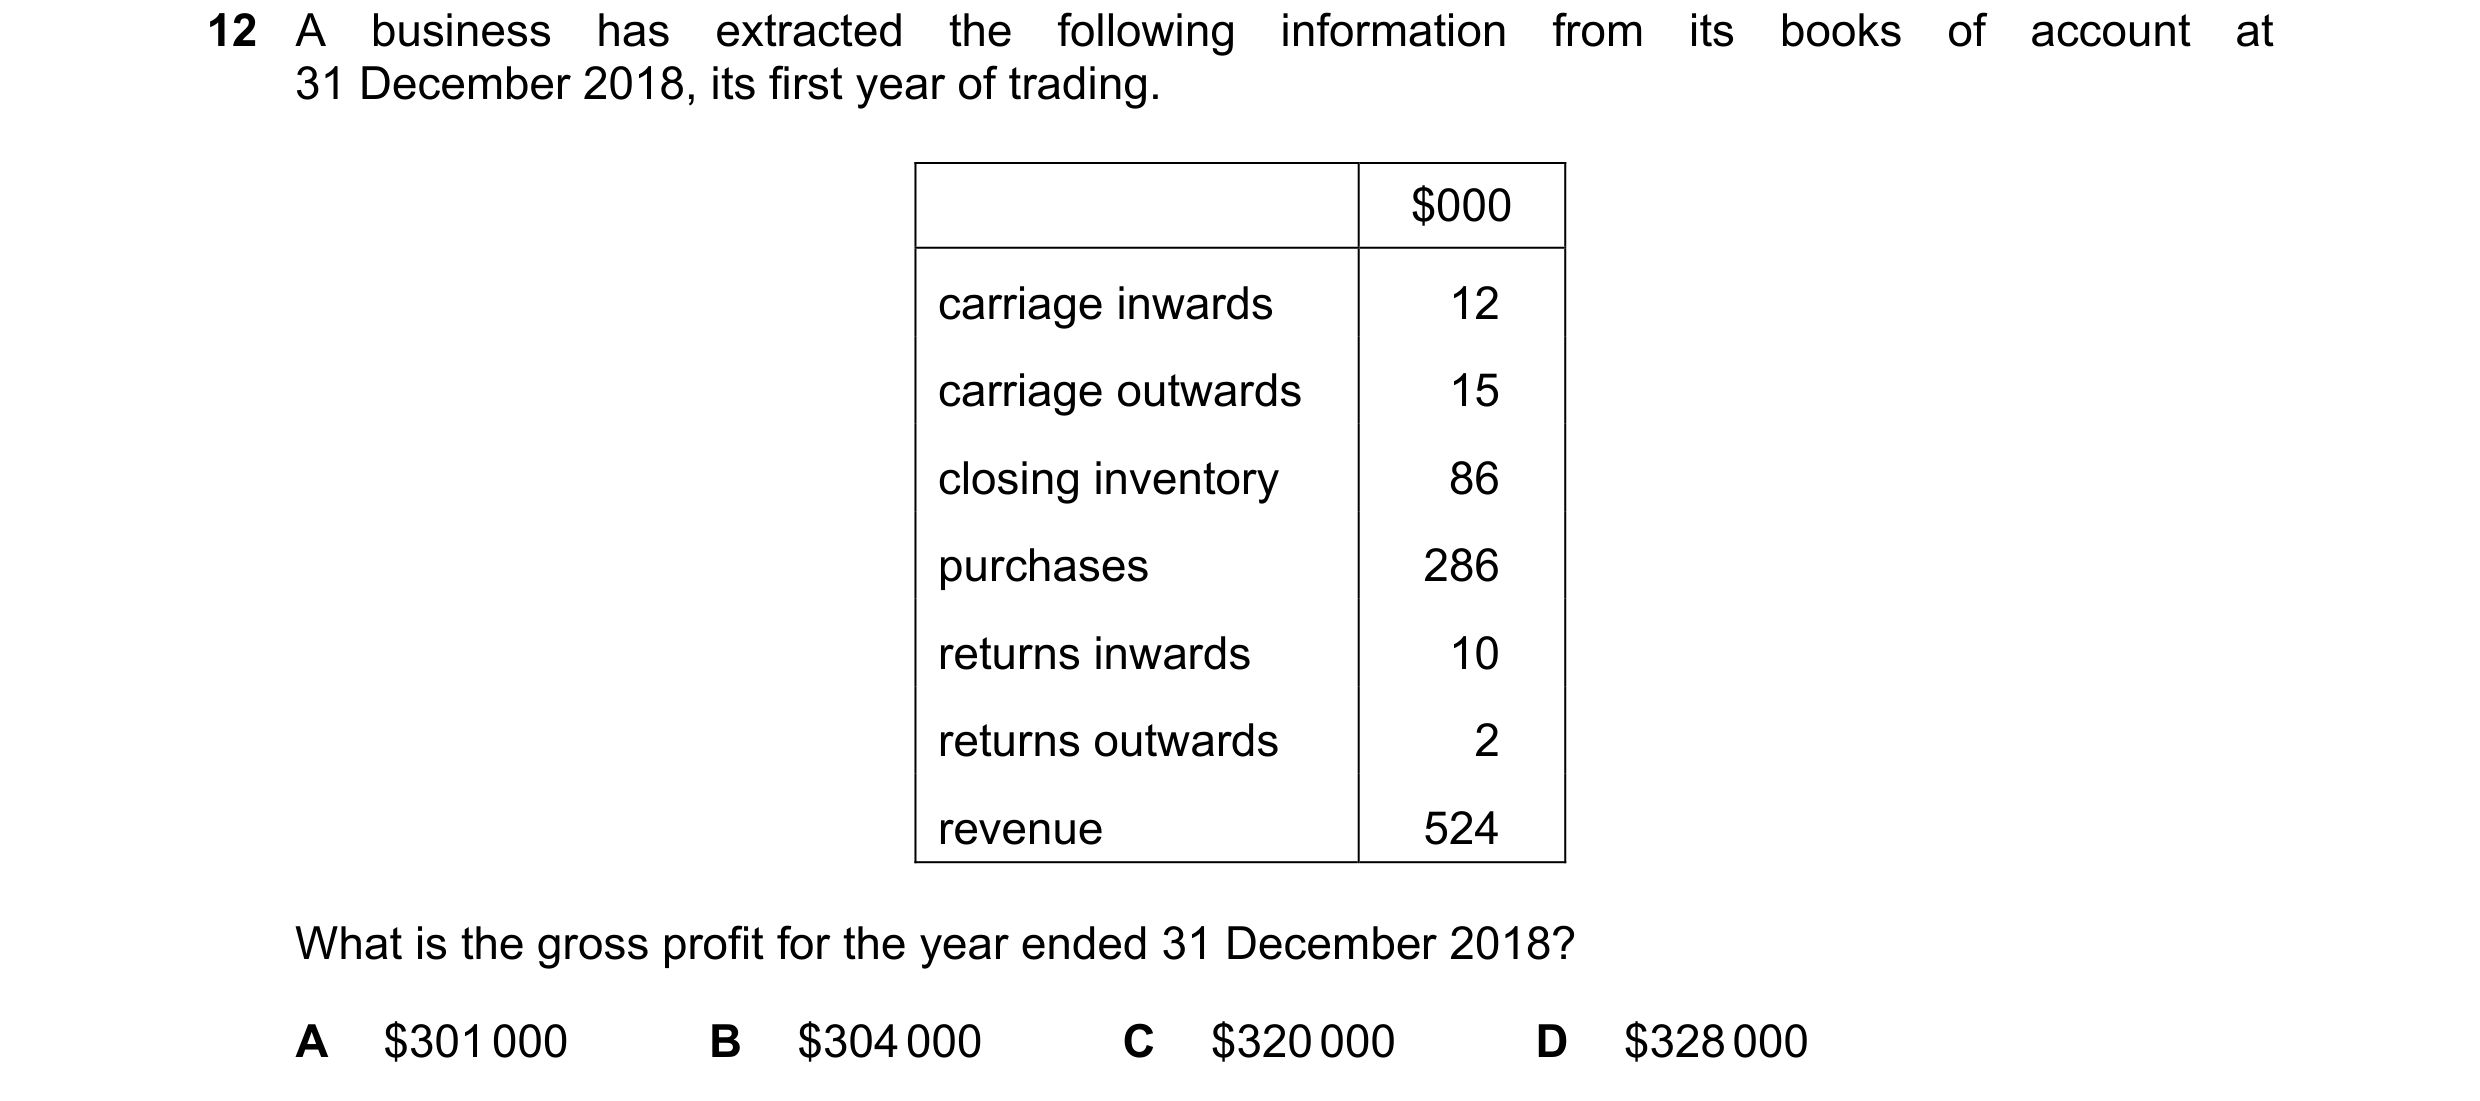 167 / 233
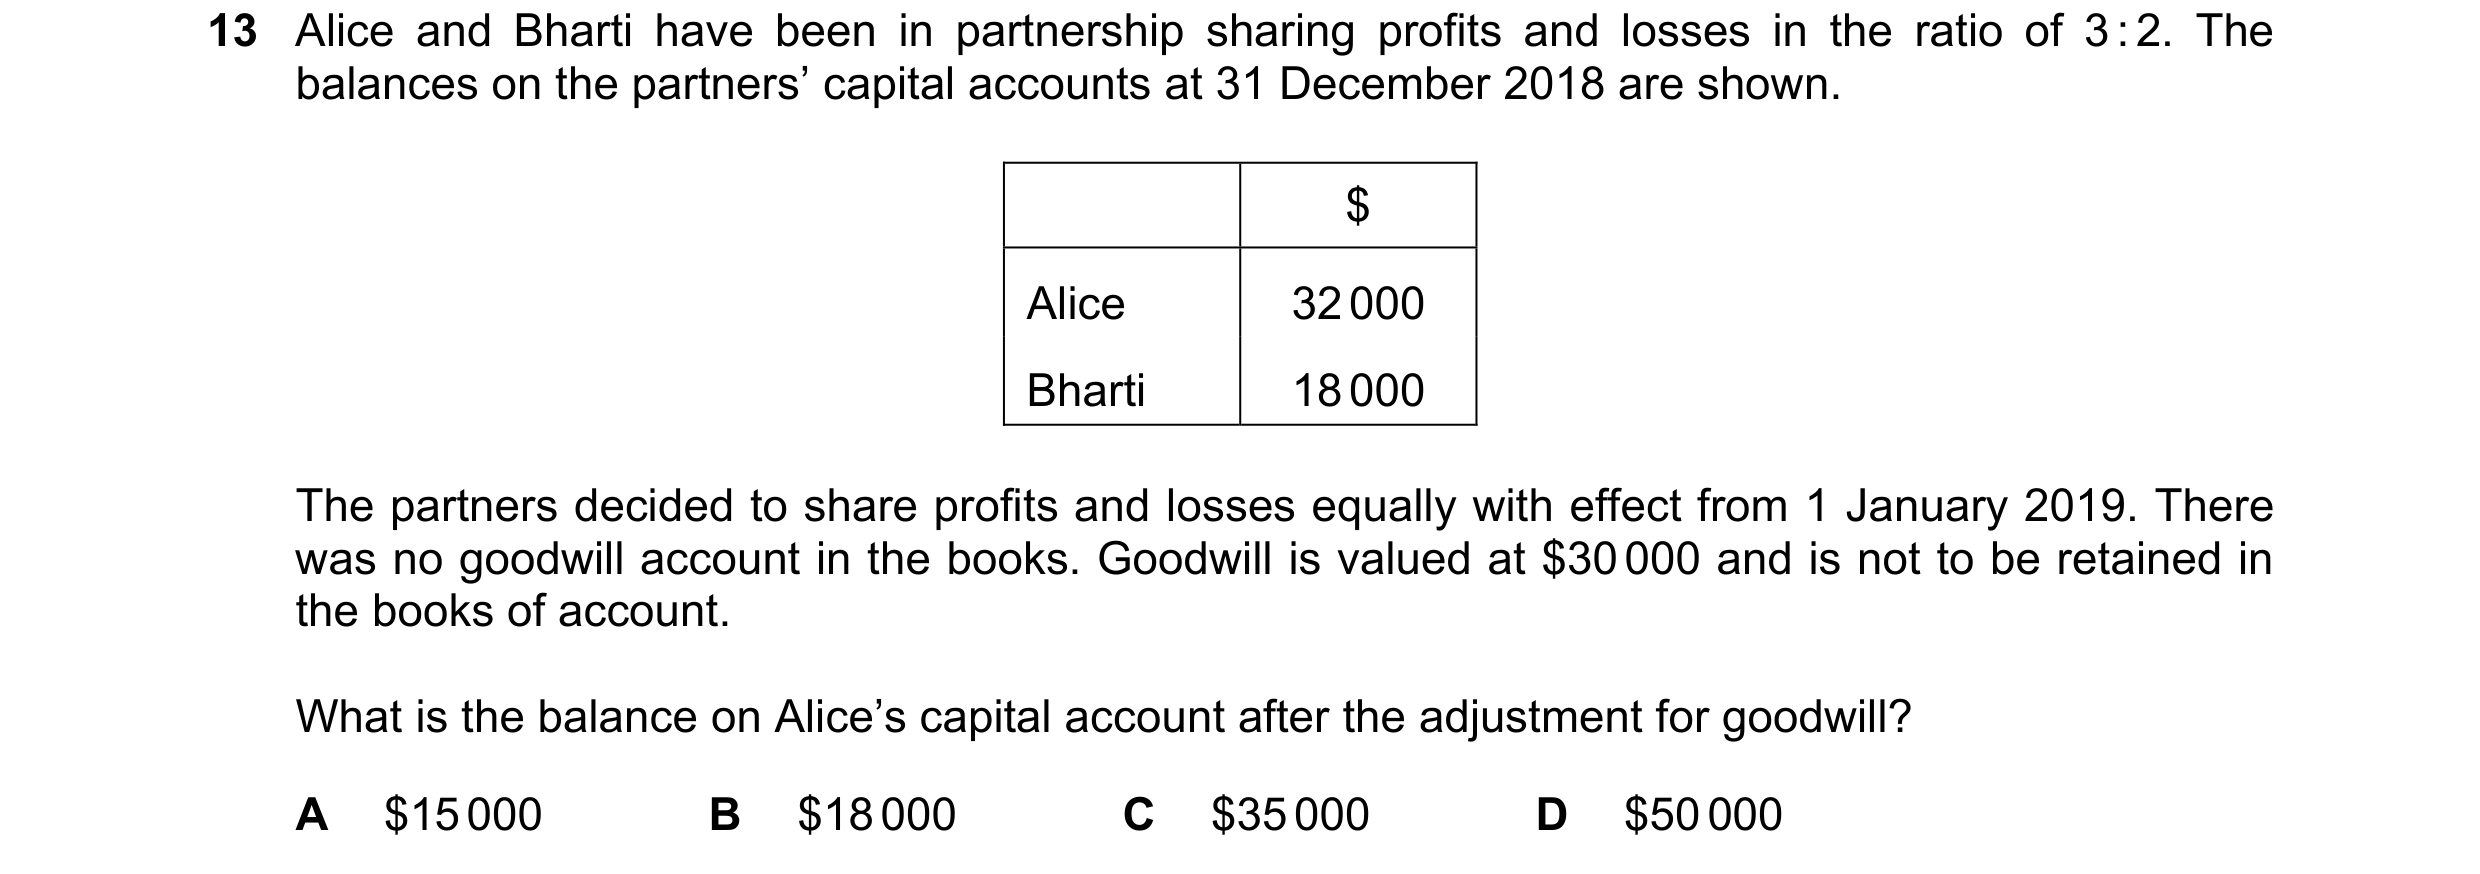
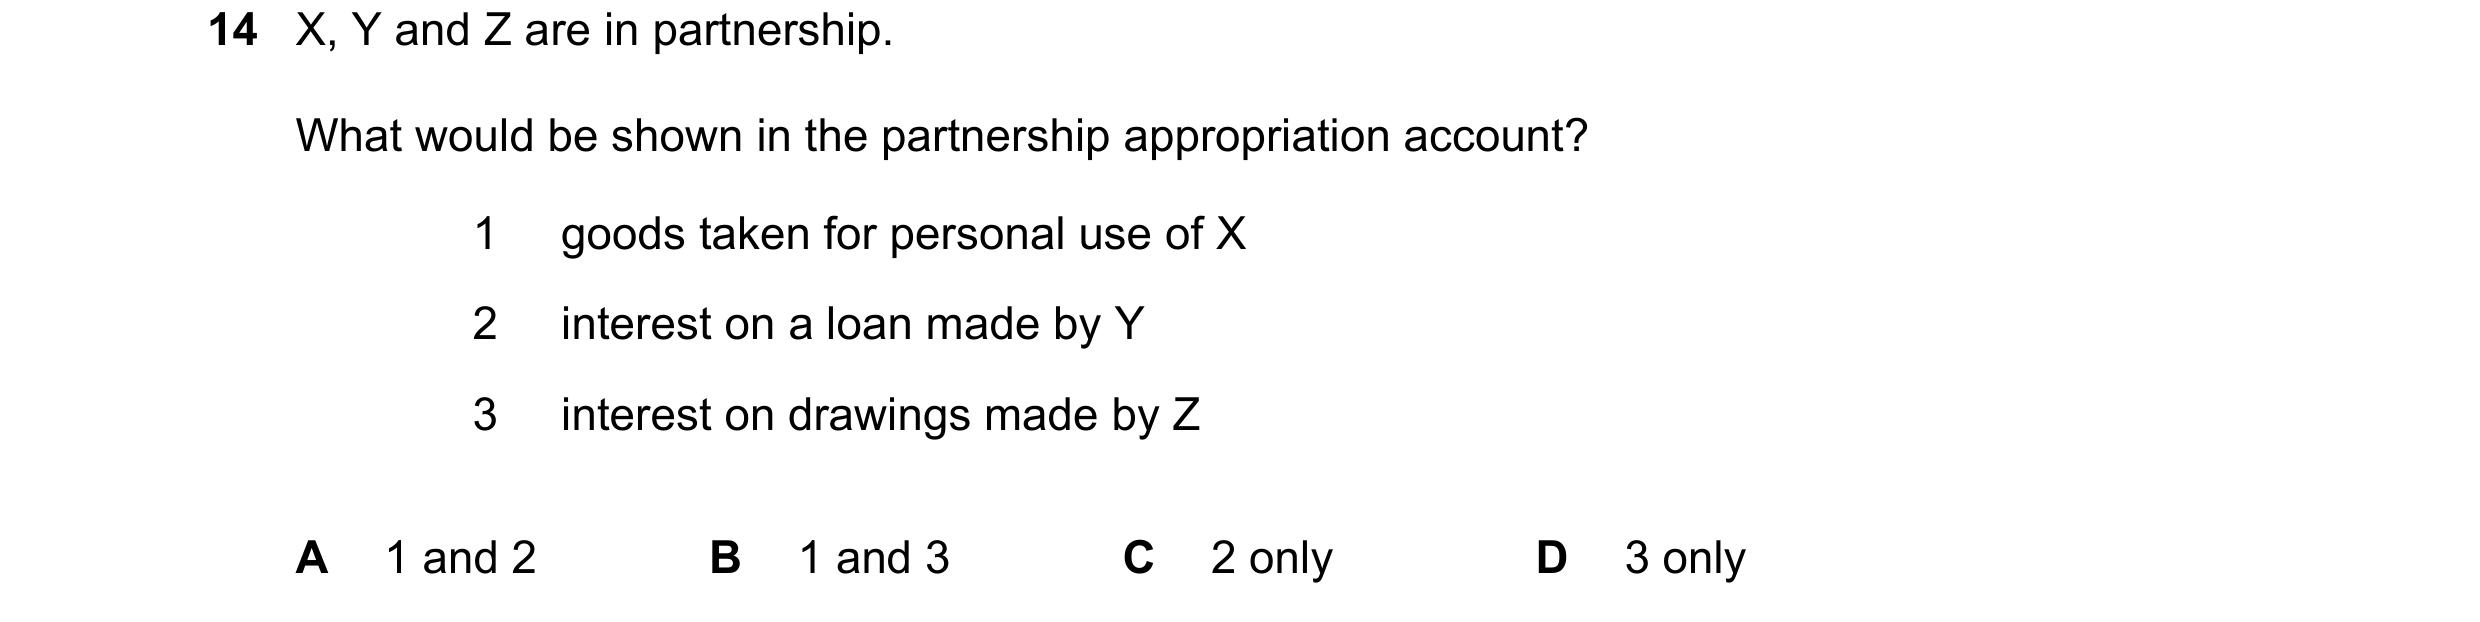
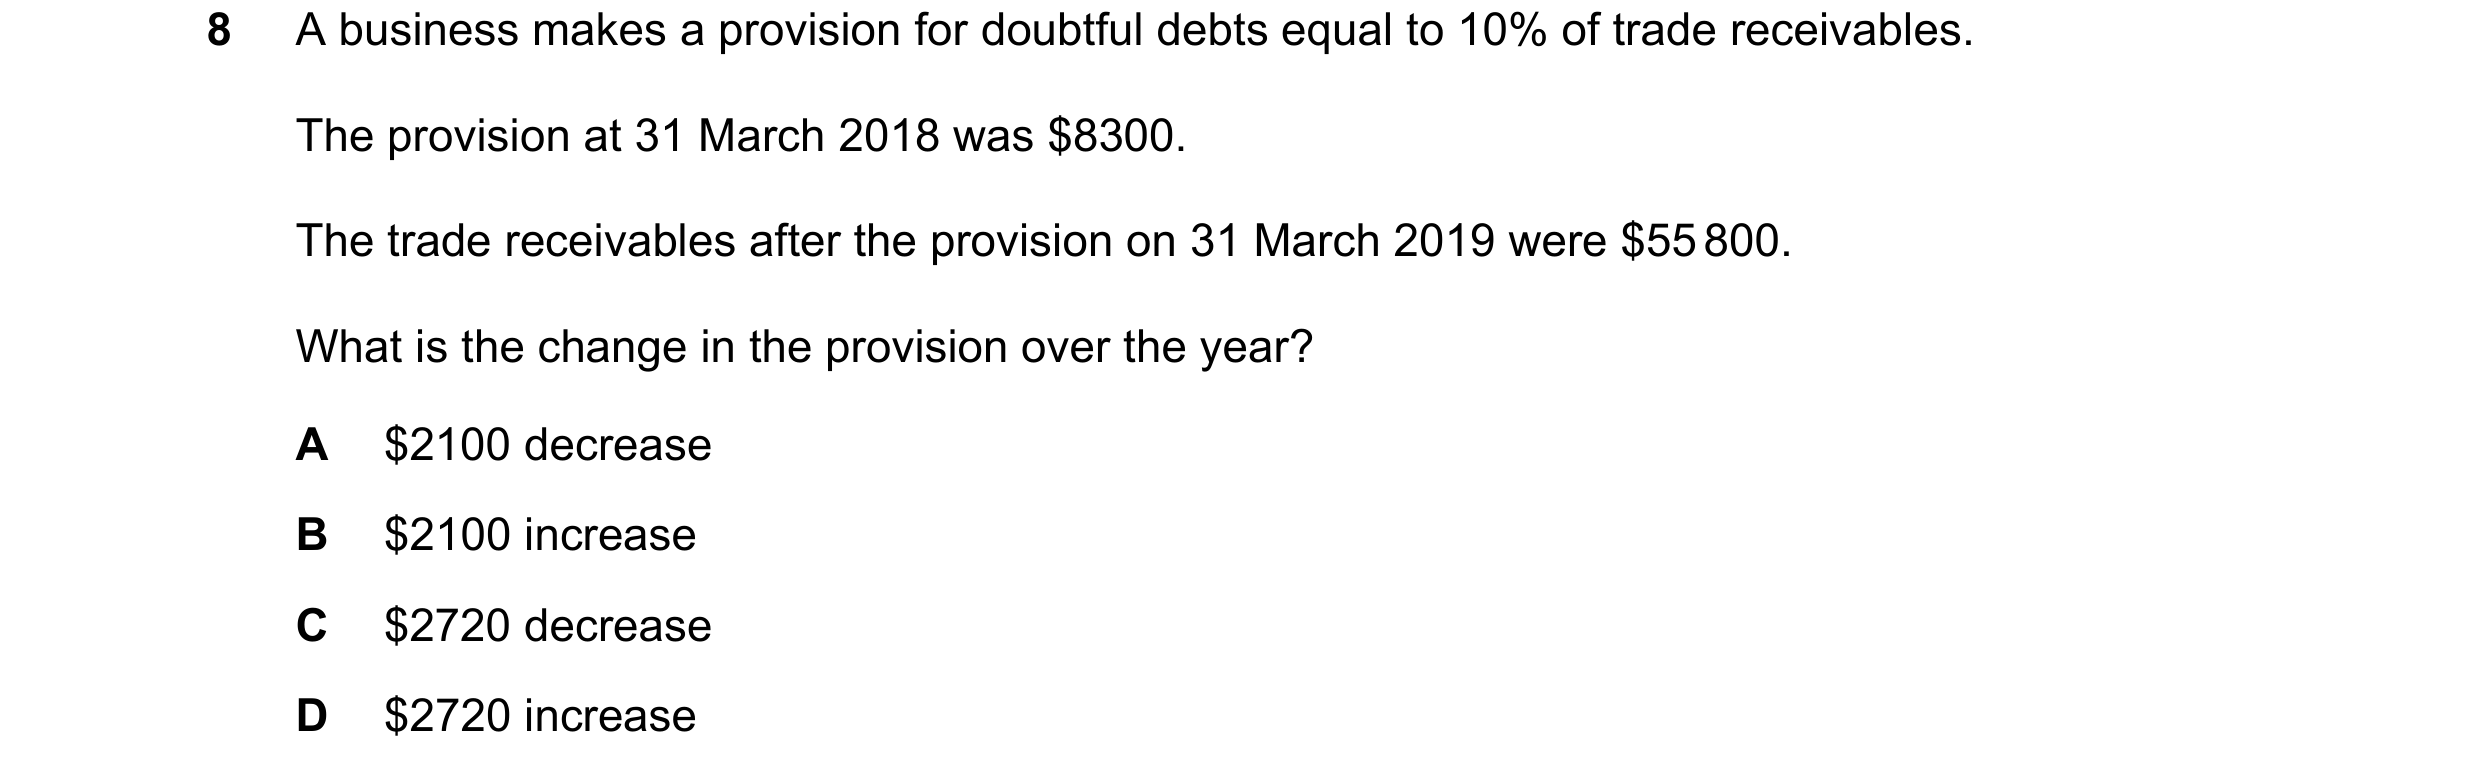
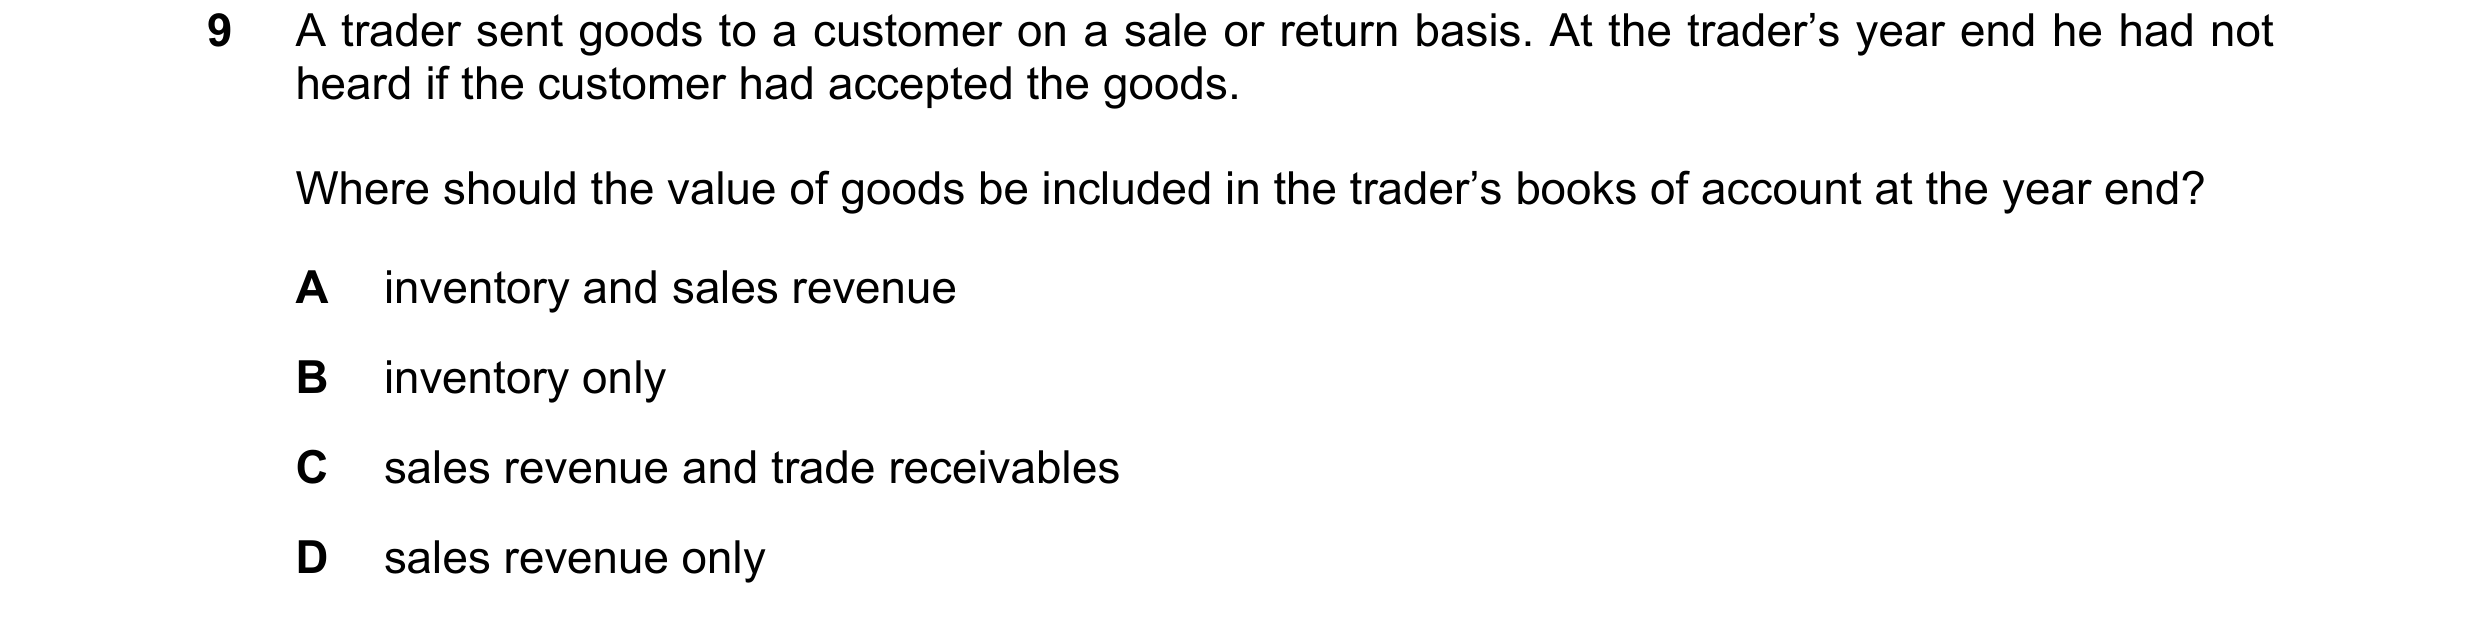 168 / 233
 169 / 233
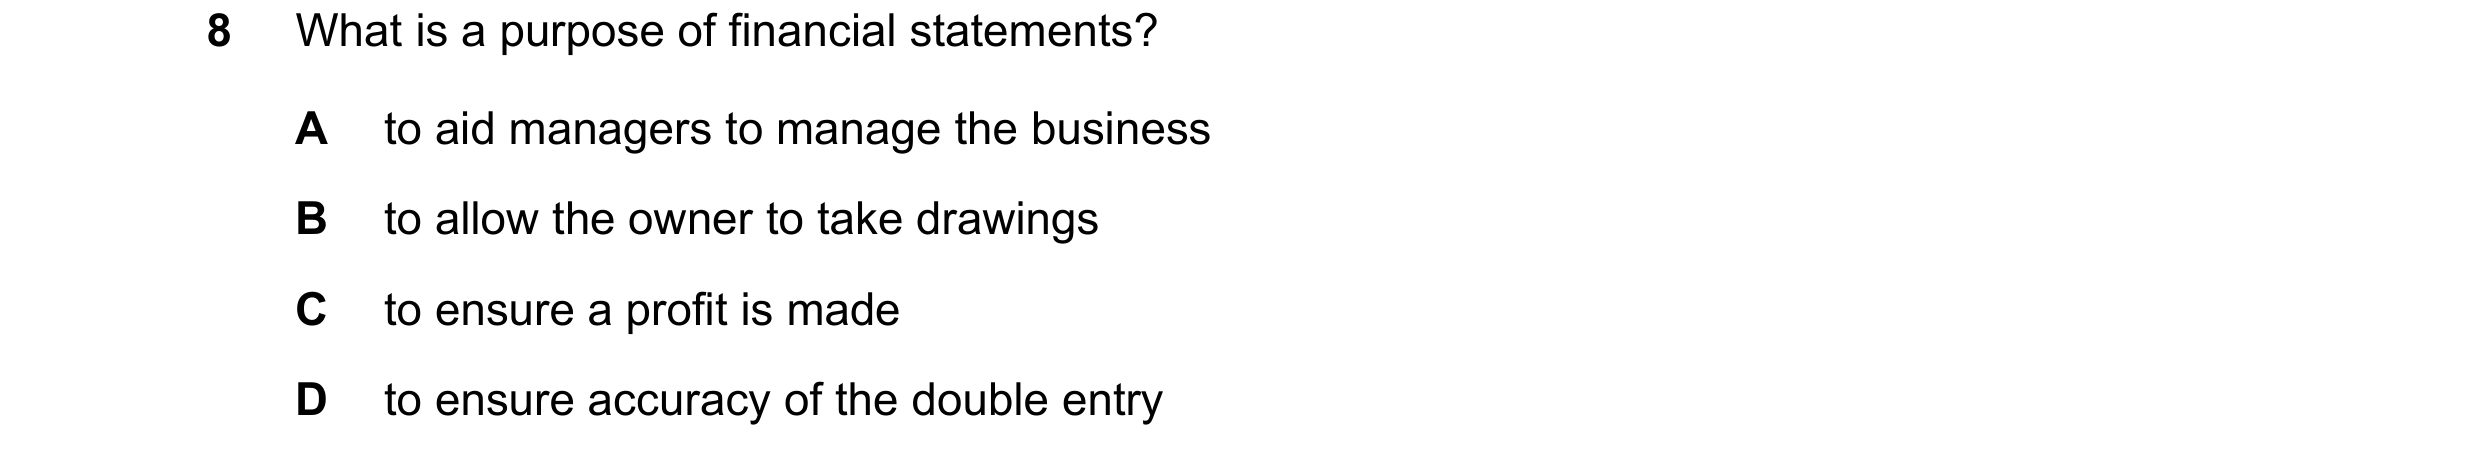
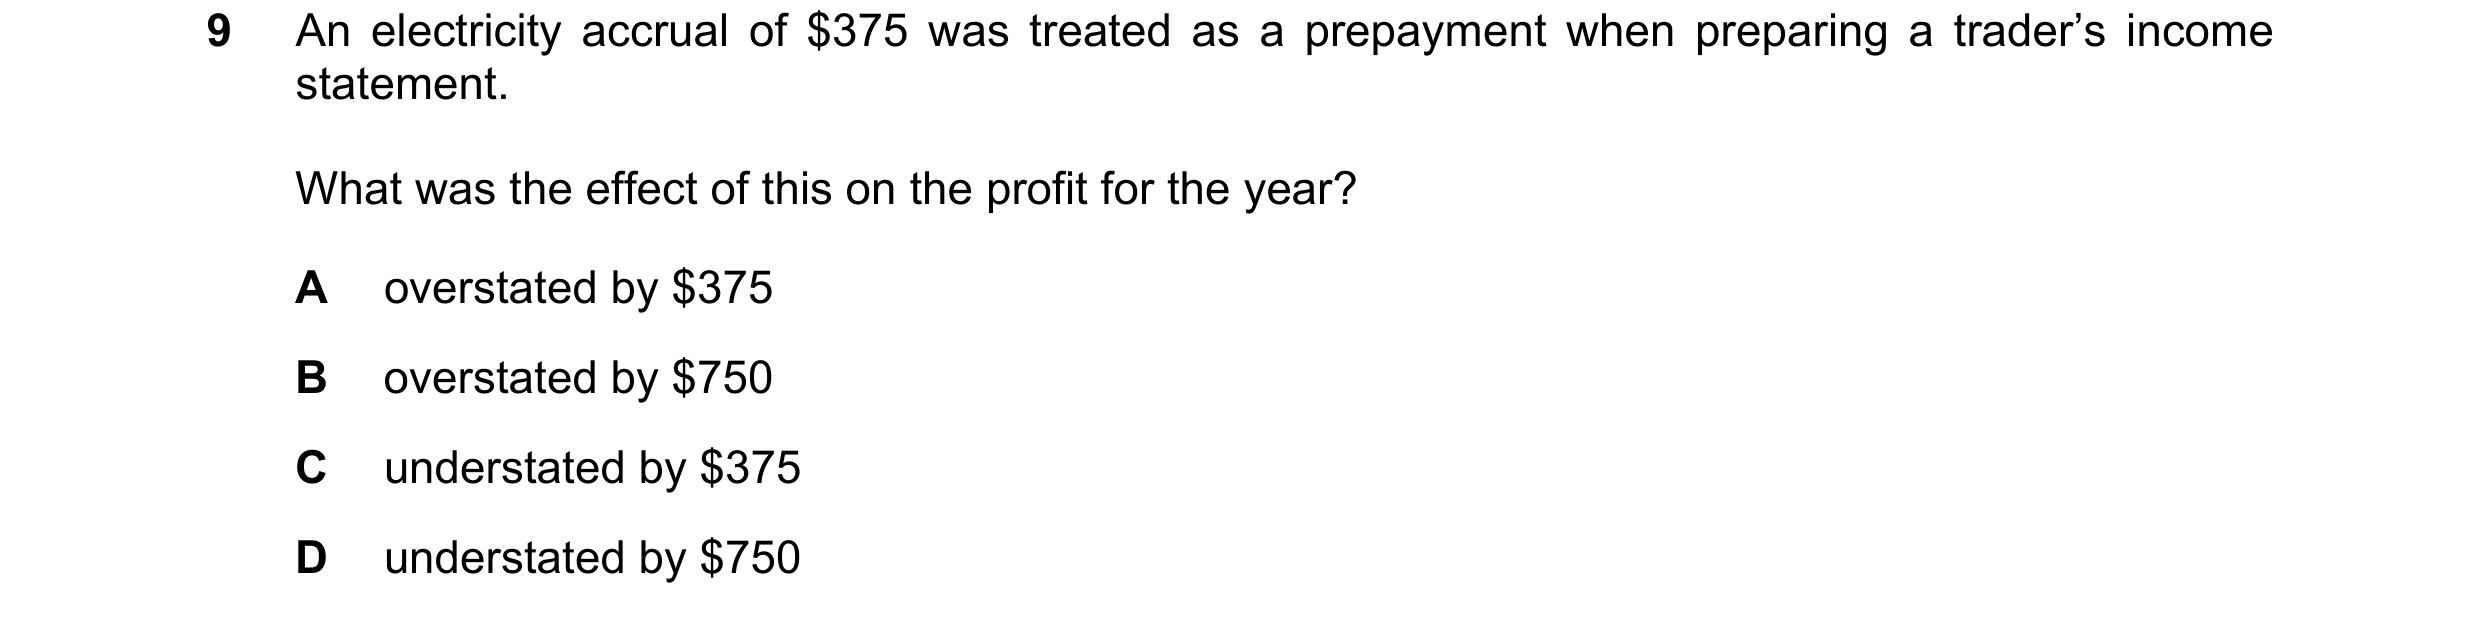
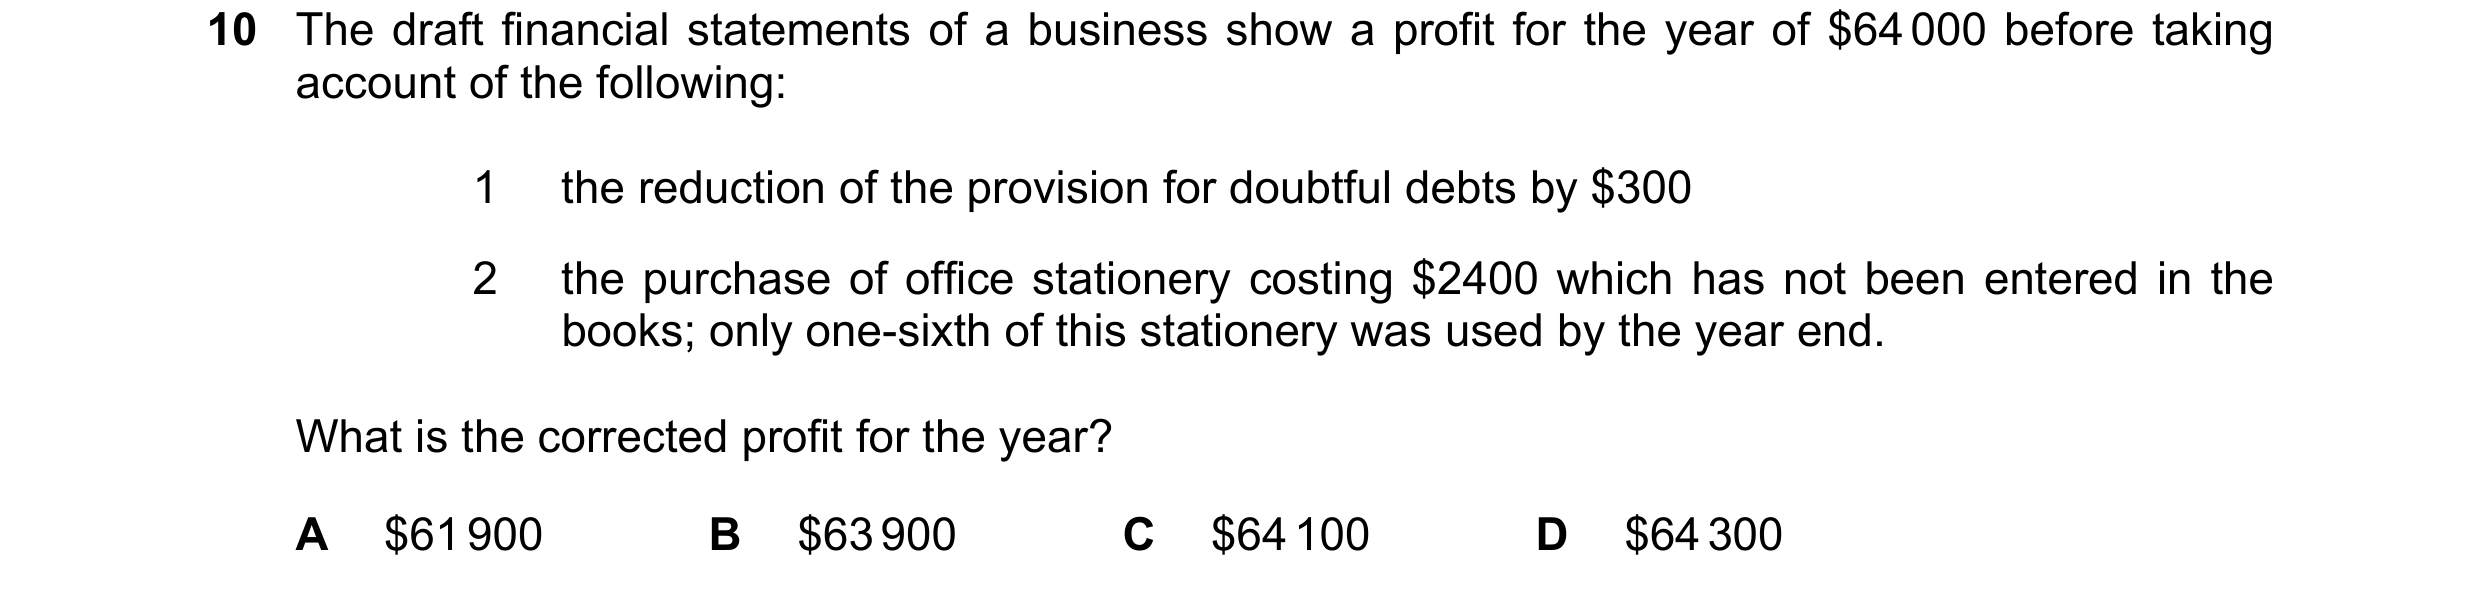 170 / 233
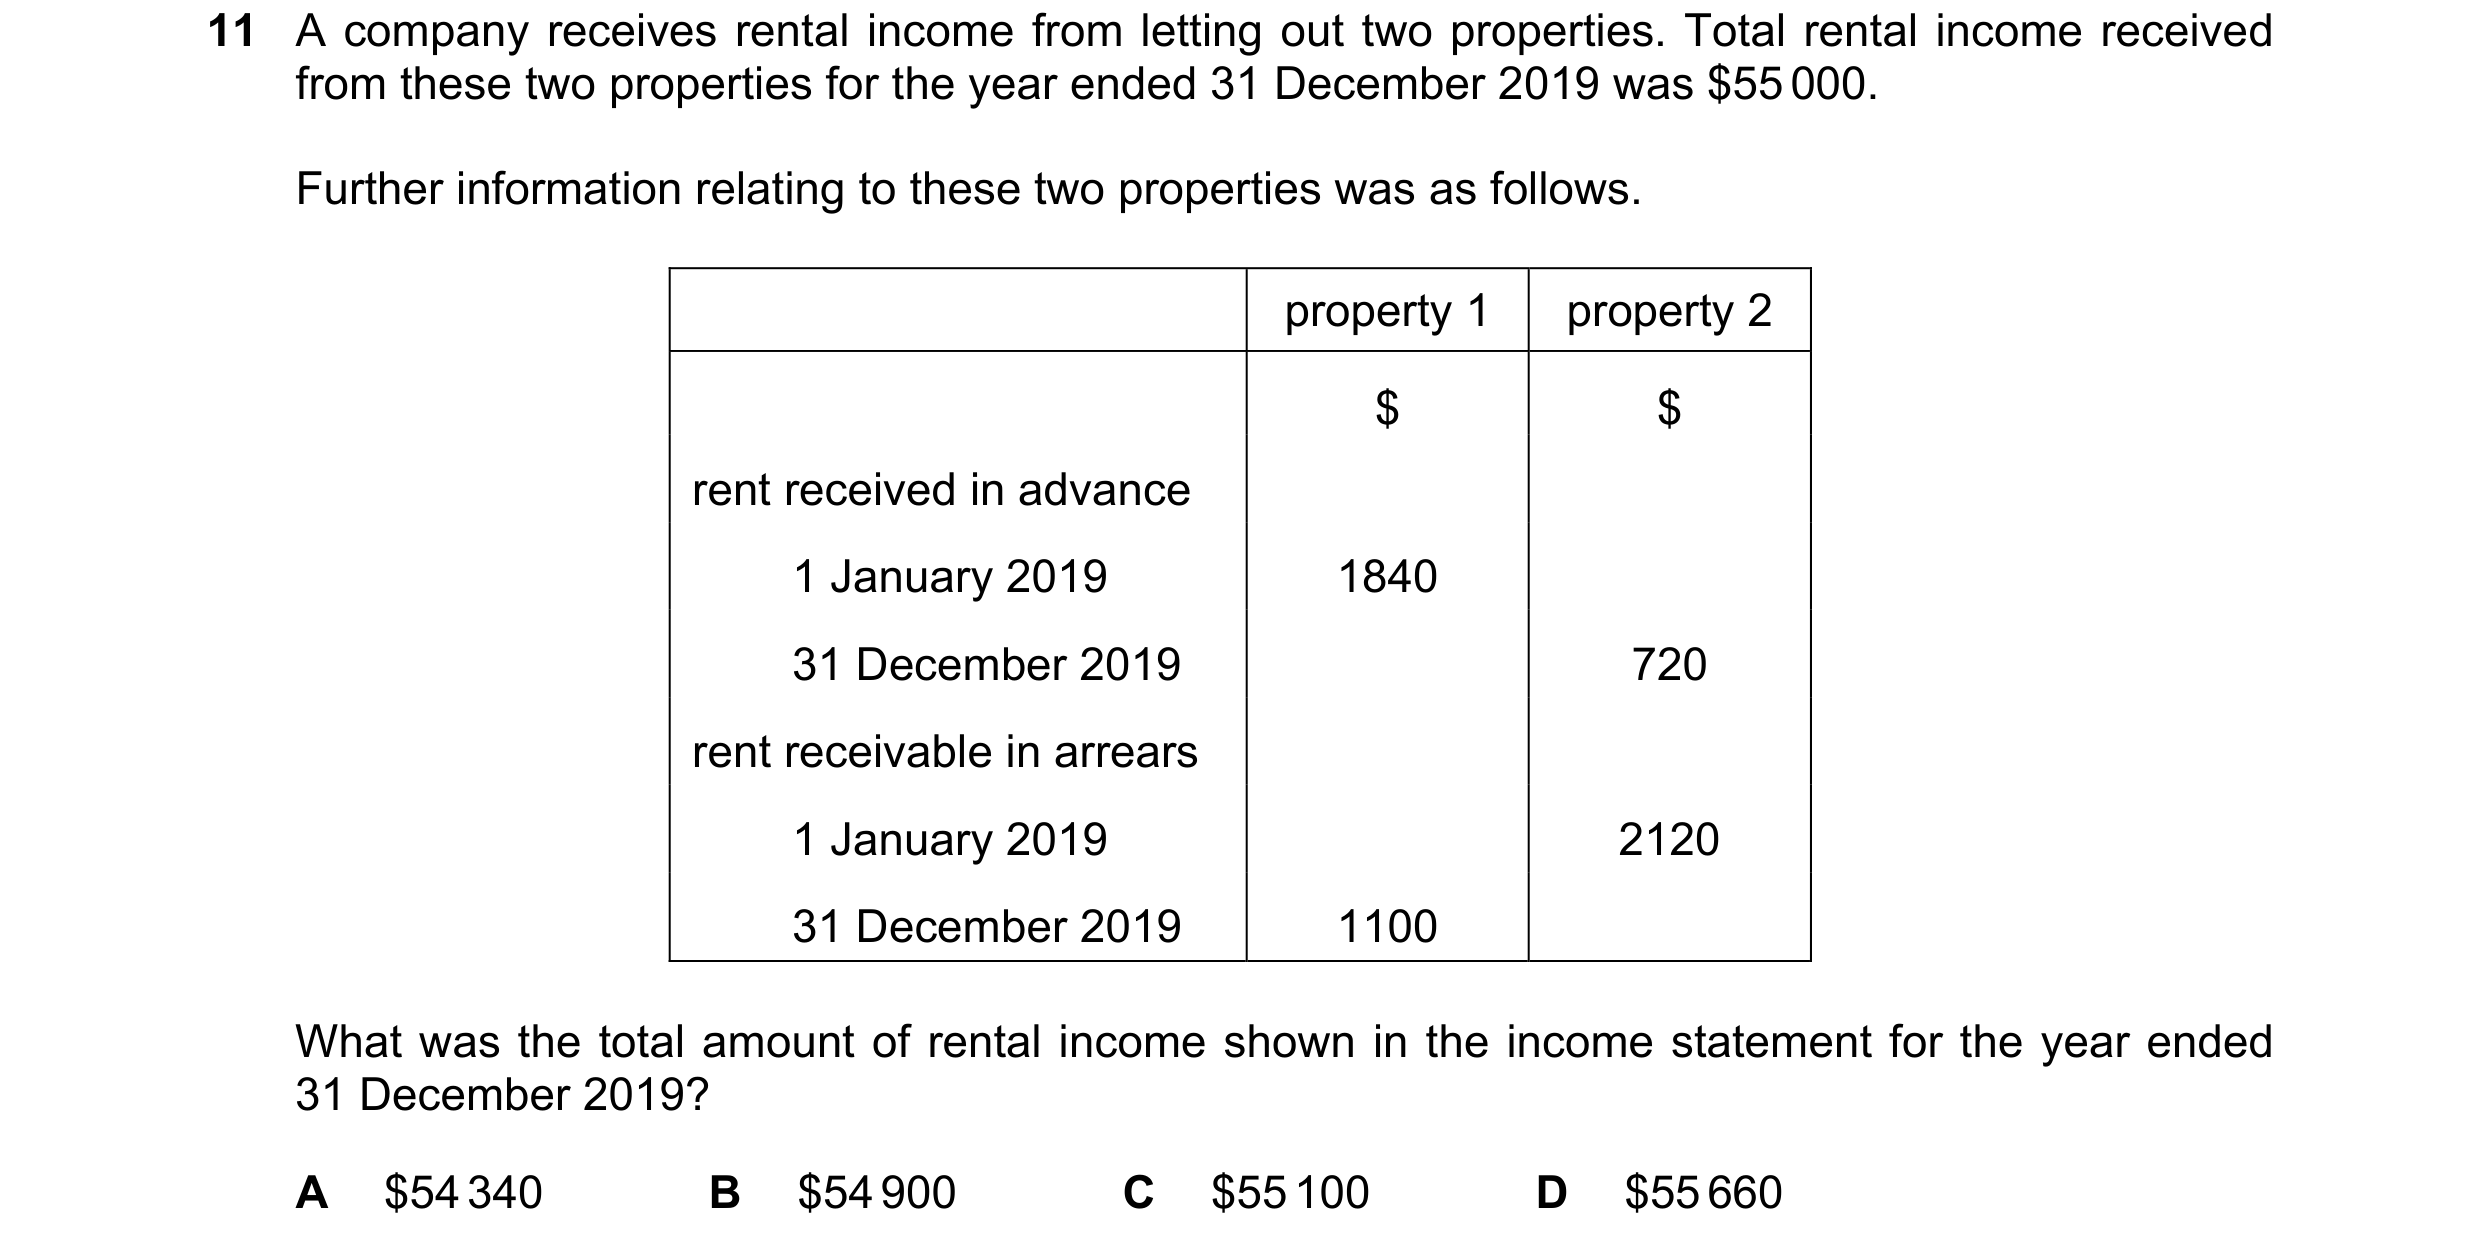
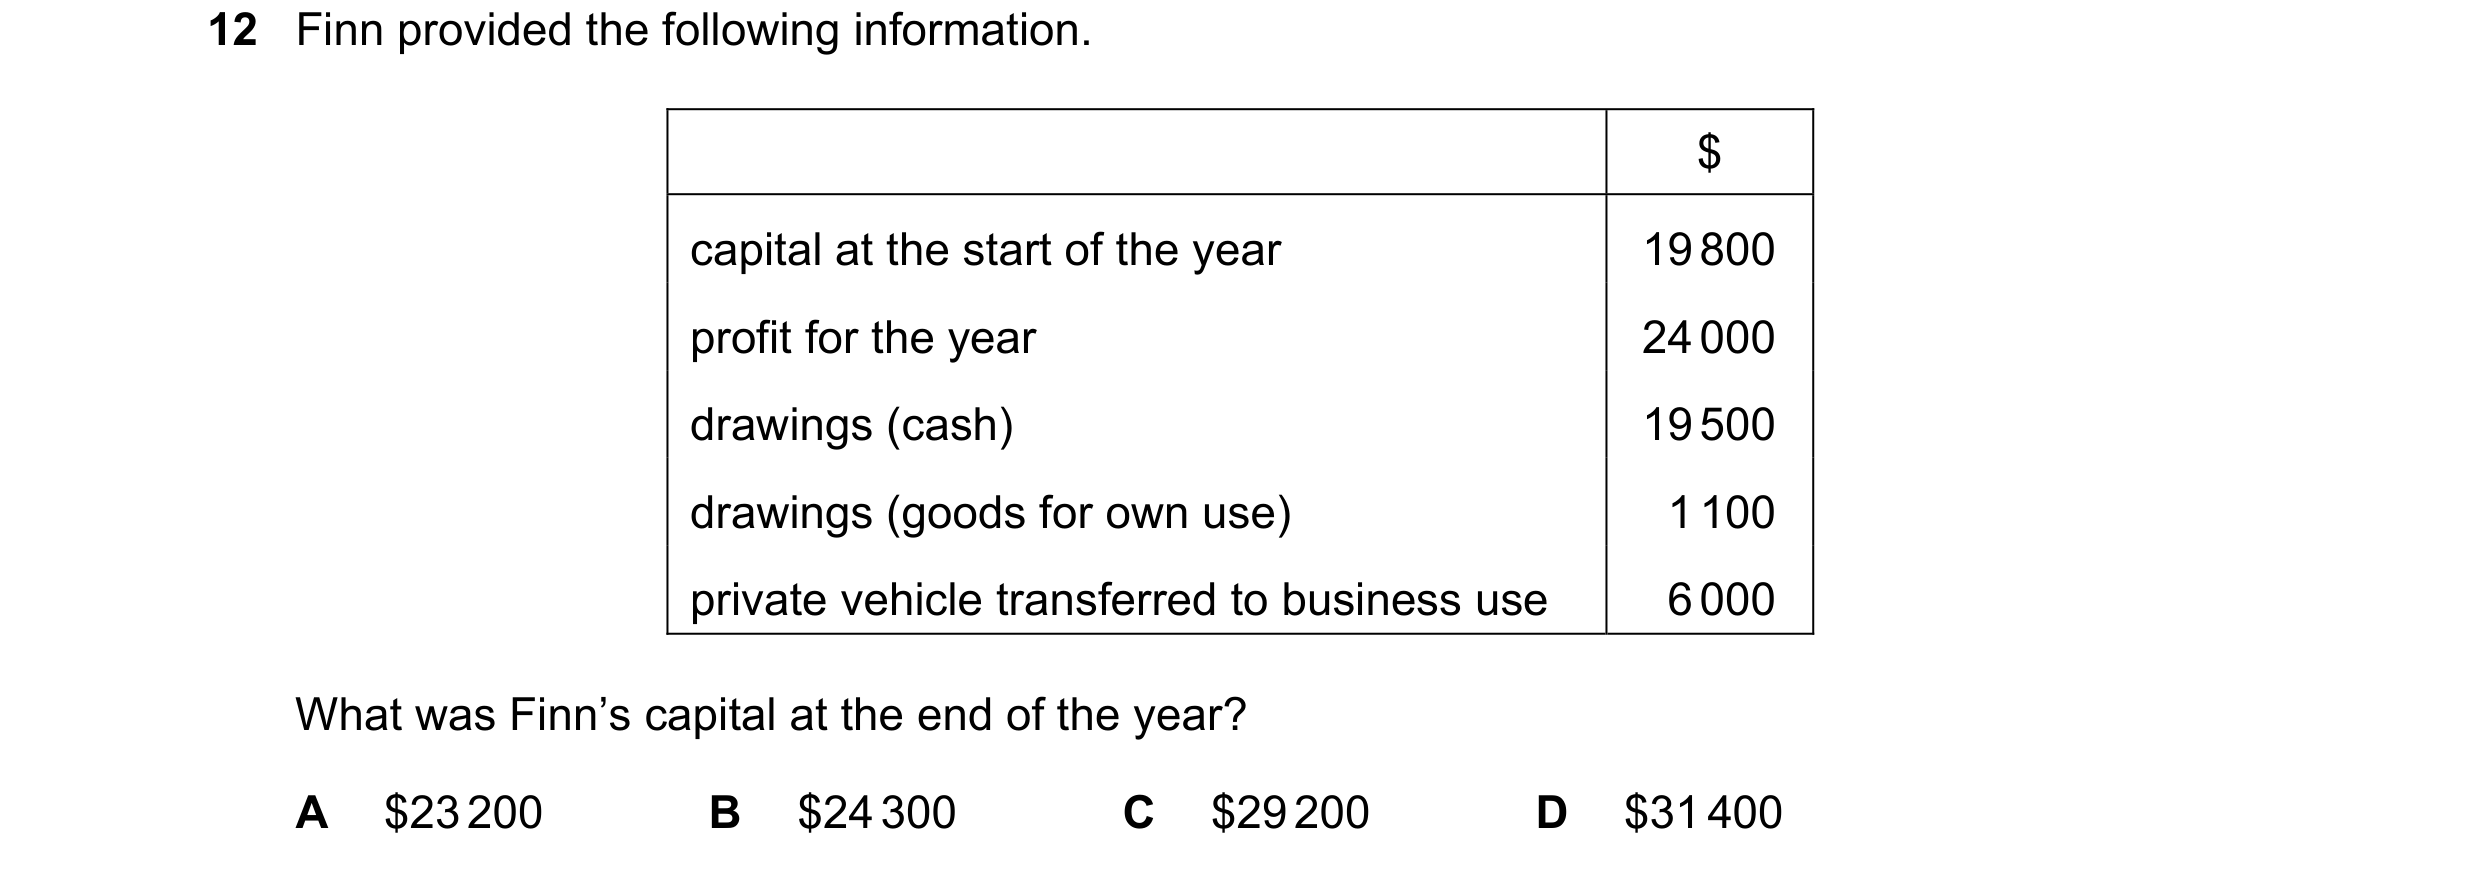
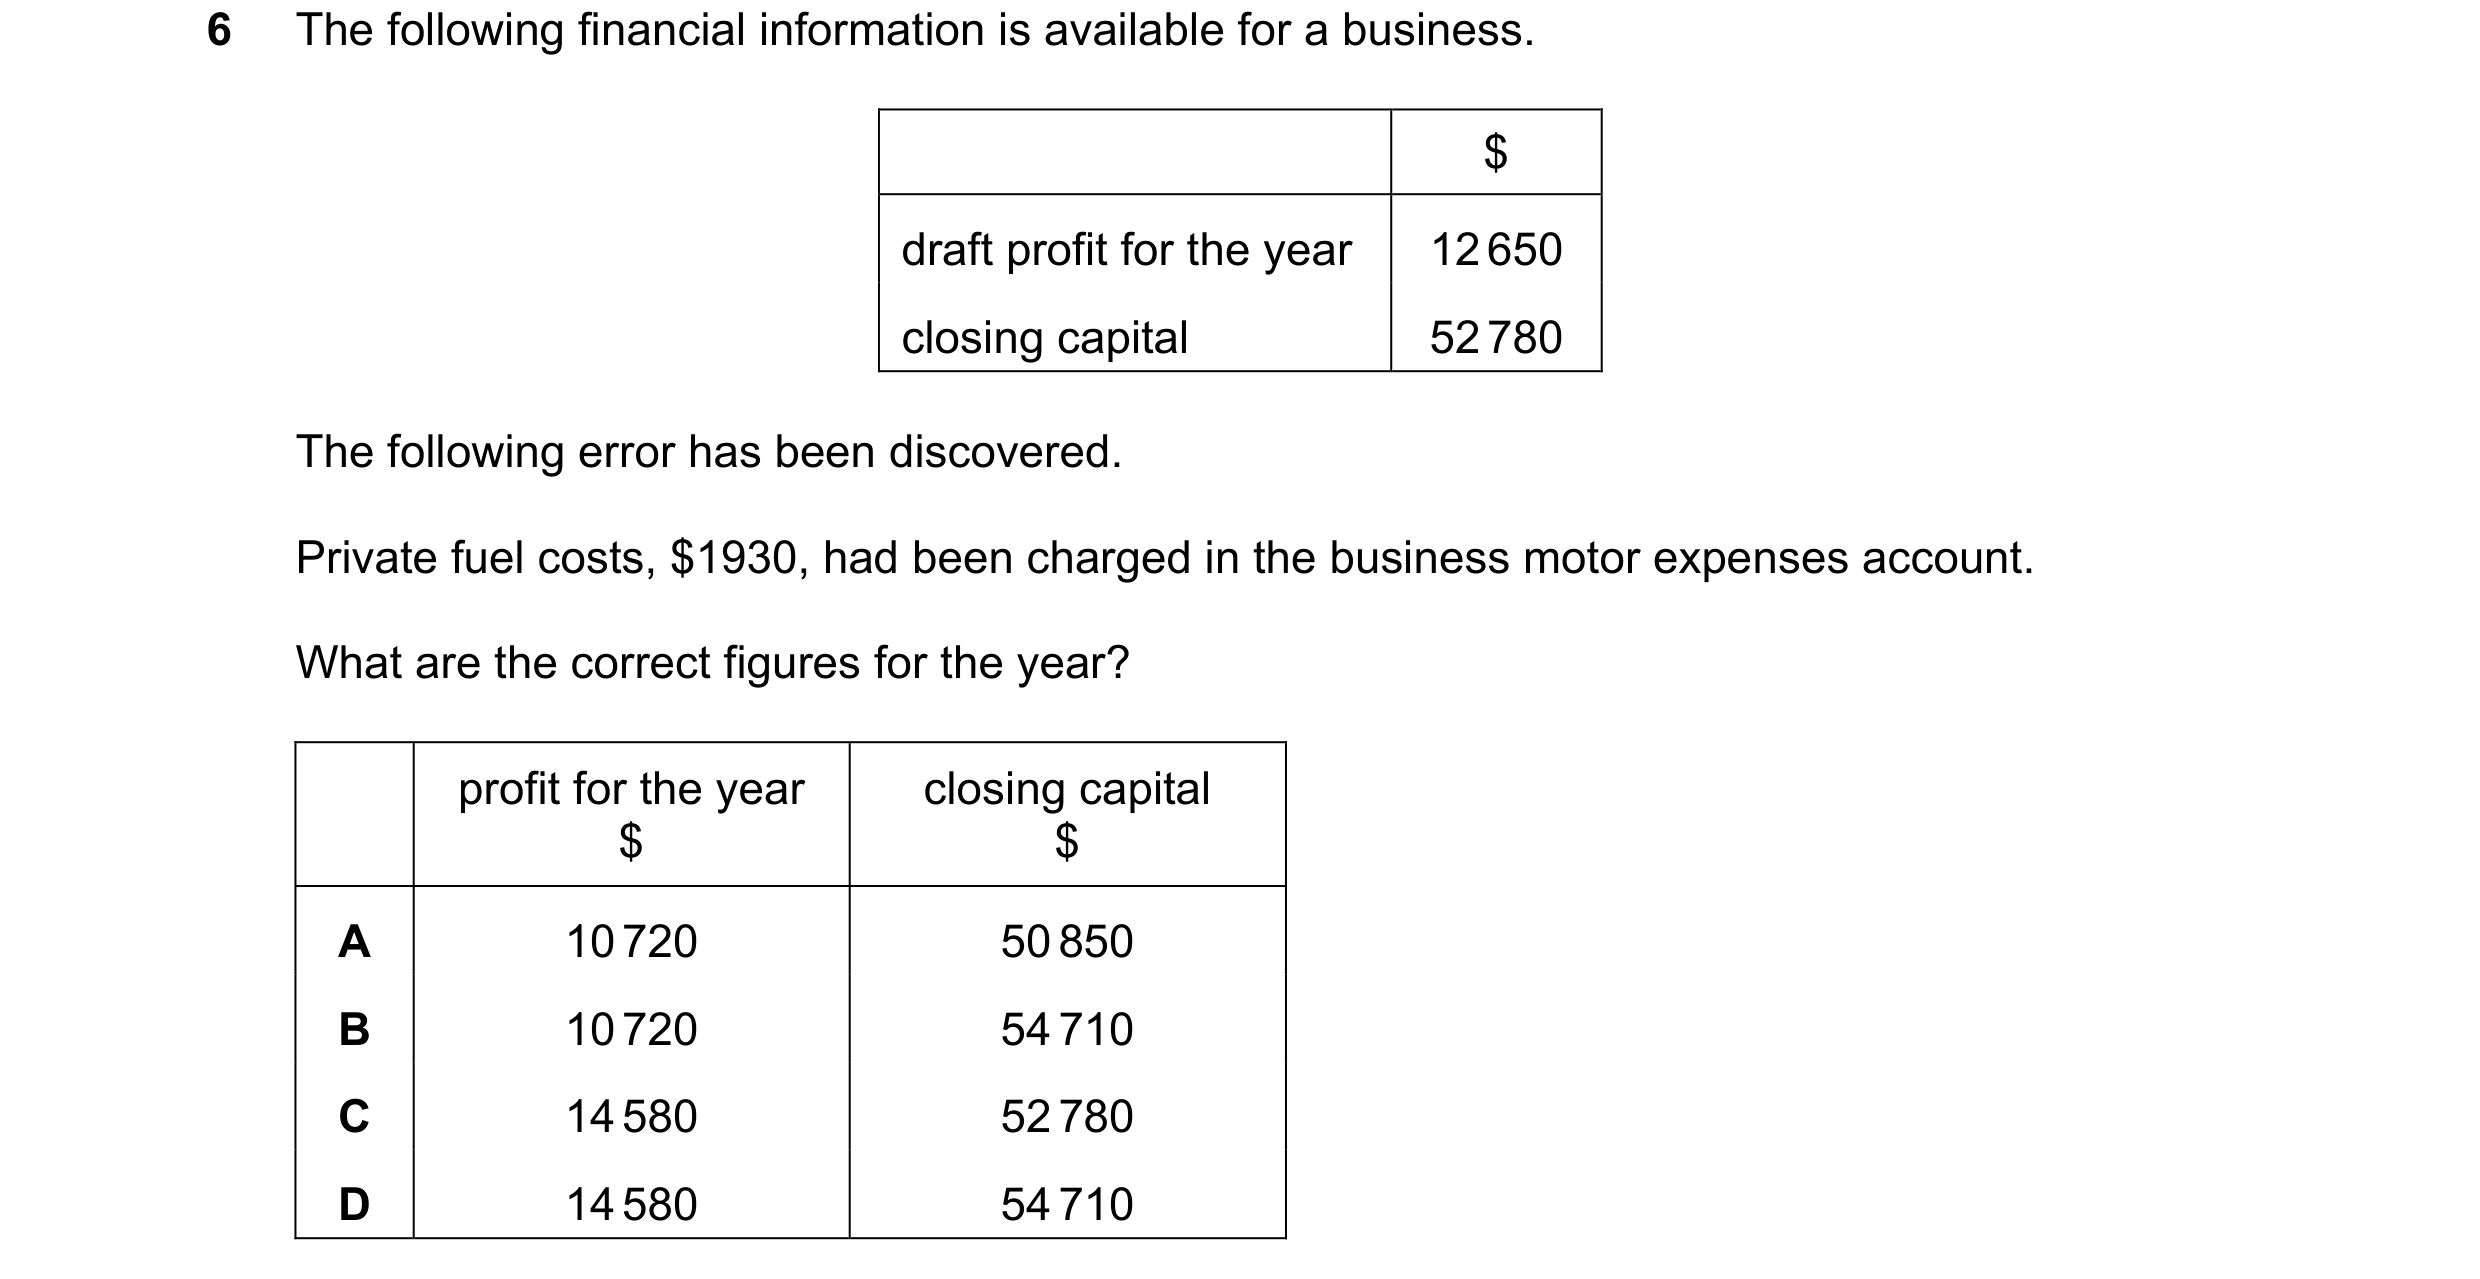 171 / 233
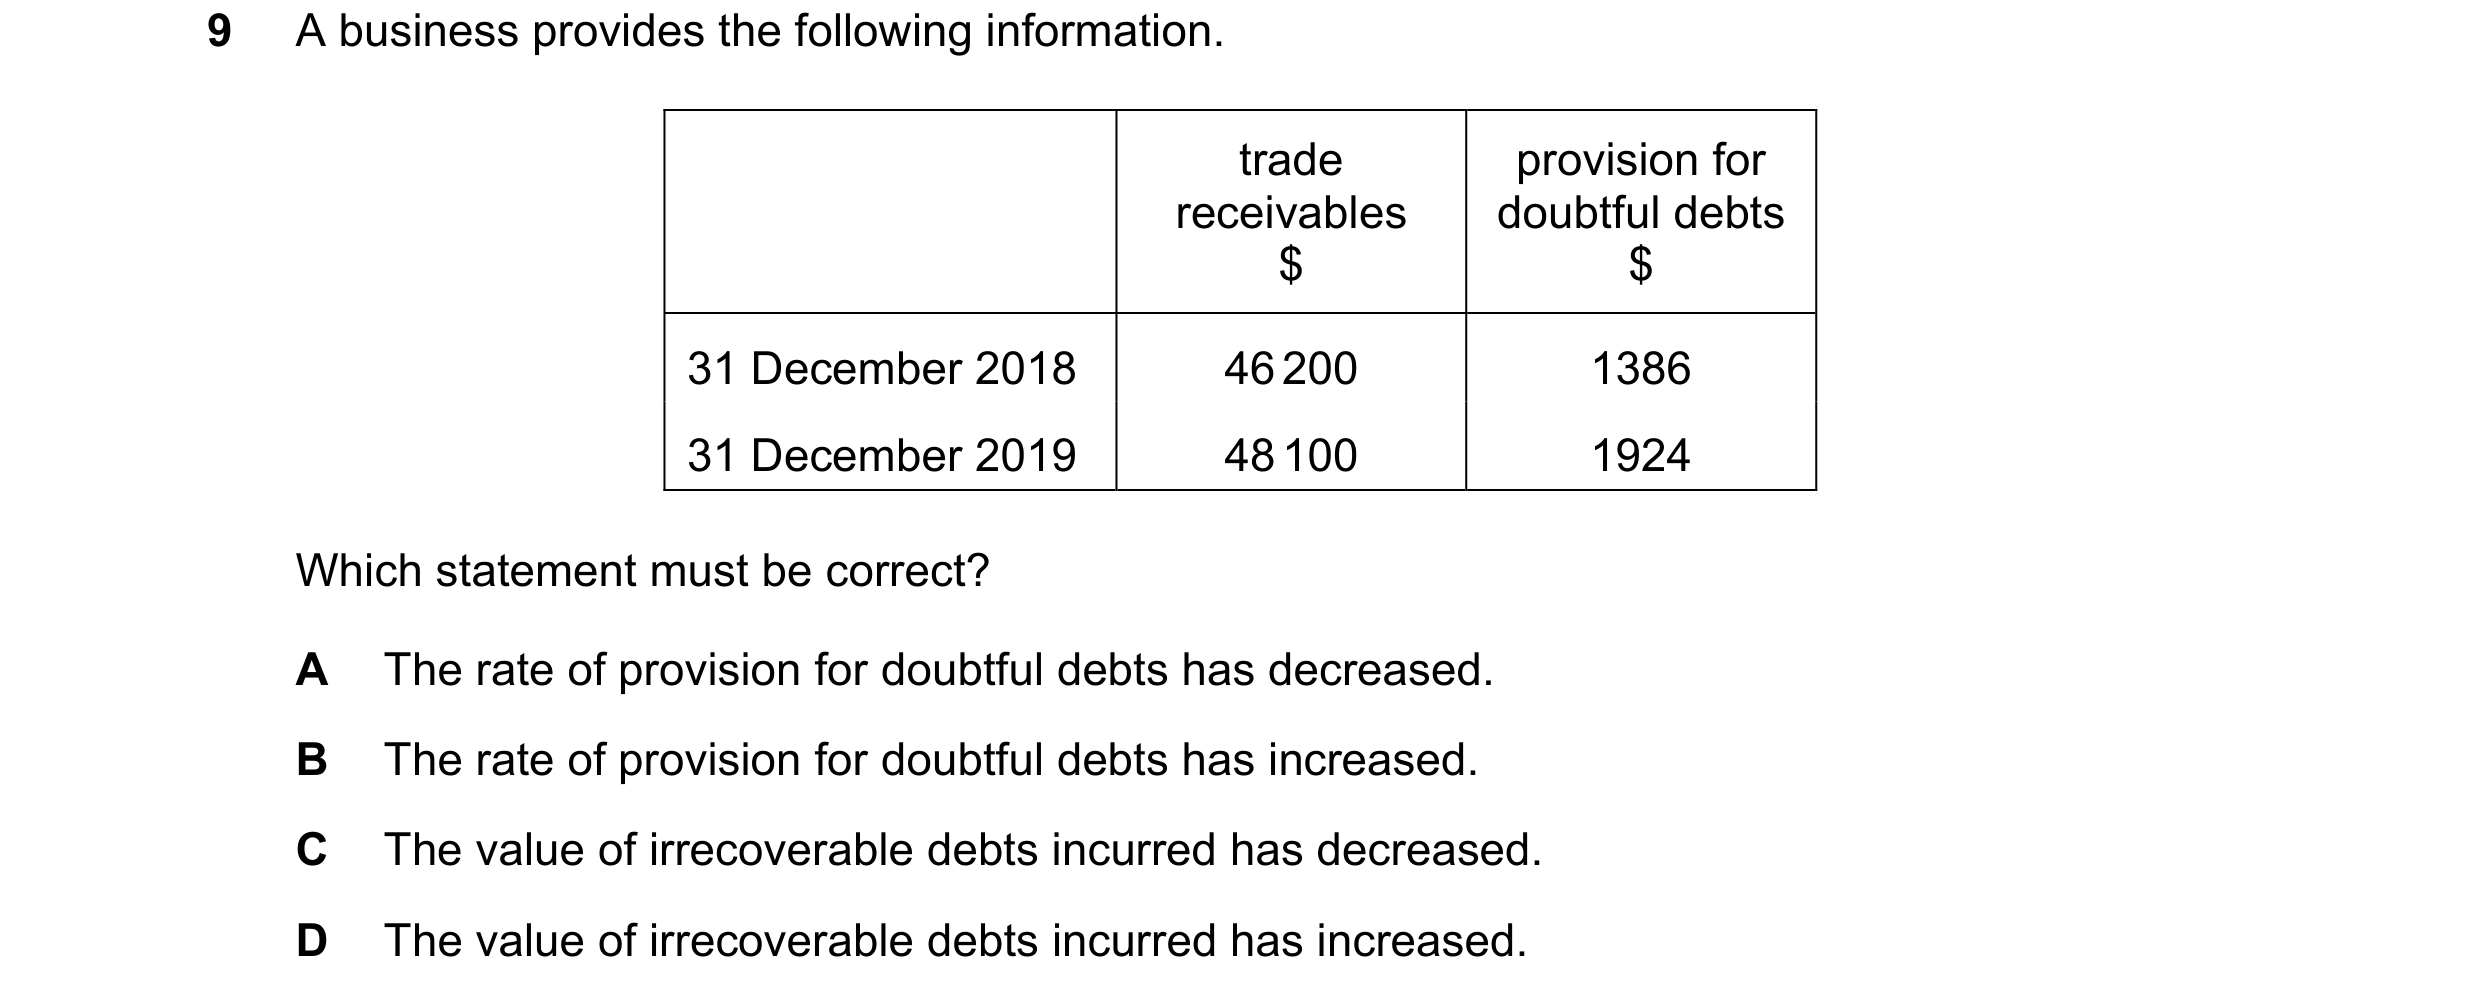
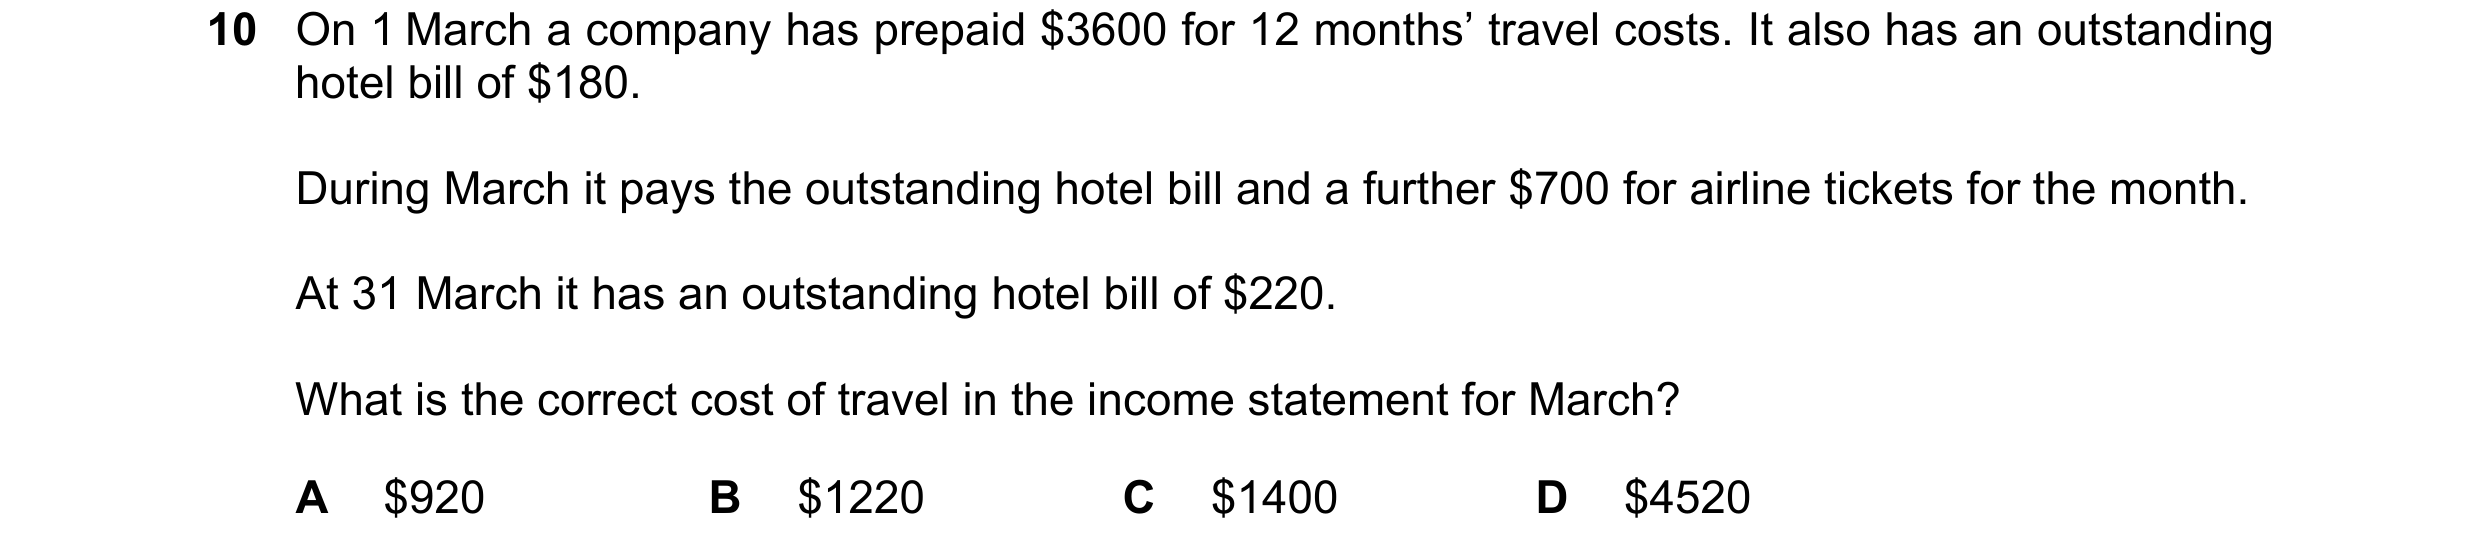
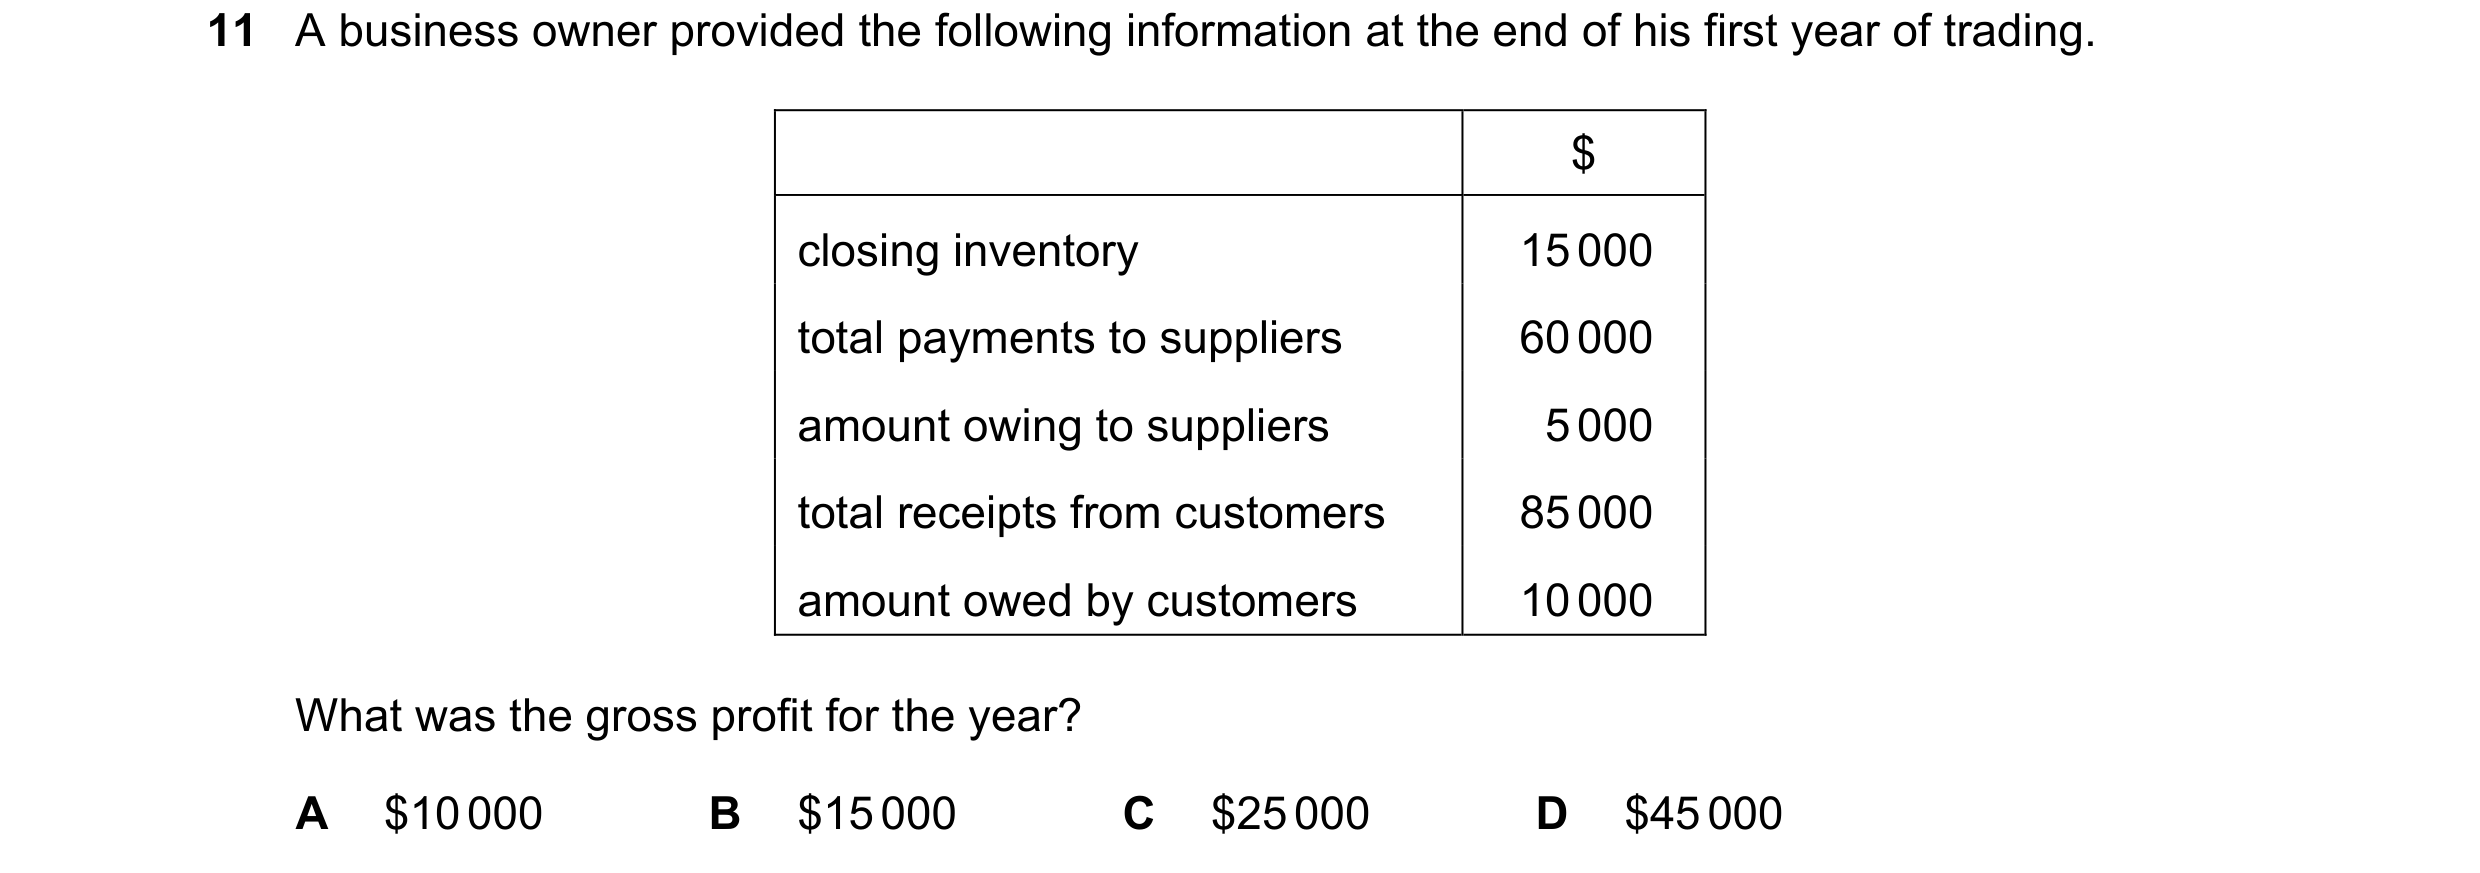
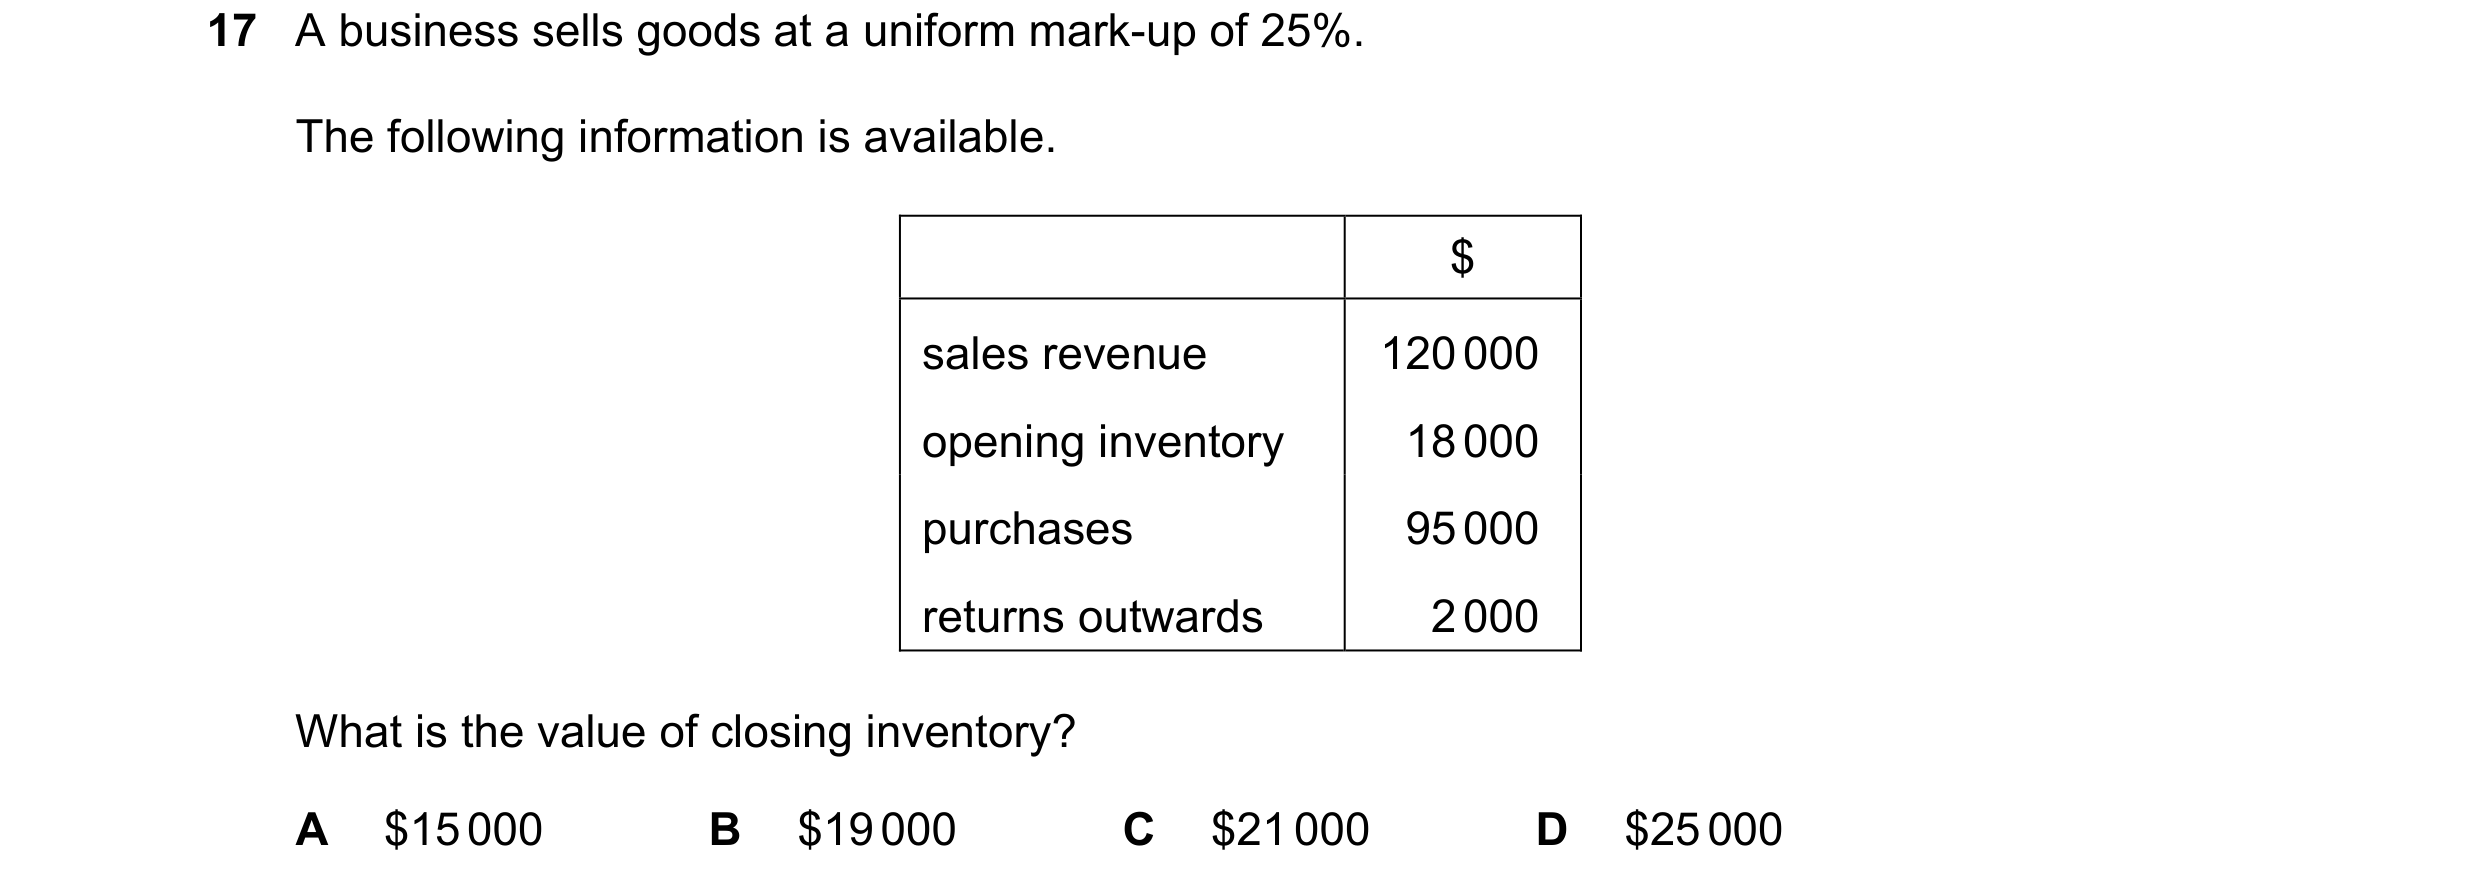 172 / 233
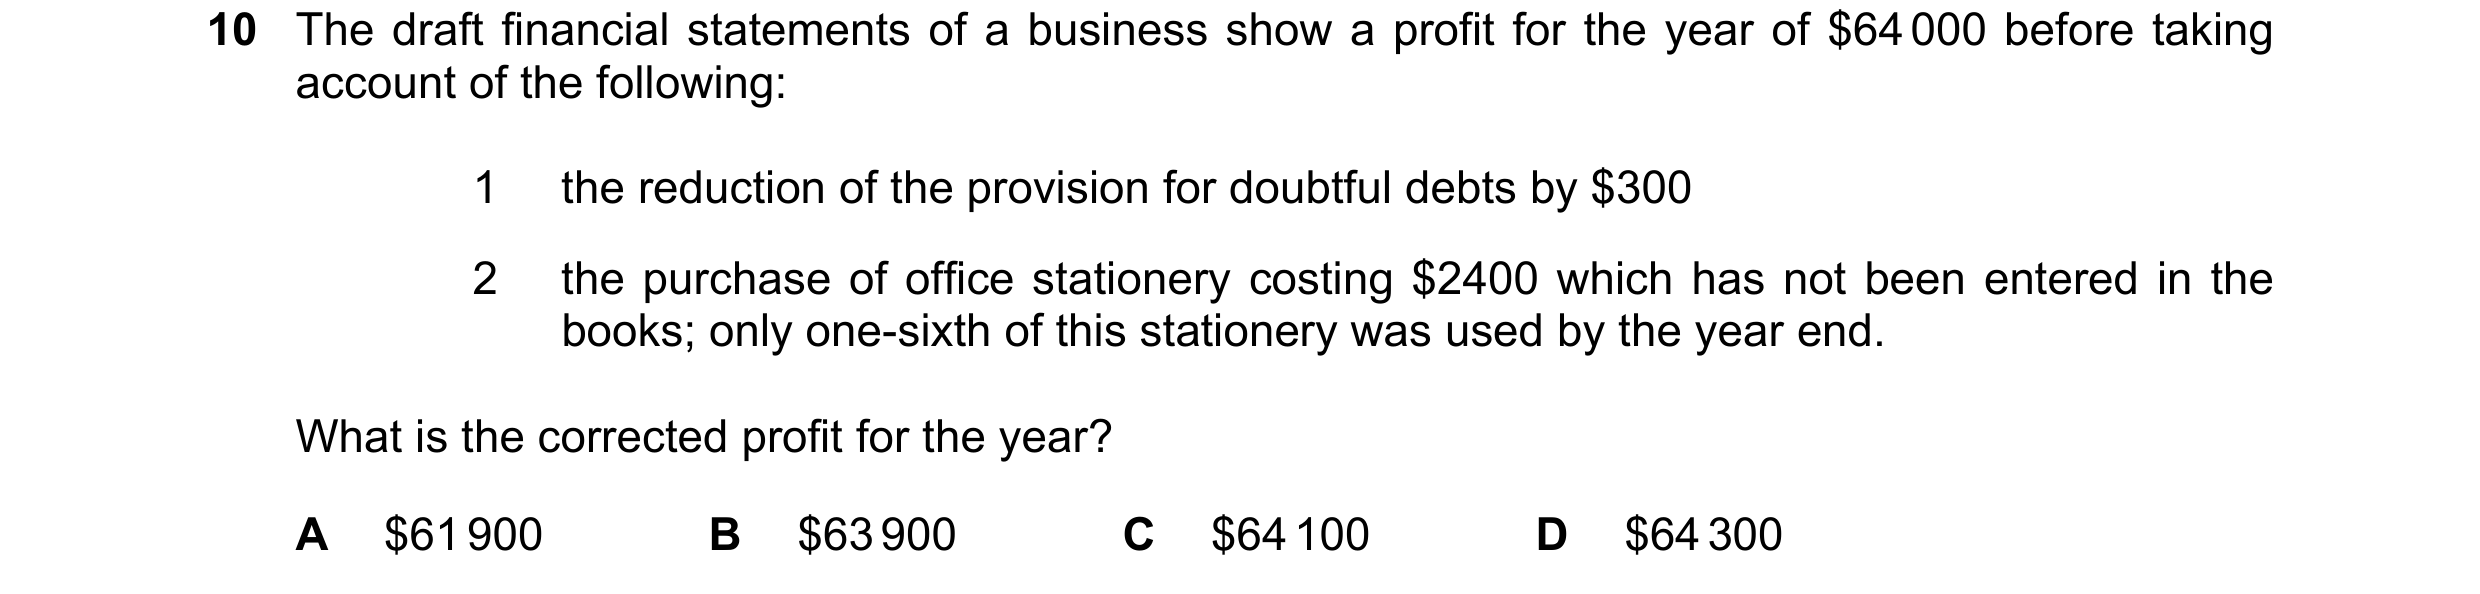
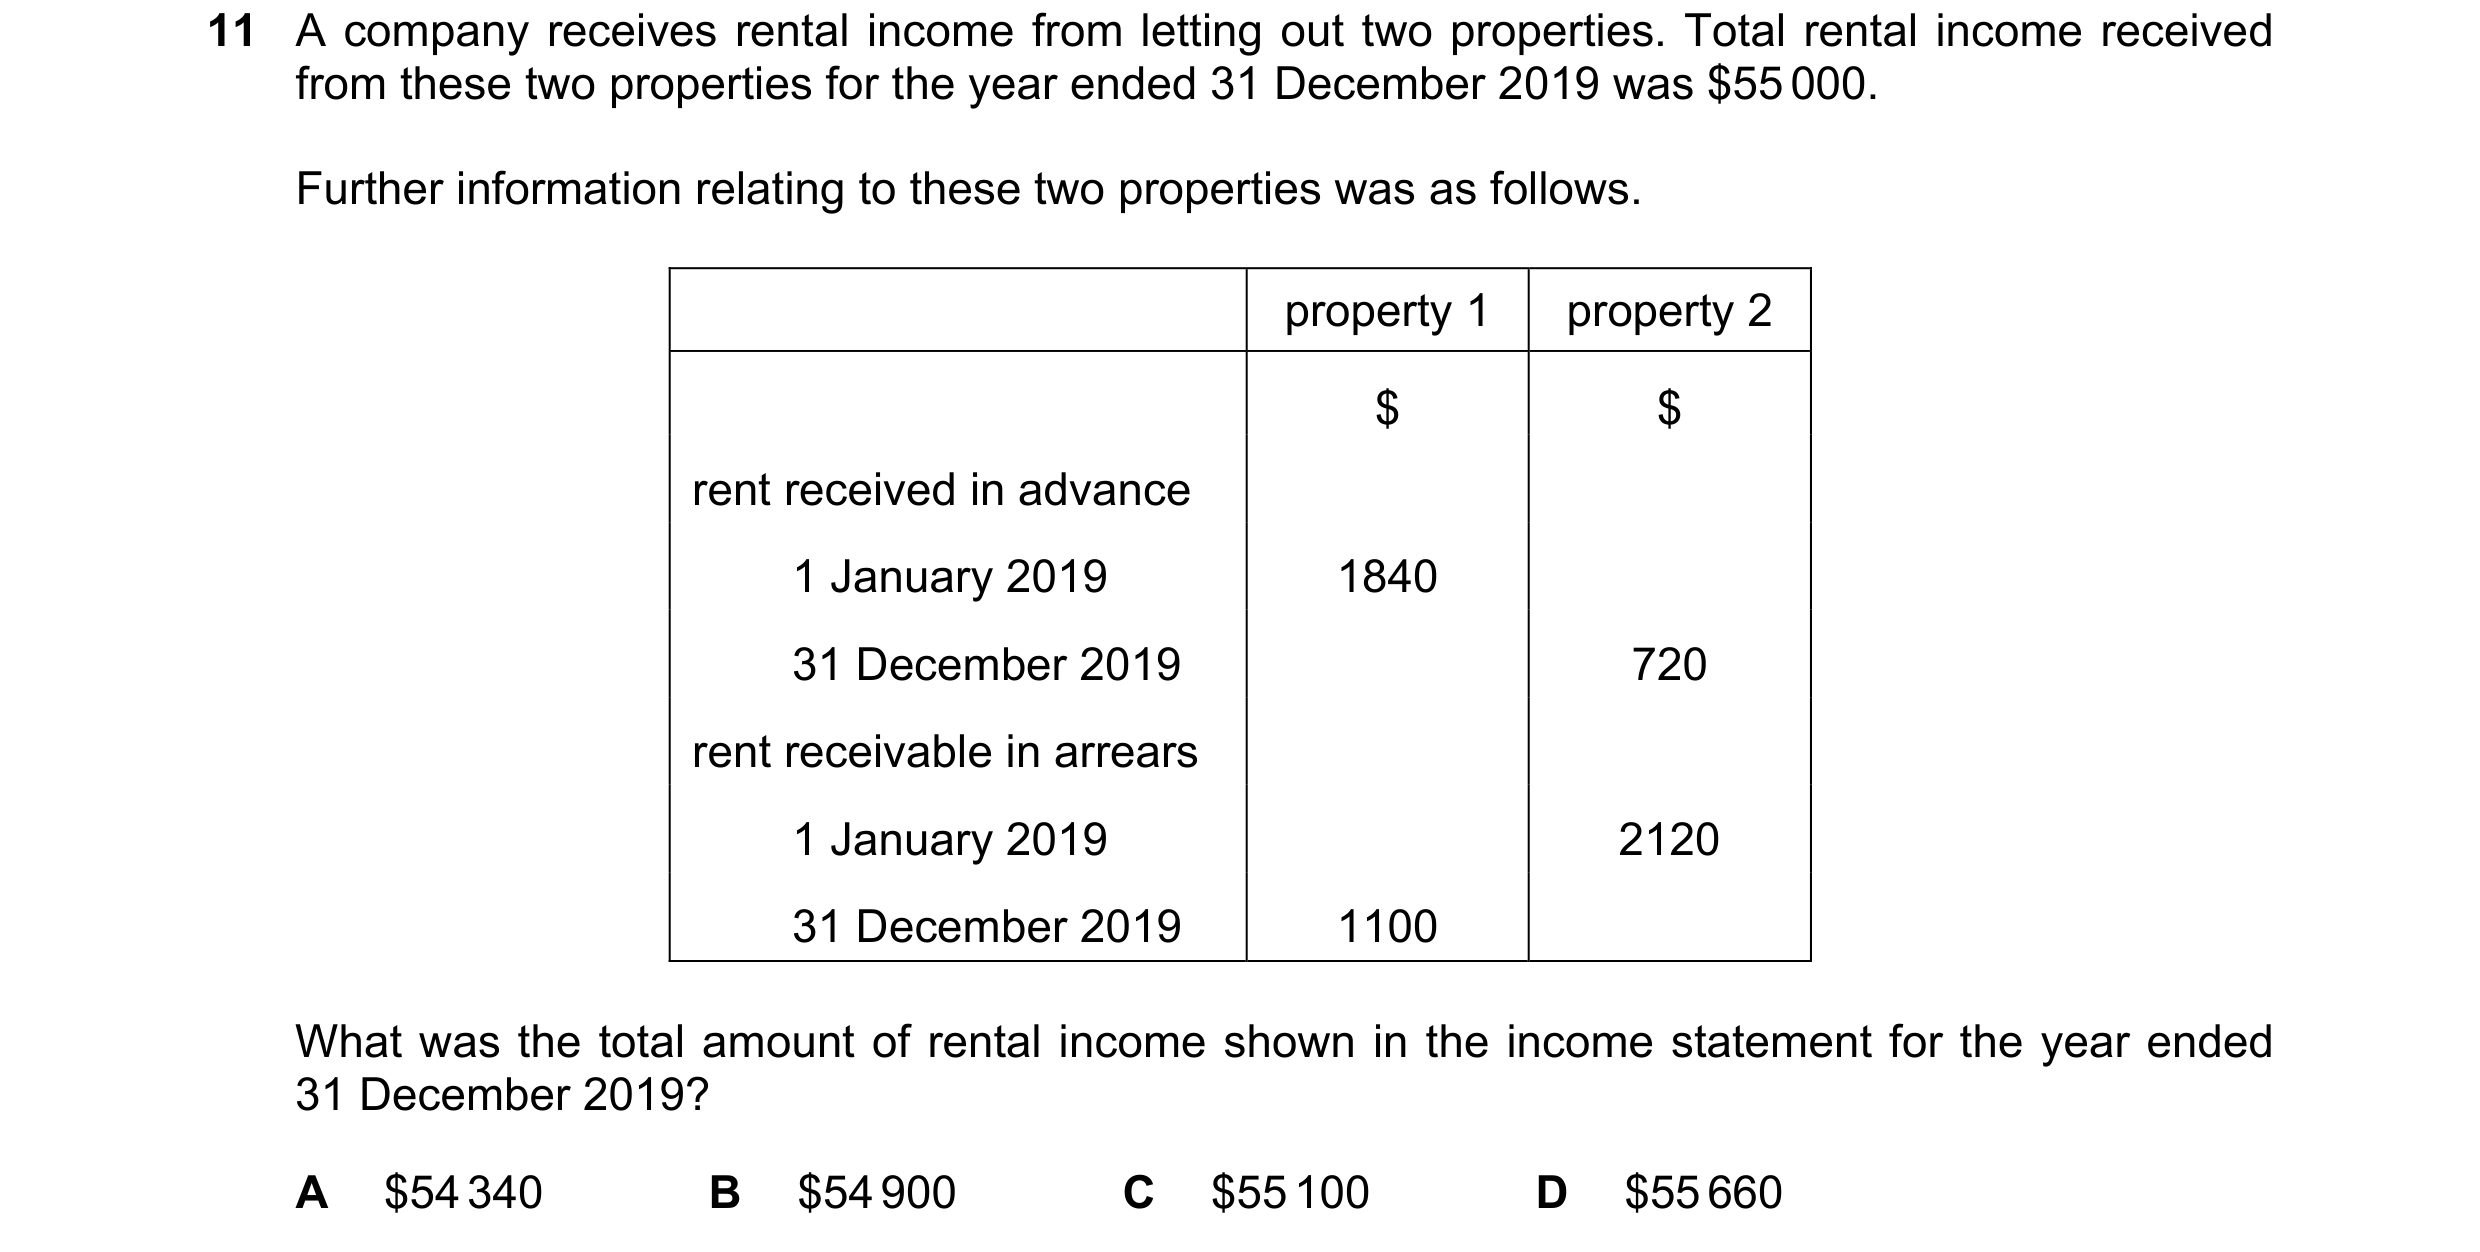 173 / 233
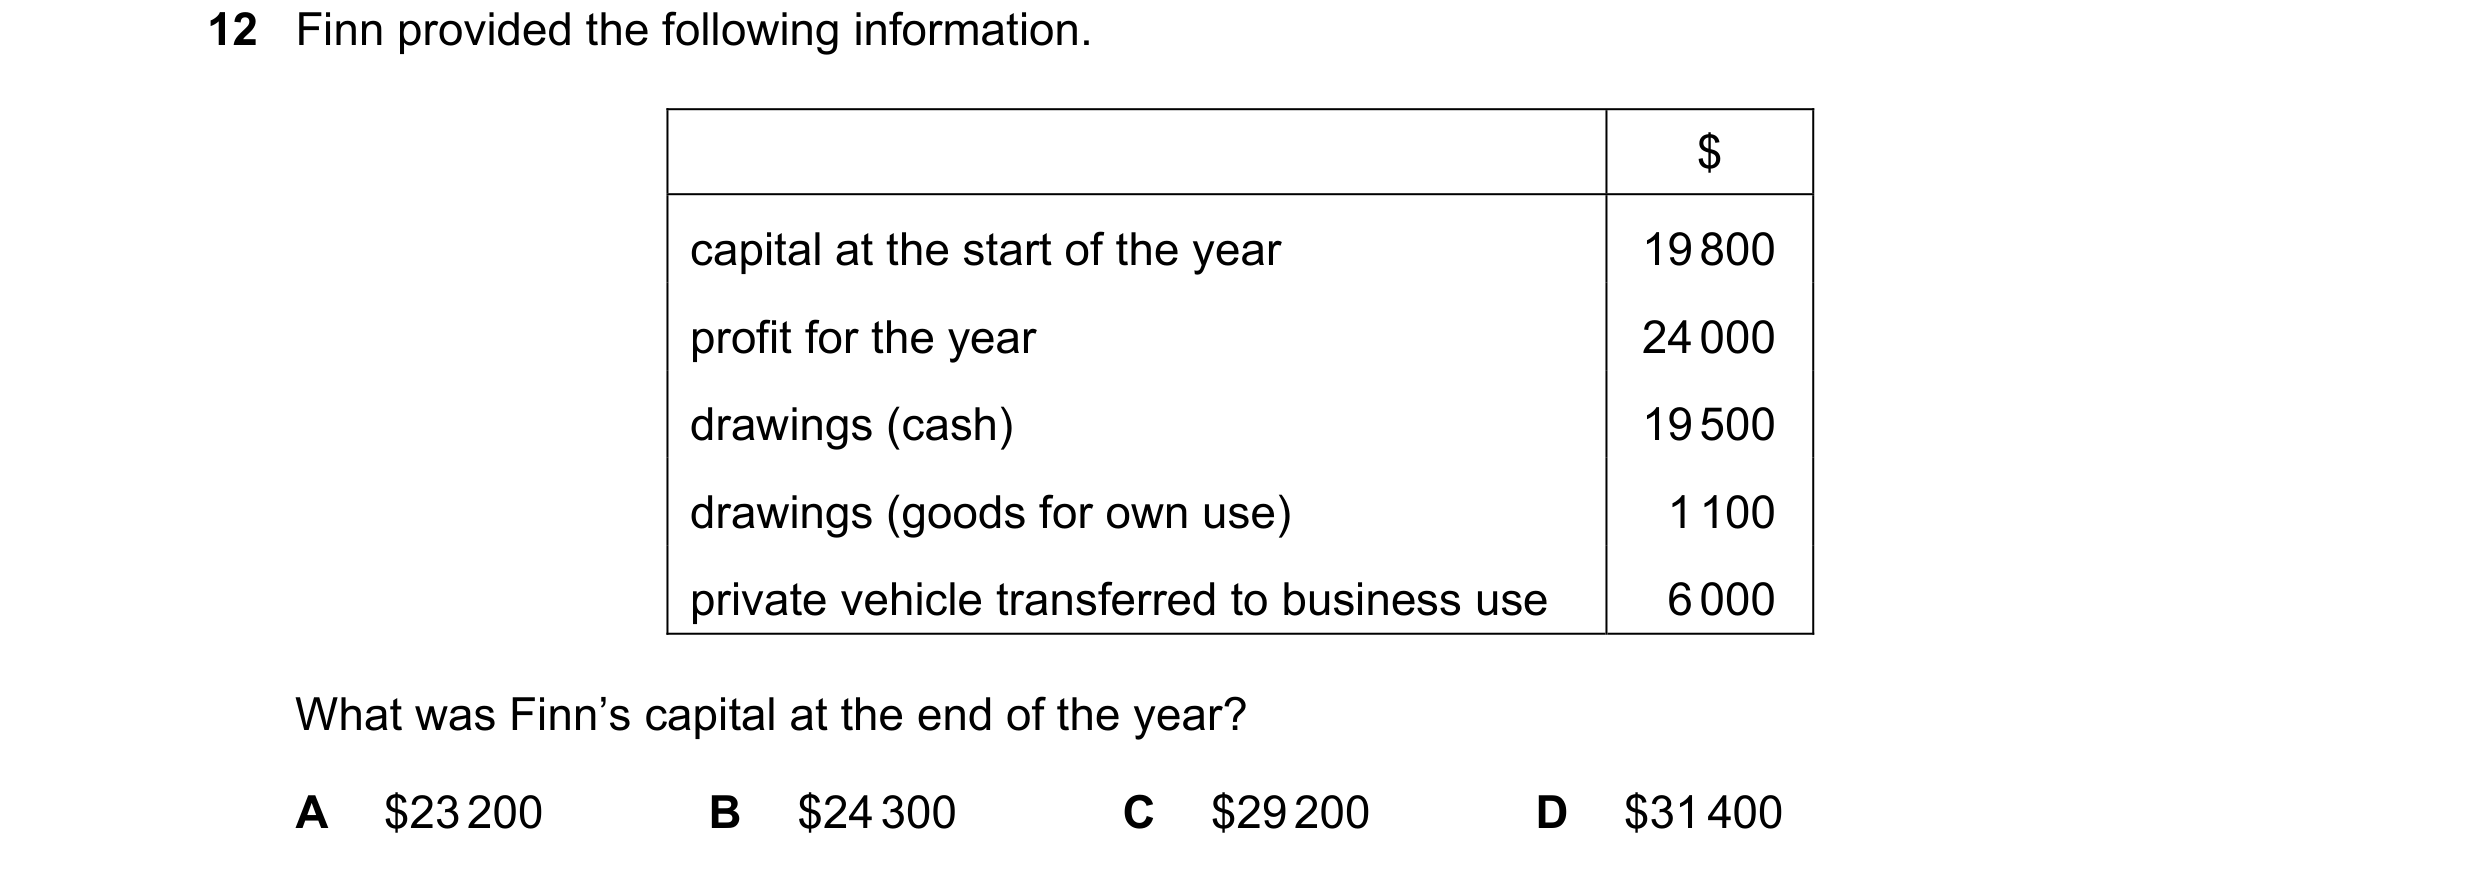
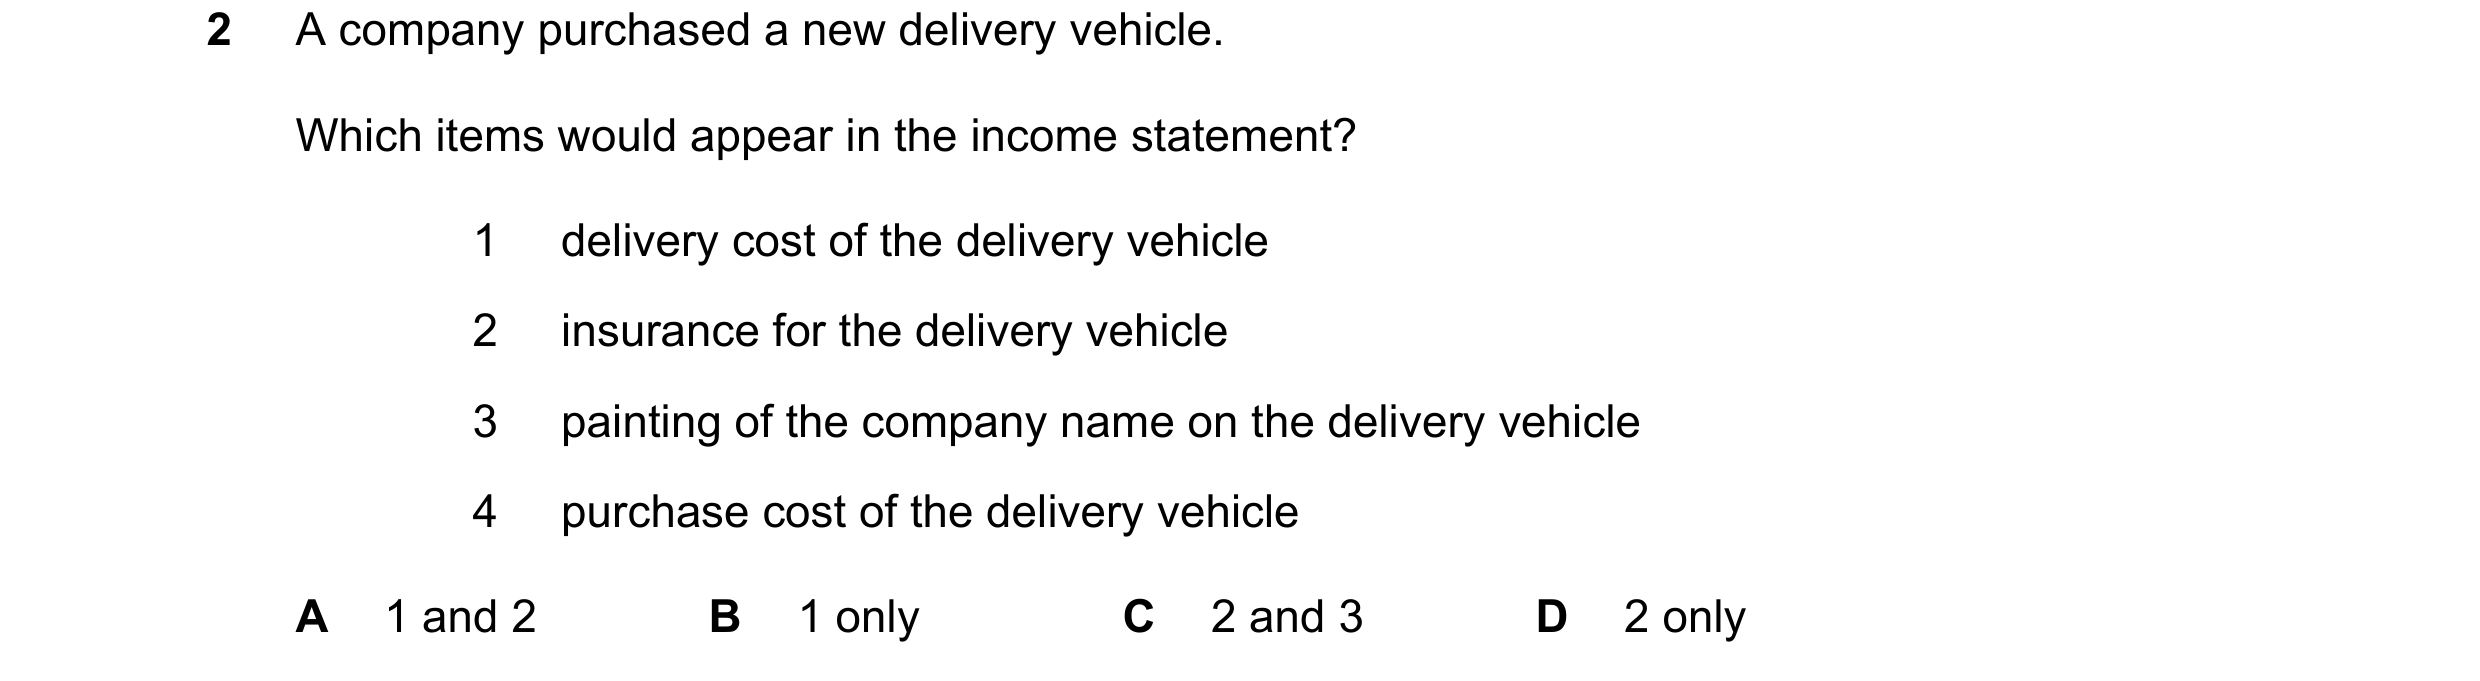
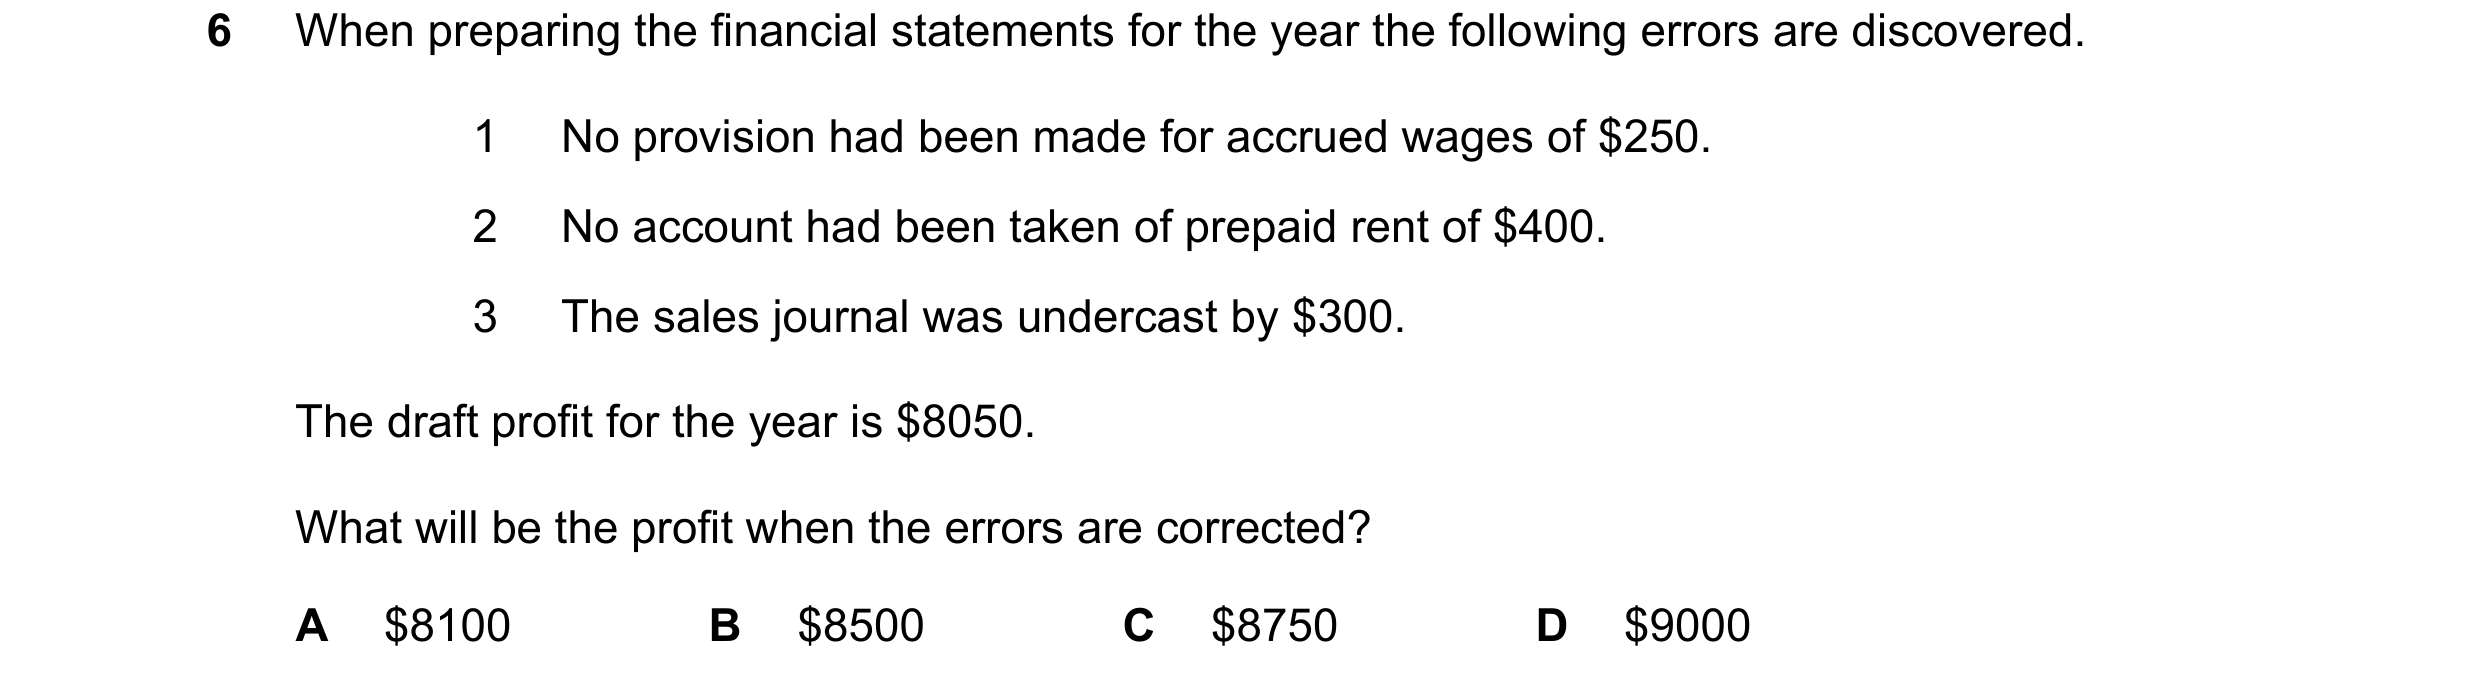
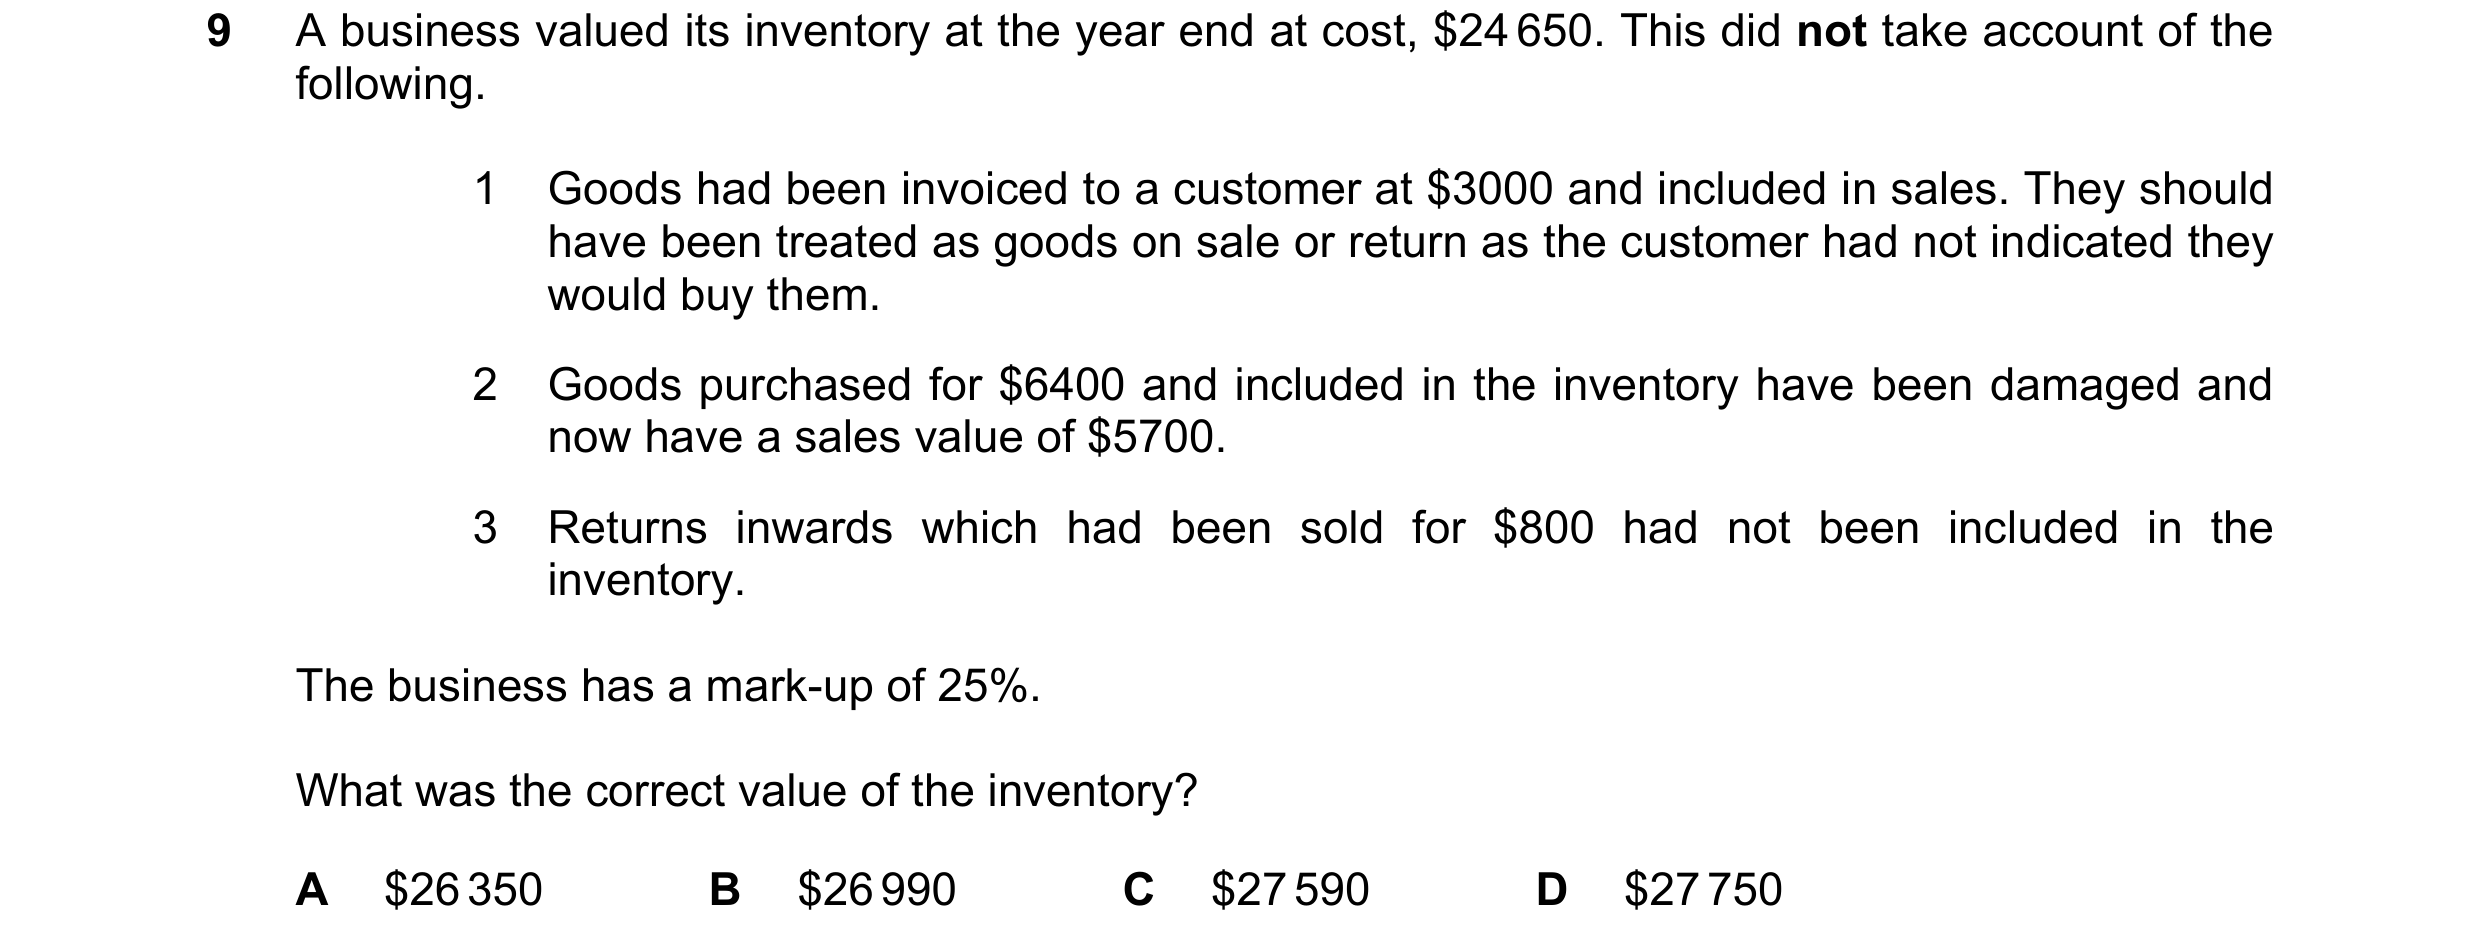 174 / 233
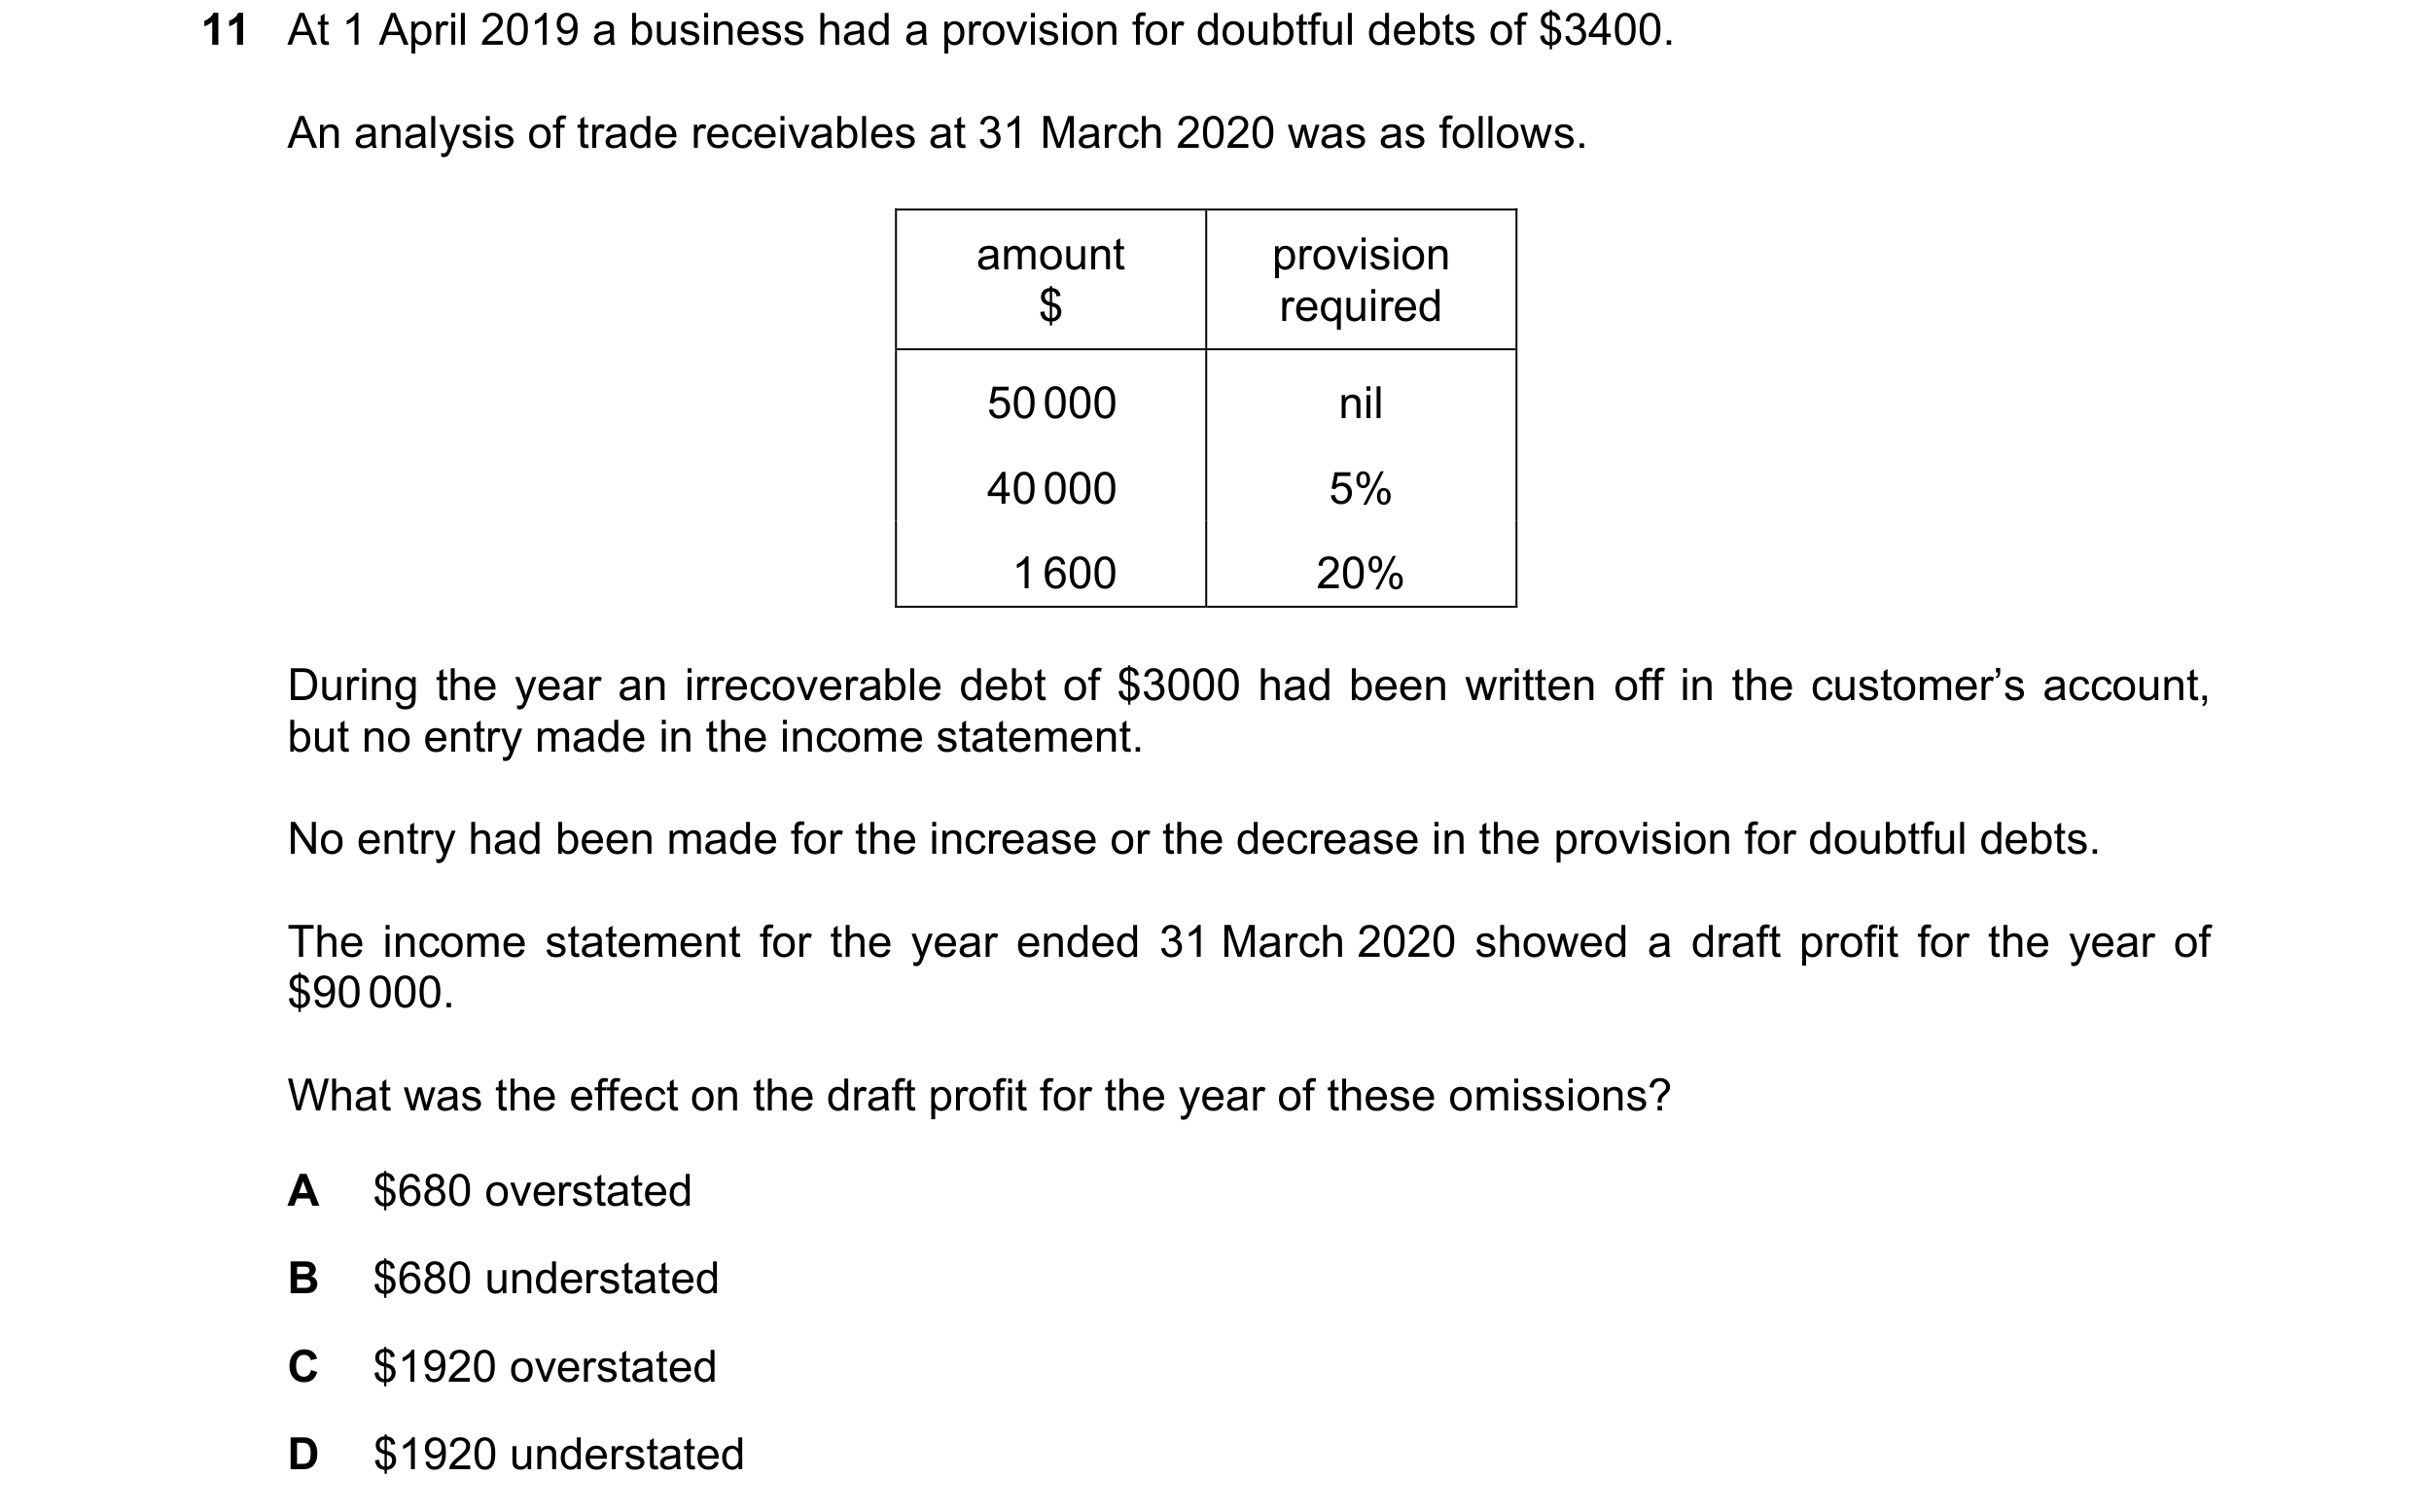
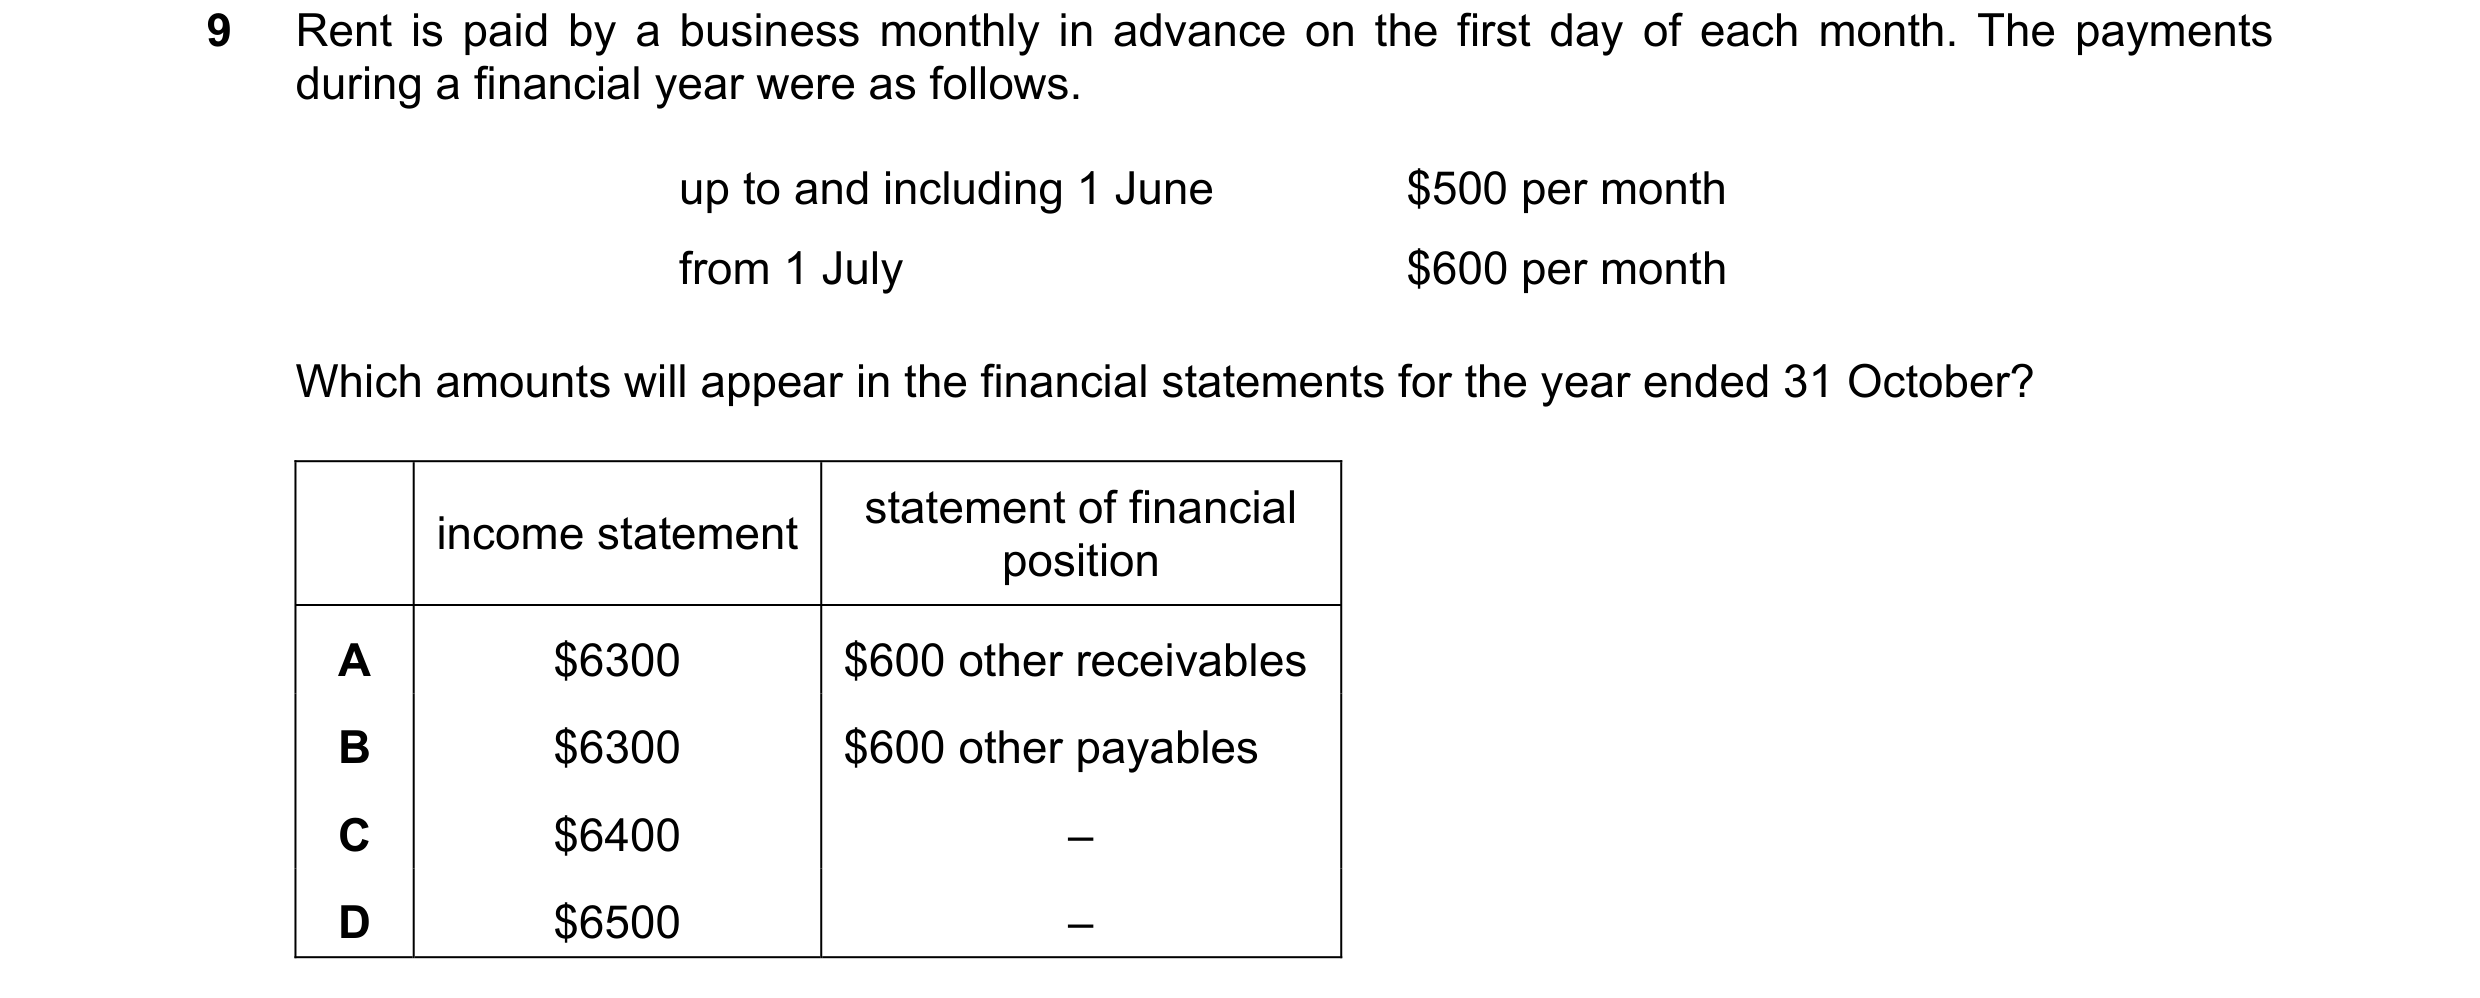
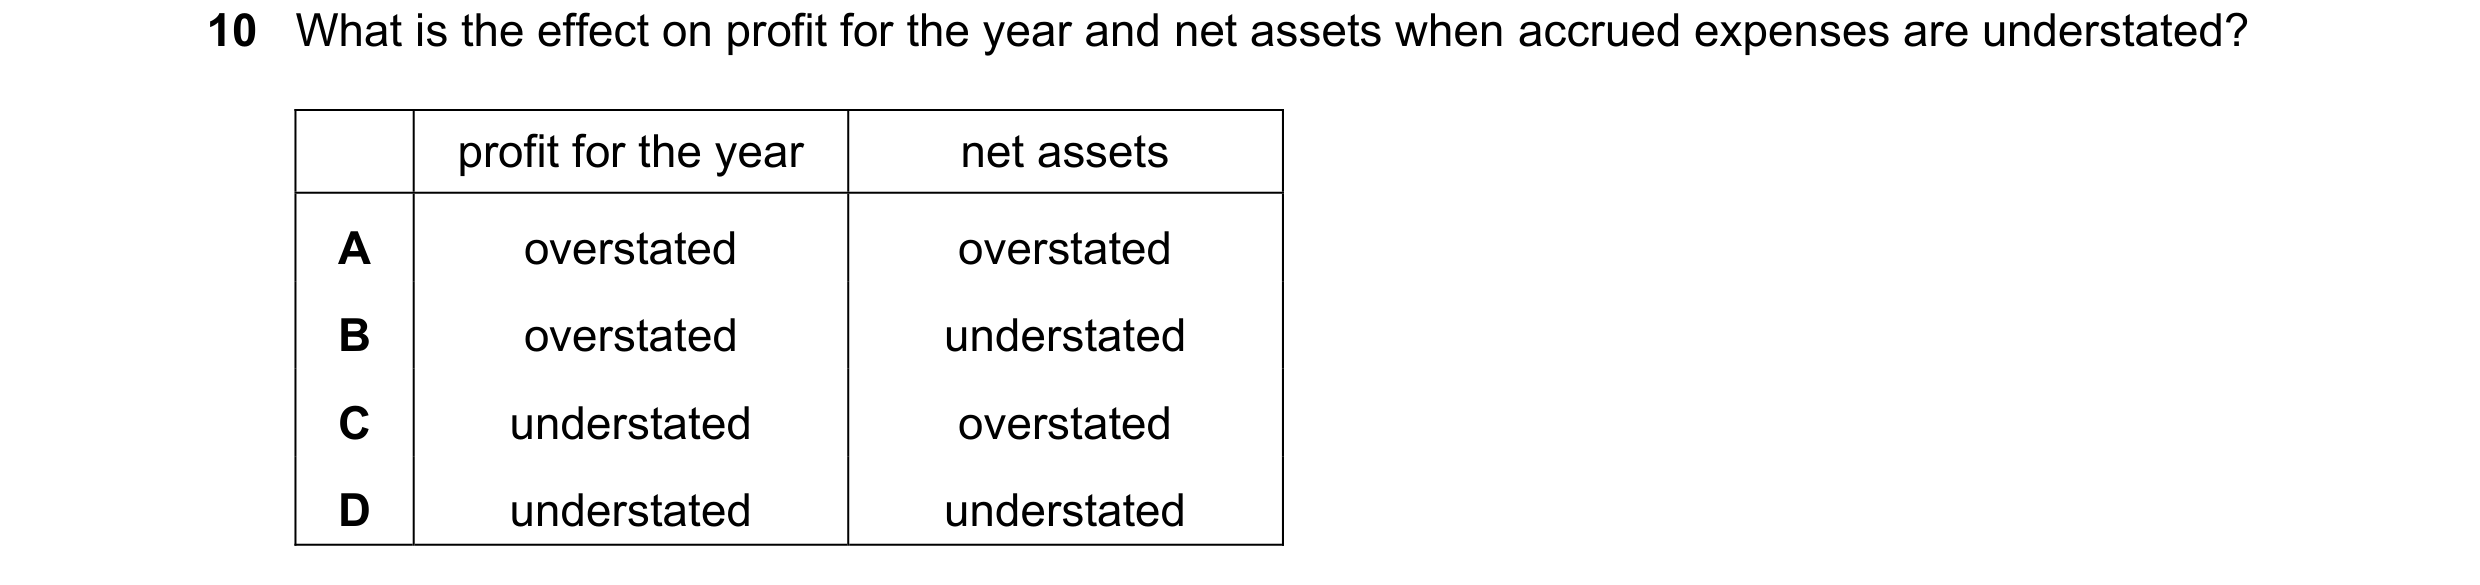 175 / 233
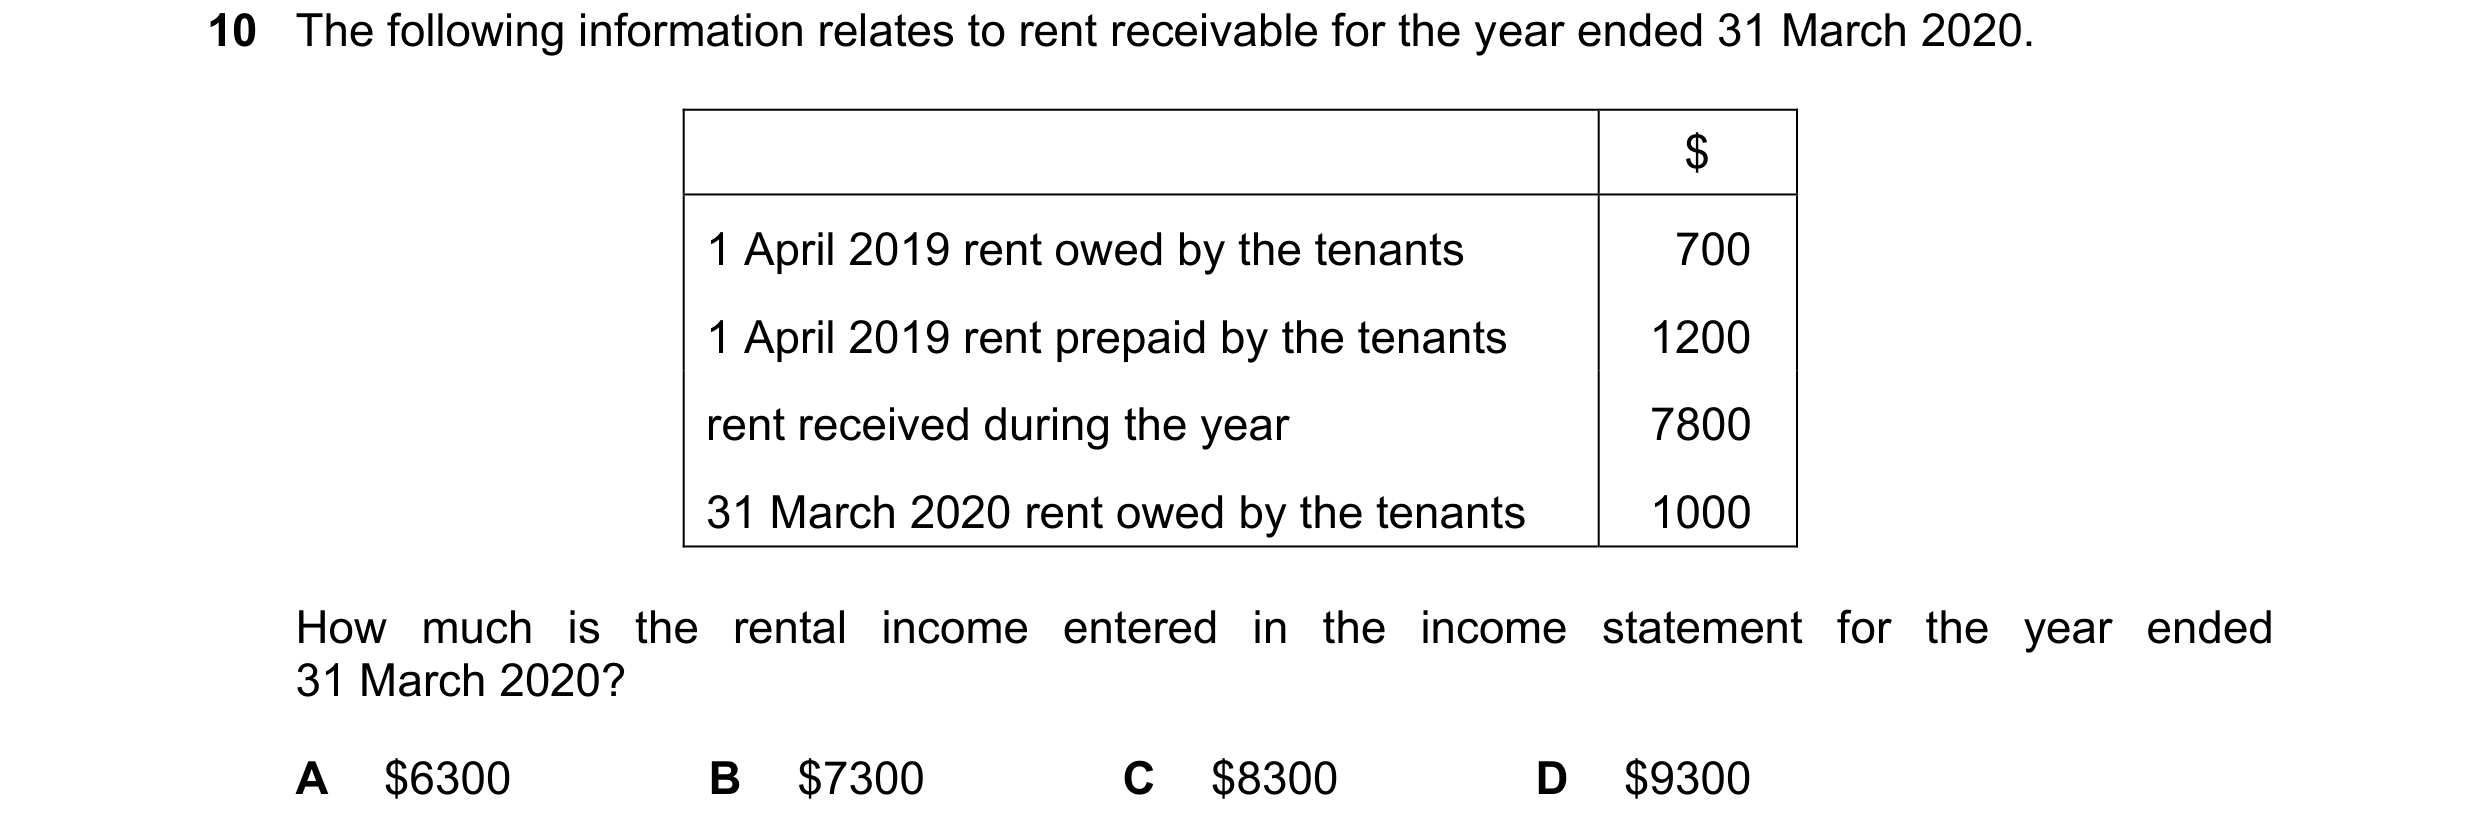
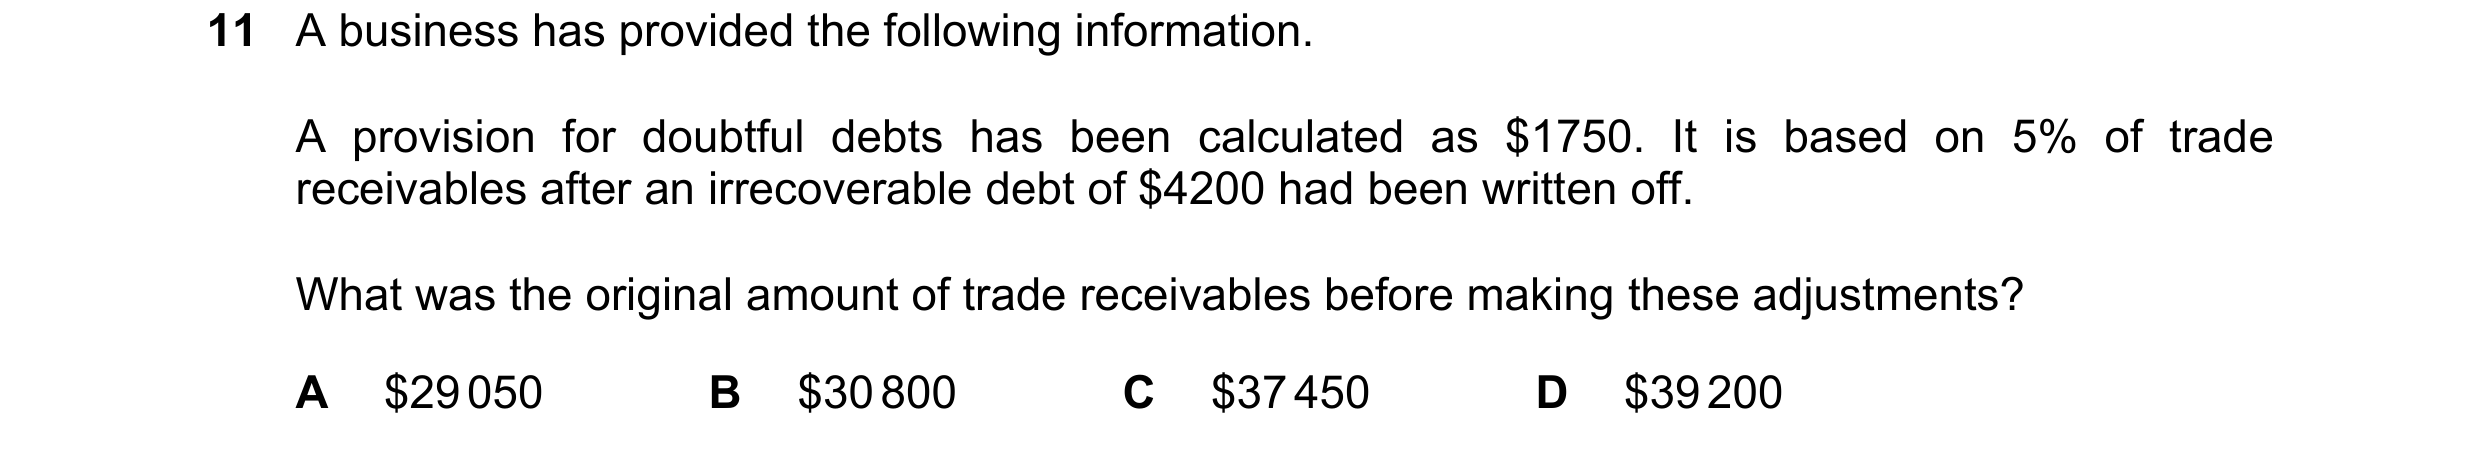 176 / 233
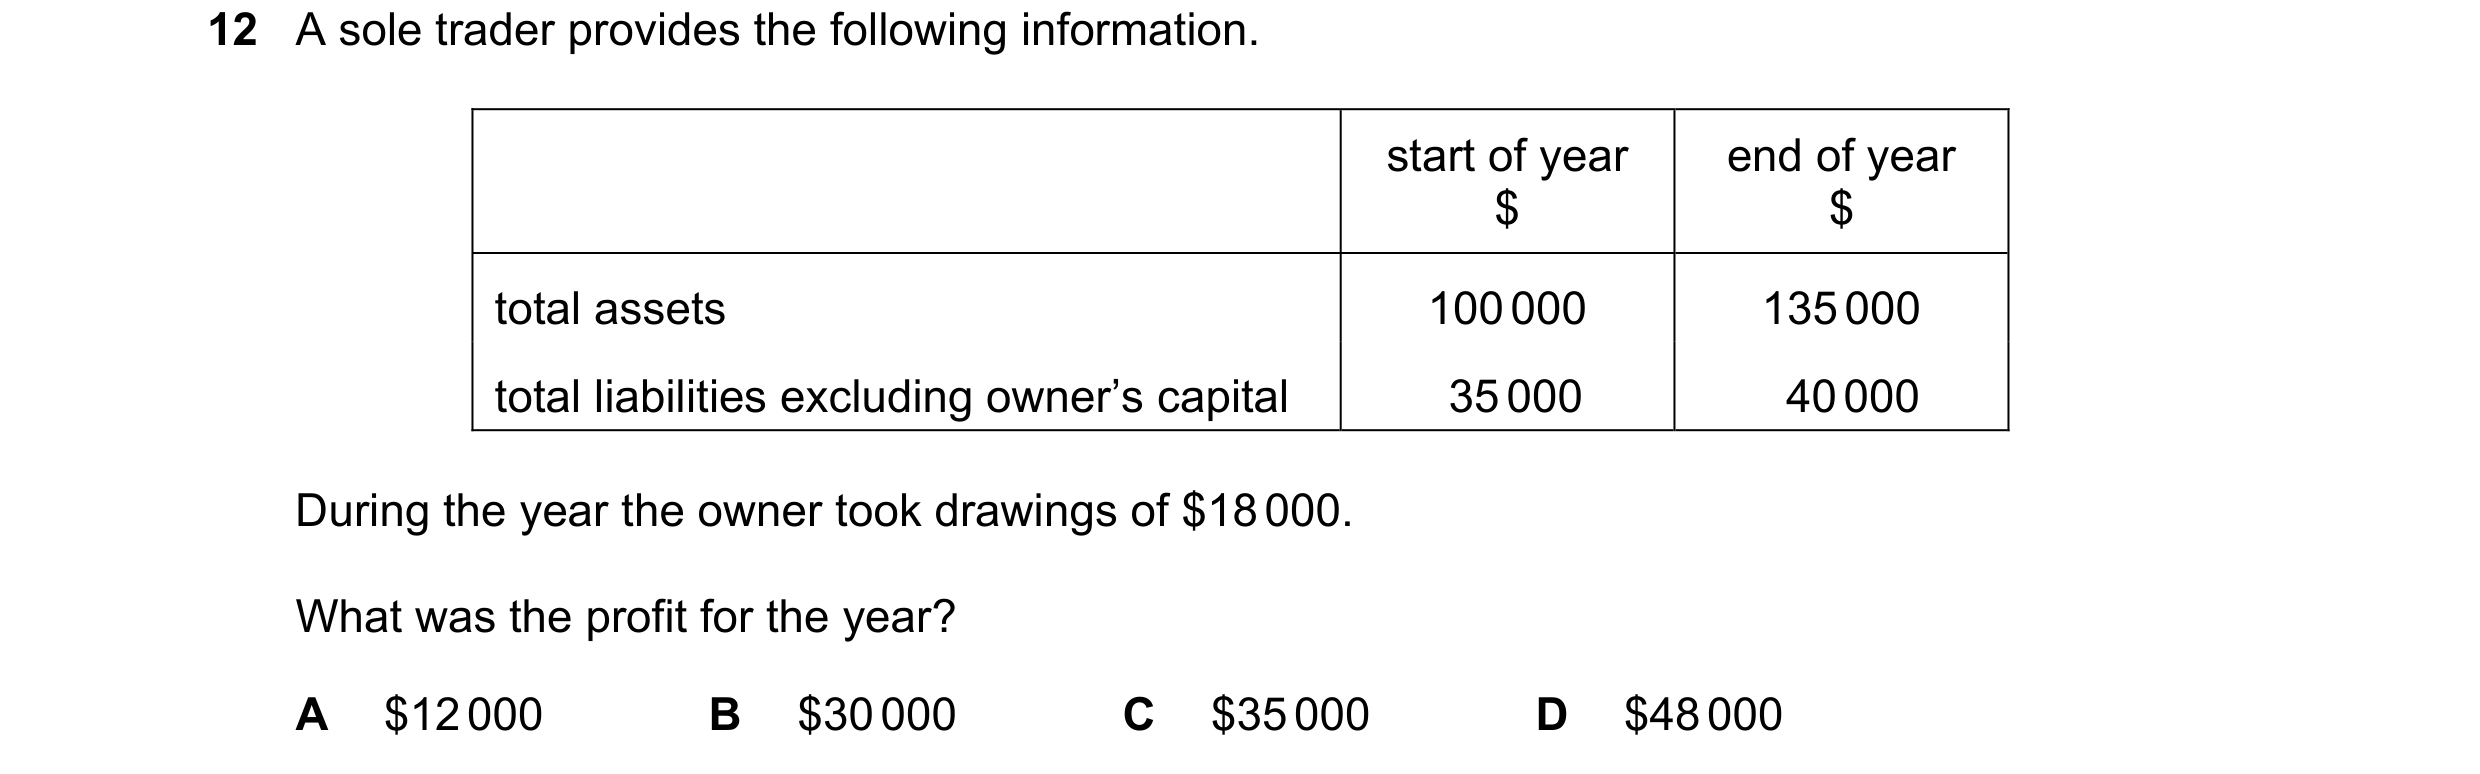
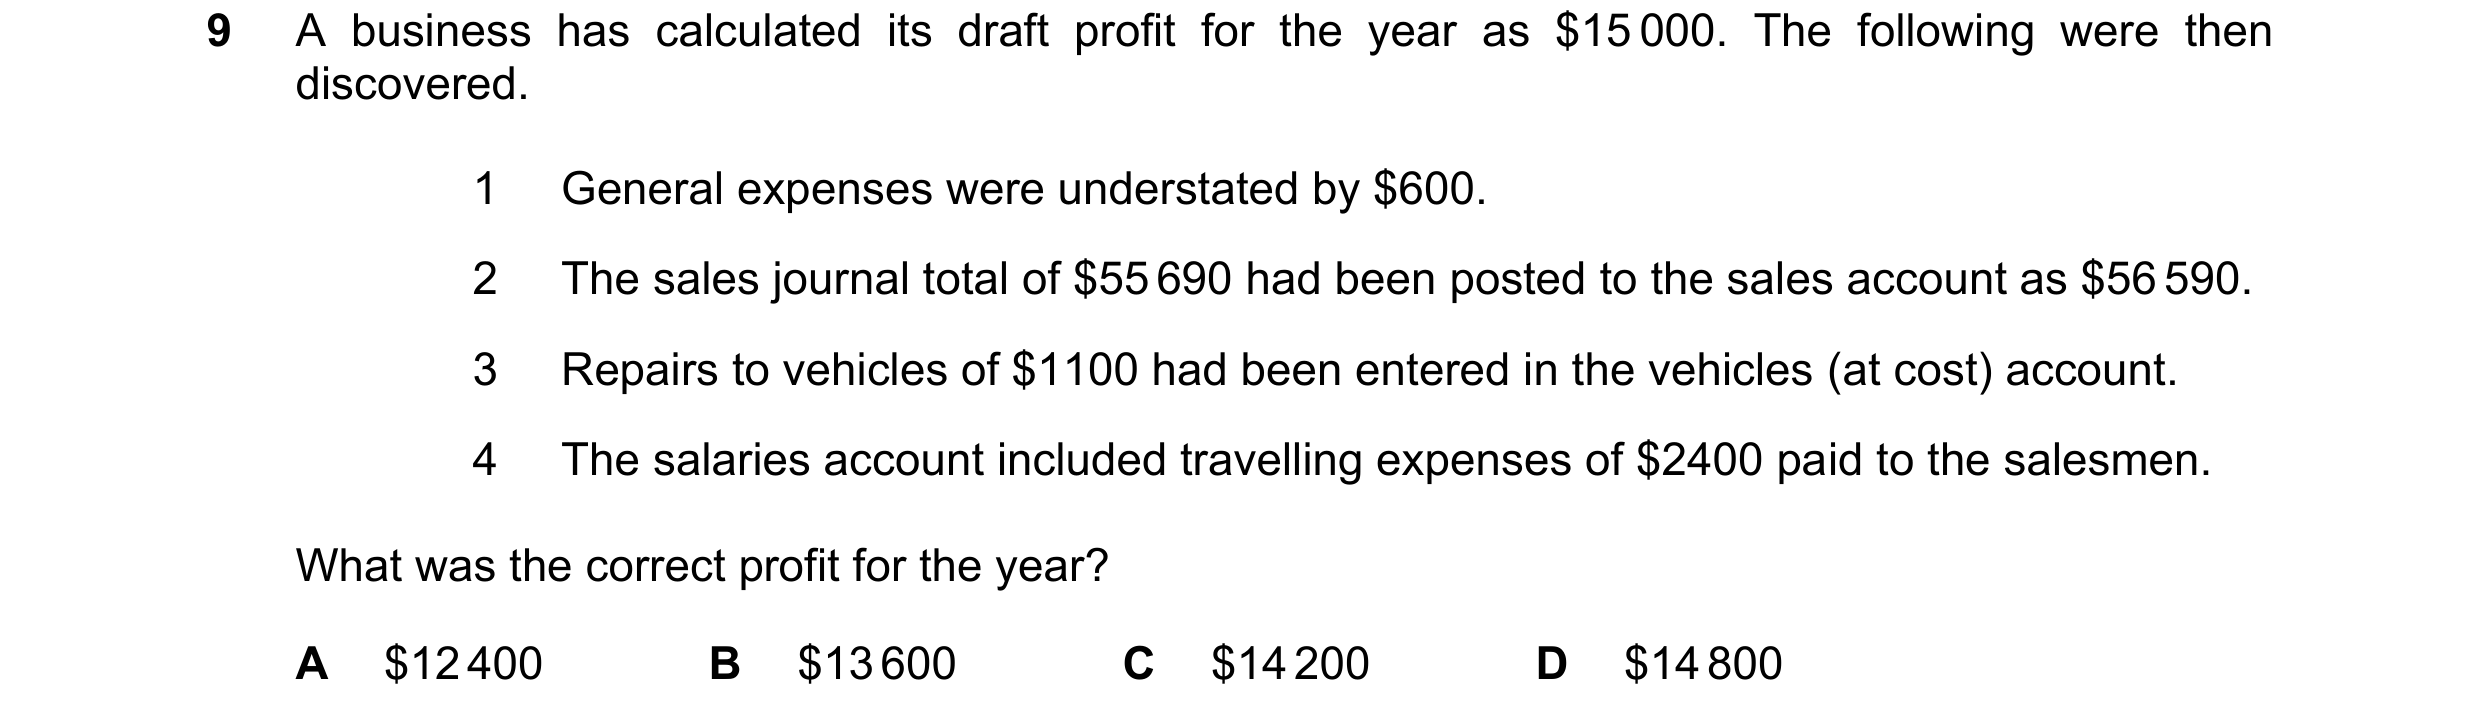
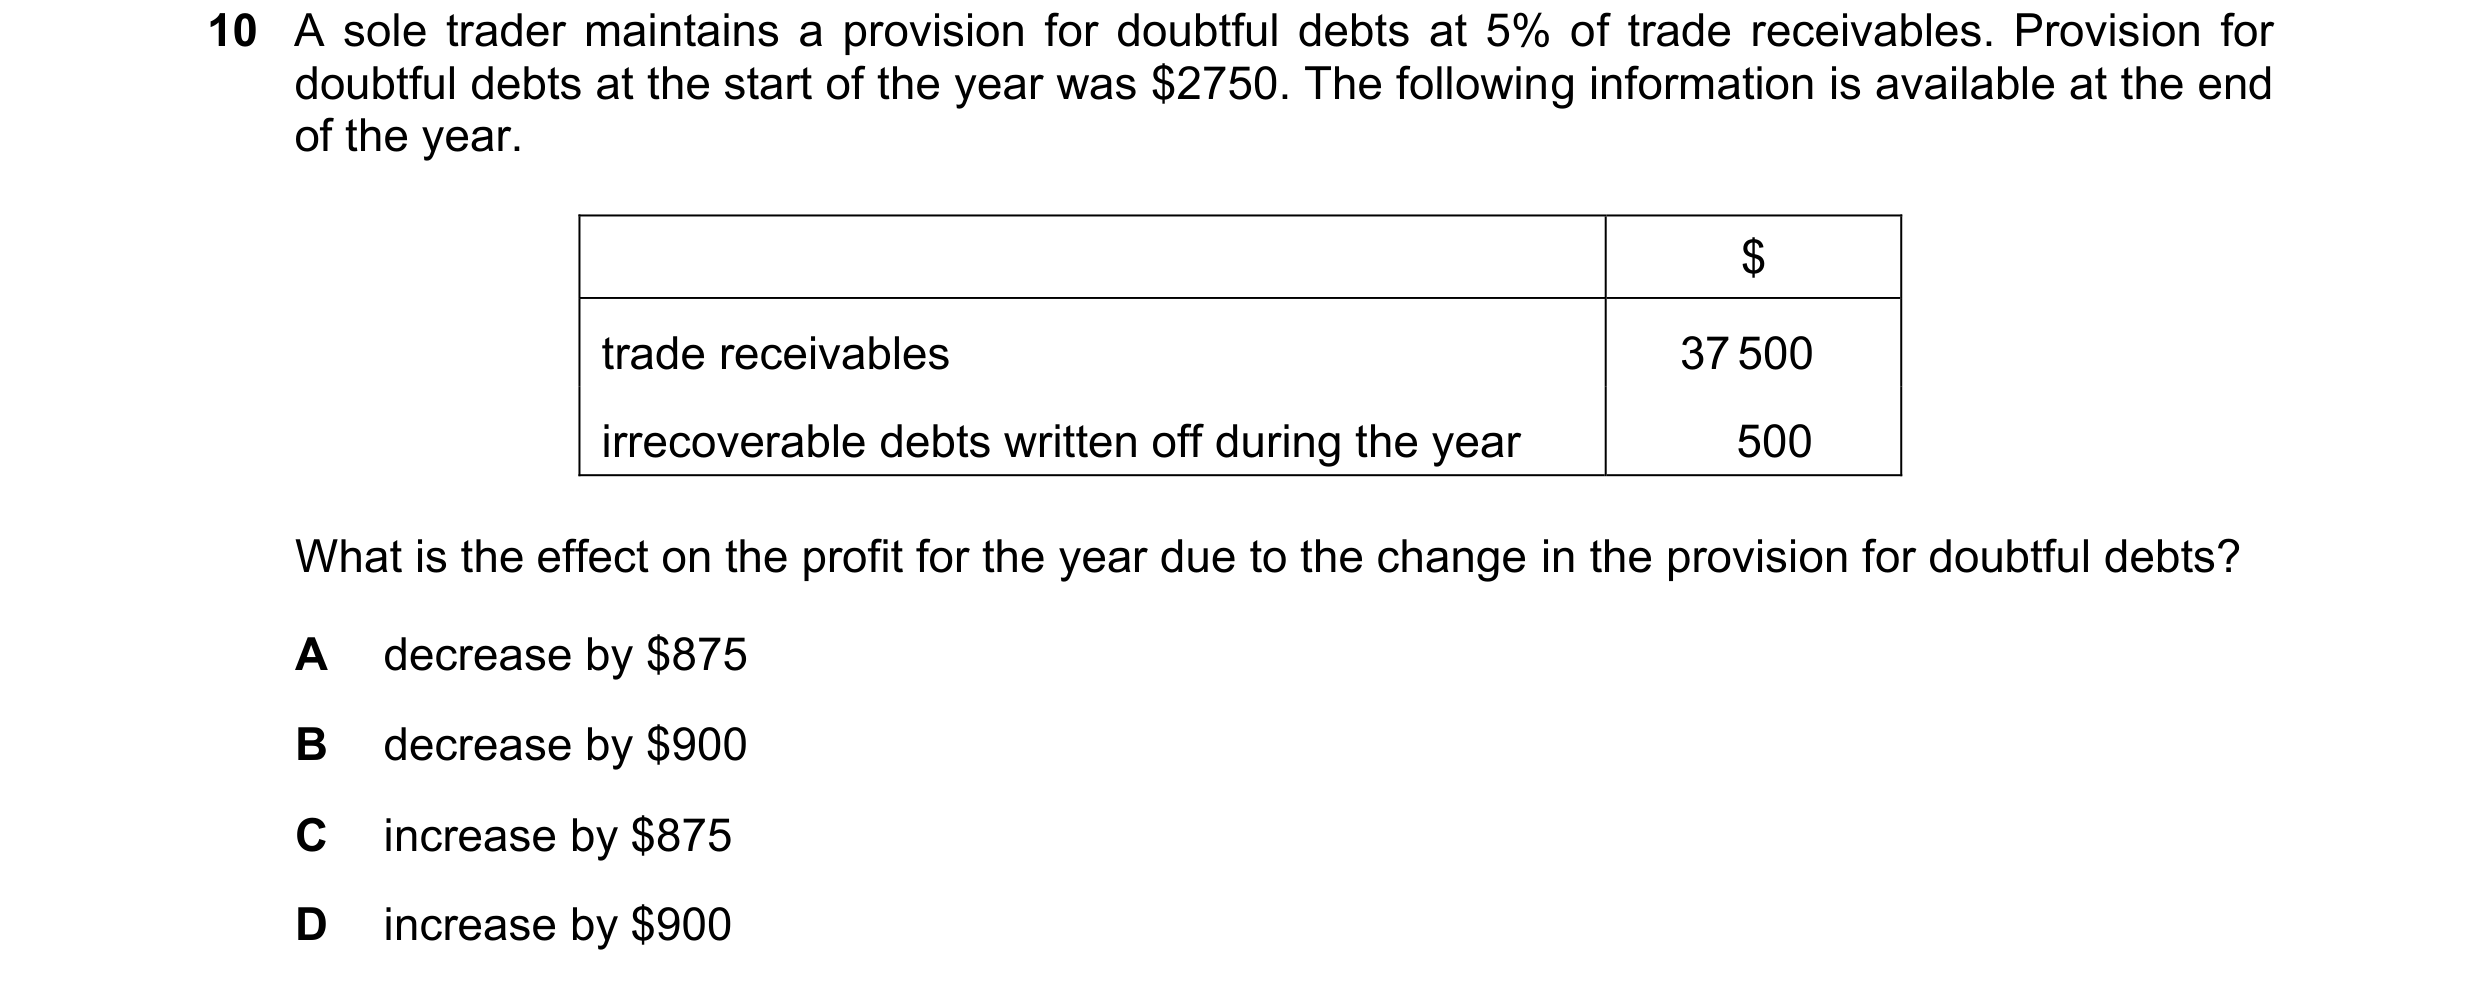
 177 / 233
 178 / 233
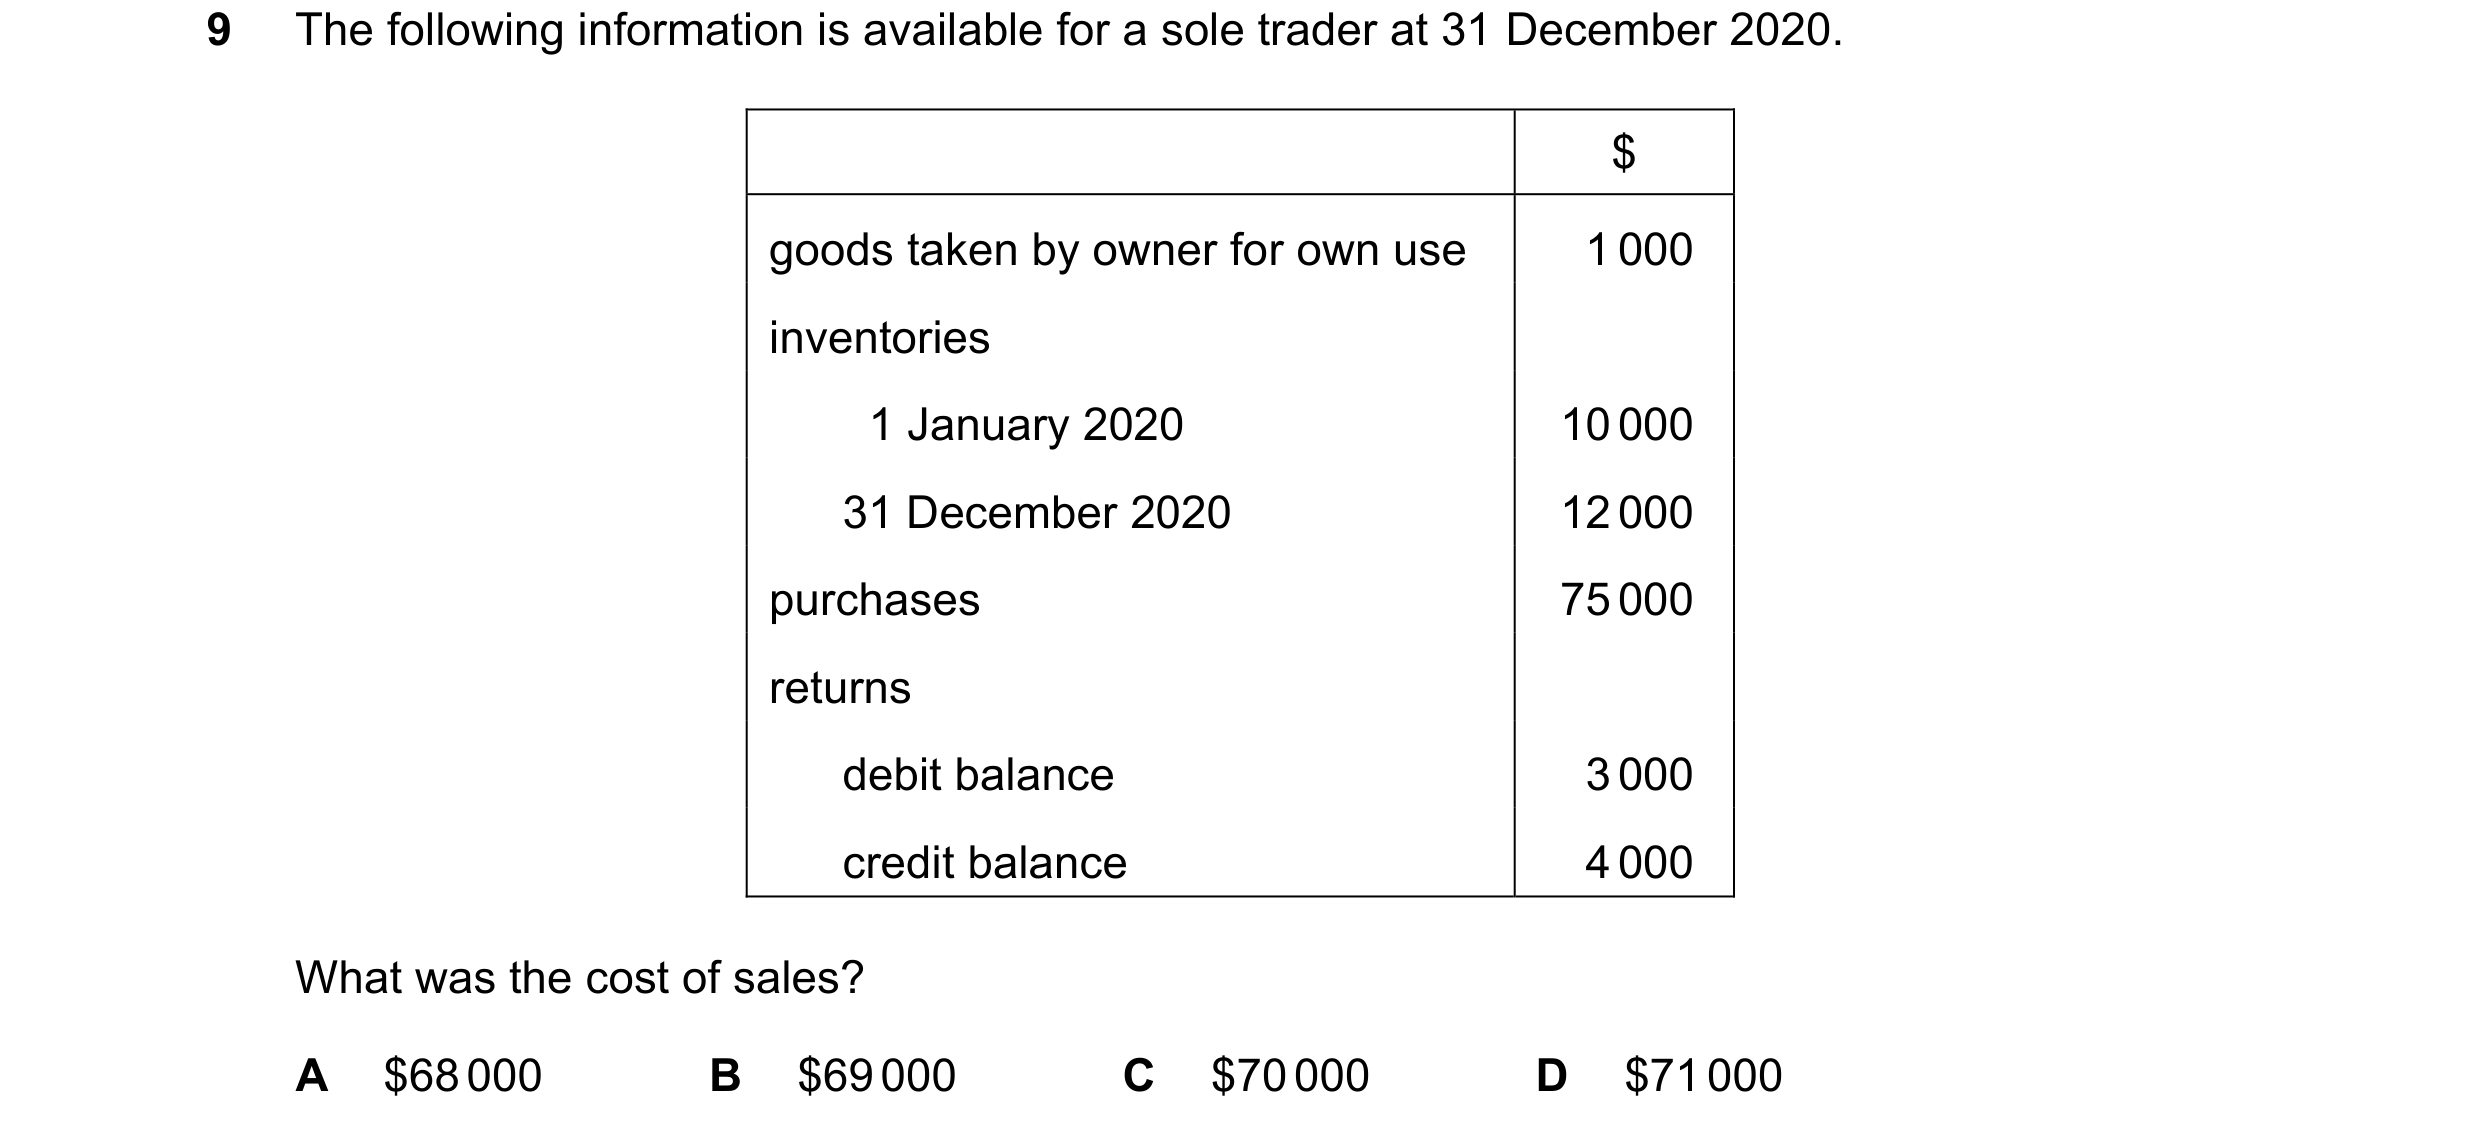
 179 / 233
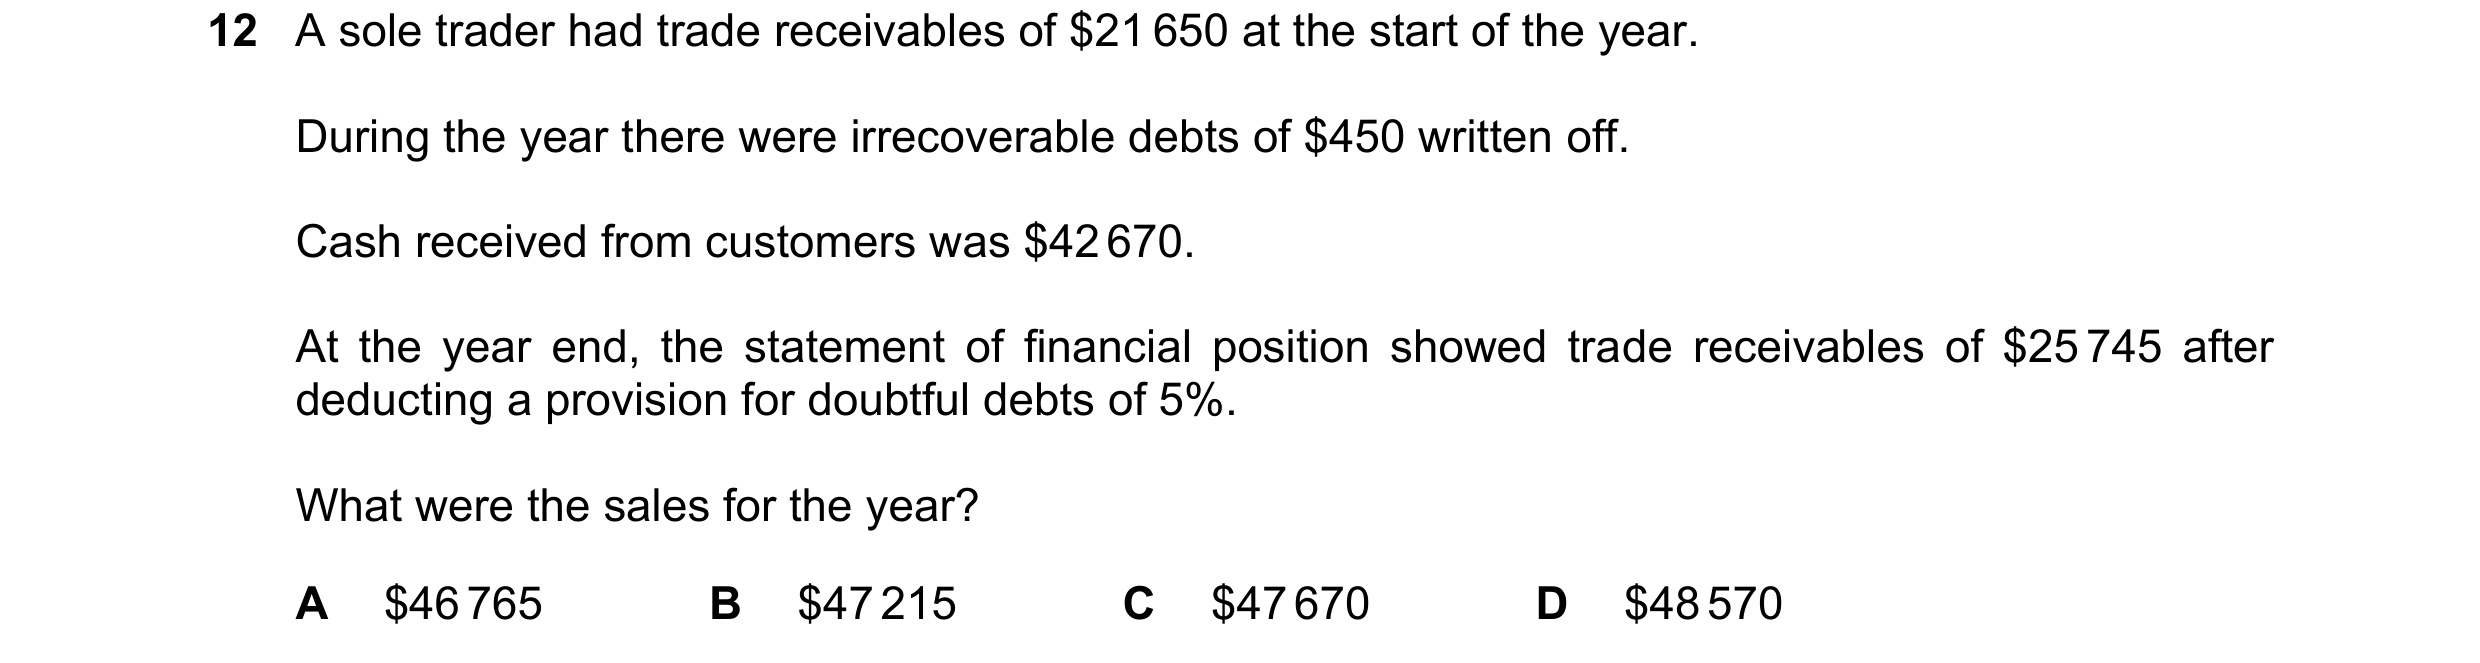
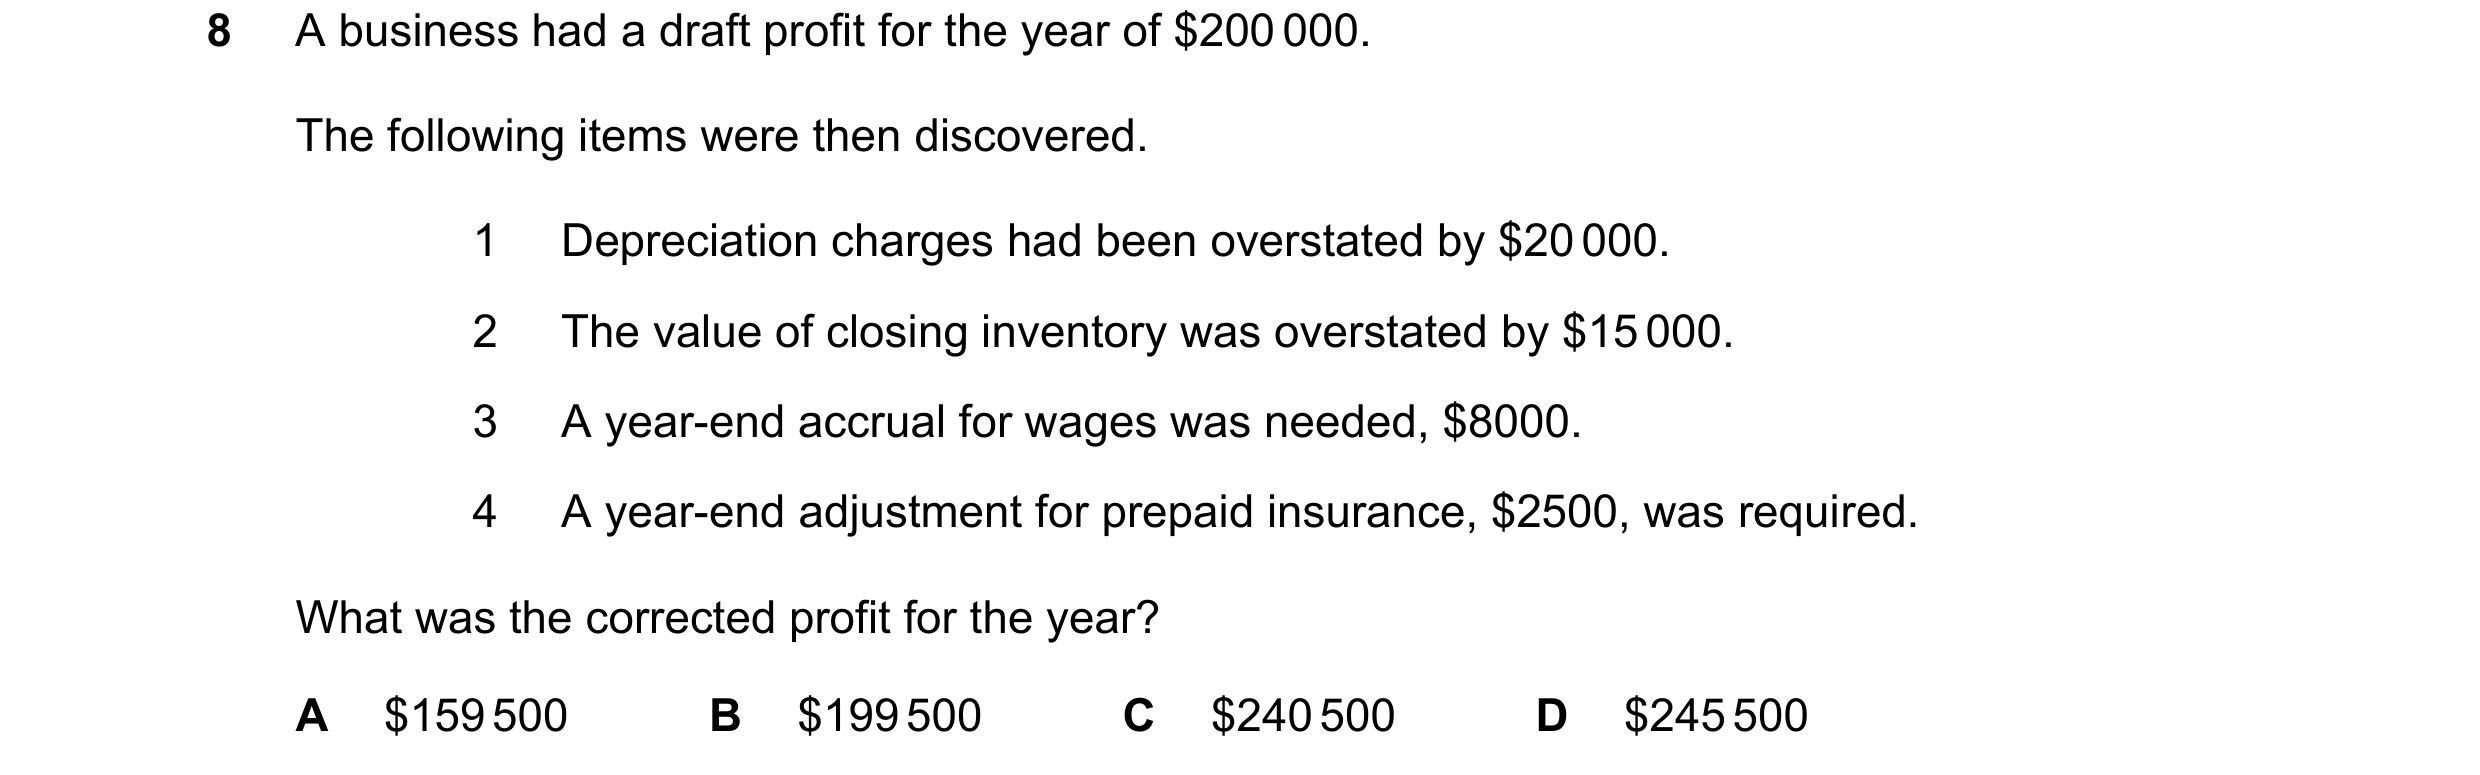
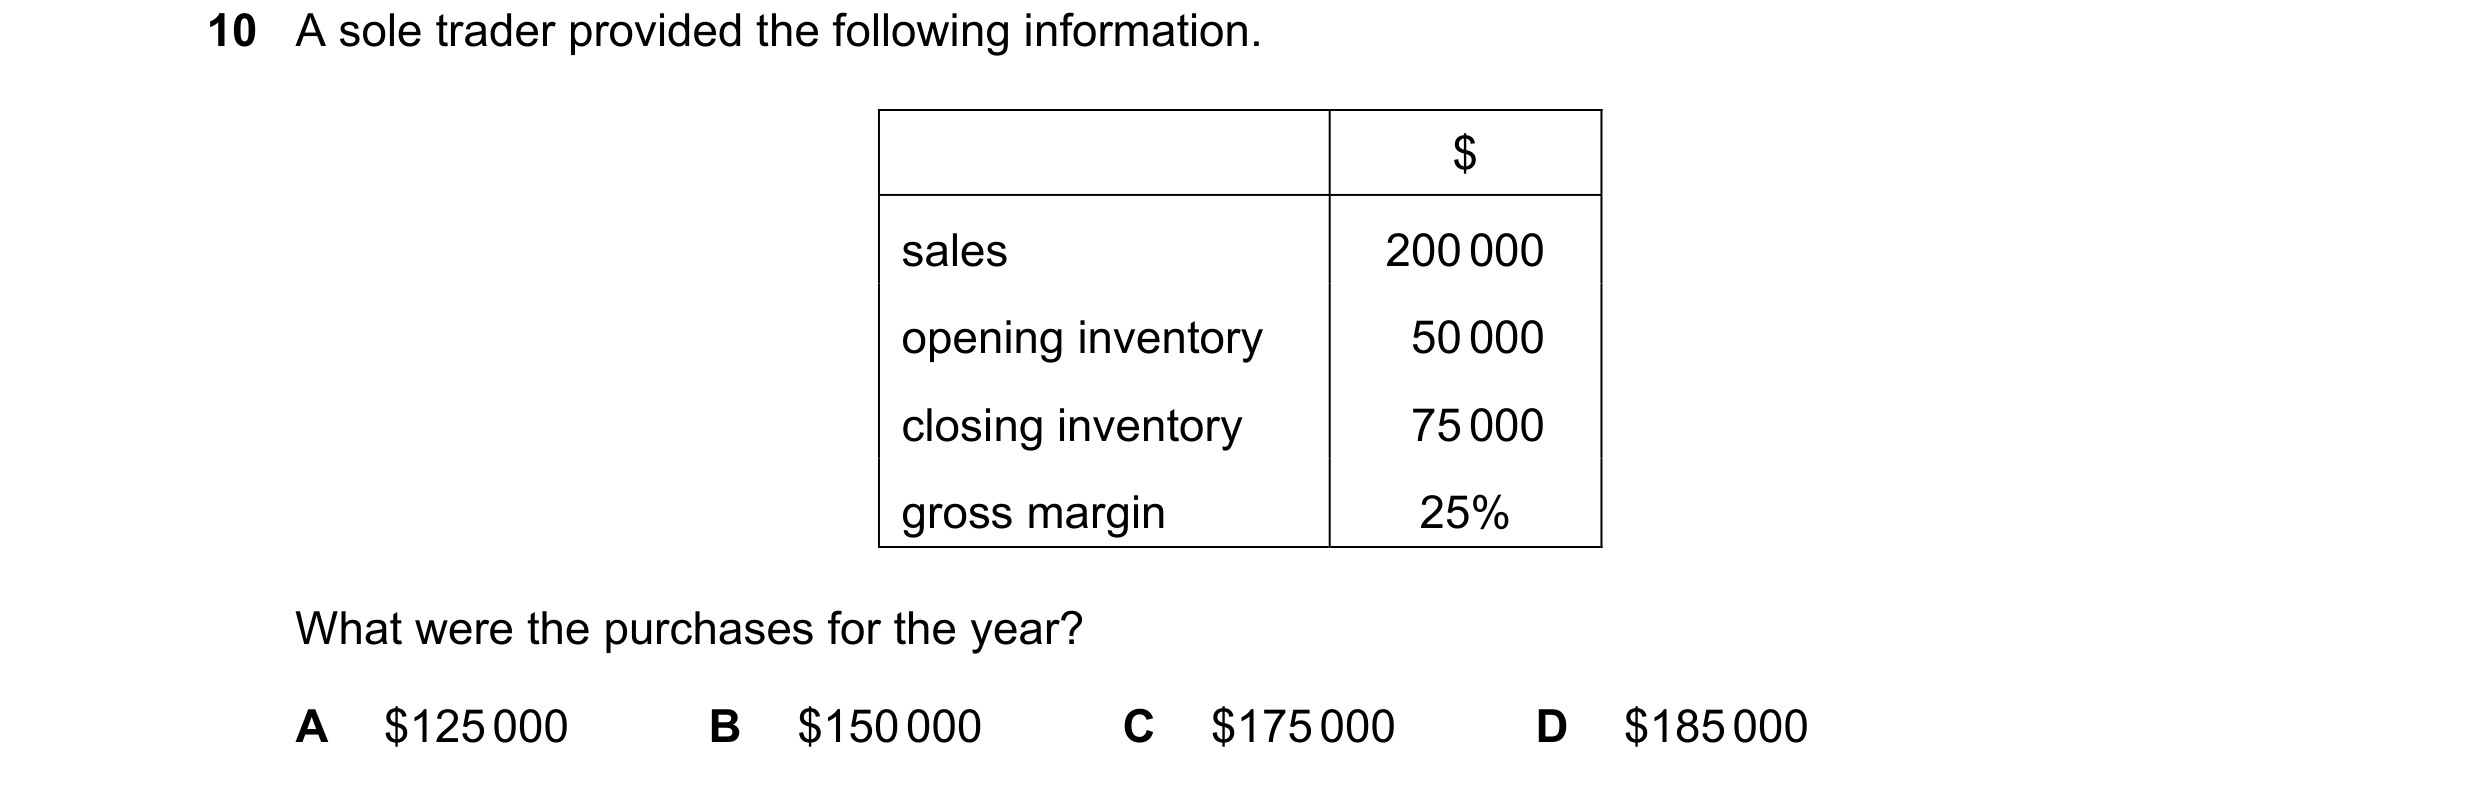
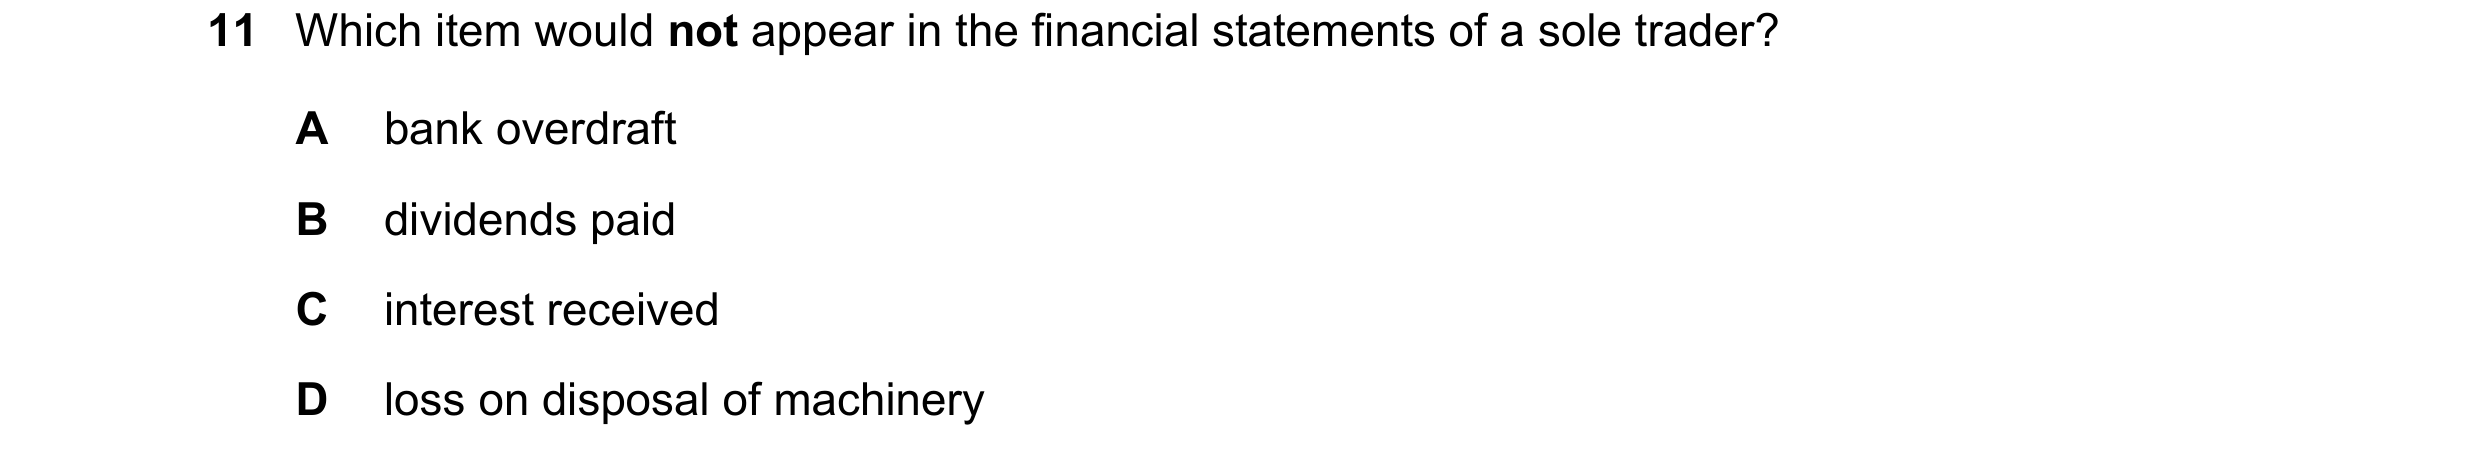
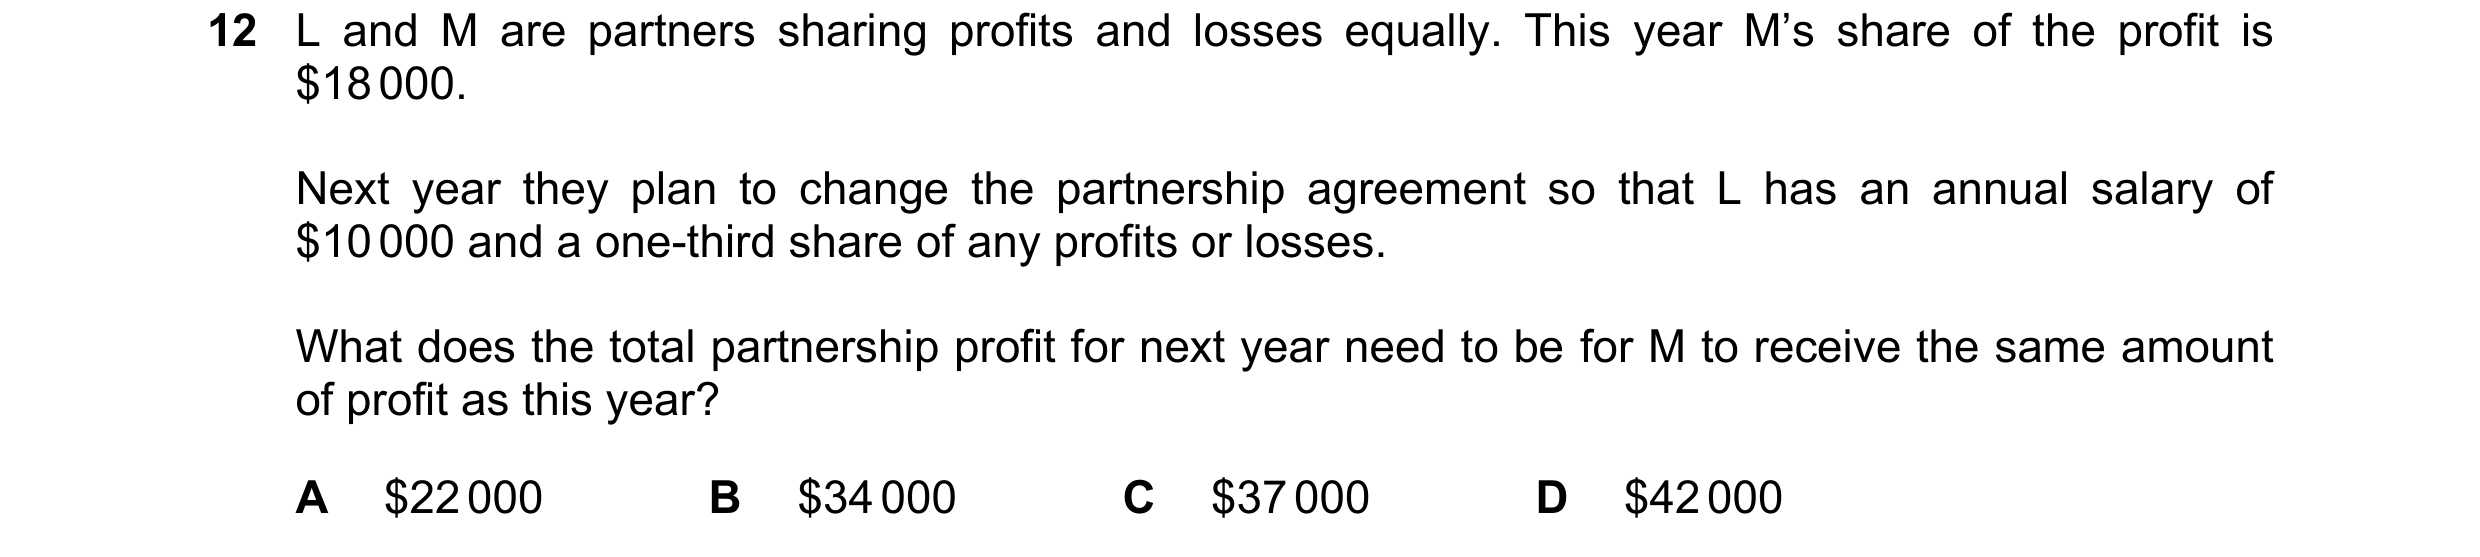 180 / 233
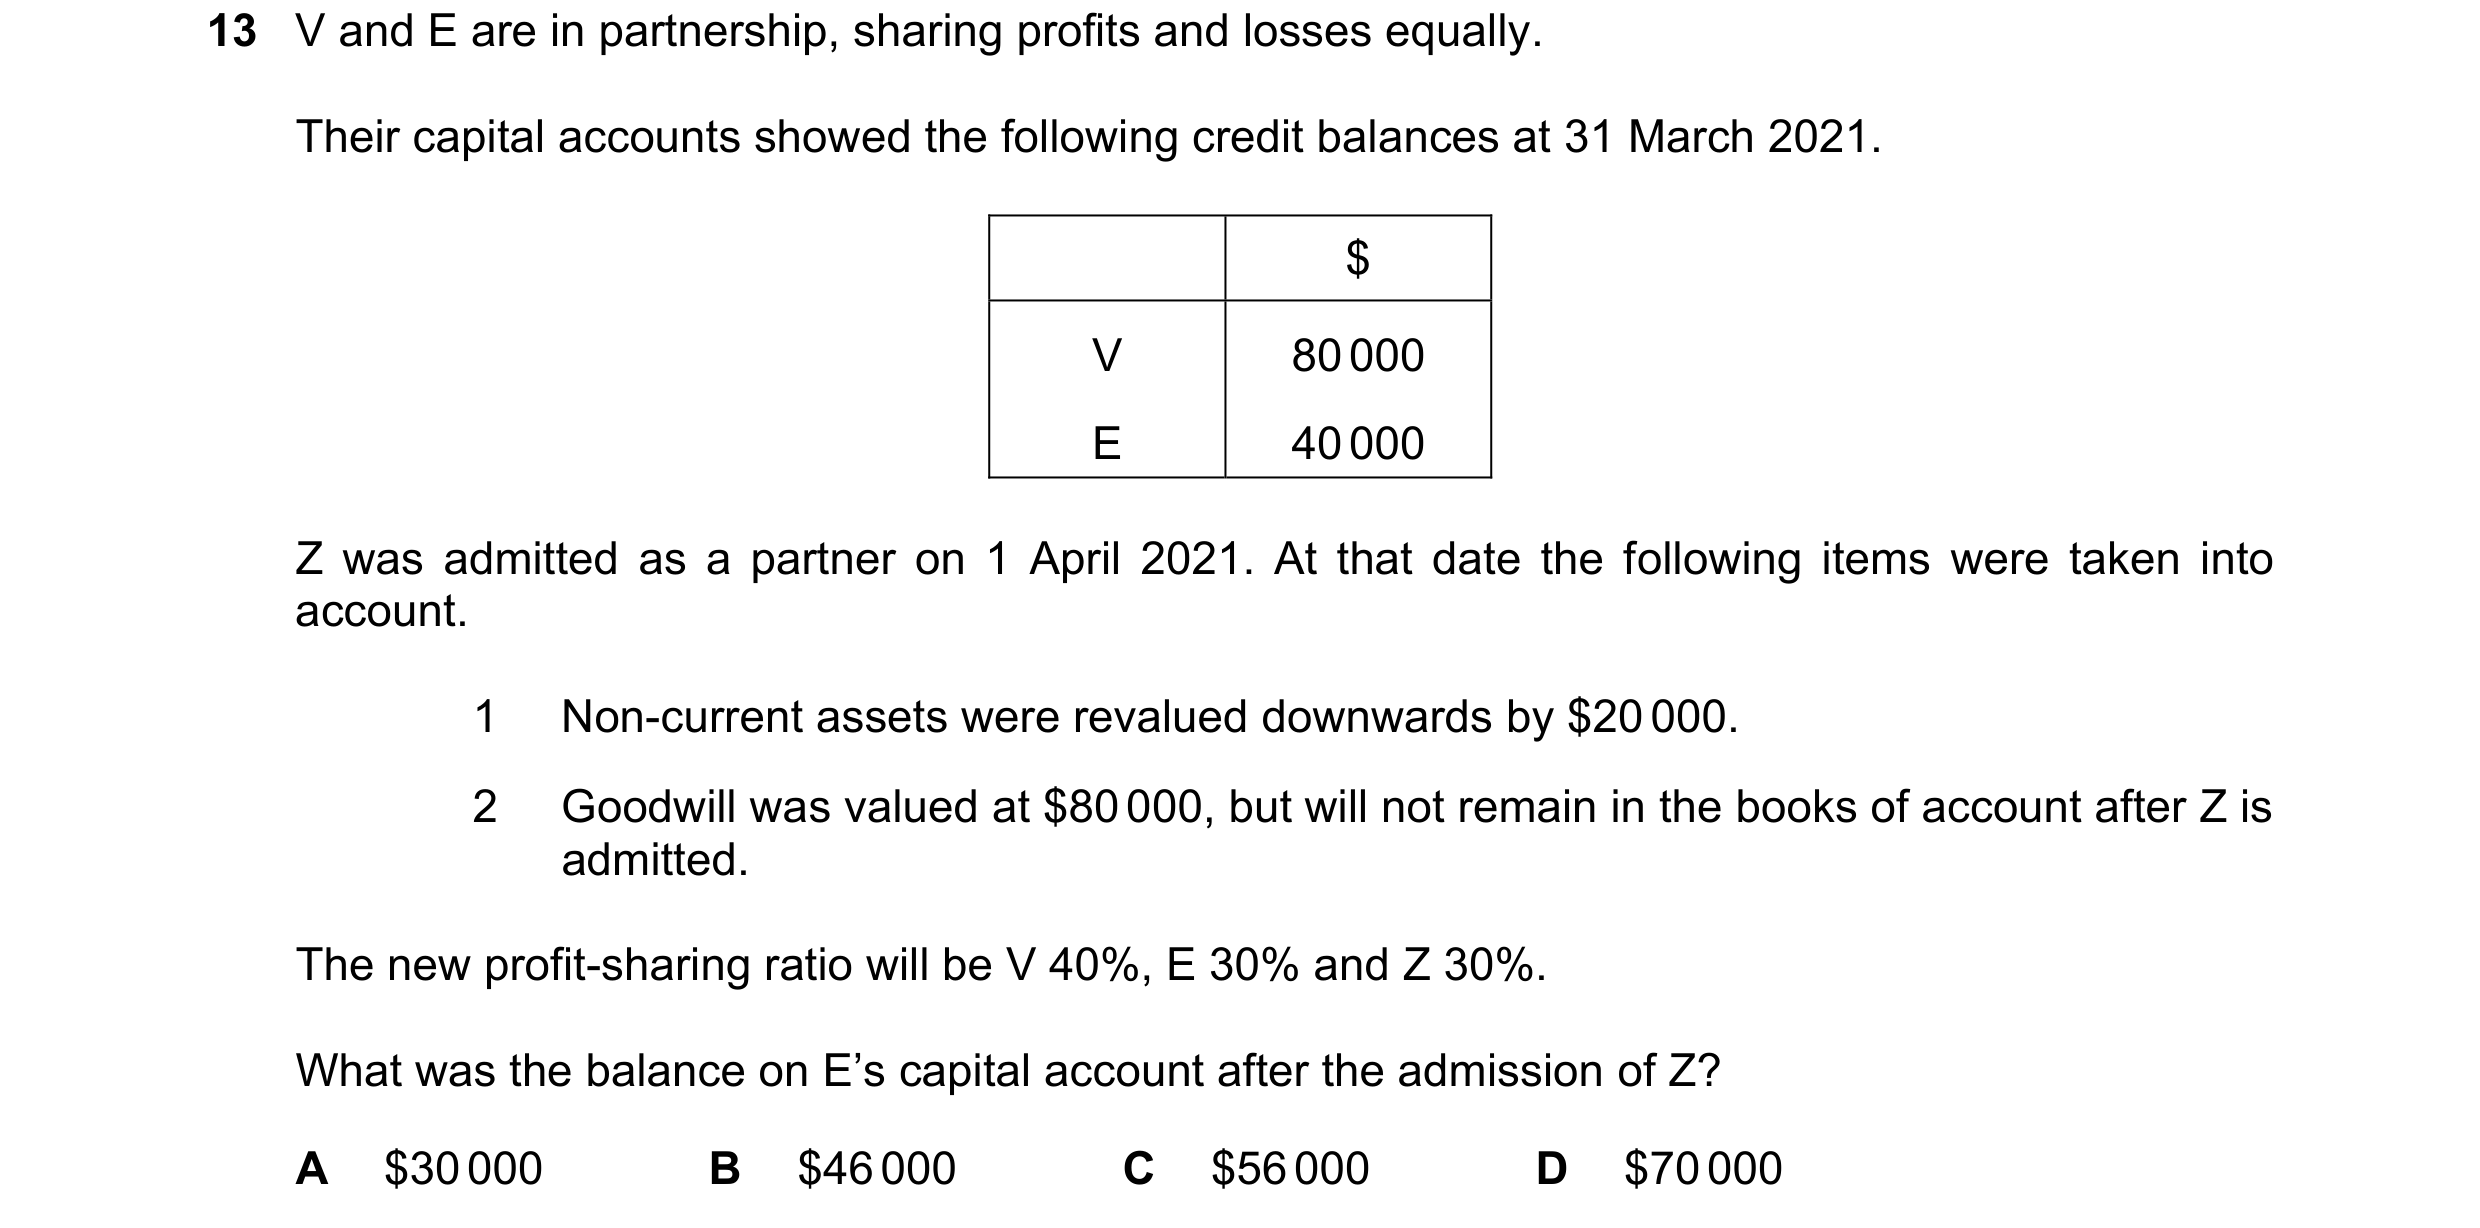
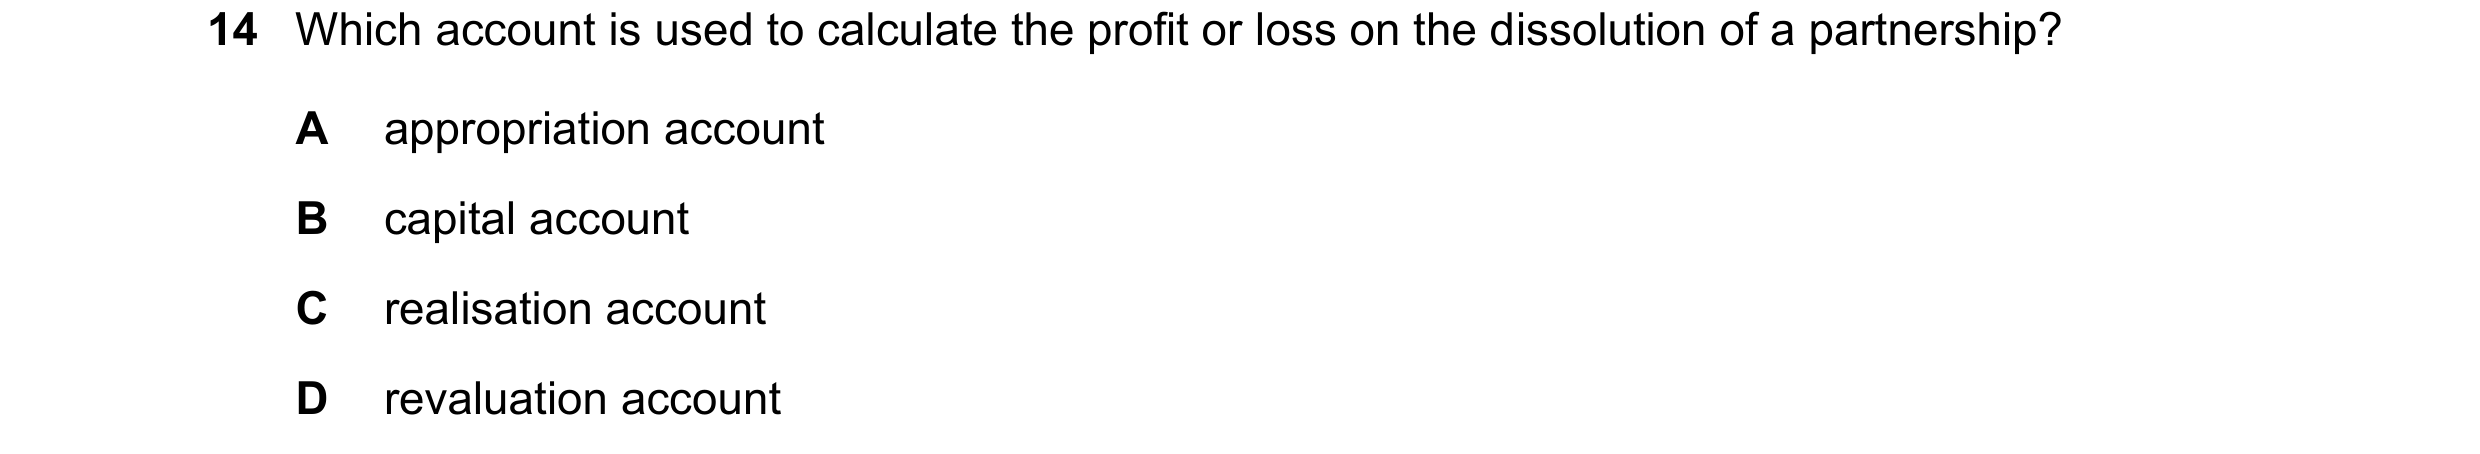
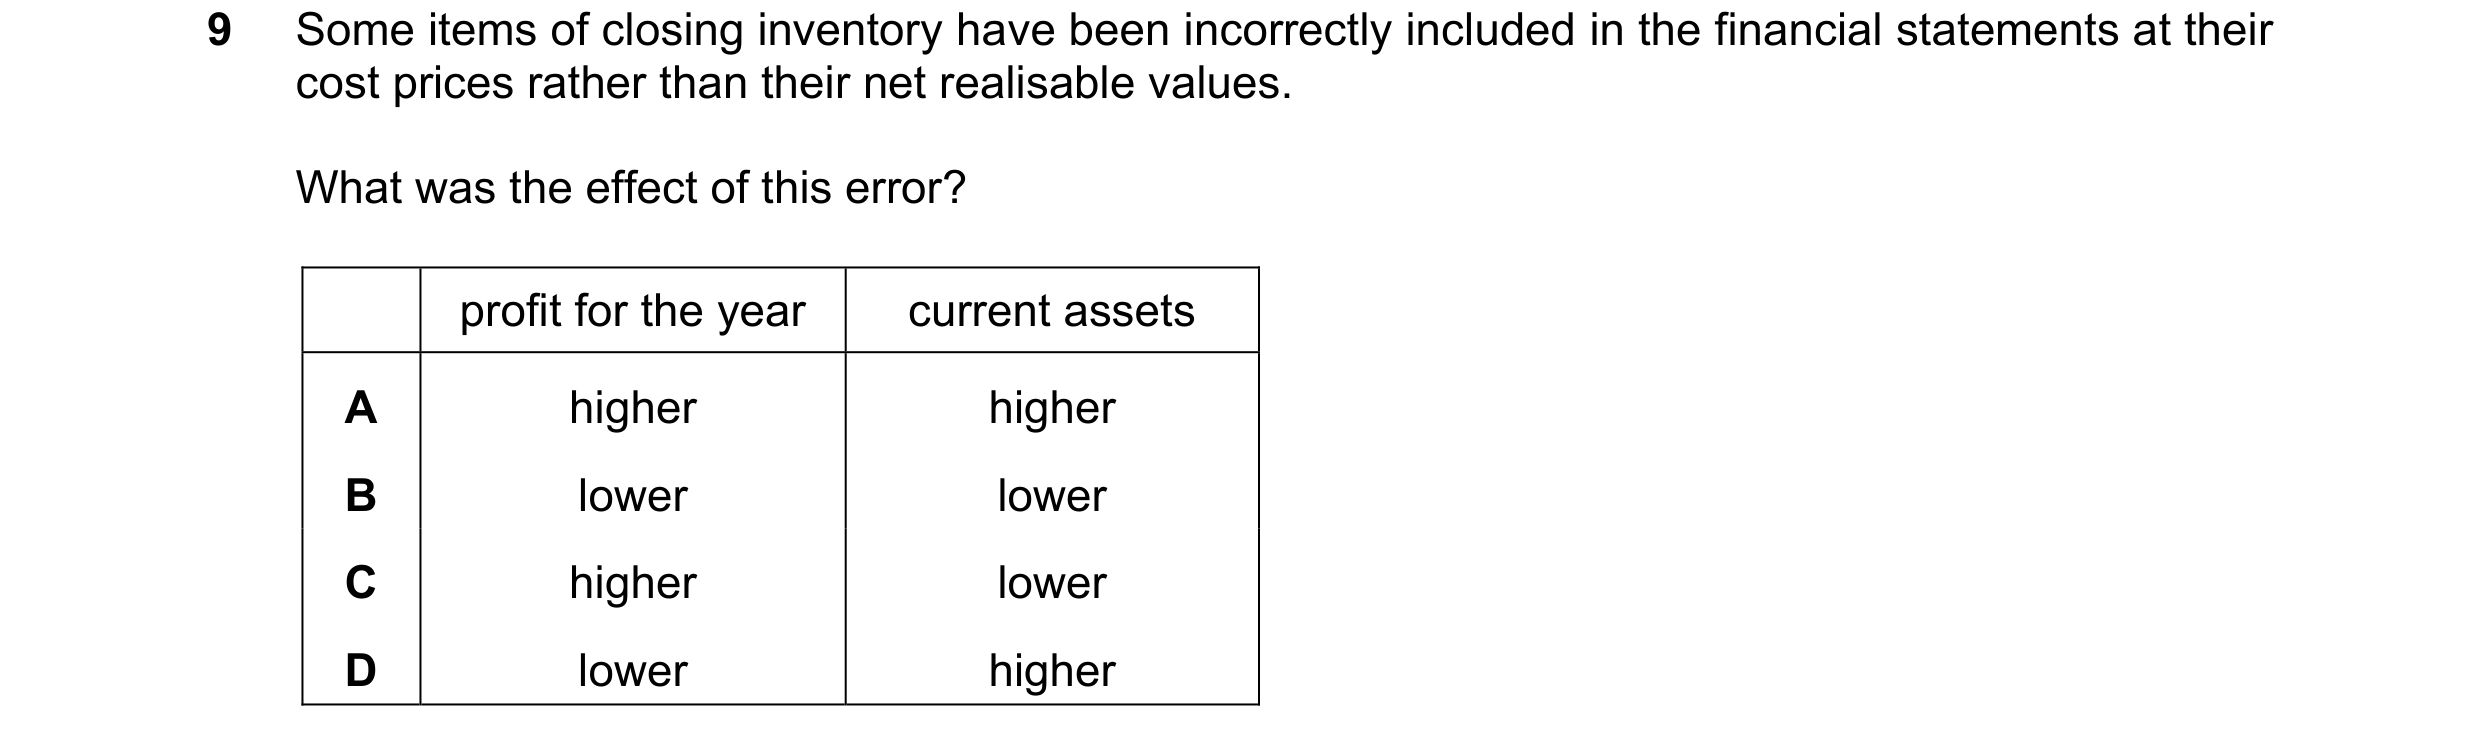 181 / 233
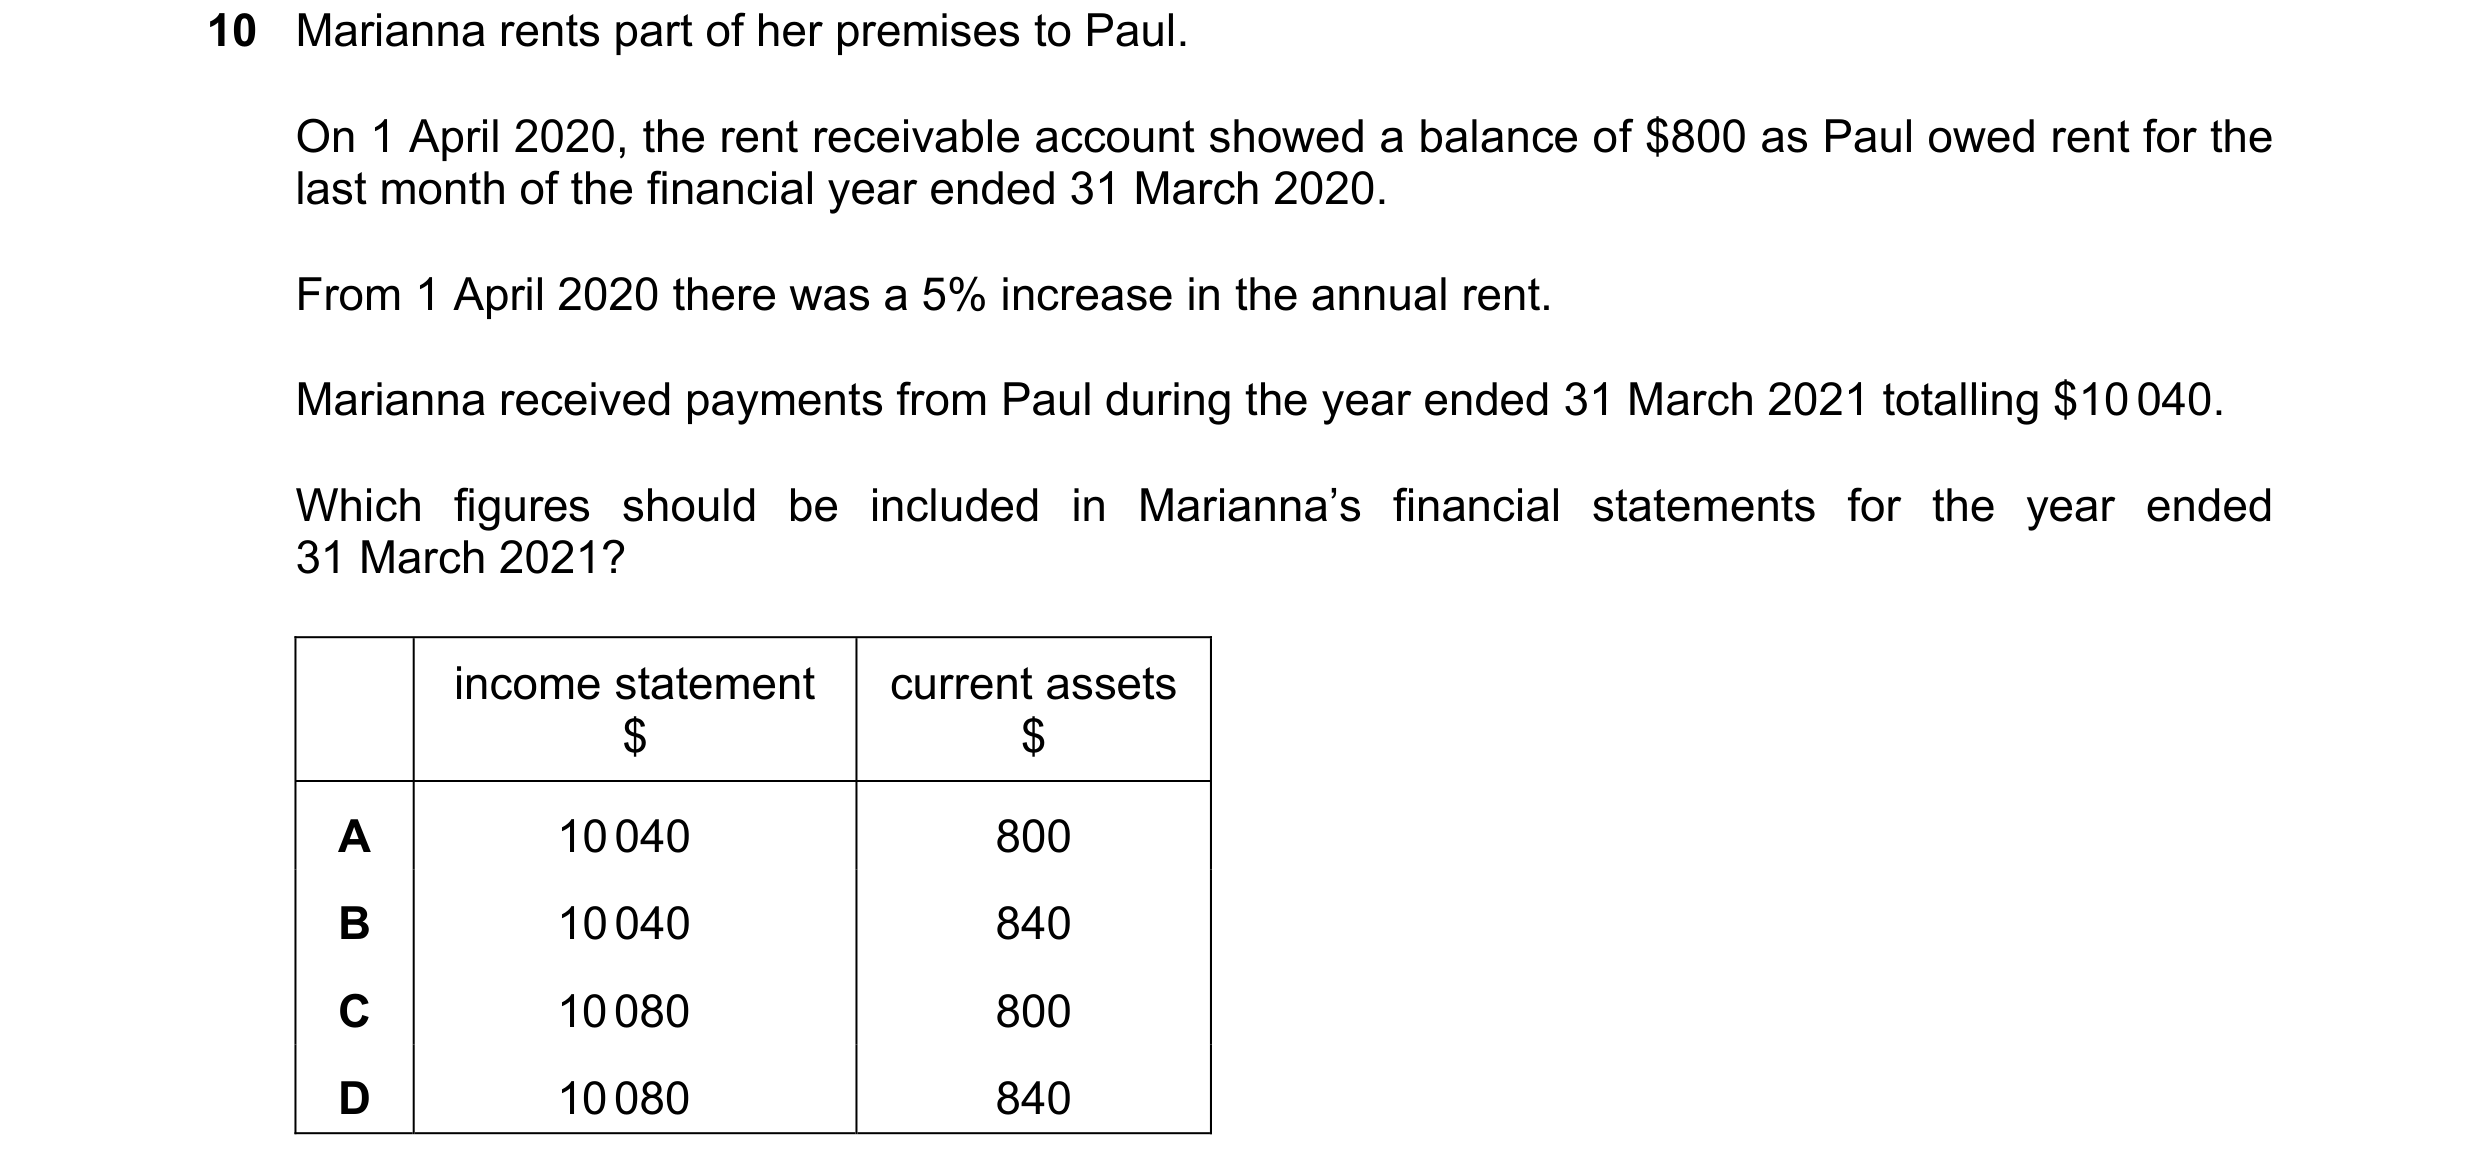
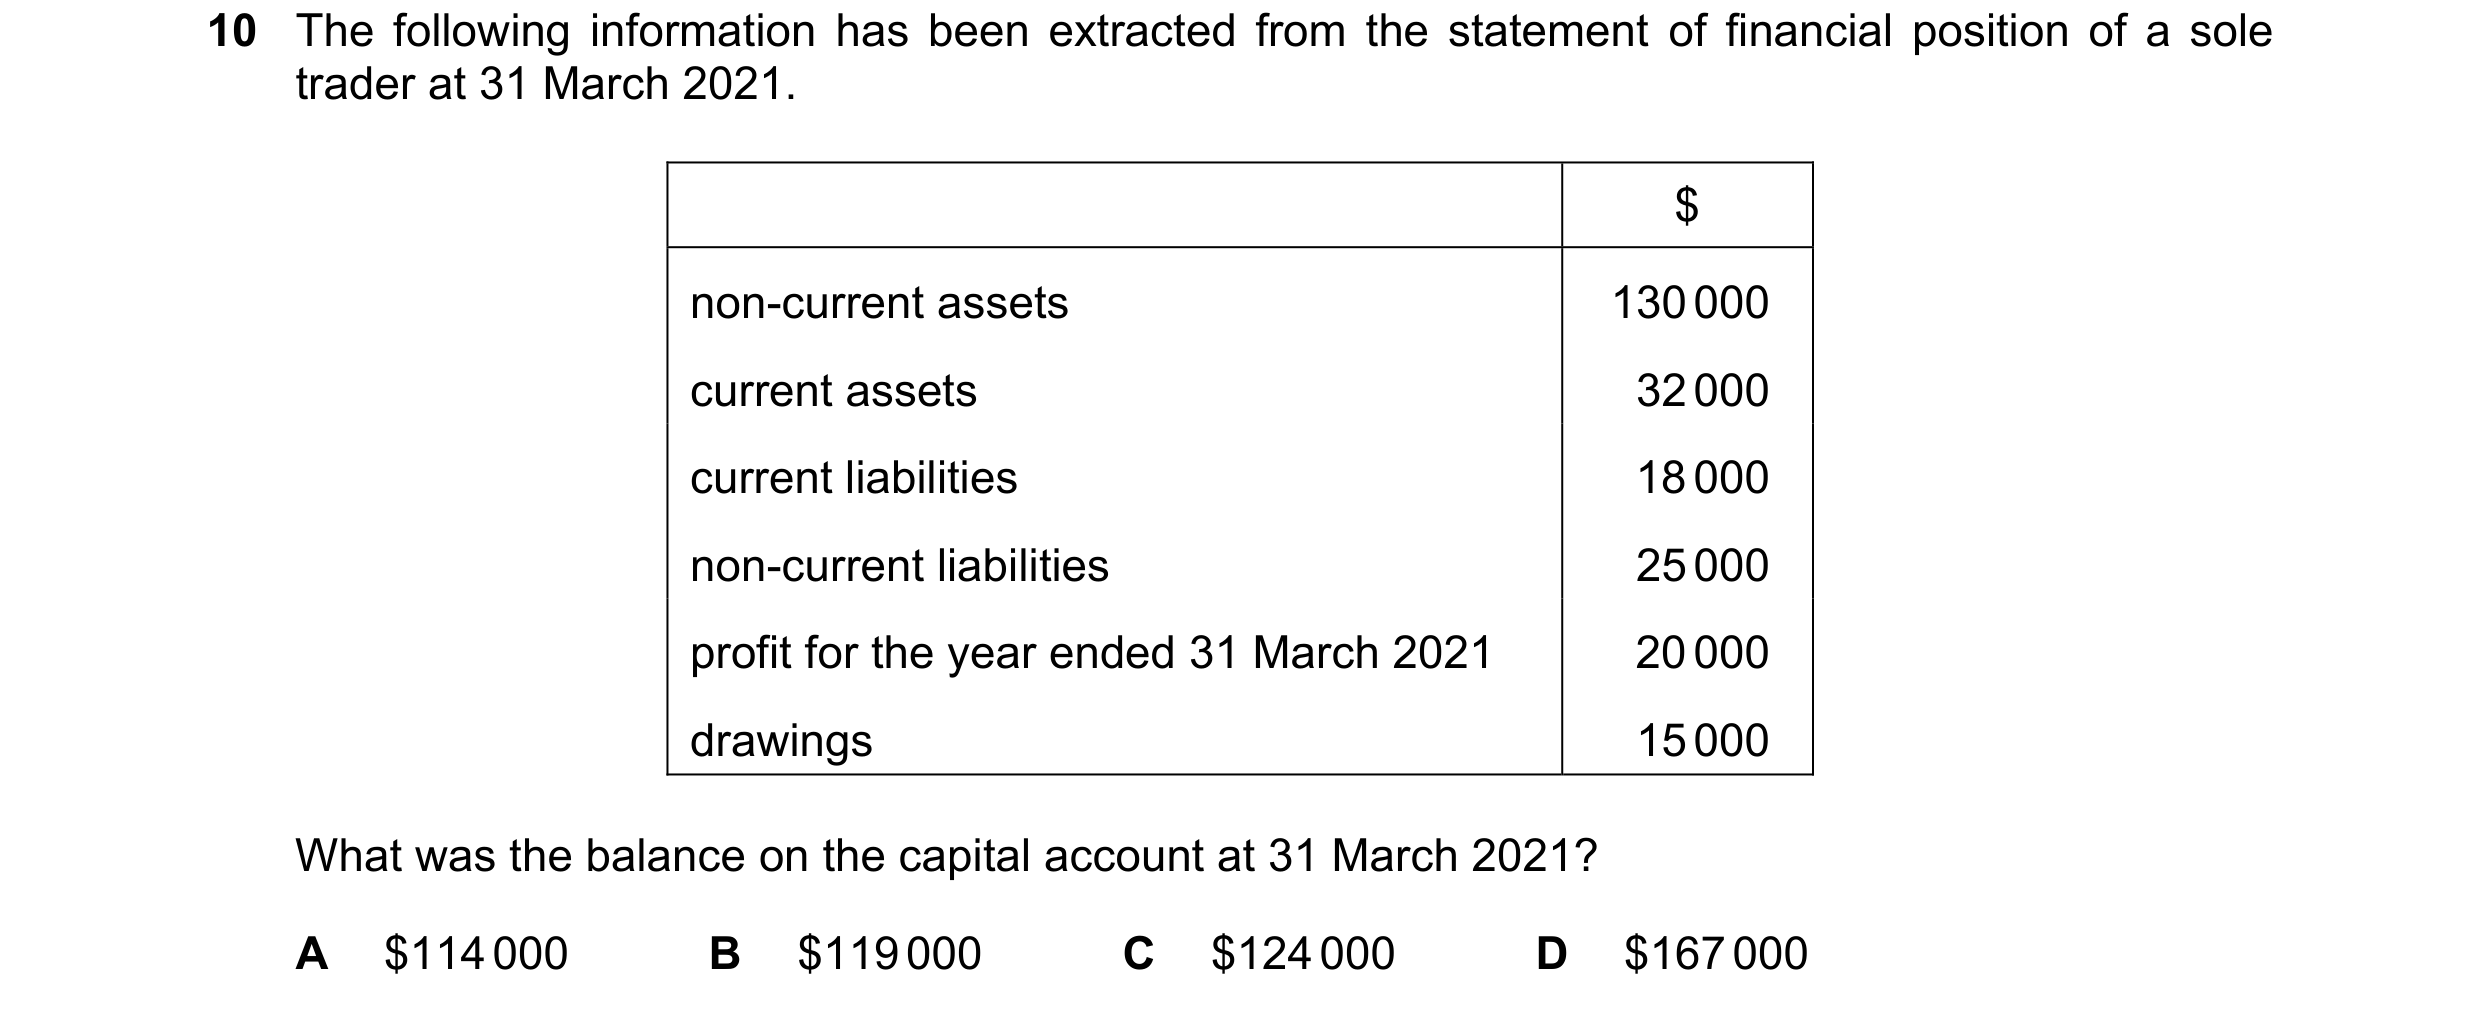 182 / 233
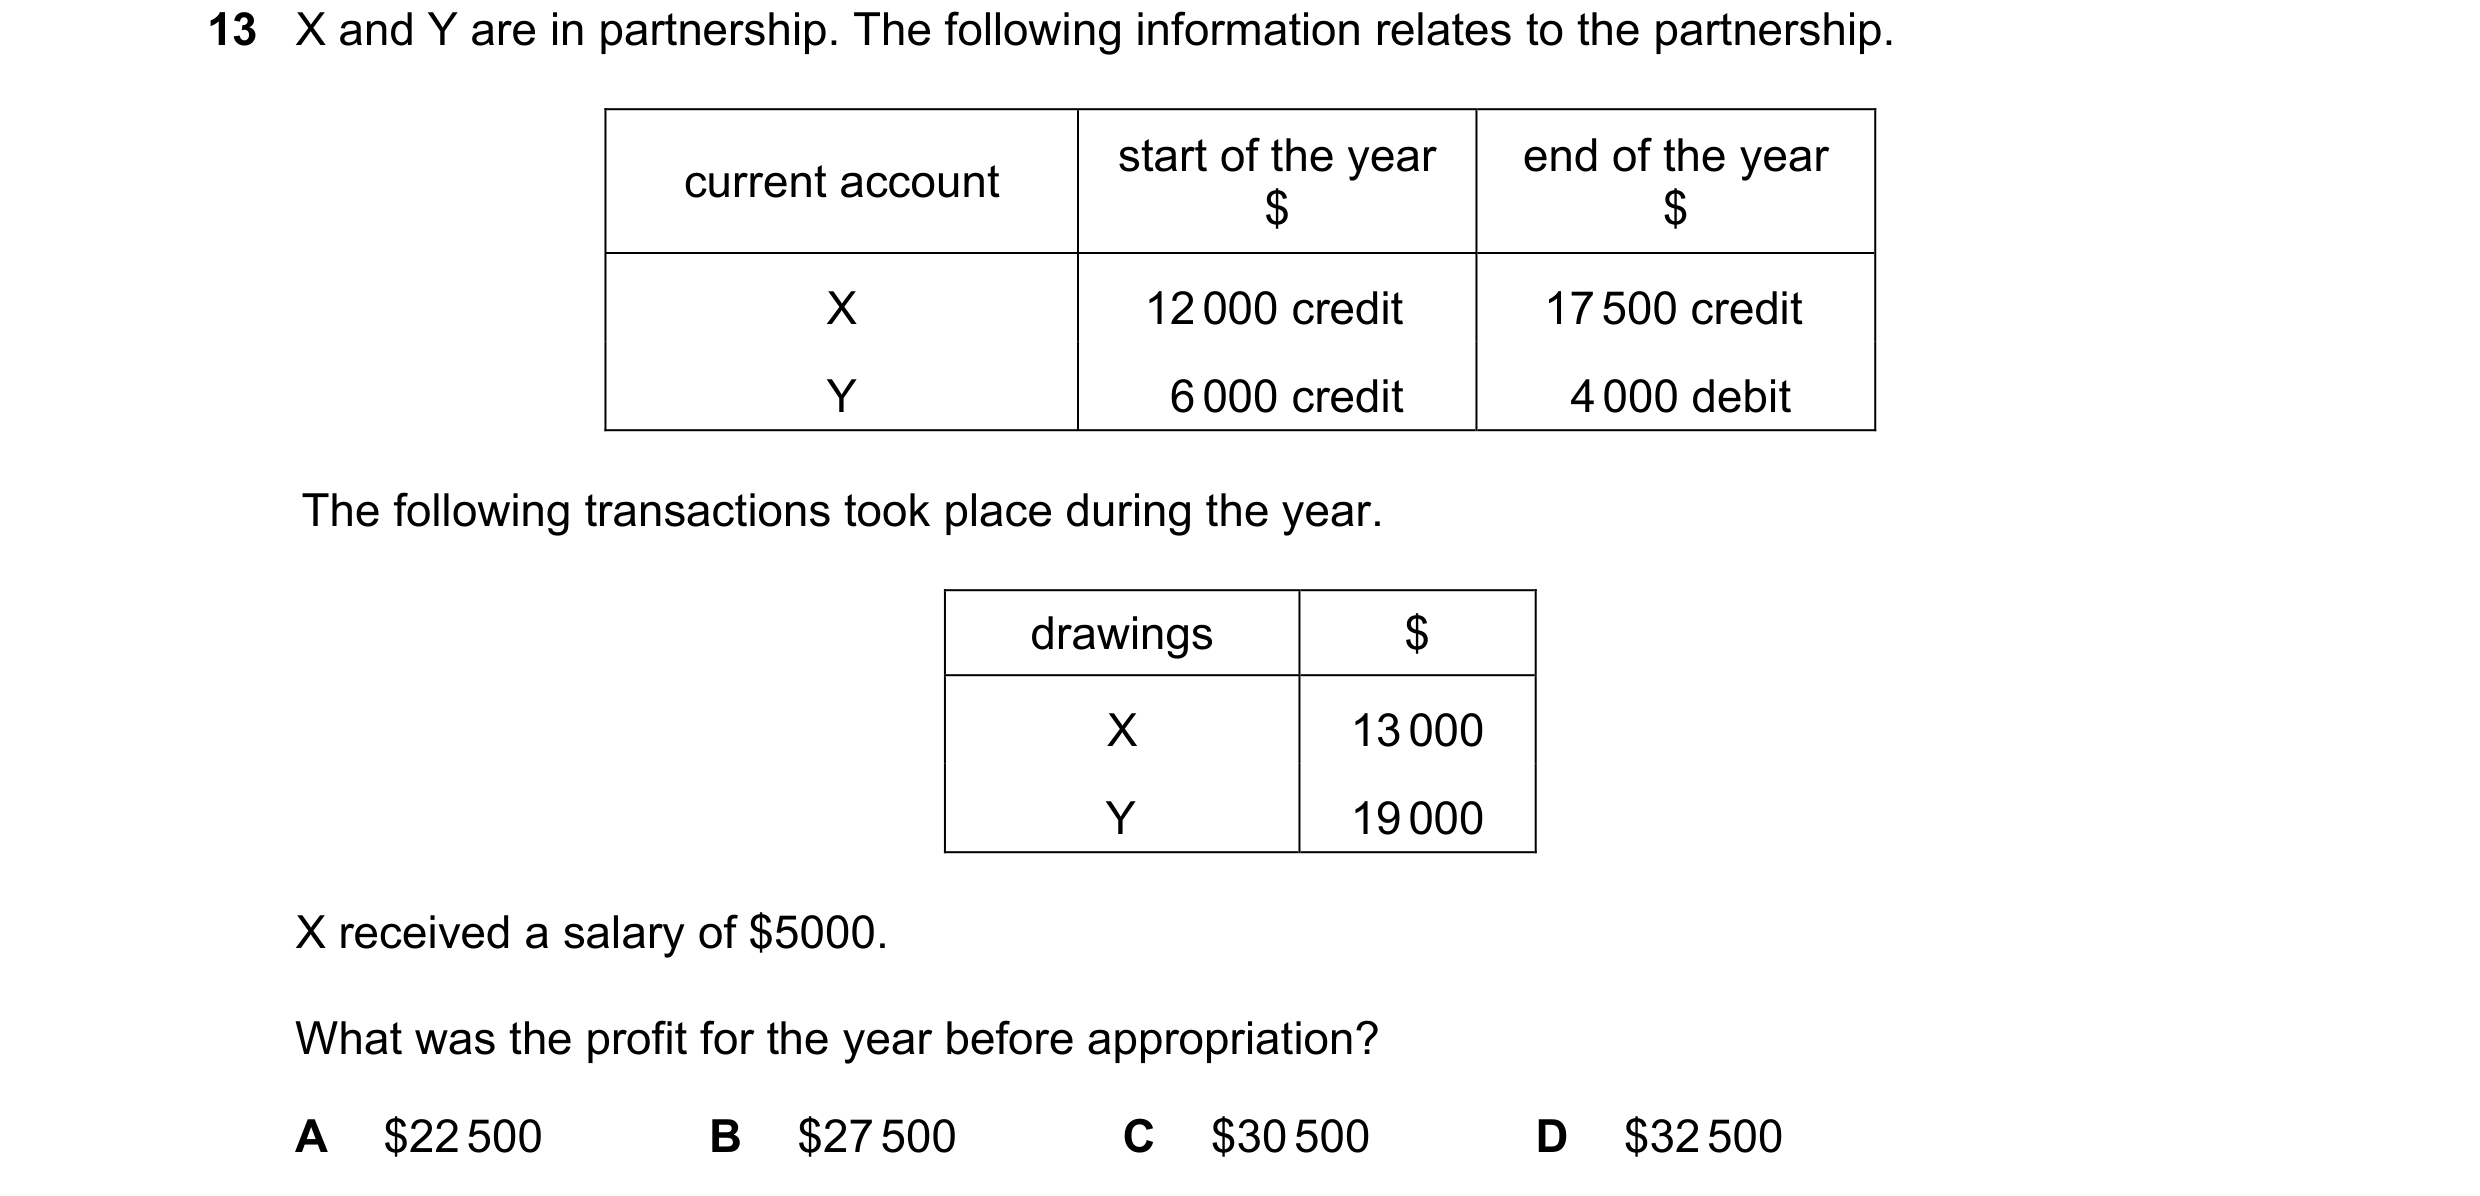
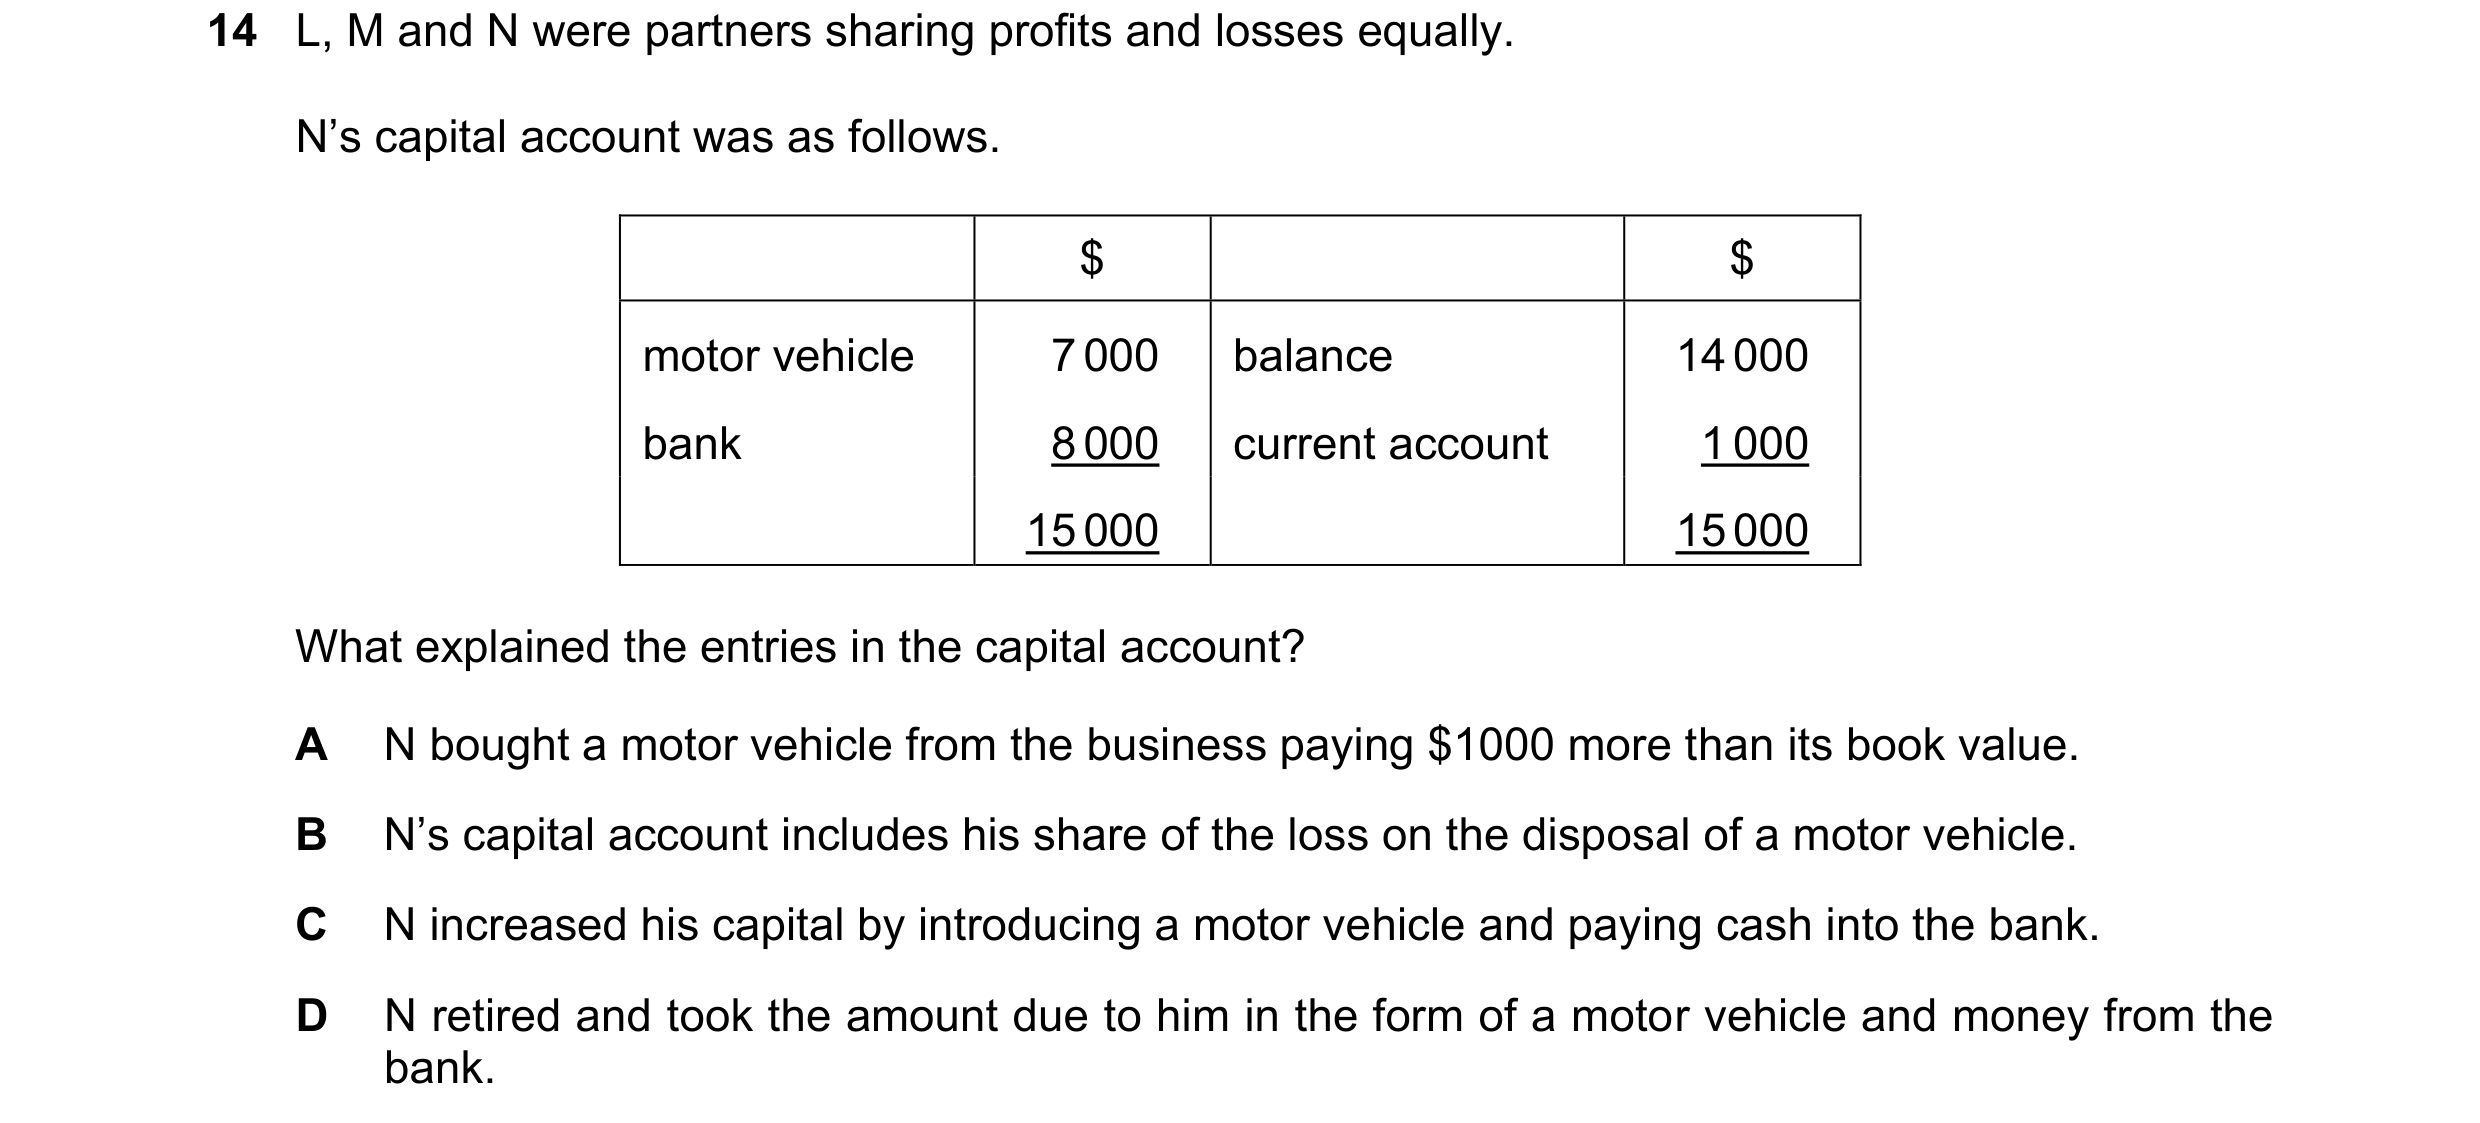 183 / 233
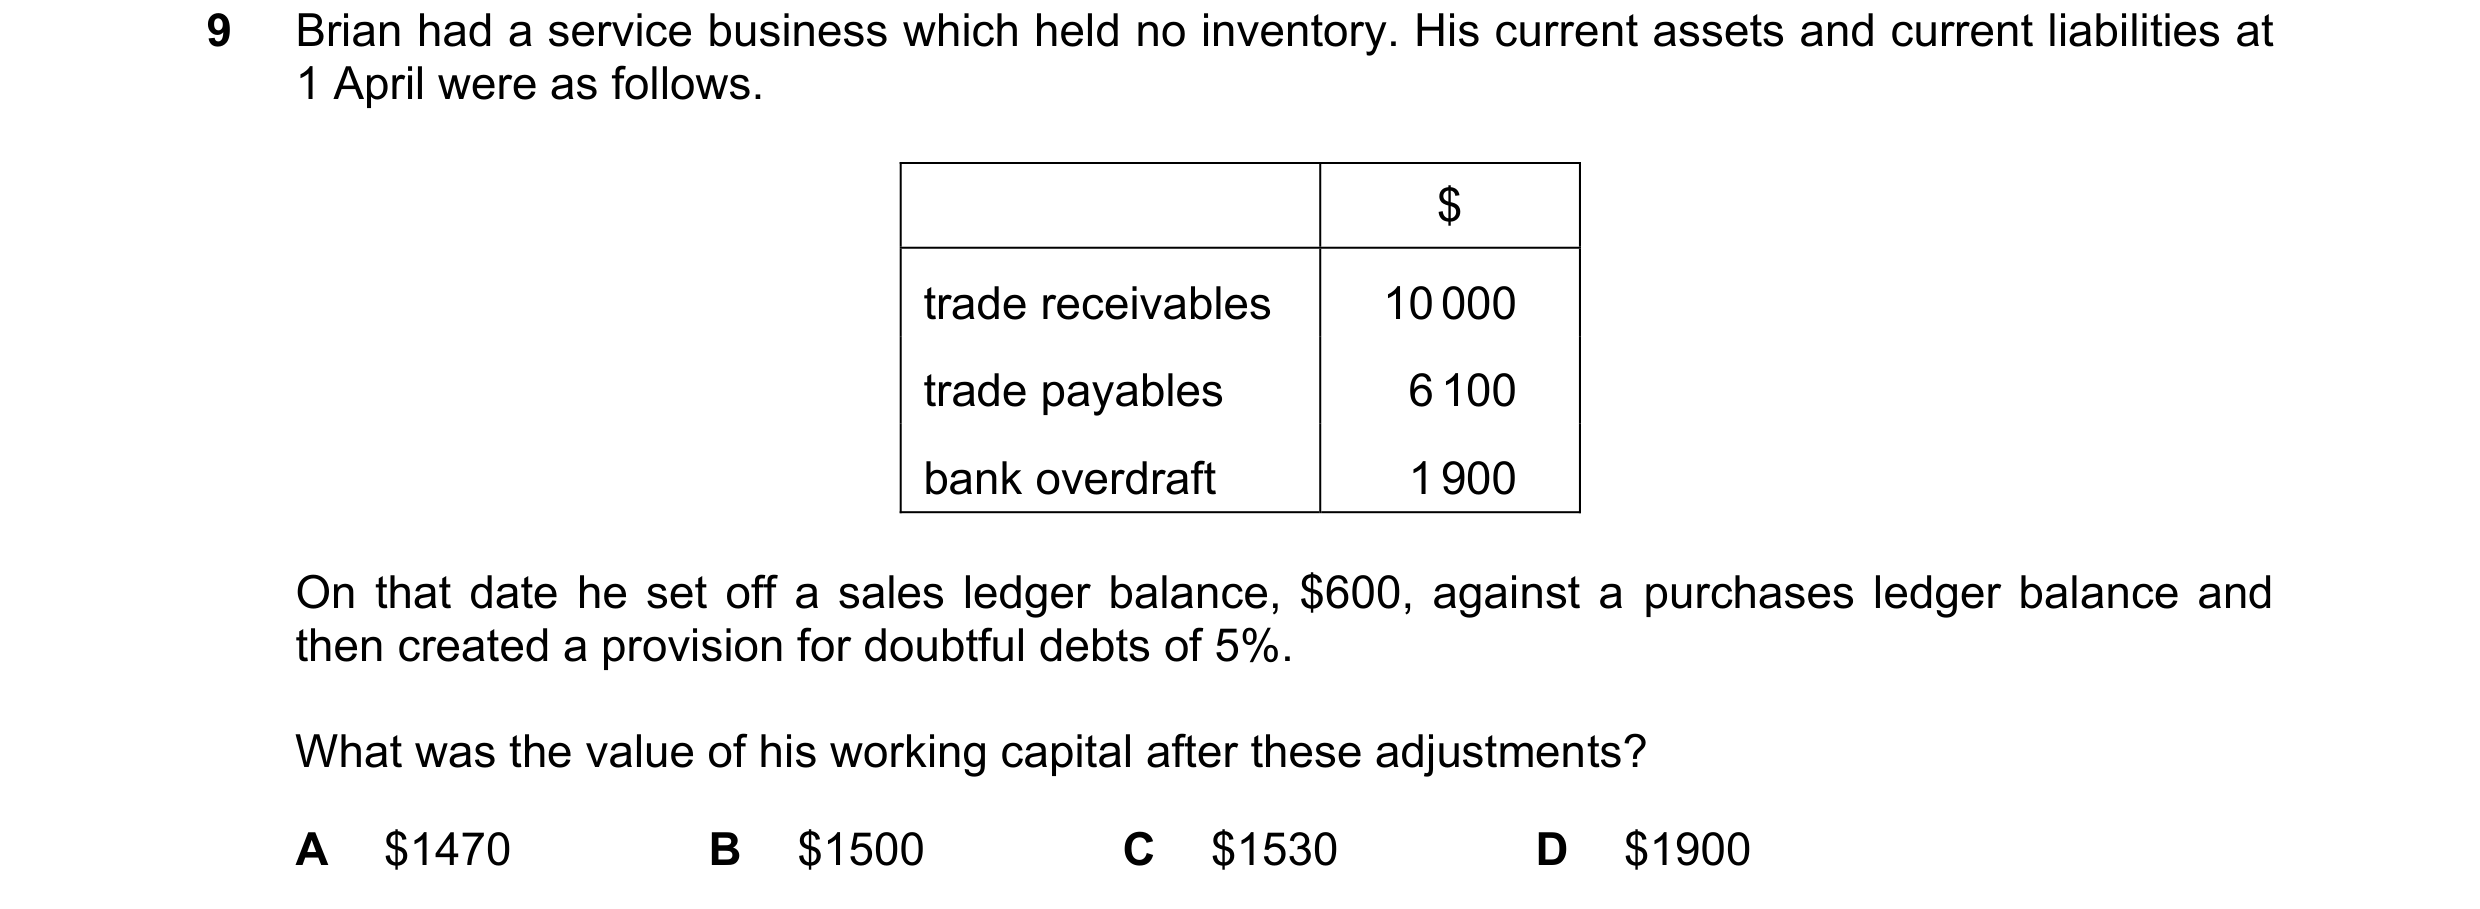
 184 / 233
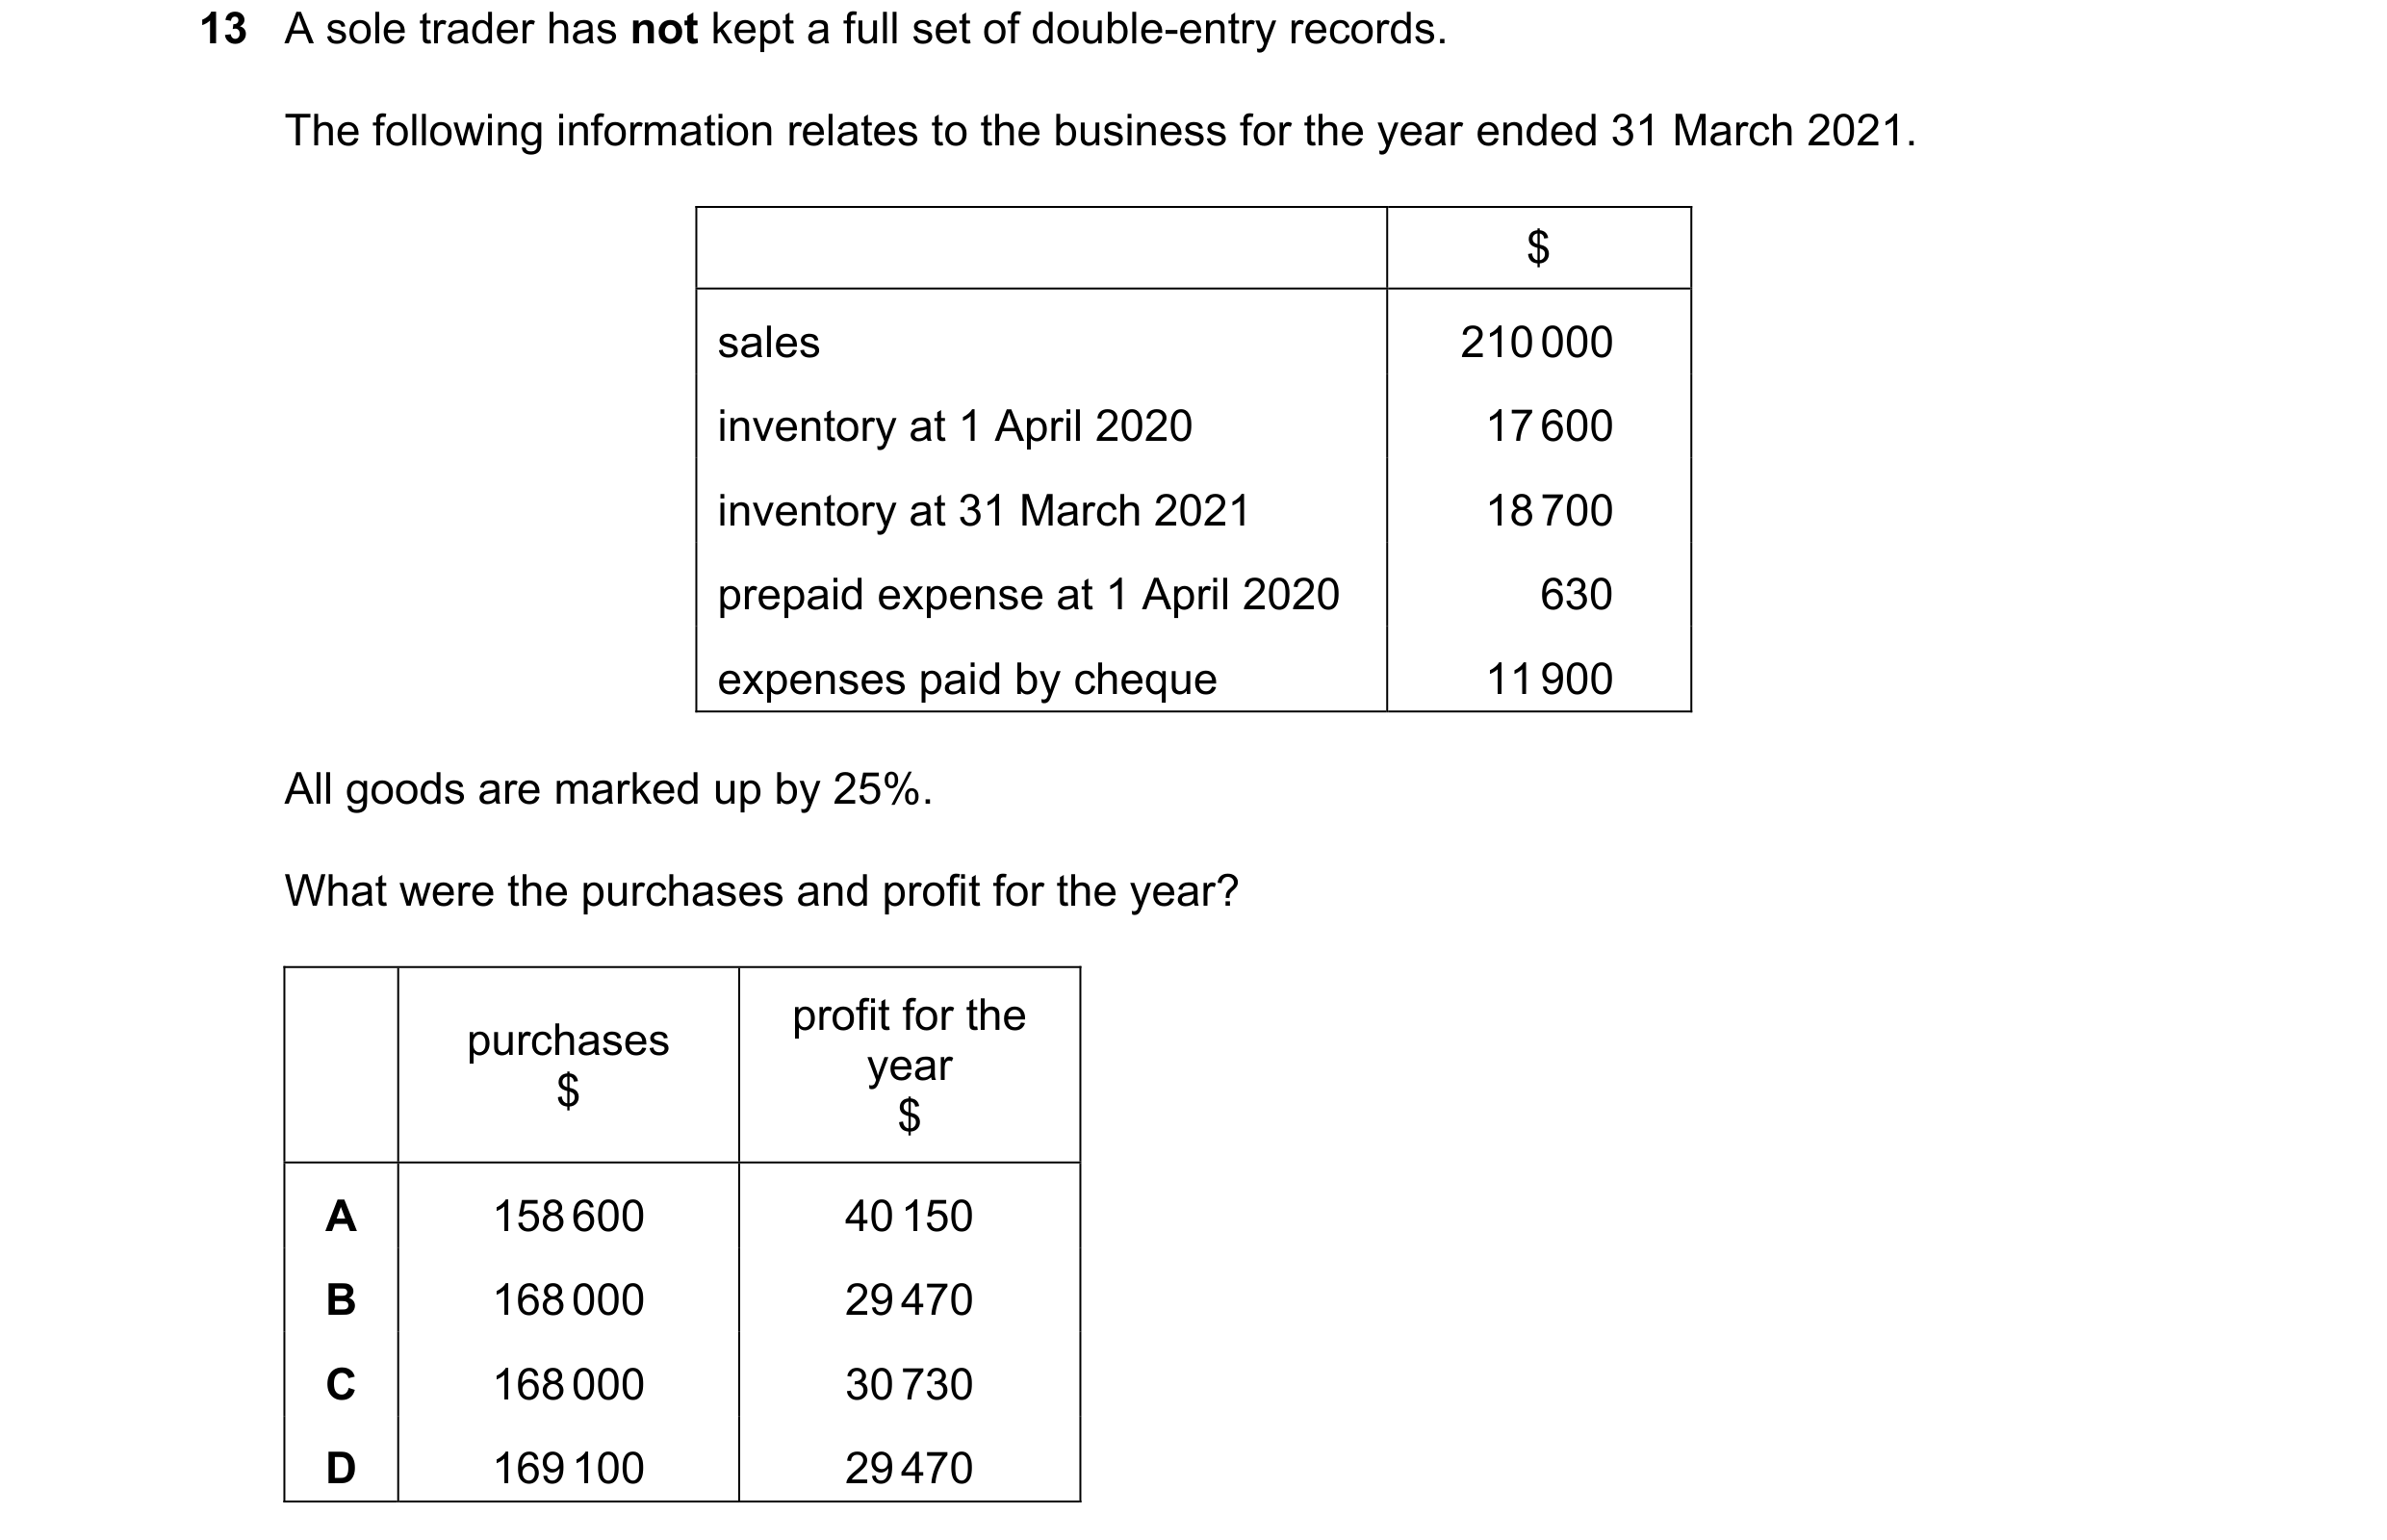
 185 / 233
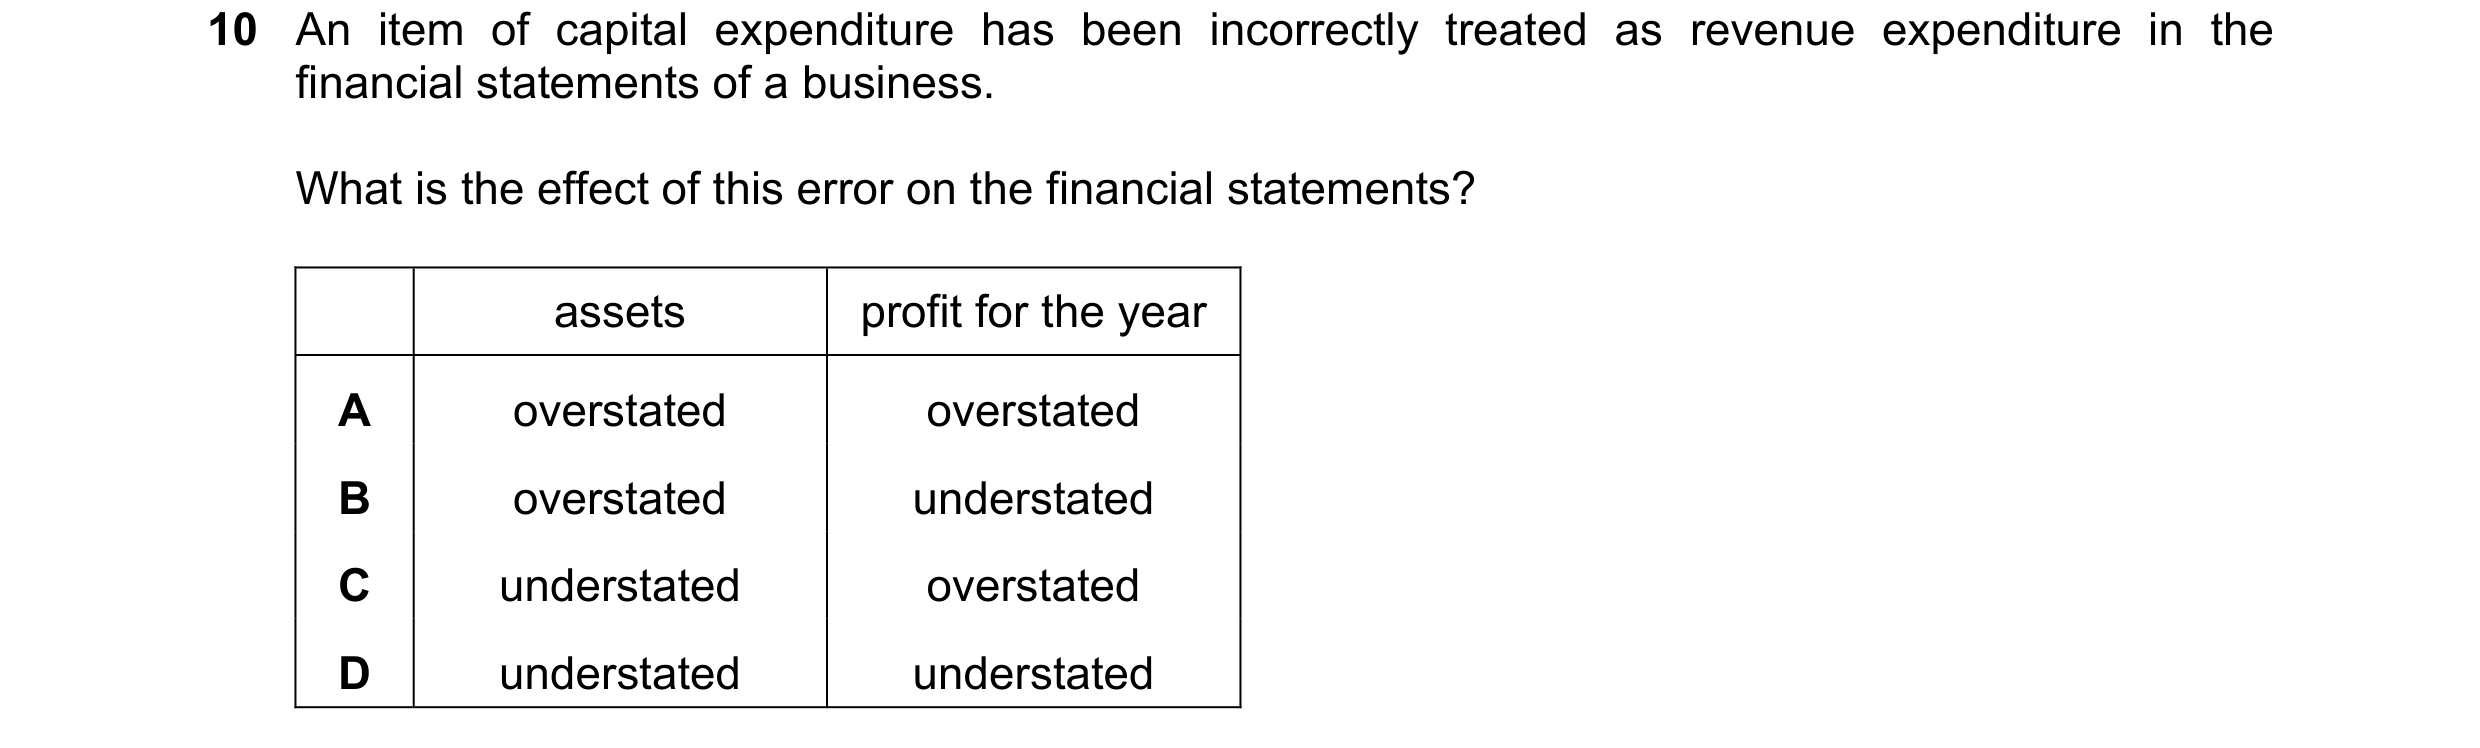
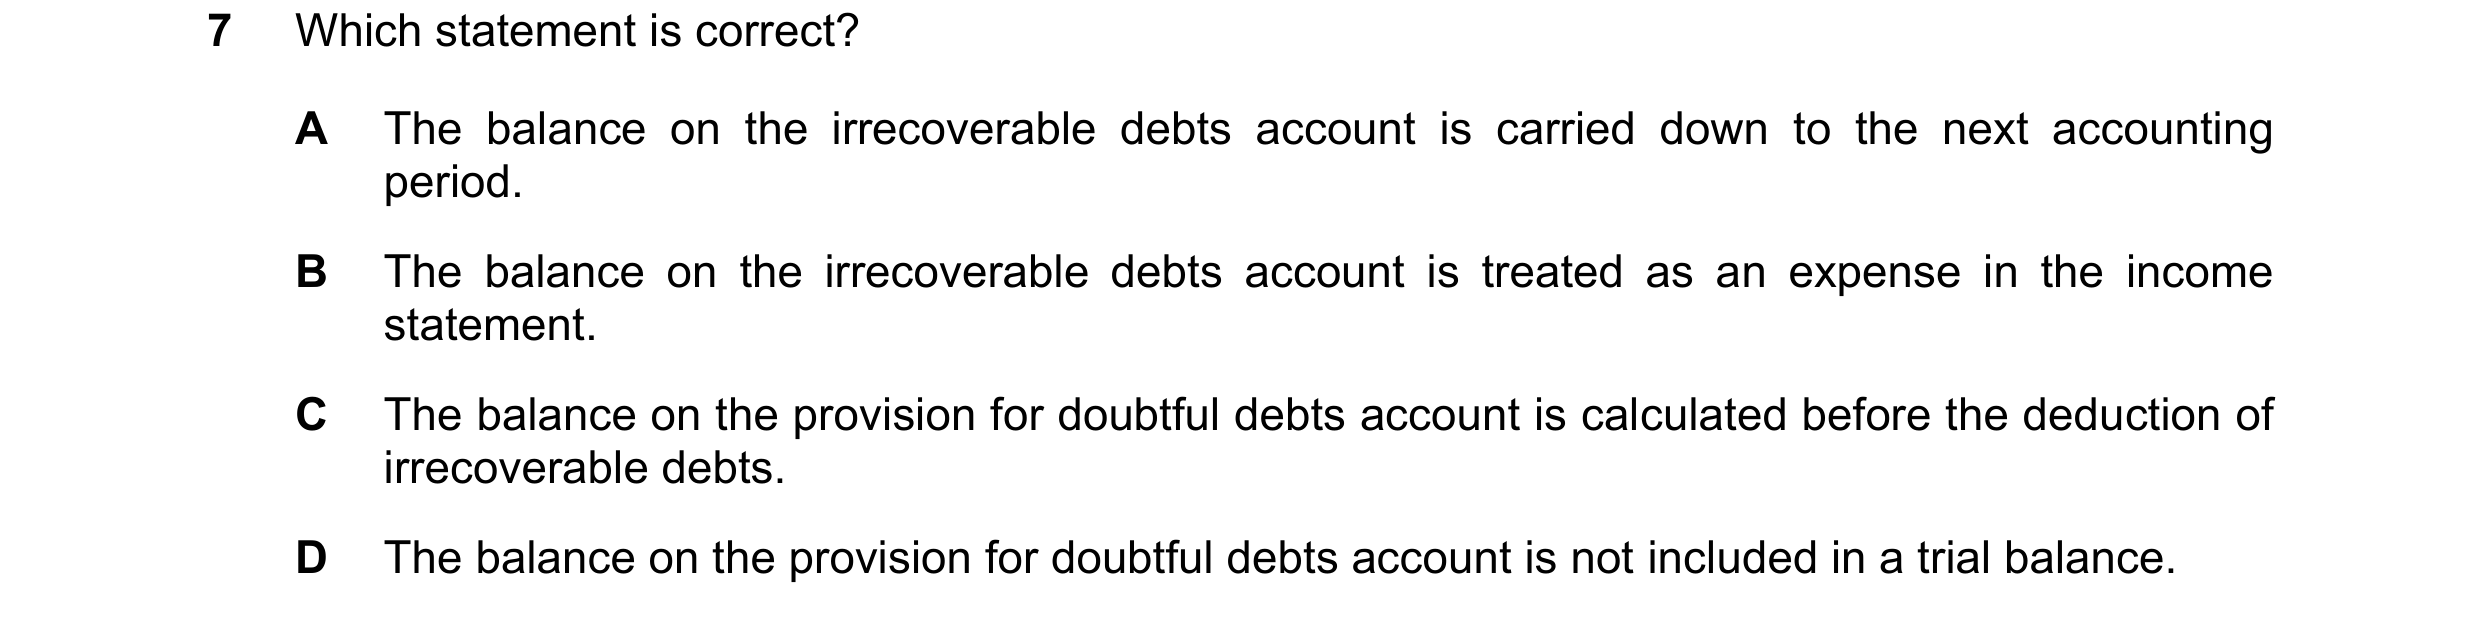 186 / 233
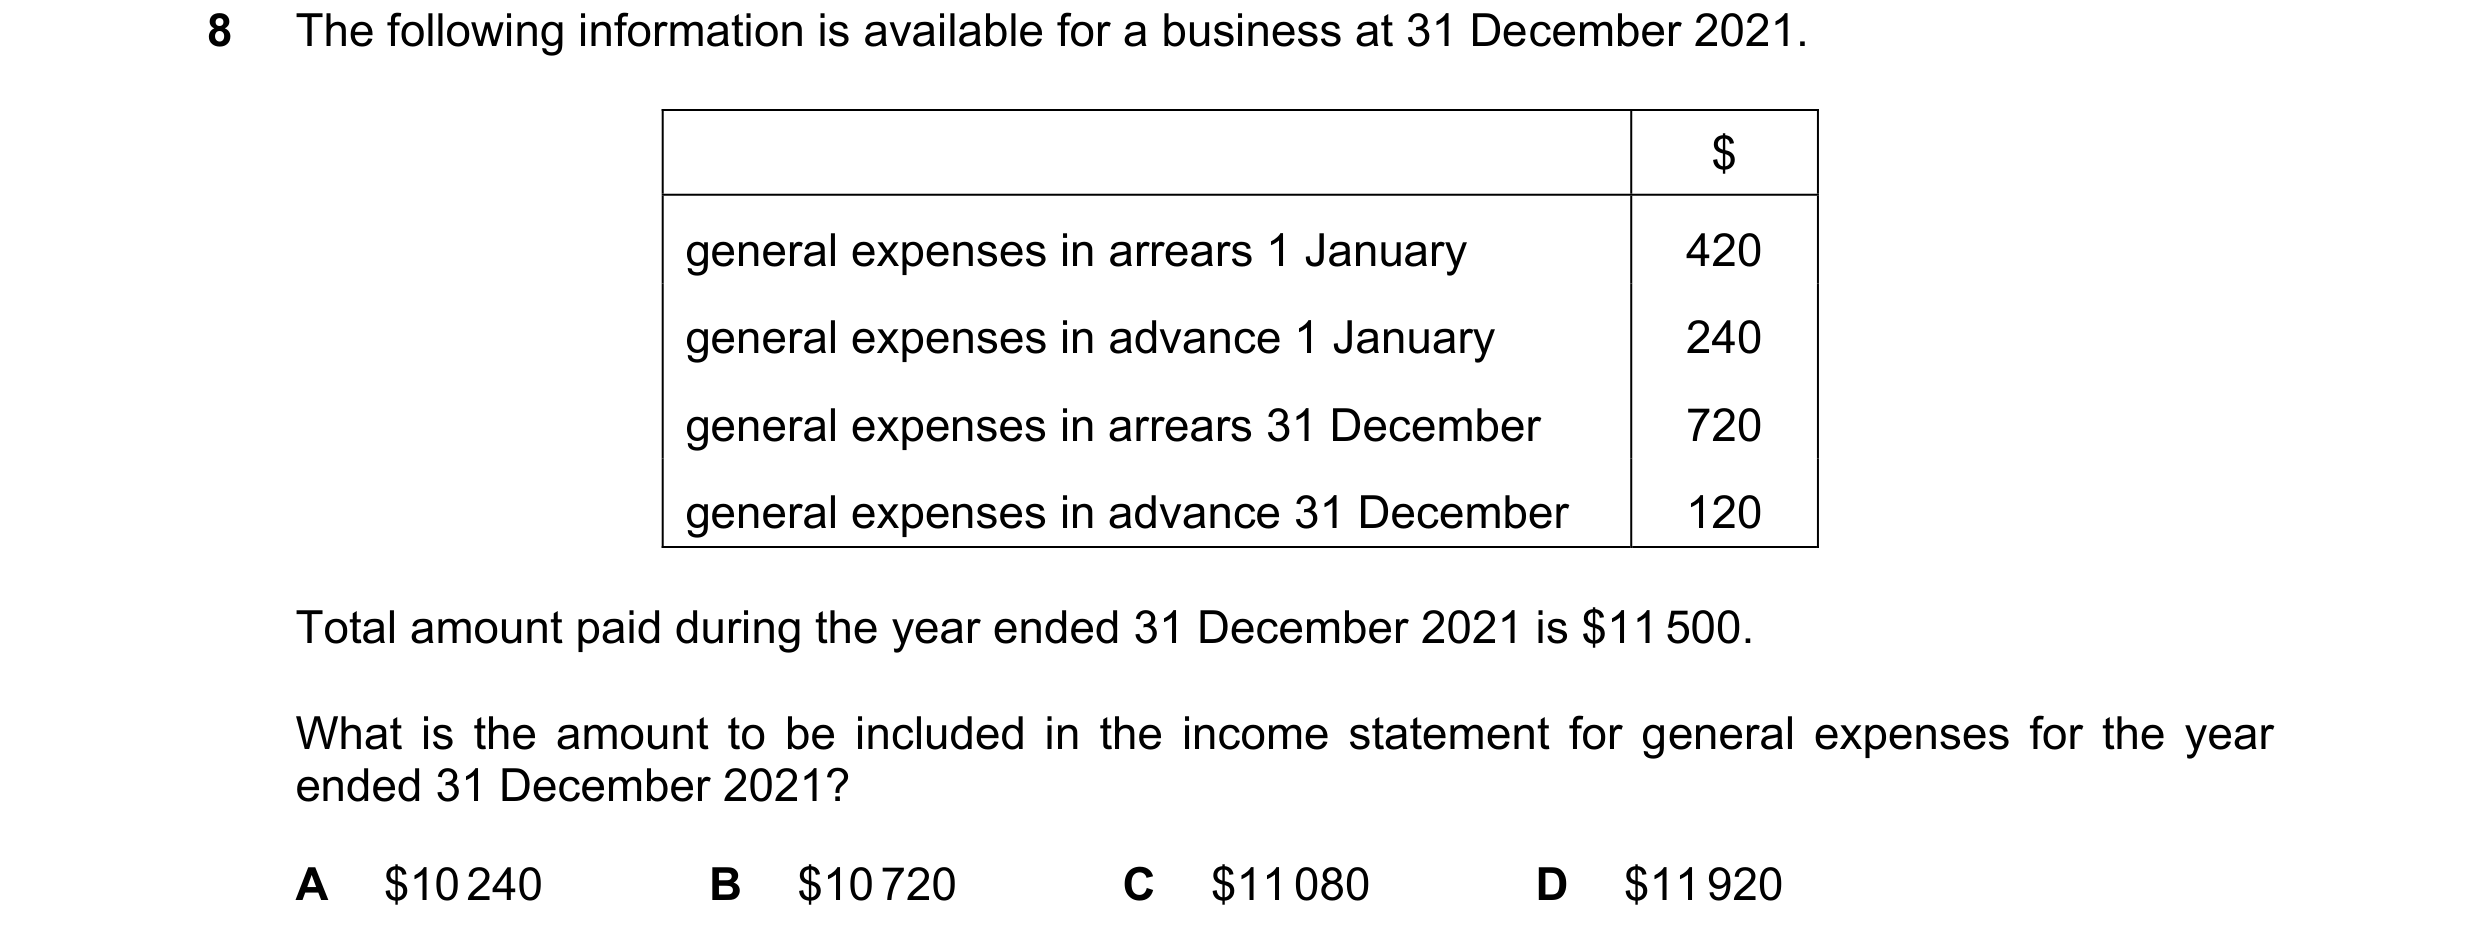
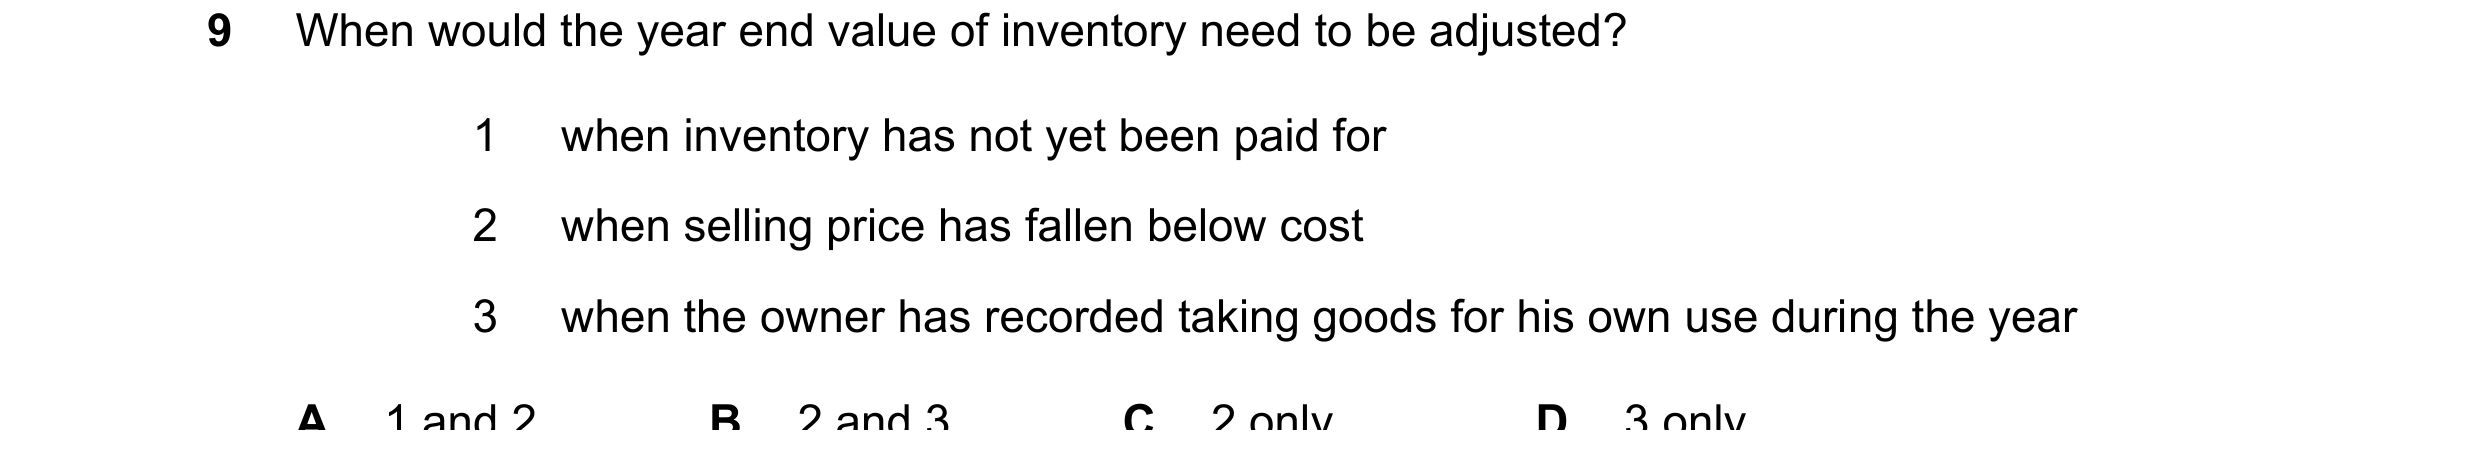
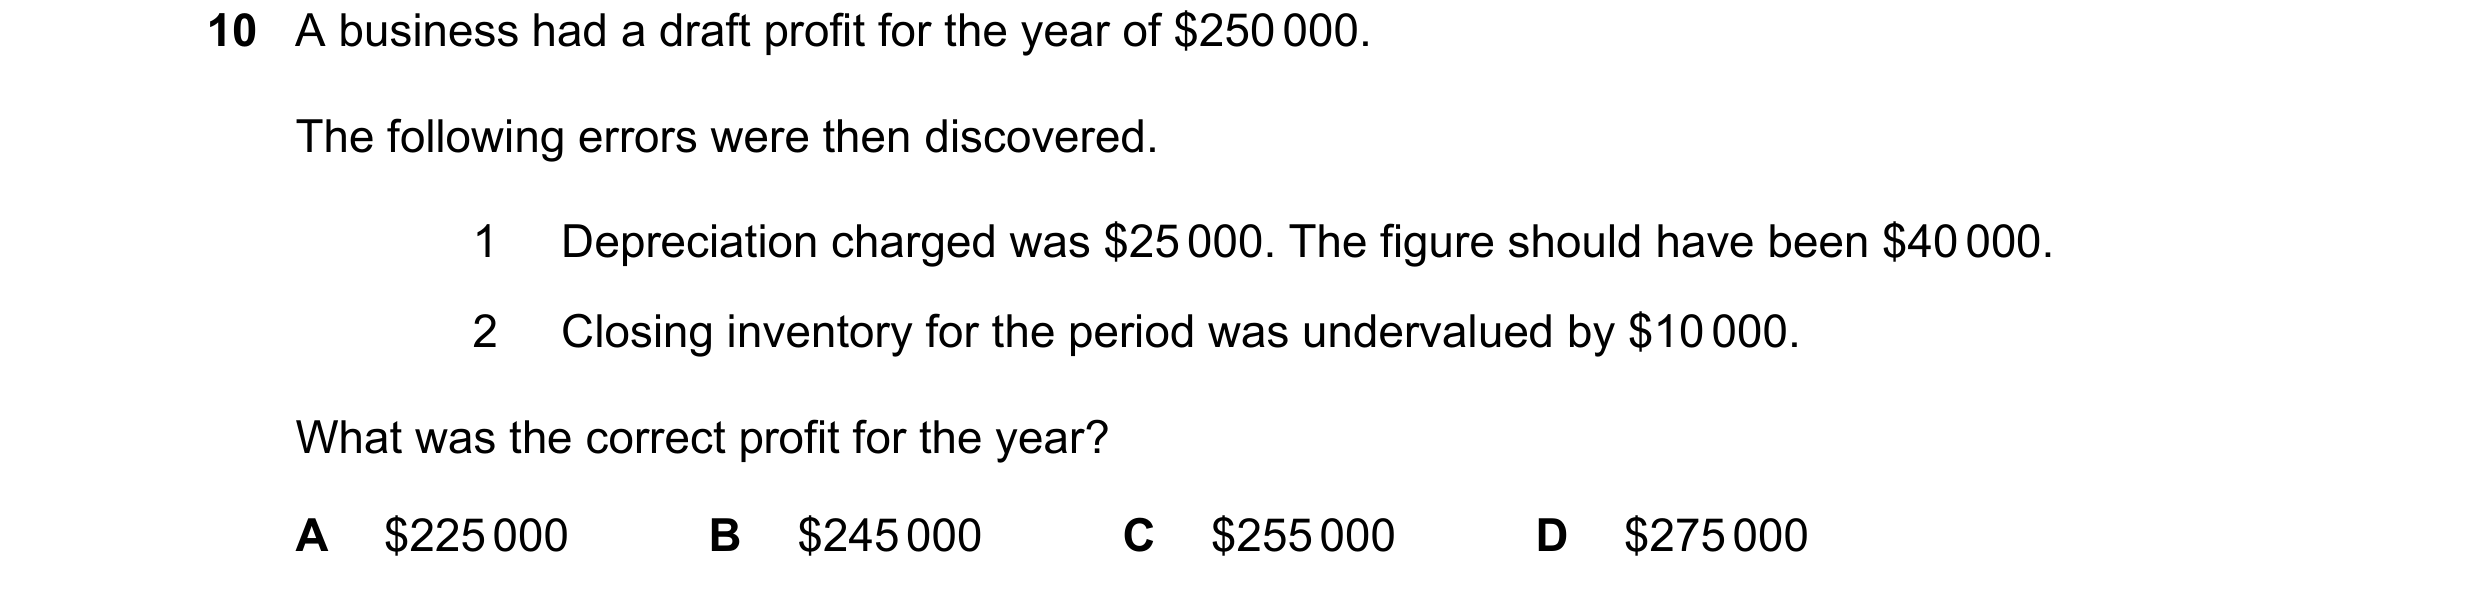
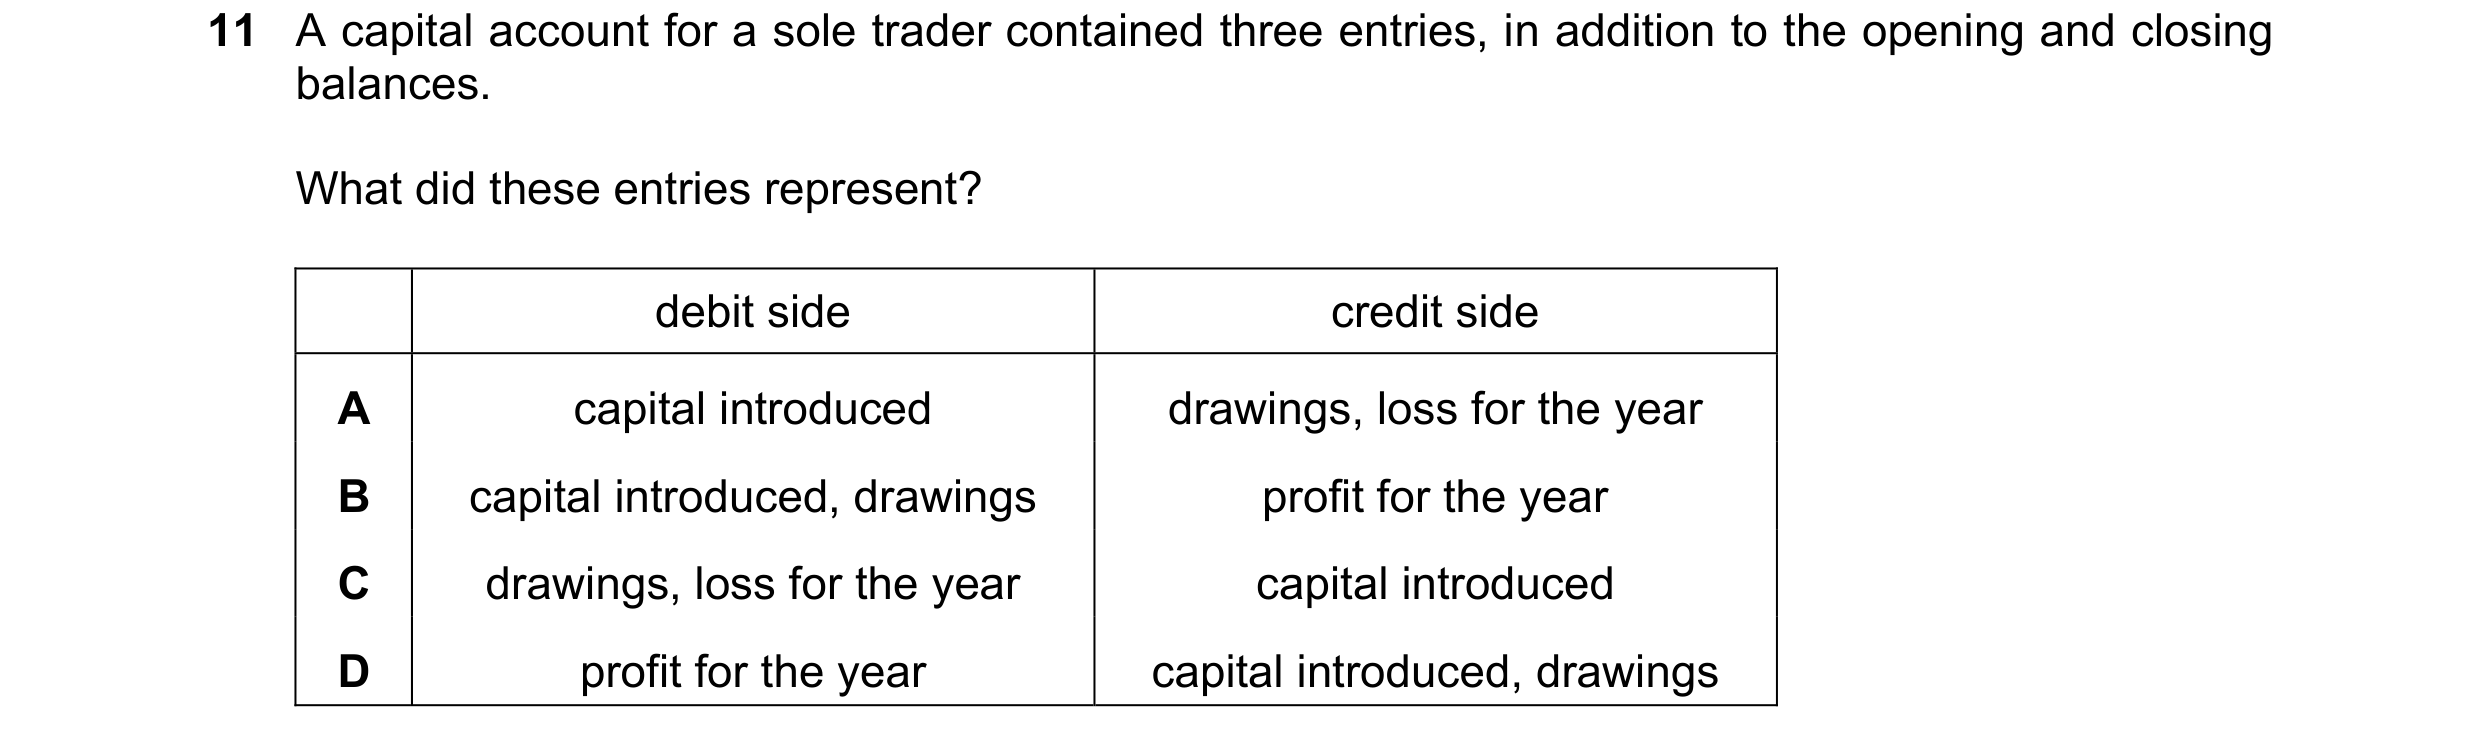 187 / 233
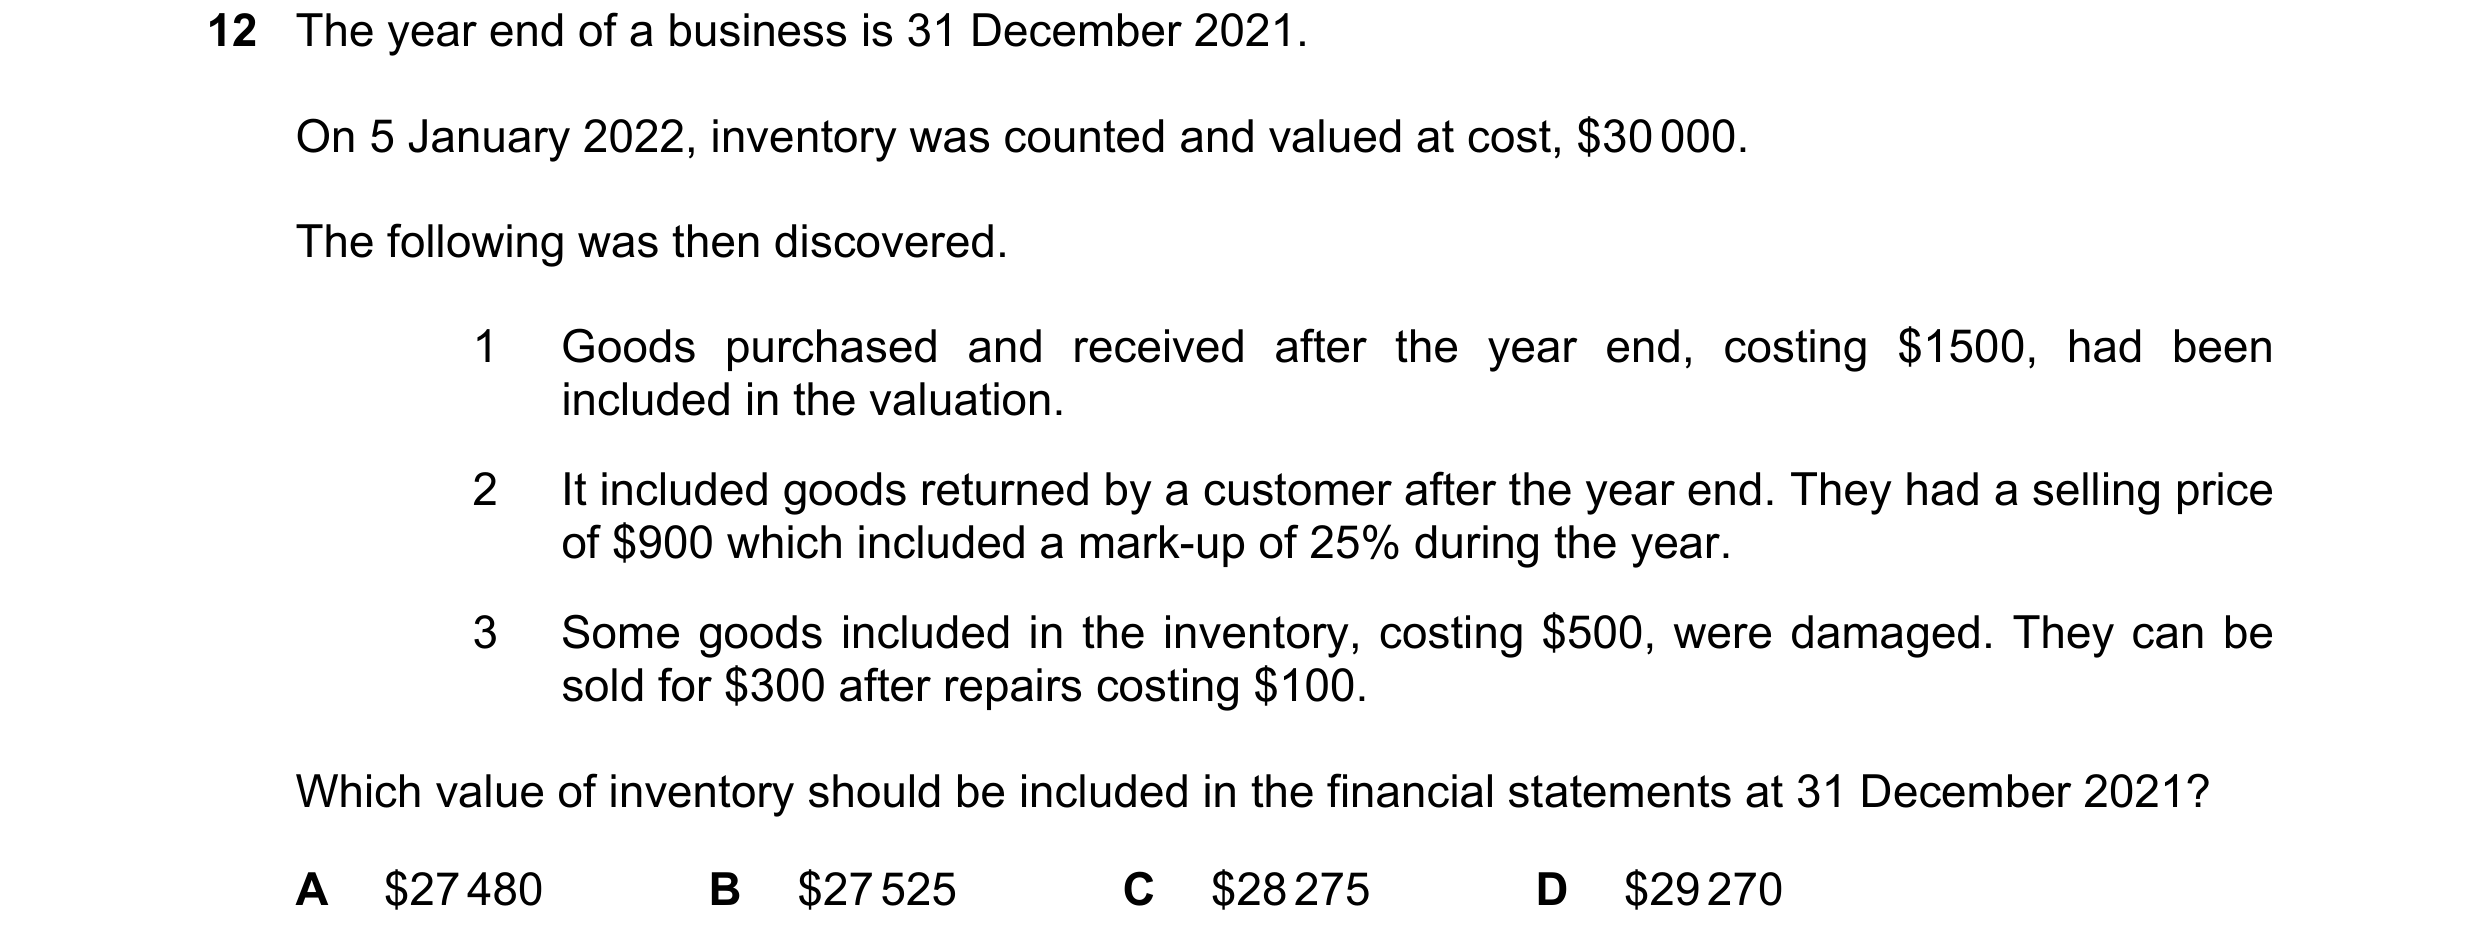
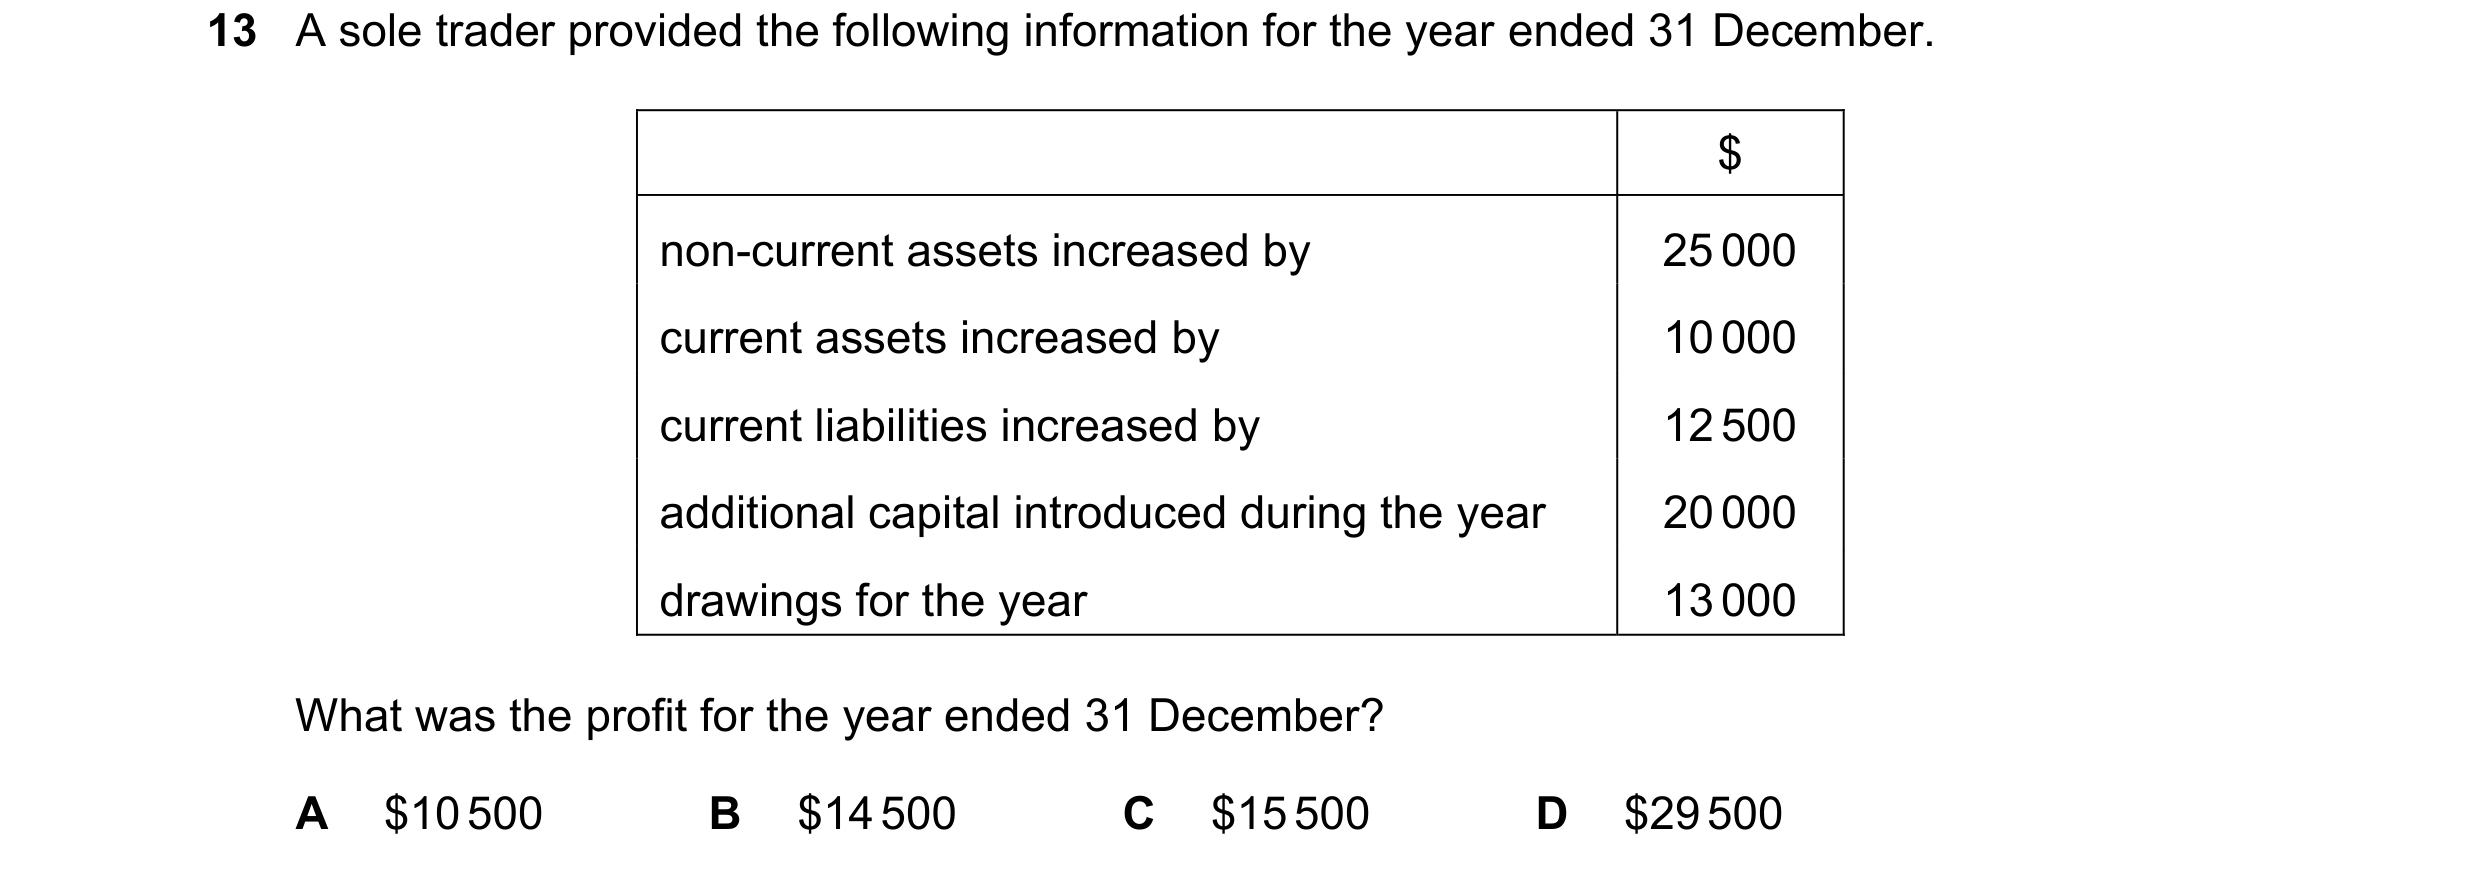
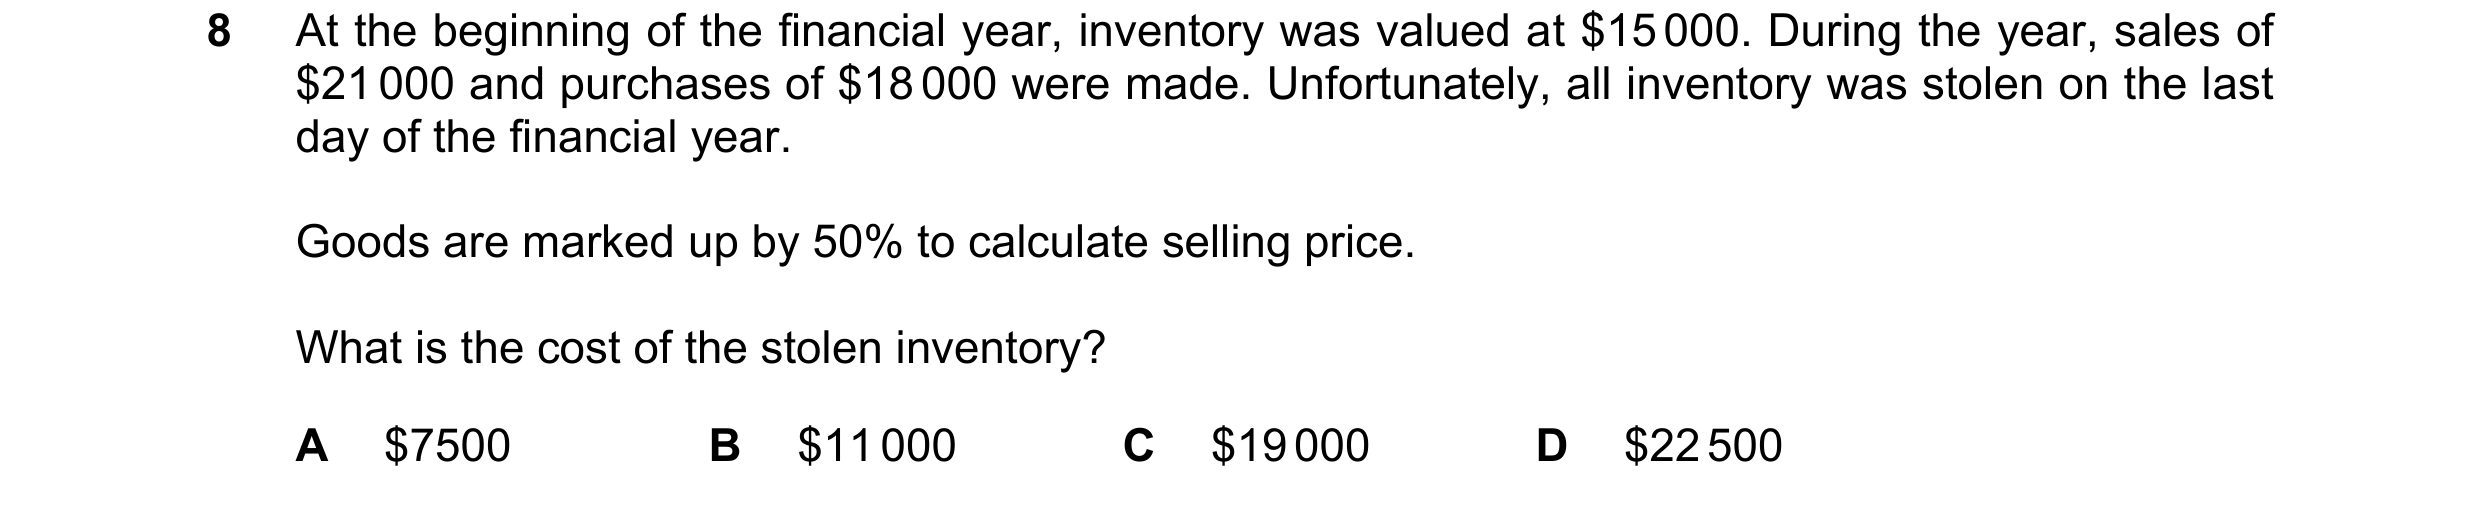
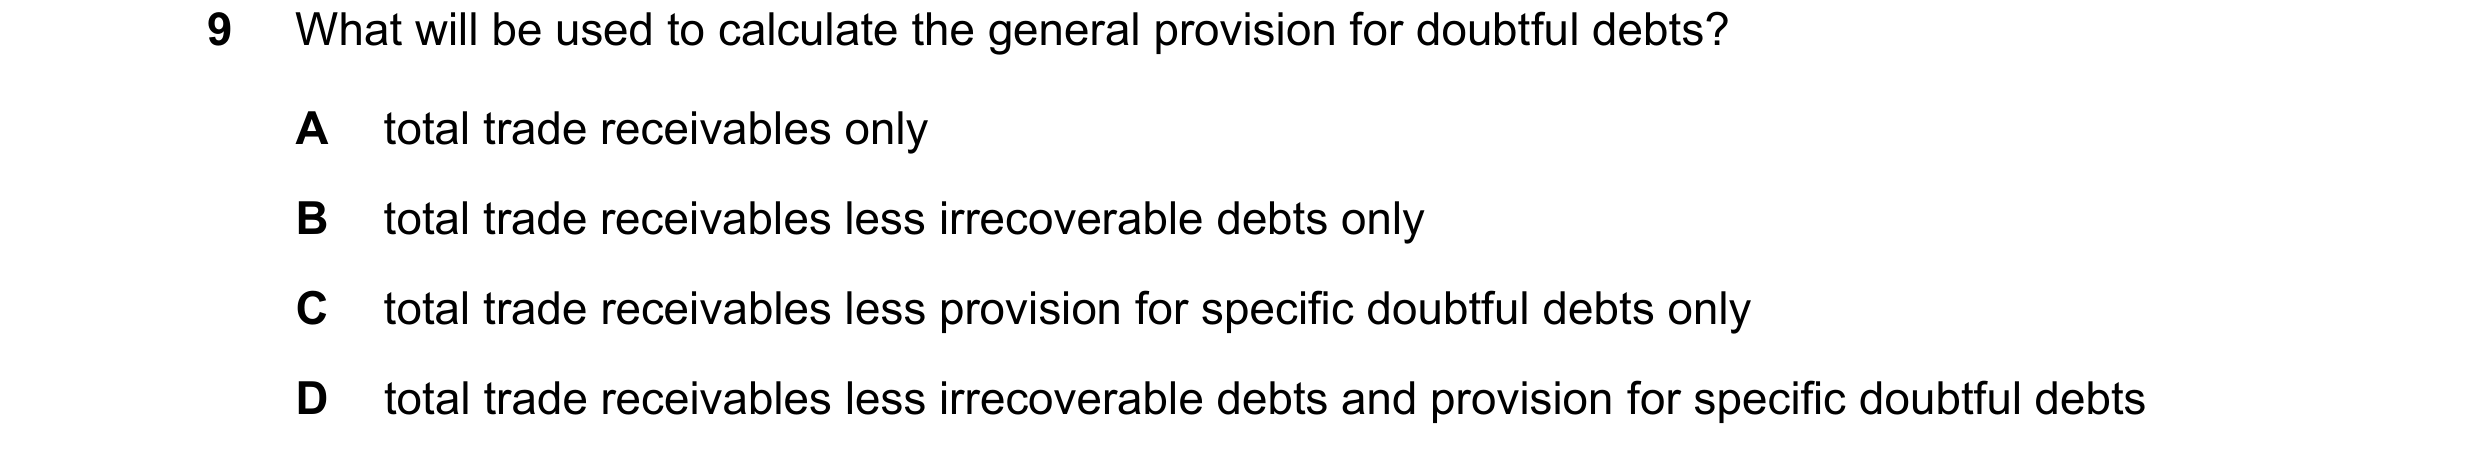 188 / 233
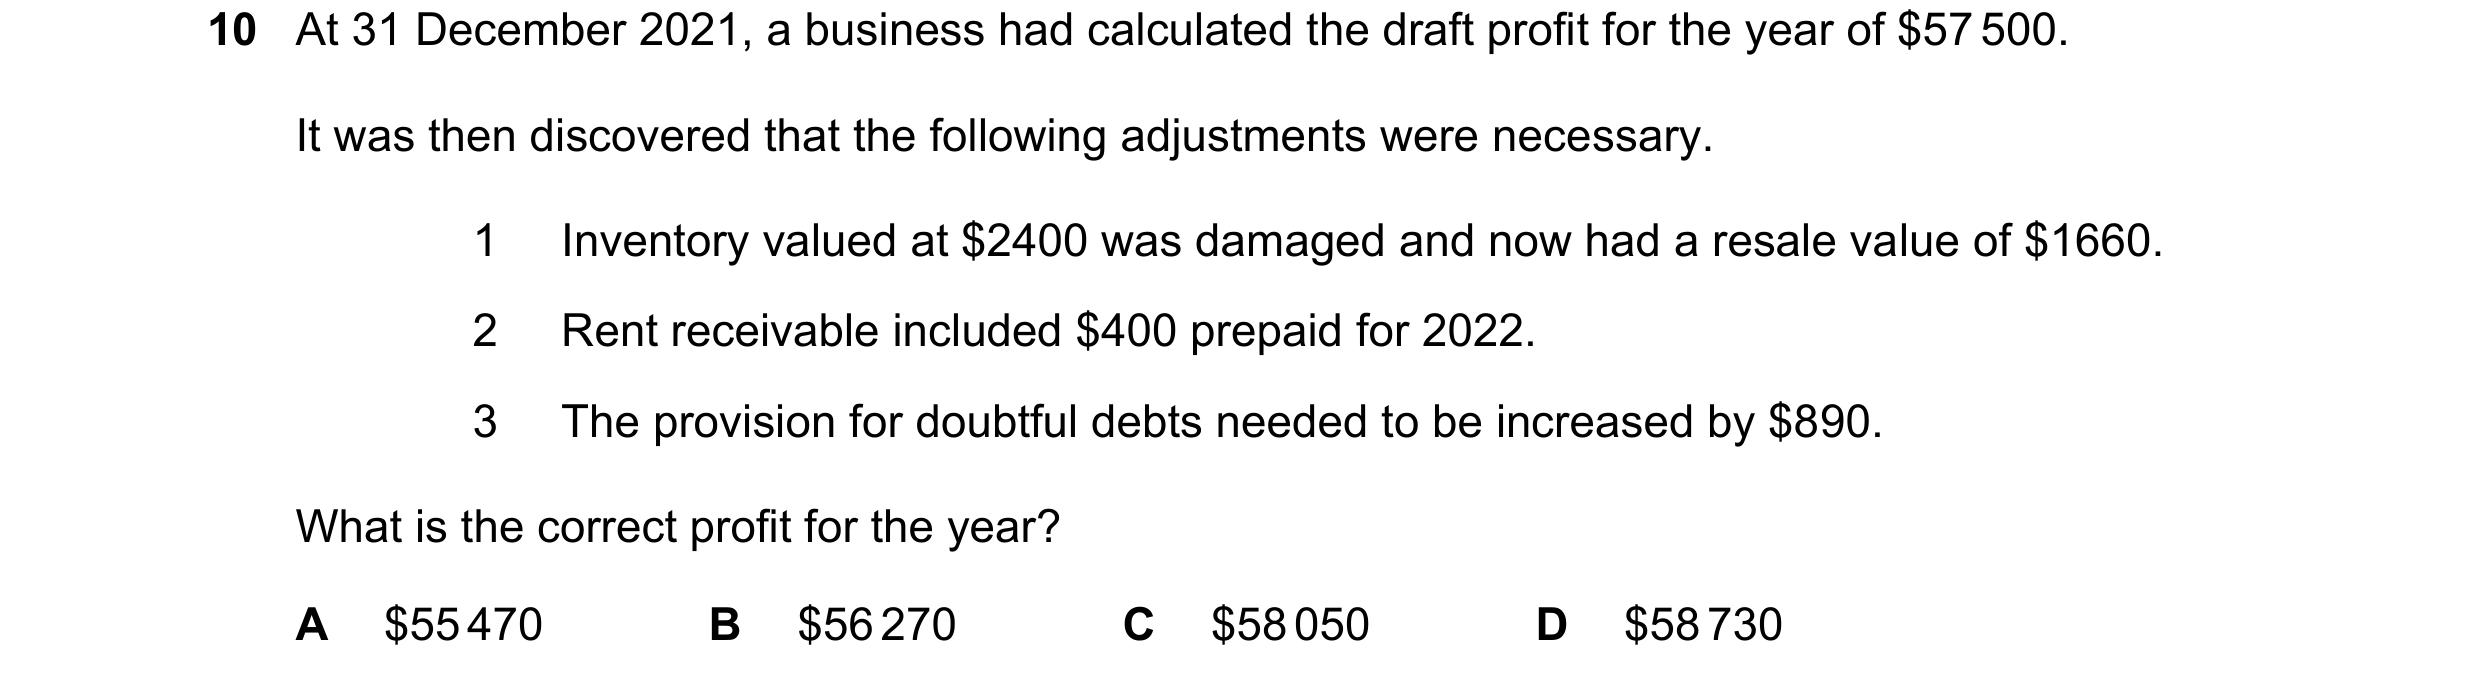
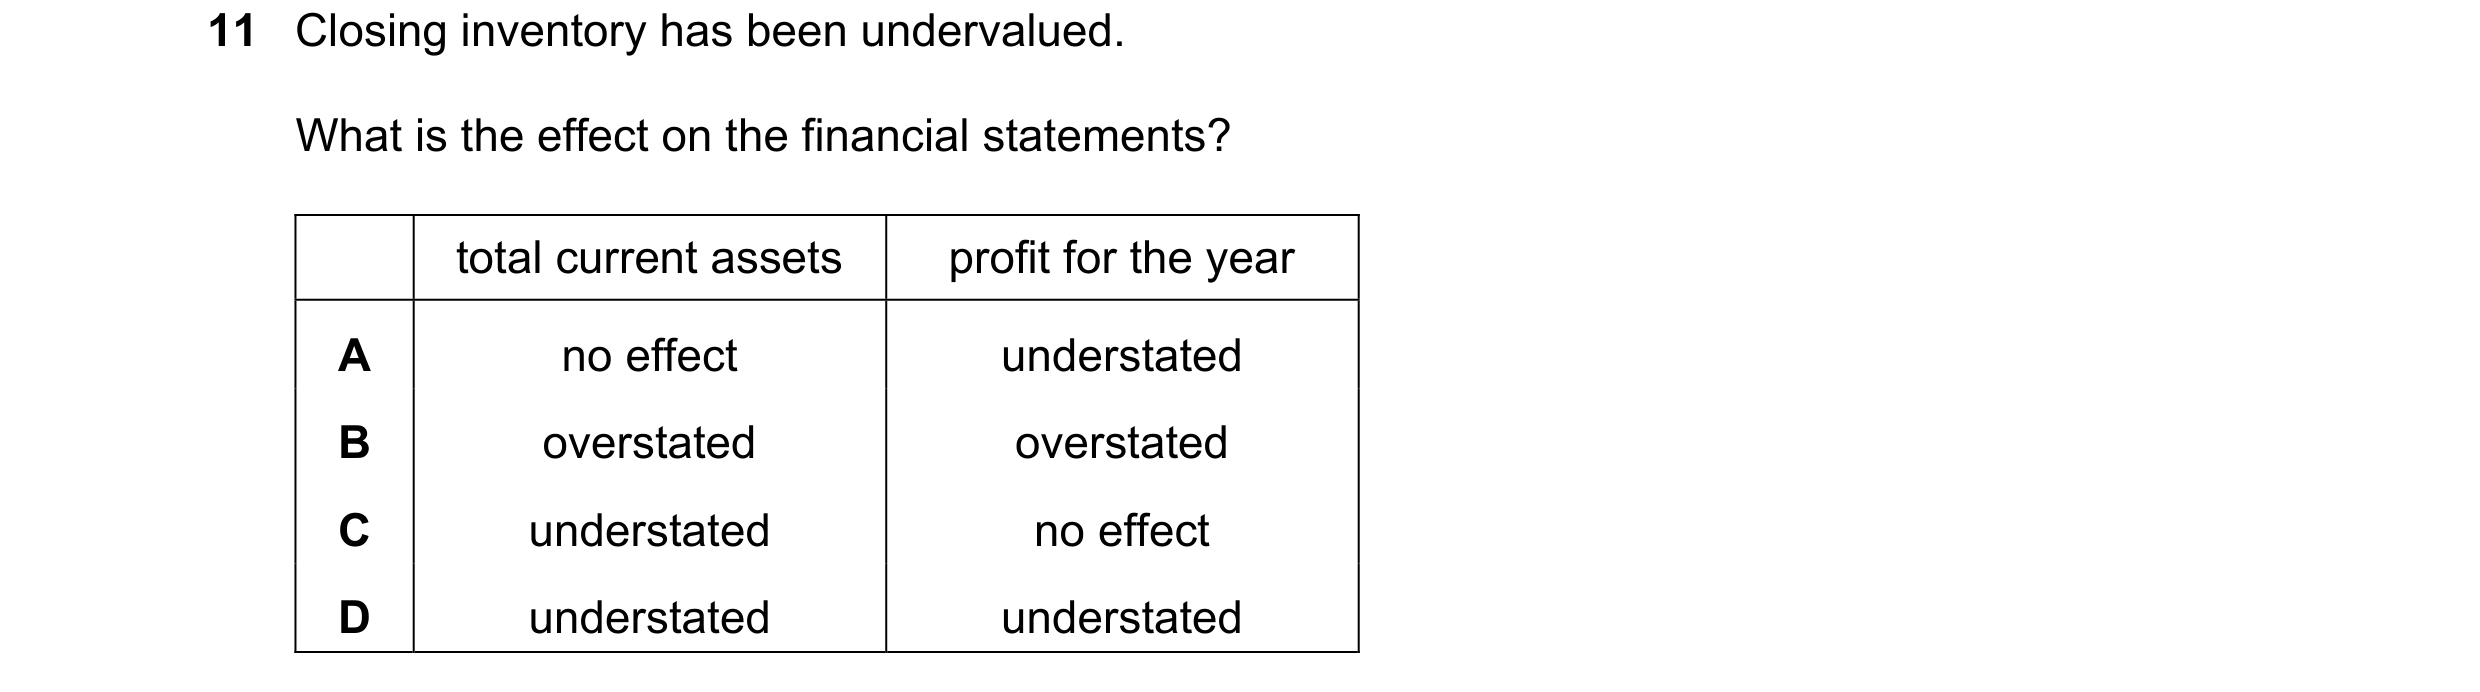
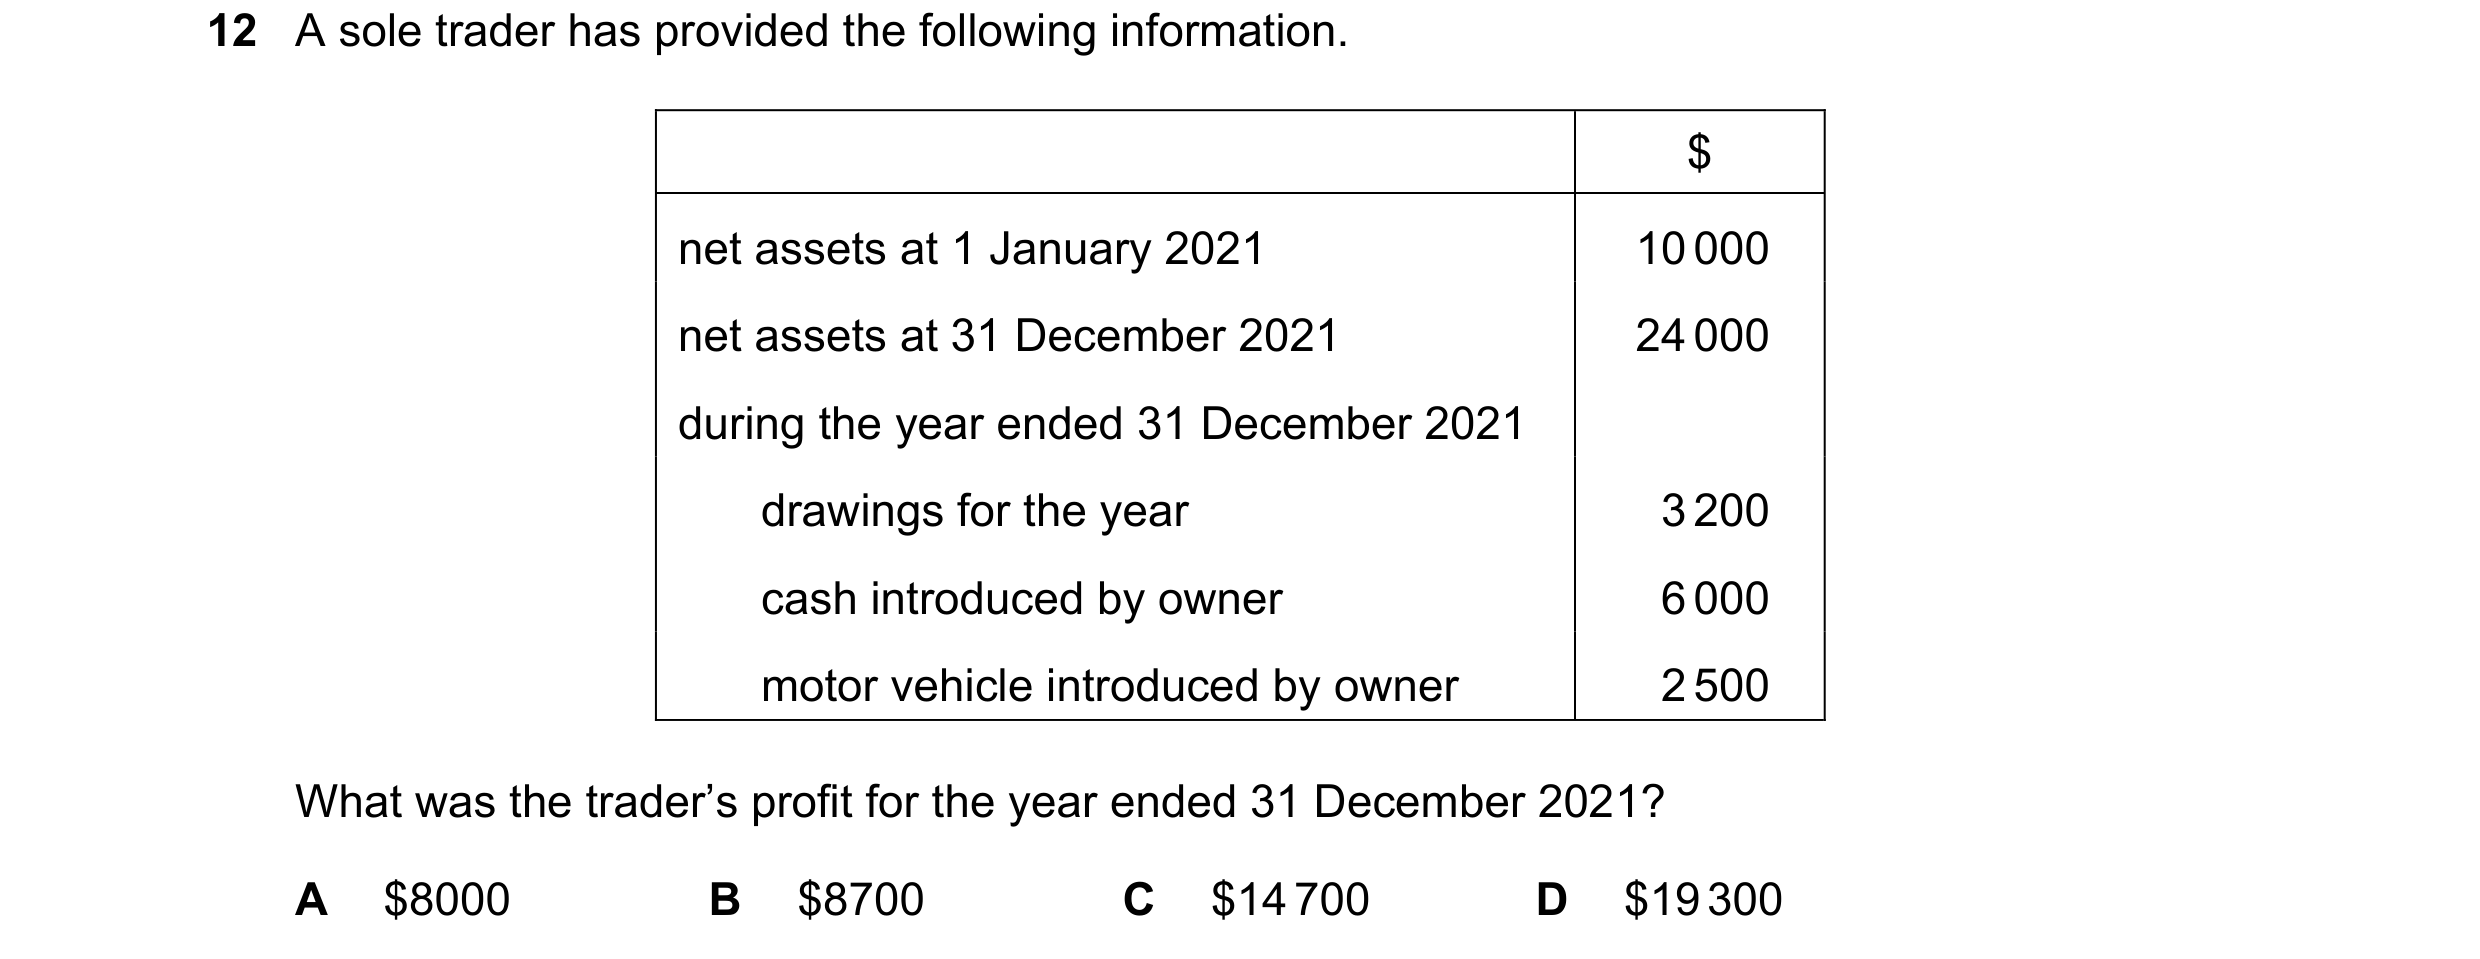
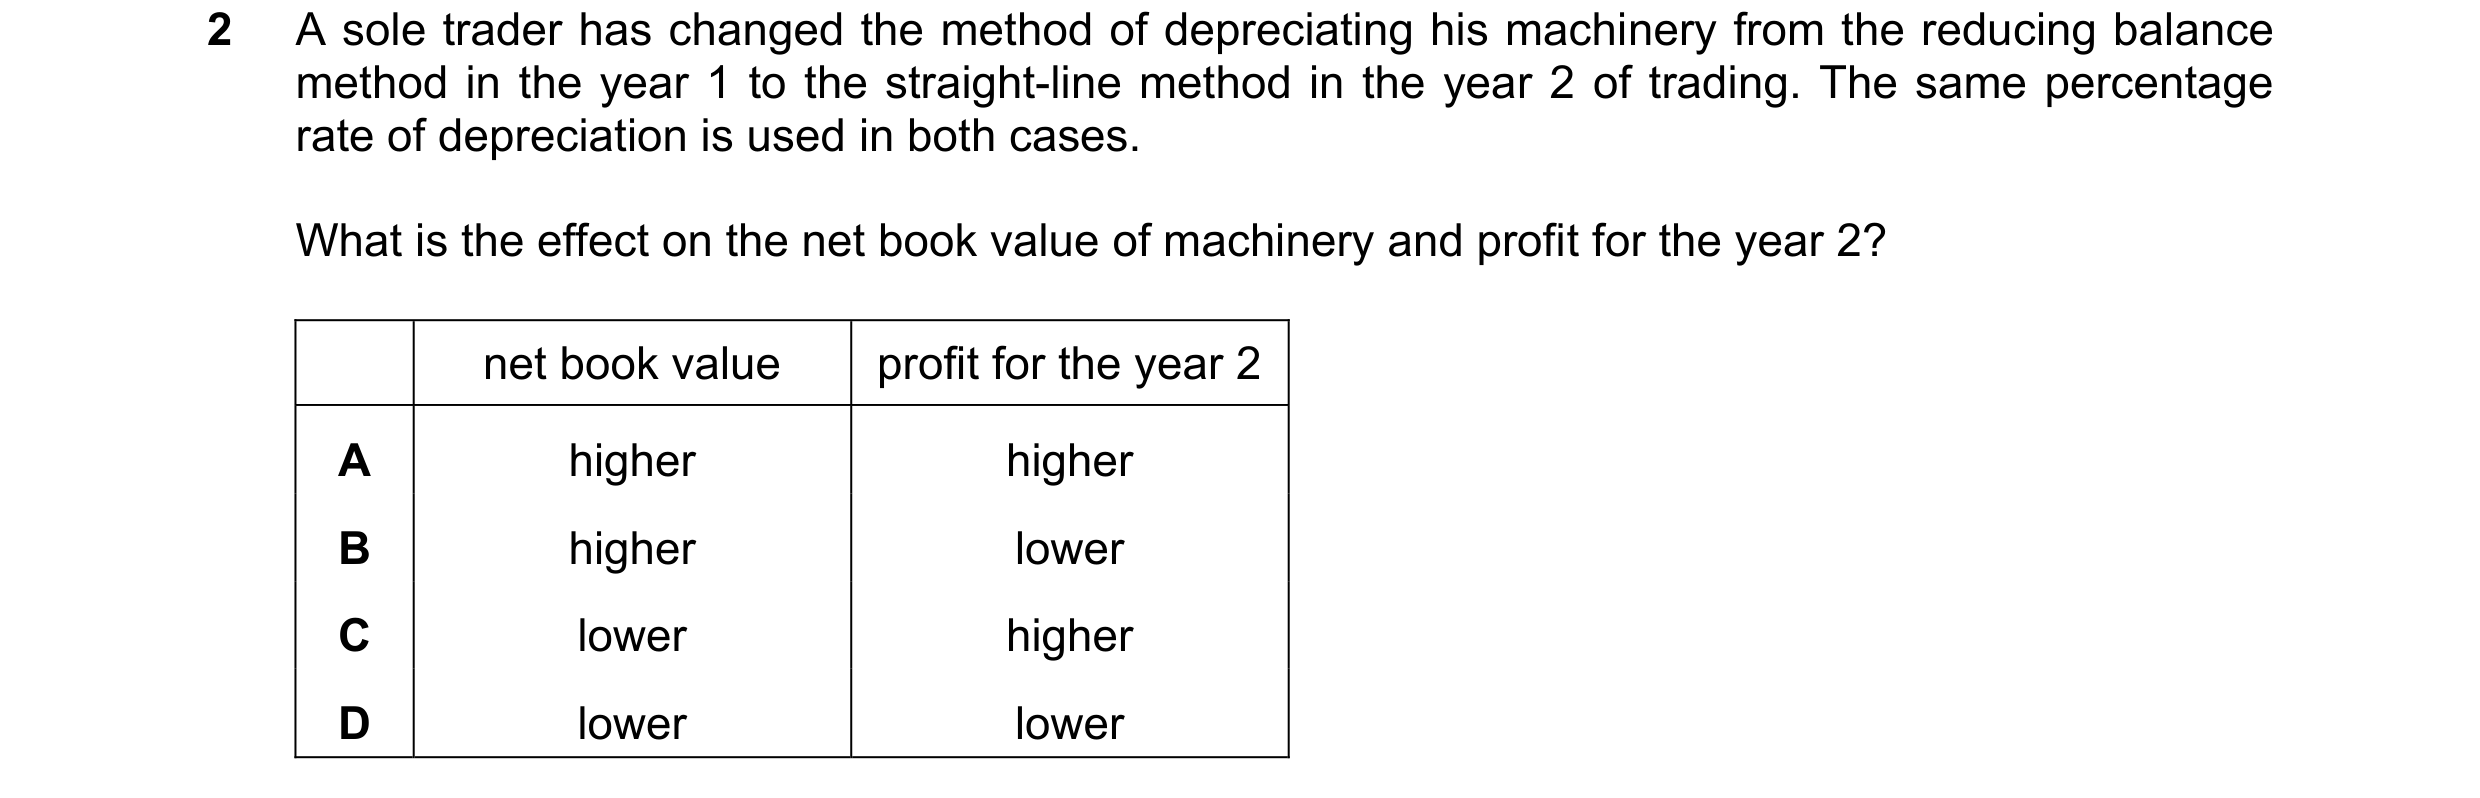 189 / 233
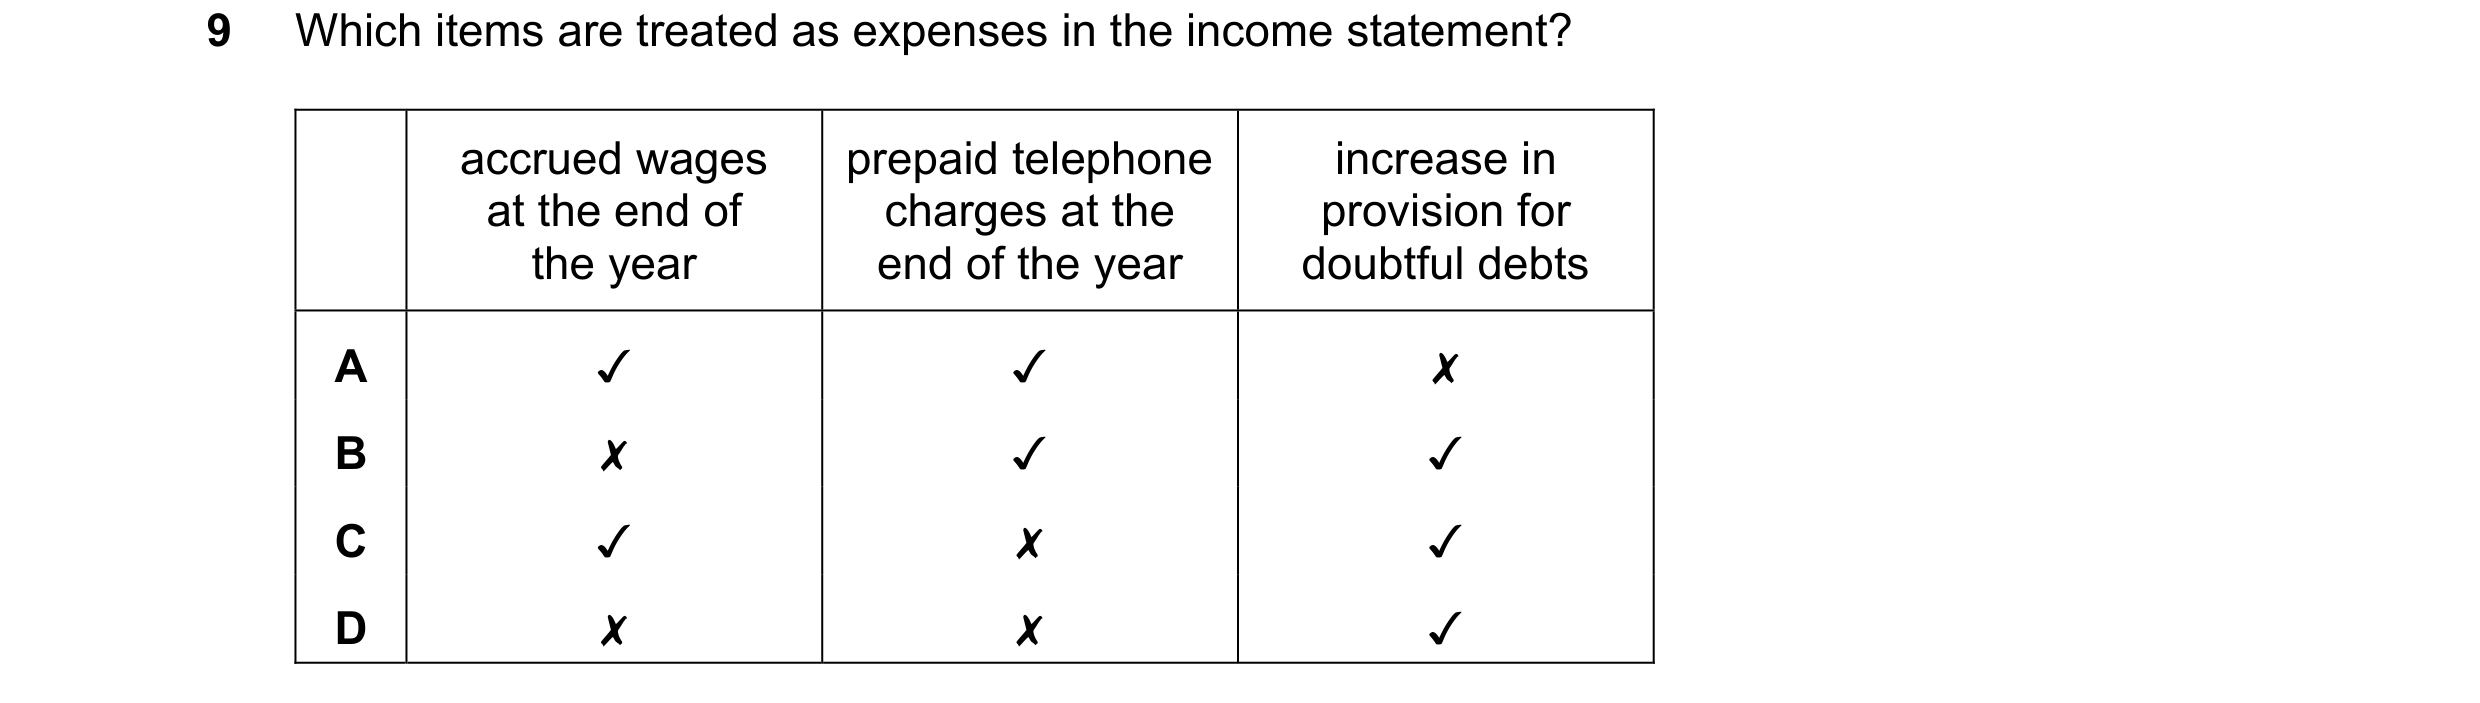
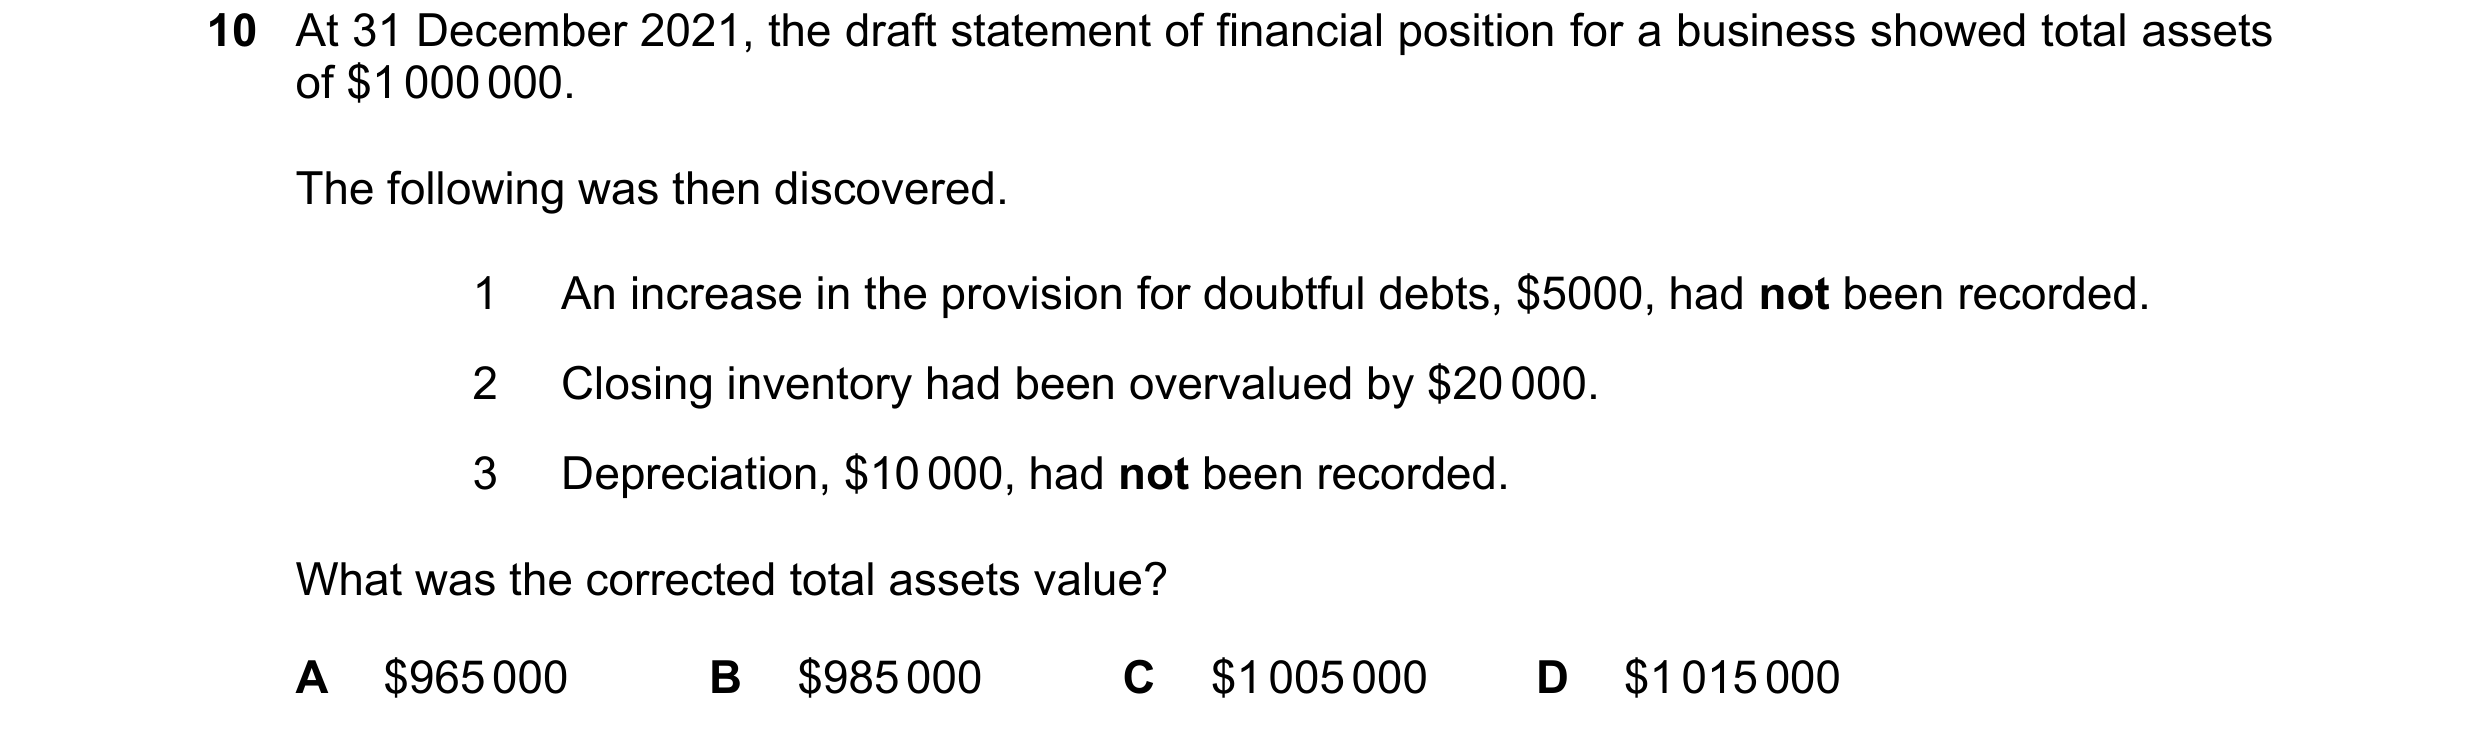 190 / 233
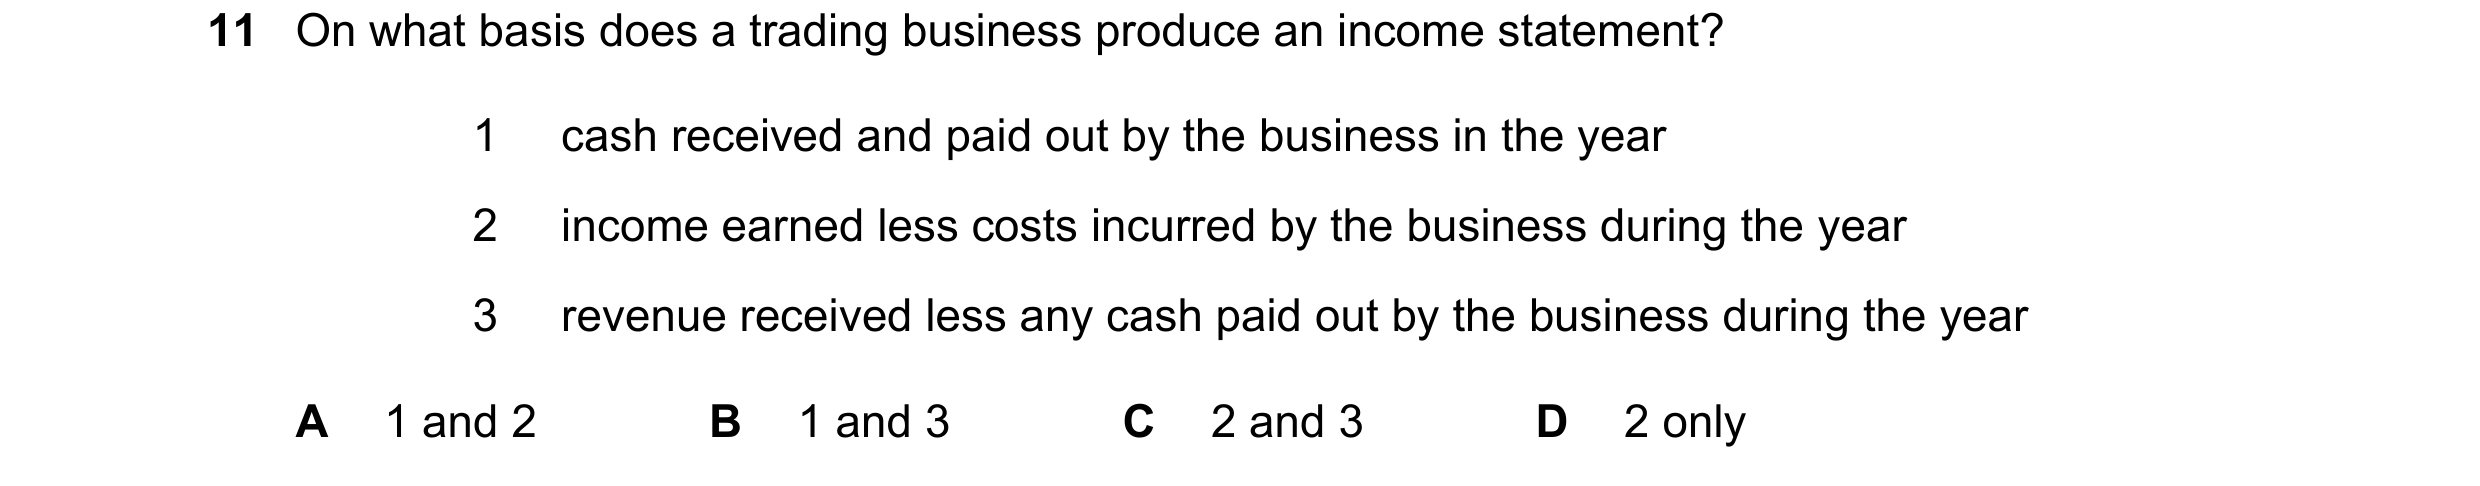
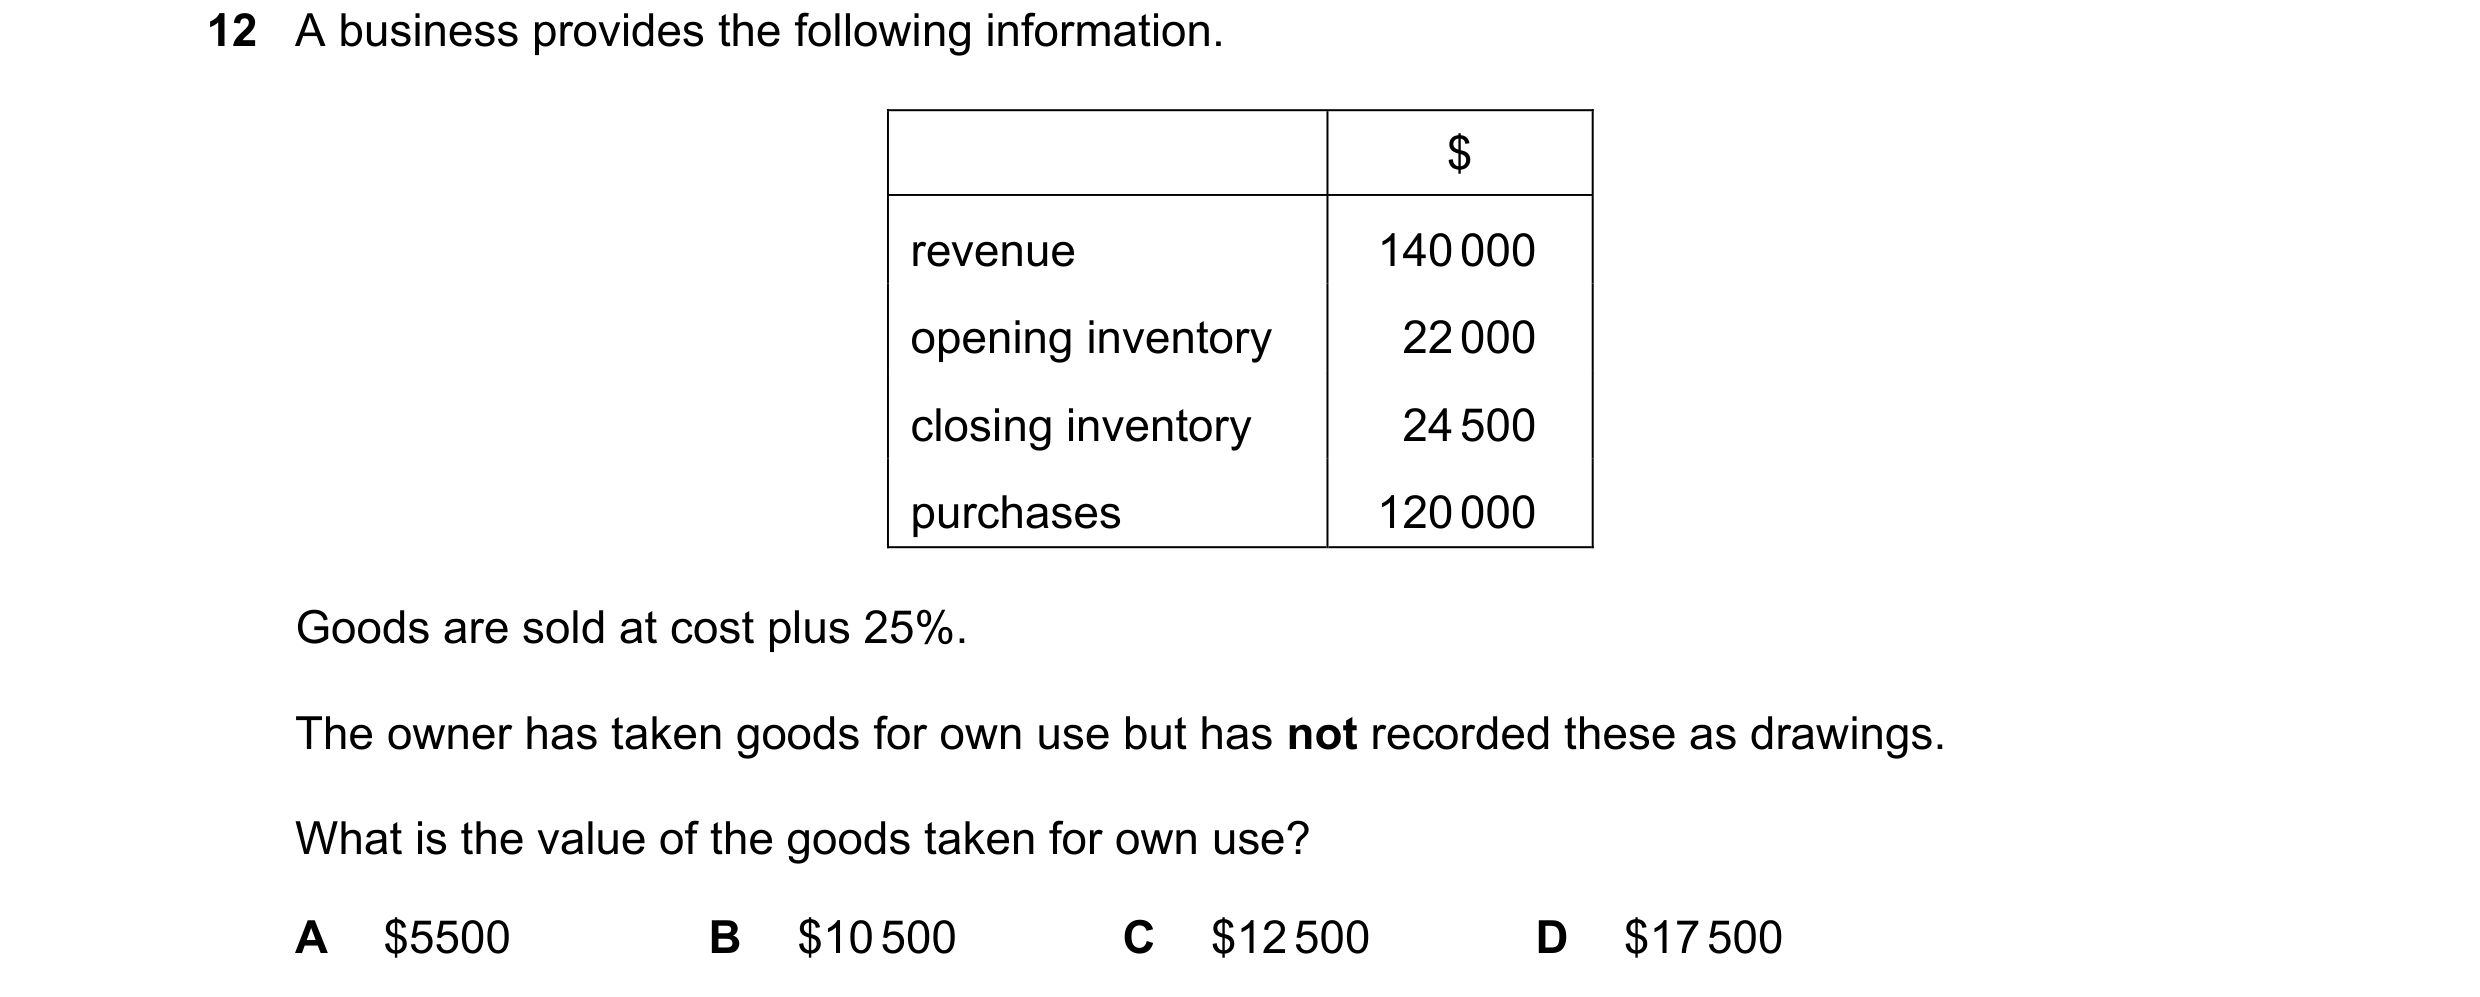
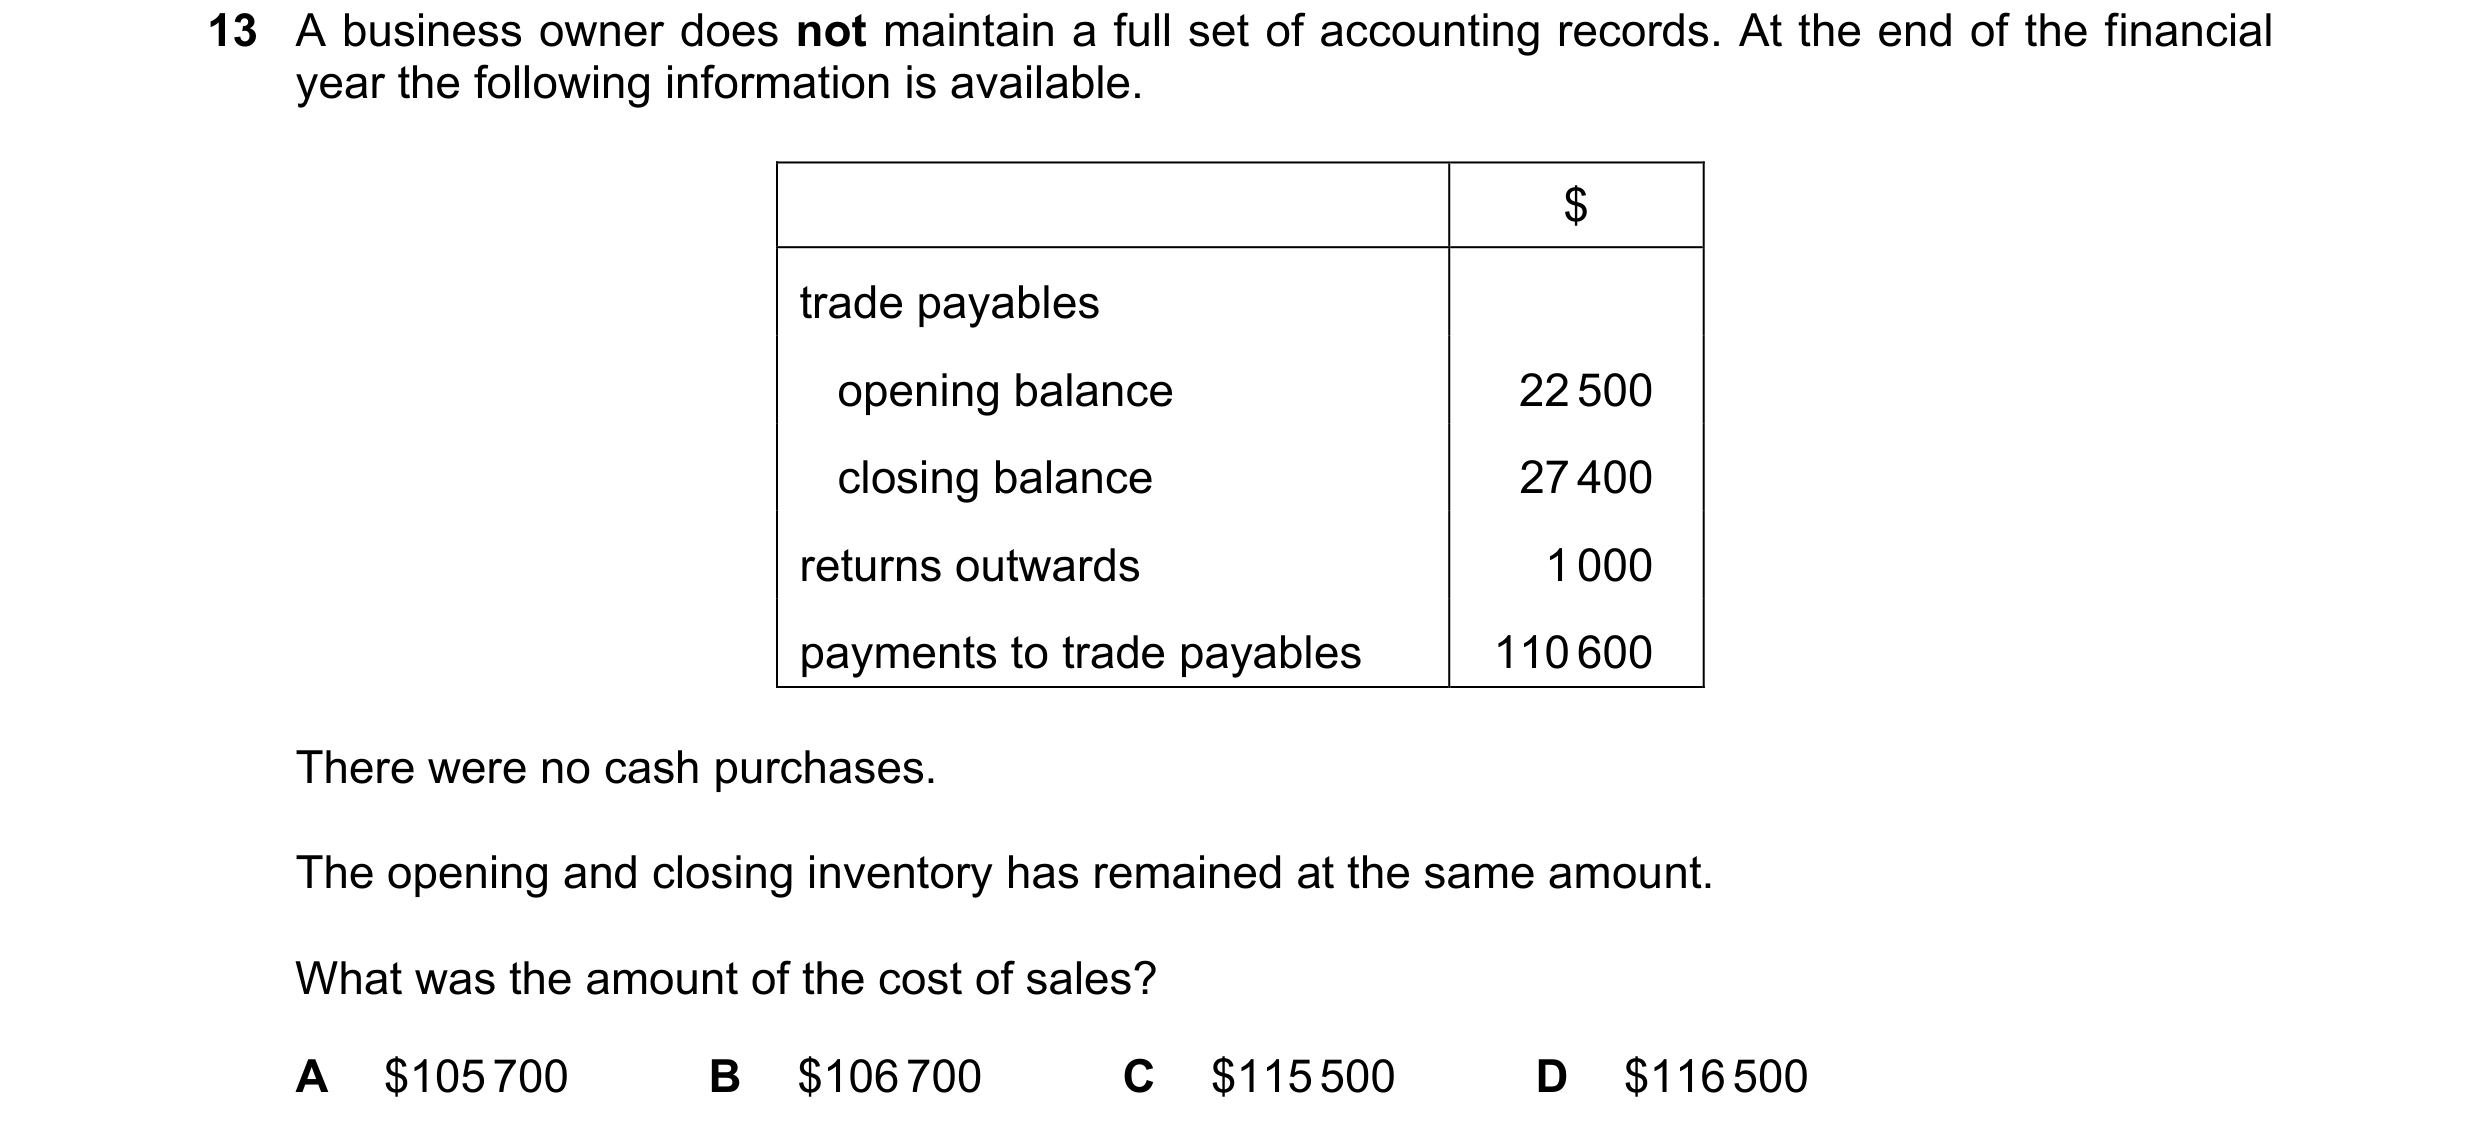 191 / 233
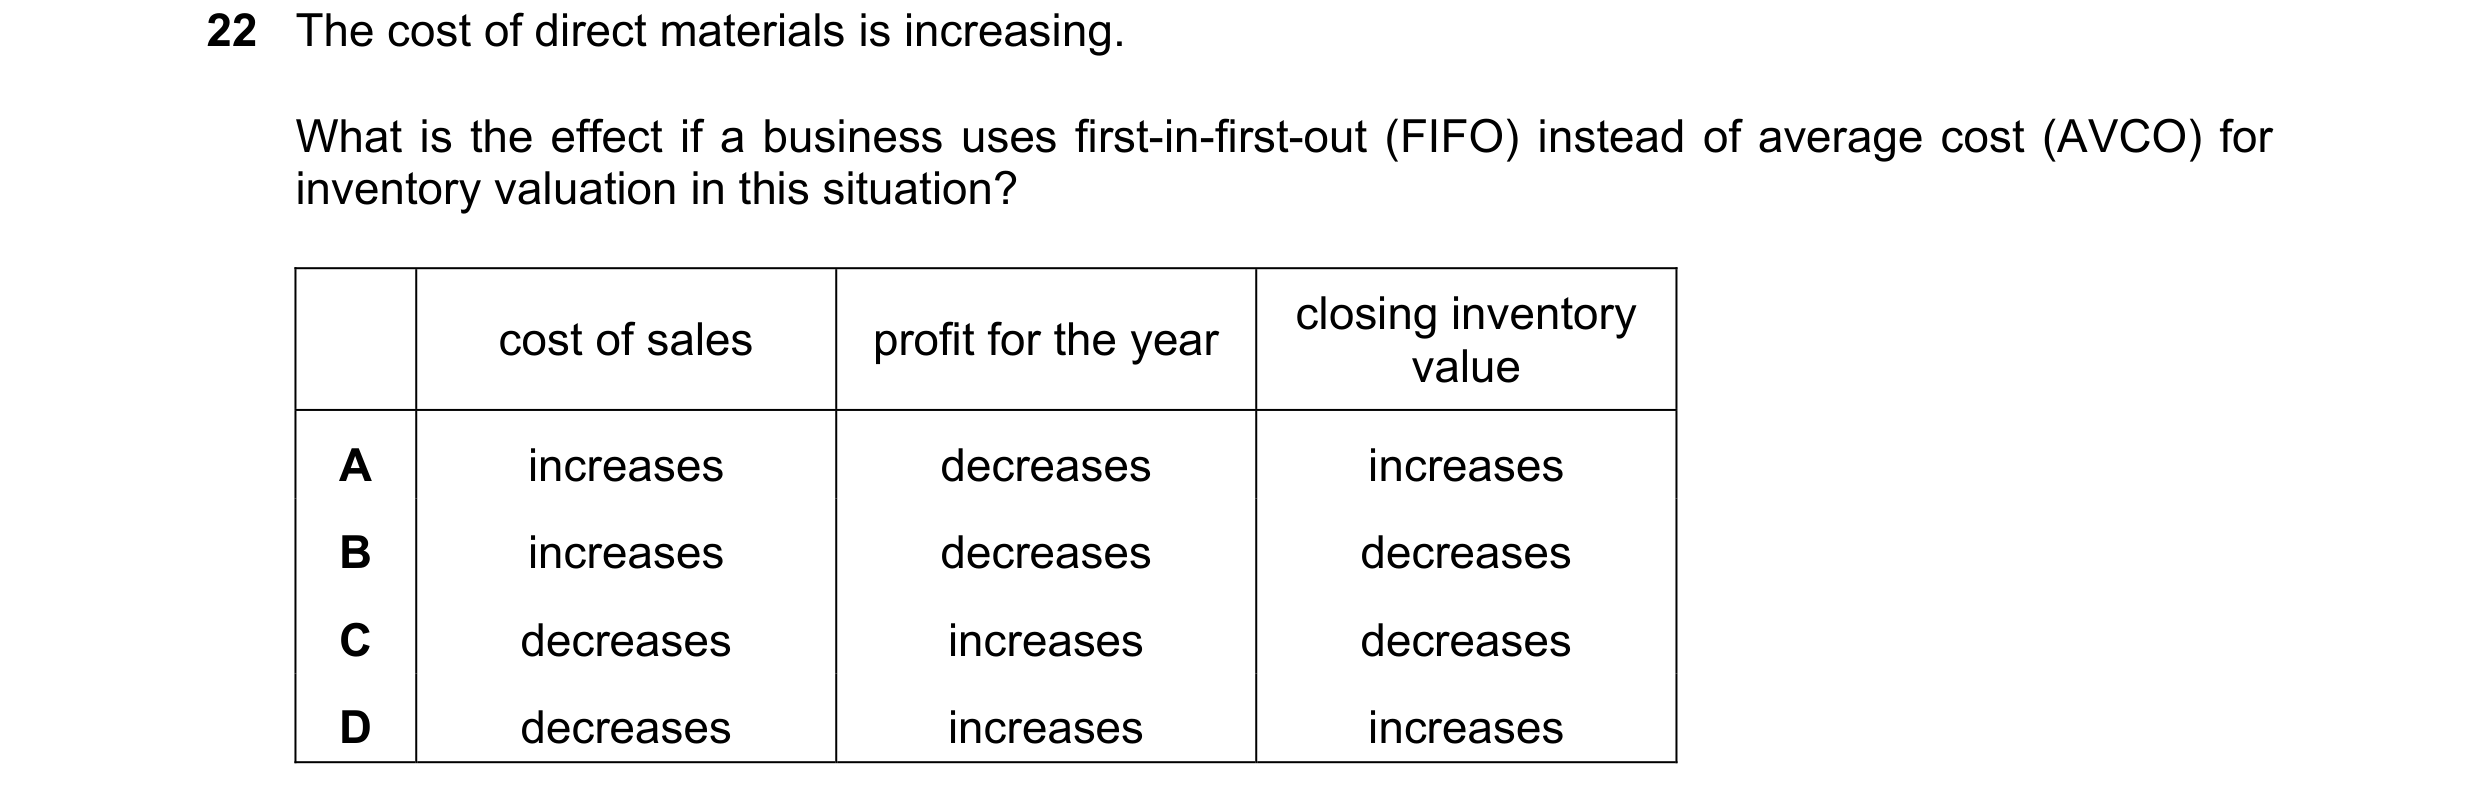
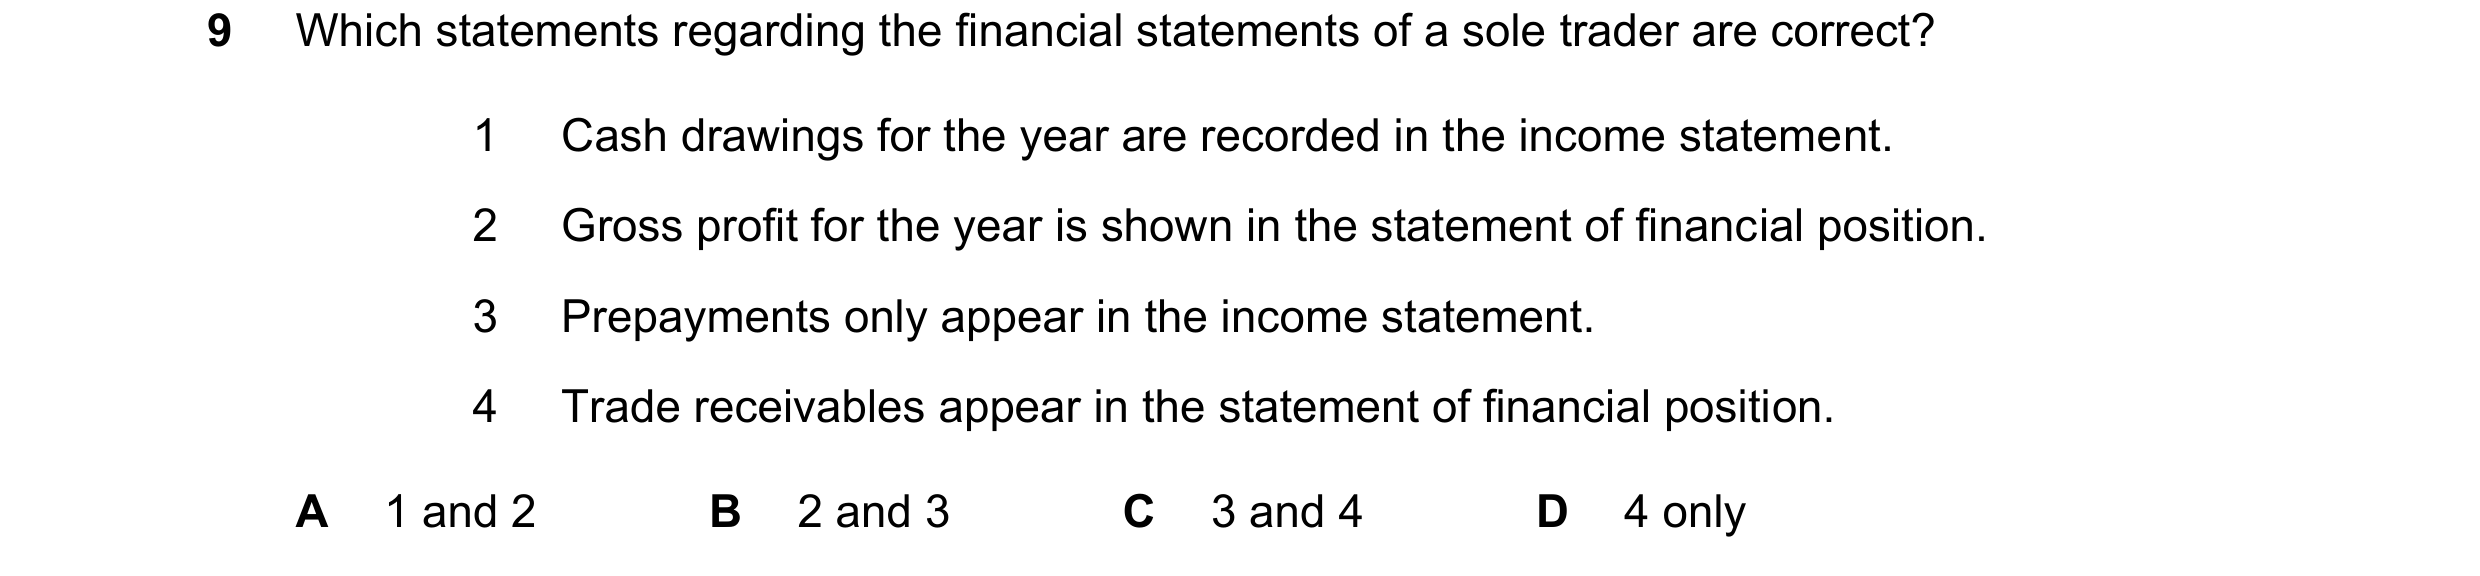
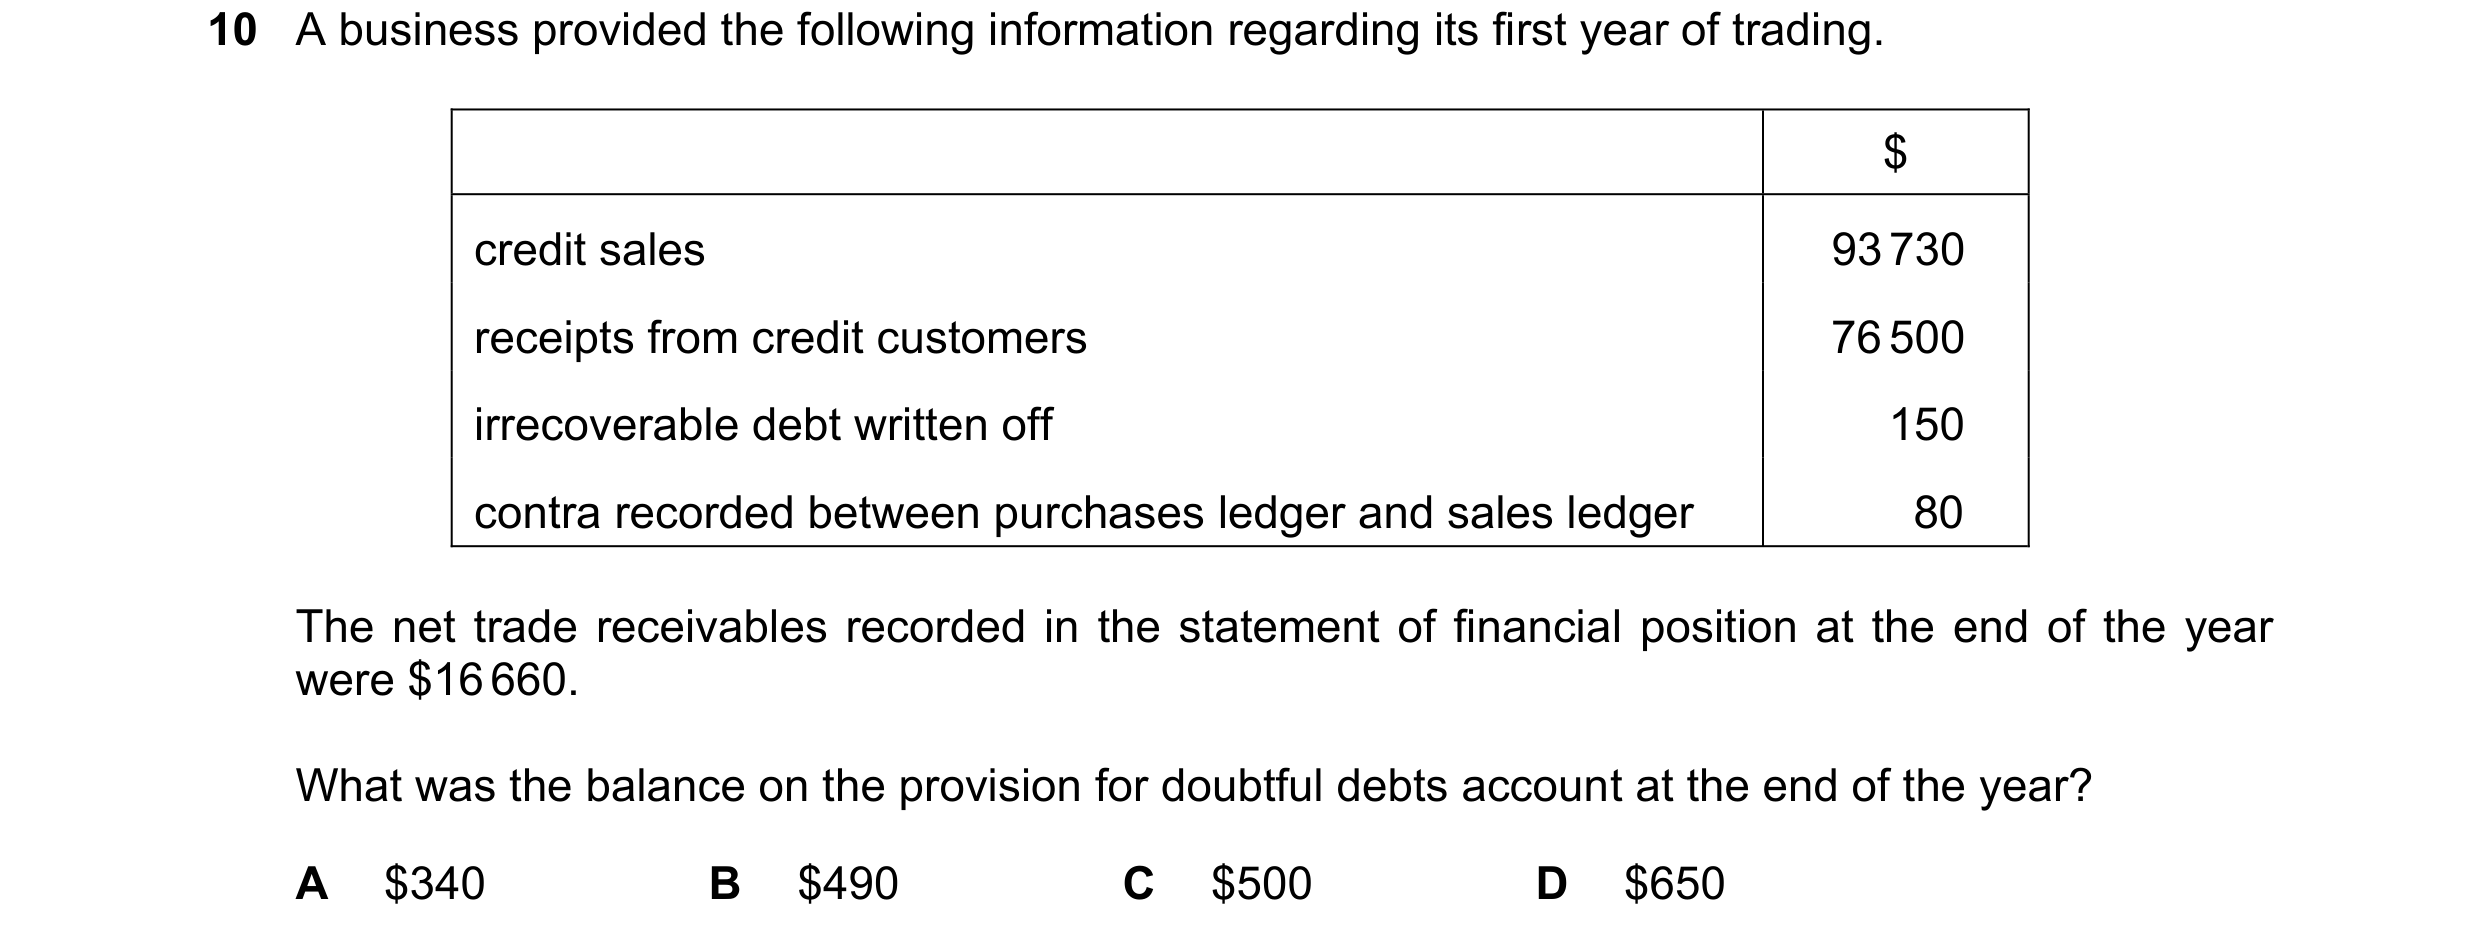
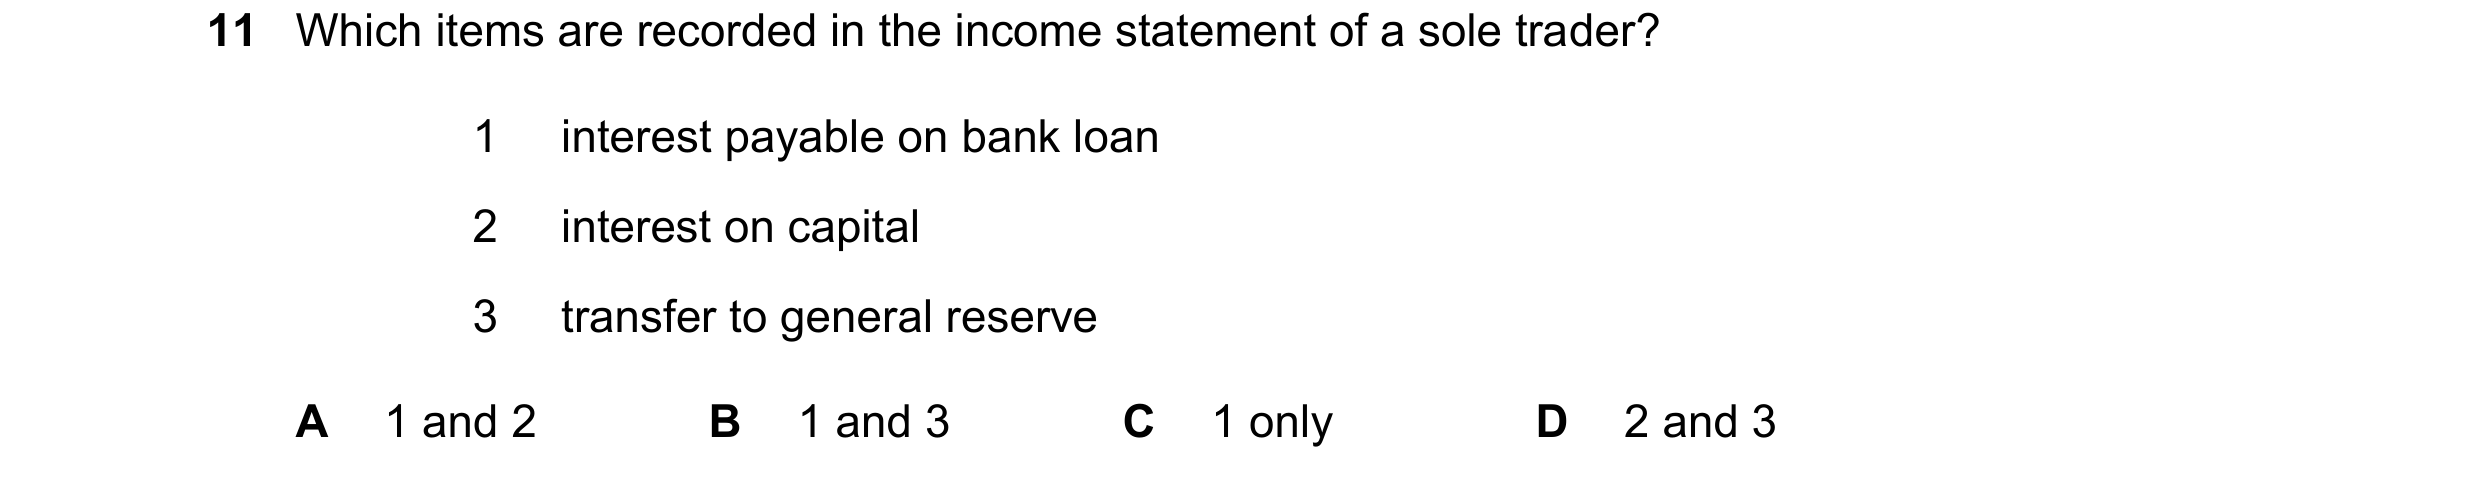 192 / 233
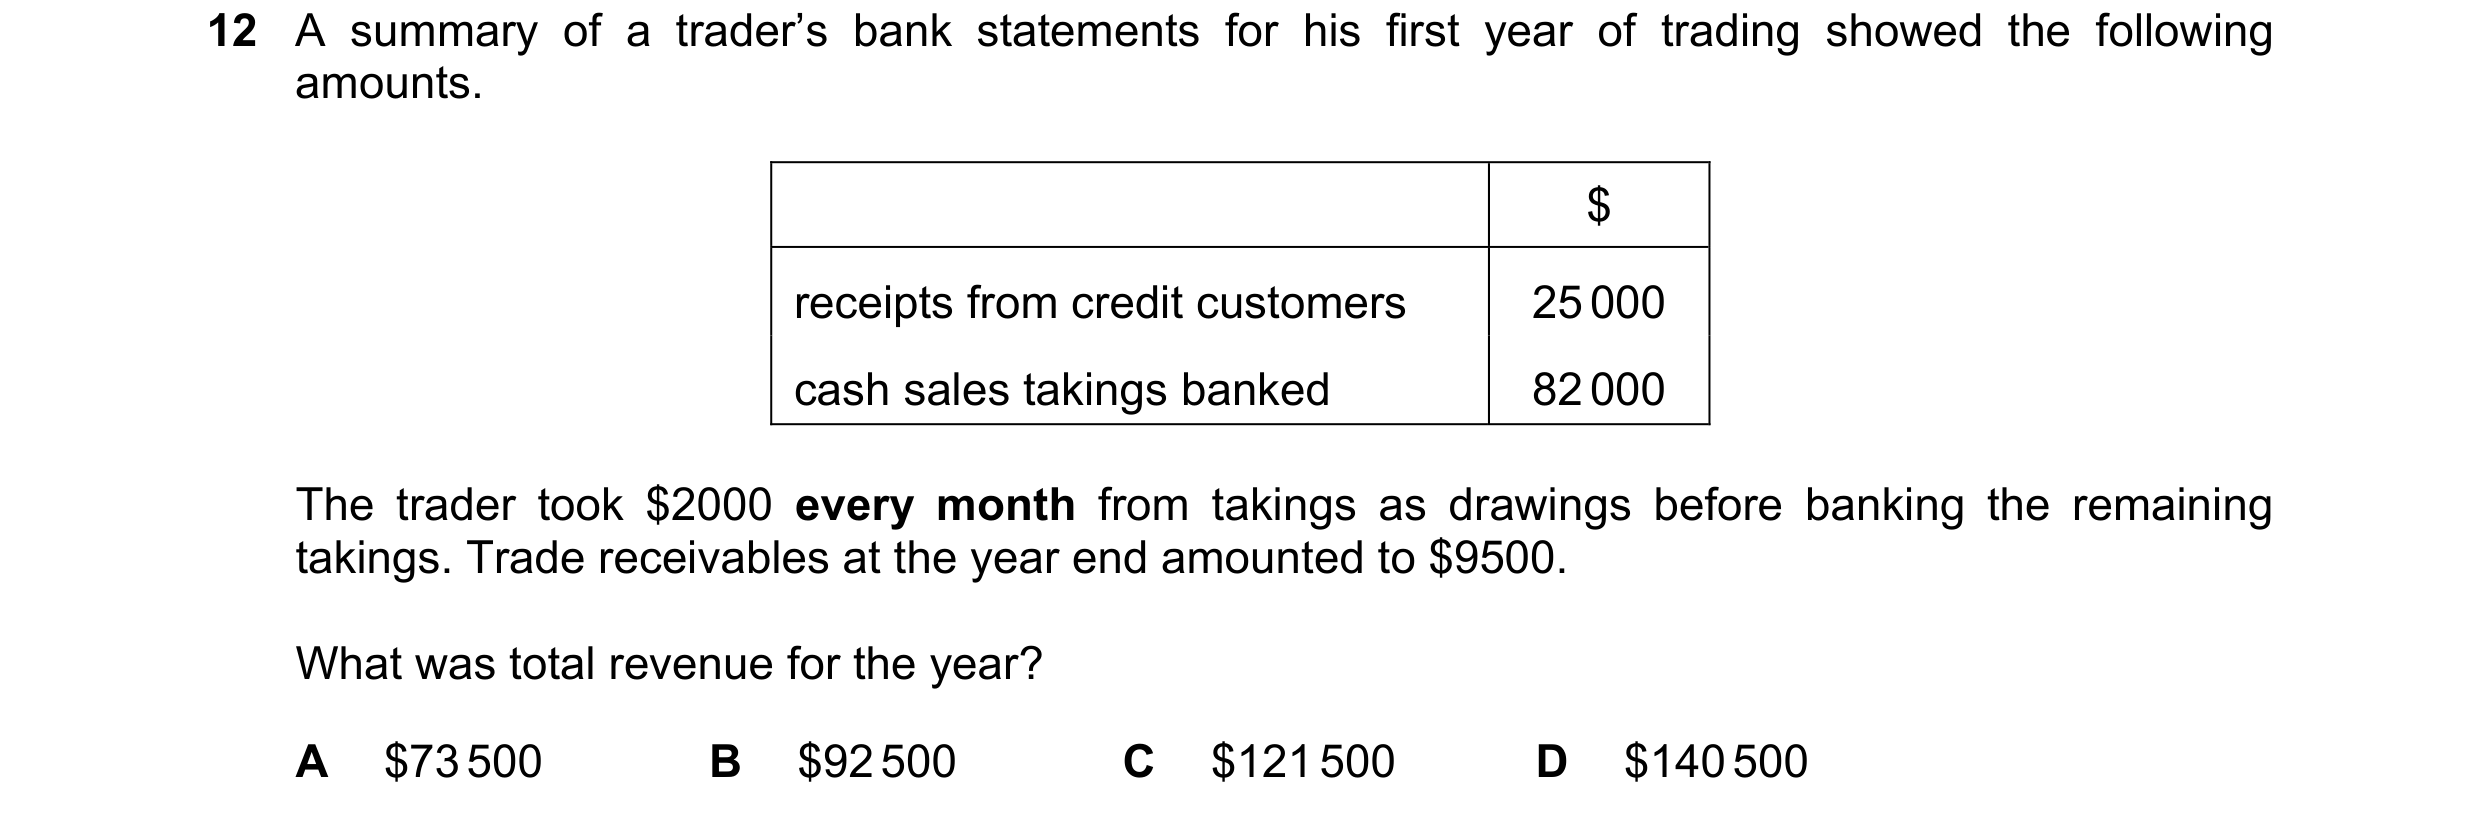
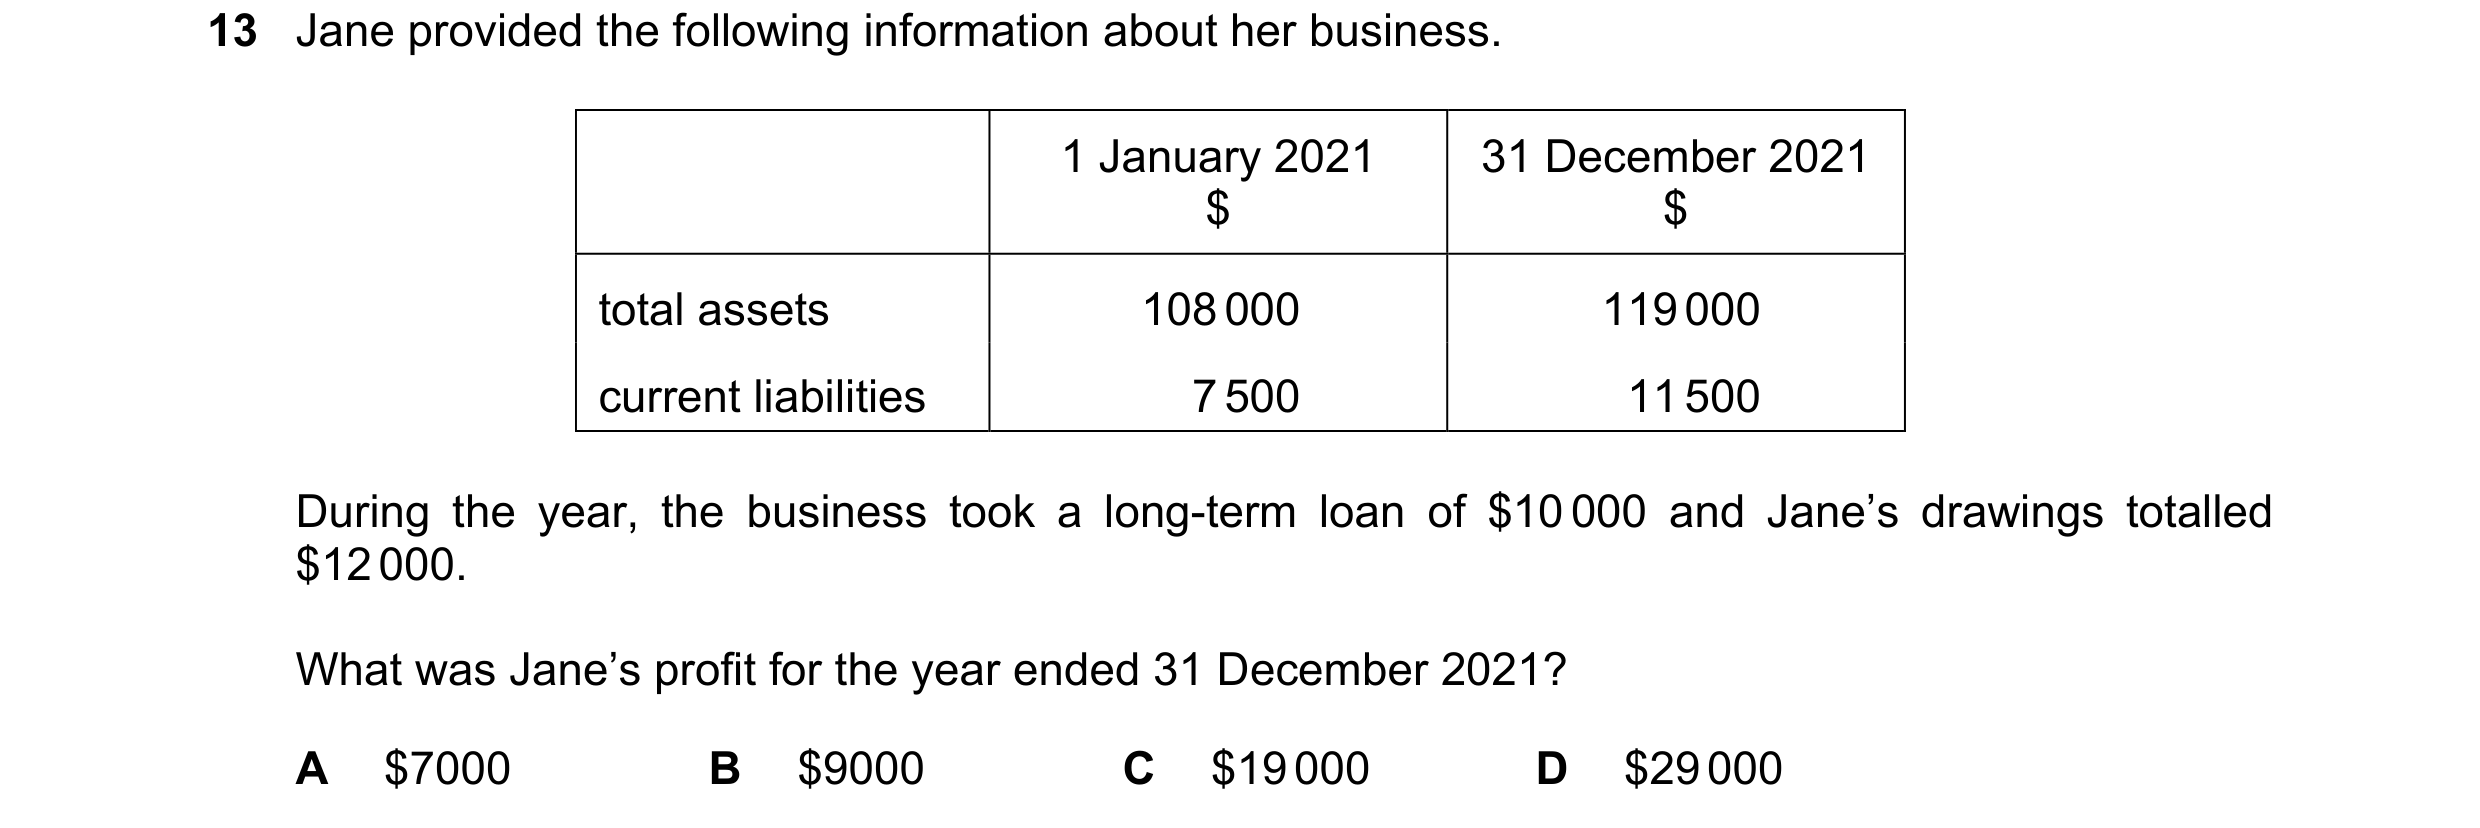
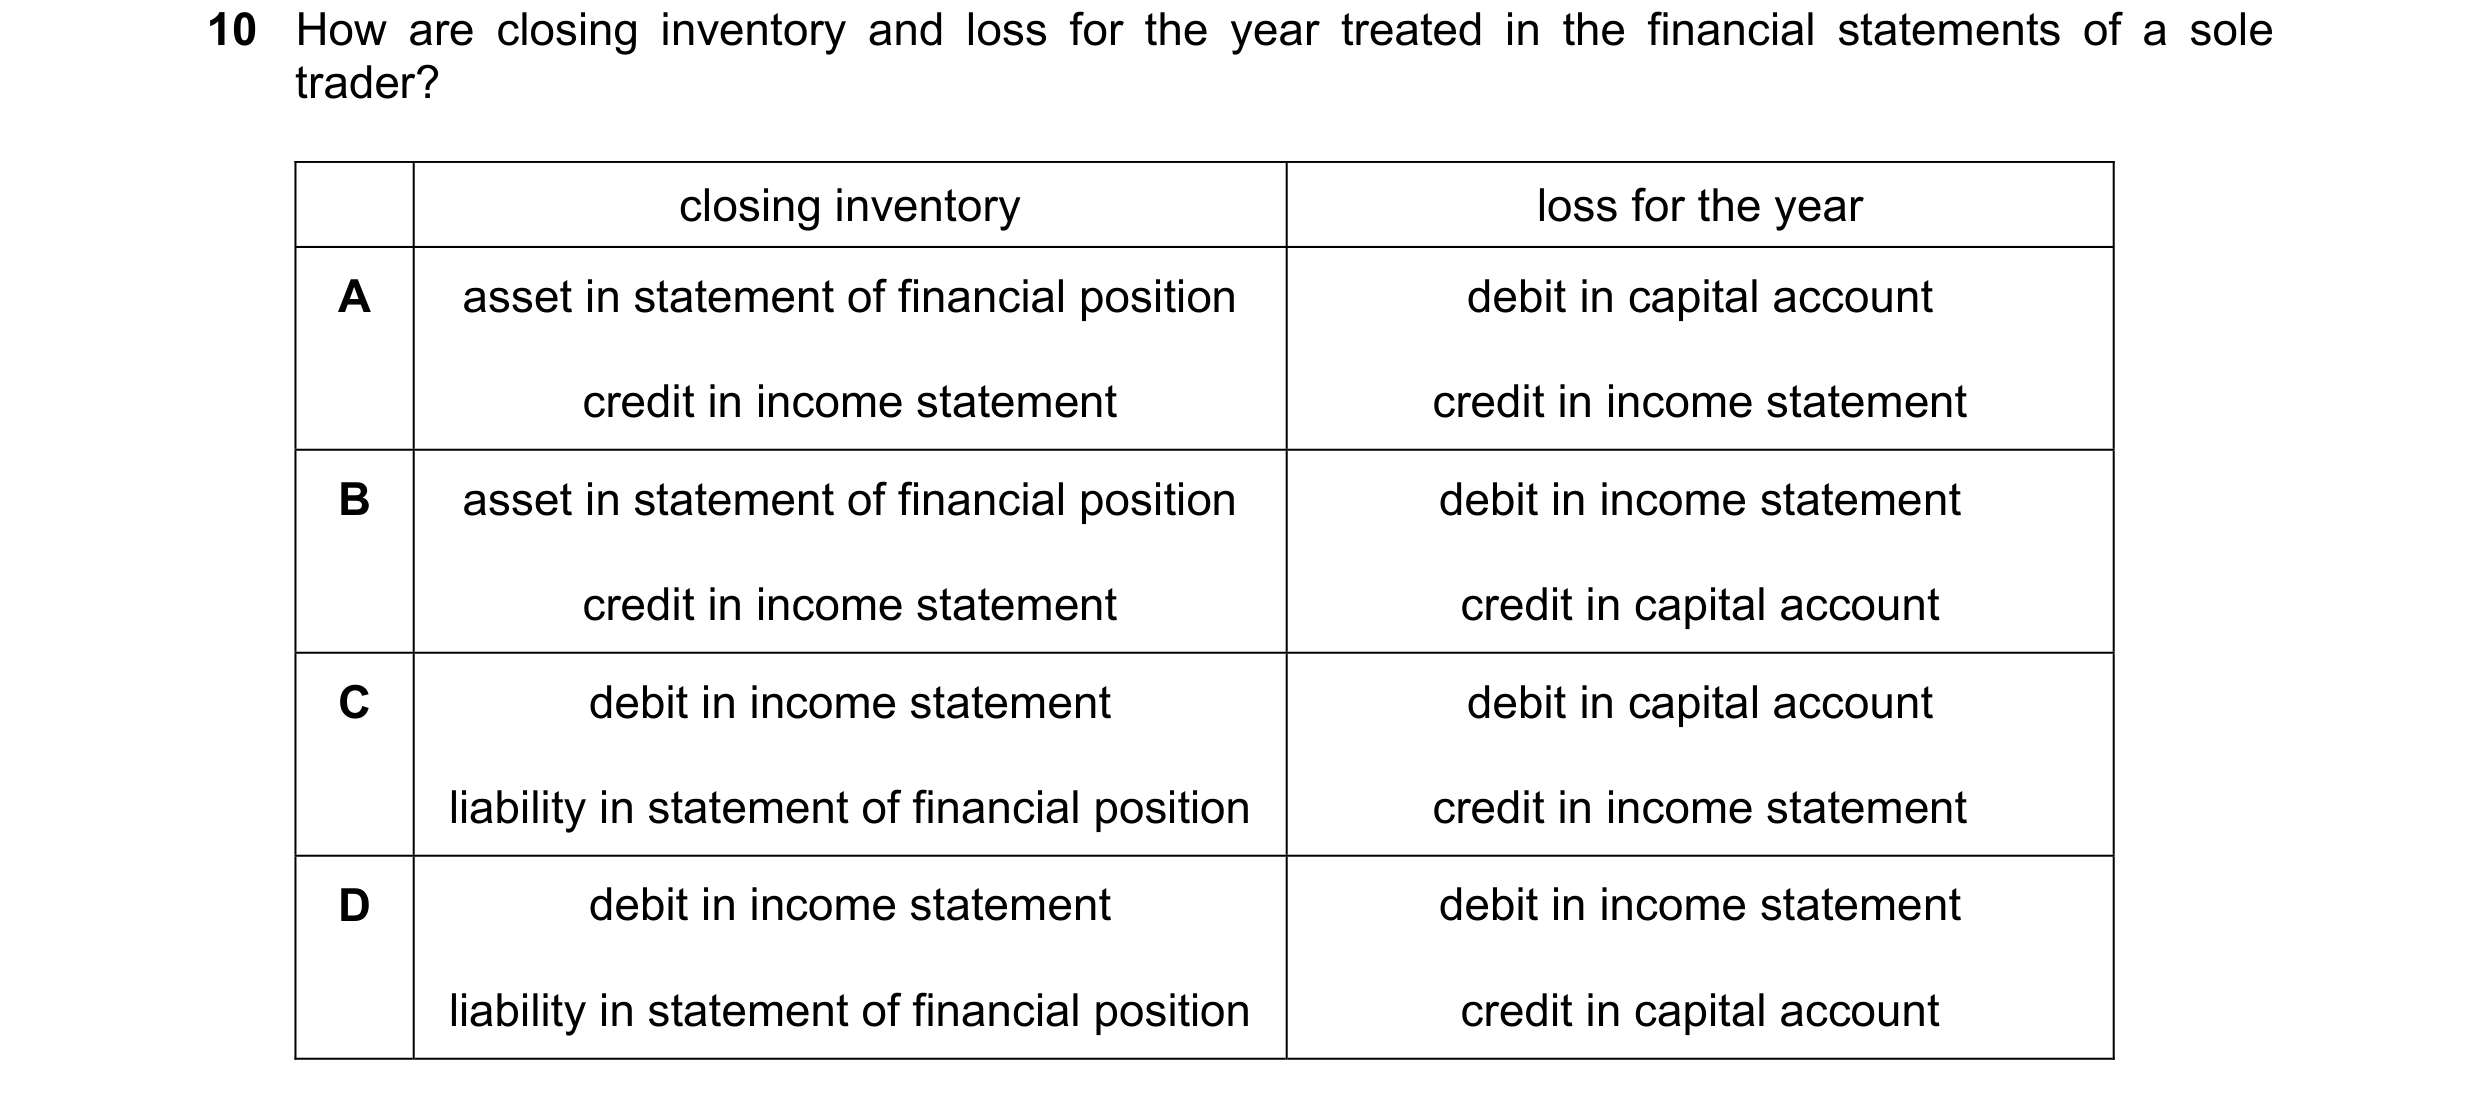 193 / 233
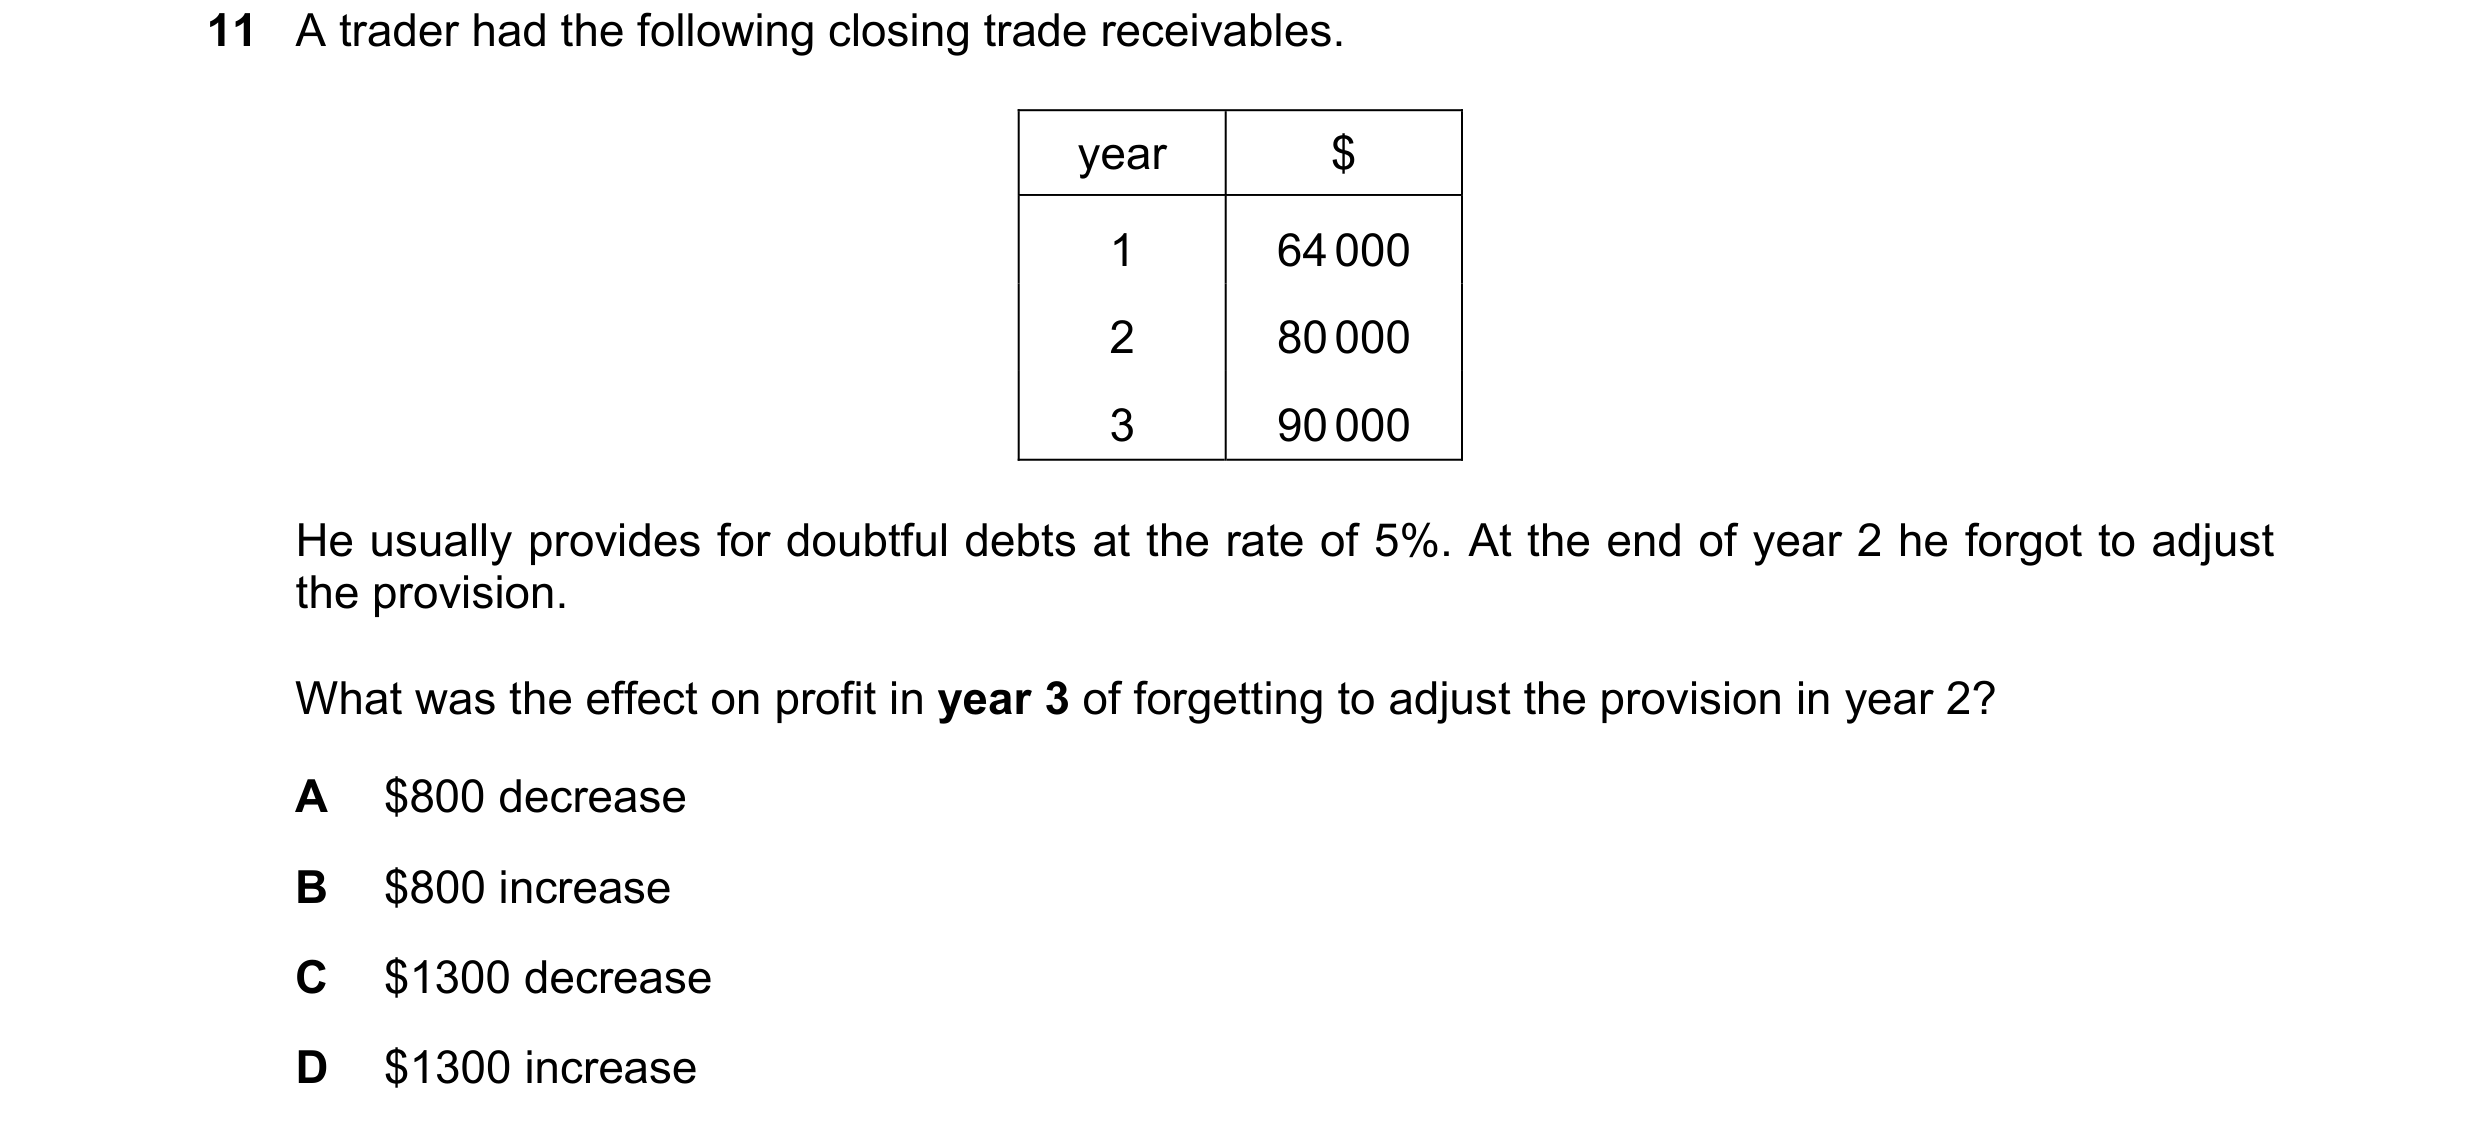
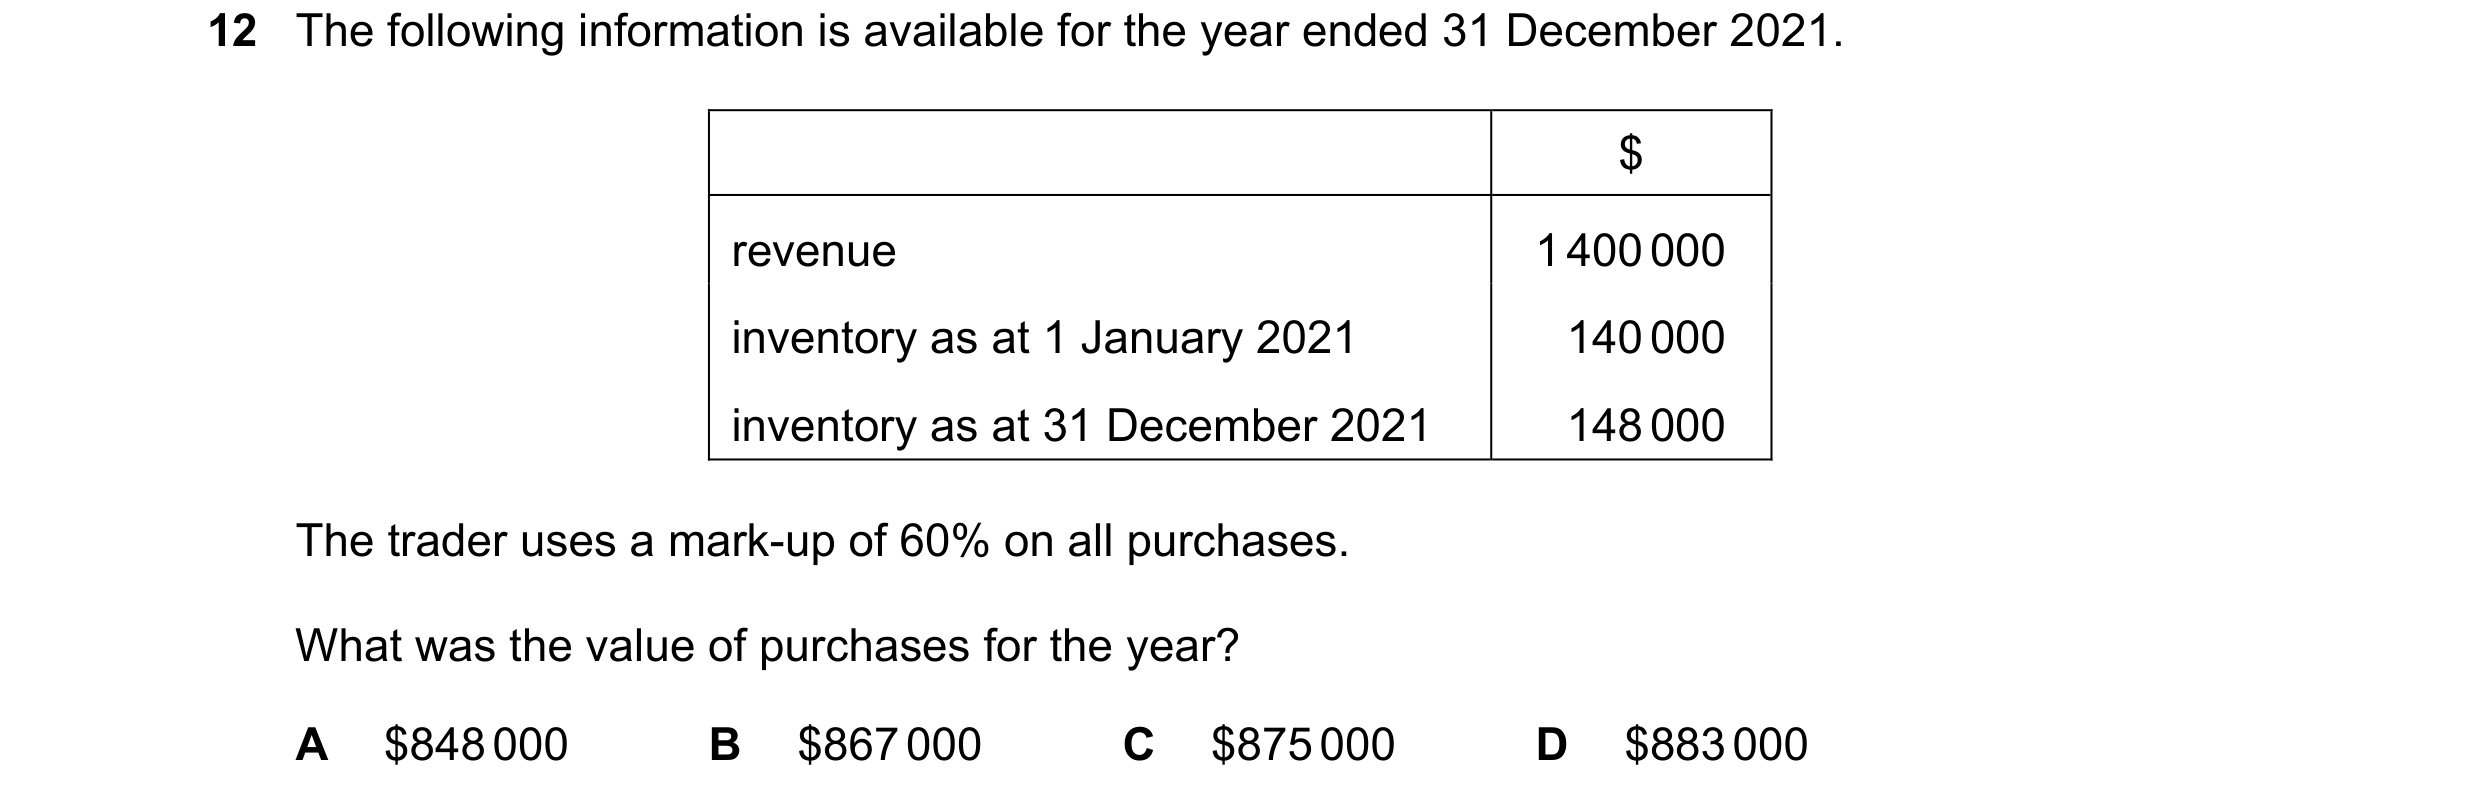
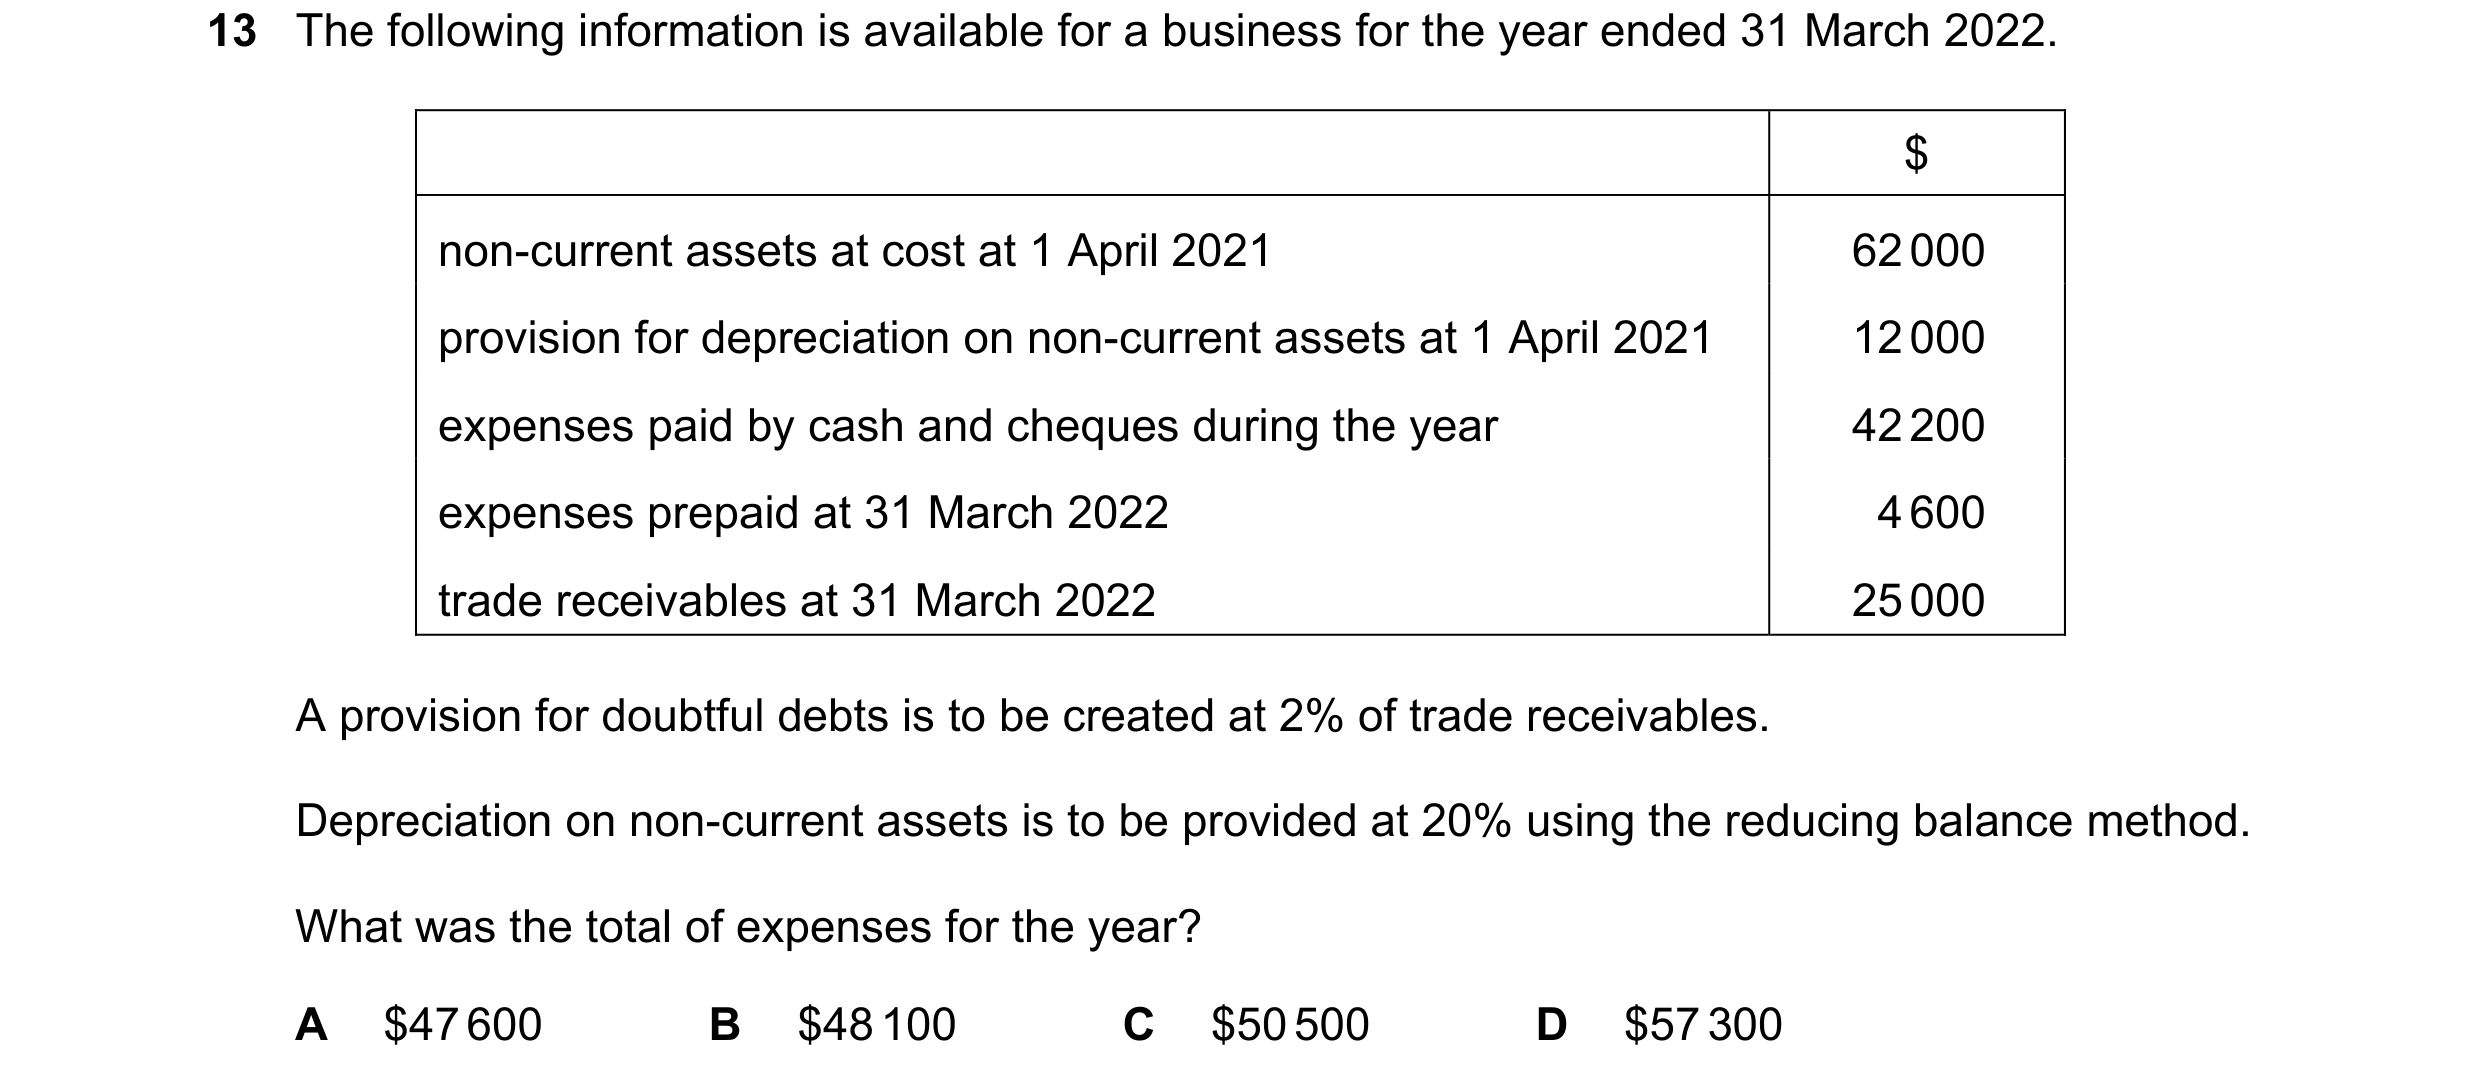 194 / 233
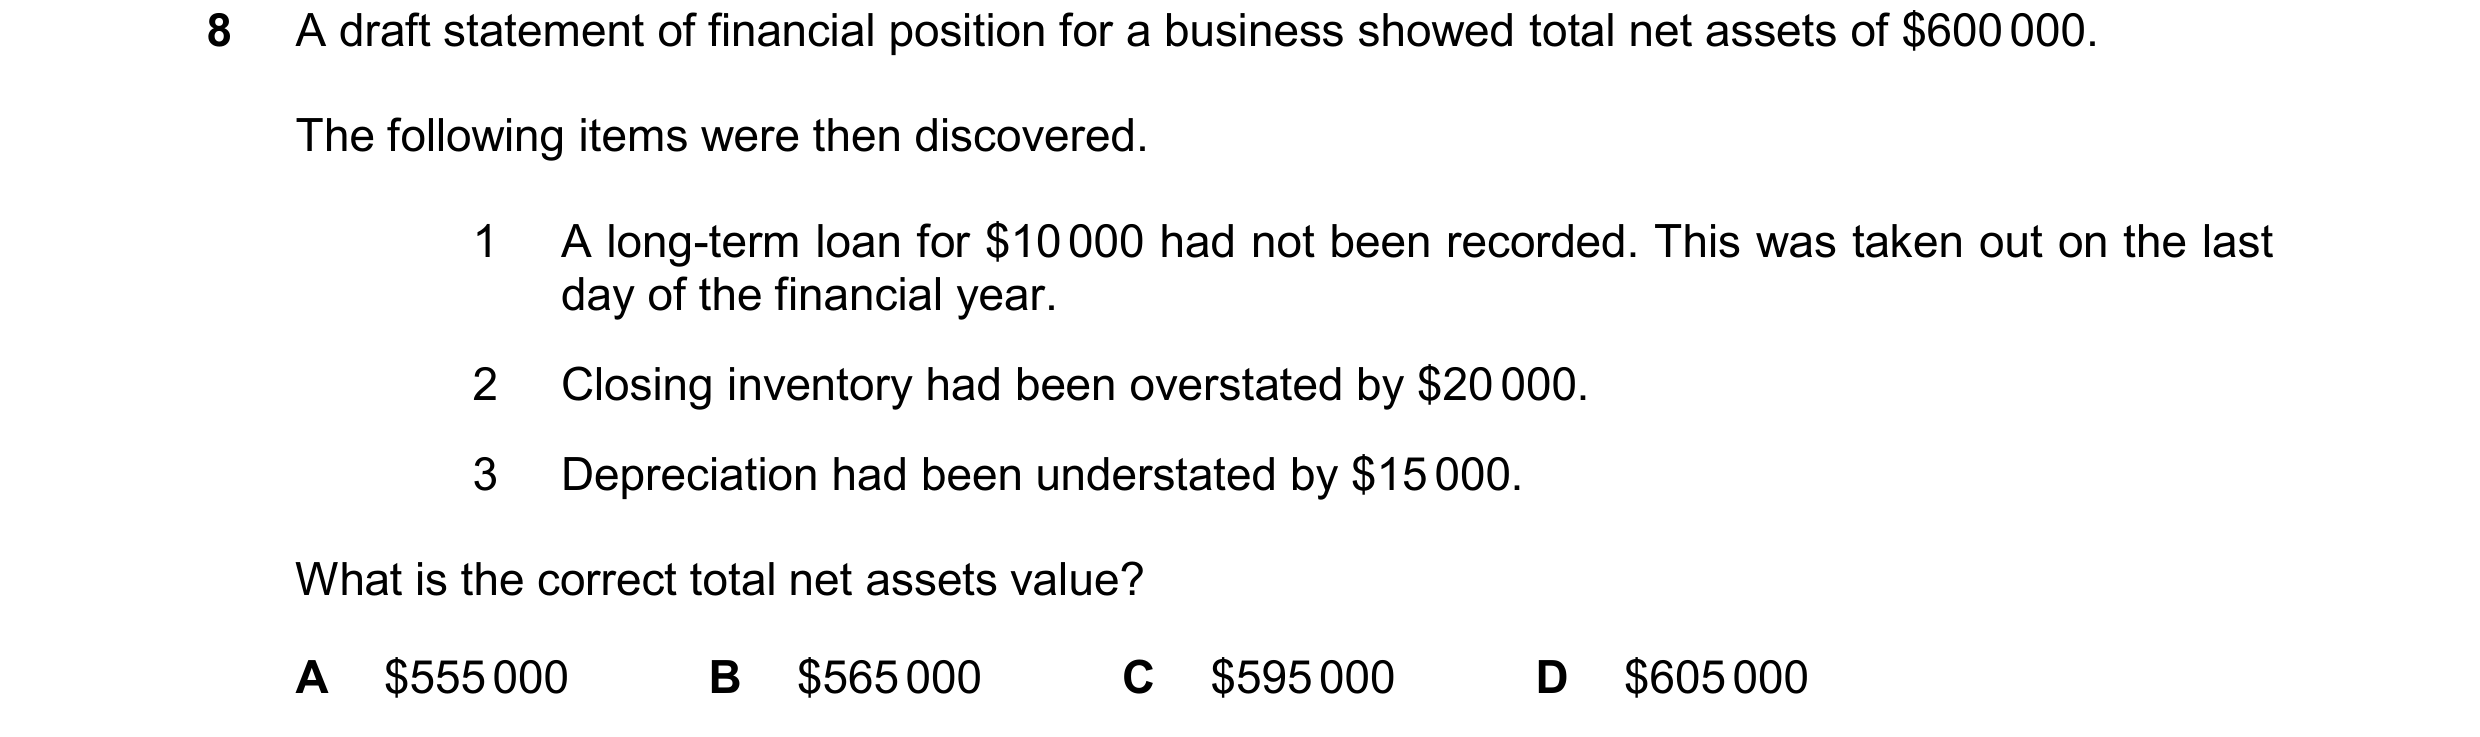
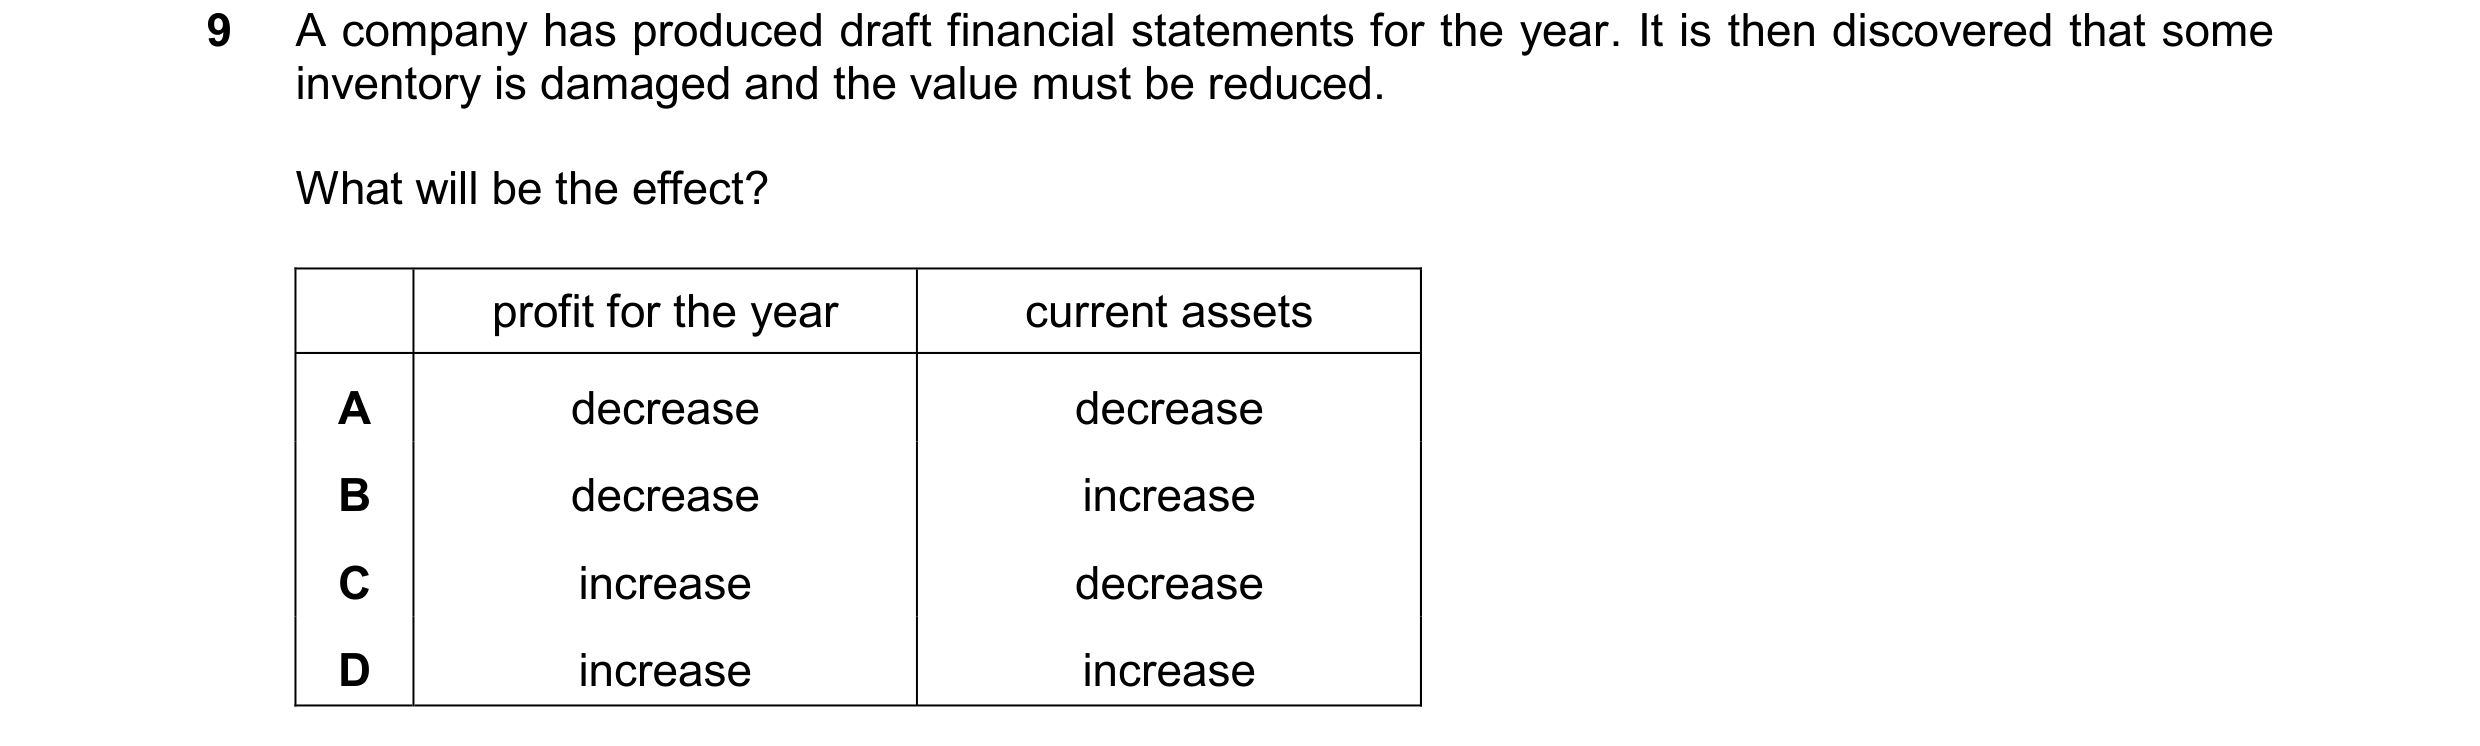
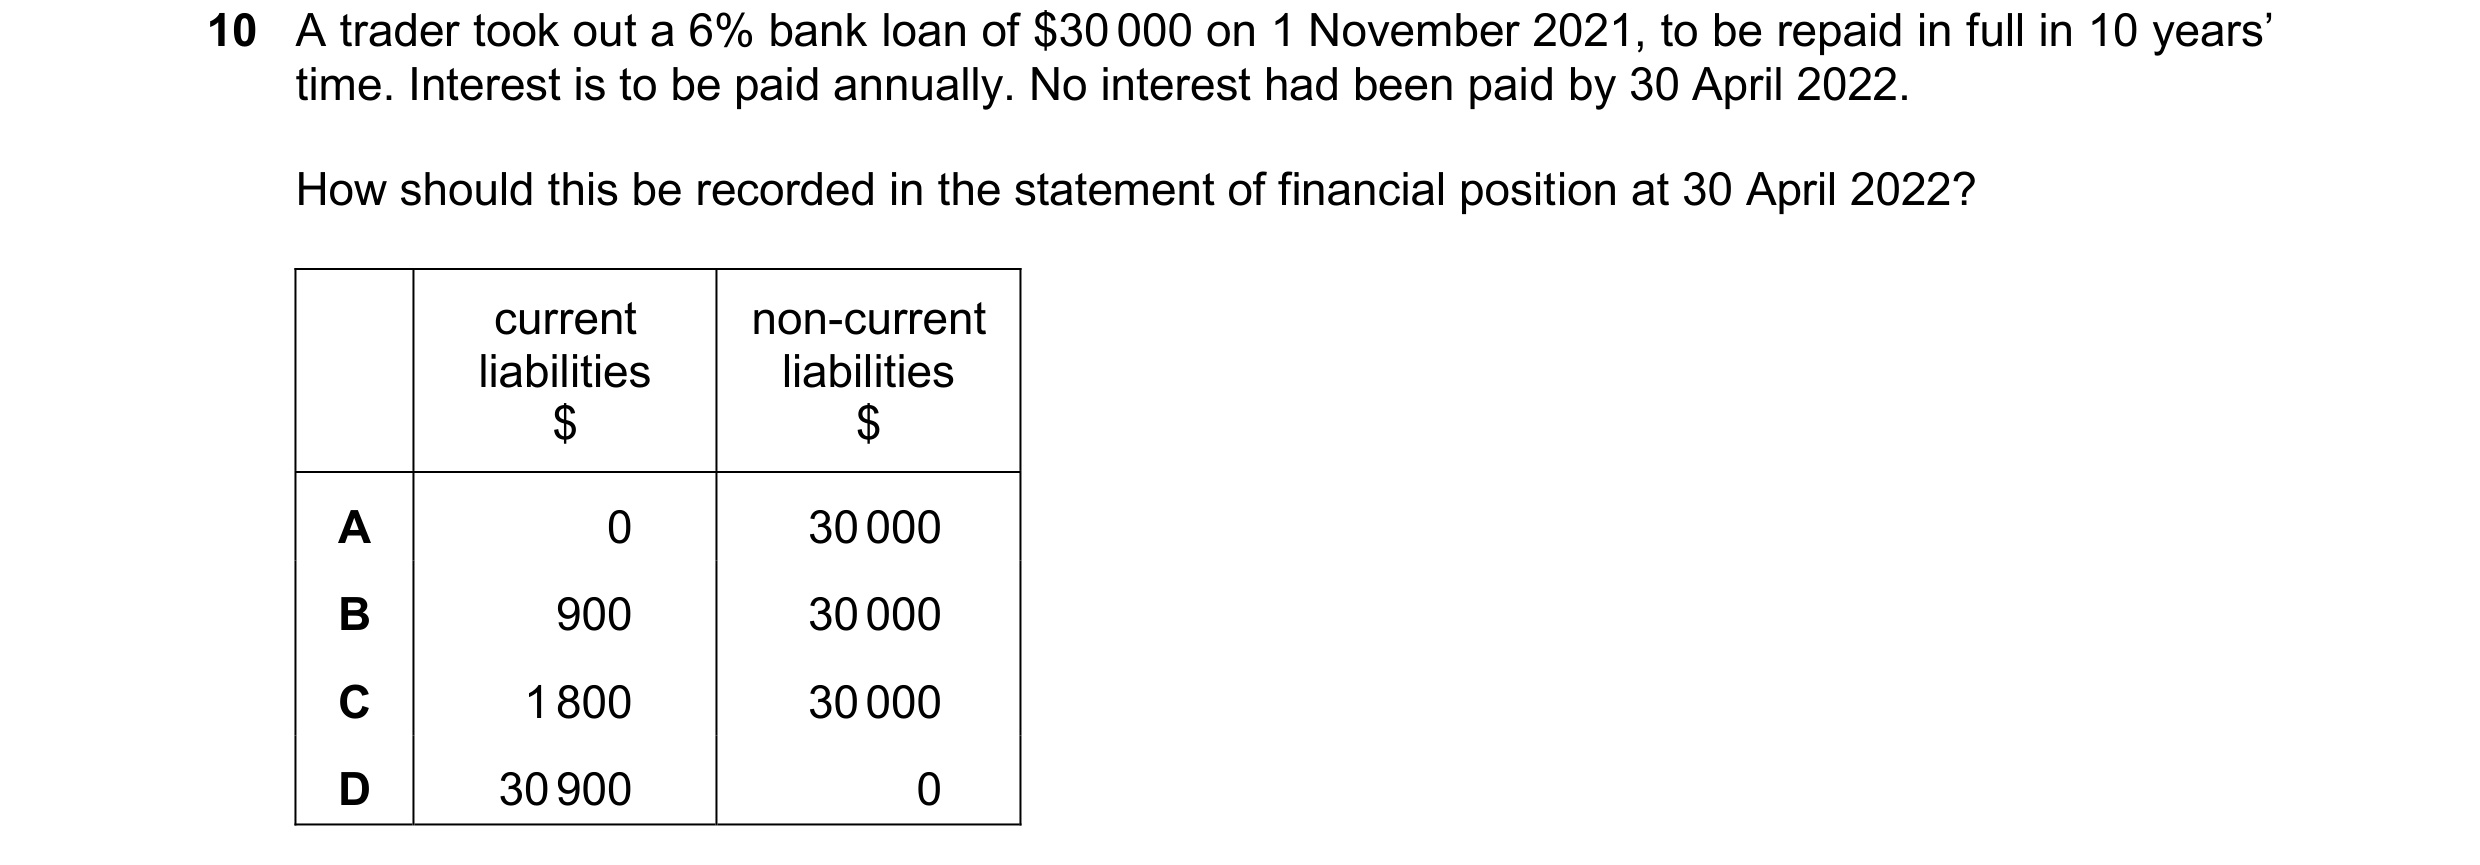
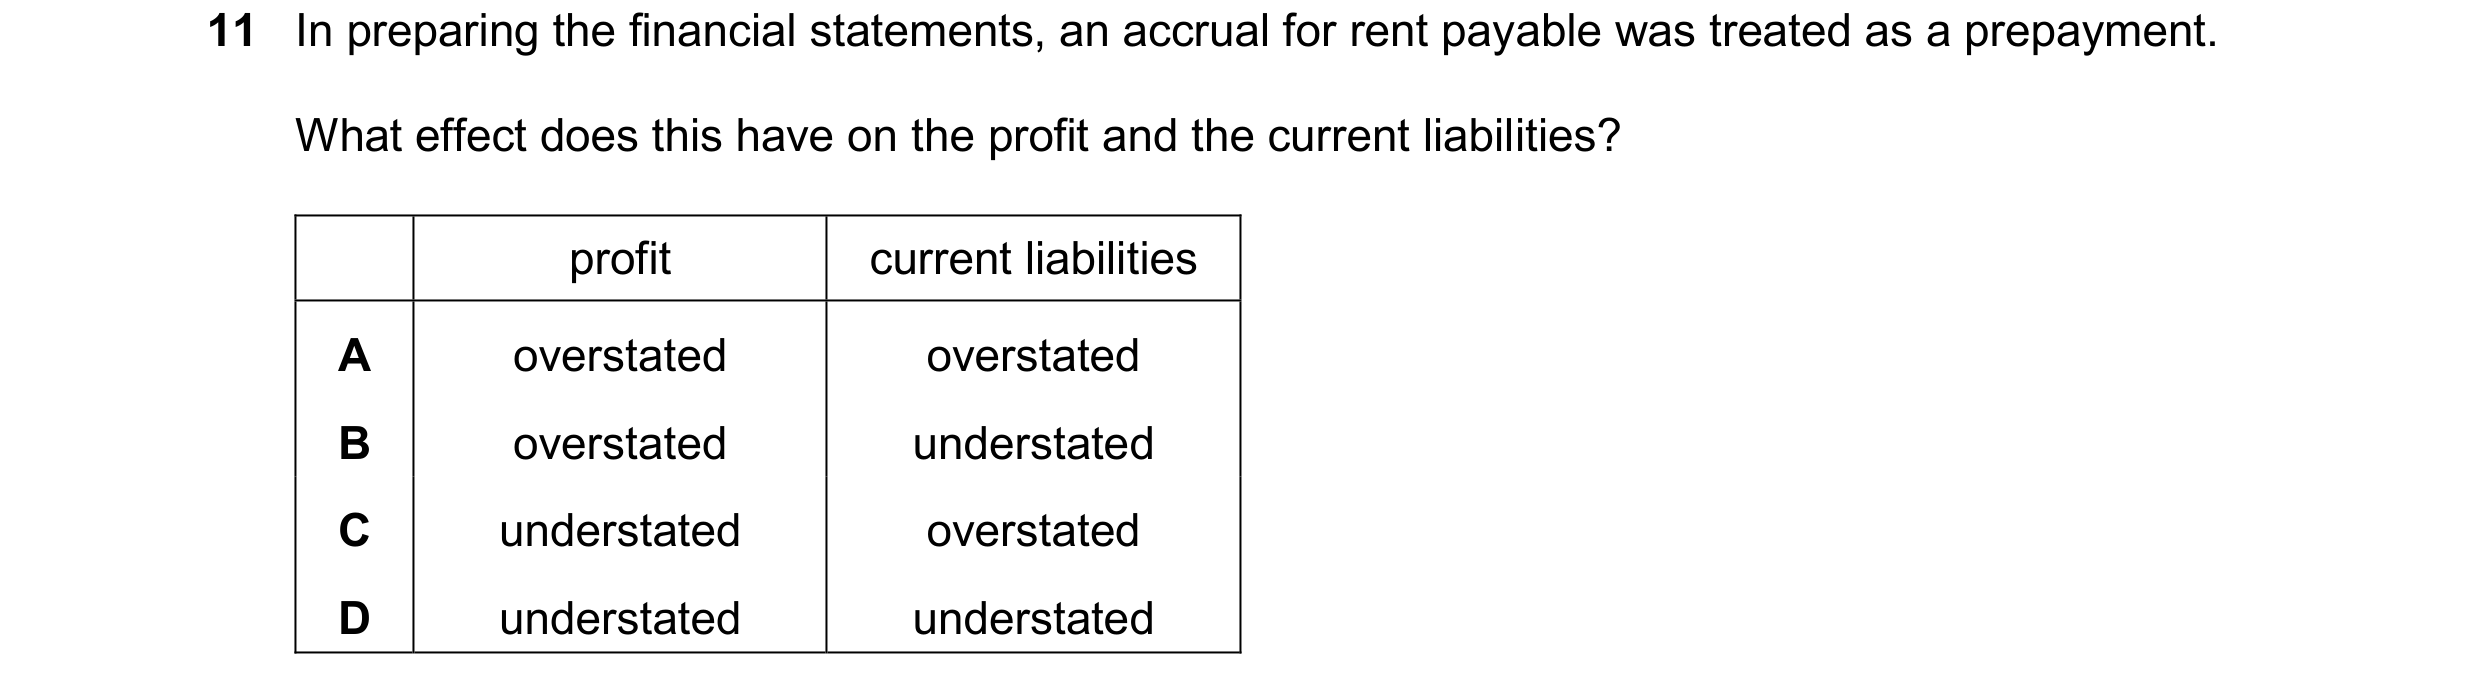 195 / 233
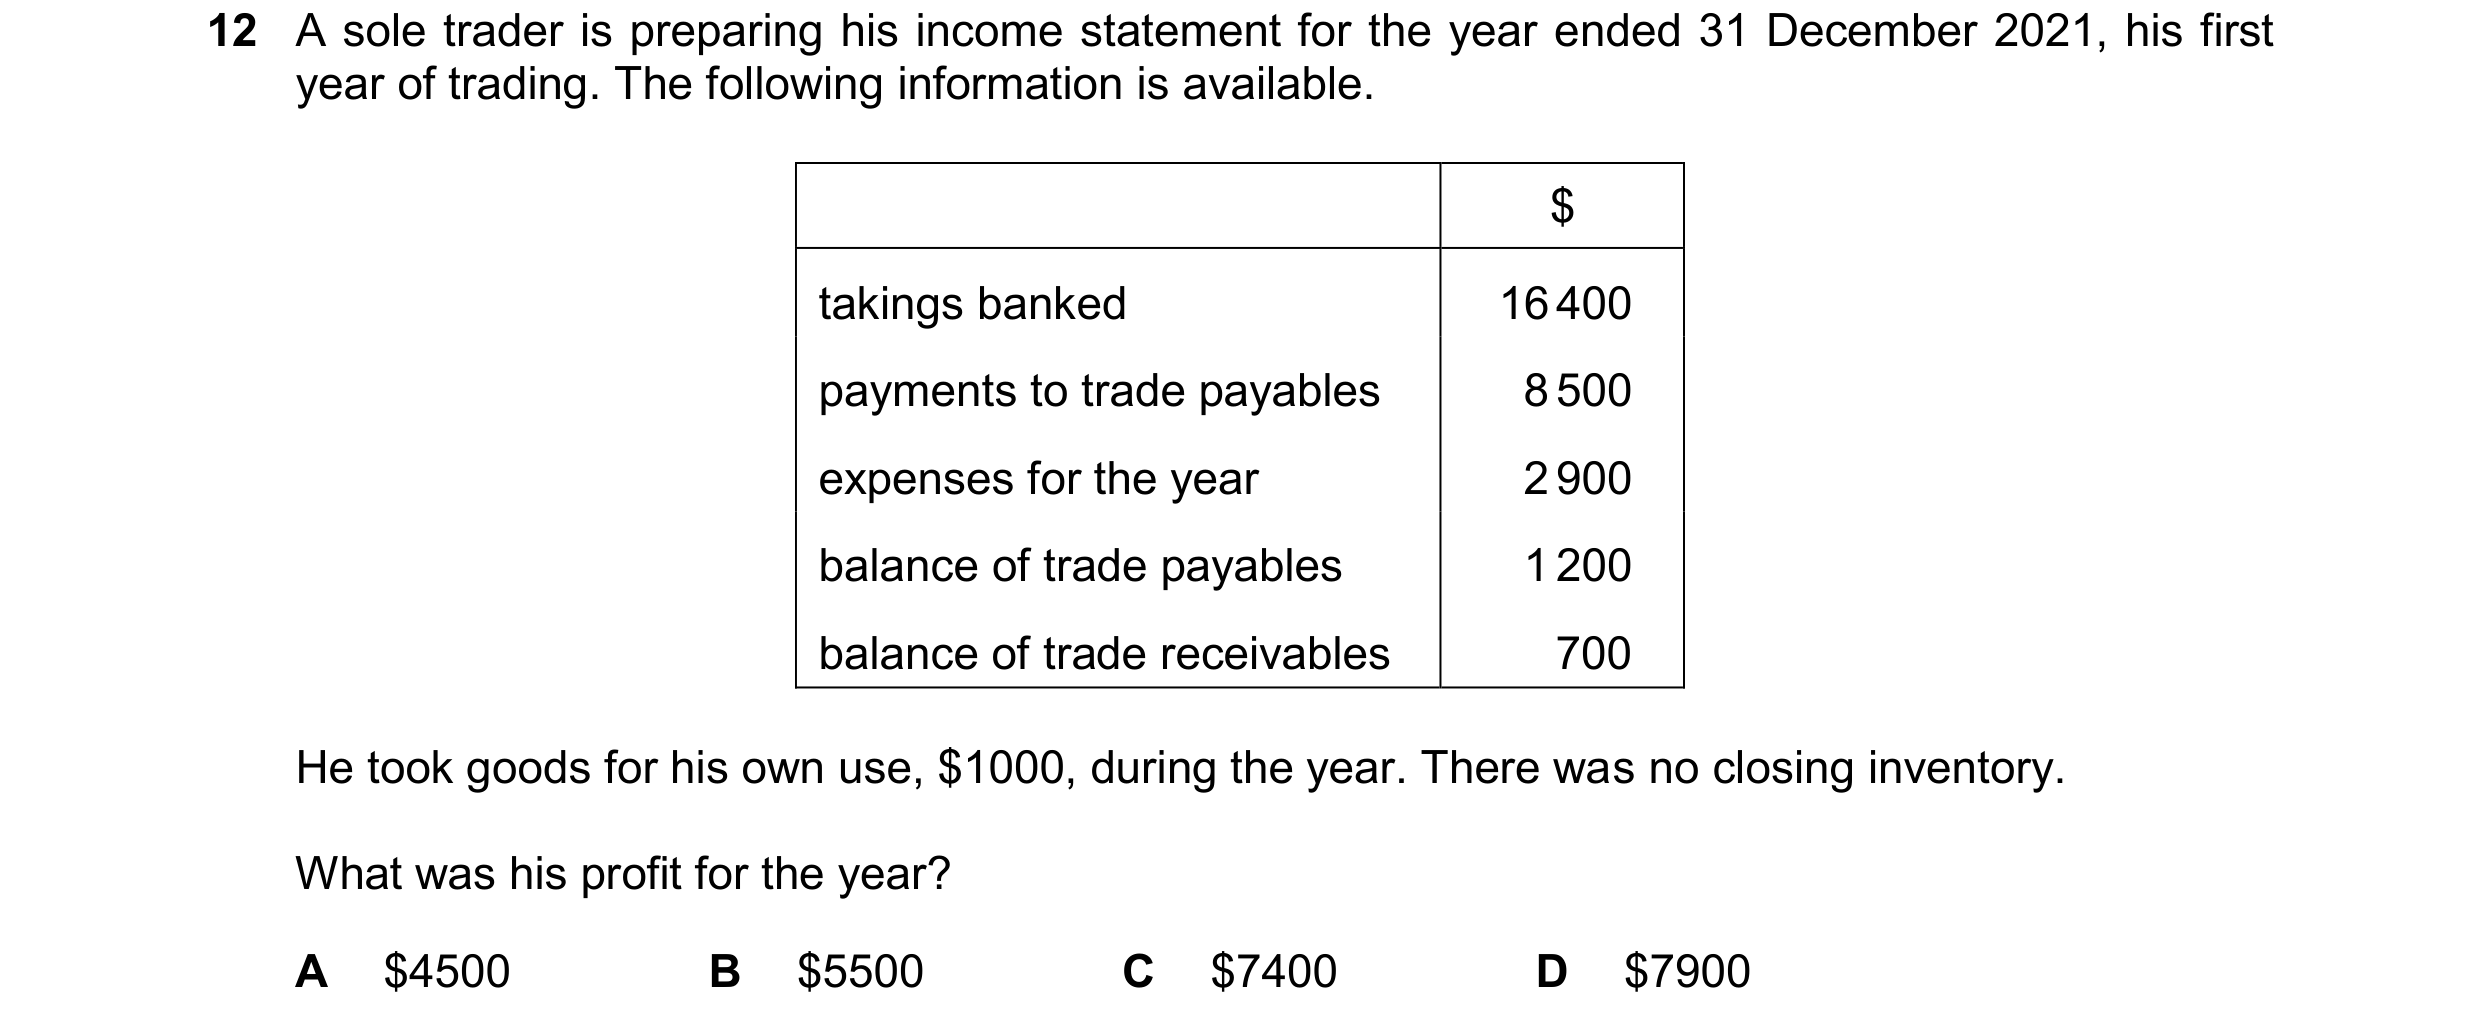
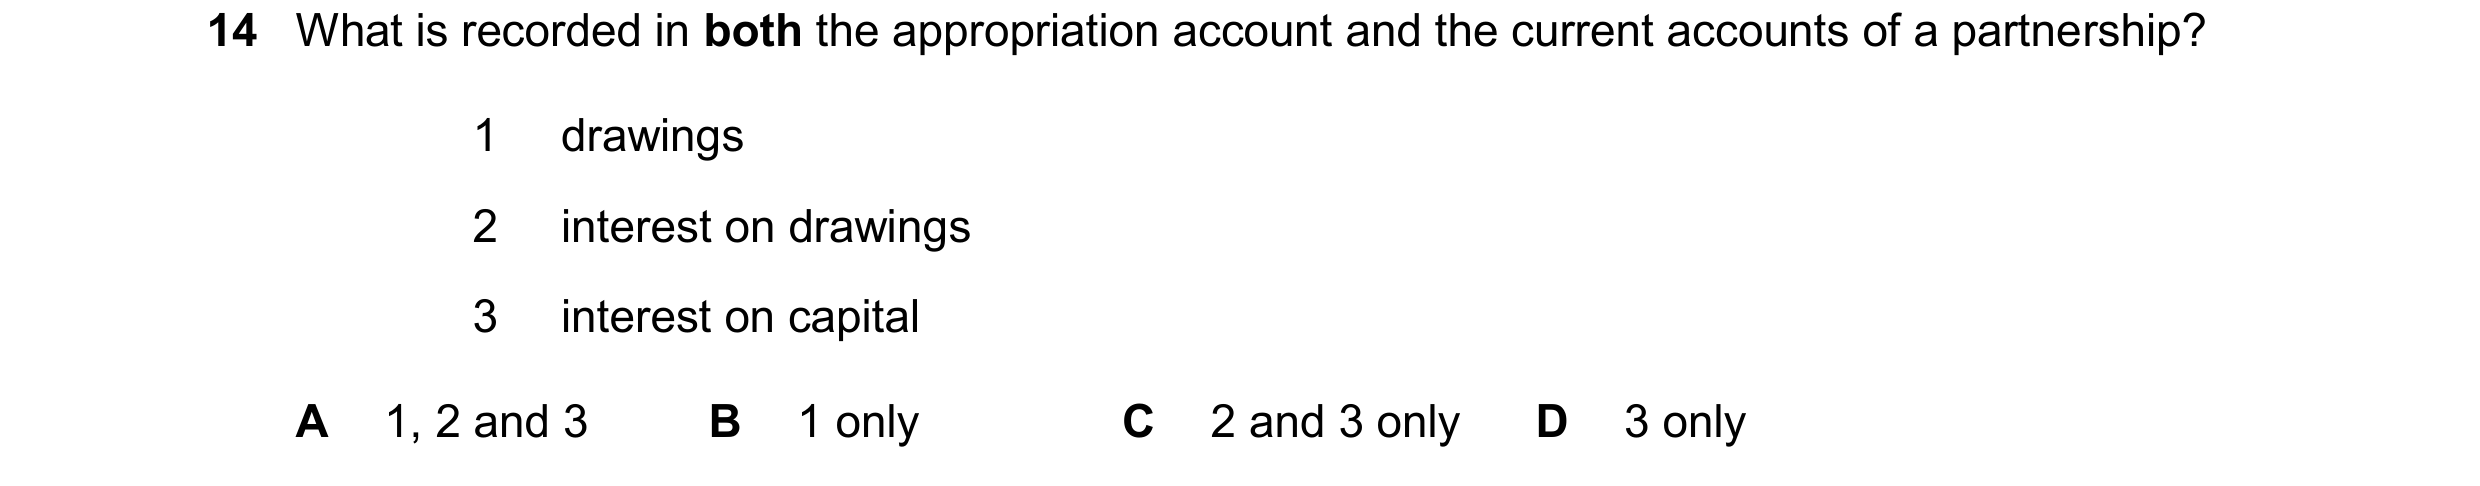
 196 / 233
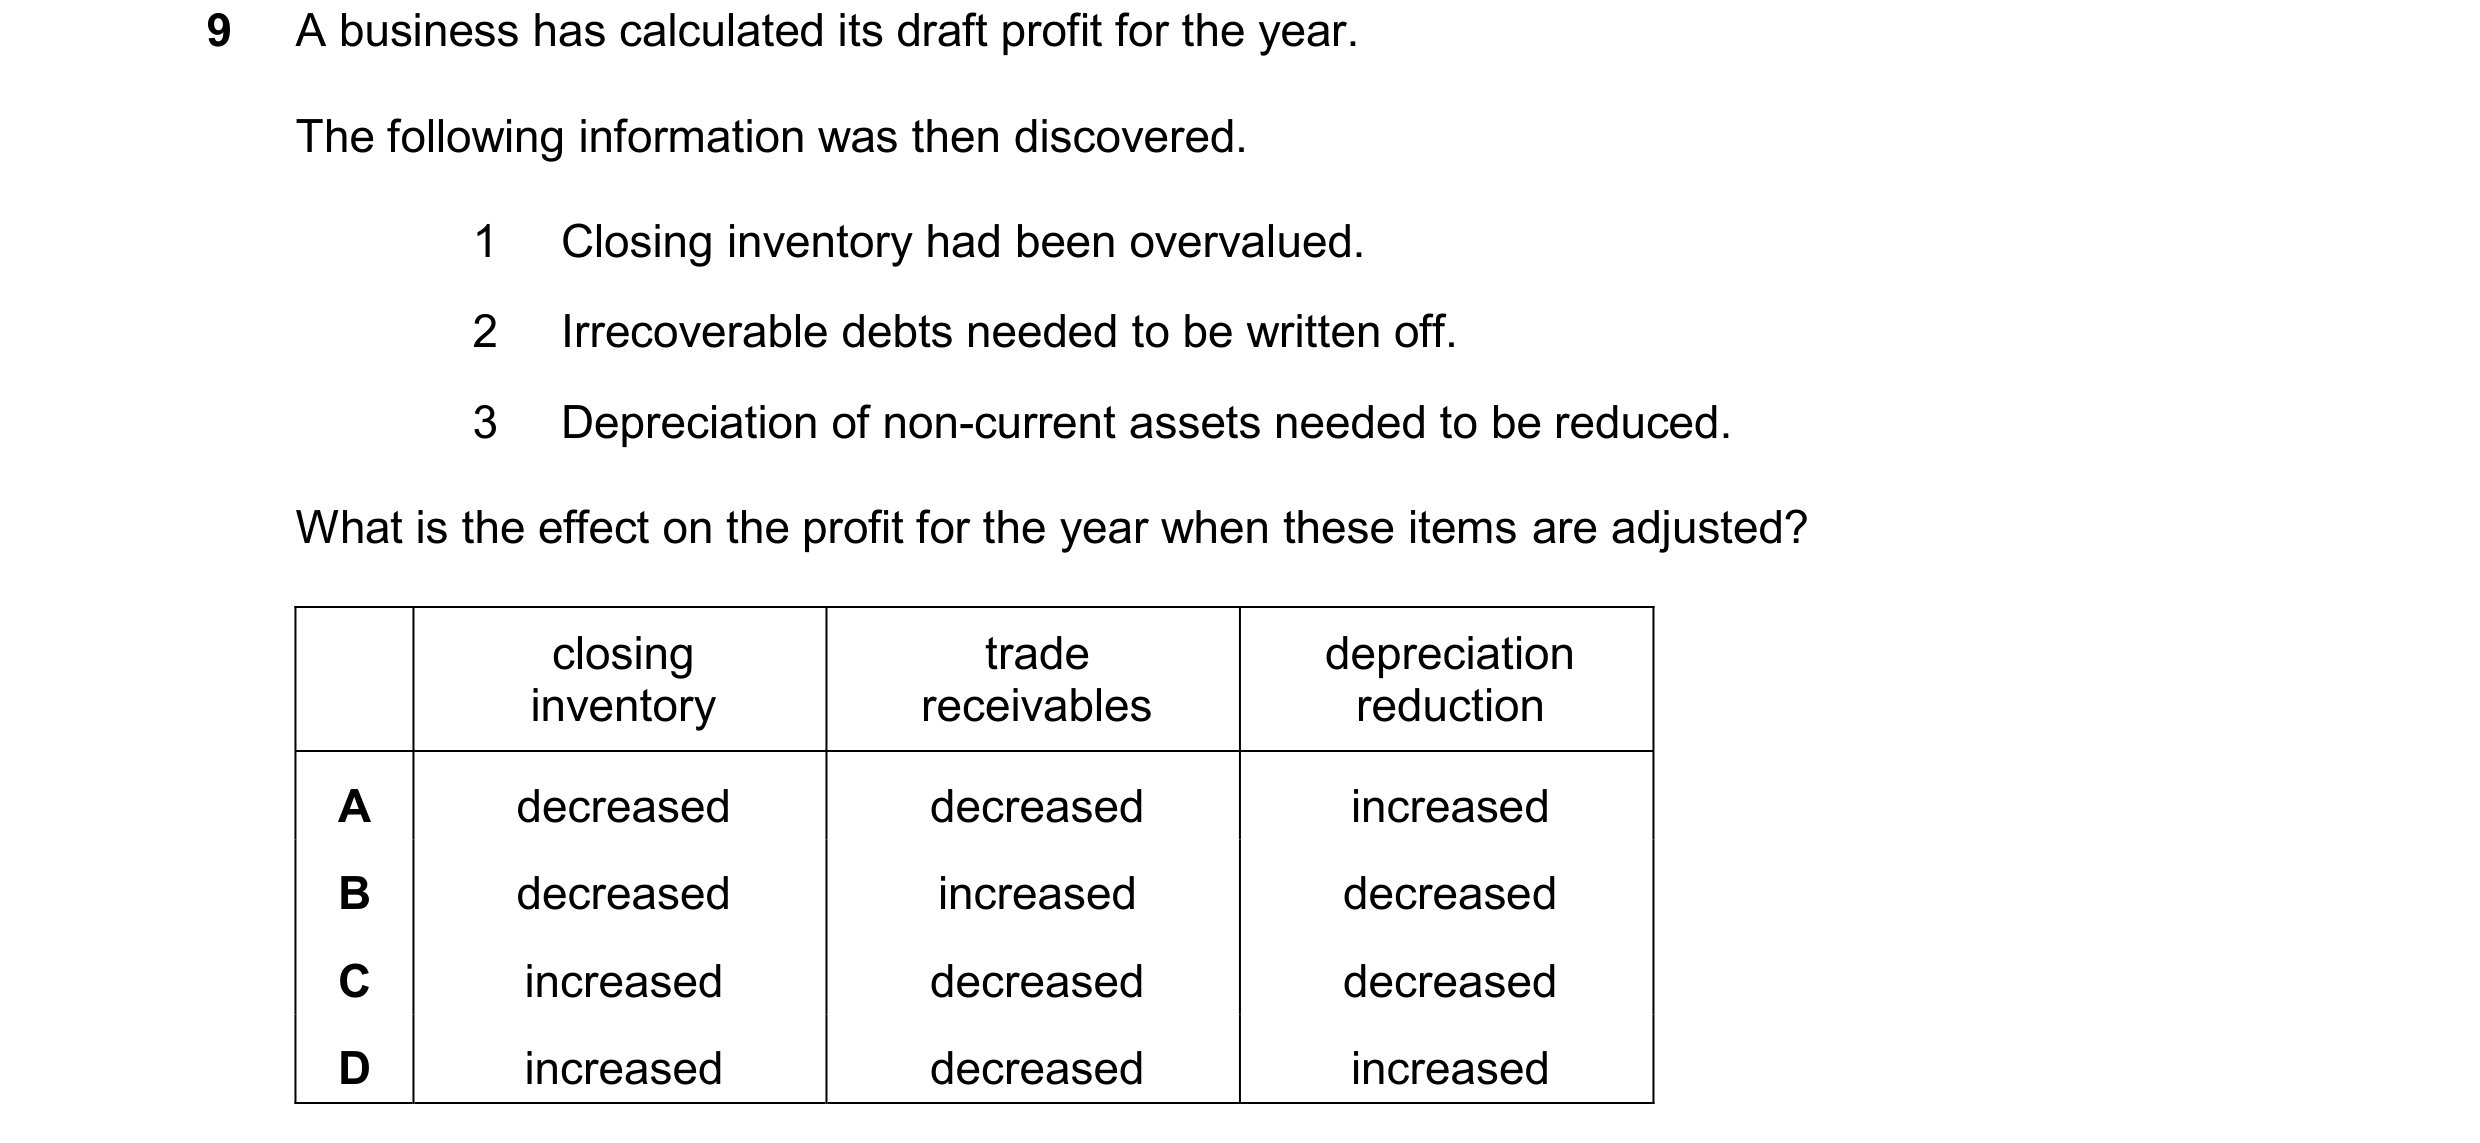
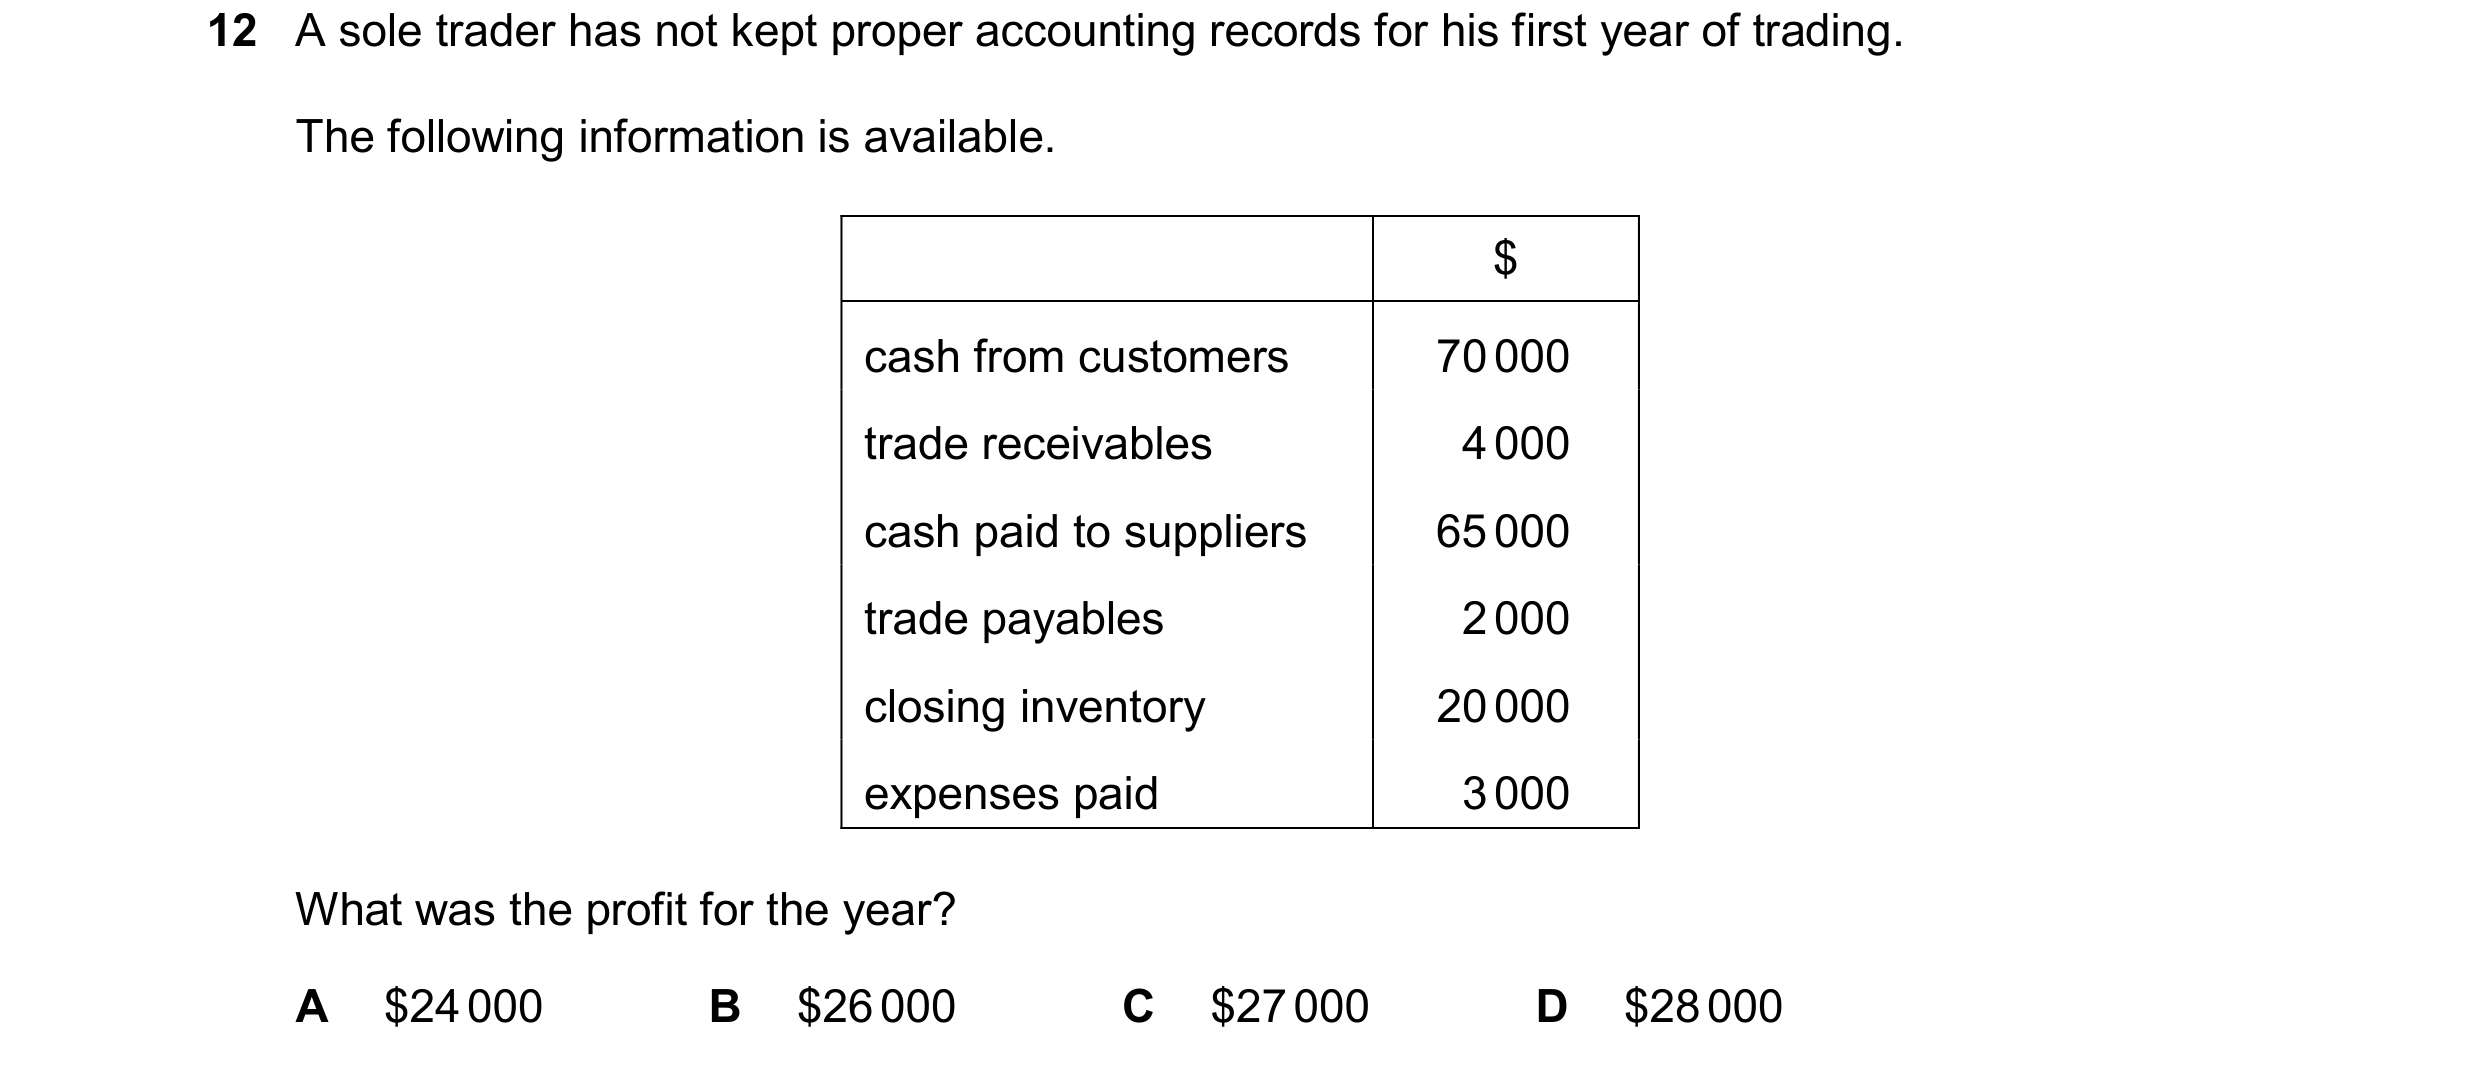 197 / 233
 198 / 233
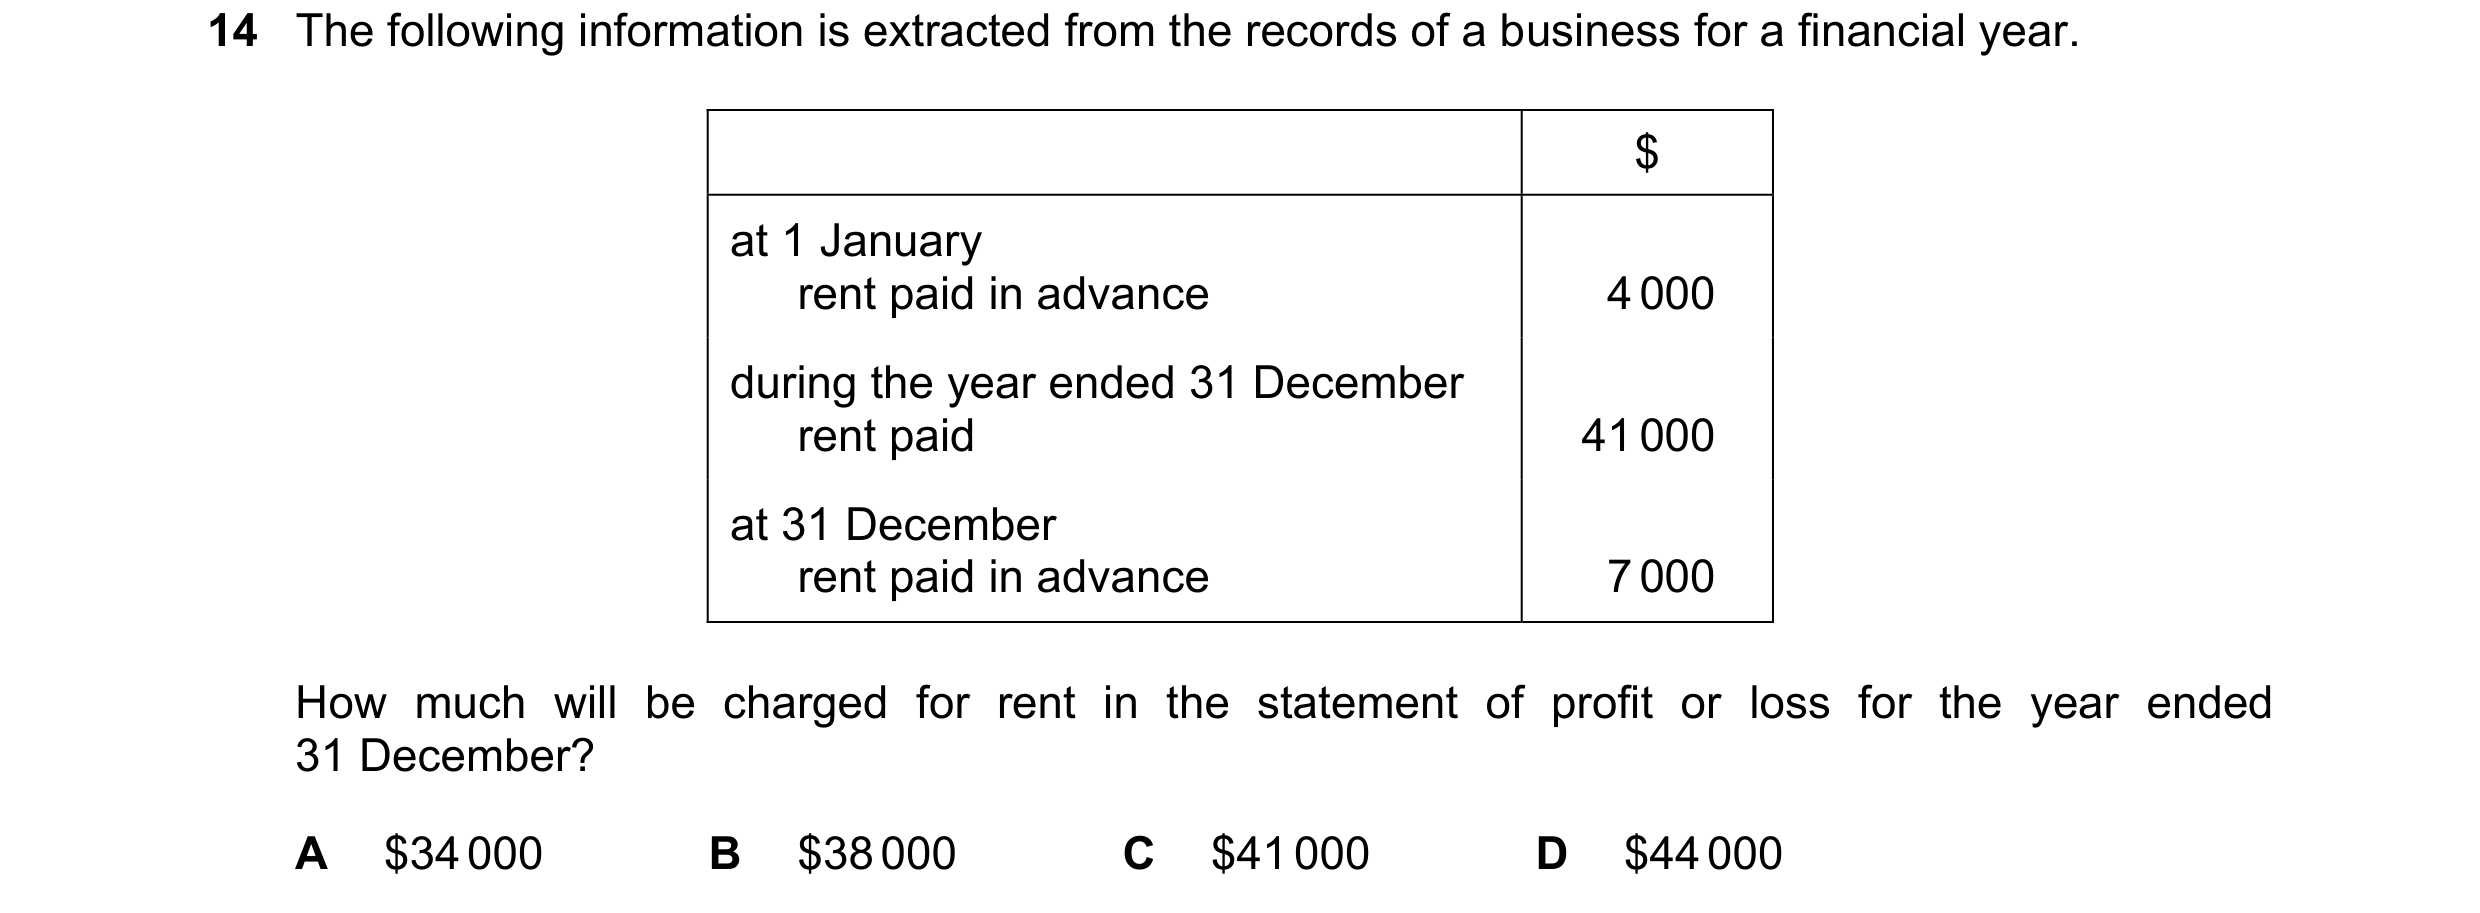
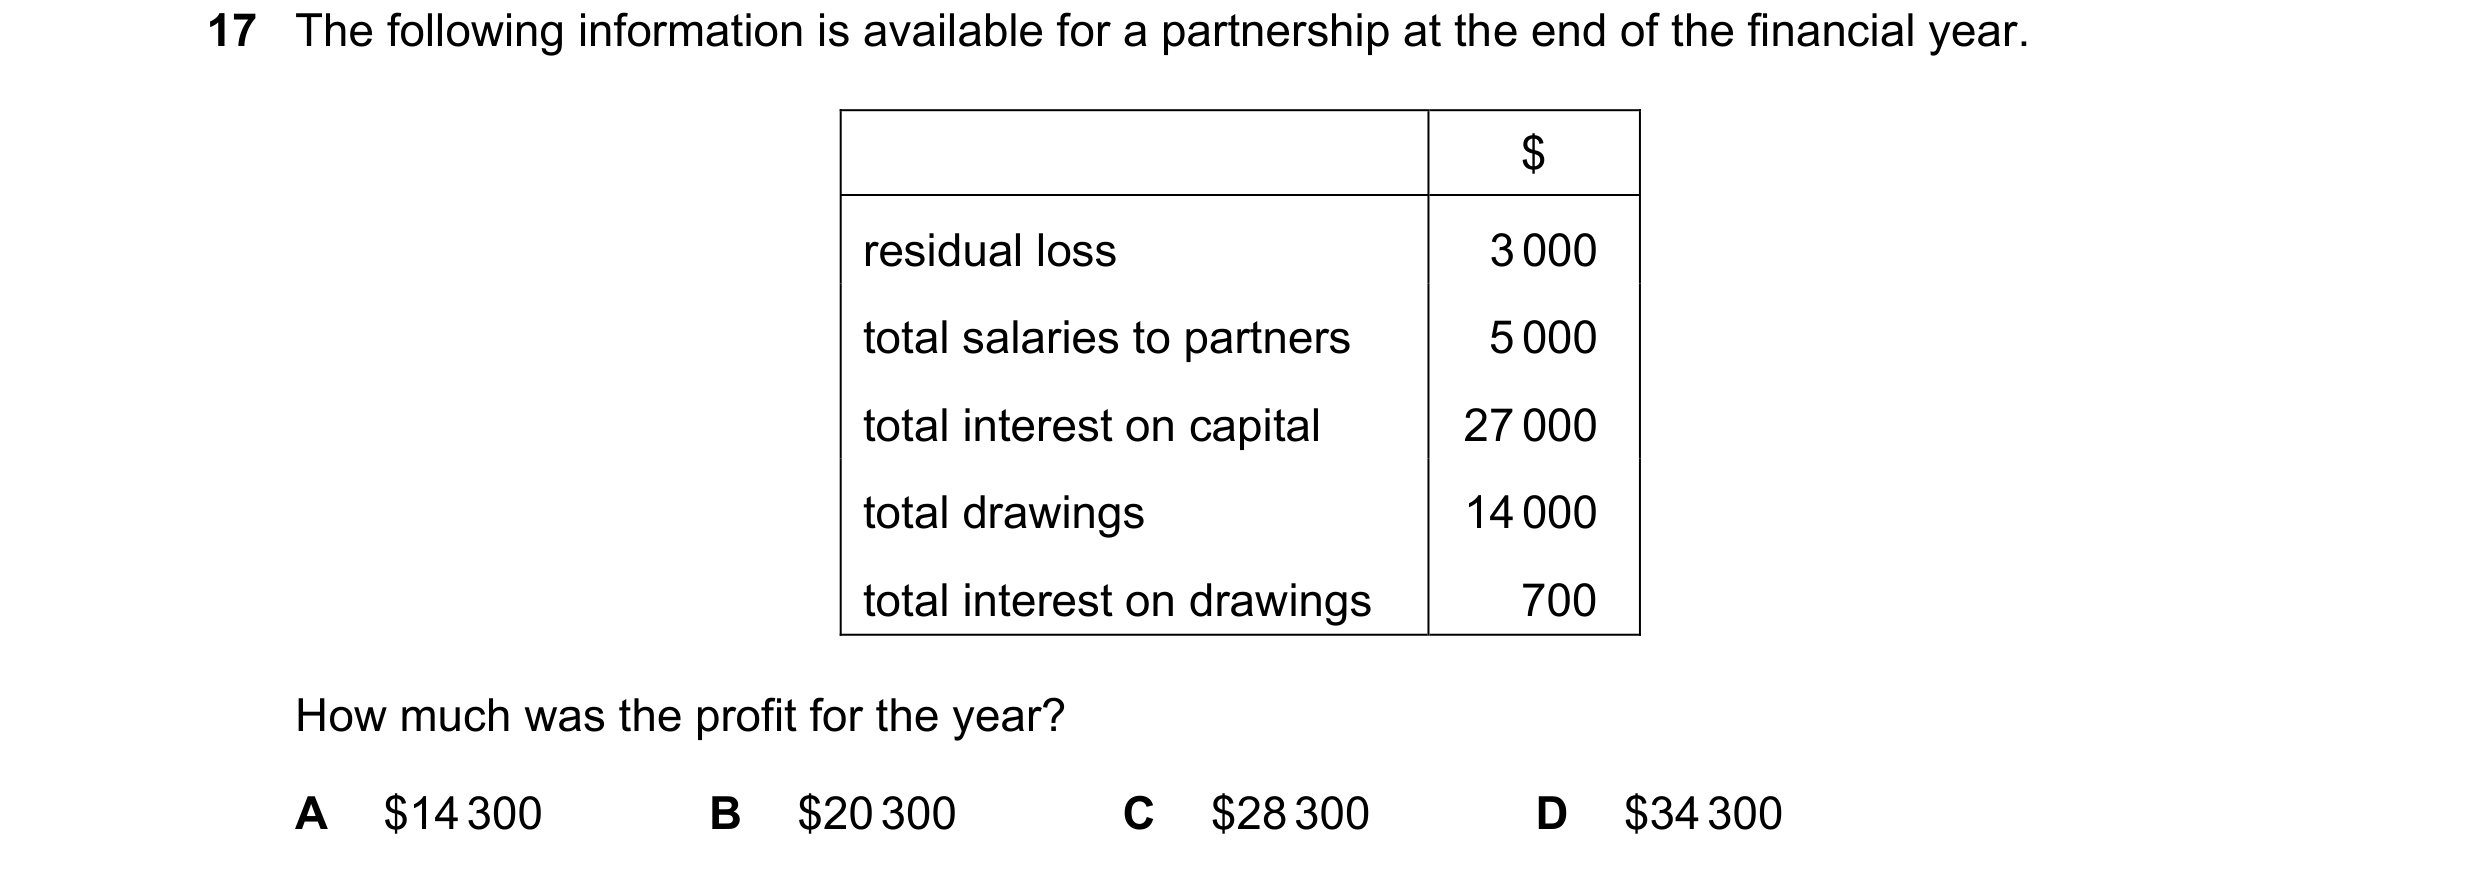 199 / 233
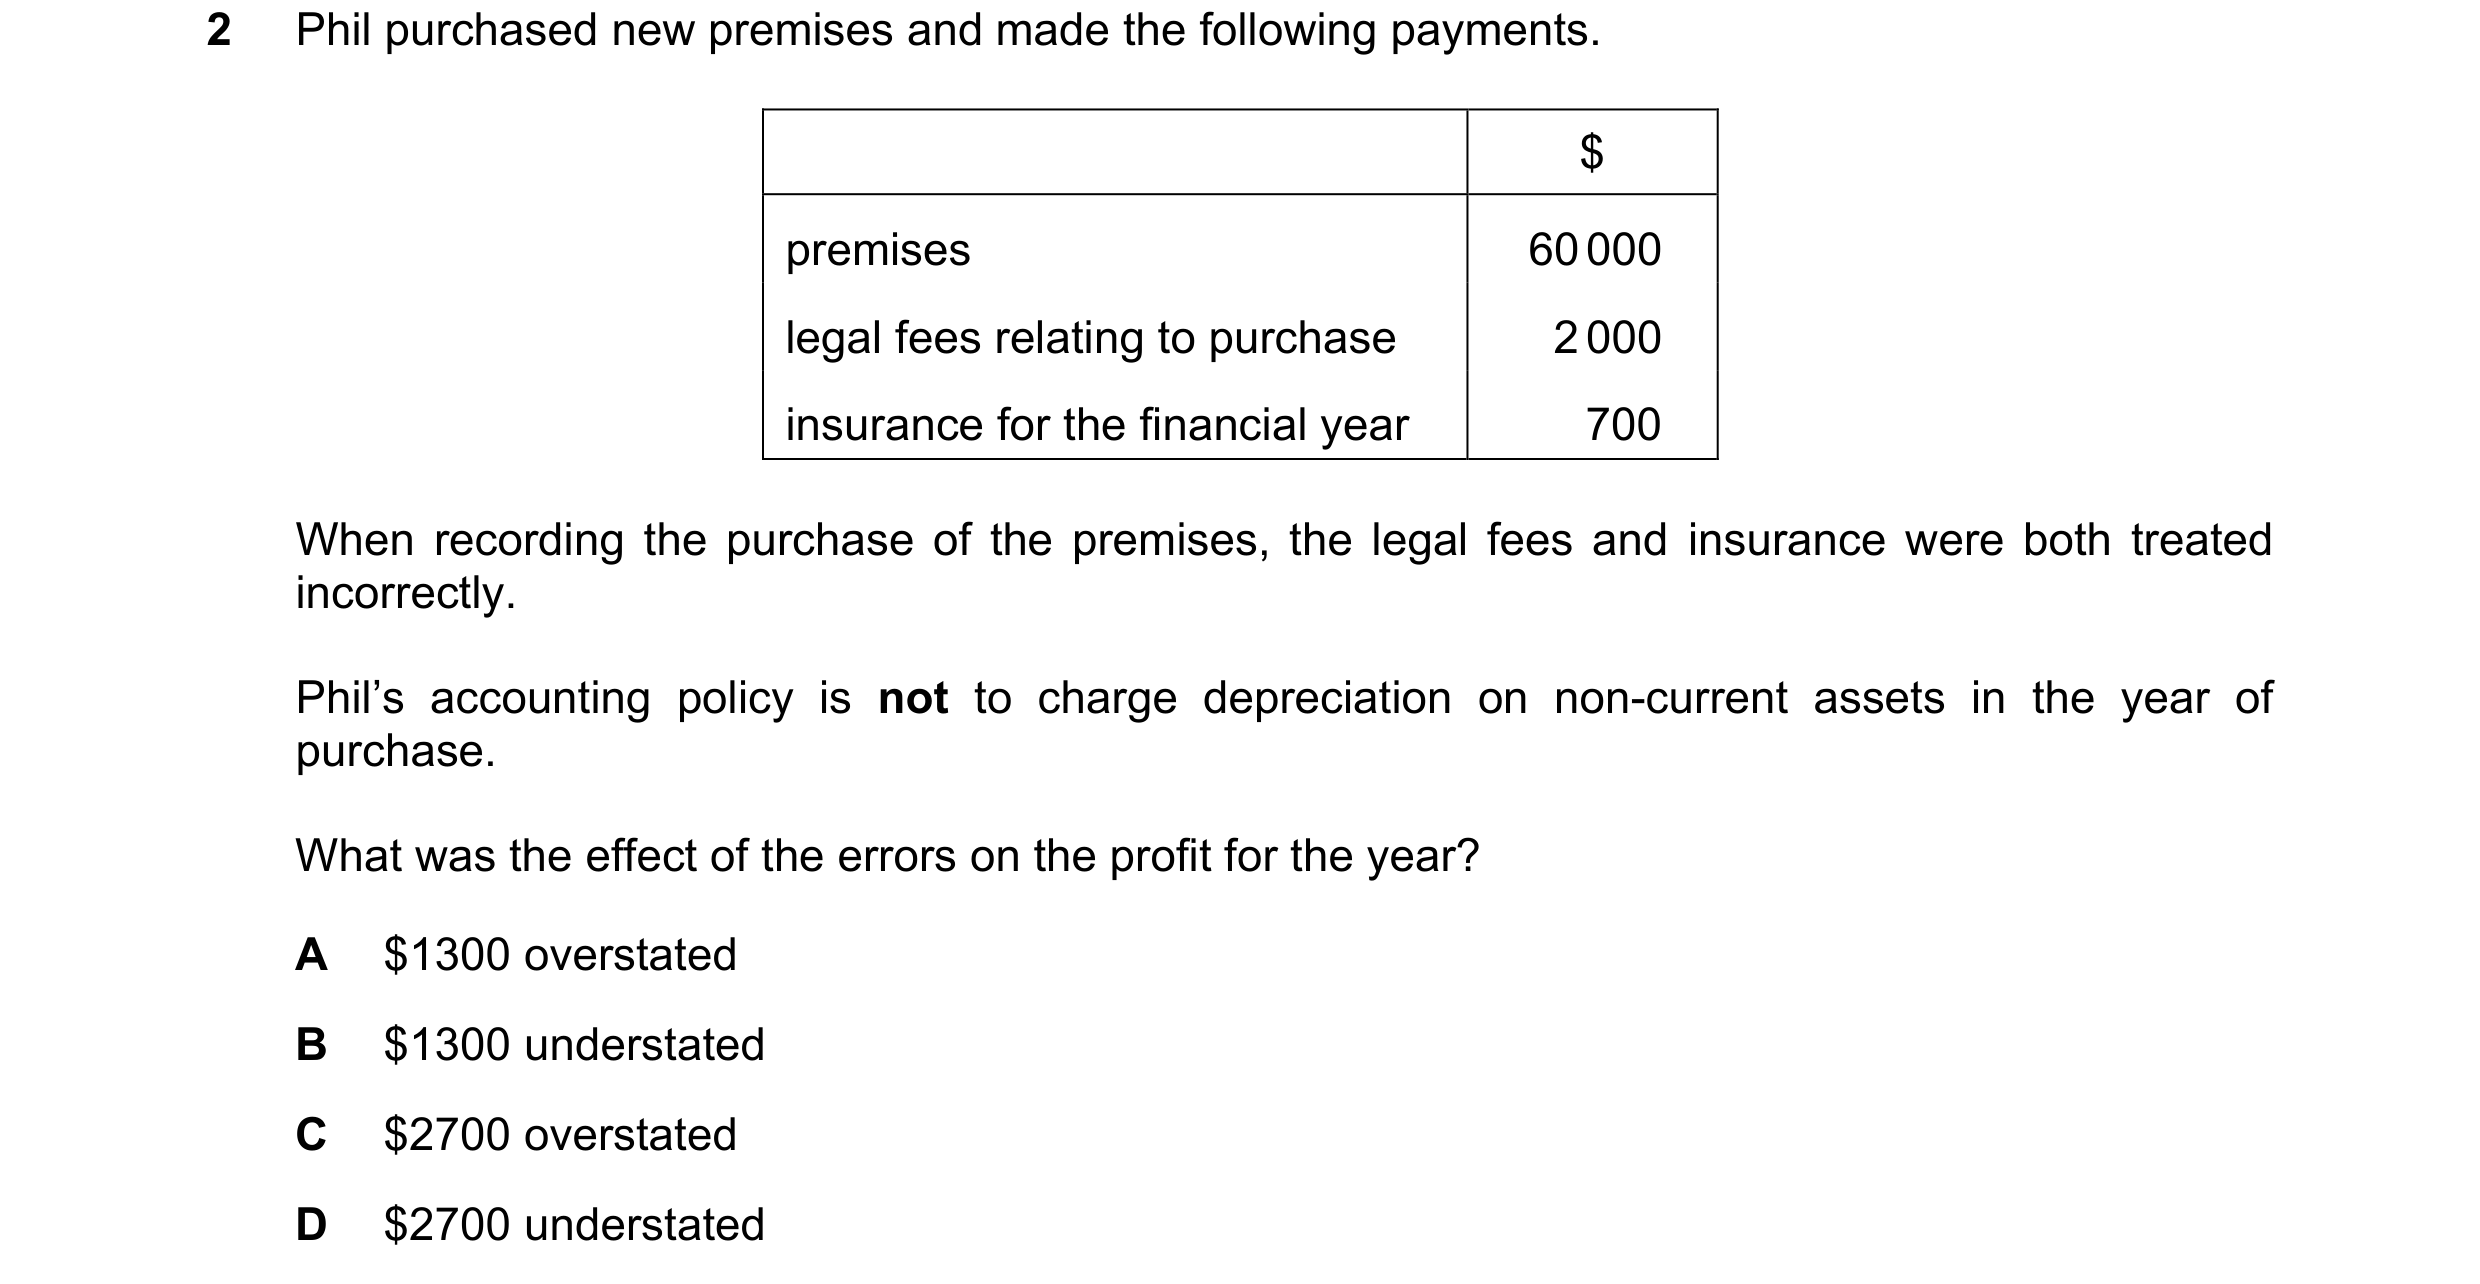
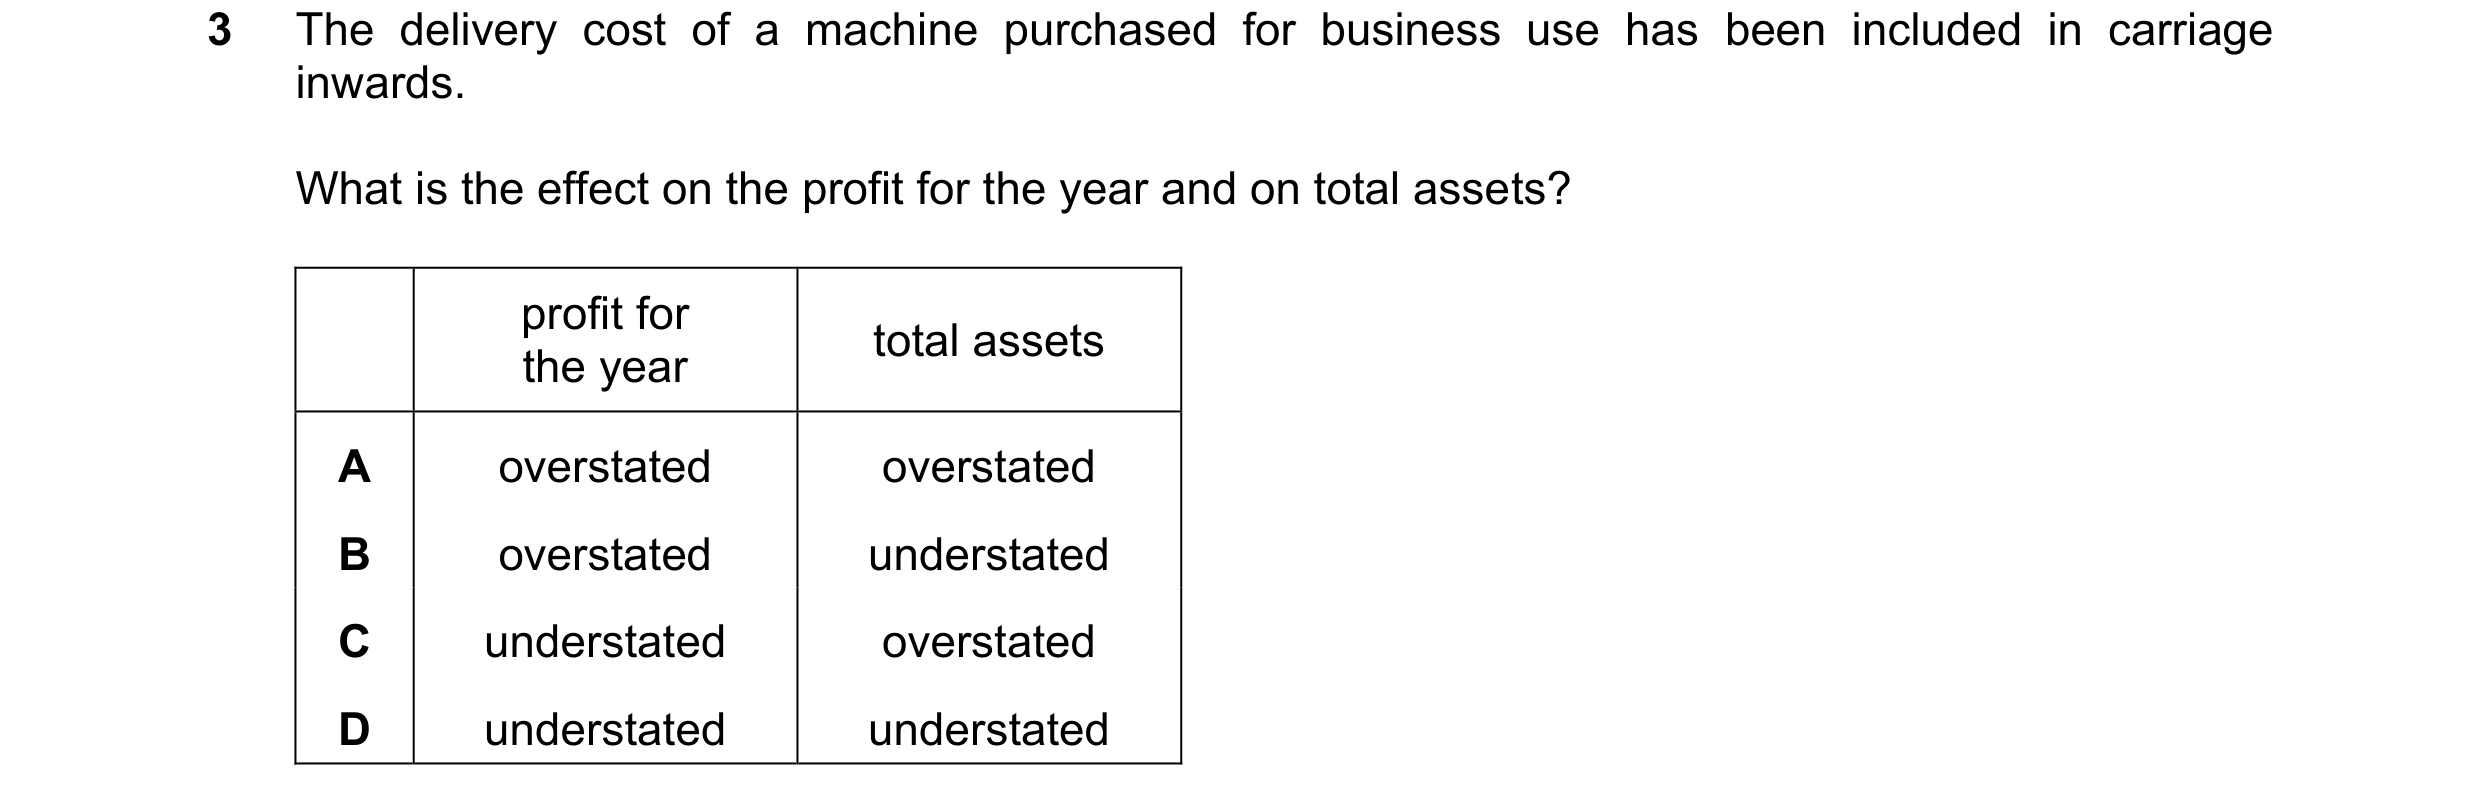
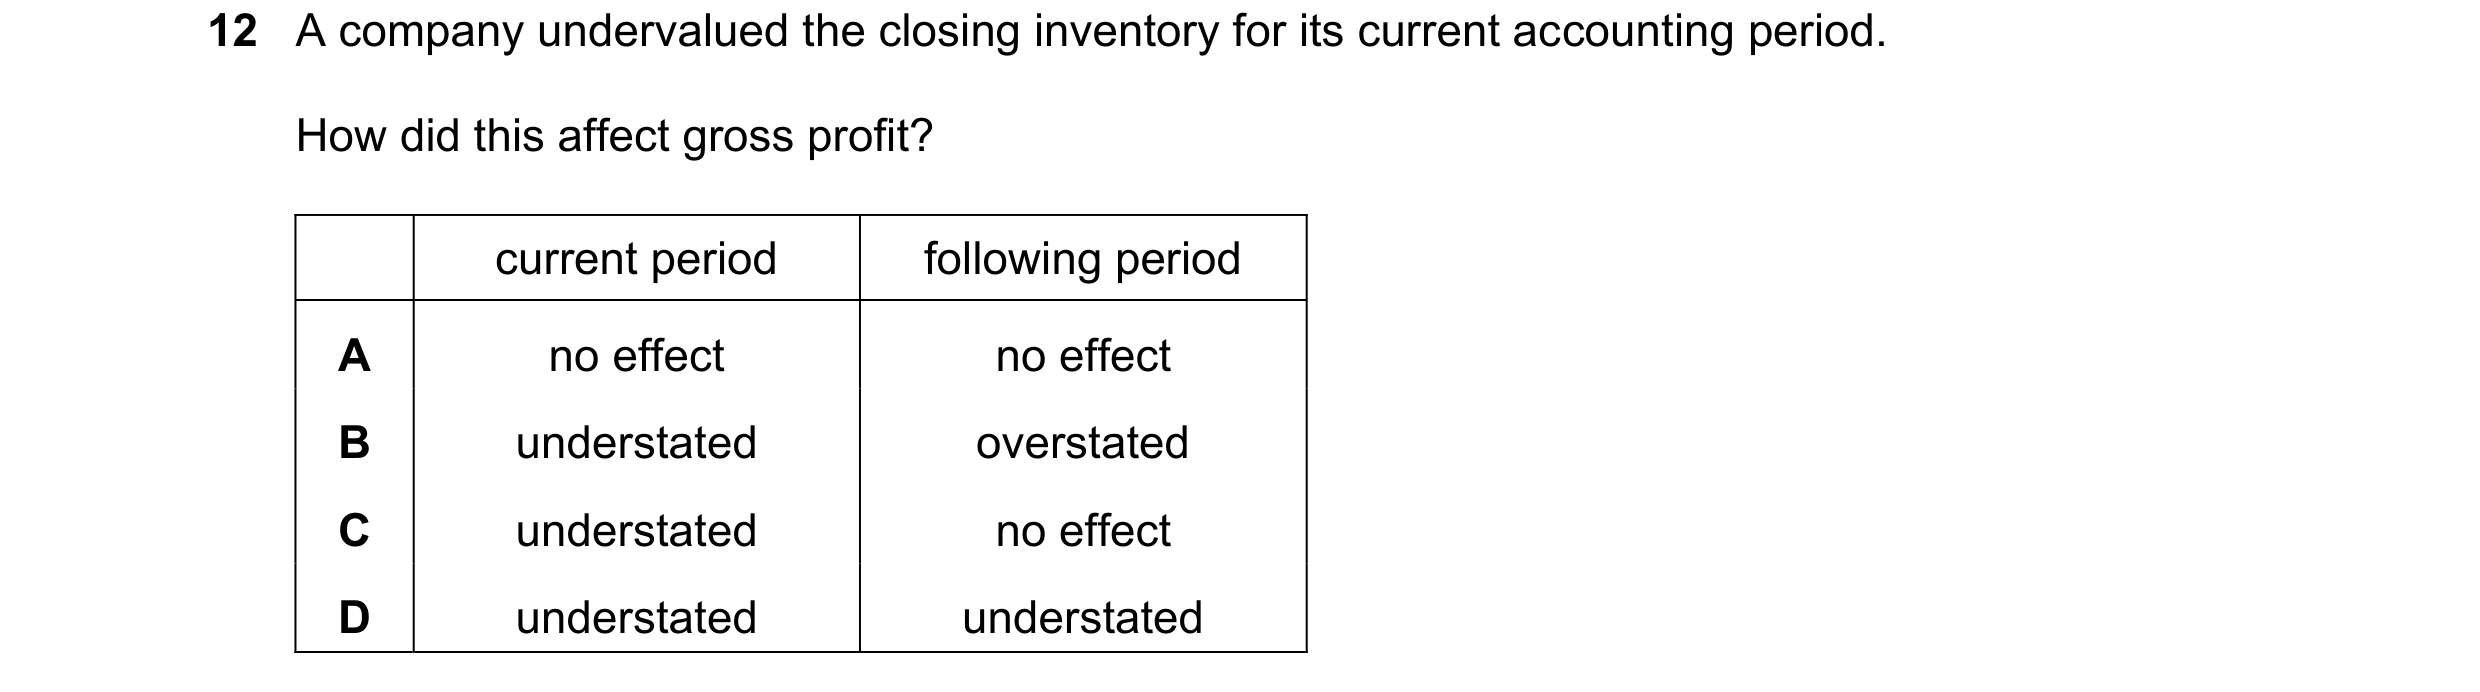 200 / 233
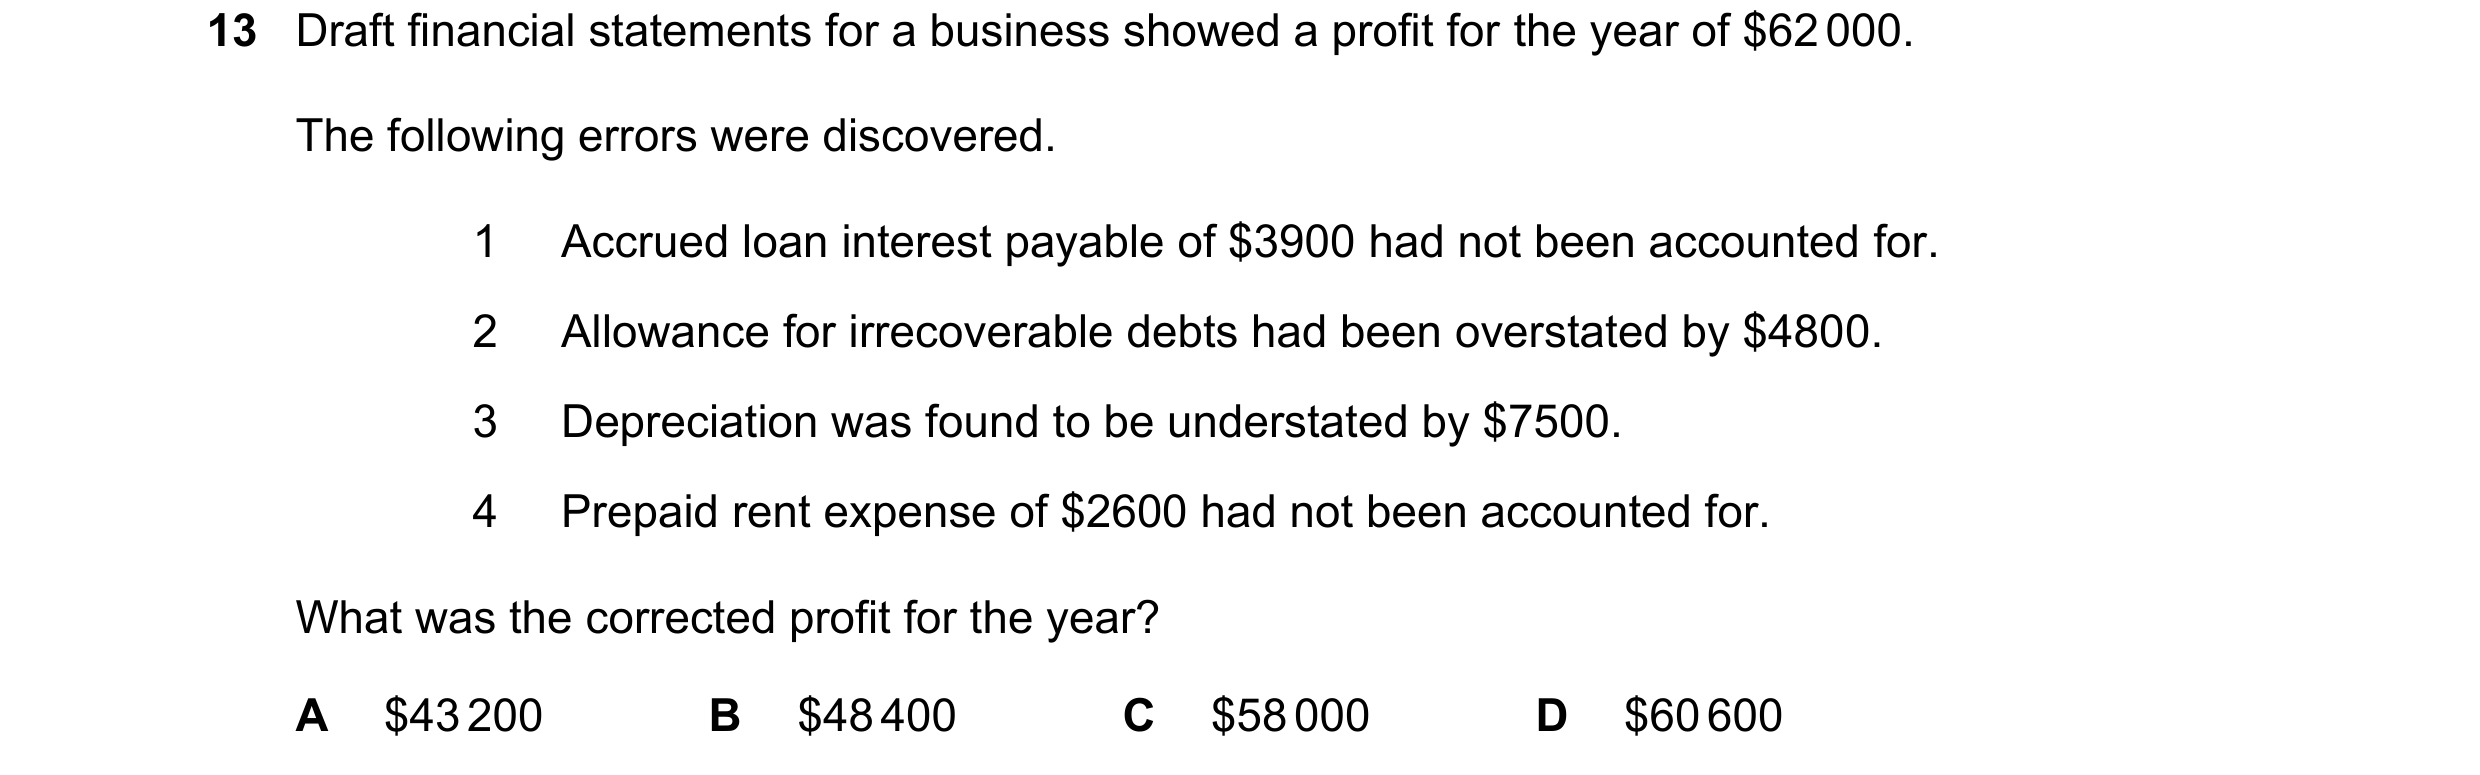
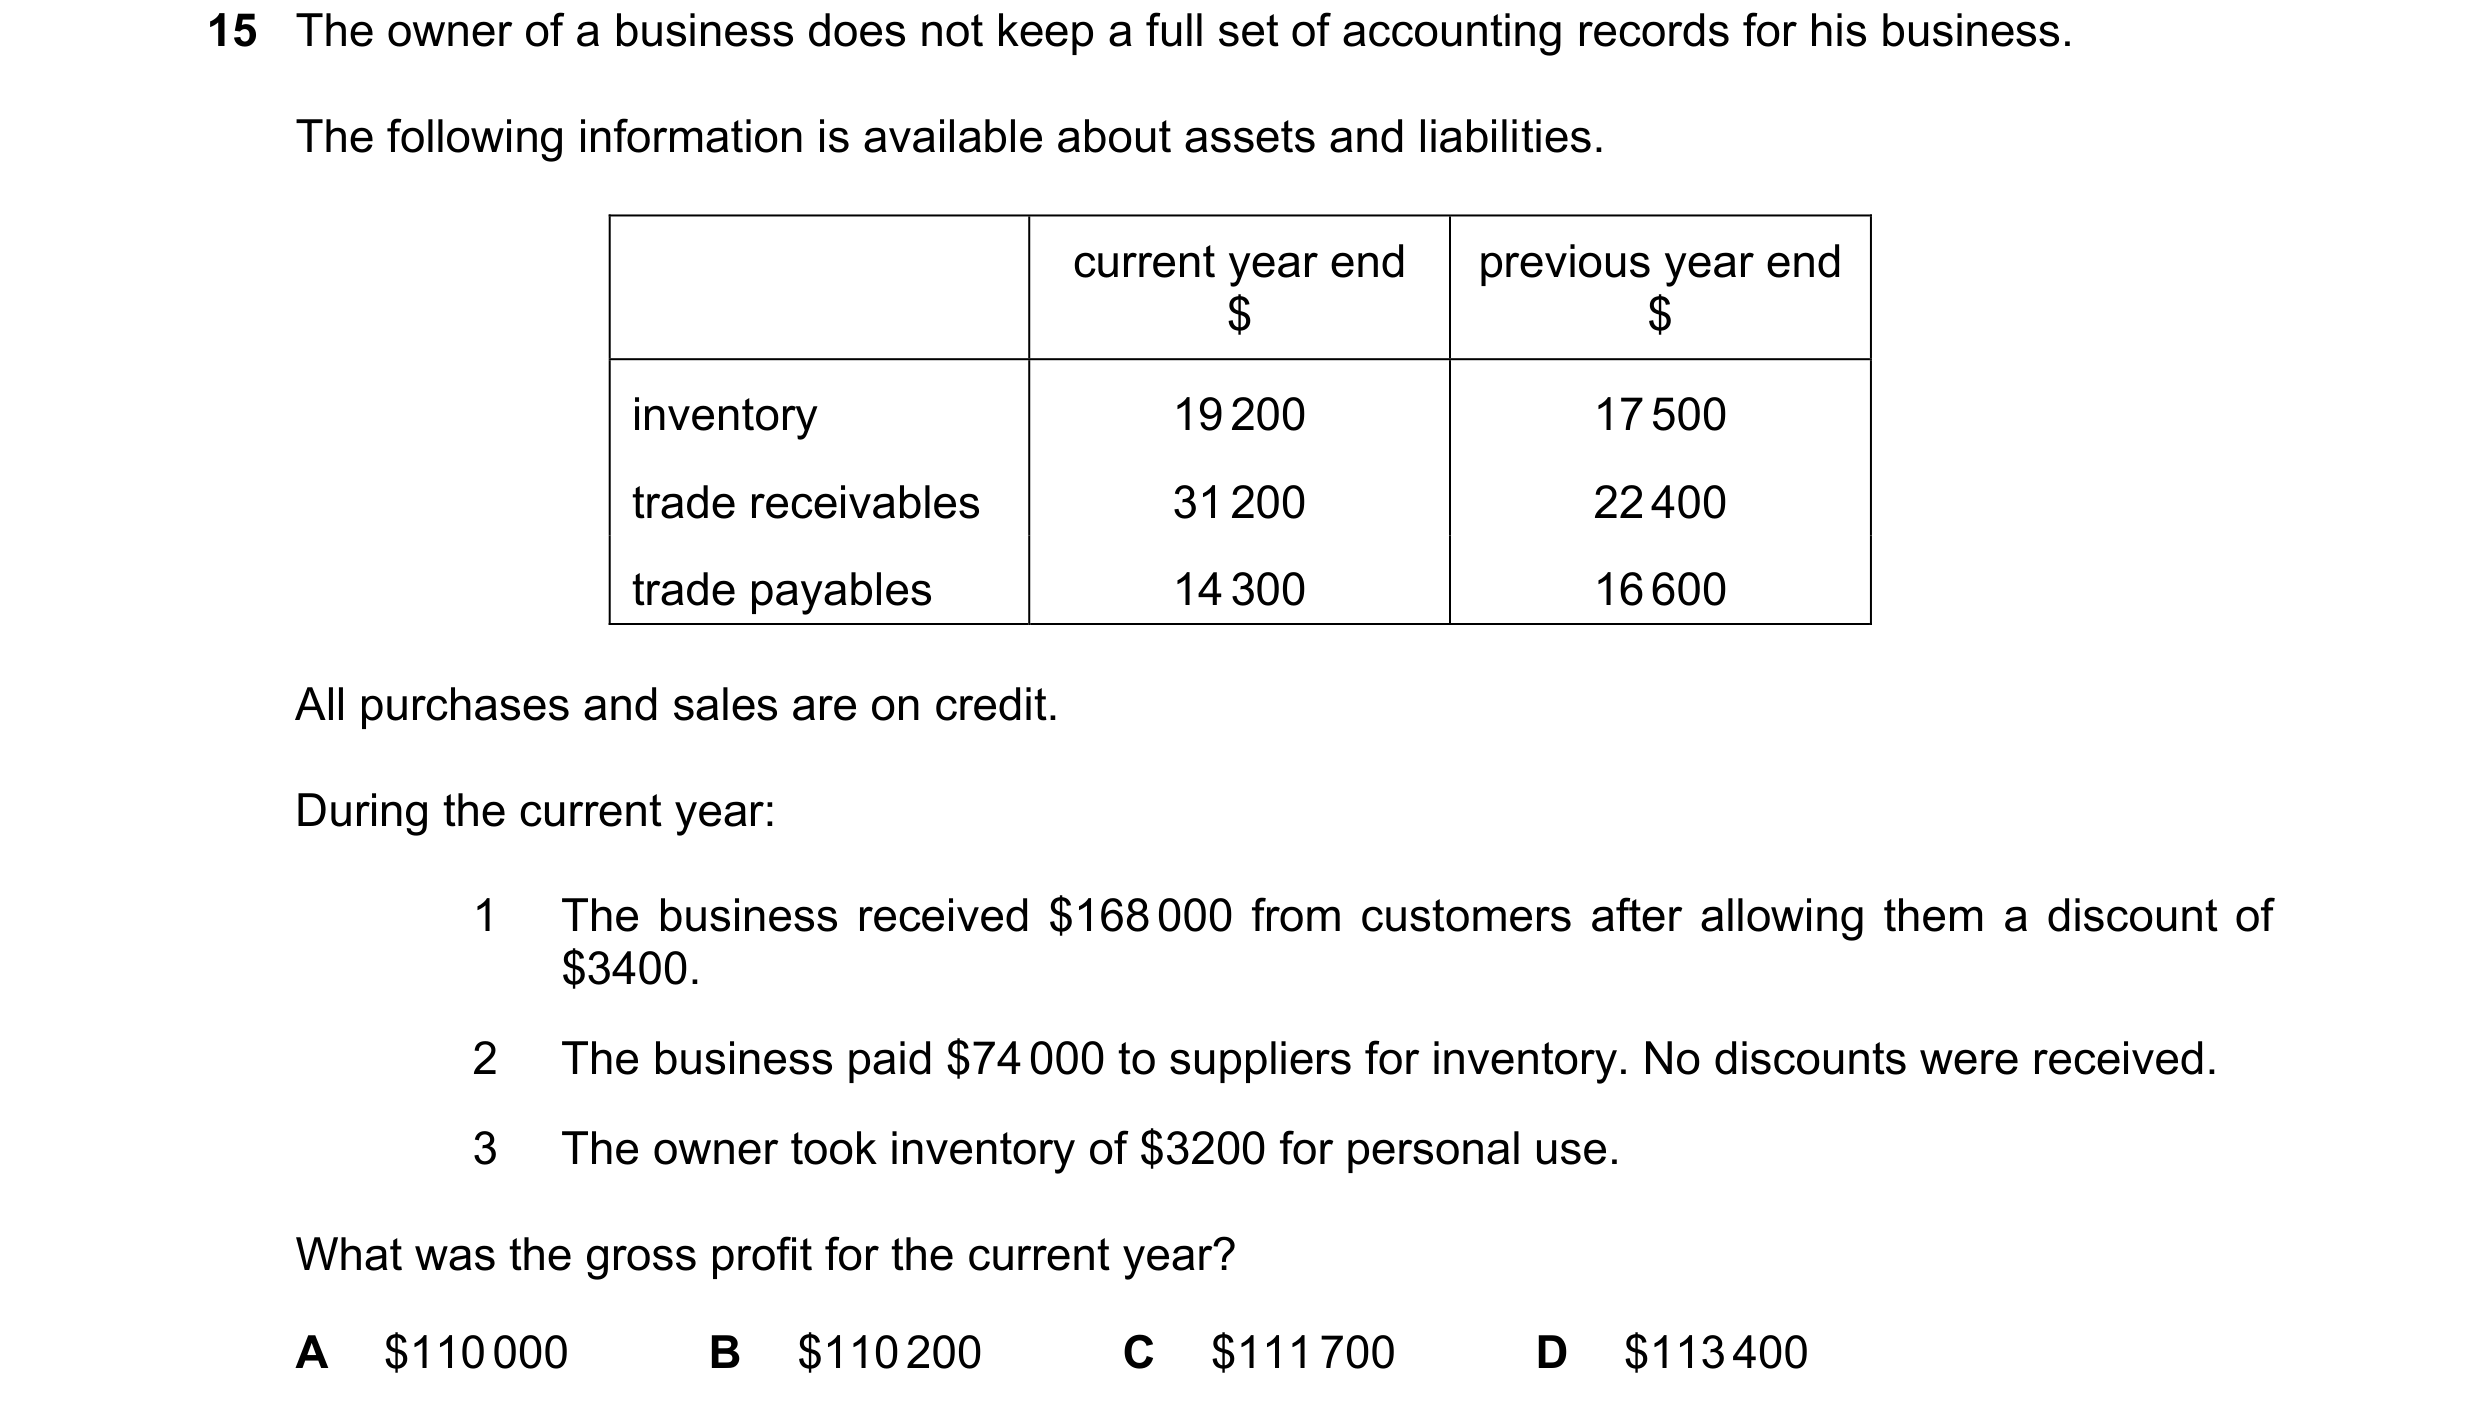
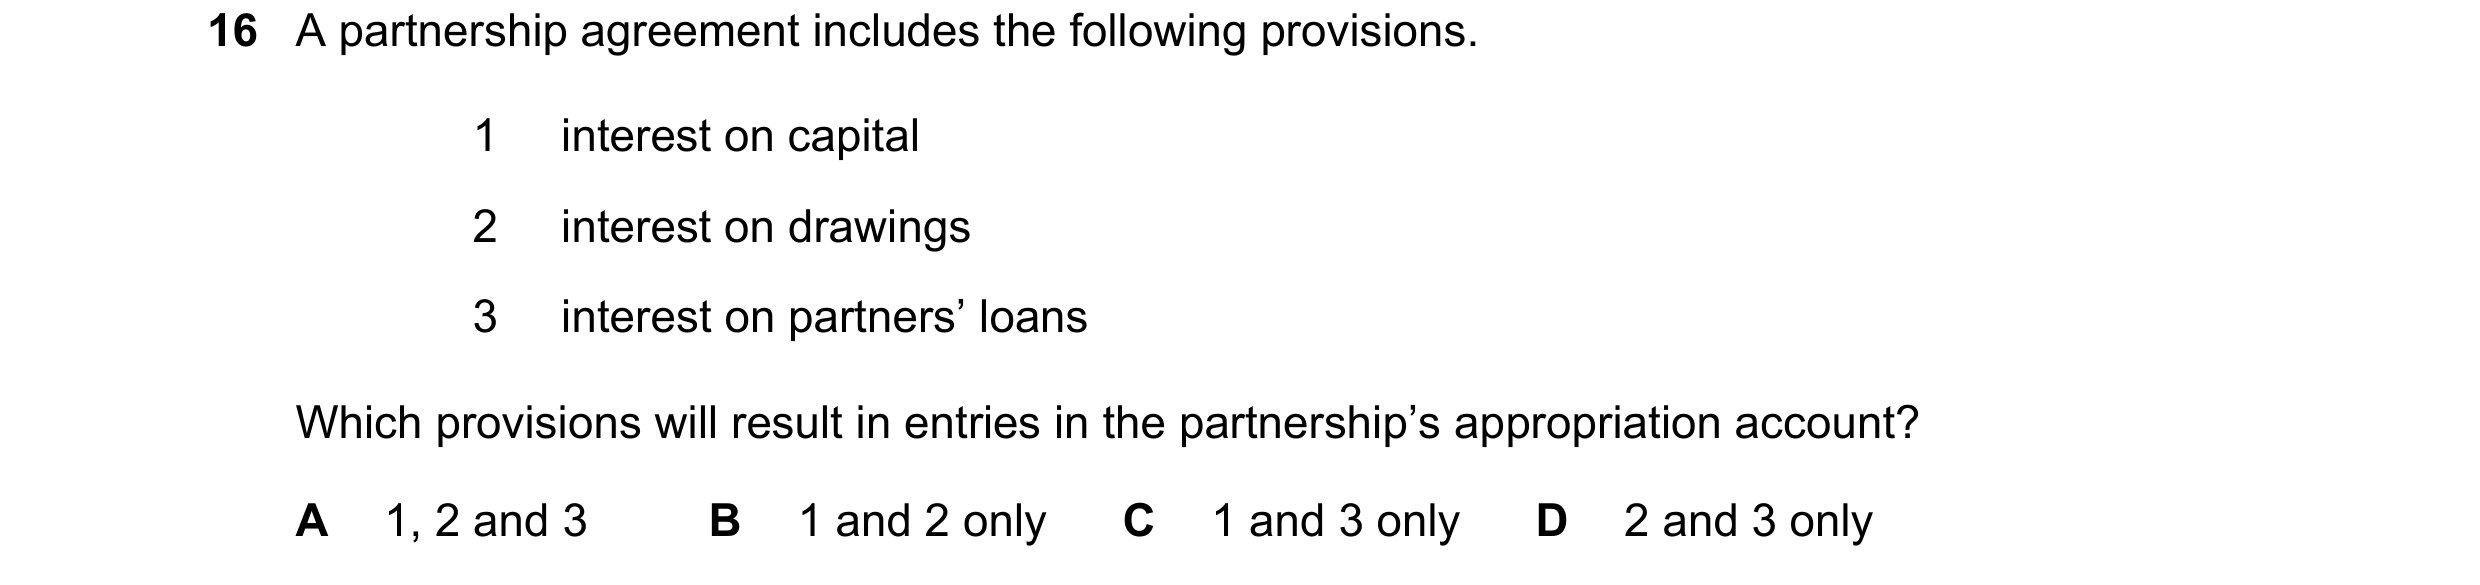 201 / 233
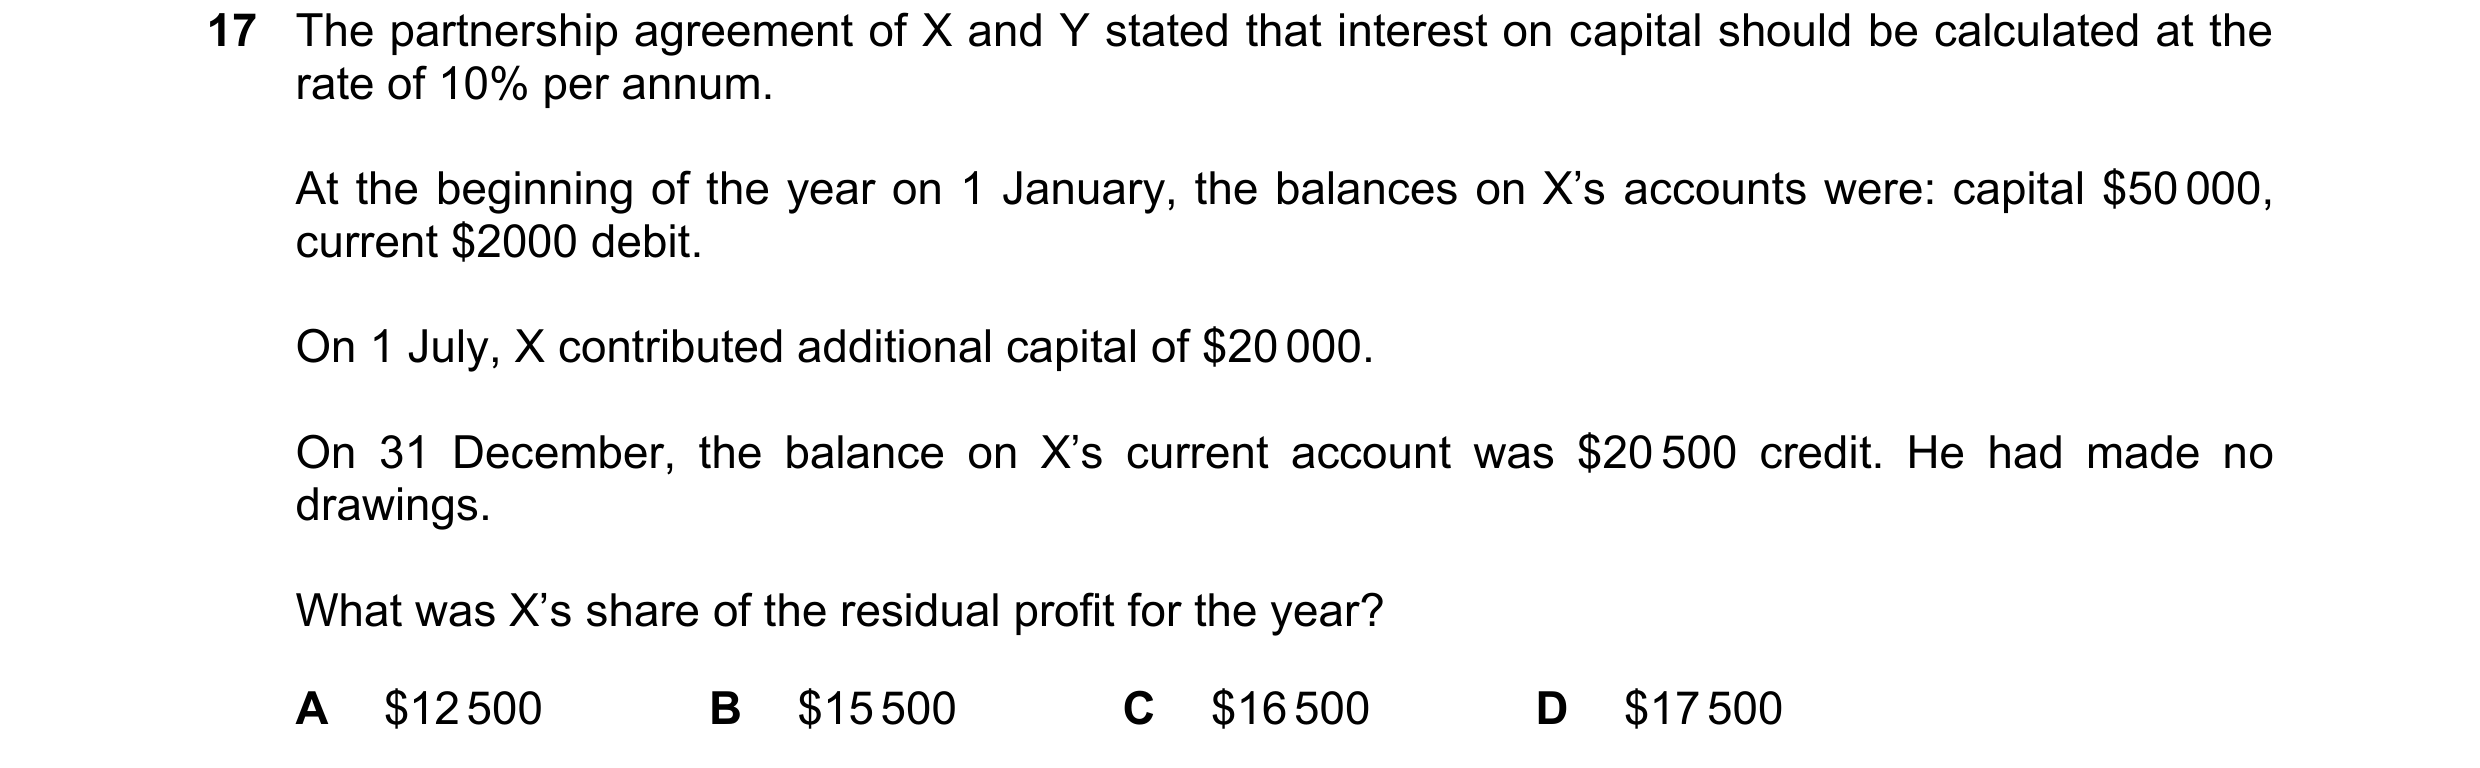
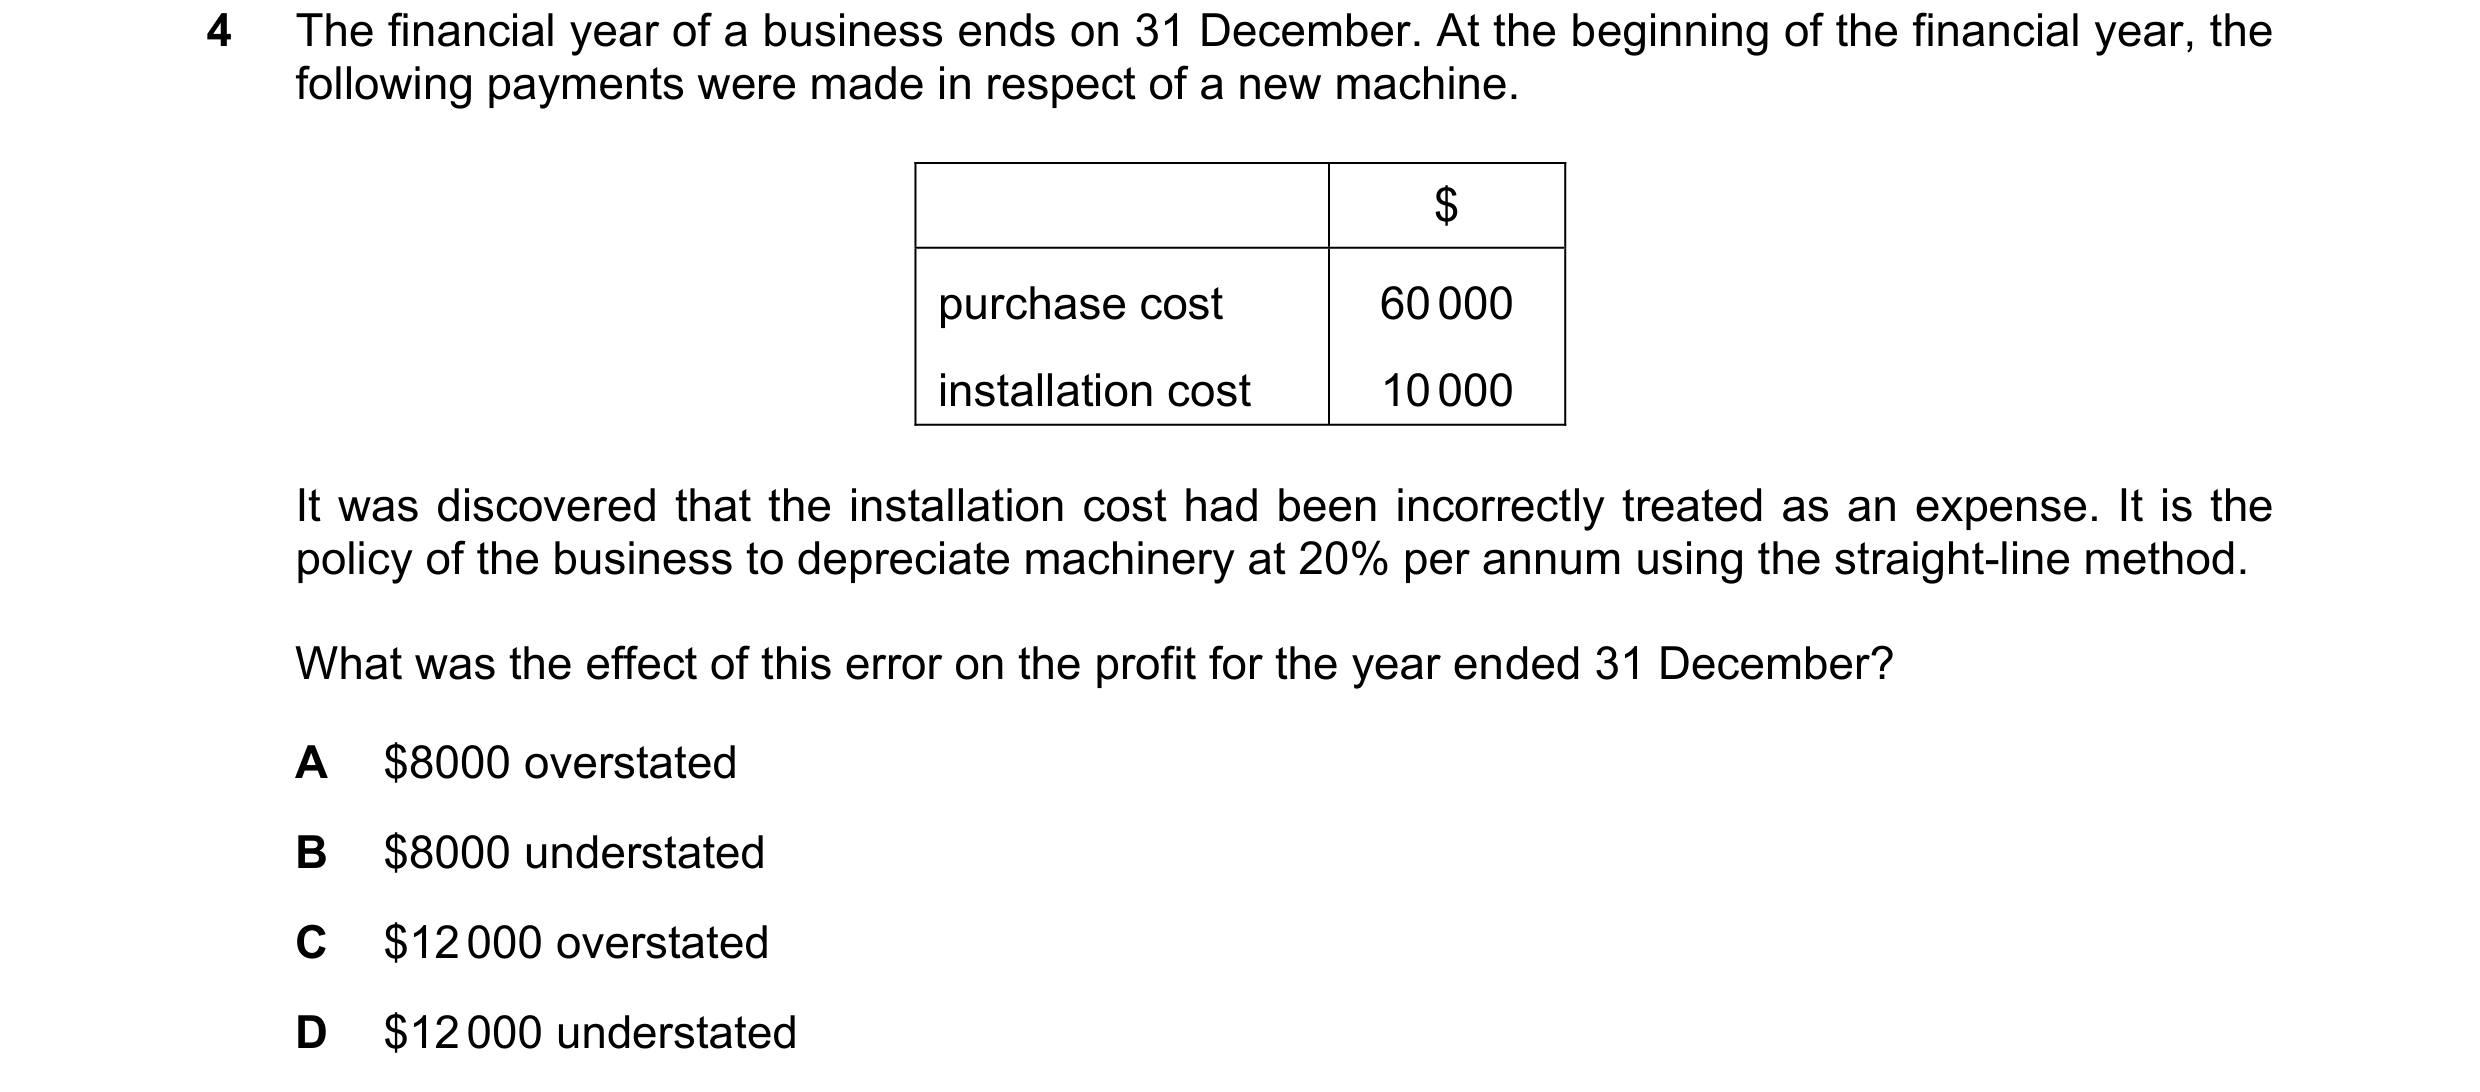
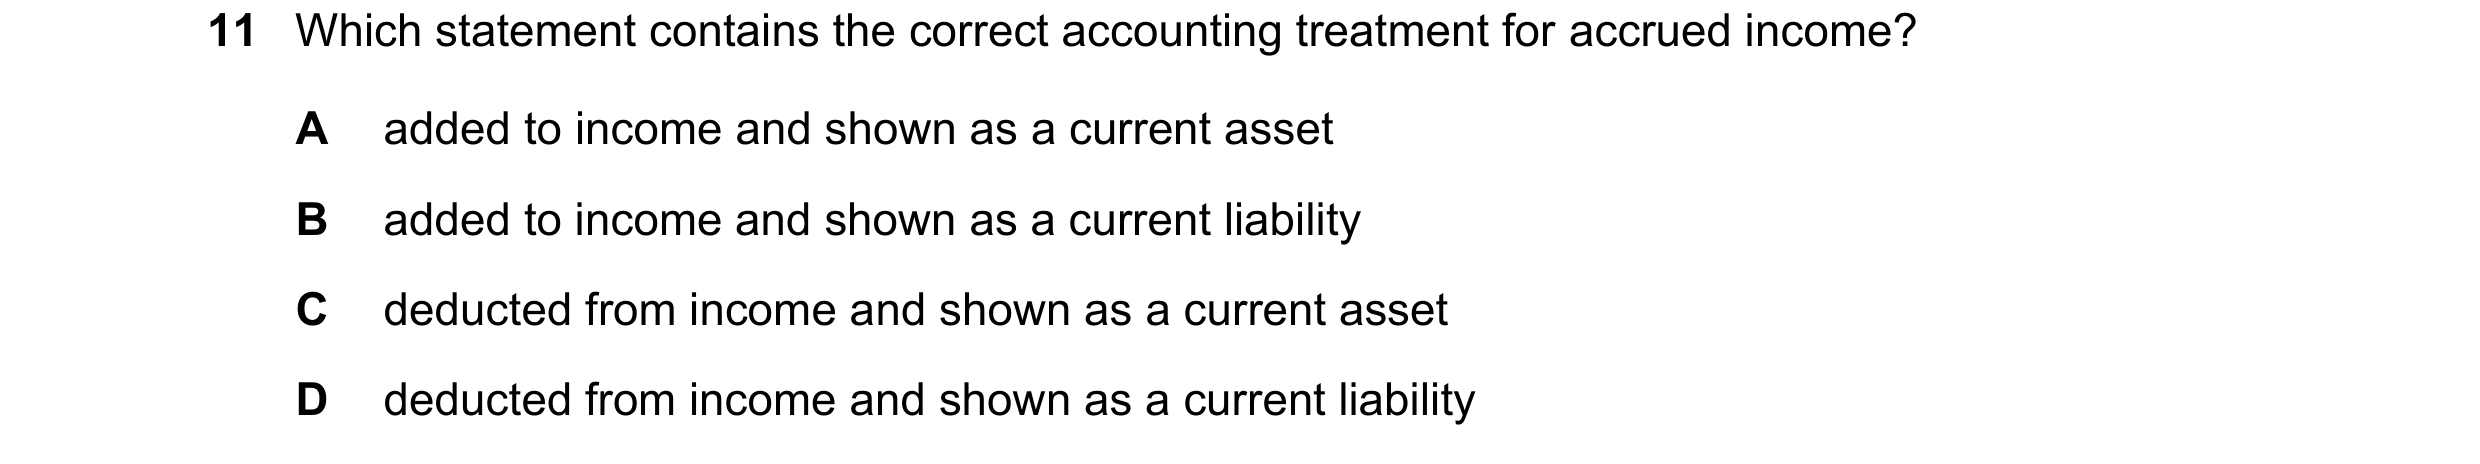 202 / 233
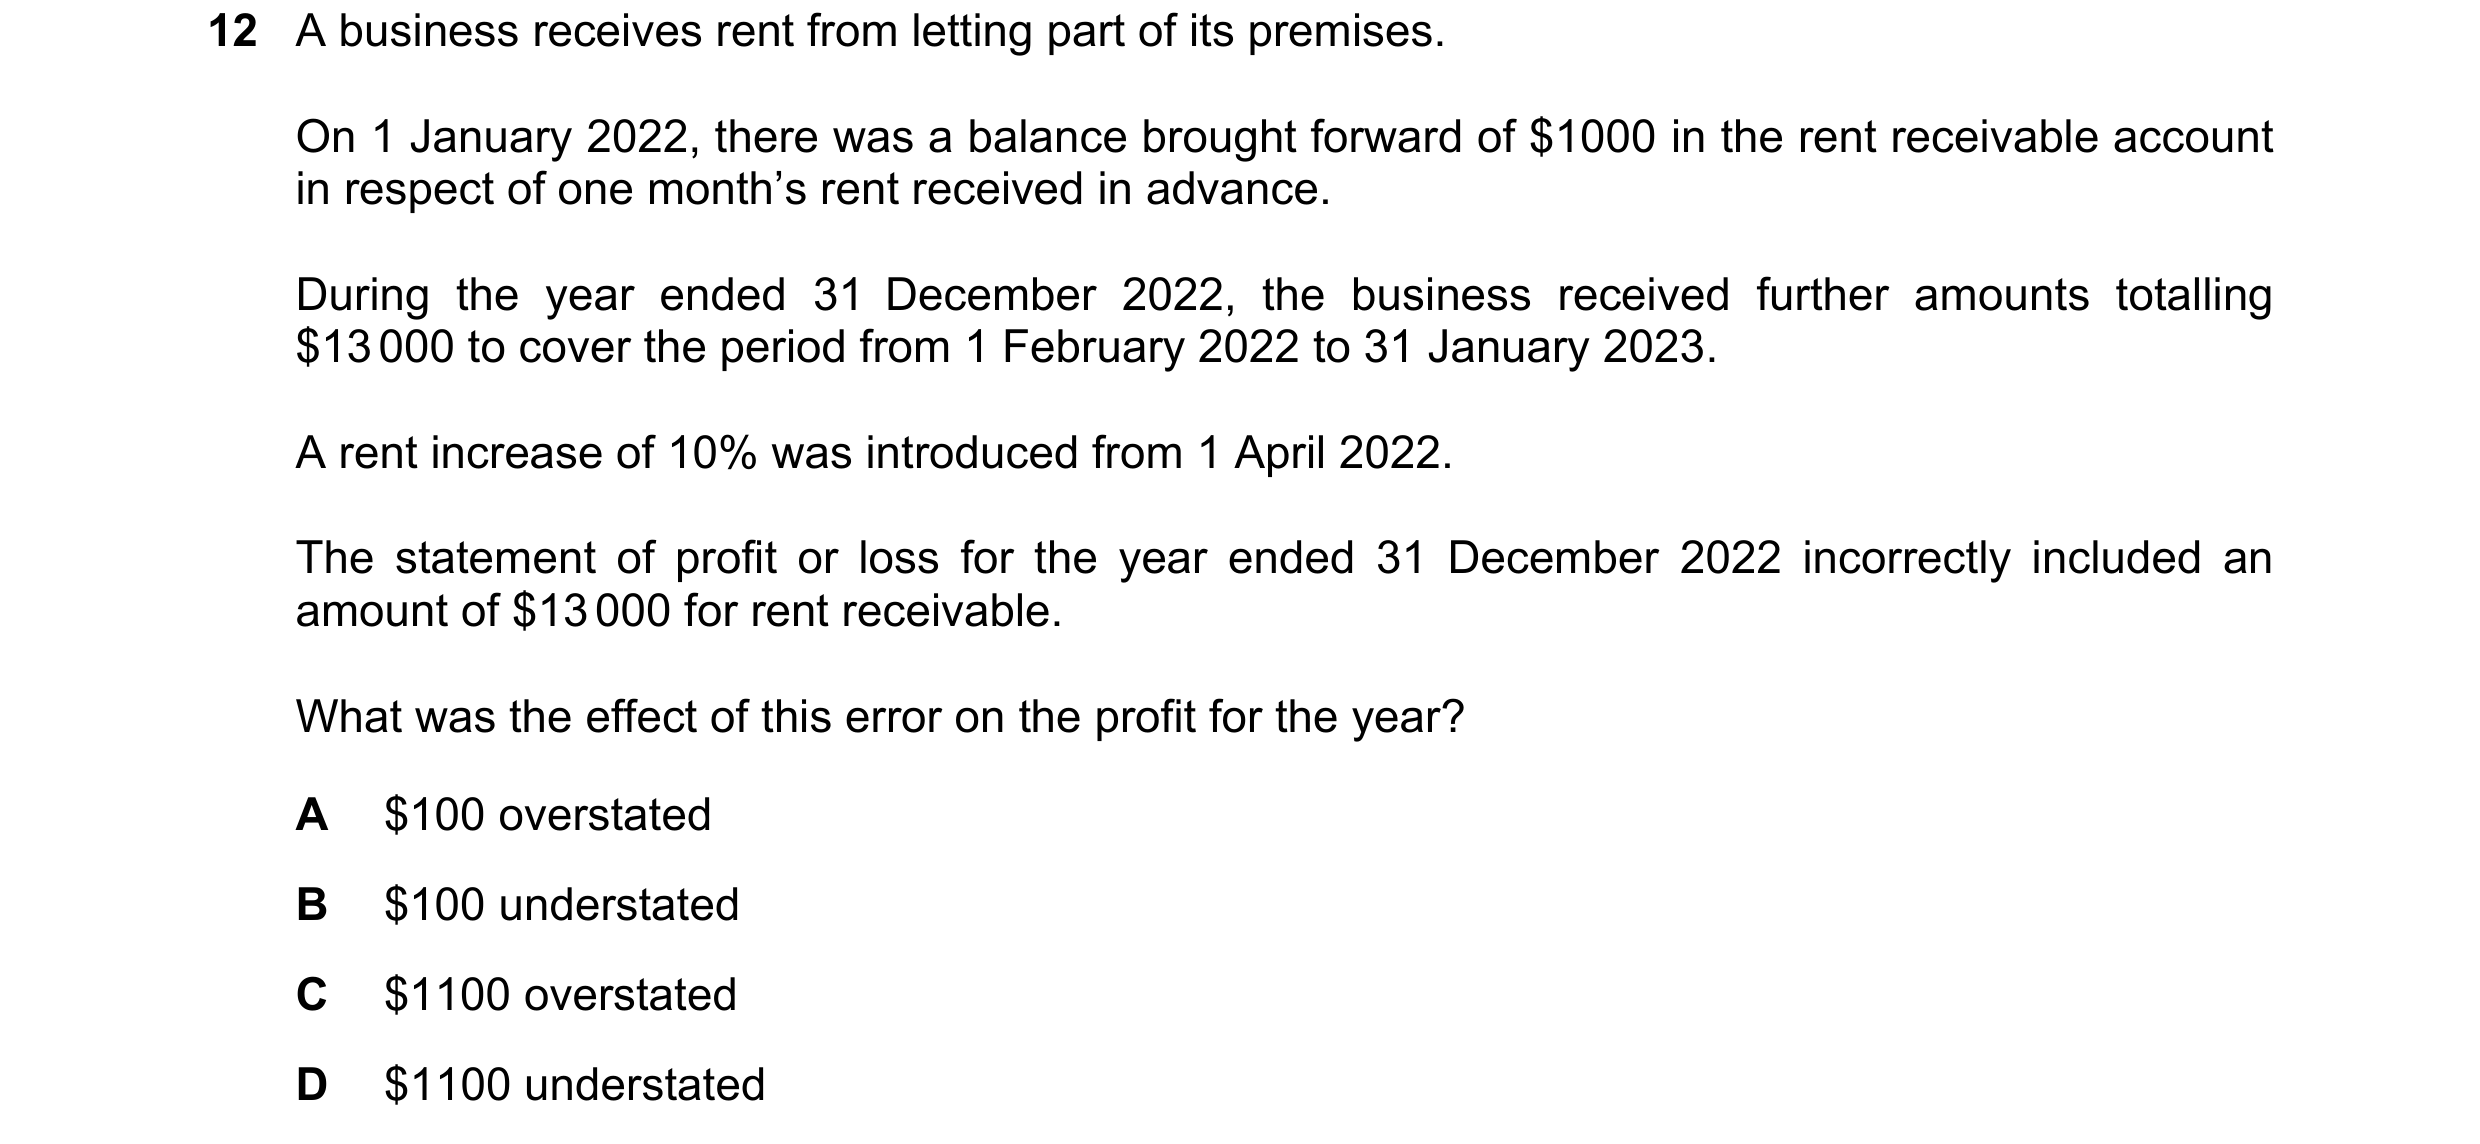
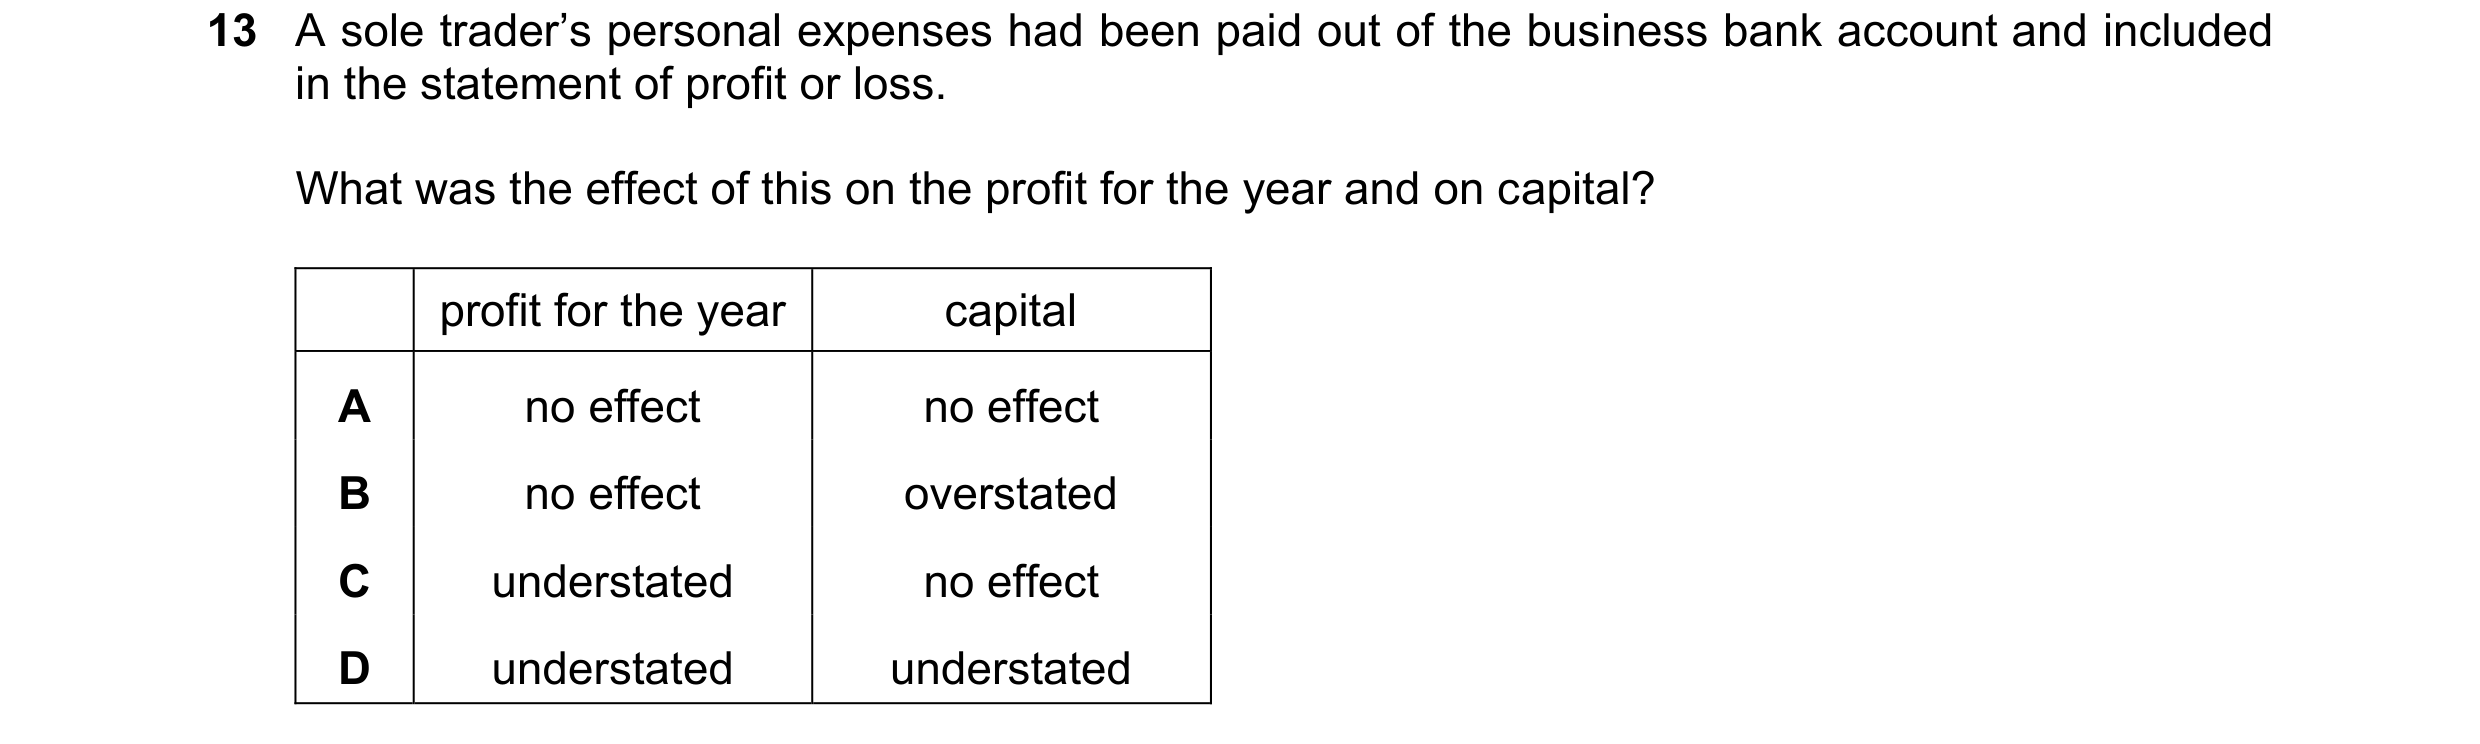
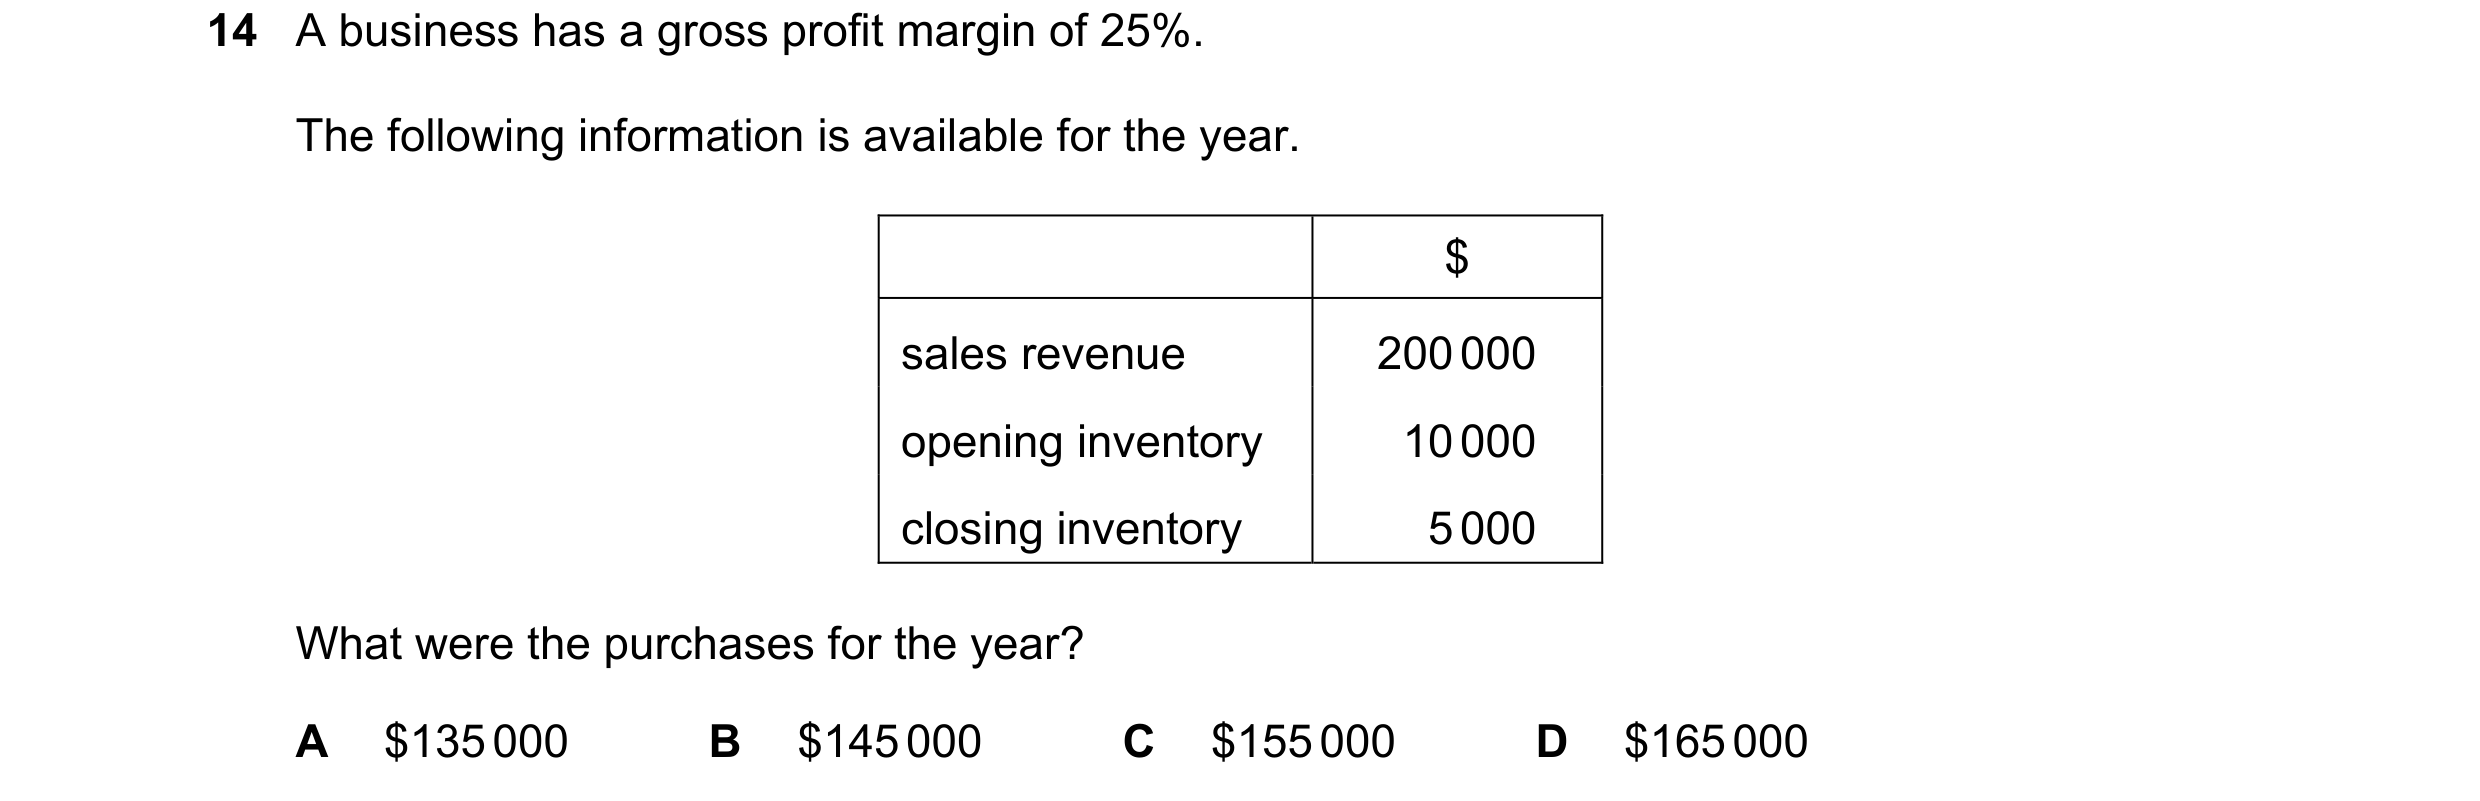
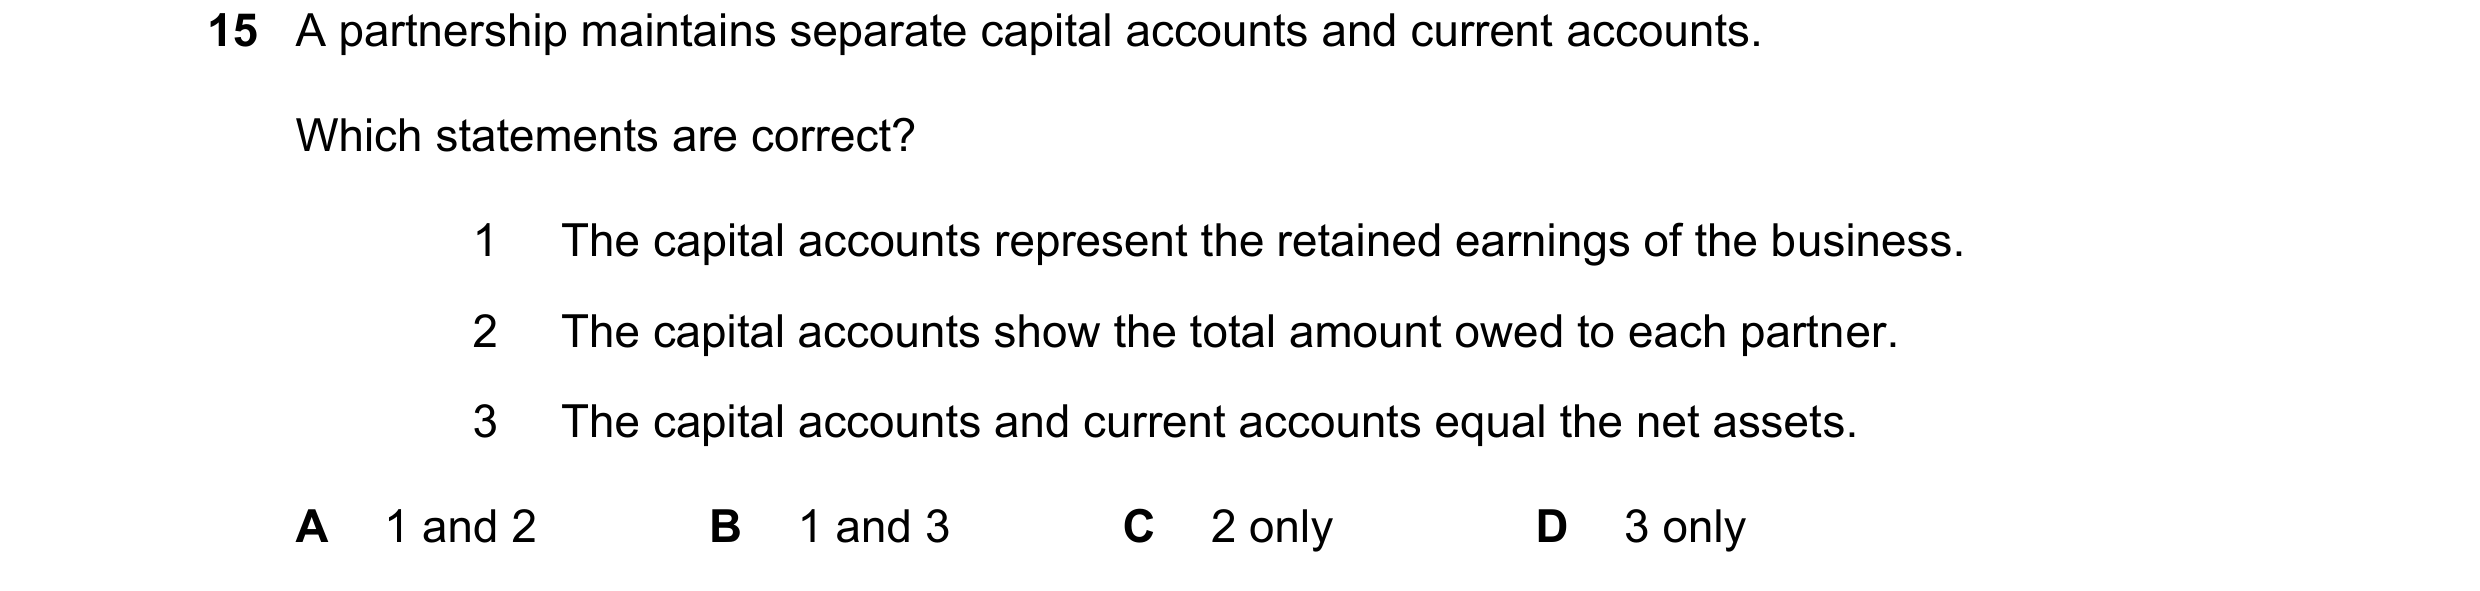 203 / 233
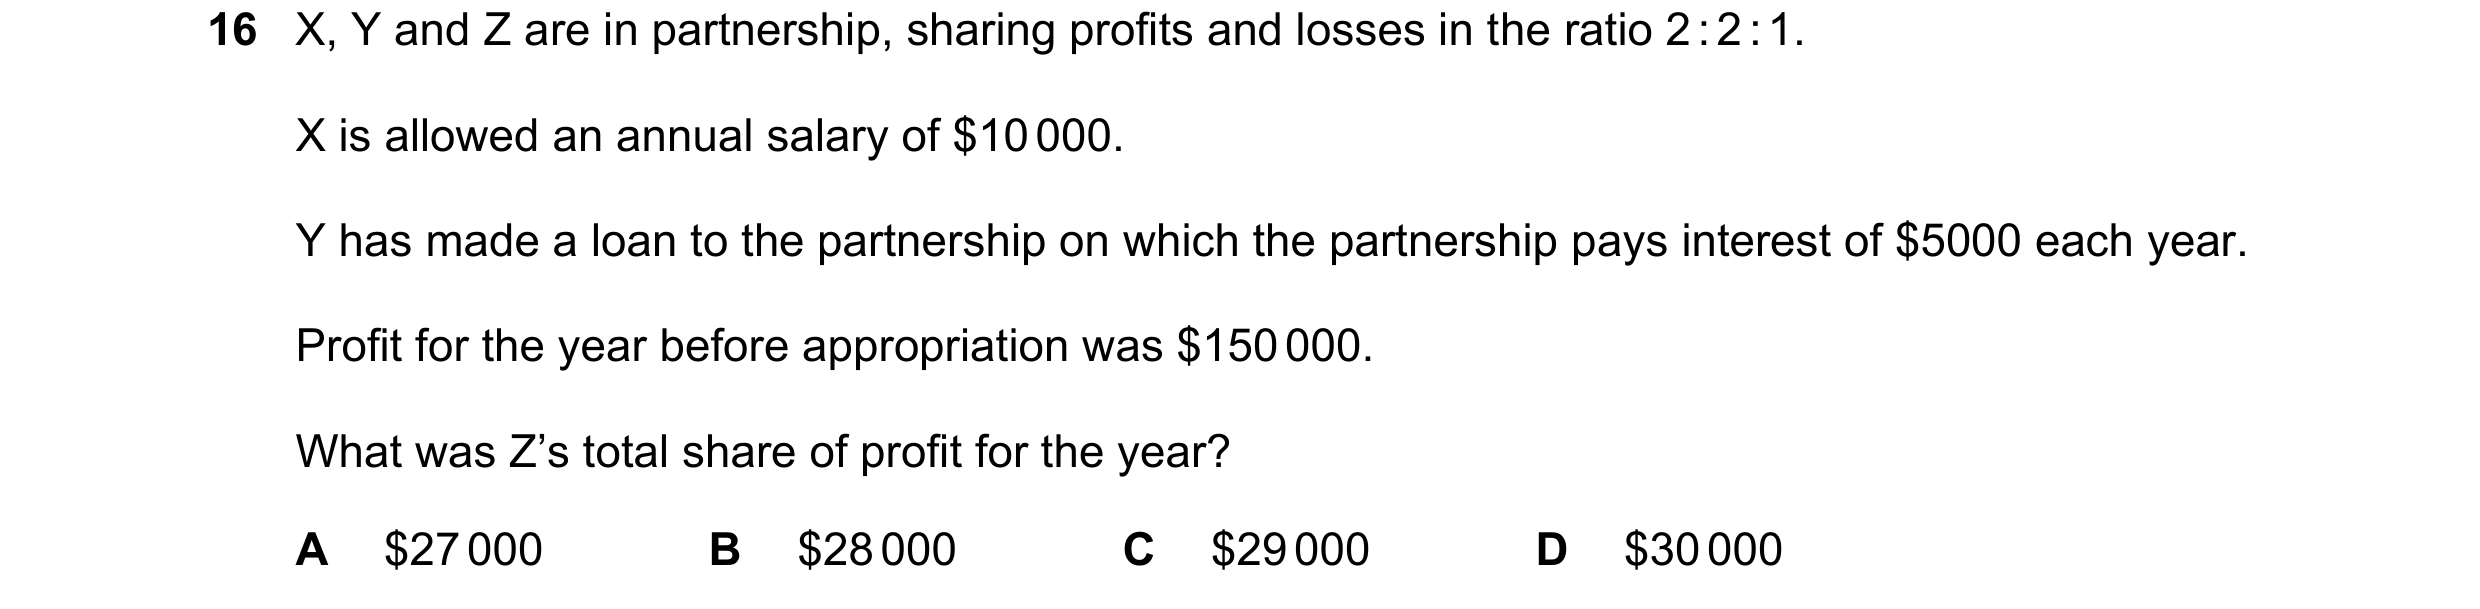
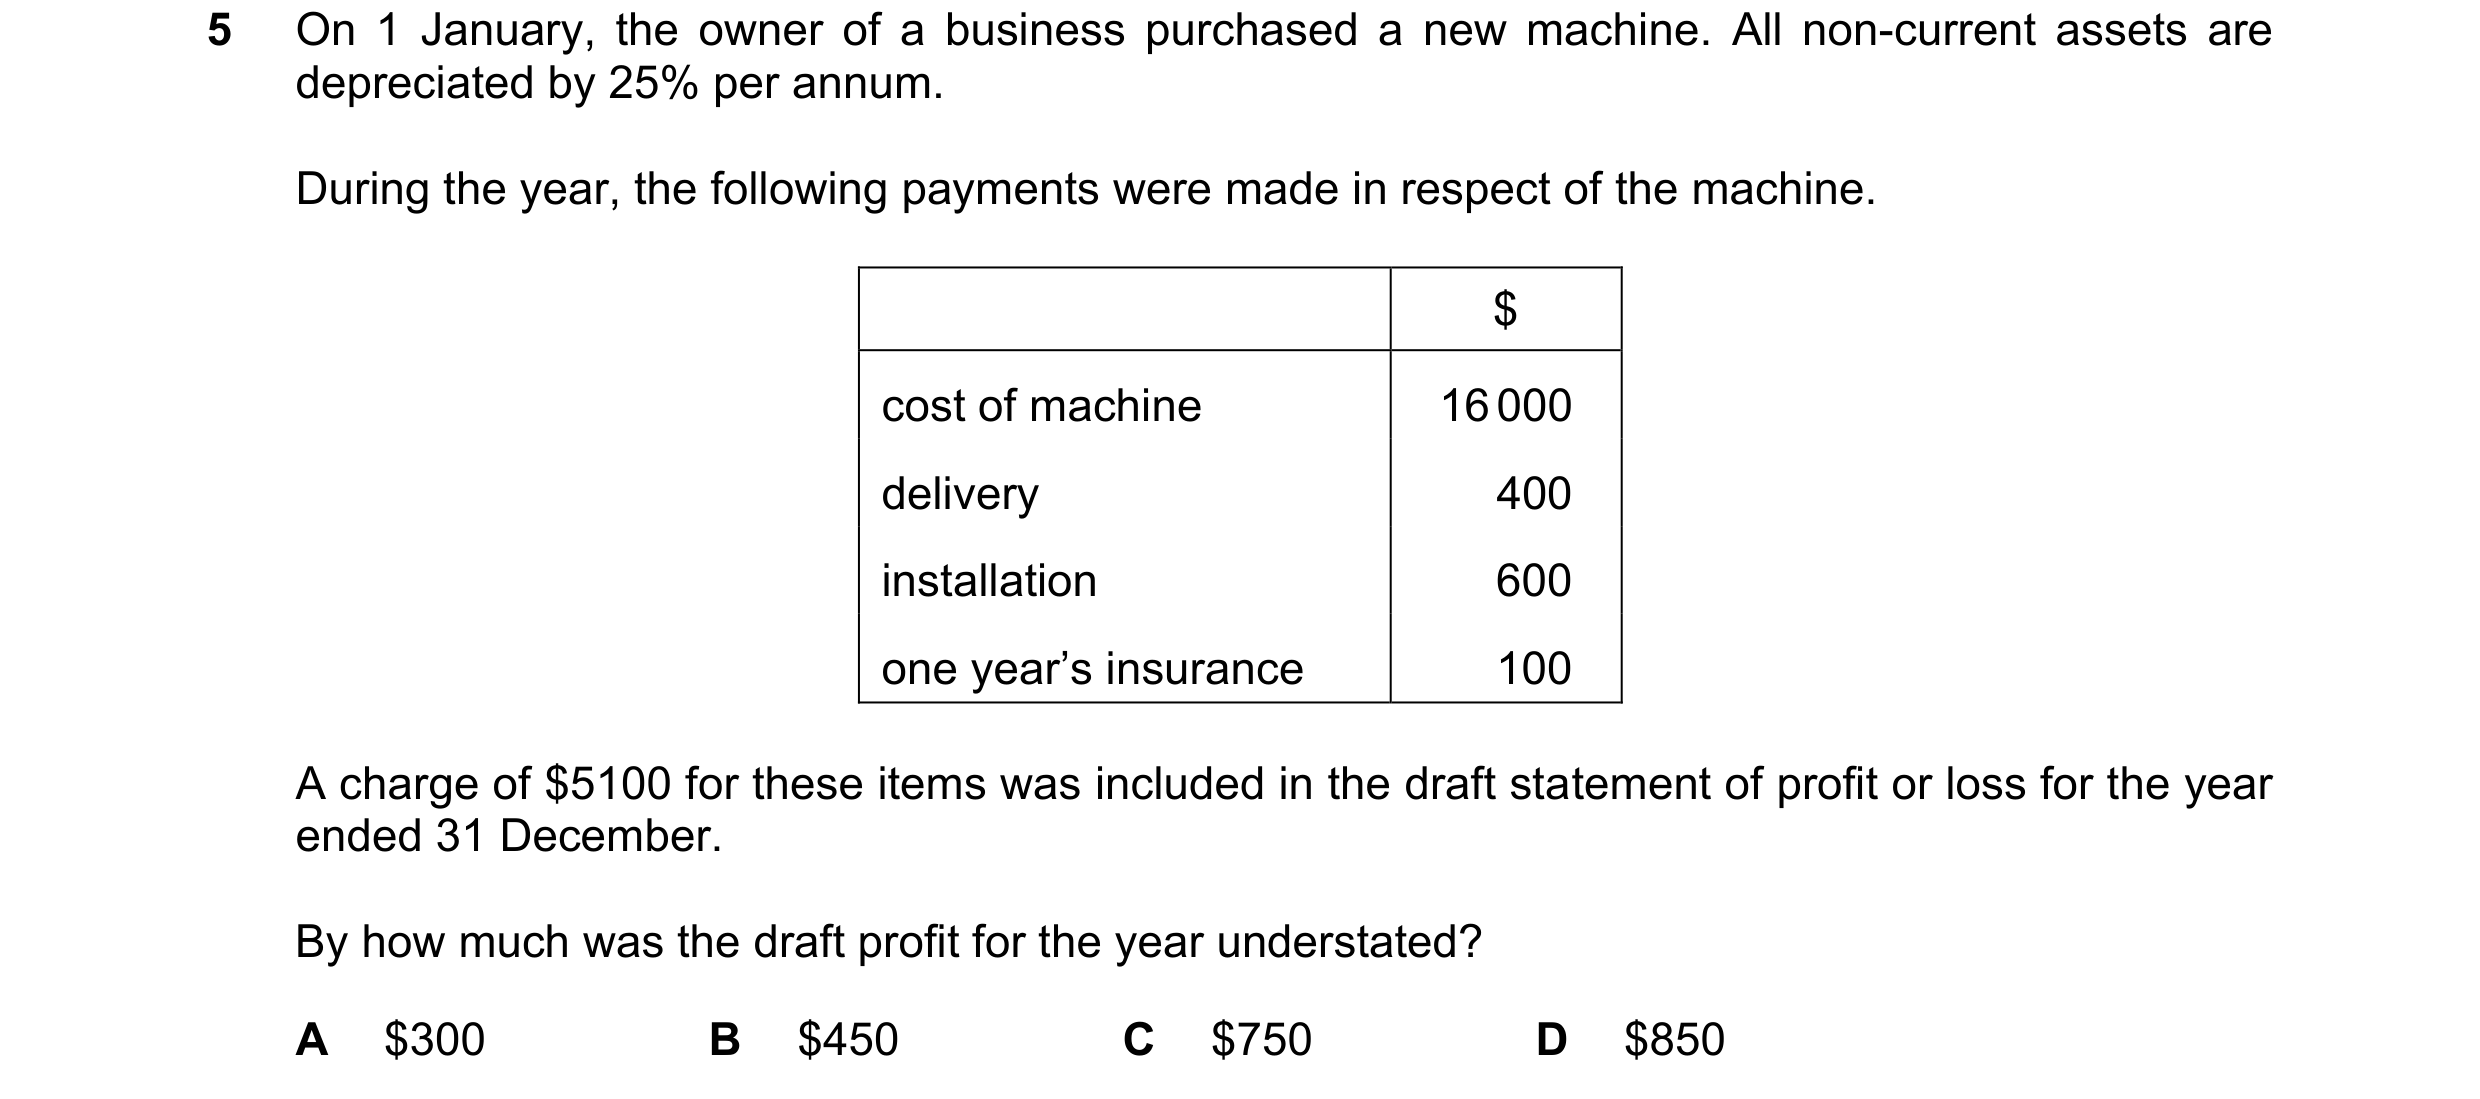
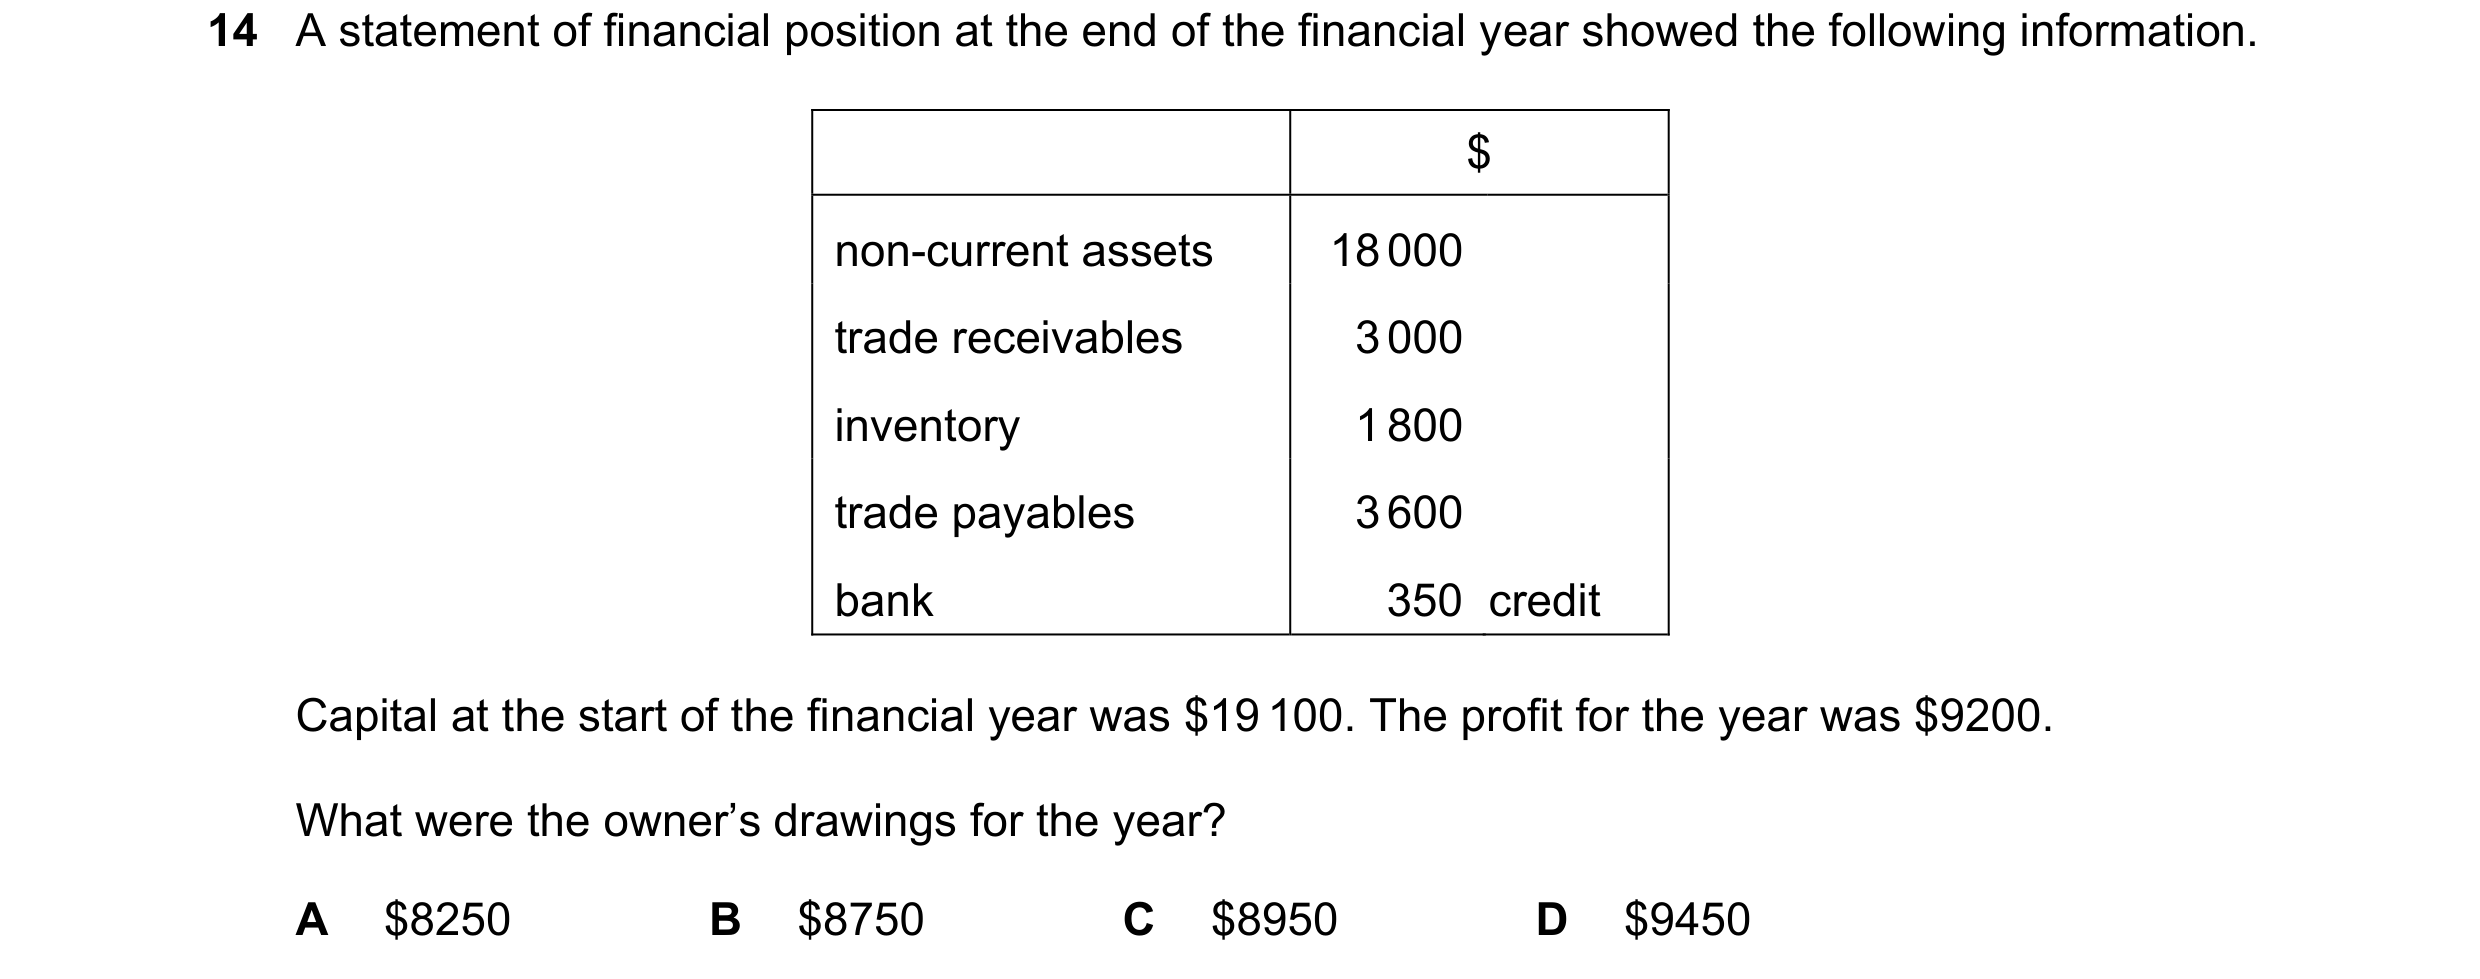 204 / 233
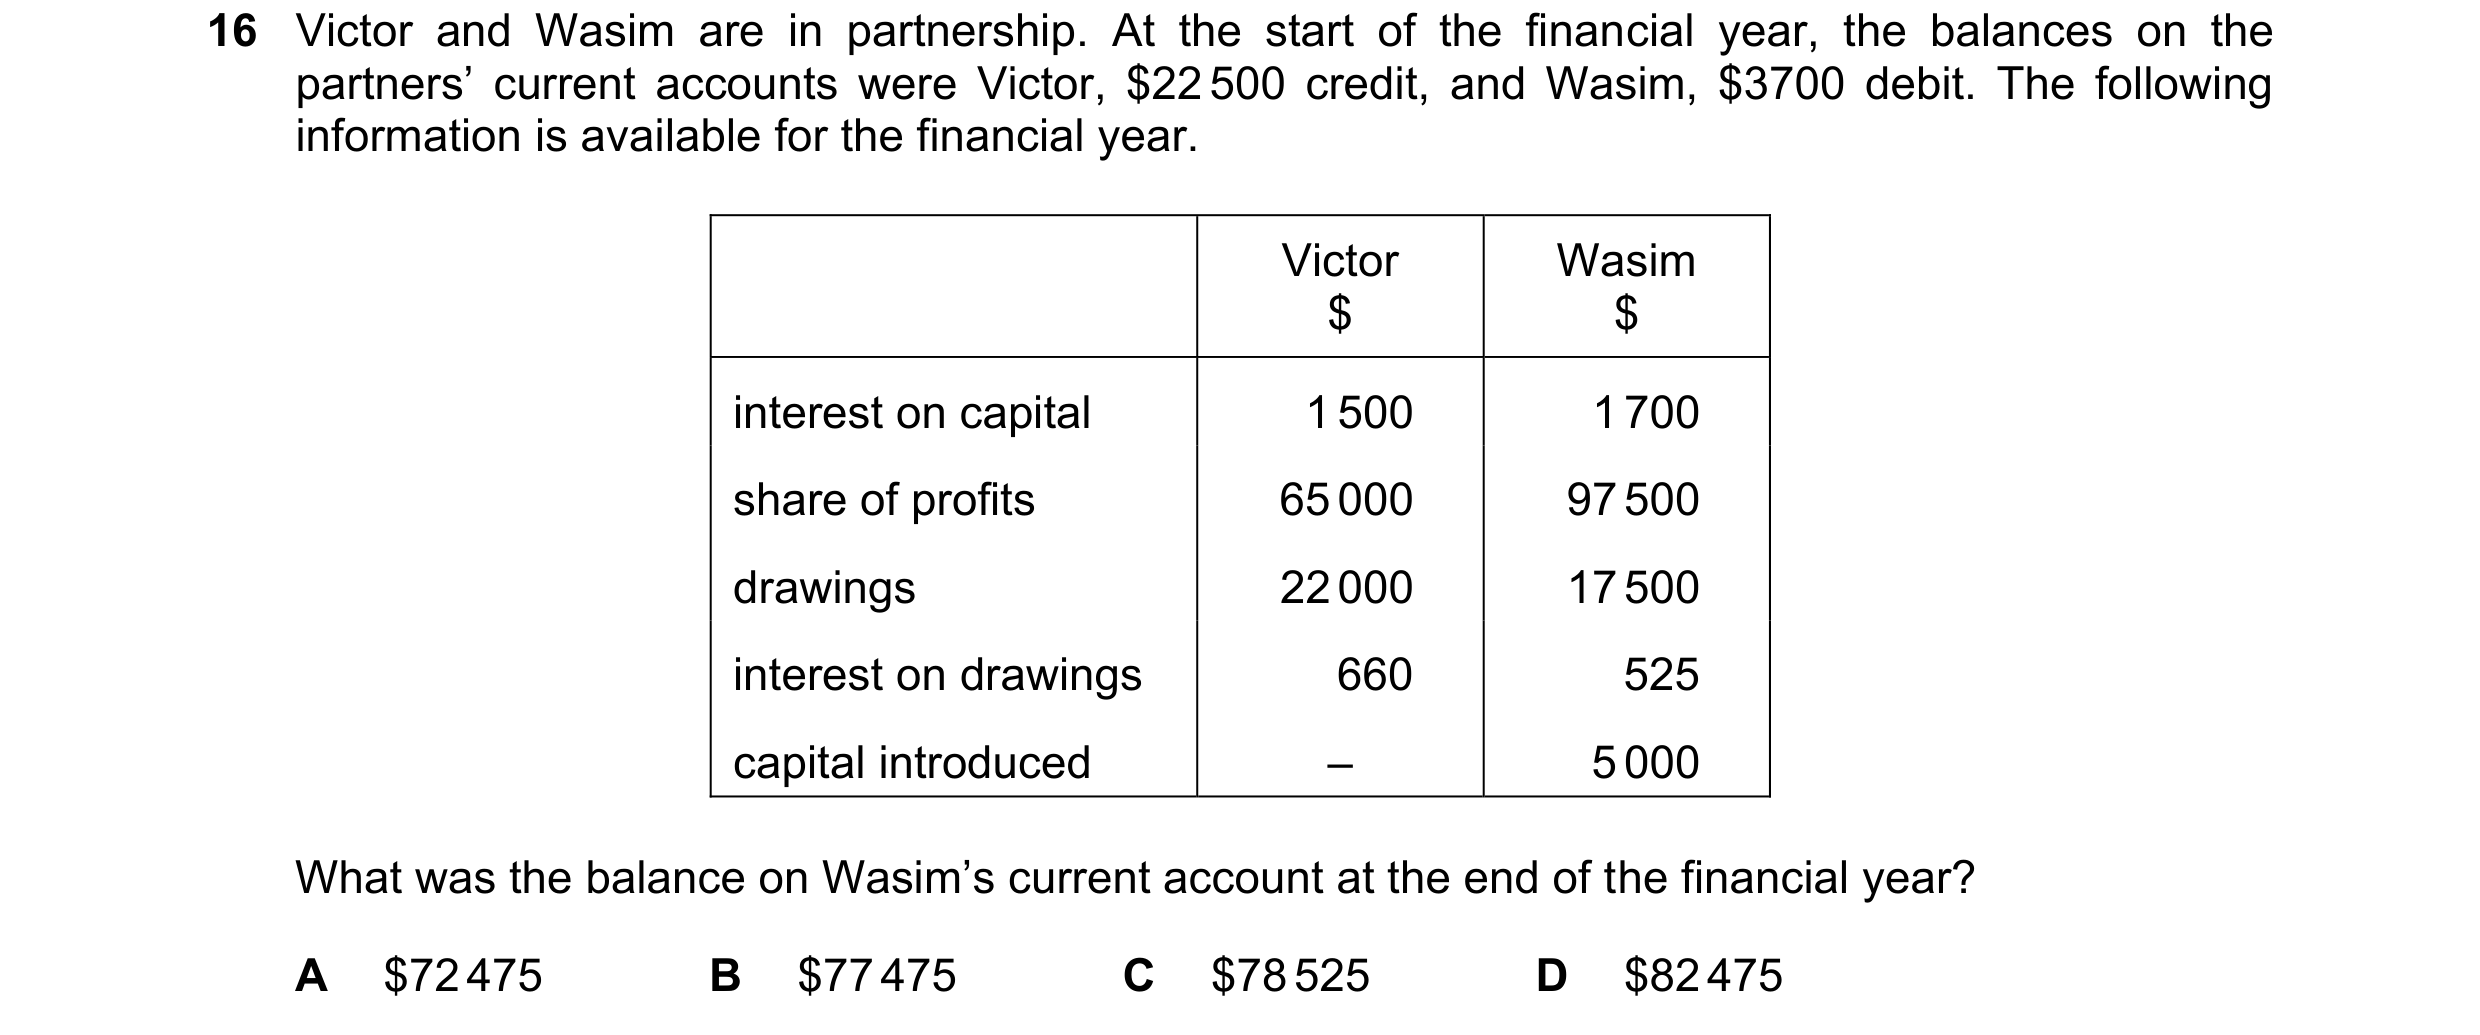
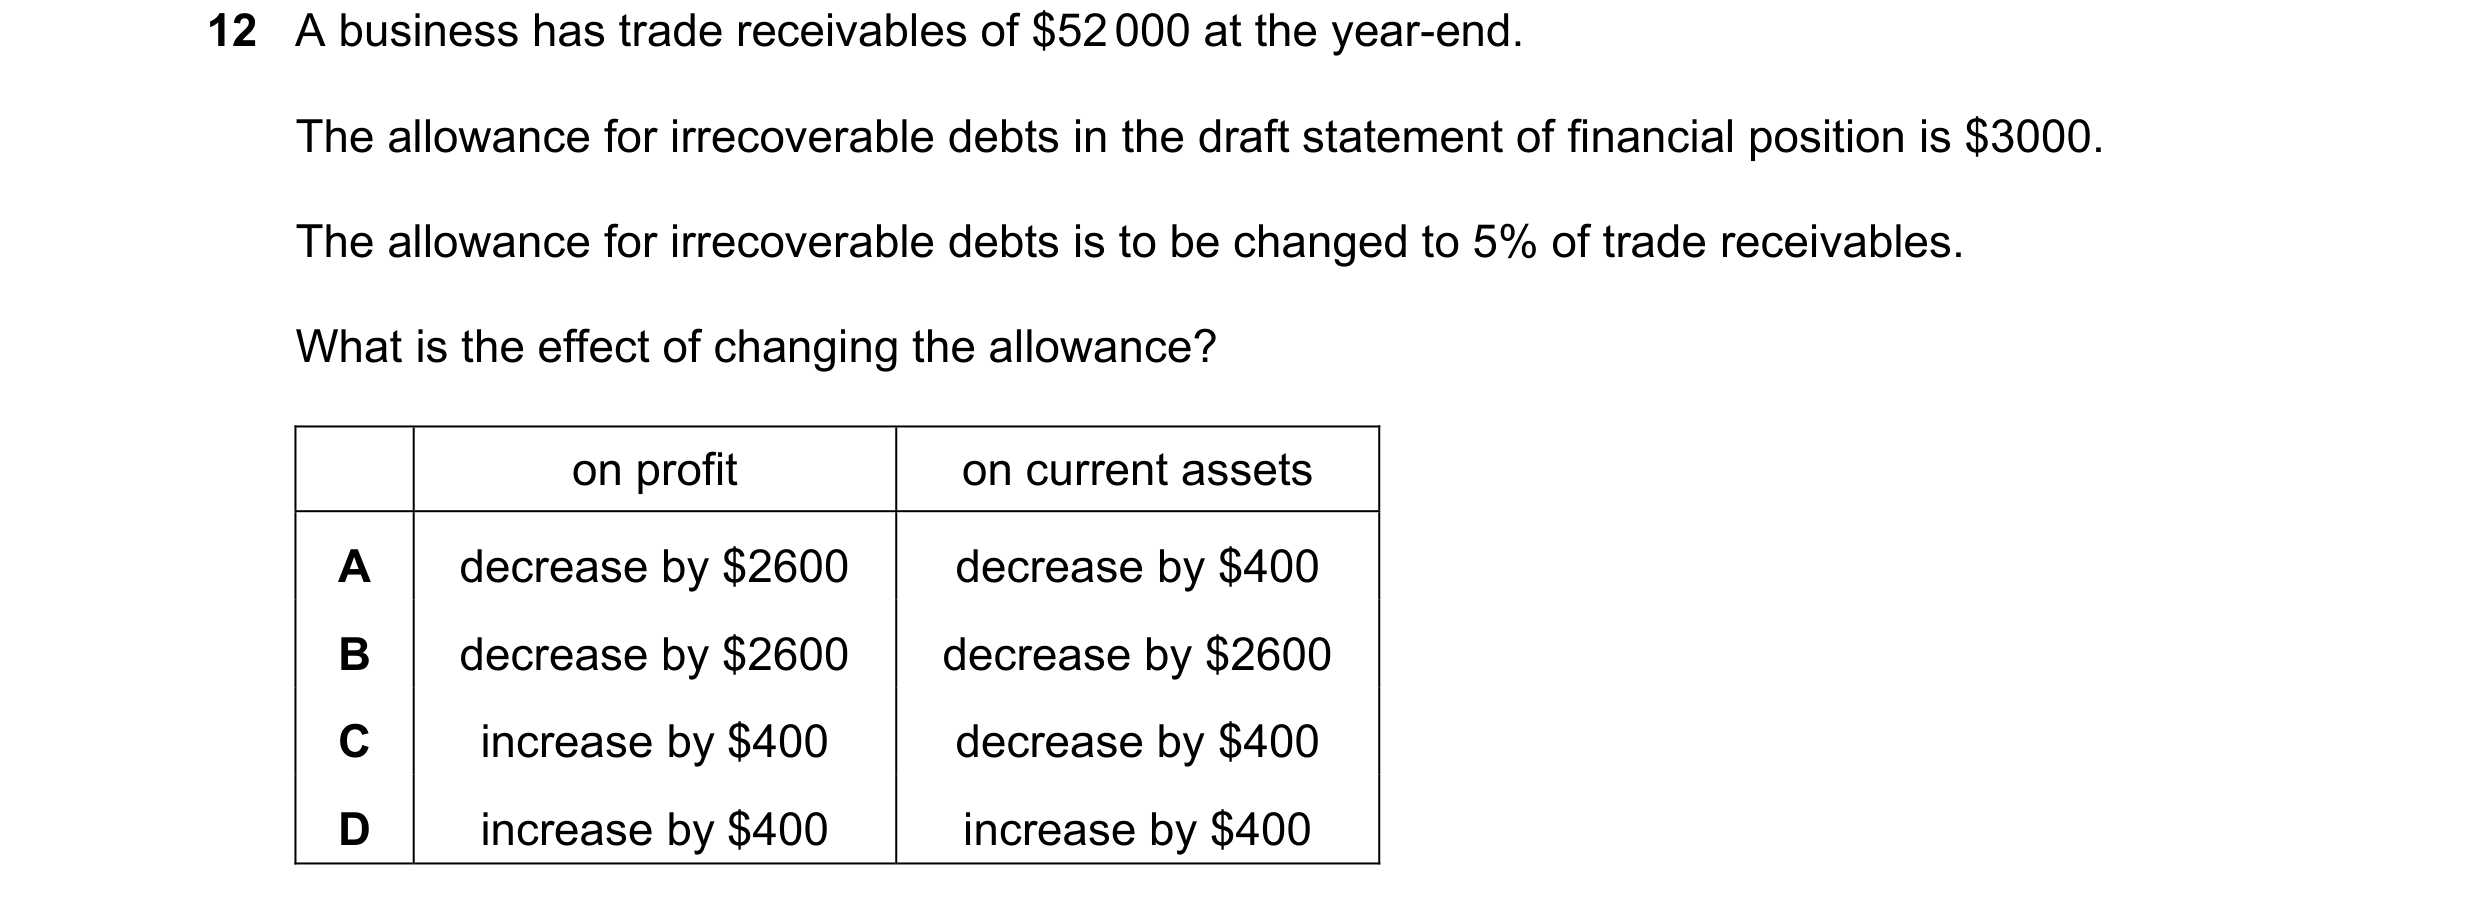
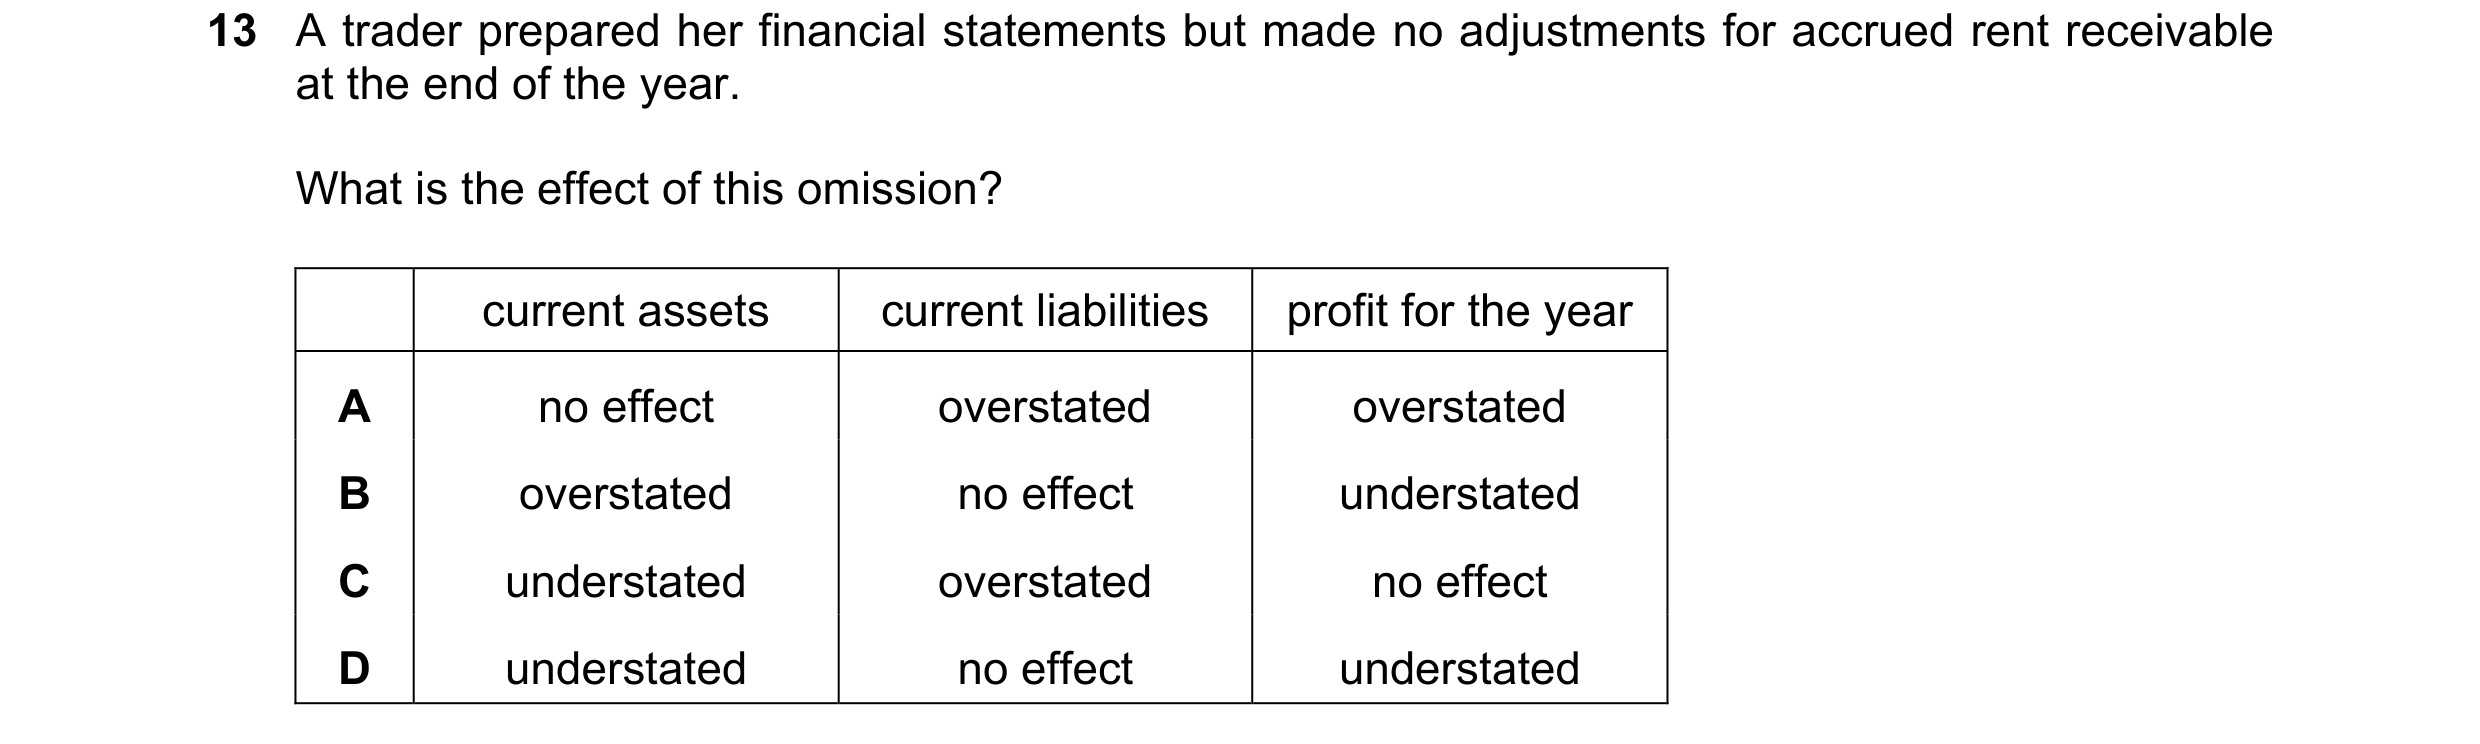 205 / 233
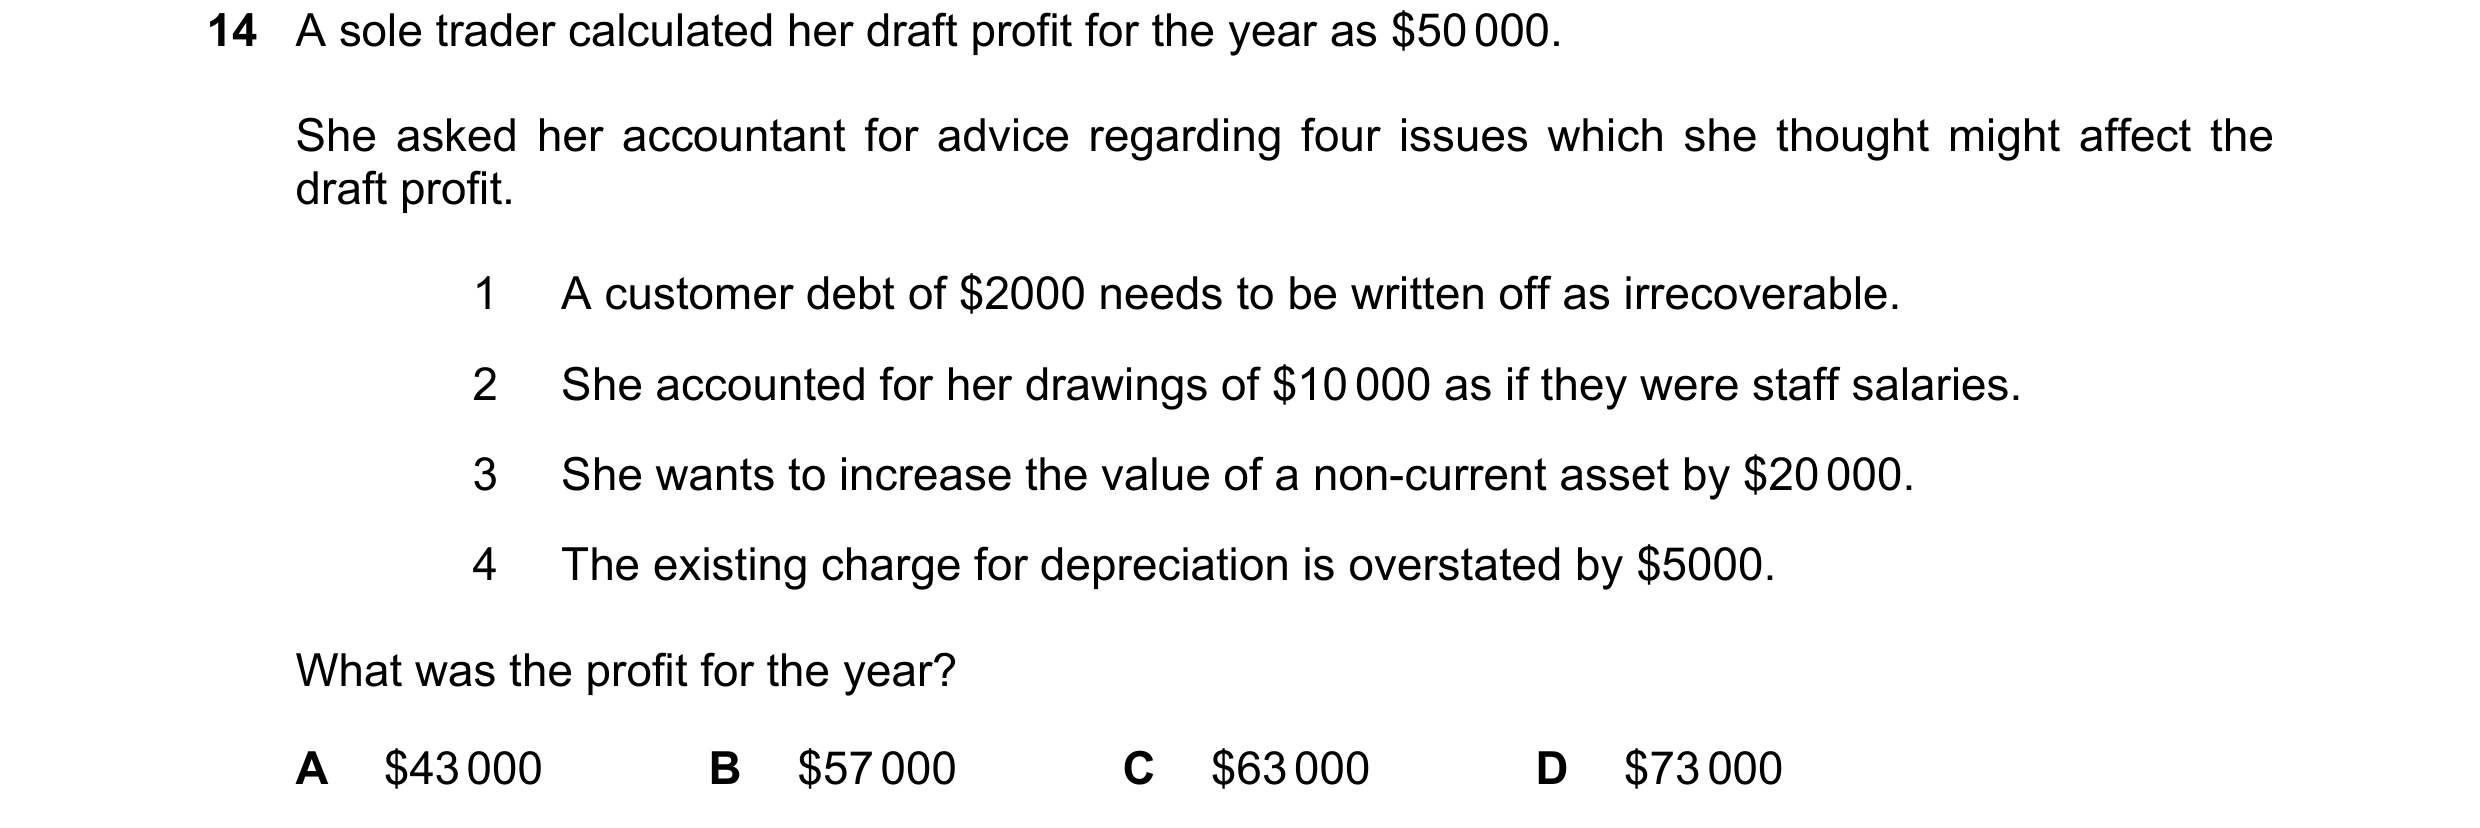
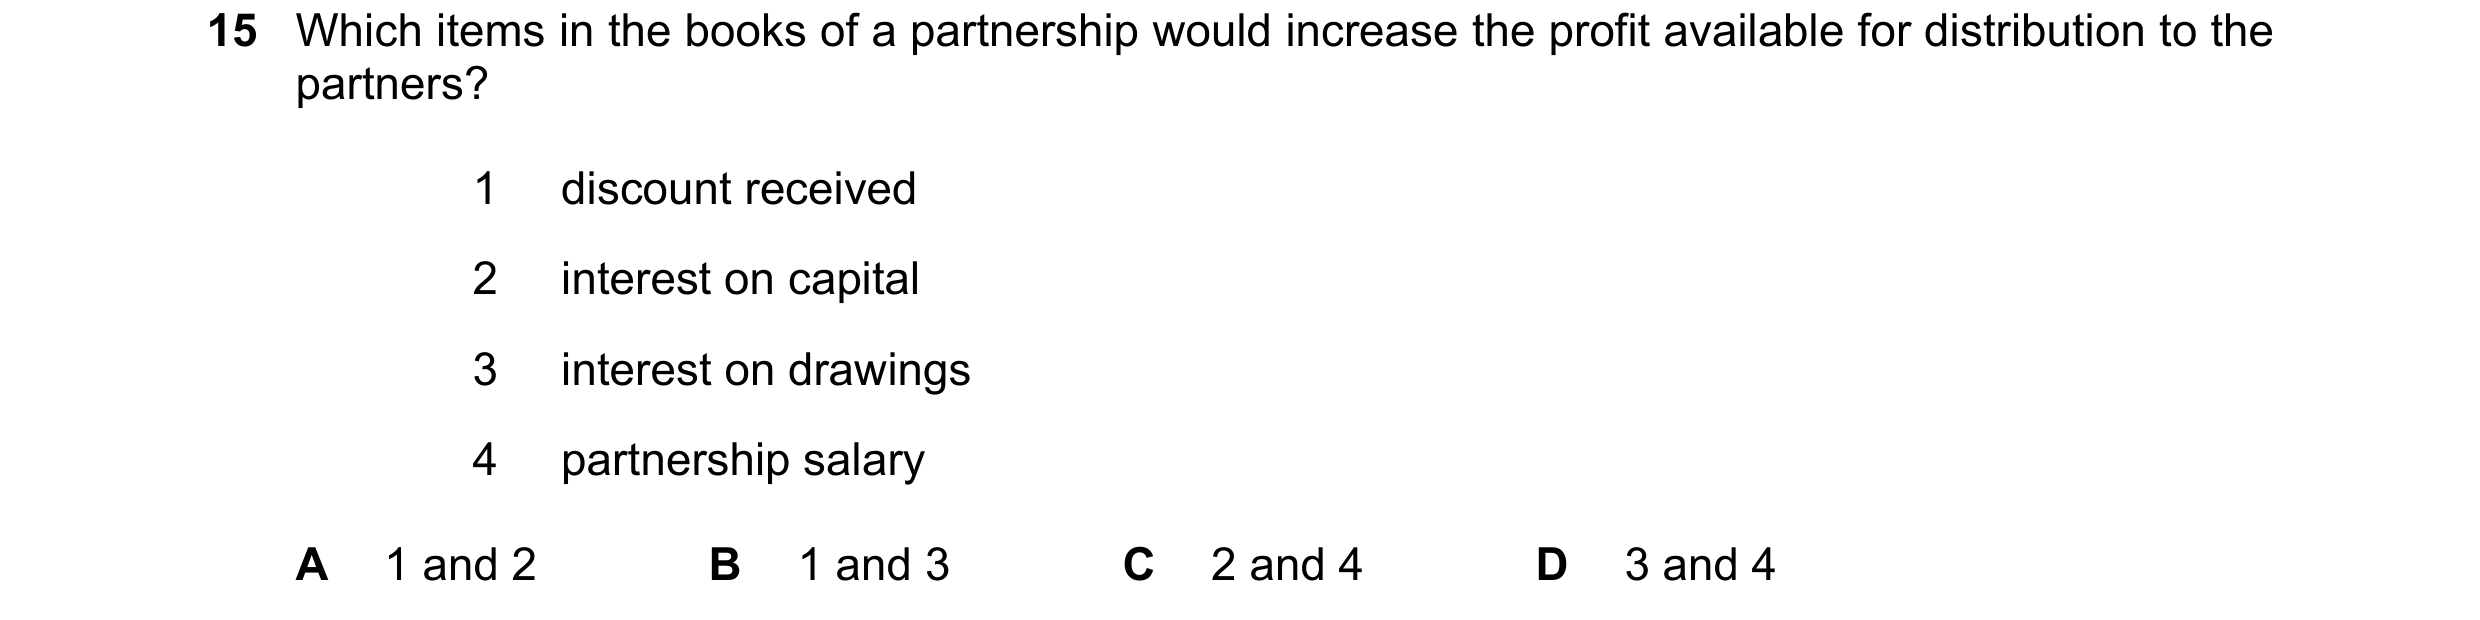
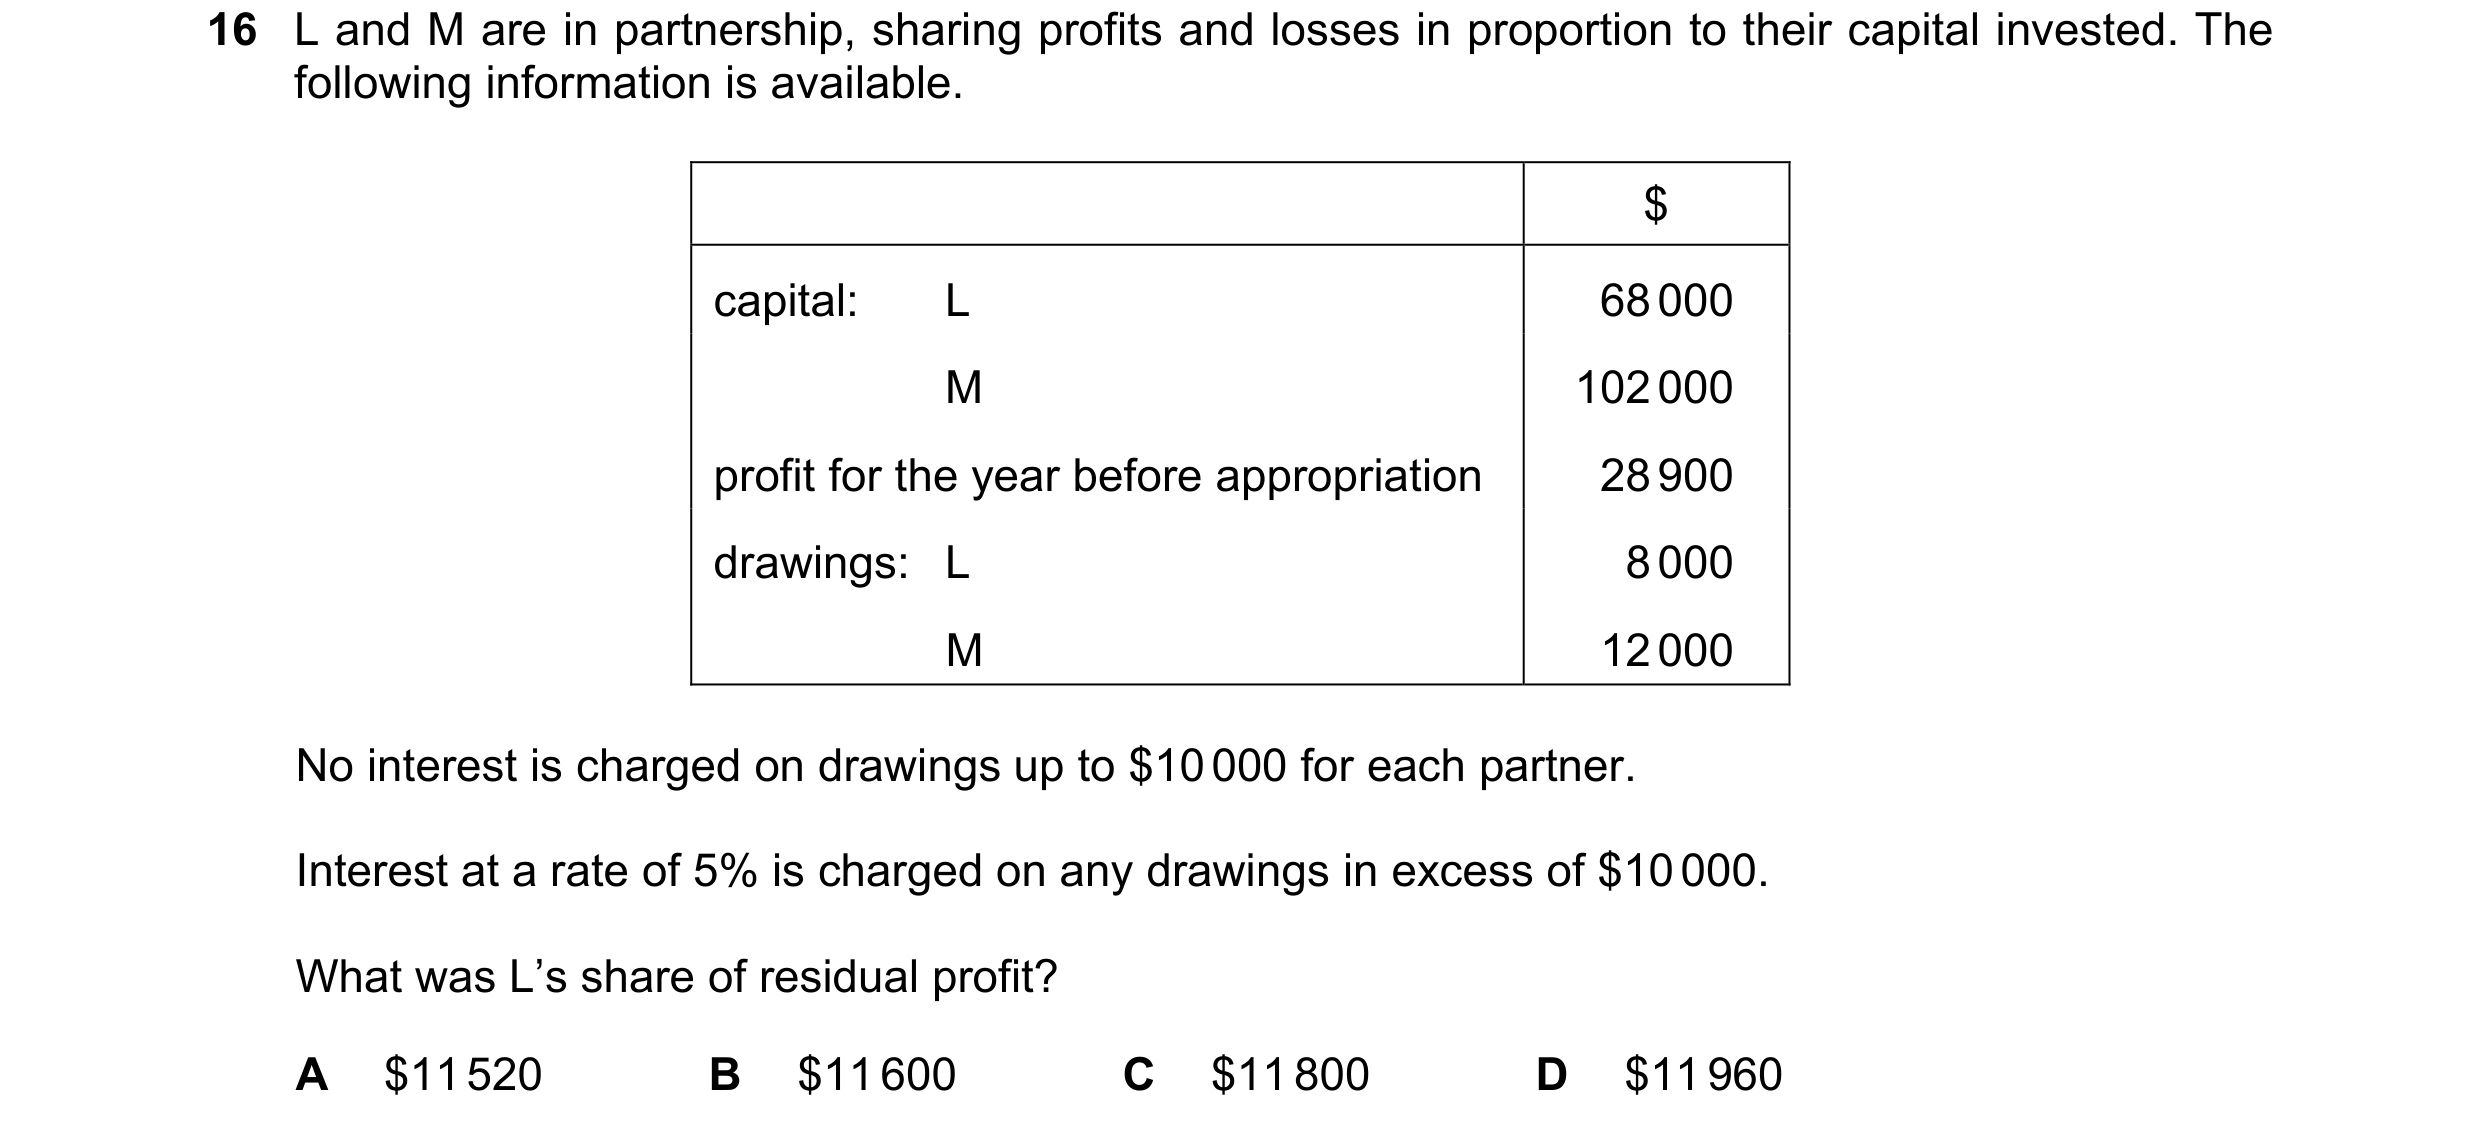 206 / 233
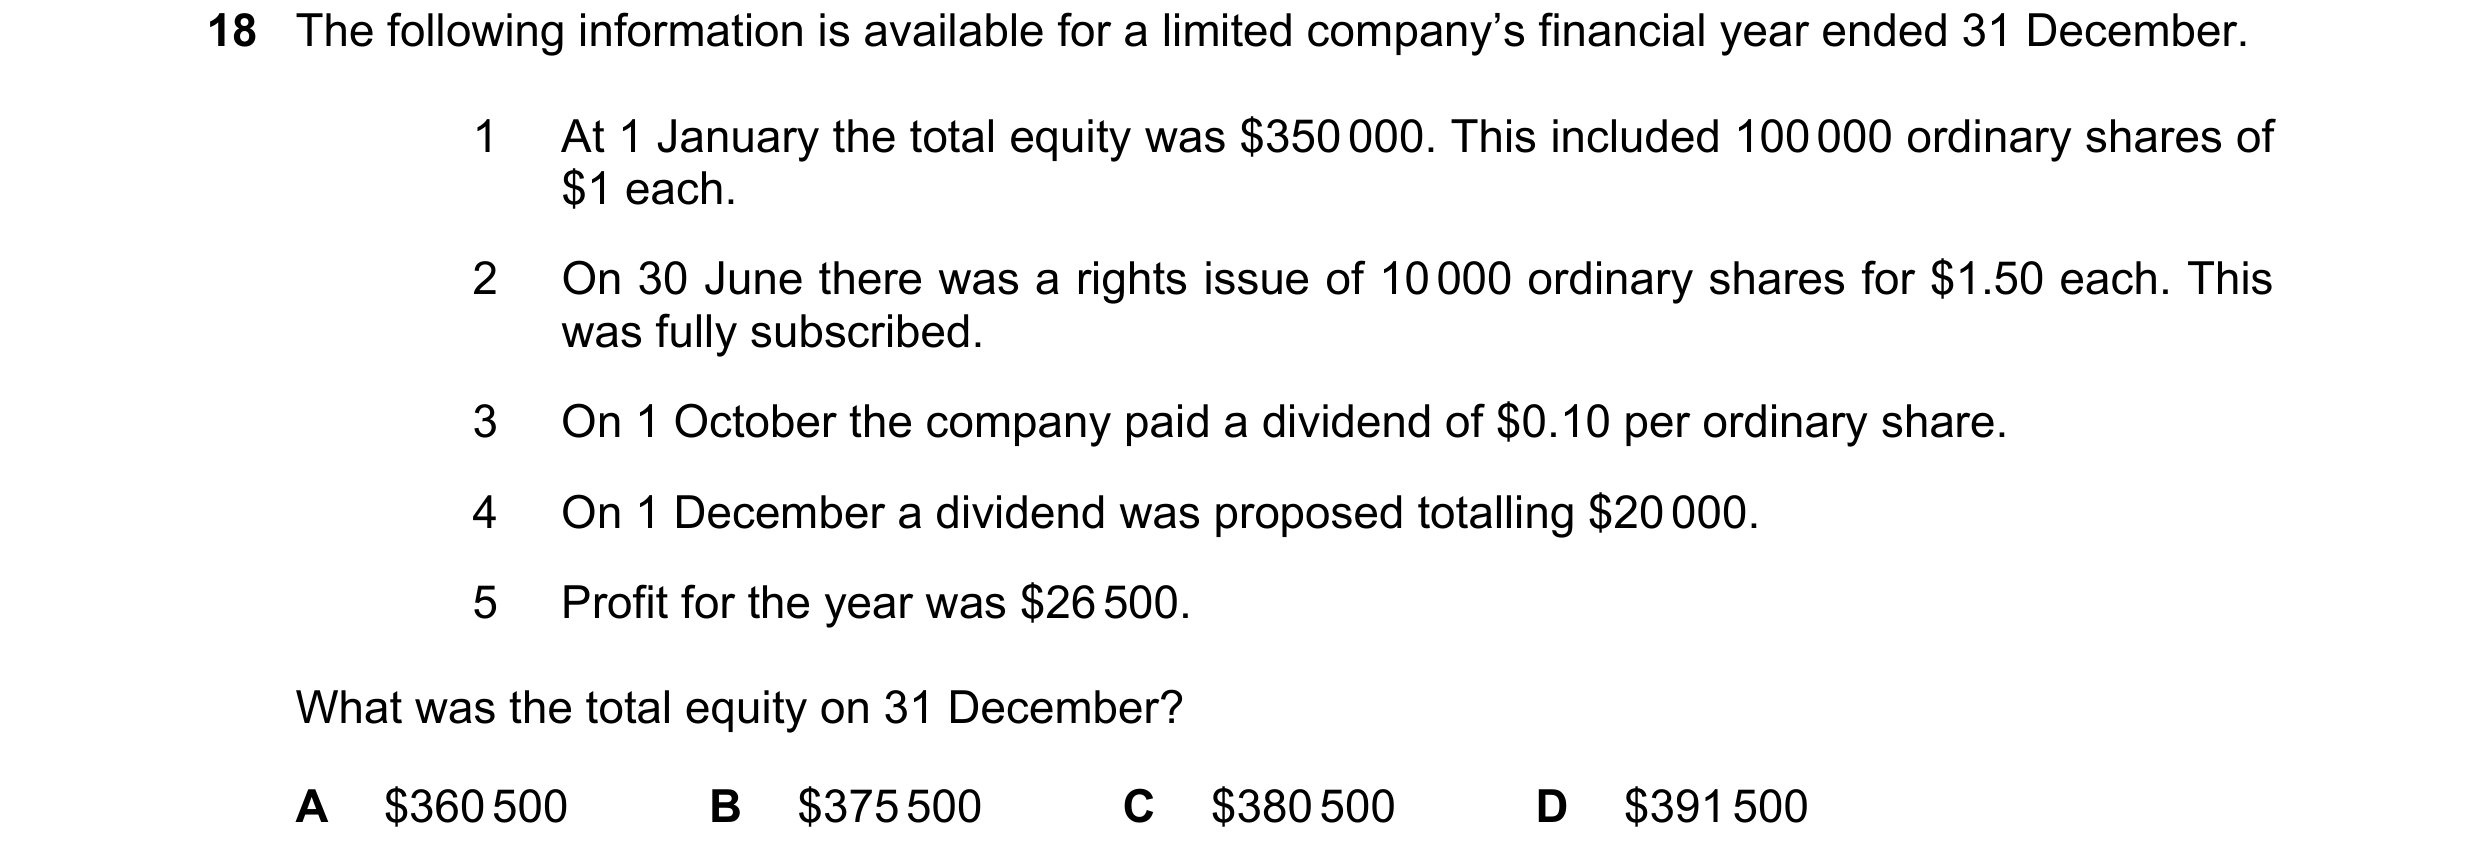
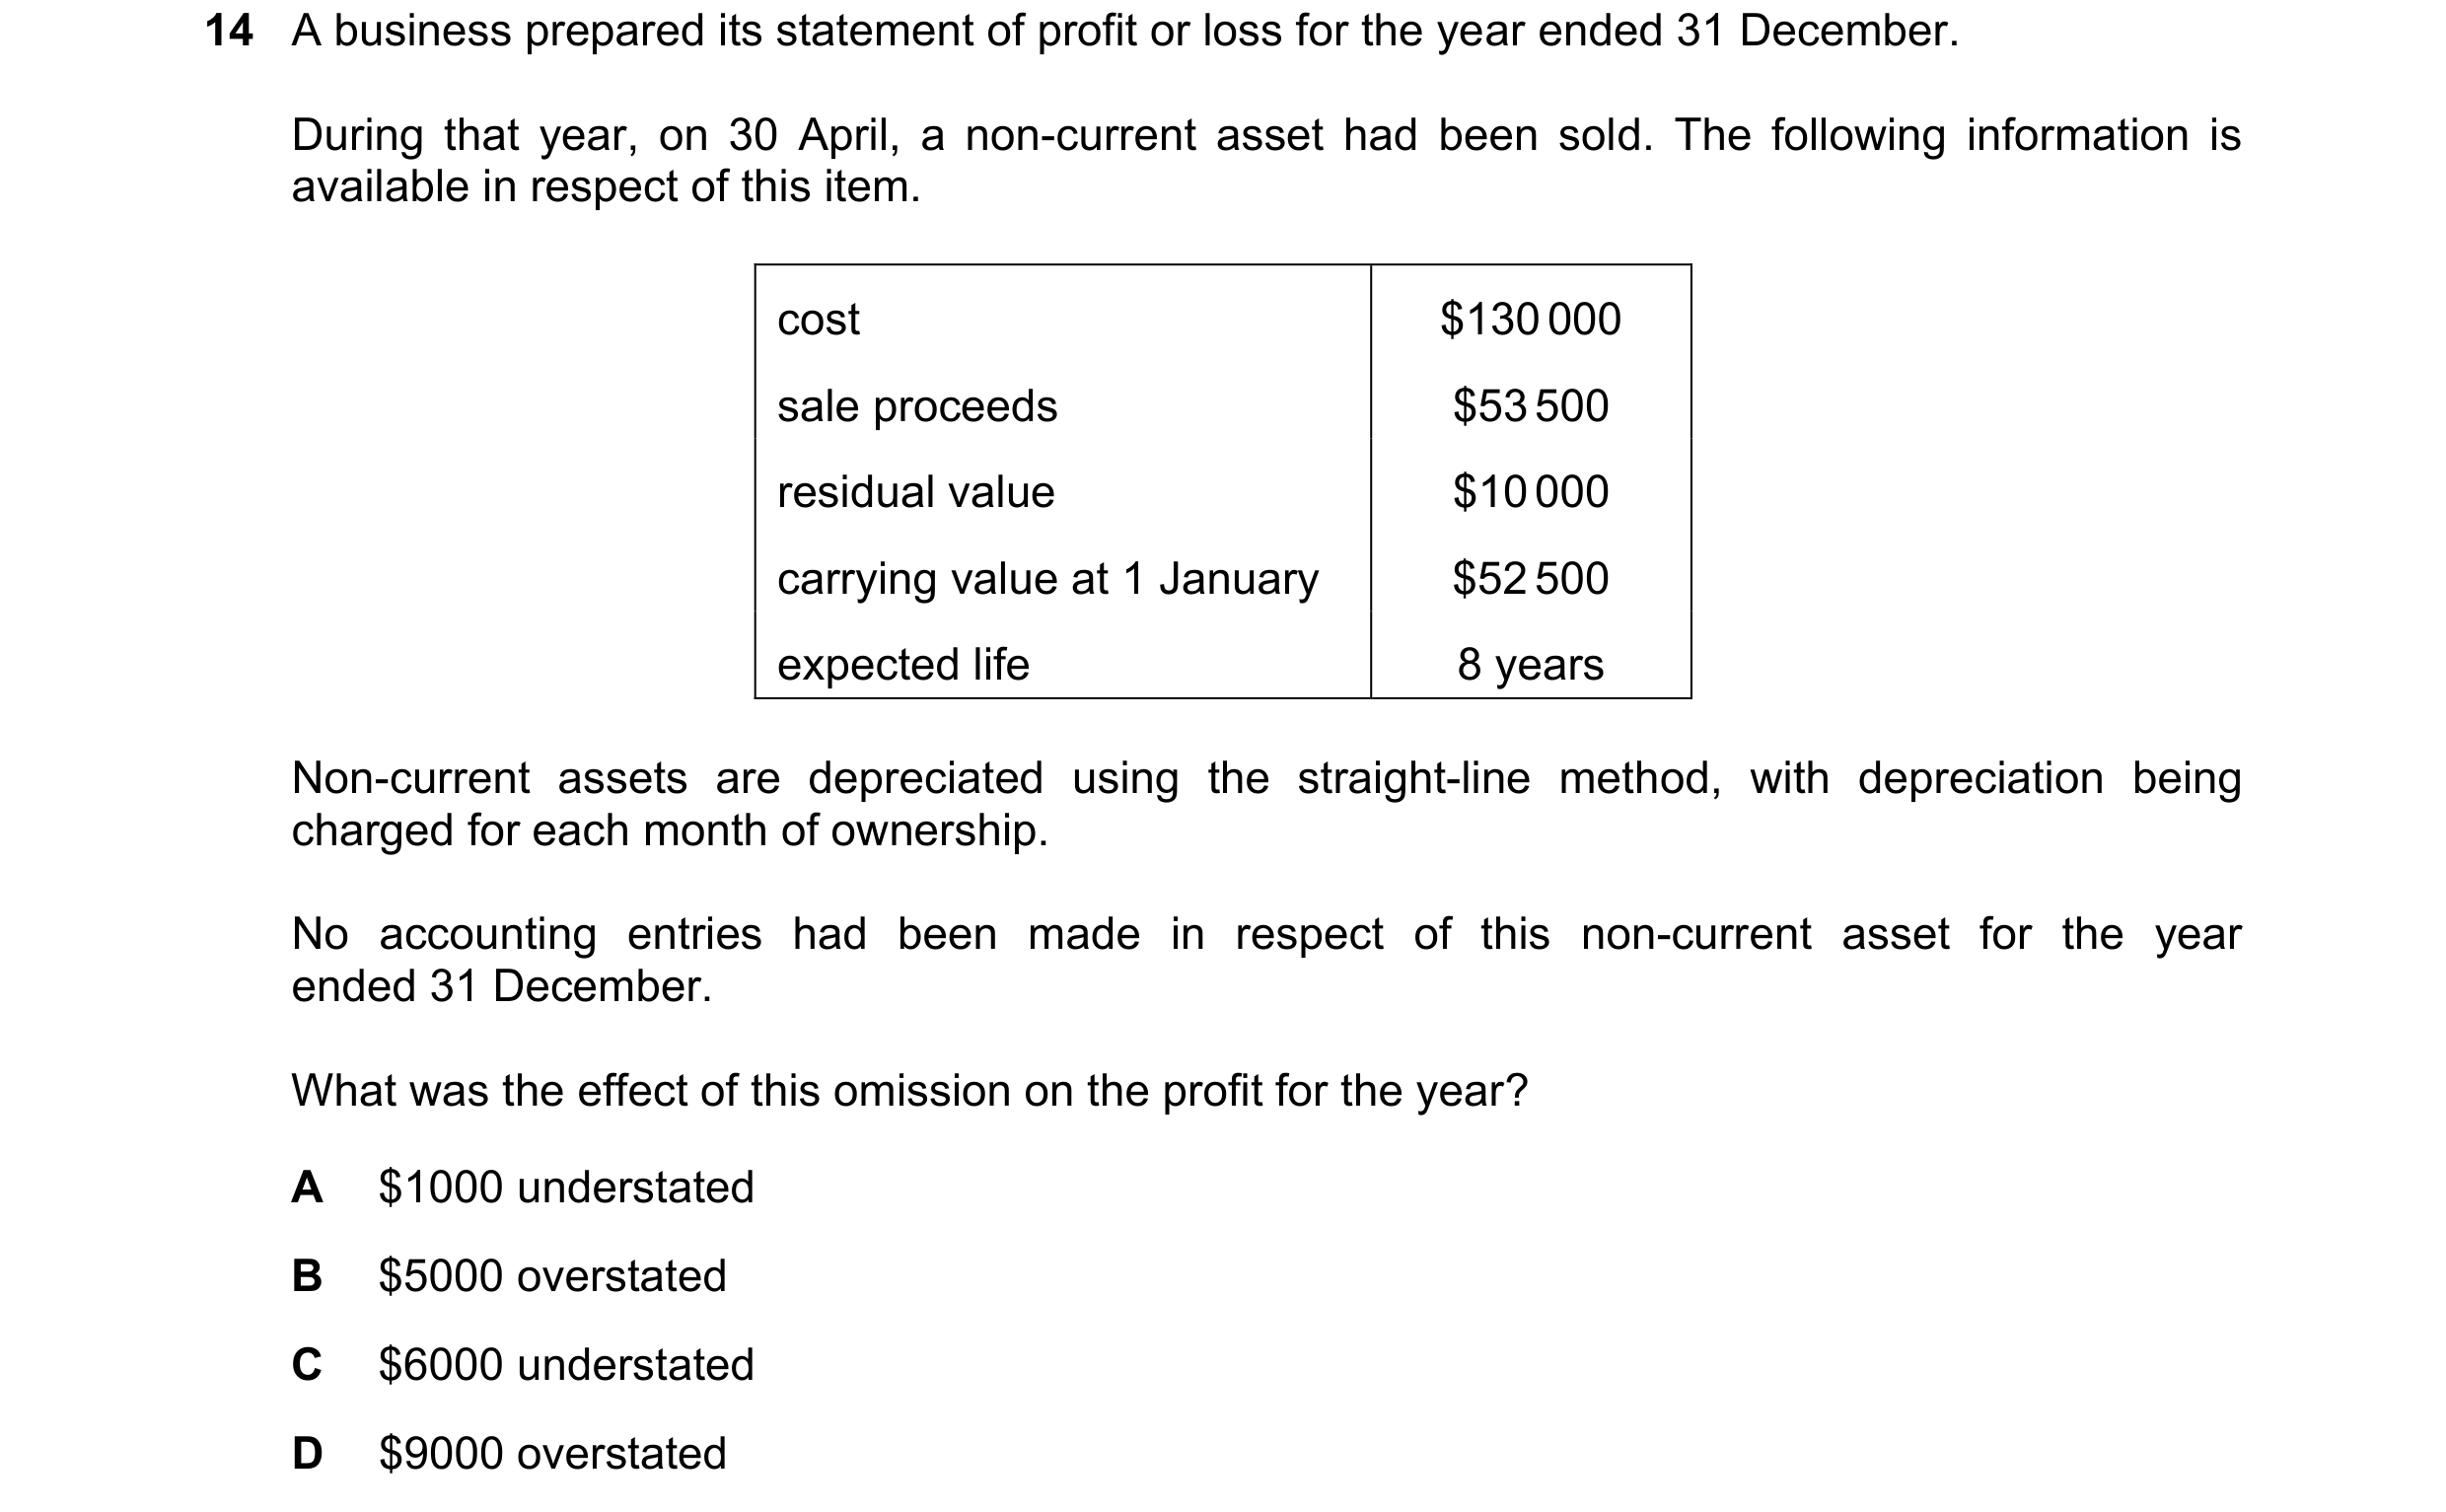
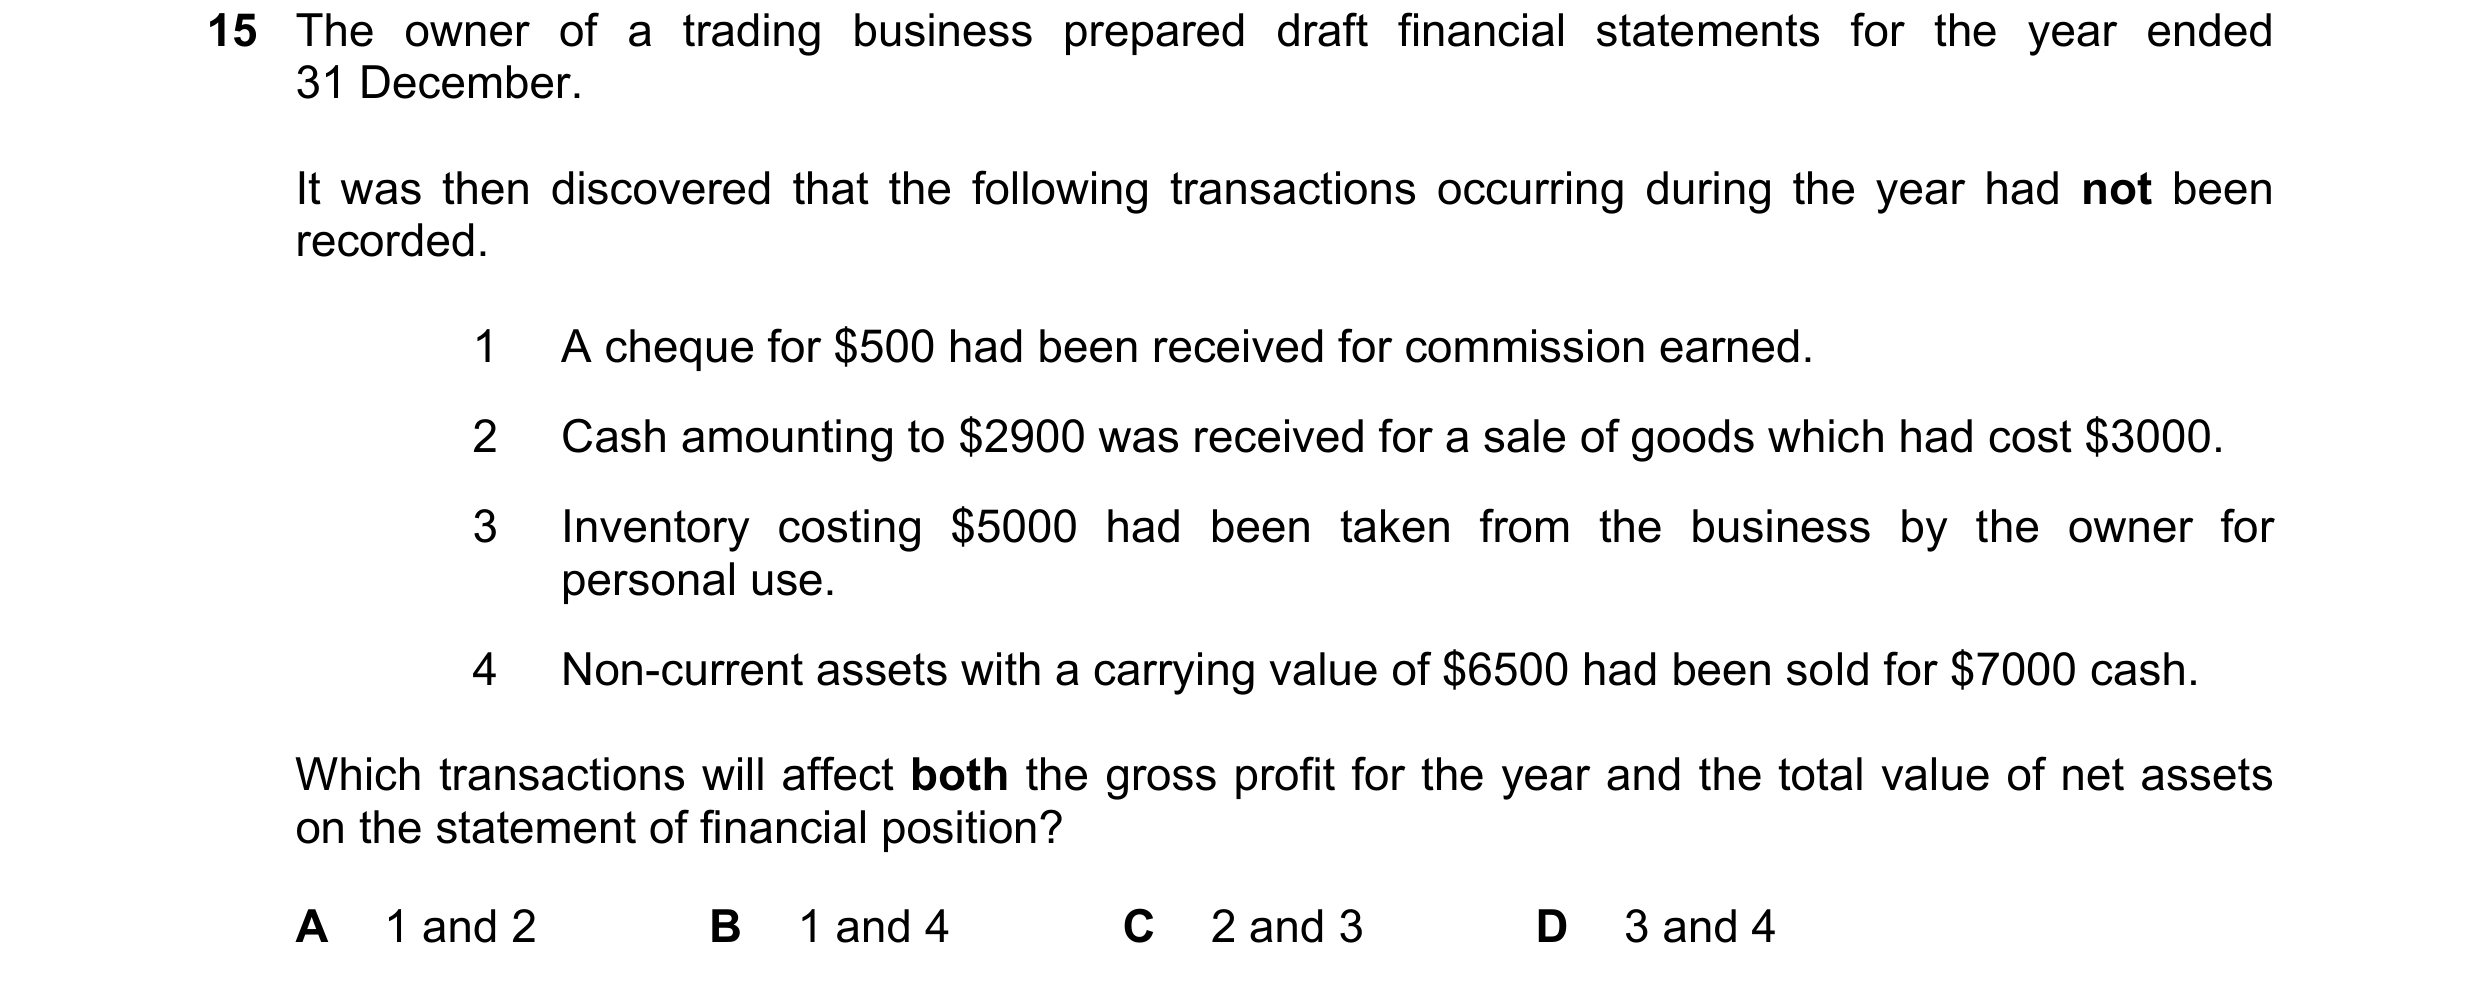 207 / 233
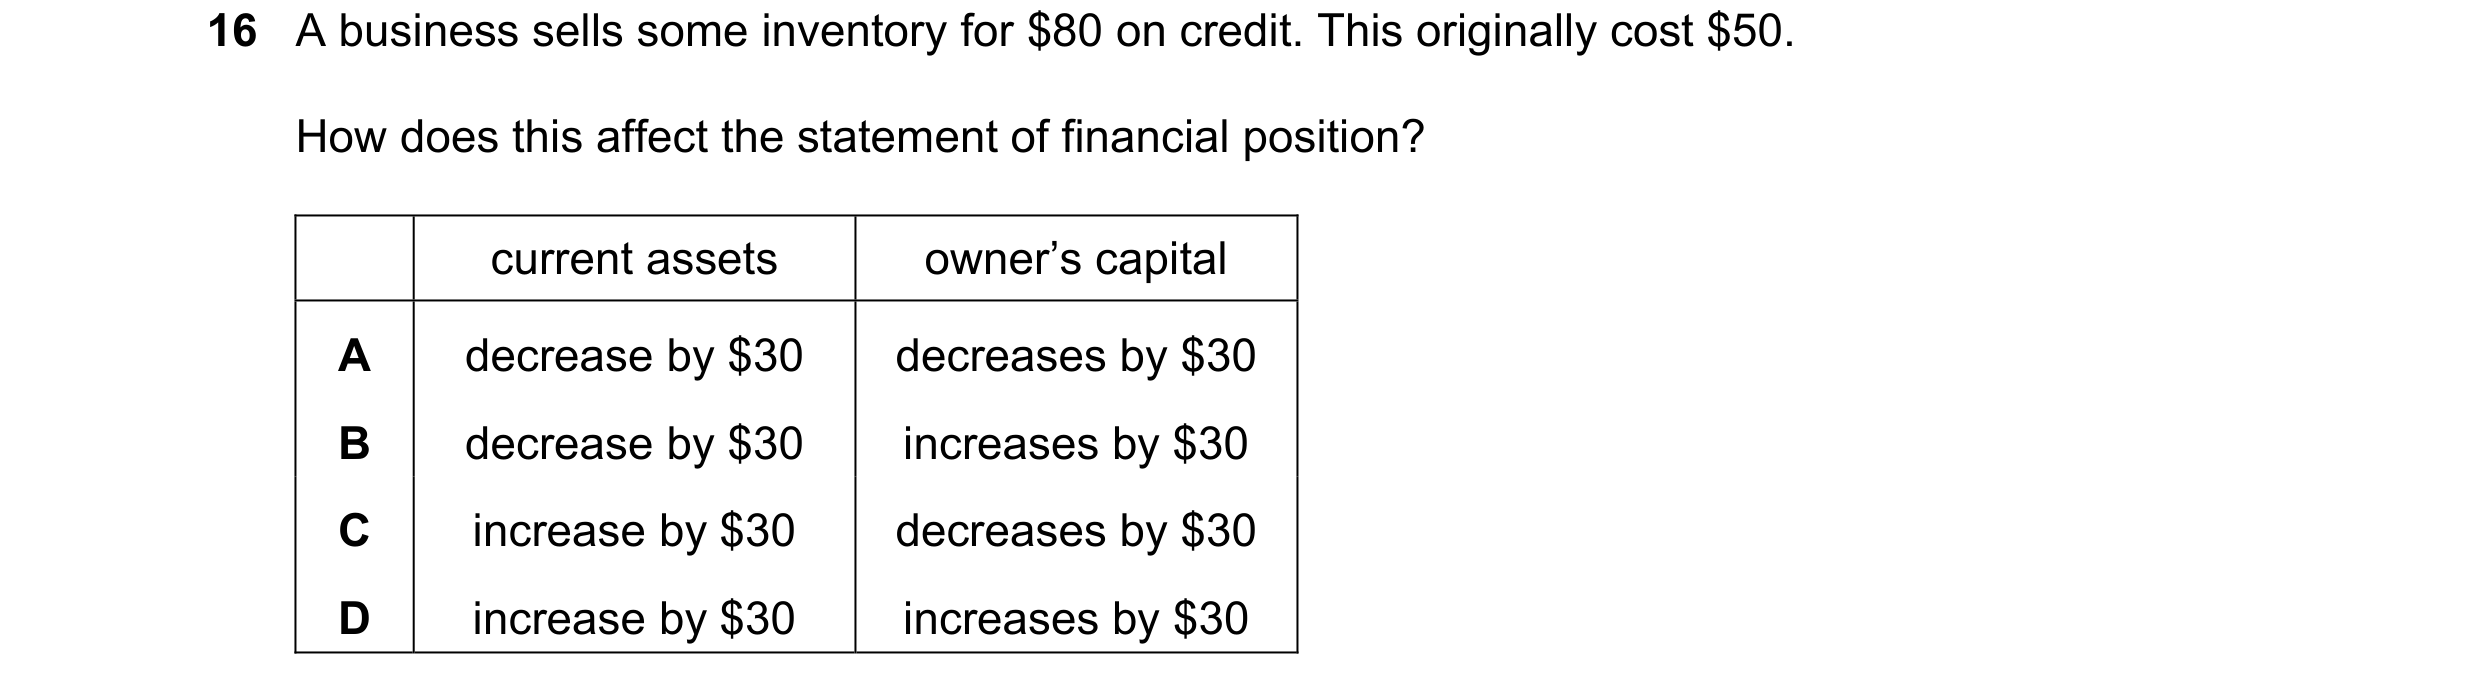
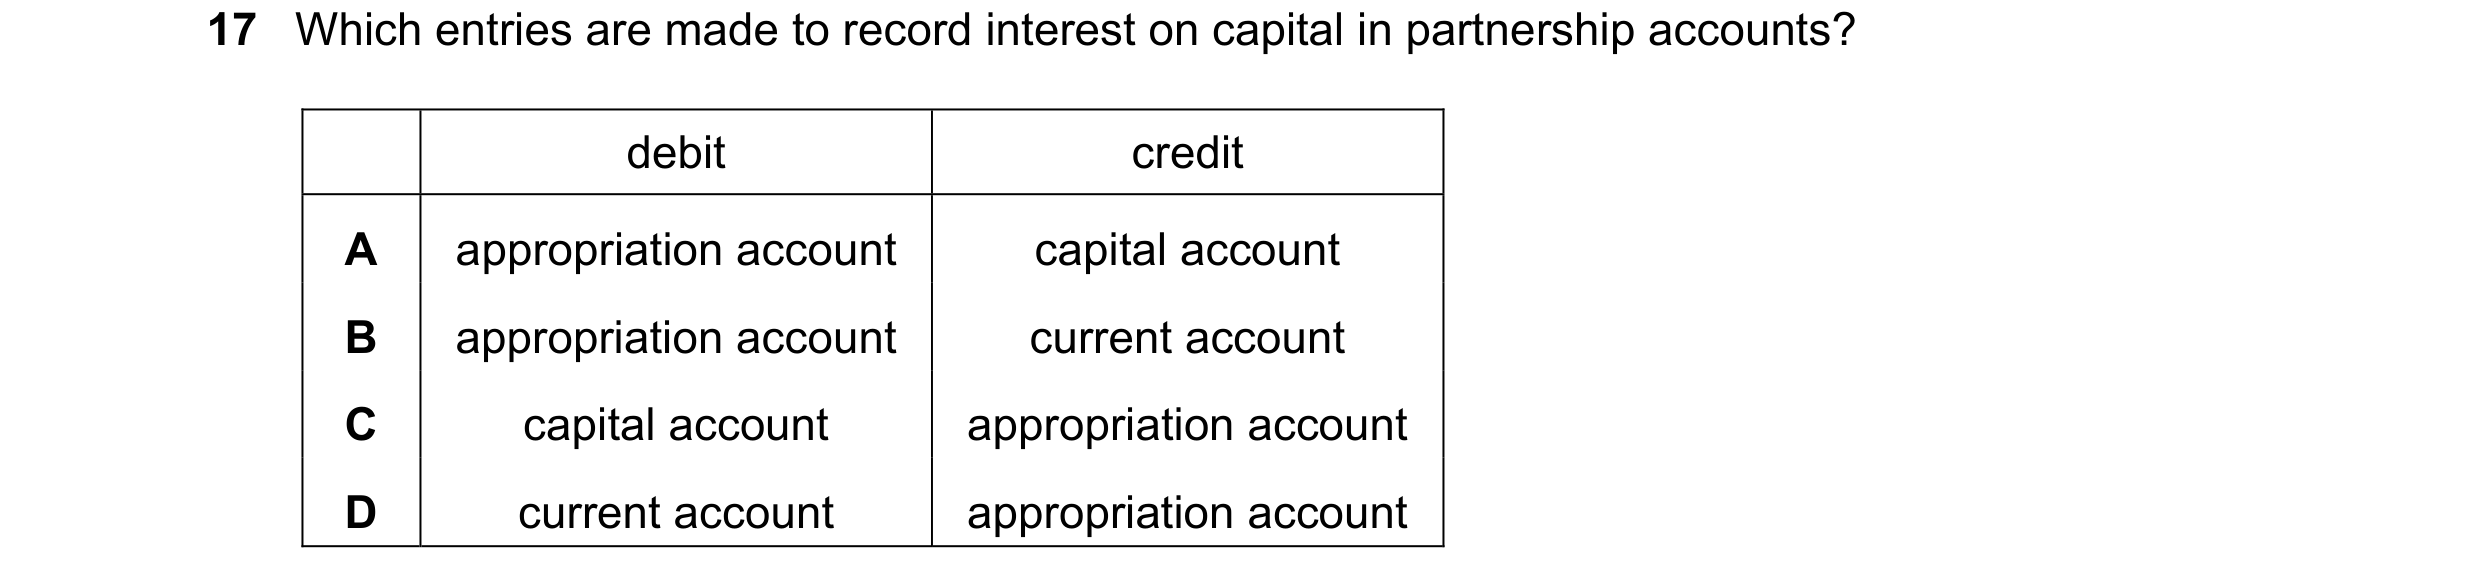
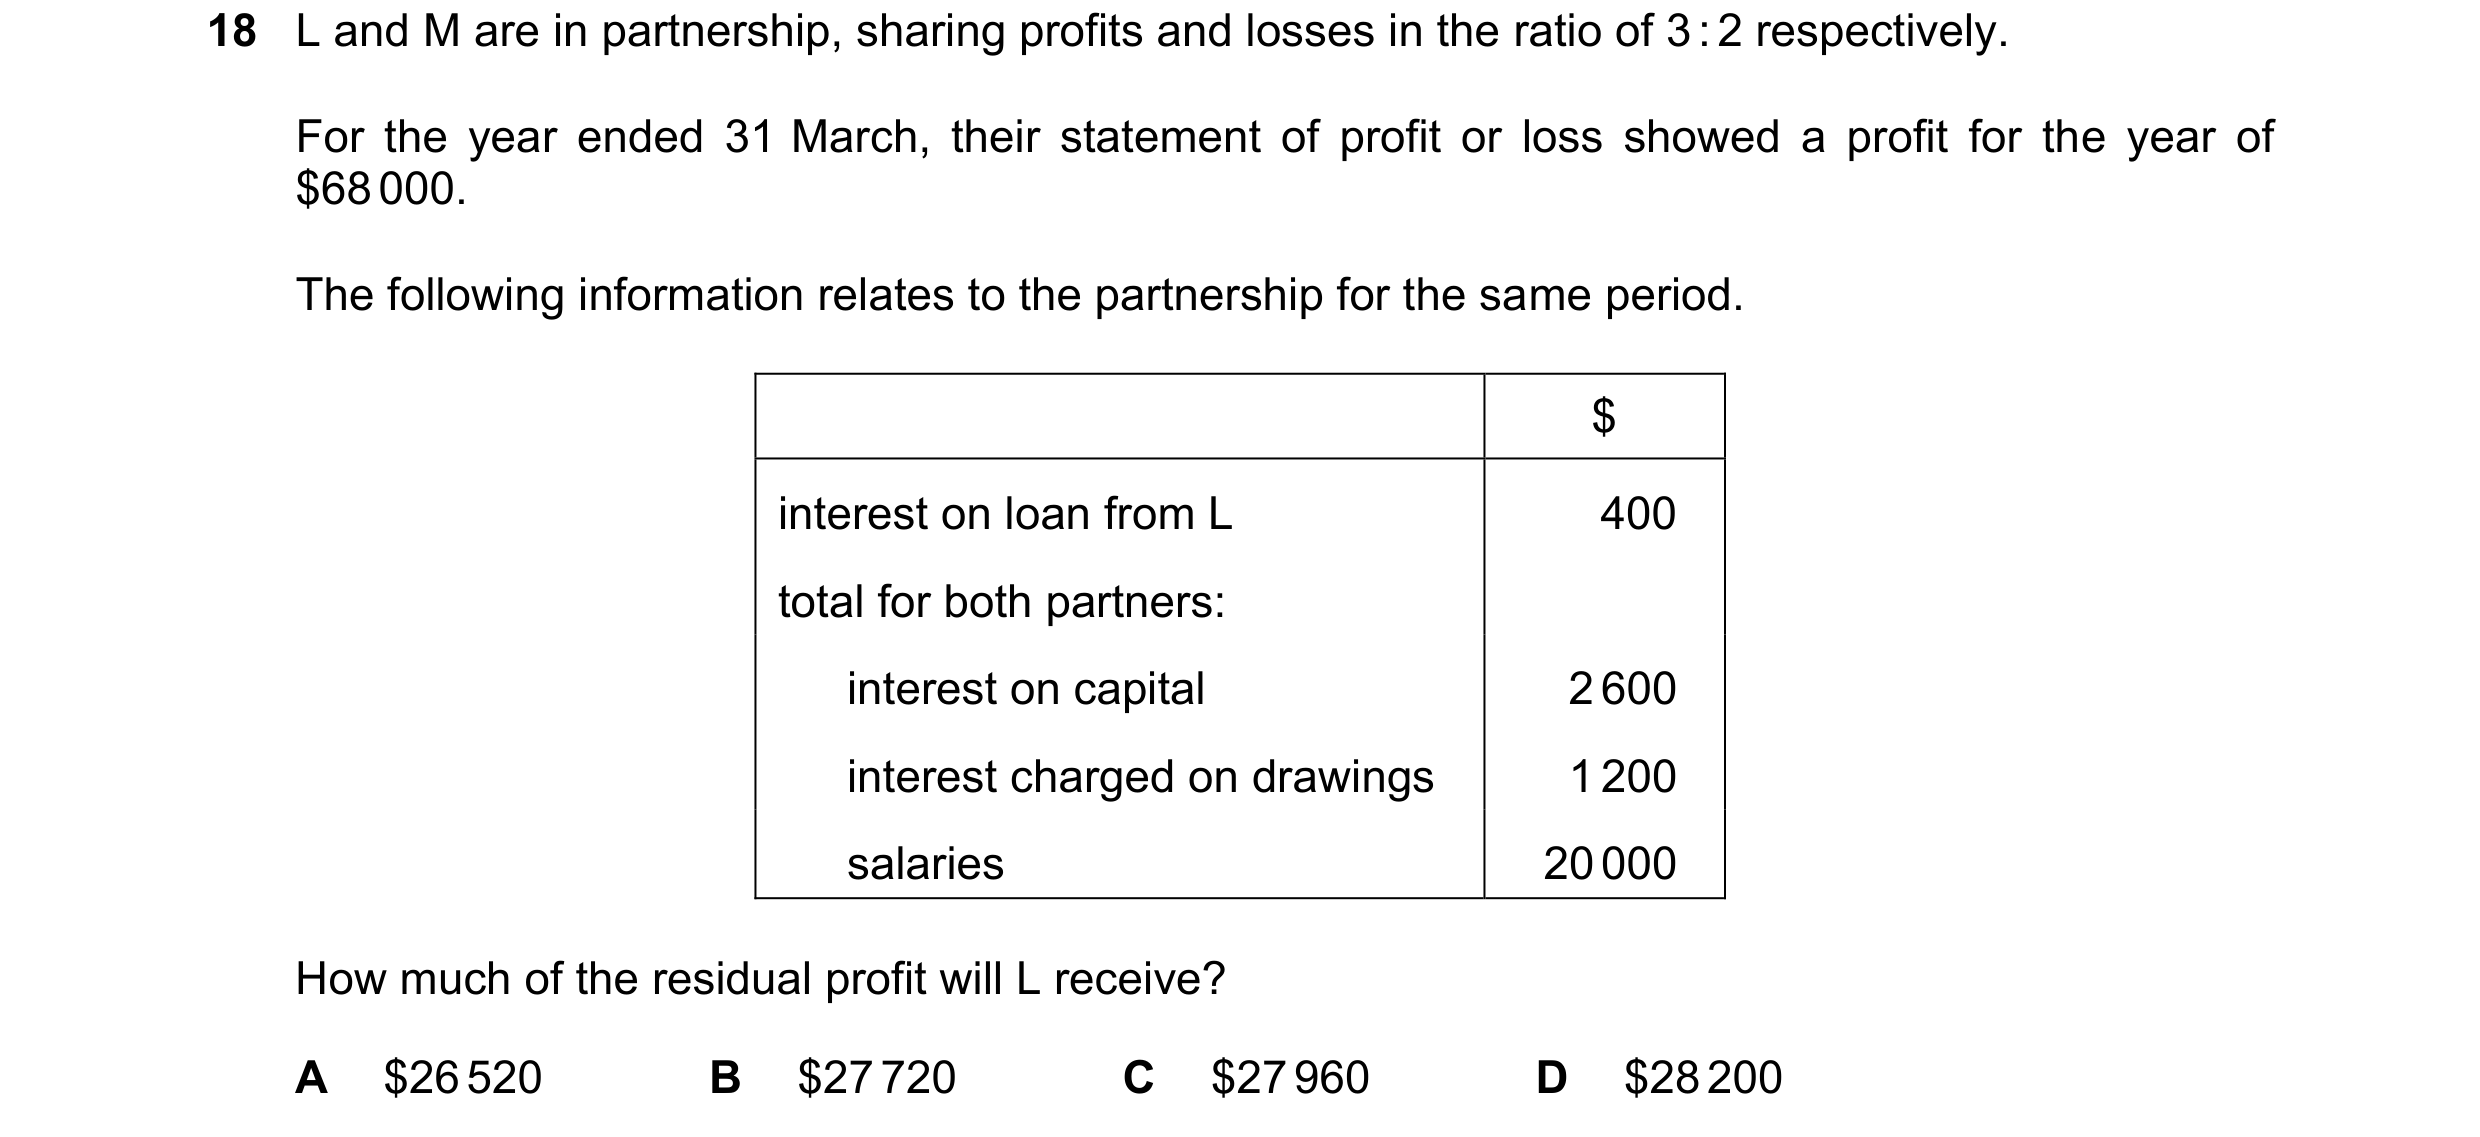 208 / 233
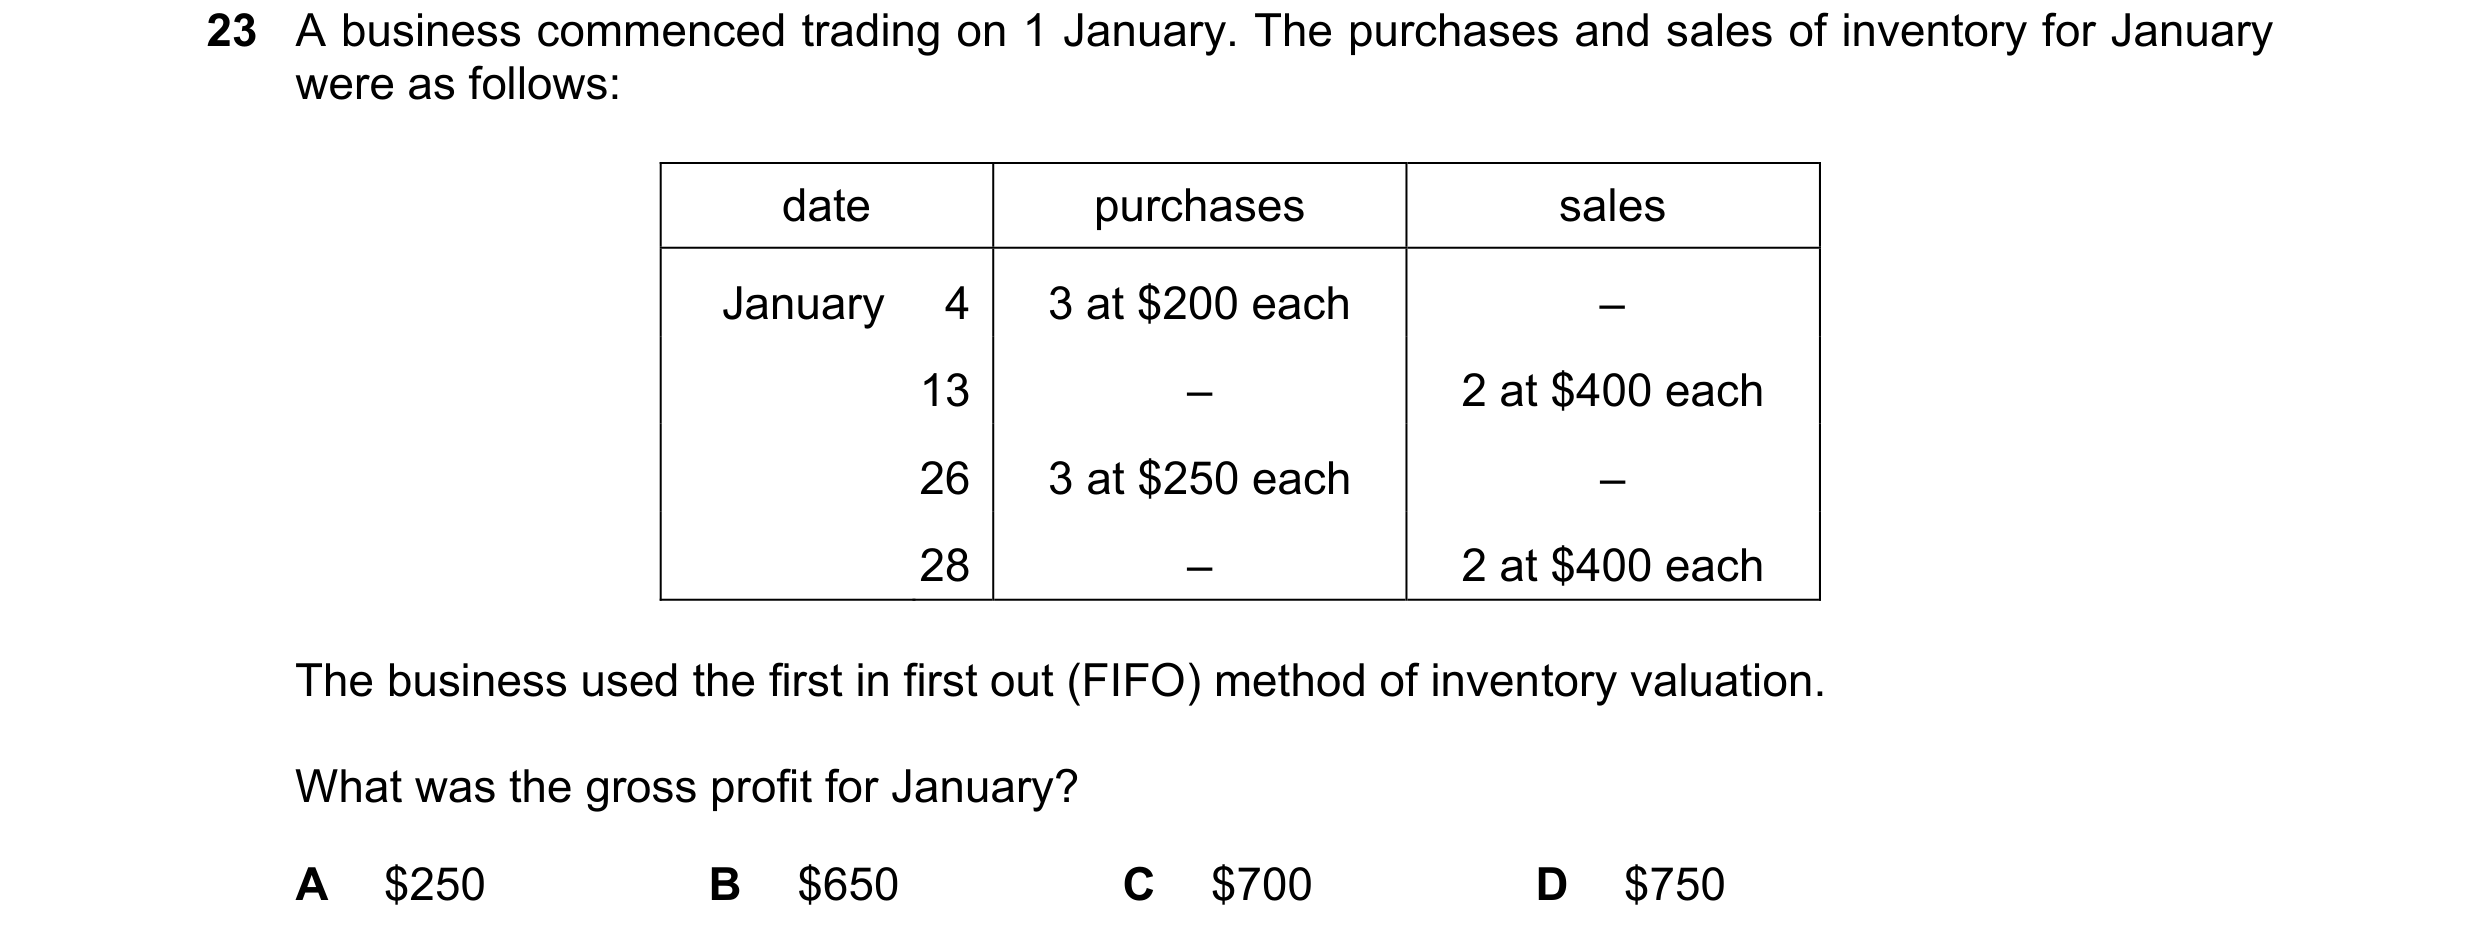
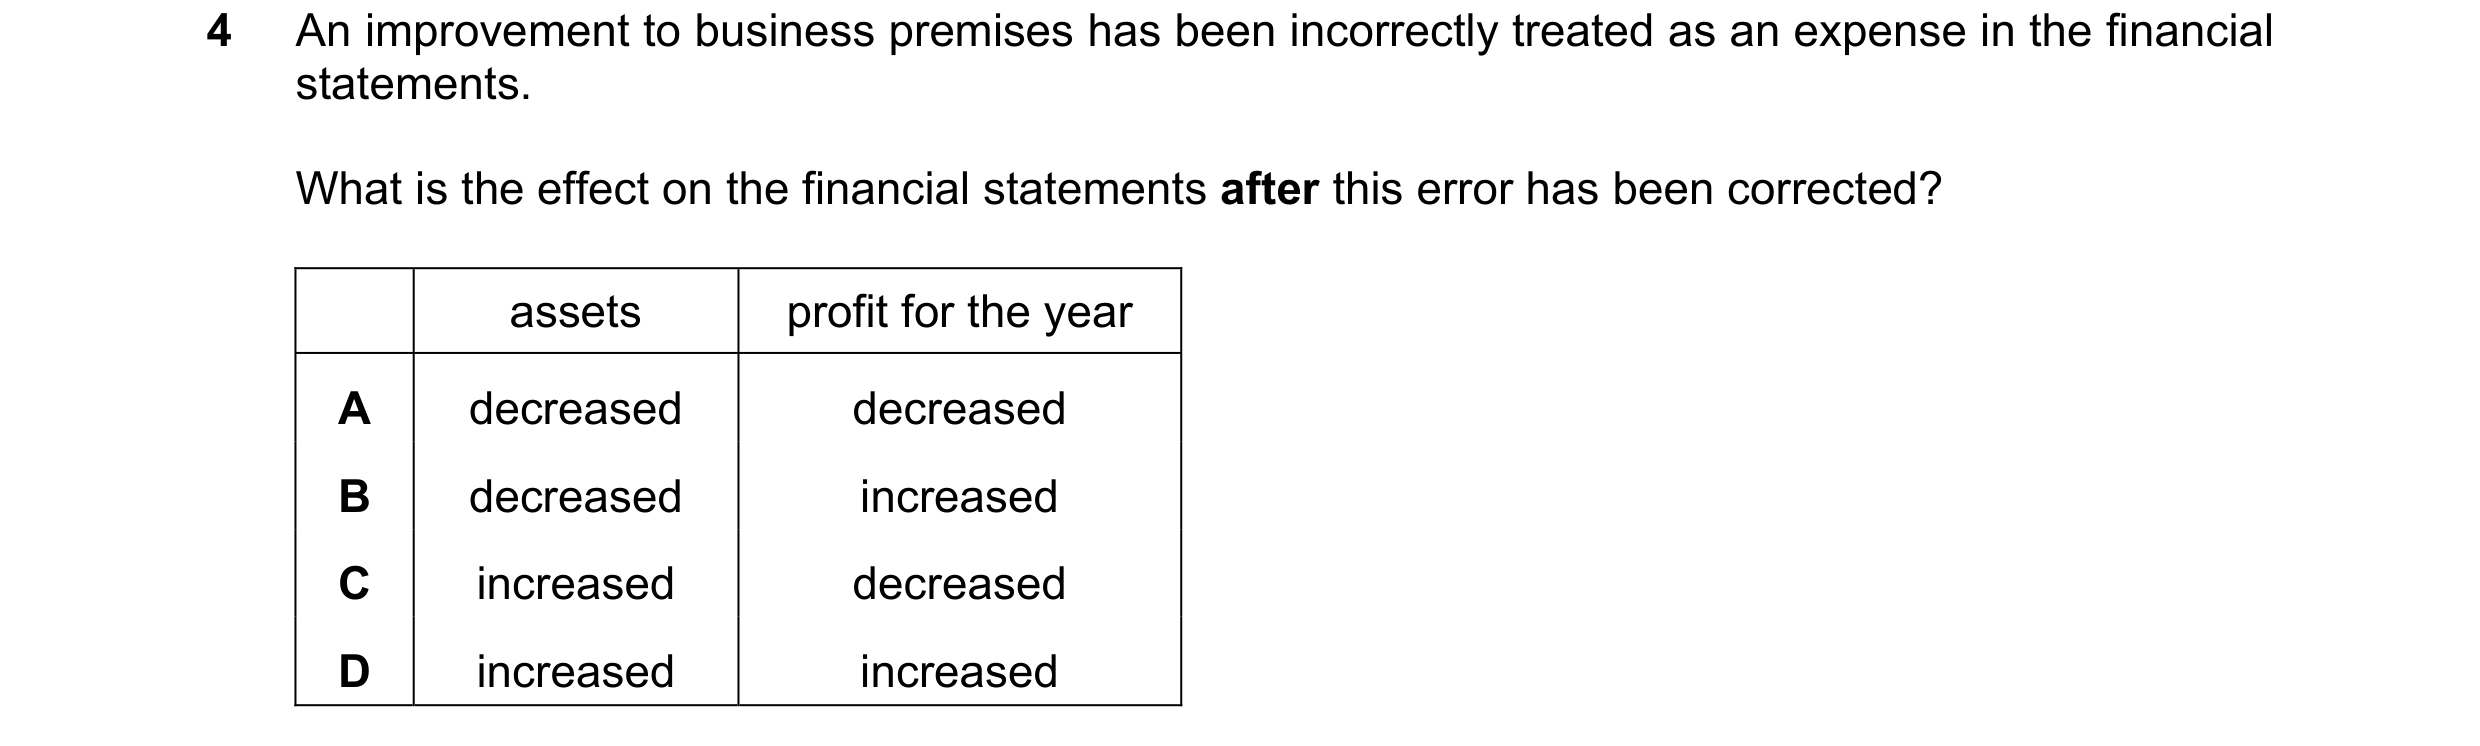
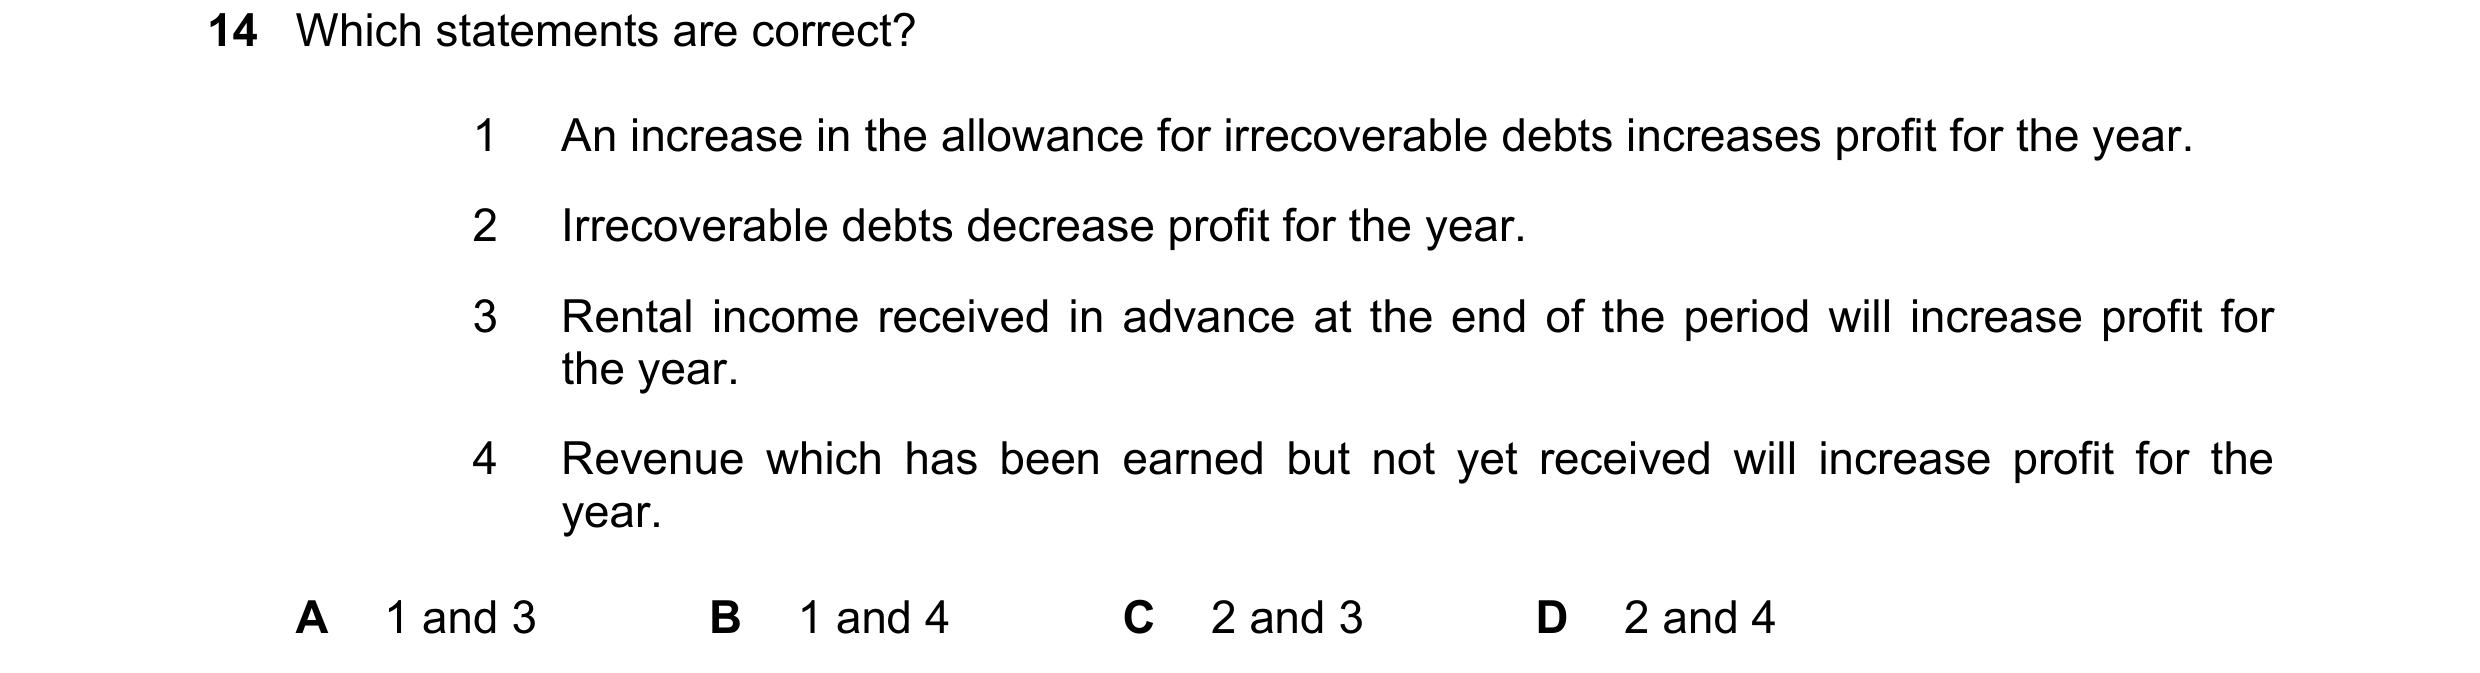 209 / 233
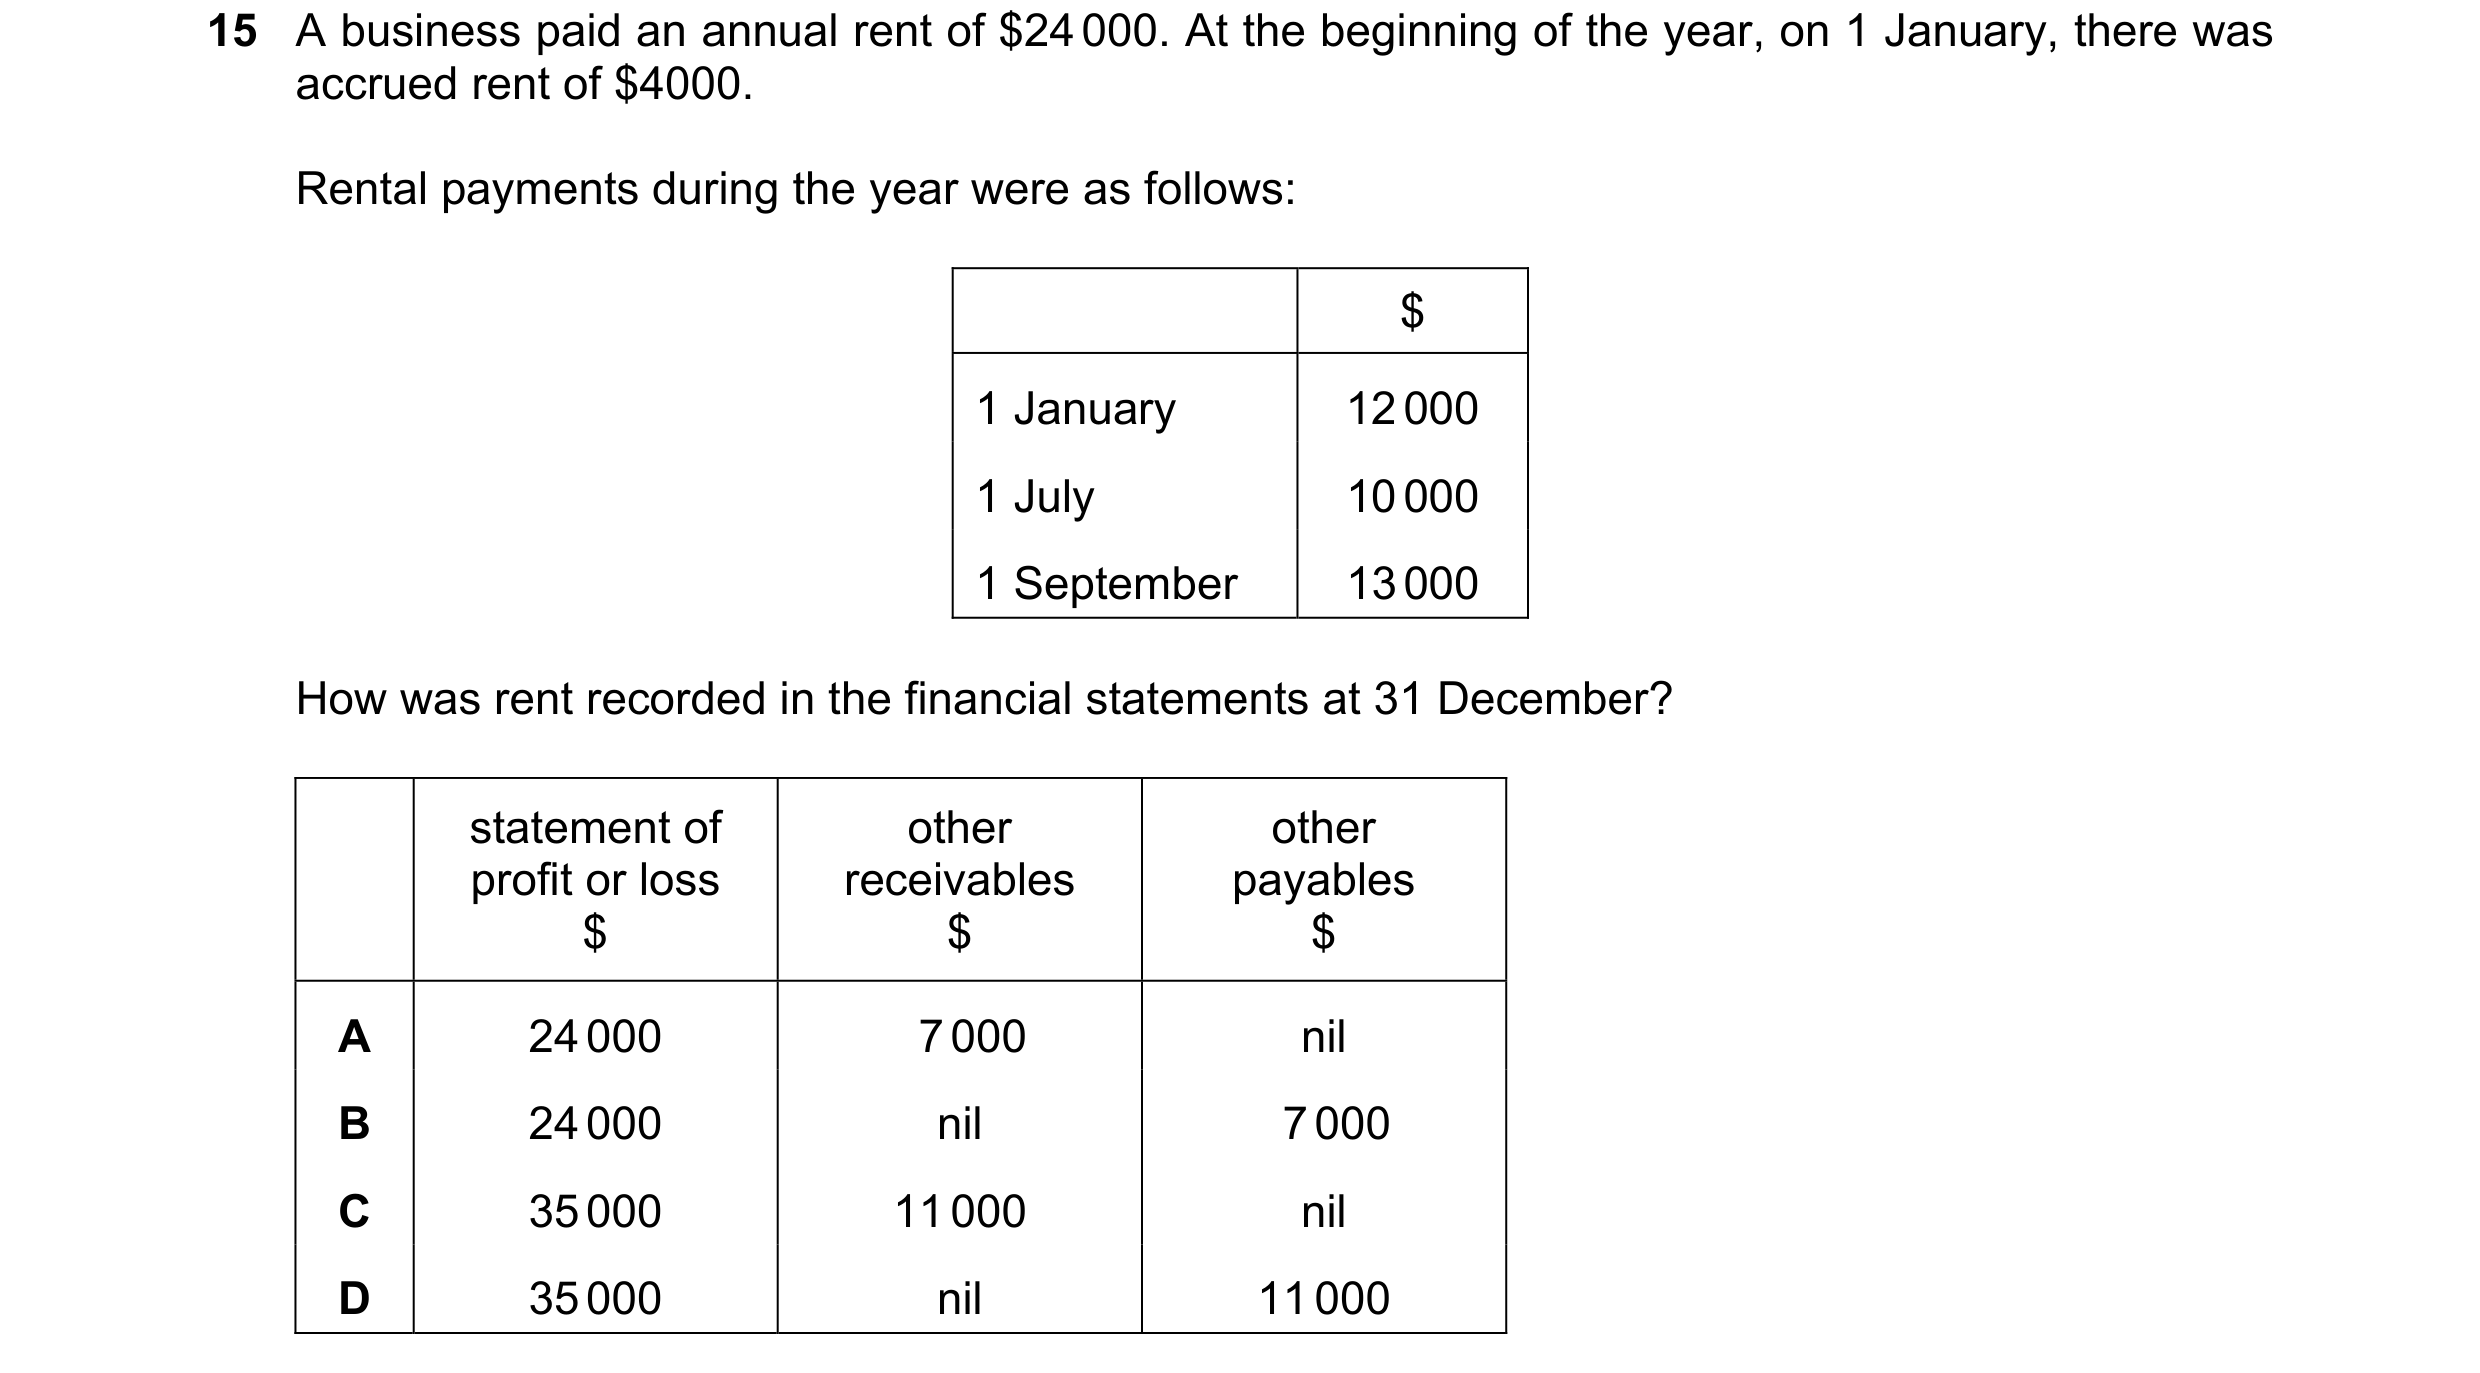
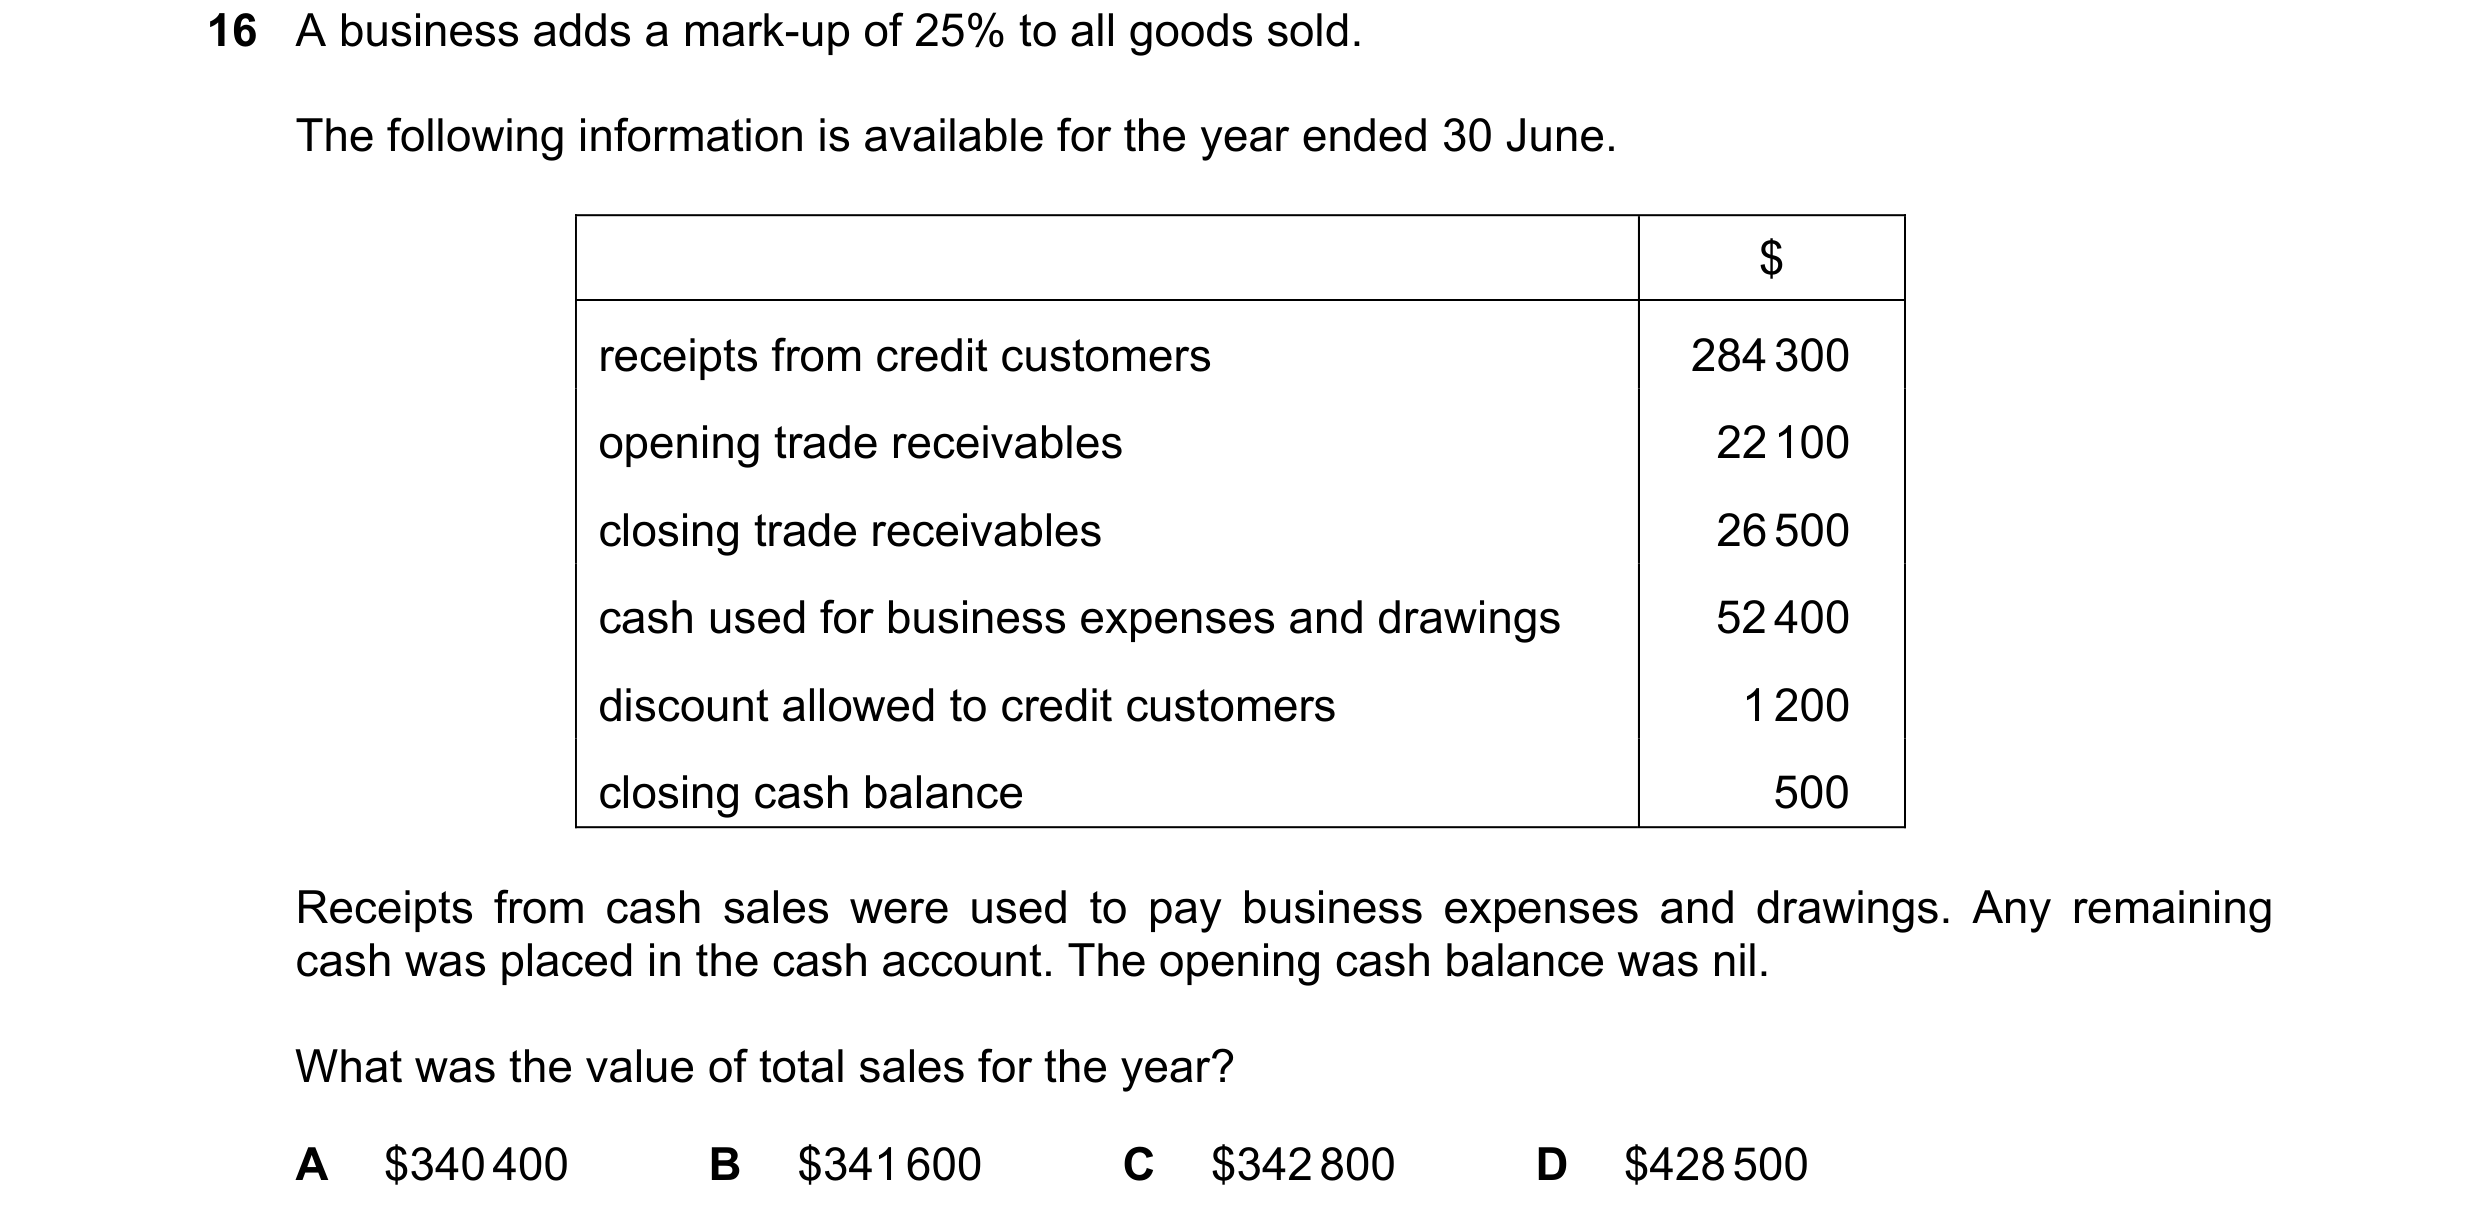
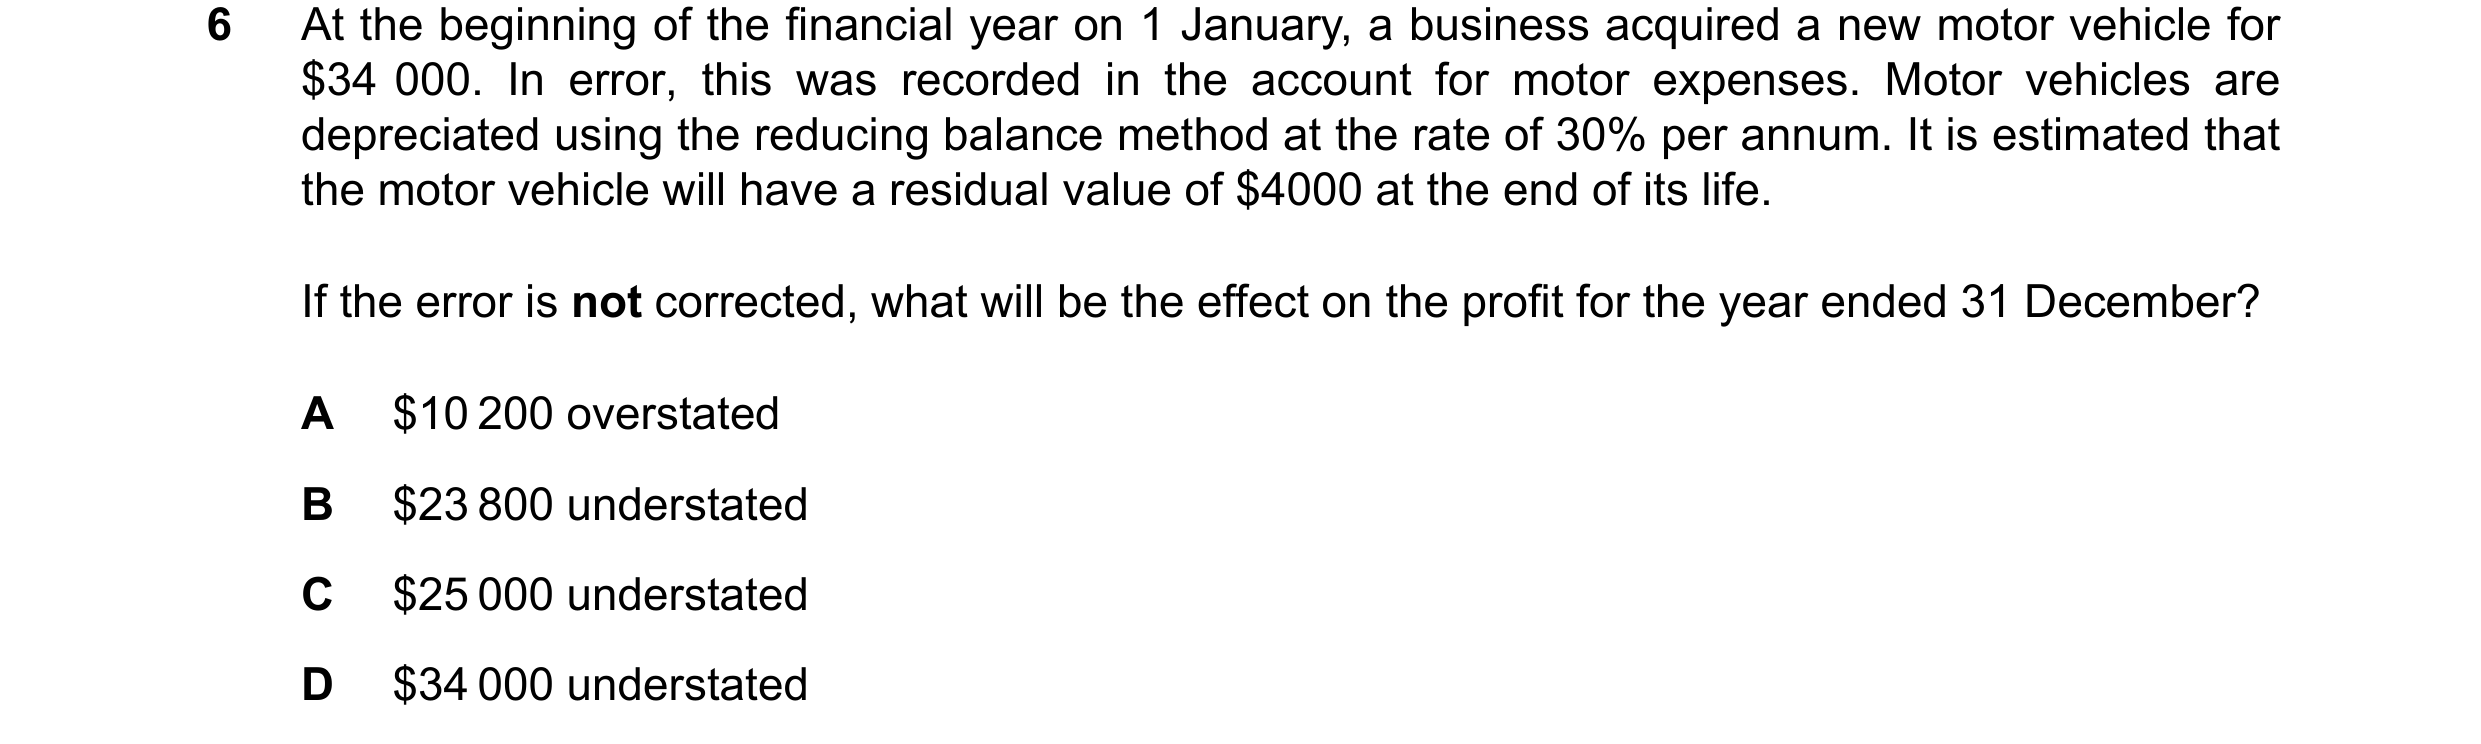 210 / 233
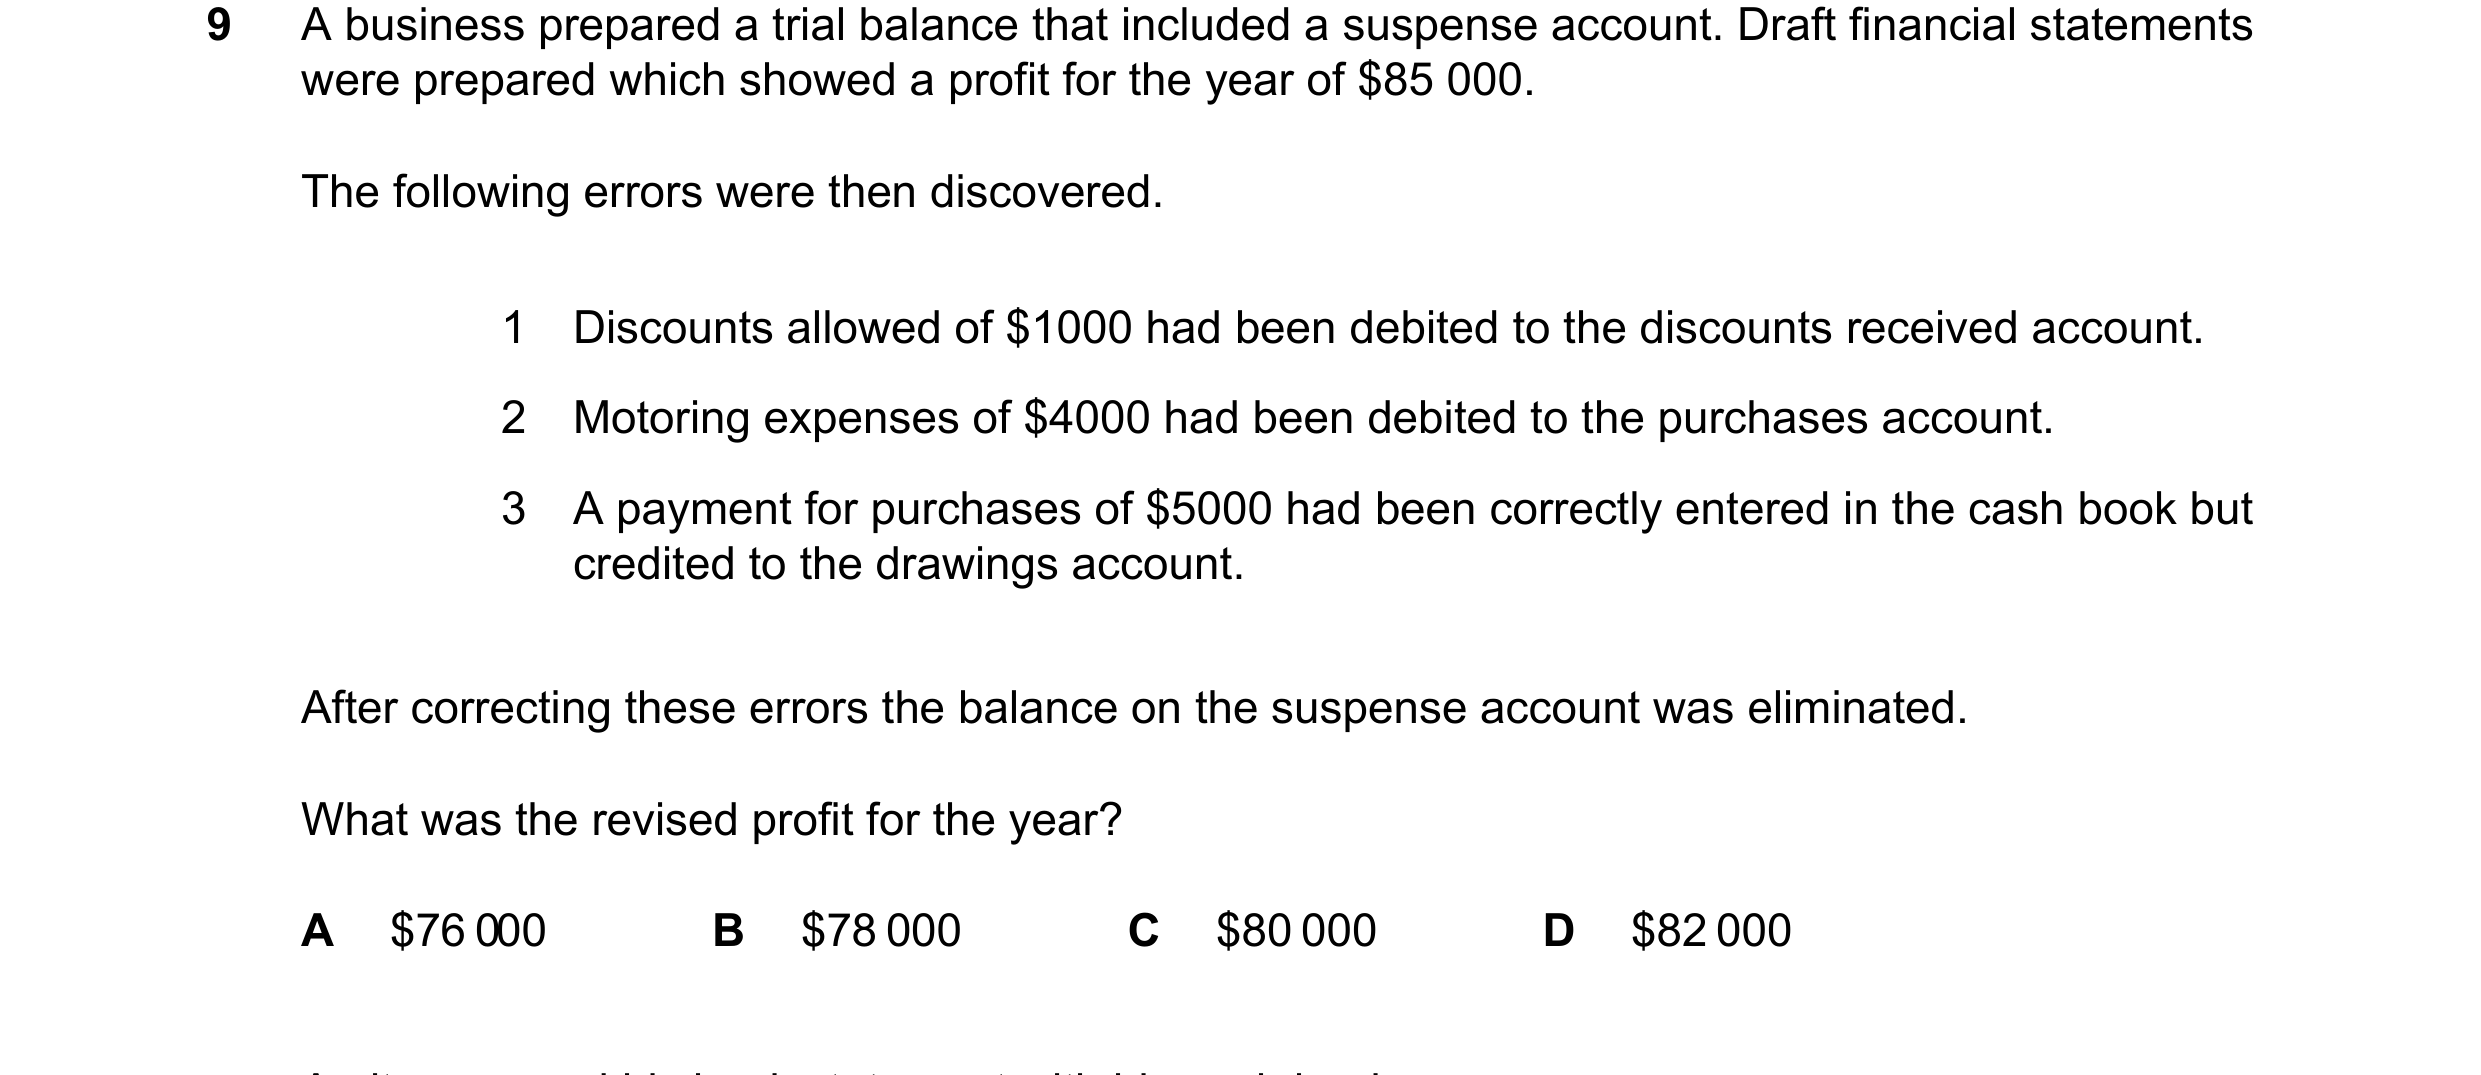
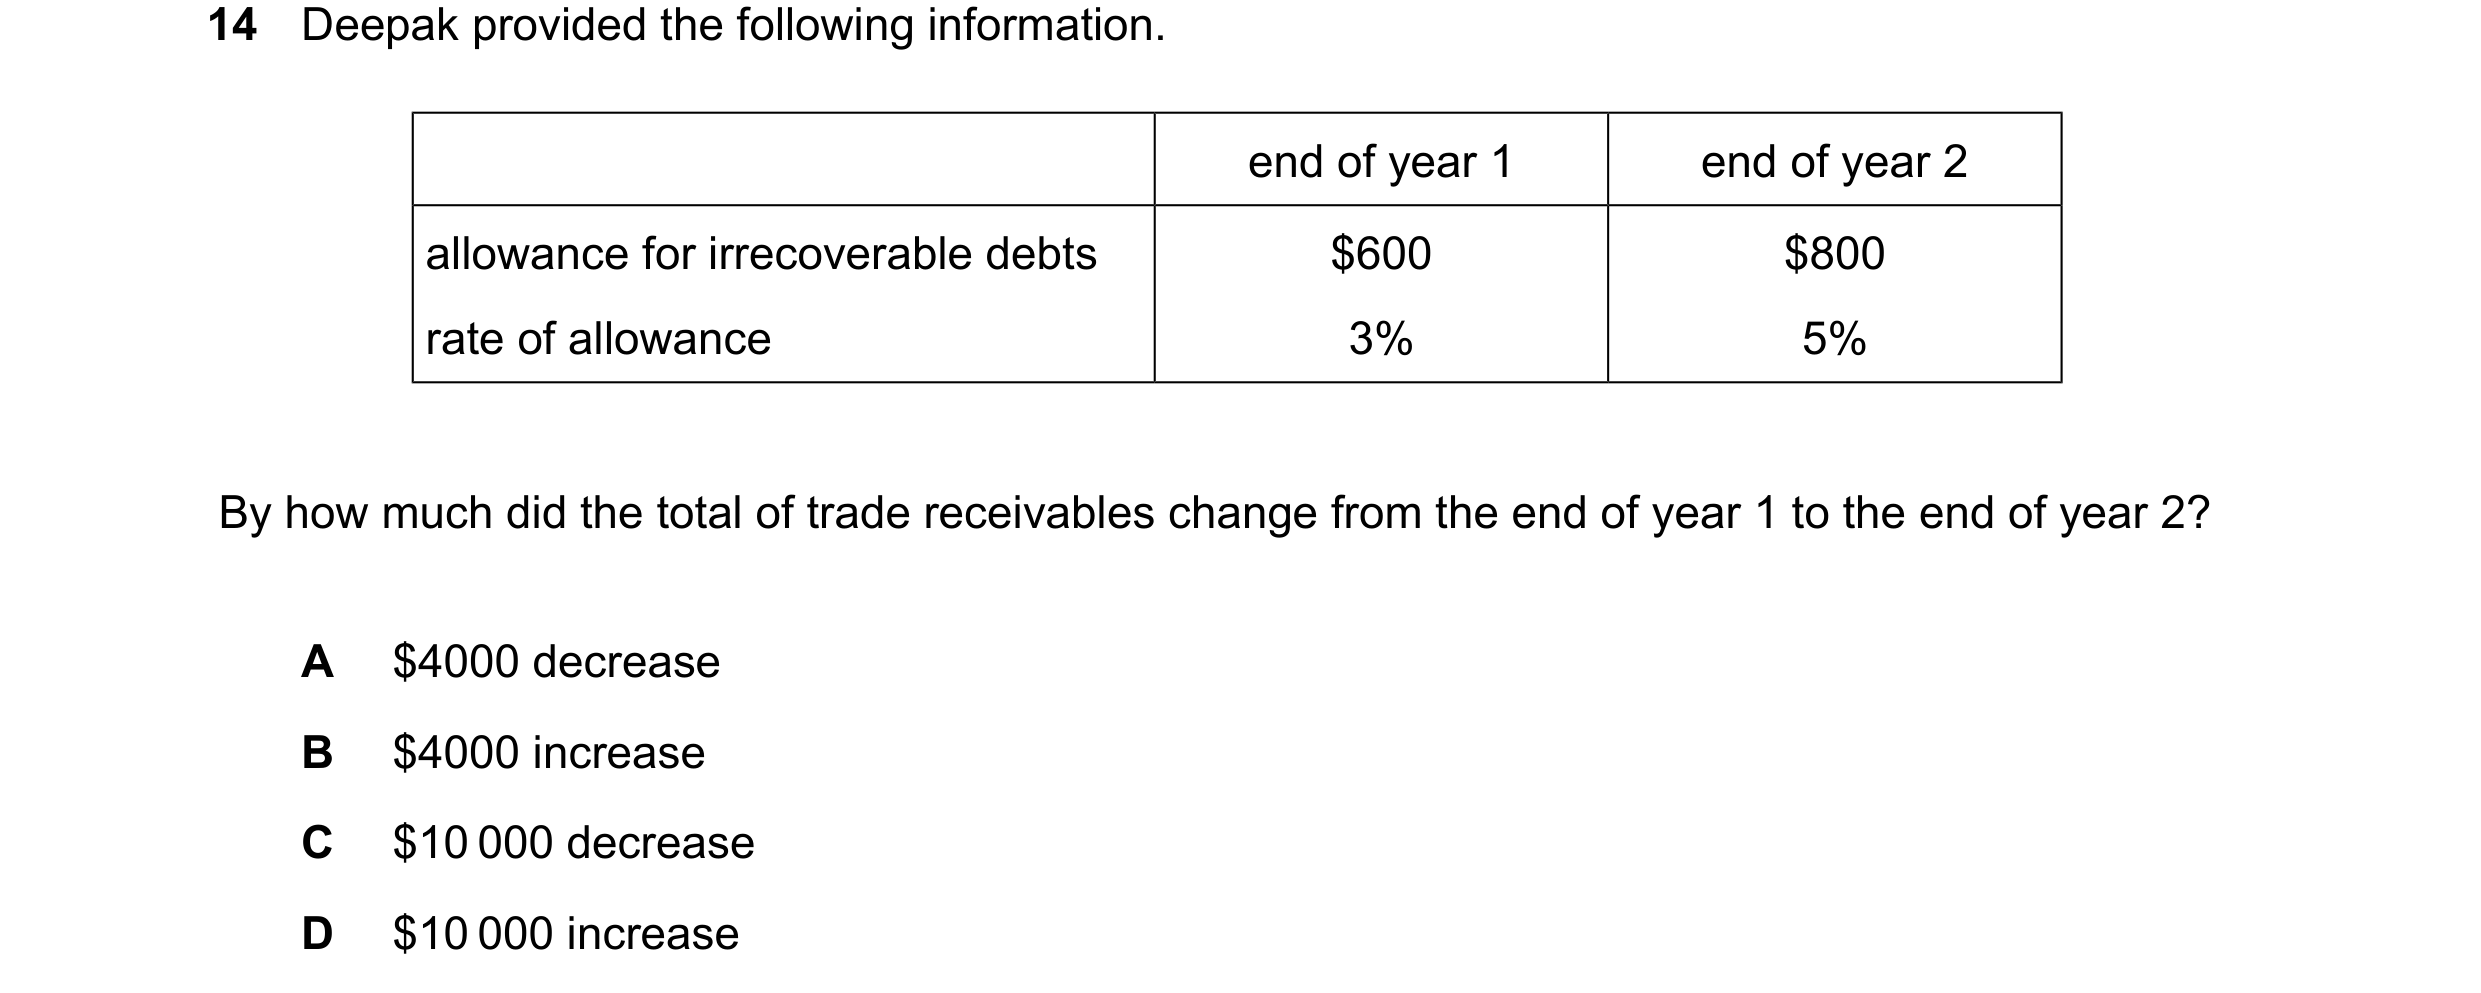
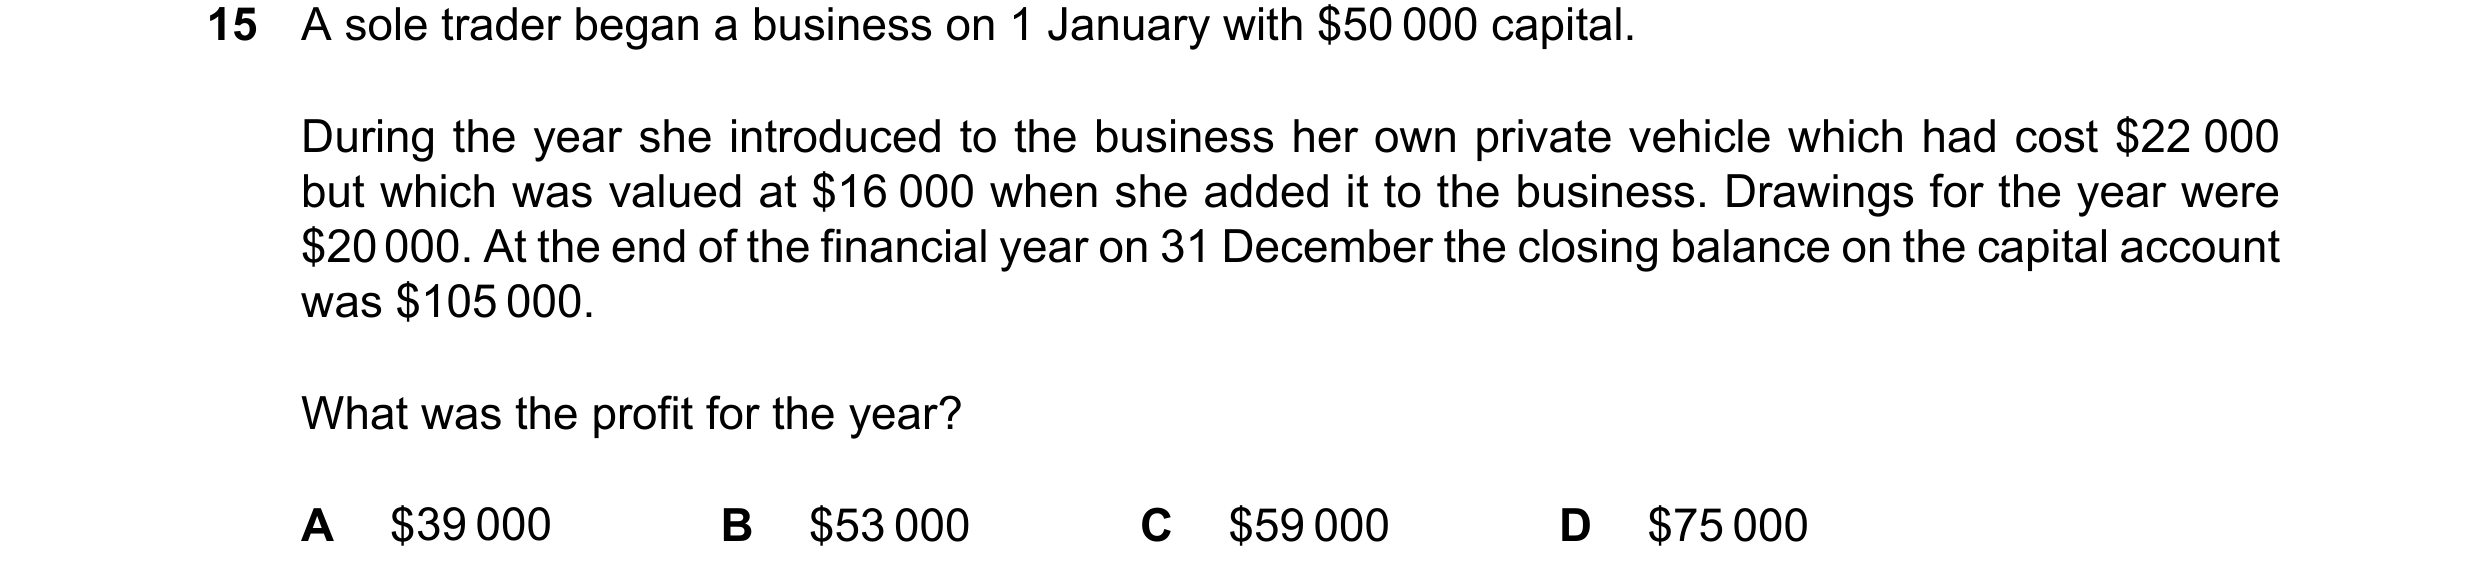 211 / 233
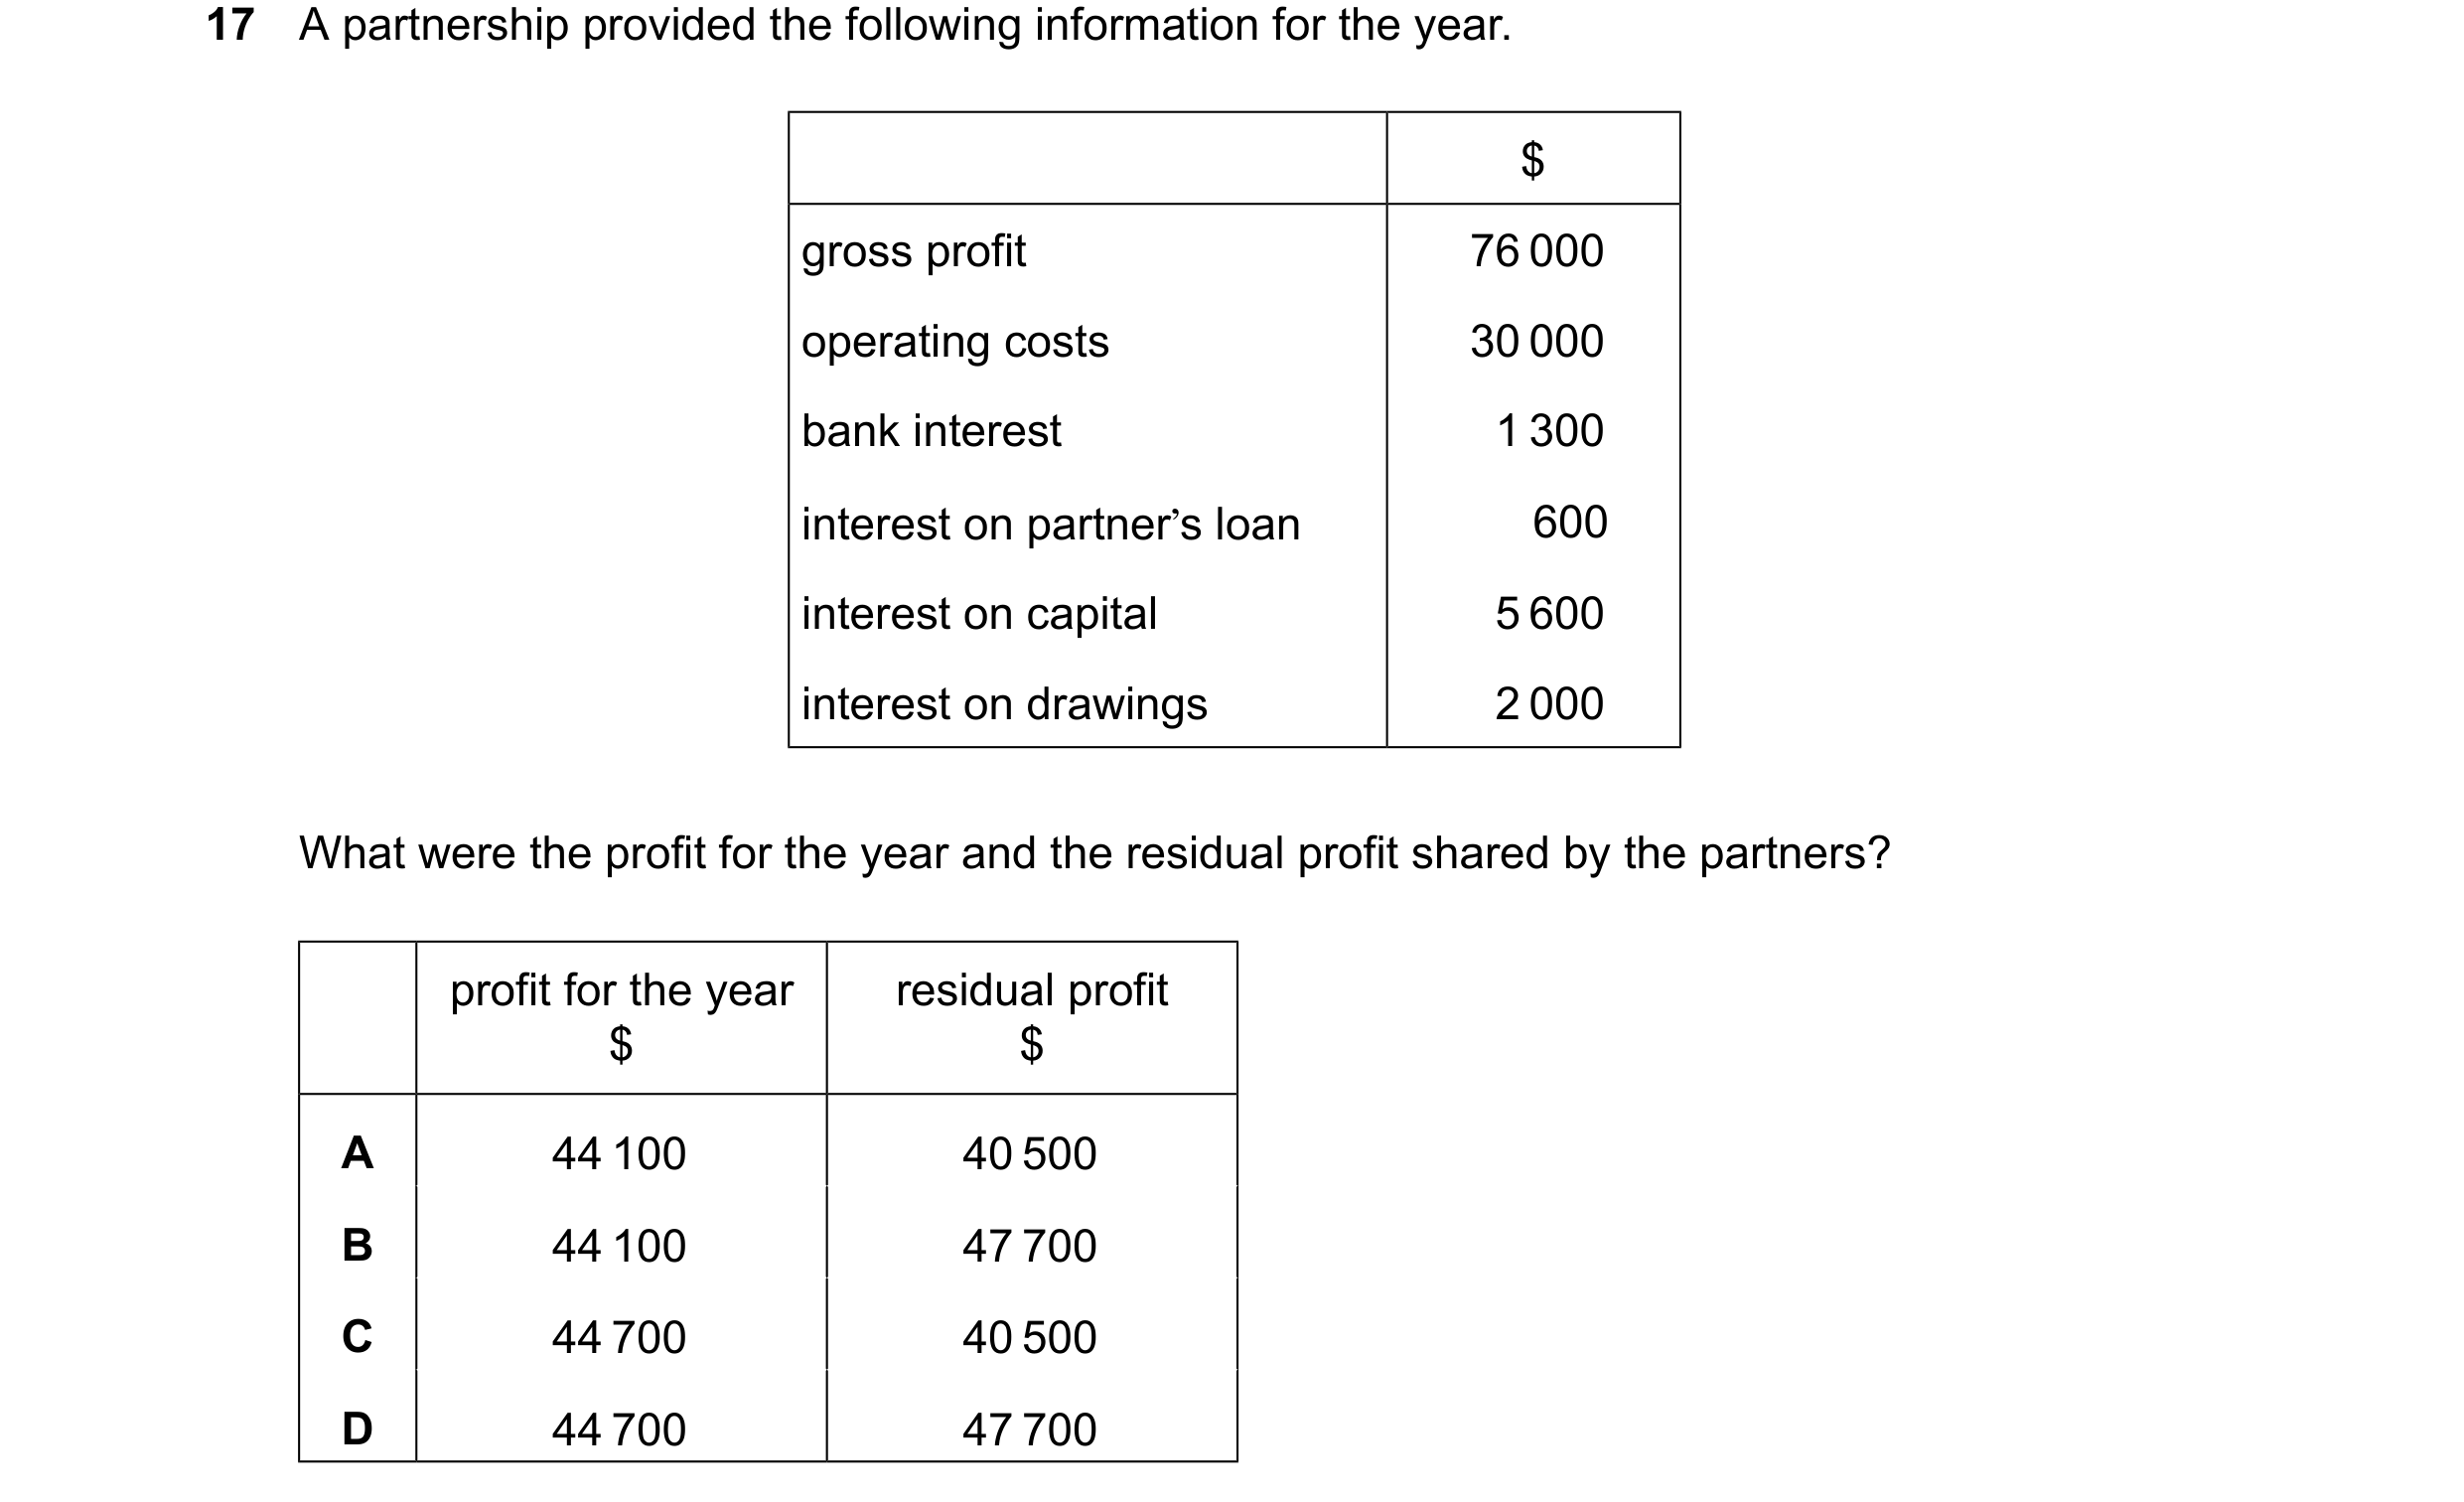
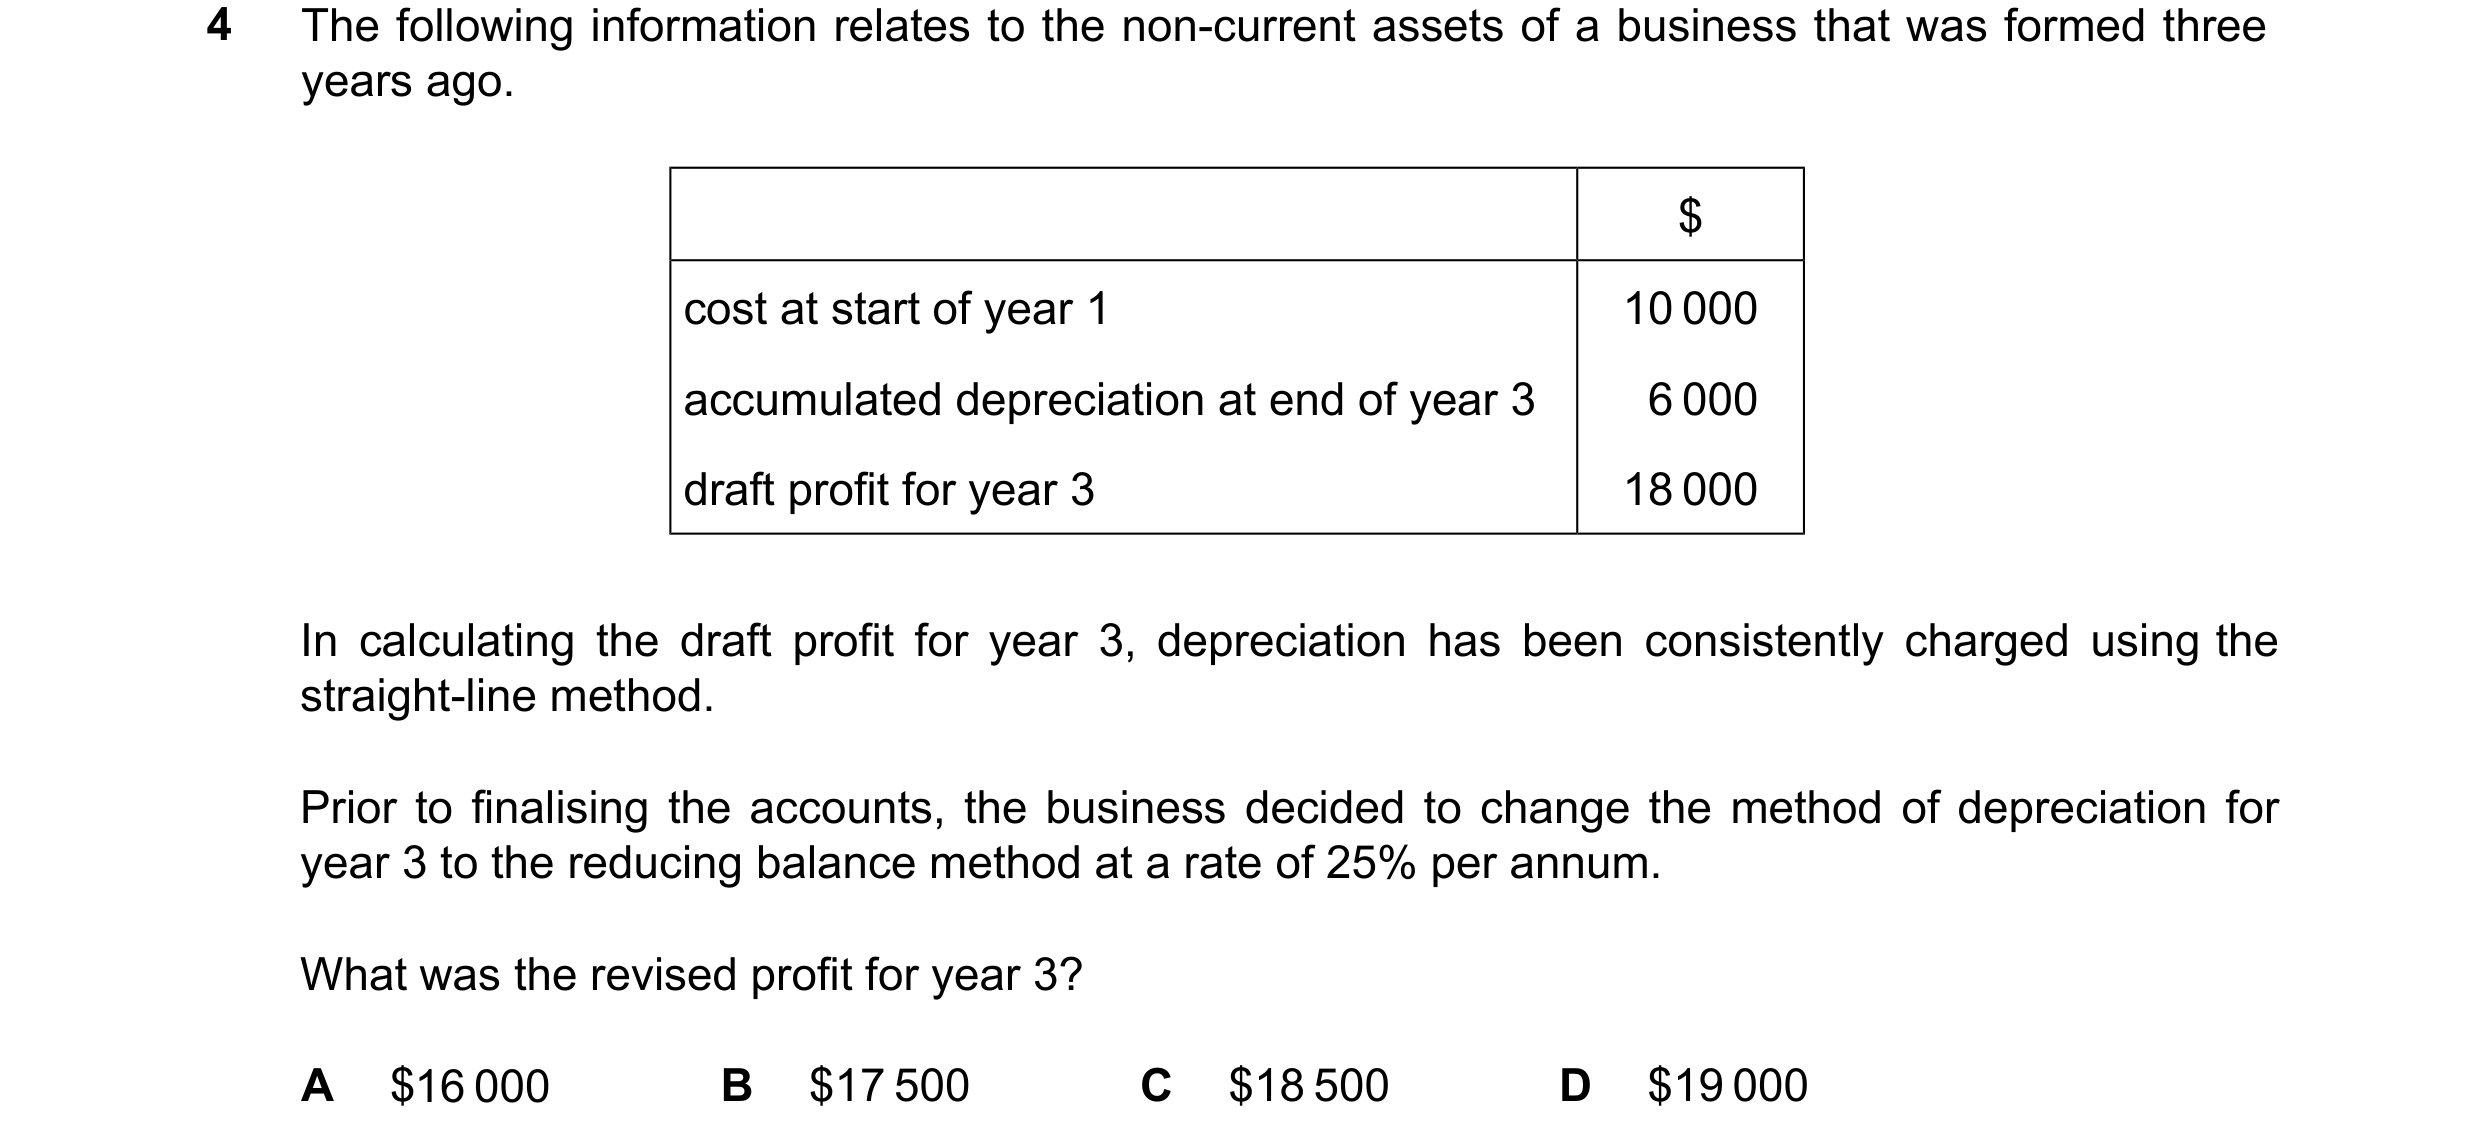
 212 / 233
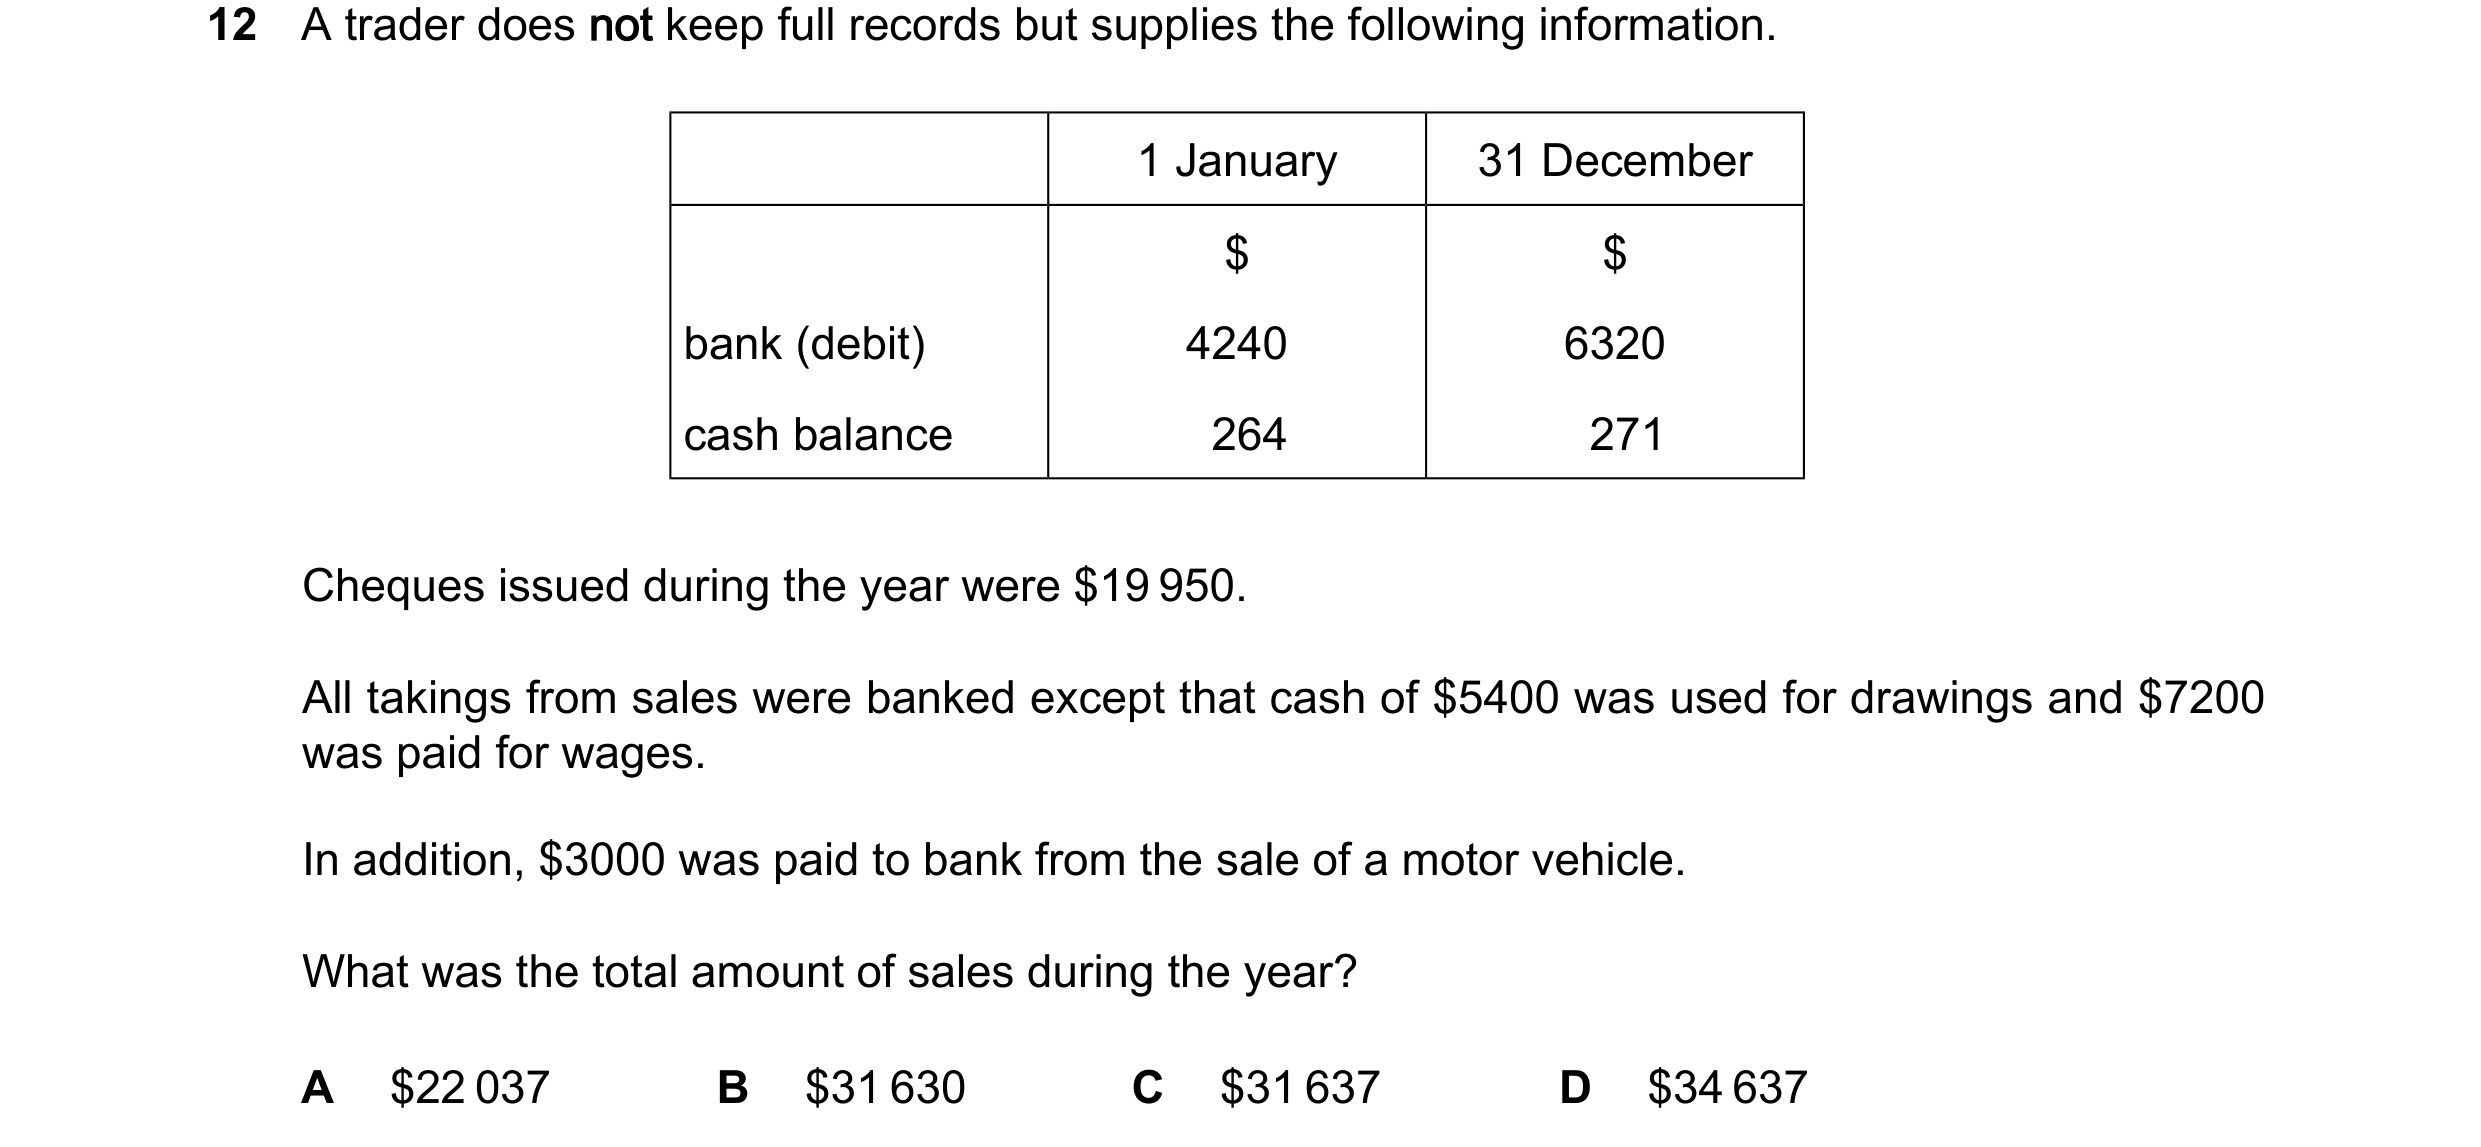
 213 / 233
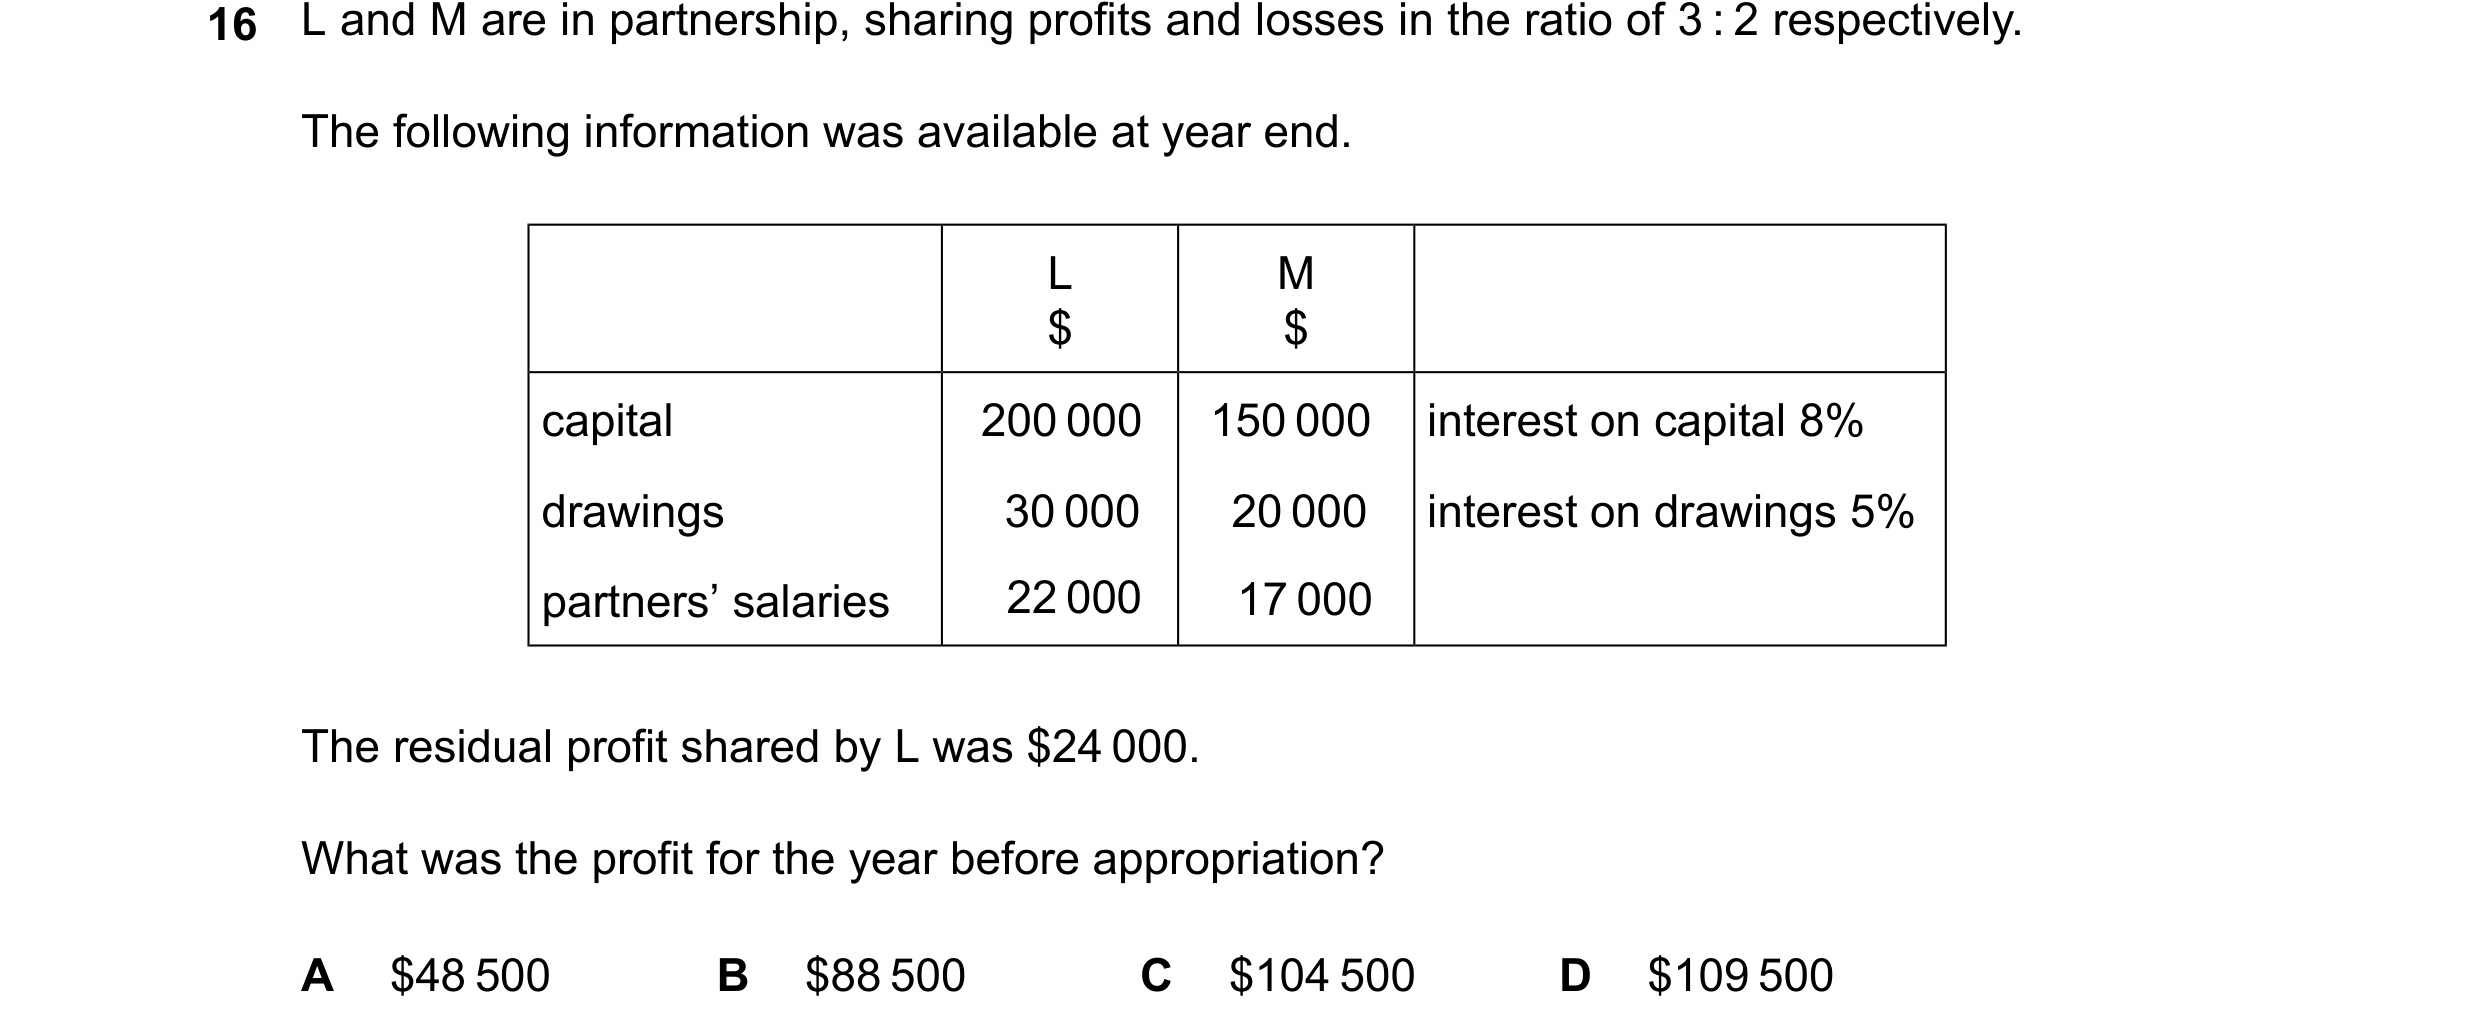
 214 / 233
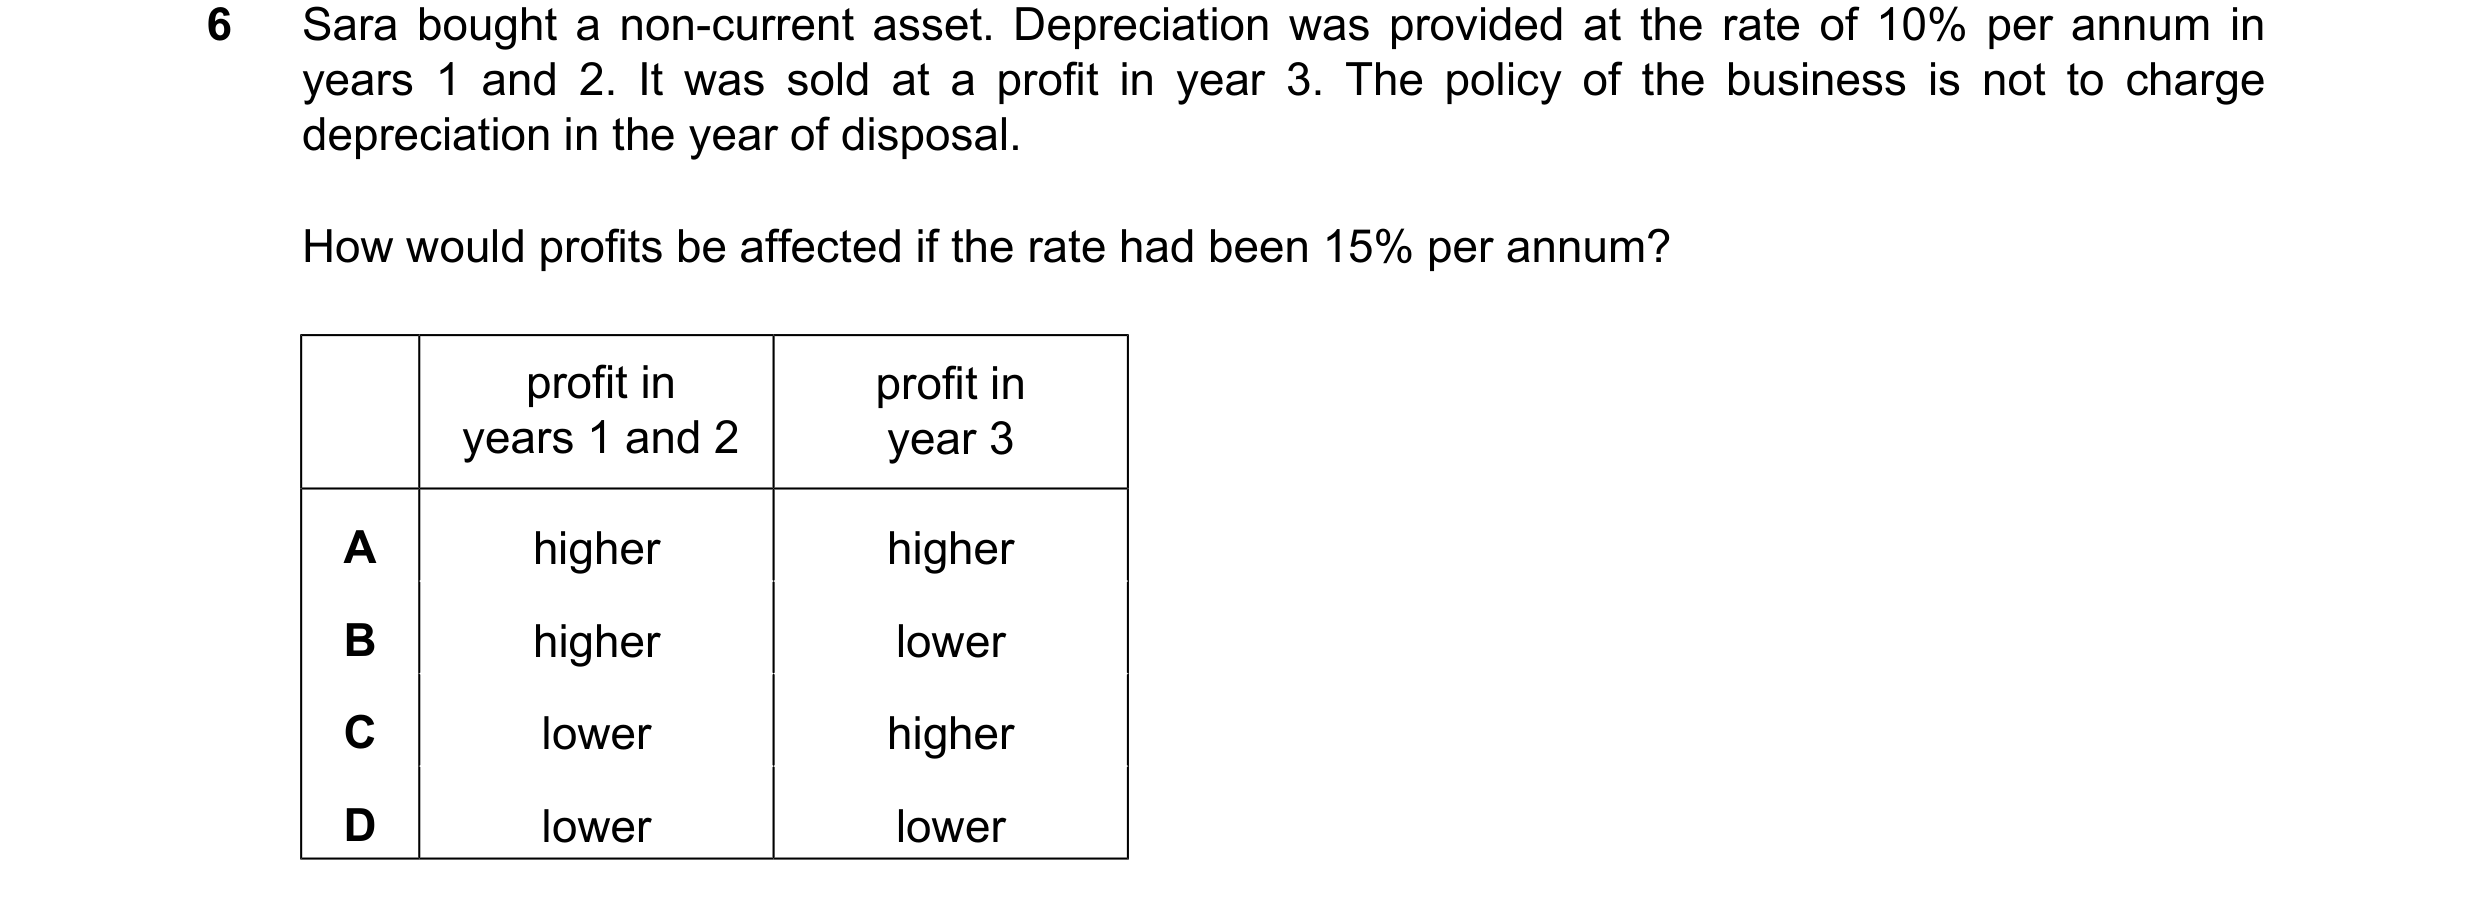
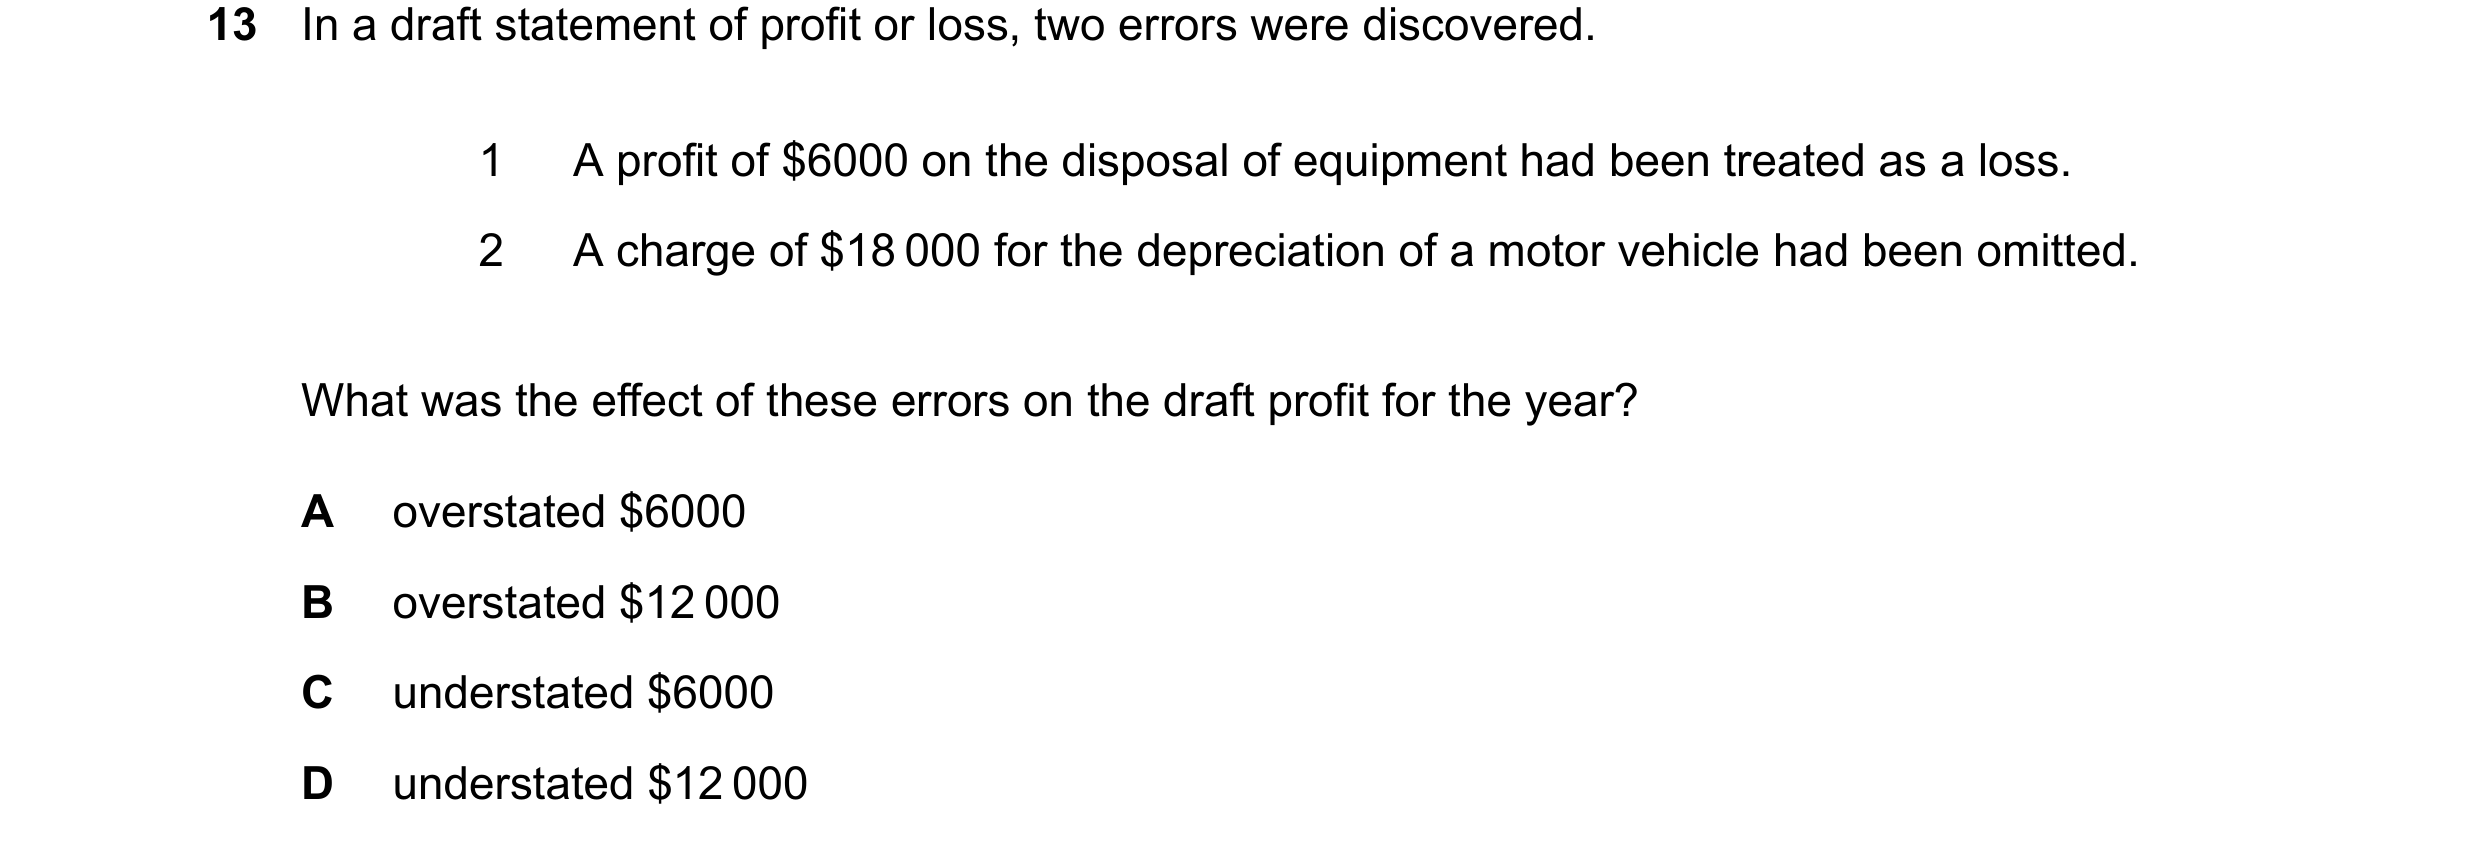 215 / 233
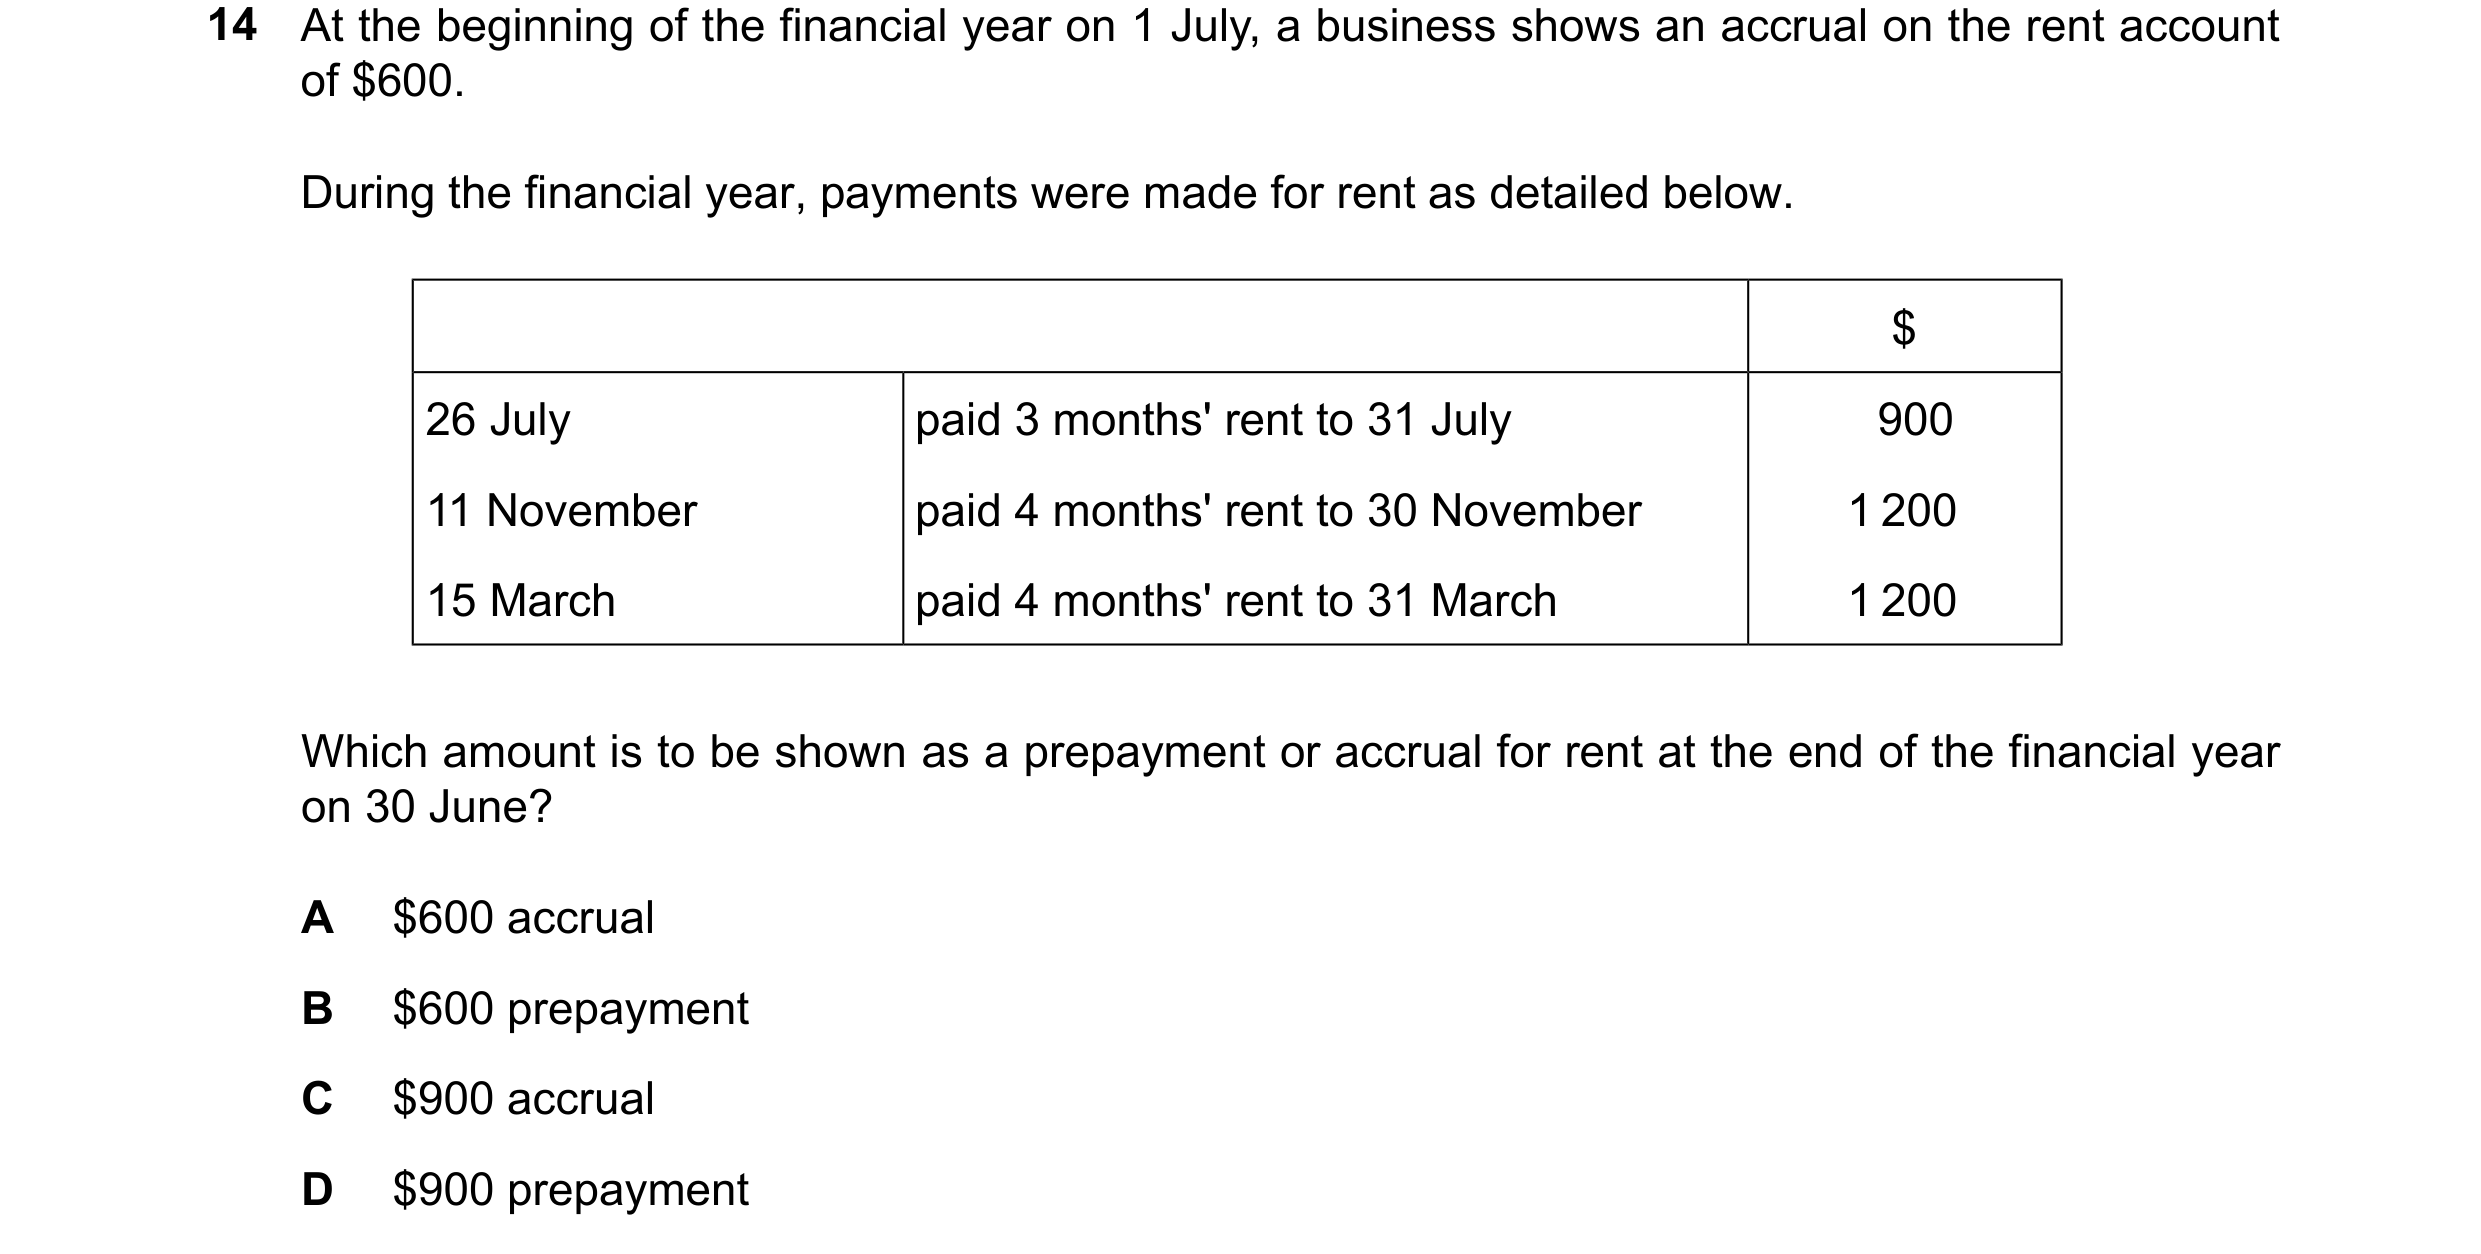
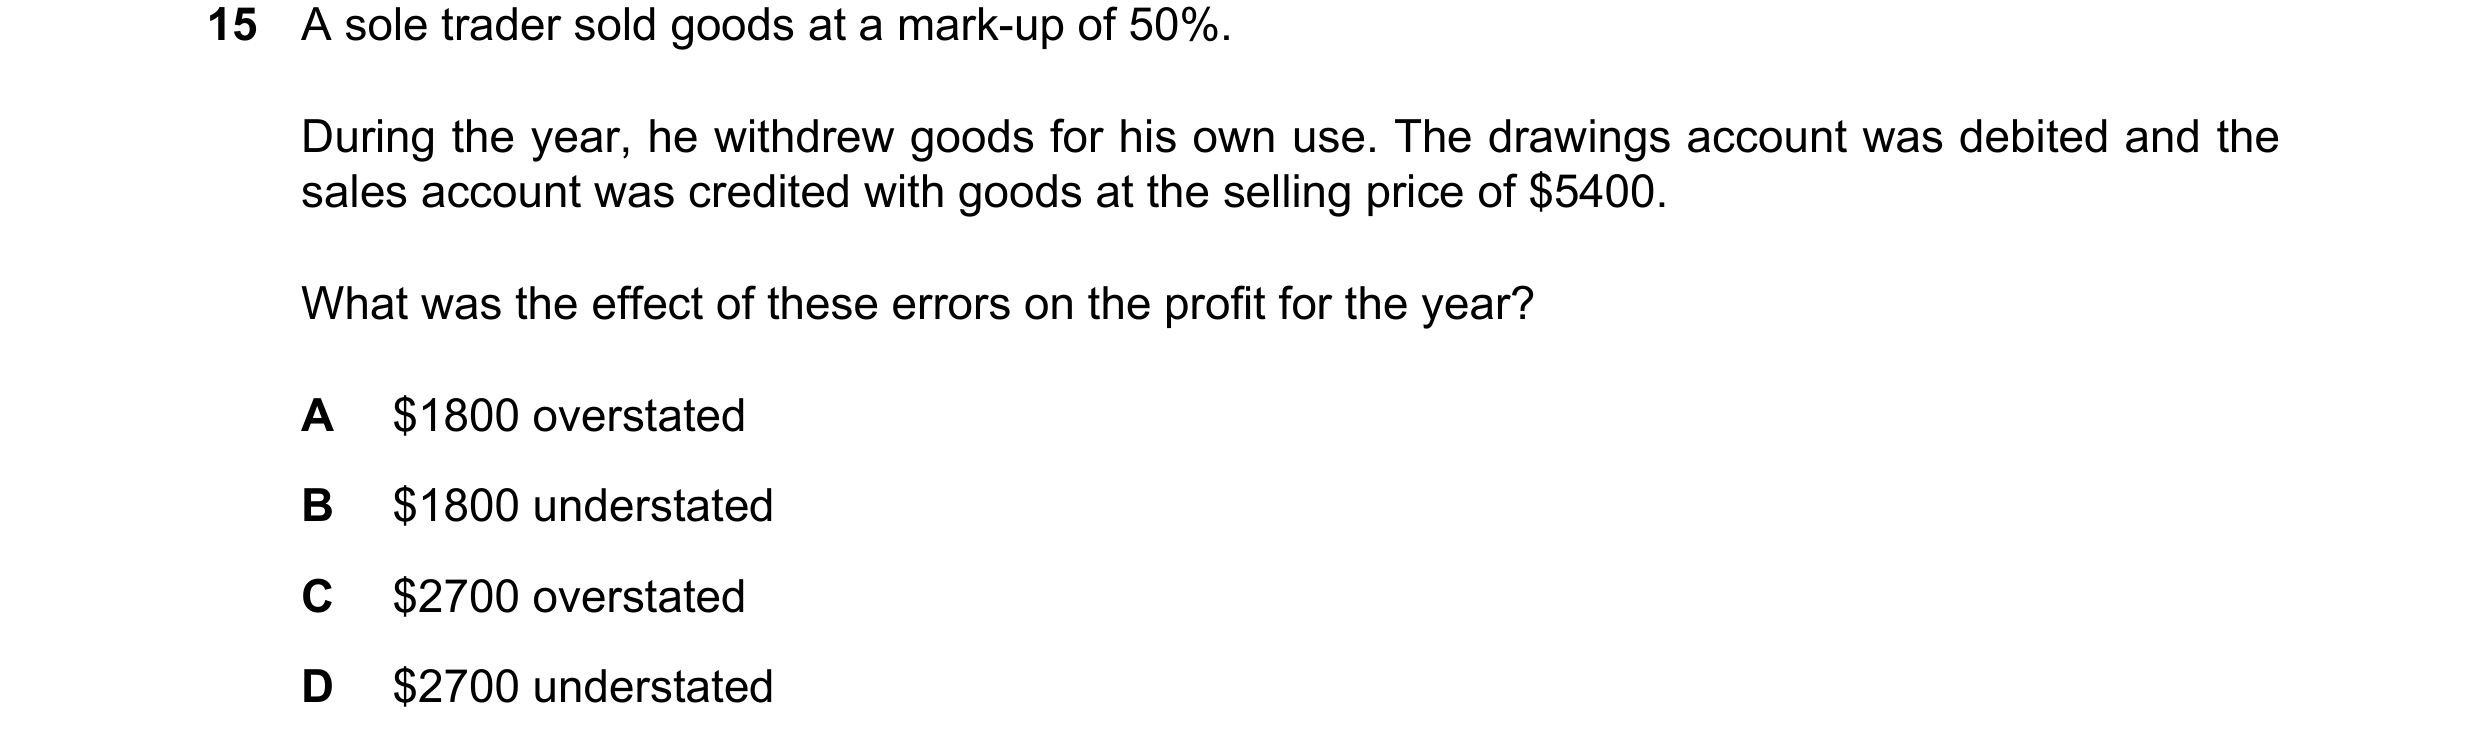
 216 / 233
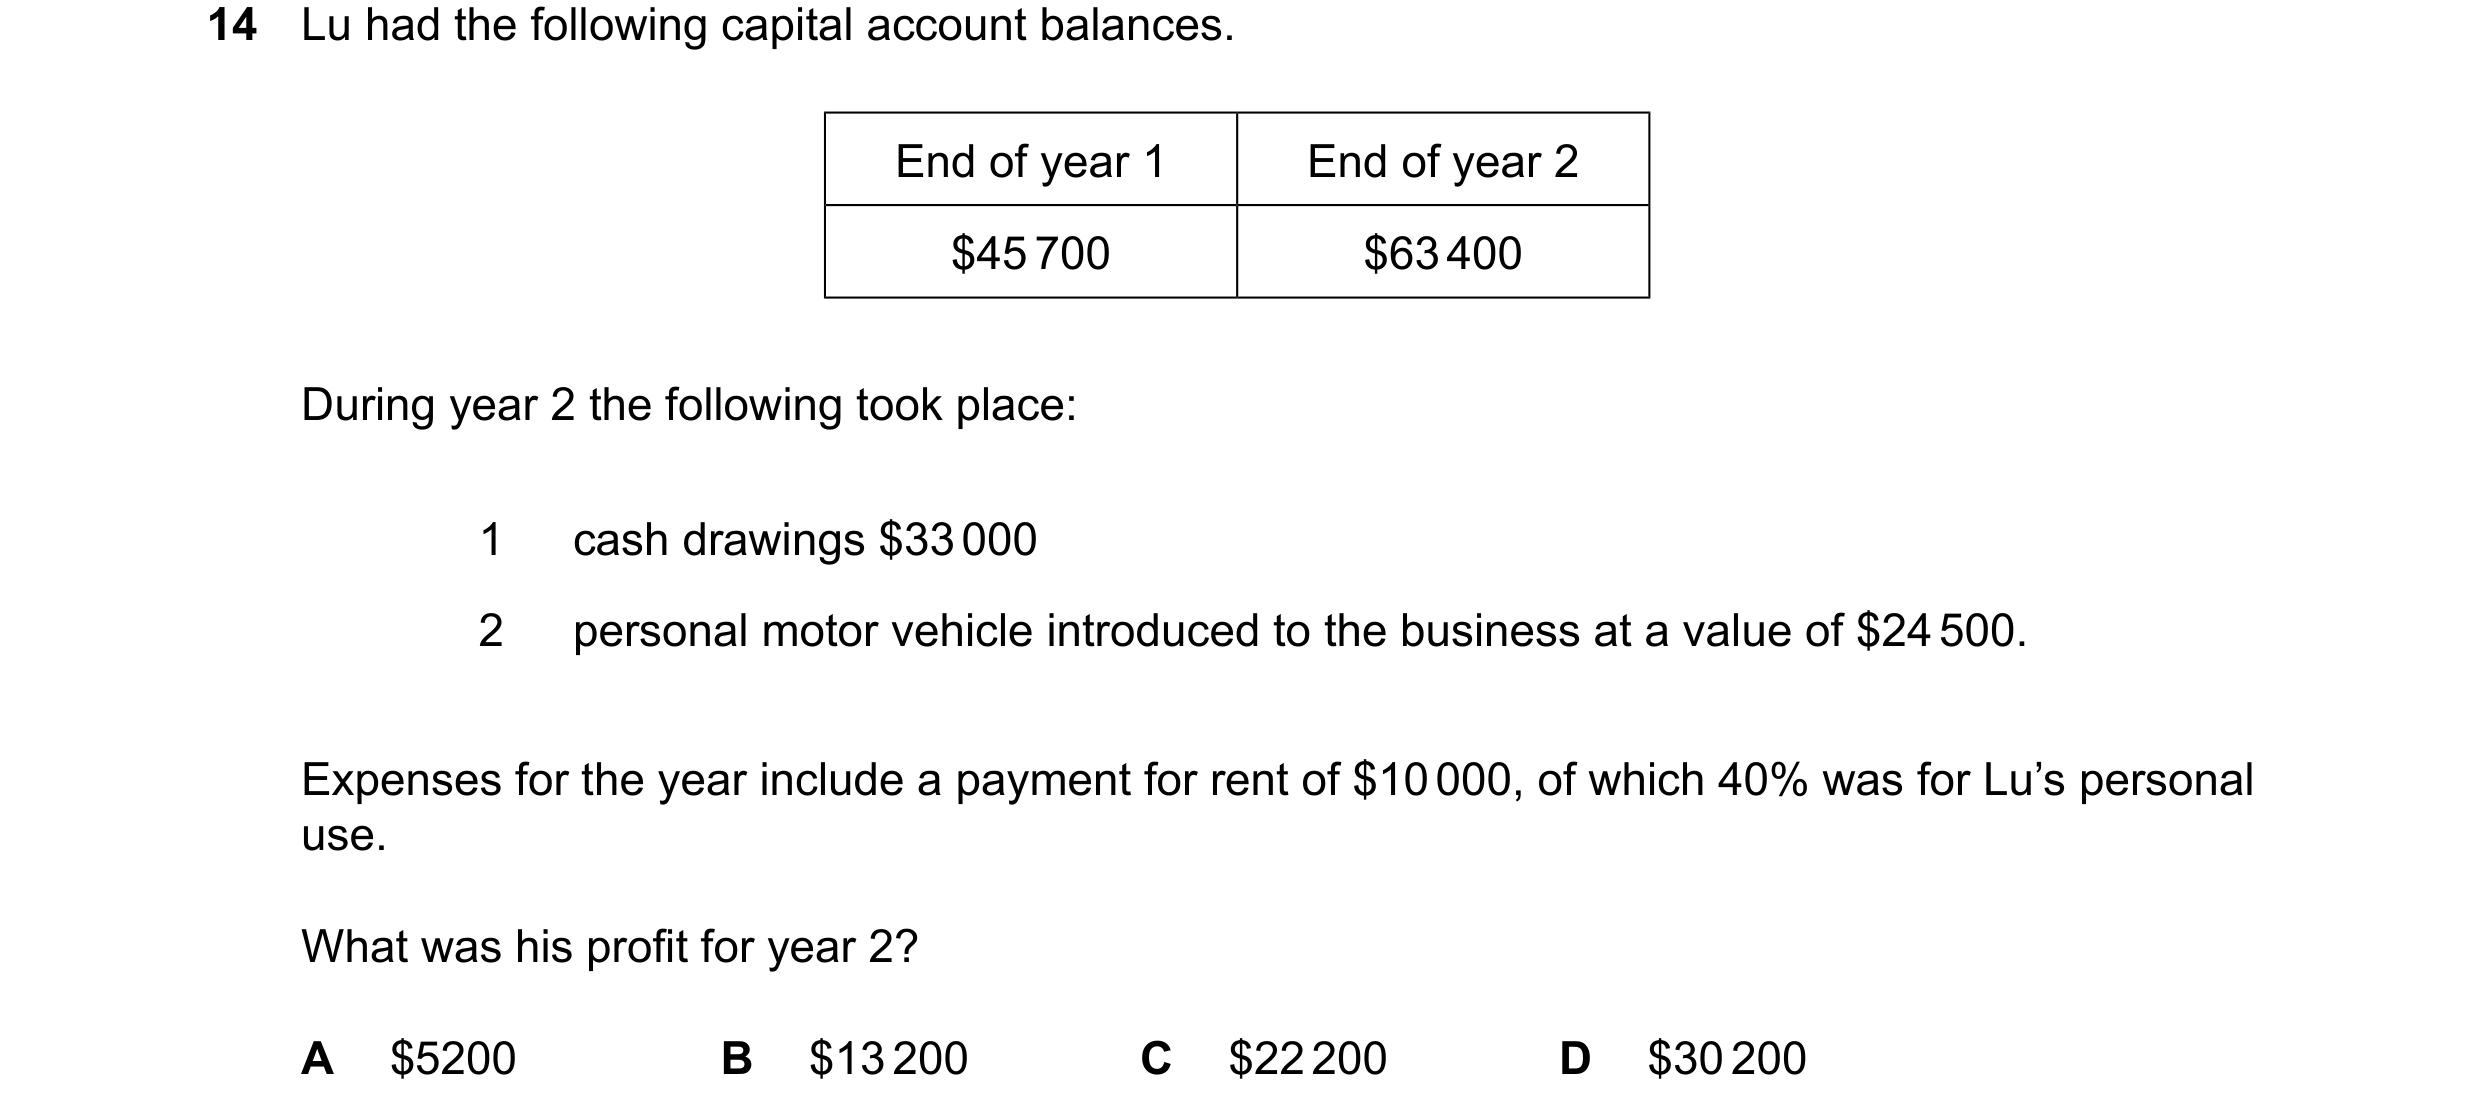 217 / 233
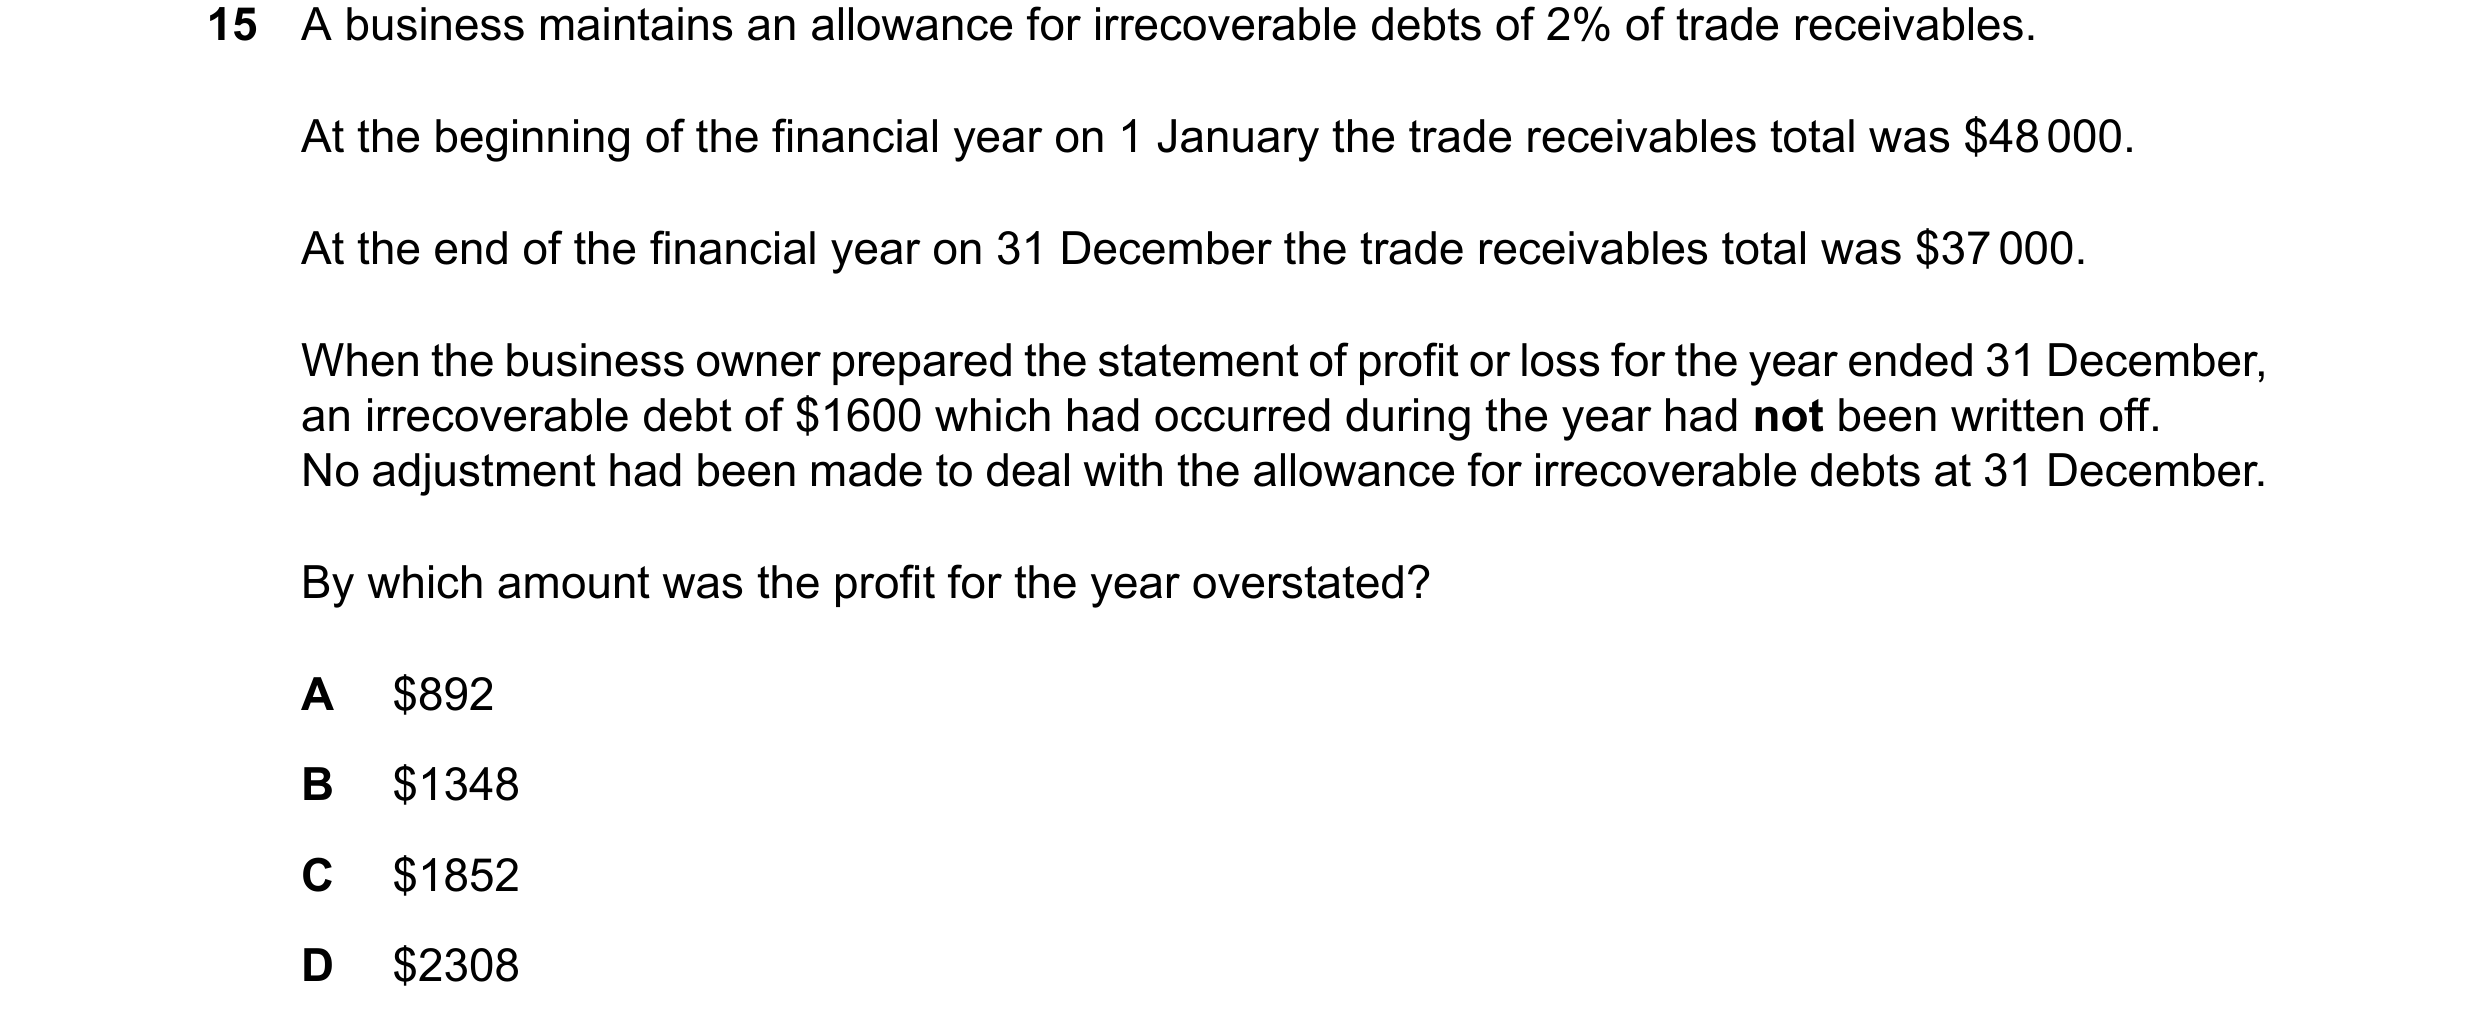
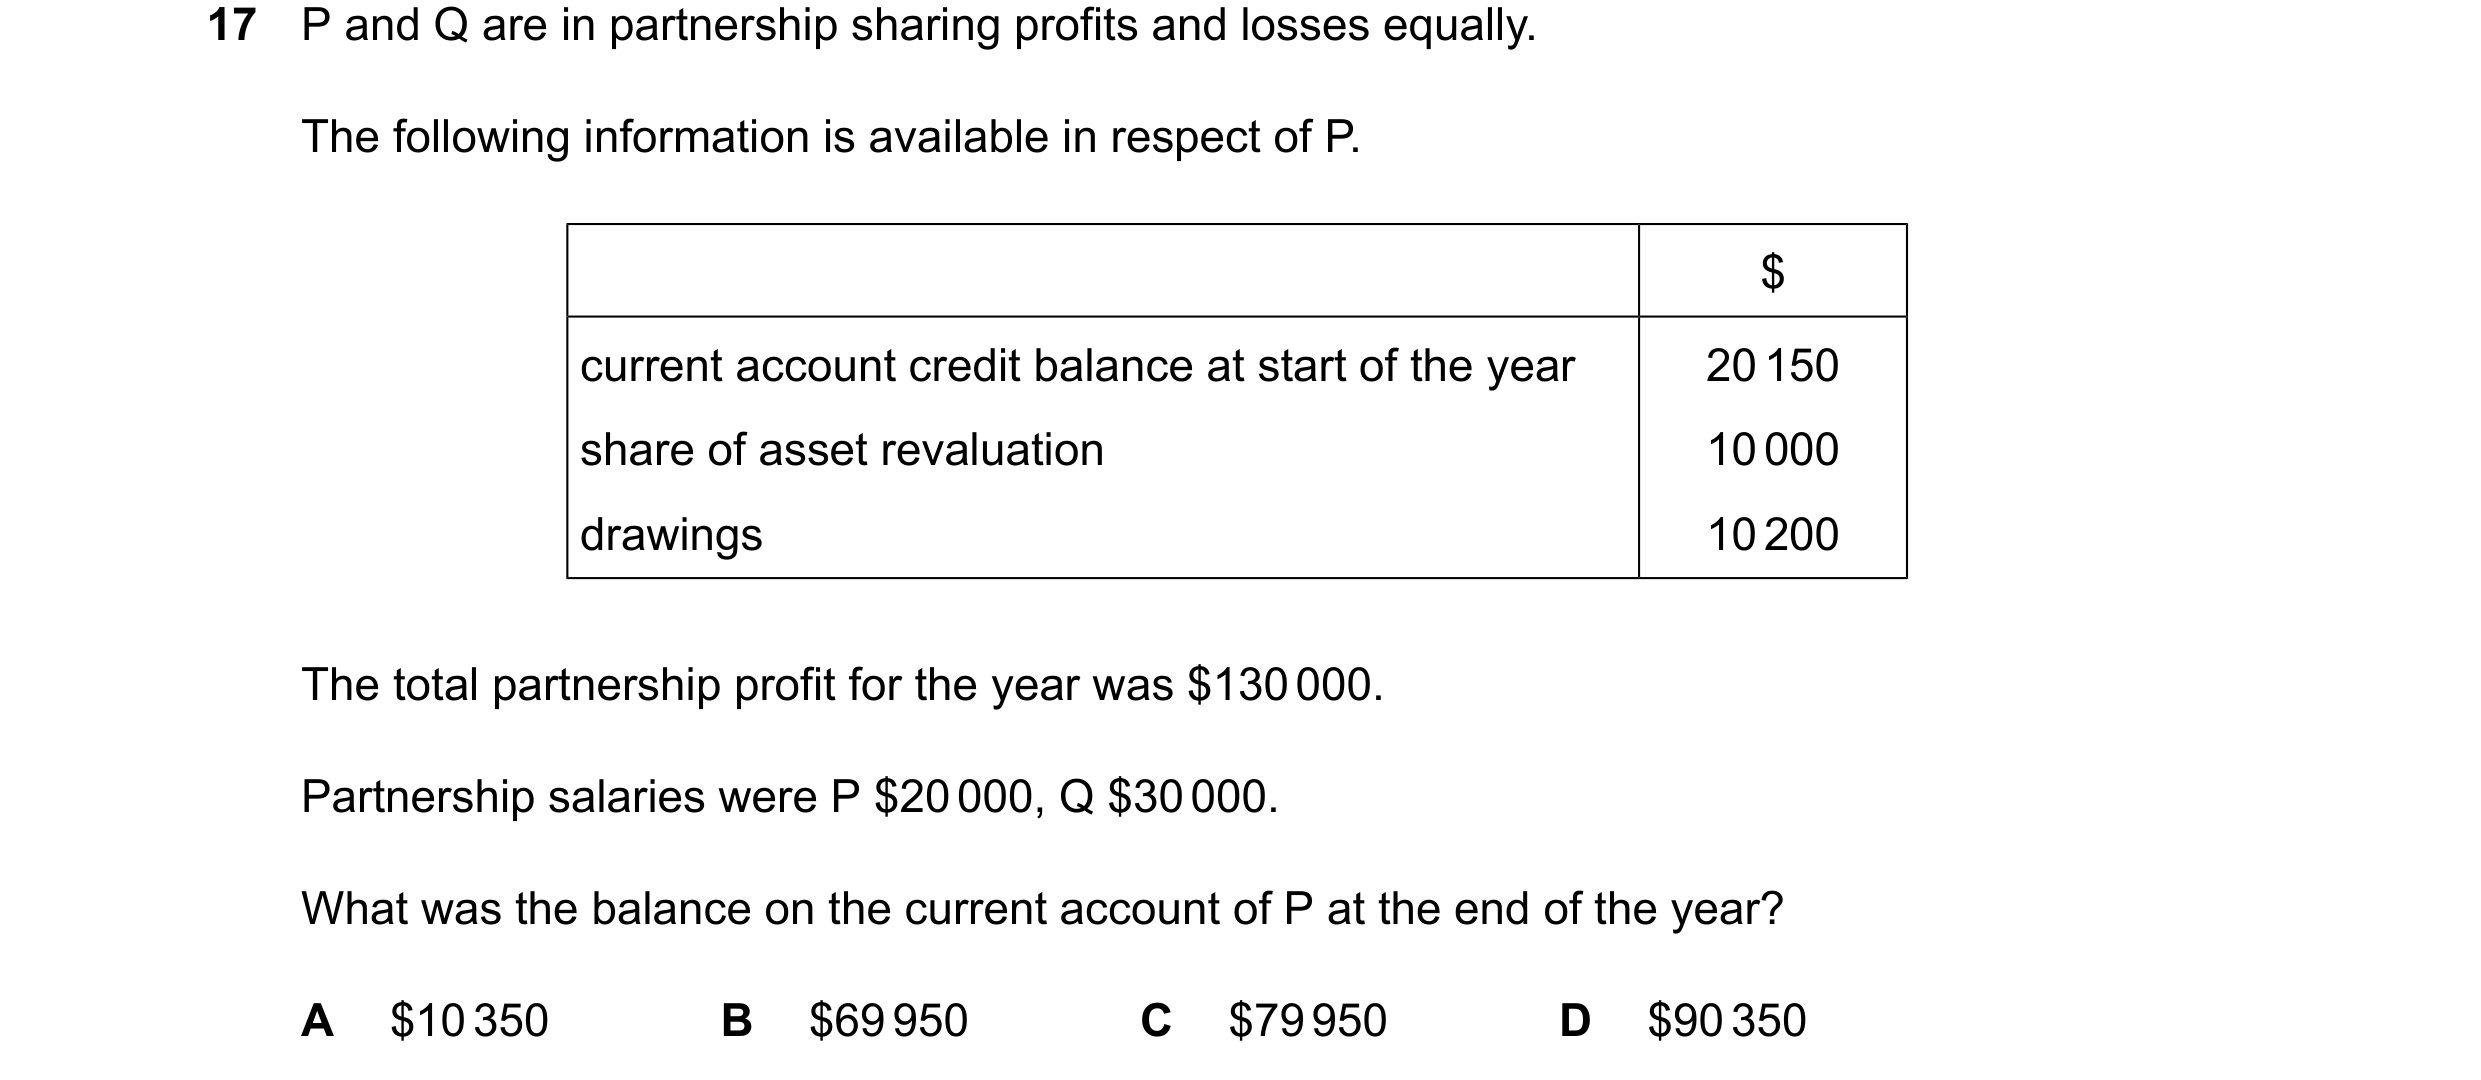
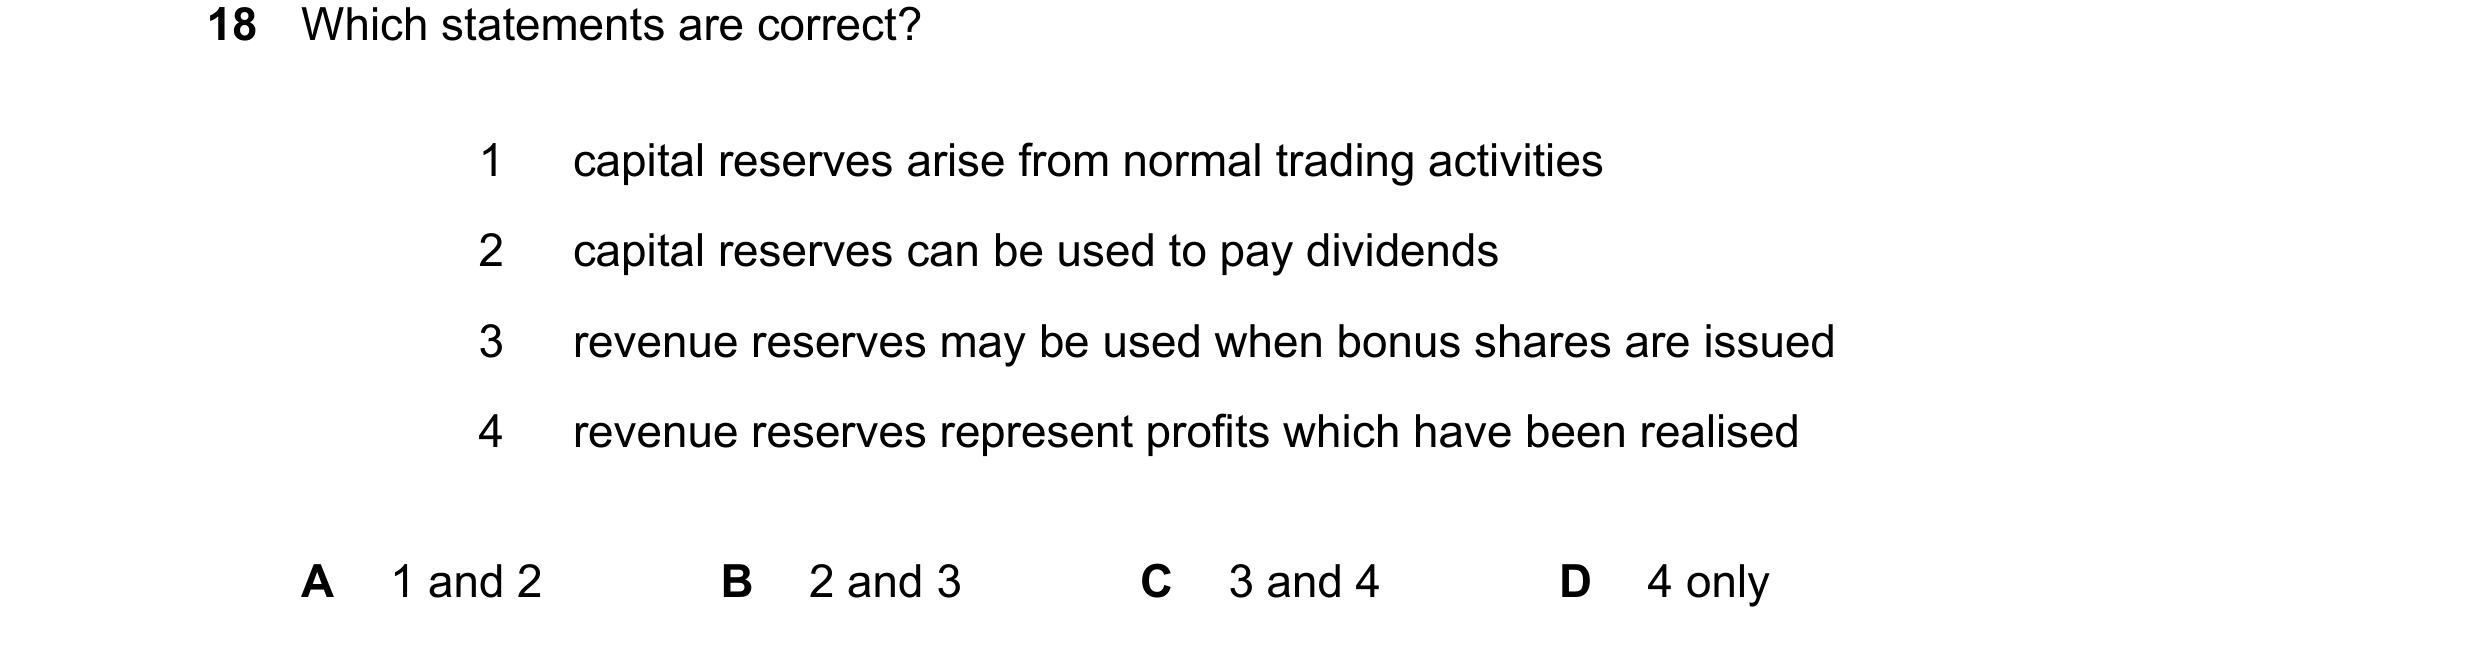 218 / 233
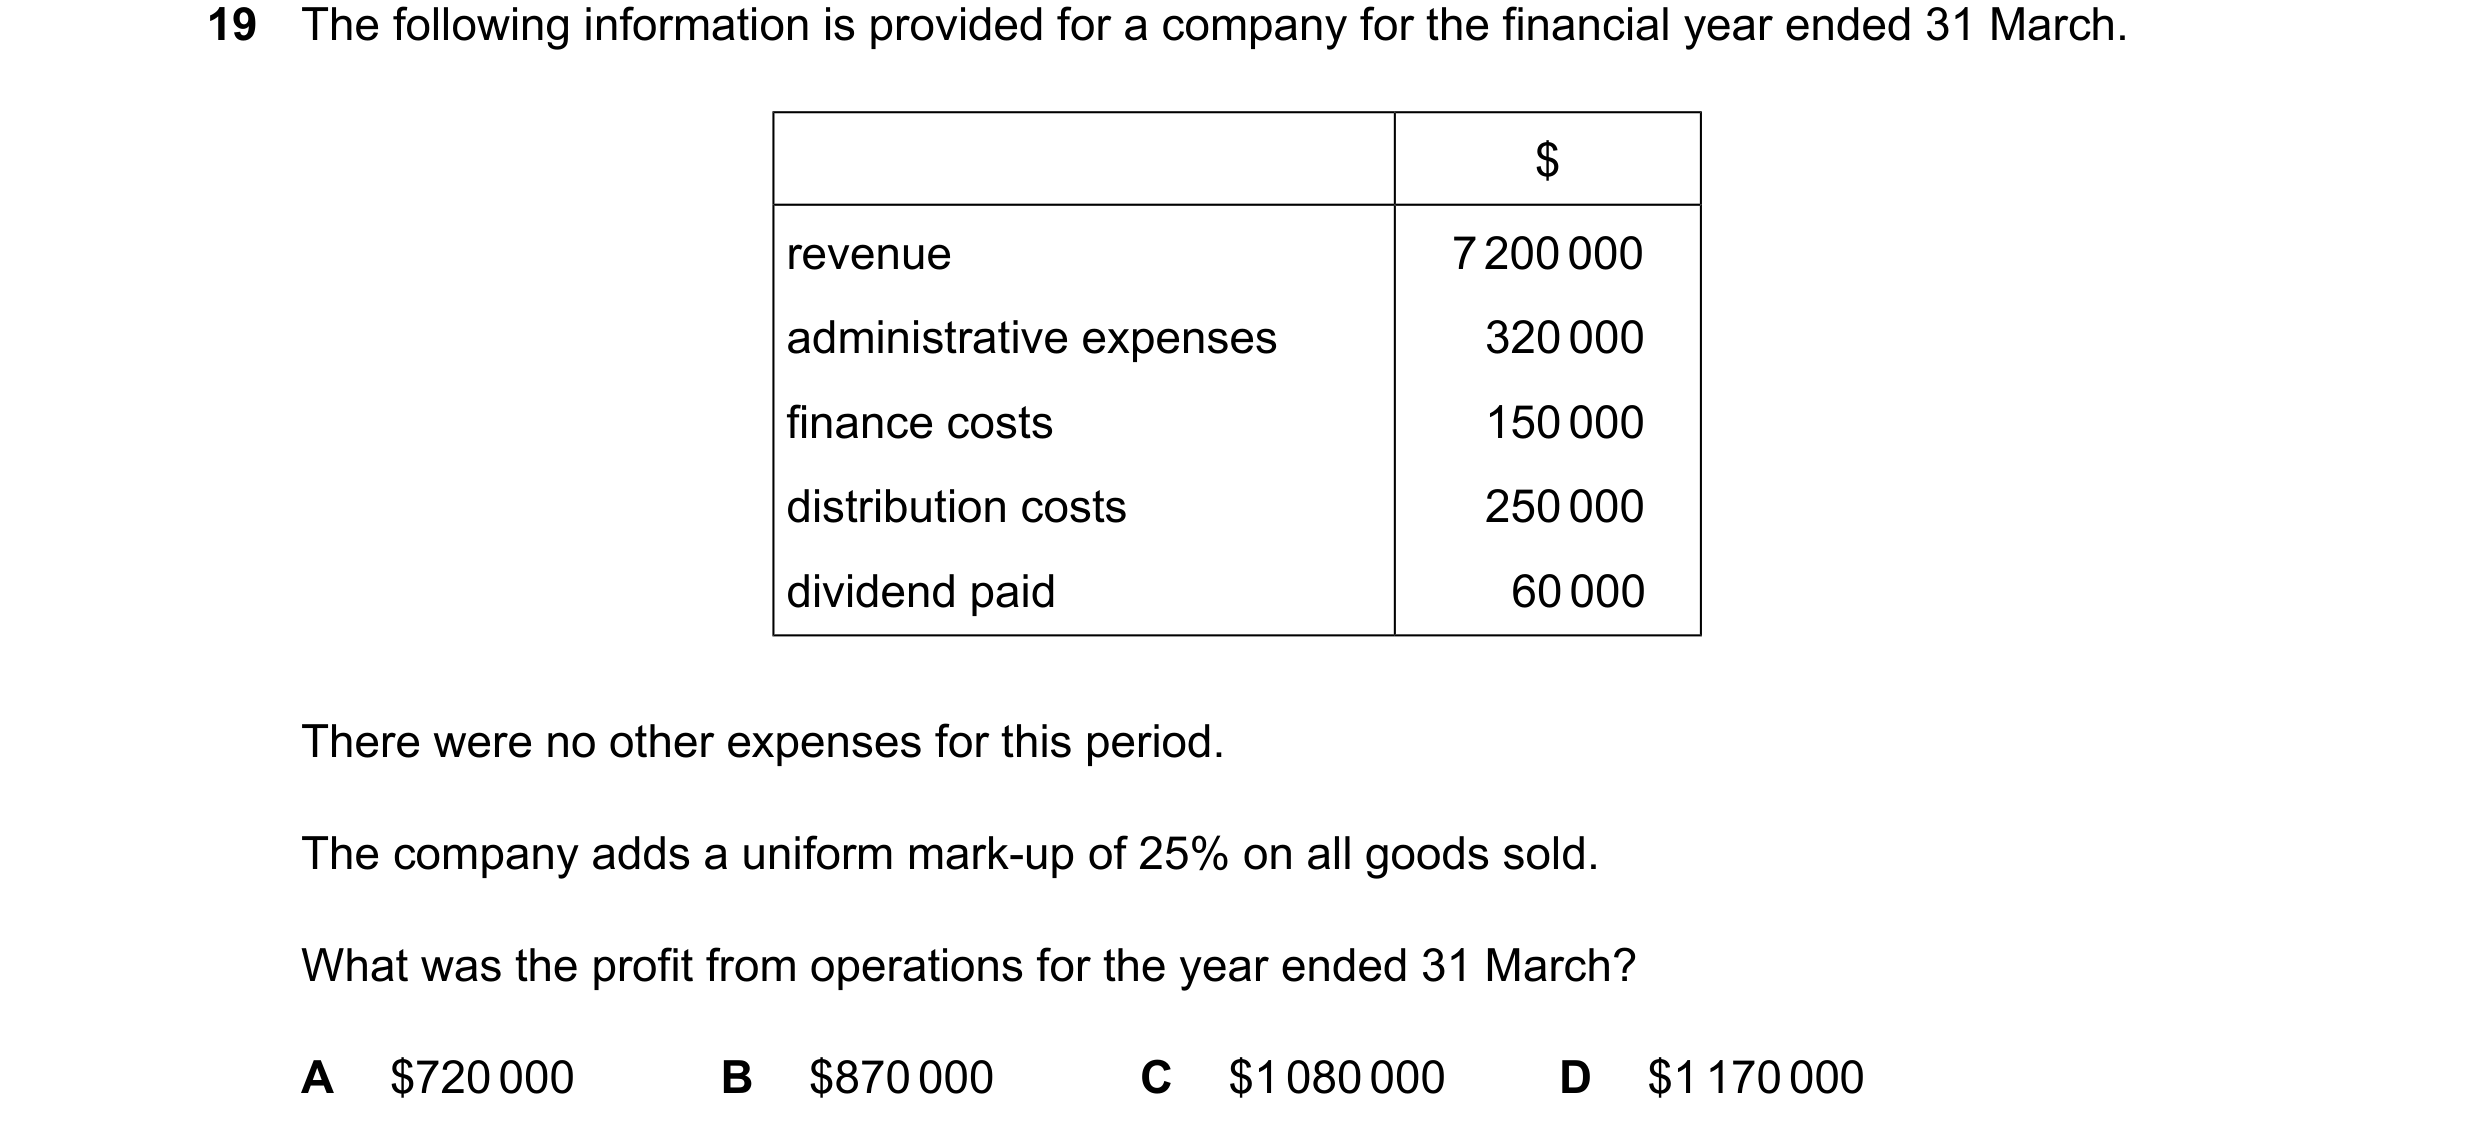
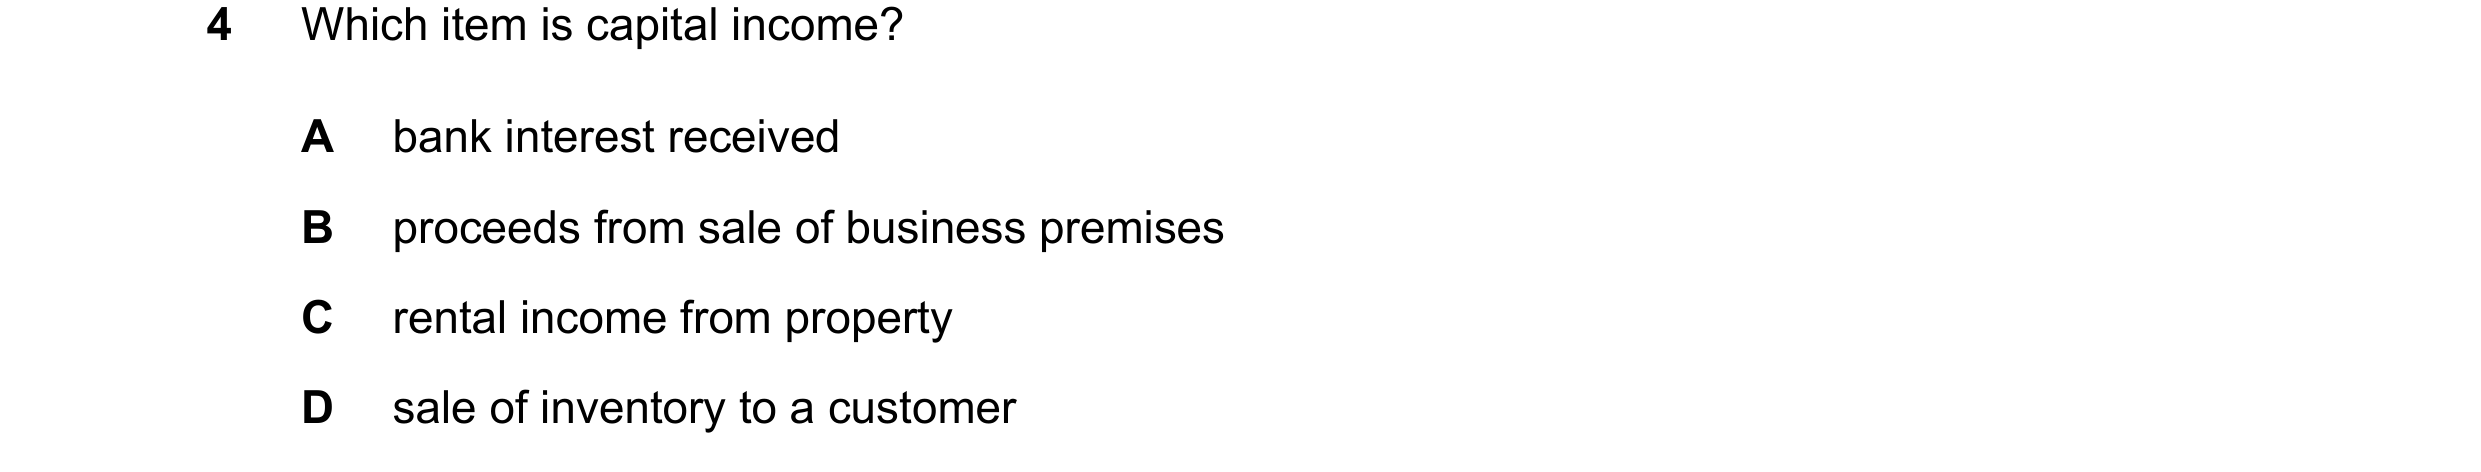
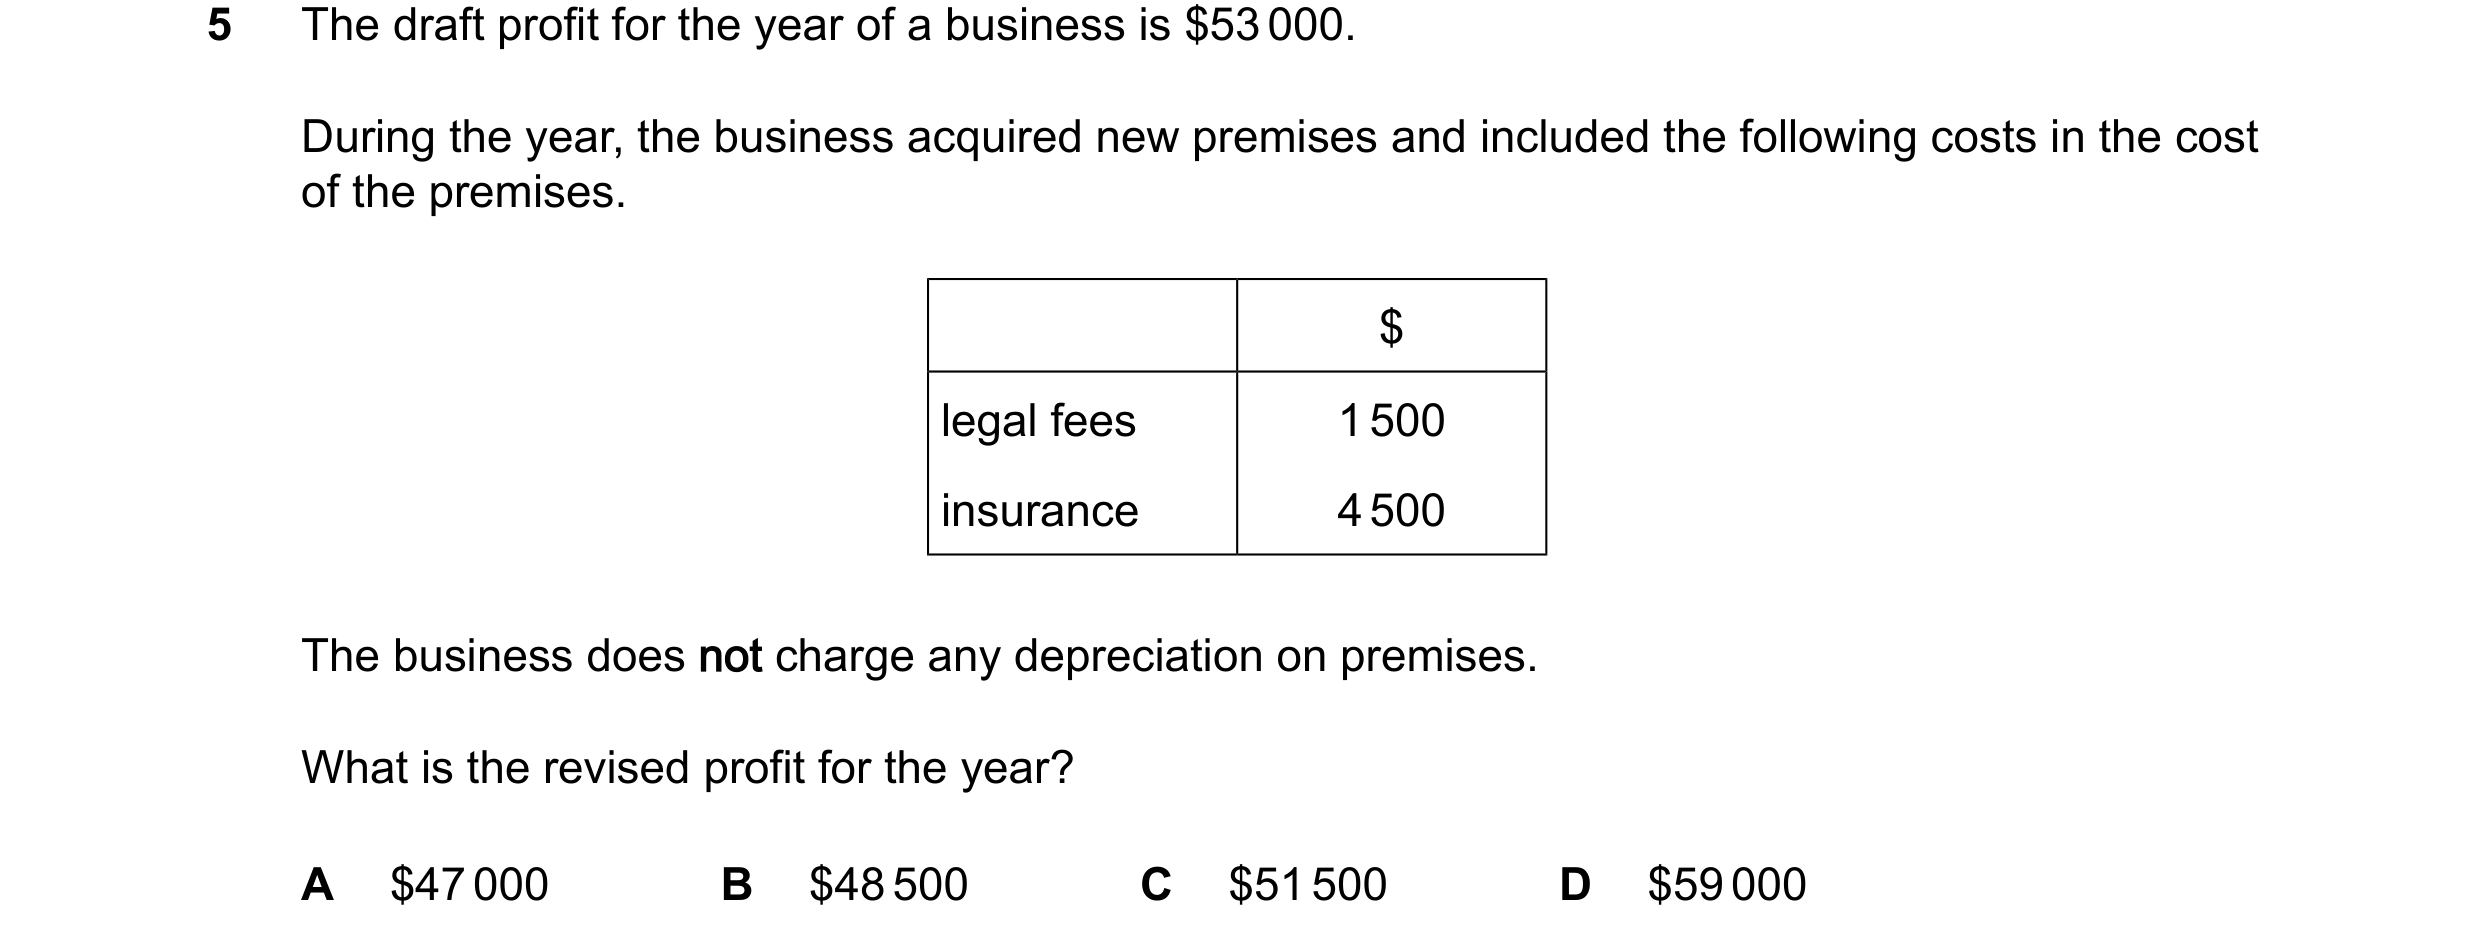
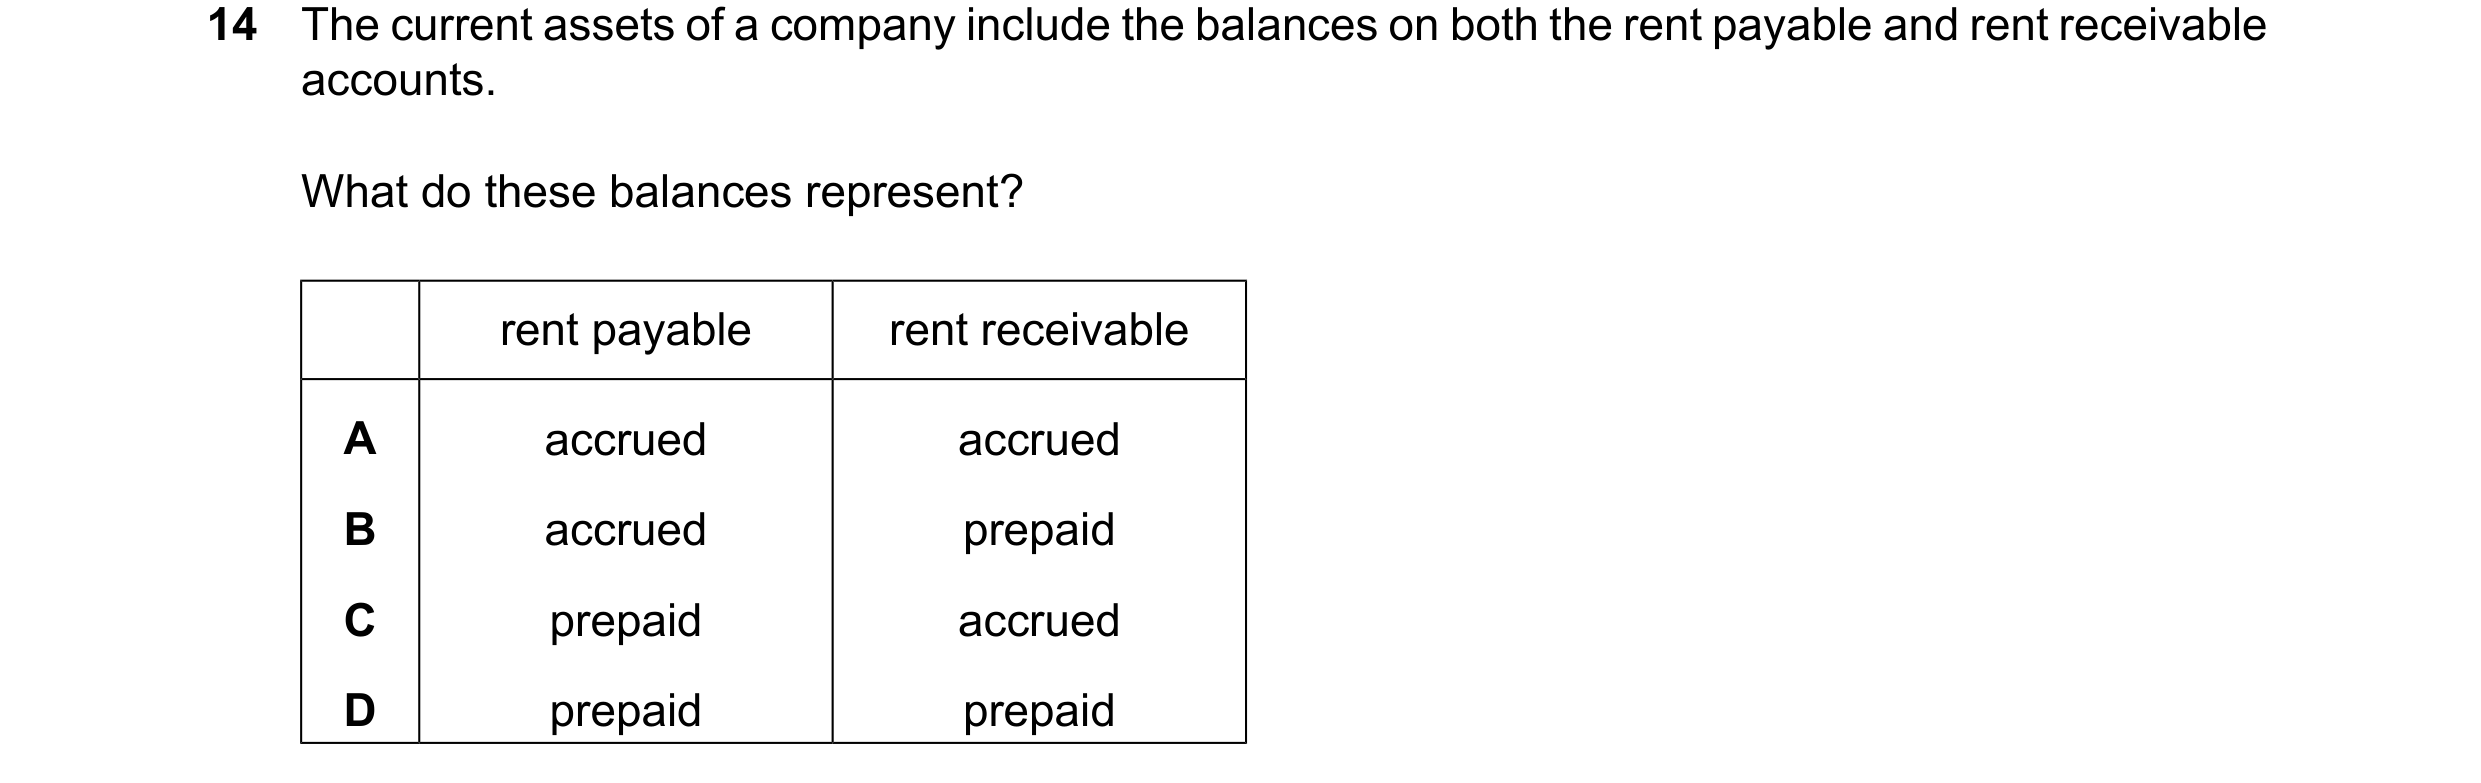 219 / 233
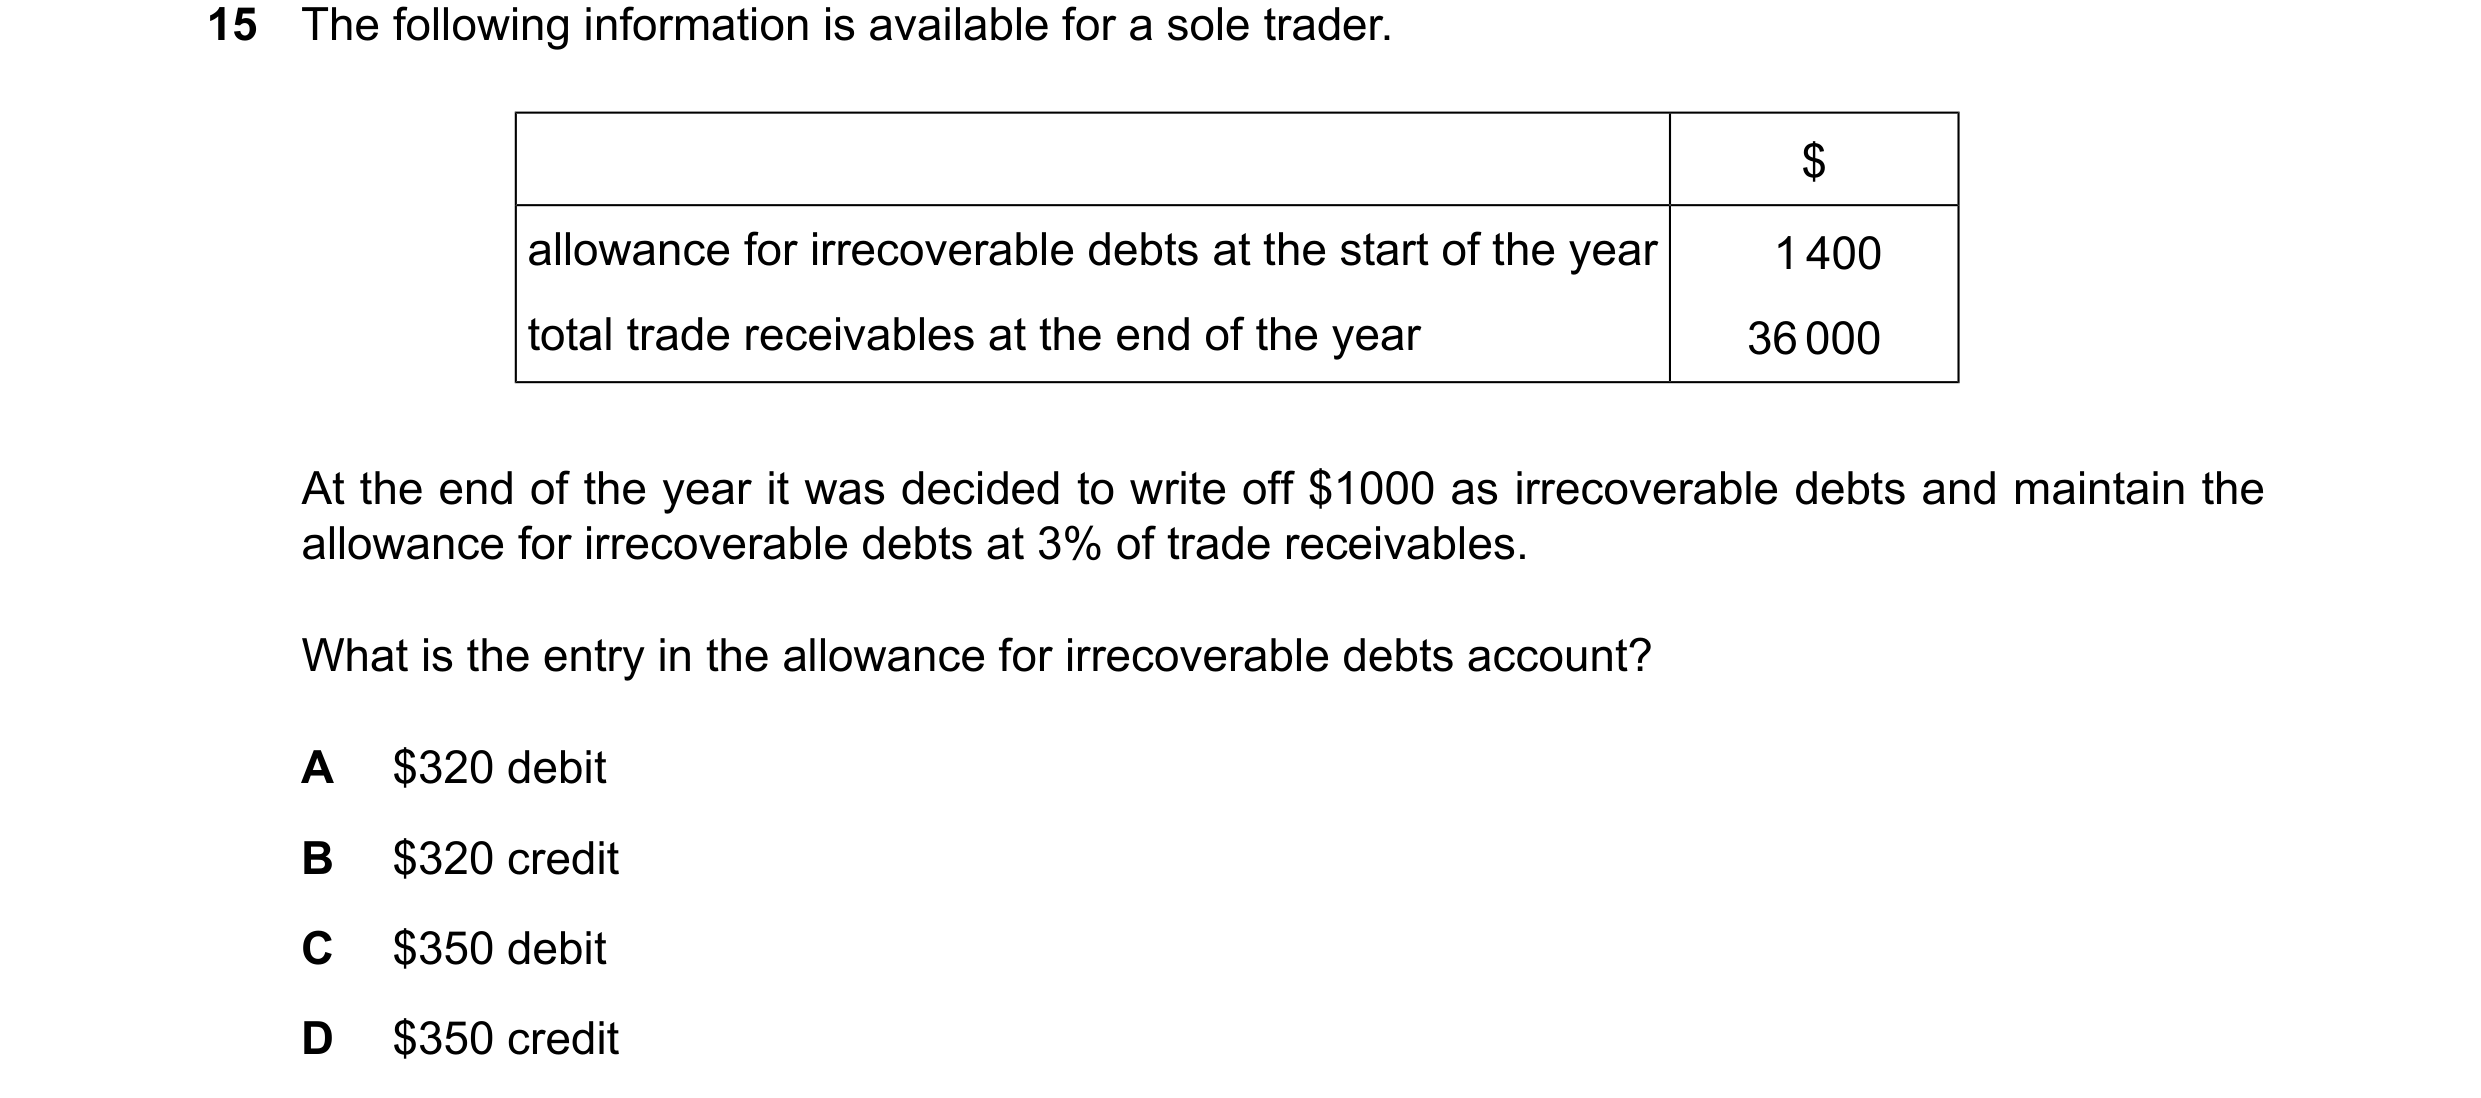
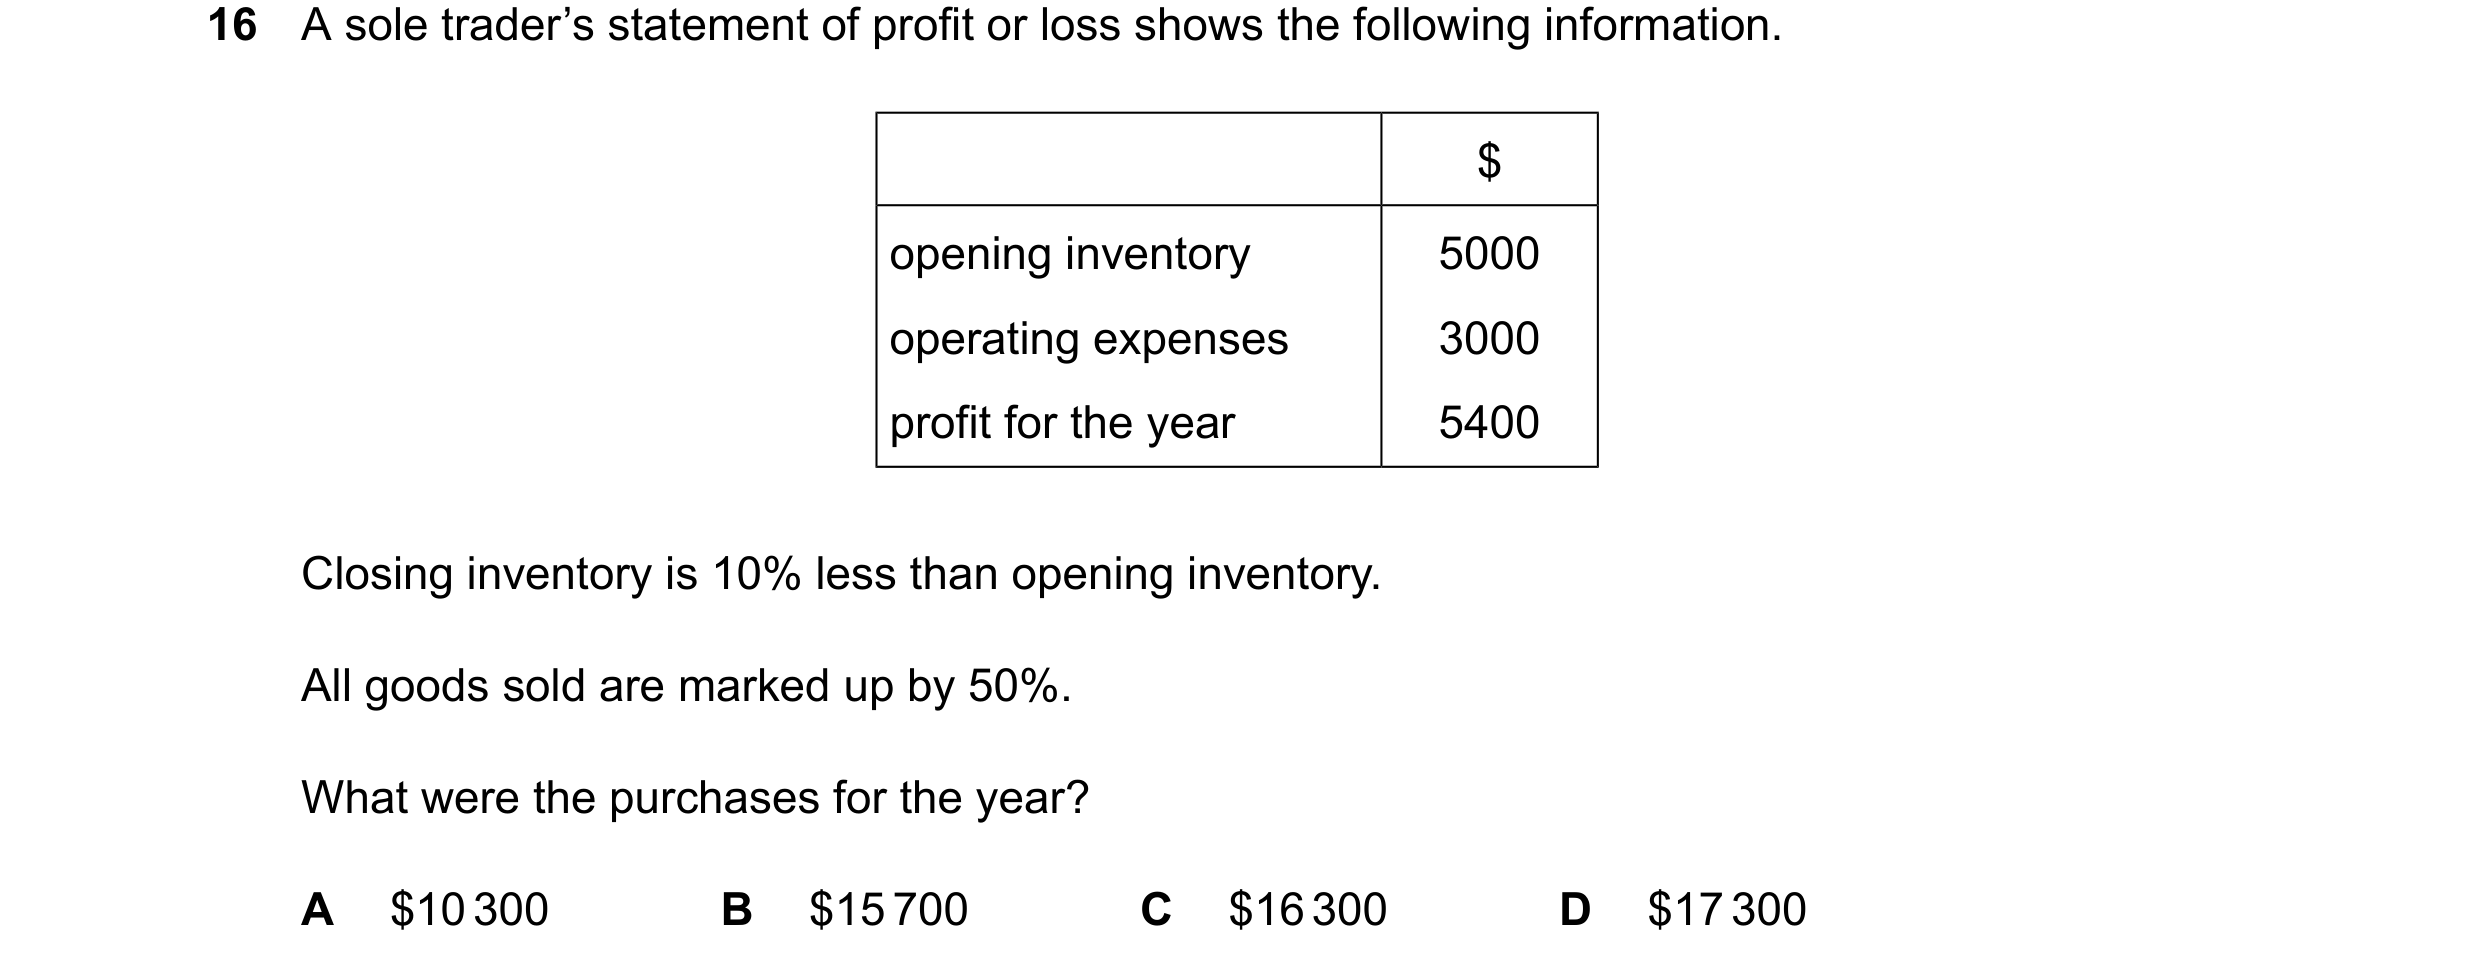 220 / 233
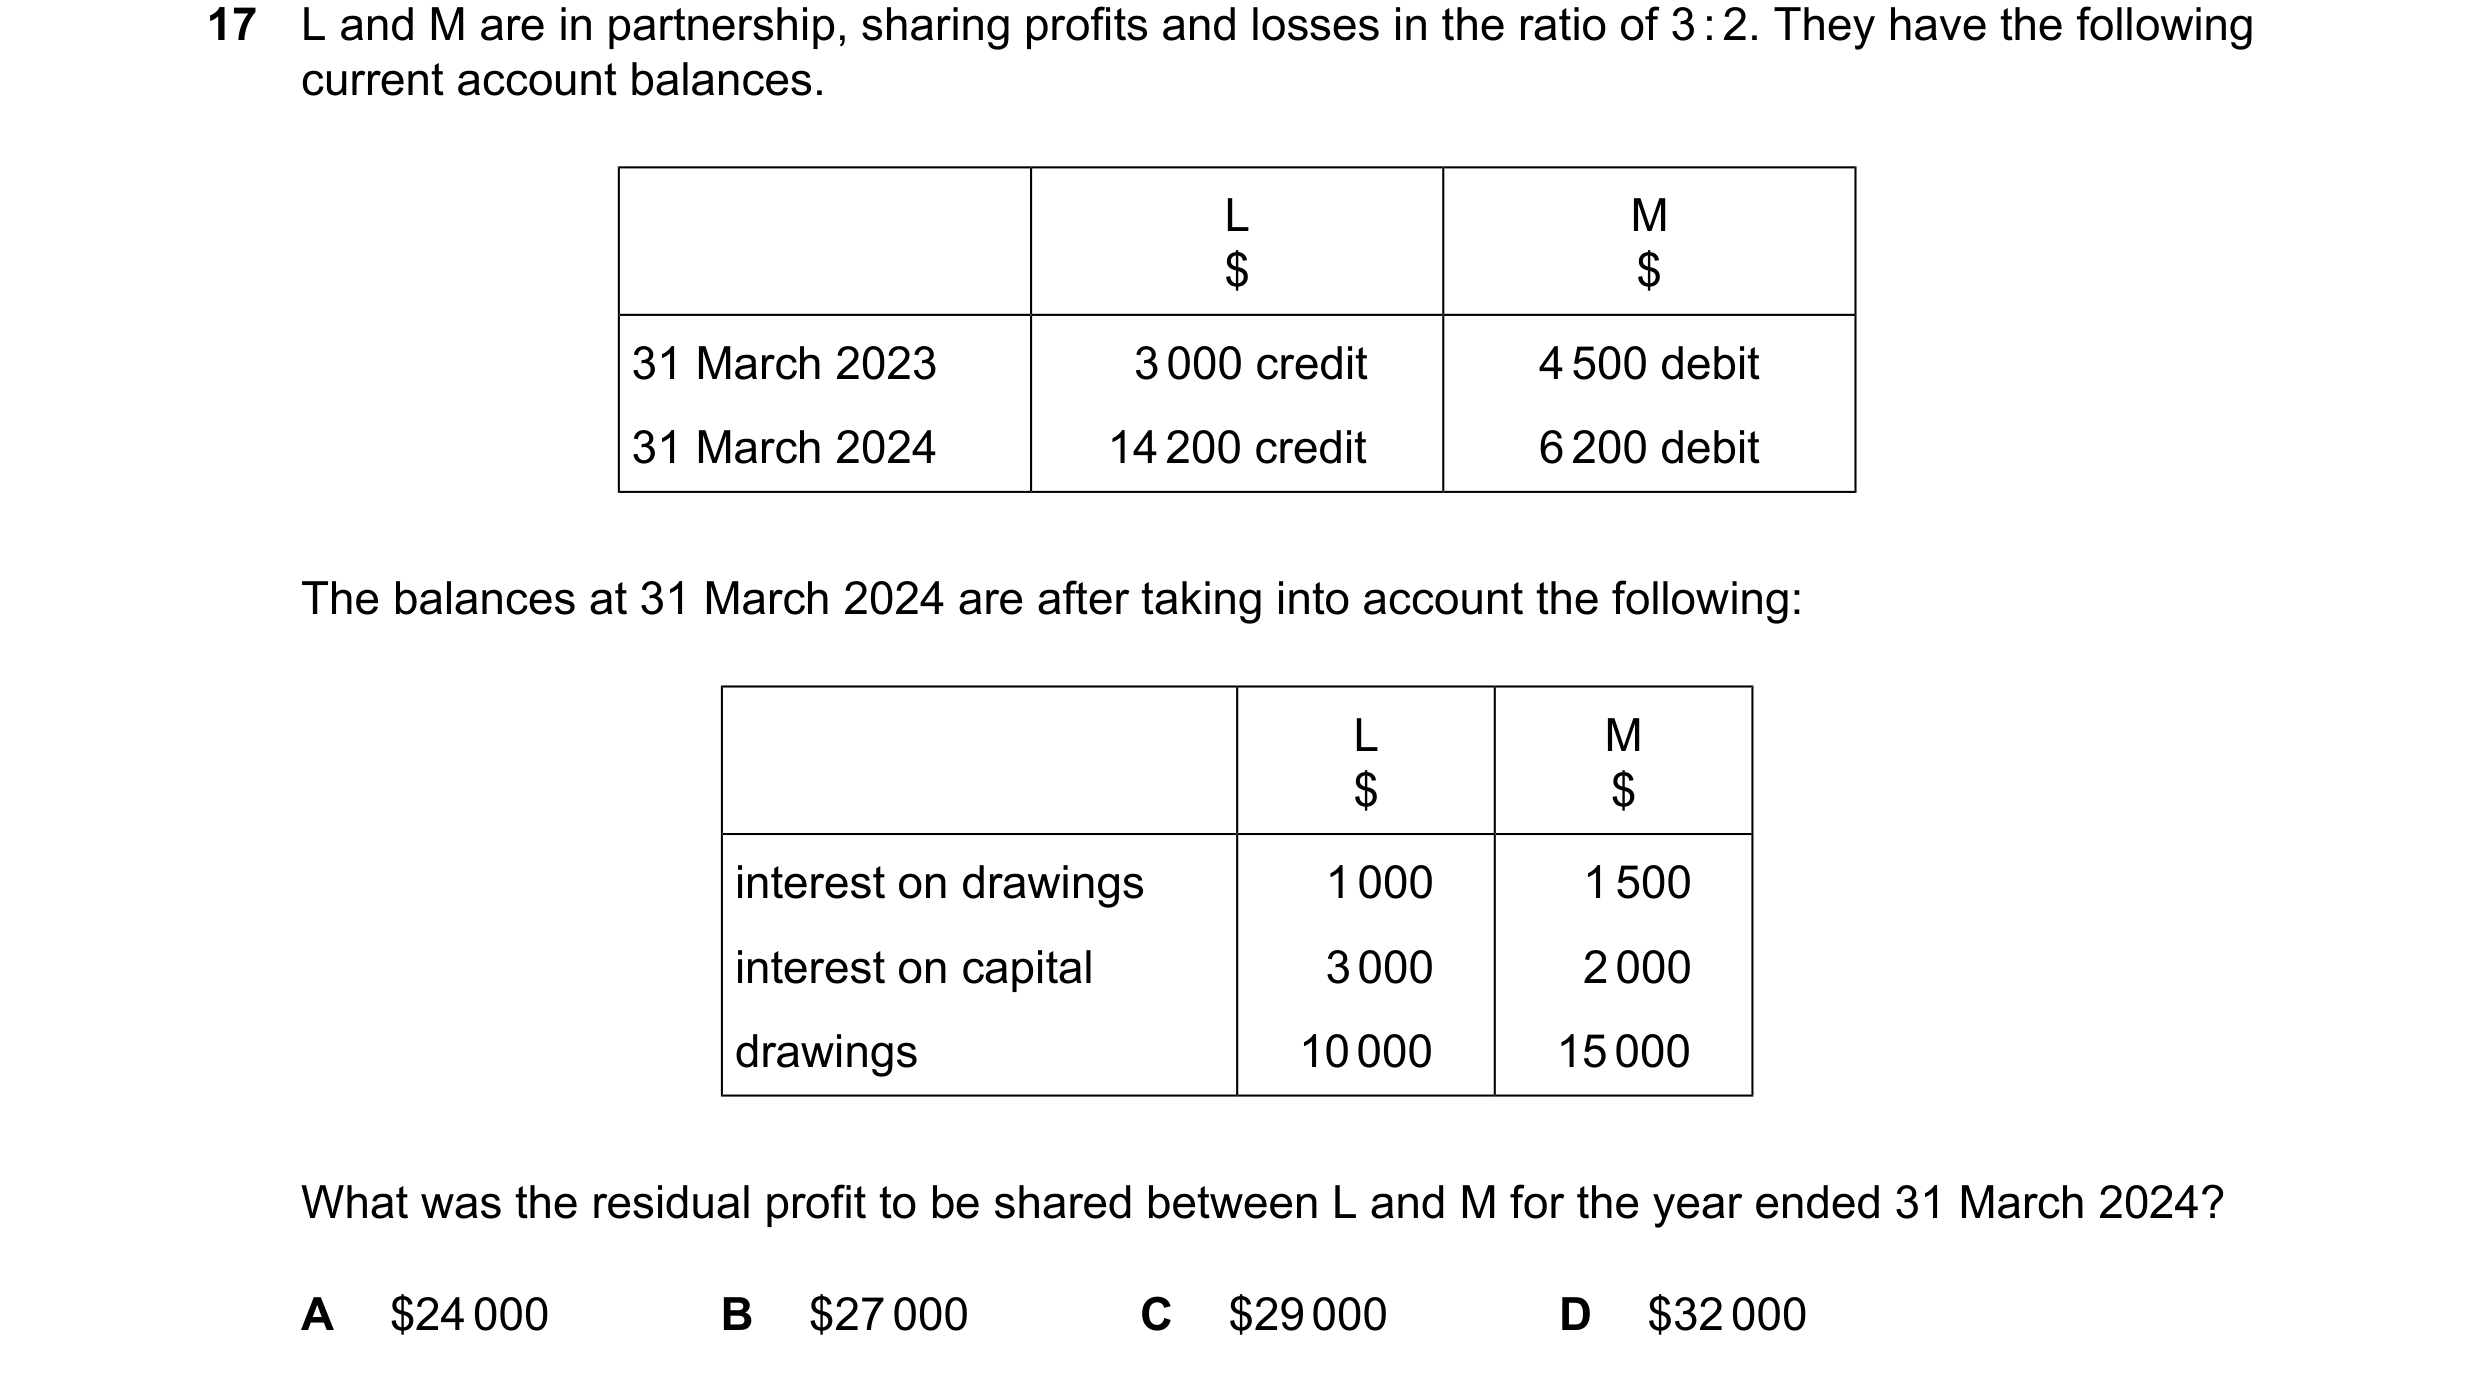
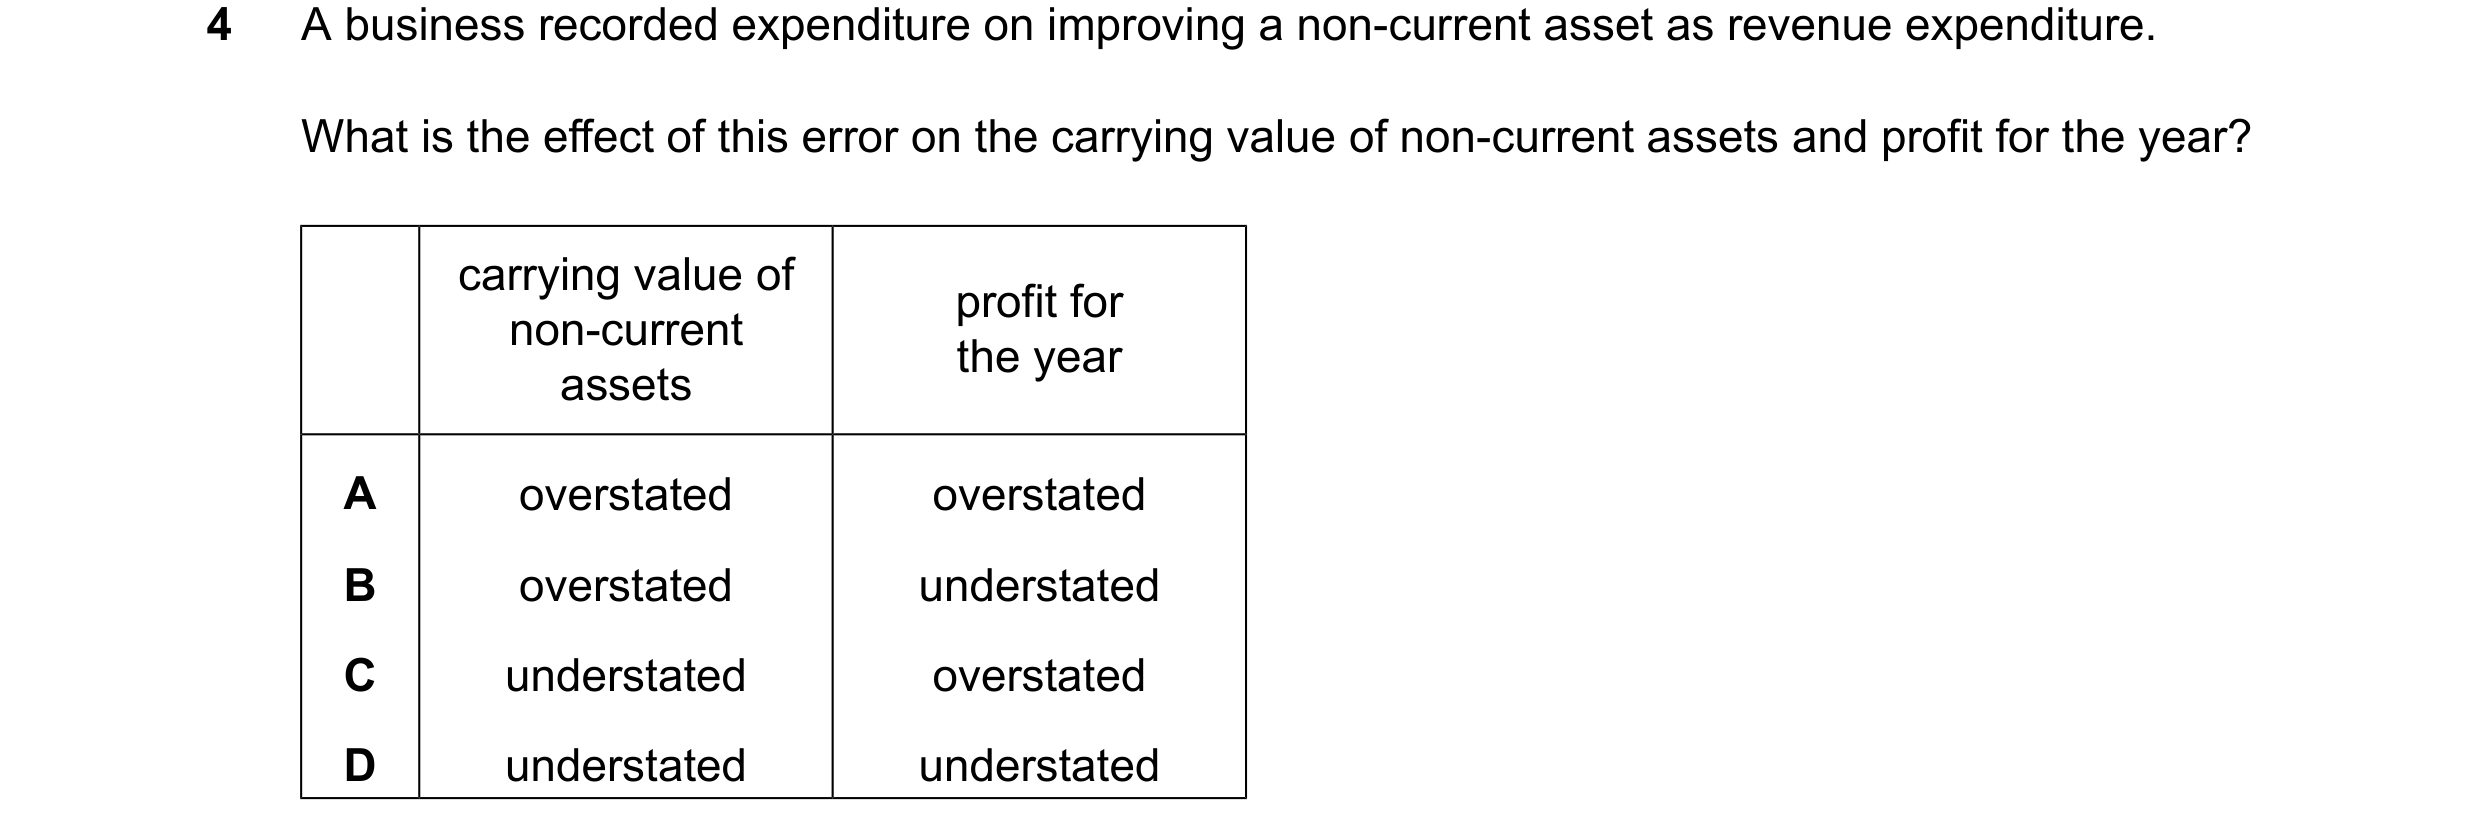
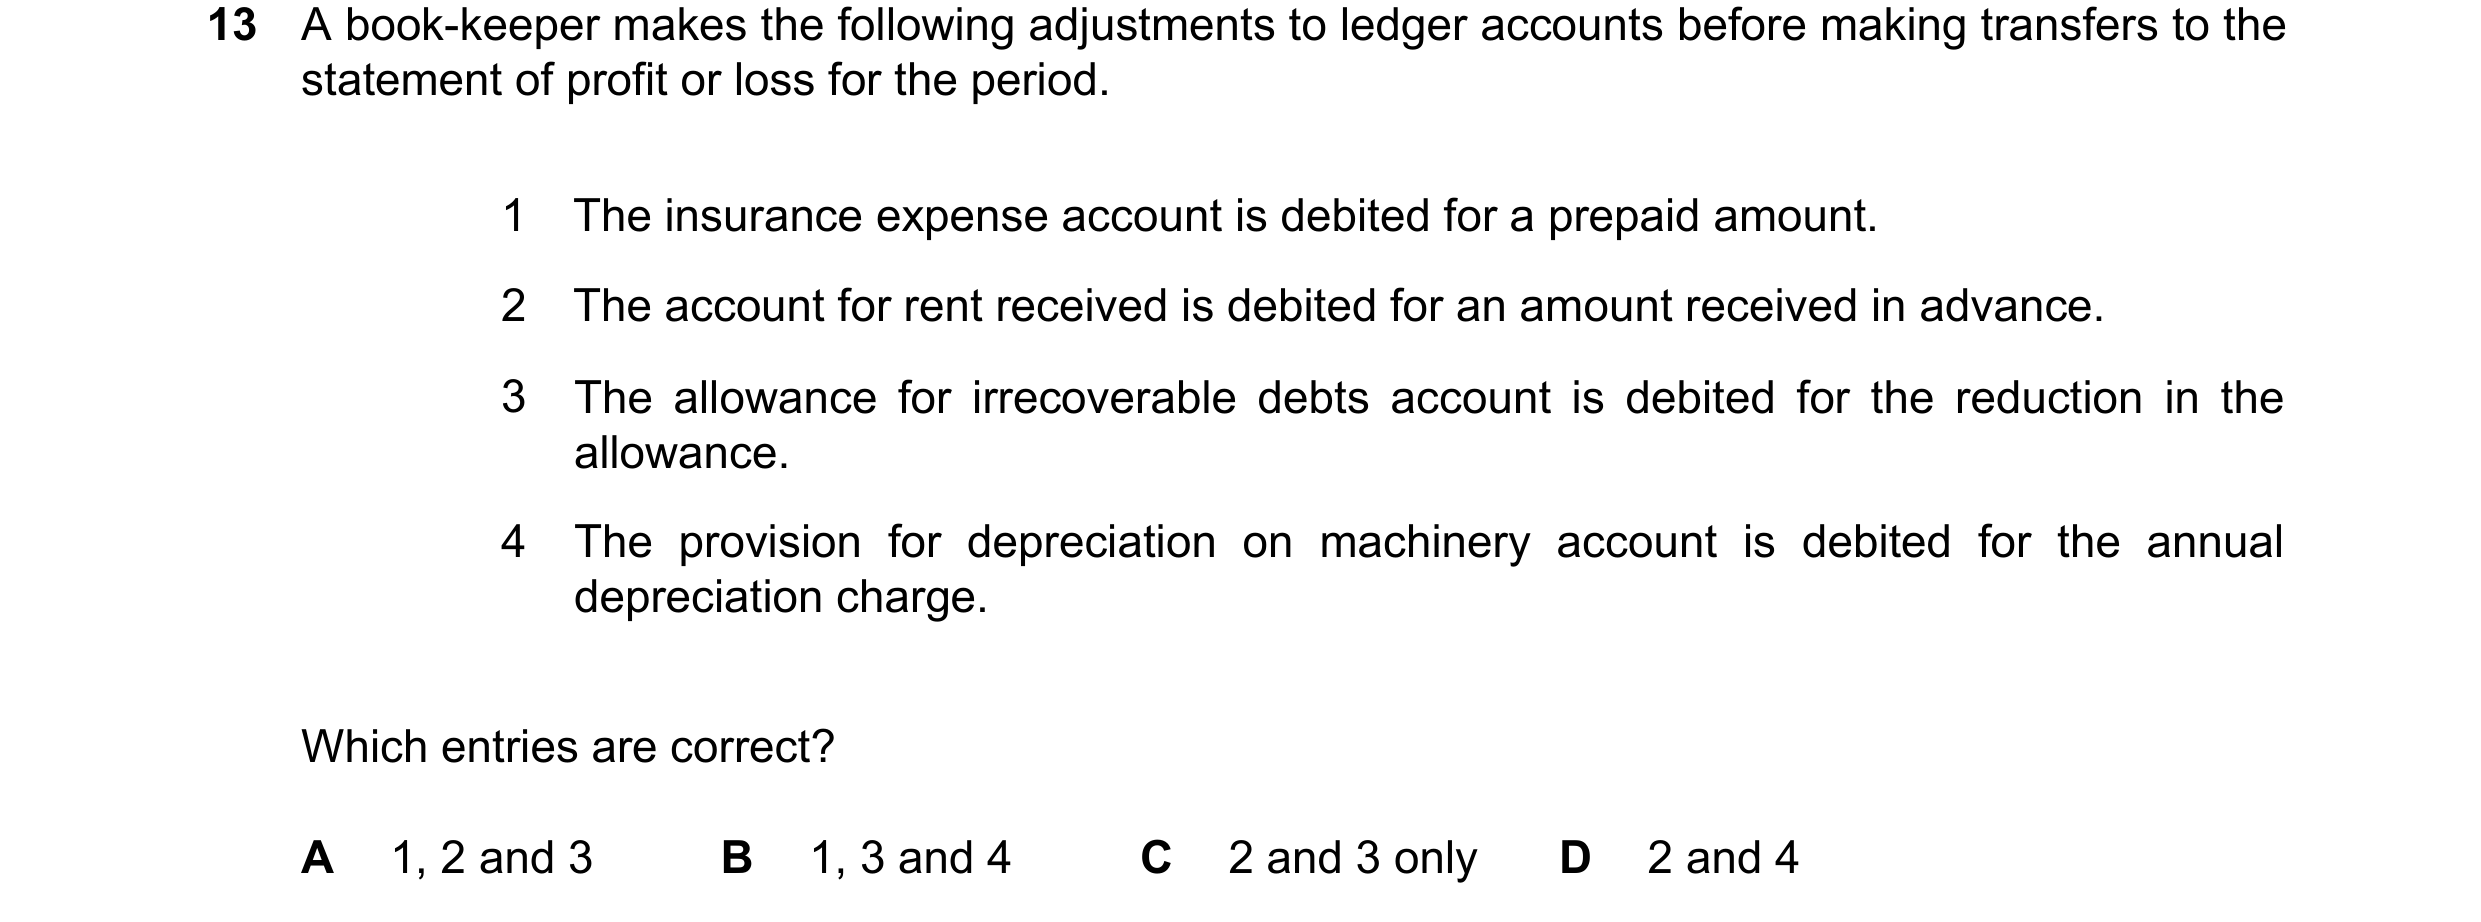 221 / 233
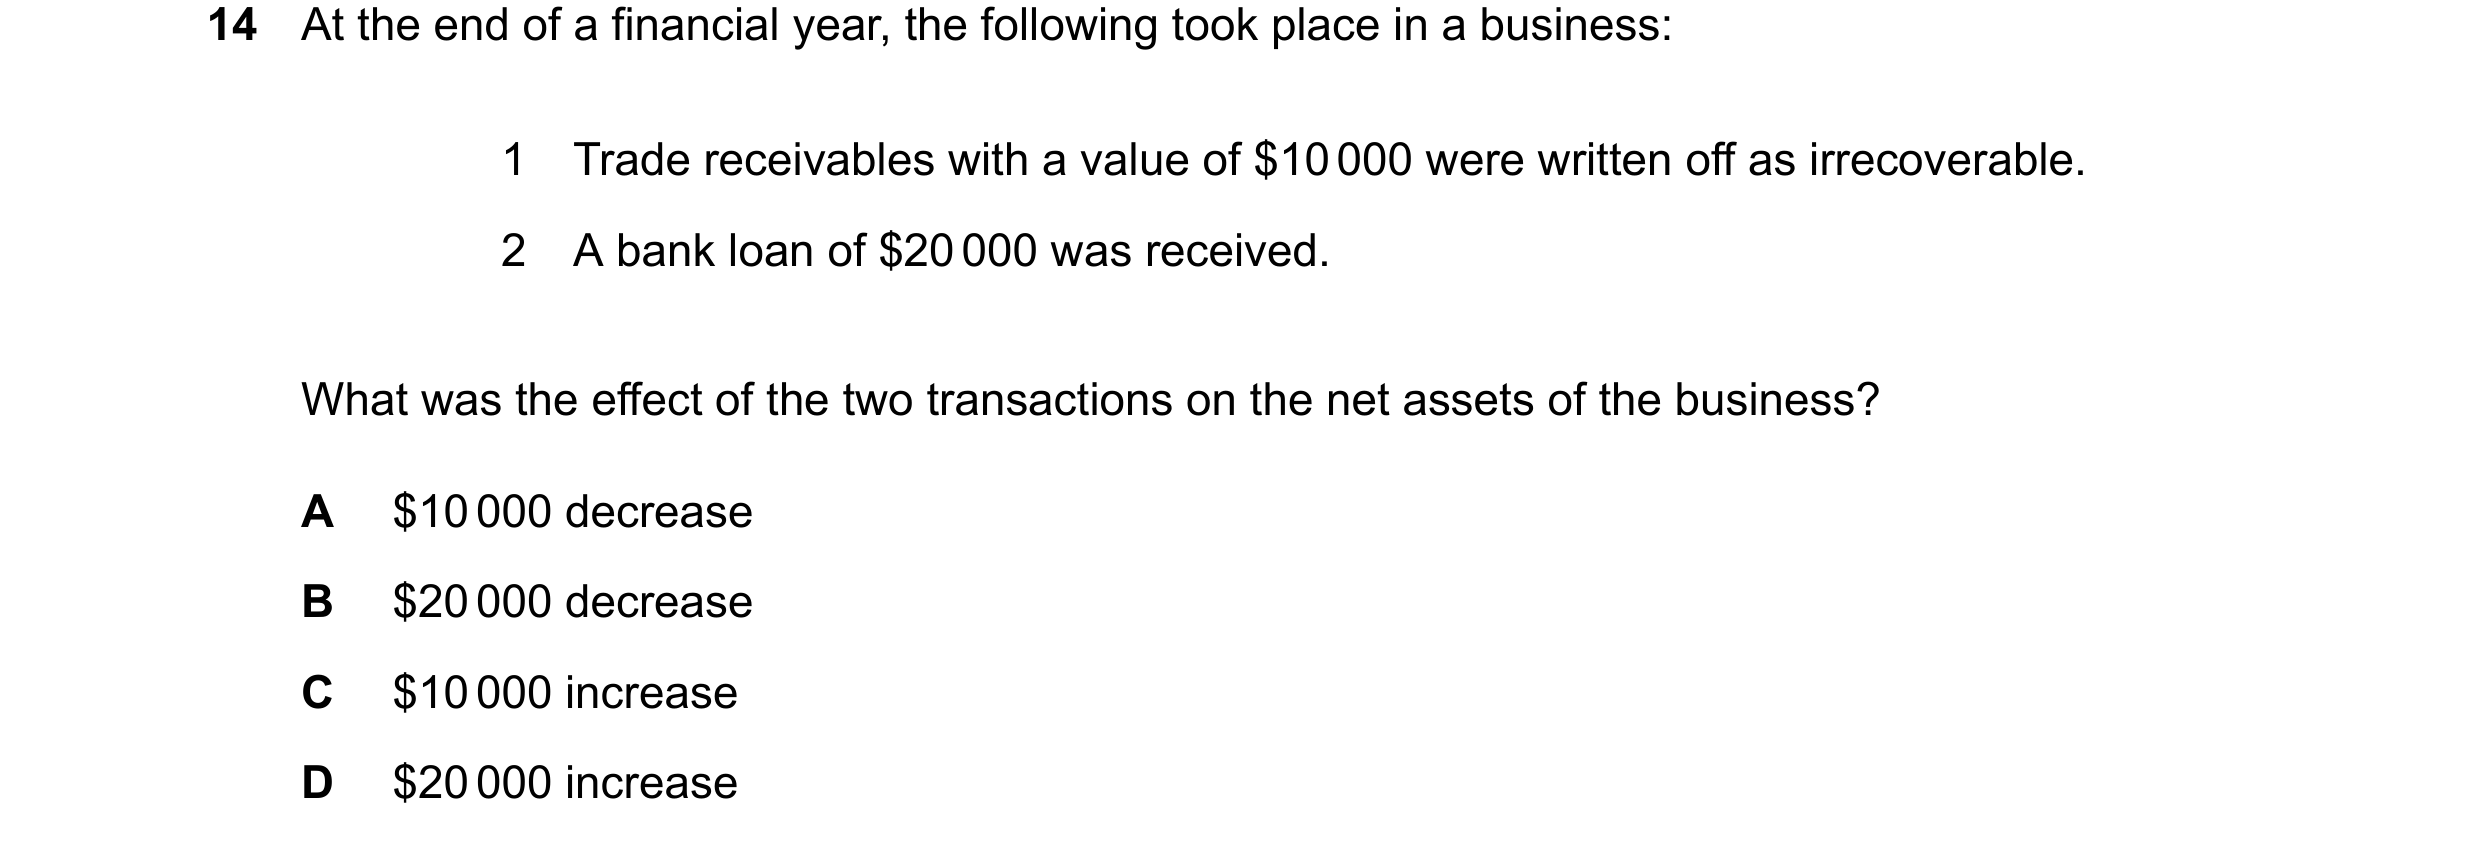
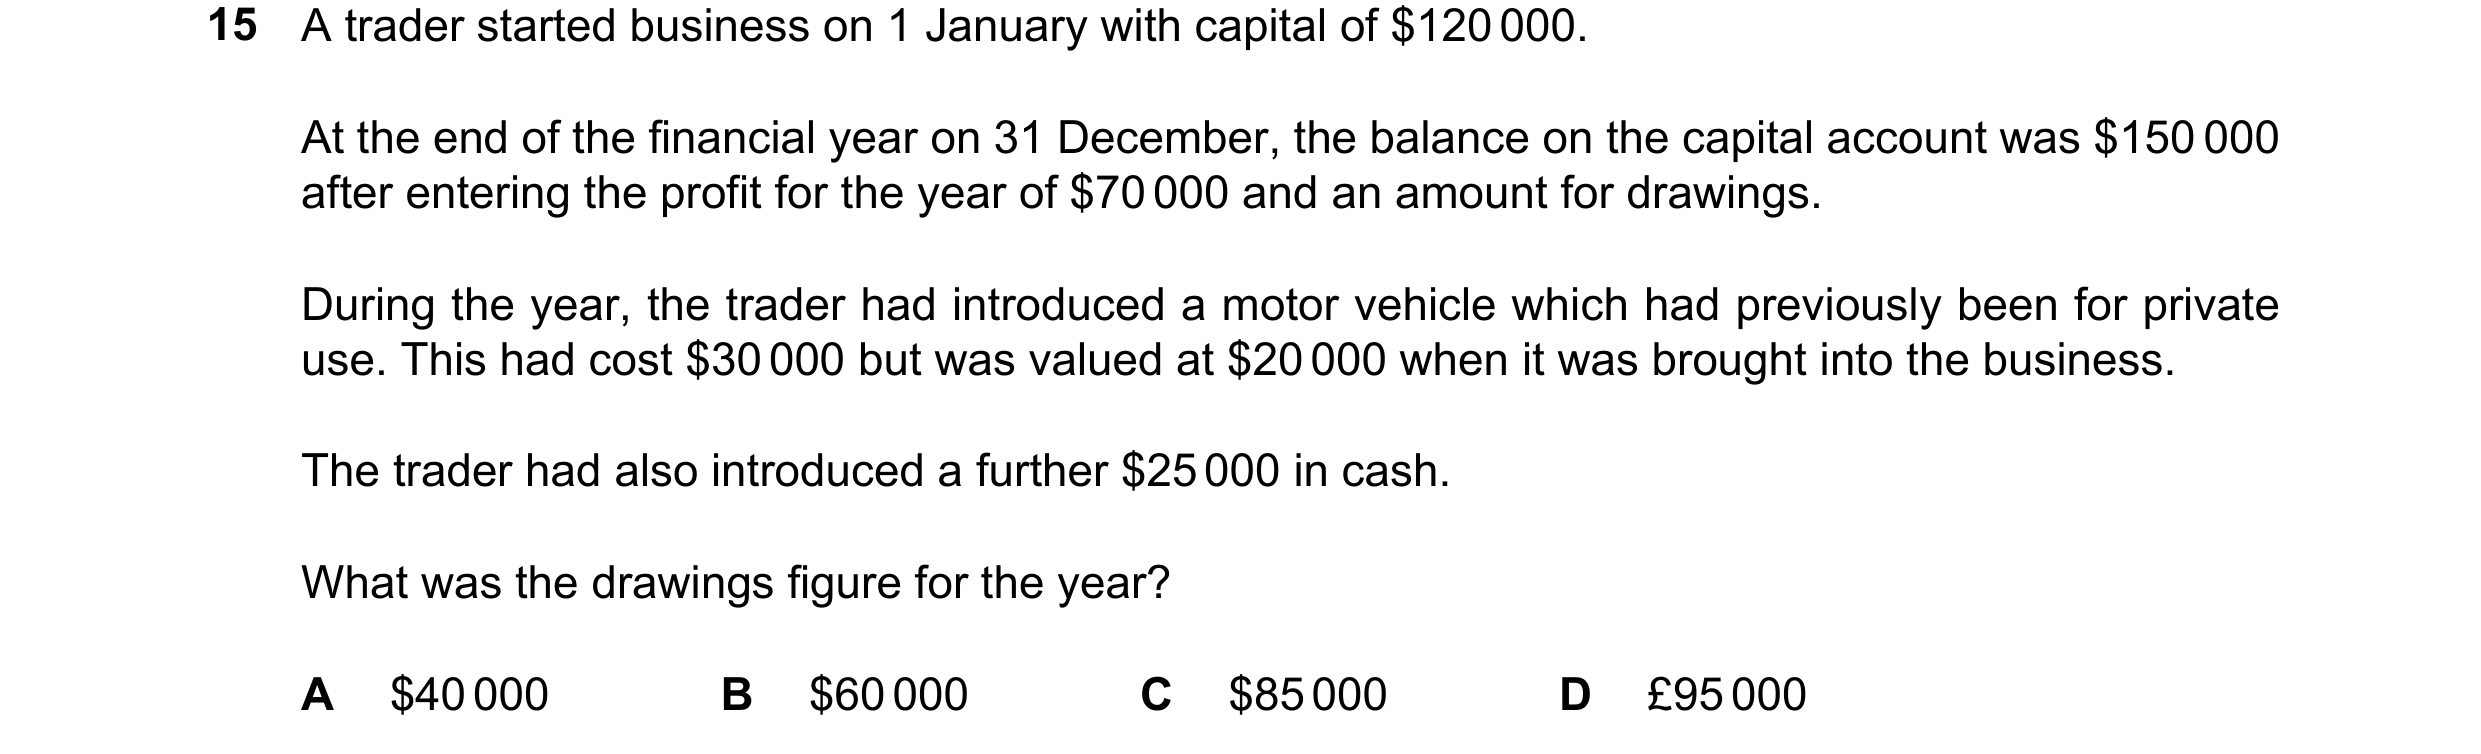
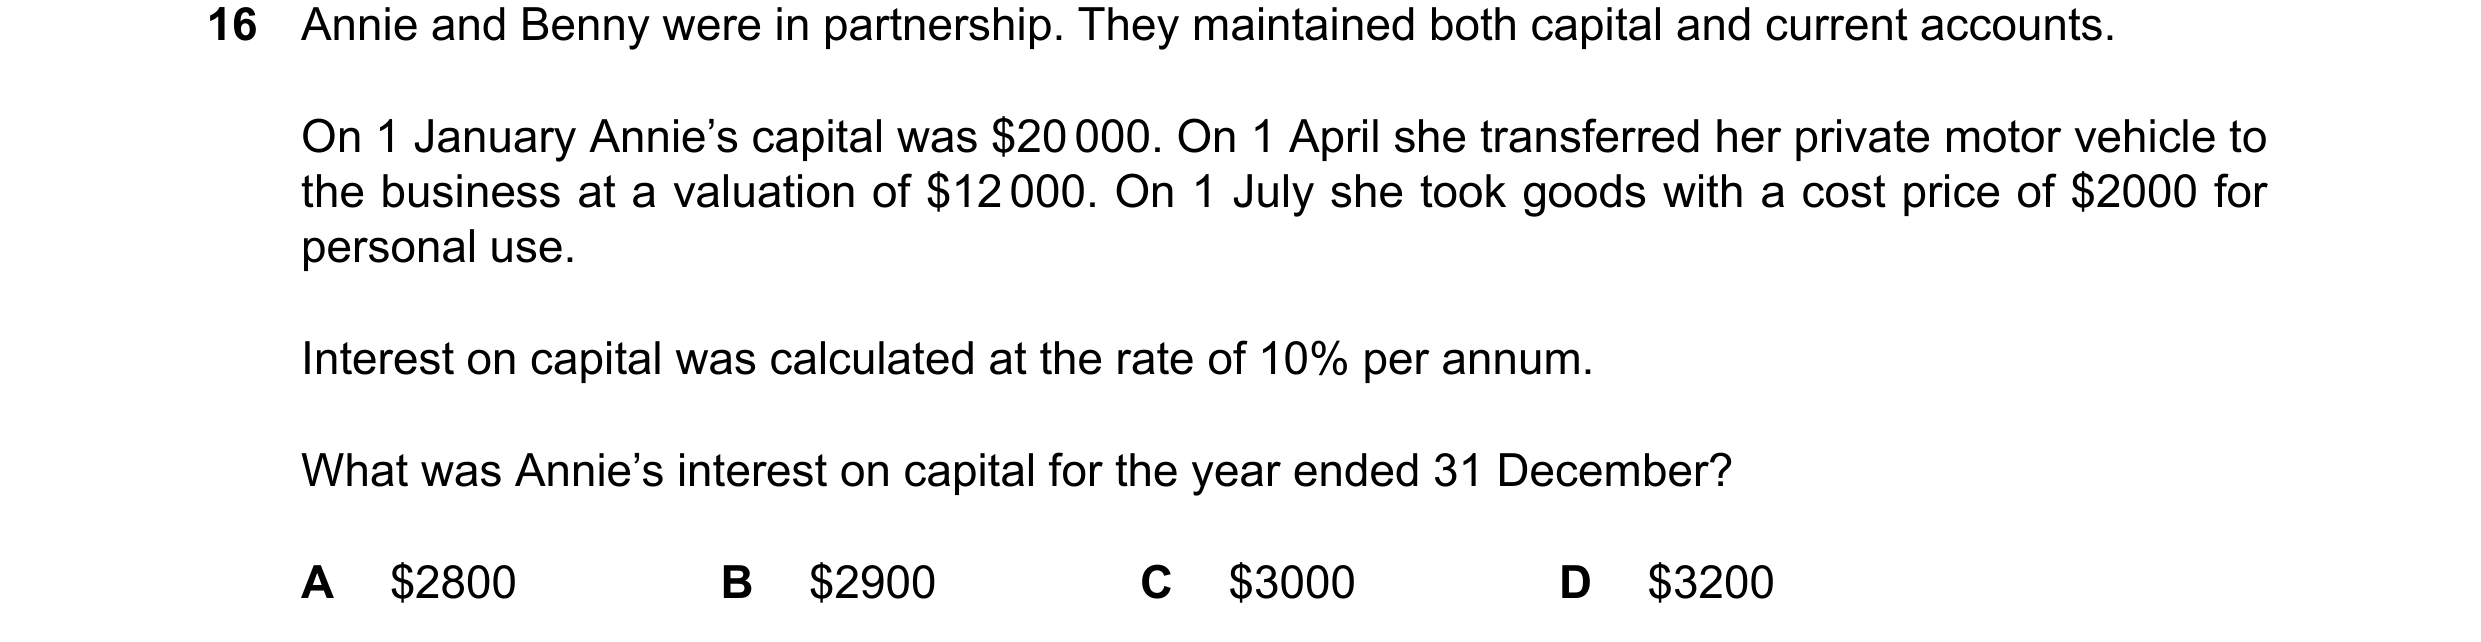
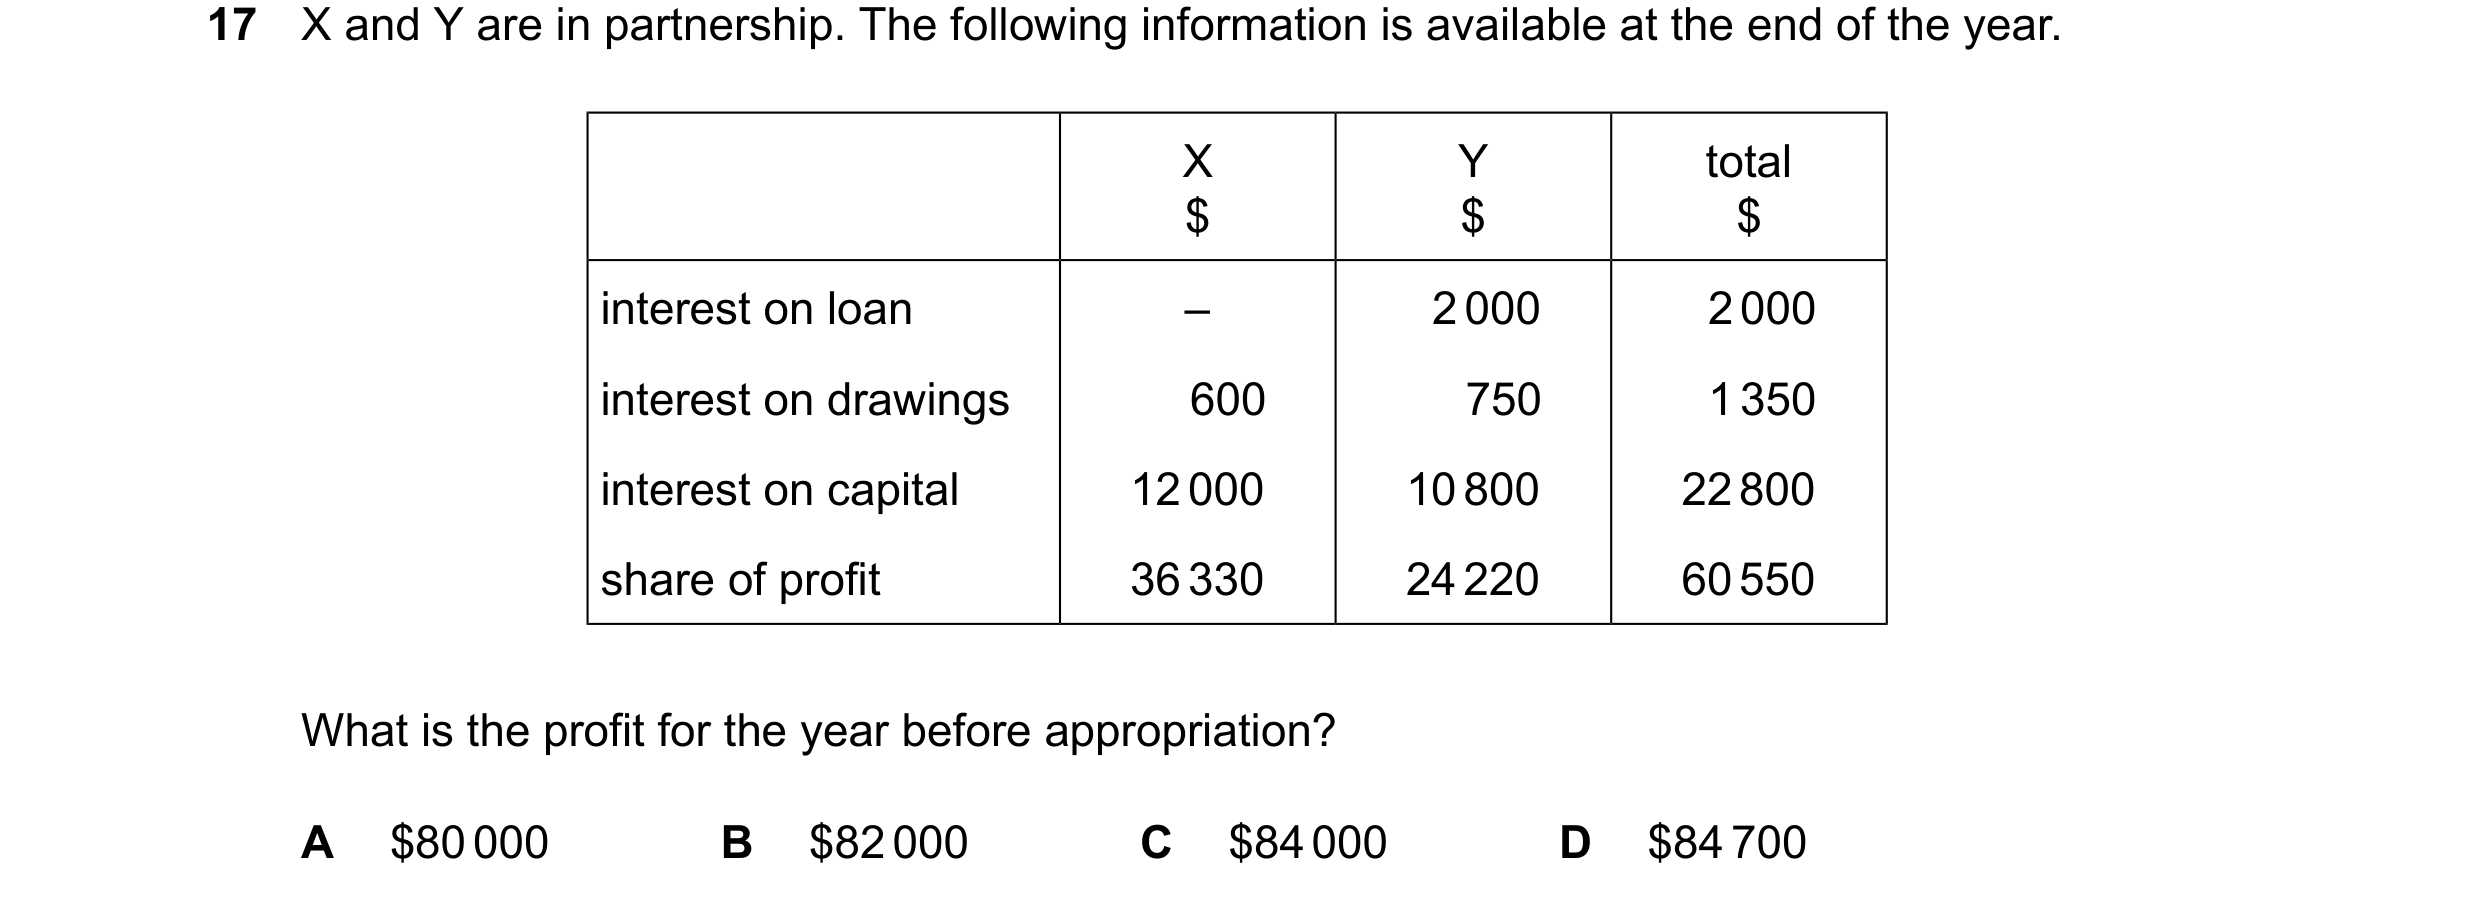 222 / 233
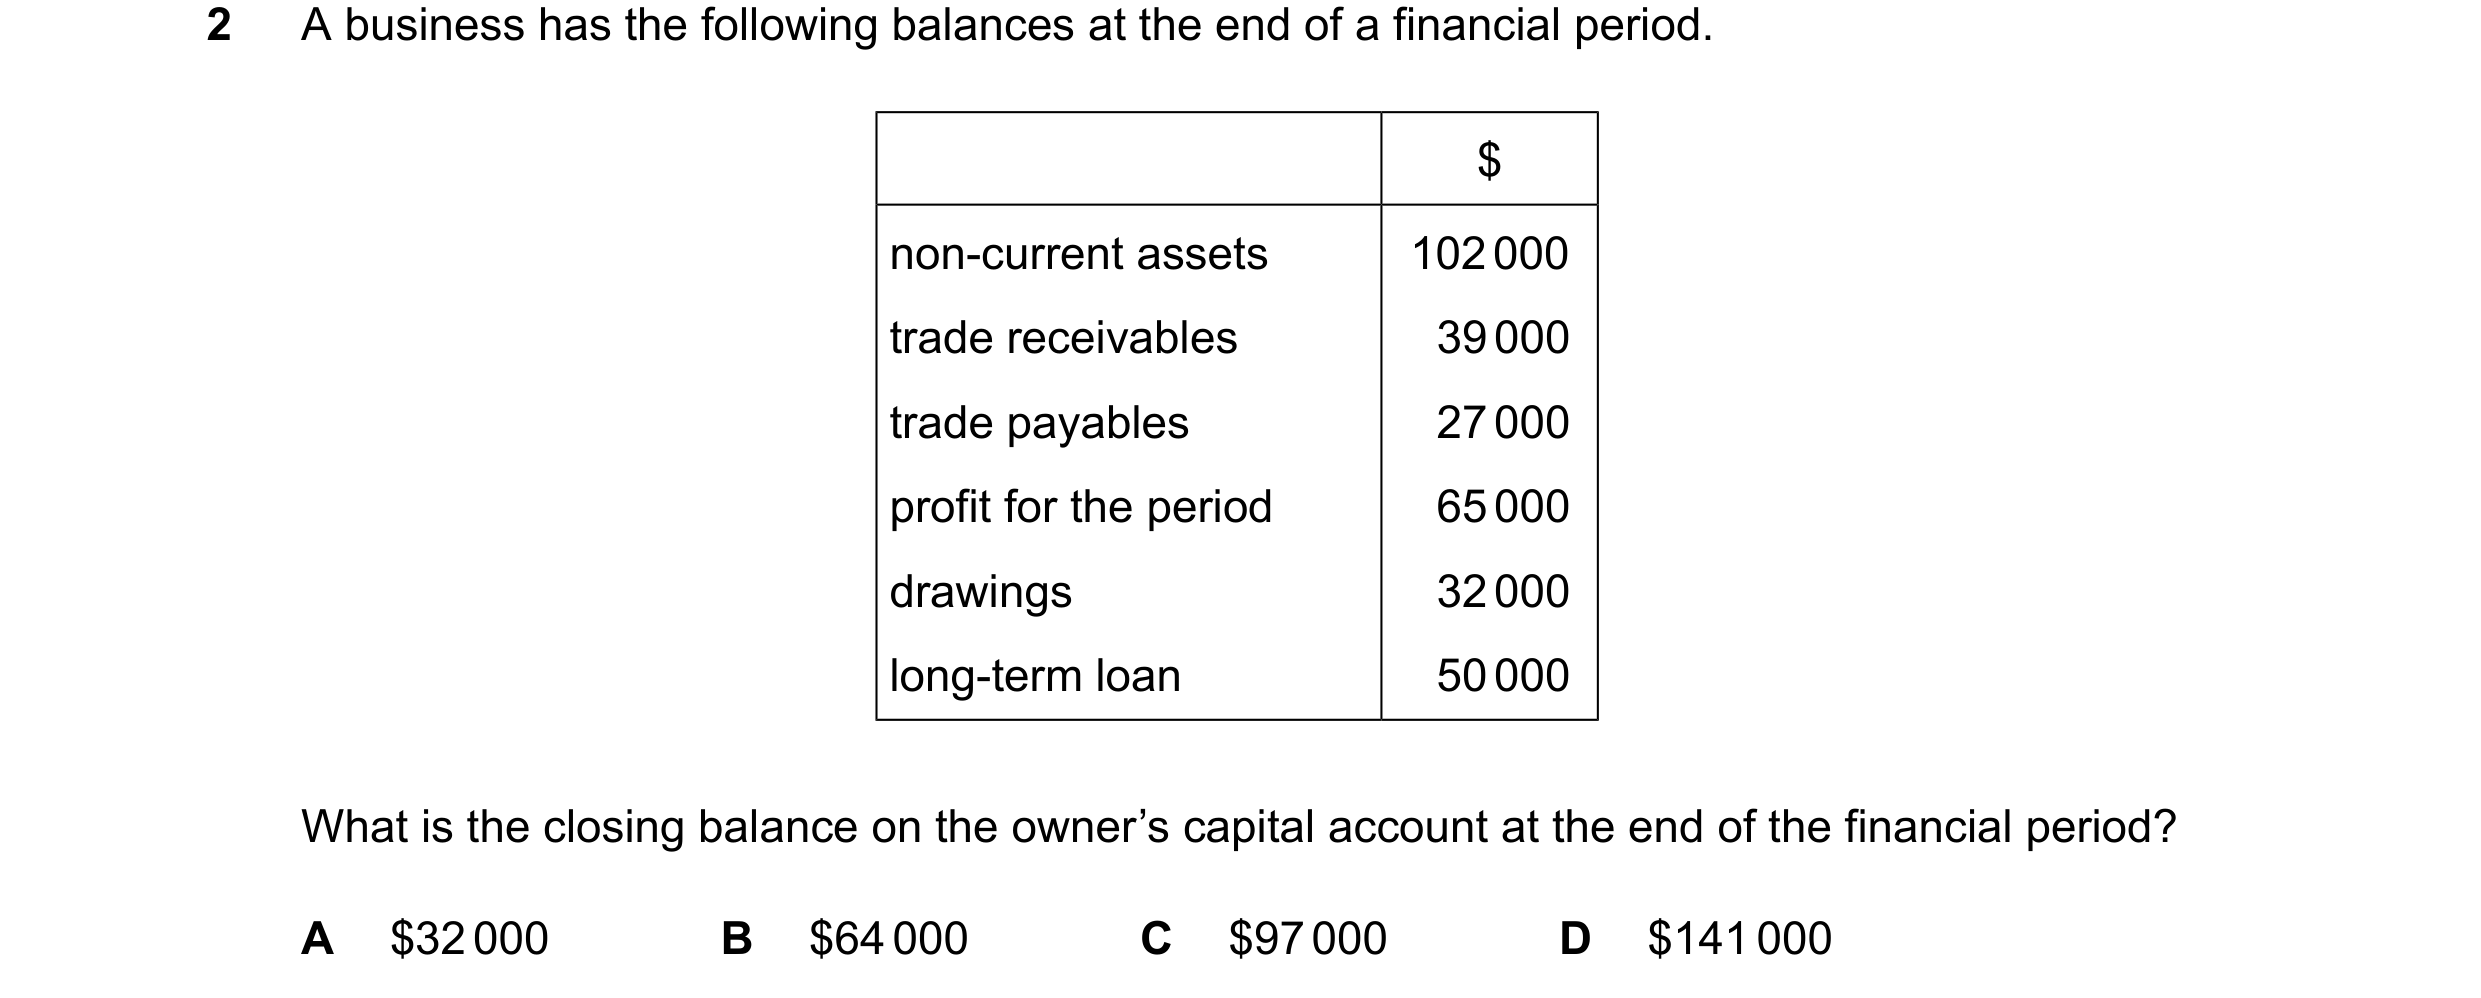
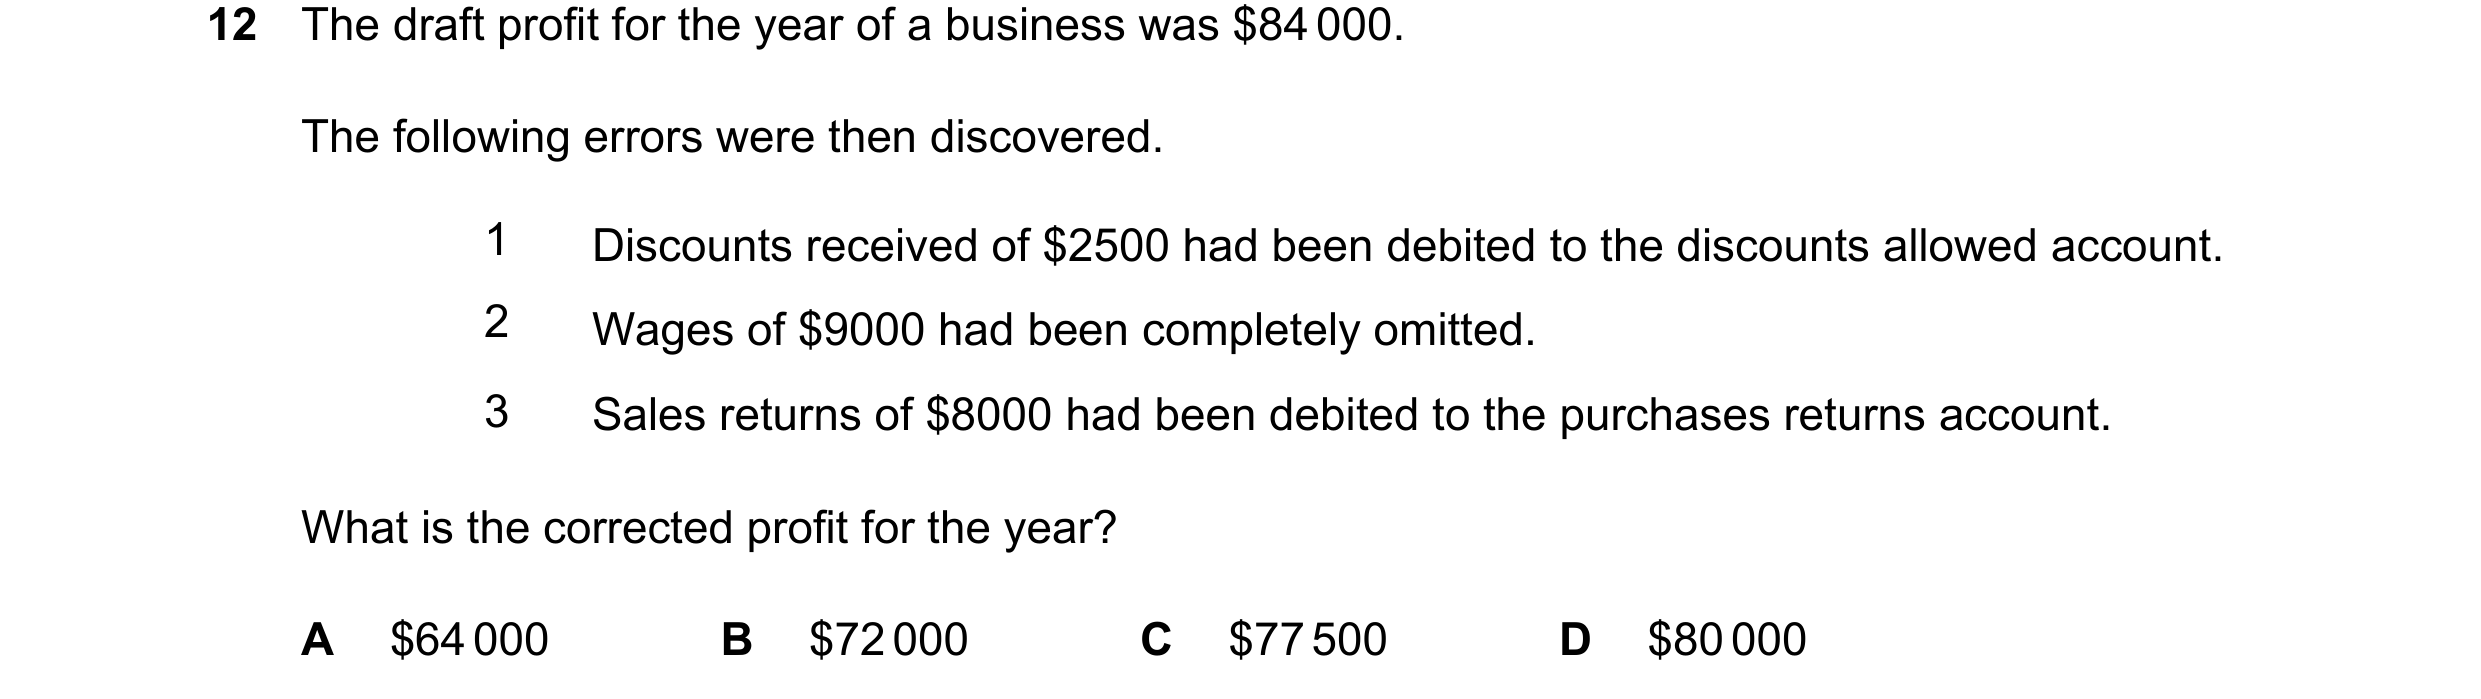
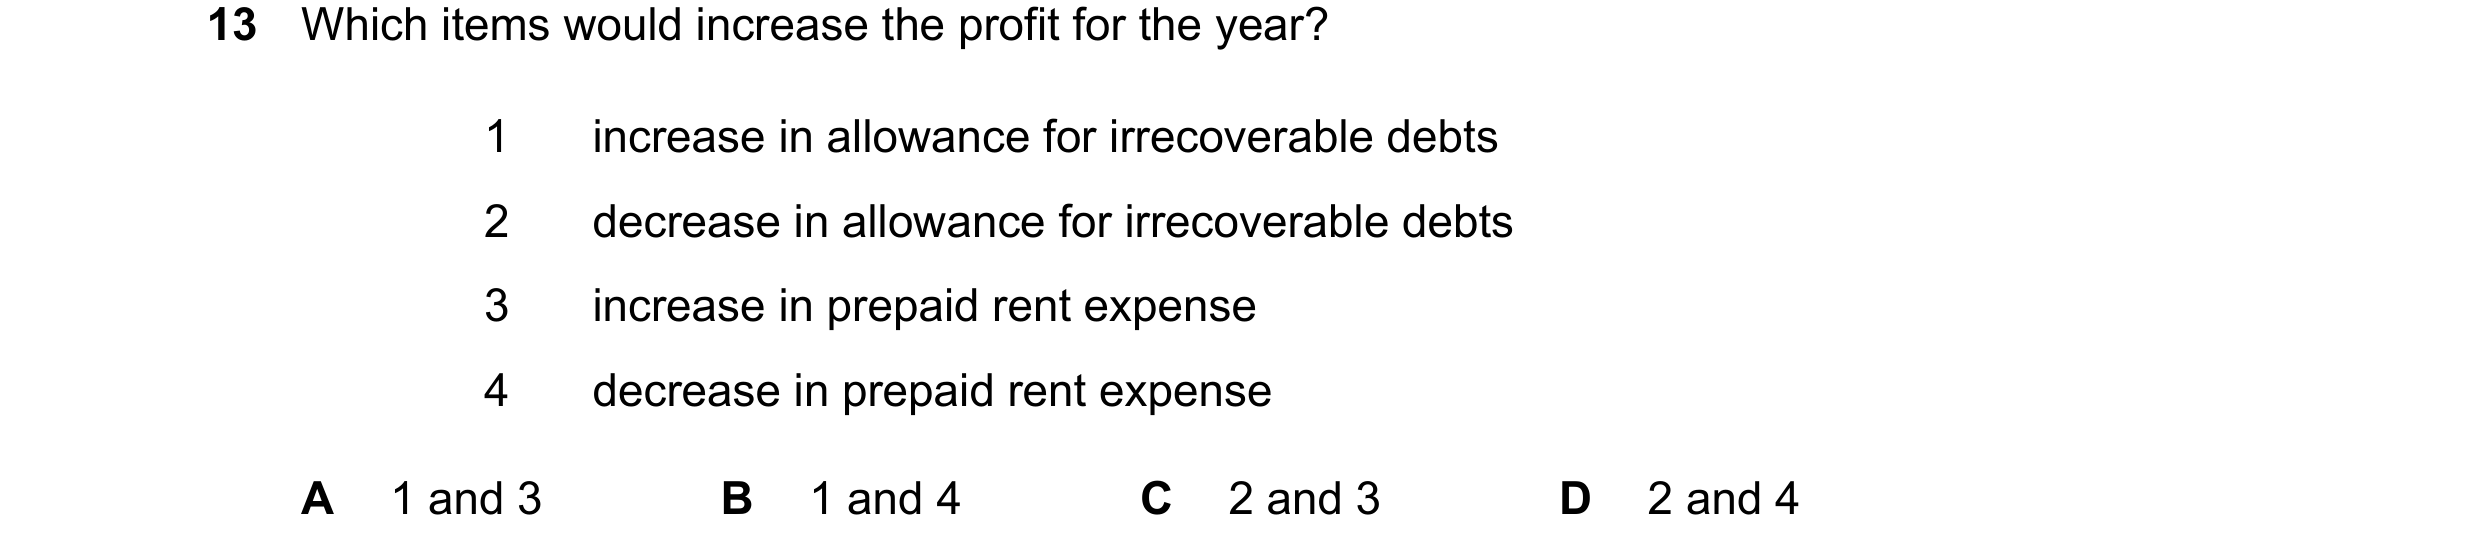
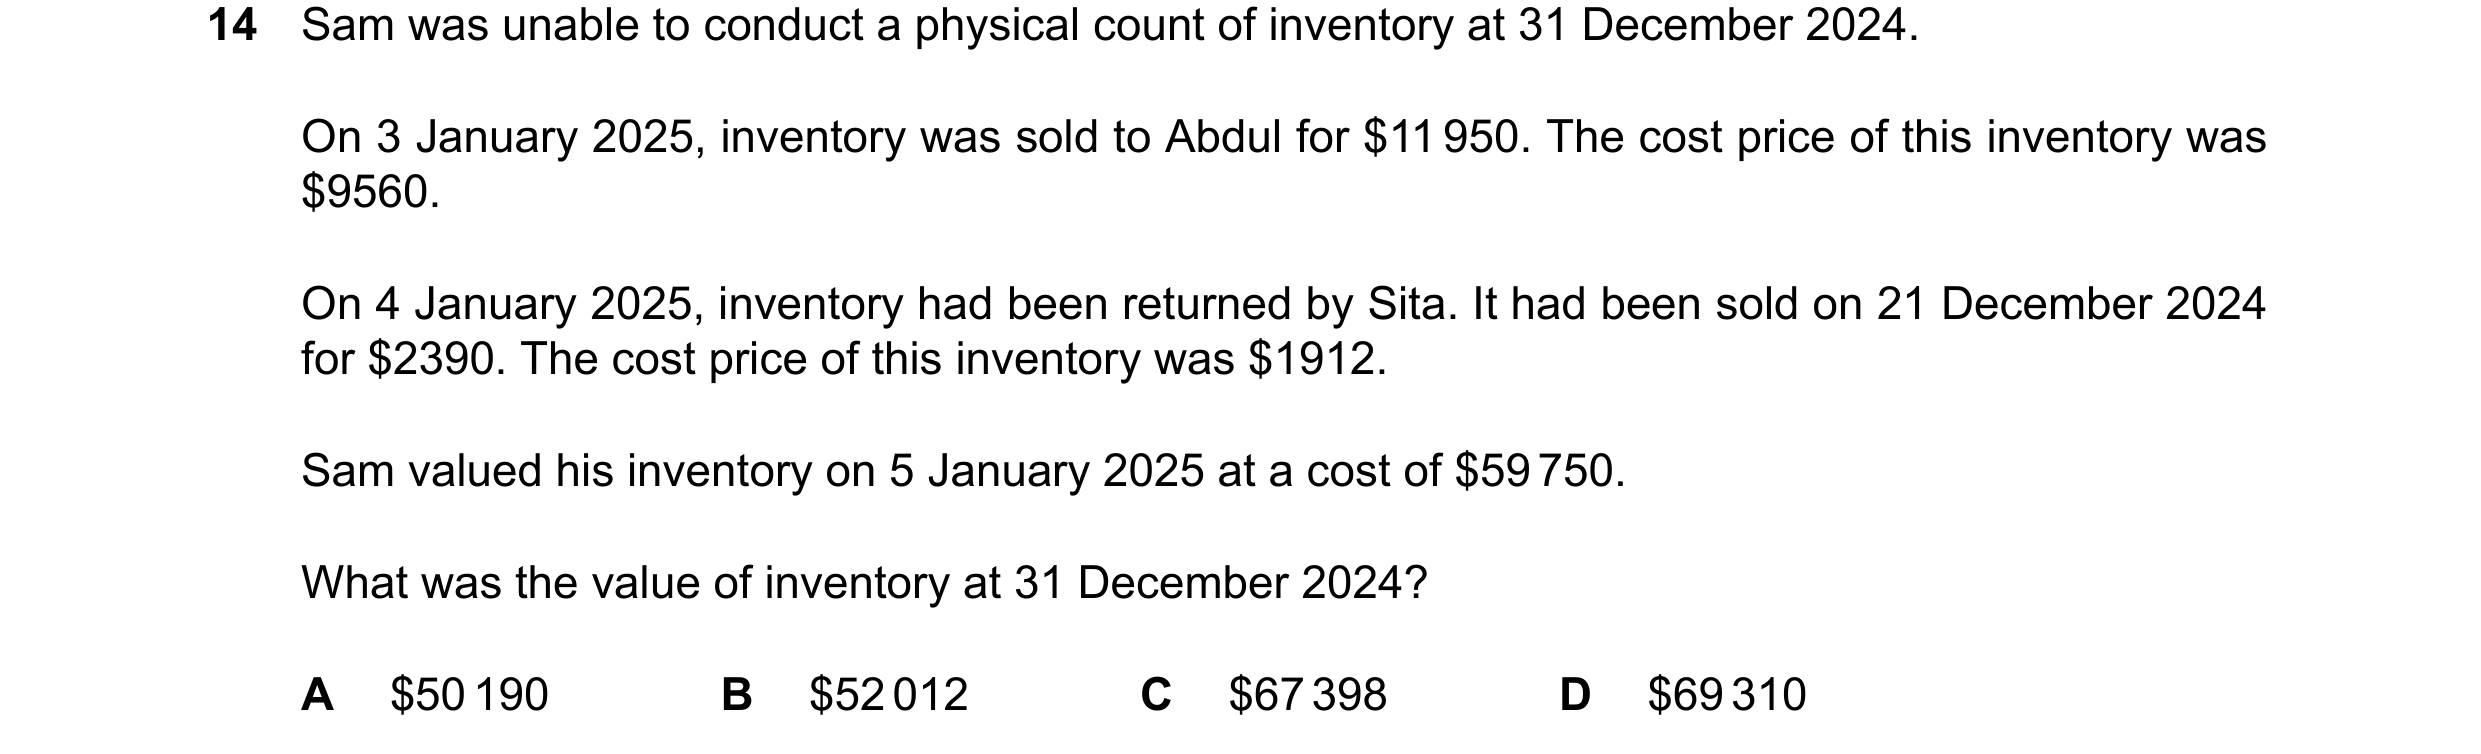 223 / 233
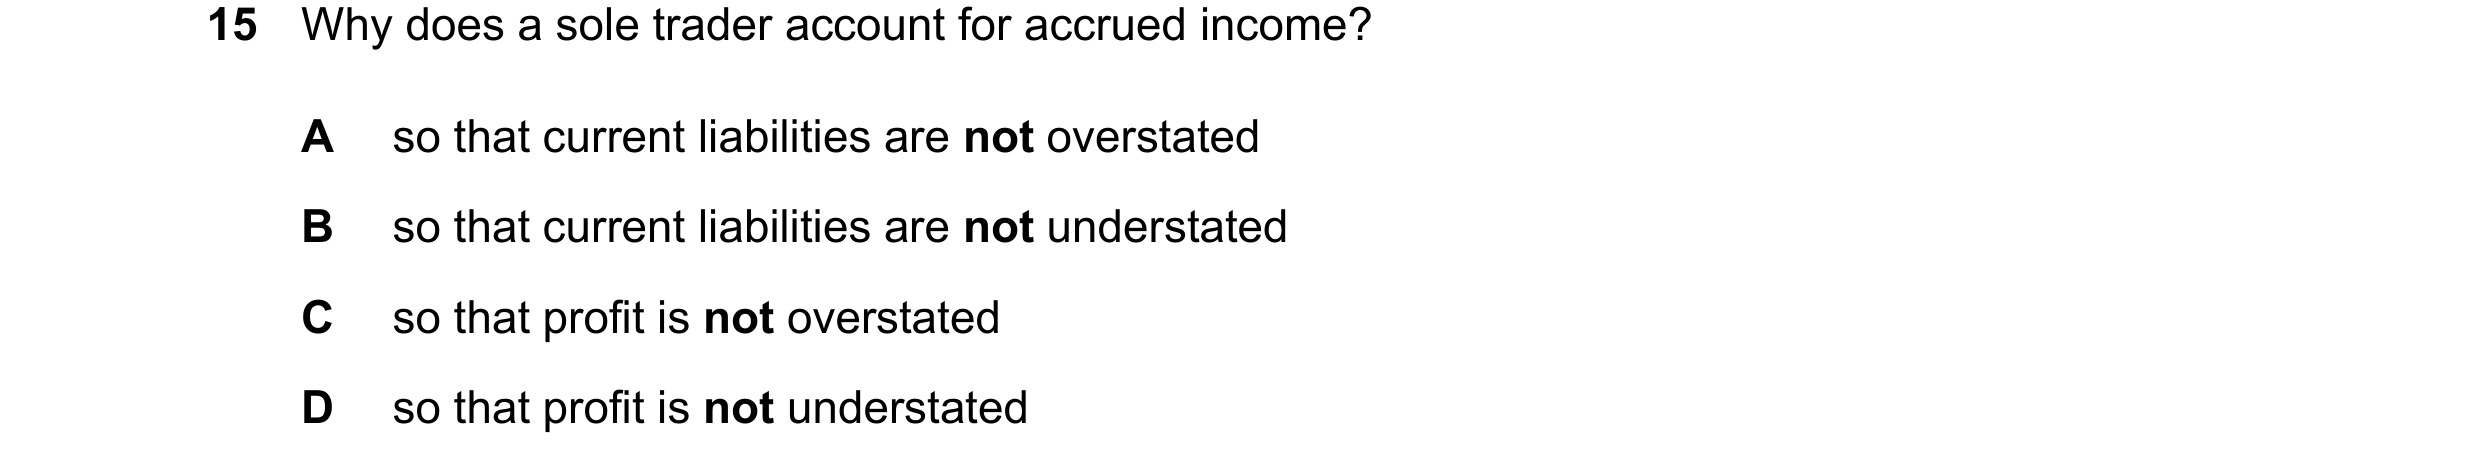
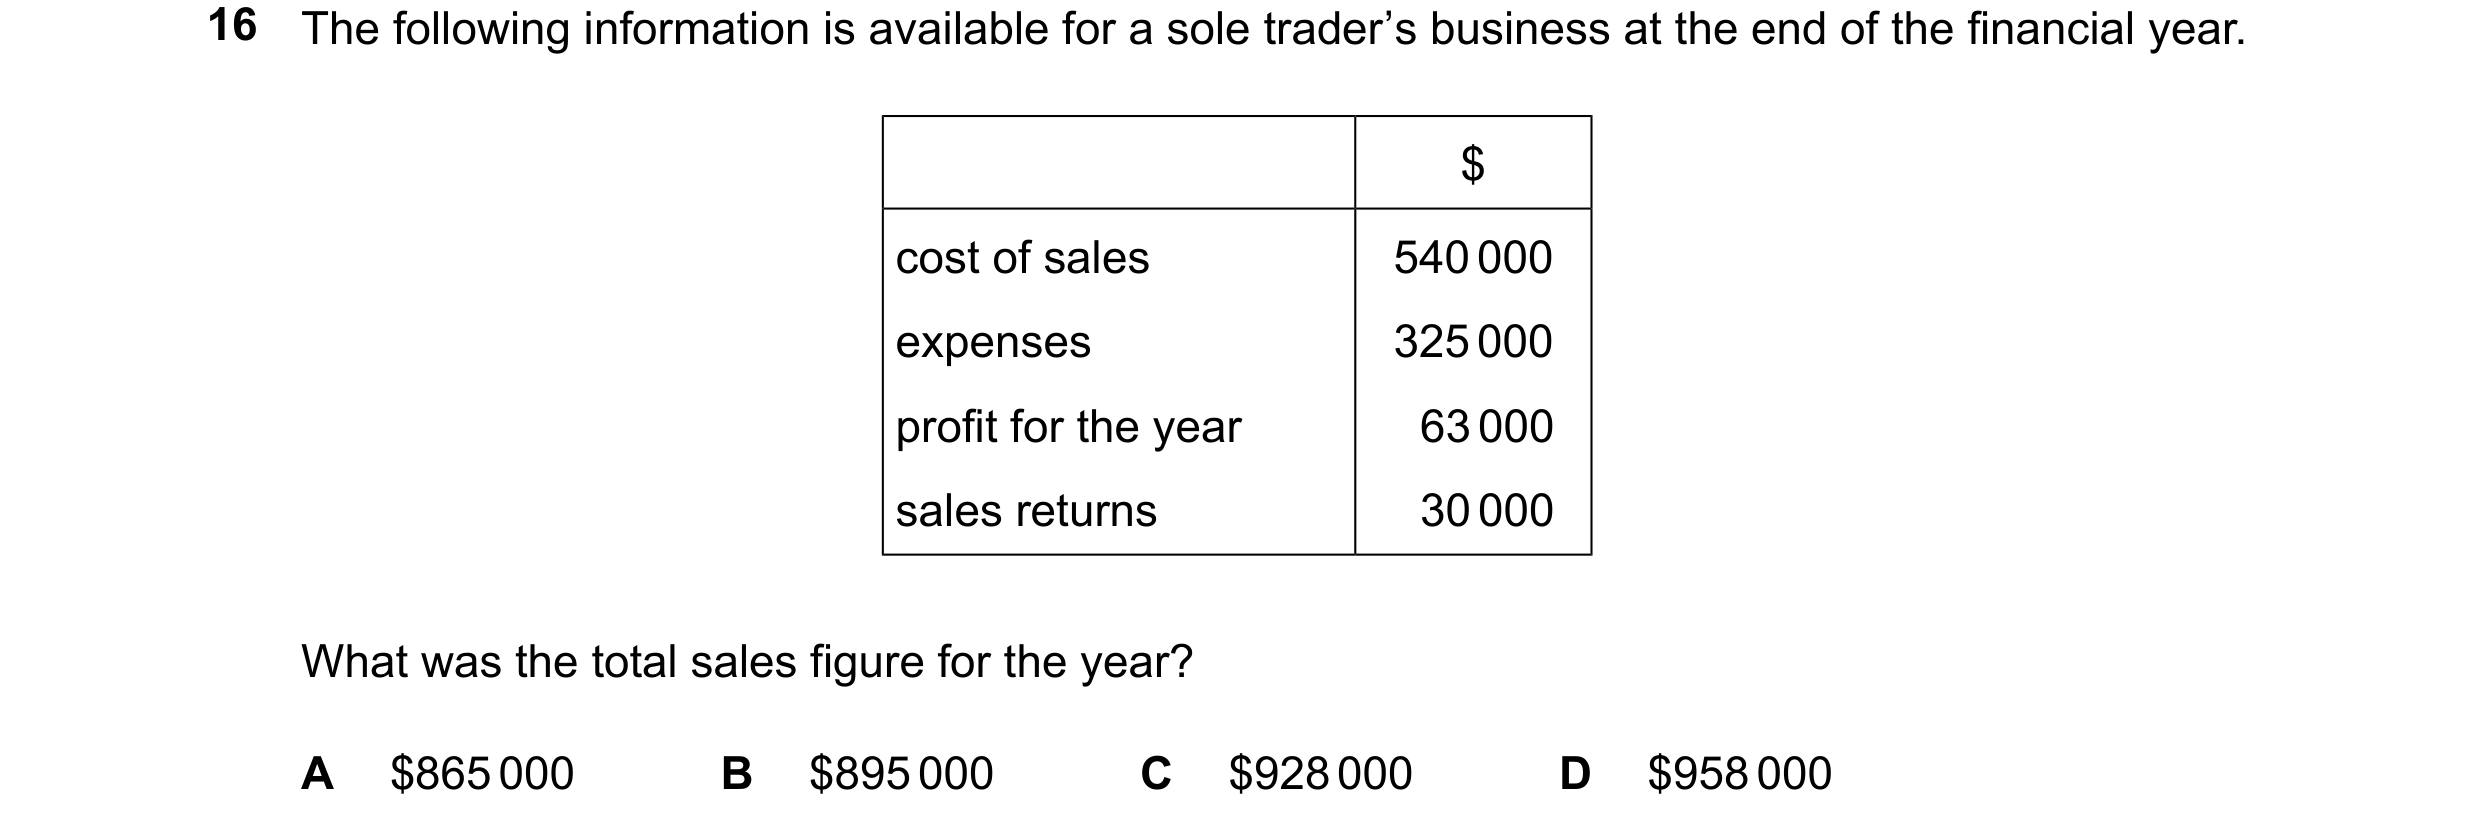
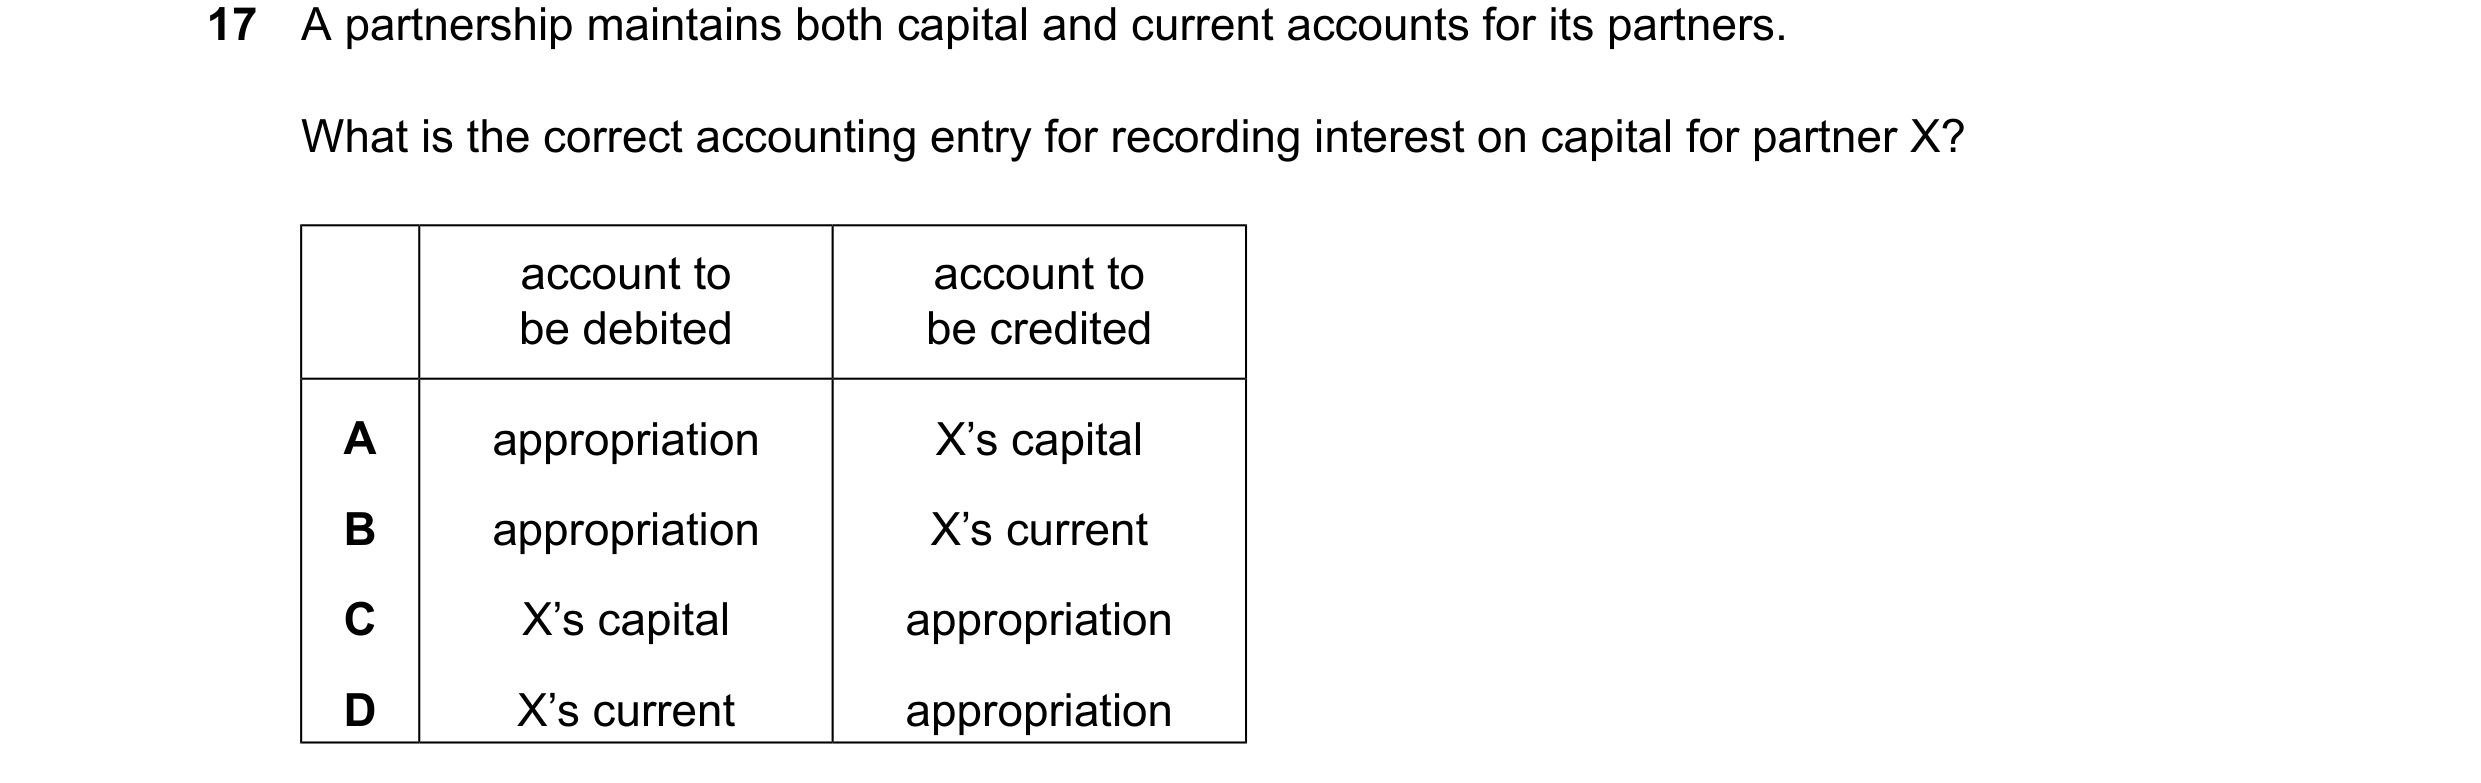
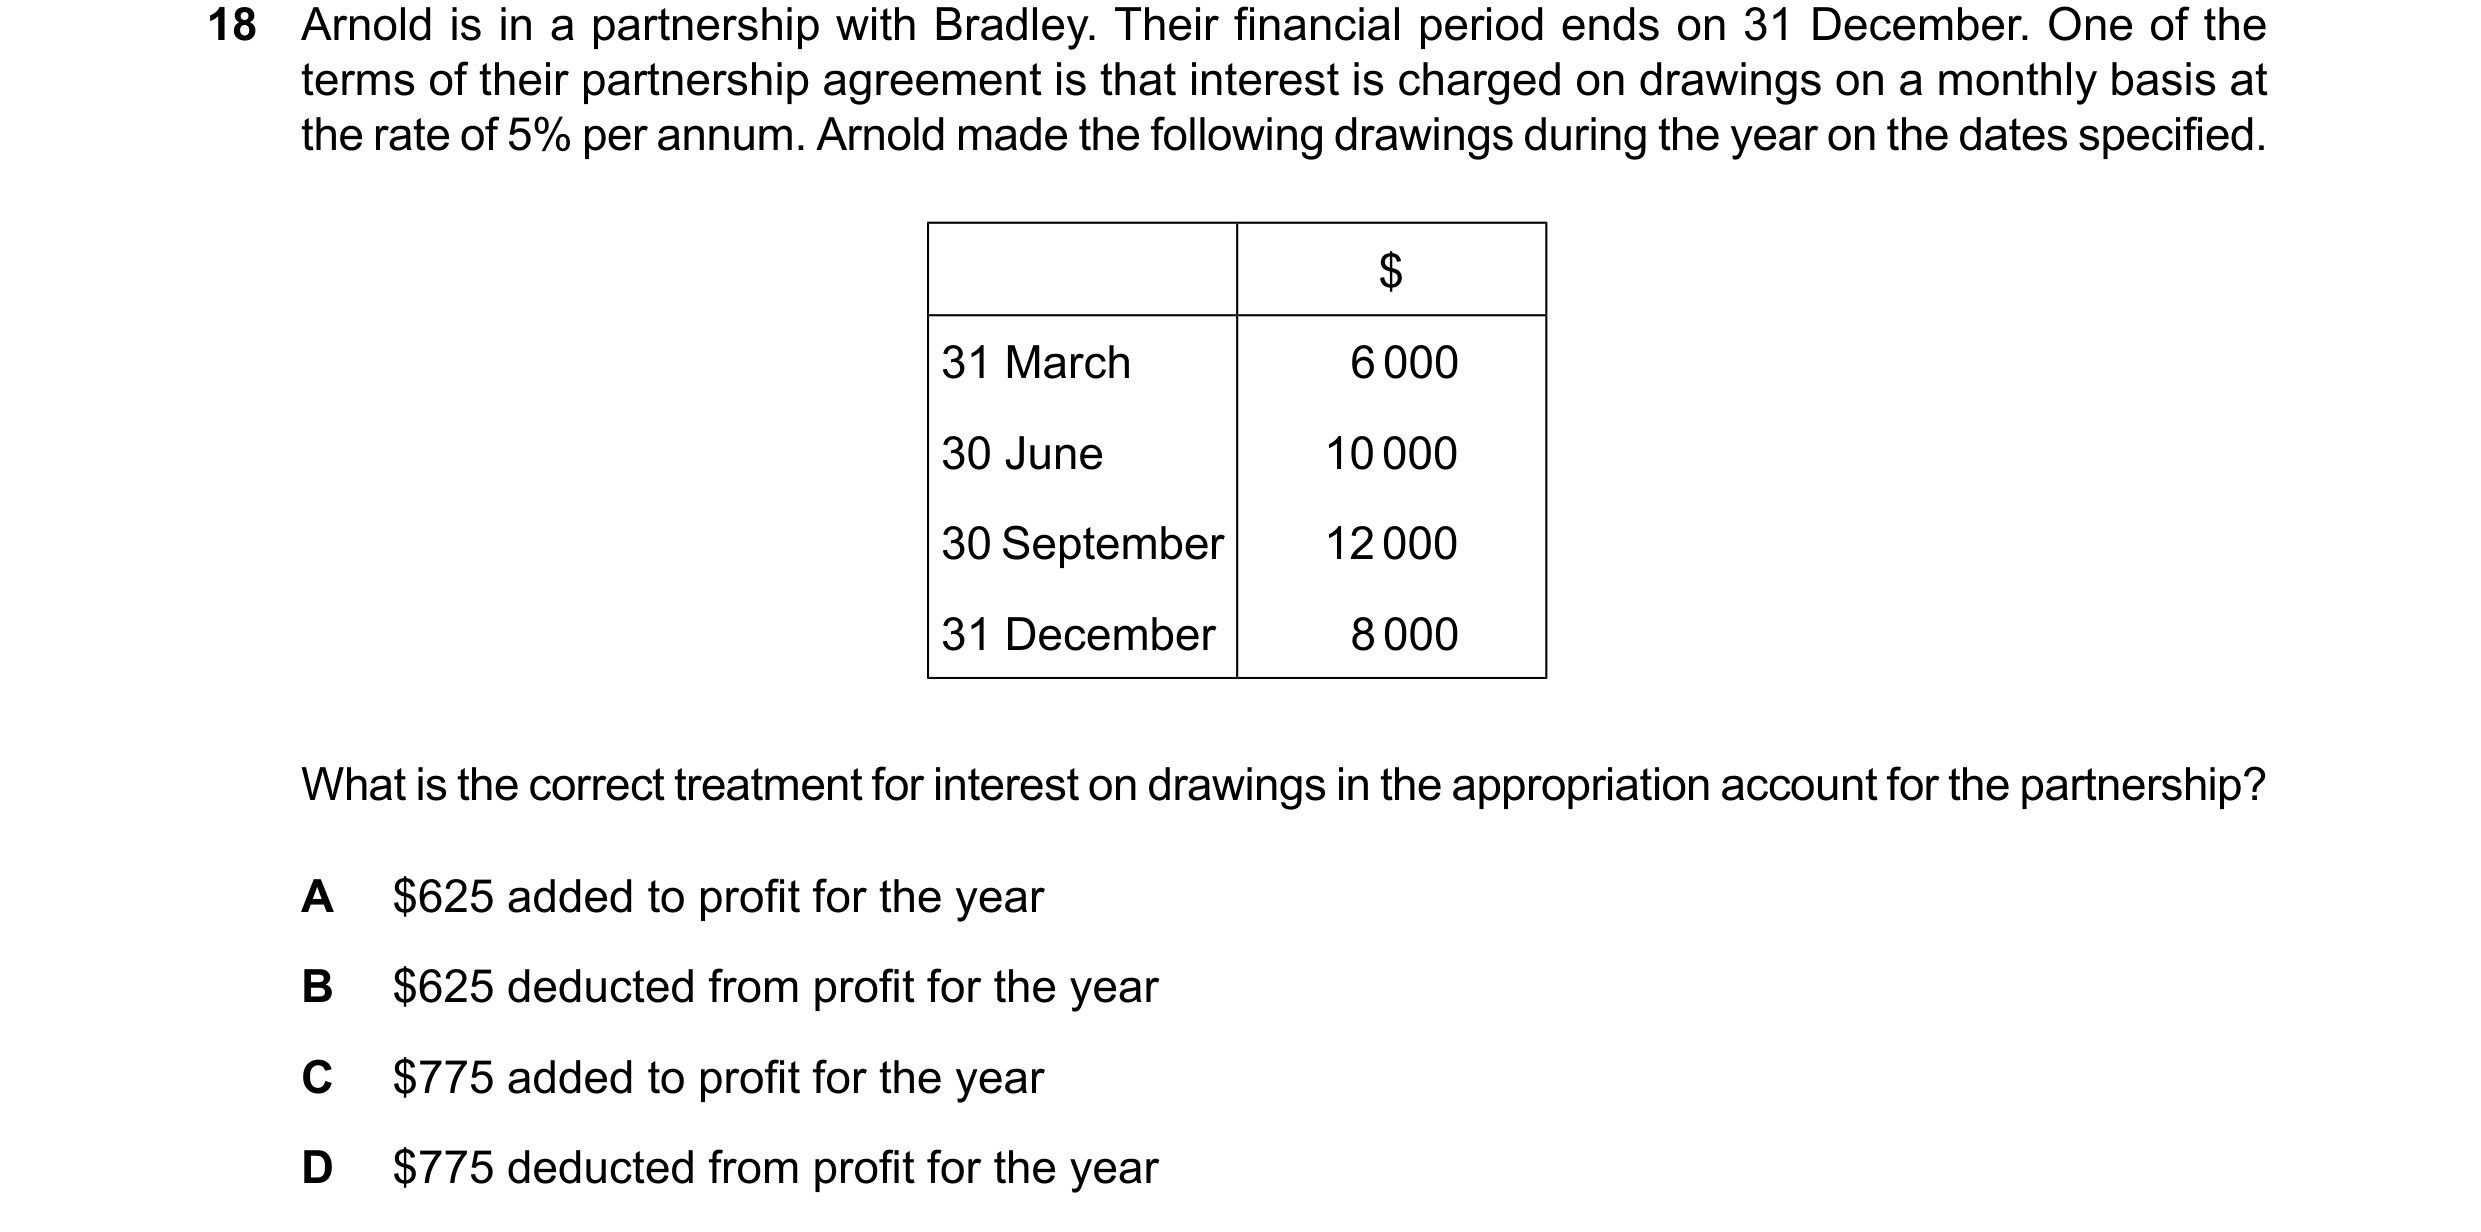 224 / 233
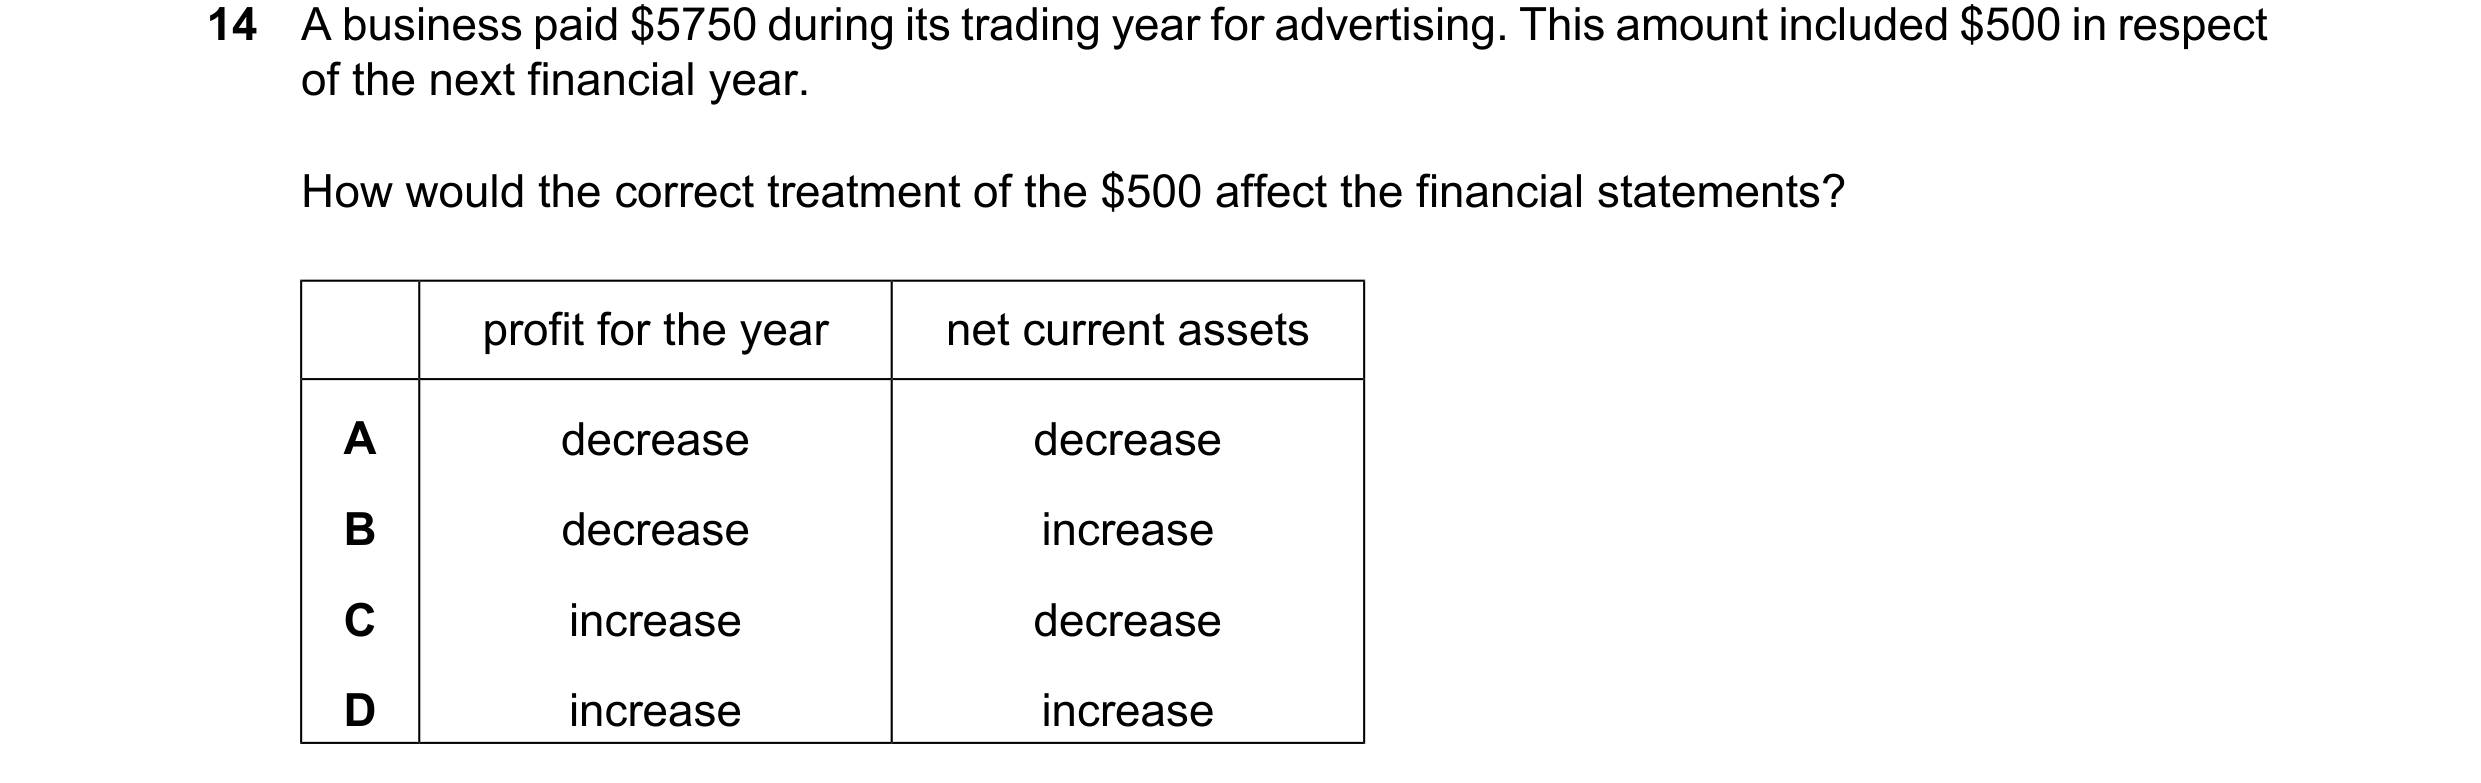
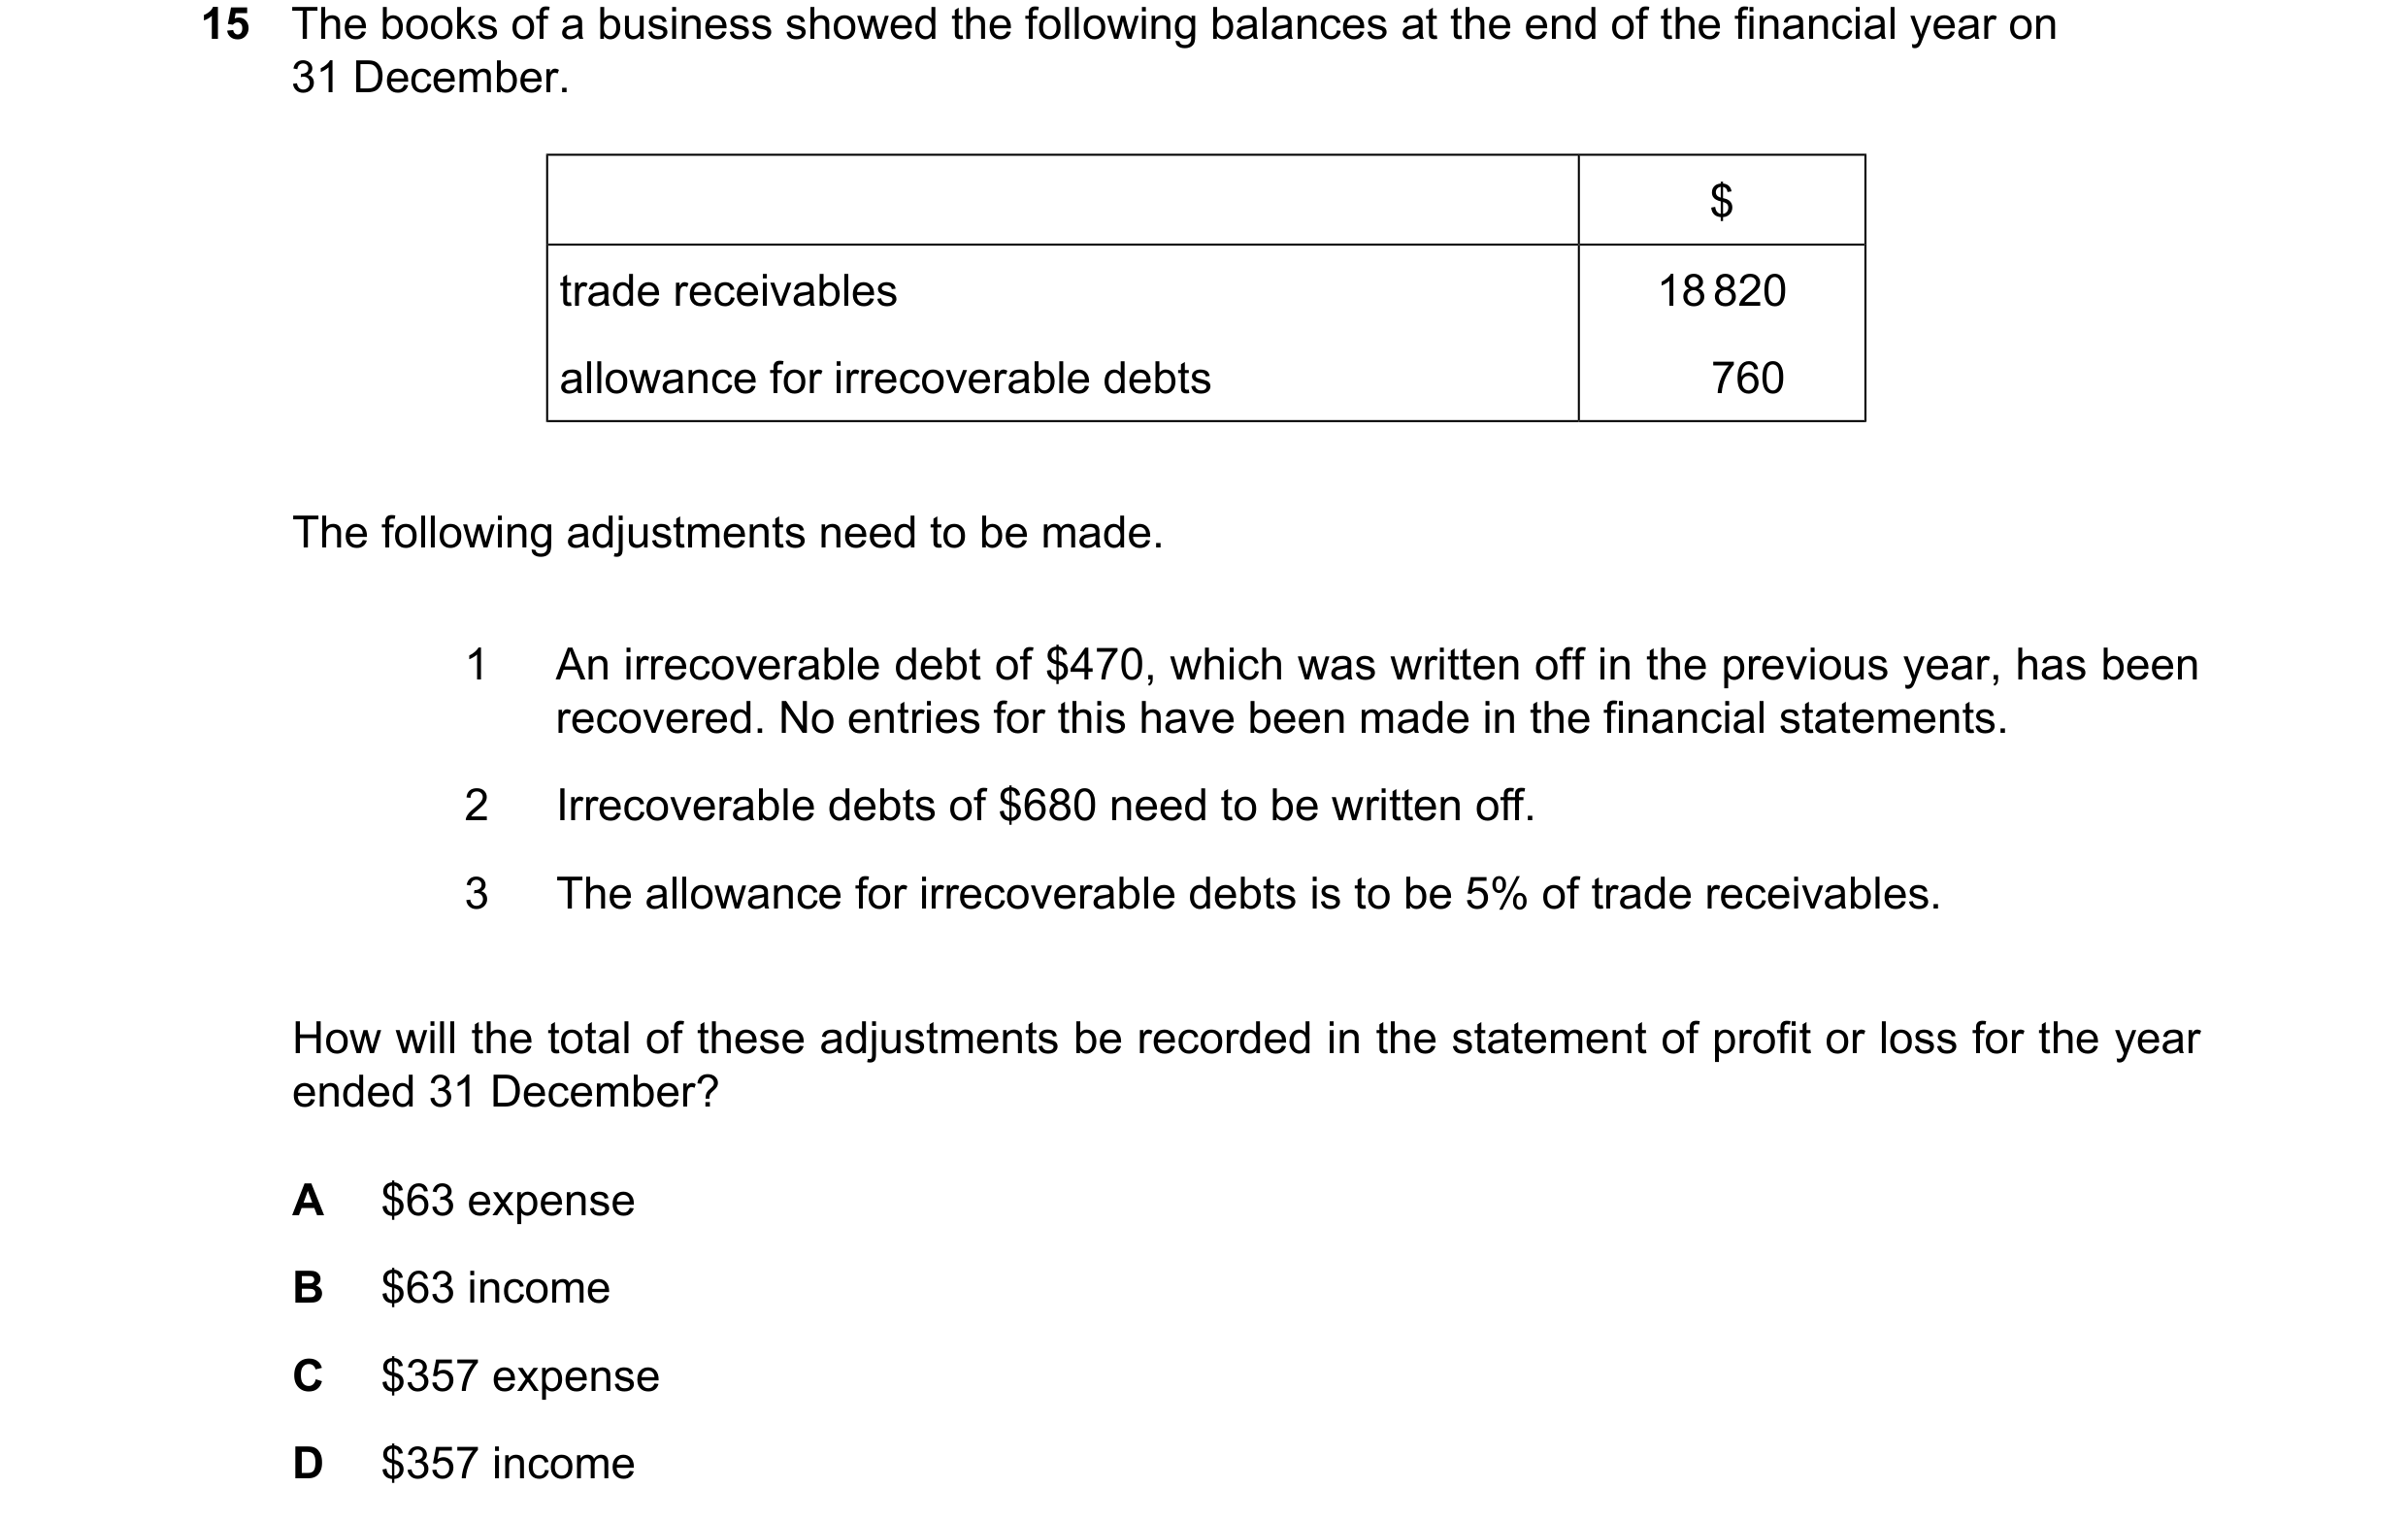
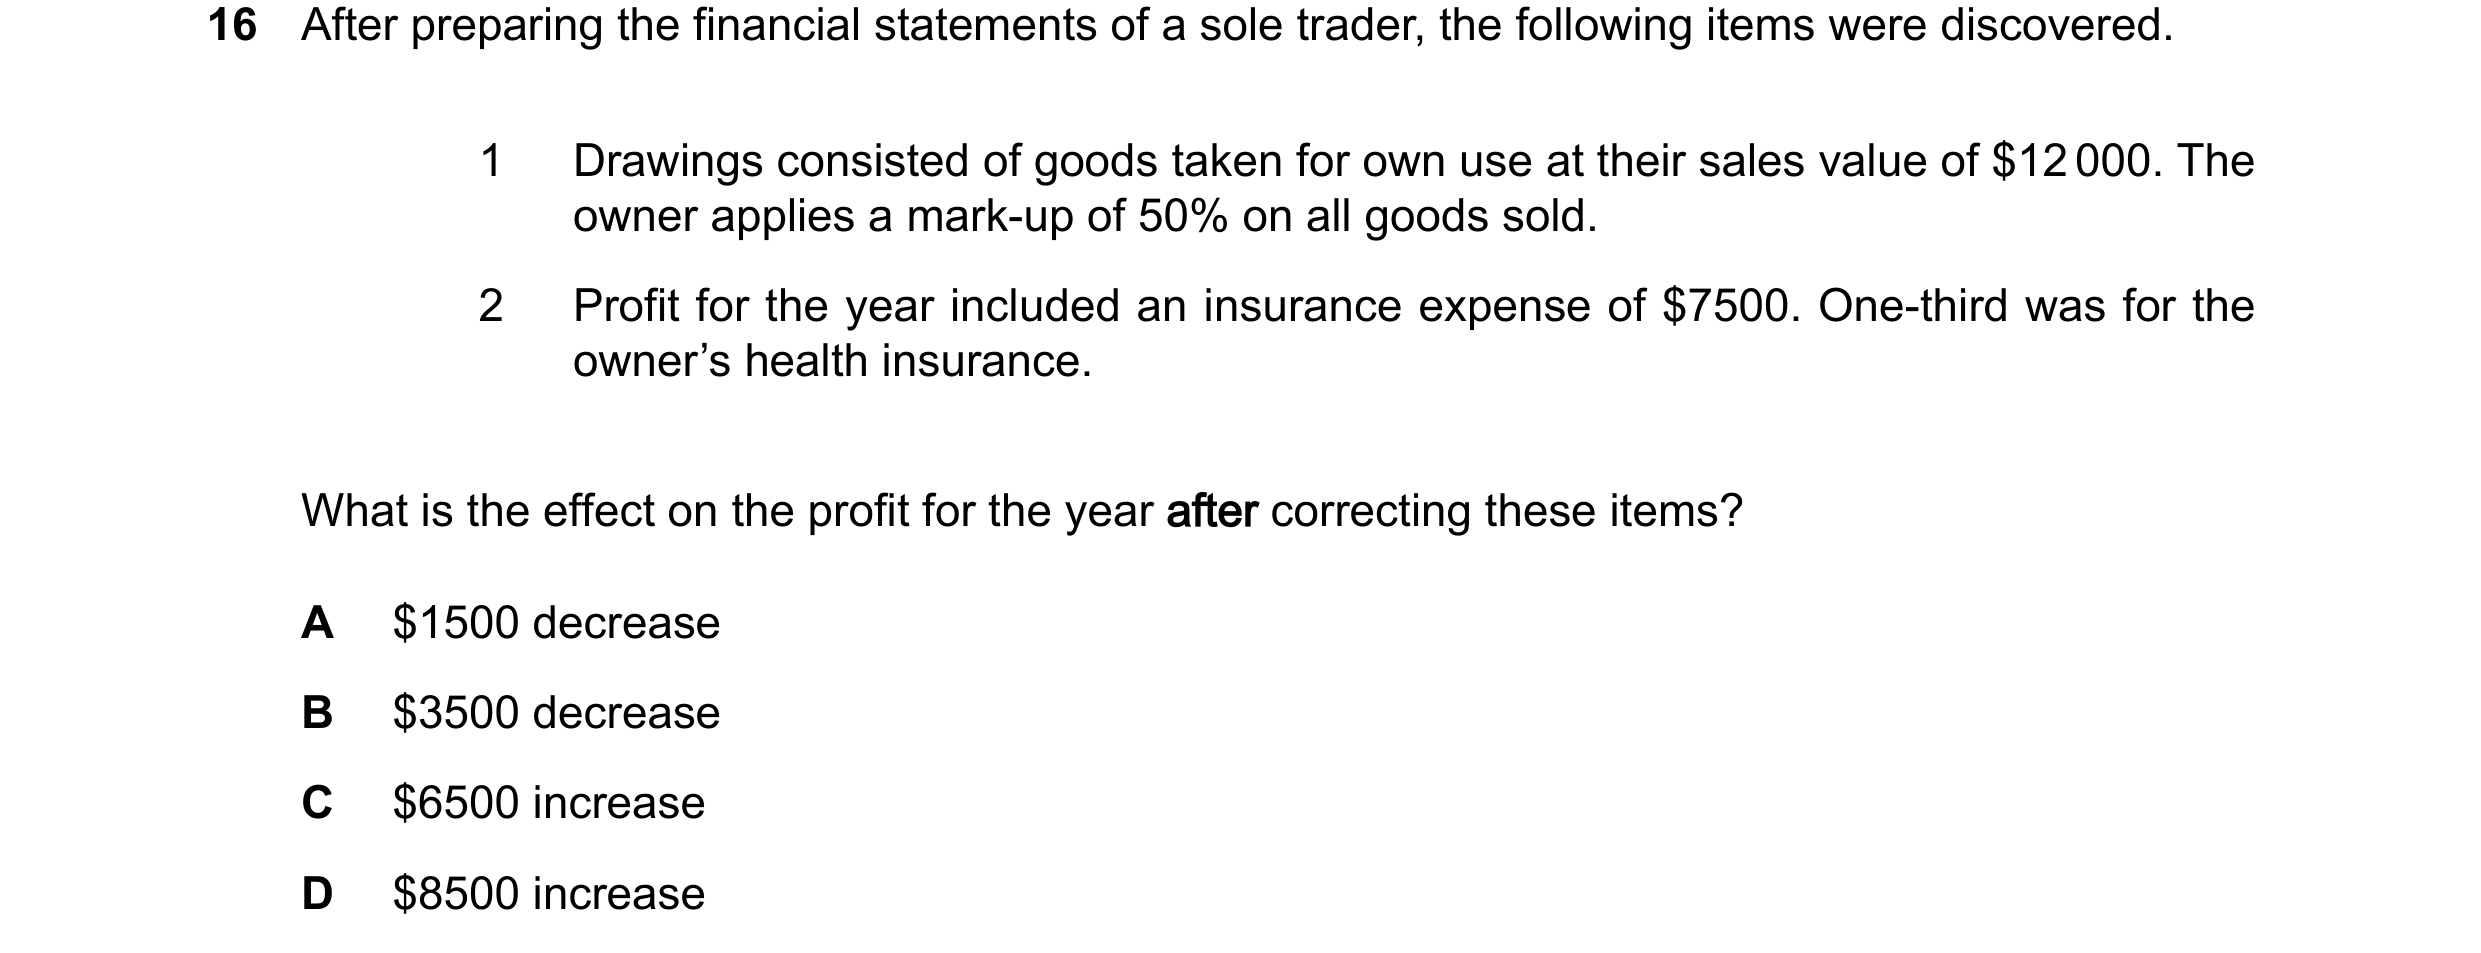 225 / 233
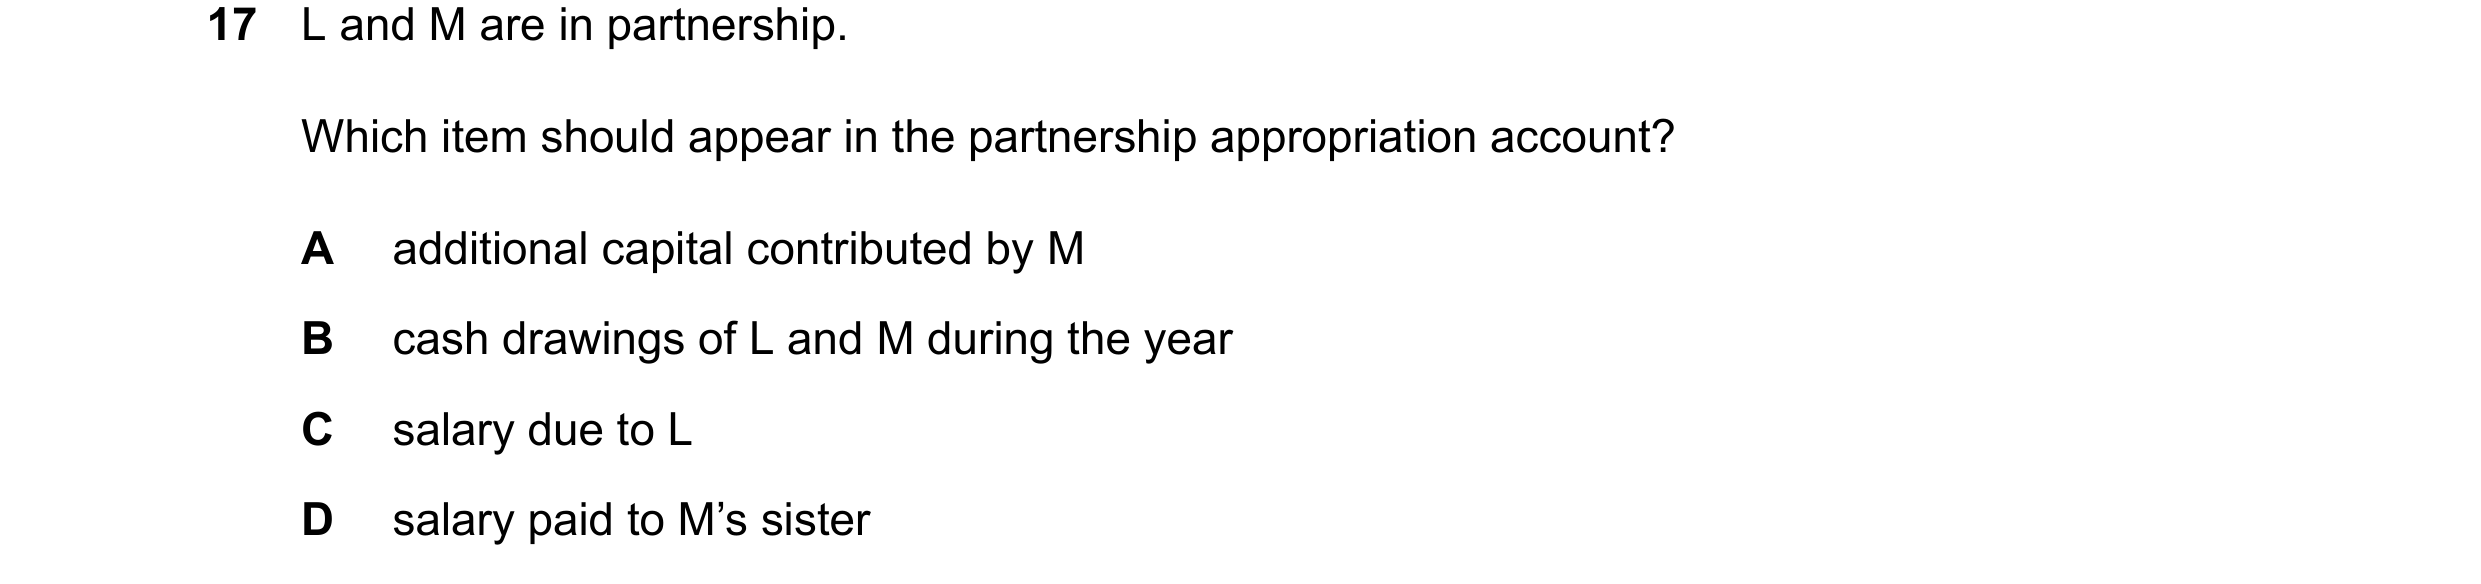
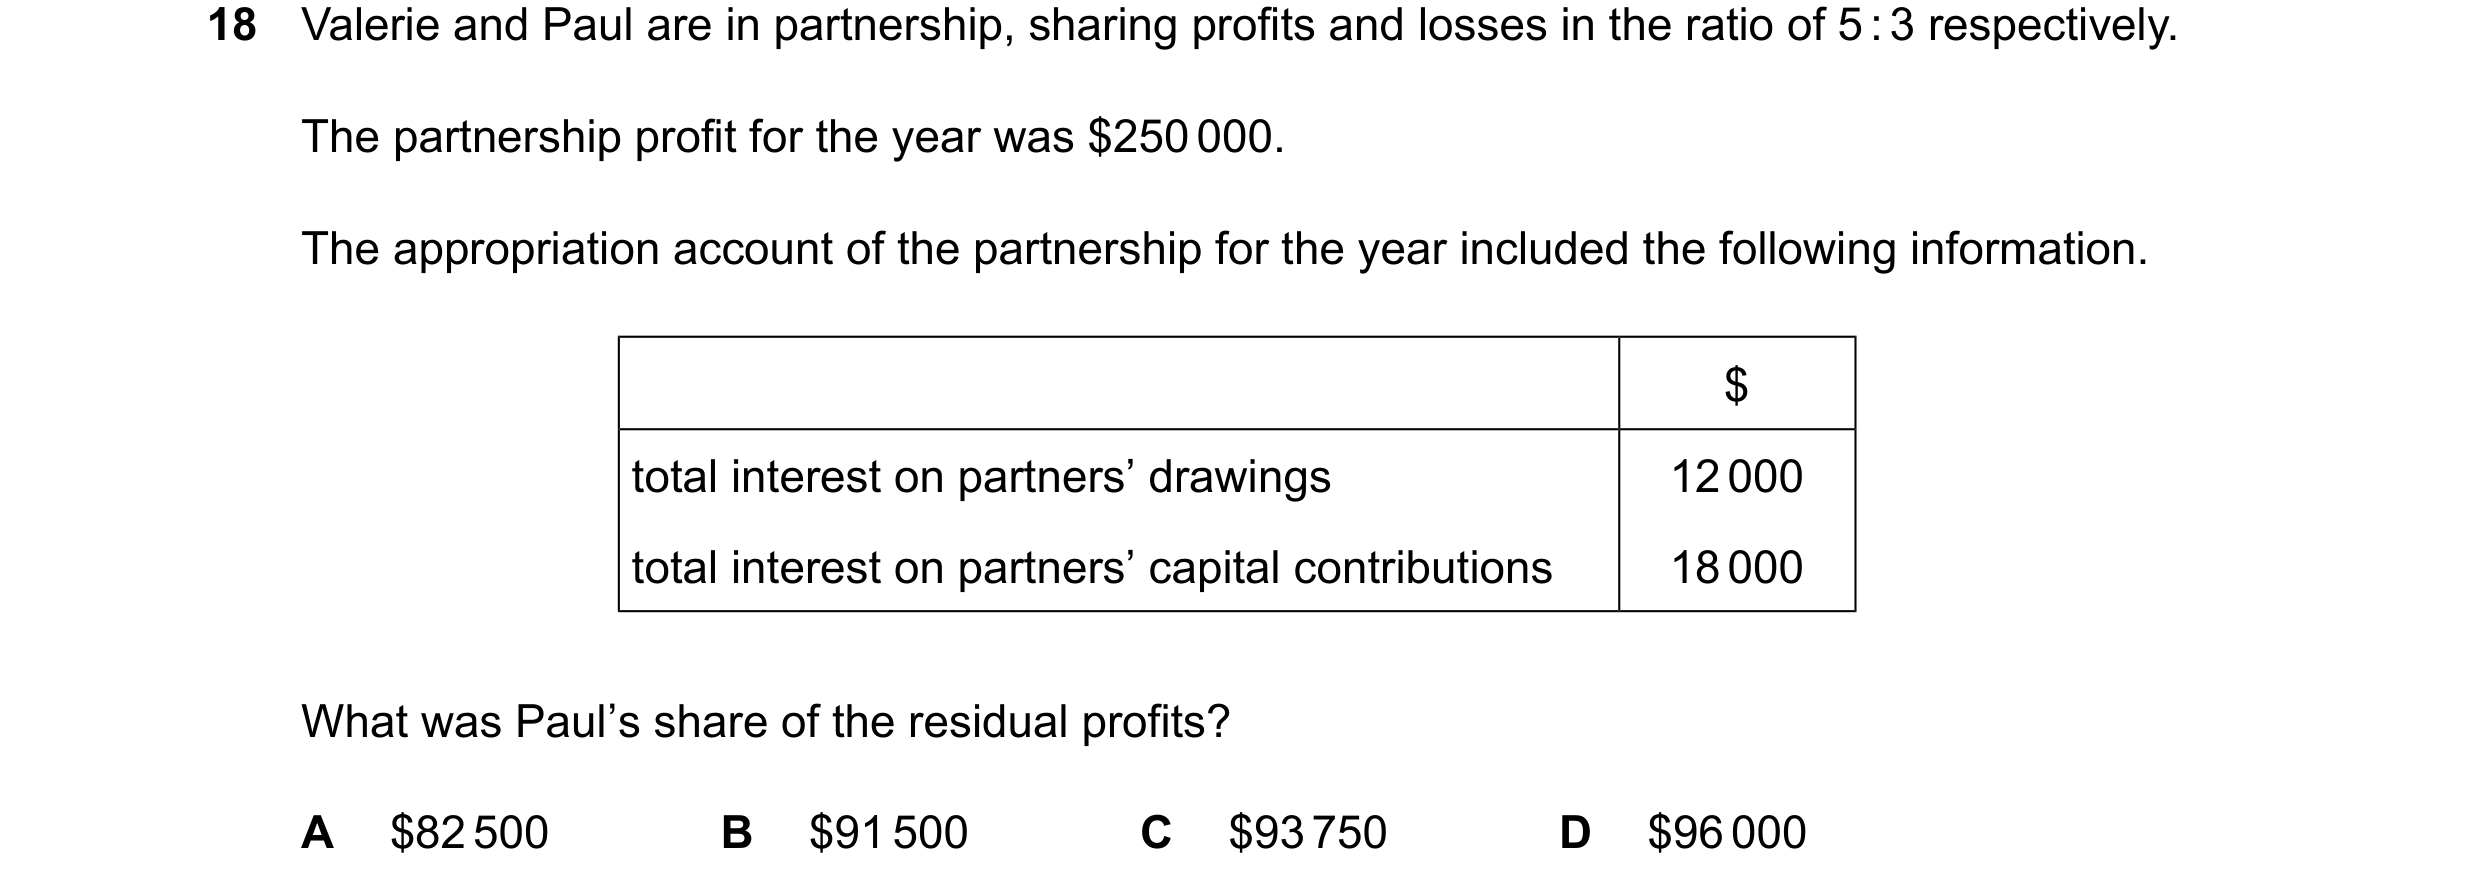
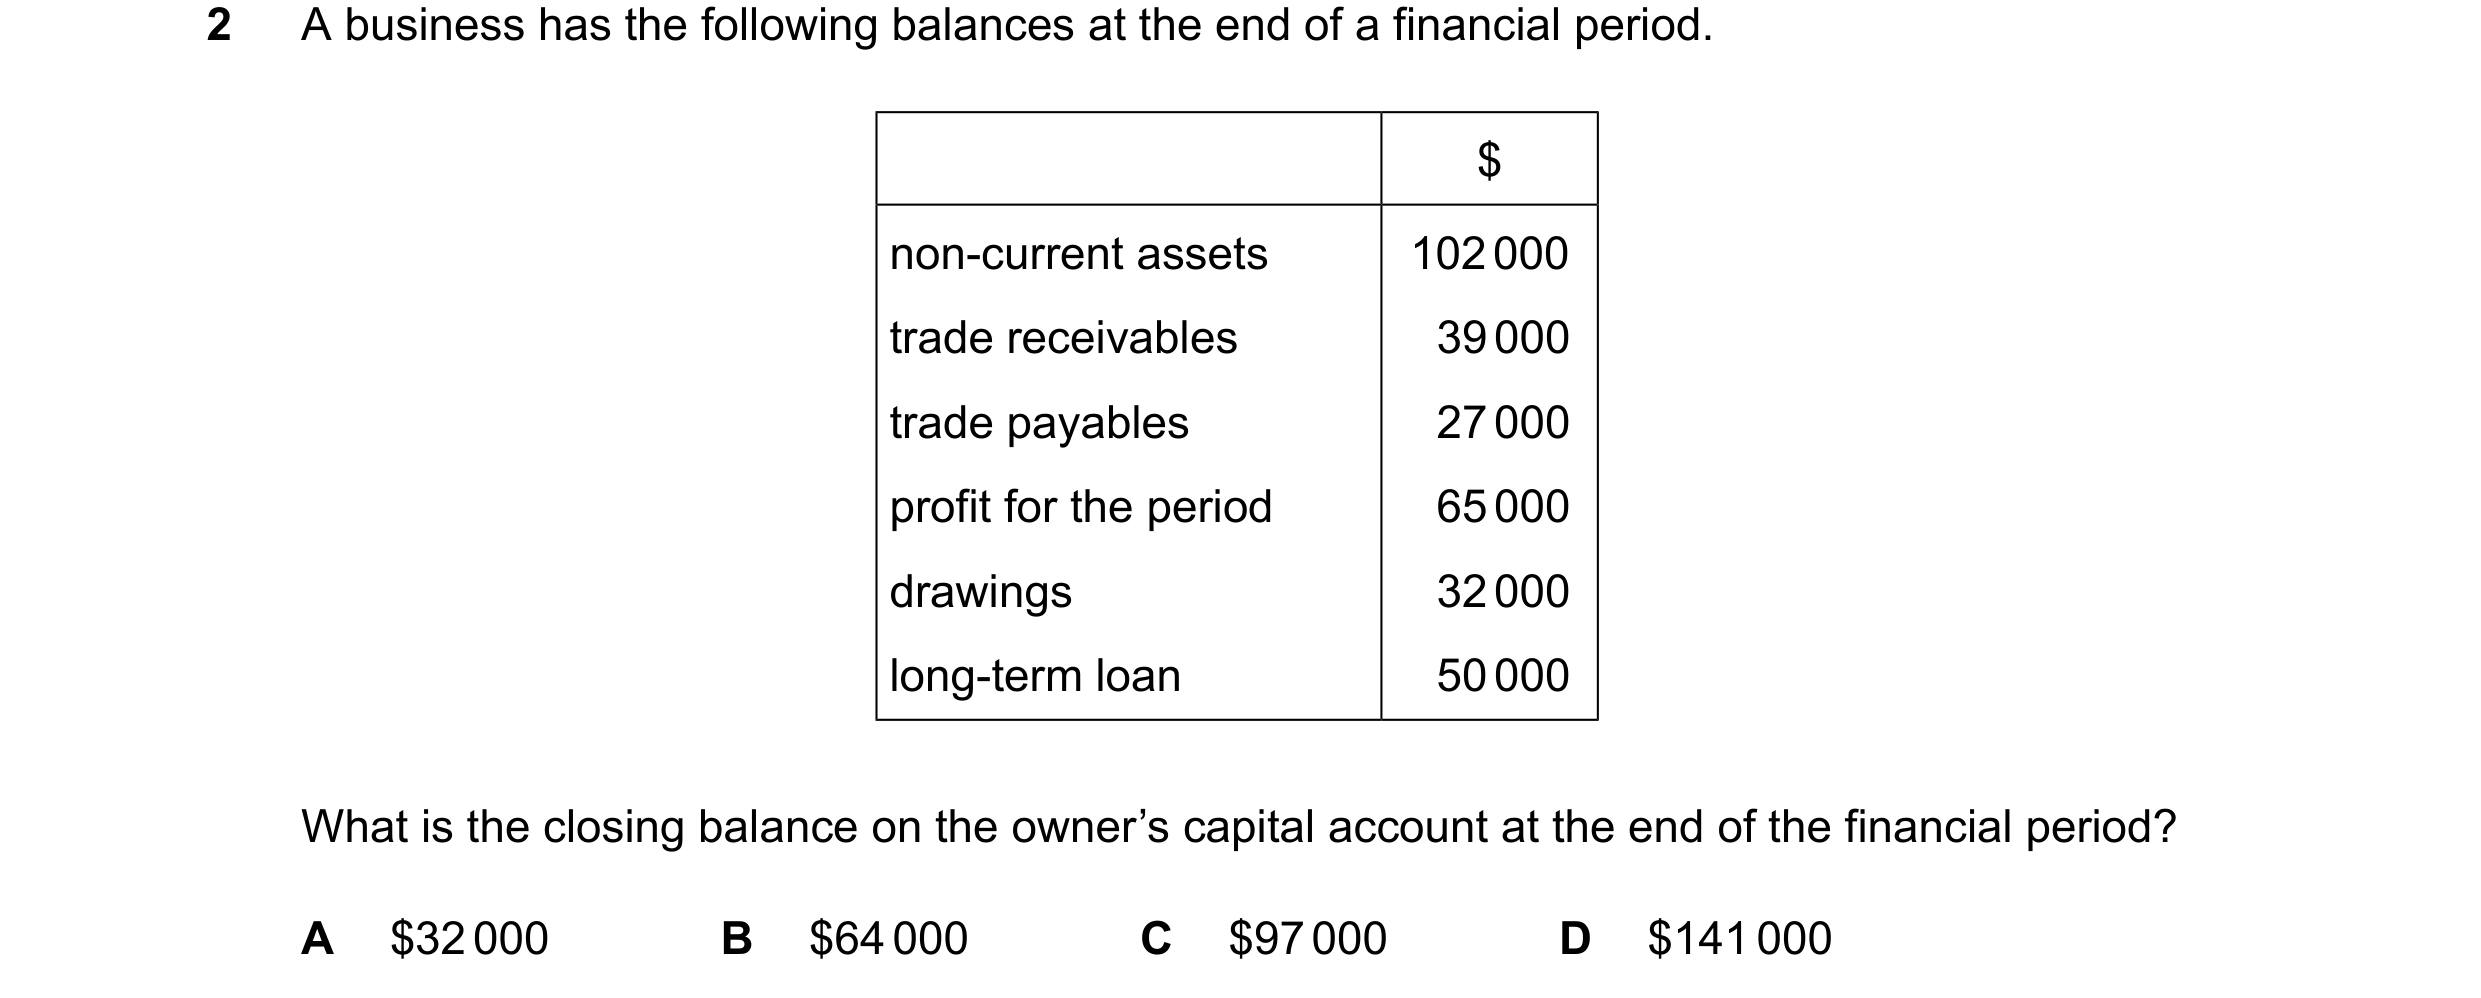
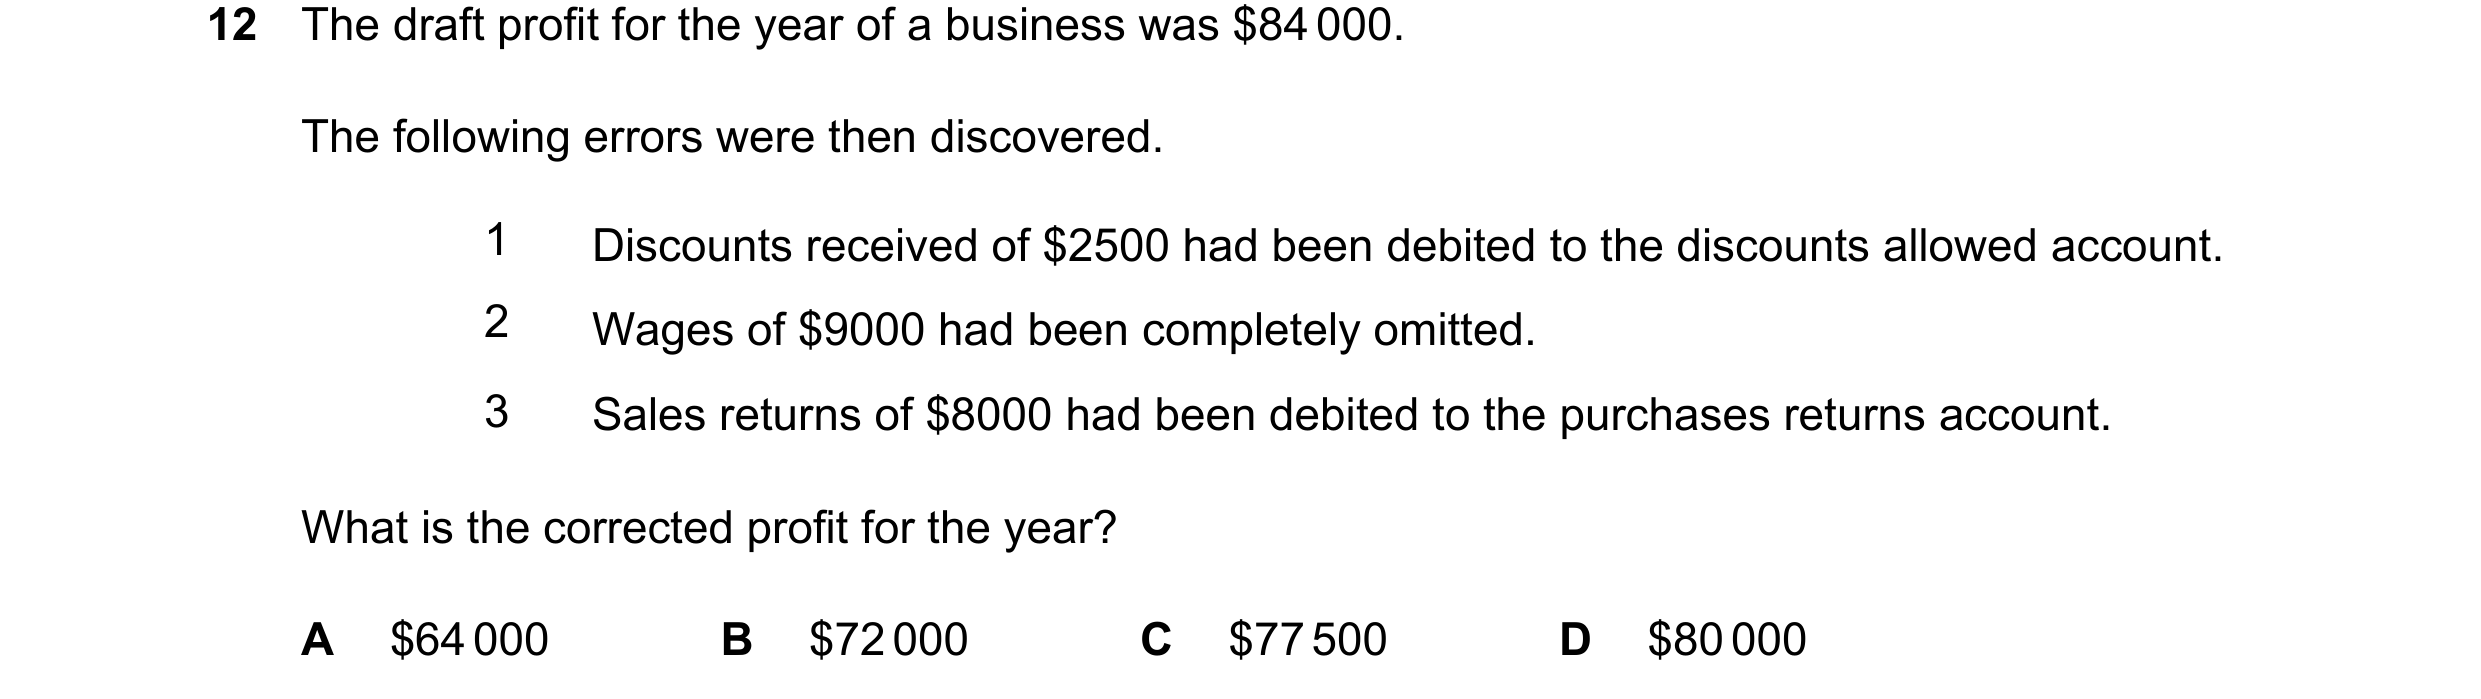 226 / 233
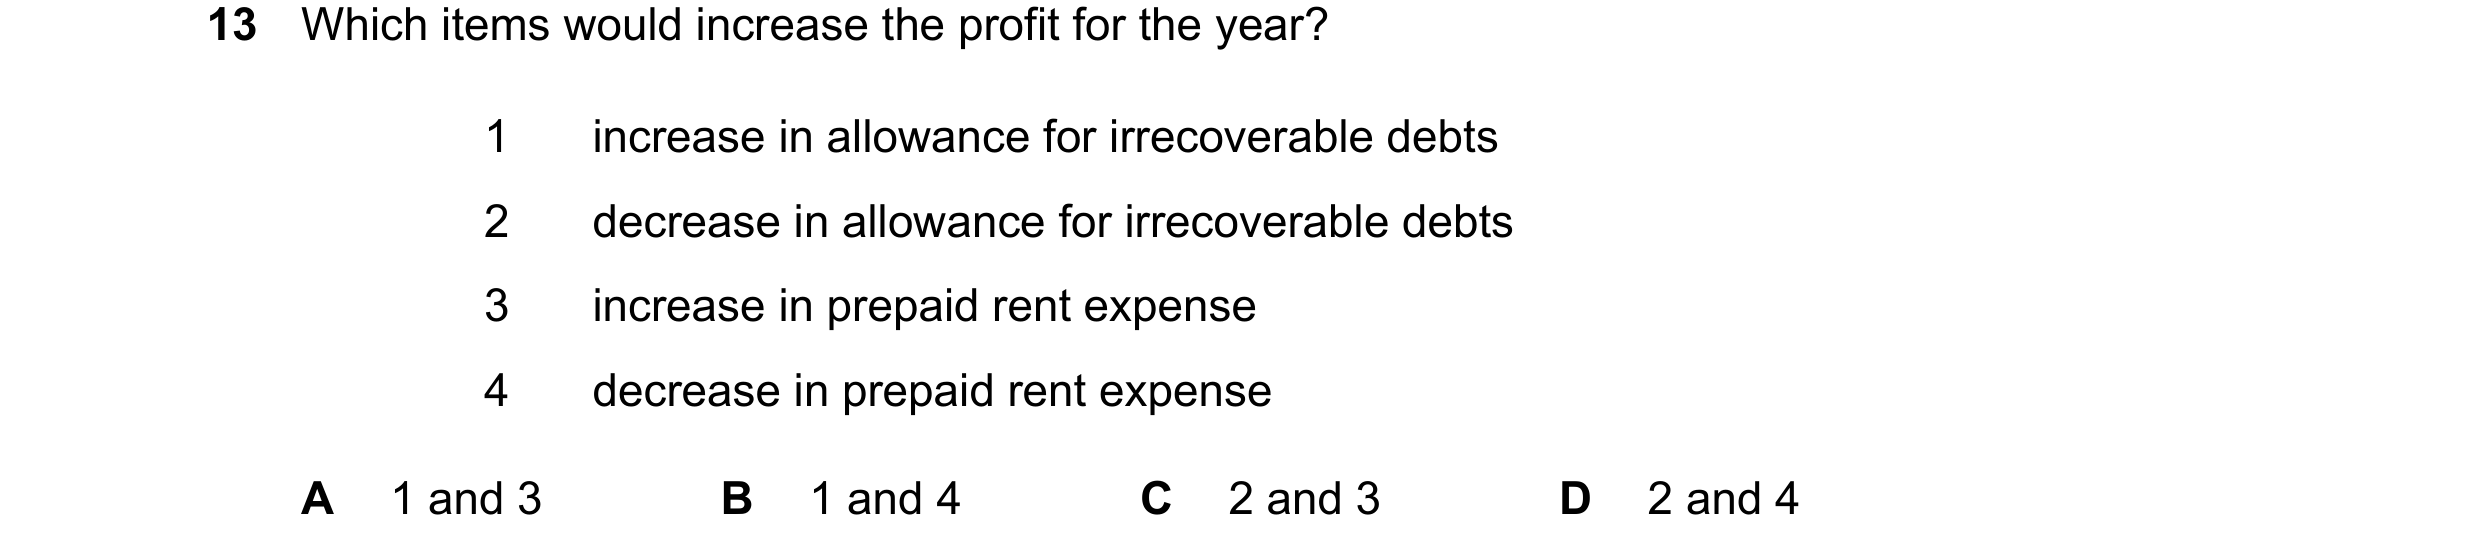
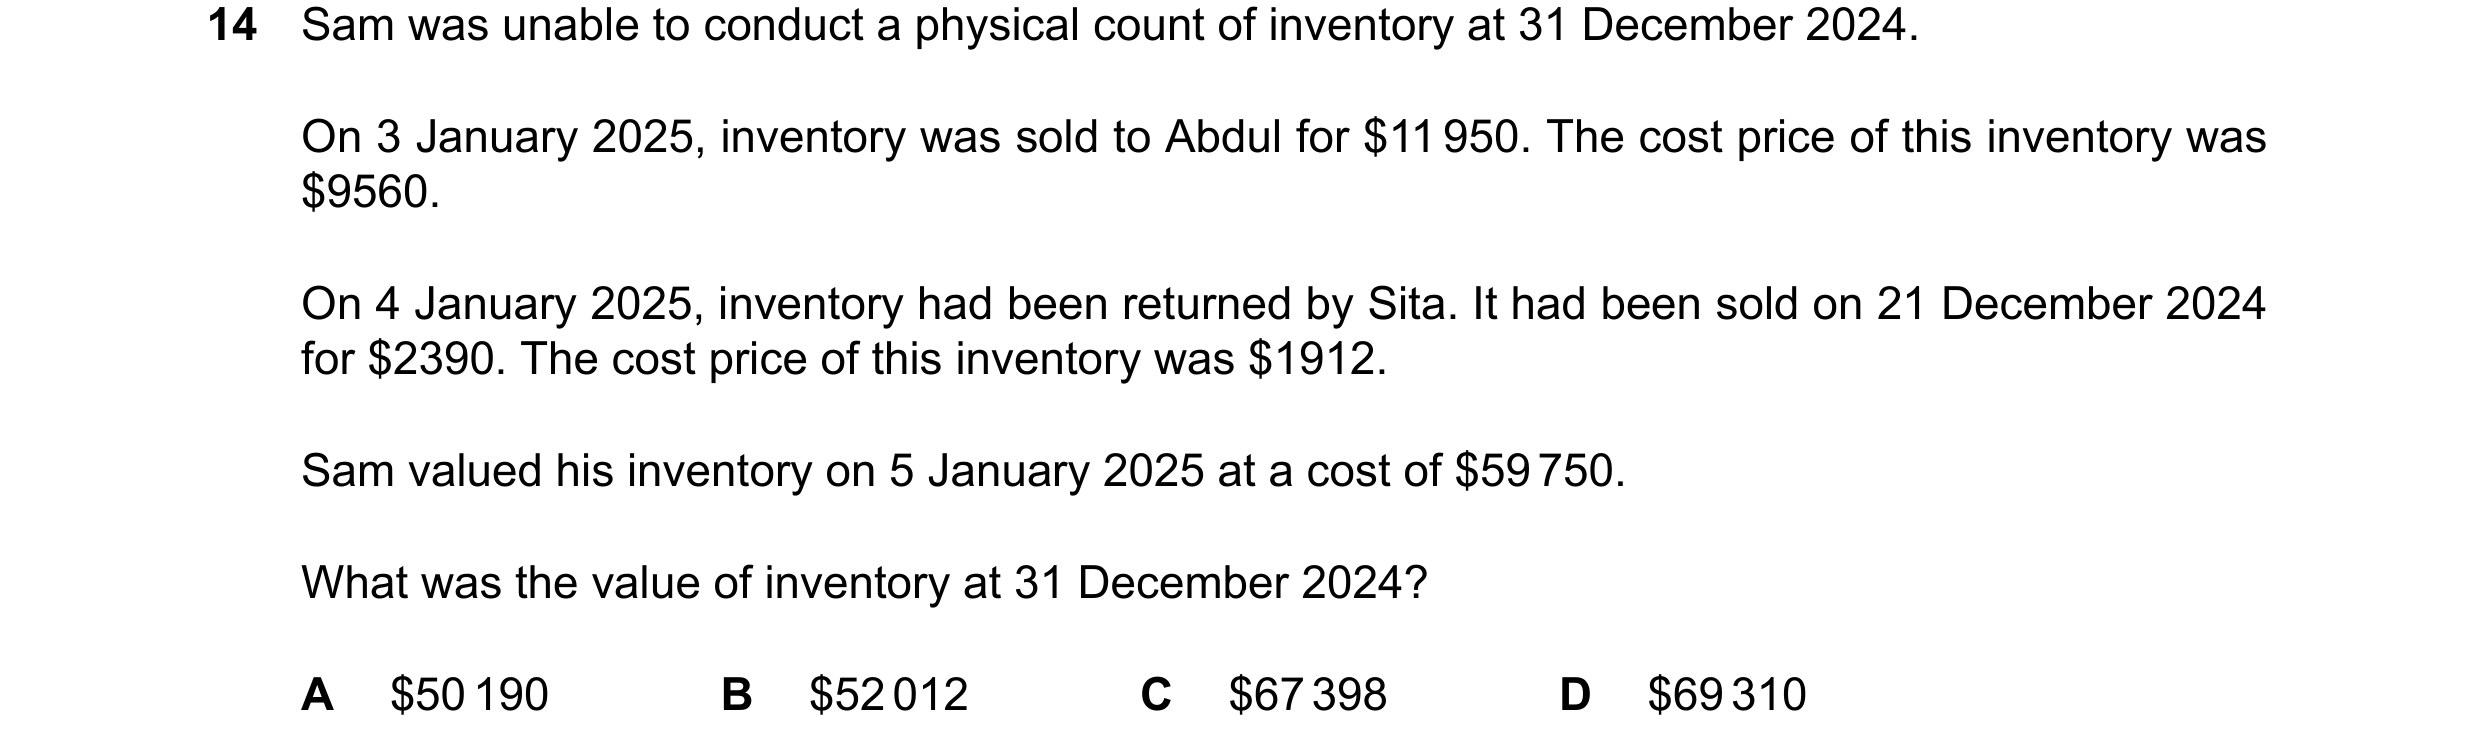
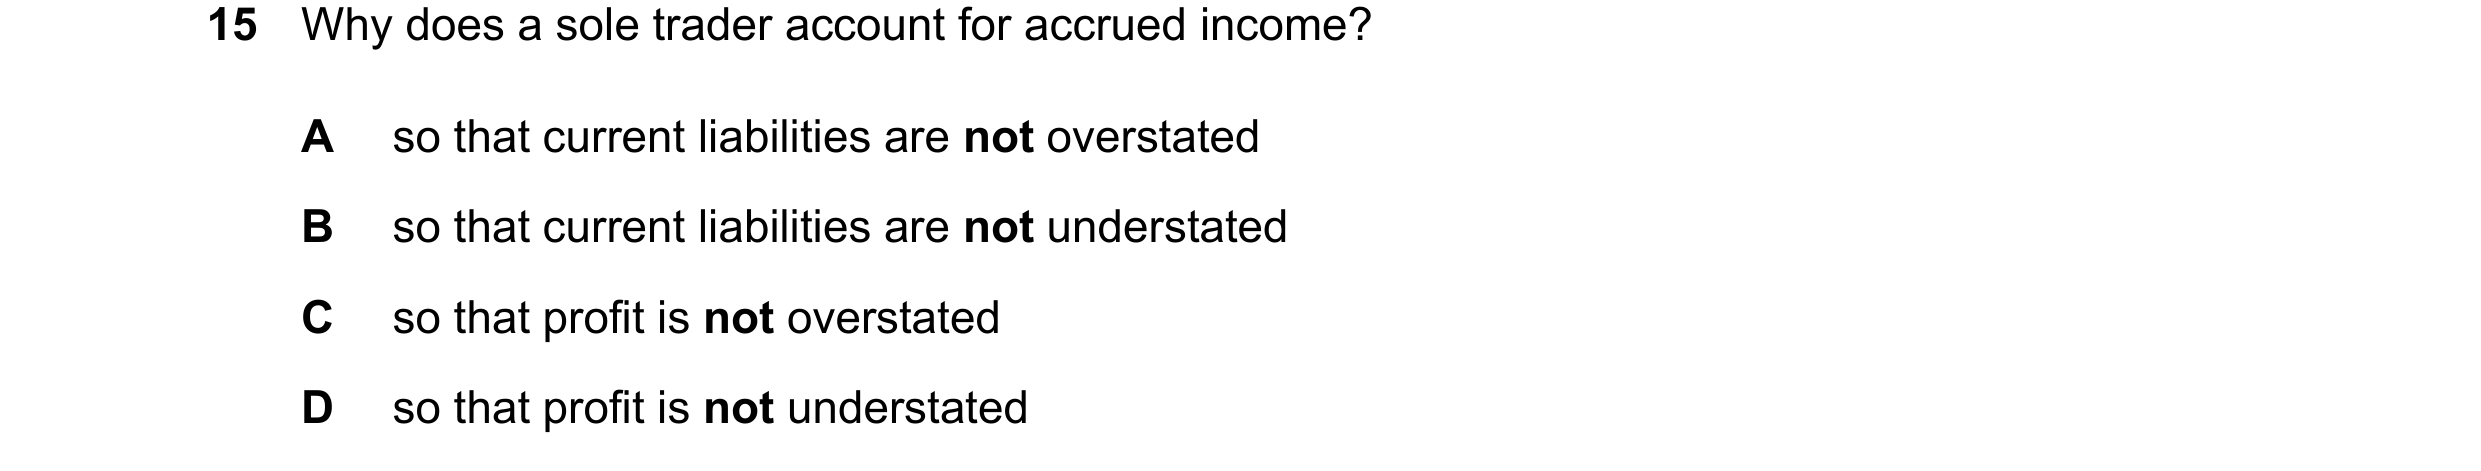
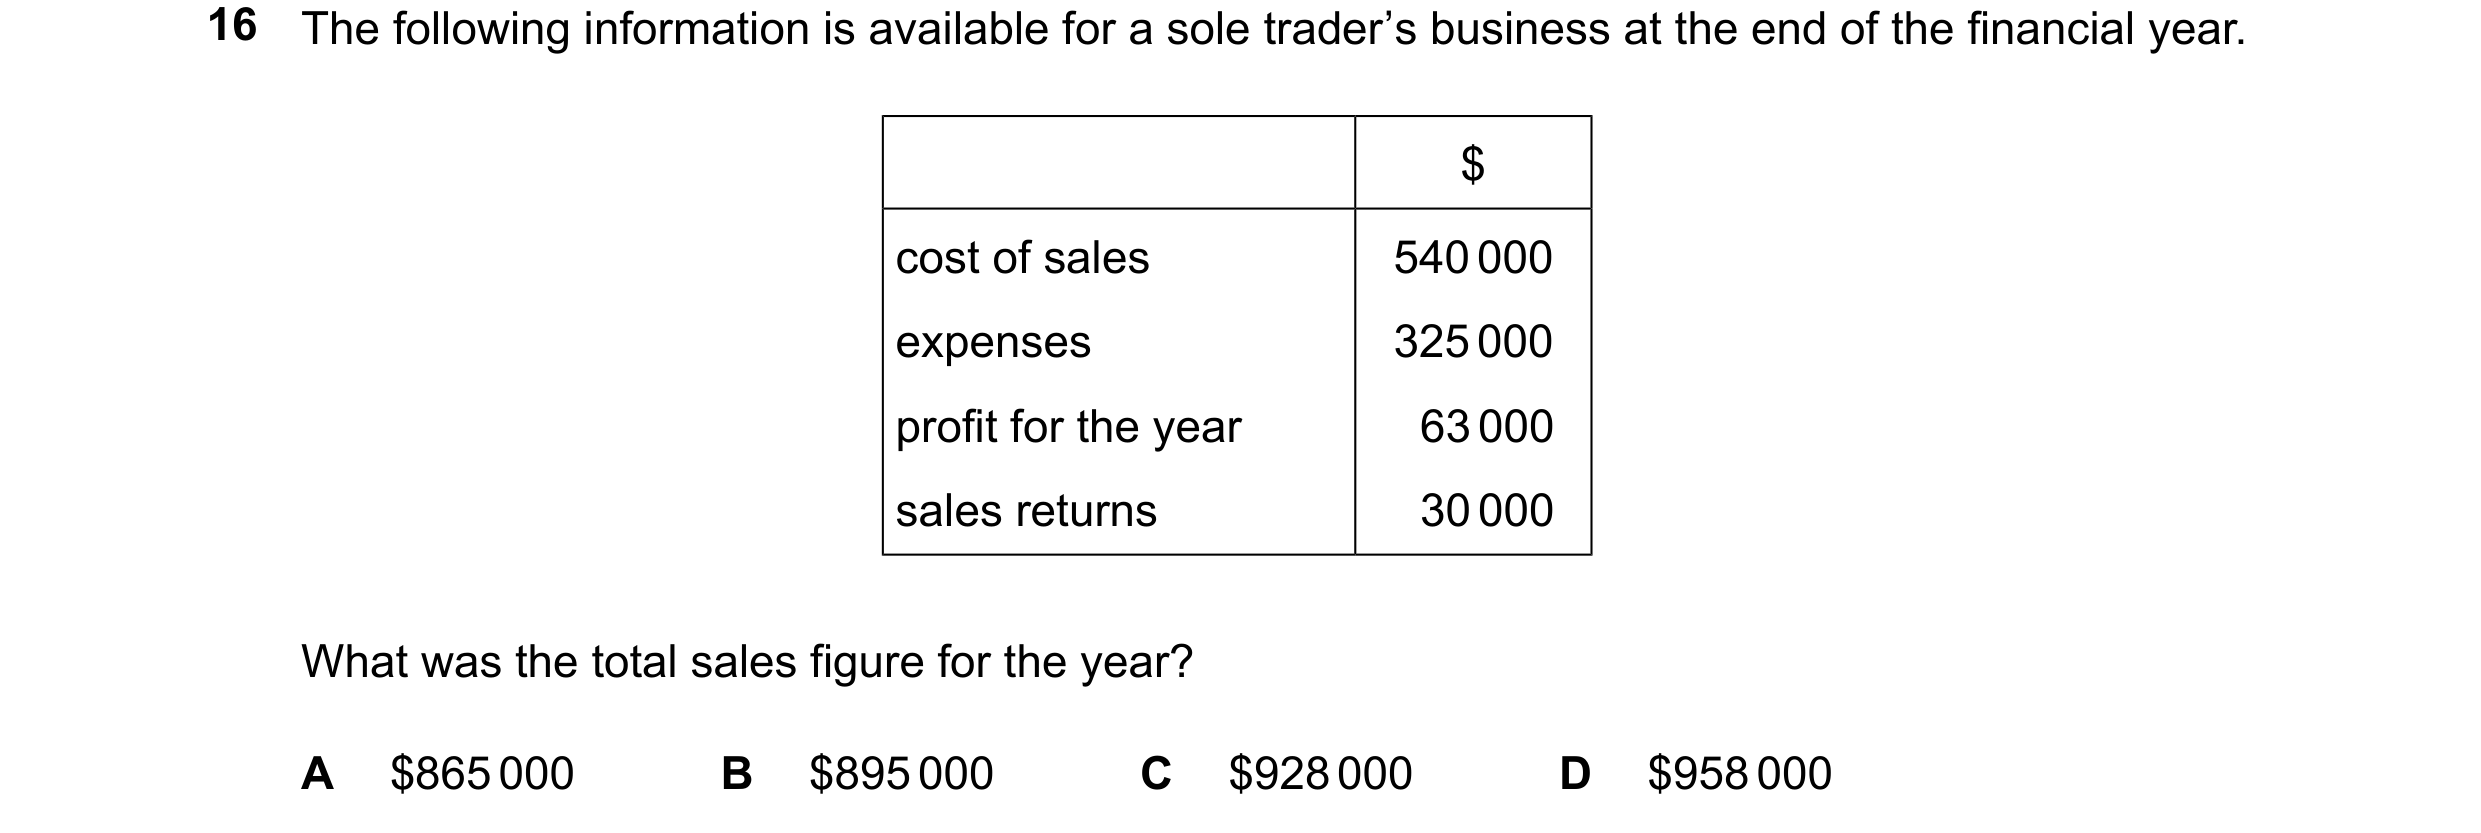 227 / 233
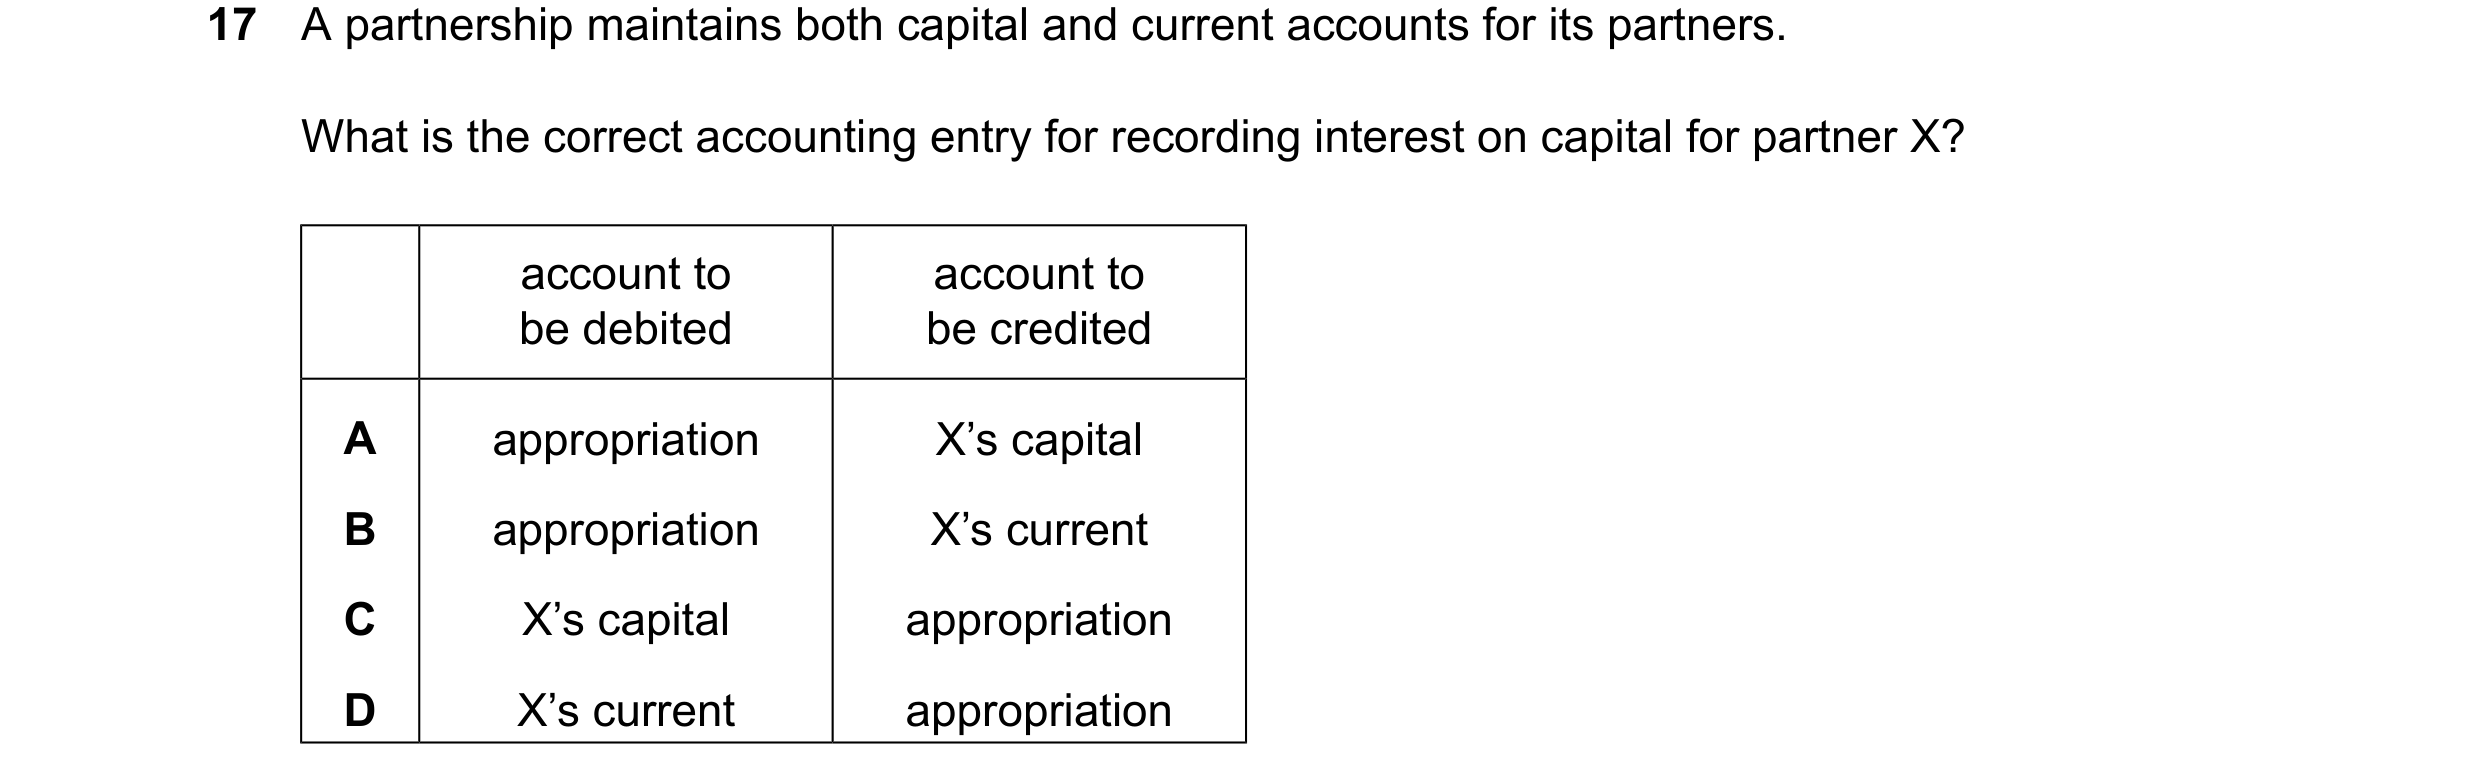
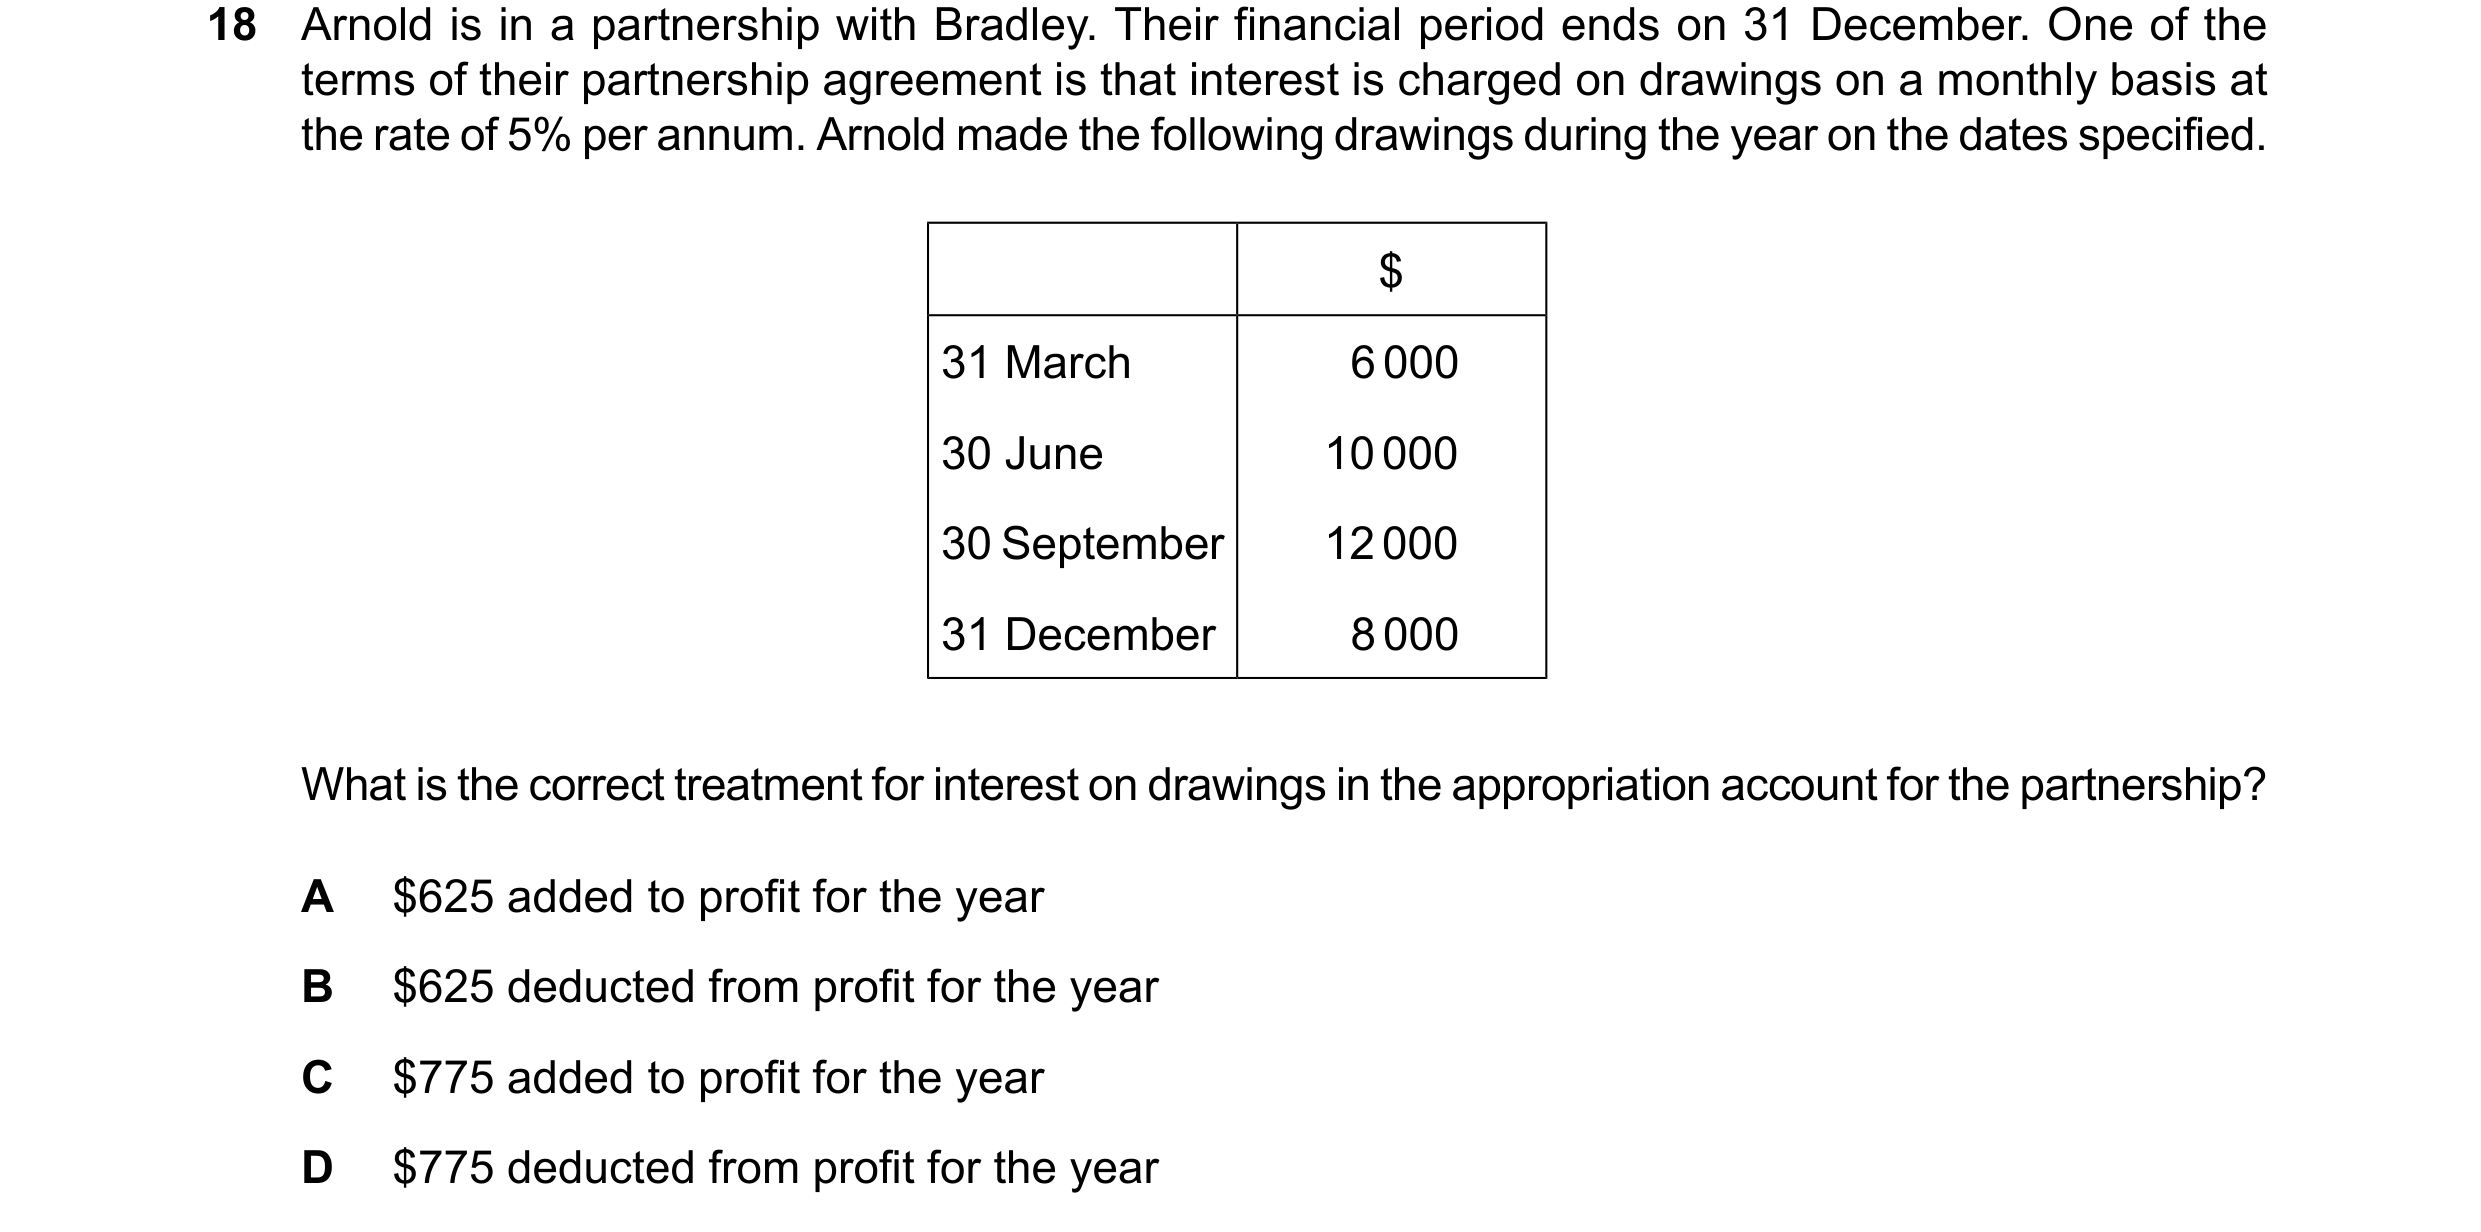
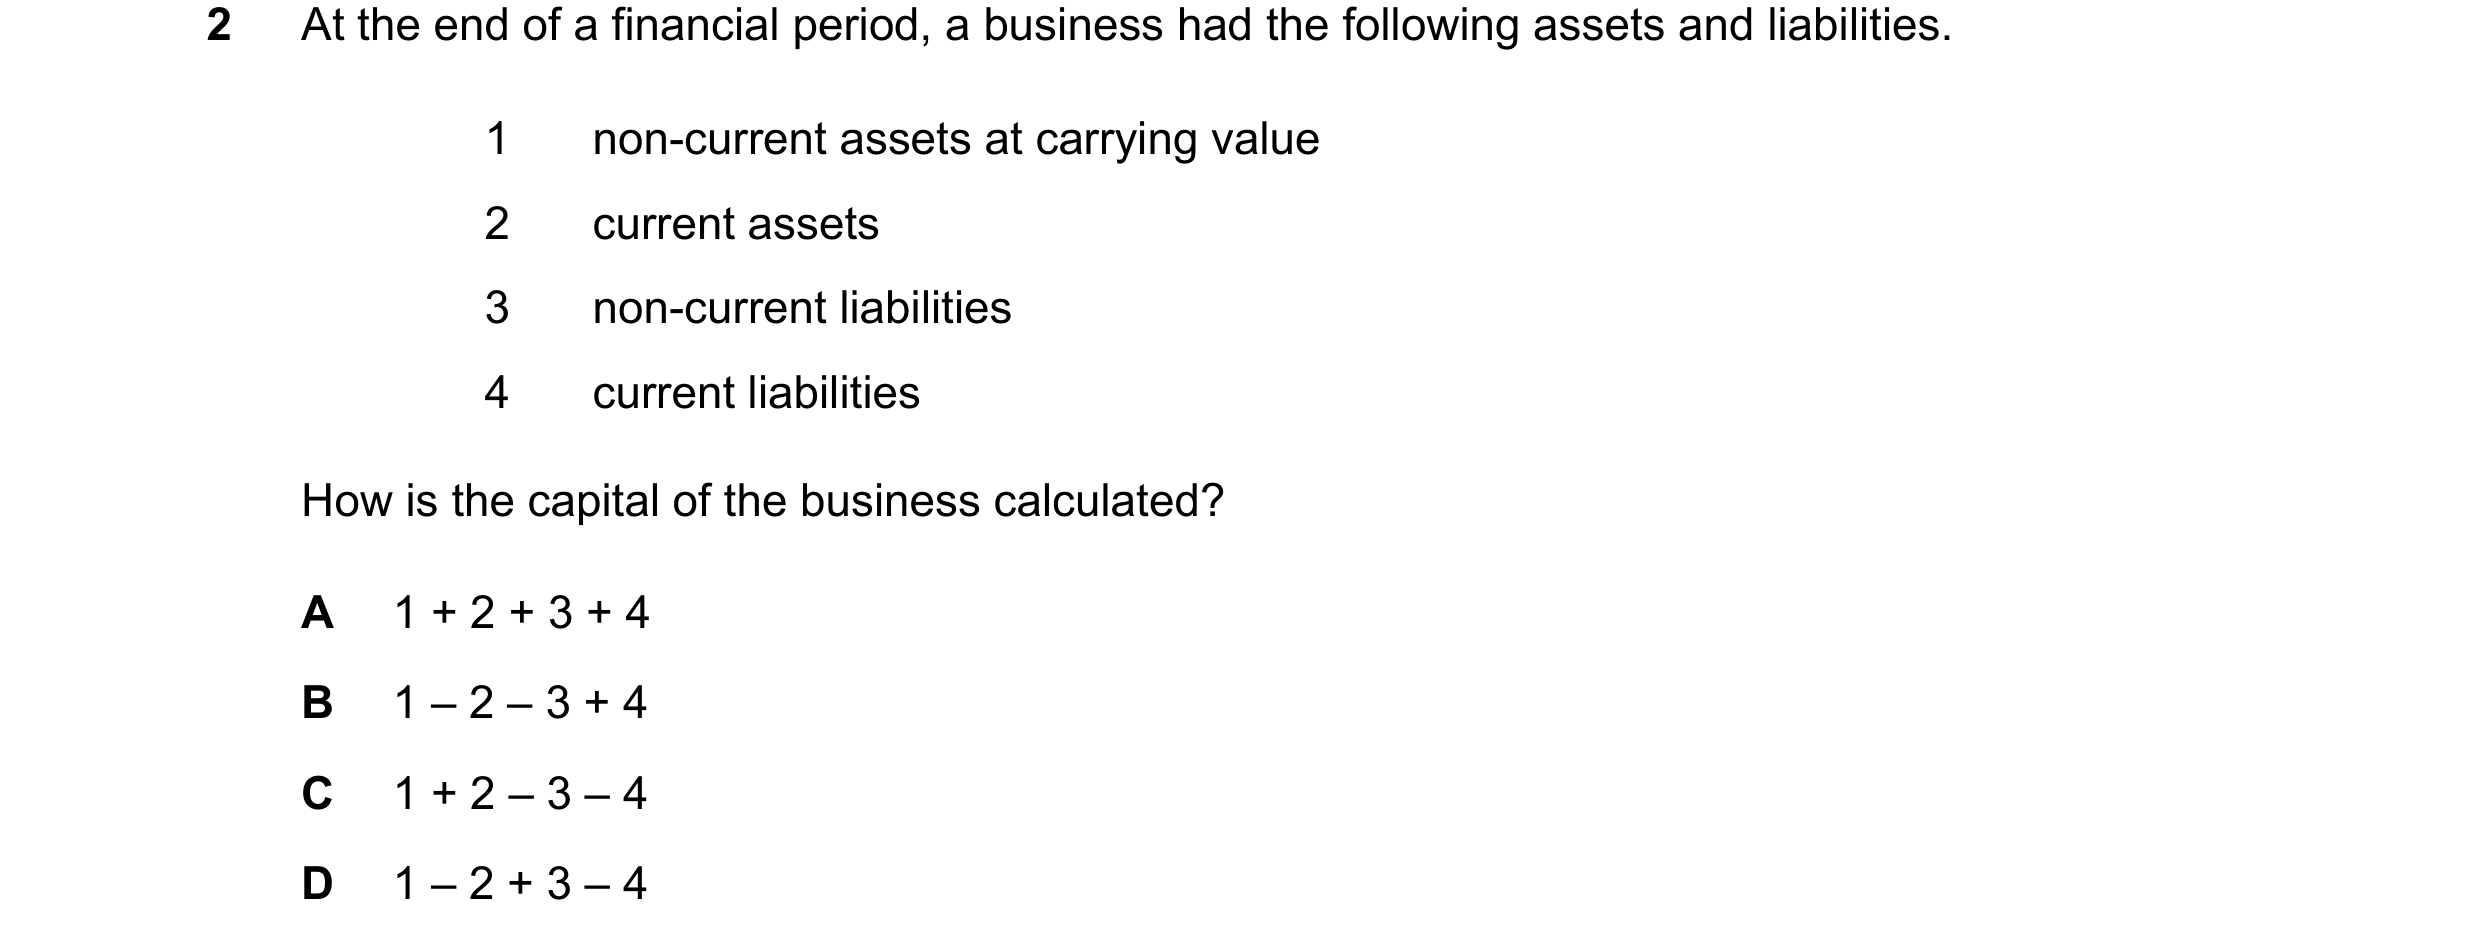 228 / 233
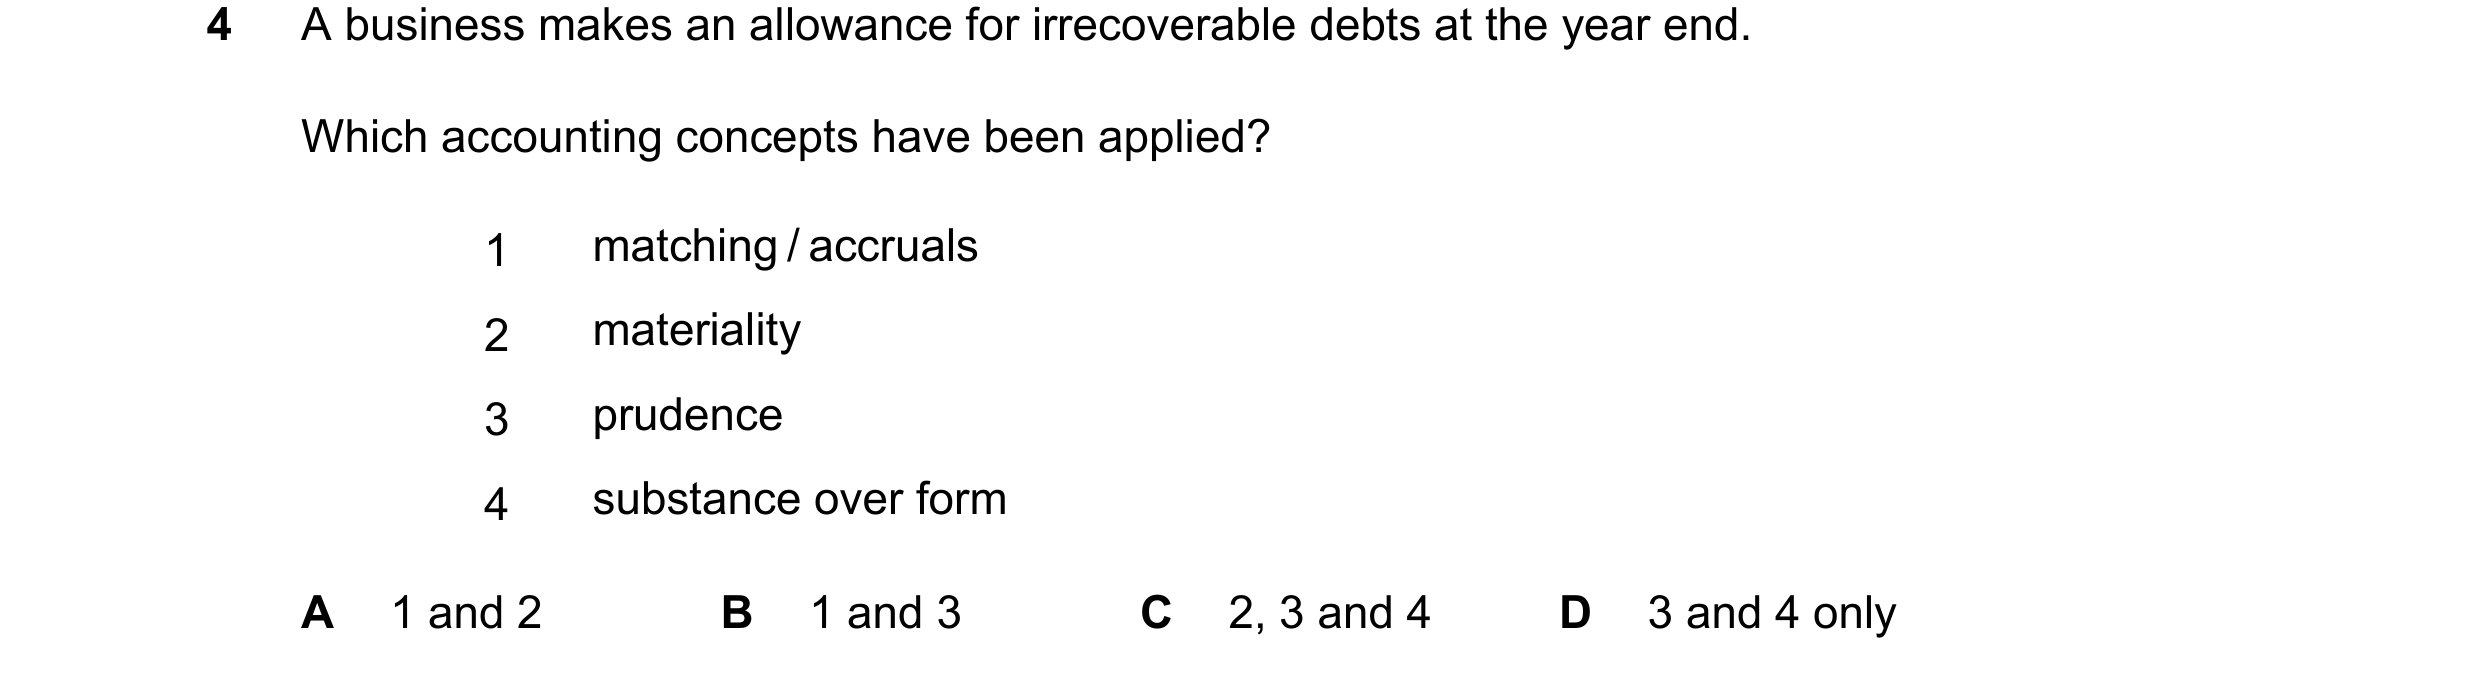
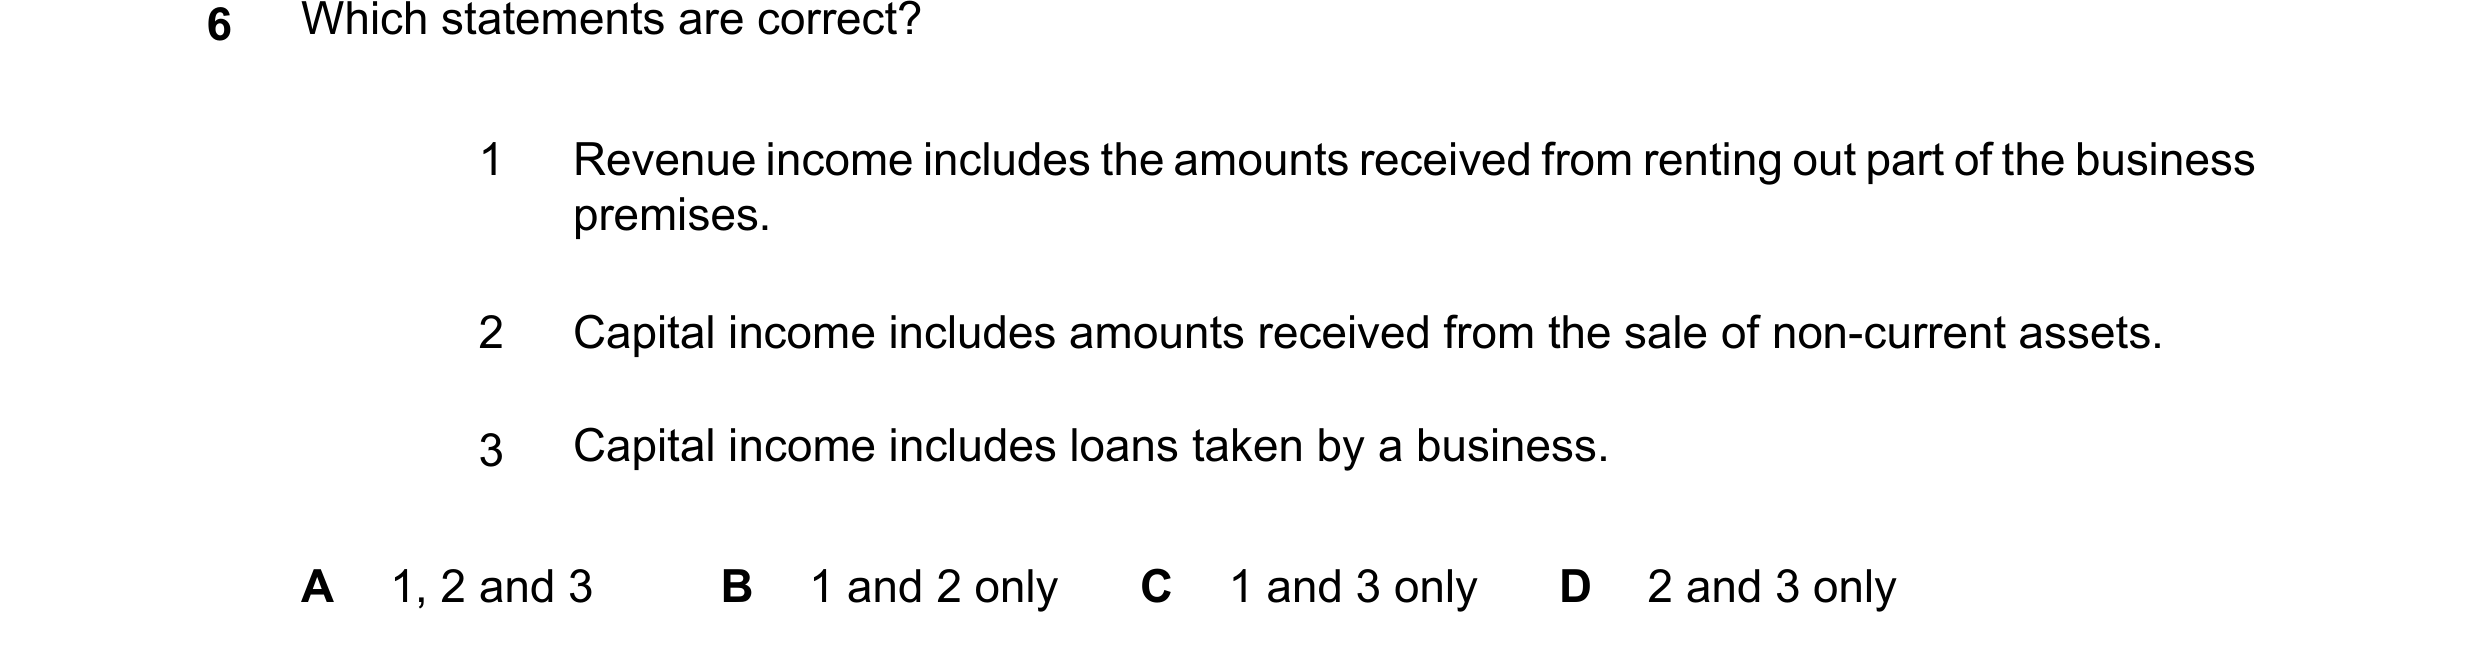
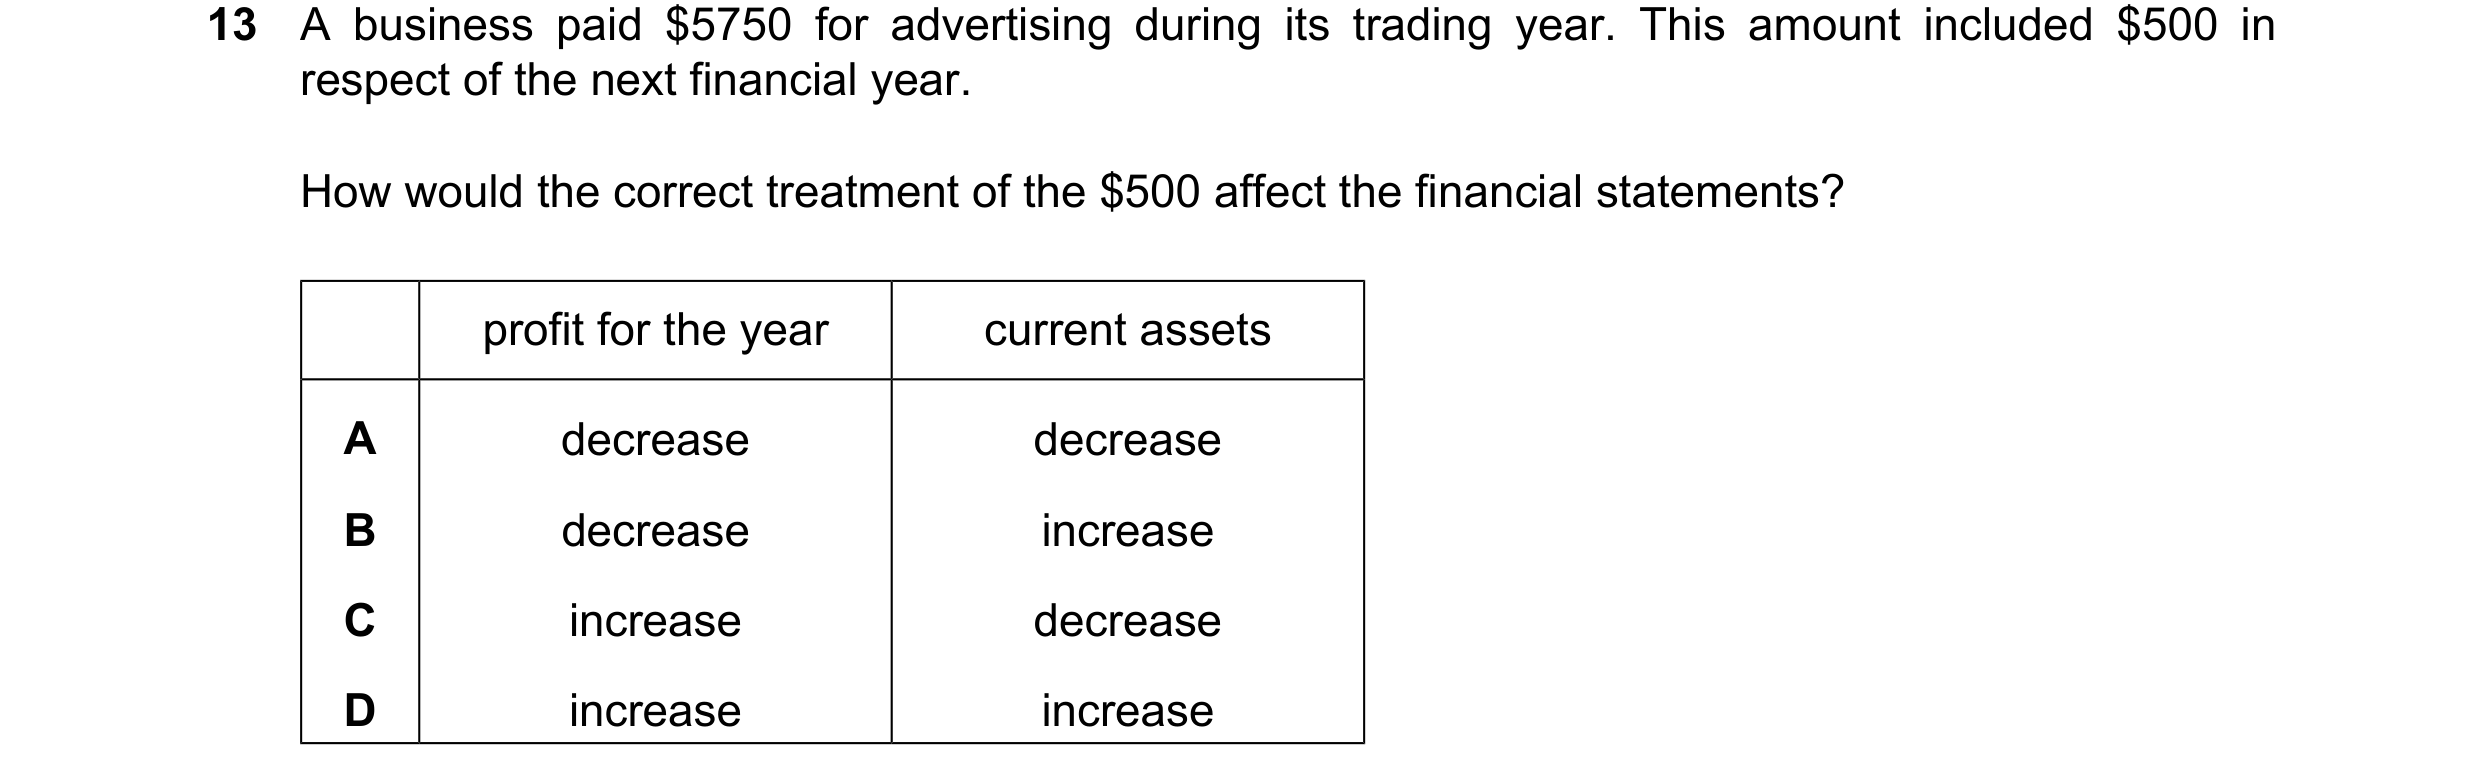
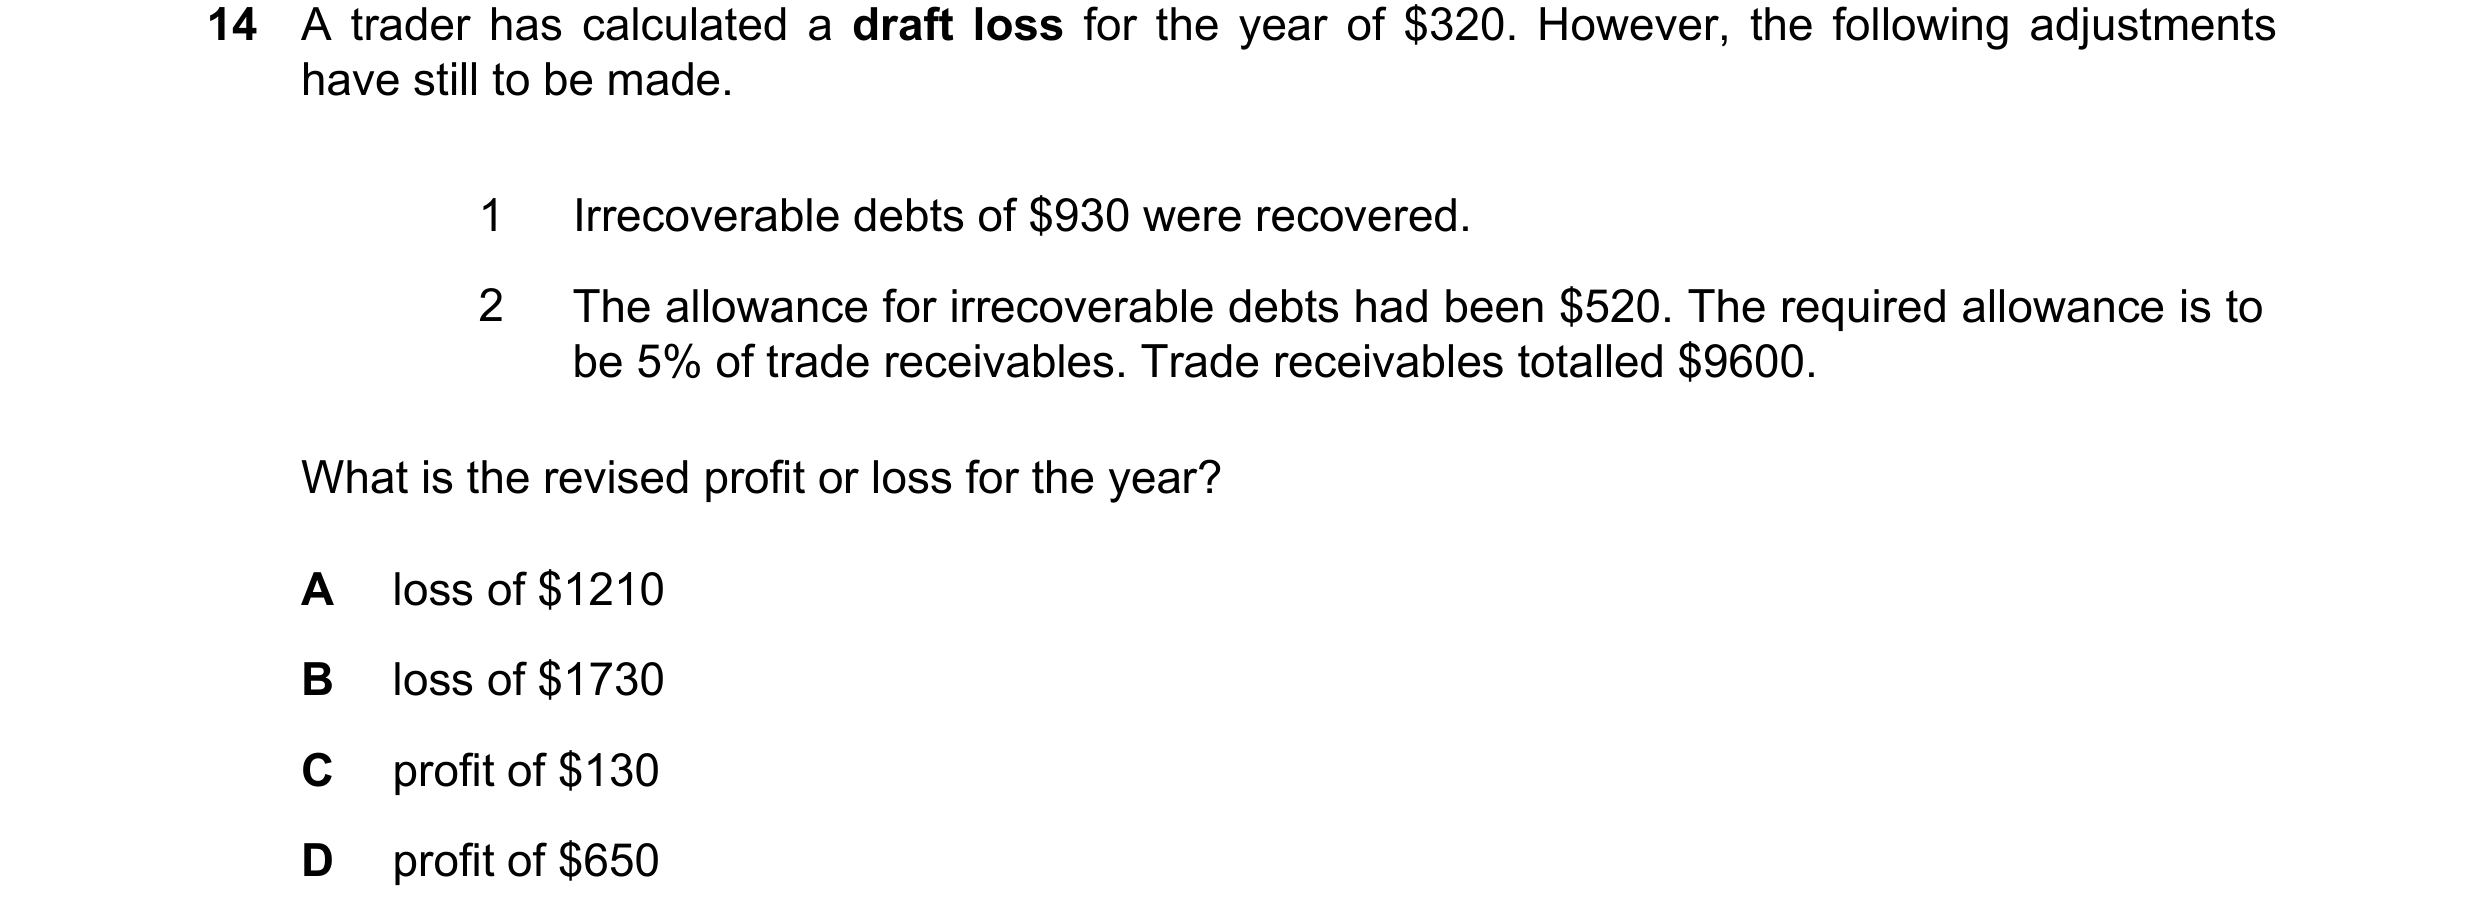 229 / 233
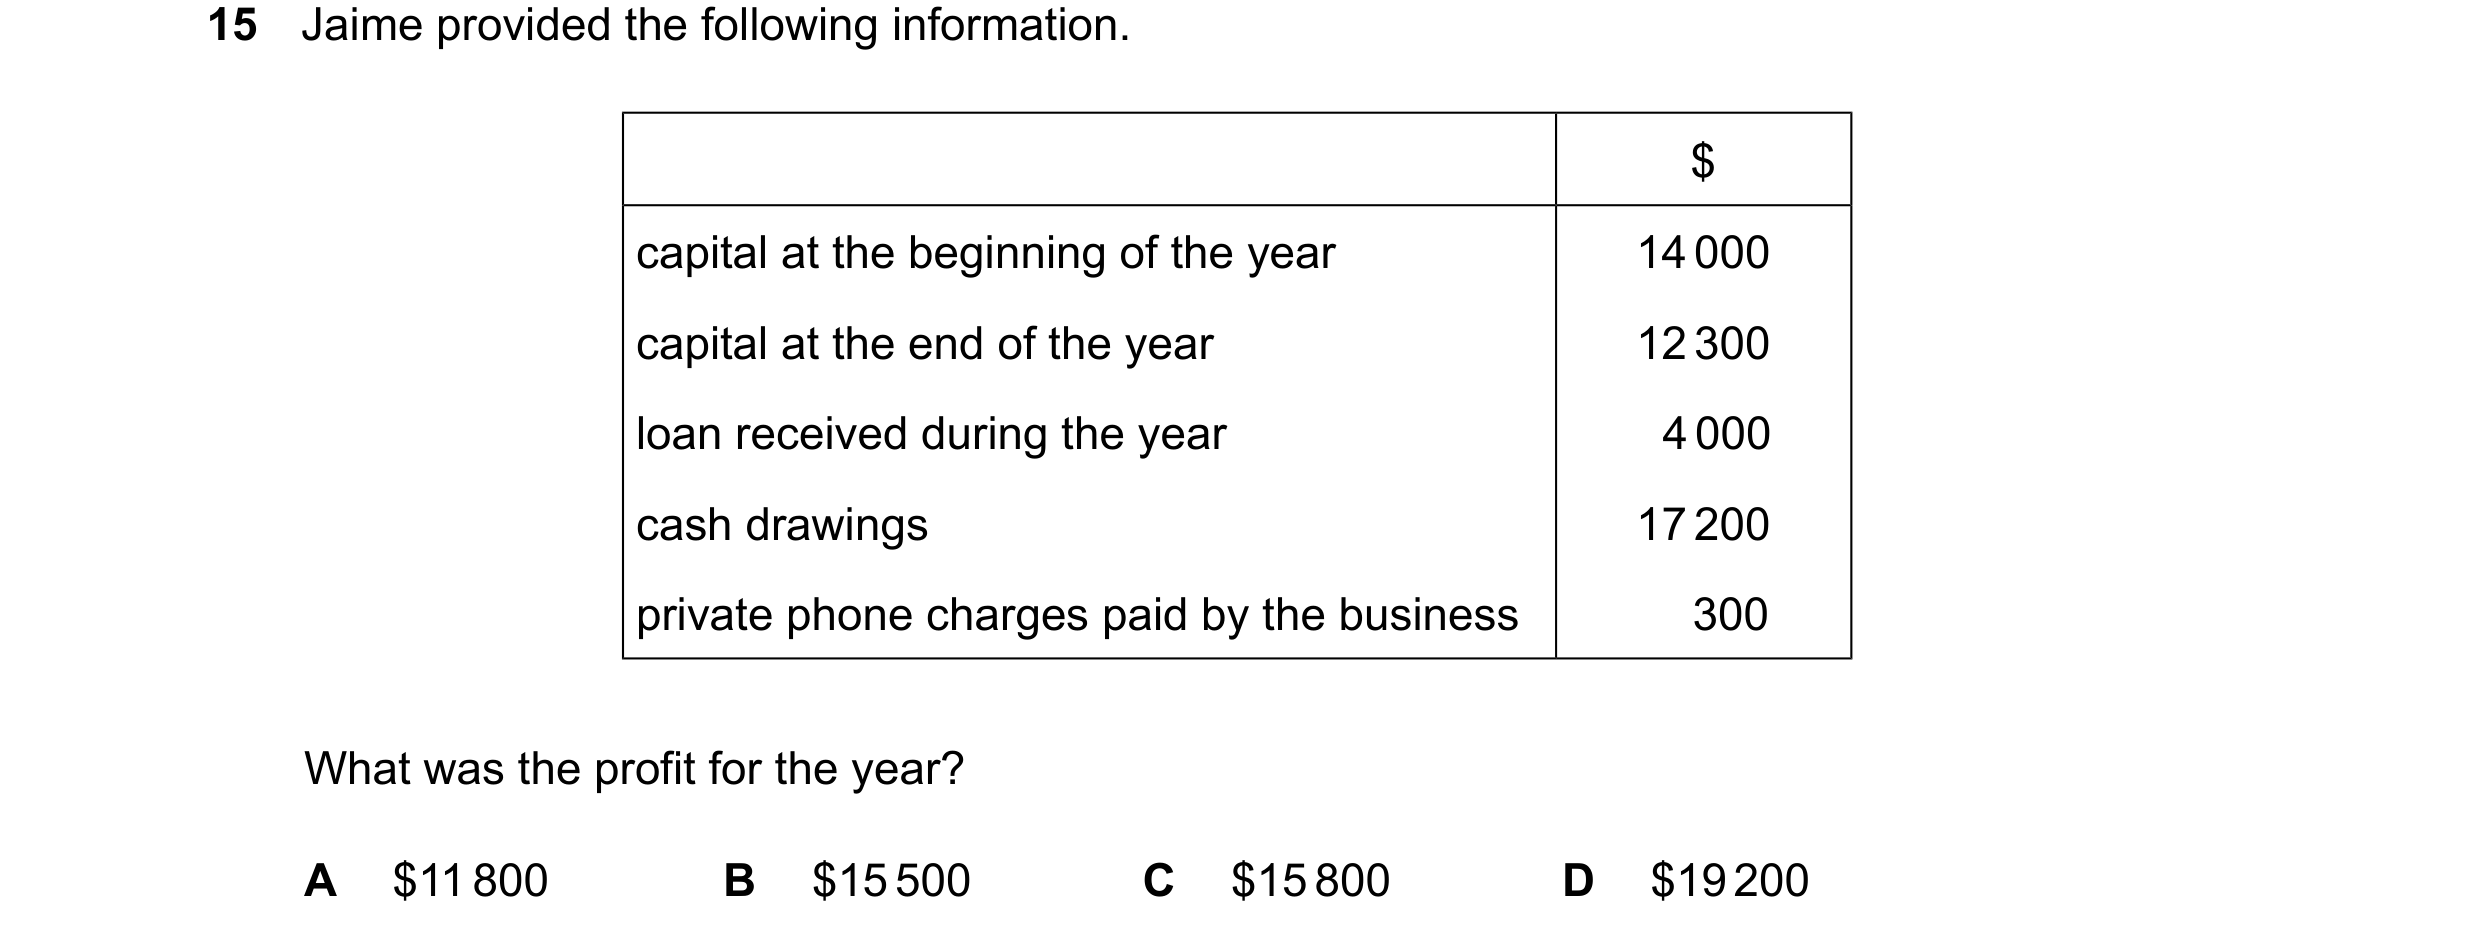
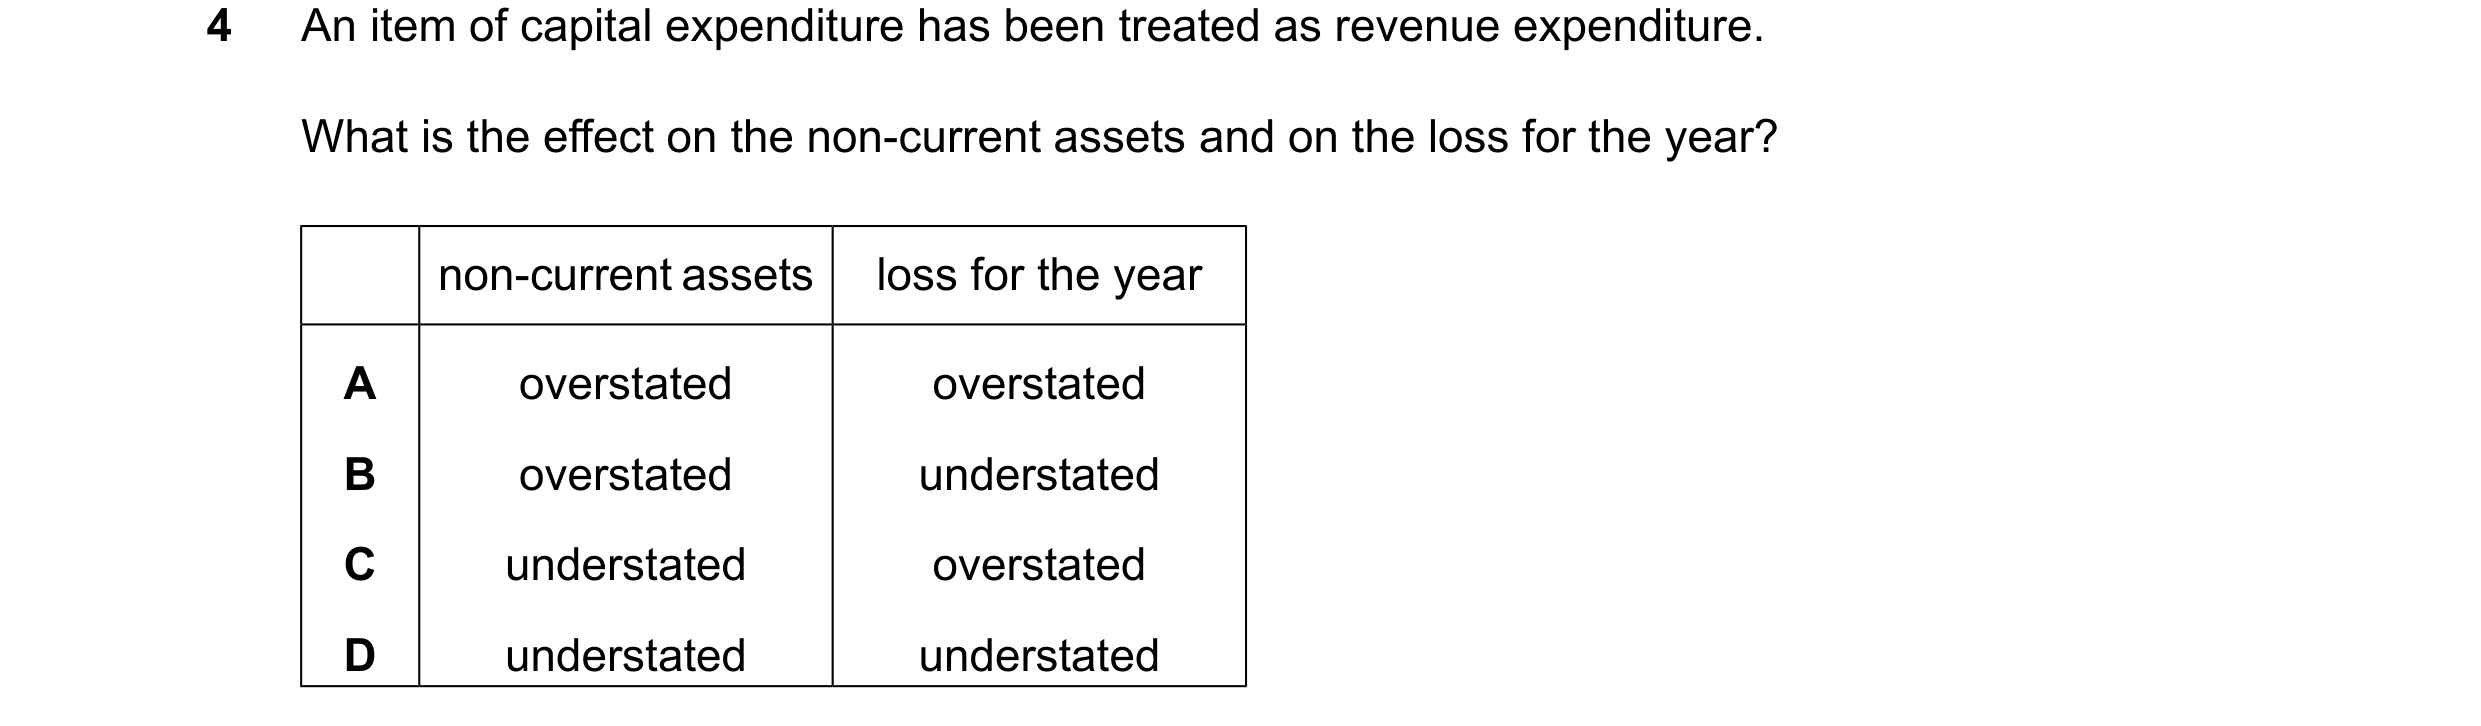
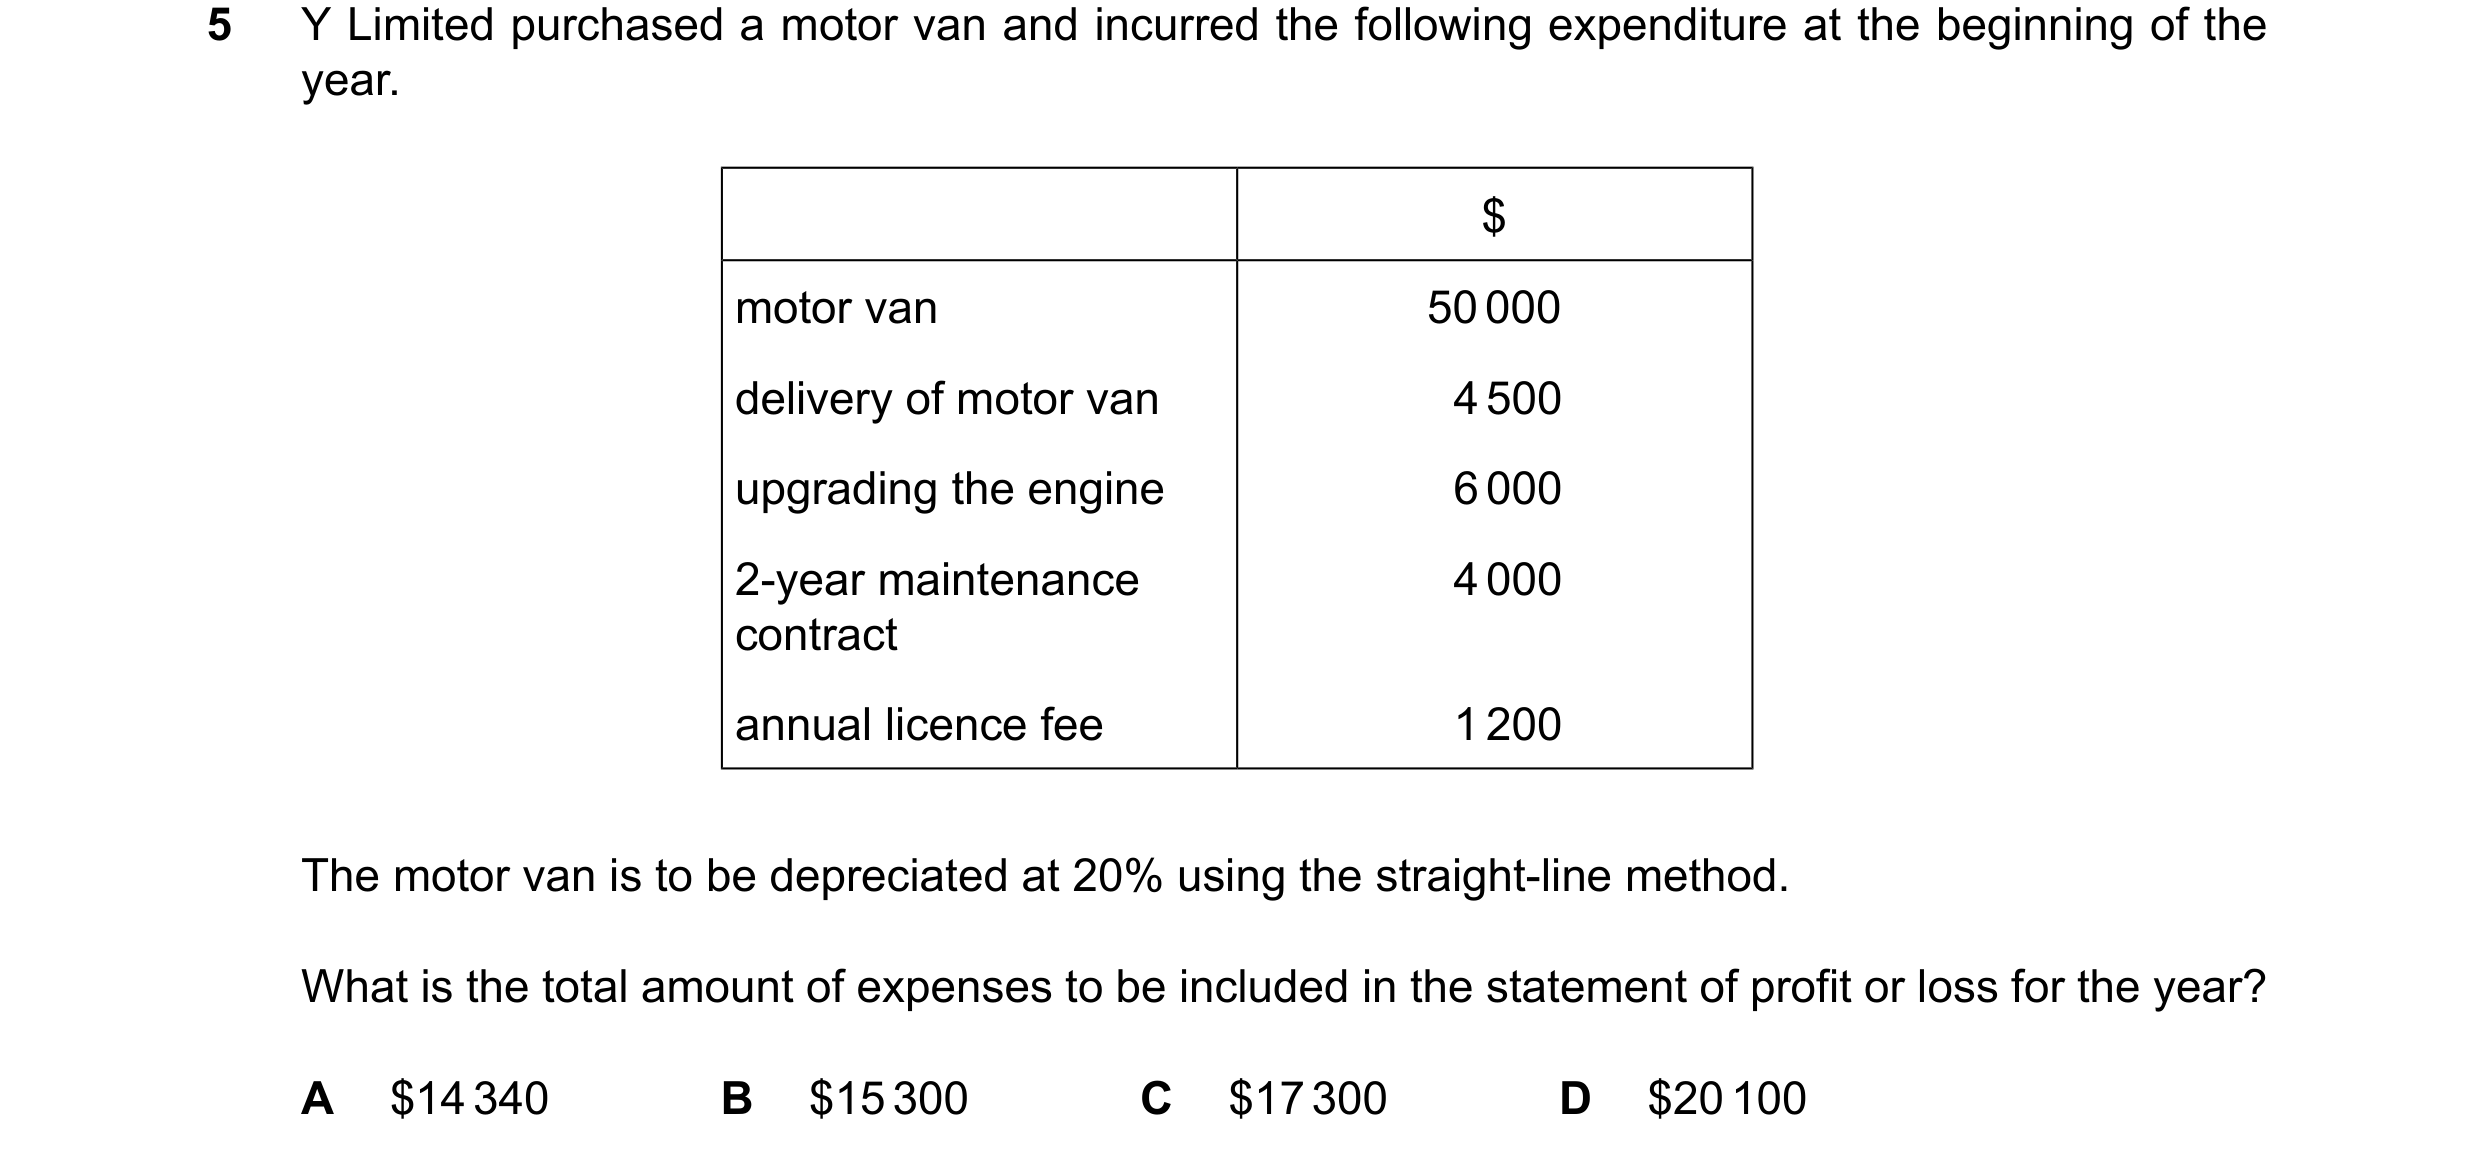
 230 / 233
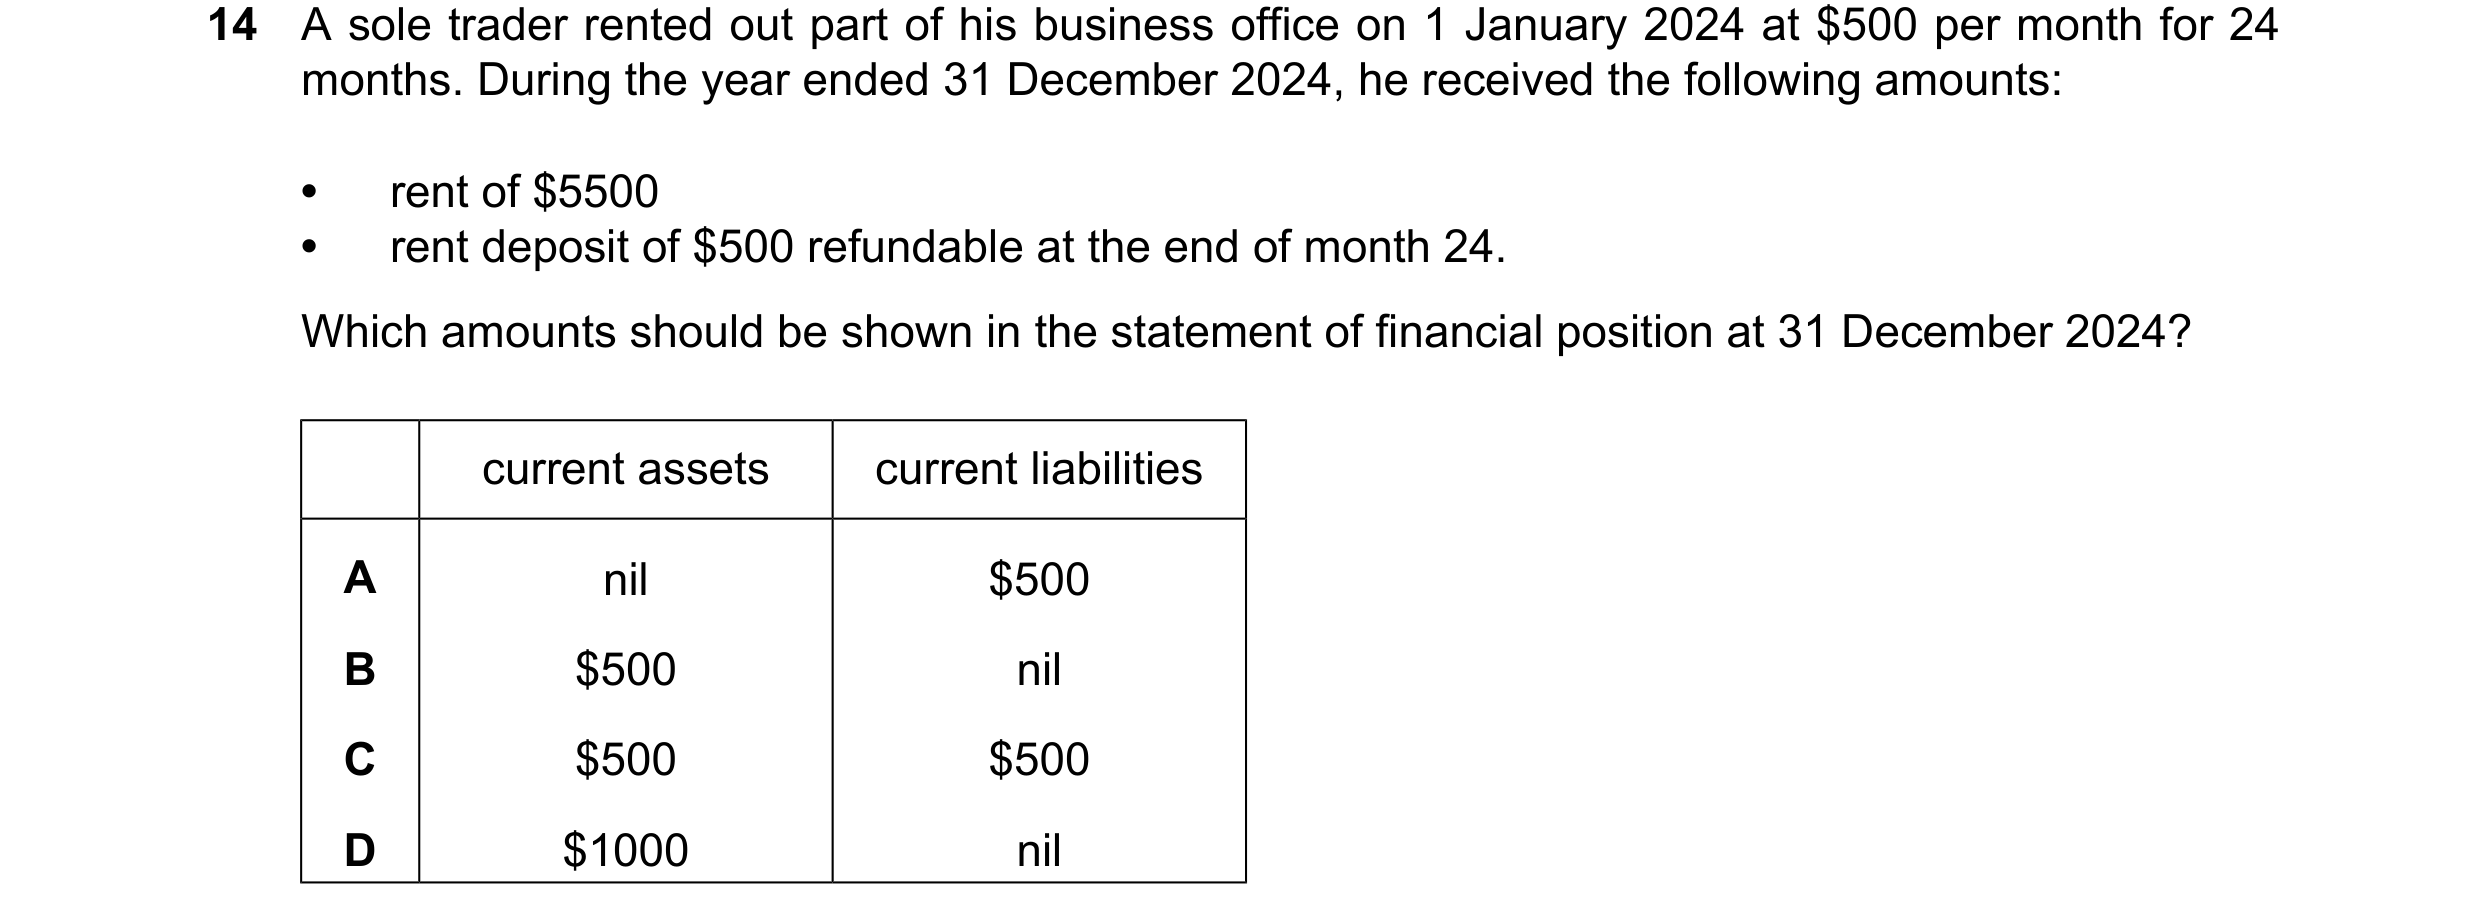
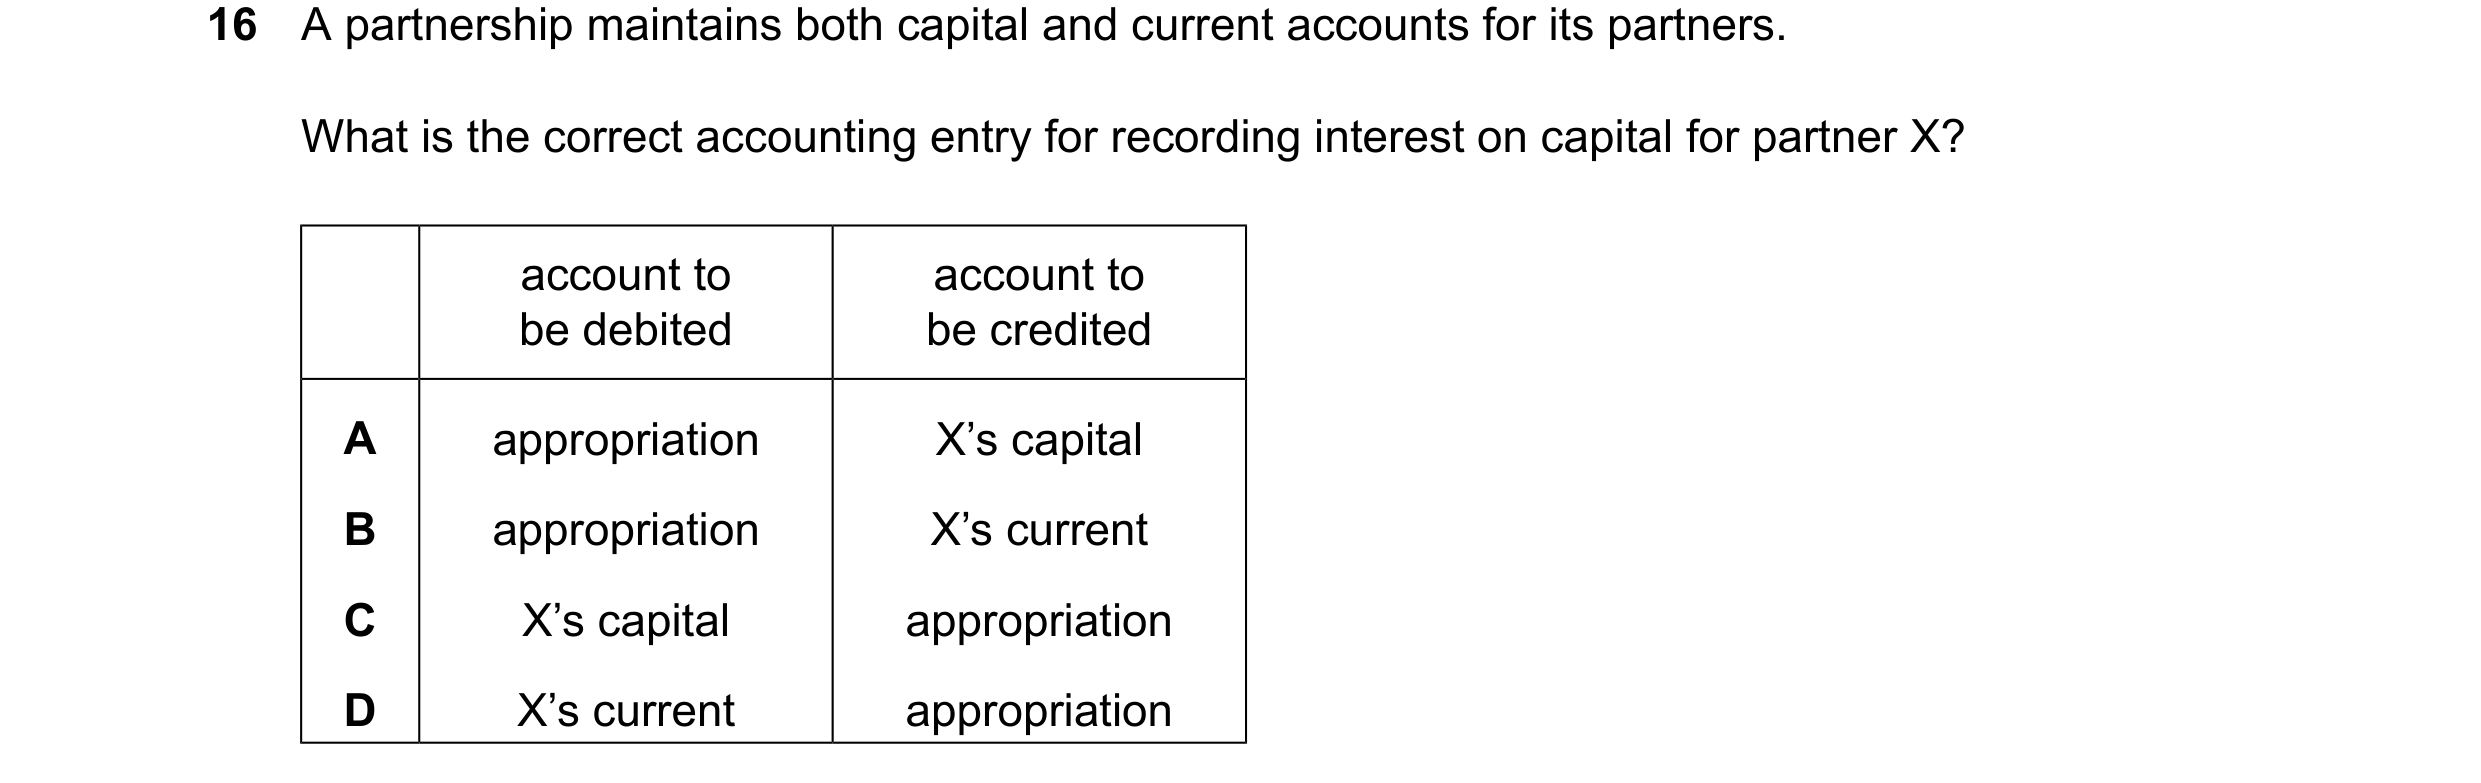
 231 / 233
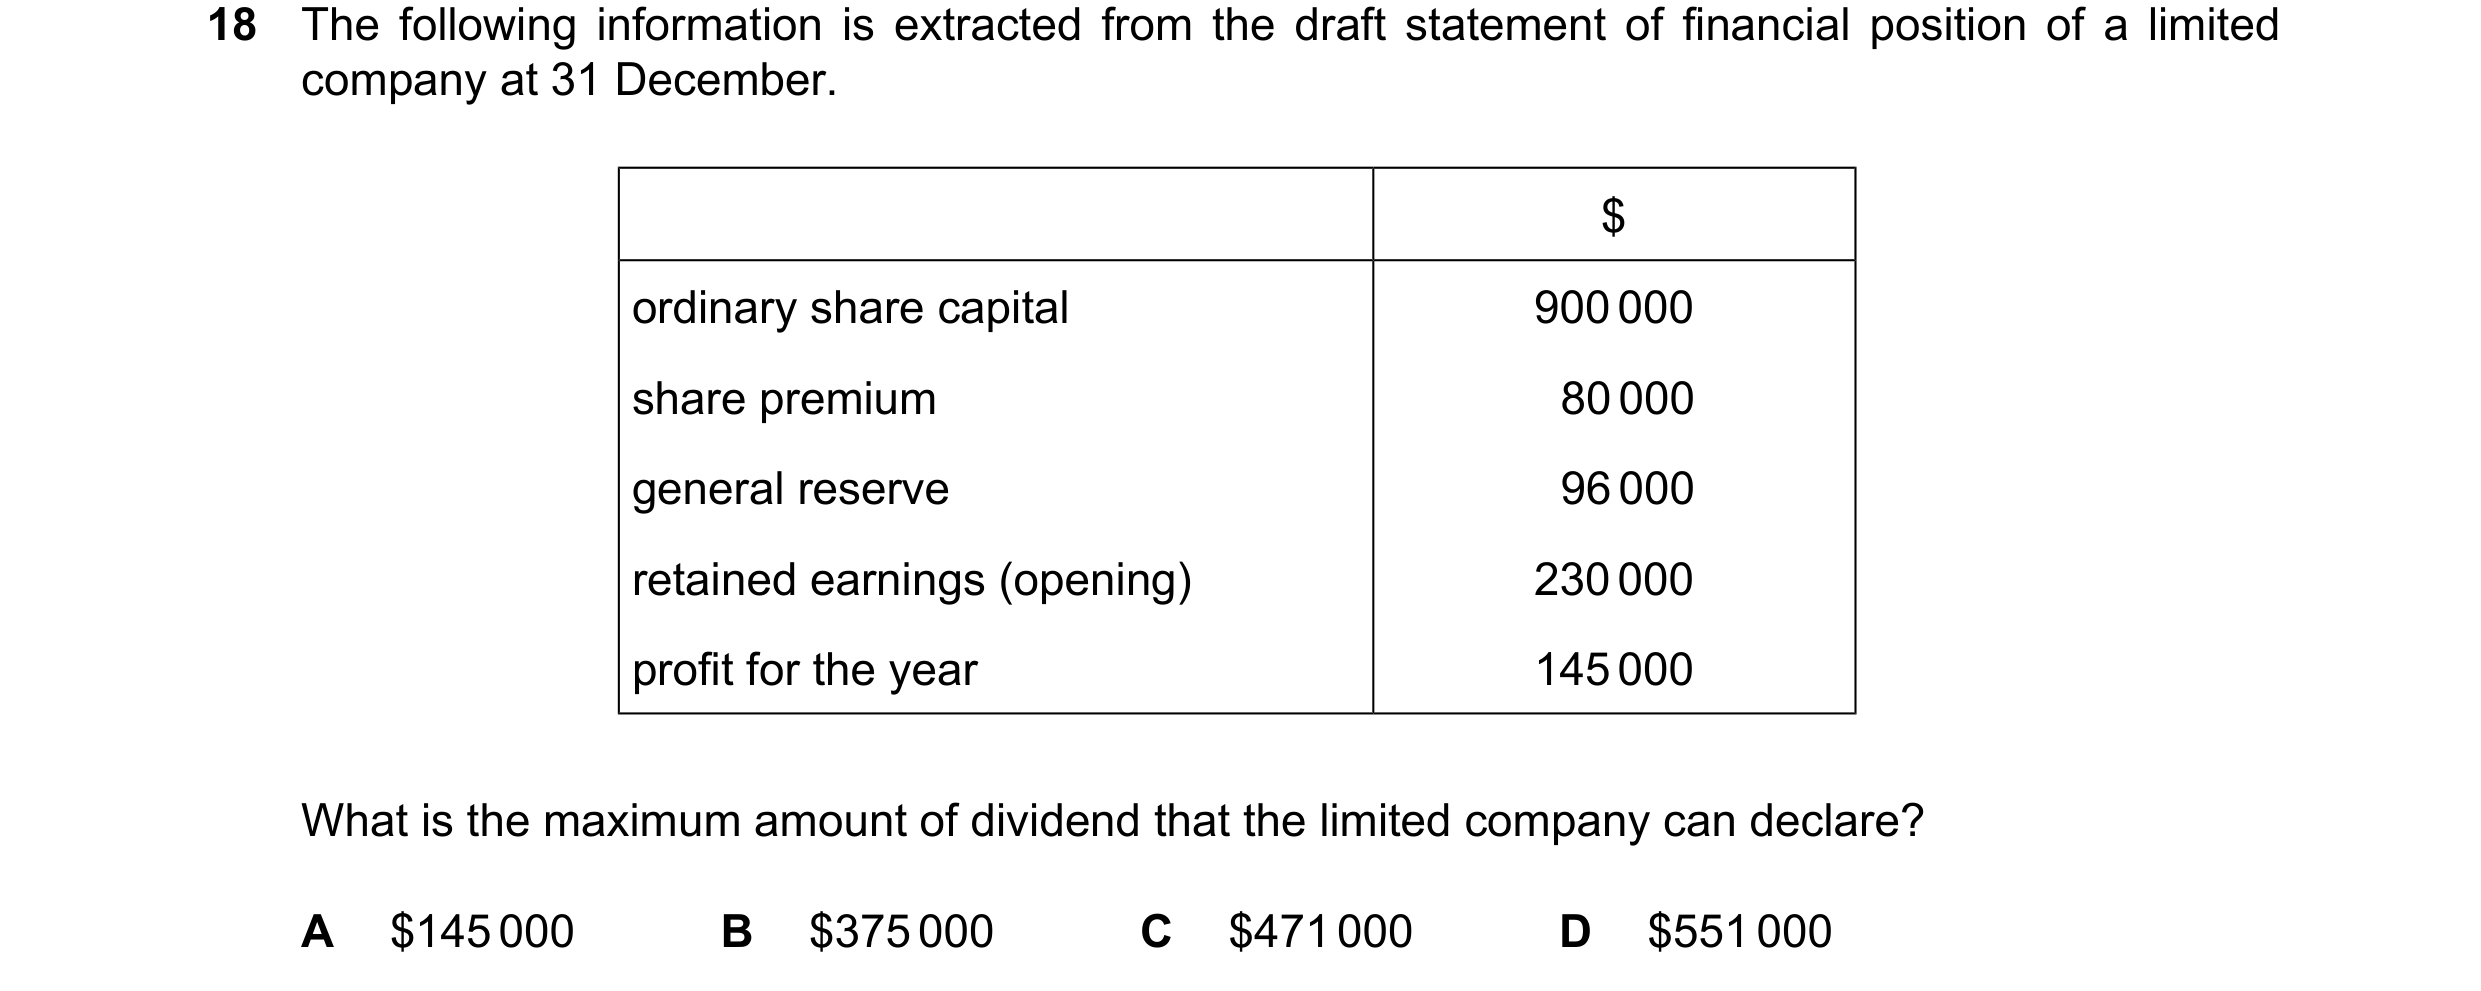
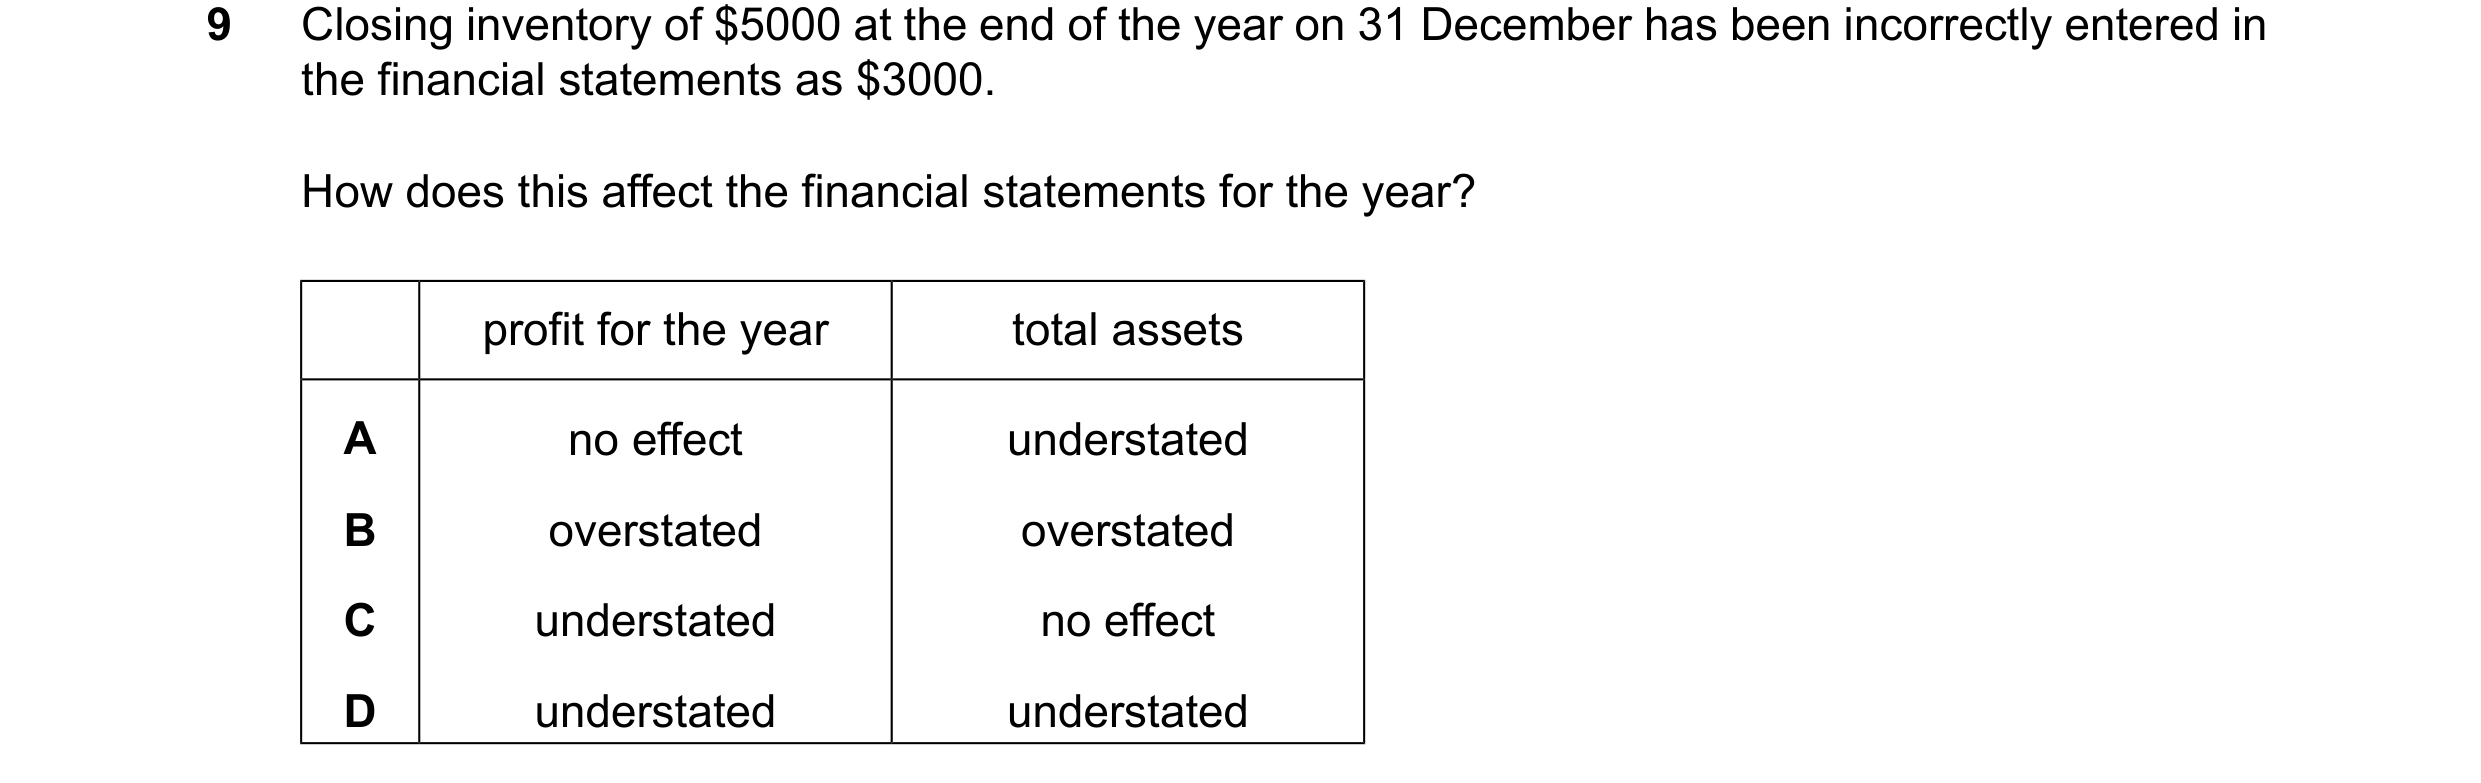
 232 / 233
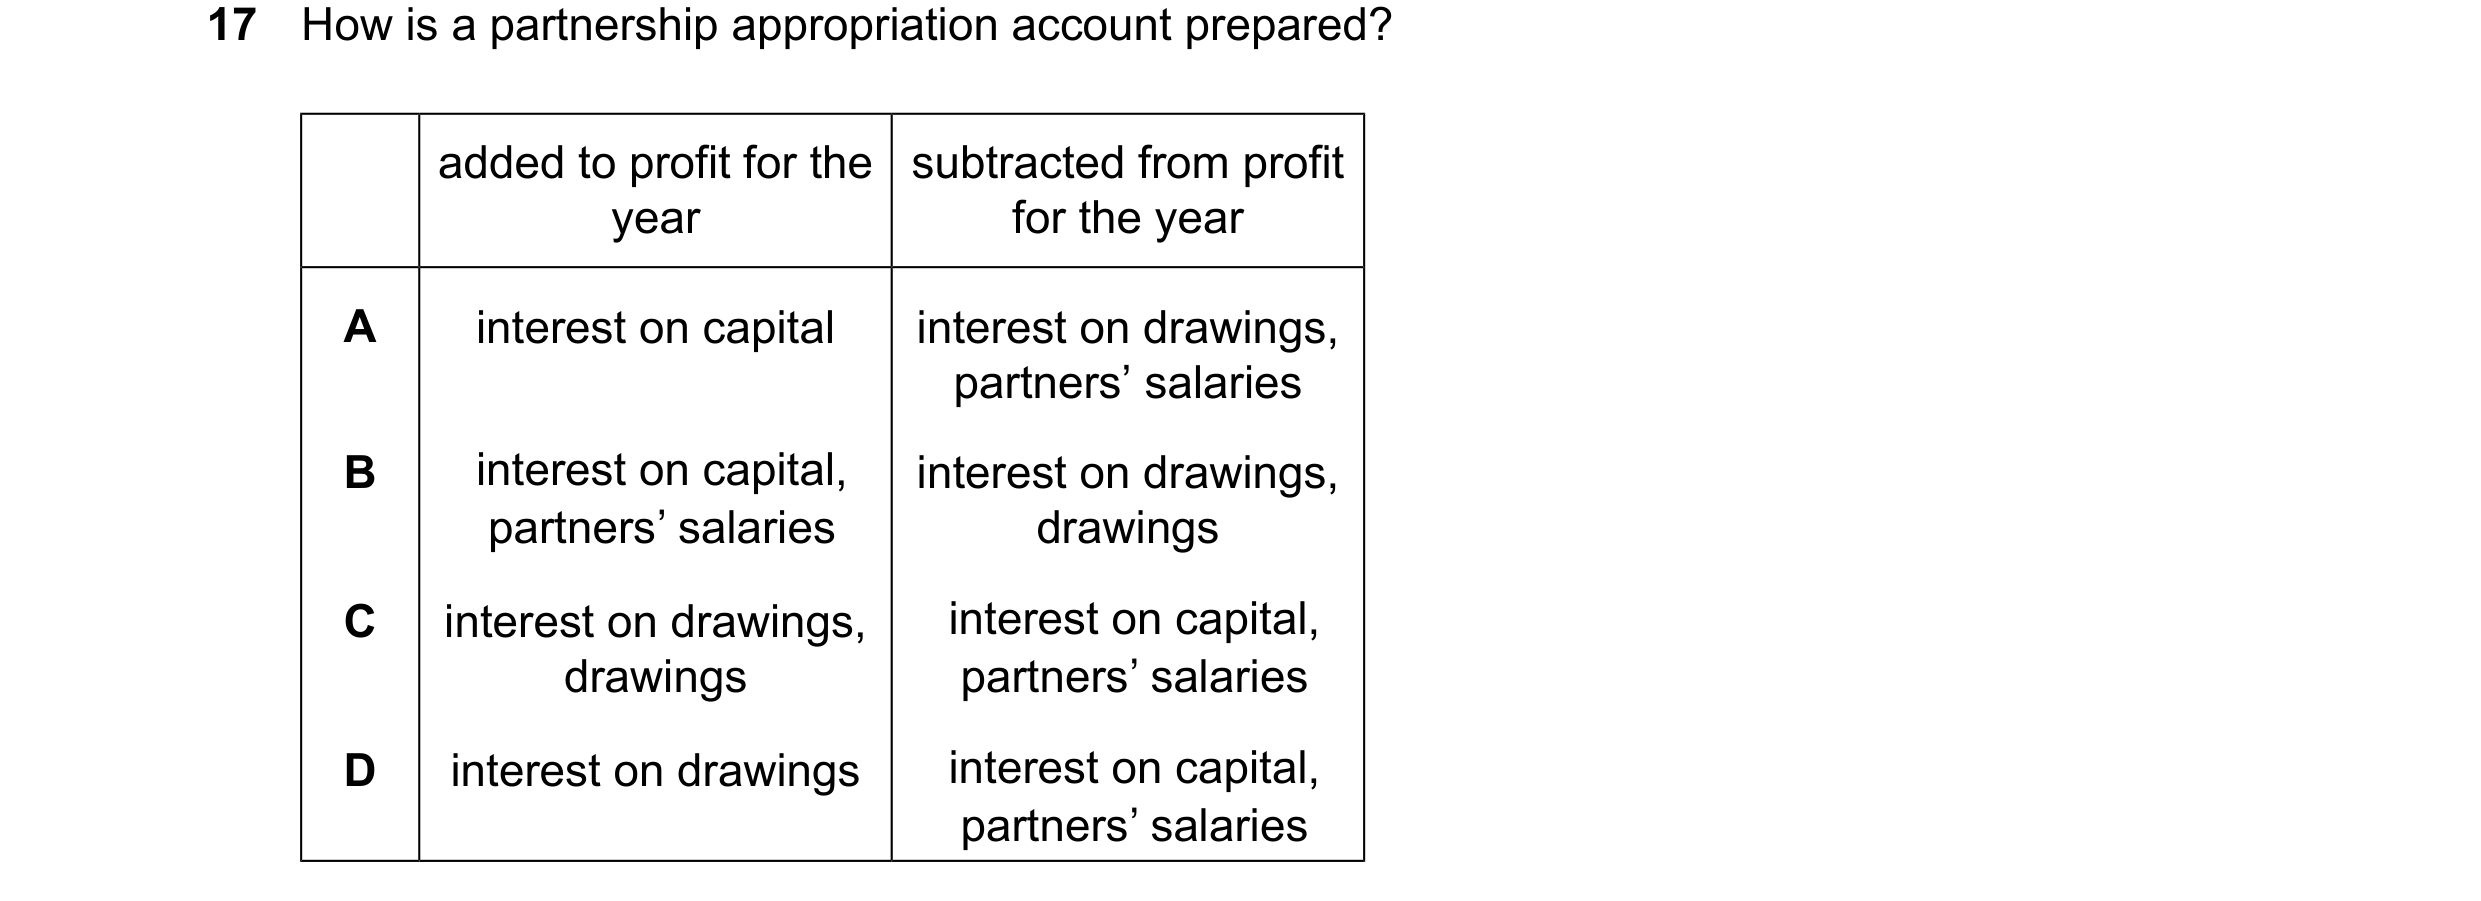
 233 / 233