Questions as text
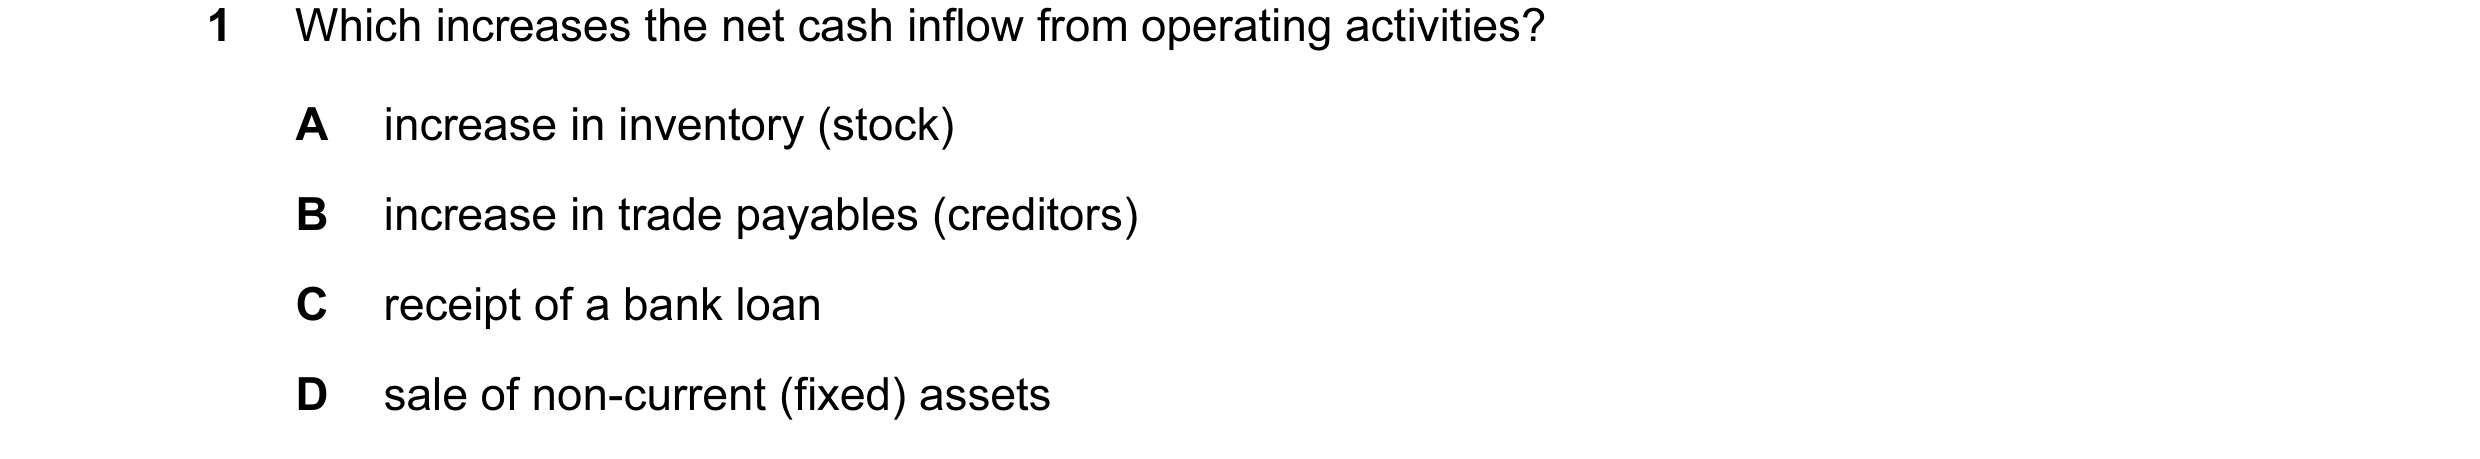
Q1 · Which increases the net cash inflow from operating activities? 9706/32 May/June 2010
1 Which increases the net cash inflow from operating activities? A increase in inventory (stock) B increase in trade payables (creditors) C receipt of a bank loan D sale of non-current (fixed) assets
1 marks
Answer: B
This question in 9706/32 May/June 2010
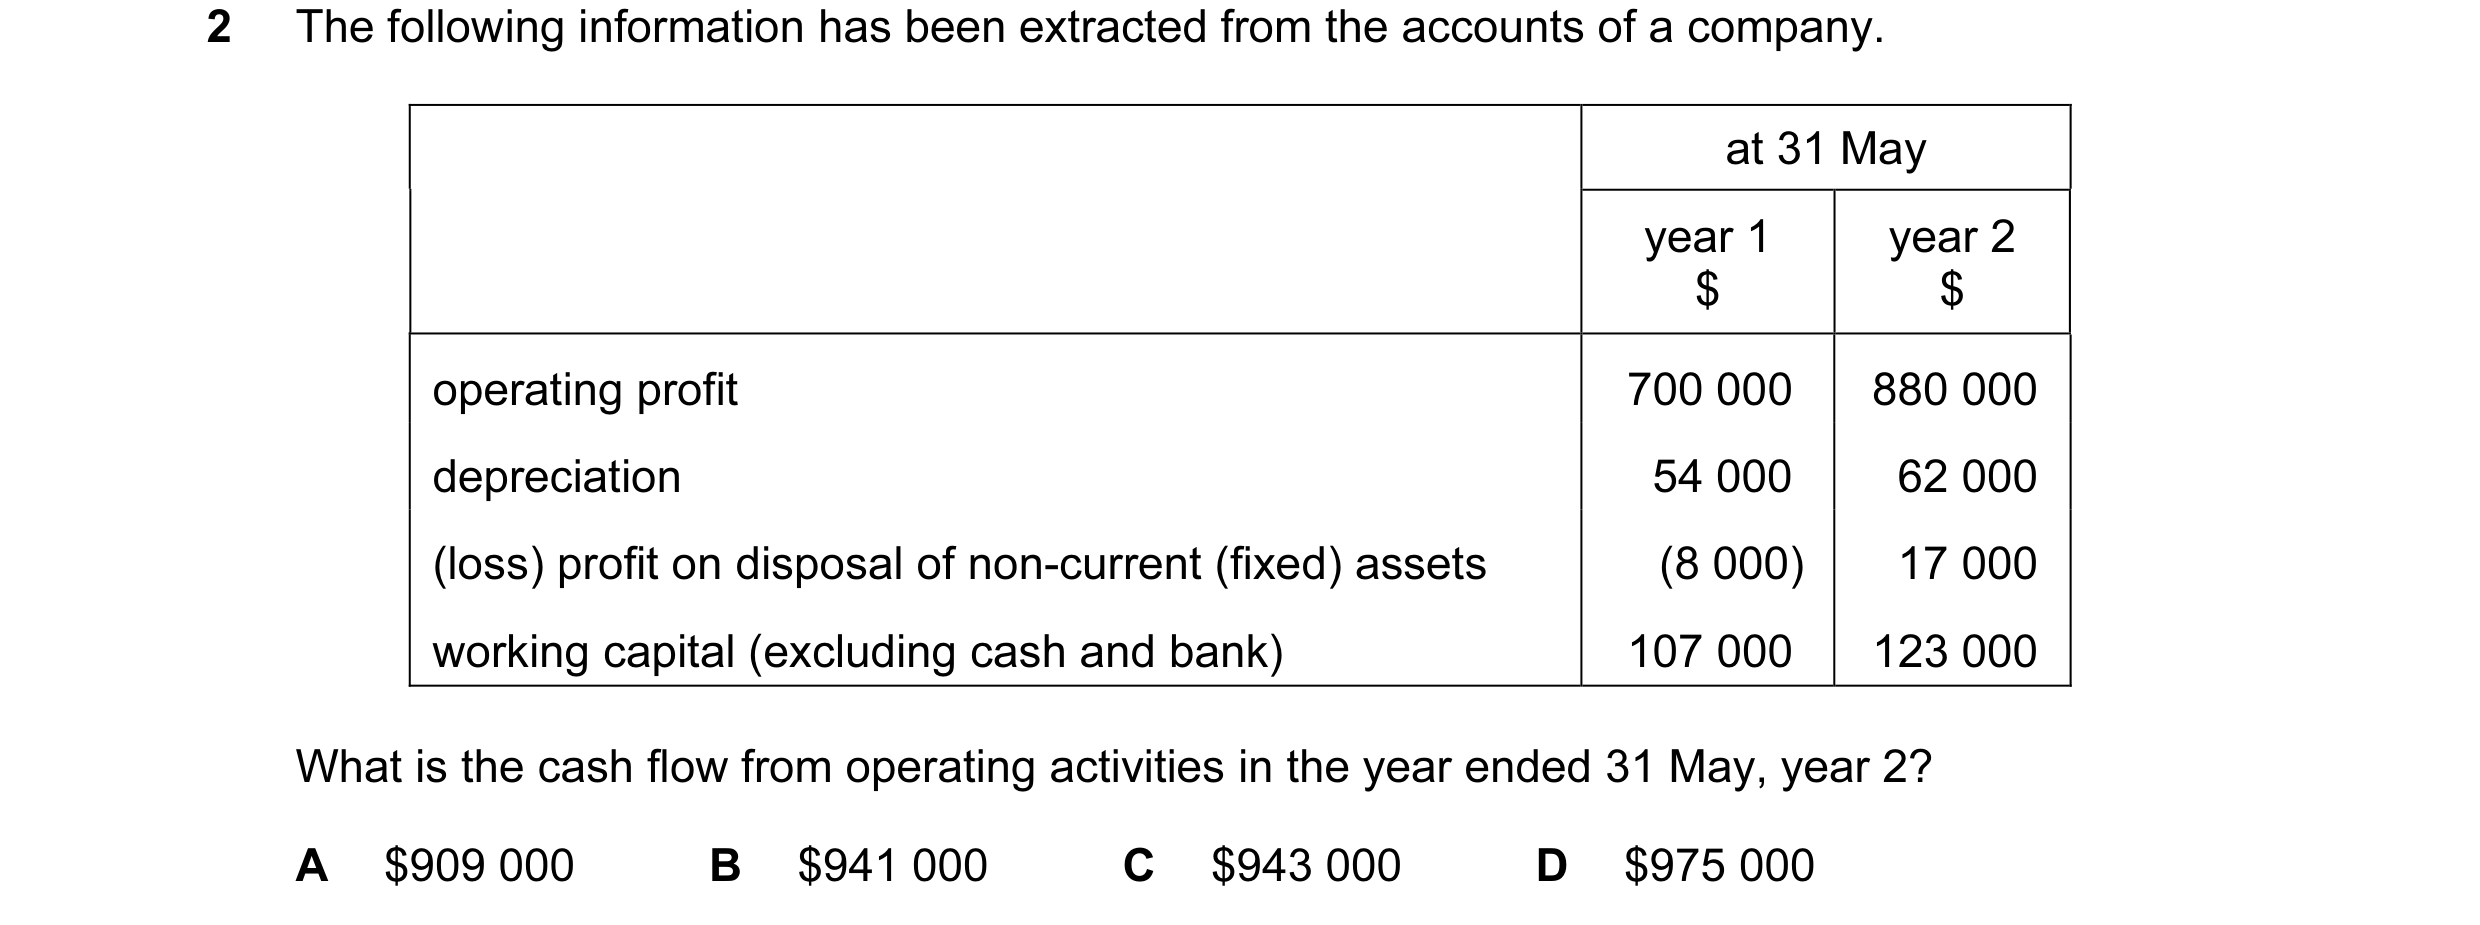
Q2 · The following information has been extracted from the accounts of a company 9706/32 May/June 2010
2 The following information has been extracted from the accounts of a company. at 31 May year 1 year 2 $ $ operating profit 700 000 880 000 depreciation 54 000 62 000 (loss) profit on disposal of non-current (fixed) assets (8 000) 17 000 working capital (excluding cash and bank) 107 000 123 000 What is the cash flow from operating activities in the year ended 31 May, year 2? A $909 000 B $941 000 C $943 000 D $975 000
1 marks
Answer: A
This question in 9706/32 May/June 2010
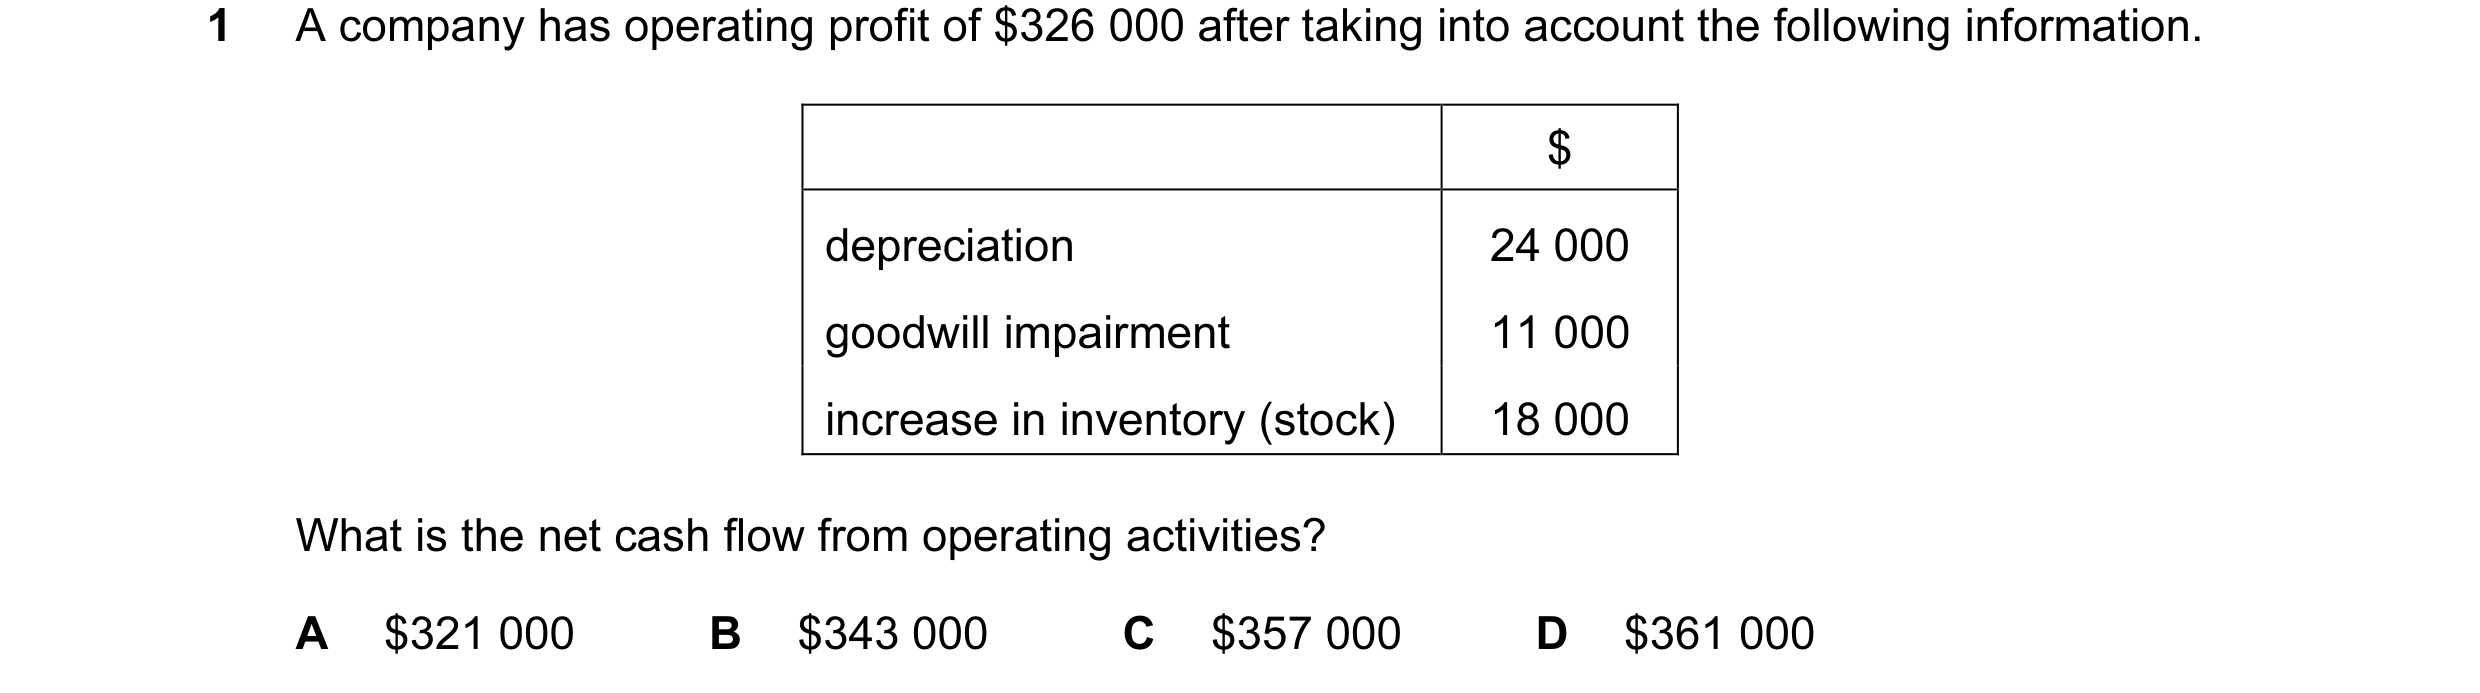
Q3 · A company has operating profit of $326 000 after taking into account the following… 9706/31 Oct/Nov 2010
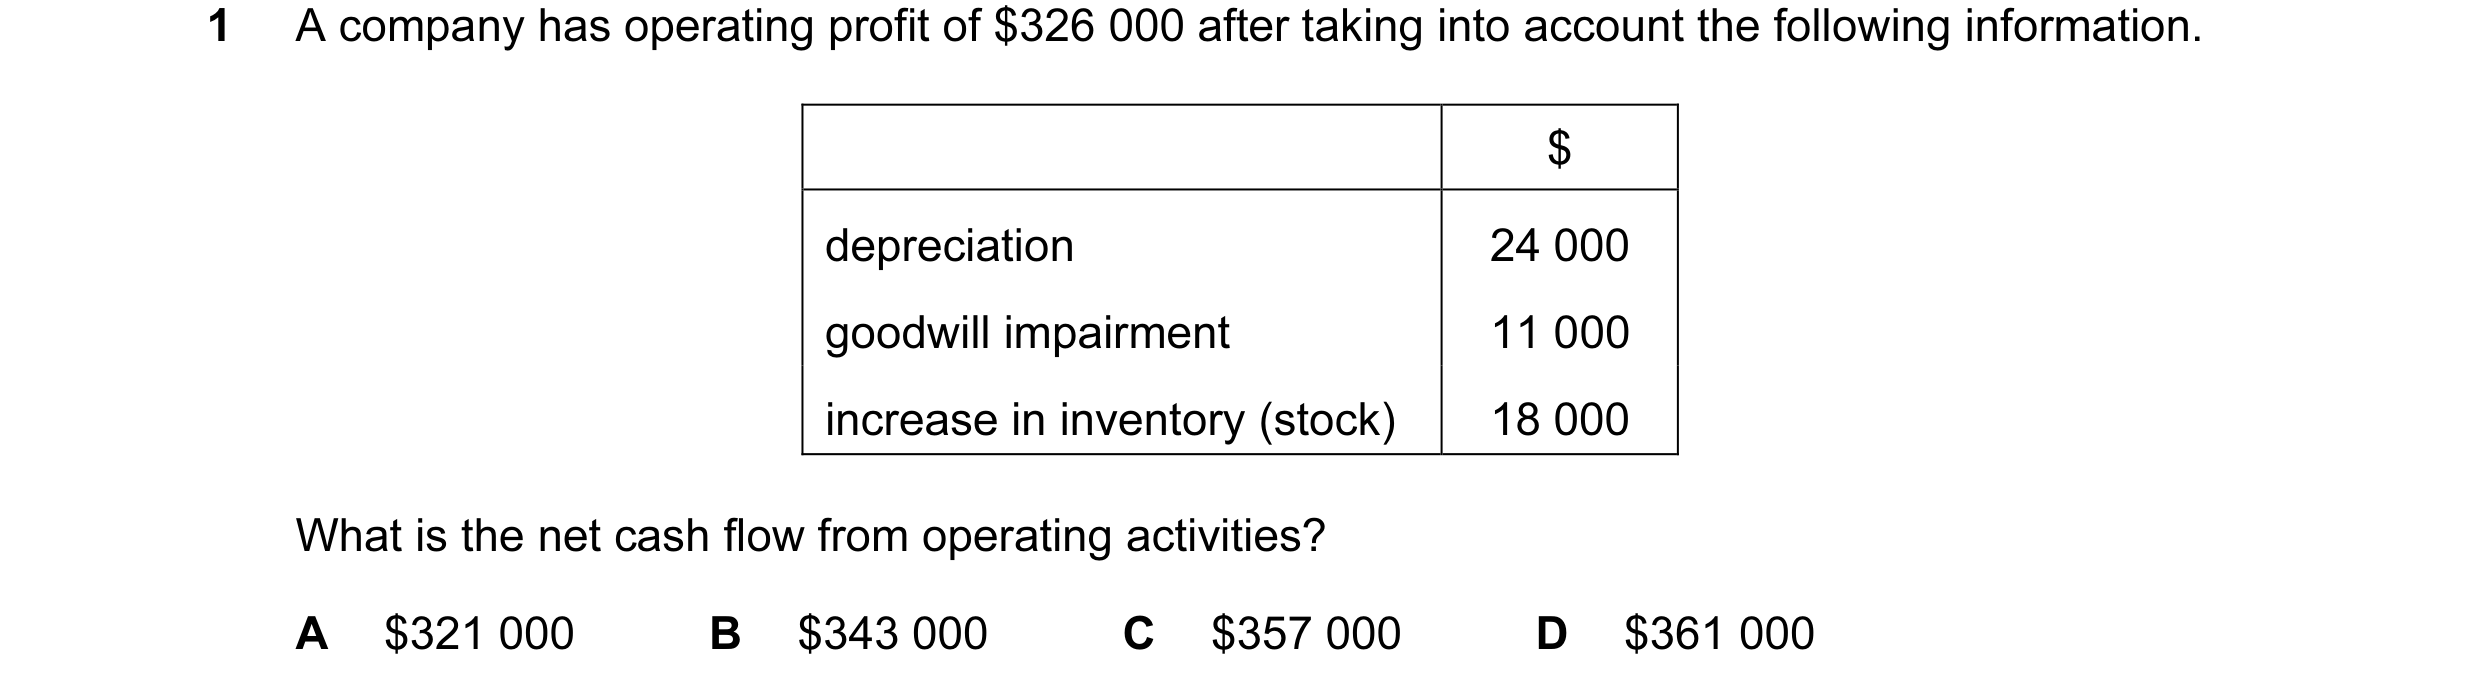
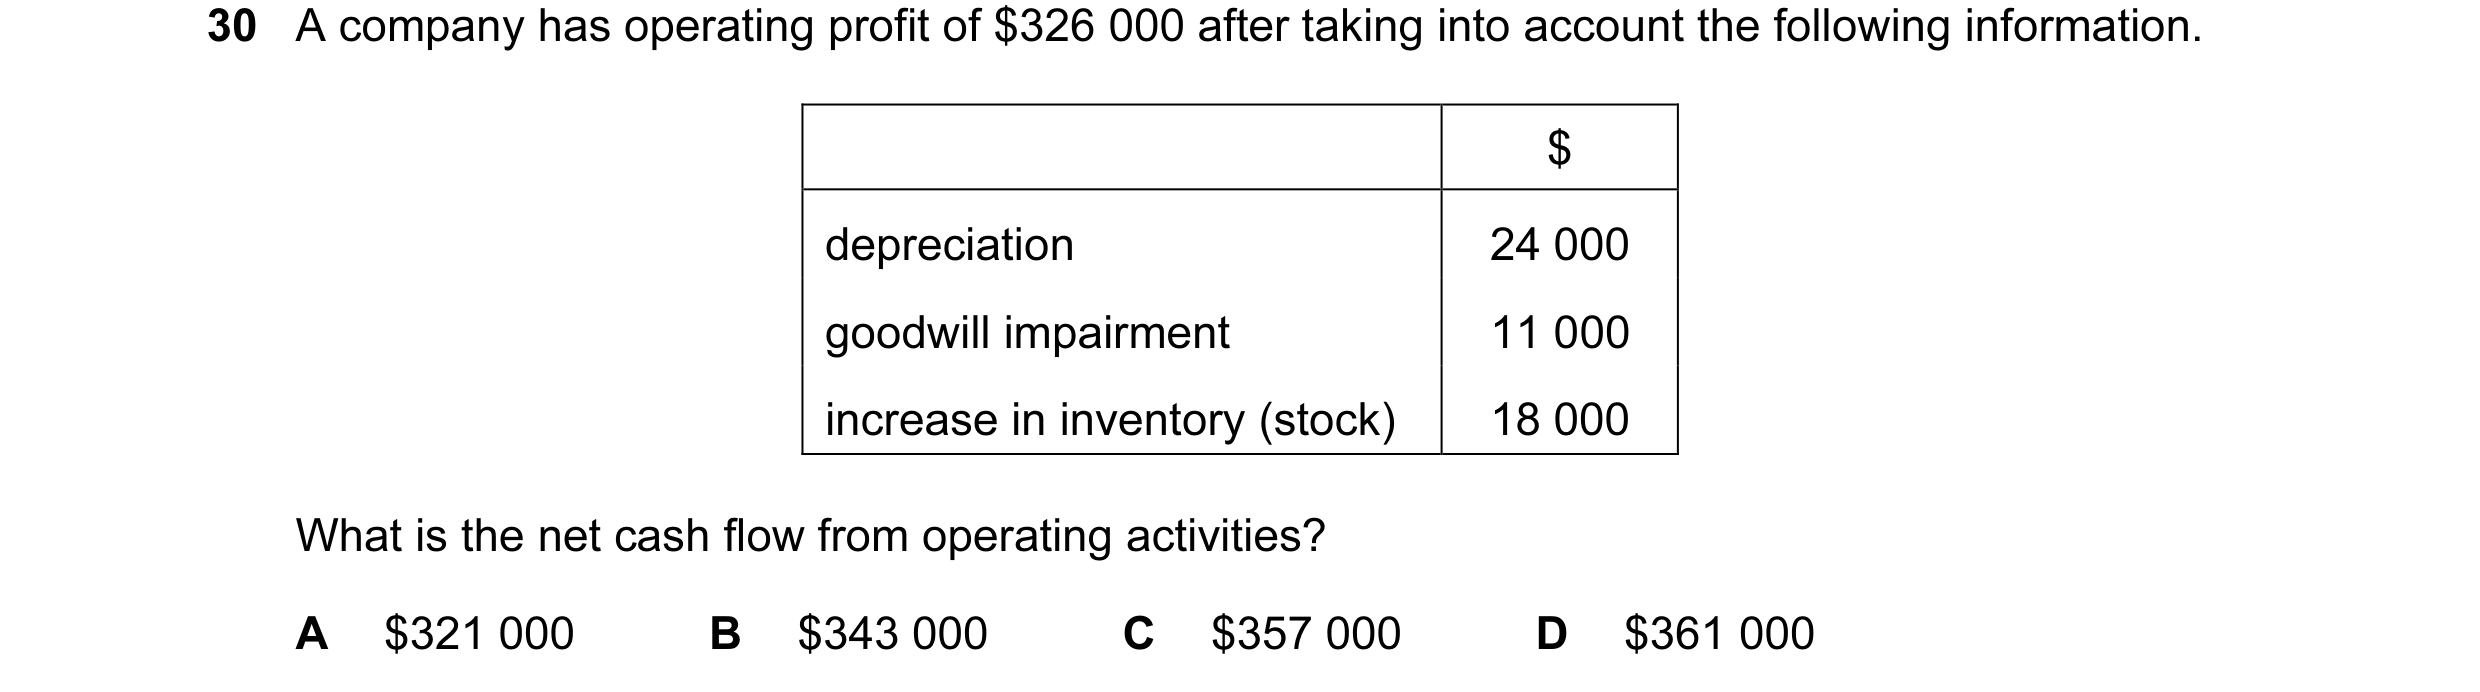
1 A company has operating profit of $326 000 after taking into account the following information. $ depreciation 24 000 goodwill impairment 11 000 increase in inventory (stock) 18 000 What is the net cash flow from operating activities? A $321 000 B $343 000 C $357 000 D $361 000
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2010
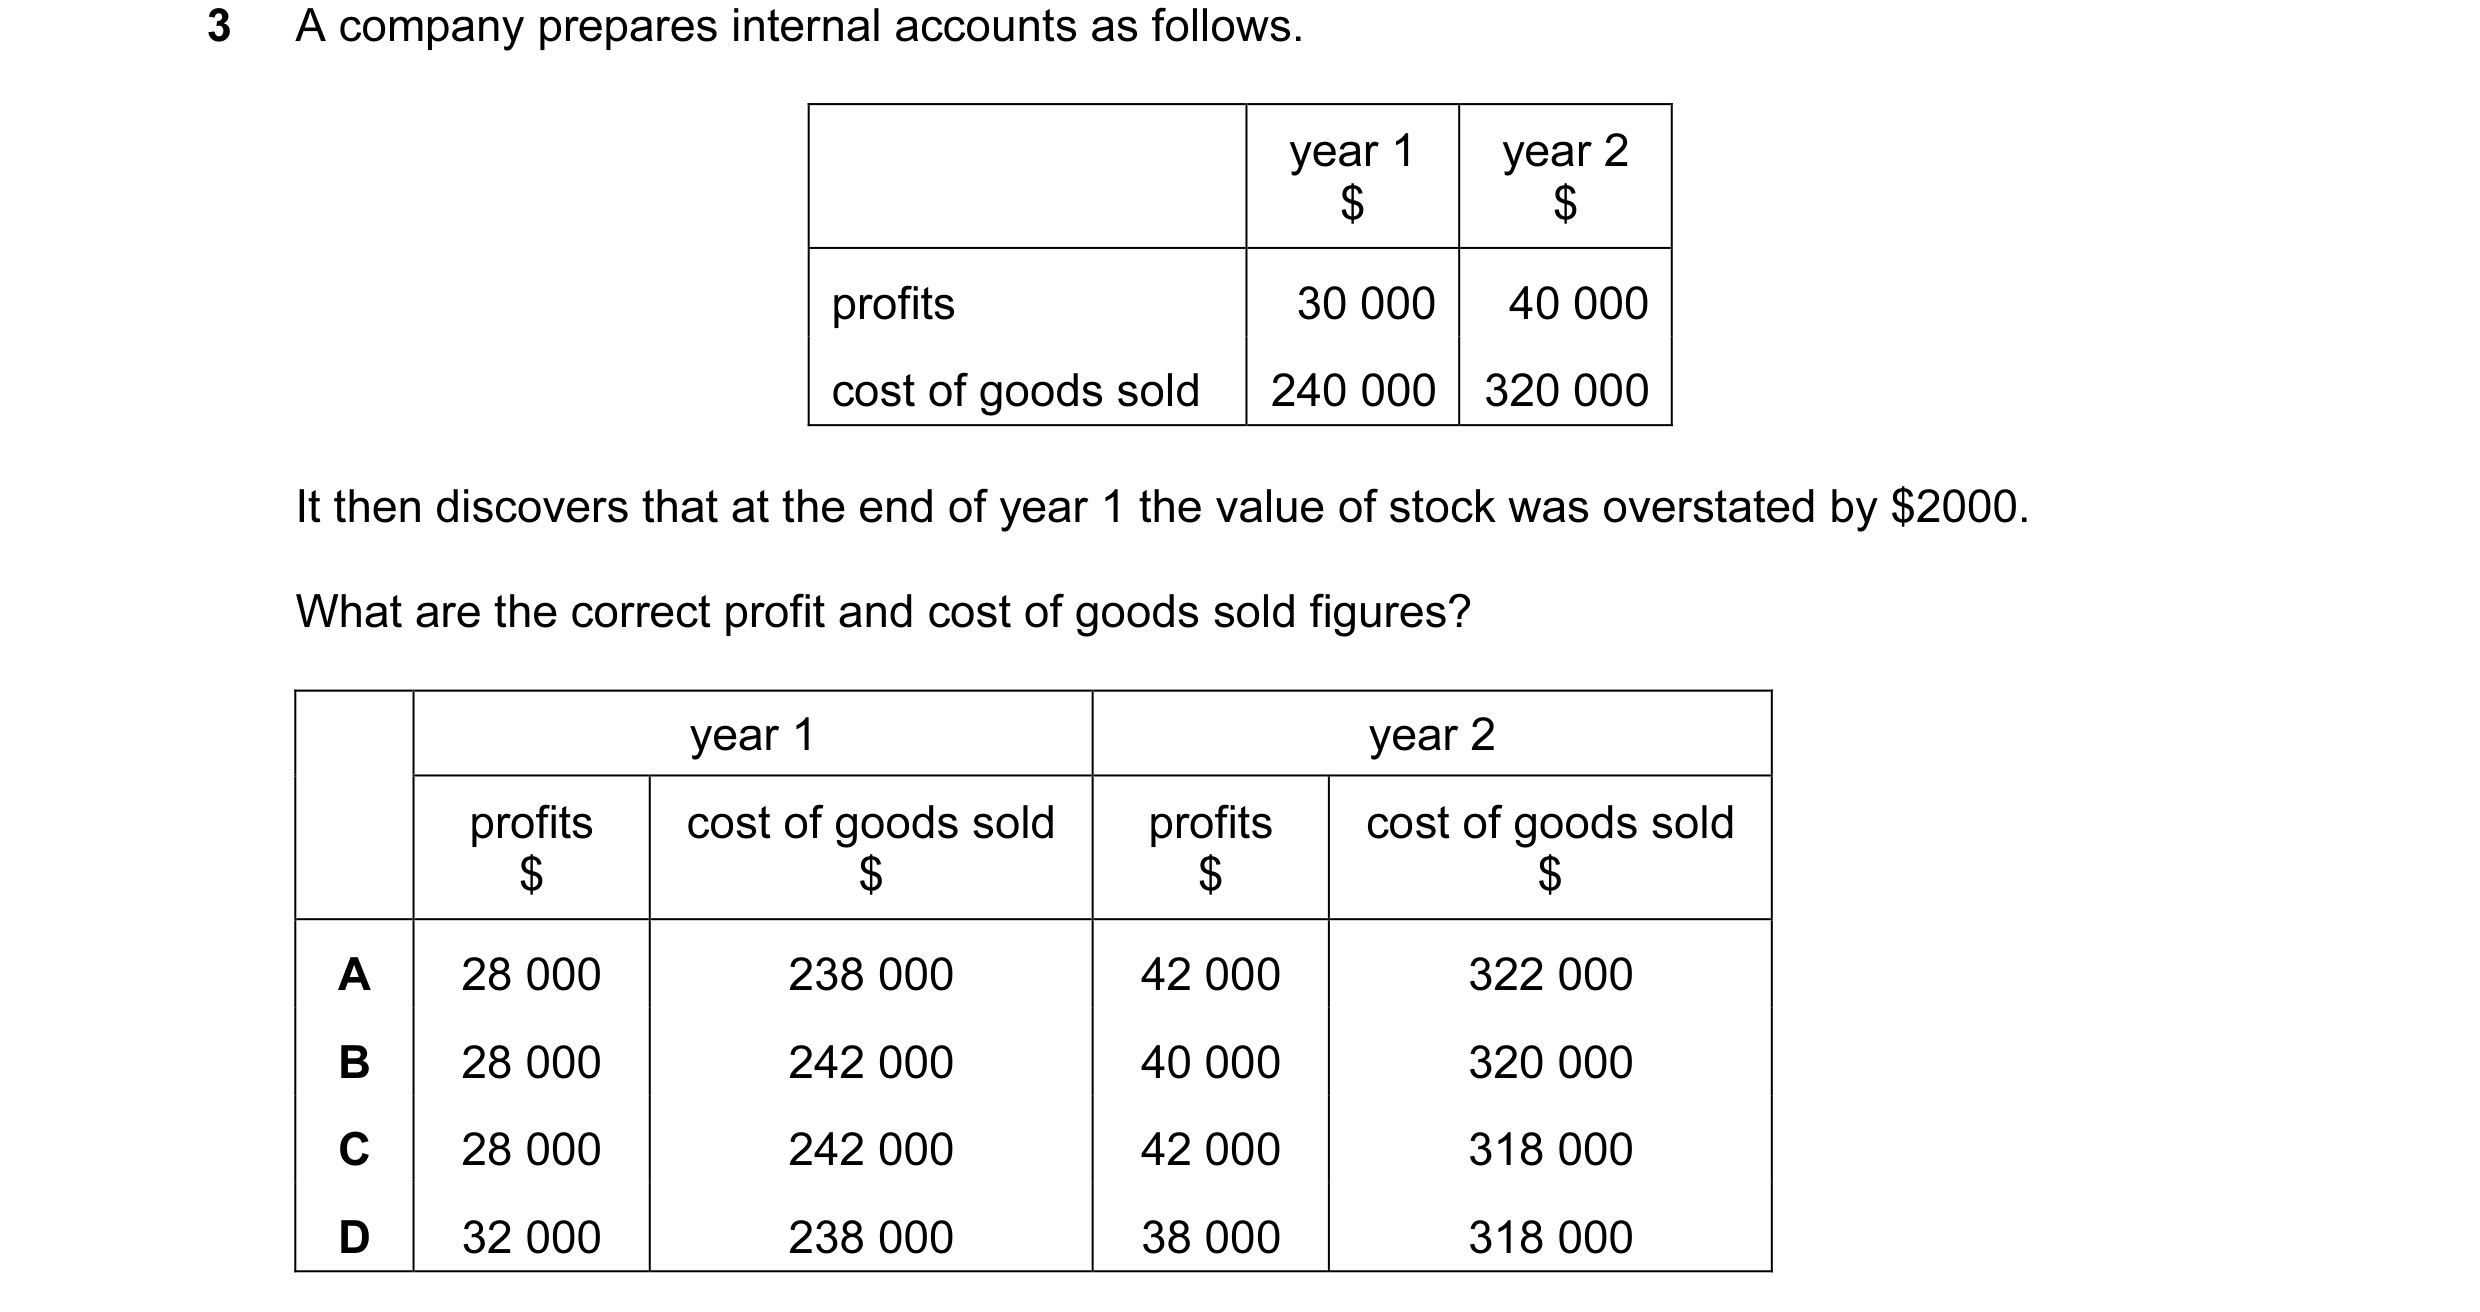
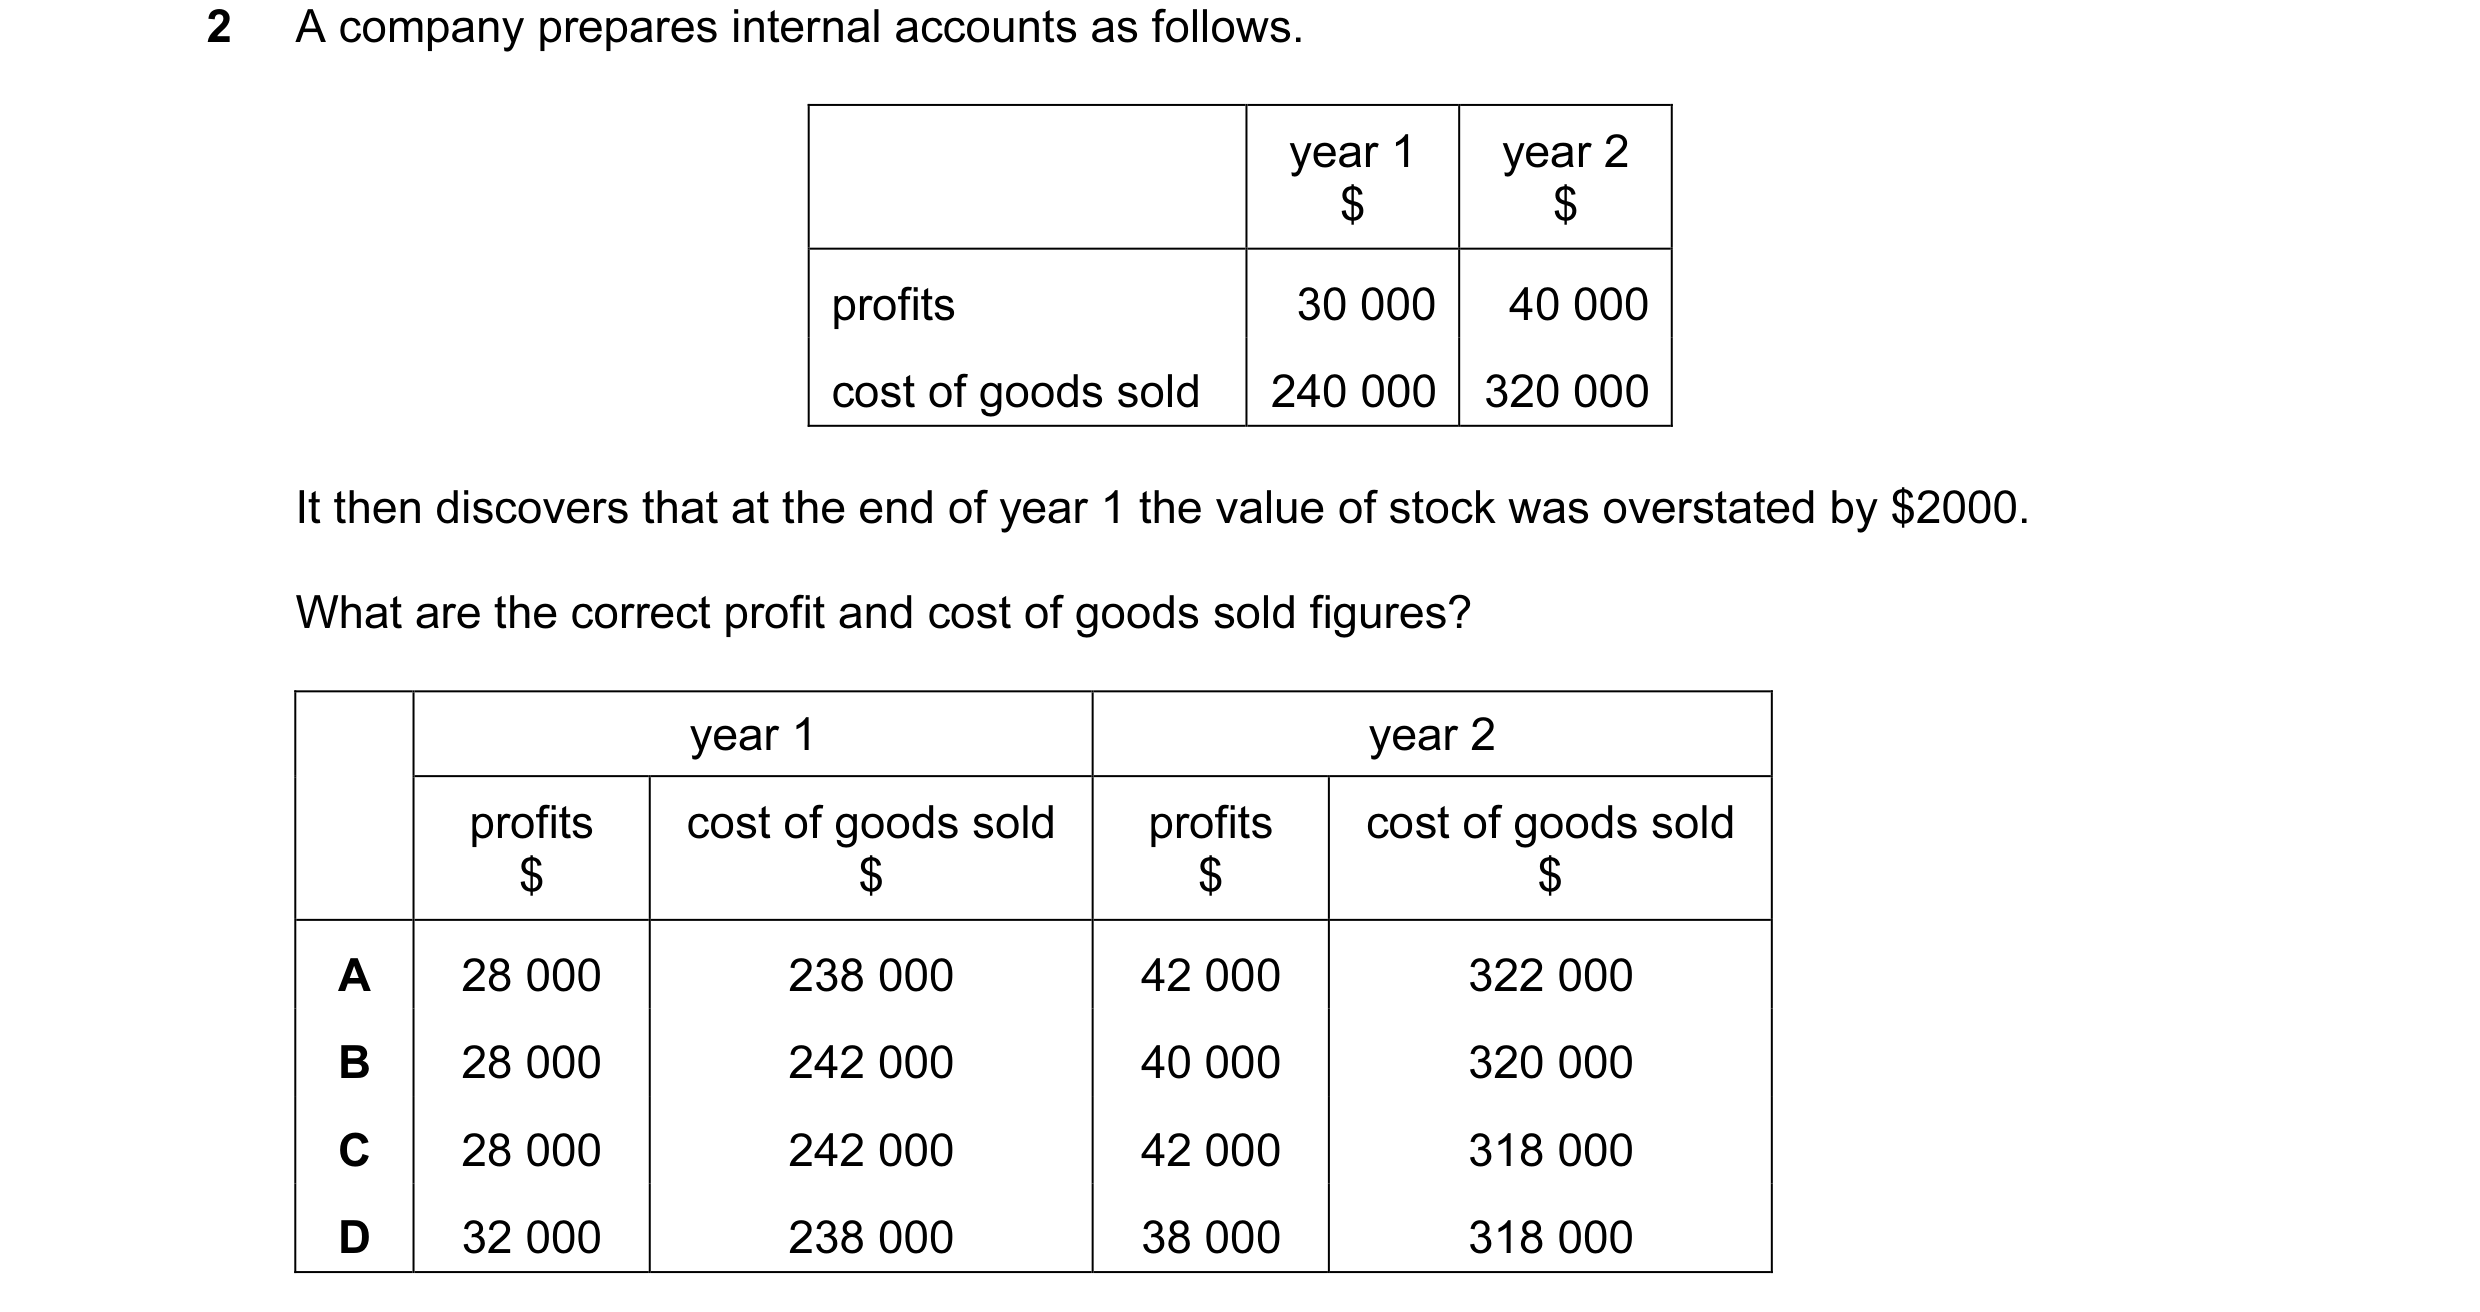
Q4 · A company prepares internal accounts as follows 9706/31 Oct/Nov 2010
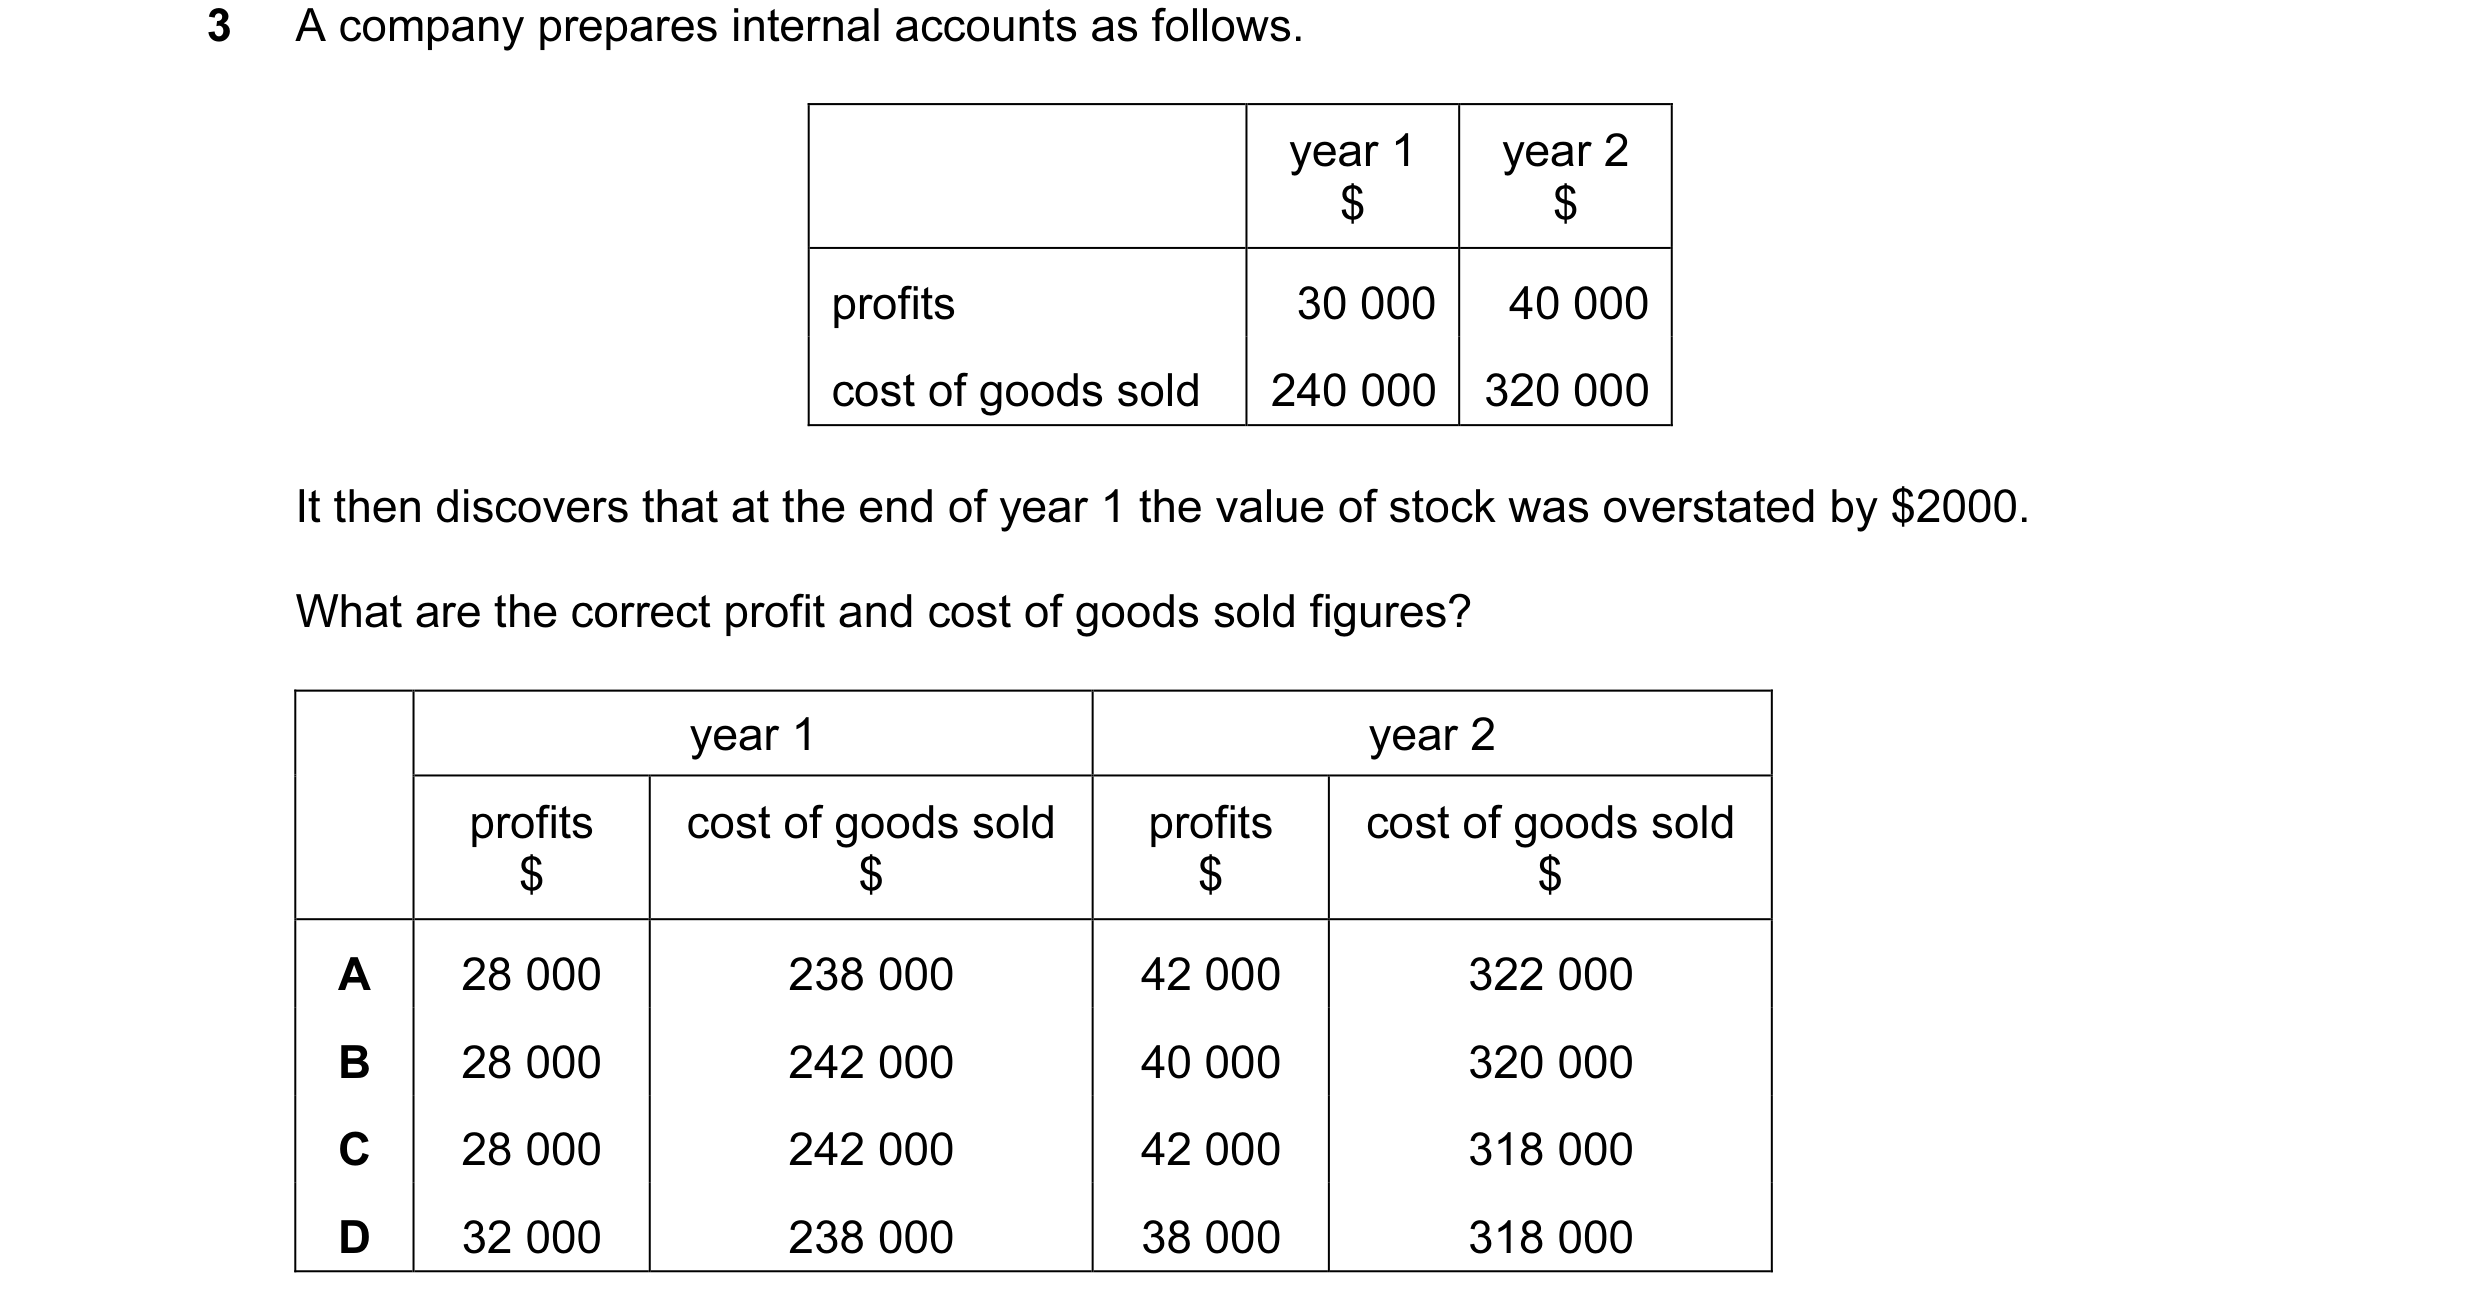
3 A company prepares internal accounts as follows. year 1 year 2 $ $ profits 30 000 40 000 cost of goods sold 240 000 320 000 It then discovers that at the end of year 1 the value of stock was overstated by $2000. What are the correct profit and cost of goods sold figures? year 1 year 2 profits cost of goods sold profits cost of goods sold $ $ $ $ A 28 000 238 000 42 000 322 000 B 28 000 242 000 40 000 320 000 C 28 000 242 000 42 000 318 000 D 32 000 238 000 38 000 318 000
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2010
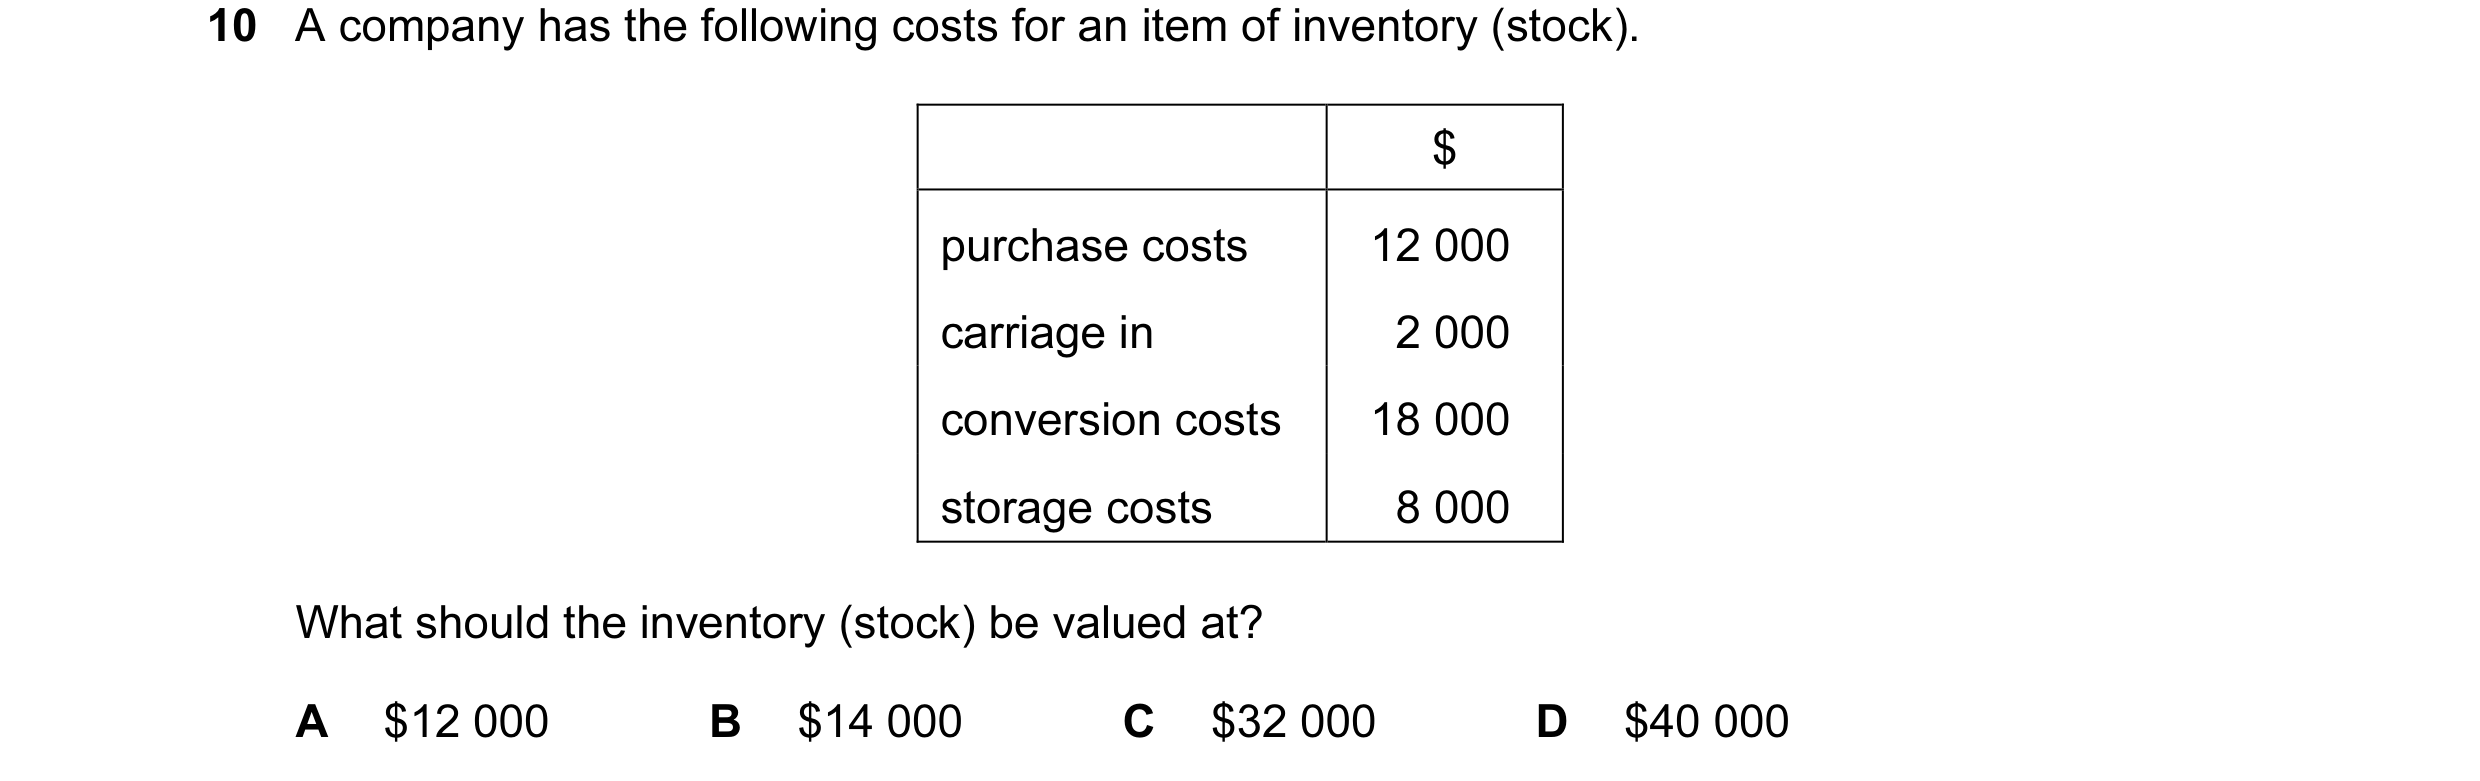
Q5 · A company has the following costs for an item of inventory (stock) 9706/31 Oct/Nov 2010
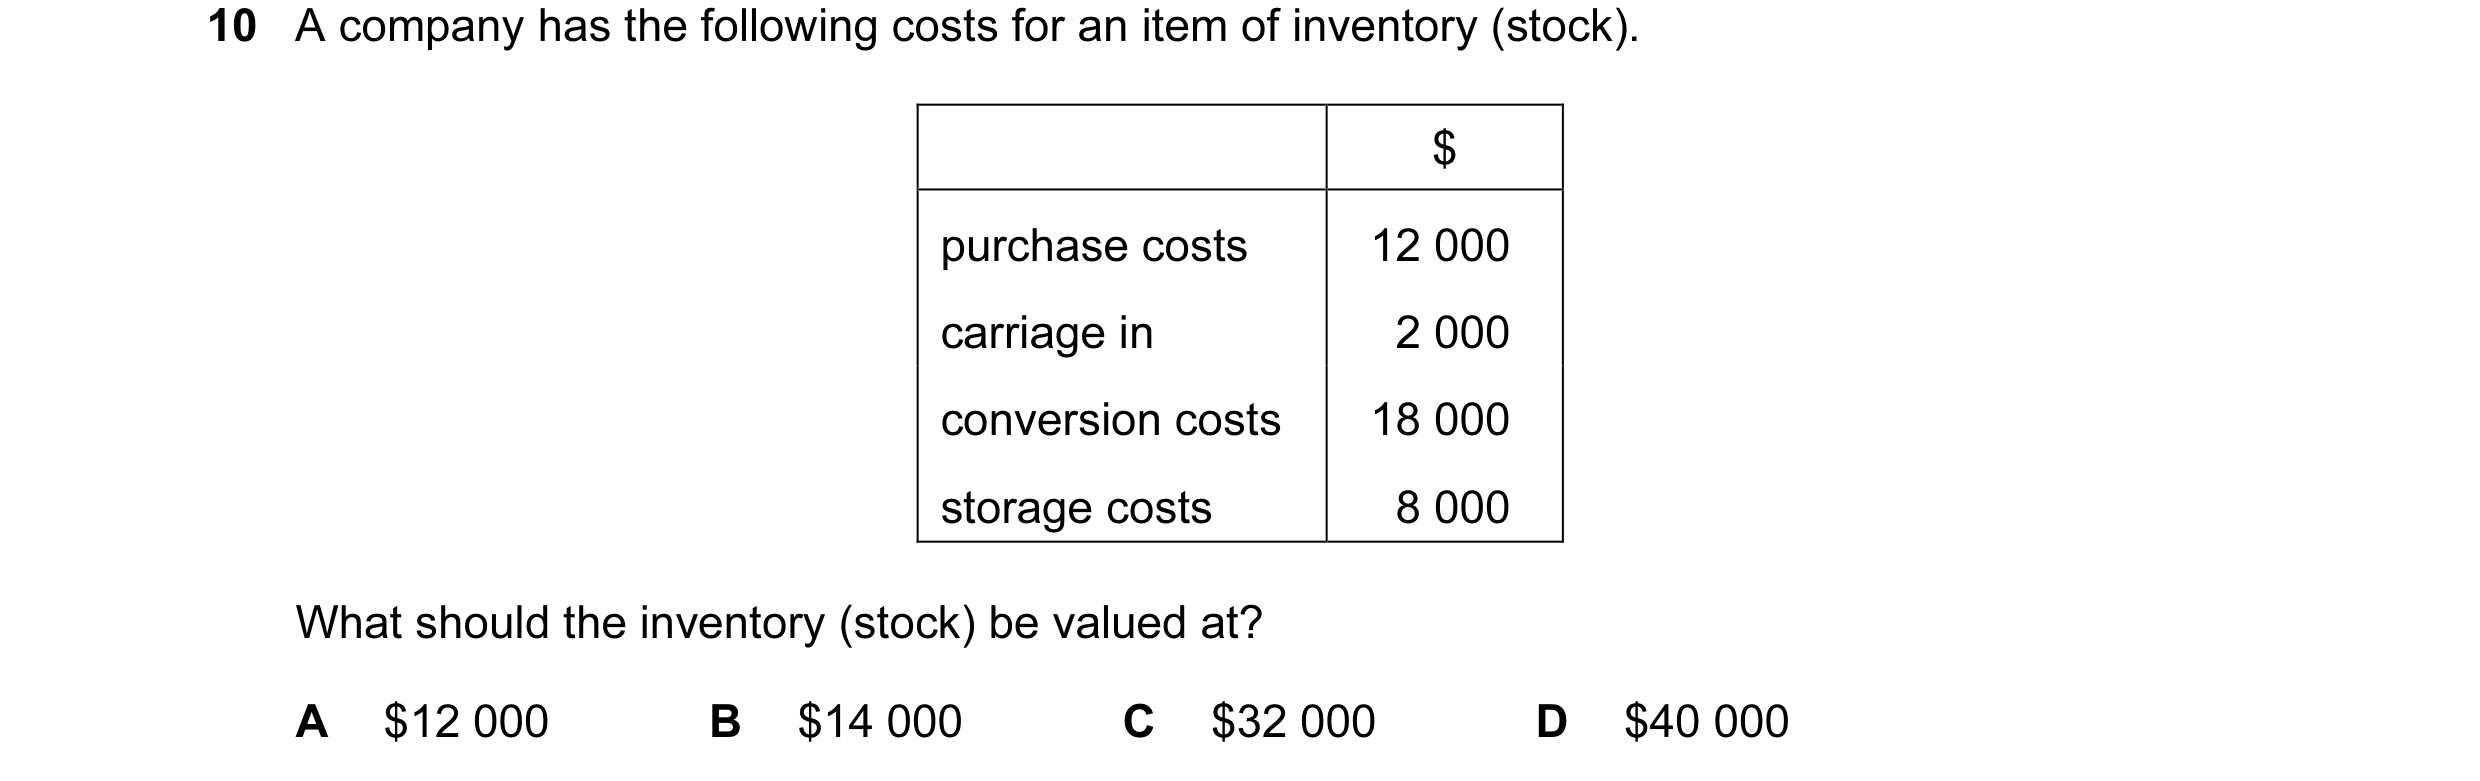
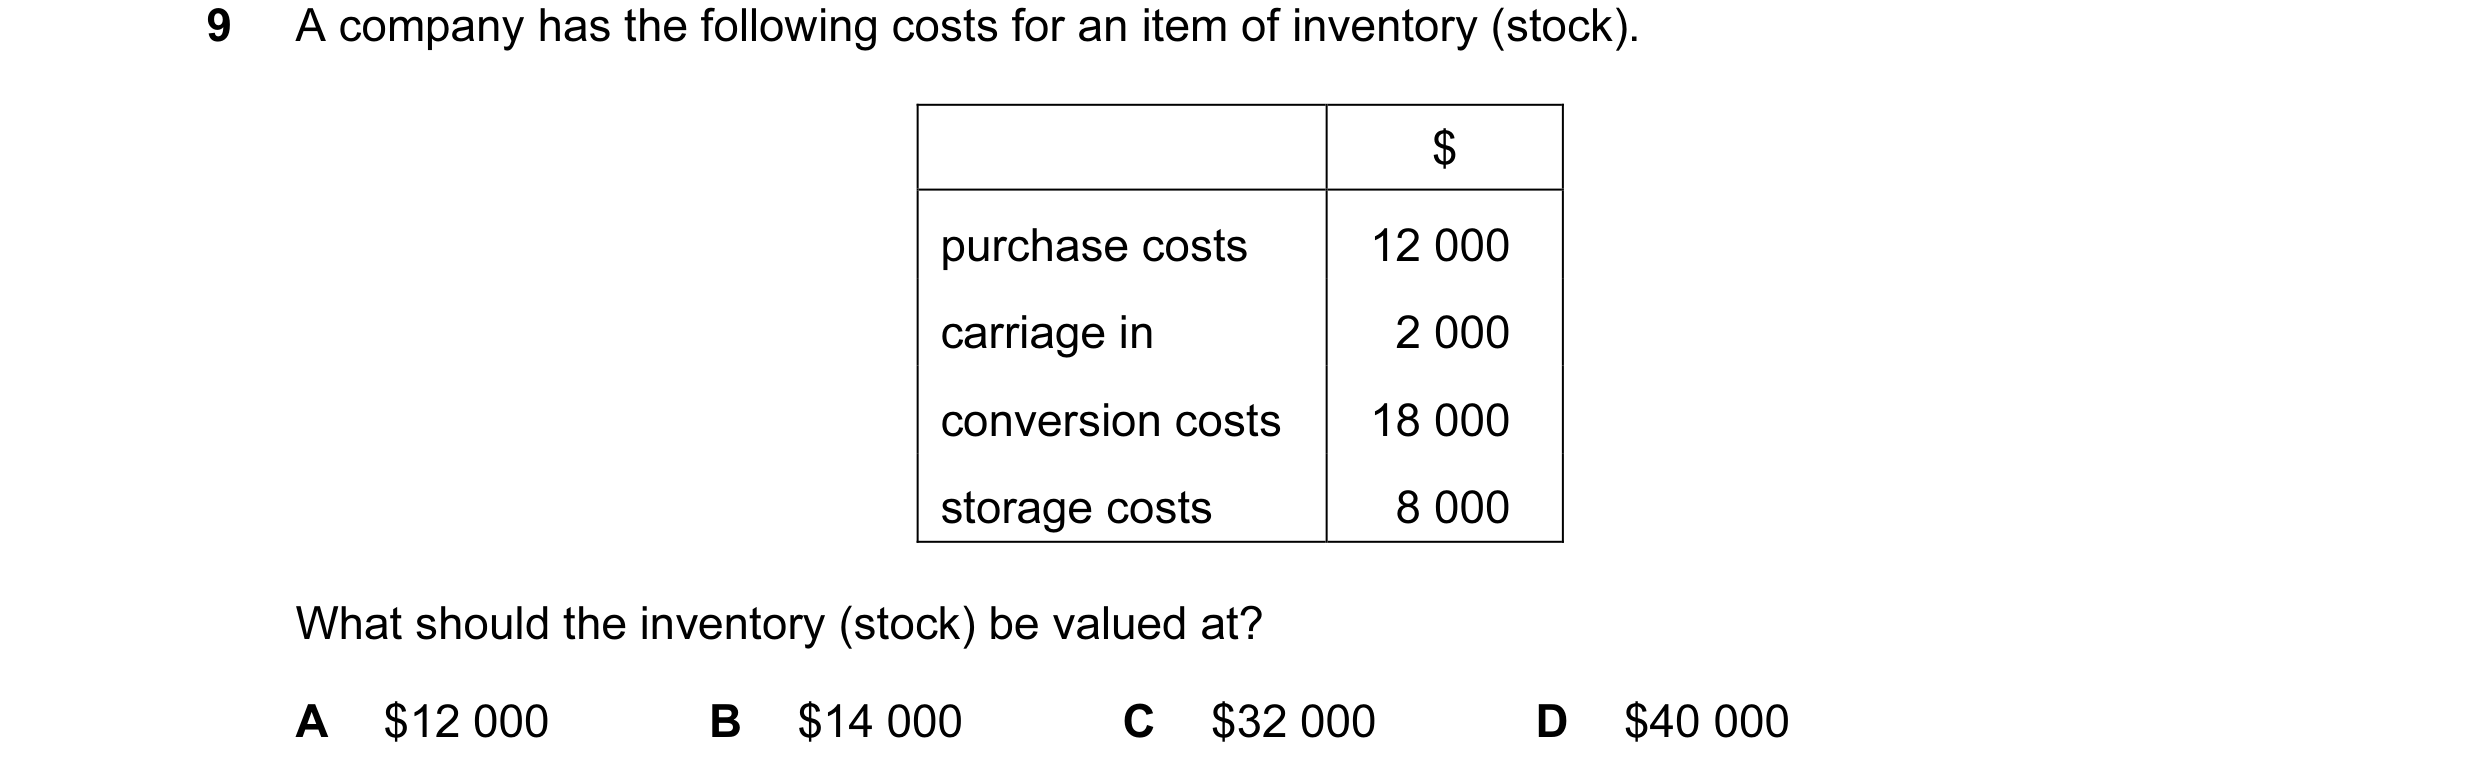
10 A company has the following costs for an item of inventory (stock). $ purchase costs 12 000 carriage in 2 000 conversion costs 18 000 storage costs 8 000 What should the inventory (stock) be valued at? A $12 000 B $14 000 C $32 000 D $40 000
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2010
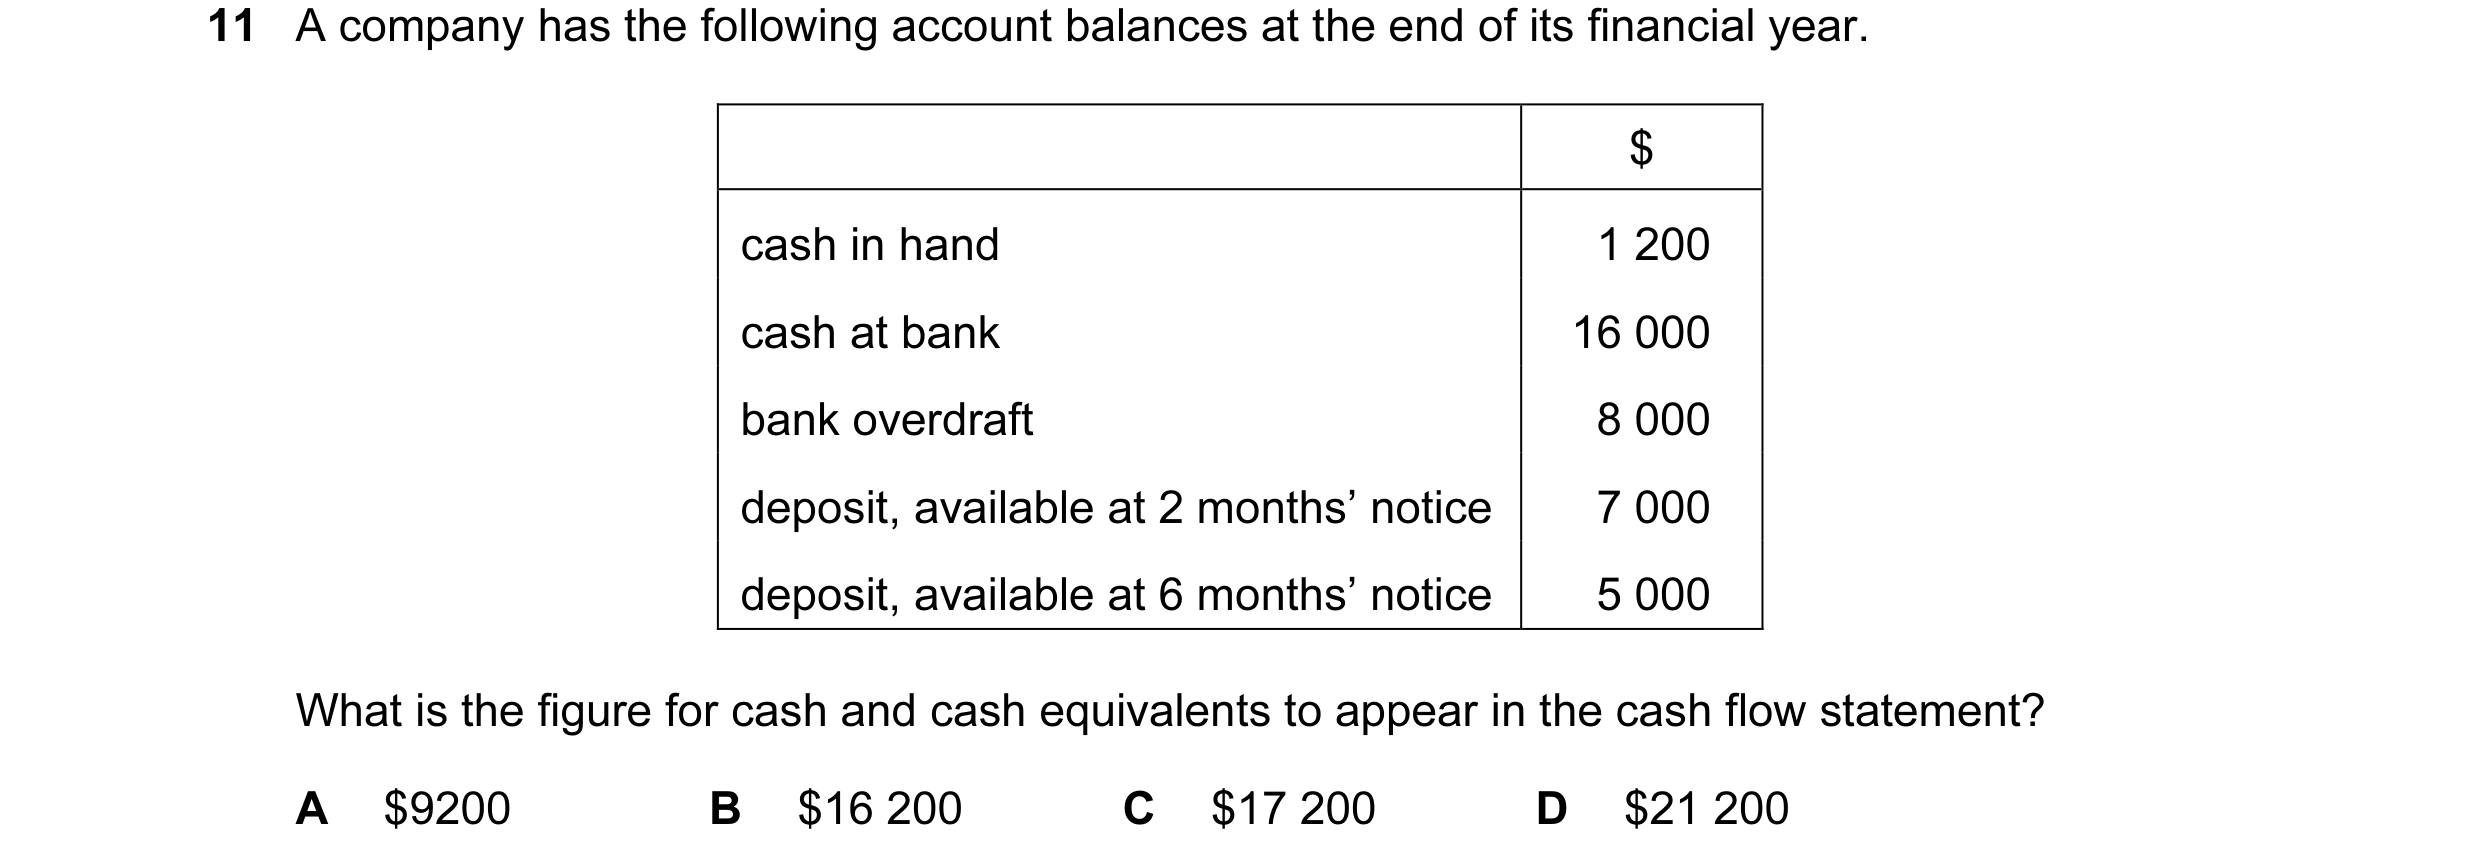
Q6 · A company has the following account balances at the end of its financial year 9706/31 Oct/Nov 2010
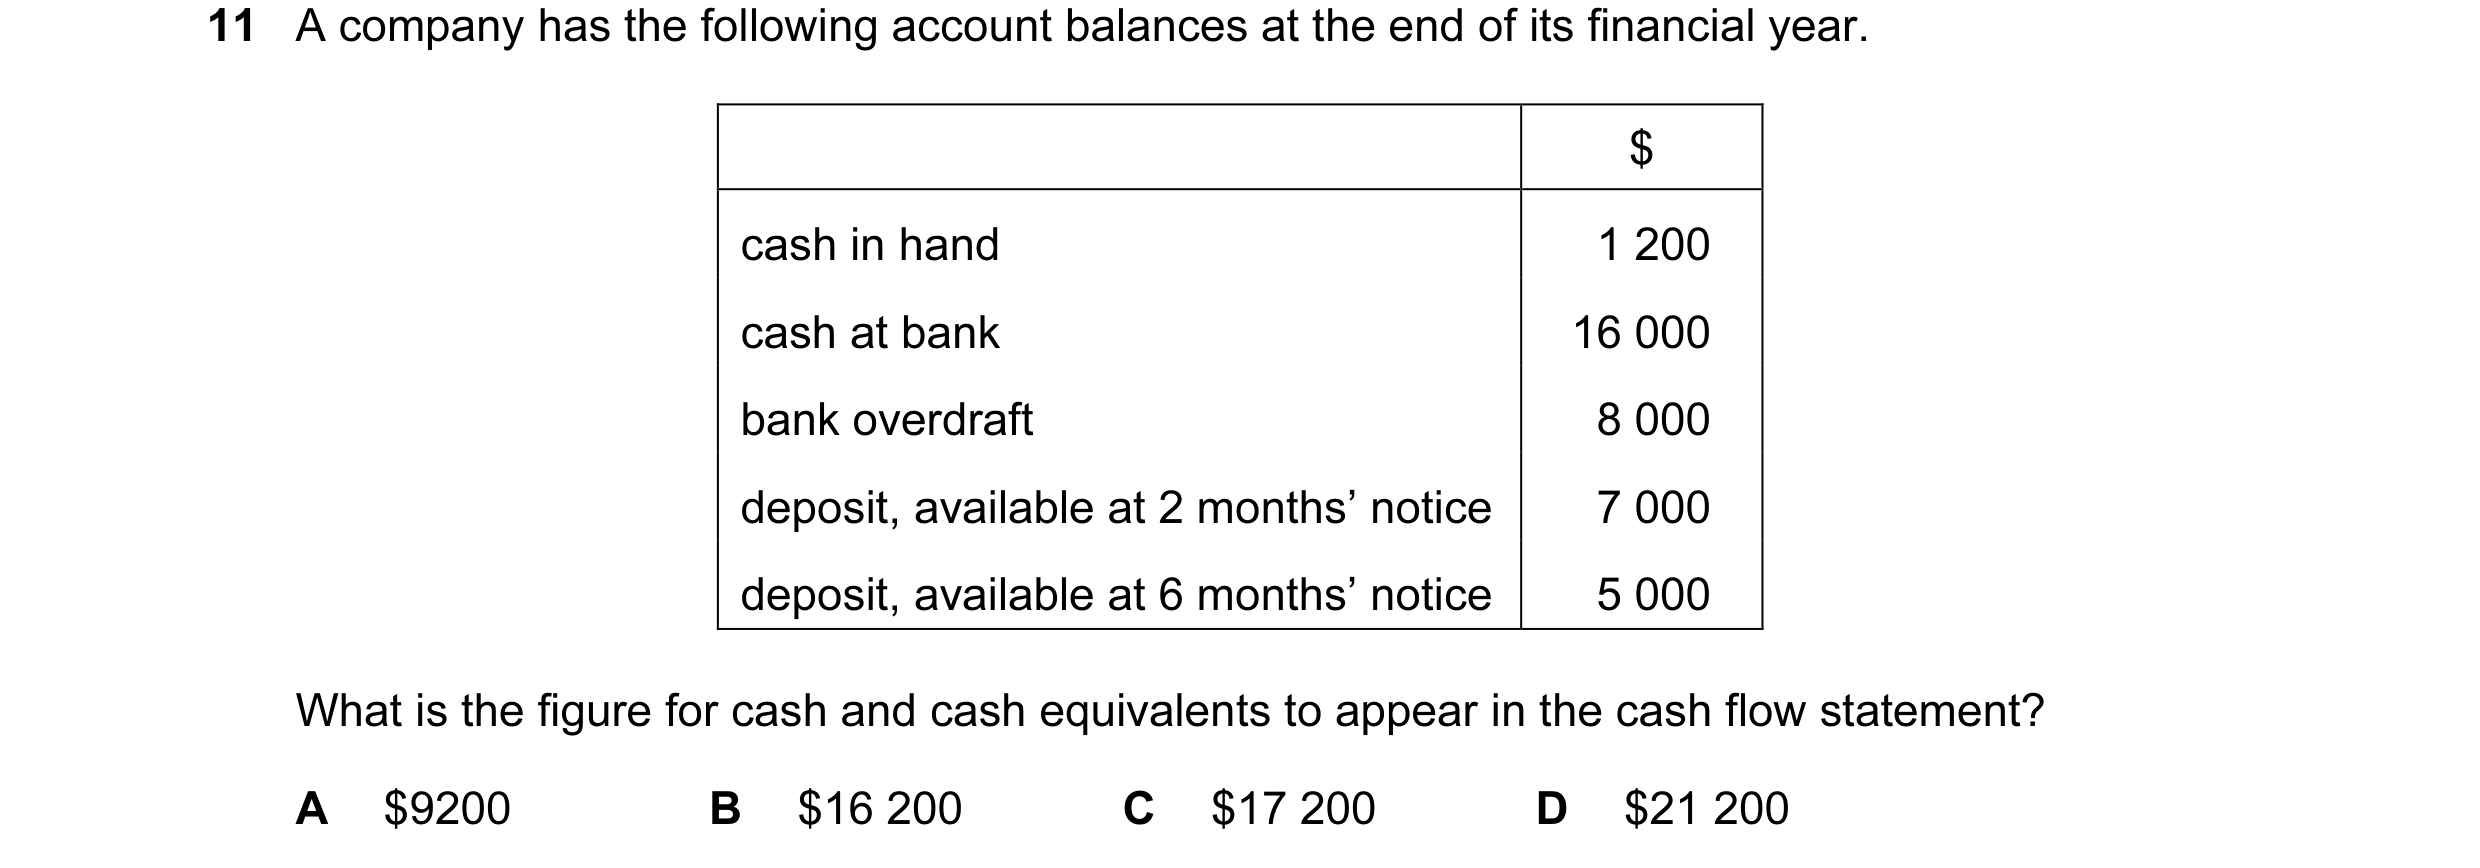
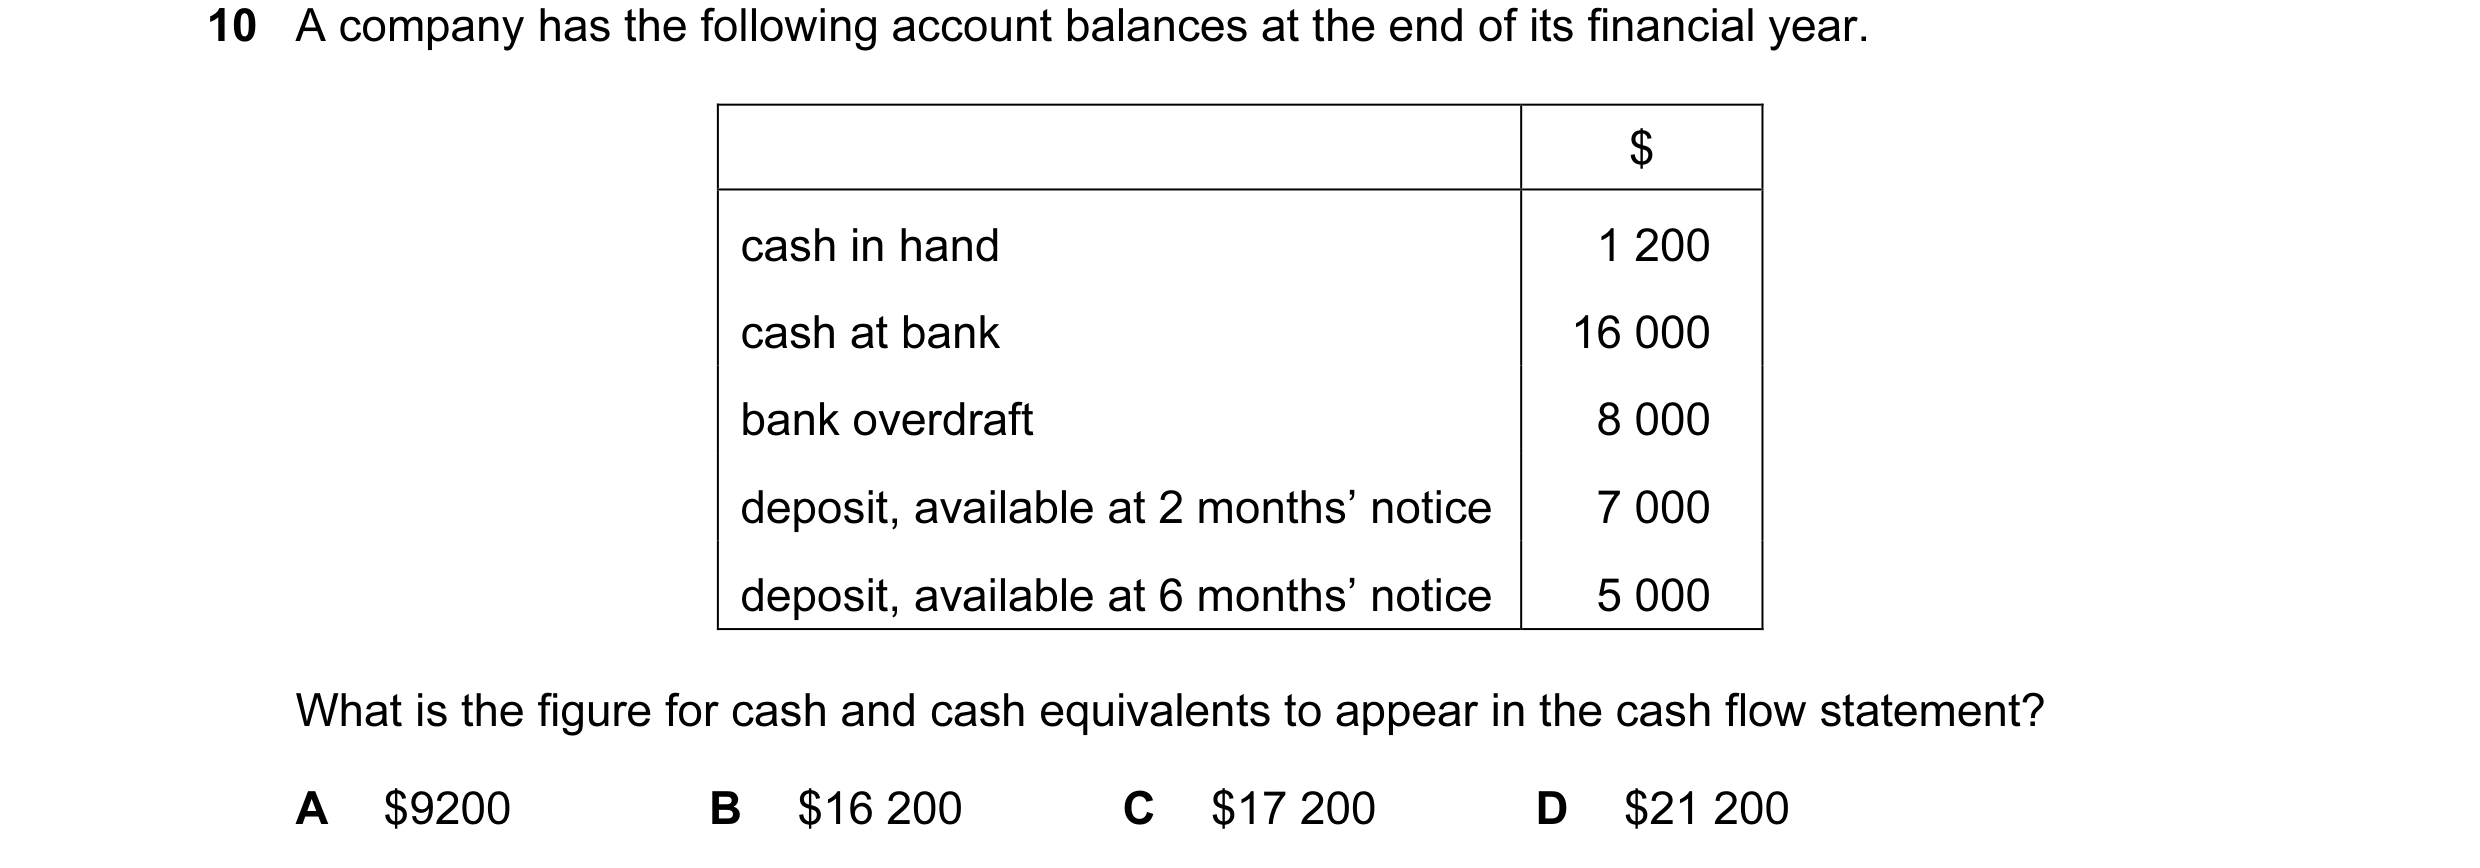
11 A company has the following account balances at the end of its financial year. $ cash in hand 1 200 cash at bank 16 000 bank overdraft 8 000 deposit, available at 2 months’ notice 7 000 deposit, available at 6 months’ notice 5 000 What is the figure for cash and cash equivalents to appear in the cash flow statement? A $9200 B $16 200 C $17 200 D $21 200
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2010
Q7 · A company has operating profit of $326 000 after taking into account the following… 9706/32 Oct/Nov 2010
1 A company has operating profit of $326 000 after taking into account the following information. $ depreciation 24 000 goodwill impairment 11 000 increase in inventory (stock) 18 000 What is the net cash flow from operating activities? A $321 000 B $343 000 C $357 000 D $361 000
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2010
Q8 · A company prepares internal accounts as follows 9706/32 Oct/Nov 2010
3 A company prepares internal accounts as follows. year 1 year 2 $ $ profits 30 000 40 000 cost of goods sold 240 000 320 000 It then discovers that at the end of year 1 the value of stock was overstated by $2000. What are the correct profit and cost of goods sold figures? year 1 year 2 profits cost of goods sold profits cost of goods sold $ $ $ $ A 28 000 238 000 42 000 322 000 B 28 000 242 000 40 000 320 000 C 28 000 242 000 42 000 318 000 D 32 000 238 000 38 000 318 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2010
Q9 · A company has the following costs for an item of inventory (stock) 9706/32 Oct/Nov 2010
10 A company has the following costs for an item of inventory (stock). $ purchase costs 12 000 carriage in 2 000 conversion costs 18 000 storage costs 8 000 What should the inventory (stock) be valued at? A $12 000 B $14 000 C $32 000 D $40 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2010
Q10 · A company has the following account balances at the end of its financial year 9706/32 Oct/Nov 2010
11 A company has the following account balances at the end of its financial year. $ cash in hand 1 200 cash at bank 16 000 bank overdraft 8 000 deposit, available at 2 months’ notice 7 000 deposit, available at 6 months’ notice 5 000 What is the figure for cash and cash equivalents to appear in the cash flow statement? A $9200 B $16 200 C $17 200 D $21 200
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2010
Q11 · A company prepares internal accounts as follows 9706/33 Oct/Nov 2010
2 A company prepares internal accounts as follows. year 1 year 2 $ $ profits 30 000 40 000 cost of goods sold 240 000 320 000 It then discovers that at the end of year 1 the value of stock was overstated by $2000. What are the correct profit and cost of goods sold figures? year 1 year 2 profits cost of goods sold profits cost of goods sold $ $ $ $ A 28 000 238 000 42 000 322 000 B 28 000 242 000 40 000 320 000 C 28 000 242 000 42 000 318 000 D 32 000 238 000 38 000 318 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2010
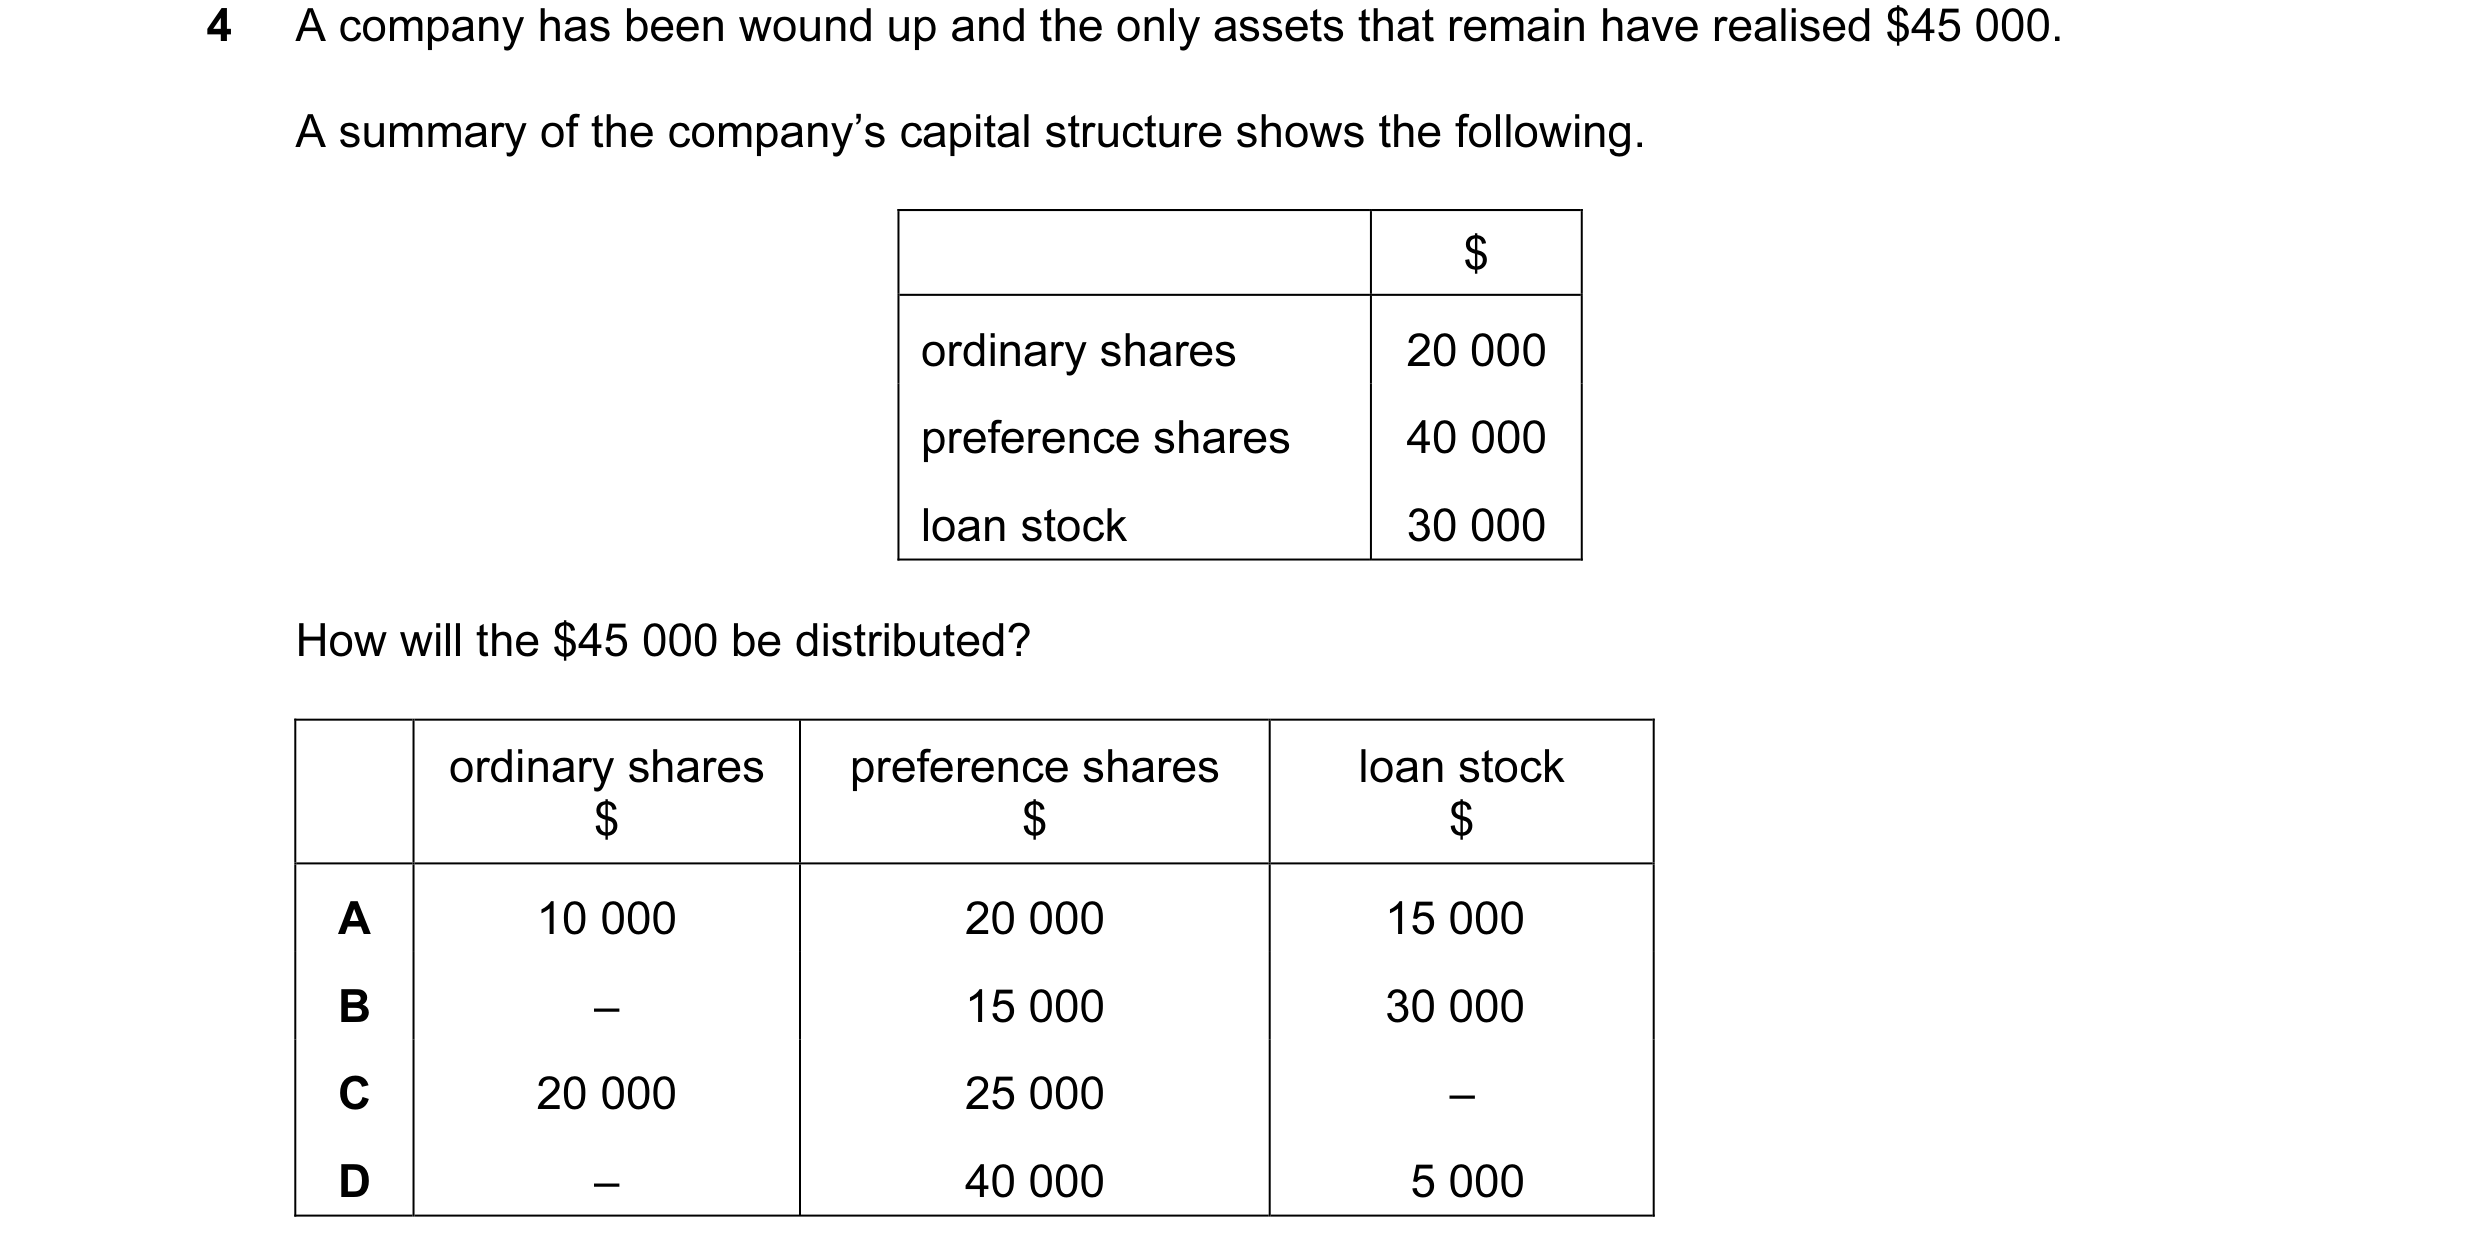
Q12 · A company has been wound up and the only assets that remain have realised $45 000 9706/33 Oct/Nov 2010
4 A company has been wound up and the only assets that remain have realised $45 000. A summary of the company’s capital structure shows the following. $ ordinary shares 20 000 preference shares 40 000 loan stock 30 000 How will the $45 000 be distributed? ordinary shares preference shares loan stock $ $ $ A 10 000 20 000 15 000 B – 15 000 30 000 C 20 000 25 000 – D – 40 000 5 000
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2010
Q13 · A company has the following costs for an item of inventory (stock) 9706/33 Oct/Nov 2010
9 A company has the following costs for an item of inventory (stock). $ purchase costs 12 000 carriage in 2 000 conversion costs 18 000 storage costs 8 000 What should the inventory (stock) be valued at? A $12 000 B $14 000 C $32 000 D $40 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2010
Q14 · A company has the following account balances at the end of its financial year 9706/33 Oct/Nov 2010
10 A company has the following account balances at the end of its financial year. $ cash in hand 1 200 cash at bank 16 000 bank overdraft 8 000 deposit, available at 2 months’ notice 7 000 deposit, available at 6 months’ notice 5 000 What is the figure for cash and cash equivalents to appear in the cash flow statement? A $9200 B $16 200 C $17 200 D $21 200
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2010
Q15 · A company has operating profit of $326 000 after taking into account the following… 9706/33 Oct/Nov 2010
30 A company has operating profit of $326 000 after taking into account the following information. $ depreciation 24 000 goodwill impairment 11 000 increase in inventory (stock) 18 000 What is the net cash flow from operating activities? A $321 000 B $343 000 C $357 000 D $361 000
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2010
Q16 · Which is not included in a statement of cash flows? 9706/32 May/June 2011
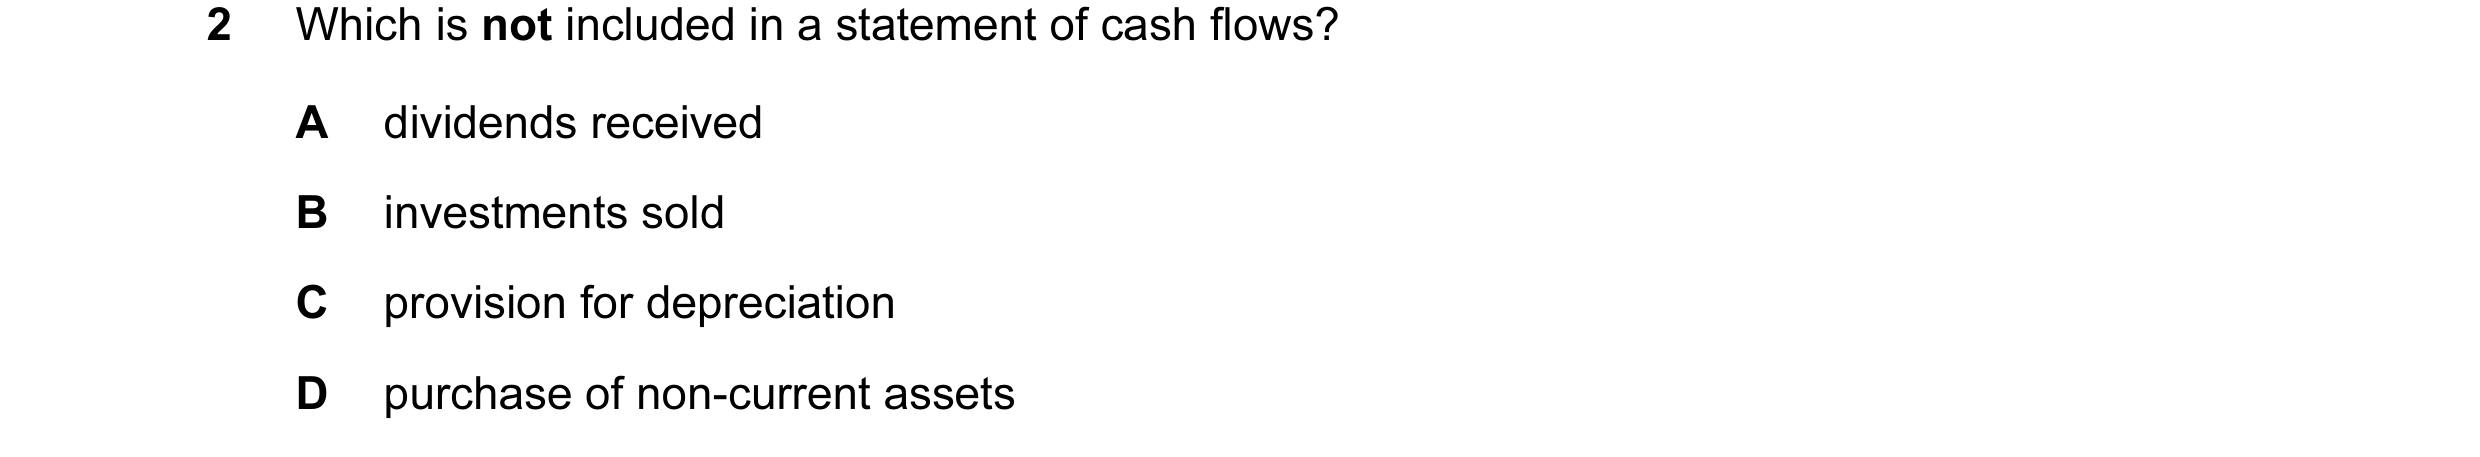
2 Which is not included in a statement of cash flows? A dividends received B investments sold C provision for depreciation D purchase of non-current assets
1 marks
Answer: C
This question in 9706/32 May/June 2011
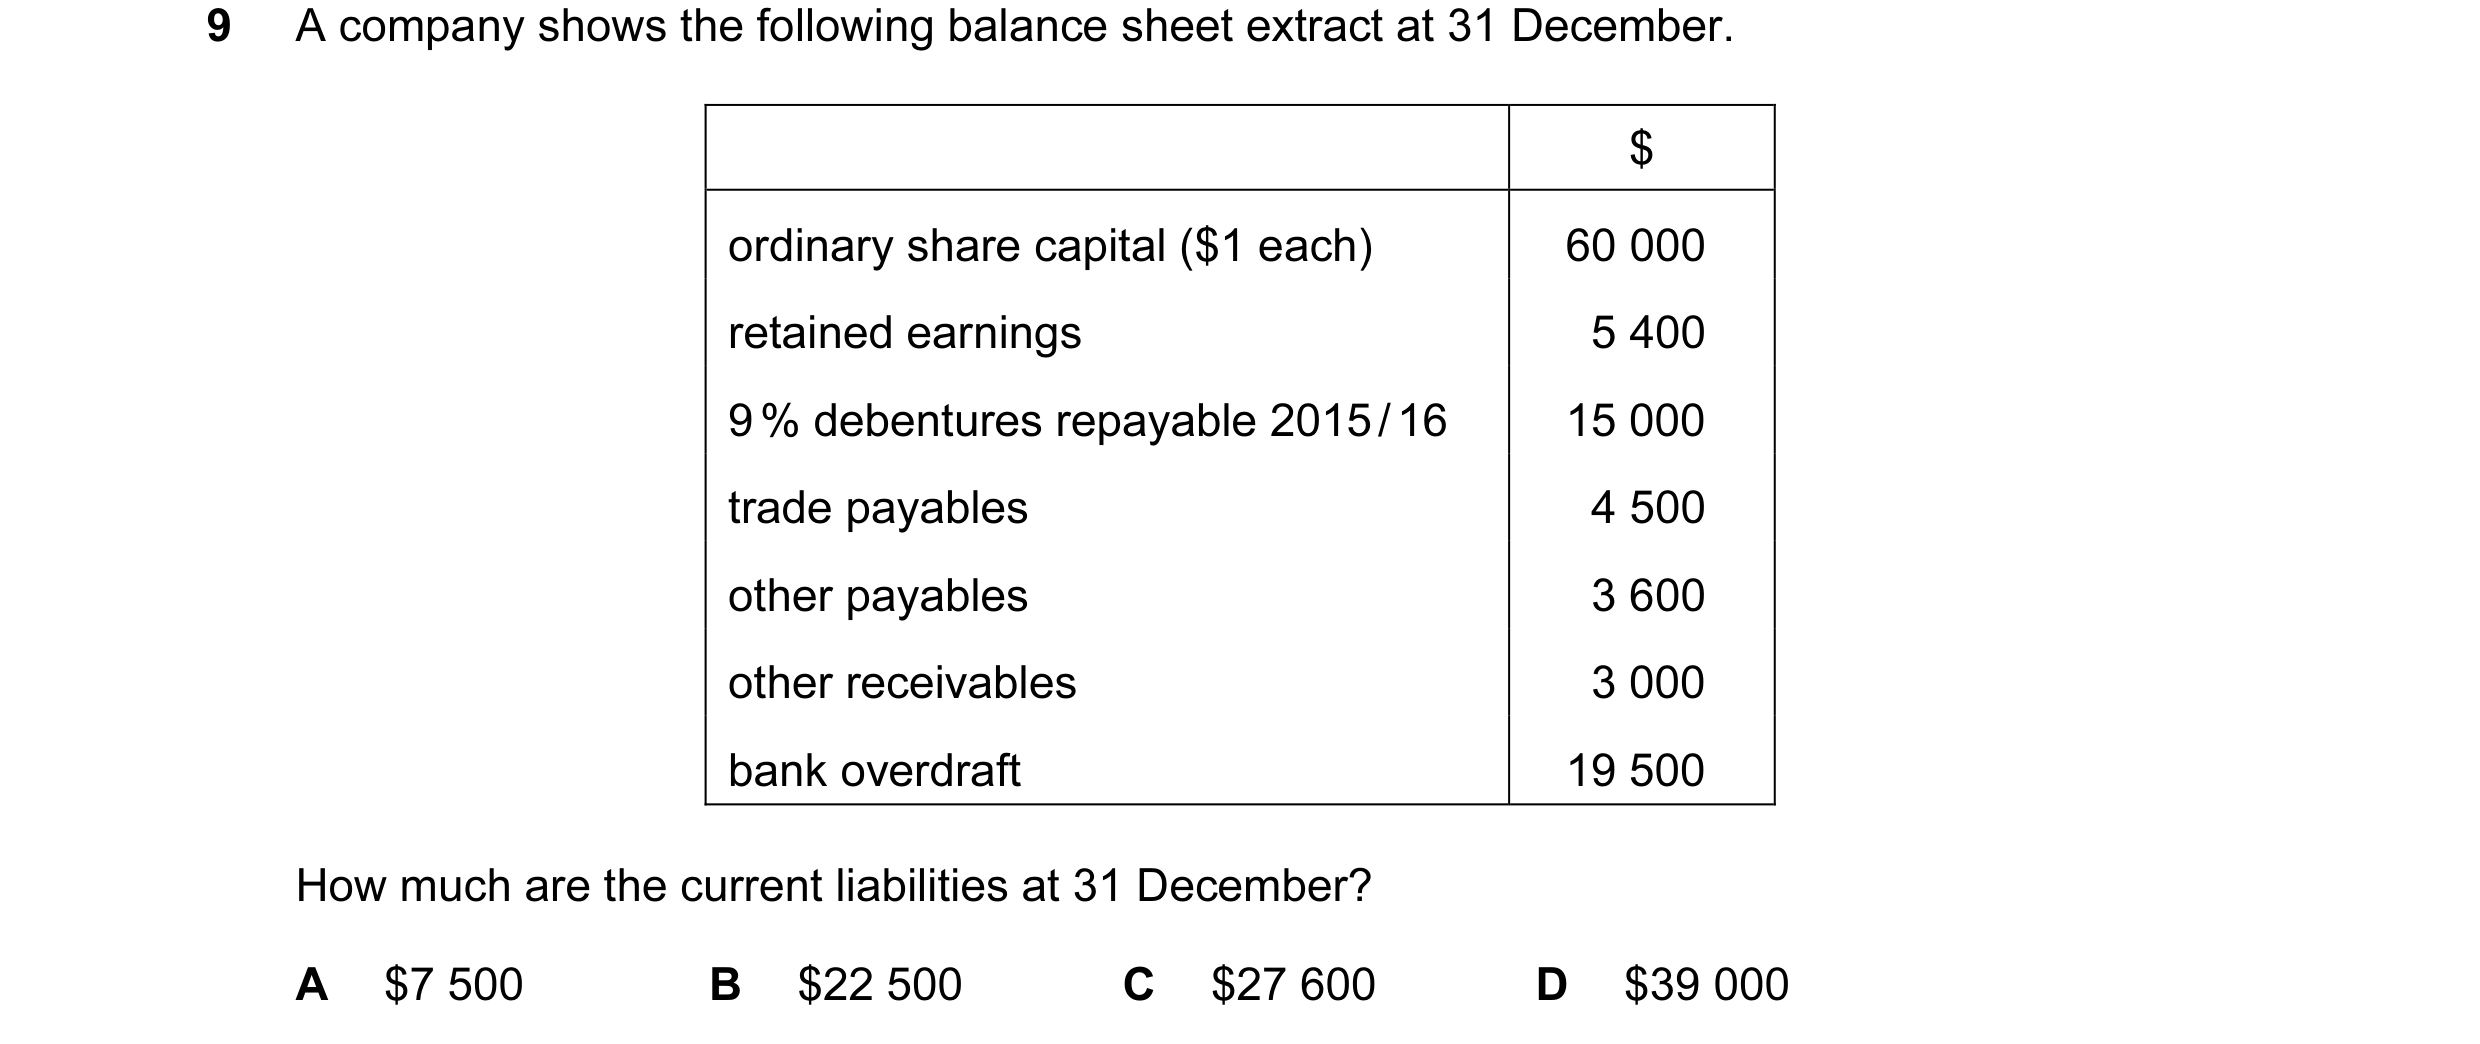
Q17 · A company shows the following balance sheet extract at 31 December 9706/31 Oct/Nov 2011
9 A company shows the following balance sheet extract at 31 December. $ ordinary share capital ($1 each) 60 000 retained earnings 5 400 9 % debentures repayable 2015 / 16 15 000 trade payables 4 500 other payables 3 600 other receivables 3 000 bank overdraft 19 500 How much are the current liabilities at 31 December? A $7 500 B $22 500 C $27 600 D $39 000
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2011
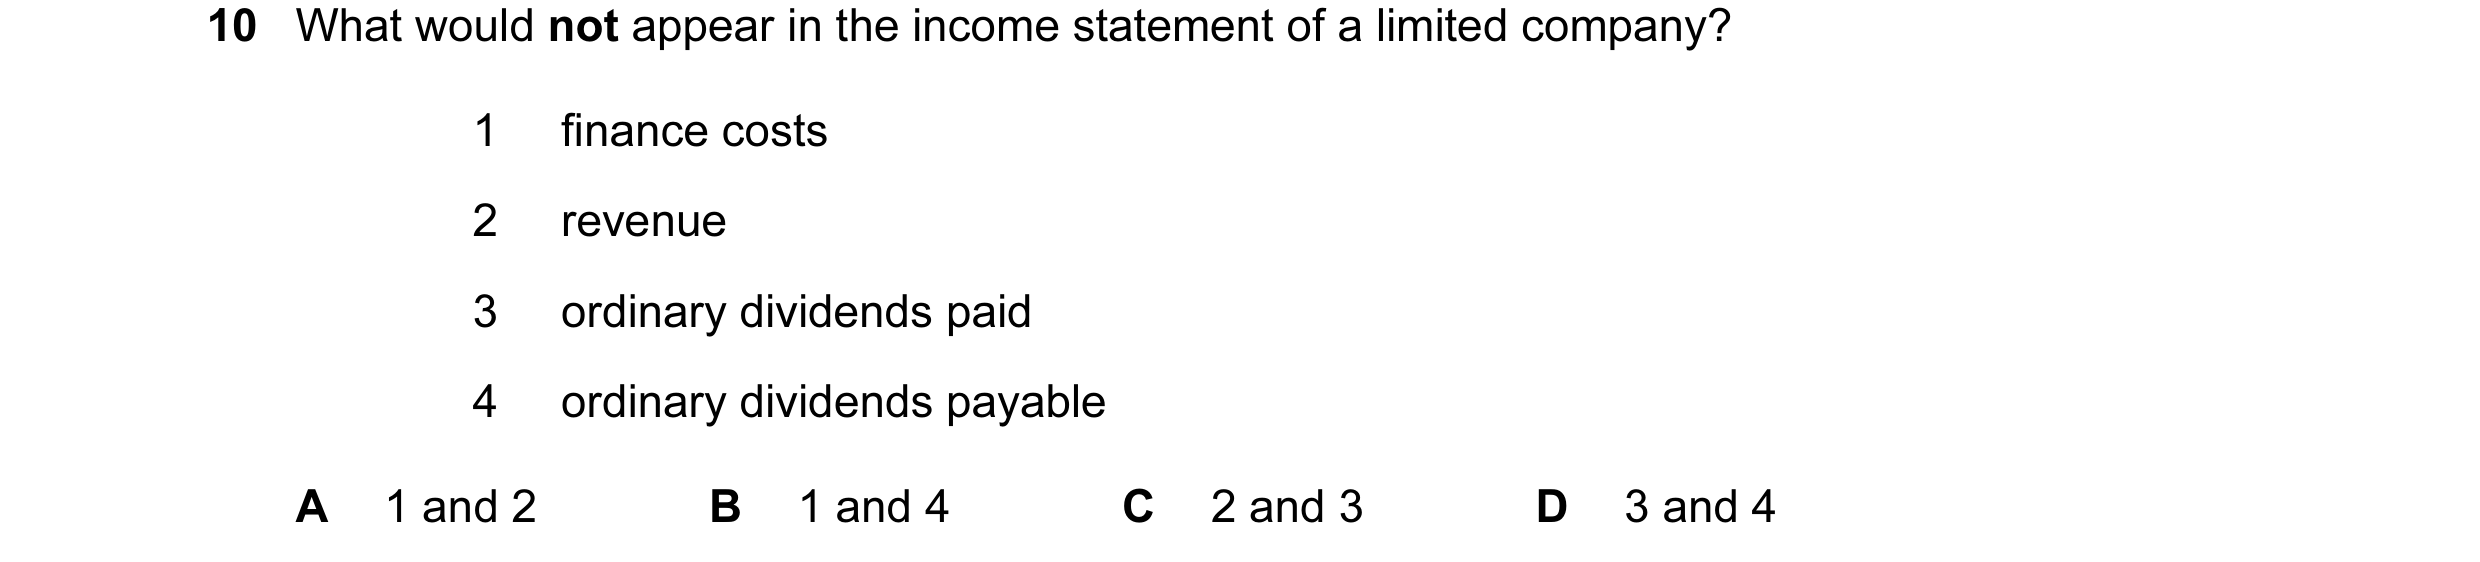
Q18 · What would not appear in the income statement of a limited company? 9706/32 Oct/Nov 2011
10 What would not appear in the income statement of a limited company? 1 finance costs 2 revenue 3 ordinary dividends paid 4 ordinary dividends payable A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2011
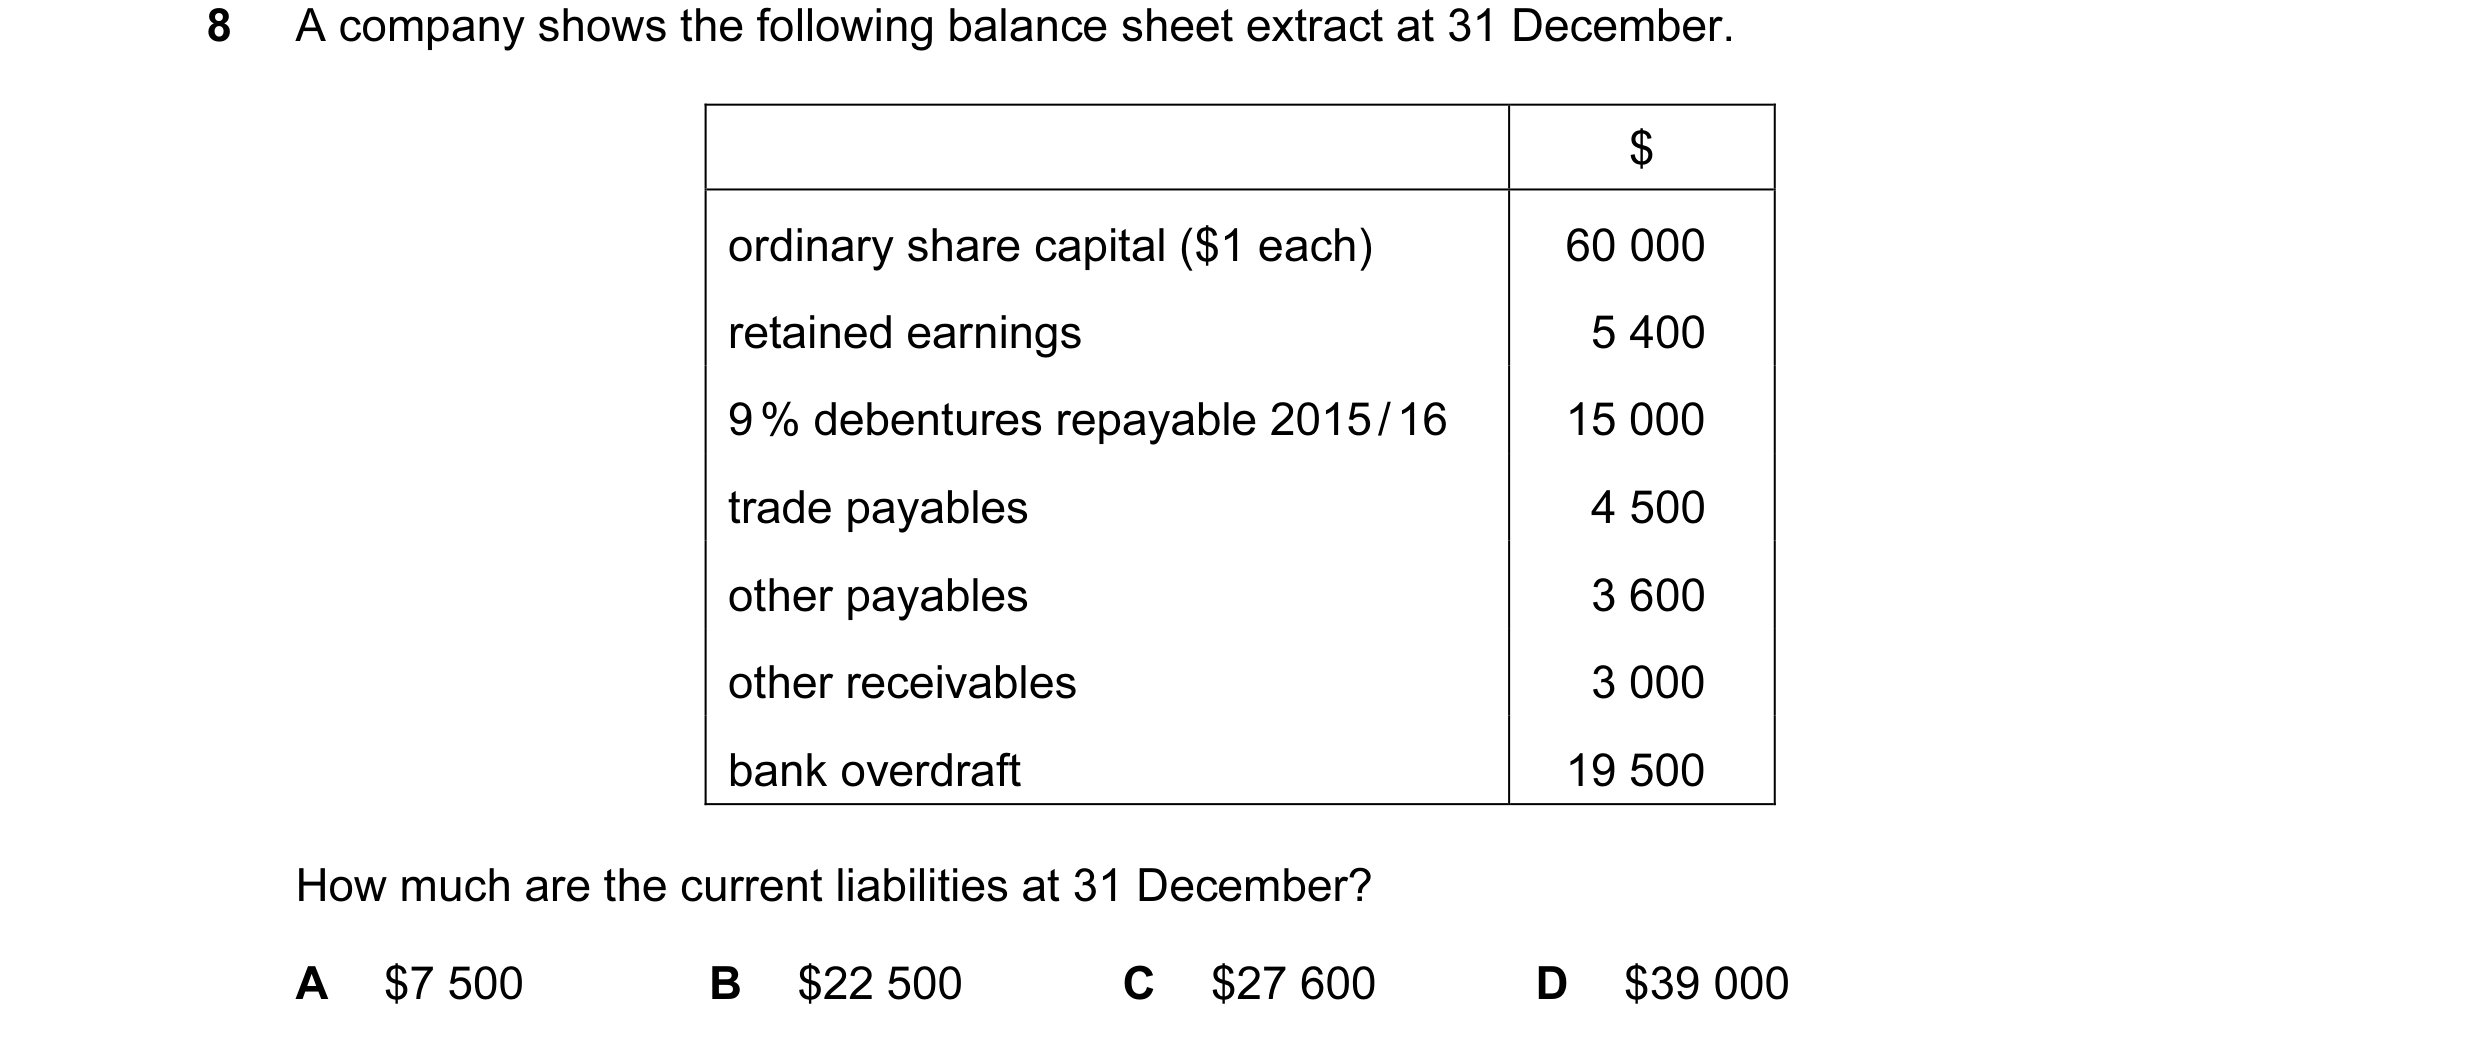
Q19 · A company shows the following balance sheet extract at 31 December 9706/33 Oct/Nov 2011
8 A company shows the following balance sheet extract at 31 December. $ ordinary share capital ($1 each) 60 000 retained earnings 5 400 9 % debentures repayable 2015 / 16 15 000 trade payables 4 500 other payables 3 600 other receivables 3 000 bank overdraft 19 500 How much are the current liabilities at 31 December? A $7 500 B $22 500 C $27 600 D $39 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2011
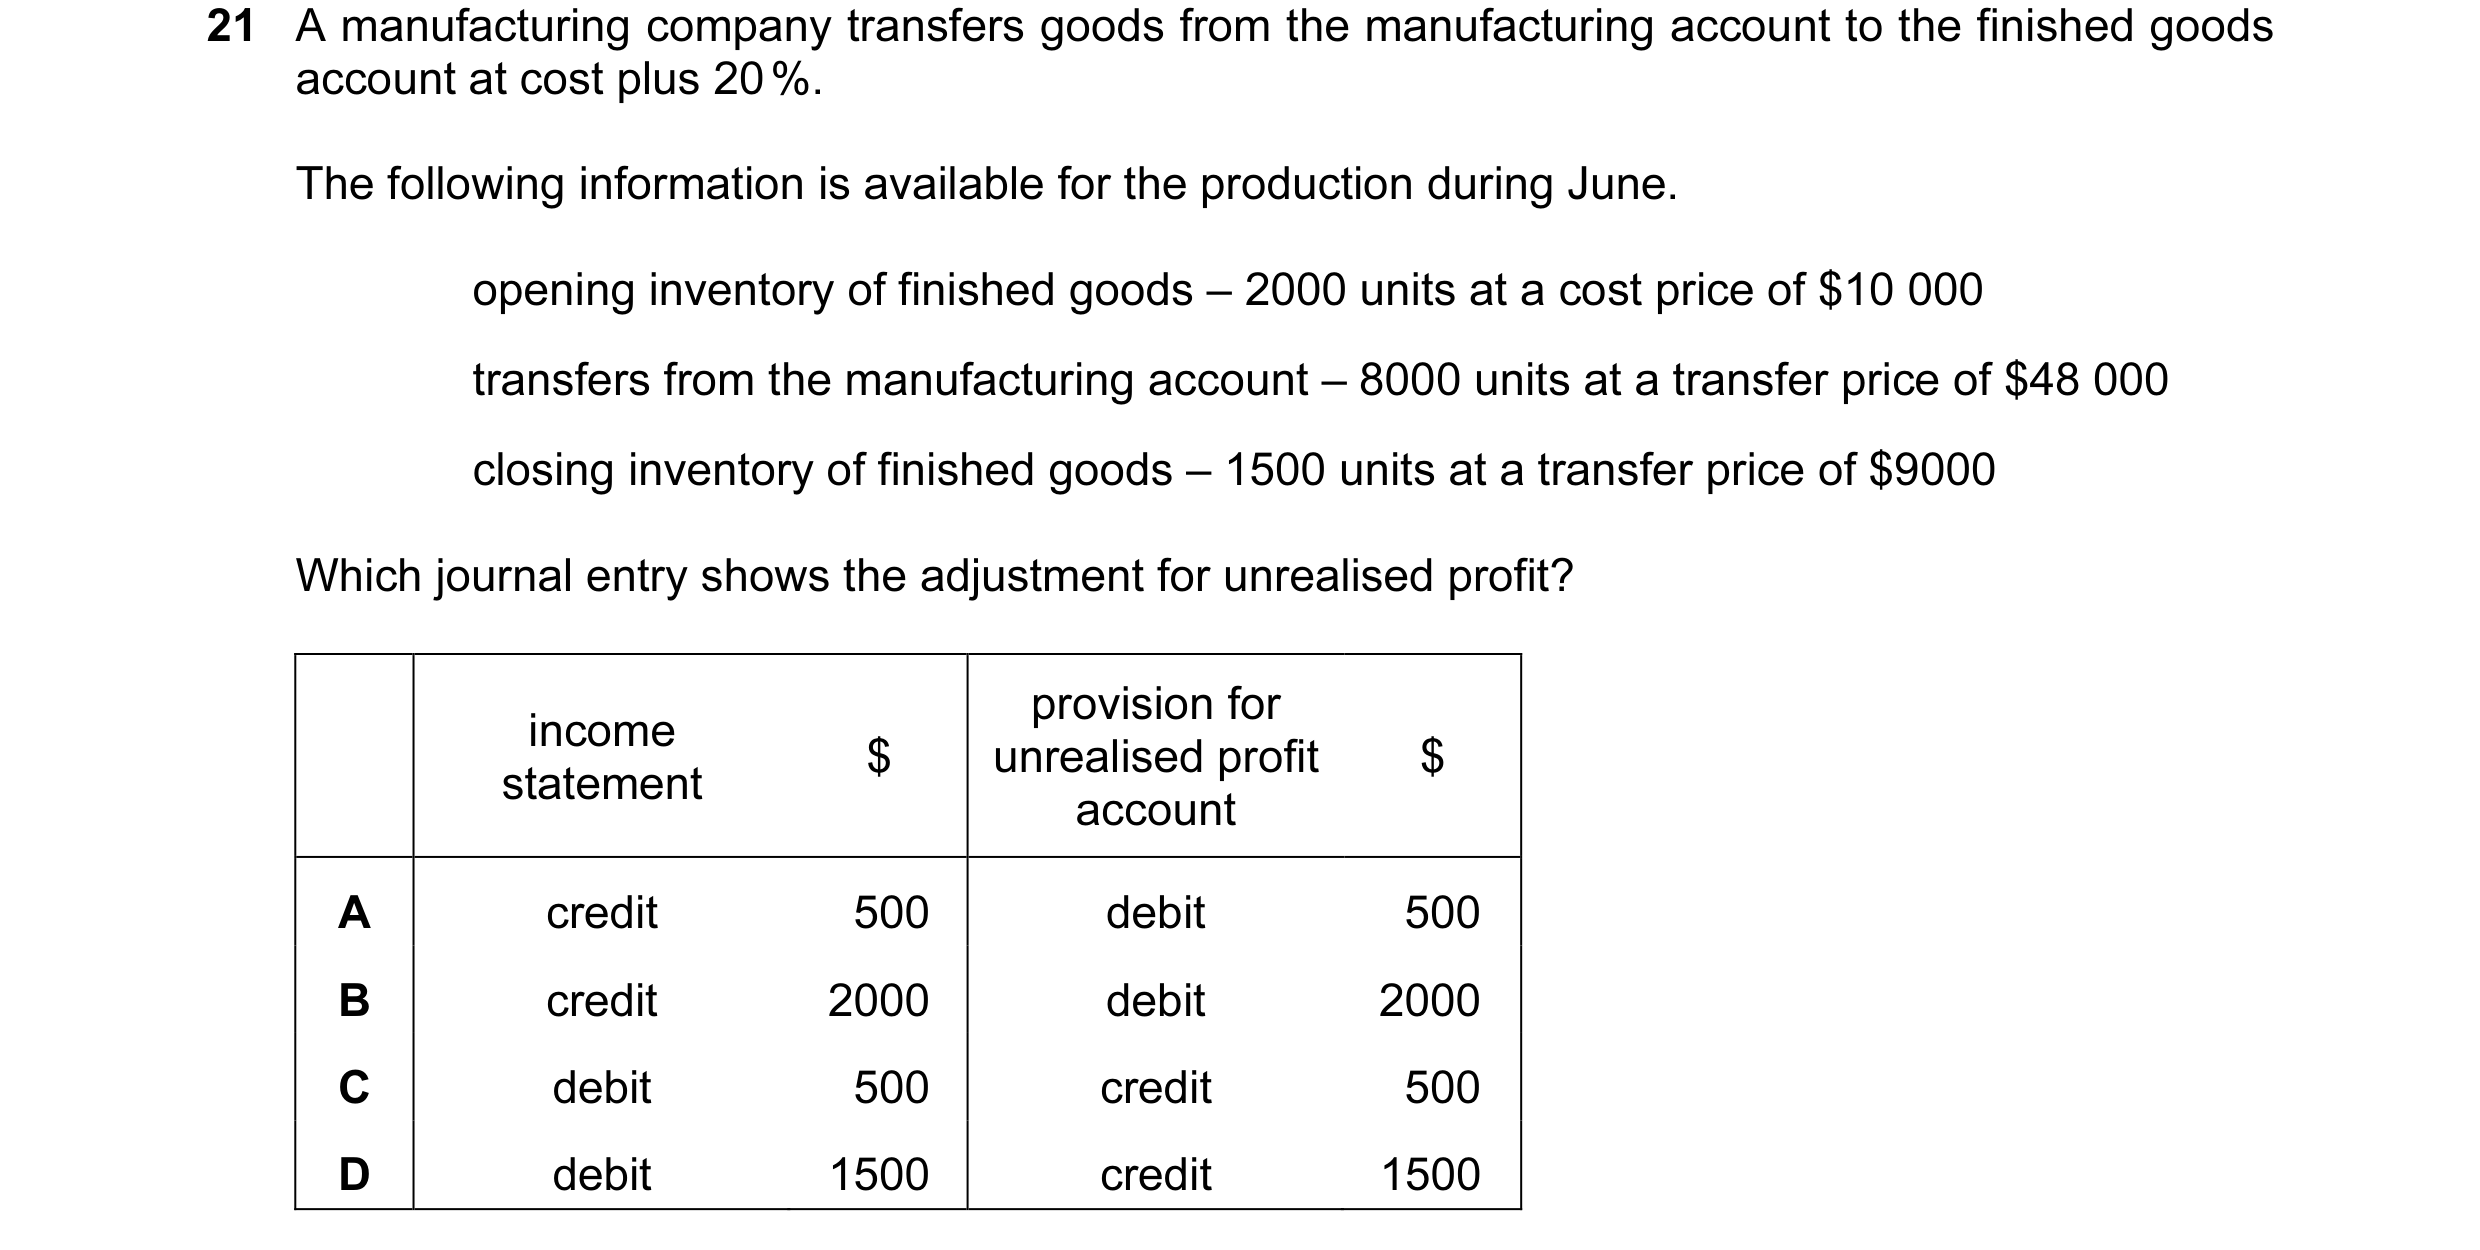
Q20 · A manufacturing company transfers goods from the manufacturing account to the finished… 9706/33 May/June 2012
21 A manufacturing company transfers goods from the manufacturing account to the finished goods account at cost plus 20 %. The following information is available for the production during June. opening inventory of finished goods – 2000 units at a cost price of $10 000 transfers from the manufacturing account – 8000 units at a transfer price of $48 000 closing inventory of finished goods – 1500 units at a transfer price of $9000 Which journal entry shows the adjustment for unrealised profit? provision for income $ unrealised profit $ statement account A credit 500 debit 500 B credit 2000 debit 2000 C debit 500 credit 500 D debit 1500 credit 1500
1 marks
Answer: A
This question in 9706/33 May/June 2012
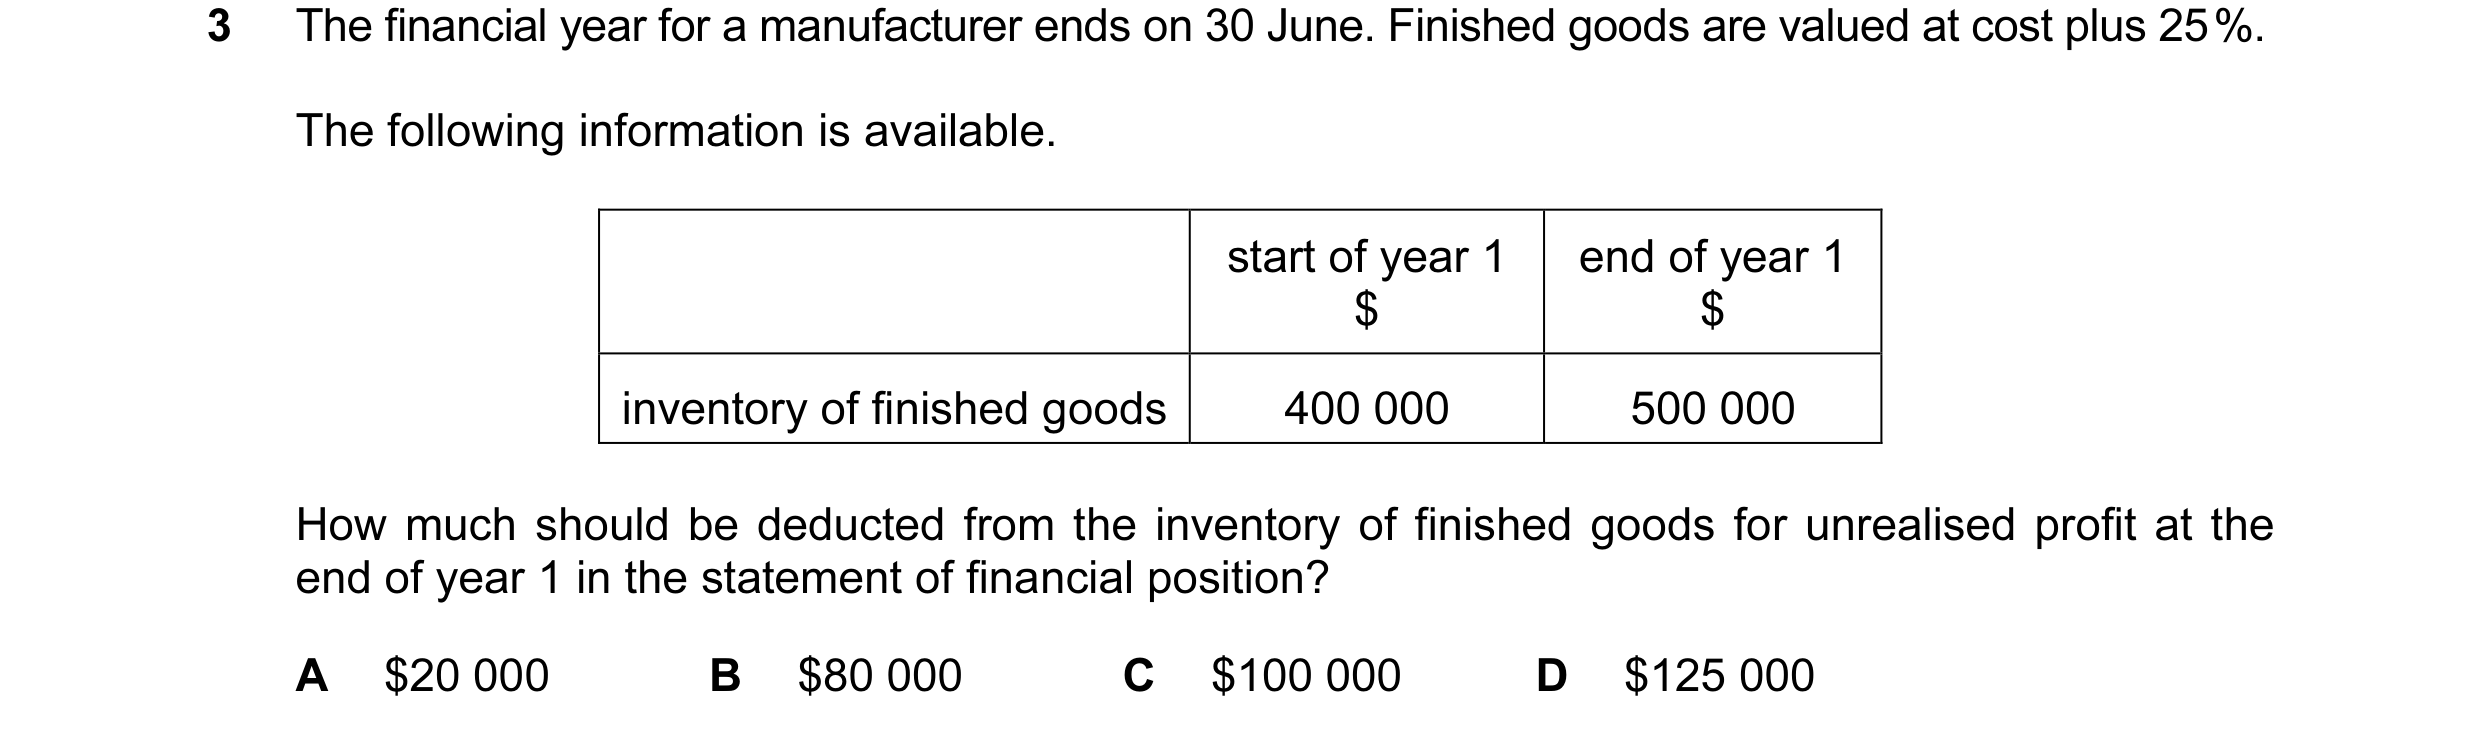
Q21 · The financial year for a manufacturer ends on 30 June 9706/32 Oct/Nov 2012
3 The financial year for a manufacturer ends on 30 June. Finished goods are valued at cost plus 25 %. The following information is available. start of year 1 end of year 1 $ $ inventory of finished goods 400 000 500 000 How much should be deducted from the inventory of finished goods for unrealised profit at the end of year 1 in the statement of financial position? A $20 000 B $80 000 C $100 000 D $125 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2012
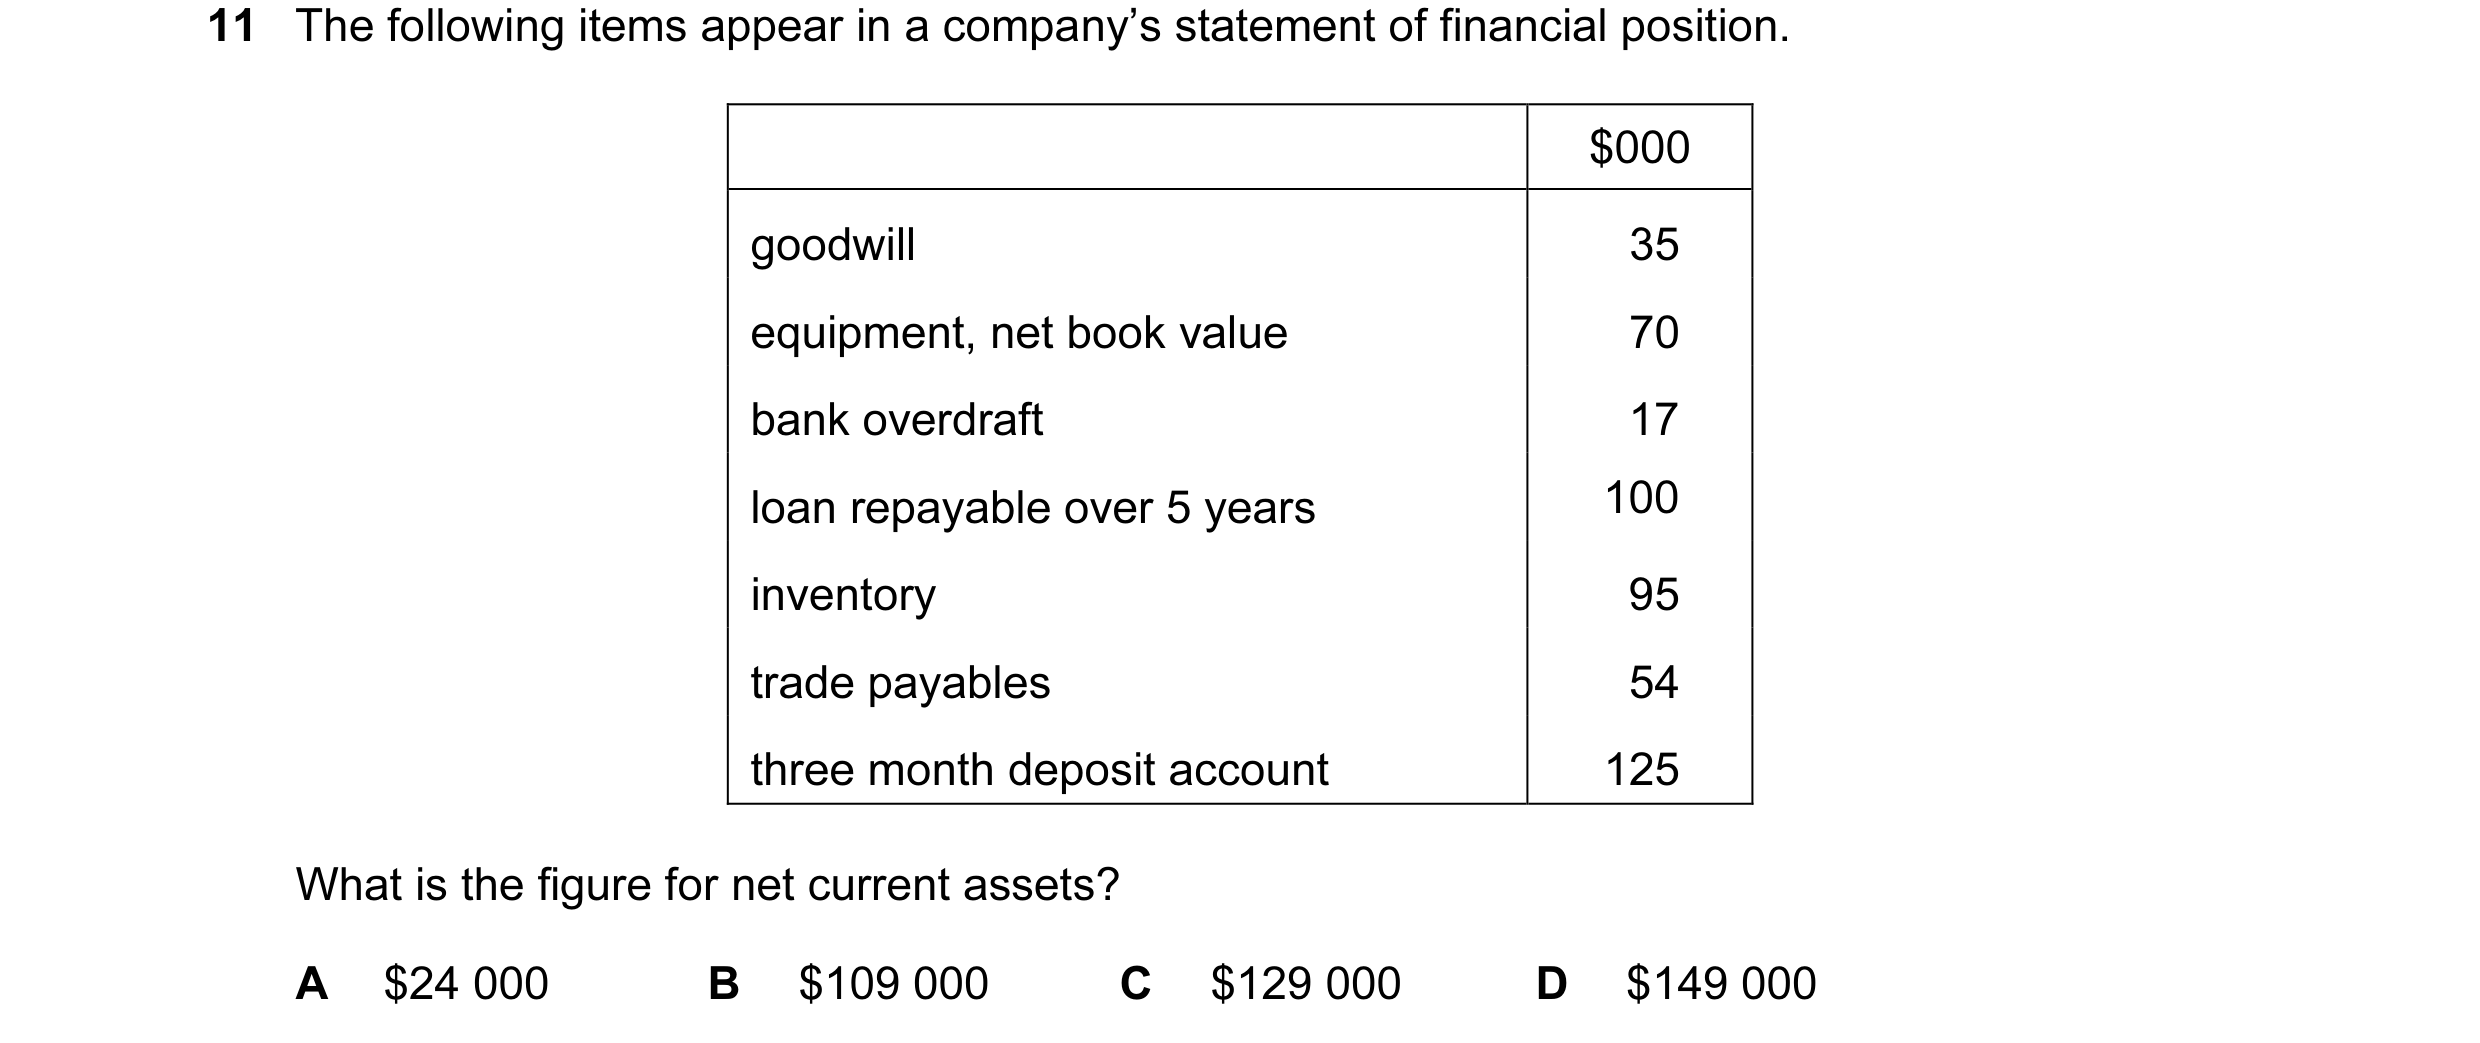
Q22 · The following items appear in a company’s statement of financial position 9706/33 Oct/Nov 2012
11 The following items appear in a company’s statement of financial position. $000 goodwill 35 equipment, net book value 70 bank overdraft 17 loan repayable over 5 years 100 inventory 95 trade payables 54 three month deposit account 125 What is the figure for net current assets? A $24 000 B $109 000 C $129 000 D $149 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
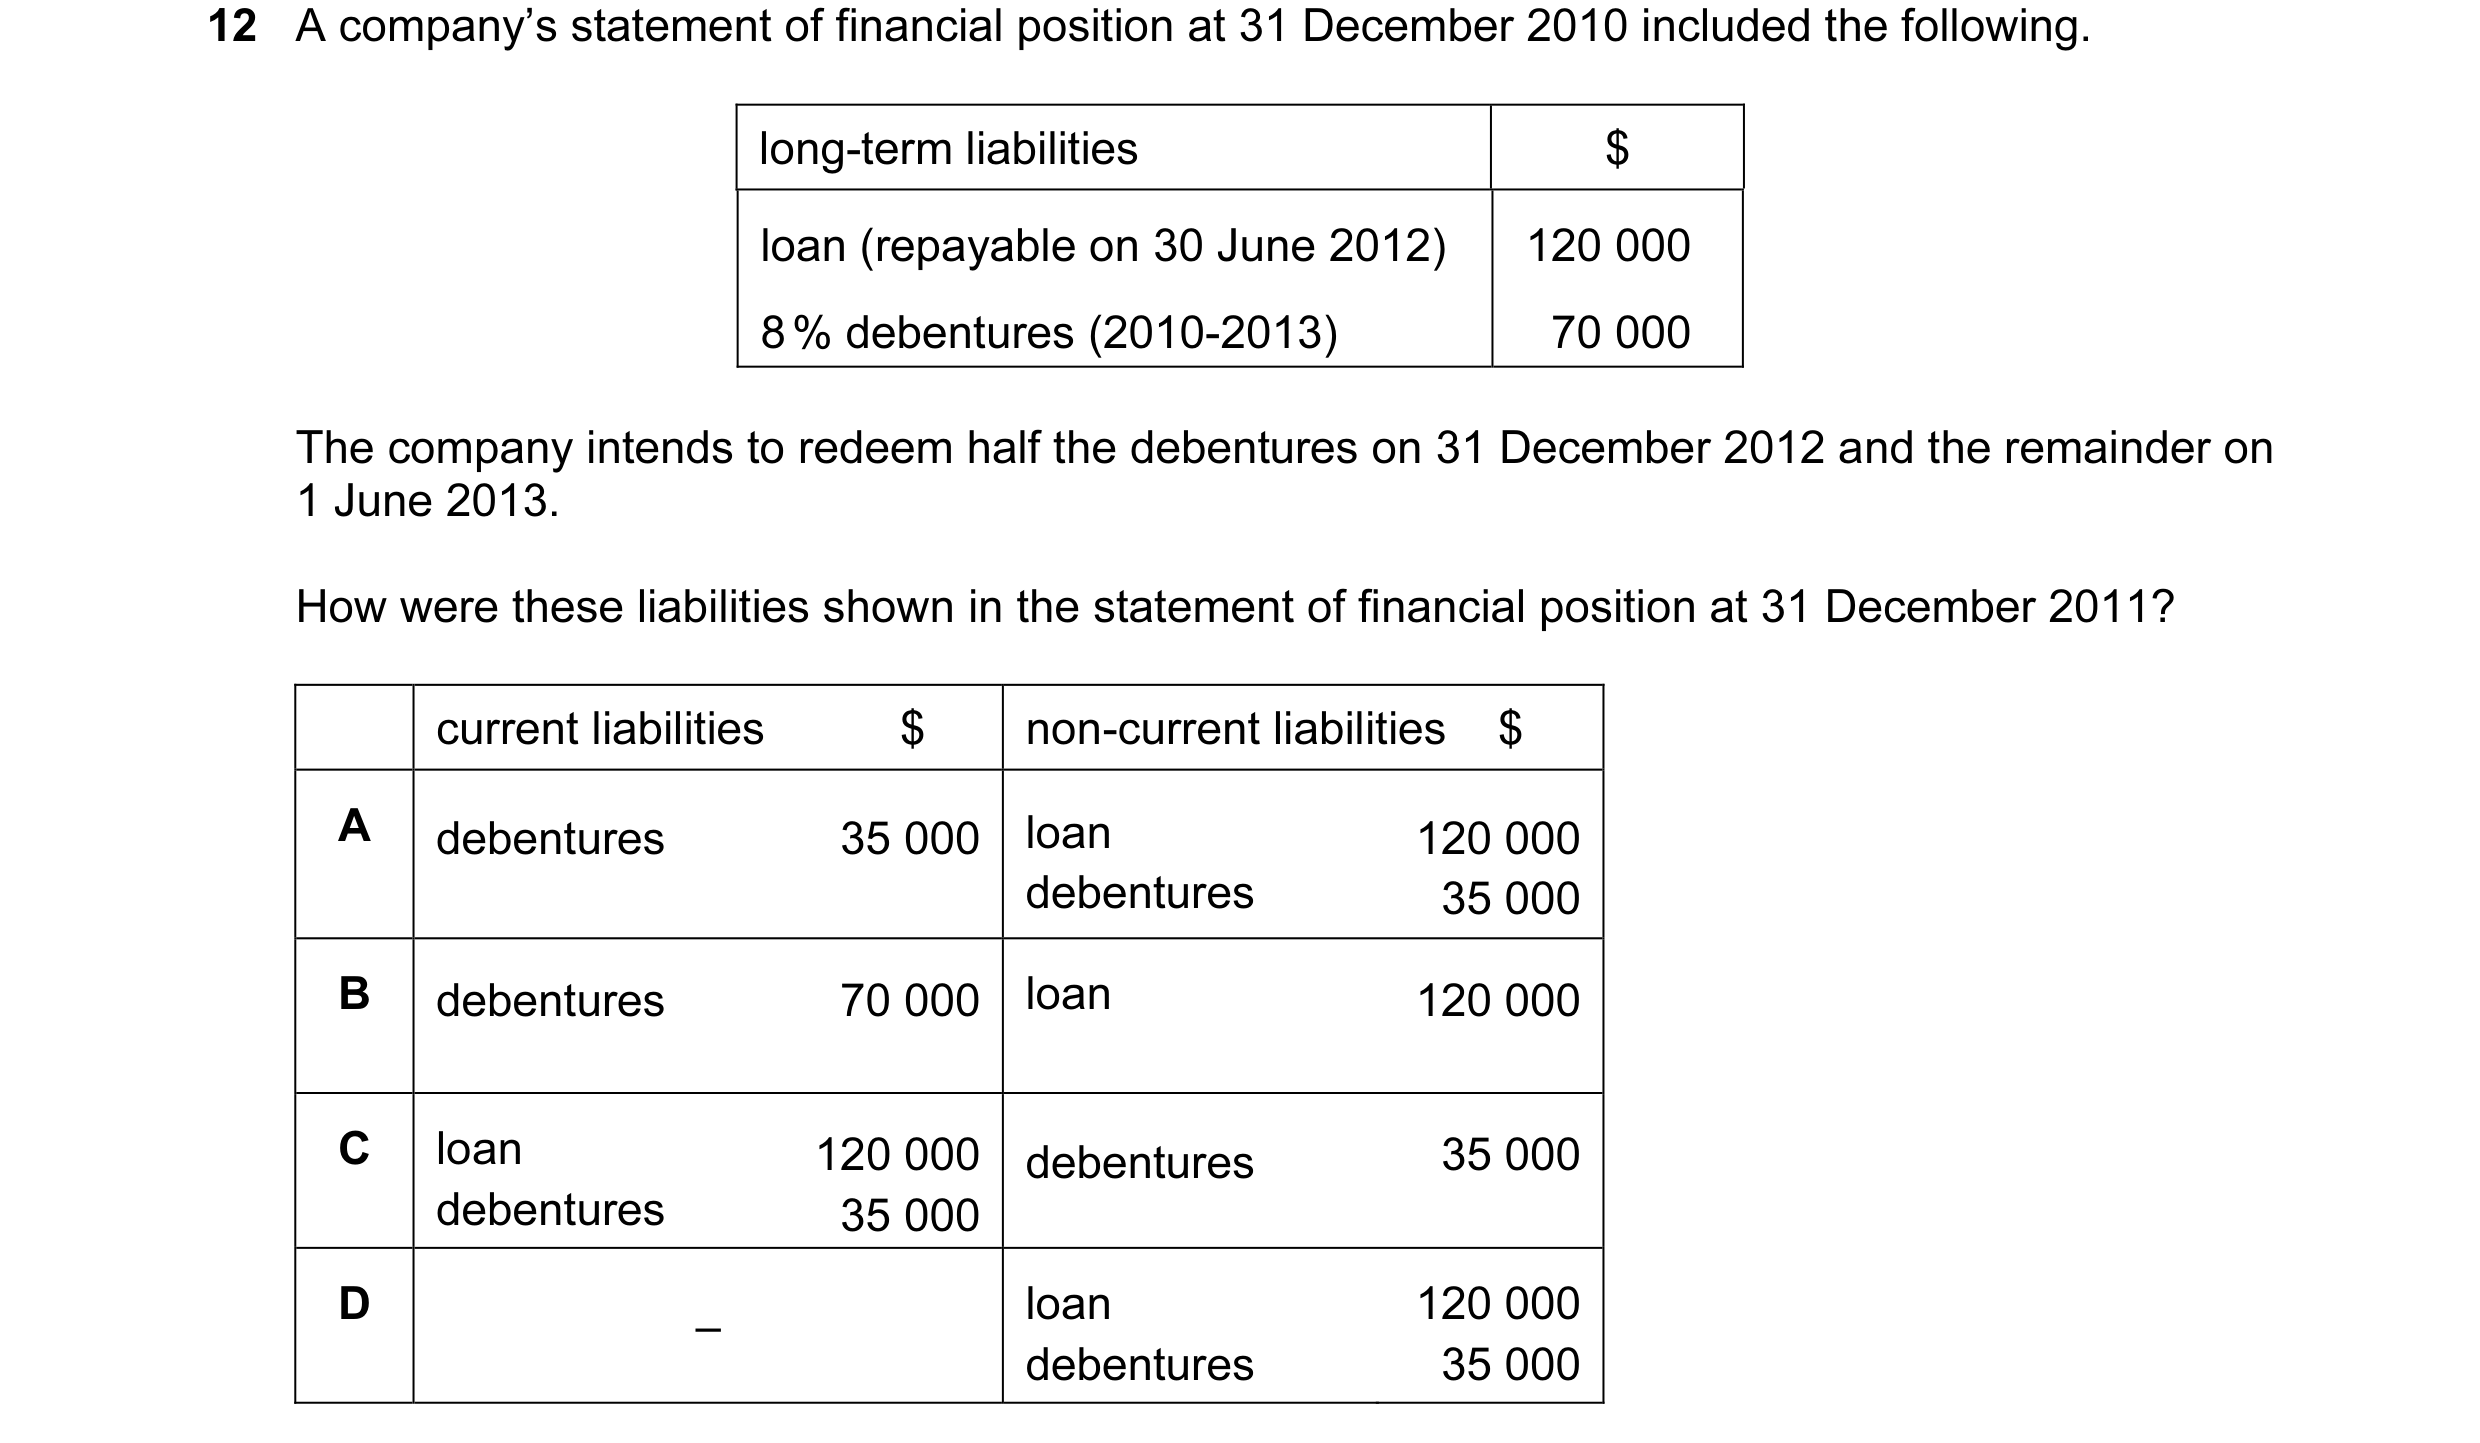
Q23 · A company’s statement of financial position at 31 December 2010 included the following 9706/33 Oct/Nov 2012
12 A company’s statement of financial position at 31 December 2010 included the following. long-term liabilities $ loan (repayable on 30 June 2012) 120 000 8 % debentures (2010-2013) 70 000 The company intends to redeem half the debentures on 31 December 2012 and the remainder on 1 June 2013. How were these liabilities shown in the statement of financial position at 31 December 2011? current liabilities $ non-current liabilities $ A debentures 35 000 loan 120 000 debentures 35 000 B debentures 70 000 loan 120 000 C loan 120 000 debentures 35 000 debentures 35 000 D loan 120 000 – debentures 35 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
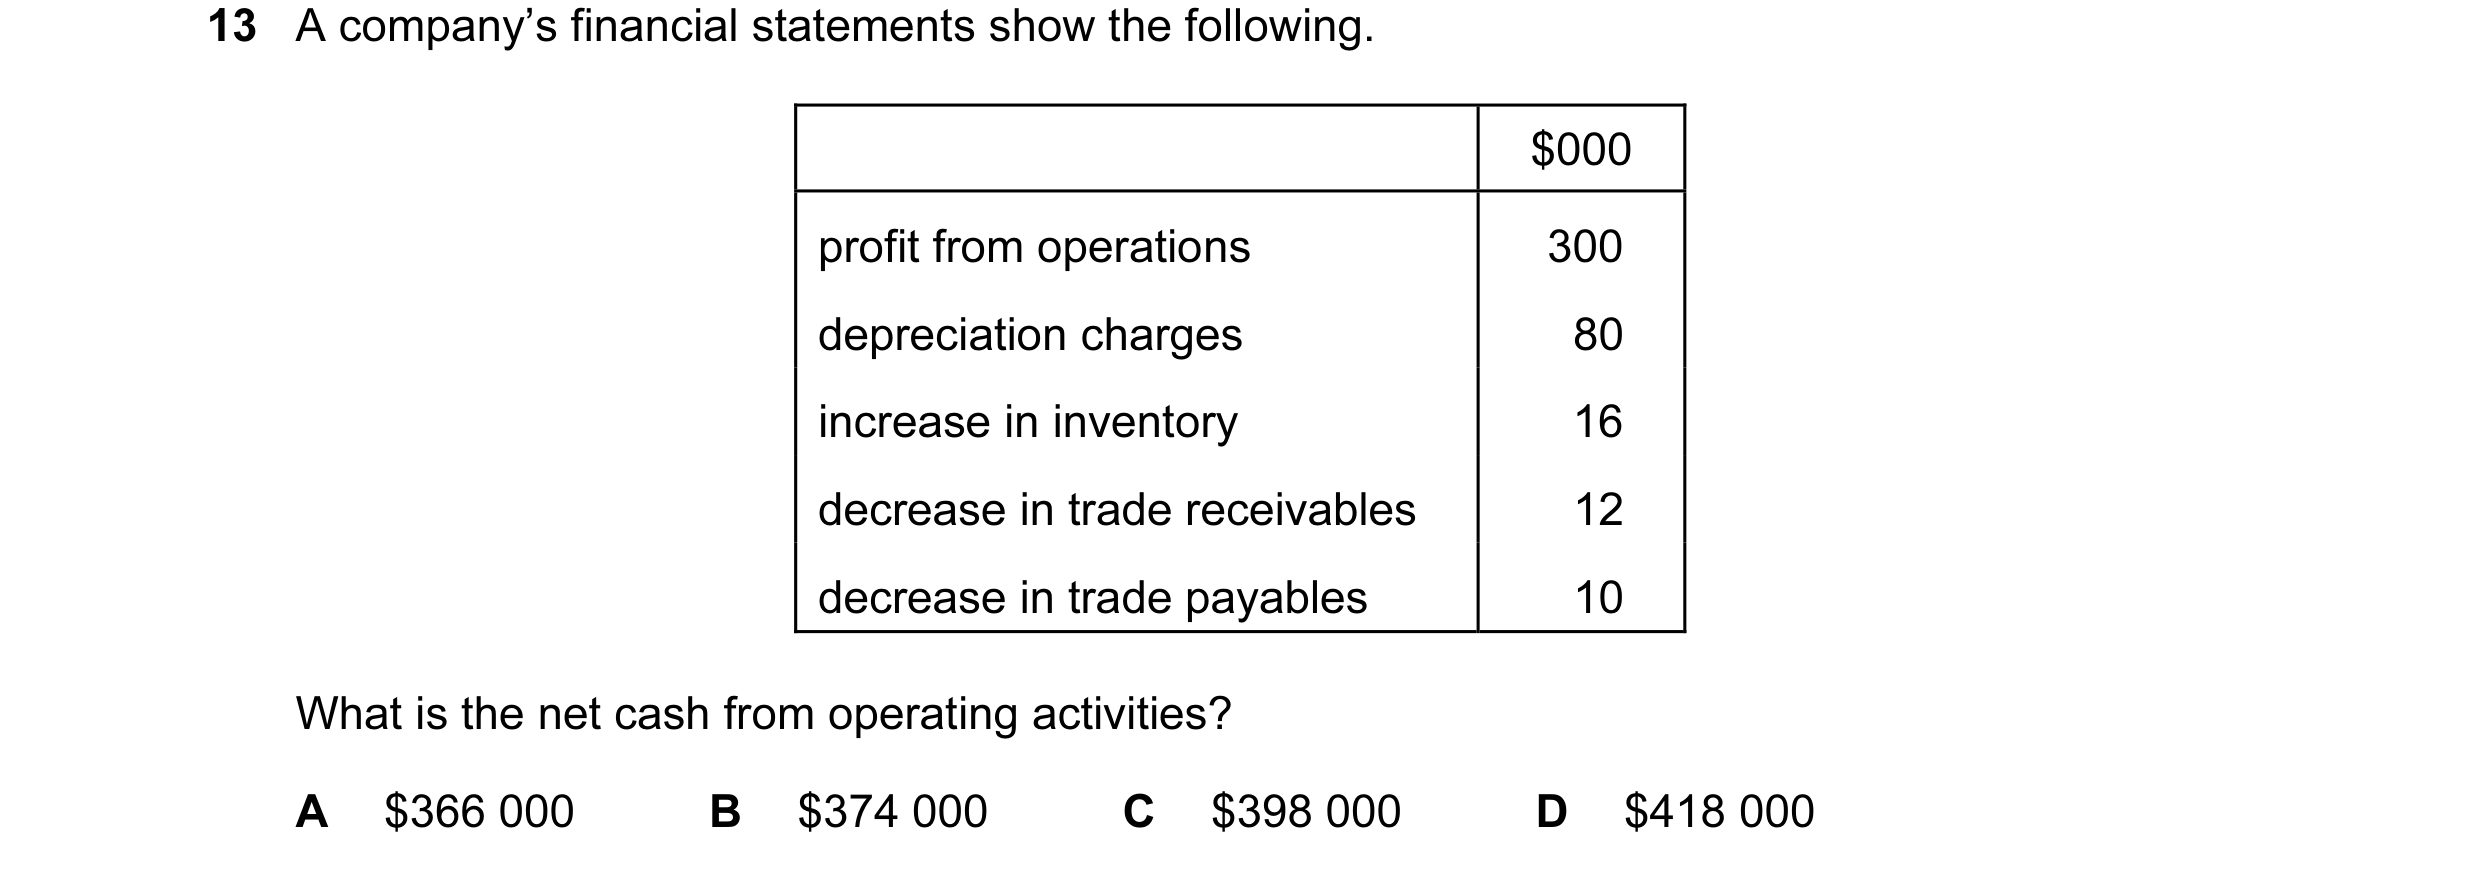
Q24 · A company’s financial statements show the following 9706/33 Oct/Nov 2012
13 A company’s financial statements show the following. $000 profit from operations 300 depreciation charges 80 increase in inventory 16 decrease in trade receivables 12 decrease in trade payables 10 What is the net cash from operating activities? A $366 000 B $374 000 C $398 000 D $418 000
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2012
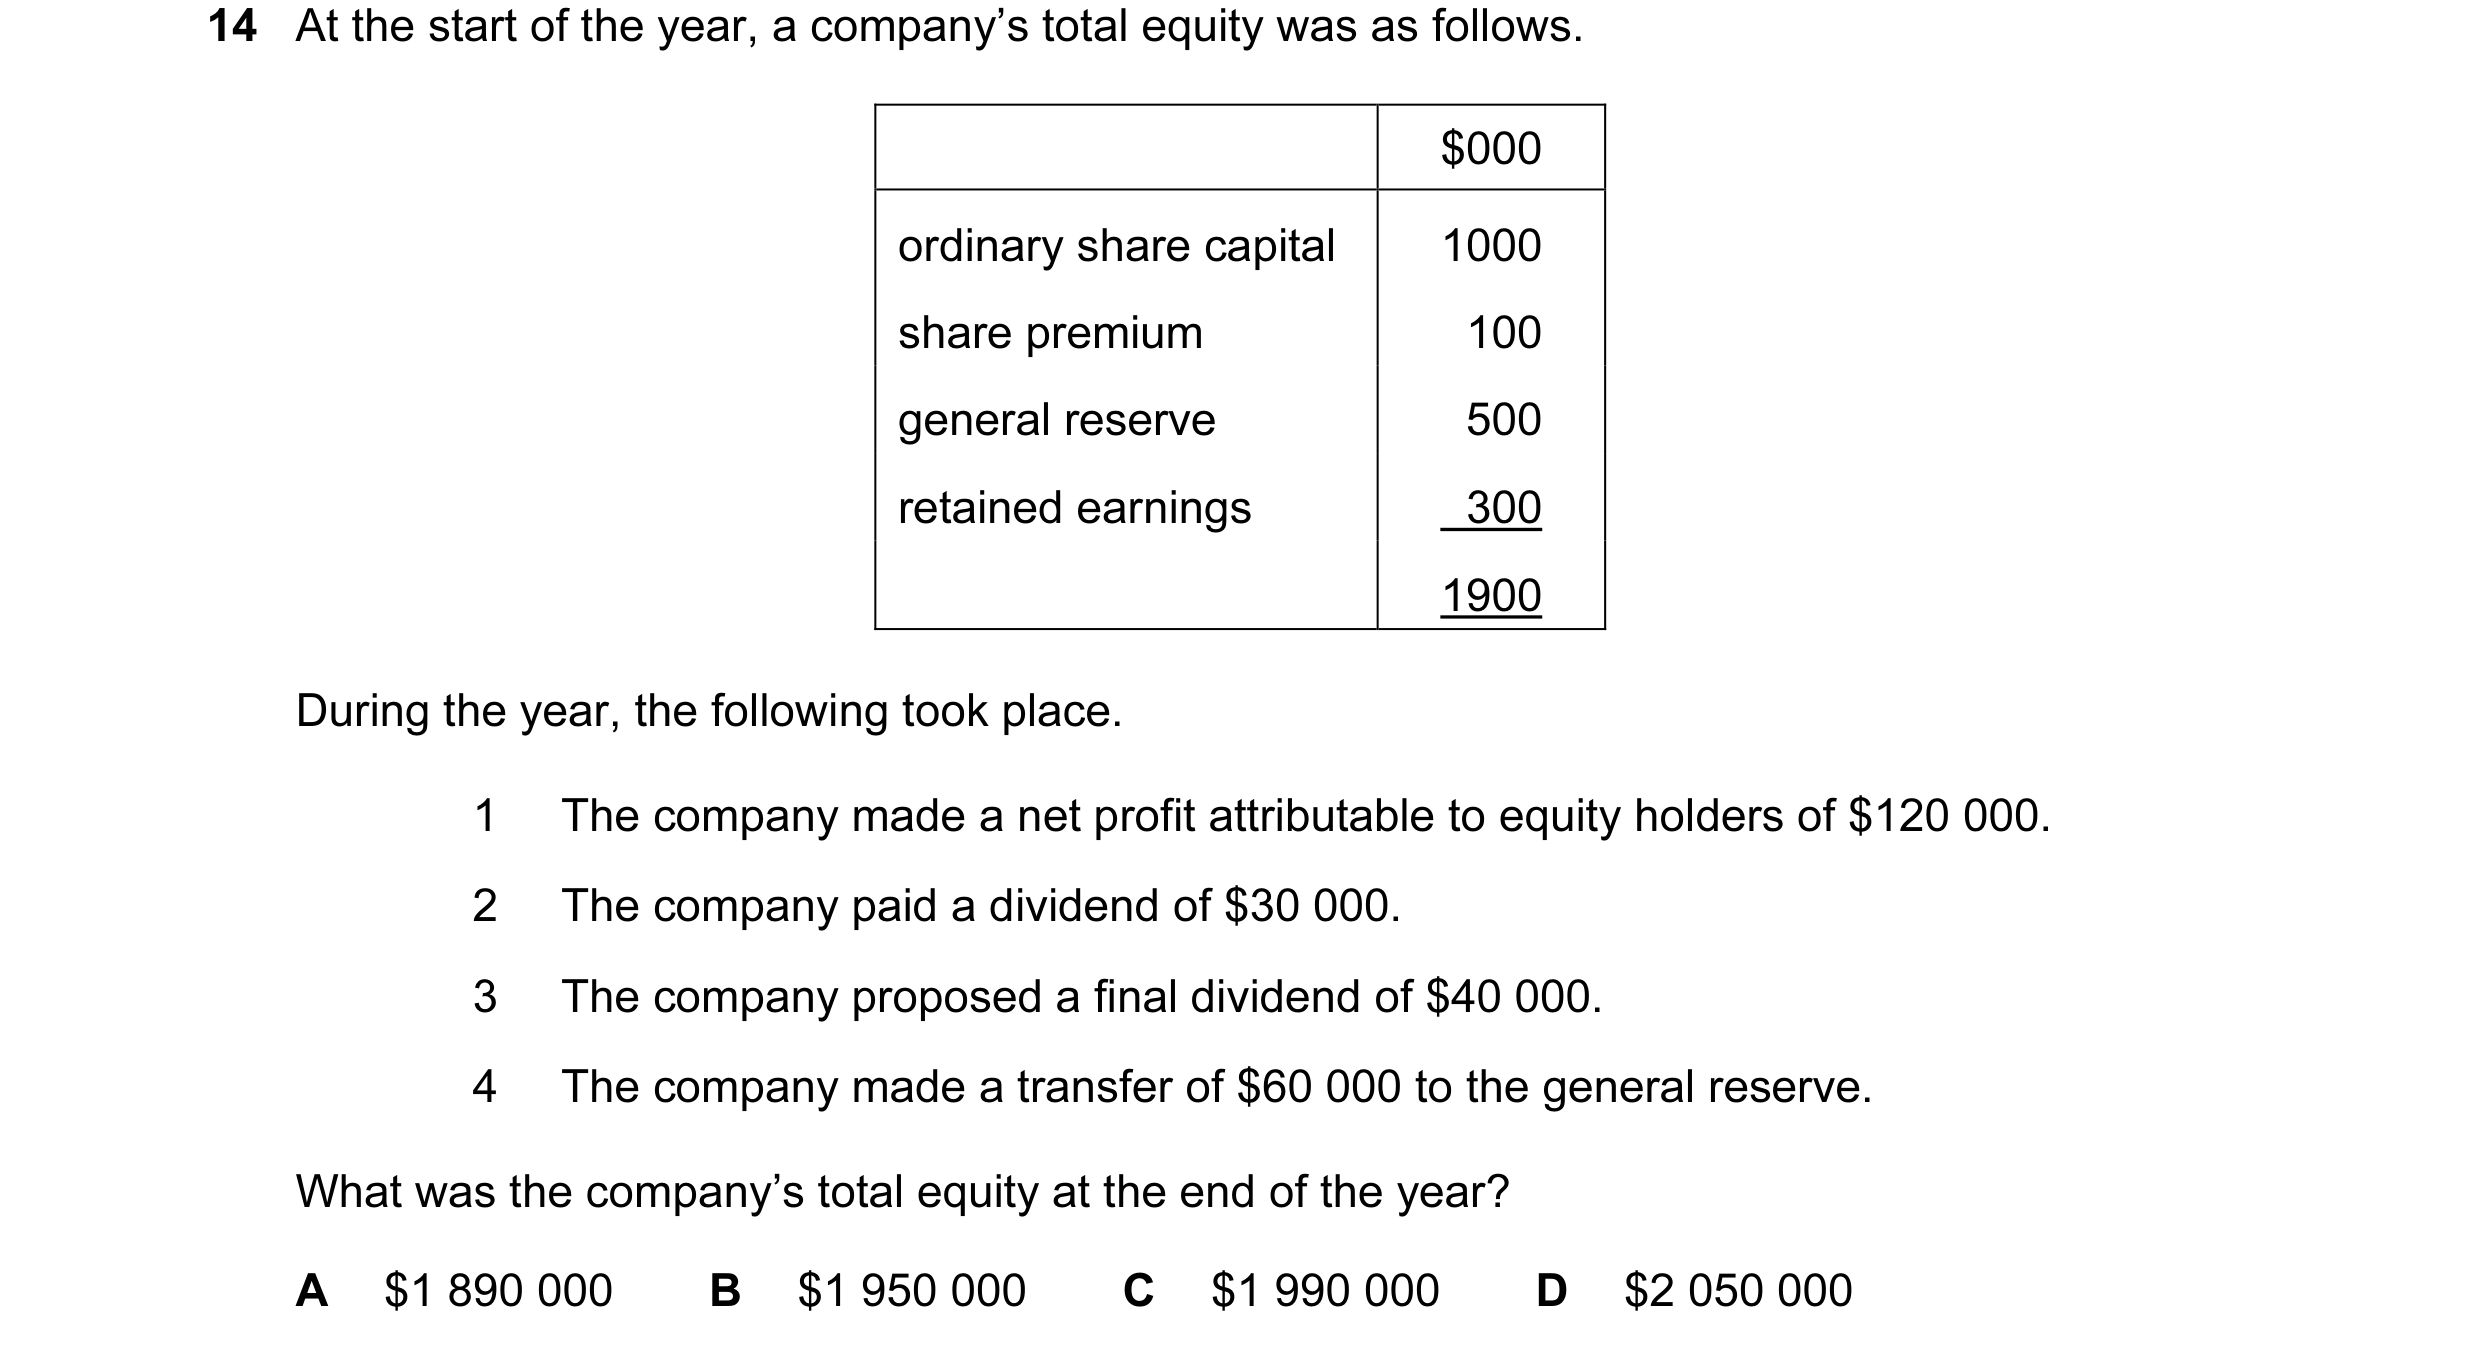
Q25 · At the start of the year, a company’s total equity was as follows 9706/33 Oct/Nov 2012
14 At the start of the year, a company’s total equity was as follows. $000 ordinary share capital 1000 share premium 100 general reserve 500 retained earnings 300 1900 During the year, the following took place. 1 The company made a net profit attributable to equity holders of $120 000. 2 The company paid a dividend of $30 000. 3 The company proposed a final dividend of $40 000. 4 The company made a transfer of $60 000 to the general reserve. What was the company’s total equity at the end of the year? A $1 890 000 B $1 950 000 C $1 990 000 D $2 050 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
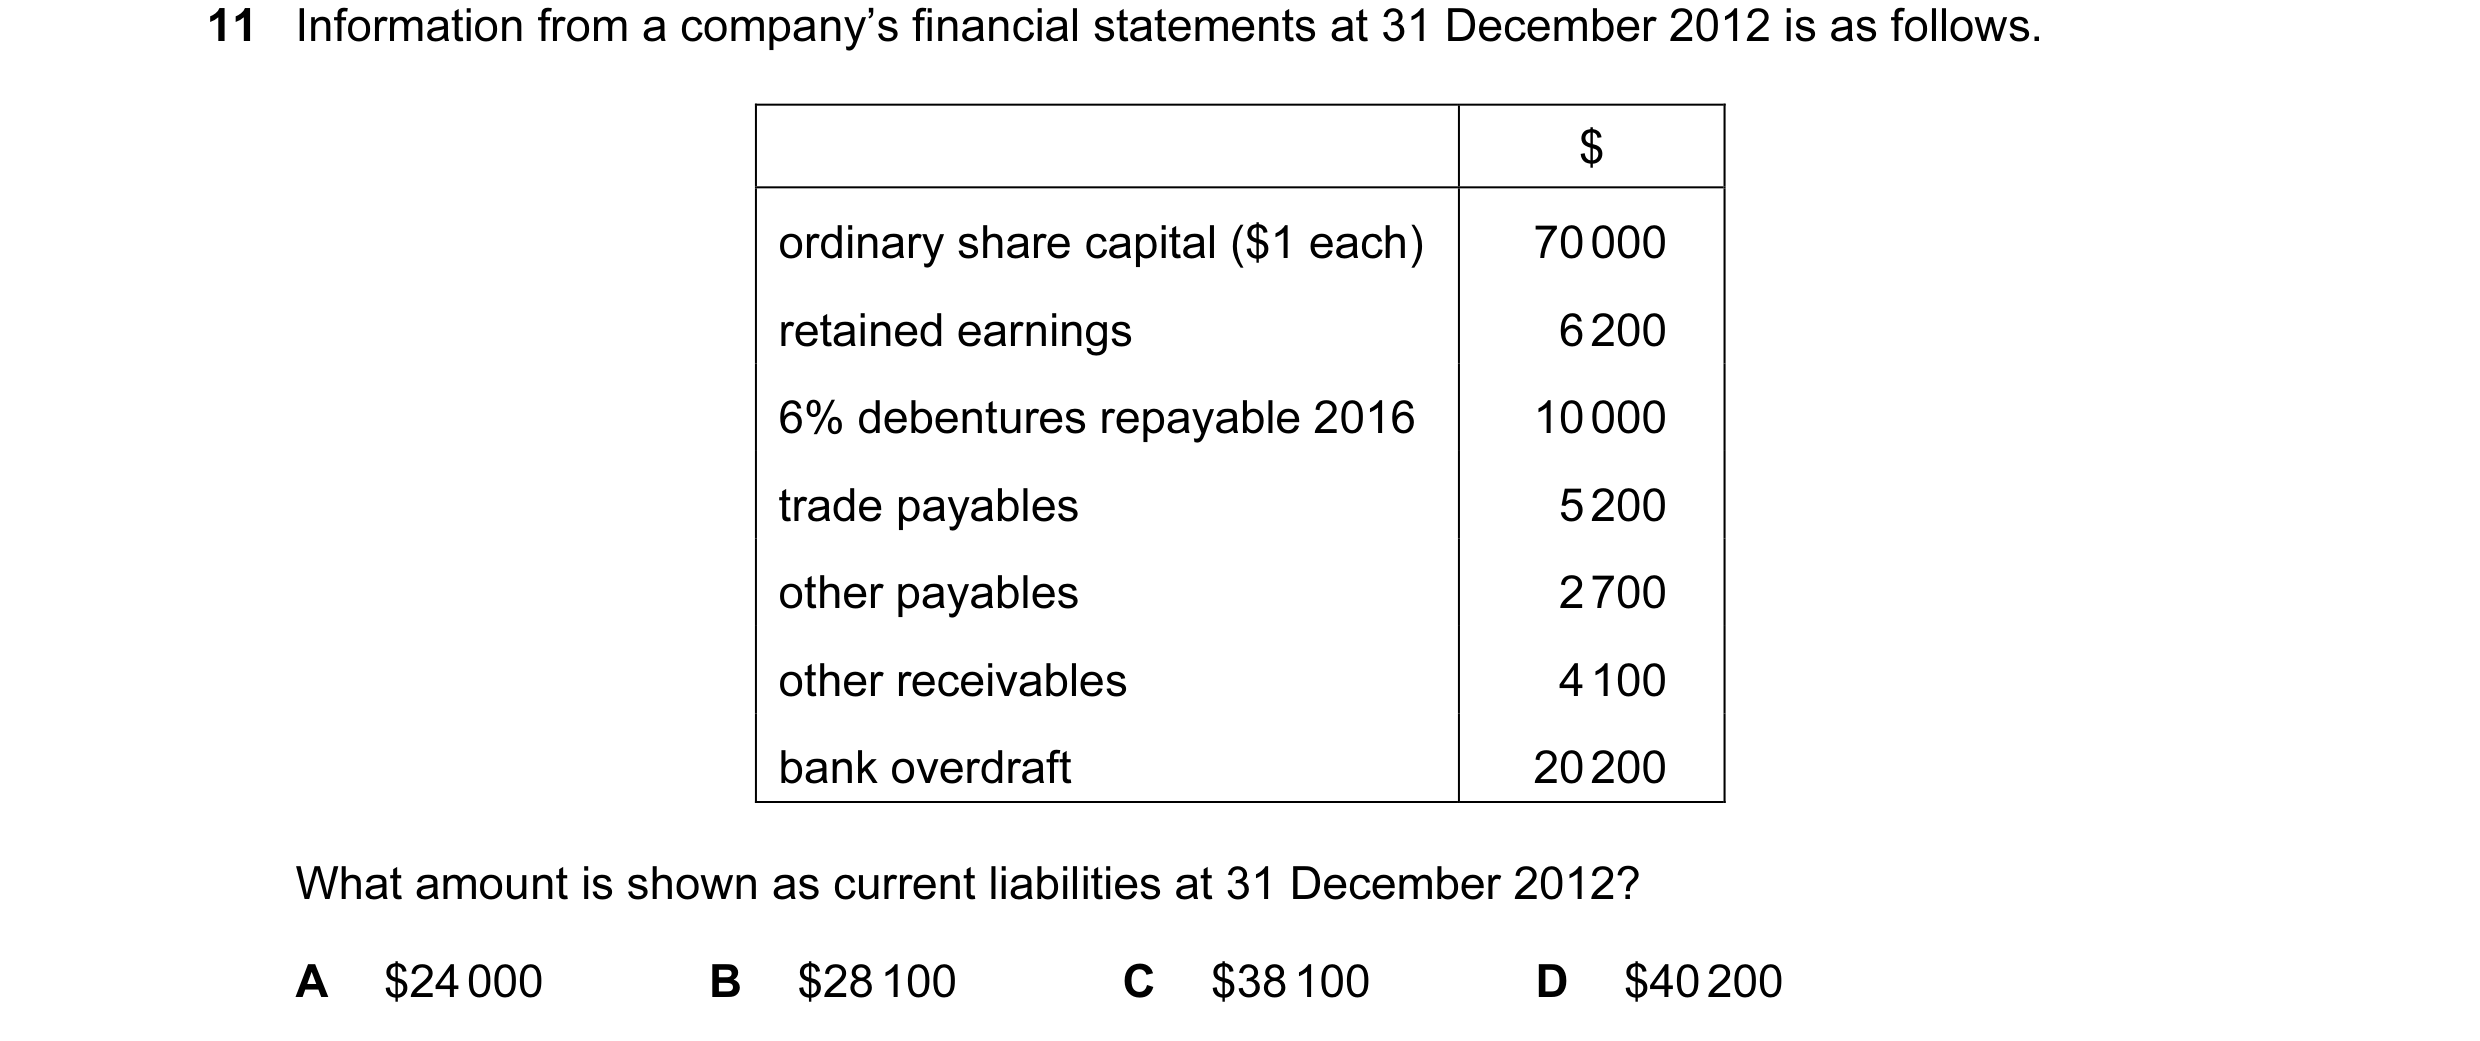
Q26 · Information from a company’s financial statements at 31 December 2012 is as follows 9706/31 May/June 2013
11 Information from a company’s financial statements at 31 December 2012 is as follows. $ ordinary share capital ($1 each) 70 000 retained earnings 6 200 6% debentures repayable 2016 10 000 trade payables 5 200 other payables 2 700 other receivables 4 100 bank overdraft 20 200 What amount is shown as current liabilities at 31 December 2012? A $24 000 B $28 100 C $38 100 D $40 200
1 marks
Answer: B
This question in 9706/31 May/June 2013
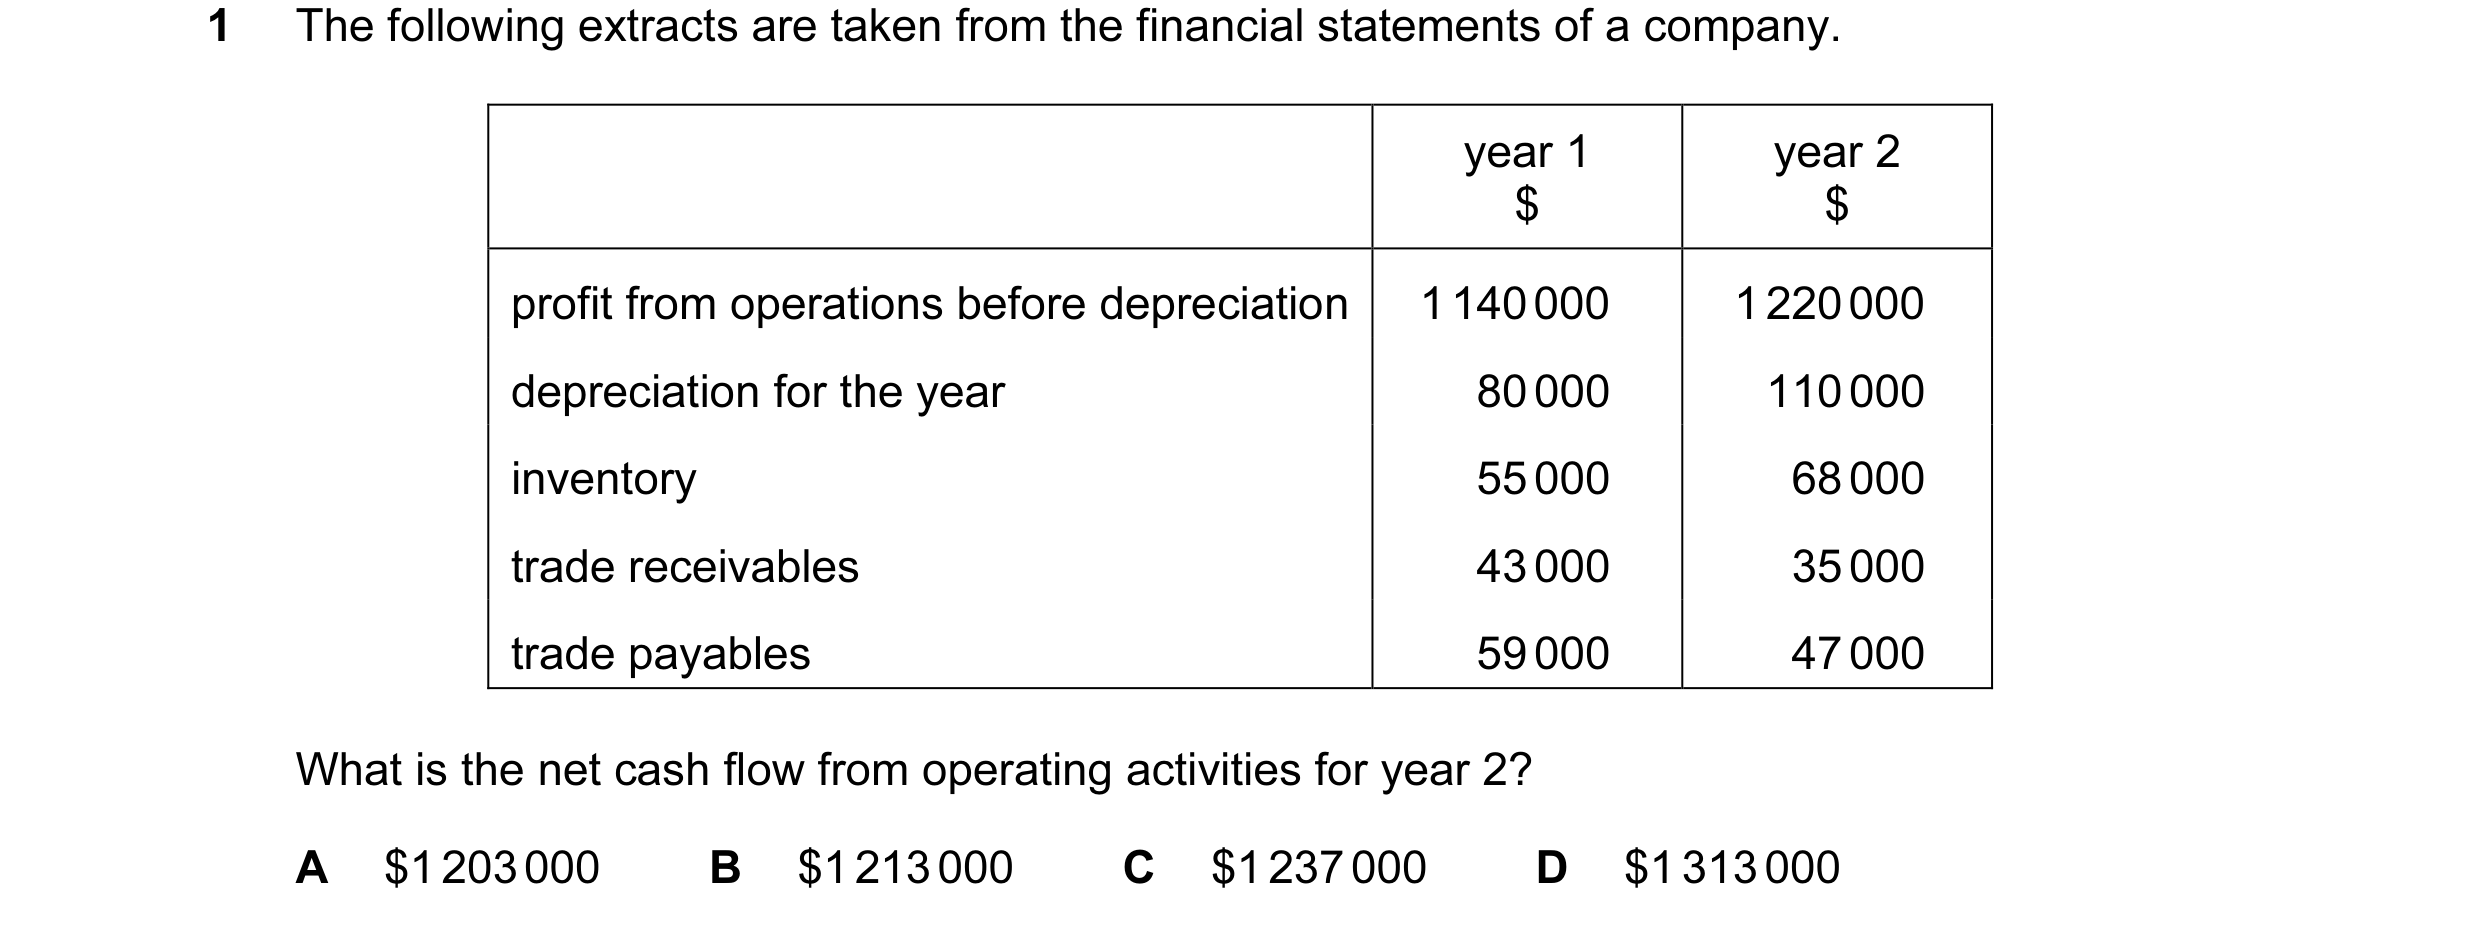
Q27 · The following extracts are taken from the financial statements of a company 9706/32 May/June 2013
1 The following extracts are taken from the financial statements of a company. year 1 year 2 $ $ profit from operations before depreciation 1 140 000 1 220 000 depreciation for the year 80 000 110 000 inventory 55 000 68 000 trade receivables 43 000 35 000 trade payables 59 000 47 000 What is the net cash flow from operating activities for year 2? A $1 203 000 B $1 213 000 C $1 237 000 D $1 313 000
1 marks
Answer: A
This question in 9706/32 May/June 2013
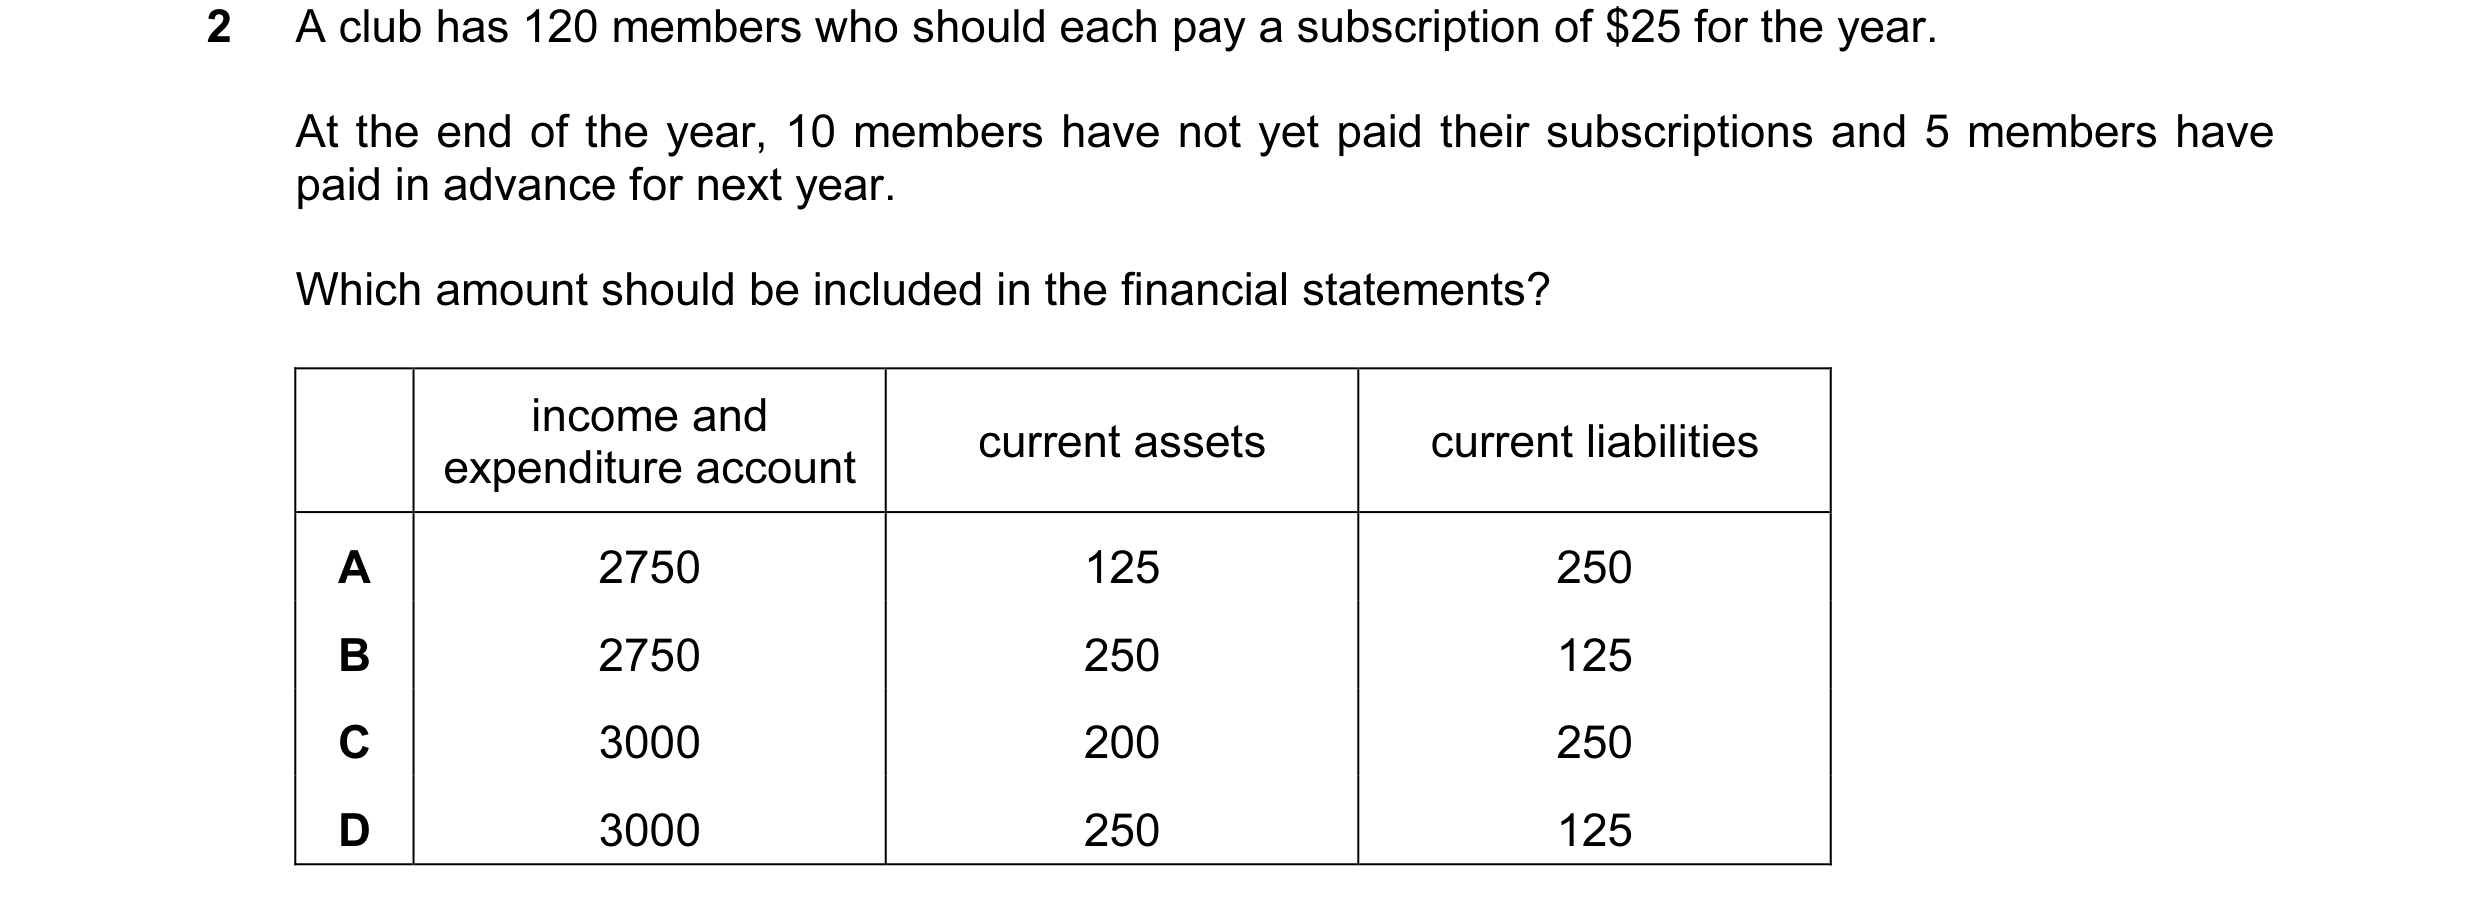
Q28 · A club has 120 members who should each pay a subscription of $25 for the year 9706/32 May/June 2013
2 A club has 120 members who should each pay a subscription of $25 for the year. At the end of the year, 10 members have not yet paid their subscriptions and 5 members have paid in advance for next year. Which amount should be included in the financial statements? income and current assets current liabilities expenditure account A 2750 125 250 B 2750 250 125 C 3000 200 250 D 3000 250 125
1 marks
Answer: D
This question in 9706/32 May/June 2013
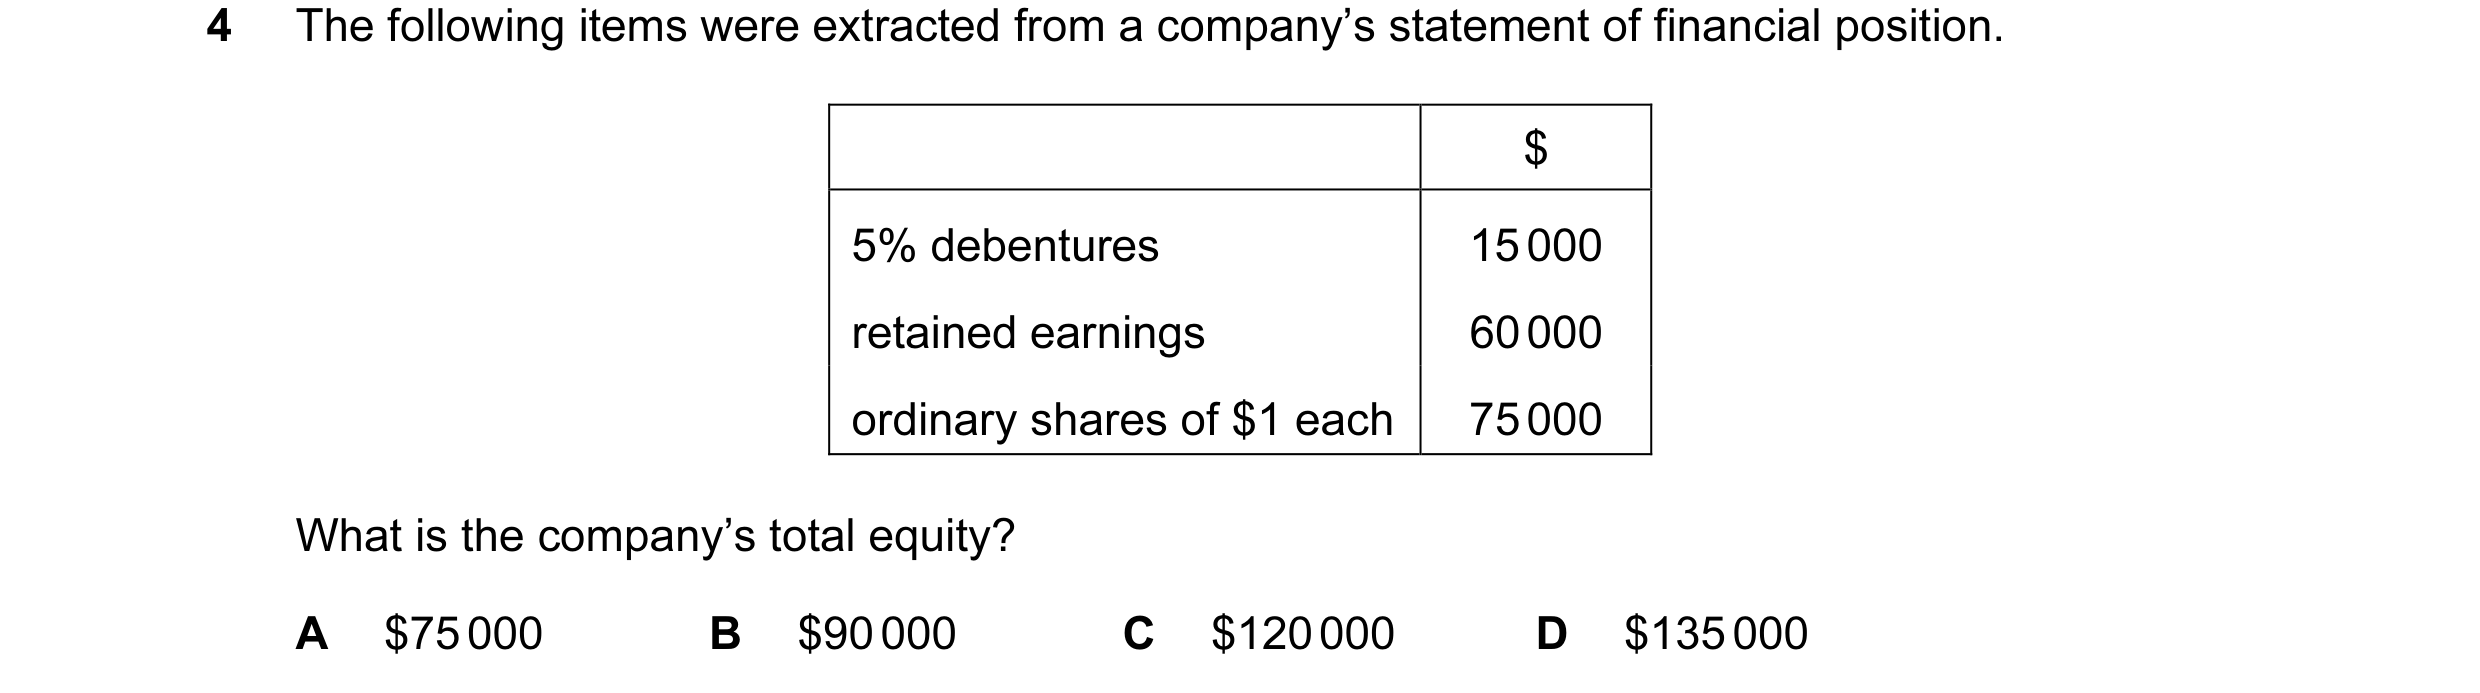
Q29 · The following items were extracted from a company’s statement of financial position 9706/32 May/June 2013
4 The following items were extracted from a company’s statement of financial position. $ 5% debentures 15 000 retained earnings 60 000 ordinary shares of $1 each 75 000 What is the company’s total equity? A $75 000 B $90 000 C $120 000 D $135 000
1 marks
Answer: D
This question in 9706/32 May/June 2013
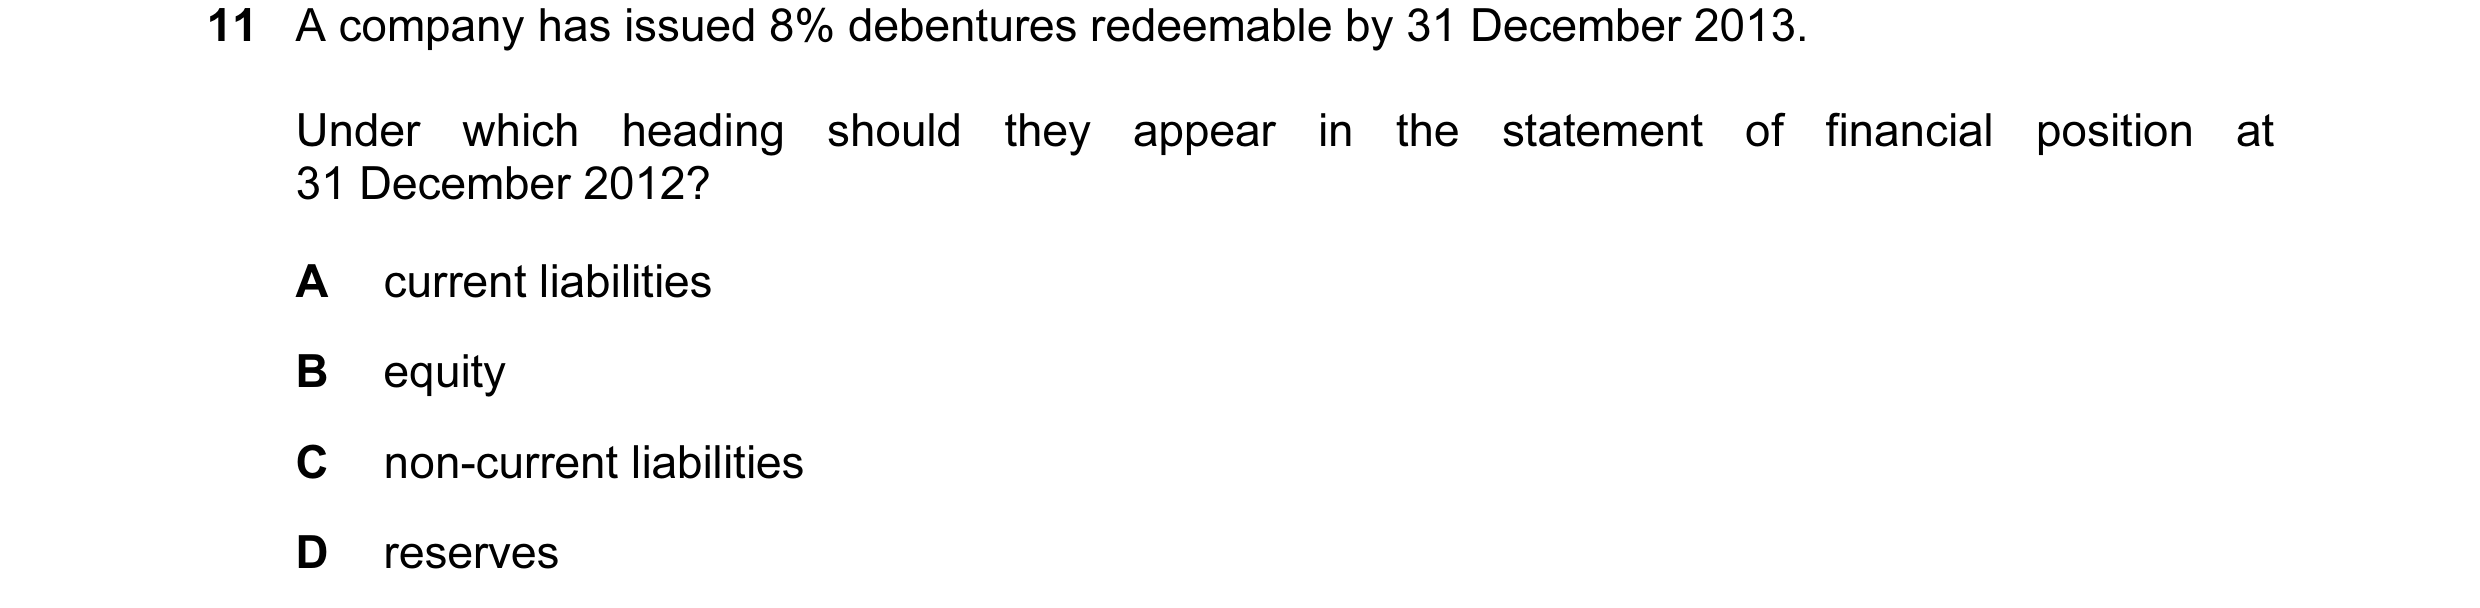
Q30 · A company has issued 8% debentures redeemable by 31 December 2013 9706/32 May/June 2013
11 A company has issued 8% debentures redeemable by 31 December 2013. Under which heading should they appear in the statement of financial position at 31 December 2012? A current liabilities B equity C non-current liabilities D reserves
1 marks
Answer: A
This question in 9706/32 May/June 2013
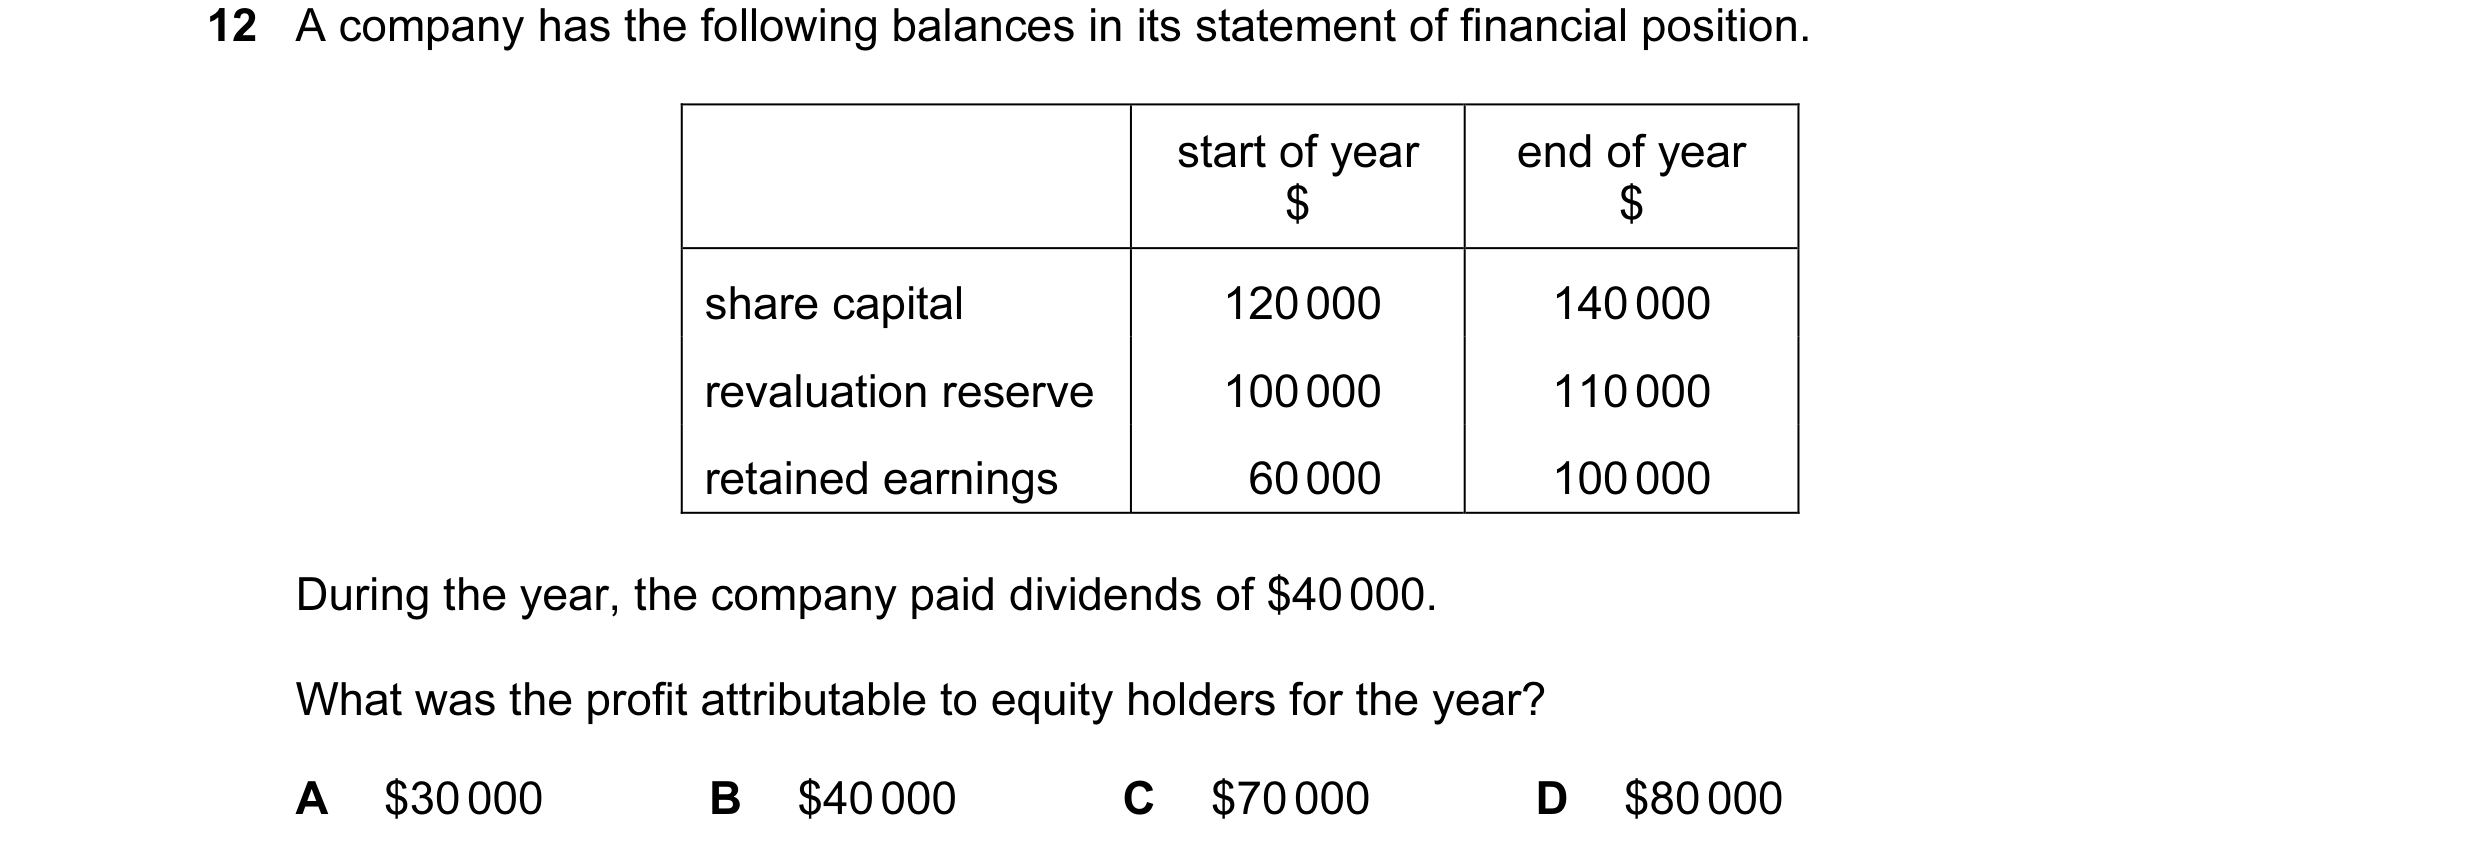
Q31 · A company has the following balances in its statement of financial position 9706/32 May/June 2013
12 A company has the following balances in its statement of financial position. start of year end of year $ $ share capital 120 000 140 000 revaluation reserve 100 000 110 000 retained earnings 60 000 100 000 During the year, the company paid dividends of $40 000. What was the profit attributable to equity holders for the year? A $30 000 B $40 000 C $70 000 D $80 000
1 marks
Answer: D
This question in 9706/32 May/June 2013
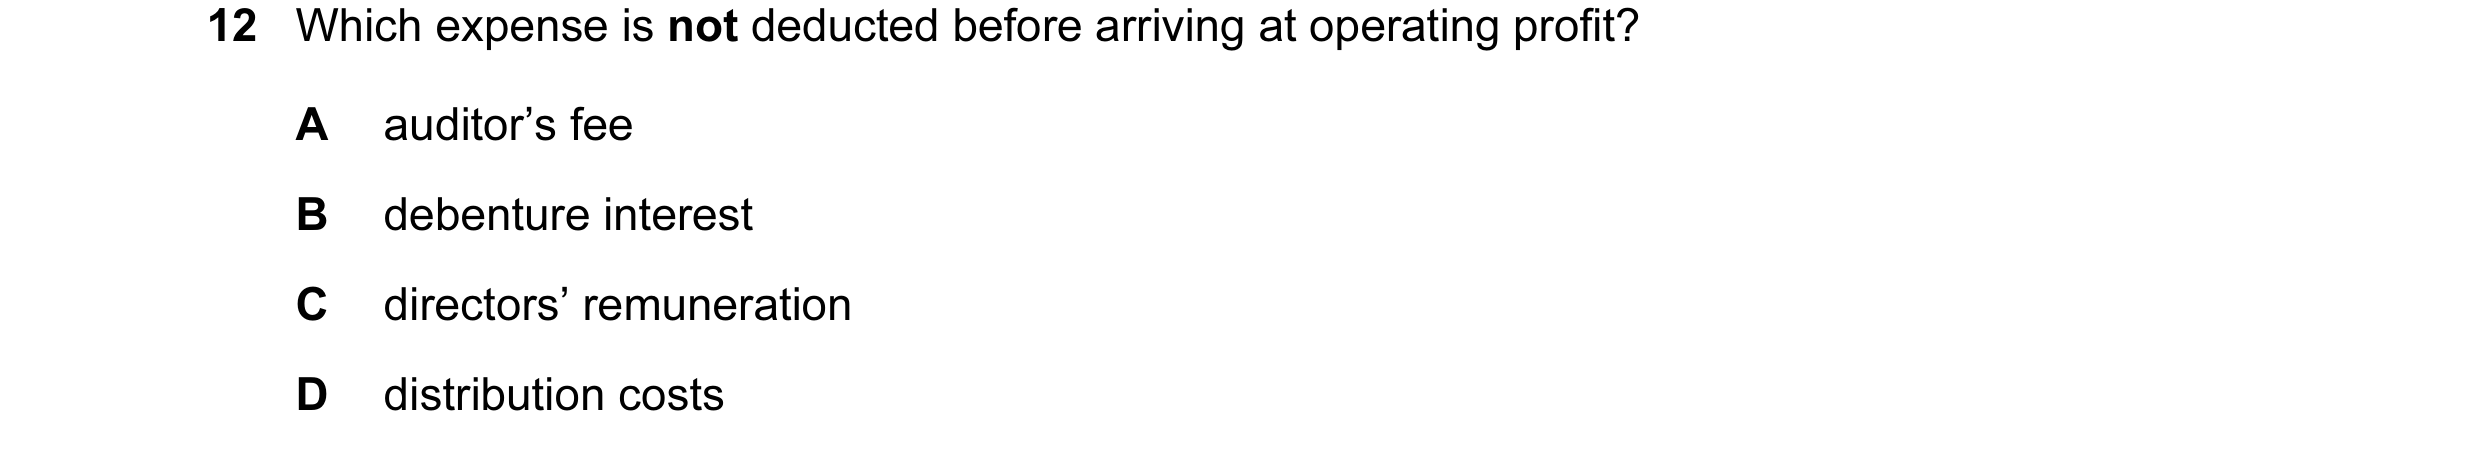
Q32 · Which expense is not deducted before arriving at operating profit? 9706/33 May/June 2013
12 Which expense is not deducted before arriving at operating profit? A auditor’s fee B debenture interest C directors’ remuneration D distribution costs
1 marks
Answer: B
This question in 9706/33 May/June 2013
Q33 · The financial year of a manufacturer ends on 31 December 9706/31 Oct/Nov 2013
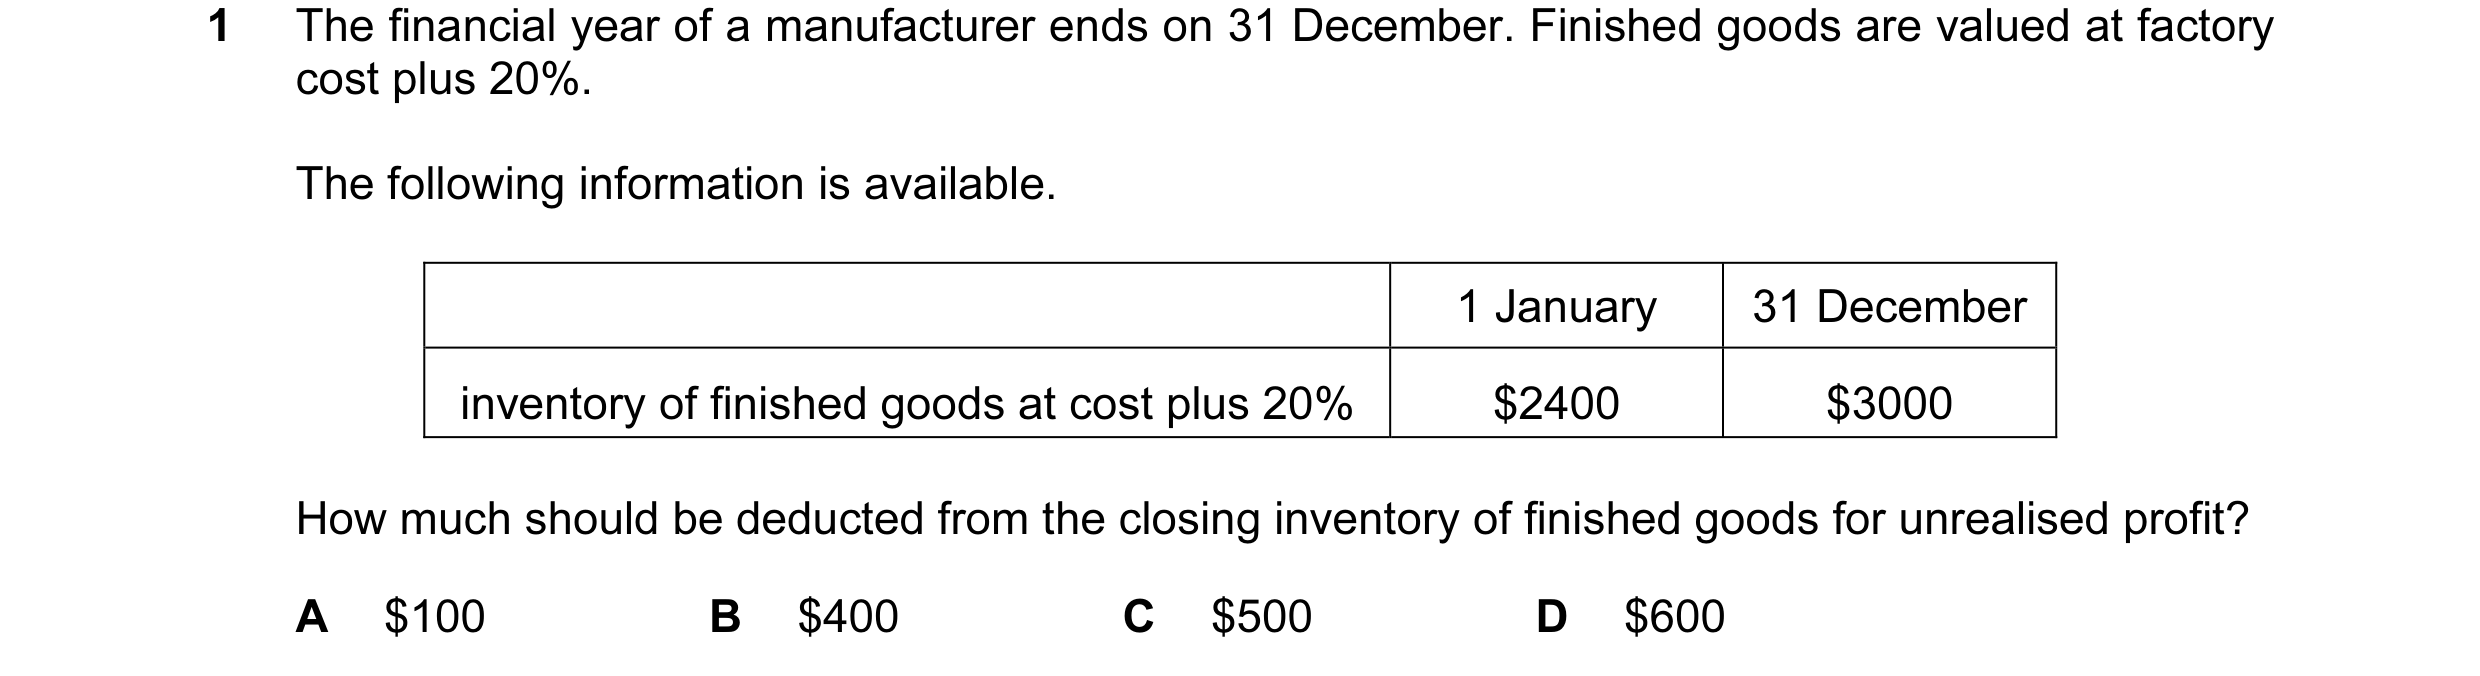
1 The financial year of a manufacturer ends on 31 December. Finished goods are valued at factory cost plus 20%. The following information is available. 1 January 31 December inventory of finished goods at cost plus 20% $2400 $3000 How much should be deducted from the closing inventory of finished goods for unrealised profit? A $100 B $400 C $500 D $600
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2013
Q34 · Which item would be included in a company’s income statement? 9706/31 Oct/Nov 2013
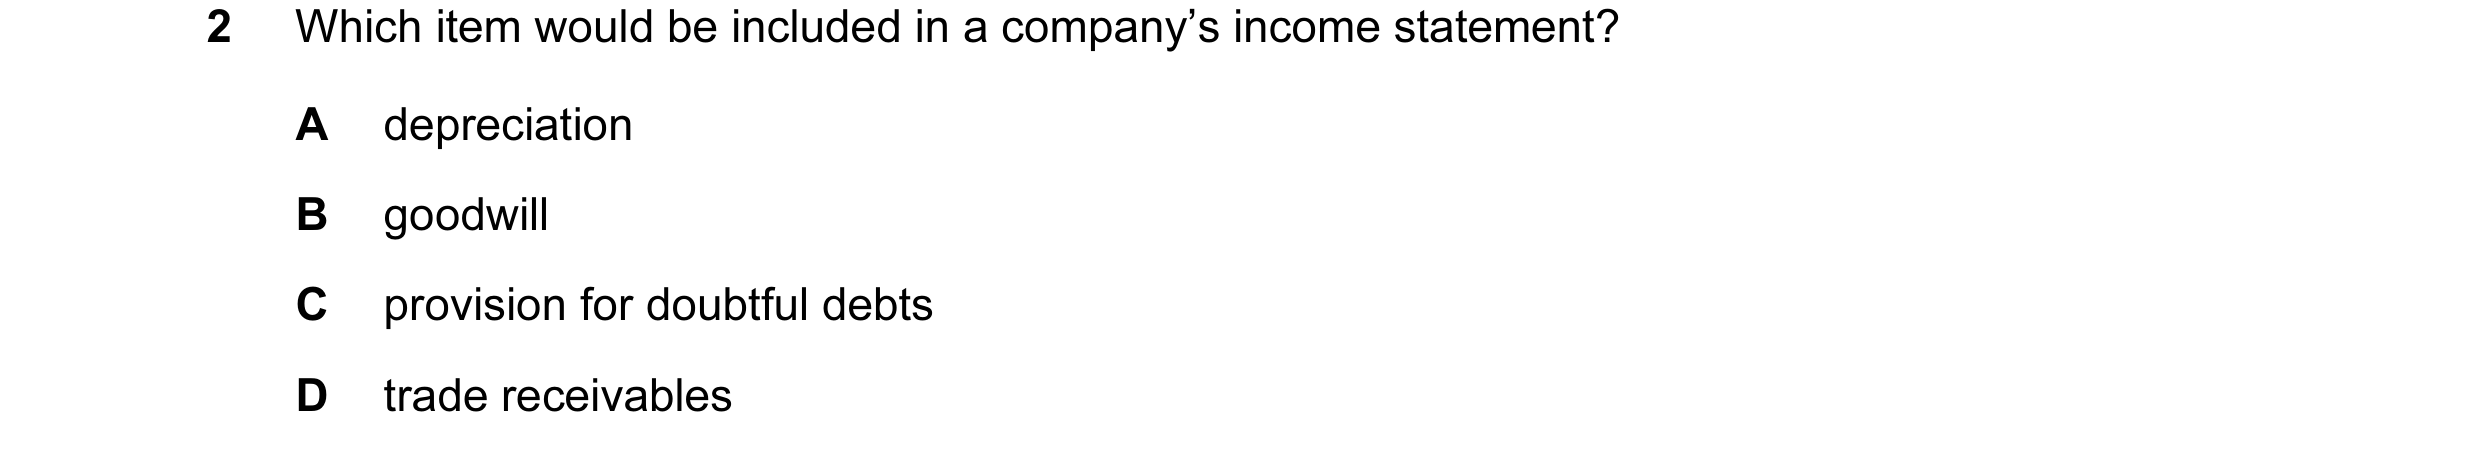
2 Which item would be included in a company’s income statement? A depreciation B goodwill C provision for doubtful debts D trade receivables
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2013
Q35 · The following information is included in a company’s financial statement 9706/31 Oct/Nov 2013
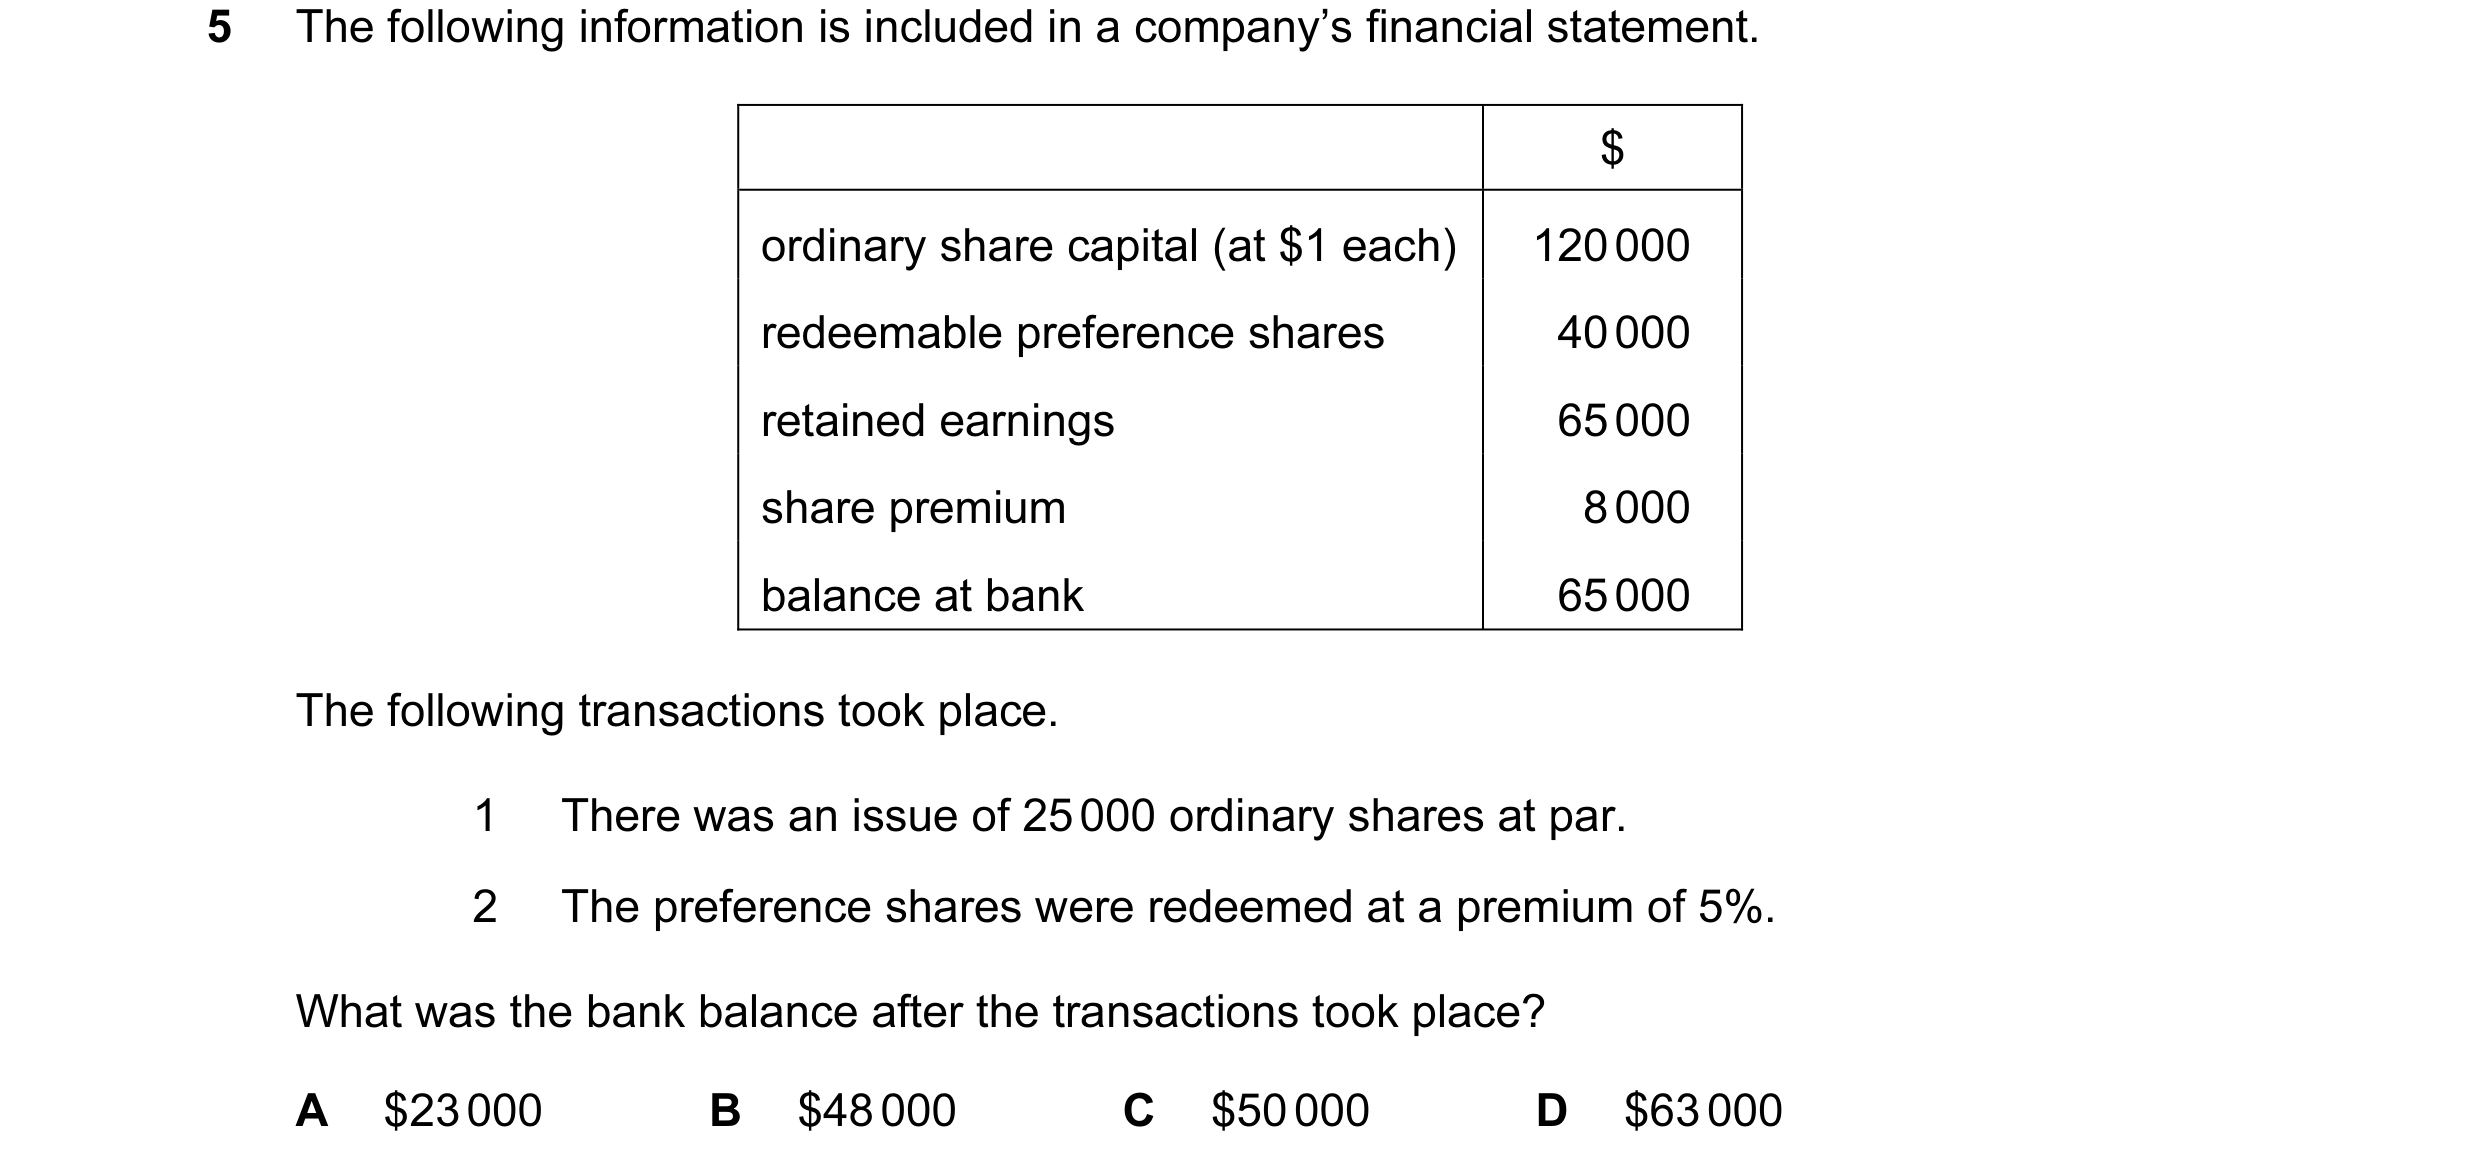
5 The following information is included in a company’s financial statement. $ ordinary share capital (at $1 each) 120 000 redeemable preference shares 40 000 retained earnings 65 000 share premium 8 000 balance at bank 65 000 The following transactions took place. 1 There was an issue of 25 000 ordinary shares at par. 2 The preference shares were redeemed at a premium of 5%. What was the bank balance after the transactions took place? A $23 000 B $48 000 C $50 000 D $63 000
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2013
Q36 · A company’s statement of financial position at 1 January included the following 9706/31 Oct/Nov 2013
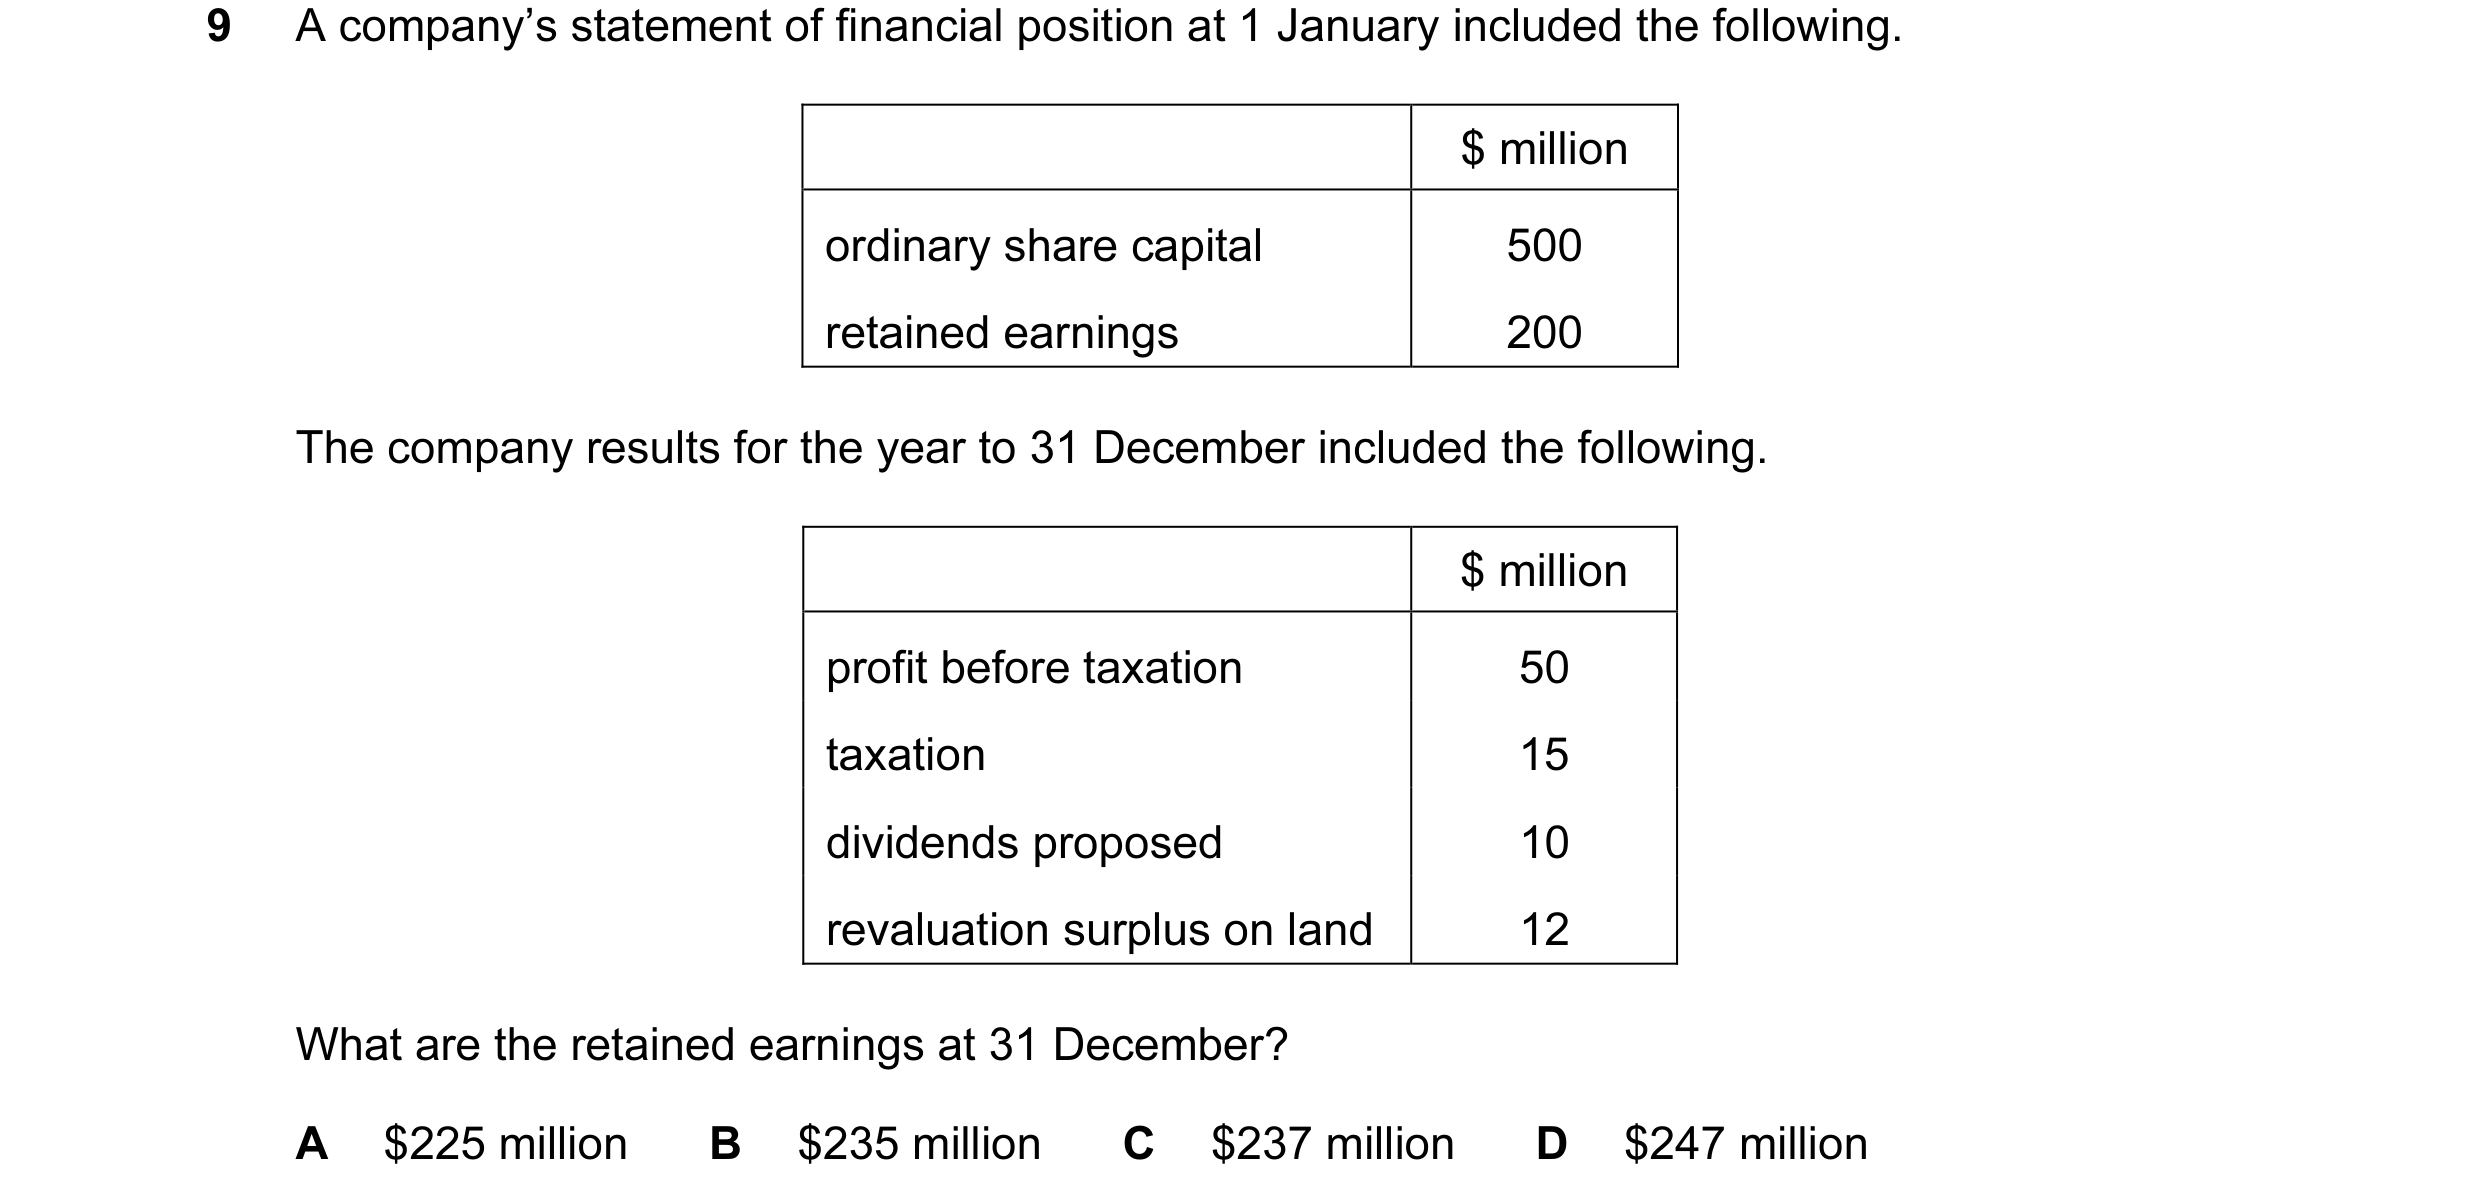
9 A company’s statement of financial position at 1 January included the following. $ million ordinary share capital 500 retained earnings 200 The company results for the year to 31 December included the following. $ million profit before taxation 50 taxation 15 dividends proposed 10 revaluation surplus on land 12 What are the retained earnings at 31 December? A $225 million B $235 million C $237 million D $247 million
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2013
Q37 · Which items will be shown in the statement of changes in equity? 9706/31 Oct/Nov 2013
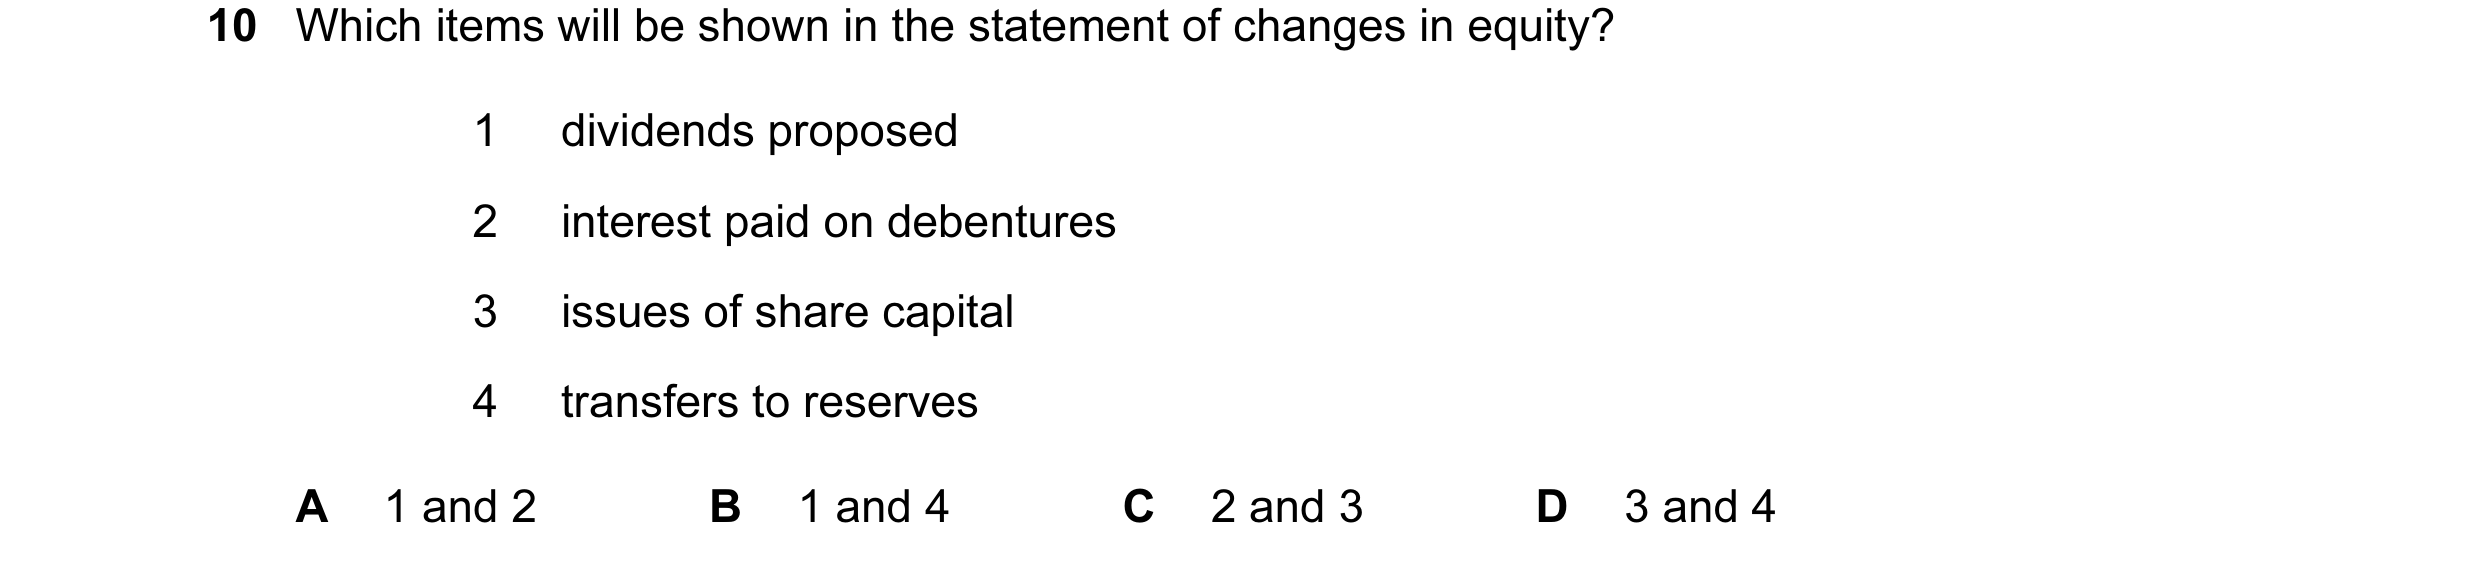
10 Which items will be shown in the statement of changes in equity? 1 dividends proposed 2 interest paid on debentures 3 issues of share capital 4 transfers to reserves A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2013
Q38 · At the year end a company had total net assets of $230 000 9706/31 Oct/Nov 2013
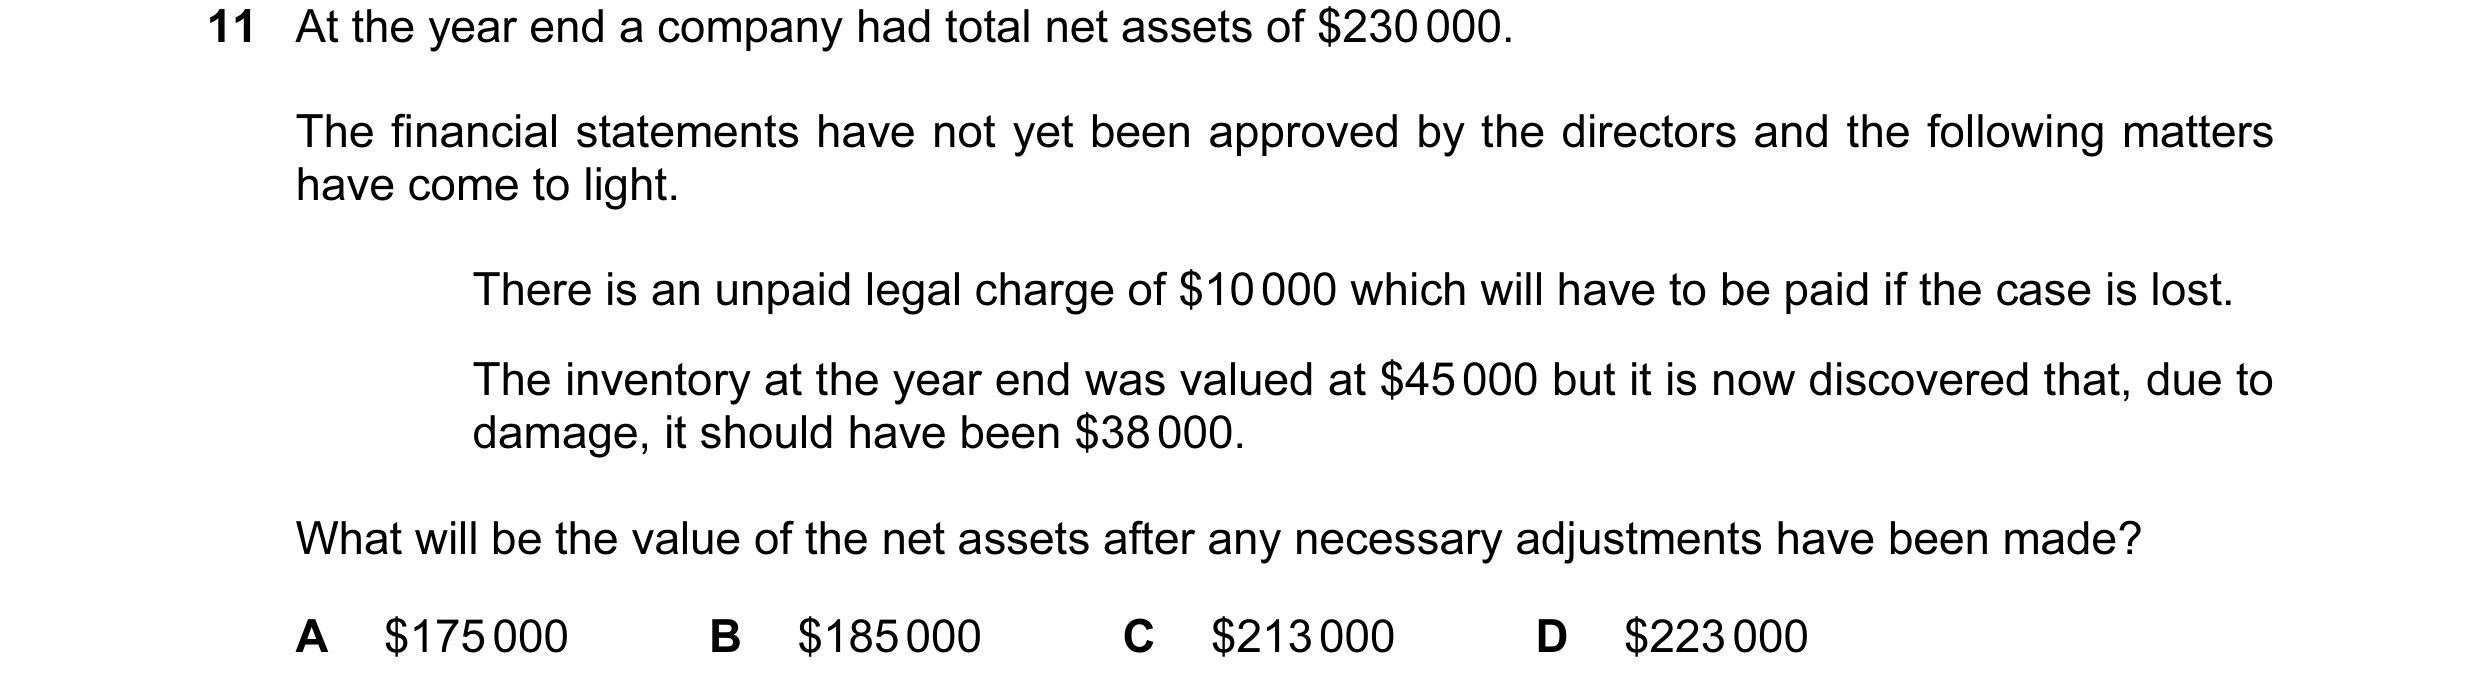
11 At the year end a company had total net assets of $230 000. The financial statements have not yet been approved by the directors and the following matters have come to light. There is an unpaid legal charge of $10 000 which will have to be paid if the case is lost. The inventory at the year end was valued at $45 000 but it is now discovered that, due to damage, it should have been $38 000. What will be the value of the net assets after any necessary adjustments have been made? A $175 000 B $185 000 C $213 000 D $223 000
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2013
Q39 · A company values its work in progress and finished goods in the way set out by IAS2 9706/31 Oct/Nov 2013
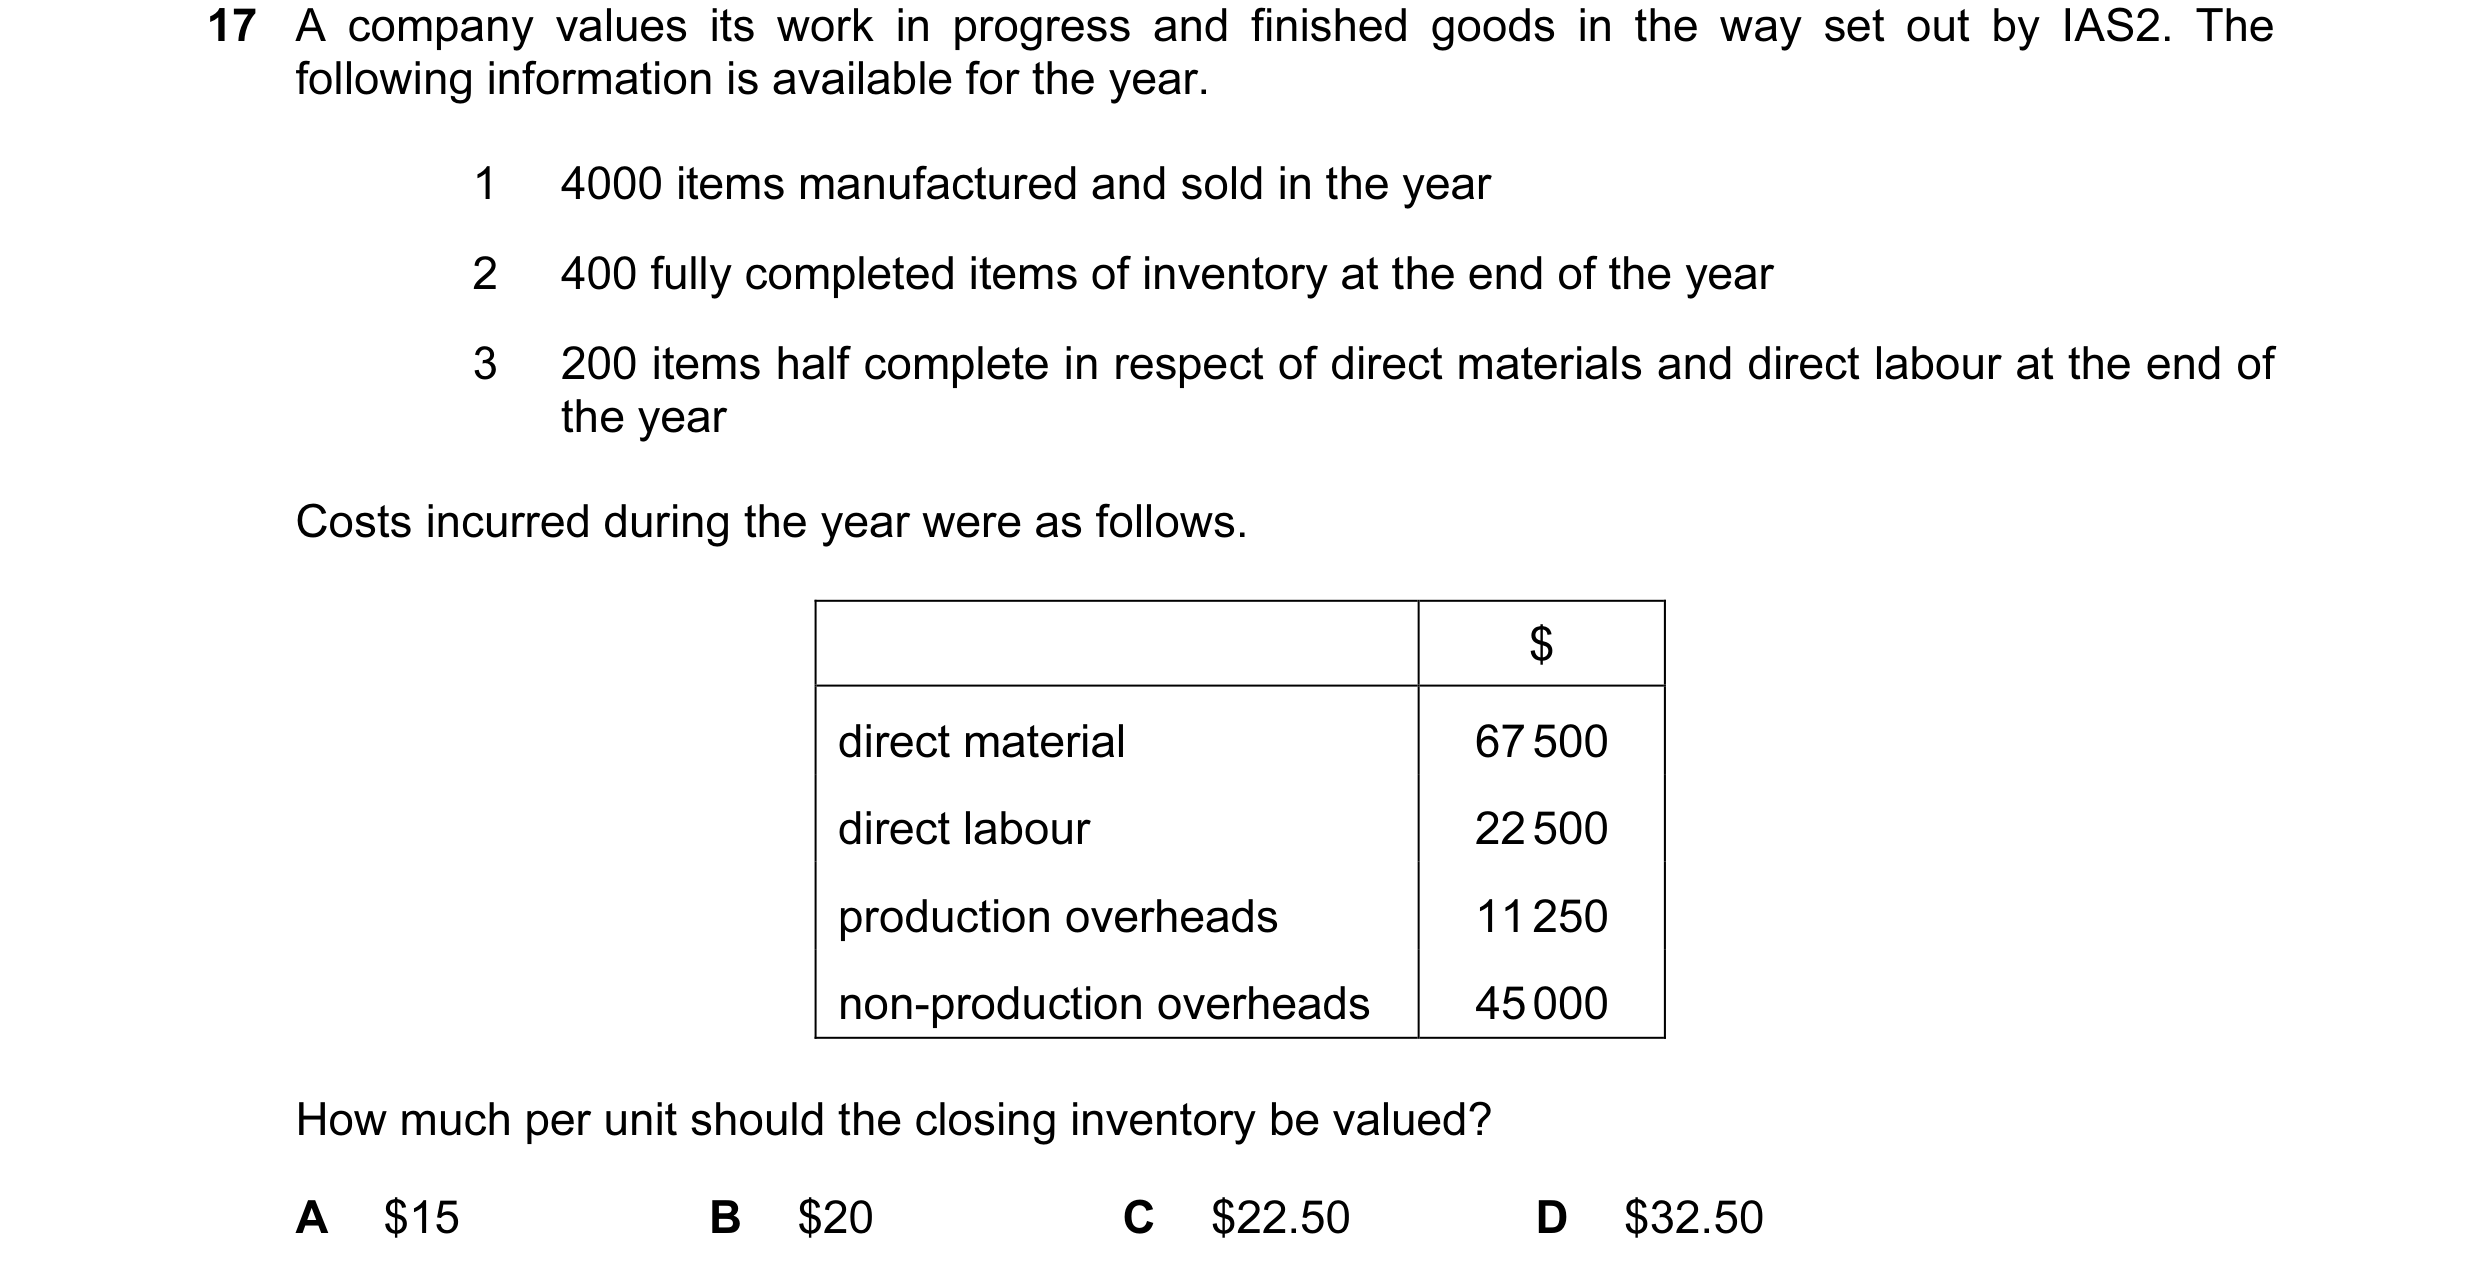
17 A company values its work in progress and finished goods in the way set out by IAS2. The following information is available for the year. 1 4000 items manufactured and sold in the year 2 400 fully completed items of inventory at the end of the year 3 200 items half complete in respect of direct materials and direct labour at the end of the year Costs incurred during the year were as follows. $ direct material 67 500 direct labour 22 500 production overheads 11 250 non-production overheads 45 000 How much per unit should the closing inventory be valued? A $15 B $20 C $22.50 D $32.50
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2013
Q40 · The equity section of the statement of financial position of a company at 1 May 2013 is… 9706/31 Oct/Nov 2013
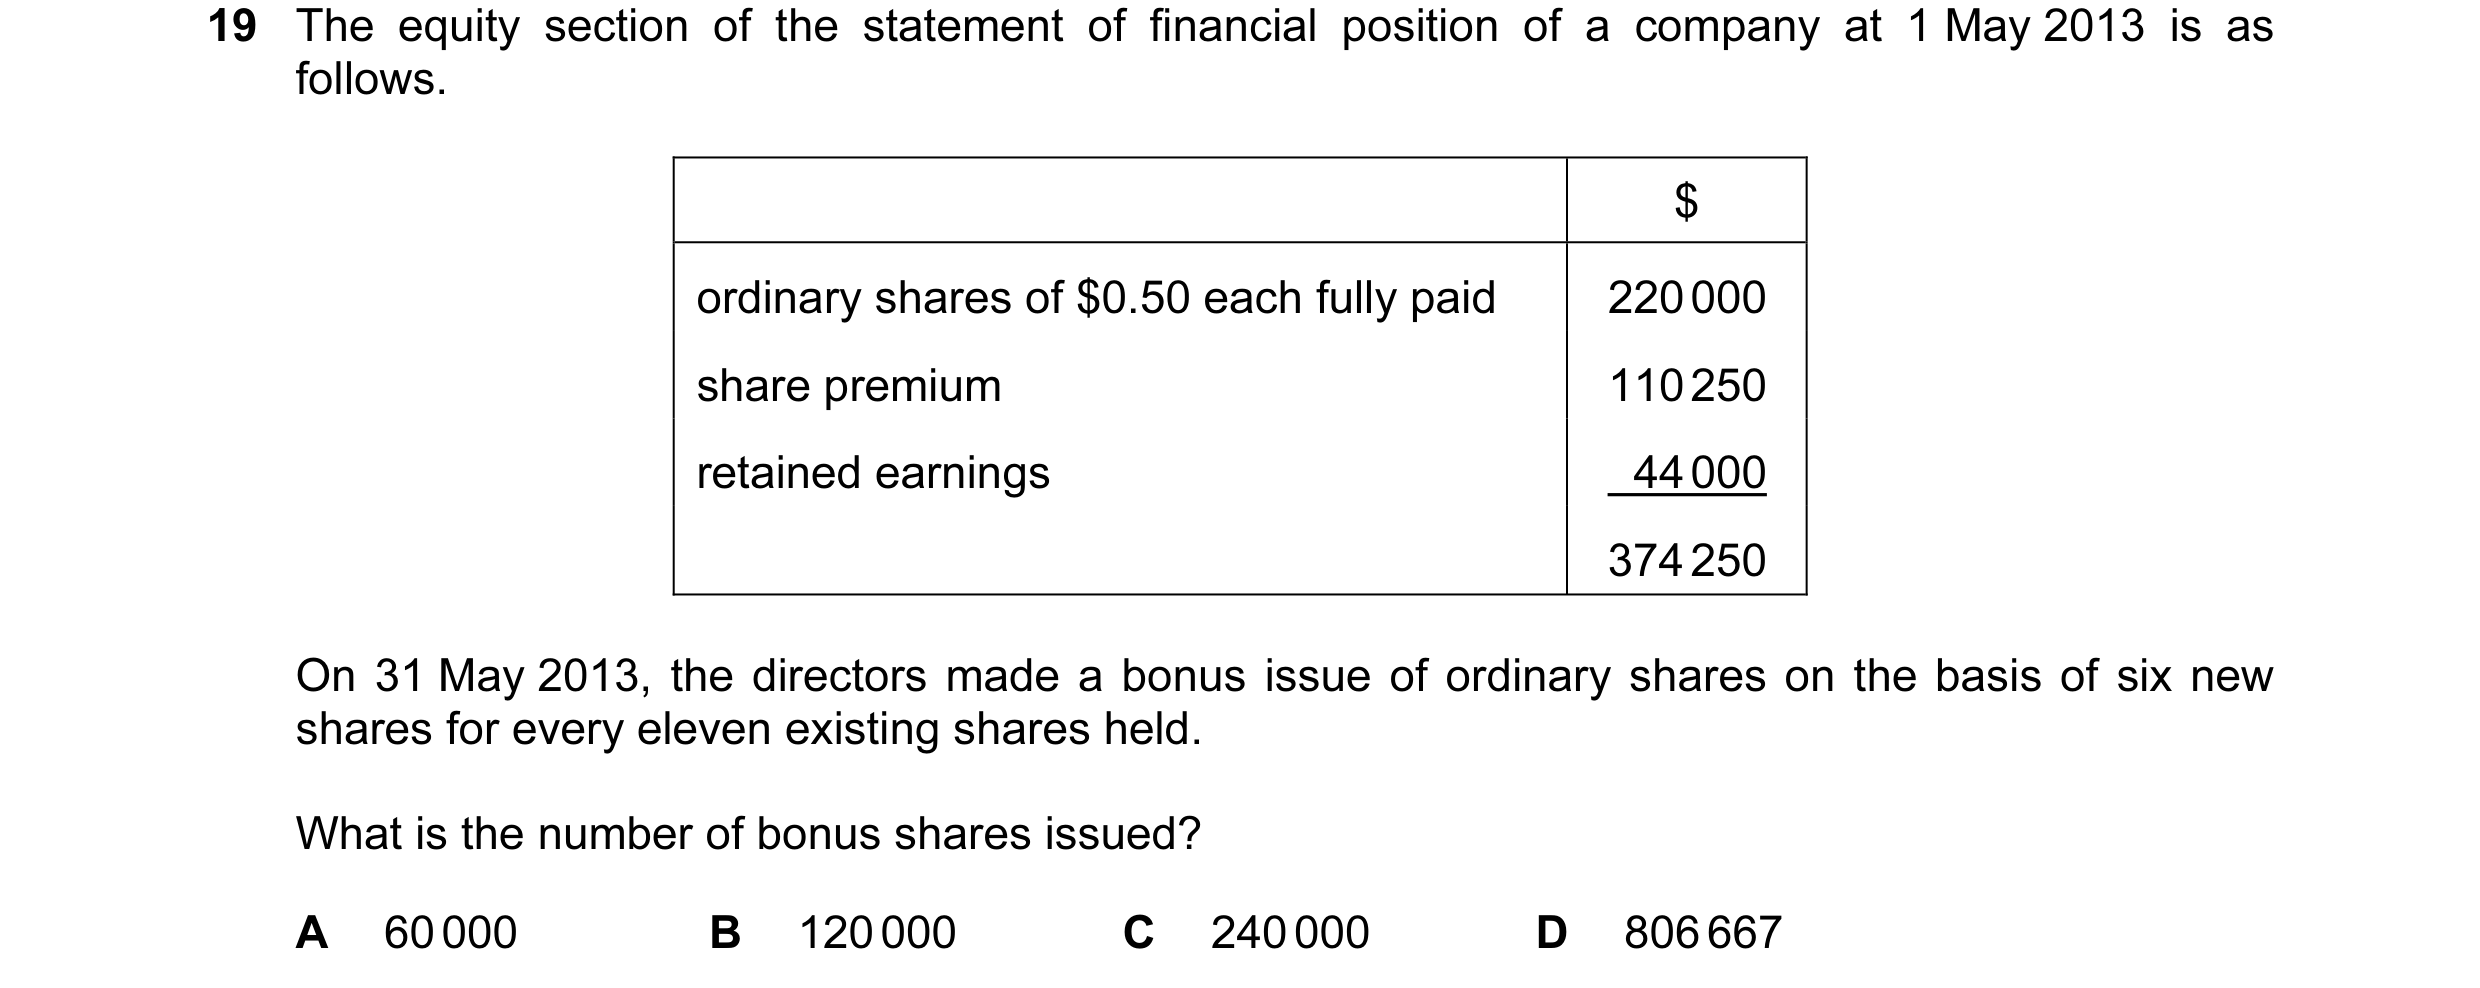
19 The equity section of the statement of financial position of a company at 1 May 2013 is as follows. $ ordinary shares of $0.50 each fully paid 220 000 share premium 110 250 retained earnings 44 000 374 250 On 31 May 2013, the directors made a bonus issue of ordinary shares on the basis of six new shares for every eleven existing shares held. What is the number of bonus shares issued? A 60 000 B 120 000 C 240 000 D 806 667
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2013
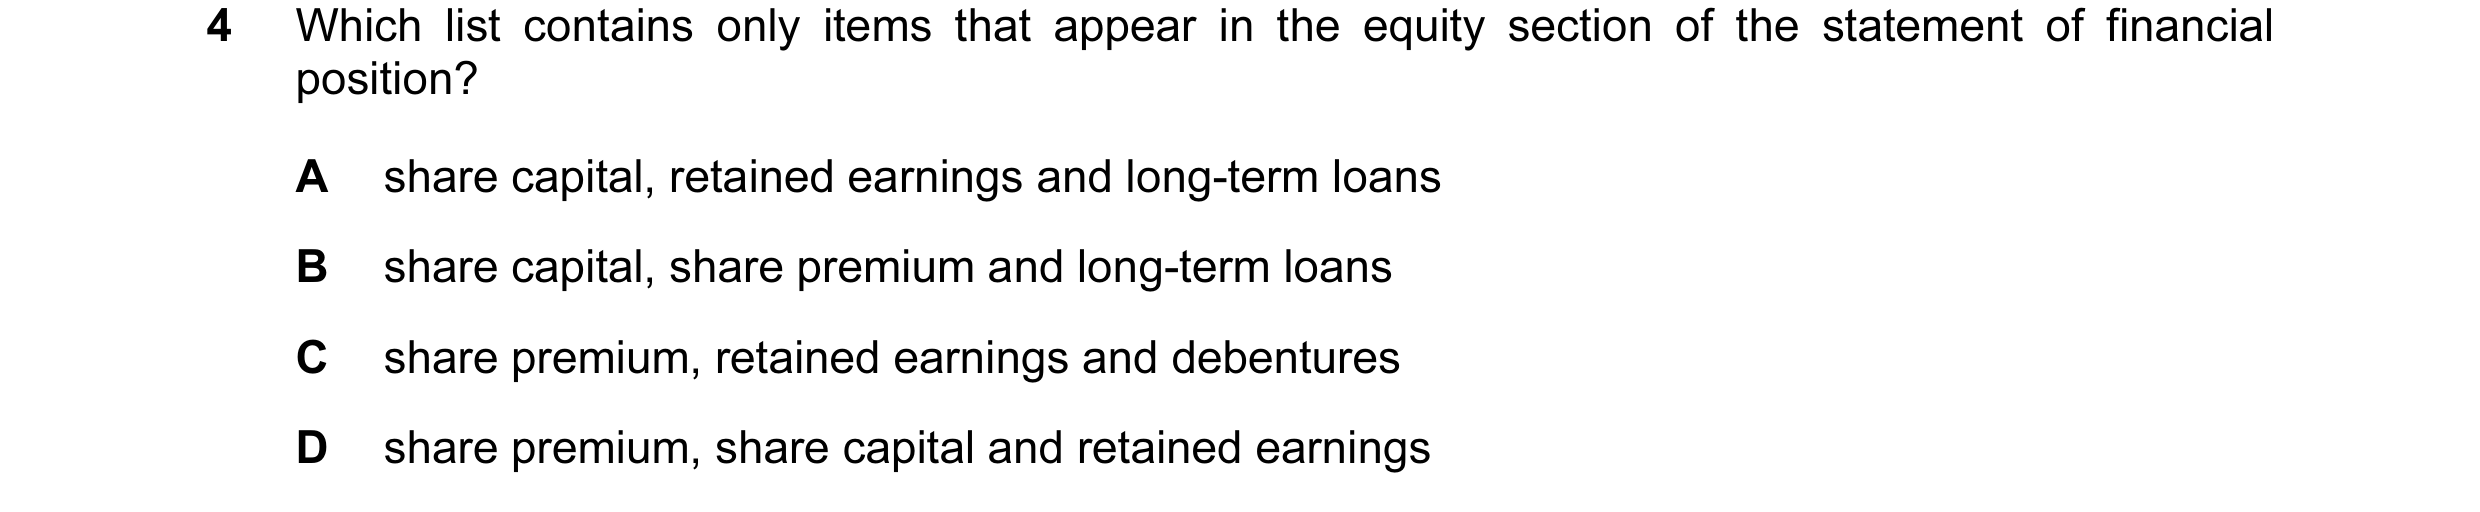
Q41 · Which list contains only items that appear in the equity section of the statement of… 9706/32 Oct/Nov 2013
4 Which list contains only items that appear in the equity section of the statement of financial position? A share capital, retained earnings and long-term loans B share capital, share premium and long-term loans C share premium, retained earnings and debentures D share premium, share capital and retained earnings
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2013
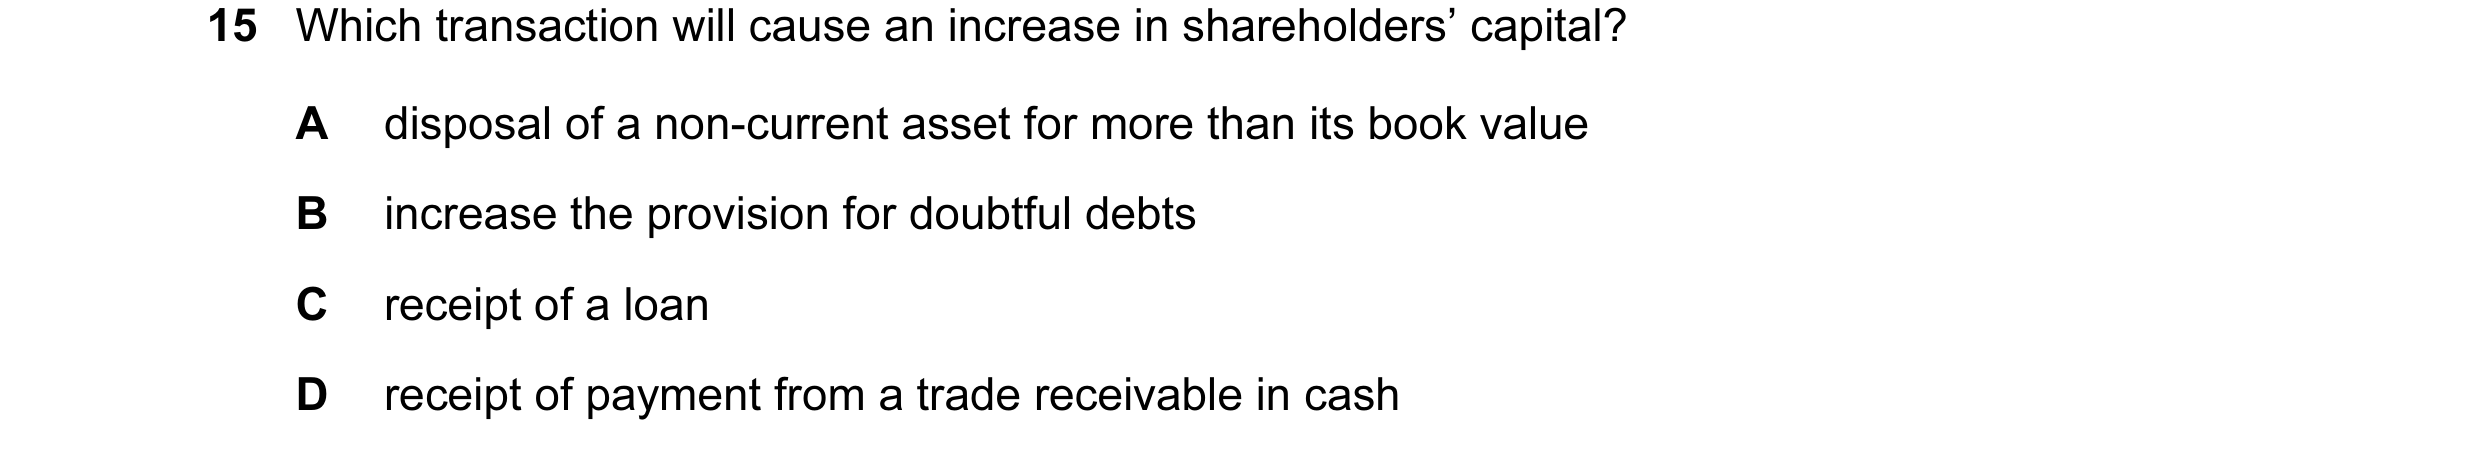
Q42 · Which transaction will cause an increase in shareholders’ capital? 9706/32 Oct/Nov 2013
15 Which transaction will cause an increase in shareholders’ capital? A disposal of a non-current asset for more than its book value B increase the provision for doubtful debts C receipt of a loan D receipt of payment from a trade receivable in cash
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2013
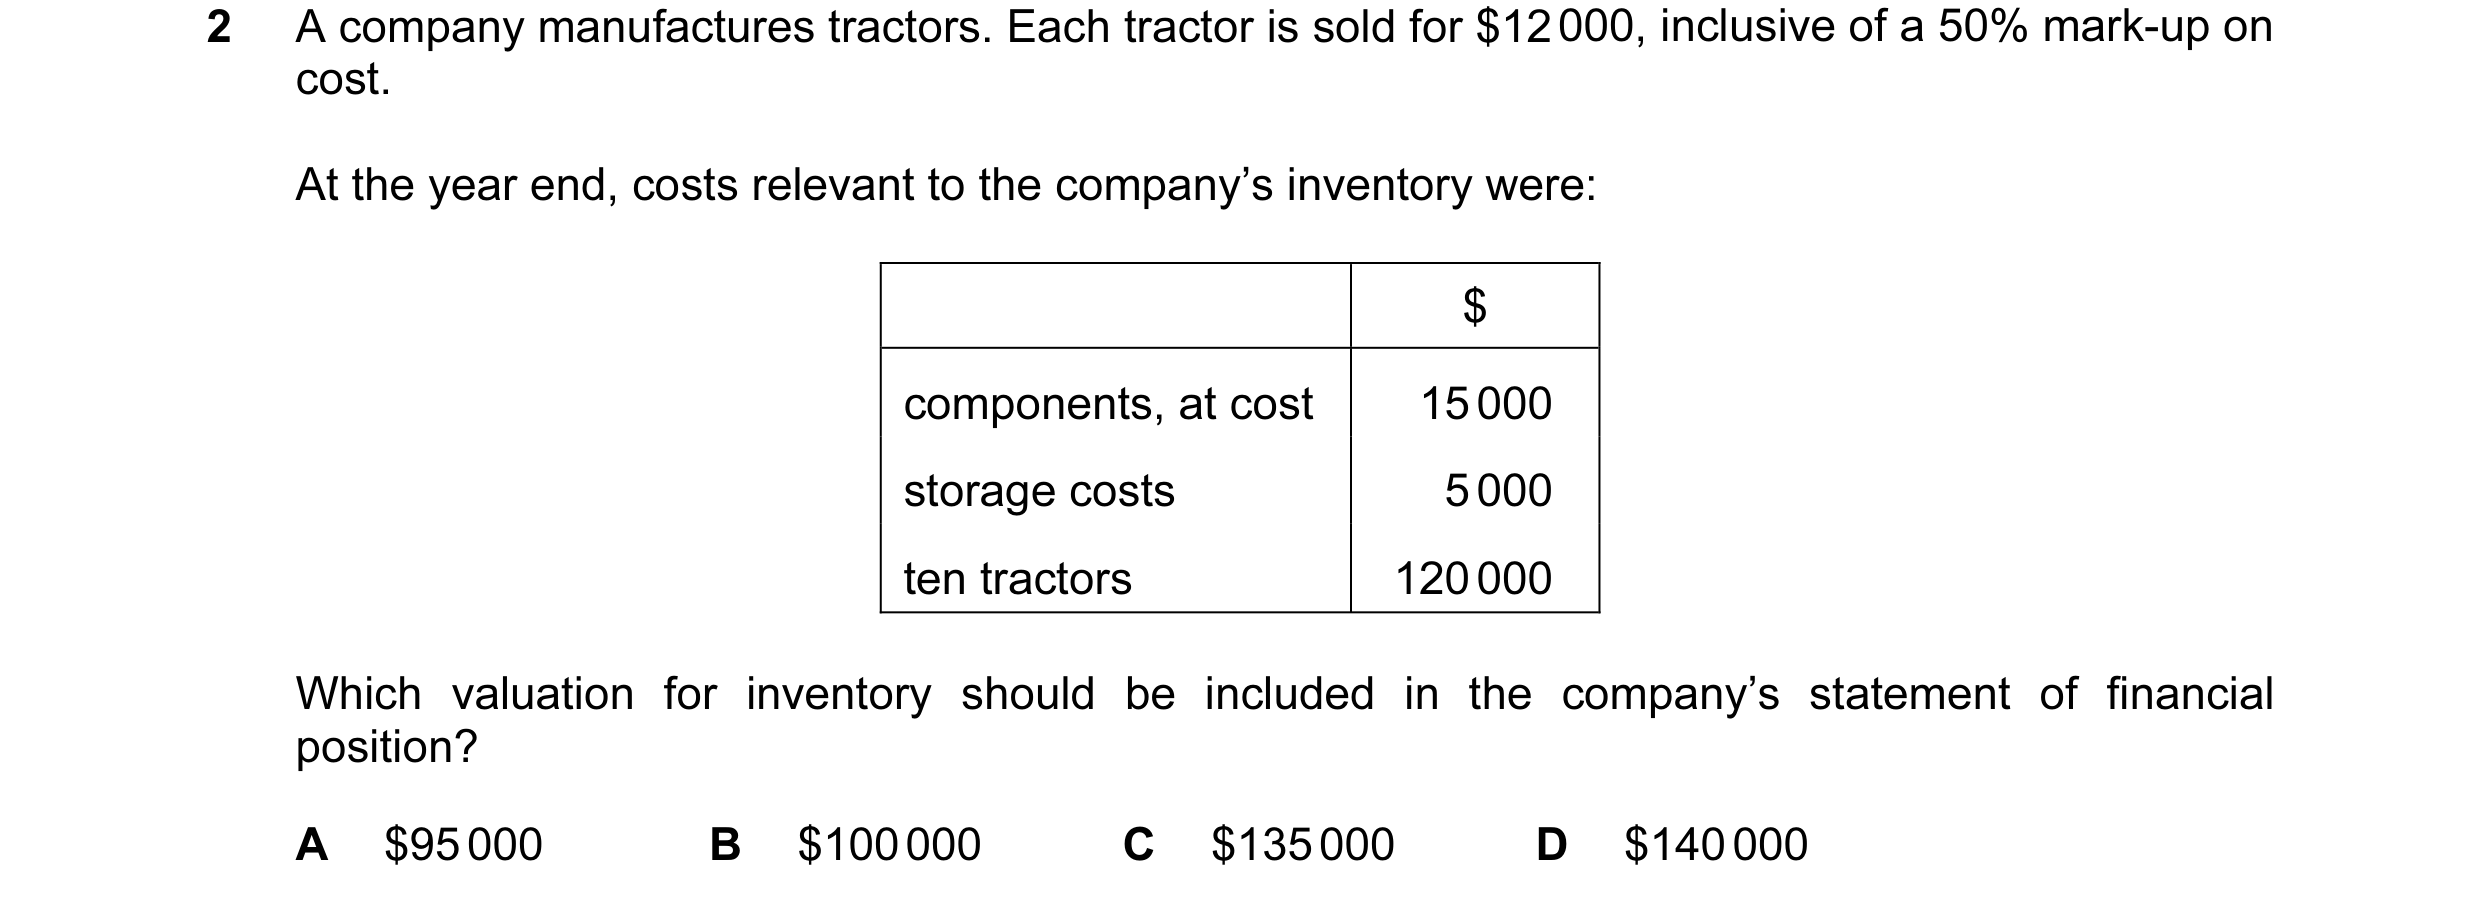
Q43 · A company manufactures tractors 9706/33 Oct/Nov 2013
2 A company manufactures tractors. Each tractor is sold for $12 000, inclusive of a 50% mark-up on cost. At the year end, costs relevant to the company’s inventory were: $ components, at cost 15 000 storage costs 5 000 ten tractors 120 000 Which valuation for inventory should be included in the company’s statement of financial position? A $95 000 B $100 000 C $135 000 D $140 000
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2013
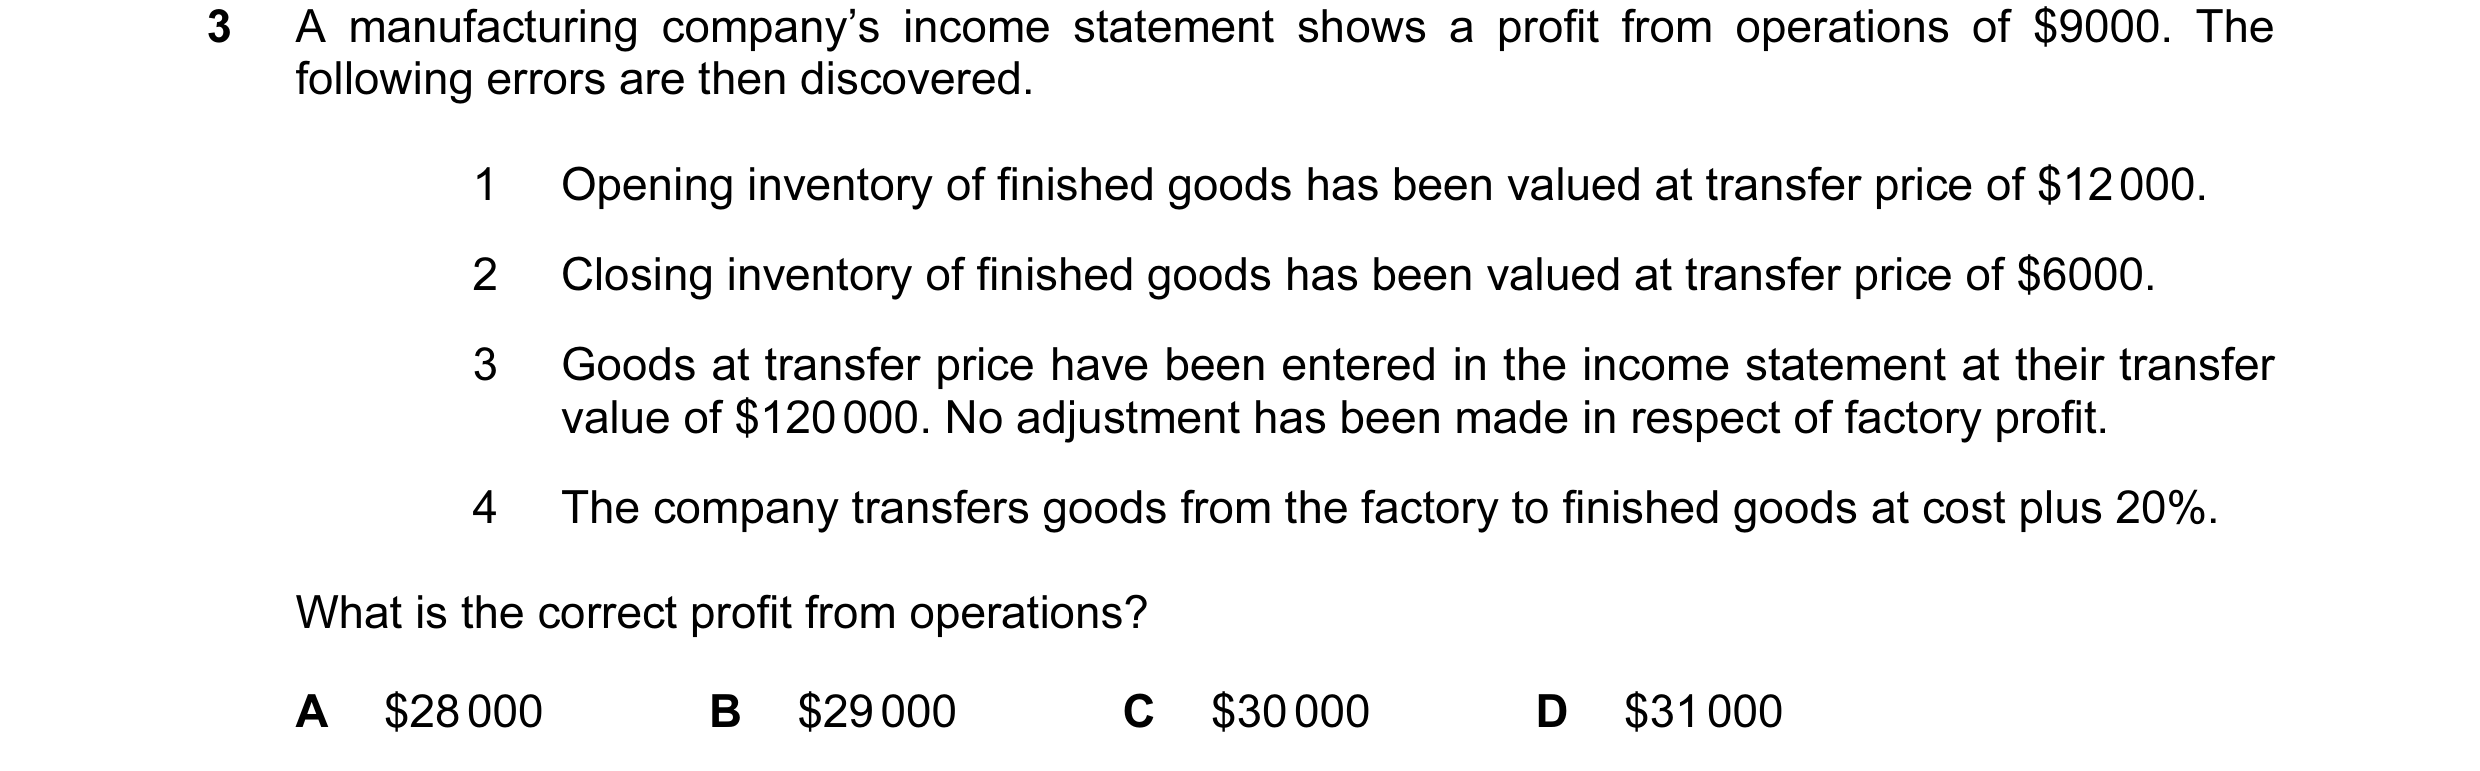
Q44 · A manufacturing company’s income statement shows a profit from operations of $9000 9706/33 Oct/Nov 2013
3 A manufacturing company’s income statement shows a profit from operations of $9000. The following errors are then discovered. 1 Opening inventory of finished goods has been valued at transfer price of $12 000. 2 Closing inventory of finished goods has been valued at transfer price of $6000. 3 Goods at transfer price have been entered in the income statement at their transfer value of $120 000. No adjustment has been made in respect of factory profit. 4 The company transfers goods from the factory to finished goods at cost plus 20%. What is the correct profit from operations? A $28 000 B $29 000 C $30 000 D $31 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2013
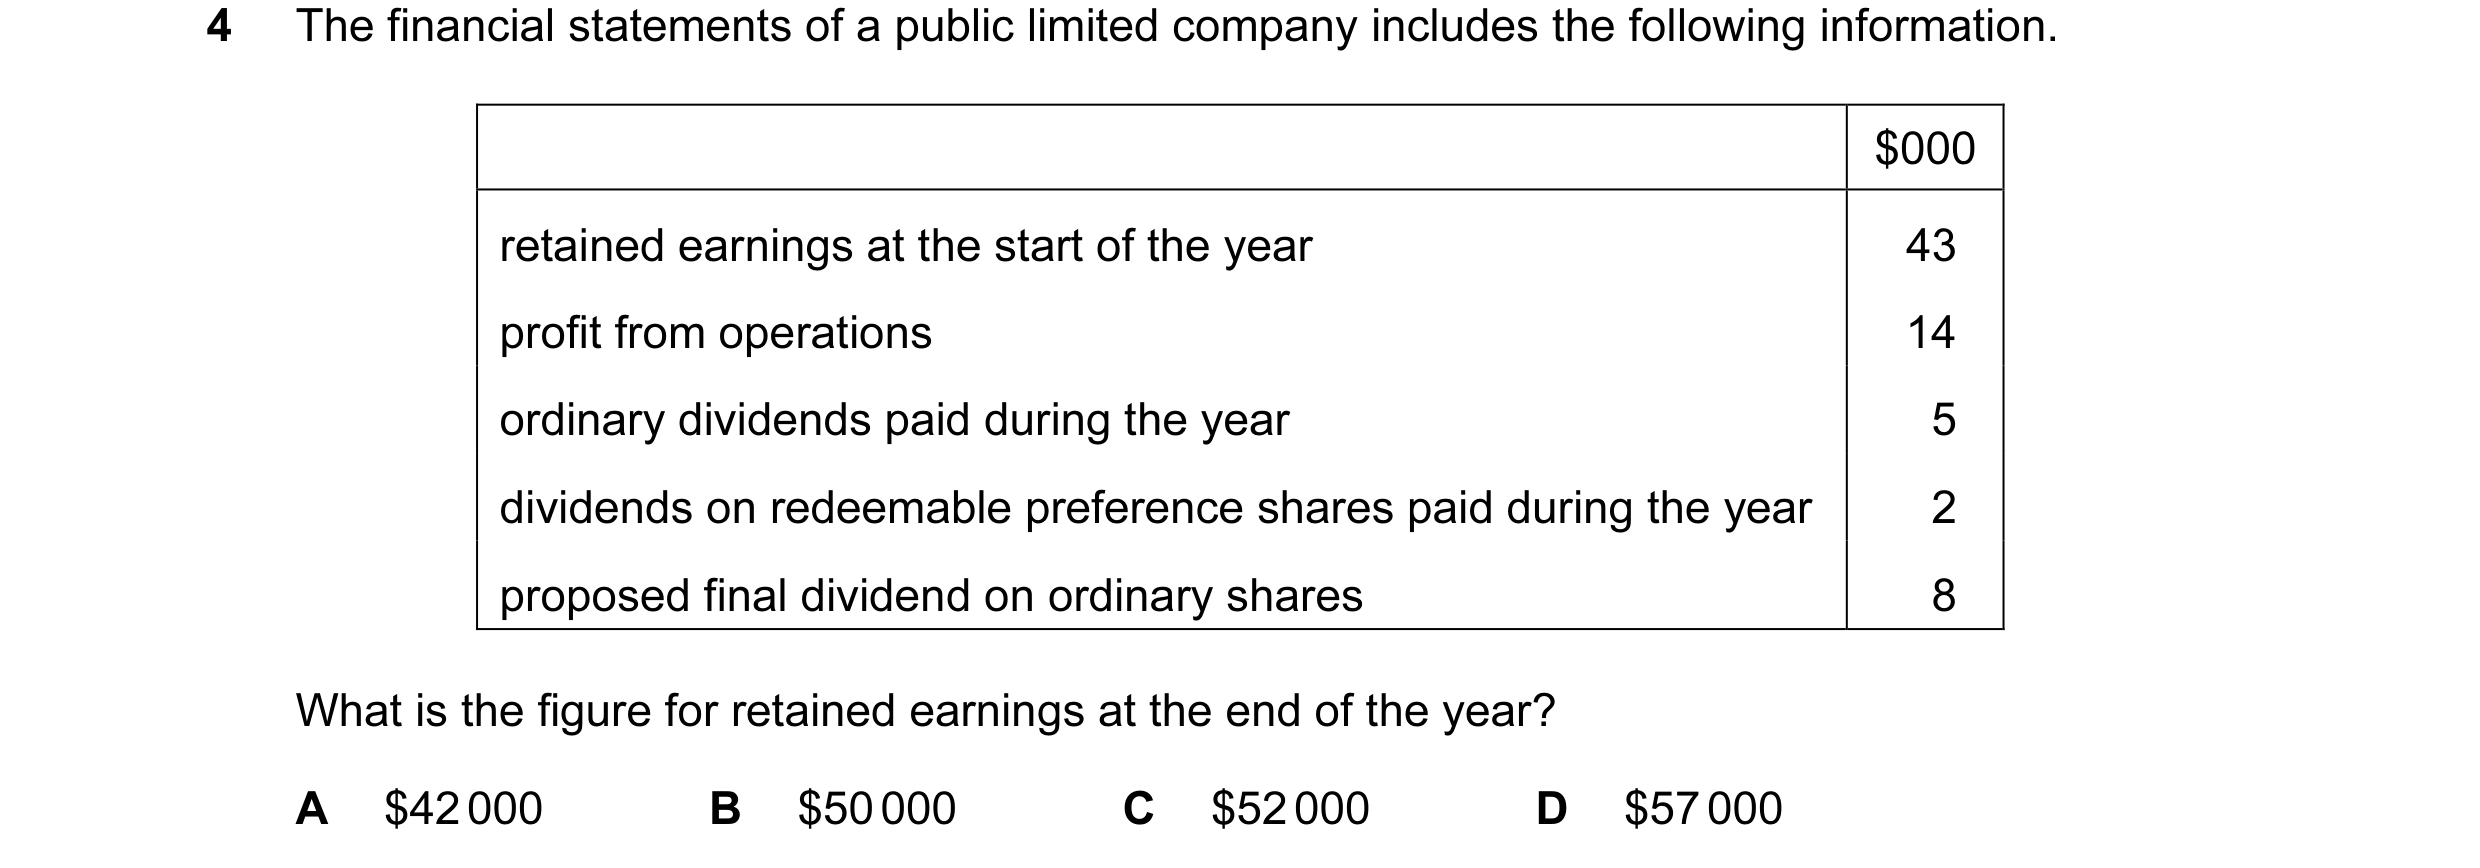
Q45 · The financial statements of a public limited company includes the following information 9706/33 Oct/Nov 2013
4 The financial statements of a public limited company includes the following information. $000 retained earnings at the start of the year 43 profit from operations 14 ordinary dividends paid during the year 5 dividends on redeemable preference shares paid during the year 2 proposed final dividend on ordinary shares 8 What is the figure for retained earnings at the end of the year? A $42 000 B $50 000 C $52 000 D $57 000
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2013
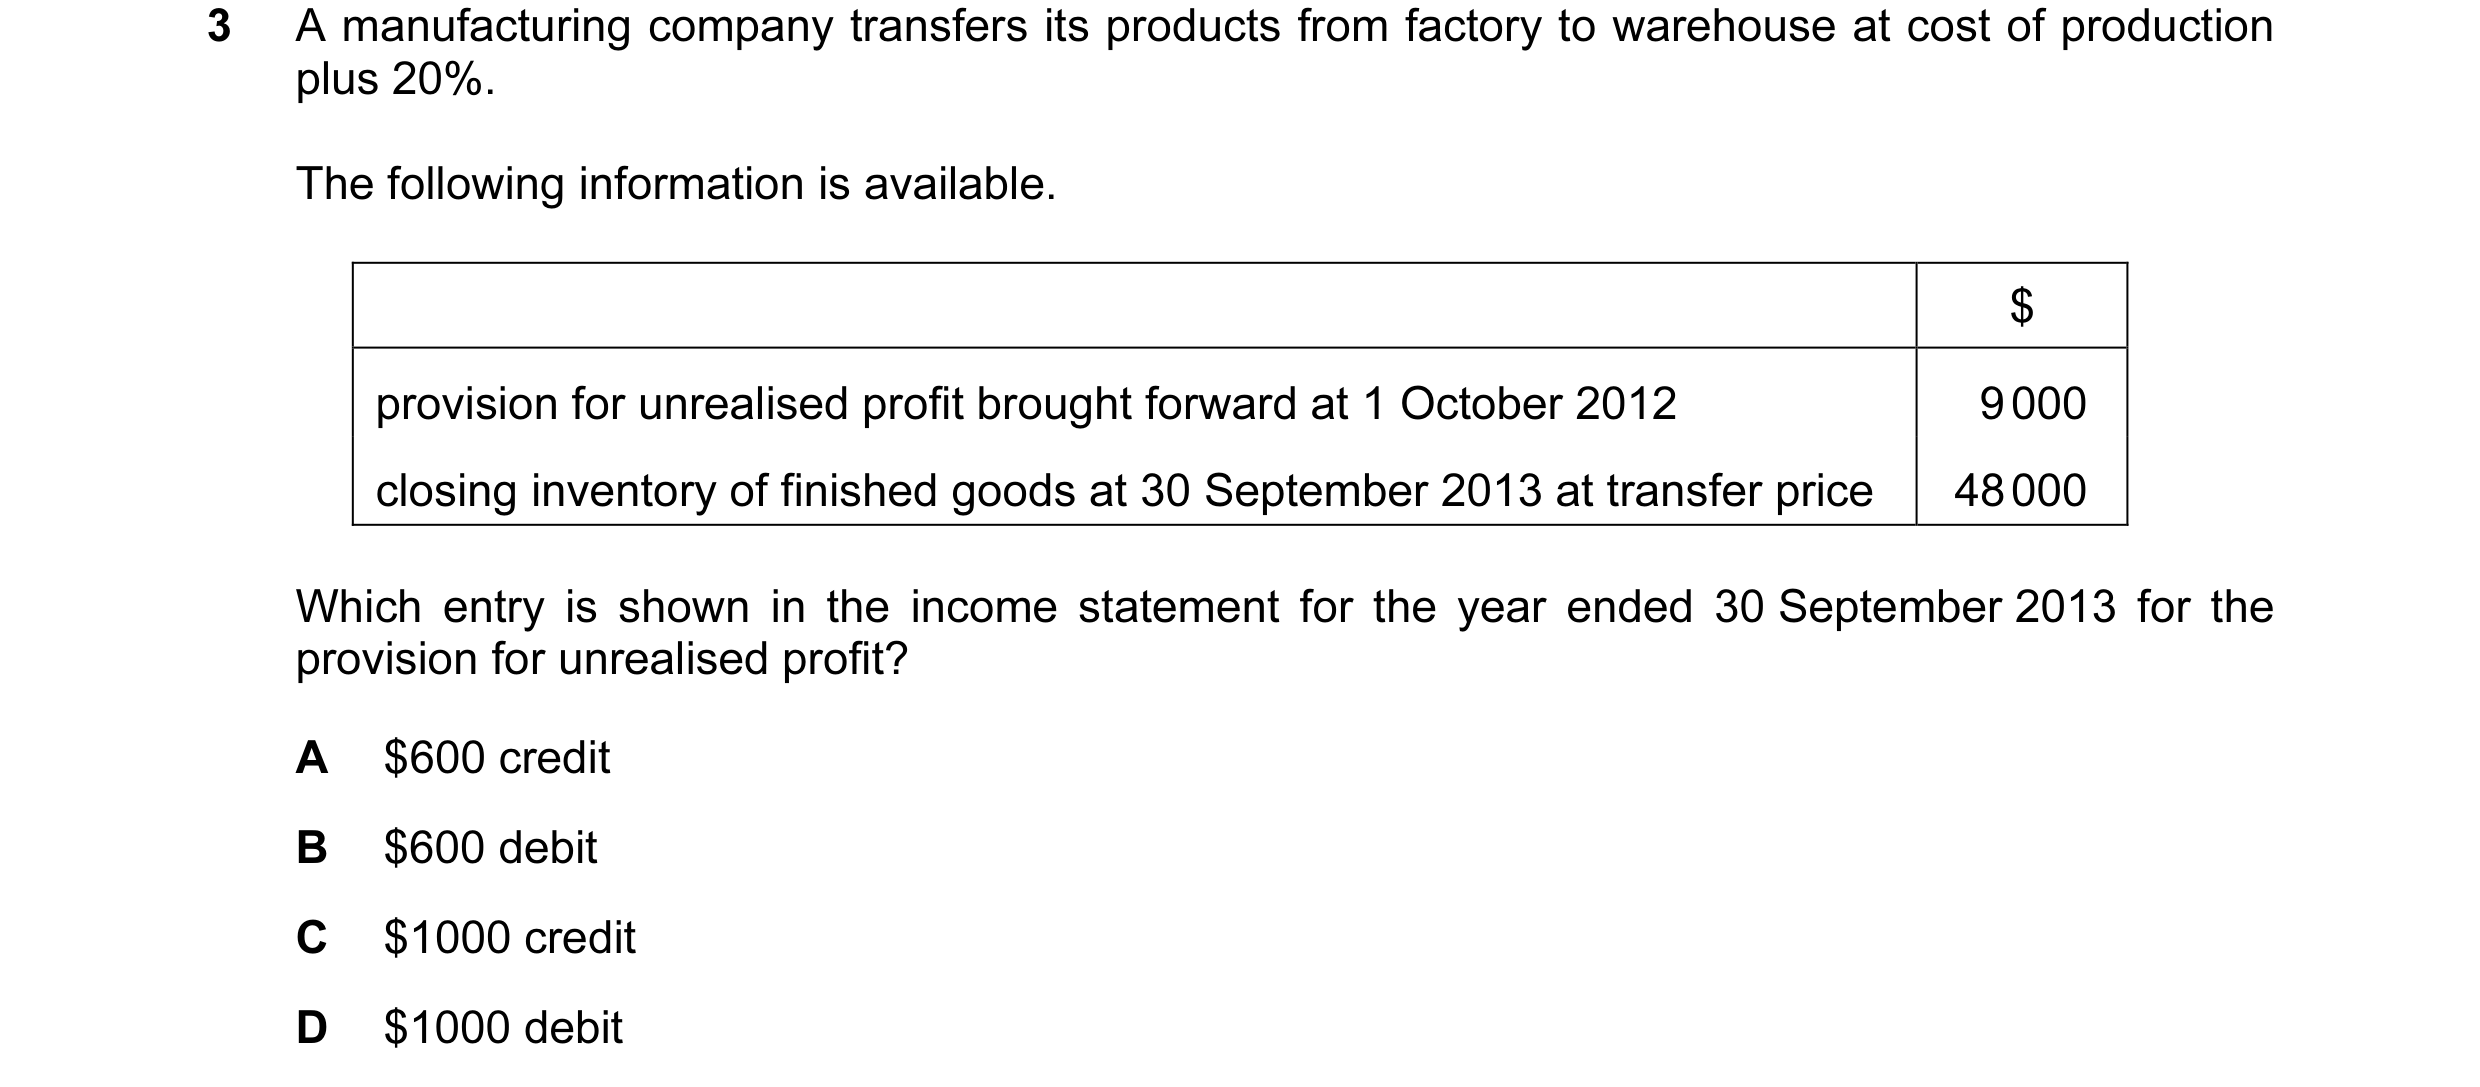
Q46 · A manufacturing company transfers its products from factory to warehouse at cost of… 9706/33 May/June 2014
3 A manufacturing company transfers its products from factory to warehouse at cost of production plus 20%. The following information is available. $ provision for unrealised profit brought forward at 1 October 2012 9 000 closing inventory of finished goods at 30 September 2013 at transfer price 48 000 Which entry is shown in the income statement for the year ended 30 September 2013 for the provision for unrealised profit? A $600 credit B $600 debit C $1000 credit D $1000 debit
1 marks
Answer: C
This question in 9706/33 May/June 2014
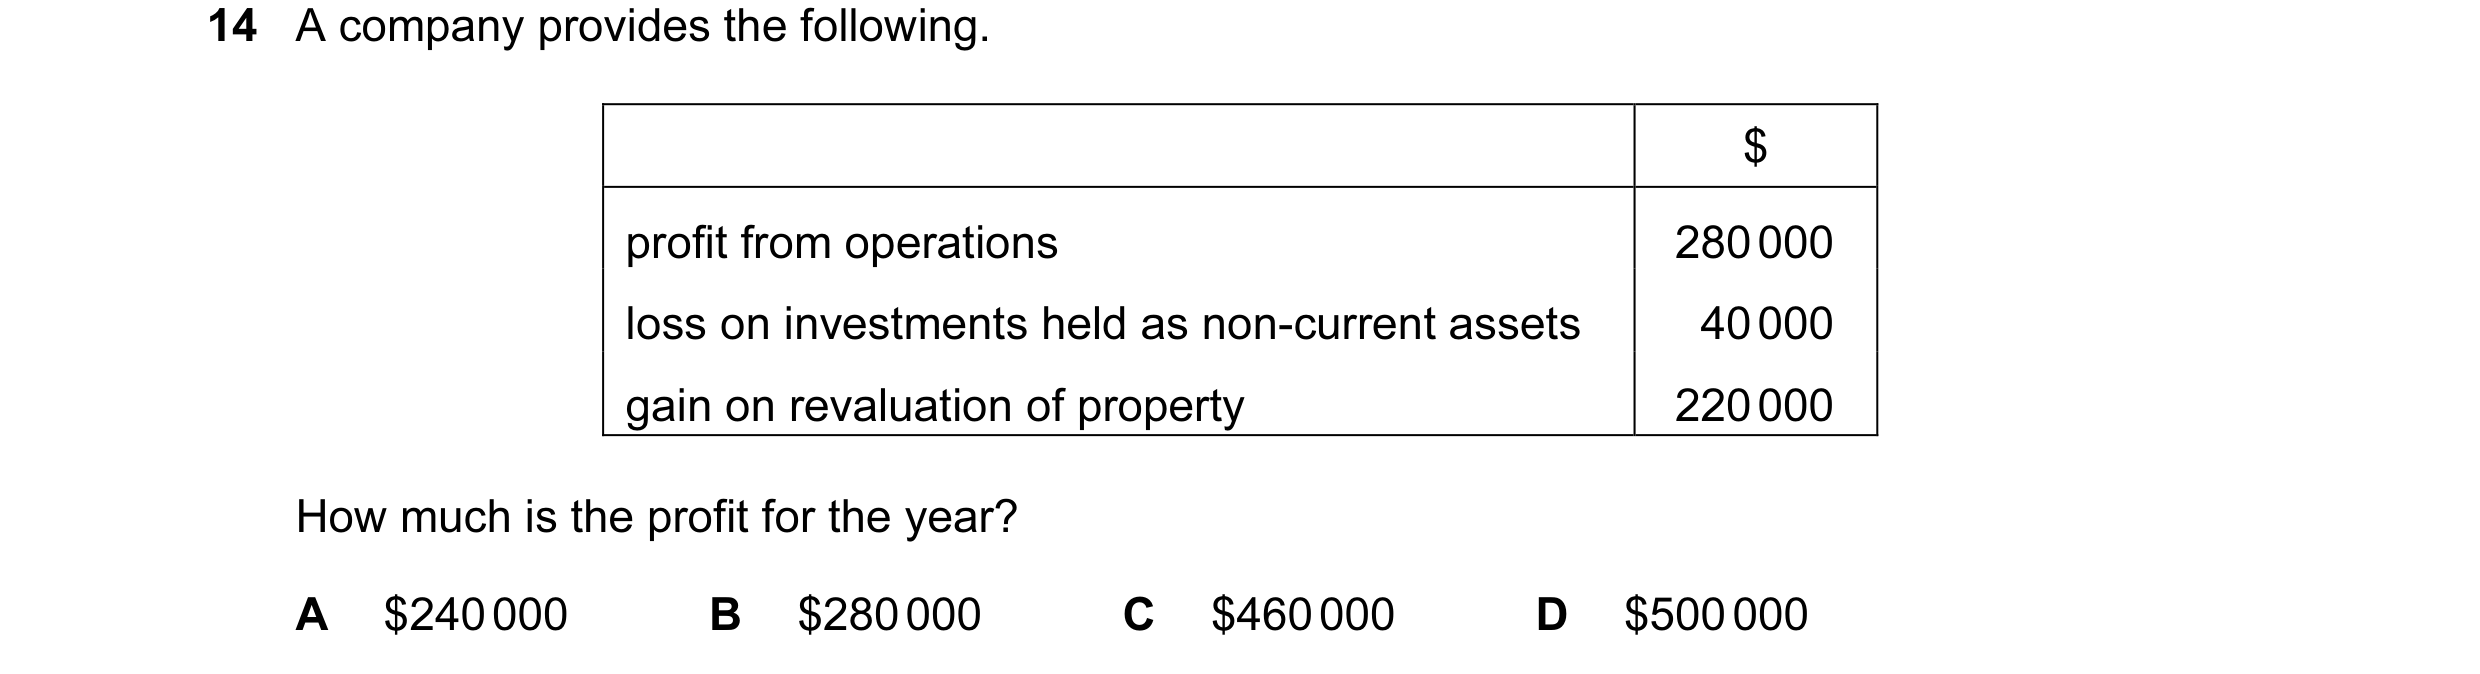
Q47 · A company provides the following 9706/33 May/June 2014
14 A company provides the following. $ profit from operations 280 000 loss on investments held as non-current assets 40 000 gain on revaluation of property 220 000 How much is the profit for the year? A $240 000 B $280 000 C $460 000 D $500 000
1 marks
Answer: A
This question in 9706/33 May/June 2014
 1 / 15
 2 / 15
 3 / 15
 4 / 15
 5 / 15
 6 / 15
 7 / 15
 8 / 15
 9 / 15
 10 / 15
 11 / 15
 12 / 15
 13 / 15
 14 / 15
 15 / 15