Questions as text
Q1 · What would not appear in a Sales Ledger Control account? 9706/11 May/June 2006
9 What would not appear in a Sales Ledger Control account? A cash received from customers B discounts allowed C discounts received D returns inwards
1 marks
Answer: C
This question in 9706/11 May/June 2006
Q2 · A sole trader has calculated a draft net profit of $56 750 9706/11 May/June 2006
10 A sole trader has calculated a draft net profit of $56 750. He then discovers the following mistakes: Discounts Received of $580 and Discounts Allowed of $665 have been recorded on the wrong sides of the Discounts Received and Allowed accounts. What is the corrected draft net profit? A $56 580 B $56 665 C $56 835 D $56 920
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q3 · The closing balance on a Purchases Ledger Control account is $163 762 9706/11 May/June 2006
11 The closing balance on a Purchases Ledger Control account is $163 762. The purchase day book (journal) has been undercast by $1000. What should be the correct closing balance on the Purchases Ledger Control account? A $162 762 B $163 762 C $164 762 D $165 762
1 marks
Answer: C
This question in 9706/11 May/June 2006
Q4 · A draft Balance Sheet shows a bank balance of $1400 9706/11 May/June 2006
12 A draft Balance Sheet shows a bank balance of $1400. The following information is now available. $ cheques issued but not yet cleared by the bank 150 bank charges not in the cash book 45 lodgements in the cash book but not on the bank statement 220 What is the figure shown on the Bank Statement? A $1285 B $1355 C $1425 D $1515
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q5 · At the beginning of the year a business has a provision for doubtful debts of $2600 9706/11 Oct/Nov 2006
4 At the beginning of the year a business has a provision for doubtful debts of $2600. At the year end the provision is to be 5 % of trade debtors. The balance on the debtors’ control account at the year end is $69 200, before writing off a bad debt of $480. The business operates a separate bad debts account. What is the entry in the Profit and Loss Account for the provision for doubtful debts? A $836 debit B $860 debit C $836 credit D $860 credit
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2006
Q6 · A trial balance fails to agree 9706/11 Oct/Nov 2006
9 A trial balance fails to agree. The debits exceed the credits. Which single error in the general (nominal) ledger would cause the difference? A A contra between the debtors’ and creditors’ ledgers has been entered on the credit side of both control accounts. B A rental receipt has been entered twice in the rent receivable account. C The closing stock at the end of the previous period has not been entered in the stock account. D The opening electricity accrual has been brought forward on the wrong side of the ledger account.
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2006
Q7 · A cheque for payment of wages of $214 has been debited to the purchases account as $241 9706/11 Oct/Nov 2006
10 A cheque for payment of wages of $214 has been debited to the purchases account as $241. A suspense account is created. What are the correcting entries? account to account to $ $ be debited be credited A purchases 214 wages 241 suspense 27 B wages 214 suspense 214 C wages 214 purchases 241 suspense 27 D purchases 241 wages 241 suspense 27
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2006
Q8 · A bank statement shows a credit balance of $8360 9706/11 Oct/Nov 2006
11 A bank statement shows a credit balance of $8360. Comparison with the cash book reveals: • Cheques totalling $18 725, sent to suppliers, have not been presented. • Cheques totalling $16 223, received from customers, have not been credited by the bank. • Bank charges of $124 have not been entered in the cash book. What is the correct cash book balance? A $5734 credit B $5734 debit C $5858 debit D $10 986 credit
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2006
Q9 · The balance on a sales ledger control account is $40 000 9706/11 Oct/Nov 2006
12 The balance on a sales ledger control account is $40 000. The following items are then discovered: $ total of sales day book understated 500 discounts allowed not entered in sales ledger control account 1 200 bad debts written off not recorded in sales ledger control account 400 provision for doubtful debts 2 500 What is the total of the balances in the sales ledger? A $37 900 B $38 600 C $38 900 D $41 100
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2006
Q10 · A business owner suspects a loss of cash has occurred 9706/11 Oct/Nov 2006
14 A business owner suspects a loss of cash has occurred. He provides the data shown. $ cash balance at the start of the month 150 cash balance at the end of the month 100 cash banked 10 200 cash sales for the month 10 500 How much cash has been lost? A $200 B $250 C $300 D $350
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2006
Q11 · A trial balance shows: Dr Cr $ $ provision for doubtful debts 1200 debtors 28 000 $2100… 9706/11 May/June 2007
4 A trial balance shows: Dr Cr $ $ provision for doubtful debts 1200 debtors 28 000 $2100 of the debtors are irrecoverable and are to be written off. The owner of the business wishes to make the provision for doubtful debts equal to 5 % of his outstanding debtors. What is the amount debited to the profit and loss account for the provision for doubtful debts? A $95 B $1295 C $1400 D $2600
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q12 · The cost of a new machine has been debited to the repairs account 9706/11 May/June 2007
7 The cost of a new machine has been debited to the repairs account. What error is this an example of? A commission B omission C principle D reversal of entries
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q13 · The following information relates to a business: $ opening debtors 280 000 cash received… 9706/11 May/June 2007
8 The following information relates to a business: $ opening debtors 280 000 cash received during the year 520 000 discounts allowed during the year 30 000 bad debts written off during the year 15 000 closing debtors 265 000 What were the sales during the year? A $490 000 B $535 000 C $550 000 D $580 000
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q14 · The total of the balances in the purchases ledger does not agree with the balance on the… 9706/11 May/June 2007
9 The total of the balances in the purchases ledger does not agree with the balance on the purchases ledger control account. It is found that a credit balance of $3100 on a supplier’s account has been listed as a debit balance. What is the effect of correcting the error on the total of the purchases ledger balances? A $3100 decrease B $3100 increase C $6200 decrease D $6200 increase
1 marks
Answer: D
This question in 9706/11 May/June 2007
Q15 · Which error would affect the balancing of a trial balance? 9706/11 May/June 2007
10 Which error would affect the balancing of a trial balance? A A purchase invoice for $259 was entered in the purchases day book and the creditor’s account as $529. B A payment for rent of $250 has been debited in the bank account. It has been entered correctly in the rent account. C A sales invoice for $180 was lost, before it could be entered in the sales day book. D A sales return of $500 was debited in the debtor’s account and credited to the purchases returns account.
1 marks
Answer: B
This question in 9706/11 May/June 2007
Q16 · A trader, whose purchases are all on credit, does not keep double entry records 9706/11 May/June 2007
11 A trader, whose purchases are all on credit, does not keep double entry records. The following information is available: $ opening creditors 51 660 payments to suppliers during the year 212 760 closing creditors 56 340 The discount received for the year amounted to $1000. What were the purchases for the period? A $209 080 B $214 940 C $217 440 D $218 440
1 marks
Answer: D
This question in 9706/11 May/June 2007
Q17 · A trial balance at 30 June, before making end of year adjustments, showed: debit credit $… 9706/11 May/June 2008
4 A trial balance at 30 June, before making end of year adjustments, showed: debit credit $ $ trade debtors 35 600 - provision for doubtful debts - 1 160 At 30 June, it was decided to write off a bad debt of $1600 and to make a provision for doubtful debts equal to 2 % of trade debtors. What was the total expense in the profit and loss account for bad and doubtful debts for the year ended 30 June? A $680 B $1120 C $2080 D $2280
1 marks
Answer: B
This question in 9706/11 May/June 2008
Q18 · At the year-end a cash book shows a credit balance of $4800 9706/11 May/June 2008
8 At the year-end a cash book shows a credit balance of $4800. The bank statement included bank charges of $25 which had not been included in the cash book. Cheque payments entered in the cash book before the year end to the value of $250 had not yet cleared the bank. How would the bank balance be shown in the balance sheet? $ A current asset 4775 B current liability 4825 C current asset 5025 D current liability 5075
1 marks
Answer: B
This question in 9706/11 May/June 2008
Q19 · A company makes purchases from X Ltd and also sells goods to X Ltd 9706/11 May/June 2008
9 A company makes purchases from X Ltd and also sells goods to X Ltd. At the year-end the company owes X Ltd $500 and X Ltd owes the company $750. What are the correct entries to contra (offset) these amounts? purchases ledger control account sales ledger control account debit credit $ $ A 250 250 B 500 500 C 750 500 D 750 750
1 marks
Answer: B
This question in 9706/11 May/June 2008
Q20 · The following information is taken from the books of a business at 30 April 9706/11 May/June 2008
10 The following information is taken from the books of a business at 30 April. $ total of sales ledger balances 84 000 balance on sales ledger control account 83 100 What could have caused the difference between the sales ledger balances and the sales ledger control account balance? A an invoice for $900 not entered in the sales journal B an invoice in the sales journal for $2100 entered in the sales ledger account as $1200 C the sales journal total for March overstated by $900 D the sales journal total for April, $9800, entered in the sales ledger control account as $8900
1 marks
Answer: D
This question in 9706/11 May/June 2008
Q21 · A loan due for repayment in 20 months’ time has been included as a current liability 9706/11 Oct/Nov 2008
2 A loan due for repayment in 20 months’ time has been included as a current liability. What will be the effect when this is corrected? A increase net assets B increase net current assets C no effect on net current assets D reduce net current assets
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2008
Q22 · A creditor for $720 transferred from the purchases ledger has been entered on the wrong… 9706/11 Oct/Nov 2008
8 A creditor for $720 transferred from the purchases ledger has been entered on the wrong side of the sales ledger control account. The sales ledger control account has a closing balance of $92 460, before correcting the transfer. A provision for doubtful debts of £1000 is to be made. What is the correct balance on the sales ledger control account? A $90 020 B $91 020 C $91 740 D $92 180
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2008
Q23 · A trader’s cash book shows a debit balance of $12 460 at 30 April 9706/11 Oct/Nov 2008
10 A trader’s cash book shows a debit balance of $12 460 at 30 April. Bank charges of $4500 have not been entered in the cash book. A cheque for $14 470 received from a debtor and a cheque for $1740 paid to a creditor appear in the cash book but not on the bank statement. What is the balance shown on the bank statement at 30 April? A $4770 credit B $4770 debit C $20 690 credit D $20 690 debit
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2008
Q24 · Entries of $700 in the discount received account had not been entered in the creditors’… 9706/11 May/June 2009
8 Entries of $700 in the discount received account had not been entered in the creditors’ ledger. During the year a machine was sold for $1000. There was only one entry made and it was a credit in the bank account. What is the balance on the suspense account? A $1700 credit B $1700 debit C $2700 credit D $2700 debit
1 marks
Answer: B
This question in 9706/11 May/June 2009
Q25 · The correct balance on the purchases ledger control account is $63 000 but has been… 9706/11 May/June 2009
9 The correct balance on the purchases ledger control account is $63 000 but has been entered in the trial balance as $36 000. The difference on the trial balance has been entered in a suspense account. Which journal entry corrects this error? account to be debited $ account to be credited $ A purchases ledger control account 27 000 suspense account 27 000 B - suspense account 27 000 C suspense account 27 000 - D suspense account 27 000 purchases ledger control account 27 000
1 marks
Answer: D
This question in 9706/11 May/June 2009
Q26 · An extract from a company’s trial balance is shown 9706/11 May/June 2009
16 An extract from a company’s trial balance is shown. debit credit $ $ debtors’ control account – debit balances 225 000 debtors’ control account – credit balances 2 800 creditors’ control account – debit balances 3 200 creditors’ control account – credit balances 261 000 investment in another company 12 000 How much should be shown as trade debtors in the company’s financial statements? A $222 200 B $228 200 C $237 400 D $240 200
1 marks
Answer: B
This question in 9706/11 May/June 2009
Q27 · A business has discovered several errors in its sales ledger 9706/11 Oct/Nov 2009
8 A business has discovered several errors in its sales ledger. All the accounts in the other ledgers have been entered correctly. Which error will not affect the agreement of the trial balance? A A sale to Clark of $2000 was debited to Clarkson’s account. B A sale to Garcia of $100 was entered in Garcia’s account as $1000. C A sale to Wong of $4700 was omitted from Wong’s account. D A sales return of $1200 was debited to Khan’s account.
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2009
Q28 · A trial balance fails to agree and the bookkeeper finds the following errors 9706/11 Oct/Nov 2009
9 A trial balance fails to agree and the bookkeeper finds the following errors. 1 A bank overdraft of $100 was shown as a debit in the trial balance. 2 A telephone bill for $400 was debited to the insurance account. 3 A cash purchase of $160 was entered in the purchases account as $150; the purchase was entered correctly in the cash account. The bookkeeper opens a suspense account in order to correct the errors. What is the opening entry in the suspense account? A credit $190 B credit $210 C debit $60 D debit $550
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2009
Q29 · A business has discovered several errors in its sales ledger 9706/12 Oct/Nov 2009
7 A business has discovered several errors in its sales ledger. All the accounts in the other ledgers have been entered correctly. Which error will not affect the agreement of the trial balance? A A sale to Clark of $2000 was debited to Clarkson’s account. B A sale to Garcia of $100 was entered in Garcia’s account as $1000. C A sale to Wong of $4700 was omitted from Wong’s account. D A sales return of $1200 was debited to Khan’s account.
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2009
Q30 · A trial balance fails to agree and the bookkeeper finds the following errors 9706/12 Oct/Nov 2009
8 A trial balance fails to agree and the bookkeeper finds the following errors. 1 A bank overdraft of $100 was shown as a debit in the trial balance. 2 A telephone bill for $400 was debited to the insurance account. 3 A cash purchase of $160 was entered in the purchases account as $150; the purchase was entered correctly in the cash account. The bookkeeper opens a suspense account in order to correct the errors. What is the opening entry in the suspense account? A credit $190 B credit $210 C debit $60 D debit $550
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2009
Q31 · An item of capital expenditure has been incorrectly treated as revenue expenditure in the… 9706/11 May/June 2010
2 An item of capital expenditure has been incorrectly treated as revenue expenditure in the accounts of a business. What is the effect of this error on the accounts of the business? assets profit A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: D
This question in 9706/11 May/June 2010
Q32 · Which item will be entered in a purchase ledger control account? 9706/11 May/June 2010
8 Which item will be entered in a purchase ledger control account? A discount allowed B discount received C prepaid rent D returns inwards
1 marks
Answer: B
This question in 9706/11 May/June 2010
Q33 · The total of the list of individual balances in the purchase ledger does not agree with… 9706/11 May/June 2010
9 The total of the list of individual balances in the purchase ledger does not agree with the balance on the purchase ledger control account. When listing the individual suppliers’ accounts a credit balance had been shown as a debit balance. What is needed to correct the mistake on the total of the purchase ledger balances? A decrease by the amount of the credit balance B decrease by twice the amount of the credit balance C increase by the amount of the credit balance D increase by twice the amount of the credit balance
1 marks
Answer: D
This question in 9706/11 May/June 2010
Q34 · Which error will cause an entry in the suspense account? 9706/11 May/June 2010
10 Which error will cause an entry in the suspense account? A a transposition error when transferring a ledger account balance to the trial balance B an error of commission where the wrong account is used for a transaction but it is the correct type of account C an error of omission D an error of principle
1 marks
Answer: A
This question in 9706/11 May/June 2010
Q35 · A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors)… 9706/11 May/June 2010
11 A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors) control account 48 500 2 900 trade payables (creditors) control account 3 600 34 800 It is then found that an invoice, $900, issued to a debtor on 27 December, has not been entered in the accounting records. What is the correct figure for trade receivables (debtors) in the balance sheet at 31 December? A $46 500 B $49 400 C $51 200 D $53 000
1 marks
Answer: D
This question in 9706/11 May/June 2010
Q36 · Which item will be entered in a purchase ledger control account? 9706/12 May/June 2010
7 Which item will be entered in a purchase ledger control account? A discount allowed B discount received C prepaid rent D returns inwards
1 marks
Answer: B
This question in 9706/12 May/June 2010
Q37 · The total of the list of individual balances in the purchase ledger does not agree with… 9706/12 May/June 2010
8 The total of the list of individual balances in the purchase ledger does not agree with the balance on the purchase ledger control account. When listing the individual suppliers’ accounts a credit balance had been shown as a debit balance. What is needed to correct the mistake on the total of the purchase ledger balances? A decrease by the amount of the credit balance B decrease by twice the amount of the credit balance C increase by the amount of the credit balance D increase by twice the amount of the credit balance
1 marks
Answer: D
This question in 9706/12 May/June 2010
Q38 · Which error will cause an entry in the suspense account? 9706/12 May/June 2010
9 Which error will cause an entry in the suspense account? A a transposition error when transferring a ledger account balance to the trial balance B an error of commission where the wrong account is used for a transaction but it is the correct type of account C an error of omission D an error of principle
1 marks
Answer: A
This question in 9706/12 May/June 2010
Q39 · A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors)… 9706/12 May/June 2010
10 A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors) control account 48 500 2 900 trade payables (creditors) control account 3 600 34 800 It is then found that an invoice, $900, issued to a debtor on 27 December, has not been entered in the accounting records. What is the correct figure for trade receivables (debtors) in the balance sheet at 31 December? A $46 500 B $49 400 C $51 200 D $53 000
1 marks
Answer: D
This question in 9706/12 May/June 2010
Q40 · Which item will be entered in a purchase ledger control account? 9706/13 May/June 2010
6 Which item will be entered in a purchase ledger control account? A discount allowed B discount received C prepaid rent D returns inwards
1 marks
Answer: B
This question in 9706/13 May/June 2010
Q41 · The total of the list of individual balances in the purchase ledger does not agree with… 9706/13 May/June 2010
7 The total of the list of individual balances in the purchase ledger does not agree with the balance on the purchase ledger control account. When listing the individual suppliers’ accounts a credit balance had been shown as a debit balance. What is needed to correct the mistake on the total of the purchase ledger balances? A decrease by the amount of the credit balance B decrease by twice the amount of the credit balance C increase by the amount of the credit balance D increase by twice the amount of the credit balance
1 marks
Answer: D
This question in 9706/13 May/June 2010
Q42 · Which error will cause an entry in the suspense account? 9706/13 May/June 2010
8 Which error will cause an entry in the suspense account? A a transposition error when transferring a ledger account balance to the trial balance B an error of commission where the wrong account is used for a transaction but it is the correct type of account C an error of omission D an error of principle
1 marks
Answer: A
This question in 9706/13 May/June 2010
Q43 · A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors)… 9706/13 May/June 2010
9 A trial balance at 31 December shows: debit credit $ $ trade receivables (debtors) control account 48 500 2 900 trade payables (creditors) control account 3 600 34 800 It is then found that an invoice, $900, issued to a debtor on 27 December, has not been entered in the accounting records. What is the correct figure for trade receivables (debtors) in the balance sheet at 31 December? A $46 500 B $49 400 C $51 200 D $53 000
1 marks
Answer: D
This question in 9706/13 May/June 2010
Q44 · Which error will not affect the trial balance? 9706/11 Oct/Nov 2010
6 Which error will not affect the trial balance? A posting of $3000 purchases to the debit of the motor vehicle account B posting of $3000 purchases to the credit of the motor vehicle account C posting of $3000 road tax refund to the debit of the motor vehicle account D posting of $3000 sales to the debit of the motor vehicle account
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2010
Q45 · The trade receivable (debtors) control account of Y shows a balance of $14 320 9706/11 Oct/Nov 2010
8 The trade receivable (debtors) control account of Y shows a balance of $14 320. Customer X, who owes Y $1000, has also supplied Y with $400 of goods. The supply of goods, $400, is to be offset by Y. What is the corrected trade receivable (debtors) control account balance? A $13 720 B $13 920 C $14 720 D $14 920
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2010
Q46 · Which error will not affect the trial balance? 9706/12 Oct/Nov 2010
6 Which error will not affect the trial balance? A posting of $3000 purchases to the debit of the motor vehicle account B posting of $3000 purchases to the credit of the motor vehicle account C posting of $3000 road tax refund to the debit of the motor vehicle account D posting of $3000 sales to the debit of the motor vehicle account
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2010
Q47 · The trade receivable (debtors) control account of Y shows a balance of $14 320 9706/12 Oct/Nov 2010
8 The trade receivable (debtors) control account of Y shows a balance of $14 320. Customer X, who owes Y $1000, has also supplied Y with $400 of goods. The supply of goods, $400, is to be offset by Y. What is the corrected trade receivable (debtors) control account balance? A $13 720 B $13 920 C $14 720 D $14 920
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2010
Q48 · At 30 June the balance sheet of a business includes the following 9706/13 Oct/Nov 2010
4 At 30 June the balance sheet of a business includes the following. $ trade receivables (debtors) 46 000 provision for doubtful debts 5 % 2 300 During July, sales of $350 000 were made of which 20 % were in cash. Credit customers paid $303 800 after deducting a 2 % cash discount. How much did the trade receivables (debtors) owe to the business at 31 July? A $15 200 B $16 000 C $22 200 D $76 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2010
Q49 · Which error will not affect the trial balance? 9706/13 Oct/Nov 2010
5 Which error will not affect the trial balance? A posting of $3000 purchases to the debit of the motor vehicle account B posting of $3000 purchases to the credit of the motor vehicle account C posting of $3000 road tax refund to the debit of the motor vehicle account D posting of $3000 sales to the debit of the motor vehicle account
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2010
Q50 · The trade receivable (debtors) control account of Y shows a balance of $14 320 9706/13 Oct/Nov 2010
7 The trade receivable (debtors) control account of Y shows a balance of $14 320. Customer X, who owes Y $1000, has also supplied Y with $400 of goods. The supply of goods, $400, is to be offset by Y. What is the corrected trade receivable (debtors) control account balance? A $13 720 B $13 920 C $14 720 D $14 920
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2010
Q51 · The cash book of a business shows a credit balance of $12 500 at 30 June 9706/11 May/June 2011
7 The cash book of a business shows a credit balance of $12 500 at 30 June. Bank charges of $2000 have not yet been entered in the cash book. A cheque for $20 000 received from a debtor, and a cheque for $3000 paid to a creditor have been entered in the cash book, but have not yet been shown on the bank statement. What is the balance shown on the bank statement at 30 June? A $2500 credit B $2500 debit C $31 500 credit D $31 500 debit
1 marks
Answer: D
This question in 9706/11 May/June 2011
Q52 · What is the main use of a computerised age analysis of debtors? 9706/11 May/June 2011
9 What is the main use of a computerised age analysis of debtors? A aid debt collection procedures B match sales invoices against orders C reconcile sales ledger balances D show credit notes issued
1 marks
Answer: A
This question in 9706/11 May/June 2011
Q53 · The cash book of a business shows a credit balance of $12 500 at 30 June 9706/12 May/June 2011
3 The cash book of a business shows a credit balance of $12 500 at 30 June. Bank charges of $2000 have not yet been entered in the cash book. A cheque for $20 000 received from a debtor, and a cheque for $3000 paid to a creditor have been entered in the cash book, but have not yet been shown on the bank statement. What is the balance shown on the bank statement at 30 June? A $2500 credit B $2500 debit C $31 500 credit D $31 500 debit
1 marks
Answer: D
This question in 9706/12 May/June 2011
Q54 · Closing inventory has been overvalued 9706/12 May/June 2011
4 Closing inventory has been overvalued. What is the effect on the financial statements? net current assets profit from operations A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/12 May/June 2011
Q55 · The cash book of a business shows a credit balance of $12 500 at 30 June 9706/13 May/June 2011
8 The cash book of a business shows a credit balance of $12 500 at 30 June. Bank charges of $2000 have not yet been entered in the cash book. A cheque for $20 000 received from a debtor, and a cheque for $3000 paid to a creditor have been entered in the cash book, but have not yet been shown on the bank statement. What is the balance shown on the bank statement at 30 June? A $2500 credit B $2500 debit C $31 500 credit D $31 500 debit
1 marks
Answer: D
This question in 9706/13 May/June 2011
Q56 · A bank statement showed an overdraft of $750 9706/11 Oct/Nov 2011
2 A bank statement showed an overdraft of $750. A cheque issued in payment of rent for $570 had not been presented, and a cheque for $624 received was omitted from the statement. The statement included a bank charge of $50 but it had not been entered in the cash book. What amount should appear in the balance sheet? A bank balance $646 B bank balance $1894 C bank overdraft $494 D bank overdraft $696
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2011
Q57 · Which error would cause an entry in the suspense account? 9706/11 Oct/Nov 2011
7 Which error would cause an entry in the suspense account? A A page total from the purchases journal was posted as $9780 rather than the correct figure of $9870. B Carriage outwards is credited to the carriage outwards account but correctly accounted for in the cash book. C Discounts allowed are debited to the discounts allowed account and credited to the purchases ledger control account. D Repairs to a vehicle are debited to the vehicles account.
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2011
Q58 · A company’s purchases ledger control account showed an opening balance of $24 640 credit 9706/11 Oct/Nov 2011
8 A company’s purchases ledger control account showed an opening balance of $24 640 credit. The following information is available for the year. $ purchases journal (including invoice for $910 entered twice) 17 100 receivables ledger control contra 850 credit notes issued by suppliers 1 250 discounts received 420 The purchases ledger control account balance at the year end was $19 870 credit. How much cash was paid to creditors during the year? A $18 440 B $20 140 C $20 940 D $22 640
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2011
Q59 · At 31 December 2010 a business provides the following information 9706/11 Oct/Nov 2011
9 At 31 December 2010 a business provides the following information. $ balance per cash book (bank column) 790 credit balance per the bank statement 800 debit unpresented cheques 30 The only other reconciling item between the cash book and the bank statement is bank charges recorded on the bank statement but not in the cash book. How much are the bank charges? A $10 B $20 C $30 D $40
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2011
Q60 · The following items are recorded in the cash book of a business but not yet recorded in… 9706/12 Oct/Nov 2011
7 The following items are recorded in the cash book of a business but not yet recorded in its bank statement: $ Cheques drawn 3000 Amounts banked 250 The cash book shows a bank overdraft of $2600. What is the balance on the bank statement? A $150 in hand B $150 overdraft C $400 in hand D $400 overdraft
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2011
Q61 · A business provides the following information 9706/12 Oct/Nov 2011
8 A business provides the following information. $ cash received from customers 200 000 opening trade receivables 40 000 closing trade receivables 30 000 discounts allowed 5 000 provision for doubtful debts 4 000 How much are the credit sales? A $190 000 B $195 000 C $199 000 D $215 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2011
Q62 · Which error will cause a trial balance not to balance? 9706/12 Oct/Nov 2011
9 Which error will cause a trial balance not to balance? A an invoice entered as a credit note on original input. B a journal entry that does not balance. C a transaction entered as the wrong amount on original input. D a transaction not entered.
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2011
Q63 · A bank statement showed an overdraft of $750 9706/13 Oct/Nov 2011
1 A bank statement showed an overdraft of $750. A cheque issued in payment of rent for $570 had not been presented, and a cheque for $624 received was omitted from the statement. The statement included a bank charge of $50 but it had not been entered in the cash book. What amount should appear in the balance sheet? A bank balance $646 B bank balance $1894 C bank overdraft $494 D bank overdraft $696
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2011
Q64 · Which error would cause an entry in the suspense account? 9706/13 Oct/Nov 2011
6 Which error would cause an entry in the suspense account? A A page total from the purchases journal was posted as $9780 rather than the correct figure of $9870. B Carriage outwards is credited to the carriage outwards account but correctly accounted for in the cash book. C Discounts allowed are debited to the discounts allowed account and credited to the purchases ledger control account. D Repairs to a vehicle are debited to the vehicles account.
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2011
Q65 · A company’s purchases ledger control account showed an opening balance of $24 640 credit 9706/13 Oct/Nov 2011
7 A company’s purchases ledger control account showed an opening balance of $24 640 credit. The following information is available for the year. $ purchases journal (including invoice for $910 entered twice) 17 100 receivables ledger control contra 850 credit notes issued by suppliers 1 250 discounts received 420 The purchases ledger control account balance at the year end was $19 870 credit. How much cash was paid to creditors during the year? A $18 440 B $20 140 C $20 940 D $22 640
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2011
Q66 · At 31 December 2010 a business provides the following information 9706/13 Oct/Nov 2011
8 At 31 December 2010 a business provides the following information. $ balance per cash book (bank column) 790 credit balance per the bank statement 800 debit unpresented cheques 30 The only other reconciling item between the cash book and the bank statement is bank charges recorded on the bank statement but not in the cash book. How much are the bank charges? A $10 B $20 C $30 D $40
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2011
Q67 · The table shows details relating to a company’s banking transactions at 31 December 9706/11 May/June 2012
6 The table shows details relating to a company’s banking transactions at 31 December. $ balance at bank as per bank statement 22 650 uncleared lodgements 3 110 unpresented cheques 6 290 bank credit recorded twice by bank in error 650 Which balance for cash at bank should appear in the statement of financial position at 31 December? A $18 820 B $20 120 C $25 180 D $26 480
1 marks
Answer: A
This question in 9706/11 May/June 2012
Q68 · The table shows details relating to a company’s banking transactions at 31 December 9706/12 May/June 2012
7 The table shows details relating to a company’s banking transactions at 31 December. $ balance at bank as per bank statement 22 650 uncleared lodgements 3 110 unpresented cheques 6 290 bank credit recorded twice by bank in error 650 Which balance for cash at bank should appear in the statement of financial position at 31 December? A $18 820 B $20 120 C $25 180 D $26 480
1 marks
Answer: A
This question in 9706/12 May/June 2012
Q69 · A company’s accounts showed a gross profit for the year of $32 500 9706/12 May/June 2012
8 A company’s accounts showed a gross profit for the year of $32 500. After the draft financial statements were prepared it was found that the opening inventory had been overstated by $2400 and the closing inventory had been understated by $3400. What is the corrected gross profit for the year? A $26 700 B $31 500 C $33 500 D $38 300
1 marks
Answer: D
This question in 9706/12 May/June 2012
Q70 · At 31 March 2012, a business’s bank statement shows that its bank account is overdrawn by… 9706/13 May/June 2012
7 At 31 March 2012, a business’s bank statement shows that its bank account is overdrawn by $10 136. Further information is as follows. $ cheques drawn, not presented 4 998 cheques paid in, not credited 5 896 bank interest charged, not in cash book 181 What is the correct bank overdraft to be shown in the business's statement of financial position at 31 March 2012? A $9 057 B $9 238 C $10 853 D $11 034
1 marks
Answer: B
This question in 9706/13 May/June 2012
Q71 · A business has a draft profit for the year of $84 000 9706/13 May/June 2012
8 A business has a draft profit for the year of $84 000. It is discovered that the closing inventory was overvalued by $4000 and that discounts received of $1500 were treated as an expense. What is the corrected profit for the year? A $81 500 B $83 000 C $89 500 D $91 000
1 marks
Answer: B
This question in 9706/13 May/June 2012
Q72 · A business increases its provision for doubtful debts by $1600 9706/11 Oct/Nov 2012
2 A business increases its provision for doubtful debts by $1600. What will be the effect of this adjustment on the financial statements? profit for the year trade receivables (net) A decrease by $1600 decrease by $1600 B decrease by $1600 increase by $1600 C increase by $1600 decrease by $1600 D increase by $1600 increase by $1600
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2012
Q73 · Alfredo received his bank statement which showed a balance of $937 overdrawn 9706/11 Oct/Nov 2012
8 Alfredo received his bank statement which showed a balance of $937 overdrawn. This did not agree with his cash book. On investigation he noted the following. • Bank charges of $76 had not been entered in the cash book. • There was an unpresented cheque of $214. • Alfredo had paid $35 cash into his bank account but this was not showing on the statement. At which value was the bank overdraft shown in the statement of financial position? A $758 B $937 C $1116 D $1192
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2012
Q74 · The purchases ledger control account has a closing balance of $15 300 9706/11 Oct/Nov 2012
9 The purchases ledger control account has a closing balance of $15 300. Discounts received of $600 have been entered on the wrong side of the control account. What is the corrected balance? A $14 100 B $14 700 C $15 900 D $16 500
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2012
Q75 · Which statement about trial balance totals is correct? 9706/11 Oct/Nov 2012
10 Which statement about trial balance totals is correct? A They may not agree since a trial balance is not a statement of financial position. B They may not agree until various adjustments are made. C They should, in the absence of errors, always agree. D They will not agree because the trial balance does not include a figure for closing inventory.
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2012
Q76 · A trial balance includes a suspense account 9706/12 Oct/Nov 2012
8 A trial balance includes a suspense account. The bank balance of $28 412 has mistakenly been entered as an overdraft and placed on the credit side as $28 142. There has also been an addition error and the debit side of the trial balance has been undercast by $450. Which entry in the suspense account would correct these errors? A credit $56 104 B debit $56 104 C credit $57 004 D debit $57 004
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2012
Q77 · A company has obtained the following information for the year ended 31 December 9706/12 Oct/Nov 2012
9 A company has obtained the following information for the year ended 31 December. $ opening balance on sales ledger control account 31 000 closing balance on sales ledger control account 35 000 discount allowed 2 300 credit sales 125 400 What was the amount of cash received from the customers? A $119 100 B $123 700 C $127 100 D $131 700
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2012
Q78 · The table shows a bank reconciliation statement prepared as at 31 December 9706/13 Oct/Nov 2012
8 The table shows a bank reconciliation statement prepared as at 31 December. $ balance per bank statement 862 523 add outstanding lodgements 73 540 bank charges not entered in cash book 15 200 951 263 less unpresented cheques 40 826 balance per cash book 910 437 Which amount will be included in the statement of financial position as at 31 December as cash at bank? A $862 523 B $877 723 C $895 237 D $910 437
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2012
Q79 · A trial balance failed to balance and a suspense account was opened 9706/13 Oct/Nov 2012
9 A trial balance failed to balance and a suspense account was opened. It was discovered that the discount received column in the cash book, which totalled $180, had been posted to the debit side of the discount allowed account. Which entry is made in the suspense account to correct this error? A credit $180 B credit $360 C debit $180 D debit $360
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2012
Q80 · What would not appear in a sales ledger control account? 9706/13 Oct/Nov 2012
10 What would not appear in a sales ledger control account? A bad debts B cash sales C discounts allowed D returns inwards
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2012
Q81 · A payment from a credit customer has been credited to cash sales 9706/11 May/June 2013
2 A payment from a credit customer has been credited to cash sales. Which entries correct this error? account to be debited account to be credited A customer bank B customer sales C sales bank D sales customer
1 marks
Answer: D
This question in 9706/11 May/June 2013
Q82 · A statement of financial position includes a 10% provision for doubtful debts totalling… 9706/11 May/June 2013
3 A statement of financial position includes a 10% provision for doubtful debts totalling $7800. The income statement shows bad debts written off of $750 and bad debts recovered of $150. What was the original value of trade receivables? A $78 000 B $78 600 C $78 750 D $78 900
1 marks
Answer: C
This question in 9706/11 May/June 2013
Q83 · At the beginning of the year a business has a provision for doubtful debts of $2600 9706/11 May/June 2013
5 At the beginning of the year a business has a provision for doubtful debts of $2600. At the year end the provision is to be 5% of trade receivables. The balance on the sales ledger control account at the year end is $69 200, before writing off a bad debt of $480. The business operates a separate bad debts account. What is the entry in the income statement for the provision for doubtful debts? A $836 credit B $836 debit C $860 credit D $860 debit
1 marks
Answer: B
This question in 9706/11 May/June 2013
Q84 · A draft statement of financial position shows a bank balance of $1400 9706/11 May/June 2013
11 A draft statement of financial position shows a bank balance of $1400. The following information is now available. $ cheques issued but not yet cleared by the bank 150 bank charges not in the cash book 45 lodgements in the cash book but not on the bank statement 220 Which figure is shown on the bank statement? A $1285 B $1355 C $1425 D $1515
1 marks
Answer: A
This question in 9706/11 May/June 2013
Q85 · A suspense account showed the following 9706/11 May/June 2013
12 A suspense account showed the following. suspense account $ $ purchases 300 balance b/d 120 Judy 180 300 300 The business did not maintain control accounts. Which errors had been made? purchases Judy A purchases journal had credit sales of $460 had been been overcast by $300 entered as $640 in Judy’s account B purchases journal had credit sales of $640 had been been overcast by $300 entered as $460 in Judy’s account C purchases journal had credit sales of $460 had been been undercast by $300 entered as $640 in Judy’s account D purchases journal had credit sales of $640 had been been undercast by $300 entered as $460 in Judy’s account
1 marks
Answer: B
This question in 9706/11 May/June 2013
Q86 · At the start of the year a business had the opening trade payables of $13 000 9706/11 May/June 2013
13 At the start of the year a business had the opening trade payables of $13 000. At the end of the year it owed $15 000 to trade payables. During the year it paid them $190 000, after taking a cash discount of $10 000. What was the amount of the credit purchases for the year? A $188 000 B $192 000 C $198 000 D $202 000
1 marks
Answer: D
This question in 9706/11 May/June 2013
Q87 · Which error must be corrected by a one-sided journal entry? 9706/11 May/June 2013
14 Which error must be corrected by a one-sided journal entry? A a cheque entered in the cash book but not posted in a ledger account B a contra entry in the sales ledger control account not entered in the purchases ledger control account C an error in the total value of sales ledger balances included in the trial balance D discount allowed entered in a customer’s account but not entered in the discount column in the cash book
1 marks
Answer: C
This question in 9706/11 May/June 2013
Q88 · A trader uses his bank statements and paying in books to produce a summary of his… 9706/11 May/June 2013
15 A trader uses his bank statements and paying in books to produce a summary of his receipts and payments for the year. Why does he do this? A in order to calculate his closing inventory B in order to prepare a bank reconciliation statement C to be able to calculate total sales and total purchases D to know the amount of bad debts written off
1 marks
Answer: C
This question in 9706/11 May/June 2013
Q89 · The draft financial statements of a business show a profit for the year of $64 000 before… 9706/12 May/June 2013
4 The draft financial statements of a business show a profit for the year of $64 000 before taking account of the following. 1 the reduction of the provision for doubtful debts by $300 2 the purchase of office stationery costing $2400 which has not been entered in the records; only one sixth of this stationery was used by the year end What is the corrected profit for the year? A $61 900 B $63 900 C $64 100 D $64 300
1 marks
Answer: B
This question in 9706/12 May/June 2013
Q90 · At the financial year end of a business the following information is available 9706/12 May/June 2013
7 At the financial year end of a business the following information is available. $ debit balance on the bank statement 1000 unpresented cheques 300 lodgements not yet credited by the bank 600 bank charges and interest charged not yet entered in the cash book 150 What is the current balance in the cash book? A $400 credit B $400 debit C $550 credit D $550 debit
1 marks
Answer: C
This question in 9706/12 May/June 2013
Q91 · Which error would result in the creation of a suspense account? 9706/12 May/June 2013
8 Which error would result in the creation of a suspense account? A crediting the commission received account with rent received B crediting the discounts allowed account with the discounts received C debiting the bank interest paid account with bank interest received D debiting the petrol account with a purchase of a new car
1 marks
Answer: C
This question in 9706/12 May/June 2013
Q92 · An error of reversal is made when recording the payment of a telephone bill for $500 9706/12 May/June 2013
10 An error of reversal is made when recording the payment of a telephone bill for $500. Which journal entries are required to record the correction of this error? debit $ credit $ A bank 500 telephone 500 B bank 1000 telephone 1000 C telephone 500 bank 500 D telephone 1000 bank 1000
1 marks
Answer: D
This question in 9706/12 May/June 2013
Q93 · Which item would result in a credit entry in an income statement? 9706/13 May/June 2013
1 Which item would result in a credit entry in an income statement? A an increase in the provision for doubtful debts B a reduction in the provision for doubtful debts C the creation of a provision for doubtful debts D the writing off of a trade receivable
1 marks
Answer: B
This question in 9706/13 May/June 2013
Q94 · The table shows figures relating to a company’s banking transactions at 31 December 9706/13 May/June 2013
8 The table shows figures relating to a company’s banking transactions at 31 December. $ balance at bank per bank statement 22 650 uncleared lodgements 3 110 unpresented cheques 6 290 bank credit recorded twice by bank in error 650 Which balance for cash at bank should appear in the statement of financial position at 31 December? A $18 820 B $20 120 C $25 180 D $26 480
1 marks
Answer: A
This question in 9706/13 May/June 2013
Q95 · A trial balance does not balance and a suspense account is opened 9706/13 May/June 2013
9 A trial balance does not balance and a suspense account is opened. Later the following errors are found and the suspense account is cleared. 1 A sales invoice for $1240 had been completely omitted from the books. 2 Rent paid of $2600 was entered correctly in the cash book but as $6200 in the rent account. 3 The purchases journal was undercast by $1980. What was the original balance on the suspense account? A $1620 credit B $4340 debit C $5580 credit D $5580 debit
1 marks
Answer: A
This question in 9706/13 May/June 2013
Q96 · The table shows information relating to a business for the year ended 31 December 2012 9706/13 May/June 2013
10 The table shows information relating to a business for the year ended 31 December 2012. $ trade receivables at 1 January 2012 280 000 bad debts written off 8 500 cash from credit customers 796 000 cash sales 69 500 credit sales 718 000 increase in provision for doubtful debts 9 500 returns inwards on credit transactions 7 500 What is the balance on the sales ledger control account at 31 December 2012? A $176 500 B $186 000 C $195 500 D $255 500
1 marks
Answer: B
This question in 9706/13 May/June 2013
Q97 · A draft income statement shows a profit for the year of $75 000 9706/13 May/June 2013
11 A draft income statement shows a profit for the year of $75 000. Discounts allowed of $4000 have been treated as discounts received and discounts received of $7000 have been treated as discounts allowed. What is the correct profit? A $69 000 B $72 000 C $78 000 D $81 000
1 marks
Answer: D
This question in 9706/13 May/June 2013
Q98 · A computer used for demonstration to customers was treated as capital expenditure 9706/11 Oct/Nov 2013
4 A computer used for demonstration to customers was treated as capital expenditure. The following year a customer purchased the computer in the ordinary course of business. Which entries are needed to adjust the cost of sales? account to be debited account to be credited A inventory computers B purchases computers C sales inventory D selling expenses sales
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2013
Q99 · The table shows information about a business 9706/11 Oct/Nov 2013
5 The table shows information about a business. $ provision for doubtful debts at 1 January 2012 700 trade receivables at 31 December 2012 (after writing off a bad 15 000 debt of $30) charge to income statement for bad and doubtful debts for year 200 ended 31 December 2012 (including the bad debt written off) What is the total percentage provision that has been made for doubtful debts at 31 December 2012? A 3.5% B 4.7% C 5.8% D 6.0%
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2013
Q100 · When preparing a bank reconciliation statement, the following information is available 9706/11 Oct/Nov 2013
8 When preparing a bank reconciliation statement, the following information is available. $ bank balance shown by the cash book 20 000 debit unpresented cheques 2 500 uncleared bankings 1 400 standing order shown on the bank statement 300 (not in the cash book) What is the balance on the bank statement? A $18 600 B $19 200 C $20 800 D $21 400
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2013
Q101 · The following financial information has been extracted from the books of account 9706/11 Oct/Nov 2013
9 The following financial information has been extracted from the books of account. $ bad debts written off 7 000 cash from credit customers 925 000 credit sales 900 000 opening trade receivables 300 000 discounts allowed 10 000 discounts received 25 000 increase in provision for doubtful debts 9 000 returns inwards 8 000 returns outwards 5 000 What is the closing balance on the sales ledger control account? A $235 000 B $241 000 C $250 000 D $253 000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2013
Q102 · Discount received of $280 has been incorrectly posted to the credit of the discount… 9706/11 Oct/Nov 2013
10 Discount received of $280 has been incorrectly posted to the credit of the discount allowed account. Which entry must be made to the discount received account to correct the error? A credit $280 B credit $560 C debit $280 D debit $560
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2013
Q103 · Y sells goods to X on credit 9706/11 Oct/Nov 2013
18 Y sells goods to X on credit. Details of X’s account are as follows. $ trade discount 250 closing balance 750 opening balance 1500 payment received 2000 contra to purchases ledger 2500 What was the value of sales? A $3500 B $3750 C $4000 D $5250
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2013
Q104 · A business is preparing a bank reconciliation and finds the following 9706/12 Oct/Nov 2013
9 A business is preparing a bank reconciliation and finds the following. $ unpresented cheques 3190 uncredited bankings 1949 The cash book has a debit balance of $5000. Which adjustments should be made to the cash book balance to reconcile it to the bank statement? A minus $3190, minus $1949 B minus $3190, plus $1949 C plus $3190, minus $1949 D plus $3190, plus $1949
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2013
Q105 · A company’s trial balance includes a suspense account 9706/12 Oct/Nov 2013
10 A company’s trial balance includes a suspense account. It was found that the only errors were discounts received of $240 and discounts allowed of $312, which had both been entered on the incorrect sides of the respective ledger accounts. What is the double entry required to clear the suspense account balance? debit credit account $ $ A discounts allowed 312 discounts received 240 suspense 72 B discounts allowed 624 discounts received 480 suspense 144 C discounts received 240 suspense 72 discounts allowed 312 D discounts received 480 suspense 144 discounts allowed 624
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2013
Q106 · Which statements about a bank reconciliation are correct? 9706/13 Oct/Nov 2013
11 Which statements about a bank reconciliation are correct? 1 Cleared cheques are excluded. 2 It can be computerised. 3 It locates all errors. 4 Uncredited deposits are included. A 1, 2 and 4 B 1 and 2 only C 2, 3 and 4 D 2 and 3 only
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2013
Q107 · A trial balance does not balance and a suspense account is opened 9706/13 Oct/Nov 2013
12 A trial balance does not balance and a suspense account is opened. On investigation, the following errors are found. 1 The debit balance of $450 on the carriage outwards account has been brought down as $540. 2 The purchases returns journal has been overcast by $100. 3 A cheque for $50 received from Alan Green has been posted to the credit account of Brian Green. 4 Rent received of $350 has been posted to the debit of rent paid account. What is the opening balance on the suspense account? A credit $690 B credit $740 C debit $690 D debit $740
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2013
Q108 · In reconciling the sales ledger control account with the balances in the sales ledger, it… 9706/13 Oct/Nov 2013
13 In reconciling the sales ledger control account with the balances in the sales ledger, it was noticed that there was an error in the sales journal. This had been overcast by $740. In addition, the total receipts from customers of $940 were recorded in the control account as $490. Which correcting entry must be made? control account list of balances A $290 credit increase by $290 B $290 debit no effect C $1190 credit decrease by $1190 D $1190 credit no effect
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2013
Q109 · Which error would give rise to a difference in a trial balance? 9706/13 Oct/Nov 2013
14 Which error would give rise to a difference in a trial balance? A bringing forward an opening balance of $9590 instead of $9950 B debiting interest paid in the cash book and crediting it to ‘interest received’ account C debiting ‘repair to motor vehicles’ account with $11 250 for a new motor vehicle D entering the sale of an item for $300 in the books as $3000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2013
Q110 · A company’s purchases ledger control account showed an opening balance of $24 640 credit 9706/11 May/June 2014
8 A company’s purchases ledger control account showed an opening balance of $24 640 credit. The following information is available for the year. $ purchases journal (including invoice for $910 entered twice) 17 100 sales ledger control account contra 850 credit notes issued by suppliers 1 250 discounts received 420 The purchases ledger control account balance at the year end was $19 870 credit. How much cash was paid to creditors during the year? A $18 440 B $20 140 C $20 940 D $22 640
1 marks
Answer: A
This question in 9706/11 May/June 2014
Q111 · A suspense account was opened when a trial balance failed to balance 9706/11 May/June 2014
9 A suspense account was opened when a trial balance failed to balance. It was then discovered that returns of $200 had been correctly entered in the supplier’s account but debited in the sales returns account. This was the only error. What was the balance on the suspense account before this error was corrected? A credit $200 B credit $400 C debit $200 D debit $400
1 marks
Answer: B
This question in 9706/11 May/June 2014
Q112 · Which statement is correct? 9706/12 May/June 2014
3 Which statement is correct? A The balance on the bad debts recovered account is carried down to the next accounting period. B The balance on the bad debts recovered account is credited to the income statement. C The balance on the provision for doubtful debts account is calculated before the deduction of bad debts. D The balance on the provision for doubtful debts account is not included in a trial balance.
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q113 · A trial balance failed to agree 9706/12 May/June 2014
7 A trial balance failed to agree. A suspense account was opened. The following errors were then discovered. 1 The sales returns journal had been undercast by $850. 2 The purchases journal had been overcast by $975. What was the opening balance on the suspense account before the correction of the errors? A $125 credit B $125 debit C $1825 credit D $1825 debit
1 marks
Answer: A
This question in 9706/12 May/June 2014
Q114 · The bank column of a cash book showed a credit balance of $5000 9706/12 May/June 2014
8 The bank column of a cash book showed a credit balance of $5000. There were unpresented cheques amounting to $1500. The bank statement showed bank charges of $700 not in the cash book. What is the balance on the bank statement? A $3300 debit B $4200 debit C $4200 credit D $5800 credit
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q115 · What would cause a trial balance not to balance? 9706/12 May/June 2014
9 What would cause a trial balance not to balance? A a casting error in the cash account B a transposition error in extracting the trial balance C discounts allowed posted to discounts received account D misposting of an invoice to a creditor’s account
1 marks
Answer: C
This question in 9706/12 May/June 2014
Q116 · X buys from and sells goods to Y 9706/12 May/June 2014
10 X buys from and sells goods to Y. At the end of the month, X owes Y $3200 and Y owes X $1941. Which double entry records the contra entry in X’s books? Dr Cr $ $ A purchases ledger control account 1259 sales ledger control account 1259 B purchases ledger control account 1941 sales ledger control account 1941 C sales ledger control account 1259 purchases ledger control account 1259 D sales ledger control account 1941 purchases ledger control account 1941
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q117 · A business owner suspects a loss of cash has occurred 9706/12 May/June 2014
14 A business owner suspects a loss of cash has occurred. He provides the data shown. $ cash balance at the start of the month 150 cash balance at the end of the month 100 cash banked 10 200 cash sales for the month 10 500 How much cash has been lost? A $200 B $250 C $300 D $350
1 marks
Answer: D
This question in 9706/12 May/June 2014
Q118 · On 31 December 2012 John’s statement of financial position showed the following 9706/13 May/June 2014
3 On 31 December 2012 John’s statement of financial position showed the following. $ trade receivables 18 000 provision for doubtful debts 720 On 31 December 2013 John decides to increase the rate of provision to 5%. His income statement shows a debit of $80 for the change in the provision. What is the value of John’s total trade receivables on 31 December 2013? A $12 800 B $14 400 C $16 000 D $20 000
1 marks
Answer: C
This question in 9706/13 May/June 2014
Q119 · At 31 December 2013 a business provides the following information 9706/13 May/June 2014
6 At 31 December 2013 a business provides the following information. $ balance per cash book 790 credit balance per the bank statement 800 debit unpresented cheques 30 The only other reconciling item between the cash book and the bank statement is bank charges recorded on the bank statement but not in the cash book. How much are the bank charges? A $10 B $20 C $30 D $40
1 marks
Answer: D
This question in 9706/13 May/June 2014
Q120 · A company accountant has prepared a reconciliation of the sales ledger control account… 9706/13 May/June 2014
7 A company accountant has prepared a reconciliation of the sales ledger control account with the sales ledger. $ balance per the control account 100 000 add: invoices not posted to the nominal ledger 10 000 cash received not posted to the sales ledger 5 000 balance per the sales ledger 115 000 Which figure for trade receivables should be shown in the financial statements? A $100 000 B $105 000 C $110 000 D $115 000
1 marks
Answer: C
This question in 9706/13 May/June 2014
Q121 · A trial balance at 31 December shows the following 9706/13 May/June 2014
8 A trial balance at 31 December shows the following. debit credit $ $ sales ledger control account 54 000 1 500 purchases ledger control account 900 46 000 It is then found that an invoice for $1700, received from a supplier on 27 December, has not been entered in the accounting records. What is the correct figure for trade payables in the statement of financial position at 31 December? A $45 800 B $47 700 C $49 200 D $52 500
1 marks
Answer: C
This question in 9706/13 May/June 2014
Q122 · A trial balance failed to agree 9706/13 May/June 2014
9 A trial balance failed to agree. The following errors have been discovered. 1 Discounts allowed $54 had been posted to the credit of the discount received account as $45. 2 The rent payable account had been undercast by $100. What was the effect of these errors on the trial balance? A credit column $109 greater than debit column B credit column $199 greater than debit column C debit column $109 greater than credit column D debit column $199 greater than credit column
1 marks
Answer: B
This question in 9706/13 May/June 2014
Q123 · A non-current liability has been included as a current liability 9706/11 Oct/Nov 2014
1 A non-current liability has been included as a current liability. What will be the effect when this is corrected? A increase net assets B increase net current assets C no effect on net current assets D reduce net current assets
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2014
Q124 · In preparing the financial statements, an accrual for rent payable was treated as a… 9706/11 Oct/Nov 2014
3 In preparing the financial statements, an accrual for rent payable was treated as a prepayment. What effect does this have on the profit and the current liabilities? profit current liabilities A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2014
Q125 · The following information is available for a business 9706/11 Oct/Nov 2014
4 The following information is available for a business. $ trade receivables at 1 January 63 000 provision for doubtful debts at 1 January 1 890 total credit sales for January 327 000 cash from customers after 4% settlement discount 324 000 A provision for doubtful debts of 2% is to be made. What adjustment is required in the income statement? A $570 credit B $570 debit C $840 credit D $840 debit
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2014
Q126 · The table shows information from a sales ledger control account 9706/11 Oct/Nov 2014
6 The table shows information from a sales ledger control account. $ opening balances 260 497 closing balances 286 190 cash received 581 640 irrecoverable debts 33 200 contra entries 17 310 What is the credit sales figure? A $556 823 B $591 443 C $623 223 D $657 843
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2014
Q127 · Where would the difference between the total debits and the total credits in a trial… 9706/11 Oct/Nov 2014
7 Where would the difference between the total debits and the total credits in a trial balance be recorded? A a control account B a suspense account C the general journal D the income statement
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2014
Q128 · The table shows extracts from a business’s bank reconciliation 9706/11 Oct/Nov 2014
8 The table shows extracts from a business’s bank reconciliation. $ balance per cash book at 31 December 2075 balance per bank statement at 31 December 2250 bank charges per bank statement not entered in cash book 150 outstanding cheques not presented at the year end 325 What is the bank balance to be shown in the financial statements? A $1600 B $1925 C $2075 D $2225
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2014
Q129 · At the end of its financial year a business had trade receivables of $16 000 and had… 9706/12 Oct/Nov 2014
1 At the end of its financial year a business had trade receivables of $16 000 and had provision for doubtful debts of $640. The provision is to be maintained at 5%. Which amount is shown in the income statement? A $160 credit B $160 debit C $800 credit D $800 debit
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2014
Q130 · A sole trader calculated a draft profit for the year of $56 750 9706/12 Oct/Nov 2014
3 A sole trader calculated a draft profit for the year of $56 750. He then discovers that discounts received of $580 and discounts allowed of $665 had been recorded on the wrong sides of their respective accounts. What is the correct profit for the year? A $56 580 B $56 665 C $56 835 D $56 920
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2014
Q131 · Opening inventory is found to be overstated by $8000 and closing inventory is overstated… 9706/12 Oct/Nov 2014
4 Opening inventory is found to be overstated by $8000 and closing inventory is overstated by $6500. What is the effect of the correction of these errors on profit for the year? A decrease of $1500 B decrease of $14 500 C increase of $1500 D increase of $14 500
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2014
Q132 · A suspense account shows a debit balance of $350 9706/12 Oct/Nov 2014
5 A suspense account shows a debit balance of $350. What could have caused this? A A purchase of $350 was debited to the rent account. B A purchase of $350 was omitted from the purchases journal. C A sale of $350 was debited to the sales account and credited to the debtors’ control account. D A sale of $350 was posted twice to the sales account.
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2014
Q133 · A cash book showed a credit bank balance of $6100 on 31 December 9706/12 Oct/Nov 2014
6 A cash book showed a credit bank balance of $6100 on 31 December. The bank statement on that date showed $60 of bank charges not in the cash book. Unpresented cheques amounted to $500. What was the balance on the bank statement? A $5540 credit B $5540 debit C $5660 credit D $5660 debit
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2014
Q134 · A purchase ledger control account shows the following: $ opening balance 1 200 closing… 9706/12 Oct/Nov 2014
7 A purchase ledger control account shows the following: $ opening balance 1 200 closing balance 1 300 purchases 18 400 payments made 17 800 discount received 300 Which entry appears in the control account to record the contra with the sales ledger control account? A $200 credit B $200 debit C $800 credit D $800 debit
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2014
Q135 · When preparing the financial statements for the year the following errors are discovered 9706/13 Oct/Nov 2014
7 When preparing the financial statements for the year the following errors are discovered. 1 The sales journal was undercast by $300. 2 No provision had been made for accrued wages of $200. 3 No account had been taken of prepaid rent of $400. The draft profit for the year is $8050. What will be the profit when the errors are corrected? A $8150 B $8550 C $8750 D $8950
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2014
Q136 · The correction of which error would require a suspense account? 9706/13 Oct/Nov 2014
8 The correction of which error would require a suspense account? A $100 paid for vehicle repairs debited to the vehicles account B a sales invoice for $45 omitted from the sales journal C drawings of $60 debited to cash and credited to drawings D the purchases journal overcast by $150
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2014
Q137 · The following items are recorded in the cash book of a business but not yet recorded in… 9706/13 Oct/Nov 2014
9 The following items are recorded in the cash book of a business but not yet recorded in its bank statement. $ cheques drawn 3000 amounts banked 250 The cash book shows a bank balance of $2600 Cr. What is the balance on the bank statement? A $150 Cr B $150 Dr C $400 Cr D $400 Dr
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2014
Q138 · Which group of items would appear on the credit side of a sales ledger control account? 9706/13 Oct/Nov 2014
10 Which group of items would appear on the credit side of a sales ledger control account? A contra, discount allowed, sales returns B contra, discount received, dishonoured cheques C discount allowed, dishonoured cheques, interest D discount received, interest, sales returns
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2014
Q139 · During the financial year a business paid its trade payables $295 000 after taking a cash… 9706/13 Oct/Nov 2014
11 During the financial year a business paid its trade payables $295 000 after taking a cash discount of $15 000. At the start of the year the trade payables balance was $25 000. At the end of the year $32 000 was owed to trade payables. What was the amount of credit purchases made during the year? A $288 000 B $302 000 C $303 000 D $317 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2014
Q140 · Which entries are required to show a decrease in the existing provision for doubtful… 9706/11 May/June 2015
1 Which entries are required to show a decrease in the existing provision for doubtful debts? debit credit A bad debts account provision for doubtful debts account B income statement provision for doubtful debts account C provision for doubtful debts account bad debts account D provision for doubtful debts account income statement
1 marks
Answer: D
This question in 9706/11 May/June 2015
Q141 · Jasmine makes purchases from X Limited and also sells goods to X Limited 9706/11 May/June 2015
4 Jasmine makes purchases from X Limited and also sells goods to X Limited. At the year-end Jasmine owes X Limited $500 and X Limited owes Jasmine $750. What are the correct entries in Jasmine’s books of accounts to contra (offset) these amounts? purchases ledger sales ledger control account control account $ $ A 250 250 B 500 500 C 750 500 D 750 750
1 marks
Answer: B
This question in 9706/11 May/June 2015
Q142 · The following figures have been extracted from the financial statements of a business 9706/11 May/June 2015
9 The following figures have been extracted from the financial statements of a business. $ trade receivables 45 000 provision for doubtful debts 2 000 bad debts from previous year written off 1 000 The trade receivable days were 71.1 days. What was the figure of credit sales for the year to the nearest dollar? A $215 612 B $220 745 C $231 013 D $241 280
1 marks
Answer: C
This question in 9706/11 May/June 2015
Q143 · A business purchases inventory on a credit basis 9706/12 May/June 2015
5 A business purchases inventory on a credit basis. Which item affects the amount paid to suppliers? A bad debts B contra with the sales ledger C discount allowed D returns inwards
1 marks
Answer: B
This question in 9706/12 May/June 2015
Q144 · A trader maintains a sales ledger control account 9706/12 May/June 2015
10 A trader maintains a sales ledger control account. How can he calculate credit sales? A balance carried down + receipts + balance brought down B balance carried down + receipts – balance brought down C balance carried down – receipts + balance brought down D balance carried down – receipts – balance brought down
1 marks
Answer: B
This question in 9706/12 May/June 2015
Q145 · A trader depreciates fixtures and fittings at the rate of 10% a year on cost 9706/13 May/June 2015
2 A trader depreciates fixtures and fittings at the rate of 10% a year on cost. On 1 January 2014 a purchase of new fixtures and fittings, $5000, was posted to the advertising account in error. What was the effect of this error on the trader’s capital account on 31 December 2014? A overstated $4500 B overstated $5000 C understated $4500 D understated $5000
1 marks
Answer: C
This question in 9706/13 May/June 2015
Q146 · A summary of a trader’s bank statements for his first year of trading showed the… 9706/13 May/June 2015
6 A summary of a trader’s bank statements for his first year of trading showed the following amounts. $ receipts from credit customers 25 000 takings from cash sales banked 82 000 The trader took $2000 a month from takings as drawings before banking them. Trade receivables at the year end amounted to $9500. What was total revenue for the year? A $73 500 B $92 500 C $121 500 D $140 500
1 marks
Answer: D
This question in 9706/13 May/June 2015
Q147 · A business maintains control accounts as part of its double entry system 9706/13 May/June 2015
8 A business maintains control accounts as part of its double entry system. Which error would cause an entry in the suspense account? A A page total from the purchases journal was posted as $9780 rather than the correct figure of $9870. B Carriage outwards is credited to the carriage outwards account but correctly accounted for in the cash book. C Discounts allowed are debited to the discounts allowed account and credited to the purchases ledger control account. D Repairs to a vehicle are debited to the vehicles account.
1 marks
Answer: B
This question in 9706/13 May/June 2015
Q148 · A business had a draft loss for the year of $4650 9706/11 Oct/Nov 2015
5 A business had a draft loss for the year of $4650. Further adjustments were required. 1 a write off of $165 for bad debts 2 a reduction of $300 in the provision for doubtful debts What was the loss for the year after these adjustments? A $4185 B $4515 C $4785 D $5115
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q149 · A business provides the following information 9706/11 Oct/Nov 2015
11 A business provides the following information. $ cash received from customers 200 000 opening trade receivables 40 000 closing trade receivables 30 000 discounts allowed 5 000 provision for doubtful debts 4 000 How much are the credit sales? A $190 000 B $195 000 C $199 000 D $215 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q150 · The trial balance of a business does not agree 9706/11 Oct/Nov 2015
12 The trial balance of a business does not agree. The difference has been entered in a suspense account. The error was caused by a cheque for $400 from Omar being debited to Omar’s account. Which entries correct this? account debited $ account credited $ A bank 400 suspense 400 B suspense 400 Omar 400 C suspense 800 Omar 800 D suspense 800 bank 800
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2015
Q151 · A business has the following balances at the end of its financial period 9706/11 Oct/Nov 2015
13 A business has the following balances at the end of its financial period. $ trade receivables 10 620 bad debt not yet written off 260 provision for doubtful debts brought forward 460 What should the business do if it wishes to maintain the bad debt provision at 5% of trade receivables? A Decrease the existing provision by $58. B Increase the existing provision by $58. C Decrease the existing provision by $71. D Increase the existing provision by $71.
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q152 · Motor vehicles purchased for $530 000 at the start of the year have been incorrectly… 9706/11 Oct/Nov 2015
14 Motor vehicles purchased for $530 000 at the start of the year have been incorrectly depreciated for the whole year at 10% instead of 25%. Ledger balances after the entries have been posted: $ motor vehicles at cost 530 000 provision for depreciation 53 000 Which entries will correct the error? account to be debited $ account to be credited $ A income statement 79 500 provision for depreciation 79 500 of motor vehicles B income statement 132 500 provision for depreciation 132 500 of motor vehicles C provision for depreciation 79 500 income statement 79 500 of motor vehicles D provision for depreciation 132 500 income statement 132 500 of motor vehicles
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2015
Q153 · An item of revenue expenditure is wrongly treated as capital expenditure 9706/12 Oct/Nov 2015
4 An item of revenue expenditure is wrongly treated as capital expenditure. What is the effect of this error? non-current profit for the assets year A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2015
Q154 · A trial balance at 30 June, before making end of year adjustments, showed the following 9706/12 Oct/Nov 2015
6 A trial balance at 30 June, before making end of year adjustments, showed the following. debit credit $ $ trade receivables 35 600 – provision for doubtful debts – 1 160 At 30 June, it was decided to write off a bad debt of $1600 and to make a provision for doubtful debts equal to 2% of trade receivables. What was the total decrease in the profit for the year ended 30 June arising from the bad and doubtful debts? A $680 B $1120 C $2080 D $2280
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2015
Q155 · A sales return of $400 has been credited to the customer’s account as $40 9706/12 Oct/Nov 2015
10 A sales return of $400 has been credited to the customer’s account as $40. A suspense account is created to complete the trial balance. What is the balance on the suspense account? A $360 Credit B $360 Debit C $440 Credit D $440 Debit
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2015
Q156 · A business provided the following information 9706/12 Oct/Nov 2015
12 A business provided the following information. $ 1 April purchases ledger credit balance 16 725 30 April credit purchases for the month 42 653 30 April payments made to trade payables 37 324 30 April purchases returns 723 What is the balance on the purchases ledger control account at 30 April? A $12 119 B $21 331 C $59 378 D $62 529
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2015
Q157 · Rachel’s trial balance did not agree and she placed the difference in a suspense account 9706/12 Oct/Nov 2015
14 Rachel’s trial balance did not agree and she placed the difference in a suspense account. The following shows how four errors have been corrected using the suspense account. suspense account $ $ difference in trial balance 200 discount received 310 discount allowed 160 sundry expenses 390 cash 340 700 700 The profit for the year before the errors were corrected was $35 400. What is the correct profit for the year? A $34 520 B $34 540 C $34 860 D $35 480
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2015
Q158 · A bank reconciliation statement has been prepared by an inexperienced book-keeper 9706/12 Oct/Nov 2015
15 A bank reconciliation statement has been prepared by an inexperienced book-keeper. $ bank statement balance (overdrawn) (68 100) cheques received not paid in 141 200 209 300 cheques paid to suppliers, not yet presented (41 800) cash book balance (overdrawn) (167 500) What is the correct bank balance according to the cash book? A $31 300 overdrawn B $31 300 C $167 500 overdrawn D $167 500
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2015
Q159 · An invoice for purchases was credited to the purchases account 9706/12 Oct/Nov 2015
16 An invoice for purchases was credited to the purchases account. How is the balance on the purchases account corrected? A decrease by the value of the invoice B decrease by twice the value of the invoice C increase by the value of the invoice D increase by twice the value of the invoice
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2015
Q160 · A business makes a provision for doubtful debts equal to 10% of trade receivables 9706/13 Oct/Nov 2015
8 A business makes a provision for doubtful debts equal to 10% of trade receivables. The provision at 31 March 2013 was $8300. The trade receivables after the provision on 31 March 2014 were $55 800. What is the change in provision over the 12 months? A $2100 decrease B $2100 increase C $2700 decrease D $2700 increase
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2015
Q161 · An entry of $700 in the discount received account had not been entered in the purchases… 9706/13 Oct/Nov 2015
9 An entry of $700 in the discount received account had not been entered in the purchases ledger. During the year a machine was sold for $1000. There was only one entry made and it was a credit in the bank account. What is the balance on the suspense account? A $1700 credit B $1700 debit C $2700 credit D $2700 debit
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q162 · A creditor for $720 transferred from the purchases ledger has been entered on the wrong… 9706/13 Oct/Nov 2015
13 A creditor for $720 transferred from the purchases ledger has been entered on the wrong side of the sales ledger control account. The sales ledger control account has a closing balance of $92 460, before correcting the transfer. A provision for doubtful debts of $1000 is to be made. What is the correct balance on the sales ledger control account? A $90 020 B $91 020 C $91 740 D $92 180
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q163 · A sales ledger control account was prepared 9706/12 Feb/March 2016
5 A sales ledger control account was prepared. An irrecoverable debt of $40 was omitted and a discount allowed of $68 was entered as $86. What was the total effect of these errors on the closing balance of the sales ledger control account? A $22 overstated B $22 understated C $58 overstated D $58 understated
1 marks
Answer: A
This question in 9706/12 Feb/March 2016
Q164 · The trial balance totals are as follows: debit $500 150 credit $500 000 Which error could… 9706/12 Feb/March 2016
6 The trial balance totals are as follows: debit $500 150 credit $500 000 Which error could have caused the difference? A A cash sale has only been recorded in the sales account. B A credit purchase has only been recorded in a supplier’s account. C A credit sale has not been recorded. D A credit sale has only been recorded in a customer’s account.
1 marks
Answer: D
This question in 9706/12 Feb/March 2016
Q165 · The total of trade payables balances in Konrad’s purchases ledger was $57 400 9706/11 May/June 2016
4 The total of trade payables balances in Konrad’s purchases ledger was $57 400. The following errors were then discovered. $ discount allowed overcast in cash book 2000 returns outwards omitted in a supplier’s account 350 payments to trade payables undercast in cash book 137 purchases journal overcast 500 What is the correct total of trade payables balances? A $54 413 B $54 913 C $55 050 D $57 050
1 marks
Answer: D
This question in 9706/11 May/June 2016
Q166 · The debit balance on a company's sales ledger control account was $125 000 9706/11 May/June 2016
5 The debit balance on a company's sales ledger control account was $125 000. The following errors were then discovered. 1 A bad debt of $800 had not been entered in the sales ledger control account. 2 An increase in the provision for doubtful debts of $500 was required. 3 The sales journal had been overcast by $1000. What was the total of the balances in the sales ledger? A $122 700 B $123 200 C $124 000 D $125 200
1 marks
Answer: B
This question in 9706/11 May/June 2016
Q167 · A business’s suspense account appears as follows 9706/11 May/June 2016
6 A business’s suspense account appears as follows. $ $ discount allowed 150 opening balance 100 sales 50 150 150 Which statements are correct? 1 Total debits had been $100 less than total credits in the trial balance. 2 The sales account had been overcast by $50. 3 The discount allowed account had been overcast by $150. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: C
This question in 9706/11 May/June 2016
Q168 · A bank statement shows a credit balance of $1500 9706/11 May/June 2016
7 A bank statement shows a credit balance of $1500. A payment of $500 and a receipt of $1250 were included in the cash book but have not yet appeared on the bank statement. Bank interest payable of $1100 had been correctly recorded in the cash book but due to a bank error had been recorded in the bank statement as $1000. What is the cash book balance? A $650 B $850 C $2150 D $3350
1 marks
Answer: C
This question in 9706/11 May/June 2016
Q169 · Which statement about the sales ledger control account is correct? 9706/12 May/June 2016
5 Which statement about the sales ledger control account is correct? A It is to verify the total of the customers' account balances in the sales ledger. B It is used to calculate the gross profit on sales. C It is used to calculate the total sales for the year. D It is used to reconcile the cash received from customers with the bank statement.
1 marks
Answer: A
This question in 9706/12 May/June 2016
Q170 · In which book of prime entry is the contra between the sales ledger control account and… 9706/12 May/June 2016
6 In which book of prime entry is the contra between the sales ledger control account and the purchase ledger control account recorded? A cash book B general journal C purchases journal D sales journal
1 marks
Answer: B
This question in 9706/12 May/June 2016
Q171 · A business omitted discounts allowed of $700 from its trial balance 9706/12 May/June 2016
7 A business omitted discounts allowed of $700 from its trial balance. During the year a machine had been sold for cash of $500 but the only accounting entry made was a debit in the bank account. What is the balance on the suspense account before these errors are corrected? A $200 debit B $1200 debit C $200 credit D $1200 credit
1 marks
Answer: A
This question in 9706/12 May/June 2016
Q172 · In an income statement carriage outwards of $5000 has been treated as carriage inwards 9706/12 May/June 2016
8 In an income statement carriage outwards of $5000 has been treated as carriage inwards. Carriage inwards of $3000 has been treated as carriage outwards. What are the effect(s) of these errors on the profit? gross profit profit for the year A overstated by $2000 understated by $2000 B overstated by $8000 no effect C understated by $2000 no effect D understated by $8000 overstated by $8000
1 marks
Answer: C
This question in 9706/12 May/June 2016
Q173 · The total of trade payables balances in Konrad’s purchases ledger was $57 400 9706/13 May/June 2016
4 The total of trade payables balances in Konrad’s purchases ledger was $57 400. The following errors were then discovered. $ discount allowed overcast in cash book 2000 returns outwards omitted in a supplier’s account 350 payments to trade payables undercast in cash book 137 purchases journal overcast 500 What is the correct total of trade payables balances? A $54 413 B $54 913 C $55 050 D $57 050
1 marks
Answer: D
This question in 9706/13 May/June 2016
Q174 · The debit balance on a company's sales ledger control account was $125 000 9706/13 May/June 2016
5 The debit balance on a company's sales ledger control account was $125 000. The following errors were then discovered. 1 A bad debt of $800 had not been entered in the sales ledger control account. 2 An increase in the provision for doubtful debts of $500 was required. 3 The sales journal had been overcast by $1000. What was the total of the balances in the sales ledger? A $122 700 B $123 200 C $124 000 D $125 200
1 marks
Answer: B
This question in 9706/13 May/June 2016
Q175 · A business’s suspense account appears as follows 9706/13 May/June 2016
6 A business’s suspense account appears as follows. $ $ discount allowed 150 opening balance 100 sales 50 150 150 Which statements are correct? 1 Total debits had been $100 less than total credits in the trial balance. 2 The sales account had been overcast by $50. 3 The discount allowed account had been overcast by $150. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: C
This question in 9706/13 May/June 2016
Q176 · A bank statement shows a credit balance of $1500 9706/13 May/June 2016
7 A bank statement shows a credit balance of $1500. A payment of $500 and a receipt of $1250 were included in the cash book but have not yet appeared on the bank statement. Bank interest payable of $1100 had been correctly recorded in the cash book but due to a bank error had been recorded in the bank statement as $1000. What is the cash book balance? A $650 B $850 C $2150 D $3350
1 marks
Answer: C
This question in 9706/13 May/June 2016
Q177 · A book-keeper compared the business bank statement with the cash book 9706/11 Oct/Nov 2016
5 A book-keeper compared the business bank statement with the cash book. He then updated the cash book and finally prepared a bank reconciliation statement. Why was the bank reconciliation statement prepared? A to ensure no transactions had been omitted from the cash book B to establish the value of unpresented cheques C to explain the difference between the cash book balance and the bank statement balance D to find out if any cheques had been dishonoured
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2016
Q178 · A suspense account was opened to record the difference on a trial balance 9706/11 Oct/Nov 2016
6 A suspense account was opened to record the difference on a trial balance. The following errors were then discovered. 1 Discount allowed of $2000 had only been entered in the sales ledger control account. 2 A cheque for $1500 paid for repairs had been entered as $5100 in the repairs account. What was the opening balance on the suspense account? A $1600 credit B $1600 debit C $5600 credit D $5600 debit
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q179 · A company’s trial balance showed trade receivables of $14 600 and an existing provision… 9706/11 Oct/Nov 2016
8 A company’s trial balance showed trade receivables of $14 600 and an existing provision for doubtful debts of $470. It was discovered that the trade receivables included an irrecoverable debt of $500. A contra entry of $400 was also to be made. The provision for doubtful debts is to be maintained at 5% of trade receivables. Which amount for doubtful debts was charged in the income statement? A $215 B $235 C $470 D $685
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q180 · A business did not maintain control accounts as part of its double entry books of account 9706/11 Oct/Nov 2016
9 A business did not maintain control accounts as part of its double entry books of account. An examination of its books revealed the following errors. 1 The purchases journal was undercast by $100. 2 A sales invoice, $180, was entered in the sales journal twice. What was the effect of the errors on the trial balance? A credit side higher by $100 B credit side higher by $280 C debit side higher by $100 D debit side higher by $280
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q181 · The year-end balance in the cash book was $23 780 9706/12 Oct/Nov 2016
5 The year-end balance in the cash book was $23 780. This was different from the balance on the bank statement. The difference was due to the following items. $ bank charges 216 a customer’s cheque which was dishonoured 1375 a bank error meant a cheque was incorrectly 560 debited to the bank account What should be the value of bank in the statement of financial position? A $21 629 B $22 189 C $25 371 D $25 931
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2016
Q182 · At the end of the year, the balance on a firm’s sales ledger control account was $12 900 9706/12 Oct/Nov 2016
6 At the end of the year, the balance on a firm’s sales ledger control account was $12 900. The total of the customers’ accounts in sales ledger was $11 900. The following errors were then discovered. 1 A customer’s account had been undercast by $700. 2 A contra with a supplier in the purchases ledger of $200 had only been entered in the sales ledger control account. 3 The discount allowed column in the cash book totalled $500. This had not been posted to the nominal ledger. What was the correct balance on the sales ledger control account? A $11 200 B $11 400 C $12 000 D $12 400
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2016
Q183 · A suspense account has a balance of $450 debit 9706/12 Oct/Nov 2016
7 A suspense account has a balance of $450 debit. What has caused this balance in the suspense account? A motor expenses of $225, correctly entered in the cash book, and posted to motor expenses as a credit B motor expenses of $225, entered in the cash book as a receipt and posted to motor expenses as a credit C motor expenses of $450, correctly entered in the cash book, and posted to motor vehicles as a debit D motor expenses of $675, entered in the cash book as a credit of $225 and posted to motor expenses as $225 debit
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2016
Q184 · A company received the bank statement dated 30 June 2016 showing a credit balance of $6890 9706/13 Oct/Nov 2016
6 A company received the bank statement dated 30 June 2016 showing a credit balance of $6890. The cash book on this date had a debit balance of $7234. The following was discovered. Bank charges of $54 have not been entered in the cash book. Suppliers have not banked cheques of $200. Deposits of $490 made to the bank on 30 June 2016 have not been shown on the bank statement. What is the value of bank in the statement of financial position? A $6600 B $6654 C $7126 D $7180
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2016
Q185 · A trial balance includes a suspense account 9706/13 Oct/Nov 2016
7 A trial balance includes a suspense account. The following errors are found. 1 A payment for the telephone bill for $75 has been entered correctly in the bank account but as $750 in the telephone account. 2 A payment from a customer for $175 has been entered correctly in the bank account but omitted from the sales ledger control account (SLCA) which forms part of the double entry system. Which journal entry corrects these errors? Debit Credit $ $ A suspense 850 telephone 675 SLCA 175 B suspense 850 telephone 675 SLCA 175 C suspense 500 telephone 675 SLCA 175 D suspense 500 telephone 675 SLCA 175
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2016
Q186 · A business had a profit for the year of $450 000 before correcting the following errors 9706/13 Oct/Nov 2016
8 A business had a profit for the year of $450 000 before correcting the following errors. 1 Closing inventory was undervalued by $15 000. 2 Sales returns of $5000 had been recorded as purchases returns. 3 The charge for depreciation was overstated by $20 000. What was the profit after correcting these errors? A $435 000 B $445 000 C $475 000 D $495 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2016
Q187 · A book-keeper reconciles the control accounts with the sales and purchase ledgers 9706/13 Oct/Nov 2016
13 A book-keeper reconciles the control accounts with the sales and purchase ledgers. Which errors are identified in this way? 1 A figure was transposed when copied from a book of prime entry to a personal account. 2 An incorrect amount was entered in a book of prime entry. 3 A total in a book of prime entry was incorrect. 4 A transaction was omitted from a book of prime entry. A 1, 2 and 3 B 1, 2 and 4 C 1 and 3 only D 2 and 4 only
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2016
Q188 · Why is a sales ledger control account used? 9706/12 Feb/March 2017
4 Why is a sales ledger control account used? 1 to control discounts received 2 to ensure credit customers pay promptly 3 to provide a trial balance figure for trade receivables A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/12 Feb/March 2017
Q189 · A purchases ledger control account was prepared but contained a number of errors 9706/12 Feb/March 2017
5 A purchases ledger control account was prepared but contained a number of errors. purchases ledger control account $ $ balance b/d 45 750 cash paid to credit suppliers 19 730 credit purchases 20 380 cash discounts received 1 500 cash purchases 19 440 refunds from credit suppliers 3 500 balance c/d 60 840 85 570 85 570 What was the correct balance carried down? A $47 100 B $48 400 C $60 840 D $67 840
1 marks
Answer: B
This question in 9706/12 Feb/March 2017
Q190 · A suspense account shows a debit balance of $350 9706/12 Feb/March 2017
6 A suspense account shows a debit balance of $350. What could have caused this? A A purchase of $350 was debited to the rent account. B A purchase of $350 was omitted from the purchases journal. C A sale of $350 was debited to the sales account and credited to the sales ledger control account. D The sales journal was overcast by $350.
1 marks
Answer: D
This question in 9706/12 Feb/March 2017
Q191 · At the year end a cash book shows a credit balance of $4800 9706/11 May/June 2017
6 At the year end a cash book shows a credit balance of $4800. The bank statement included bank charges of $25 which had not been included in the cash book. Cheque payments entered in the cash book before the year end to the value of $250 had not yet cleared the bank. How would the bank balance be shown in the statement of financial position? $ A current asset 4775 B current liability 4825 C current asset 5025 D current liability 5075
1 marks
Answer: B
This question in 9706/11 May/June 2017
Q192 · A purchases ledger control account has been reconciled with the purchases ledger balances… 9706/11 May/June 2017
7 A purchases ledger control account has been reconciled with the purchases ledger balances as follows. $ balance of the control account 70 000 total of a page in the purchases journal 2 000 not posted to general ledger discount allowed by trade payables not 1 500 posted to the purchases ledger total of balances in the purchases ledger 73 500 Which value for trade payables should be shown in the statement of financial position? A $68 000 B $70 500 C $72 000 D $73 500
1 marks
Answer: C
This question in 9706/11 May/June 2017
Q193 · Trade receivable balances at the start of a period were $30 000 and were $38 000 at the… 9706/11 May/June 2017
8 Trade receivable balances at the start of a period were $30 000 and were $38 000 at the end. During that period: $ credit sales 60 000 irrecoverable debt written off 1 000 customer discounts allowed 2 000 How much did the company receive from its customers in the period? A $49 000 B $52 000 C $65 000 D $68 000
1 marks
Answer: A
This question in 9706/11 May/June 2017
Q194 · The following errors were found after a suspense account was opened 9706/12 May/June 2017
5 The following errors were found after a suspense account was opened. 1 Motor repairs of $400 were credited to the motor vehicle at cost account. 2 A payment for electricity was debited in the electricity account as $2500 instead of $5200. 3 A $450 cash purchase of goods for resale had been completely omitted from the books. 4 Discount allowed of $50 had been debited to the discounts received account. Which items would be entered in the suspense account? A 1 and 2 B 2 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: A
This question in 9706/12 May/June 2017
Q195 · Which items appear in a sales ledger control account? 9706/12 May/June 2017
6 Which items appear in a sales ledger control account? 1 cash discount allowed 2 credit sales 3 payments to trade payables 4 returns inwards A 1, 2 and 3 B 1, 2 and 4 C 1, 3 and 4 D 2, 3 and 4
1 marks
Answer: B
This question in 9706/12 May/June 2017
Q196 · The following items are recorded in the cash book of a business but not yet recorded in… 9706/12 May/June 2017
8 The following items are recorded in the cash book of a business but not yet recorded in its bank statement. $ cheques drawn 3000 amounts banked 250 The cash book shows a bank balance of $2600 credit. What is the balance on the bank statement? A $150 credit B $150 debit C $400 credit D $400 debit
1 marks
Answer: A
This question in 9706/12 May/June 2017
Q197 · The purchases ledger control account had a closing balance of $20 000 9706/13 May/June 2017
6 The purchases ledger control account had a closing balance of $20 000. Purchases returns of $1500 had been entered on the wrong side of the control account. What was the correct balance? A $17 000 B $18 500 C $21 500 D $23 000
1 marks
Answer: A
This question in 9706/13 May/June 2017
Q198 · The cash book of a business shows a debit balance of $4200 at 30 April 9706/13 May/June 2017
7 The cash book of a business shows a debit balance of $4200 at 30 April. A direct debit payment of $200 for insurance appeared on the bank statement but had not yet been entered in the cash book. A cheque paid to a supplier, correctly entered as $650 in the cash book, appeared as $690 on the bank statement. What is the value of bank shown in the statement of financial position at 30 April? A $3960 B $4000 C $4360 D $4400
1 marks
Answer: B
This question in 9706/13 May/June 2017
Q199 · A bookkeeper prepared a sales ledger control account 9706/13 May/June 2017
8 A bookkeeper prepared a sales ledger control account. The following errors were then discovered. 1 An invoice posted to an individual customer’s account had been recorded as $95 instead of $59. 2 The total of receipts from customers had been undercast by $200. 3 Discount received from suppliers had been included in the control account. 4 A provision for doubtful debts had been included in the control account. Which errors would result in the closing balance on the control account failing to agree with the total of the customers’ account balances? A 1, 2, 3 and 4 B 1, 2 and 3 only C 1 and 4 only D 3 and 4 only
1 marks
Answer: A
This question in 9706/13 May/June 2017
Q200 · The owner of a transport business purchased a motor vehicle 9706/11 Oct/Nov 2017
5 The owner of a transport business purchased a motor vehicle. This was charged to the motor expenses account. What were the effects of this on the end-of-year statement of financial position? non-current assets current assets capital account A overstated no effect overstated B overstated overstated no effect C understated no effect understated D understated understated no effect
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2017
Q201 · A company has obtained the following information for the year ended 31 December 9706/11 Oct/Nov 2017
6 A company has obtained the following information for the year ended 31 December. $ opening balance on sales ledger control account 31 000 closing balance on sales ledger control account 35 000 discount allowed 2 300 credit sales 125 400 What was the amount of cash received from the customers? A $119 100 B $123 700 C $127 100 D $131 700
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2017
Q202 · X sent goods to Y on a sale or return basis but treated them as a sale of $1200 9706/11 Oct/Nov 2017
7 X sent goods to Y on a sale or return basis but treated them as a sale of $1200. The goods had a cost price of $750. A trial balance was extracted from the ledger and the following balances were included. account $ revenue 31 250 trade receivables 14 100 Inventory had been valued at $2300. What should have been the correct values? revenue trade receivables inventory $ $ $ A 30 050 12 900 3050 B 30 050 13 650 3050 C 30 800 13 650 3500 D 30 800 14 850 3500
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2017
Q203 · A business owner suspects that a loss of cash has occurred 9706/11 Oct/Nov 2017
8 A business owner suspects that a loss of cash has occurred. He provides the data shown. $ cash balance at the start of the month 150 cash balance at the end of the month 100 cash banked 10 200 cash sales for the month 10 500 How much cash has been lost? A $200 B $250 C $300 D $350
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2017
Q204 · Henry received a credit note from a supplier 9706/11 Oct/Nov 2017
9 Henry received a credit note from a supplier. He treated this in error as an invoice received and entered it in his purchases journal. When was the error revealed? A when Henry compared his cash book with his bank statement B when Henry compared his purchases ledger with statements of account received C when Henry prepared a purchases ledger control account D when Henry prepared a trial balance
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2017
Q205 · Why does a business keep a sales ledger control account? 9706/12 Oct/Nov 2017
5 Why does a business keep a sales ledger control account? 1 It helps deter fraud. 2 It helps with the preparation of financial statements. 3 It identifies doubtful debt easily. 4 It predicts the sales for the coming year. A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2017
Q206 · A sales ledger control account had a debit balance of $38 600 9706/12 Oct/Nov 2017
6 A sales ledger control account had a debit balance of $38 600. The total of individual sales ledger debit balances was $36 500. The only errors found were as follows. An irrecoverable debt had been recorded in the ledger of Smith but not the control account. The sales journal was undercast by $1500. A contra of $1750 had been correctly recorded in the control account but only $1250 recorded in the ledgers. What was the value of the irrecoverable debt? A $100 B $1100 C $3100 D $4100
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2017
Q207 · The following information is available 9706/12 Oct/Nov 2017
7 The following information is available. $ provision for doubtful debts at the beginning of the year 6 250 trade receivables at the end of the year 93 750 Provision for doubtful debts is to be maintained at 6% of trade receivables. Which effect will the provision for doubtful debts have on profit for the year in the income statement? A decrease by $625 B decrease by $5625 C increase by $625 D increase by $5625
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2017
Q208 · At 31 December the following information is available about a company’s banking… 9706/12 Oct/Nov 2017
8 At 31 December the following information is available about a company’s banking transactions. $ balance at bank per bank statement 22 650 uncleared deposits 3 110 unpresented cheques 6 290 bank credit recorded twice by bank in error 650 Which value for bank should be recorded in the statement of financial position at 31 December? A $18 820 B $20 120 C $25 180 D $26 480
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2017
Q209 · The following errors in the accounting records have been found and corrected: 1 A… 9706/13 Oct/Nov 2017
5 The following errors in the accounting records have been found and corrected: 1 A purchase invoice for $250 was omitted from the books of account. 2 A sale for $120 to X was debited to the account of Y. 3 The sales journal was over-added by $100. The gross profit for the year before correcting the errors was $60 200. What is the correct gross profit for the year? A $59 850 B $59 970 C $60 350 D $60 550
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2017
Q210 · A trial balance does not agree and the book-keeper finds the following errors 9706/13 Oct/Nov 2017
6 A trial balance does not agree and the book-keeper finds the following errors. 1 A bank overdraft of $100 was shown as a debit in the trial balance. 2 A telephone invoice for $400 was debited to the insurance account. 3 A cash purchase of $160 was entered in the purchases account as $150; the purchase was entered correctly in the cash account. The book-keeper opens a suspense account in order to correct the errors. What is the opening entry in the suspense account? A credit $190 B credit $210 C debit $60 D debit $550
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2017
Q211 · For which of these purposes can the purchases ledger control account be used? 9706/13 Oct/Nov 2017
7 For which of these purposes can the purchases ledger control account be used? 1 to warn of possible errors in the purchases ledger 2 to show that there are errors in the purchases journal 3 to provide quick totals of trade payables 4 to guarantee the accuracy of the purchases ledger A 1 and 2 B 1 and 3 C 1 and 4 D 2 and 3
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2017
Q212 · At 31 December a business provides the following information 9706/13 Oct/Nov 2017
10 At 31 December a business provides the following information. $ balance per the cash book 790 credit balance per the bank statement 800 debit unpresented cheques 30 The only other reconciling item between the cash book and the bank statement is bank charges recorded on the bank statement but not in the cash book. How much are the bank charges? A $10 B $20 C $30 D $40
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2017
Q213 · Which errors cannot be identified by reconciling a sales ledger control account with the… 9706/13 Oct/Nov 2017
11 Which errors cannot be identified by reconciling a sales ledger control account with the sales ledger balances? 1 entering an incorrect amount from a customer’s invoice into the sales journal 2 not recording a discount allowed to a customer into the three column cash book 3 posting the value of a dishonoured cheque from the cash book to the credit side of the sales ledger control account 4 posting the sales returns journal total to the debit side of the sales ledger control account A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2017
Q214 · The table shows information in a purchases ledger control account at the year-end 9706/12 Feb/March 2018
5 The table shows information in a purchases ledger control account at the year-end. $ cash paid to suppliers 36 000 credit purchases 55 000 discount received 7 800 balance carried down (balancing figure) 35 000 What was the credit balance brought down at the beginning of the year? A $8200 B $23 800 C $46 200 D $61 800
1 marks
Answer: B
This question in 9706/12 Feb/March 2018
Q215 · Which error would affect the balancing of a trial balance? 9706/12 Feb/March 2018
7 Which error would affect the balancing of a trial balance? A A payment for rent of $250 has been debited in the bank account. It has been entered correctly in the rent account. B A purchase invoice for $259 was entered in the purchases journal. C A sales invoice for $180 was lost, before it could be entered in the sales journal. D A sales return of $500 was debited in the customer’s account and credited to the purchases returns account.
1 marks
Answer: A
This question in 9706/12 Feb/March 2018
Q216 · Which group would appear only on the credit side of a sales ledger control account? 9706/12 Feb/March 2018
8 Which group would appear only on the credit side of a sales ledger control account? A cash refunds, contras with the purchases ledger control accounts, sales B cash refunds, contras with the purchases ledger control accounts, sales returns C irrecoverable debts written off, cash received, discounts allowed D irrecoverable debts written off, cash refunds, sales
1 marks
Answer: C
This question in 9706/12 Feb/March 2018
Q217 · A business has provided the following information 9706/11 May/June 2018
5 A business has provided the following information. $ provision for doubtful debts at 1 January 2017 2 950 trade receivables at 31 December 2017 75 000 The provision for doubtful debts is to be maintained at 5% of trade receivables. Which entries are made at 31 December 2017? income provision for doubtful statement debts account A $800 credit $800 debit B $800 debit $800 credit C $3750 credit $3750 debit D $3750 debit $3750 credit
1 marks
Answer: B
This question in 9706/11 May/June 2018
Q218 · What is the use of a sales ledger control account? 9706/11 May/June 2018
6 What is the use of a sales ledger control account? A to assist in the location of errors B to calculate the value of irrecoverable debts to be written off C to determine the value of total sales revenue D to identify possible contras with purchases ledger control account
1 marks
Answer: A
This question in 9706/11 May/June 2018
Q219 · A business provided the following information for a month 9706/11 May/June 2018
8 A business provided the following information for a month. $ credit sales 16 810 sales returns 1 150 discounts allowed 276 irrecoverable debts written off 100 increase in provision for doubtful debts 600 increase in trade receivables 406 How much cash was received from trade receivables during the month? A $14 278 B $14 878 C $15 154 D $15 690
1 marks
Answer: B
This question in 9706/11 May/June 2018
Q220 · At the end of the year, the debit balance on a sales ledger control account was $15 000 9706/11 May/June 2018
9 At the end of the year, the debit balance on a sales ledger control account was $15 000. It was later discovered that when a customer who owed the business $500 had paid, she had taken a cash discount of $20. This was correctly entered in the discount column of the cash book and the full $500 was entered in the bank column. Which value for trade receivables should be included in the statement of financial position? A $14 520 B $14 980 C $15 000 D $15 020
1 marks
Answer: D
This question in 9706/11 May/June 2018
Q221 · A returns inward of $180 has been wrongly recorded as carriage inwards 9706/11 May/June 2018
10 A returns inward of $180 has been wrongly recorded as carriage inwards. What is the impact on profit of the correction of this error? A decreased by $360 B increased by $180 C increased by $360 D no effect
1 marks
Answer: D
This question in 9706/11 May/June 2018
Q222 · The correction of which error requires an entry in the suspense account? 9706/11 May/June 2018
12 The correction of which error requires an entry in the suspense account? A A cheque, $1000, paid to Kong had been debited to Kang’s account. B A purchase of stamps, $50, had been debited to the purchases account. C Commission income, $170, had been debited to a loan interest account. D The insurance account had been undercast by $200 and the wages account had been overcast by $200.
1 marks
Answer: C
This question in 9706/11 May/June 2018
Q223 · Errors can exist in the preparation of both the sales ledger and the sales ledger control… 9706/12 May/June 2018
6 Errors can exist in the preparation of both the sales ledger and the sales ledger control account. Which error would require an adjustment in the sales ledger control account only to correct it? A sales journal being overcast B sales transaction amount originally entered incorrectly C sales transaction omitted completely D sales transaction recorded in wrong customer account
1 marks
Answer: A
This question in 9706/12 May/June 2018
Q224 · The trial balance of a business did not balance 9706/12 May/June 2018
7 The trial balance of a business did not balance. The following errors were found. 1 The total of the purchases journal of $33 030 had been posted to the purchases account in the general ledger as $33 000. 2 Discount received of $50 had been entered on the debit side of the discount received account. What was the original balance on the suspense account? A $20 credit B $20 debit C $70 credit D $70 debit
1 marks
Answer: C
This question in 9706/12 May/June 2018
Q225 · The bank column of a cash book showed a credit balance of $5000 9706/12 May/June 2018
8 The bank column of a cash book showed a credit balance of $5000. There were unpresented cheques amounting to $1500. The bank statement showed bank charges, $700, which were not recorded in the cash book. What is the balance on the bank statement? A $4200 credit B $4200 debit C $5800 credit D $5800 debit
1 marks
Answer: B
This question in 9706/12 May/June 2018
Q226 · Fred wishes to identify the unpresented cheques of his business 9706/13 May/June 2018
5 Fred wishes to identify the unpresented cheques of his business. Which side of the cash book and which column of the bank statement does he need to compare? cash book bank statement A credit side credit column B credit side debit column C debit side credit column D debit side debit column
1 marks
Answer: B
This question in 9706/13 May/June 2018
Q227 · A purchases ledger control account shows the following 9706/13 May/June 2018
8 A purchases ledger control account shows the following. $ opening balance 1 200 closing balance 1 300 purchases 18 400 payments made 17 800 discount received 300 Which entry appears in the control account to record the contra with the sales ledger control account? A $200 credit B $200 debit C $800 credit D $800 debit
1 marks
Answer: B
This question in 9706/13 May/June 2018
Q228 · Which error would result in the creation of a suspense account? 9706/13 May/June 2018
9 Which error would result in the creation of a suspense account? A crediting the commission received account with rent received B crediting the discounts allowed account with the discounts received C debiting the bank interest paid account with bank interest received D debiting the motor expenses account with a purchase of a new car
1 marks
Answer: C
This question in 9706/13 May/June 2018
Q229 · At the start of the year a business had trade payables of $13 000 9706/13 May/June 2018
11 At the start of the year a business had trade payables of $13 000. At the end of the year it owed $15 000 to trade payables. During the year it paid them $190 000, after taking a cash discount of $10 000. What was the amount of the credit purchases for the year? A $188 000 B $192 000 C $198 000 D $202 000
1 marks
Answer: D
This question in 9706/13 May/June 2018
Q230 · Which items will be debited to accounts in the purchases ledger? 9706/11 Oct/Nov 2018
4 Which items will be debited to accounts in the purchases ledger? 1 discount allowed 2 payments to suppliers 3 purchases 4 purchases returns A 1 and 2 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2018
Q231 · A business keeps a separate sales ledger 9706/11 Oct/Nov 2018
5 A business keeps a separate sales ledger. Its nominal ledger includes a sales ledger control account. Which entry corrects the nominal ledger when the sales journal is undercast? account to debit account to credit A sales suspense B sales trade receivables C suspense sales D trade receivables sales
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2018
Q232 · Which statement is correct? 9706/11 Oct/Nov 2018
6 Which statement is correct? A The balance on the irrecoverable debts account is carried down to the next accounting period. B The balance on the irrecoverable debts account is treated as an expense in the income statement. C The balance on the provision for doubtful debts account is calculated before the deduction of irrecoverable debts. D The balance on the provision for doubtful debts account is not included in a trial balance.
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2018
Q233 · A trader has extracted the following information from his books of account at 31 March… 9706/12 Oct/Nov 2018
6 A trader has extracted the following information from his books of account at 31 March 2018. $ purchase ledger balances at 1 March 2018 32 100 credit purchases for March 26 400 cheques paid to credit suppliers in March 29 700 contra to sales ledger 600 discount received 400 What was the closing balance on the purchases ledger control account at 31 March 2018? A $27 800 B $29 800 C $29 000 D $34 400
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2018
Q234 · The table shows extracts from a business’s bank reconciliation 9706/12 Oct/Nov 2018
7 The table shows extracts from a business’s bank reconciliation. $ balance per cash book at 31 December 2075 debit balance per bank statement at 31 December 2250 credit bank charges per bank statement not entered in cash book 150 outstanding cheques not presented at the year end 325 What is the bank balance to be shown in the financial statements? A $1600 B $1925 C $2075 D $2225
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2018
Q235 · Bank interest income, $1800, had been correctly entered in the bank account but recorded… 9706/12 Oct/Nov 2018
8 Bank interest income, $1800, had been correctly entered in the bank account but recorded as interest expense. Which entries in the ledger will correct the error? account to account to $ $ be debited be credited A interest expense 1800 suspense 1800 B interest income 1800 suspense 1800 interest expense 1800 C suspense 1800 interest income 1800 D suspense 3600 interest income 1800 interest expense 1800
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2018
Q236 · A business maintains control accounts as part of its double entry 9706/13 Oct/Nov 2018
8 A business maintains control accounts as part of its double entry. The trial balance of the business did not balance and the difference was posted to a suspense account. On investigation, the following errors were found. The purchases journal had been overcast by $300. Discounts allowed of $100 had been posted to the credit of discounts received account. What was the balance on the suspense account before the correction of these errors? A $200 credit B $200 debit C $400 credit D $400 debit
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2018
Q237 · The closing balance on a purchases ledger control account is $163 762 9706/13 Oct/Nov 2018
10 The closing balance on a purchases ledger control account is $163 762. The purchases journal has been undercast by $1000. What is the correct closing balance on the purchases ledger control account? A $162 762 B $163 762 C $164 762 D $165 762
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2018
Q238 · What is not a purpose of control accounts? 9706/12 Feb/March 2019
6 What is not a purpose of control accounts? A to assist in the preparation of financial statements B to identify all errors where the trial balance agrees C to provide a total for trade receivables and trade payables D to verify the accuracy of the individual ledger accounts
1 marks
Answer: B
This question in 9706/12 Feb/March 2019
Q239 · The balance on a sales ledger control account was $21 500 9706/12 Feb/March 2019
7 The balance on a sales ledger control account was $21 500. This did not agree with the total of the sales ledger account balances. It was discovered that a credit note for $200 sent to a credit customer had been posted to the debit of the customer’s account. What was the total of balances in the business’s sales ledger before the error was corrected? A $21 100 B $21 300 C $21 700 D $21 900
1 marks
Answer: D
This question in 9706/12 Feb/March 2019
Q240 · During the month of June, a business recorded the following information 9706/12 Feb/March 2019
8 During the month of June, a business recorded the following information. $ payments to credit suppliers during June 16 380 credit purchases for June 21 650 discount received 850 purchases ledger balances at the start of June 5 730 purchases returns during June 1 200 What was the purchases ledger control account balance at the end of June? A $8950 B $10 650 C $15 570 D $27 380
1 marks
Answer: A
This question in 9706/12 Feb/March 2019
Q241 · A bank statement shows a credit balance of $1500 9706/11 May/June 2019
5 A bank statement shows a credit balance of $1500. A payment of $500 and a receipt of $1250 were included in the cash book but have not yet appeared on the bank statement. Bank interest payable of $1100 had been correctly recorded in the cash book but due to a bank error had been recorded in the bank statement as $1000. What is the cash book balance? A $650 B $850 C $2150 D $3350
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q242 · A sales invoice to Jane has not been recorded in the books of prime entry 9706/11 May/June 2019
6 A sales invoice to Jane has not been recorded in the books of prime entry. Which accounts are affected by this error? sales ledger control Jane A no no B no yes C yes no D yes yes
1 marks
Answer: D
This question in 9706/11 May/June 2019
Q243 · A business’s suspense account appears as follows: $ $ discount allowed 150 opening… 9706/11 May/June 2019
7 A business’s suspense account appears as follows: $ $ discount allowed 150 opening balance 100 sales 50 150 150 Which statements are correct? 1 Total debits had been $100 less than total credits in the trial balance. 2 The sales account had been overcast by $50. 3 The discount allowed account had been overcast by $150. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q244 · The following information is available for a business 9706/11 May/June 2019
8 The following information is available for a business. The balance on its purchases ledger control account was $5900. The total of the balances in its purchases ledger was $5510. The following errors were discovered. 1 The purchases journal had been overcast by $250. 2 A sales ledger contra of $340 had been omitted from the purchases ledger control account. 3 A supplier was paid $400 which was correctly entered in the cash book but had been entered in the supplier’s account as $200. What is the correct value of trade payables? A $5110 B $5250 C $5310 D $5510
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q245 · A book-keeper compared the business bank statement with the cash book 9706/12 May/June 2019
5 A book-keeper compared the business bank statement with the cash book. He then updated the cash book and finally prepared a bank reconciliation statement. Why was the bank reconciliation statement prepared? A to ensure no transactions had been omitted from the cash book B to establish the value of unpresented cheques C to explain the difference between the cash book balance and the bank statement balance D to find out if any cheques had been dishonoured
1 marks
Answer: C
This question in 9706/12 May/June 2019
Q246 · On 31 December 2018, a business had the following balances 9706/12 May/June 2019
6 On 31 December 2018, a business had the following balances. $ sales ledger 12 800 sales ledger control account 15 200 Which error explains the difference between the two figures? A A credit balance of $1200 was brought forward as a debit balance in the sales ledger control account. B An irrecoverable debt of $2400 was omitted in a customer’s personal account in the sales ledger. C Purchases returns, $1200, were wrongly entered on the debit side of the sales ledger control account. D Sales returns, $1200, were entered twice in a customer’s personal account in the sales ledger.
1 marks
Answer: A
This question in 9706/12 May/June 2019
Q247 · The sales ledger control account of a business had a closing balance of $21 650 9706/13 May/June 2019
5 The sales ledger control account of a business had a closing balance of $21 650. This did not agree with the total of the sales ledger balances. The following errors were discovered. Discount allowed of $1460 was entered in the debit of the sales ledger control account. A sales invoice of $1200 to J Ravi had been entered in the account of J Rajid. A contra to the purchase ledger had been entered in the sales ledger correctly as $600 but in the sales ledger control account as $900. What is the correct balance of the sales ledger control account? A $19 030 B $20 490 C $24 870 D $25 770
1 marks
Answer: A
This question in 9706/13 May/June 2019
Q248 · A bank reconciliation statement shows a credit balance of $400 in the cash book and a… 9706/13 May/June 2019
6 A bank reconciliation statement shows a credit balance of $400 in the cash book and a balance in hand of $100 in the bank statements. The bank reconciliation statement includes unpresented cheques of $700 in addition to cheques banked and not yet credited in the bank statements. What is the total of cheques banked and not yet credited? A $200 B $400 C $1000 D $1200
1 marks
Answer: A
This question in 9706/13 May/June 2019
Q249 · A suspense account was opened when a trial balance failed to balance 9706/13 May/June 2019
7 A suspense account was opened when a trial balance failed to balance. It was then discovered that returns of $200 had been correctly entered in the supplier’s account but debited in the sales returns account. This was the only error. What was the balance on the suspense account before this error was corrected? A credit $200 B credit $400 C debit $200 D debit $400
1 marks
Answer: B
This question in 9706/13 May/June 2019
Q250 · A company prepared its purchases ledger control account which showed a balance of $15 960 9706/11 Oct/Nov 2019
5 A company prepared its purchases ledger control account which showed a balance of $15 960. The following items were then discovered. 1 Discounts received of $450 had been entered into the purchases ledger control account as $540. 2 A payment of $720 to a supplier had not been entered in his account. 3 The purchases ledger debit balances carried down totalling $110 had been omitted from the control account. 4 A contra of $170 had been entered in the purchases ledger but not in the purchases ledger control account. What was the correct total of the trade payables? A $15 050 B $15 240 C $15 990 D $16 150
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2019
Q251 · An accountant prepared a bank reconciliation statement 9706/11 Oct/Nov 2019
6 An accountant prepared a bank reconciliation statement. He discovered the following differences between the bank statement and the cash book. 1 an amount received from a customer by credit transfer 2 bank charges 3 unpresented cheques Which differences will need to be entered in the cash book to update it? A 1 and 2 only B 1, 2 and 3 C 1 and 3 only D 2 and 3 only
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2019
Q252 · A company prepared a sales ledger control account 9706/12 Oct/Nov 2019
5 A company prepared a sales ledger control account. The balance did not agree with the total of the sales ledger balances, which were $42 650. The following was discovered. 1 An irrecoverable debt of $500 in the general journal has not been recorded in the sales ledger. 2 The sales journal has been incorrectly added and must be reduced by $750. 3 The sales ledger control account includes the discount received of $400. It should have been discount allowed, $600. 4 Sales to J Brown, $640, have not been entered in his account. What was the correct total of the sales ledger balances? A $41 700 B $41 840 C $42 510 D $42 790
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2019
Q253 · The correction of which error would require an entry in the suspense account? 9706/12 Oct/Nov 2019
6 The correction of which error would require an entry in the suspense account? A $100 paid for vehicle repairs were debited to the vehicles account. B A sales invoice for $45 was omitted from the sales journal. C Drawings of $60 were debited in the cash book and were credited to the drawings account. D Wages, $150, were correctly recorded in the wages account and debited in the cash book.
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2019
Q254 · Which statement is not correct about the benefit to a business of maintaining control… 9706/13 Oct/Nov 2019
5 Which statement is not correct about the benefit to a business of maintaining control accounts? A ensures that all types of errors can be detected B helps in the preparation of financial statements C provides immediate totals of trade receivables and trade payables D reduces risk of fraud as jobs are performed by different staff members
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2019
Q255 · The sales ledger control account of a business showed a balance of $14 320 9706/13 Oct/Nov 2019
6 The sales ledger control account of a business showed a balance of $14 320. A customer, who owes $1000, has also supplied the business with $400 of goods. This was offset against the amount owed by the customer. What was the sales ledger control account balance after the offset? A $13 720 B $13 920 C $14 720 D $14 920
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2019
Q256 · A trader has suffered inventory losses due to theft during the year 9706/13 Oct/Nov 2019
11 A trader has suffered inventory losses due to theft during the year. What is necessary to calculate the value of the inventory stolen? 1 amounts banked for sales and spent on purchases 2 amounts spent for business expenses 3 inventory at the beginning and end of the year 4 percentage of mark-up on purchase price A 1, 2 and 3 B 1, 2 and 4 C 1, 3 and 4 D 2, 3 and 4
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2019
Q257 · A trial balance does not balance and a suspense account is opened 9706/12 Feb/March 2020
5 A trial balance does not balance and a suspense account is opened. Later the following errors are found and the suspense account is cleared. 1 A sales invoice for $1240 had been completely omitted from the books. 2 Purchases had been entered as $85 600. The correct amount should have been $87 580. 3 Rent paid of $2600 was entered correctly in the cash book but as $6200 in the rent account. What was the original balance on the suspense account? A $1620 credit B $1620 debit C $5580 credit D $5580 debit
1 marks
Answer: A
This question in 9706/12 Feb/March 2020
Q258 · A sales ledger control account included the following entries 9706/12 Feb/March 2020
6 A sales ledger control account included the following entries. 1 contra with the purchases ledger control account $500, debit 2 discount allowed $600, debit 3 irrecoverable debts written off $1200, debit Which entries must be corrected? A 1 and 2 only B 1 and 3 only C 1, 2 and 3 D 2 and 3 only
1 marks
Answer: C
This question in 9706/12 Feb/March 2020
Q259 · A company’s bank statement showed a credit balance of $2000 9706/12 Feb/March 2020
7 A company’s bank statement showed a credit balance of $2000. The following errors were found. 1 A receipt of $2700 and a payment for $3000 were recorded on the bank statement. Both had been omitted from the cash book. 2 Bank charges of $500 were correctly shown on the bank statement but had been recorded as $600 in the cash book. What was the cash book balance before the errors were corrected? A $1600 B $1800 C $2200 D $2400
1 marks
Answer: C
This question in 9706/12 Feb/March 2020
Q260 · What does the debit side closing balance carried down and the credit side opening balance… 9706/11 May/June 2020
5 What does the debit side closing balance carried down and the credit side opening balance brought down represent in a sales ledger control account? debit side closing credit side opening balance carried down balance brought down A owing from customers owing from customers B owing from customers owing to customers C owing to customers owing from customers D owing to customers owing to customers
1 marks
Answer: D
This question in 9706/11 May/June 2020
Q261 · The trial balance of a business did not agree and a suspense account was opened 9706/11 May/June 2020
6 The trial balance of a business did not agree and a suspense account was opened. The following errors were then discovered. 1 The sales journal total of $9150 had been credited to both the sales account and the sales ledger control account. 2 The purchases journal total of $3450 had been entered correctly in the purchases account but as $3350 in the purchases ledger control account. 3 Motor expenses of $6450 paid by cheque had only been entered in the bank account. What was the opening balance in the suspense account? A $15 700 credit B $15 700 debit C $24 650 credit D $24 650 debit
1 marks
Answer: D
This question in 9706/11 May/June 2020
Q262 · A bank statement showed an overdraft of $750 9706/11 May/June 2020
7 A bank statement showed an overdraft of $750. The following was then discovered. 1 A cheque issued in payment of rent for $570 had not been presented. 2 A cheque for $624 received was not shown on the bank statement. 3 The bank statement included a bank charge of $50 which had not been entered in the cash book. What amount of overdraft should appear in the statement of financial position? A $646 B $696 C $754 D $1894
1 marks
Answer: B
This question in 9706/11 May/June 2020
Q263 · A trader’s trial balance did not agree at the end of the financial period and a suspense… 9706/12 May/June 2020
5 A trader’s trial balance did not agree at the end of the financial period and a suspense account was opened. The following errors were discovered. 1 No entry had been made in the books of account for a purchase of inventory, $650. 2 Purchase of a vehicle by cheque had been credited to bank but debited to motor expenses. 3 The discount received of $300 had been correctly recorded in the purchases ledger control account and was debited to discount allowed account. 4 The purchases account for the year had been incorrectly totalled. Which errors would affect the suspense account? A 1, 2 and 3 B 1 and 3 only C 2 and 4 only D 3 and 4 only
1 marks
Answer: D
This question in 9706/12 May/June 2020
Q264 · A sales ledger control account has a closing balance of $21 000 9706/12 May/June 2020
7 A sales ledger control account has a closing balance of $21 000. It was discovered that a contra entry with the purchases ledger control account for $700 had been incorrectly entered on the wrong side of the sales ledger control account. What was the correct sales ledger control account balance? A $19 600 B $20 300 C $21 700 D $22 400
1 marks
Answer: A
This question in 9706/12 May/June 2020
Q265 · A sole trader does not keep a complete set of books of account 9706/12 May/June 2020
8 A sole trader does not keep a complete set of books of account. He believes a staff member has stolen some cash. Which items will not be needed to calculate the amount missing? 1 cash in hand at the beginning and end of the year 2 owner’s drawings taken from the bank 3 cheques received from customers 4 totals of cash sales and cash purchases A 1 and 4 B 2 and 3 C 2 only D 3 only
1 marks
Answer: B
This question in 9706/12 May/June 2020
Q266 · What does the debit side closing balance carried down and the credit side opening balance… 9706/13 May/June 2020
5 What does the debit side closing balance carried down and the credit side opening balance brought down represent in a sales ledger control account? debit side closing credit side opening balance carried down balance brought down A owing from customers owing from customers B owing from customers owing to customers C owing to customers owing from customers D owing to customers owing to customers
1 marks
Answer: D
This question in 9706/13 May/June 2020
Q267 · The trial balance of a business did not agree and a suspense account was opened 9706/13 May/June 2020
6 The trial balance of a business did not agree and a suspense account was opened. The following errors were then discovered. 1 The sales journal total of $9150 had been credited to both the sales account and the sales ledger control account. 2 The purchases journal total of $3450 had been entered correctly in the purchases account but as $3350 in the purchases ledger control account. 3 Motor expenses of $6450 paid by cheque had only been entered in the bank account. What was the opening balance in the suspense account? A $15 700 credit B $15 700 debit C $24 650 credit D $24 650 debit
1 marks
Answer: D
This question in 9706/13 May/June 2020
Q268 · A bank statement showed an overdraft of $750 9706/13 May/June 2020
7 A bank statement showed an overdraft of $750. The following was then discovered. 1 A cheque issued in payment of rent for $570 had not been presented. 2 A cheque for $624 received was not shown on the bank statement. 3 The bank statement included a bank charge of $50 which had not been entered in the cash book. What amount of overdraft should appear in the statement of financial position? A $646 B $696 C $754 D $1894
1 marks
Answer: B
This question in 9706/13 May/June 2020
Q269 · Which errors will result in a difference between the total of the individual customer… 9706/11 Oct/Nov 2020
5 Which errors will result in a difference between the total of the individual customer account balance in the sales ledger and the balance on the sales ledger control account? 1 An irrecoverable debt has been posted to the debit of a customer's account. 2 Discount allowed has only been credited to the customer’s account. 3 Returns by a customer have been omitted from the customer’s account. A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2020
Q270 · When preparing the financial statements for the year the following errors are discovered 9706/11 Oct/Nov 2020
6 When preparing the financial statements for the year the following errors are discovered. 1 No provision had been made for accrued wages of $250. 2 No account had been taken of prepaid rent of $400. 3 The sales journal was undercast by $300. The draft profit for the year is $8050. What will be the profit when the errors are corrected? A $8100 B $8500 C $8750 D $9000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2020
Q271 · The following information relates to a company’s banking transactions at 31 December 9706/11 Oct/Nov 2020
7 The following information relates to a company’s banking transactions at 31 December. $ balance at bank as per bank statement 22 650 credit uncleared bankings 3 110 unpresented cheques 6 290 bank interest received recorded twice by bank in error 650 What amount should appear as the bank balance in the statement of financial position at 31 December? A $18 820 B $20 120 C $25 180 D $26 480
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2020
Q272 · John did not keep sales or purchases ledger control accounts 9706/11 Oct/Nov 2020
8 John did not keep sales or purchases ledger control accounts. His trial balance did not balance and a suspense account was opened. The following errors were discovered. 1 Sales of $200 had been entered as a credit in both a customer’s account and the sales account. 2 Purchases of $350 from J Brown had been entered as a credit in E Brown’s account. 3 Machinery repairs of $600 had been entered in the machinery at cost account. 4 Returns inwards of $450 had been entered in the sales returns account but omitted from the customer’s account. What was the amount of opening balance on the suspense account? A $400 B $500 C $650 D $850
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2020
Q273 · A trader depreciates fixtures and fittings at the rate of 10% per annum on cost 9706/12 Oct/Nov 2020
3 A trader depreciates fixtures and fittings at the rate of 10% per annum on cost. On 1 January 2019 a purchase of new fixtures and fittings, $5000, was posted to the advertising account in error. What was the effect of this error on the trader’s capital account on 31 December 2019? A overstated $4500 B overstated $5000 C understated $4500 D understated $5000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2020
Q274 · Which item is recorded on the debit side of a sales ledger control account? 9706/12 Oct/Nov 2020
5 Which item is recorded on the debit side of a sales ledger control account? A interest charged on overdue accounts of customers B irrecoverable debts written off C returns of goods supplied to credit customers D total of cash sales
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2020
Q275 · A trader prepared a trial balance which did not balance 9706/12 Oct/Nov 2020
6 A trader prepared a trial balance which did not balance. The difference was posted to a suspense account. The following errors have now been found. 1 The returns inwards account had been overcast by $90. 2 A payment of $200 for rent had been entered correctly in the cash book but had not been posted to the rent account. What was the opening balance on the suspense account? A $110 credit B $110 debit C $290 credit D $290 debit
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2020
Q276 · An invoice for purchases was credited to the purchases account 9706/12 Oct/Nov 2020
8 An invoice for purchases was credited to the purchases account. How will the balance on the purchases account be corrected? A decrease by the value of the invoice B decrease by twice the value of the invoice C increase by the value of the invoice D increase by twice the value of the invoice
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2020
Q277 · A business owner suspects that a loss of cash has occurred 9706/13 Oct/Nov 2020
5 A business owner suspects that a loss of cash has occurred. He provides the data shown. $ cash balance at the start of the month 150 cash balance at the end of the month 100 cash banked 10 200 cash sales for the month 10 500 How much cash has been lost? A $200 B $250 C $300 D $350
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2020
Q278 · The difference on a trial balance is entered in a suspense account 9706/13 Oct/Nov 2020
6 The difference on a trial balance is entered in a suspense account. It is discovered that a discount received has been debited to the discount allowed account. Which journal entry corrects the error? account(s) to be debited account(s) to be credited A discount received suspense B discount allowed suspense discount received C suspense discount allowed D suspense discount allowed discount received
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2020
Q279 · Which items will be entered in the debit side of the purchases ledger control account? 9706/13 Oct/Nov 2020
7 Which items will be entered in the debit side of the purchases ledger control account? 1 contra with sales ledger control account 2 discount received 3 returns inwards A 1 and 2 B 2 and 3 C 2 only D 3 only
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2020
Q280 · The bank column of a business cash book showed a debit balance of $25 000 9706/13 Oct/Nov 2020
8 The bank column of a business cash book showed a debit balance of $25 000. The following was then discovered. $ direct debit payments not recorded in the cash book 6500 payments for sales made directly into the bank by 5500 customers but not recorded in the cash book bank charges not recorded in the cash book 1500 payment made by the business but not yet shown in 4500 the bank statement What was the correct cash book balance? A $18 000 B $19 500 C $22 500 D $27 500
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2020
Q281 · The bank statement of a business showed a credit balance of $4520 9706/12 Feb/March 2021
6 The bank statement of a business showed a credit balance of $4520. This did not agree with the cash book. The following were discovered. 1 Bank charges of $89 had not been entered in the cash book. 2 There were unpresented cheques paid to suppliers of $680. 3 A dishonoured cheque for $210 appeared on the bank statement, but was not shown in the cash book. 4 Sales receipts of $750 had been entered in the cash book, but did not appear on the bank statement. What is the bank balance to be shown in the statement of financial position? A current asset $4501 B current asset $4590 C current liability $4450 D current liability $4539
1 marks
Answer: B
This question in 9706/12 Feb/March 2021
Q282 · What may help a book-keeper detect errors in the accounting records of a business? 9706/12 Feb/March 2021
7 What may help a book-keeper detect errors in the accounting records of a business? 1 books of original entry 2 sales ledger control account 3 statement of financial position 4 trial balance A 1 and 3 B 2 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: C
This question in 9706/12 Feb/March 2021
Q283 · The closing balance on a purchases ledger control account is $163 762 9706/12 Feb/March 2021
8 The closing balance on a purchases ledger control account is $163 762. The purchases journal has been undercast by $1000. What is the correct closing balance on the purchases ledger control account? A $162 762 B $163 762 C $164 762 D $165 762
1 marks
Answer: C
This question in 9706/12 Feb/March 2021
Q284 · A business has calculated its draft profit for the year as $15 000 9706/12 Feb/March 2021
9 A business has calculated its draft profit for the year as $15 000. The following were then discovered. 1 General expenses were understated by $600. 2 The sales journal total of $55 690 had been posted to the sales account as $56 590. 3 Repairs to vehicles of $1100 had been entered in the vehicles (at cost) account. 4 The salaries account included travelling expenses of $2400 paid to the salesmen. What was the correct profit for the year? A $12 400 B $13 600 C $14 200 D $14 800
1 marks
Answer: A
This question in 9706/12 Feb/March 2021
Q285 · When preparing a bank reconciliation statement, the following information is available 9706/11 May/June 2021
5 When preparing a bank reconciliation statement, the following information is available. $ bank balance shown by the cash book 20 000 debit unpresented cheques 2 500 uncleared bankings 1 400 standing order shown on the bank statement 300 not entered in the cash book What is the balance on the bank statement? A $18 600 B $19 200 C $20 800 D $21 400
1 marks
Answer: C
This question in 9706/11 May/June 2021
Q286 · Why does a business keep both a sales ledger control account and individual sales ledger… 9706/11 May/June 2021
6 Why does a business keep both a sales ledger control account and individual sales ledger accounts for credit customers? 1 to check accuracy of the sales journal 2 to check accuracy of the individual customer accounts 3 to ensure payments have been received from customers 4 to monitor whether customers have exceeded their credit limits A 1, 2 and 3 B 1 and 2 only C 2 and 3 only D 3 and 4
1 marks
Answer: B
This question in 9706/11 May/June 2021
Q287 · A sole trader has a draft profit for the year of $47 500 9706/11 May/June 2021
11 A sole trader has a draft profit for the year of $47 500. No entries have been made in respect of the following. 1 At the end of the year trade receivables were $5600 more than the previous year. However, an irrecoverable debt of $360 had not been written off. The trader maintains a provision of doubtful debts of 5%. 2 A machine had been sold for $4000. It had a net book value of $3500. What will be the correct profit for the year? A $46 360 B $47 378 C $47 902 D $47 920
1 marks
Answer: B
This question in 9706/11 May/June 2021
Q288 · A sole trader had trade receivables of $21 650 at the start of the year 9706/11 May/June 2021
12 A sole trader had trade receivables of $21 650 at the start of the year. During the year there were irrecoverable debts of $450 written off. Cash received from customers was $42 670. At the year end, the statement of financial position showed trade receivables of $25 745 after deducting a provision for doubtful debts of 5%. What were the sales for the year? A $46 765 B $47 215 C $47 670 D $48 570
1 marks
Answer: D
This question in 9706/11 May/June 2021
Q289 · Which statements about an unpresented cheque are correct? 9706/12 May/June 2021
5 Which statements about an unpresented cheque are correct? 1 It arises as the result of an error of omission. 2 It arises from a timing difference. 3 It is used when preparing a bank reconciliation statement. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: C
This question in 9706/12 May/June 2021
Q290 · The balance on the purchases ledger control account did not agree with the total of… 9706/12 May/June 2021
6 The balance on the purchases ledger control account did not agree with the total of balances from the purchases ledger accounts. The following errors were then discovered. 1 Contra entries had not been entered in the general journal. 2 Debit balances on the purchases ledger had not been included in the control account. 3 Discount allowed total had been included in the control account. 4 Goods returned to a supplier had not been recorded in the purchases returns journal. Which errors will require entries being made in the purchases ledger? A 1, 2 and 3 B 1, 2 and 4 C 2 and 3 only D 1 and 4 only
1 marks
Answer: D
This question in 9706/12 May/June 2021
Q291 · The correction of which error requires an entry in the suspense account? 9706/12 May/June 2021
7 The correction of which error requires an entry in the suspense account? A A cheque, $1000, paid to Kong had been debited to Kang’s account. B A purchase of stamps, $50, had been debited to the purchases account. C Commission income, $170, had been debited to the loan interest account. D The insurance account had been undercast by $200 and the wages account overcast by $200.
1 marks
Answer: C
This question in 9706/12 May/June 2021
Q292 · X sold Y goods on credit with a list price of $5000 9706/13 May/June 2021
6 X sold Y goods on credit with a list price of $5000. When X prepared the invoice, he forgot to give Y 10% trade discount. What was the effect of this error in X’s books of account? 1 A suspense account with a credit balance of $500 was opened. 2 A suspense account with a debit balance of $500 was opened. 3 Assets were overstated by $500. 4 Assets were understated by $500. A 1 and 3 B 2 and 4 C 3 only D 4 only
1 marks
Answer: C
This question in 9706/13 May/June 2021
Q293 · At the end of a financial year, the debit balance on a trader’s sales ledger control… 9706/13 May/June 2021
7 At the end of a financial year, the debit balance on a trader’s sales ledger control account was $26 800. At the same date, his sales ledger balances totalled $30 000. He discovered the following. 1 A dishonoured cheque of $1000 had been omitted from the sales ledger control account. 2 A sales ledger credit balance of $500 had been listed as a debit balance. 3 The sales journal had been undercast by $1200. What was the amount of trade receivables to be included in the statement of financial position? A $26 600 B $29 000 C $29 500 D $31 000
1 marks
Answer: B
This question in 9706/13 May/June 2021
Q294 · A trader extracted the following information from his books of account at 31 March 2021 9706/13 May/June 2021
8 A trader extracted the following information from his books of account at 31 March 2021. $ purchases ledger balances at 1 March 2021 32 100 credit purchases for March 26 400 cheques paid to credit suppliers in March 29 700 contra with sales ledger 600 discount received 400 What was the closing balance on the purchases ledger control account at 31 March 2021? A $27 800 B $29 800 C $29 000 D $34 400
1 marks
Answer: A
This question in 9706/13 May/June 2021
Q295 · Which items will be found on the credit side of a sales ledger control account? 9706/11 Oct/Nov 2021
6 Which items will be found on the credit side of a sales ledger control account? 1 allowance for irrecoverable debts 2 contra with purchases ledger control account 3 irrecoverable debts written off 4 refund to customers who overpaid A 1 and 3 B 1 only C 2, 3 and 4 D 2 and 3 only
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2021
Q296 · A business omitted discounts allowed of $700 from its trial balance 9706/11 Oct/Nov 2021
7 A business omitted discounts allowed of $700 from its trial balance. During the year a machine had been sold for cash, $500, but the only accounting entry made was a debit in the bank account. What is the balance on the suspense account before these errors are corrected? A $200 debit B $1200 debit C $200 credit D $1200 credit
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2021
Q297 · Felix drew $200 out of his business bank account in order to top up his petty cash float 9706/11 Oct/Nov 2021
8 Felix drew $200 out of his business bank account in order to top up his petty cash float. When recording this transaction in his cash book he reversed the entries. Despite this error the bank balance showing in his cash book was equal to the balance on his bank statement at the same date. How was this possible? A There was an uncredited deposit of $200. B There was an uncredited deposit of $400. C There was an unpresented cheque for $200. D There was an unpresented cheque for $400.
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2021
Q298 · A sales ledger control account showed a debit balance of $15 000 9706/12 Oct/Nov 2021
6 A sales ledger control account showed a debit balance of $15 000. The following errors were discovered. 1 Returns outwards, $200, had been credited in the sales ledger control account. 2 A contra entry with the purchases ledger control account, $400, had been debited in the sales ledger control account. 3 A customer balance, $300, had been written off in the sales ledger control account but no entry had been made in the sales ledger. Which figure for trade receivables should appear in the statement of financial position? A $14 400 B $15 200 C $15 600 D $15 700
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2021
Q299 · The bank account had a debit balance of $5760 in the cash book at 31 May 9706/12 Oct/Nov 2021
7 The bank account had a debit balance of $5760 in the cash book at 31 May. The following items were identified when reconciling the bank account with the bank statement. $ amount not yet credited by bank 900 bank charges 120 dishonoured cheque 340 unpresented cheque 740 What was the amount shown in the bank statement at 31 May? A $3660 B $5140 C $5460 D $5820
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2021
Q300 · The sales ledger control account of a business showed a debit balance of $26 400 9706/13 Oct/Nov 2021
6 The sales ledger control account of a business showed a debit balance of $26 400. This did not agree with the total of the sales ledger balances. The following items appeared in the sales ledger accounts but had been omitted from the sales ledger control account. 1 a contra item, $340 2 discount allowed, $56 3 dishonoured cheque, $62 4 irrecoverable debt written off, $438 What was the correct balance on the sales ledger control account? A $25 504 B $25 628 C $26 066 D $26 308
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2021
Q301 · Which are reasons for preparing a trial balance? 9706/13 Oct/Nov 2021
7 Which are reasons for preparing a trial balance? 1 to assist in the preparation of draft financial statements 2 to detect all errors in the books of account 3 to find out the balance of the suspense account A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2021
Q302 · What is entered in the sales ledger control account? 9706/12 Feb/March 2022
5 What is entered in the sales ledger control account? 1 cash sales 2 increase in provision for doubtful debts 3 returns inwards A 1 and 2 B 1 and 3 C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/12 Feb/March 2022
Q303 · A trial balance included a suspense account 9706/12 Feb/March 2022
6 A trial balance included a suspense account. The bank balance of $28 412 had mistakenly been entered as an overdraft and placed on the credit side as $28 142. There had also been an addition error and the debit side of the trial balance had been undercast by $450. Which entry in the suspense account will correct these errors? A credit $56 104 B debit $56 104 C credit $57 004 D debit $57 004
1 marks
Answer: C
This question in 9706/12 Feb/March 2022
Q304 · Which statement about control accounts is not correct? 9706/11 May/June 2022
5 Which statement about control accounts is not correct? A Only cash book entries need to be checked to identify errors. B They help to identify where errors have been made. C They make the totals of trade receivables and trade payables more easy to obtain. D They reduce the possibility of fraud.
1 marks
Answer: A
This question in 9706/11 May/June 2022
Q305 · At the end of a financial period, the trial balance of a business did not agree and a… 9706/11 May/June 2022
6 At the end of a financial period, the trial balance of a business did not agree and a suspense account was opened. The following was then discovered. 1 A cheque for $7800 was correctly entered in the customer’s account but had been debited in the bank account as $7000. 2 A credit purchase of $2500 had been omitted from the books of account. 3 Discounts received of $9600 had been entered on the debit side of discounts allowed account. 4 The sales account had been overcast by $18 200. After adjusting these items, the suspense account was cleared. What was the opening balance of the suspense account? A $200 credit B $2700 credit C $9400 debit D $19 000 debit
1 marks
Answer: A
This question in 9706/11 May/June 2022
Q306 · Which statements about a bank reconciliation are correct? 9706/11 May/June 2022
7 Which statements about a bank reconciliation are correct? 1 Cleared cheques are excluded. 2 It locates all errors. 3 It locates any fraud. 4 Uncredited deposits are included. A 1 and 3 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: B
This question in 9706/11 May/June 2022
Q307 · Why does a business maintain sales and purchases ledger control accounts as part of the… 9706/12 May/June 2022
5 Why does a business maintain sales and purchases ledger control accounts as part of the double entry accounting system? 1 It allows a trial balance to be prepared easily from the nominal ledger. 2 It can involve separate employees which makes fraud more difficult. 3 There is no need to keep sales and purchases journals. 4 There is no need to reconcile with personal accounts for customers and suppliers. A 1 and 2 only B 1, 2 and 3 C 1, 3 and 4 D 2, 3 and 4
1 marks
Answer: A
This question in 9706/12 May/June 2022
Q308 · Doug received his business bank statement 9706/12 May/June 2022
6 Doug received his business bank statement. He updated the cash book and prepared the bank reconciliation statement. Which items appeared on the bank reconciliation statement? customer bank uncredited payments by charges deposits direct debit A no no yes B no yes yes C yes no no D yes yes no
1 marks
Answer: A
This question in 9706/12 May/June 2022
Q309 · At 31 December 2021, the sales ledger control account had a balance of $19 100 while the… 9706/12 May/June 2022
7 At 31 December 2021, the sales ledger control account had a balance of $19 100 while the total balances in the sales ledger were $20 900. The following reconciliation statement had been prepared after the errors were located. $ balance of sales ledger control account 19 100 credit sales omitted from the sales journal 1 600 discount allowed understated in sales ledger 200 total of balances in the sales ledger 20 900 What is the correct amount of total trade receivables as shown in the statement of financial position? A $17 500 B $18 900 C $19 300 D $20 700
1 marks
Answer: D
This question in 9706/12 May/June 2022
Q310 · Which item is recorded on the credit side of a sales ledger control account? 9706/13 May/June 2022
5 Which item is recorded on the credit side of a sales ledger control account? A discount received B dishonoured cheques C interest on overdue accounts D set-off of amounts in the purchases ledger
1 marks
Answer: D
This question in 9706/13 May/June 2022
Q311 · The bank column of the cash book showed a credit balance of $2915 9706/13 May/June 2022
6 The bank column of the cash book showed a credit balance of $2915. This did not agree with the balance shown on the bank statement. It was then discovered that: 1 a bank transfer, $150, from a customer was not recorded in the cash book 2 a cheque, $450, received from a customer was not recorded on the bank statement 3 a cheque, $530, issued to a supplier was incorrectly recorded in the cash book as $350 but was correctly recorded by the bank 4 bank charge, $25, was not recorded in the cash book. When these items were adjusted, the cash book balance agreed with the bank statement balance. What was the balance shown on the bank statement before any adjustments were made? A $2520 debit B $2520 credit C $3420 debit D $3420 credit
1 marks
Answer: C
This question in 9706/13 May/June 2022
Q312 · The correction of which error would require an entry in the suspense account? 9706/13 May/June 2022
7 The correction of which error would require an entry in the suspense account? A A sales invoice, $45, was omitted from the sales journal. B Drawings, $60, were debited in the cash book and were credited to the drawings account. C Vehicle repairs, $100, were debited to the vehicles at cost account. D Wages, $150, were correctly recorded in the wages account and debited in the cash book.
1 marks
Answer: D
This question in 9706/13 May/June 2022
Q313 · Which items will be included in the sales ledger control account? 9706/11 Oct/Nov 2022
5 Which items will be included in the sales ledger control account? 1 amounts owed by credit customers at the end of the previous month 2 provision for doubtful debts 3 total of the invoices sent out to credit customers 4 total of the sales returns journal A 1, 2 and 3 B 1, 2 and 4 C 1, 3 and 4 D 2, 3 and 4
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2022
Q314 · Which error would affect the balancing of a trial balance? 9706/11 Oct/Nov 2022
6 Which error would affect the balancing of a trial balance? A A payment for rent of $250 had been debited in the bank account. It had been entered correctly in the rent account. B A purchase invoice for $259 was entered in the purchases journal as $295. C A sales invoice for $180 was lost before it could be entered in the sales journal. D A sales return of $500 was debited in the customer’s account and credited to the purchases returns account.
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2022
Q315 · The balance on a purchases ledger control account at 1 March was $71 300 9706/11 Oct/Nov 2022
7 The balance on a purchases ledger control account at 1 March was $71 300. During the month ended 31 March, the following transactions took place. $ payments to trade payables by cheque 133 200 credit purchases 149 000 purchases returns 3 000 cash purchases 2 000 contra with sales ledger 1 600 What was the trade payables balance at 31 March? A $80 500 B $82 500 C $83 700 D $85 700
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2022
Q316 · Which item is an error of principle? 9706/12 Oct/Nov 2022
5 Which item is an error of principle? A No record was made of inventory withdrawn by the owner for private use. B Sales returns were credited to the returns inwards account. C The amount shown on a purchases invoice for goods for resale was incorrectly recorded in the purchases journal. D The cost of machinery repairs was debited to the machinery at cost account.
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2022
Q317 · The sales ledger control account of a business had a balance of $17 640 9706/12 Oct/Nov 2022
6 The sales ledger control account of a business had a balance of $17 640. This did not agree with the total of the individual customer accounts in the sales ledger. The following errors have been discovered. 1 An invoice in the sales journal for $460 has been entered wrongly in the sales ledger as $640. 2 Credit balances on the sales ledger, $470, have been omitted from the sales ledger control account. 3 Discounts allowed have been incorrectly totalled as $310 instead of $325. 4 Goods sold to Harry for $690 have been entered in the account of Barry in error. What is the correct balance on the sales ledger control account? A $16 975 B $17 155 C $17 185 D $18 125
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2022
Q318 · The totals on a trial balance were: debit $500 150 credit $500 000 Which error could have… 9706/12 Oct/Nov 2022
7 The totals on a trial balance were: debit $500 150 credit $500 000 Which error could have caused the difference? A A cash sale has only been recorded in the sales account. B A credit purchase has only been recorded in a supplier’s account. C A credit sale has not been recorded. D A credit sale has only been recorded in a customer’s account.
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2022
Q319 · The following information is available for the year ended 31 December 2021 9706/12 Oct/Nov 2022
13 The following information is available for the year ended 31 December 2021. $ trade payables at 1 January 2021 18 000 trade payables at 31 December 2021 14 000 discount received 6 000 payments to credit suppliers 158 000 returns outwards 3 000 contra to sales ledger control account 2 000 What were the credit purchases for the year? A $143 000 B $161 000 C $165 000 D $173 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2022
Q320 · Which error would result in an entry in the suspense account? 9706/13 Oct/Nov 2022
5 Which error would result in an entry in the suspense account? 1 a balance is omitted when extracting the trial balance 2 an item is posted to the correct side of the wrong account 3 entries for an item are reversed A 1 and 2 B 1 and 3 C 1 only D 2 and 3
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2022
Q321 · The balance of a purchases ledger control account was $7270 9706/13 Oct/Nov 2022
6 The balance of a purchases ledger control account was $7270. However, the total of the accounts of trade payables was $6860. The following errors have been discovered. 1 A credit note received from a supplier for $100 had been omitted from the book of prime entry. 2 The discounts received column in the cash book had been understated by $50. When these errors were corrected the balance on the purchases ledger control account still did not match the total of the accounts of trade payables. What were the updated amounts after the corrections? purchases ledger total of the accounts control account balance of trade payables $ $ A 7120 6710 B 7120 6760 C 7170 6810 D 7220 6710
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2022
Q322 · Which group would appear only on the credit side of a sales ledger control account? 9706/13 Oct/Nov 2022
7 Which group would appear only on the credit side of a sales ledger control account? A cash refunds, contras with the purchases ledger control accounts, sales B cash refunds, contras with the purchases ledger control accounts, sales returns C irrecoverable debts written off, cash received, discounts allowed D irrecoverable debts written off, cash refunds, sales
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2022
Q323 · A business has incorrectly recorded a vehicle purchase as a vehicle repair 9706/12 Feb/March 2023
5 A business has incorrectly recorded a vehicle purchase as a vehicle repair. The business does not charge depreciation on assets in the year of purchase. What is the effect of this error on the financial statements? statement of statement of profit or loss financial position A profit overstated assets overstated B profit overstated assets understated C profit understated assets overstated D profit understated assets understated
1 marks
Answer: D
This question in 9706/12 Feb/March 2023
Q324 · The cost of repainting a property was debited to the property account 9706/12 Feb/March 2023
7 The cost of repainting a property was debited to the property account. Which type of error was made? A commission B compensating C original entry D principle
1 marks
Answer: D
This question in 9706/12 Feb/March 2023
Q325 · A trial balance does not balance 9706/12 Feb/March 2023
8 A trial balance does not balance. The difference has been entered in a suspense account. The following errors are found. 1 A cash payment of $630 for rent has been credited in the cash book and debited to the irrecoverable debts account. 2 The provision for depreciation account has been overcast by $960. 3 The purchases ledger control account balance of $48 300 has been included as a debit balance. What is the correcting debit entry to the suspense account? A $47 340 B $95 010 C $95 640 D $97 560
1 marks
Answer: C
This question in 9706/12 Feb/March 2023
Q326 · What are the benefits of preparing a bank reconciliation statement? 9706/12 Feb/March 2023
9 What are the benefits of preparing a bank reconciliation statement? 1 acts as a deterrent to fraud 2 identifies out-of-date cheques 3 prevents the business going into overdraft 4 provides the correct bank balance for financial statements A 1, 2 and 3 B 1, 2 and 4 C 1, 3 and 4 D 2, 3 and 4
1 marks
Answer: B
This question in 9706/12 Feb/March 2023
Q327 · At the month end, a business bank statement showed a credit balance of $12 697 9706/12 Feb/March 2023
10 At the month end, a business bank statement showed a credit balance of $12 697. This did not agree with the cash book balance. The following differences were found. 1 A cheque received, $7170, was entered as $7710 in the cash book. 2 A cheque paid in, $2400, had not been cleared by the bank. 3 A standing order, $450, was recorded in the cash book but had not been paid by the bank. 4 Bank interest payable of $642 had not been entered in the cash book. What was the cash book balance before the necessary corrections were made? A $9565 B $13 429 C $14 995 D $15 829
1 marks
Answer: D
This question in 9706/12 Feb/March 2023
Q328 · Which statements identify the advantages of using a purchases ledger control account as… 9706/12 Feb/March 2023
11 Which statements identify the advantages of using a purchases ledger control account as part of the accounting system? 1 Compensating errors within the purchases ledger can be found more easily. 2 Errors of commission within the purchases ledger will be detected. 3 The honesty of staff working on the accounts of trade payables is checked. 4 The total amount owing to trade payables can be ascertained quickly. A 1, 2 and 3 B 2, 3 and 4 C 2 and 4 only D 3 and 4 only
1 marks
Answer: D
This question in 9706/12 Feb/March 2023
Q329 · The sales ledger control account of a trader showed a debit balance of $28 500 at the end… 9706/12 Feb/March 2023
12 The sales ledger control account of a trader showed a debit balance of $28 500 at the end of the financial period. This did not agree with the total of the individual trade receivables accounts in the sales ledger. The following errors were discovered. 1 A dishonoured cheque for $300 from a credit customer had been entered on the credit side of the sales ledger control account. 2 Contras of $500 entered correctly in the sales ledger had been omitted from the sales ledger control account. 3 Discounts allowed of $700 had not been entered in the sales ledger control account. Which figure should be used for trade receivables in the financial statements? A $27 600 B $27 900 C $28 900 D $29 300
1 marks
Answer: B
This question in 9706/12 Feb/March 2023
Q330 · Why would a book-keeper make use of verification procedures? 9706/11 May/June 2023
6 Why would a book-keeper make use of verification procedures? A to assist in the location of errors B to check that accounting policies have been applied consistently C to ensure that all transactions have been recorded D to identify debts that have become irrecoverable
1 marks
Answer: A
This question in 9706/11 May/June 2023
Q331 · Douglas prepared a trial balance and found that the total of the debit column was $50… 9706/11 May/June 2023
7 Douglas prepared a trial balance and found that the total of the debit column was $50 higher than the total of the credit column. The following errors were discovered. error 1 a purchases invoice for $100 had been incorrectly recorded error 2 an irrecoverable debt of $50 had been incorrectly recorded Which combination of the two errors together caused the difference in the totals? error 1 error 2 A recorded in purchases journal at $50 both entries reversed B recorded in purchases journal at $50 not recorded at all C recorded in sales journal recorded in expense account only rather than purchases journal D recorded in sales journal recorded in sales ledger account only rather than purchases journal
1 marks
Answer: C
This question in 9706/11 May/June 2023
Q332 · When preparing a bank reconciliation statement, which item is an uncredited deposit? 9706/11 May/June 2023
8 When preparing a bank reconciliation statement, which item is an uncredited deposit? A a cheque to a credit supplier not yet recorded on the bank statement B a credit transfer from a credit customer not yet recorded in the cash book C an amount charged by the bank not yet recorded in the cash book D an amount paid into the bank not yet recorded on the bank statement
1 marks
Answer: D
This question in 9706/11 May/June 2023
Q333 · A company received its bank statement dated 30 June showing a credit balance of $6890 9706/11 May/June 2023
9 A company received its bank statement dated 30 June showing a credit balance of $6890. The cash book on this date had a debit balance of $7234. The following items were discovered. 1 Bank charges of $54 had not been entered in the cash book. 2 Deposits made to the bank on 30 June for $490 had not been shown on the bank statement. 3 Suppliers had not banked cheques for $200. Which figure should be used for bank in the statement of financial position at 30 June? A $6600 B $6654 C $7126 D $7180
1 marks
Answer: D
This question in 9706/11 May/June 2023
Q334 · Where is discount allowed recorded? 9706/11 May/June 2023
10 Where is discount allowed recorded? discount allowed sales ledger cash book account control account A credit side credit side credit side B credit side debit side debit side C debit side debit side credit side D debit side credit side debit side
1 marks
Answer: C
This question in 9706/11 May/June 2023
Q335 · The closing balance on a sales ledger control account was $10 150 9706/11 May/June 2023
11 The closing balance on a sales ledger control account was $10 150. It was then discovered that: 1 a sales invoice for $270 had been correctly entered in the sales journal but posted to the customer’s account as $200 2 goods returned by a credit customer for $90 had not been entered in the sales returns journal. What was the total of the individual sales ledger balances before the correction of these errors? A $9990 B $10 080 C $10 170 D $10 220
1 marks
Answer: B
This question in 9706/11 May/June 2023
Q336 · Which error would not affect the agreement of the totals of a trial balance? 9706/12 May/June 2023
6 Which error would not affect the agreement of the totals of a trial balance? A A credit note for $56 received from a supplier was entered in the book of prime entry as $65. B Goods taken for own use by the owner for $180 were debited to the cash account and debited to the drawings account. C The discounts received total in the cash book was not transferred to the general ledger. D The purchases returns account was understated by $50 and the cash account was overstated by $50.
1 marks
Answer: A
This question in 9706/12 May/June 2023
Q337 · A trial balance did not agree and the book-keeper found the following errors 9706/12 May/June 2023
7 A trial balance did not agree and the book-keeper found the following errors. 1 A bank overdraft of $100 had been shown as a debit in the trial balance. 2 A cash purchase of $160 had been entered in the purchases account as $150; the purchase was entered correctly in the cash account. 3 A telephone invoice for $400 had been debited to the insurance account. The book-keeper opened a suspense account in order to correct the errors. What was the opening entry in the suspense account? A credit $190 B credit $210 C debit $60 D debit $550
1 marks
Answer: A
This question in 9706/12 May/June 2023
Q338 · A bank statement shows a credit balance of $8360 9706/12 May/June 2023
8 A bank statement shows a credit balance of $8360. Comparison with the cash book reveals: 1 bank charges of $124 have not been entered in the cash book 2 cheques received from customers for $16 223 have not been credited by the bank 3 cheques sent to suppliers for $18 725 have not been presented. What is the correct cash book balance? A $5734 credit B $5734 debit C $5858 debit D $10 986 credit
1 marks
Answer: C
This question in 9706/12 May/June 2023
Q339 · Which statements are benefits of control accounts? 9706/12 May/June 2023
9 Which statements are benefits of control accounts? 1 They check the numerical accuracy of the ledgers. 2 They help to identify missing entries in books of prime entry. 3 They provide details of individual transactions. 4 They provide information for financial statements quickly. A 1 and 2 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: B
This question in 9706/12 May/June 2023
Q340 · A company has obtained the following information for the year ended 31 December 9706/12 May/June 2023
10 A company has obtained the following information for the year ended 31 December. $ opening balance on sales ledger control account 31 000 closing balance on sales ledger control account 35 000 discount allowed 2 300 credit sales 125 400 What was the amount received from credit customers? A $119 100 B $123 700 C $127 100 D $131 700
1 marks
Answer: A
This question in 9706/12 May/June 2023
Q341 · Which statement about the purpose of a trial balance is correct? 9706/13 May/June 2023
2 Which statement about the purpose of a trial balance is correct? A It assists the subsequent preparation of financial statements. B It ensures that all double-entry postings to ledgers are accurate. C It ensures that all postings to books of prime entry are accurate. D It shows that all transactions in a period have been recorded.
1 marks
Answer: A
This question in 9706/13 May/June 2023
Q342 · The totals of a trial balance did not agree and the following errors were discovered 9706/13 May/June 2023
8 The totals of a trial balance did not agree and the following errors were discovered. 1 A cheque for $27 000 for the sale of a non-current asset had been credited to the sales account. The corresponding entry was correct. 2 The purchase on credit of a new motor vehicle for $27 000 had been omitted from the supplier’s account. The corresponding entry was correct. 3 Entries in the cash book for a transfer from cash to bank for $27 000 had been reversed. 4 The purchases account had been overcast by $27 000. Which errors would have led to the trial balance totals being different? A 1 and 2 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: D
This question in 9706/13 May/June 2023
Q343 · A suspense account had a balance of $450 debit 9706/13 May/June 2023
9 A suspense account had a balance of $450 debit. What caused this balance in the suspense account? A motor expenses of $225 correctly entered in the cash book and posted to motor expenses as a credit B motor expenses of $225 entered in the cash book as a receipt and posted to motor expenses as a credit C motor expenses of $450 correctly entered in the cash book and posted to motor vehicles as a debit D motor expenses of $675 entered in the cash book as a credit of $225 and posted to motor expenses as a debit of $225
1 marks
Answer: A
This question in 9706/13 May/June 2023
Q344 · What is a benefit of preparing a bank reconciliation? 9706/13 May/June 2023
10 What is a benefit of preparing a bank reconciliation? A to identify differences between the cash book and bank statement B to know whether any bank overdraft limit has been reached C to know whether the balance at the bank is a debit or credit D to use the bank statement balance in the statement of financial position
1 marks
Answer: A
This question in 9706/13 May/June 2023
Q345 · A bank statement shows a credit balance of $1500 9706/13 May/June 2023
11 A bank statement shows a credit balance of $1500. A payment of $500 and a receipt of $1250 were included in the cash book but have not yet appeared on the bank statement. Bank interest payable of $1100 had been correctly recorded in the cash book but due to a bank error had been recorded in the bank statement as $1000. What is the cash book balance? A $650 B $850 C $2150 D $3350
1 marks
Answer: C
This question in 9706/13 May/June 2023
Q346 · A business is preparing a sales ledger control account 9706/13 May/June 2023
12 A business is preparing a sales ledger control account. Which statements are correct? 1 All sales are debited to the sales ledger control account. 2 Contra entries are credited to the sales ledger control account. 3 Discounts allowed are credited to the sales ledger control account. 4 The allowance for irrecoverable debts is credited to the sales ledger control account. A 1 and 2 B 1 and 3 C 2, 3 and 4 D 2 and 3 only
1 marks
Answer: D
This question in 9706/13 May/June 2023
Q347 · At the end of a financial period, the total of the individual balances in the purchases… 9706/13 May/June 2023
13 At the end of a financial period, the total of the individual balances in the purchases ledger was $149 000. The following errors were then discovered. 1 A contra for $2500 had been omitted from a supplier account. 2 Discounts received of $1200 had been credited to a supplier’s account as $2100. 3 No entries had been made for a credit purchase of $5100 from a supplier. 4 Purchases returns of $3000 had been credited to a supplier’s account. What was the corrected total of the individual balances in the purchases ledger at the end of the period? A $142 300 B $144 700 C $146 500 D $147 300
1 marks
Answer: A
This question in 9706/13 May/June 2023
Q348 · Which error would not be identified by preparing a trial balance? 9706/11 Oct/Nov 2023
7 Which error would not be identified by preparing a trial balance? A A contra entry of $650 had been entered twice in the sales ledger control account. B A purchase invoice of $495 had been recorded as $459 in the purchases journal. C Carriage inwards of $57 in the cash book had been recorded as $75 in the carriage inwards account. D Discount allowed of $35 had been credited to the discount received account.
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2023
Q349 · During the year a sole trader withdrew $3000 cash from the business bank account 9706/11 Oct/Nov 2023
8 During the year a sole trader withdrew $3000 cash from the business bank account. Accounting entries made were a debit of $300 to the drawings account and a credit of $3000 to the bank account. In addition, $500 had been omitted from the discount received account in the trial balance. What was the balance on the suspense account before these errors were corrected? A $2200 debit B $2200 credit C $3200 debit D $3200 credit
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2023
Q350 · A company’s bank statement showed a credit balance of $2000 9706/11 Oct/Nov 2023
9 A company’s bank statement showed a credit balance of $2000. The following issues were found. 1 A receipt of $2700 and a payment for $3000 were recorded on the bank statement. Both had been omitted from the cash book. 2 Bank charges of $500 were correctly shown on the bank statement but had been recorded as $600 in the cash book. What was the cash book balance before any necessary adjustments were made? A $1600 B $1800 C $2200 D $2400
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2023
Q351 · Why might a business maintain a sales ledger control account as part of the double entry… 9706/11 Oct/Nov 2023
10 Why might a business maintain a sales ledger control account as part of the double entry accounting system? 1 to facilitate prompt preparation of financial statements 2 to help reduce fraud 3 to provide details of all sales transactions A 1 and 2 B 1 only C 2 and 3 D 2 only
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2023
Q352 · The purchases ledger control account showed a balance of $79 500 before the following… 9706/11 Oct/Nov 2023
11 The purchases ledger control account showed a balance of $79 500 before the following errors were taken into account. 1 A contra of $5300 between the purchases and sales ledger control accounts had been omitted. 2 Cash purchases of $1200 made on the last day of the period had not been recorded. 3 The discount received column in the cash book had been overcast by $6200. 4 The returns inwards journal had been undercast by $1500. Which figure for trade payables should be included in the statement of financial position? A $78 900 B $80 100 C $80 400 D $81 600
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2023
Q353 · Maria recorded a cheque for $475 received from Josh, a credit customer 9706/12 Oct/Nov 2023
3 Maria recorded a cheque for $475 received from Josh, a credit customer. Josh had deducted a 5% cash discount. The cheque has now been returned as dishonoured. What is the correct entry to record the return of the cheque in Maria’s books? debit $ credit $ A bank 475 Josh 500 discount received 25 B Josh 500 bank 475 discount received 25 C bank 475 Josh 500 discount allowed 25 D Josh 500 bank 475 discount allowed 25
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2023
Q354 · A business received $100 cash from a credit customer in settlement of a debt 9706/12 Oct/Nov 2023
7 A business received $100 cash from a credit customer in settlement of a debt. When recording it, an error of commission was made. Which statement about the debit and credit columns of the trial balance is correct? A The total of the credit column was $100 higher than the total of the debit column. B The total of the debit column was $100 higher than the total of the credit column. C The totals of both columns were the same as if the error had not taken place. D The totals of both columns were understated by the same amount.
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2023
Q355 · A company’s trial balance includes a suspense account 9706/12 Oct/Nov 2023
8 A company’s trial balance includes a suspense account. It was found that the only errors were discounts received of $240 and discounts allowed of $312, which had both been entered on the incorrect sides of the respective ledger accounts. What is the double entry required to clear the suspense account balance? debit credit account $ $ A discounts allowed 312 discounts received 240 suspense 72 B discounts allowed 624 discounts received 480 suspense 144 C discounts received 240 suspense 72 discounts allowed 312 D discounts received 480 suspense 144 discounts allowed 624
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2023
Q356 · Which statements describe the benefits of preparing a bank reconciliation statement? 9706/12 Oct/Nov 2023
9 Which statements describe the benefits of preparing a bank reconciliation statement? 1 checks the accuracy of transactions recorded on the bank statement 2 ensures that cash in the till agrees with the total of the cash column in the cash book 3 eliminates the possibility of fraud by members of staff 4 ensures that the trial balance and financial statements contain an up-to-date figure for cash at bank A 1 and 2 B 1, 3 and 4 C 1 and 4 only D 2 and 3
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2023
Q357 · A trader’s cash book shows a debit balance of $12 460 at 30 April 9706/12 Oct/Nov 2023
10 A trader’s cash book shows a debit balance of $12 460 at 30 April. Bank charges of $4500 have not been entered in the cash book. A cheque for $14 470 received from a credit customer and a cheque for $1740 paid to a supplier appear in the cash book but not on the bank statement. What is the balance shown on the bank statement at 30 April? A $4770 credit B $4770 debit C $20 690 credit D $20 690 debit
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2023
Q358 · A credit customer gave cash to a sales ledger clerk in part settlement of her debt 9706/12 Oct/Nov 2023
11 A credit customer gave cash to a sales ledger clerk in part settlement of her debt. The clerk was dishonest and kept the cash for himself. He entered the receipt in the customer’s sales ledger account but made no entry in the cash book. What caused the theft to be discovered? A A bank reconciliation statement was prepared. B A sales ledger control account reconciliation statement was prepared. C A statement of account was sent to and checked by the customer. D A trial balance was extracted from the books of account.
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2023
Q359 · The following information is available 9706/12 Oct/Nov 2023
12 The following information is available. $ balance of trade receivables at the start of the year 48 000 balance of trade receivables at the end of the year 65 300 trade discount given to credit customers 3 000 cash discount taken by credit customers 4 500 irrecoverable debt written off during the year 6 200 increase in allowance for irrecoverable debts for the year 2 700 cash received from credit customers during the year 516 000 What is the total value of credit sales for the year? A $541 000 B $544 000 C $546 700 D $547 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2023
Q360 · Sammy paid a credit supplier $190 in full settlement of a debt of $200 9706/13 Oct/Nov 2023
8 Sammy paid a credit supplier $190 in full settlement of a debt of $200. He omitted to record the discount. How did the correction of this error affect Sammy’s statement of financial position? bank capital trade payables A decreased decreased no effect B increased no effect decreased C no effect decreased increased D no effect increased decreased
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2023
Q361 · The trial balance of a business did not agree and a suspense account was opened 9706/13 Oct/Nov 2023
9 The trial balance of a business did not agree and a suspense account was opened. The following errors were then discovered. 1 The sales journal total of $9150 had been credited to both the sales account and the sales ledger control account. 2 The purchases journal total of $3450 had been entered correctly in the purchases account but as $3350 in the purchases ledger control account. 3 Motor expenses of $6450 paid by cheque had only been entered in the bank account. What was the opening balance in the suspense account? A $15 700 credit B $15 700 debit C $24 650 credit D $24 650 debit
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2023
Q362 · Which items are used to update the cash book when preparing a bank reconciliation… 9706/13 Oct/Nov 2023
10 Which items are used to update the cash book when preparing a bank reconciliation statement? 1 an amount directly collected by a supplier from the business’s bank account 2 an amount directly transferred by a customer to the business’s bank account 3 an amount not yet credited to the business’s bank account 4 an amount not yet debited to the business’s bank account A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2023
Q363 · The year-end balance in the cash book was $23 780 9706/13 Oct/Nov 2023
11 The year-end balance in the cash book was $23 780. This was different from the balance on the bank statement. The difference was due to the following items. $ a bank error meant a cheque was incorrectly 560 debited to the bank account a customer’s cheque which was dishonoured 1 375 bank charges 216 Which figure should be included as cash at bank in the statement of financial position? A $21 629 B $22 189 C $25 371 D $25 931
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2023
Q364 · Which item is not recorded in the sales ledger control account? 9706/13 Oct/Nov 2023
12 Which item is not recorded in the sales ledger control account? A allowance for irrecoverable debts B dishonoured cheque C returns inwards D settlement discount
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2023
Q365 · The closing balance of a purchases ledger control account was $7480 9706/13 Oct/Nov 2023
13 The closing balance of a purchases ledger control account was $7480. It did not agree with the total of the suppliers’ balances in the purchases ledger. The following two errors were found. 1 An error of original entry occurred when a credit note from a supplier for $120 had been recorded as $210. 2 Interest charged on an overdue supplier’s account of $40 had been debited to the purchases ledger control account. What is the corrected balance of the purchases ledger control account? A $7470 B $7490 C $7520 D $7650
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2023
Q366 · Which error will cause a trial balance not to balance? 9706/12 Feb/March 2024
8 Which error will cause a trial balance not to balance? A an invoice entered as a credit note on original input B a journal entry that does not balance C a transaction entered as the wrong amount on original input D a transaction not entered in the books of account
1 marks
Answer: B
This question in 9706/12 Feb/March 2024
Q367 · A business prepared a trial balance that included a suspense account 9706/12 Feb/March 2024
9 A business prepared a trial balance that included a suspense account. Draft financial statements were prepared which showed a profit for the year of $85 000. The following errors were then discovered. 1 Discounts allowed of $1000 had been debited to the discounts received account. 2 Motoring expenses of $4000 had been debited to the purchases account. 3 A payment for purchases of $5000 had been correctly entered in the cash book but credited to the drawings account. After correcting these errors the balance on the suspense account was eliminated. What was the revised profit for the year? A $76 000 B $78 000 C $80 000 D $82 000 Amit compared his bank statement with his cash book.
1 marks
Answer: C
This question in 9706/12 Feb/March 2024
Q368 · How did Amit deal with the items revealed by this comparison? 9706/12 Feb/March 2024
10 How did Amit deal with the items revealed by this comparison? including in bank updating his cash reconciliation book statement A bank charges timing differences and bank errors B bank charges and timing differences bank errors C timing differences bank charges and bank errors D timing differences bank charges and bank errors
1 marks
Answer: A
This question in 9706/12 Feb/March 2024
Q369 · The bank statement of a business shows a credit balance of $1570 at 31 December 9706/12 Feb/March 2024
11 The bank statement of a business shows a credit balance of $1570 at 31 December. The following differences were discovered on comparing the cash book with the bank statement. $ unpresented cheques 1250 uncredited bankings 1800 A direct debit of $230 was shown as $320 in the cash book. What is the updated cash book balance at 31 December? A $930 B $1020 C $2030 D $2120
1 marks
Answer: D
This question in 9706/12 Feb/March 2024
Q370 · What are the benefits of preparing a sales ledger control account? 9706/12 Feb/March 2024
12 What are the benefits of preparing a sales ledger control account? 1 detecting errors of original entry 2 helping reduce the possibility of fraud 3 providing totals of trade receivables for inclusion in financial statements A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: D
This question in 9706/12 Feb/March 2024
Q371 · A company prepared its purchases ledger control account, which showed a balance of $15 960 9706/12 Feb/March 2024
13 A company prepared its purchases ledger control account, which showed a balance of $15 960. The following items were then discovered. 1 Discounts received of $450 had been entered into the purchases ledger control account as $540. 2 A payment of $720 to a supplier had not been entered in his account. 3 The purchases ledger debit balances carried down totalling $110 had been omitted from the control account. 4 A contra of $170 had been entered in the purchases ledger but not in the purchases ledger control account. What was the correct total of the trade payables? A $15 050 B $15 240 C $15 990 D $16 150
1 marks
Answer: C
This question in 9706/12 Feb/March 2024
Q372 · Why does a business maintain a sales ledger control account? 9706/11 May/June 2024
5 Why does a business maintain a sales ledger control account? A to ensure that statements are sent out promptly to customers B to record the total of discounts received C to reduce the risk of irrecoverable debts D to verify the arithmetical accuracy of entries in the sales ledger
1 marks
Answer: D
This question in 9706/11 May/June 2024
Q373 · Iga is worried that her book-keeper may have been forgetting to record credit notes… 9706/11 May/June 2024
6 Iga is worried that her book-keeper may have been forgetting to record credit notes received. What should she do to find out? 1 check purchases ledger balances against statements of account 2 extract a trial balance showing individual purchases ledger accounts 3 prepare a purchases ledger control account A 1 and 2 B 1 only C 2 and 3 only D 3 only A trial balance does not balance and a suspense account is opened.
1 marks
Answer: B
This question in 9706/11 May/June 2024
Q374 · On investigation, the following errors are found 9706/11 May/June 2024
7 On investigation, the following errors are found. 1 The debit balance of $450 on the carriage outwards account has been brought down as $540. 2 The purchases returns journal has been overcast by $100. 3 A cheque for $50 received from Alan Green has been posted to the credit account of Brian Green. 4 Rent received of $350 has been posted to the debit of rent paid account. What is the opening balance on the suspense account? A credit $690 B credit $740 C debit $690 D debit $740
1 marks
Answer: A
This question in 9706/11 May/June 2024
Q375 · The table shows extracts from a business’s bank reconciliation 9706/11 May/June 2024
8 The table shows extracts from a business’s bank reconciliation. $ balance per cash book at 31 December 2075 debit balance per bank statement at 31 December 2250 credit bank charges per bank statement not entered in cash book 150 outstanding cheques not presented at year end 325 What is the bank balance to be shown in the financial statements? A $1600 B $1925 C $2075 D $2225
1 marks
Answer: B
This question in 9706/11 May/June 2024
Q376 · The total of trade payables balances in Konrad’s purchases ledger was $57 400 9706/11 May/June 2024
9 The total of trade payables balances in Konrad’s purchases ledger was $57 400. The following errors were then discovered. $ discount allowed overcast in cash book 2000 returns outwards omitted in a supplier’s account 350 payments to trade payables undercast in cash book 137 purchases journal overcast 500 What is the correct total of trade payables balances? A $54 413 B $54 913 C $55 050 D $57 050
1 marks
Answer: D
This question in 9706/11 May/June 2024
Q377 · Which statement is not correct? 9706/11 May/June 2024
10 Which statement is not correct? A Control accounts reveal whether there are errors in sales and purchases ledgers. B Credit balances in a sales ledger are trade receivables. C Debit balances in a purchases ledger are current assets. D A sales ledger control account includes irrecoverable debts.
1 marks
Answer: B
This question in 9706/11 May/June 2024
Q378 · Jake sold a non-current asset which was not fully depreciated 9706/13 May/June 2024
5 Jake sold a non-current asset which was not fully depreciated. He mistakenly recorded this by debiting the bank account and crediting the sales account with the proceeds. What was the effect of this error? 1 Assets were overstated. 2 Assets were understated. 3 Profit was overstated. 4 Profit was understated. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/13 May/June 2024
Q379 · Which errors would be identified by preparing a trial balance? 9706/13 May/June 2024
8 Which errors would be identified by preparing a trial balance? 1 A bank payment of $275 for rent has been entered as $257 in the cash book. 2 A discount received of $47 has been entered twice in the account. 3 The purchase of a new motor vehicle costing $12 500 has been entered in the purchases account. 4 The total sales of $34 670 from the sales journal has been posted to the sales account as $34 760. A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: C
This question in 9706/13 May/June 2024
Q380 · A suspense account was opened to record the difference on a trial balance 9706/13 May/June 2024
9 A suspense account was opened to record the difference on a trial balance. The following errors were then discovered. 1 The discount allowed of $2000 had only been entered in the sales ledger control account. 2 A cheque for $1500 paid for repairs had been entered as $5100 in the repairs account. What was the opening balance on the suspense account? A $1600 credit B $1600 debit C $5600 credit D $5600 debit
1 marks
Answer: A
This question in 9706/13 May/June 2024
Q381 · At the financial year end of a business, the following information is available 9706/13 May/June 2024
10 At the financial year end of a business, the following information is available. $ debit balance on the bank statement 1000 unpresented cheques 300 lodgements not yet credited by the bank 600 bank charges and interest charged not yet entered in the cash book 150 What is the current balance in the cash book? A $400 credit B $400 debit C $550 credit D $550 debit
1 marks
Answer: C
This question in 9706/13 May/June 2024
Q382 · What do the debit side closing balance carried down and the credit side opening balance… 9706/13 May/June 2024
11 What do the debit side closing balance carried down and the credit side opening balance brought down represent in a sales ledger control account? debit side closing credit side opening balance carried down balance brought down A owing from customers owing from customers B owing from customers owing to customers C owing to customers owing from customers D owing to customers owing to customers
1 marks
Answer: D
This question in 9706/13 May/June 2024
Q383 · The purchases ledger control account for a business shows a closing balance of $7640 9706/13 May/June 2024
12 The purchases ledger control account for a business shows a closing balance of $7640. The following items were then discovered. 1 A purchase invoice for $250 had been entered in the purchases ledger but not in the purchases journal. 2 A sales ledger contra of $630 had not been entered. 3 A supplier’s account with a debit balance of $70 had been omitted from the control account. 4 Returns inwards of $540 had been entered on the debit side of the control account. What was the credit balance to carry down after adjusting for these items? A $7330 B $7410 C $7730 D $7870
1 marks
Answer: D
This question in 9706/13 May/June 2024
Q384 · The following errors were found after a suspense account was opened 9706/11 Oct/Nov 2024
8 The following errors were found after a suspense account was opened. 1 A cash purchase of goods for resale for $450 had been completely omitted from the books. 2 A payment for electricity was debited in the electricity account as $2500 instead of $5200. 3 Discount allowed of $50 had been debited to the discounts received account. 4 Motor repairs of $400 were credited to the motor vehicle at cost account. Which errors would be entered in the suspense account? A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2024
Q385 · A business is preparing a bank reconciliation statement 9706/11 Oct/Nov 2024
9 A business is preparing a bank reconciliation statement. The following information is available. $ uncleared lodgements 3450 unpresented cheques 2950 cash book balance 7650 credit What is the debit balance on the bank statement? A $1250 B $7150 C $8150 D $14050
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2024
Q386 · Which sources of information will be required to prepare a sales ledger control account? 9706/11 Oct/Nov 2024
10 Which sources of information will be required to prepare a sales ledger control account? 1 cash book 2 general journal 3 sales and sales returns journals A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2024
Q387 · The opening balance on a purchases ledger control account was $18400 9706/11 Oct/Nov 2024
11 The opening balance on a purchases ledger control account was $18400. The following errors or omissions were then discovered. 1 A supplier’s invoice for $860 had been entered as $680 in the purchases journal. 2 An item for $250 in the purchases returns journal had been credited to the supplier’s account. 3 Discounts received of $400 had been credited to the purchases ledger control account. 4 It had been agreed to set-off $150 owing to a customer against their account in the sales ledger. No entries had been made to the sales or purchases ledger control accounts. What was the corrected balance on the purchases ledger control account? A $17630 B $17780 C $17970 D $18180
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2024
Q388 · The totals of the trial balance of a business did not agree 9706/12 Oct/Nov 2024
8 The totals of the trial balance of a business did not agree. The following errors were discovered. 1 The wages account had been overcast by $550. 2 The sales account had been undercast by $400. 3 A credit sale of $150 had been recorded on the sales invoice as $510. After the appropriate corrections were made, the trial balance totals agreed. What was the difference between the trial balance totals before the corrections were made? A $150 B $510 C $590 D $950
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2024
Q389 · In the books of a trader, discounts received of $1400 have been posted correctly in the… 9706/12 Oct/Nov 2024
9 In the books of a trader, discounts received of $1400 have been posted correctly in the suppliers’ accounts but debited in the discounts allowed account. What are the correcting entries? account to be debited $ account to be credited $ A suspense 2800 discounts allowed 1400 discounts received 1400 B discounts allowed 1400 suspense 2800 discounts received 1400 C discounts received 1400 discounts allowed 1400 D discounts allowed 1400 discounts received 1400
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2024
Q390 · What are the advantages of preparing a bank reconciliation statement? 9706/12 Oct/Nov 2024
10 What are the advantages of preparing a bank reconciliation statement? 1 It eliminates the risk of fraud in banking transactions. 2 It helps to identify errors in bank statements. 3 It helps to identify out-of-date cheques. A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2024
Q391 · The cash book of a business showed a debit bank balance of $3900 9706/12 Oct/Nov 2024
11 The cash book of a business showed a debit bank balance of $3900. This differed from the bank statement balance. The bank statement included bank charges of $250, a direct debit of $3280 and a credit transfer of $300. None of these amounts had been entered in the cash book. A payment of $620 entered in the cash book had not yet been presented for payment. What was the balance on the updated cash book? A $70 B $670 C $1290 D $7130
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2024
Q392 · Which items will be entered in the debit side of the purchases ledger control account? 9706/12 Oct/Nov 2024
12 Which items will be entered in the debit side of the purchases ledger control account? 1 contra with sales ledger control account 2 discount received 3 returns inwards A 1 and 2 B 2 and 3 C 2 only D 3 only
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2024
Q393 · A company prepared a sales ledger control account 9706/12 Oct/Nov 2024
13 A company prepared a sales ledger control account. The balance did not agree with the total of the sales ledger balances, which were $42 650. The following errors or omissions were discovered. 1 An irrecoverable debt of $500 in the general journal has not been recorded in the sales ledger. 2 The sales journal has been incorrectly added and must be reduced by $750. 3 The sales ledger control account includes the discount received of $400. It should have been discount allowed, $600. 4 Sales to J Brown of $640 have not been entered in his account. What was the correct total of the sales ledger balances? A $41700 B $41840 C $42510 D $42790
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2024
Q394 · Janet paid Samir after purchasing goods from him on credit 9706/13 Oct/Nov 2024
8 Janet paid Samir after purchasing goods from him on credit. Samir made an error of reversal when recording the cash discount. What was the double entry made by Samir in error in his books of account? debit entry credit entry A discount allowed Janet B discount received Janet C Janet discount allowed D Janet discount received
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2024
Q395 · There were two errors in Bernie’s books of account 9706/13 Oct/Nov 2024
9 There were two errors in Bernie’s books of account. 1 The sales journal had been undercast by $200. 2 A payment for insurance of $120 was correctly entered in the cash book but recorded in the insurance account as $102. What was the opening balance in the suspense account? A $182 on the credit side B $182 on the debit side C $218 on the credit side D $218 on the debit side
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2024
Q396 · The bank column of a business cash book showed a debit balance of $25000 9706/13 Oct/Nov 2024
10 The bank column of a business cash book showed a debit balance of $25000. The following information was then discovered. $ direct debit payments not recorded in the cash book 6500 payments for sales made directly into the bank by 5500 customers but not recorded in the cash book bank charges not recorded in the cash book 1500 payment made by the business but not yet shown in 4500 the bank statement What was the correct balance in the cash book? A $18000 B $19500 C $22500 D $27500
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2024
Q397 · Henry received a credit note from a supplier 9706/13 Oct/Nov 2024
11 Henry received a credit note from a supplier. He treated this in error as an invoice received and entered it in his purchases journal. When was the error revealed? A when Henry compared his cash book with his bank statement B when Henry compared his purchases ledger with statements of account received C when Henry prepared a purchases ledger control account D when Henry prepared a trial balance
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2024
Q398 · At the end of the year, the balance on a firm’s sales ledger control account was $12900 9706/13 Oct/Nov 2024
12 At the end of the year, the balance on a firm’s sales ledger control account was $12900. The total of the customers’ accounts in the sales ledger was $11900. The following errors were then discovered. 1 A customer’s account had been undercast by $700. 2 A contra with a supplier in the purchases ledger of $200 had only been entered in the sales ledger control account. 3 The discount allowed column in the cash book totalled $500. This had not been posted to the nominal ledger. What was the correct balance on the sales ledger control account? A $11200 B $11400 C $12000 D $12400
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2024
Q399 · A business maintains control accounts as part of its double entry system 9706/11 May/June 2025
7 A business maintains control accounts as part of its double entry system. Which error would cause an entry in the suspense account? A A purchases journal total of $9870 is incorrectly posted as $9780. B Carriage outwards is credited to the carriage outwards account but correctly accounted for in the cash book. C Discounts allowed are debited to the discounts allowed account and credited to the purchases ledger control account. D Repairs to a vehicle are debited to the vehicles account.
1 marks
Answer: B
This question in 9706/11 May/June 2025
Q400 · Which item is not likely to be updated in the cash book when preparing the bank… 9706/11 May/June 2025
8 Which item is not likely to be updated in the cash book when preparing the bank reconciliation statement? A direct debit B dishonoured cheque C standing order D unpresented cheque
1 marks
Answer: D
This question in 9706/11 May/June 2025
Q401 · A draft statement of financial position shows a bank balance of $1400 9706/11 May/June 2025
9 A draft statement of financial position shows a bank balance of $1400. The following information is now available. $ cheques issued but not yet cleared by the bank 150 bank charges not in the cash book 45 lodgements in the cash book but not on the bank statement 220 Which figure is shown on the bank statement? A $1285 B $1355 C $1425 D $1515
1 marks
Answer: A
This question in 9706/11 May/June 2025
Q402 · Which item should be recorded as a debit entry in a sales ledger control account? 9706/11 May/June 2025
10 Which item should be recorded as a debit entry in a sales ledger control account? A contra entry between the sales ledger and the purchases ledger B interest charged on an overdue credit customer’s account C irrecoverable debt written off D total of sales returns
1 marks
Answer: B
This question in 9706/11 May/June 2025
Q403 · Some errors were made when preparing a purchases ledger control account 9706/11 May/June 2025
11 Some errors were made when preparing a purchases ledger control account. The incorrect balance was $15830. The following errors were discovered. 1 Refunds of $270, from credit suppliers, had been omitted from the control account. 2 The total of discounts received of $480 had been posted to the wrong side of the control account. What was the corrected balance of the purchases ledger control account? A $14600 B $15080 C $15140 D $15620
1 marks
Answer: C
This question in 9706/11 May/June 2025
Q404 · The draft profit for the year of a business was $84000 9706/11 May/June 2025
12 The draft profit for the year of a business was $84000. The following errors were then discovered. 1 Discounts received of $2500 had been debited to the discounts allowed account. 2 Wages of $9000 had been completely omitted. 3 Sales returns of $8000 had been debited to the purchases returns account. What is the corrected profit for the year? A $64000 B $72000 C $77500 D $80000
1 marks
Answer: D
This question in 9706/11 May/June 2025
Q405 · After the profit for the year was calculated, the following errors were discovered 9706/12 May/June 2025
8 After the profit for the year was calculated, the following errors were discovered. 1 Discount allowed of $550 was recorded as discount received. 2 Rental income of $3500 was recorded as an expense. 3 Wages of $4500 were recorded as $5400. What will be the effect on the profit for the year after correcting these errors? A decrease by $3850 B decrease by $6800 C increase by $3850 D increase by $6800
1 marks
Answer: D
This question in 9706/12 May/June 2025
Q406 · A business’s suspense account appears as follows: $ $ discount allowed 150 opening… 9706/12 May/June 2025
9 A business’s suspense account appears as follows: $ $ discount allowed 150 opening balance 100 sales 50 150 150 Which statements are correct? 1 Total debits had been $100 less than total credits in the trial balance. 2 The sales account had been overcast by $50. 3 The discount allowed account had been overcast by $150. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: C
This question in 9706/12 May/June 2025
Q407 · Why does a business prepare a bank reconciliation statement? 9706/12 May/June 2025
10 Why does a business prepare a bank reconciliation statement? A to determine the cash in hand balance B to explain the difference between the cash book balance and the bank statement balance C to identify dishonoured cheques from trade payables D to prepare a statement of profit or loss
1 marks
Answer: B
This question in 9706/12 May/June 2025
Q408 · A debit balance of $2600 was shown for the bank in the cash book of a business at the end… 9706/12 May/June 2025
11 A debit balance of $2600 was shown for the bank in the cash book of a business at the end of the month. The bank statement included bank charges of $1200 and interest received of $500, both of which had not been entered in the cash book. The bank column of the cash book had been overcast by $200. The cash book included a payment of $800 which had not yet appeared on the bank statement. What was the credit balance shown on the bank statement at the end of the month? A $900 B $1700 C $2500 D $2700
1 marks
Answer: C
This question in 9706/12 May/June 2025
Q409 · Why is a sales ledger control account used? 9706/12 May/June 2025
12 Why is a sales ledger control account used? 1 to control discounts received 2 to ensure credit customers pay promptly 3 to provide a trial balance figure for trade receivables A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/12 May/June 2025
Q410 · A bookkeeper is given the task of reconciling the sales ledger control account with… 9706/12 May/June 2025
13 A bookkeeper is given the task of reconciling the sales ledger control account with balances in the sales ledger at the end of each month. The sales ledger control account showed a debit balance of $26000 before the bookkeeper discovered the following: 1 Contra entries of $1800 in the sales ledger had been omitted from the control account. 2 Discounts allowed of $3600 had been debited to the sales ledger control account. 3 The allowance for irrecoverable debts had been increased by $1200. What is the correct figure for trade receivables at the end of the month? A $15800 B $17000 C $18800 D $20600
1 marks
Answer: B
This question in 9706/12 May/June 2025
Q411 · A business maintains control accounts as part of its double entry system 9706/13 May/June 2025
7 A business maintains control accounts as part of its double entry system. Which error would cause an entry in the suspense account? A A purchases journal total of $9870 is incorrectly posted as $9780. B Carriage outwards is credited to the carriage outwards account but correctly accounted for in the cash book. C Discounts allowed are debited to the discounts allowed account and credited to the purchases ledger control account. D Repairs to a vehicle are debited to the vehicles account.
1 marks
Answer: B
This question in 9706/13 May/June 2025
Q412 · Which item is not likely to be updated in the cash book when preparing the bank… 9706/13 May/June 2025
8 Which item is not likely to be updated in the cash book when preparing the bank reconciliation statement? A direct debit B dishonoured cheque C standing order D unpresented cheque
1 marks
Answer: D
This question in 9706/13 May/June 2025
Q413 · A draft statement of financial position shows a bank balance of $1400 9706/13 May/June 2025
9 A draft statement of financial position shows a bank balance of $1400. The following information is now available. $ cheques issued but not yet cleared by the bank 150 bank charges not in the cash book 45 lodgements in the cash book but not on the bank statement 220 Which figure is shown on the bank statement? A $1285 B $1355 C $1425 D $1515
1 marks
Answer: A
This question in 9706/13 May/June 2025
Q414 · Which item should be recorded as a debit entry in a sales ledger control account? 9706/13 May/June 2025
10 Which item should be recorded as a debit entry in a sales ledger control account? A contra entry between the sales ledger and the purchases ledger B interest charged on an overdue credit customer’s account C irrecoverable debt written off D total of sales returns
1 marks
Answer: B
This question in 9706/13 May/June 2025
Q415 · Some errors were made when preparing a purchases ledger control account 9706/13 May/June 2025
11 Some errors were made when preparing a purchases ledger control account. The incorrect balance was $15830. The following errors were discovered. 1 Refunds of $270, from credit suppliers, had been omitted from the control account. 2 The total of discounts received of $480 had been posted to the wrong side of the control account. What was the corrected balance of the purchases ledger control account? A $14600 B $15080 C $15140 D $15620
1 marks
Answer: C
This question in 9706/13 May/June 2025
Q416 · The draft profit for the year of a business was $84000 9706/13 May/June 2025
12 The draft profit for the year of a business was $84000. The following errors were then discovered. 1 Discounts received of $2500 had been debited to the discounts allowed account. 2 Wages of $9000 had been completely omitted. 3 Sales returns of $8000 had been debited to the purchases returns account. What is the corrected profit for the year? A $64000 B $72000 C $77500 D $80000
1 marks
Answer: D
This question in 9706/13 May/June 2025
Q417 · Motor vehicles purchased for $530000, at the start of the year, have been incorrectly… 9706/11 Oct/Nov 2025
7 Motor vehicles purchased for $530000, at the start of the year, have been incorrectly depreciated for the whole year, using the straight-line method at 10% instead of 25%. Ledger balances after the entries have been posted are as follows: $ motor vehicles at cost 530000 provision for depreciation of motor vehicles 53000 Which entries will correct the error? account to be debited $ account to be credited $ A statement of profit 79500 provision for depreciation 79500 or loss of motor vehicles B statement of profit 132500 provision for depreciation 132500 or loss of motor vehicles C provision for depreciation 79500 statement of profit 79500 of motor vehicles or loss D provision for depreciation 132500 statement of profit 132500 of motor vehicles or loss
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2025
Q418 · A trial balance does not balance and a suspense account is opened 9706/11 Oct/Nov 2025
9 A trial balance does not balance and a suspense account is opened. Later the following errors are found and the suspense account is cleared. 1 A sales invoice for $1240 had been completely omitted from the books. 2 The figure for total purchases had been entered as $85 600. The correct amount should have been $87 580. 3 Rent paid of $2600 had been entered correctly in the cash book but entered as $6200 in the rent account. What was the original balance on the suspense account? A $1620 credit B $1620 debit C $5580 credit D $5580 debit
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2025
Q419 · When Neil received a bank statement, he updated the cash book 9706/11 Oct/Nov 2025
10 When Neil received a bank statement, he updated the cash book. He then prepared a bank reconciliation statement. Which item appeared on the bank reconciliation statement? A bank charges shown on the bank statement B cheques not presented for payment C credit transfers received directly by the bank D errors discovered in the cash book
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2025
Q420 · A sales invoice to Jane has not been recorded in the books of prime entry 9706/11 Oct/Nov 2025
11 A sales invoice to Jane has not been recorded in the books of prime entry. Which accounts are affected by this error? sales ledger control Jane A no no B no yes C yes no D yes yes
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2025
Q421 · A business makes all sales on credit 9706/11 Oct/Nov 2025
12 A business makes all sales on credit. Its sales ledger control account had a balance of $20 000 at the end of July. During August, the following transactions were recorded. $ credit sales 150000 receipts from credit customers 135000 returned cheques 5000 returns inwards 11000 What was the sales ledger control account balance at the end of August? A $11000 B $19000 C $29000 D $30000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2025
Q422 · The totals of a trial balance did not agree 9706/12 Oct/Nov 2025
8 The totals of a trial balance did not agree. As a result, a suspense account was opened with a credit balance of $1720. So far, two errors have been discovered: 1 The balance of the purchases returns account of $440 was omitted from the trial balance. 2 The bank overdraft balance was understated by $90. What will be the updated credit balance of the suspense account after these errors are corrected? A $1190 B $1370 C $2070 D $2250
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2025
Q423 · The total of the discount column on the debit side of the cash book had been debited to… 9706/12 Oct/Nov 2025
9 The total of the discount column on the debit side of the cash book had been debited to the discount received account. Which accounts will be used to correct this error? 1 discount allowed 2 discount received 3 suspense A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2025
Q424 · At 31 December, the following information is available about a company’s banking… 9706/12 Oct/Nov 2025
10 At 31 December, the following information is available about a company’s banking transactions. $ balance at bank per bank statement 22650 uncleared deposits 3110 unpresented cheques 6290 bank credit recorded twice by bank in error 650 Which value for bank should be recorded in the statement of financial position at 31 December? A $18820 B $20120 C $25180 D $26480
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2025
Q425 · A business maintains control accounts as a part of its double entry system 9706/12 Oct/Nov 2025
11 A business maintains control accounts as a part of its double entry system. The balance of the purchases ledger control account is $8232. However, this does not agree with the total of balances in the purchases ledger. The following account for the difference. 1 An entry in the purchases returns journal for $72 has been posted to the credit side of the individual trade payable’s account in the purchases ledger. 2 An entry for discounts received in the cash book for $54 has been debited to the individual trade payable’s account in the purchases ledger as $45. What is the total of balances in the purchases ledger before these errors are corrected? A $8079 B $8097 C $8367 D $8385
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2025
Q426 · A sales ledger control account included the following entries: 1 contra with the… 9706/12 Oct/Nov 2025
12 A sales ledger control account included the following entries: 1 contra with the purchases ledger control account $500, debit 2 discount allowed $600, debit 3 irrecoverable debts written off $1200, debit Which entries must be corrected? A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2025
Q427 · The cost of a new machine has been debited to the repairs account 9706/13 Oct/Nov 2025
10 The cost of a new machine has been debited to the repairs account. What type of error is this? A commission B omission C principle D reversal of entries
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2025
Q428 · A suspense account was opened to record the difference on a trial balance 9706/13 Oct/Nov 2025
11 A suspense account was opened to record the difference on a trial balance. After further investigation, the following errors were discovered. 1 Discount received of $250 had been debited to the discount allowed account. The entry to the trade payable account was correctly made. 2 Electricity refund of $170, entered correctly in the cash book, had been treated as electricity expense. 3 Machine installation of $440 had been treated as machine repairs. After correcting the errors, the trial balance agreed. What was the opening credit balance on the suspense account? A $160 B $400 C $670 D $840
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2025
Q429 · An accountant prepared a bank reconciliation statement 9706/13 Oct/Nov 2025
12 An accountant prepared a bank reconciliation statement. He discovered the following differences between the bank statement and the cash book. 1 an amount received from a customer by credit transfer 2 bank charges 3 unpresented cheques Which differences will need to be entered in the cash book to update it? A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2025
Q430 · A business maintains control accounts as a part of the double entry system 9706/13 Oct/Nov 2025
13 A business maintains control accounts as a part of the double entry system. At 31 December, the balance of $23 400 in the sales ledger control account did not agree with the total of the individual sales ledger balances. The following errors were discovered. 1 A sales invoice for $1800 had been entered in the sales journal as $1880. 2 A discount allowed of $200 to a customer had not been recorded. 3 Sales of $1200 had been entered on the wrong side of a customer’s account. What is the correct balance in the sales ledger control account at 31 December? A $23120 B $23520 C $25520 D $25600
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2025
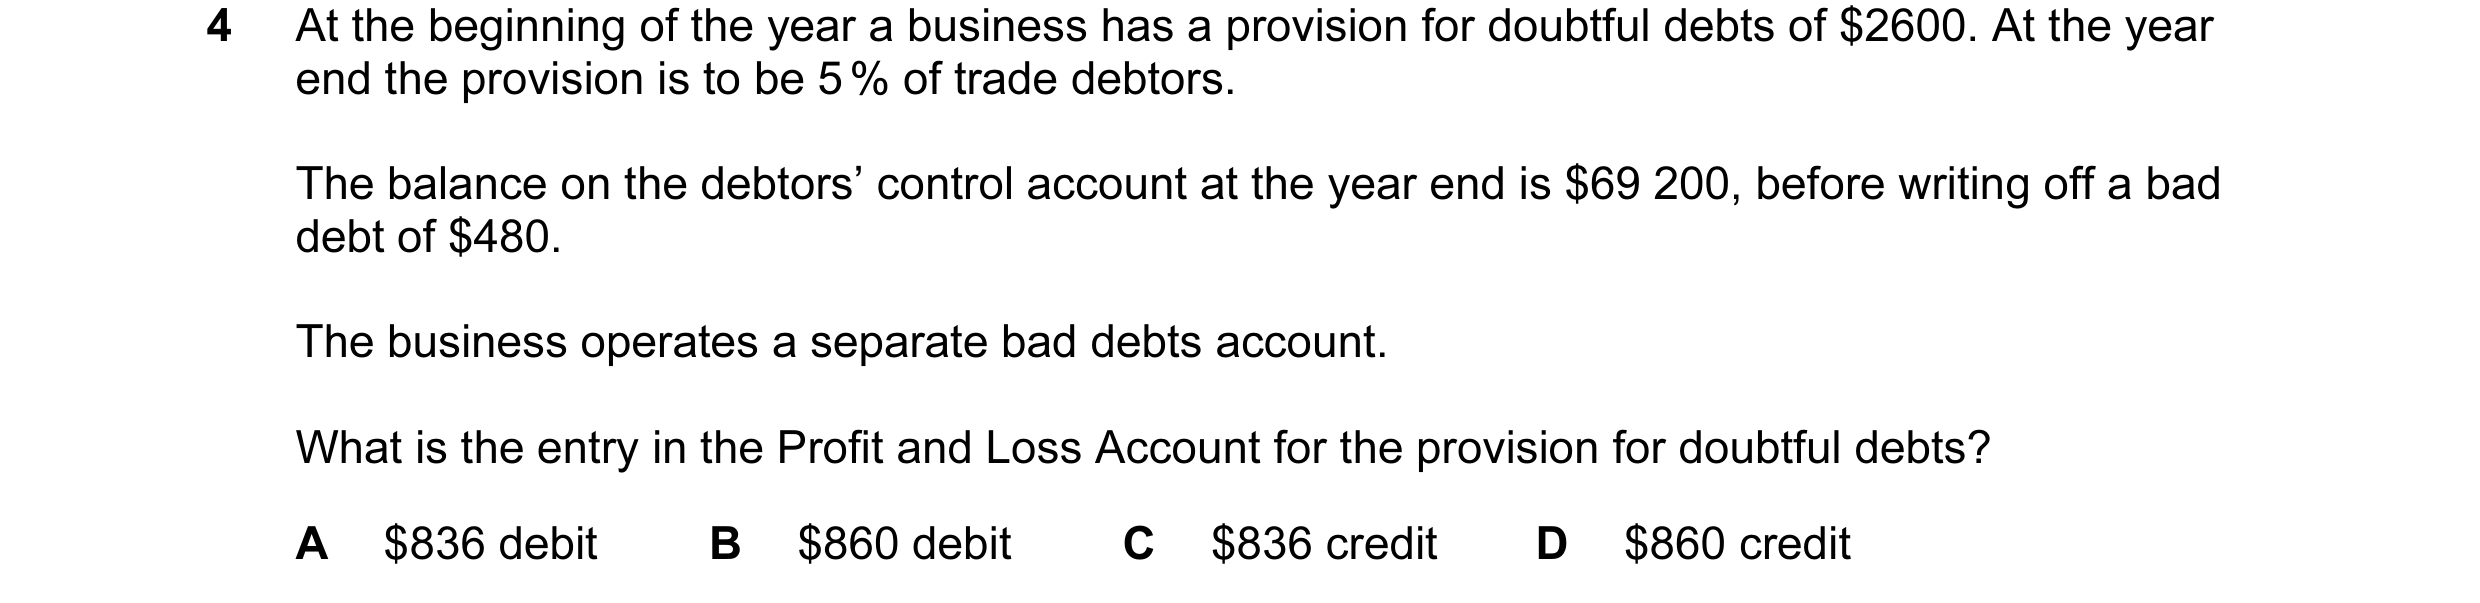 1 / 110
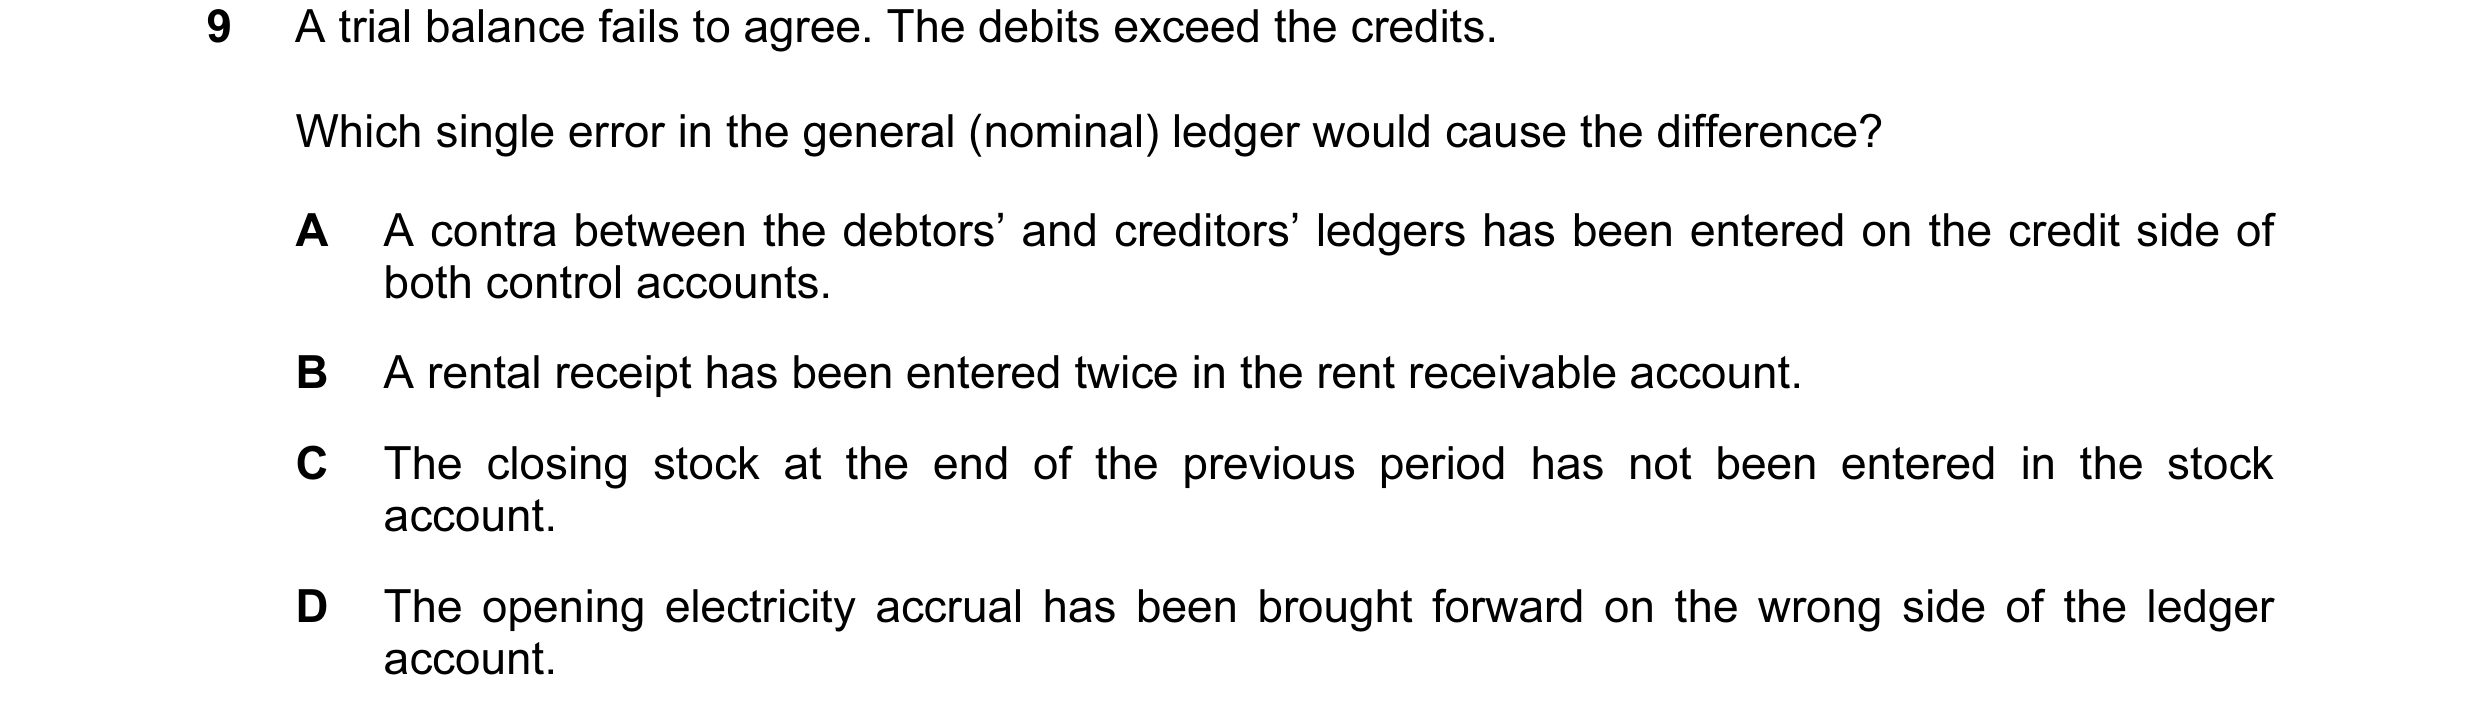
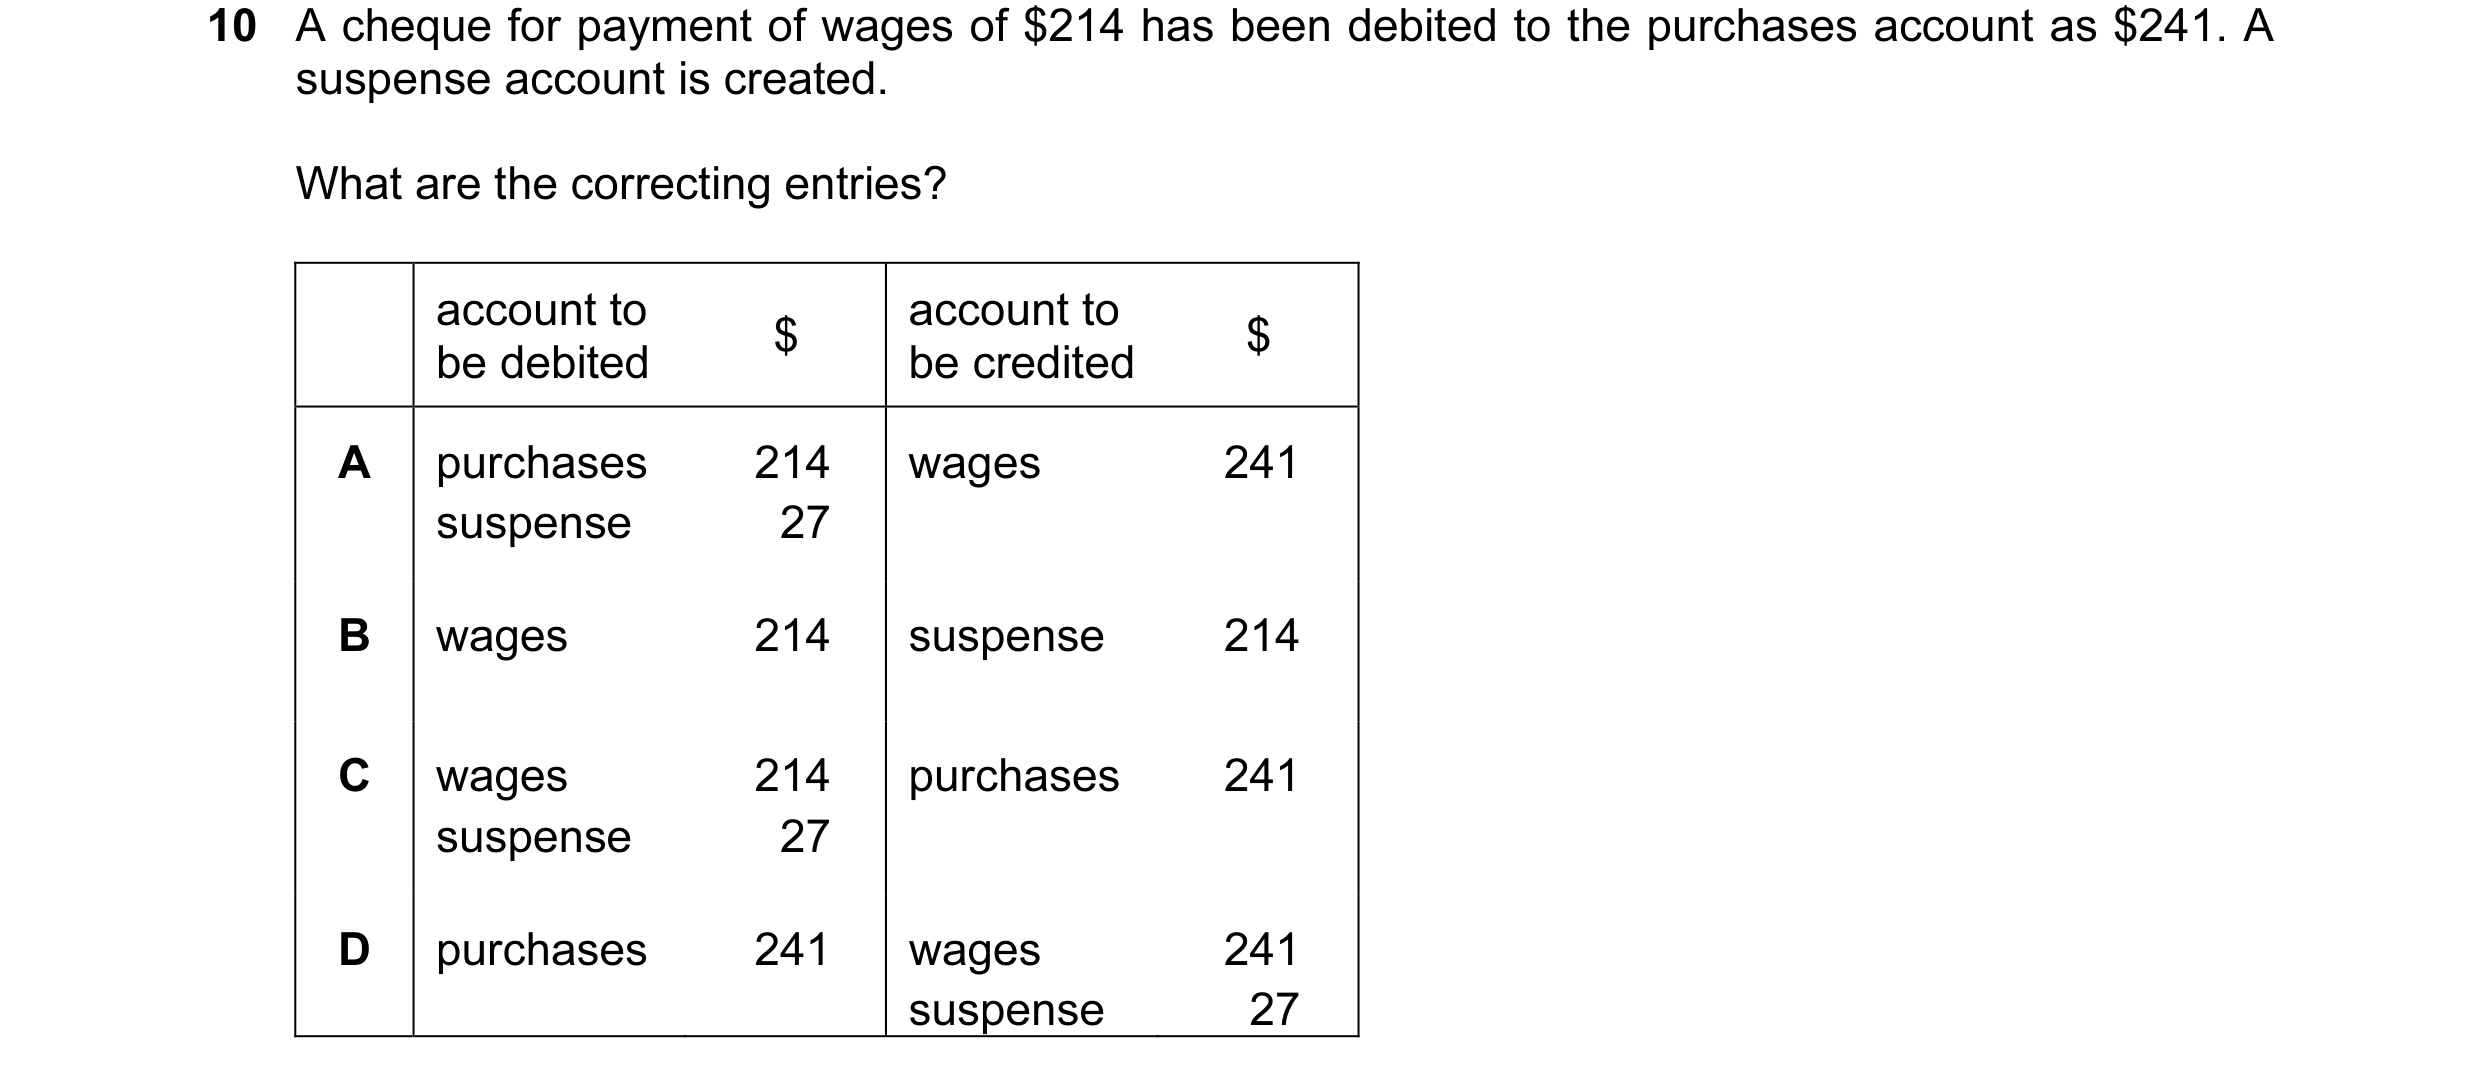
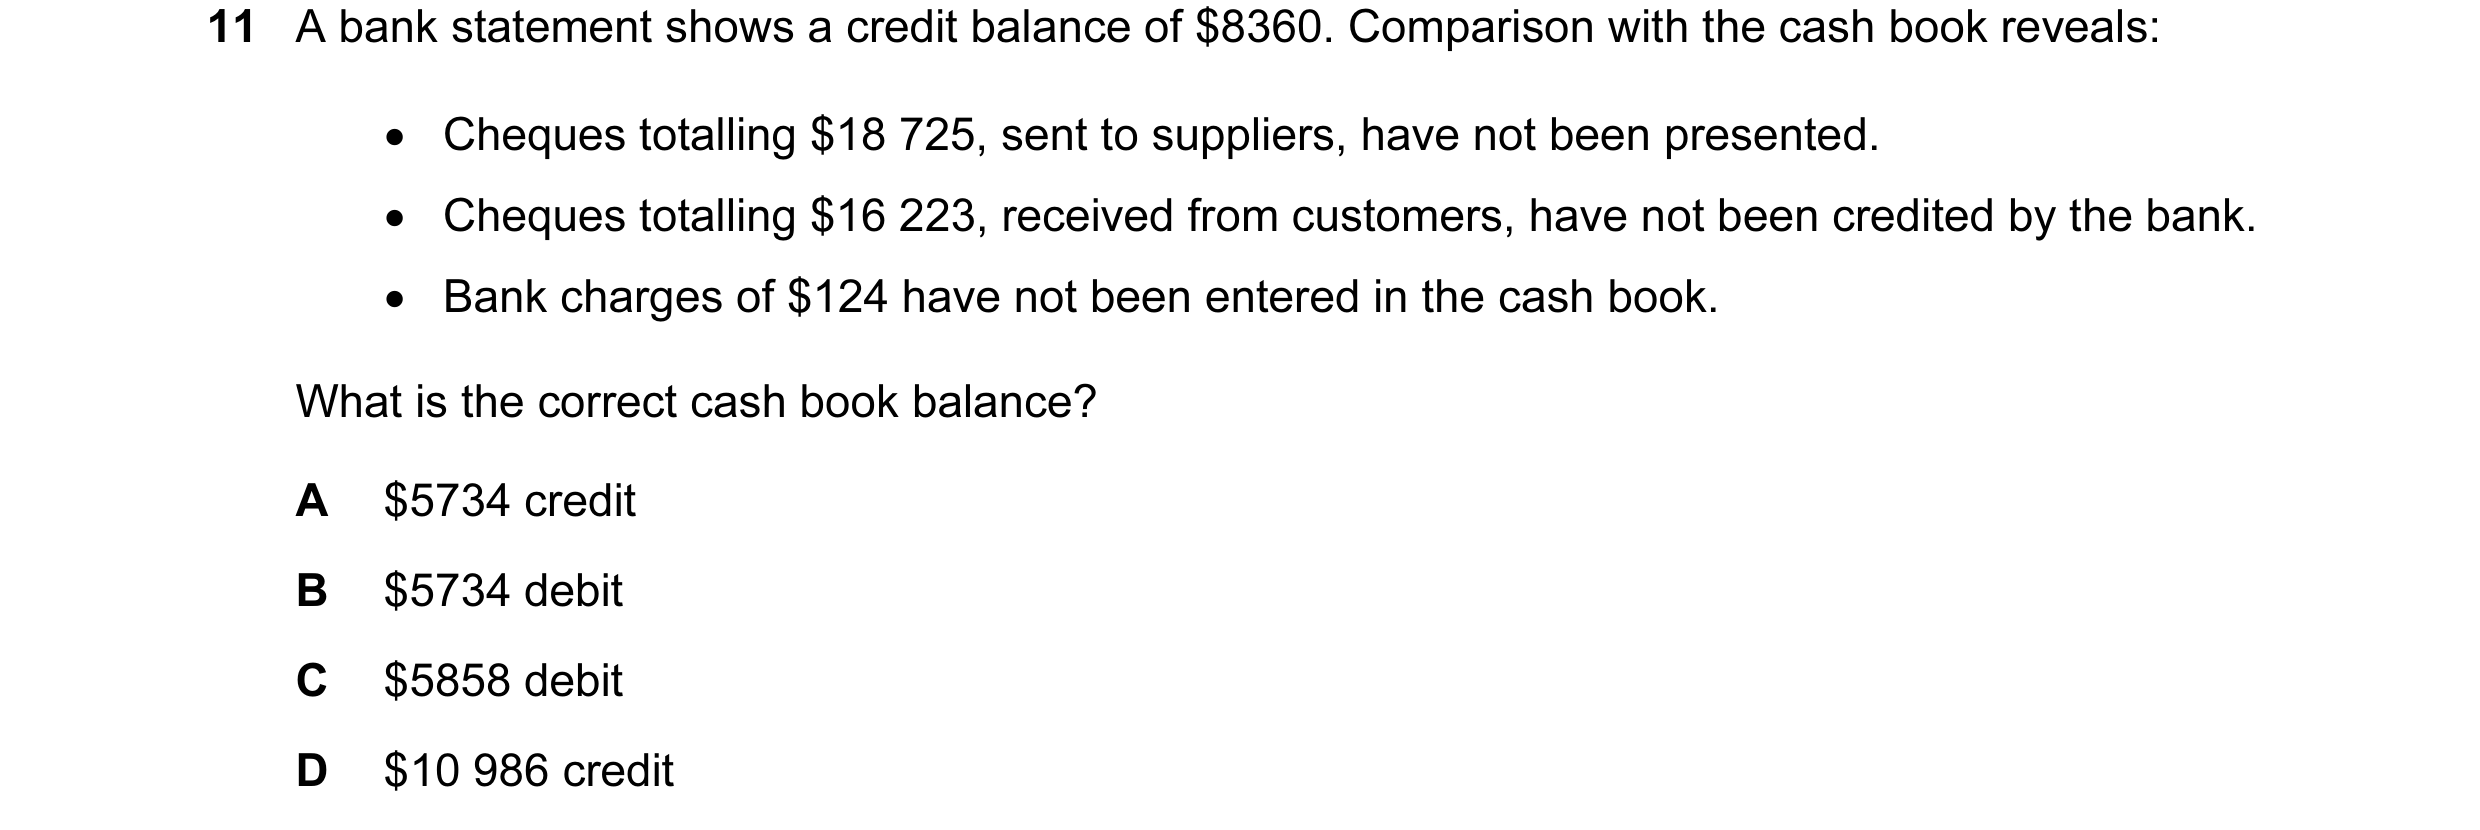 2 / 110
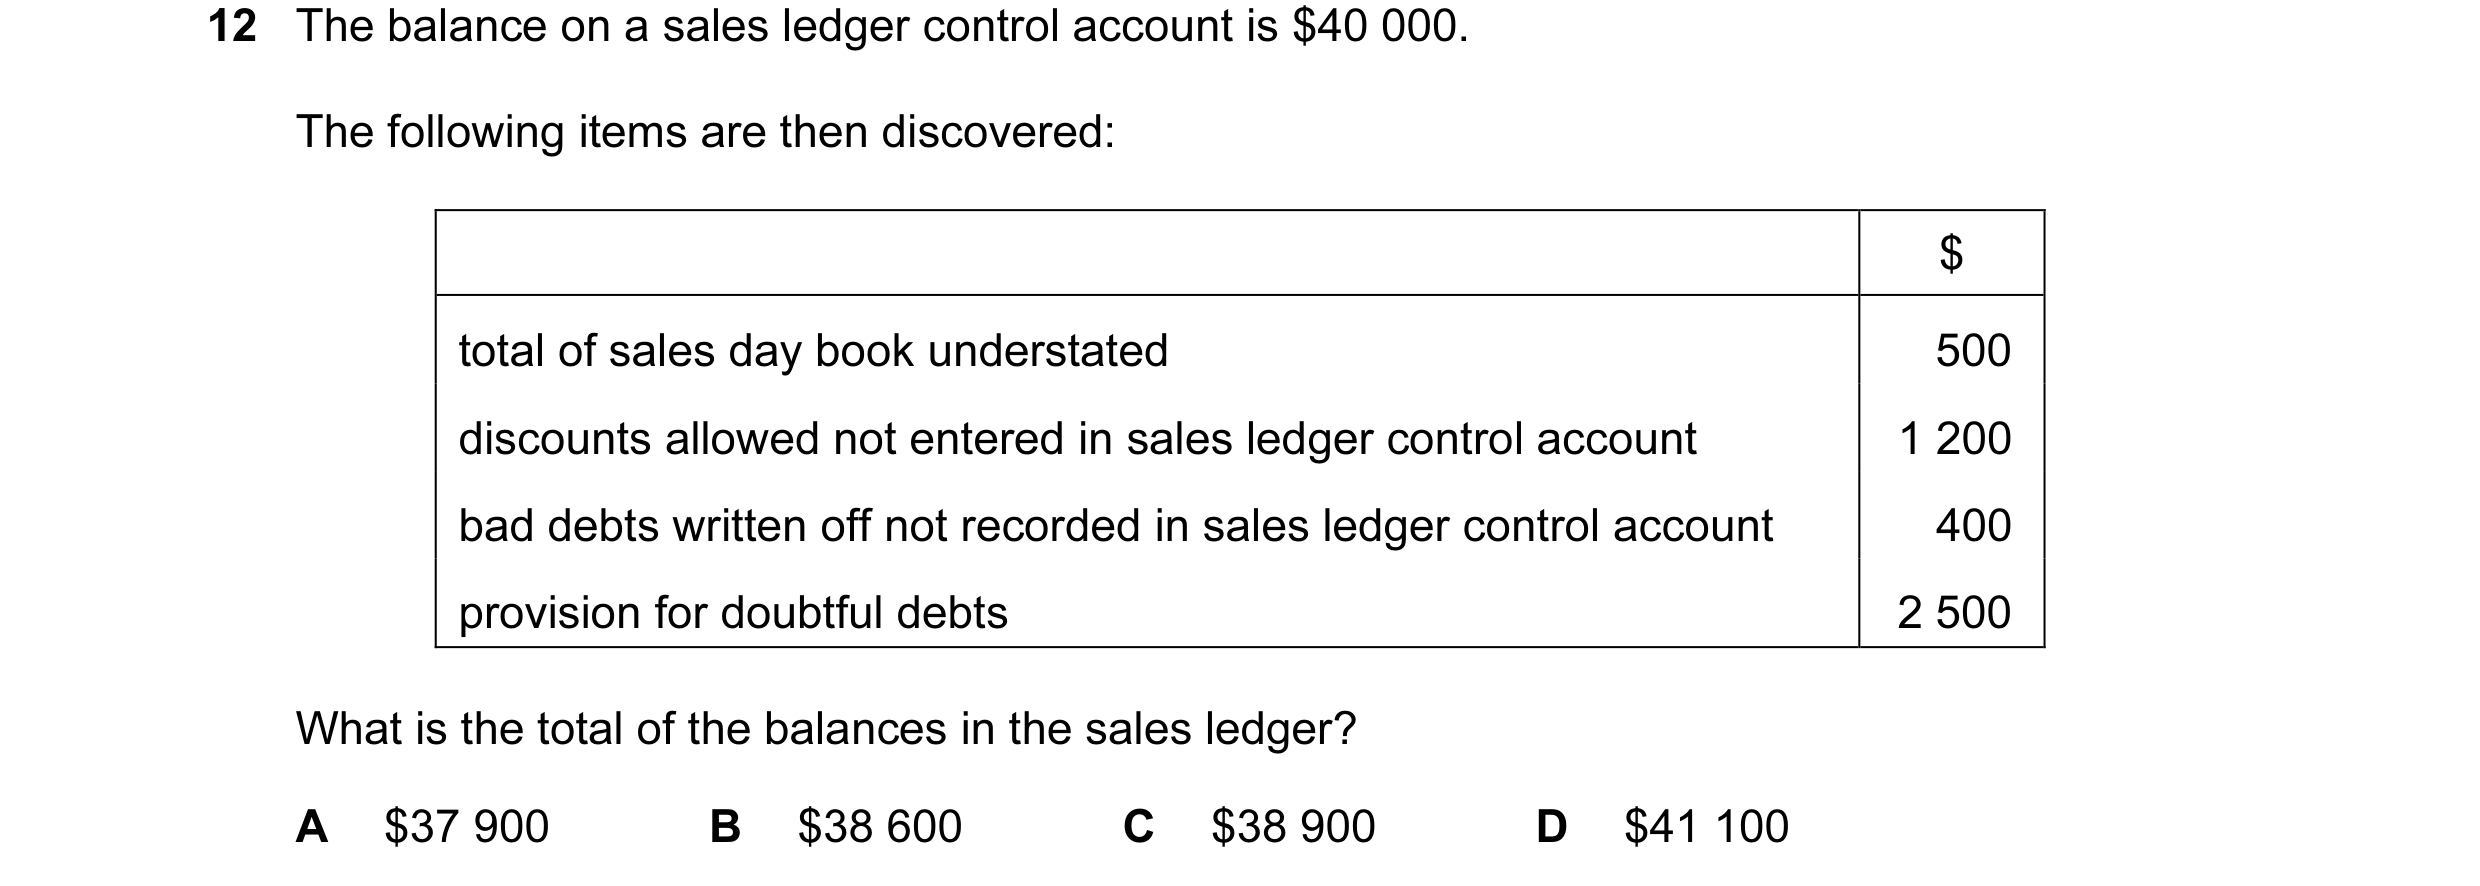
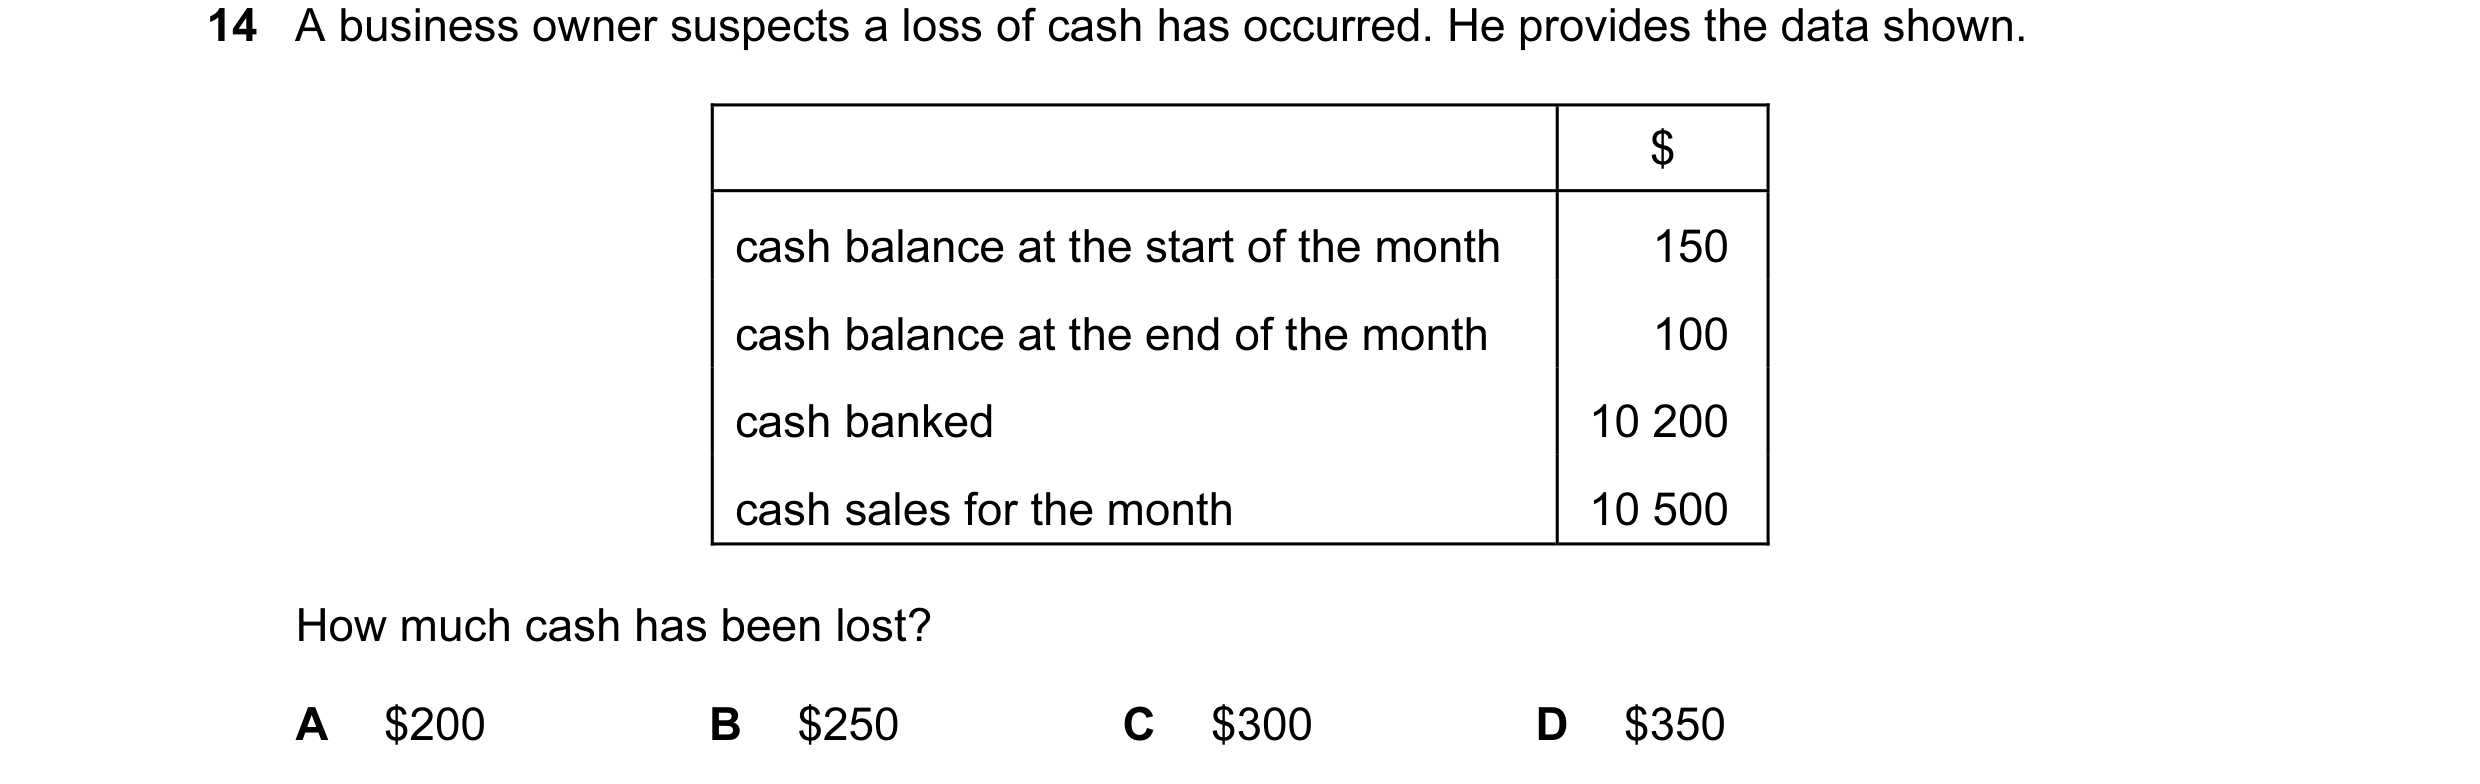
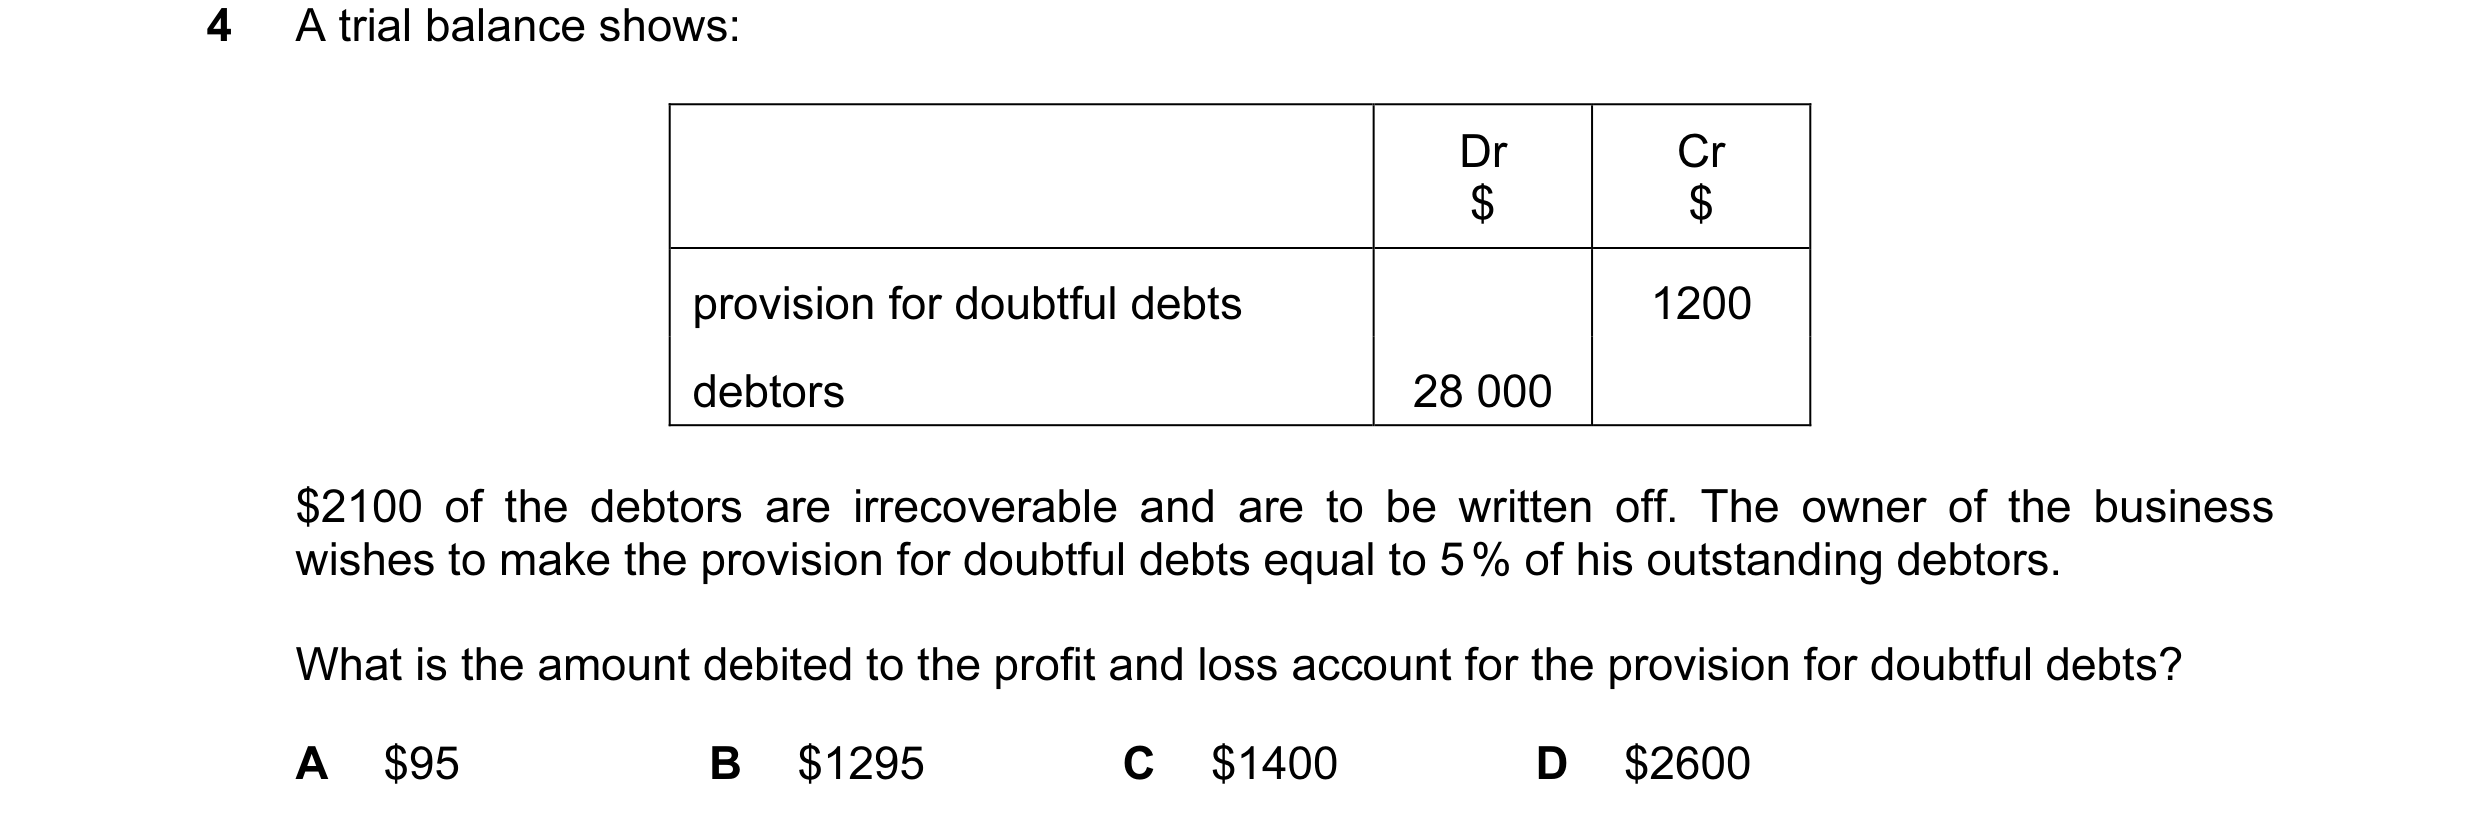
 3 / 110
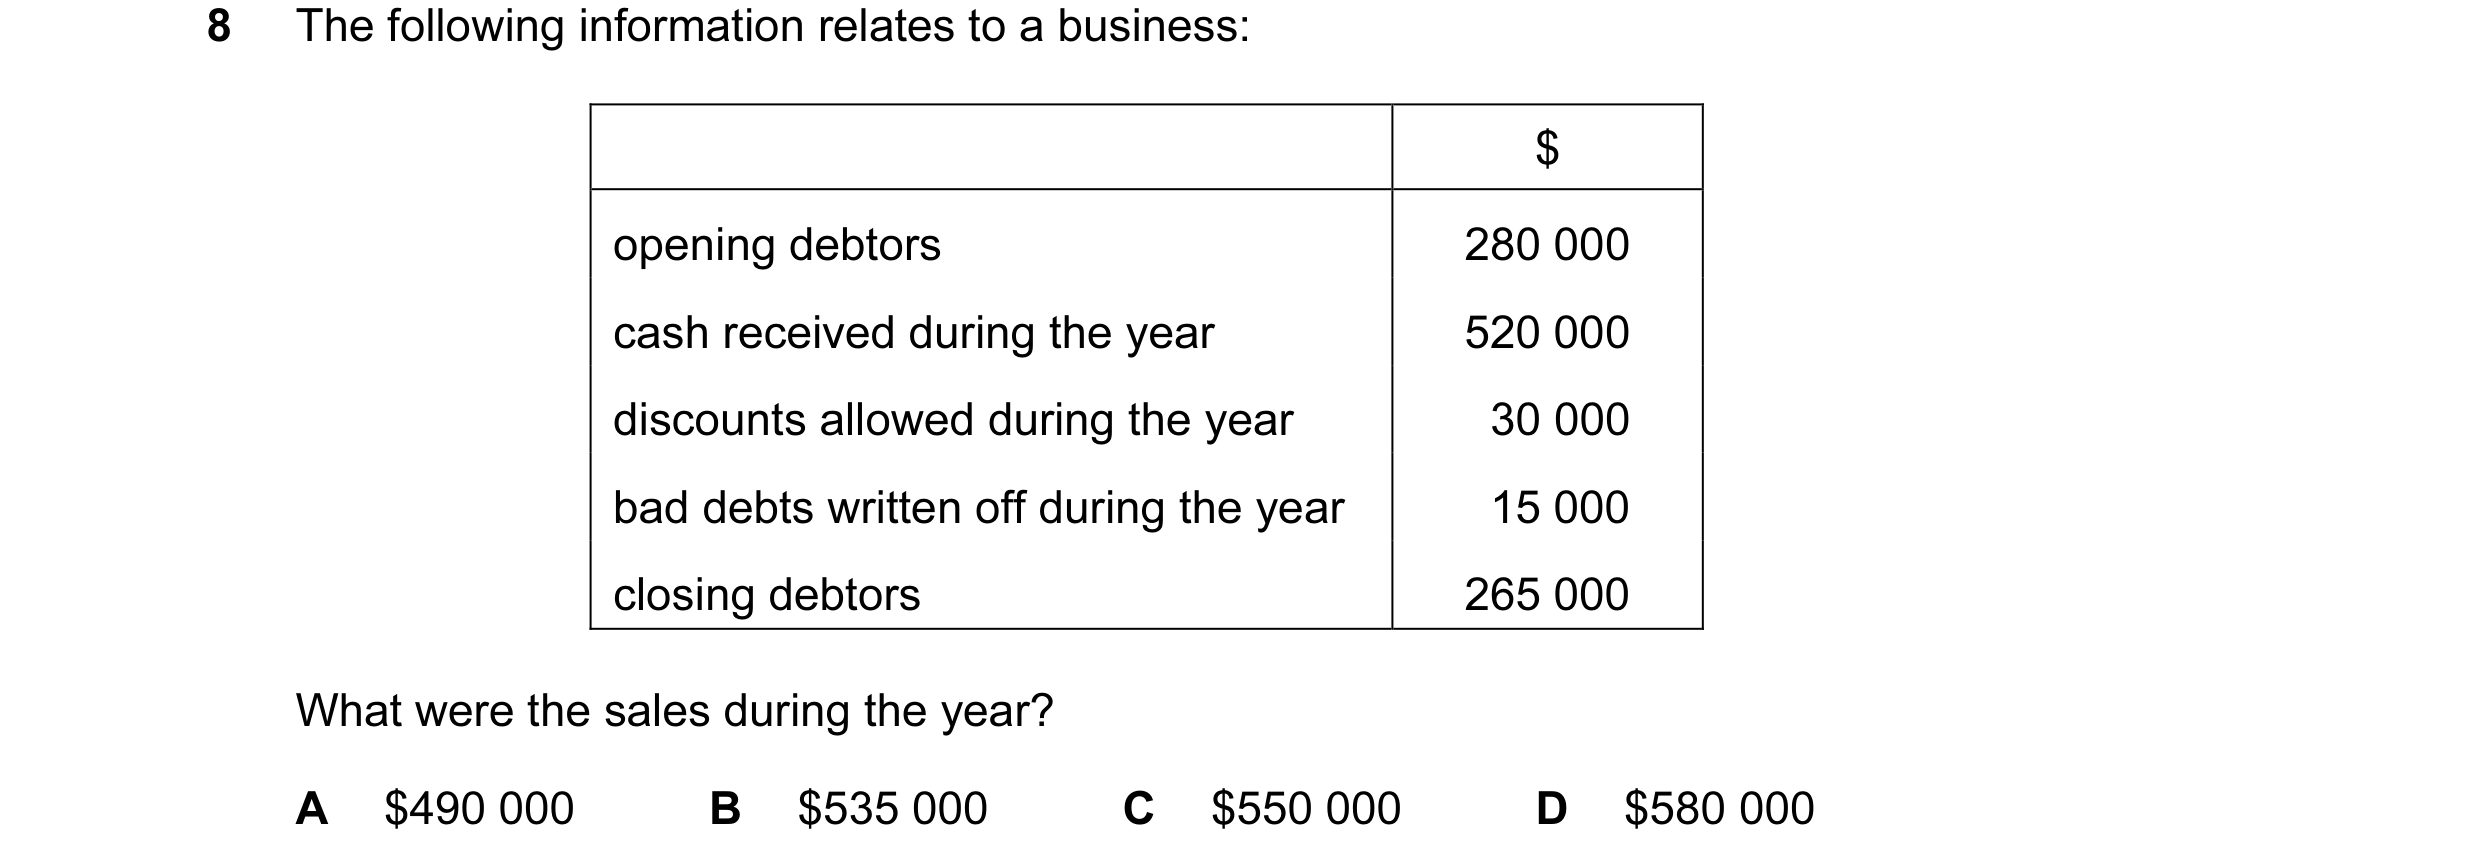
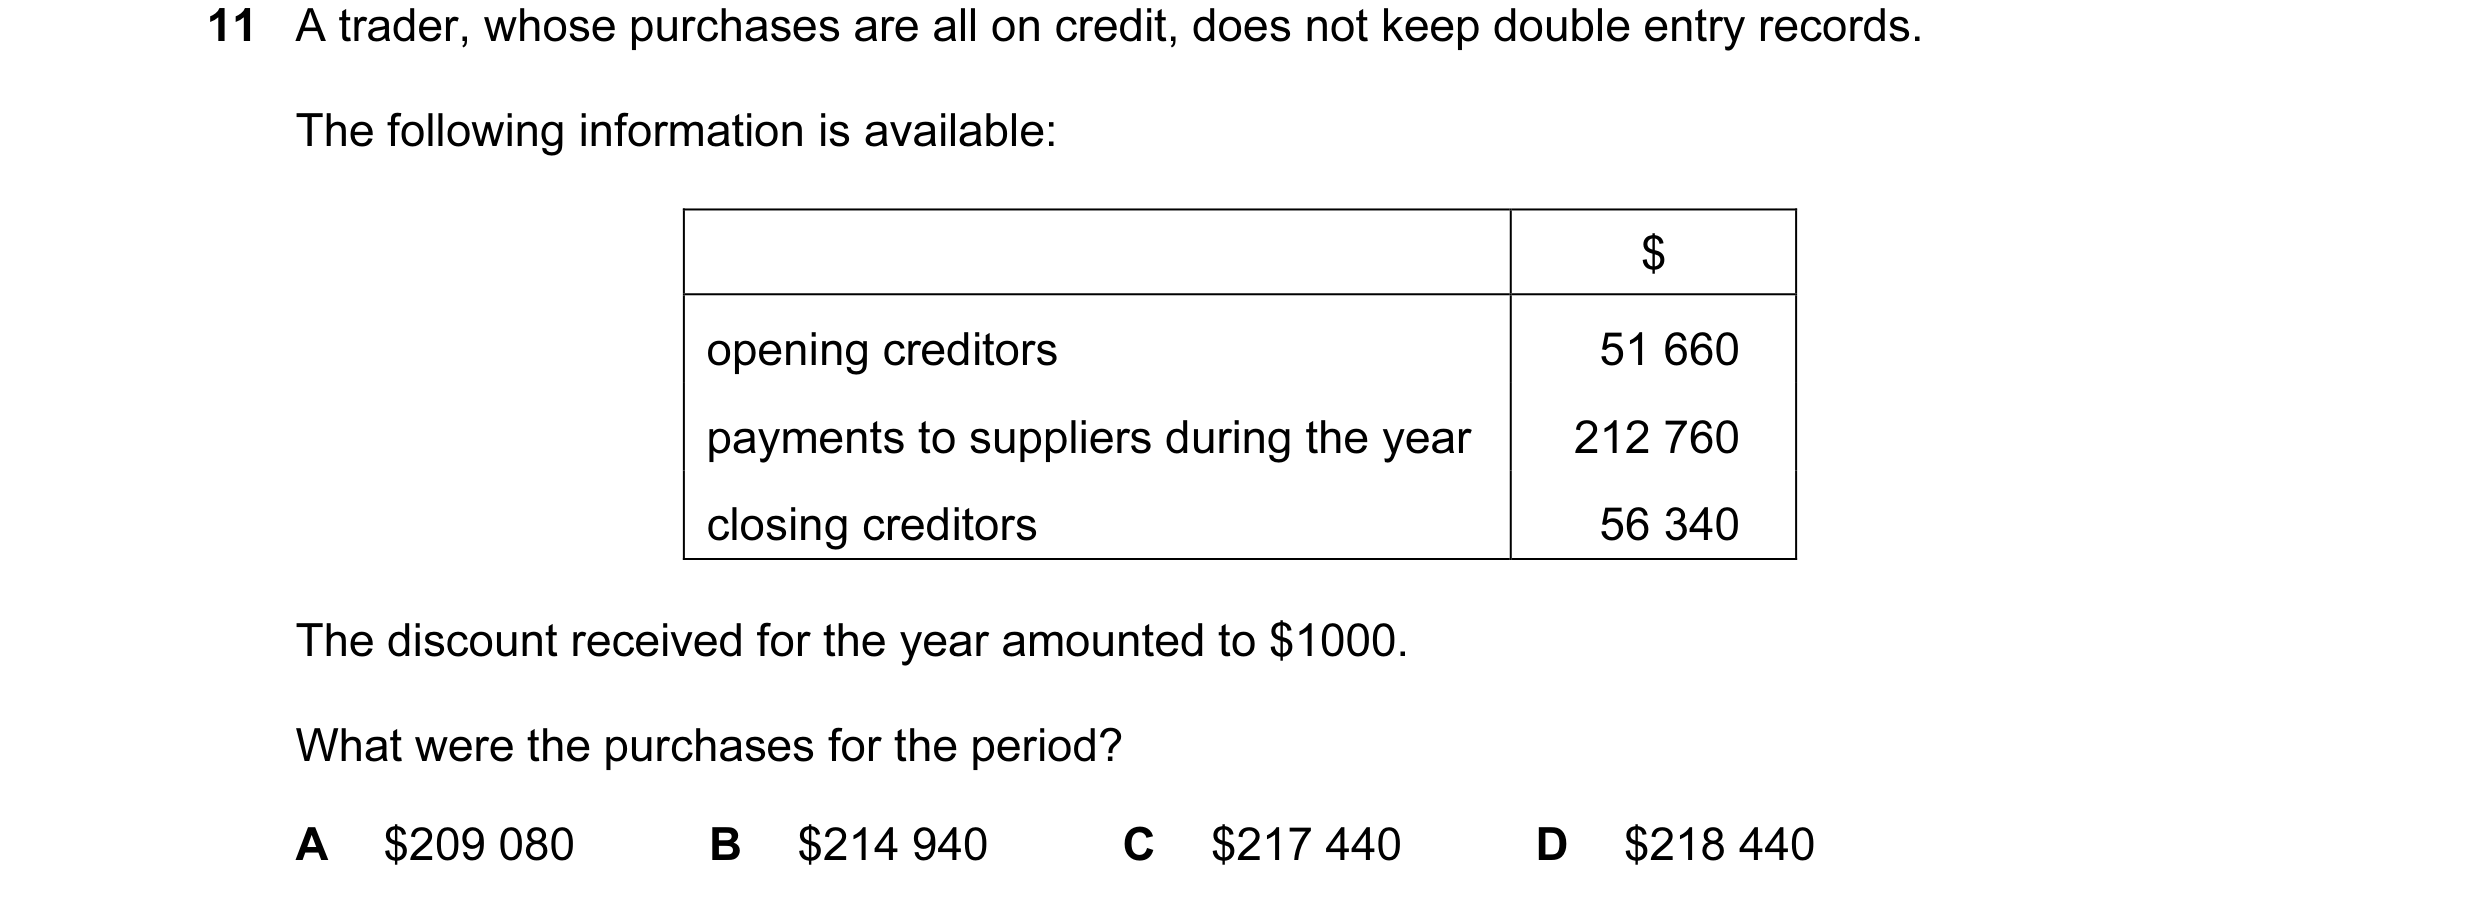 4 / 110
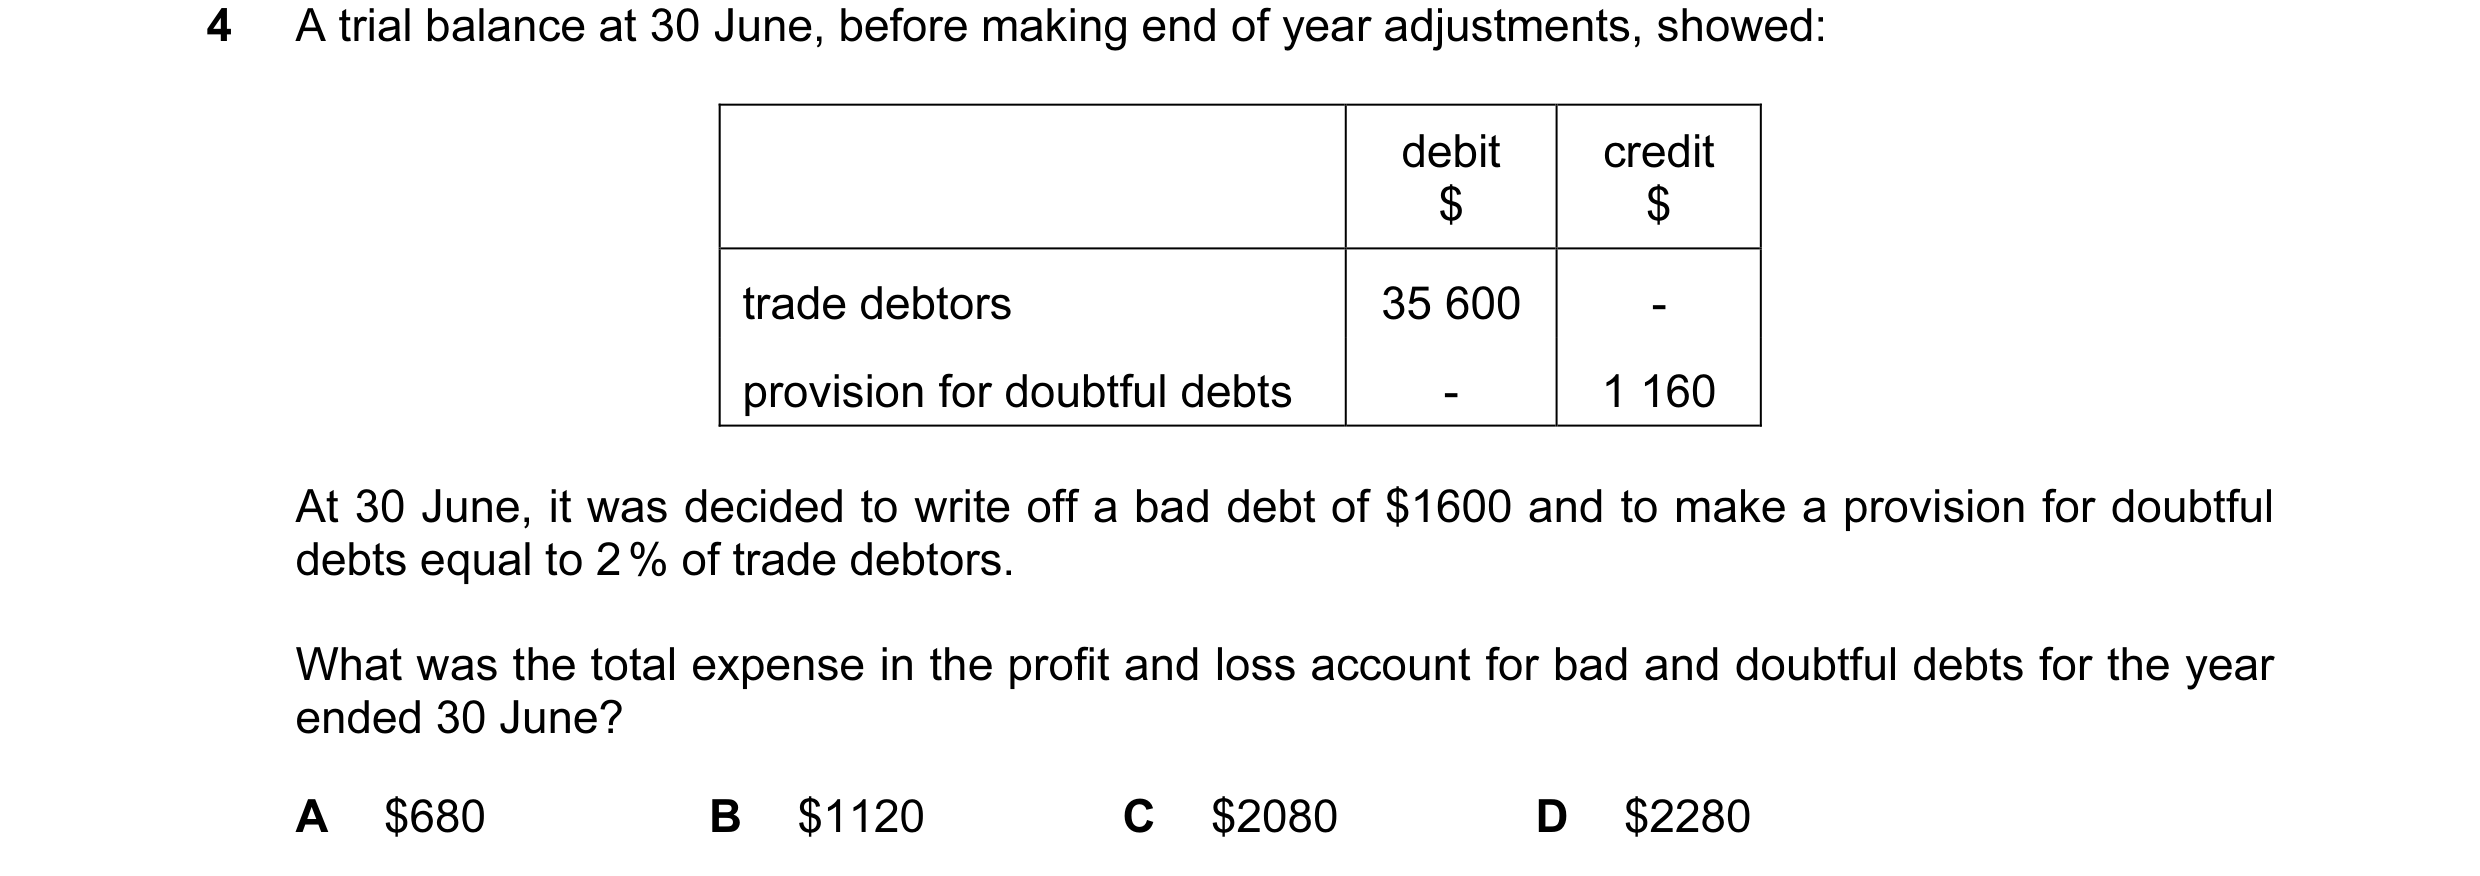
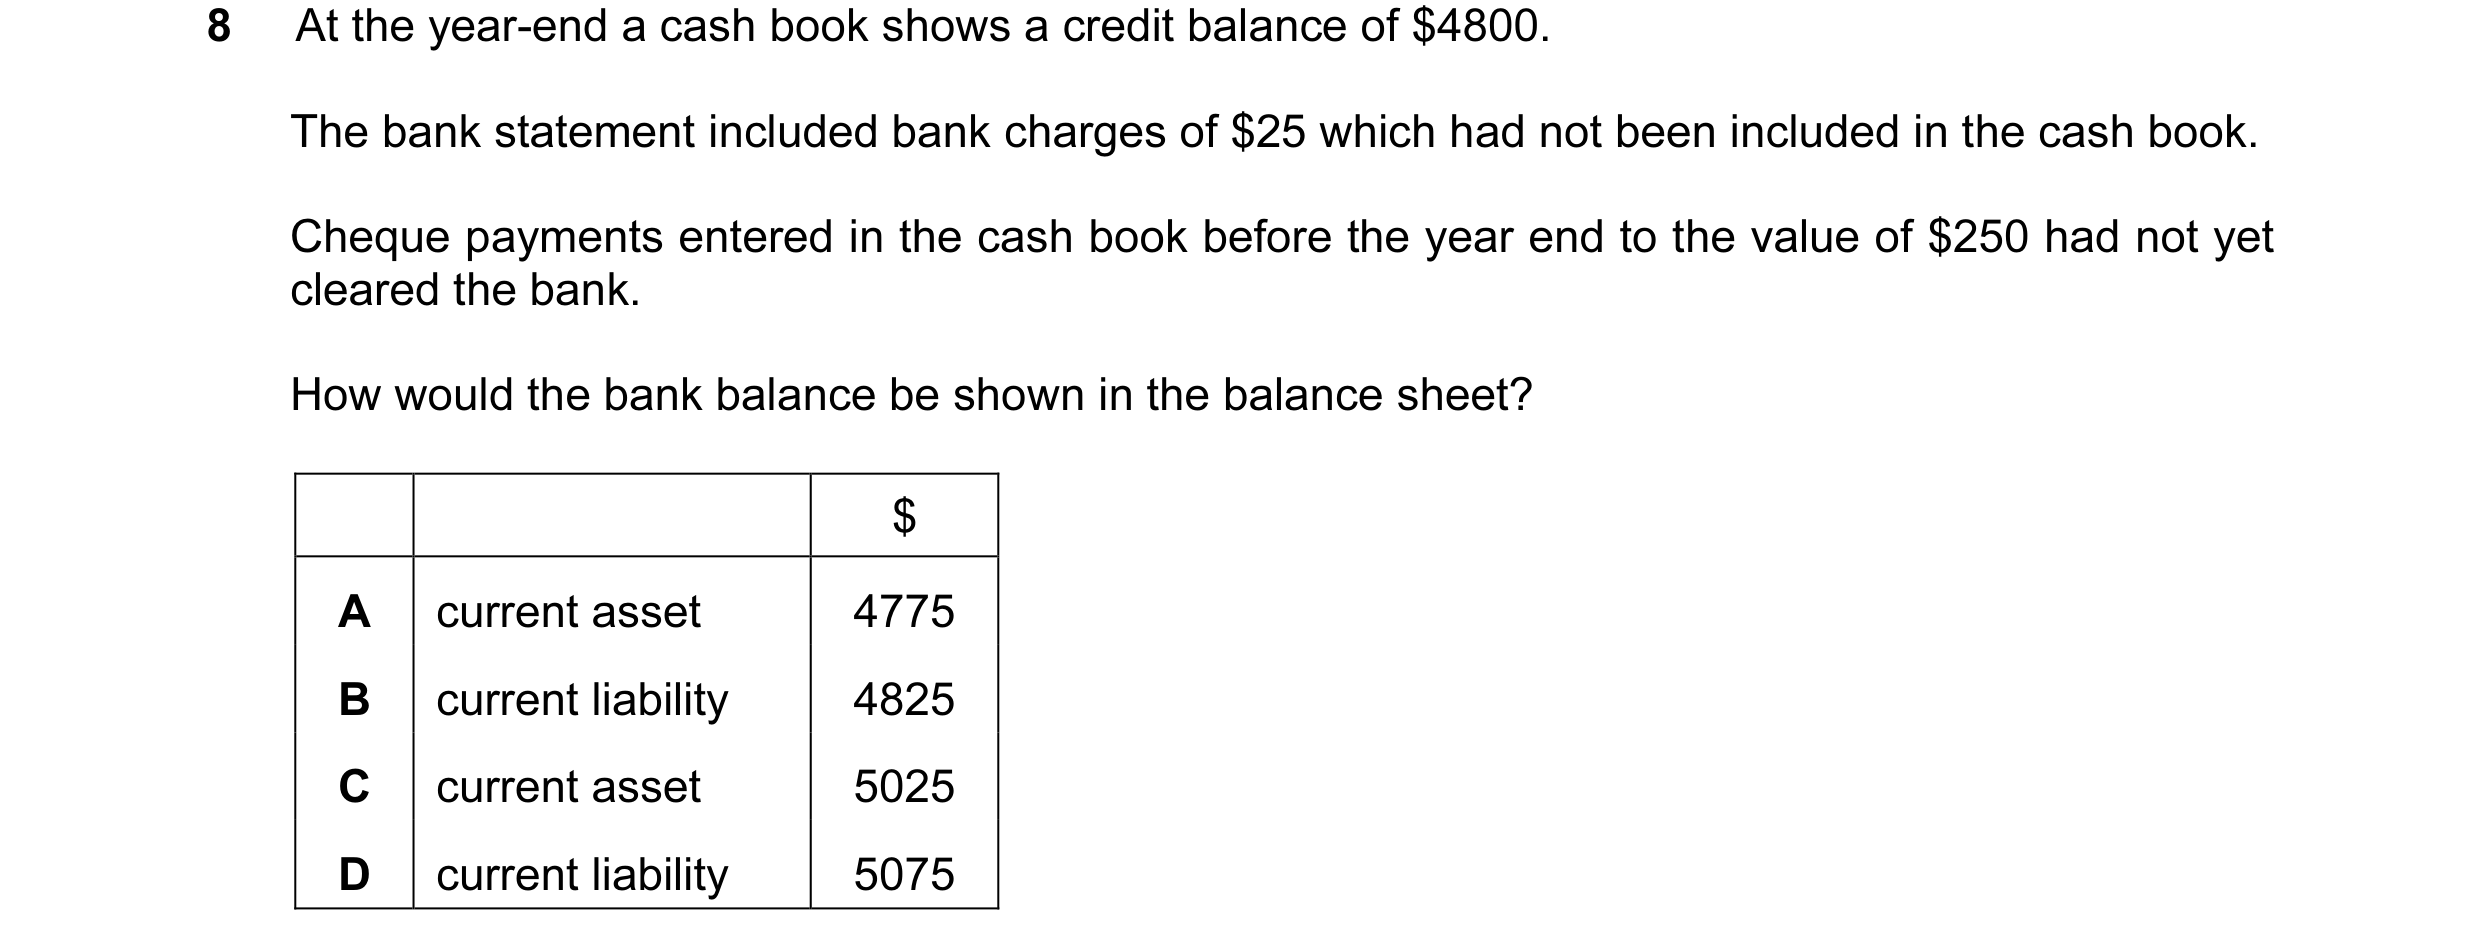
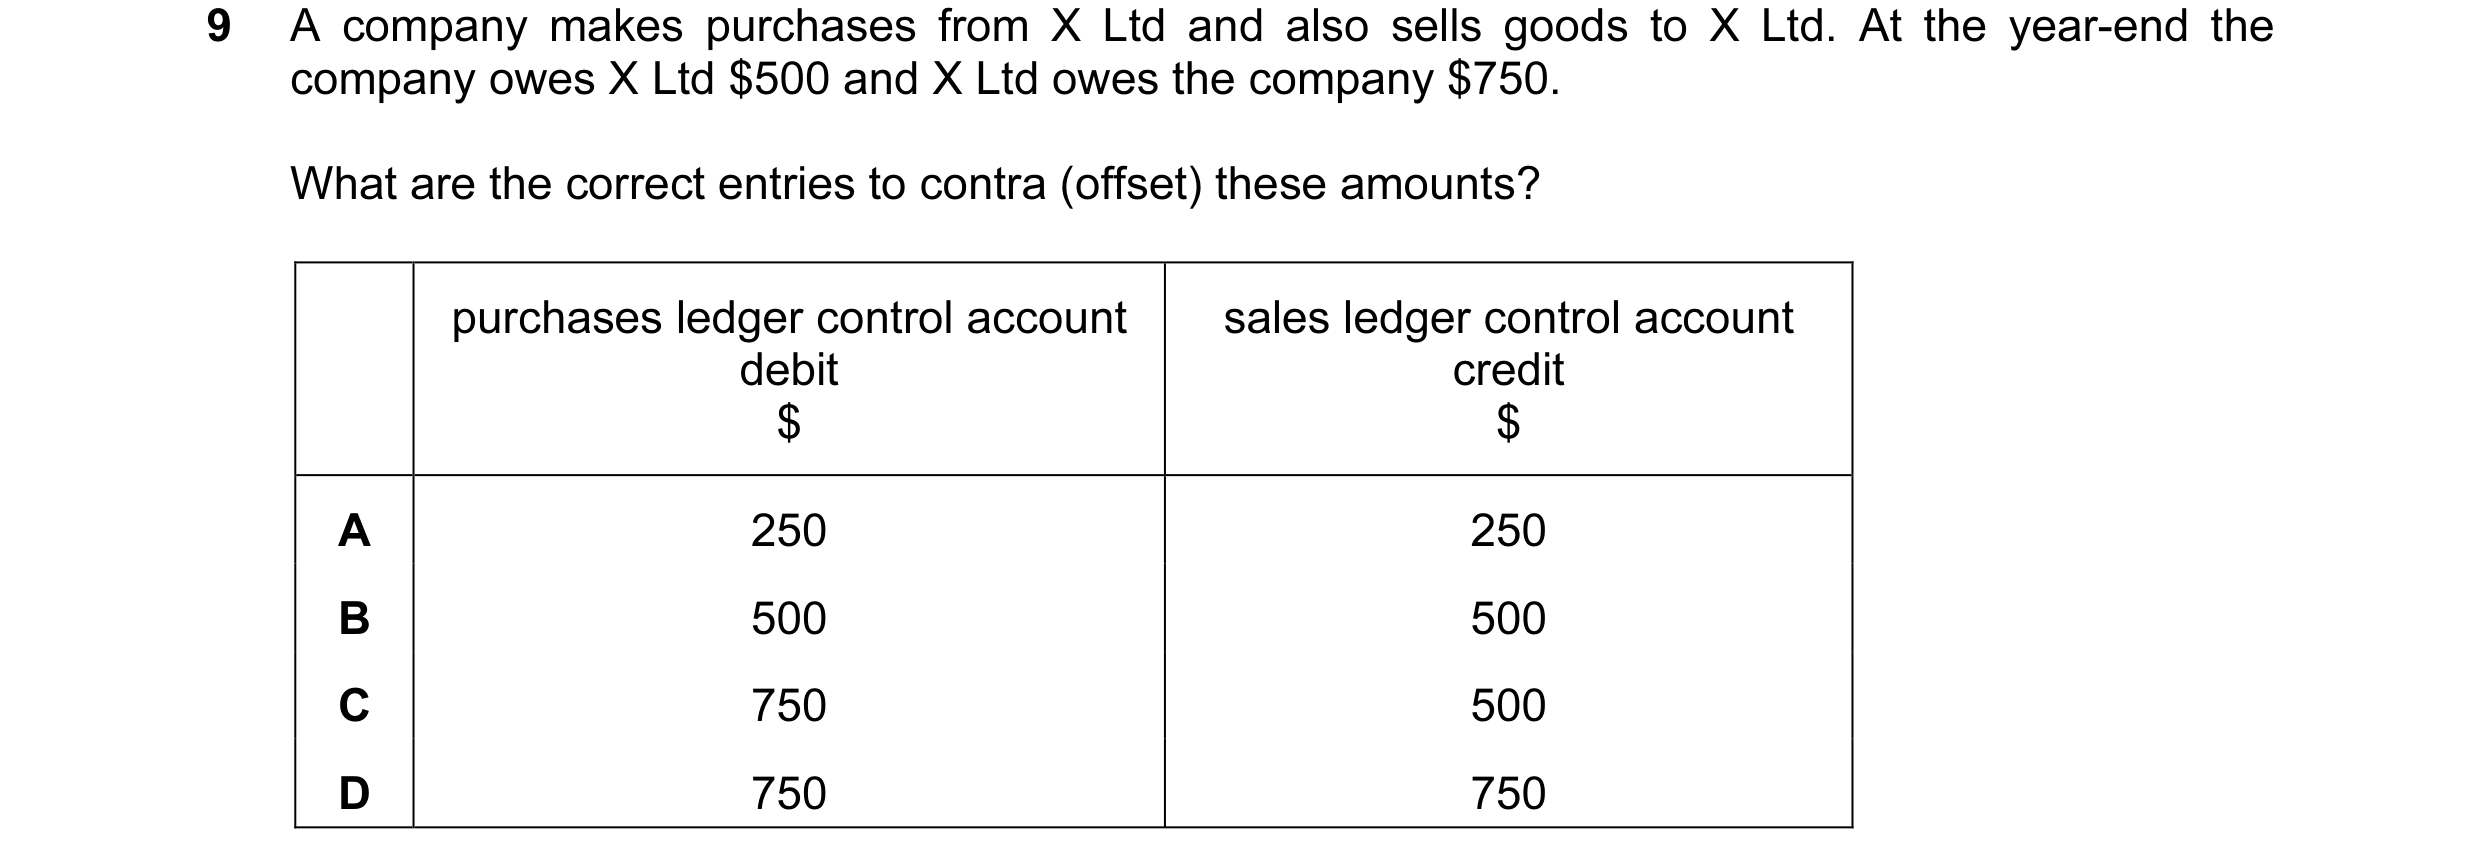 5 / 110
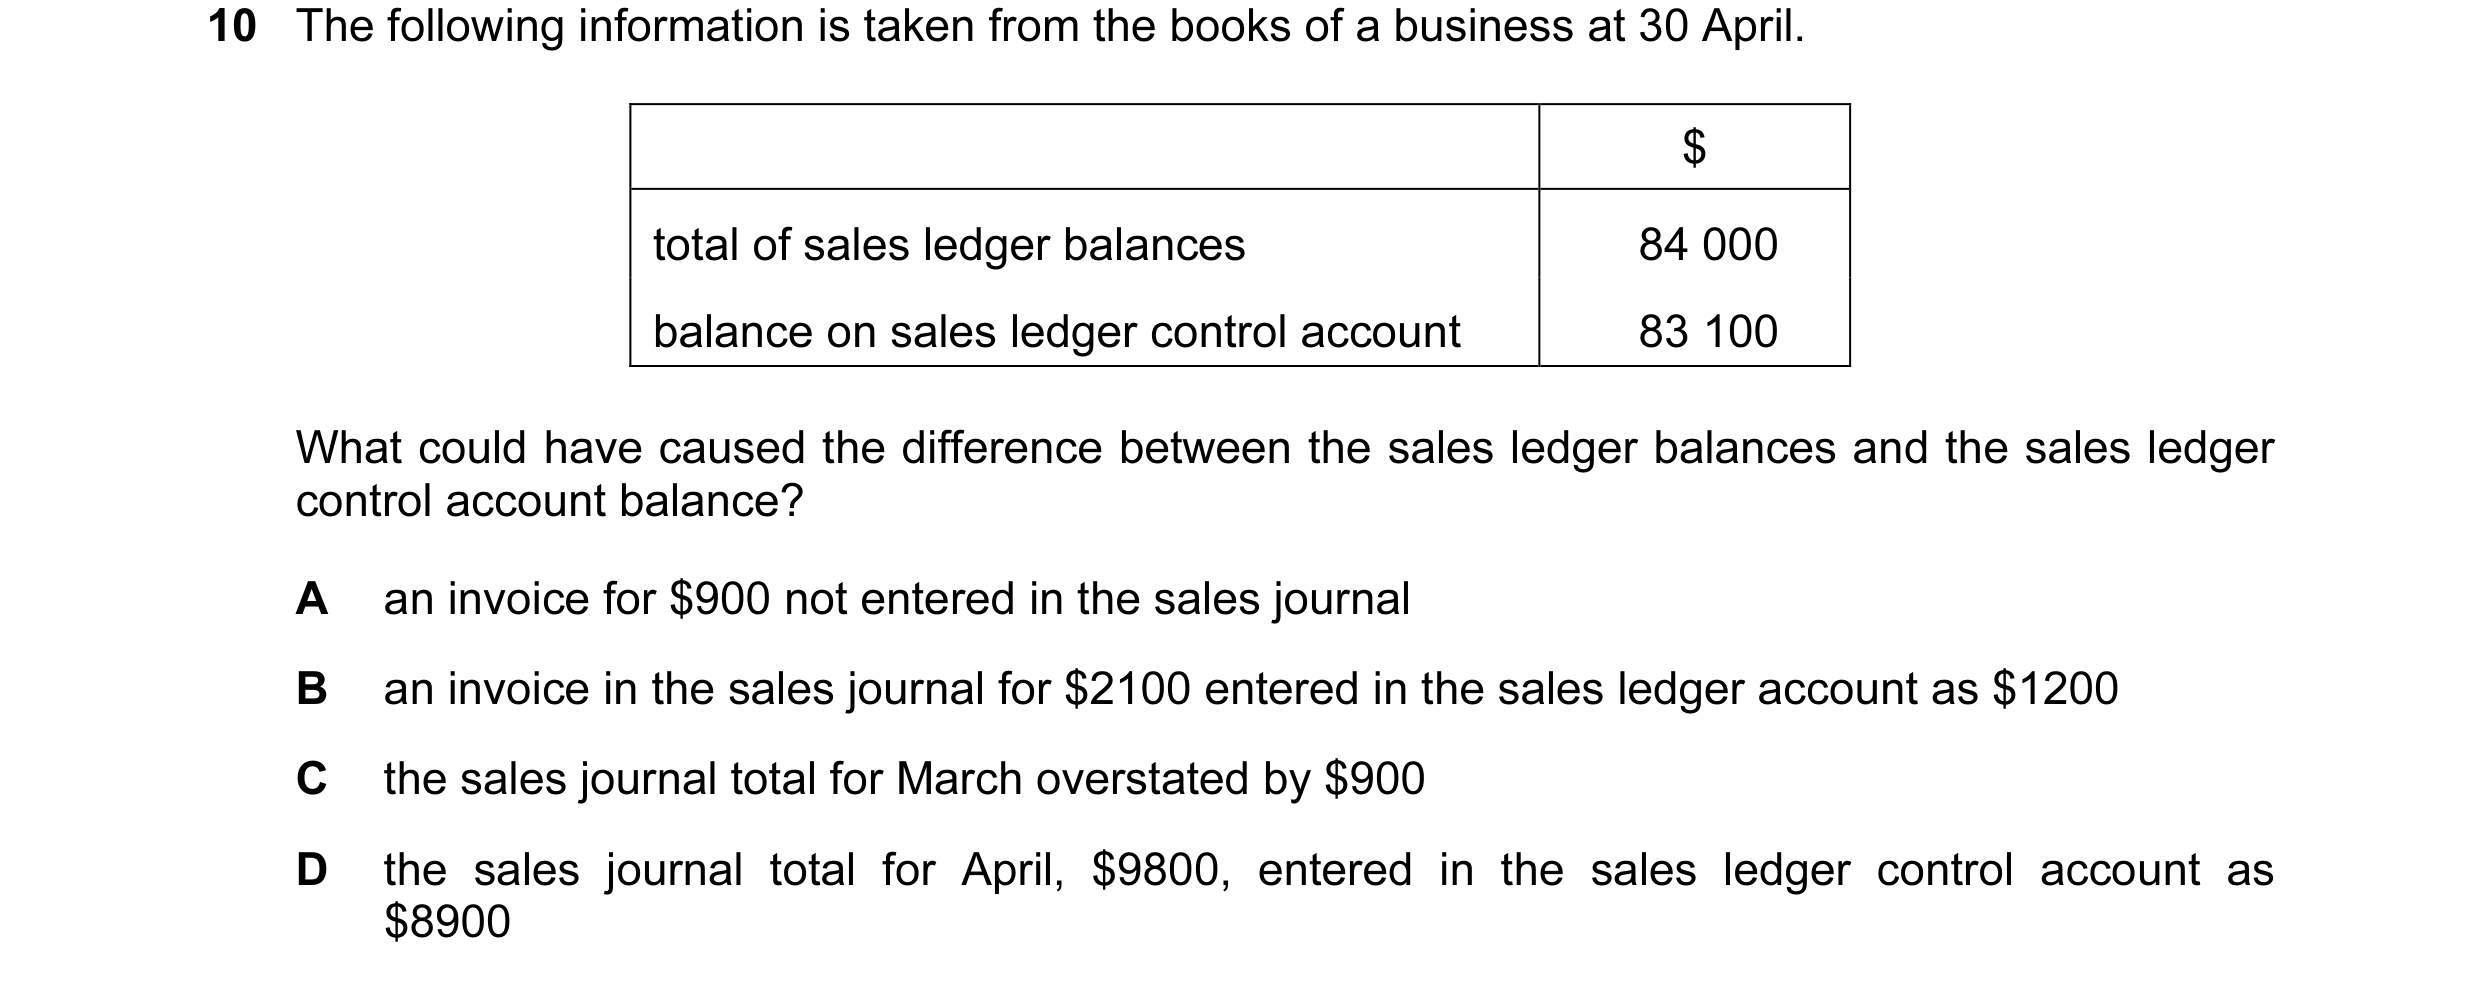
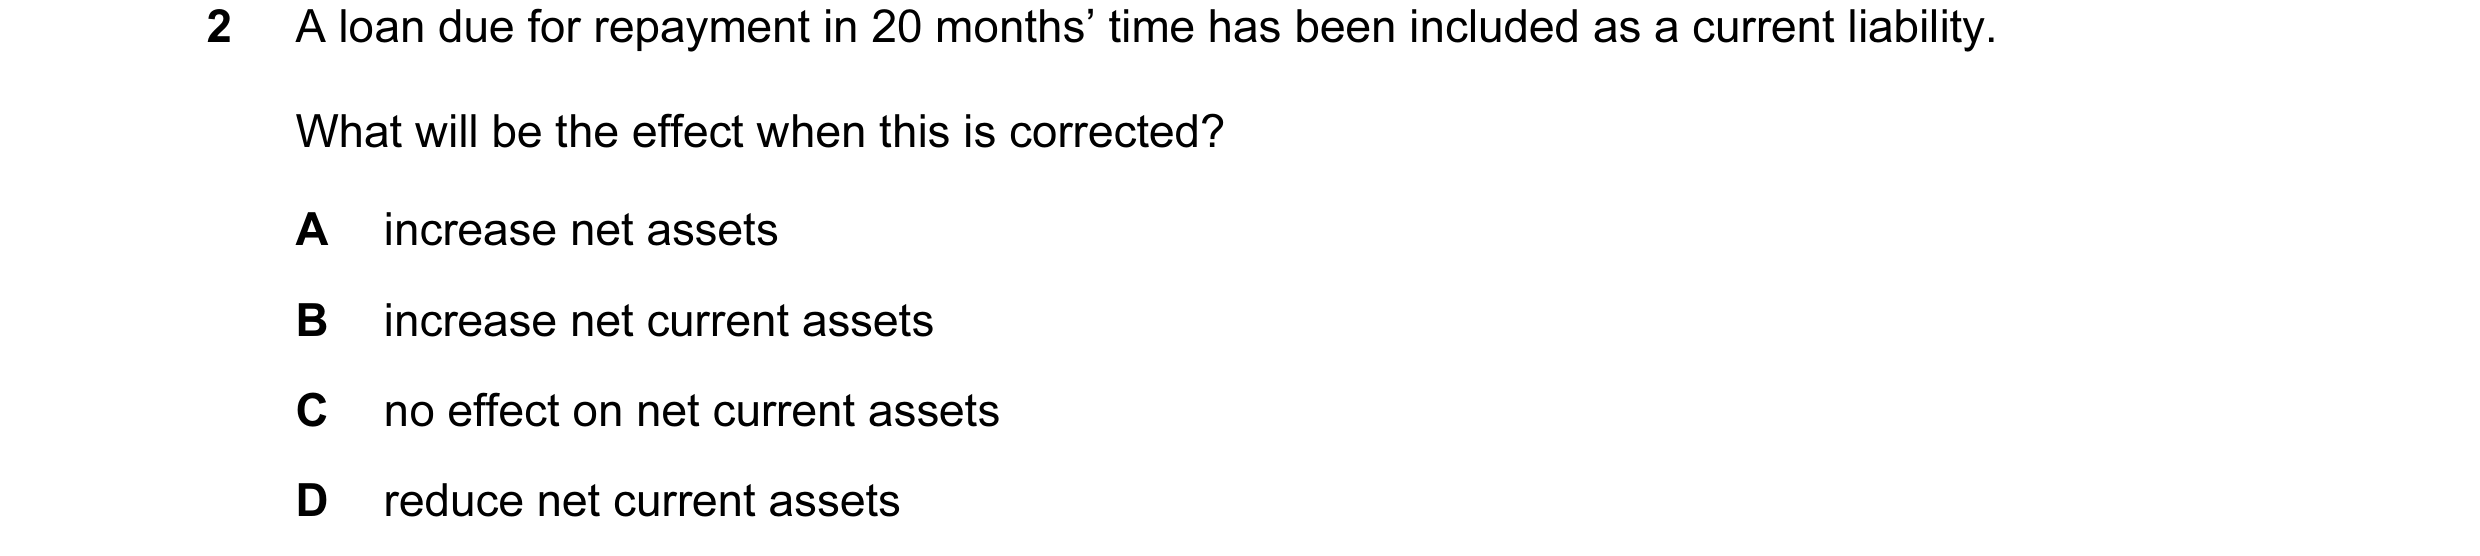
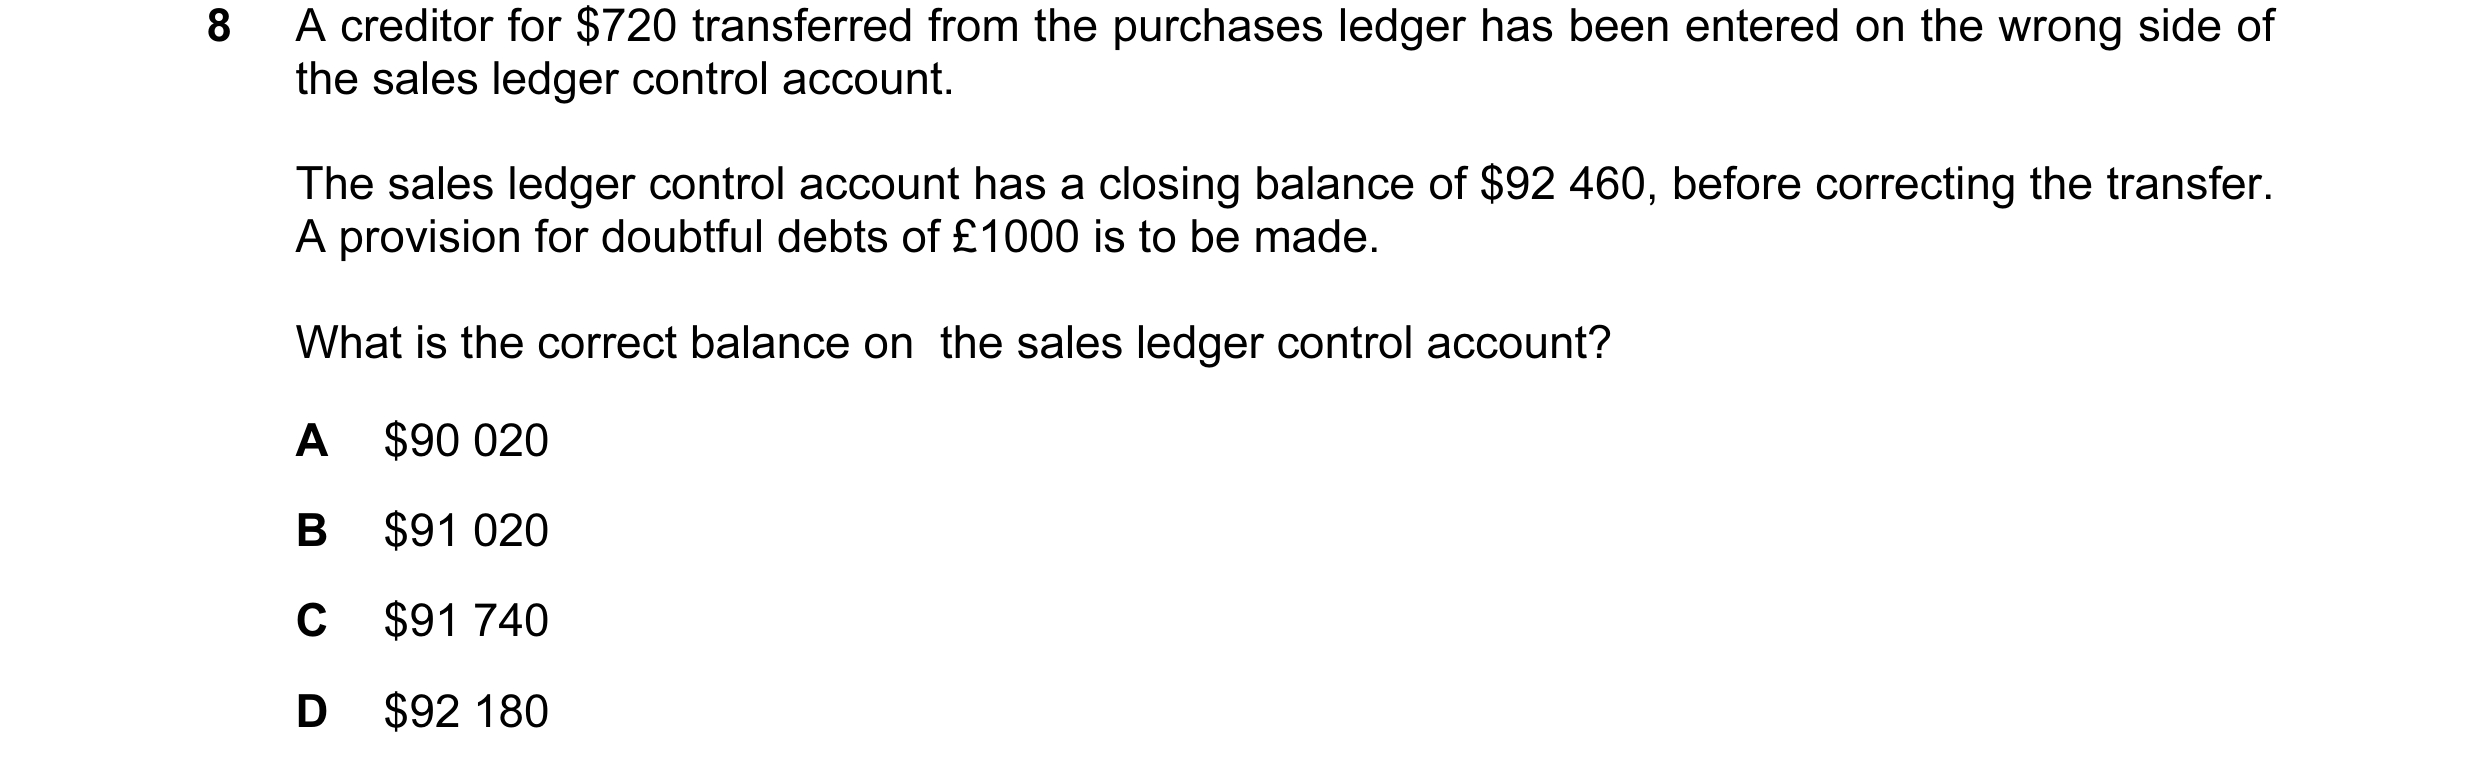
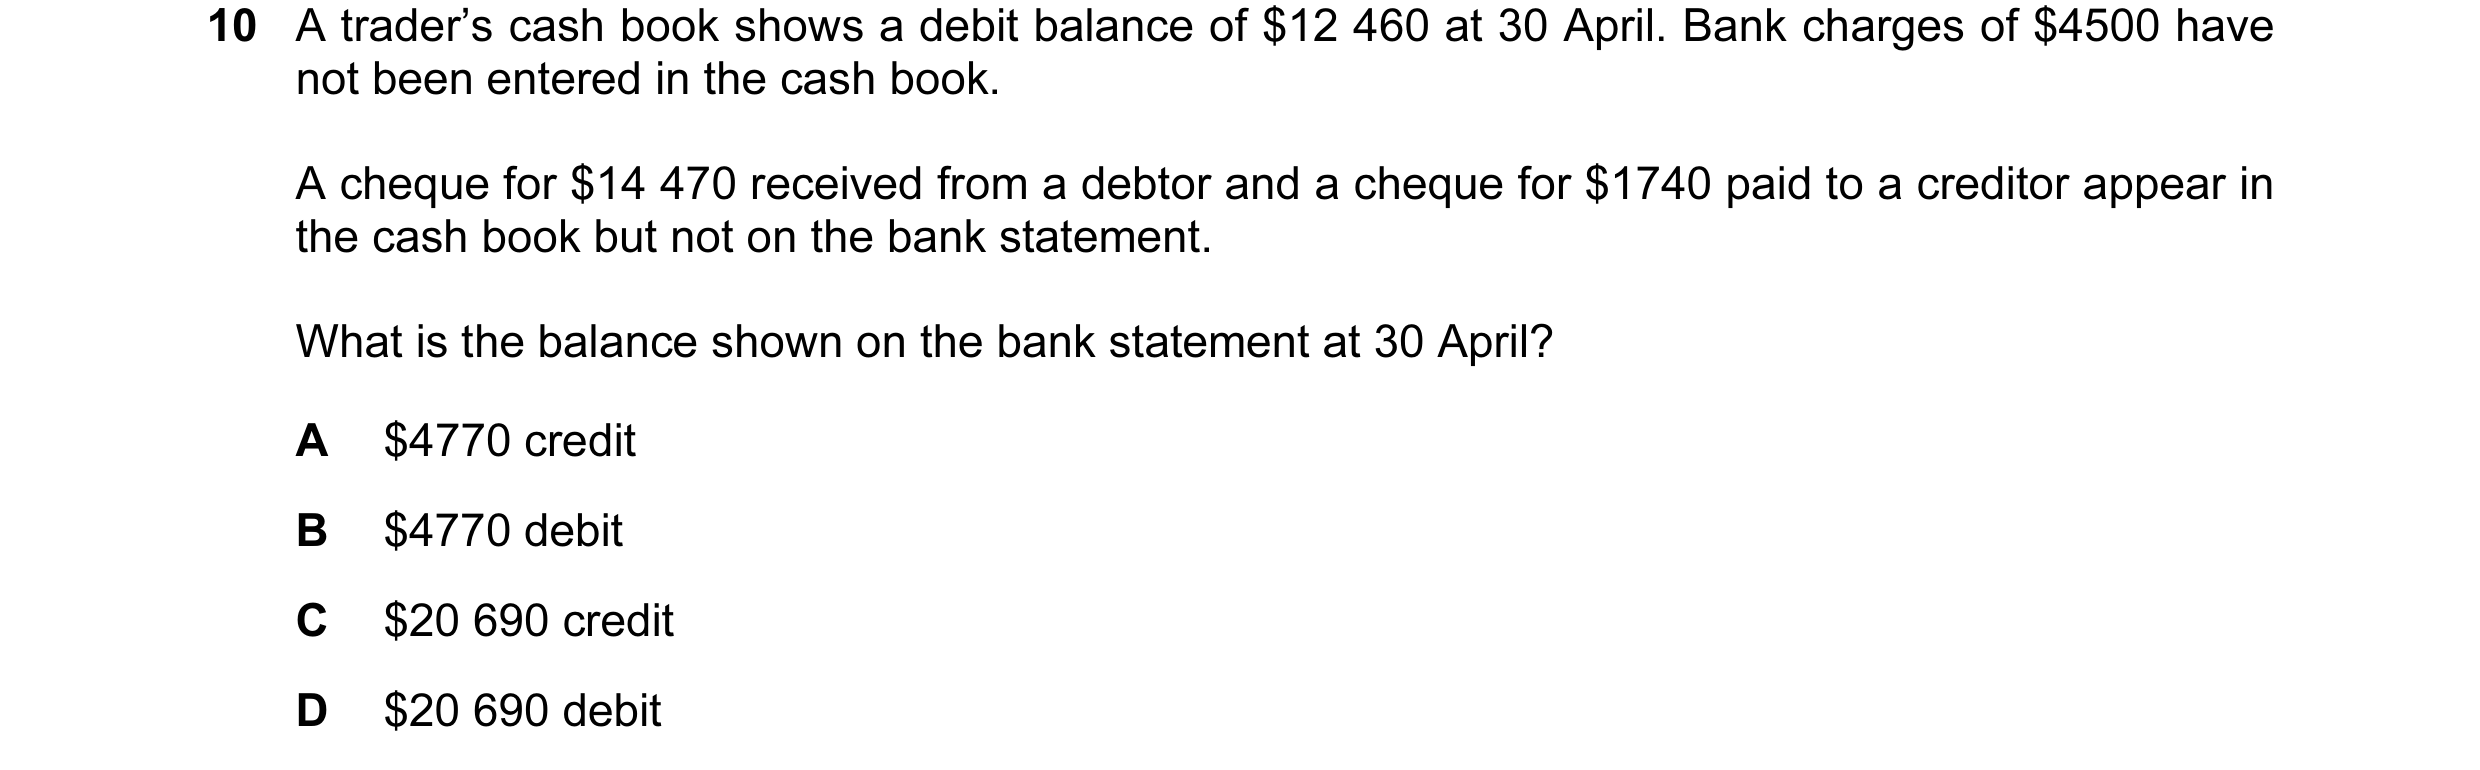 6 / 110
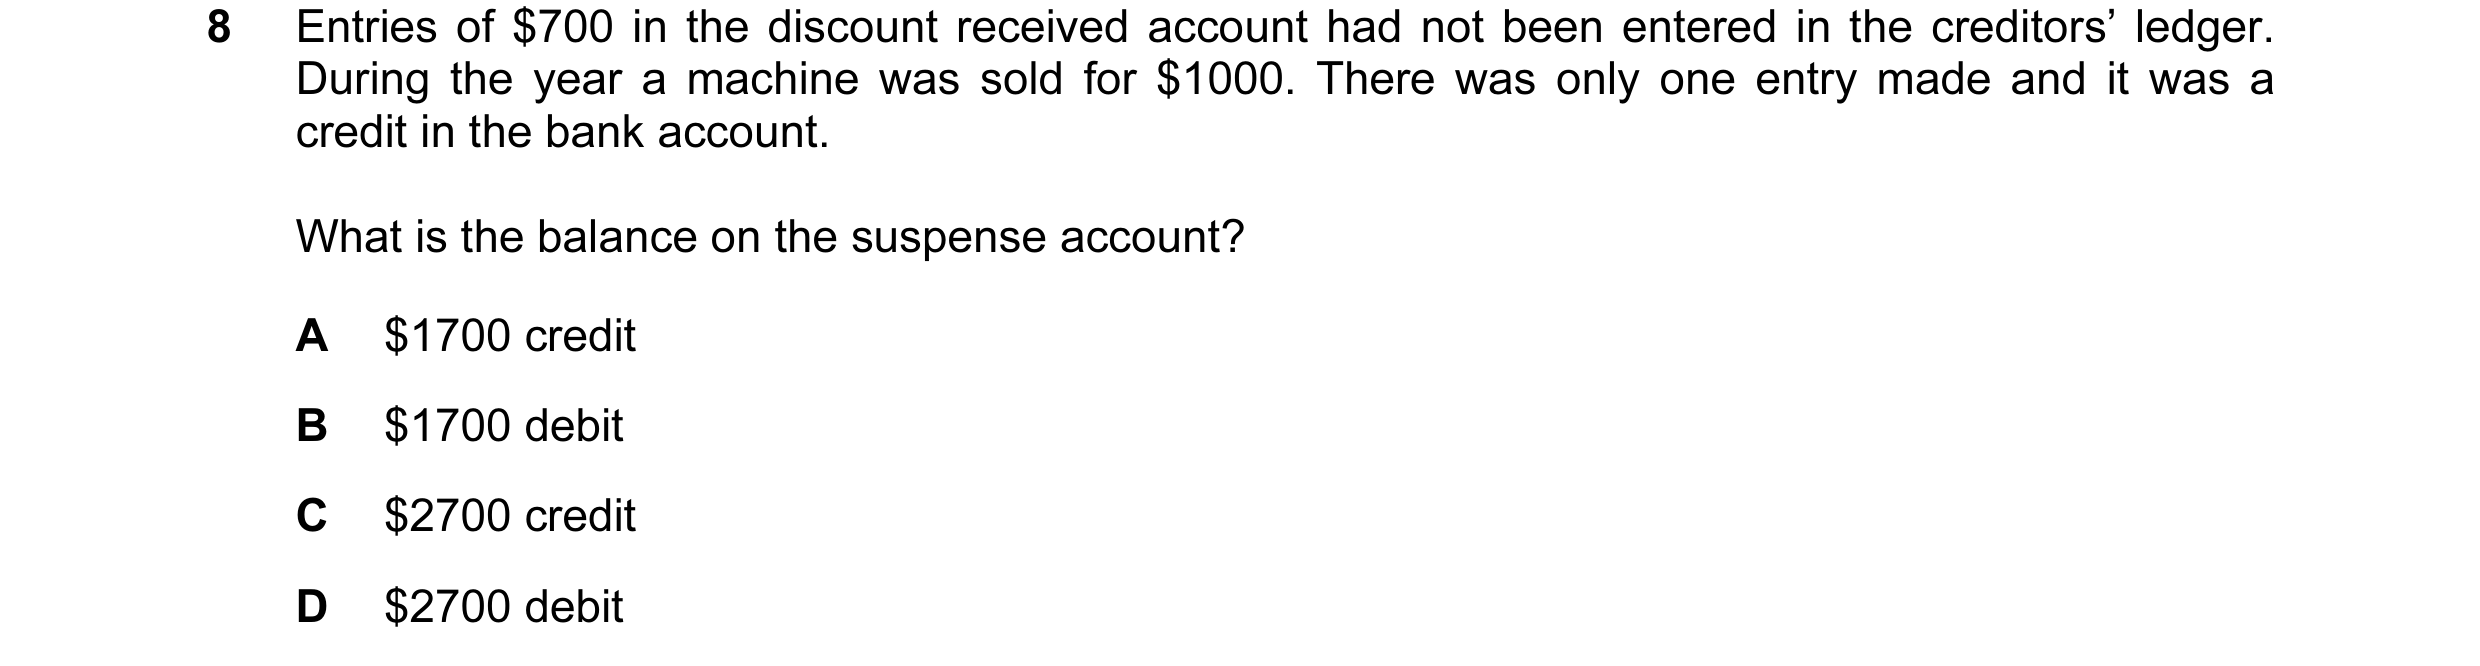
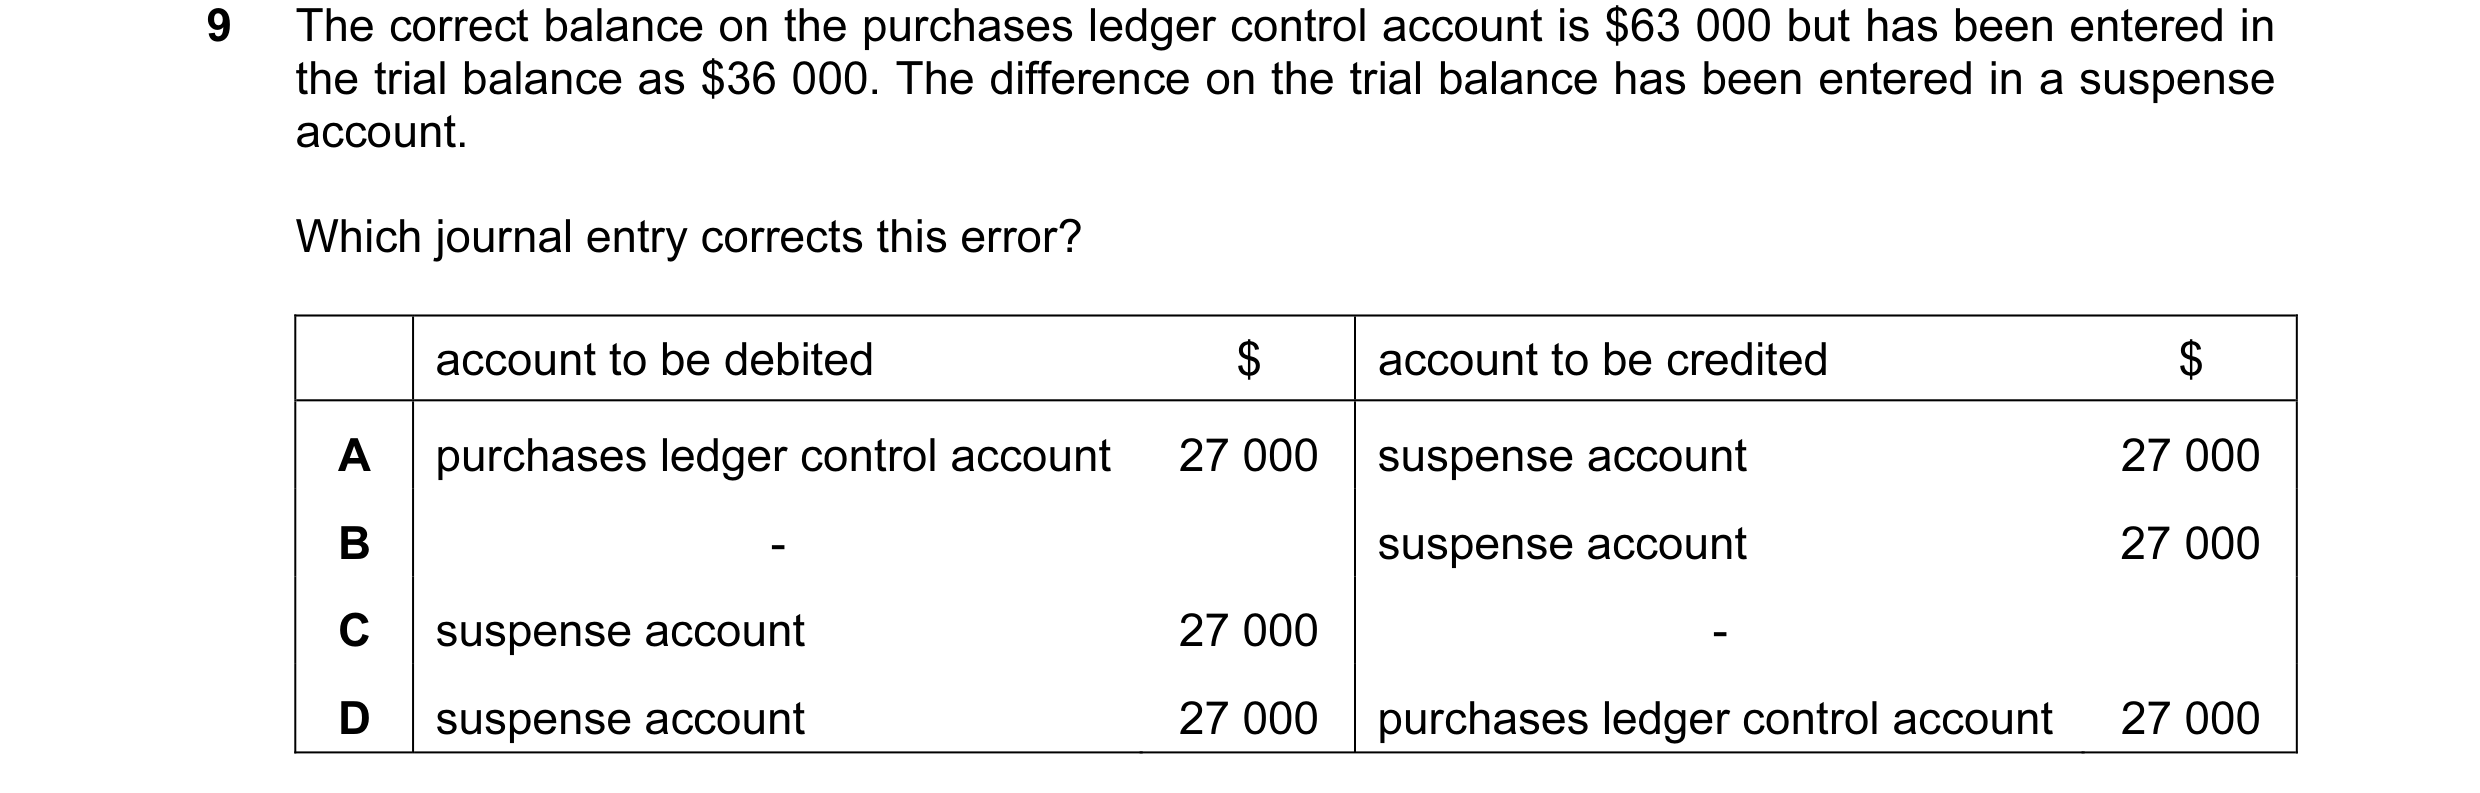
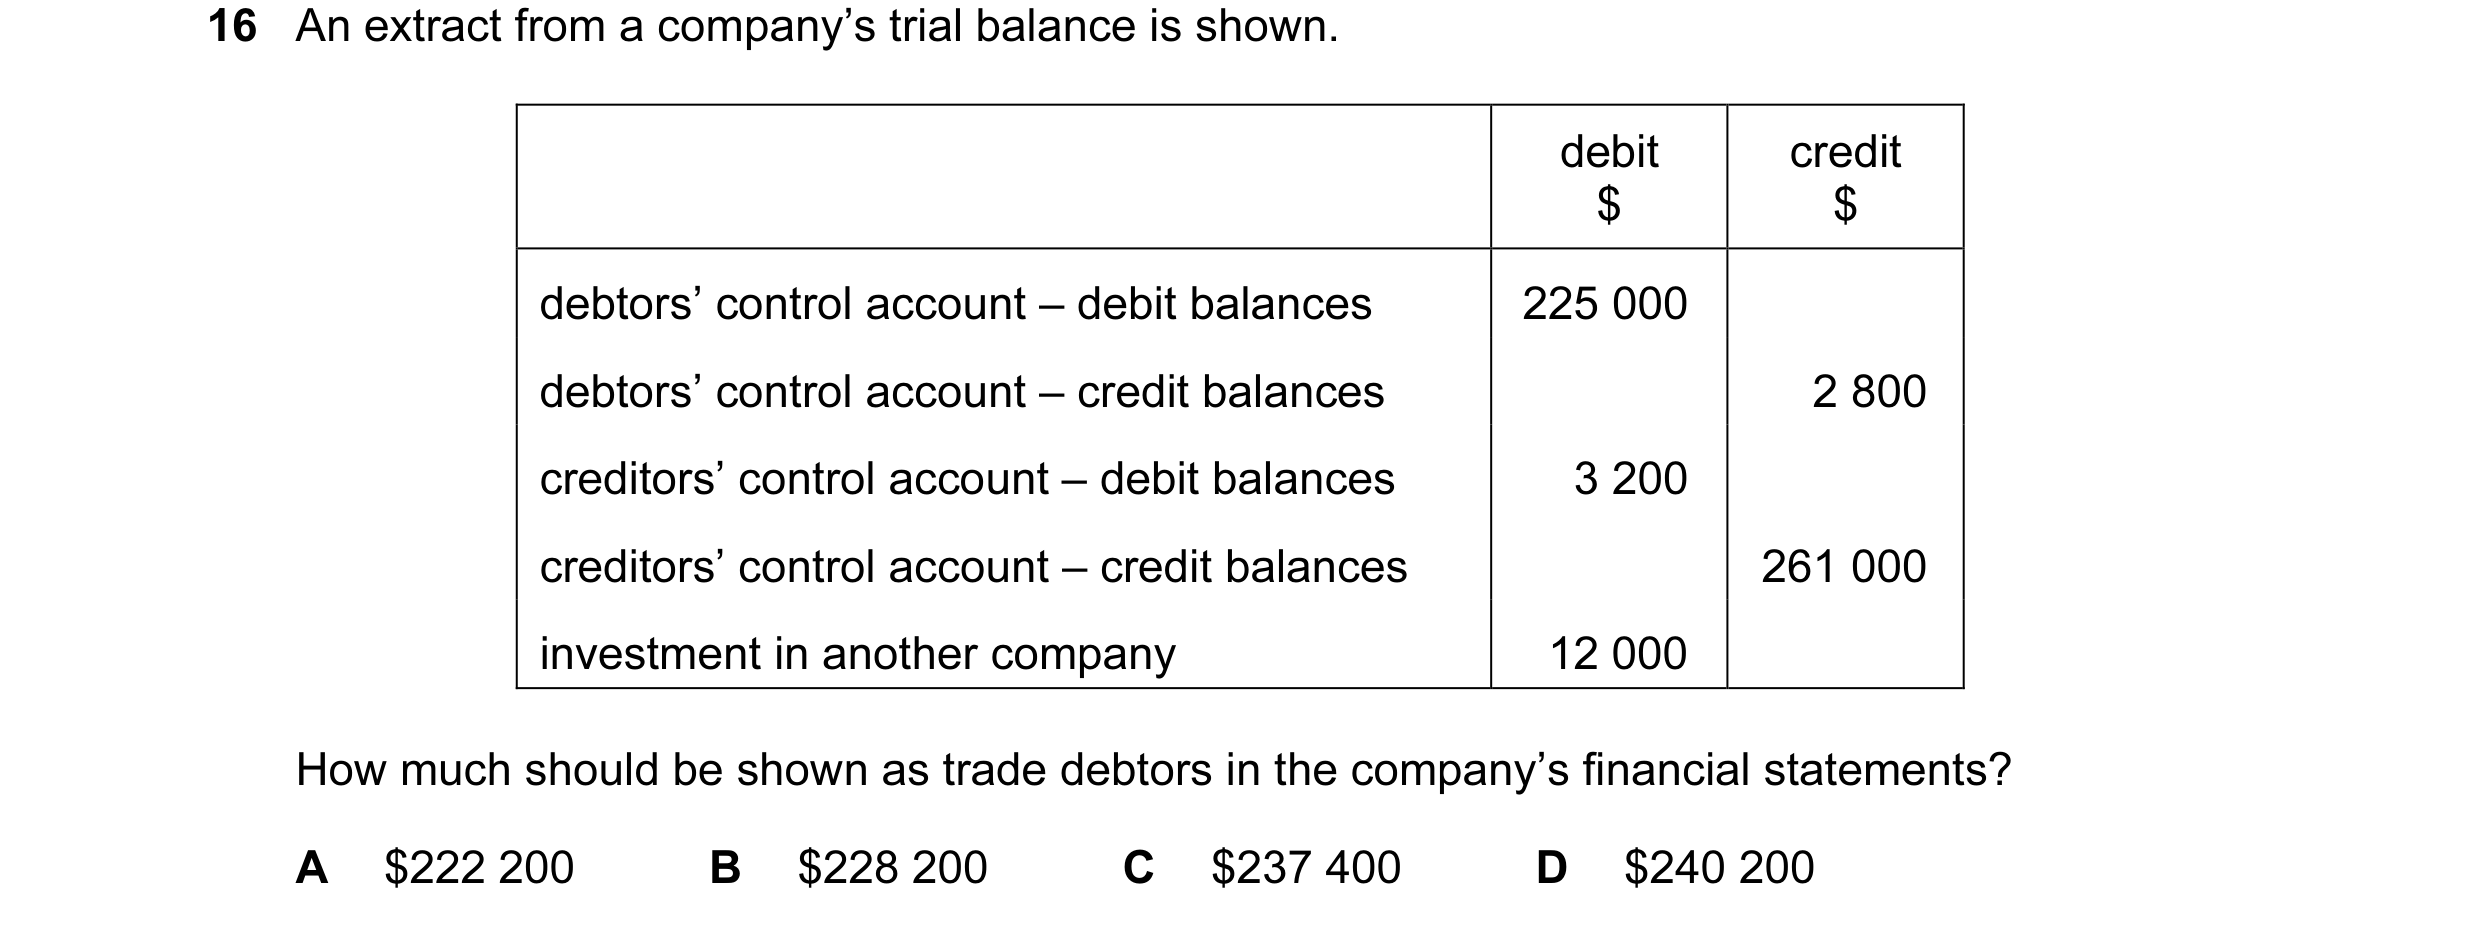
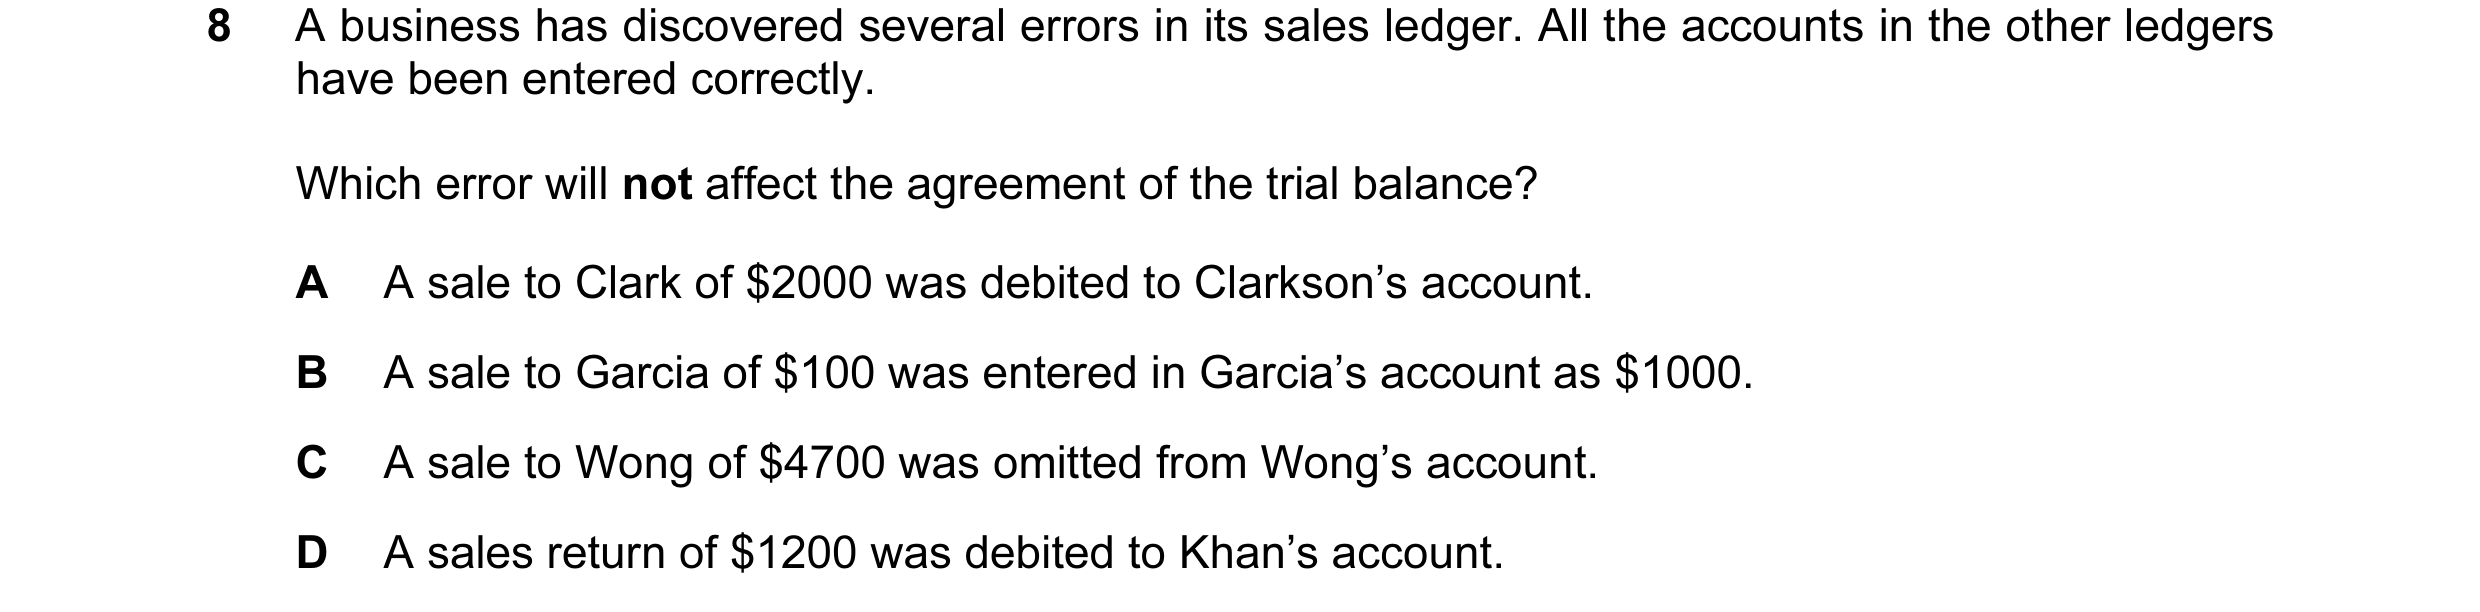 7 / 110
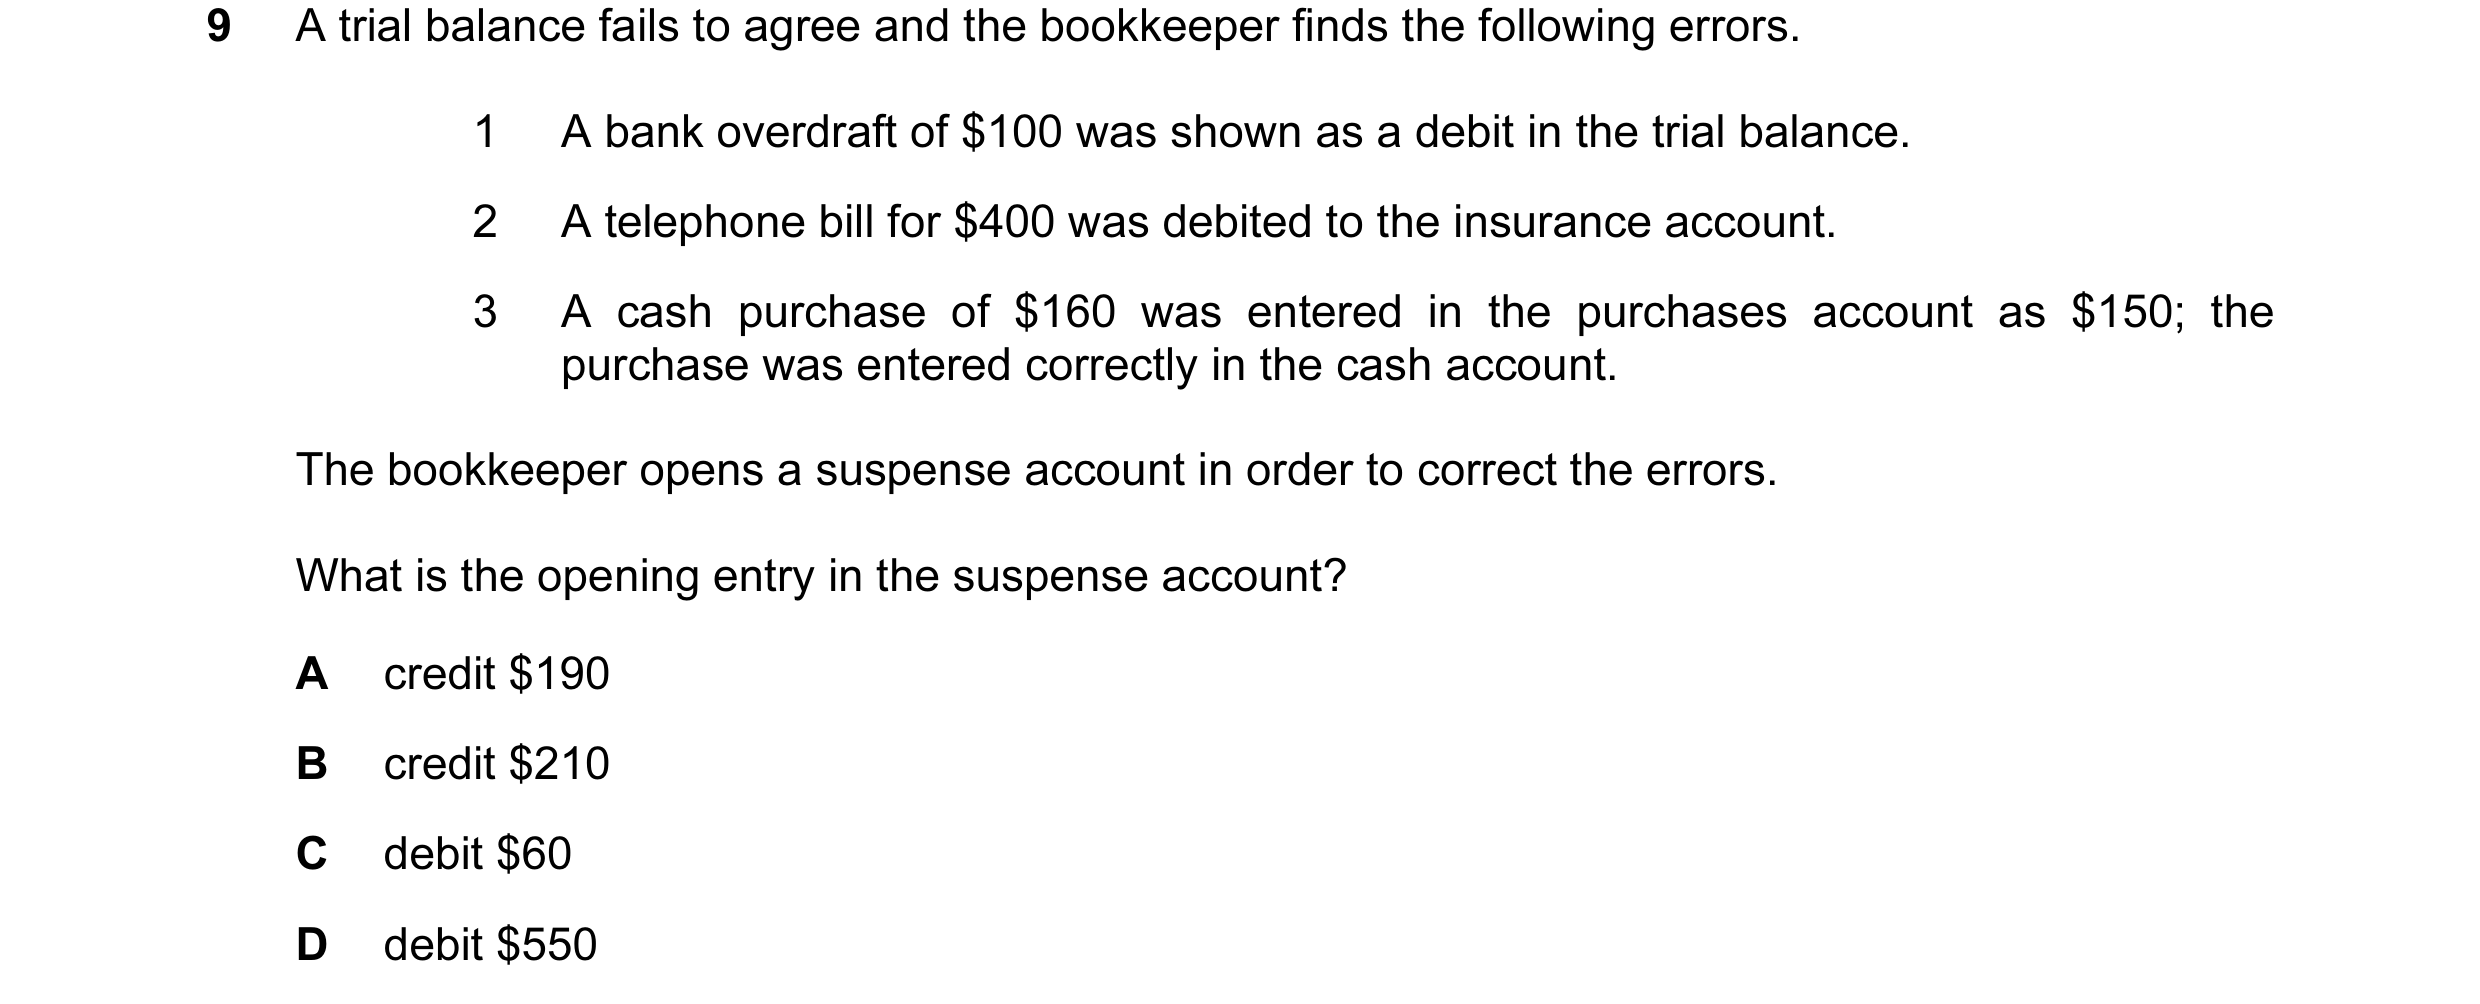
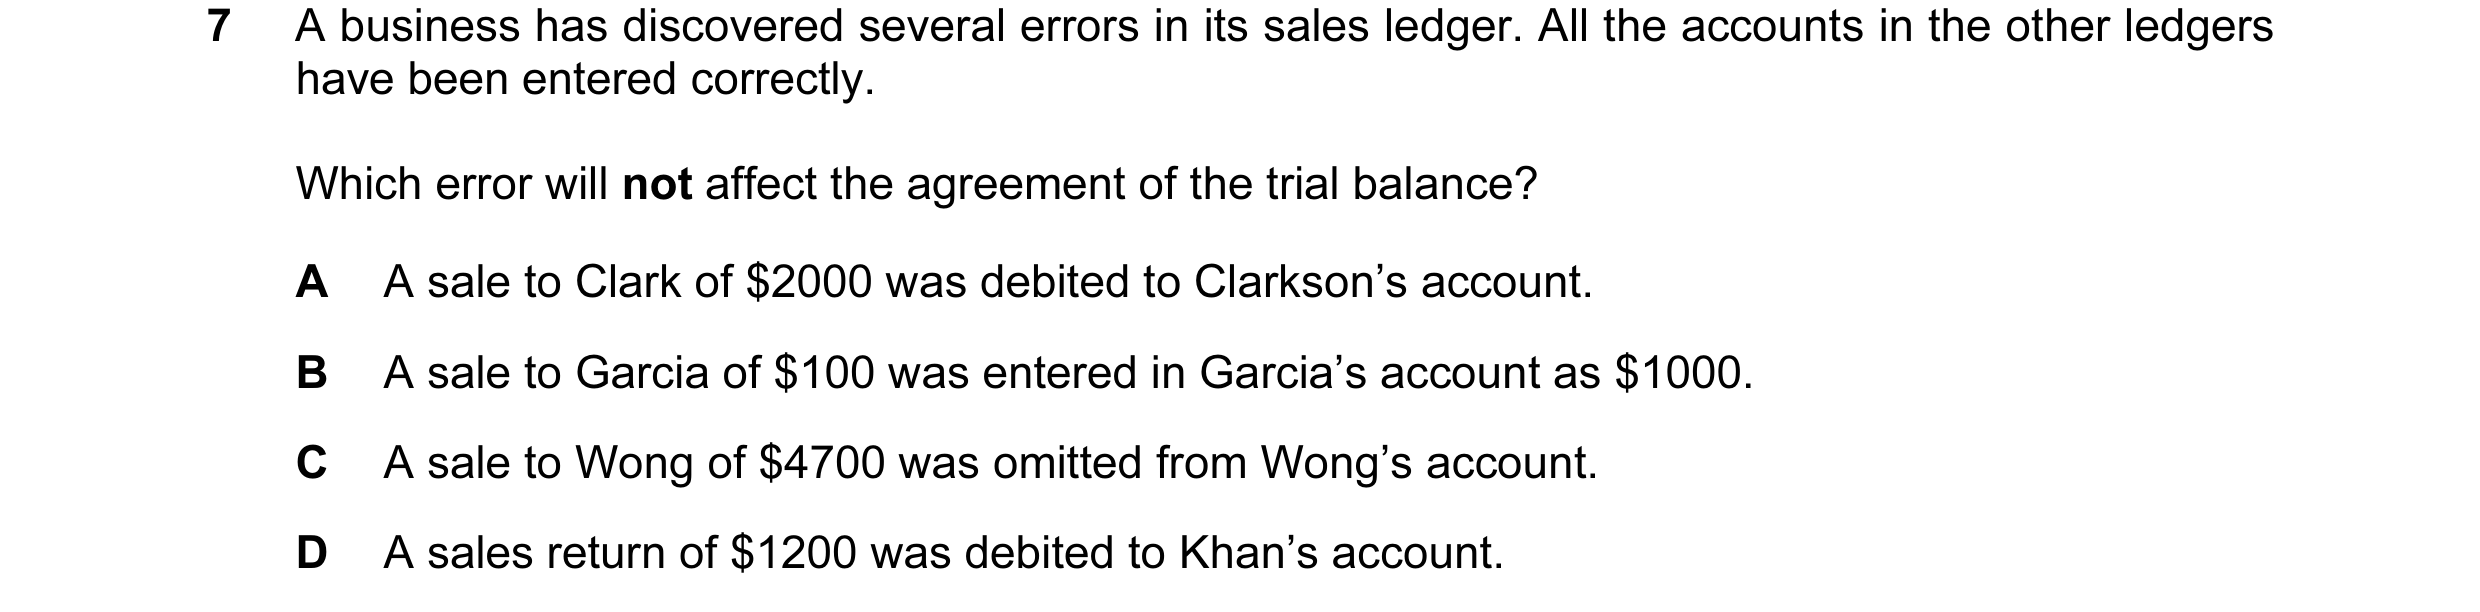
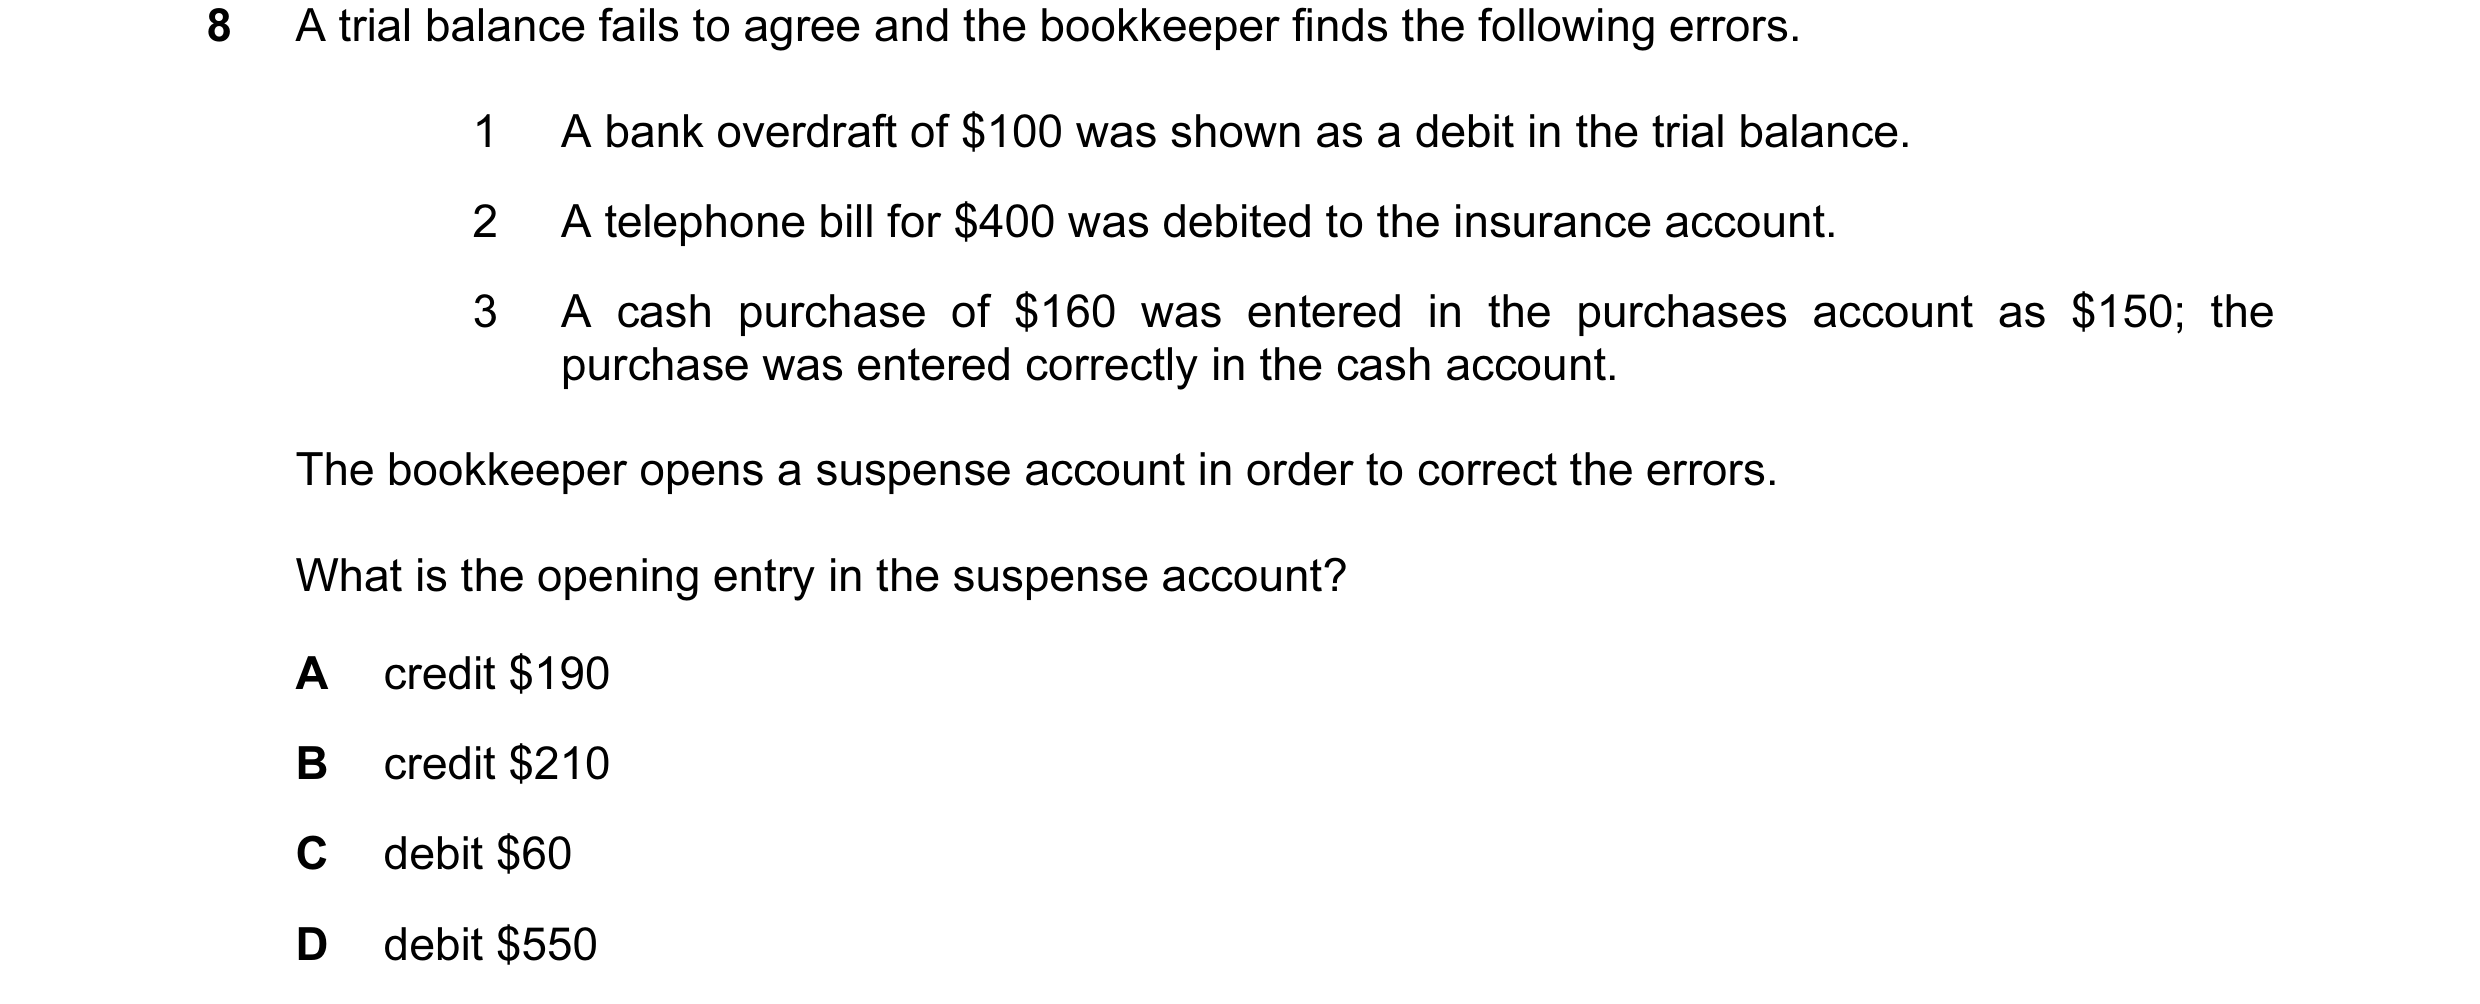 8 / 110
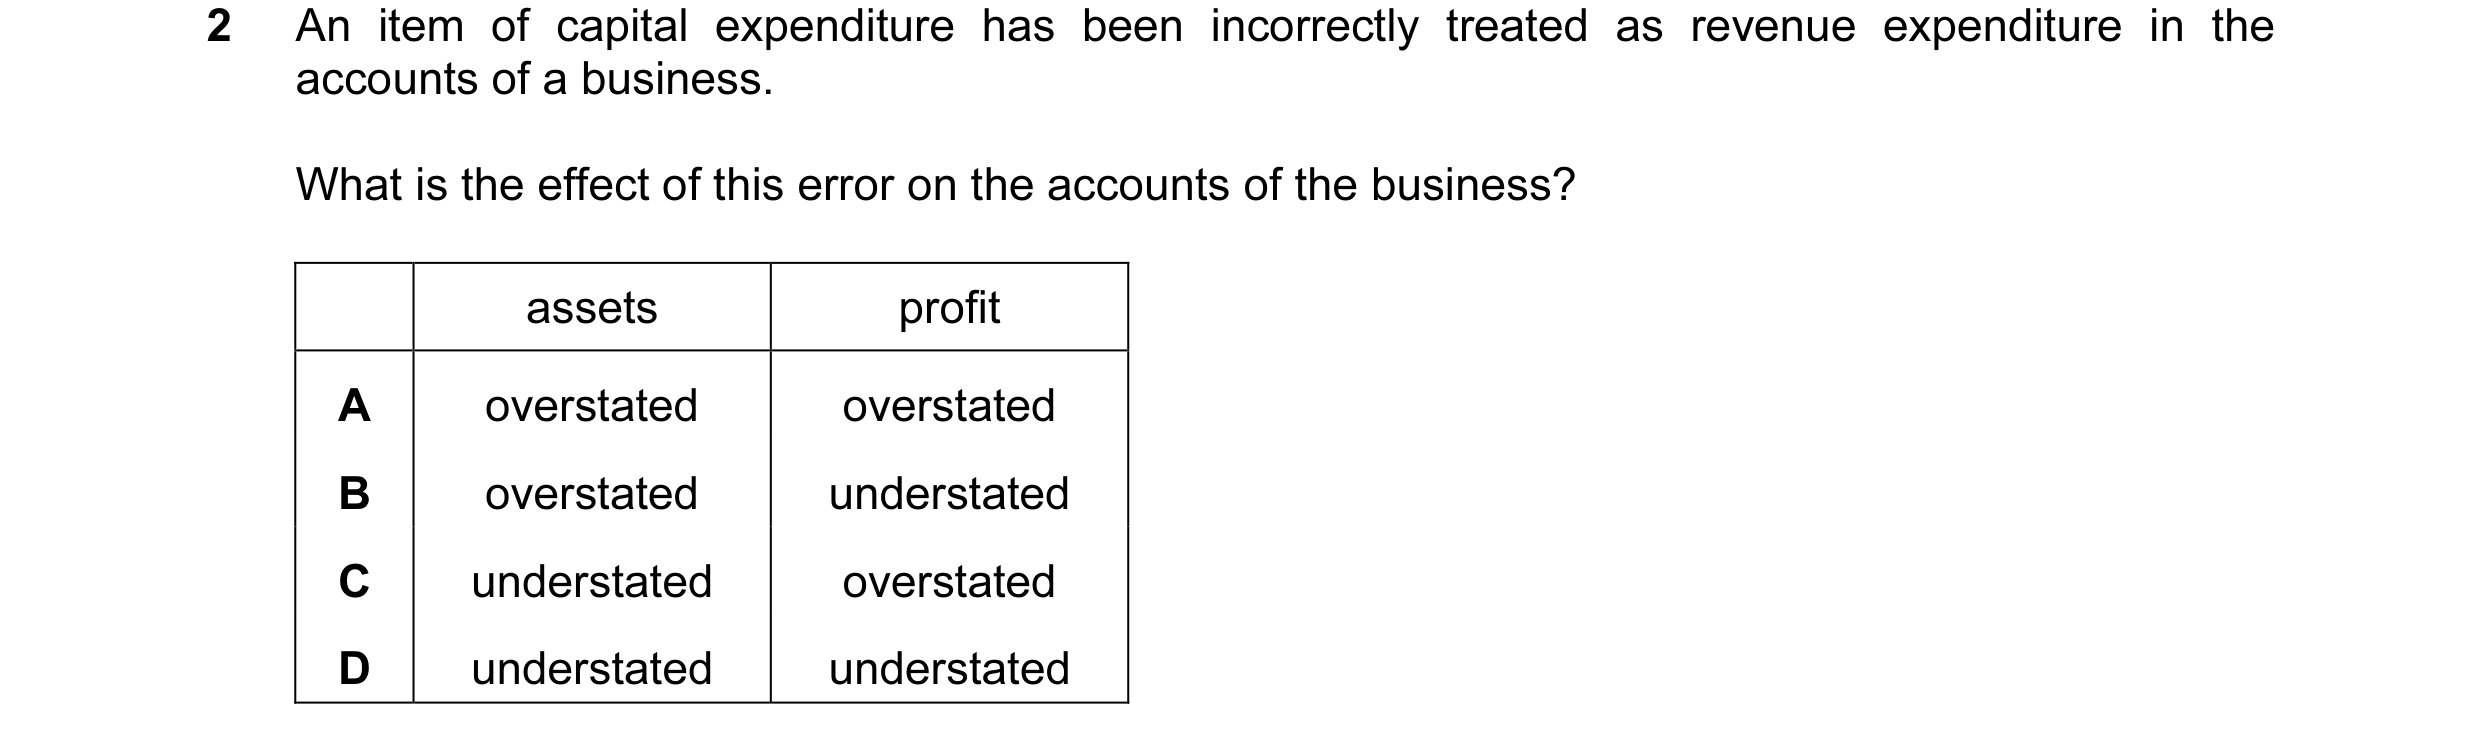
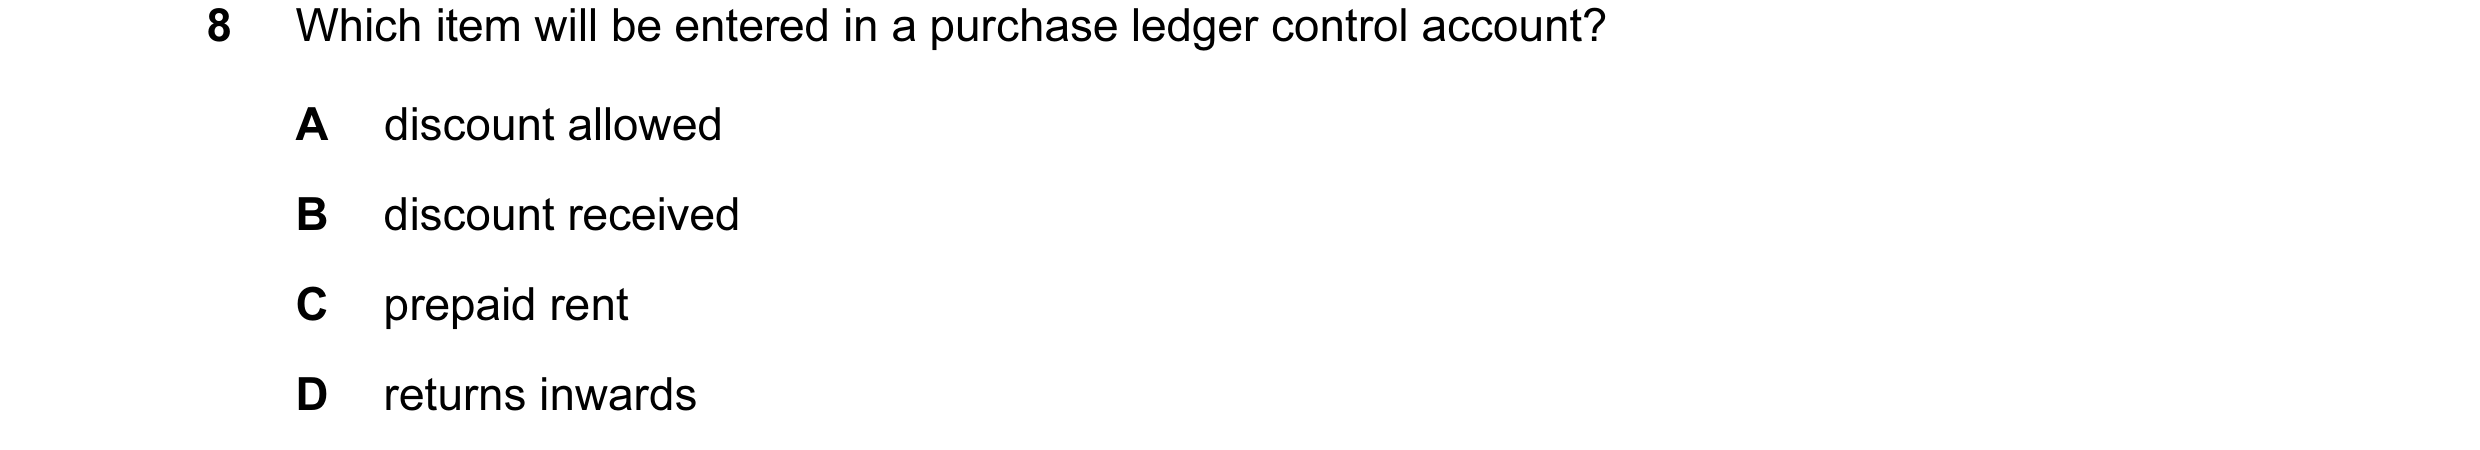
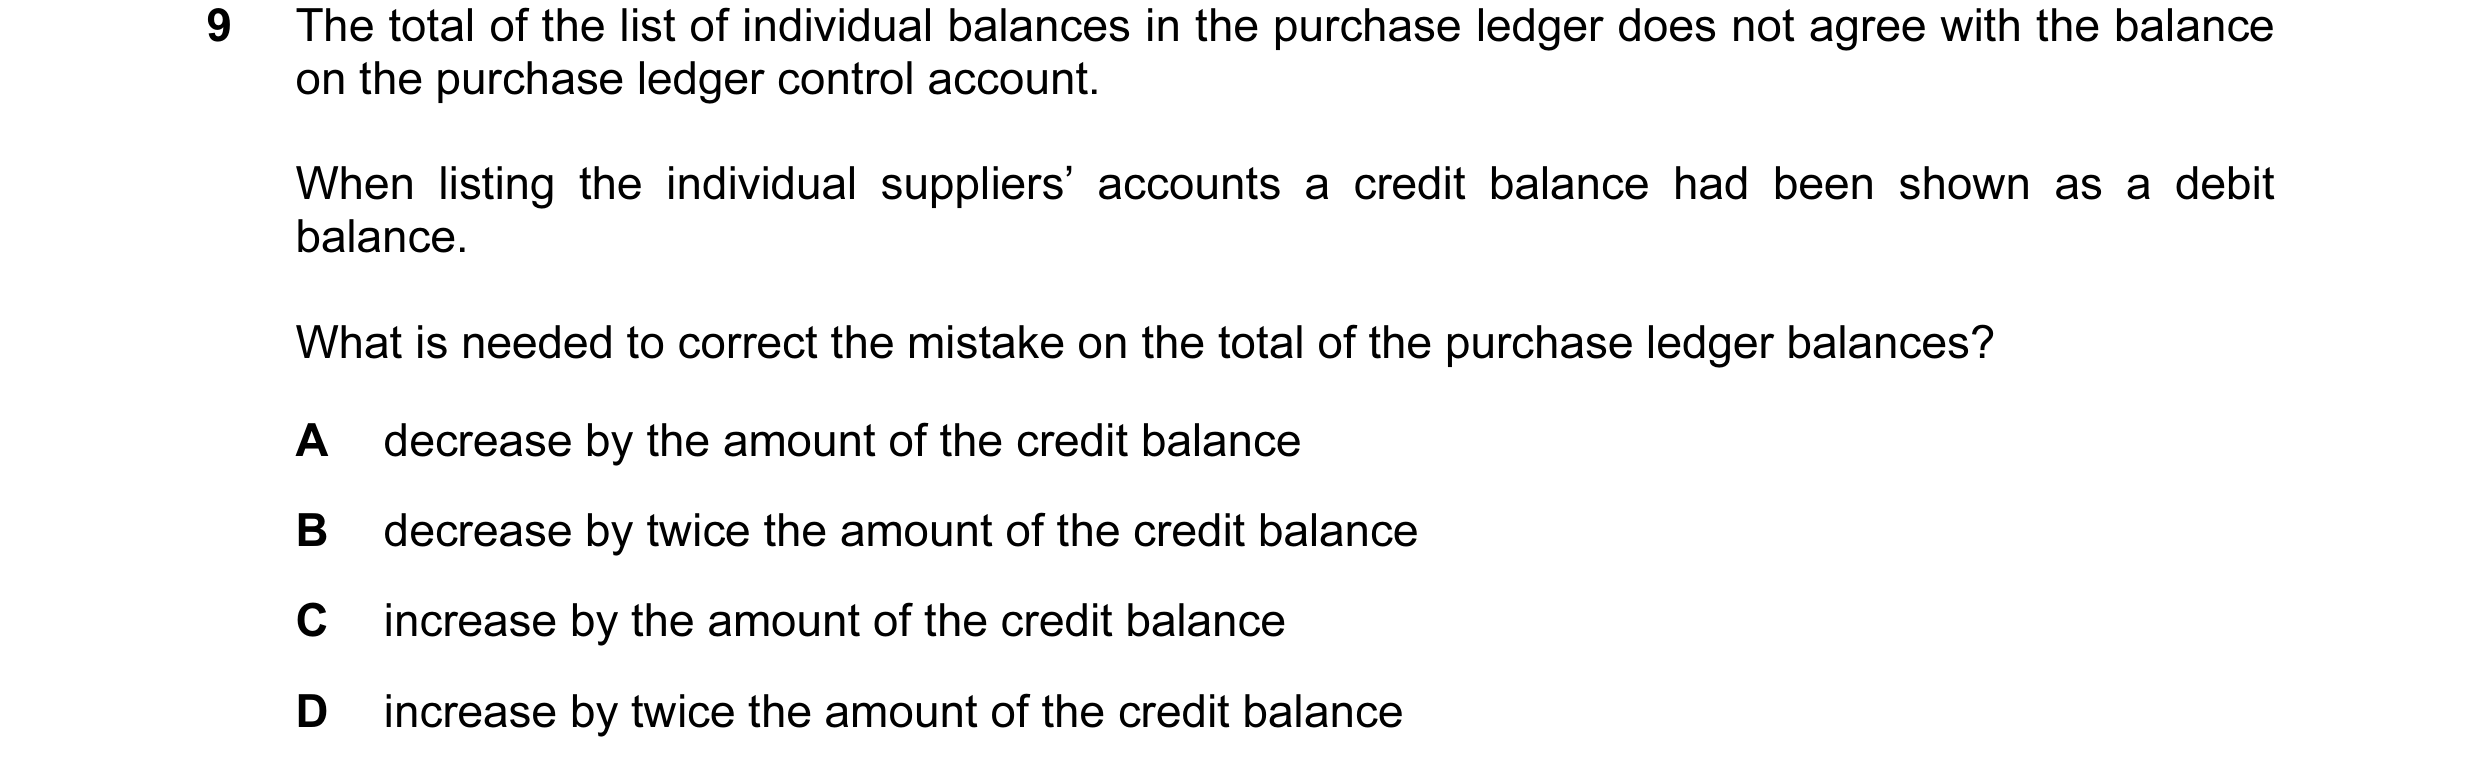
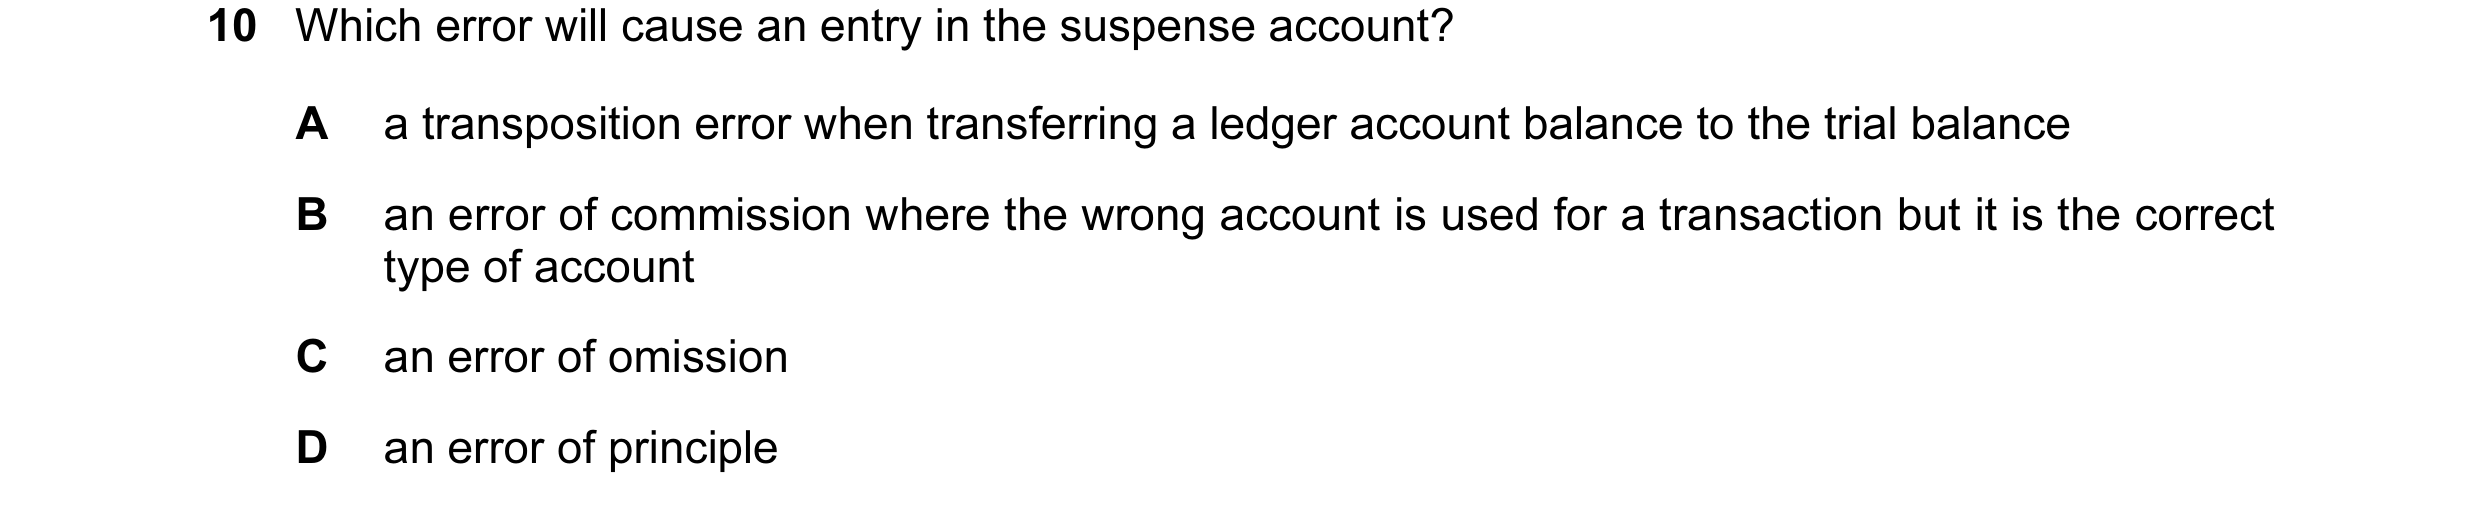 9 / 110
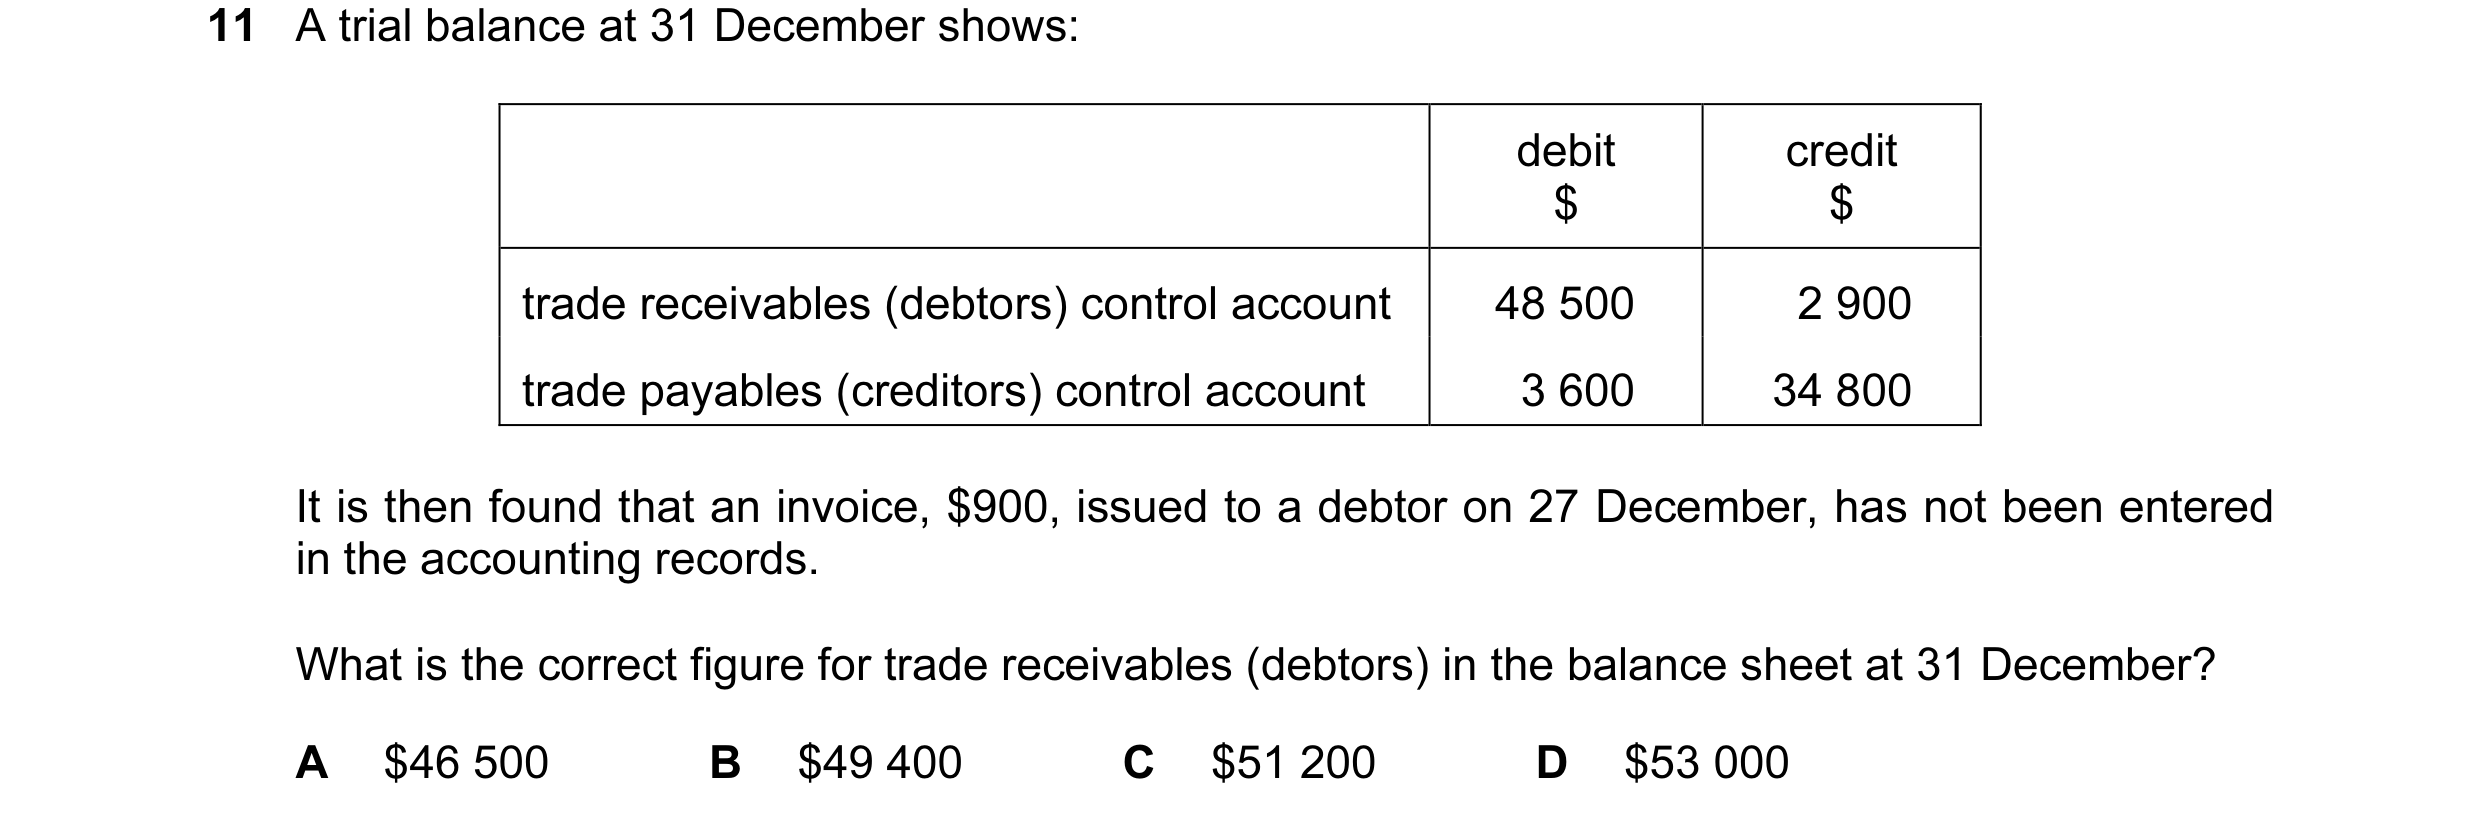
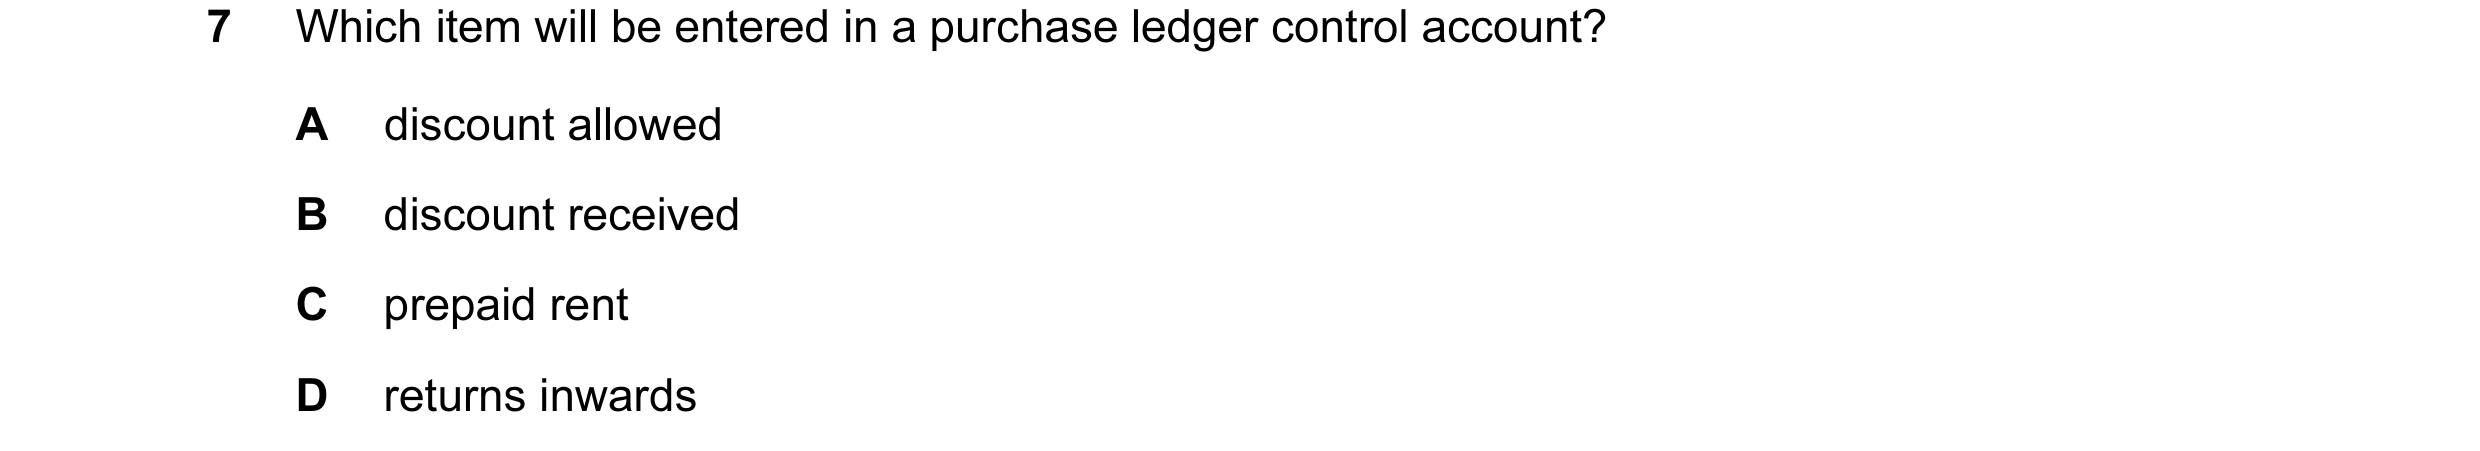
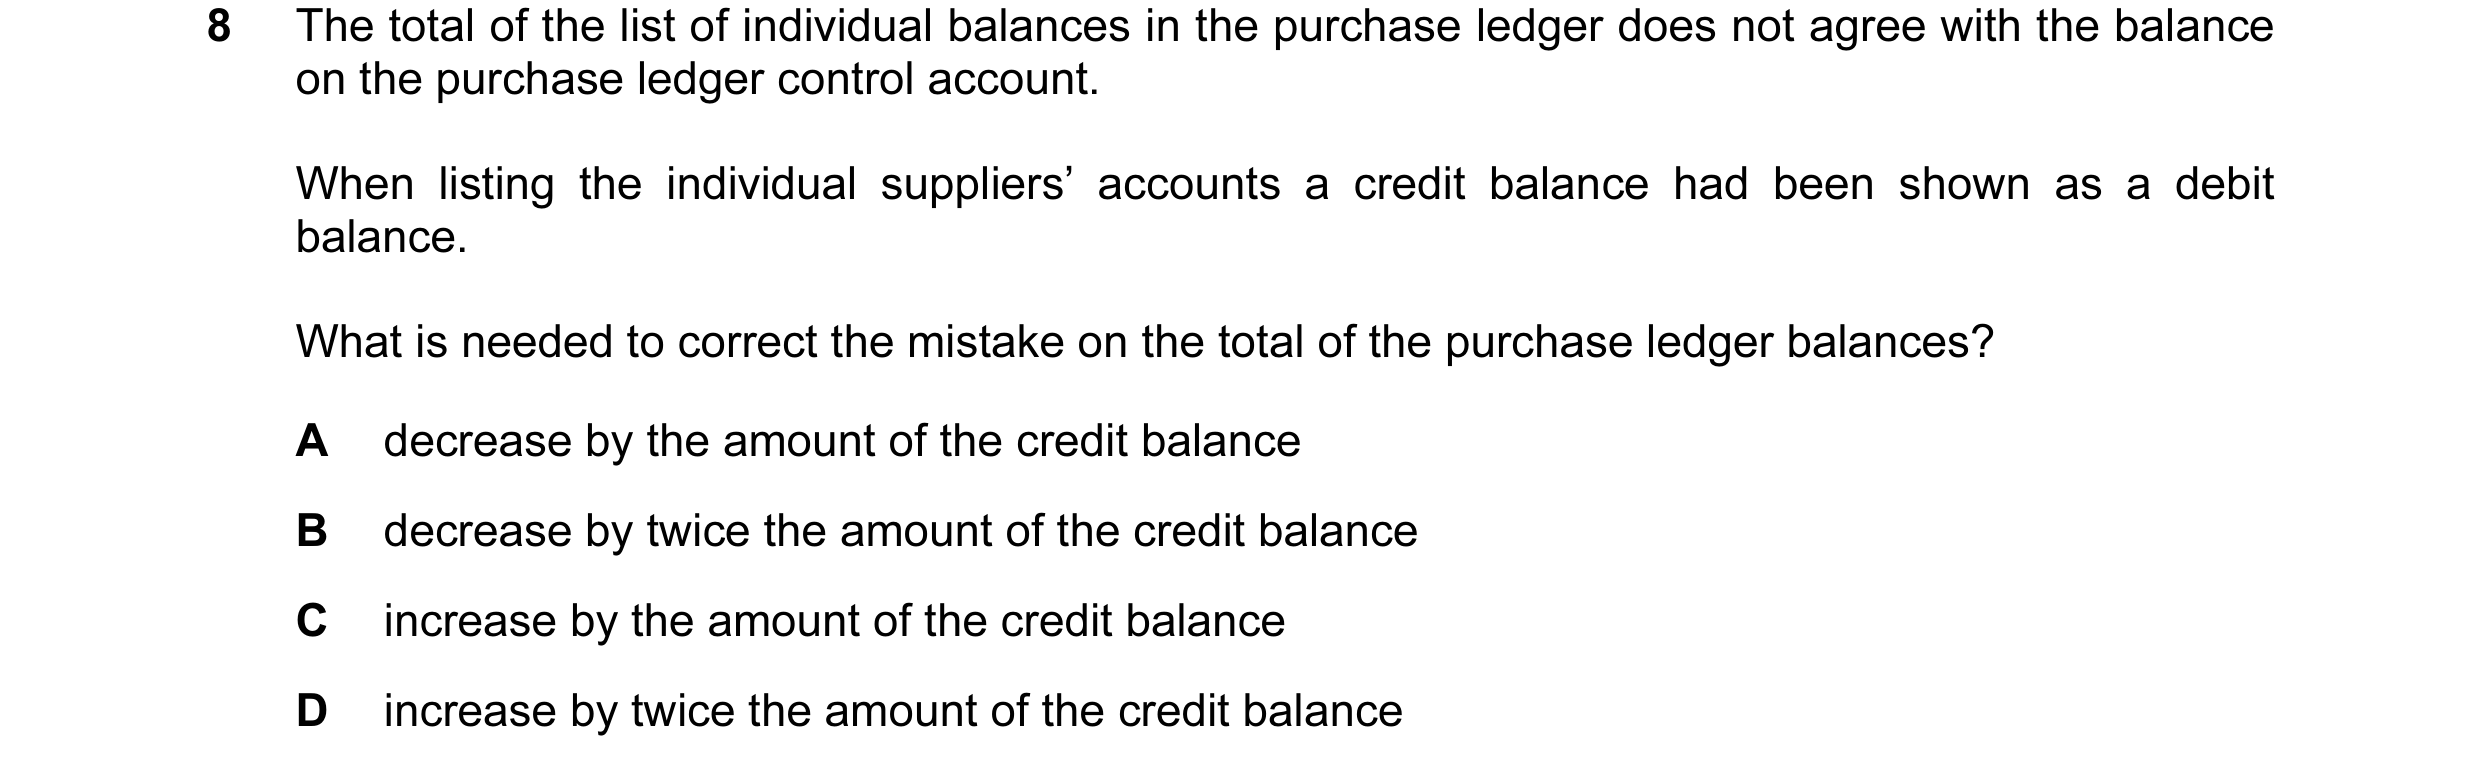
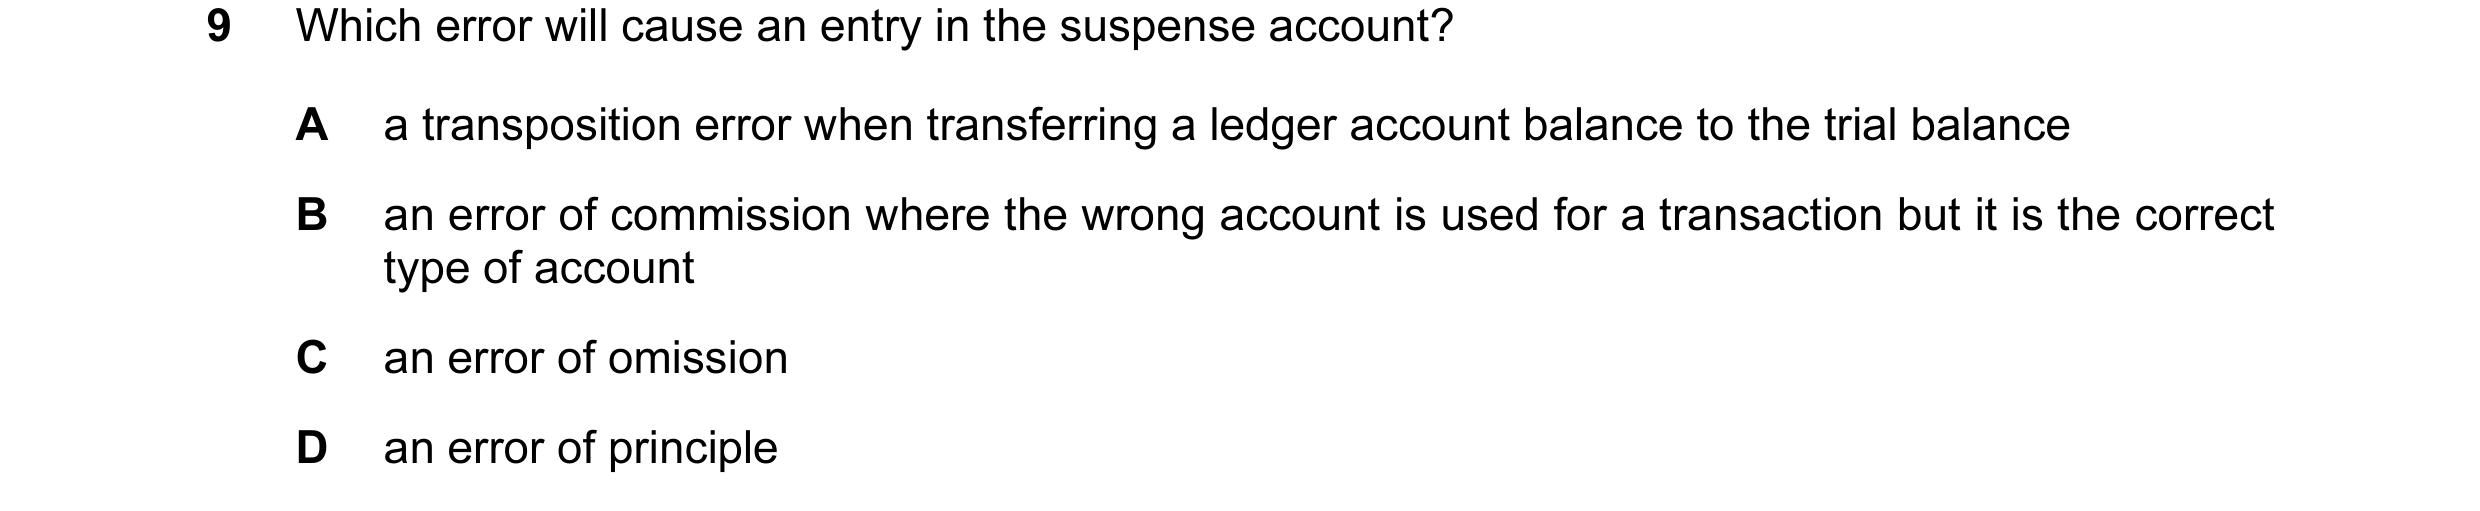 10 / 110
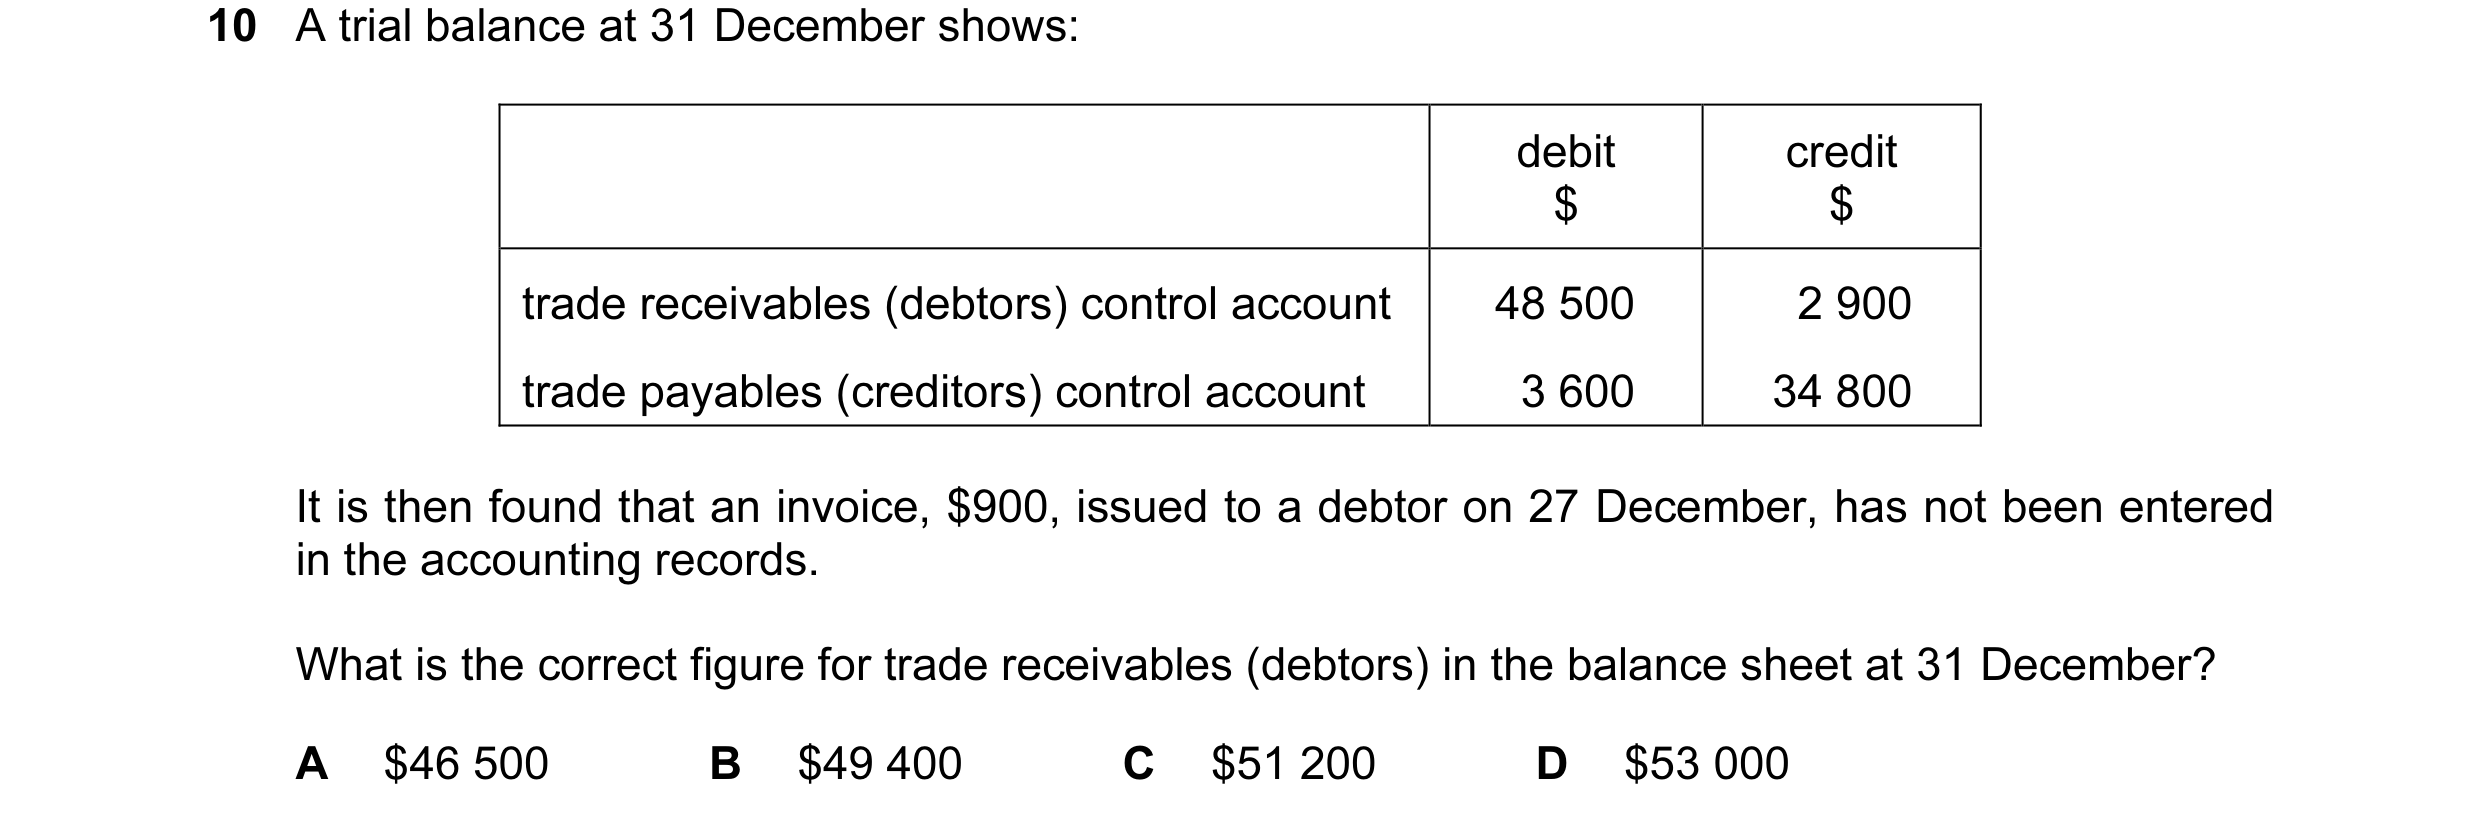
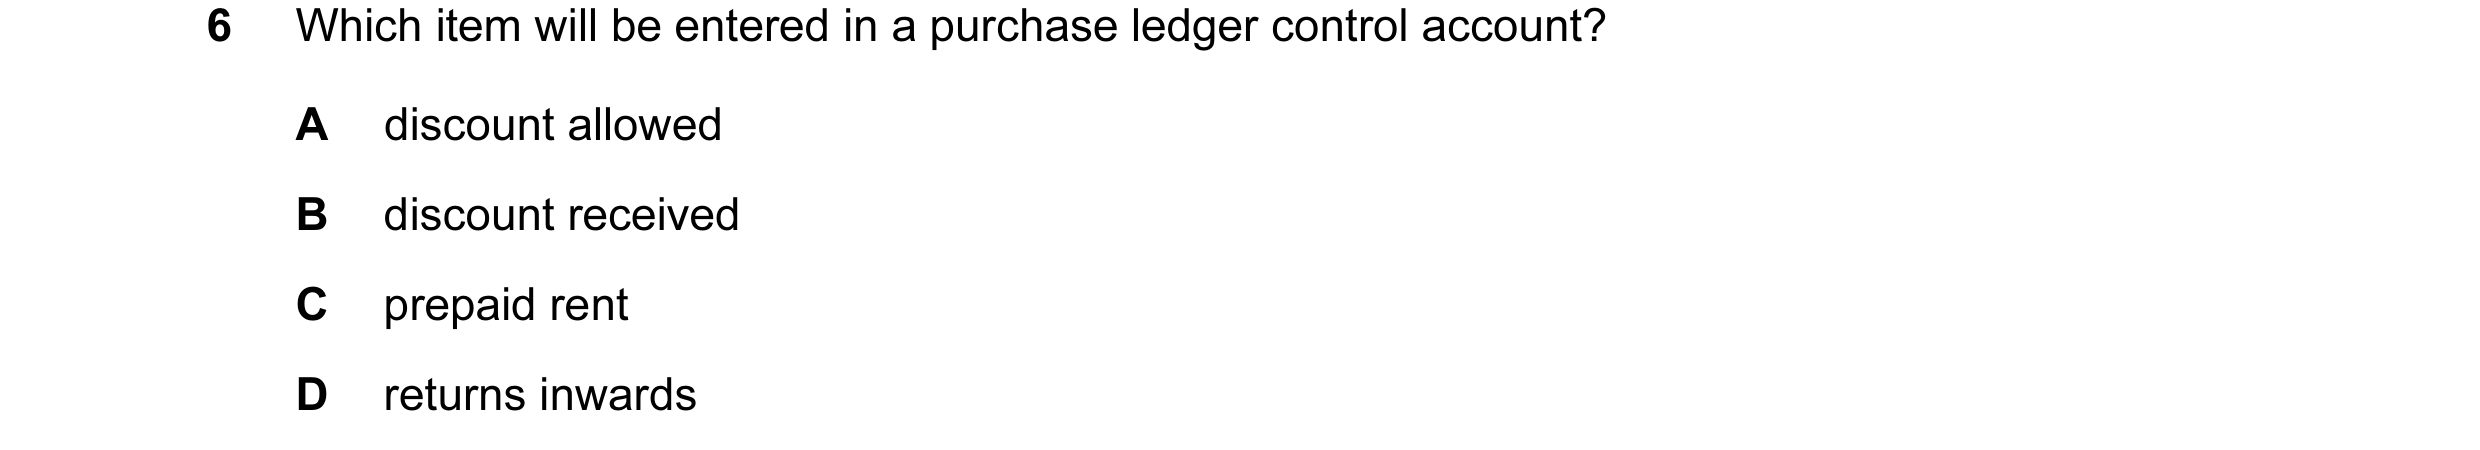
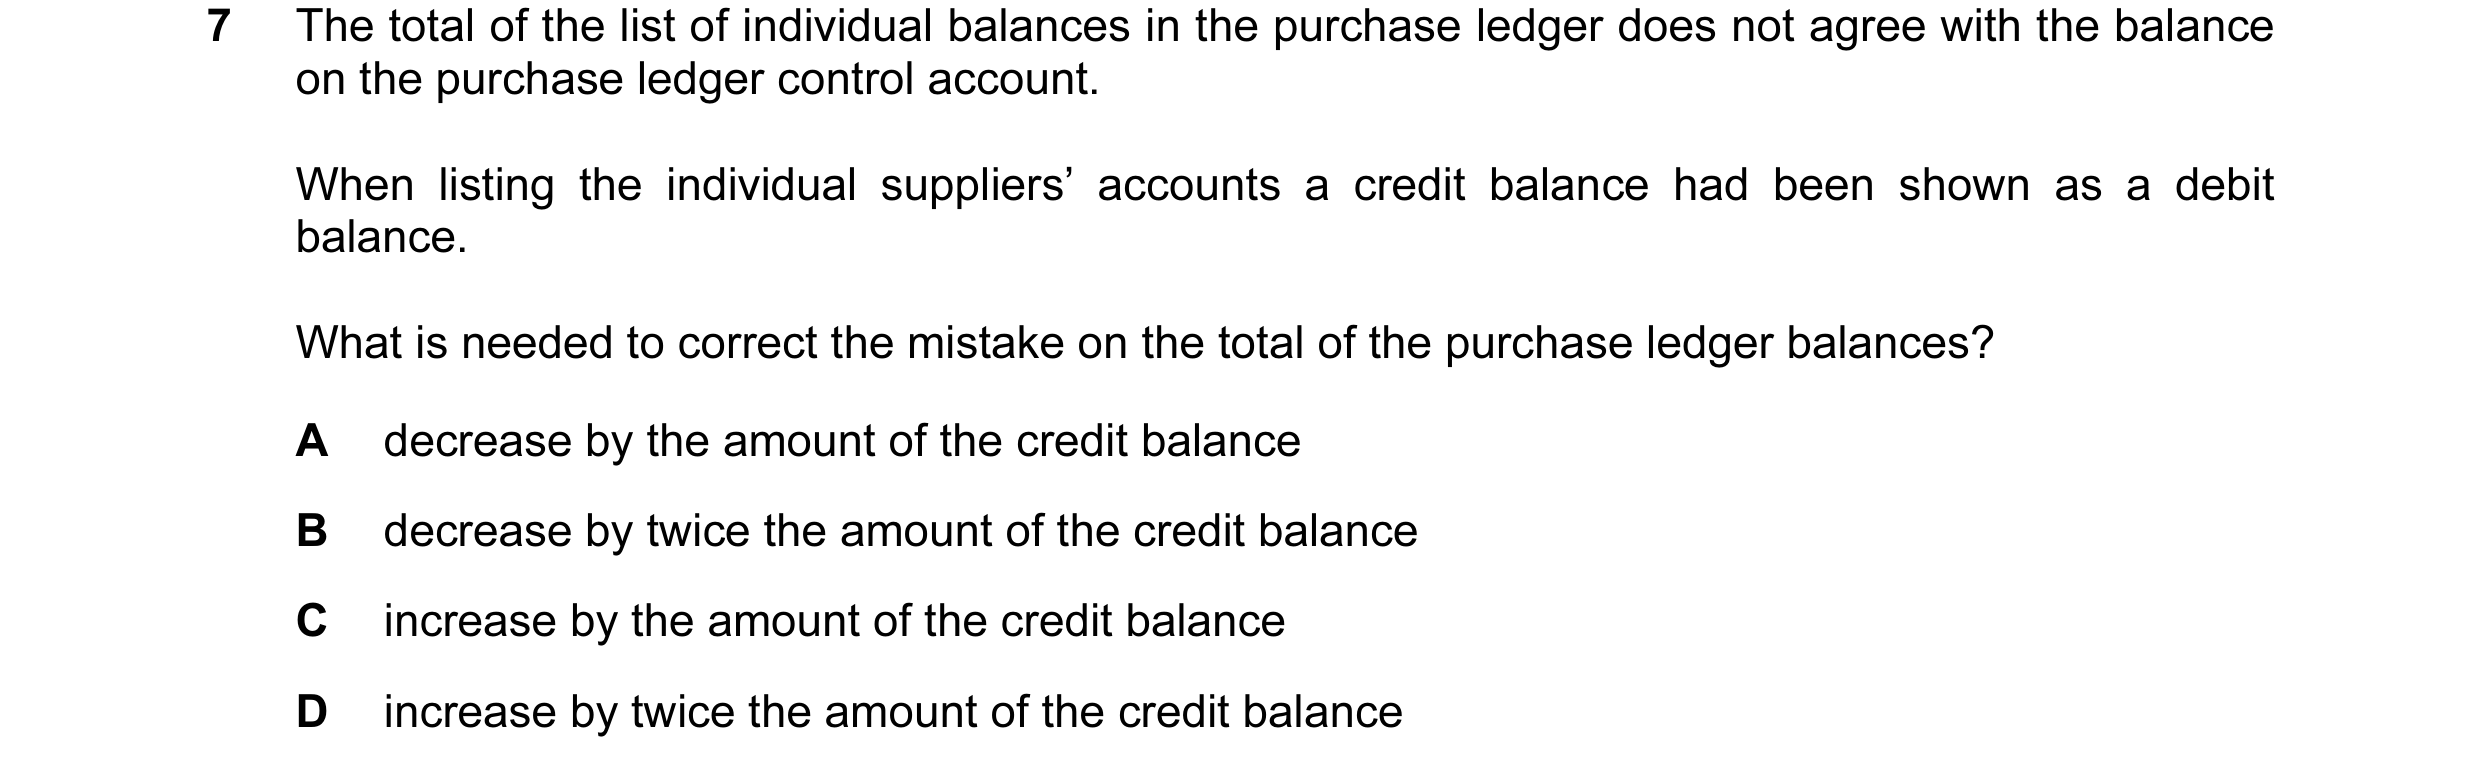
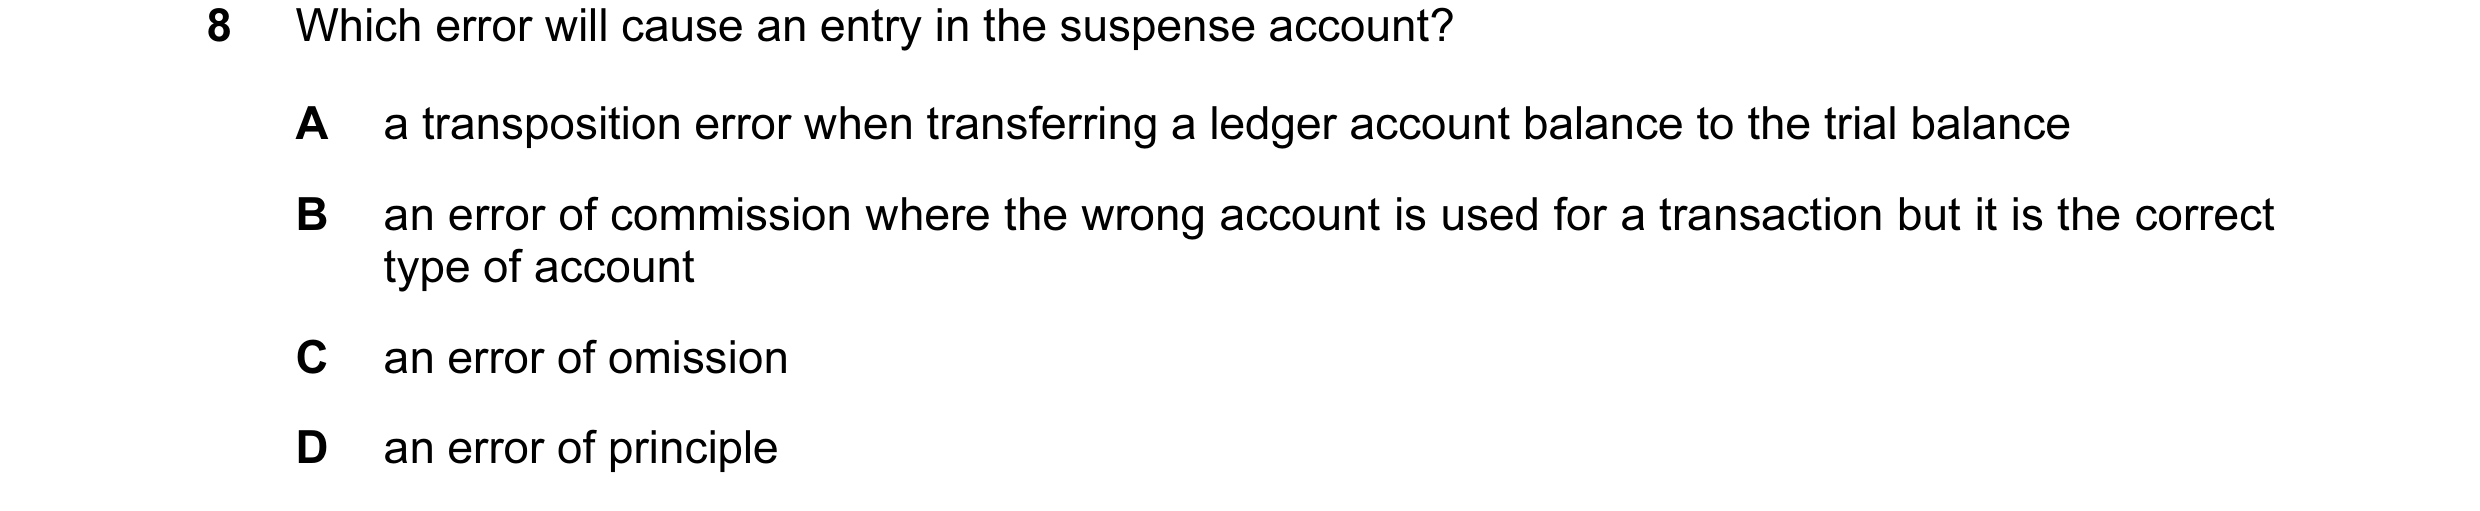 11 / 110
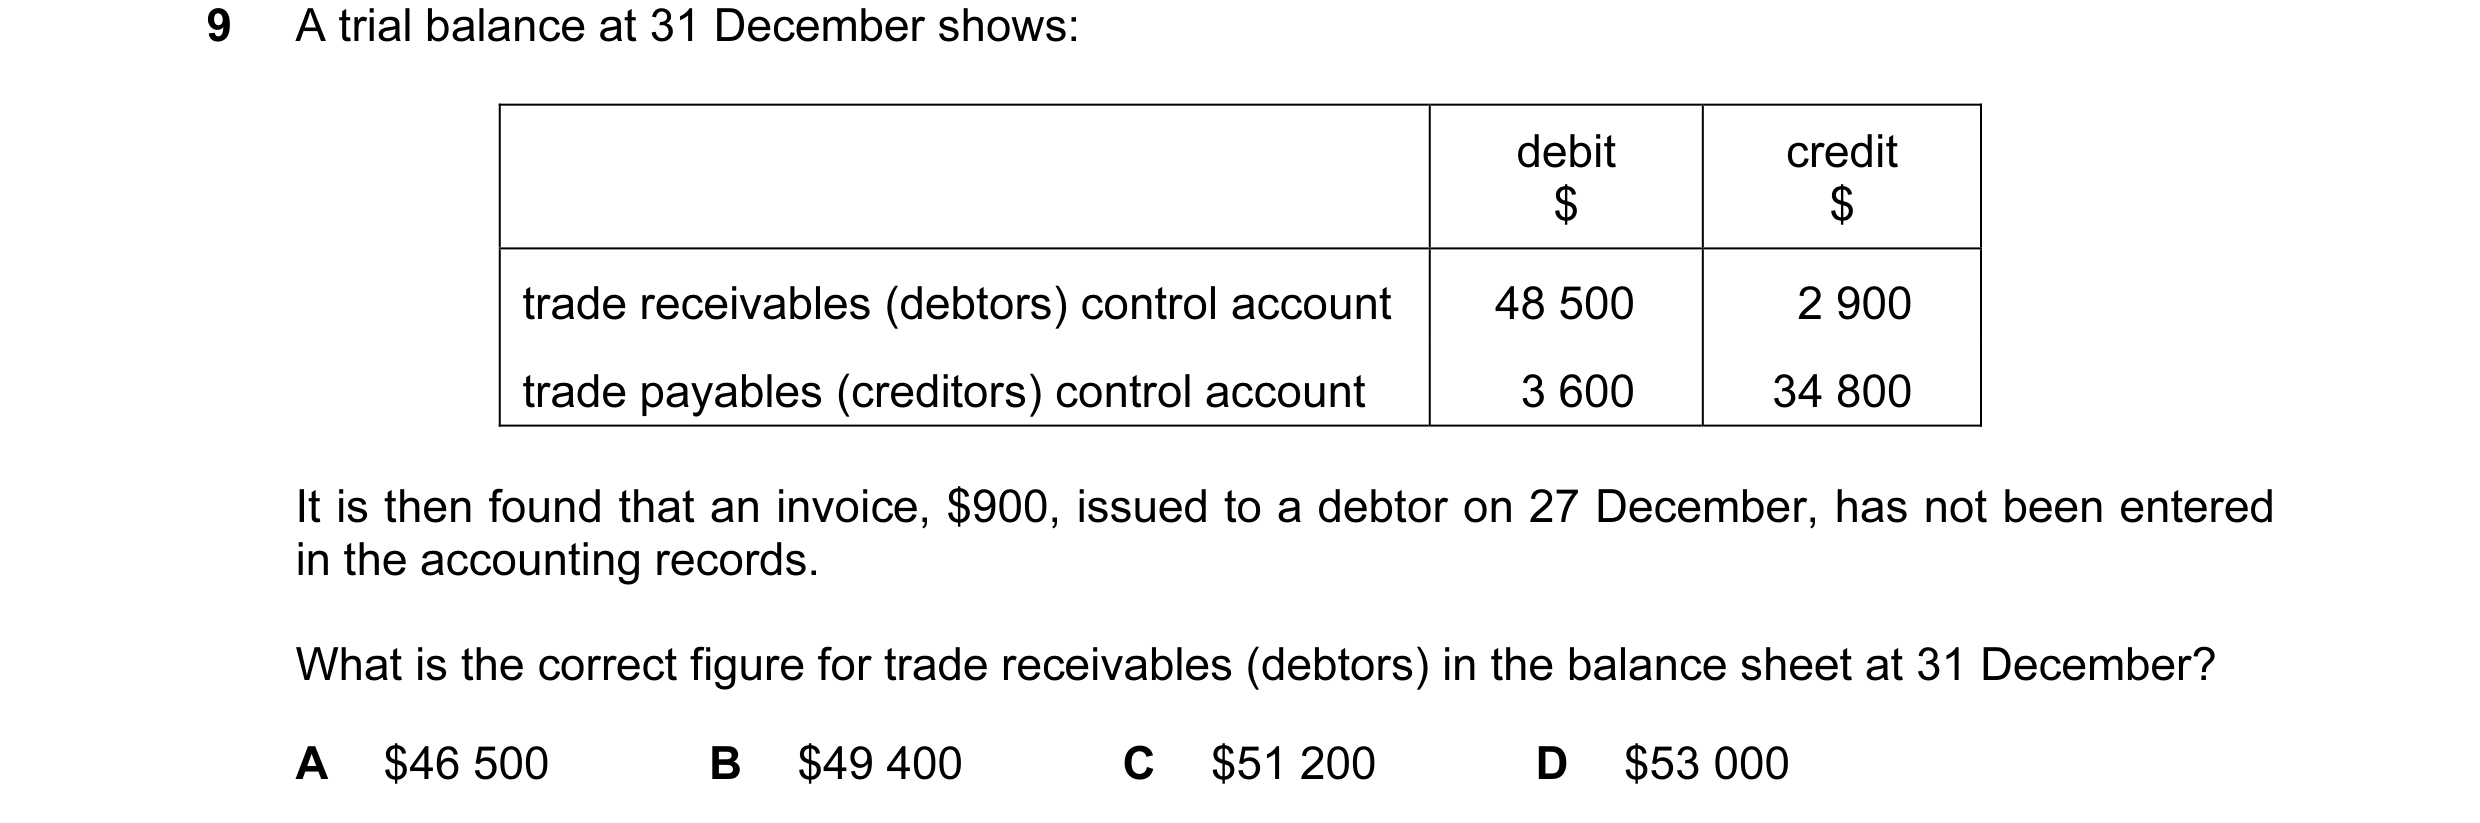
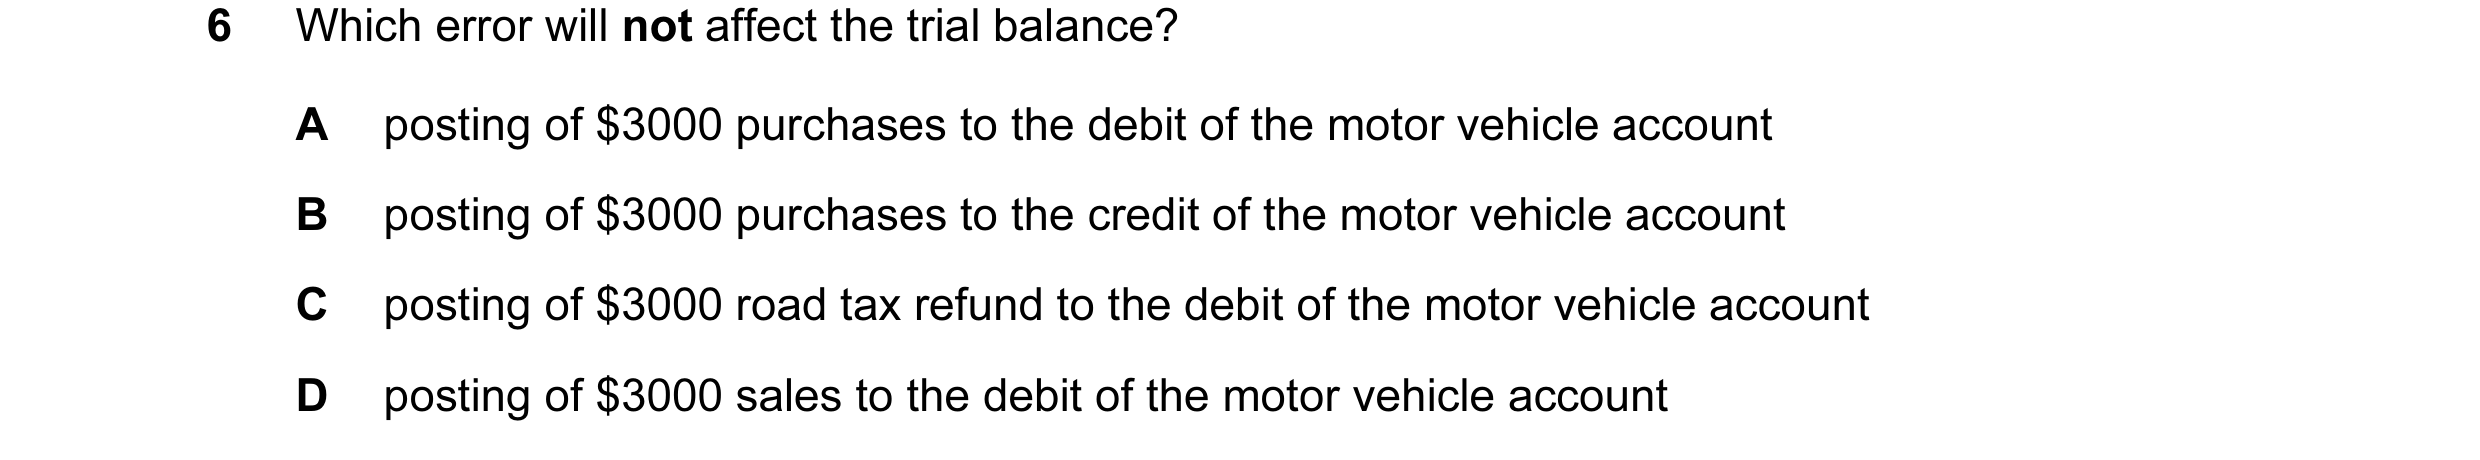
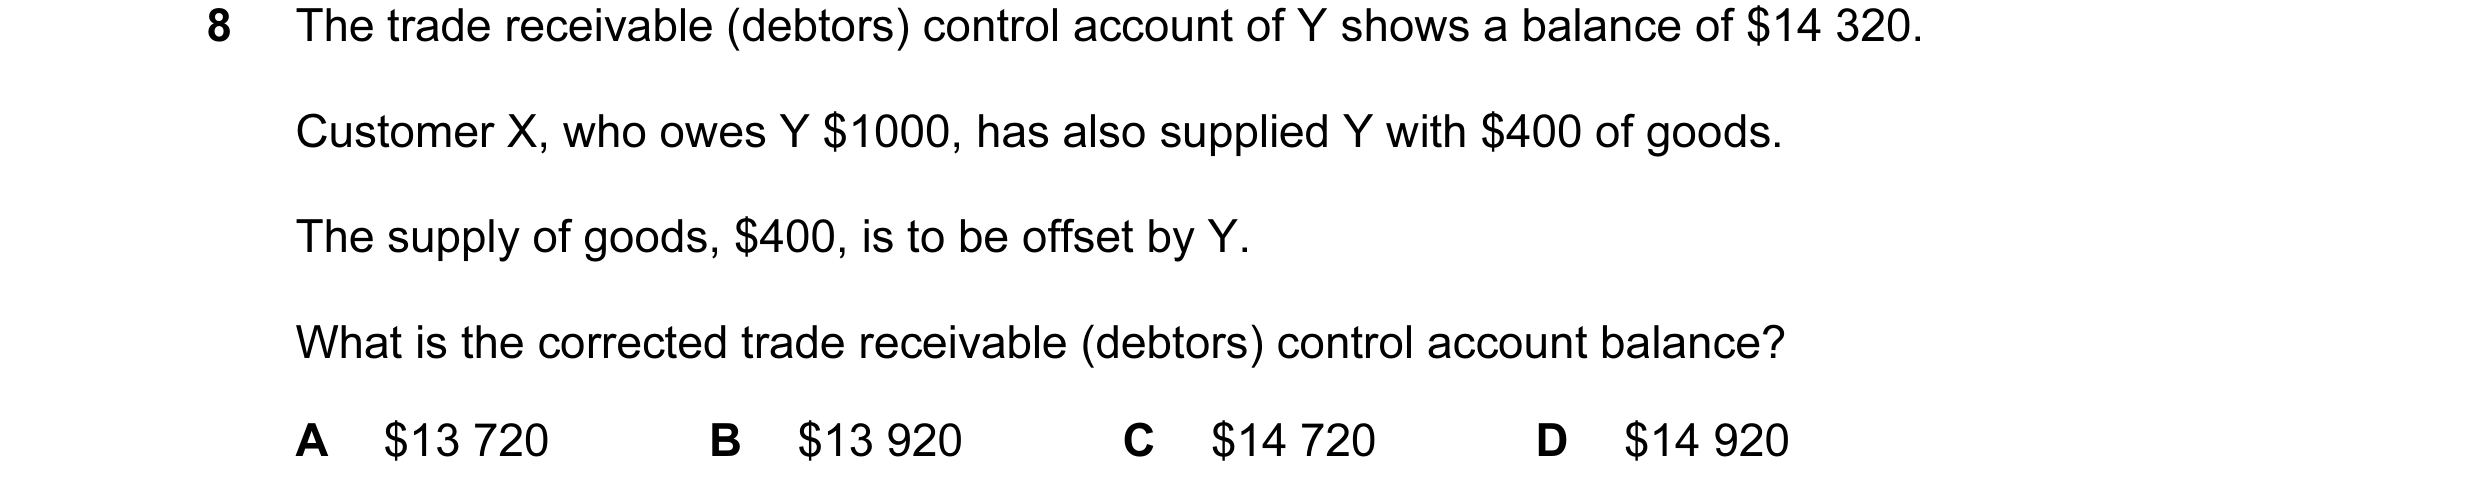
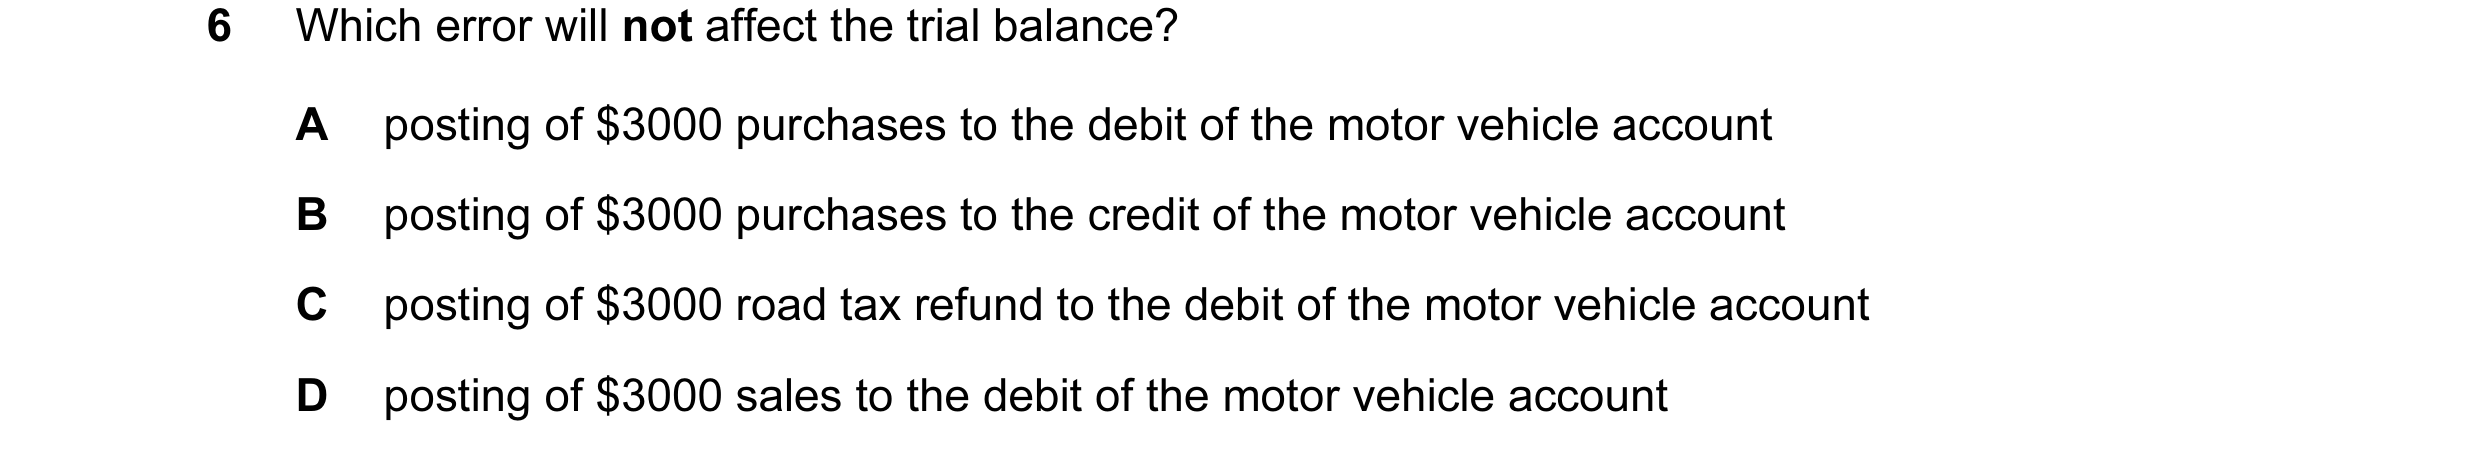
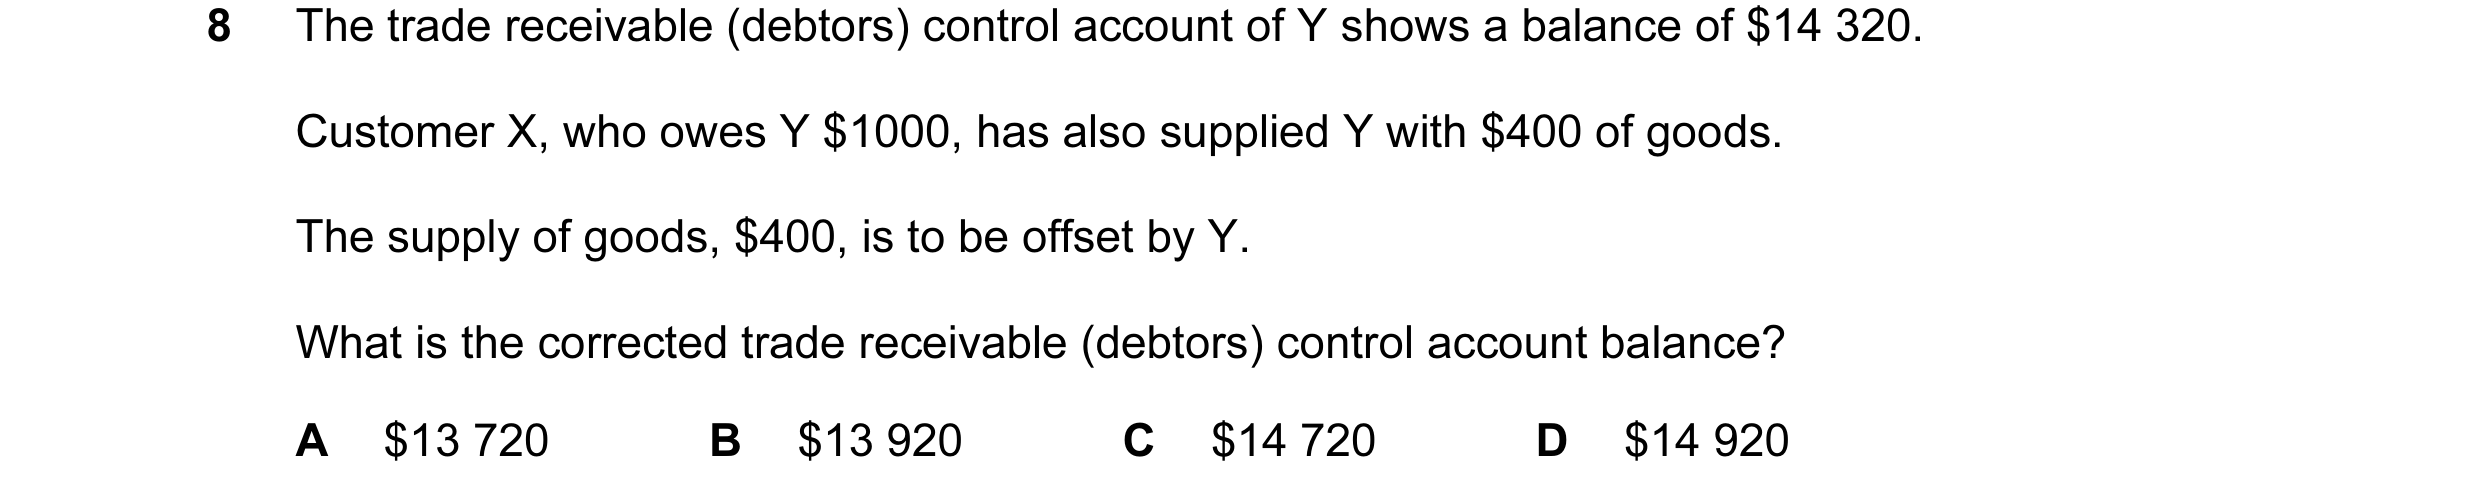 12 / 110
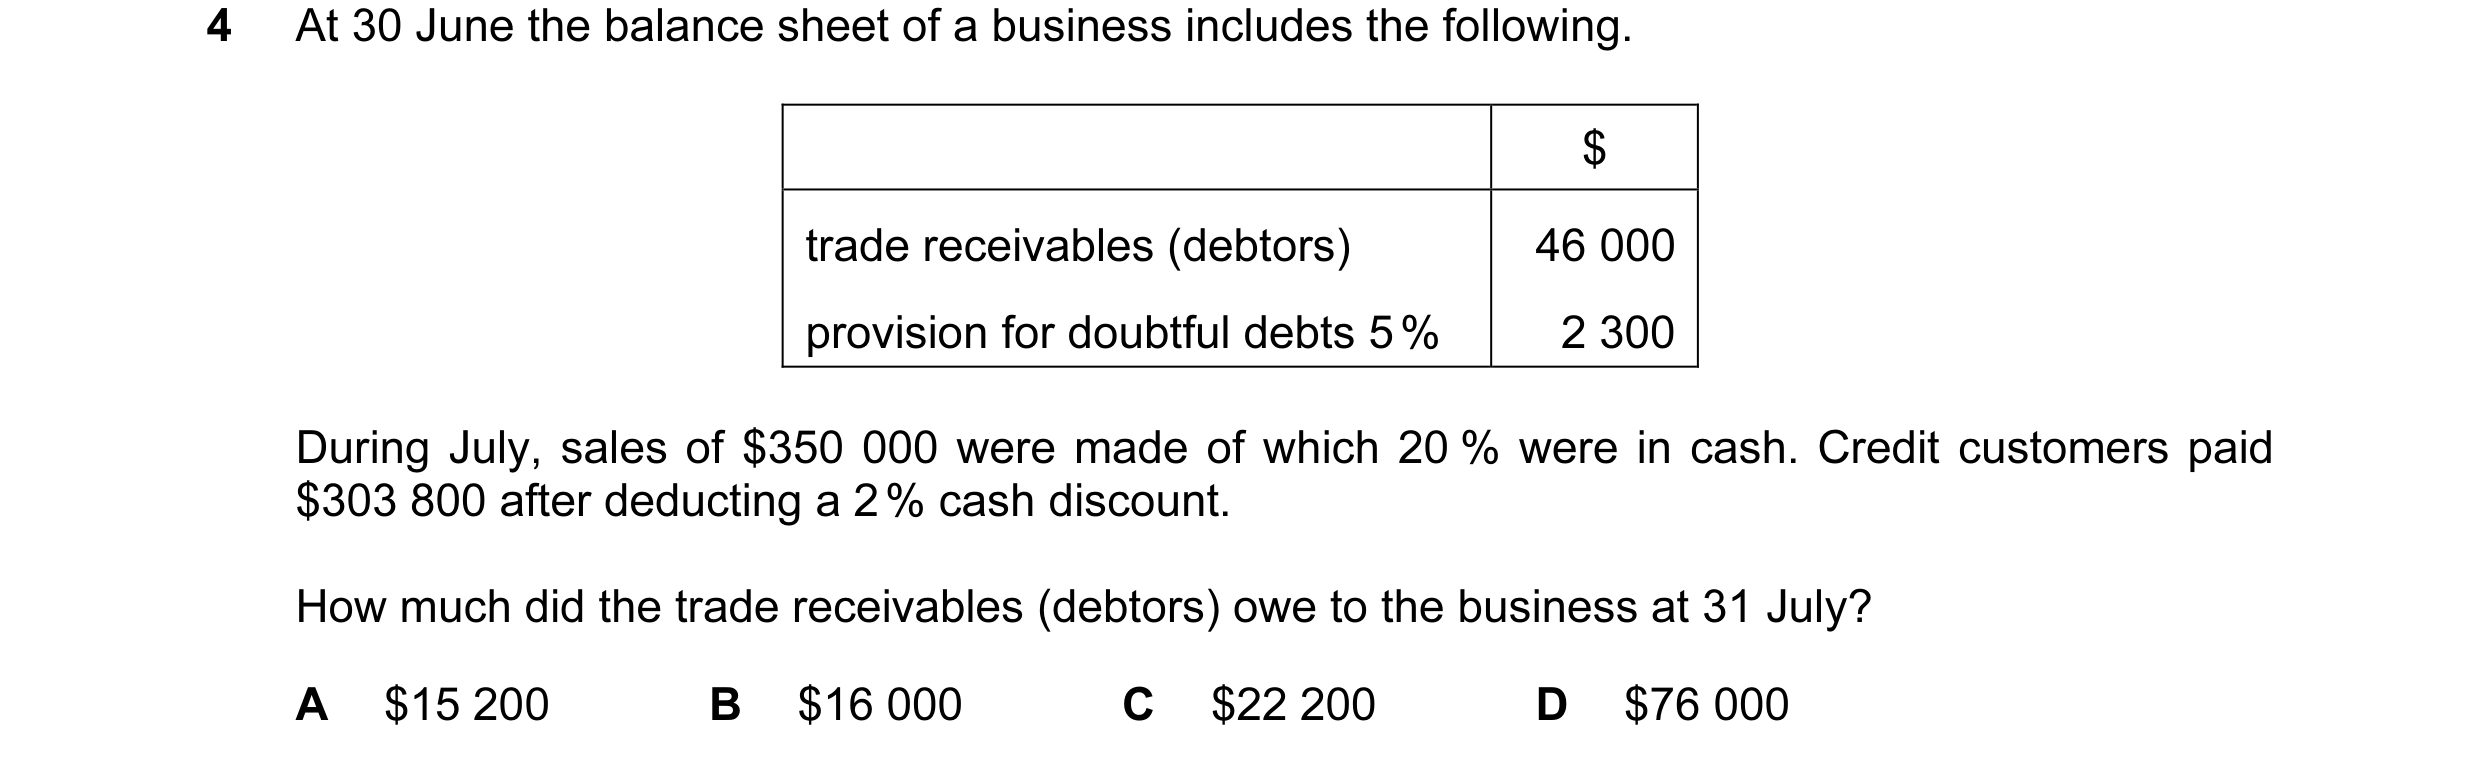
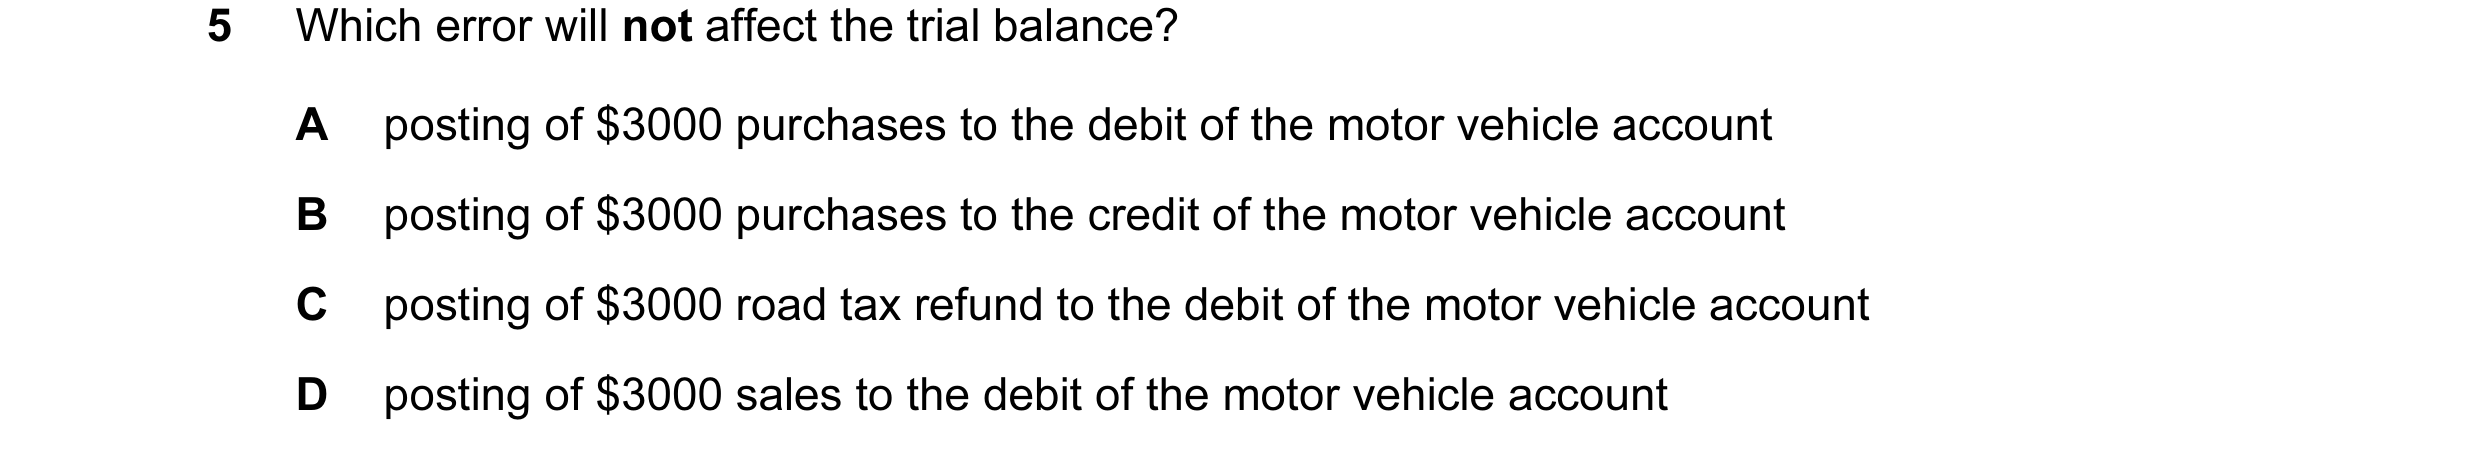
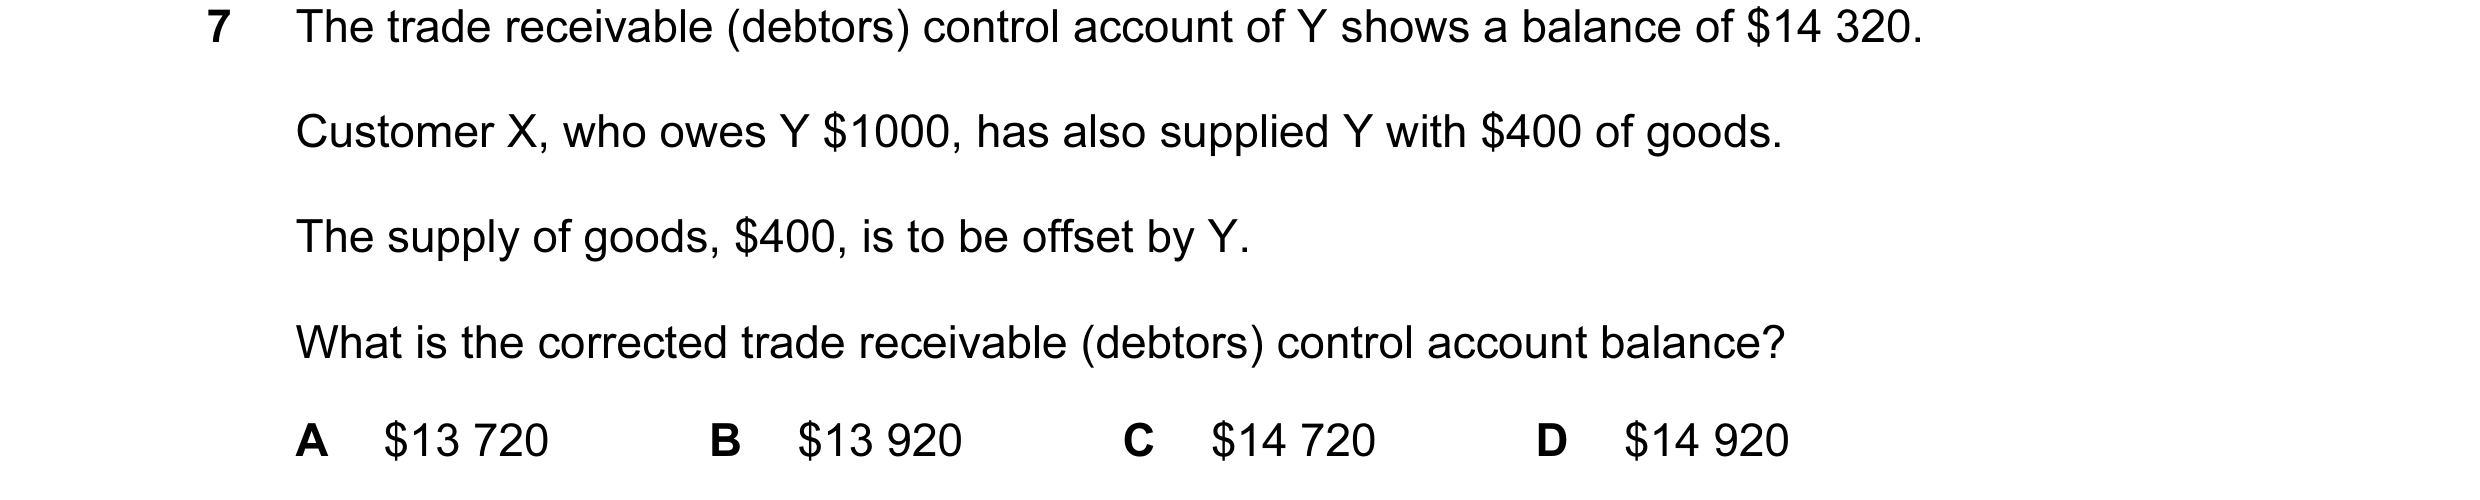
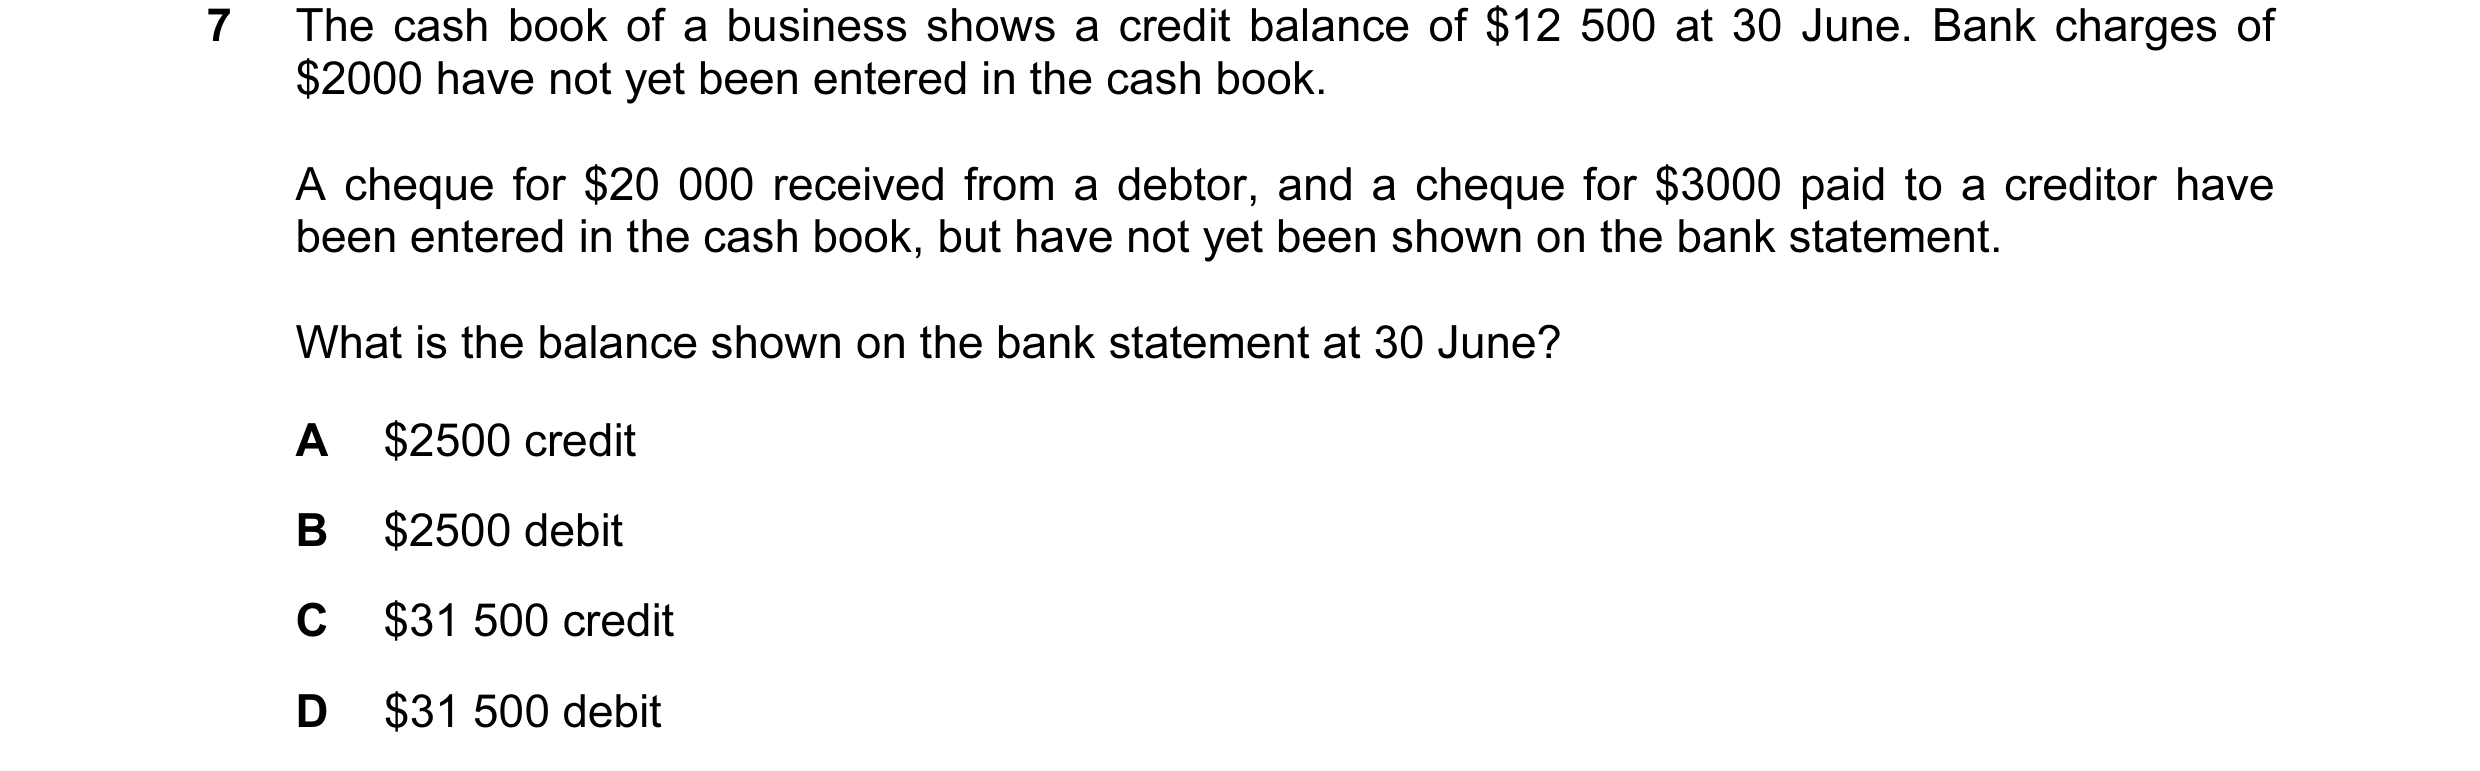
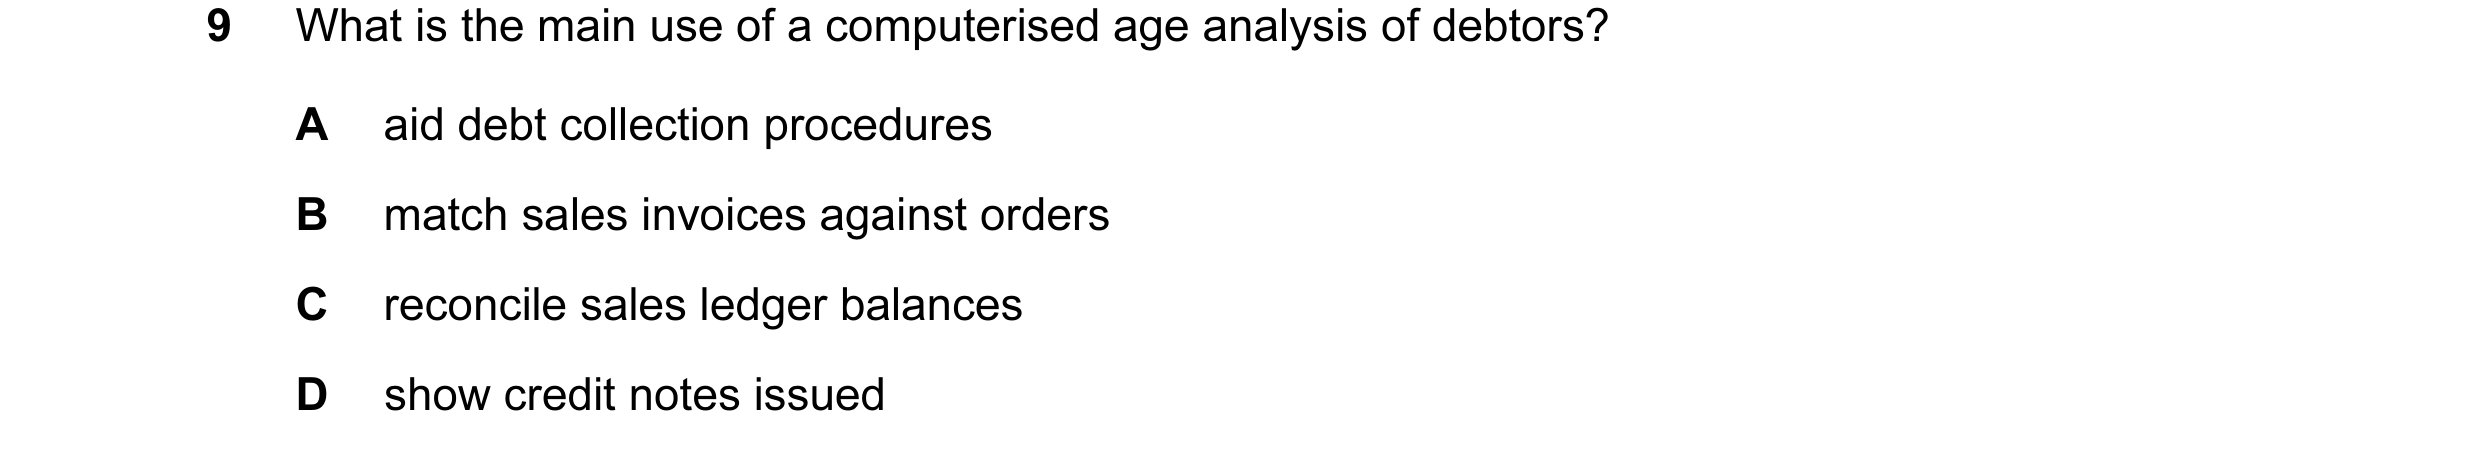 13 / 110
 14 / 110
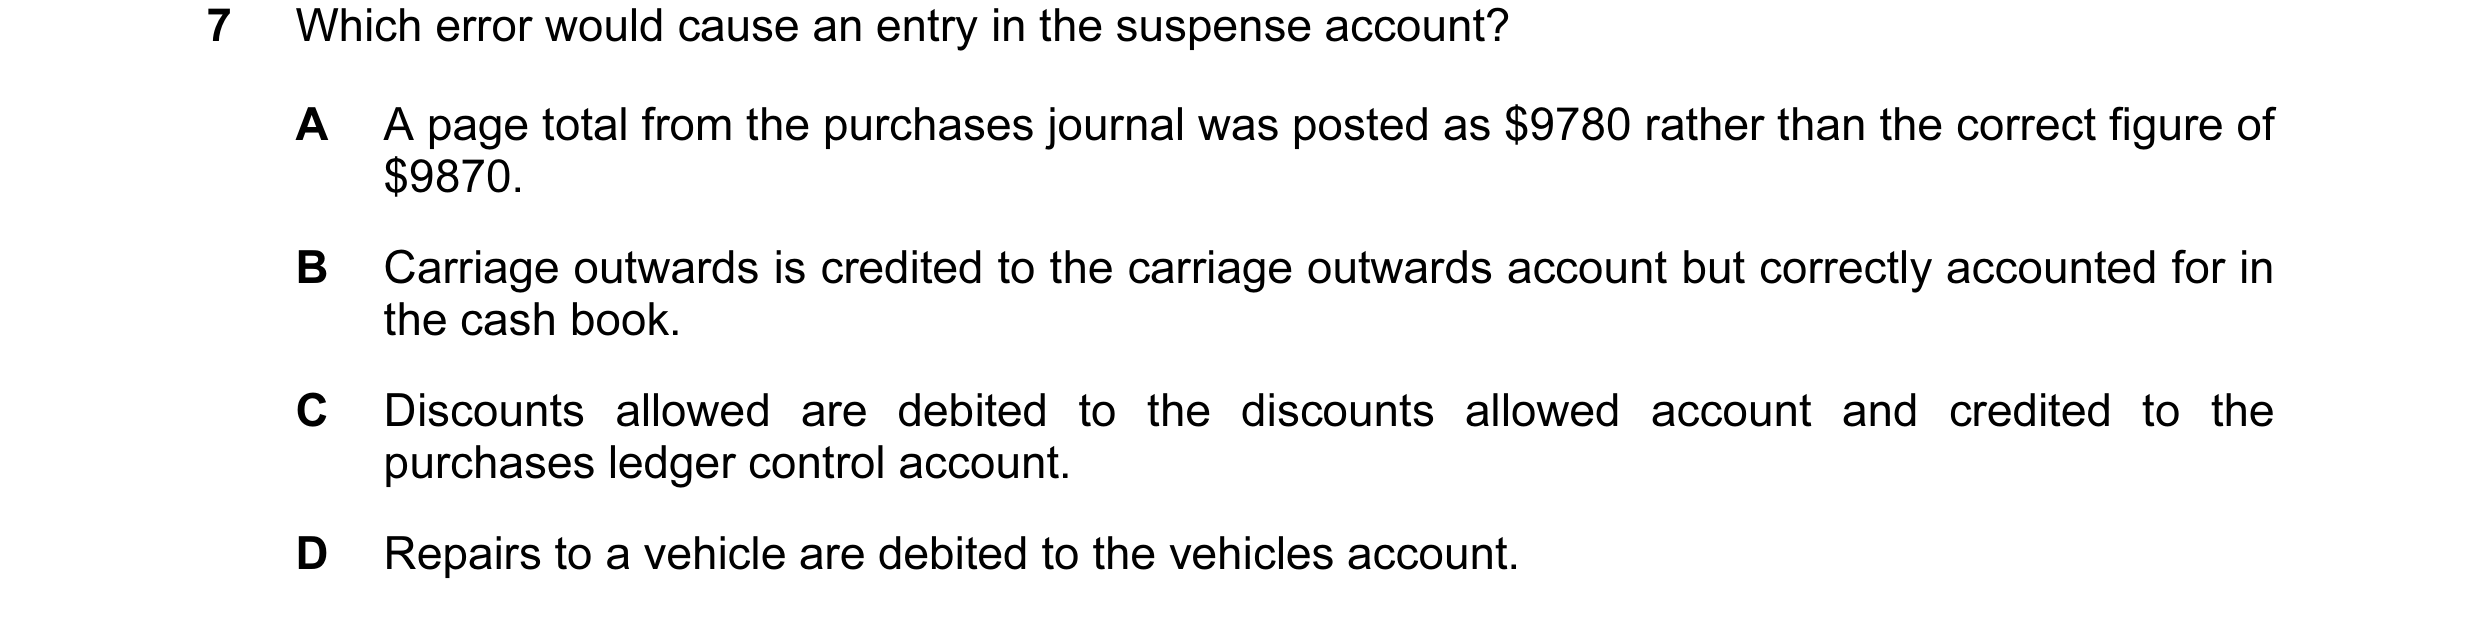
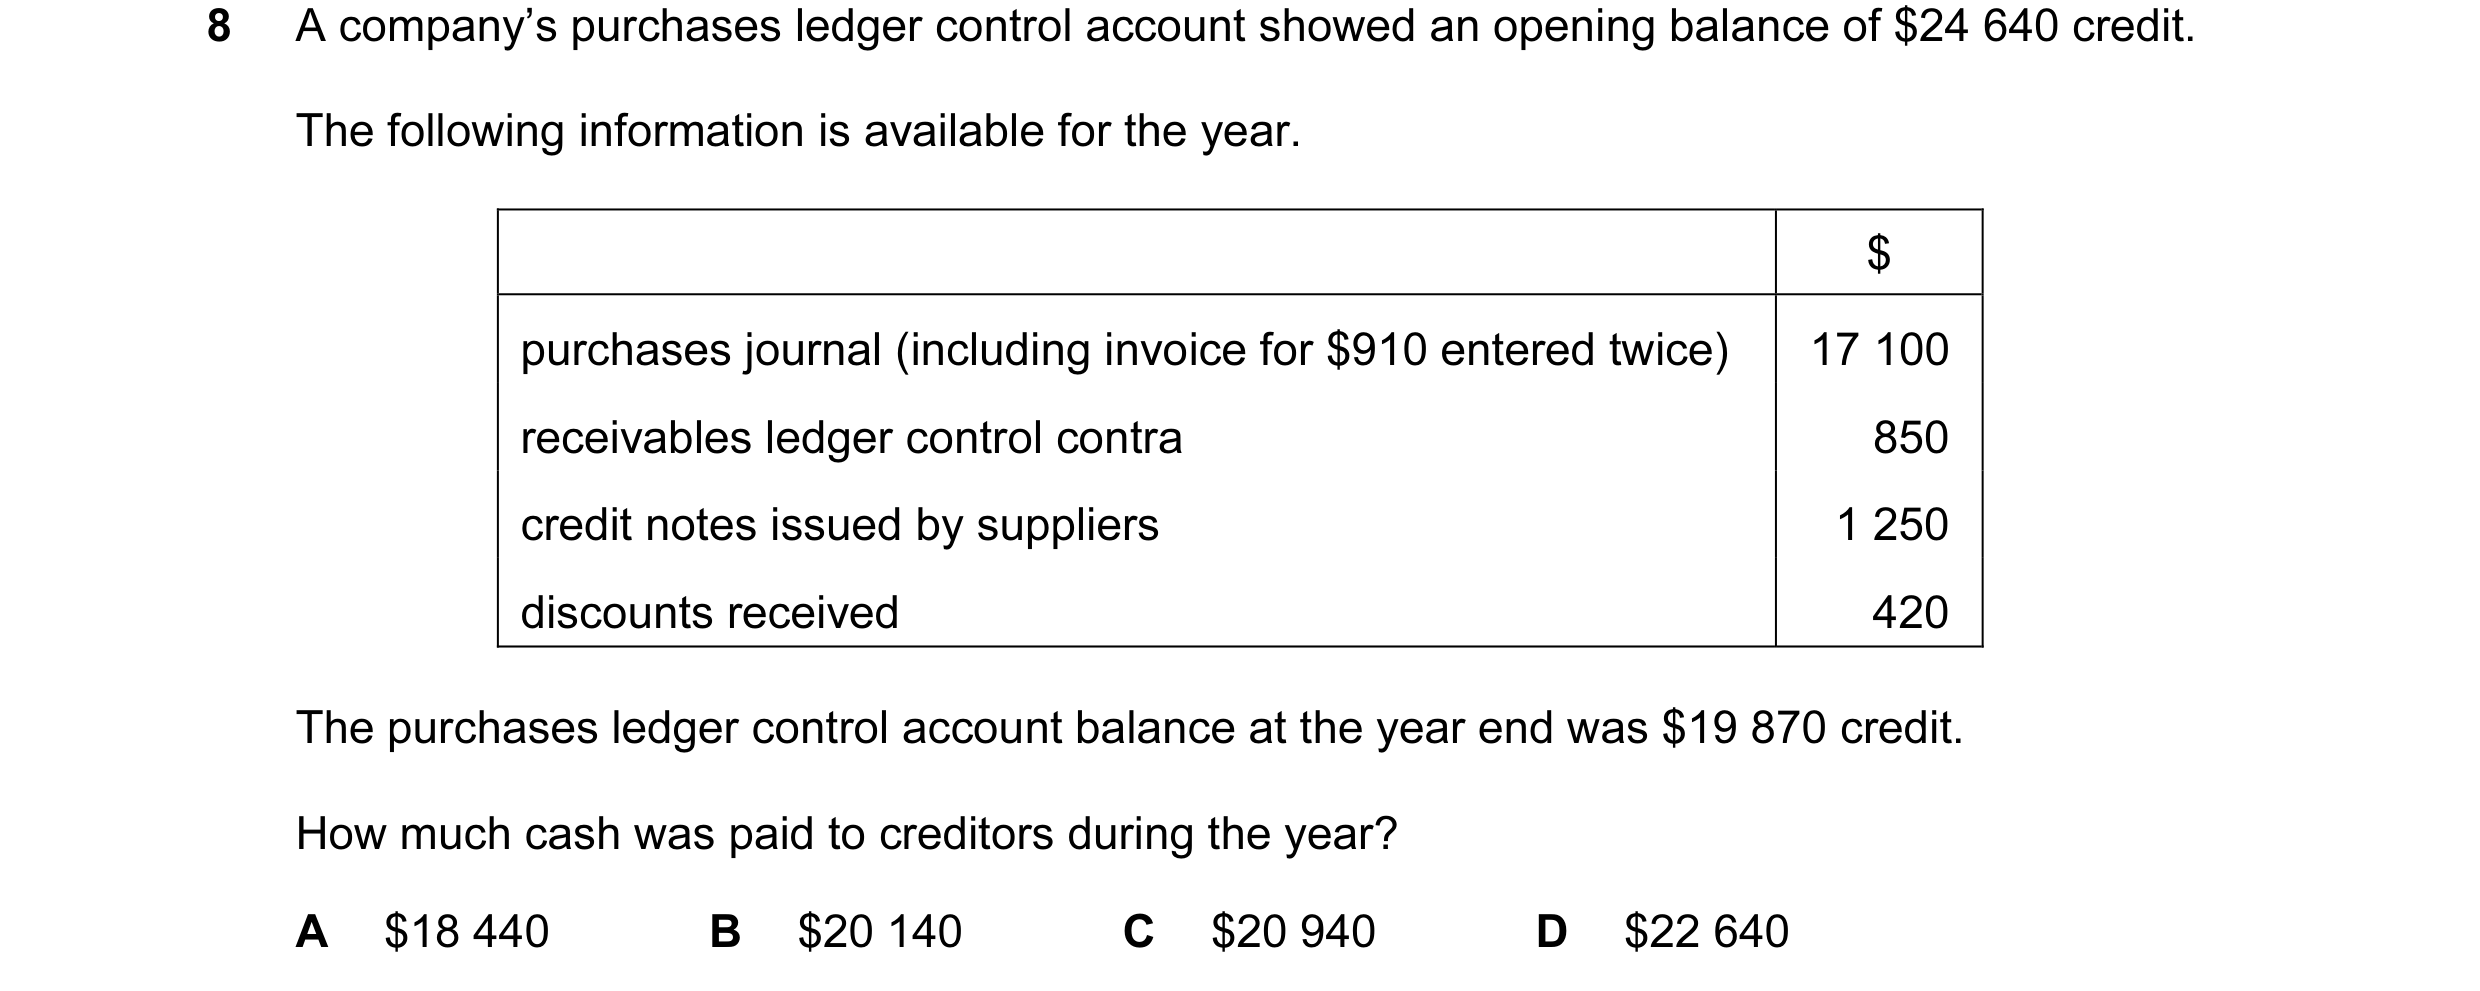
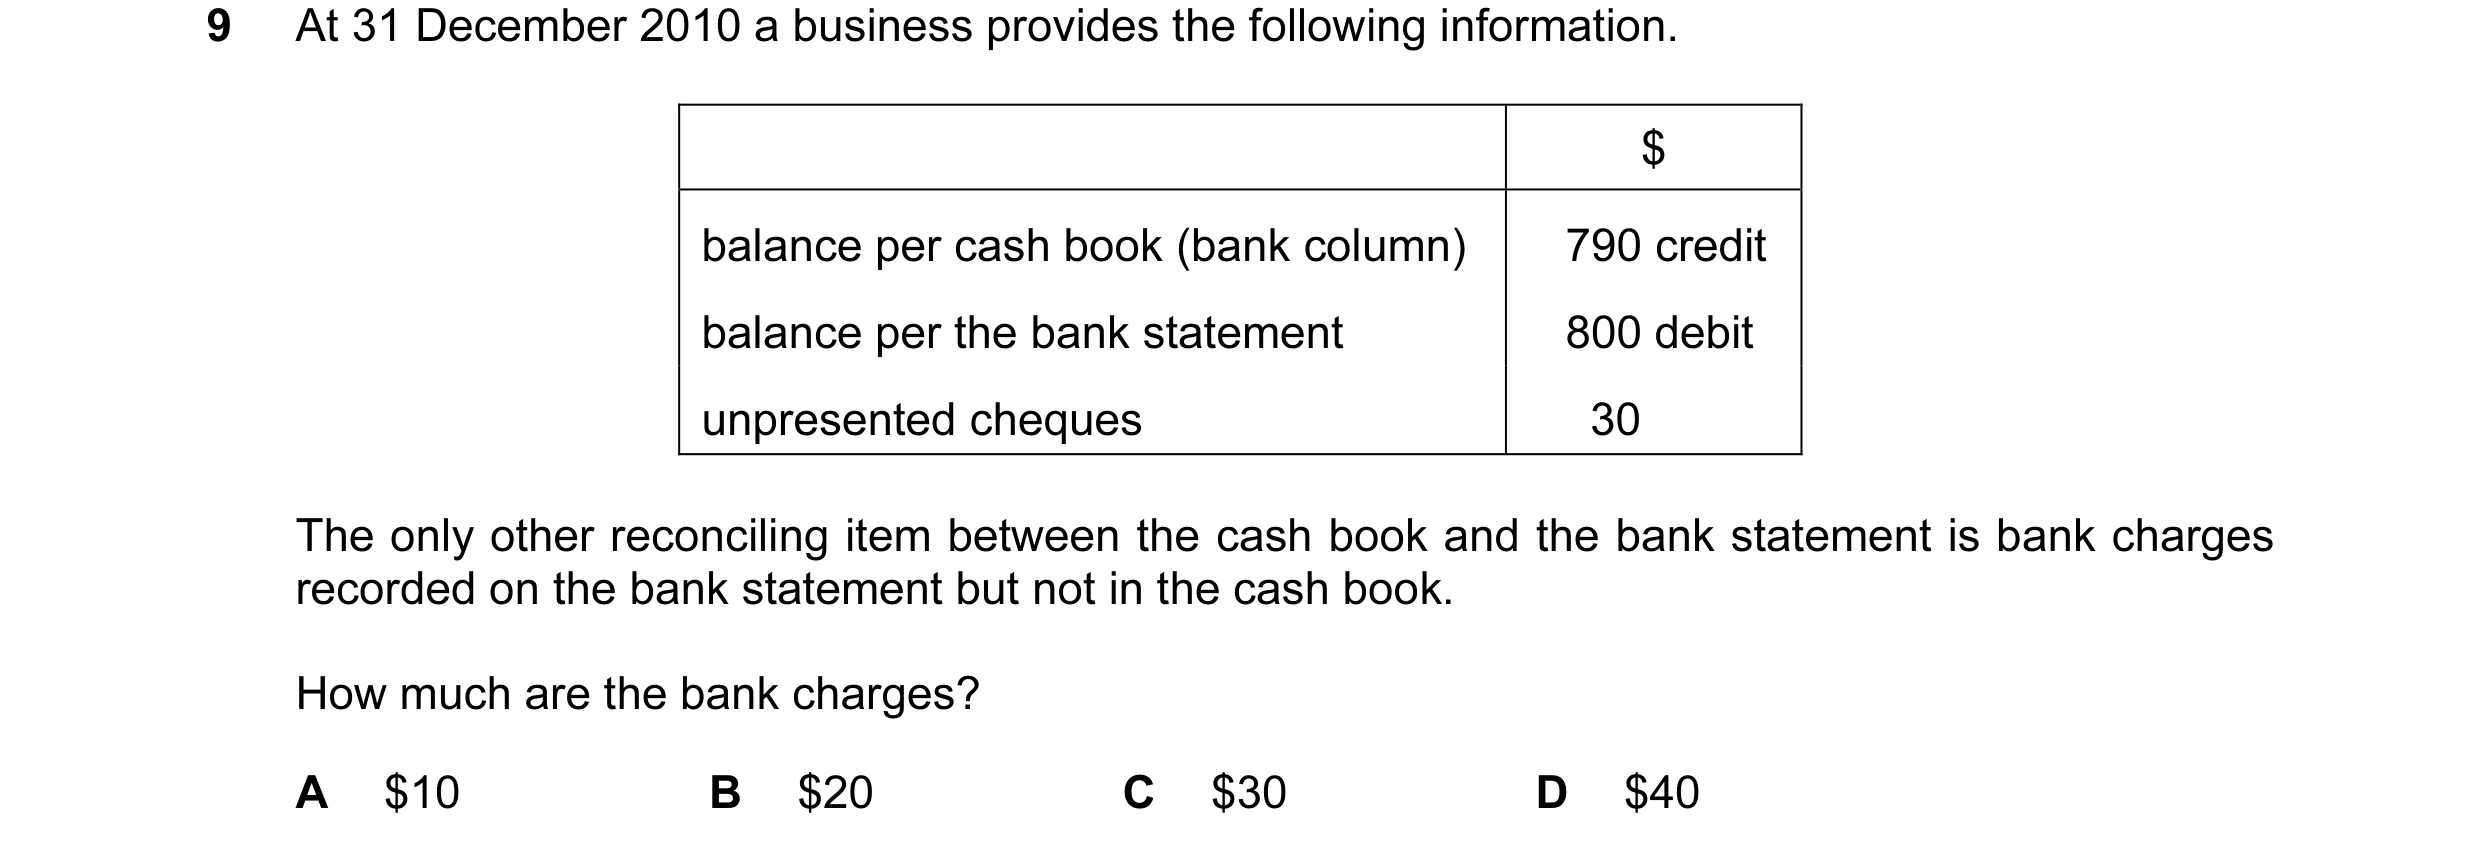 15 / 110
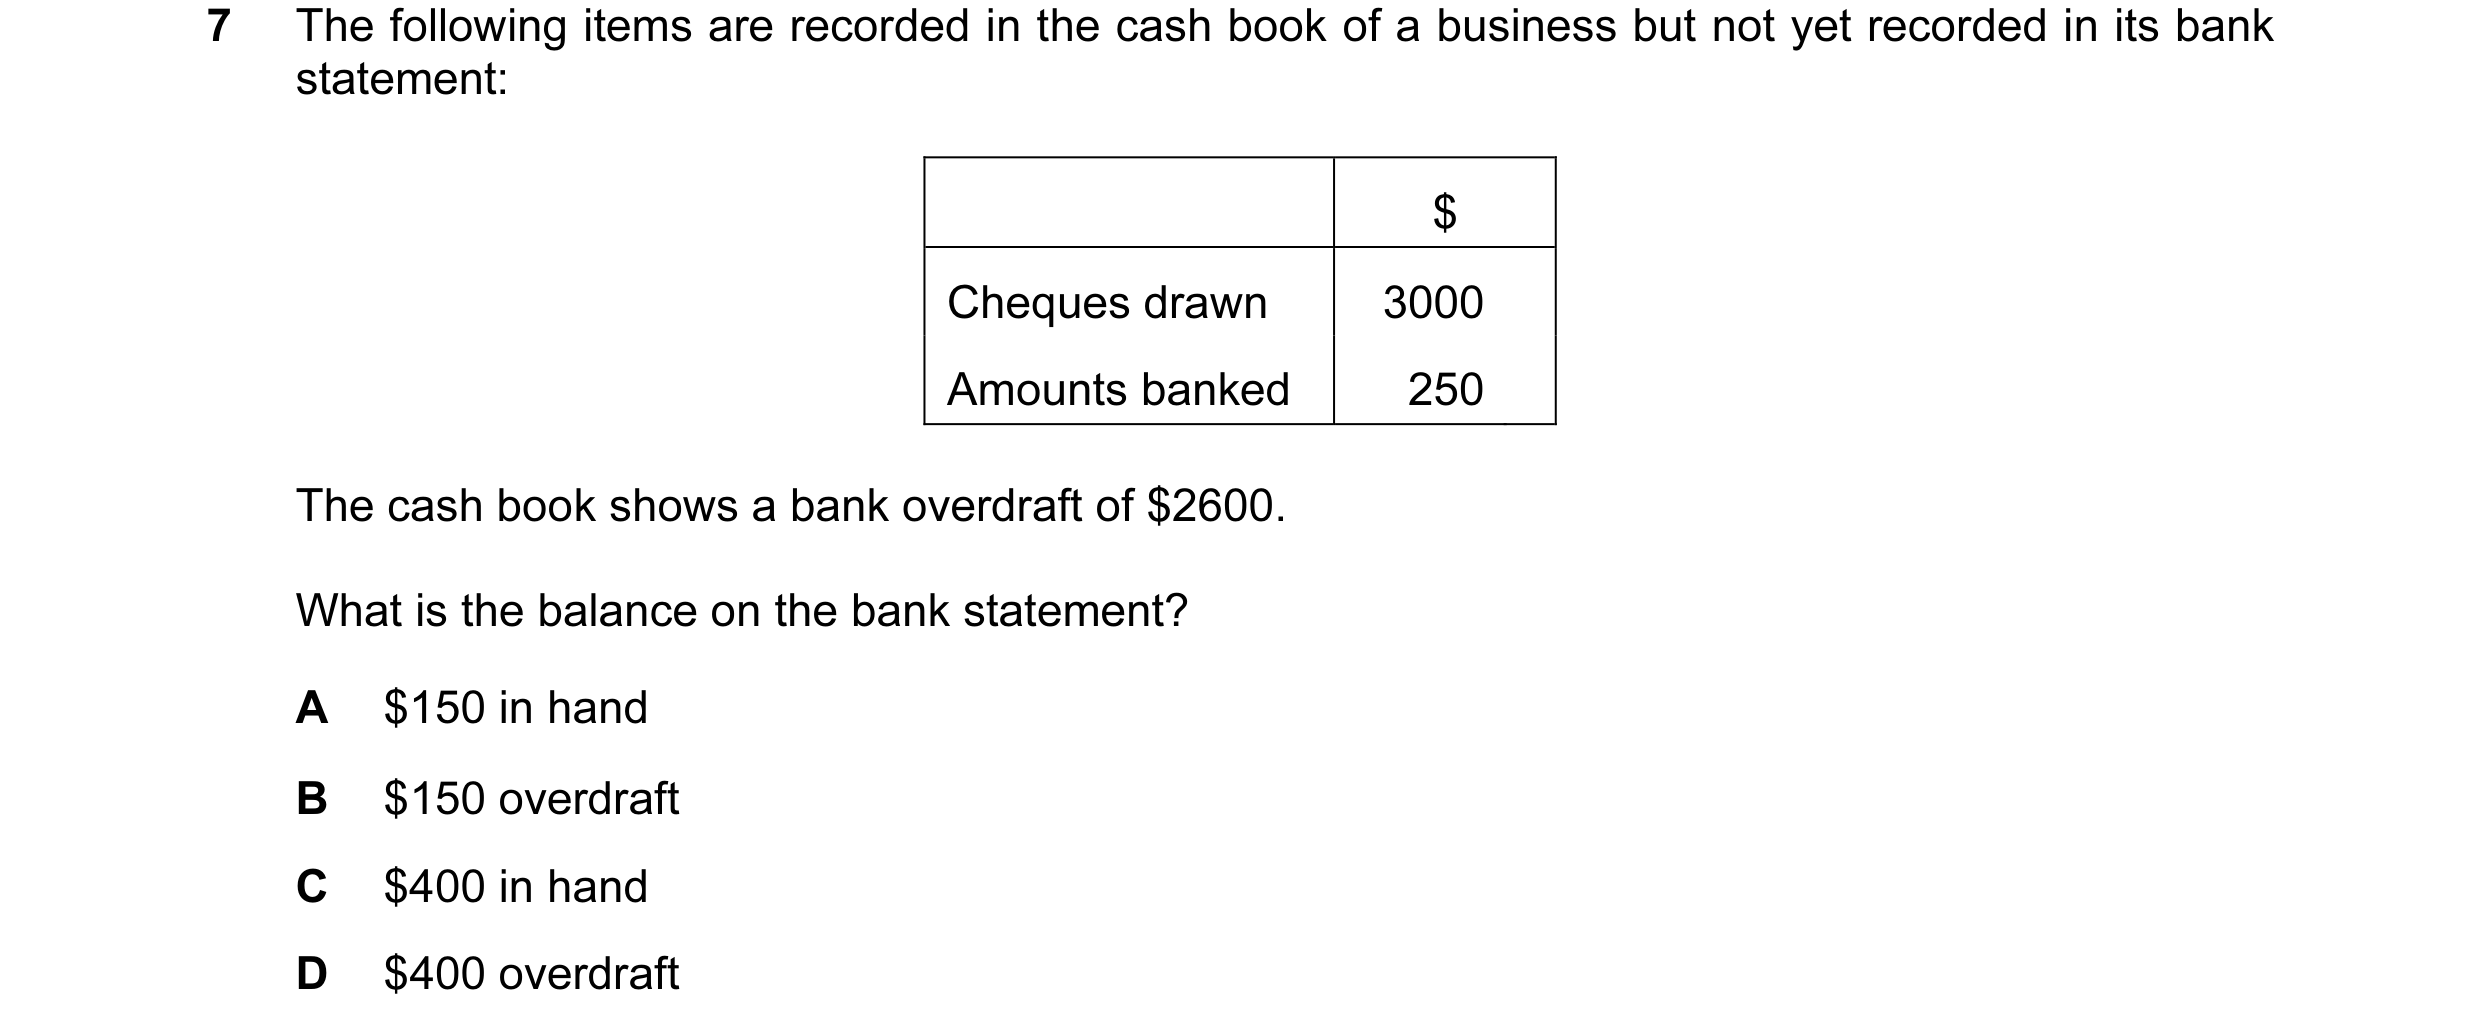
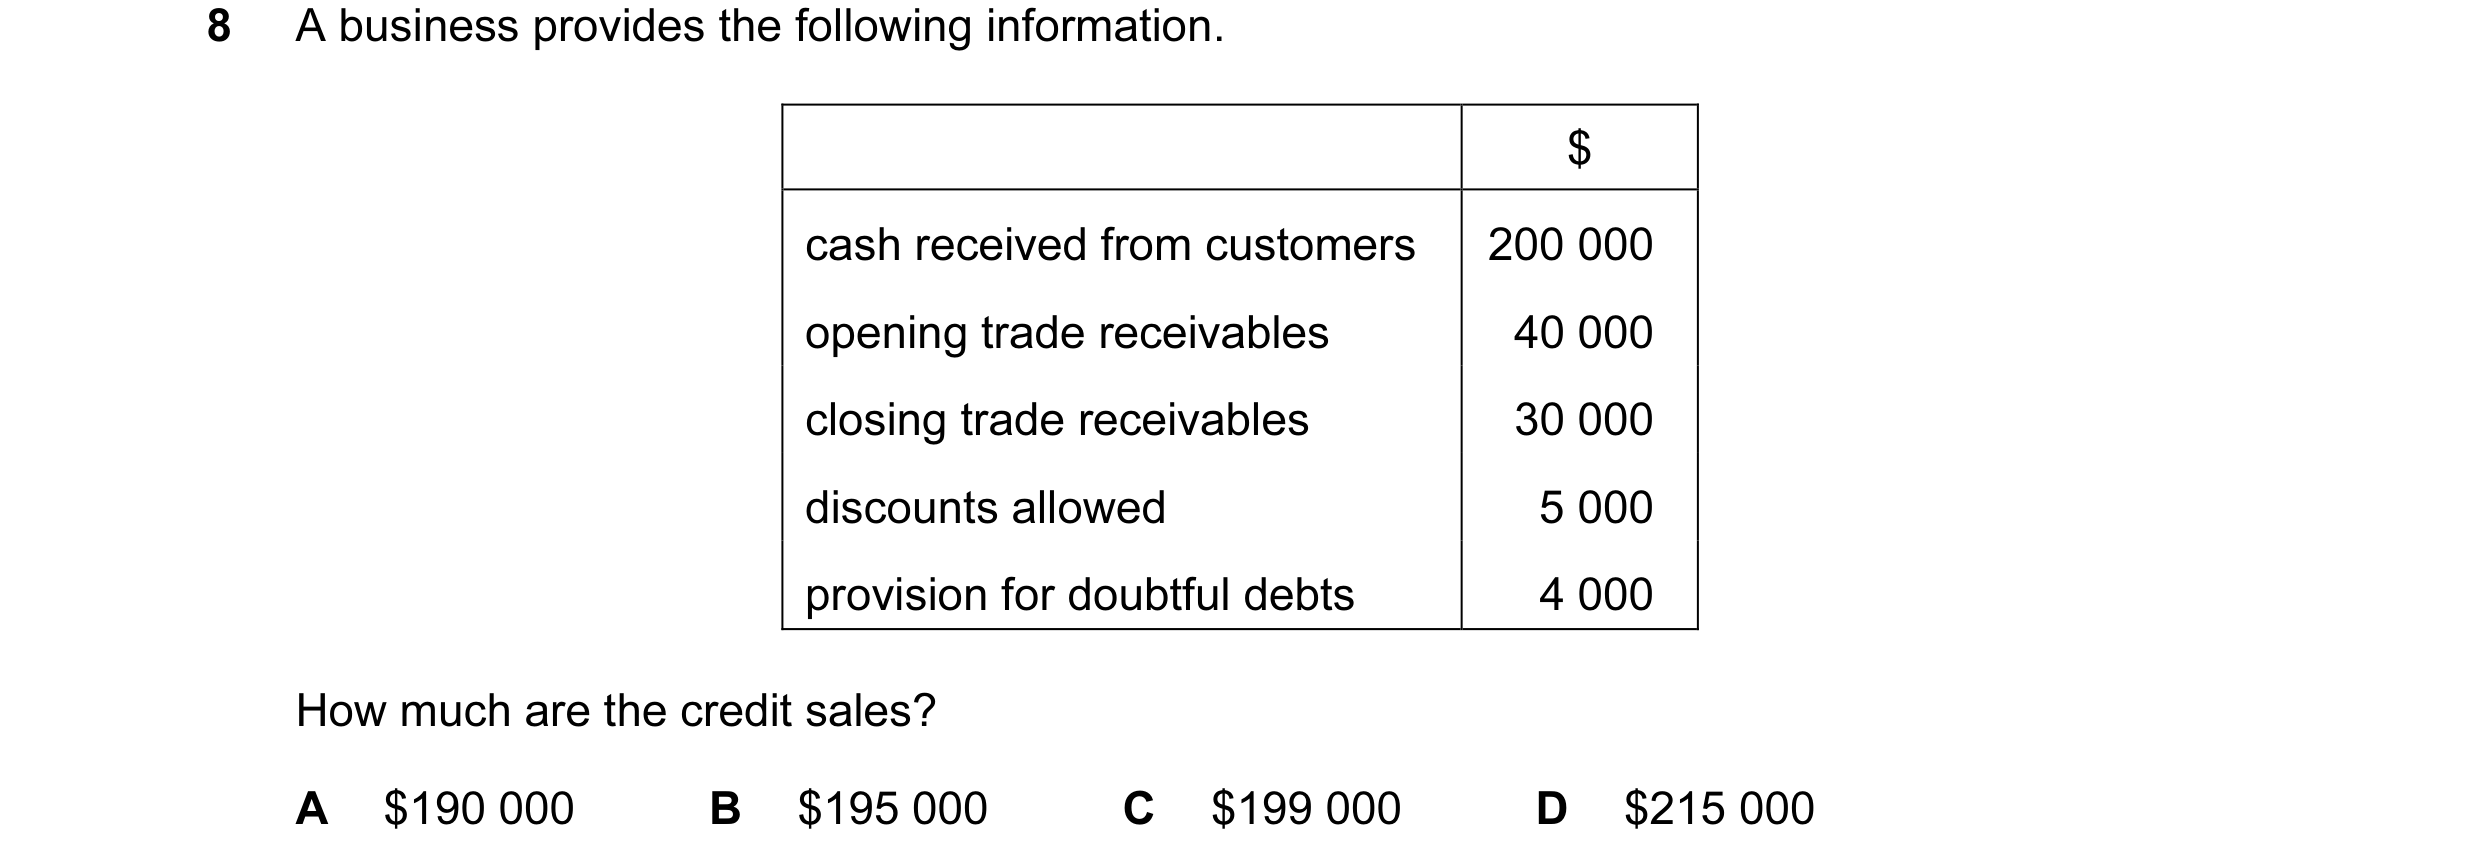
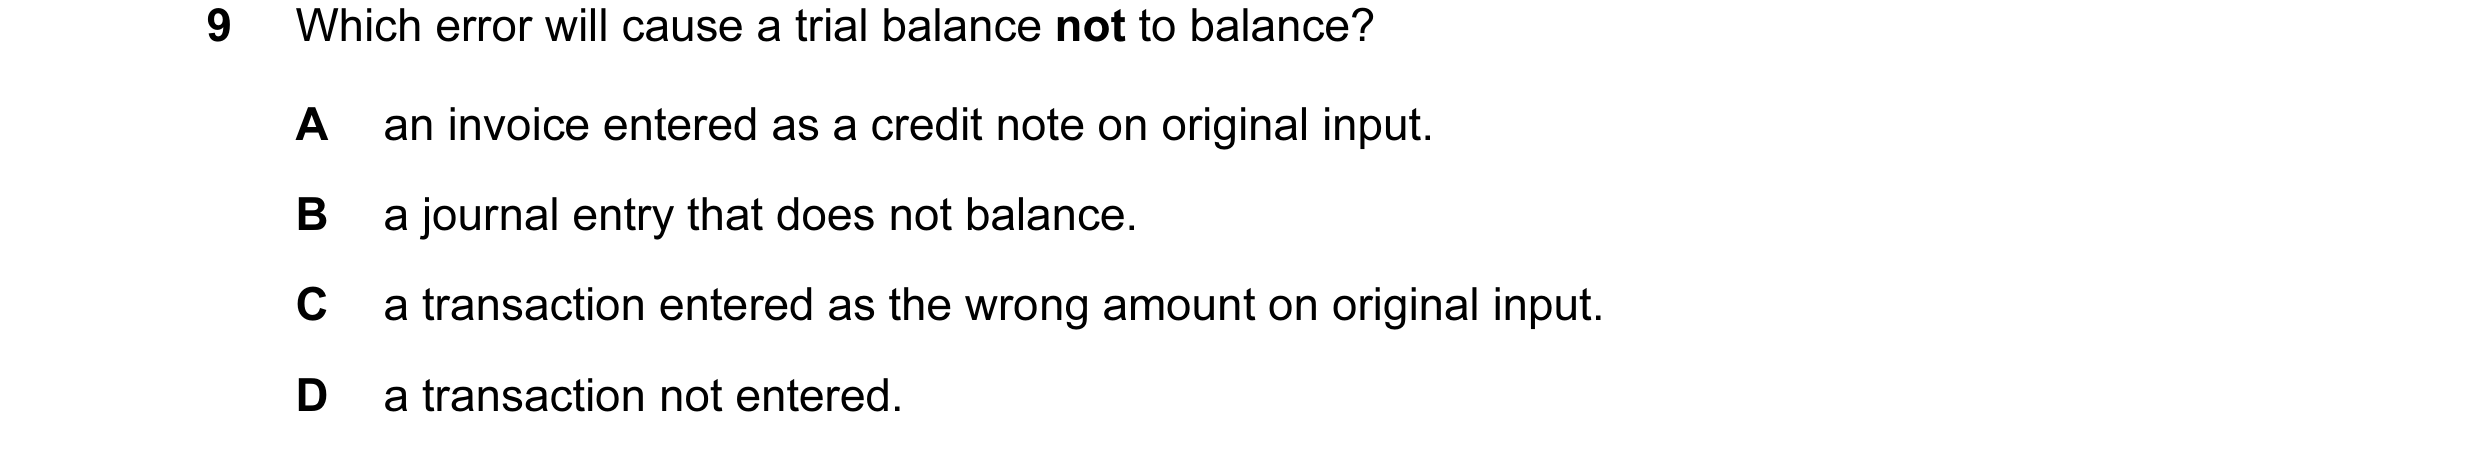
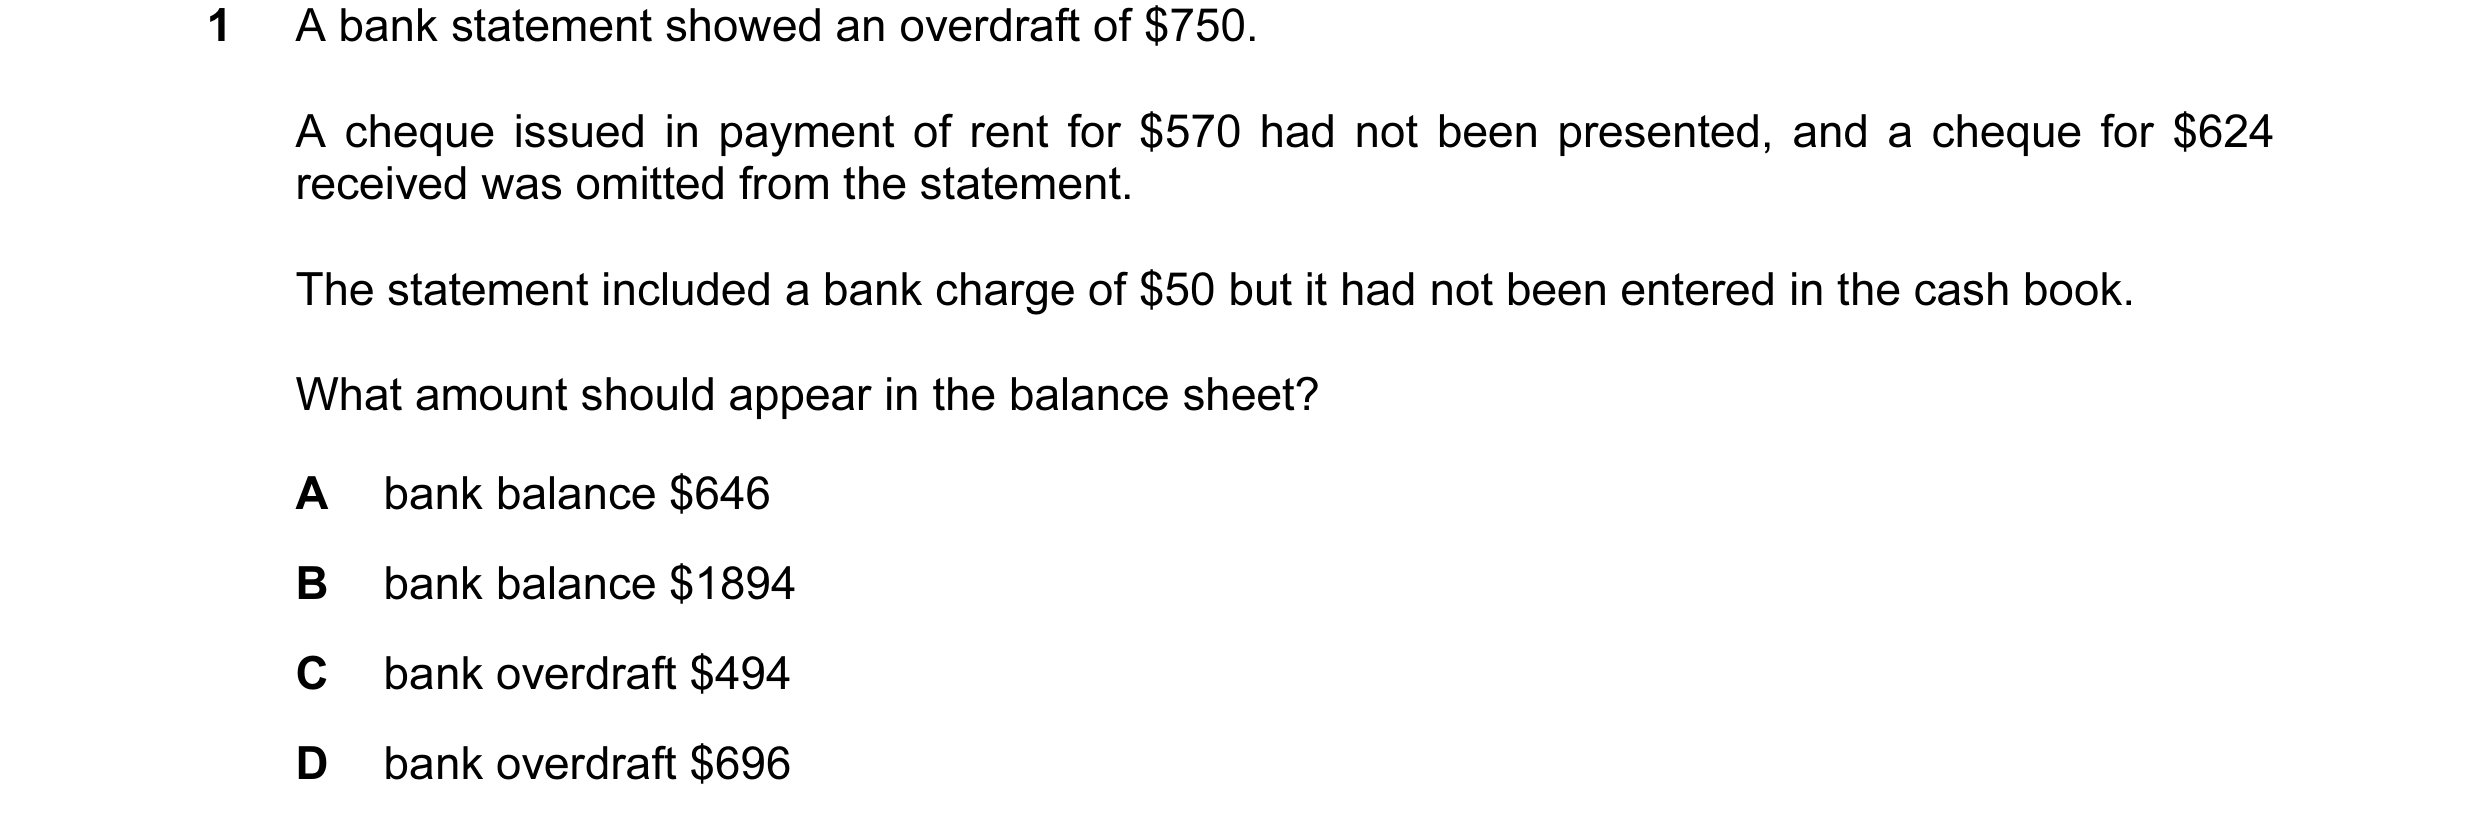 16 / 110
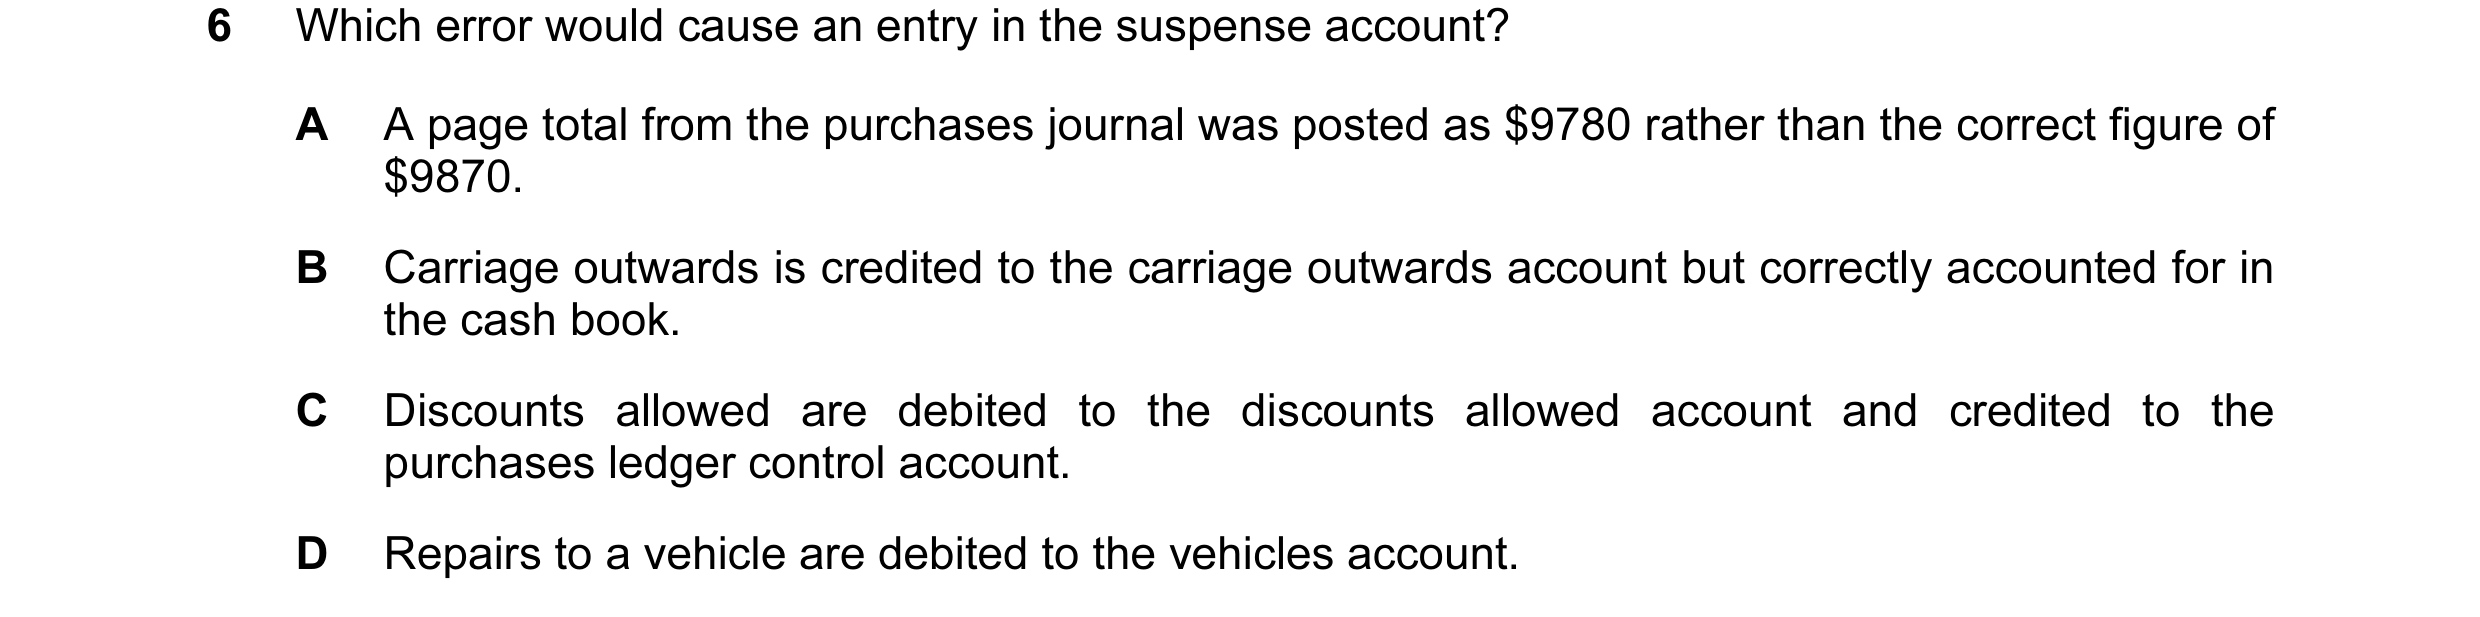
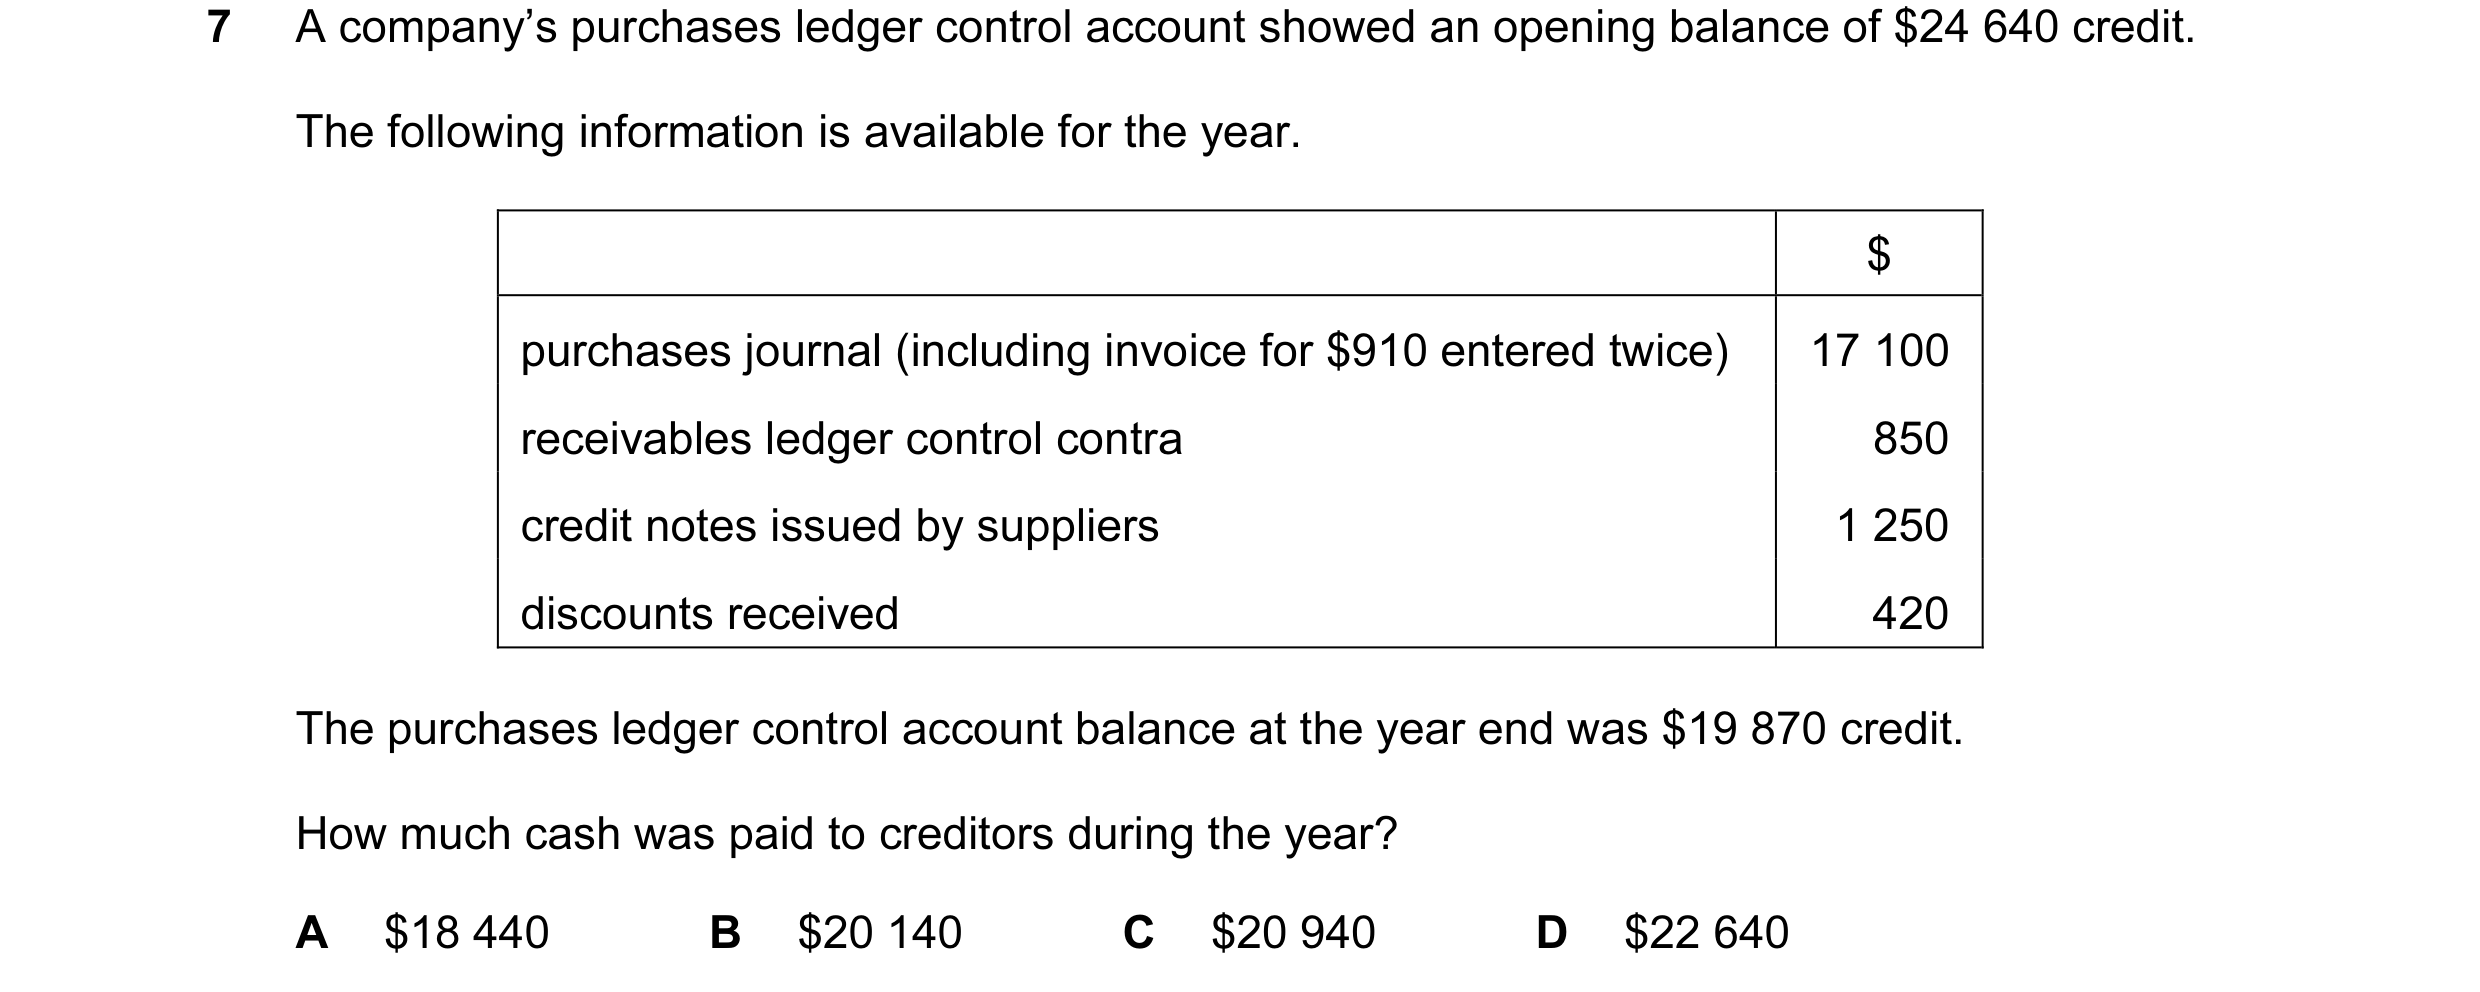
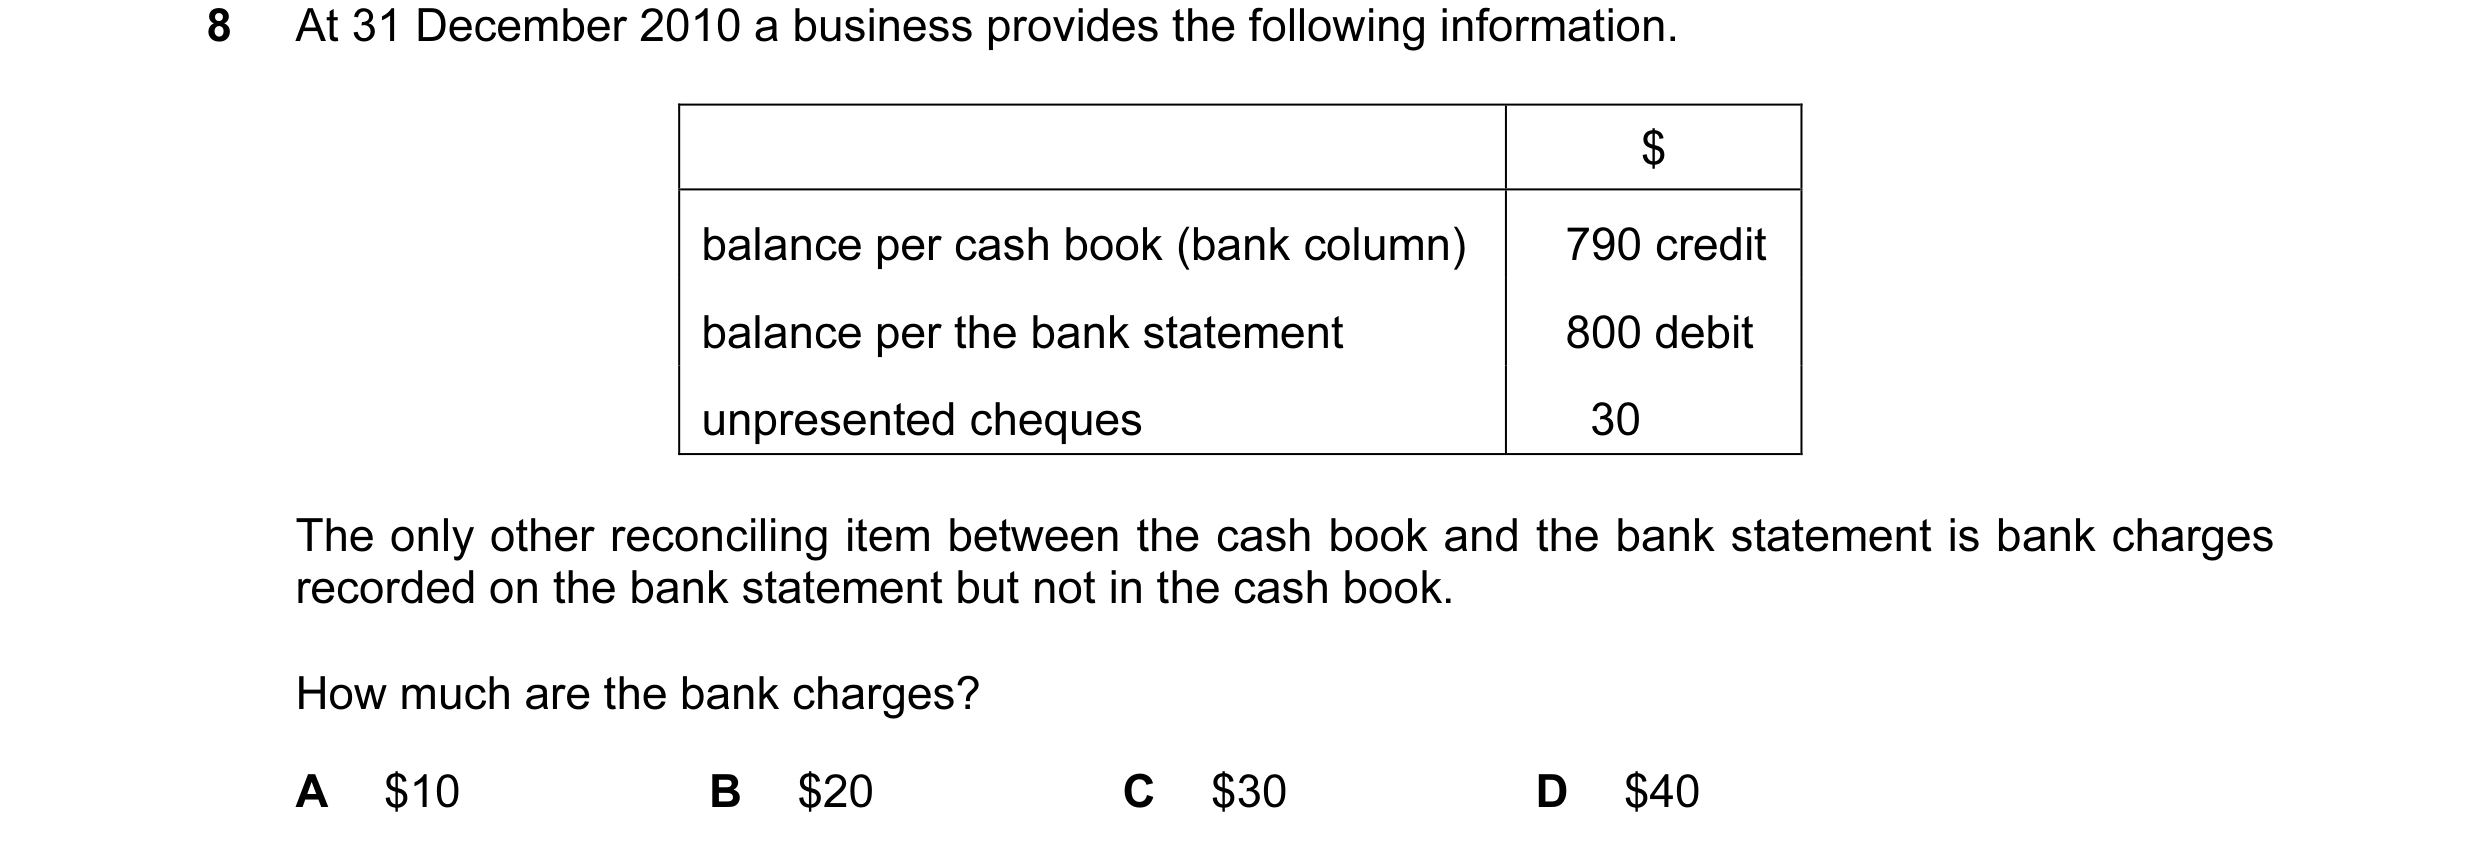
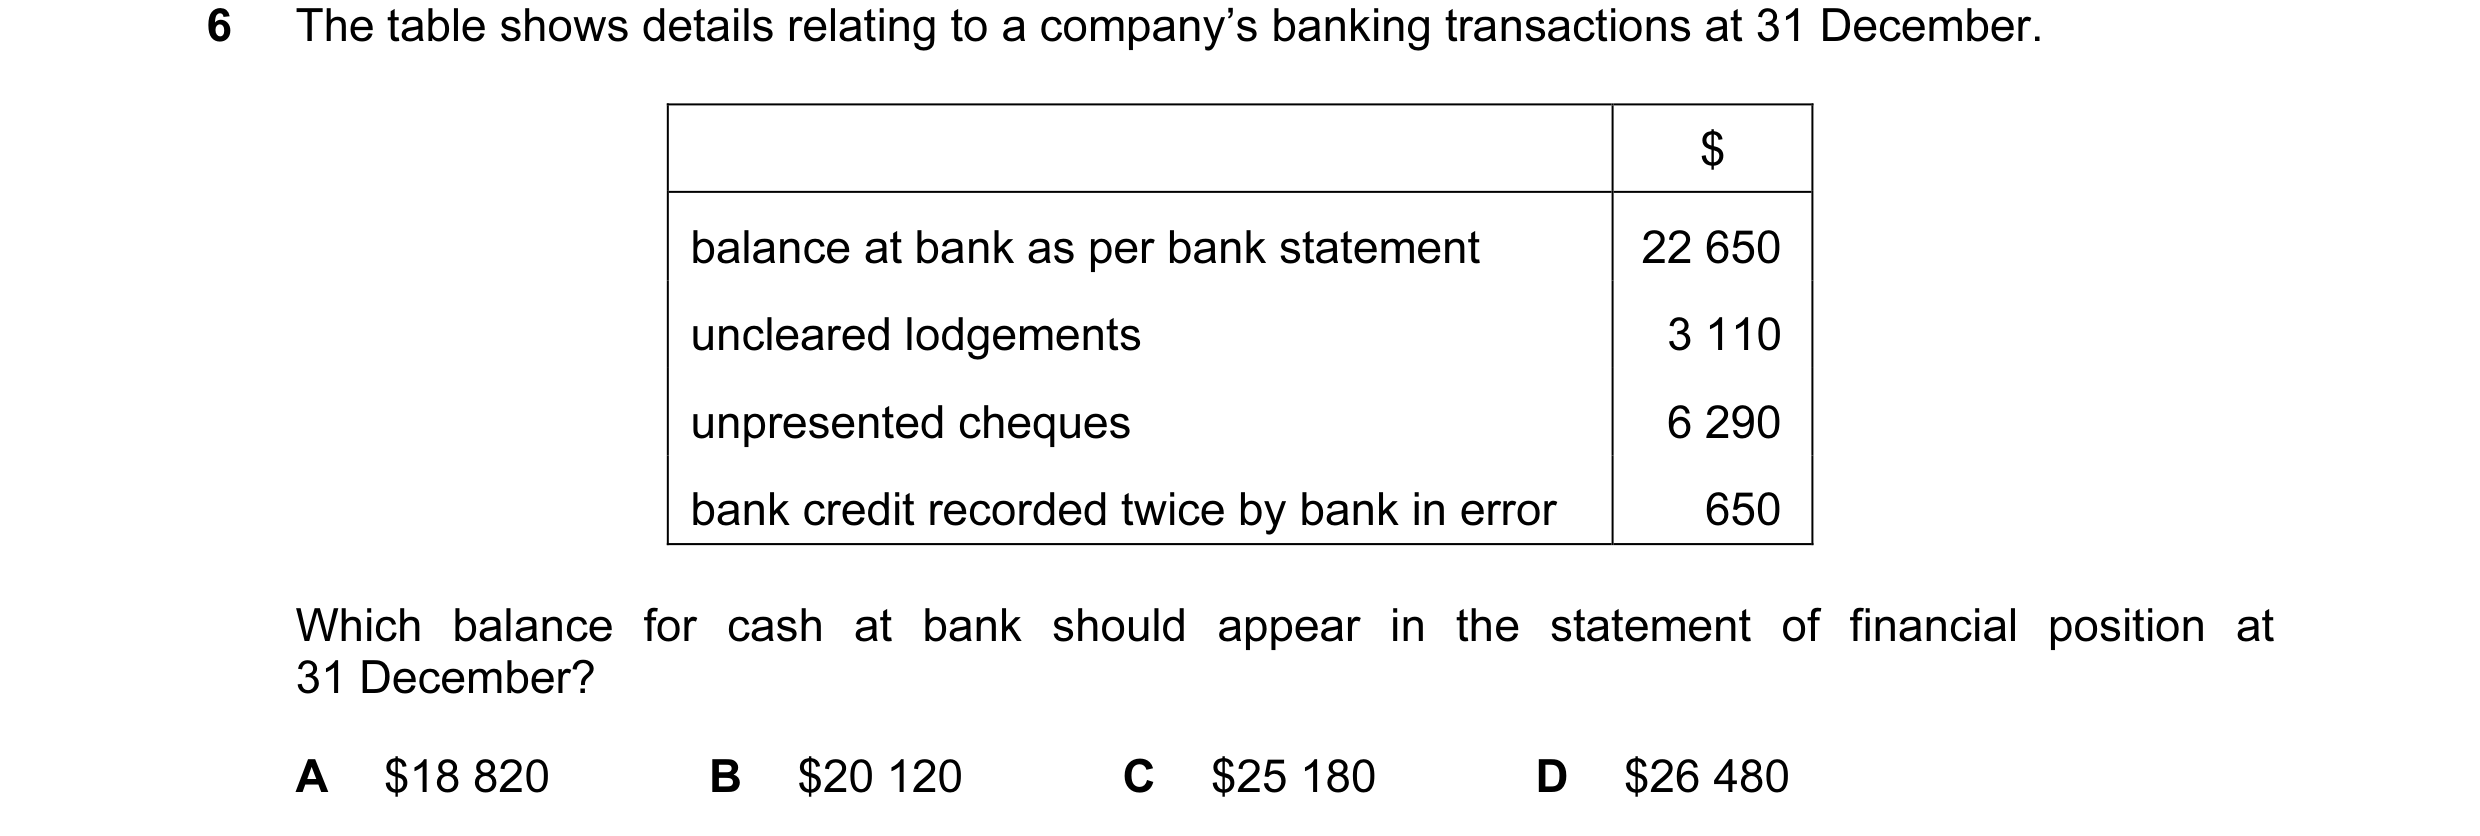 17 / 110
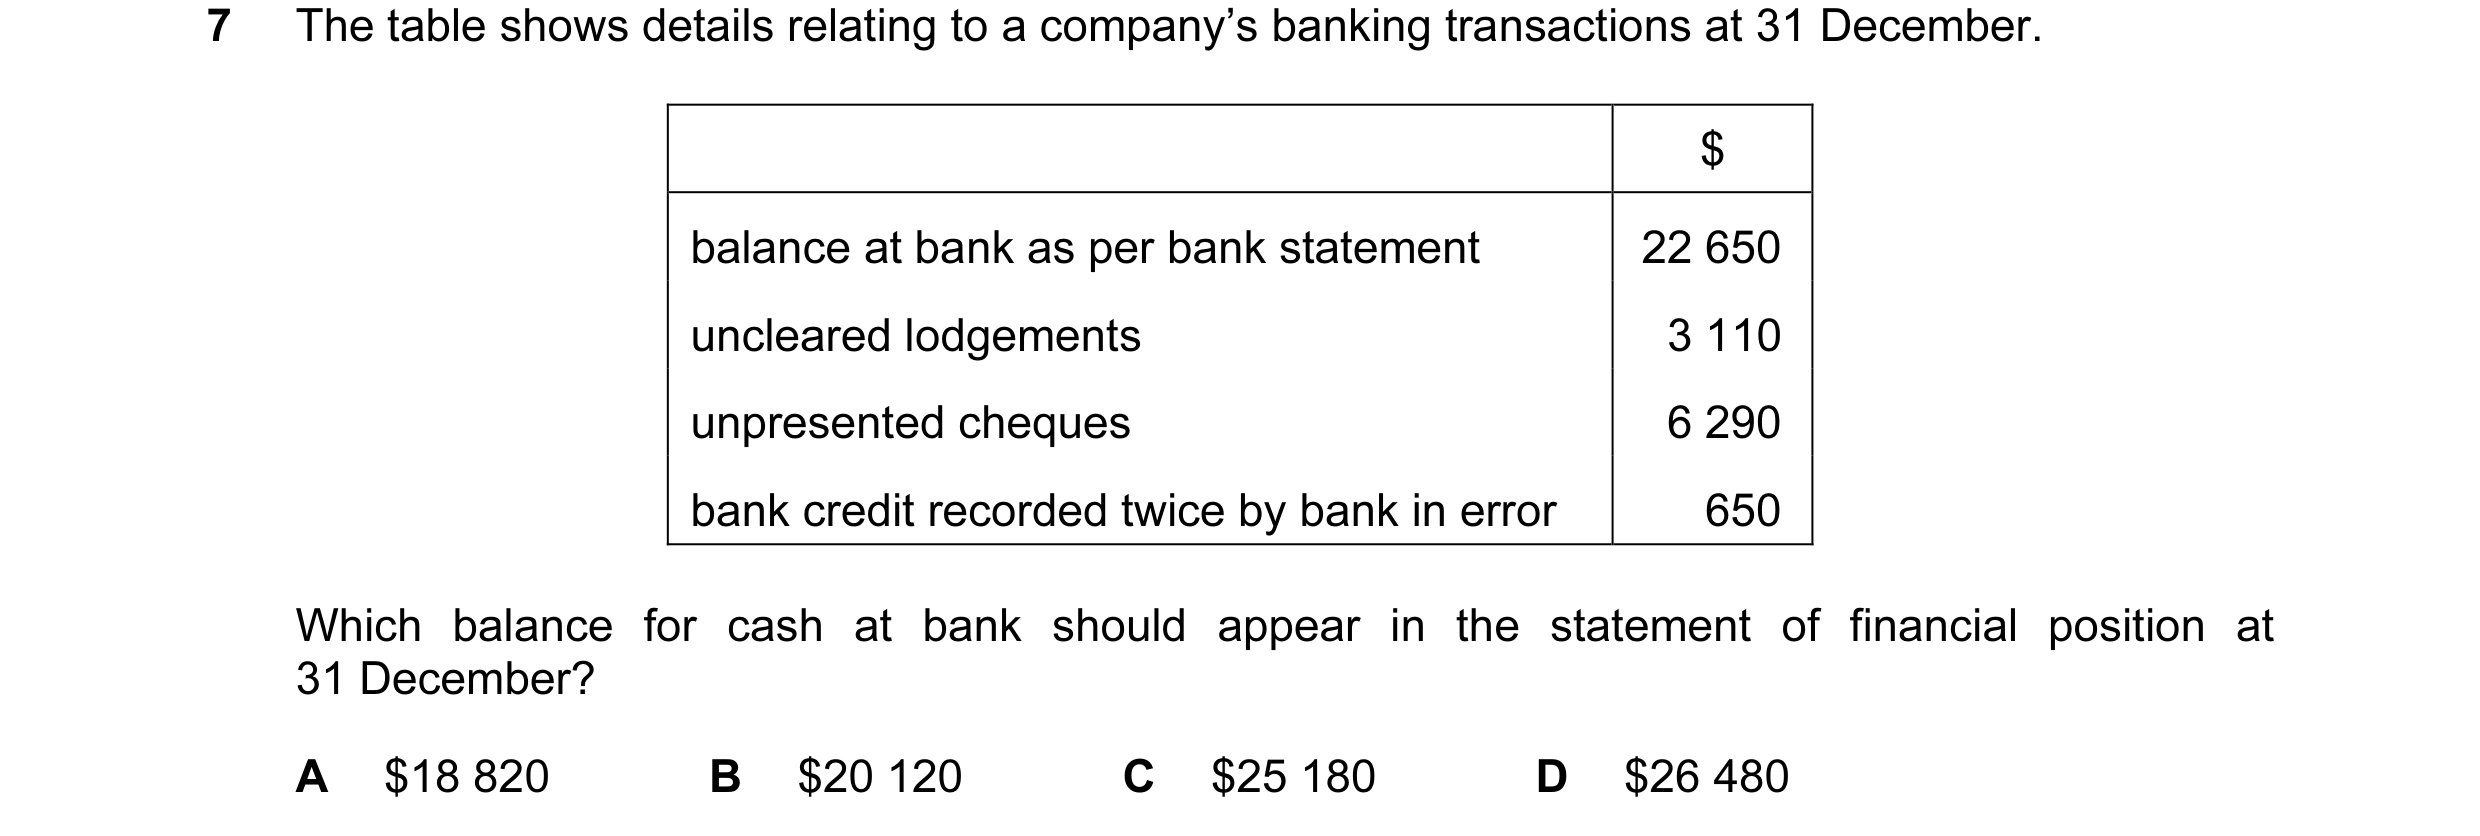
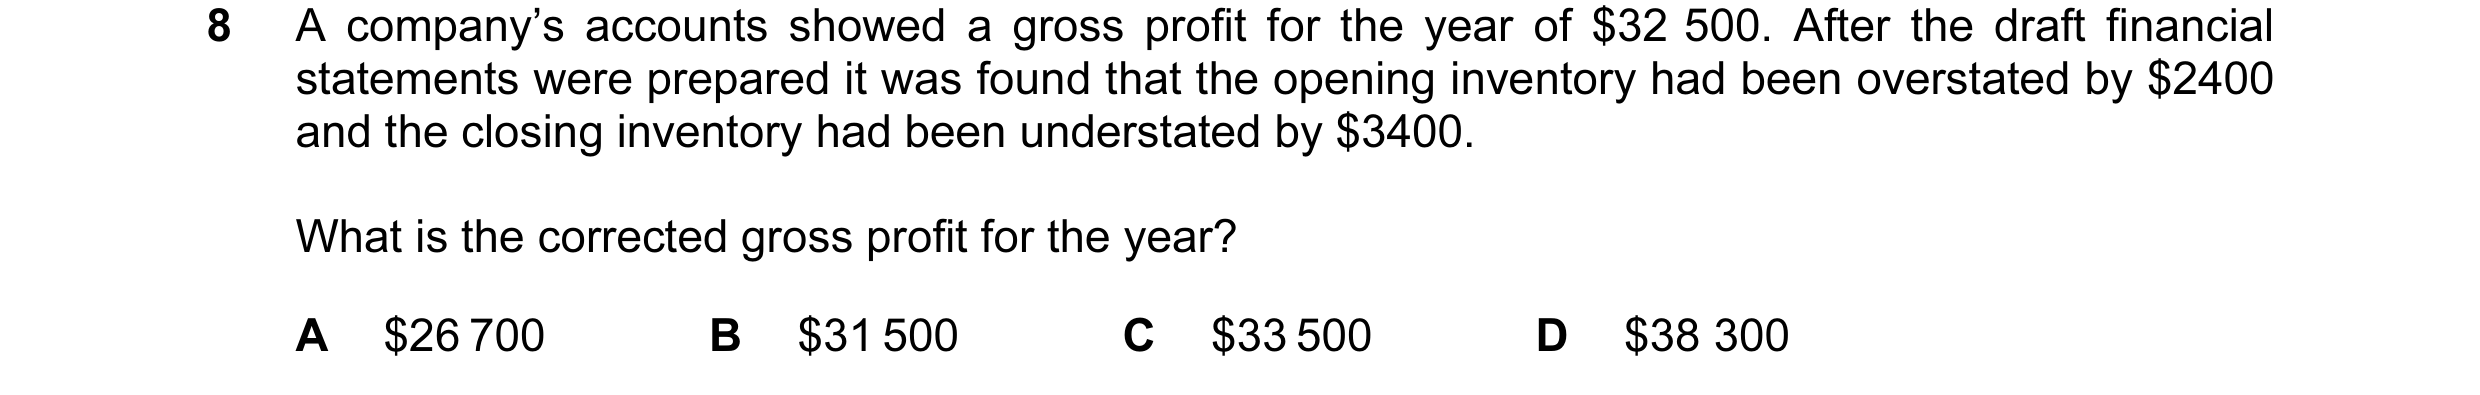
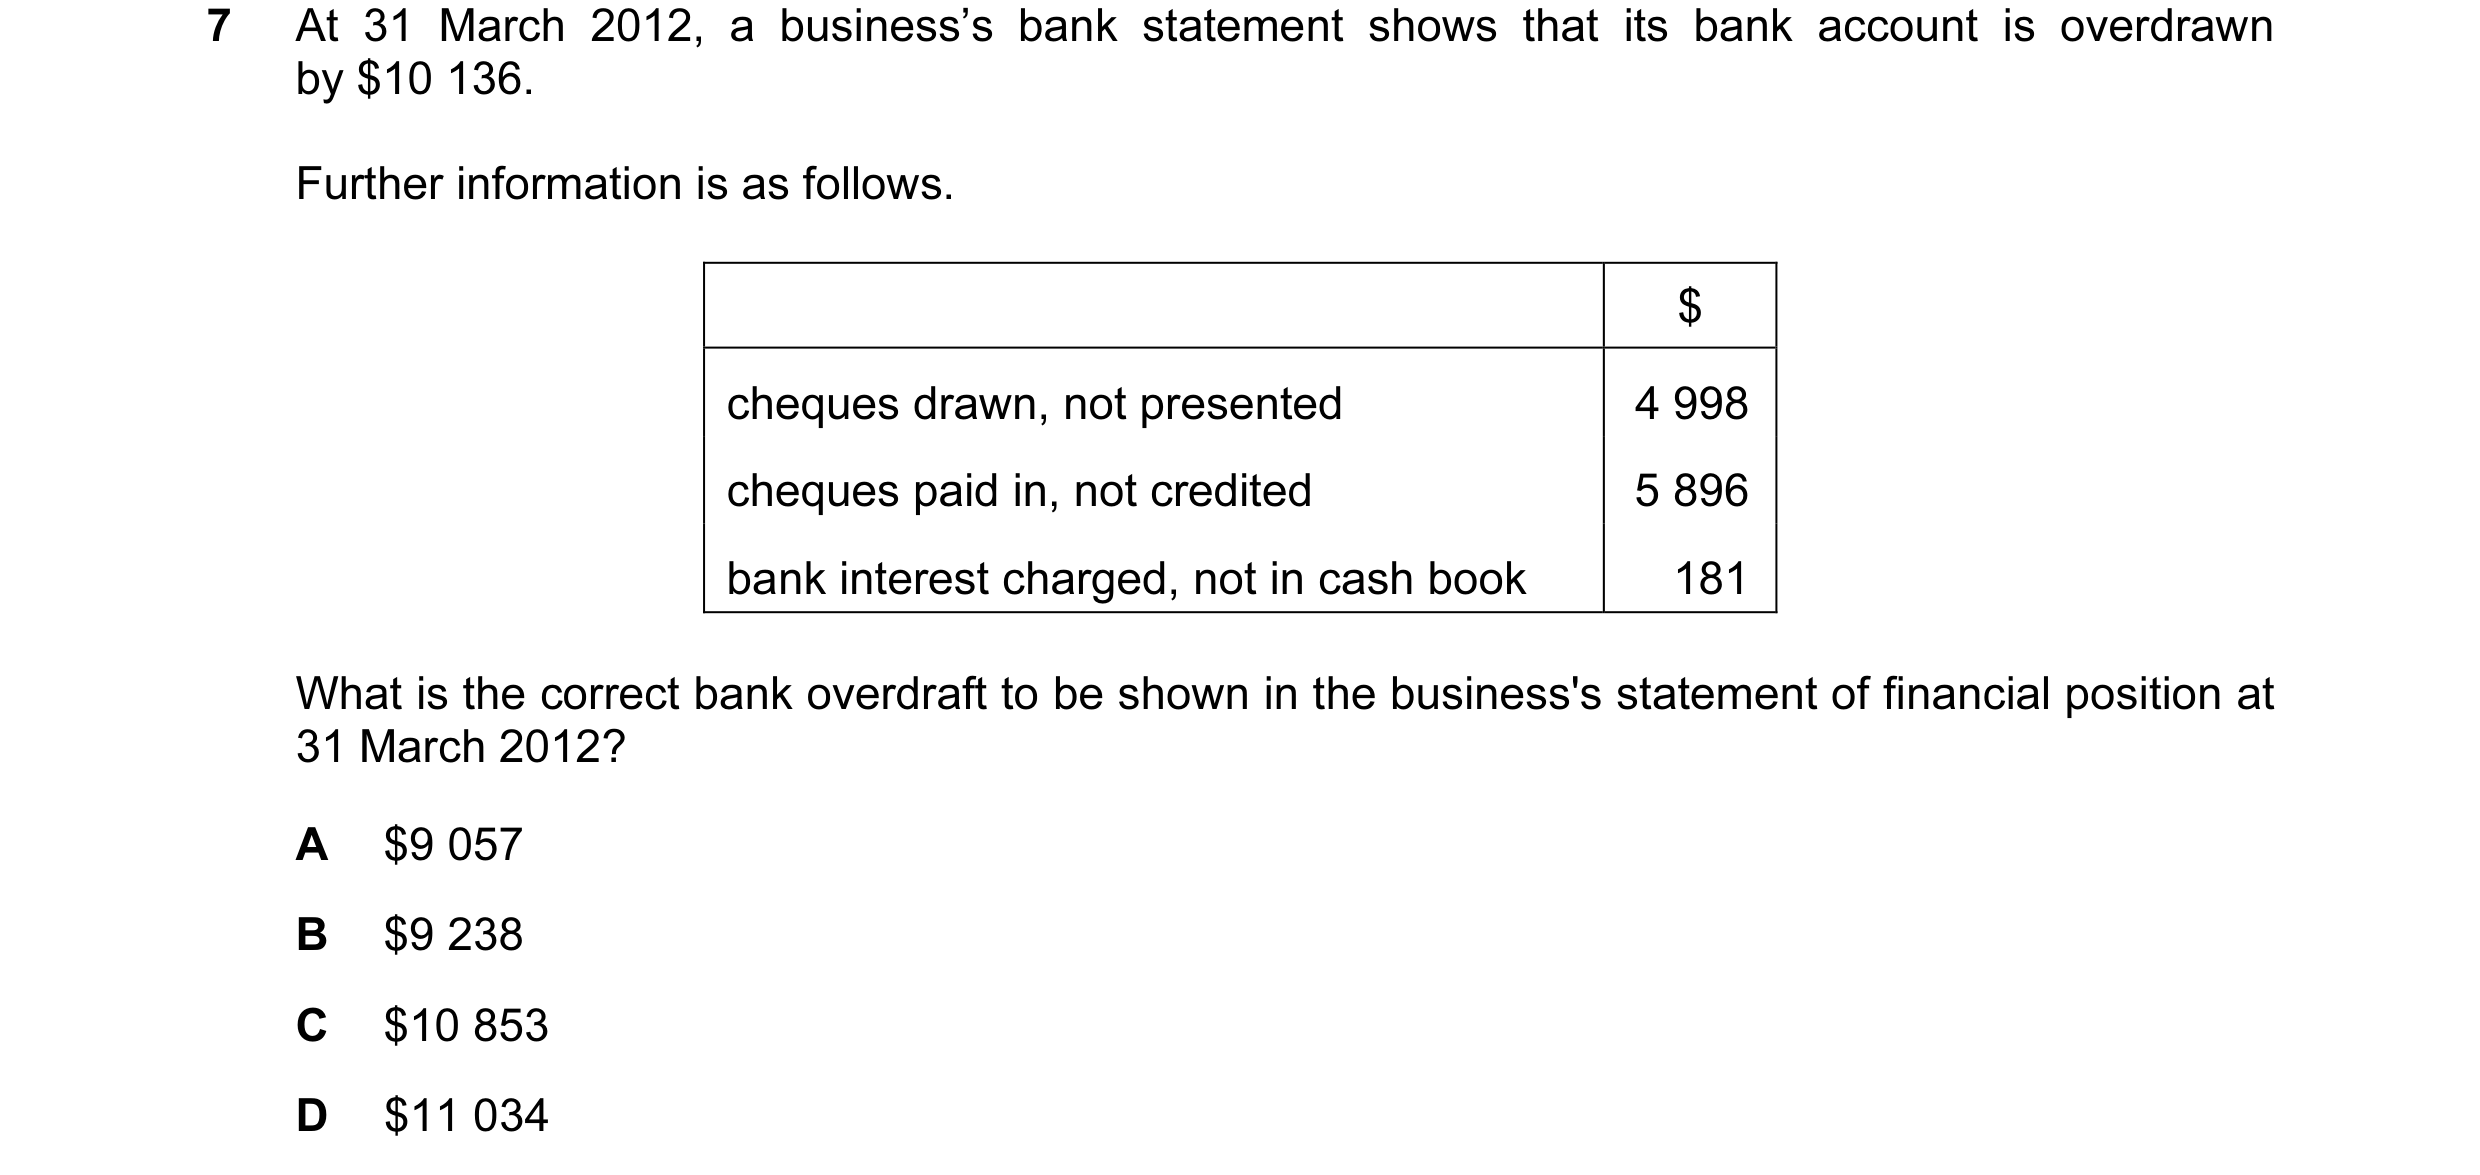
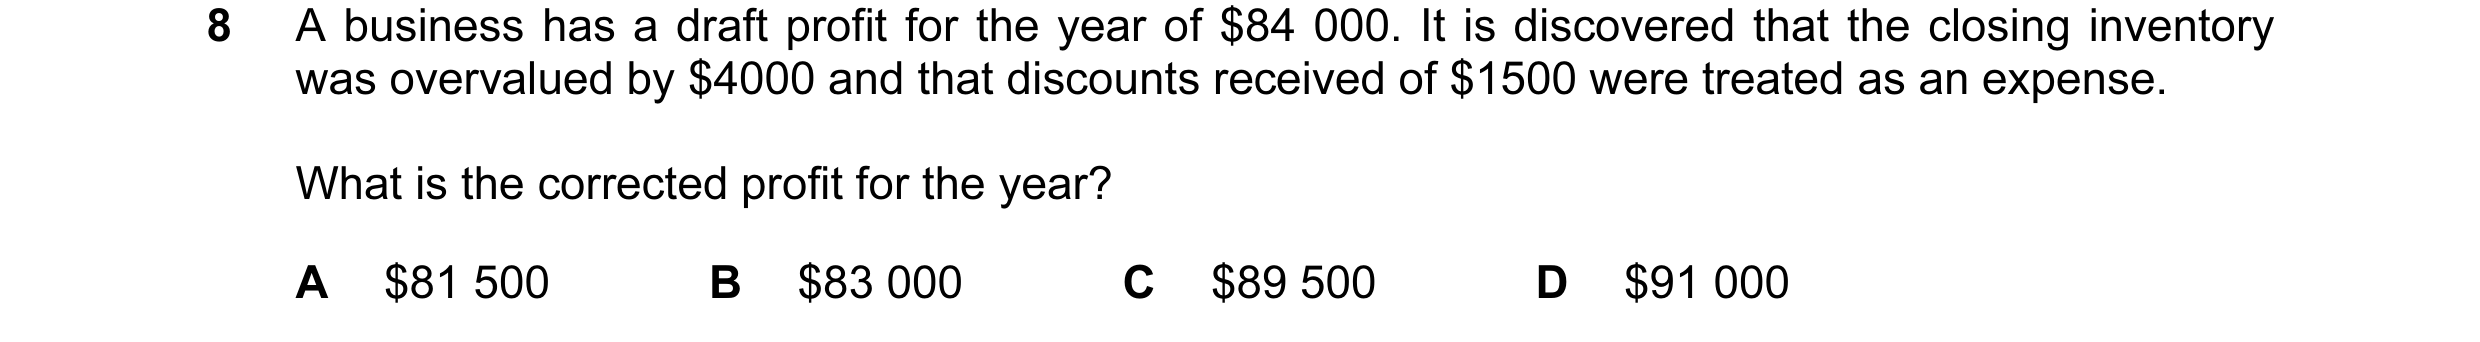 18 / 110
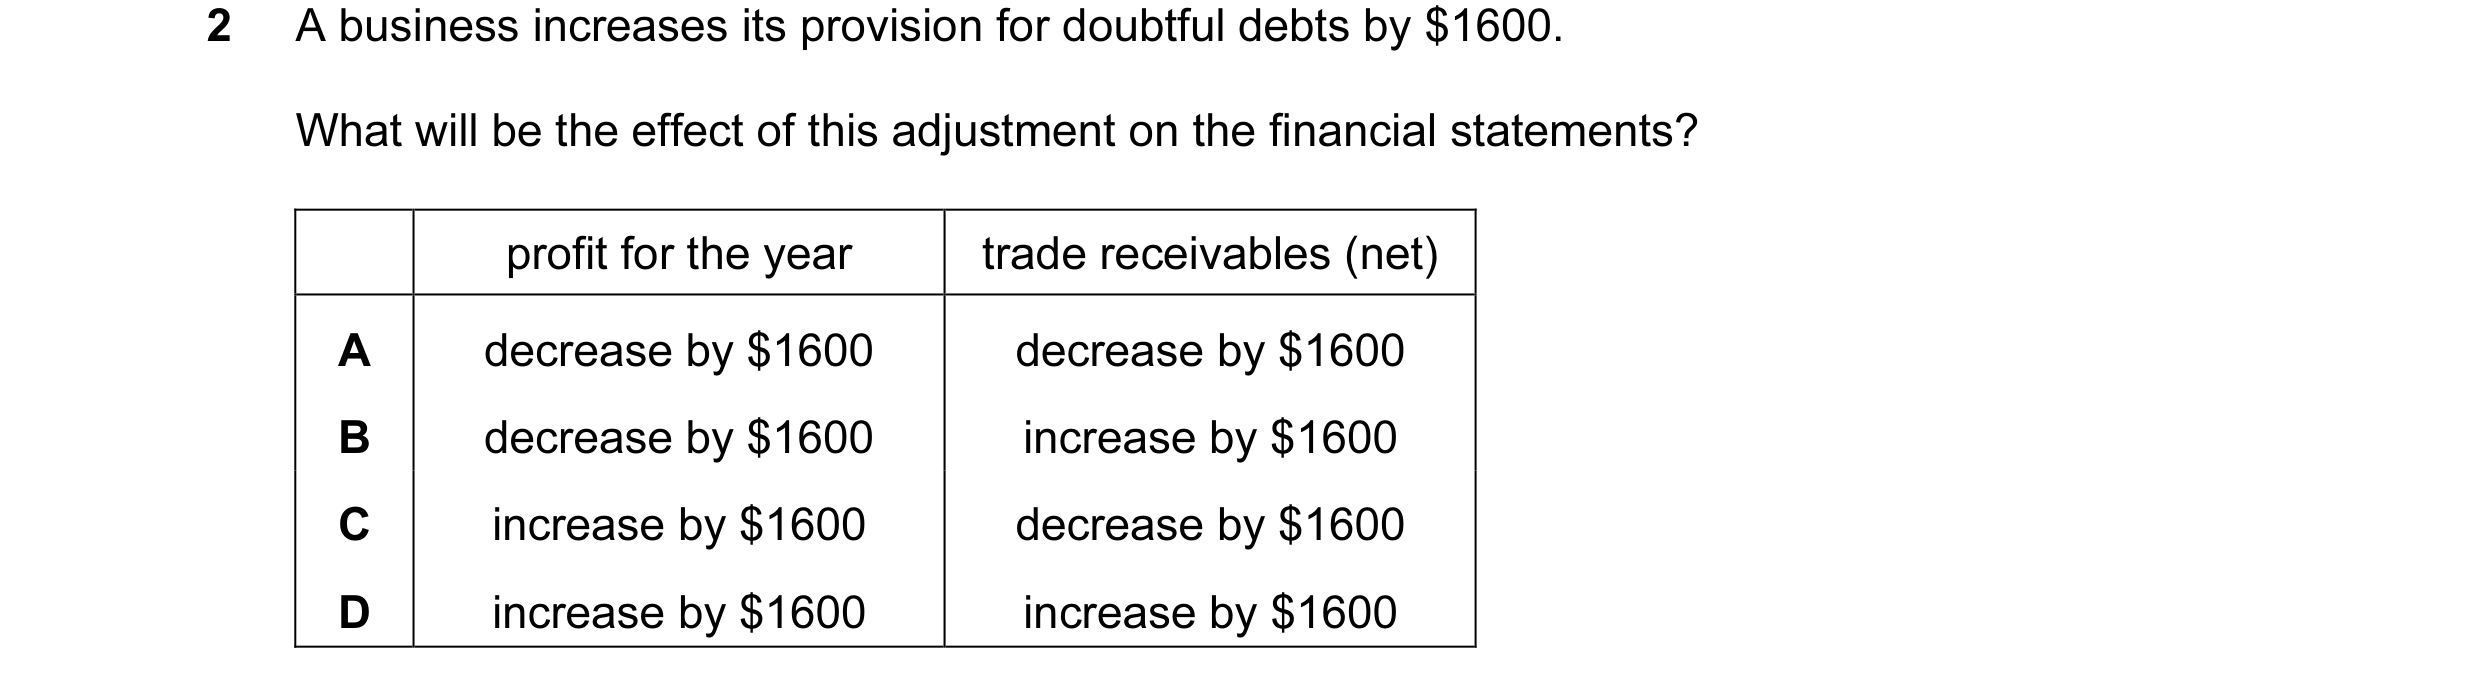
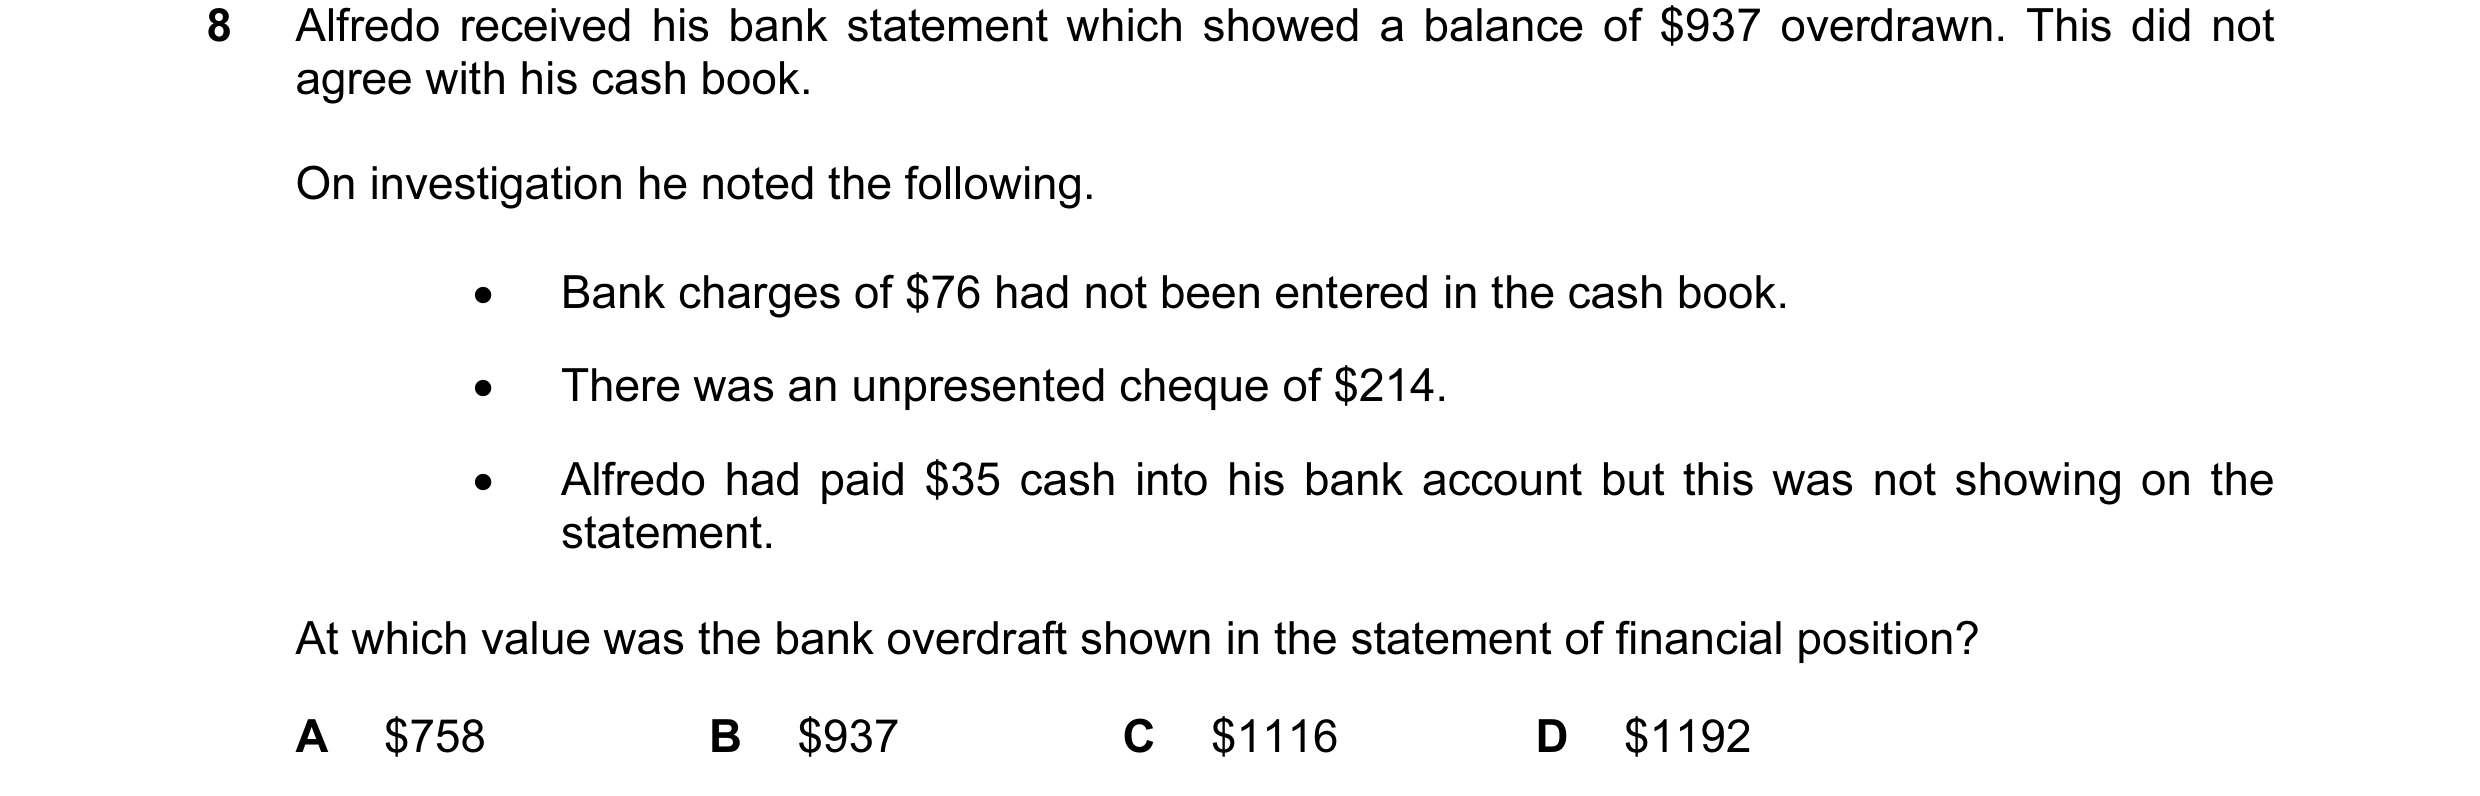
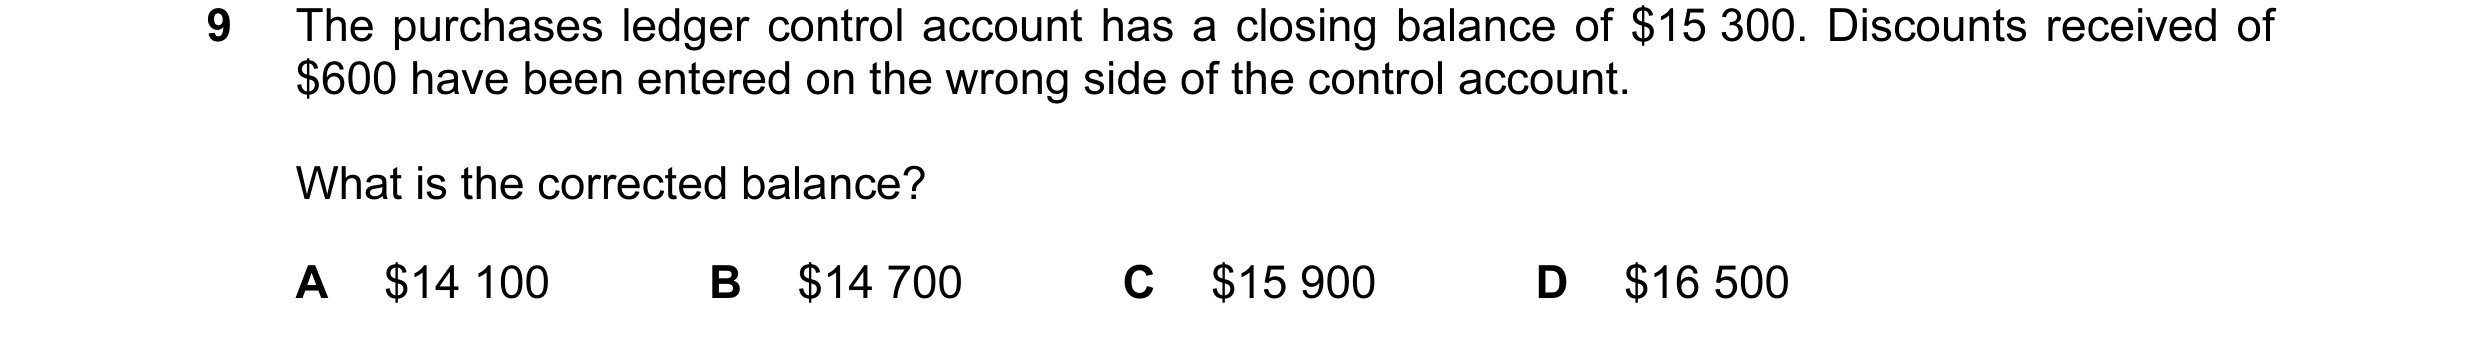
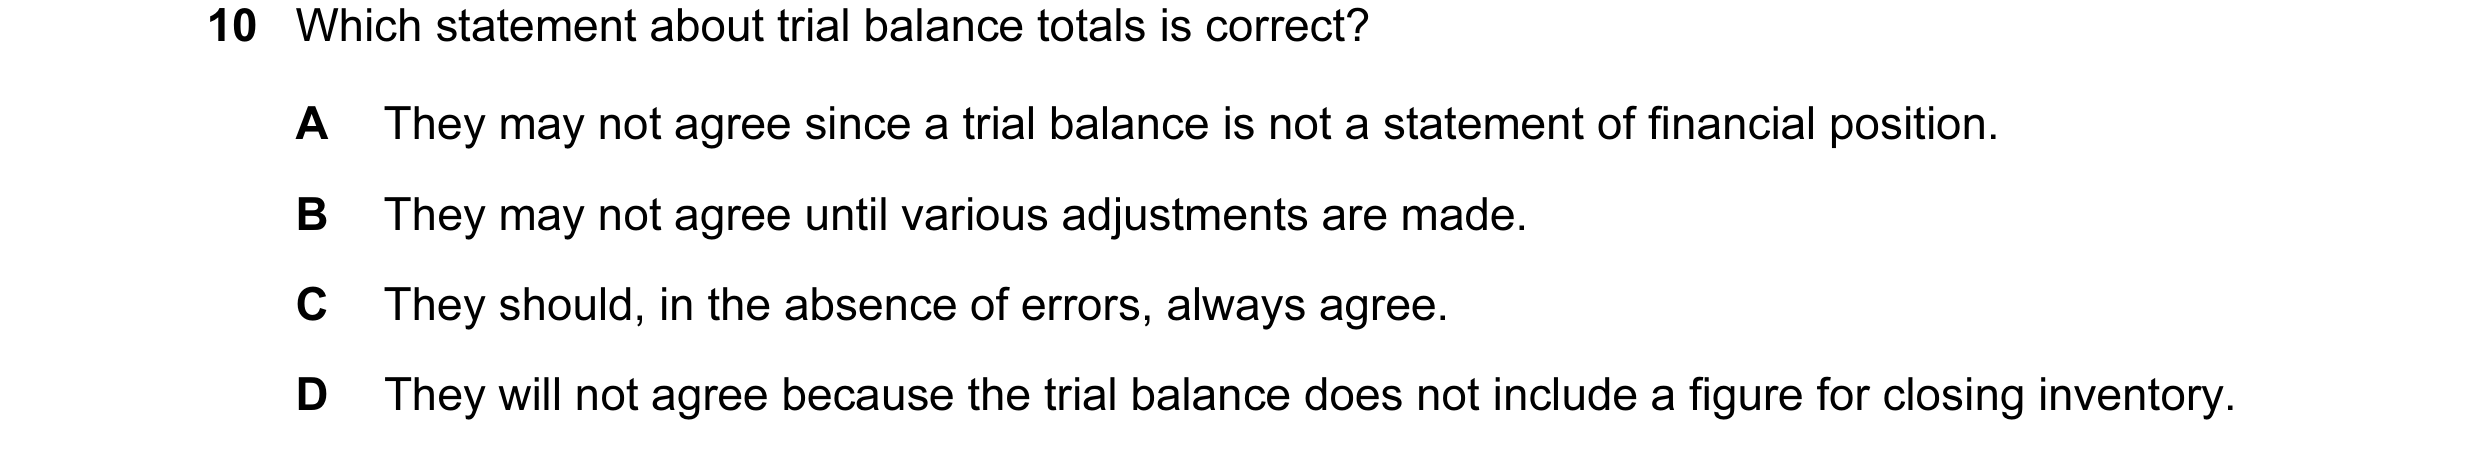
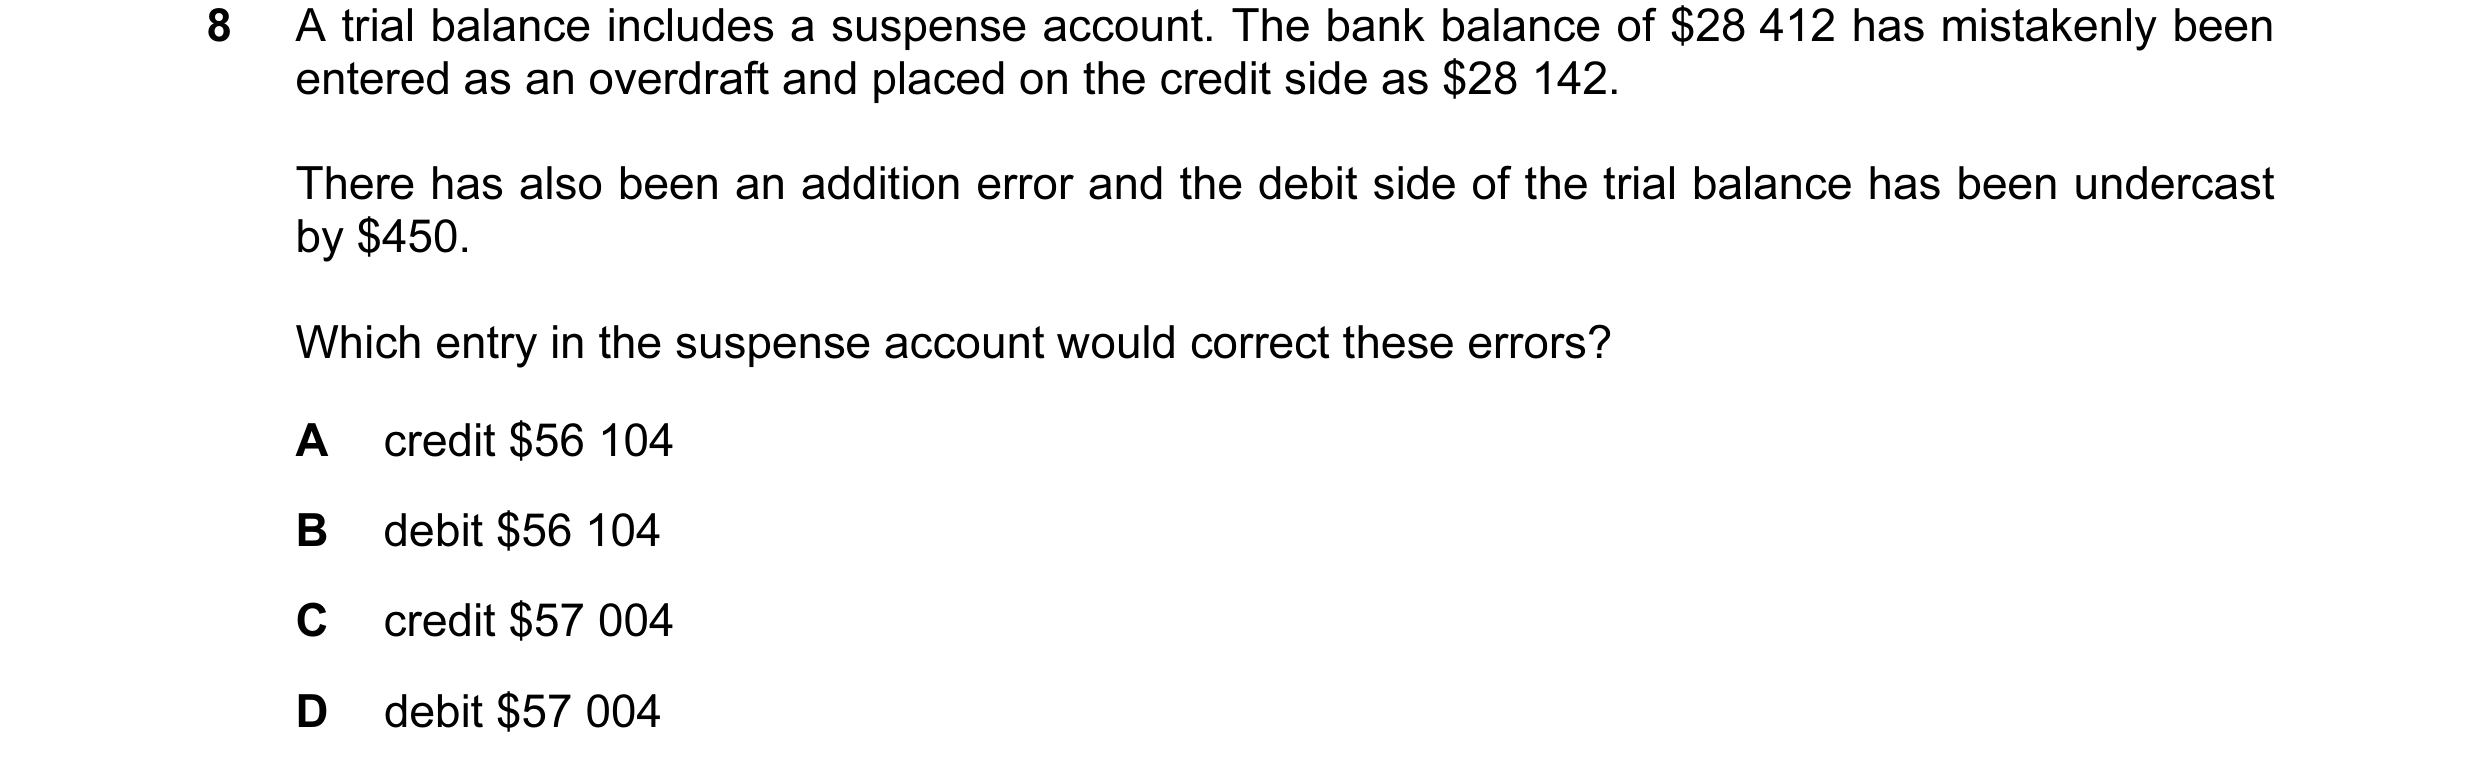 19 / 110
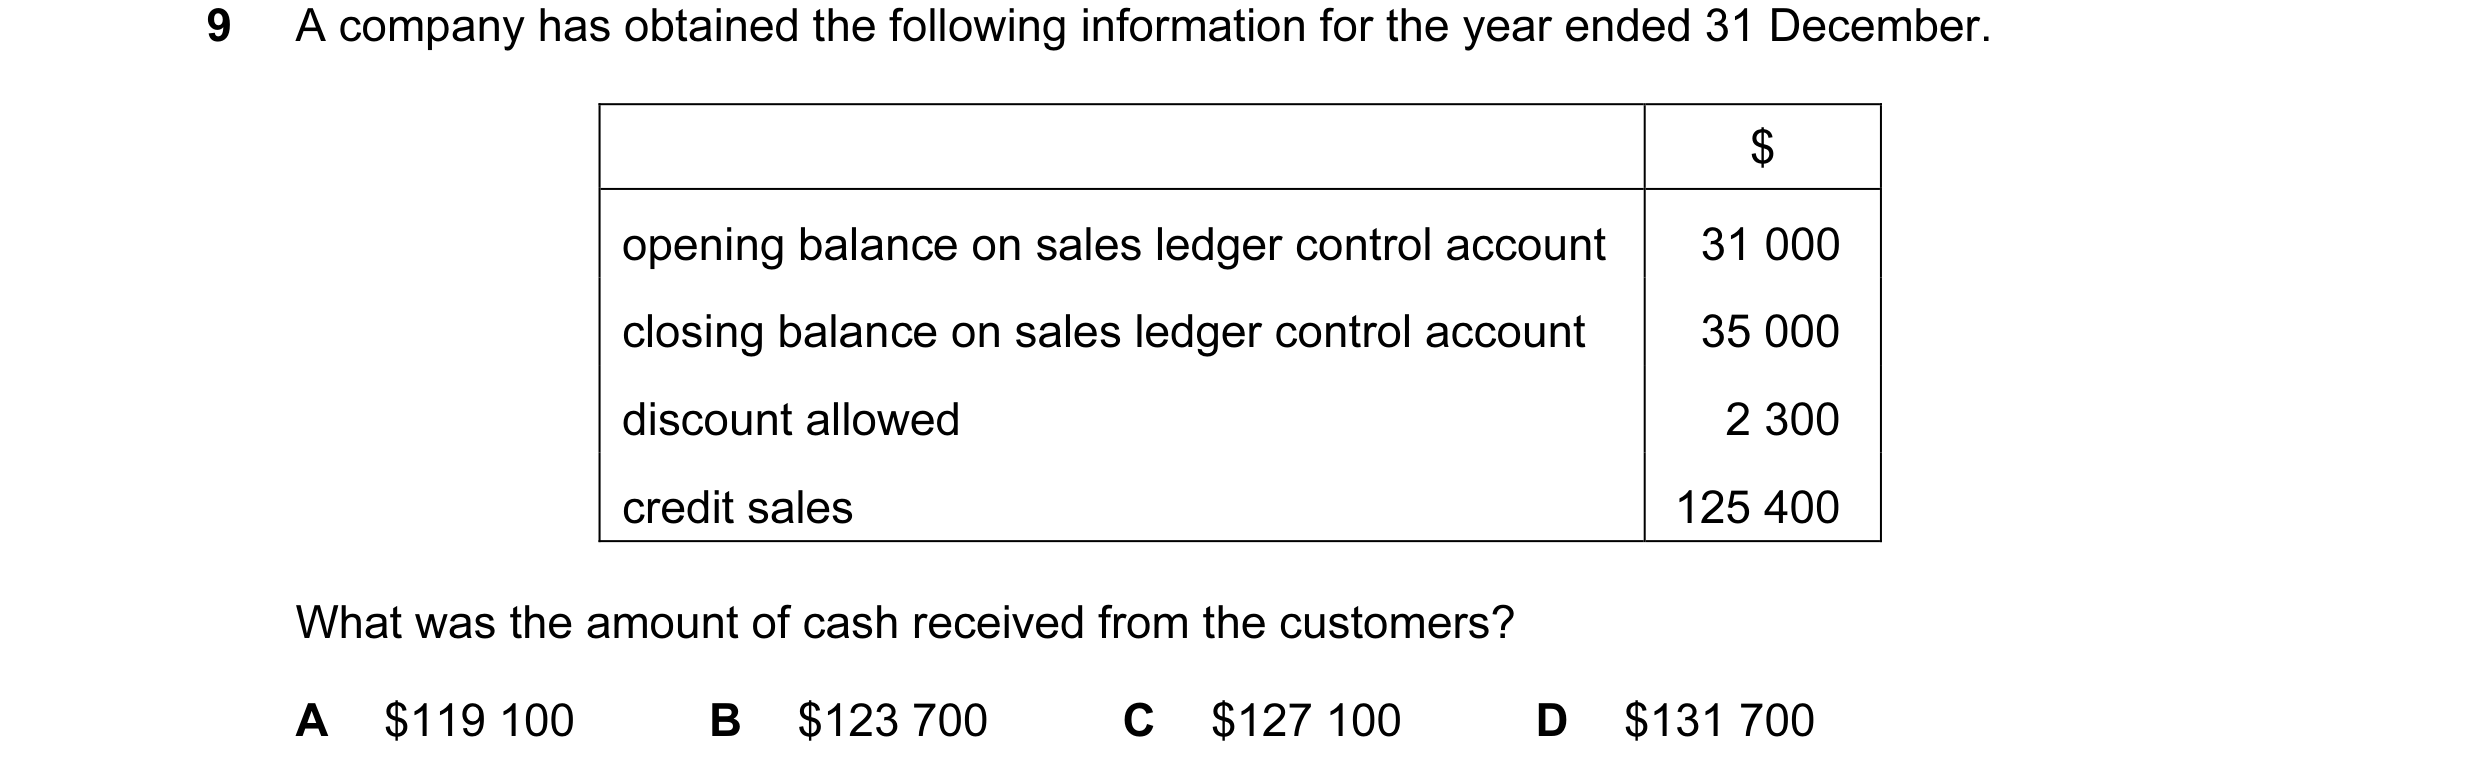
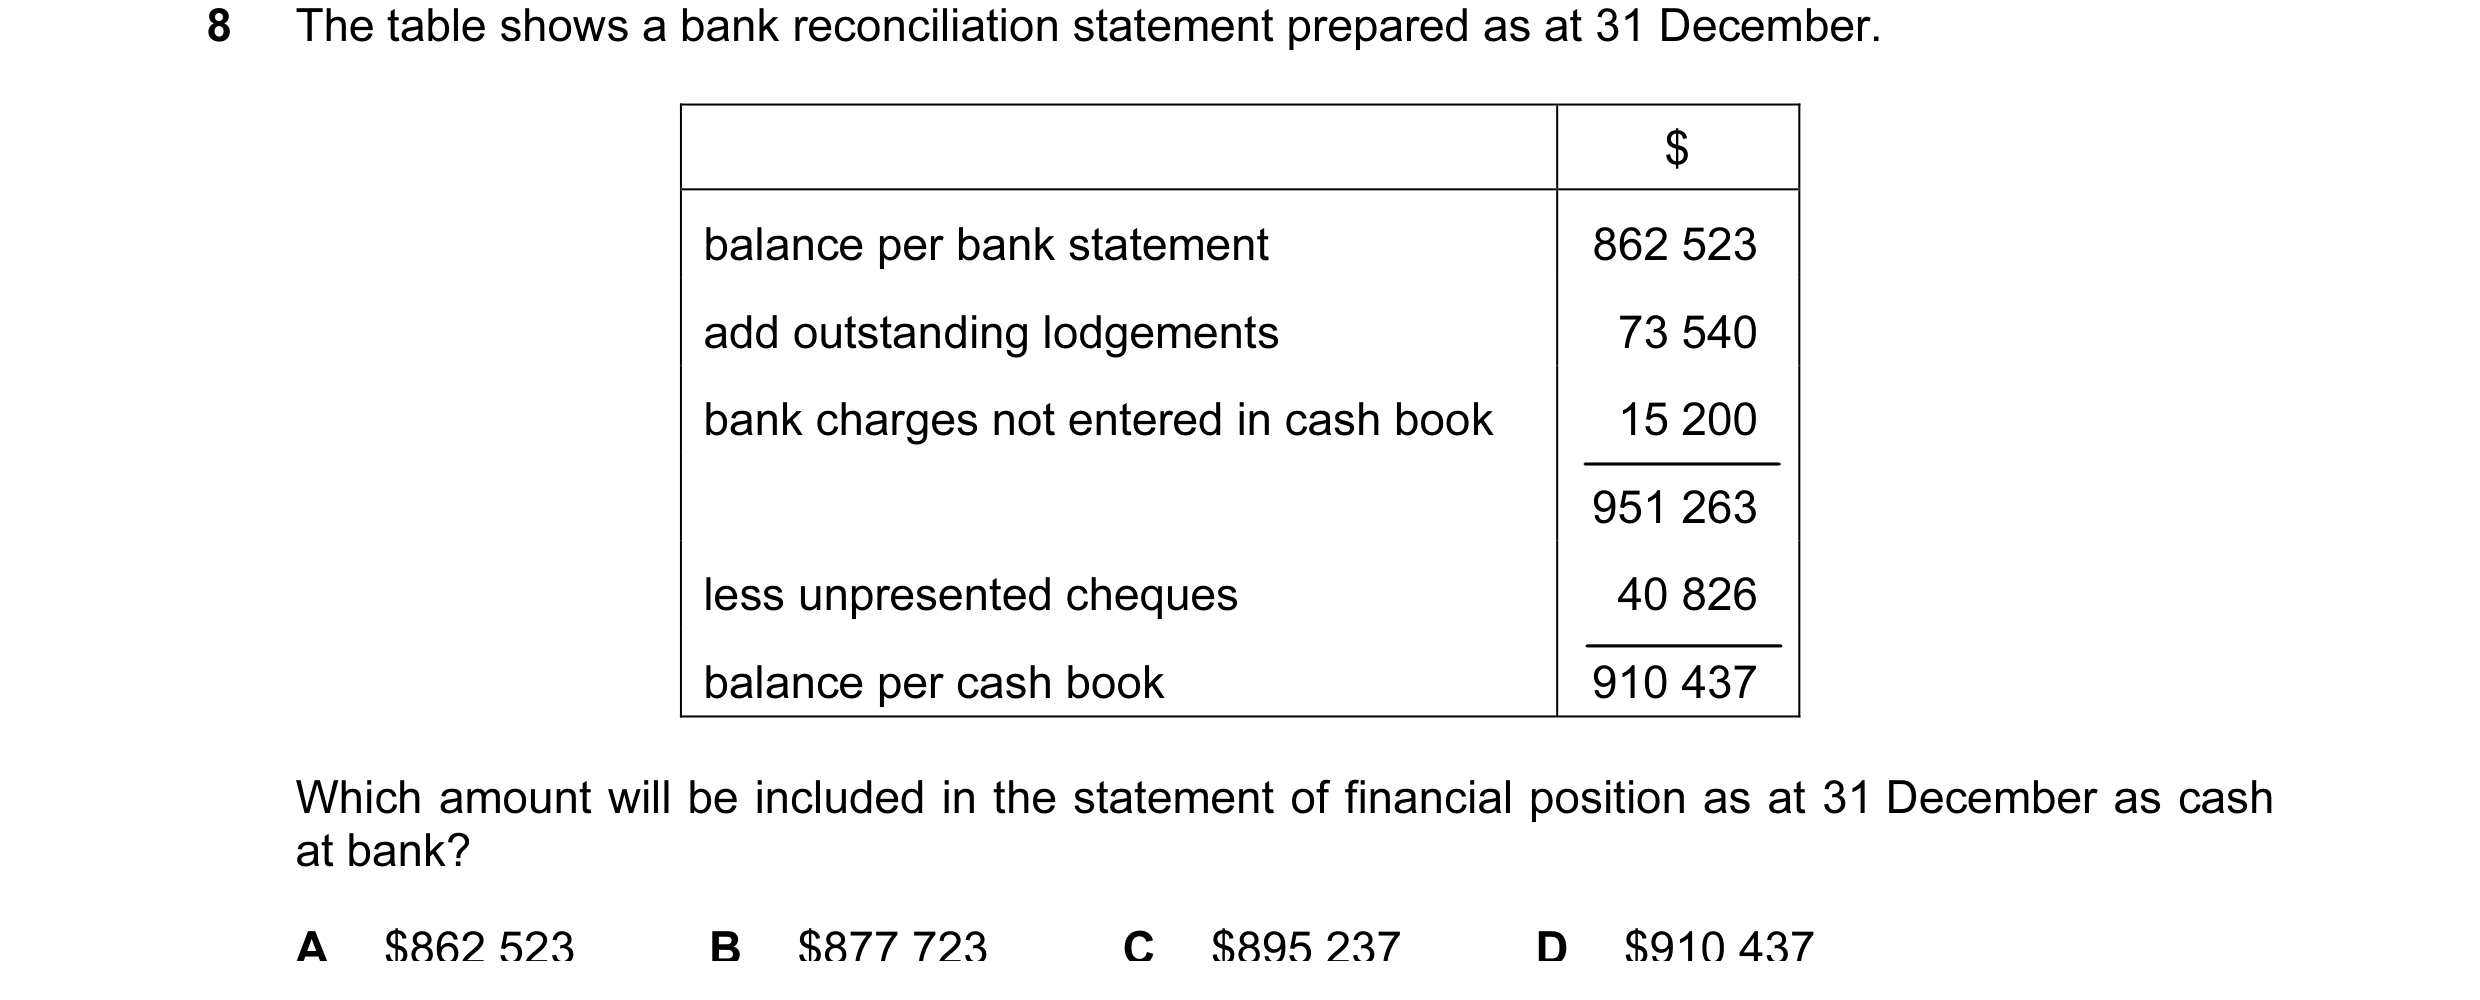
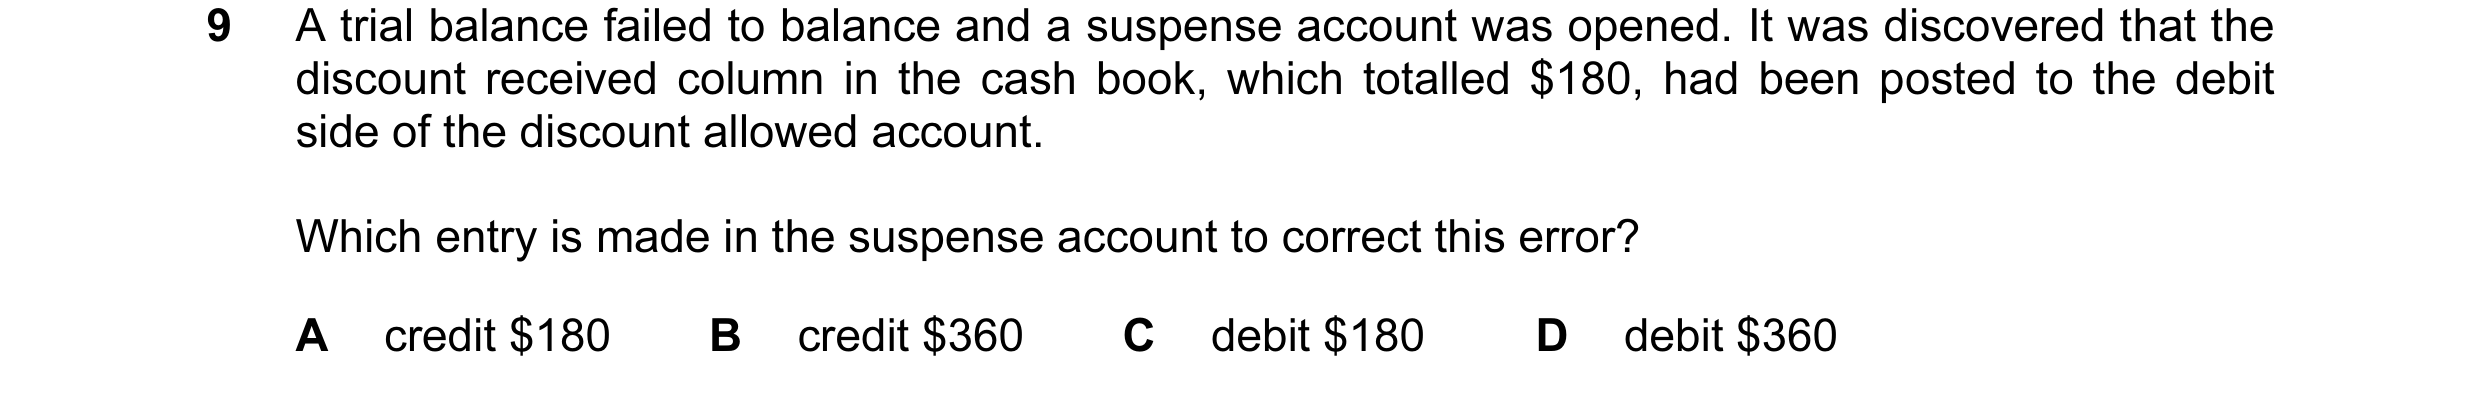
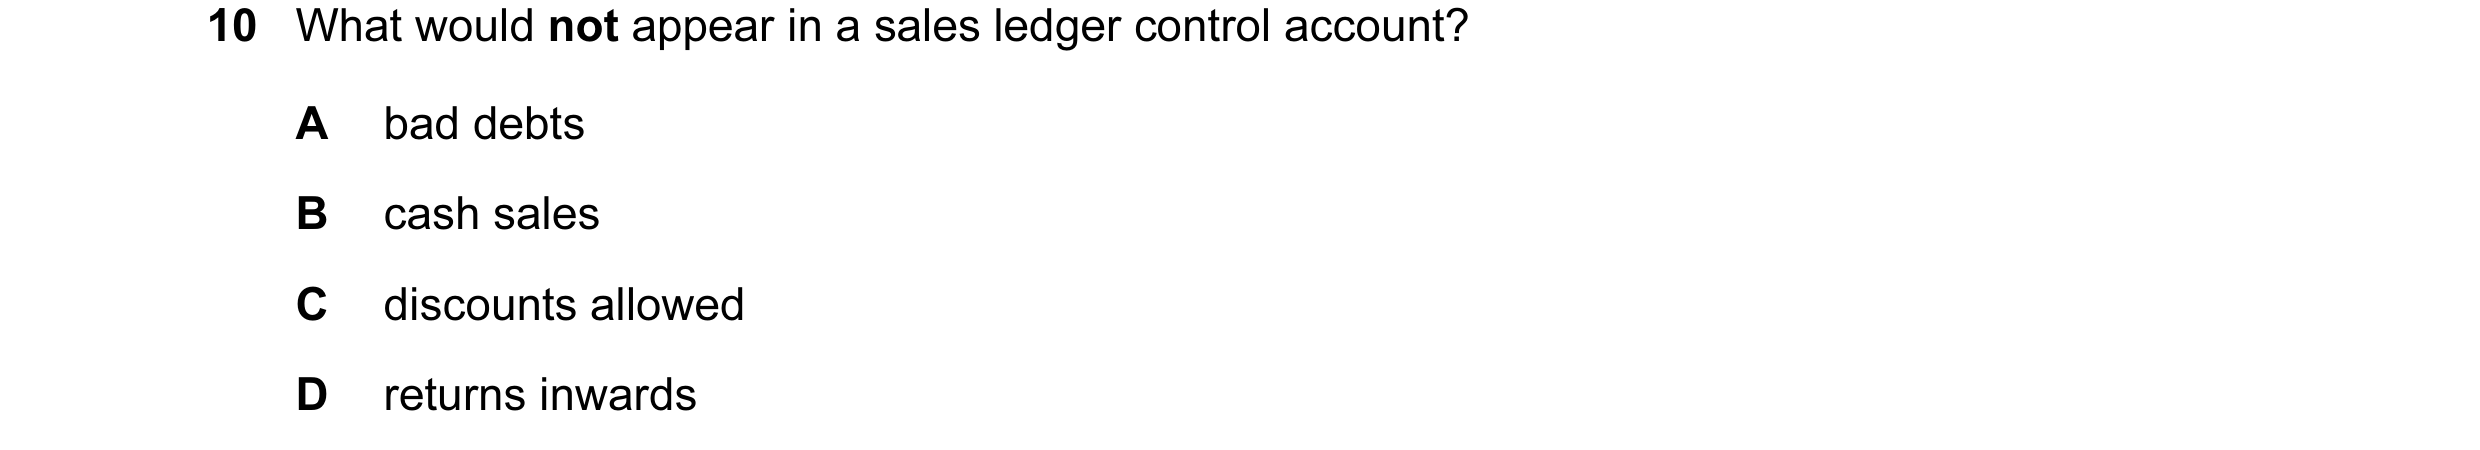 20 / 110
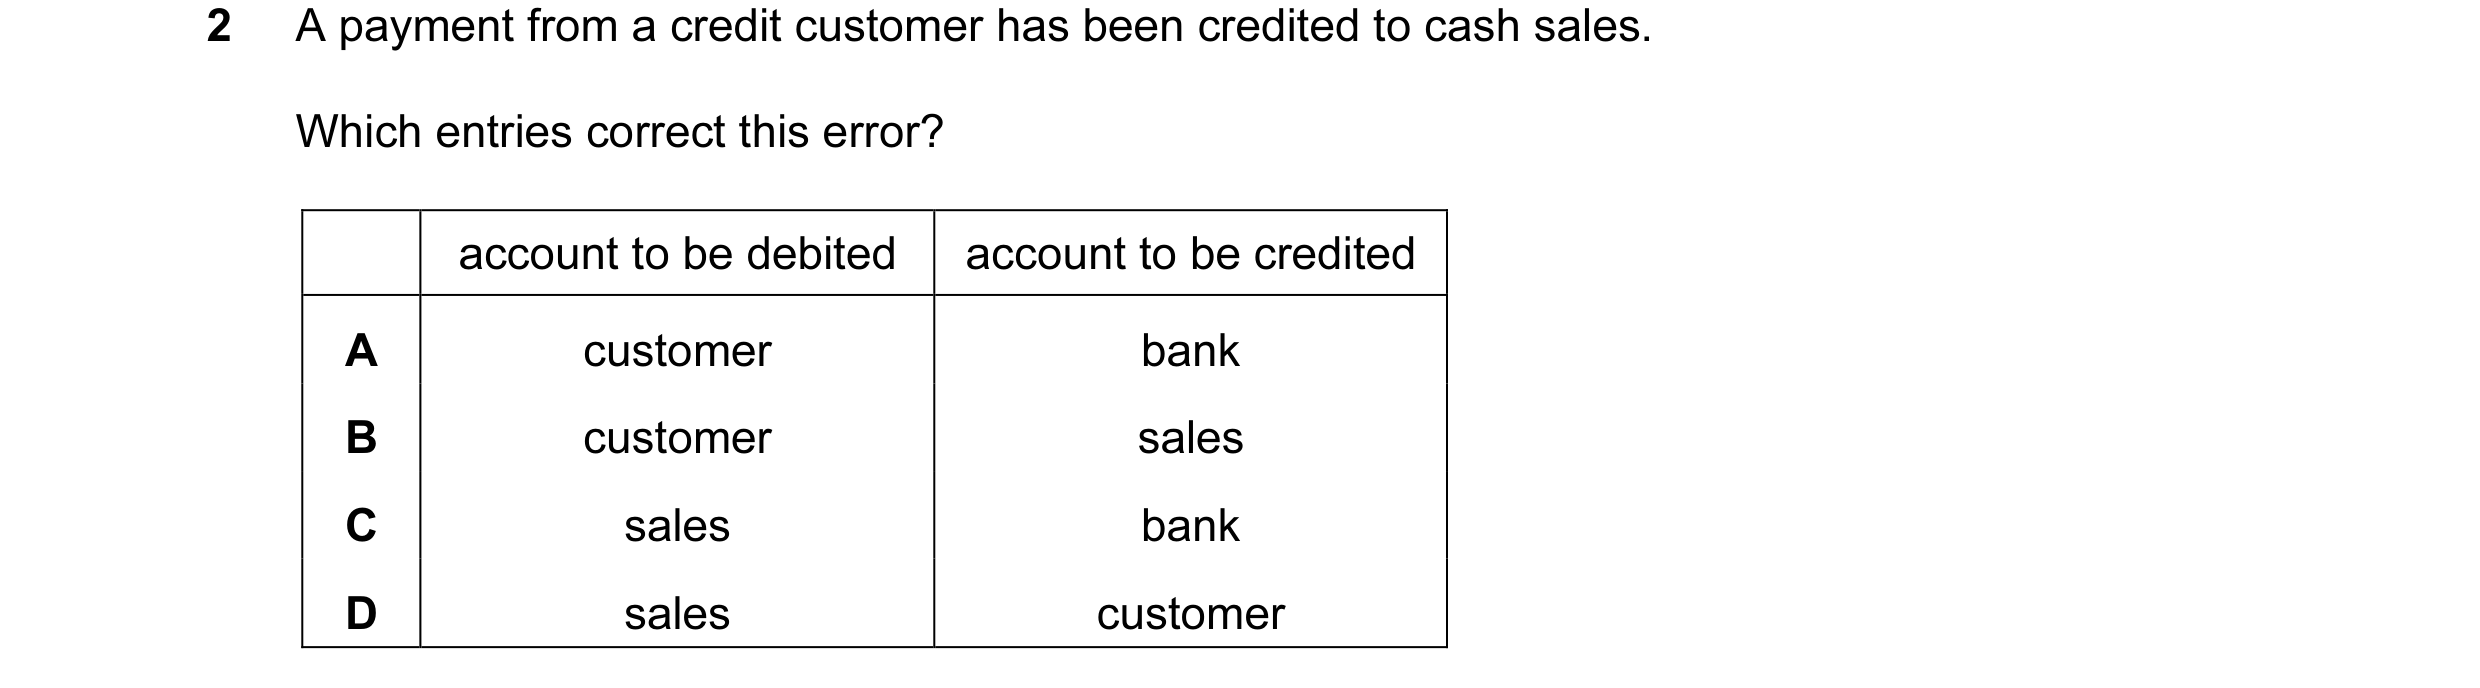
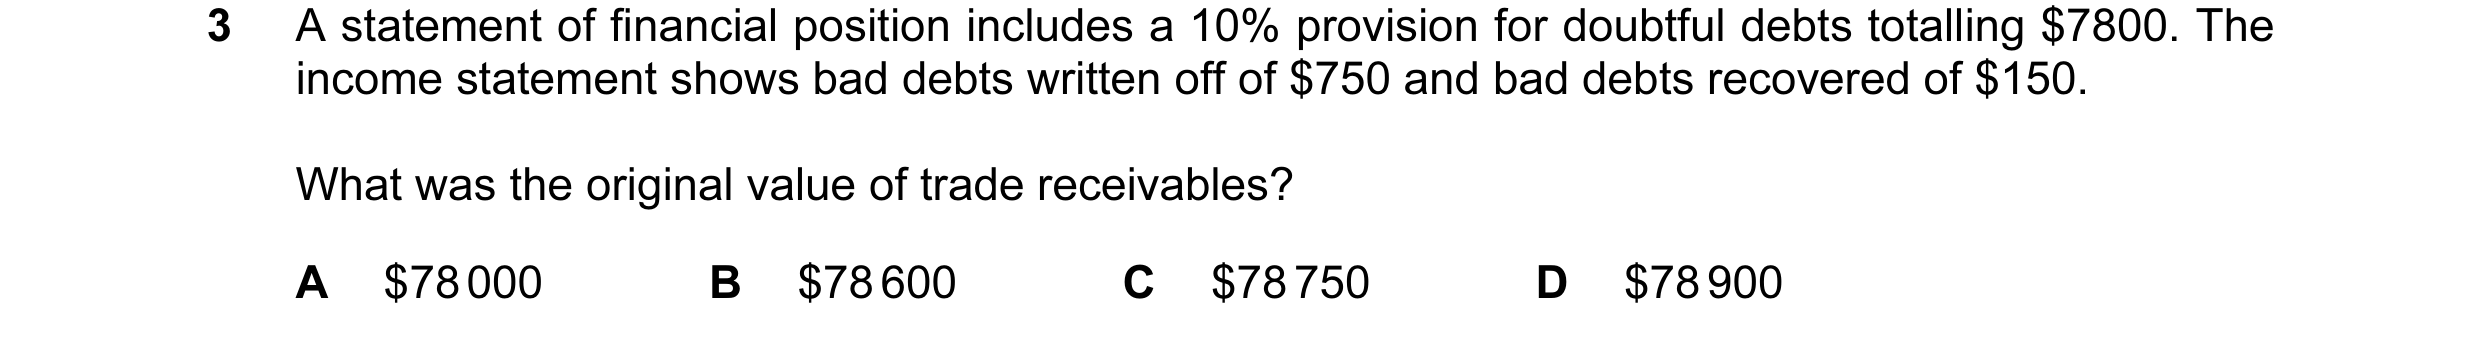
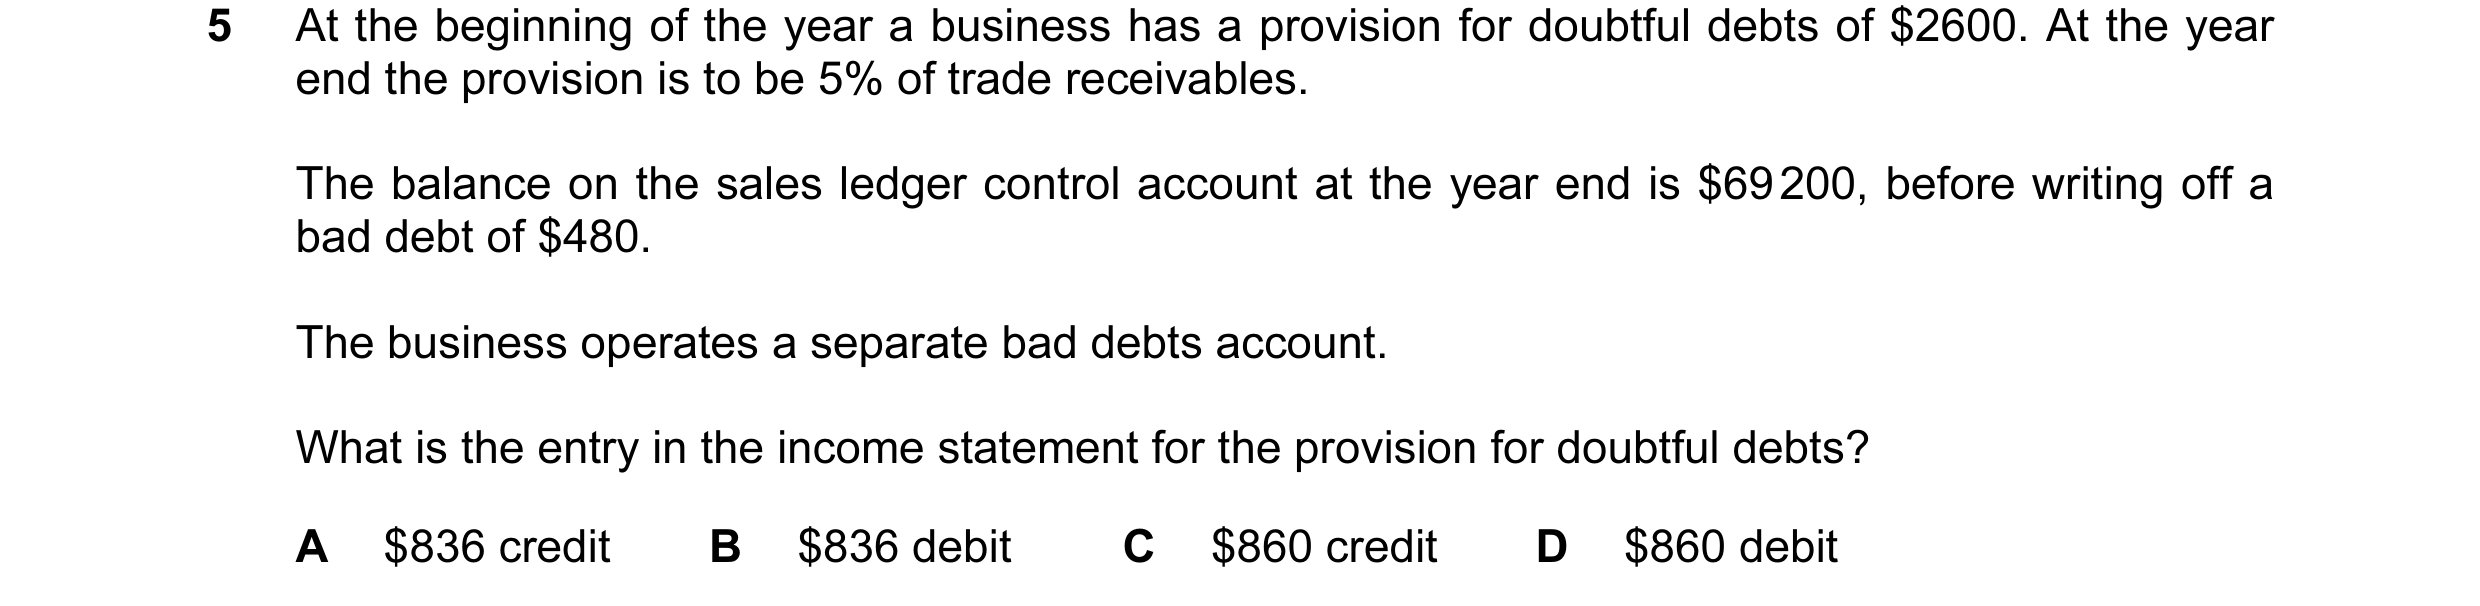
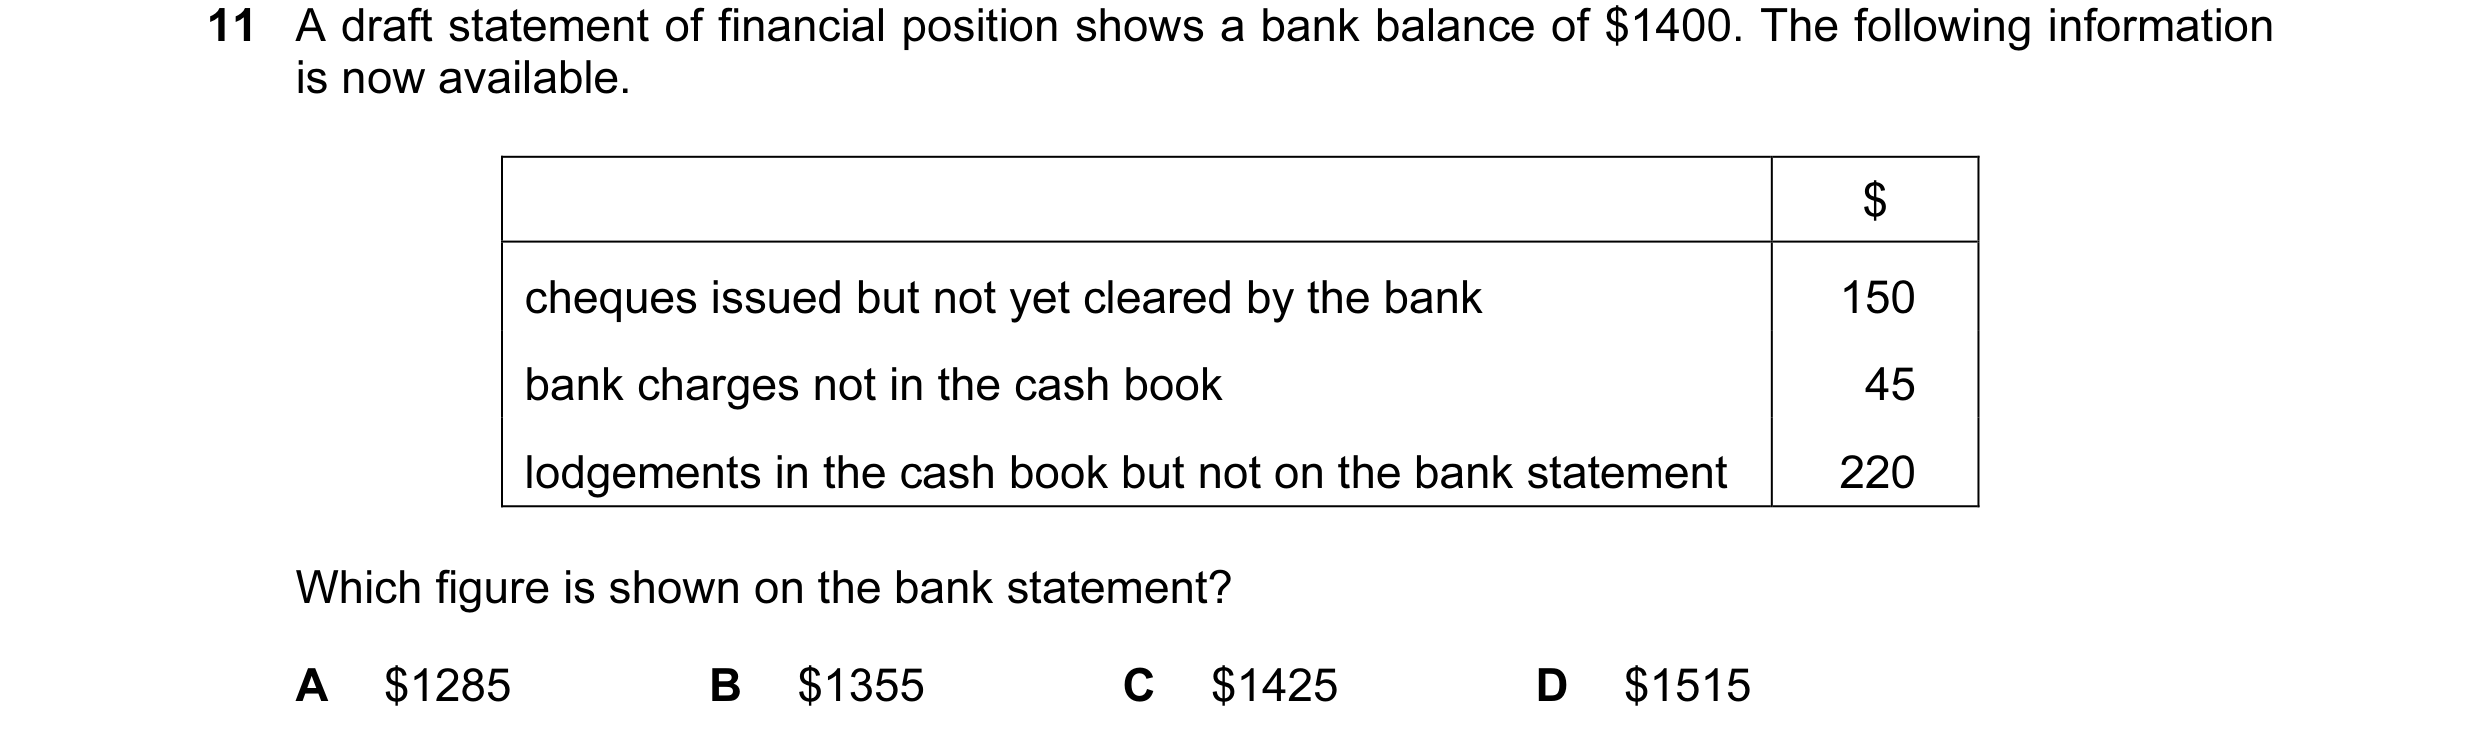 21 / 110
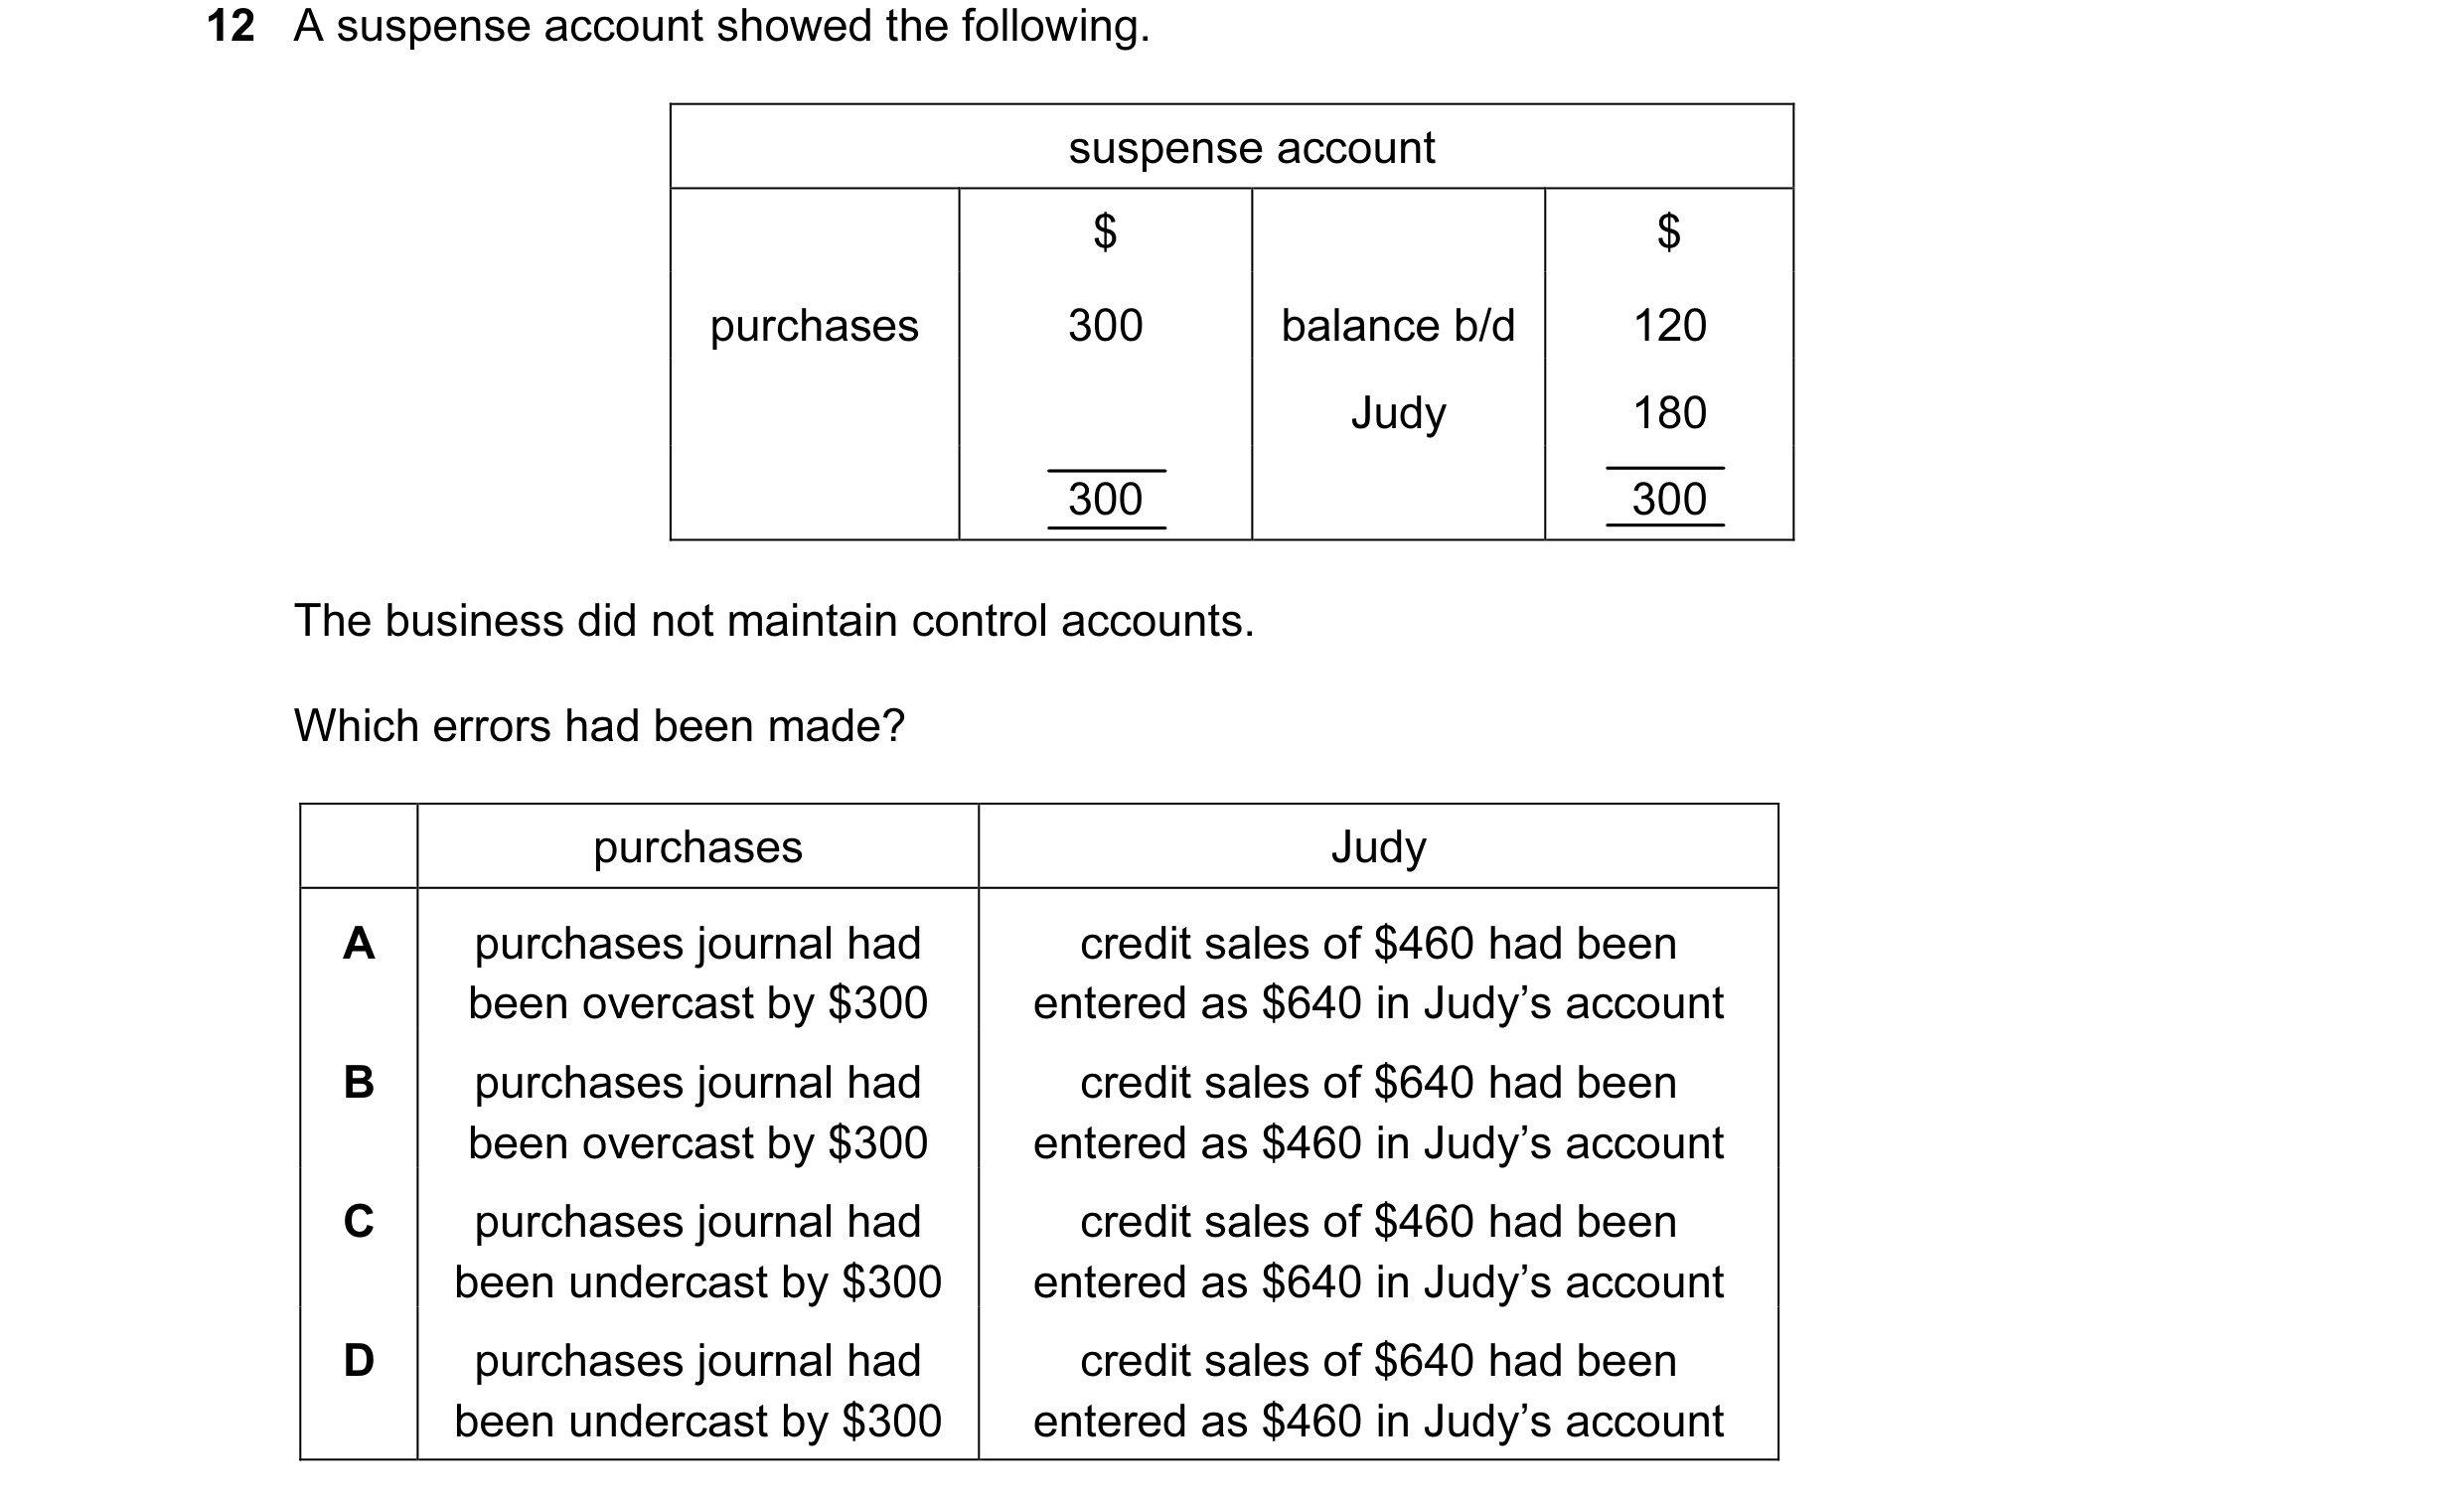
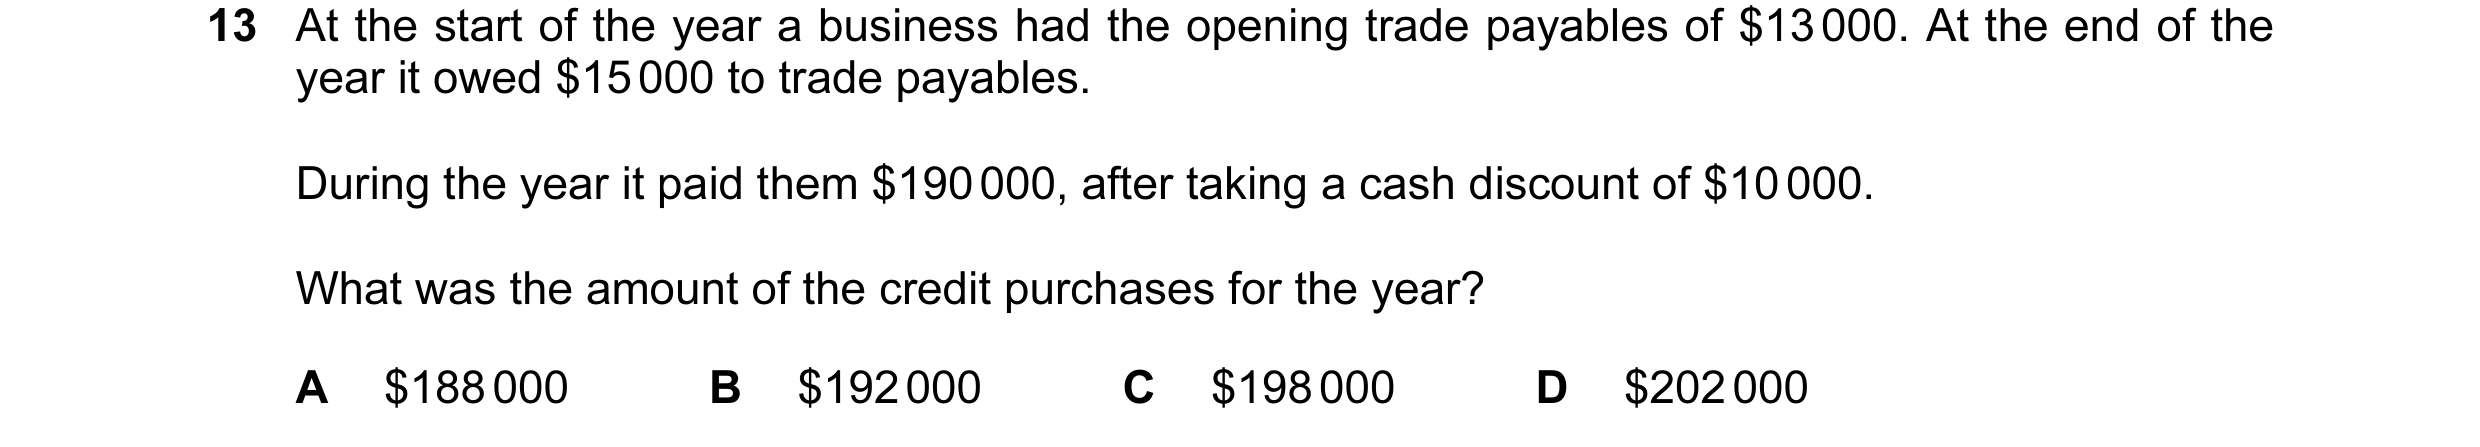
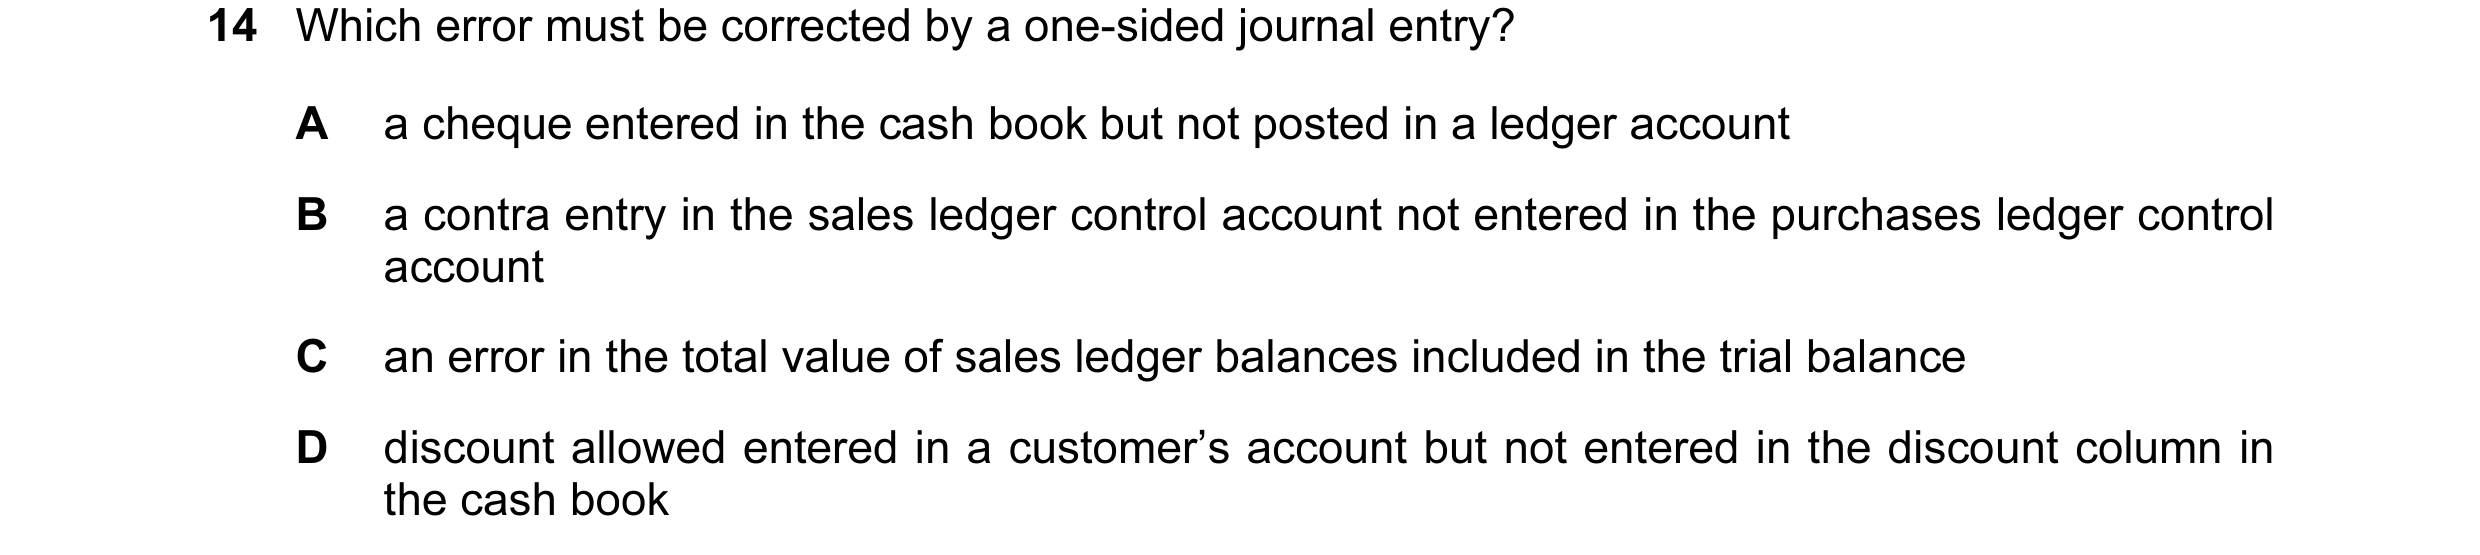
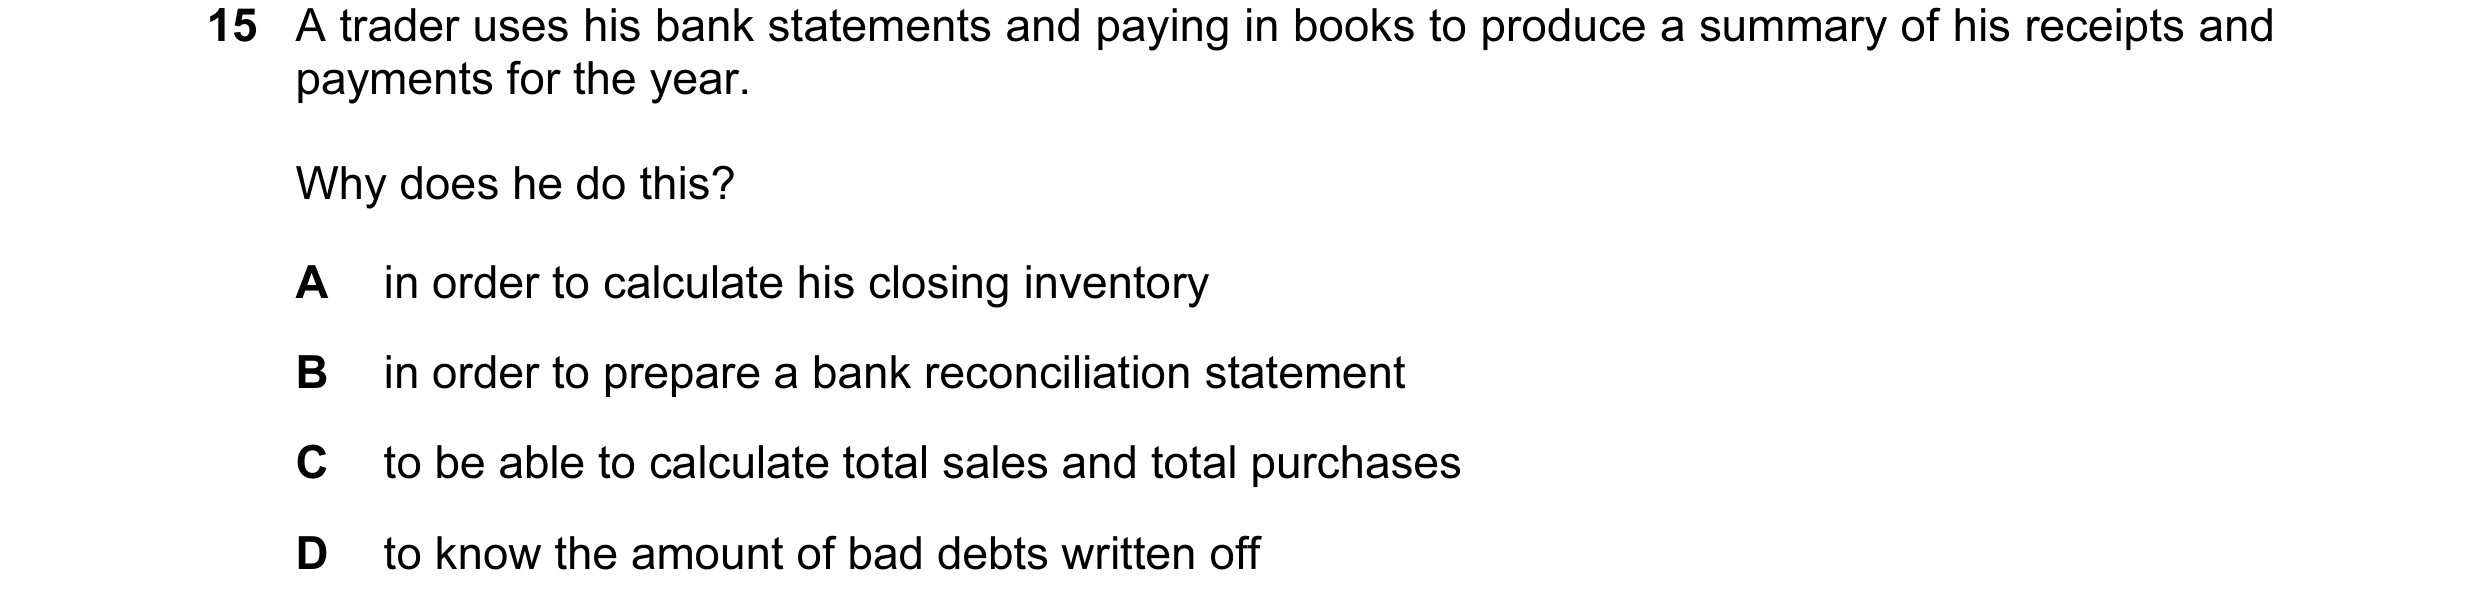 22 / 110
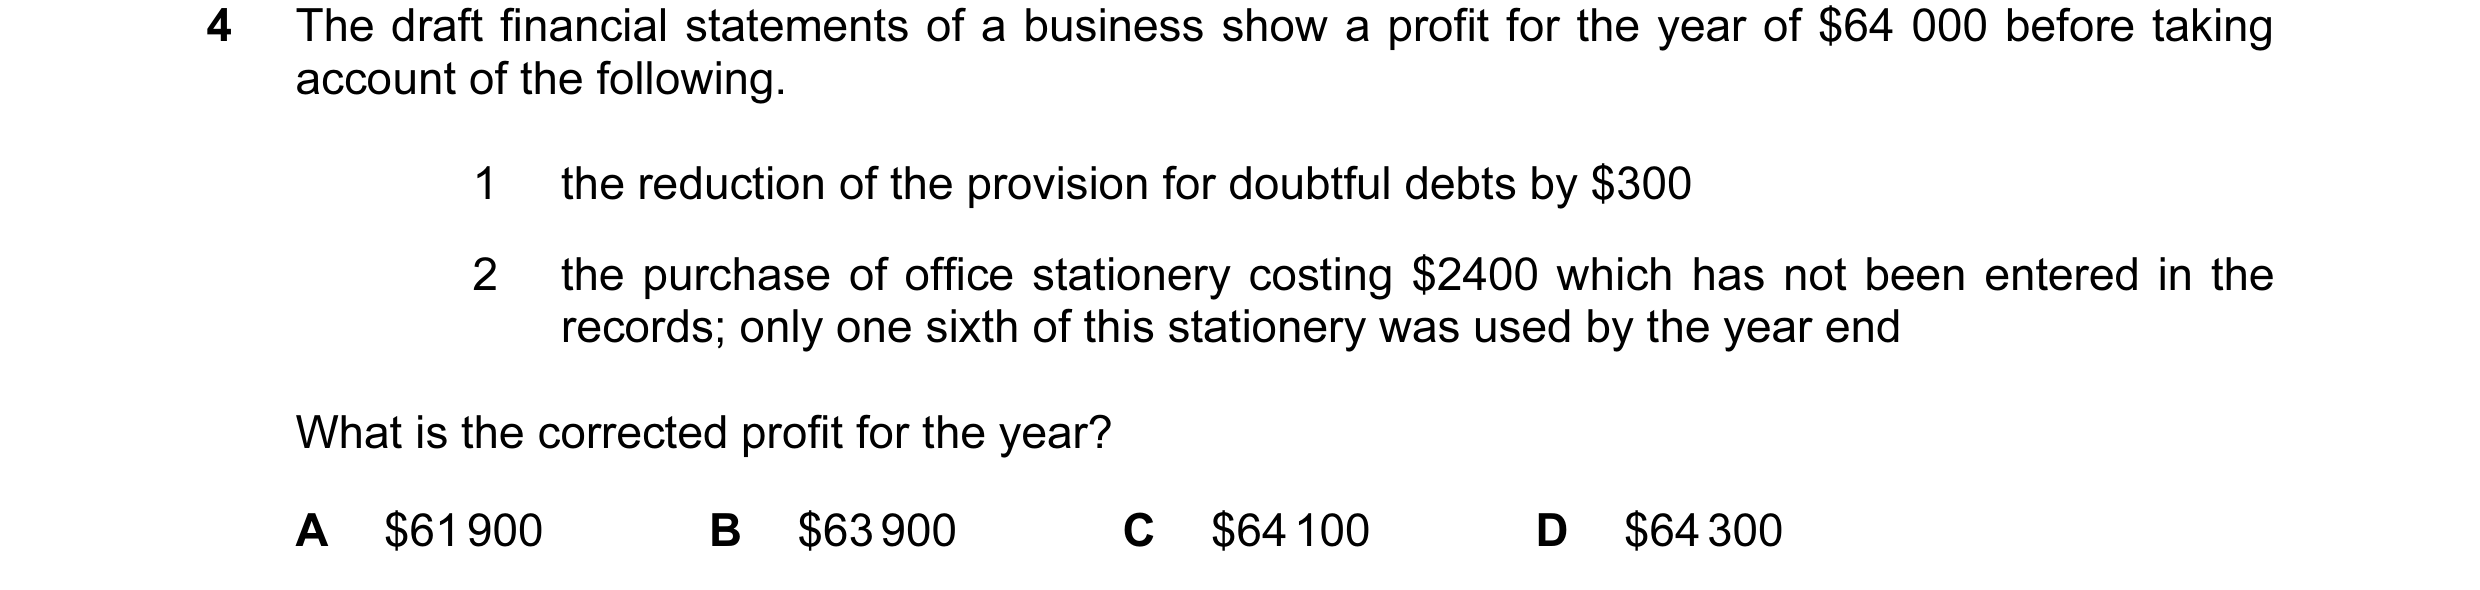
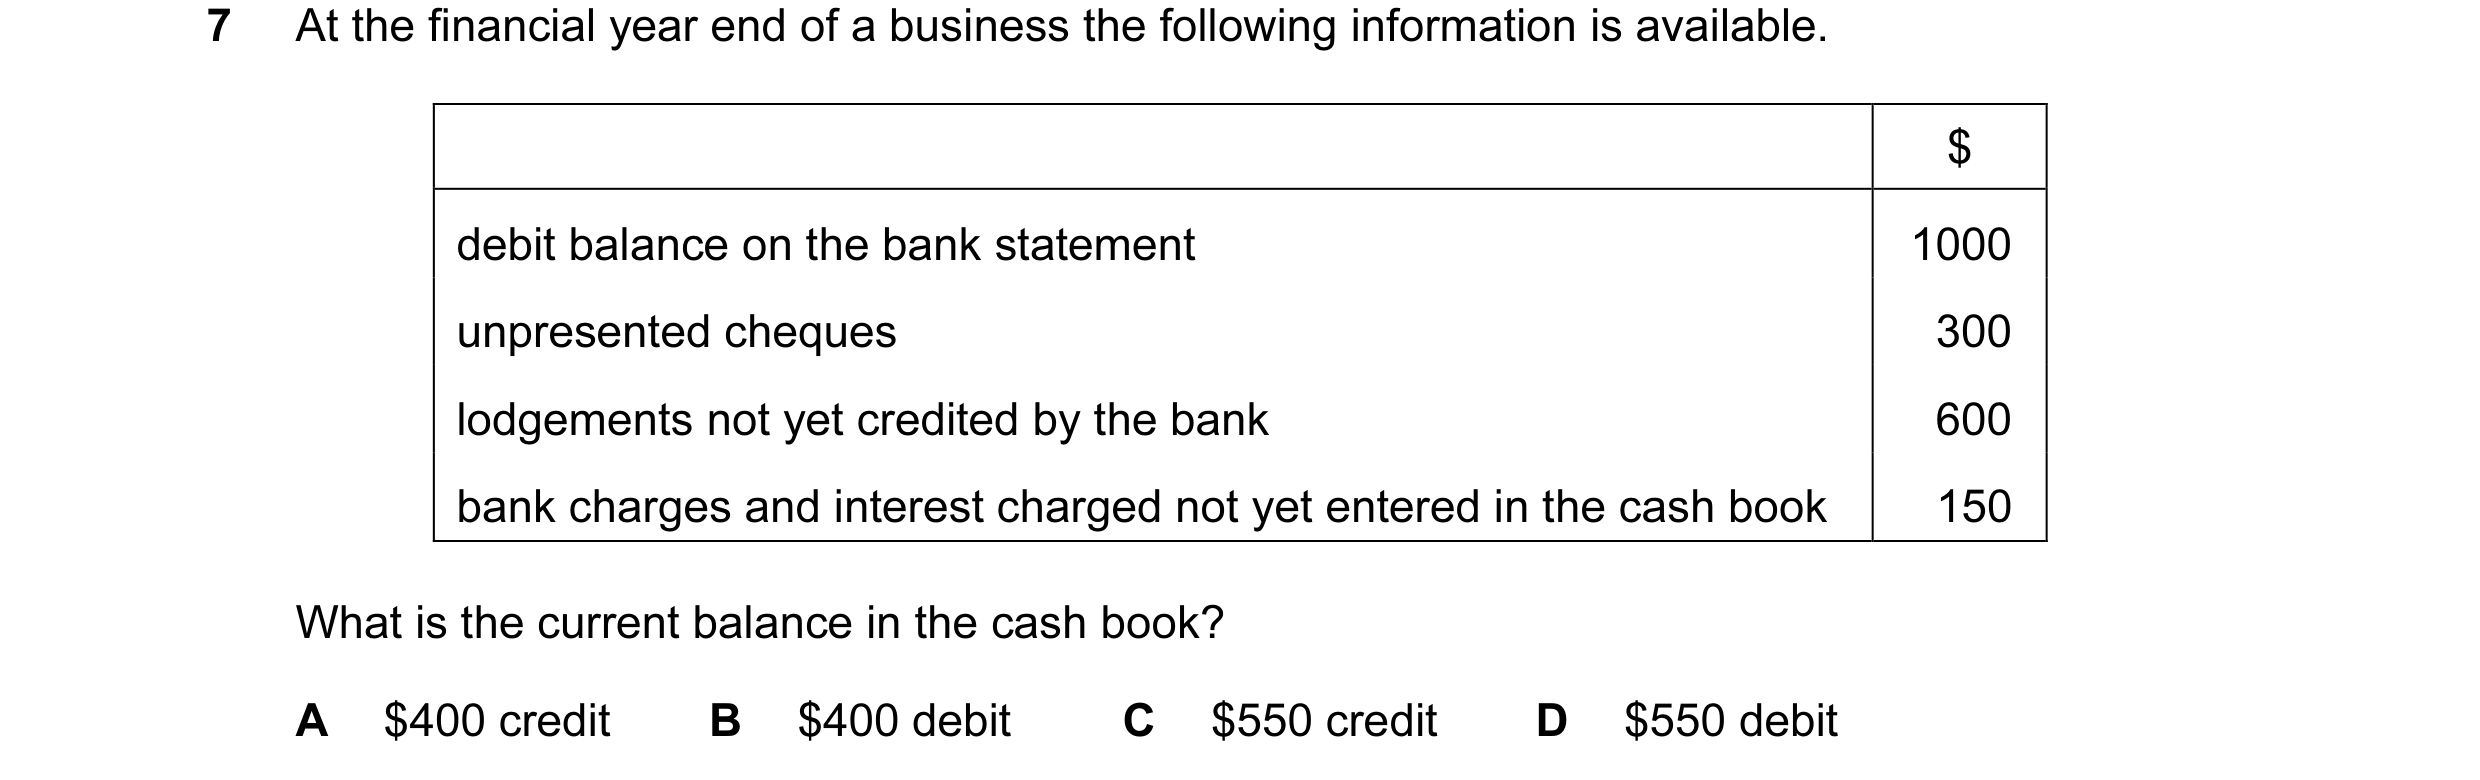
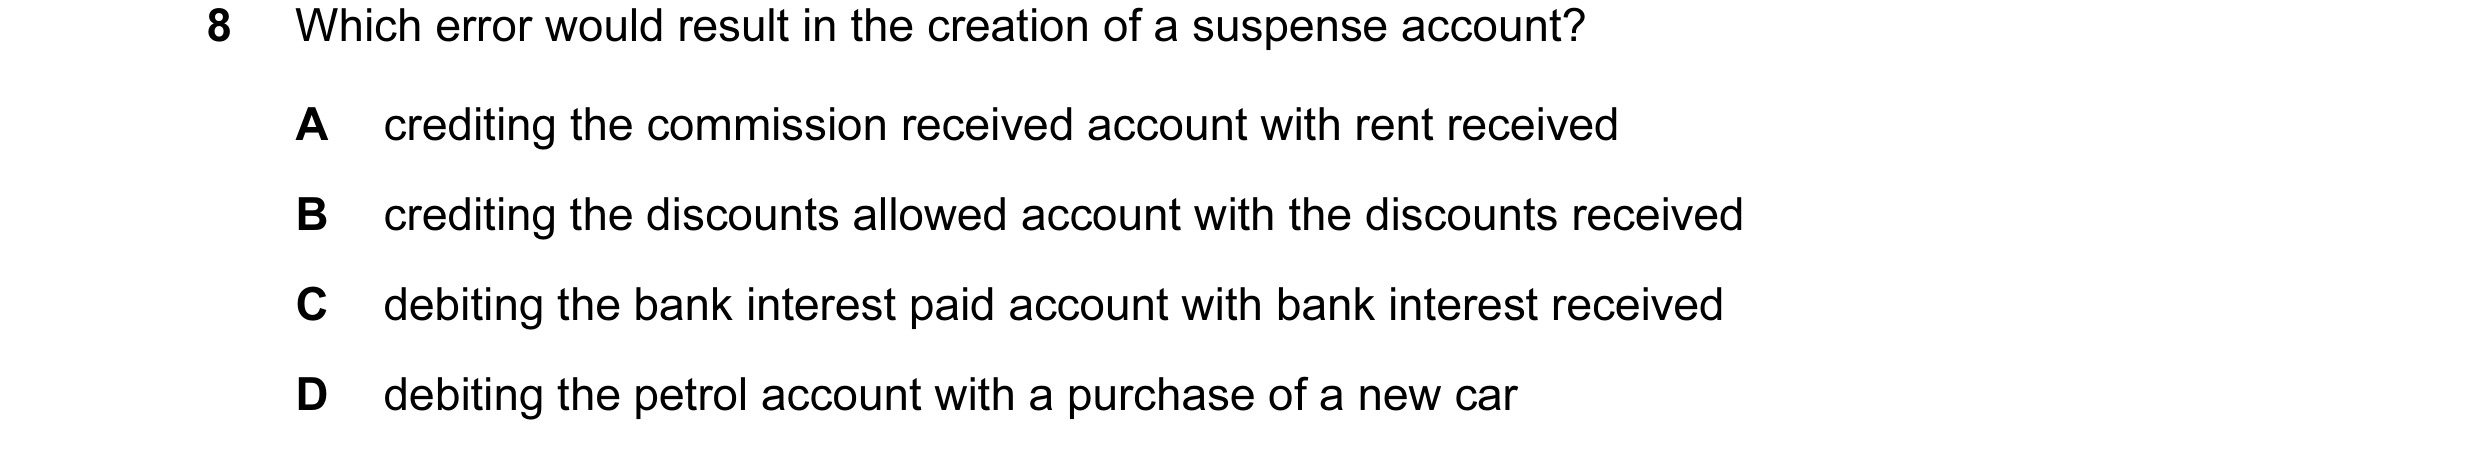
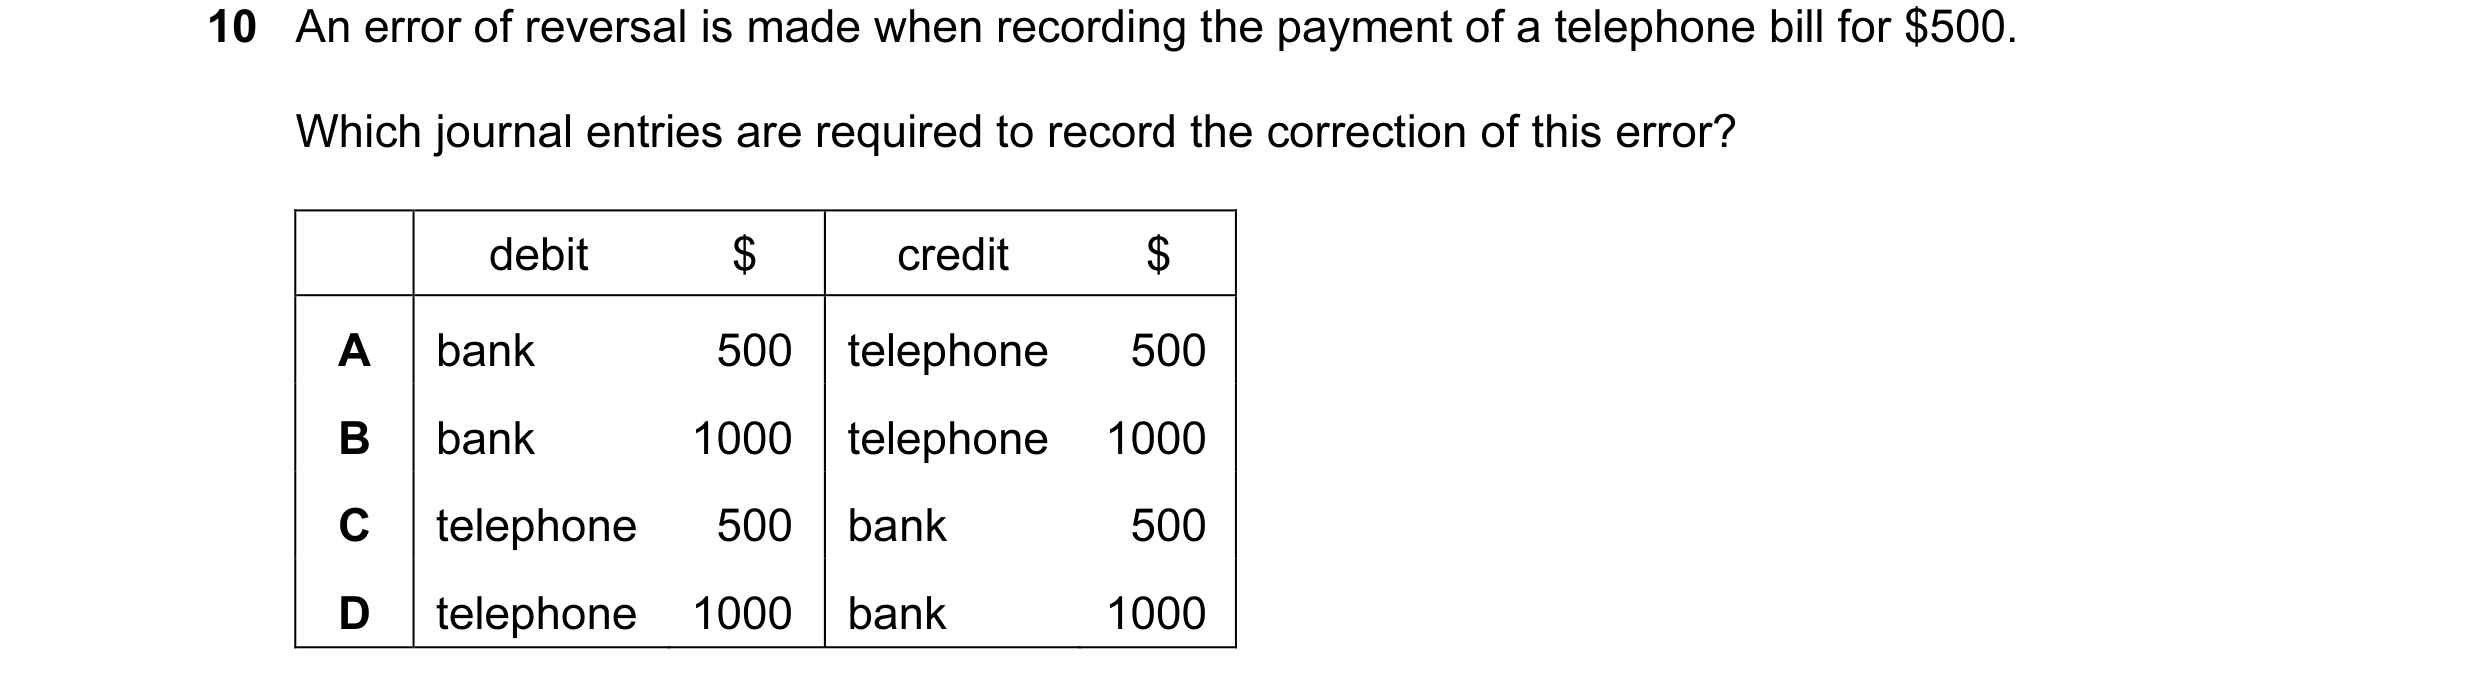
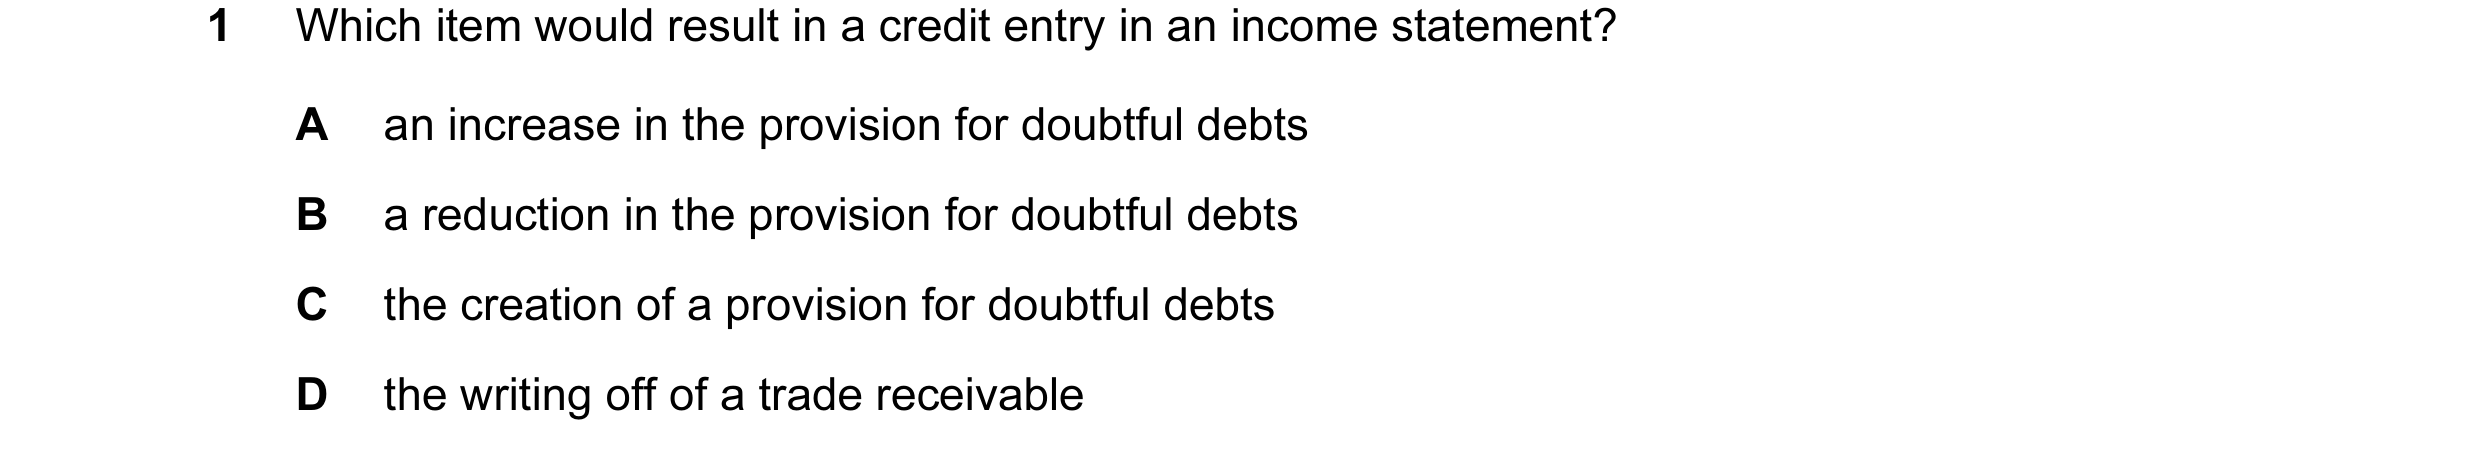 23 / 110
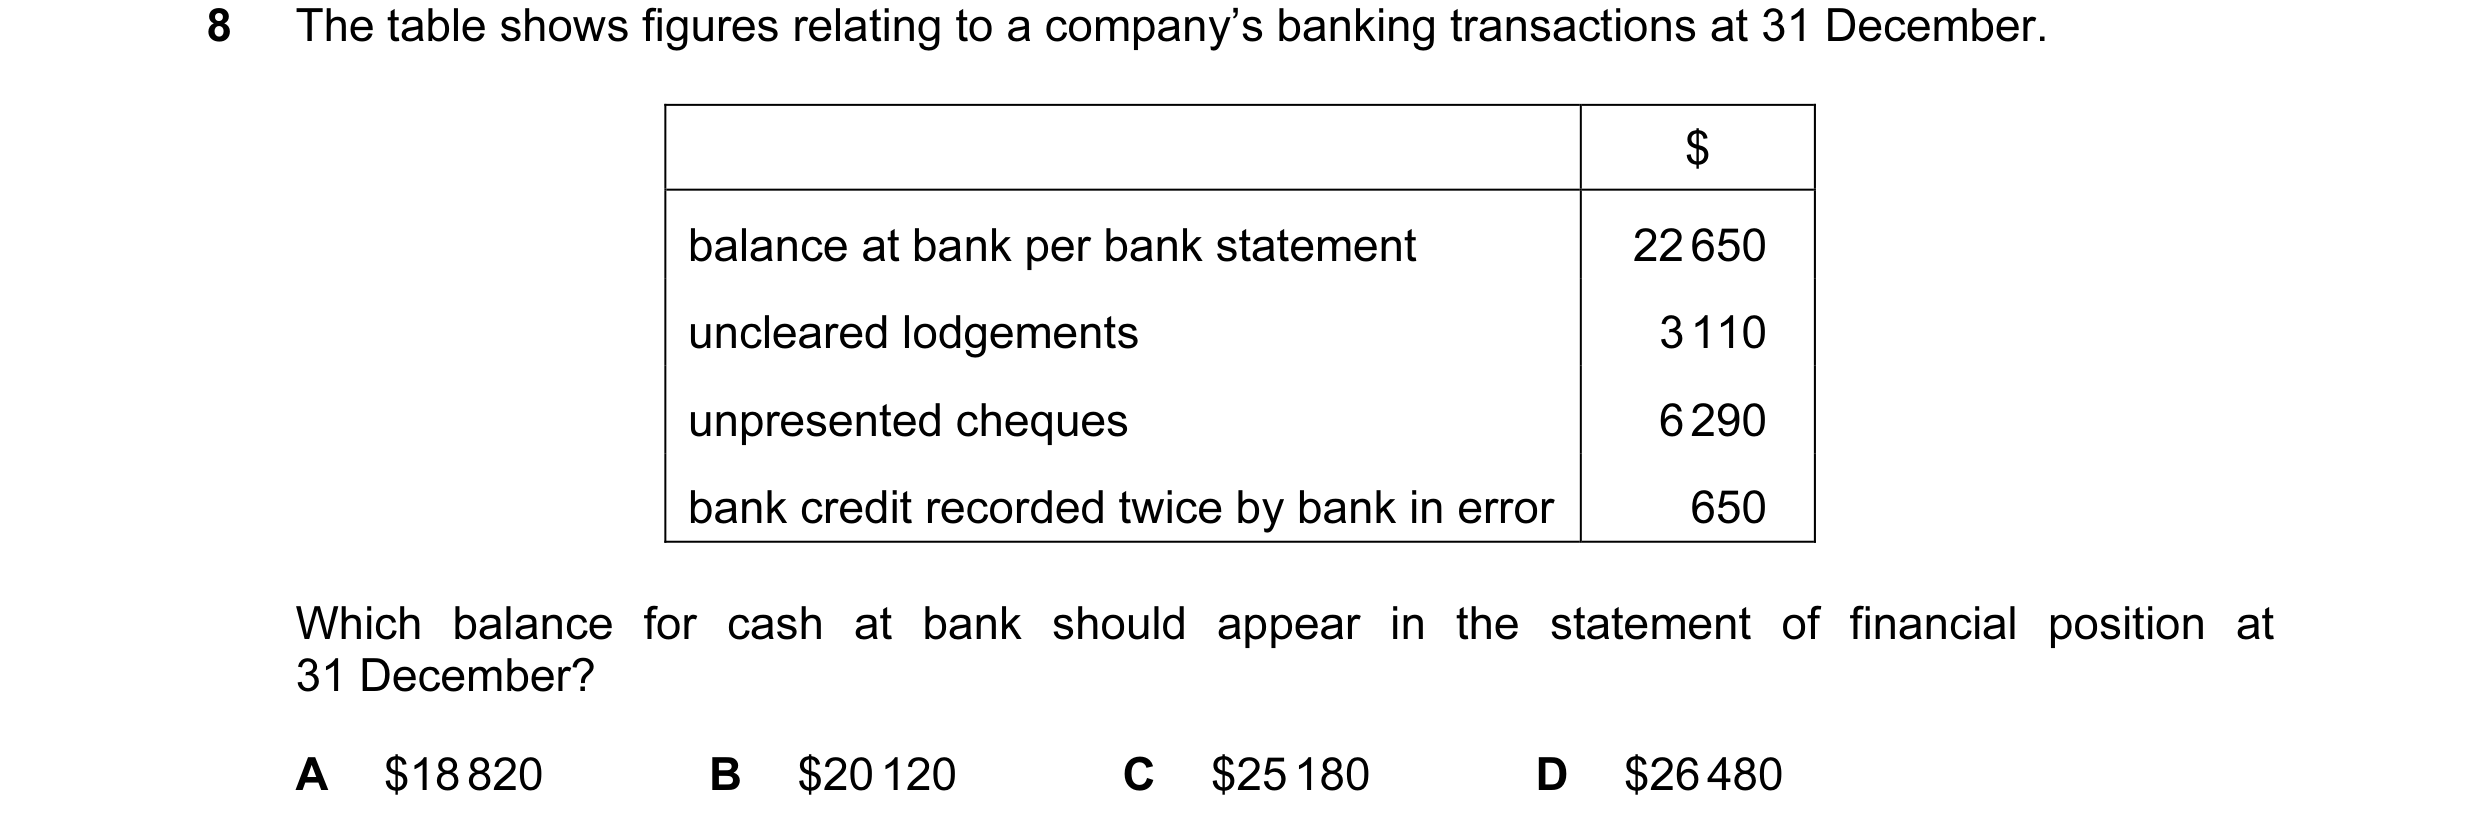
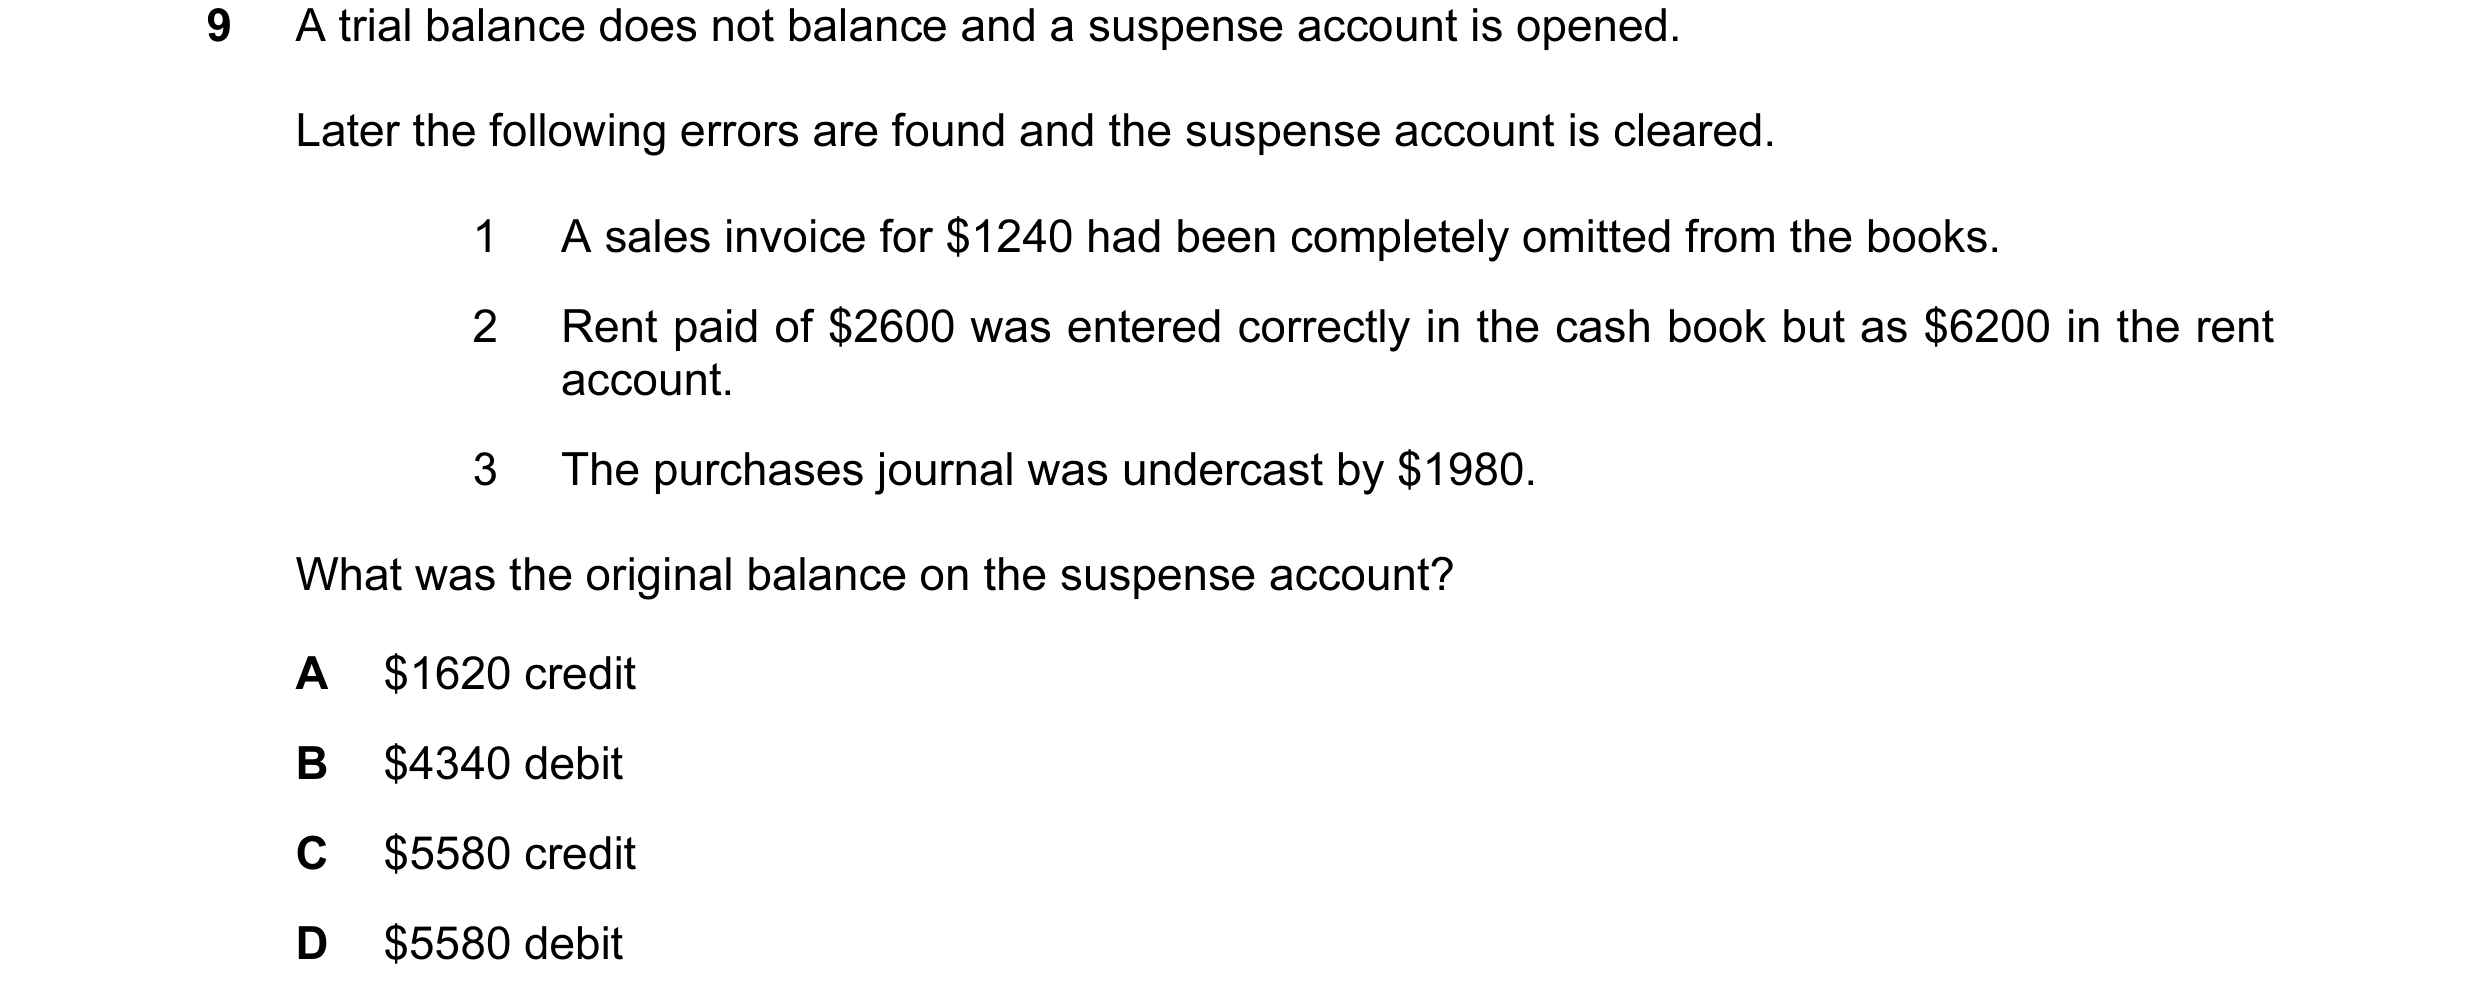
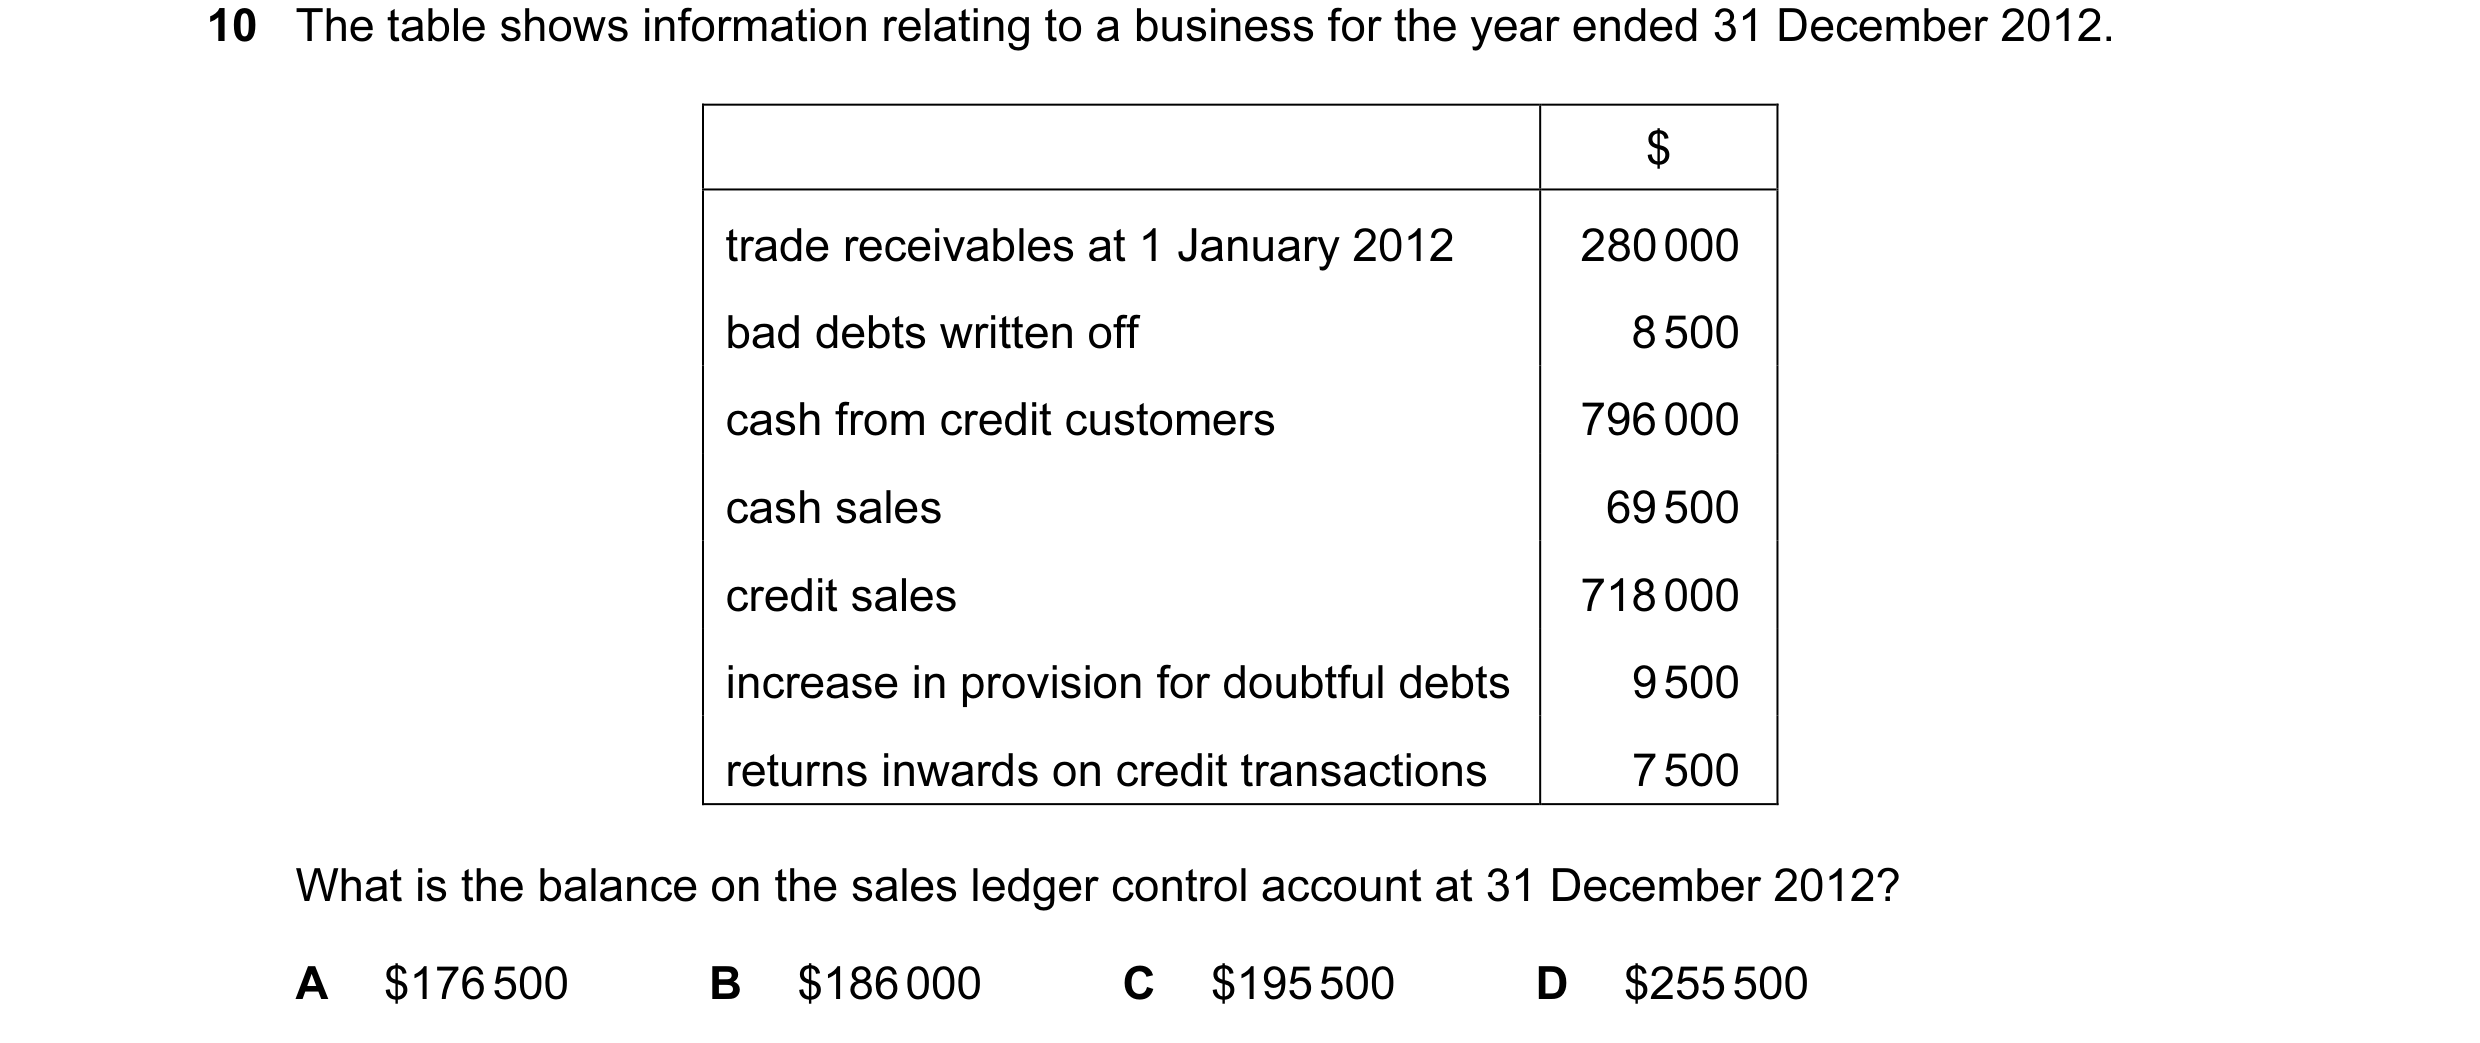
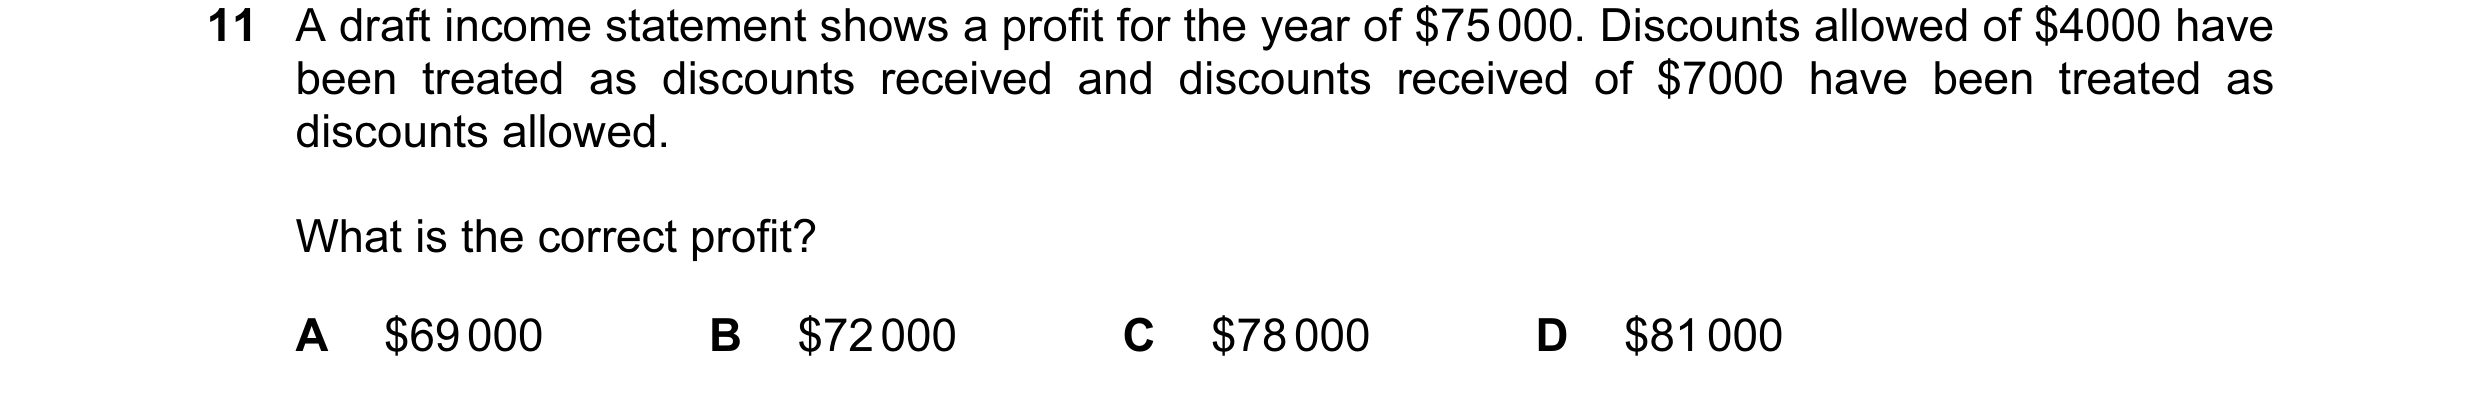 24 / 110
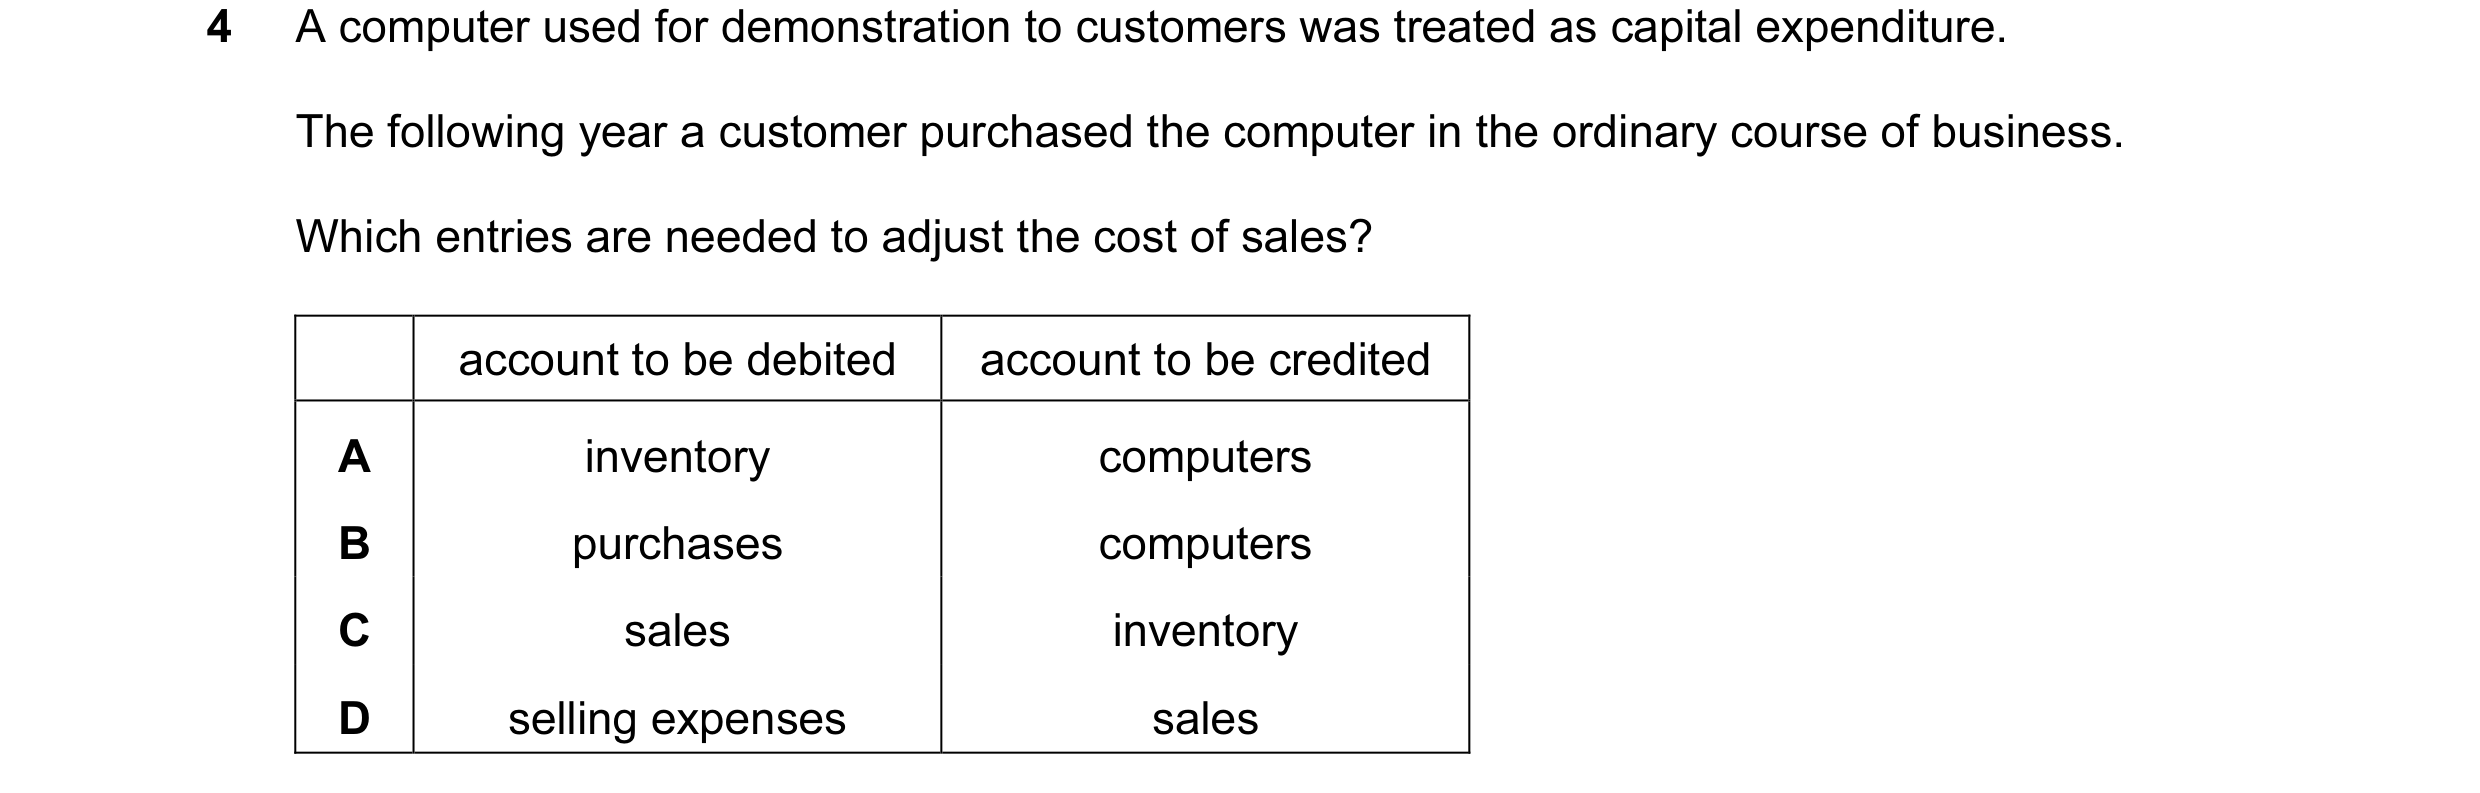
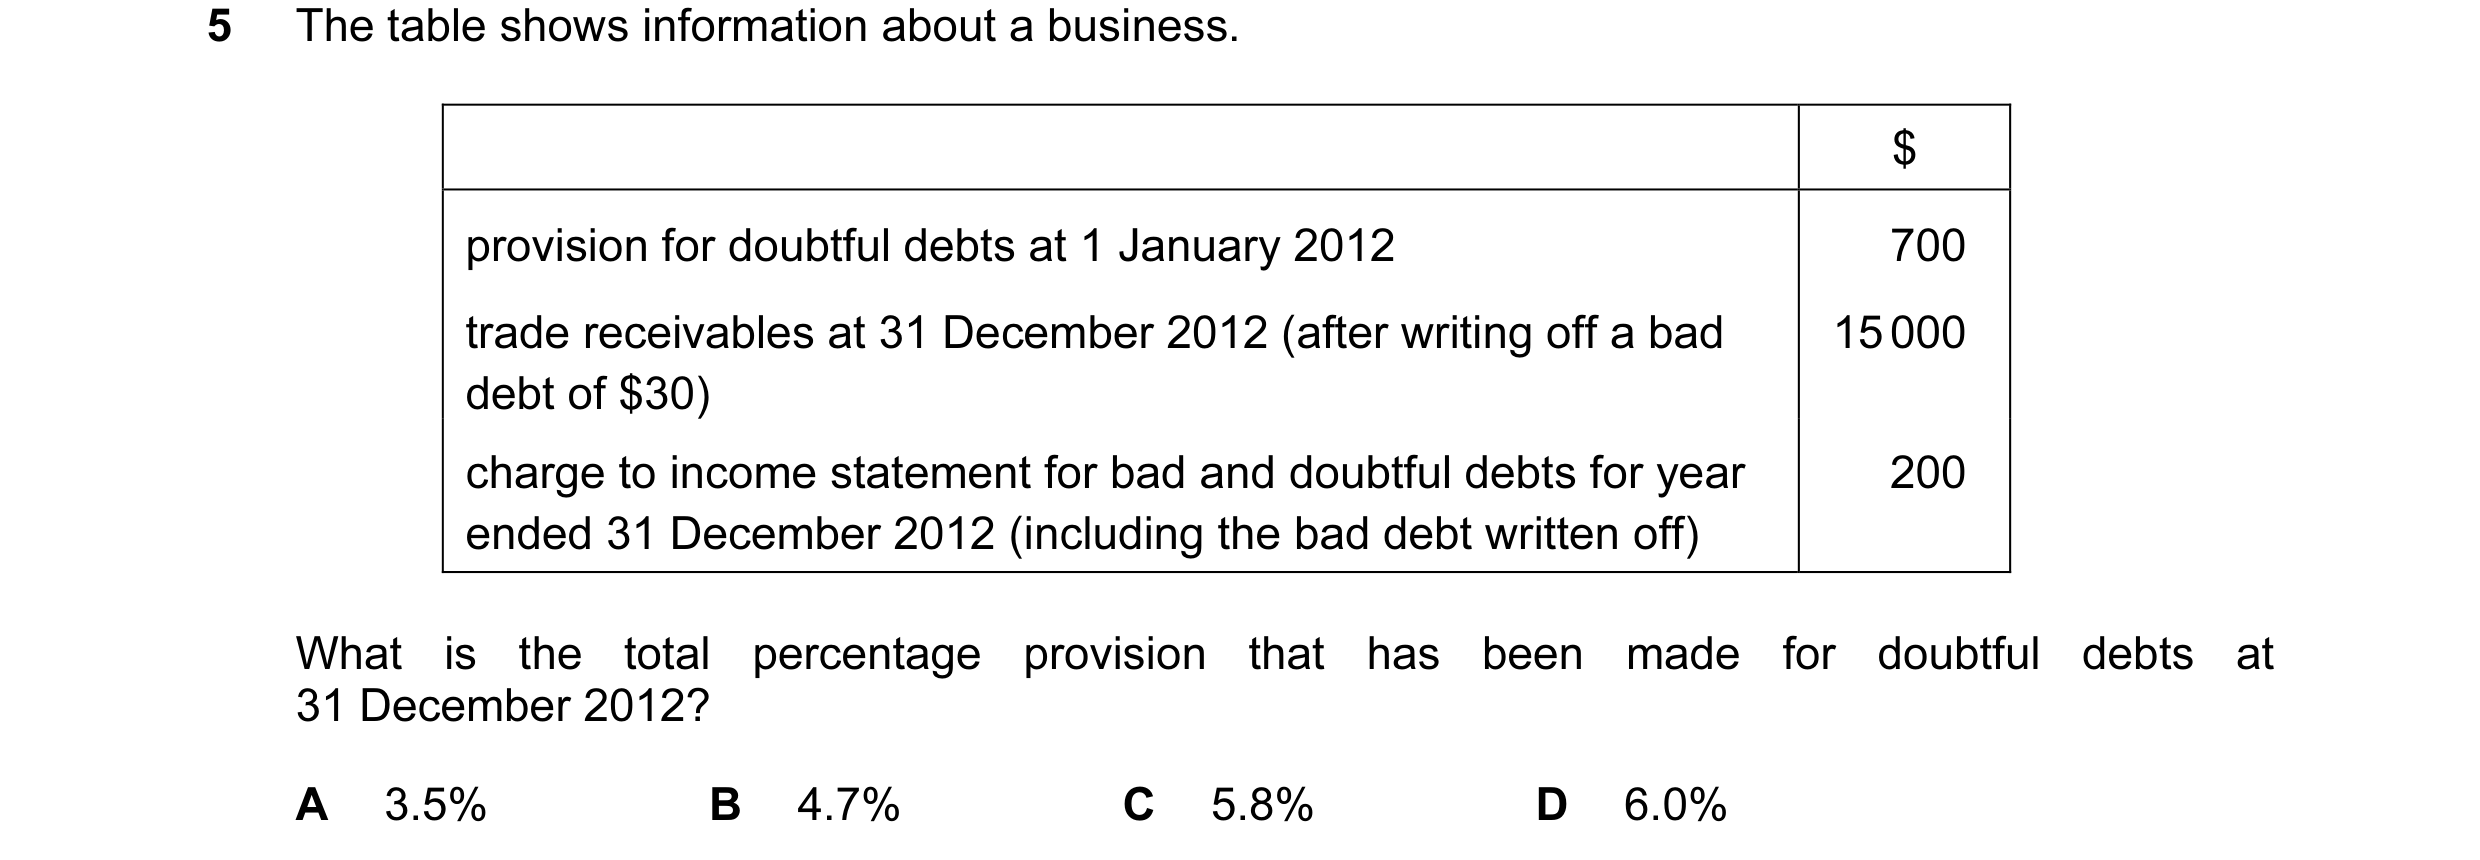
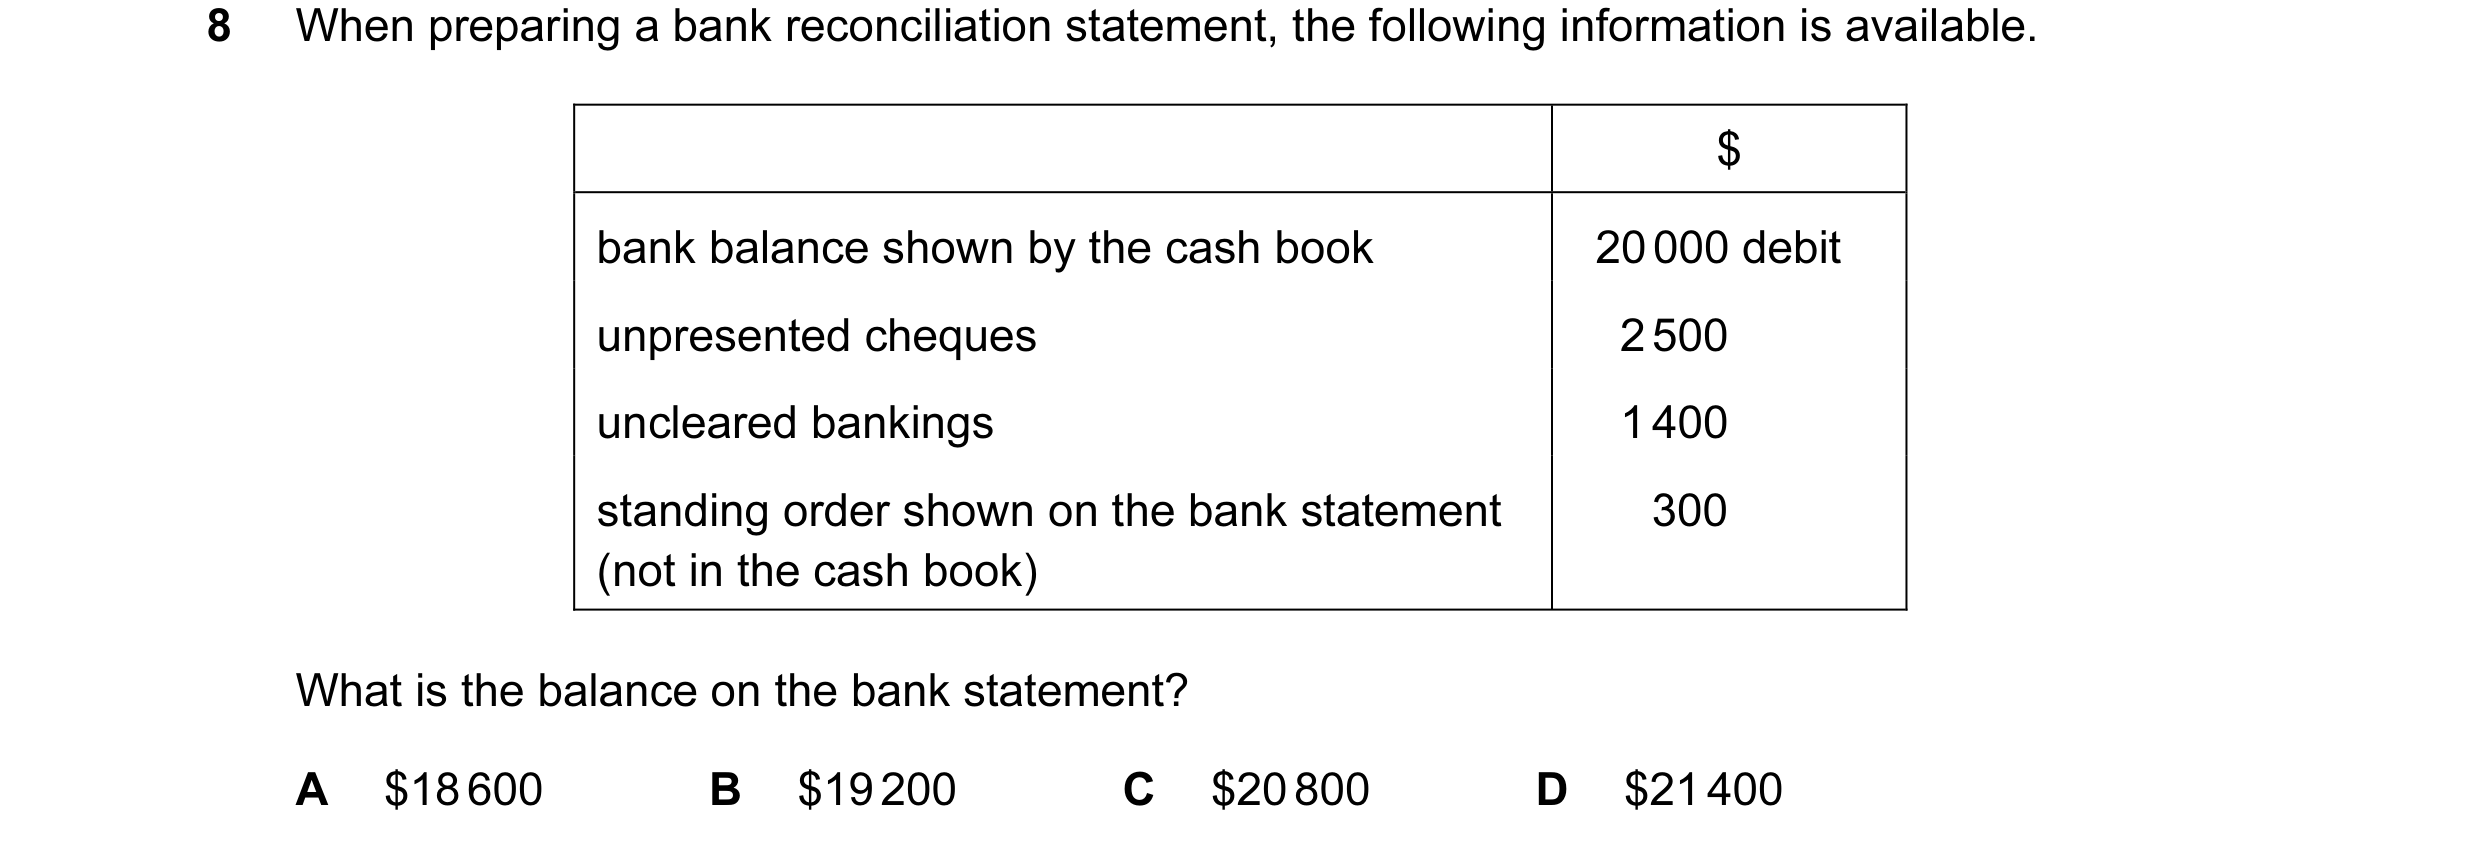 25 / 110
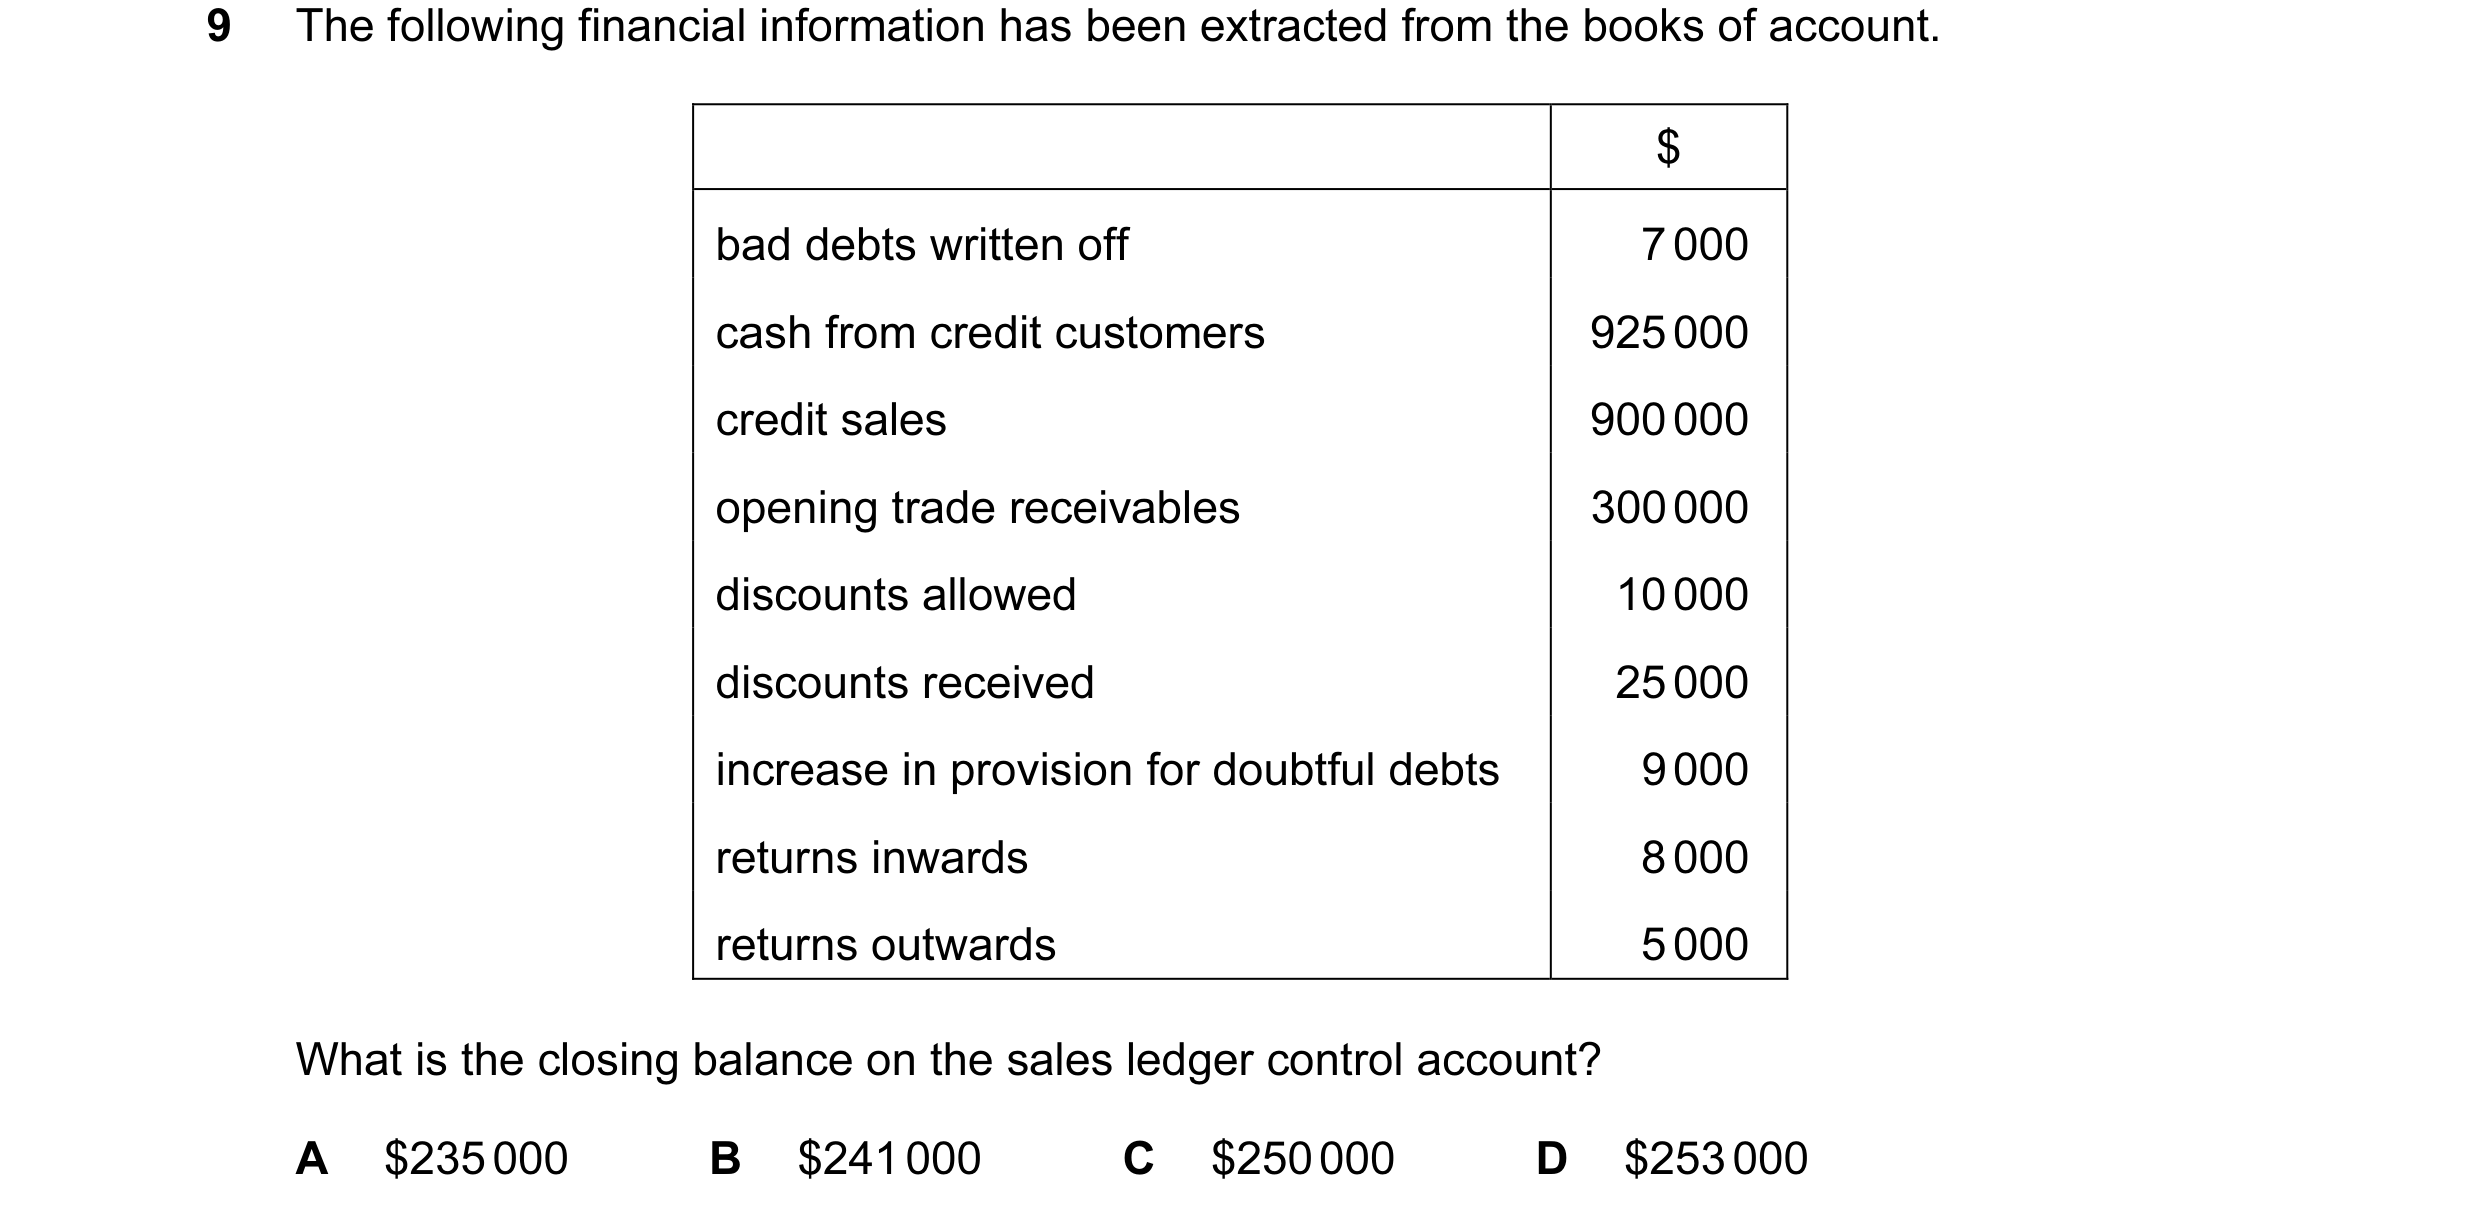
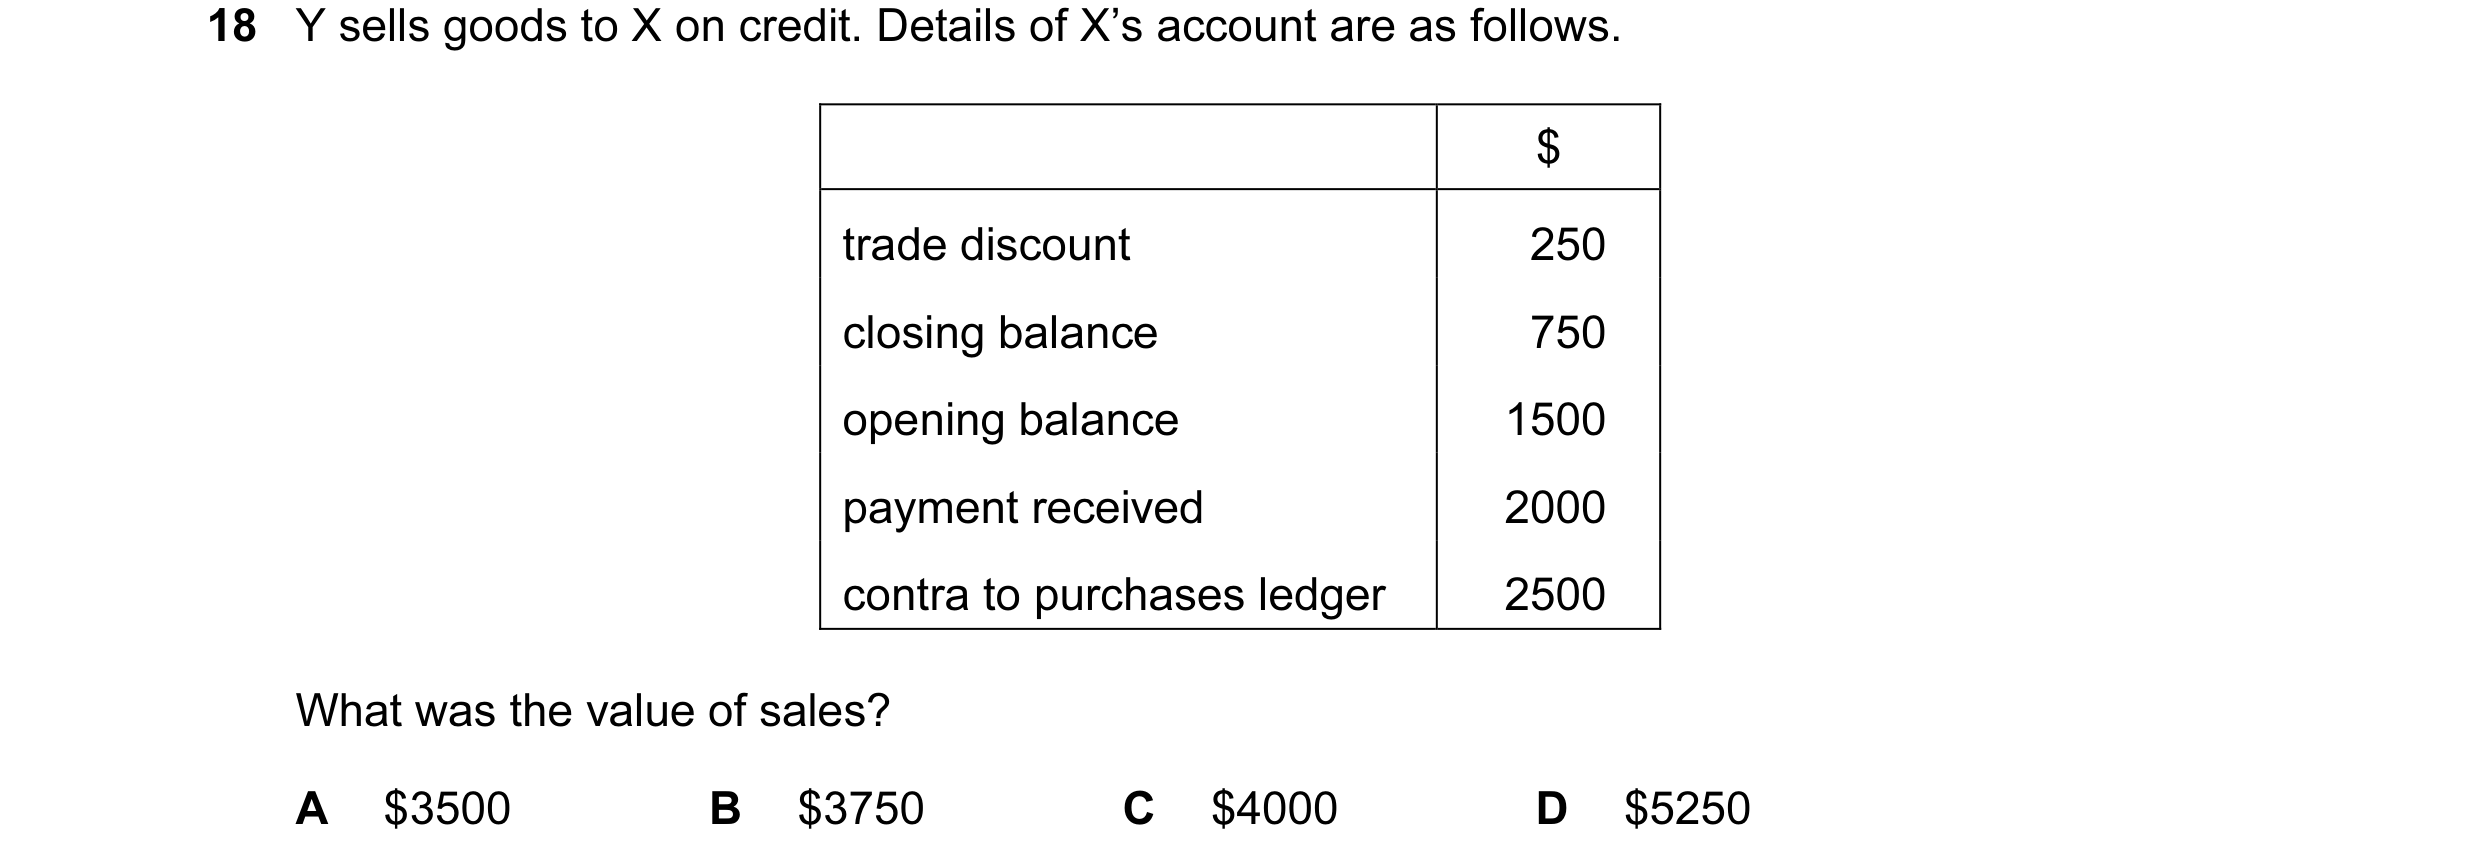 26 / 110
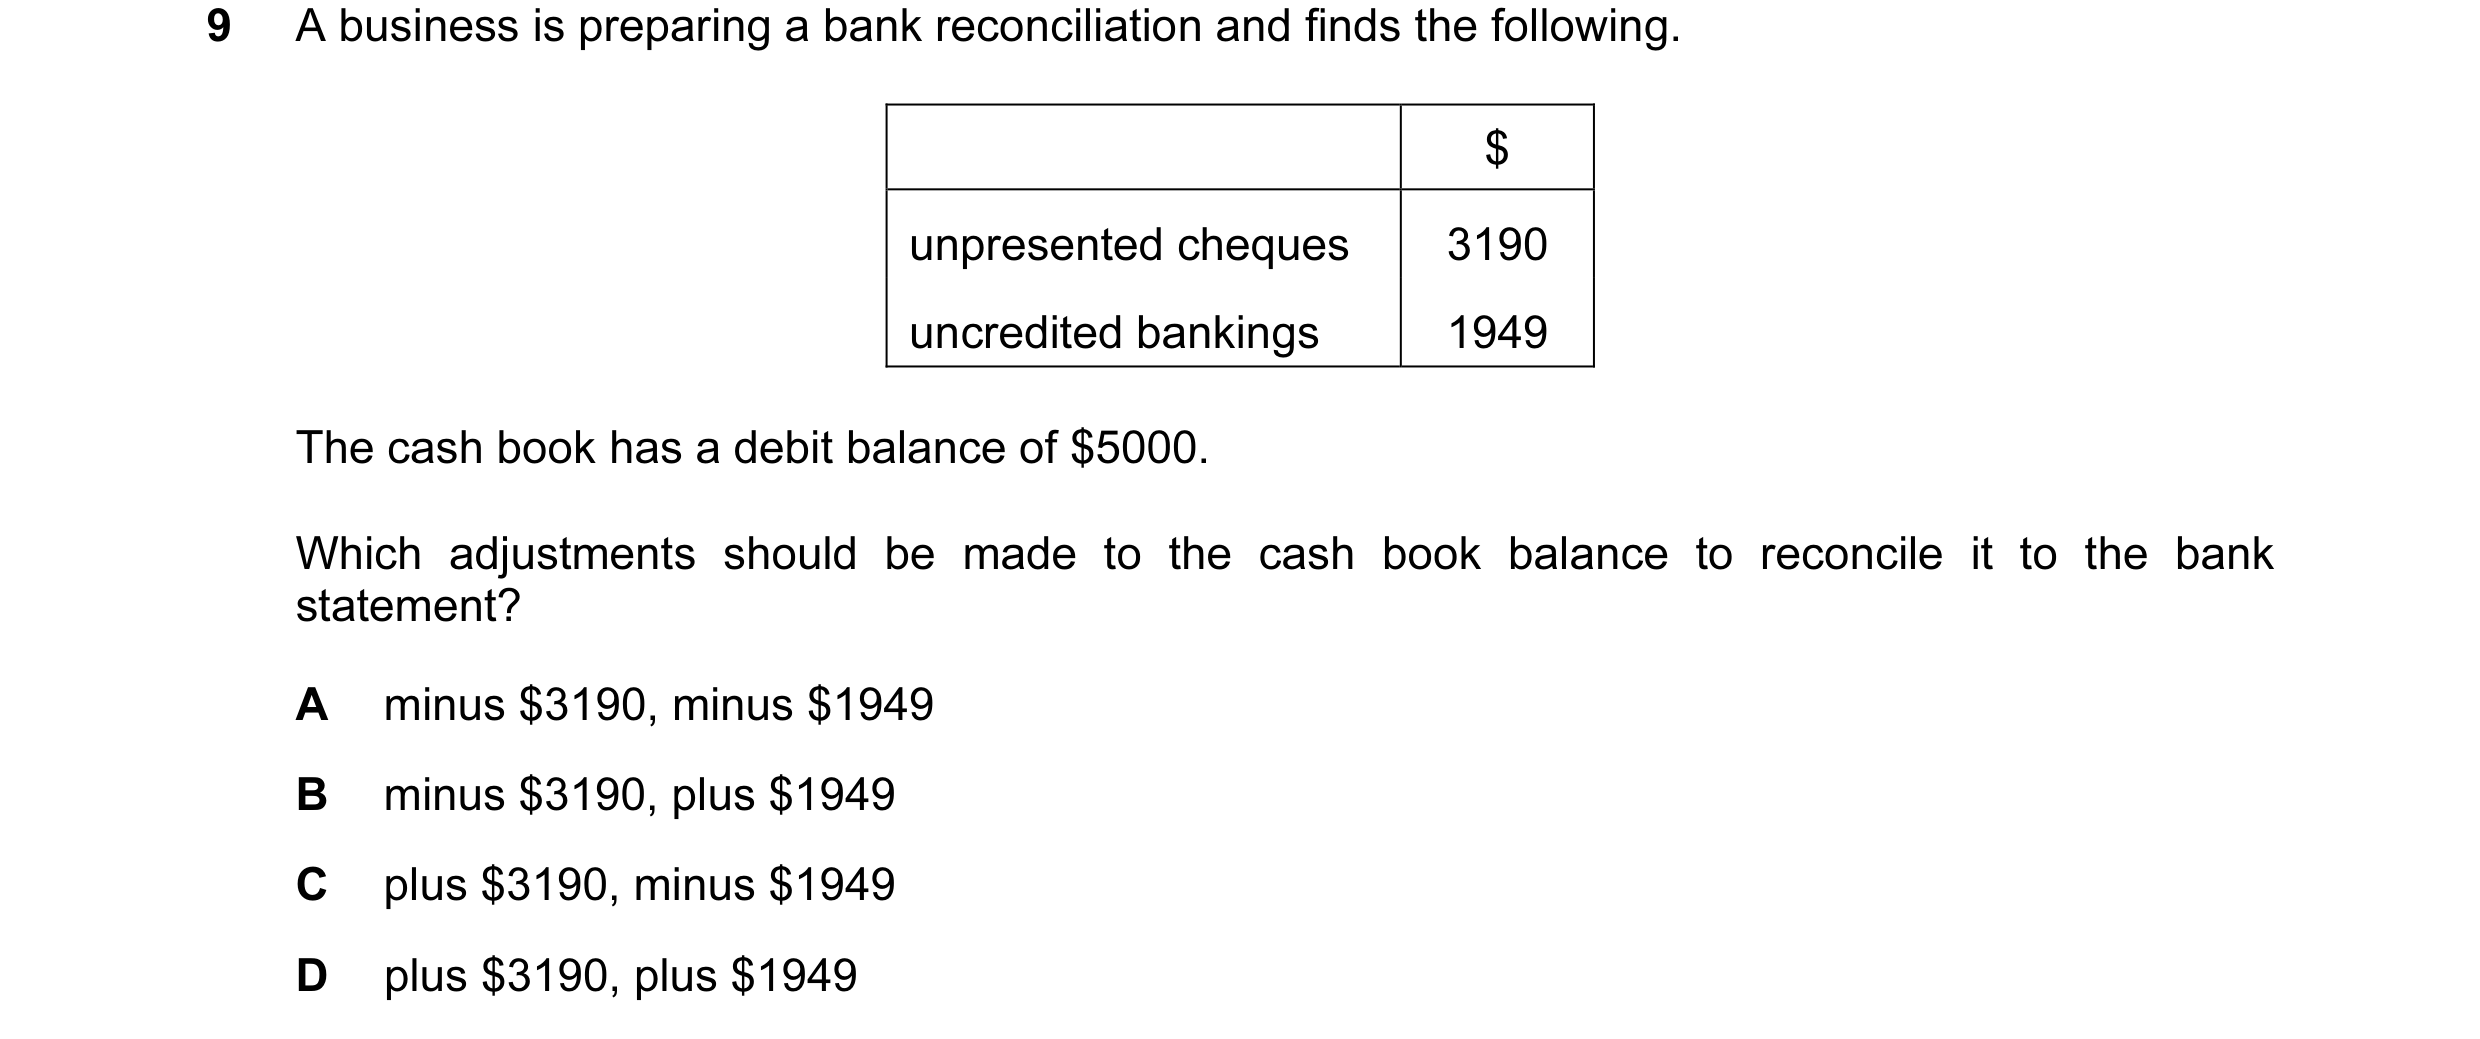
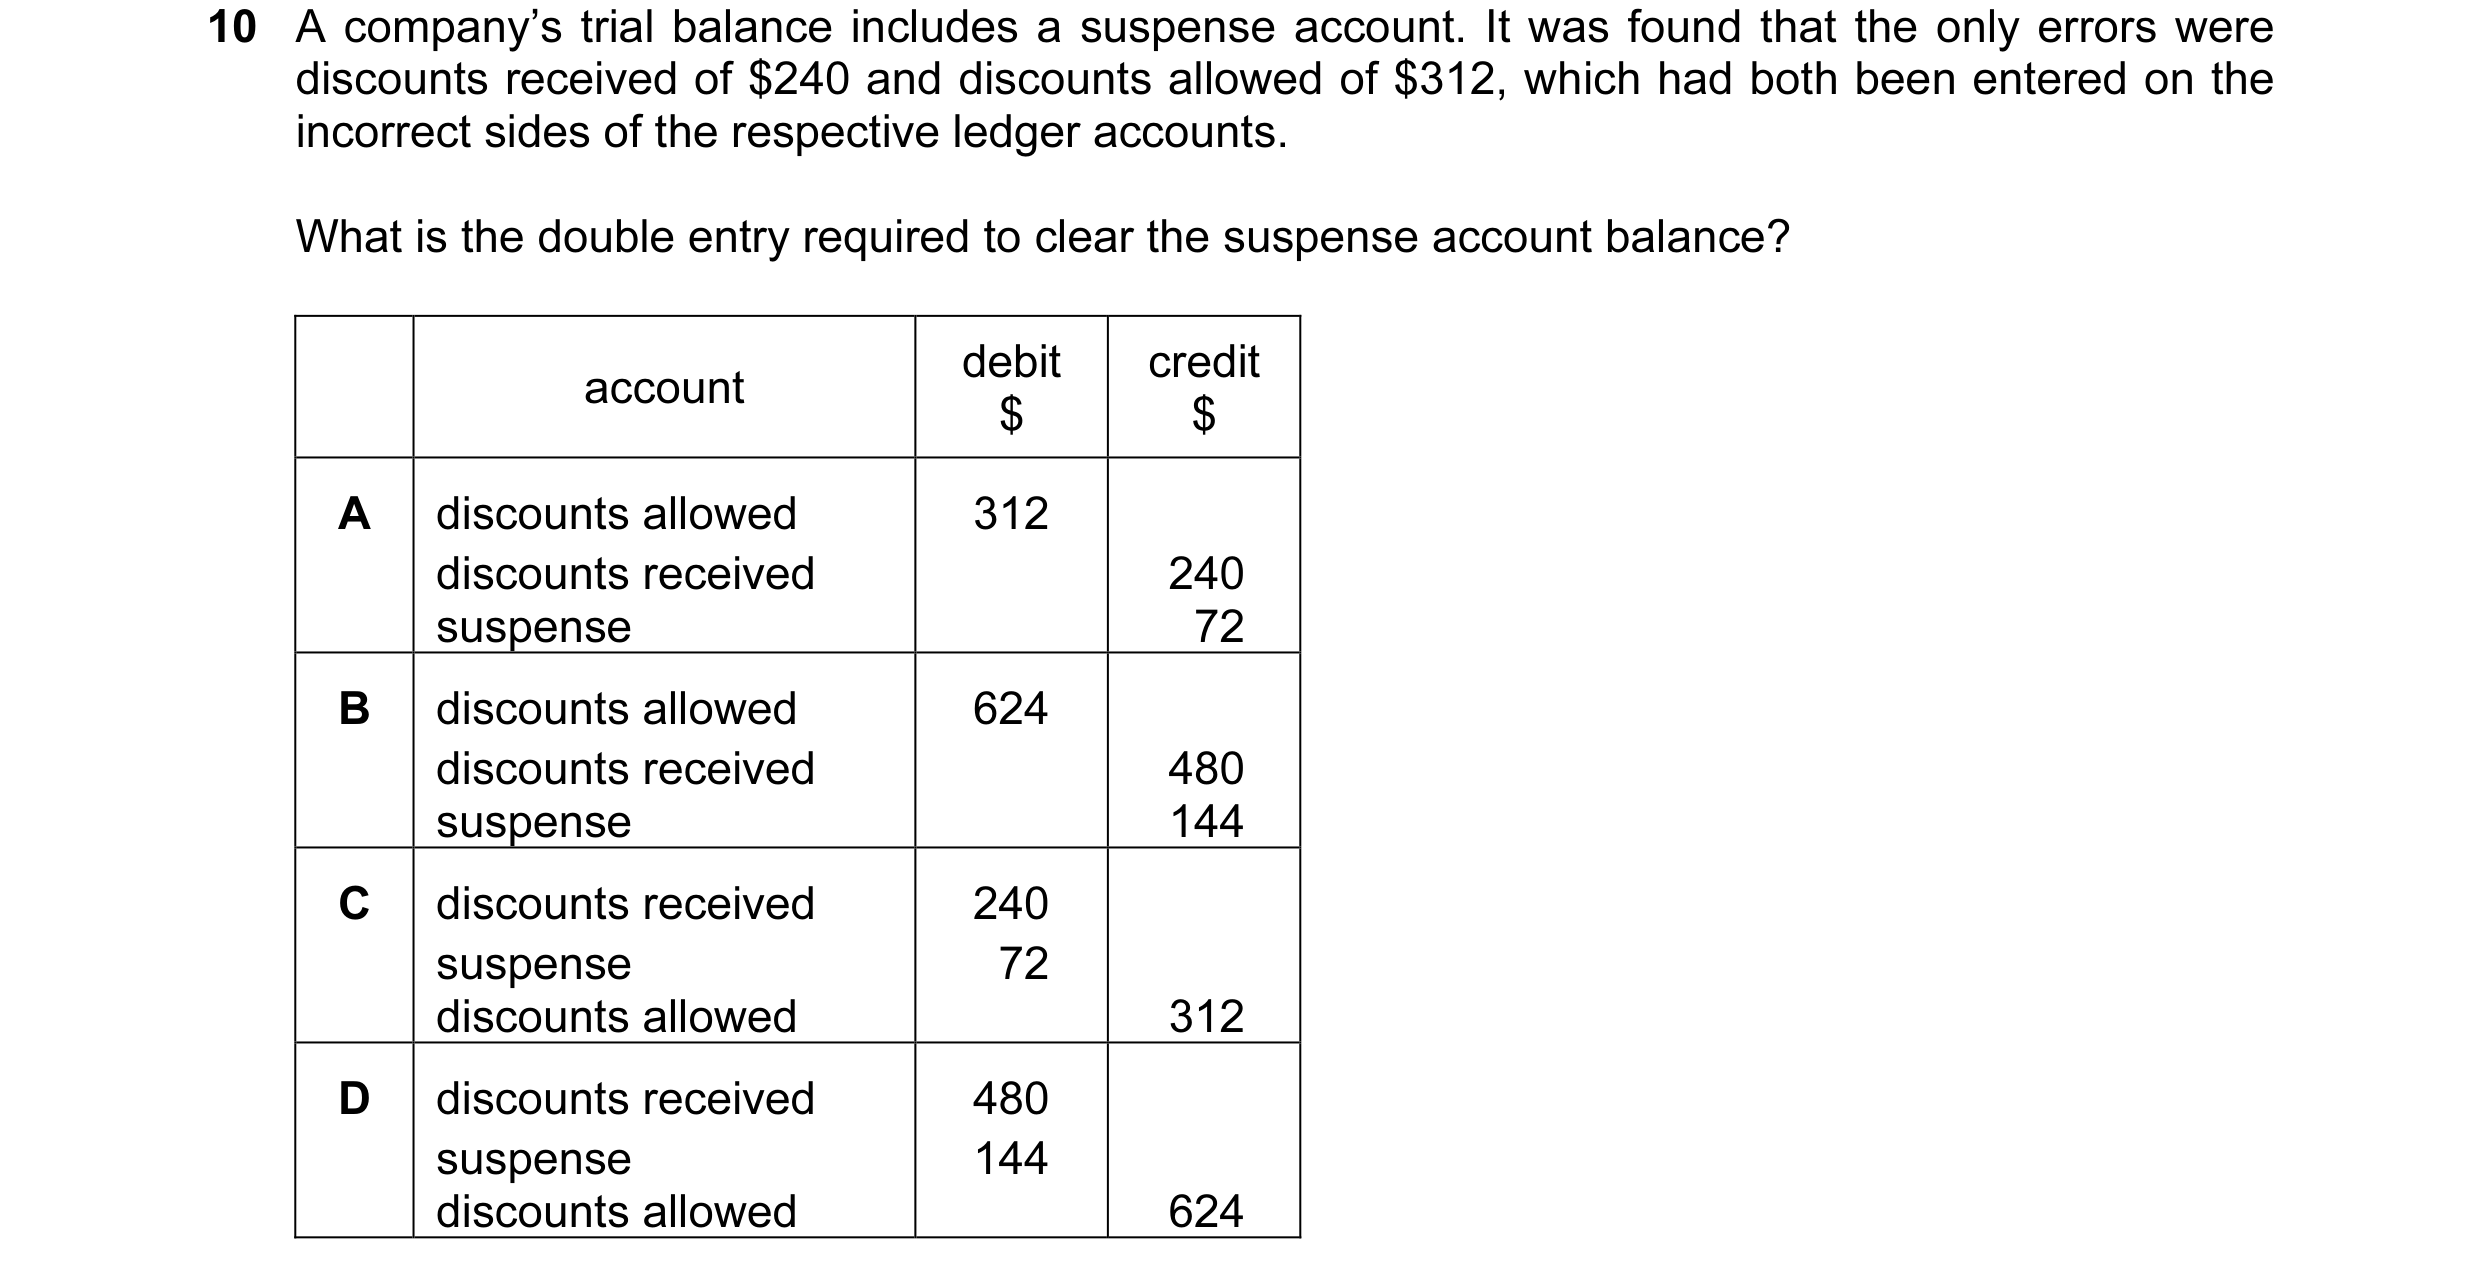
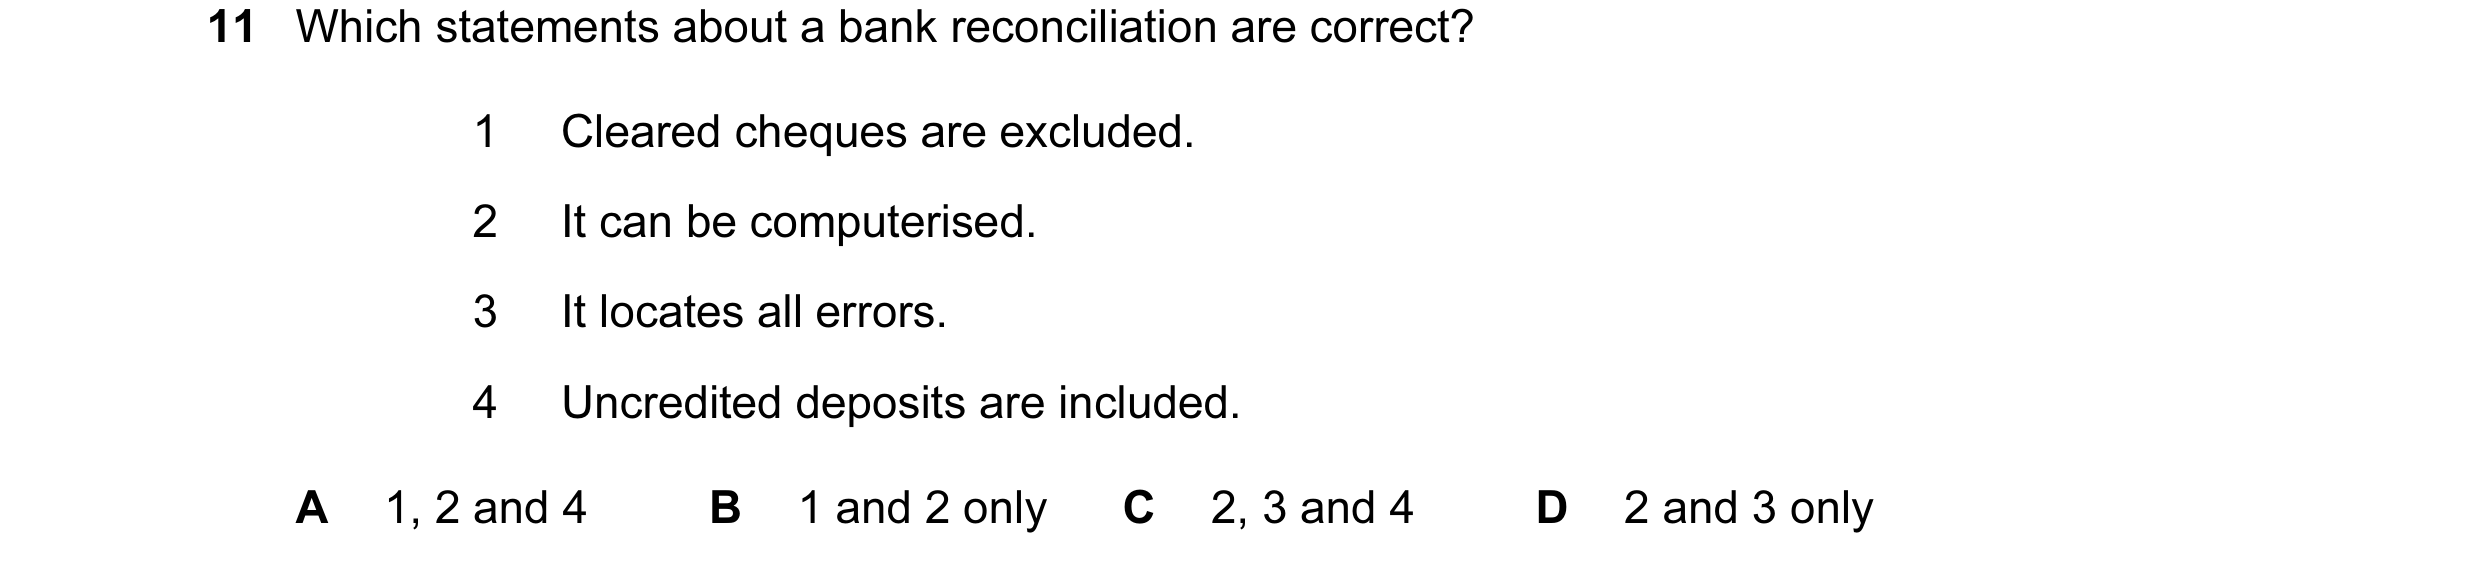 27 / 110
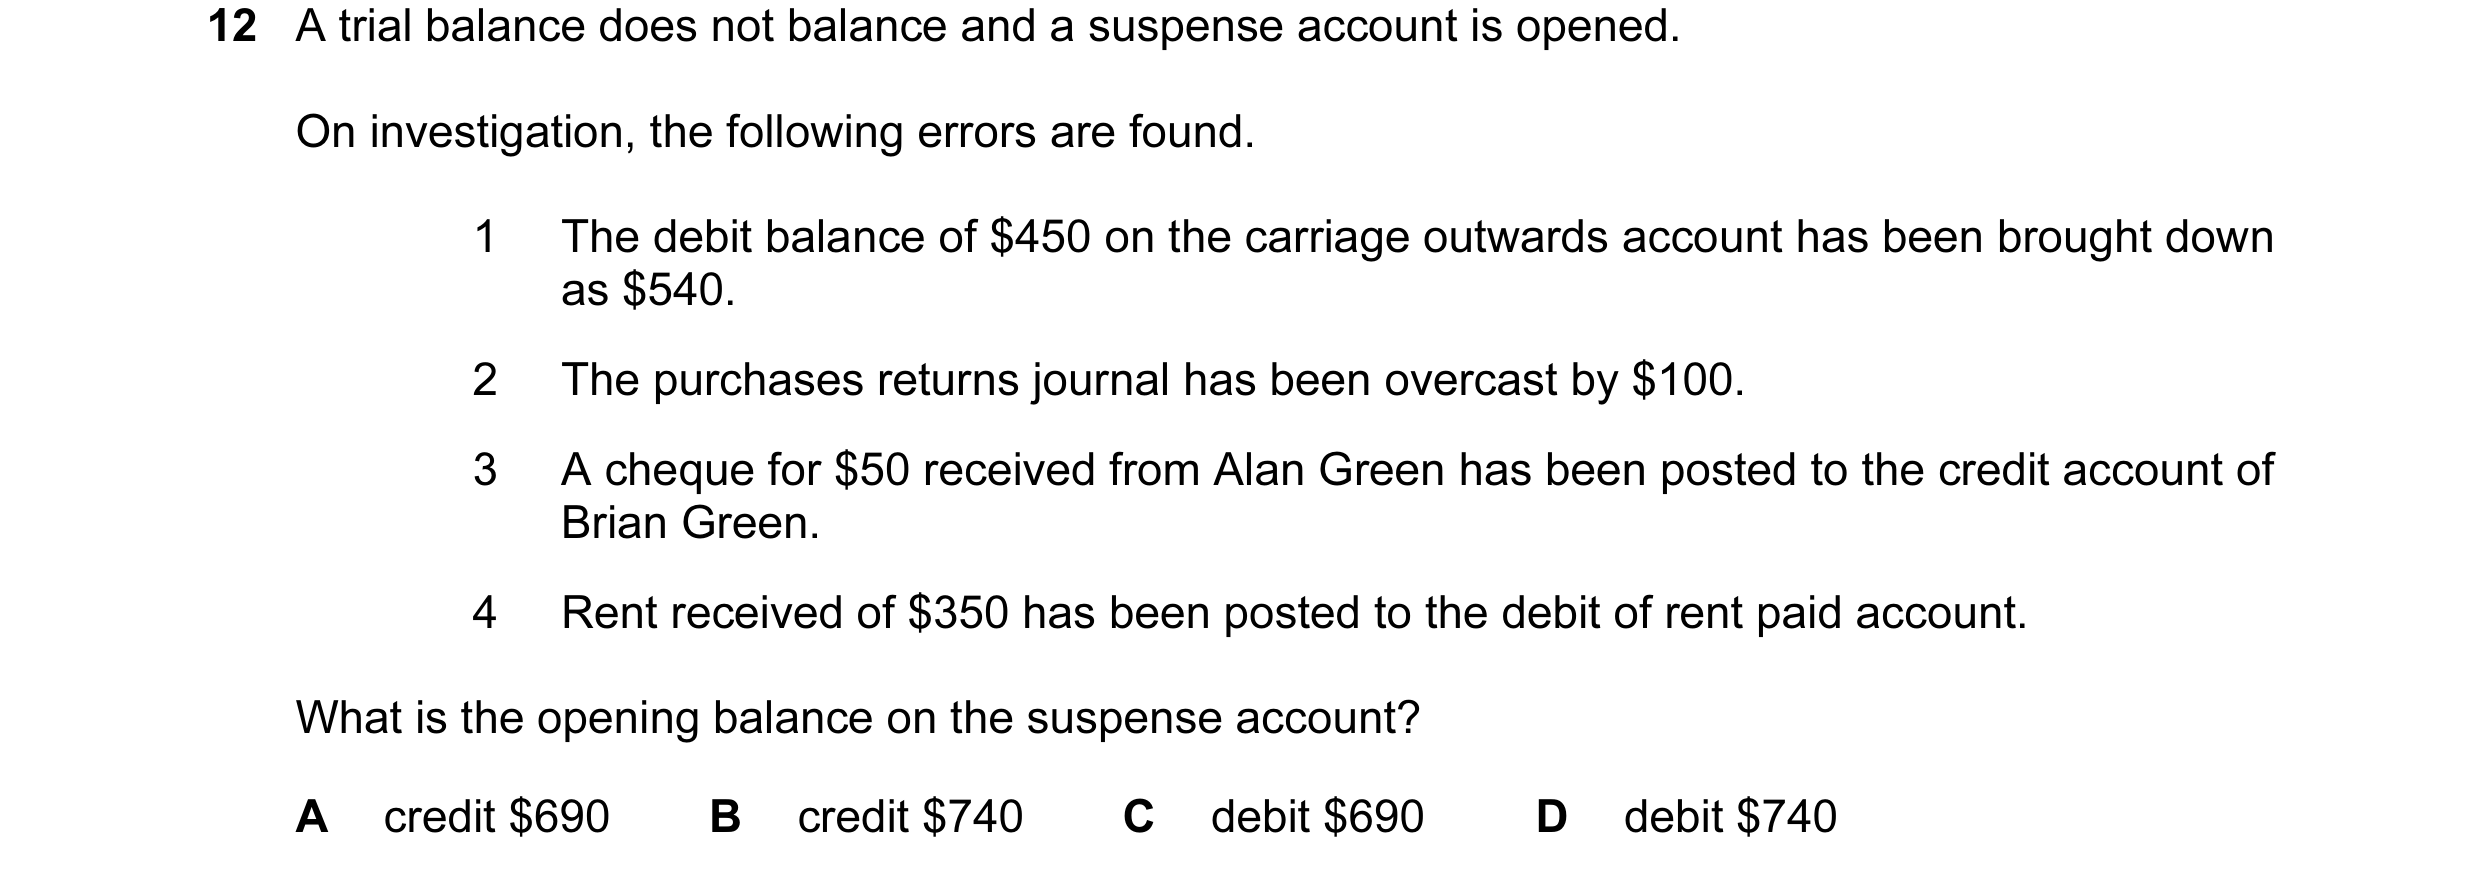
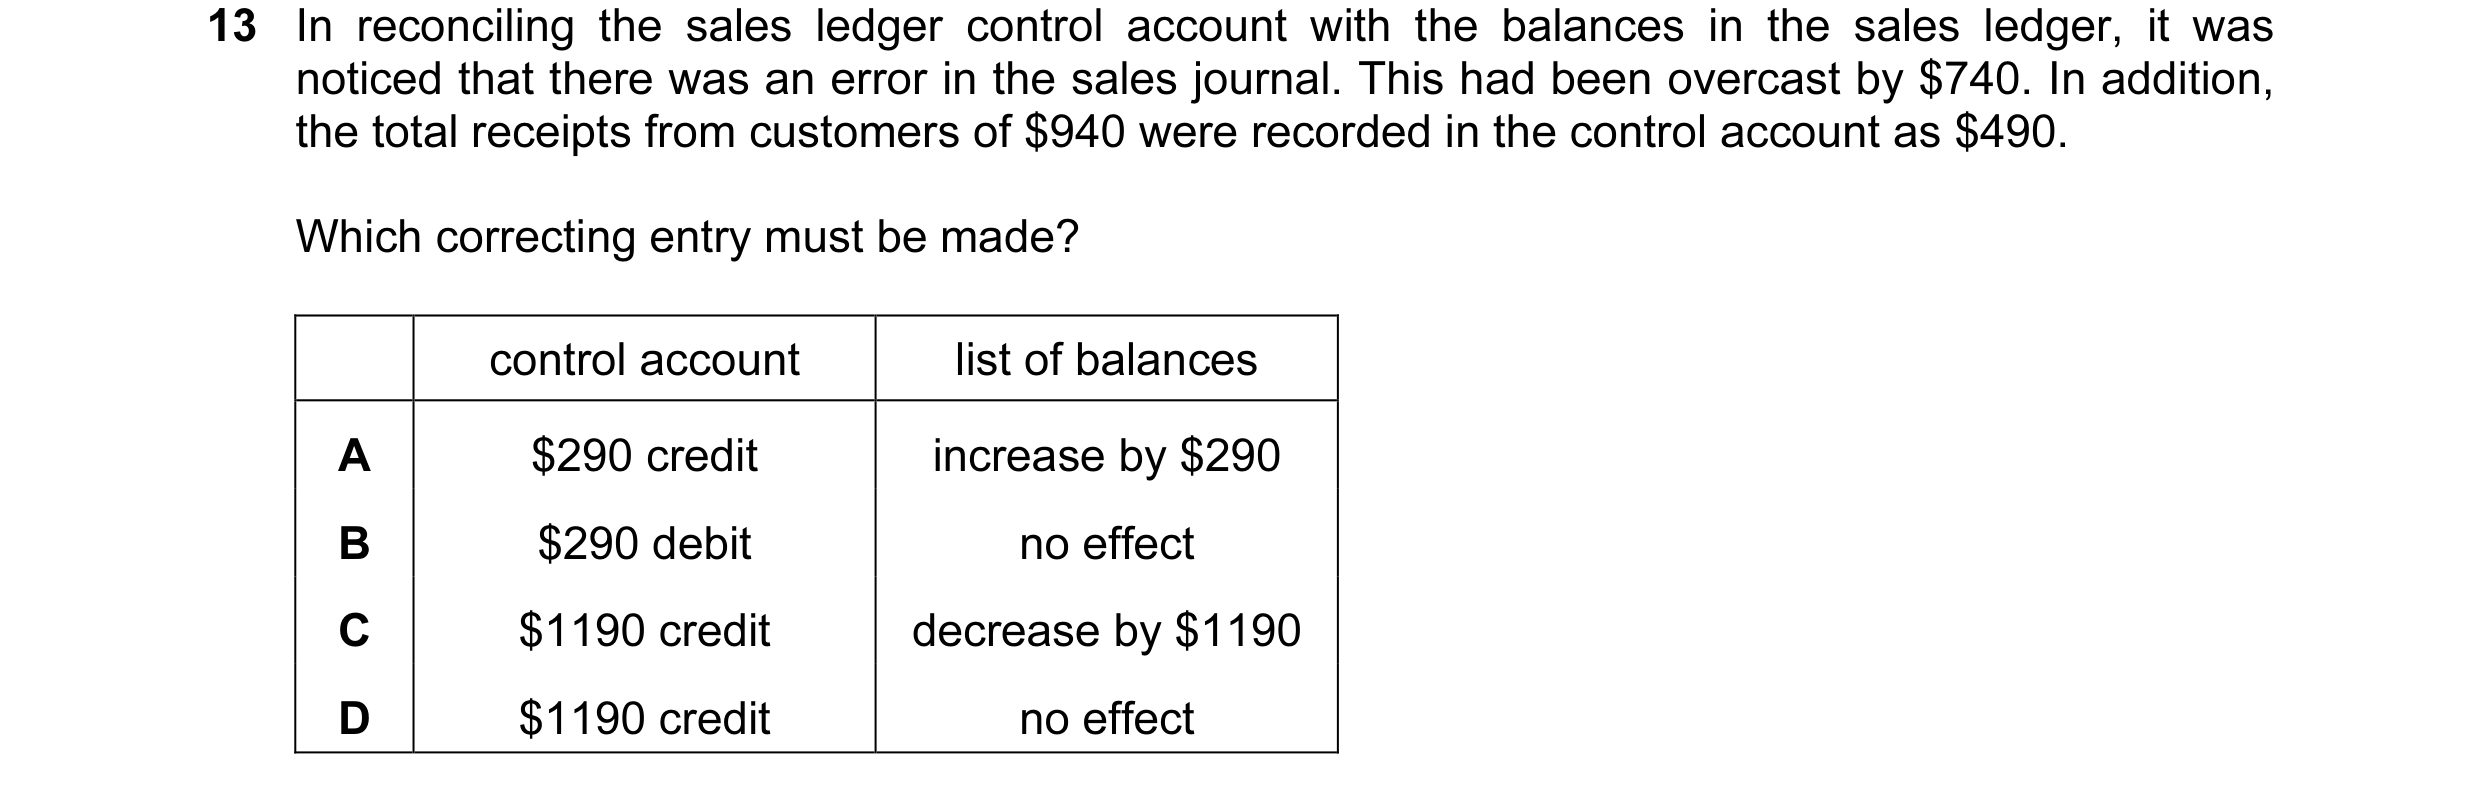
 28 / 110
 29 / 110
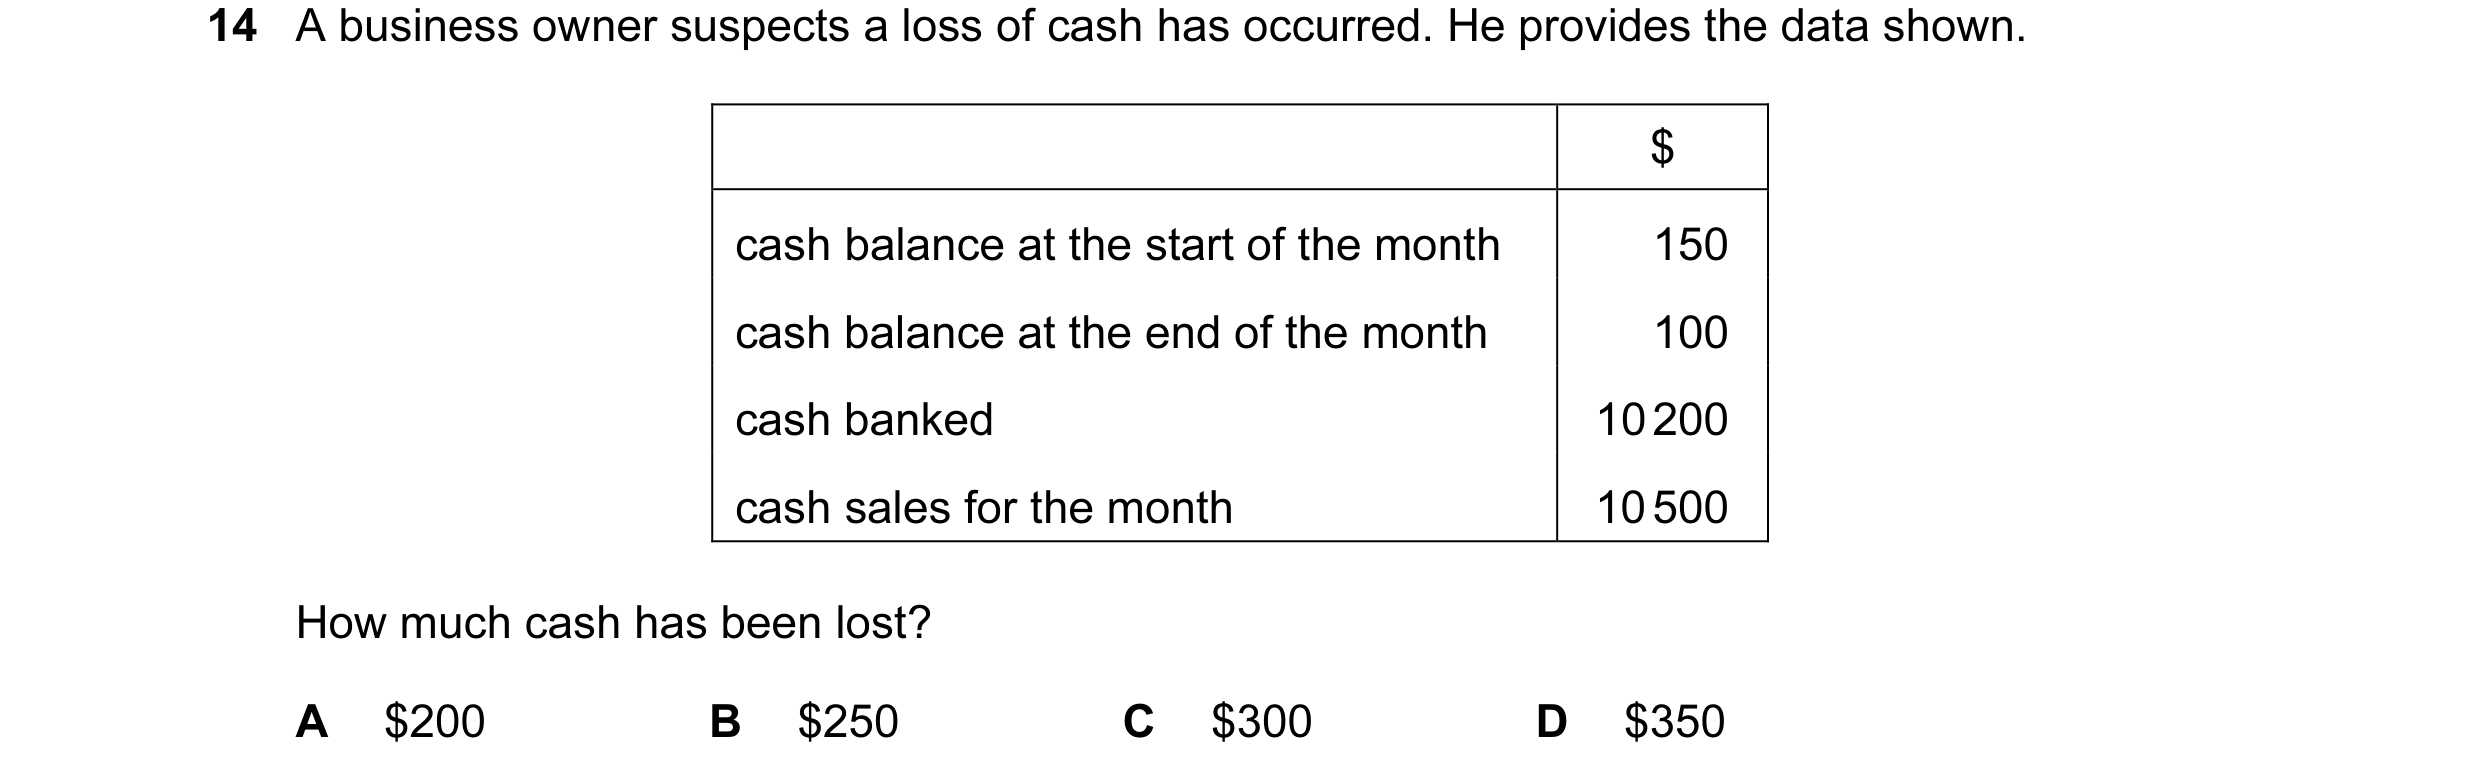
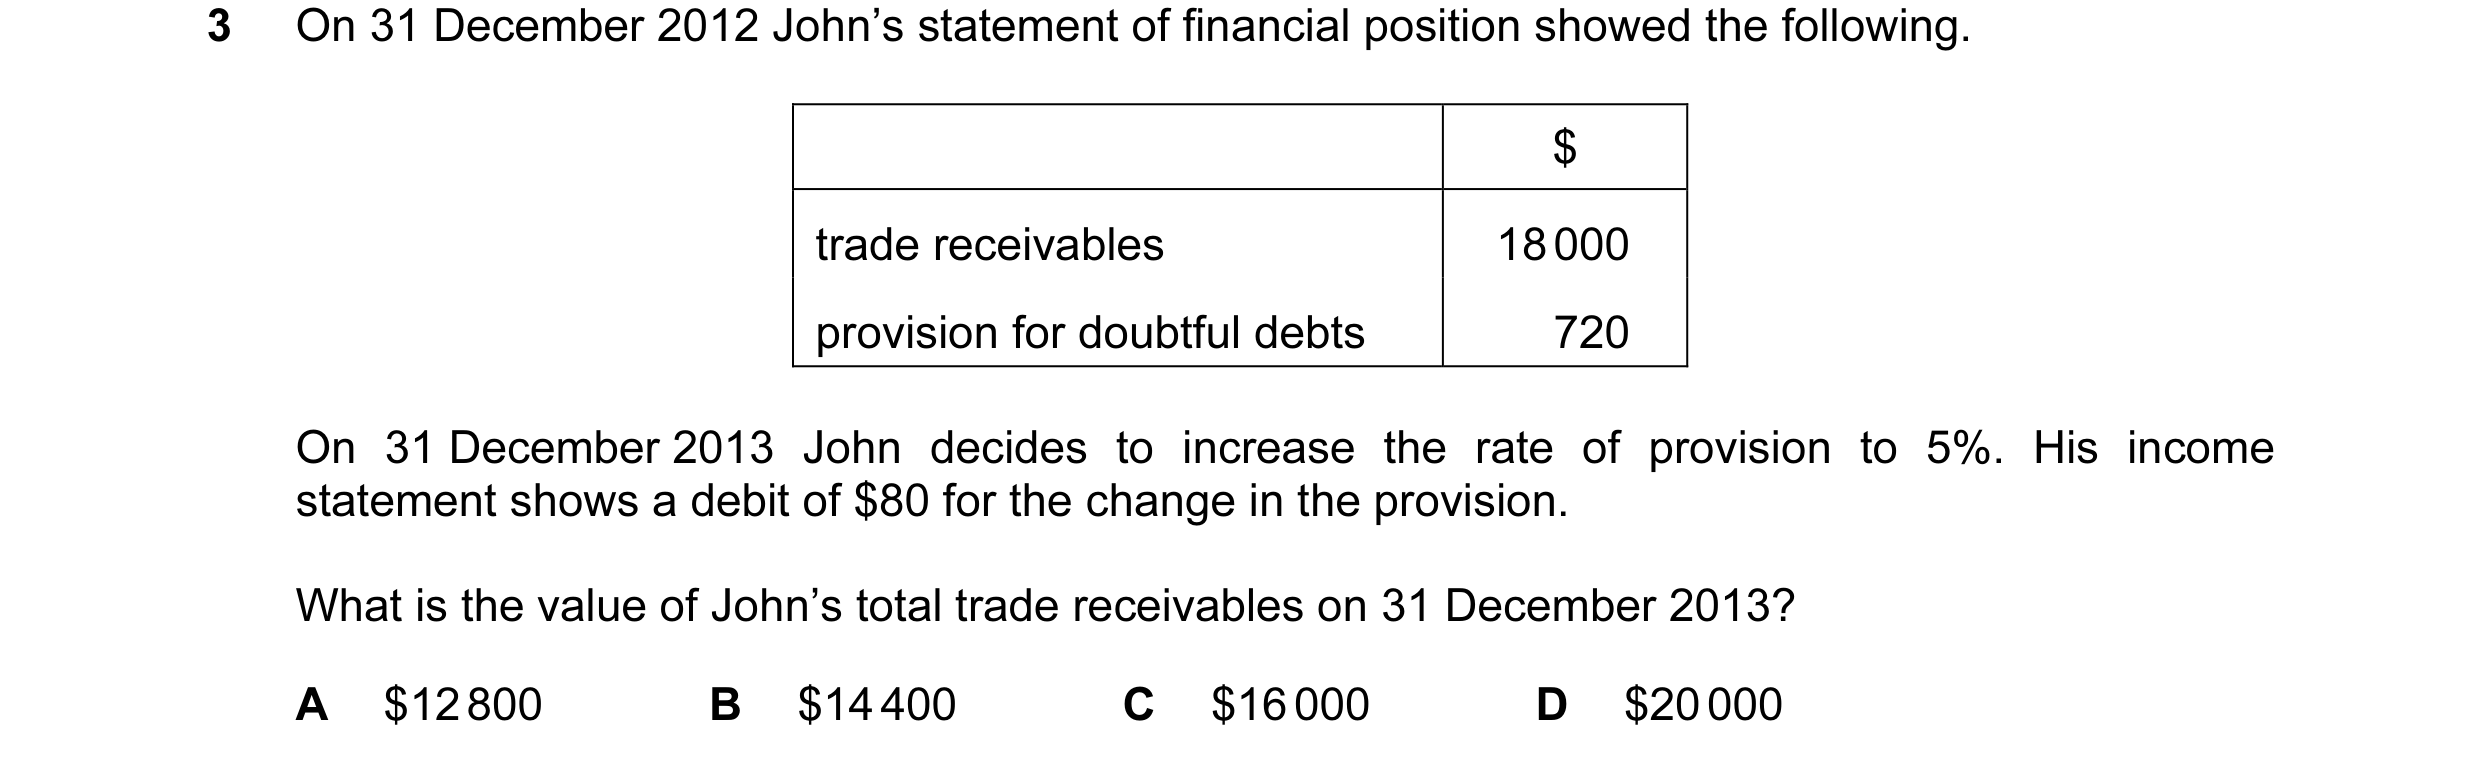 30 / 110
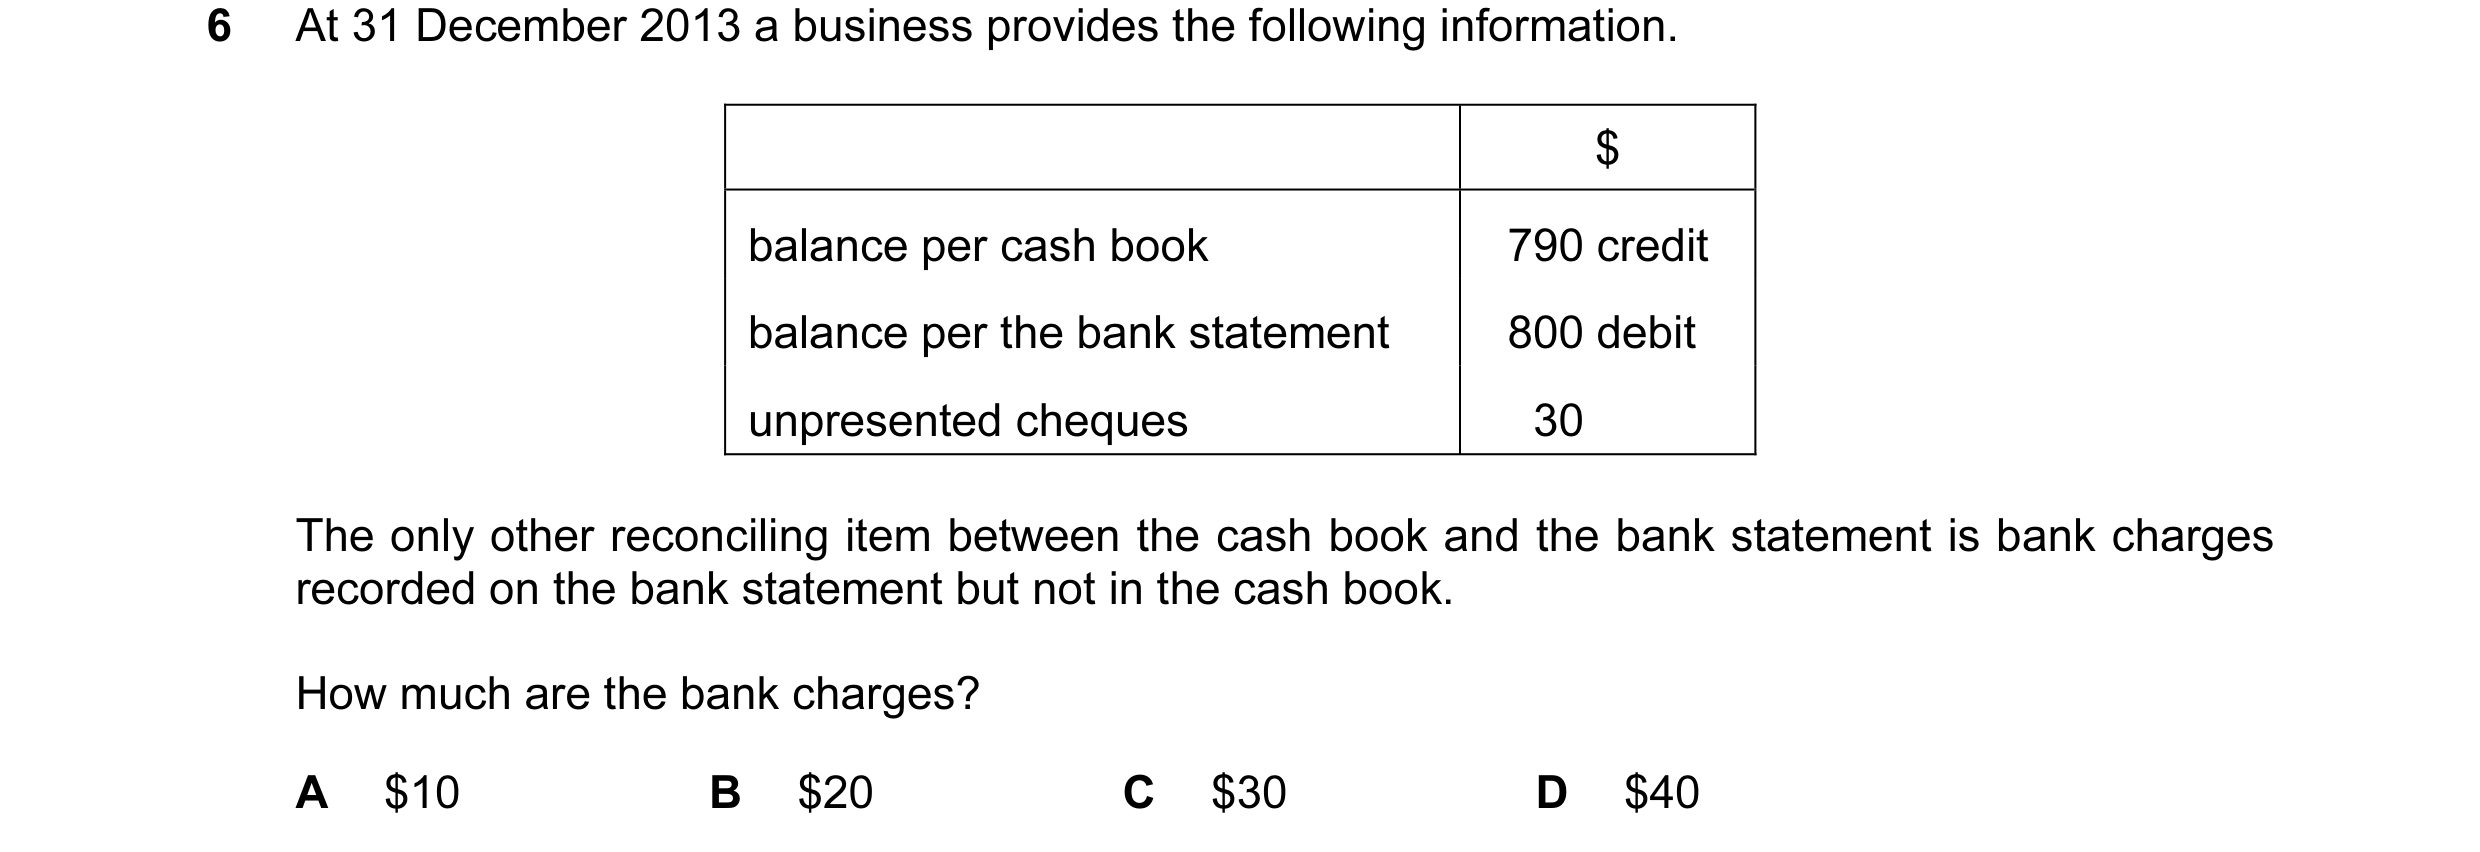
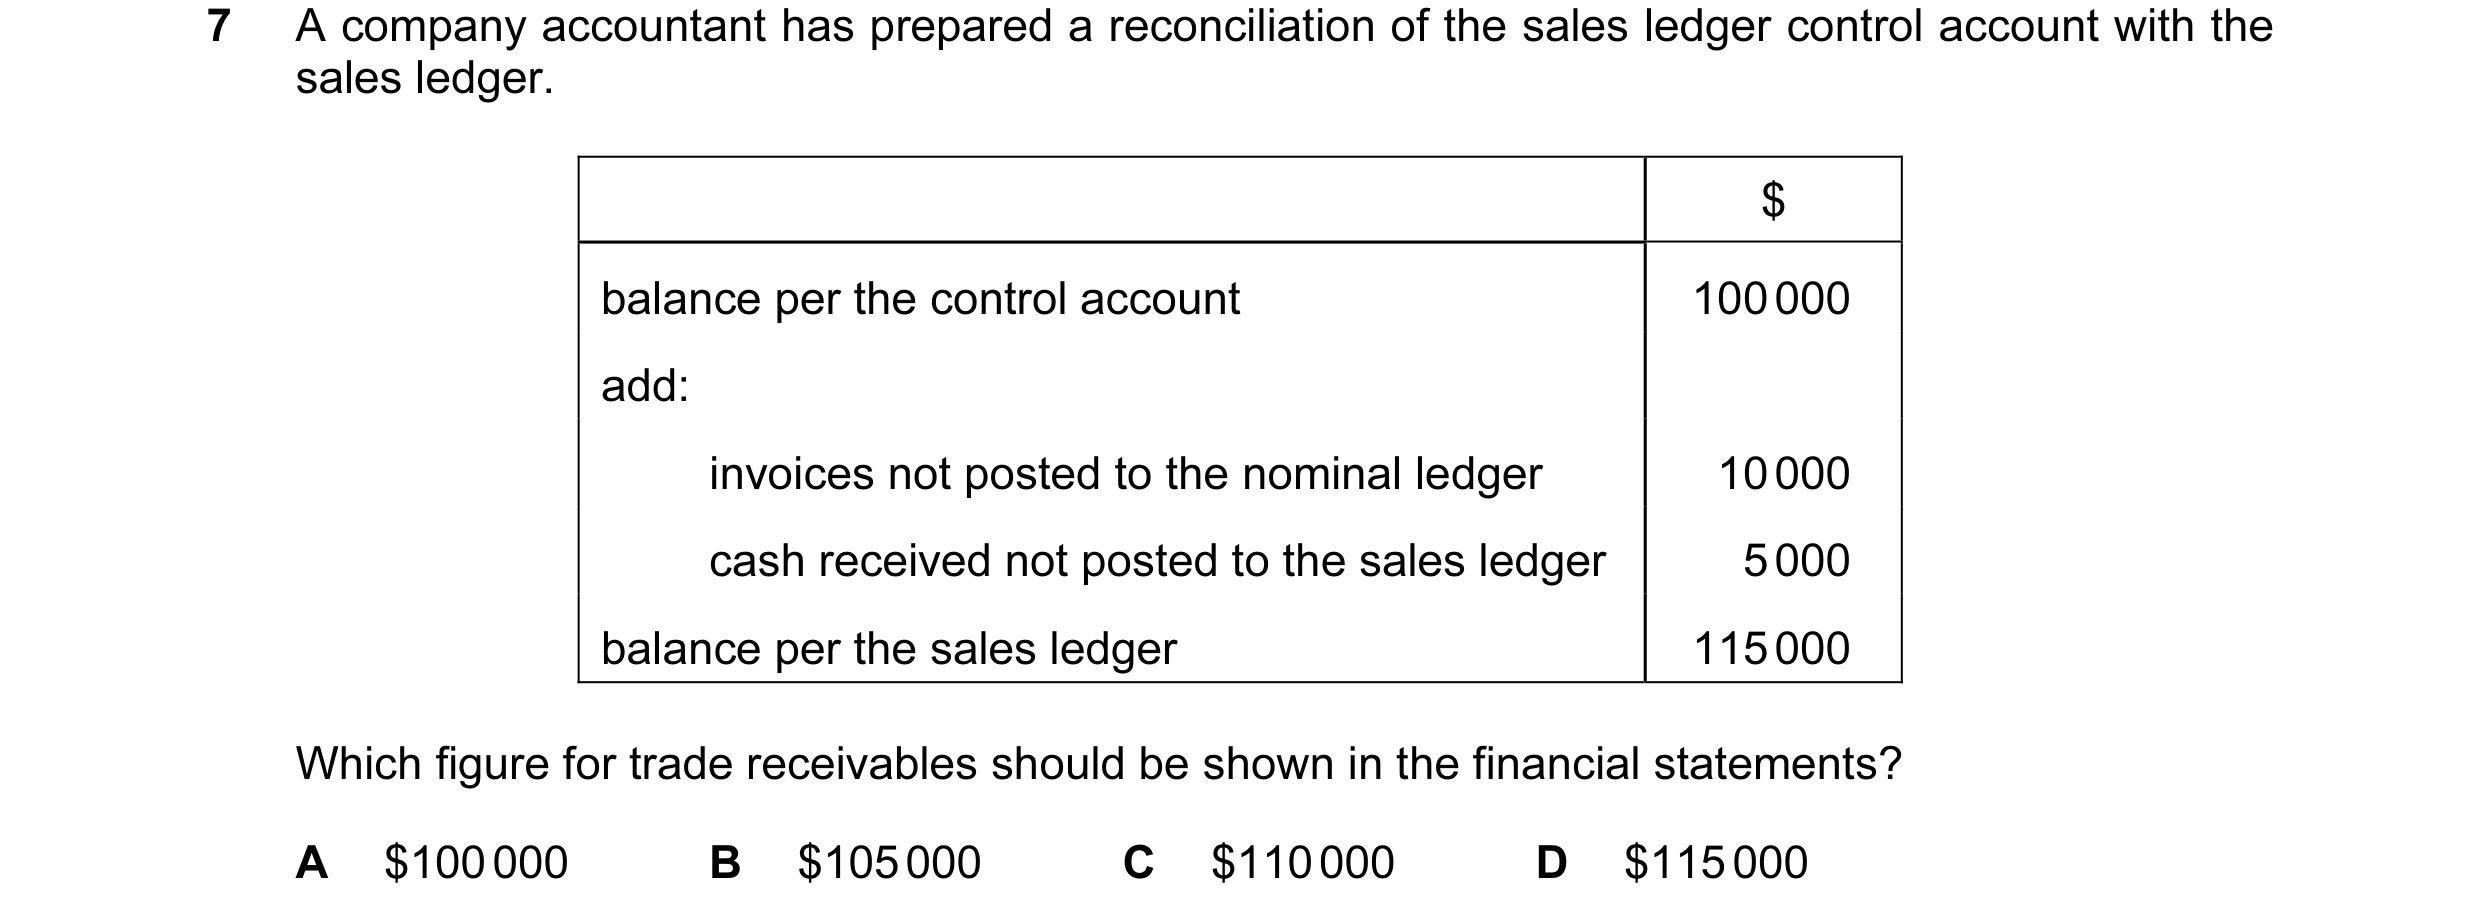
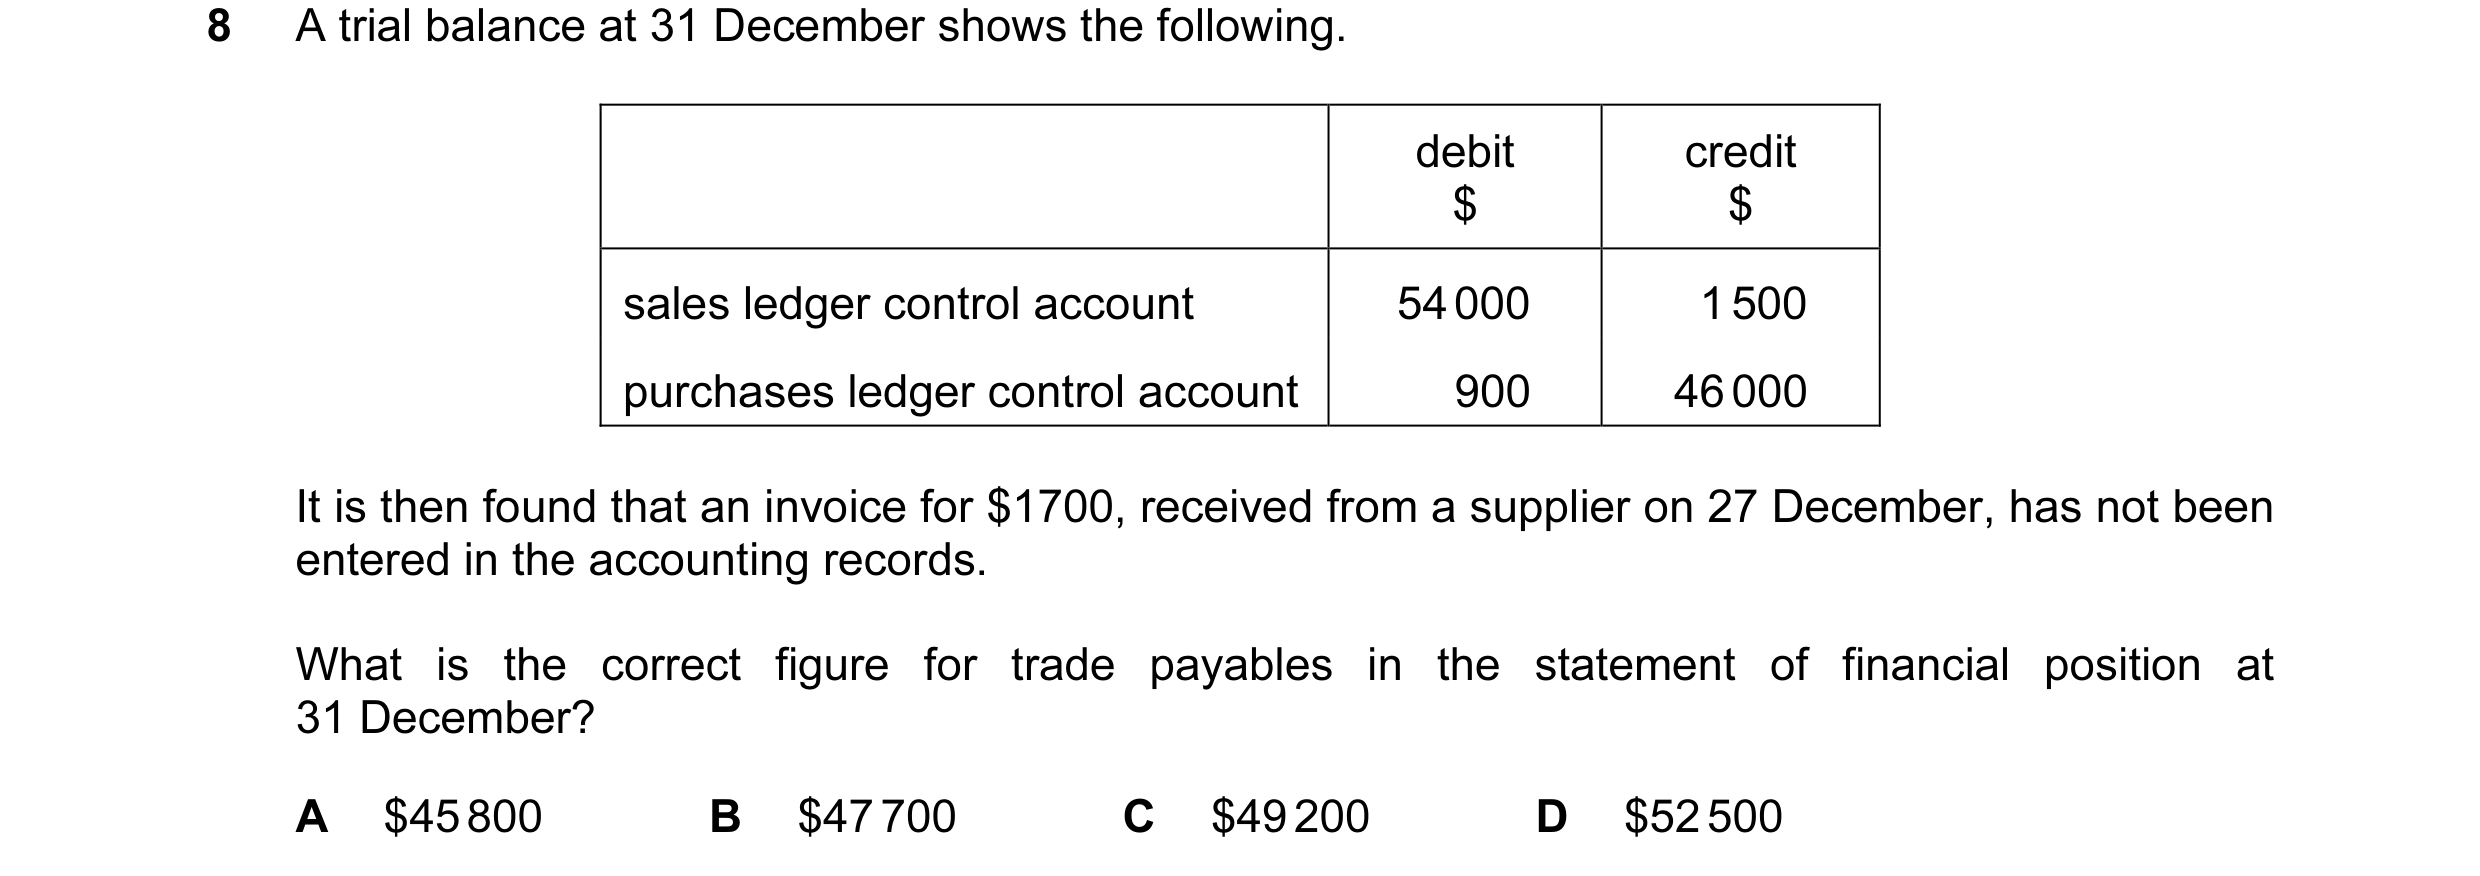 31 / 110
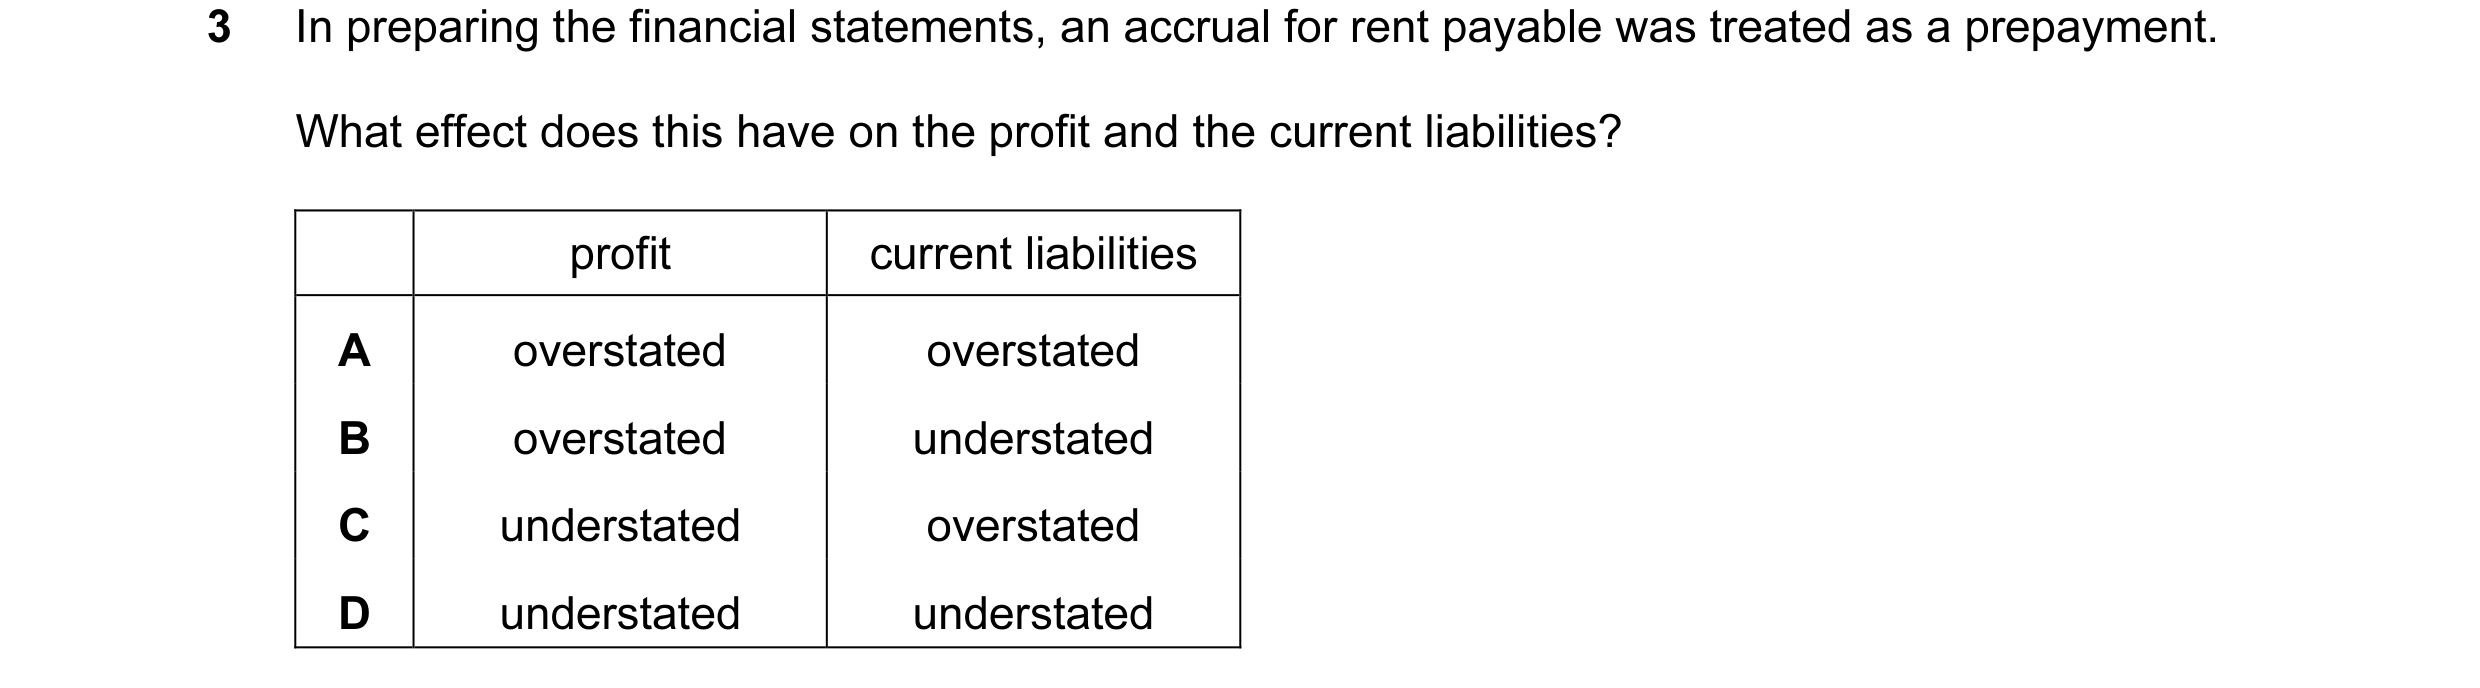
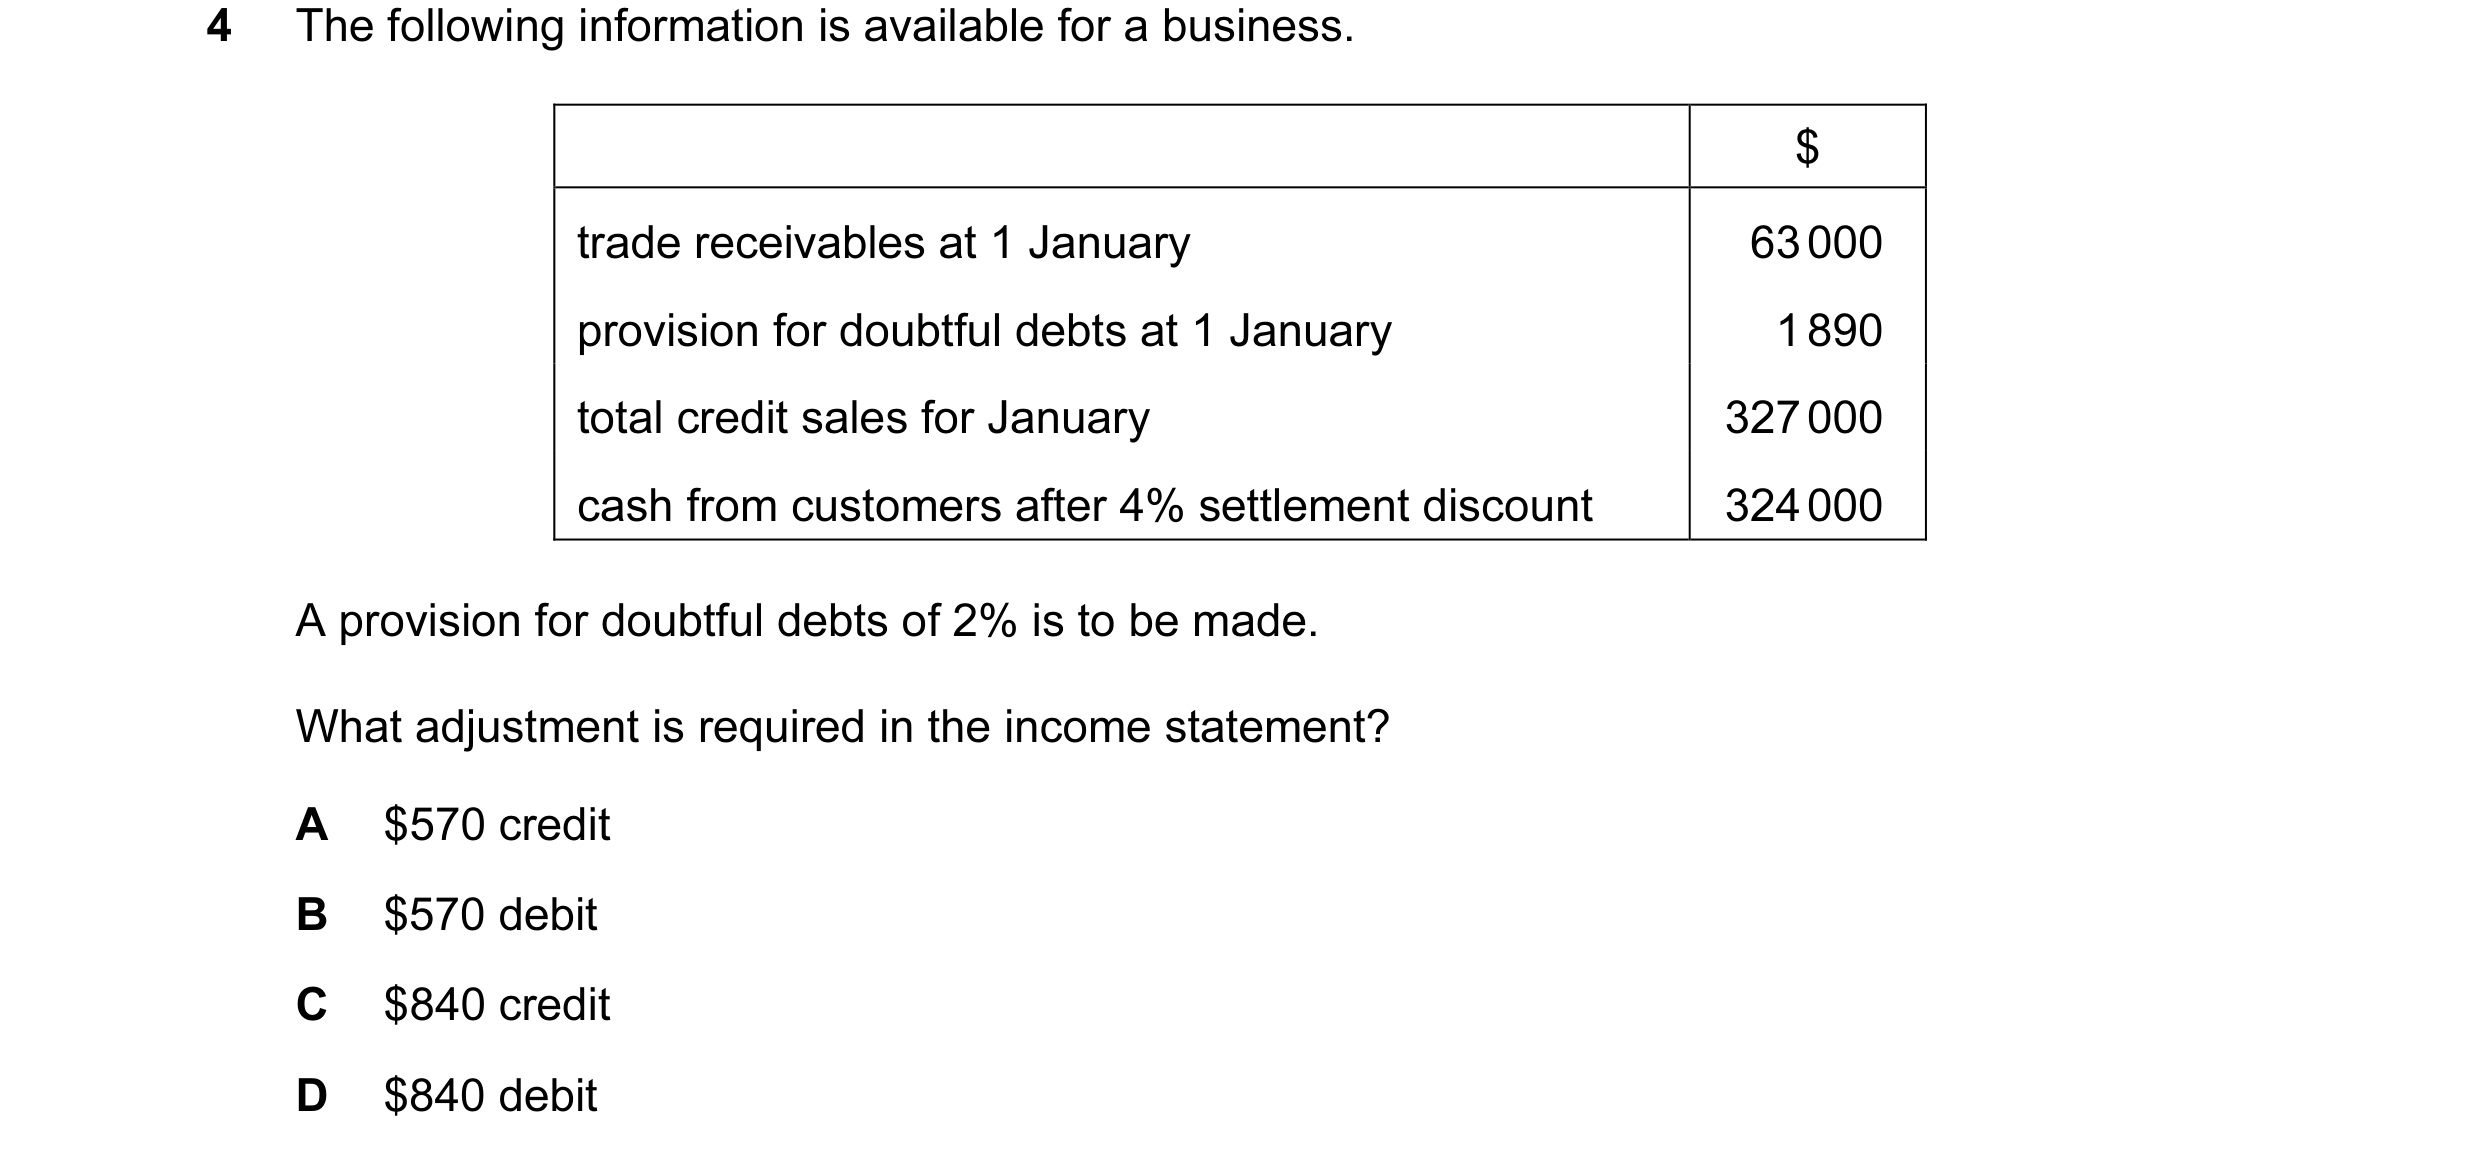 32 / 110
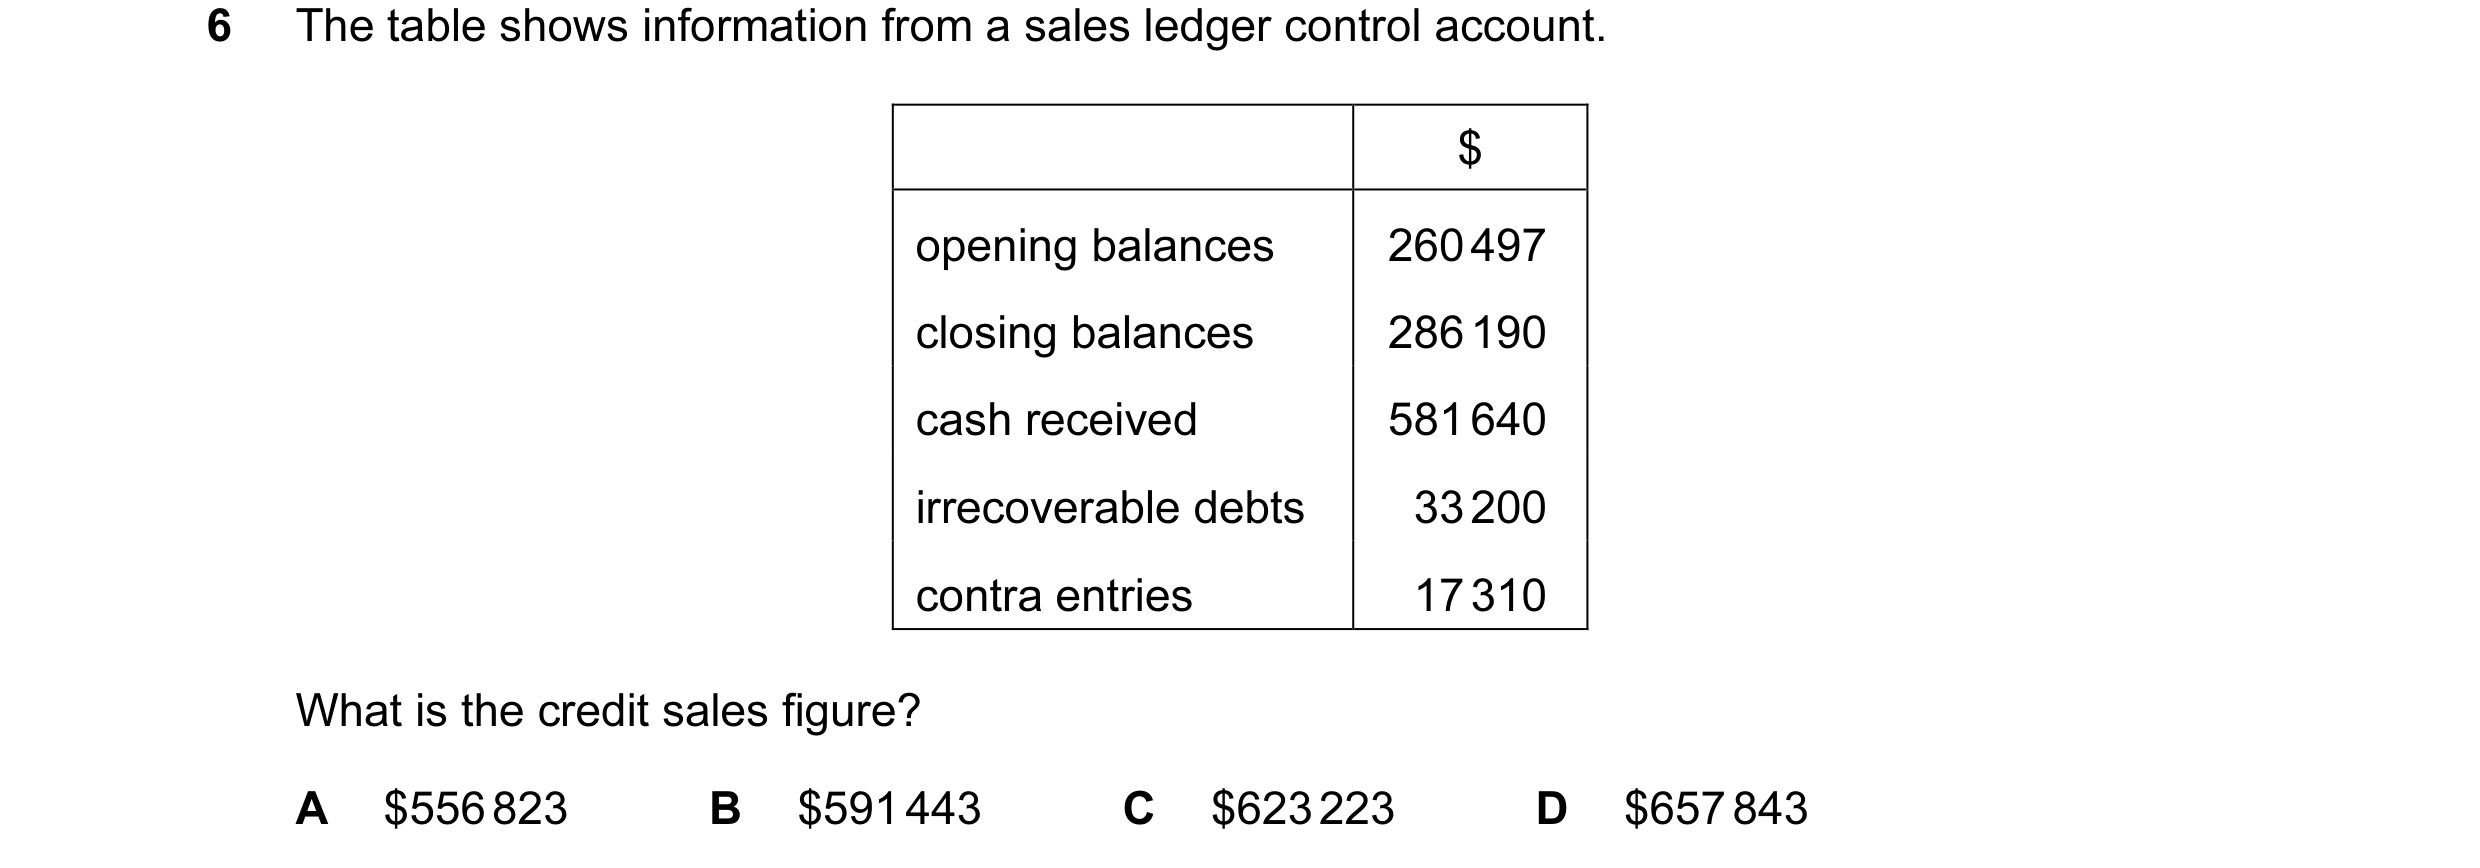
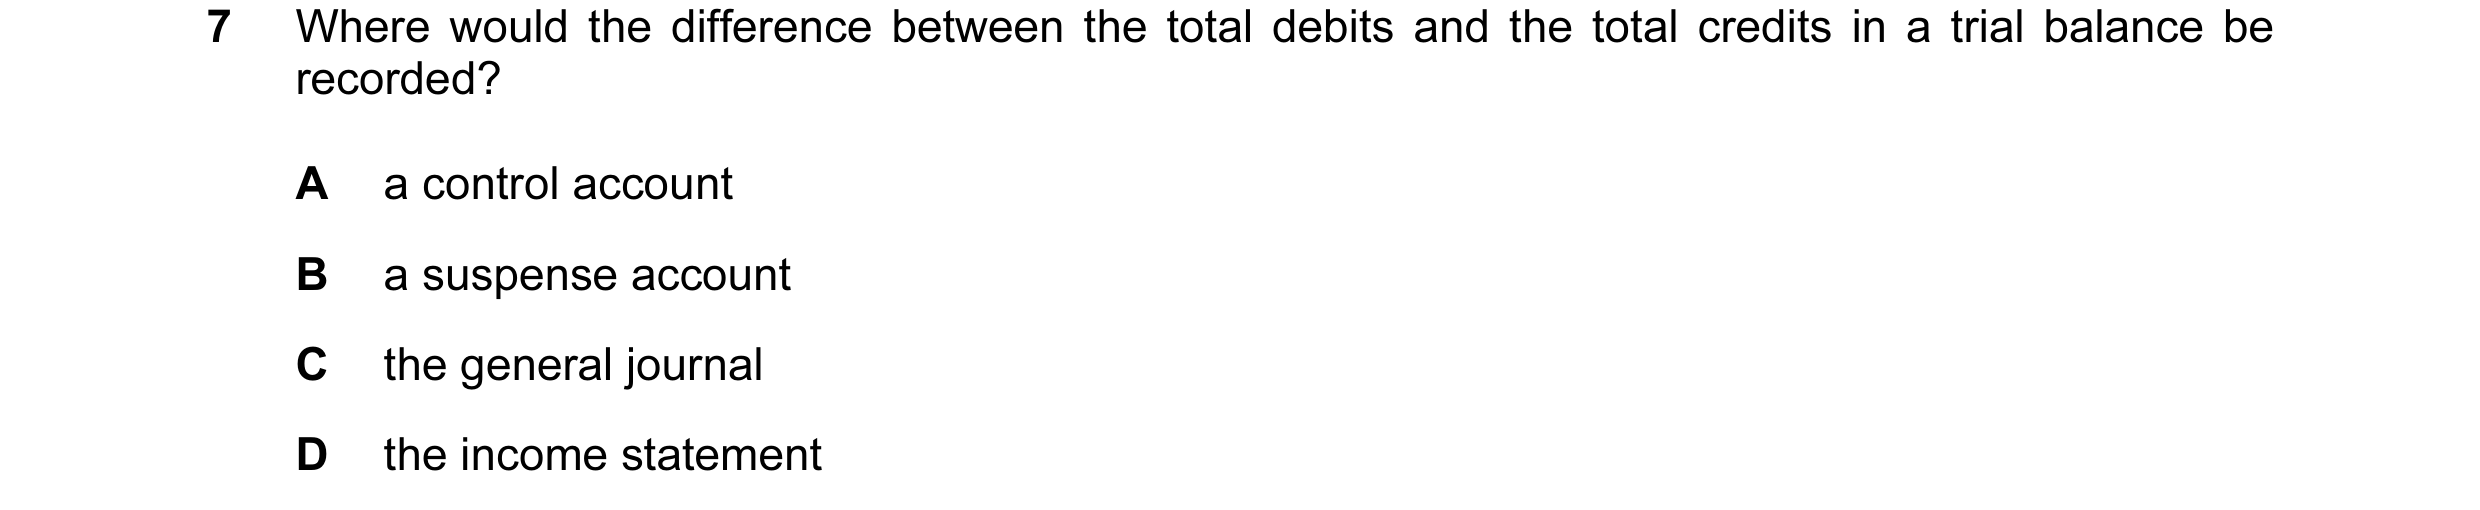
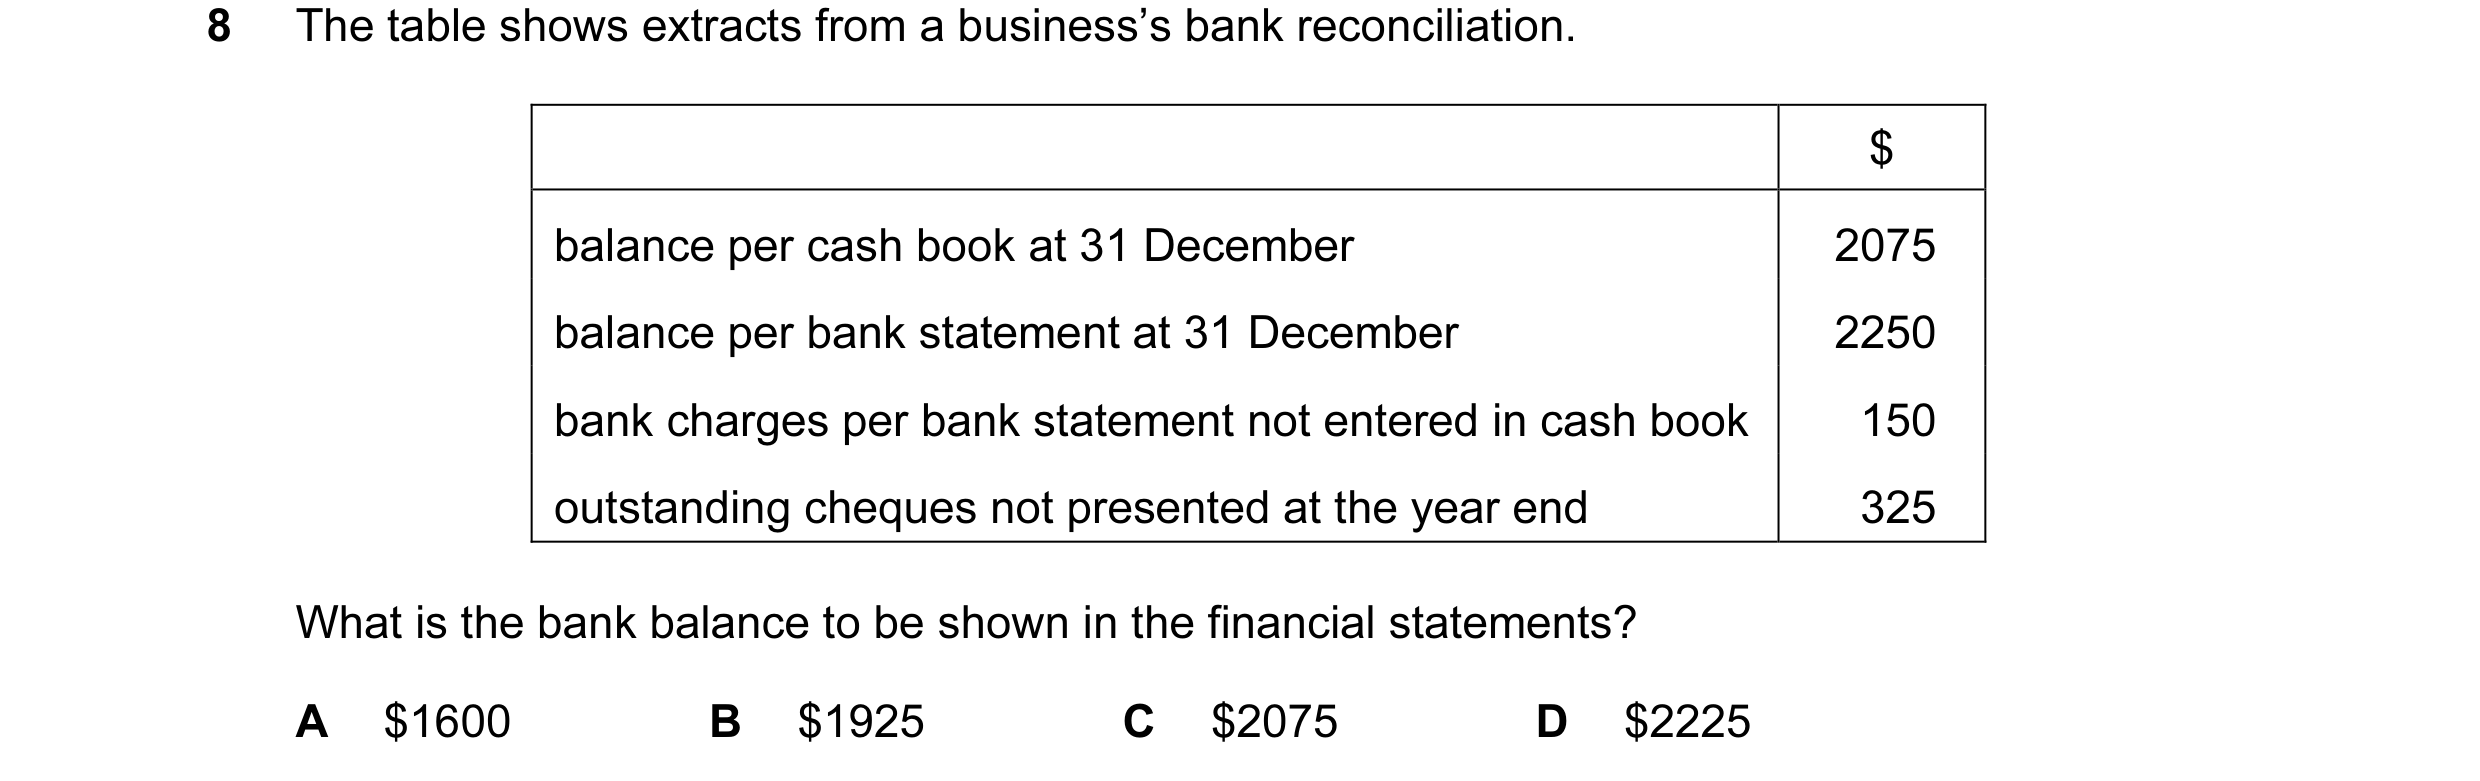
 33 / 110
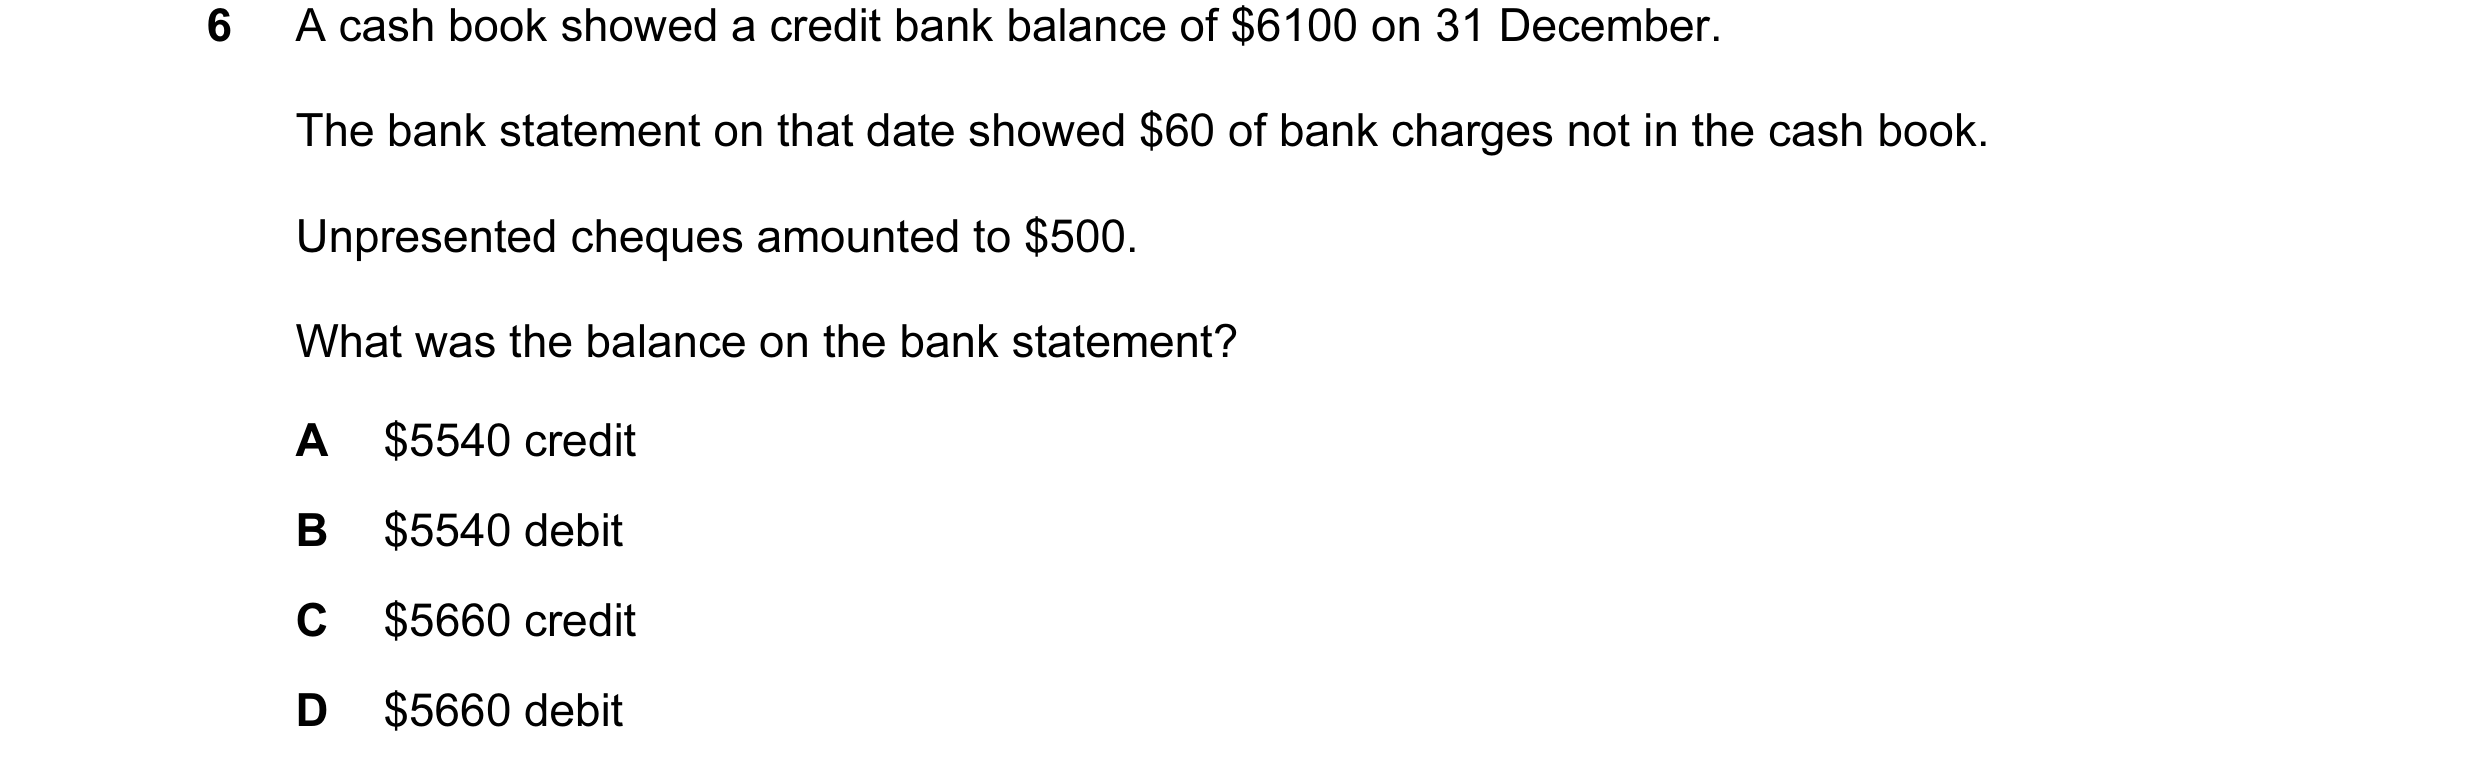
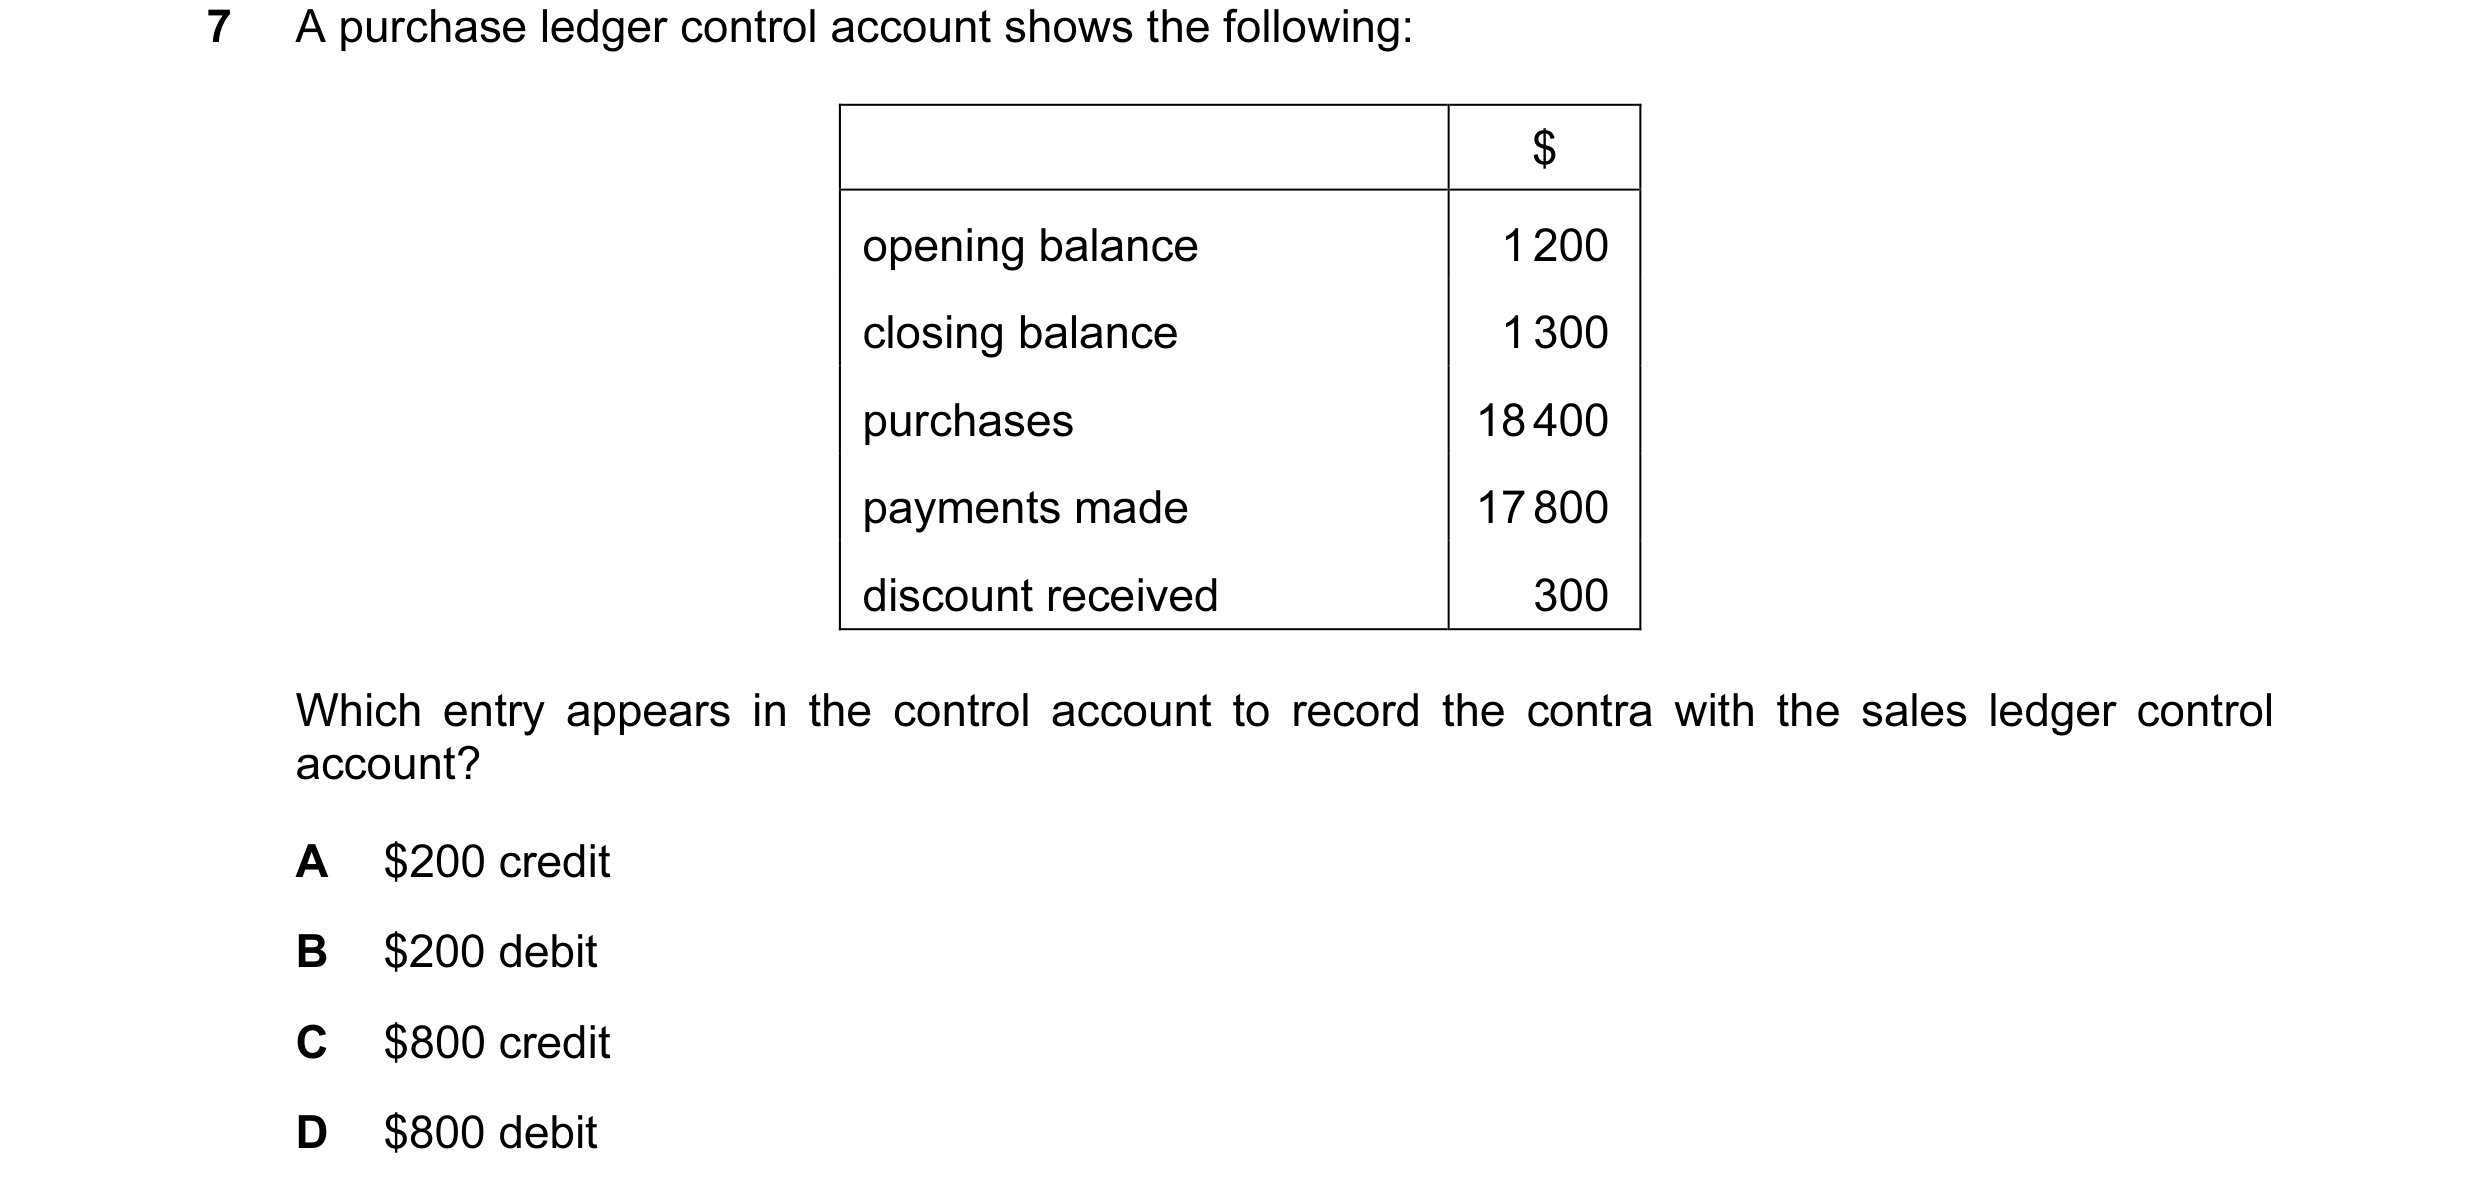 34 / 110
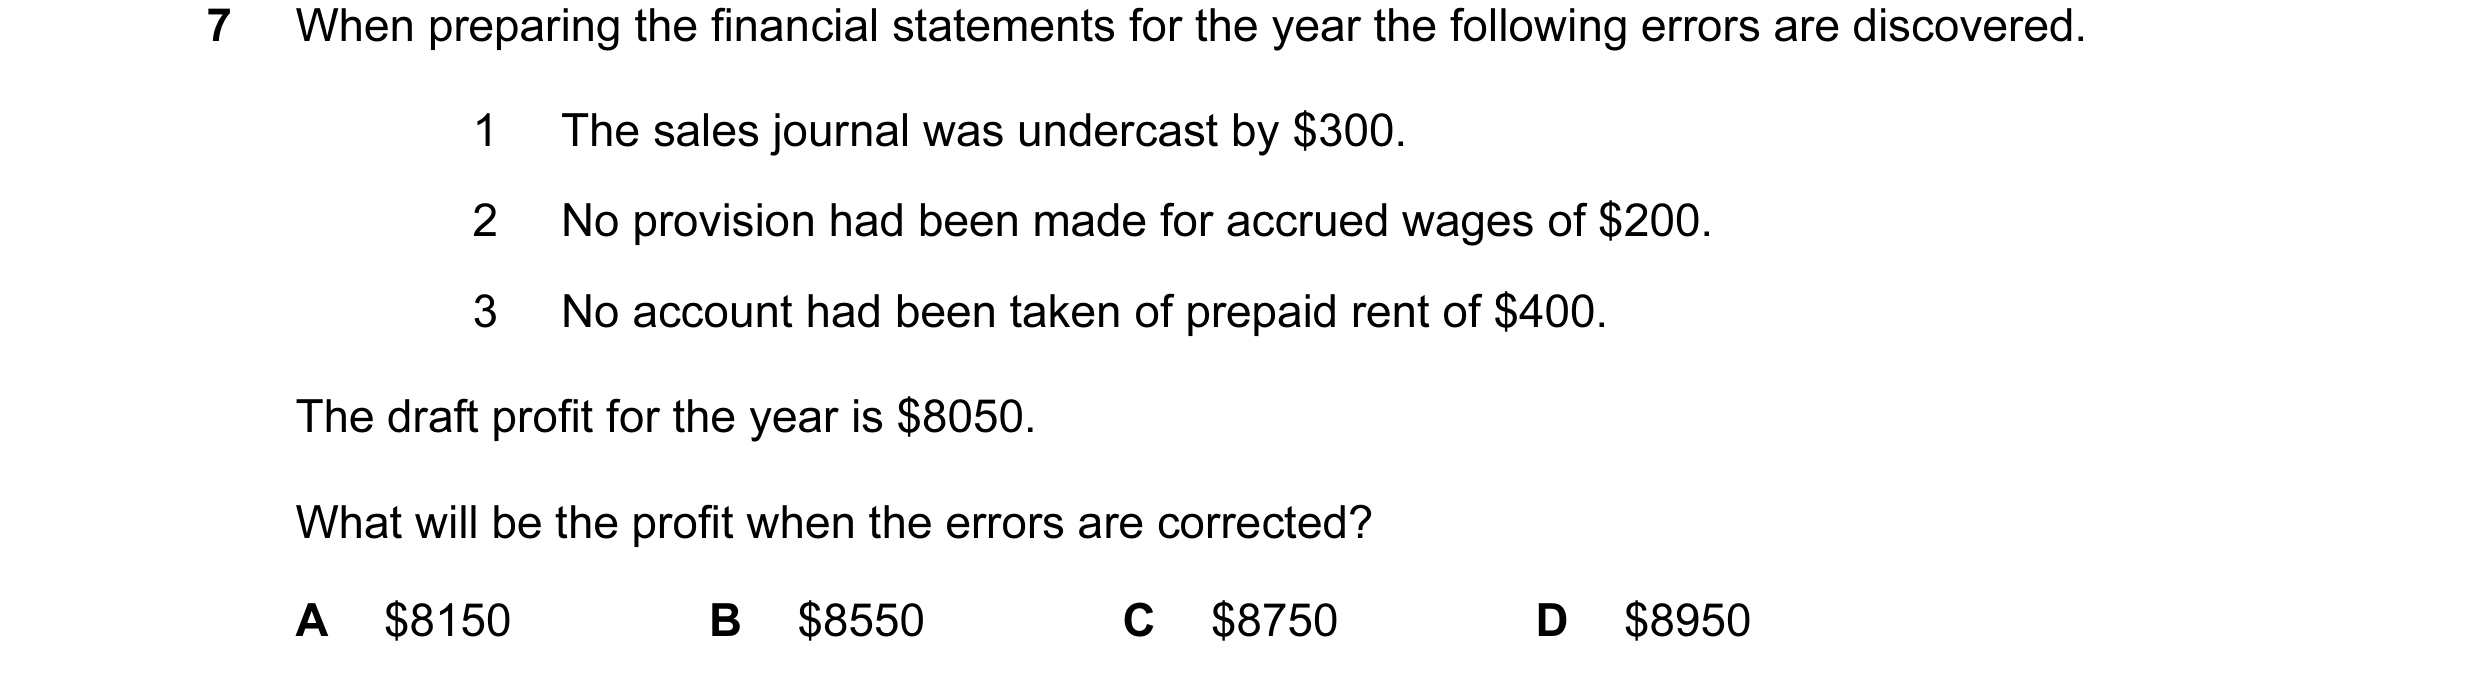
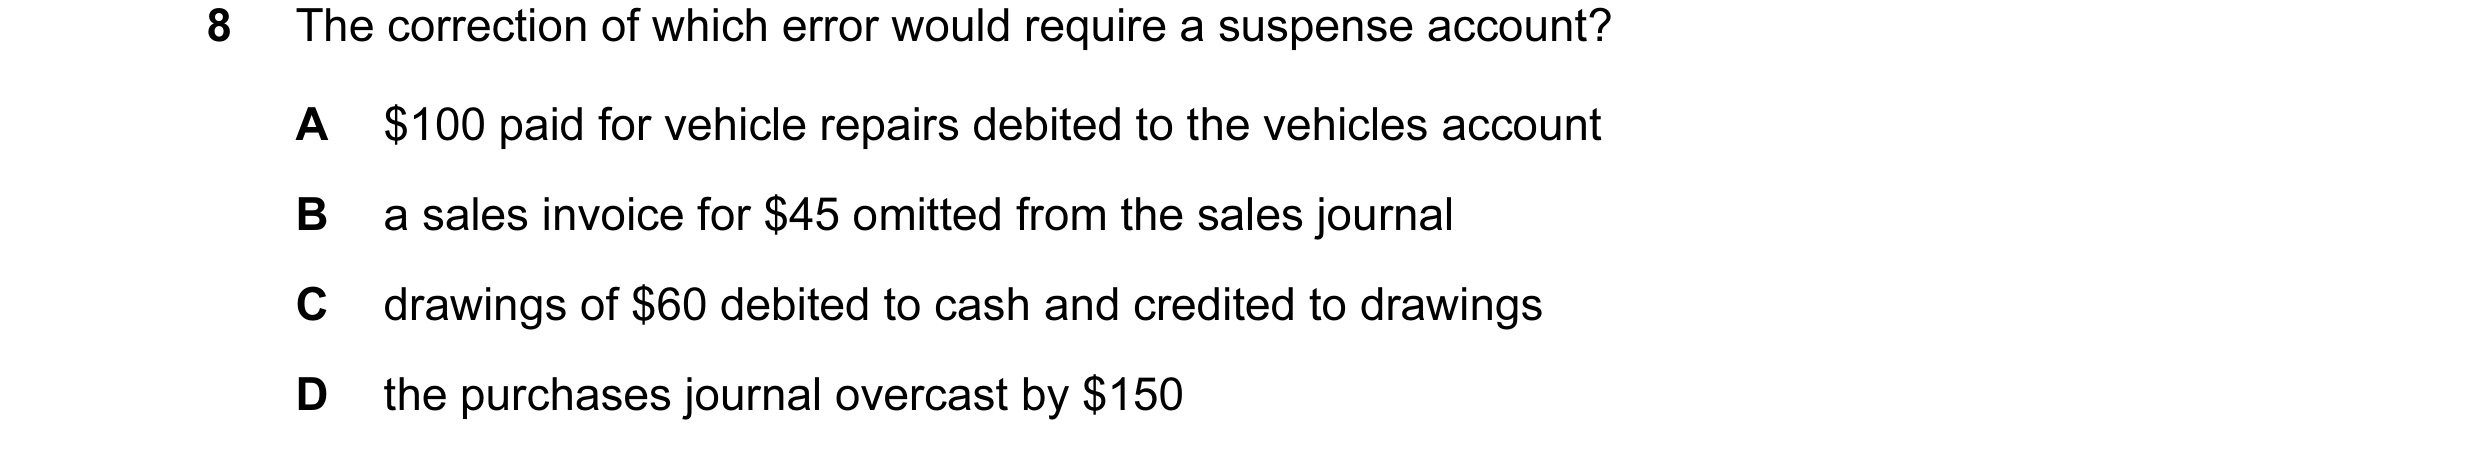
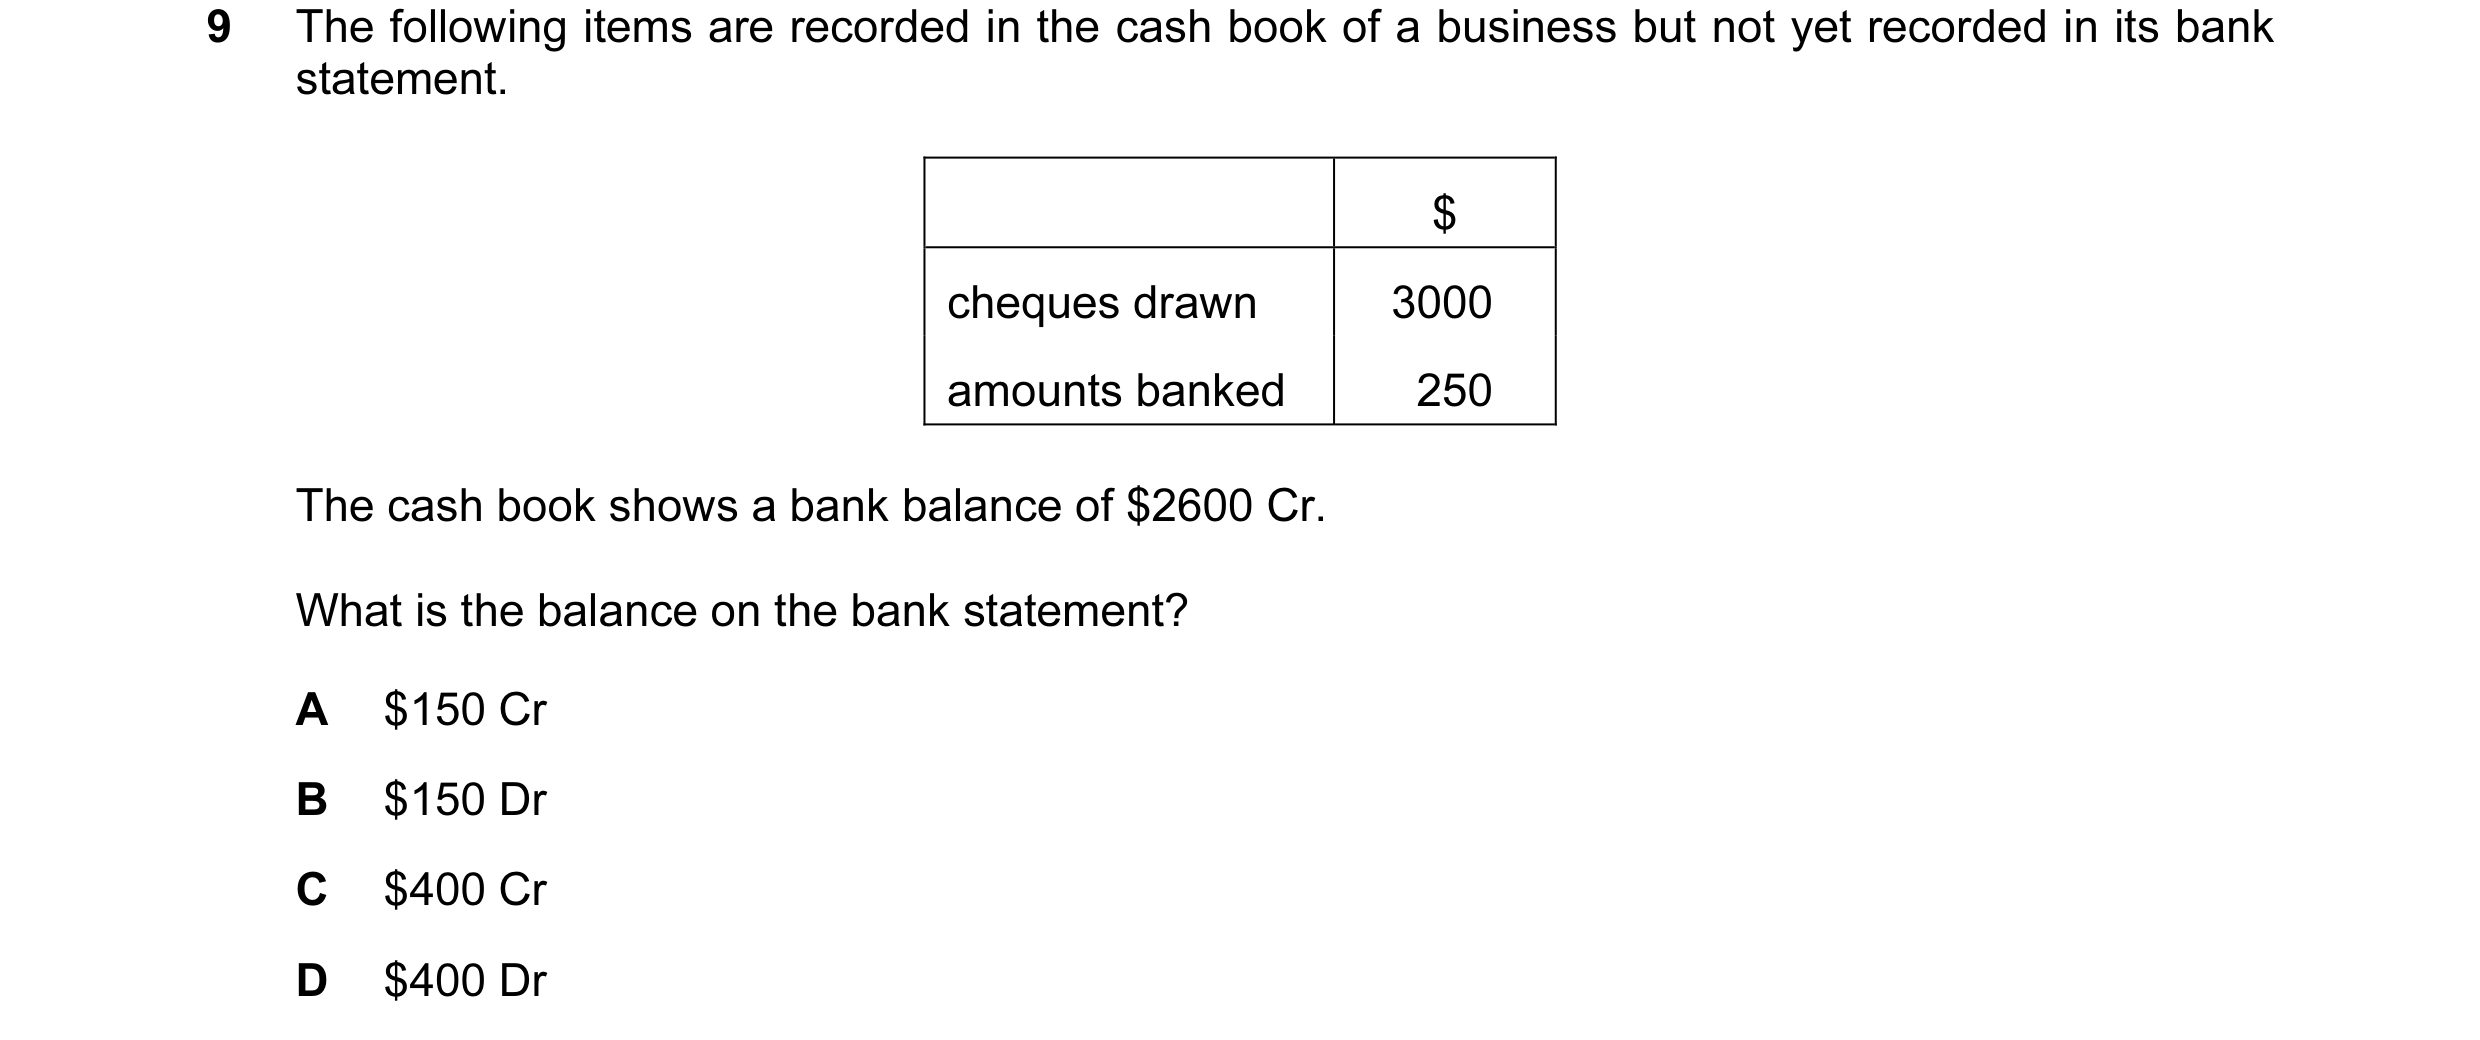
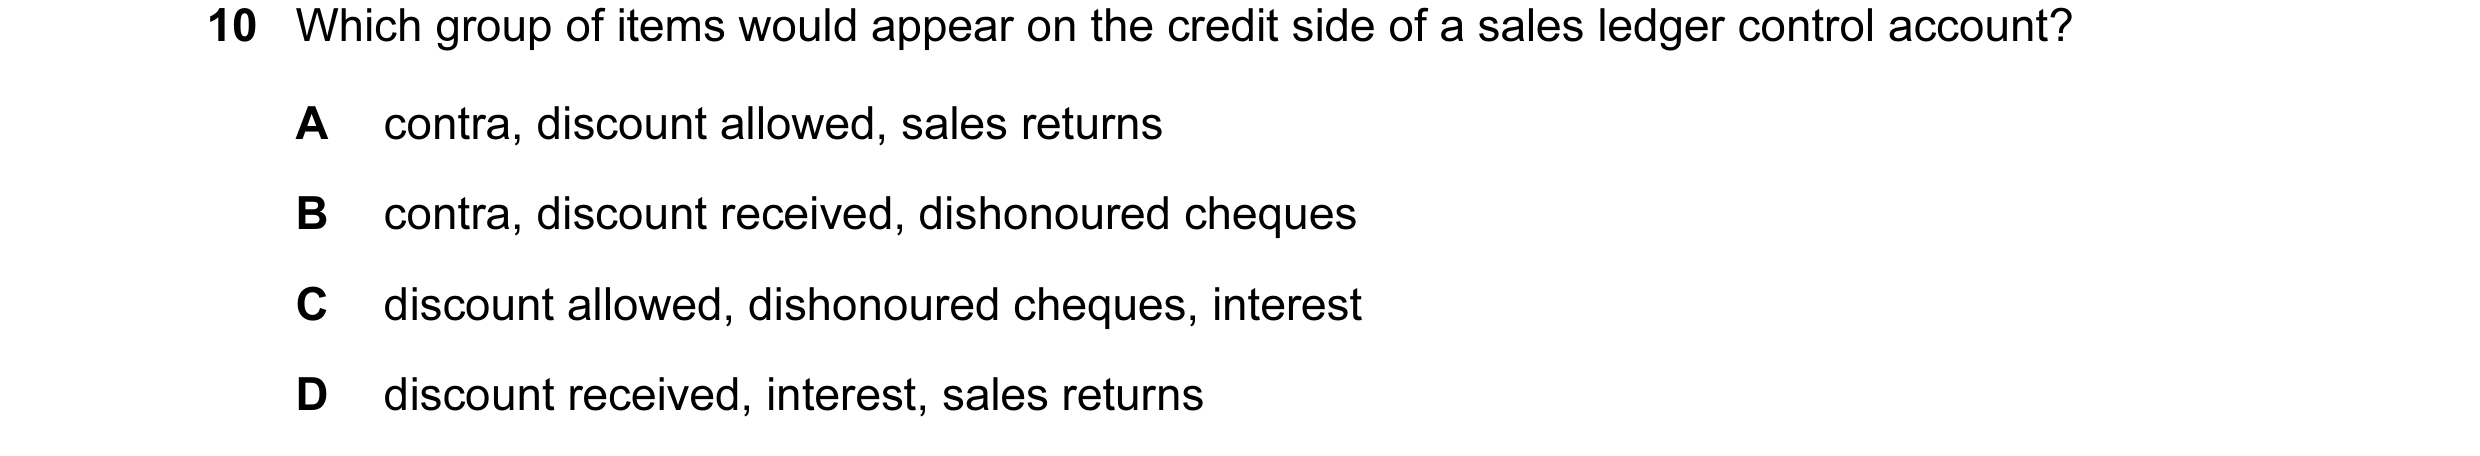
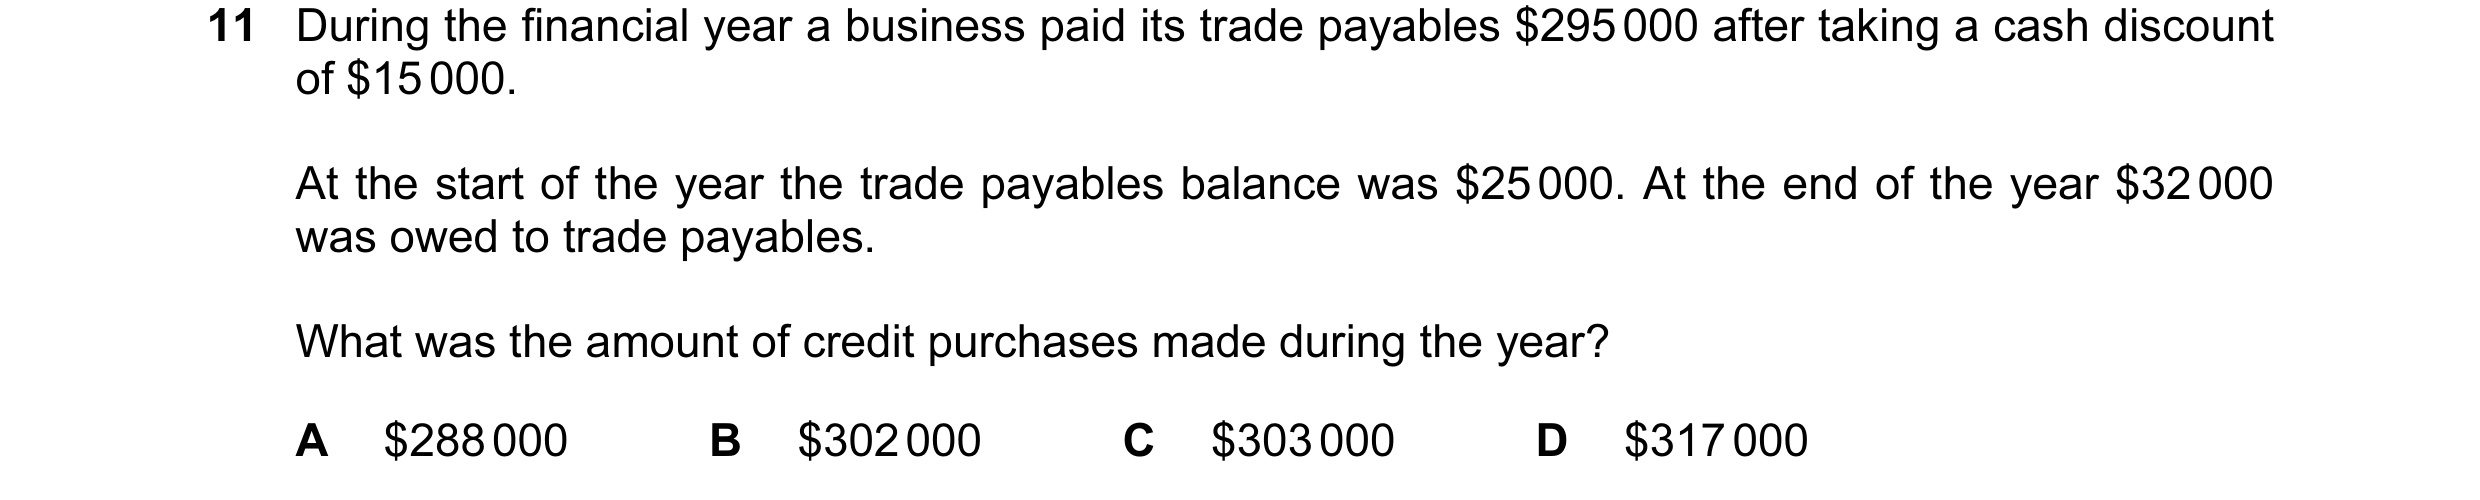 35 / 110
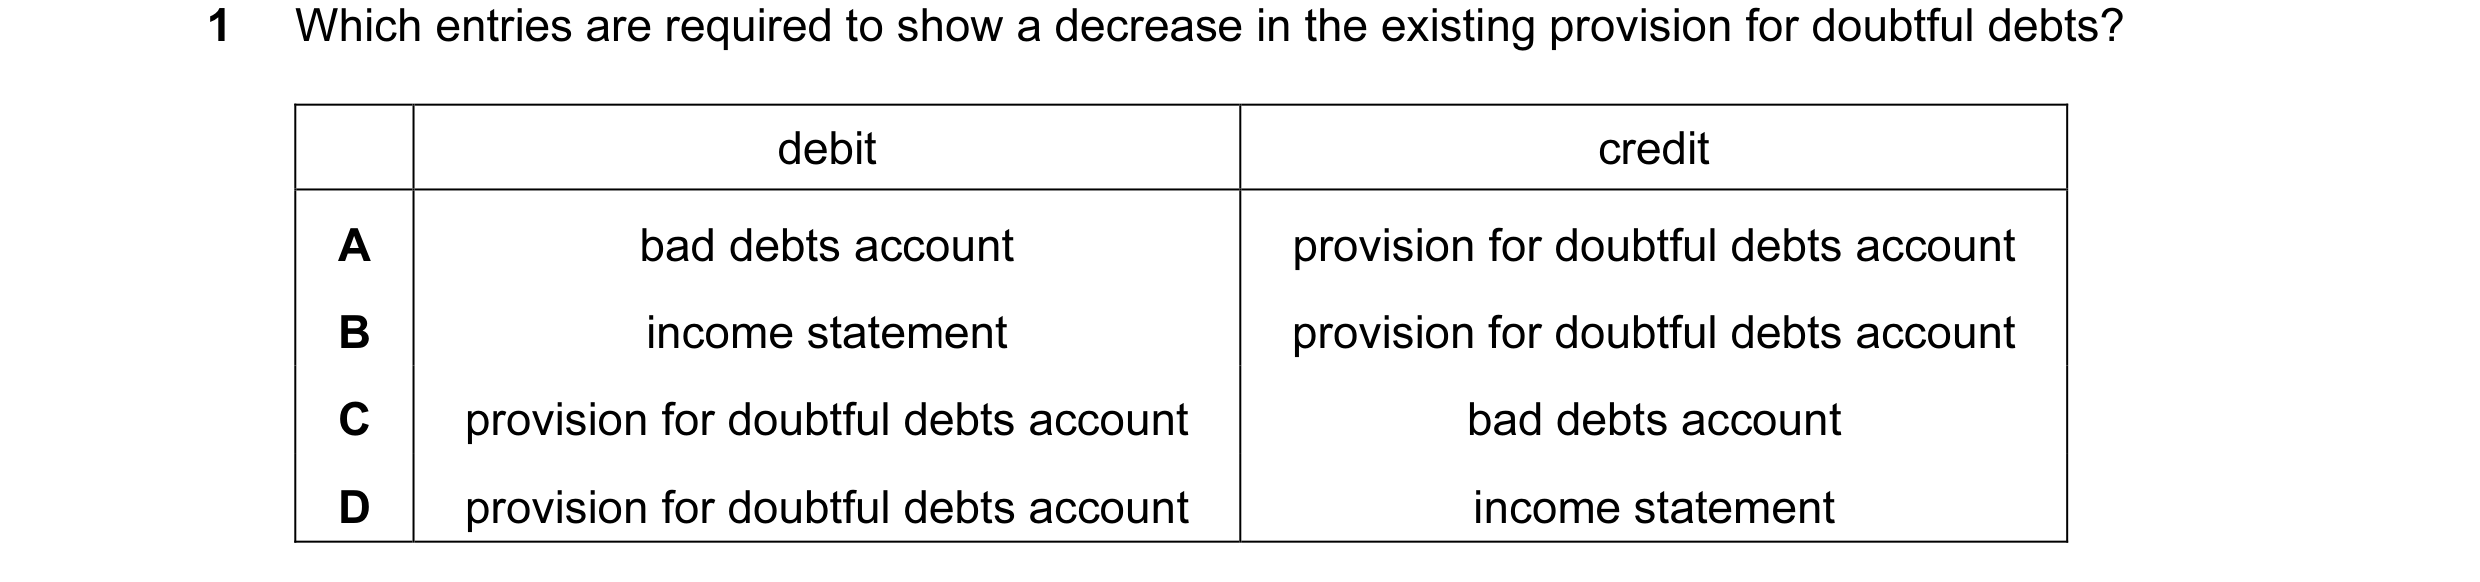
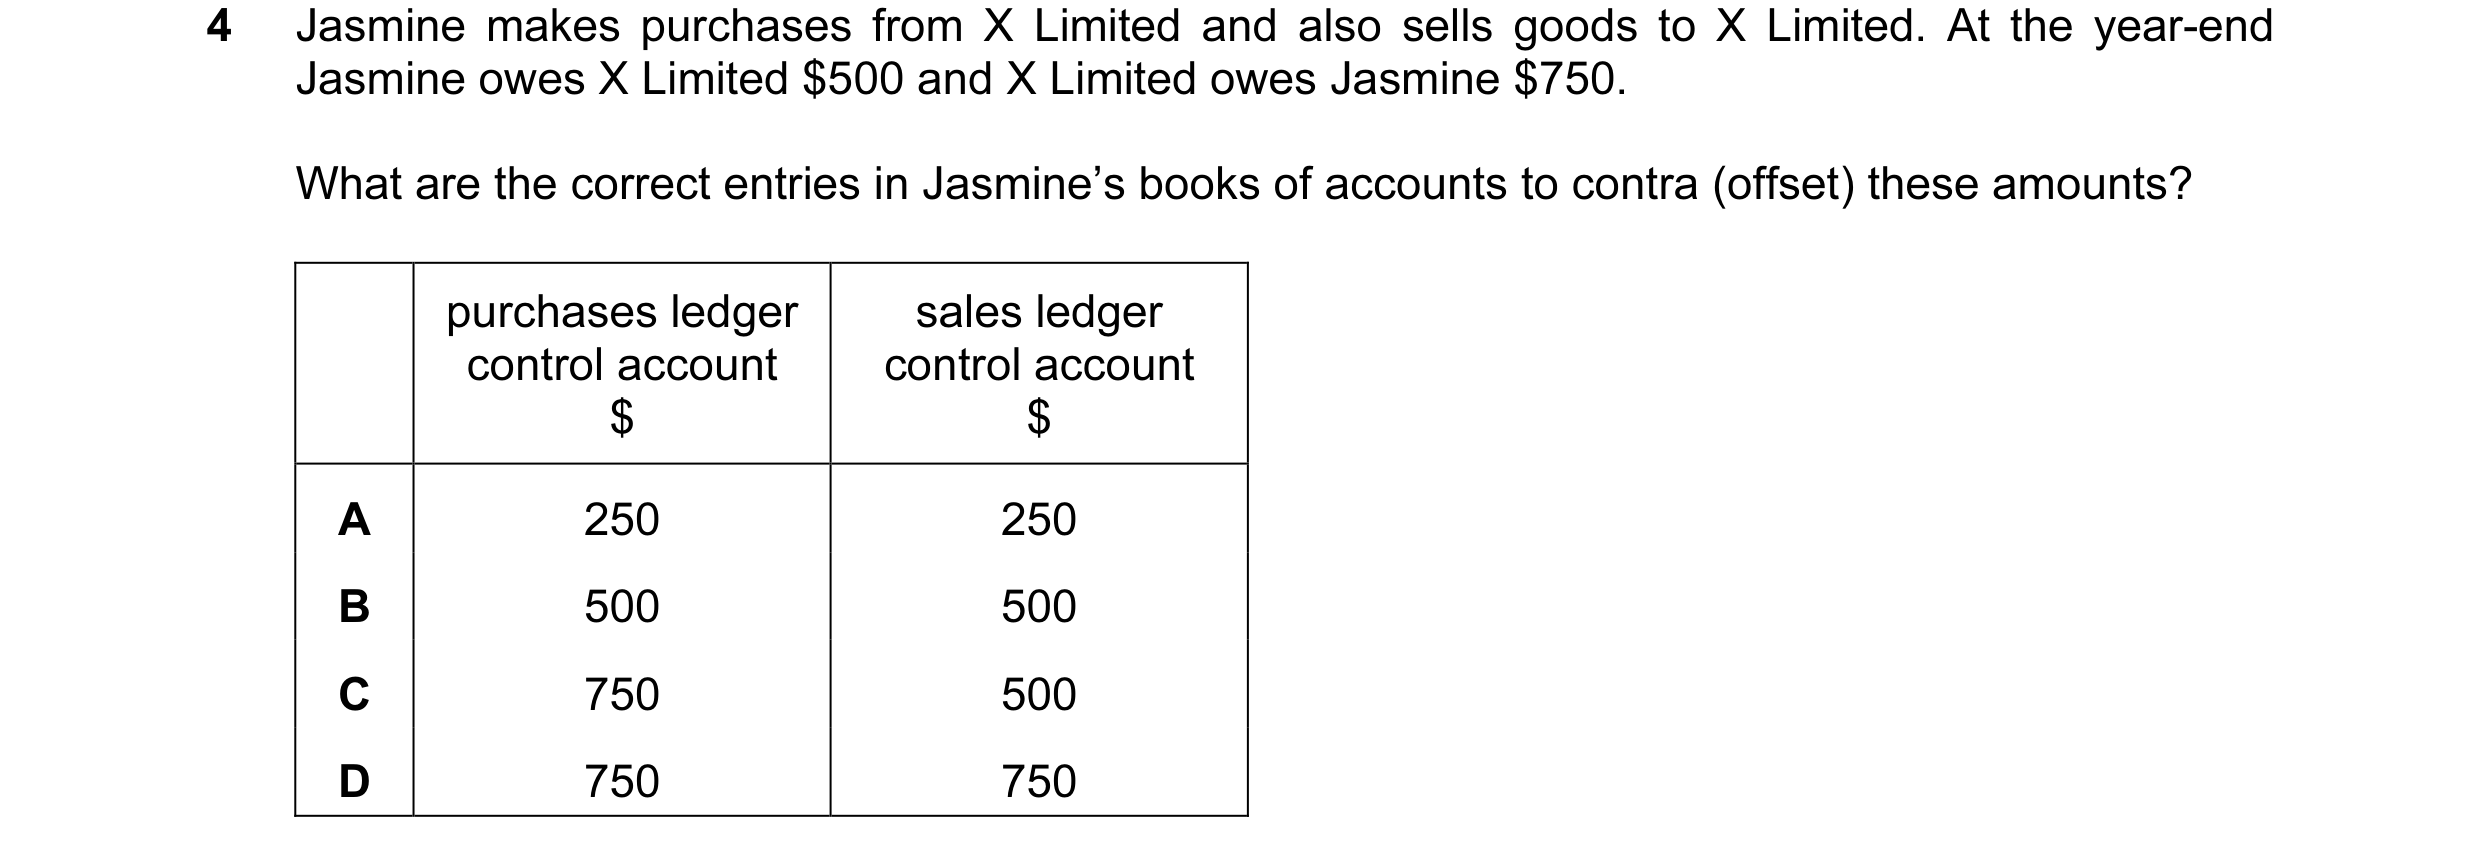
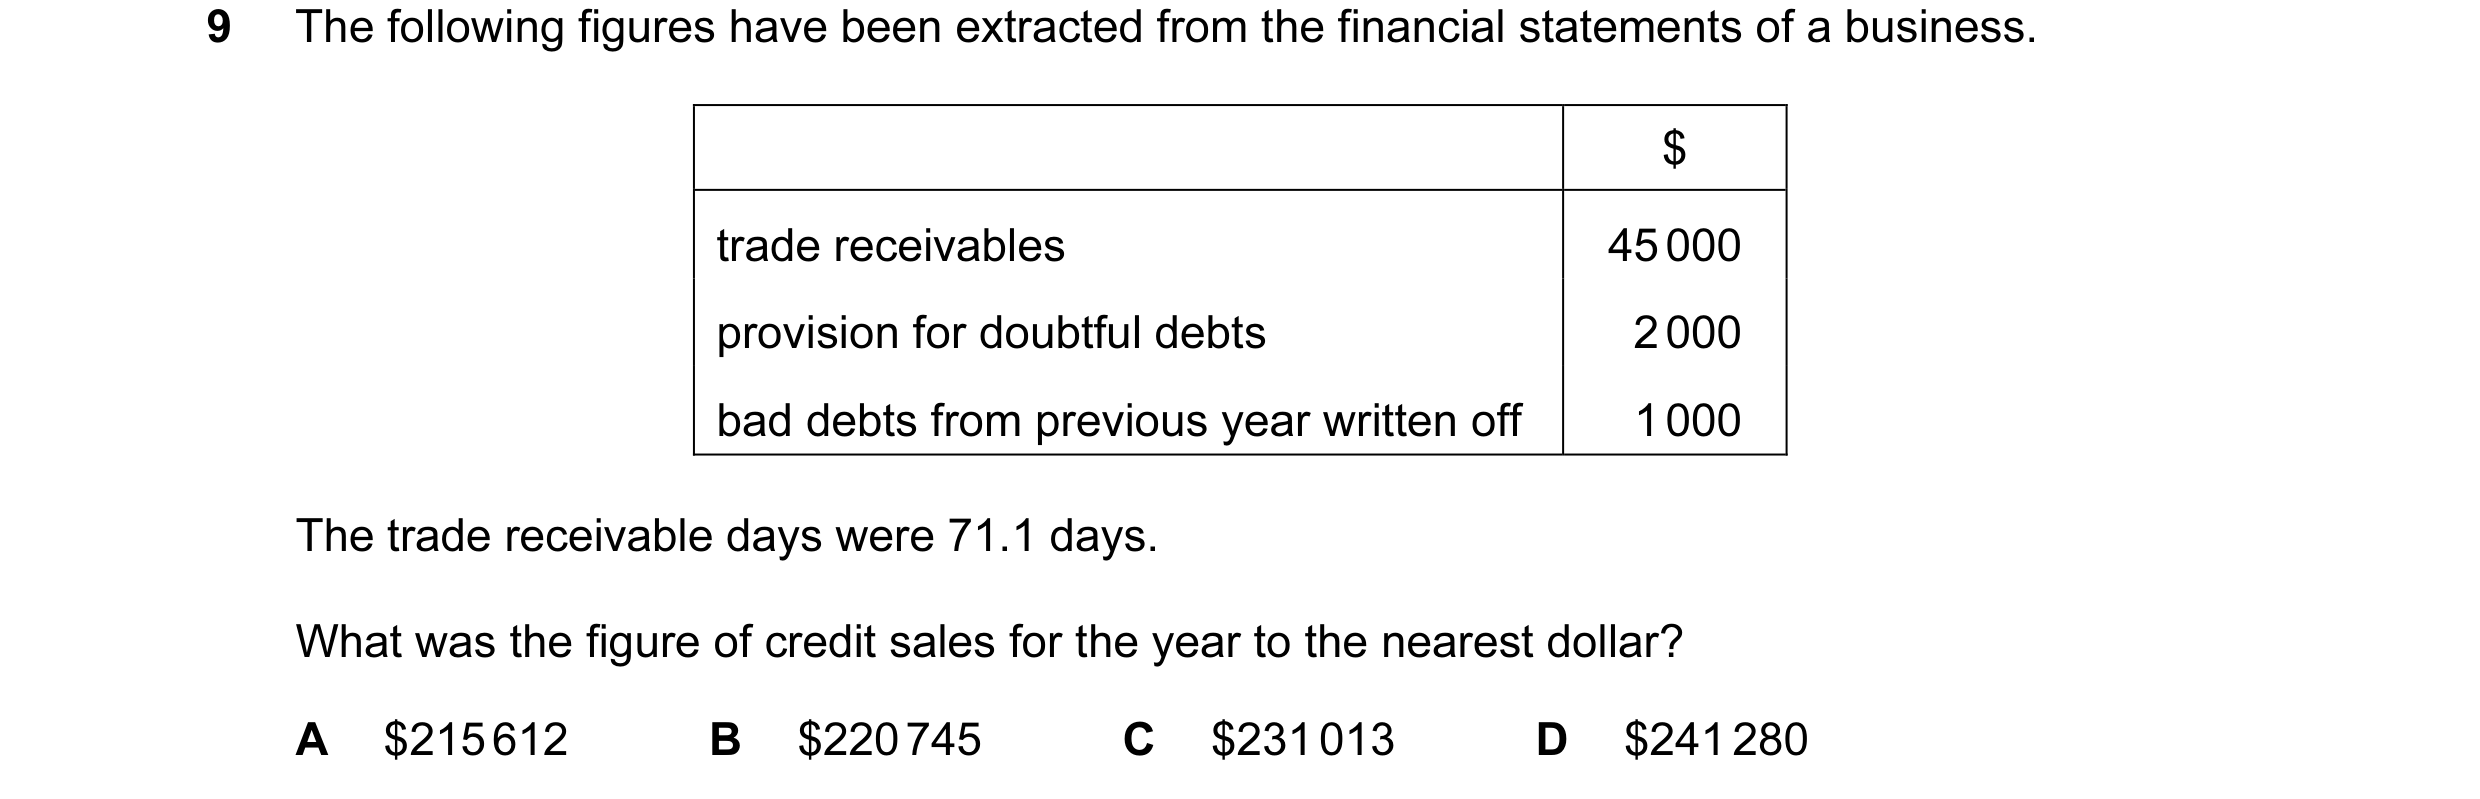
 36 / 110
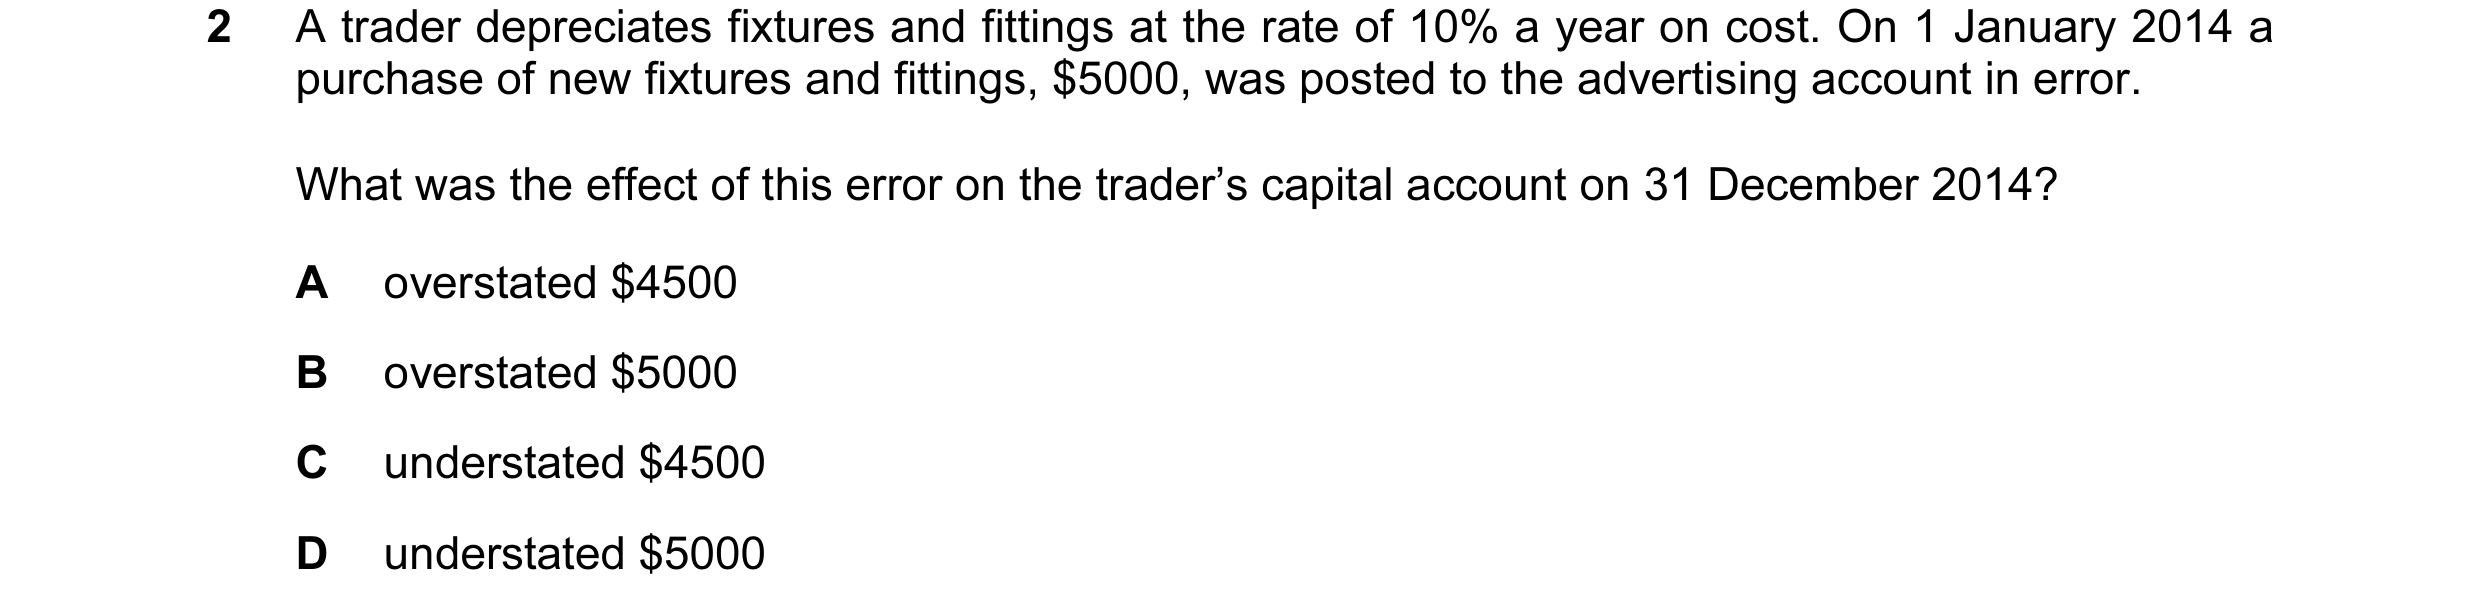
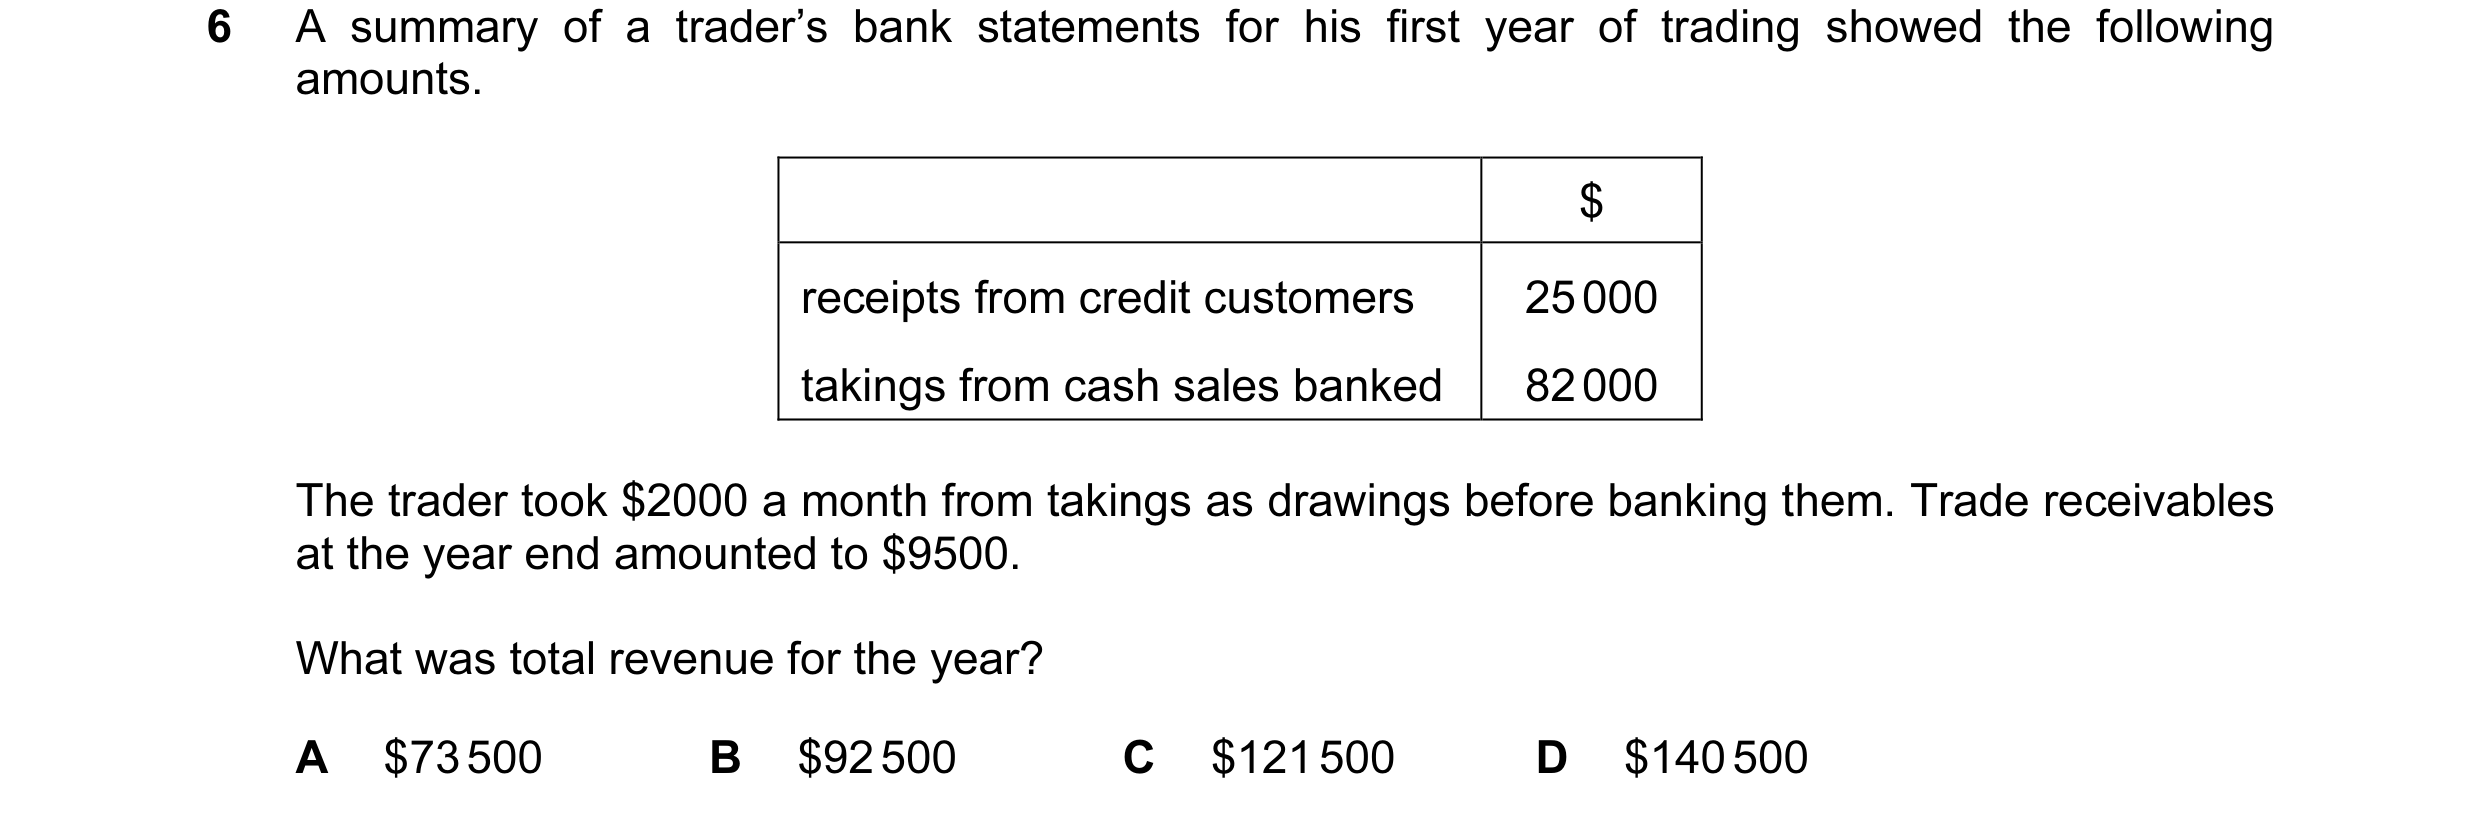
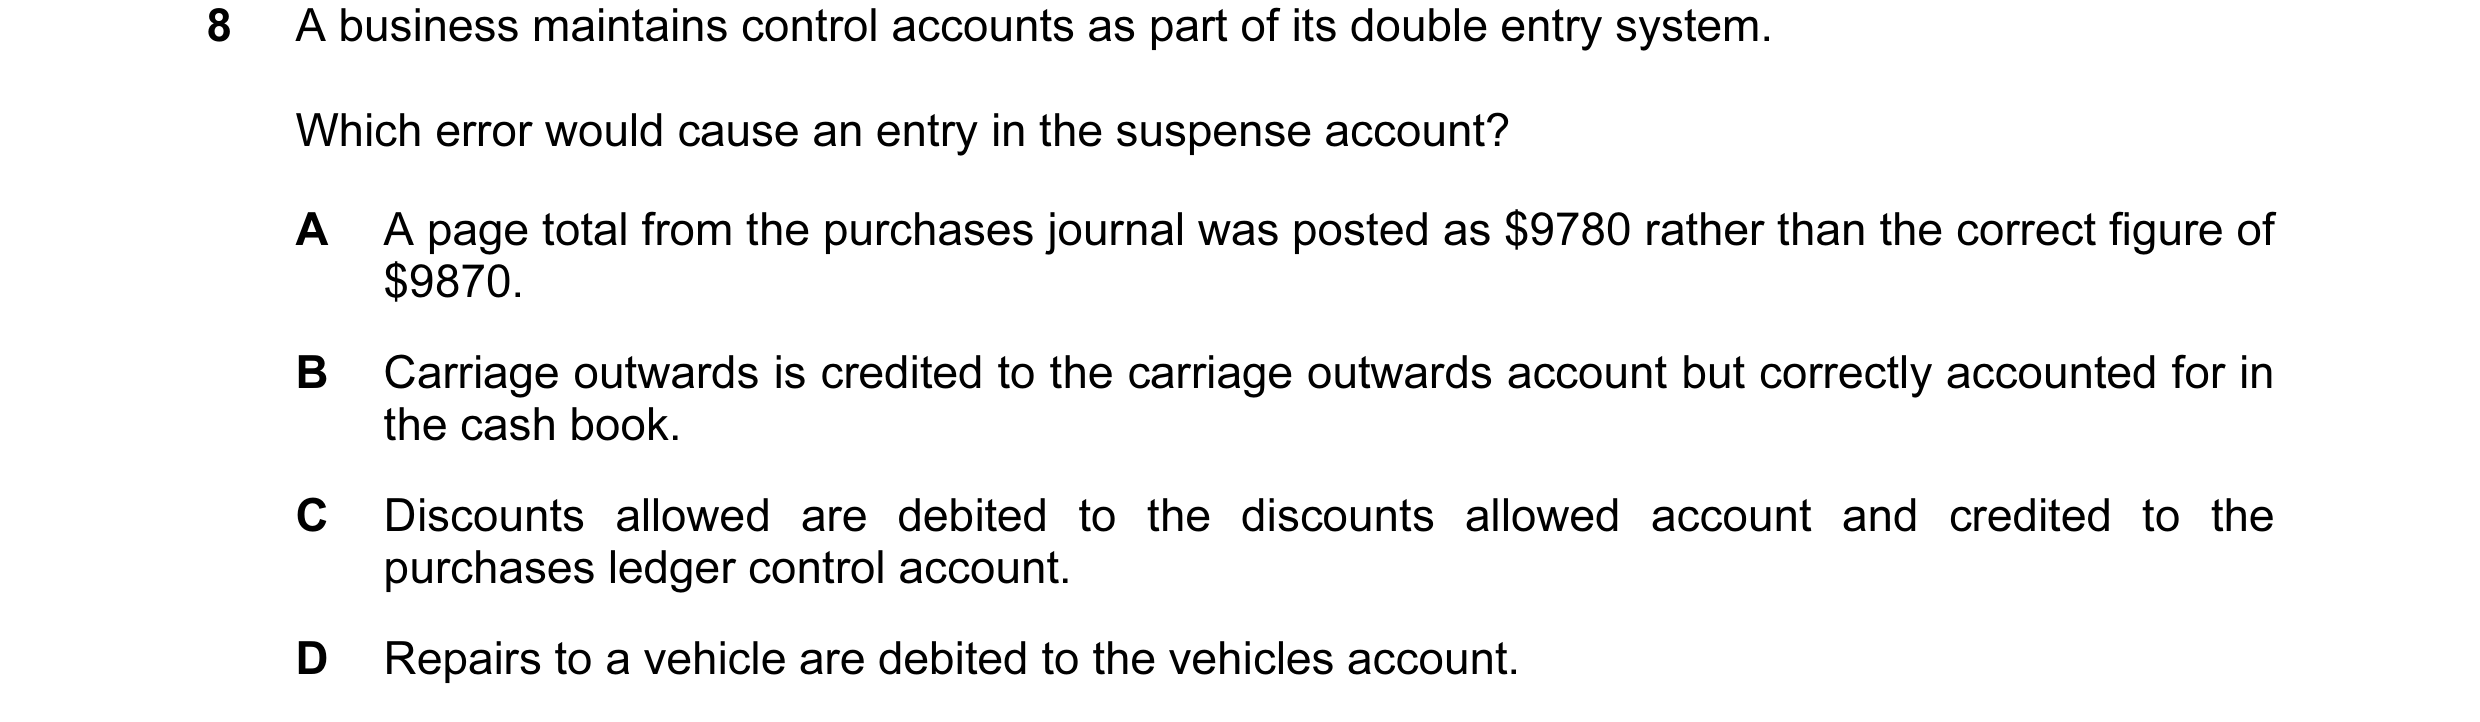
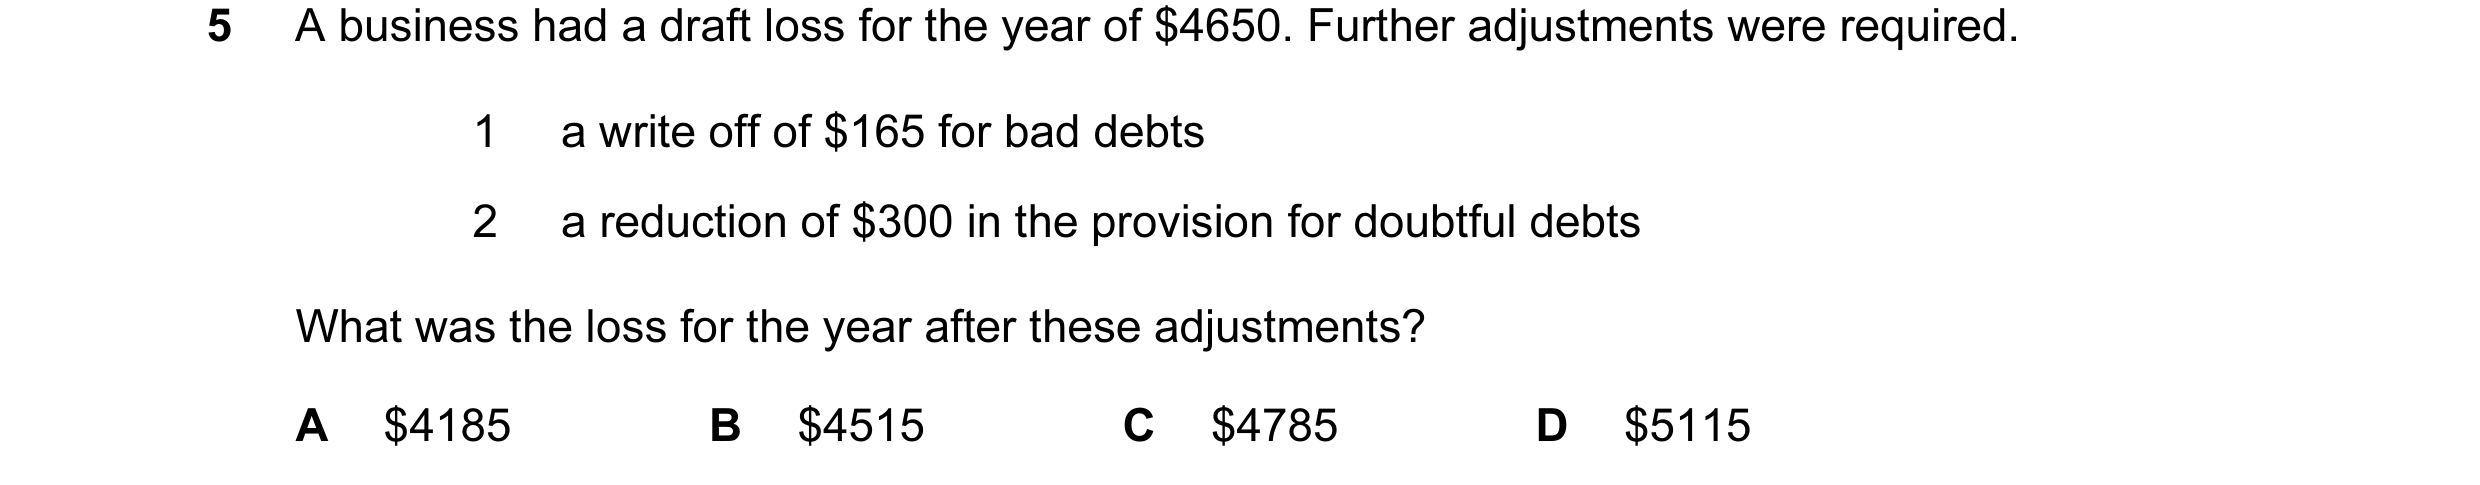 37 / 110
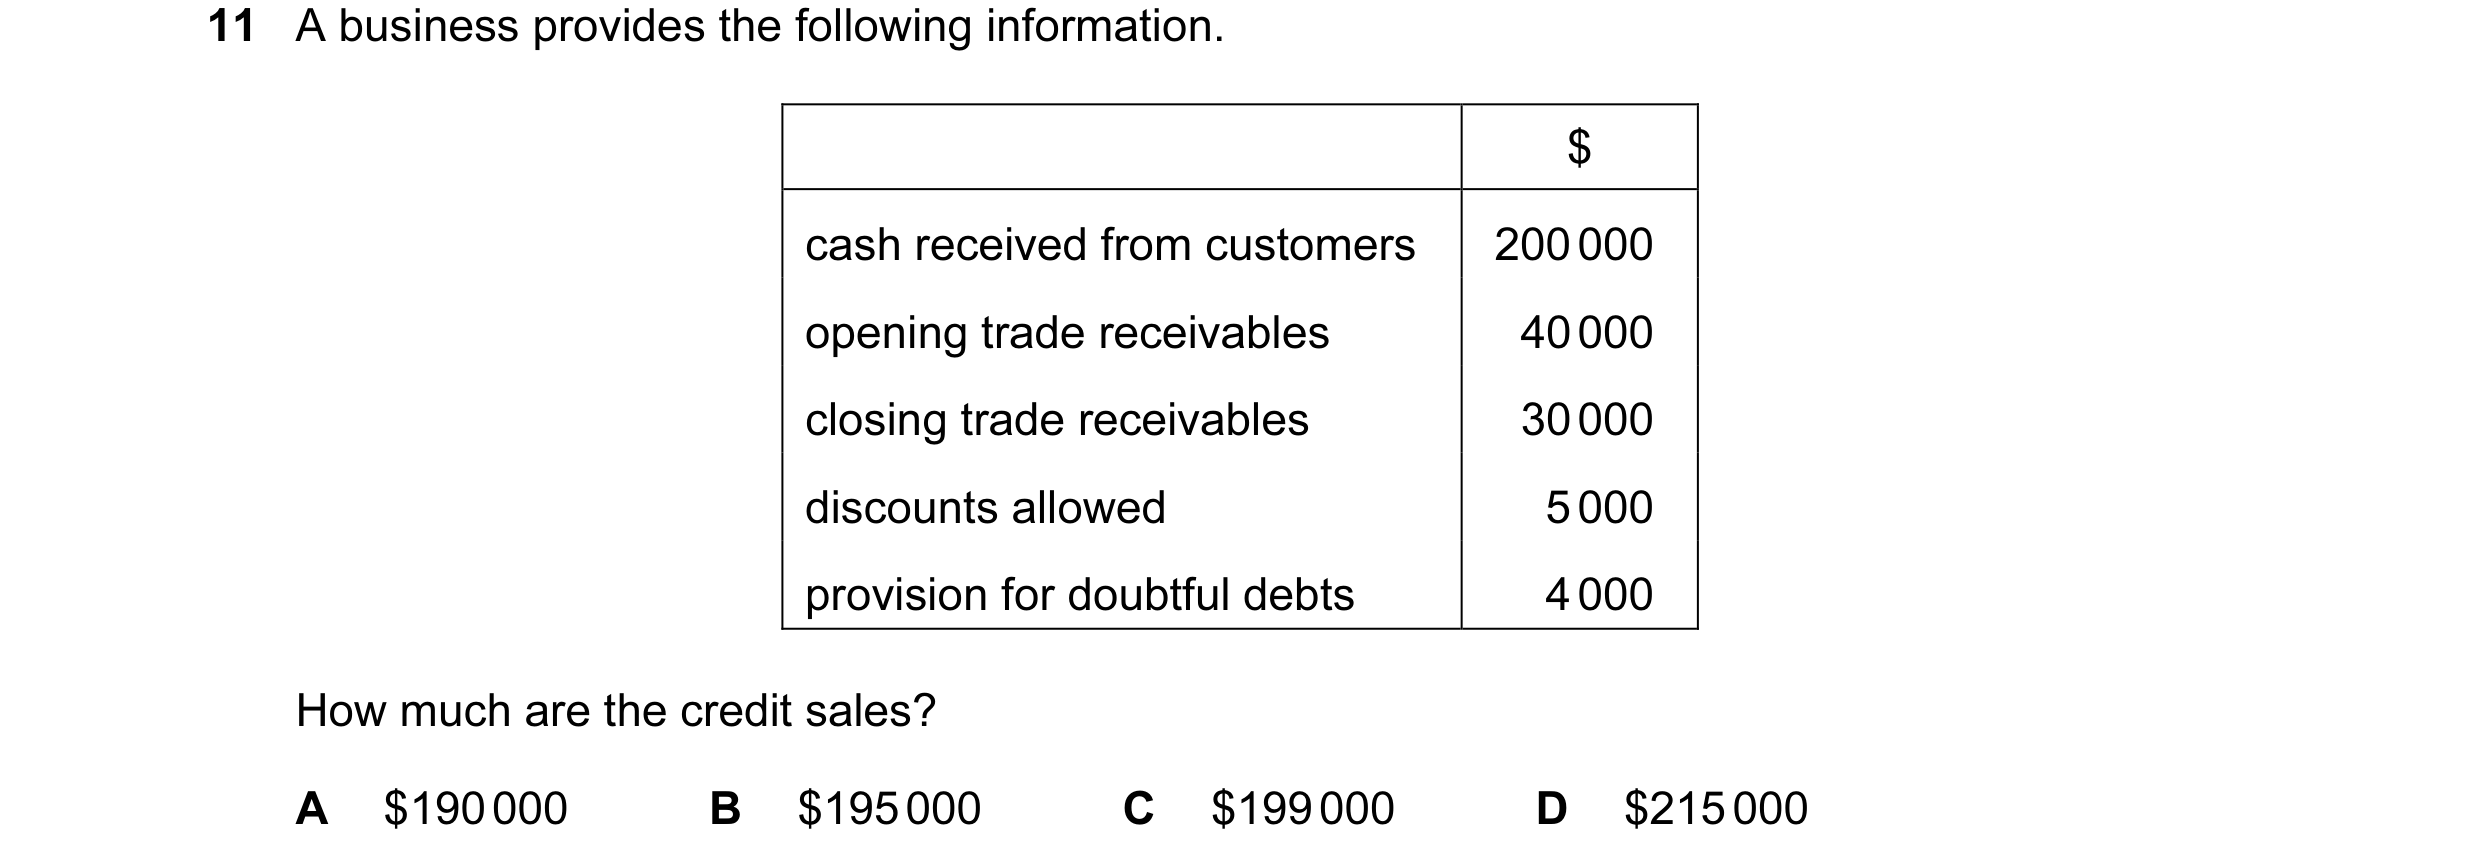
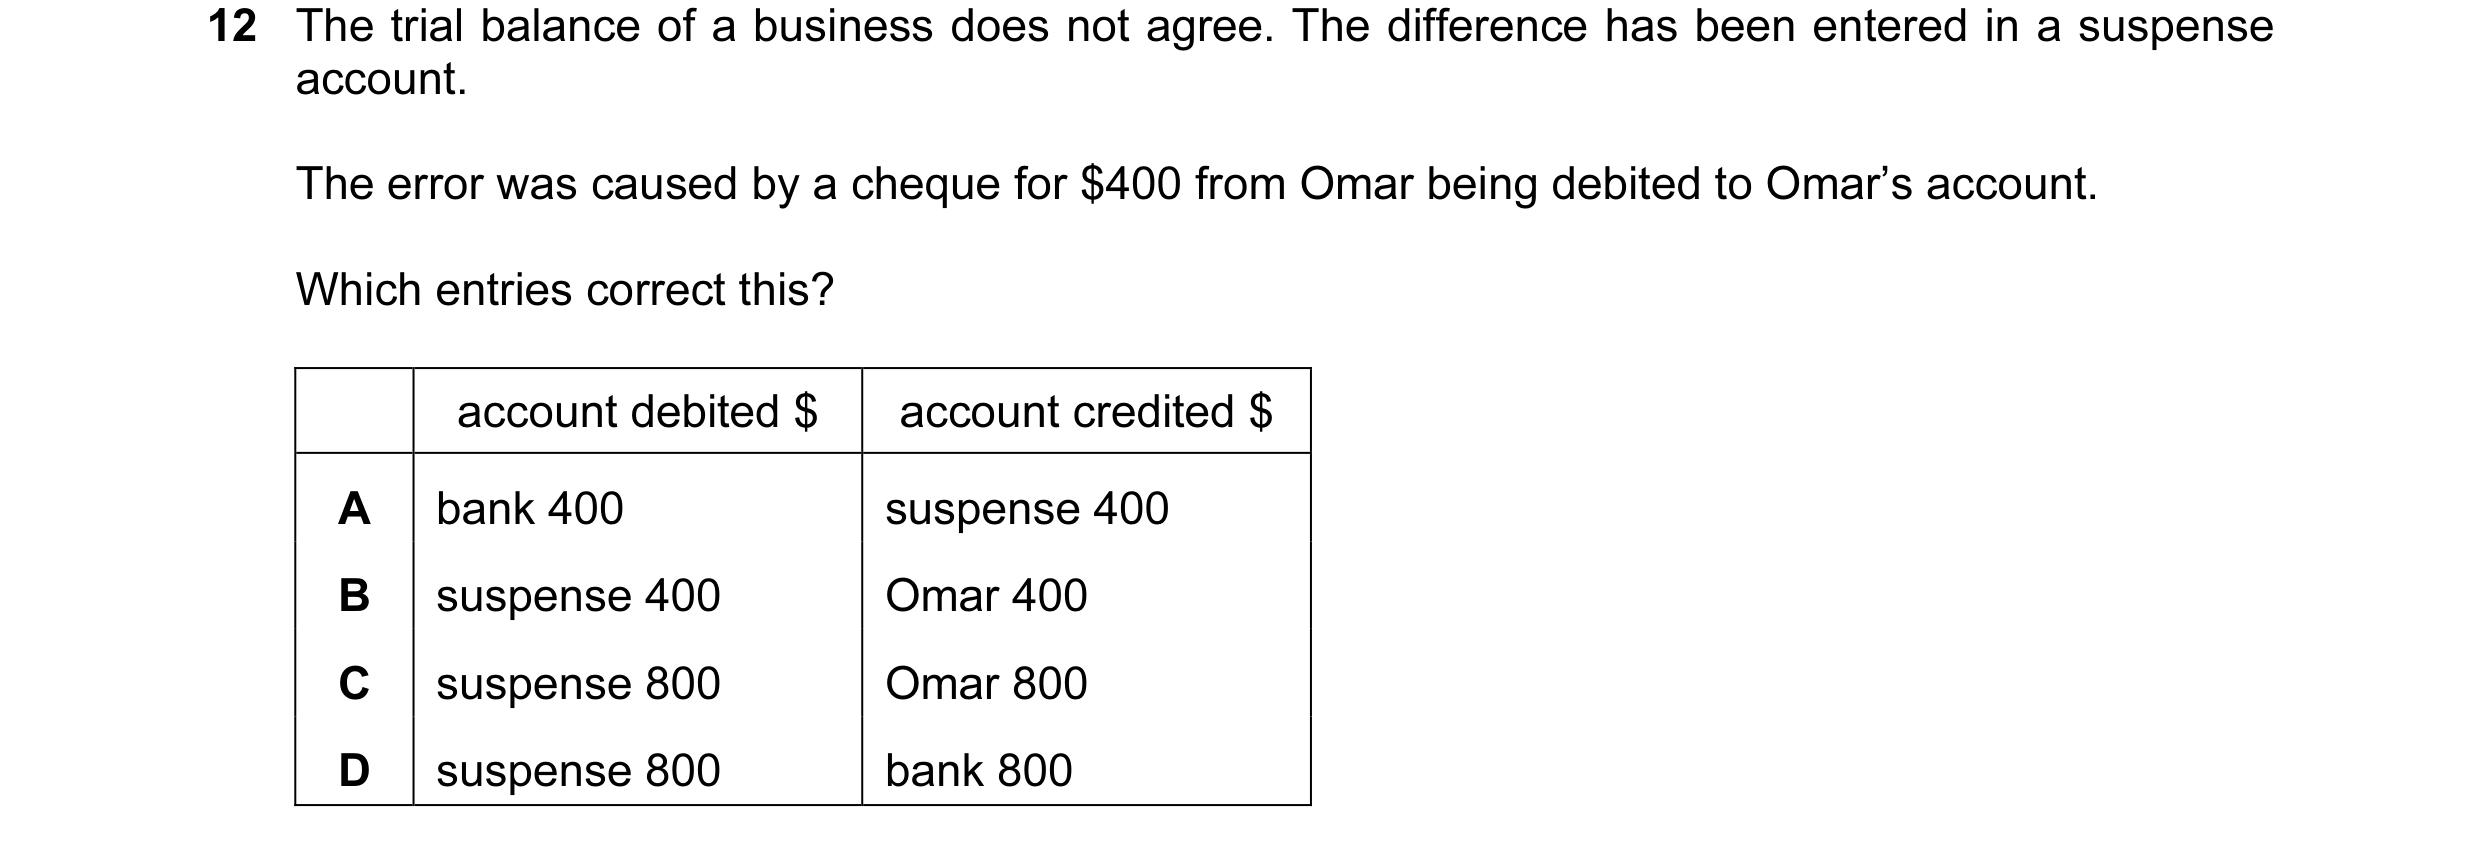
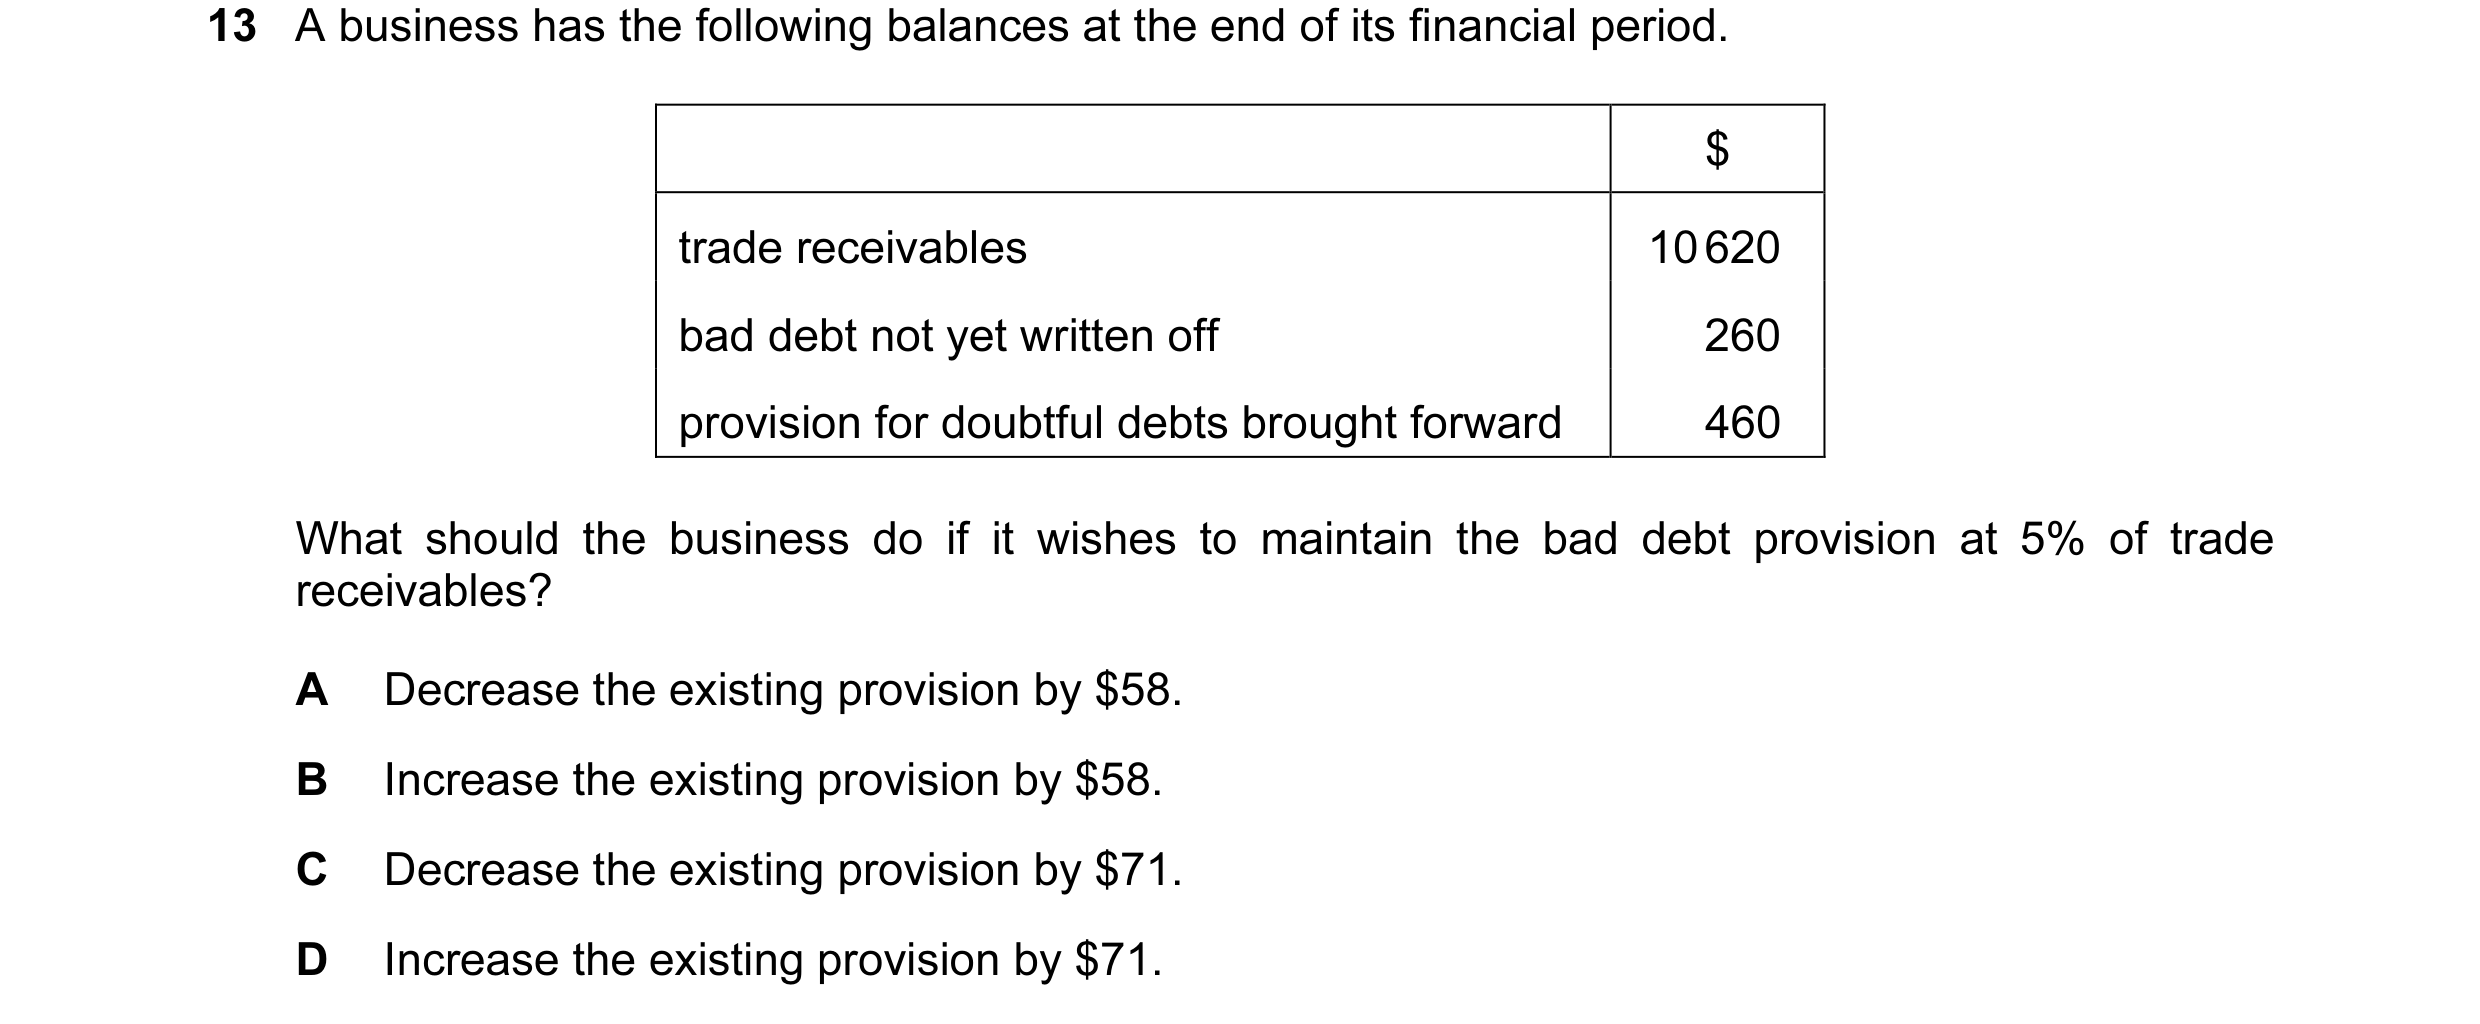 38 / 110
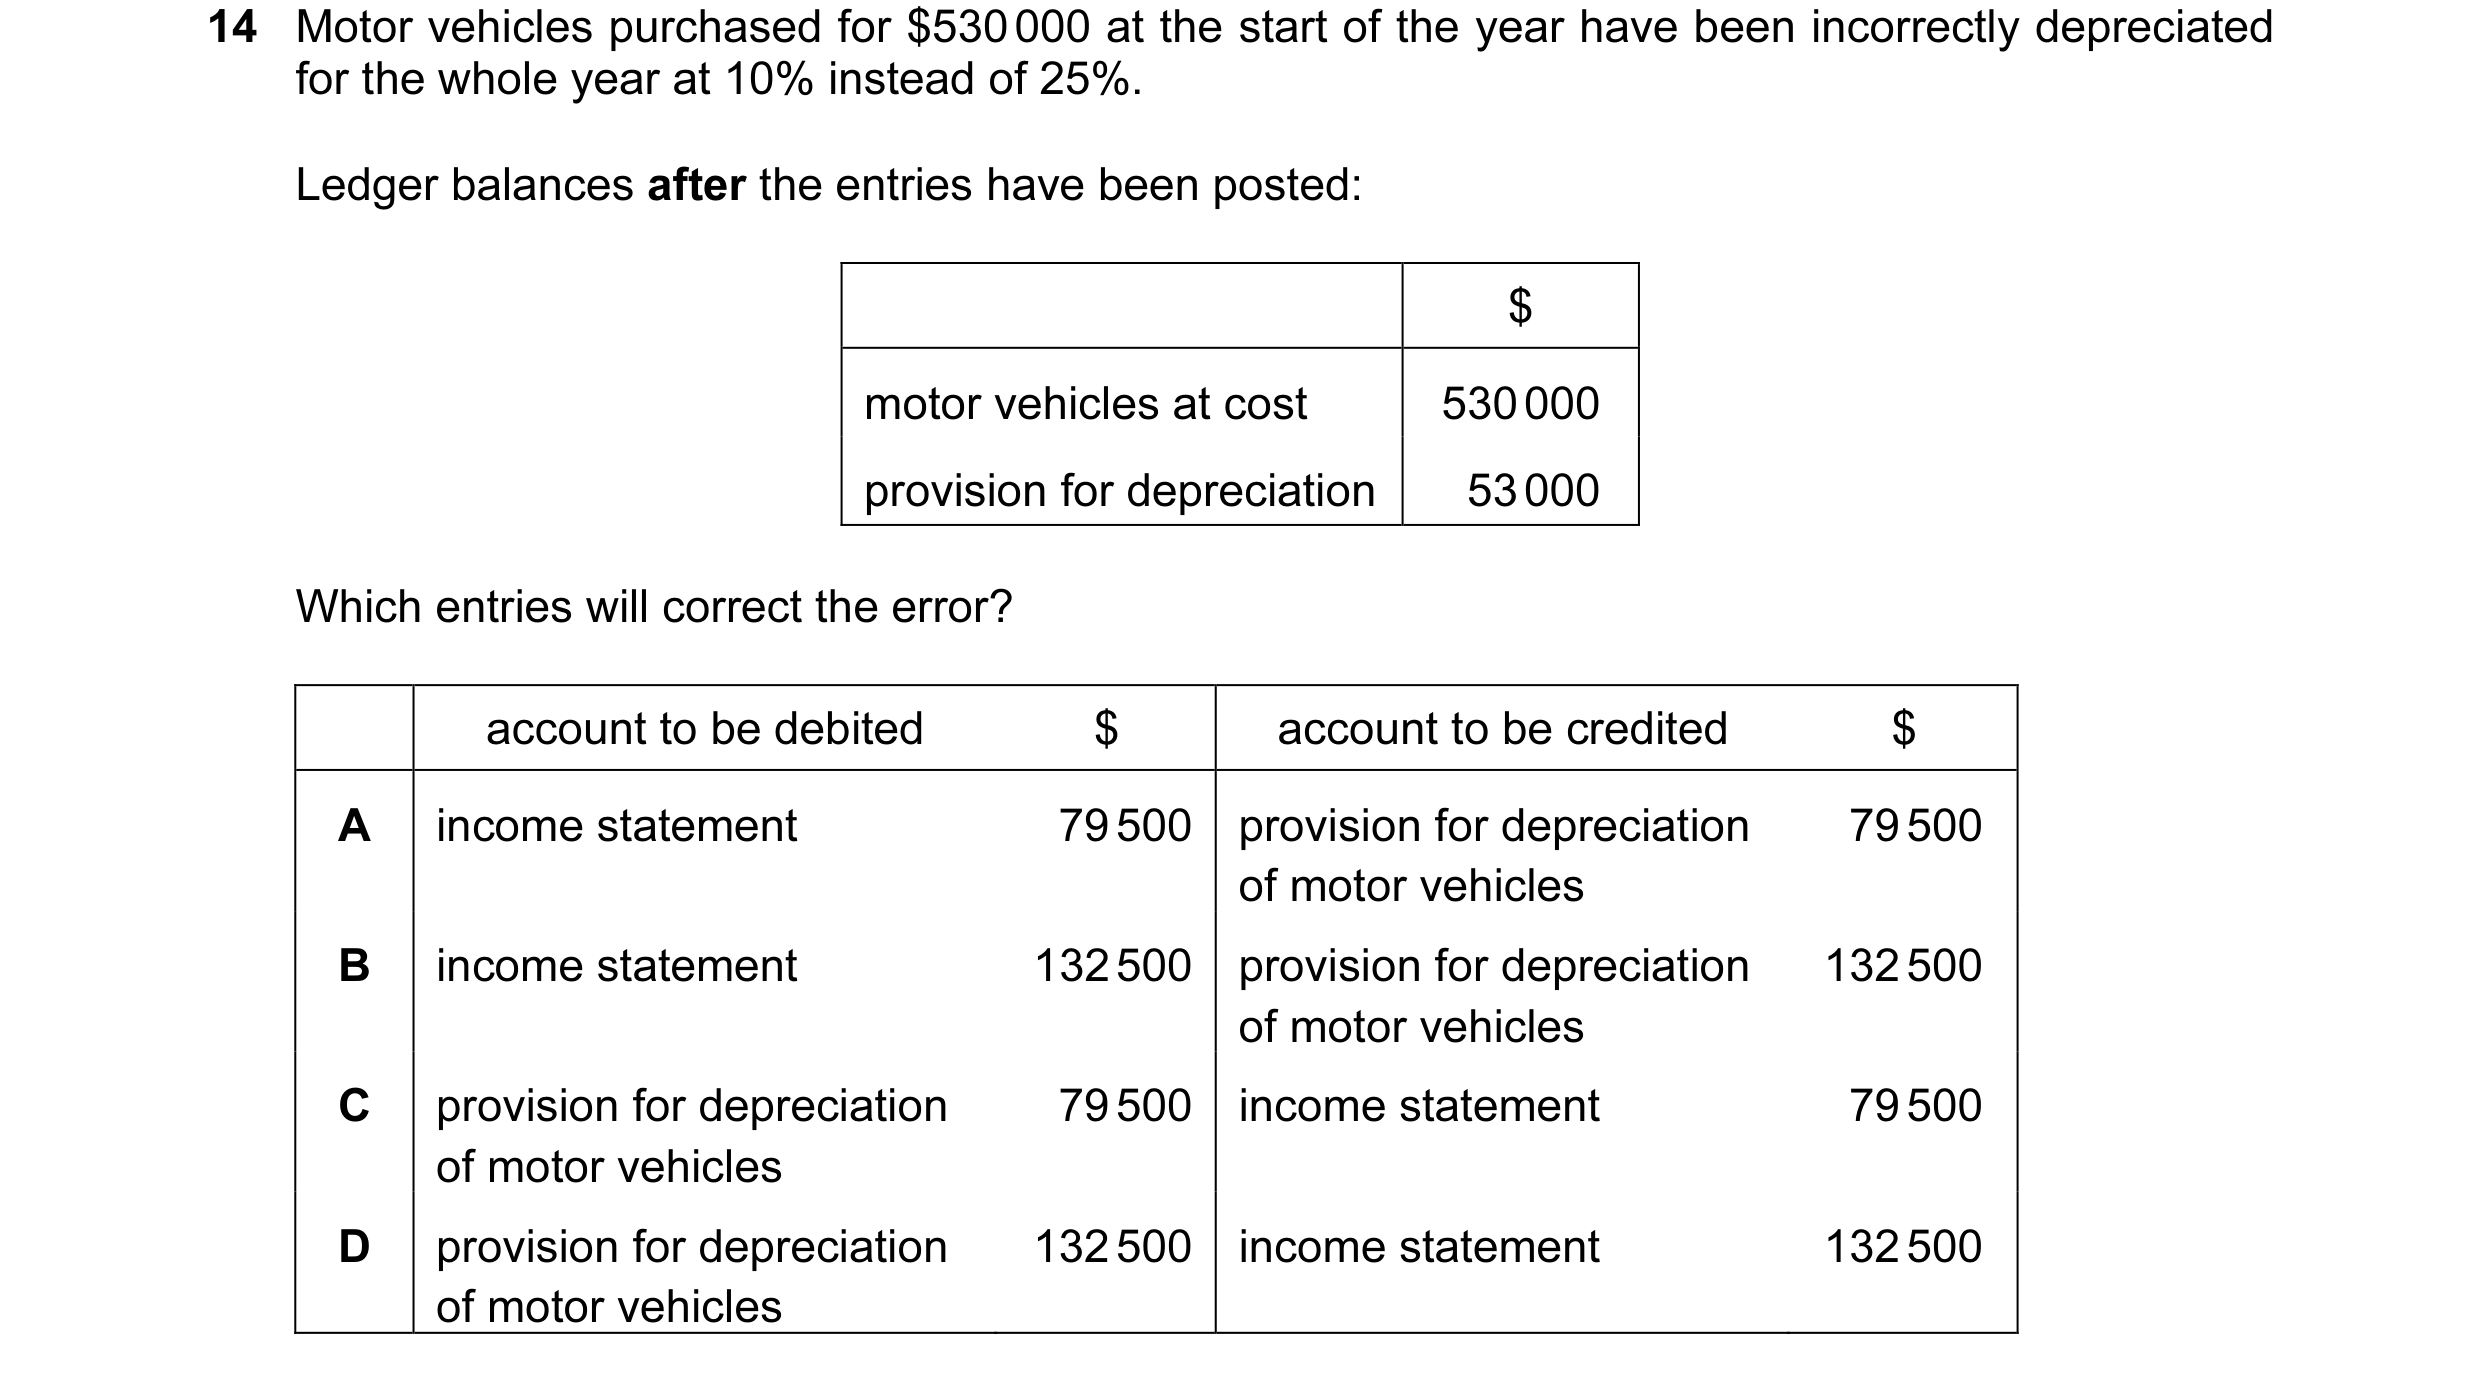
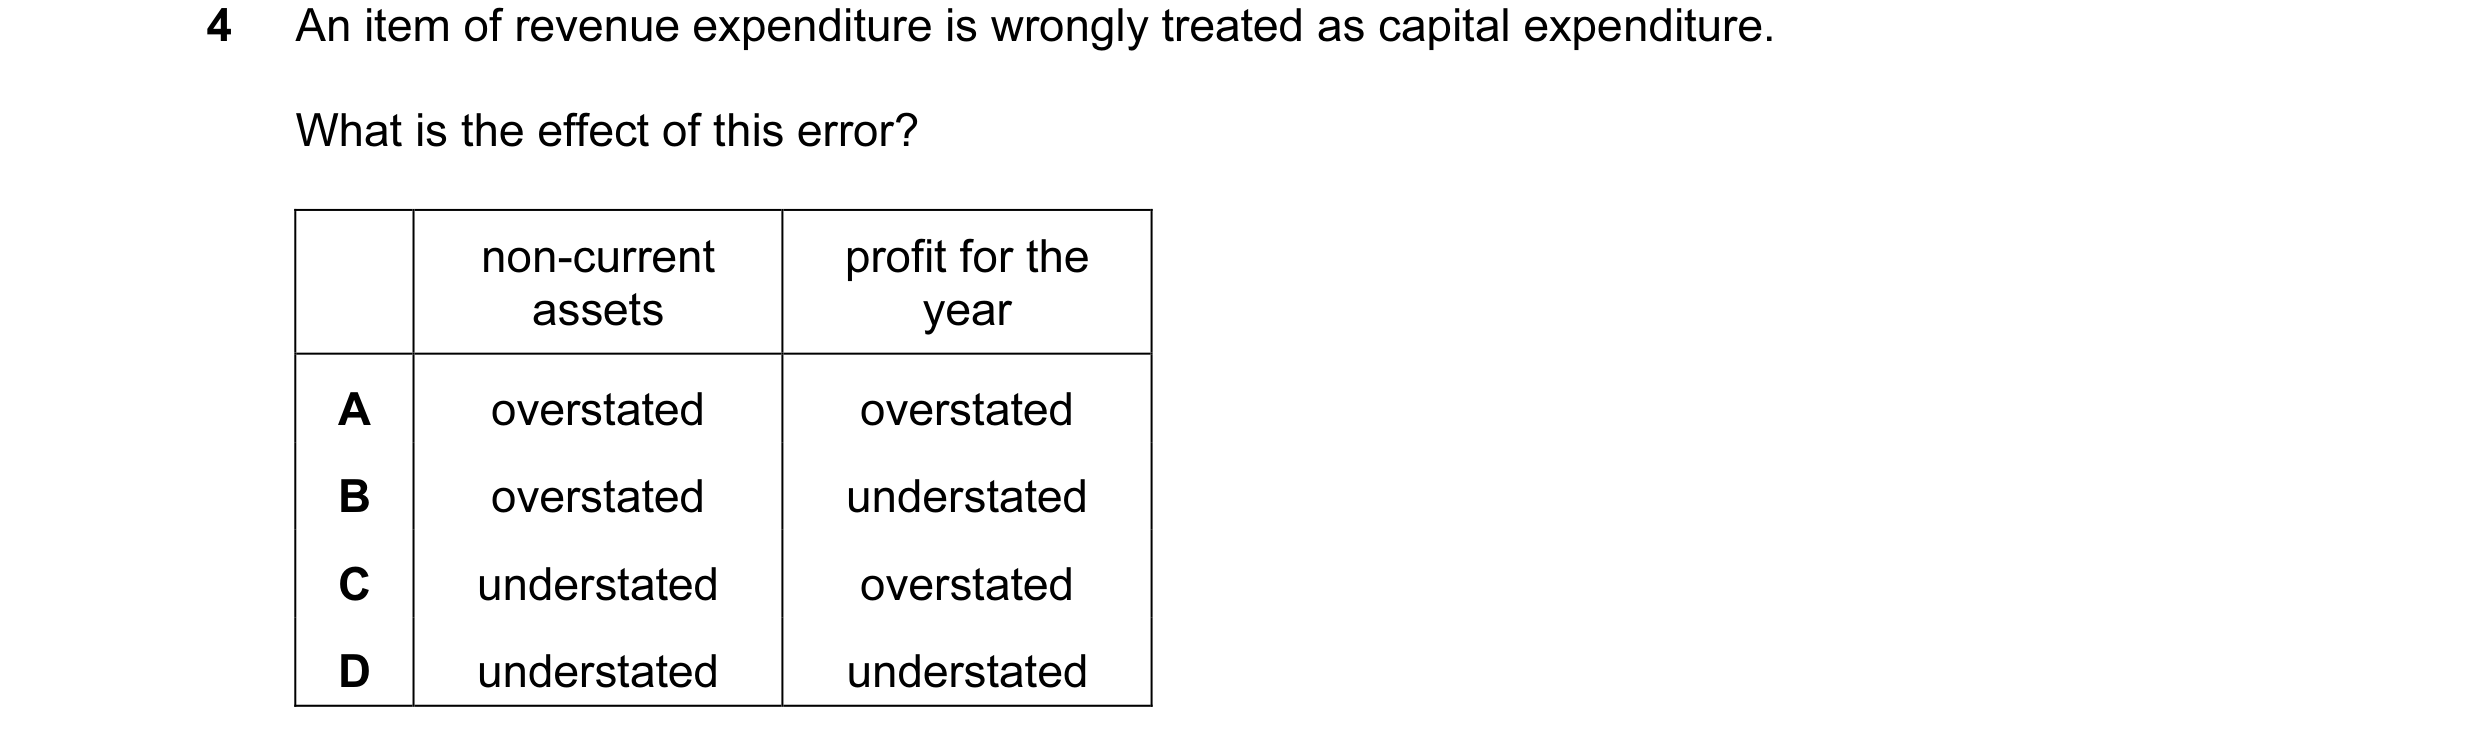
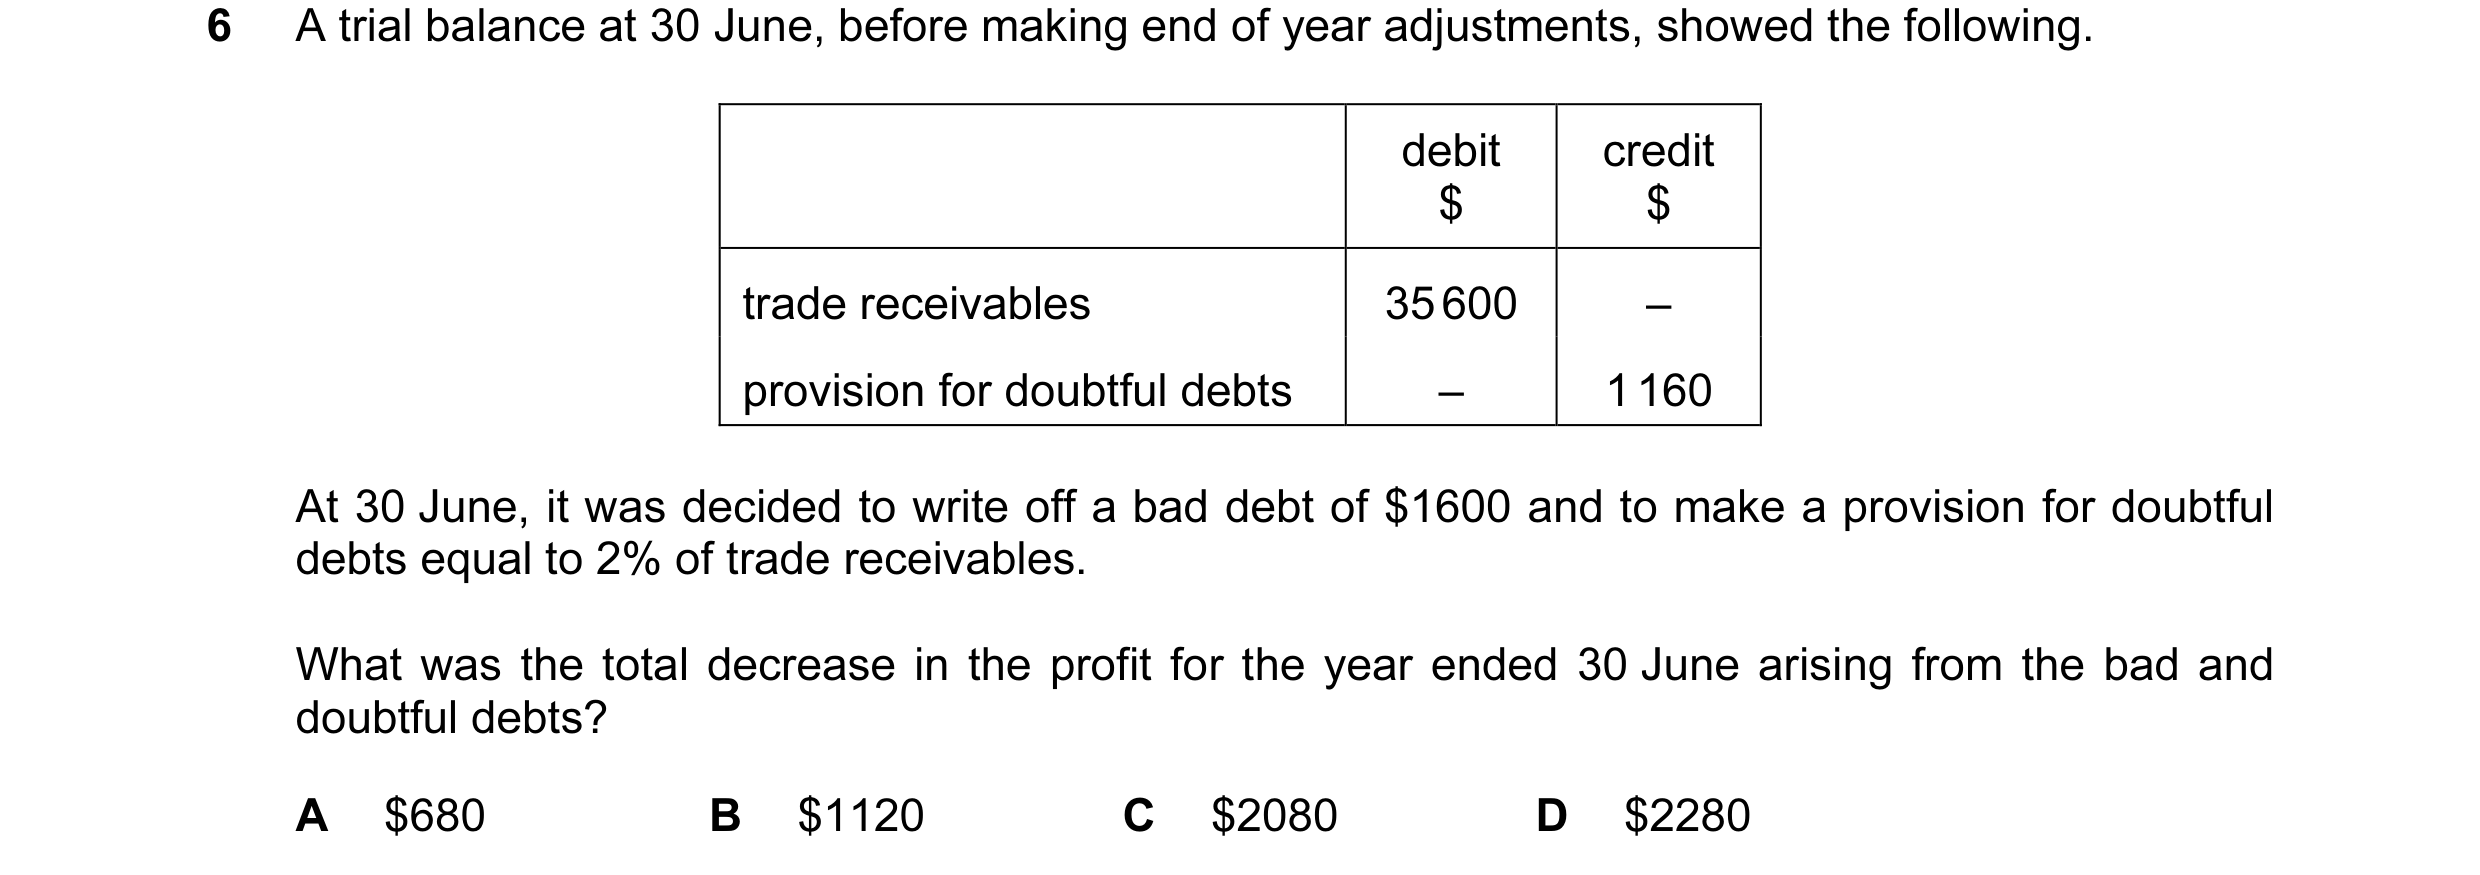 39 / 110
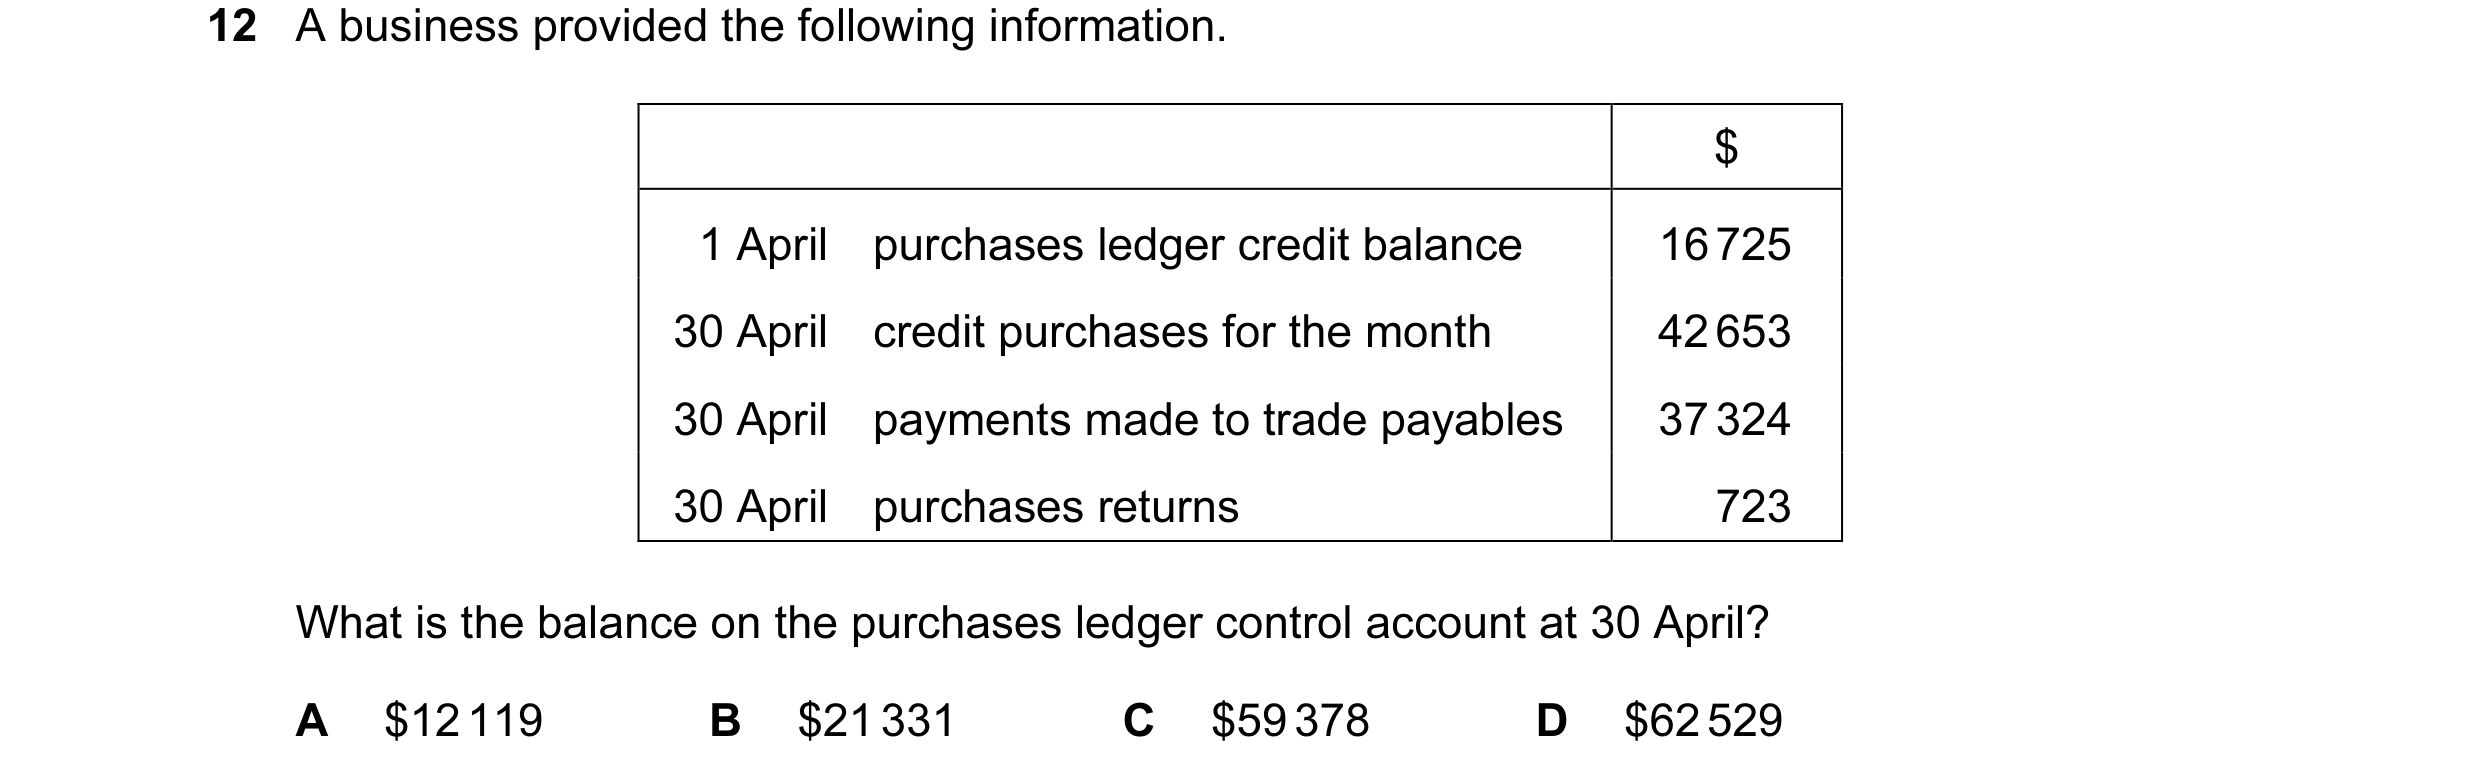
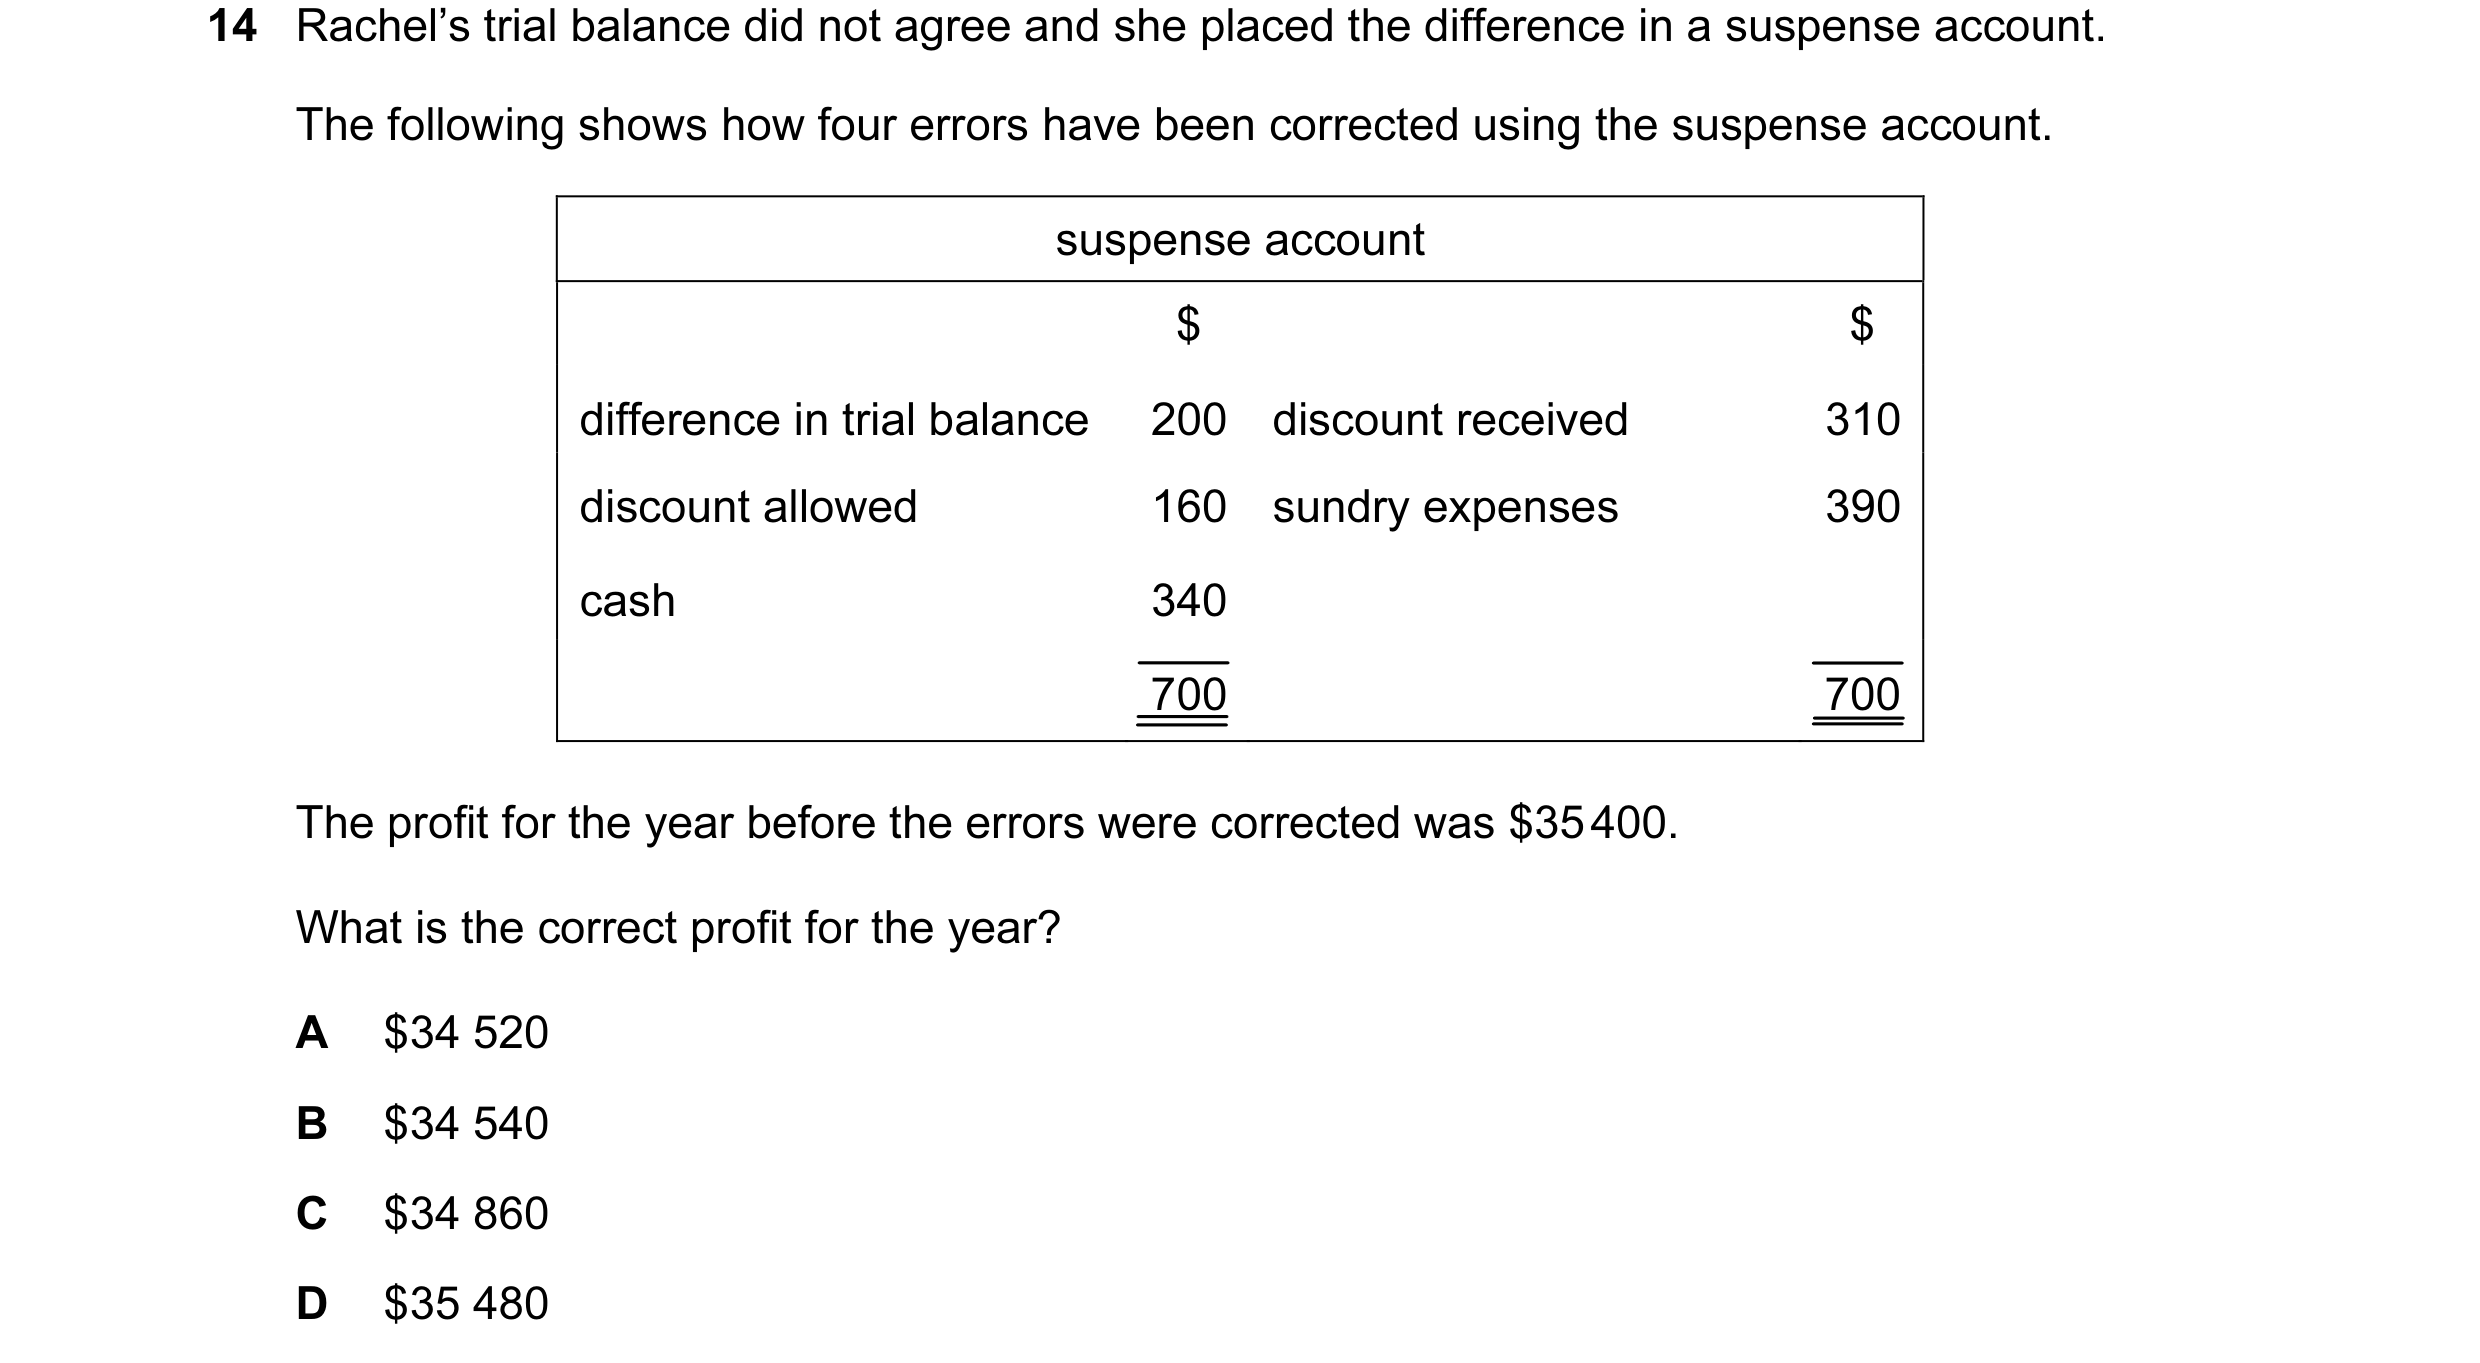 40 / 110
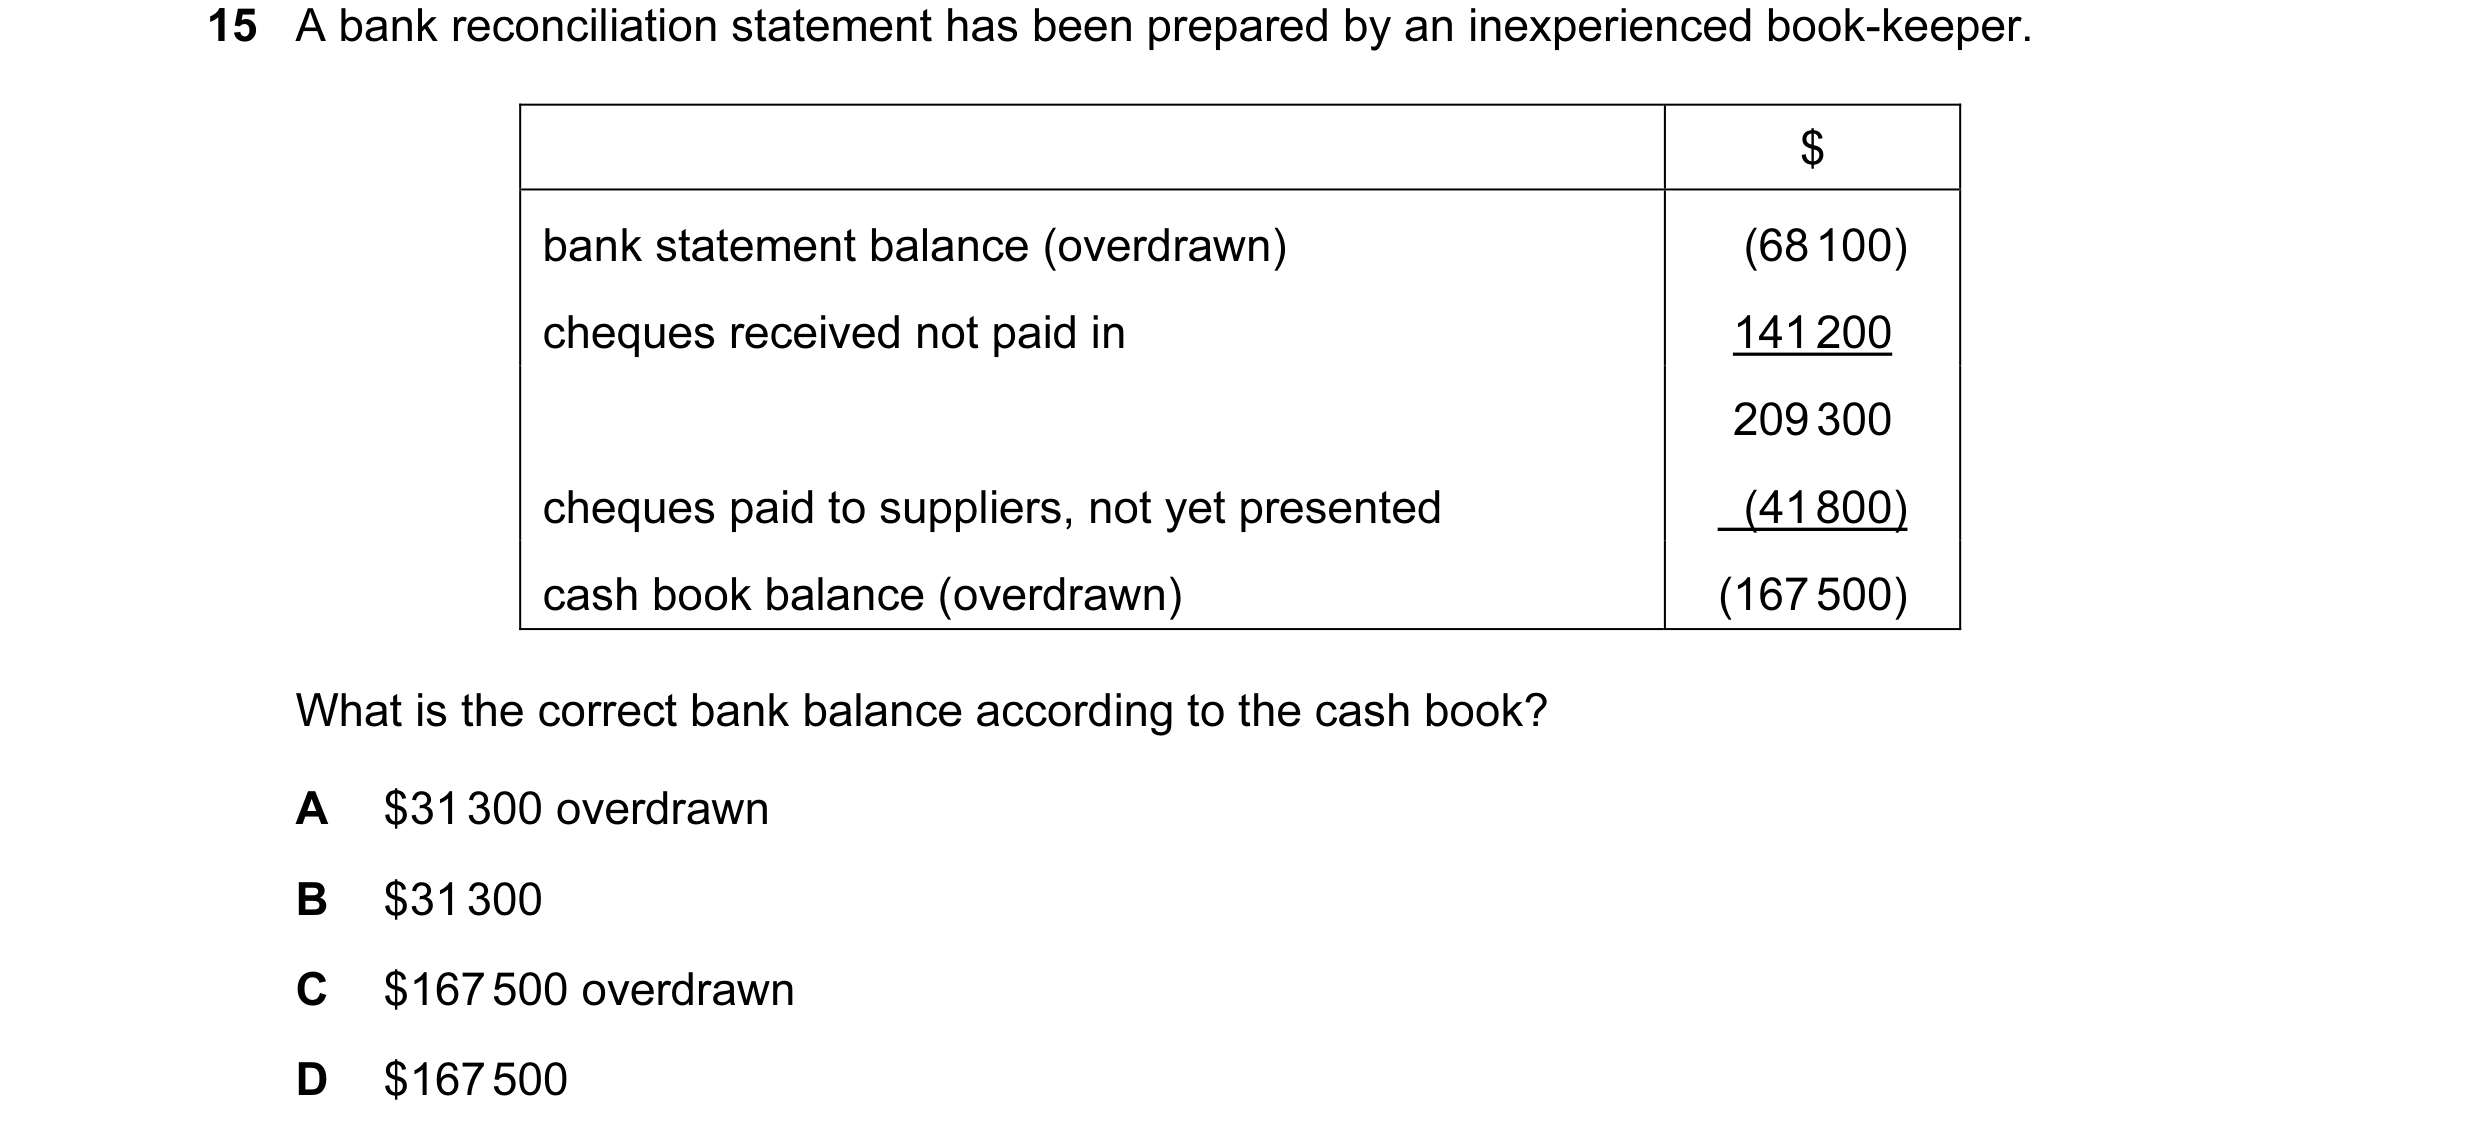
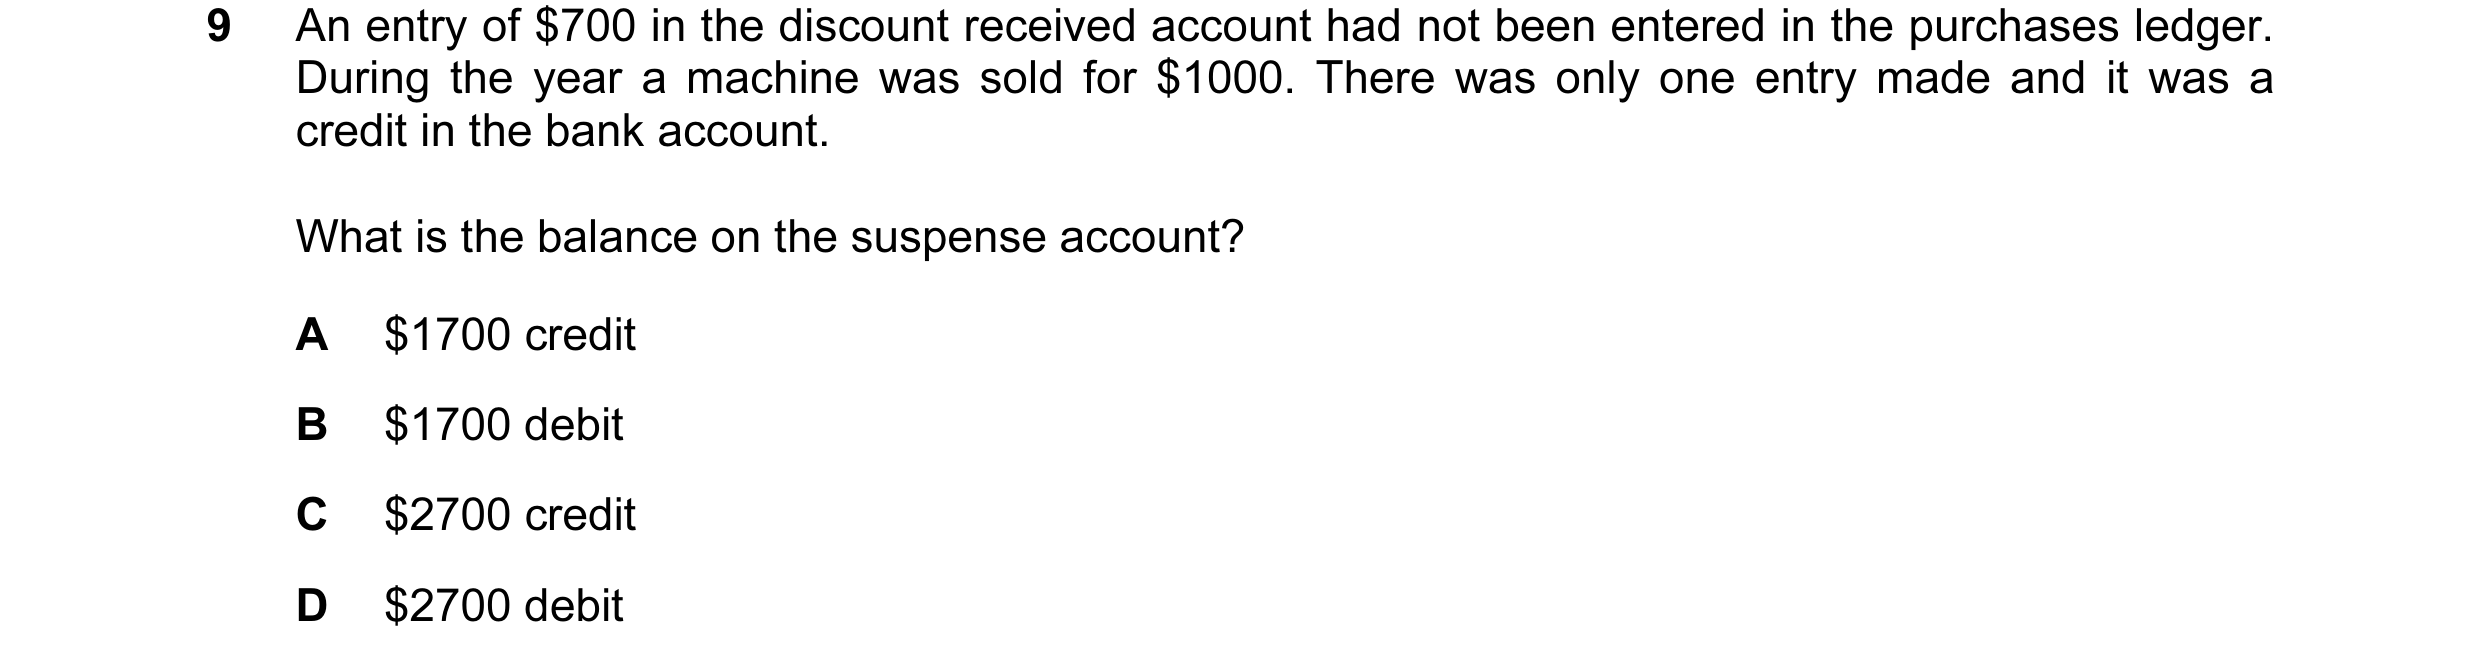 41 / 110
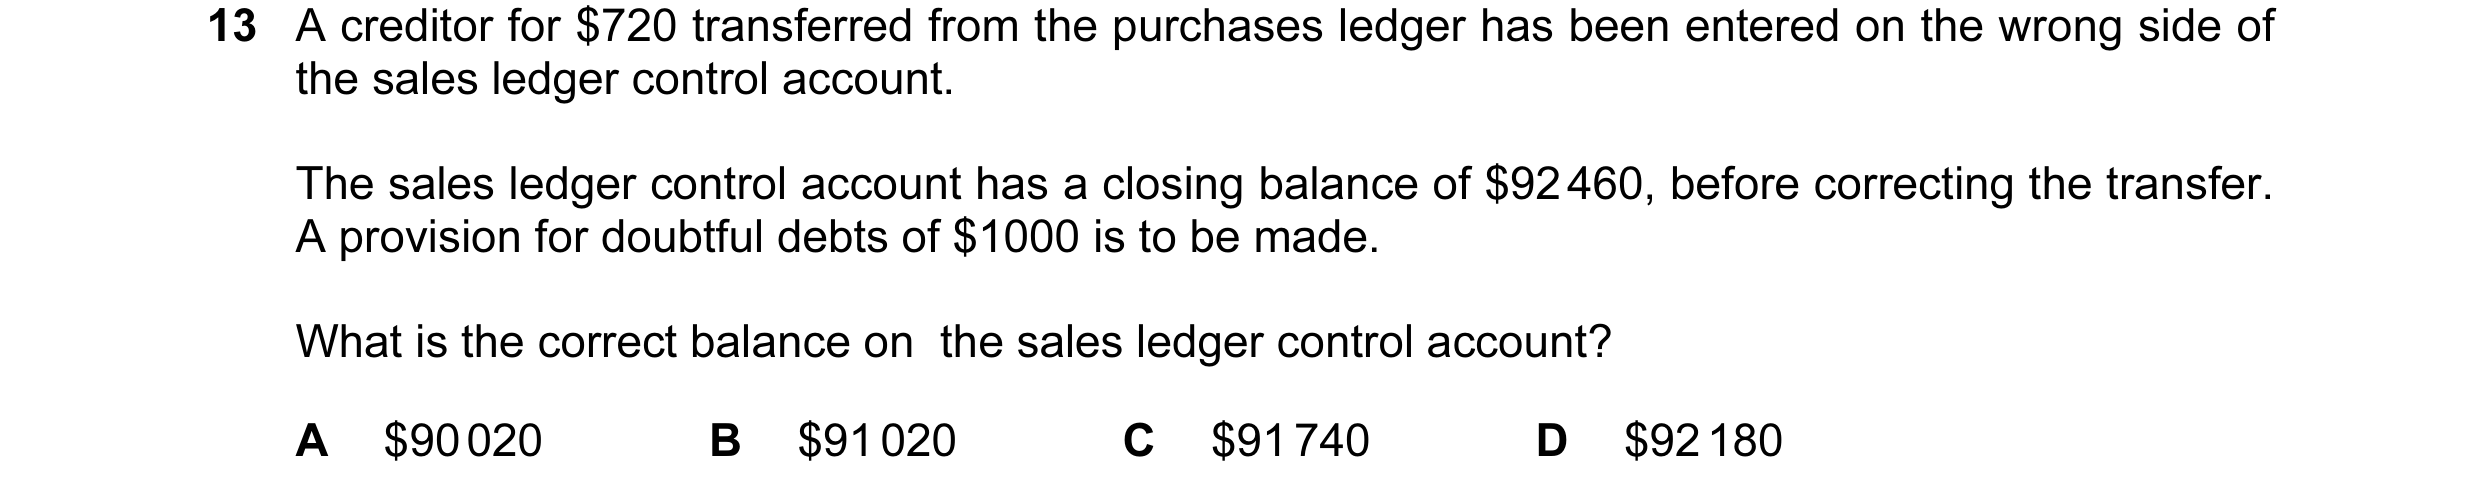
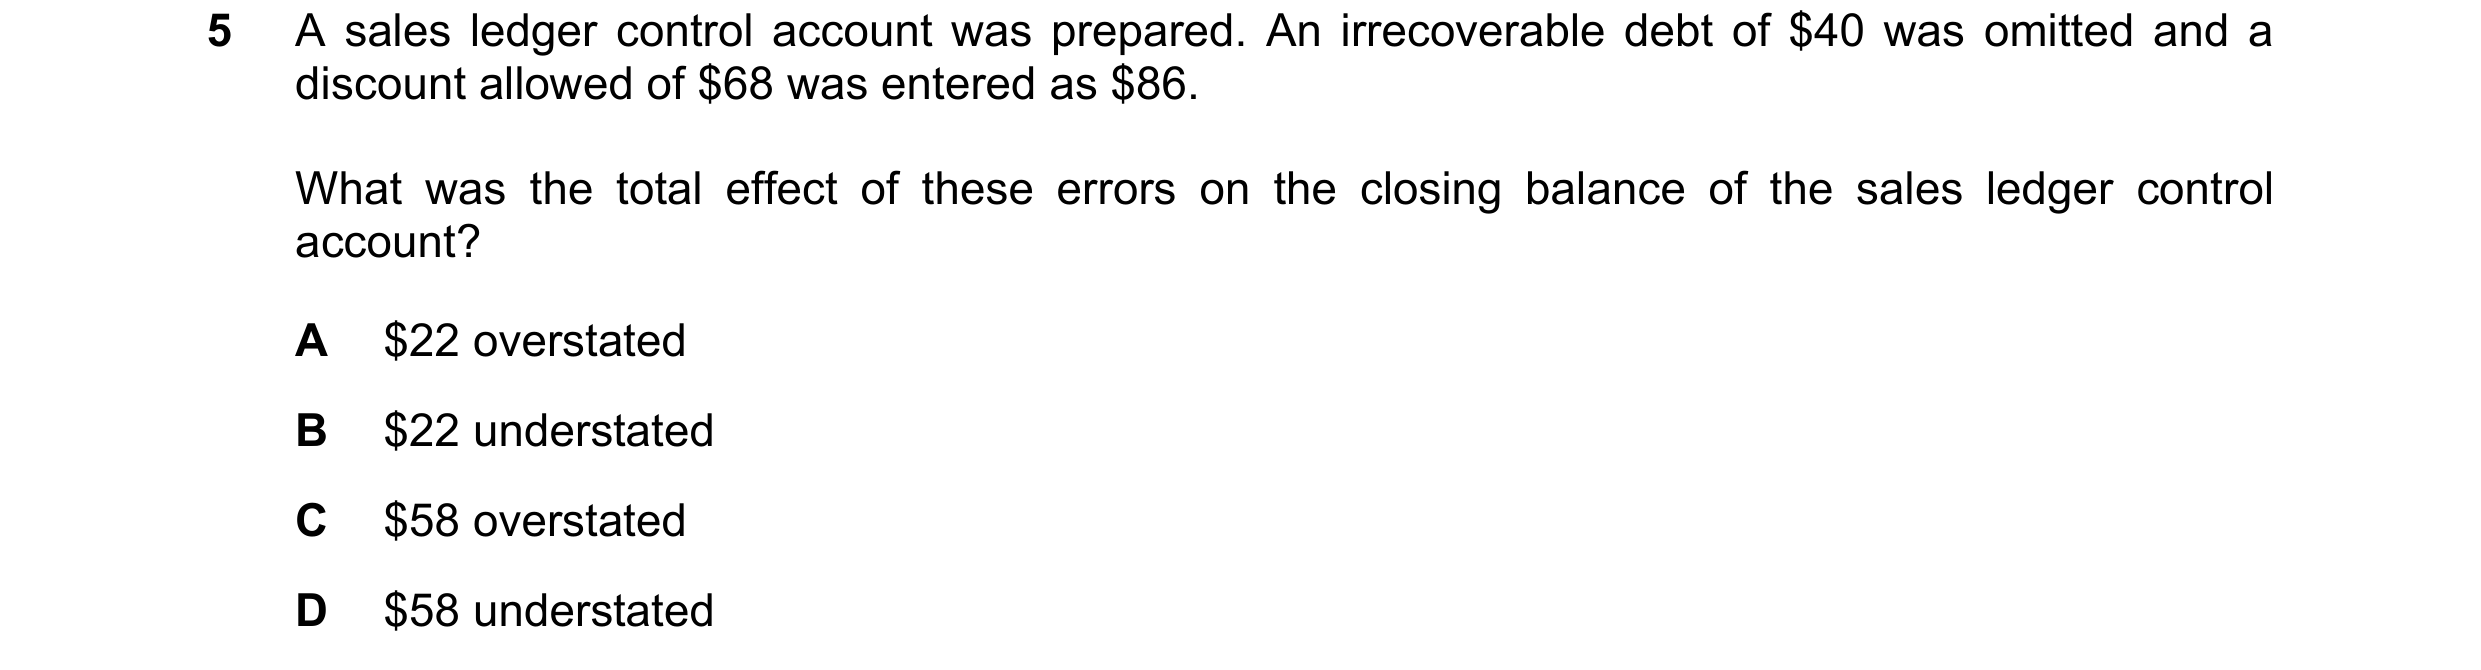
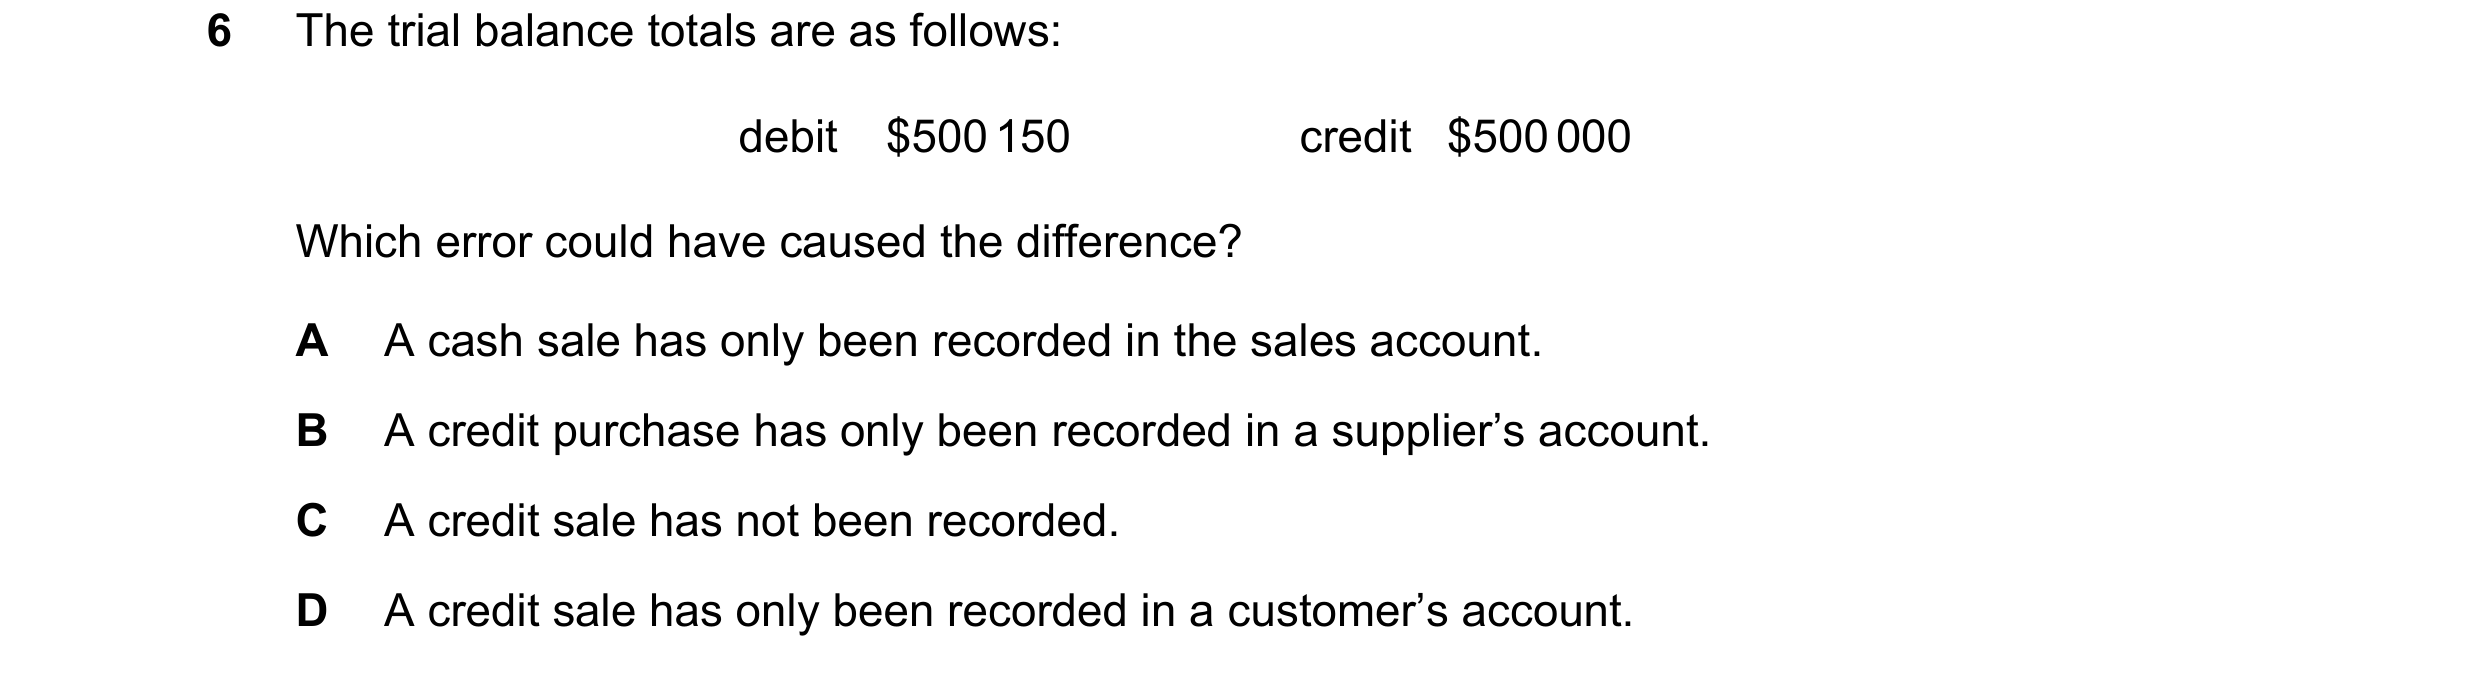
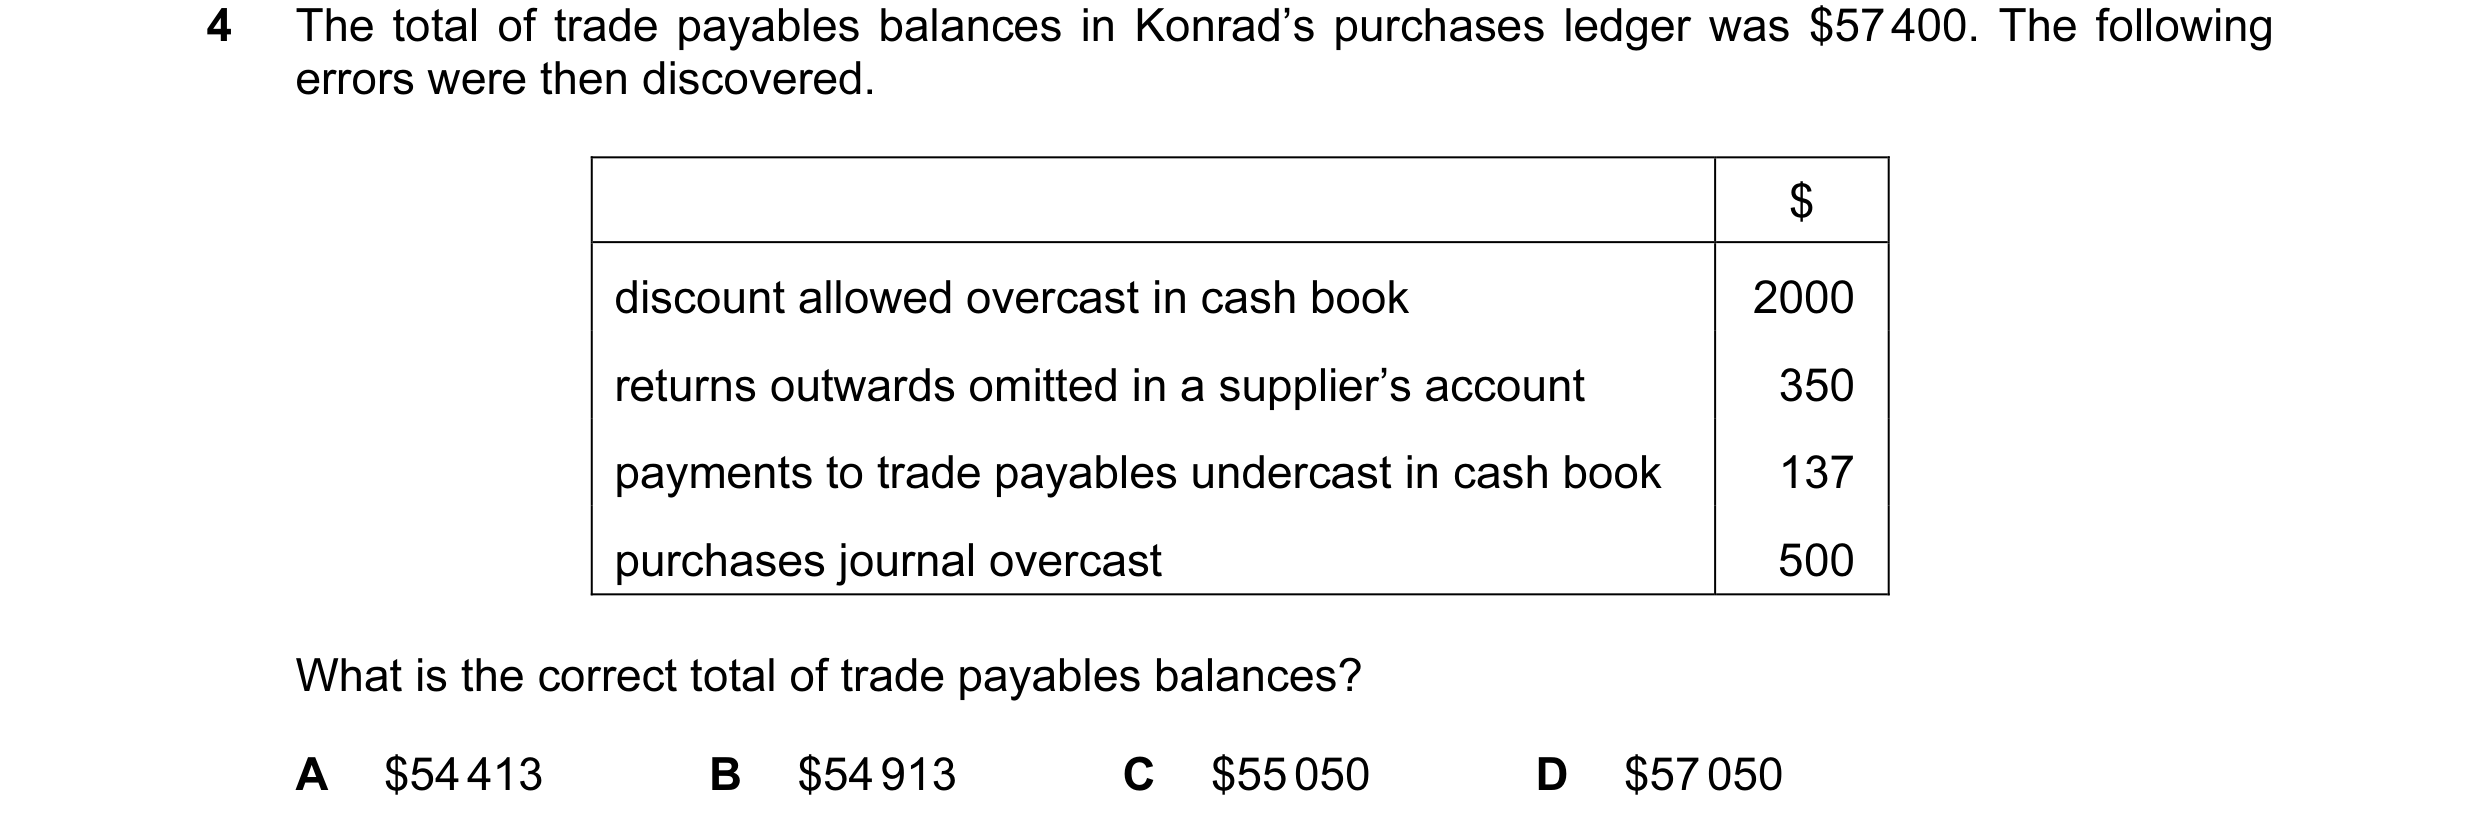 42 / 110
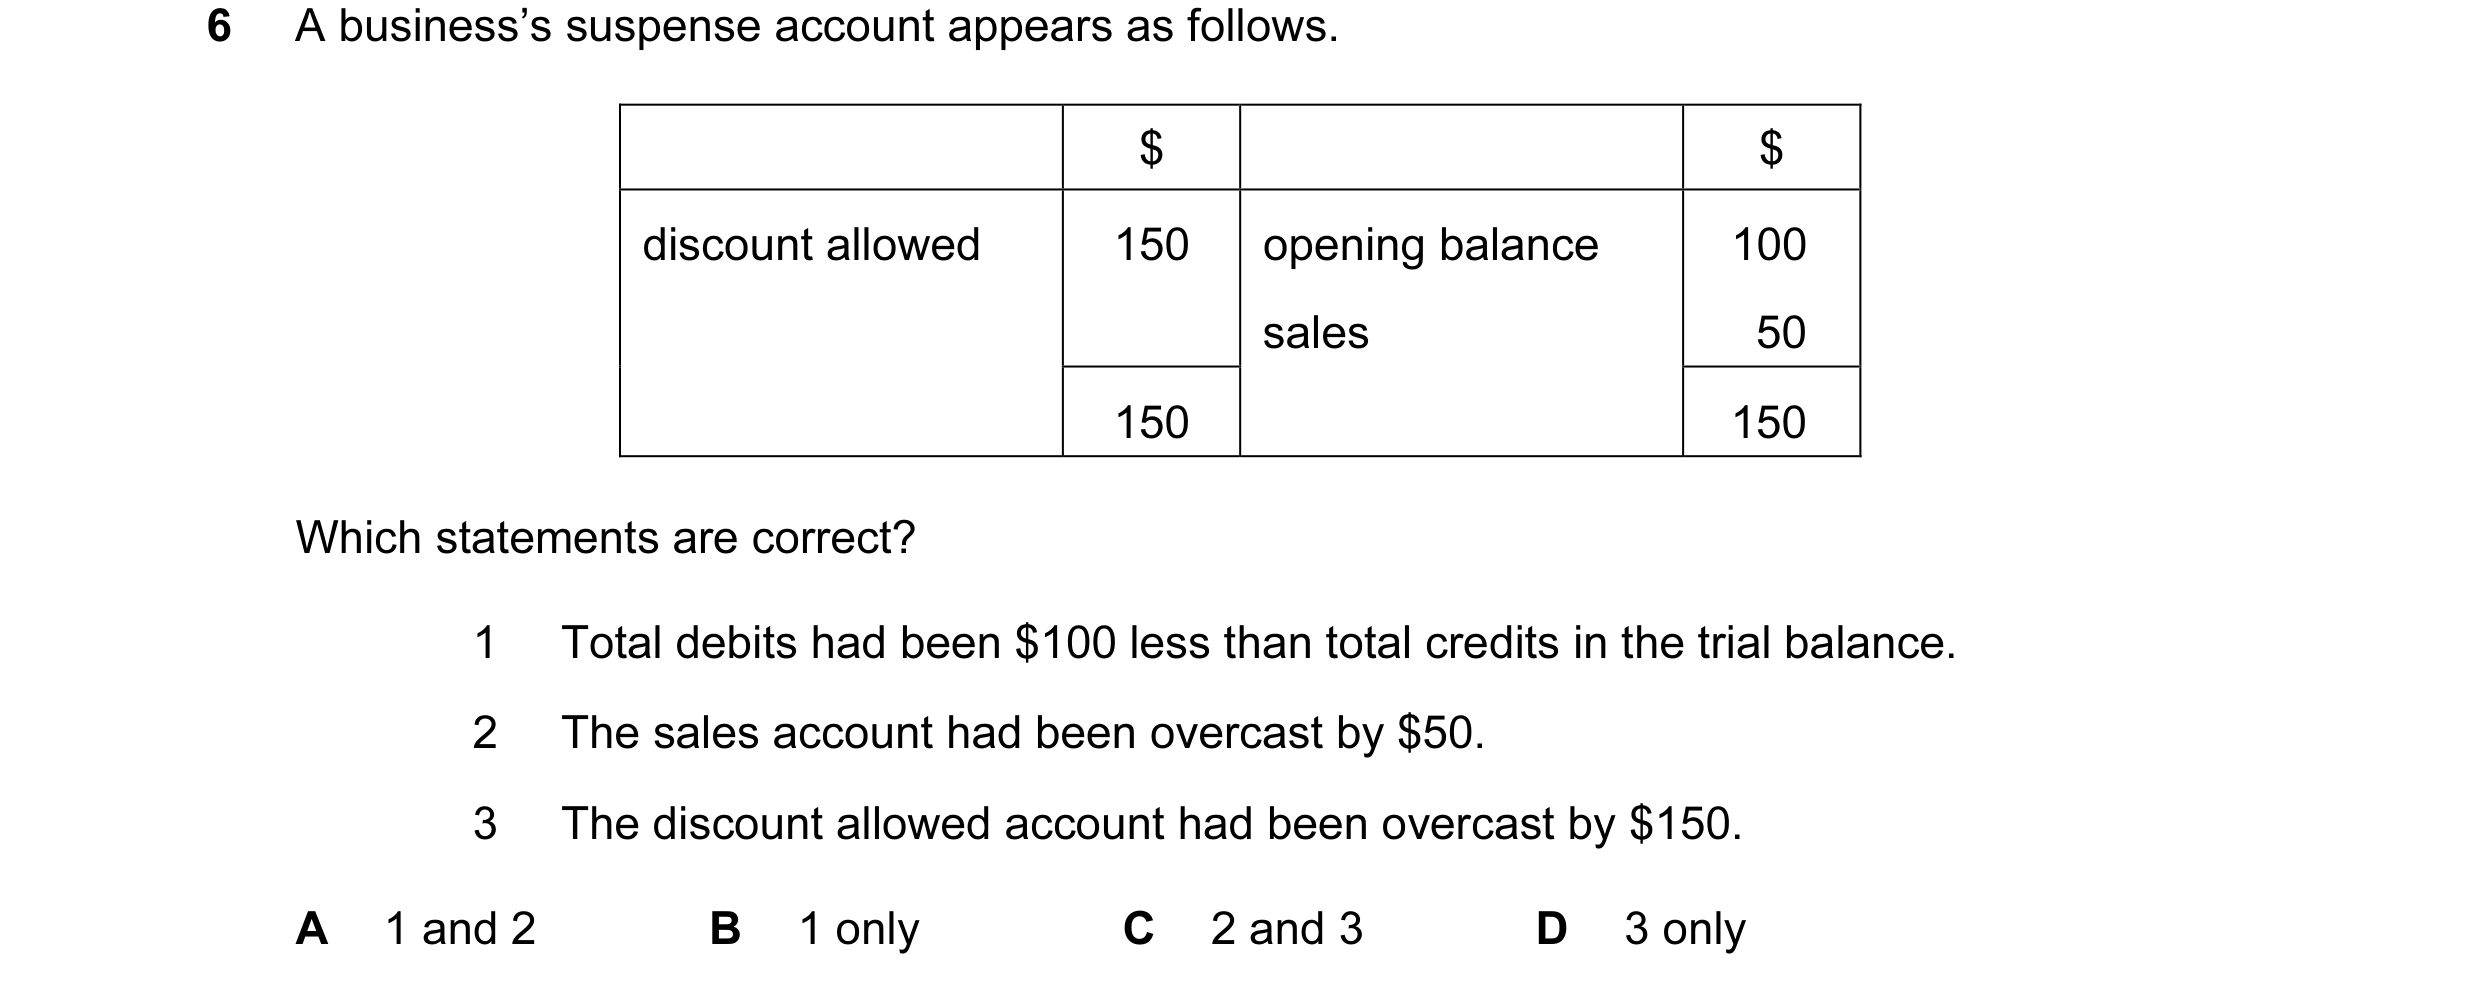
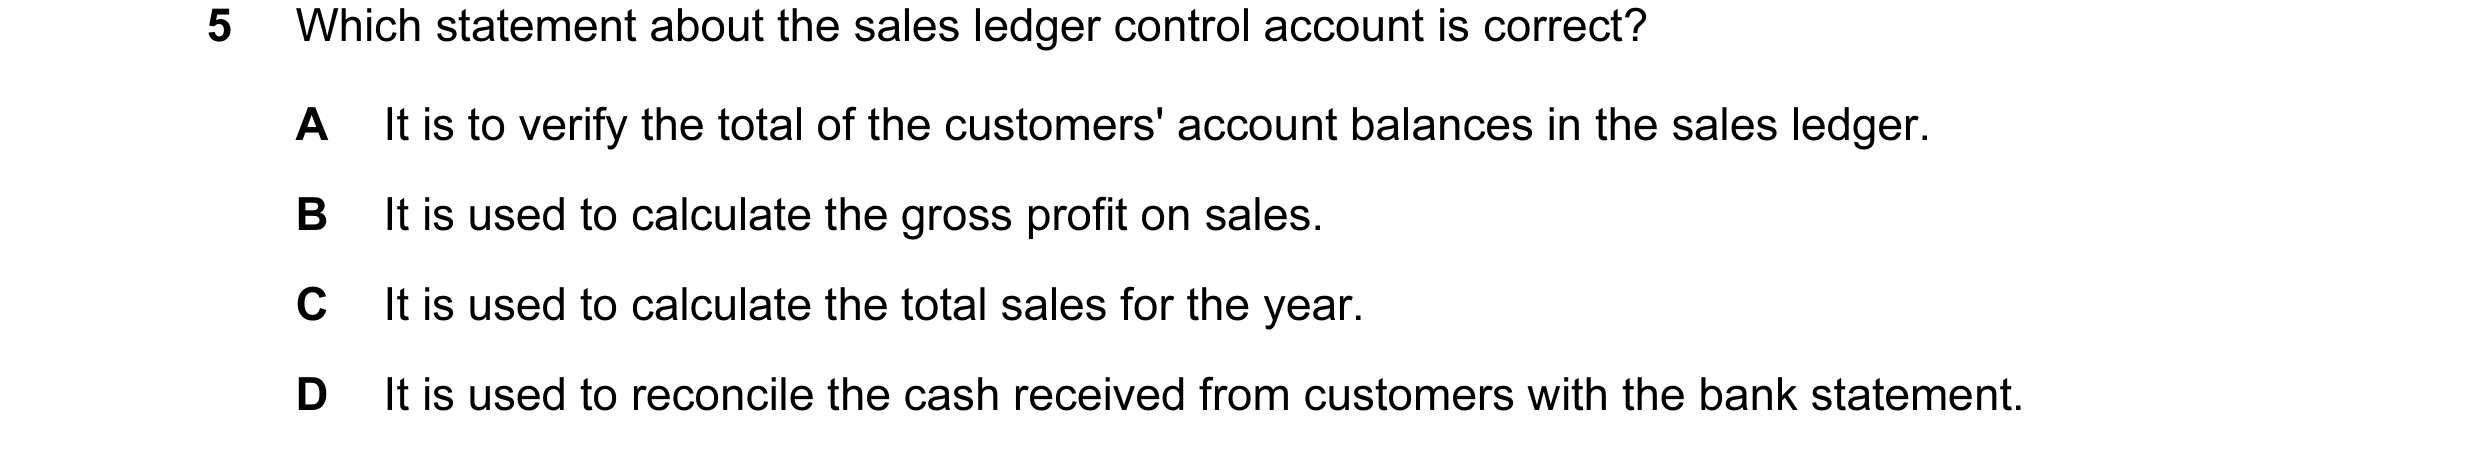
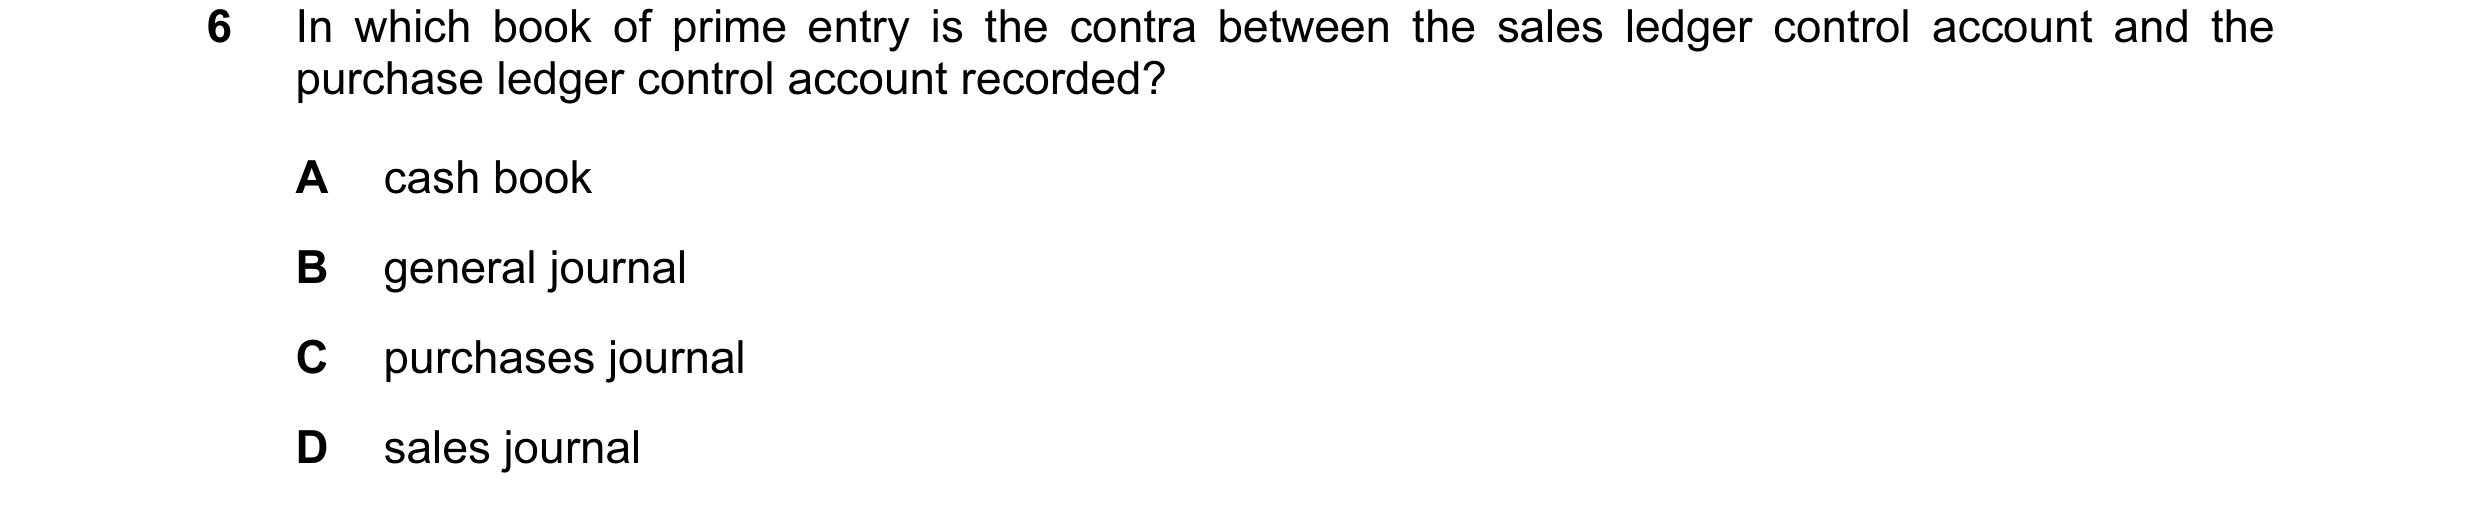 43 / 110
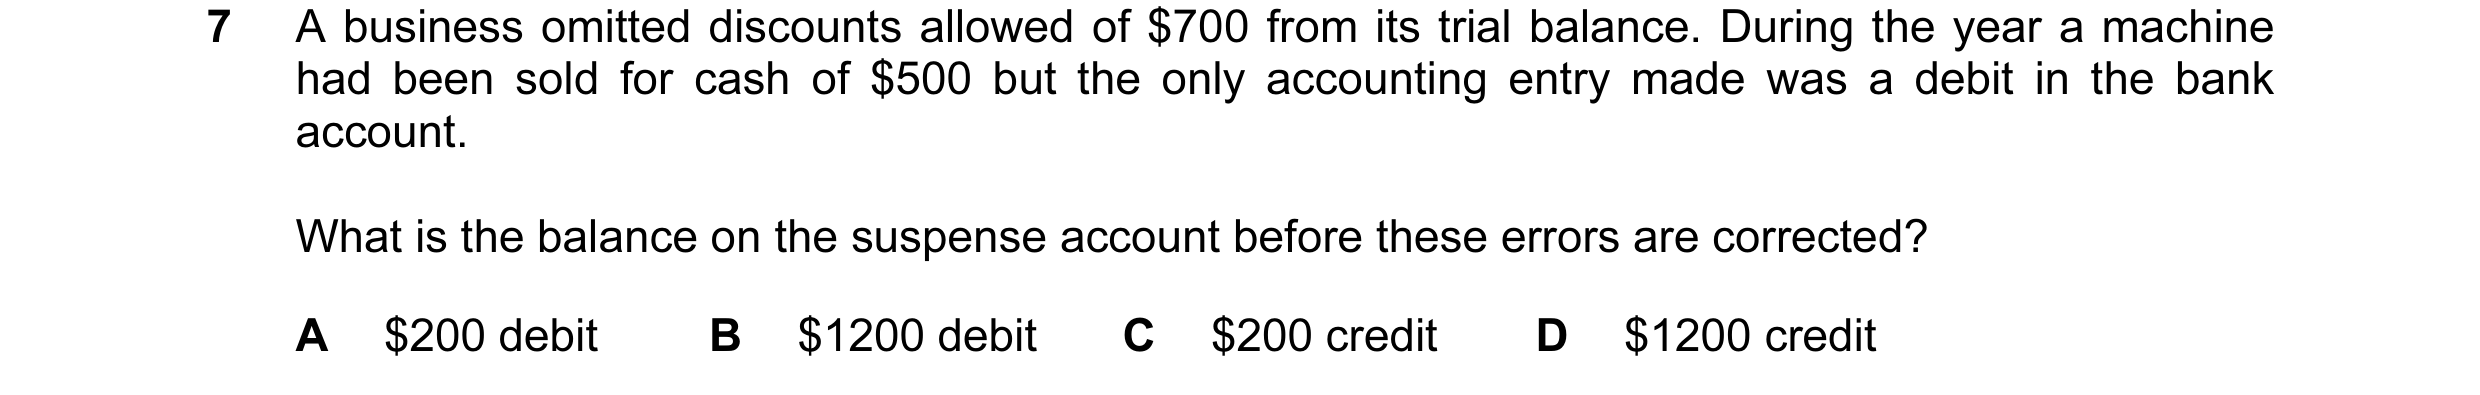
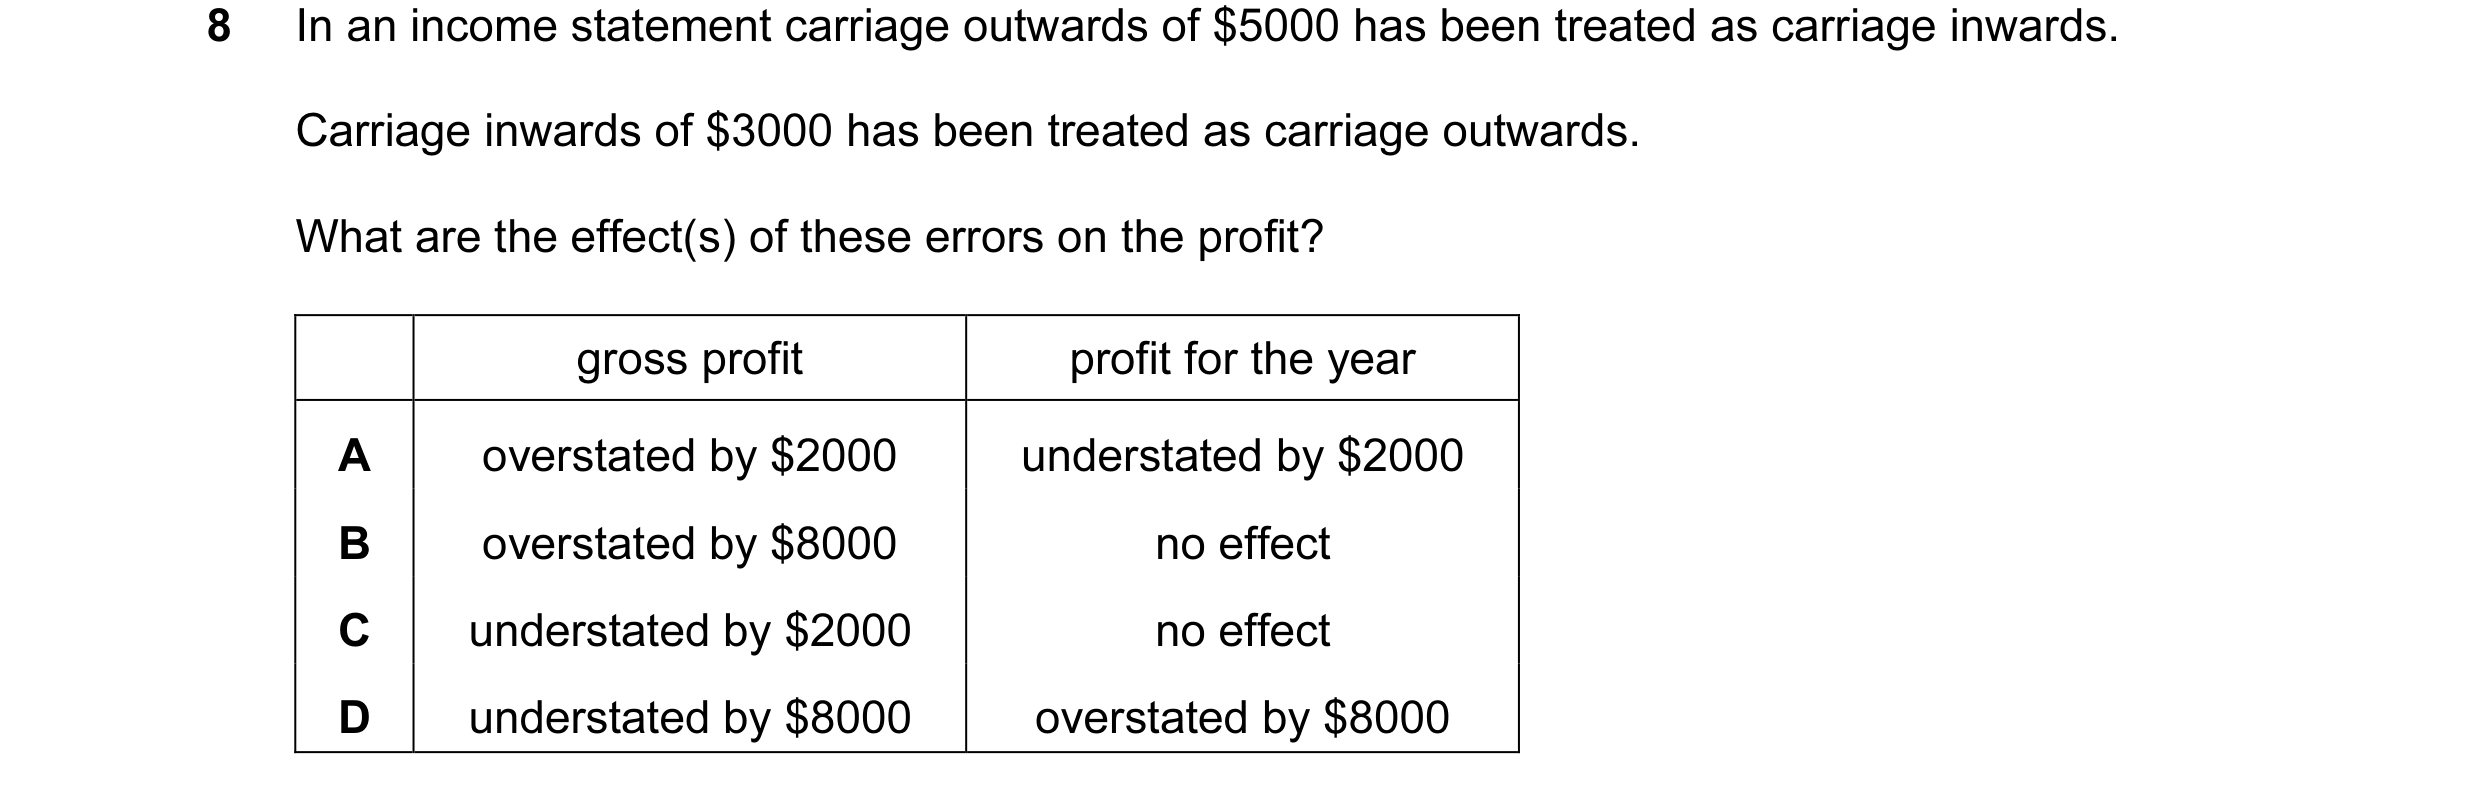
 44 / 110
 45 / 110
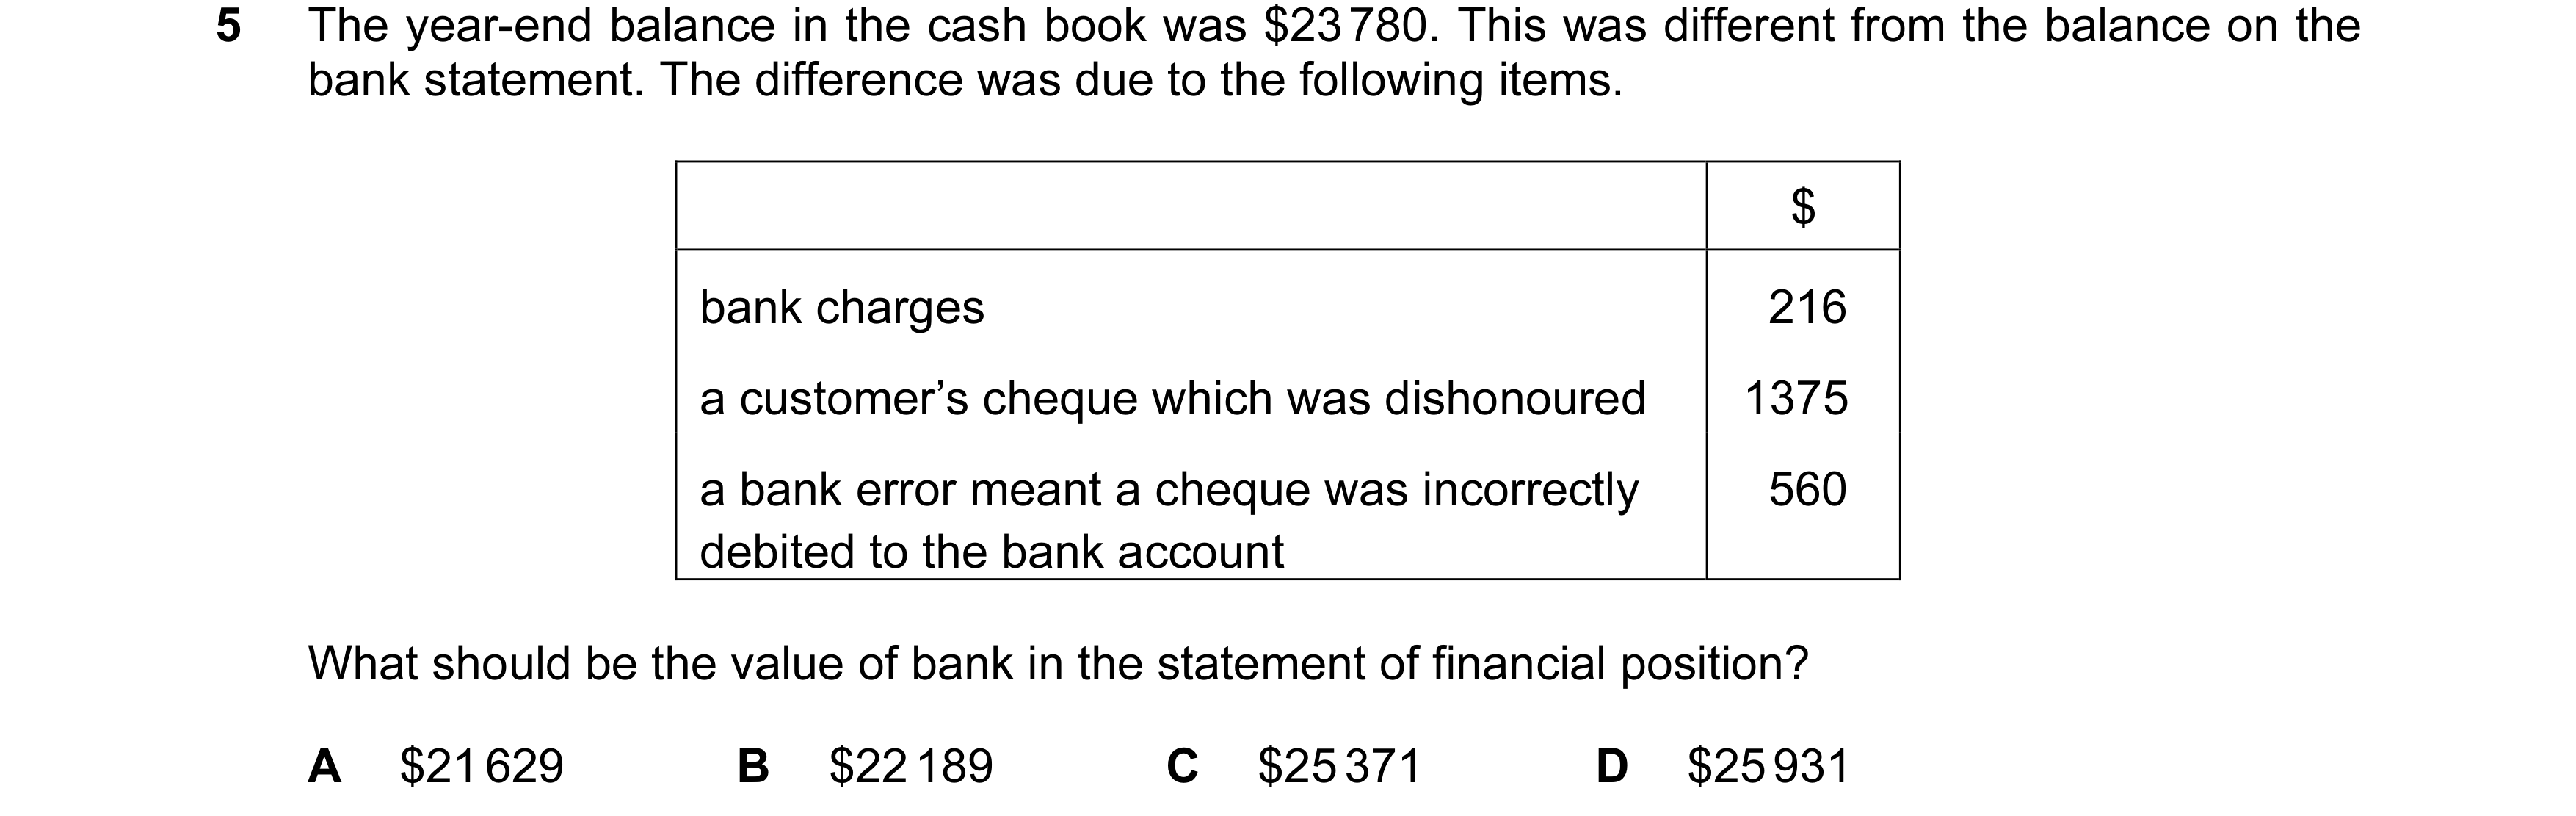
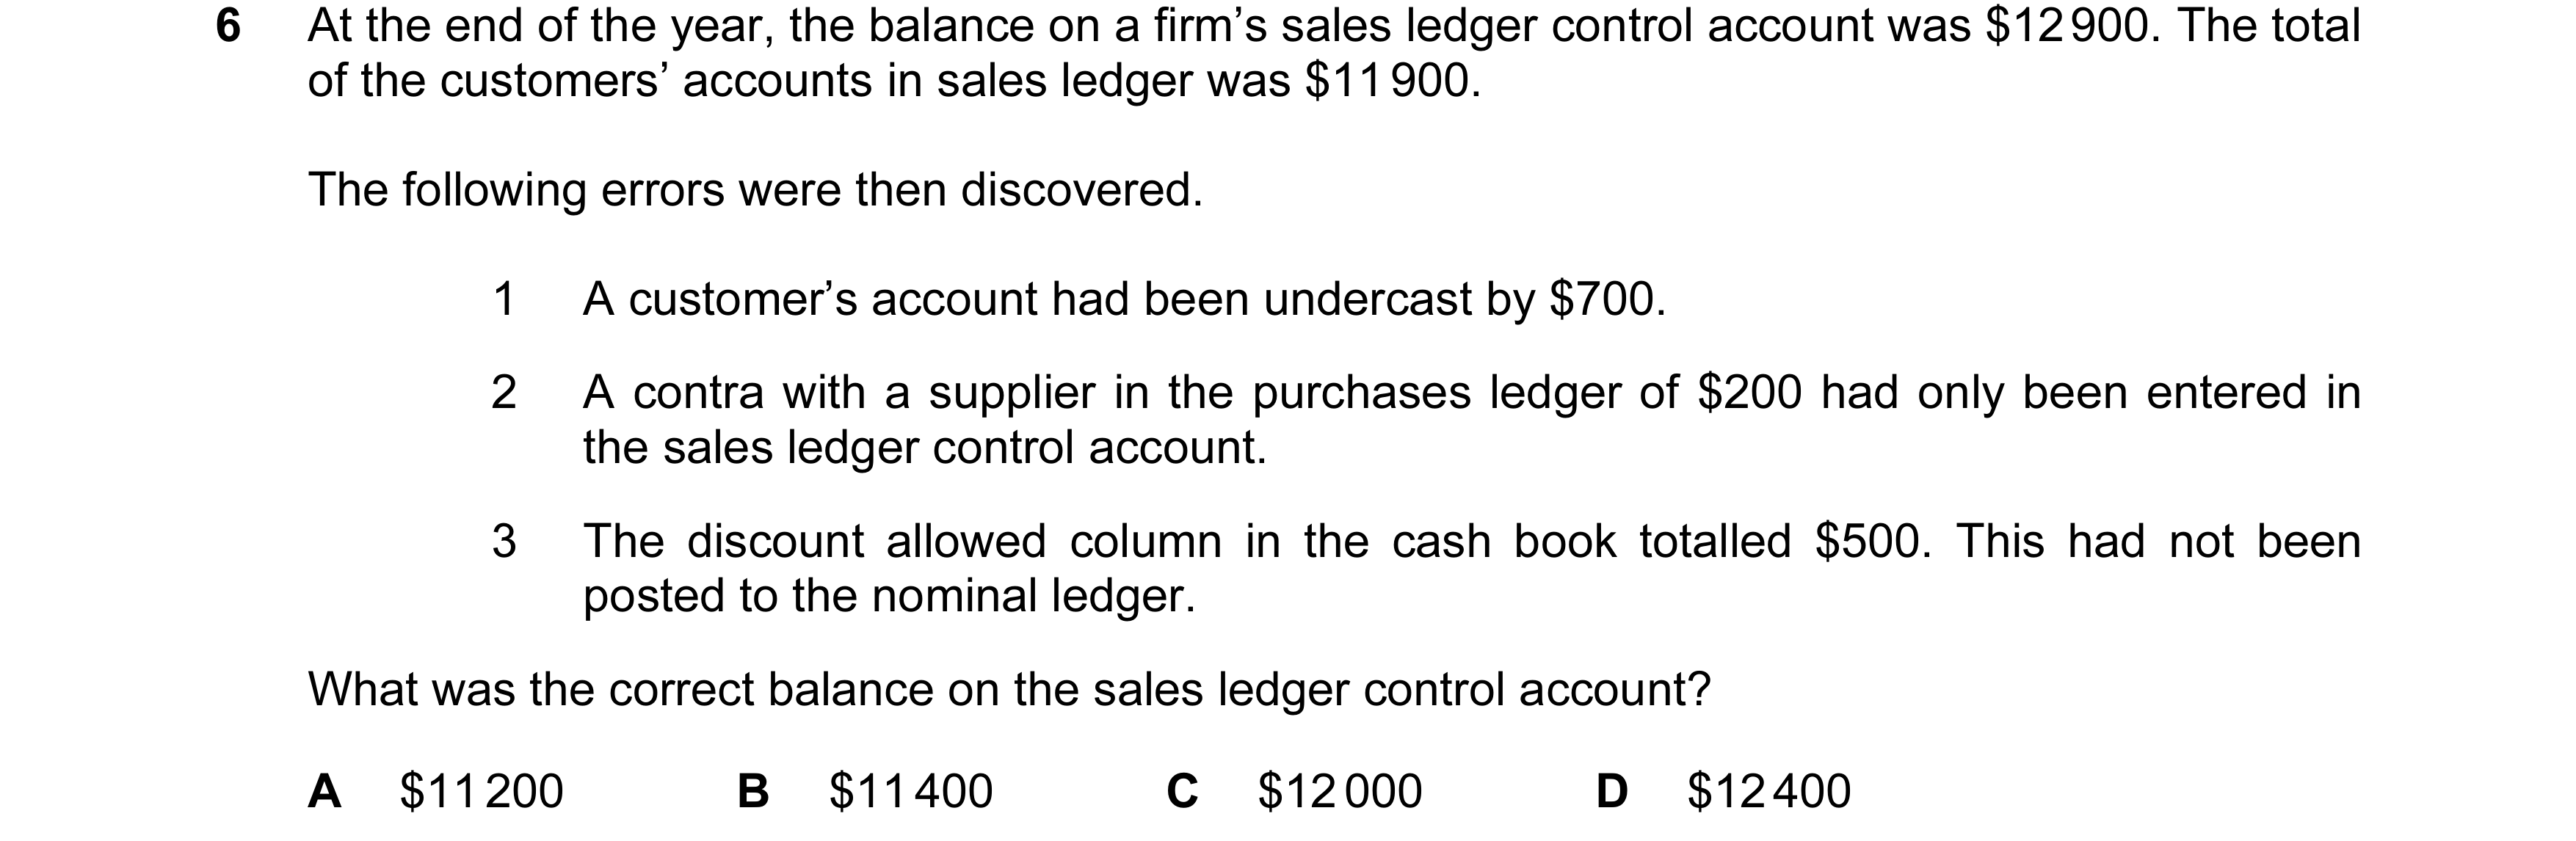 46 / 110
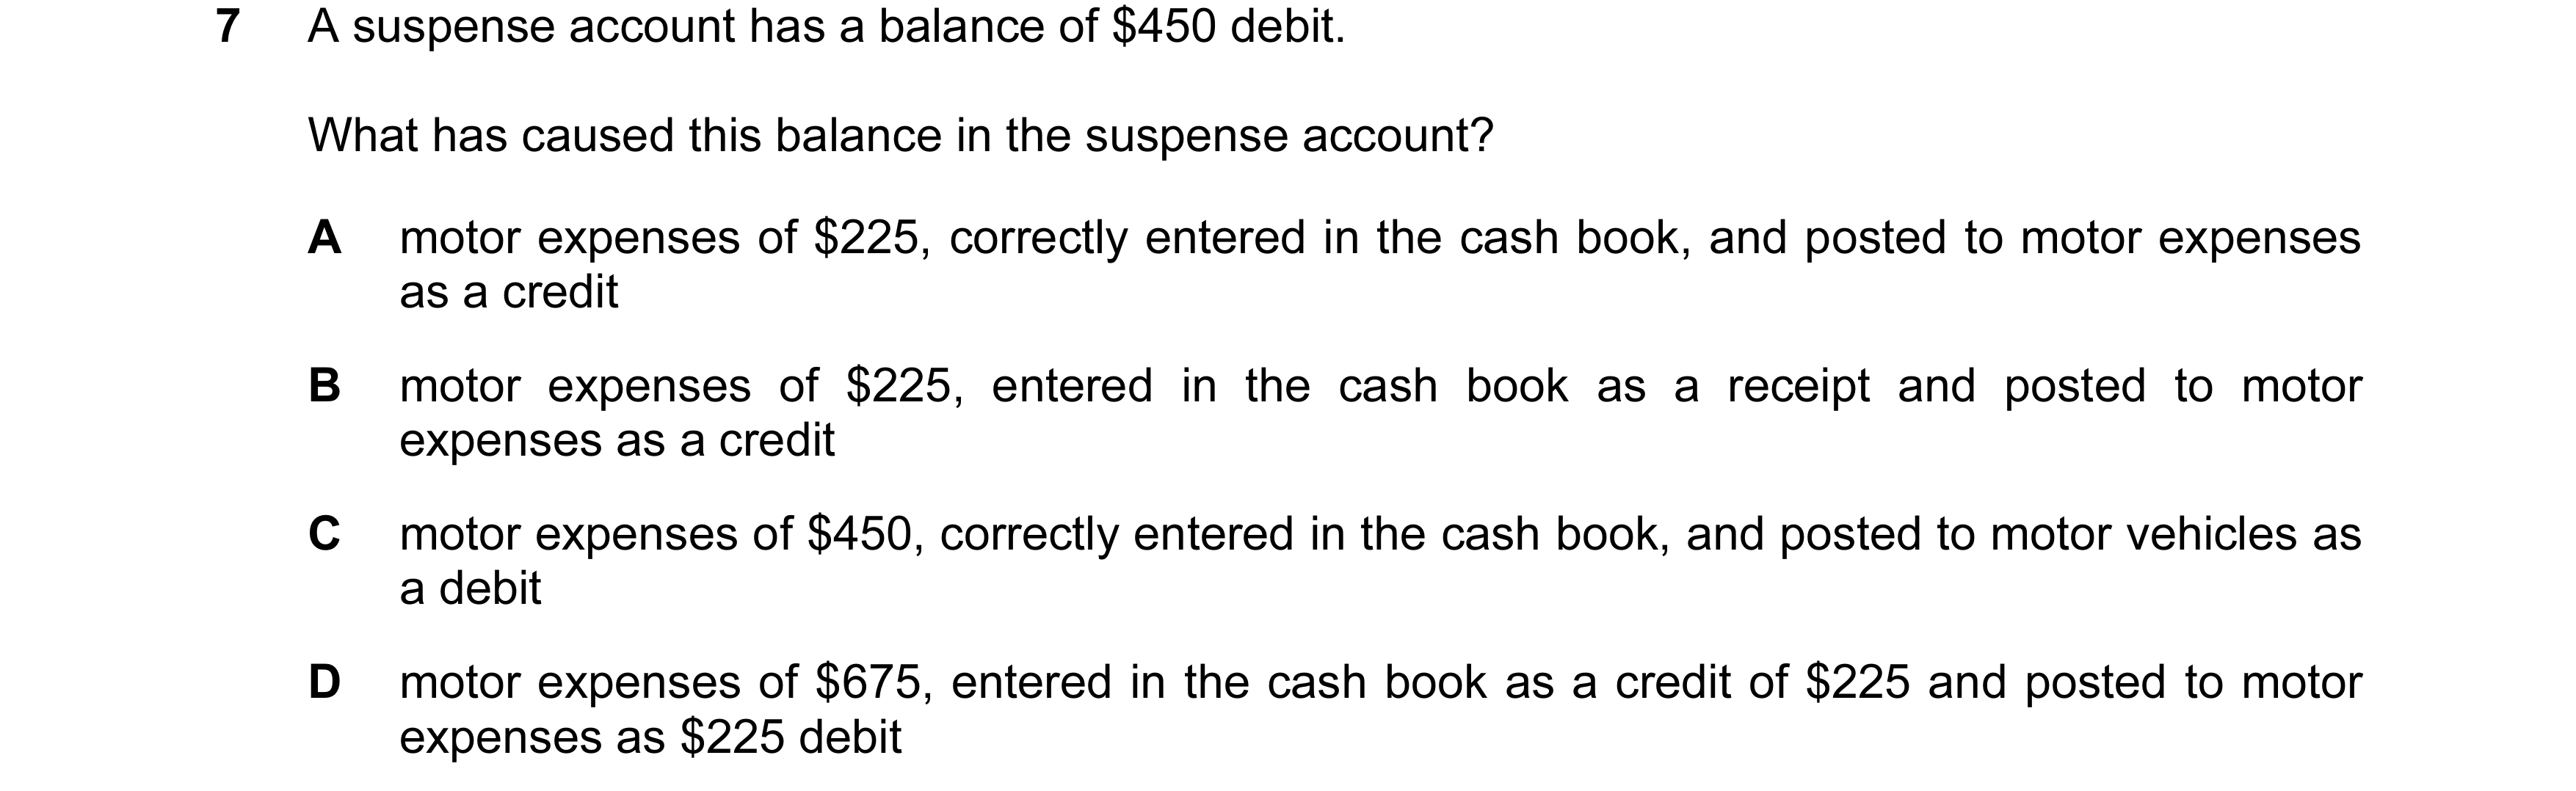
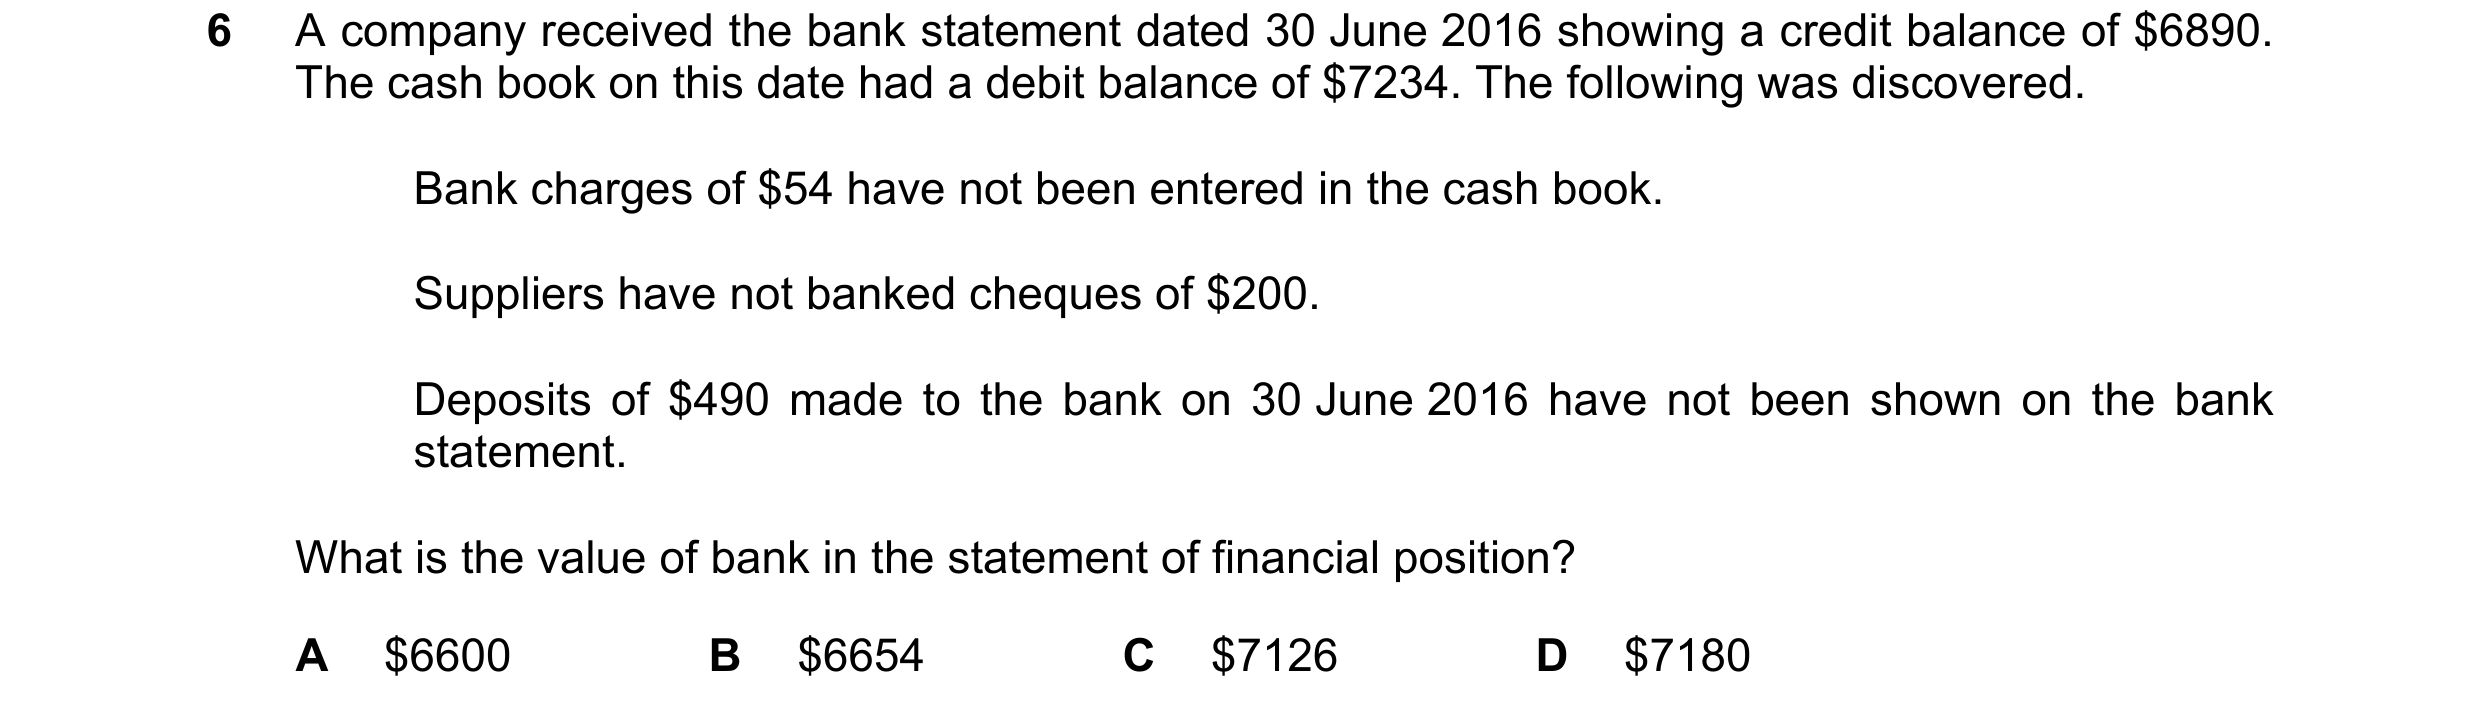
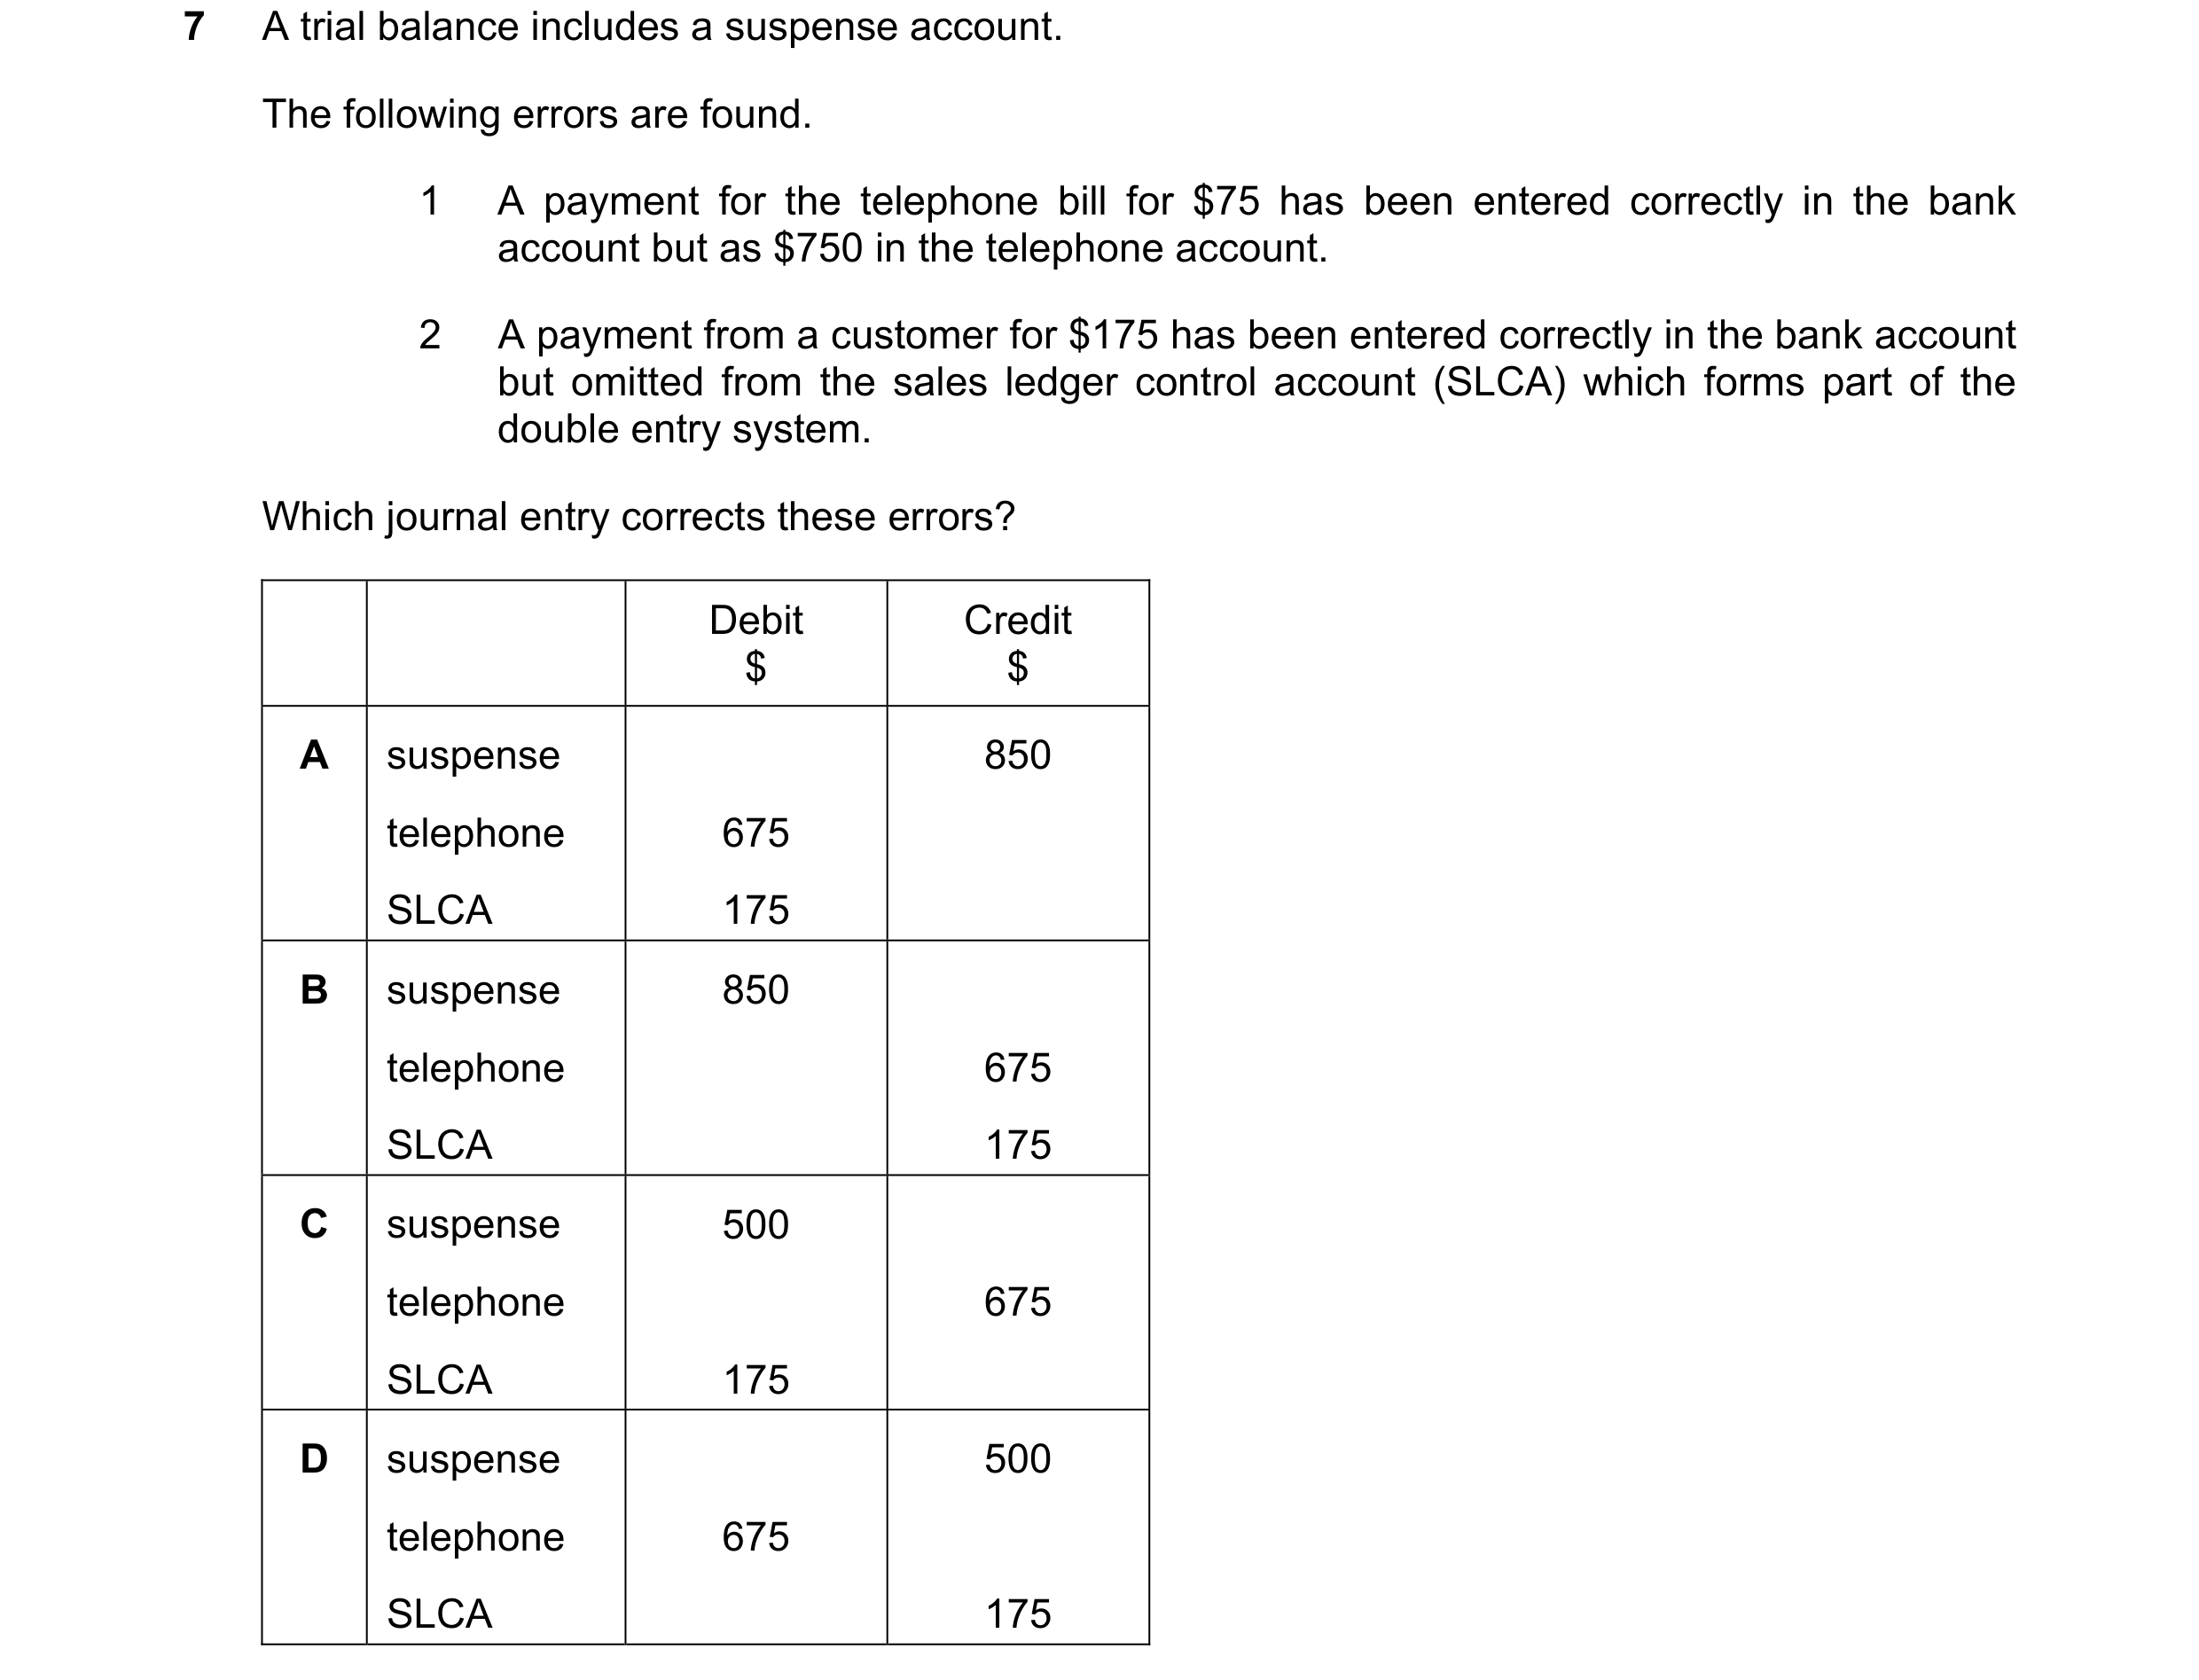 47 / 110
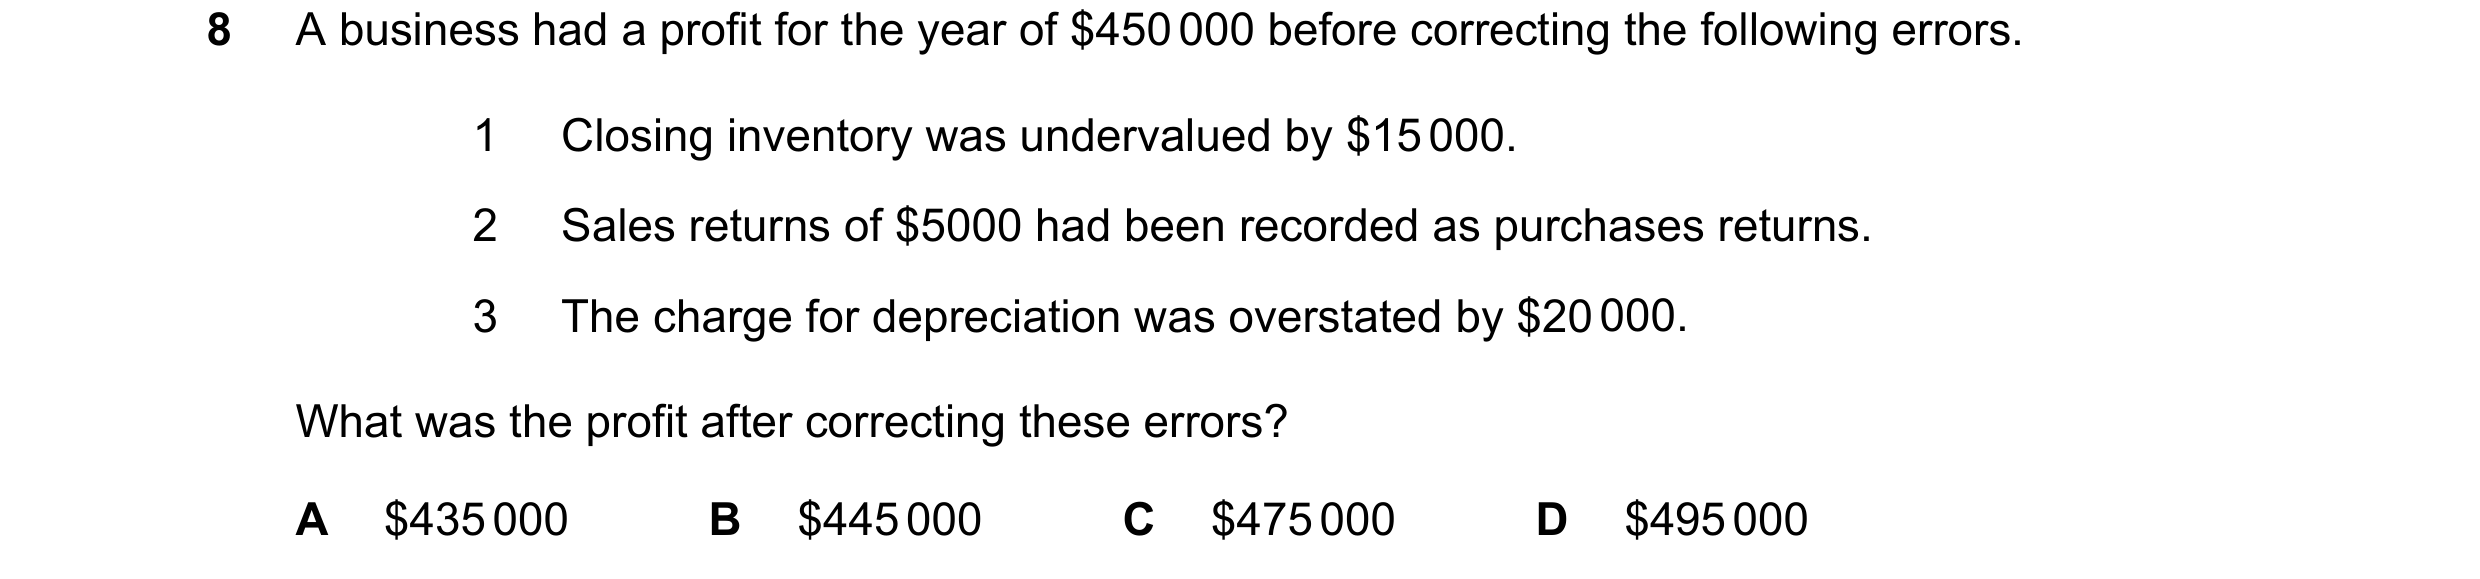
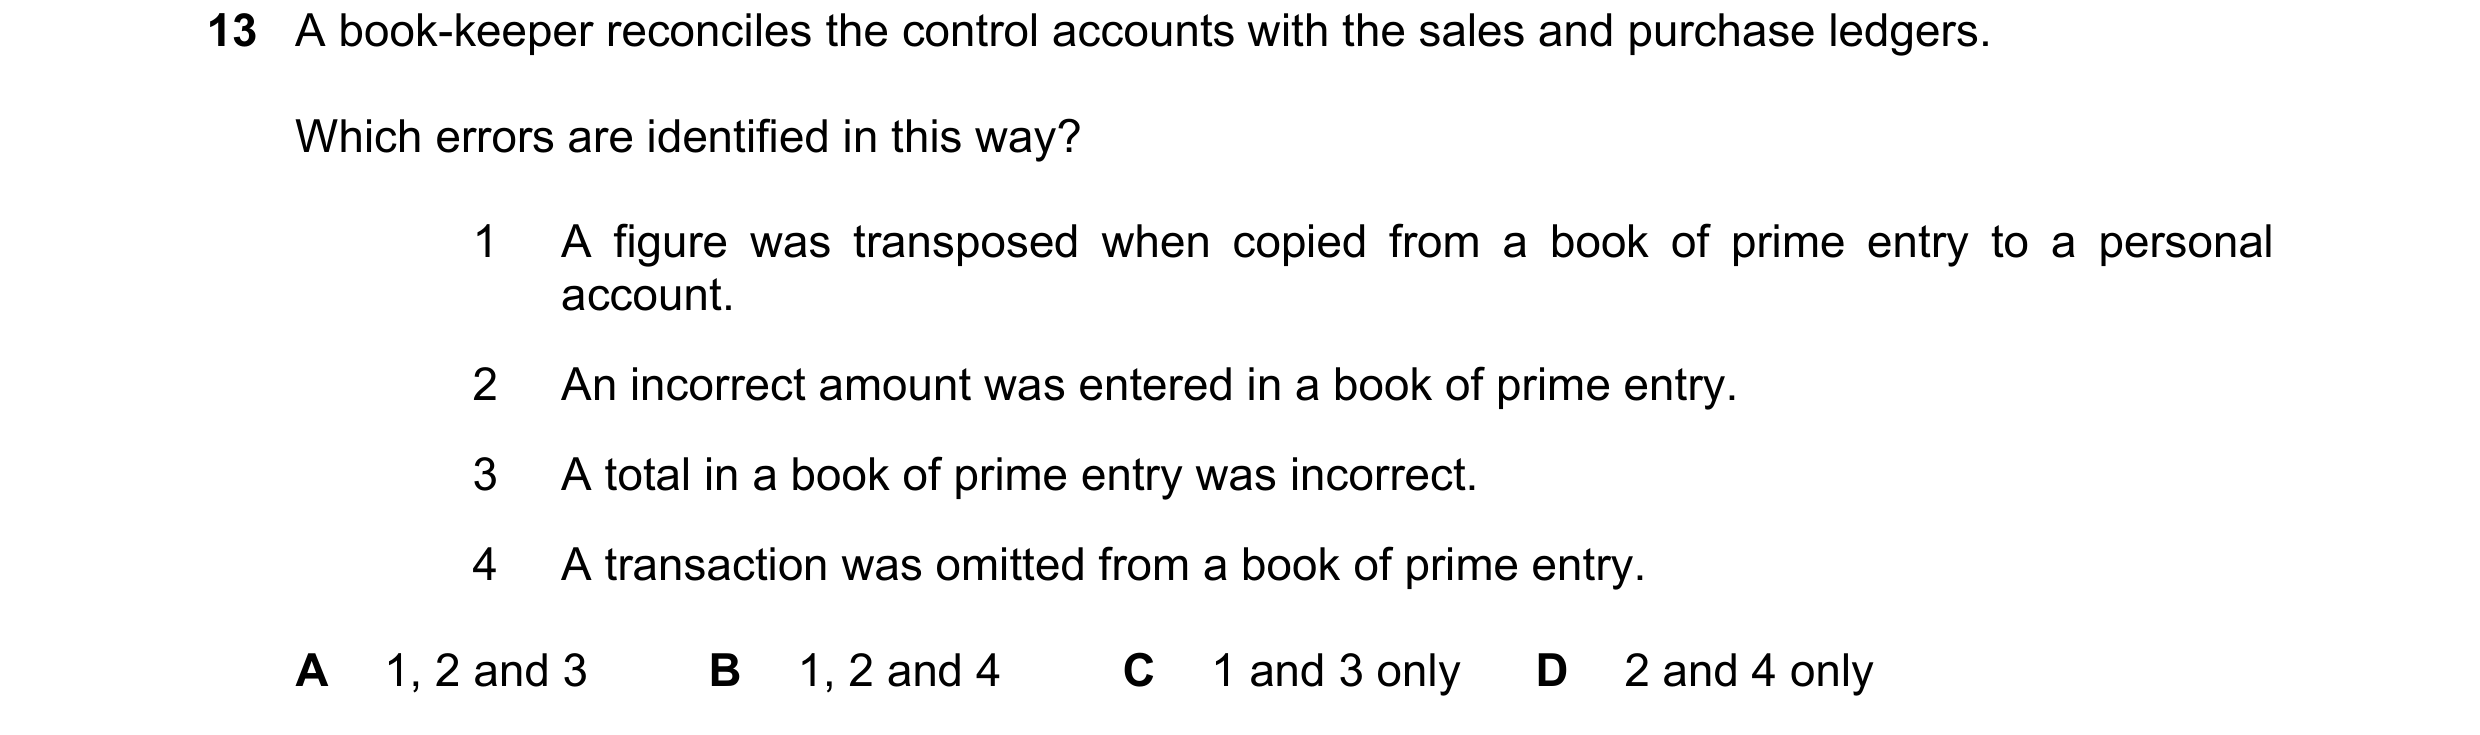
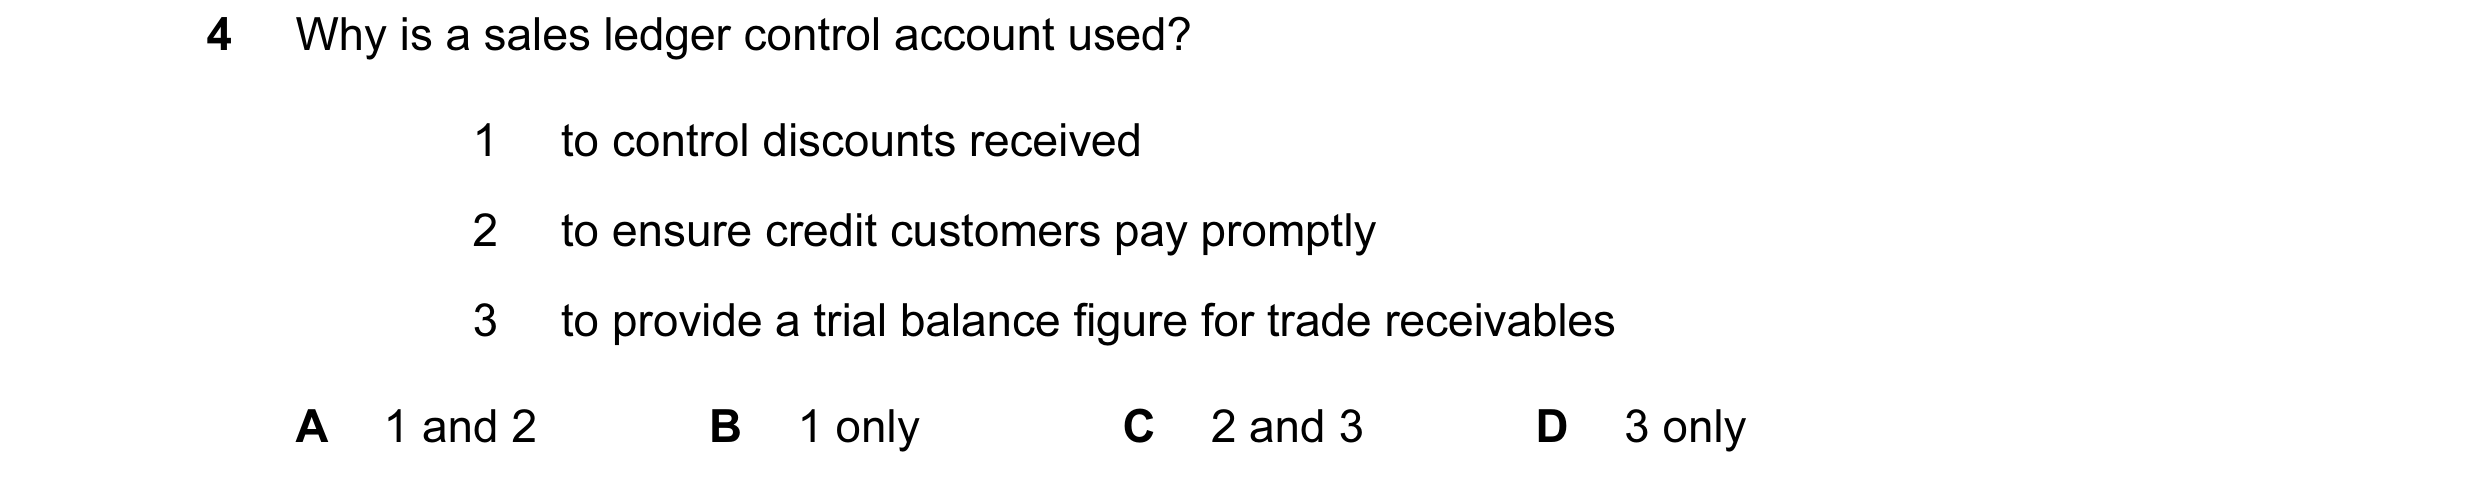
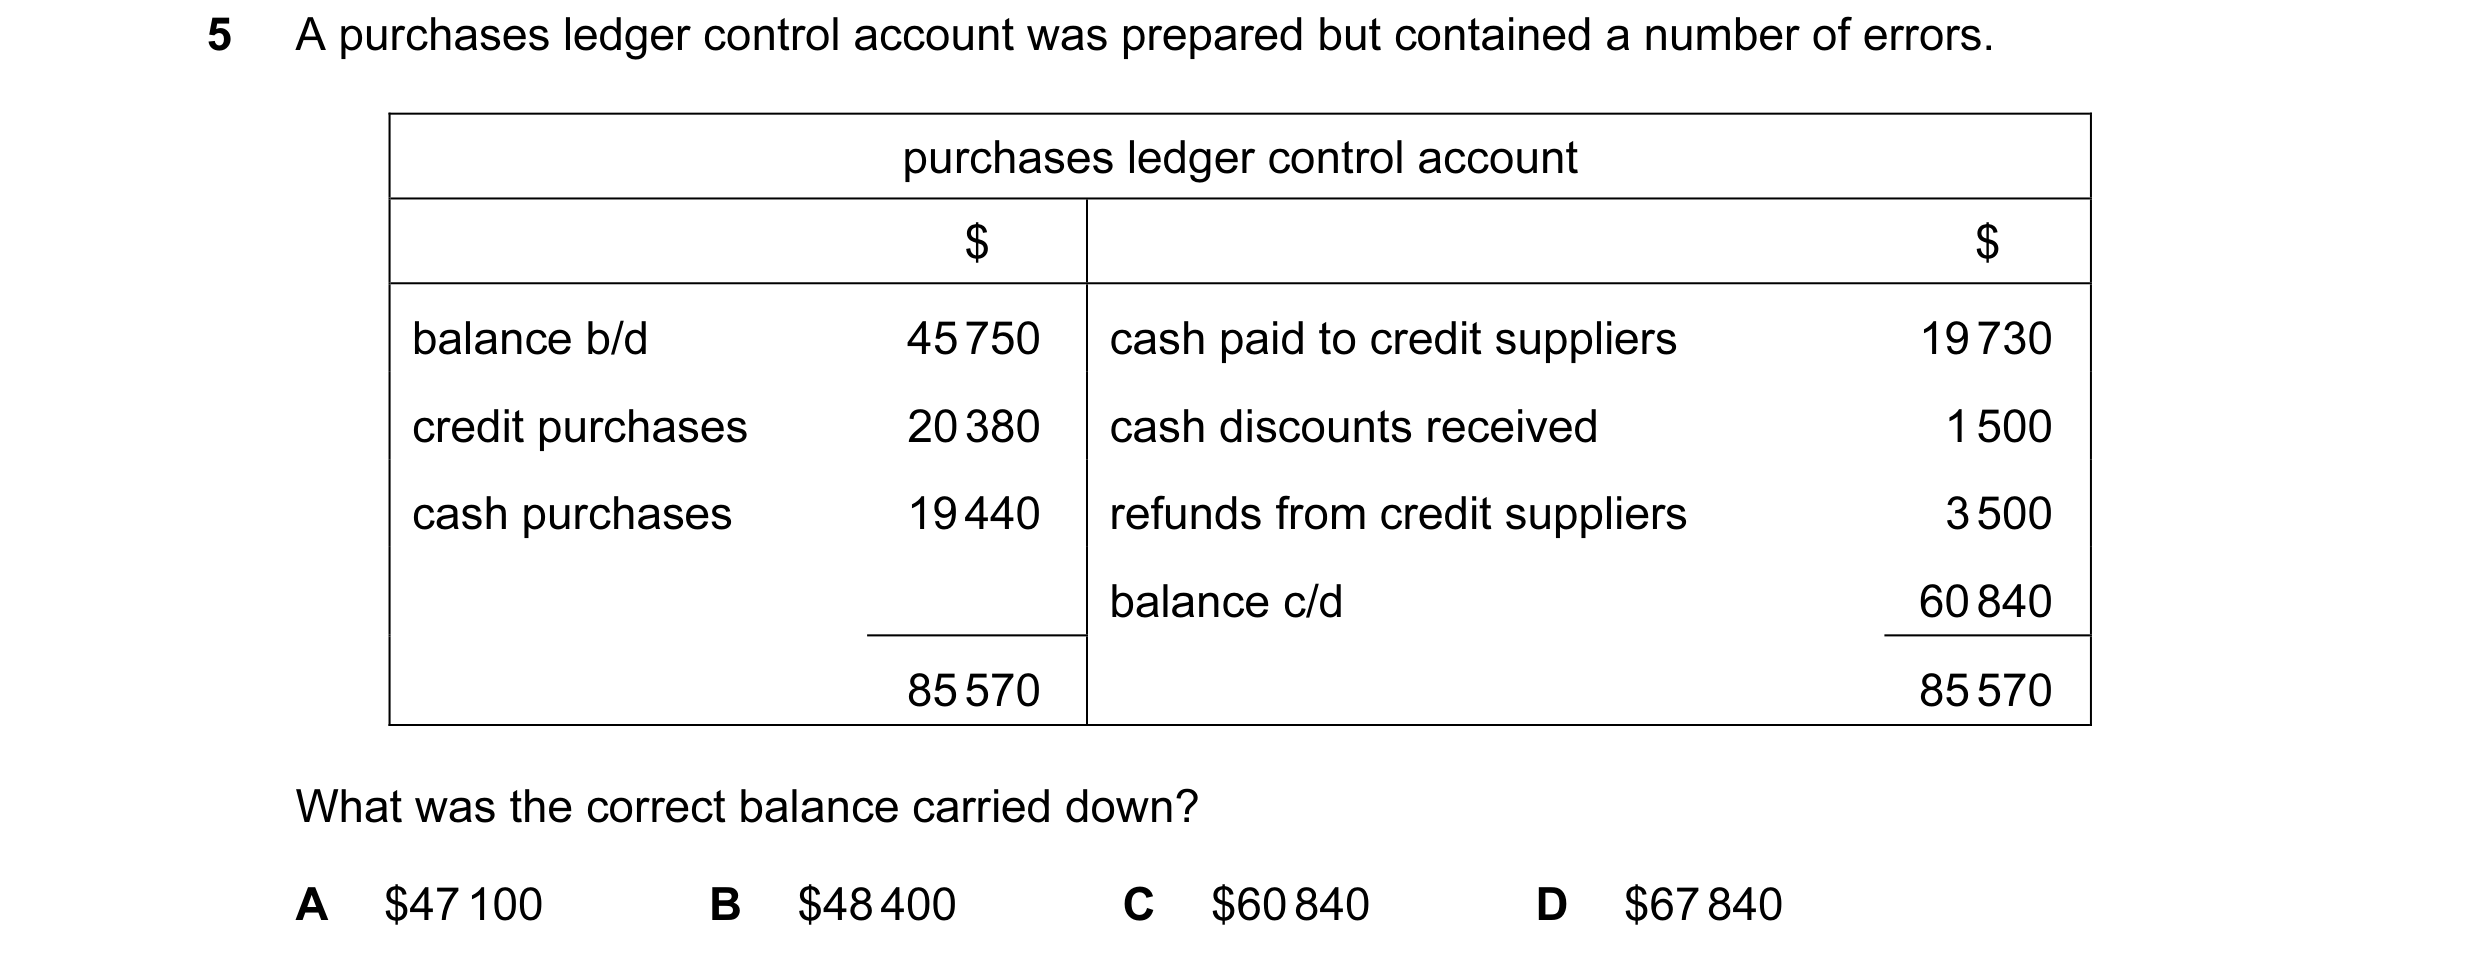 48 / 110
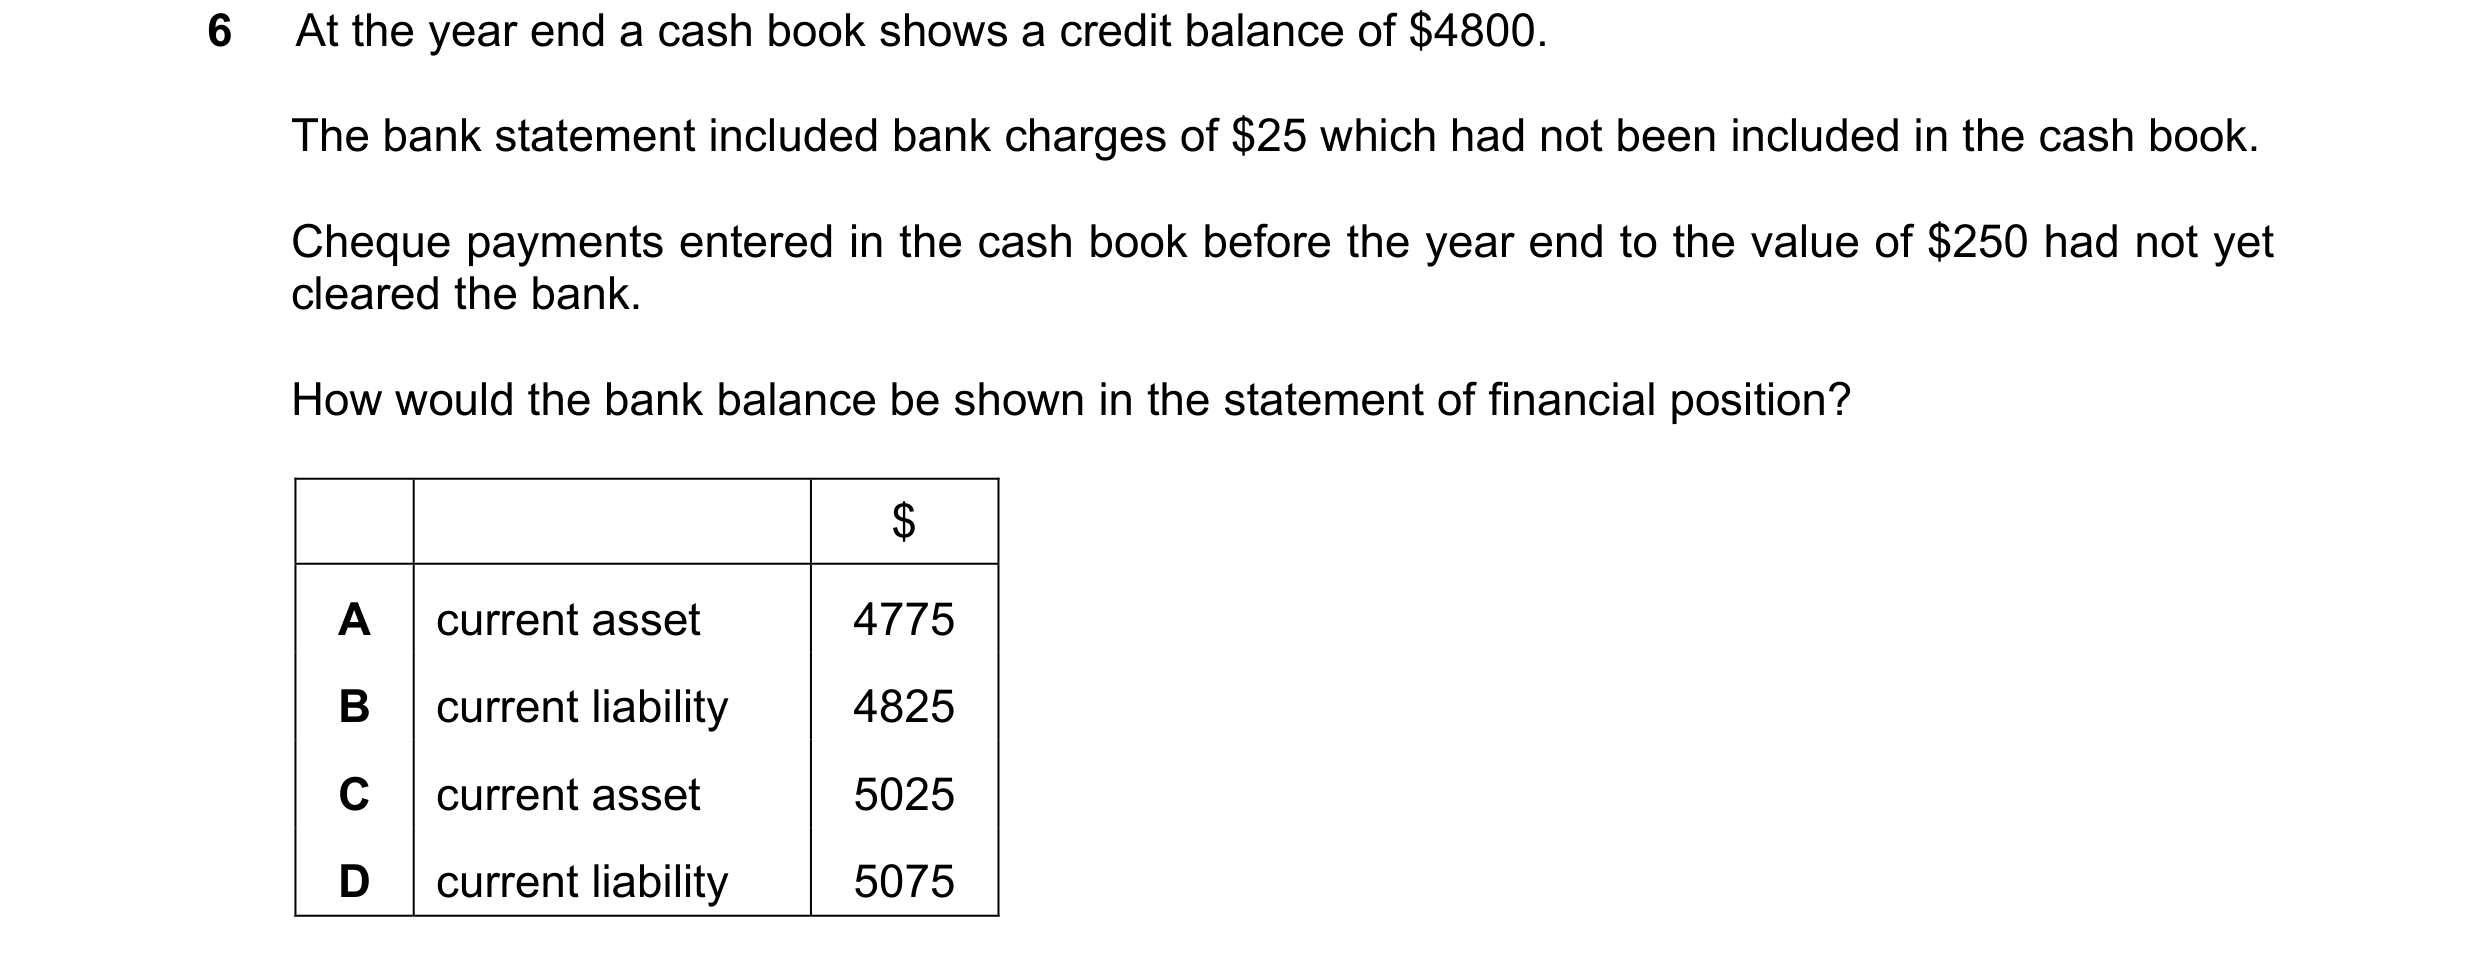
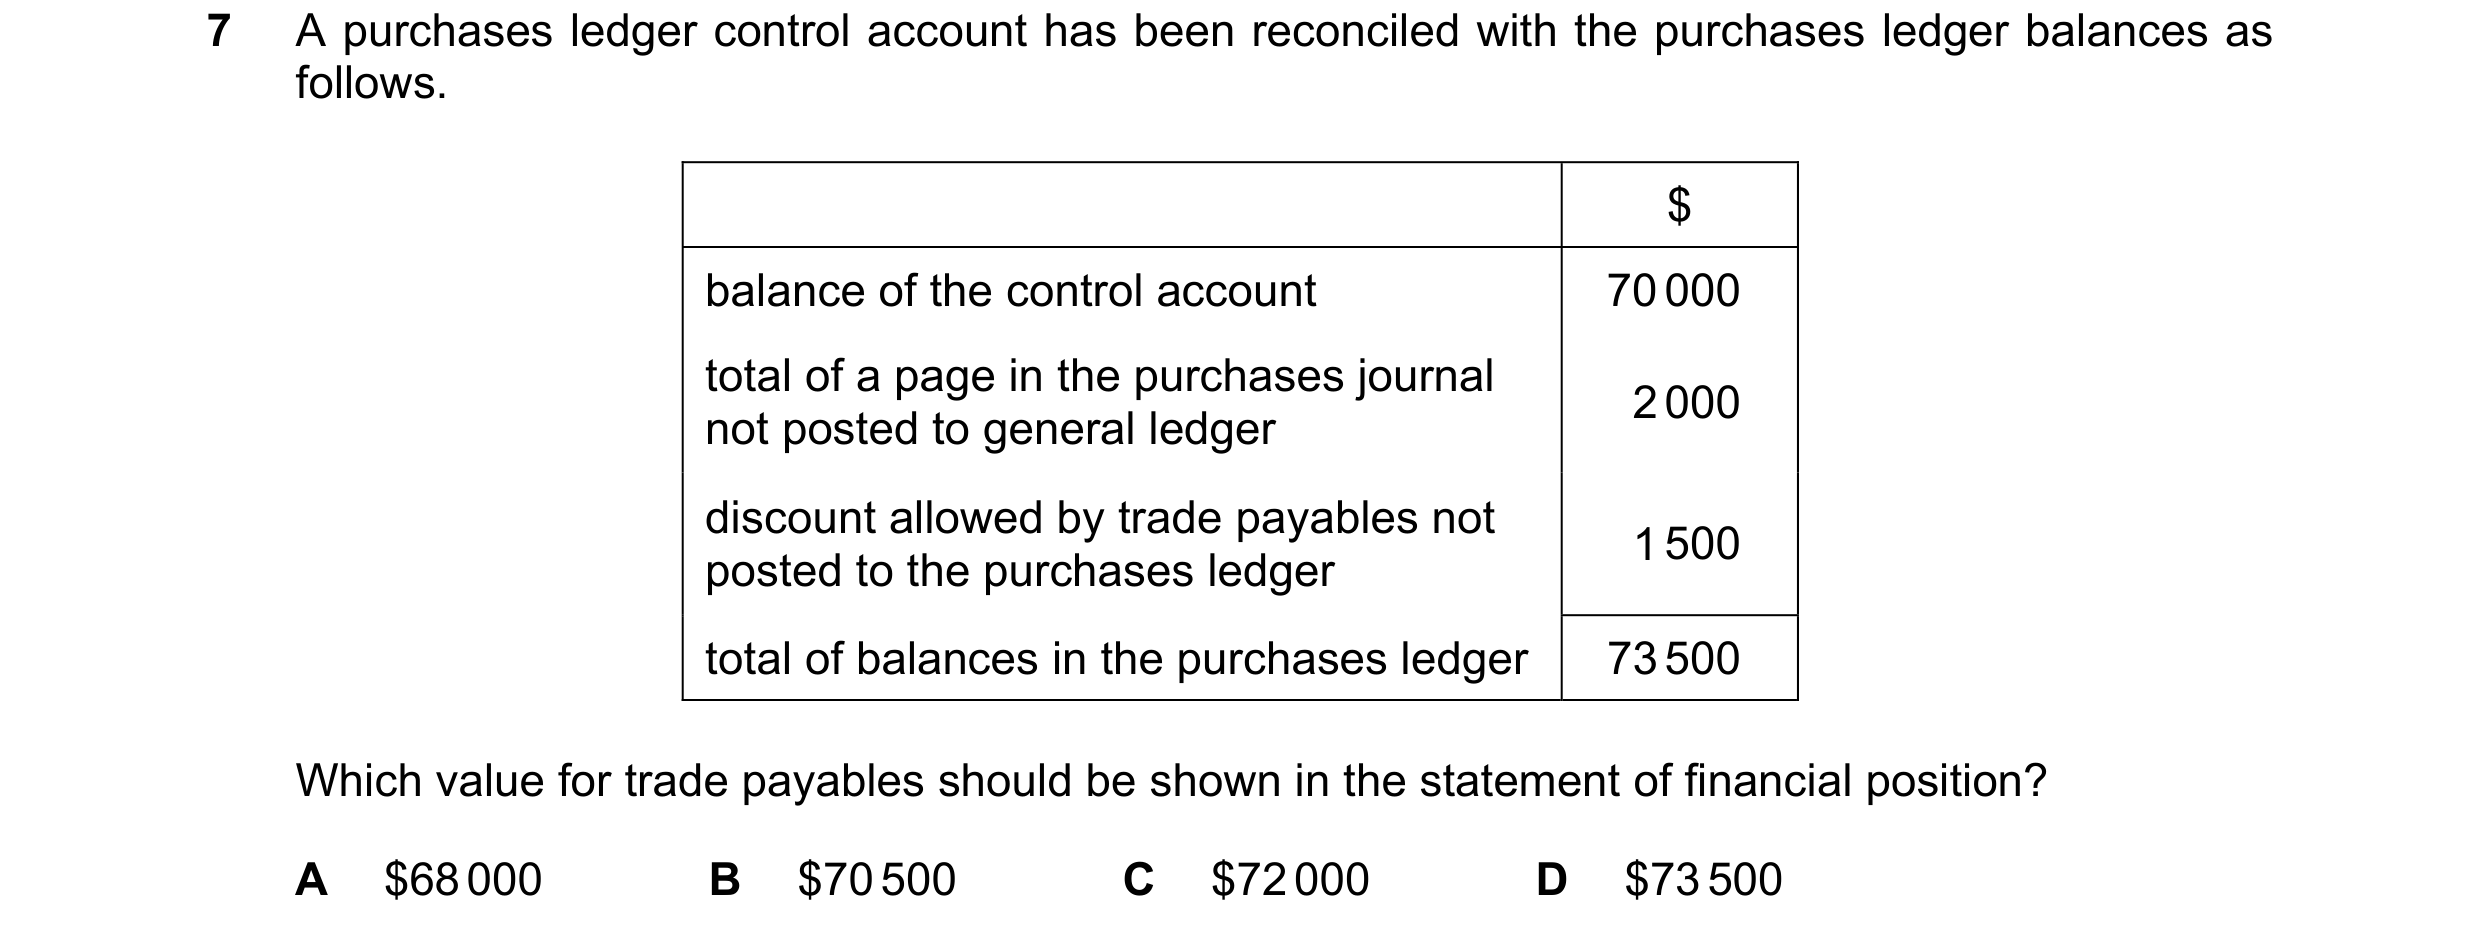
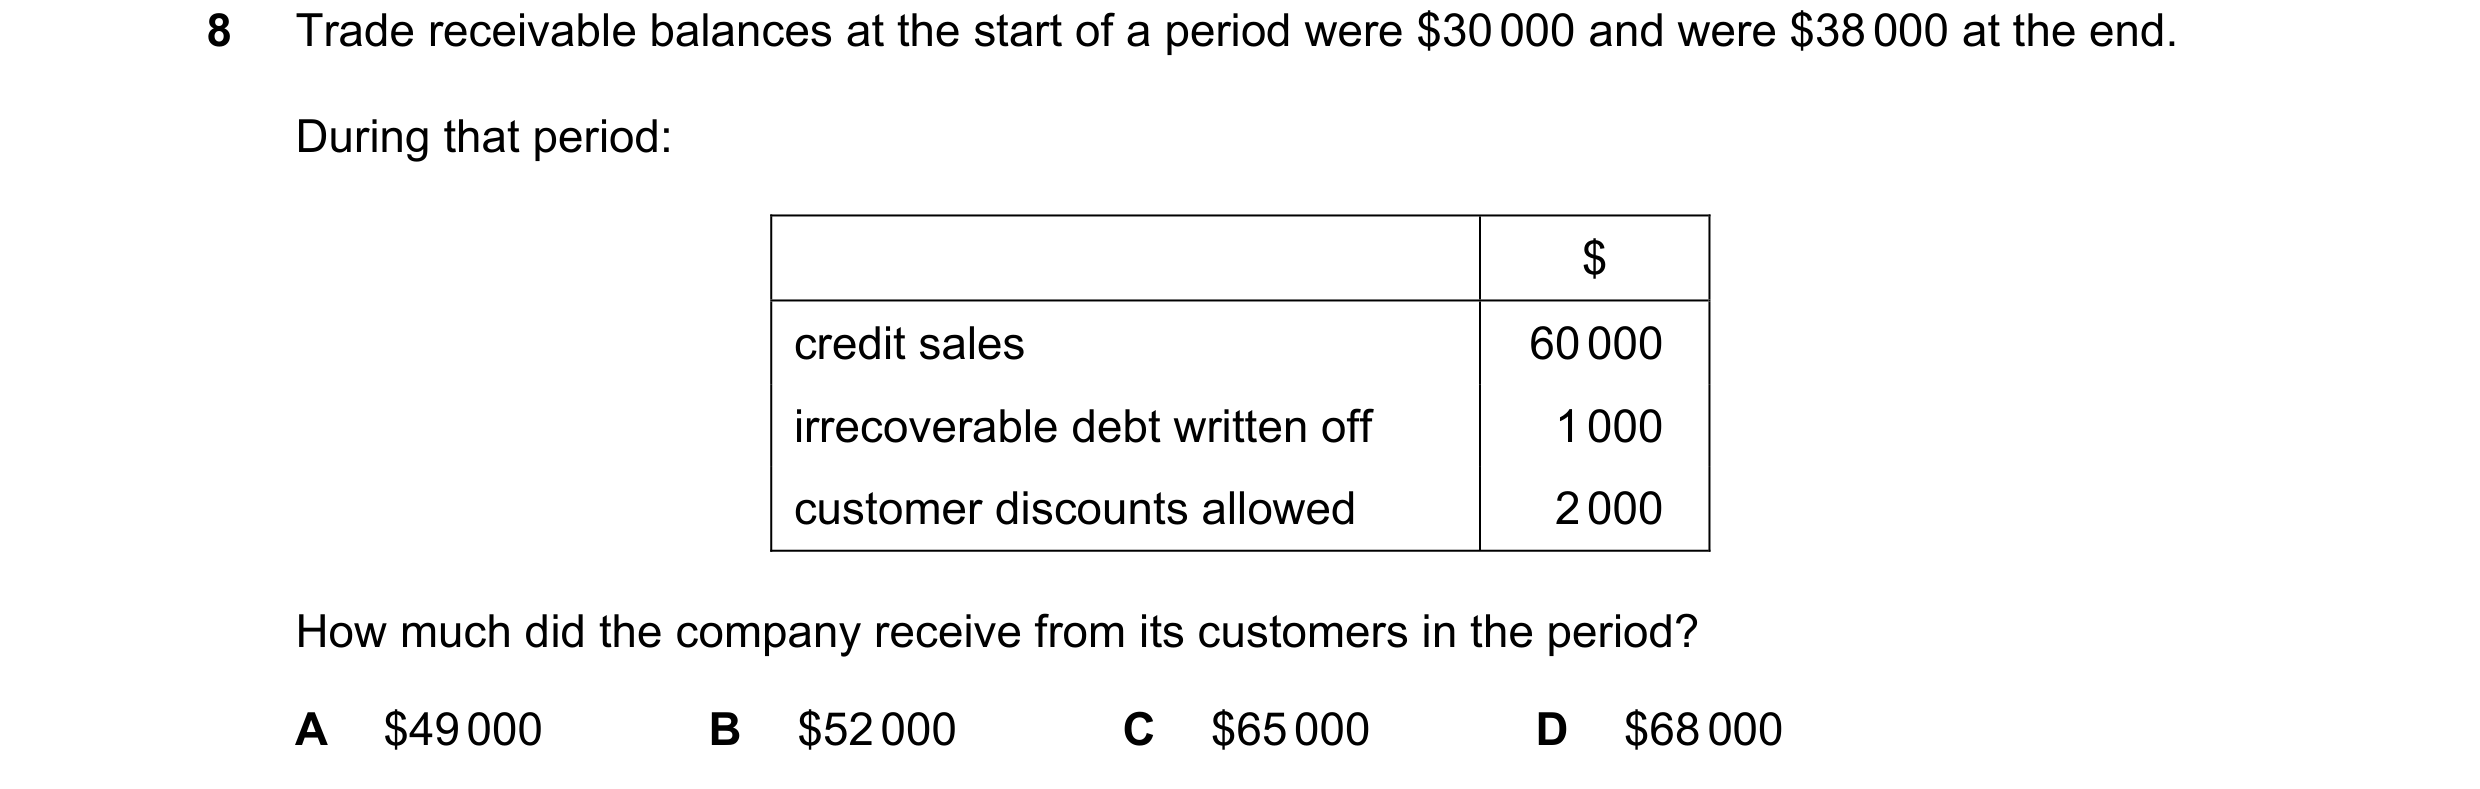 49 / 110
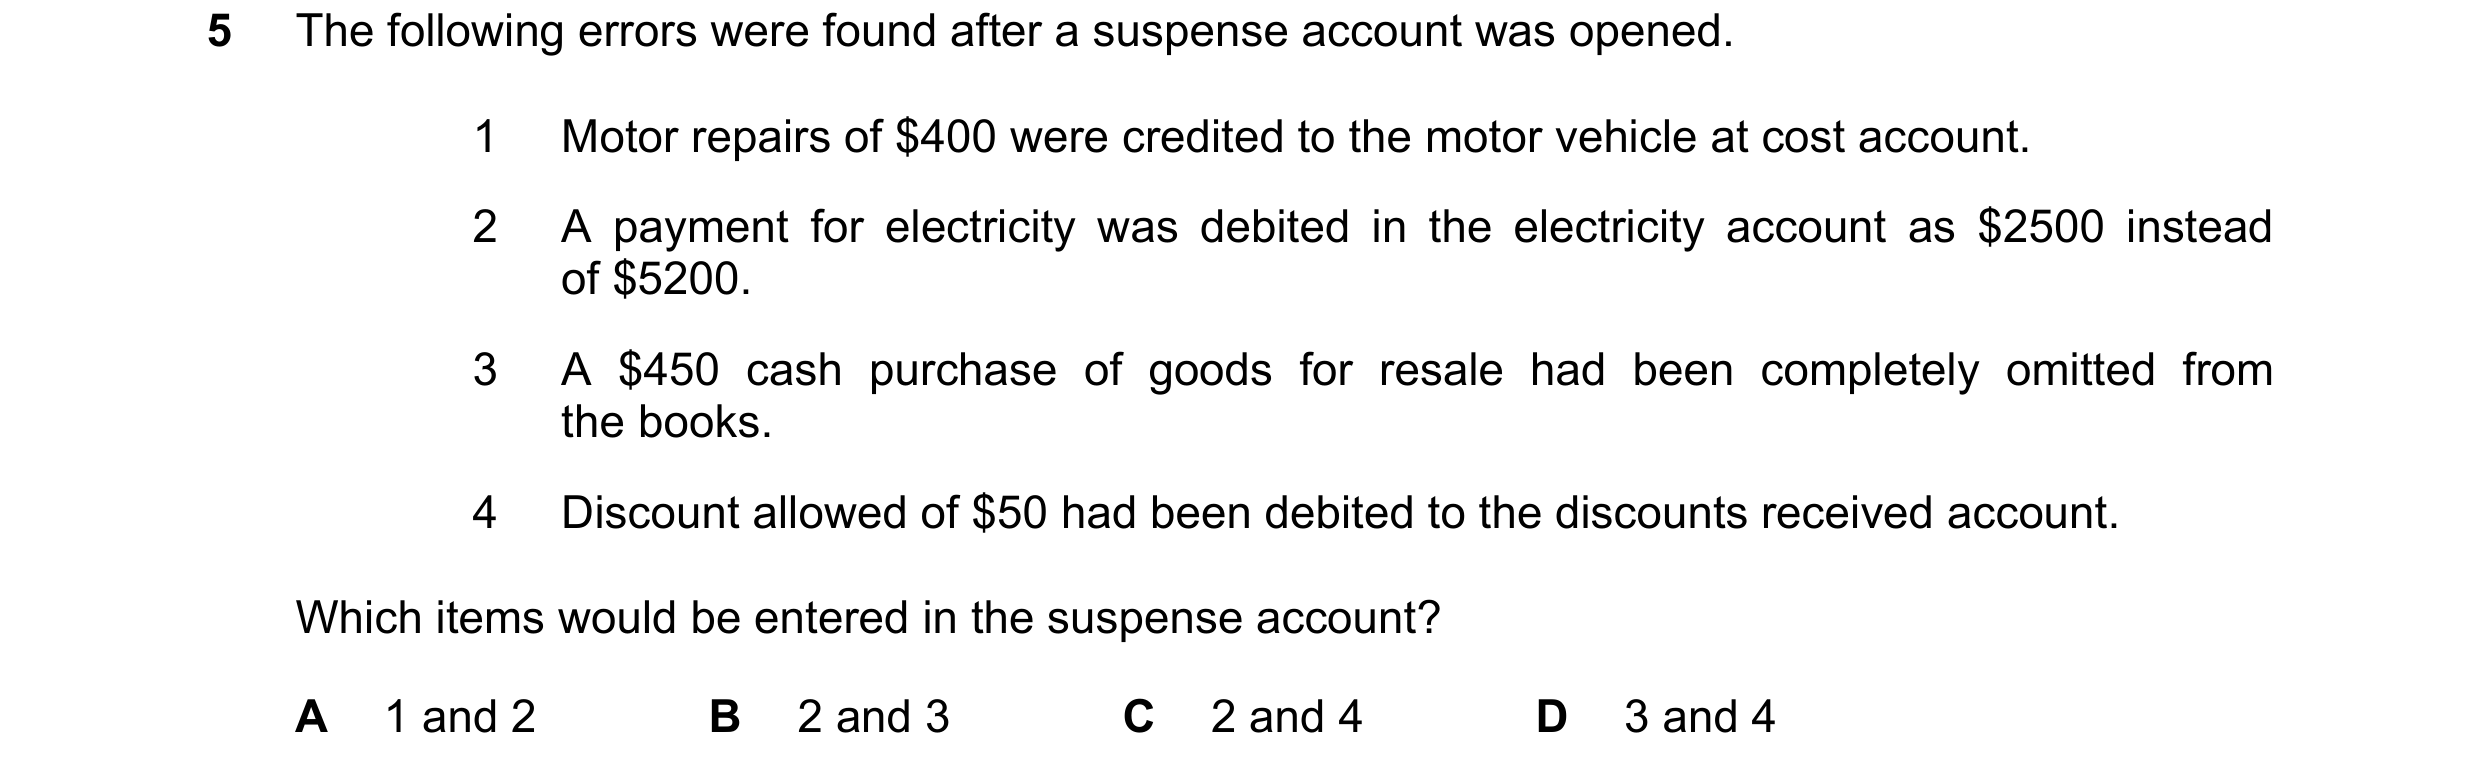
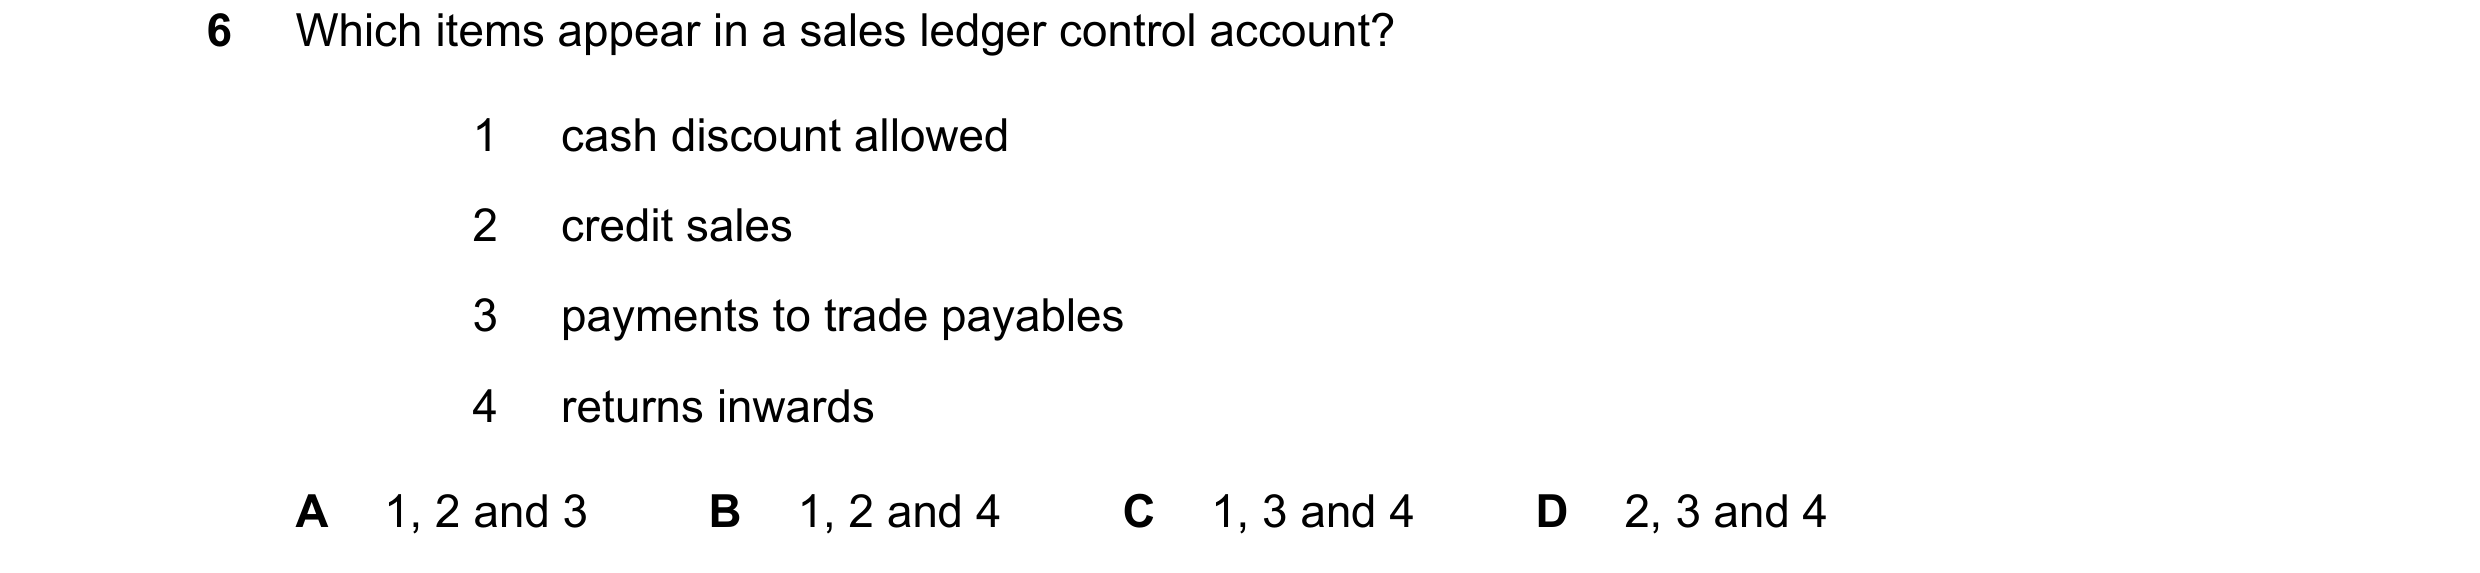
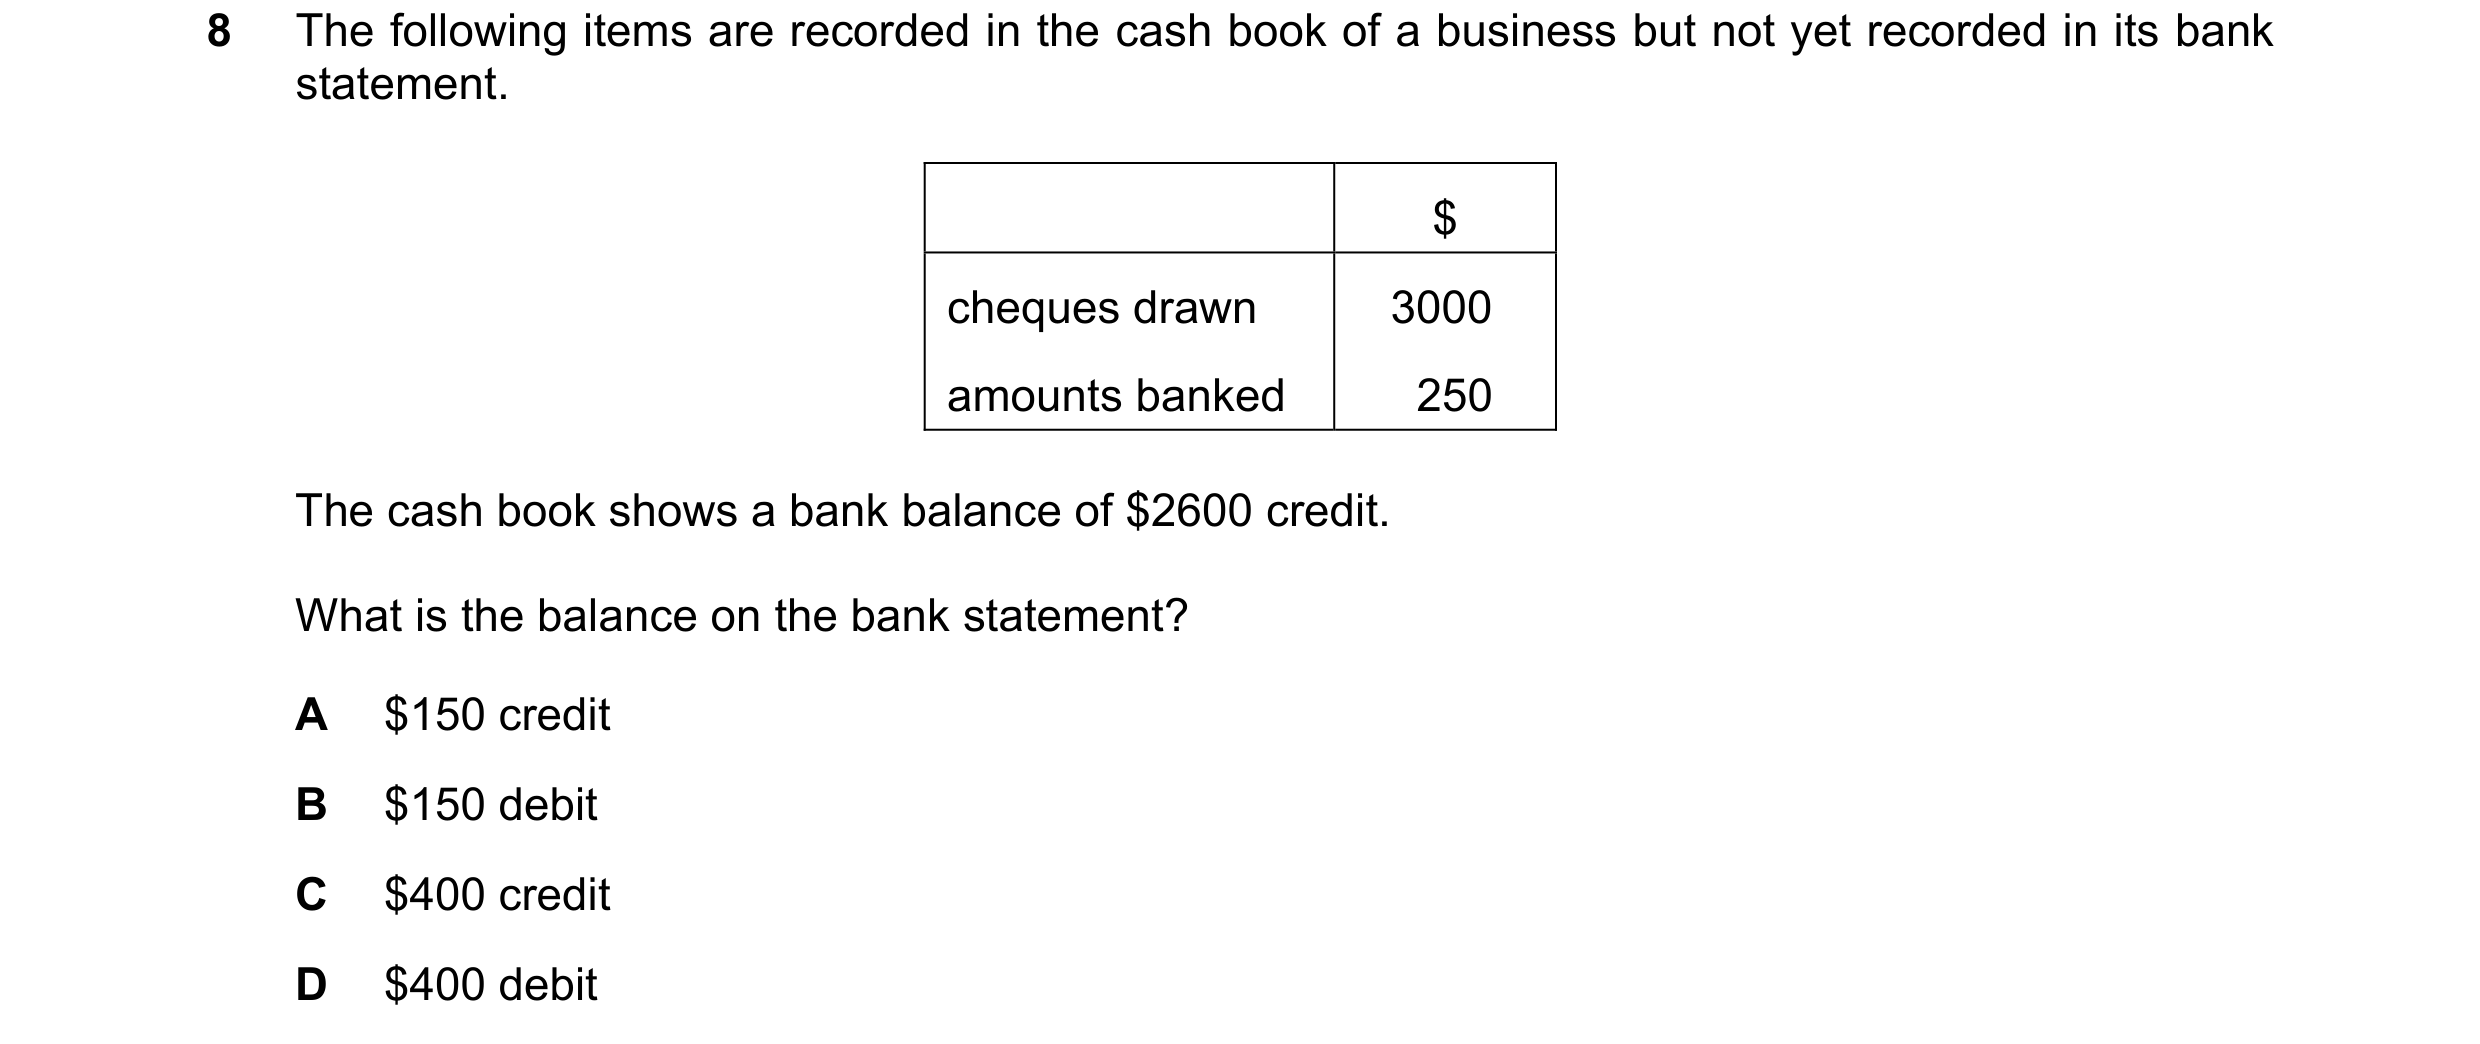
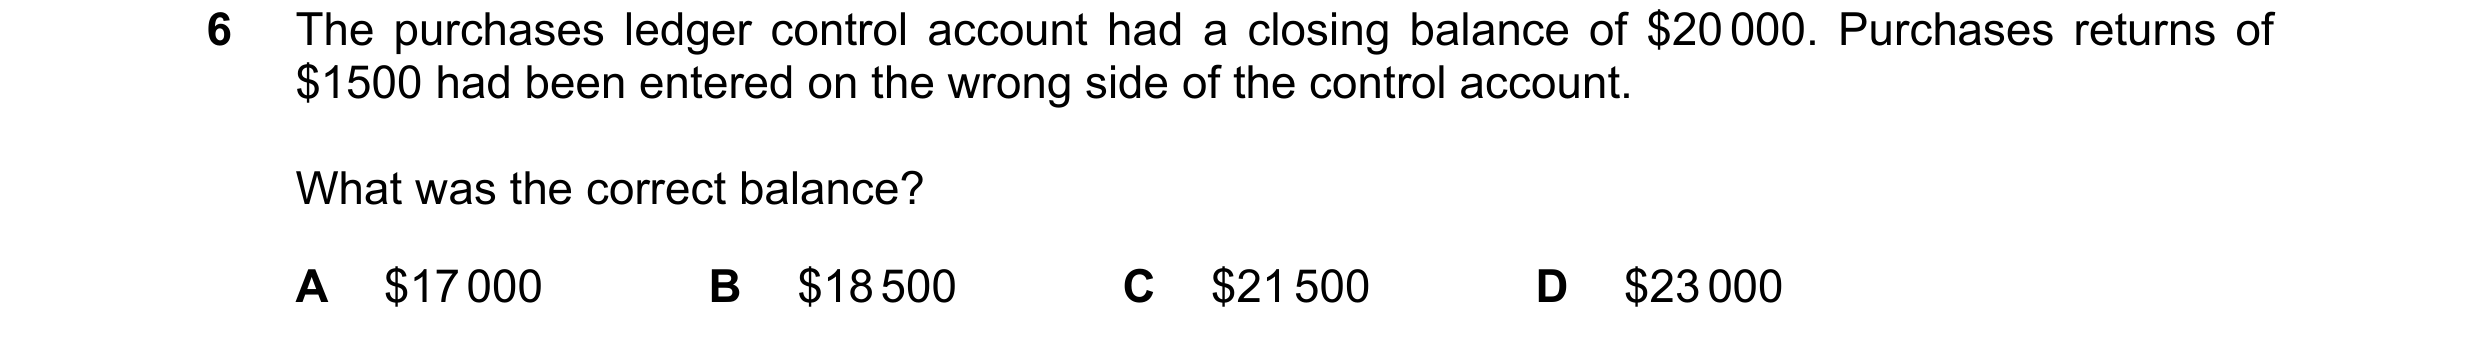 50 / 110
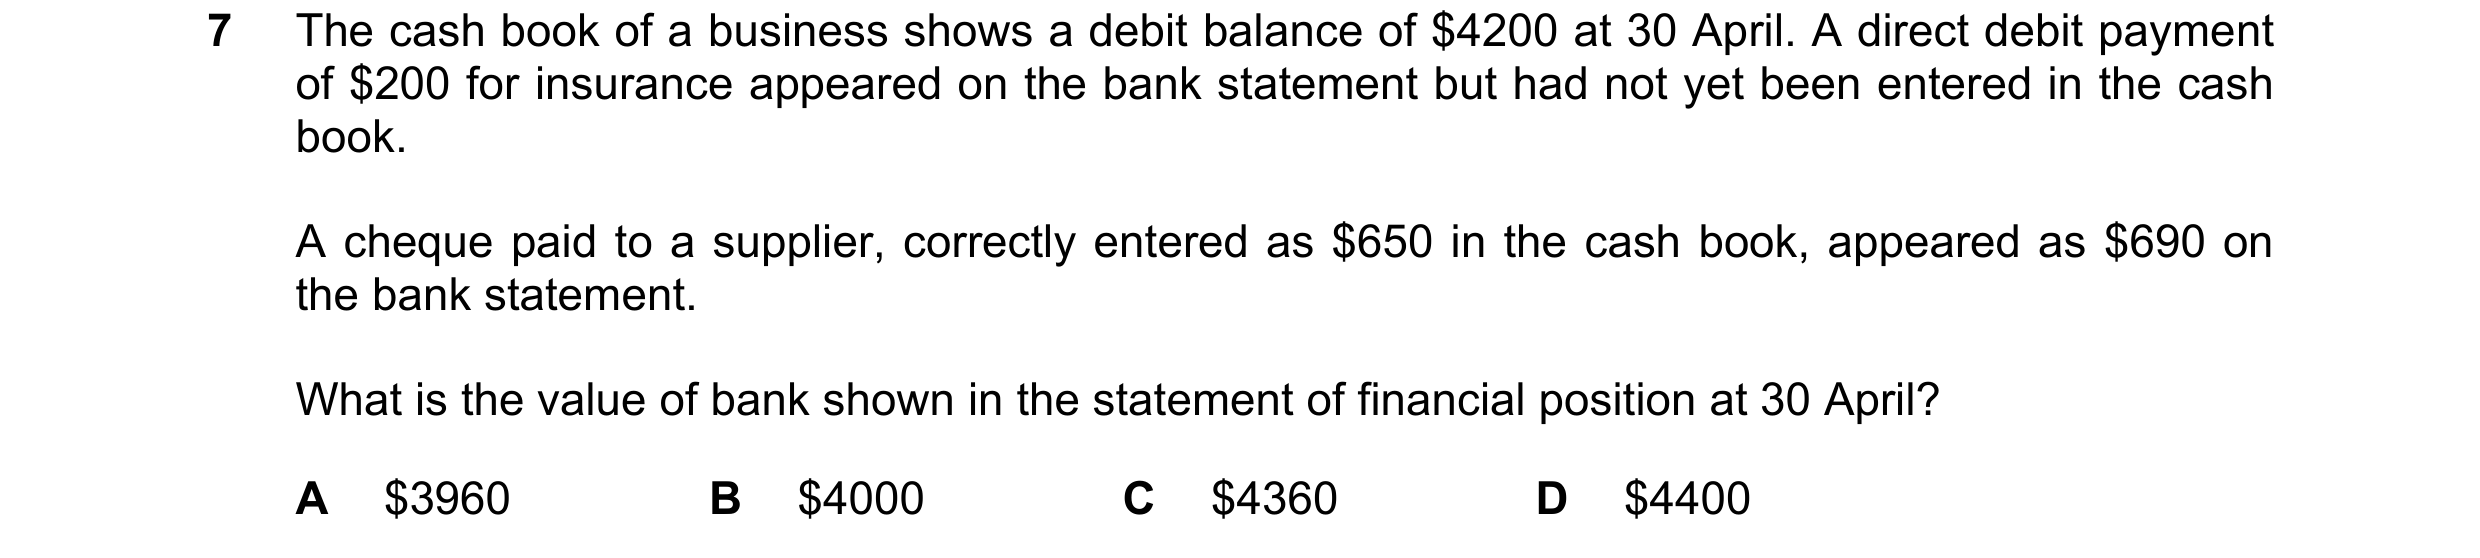
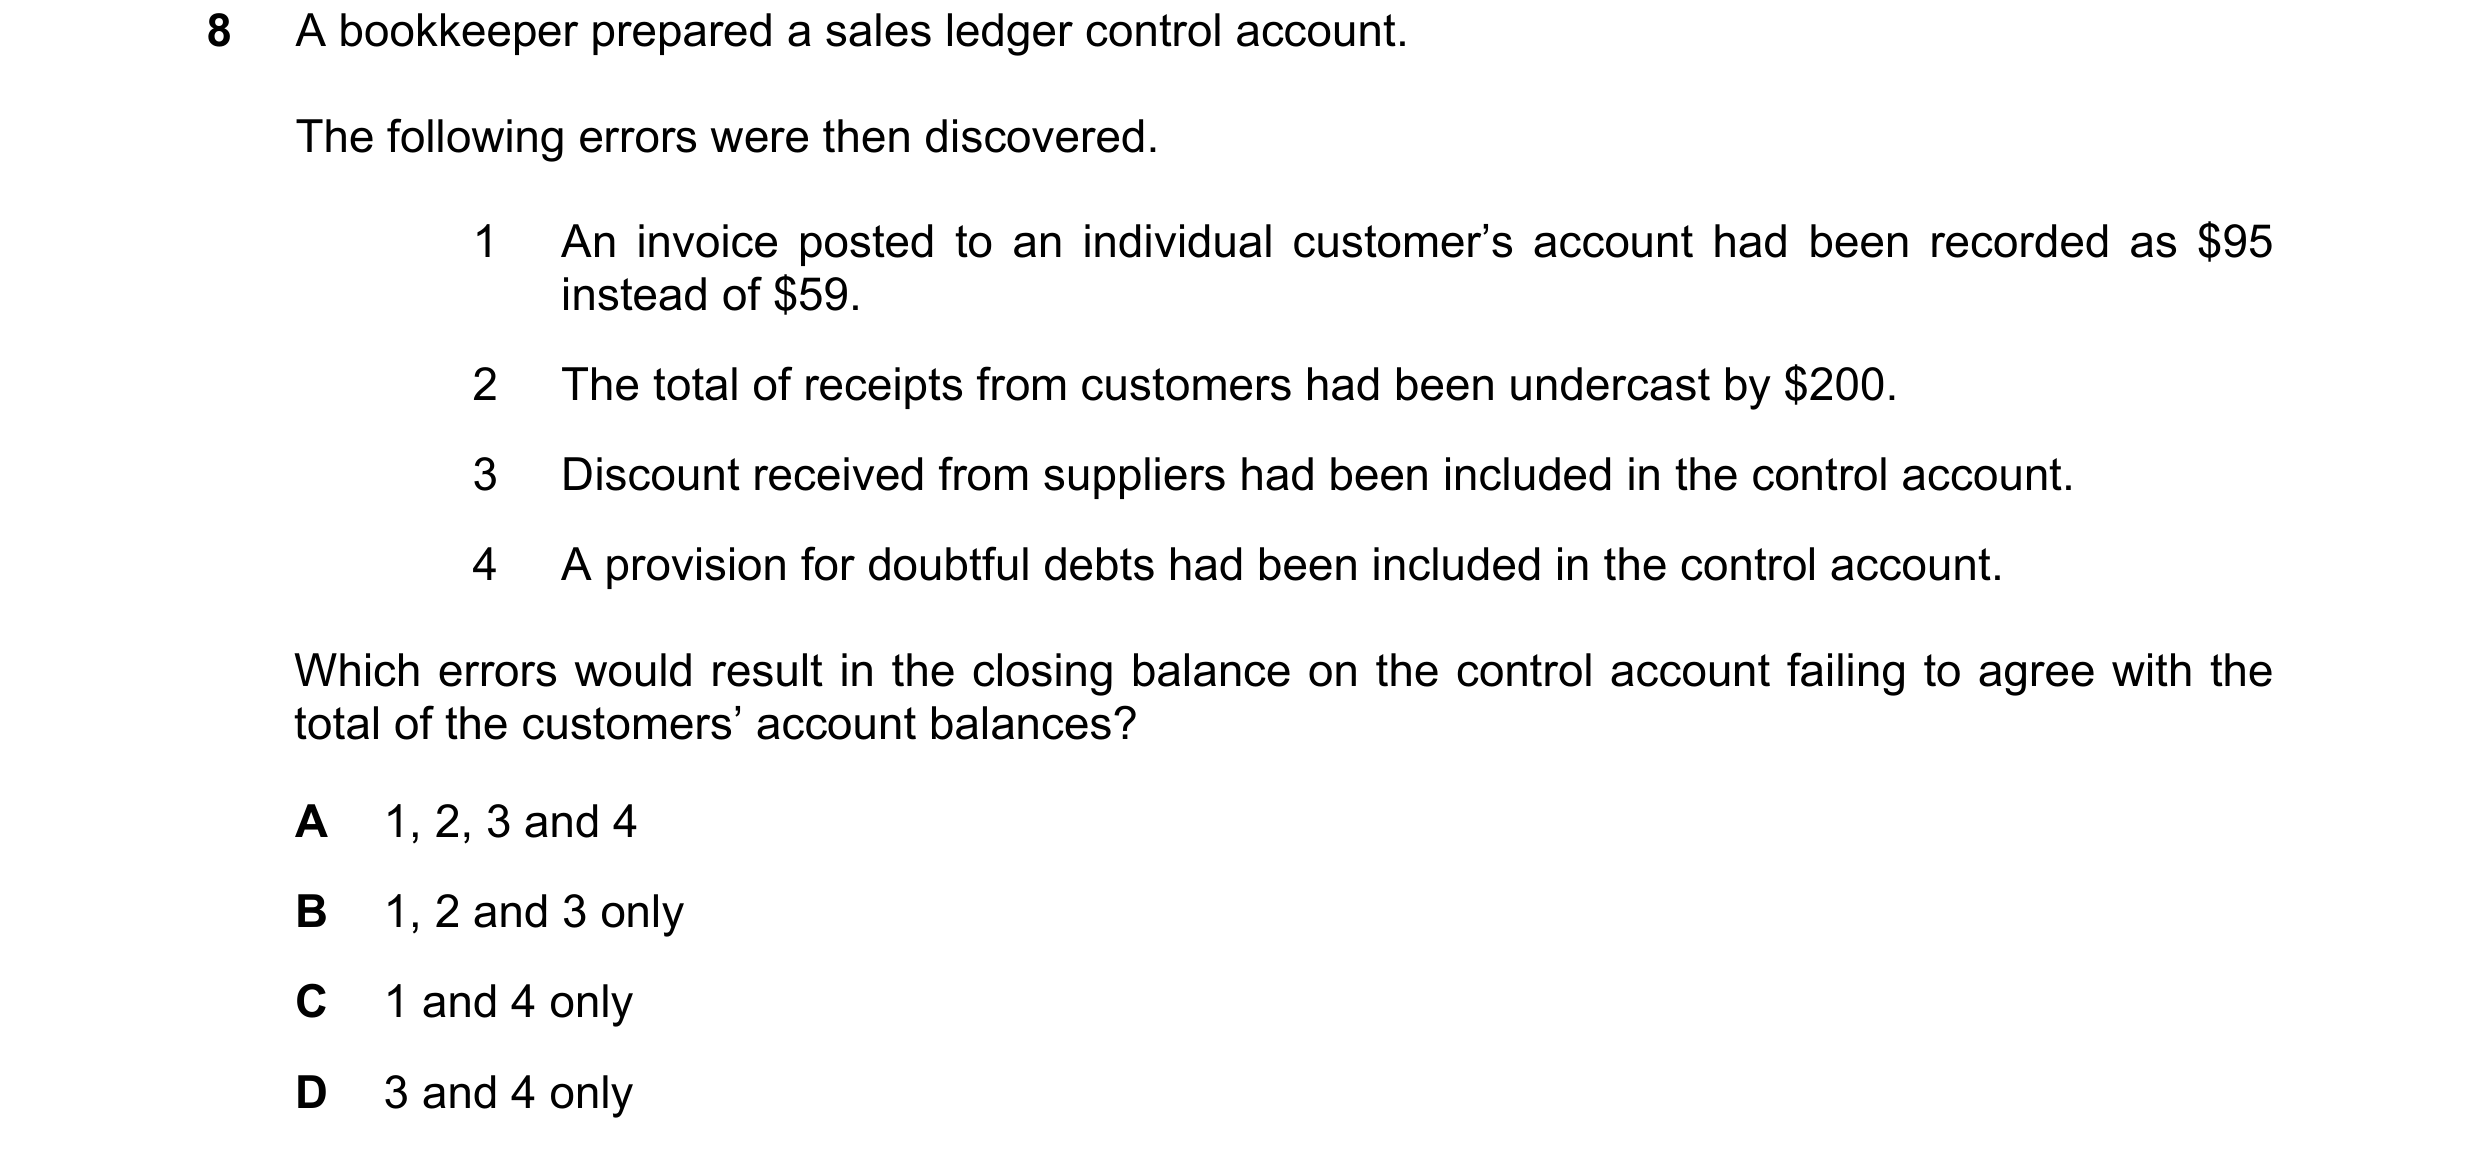
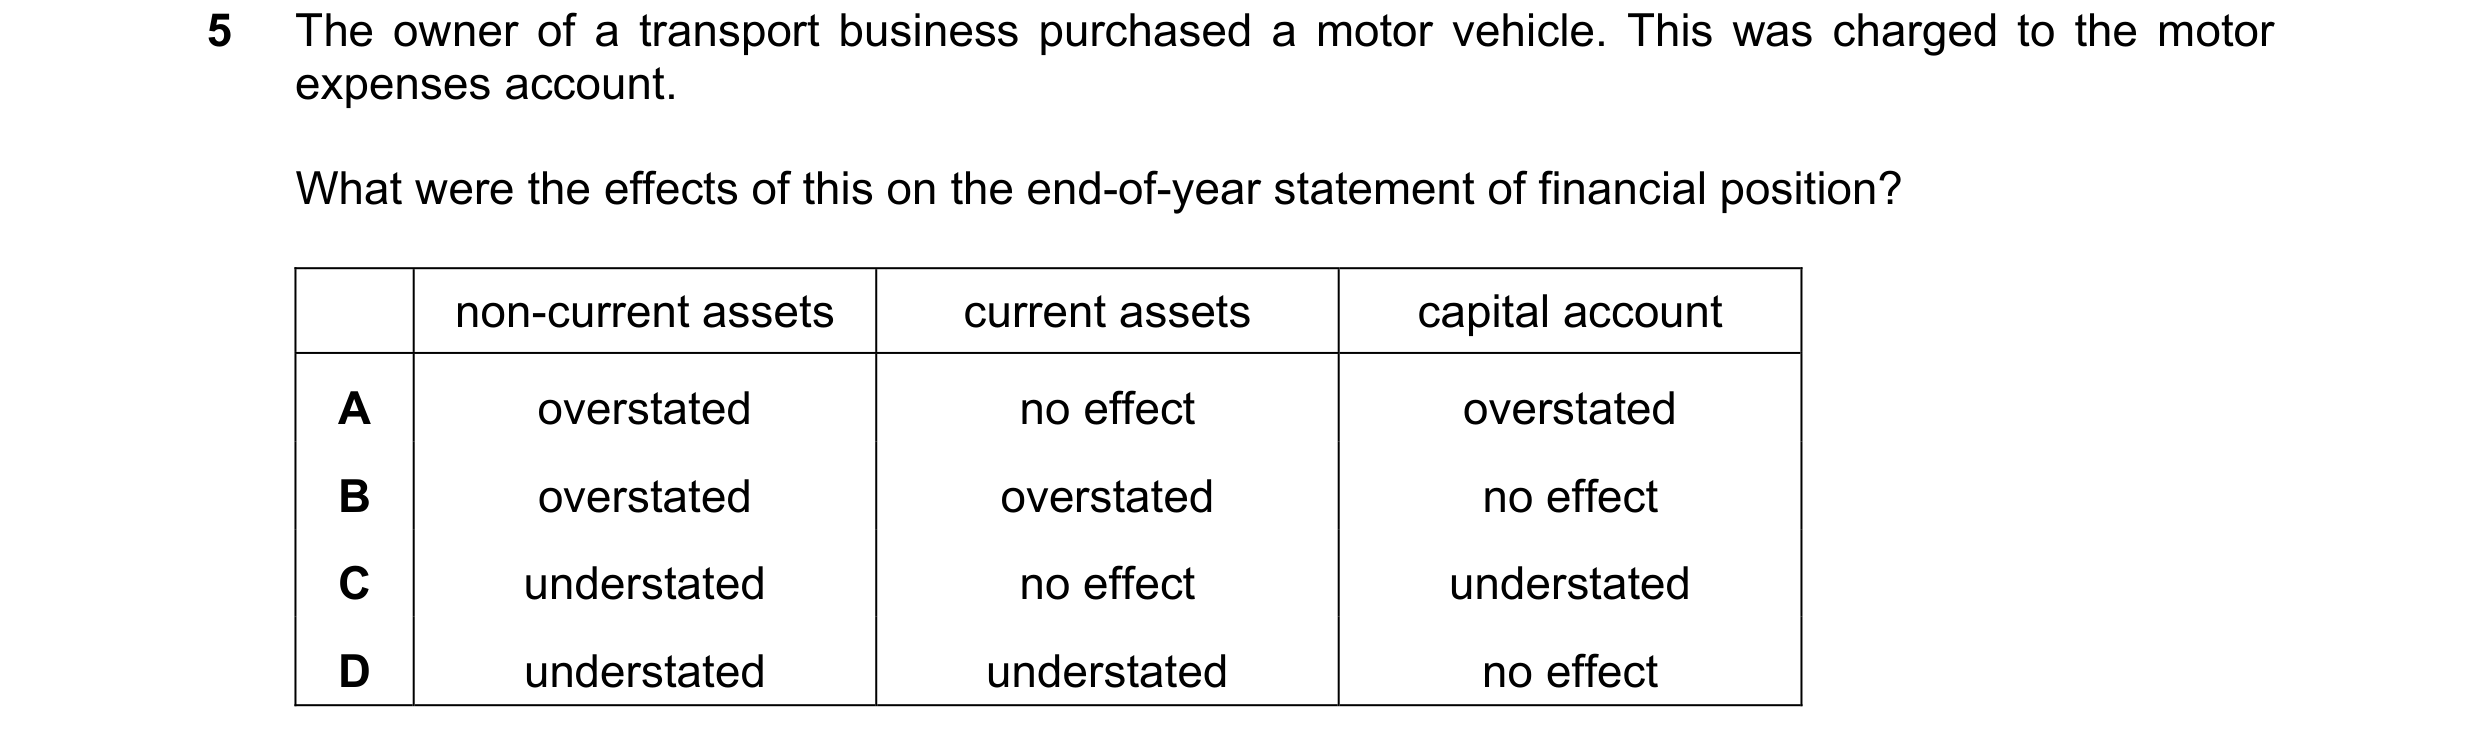
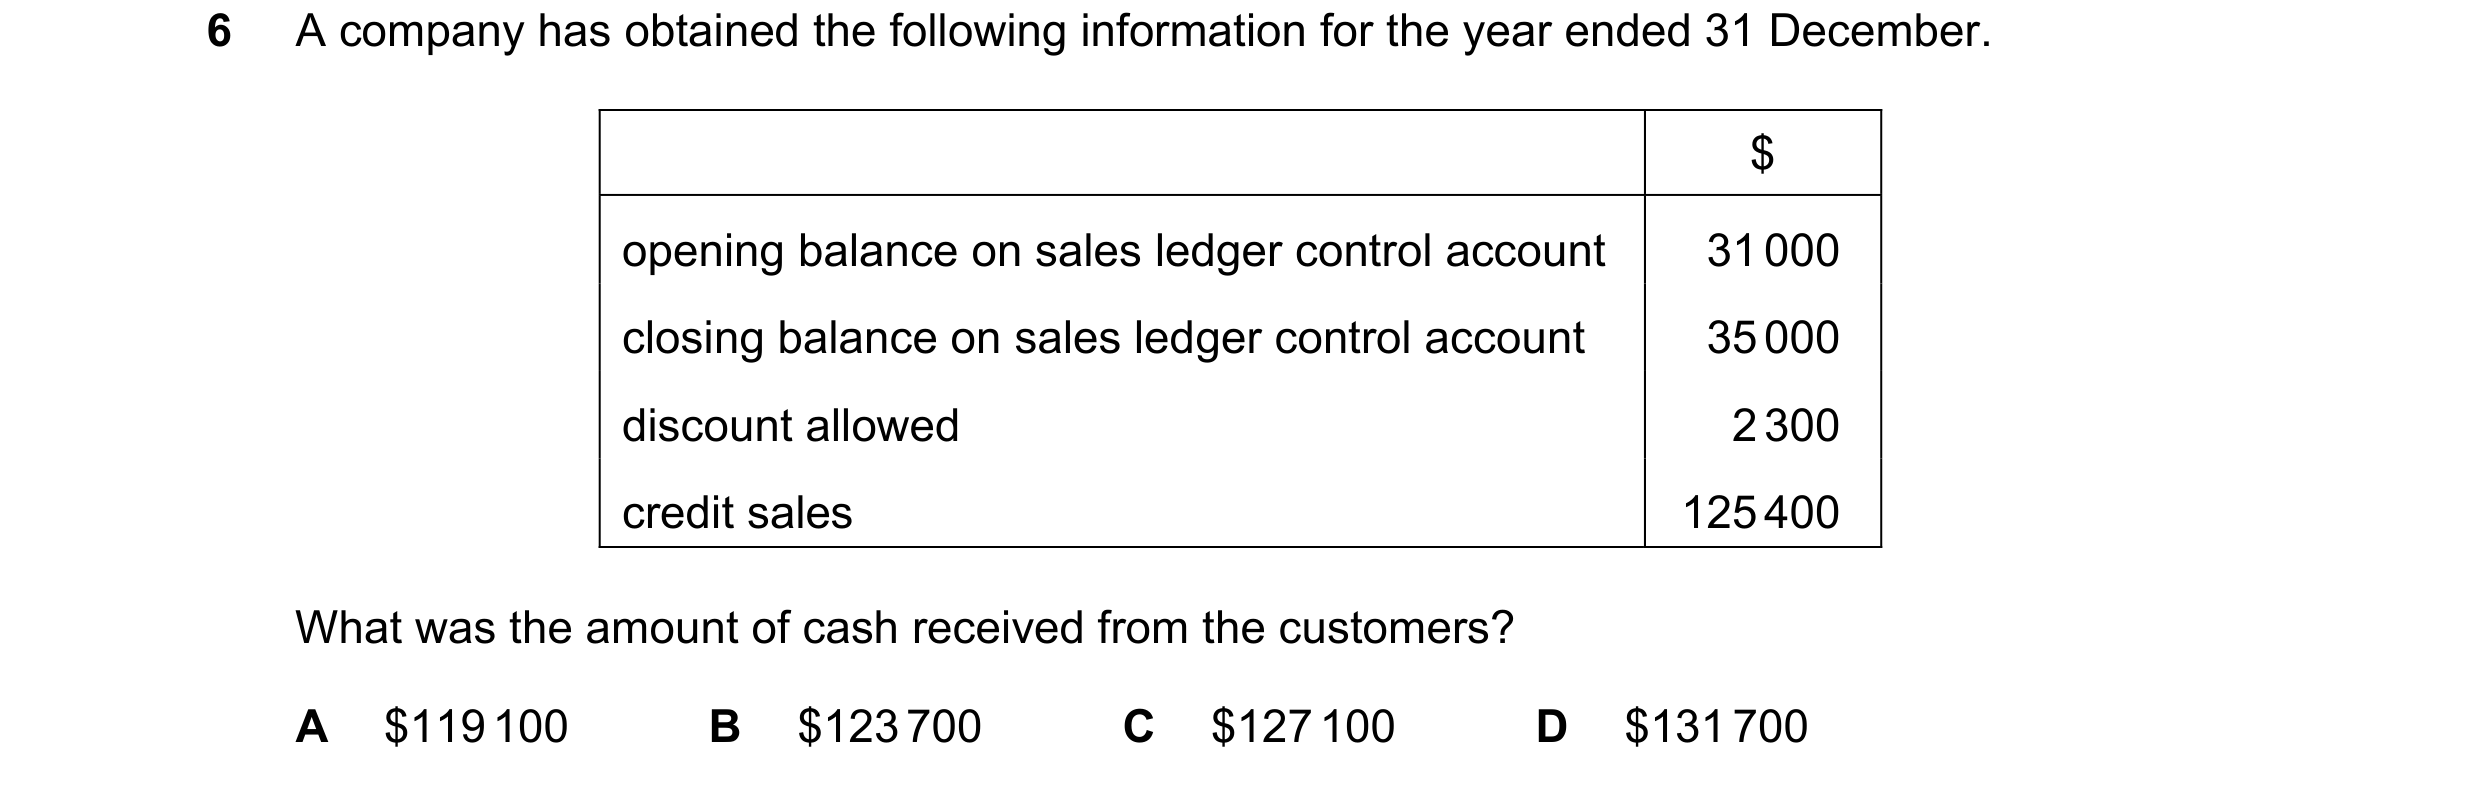 51 / 110
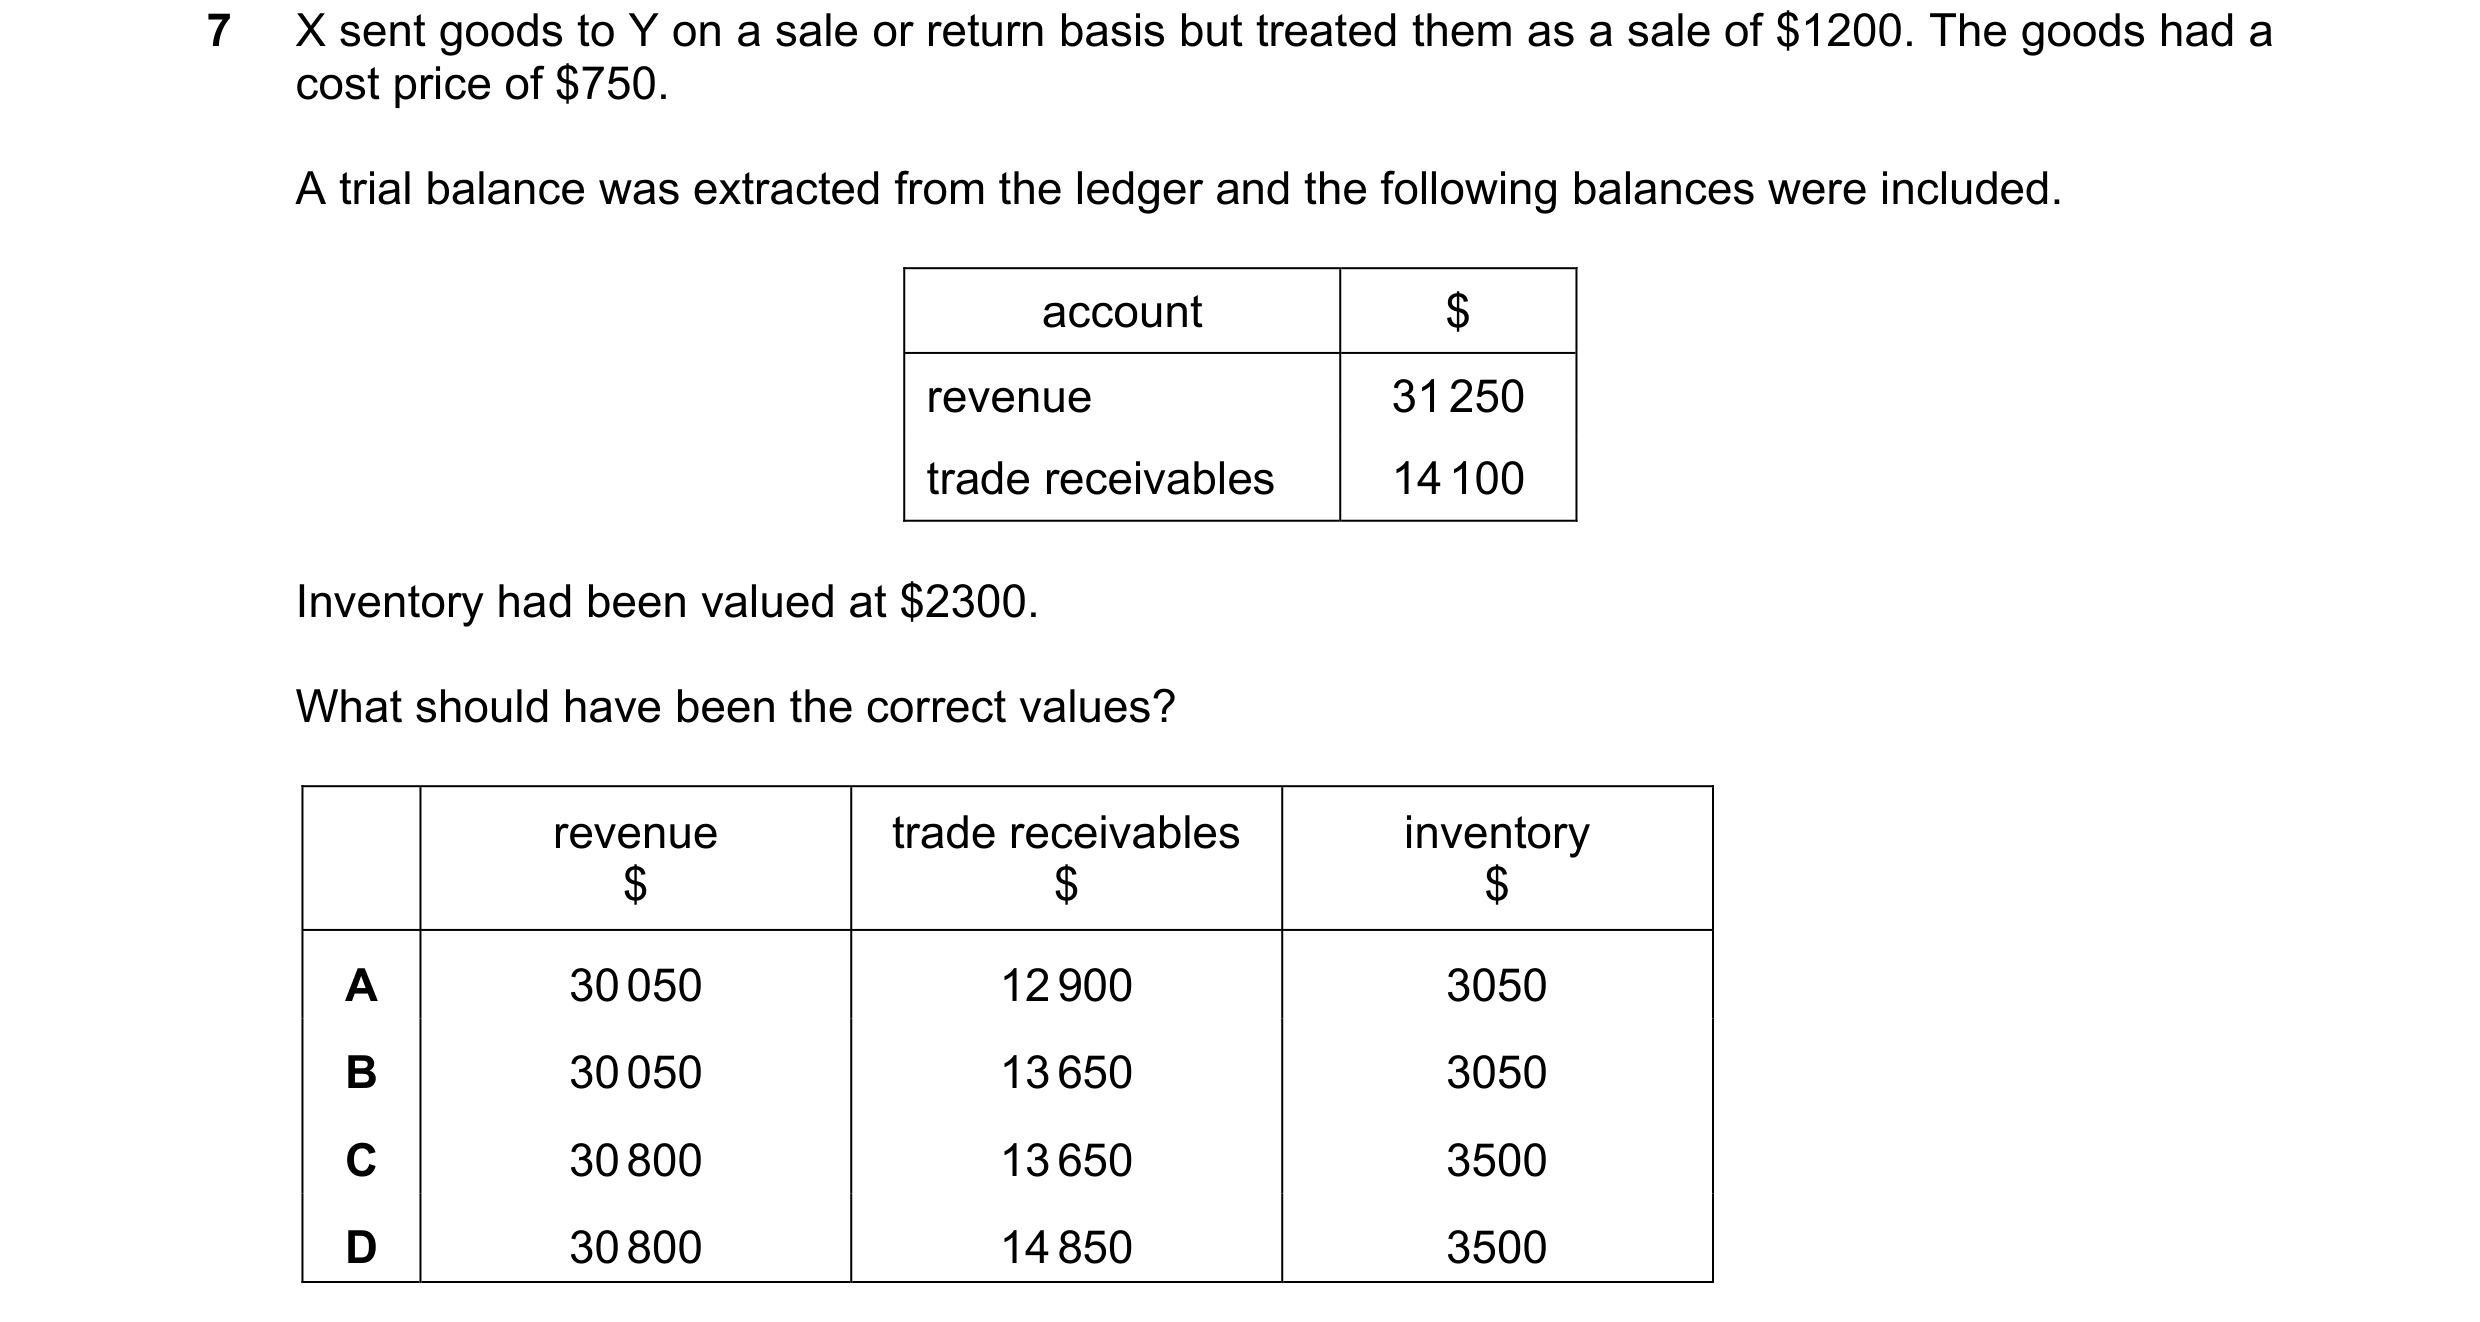
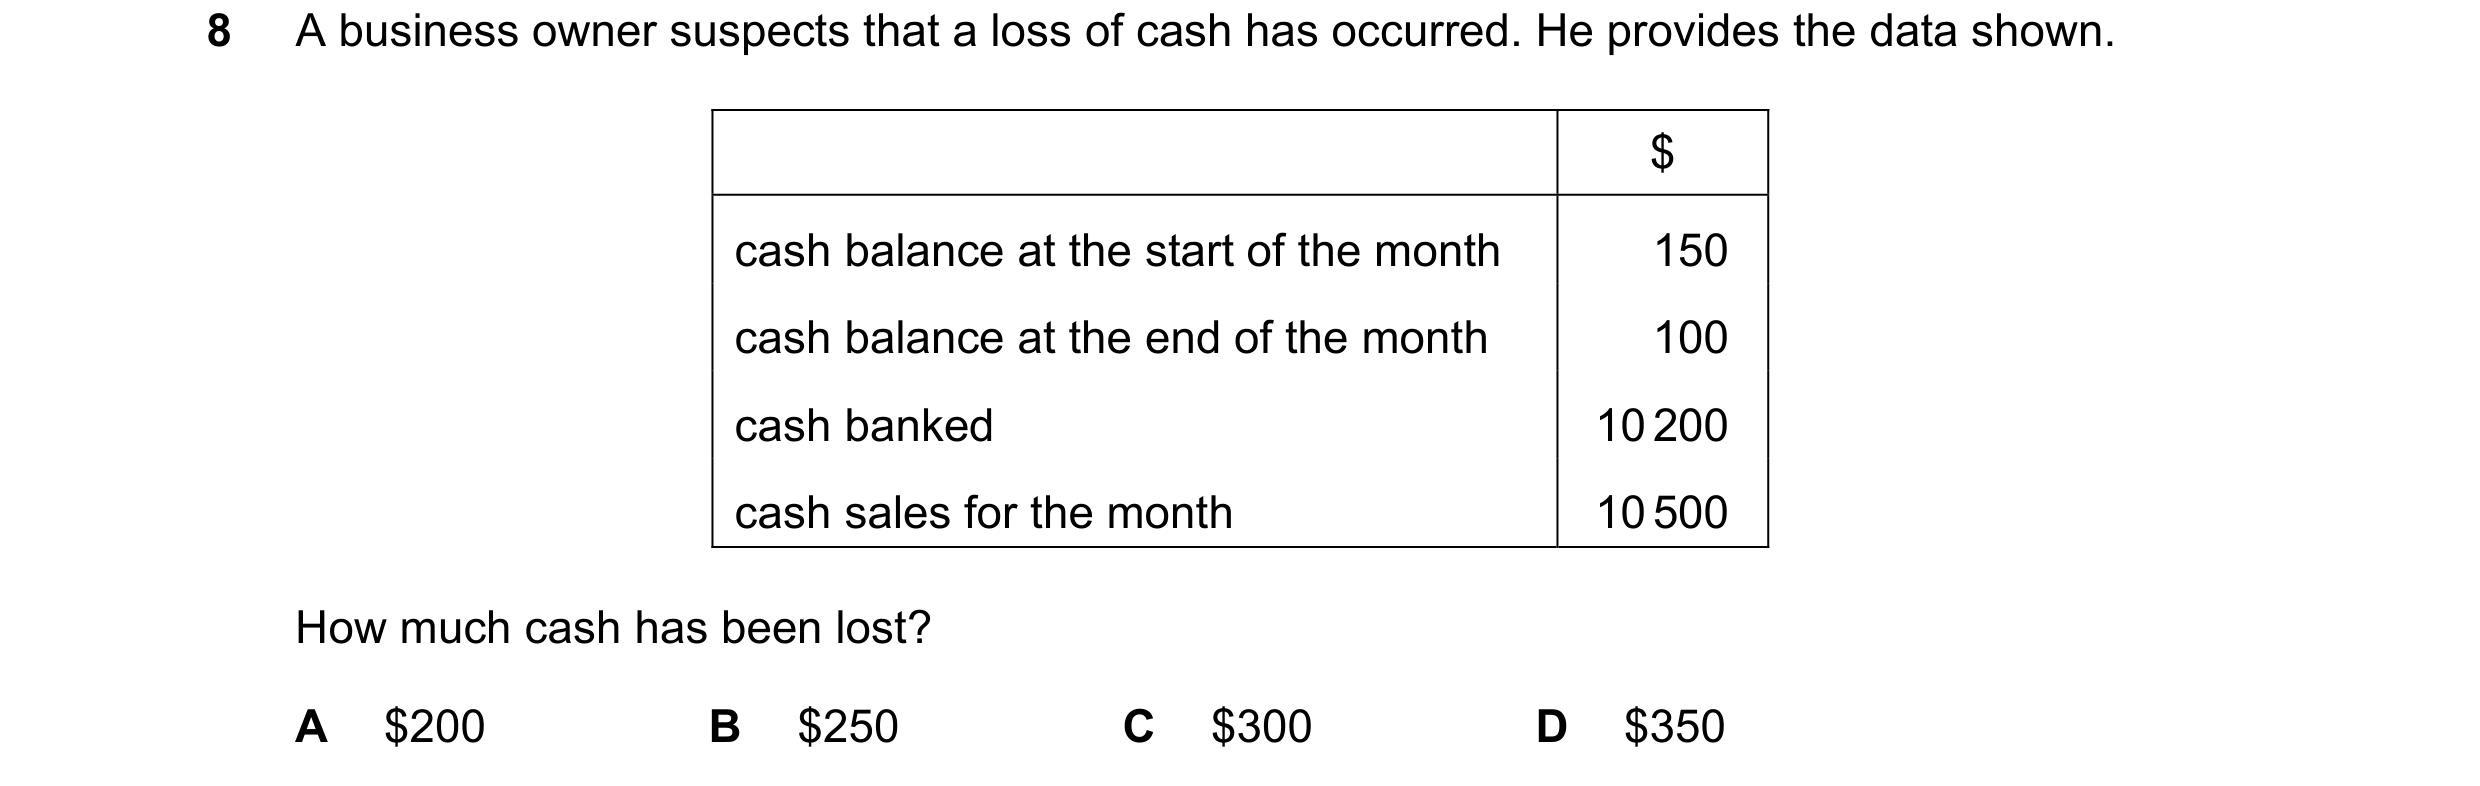
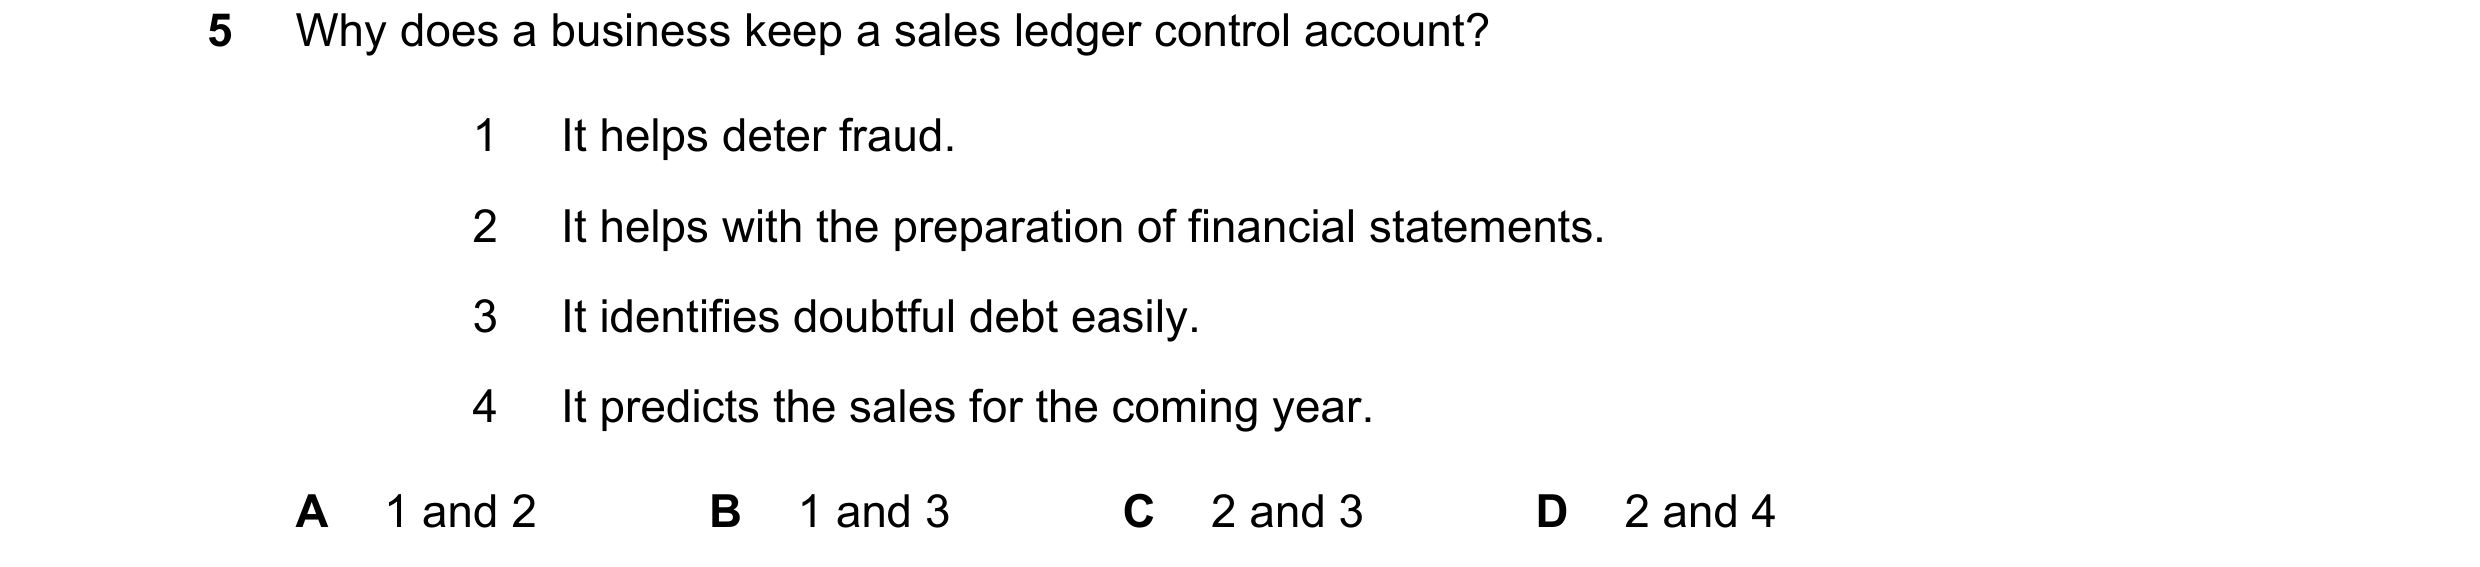 52 / 110
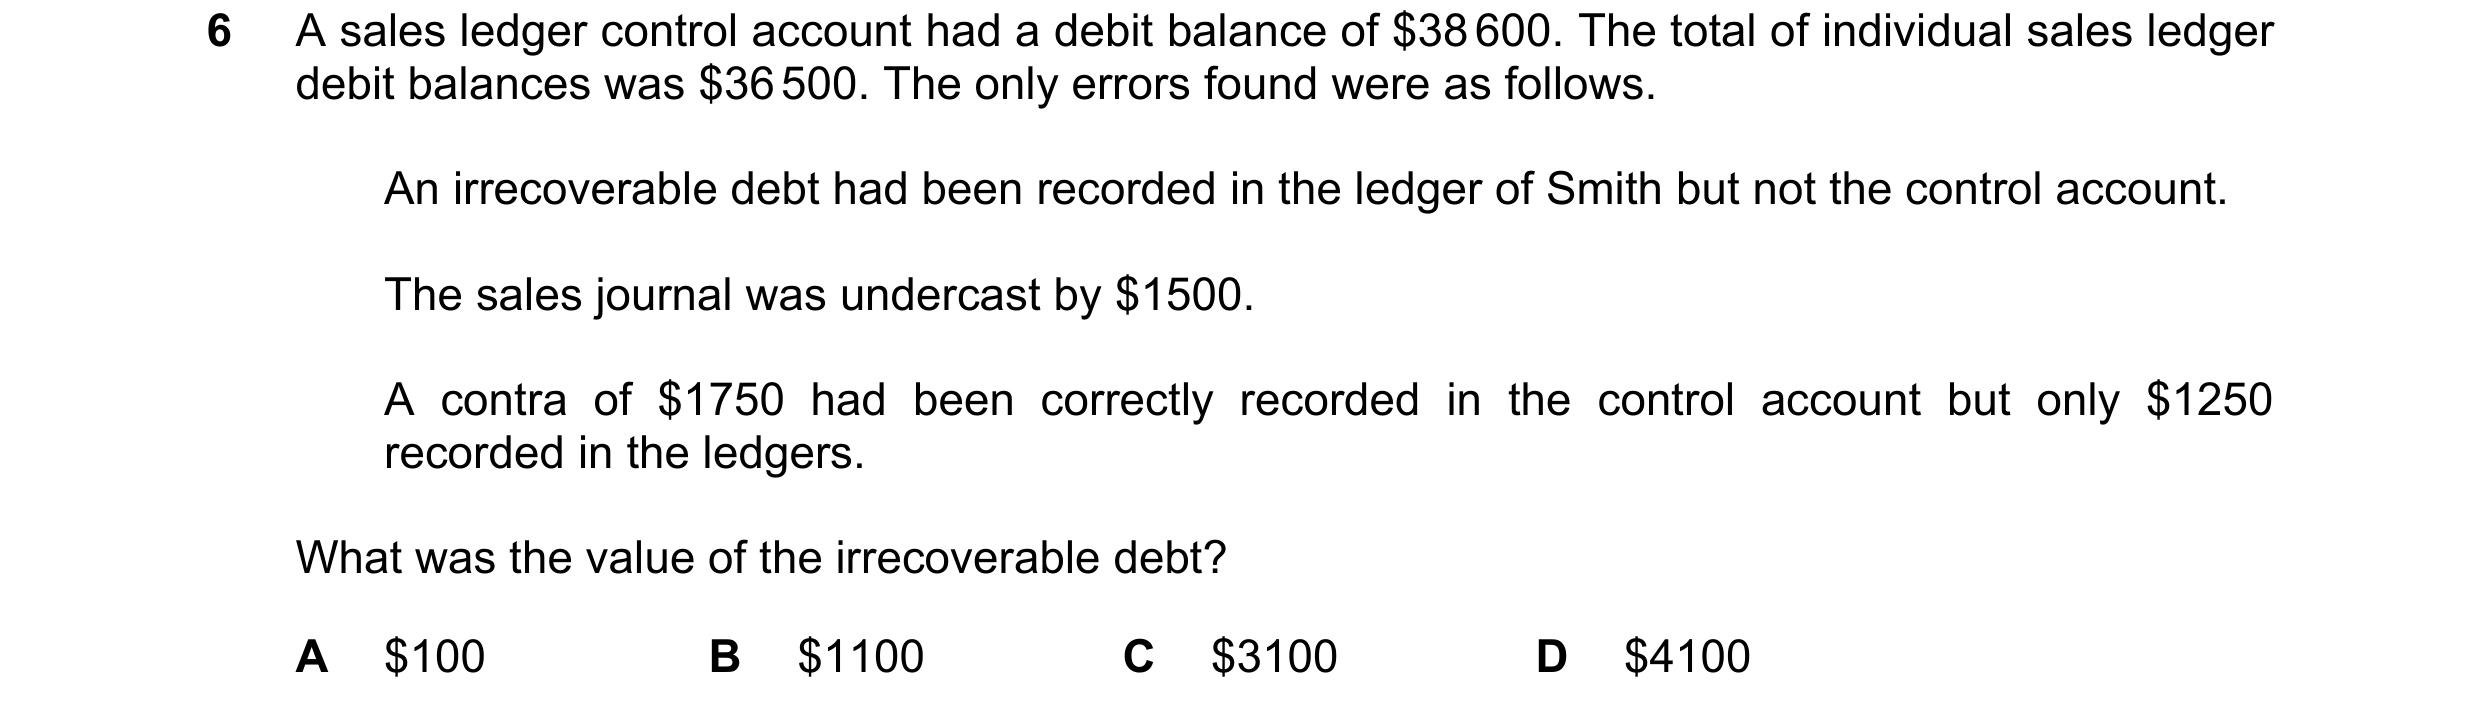
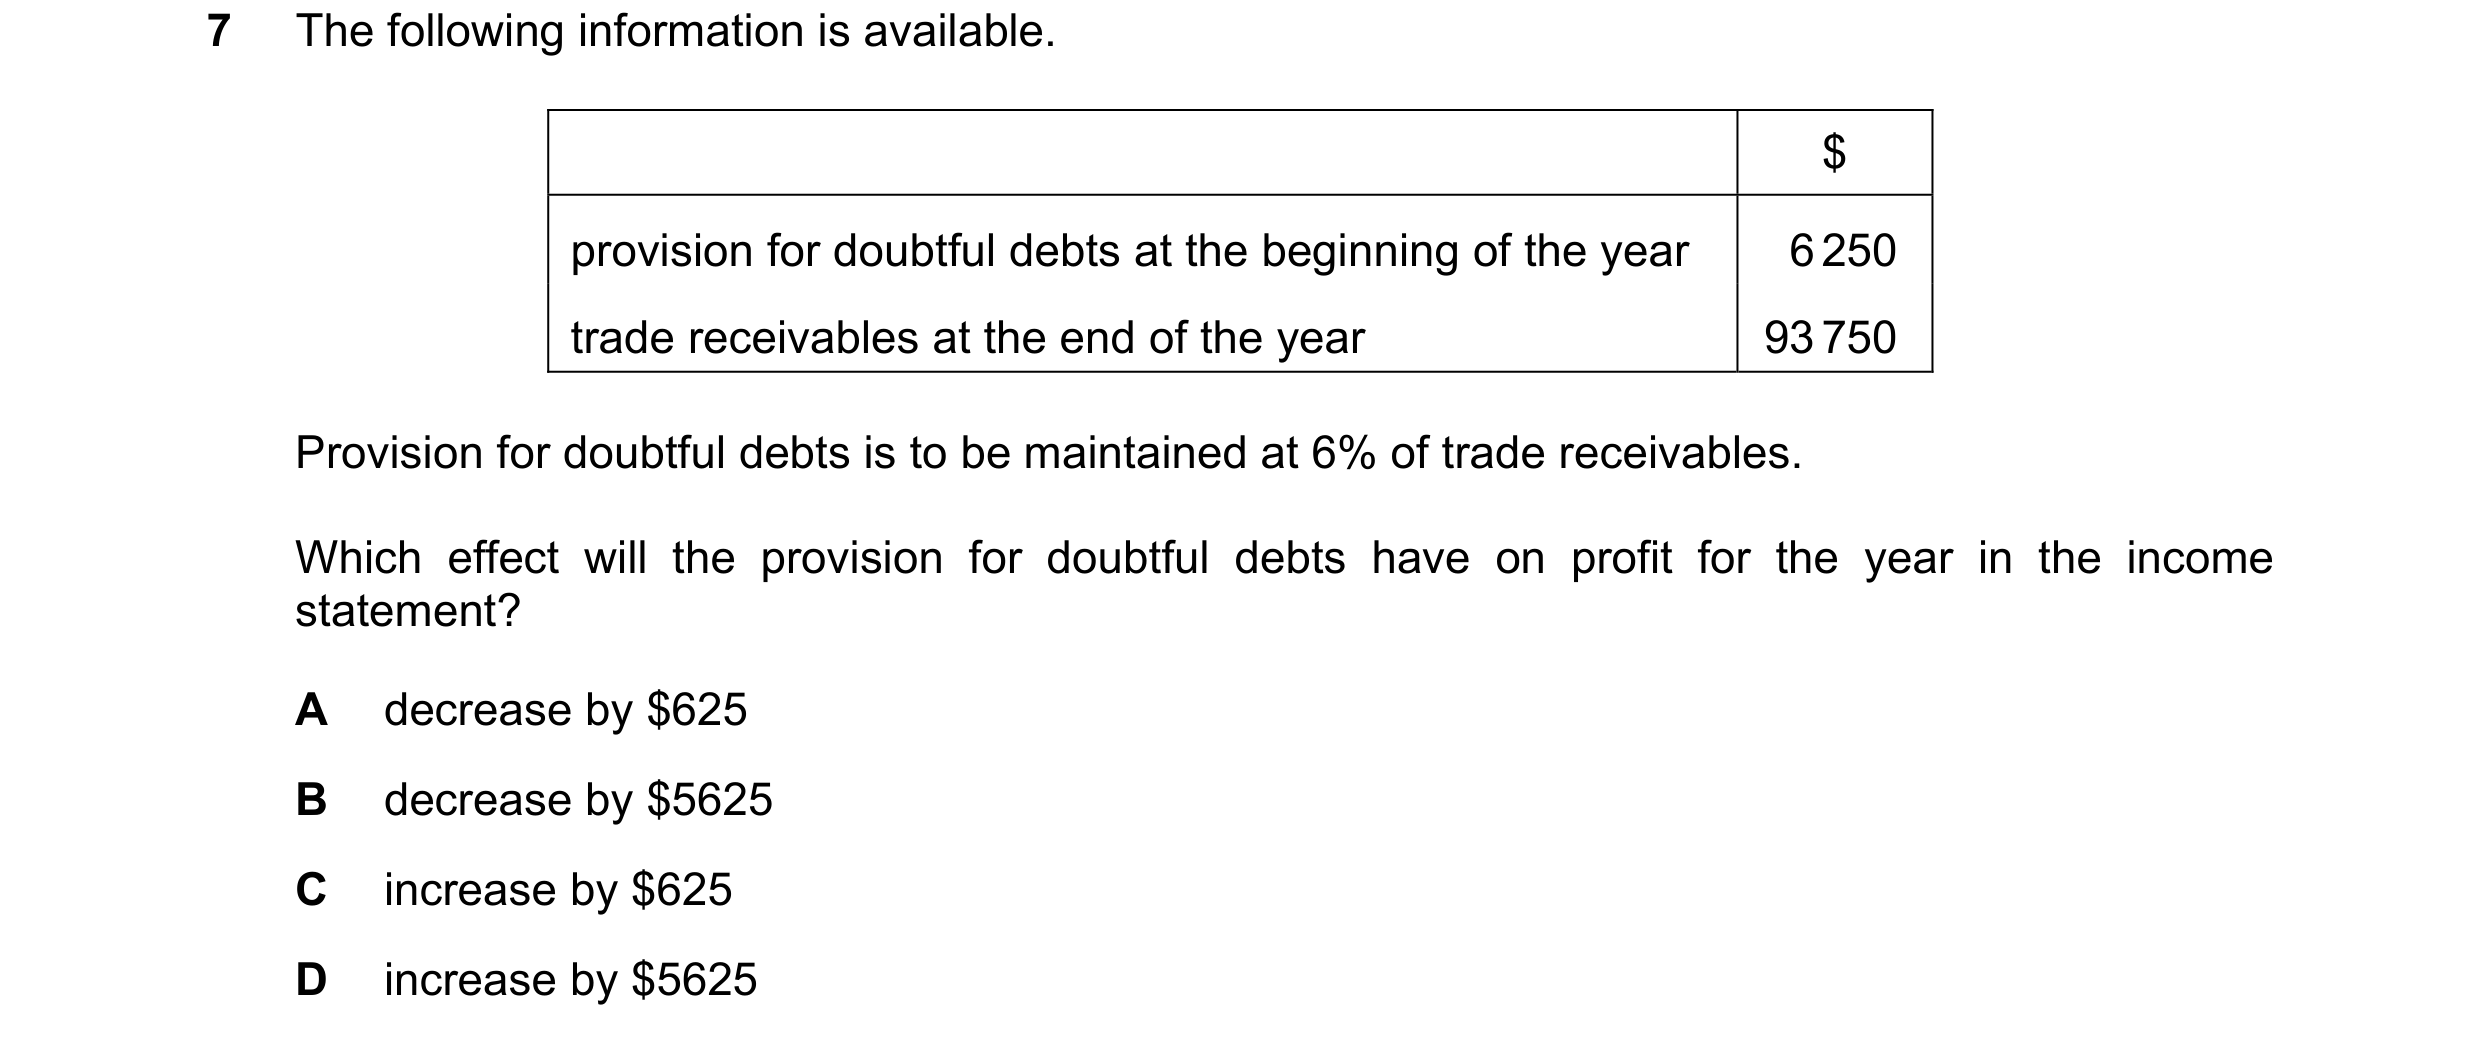
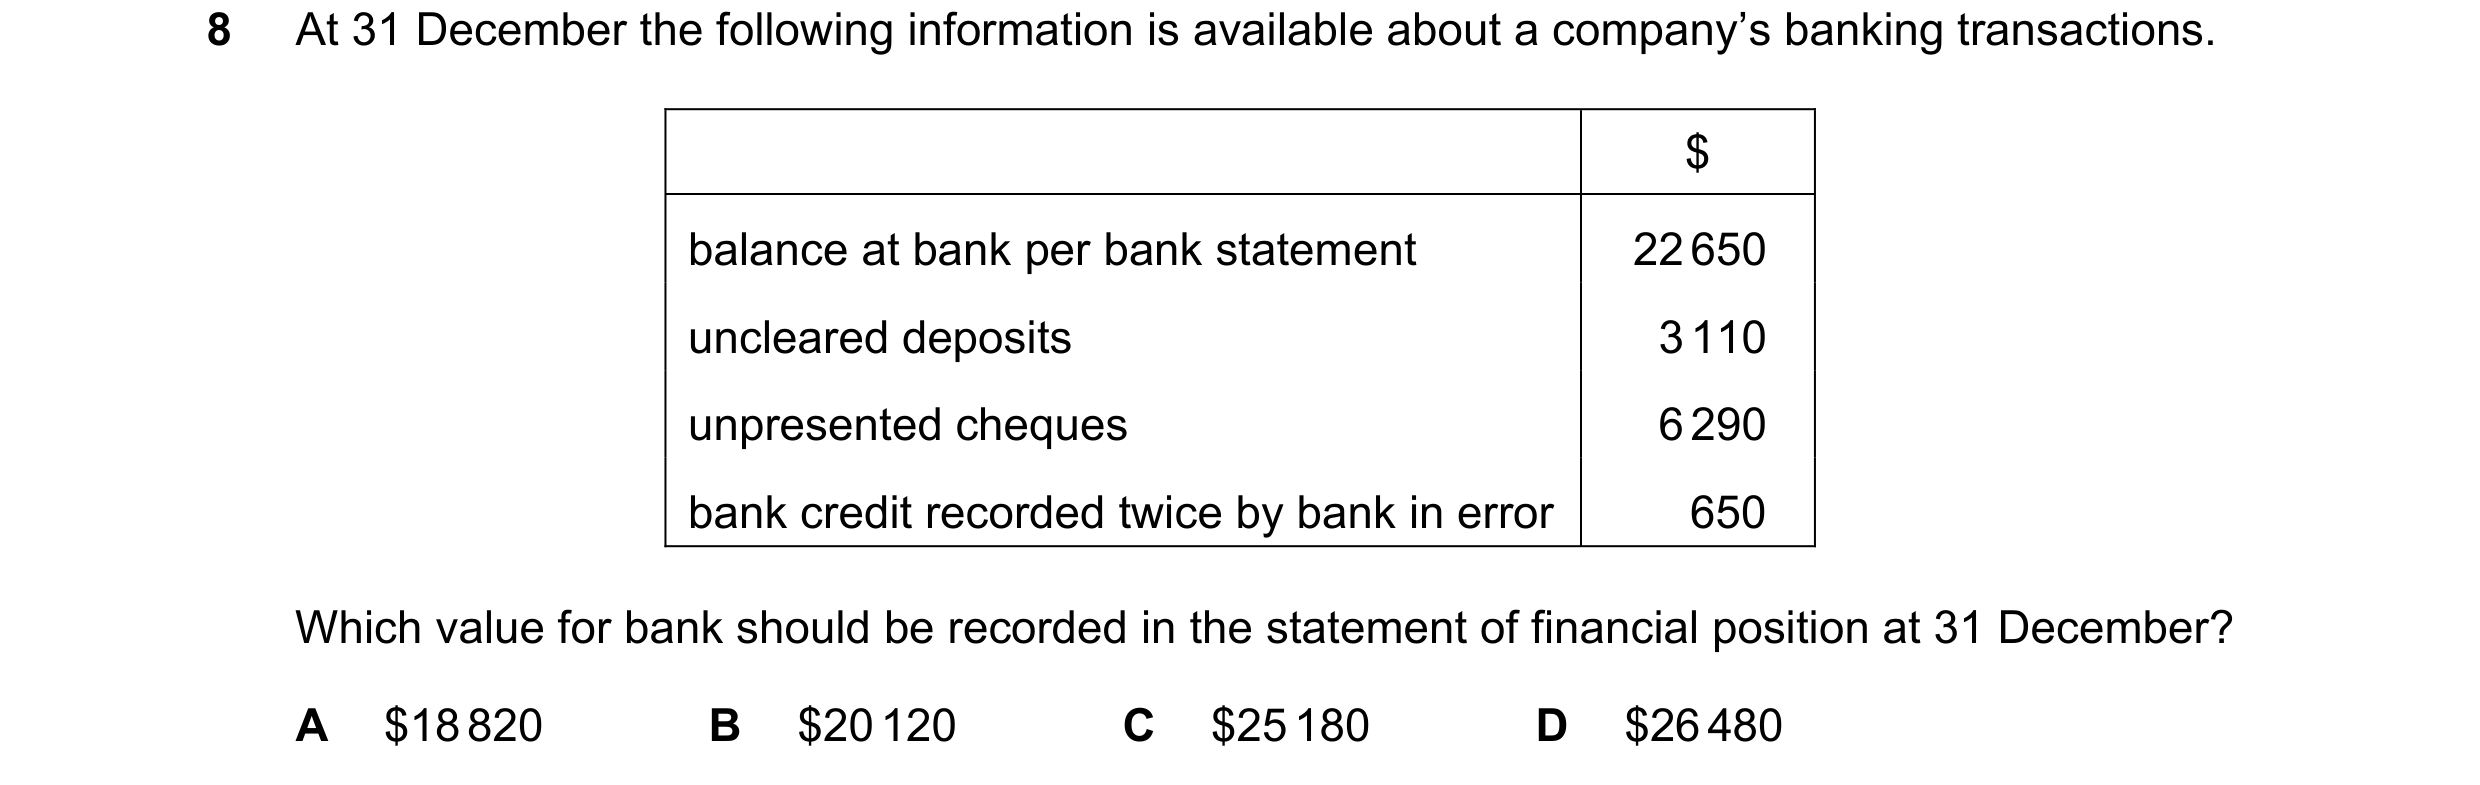
 53 / 110
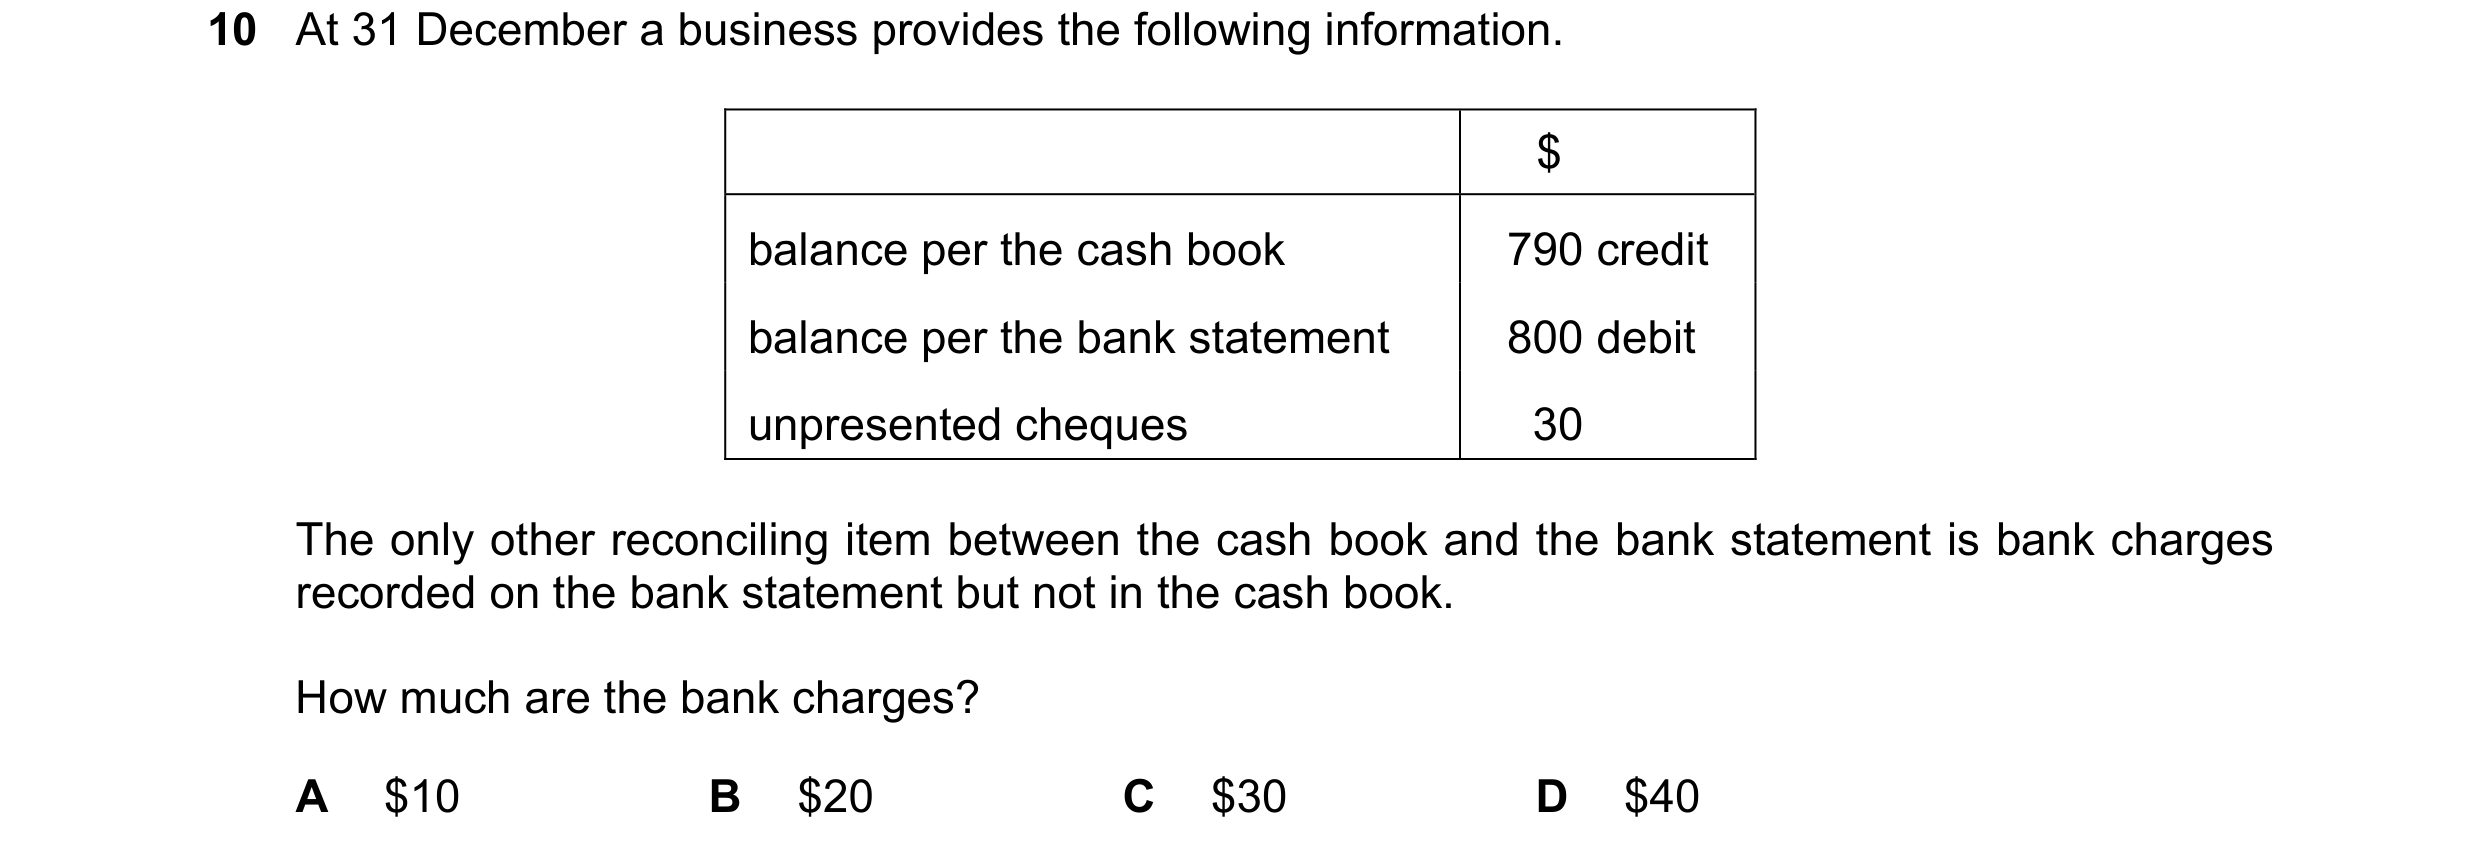
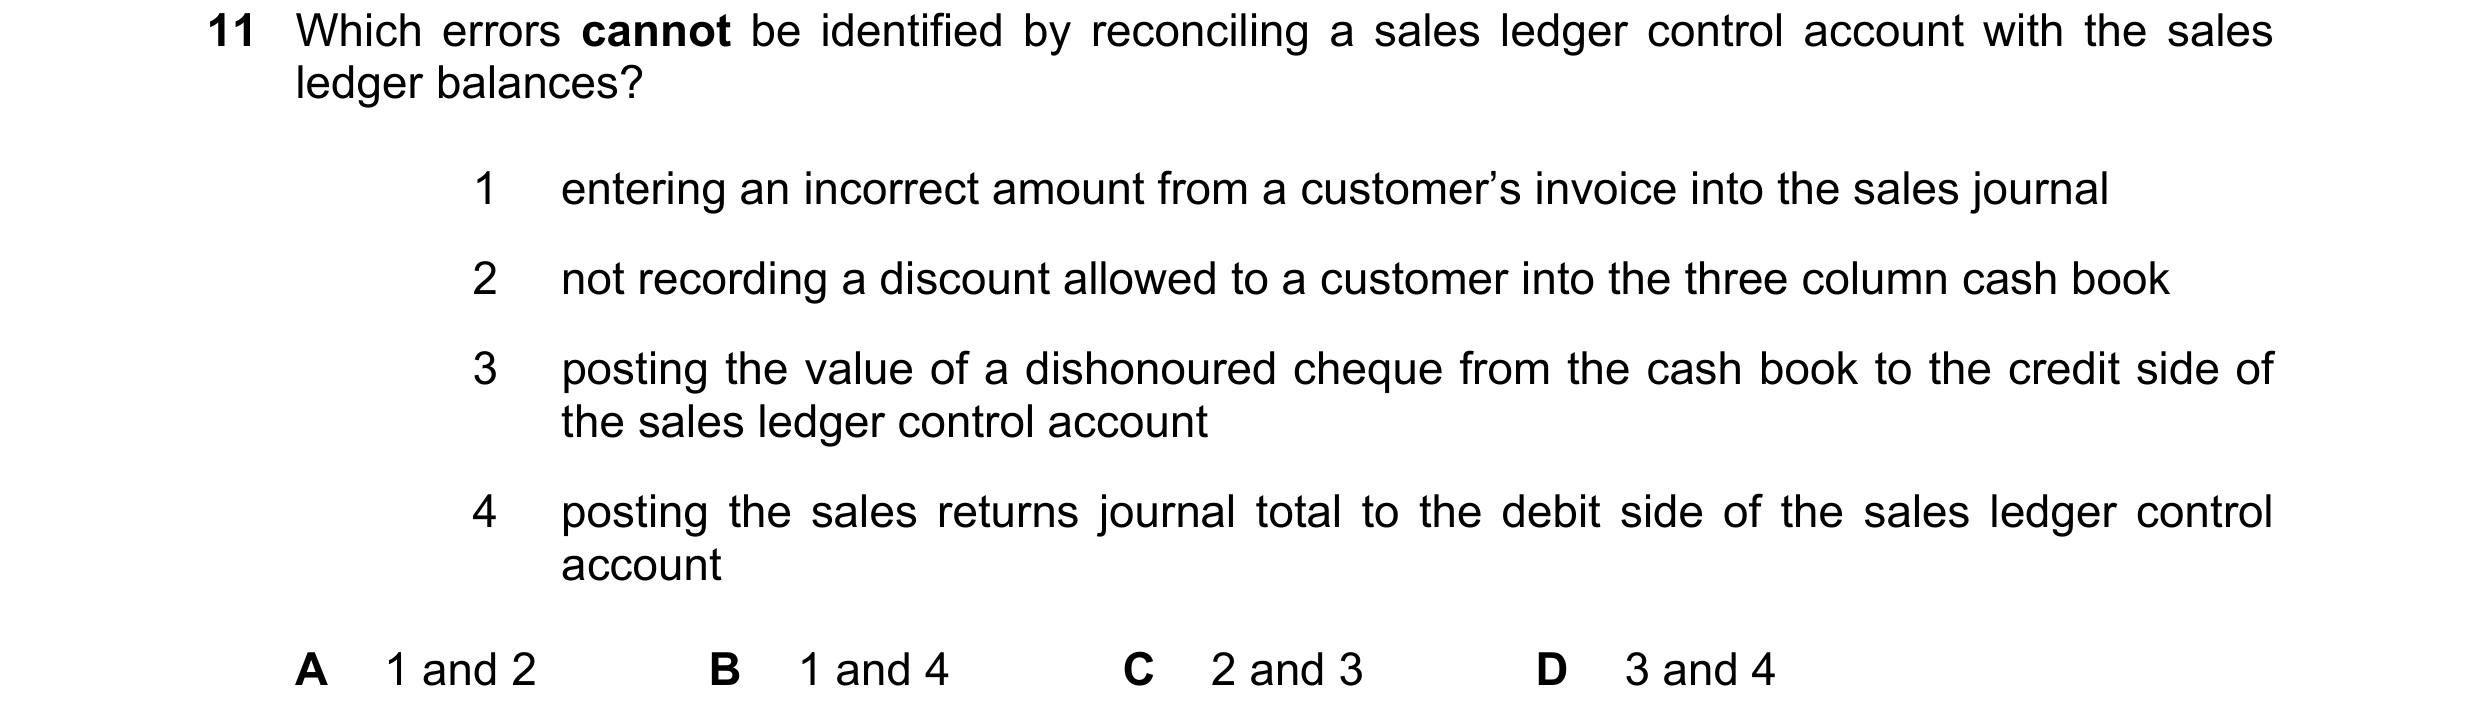 54 / 110
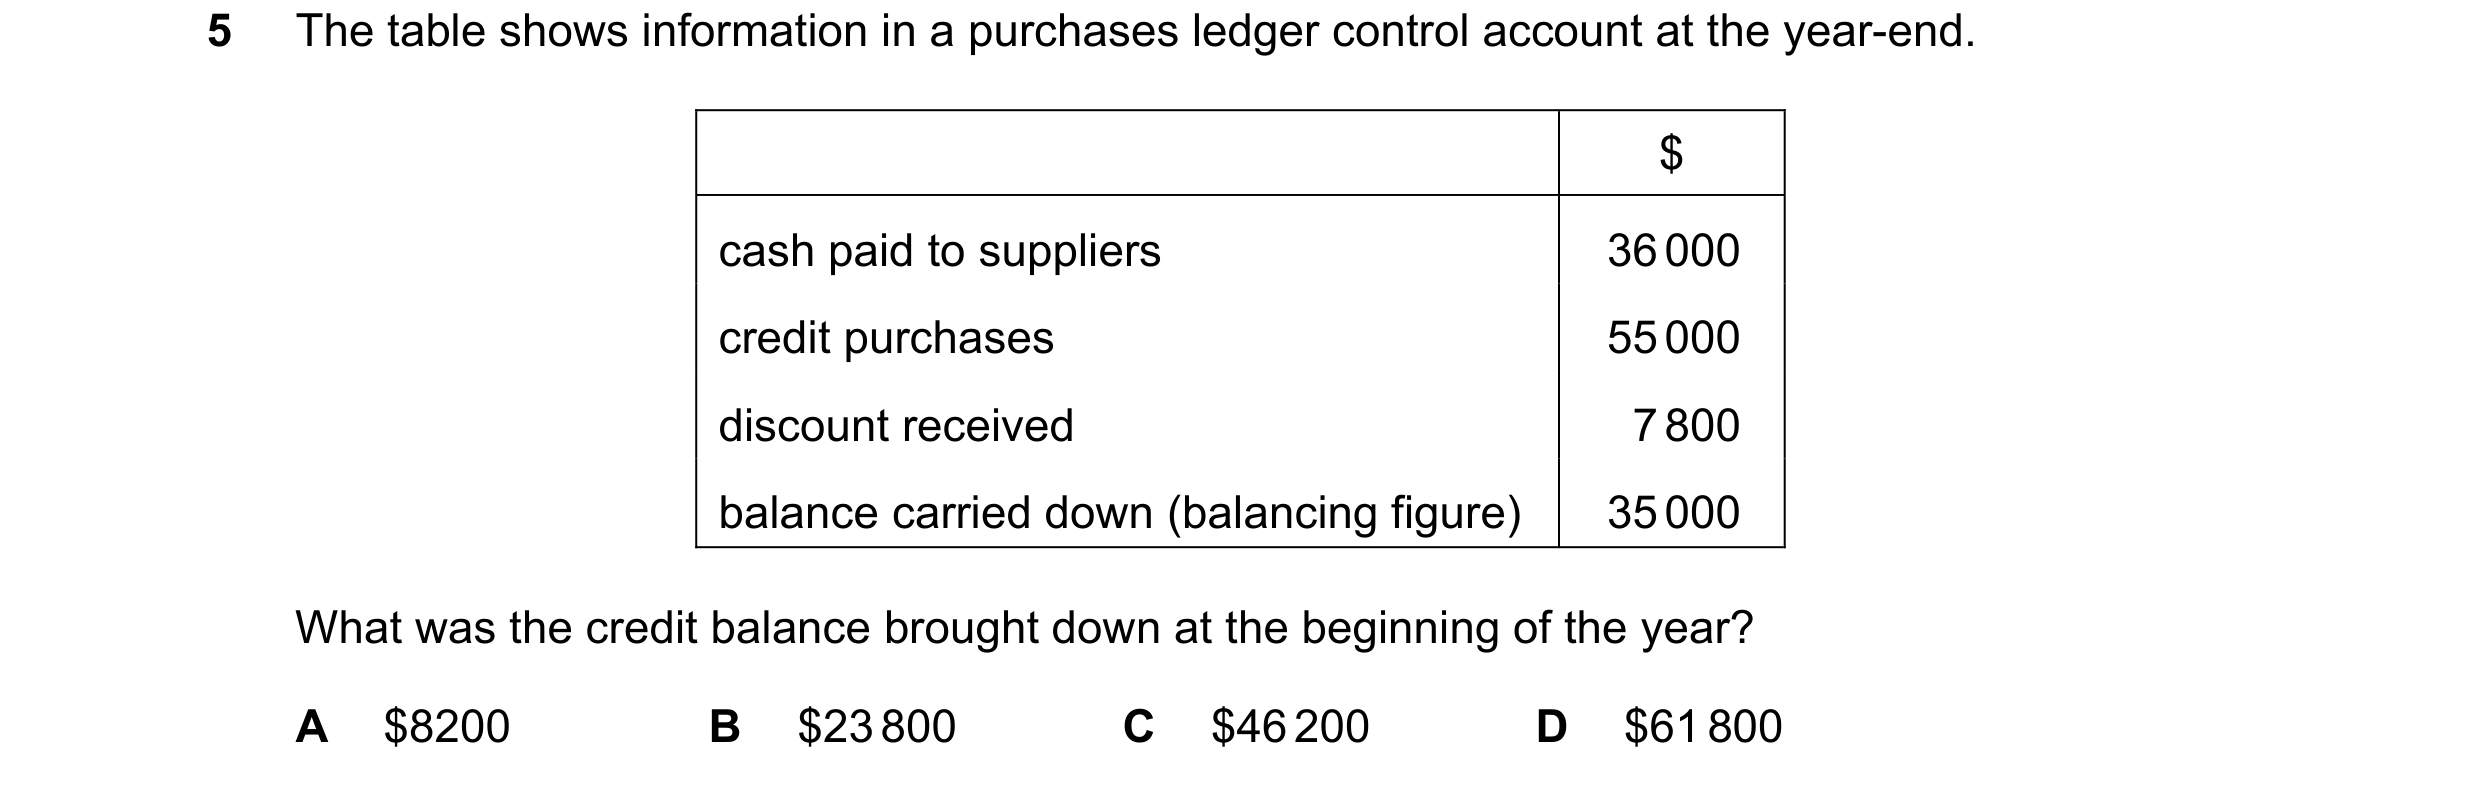
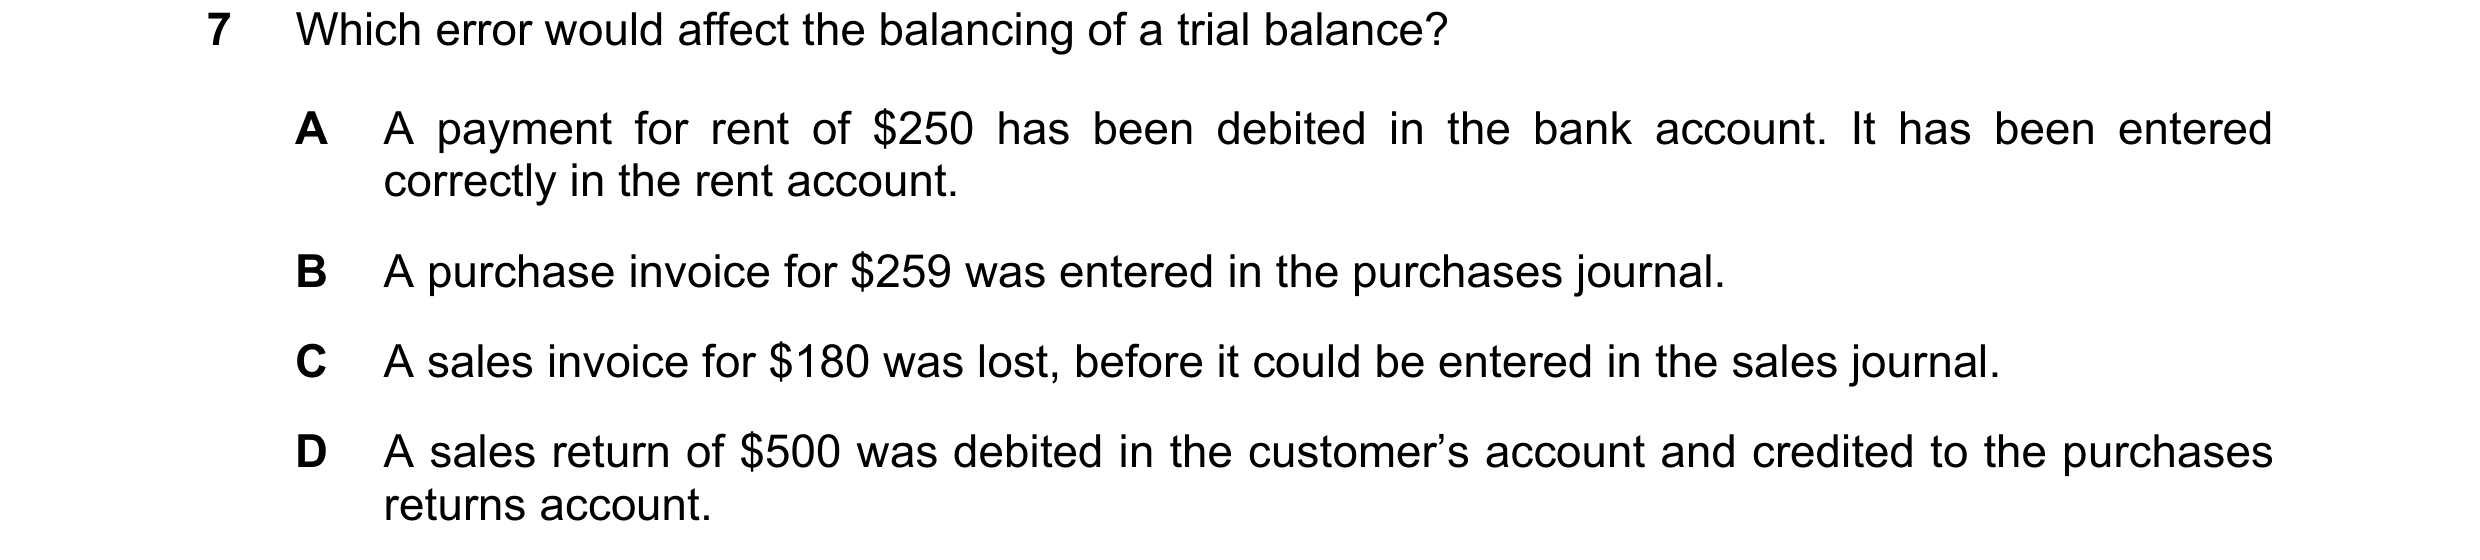
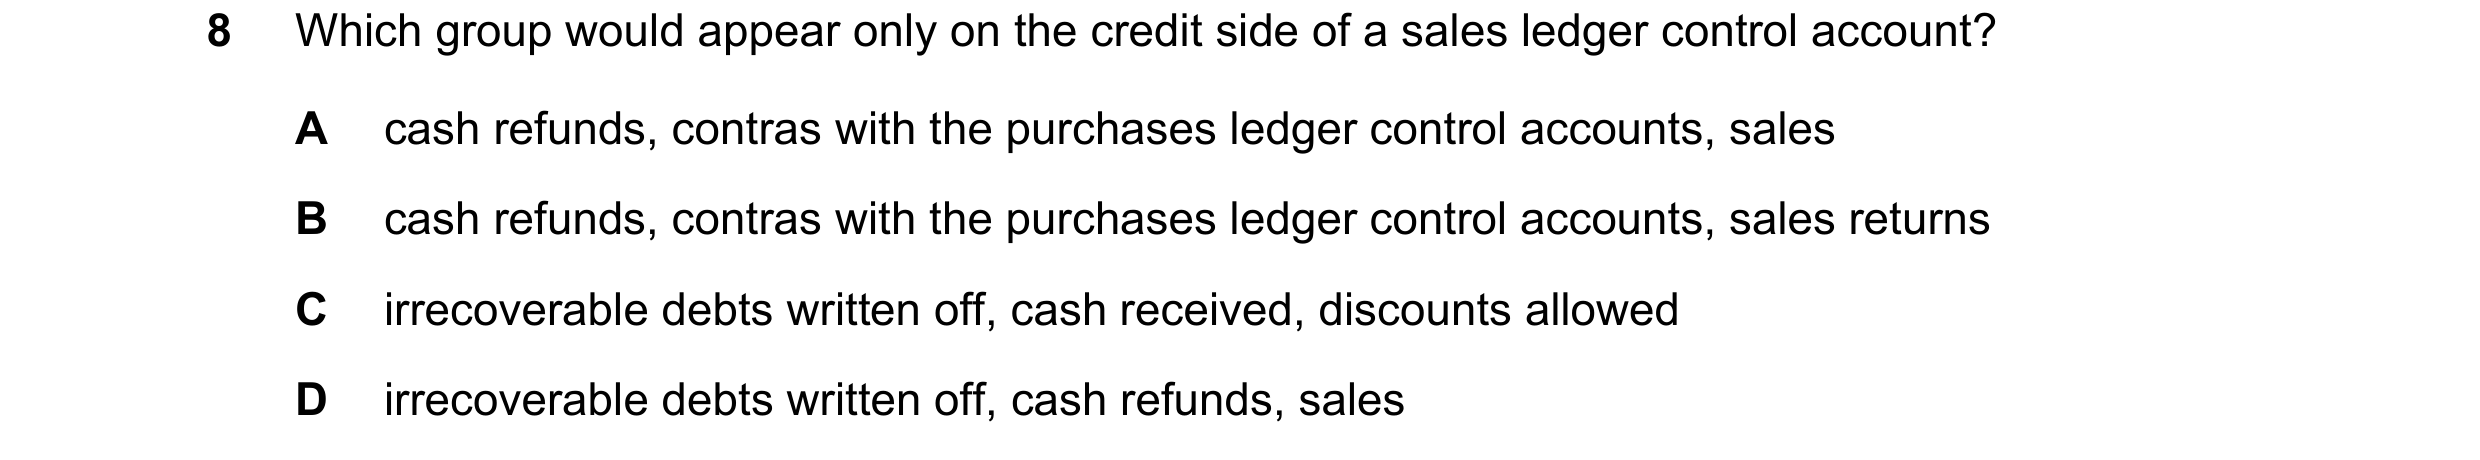
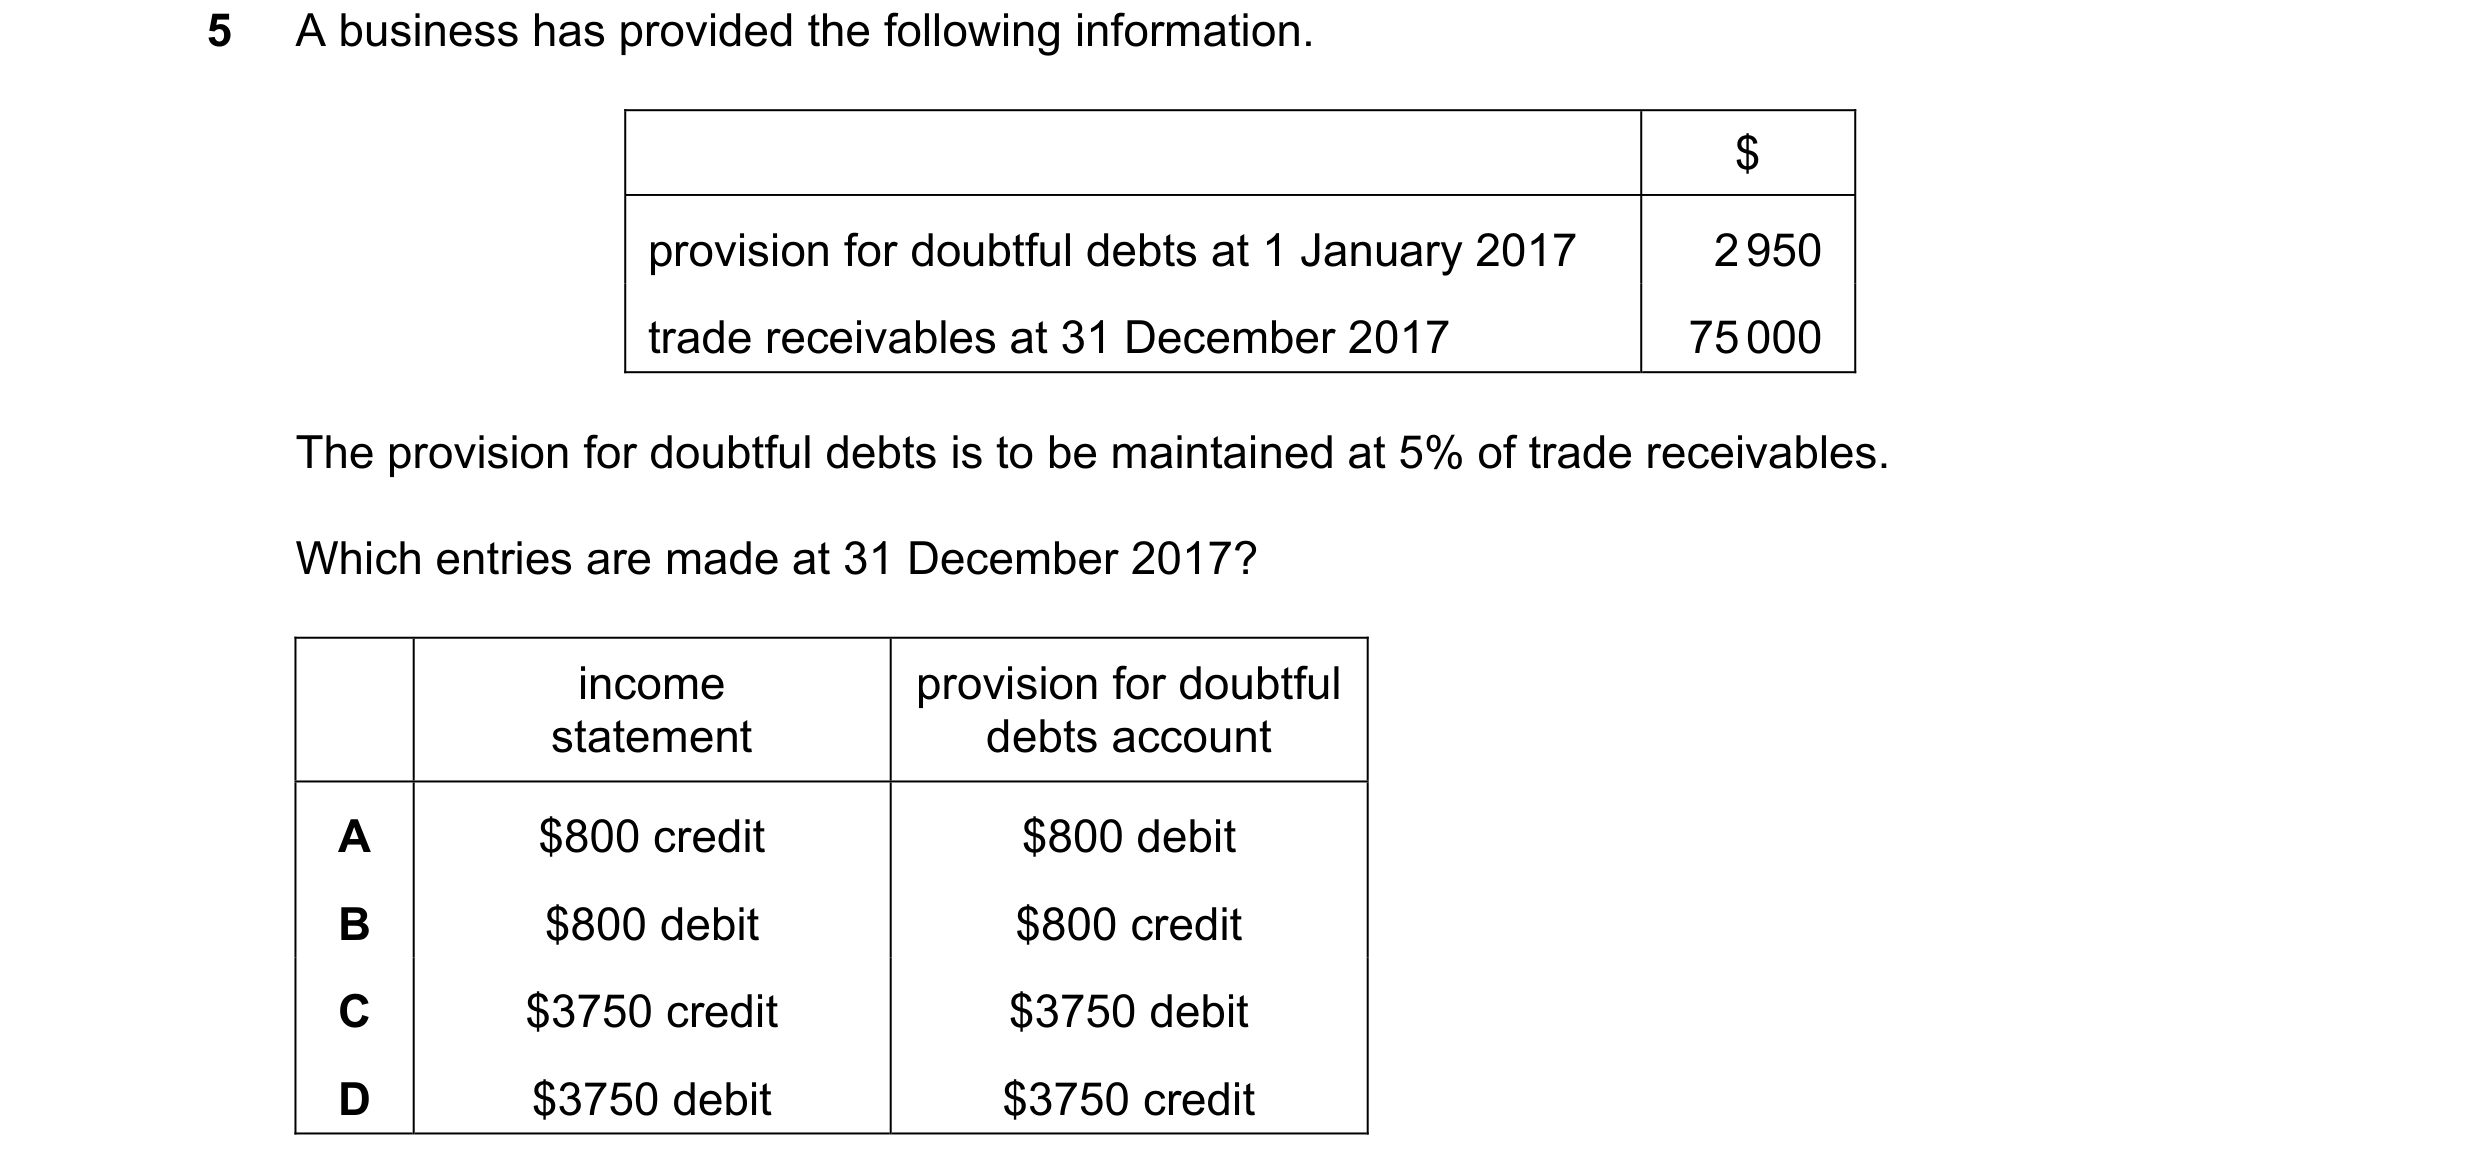 55 / 110
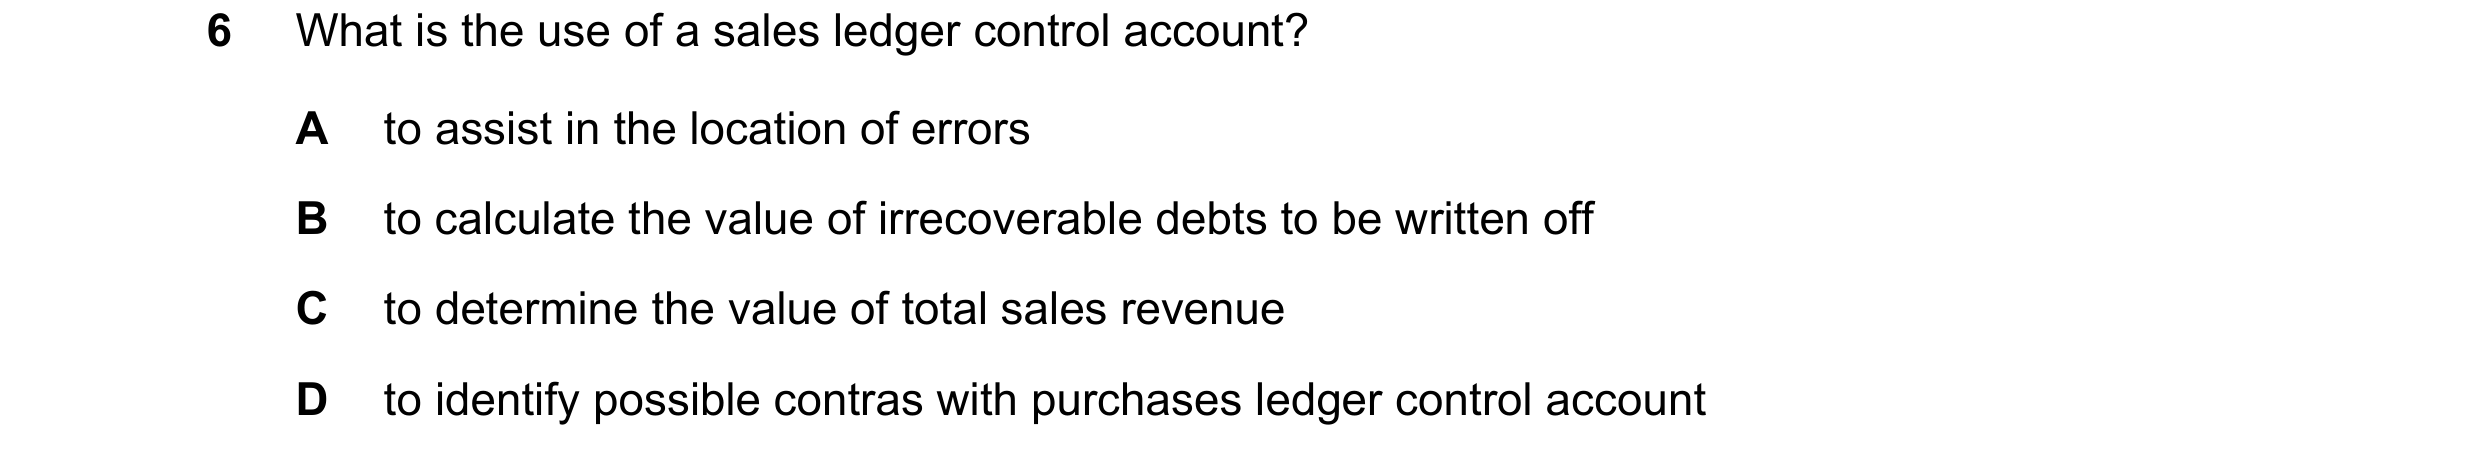
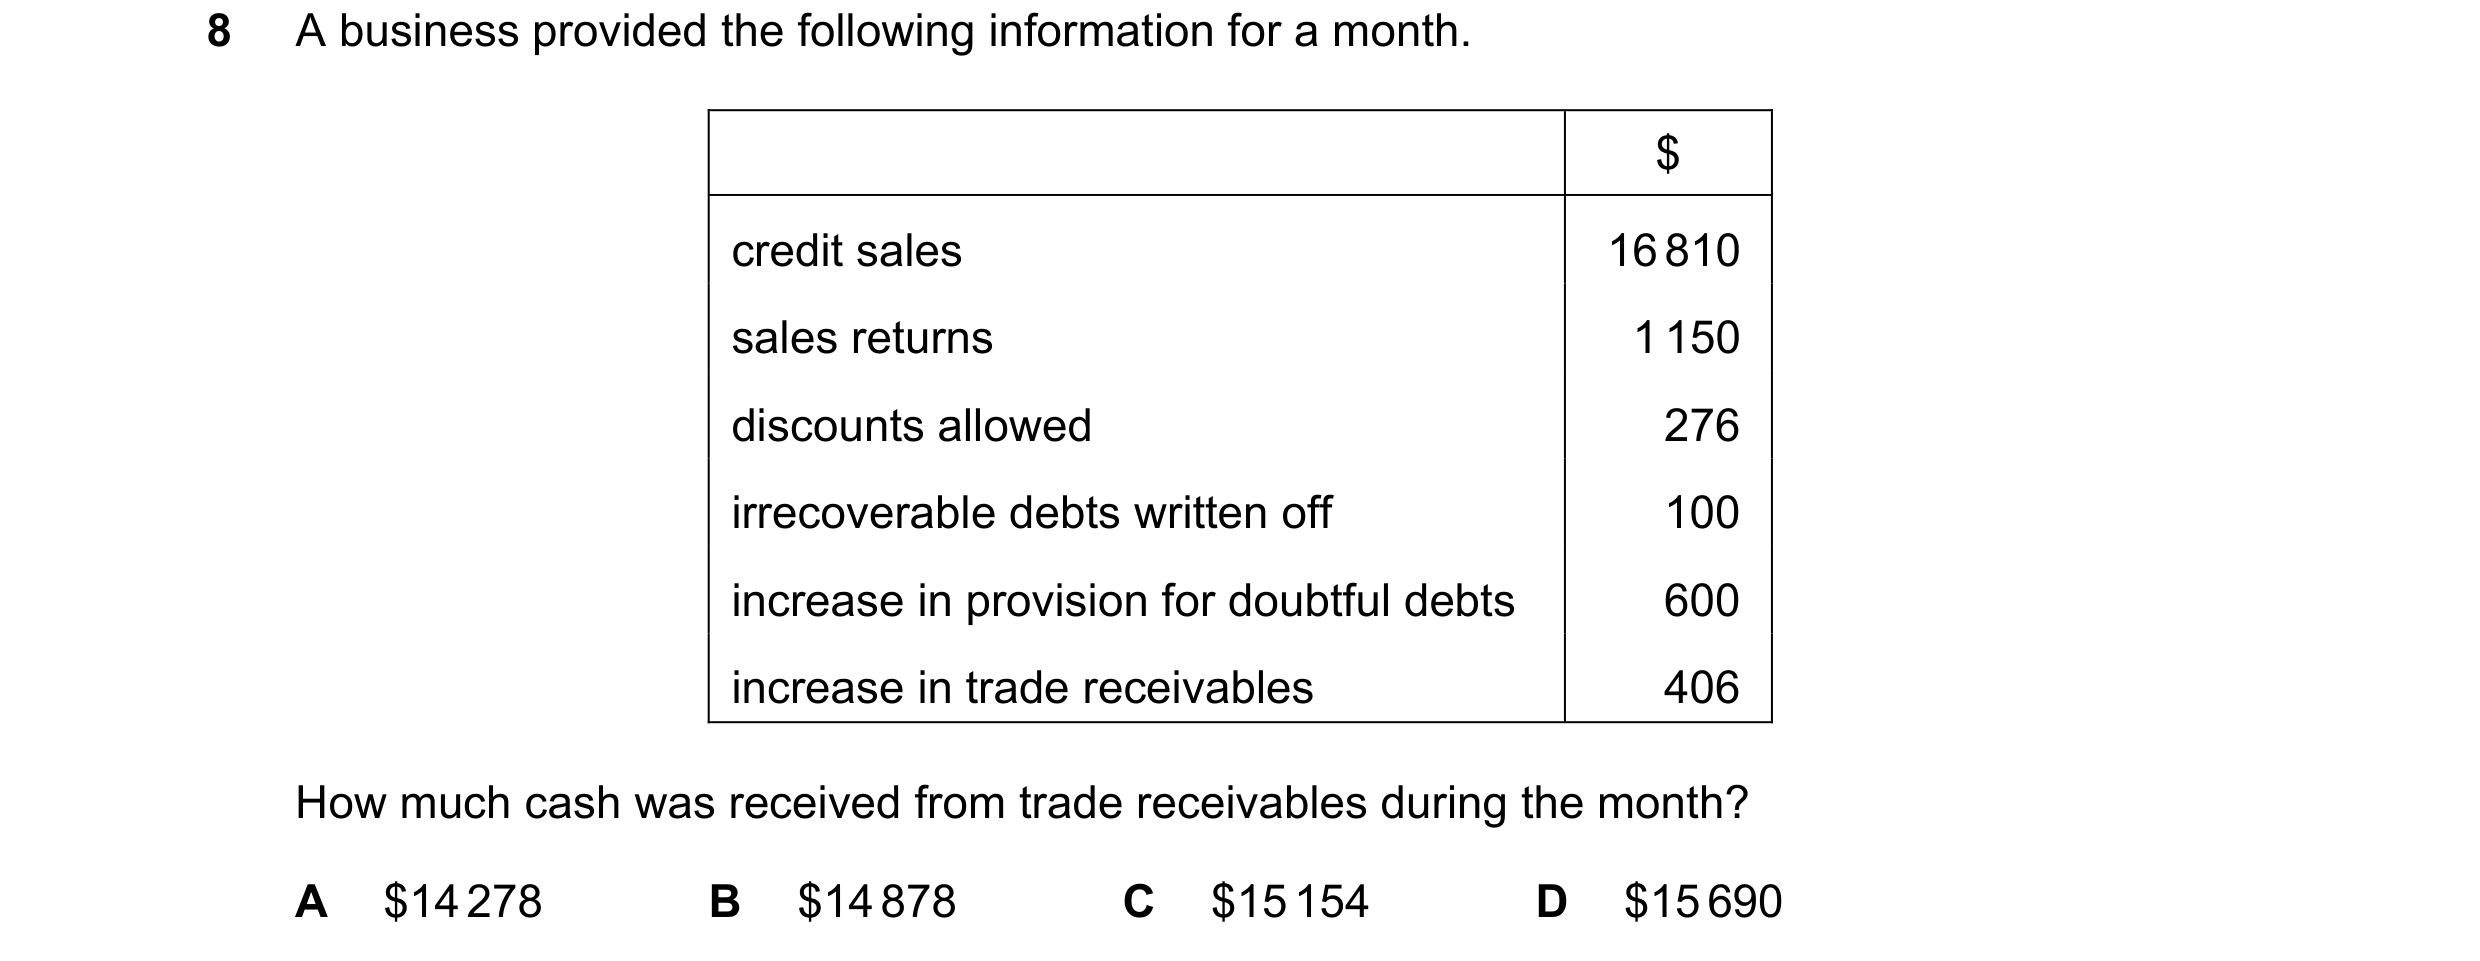
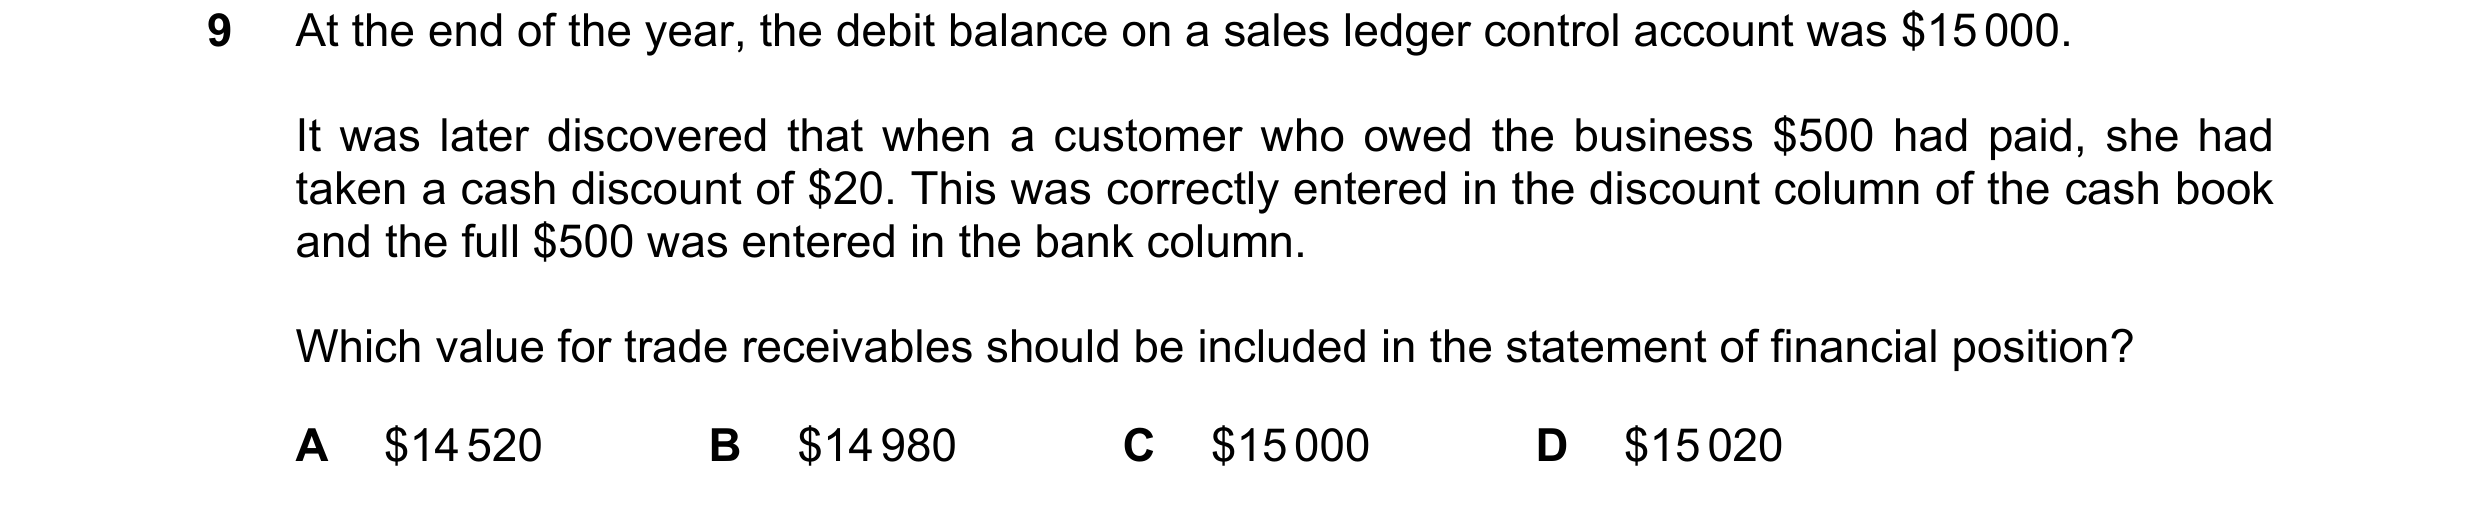
 56 / 110
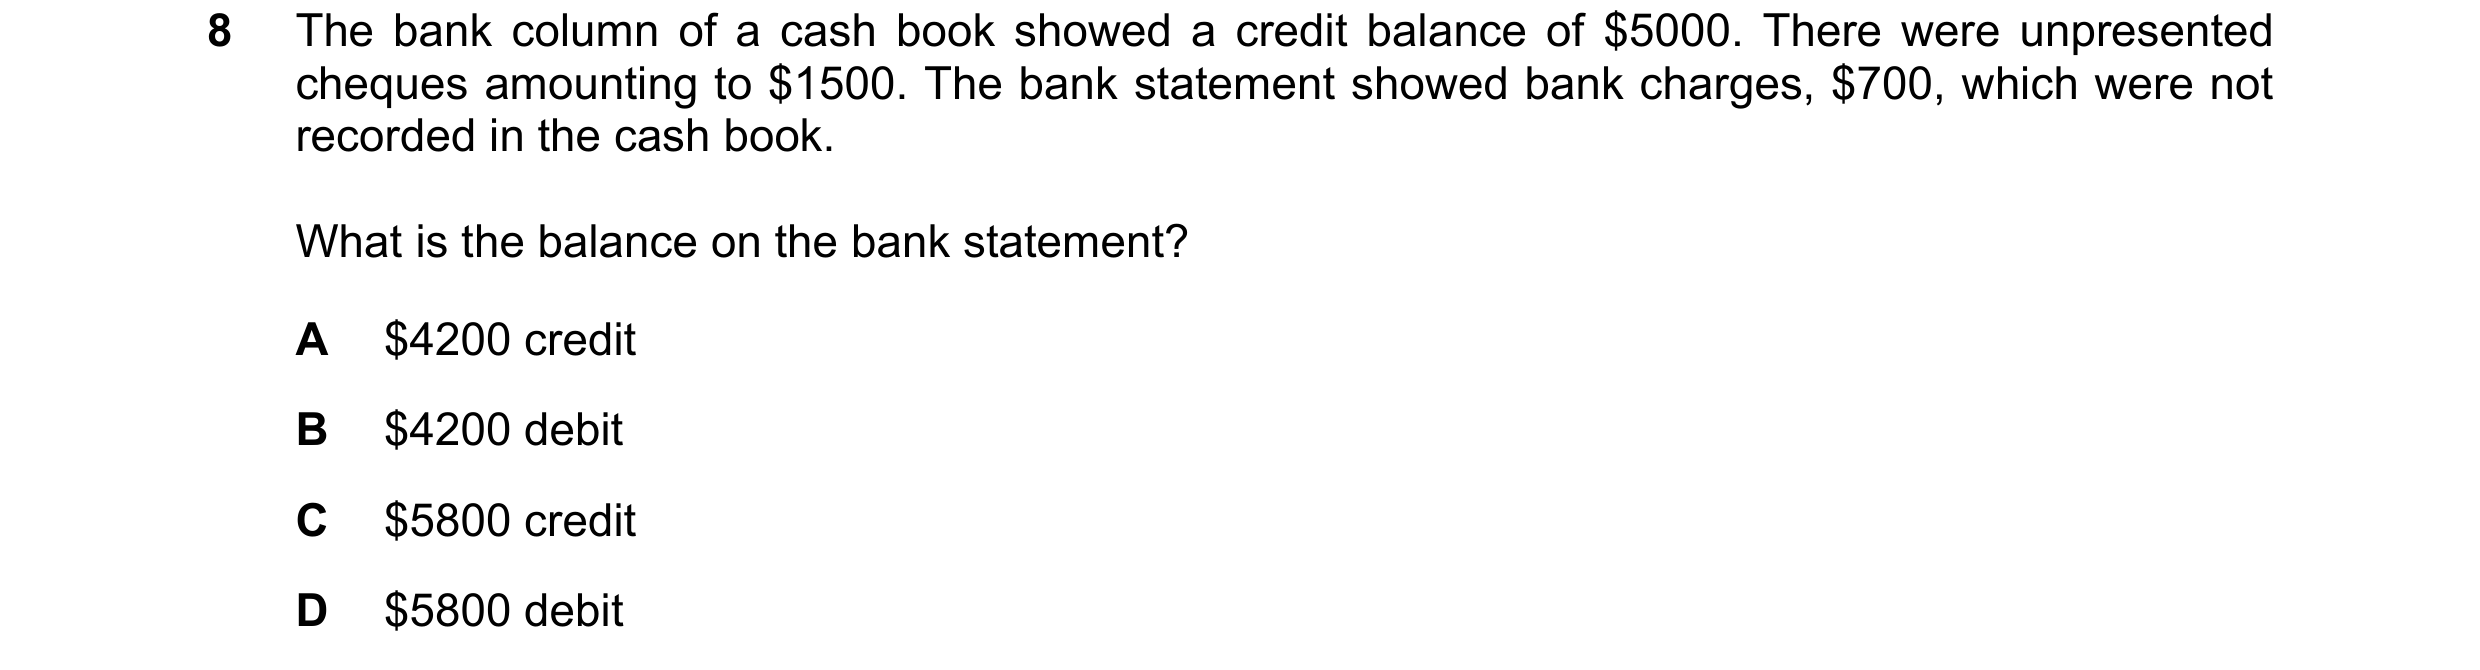
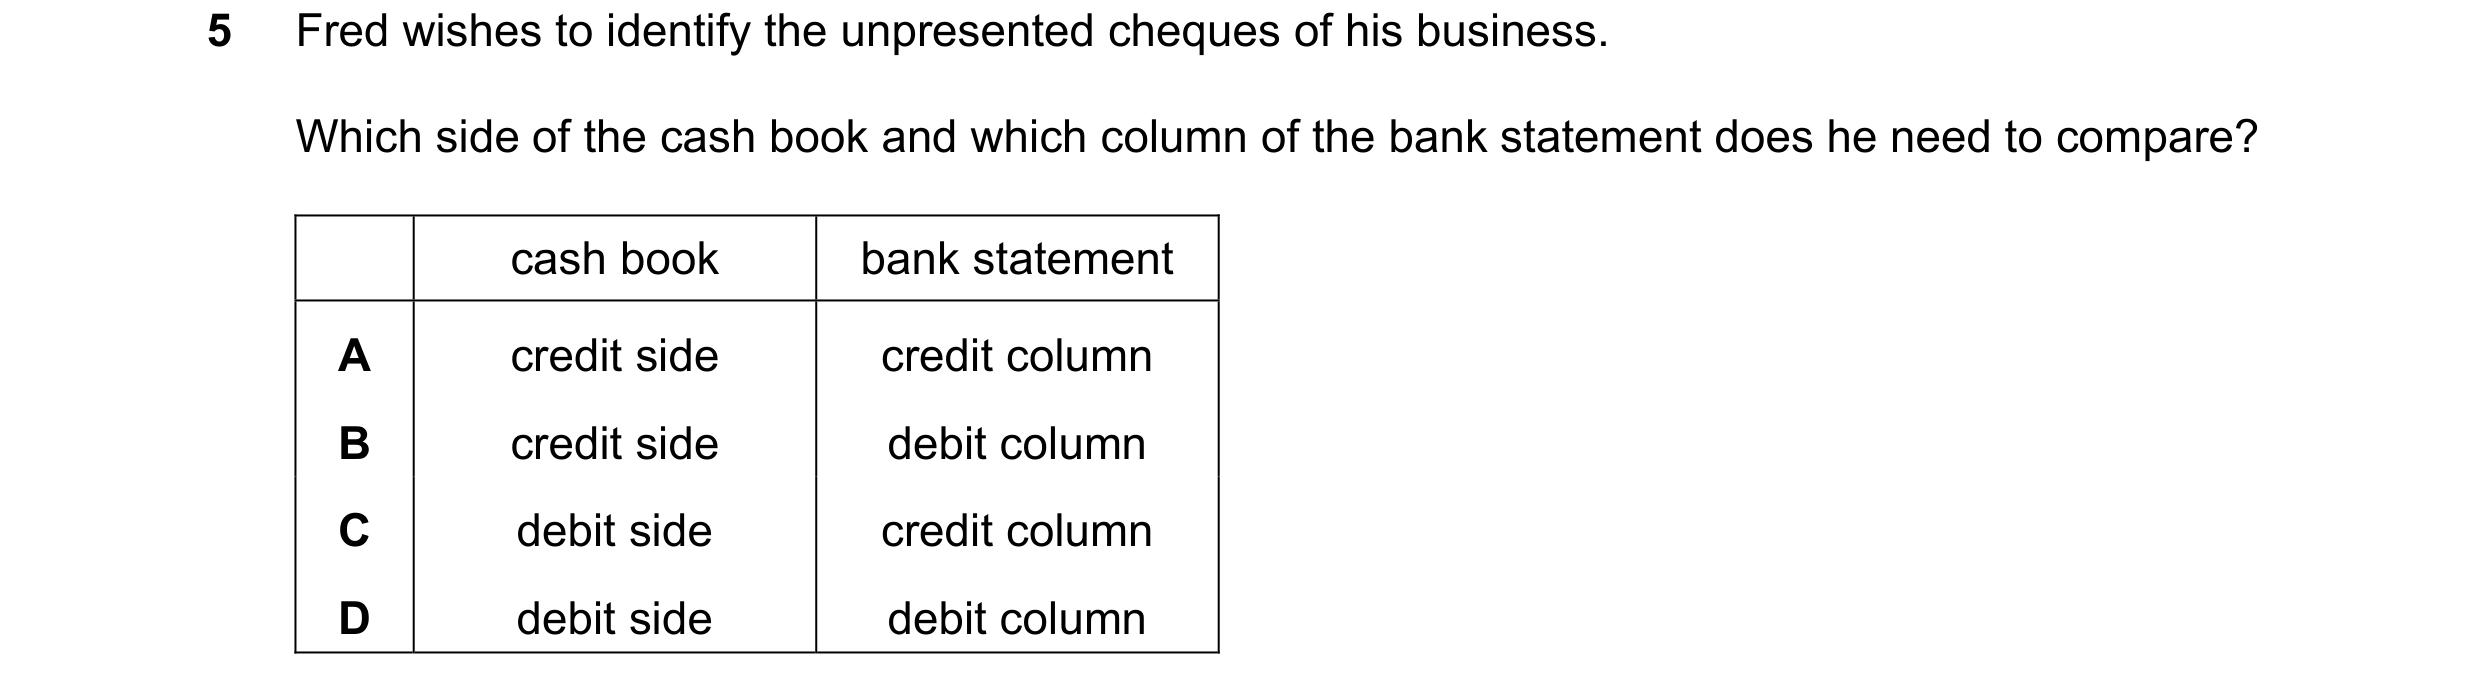 57 / 110
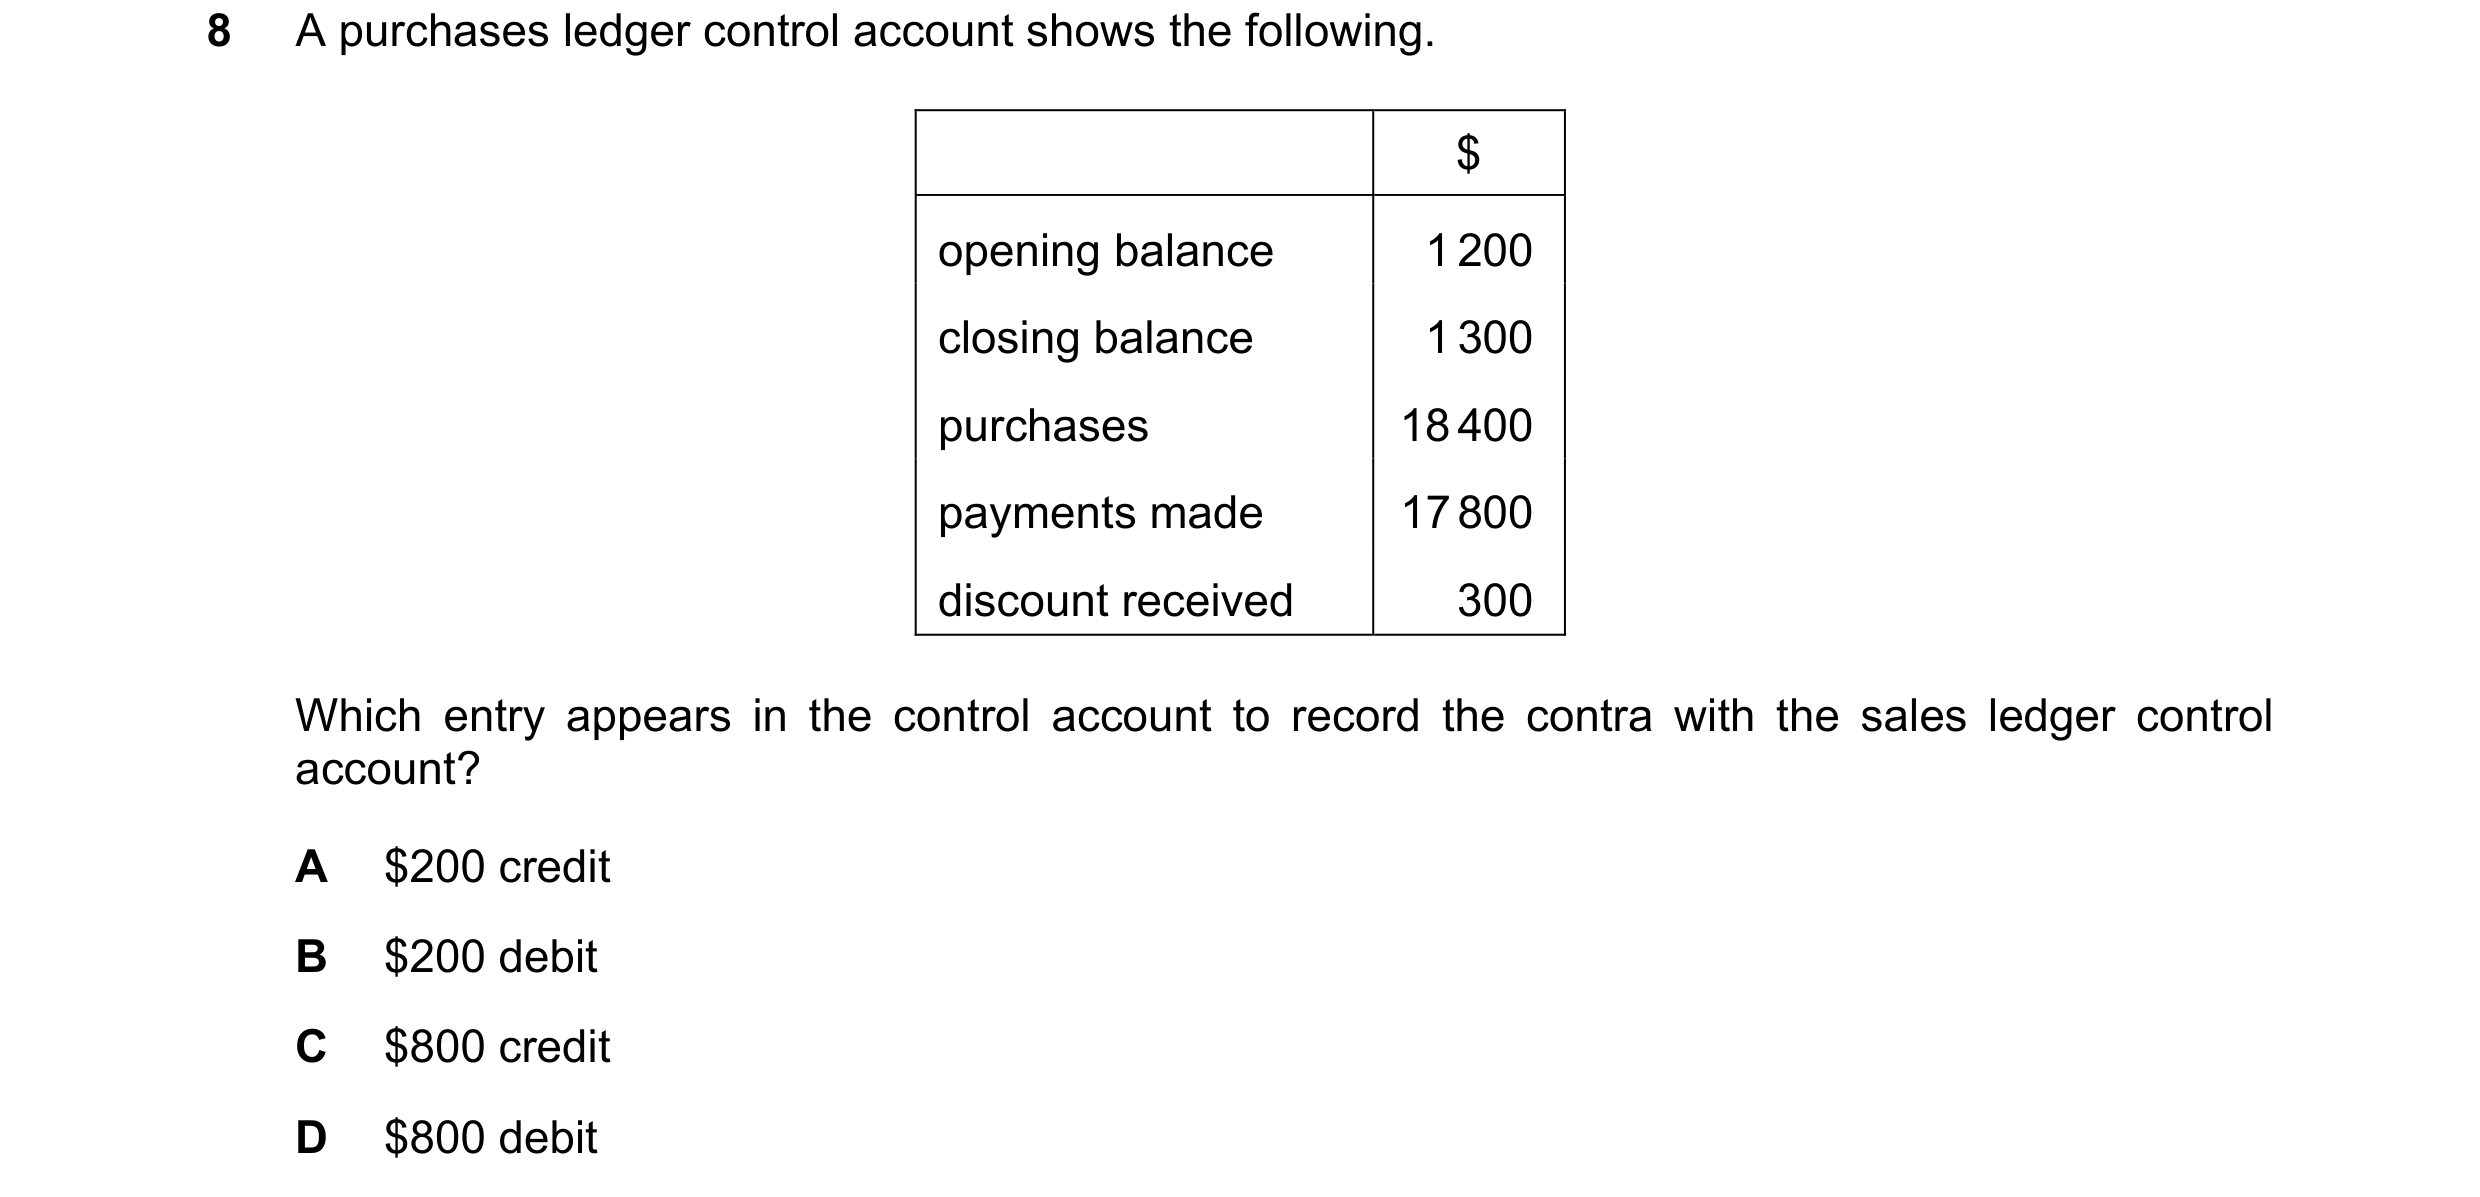
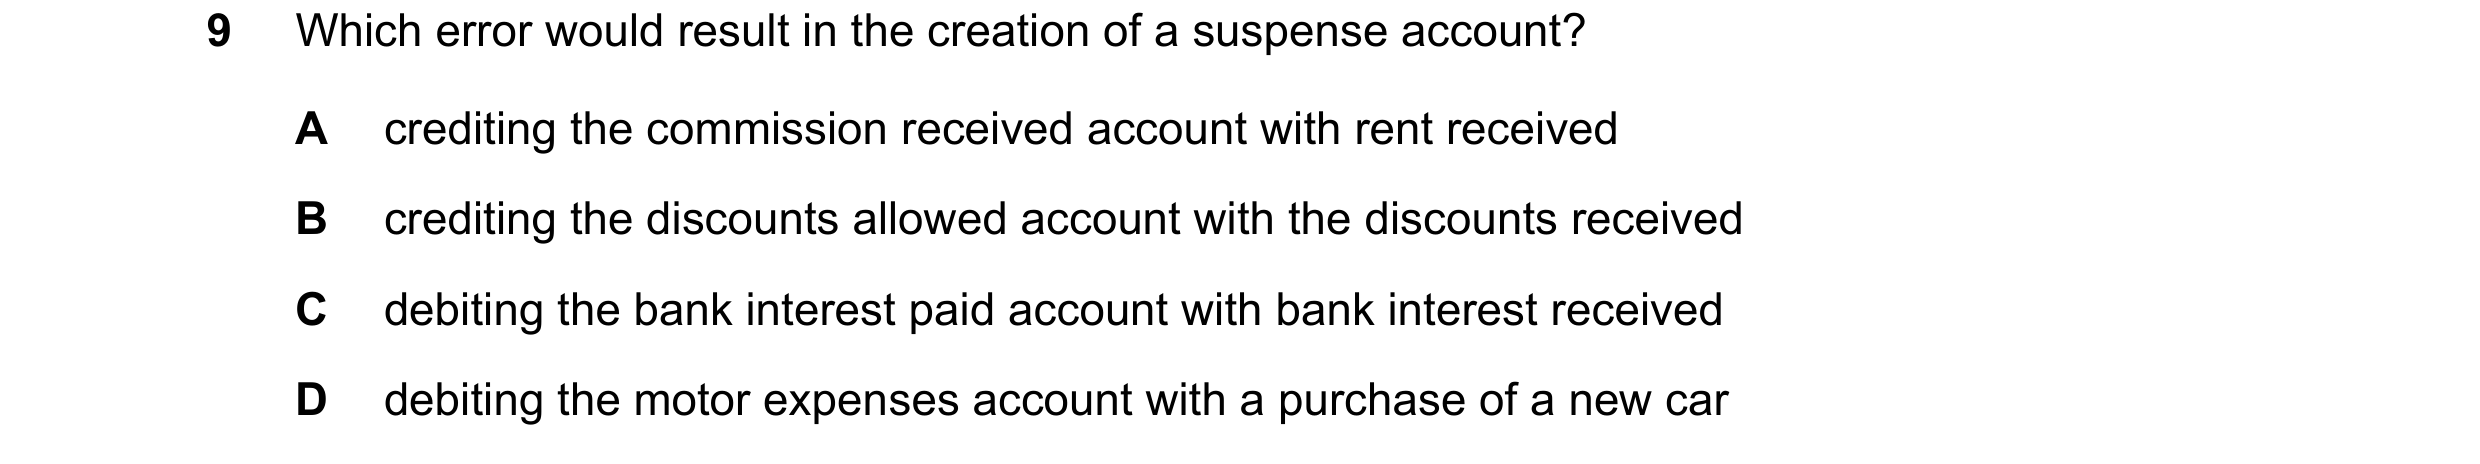
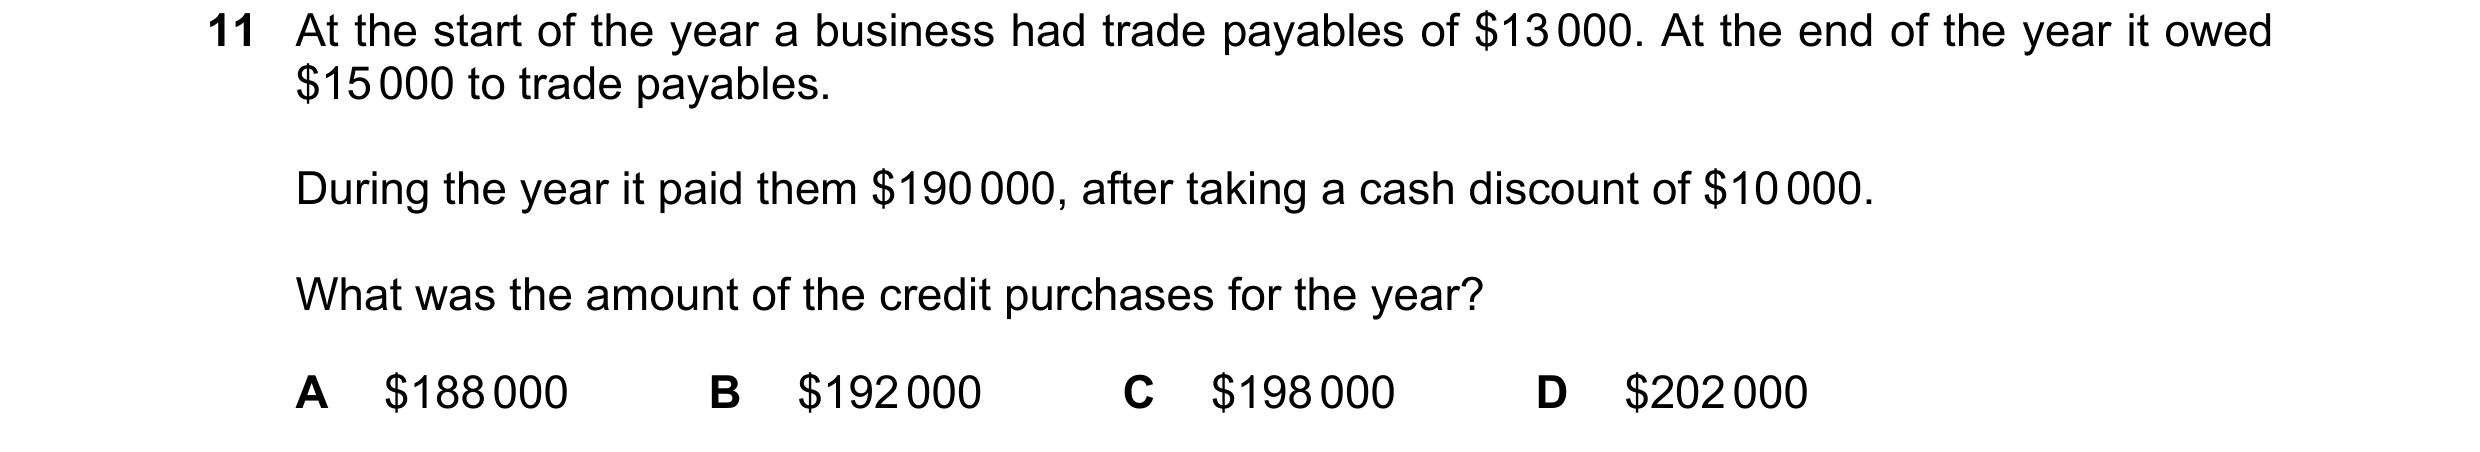
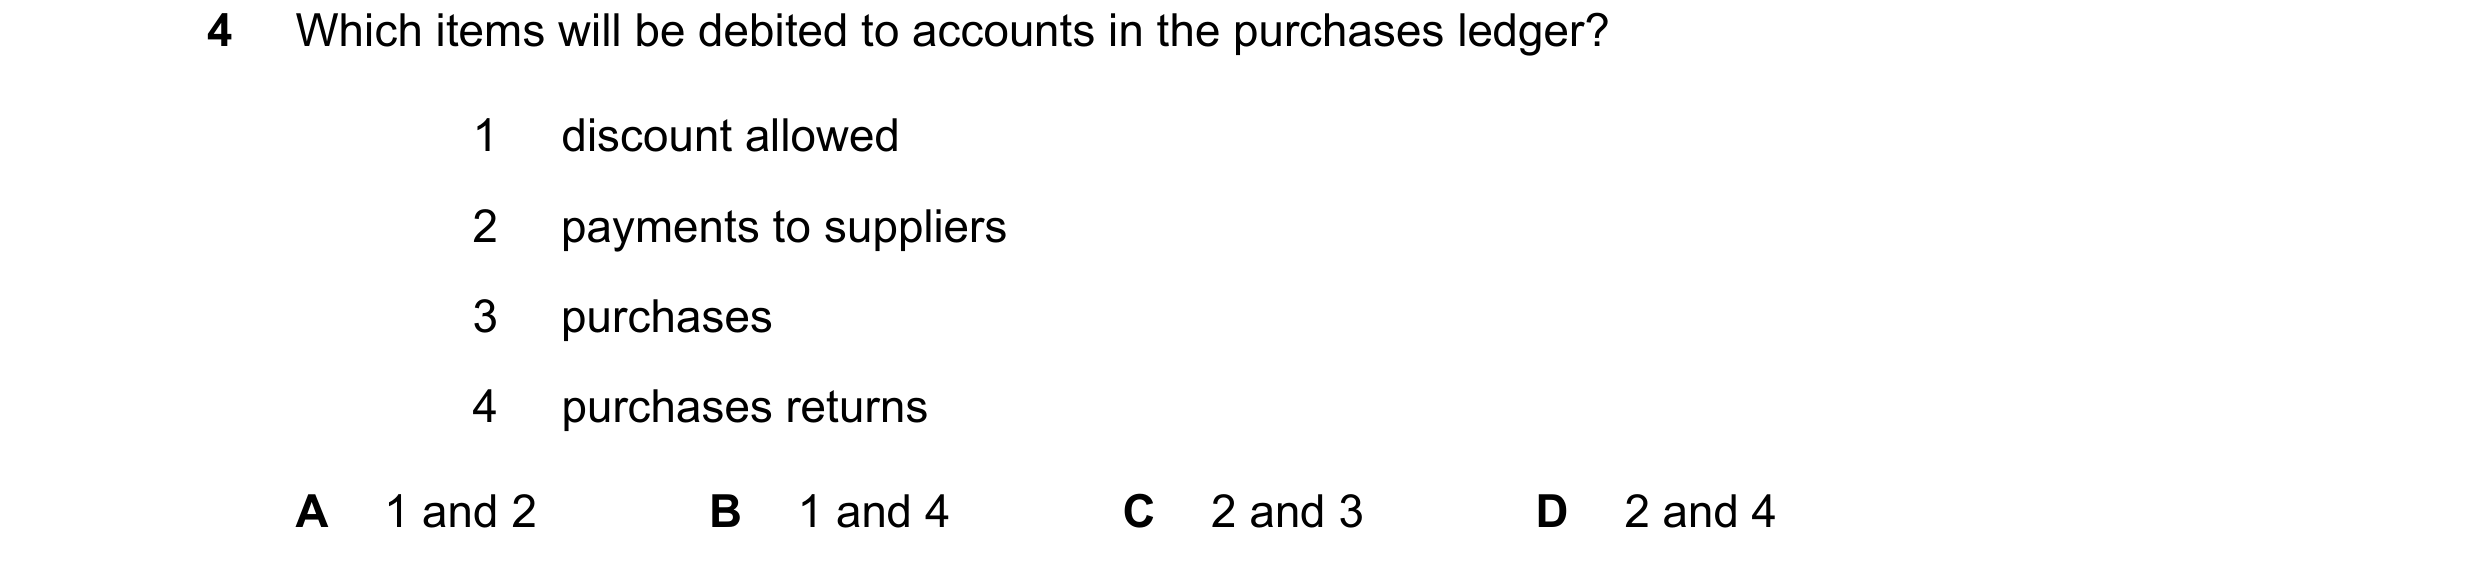 58 / 110
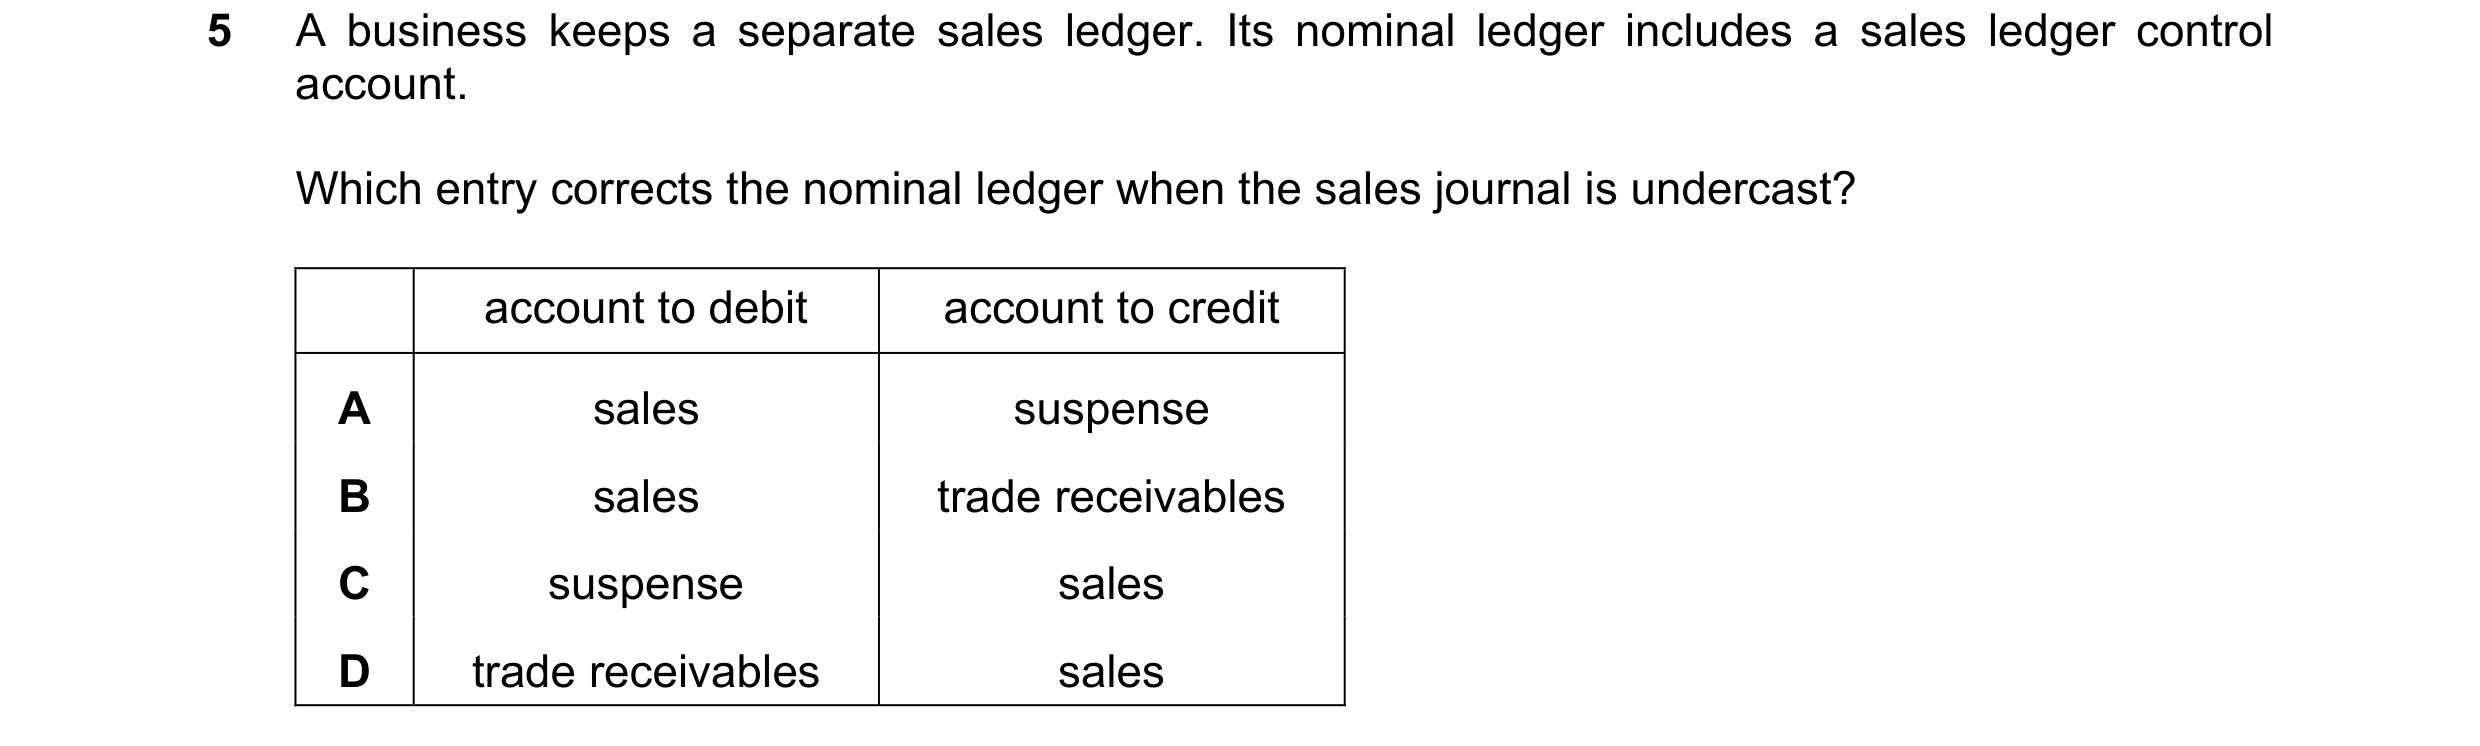
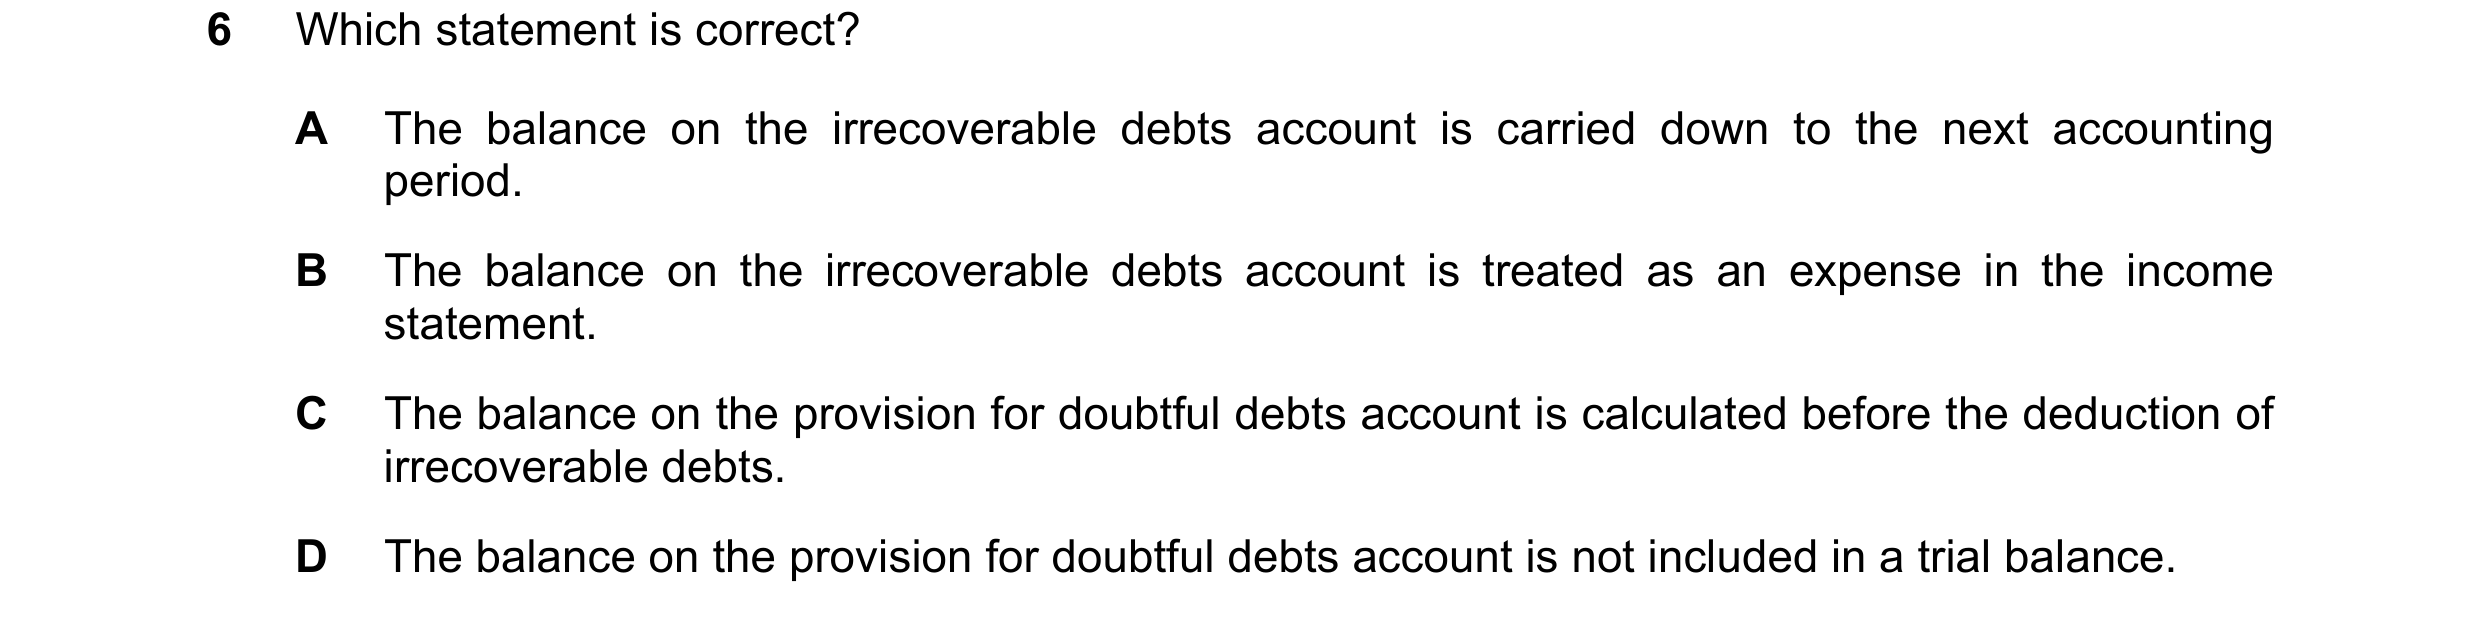
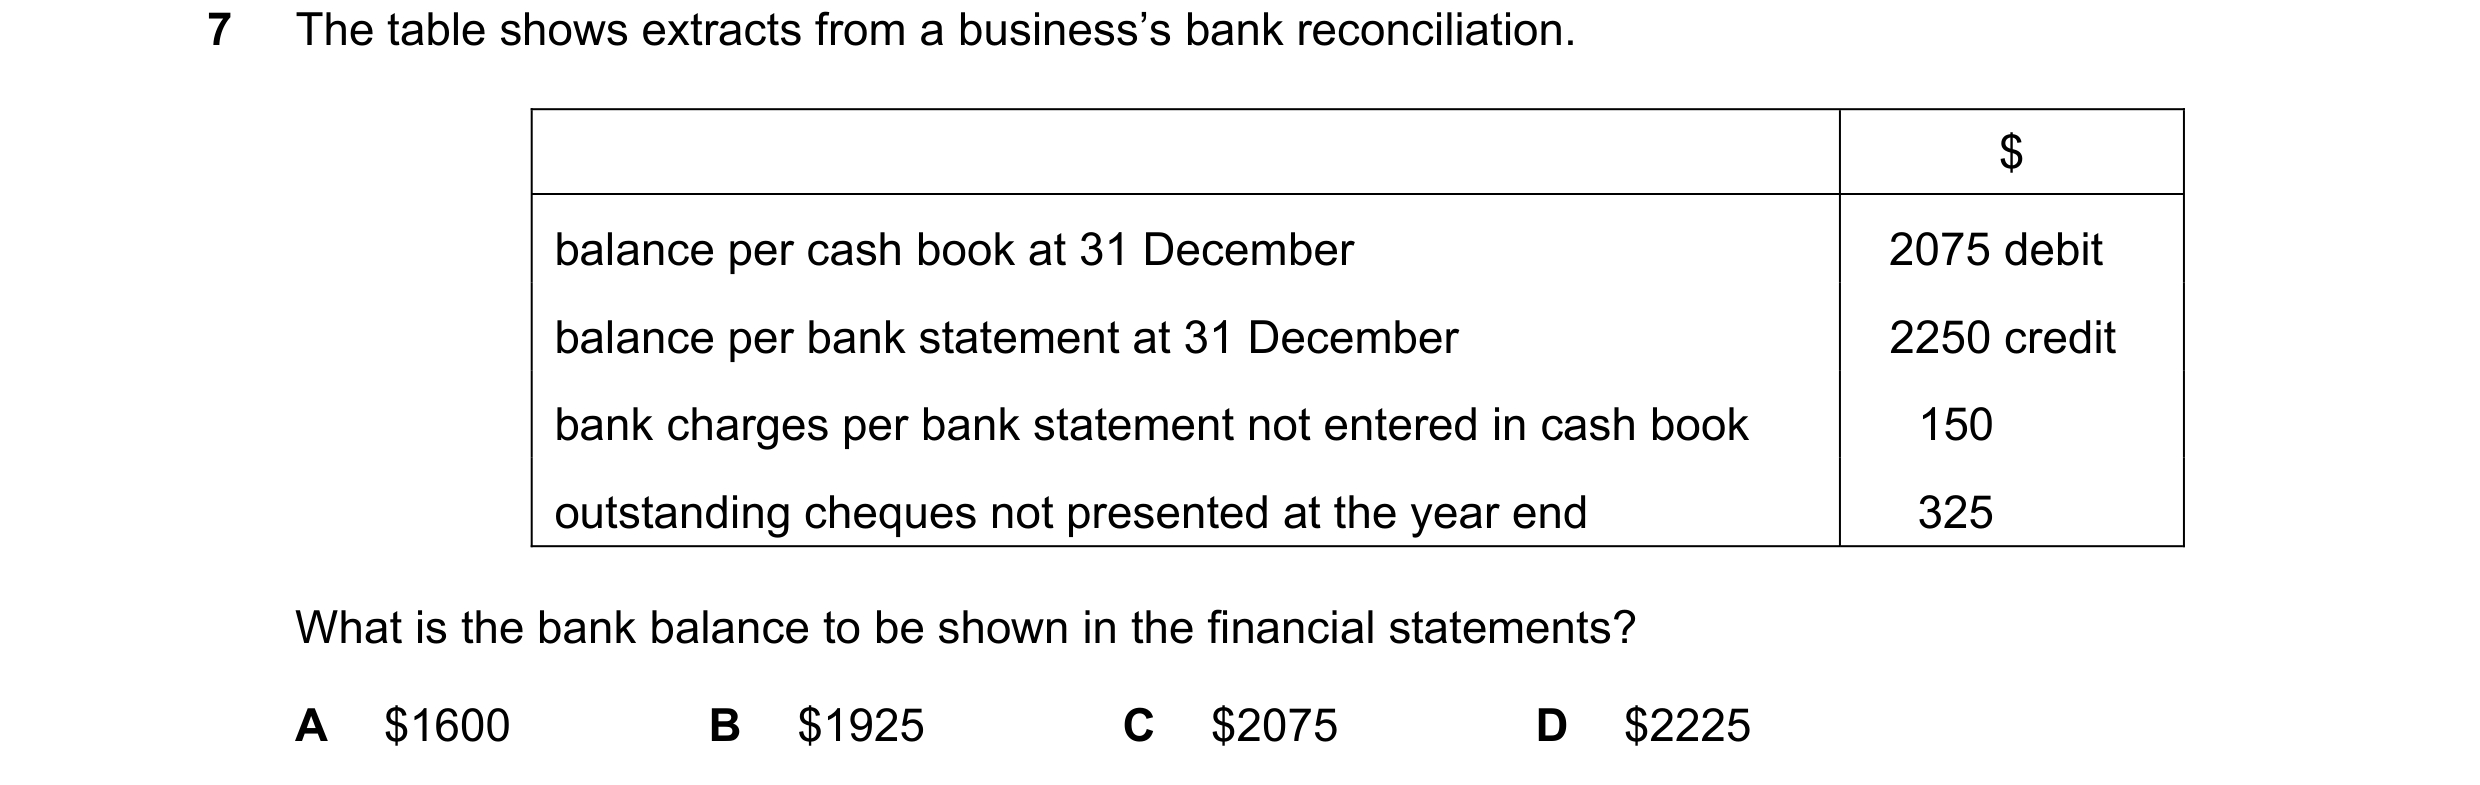 59 / 110
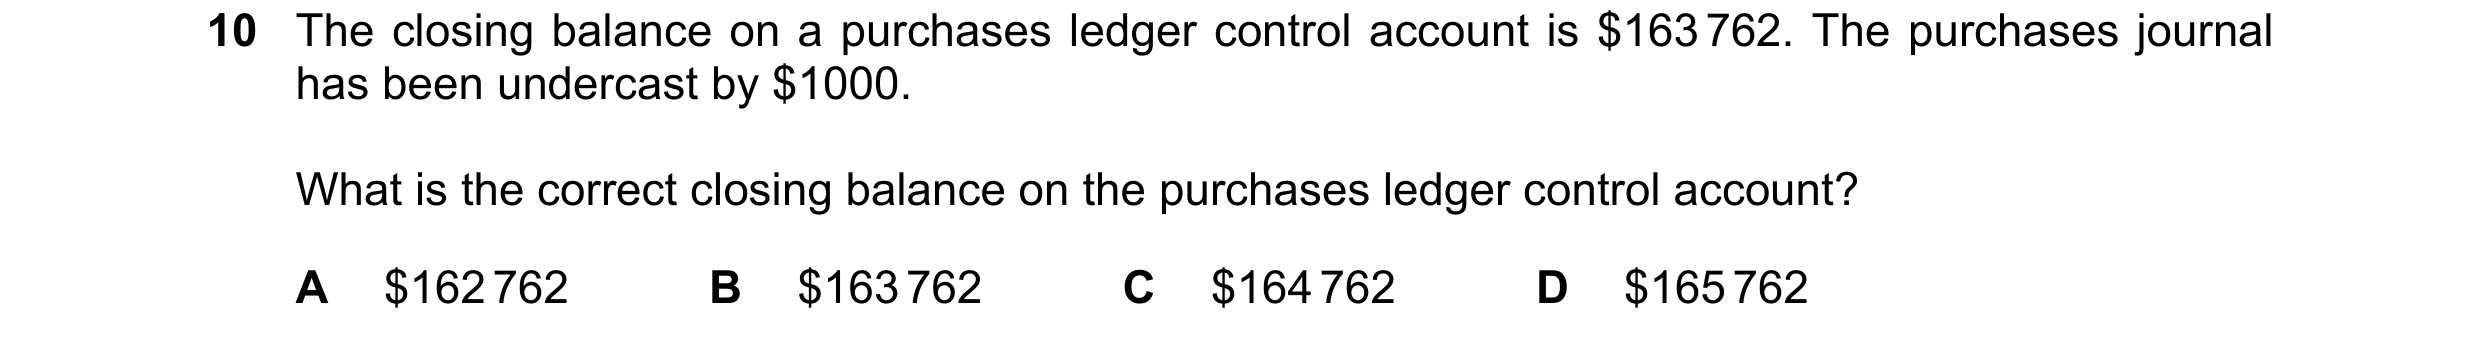
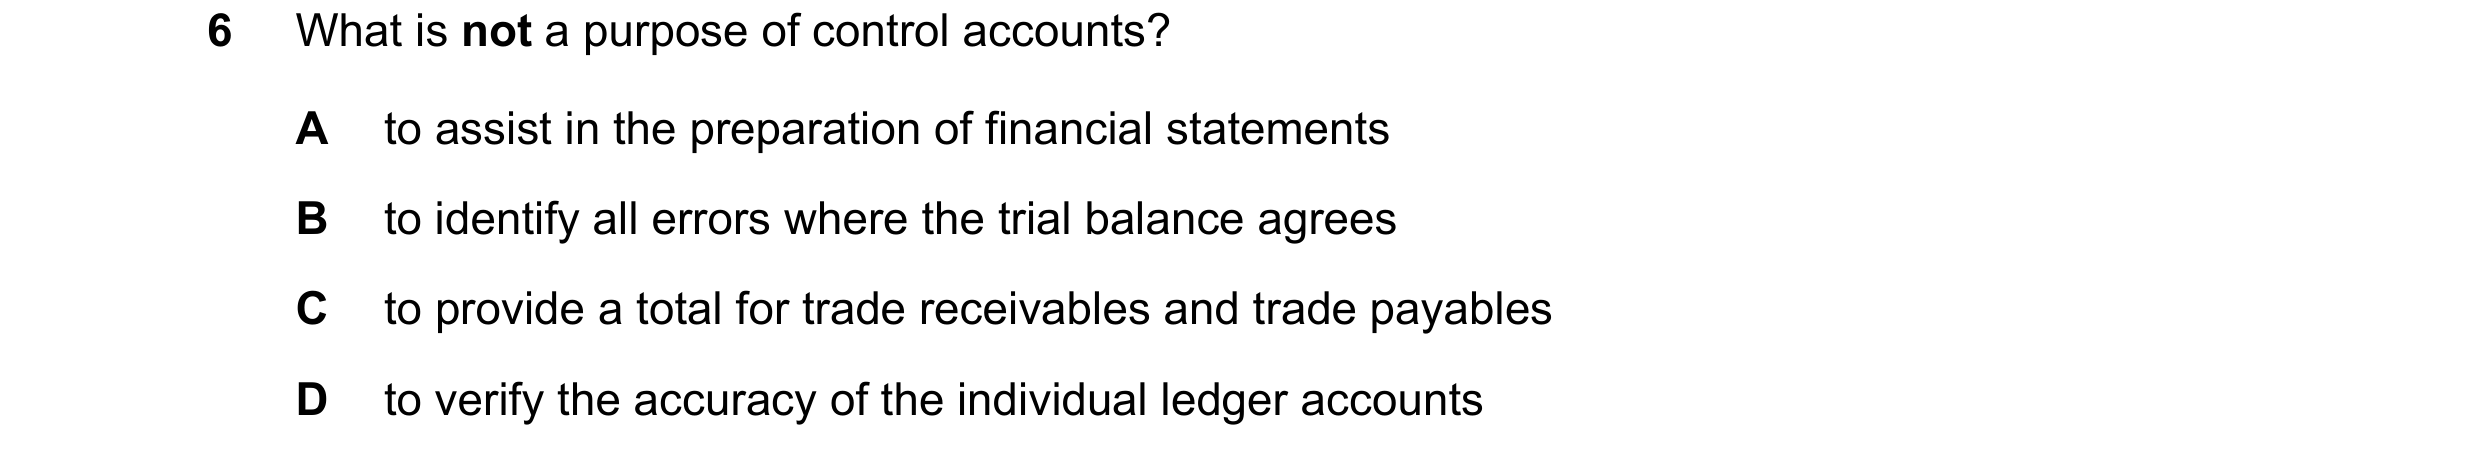
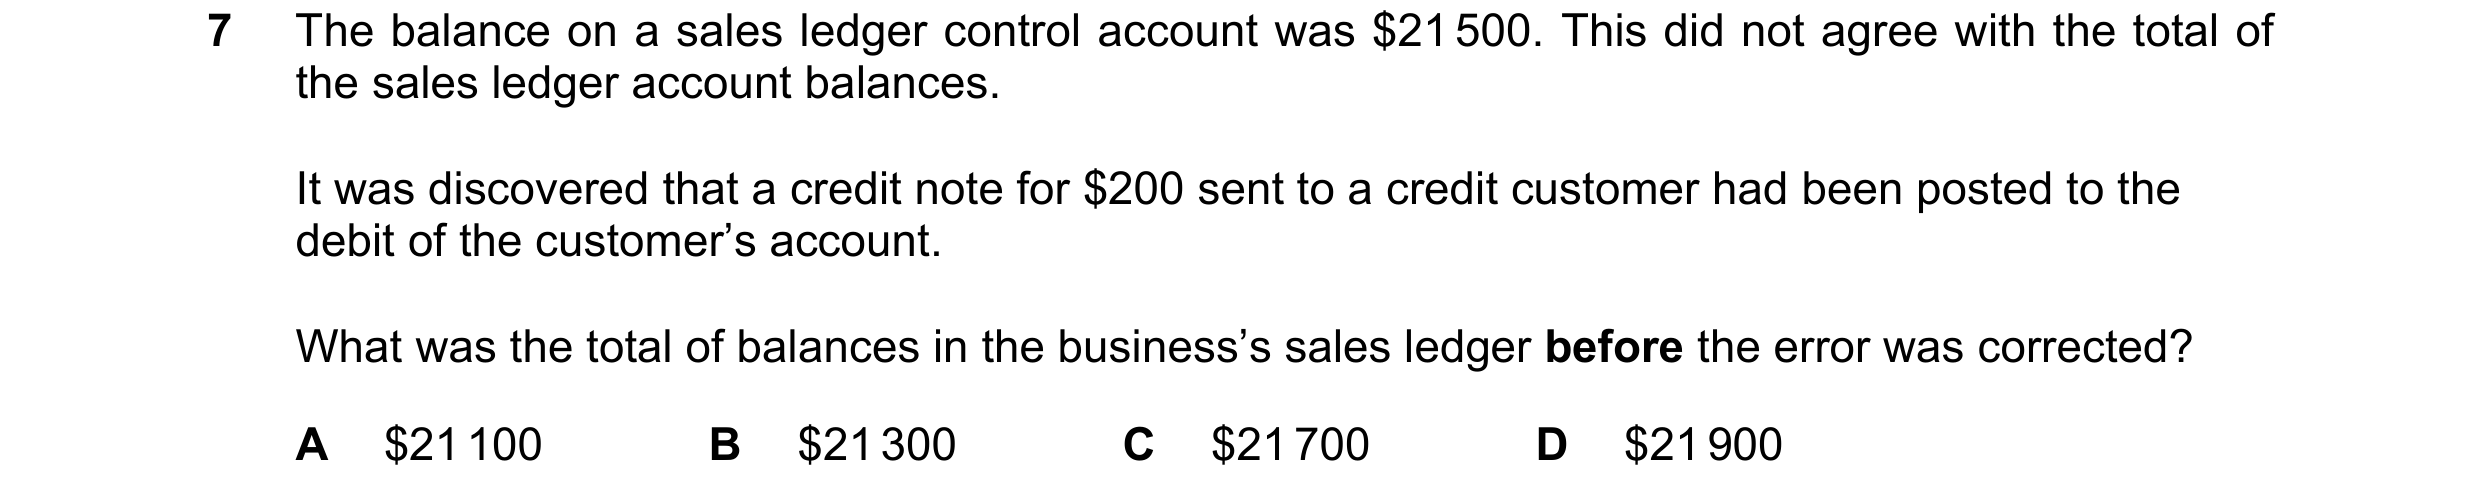 60 / 110
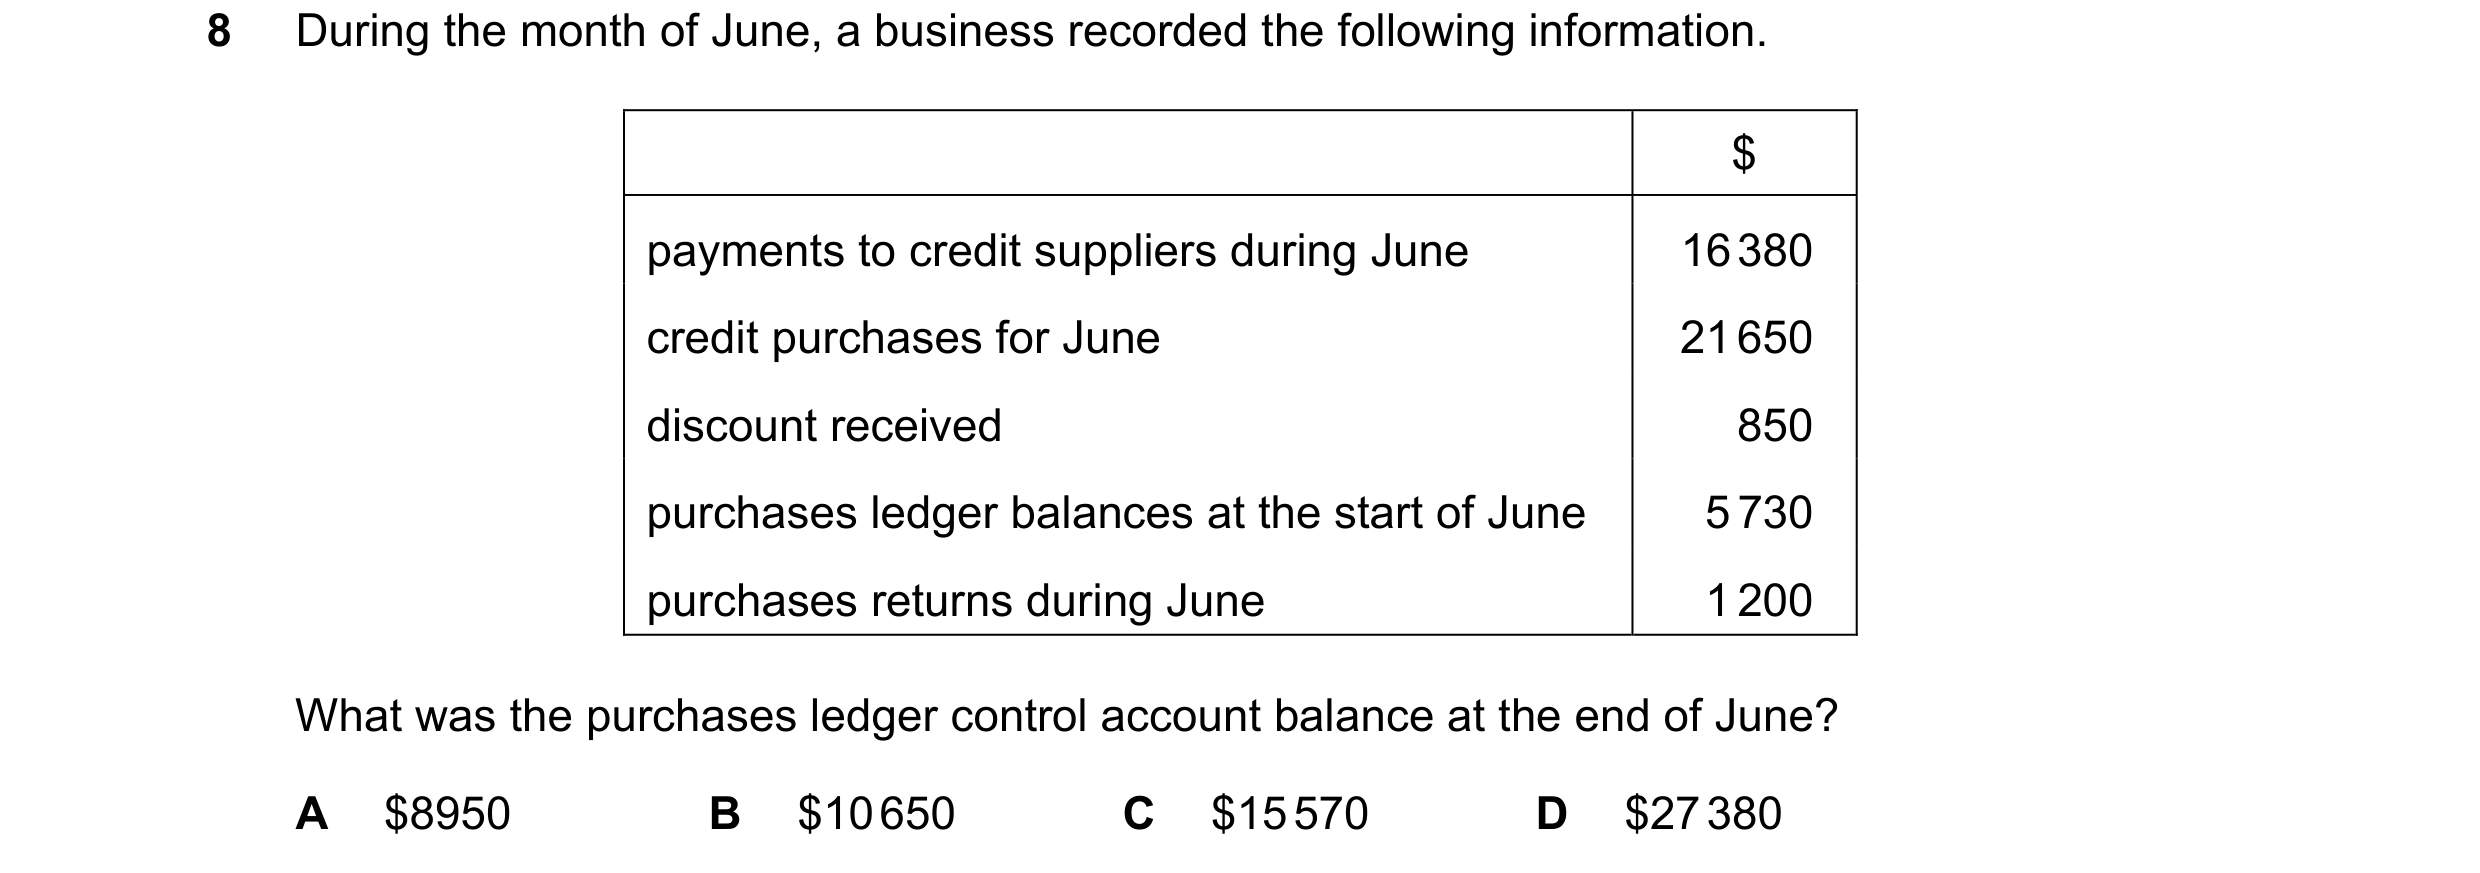
 61 / 110
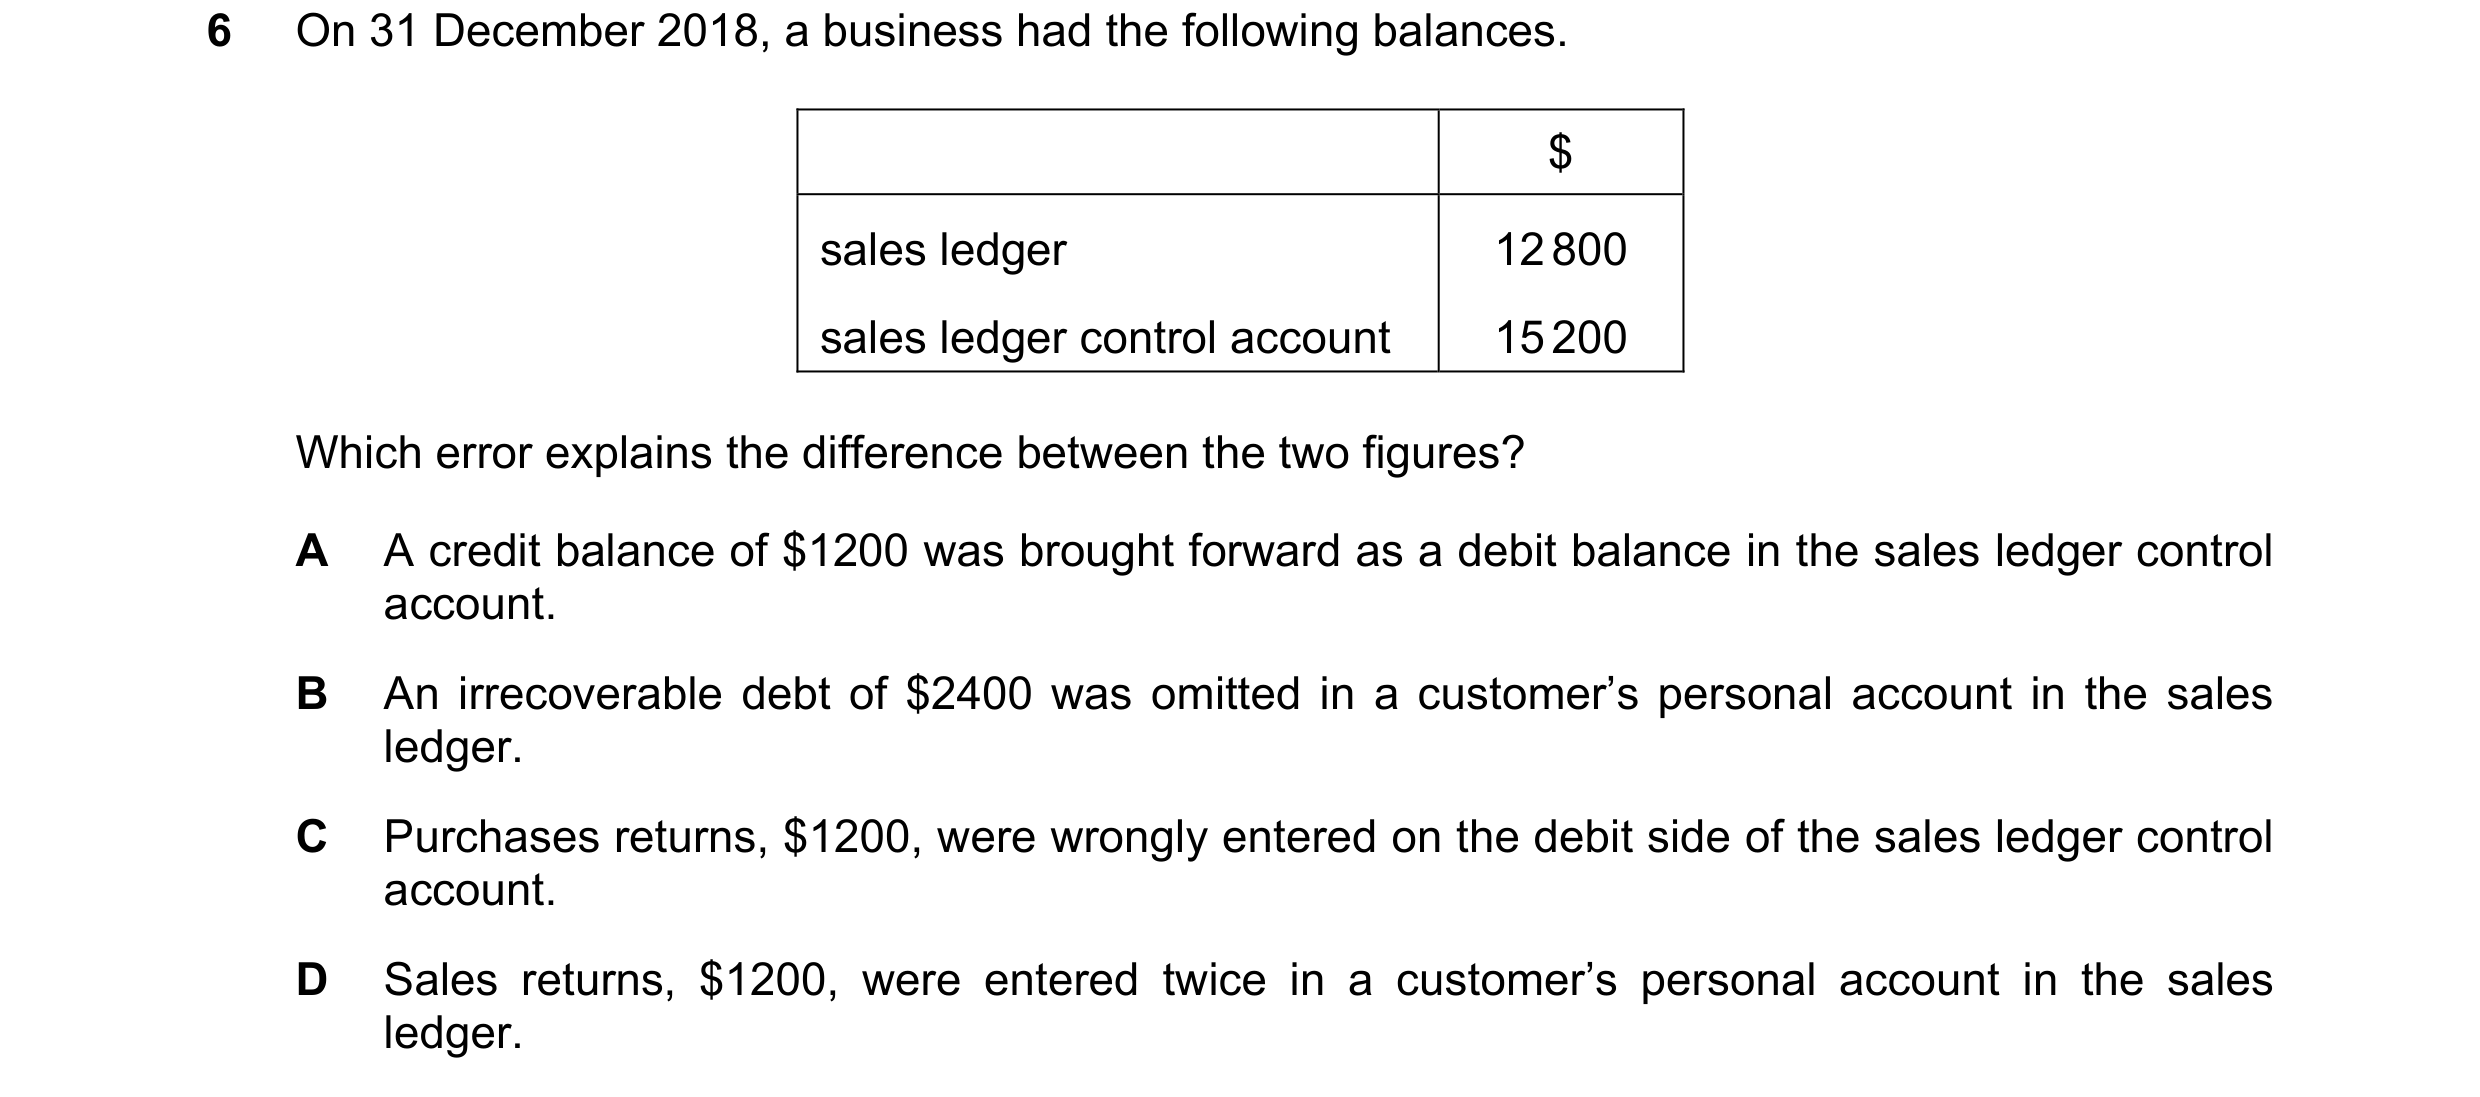 62 / 110
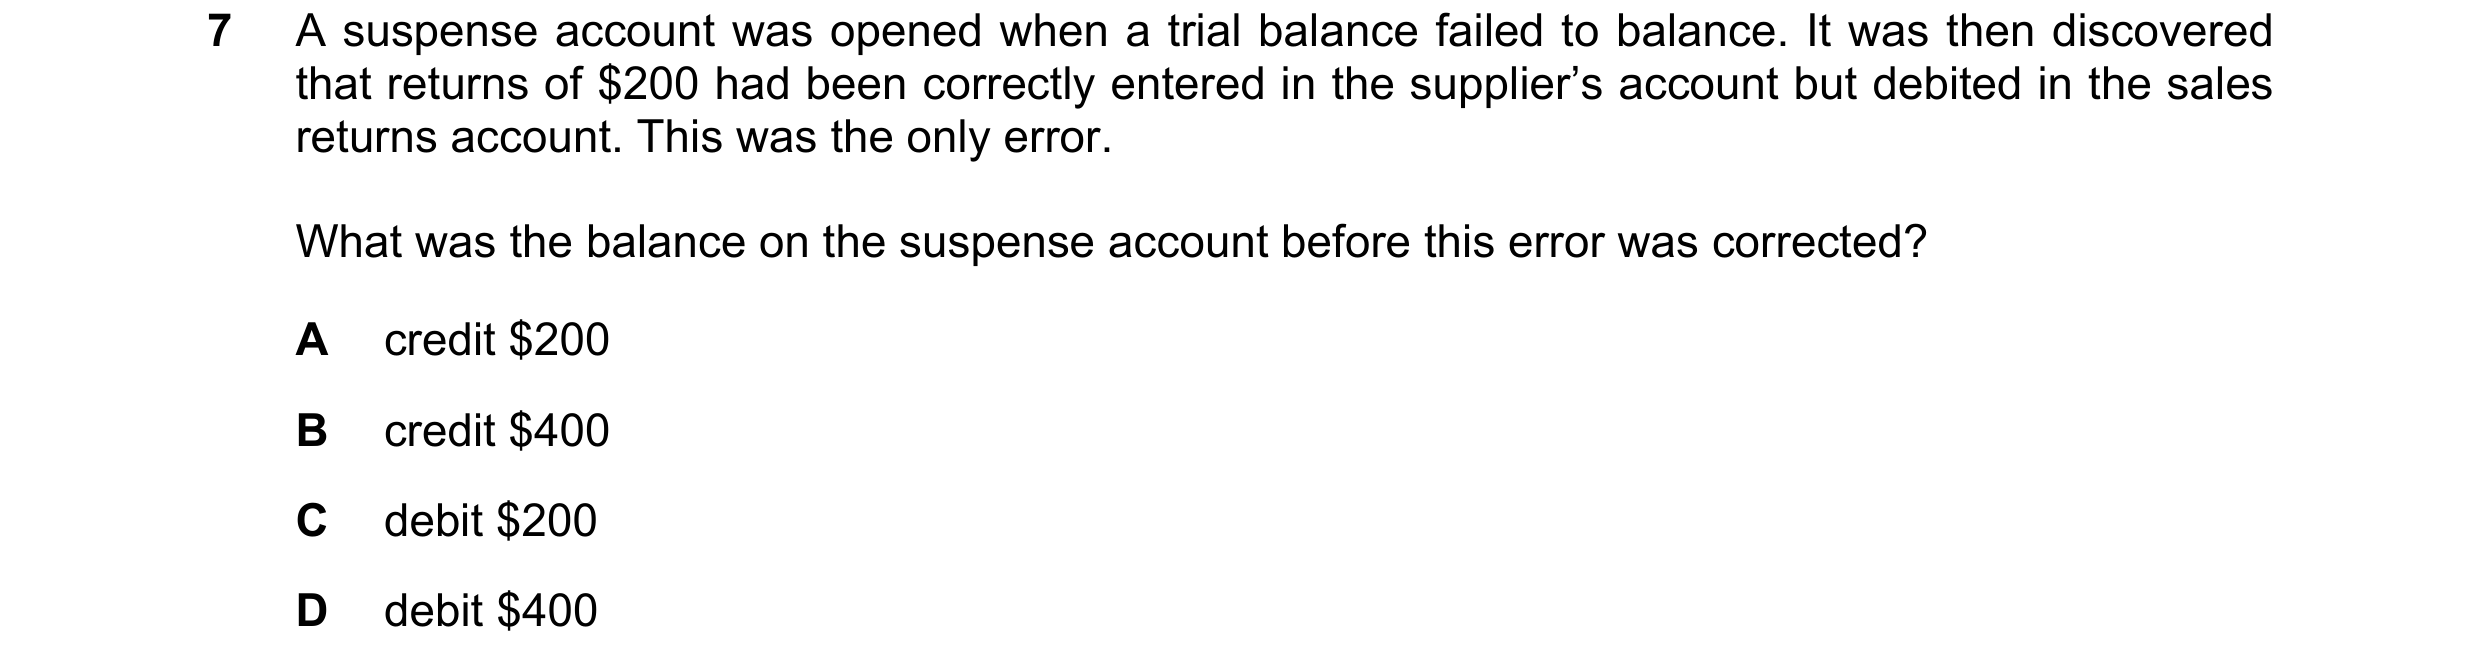
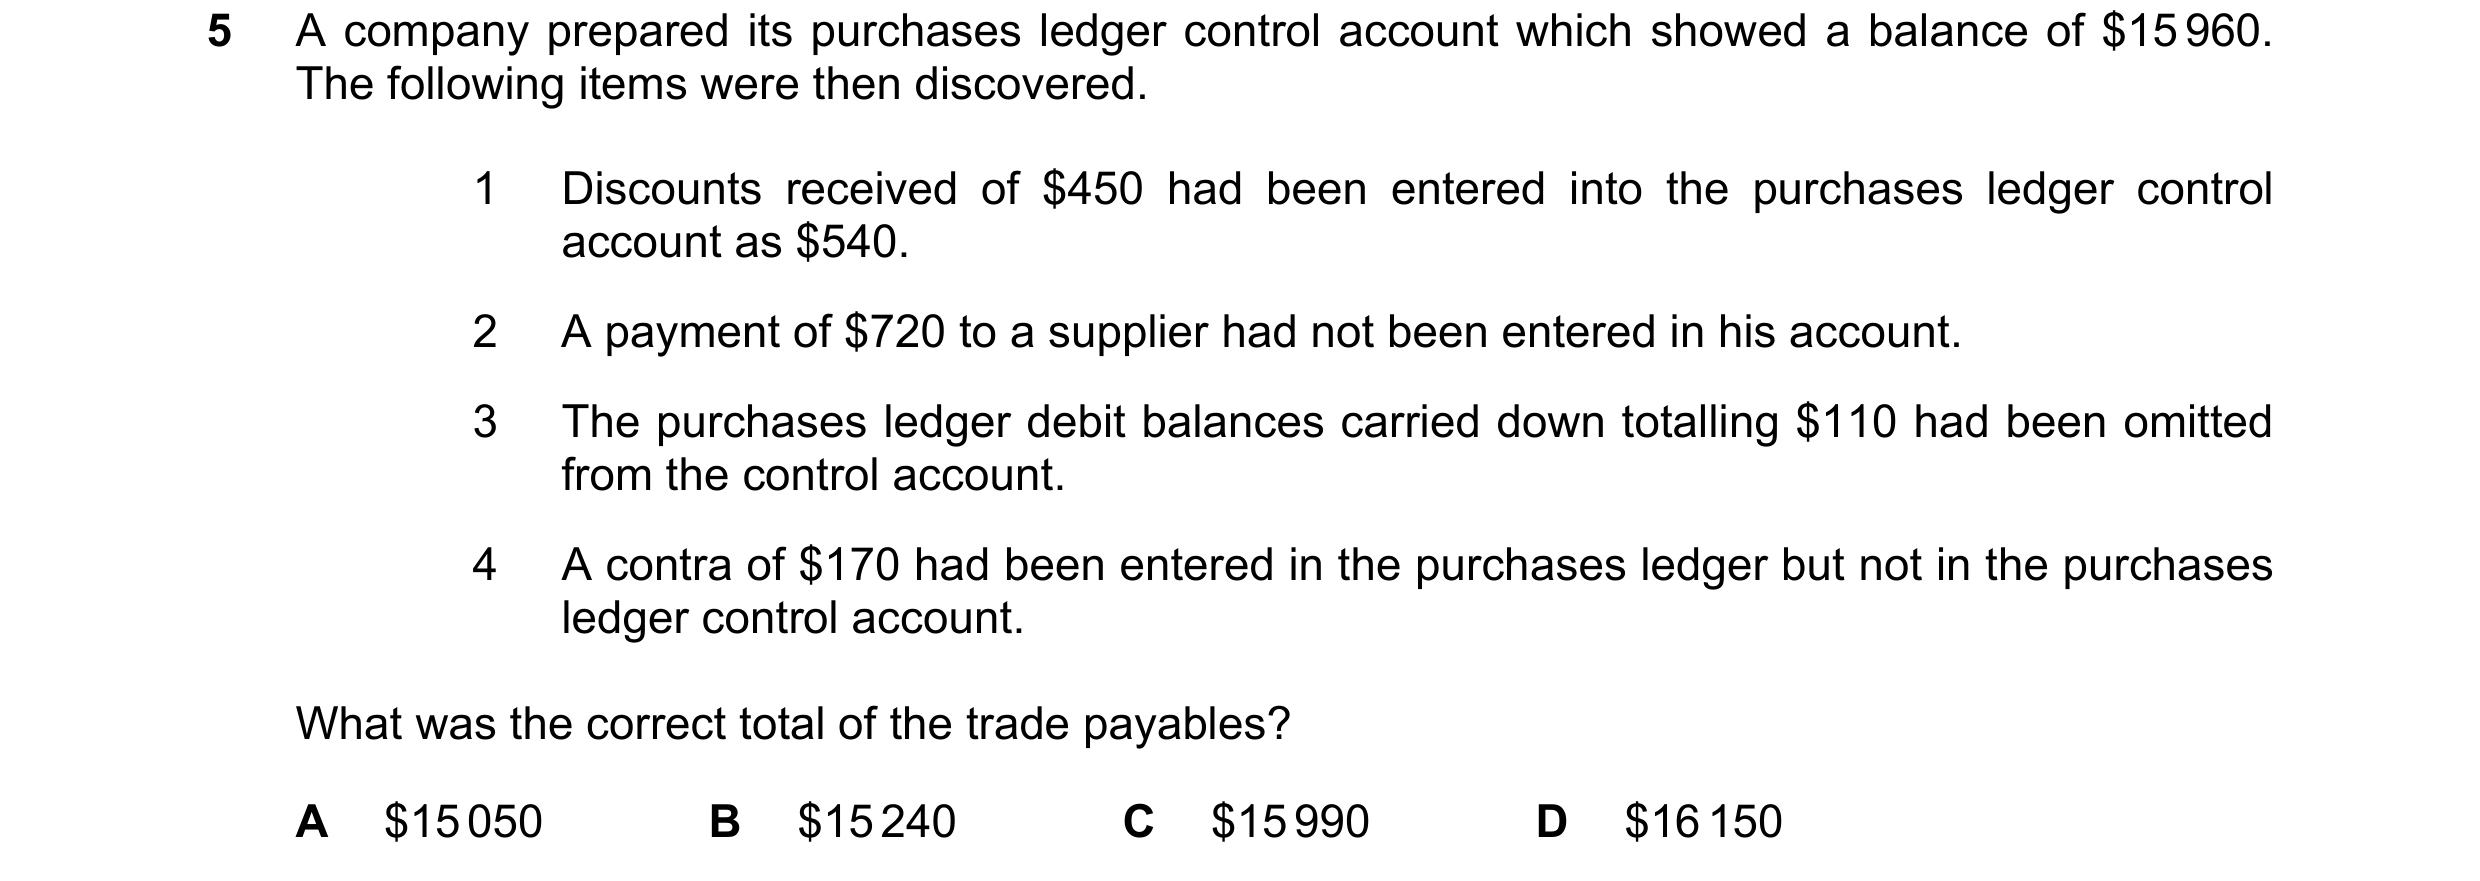 63 / 110
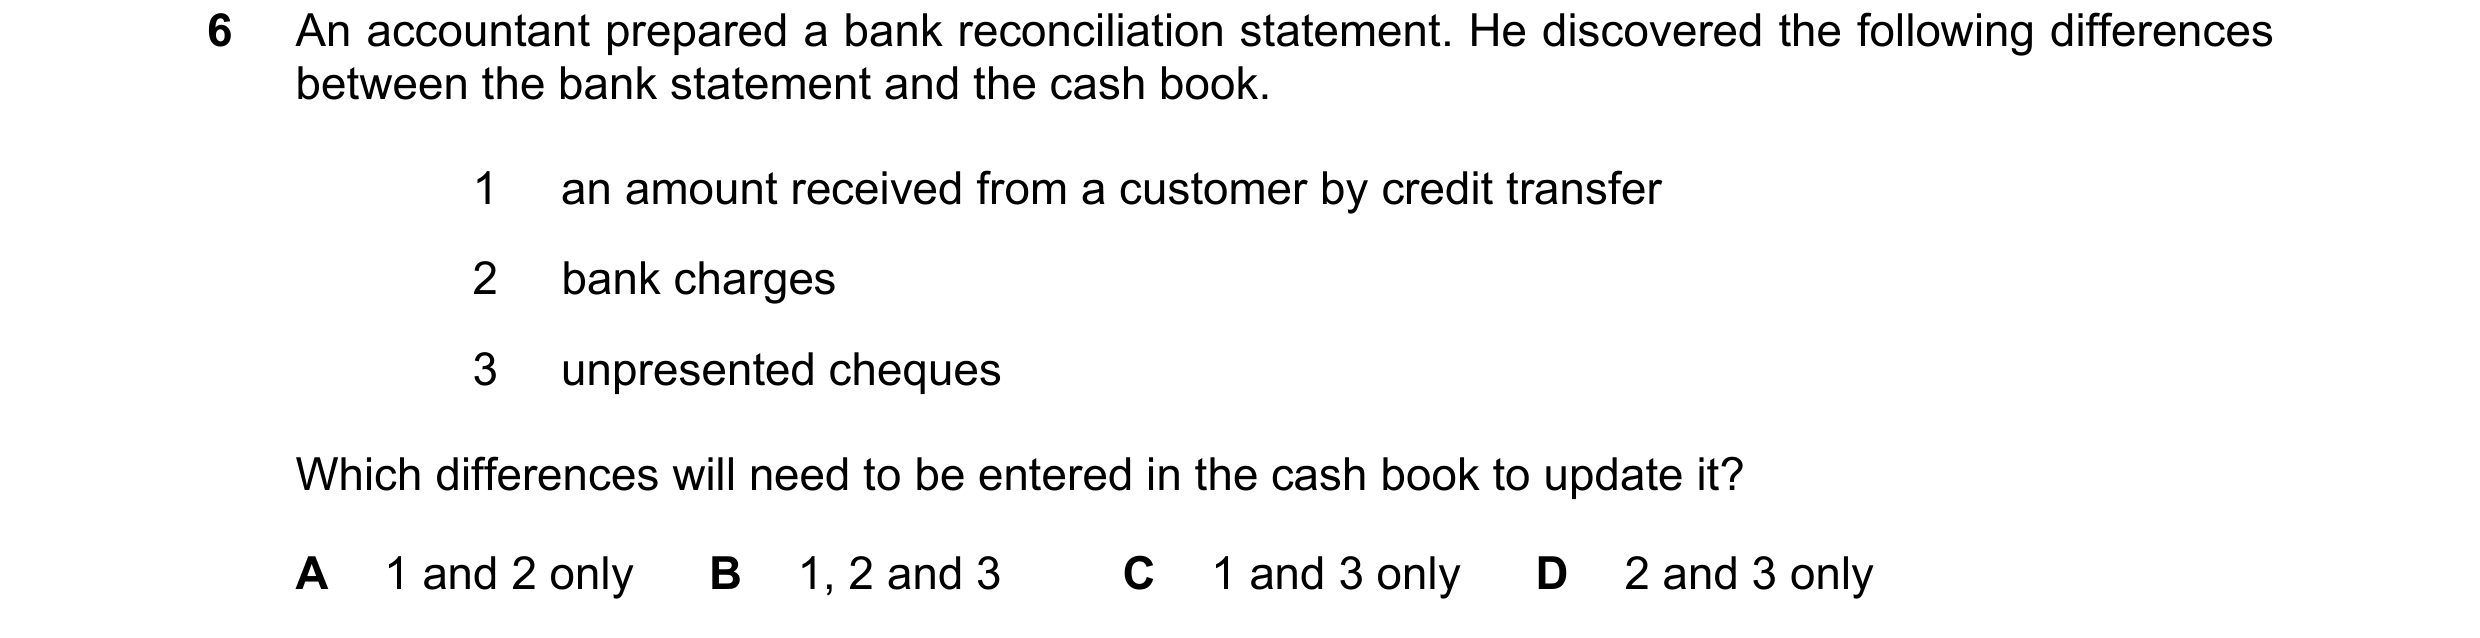
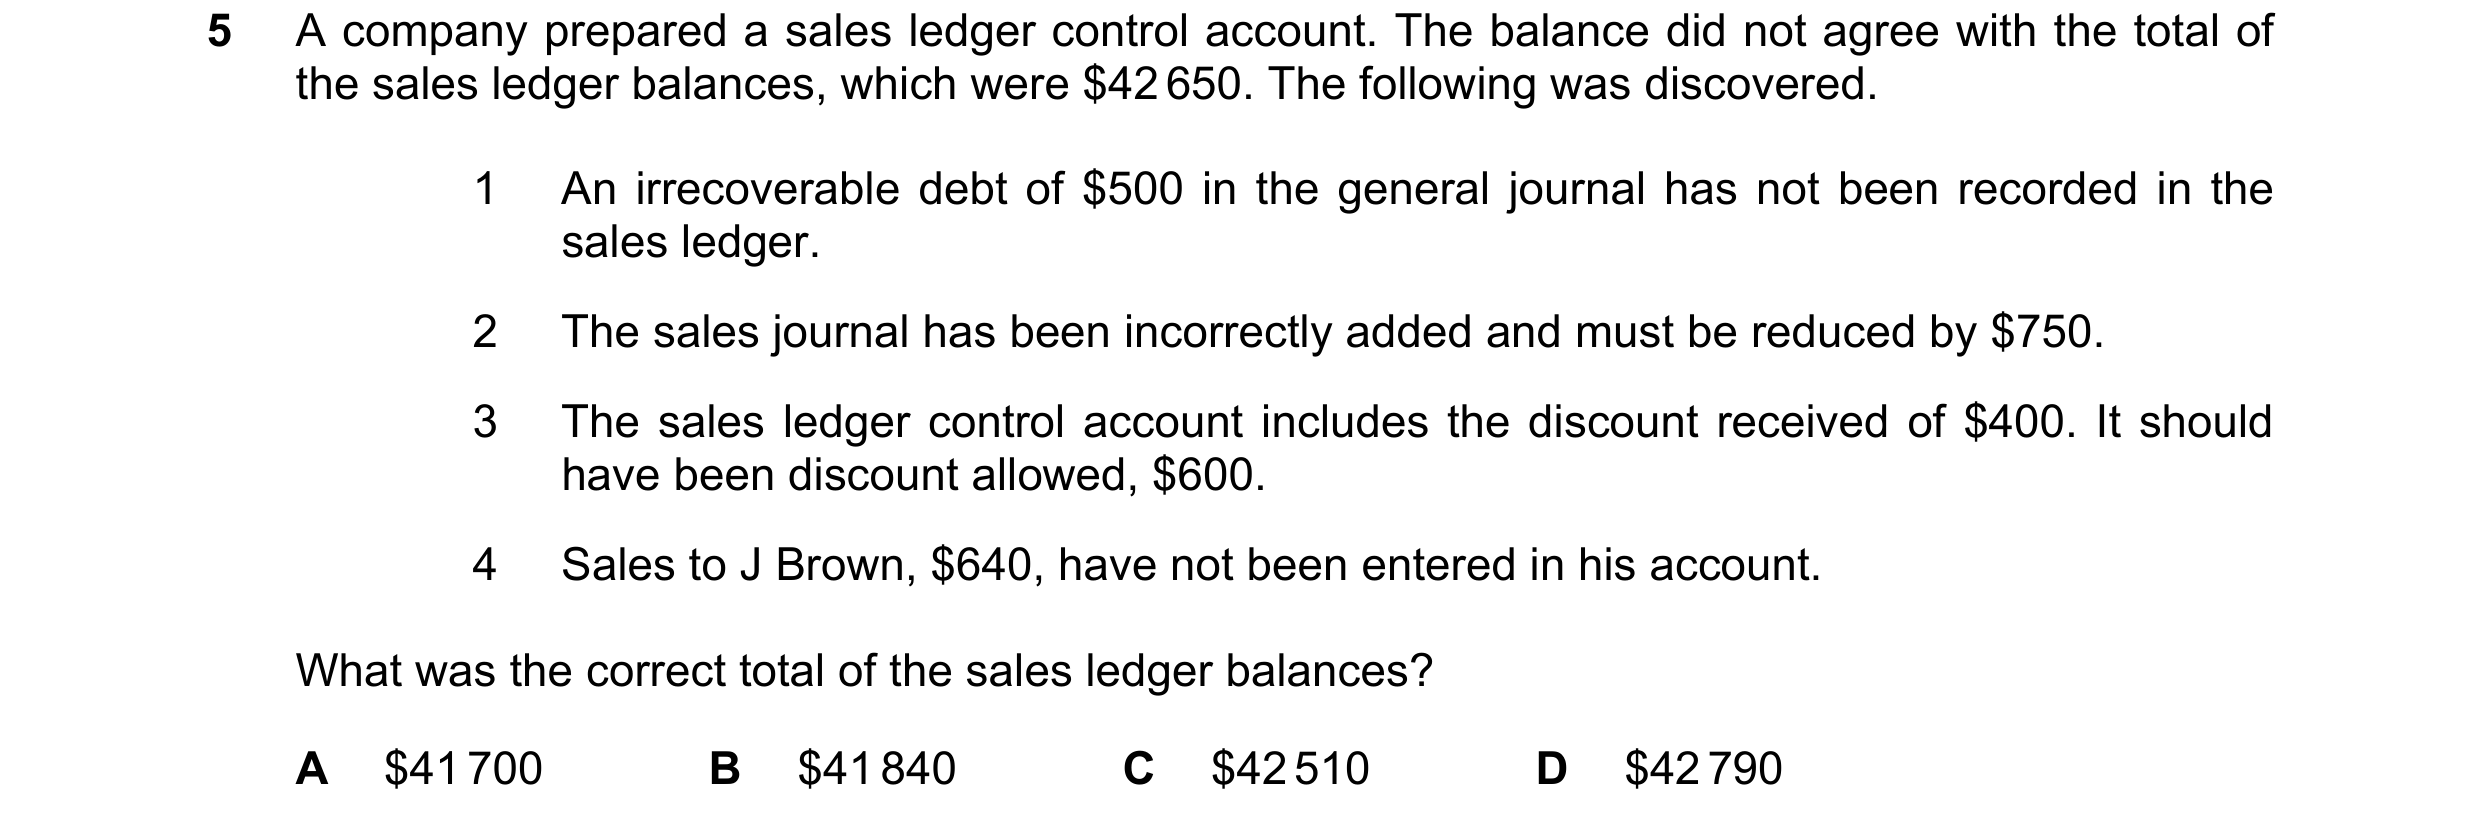
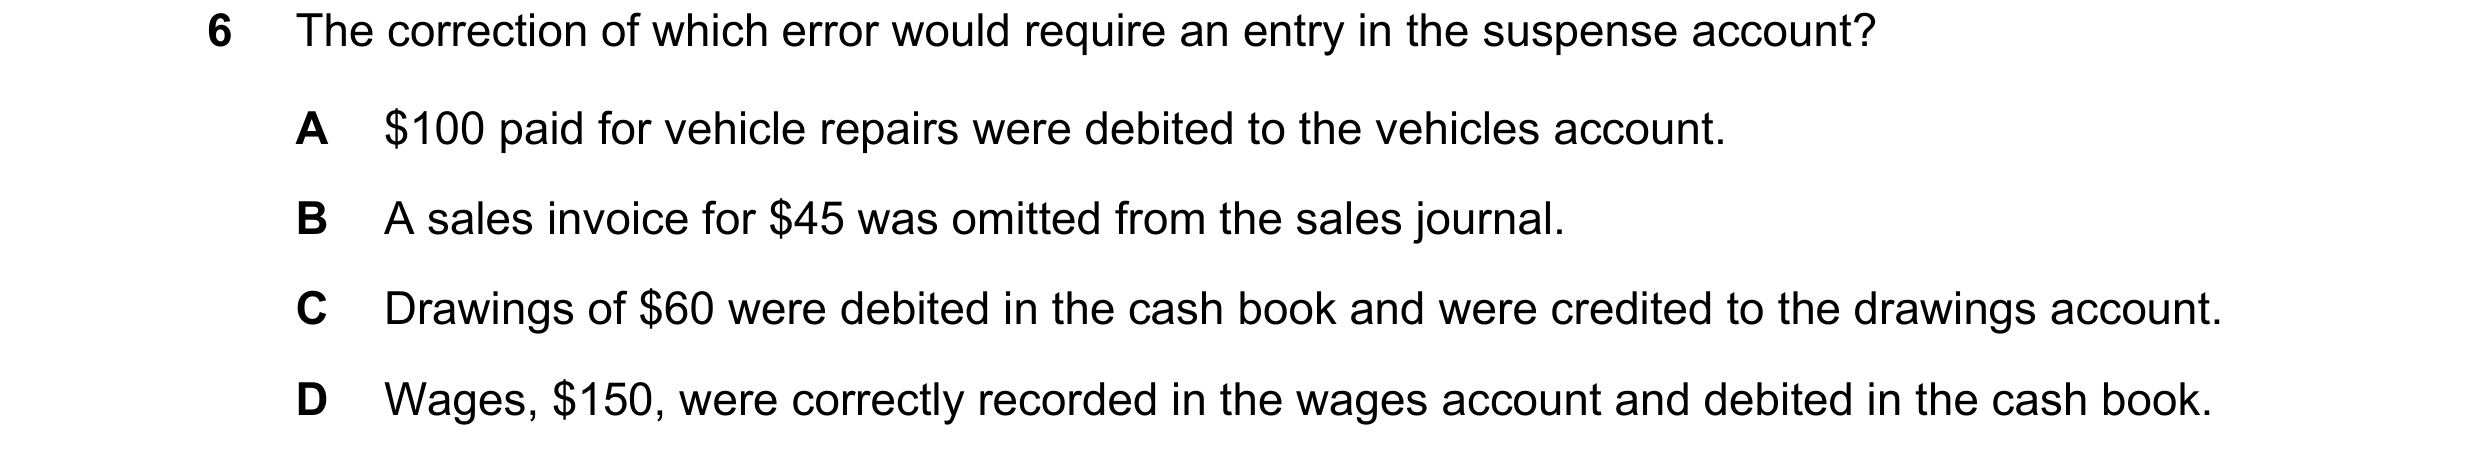
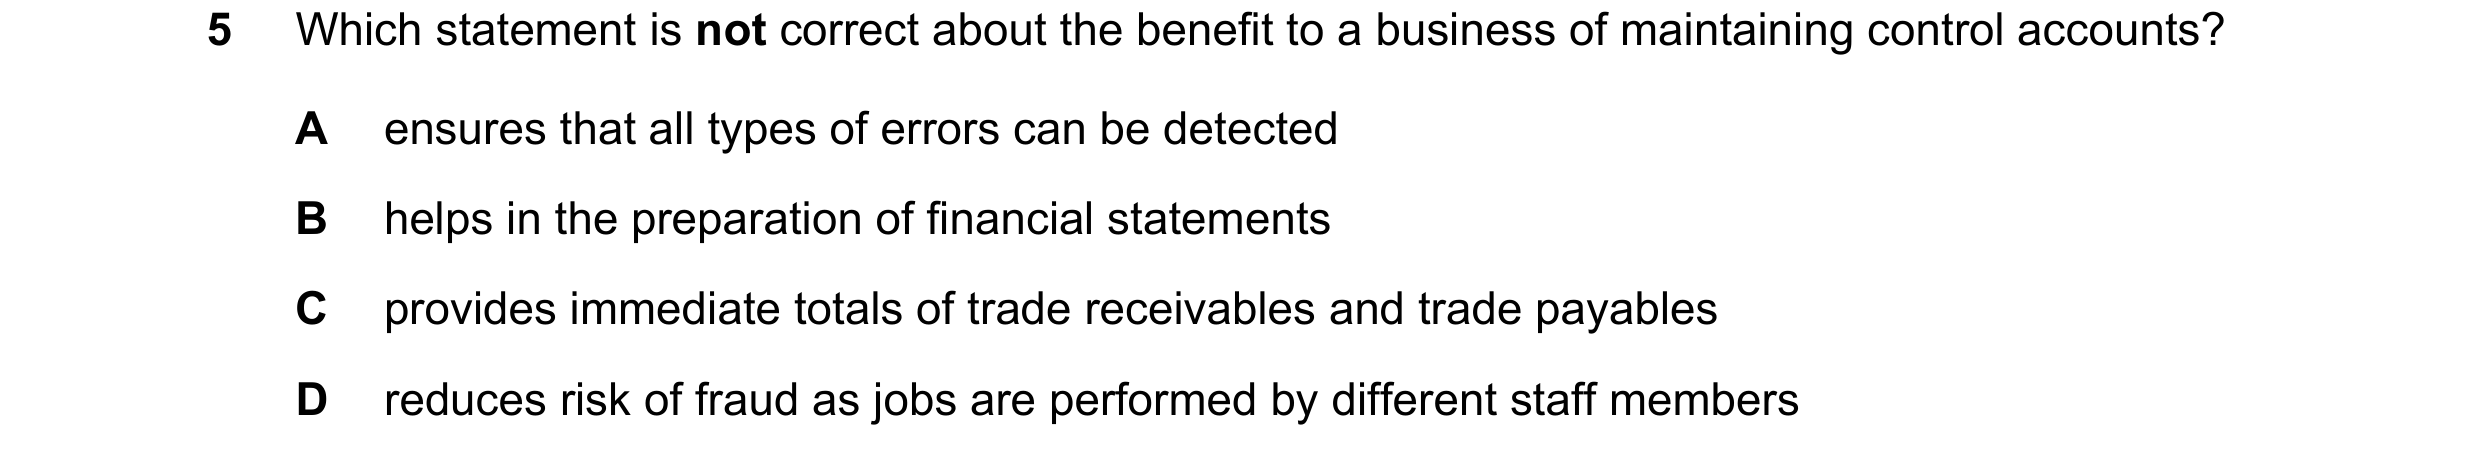
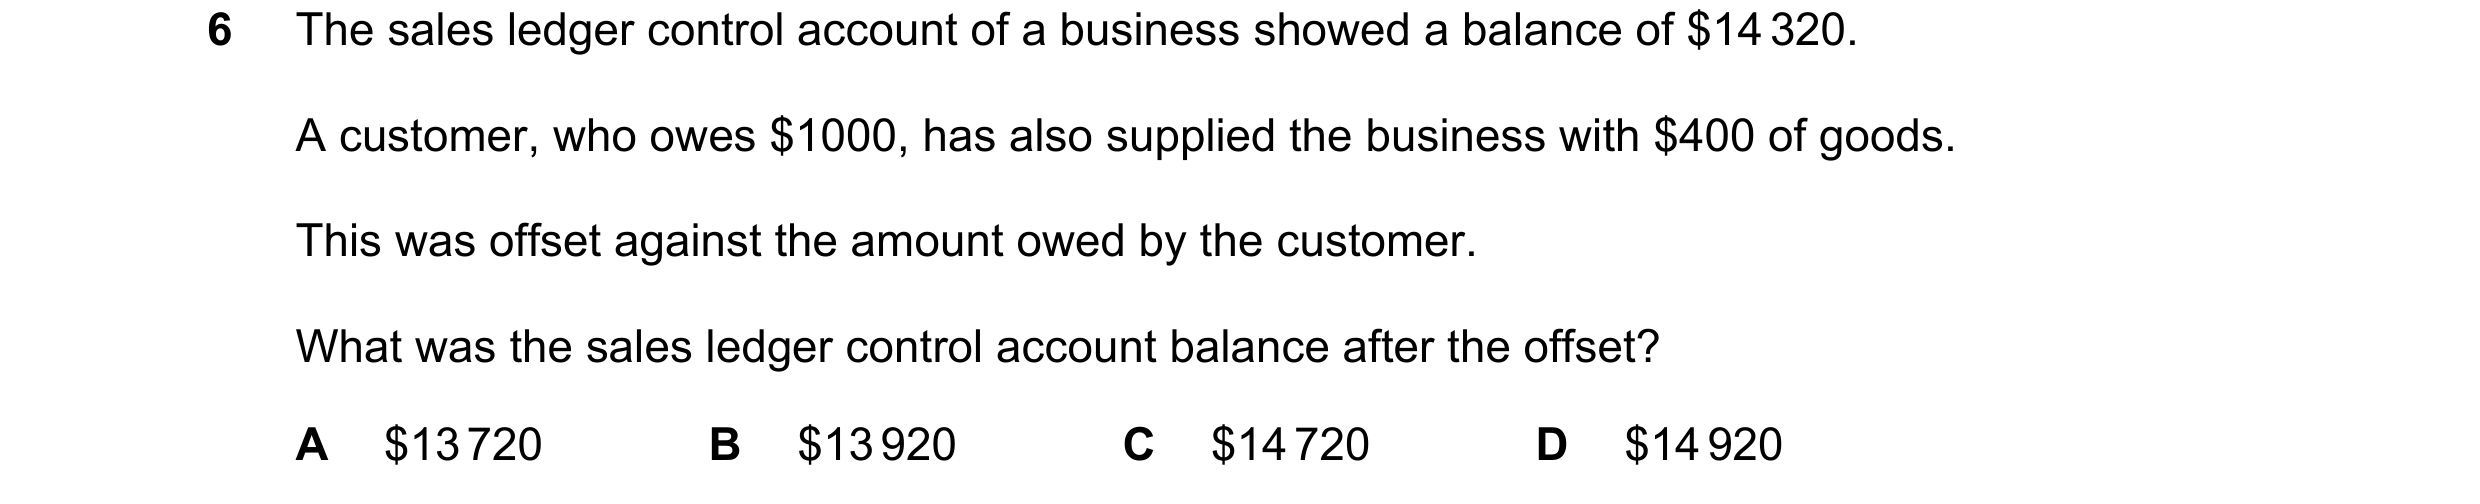 64 / 110
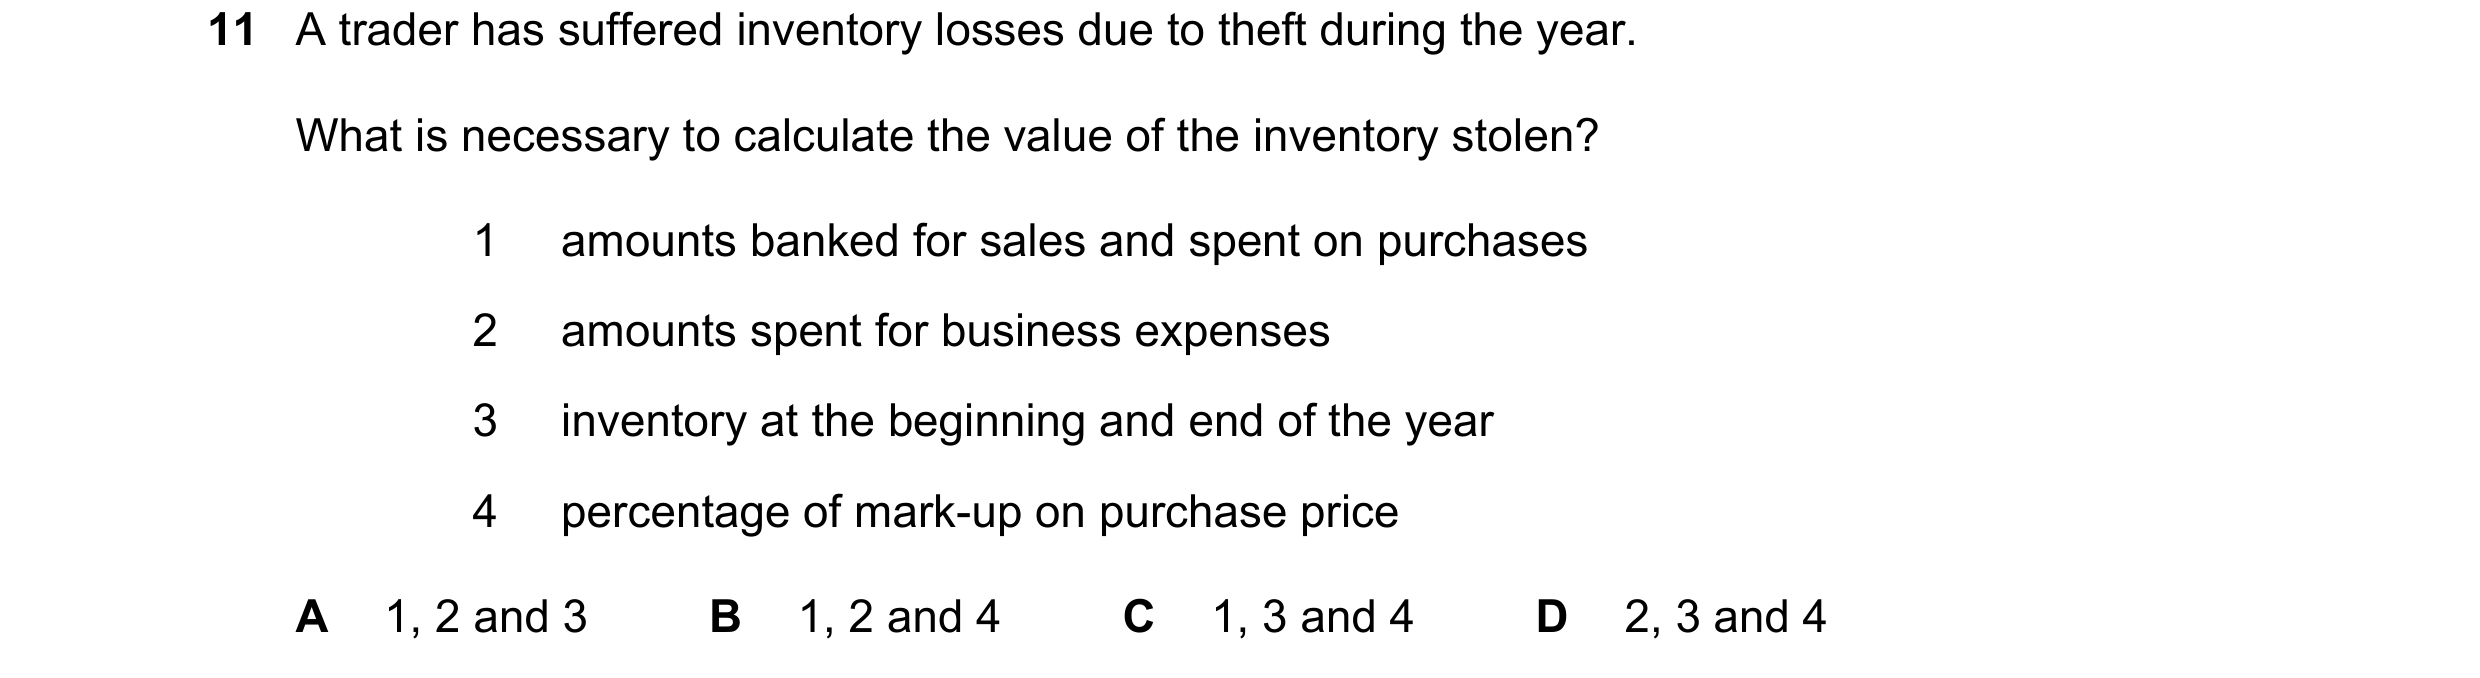
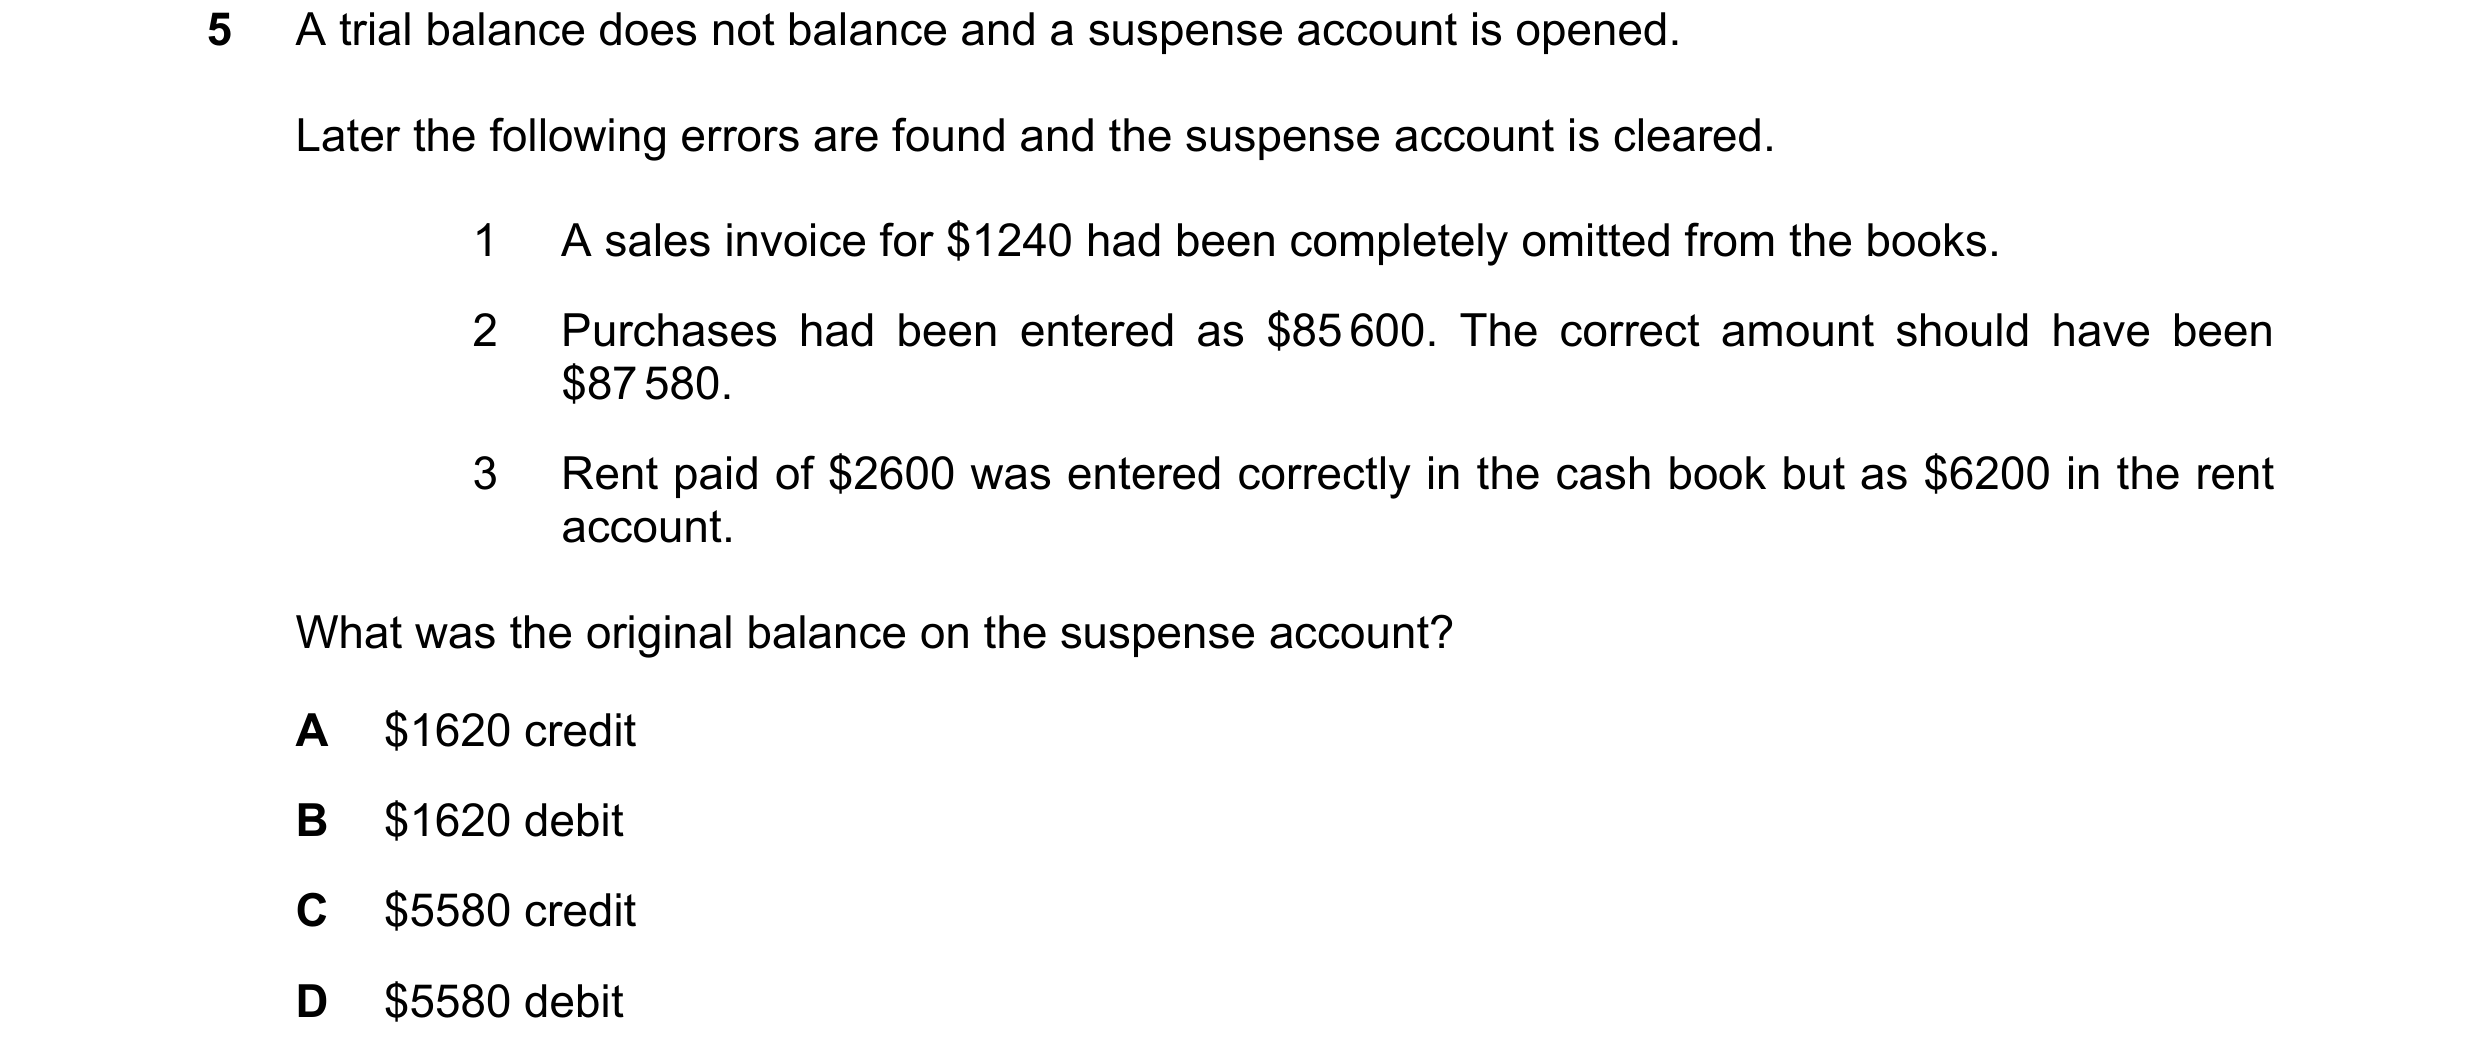
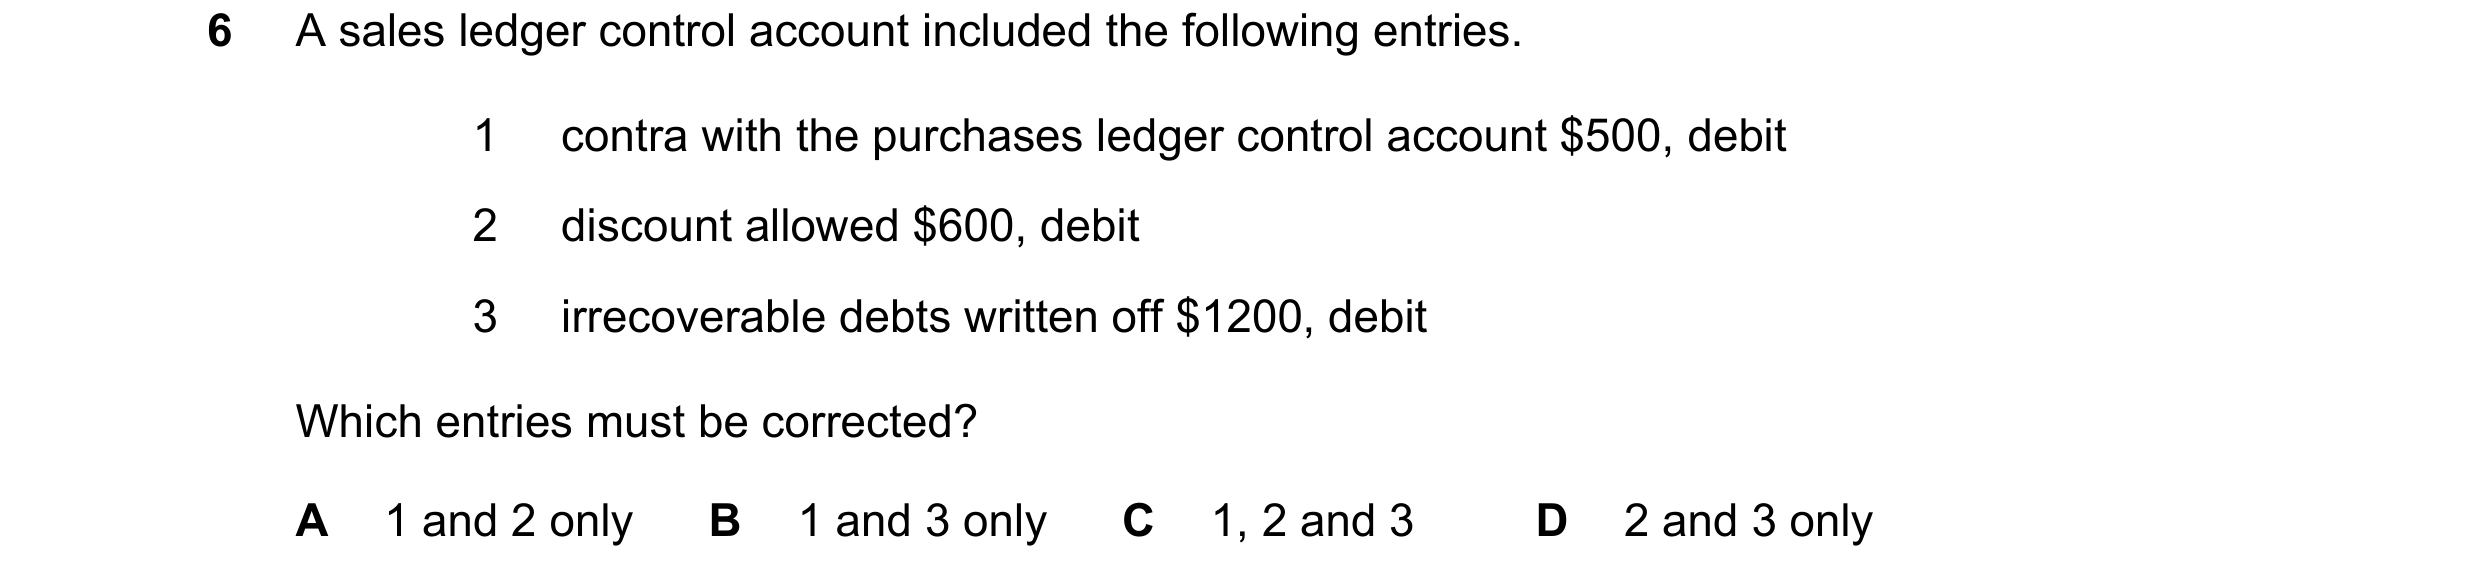
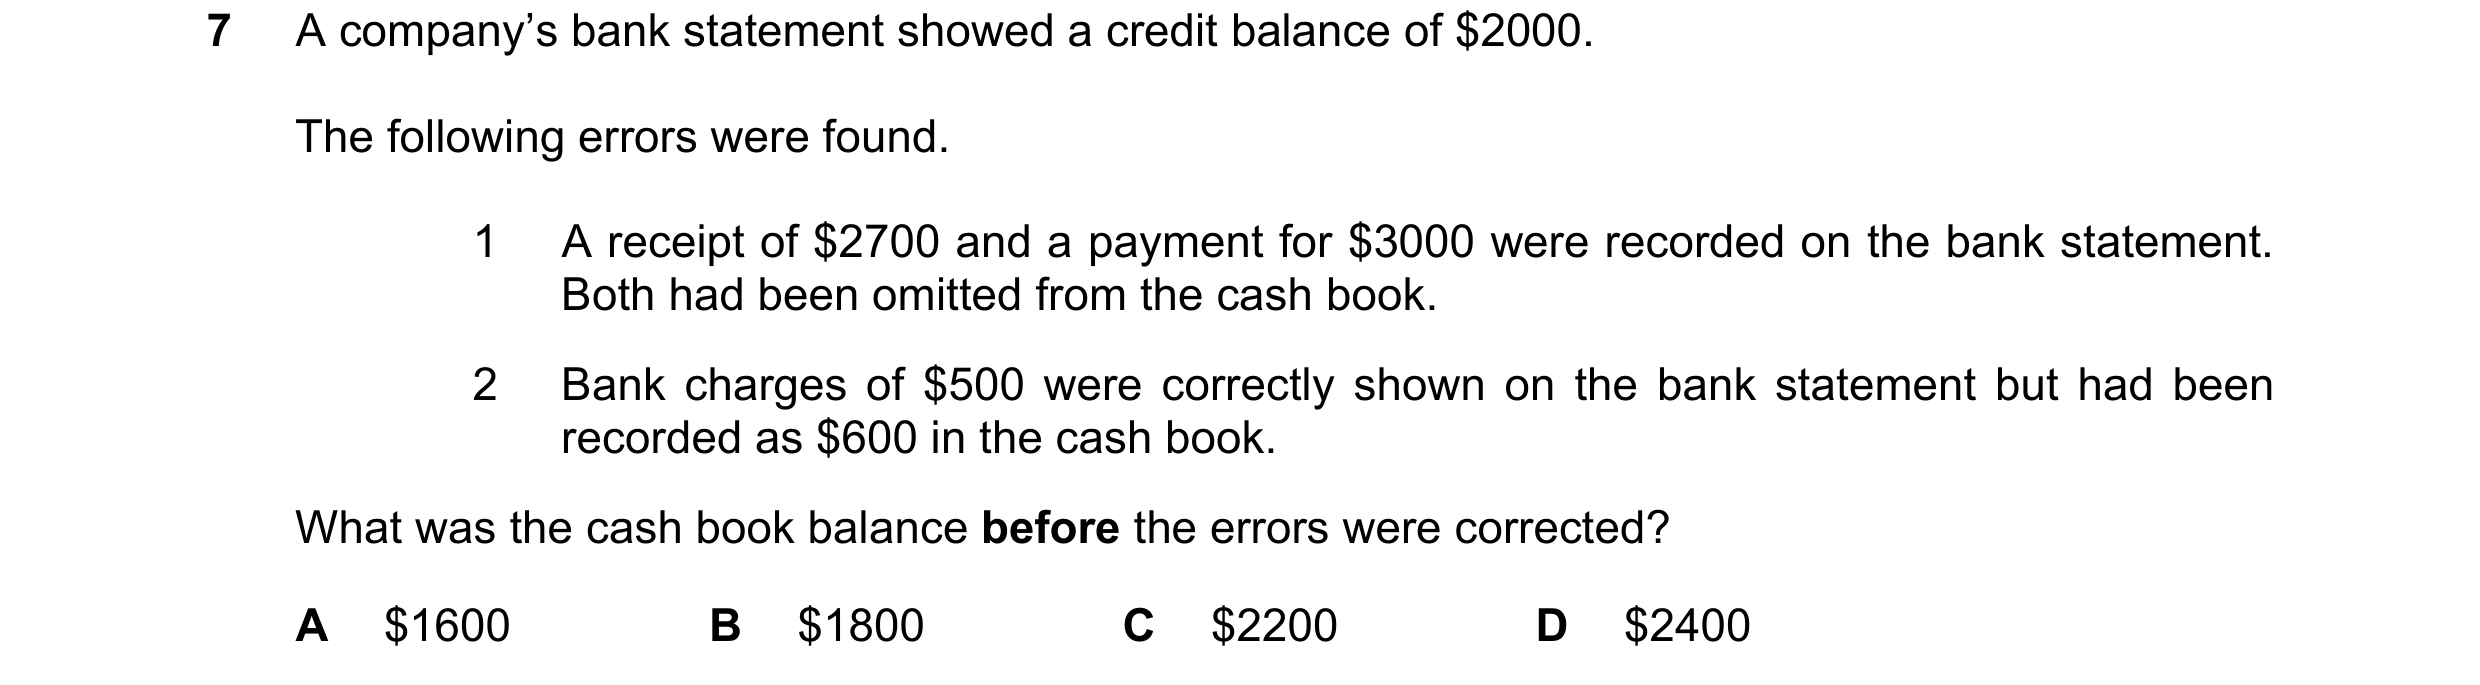 65 / 110
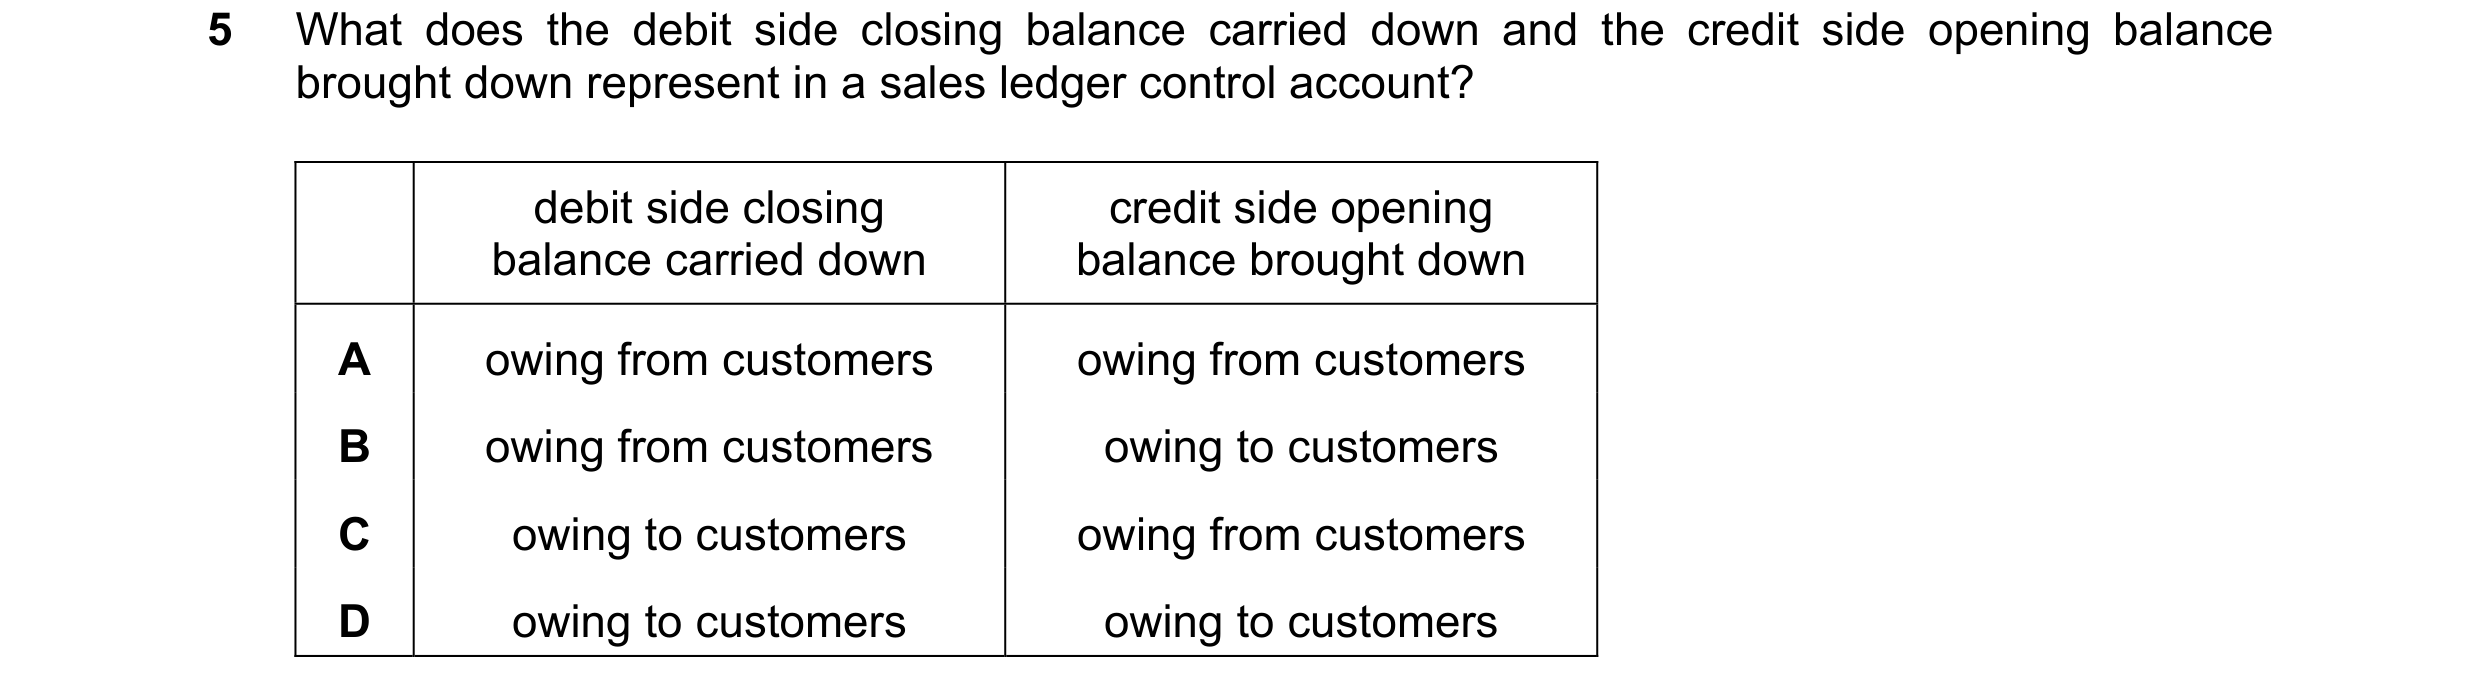
 66 / 110
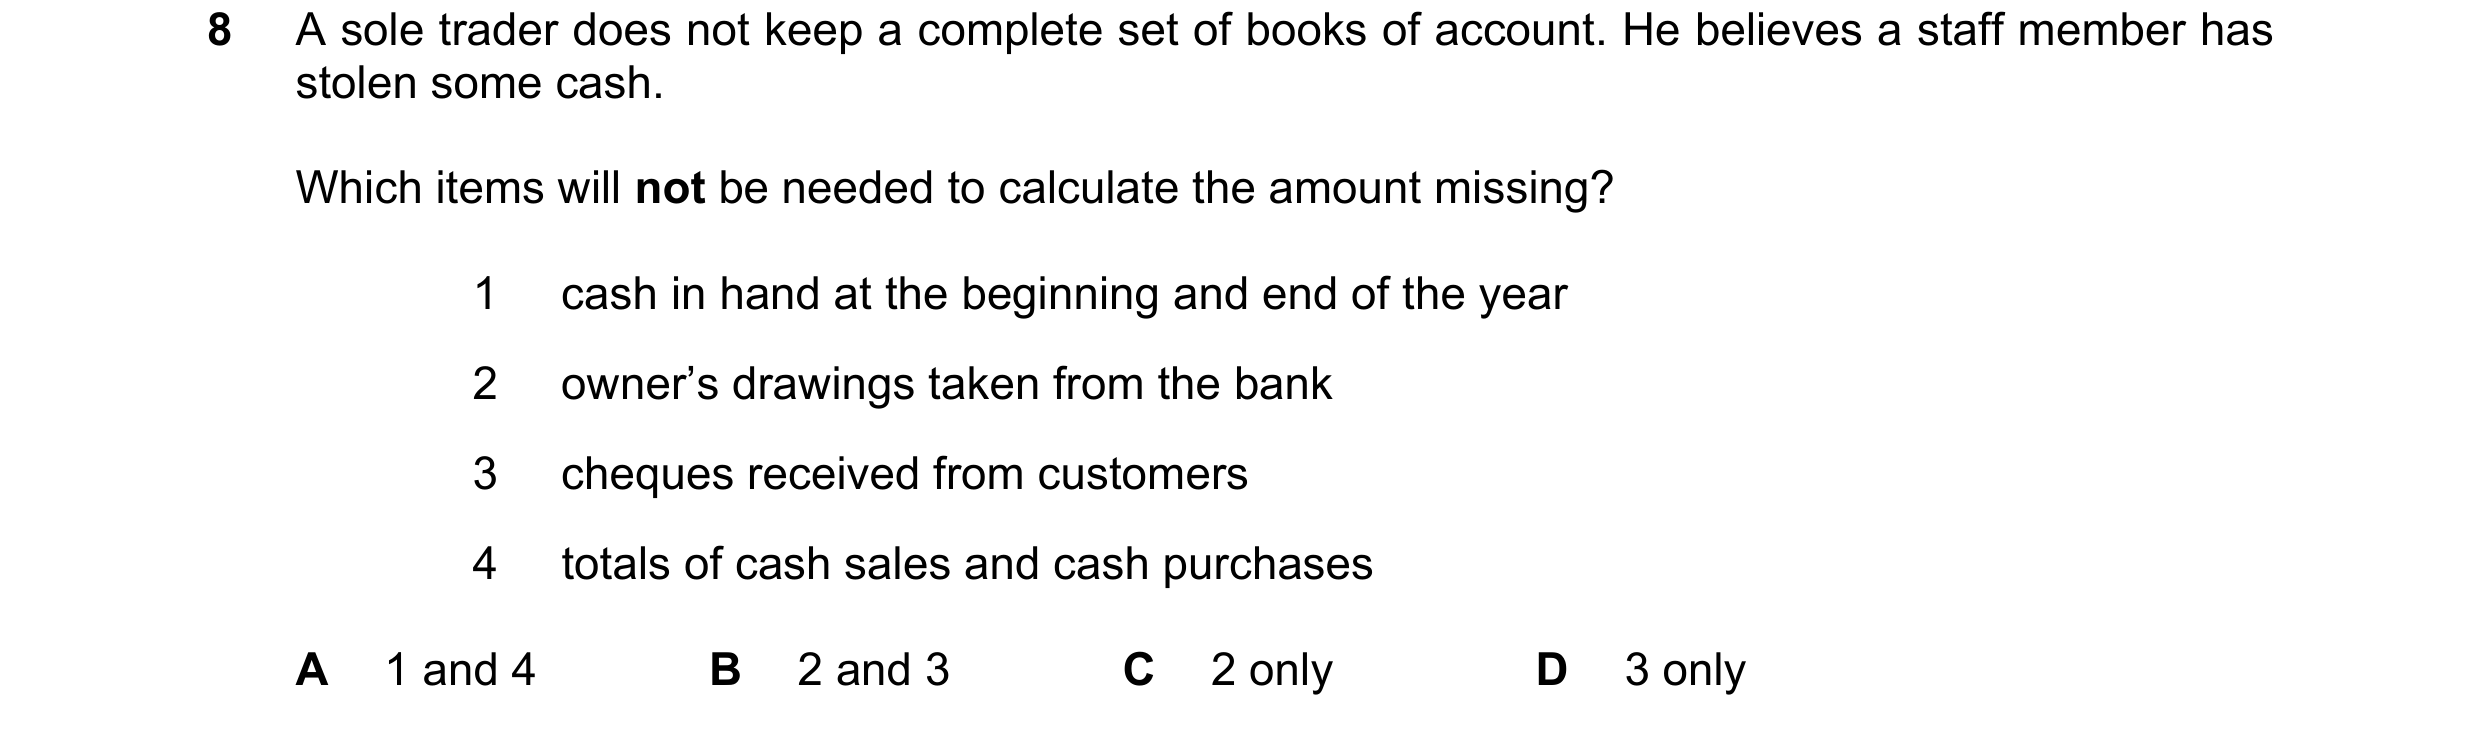
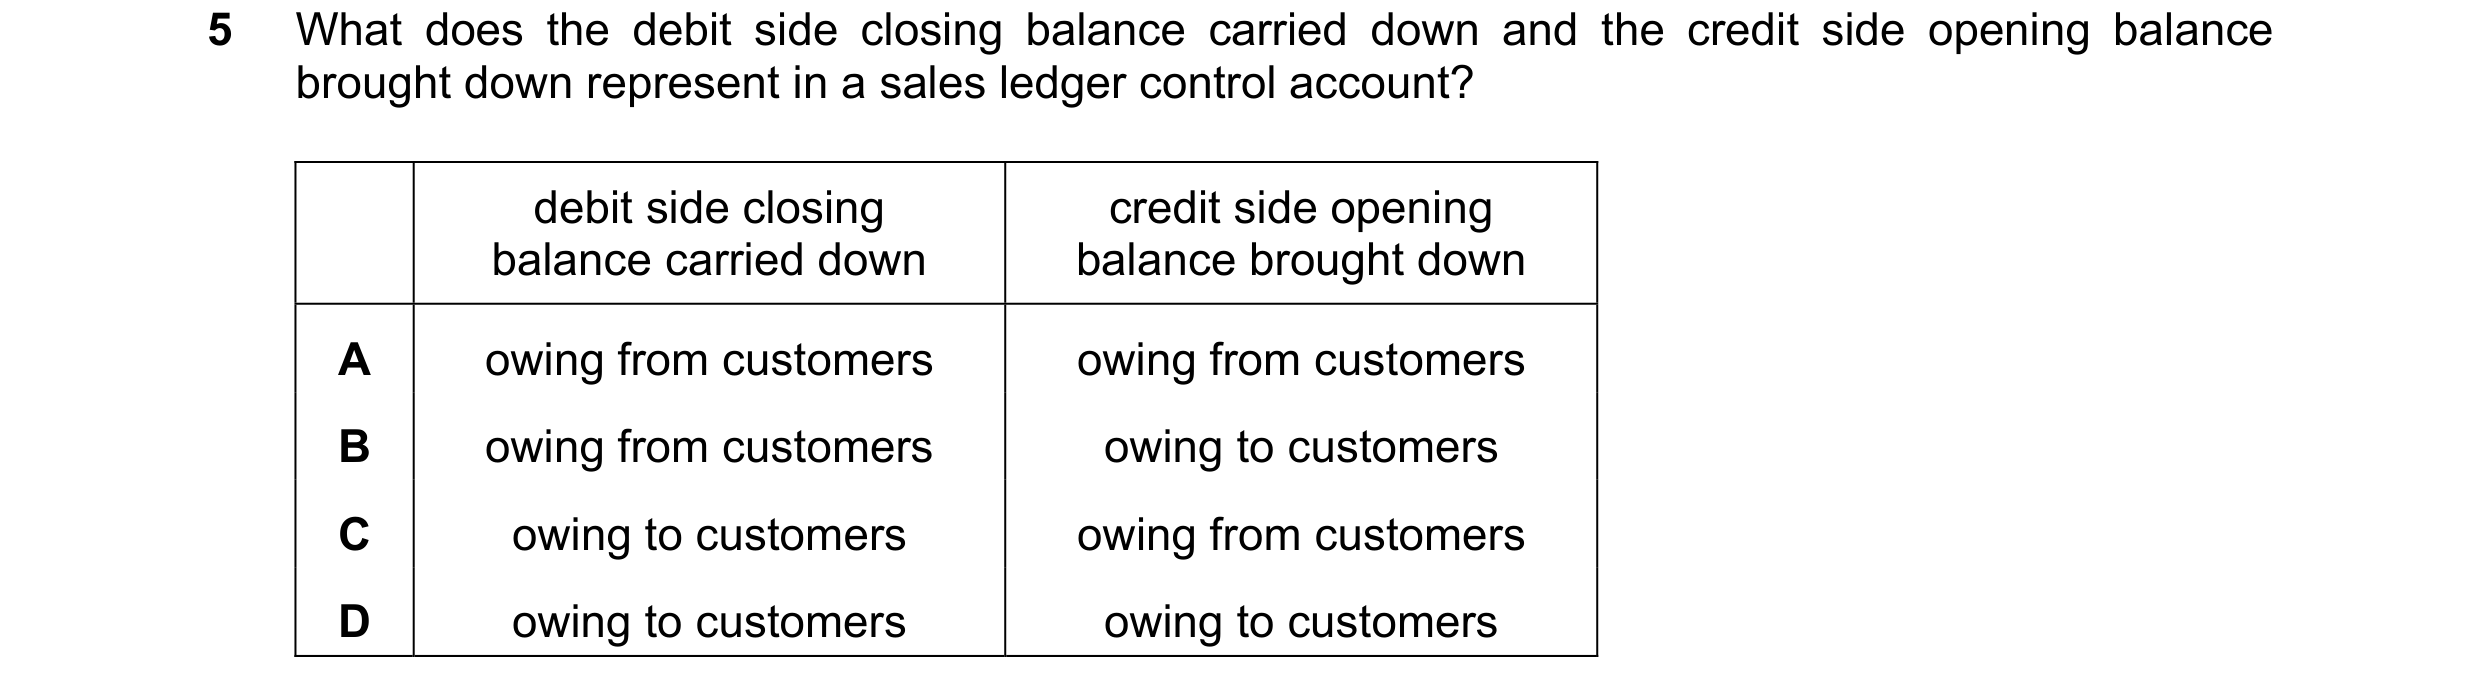 67 / 110
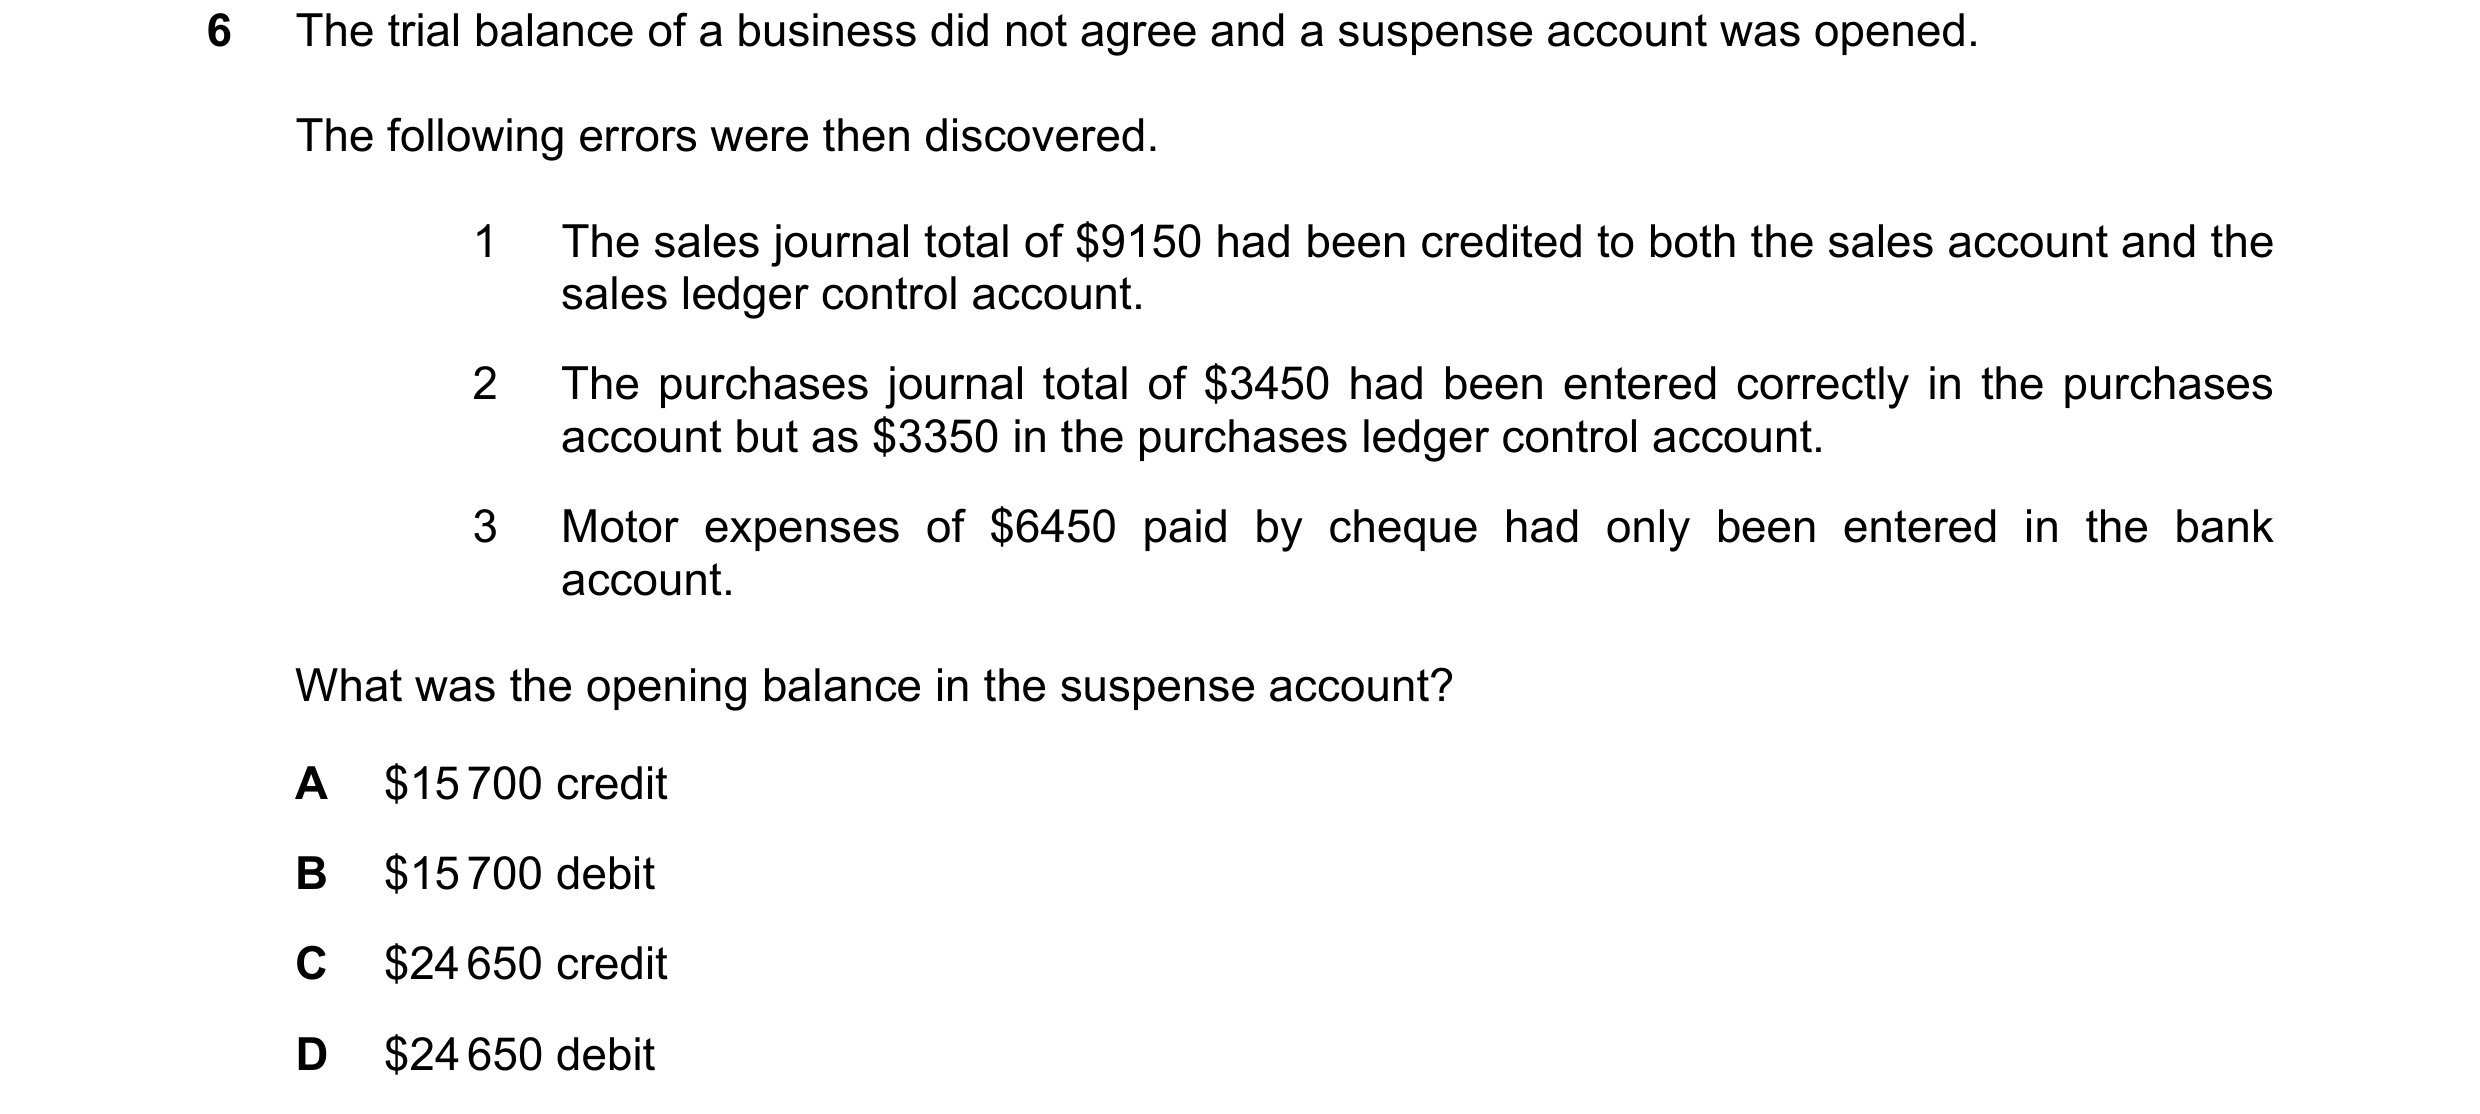
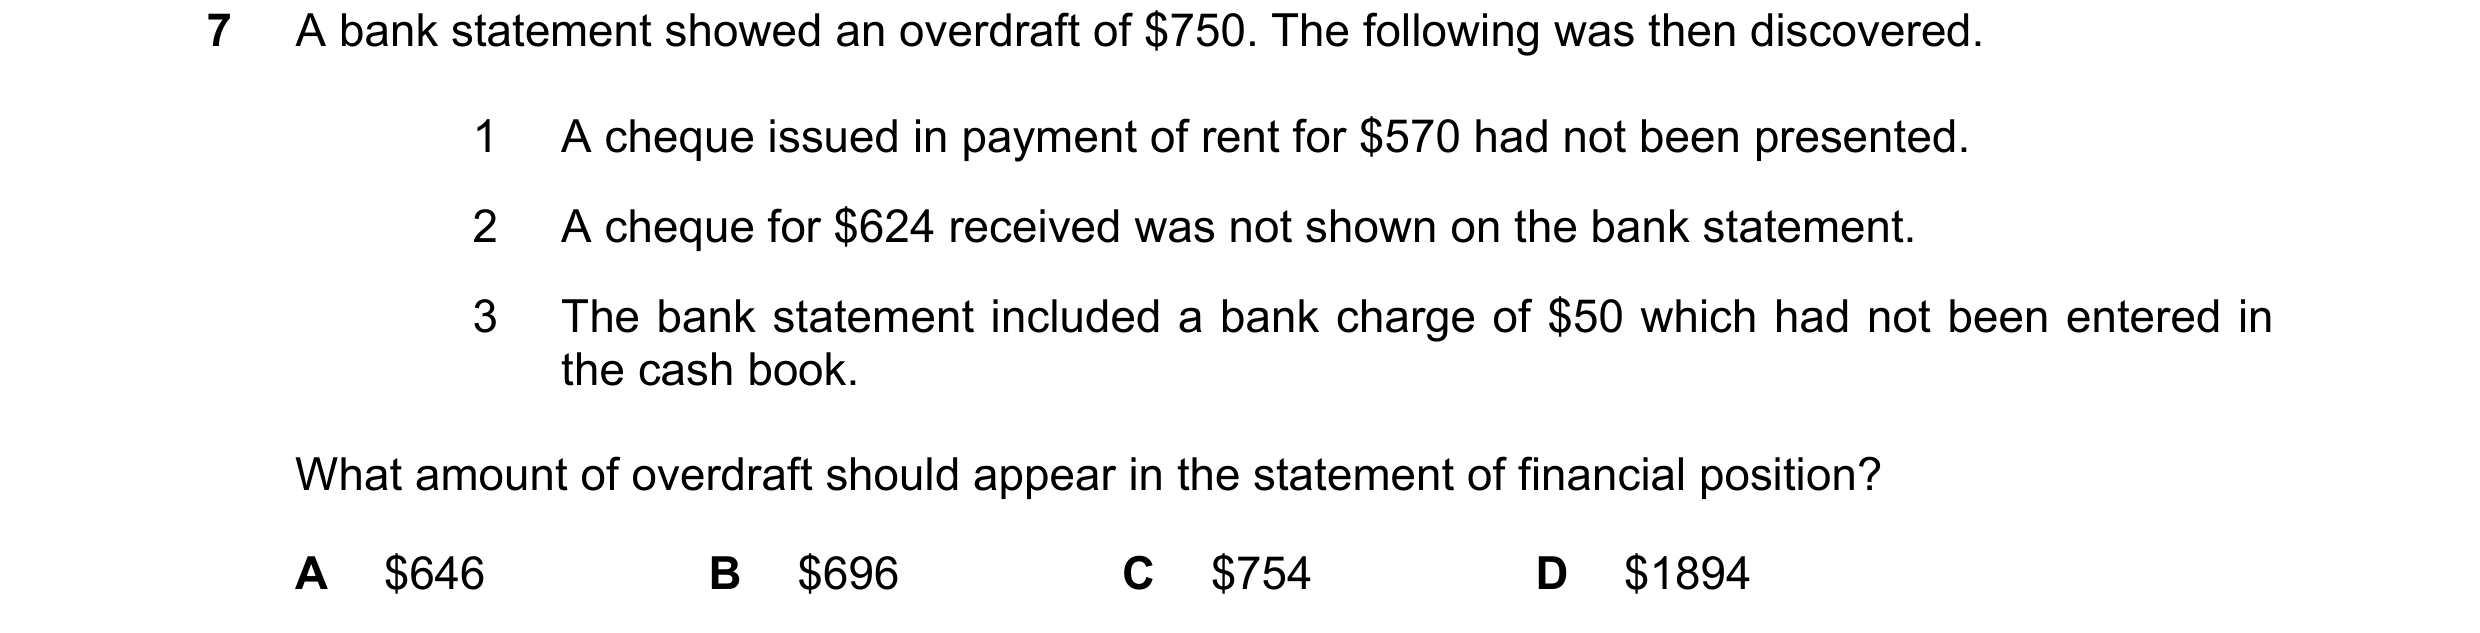
 68 / 110
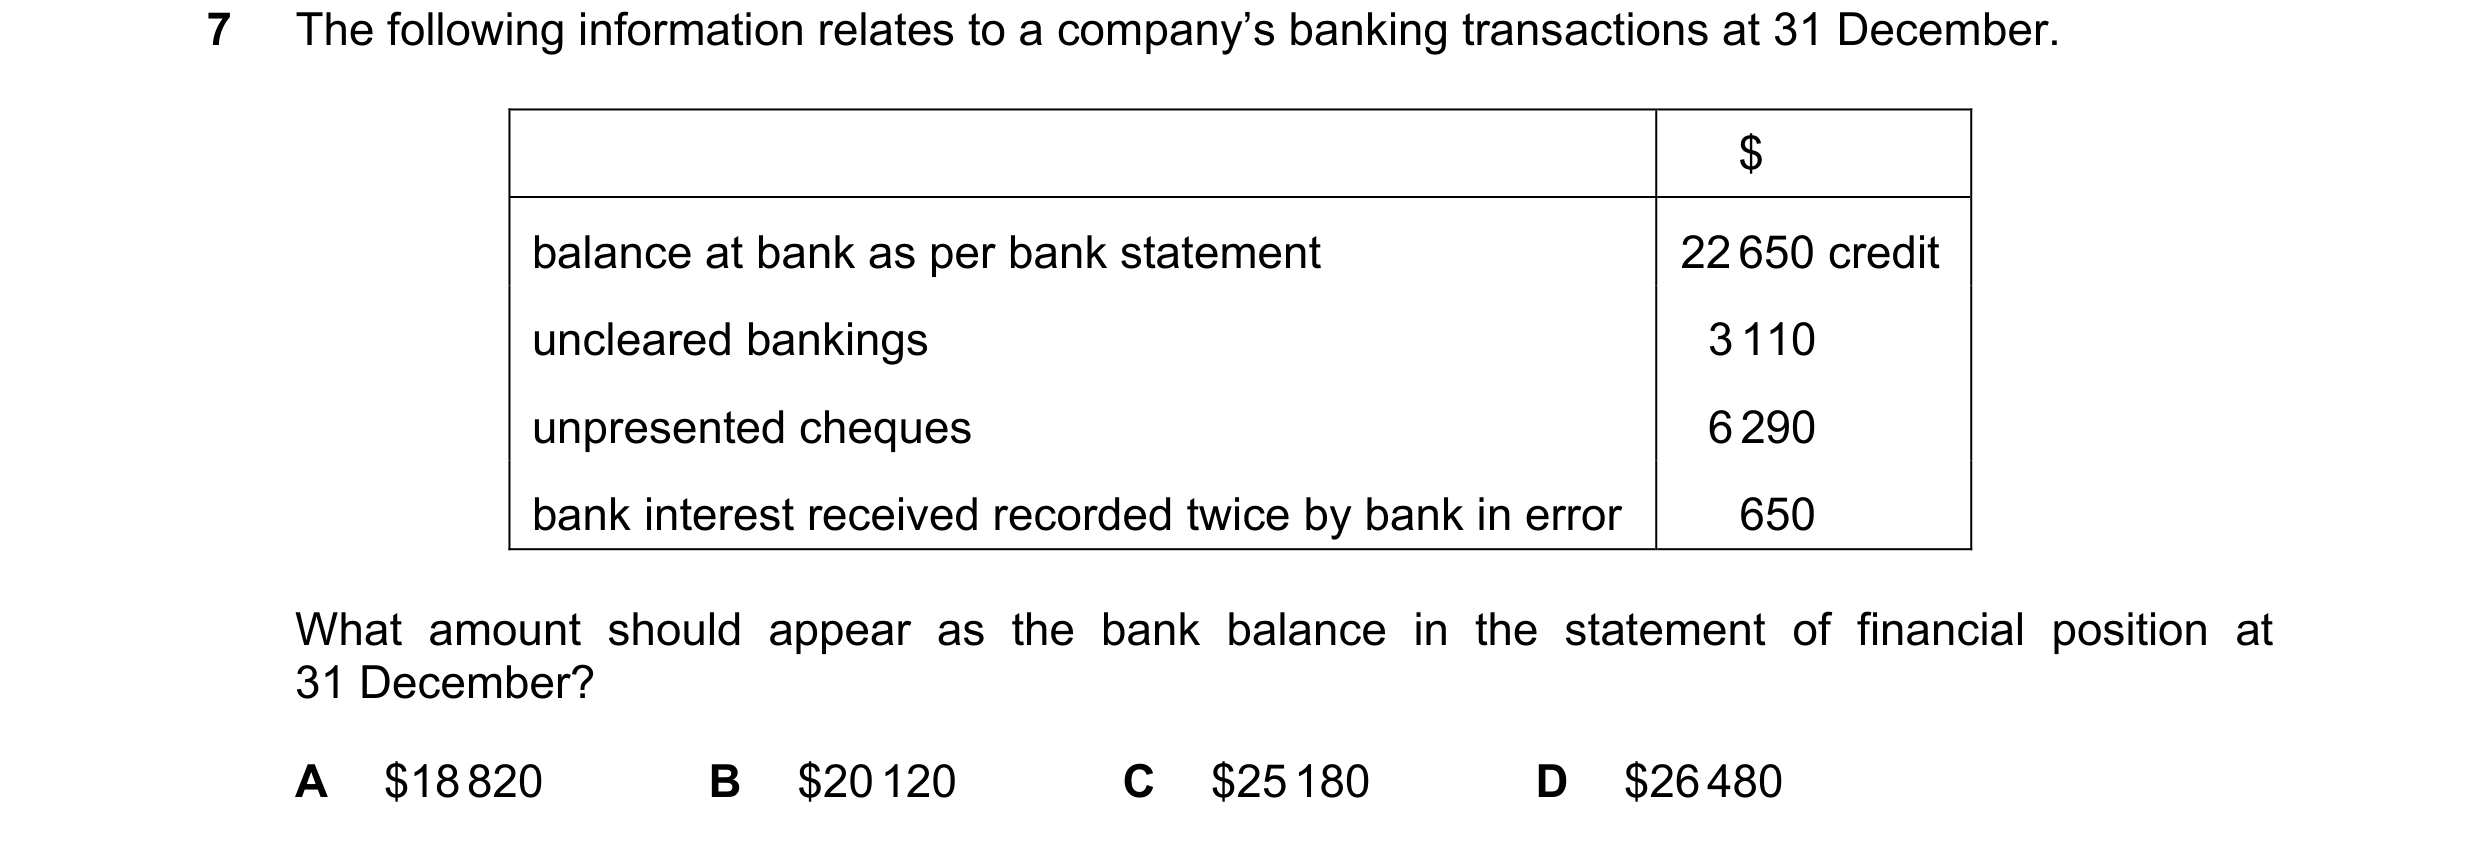
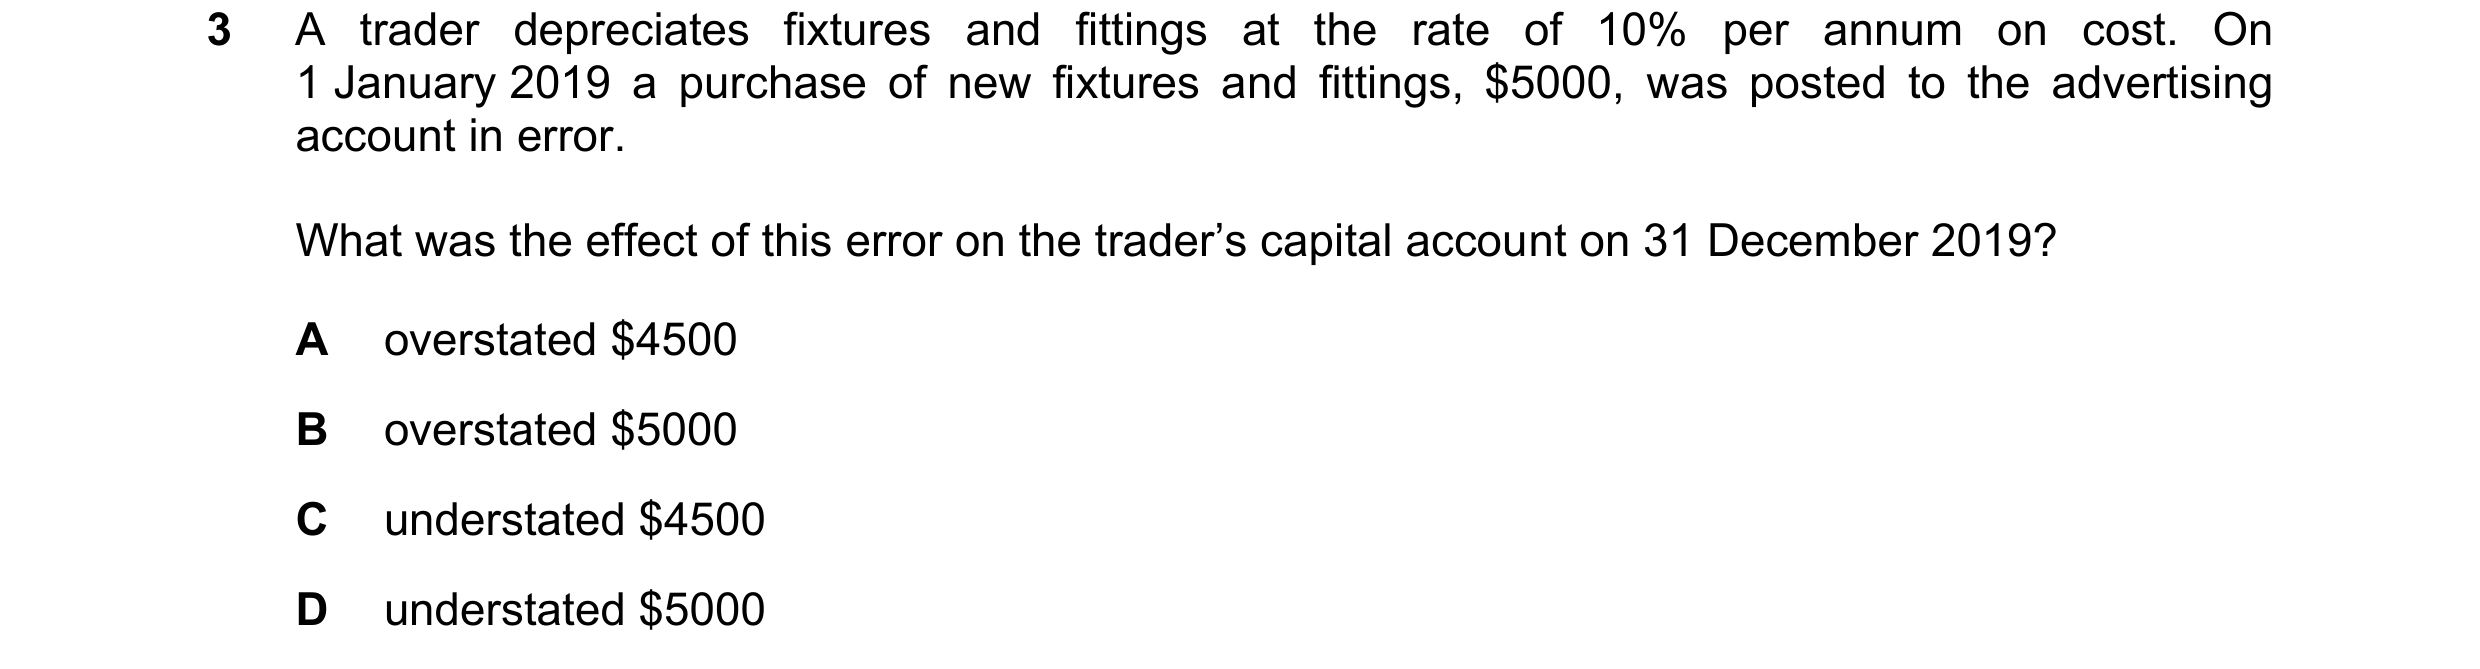
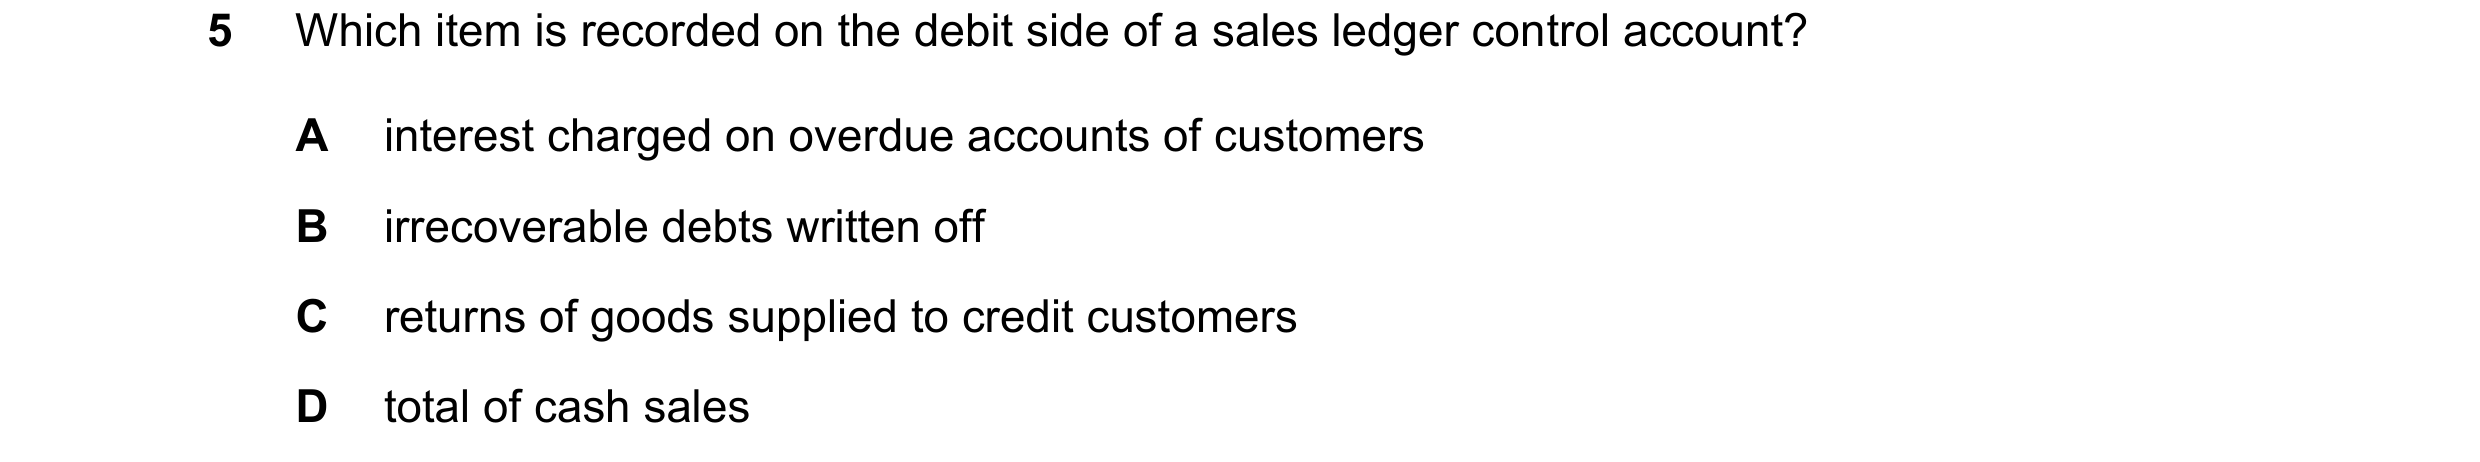 69 / 110
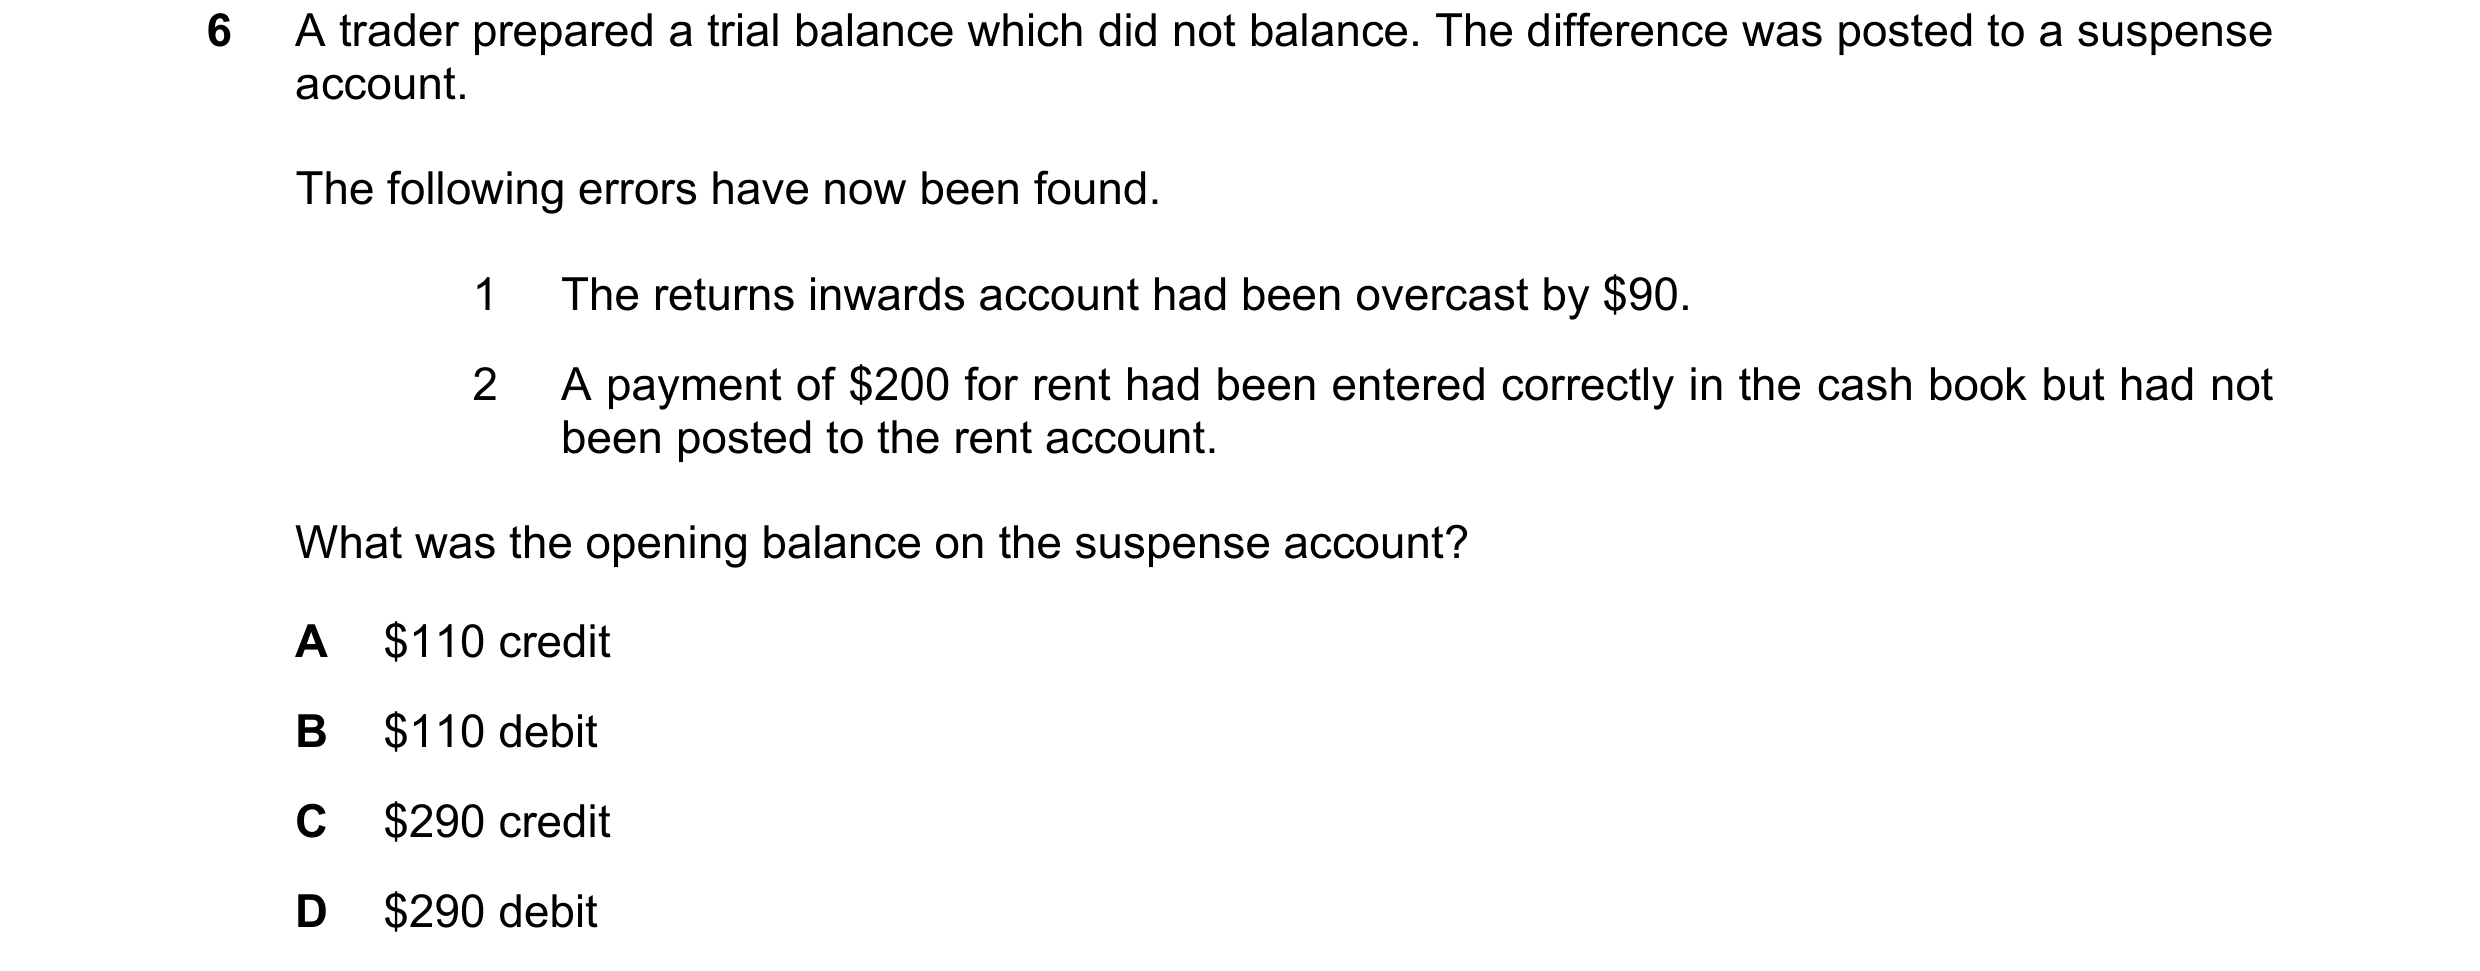
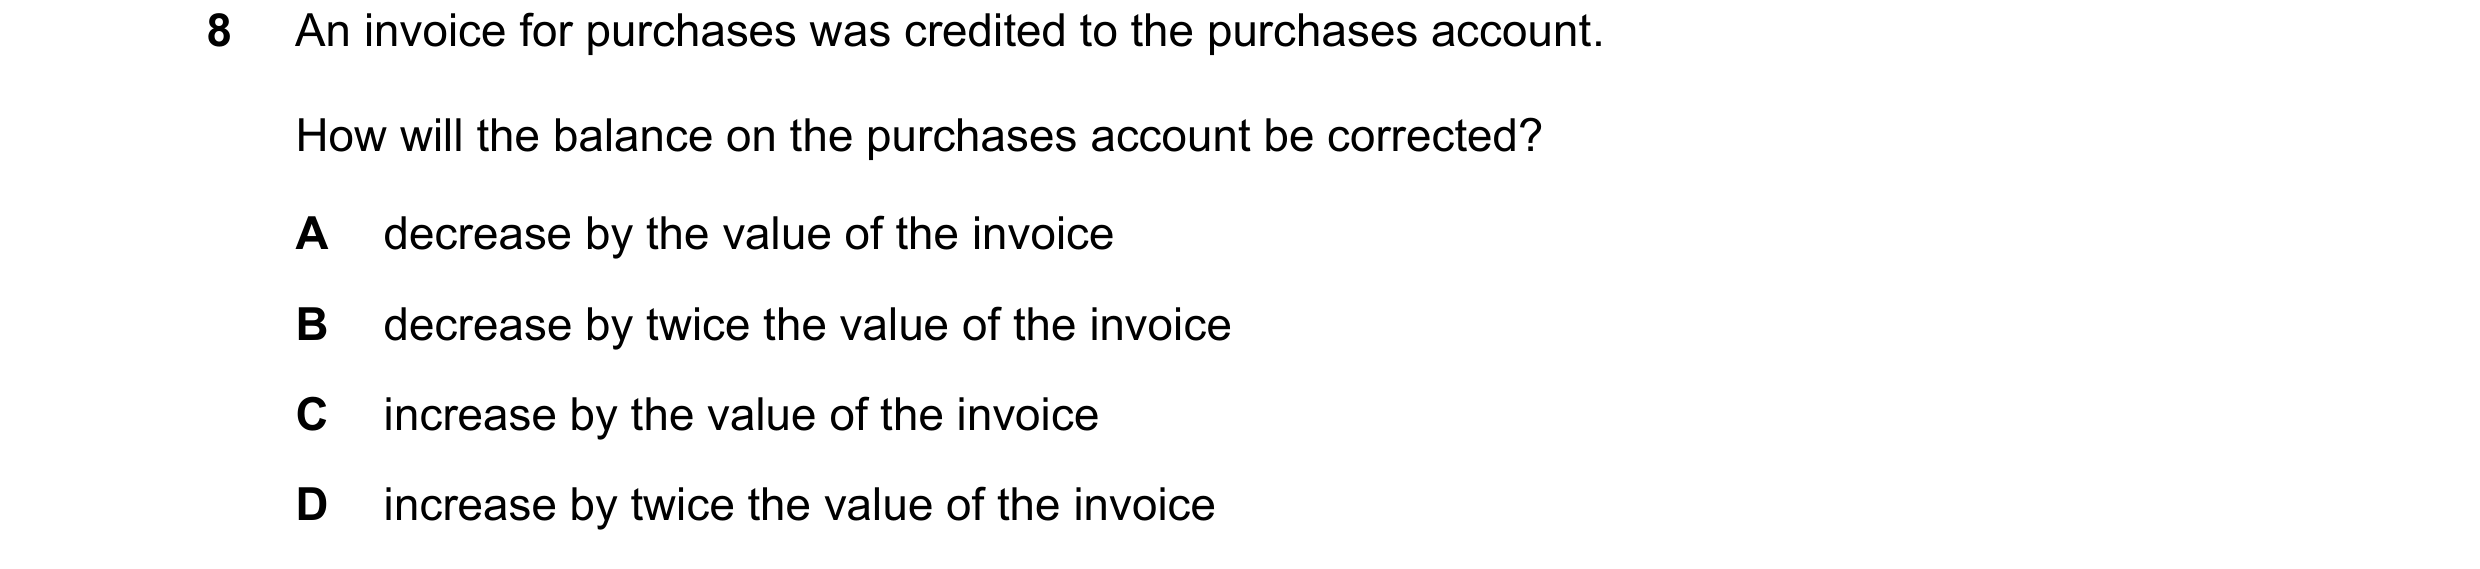
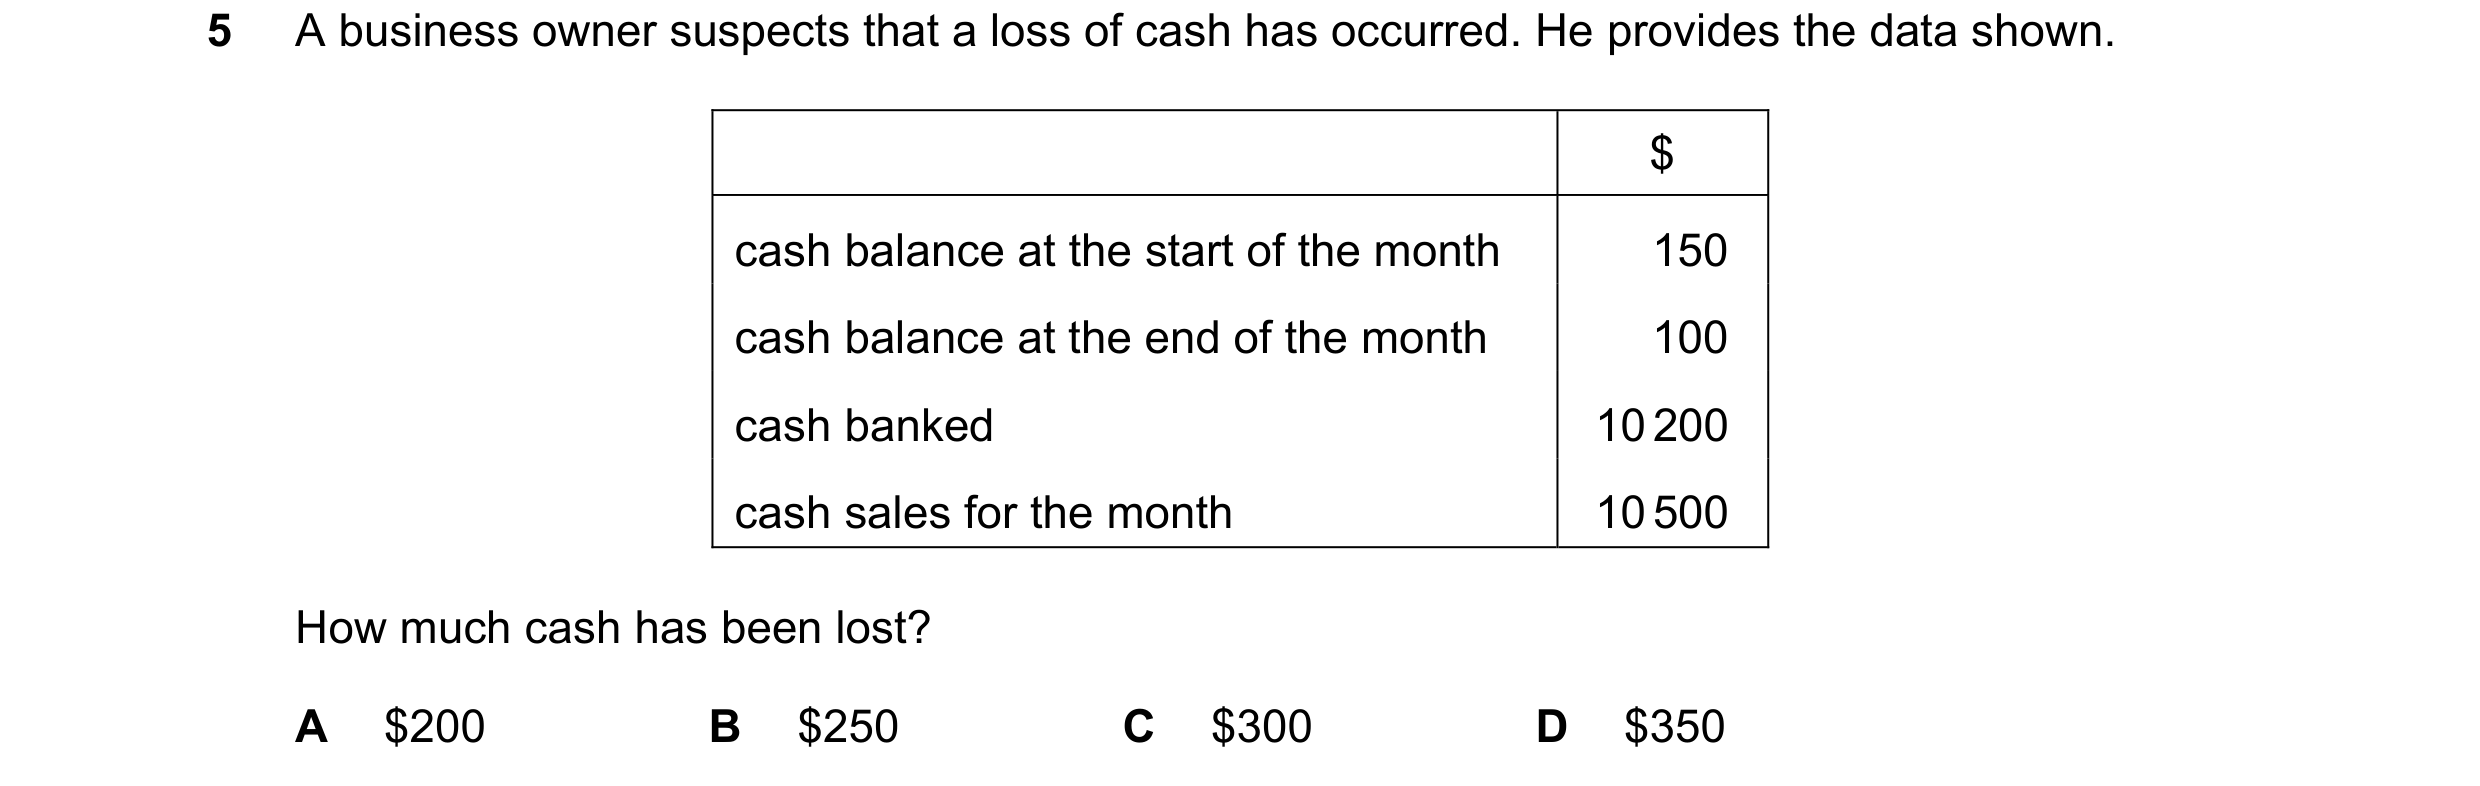
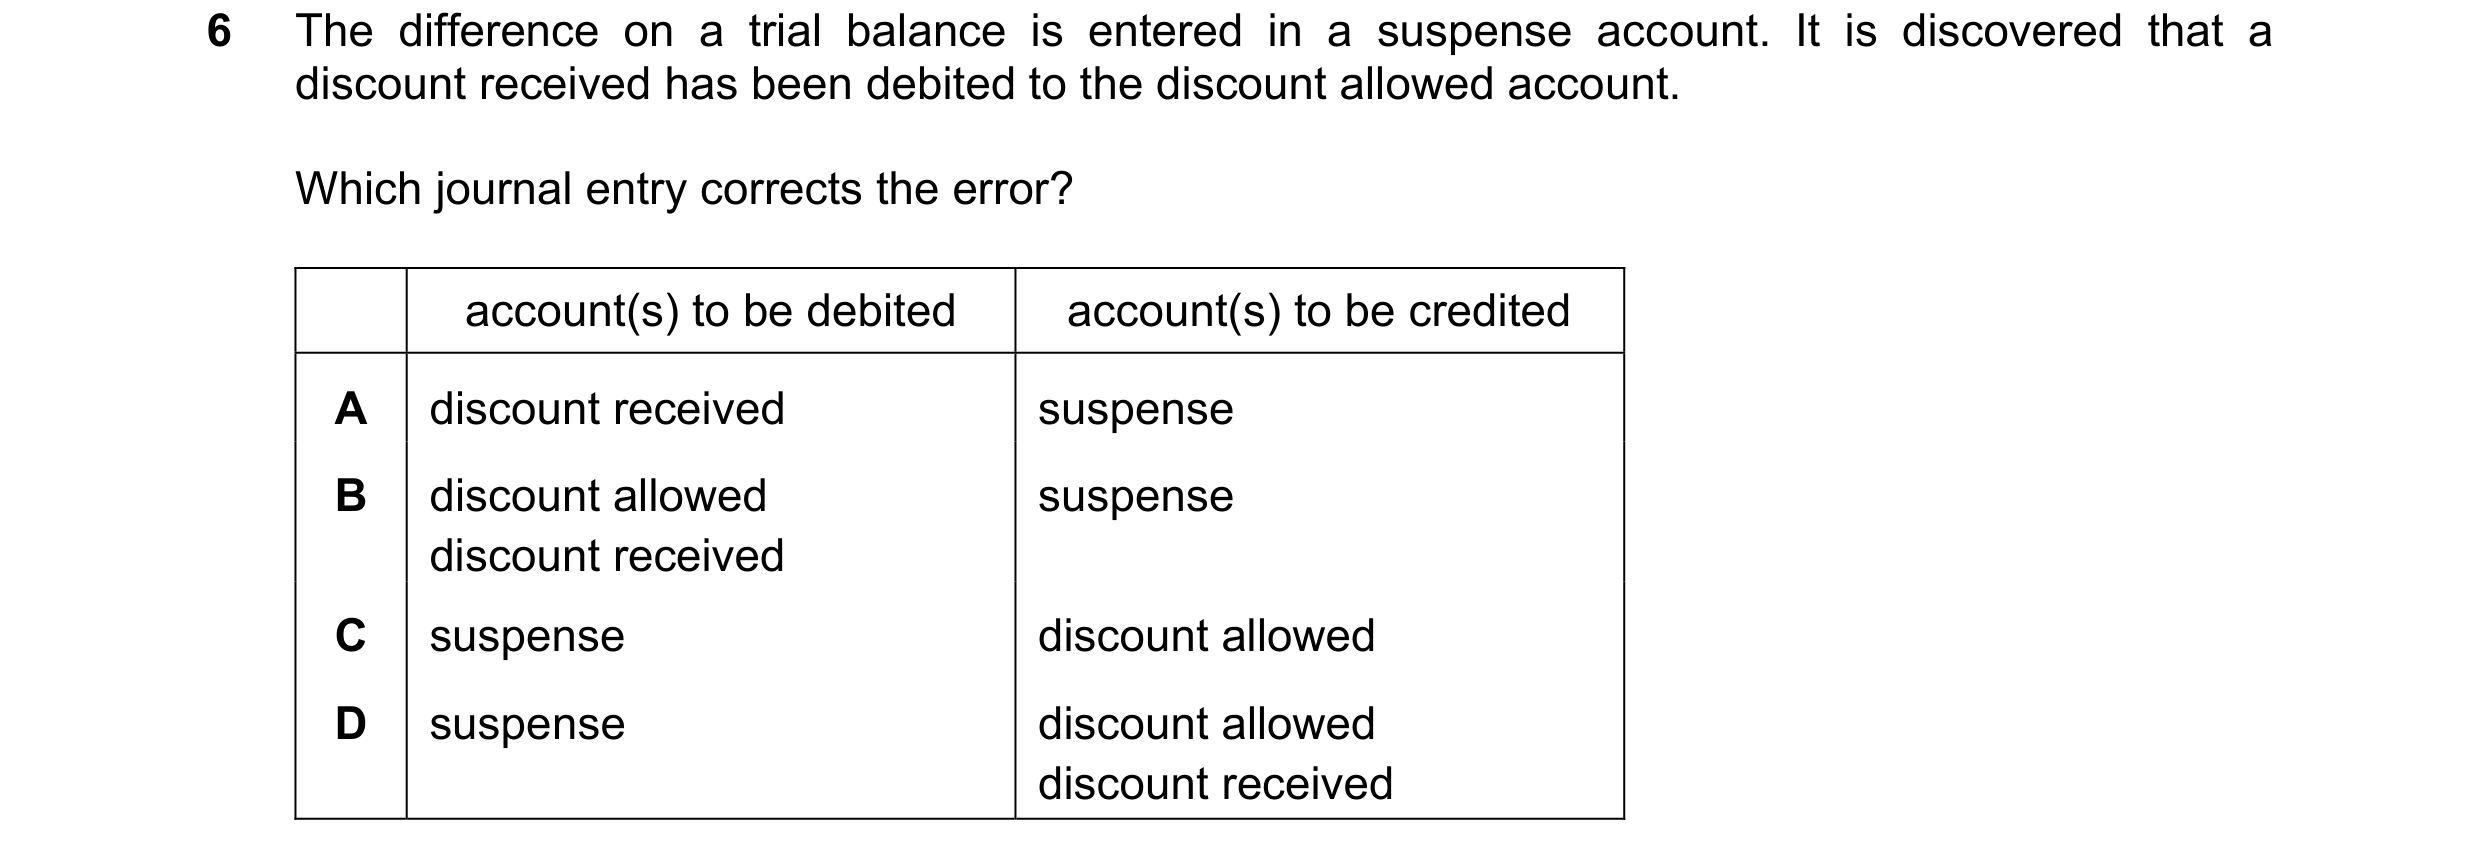 70 / 110
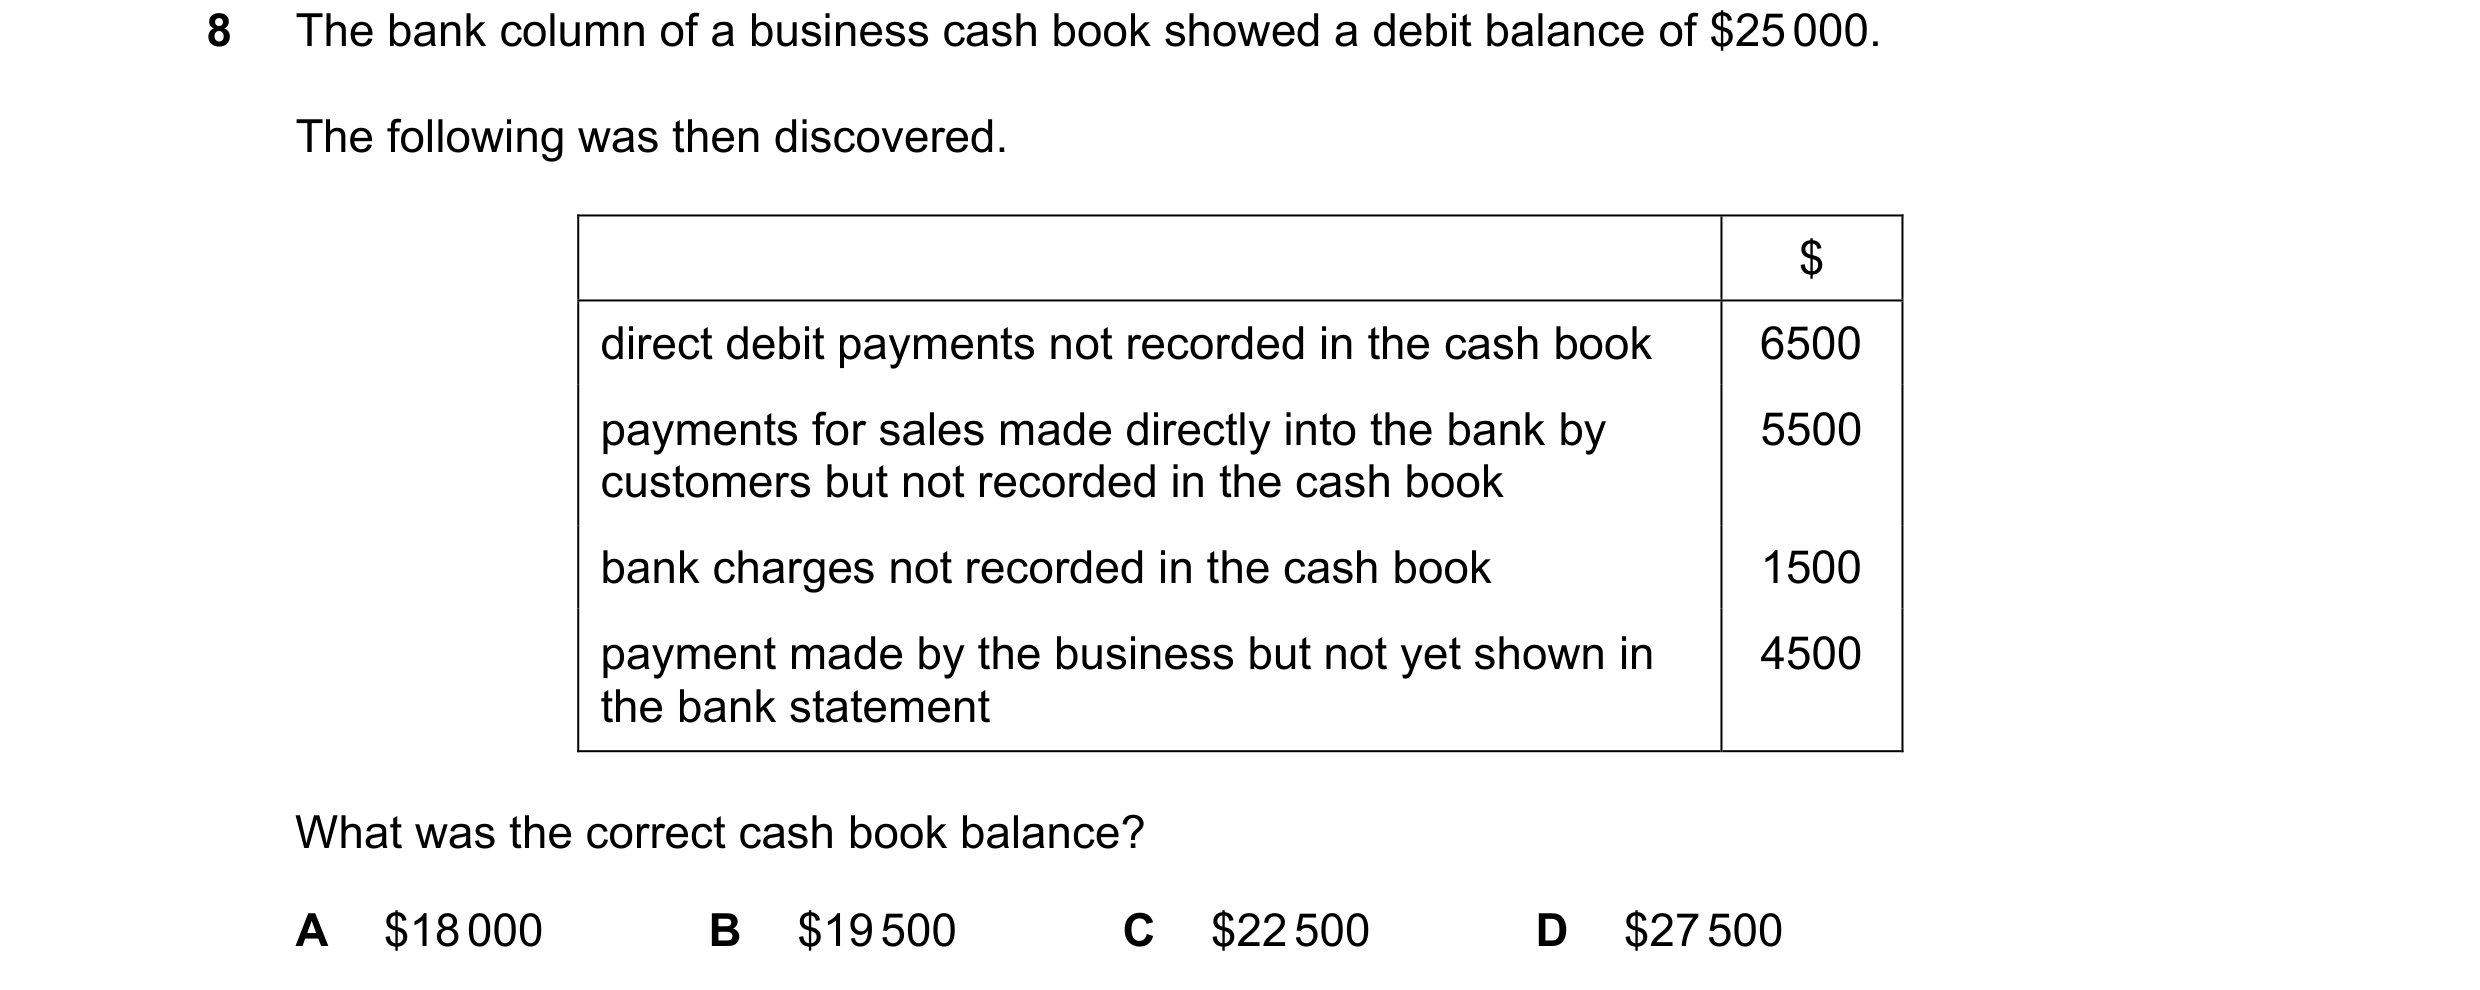
 71 / 110
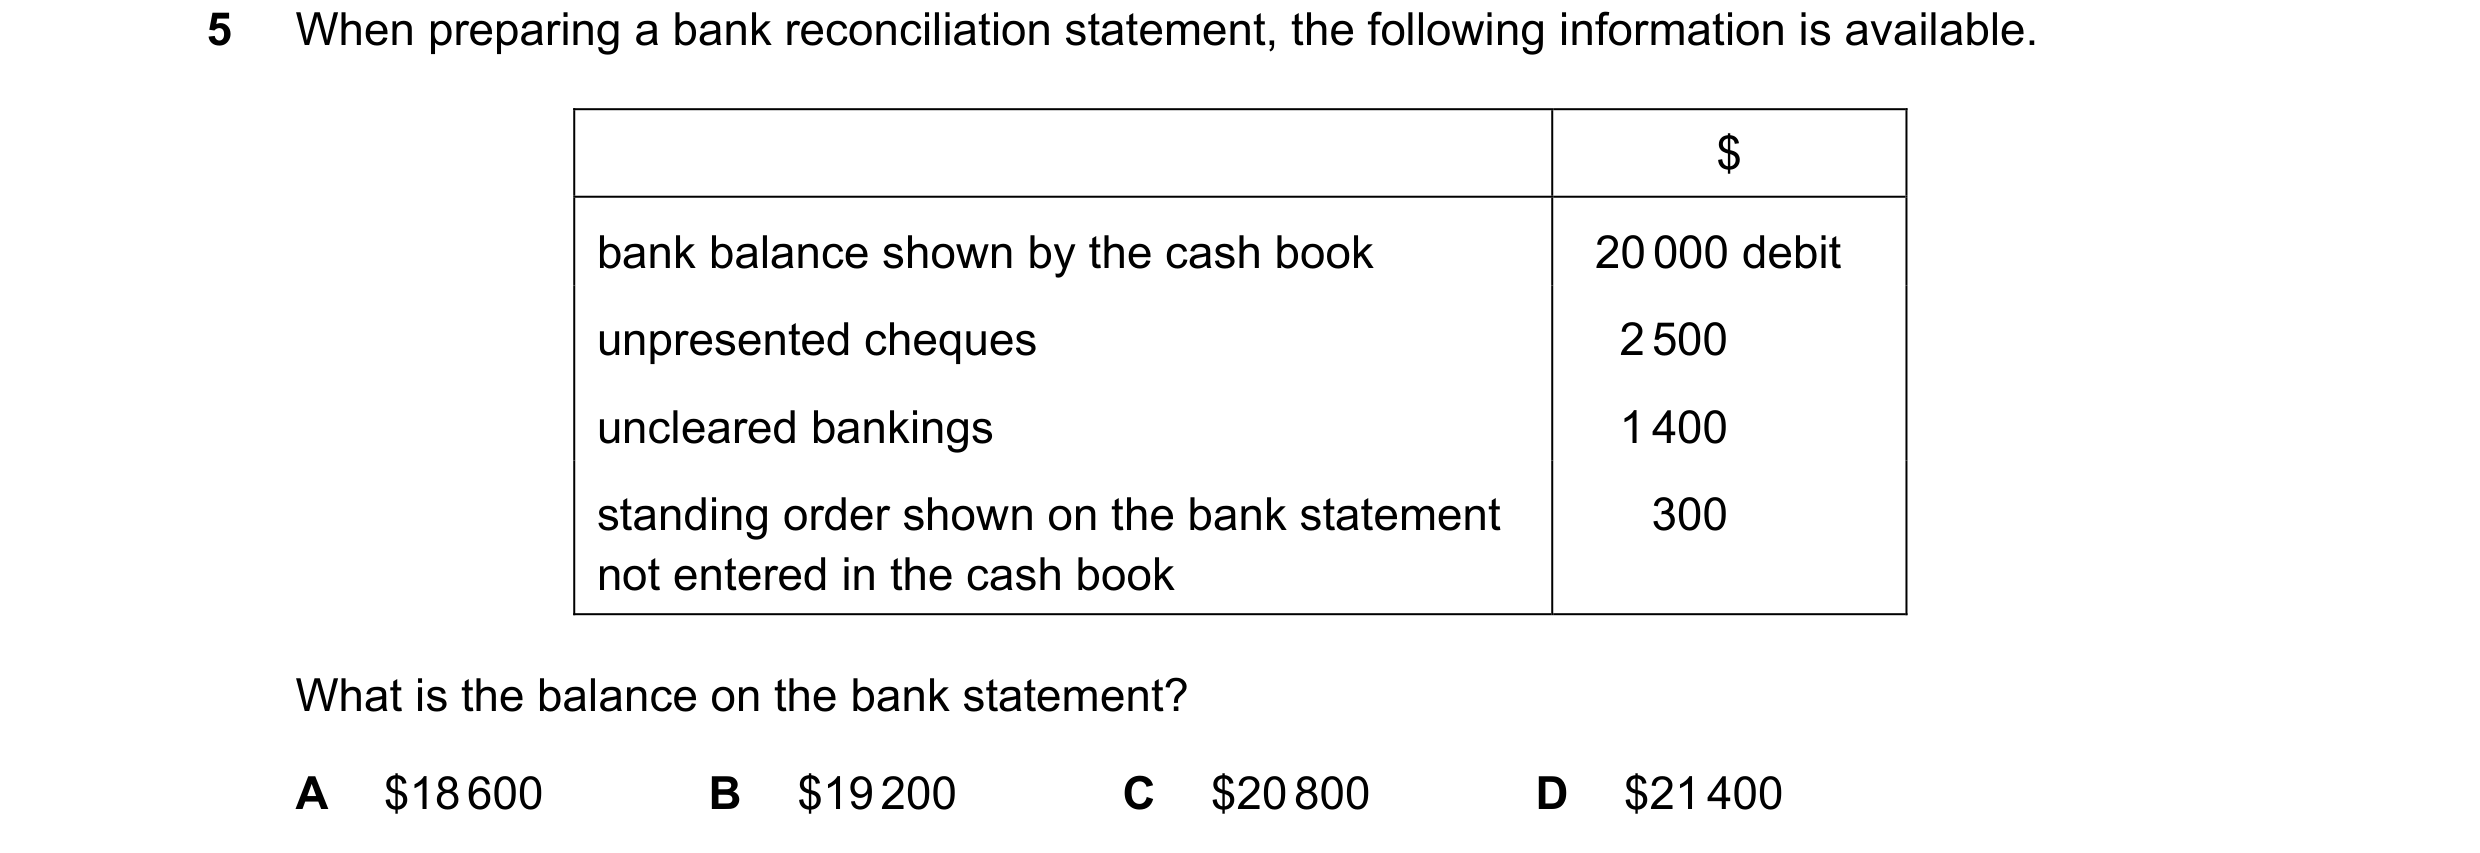
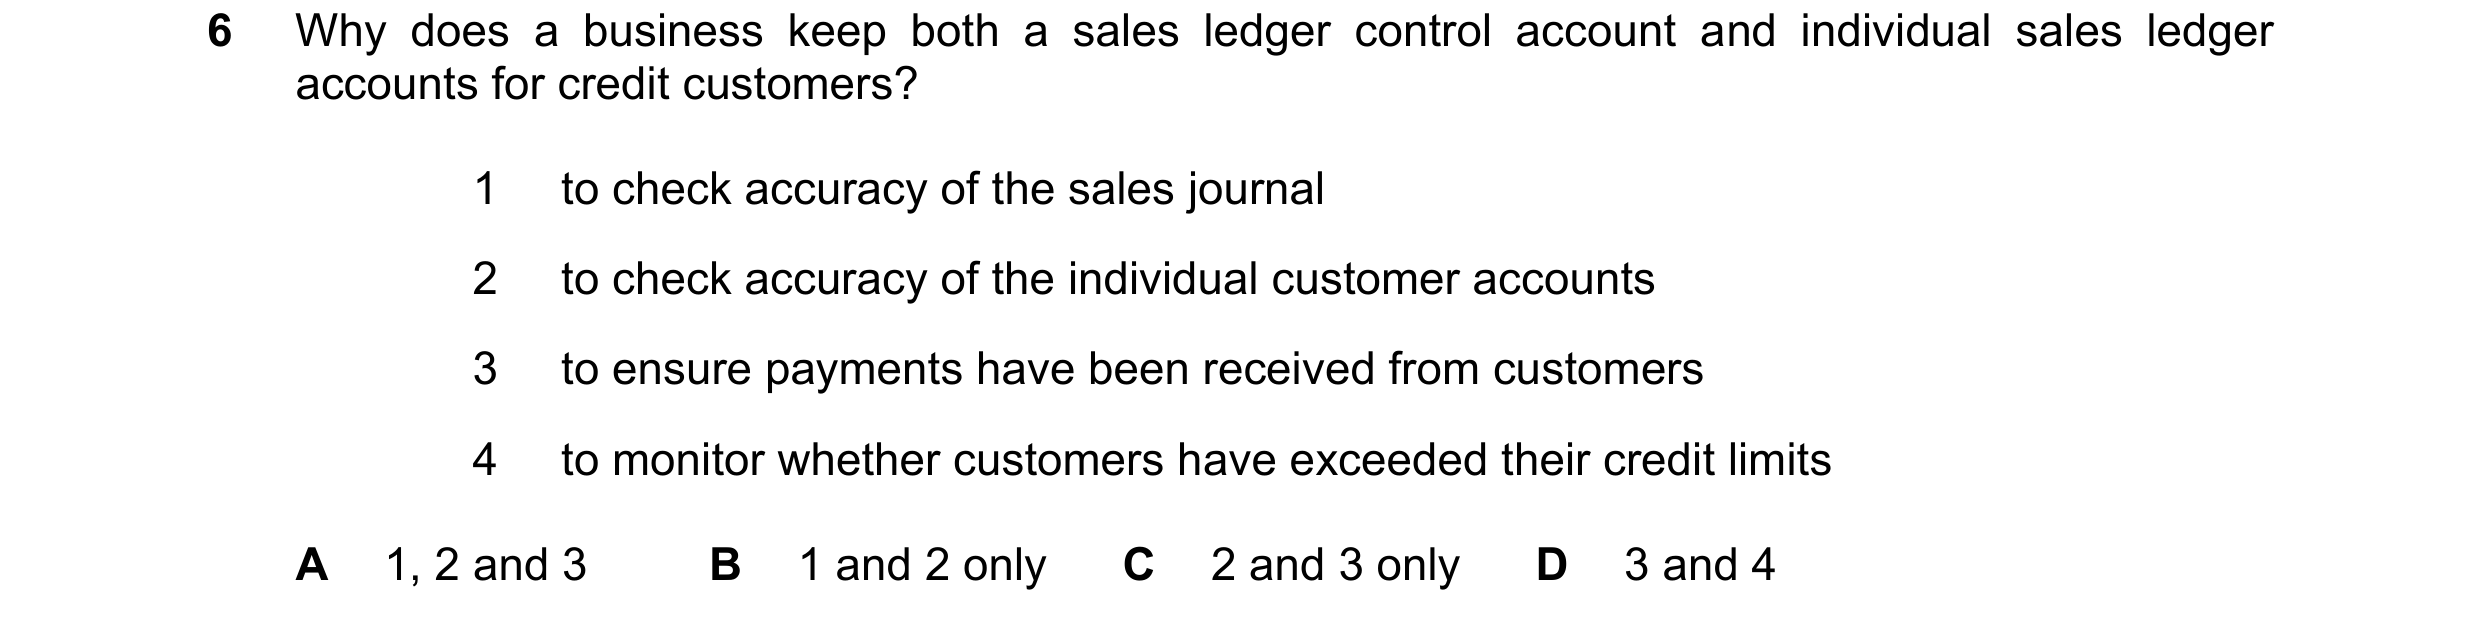
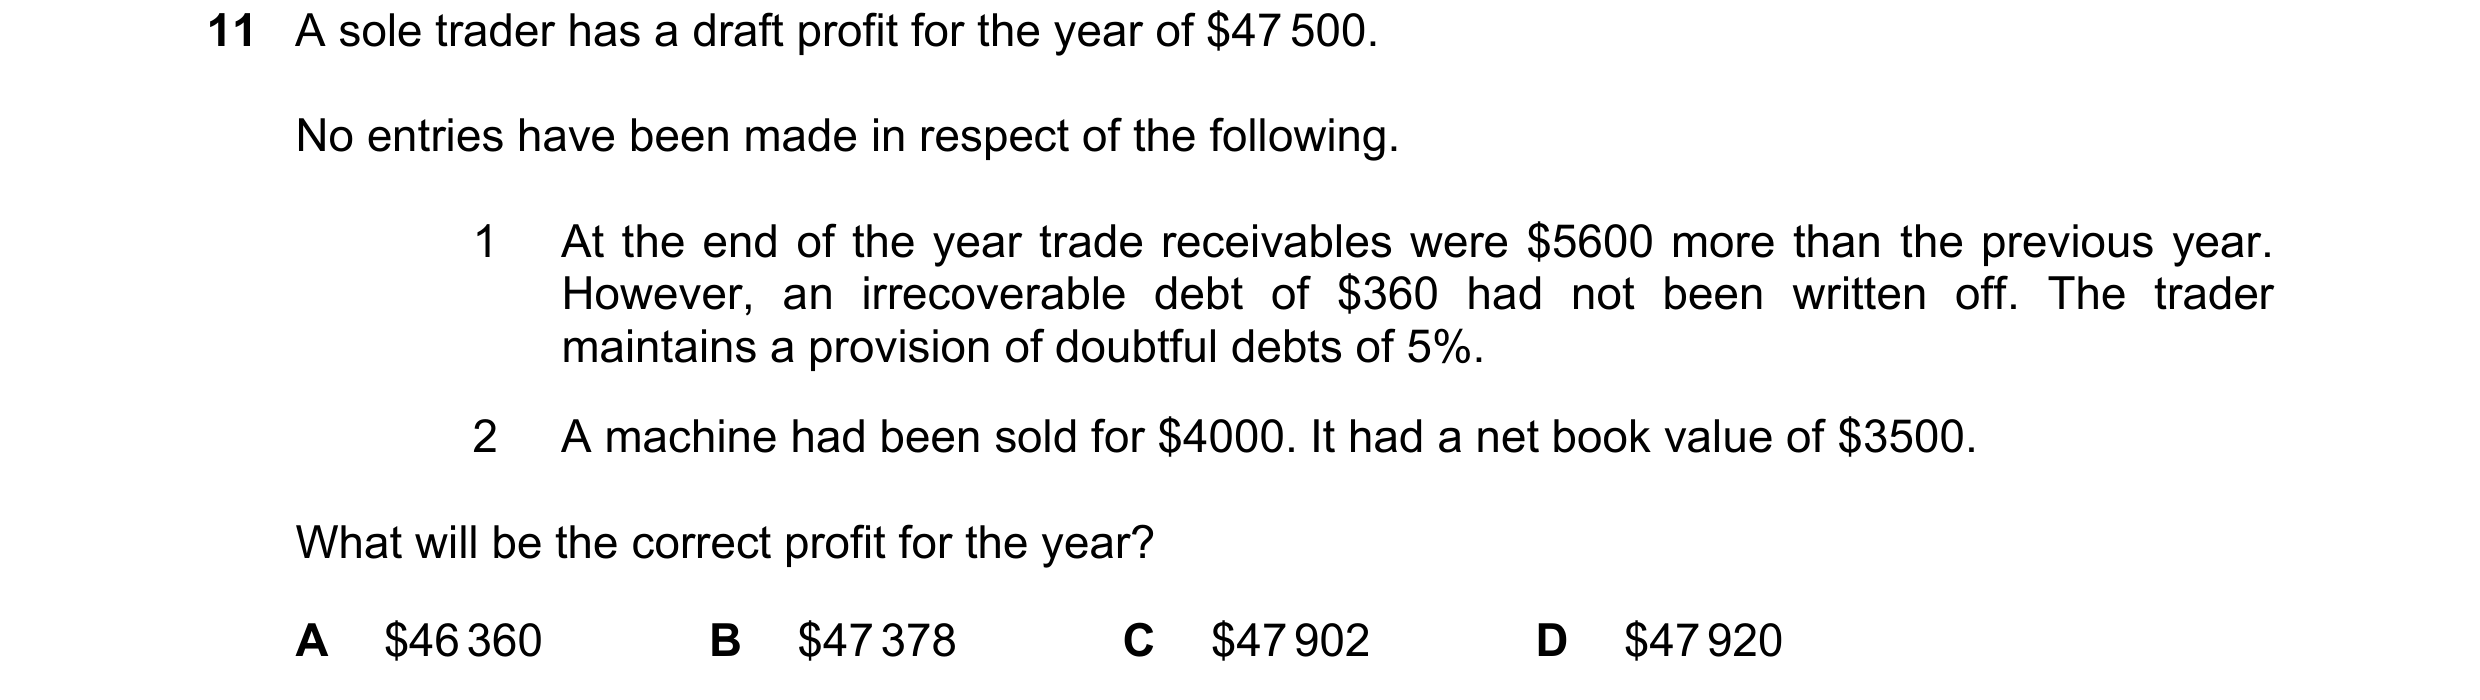 72 / 110
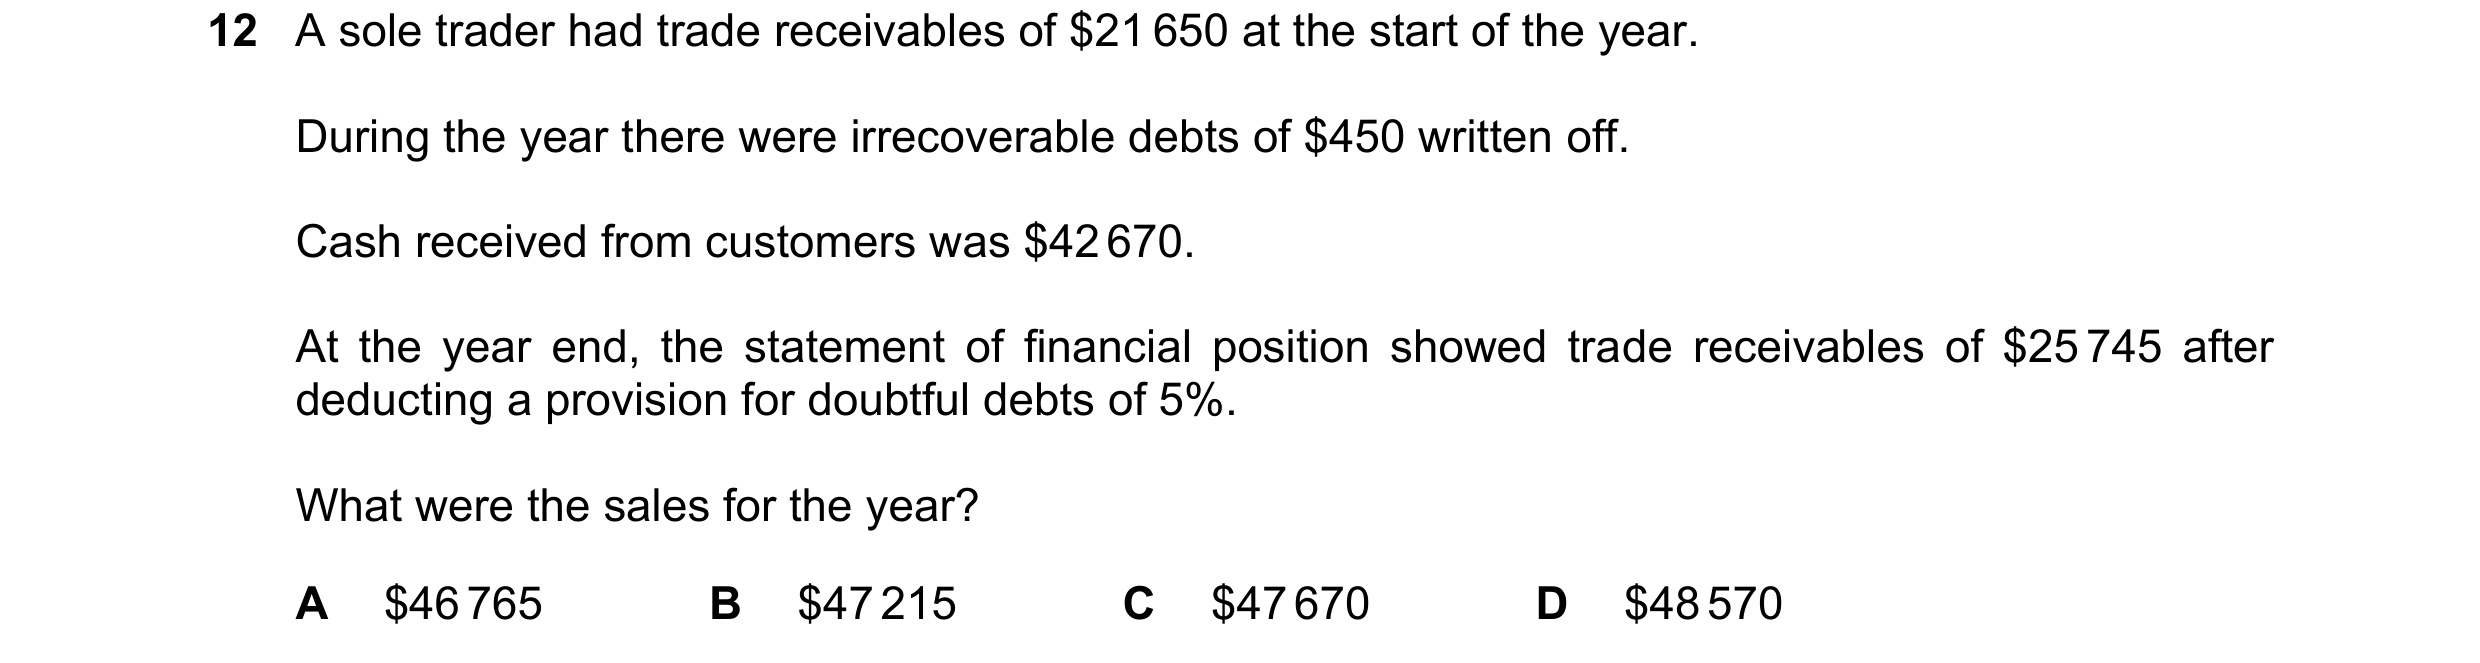
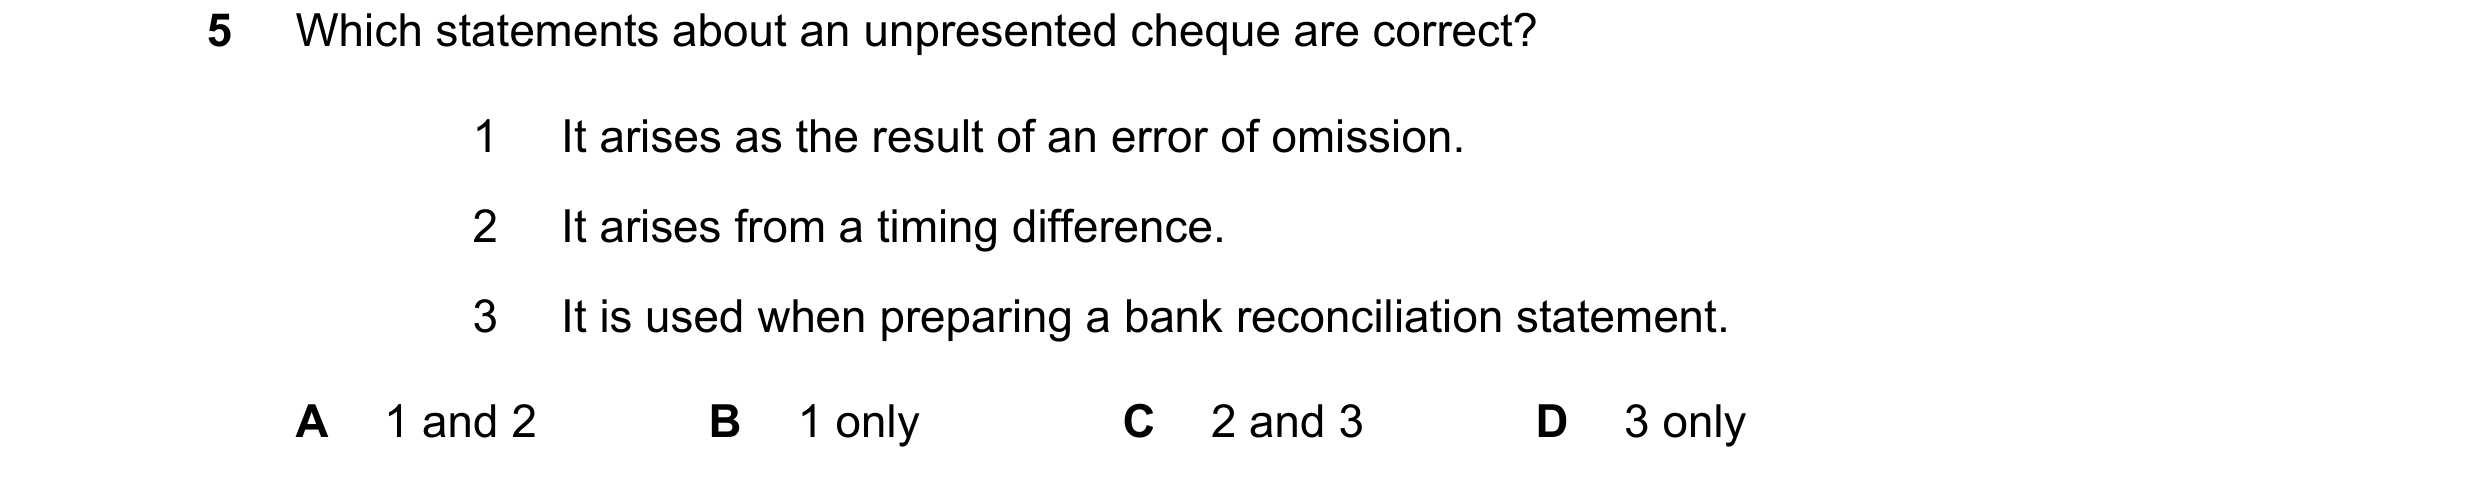
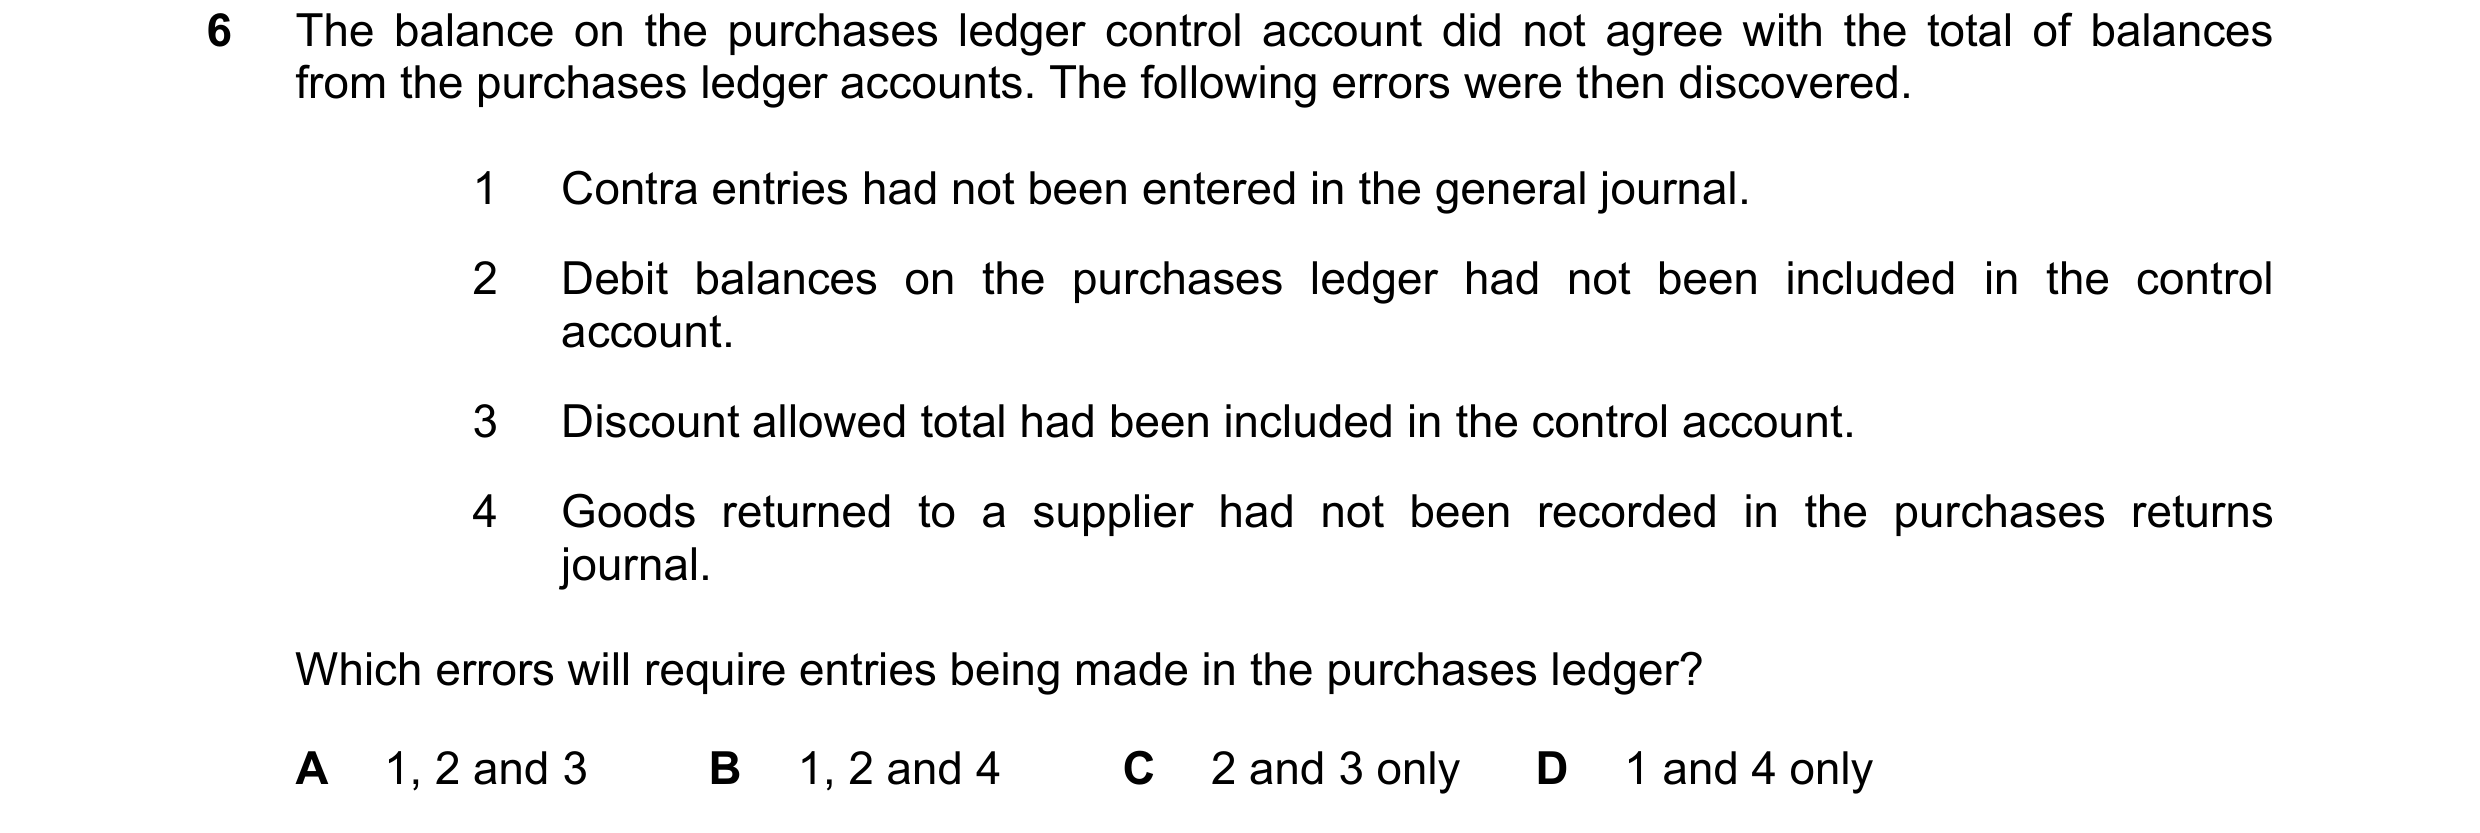
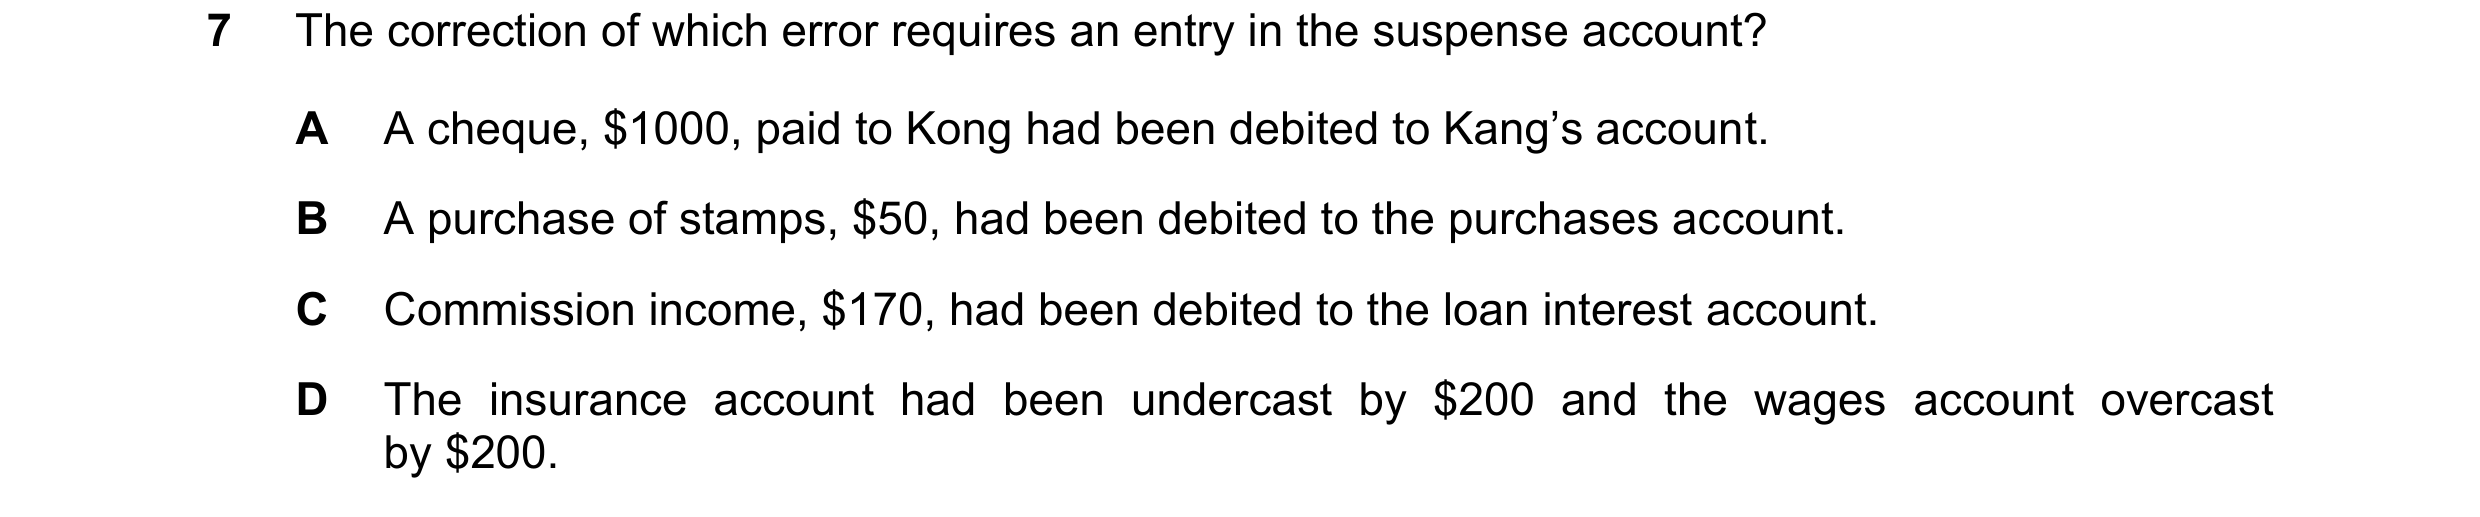
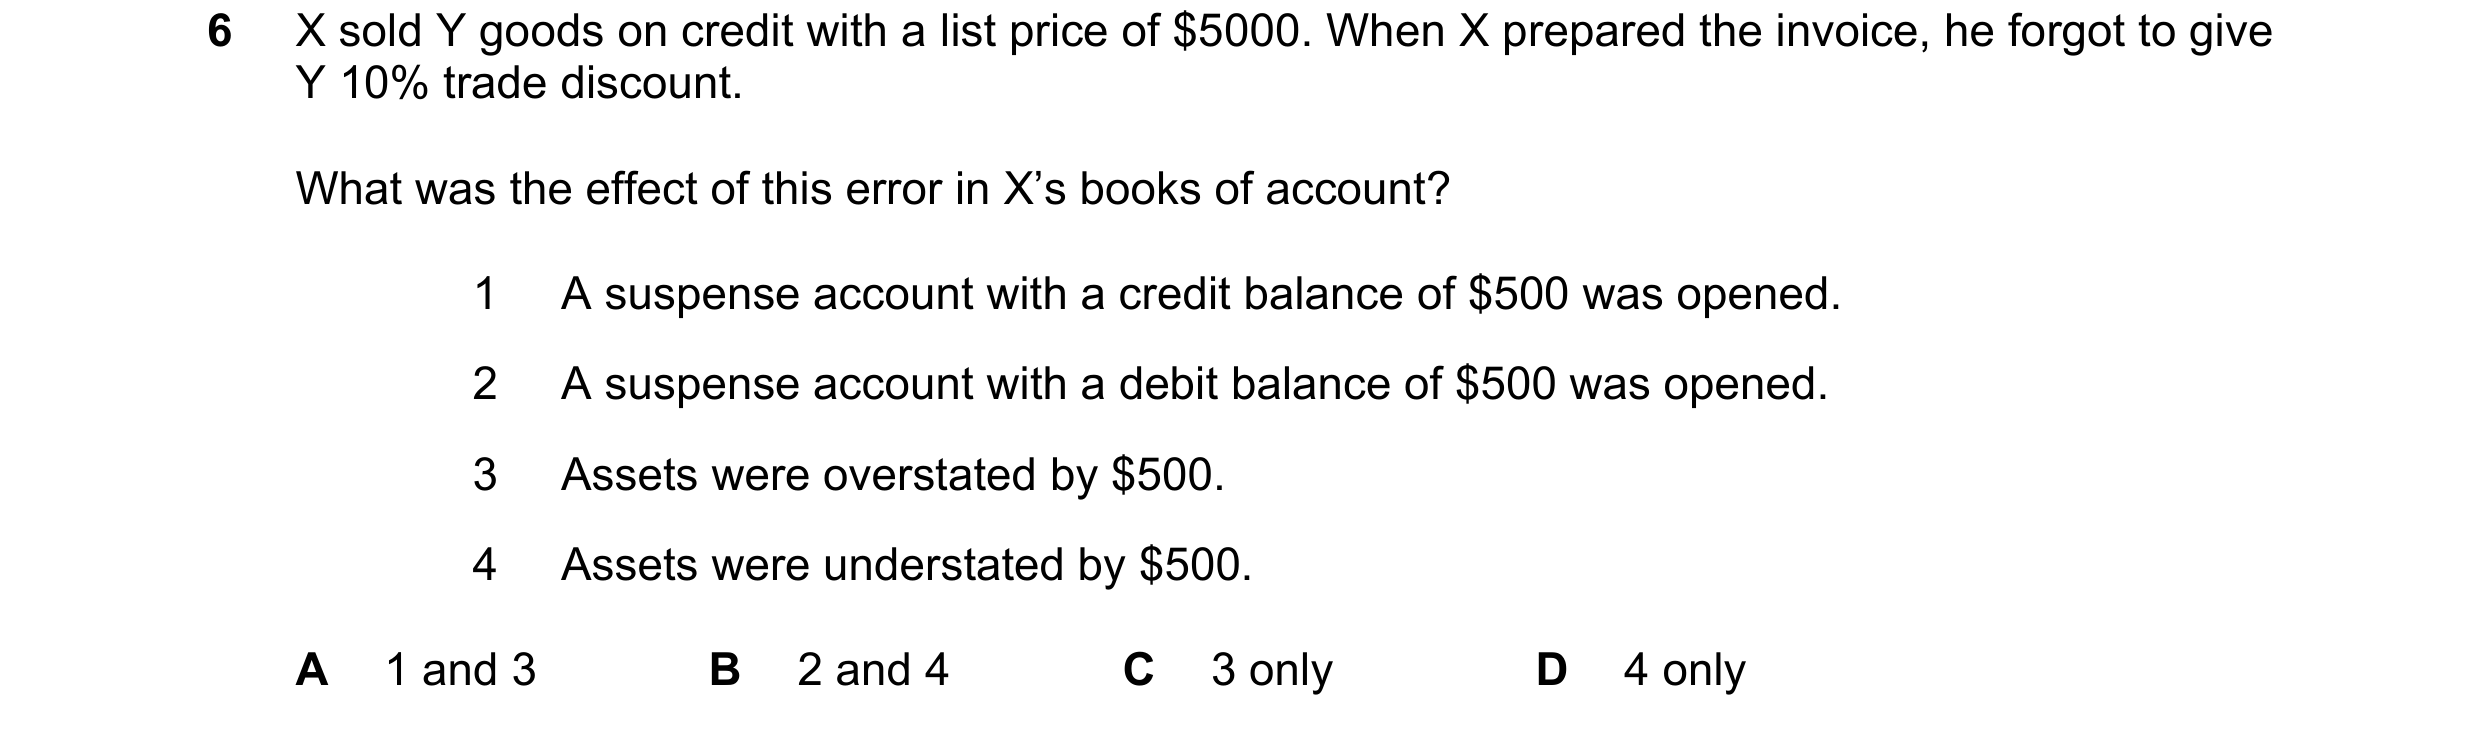 73 / 110
 74 / 110
 75 / 110
 76 / 110
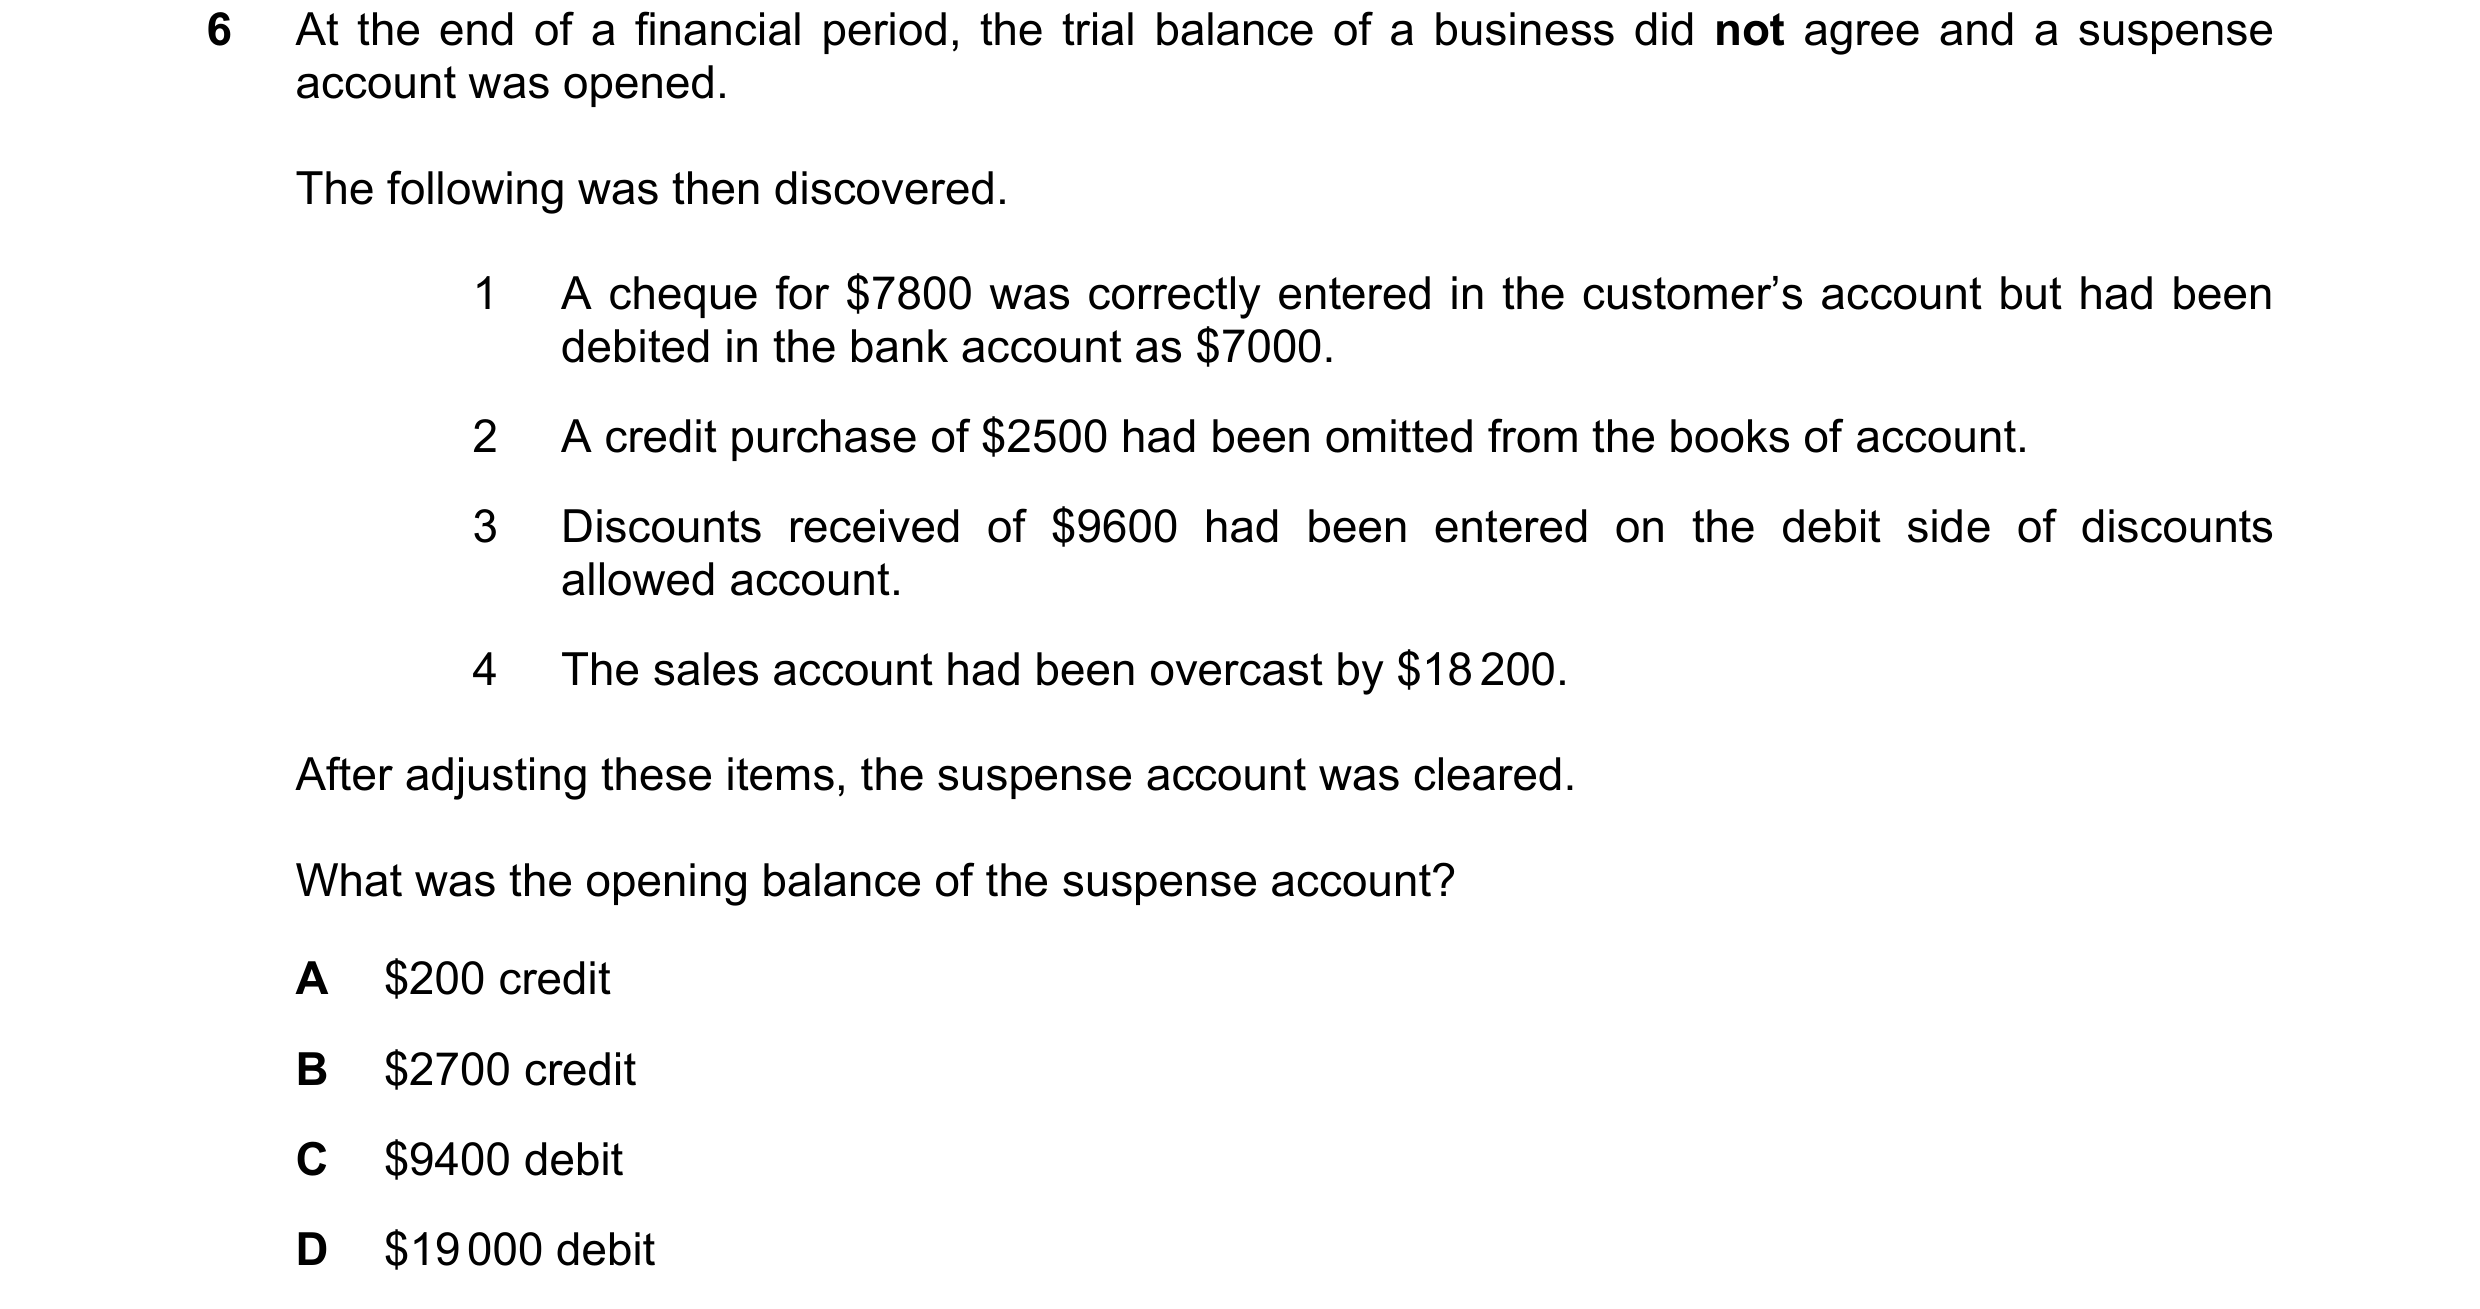
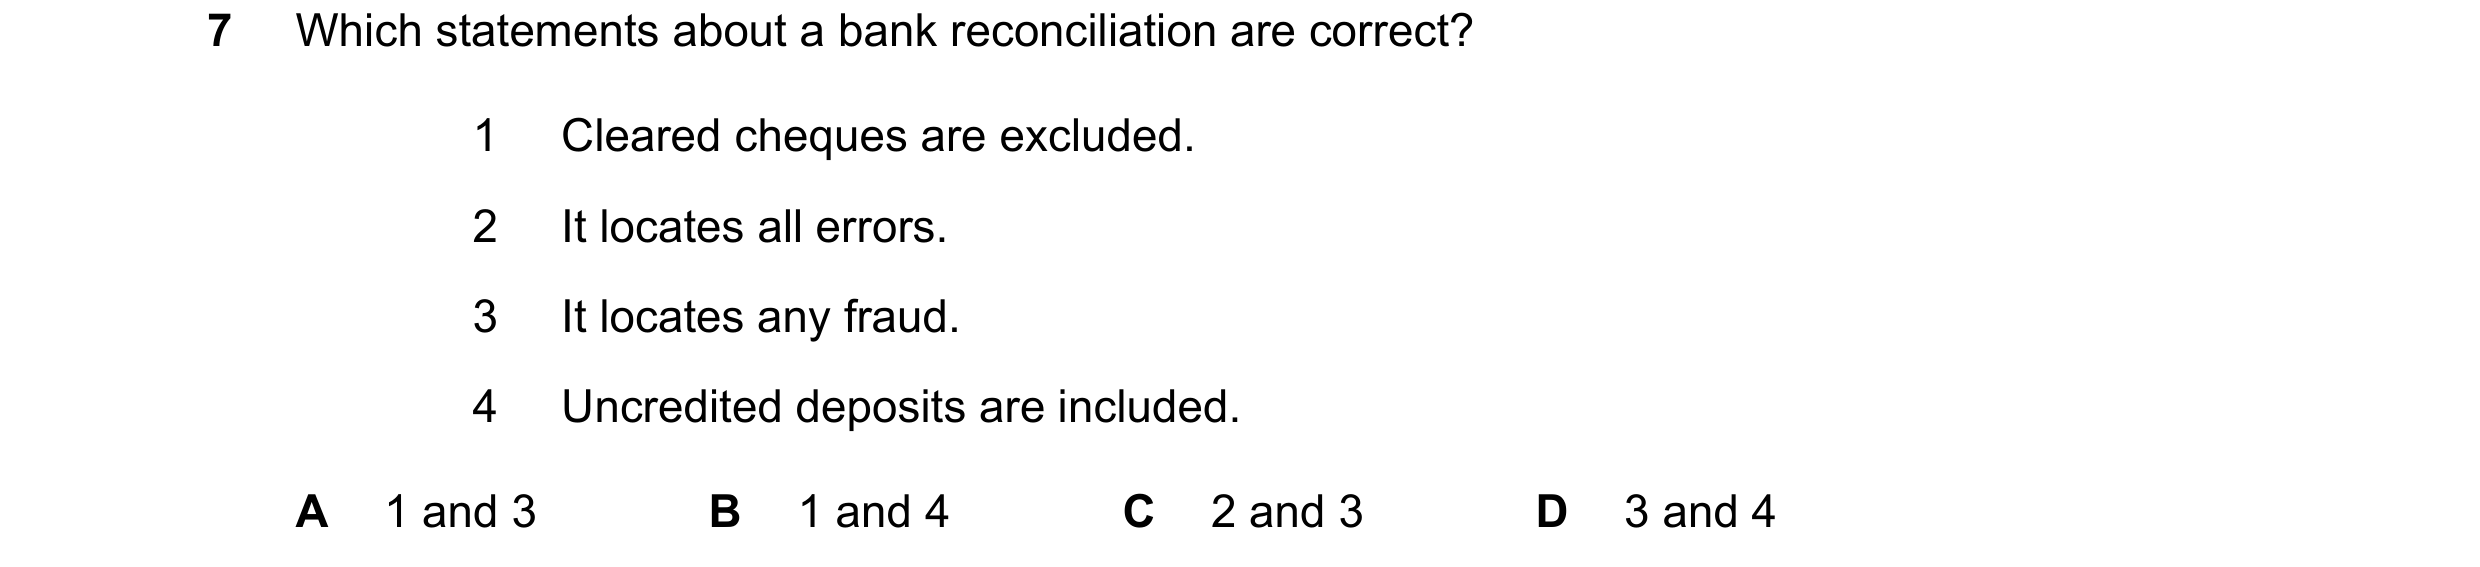
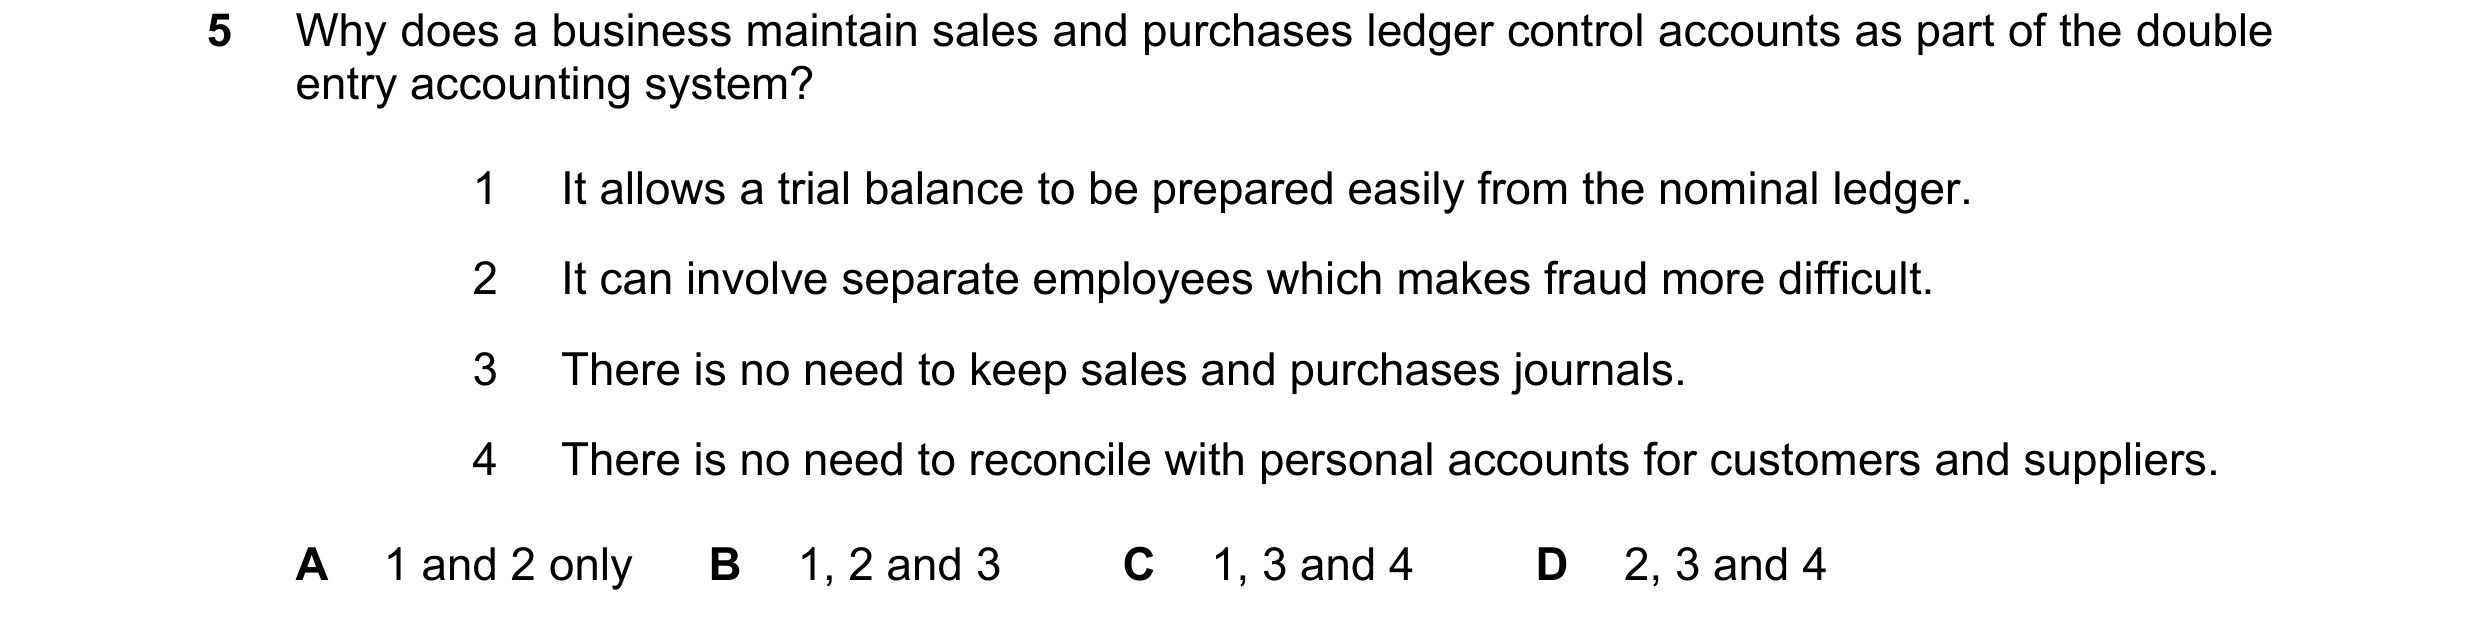 77 / 110
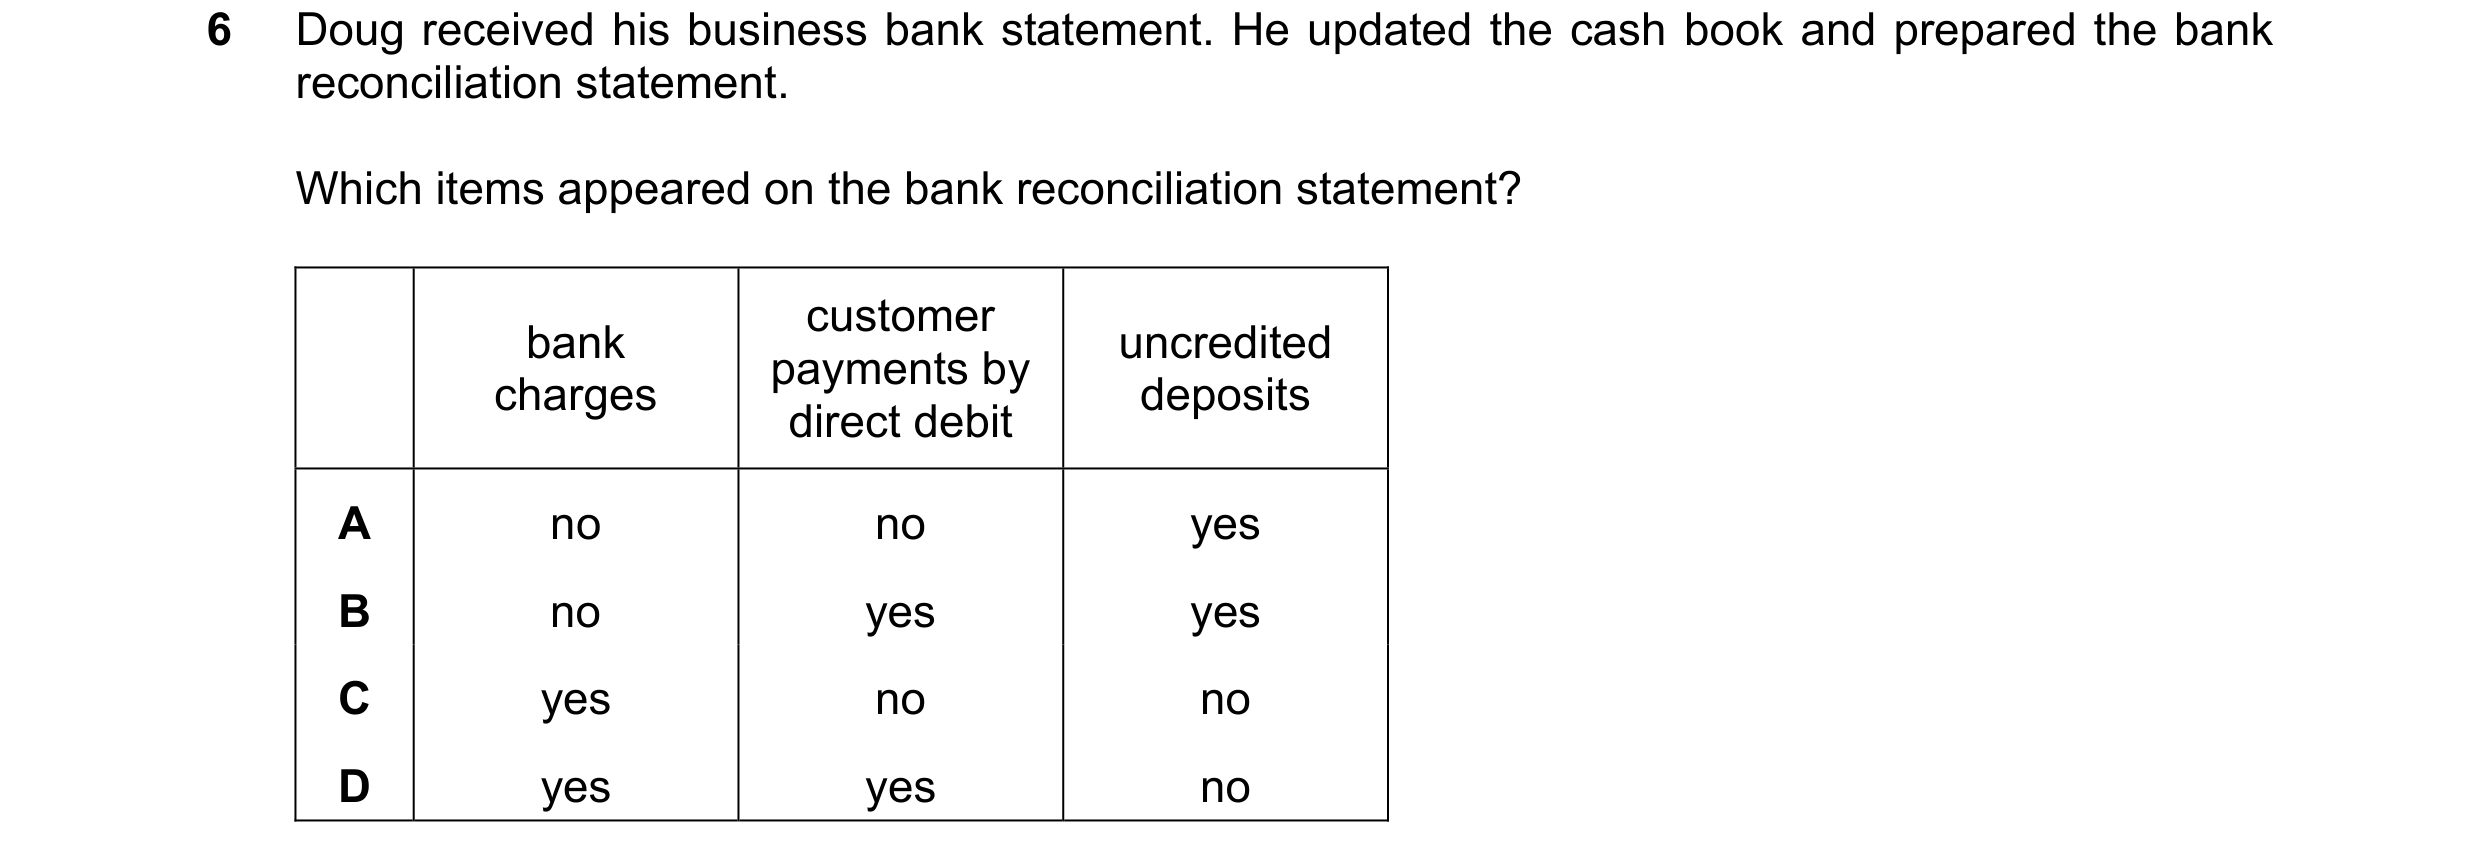
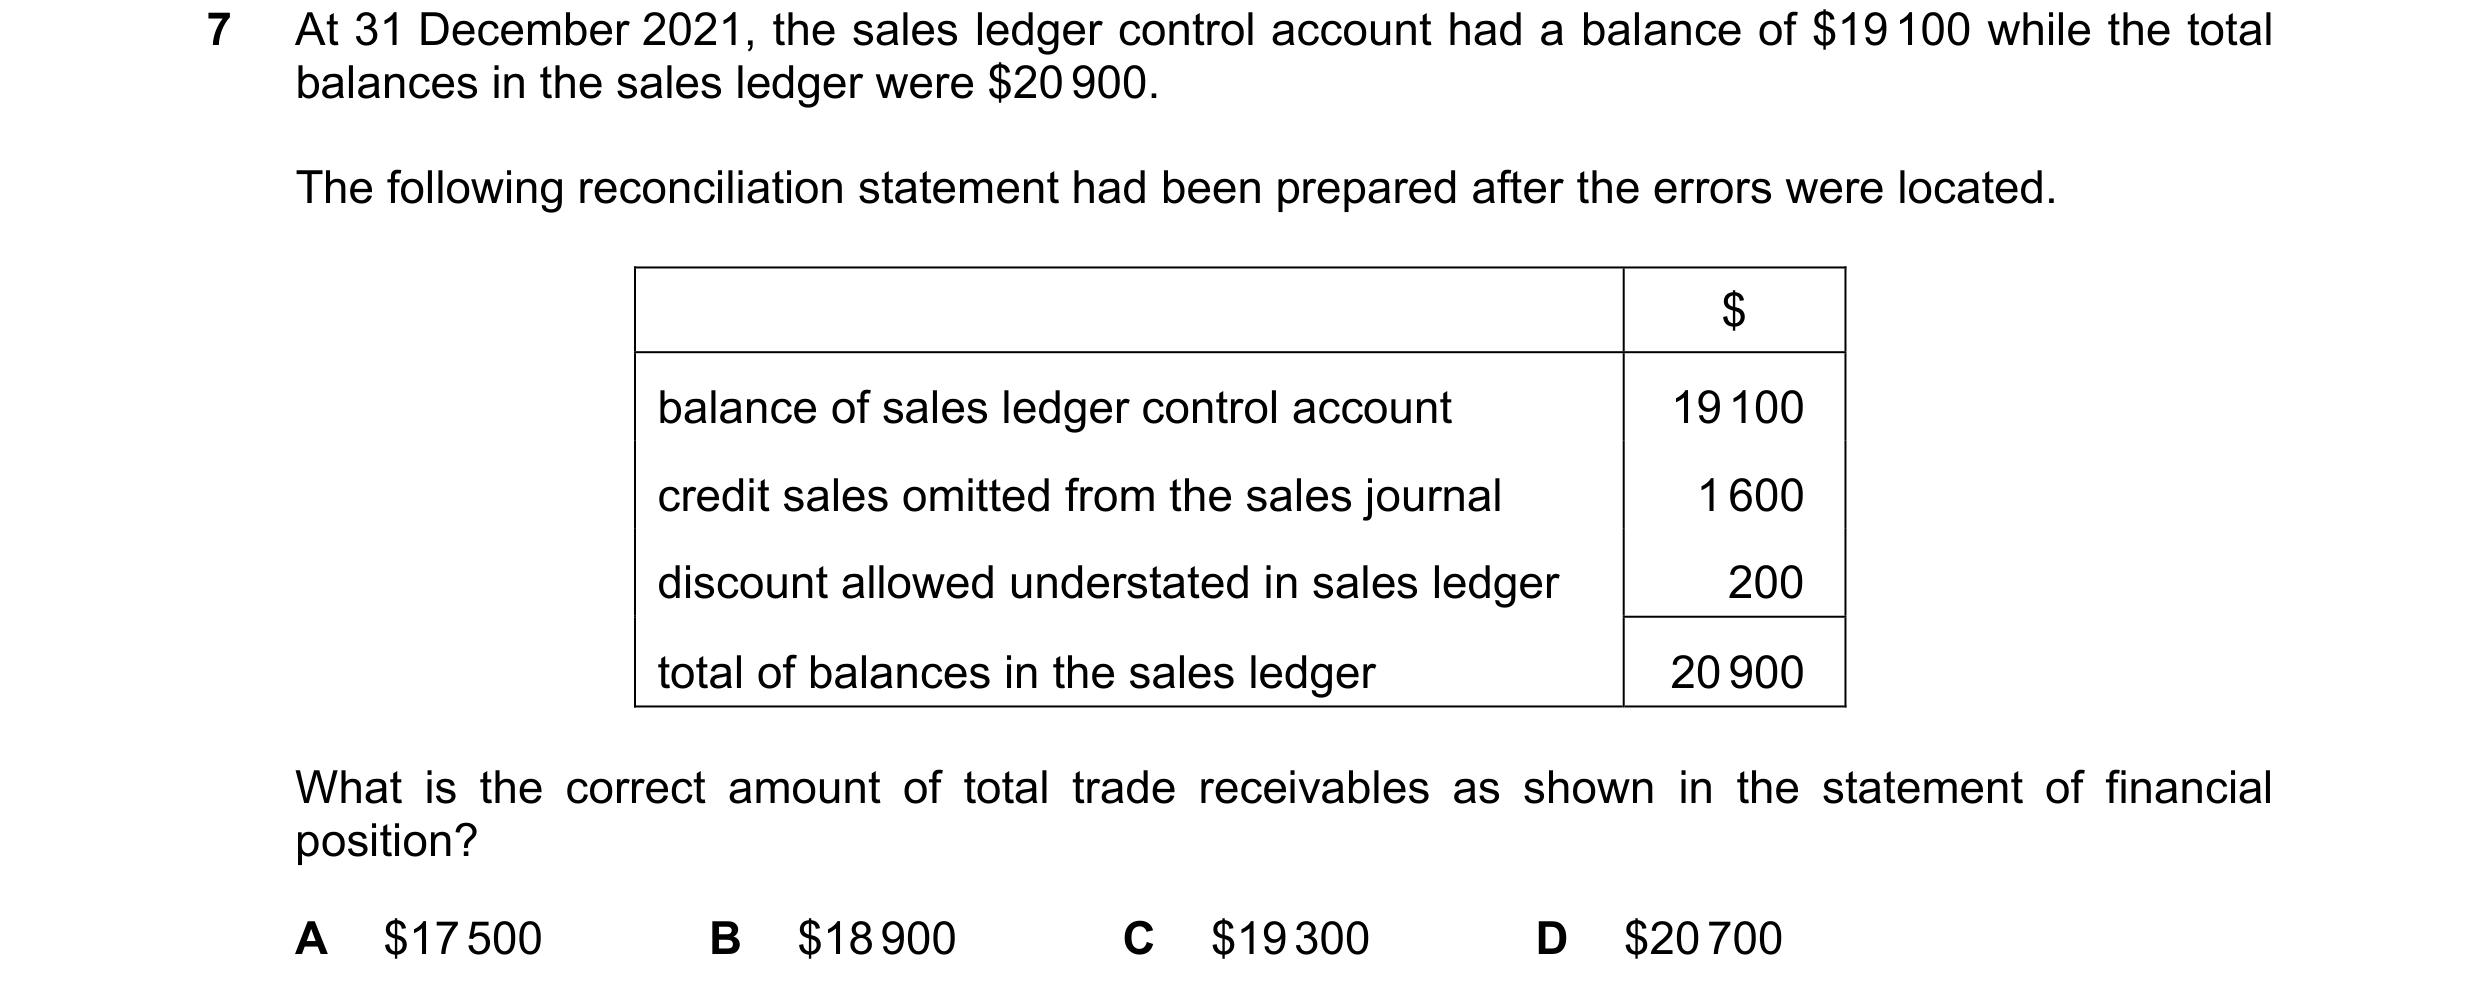
 78 / 110
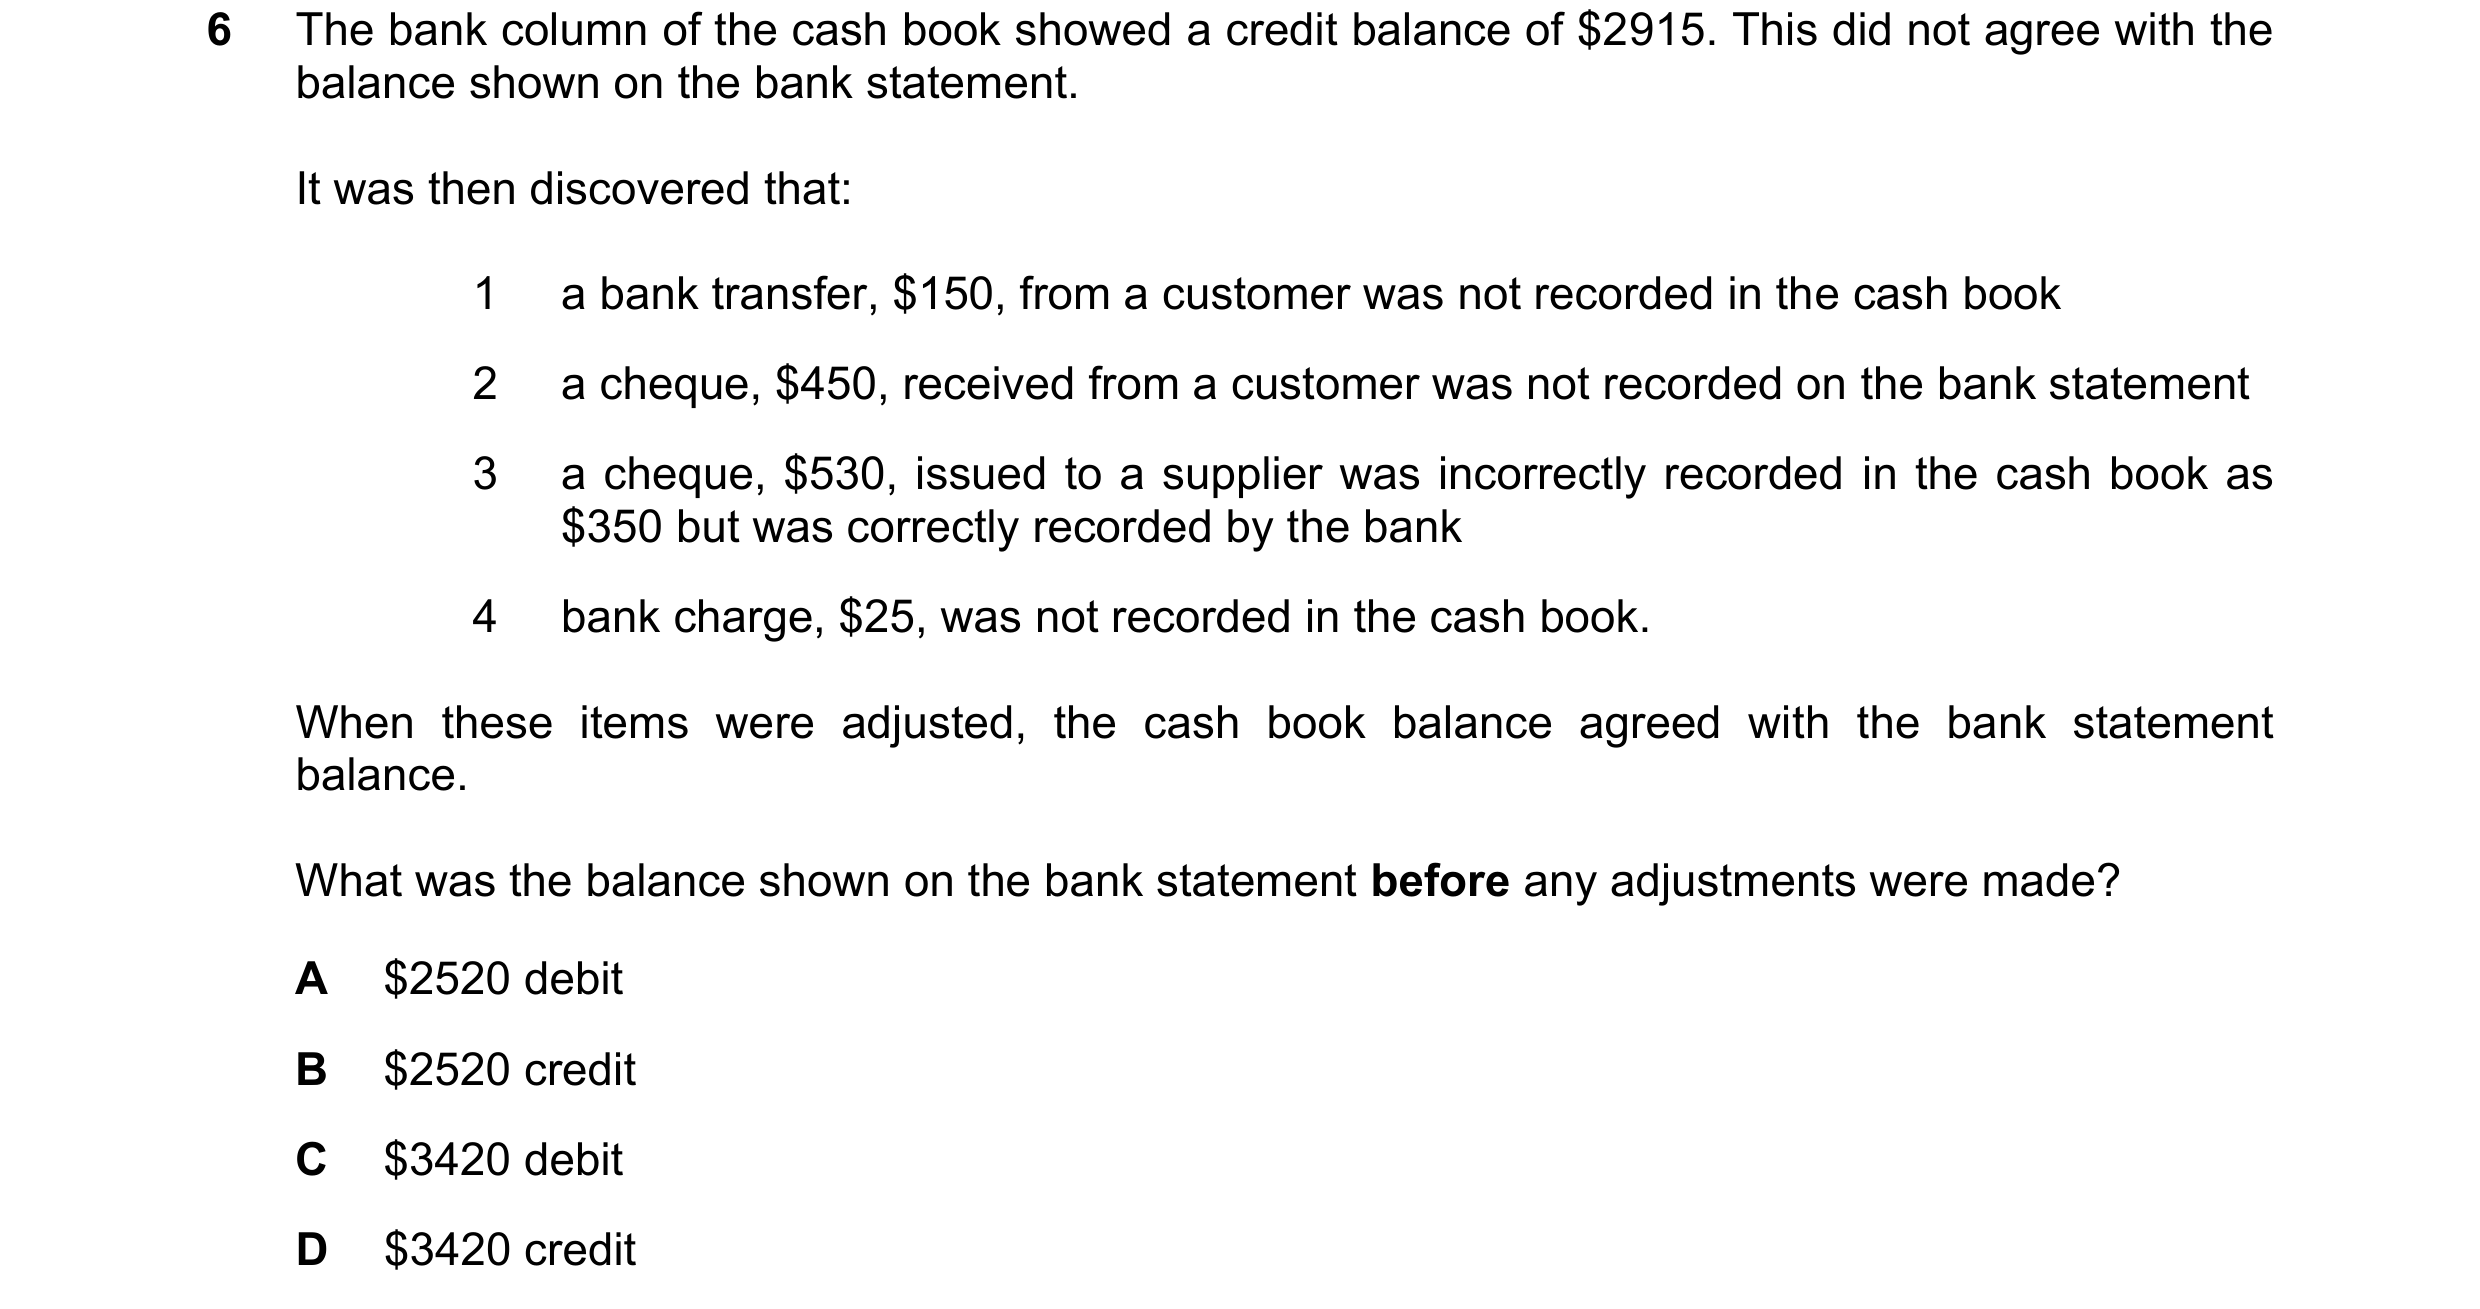
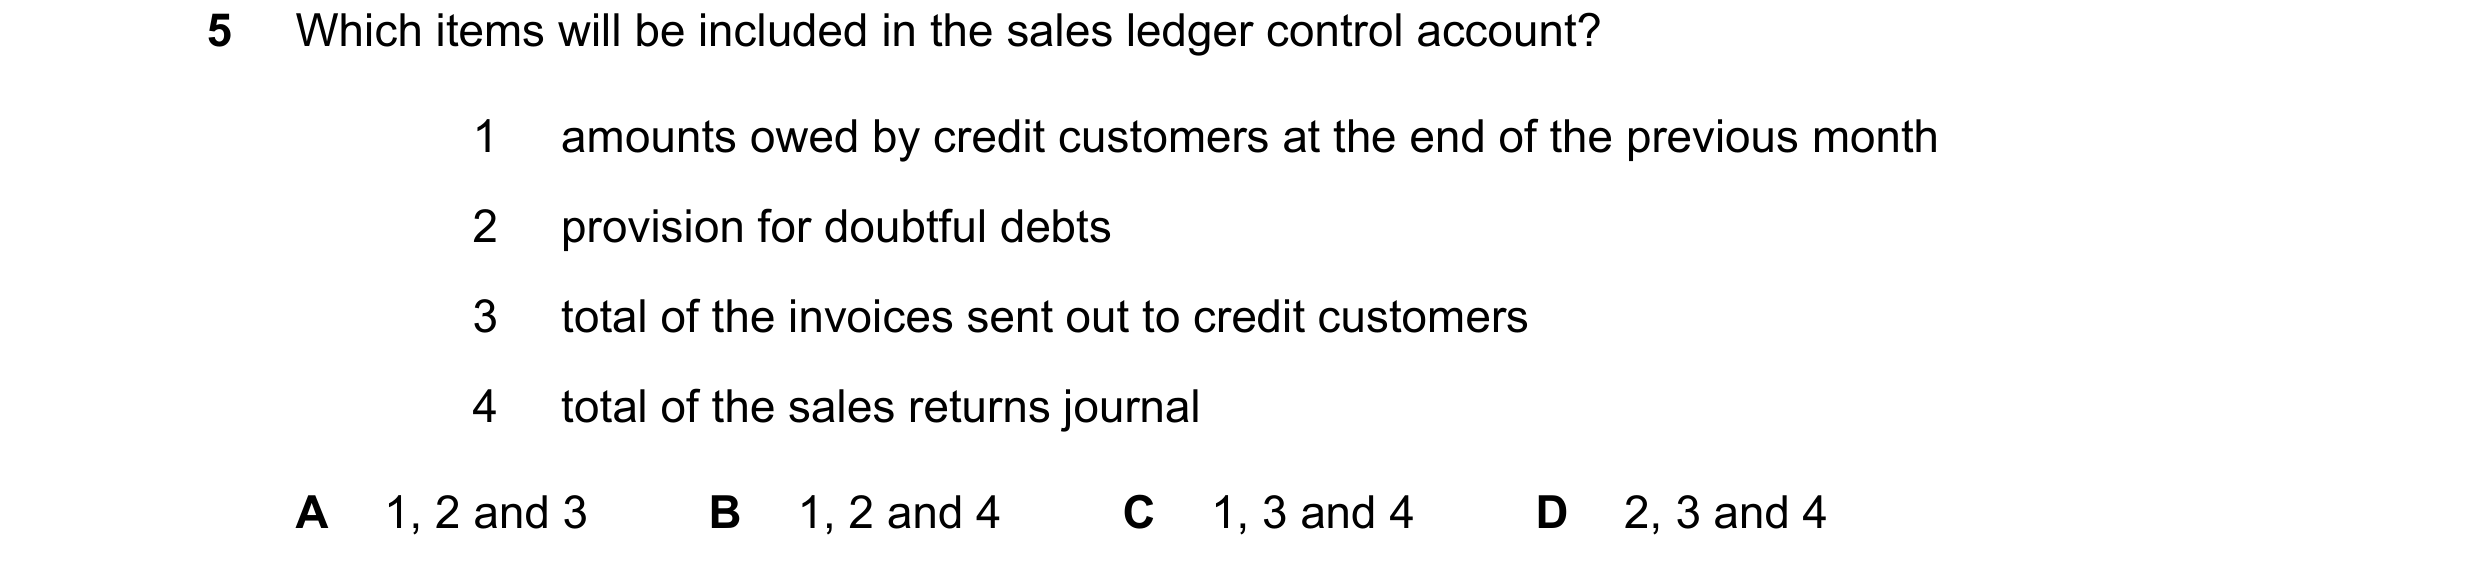
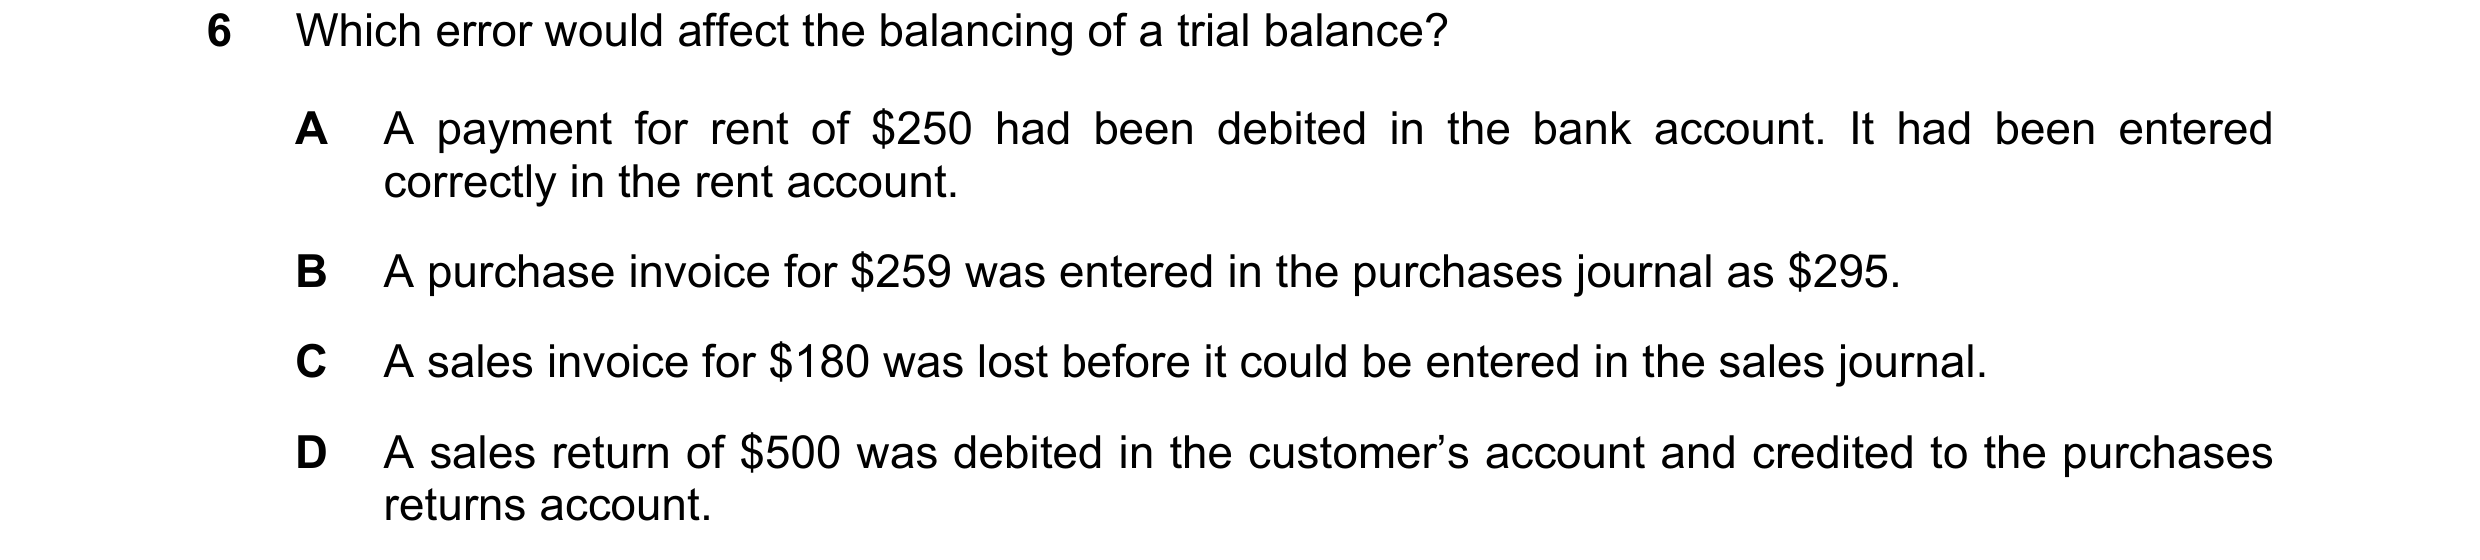 79 / 110
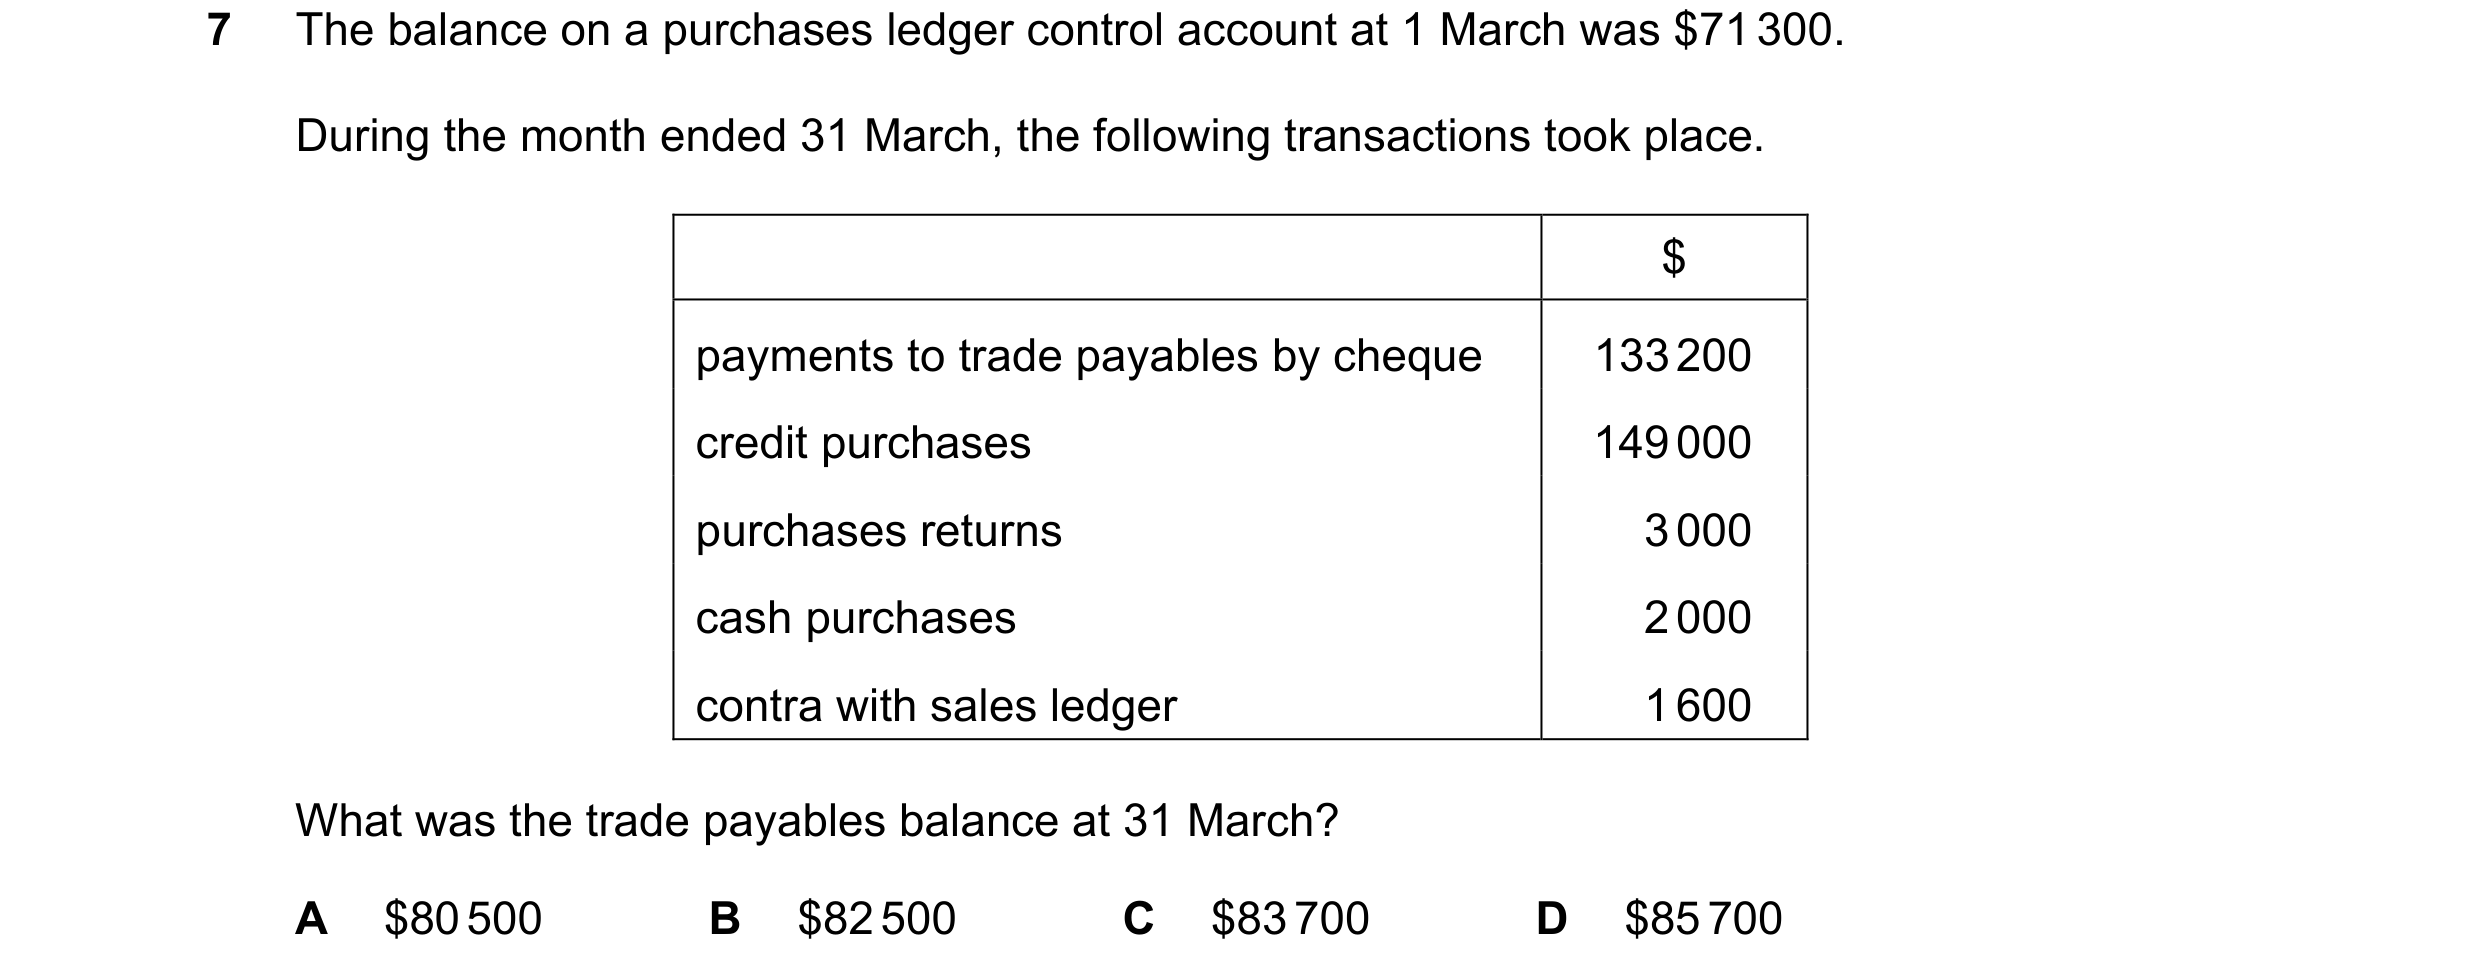
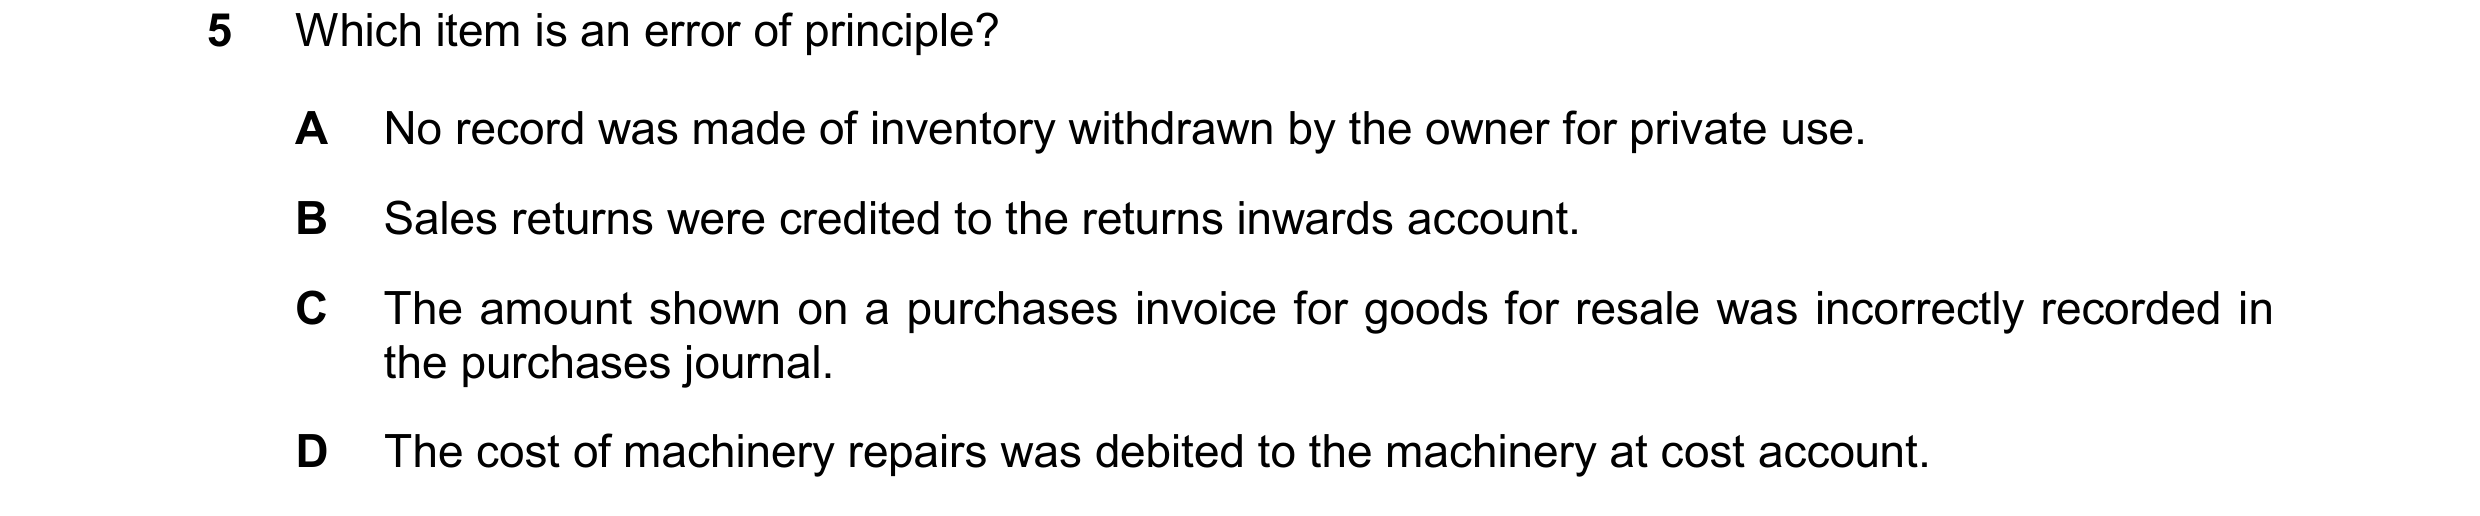
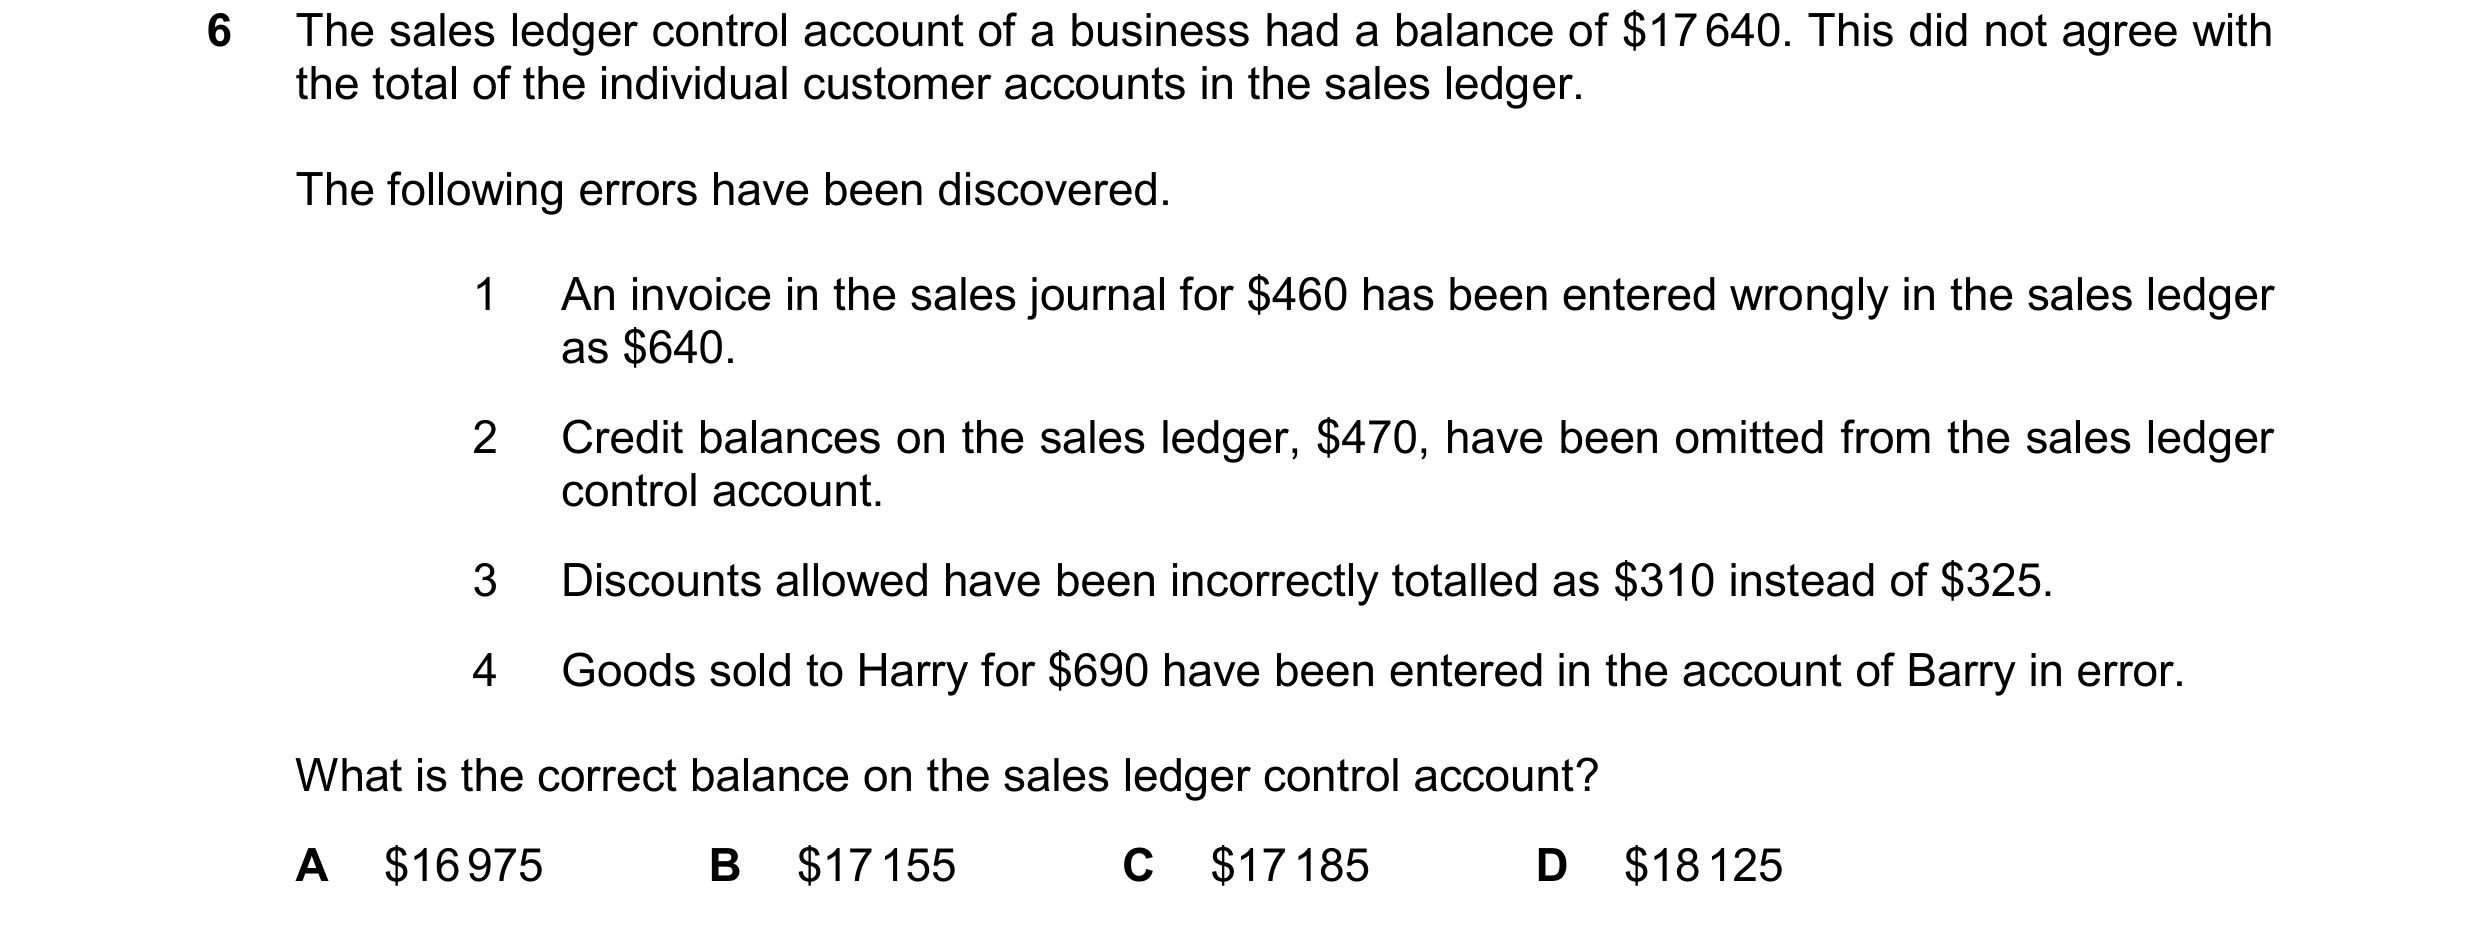
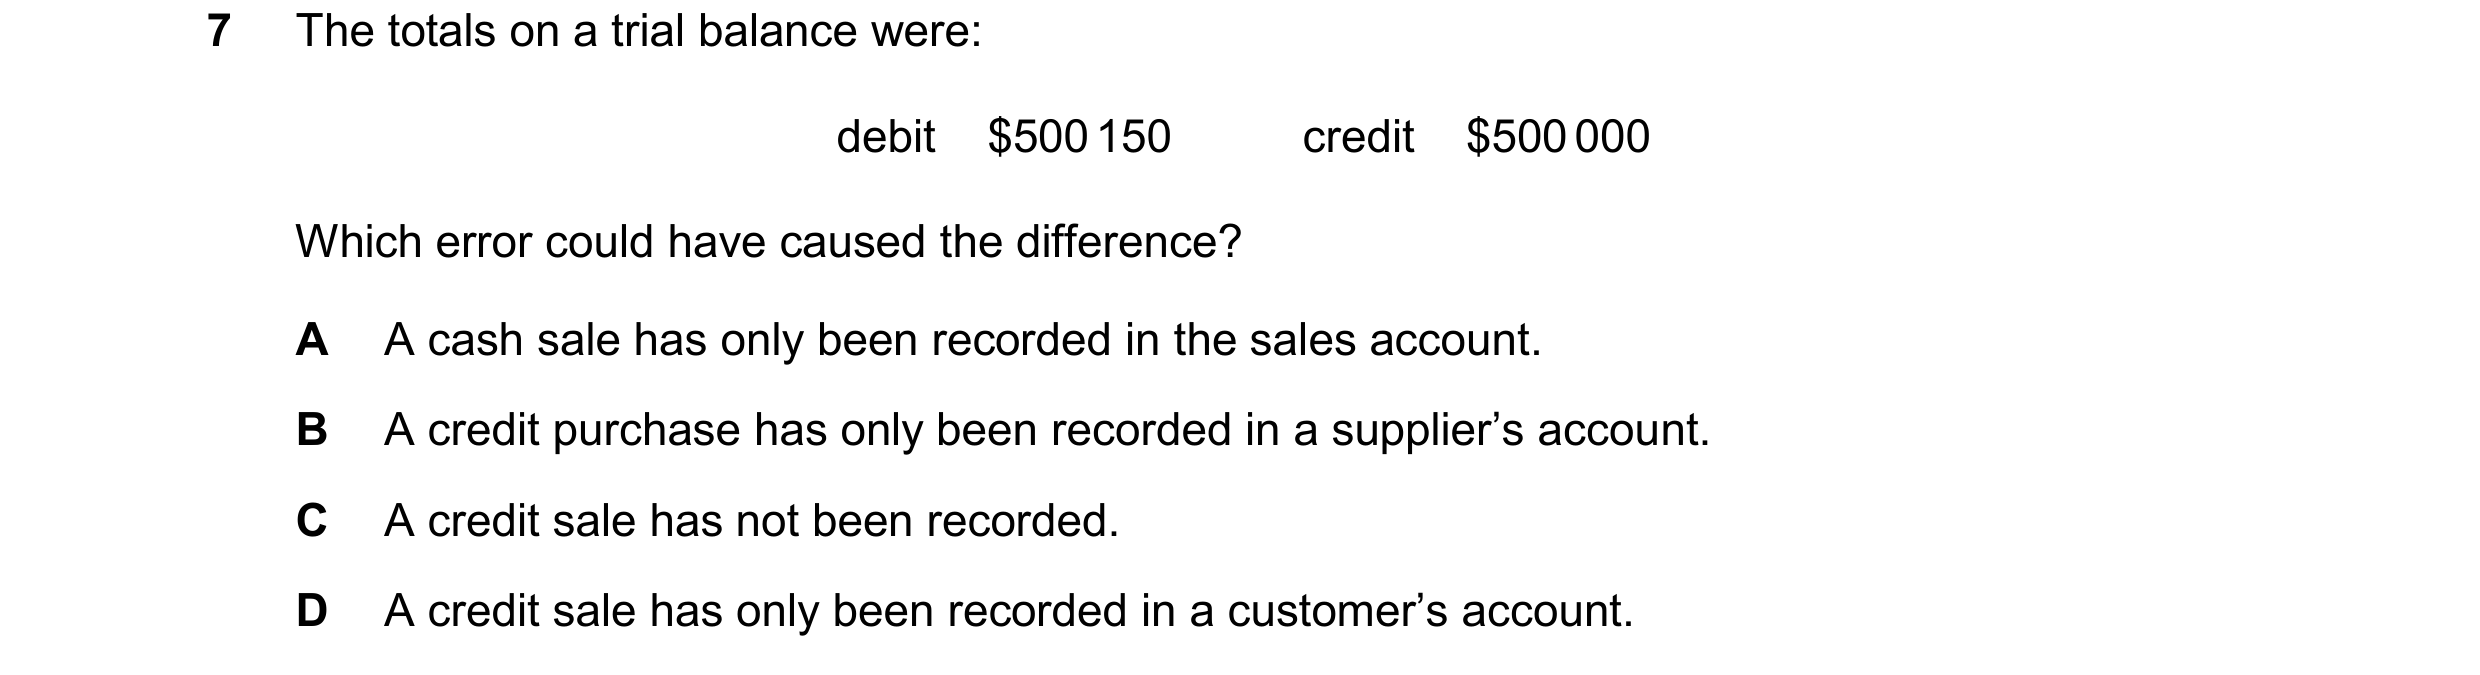 80 / 110
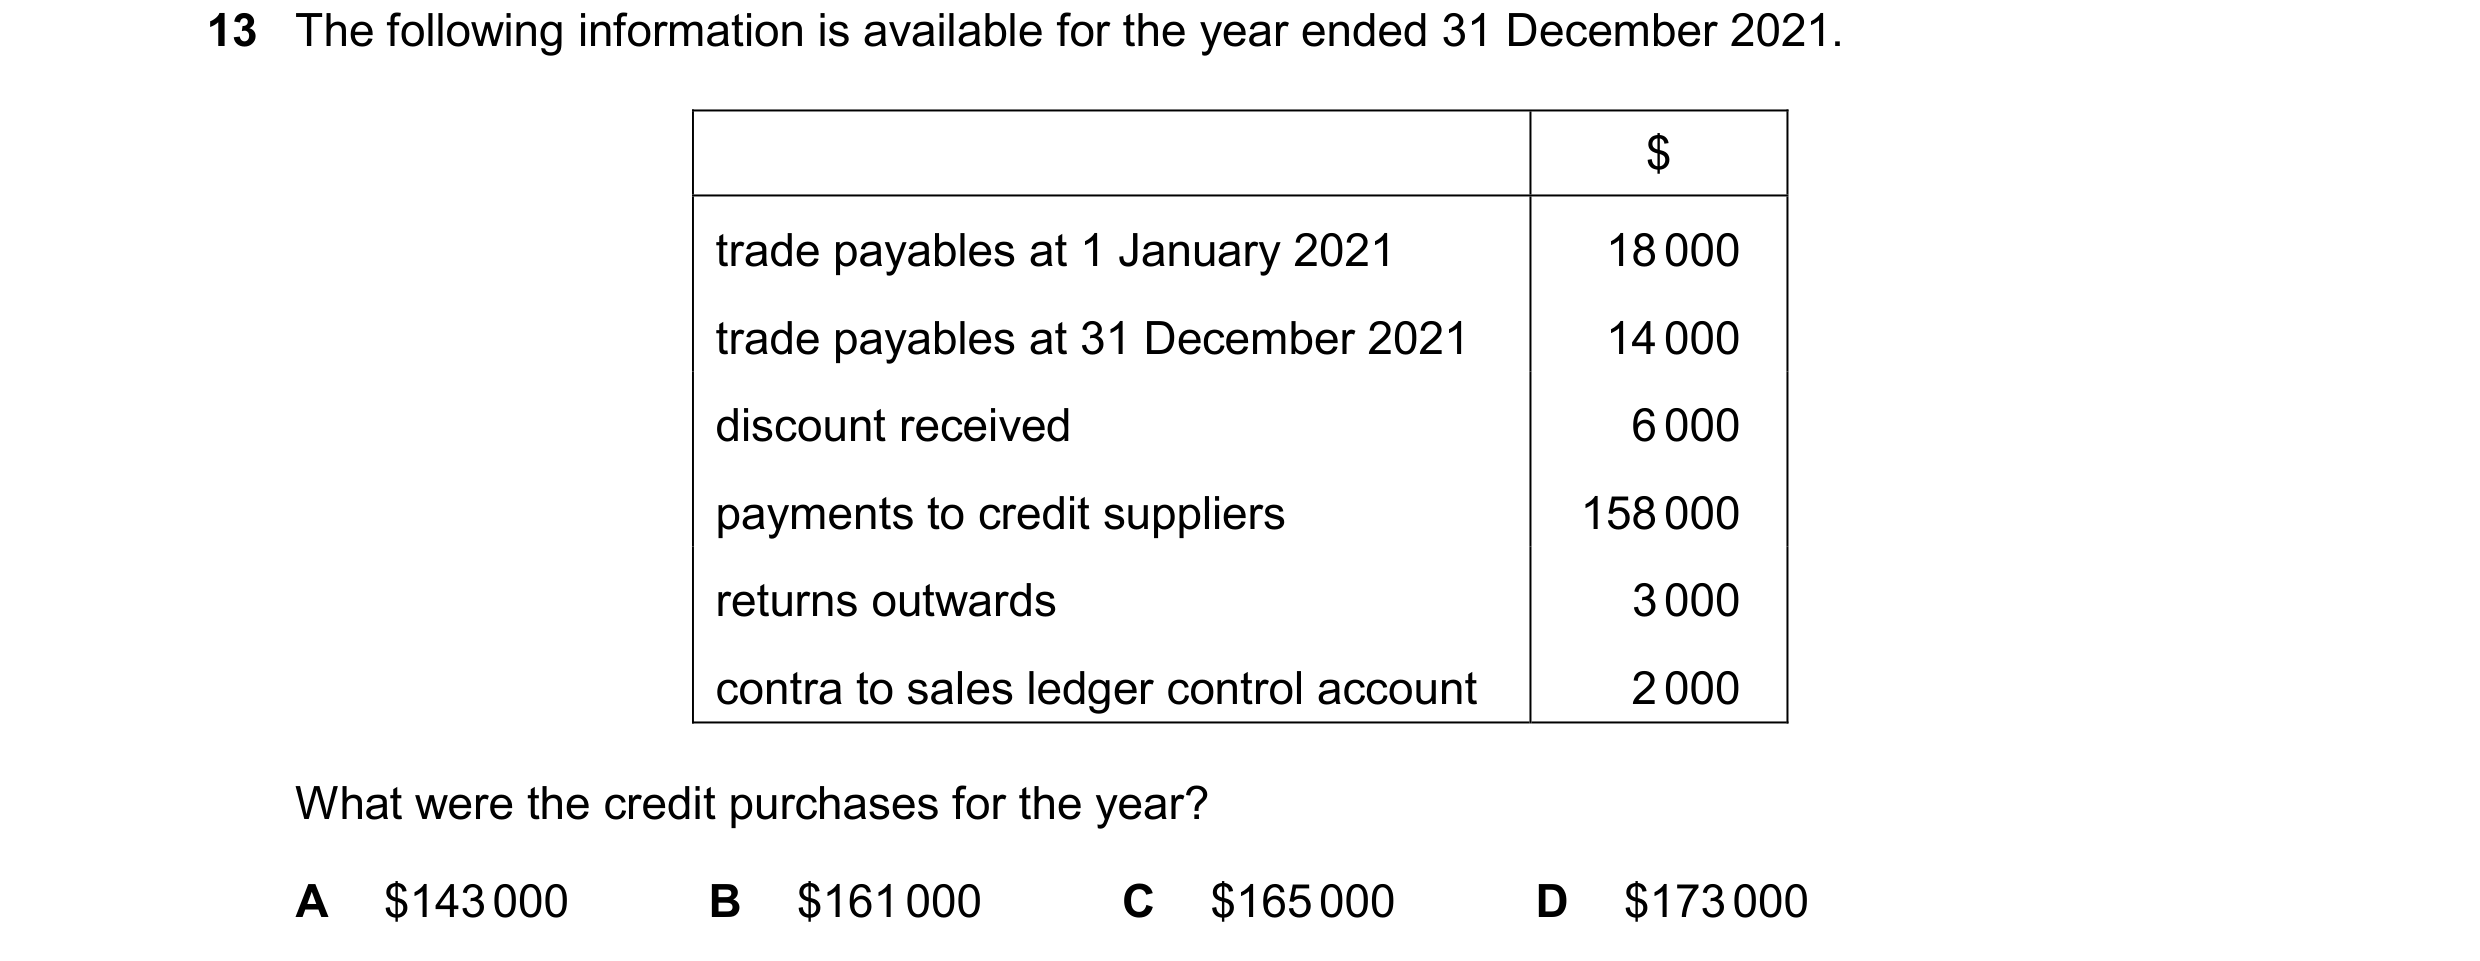
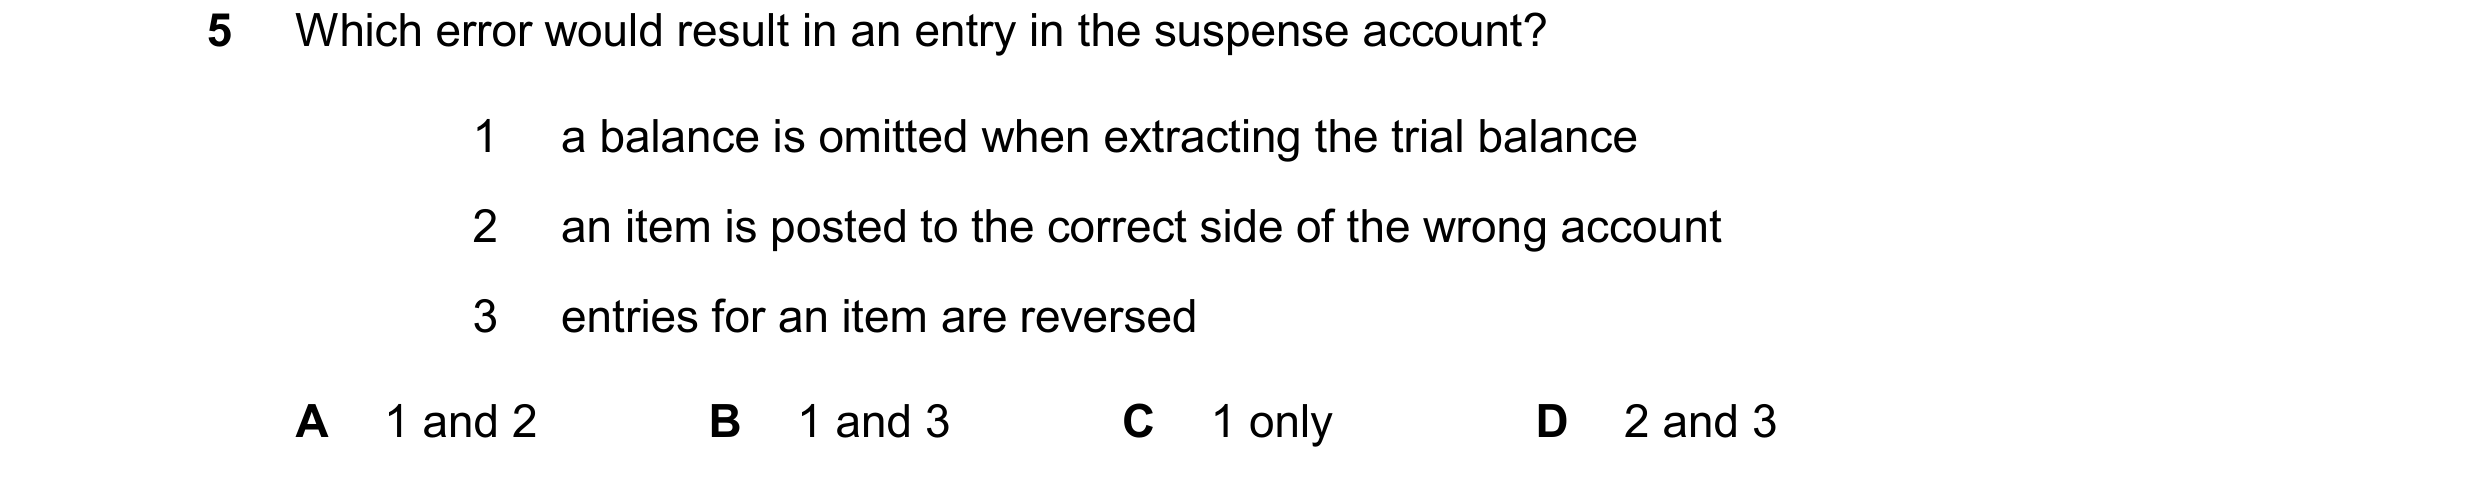
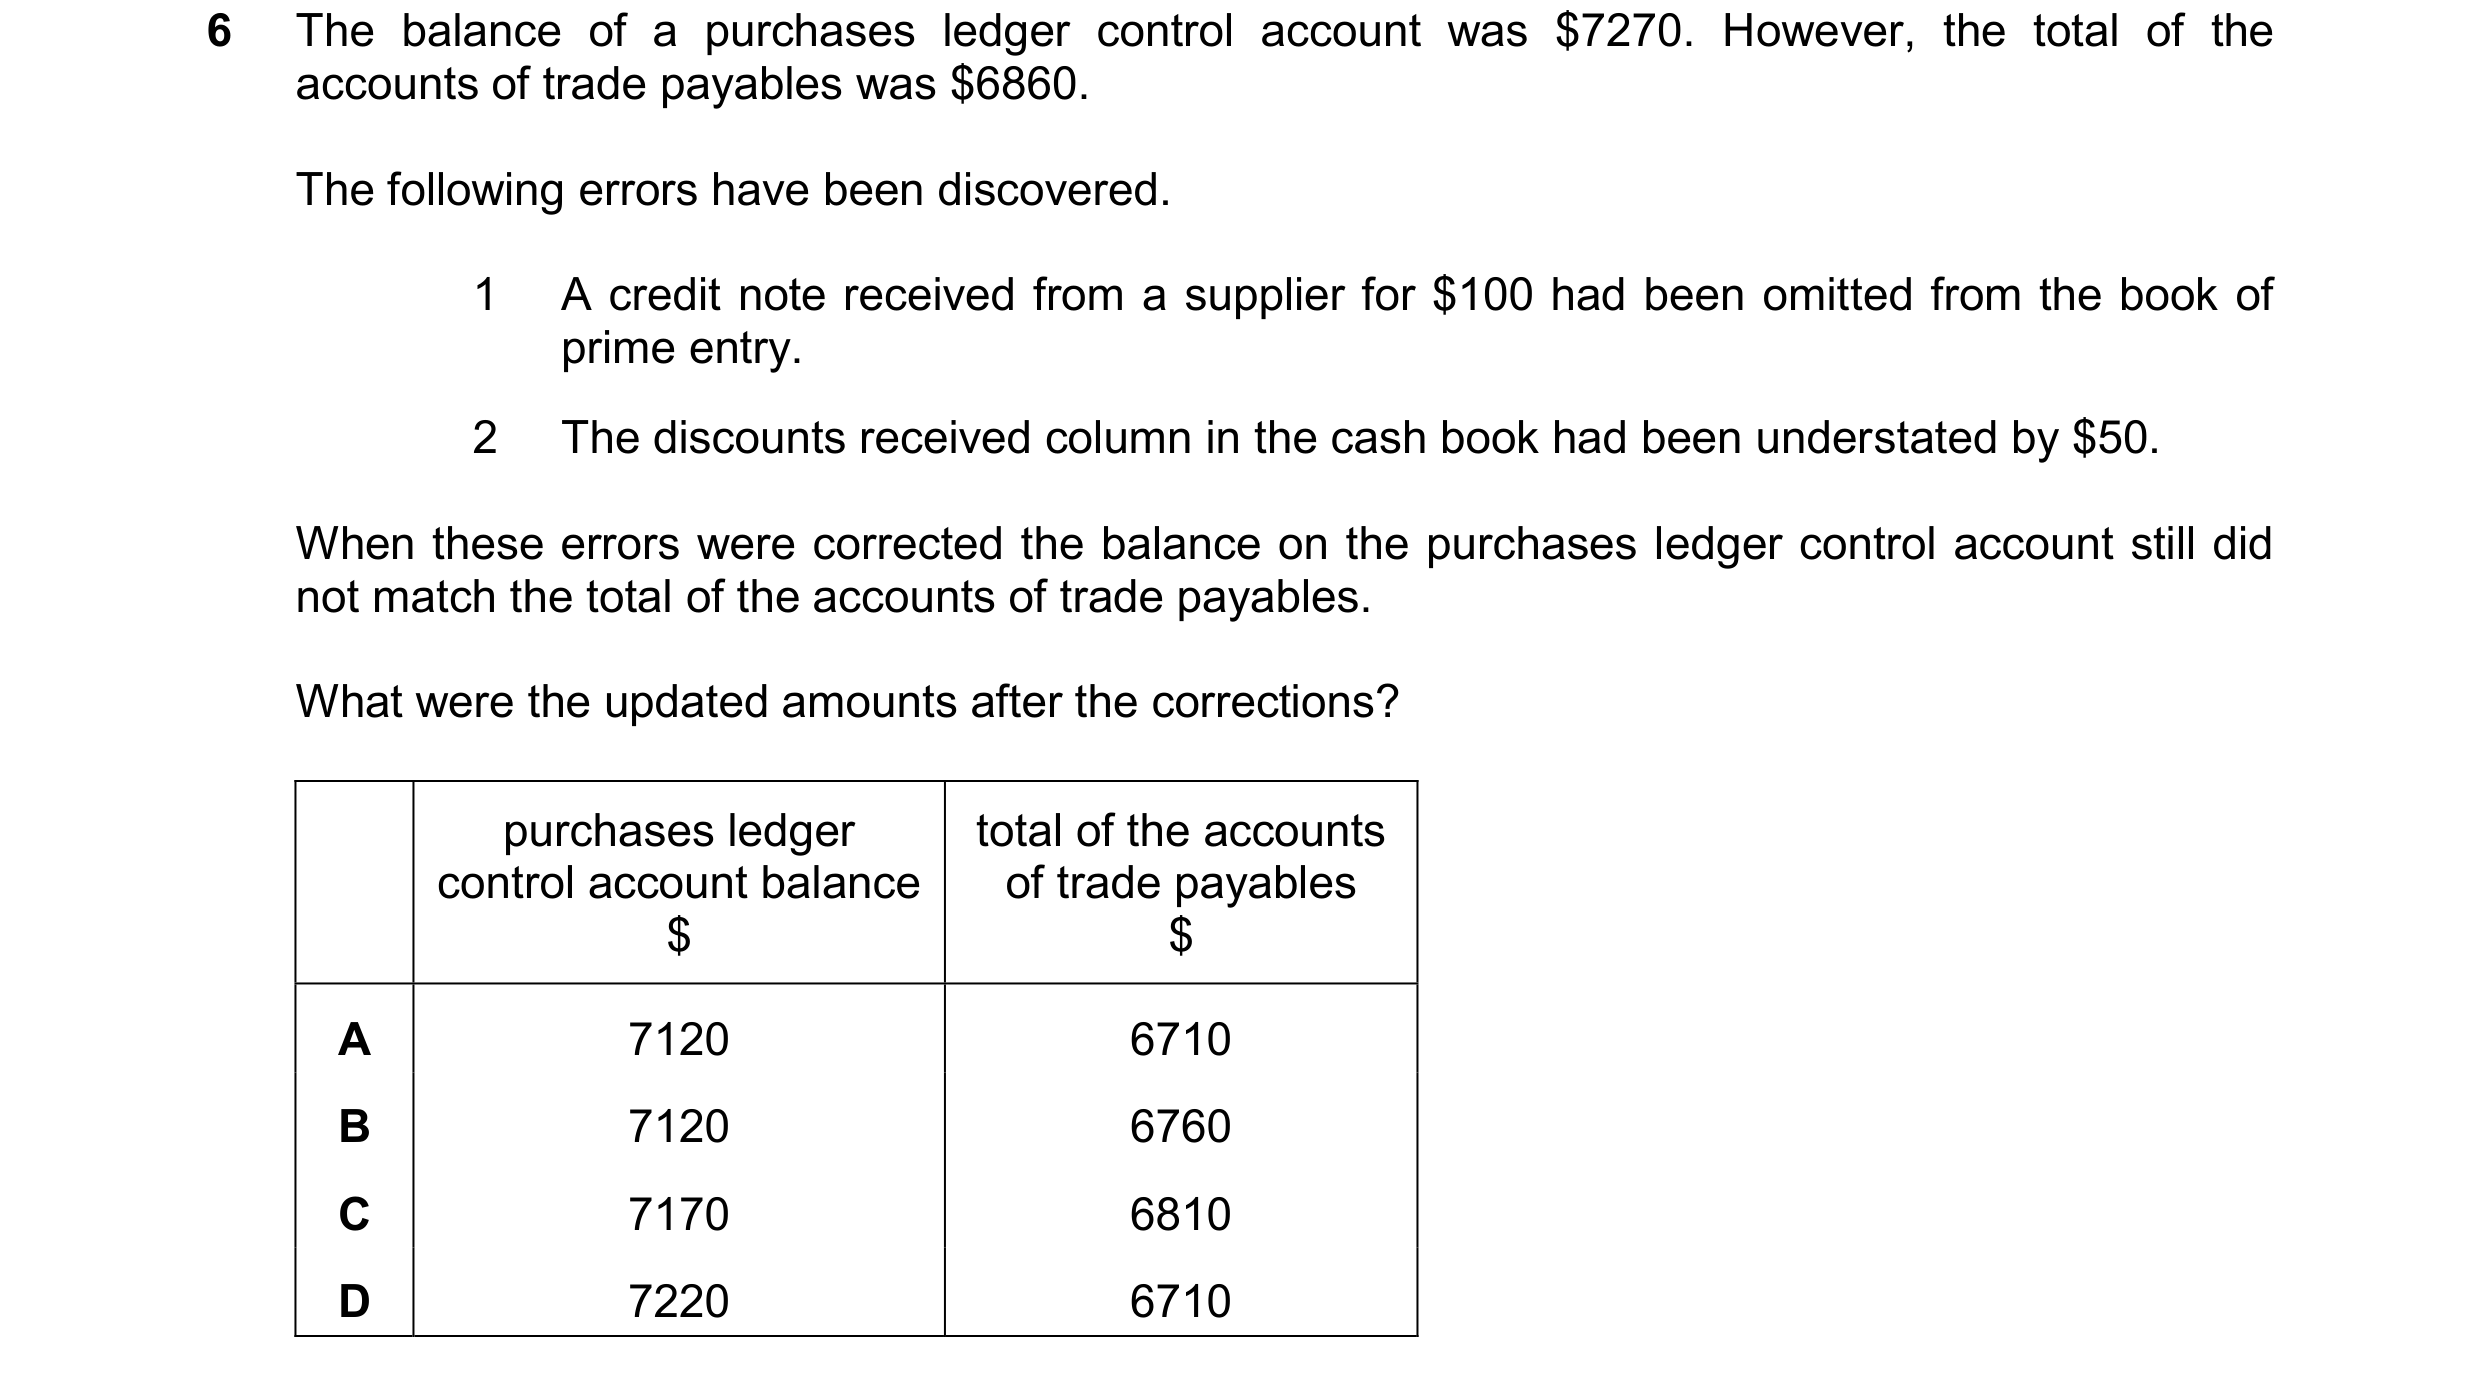
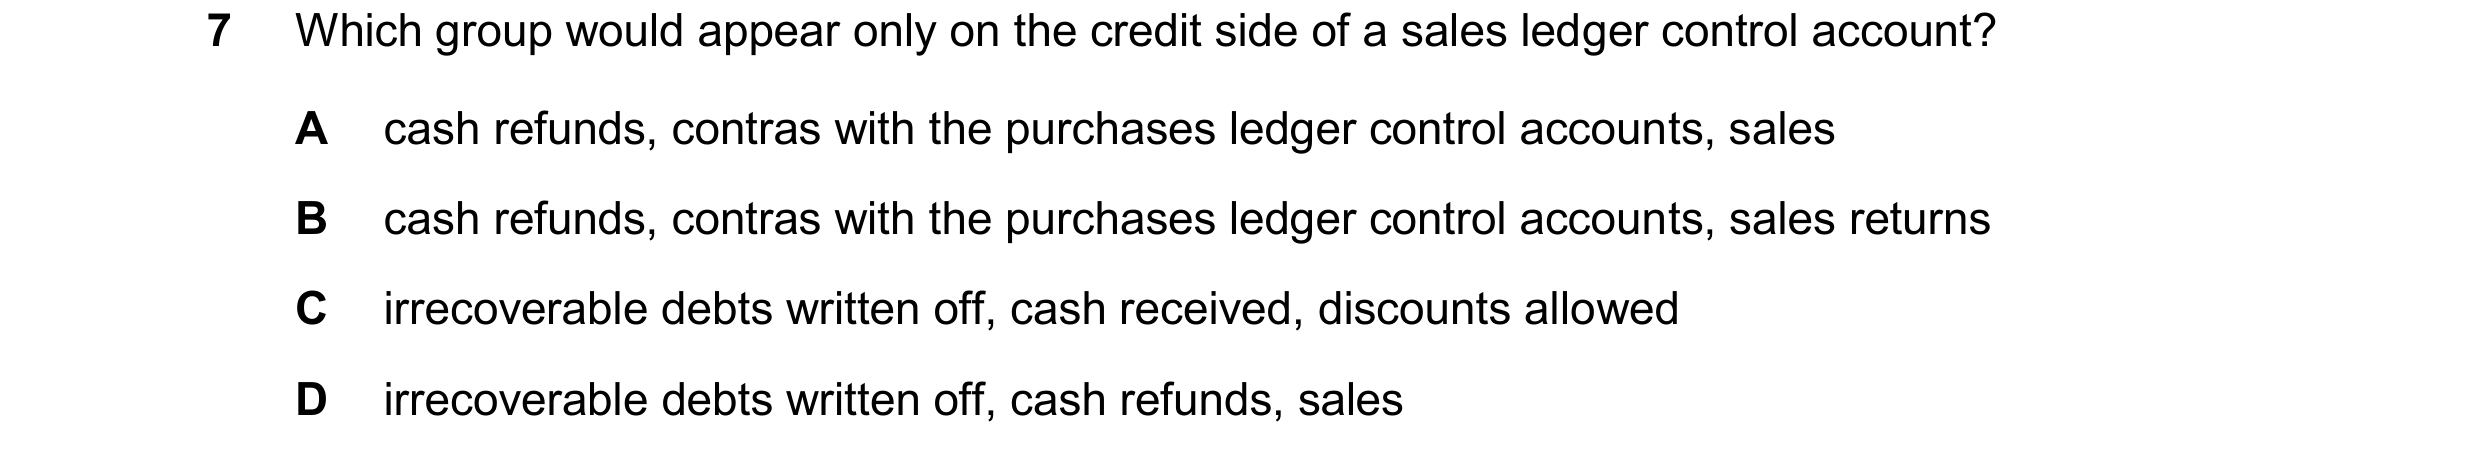 81 / 110
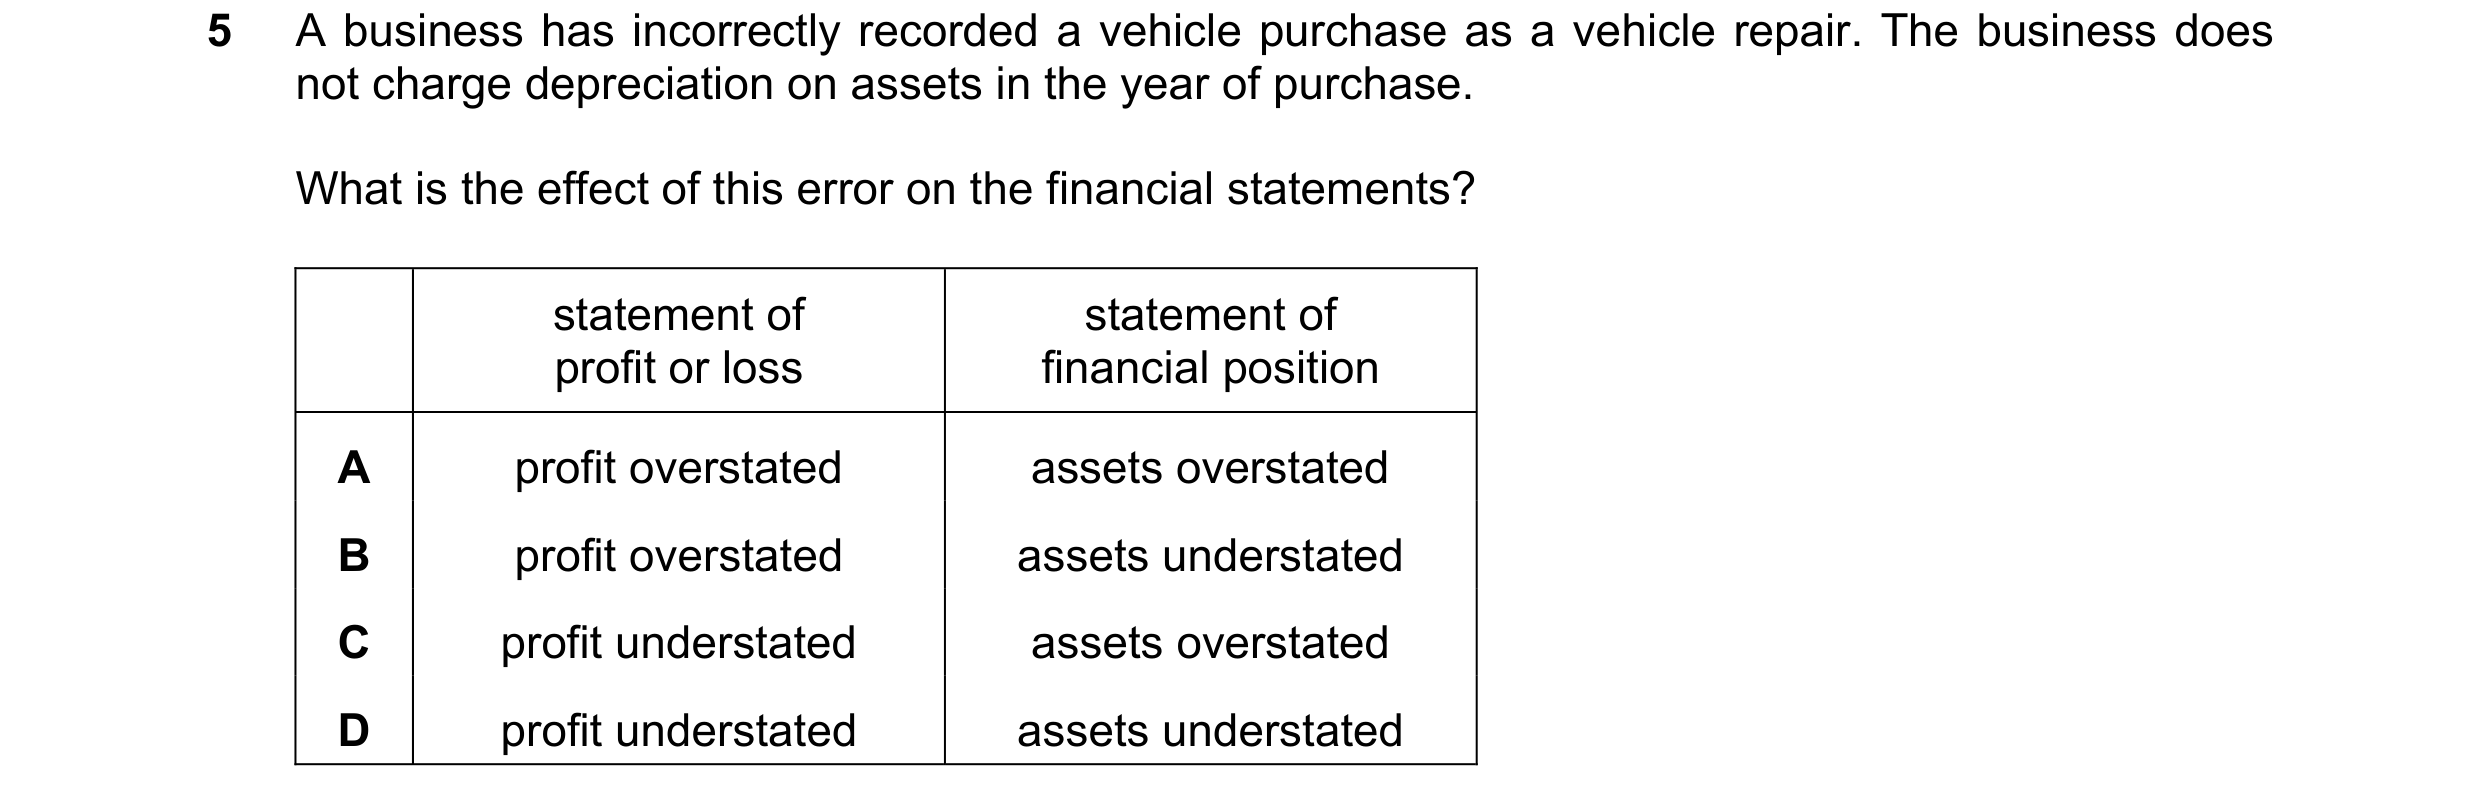
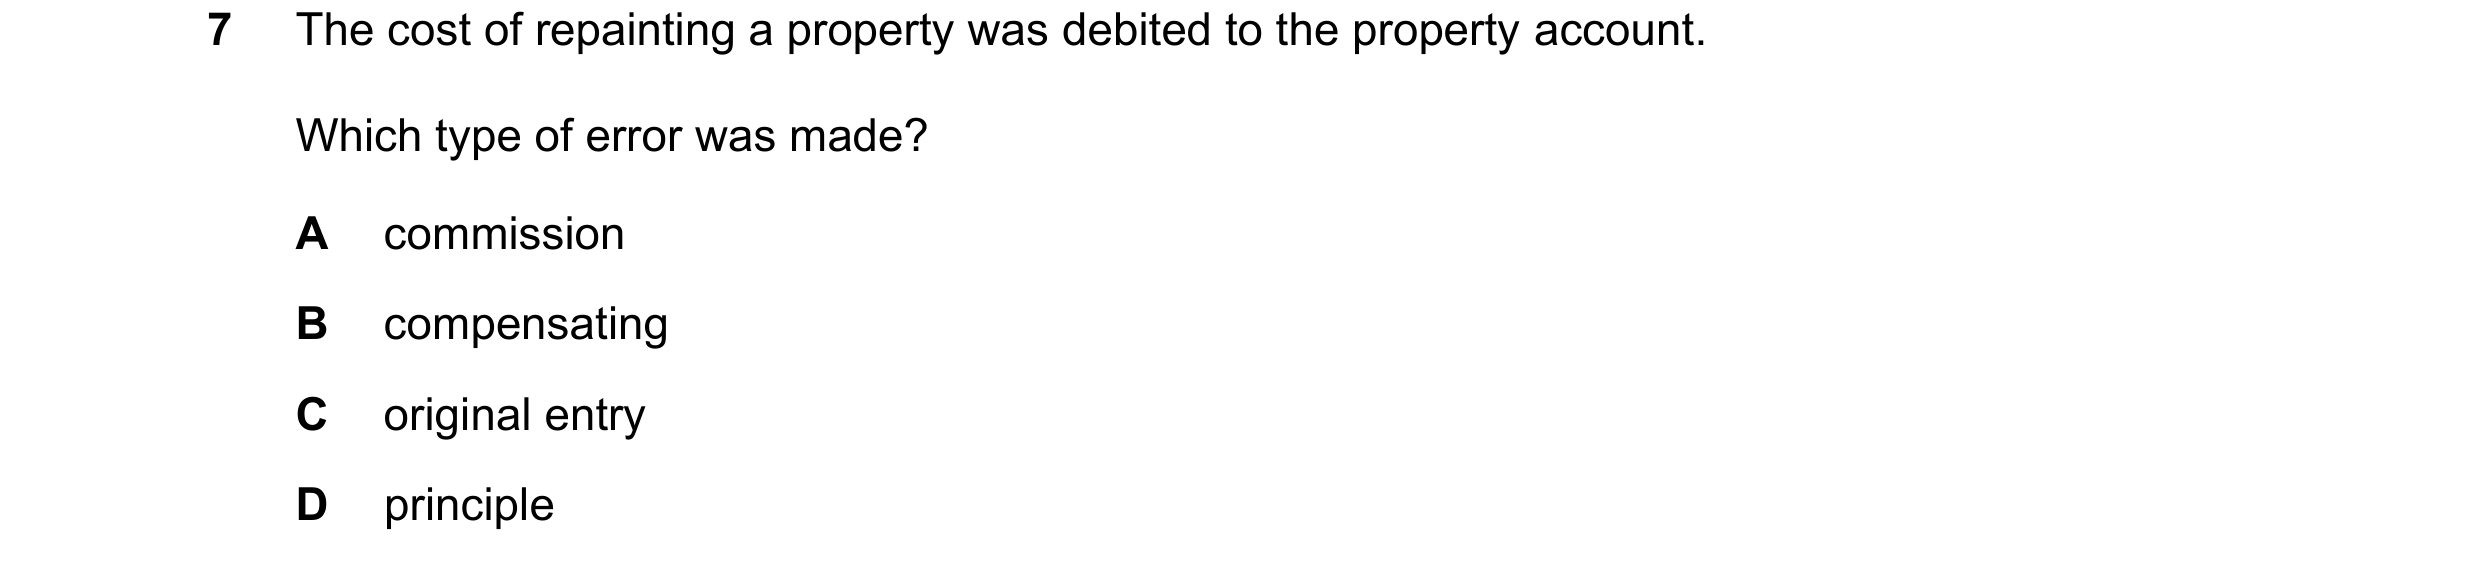
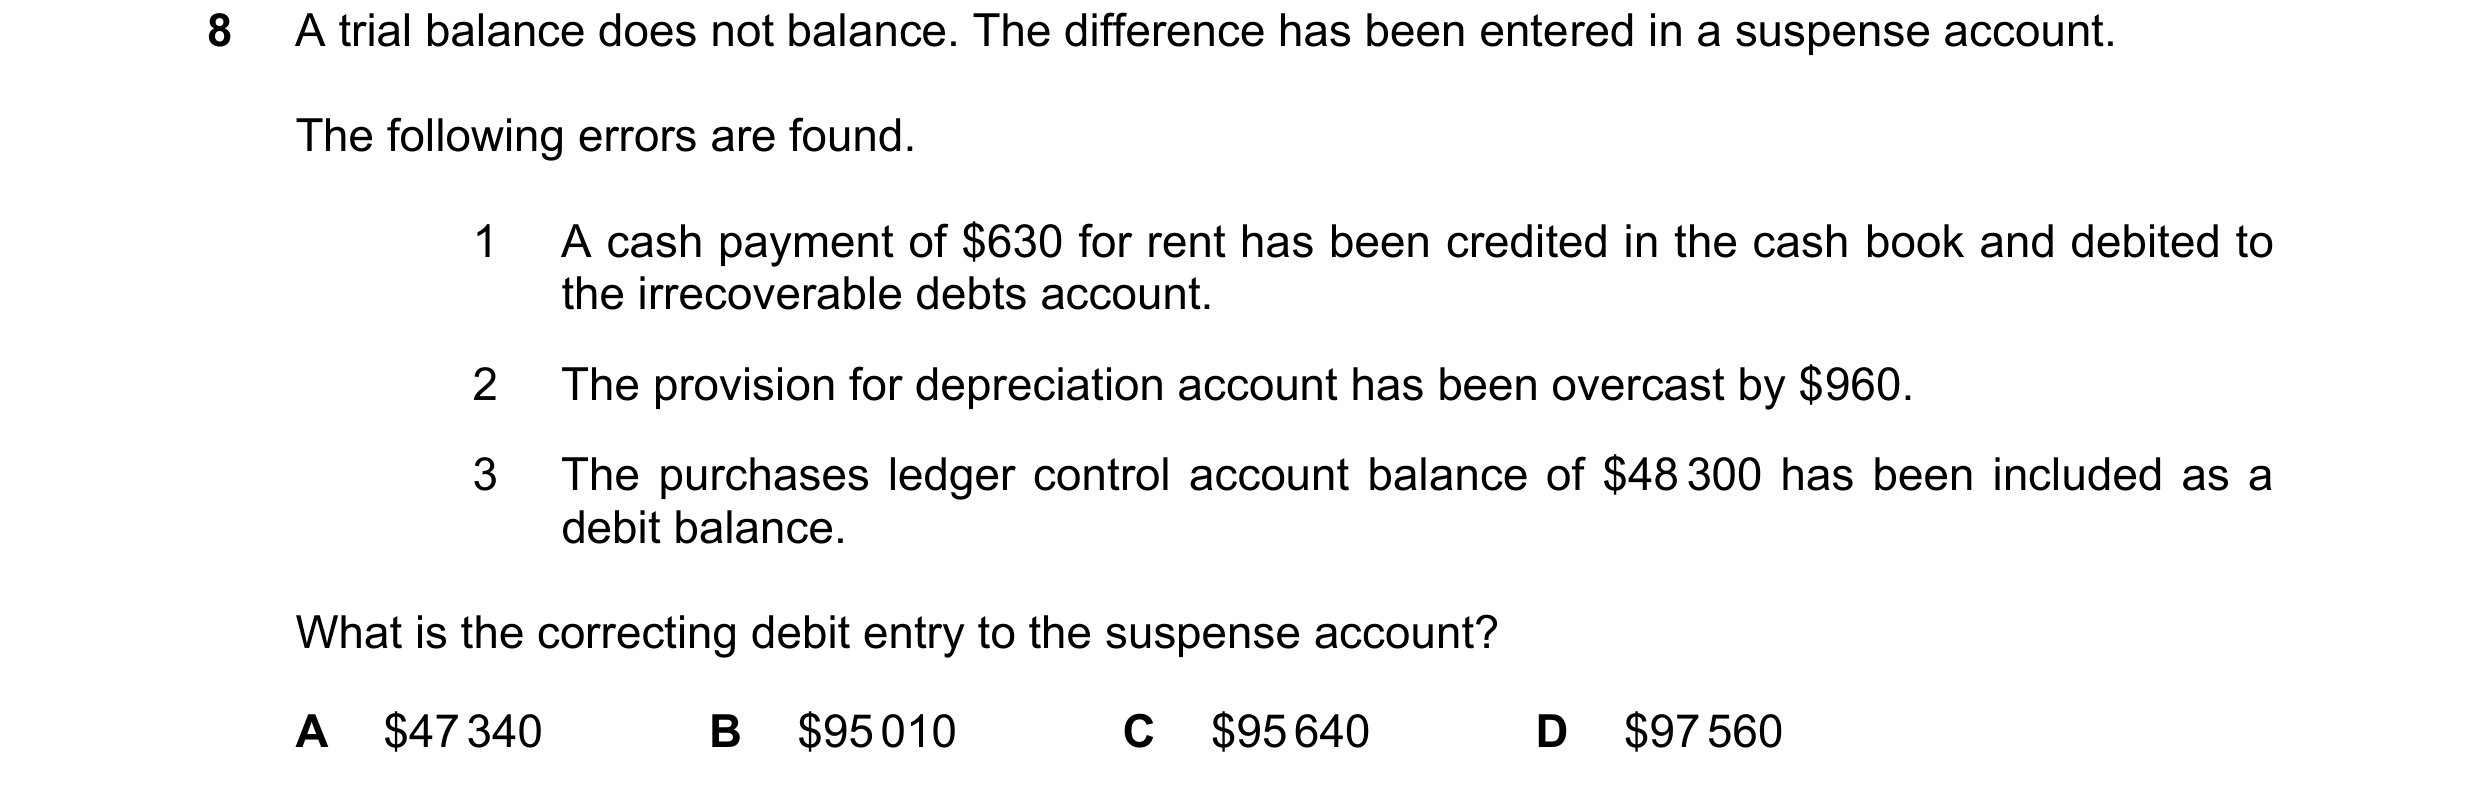
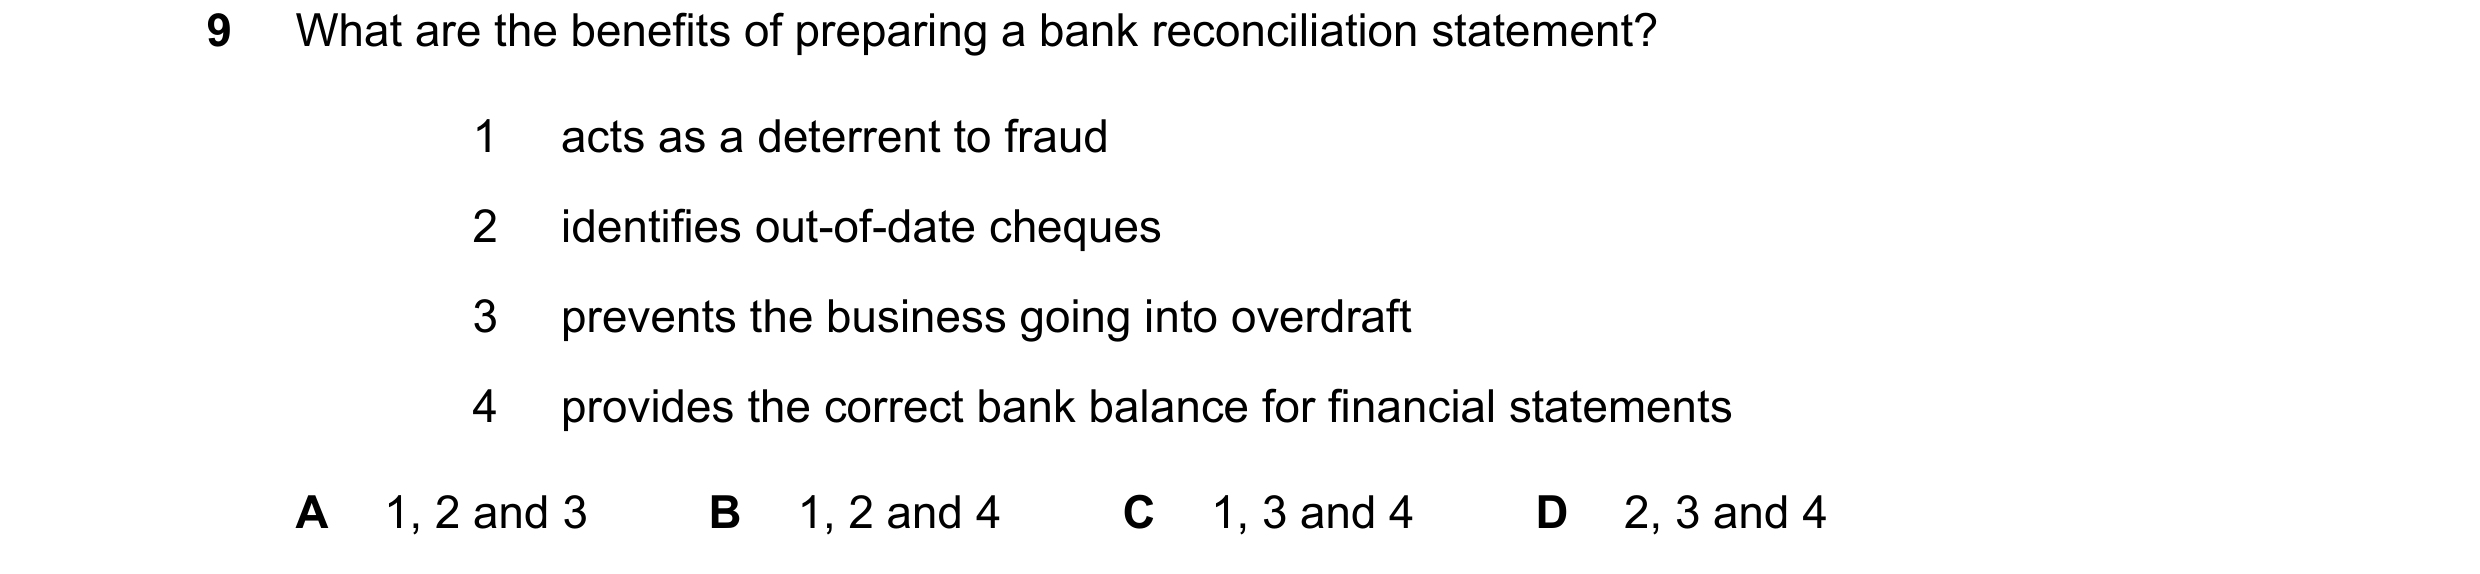 82 / 110
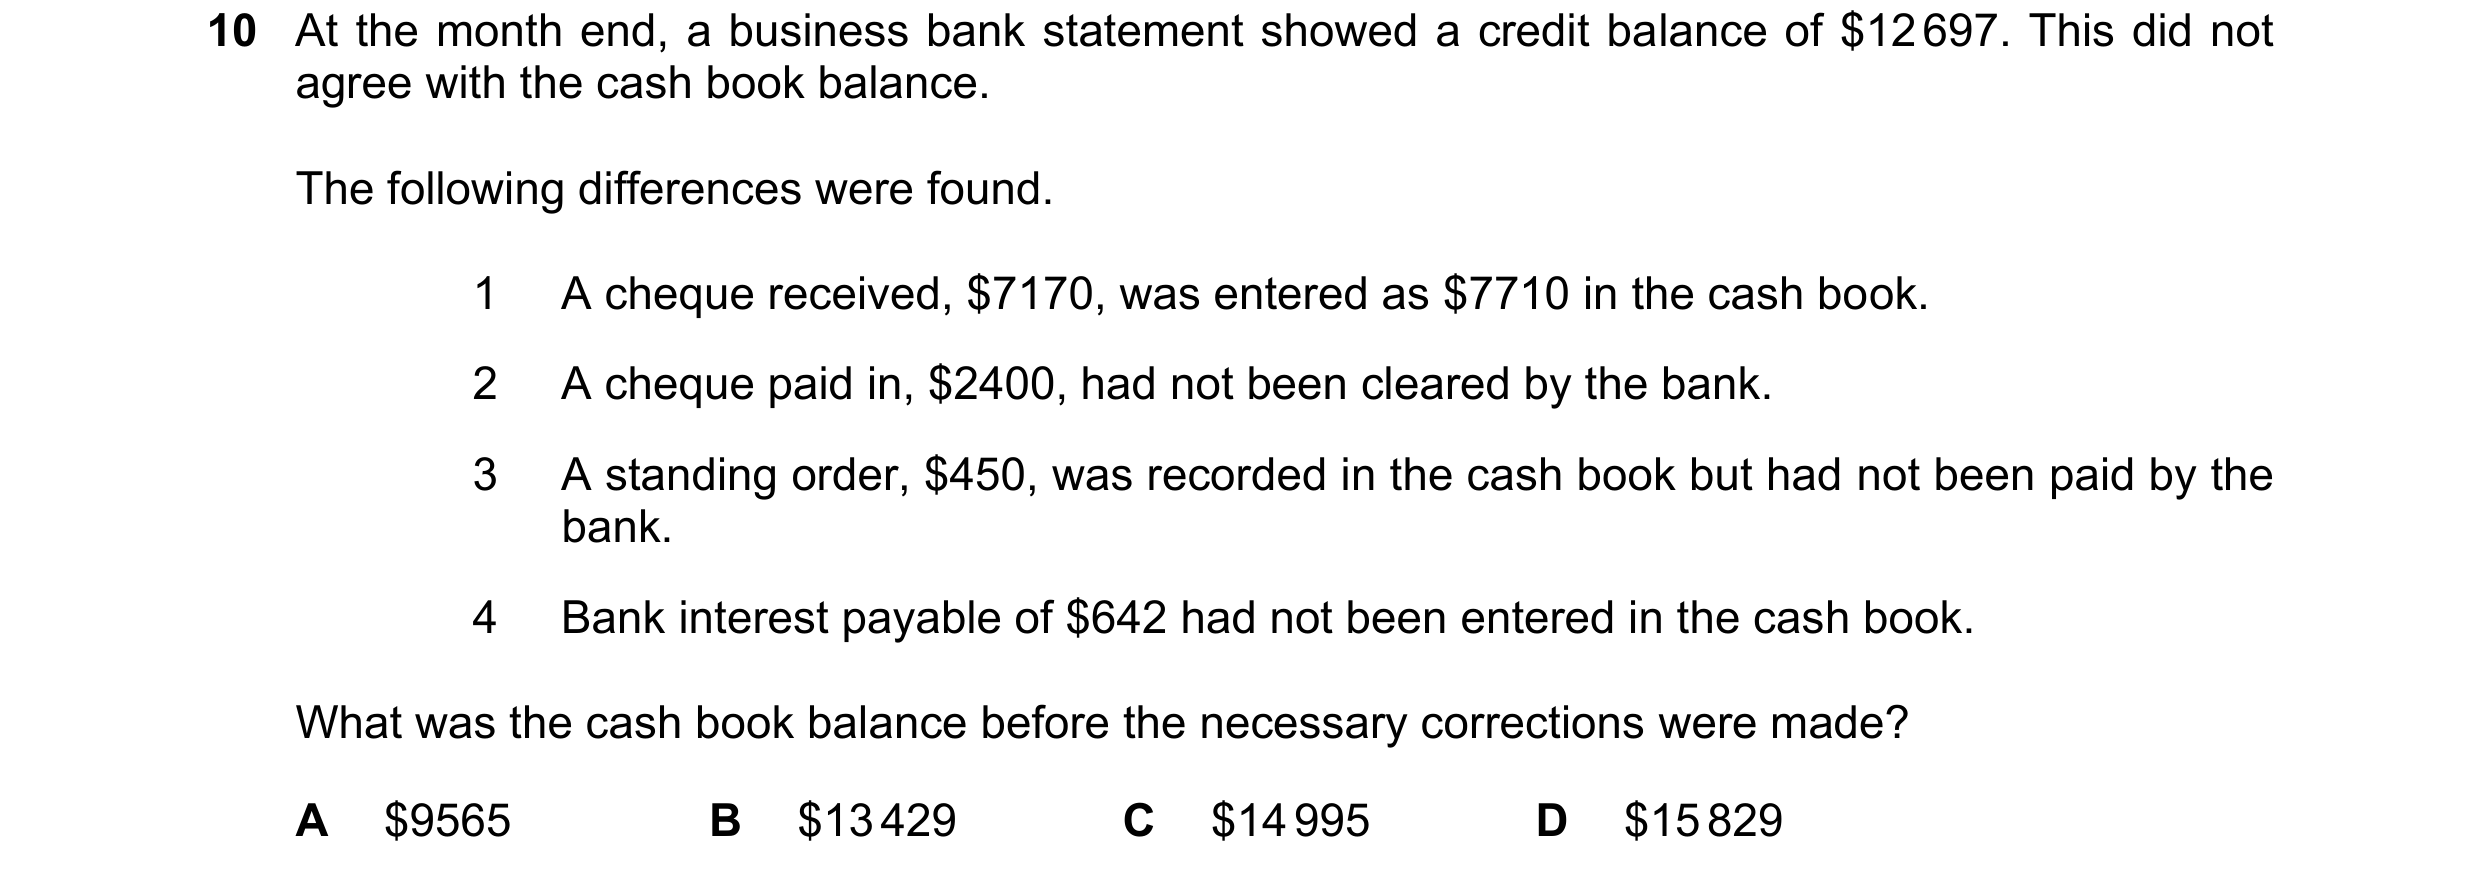
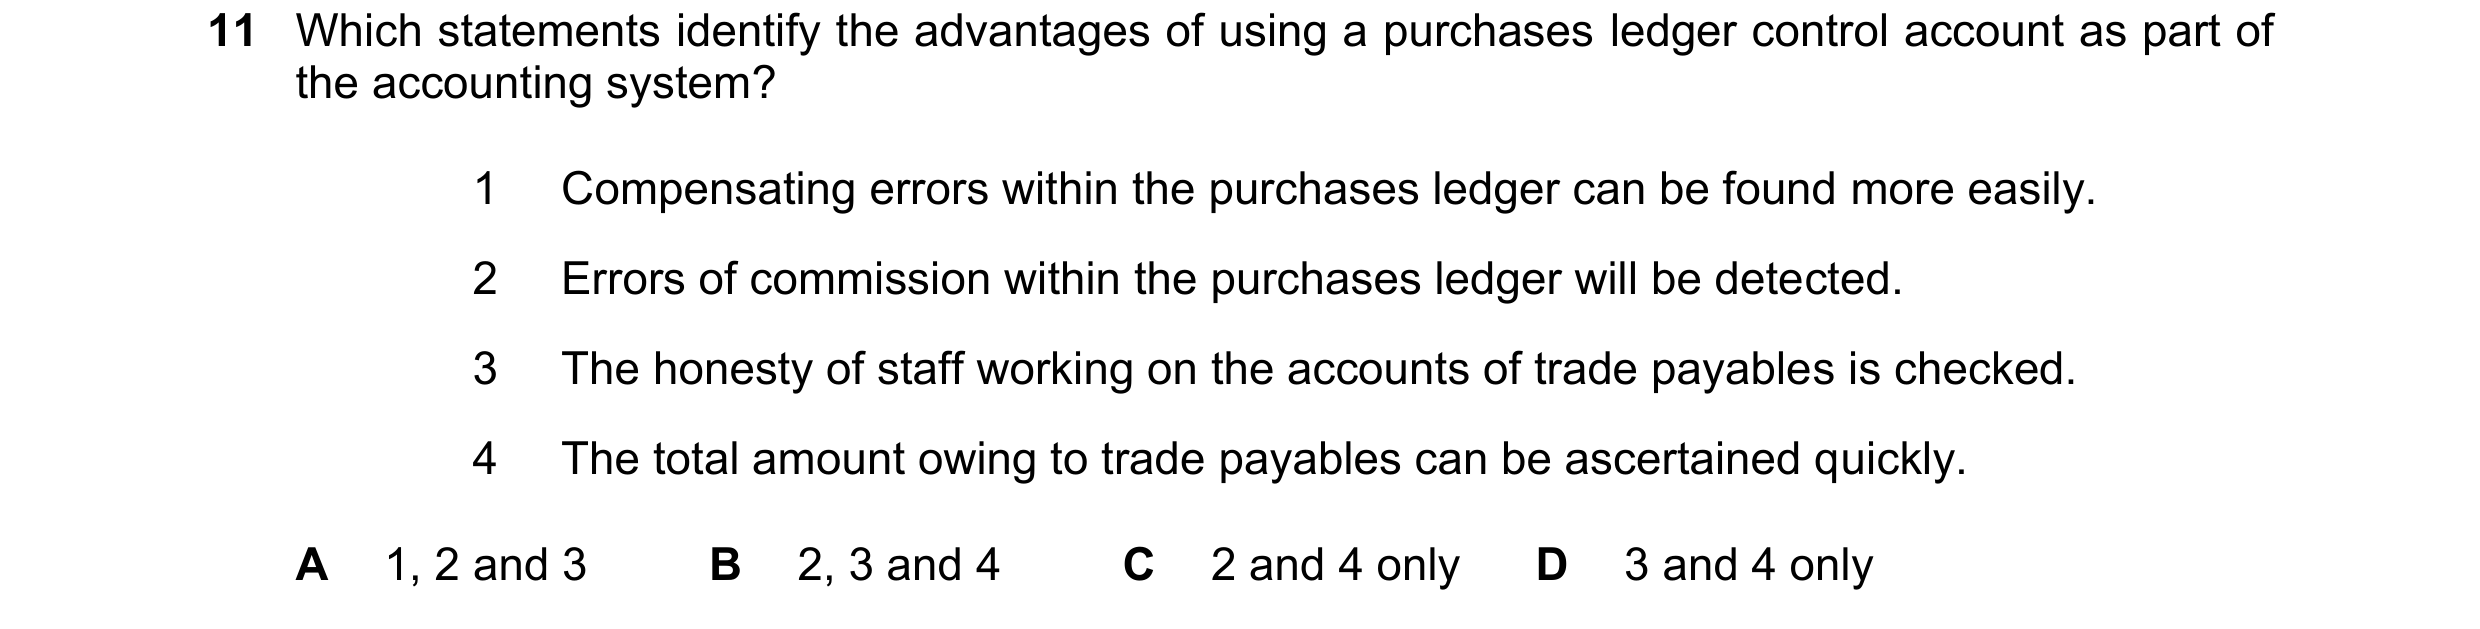
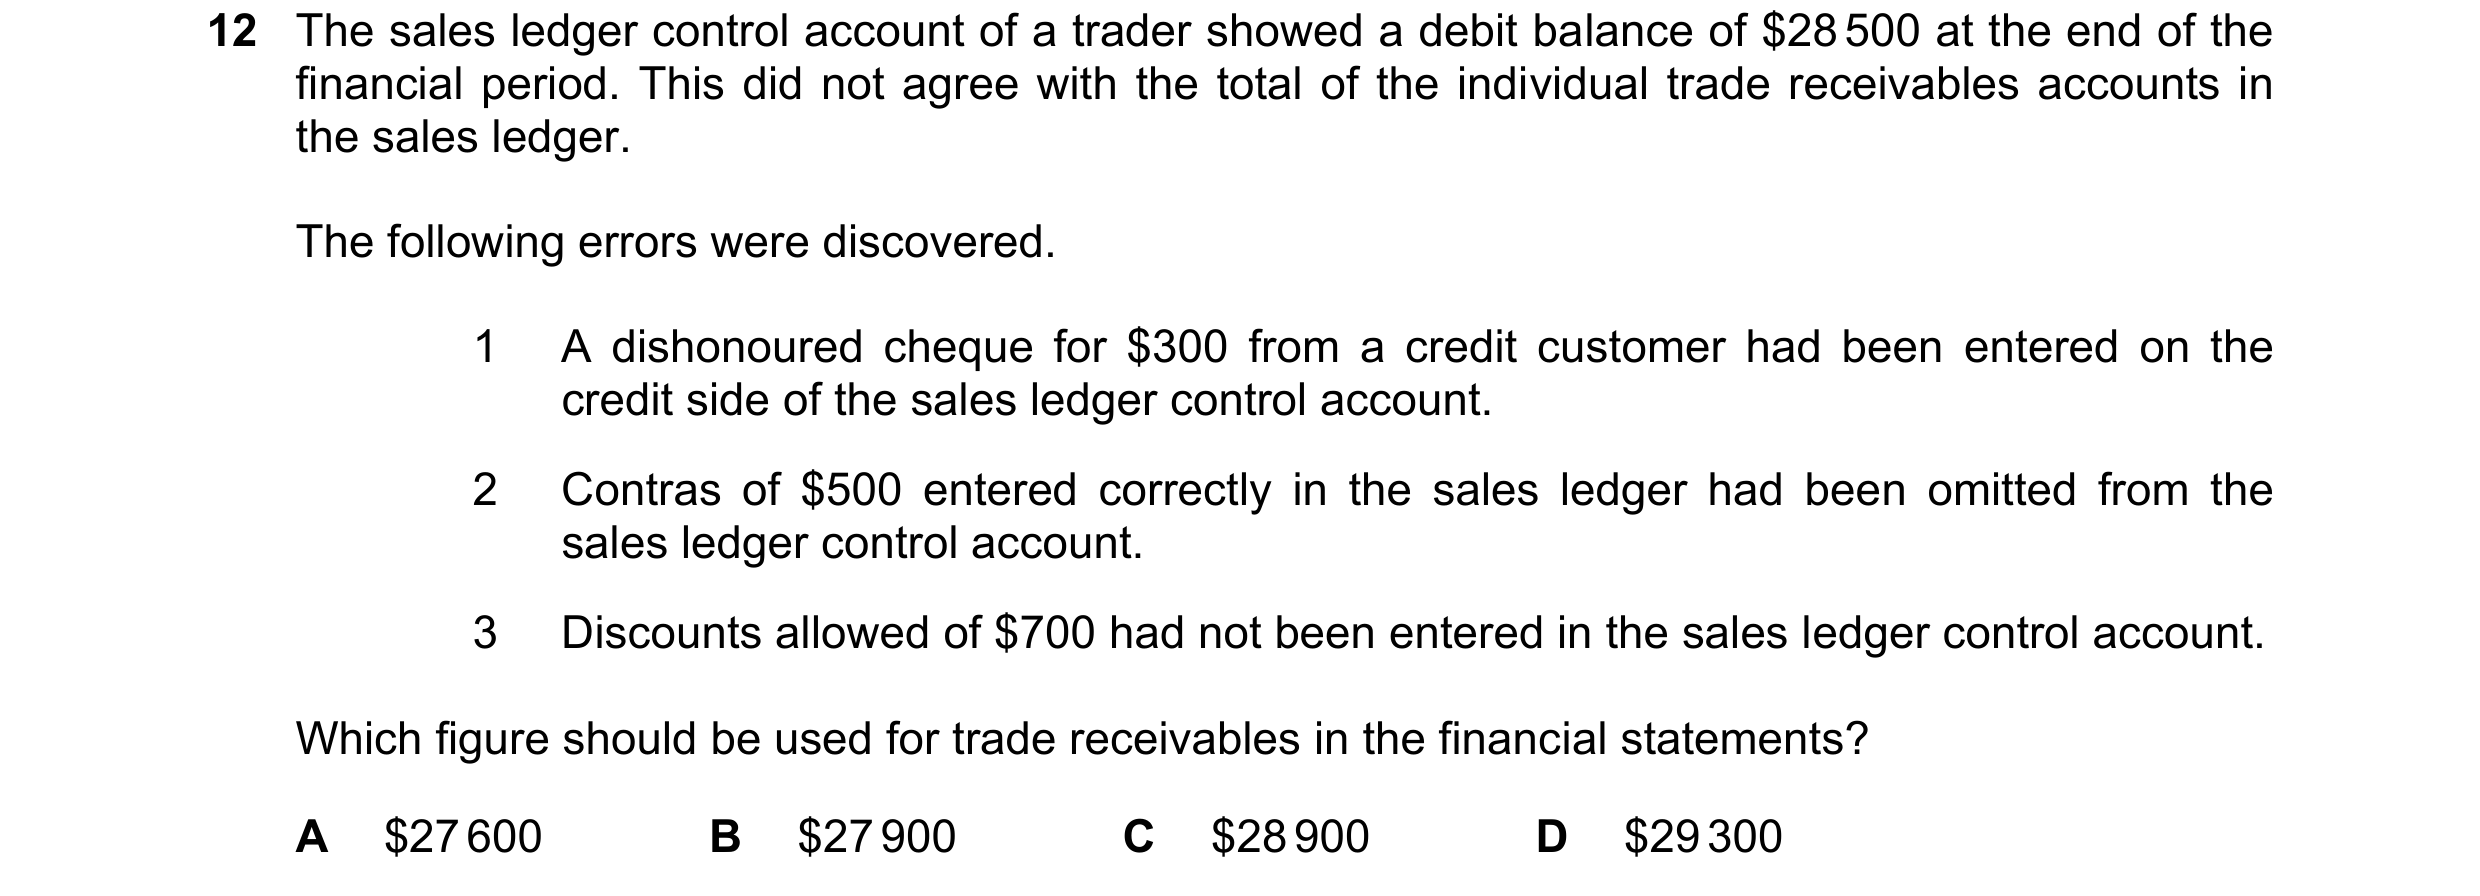
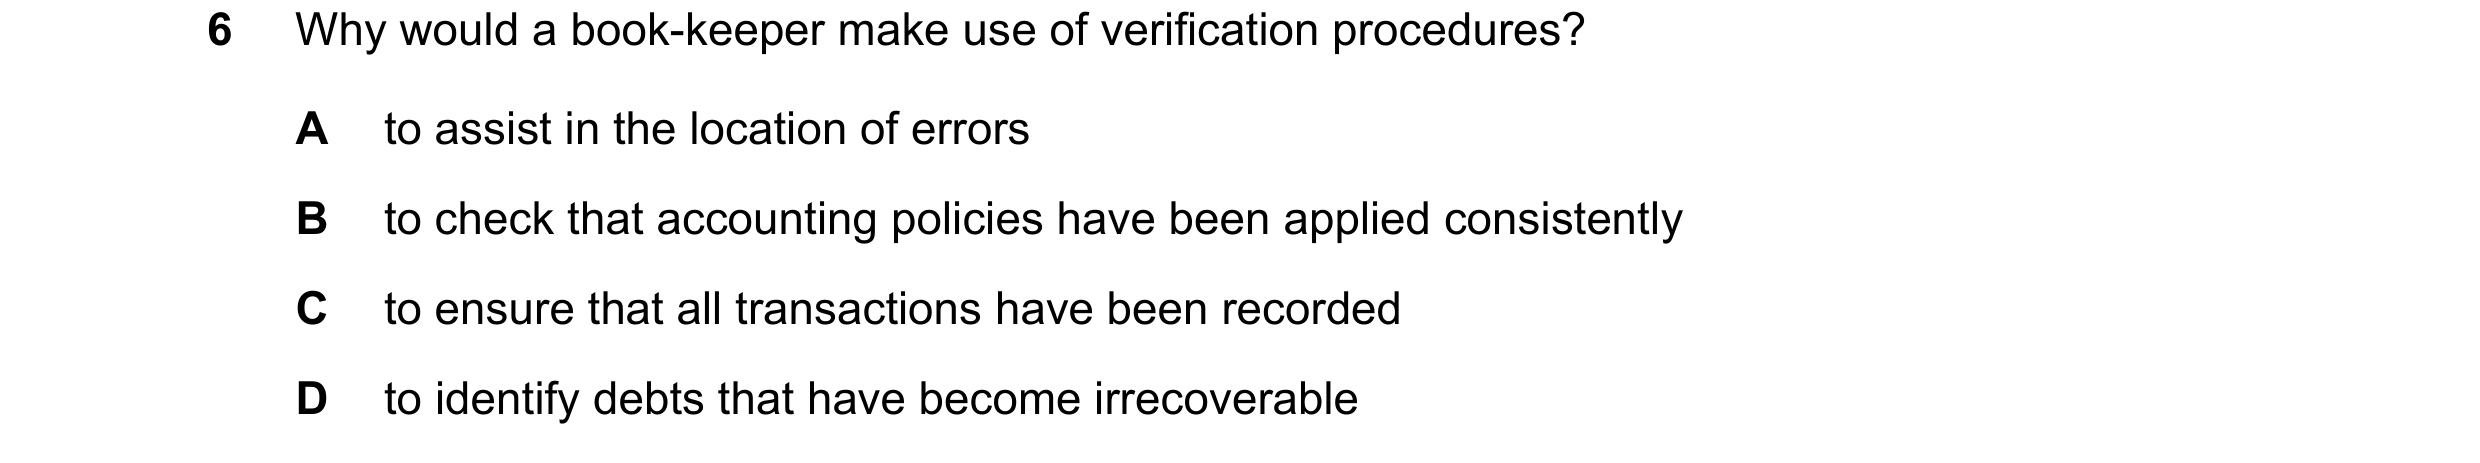 83 / 110
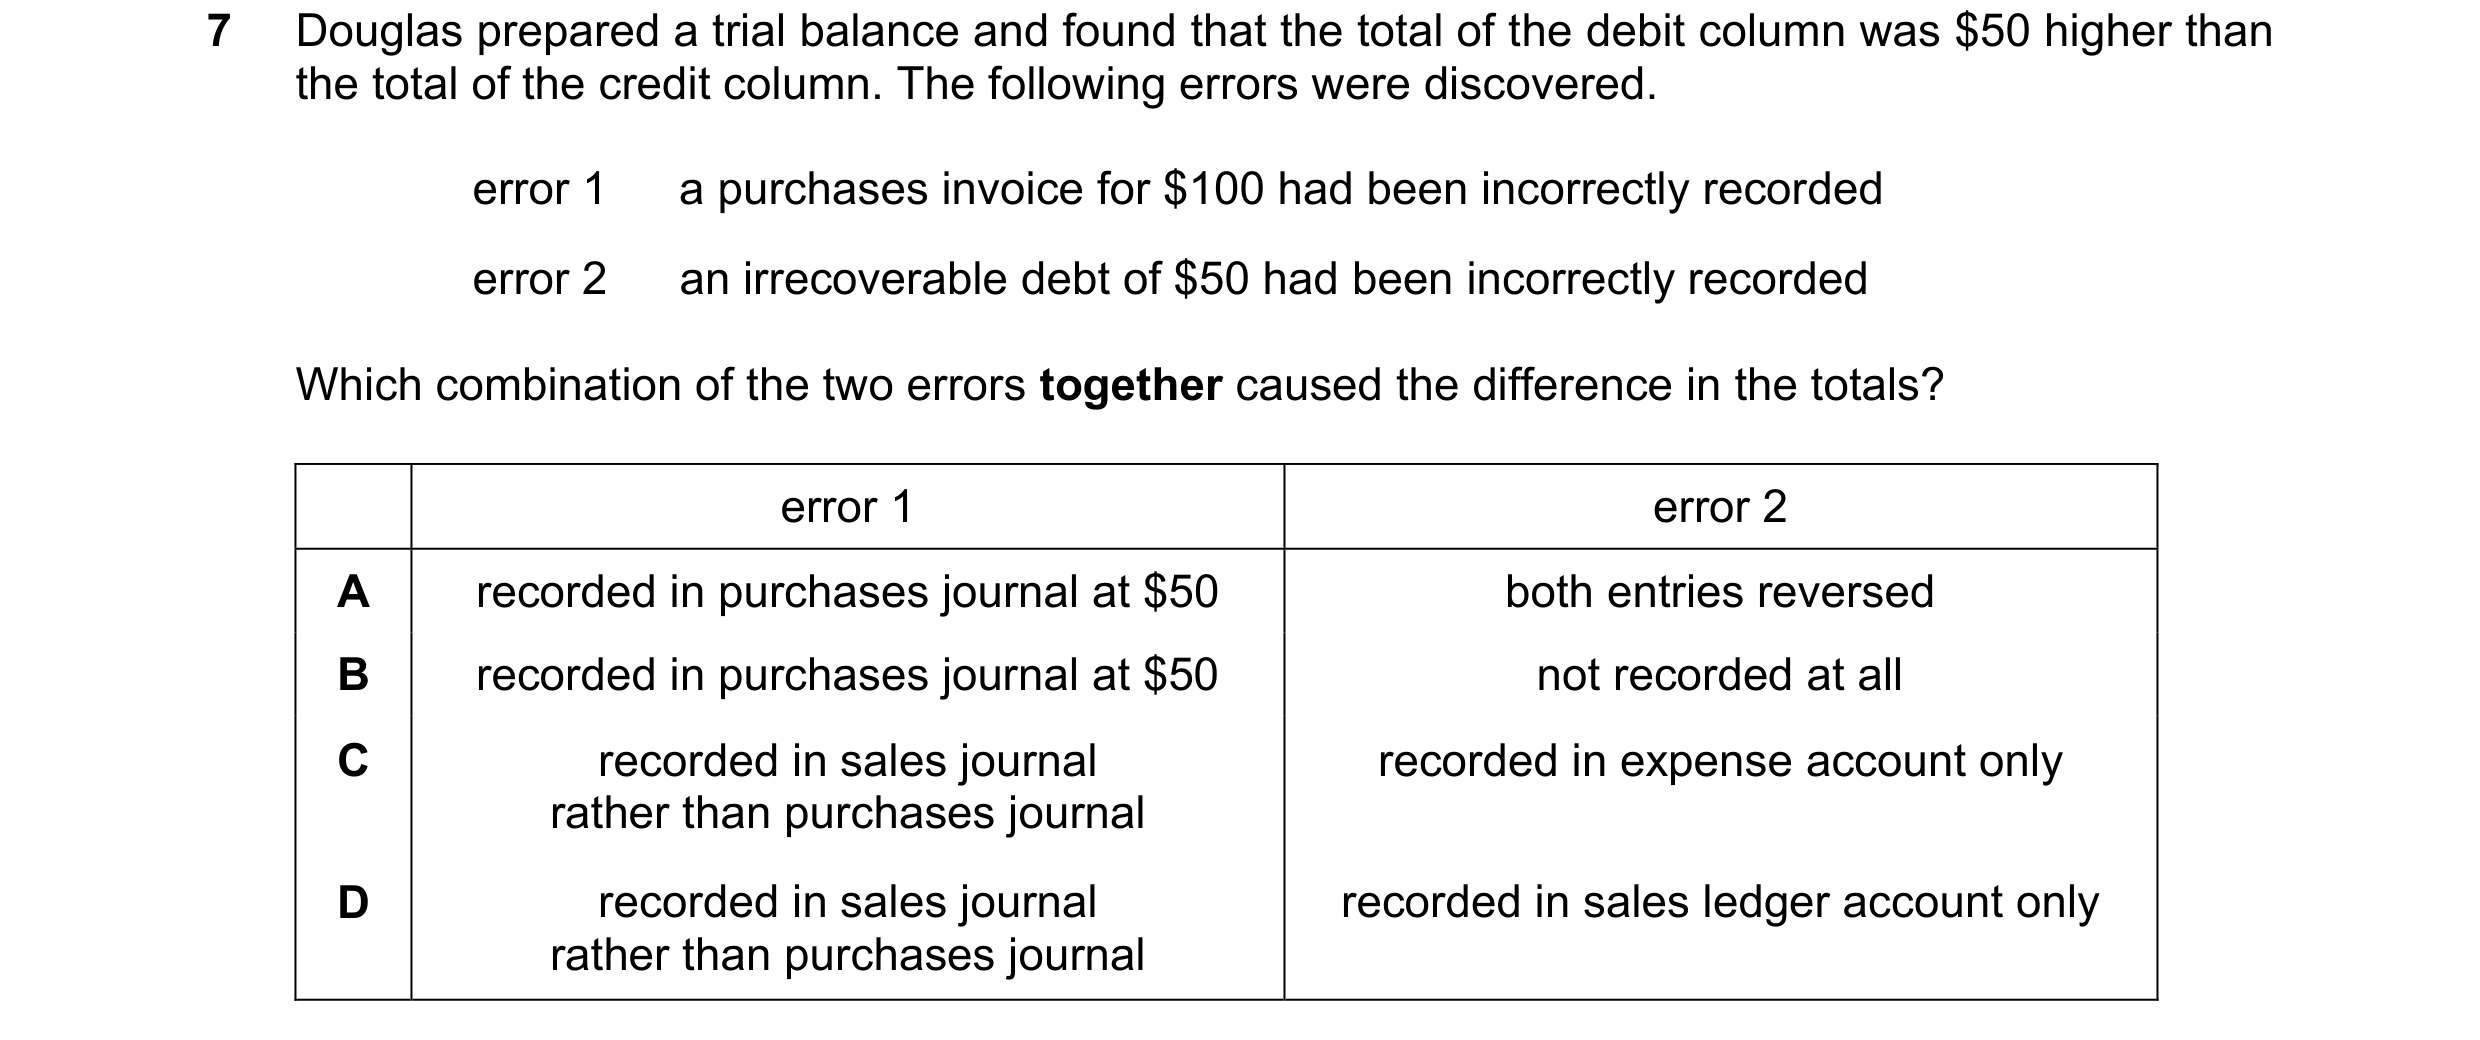
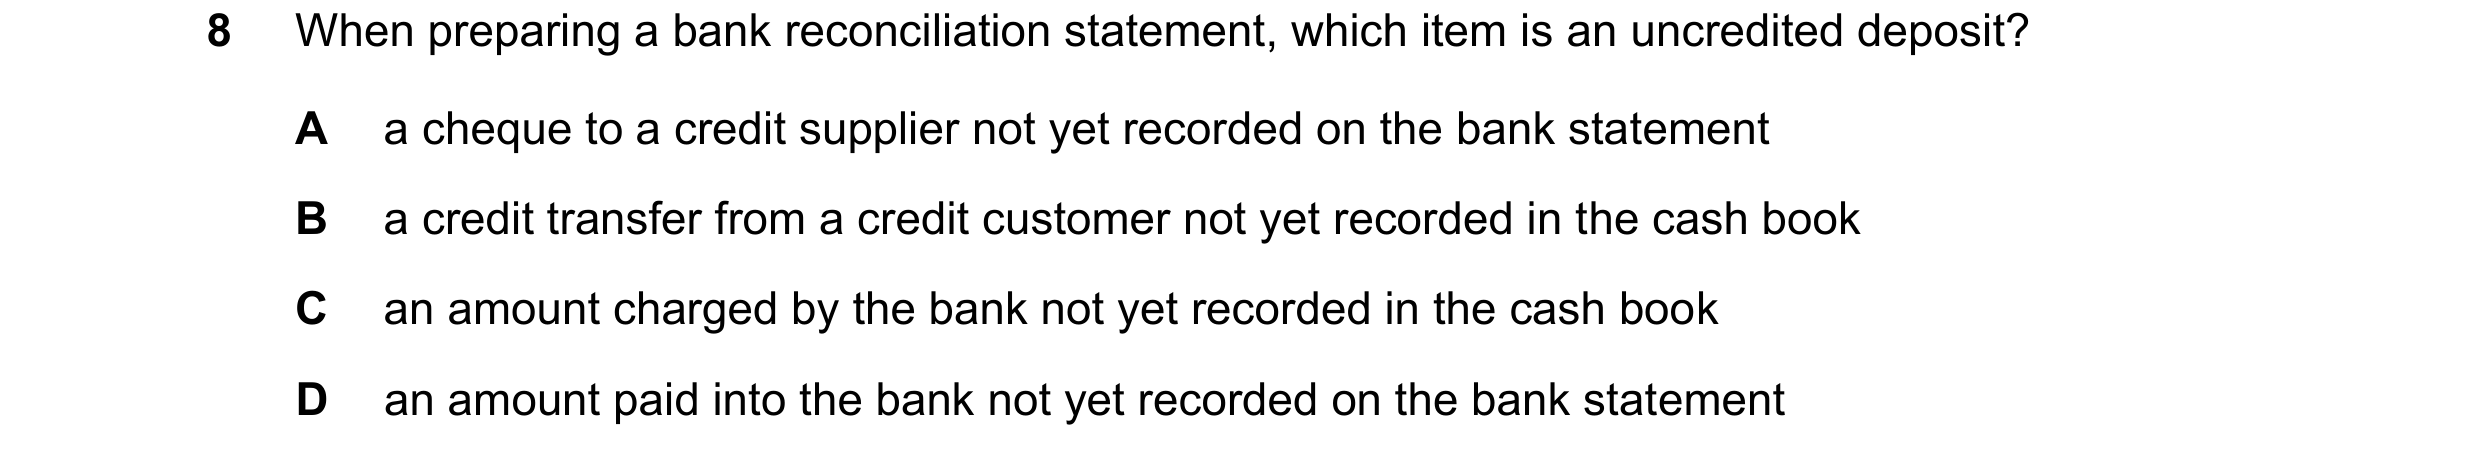
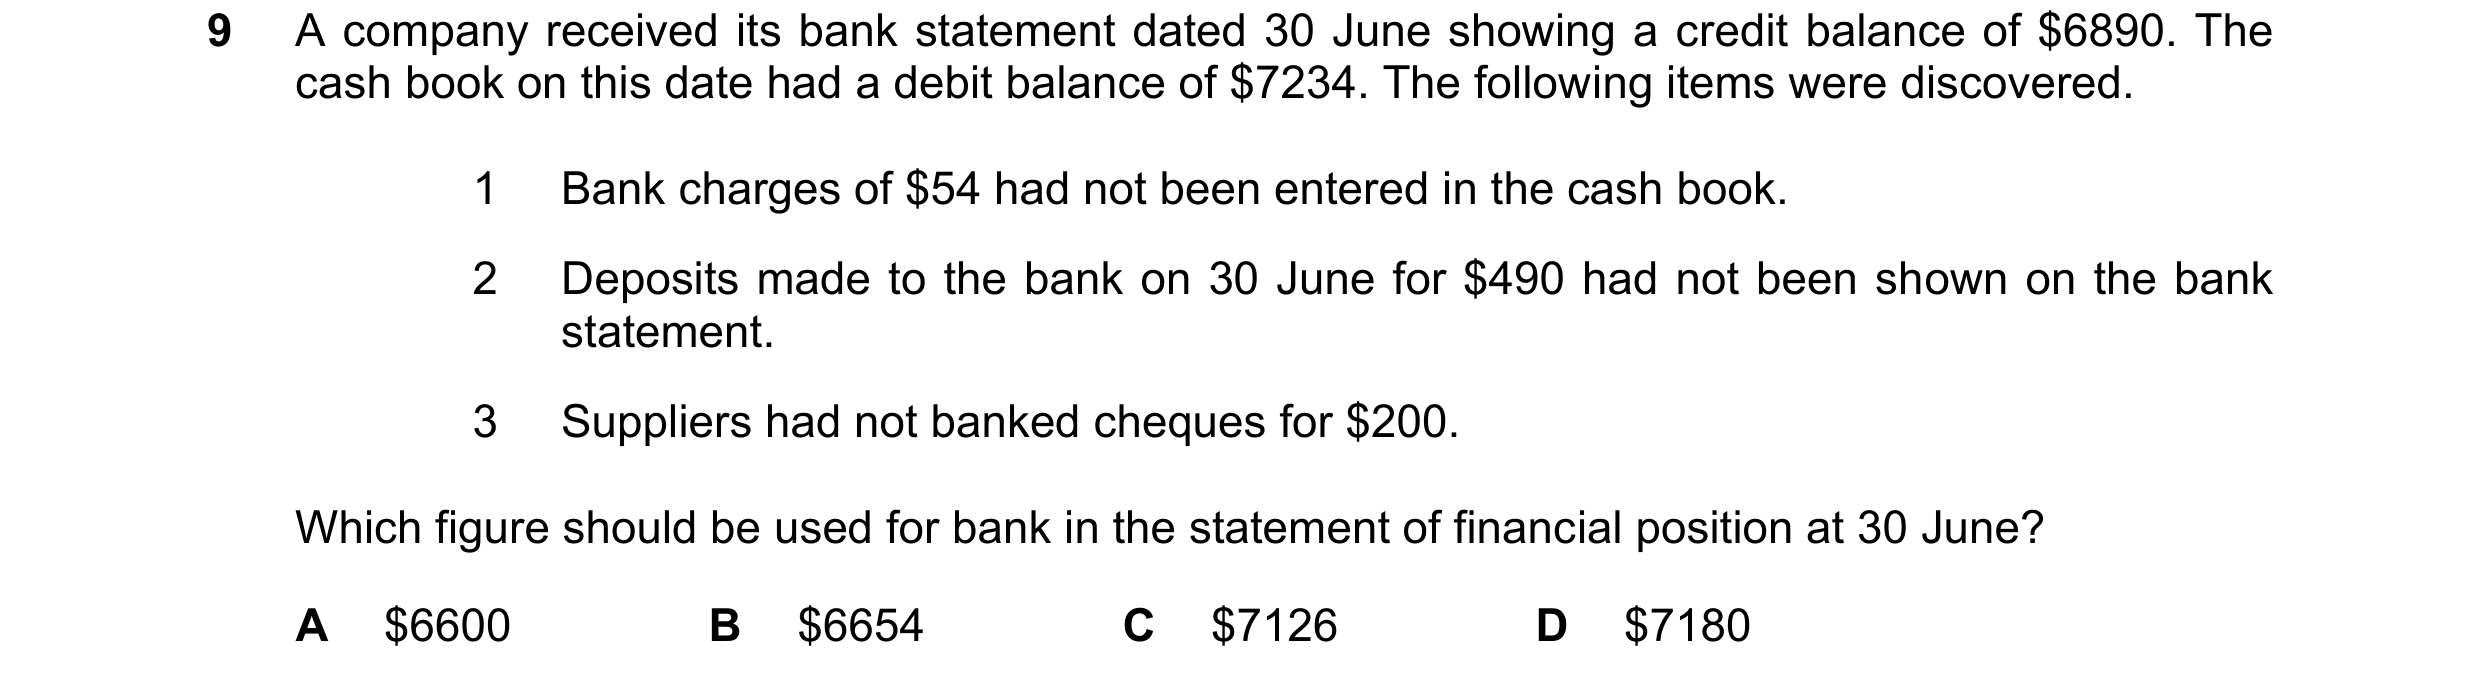
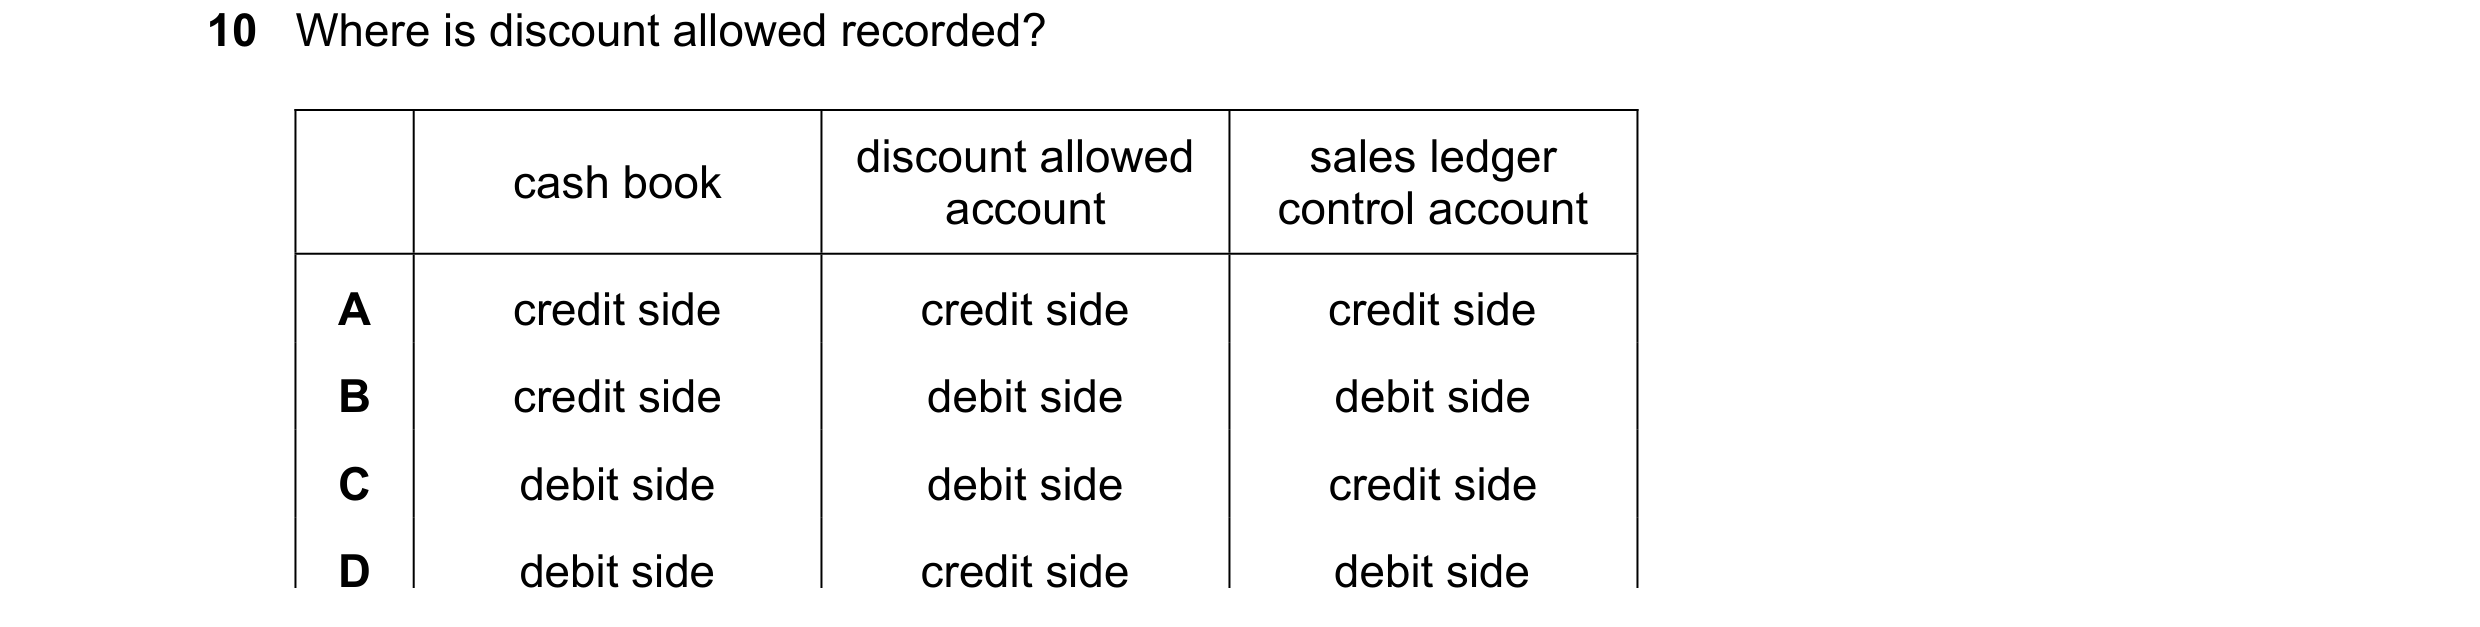 84 / 110
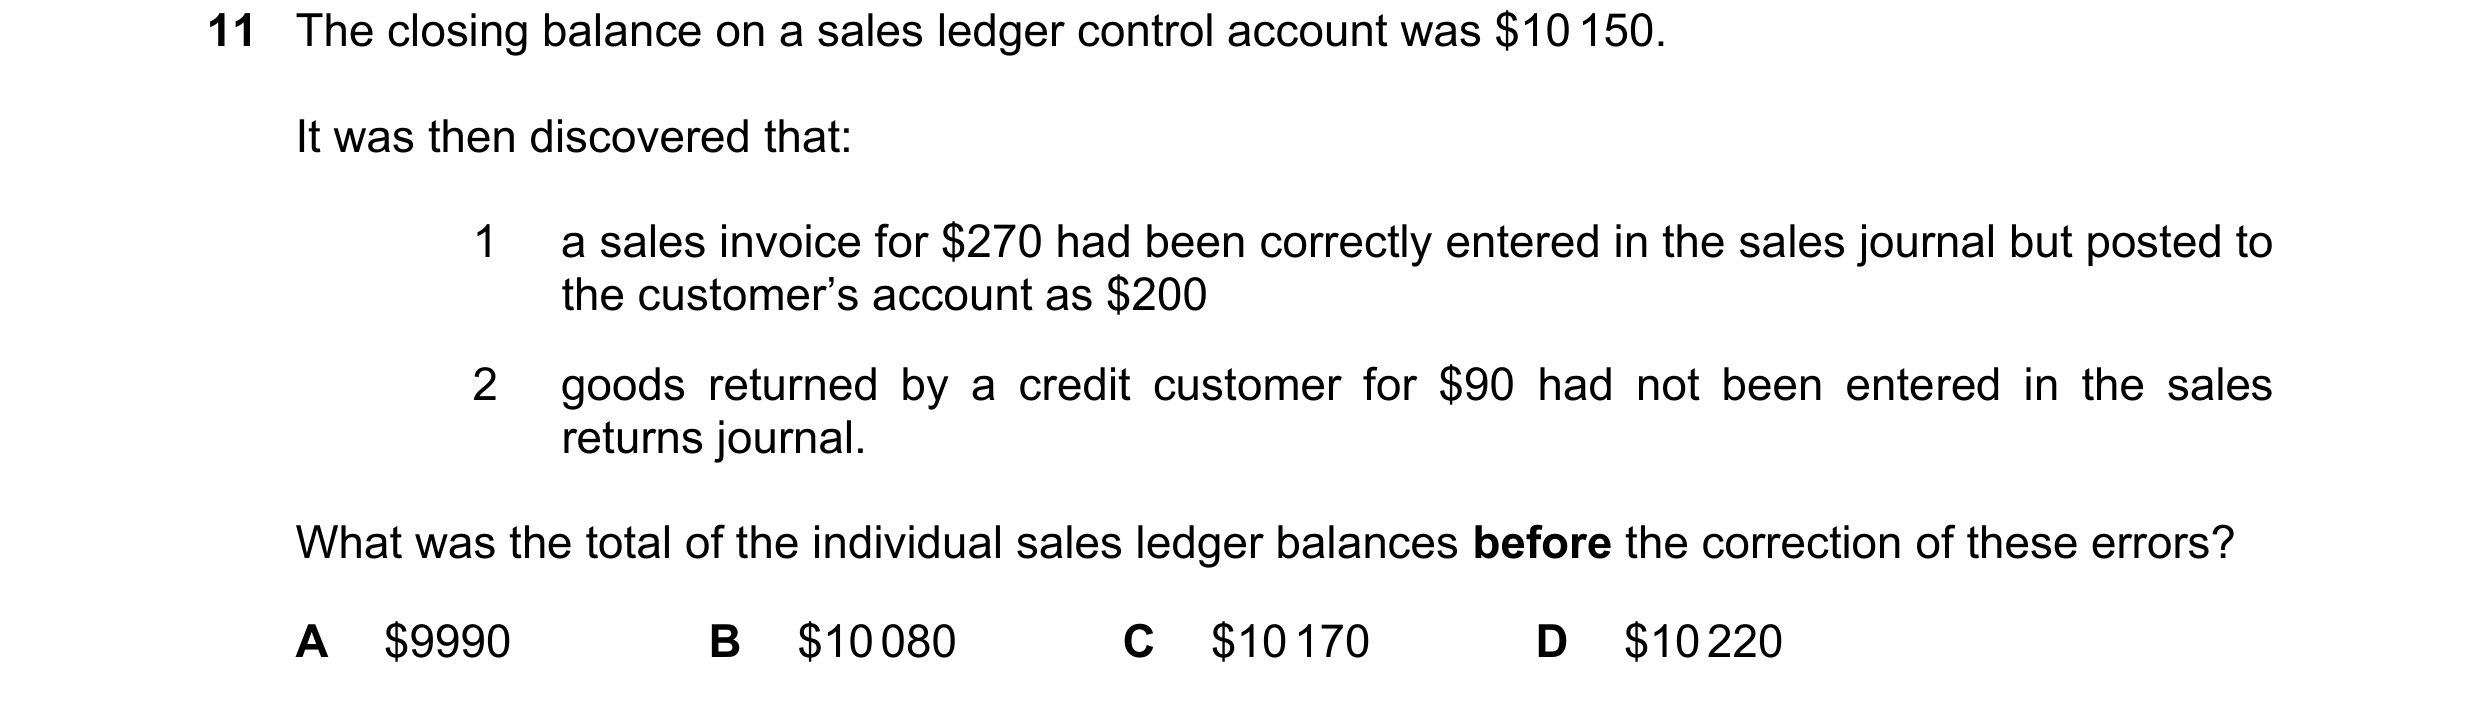
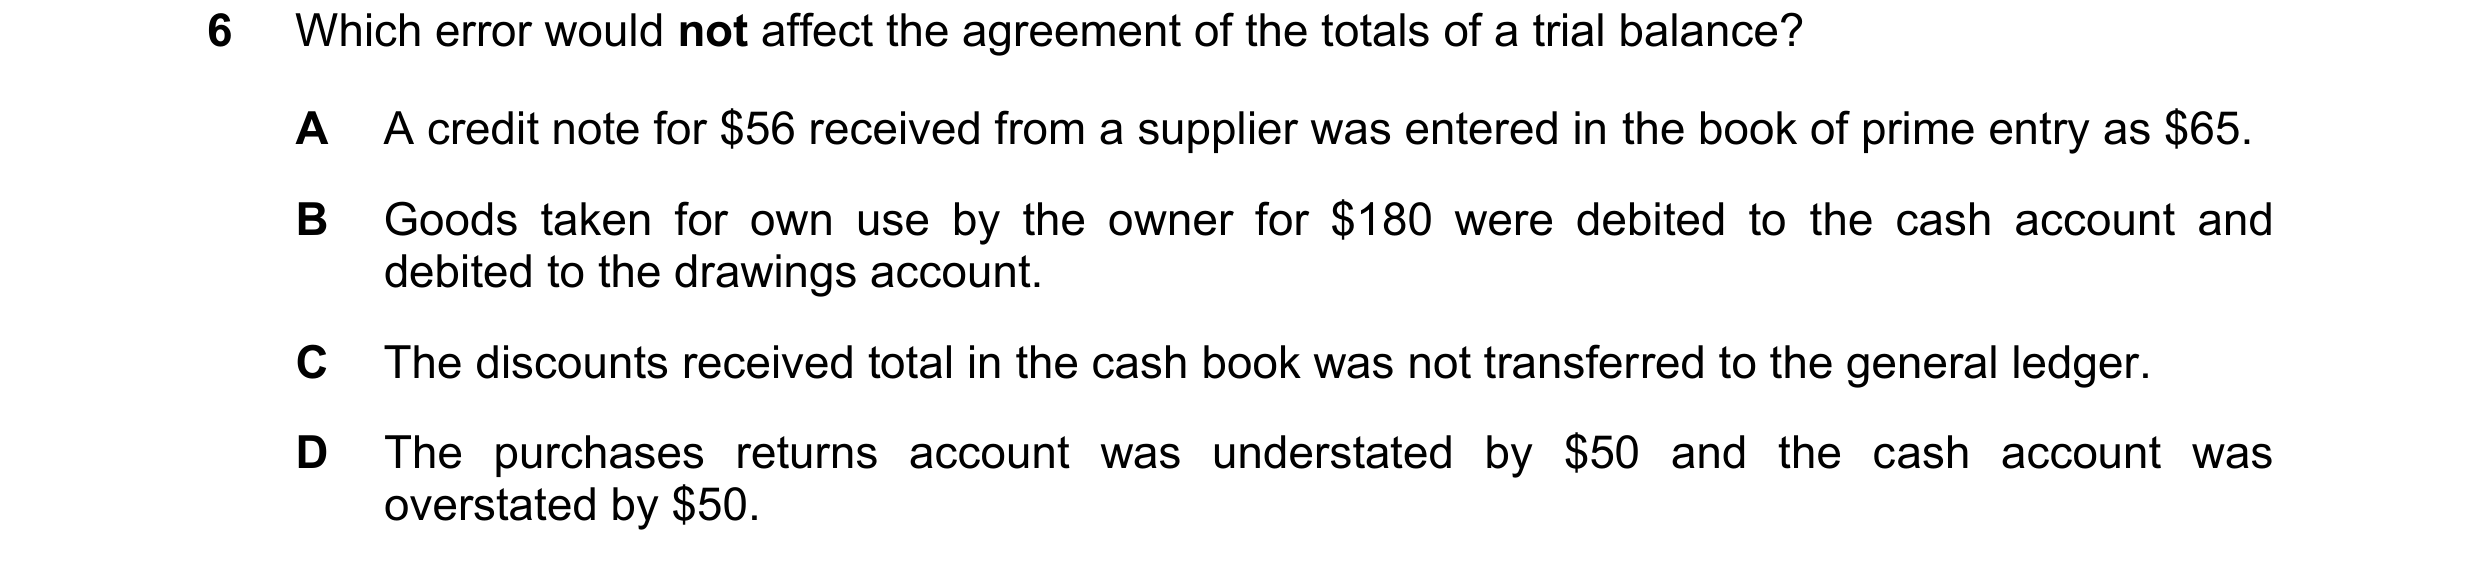
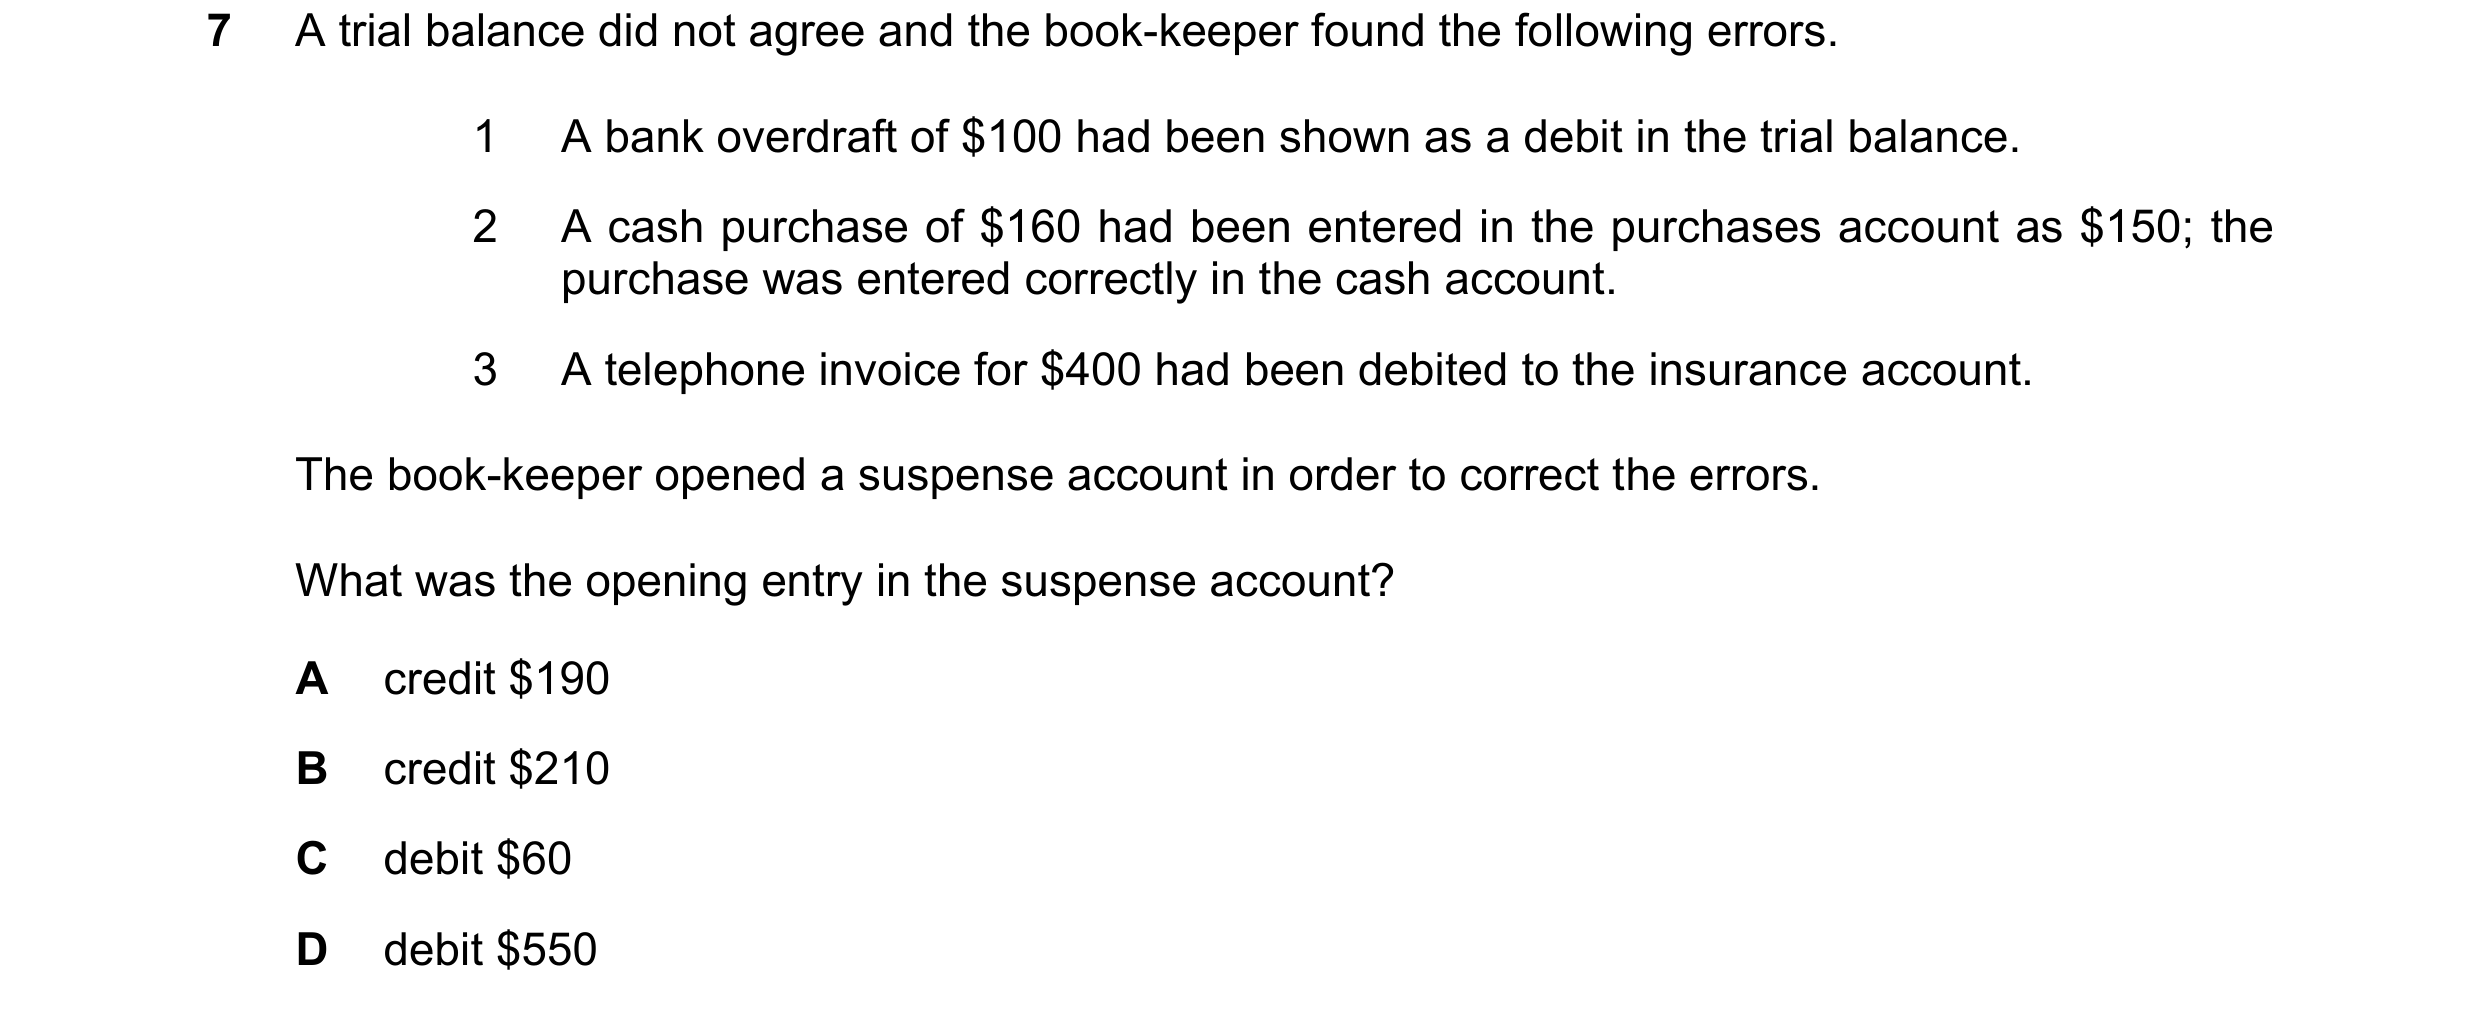
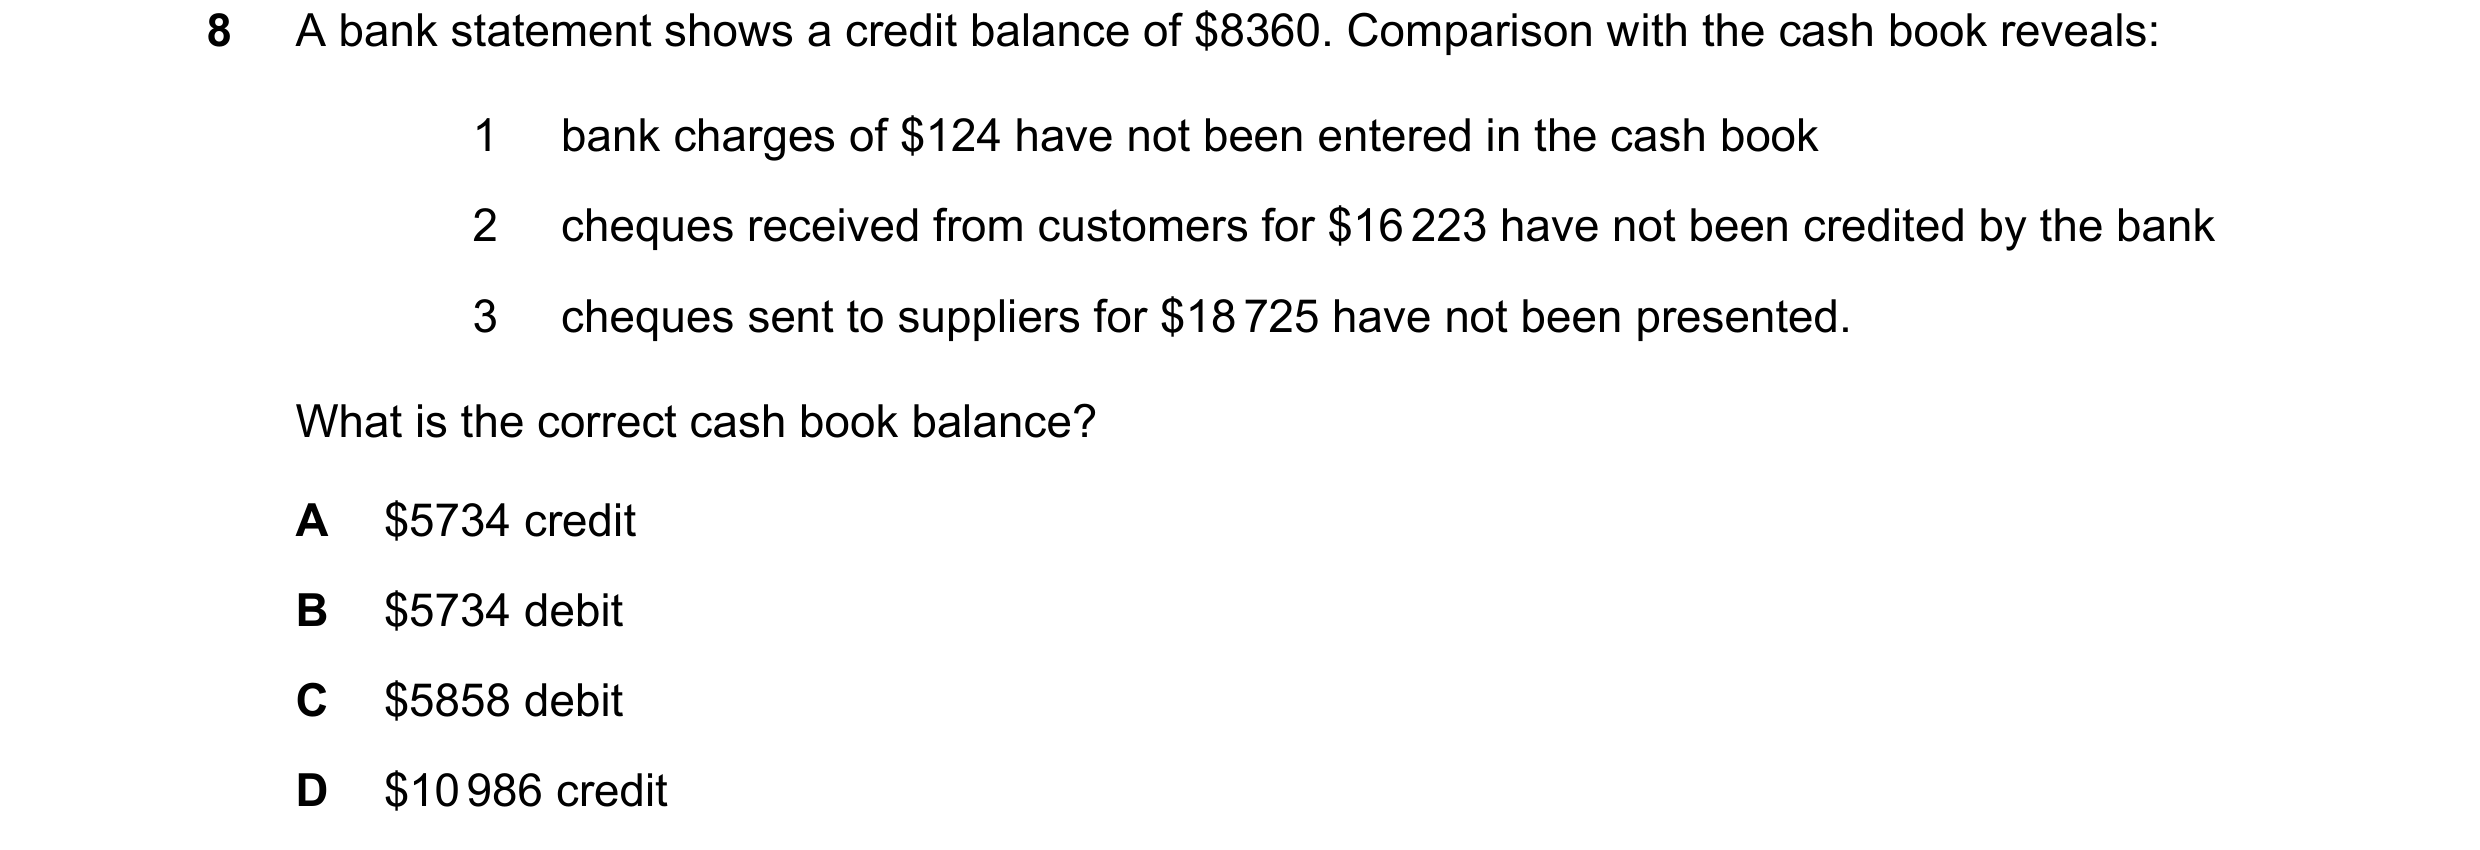 85 / 110
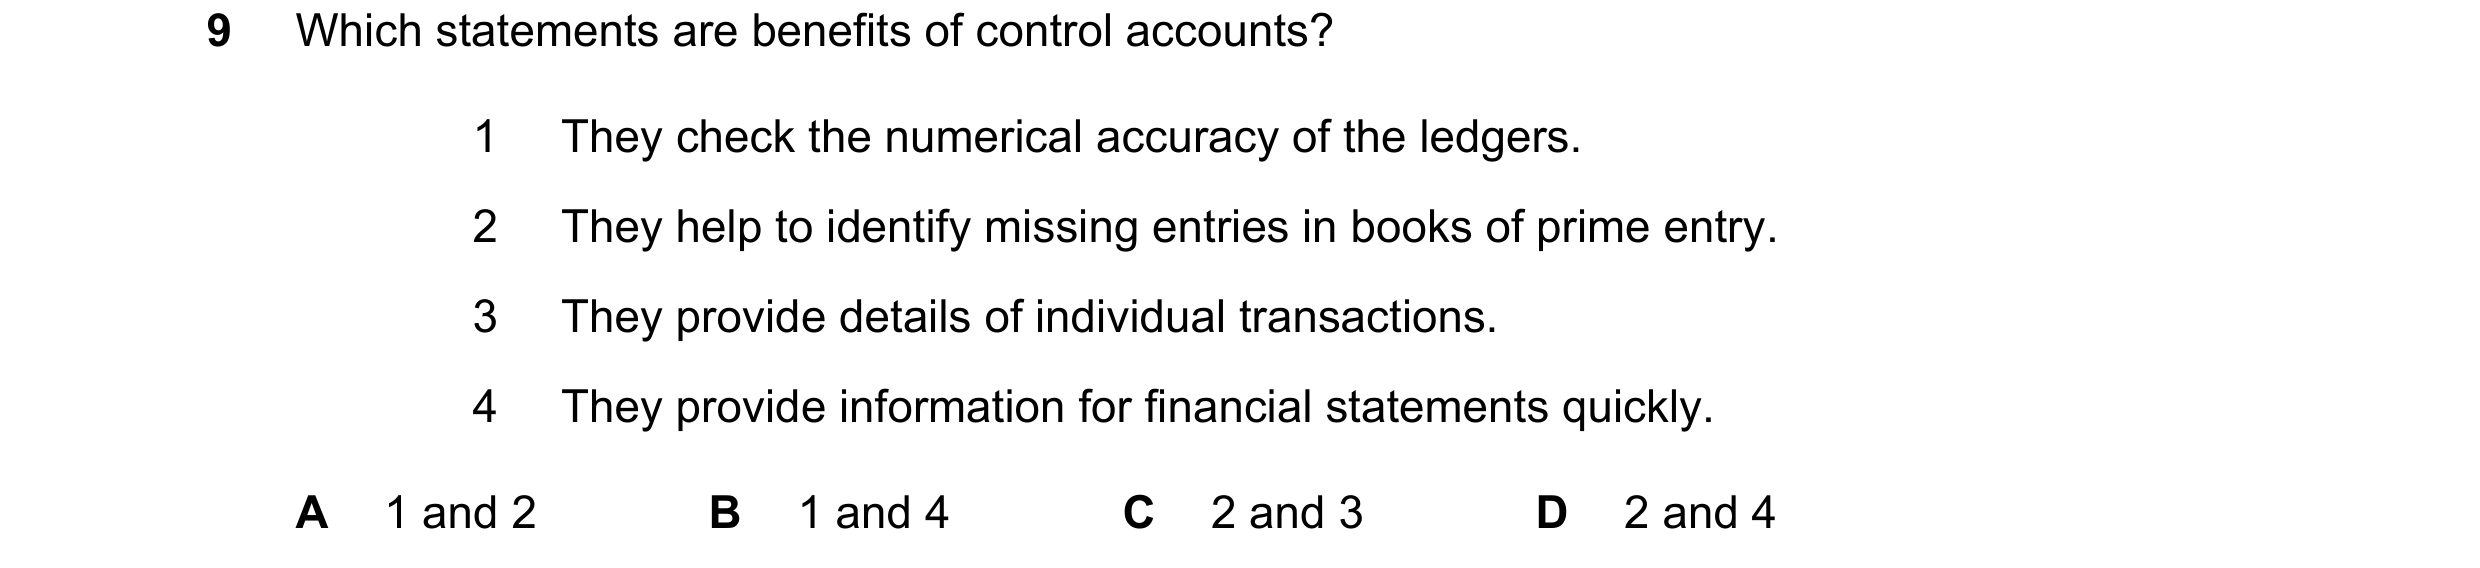
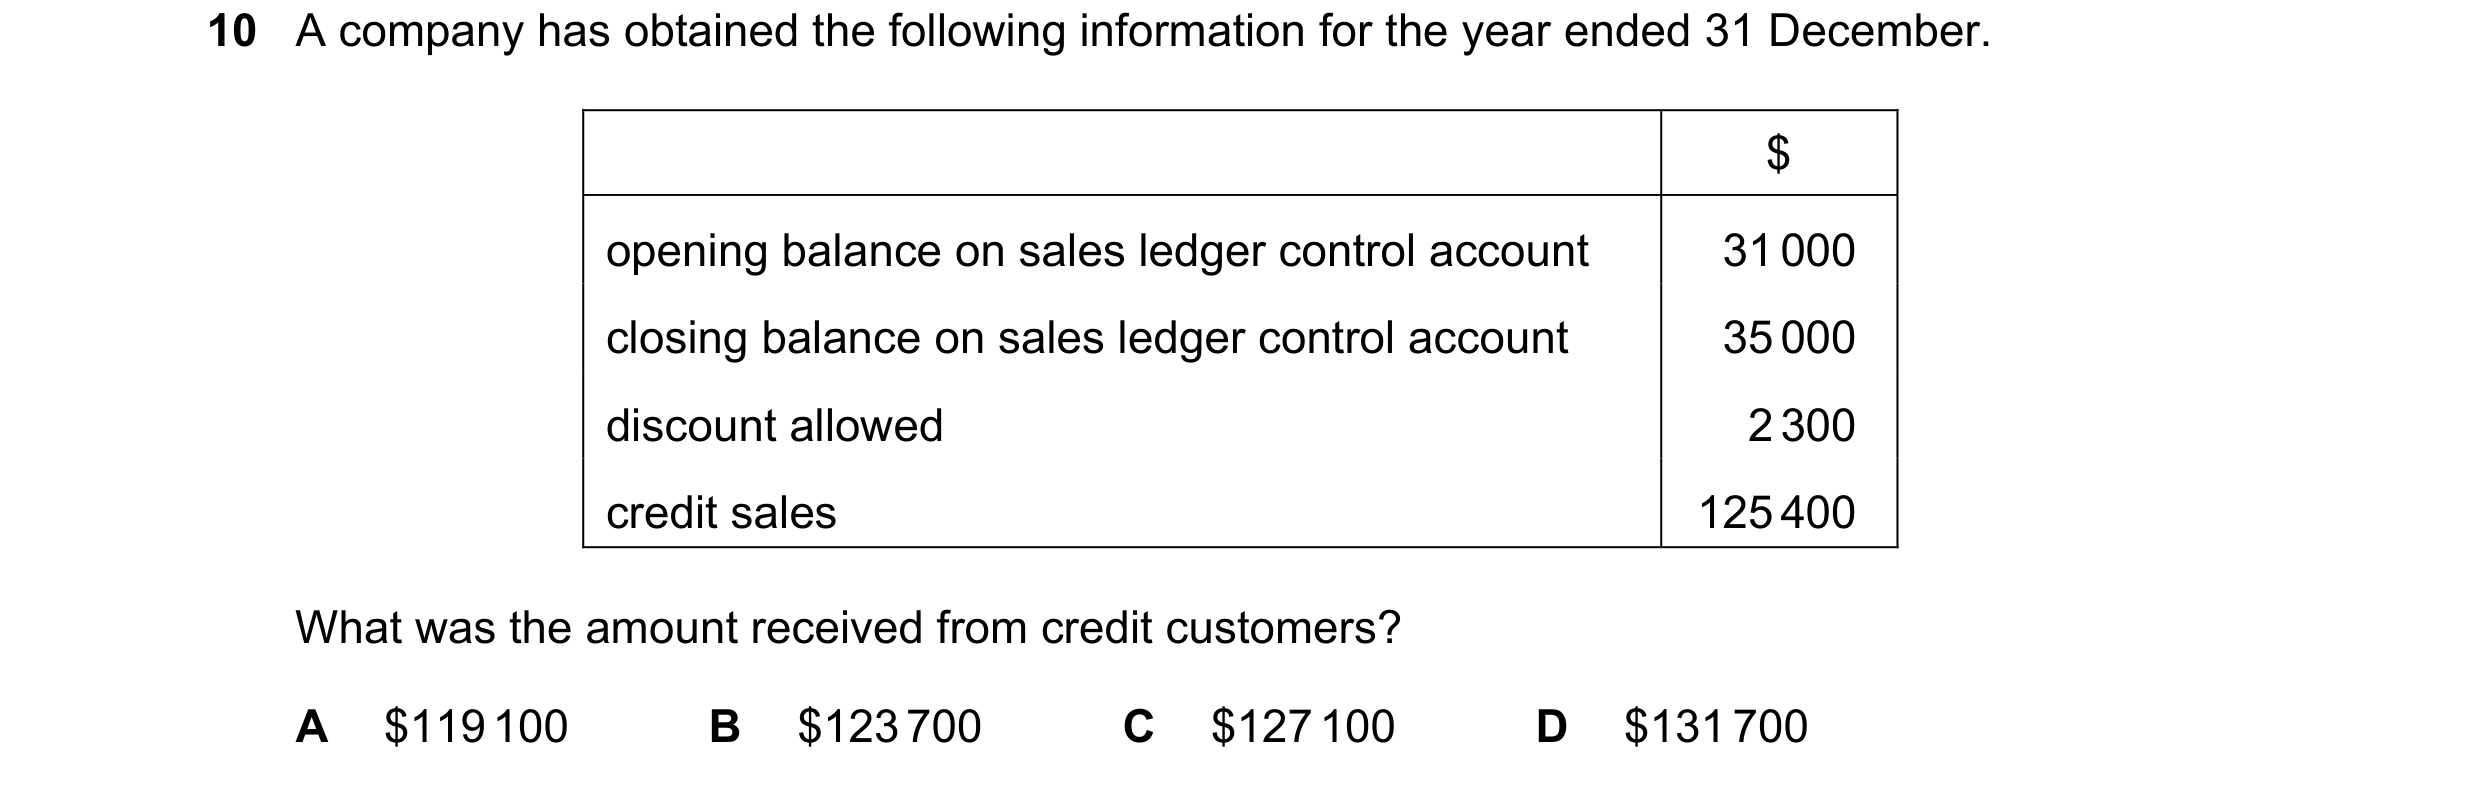
 86 / 110
 87 / 110
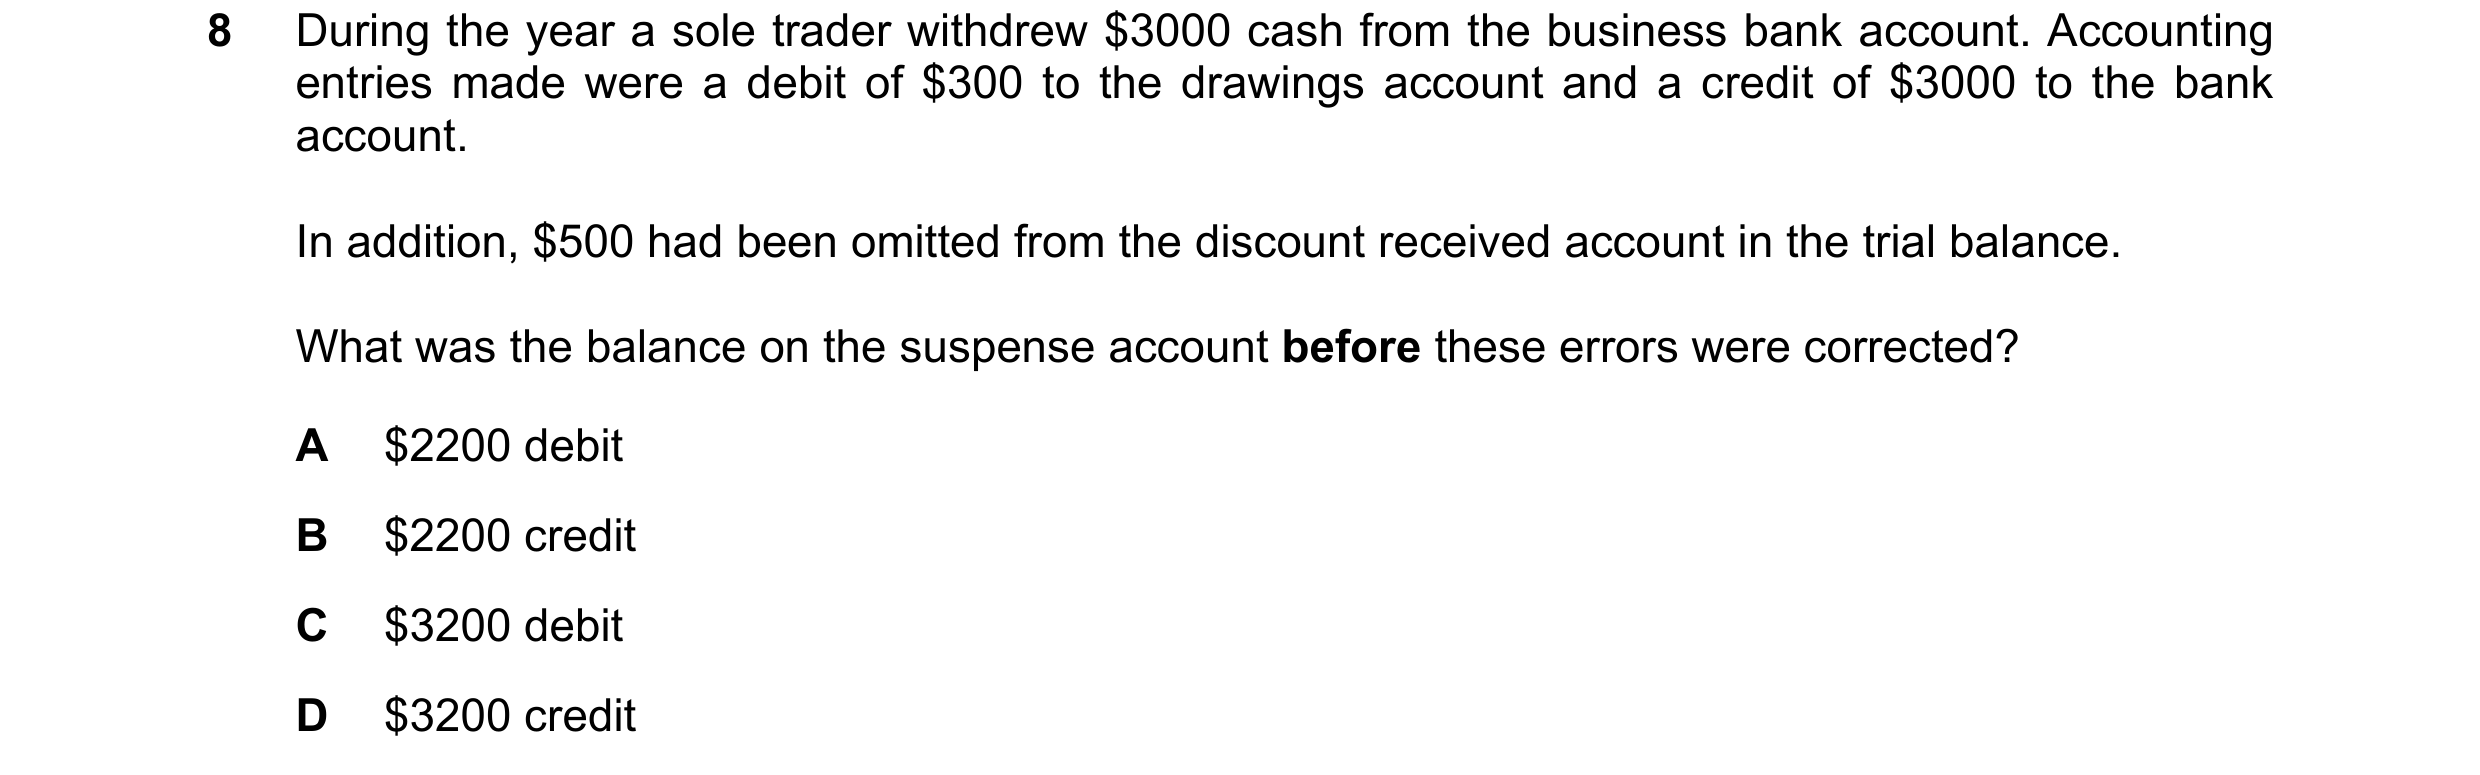
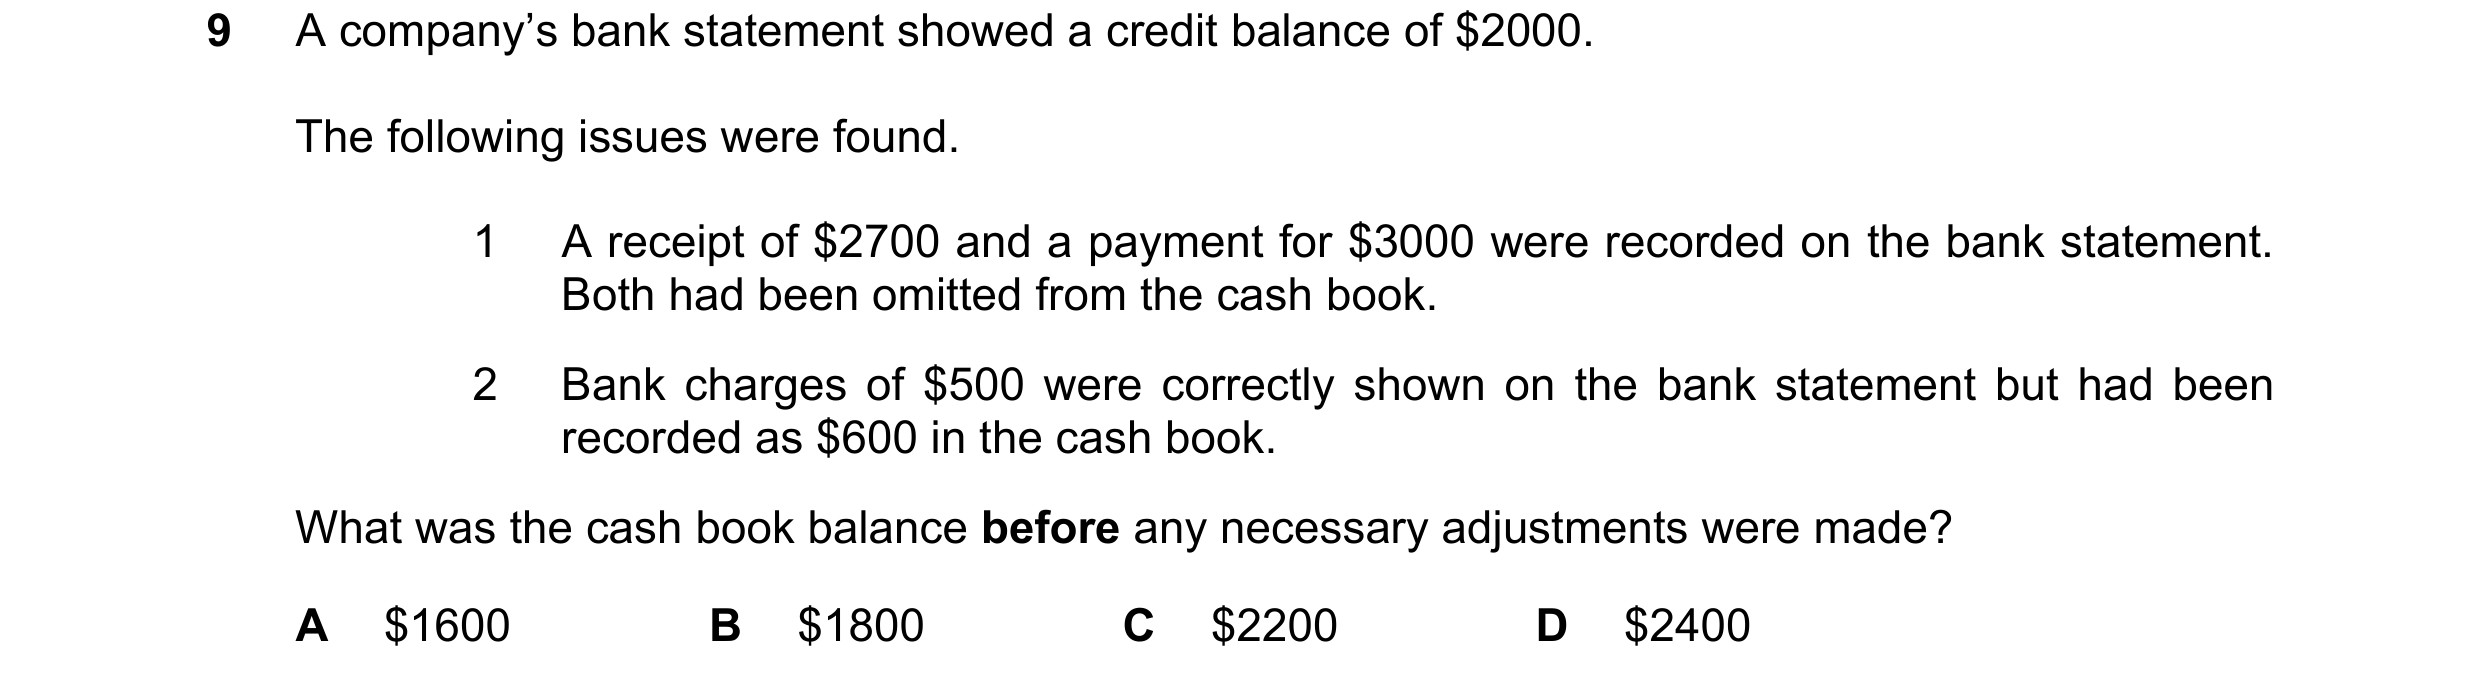 88 / 110
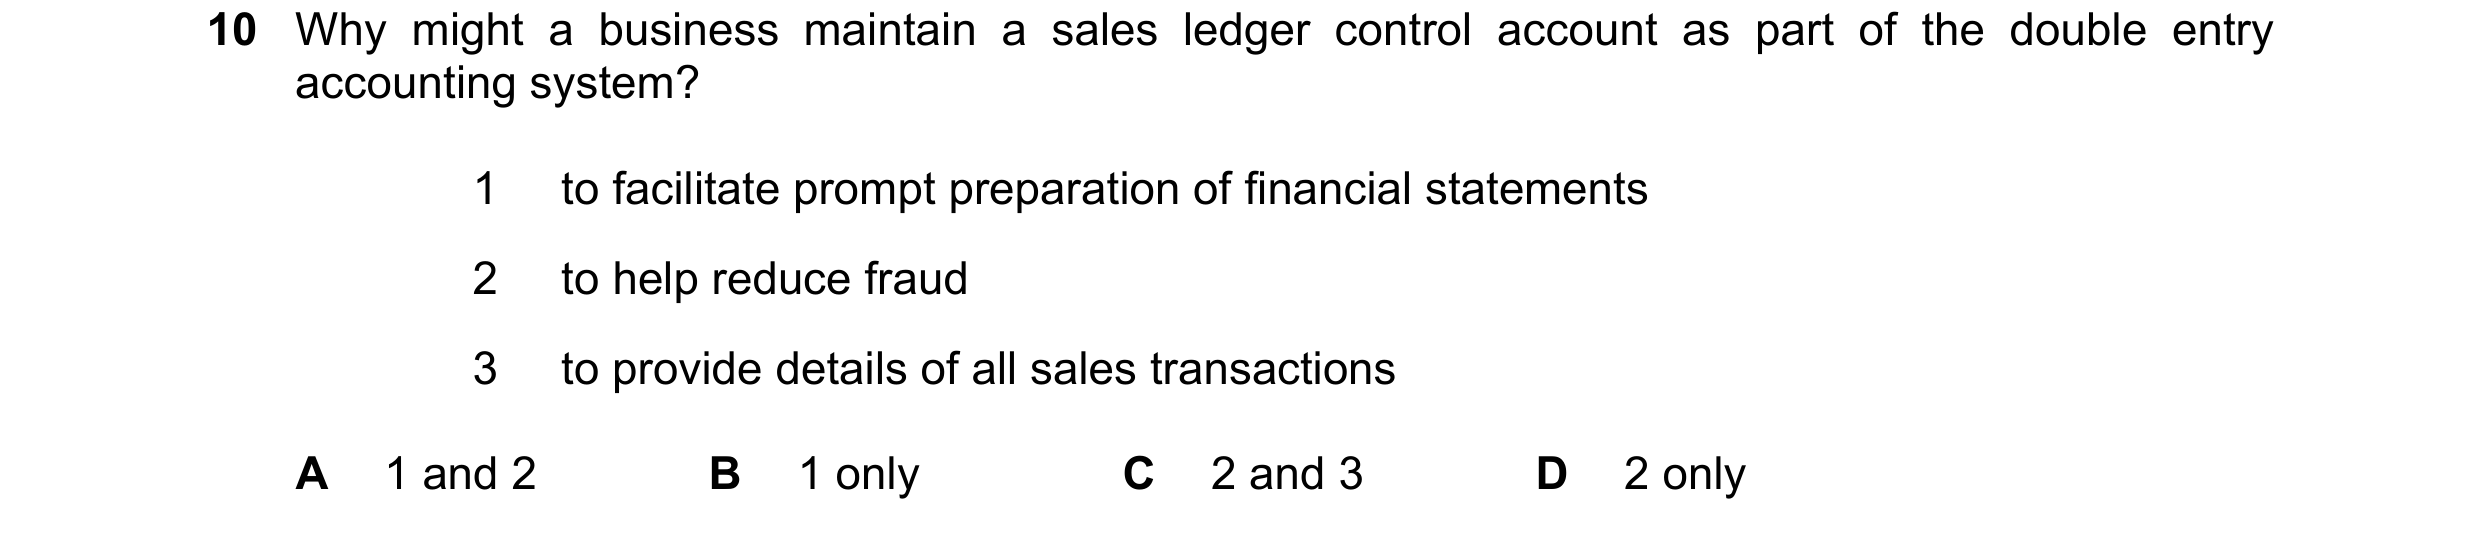
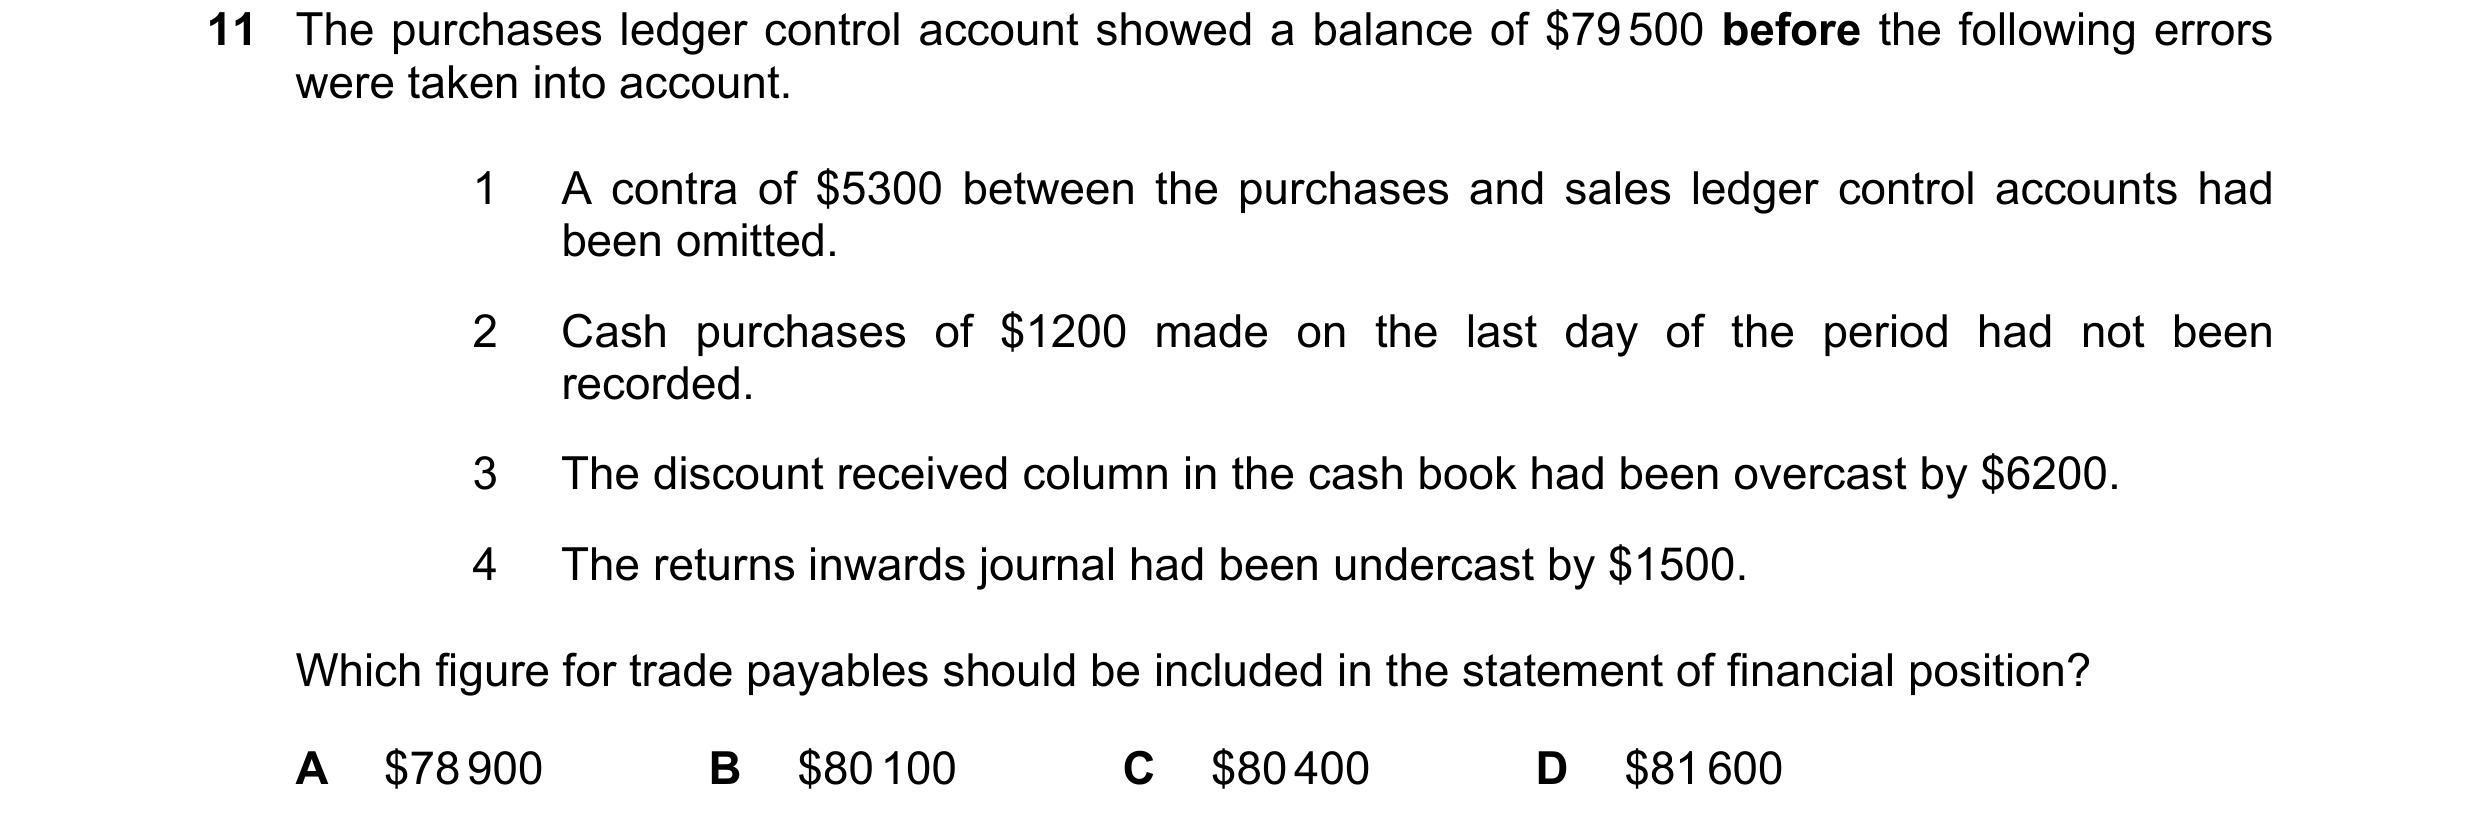
 89 / 110
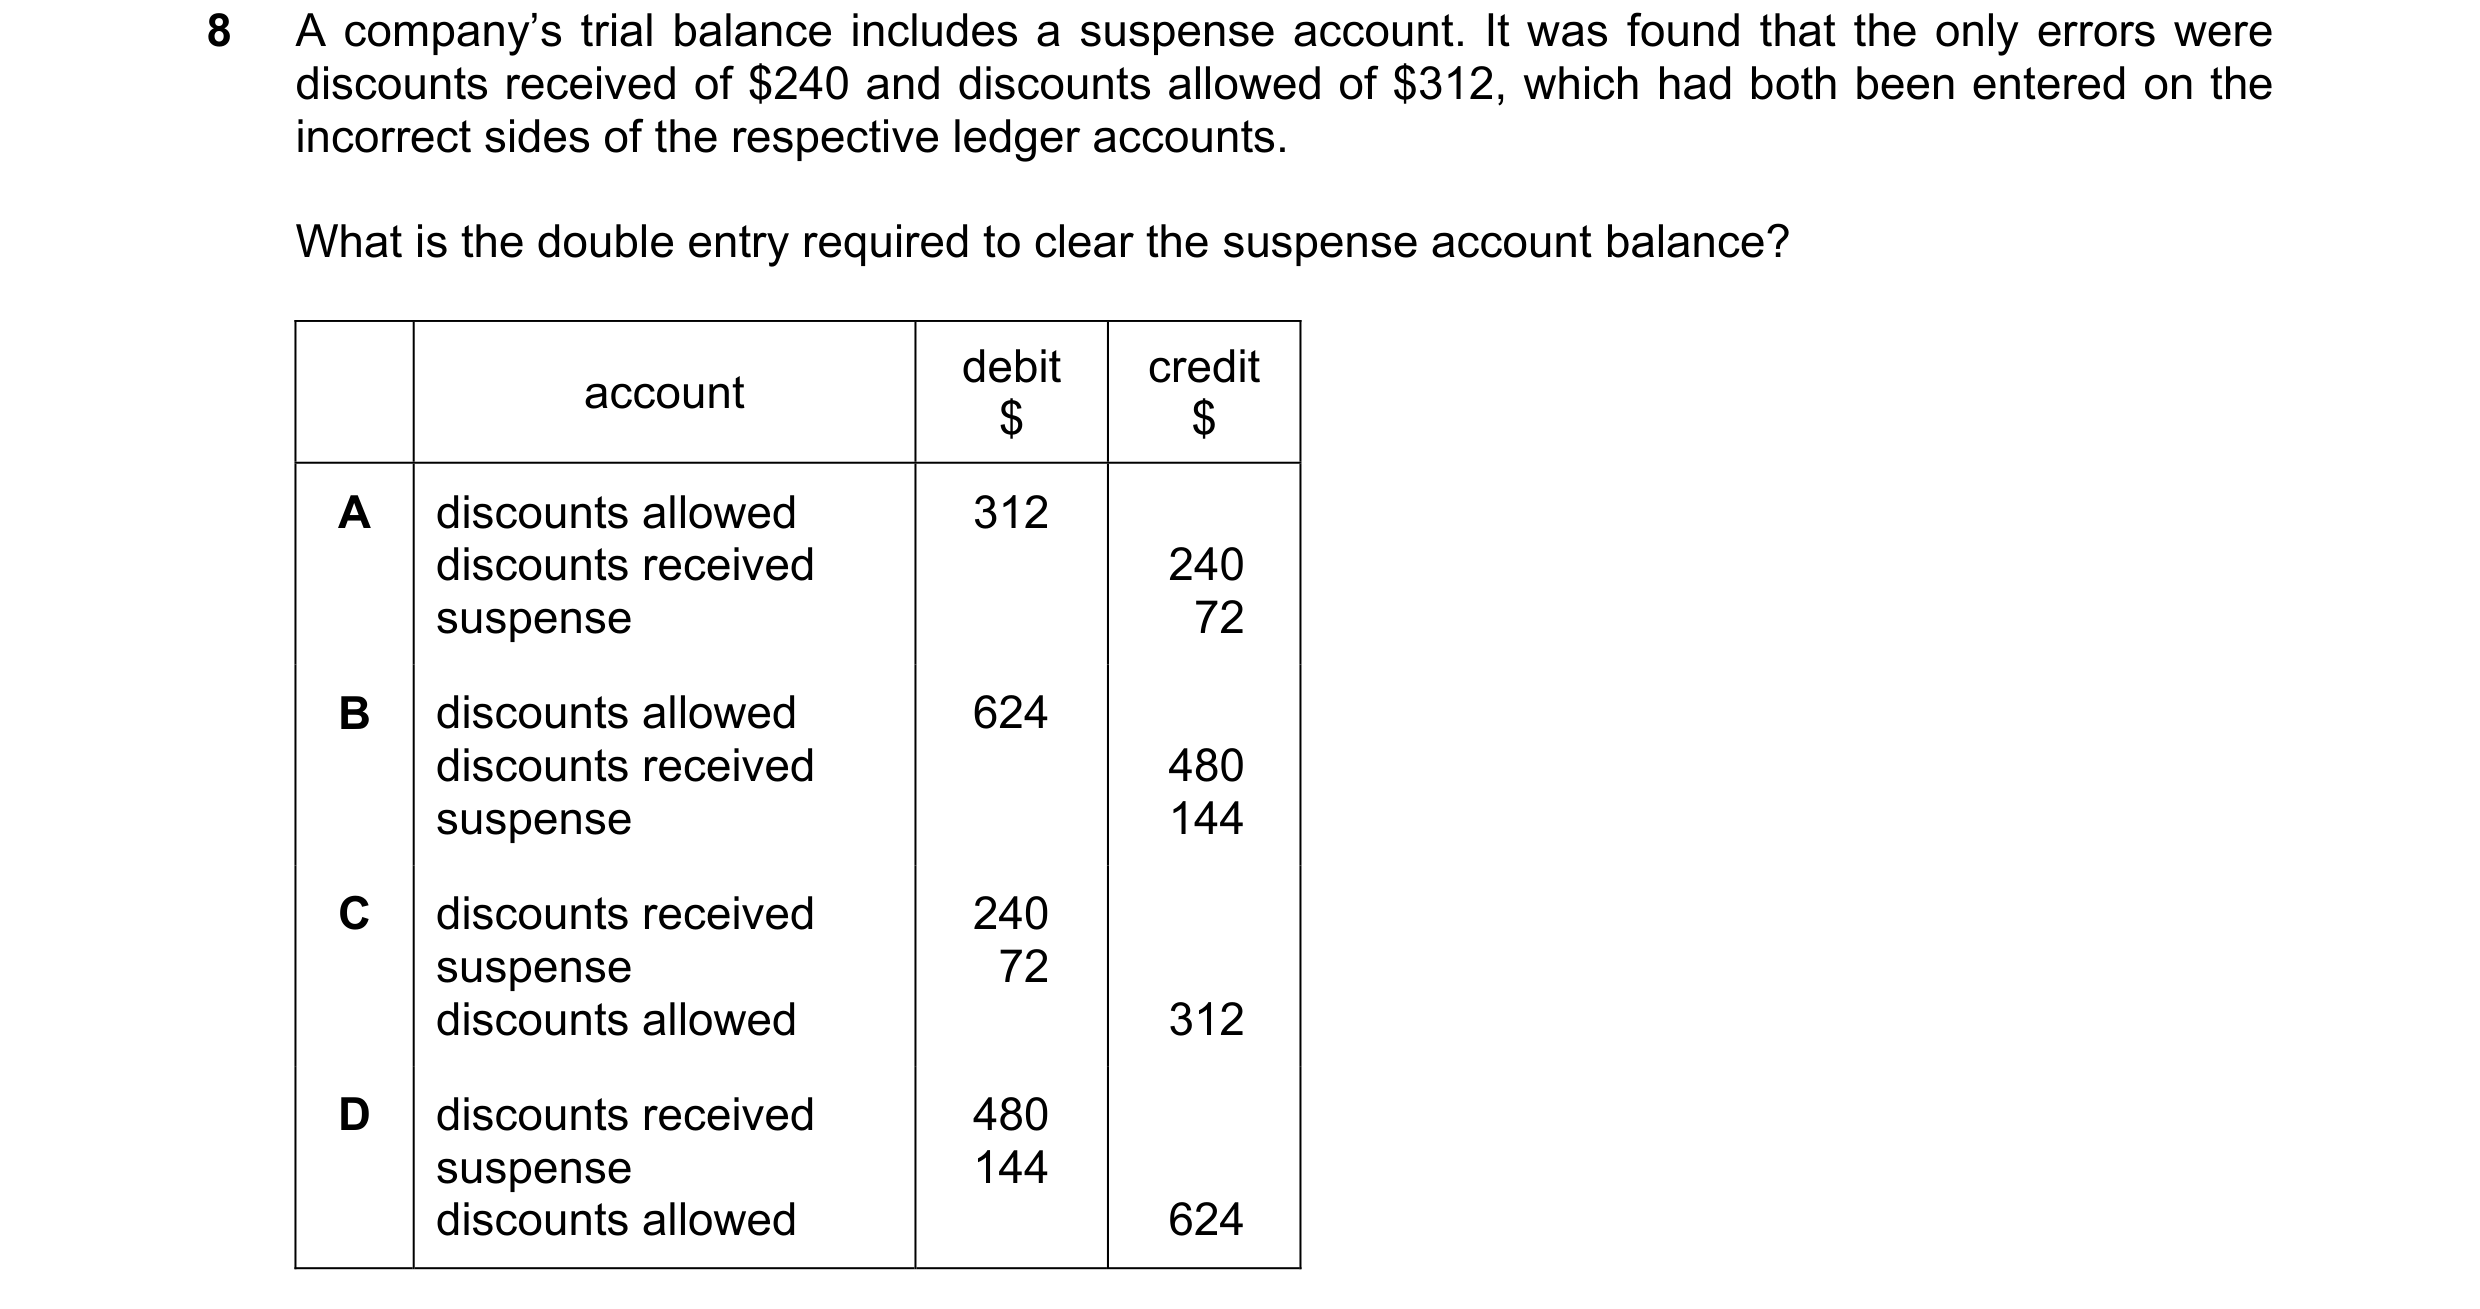
 90 / 110
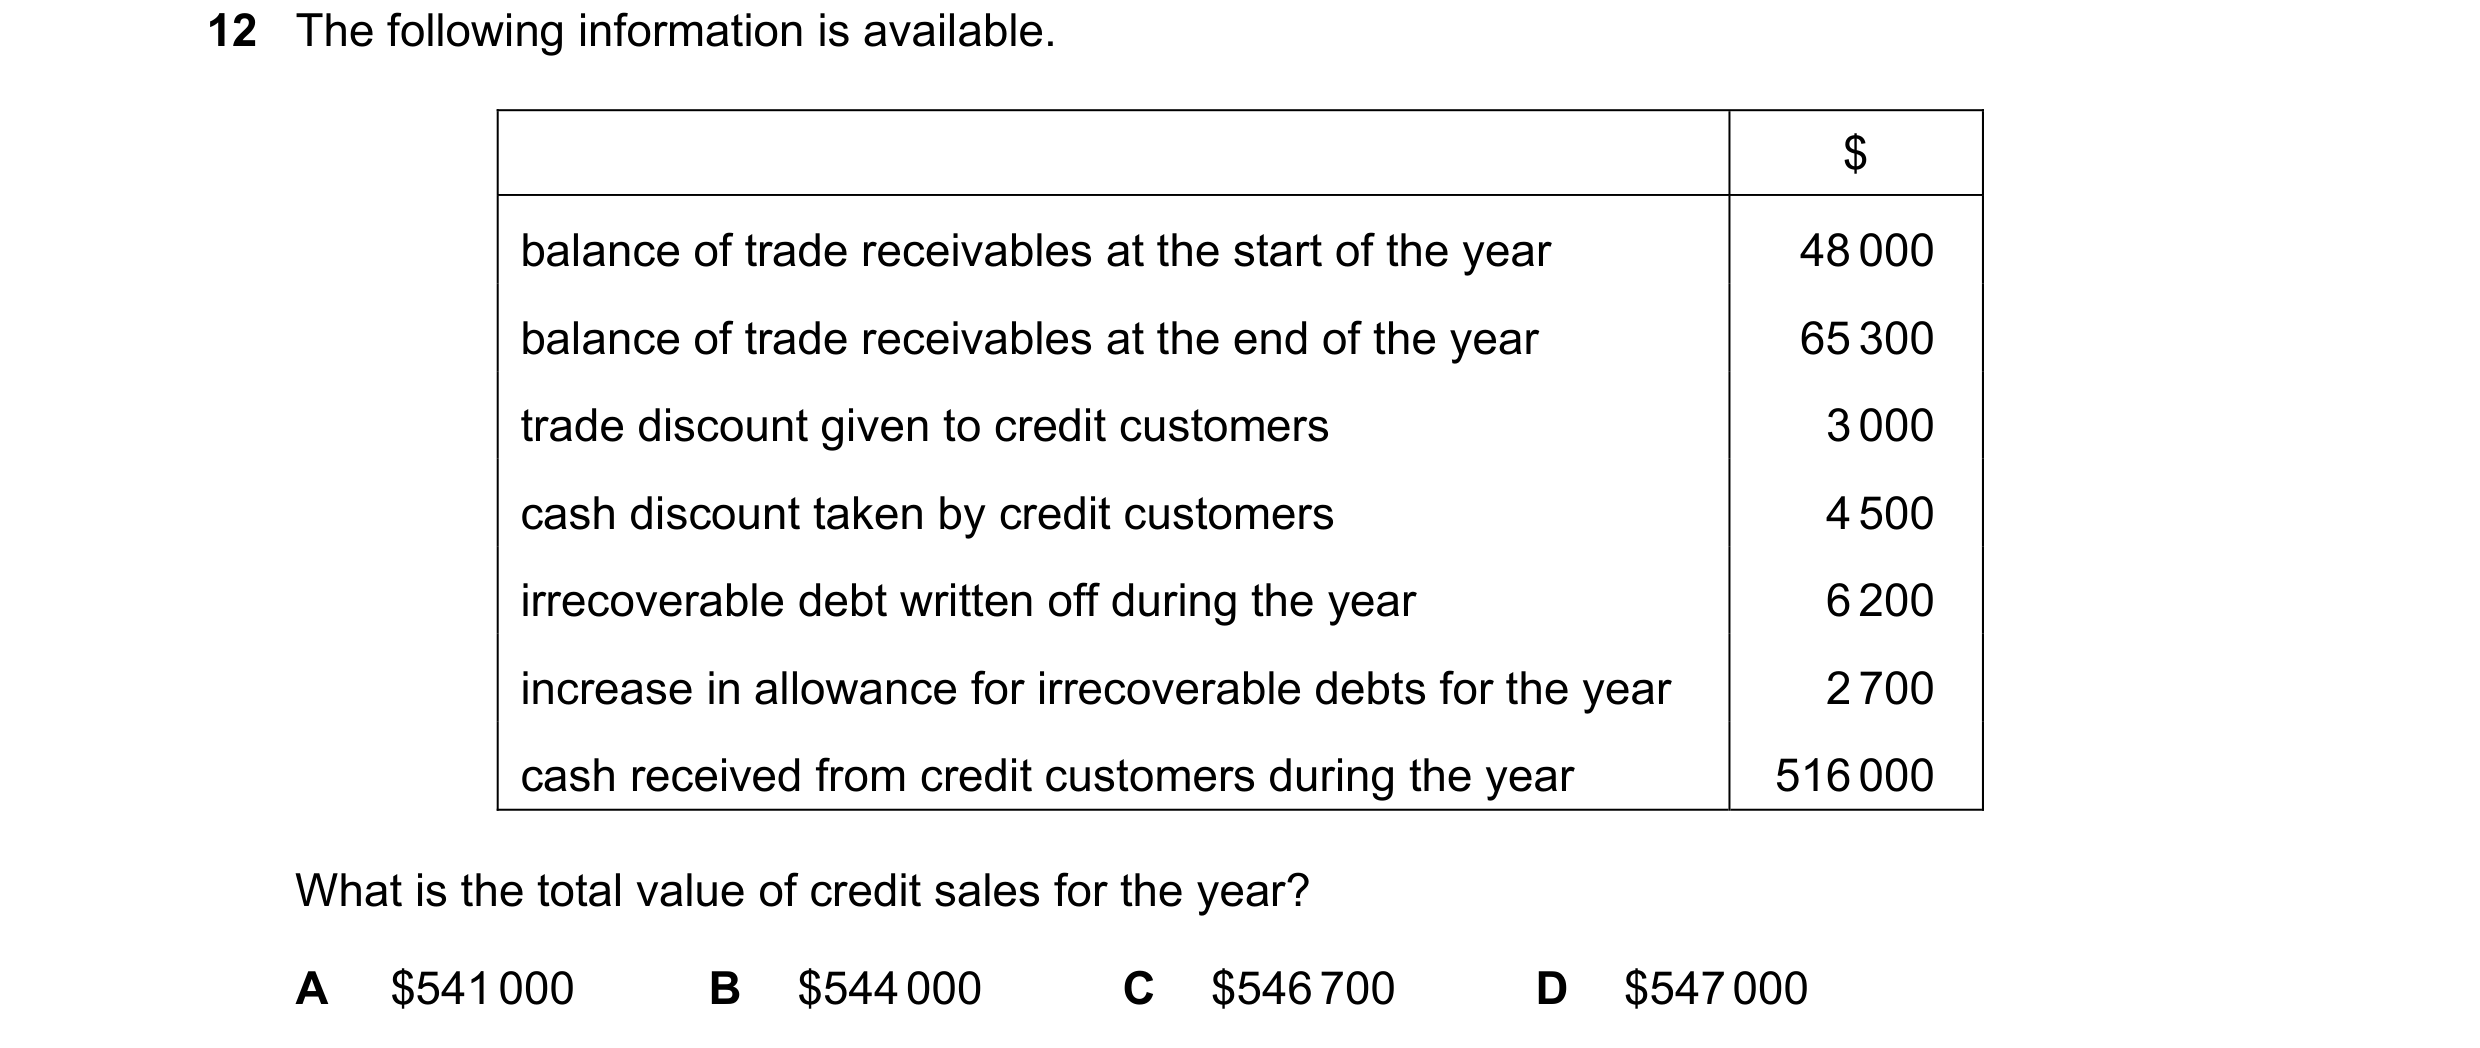
 91 / 110
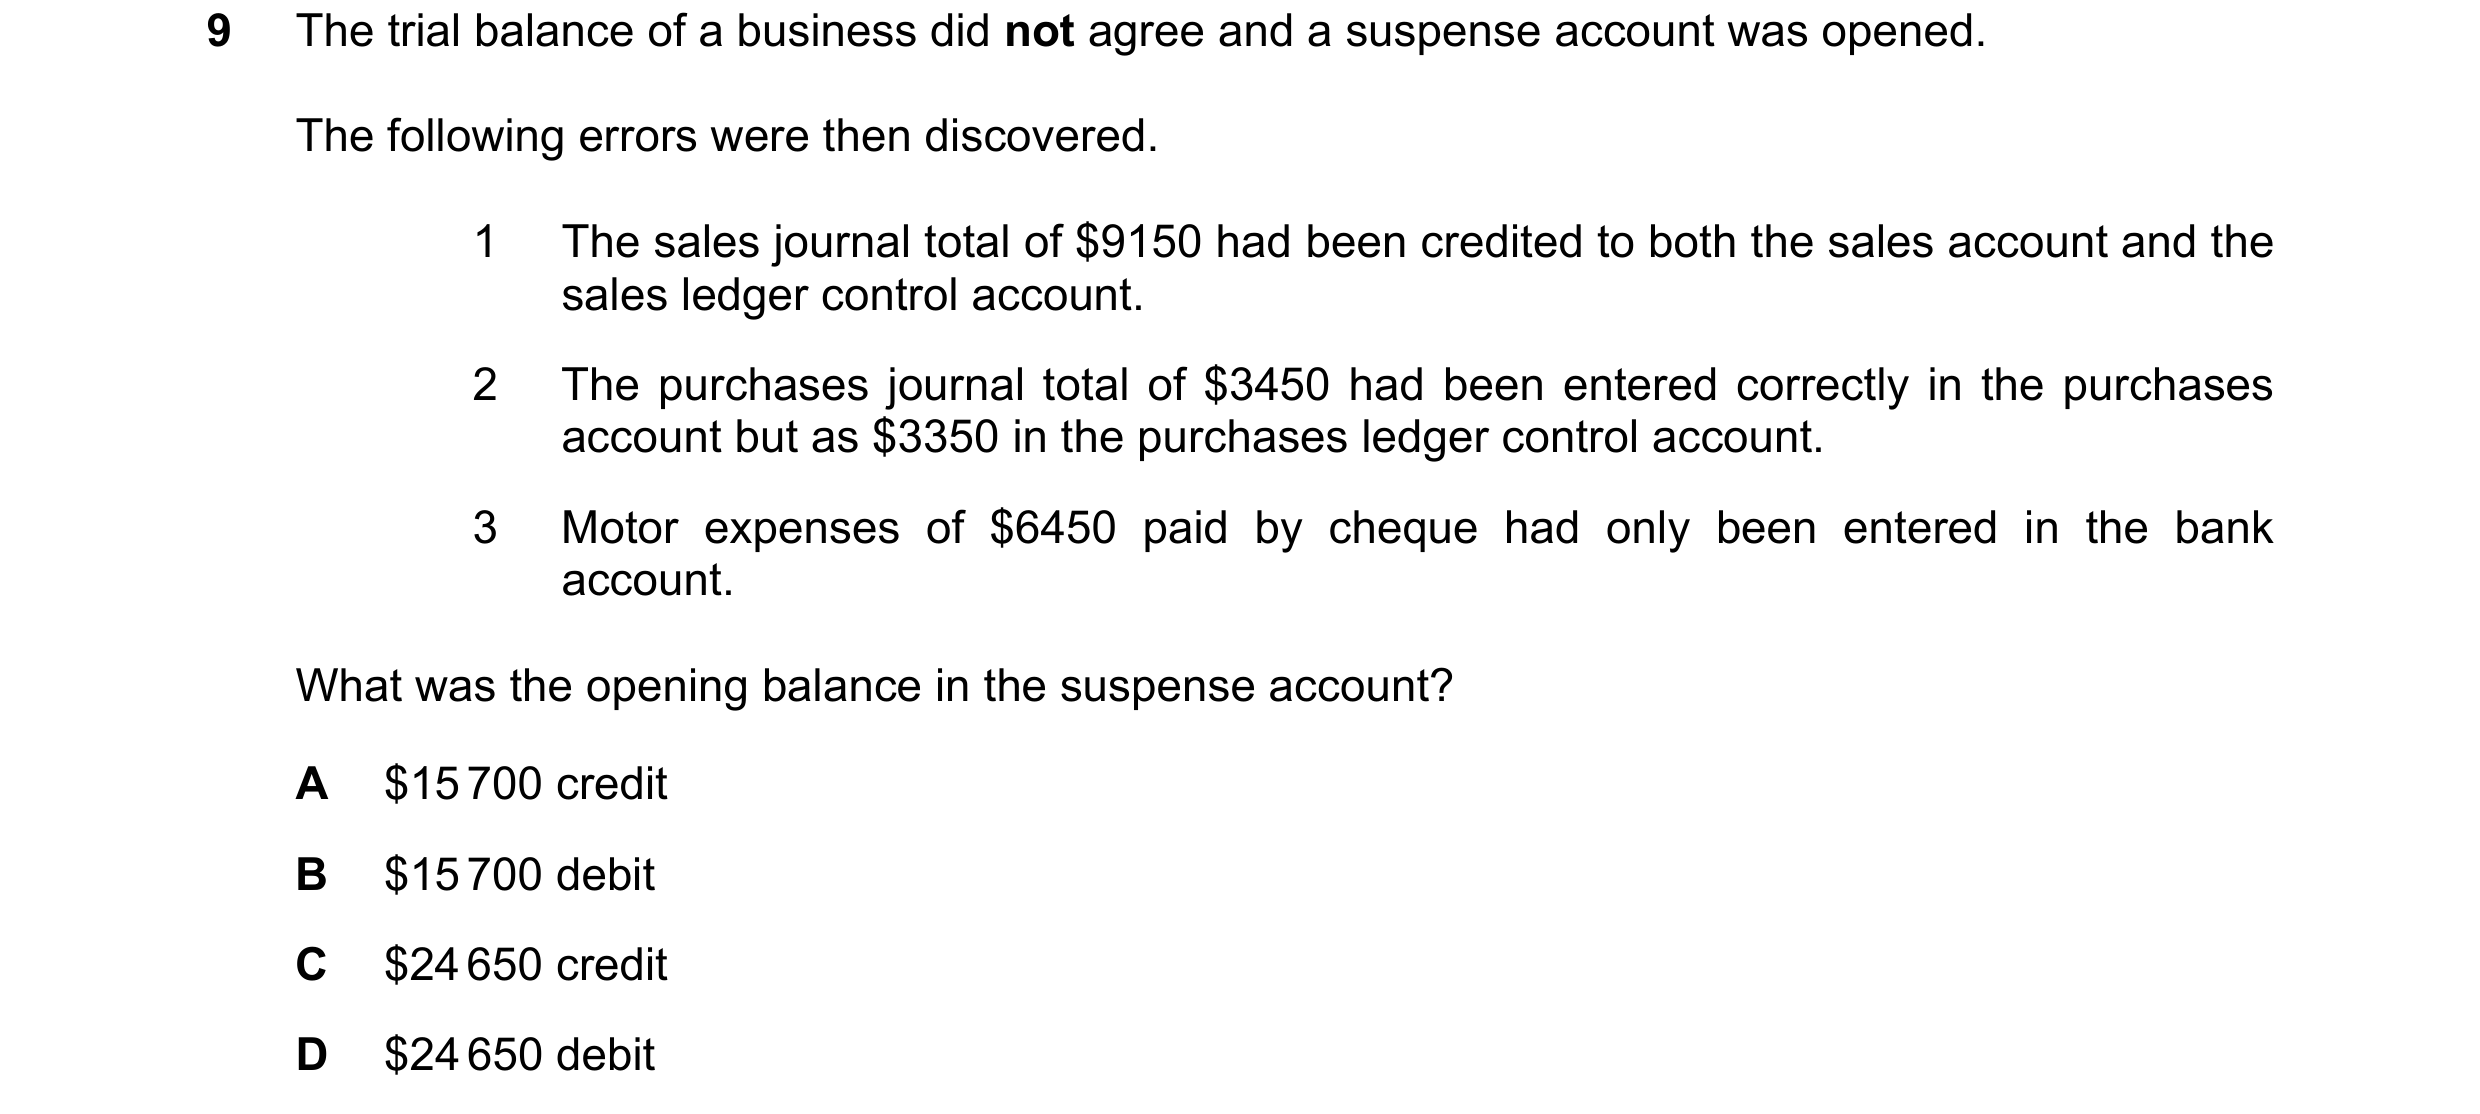
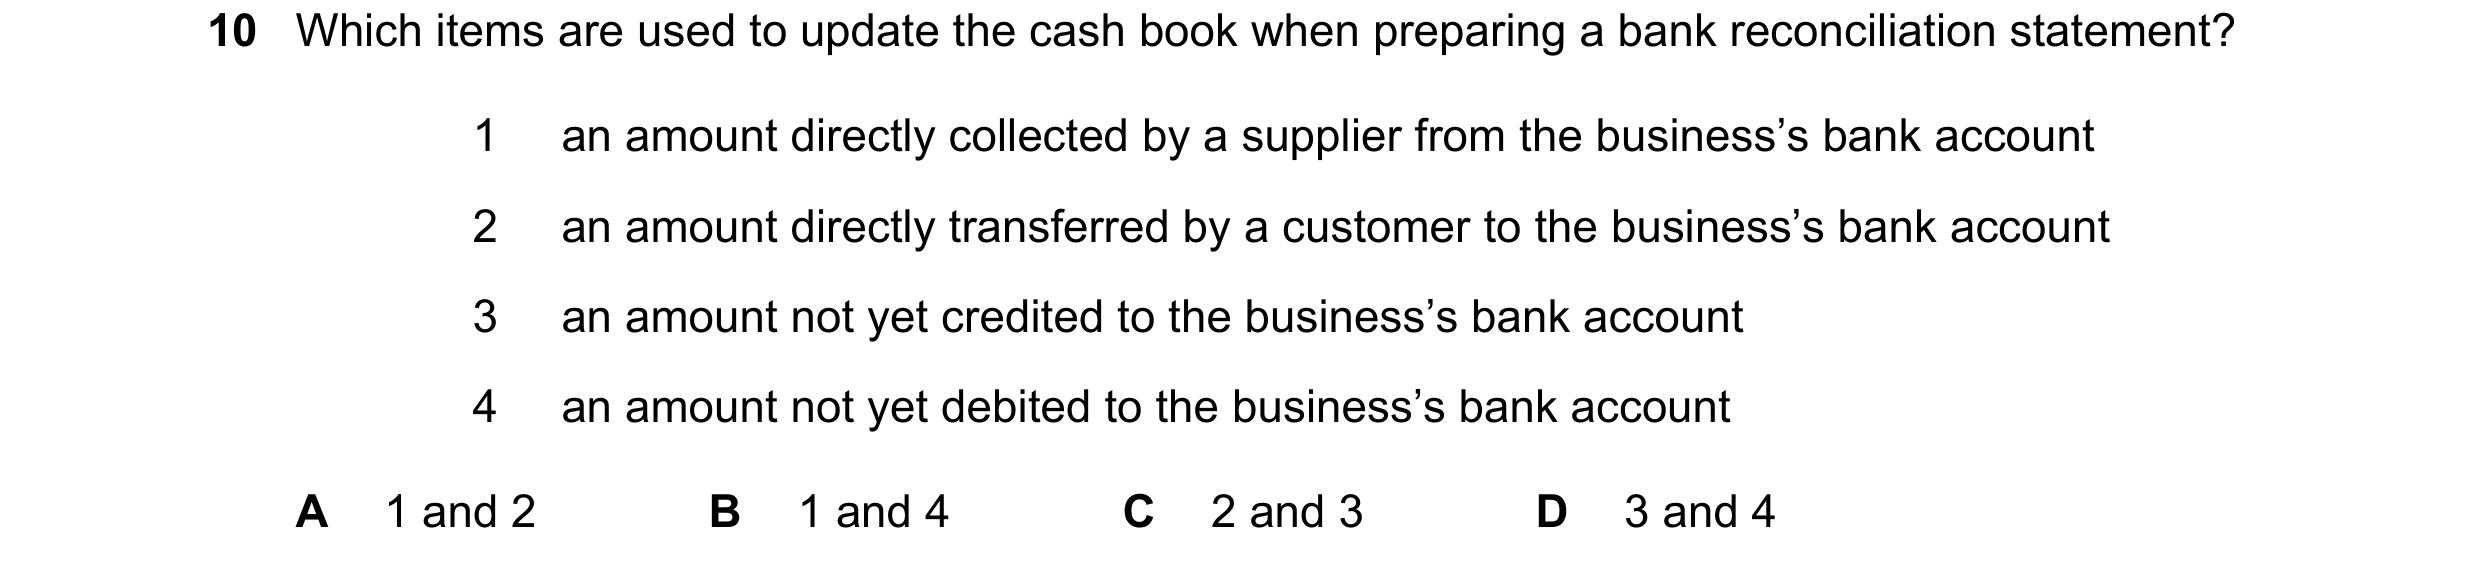
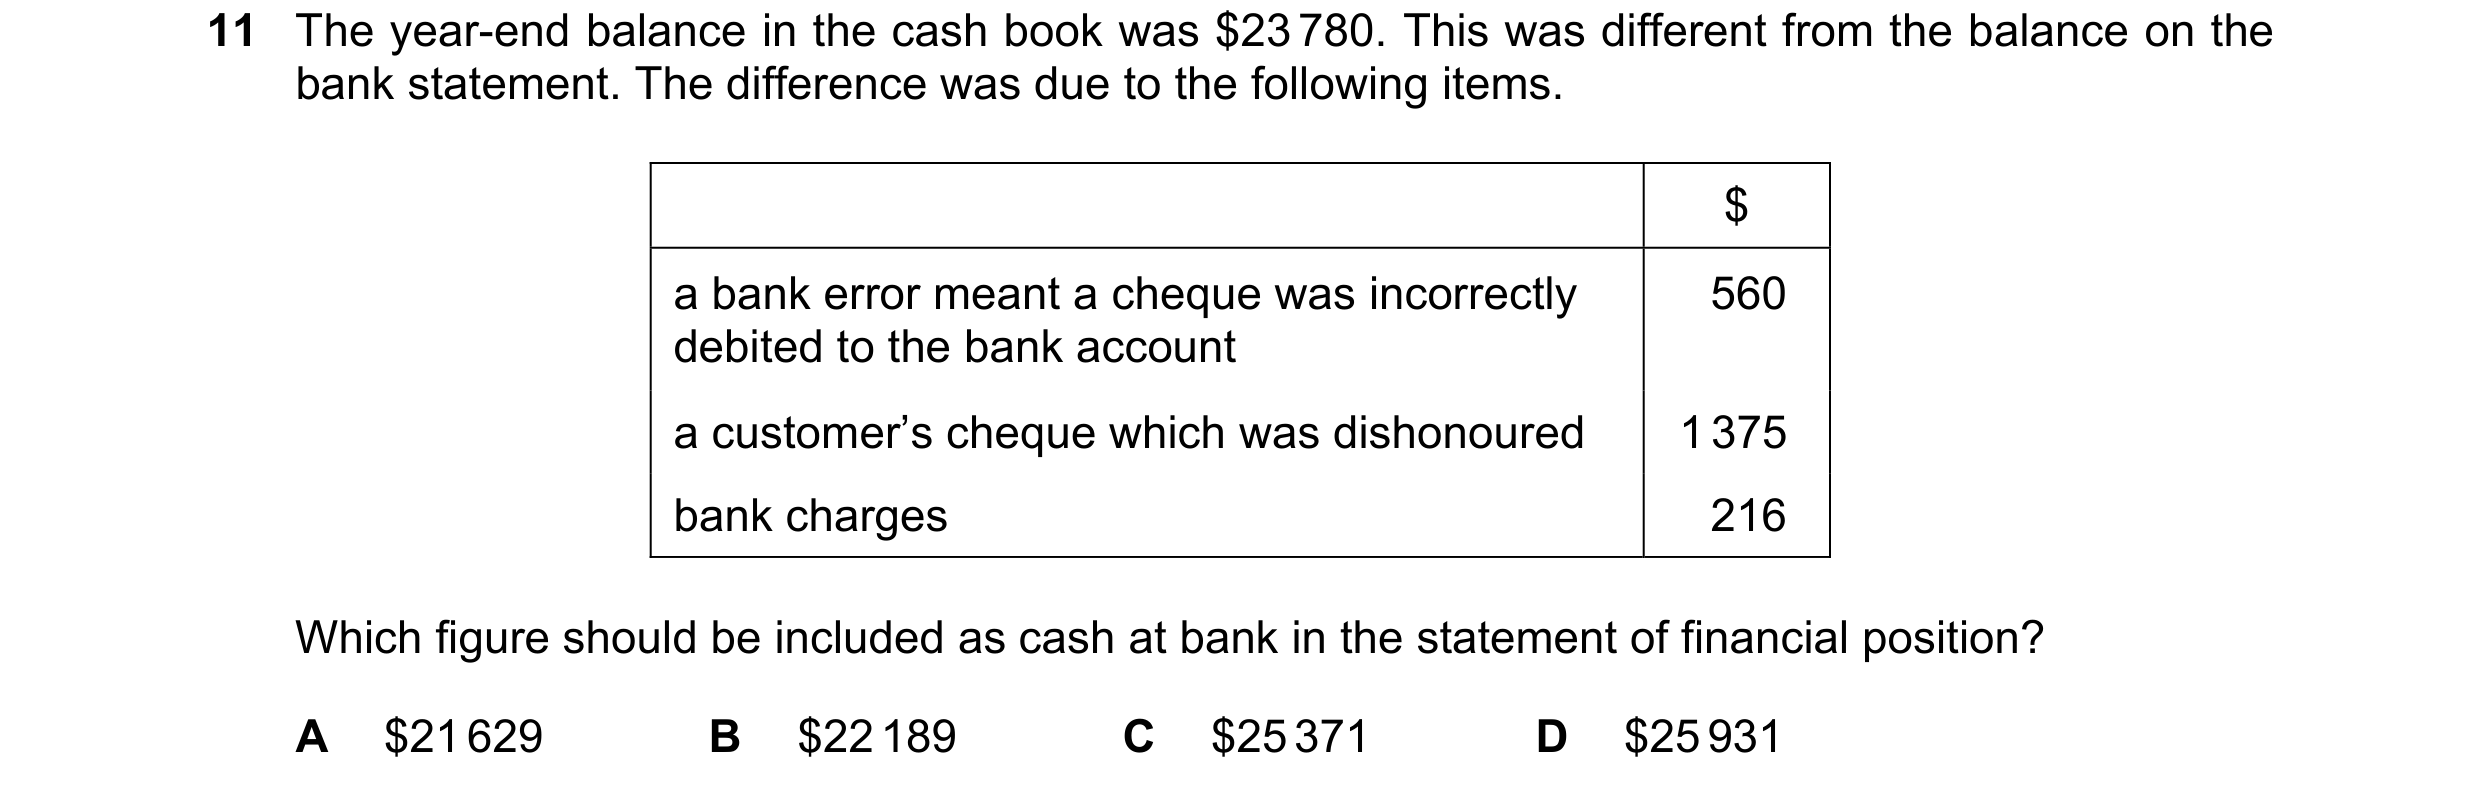
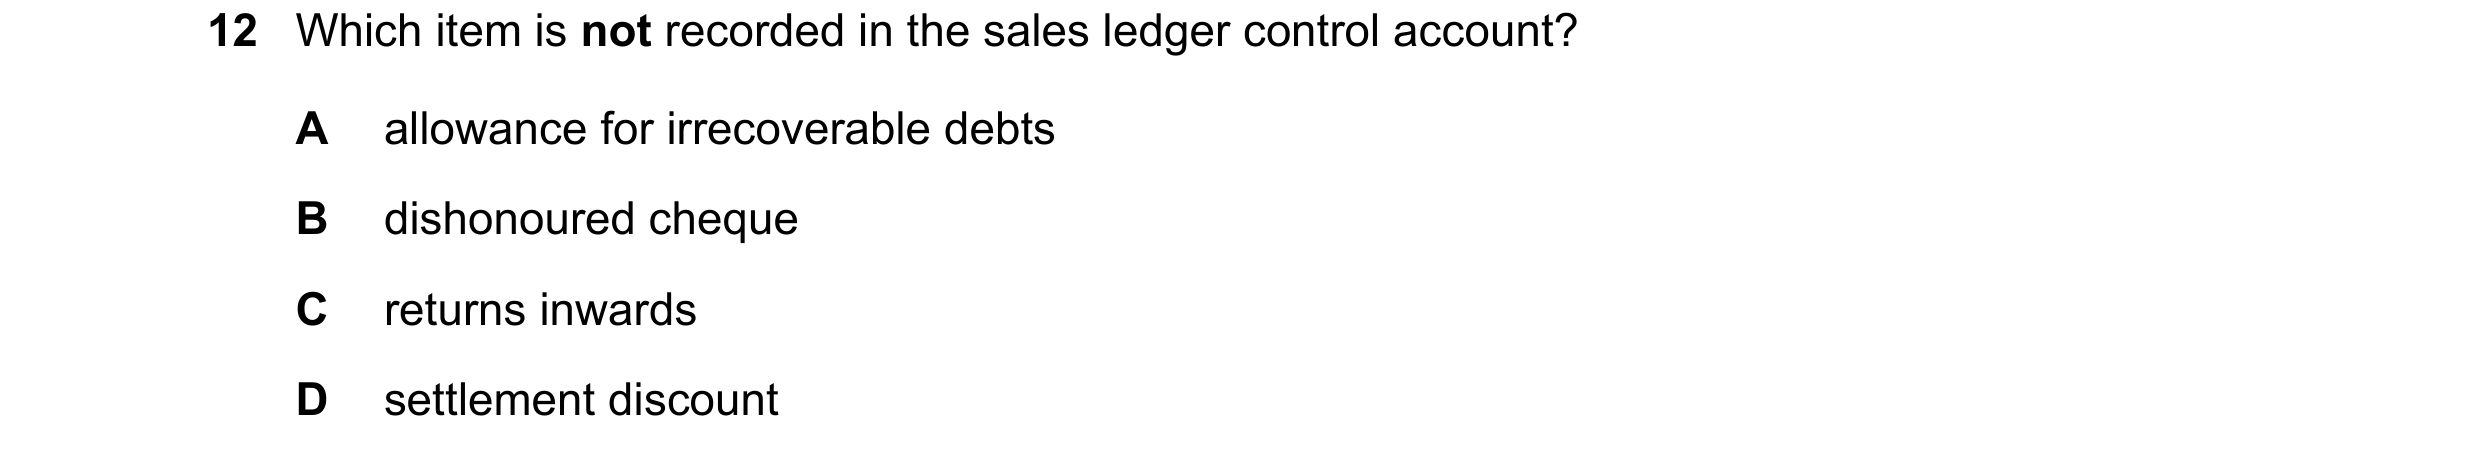 92 / 110
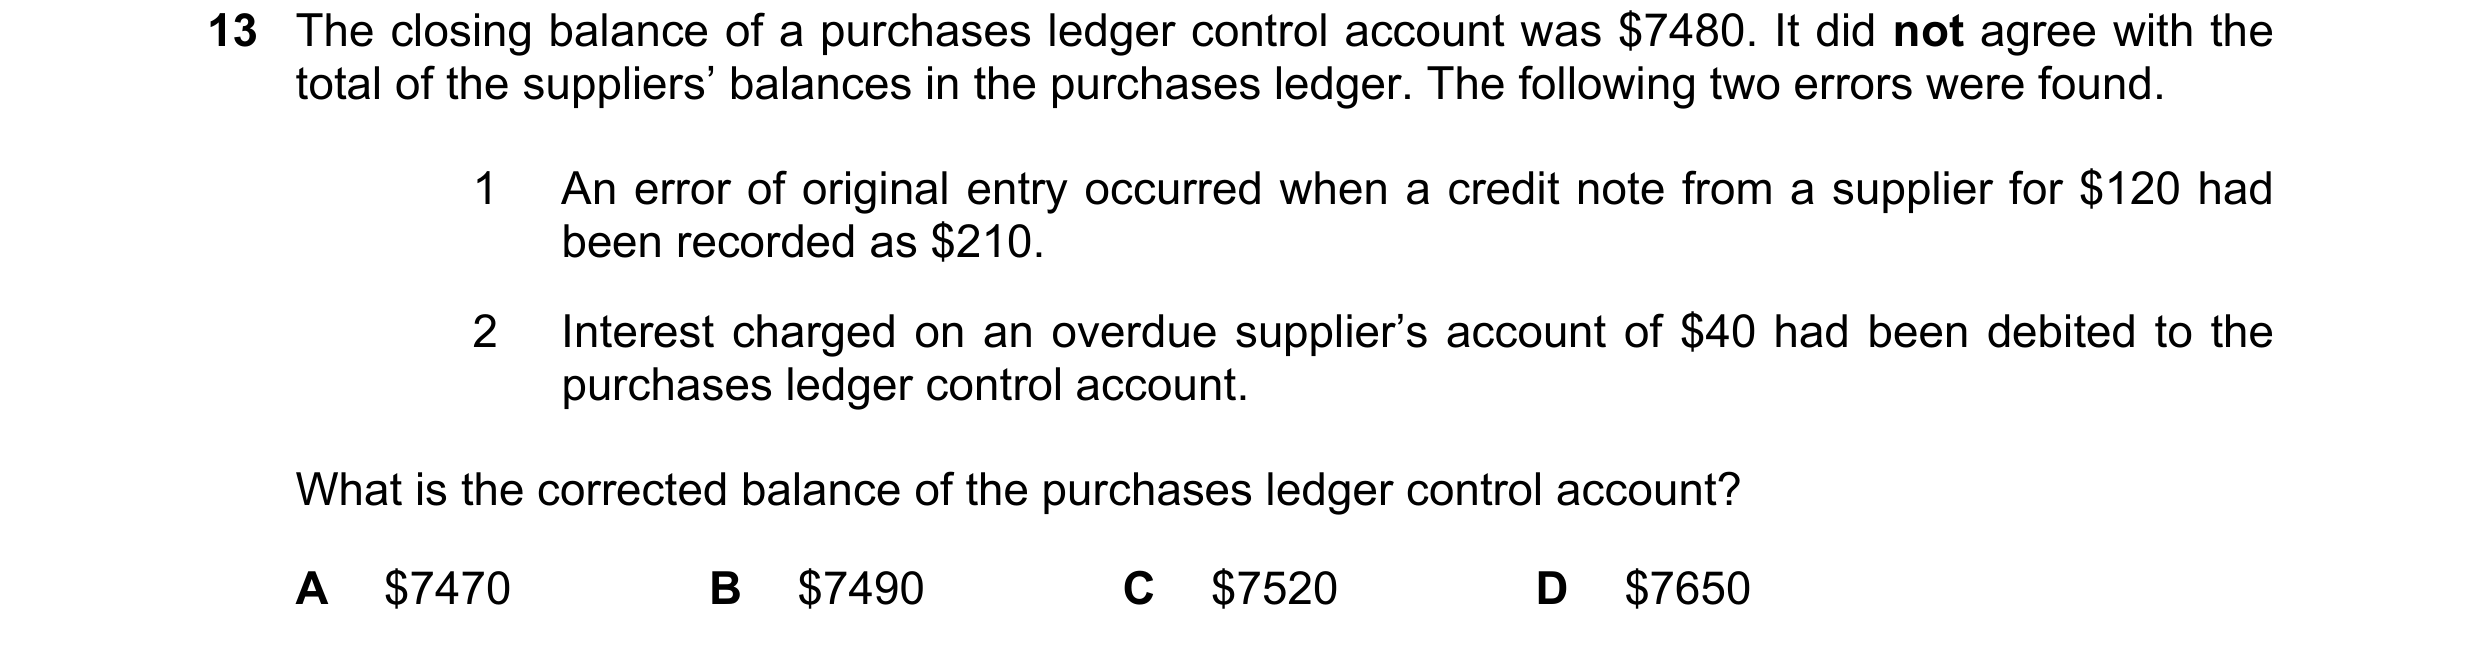
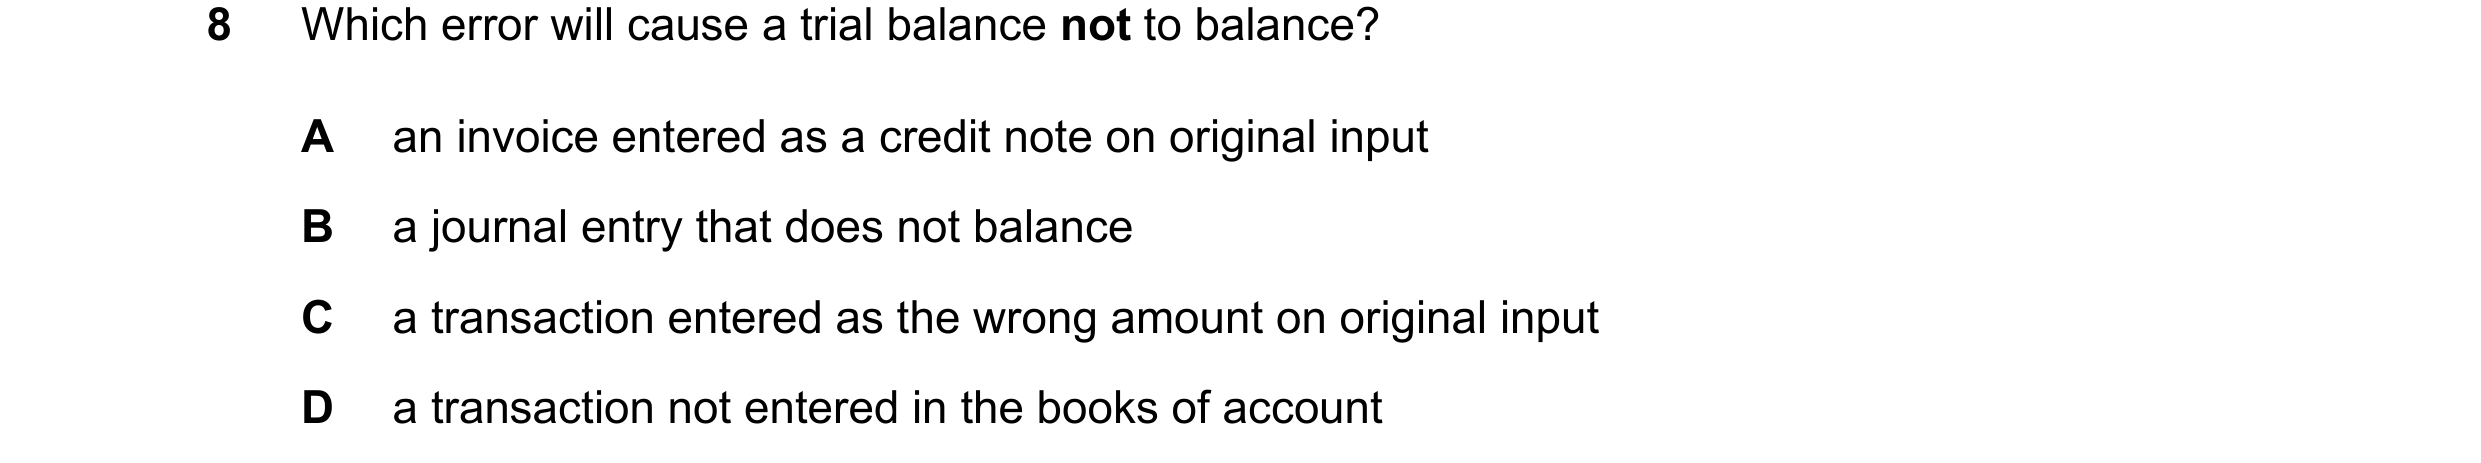
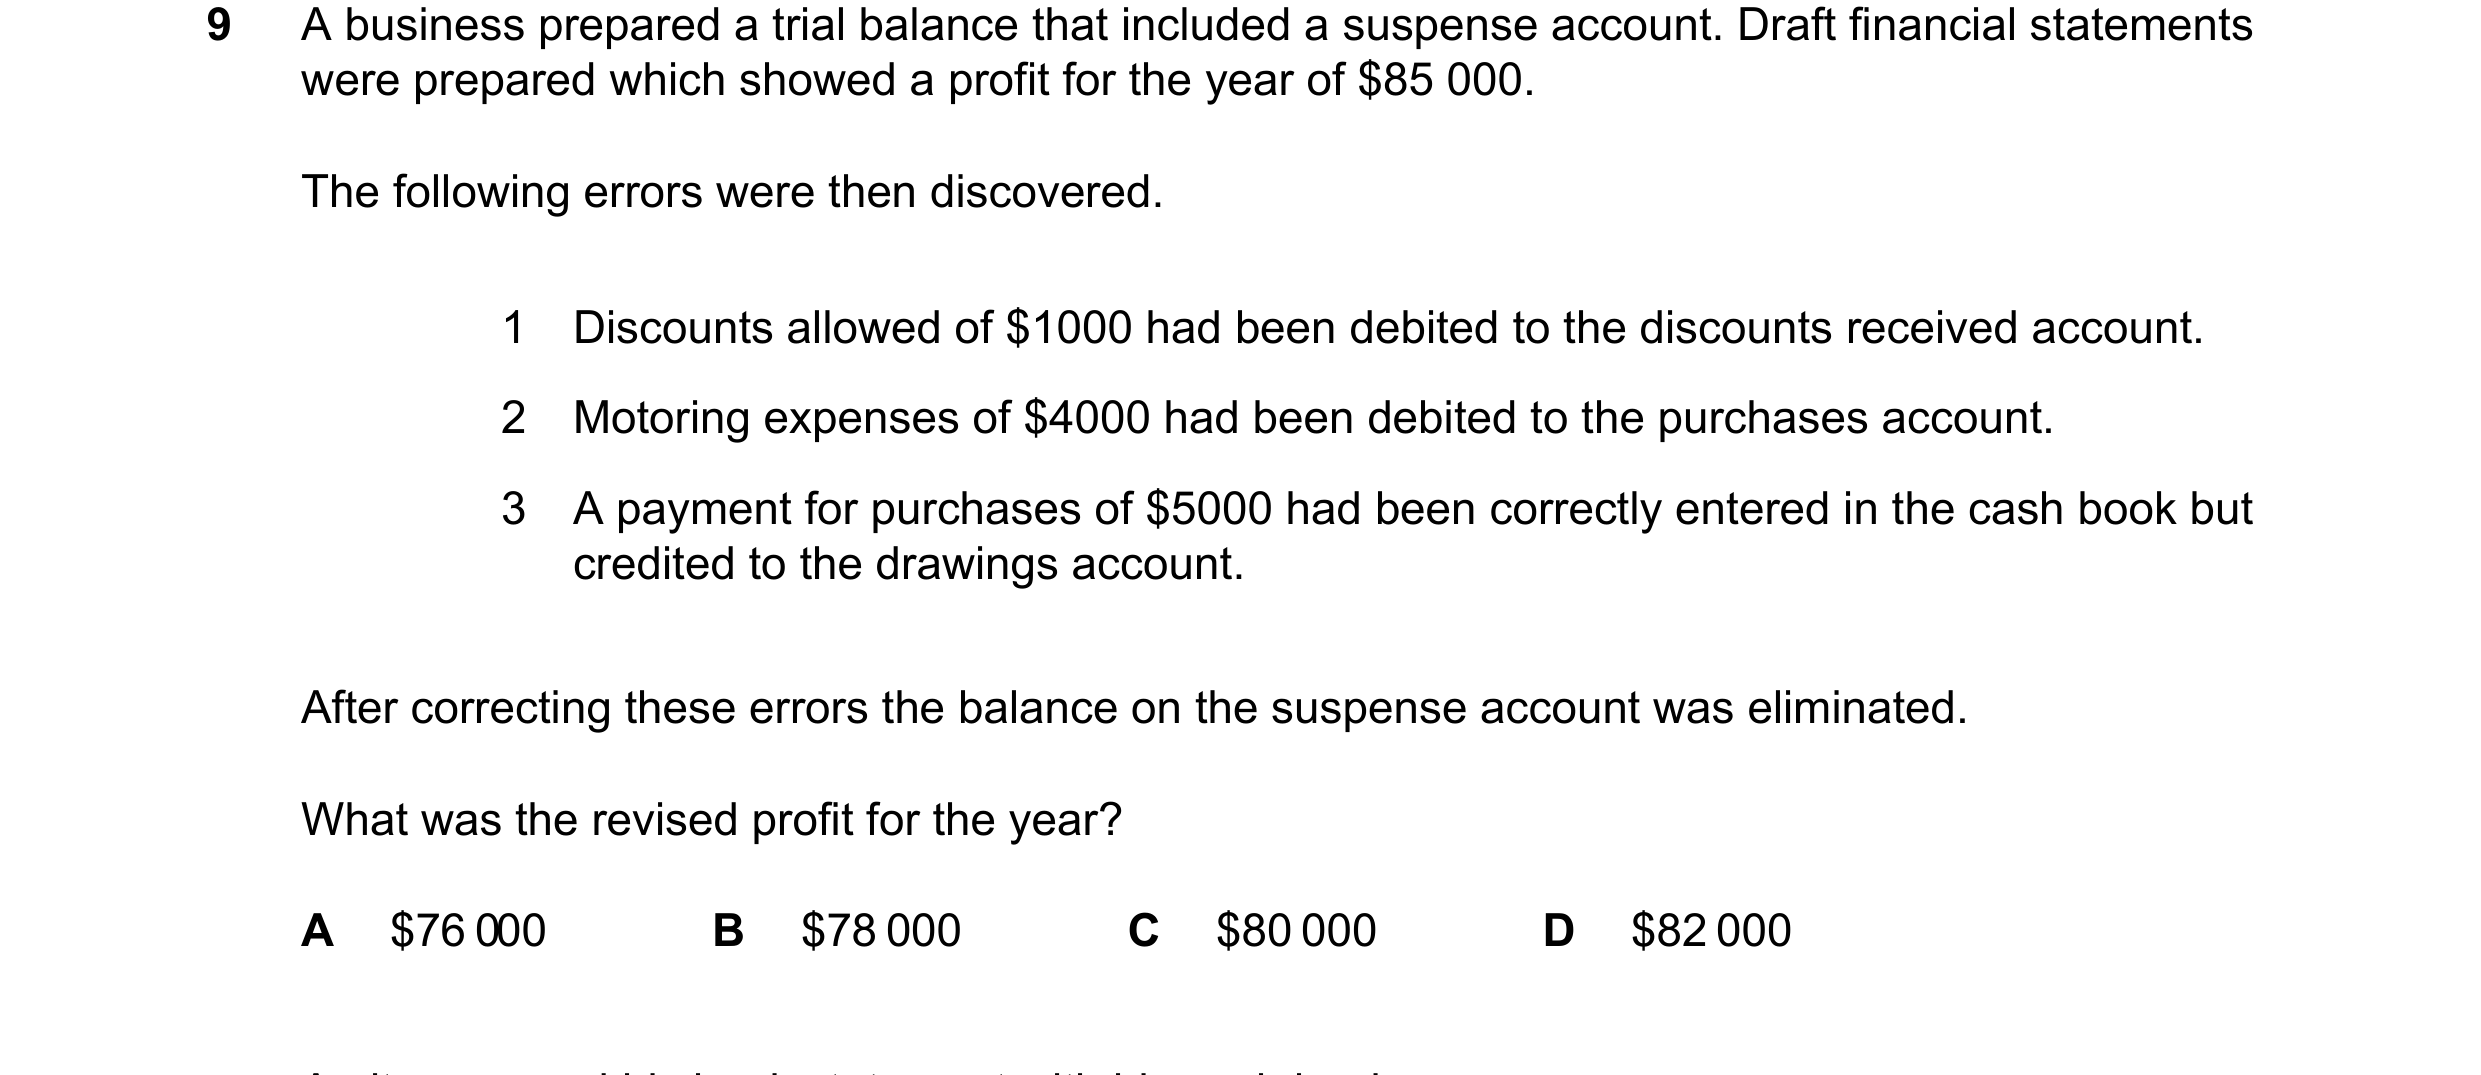
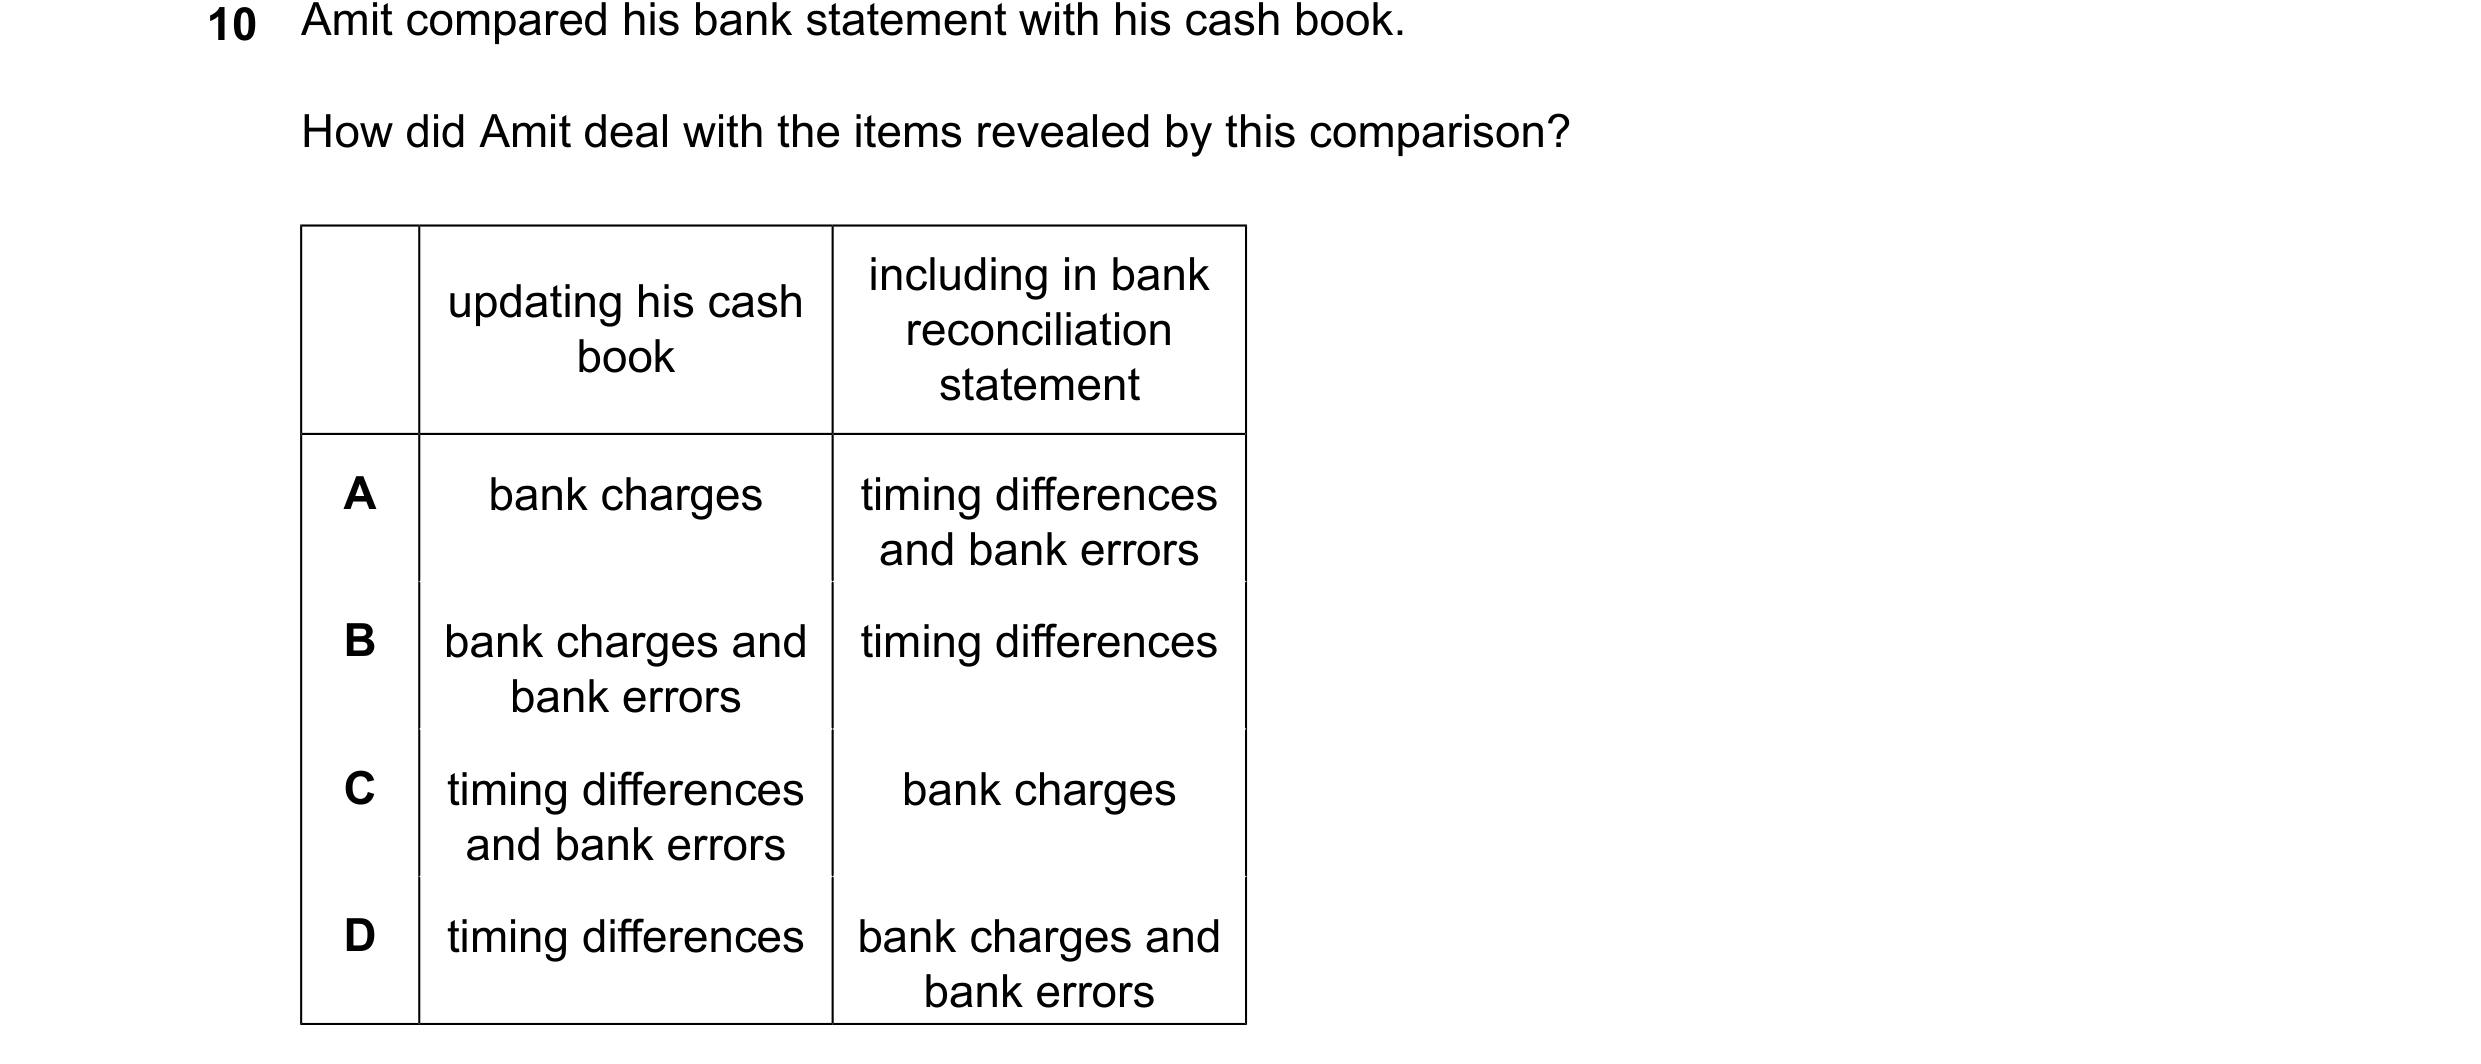 93 / 110
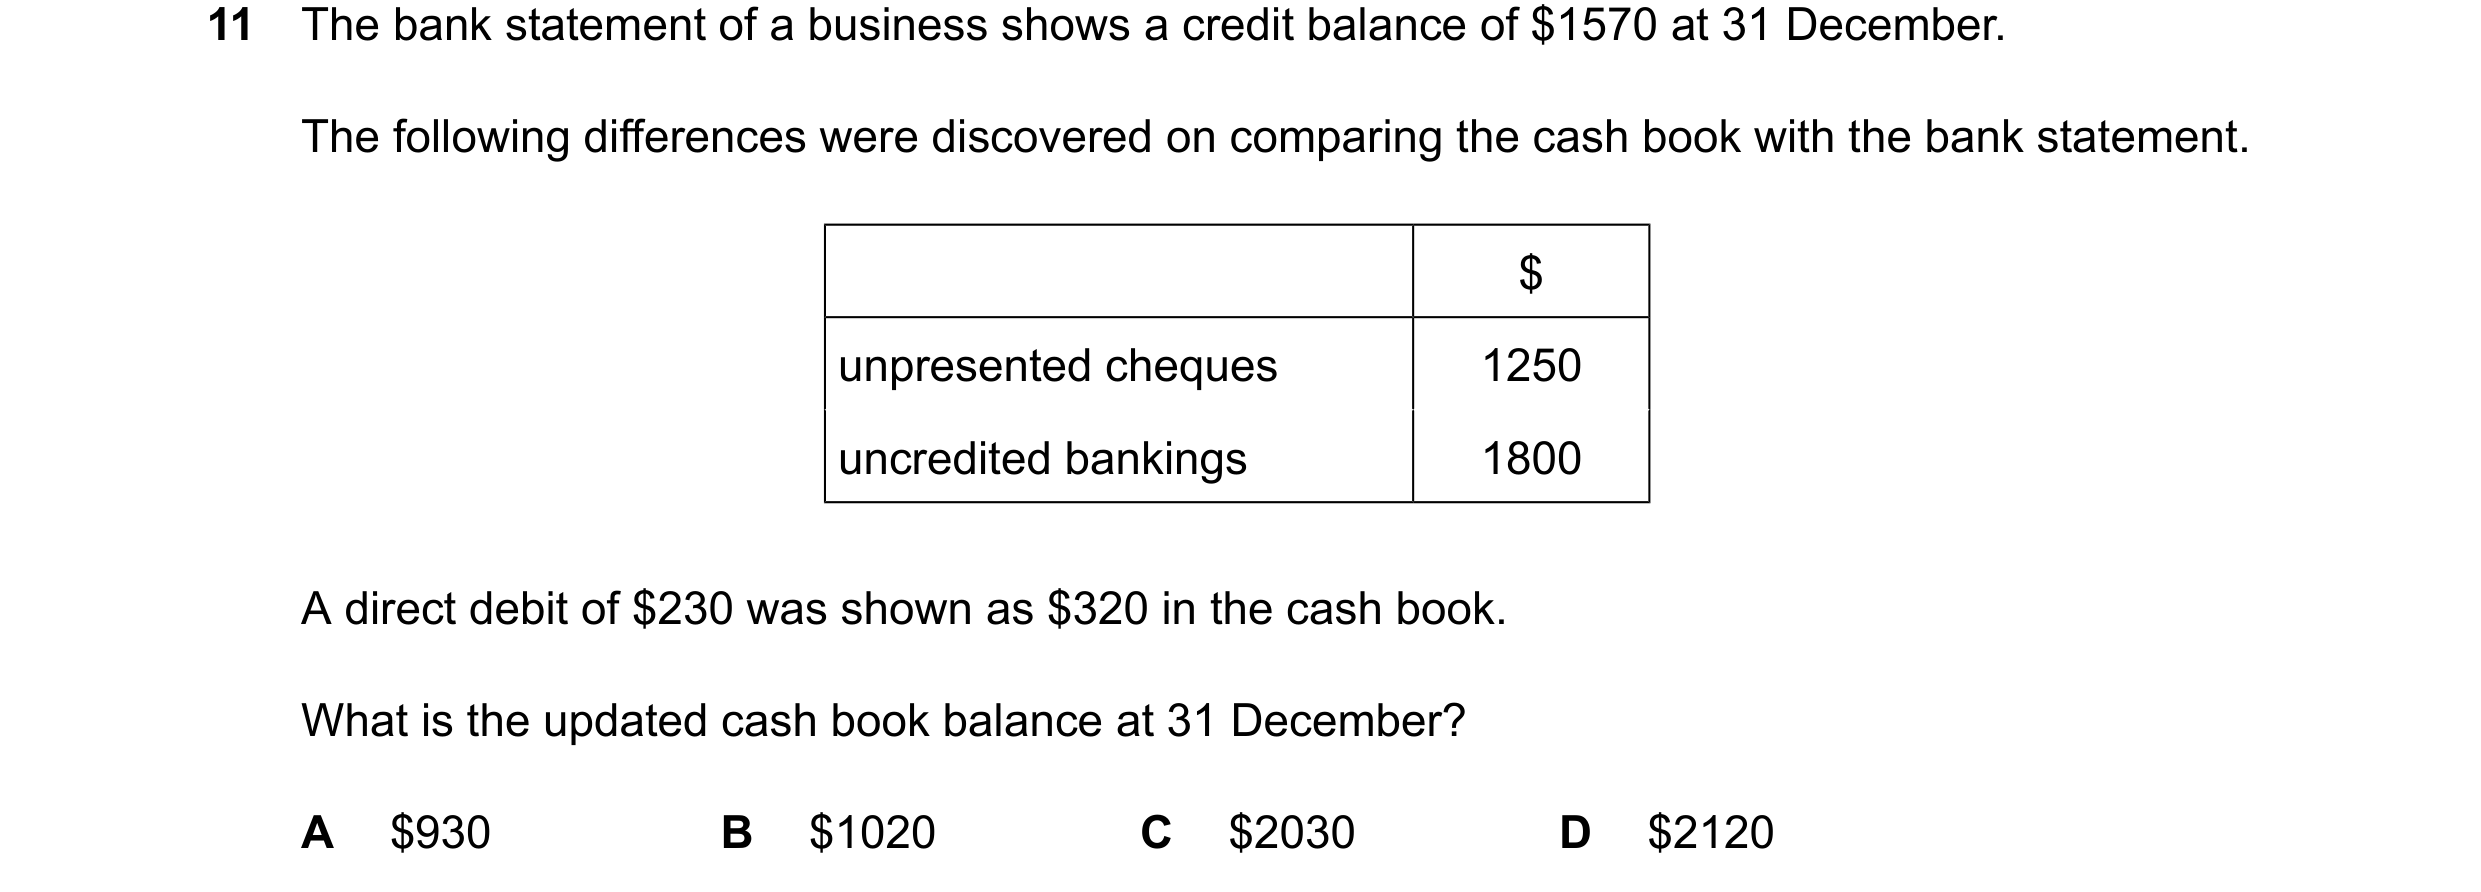
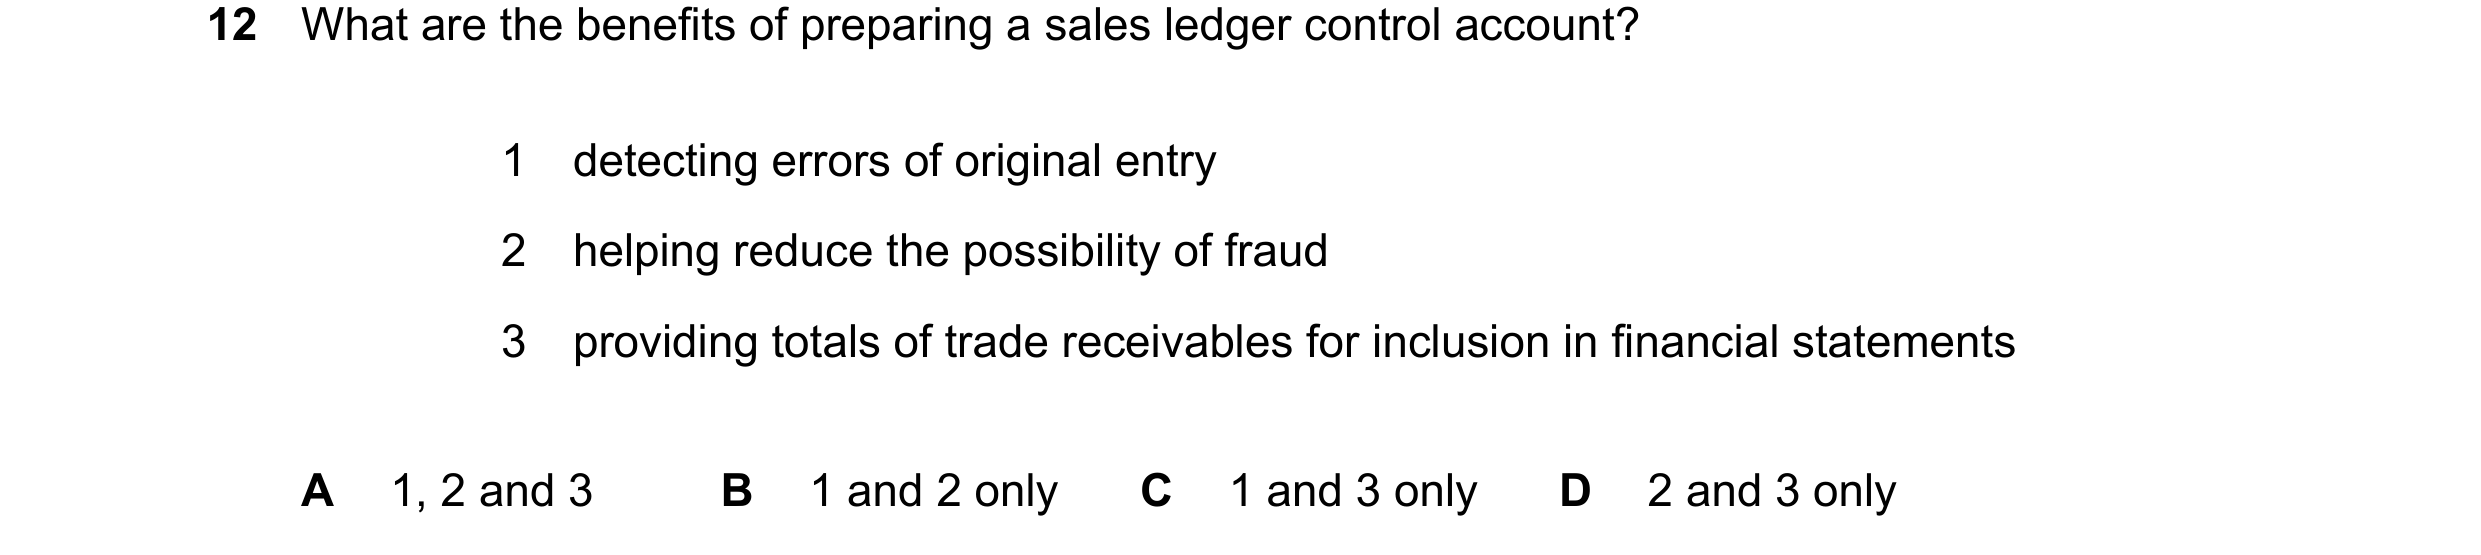
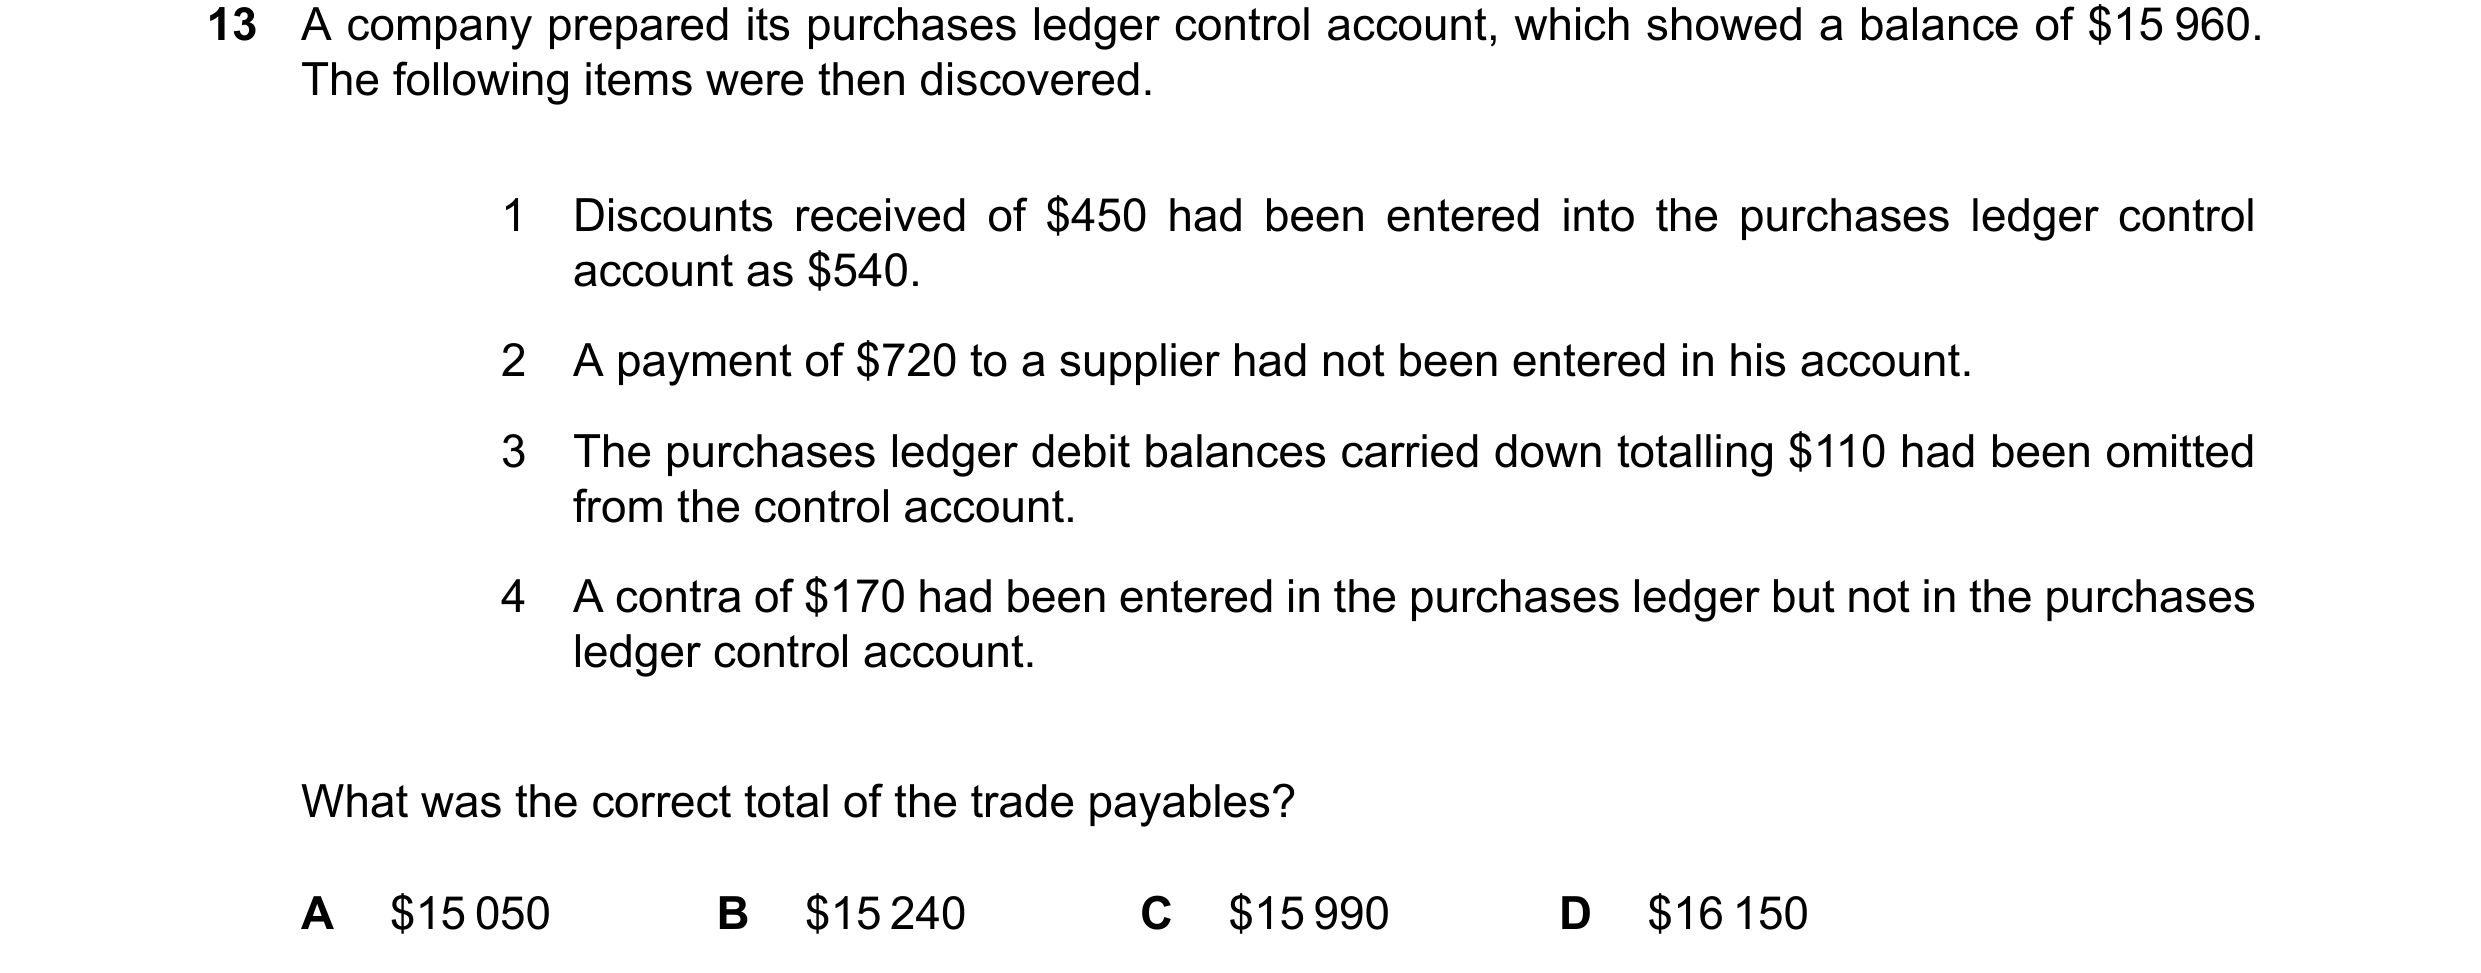
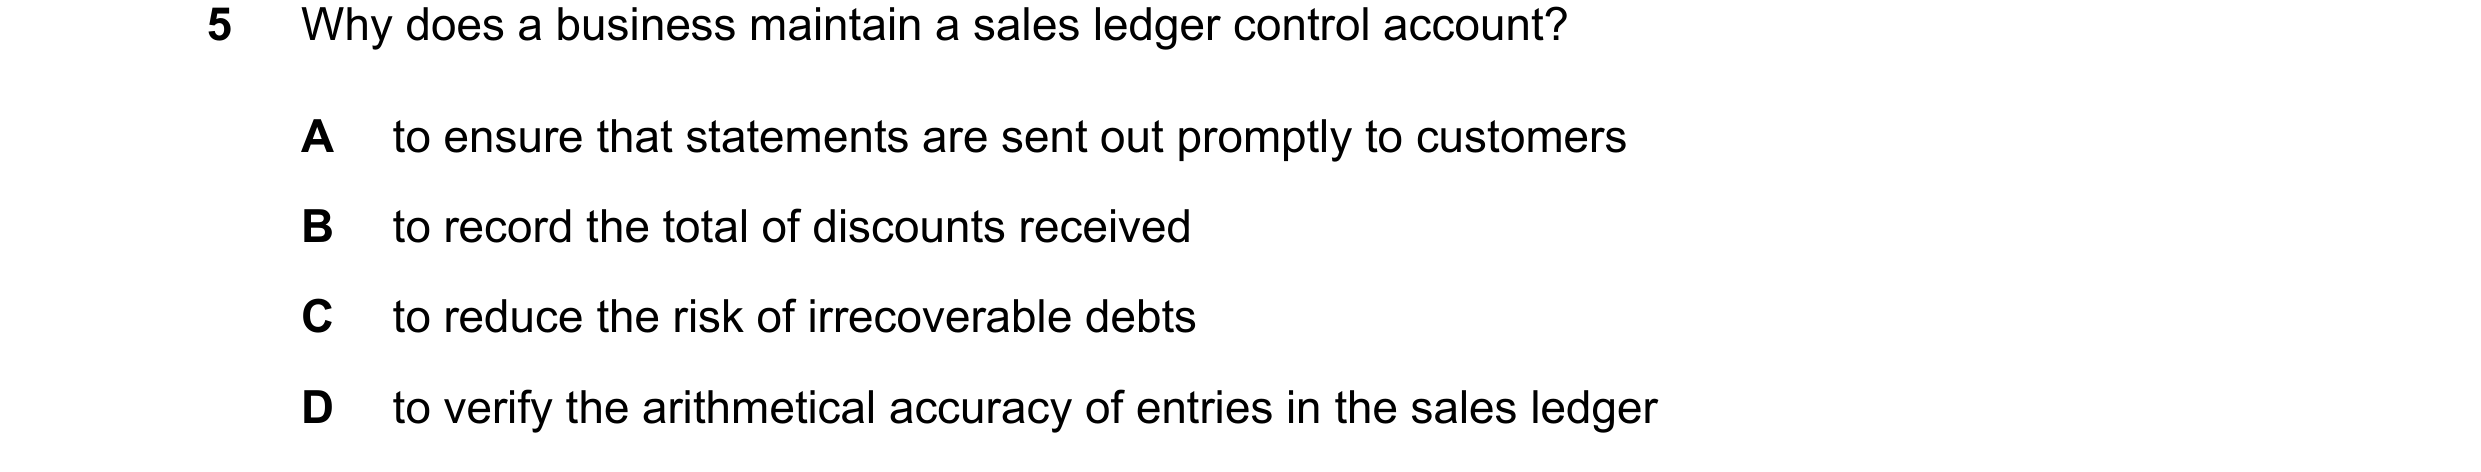 94 / 110
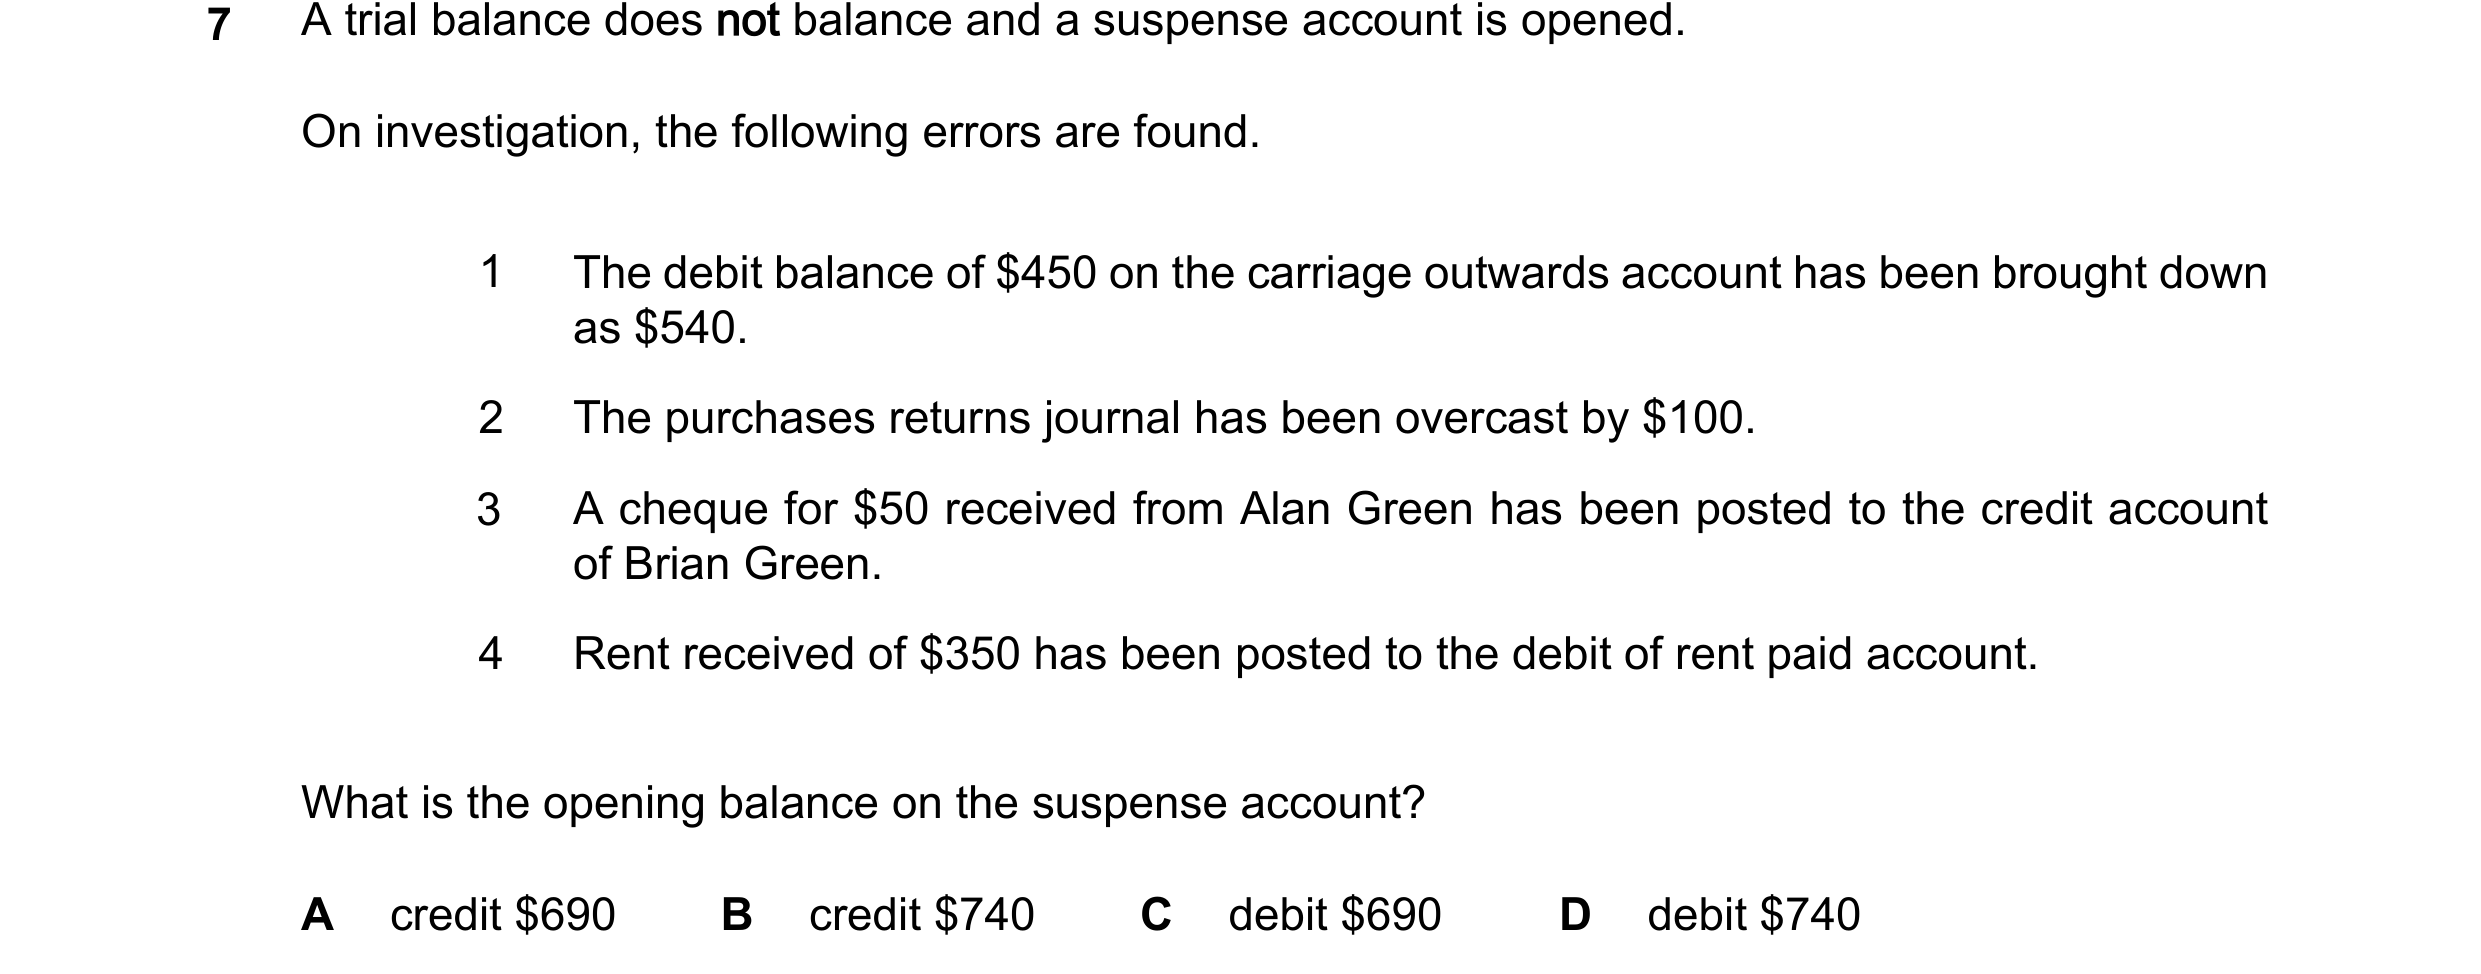
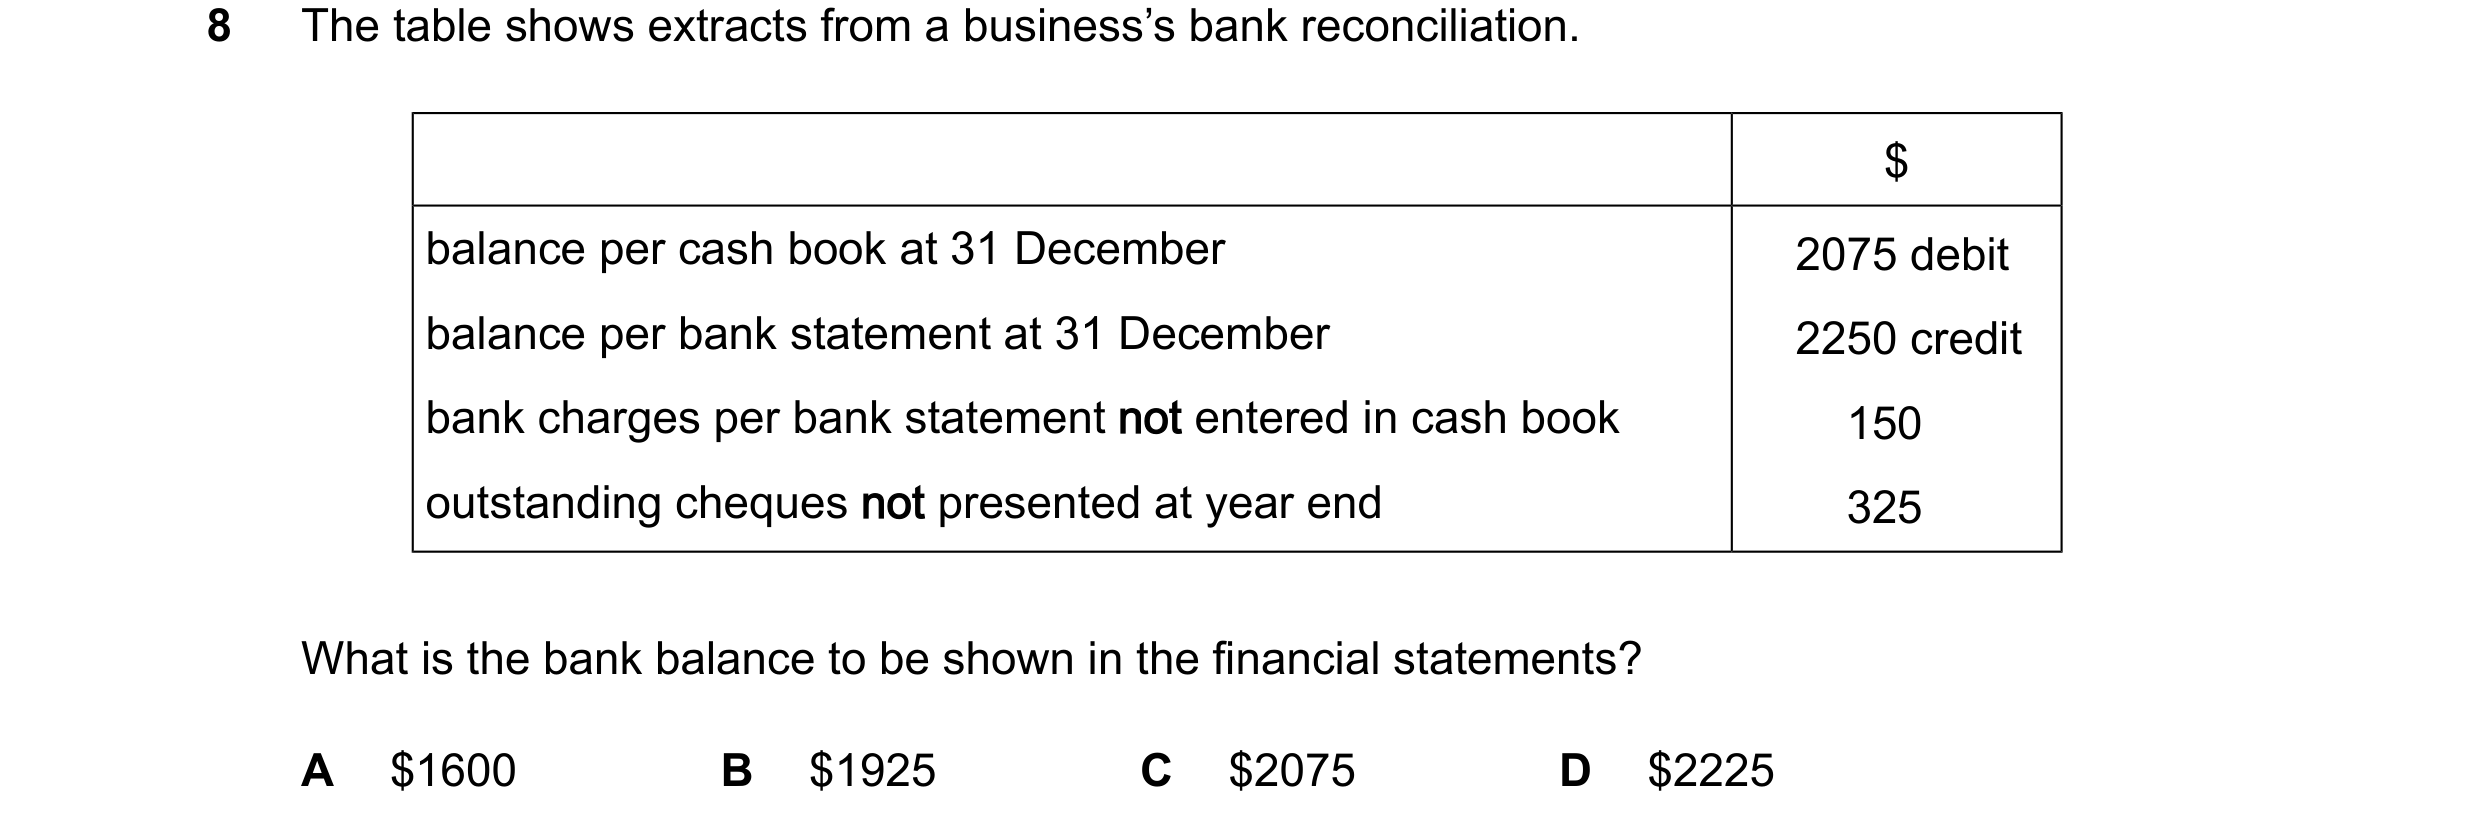 95 / 110
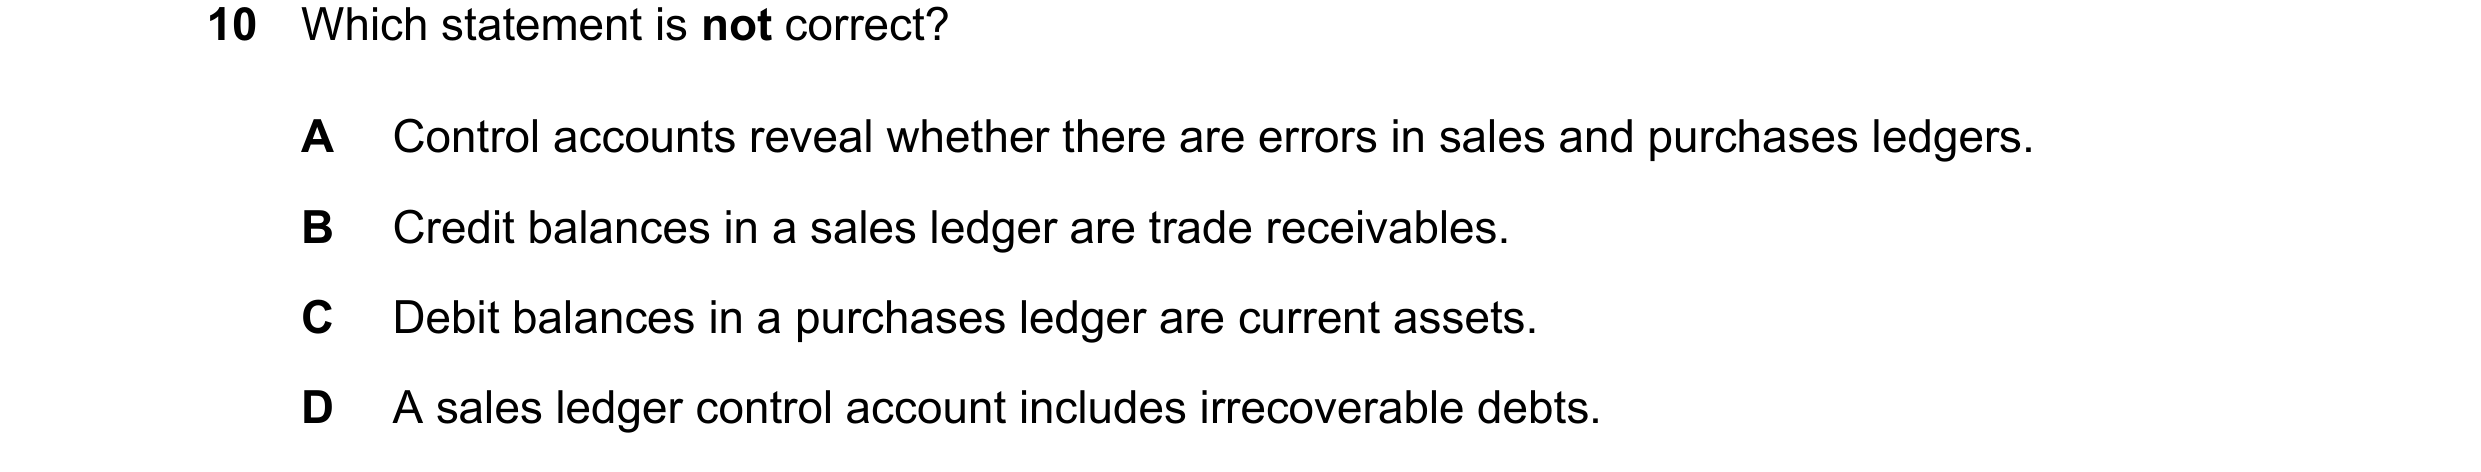
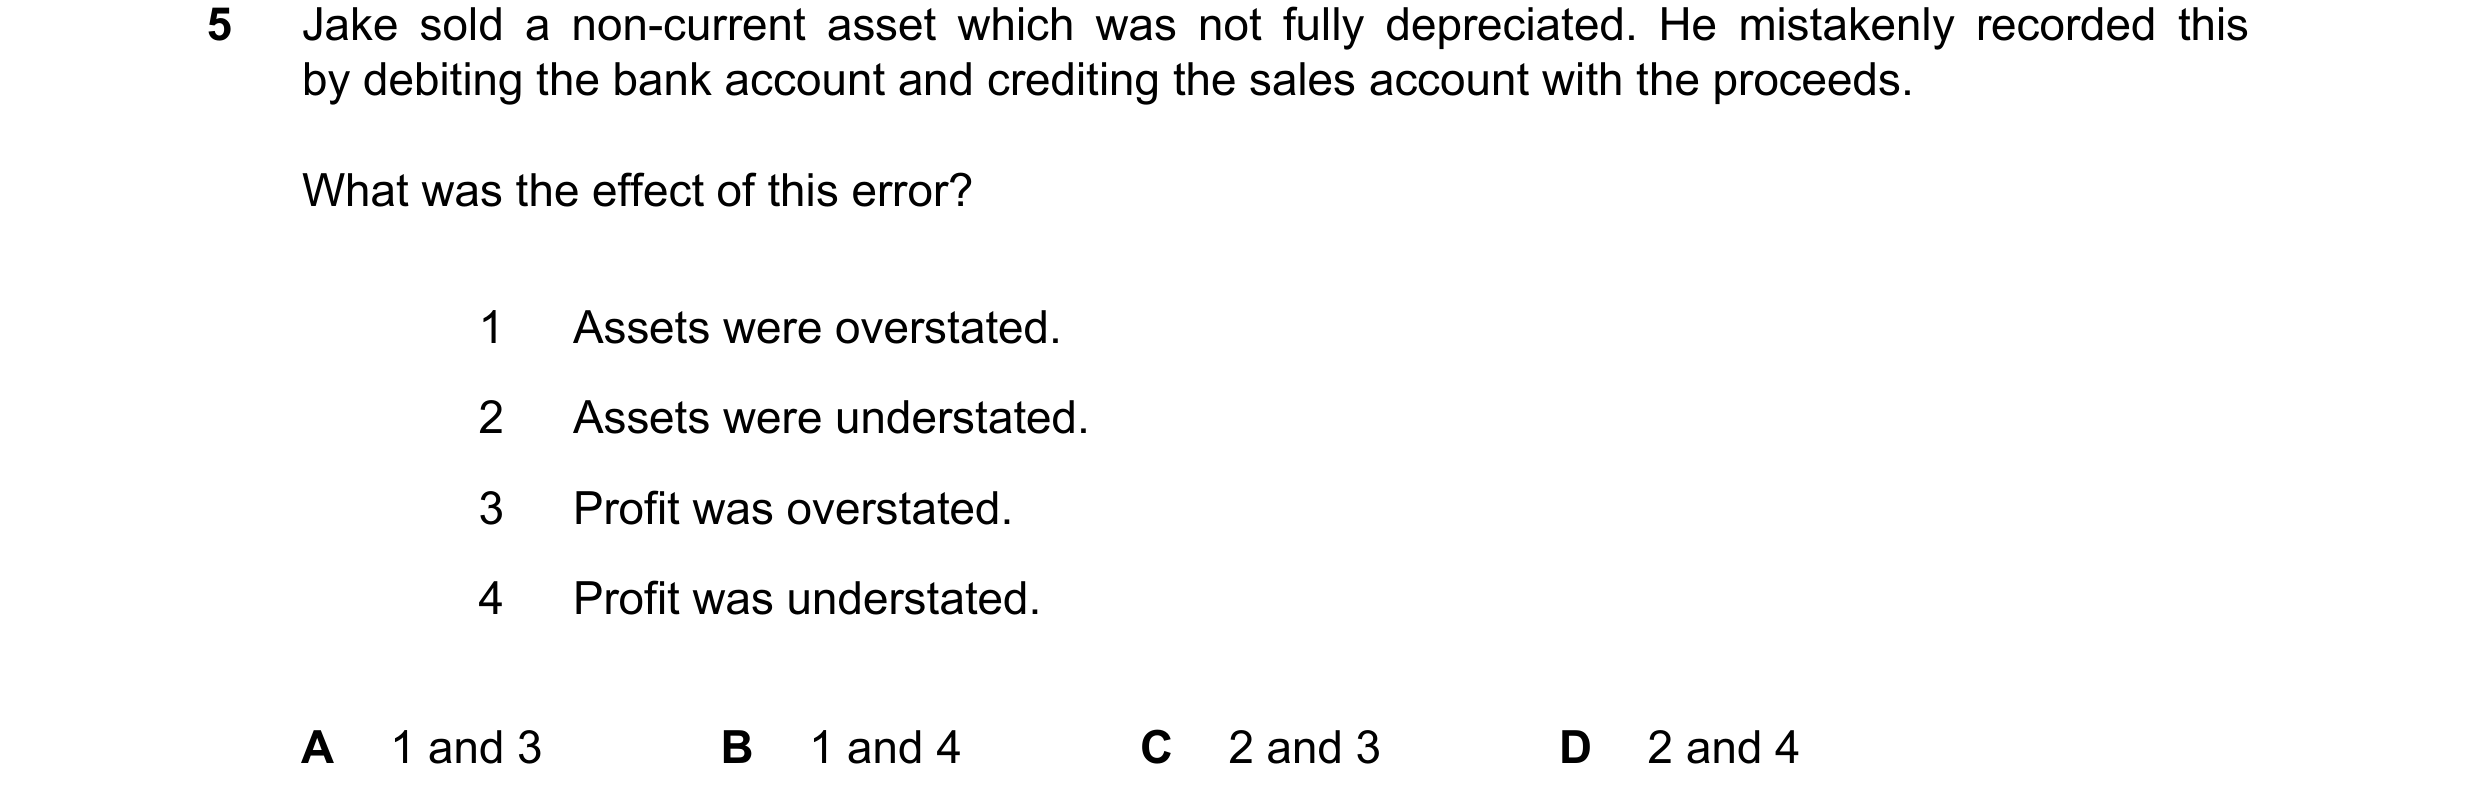
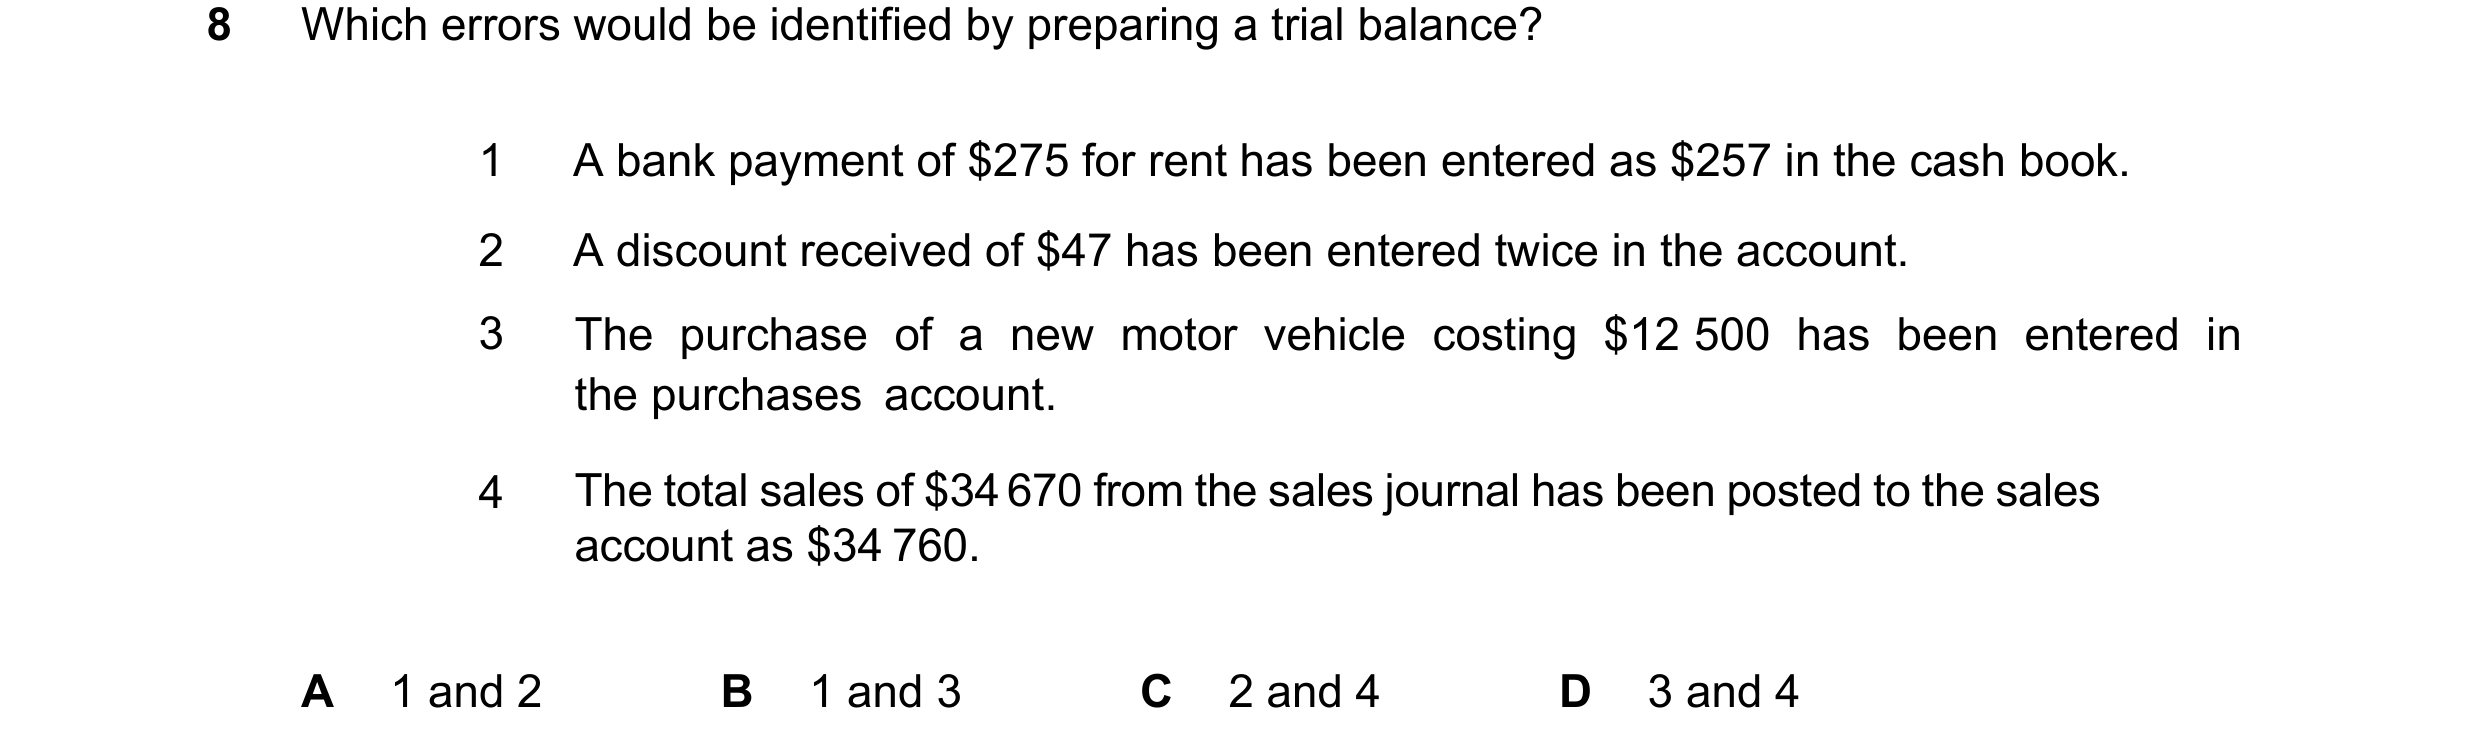 96 / 110
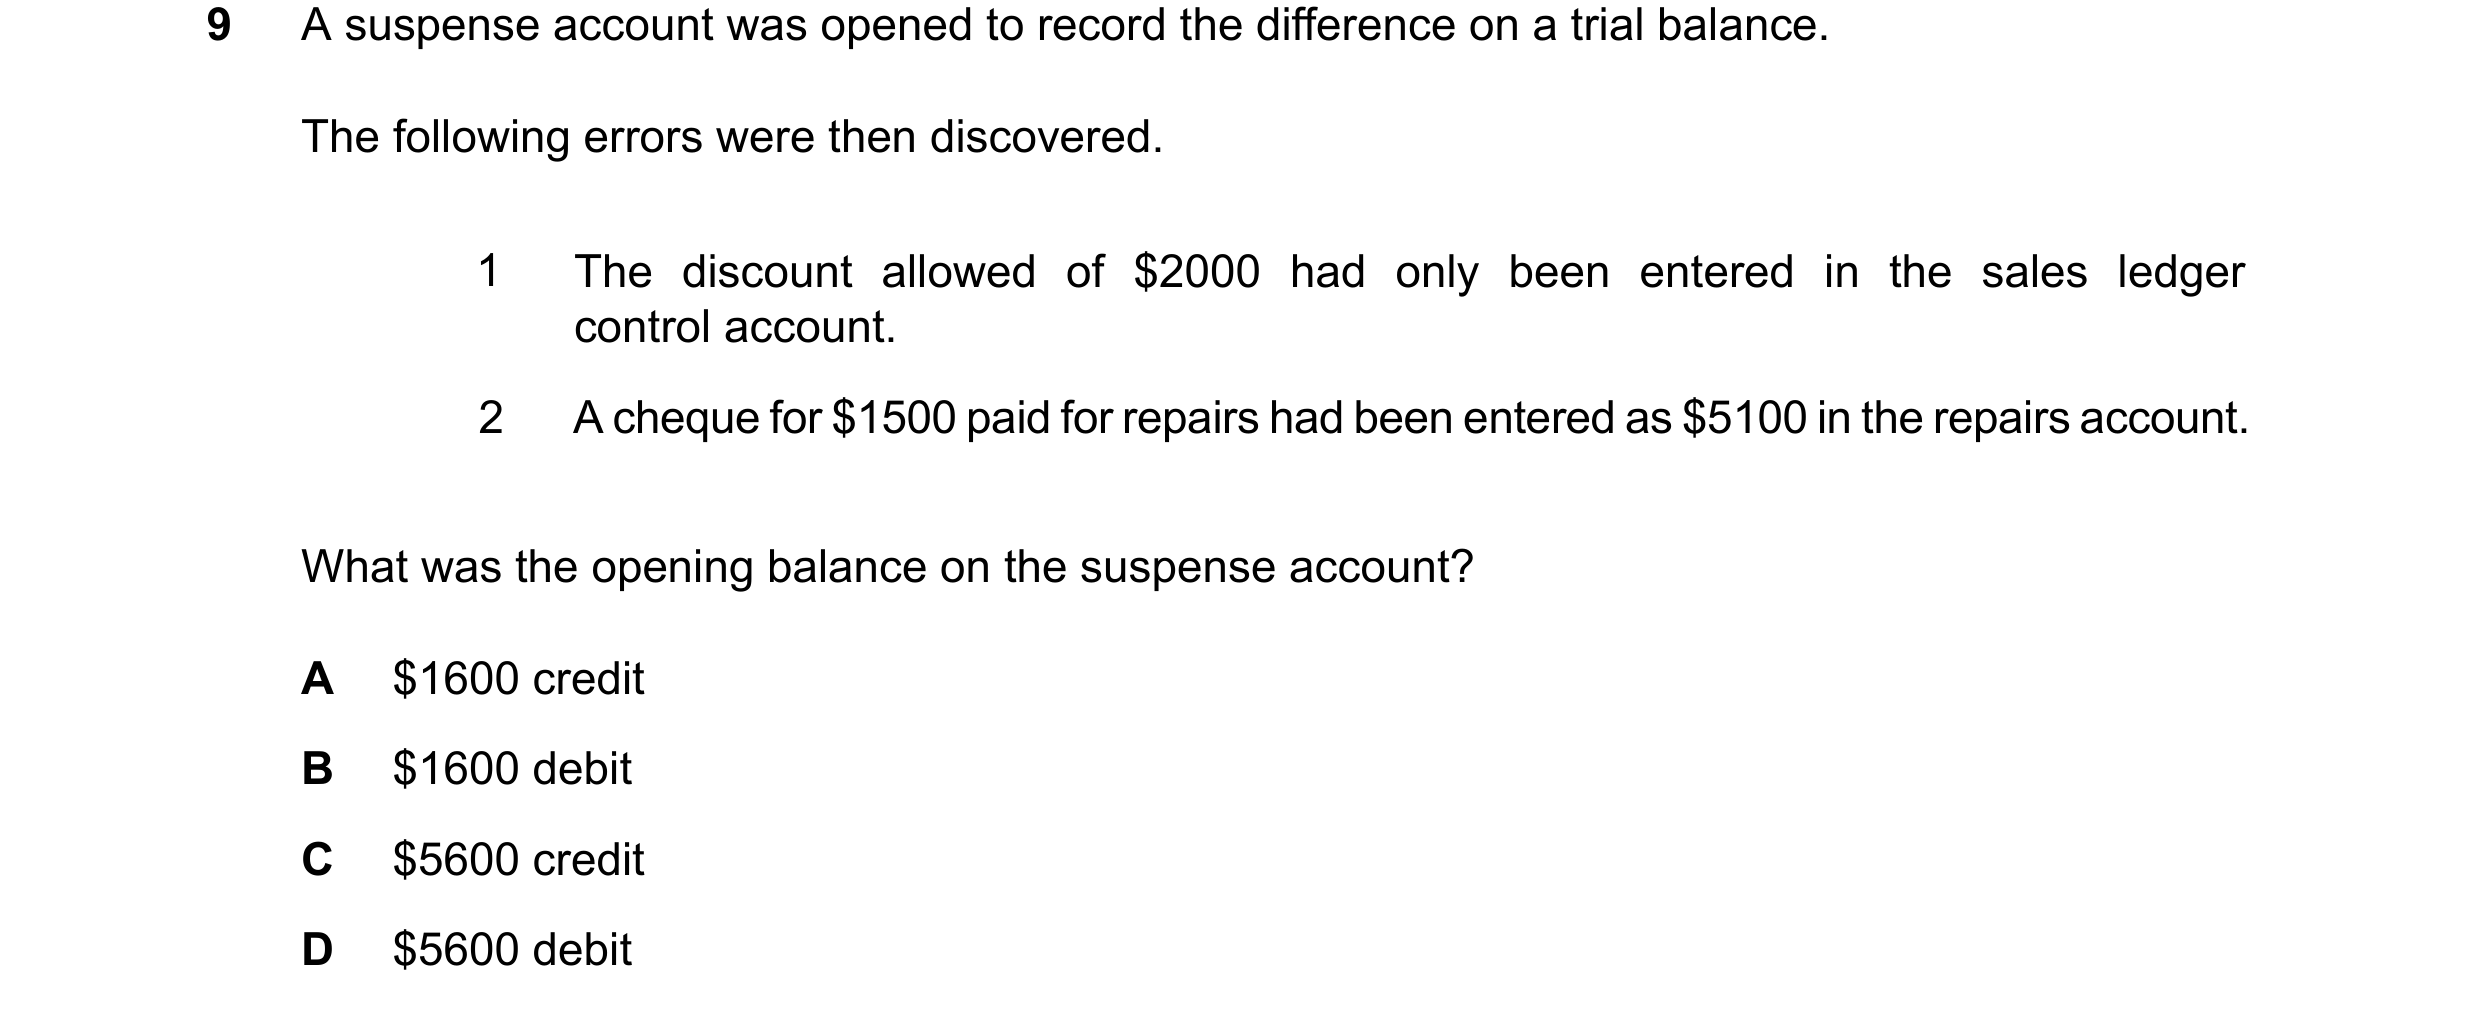
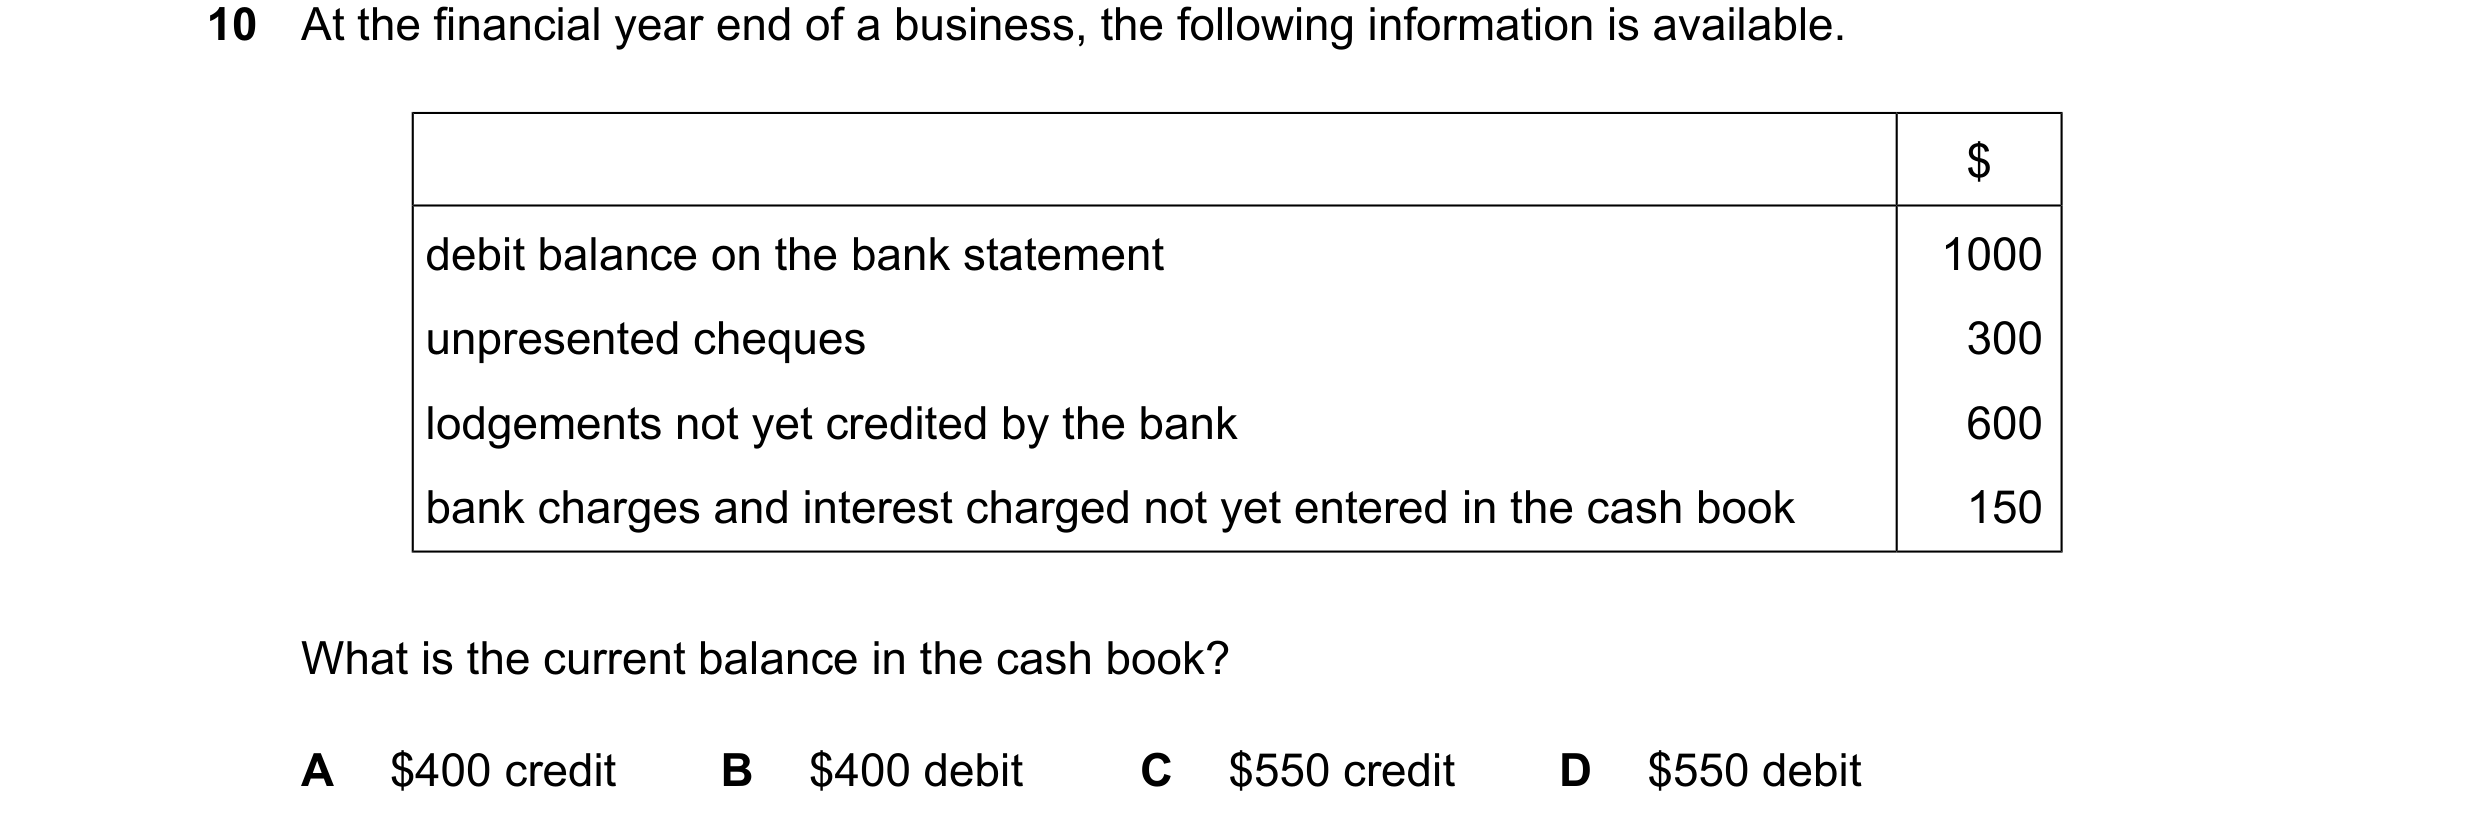
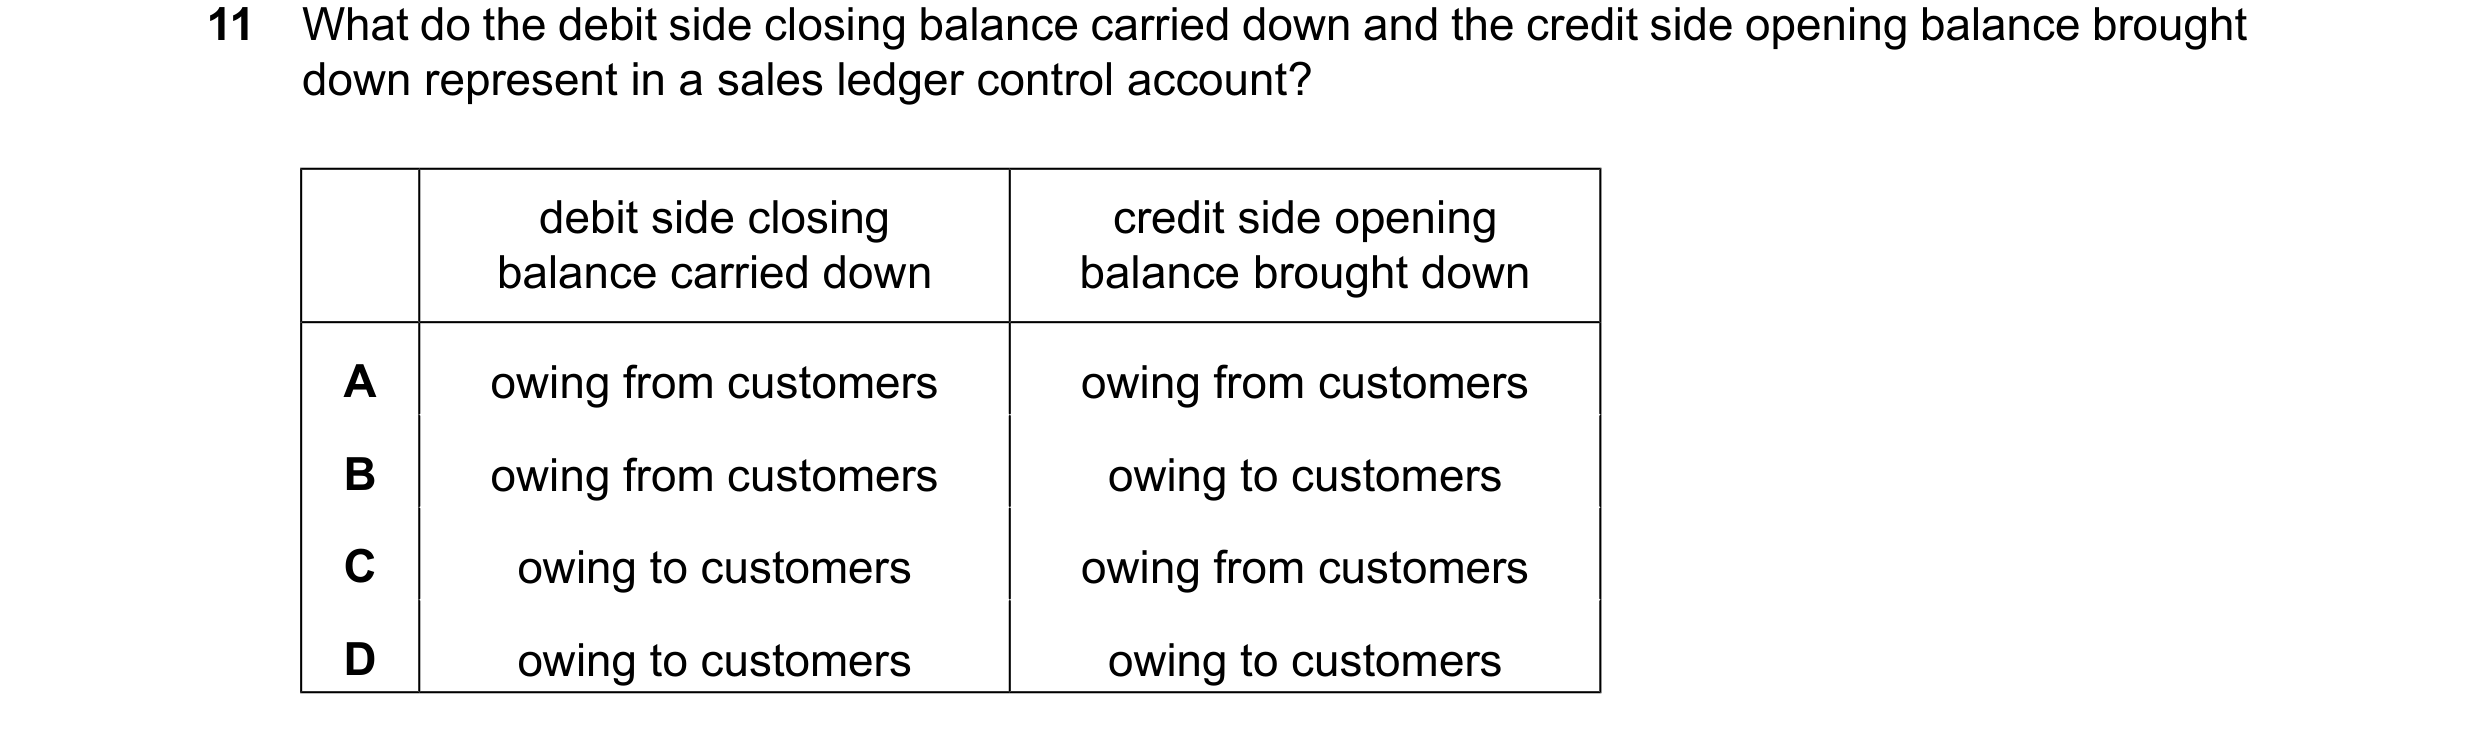 97 / 110
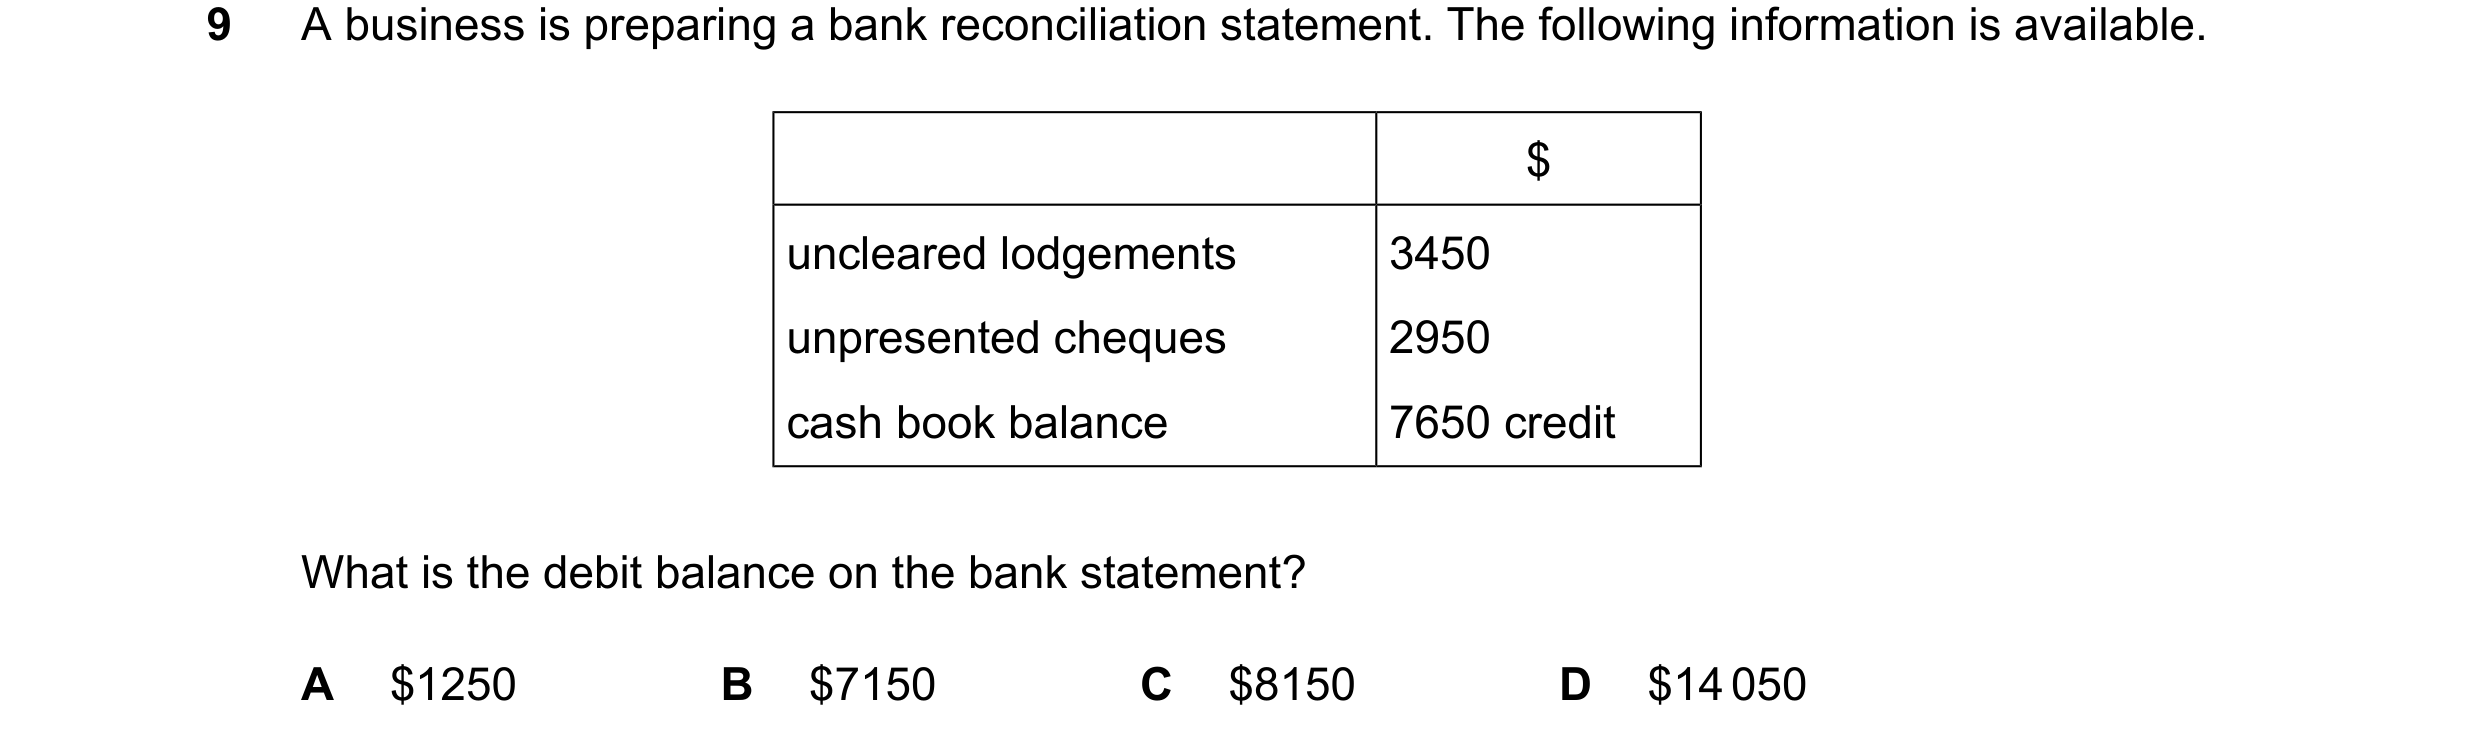
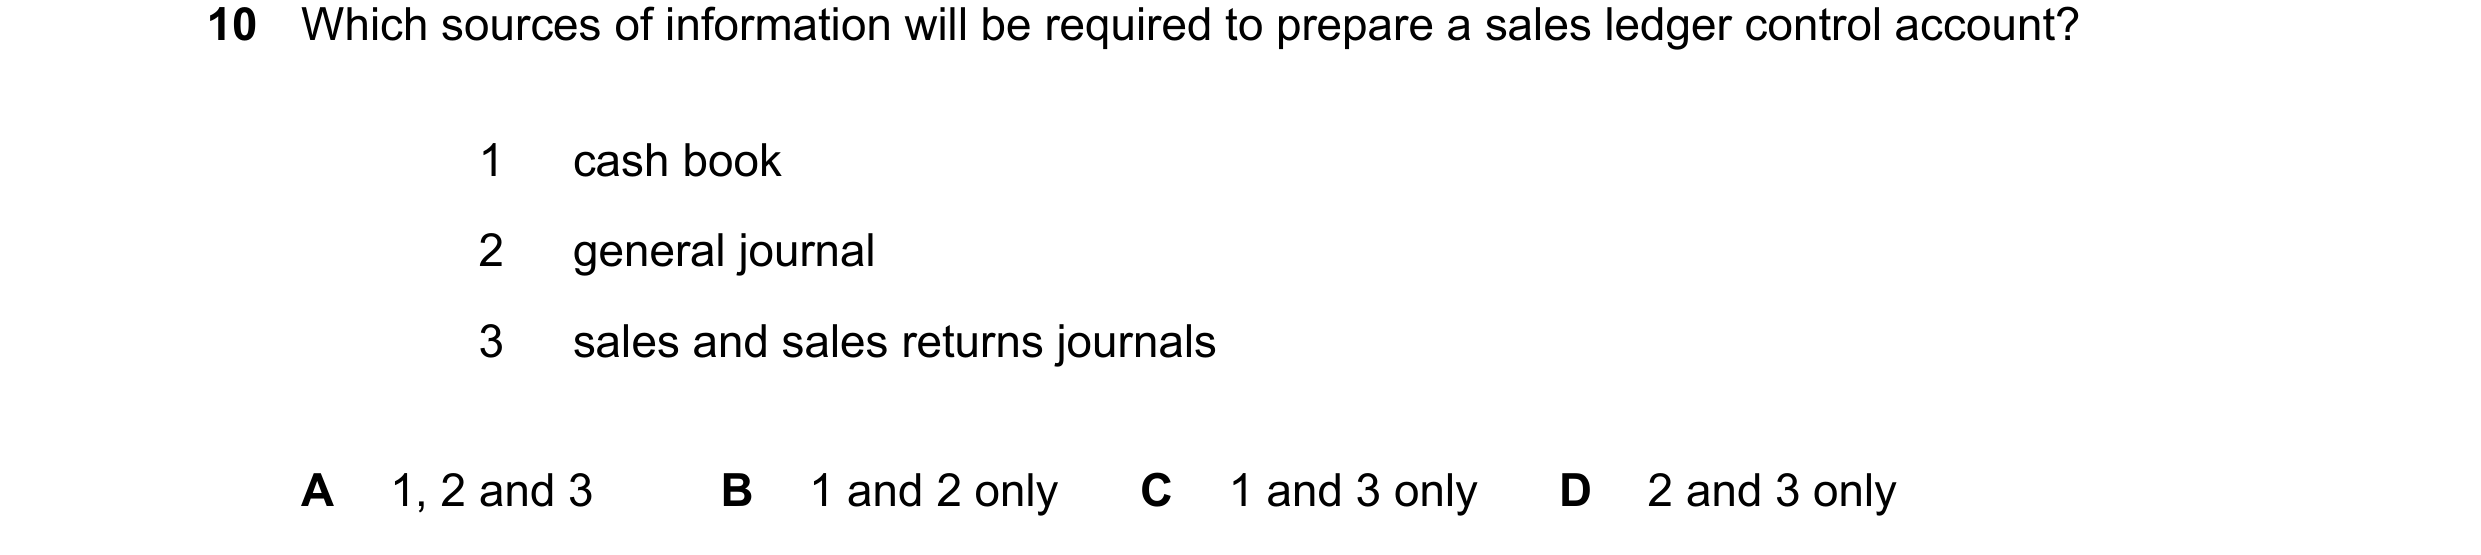 98 / 110
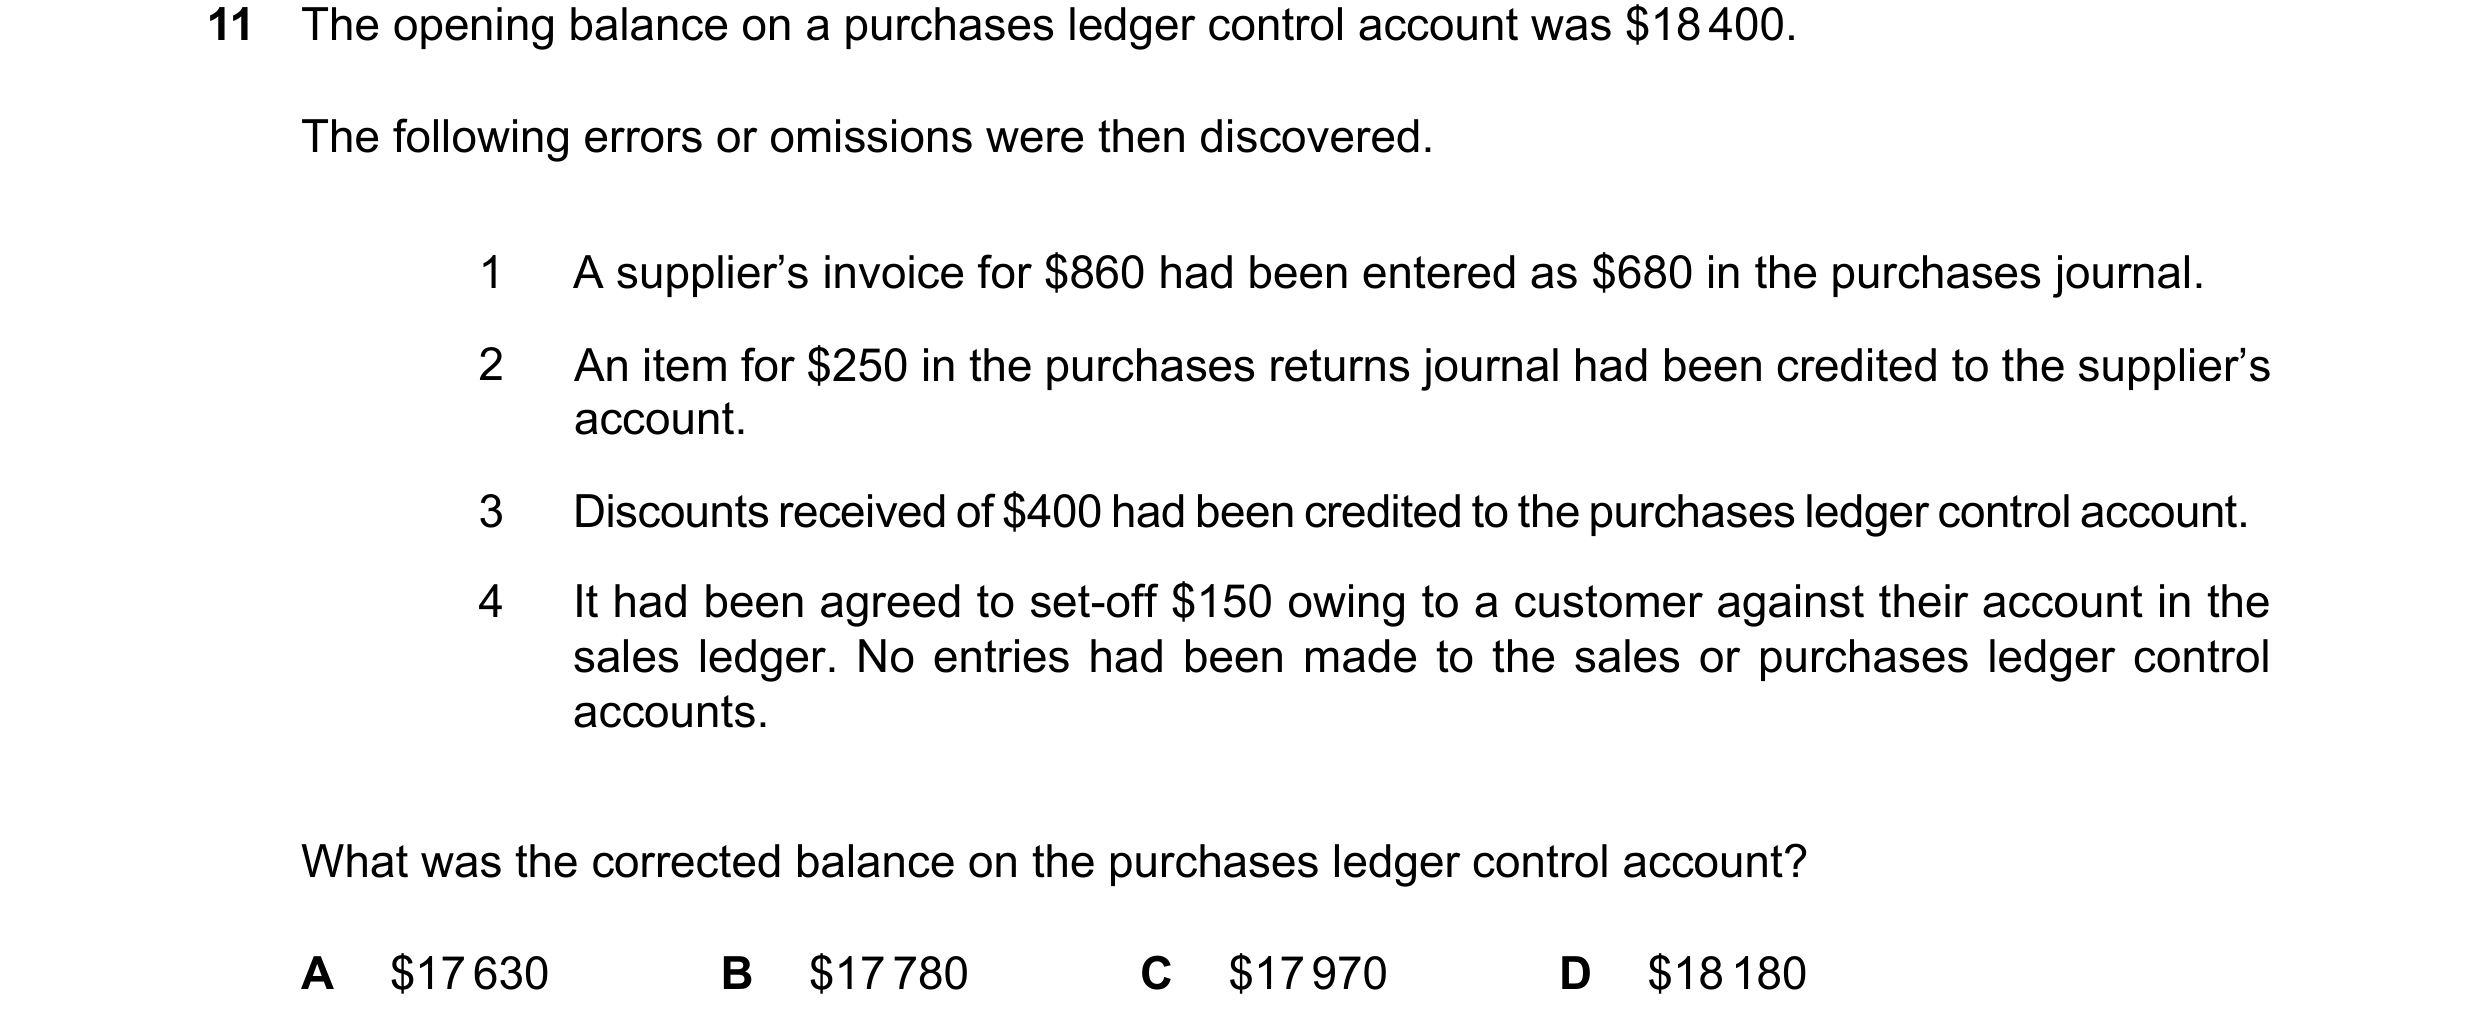
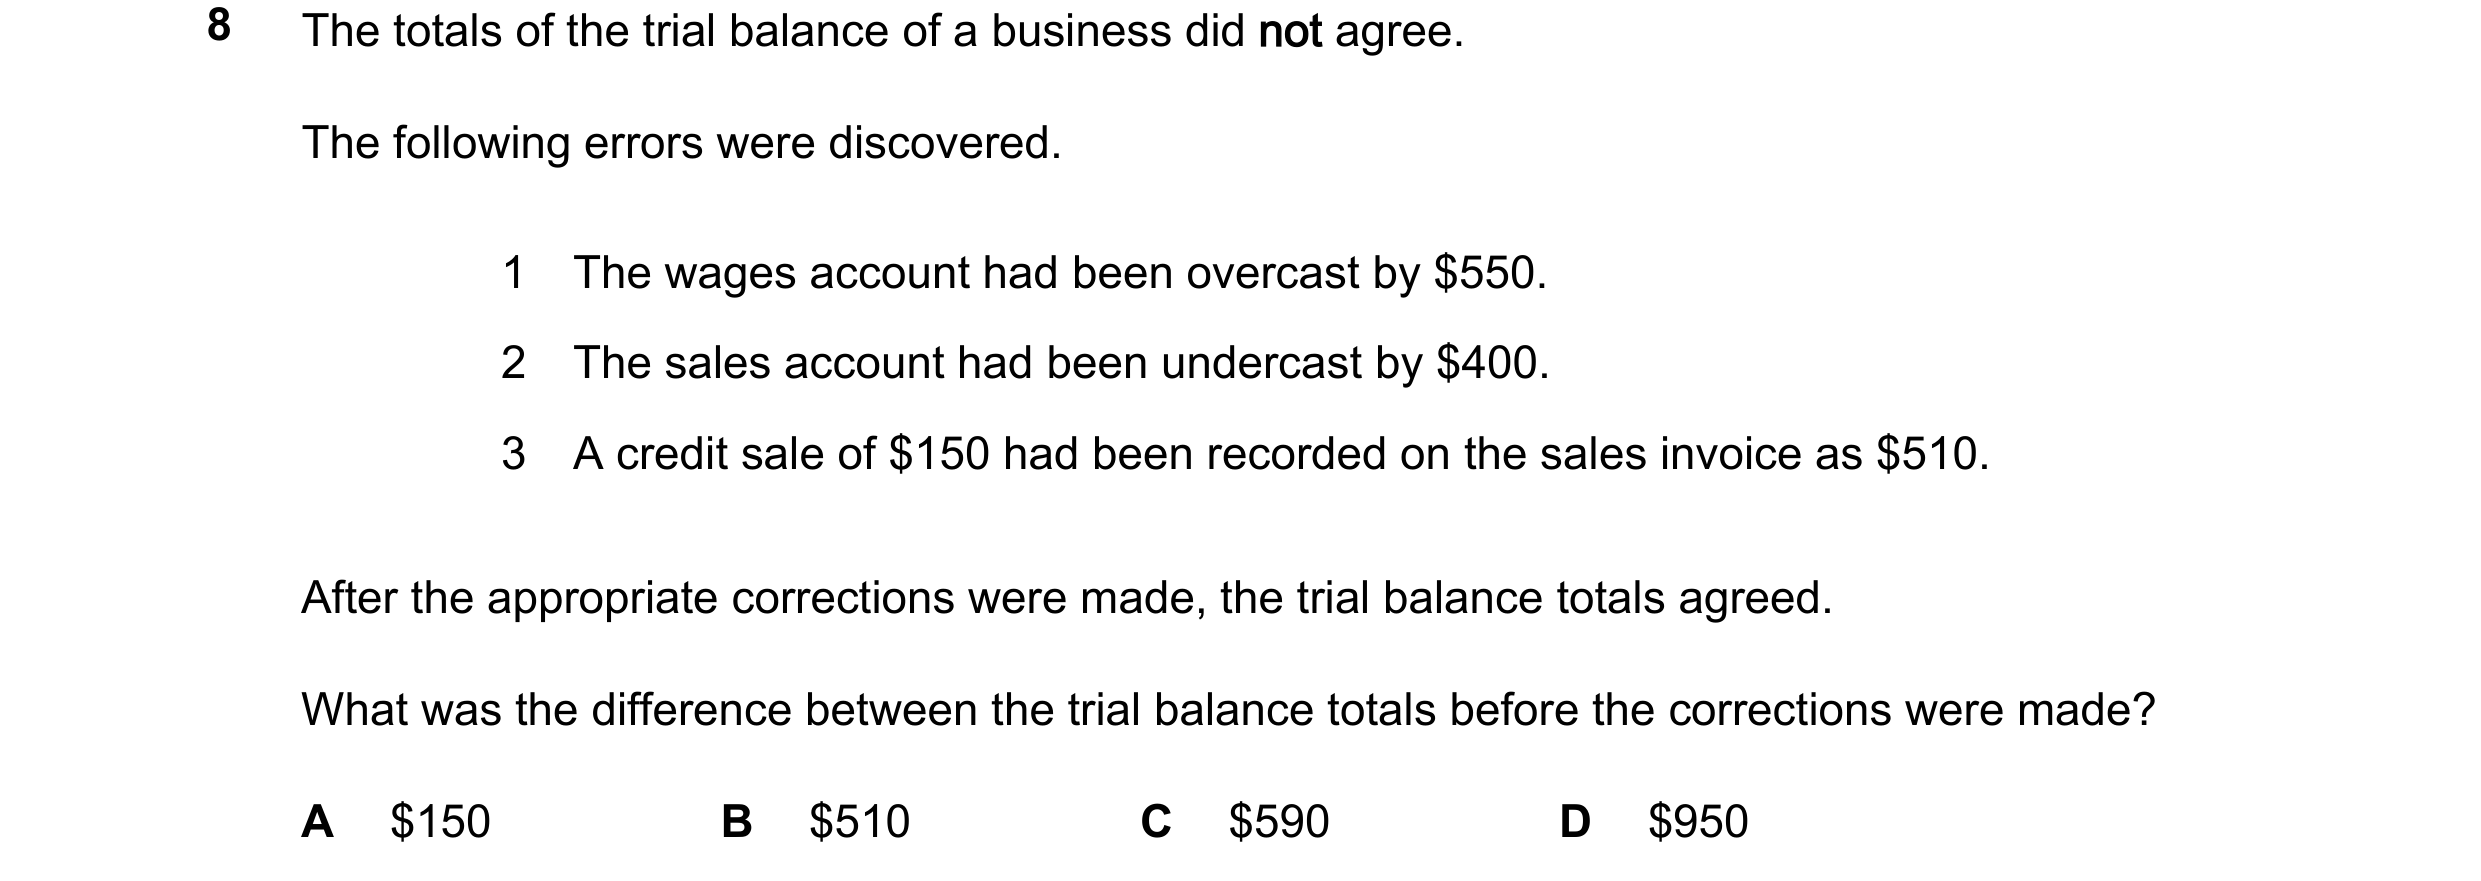
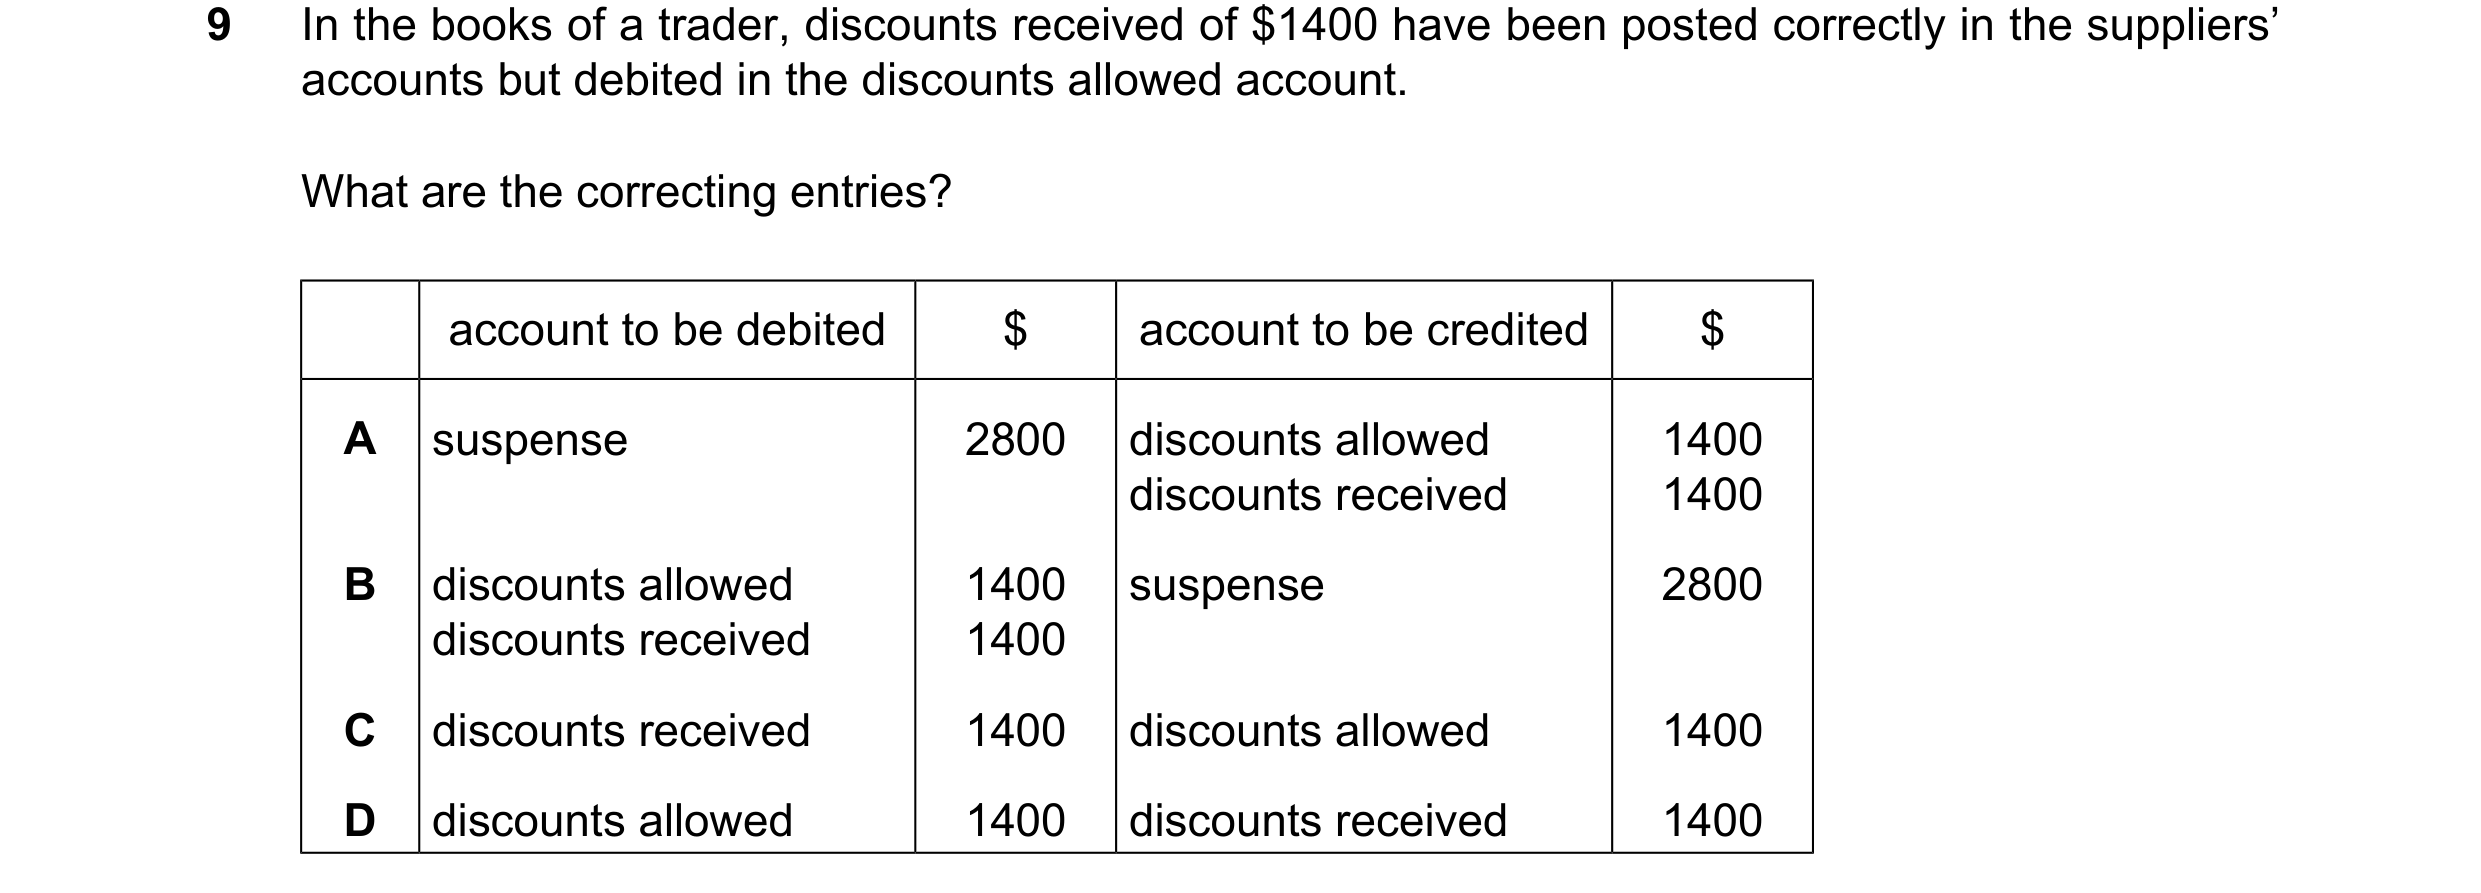 99 / 110
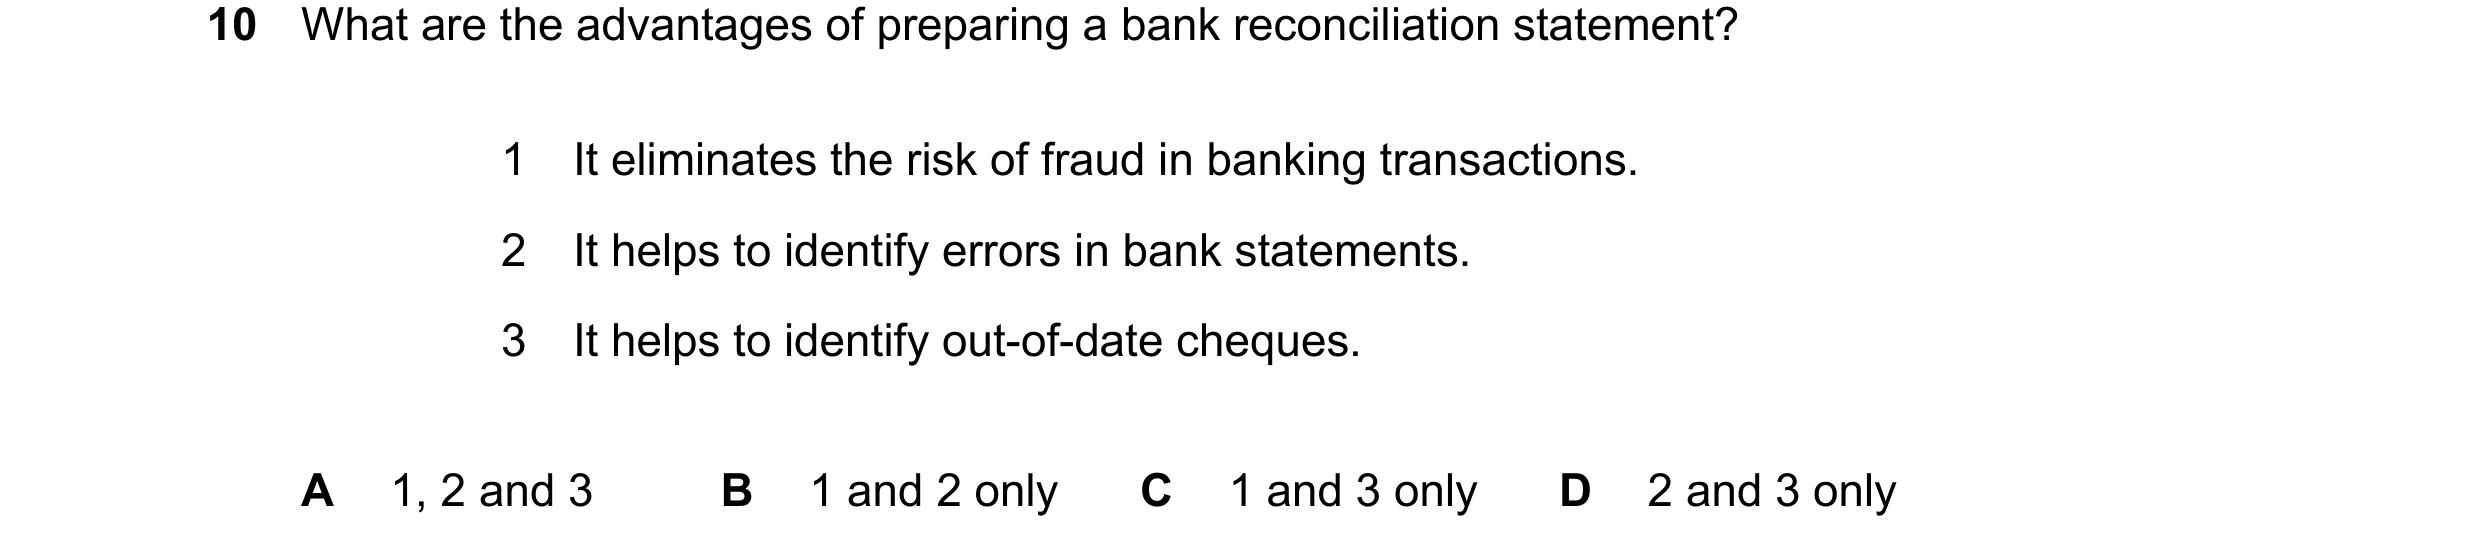
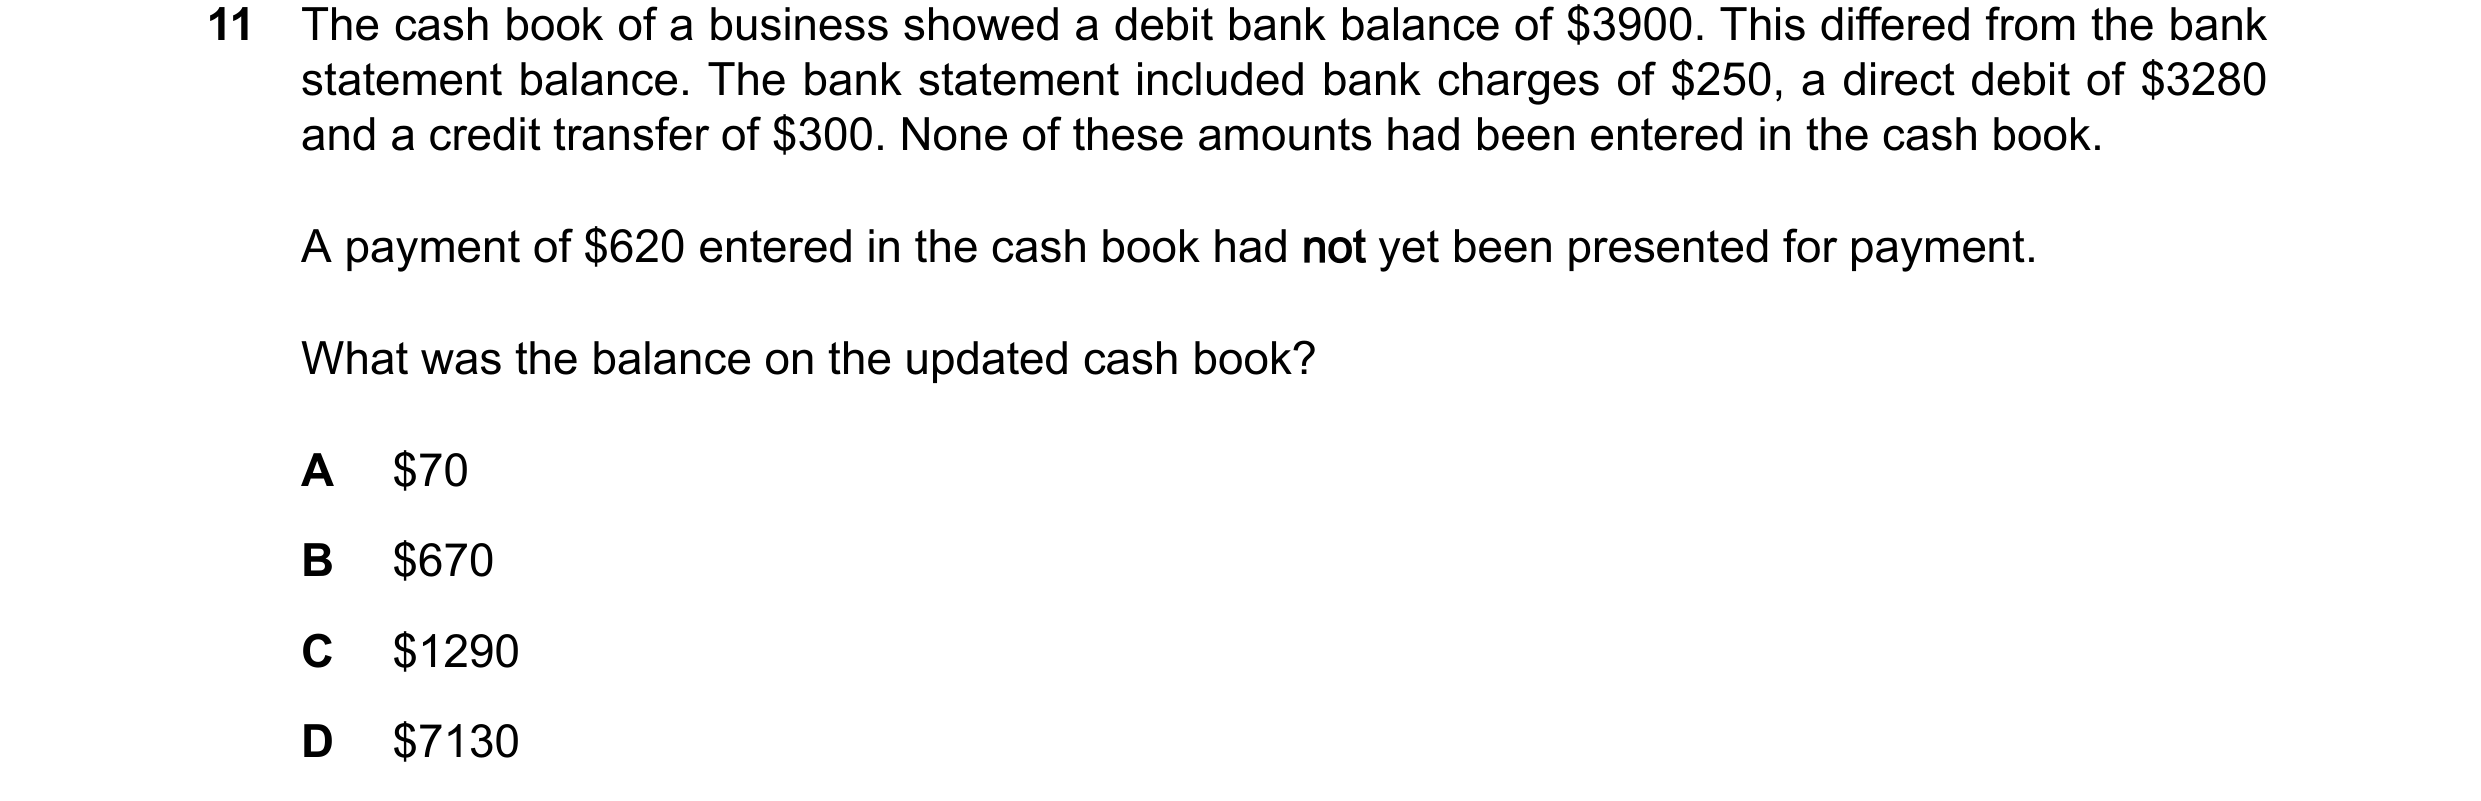
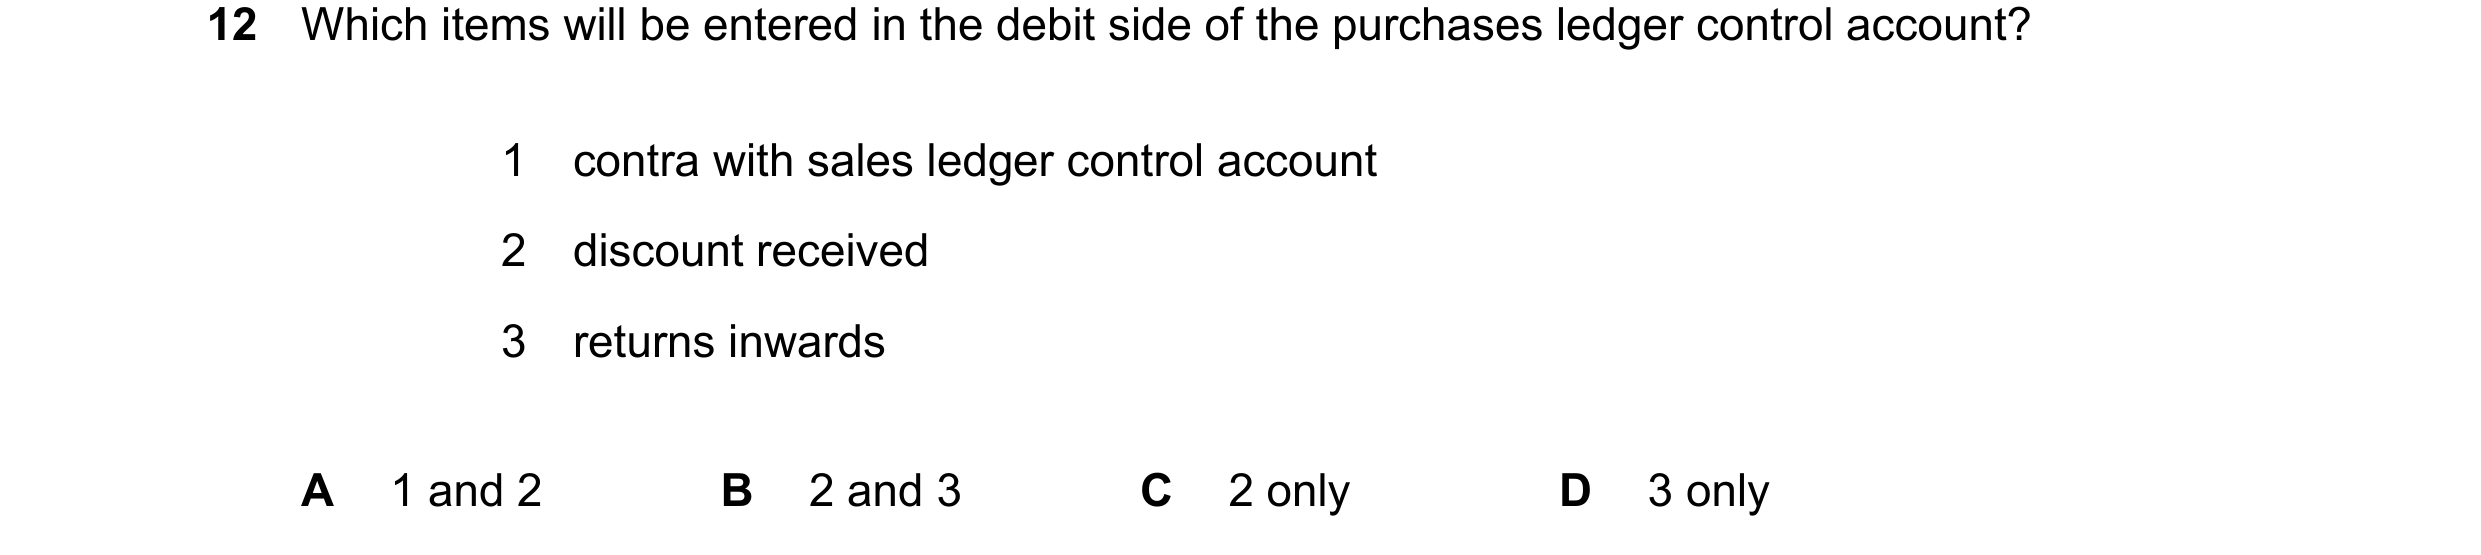
 100 / 110
 101 / 110
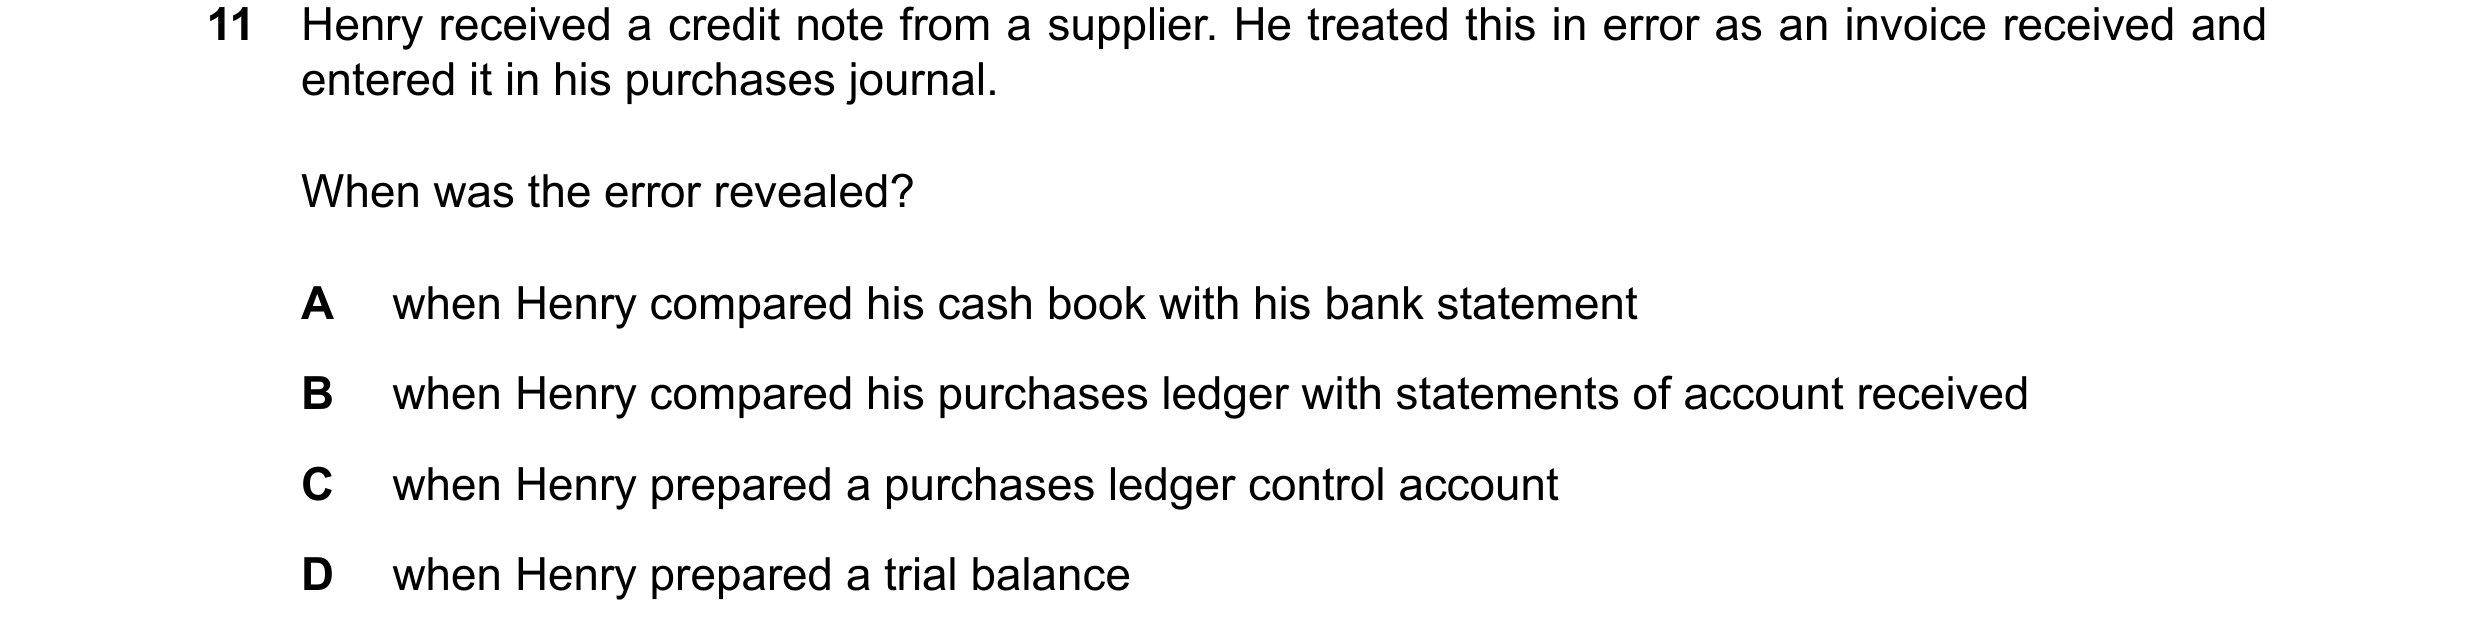
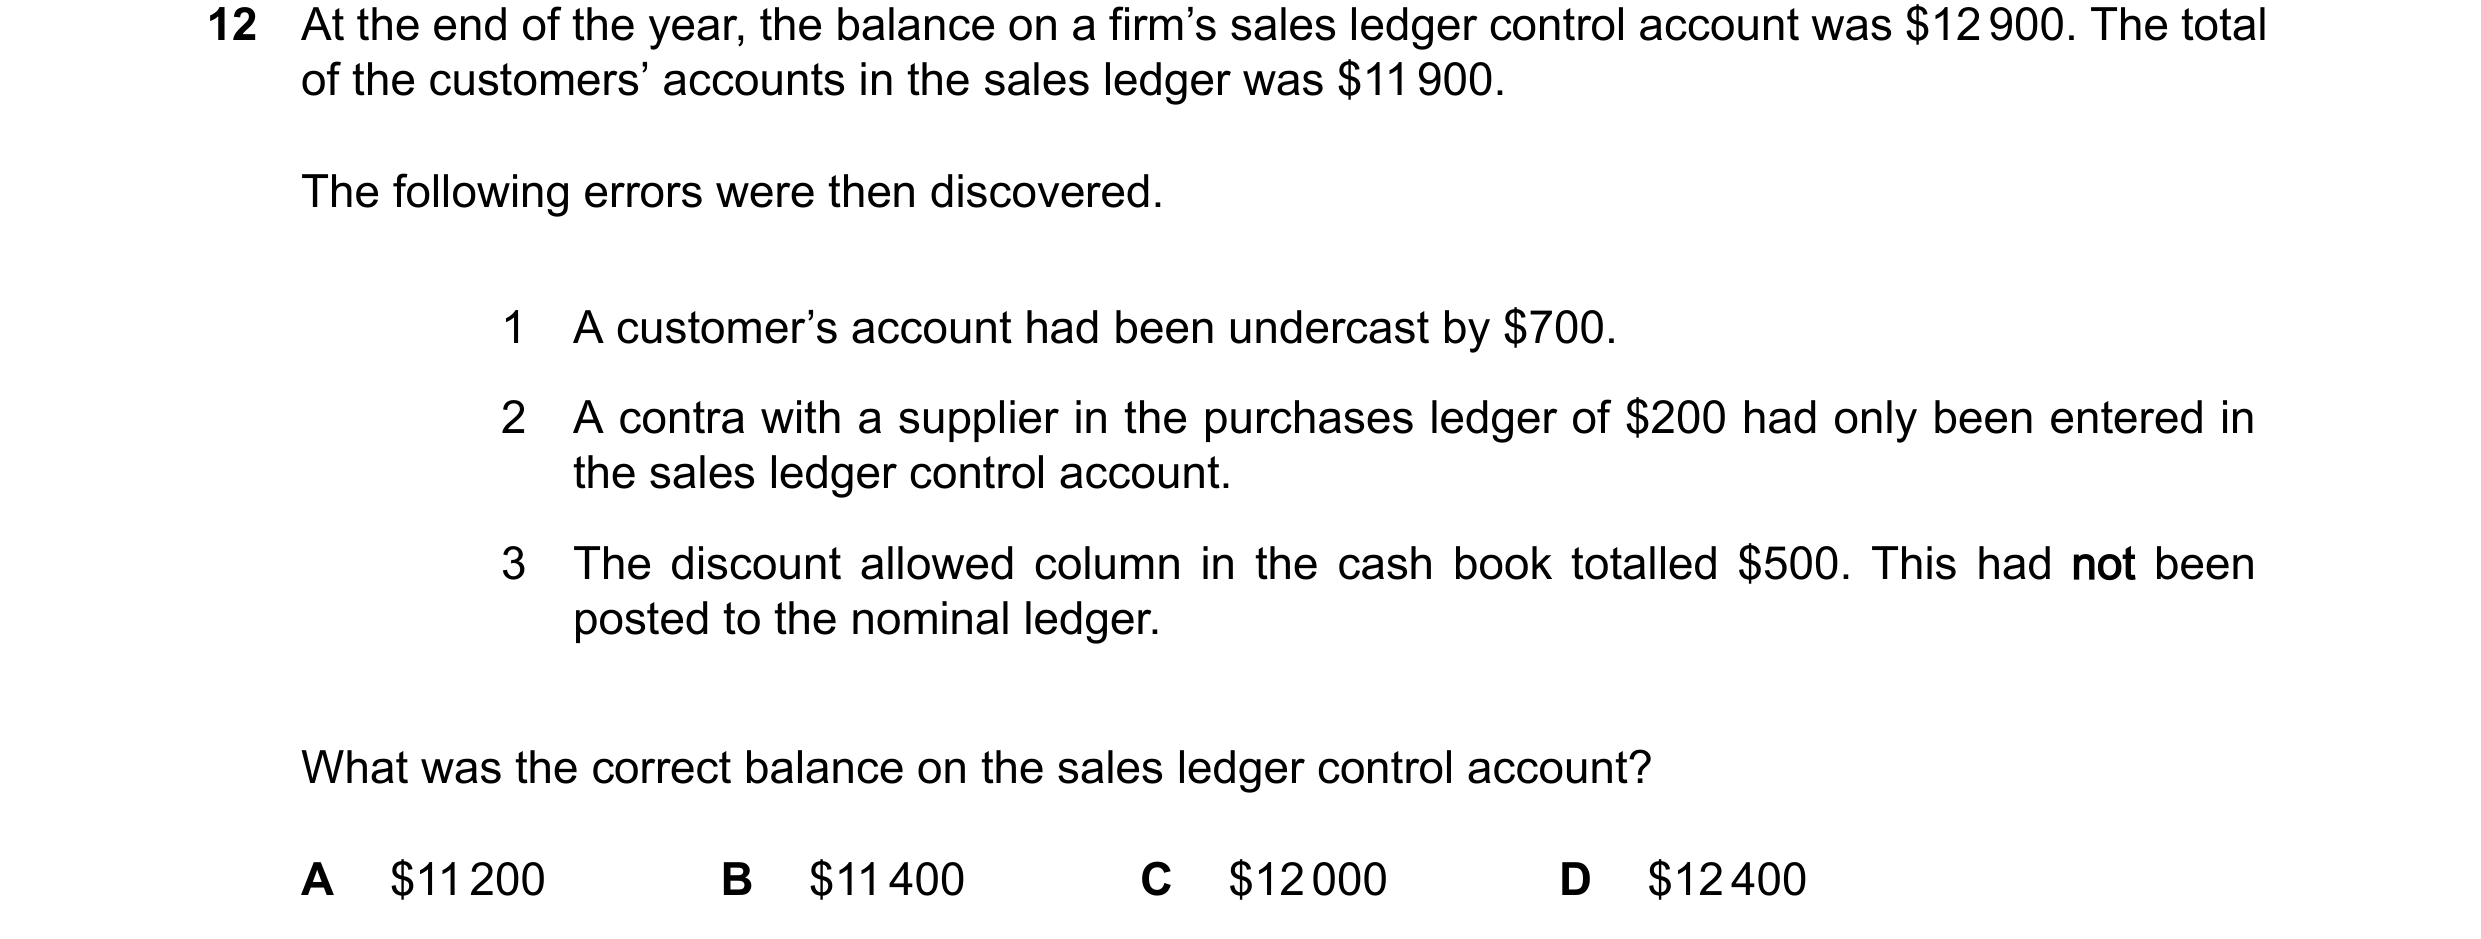
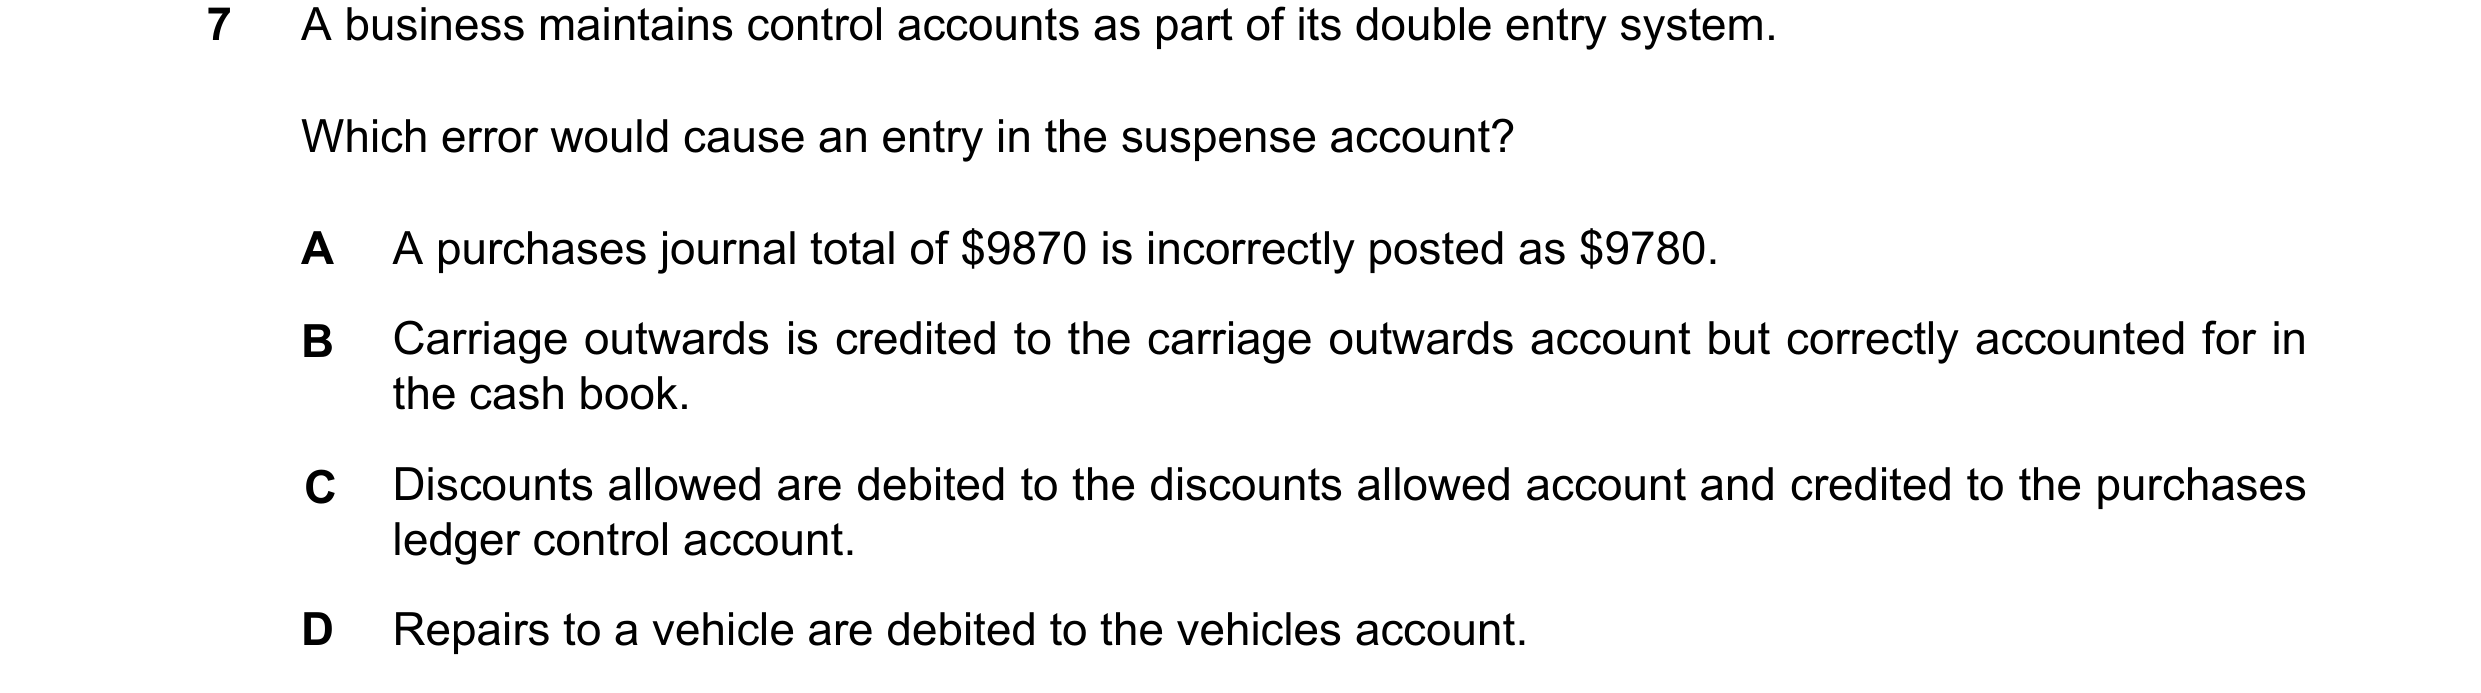
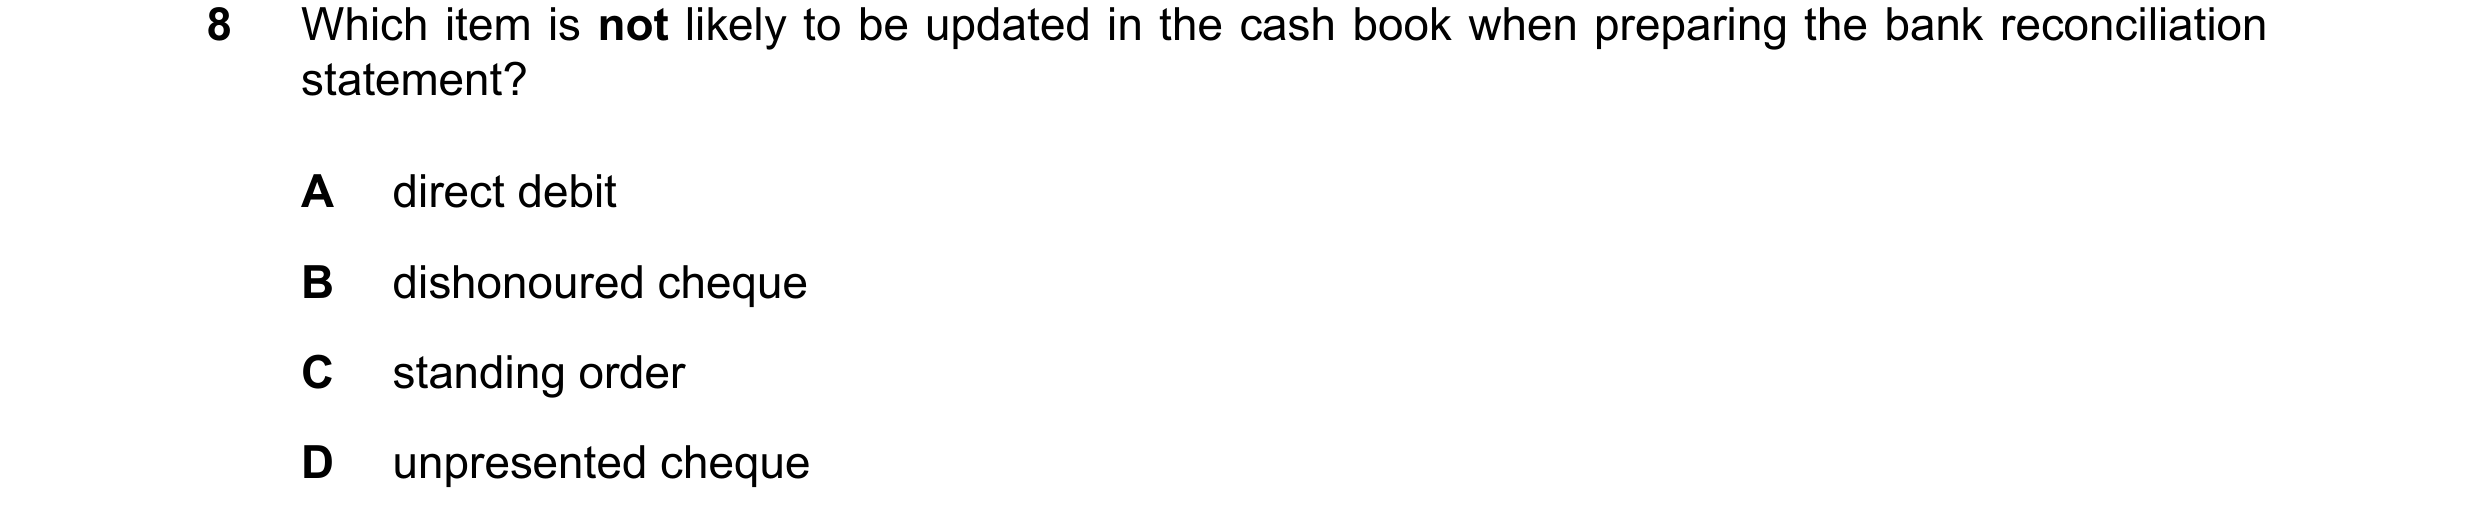 102 / 110
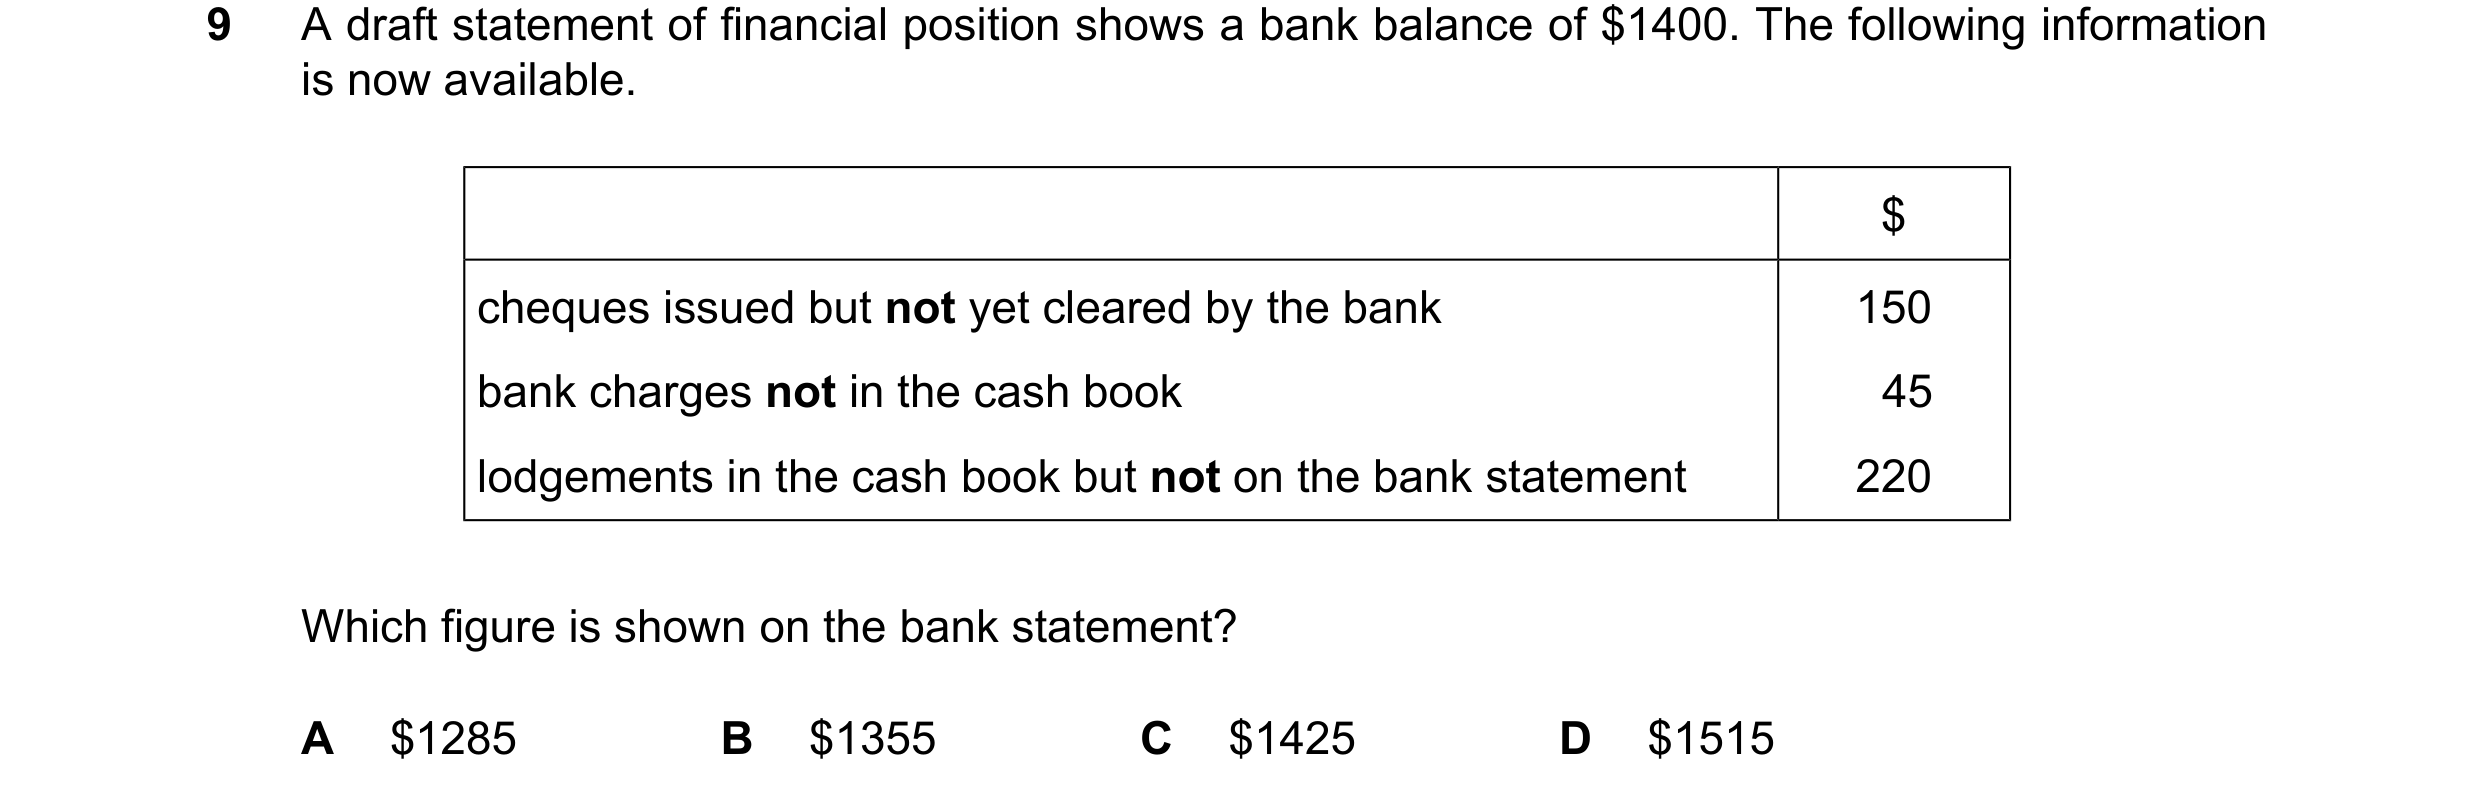
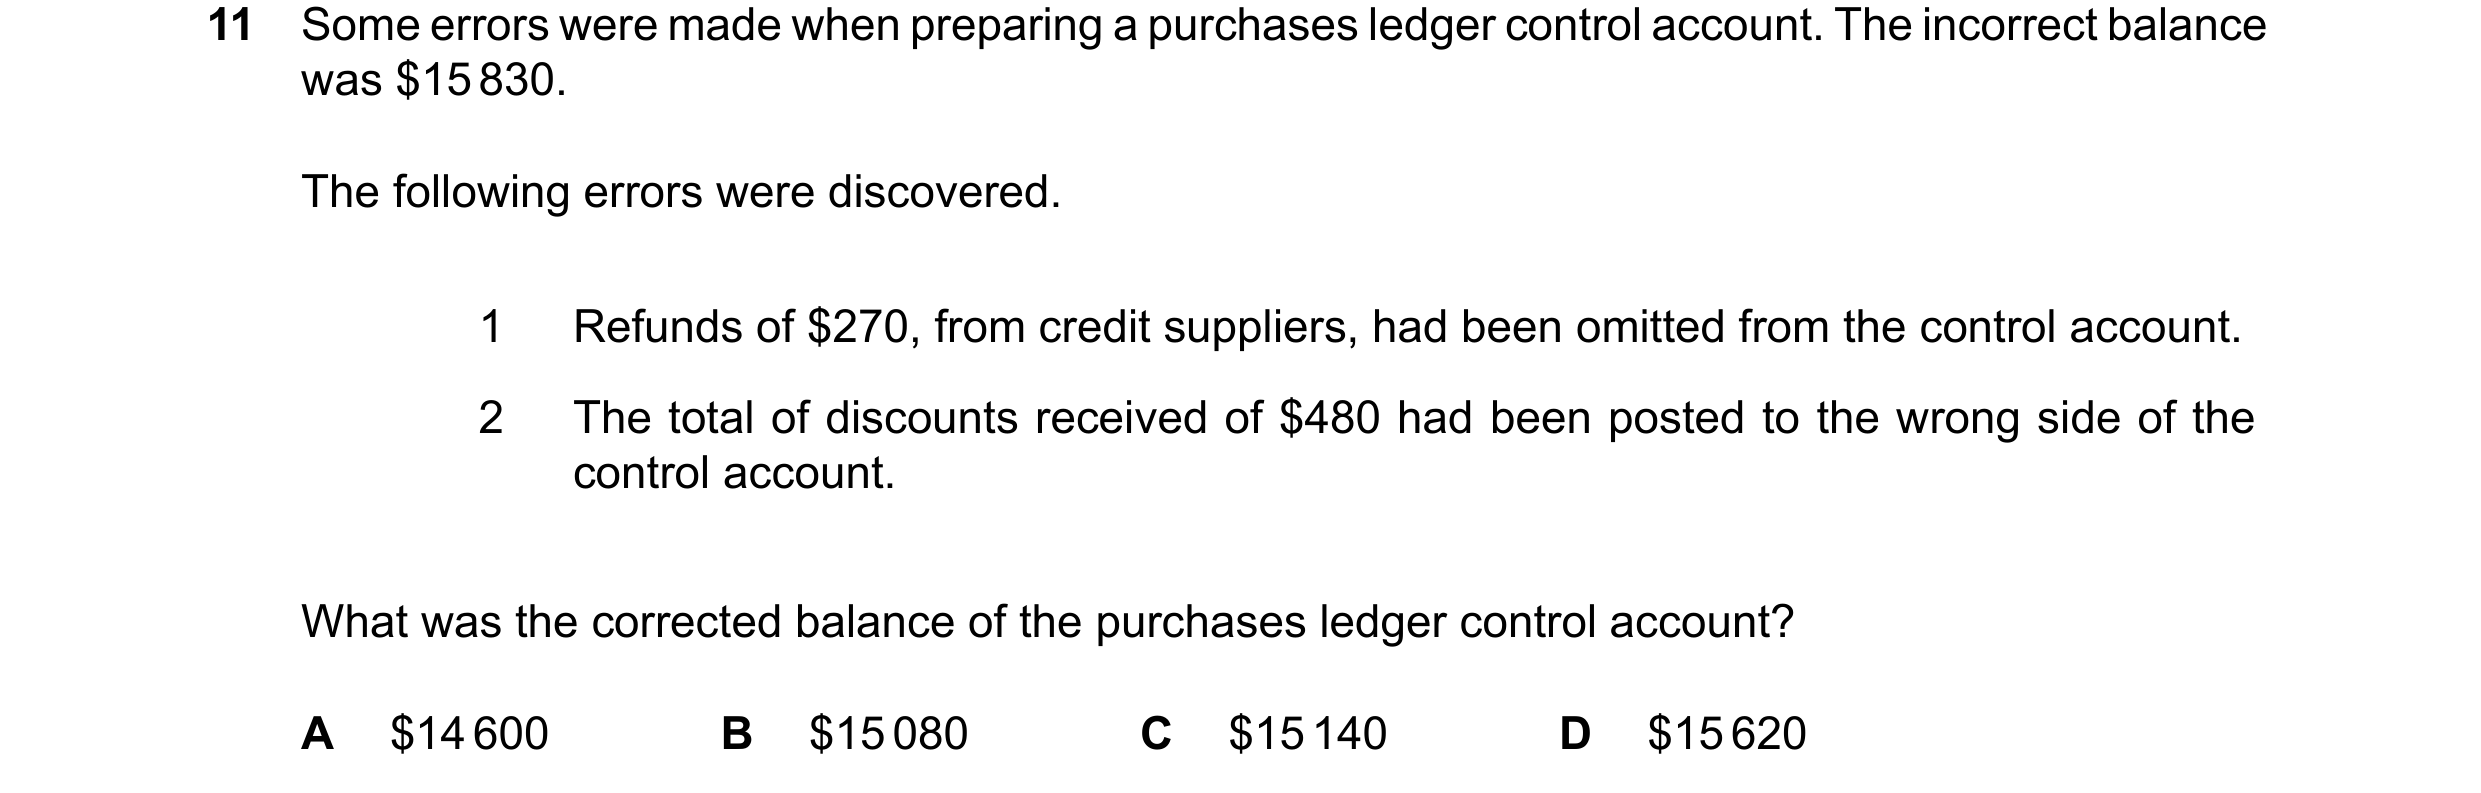
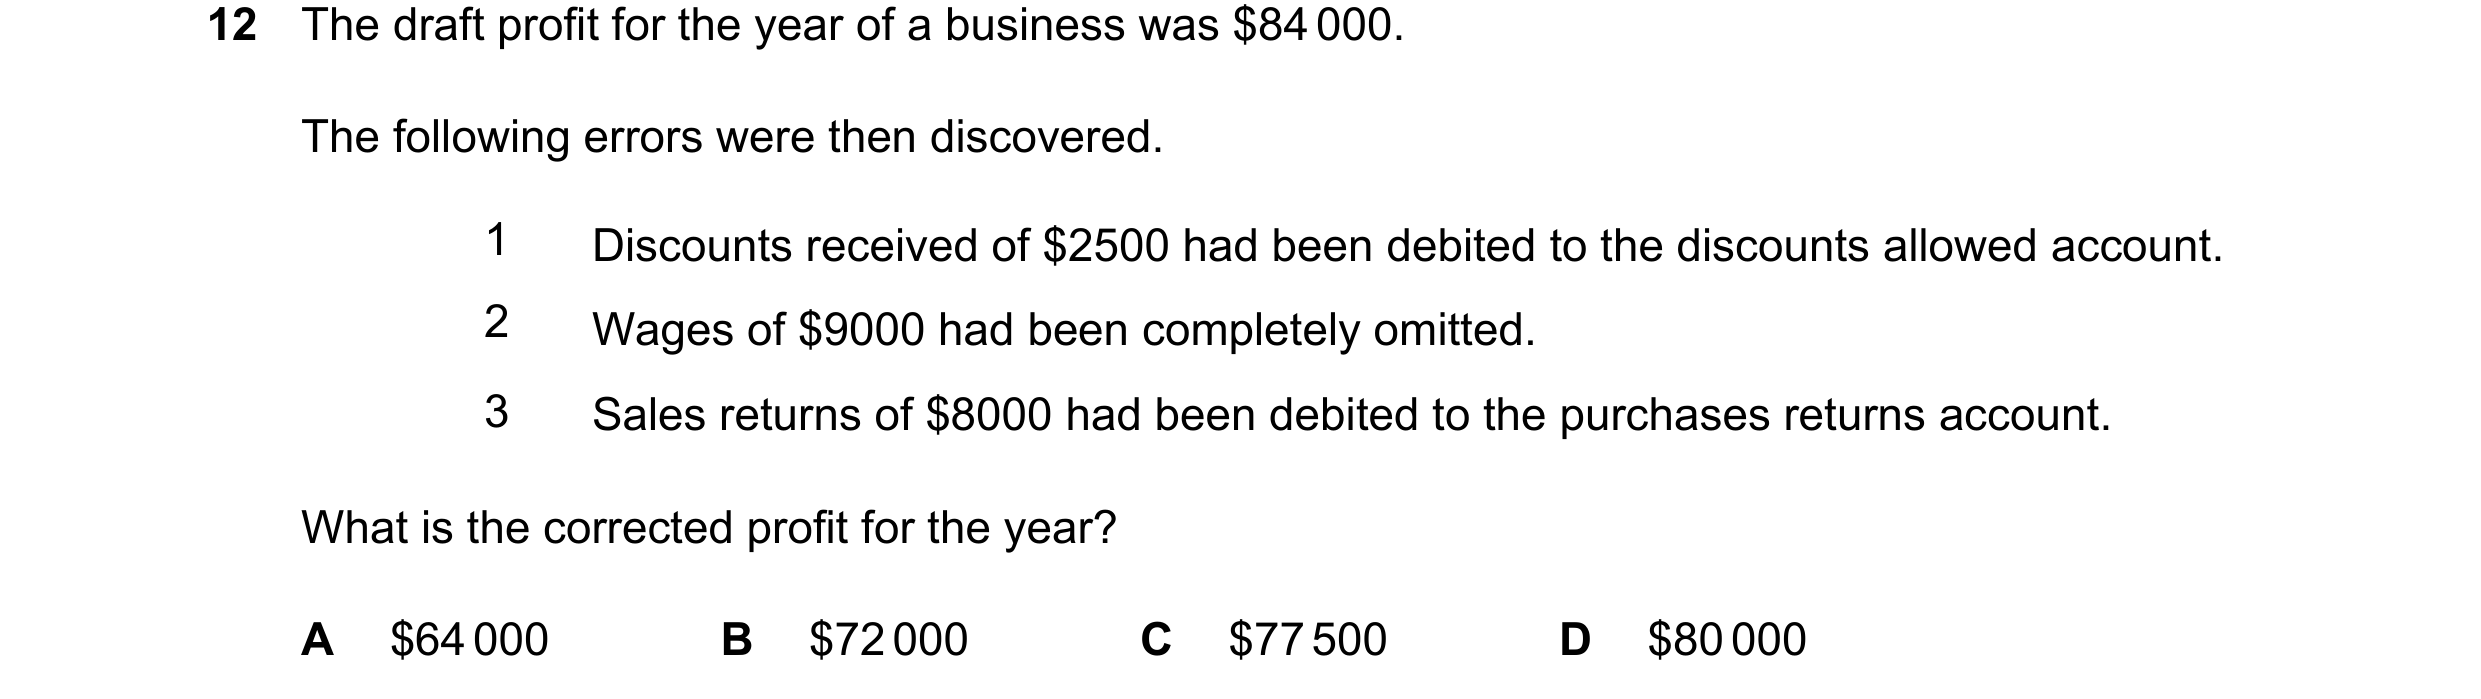 103 / 110
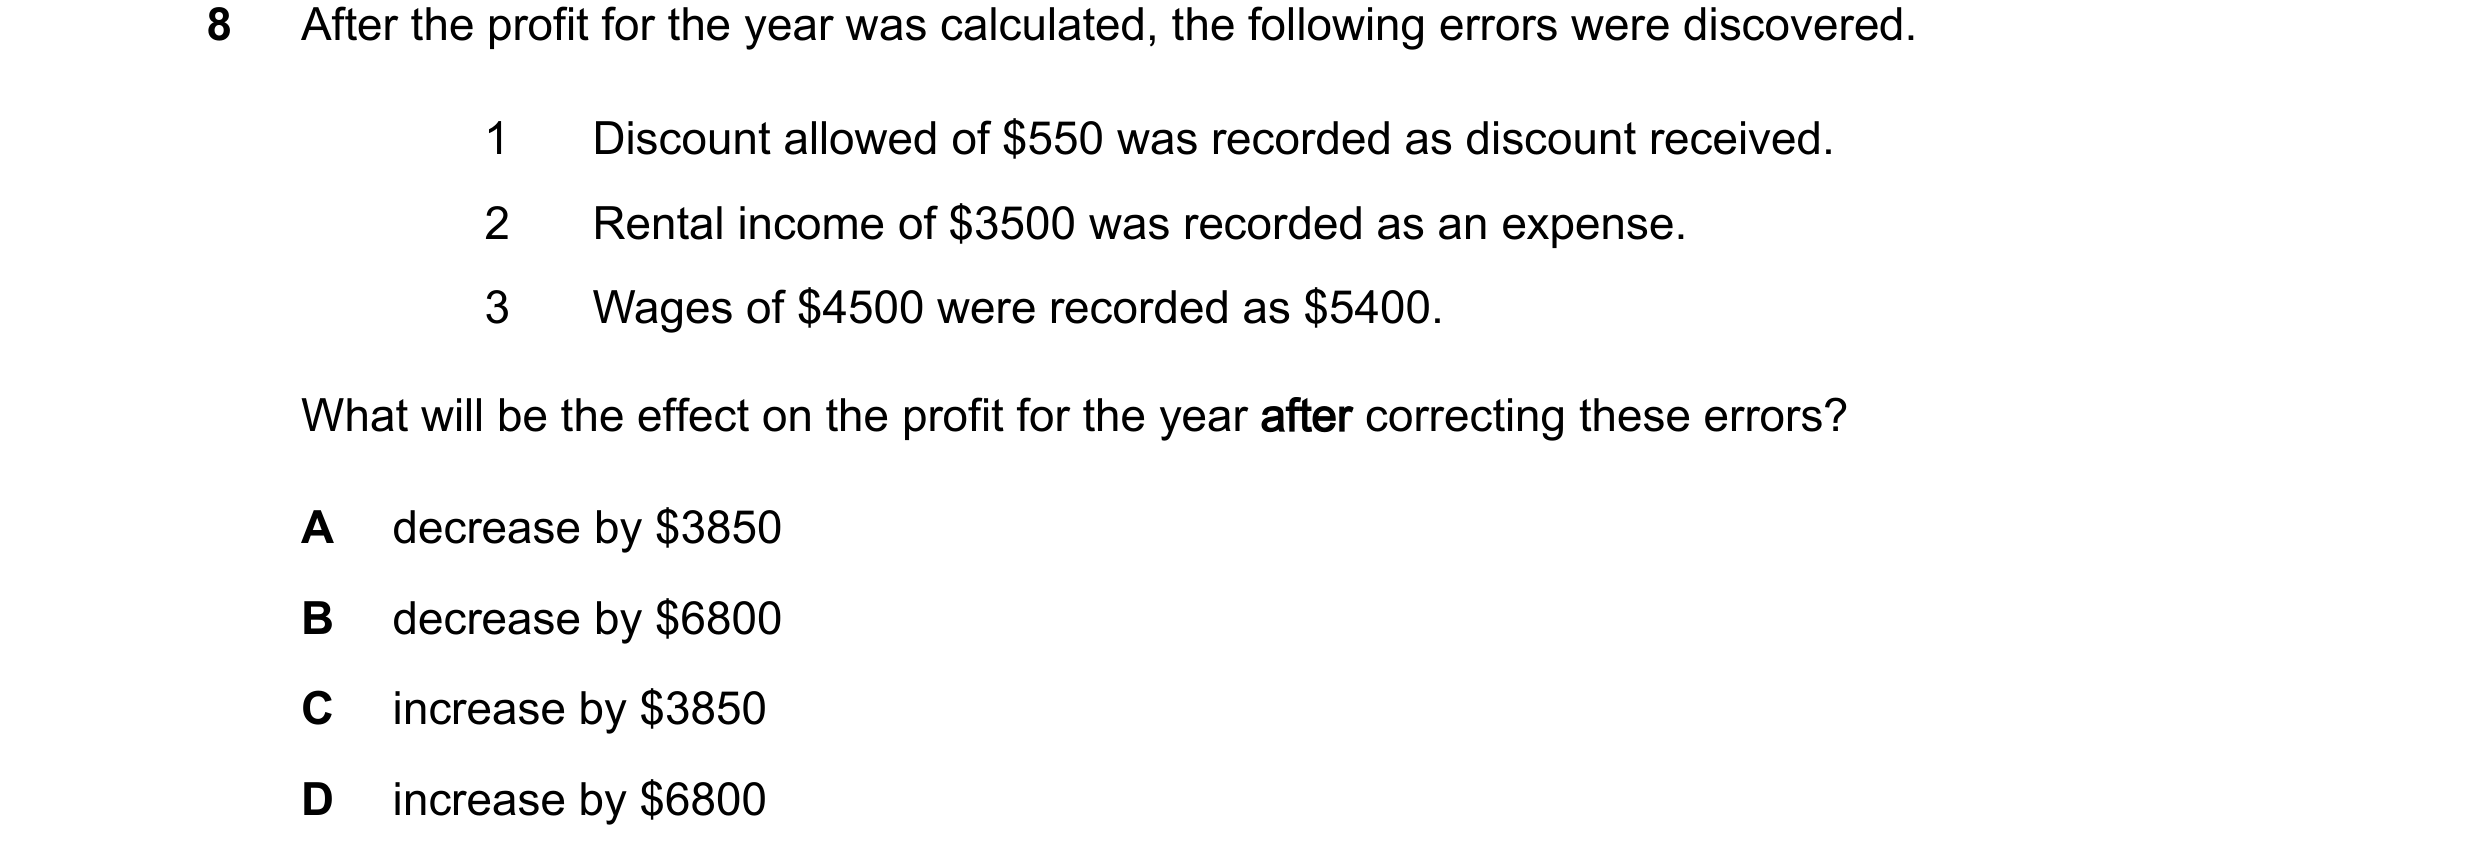
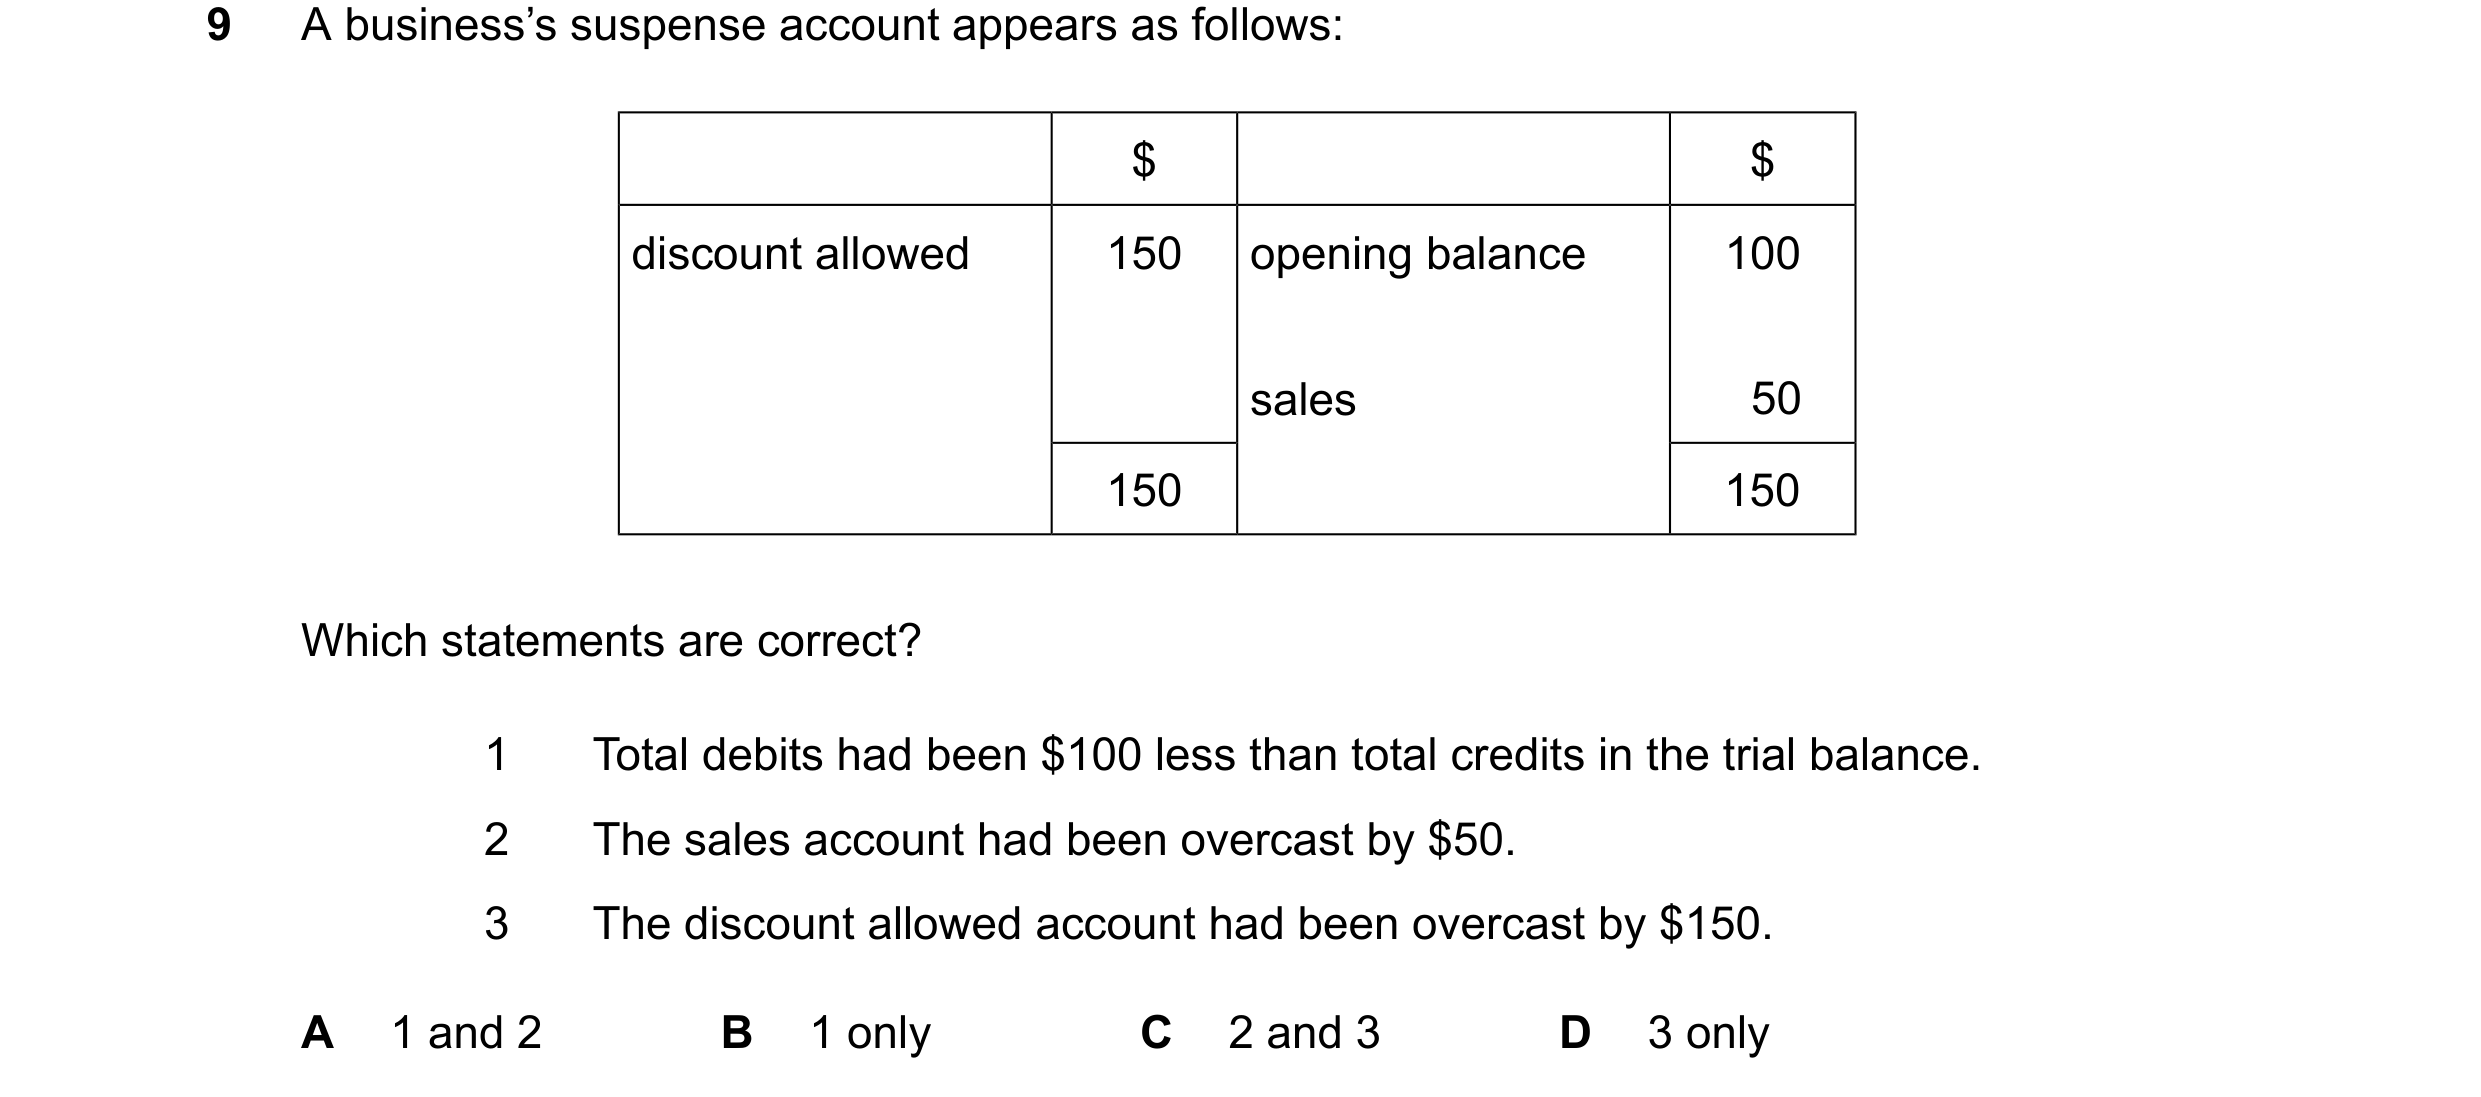
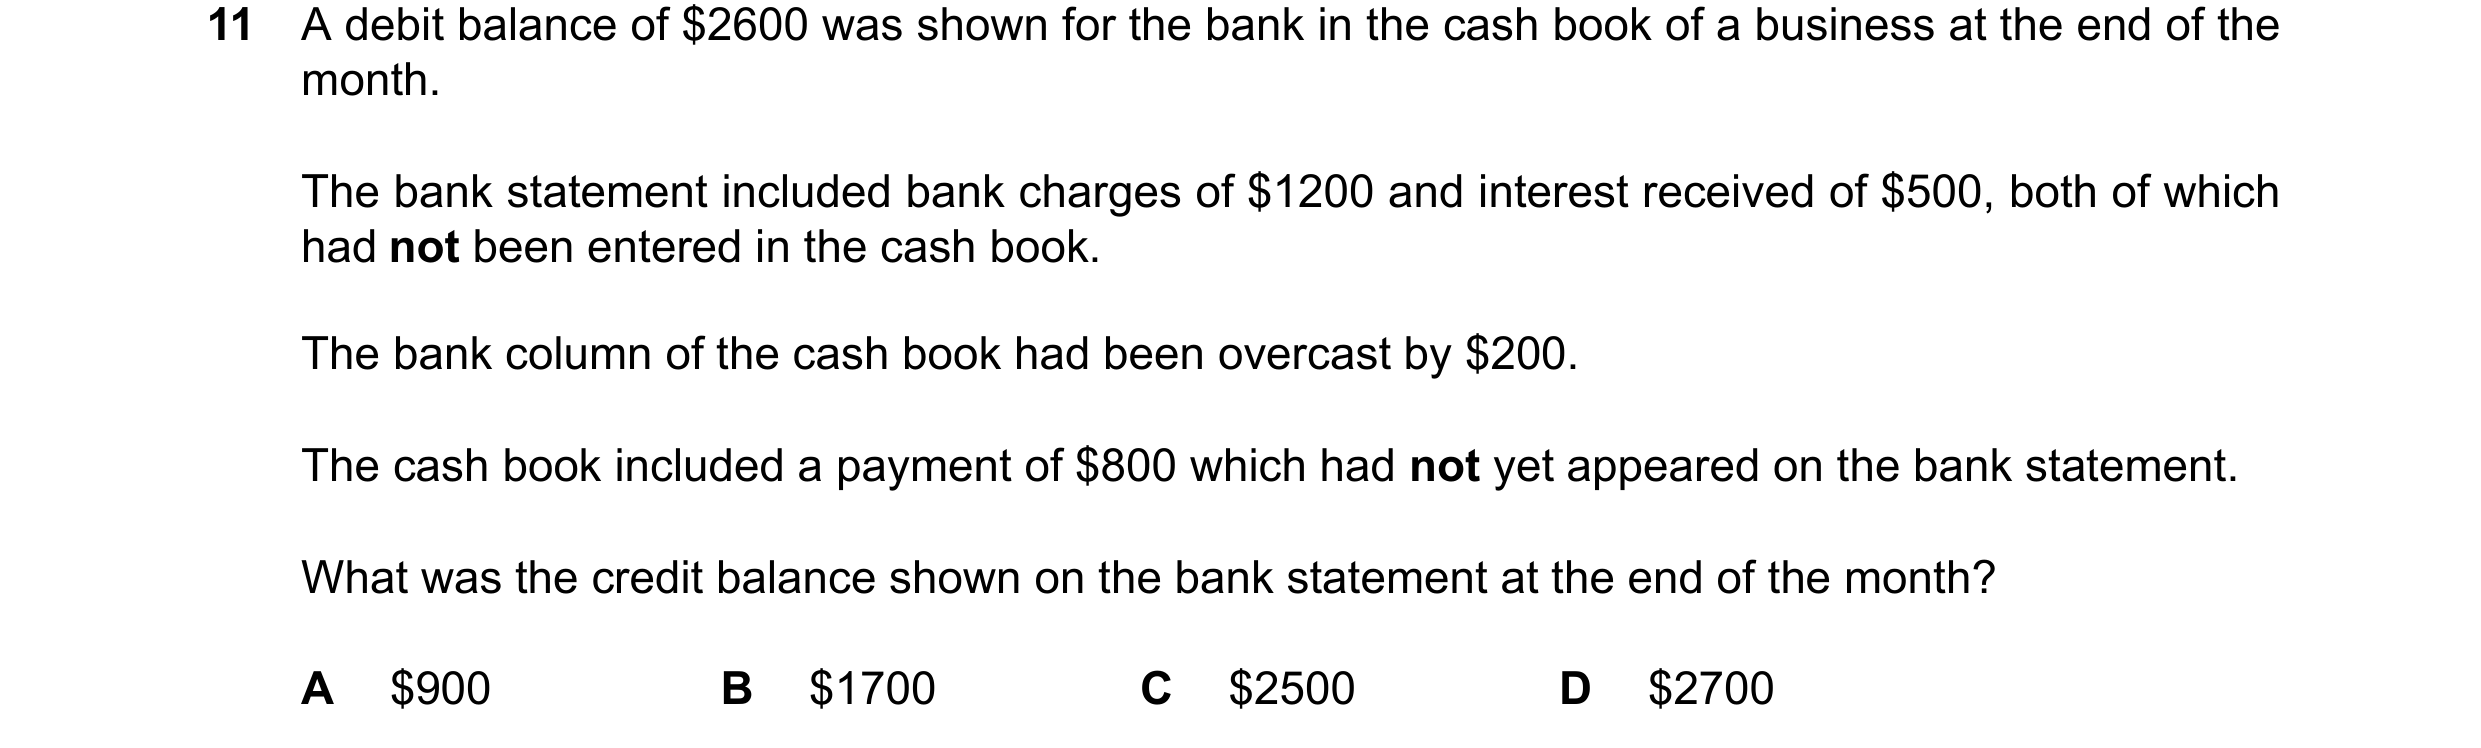 104 / 110
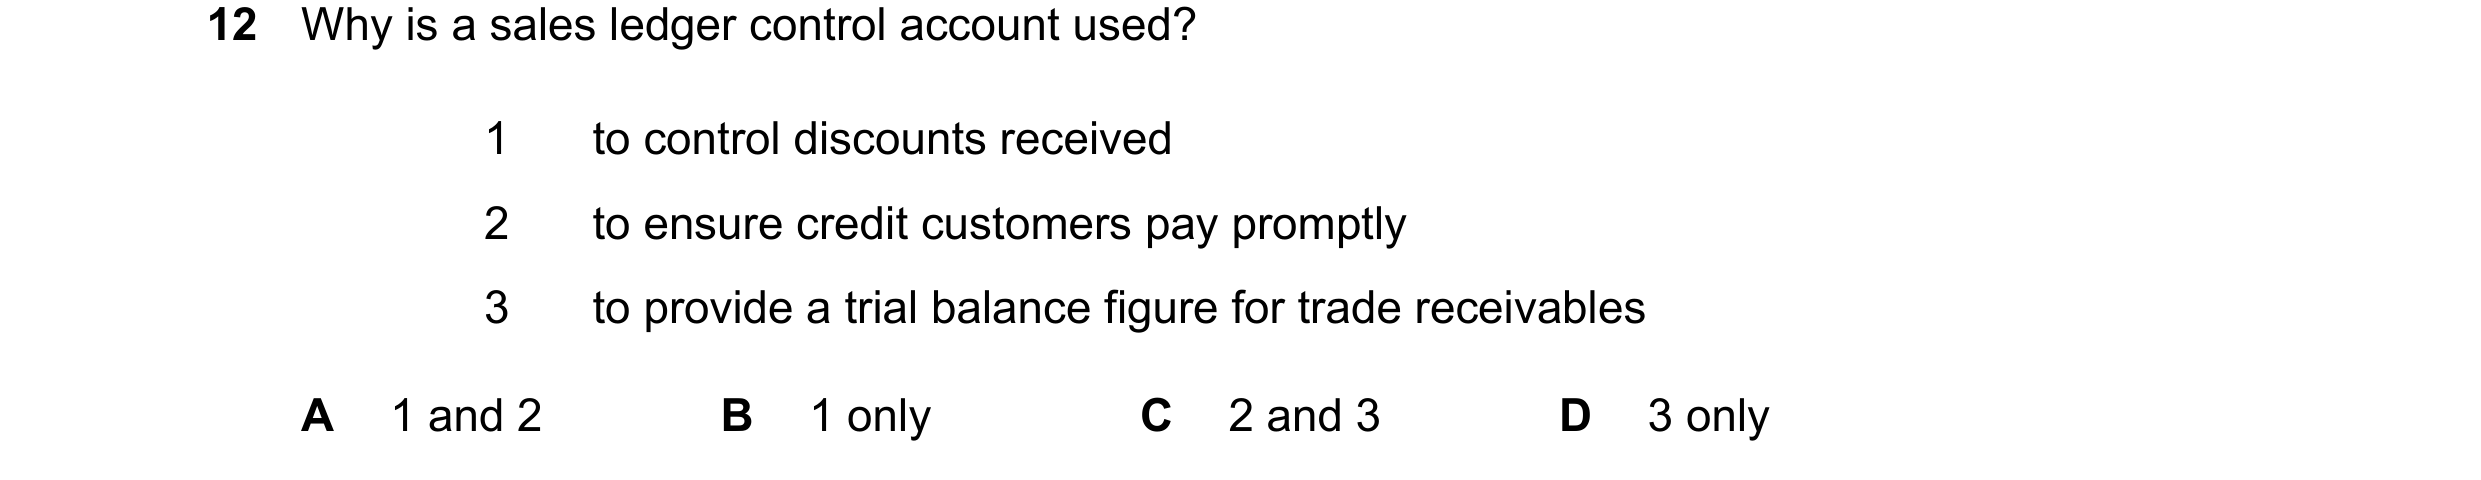
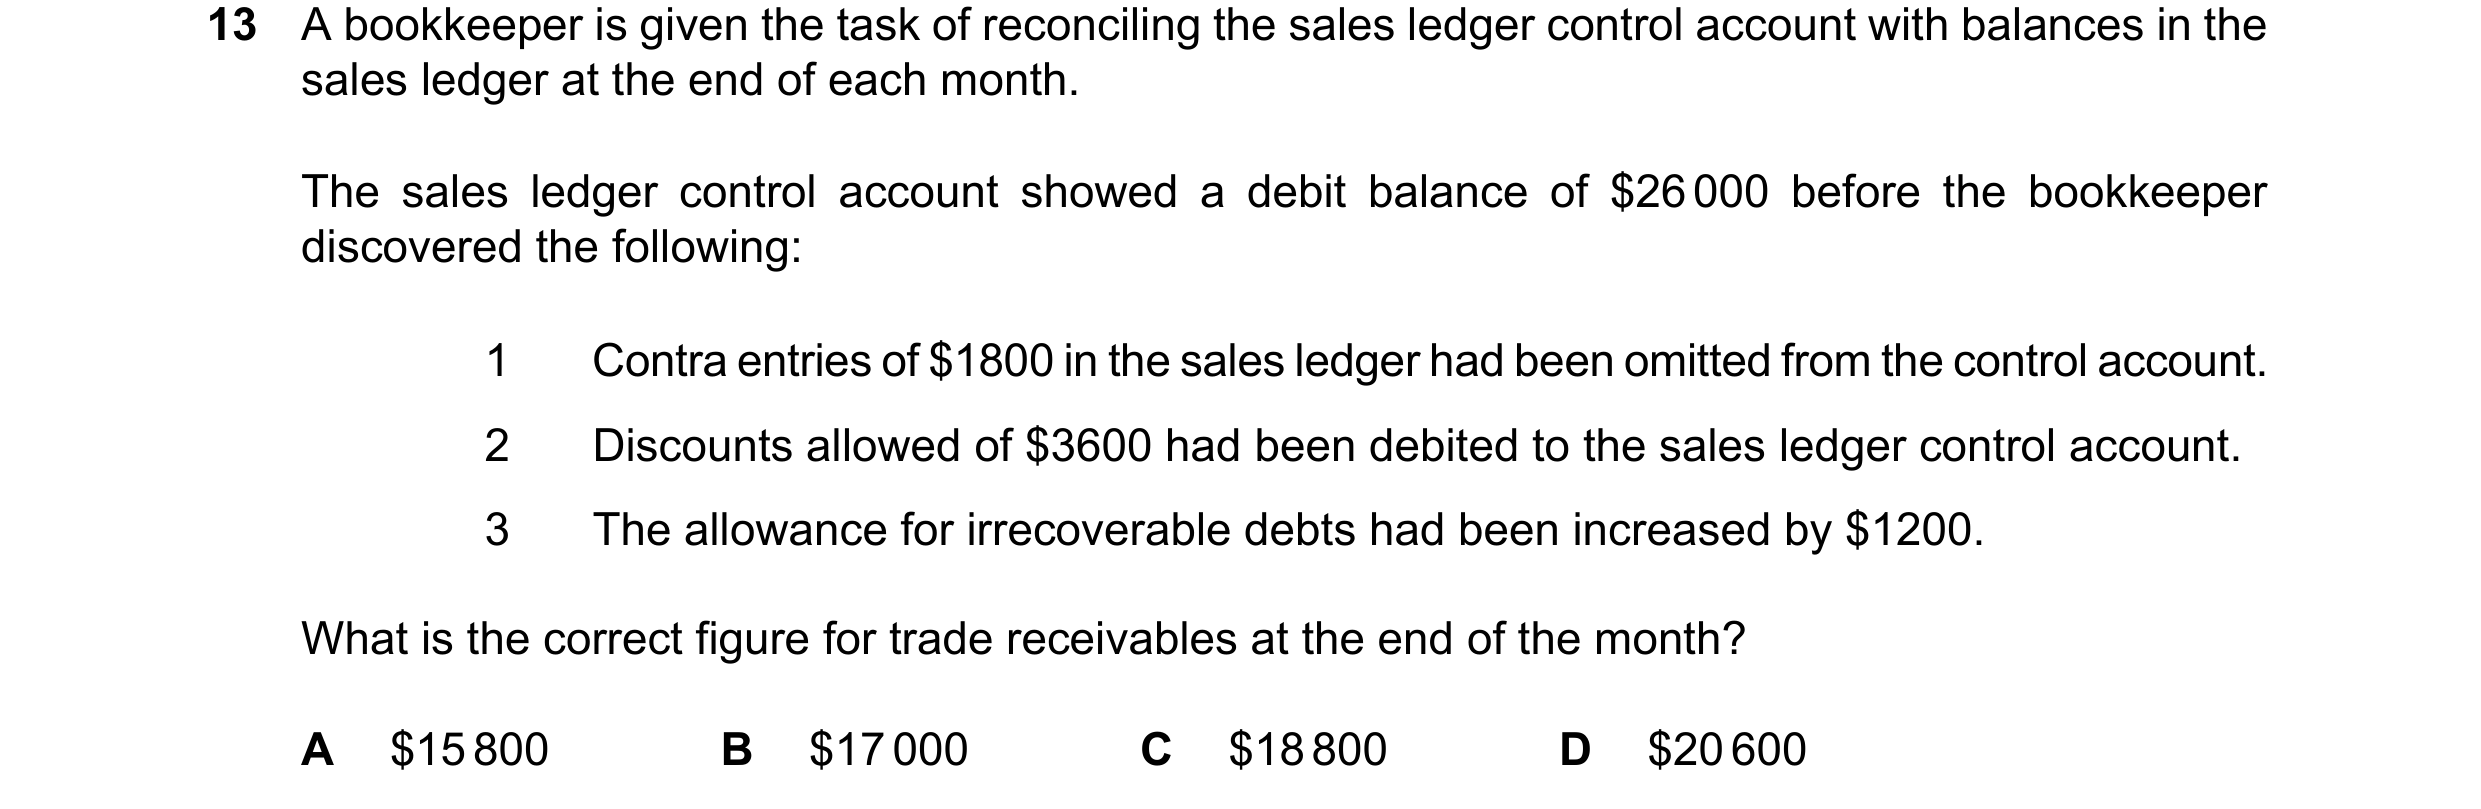
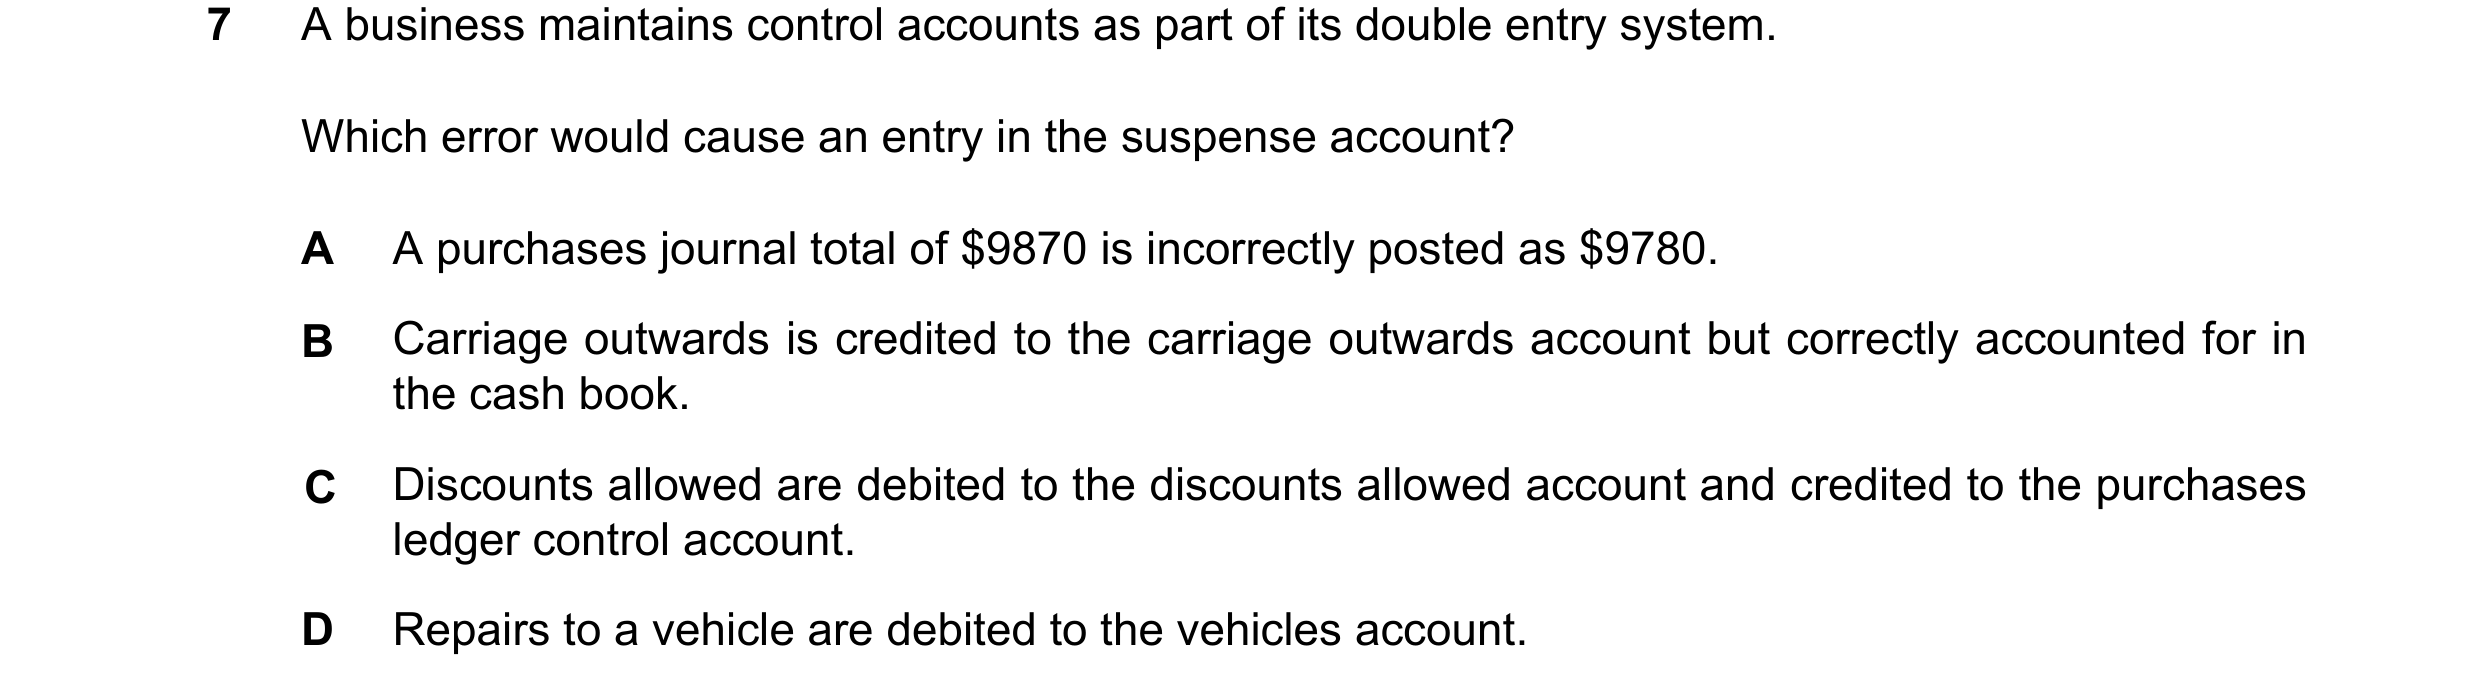
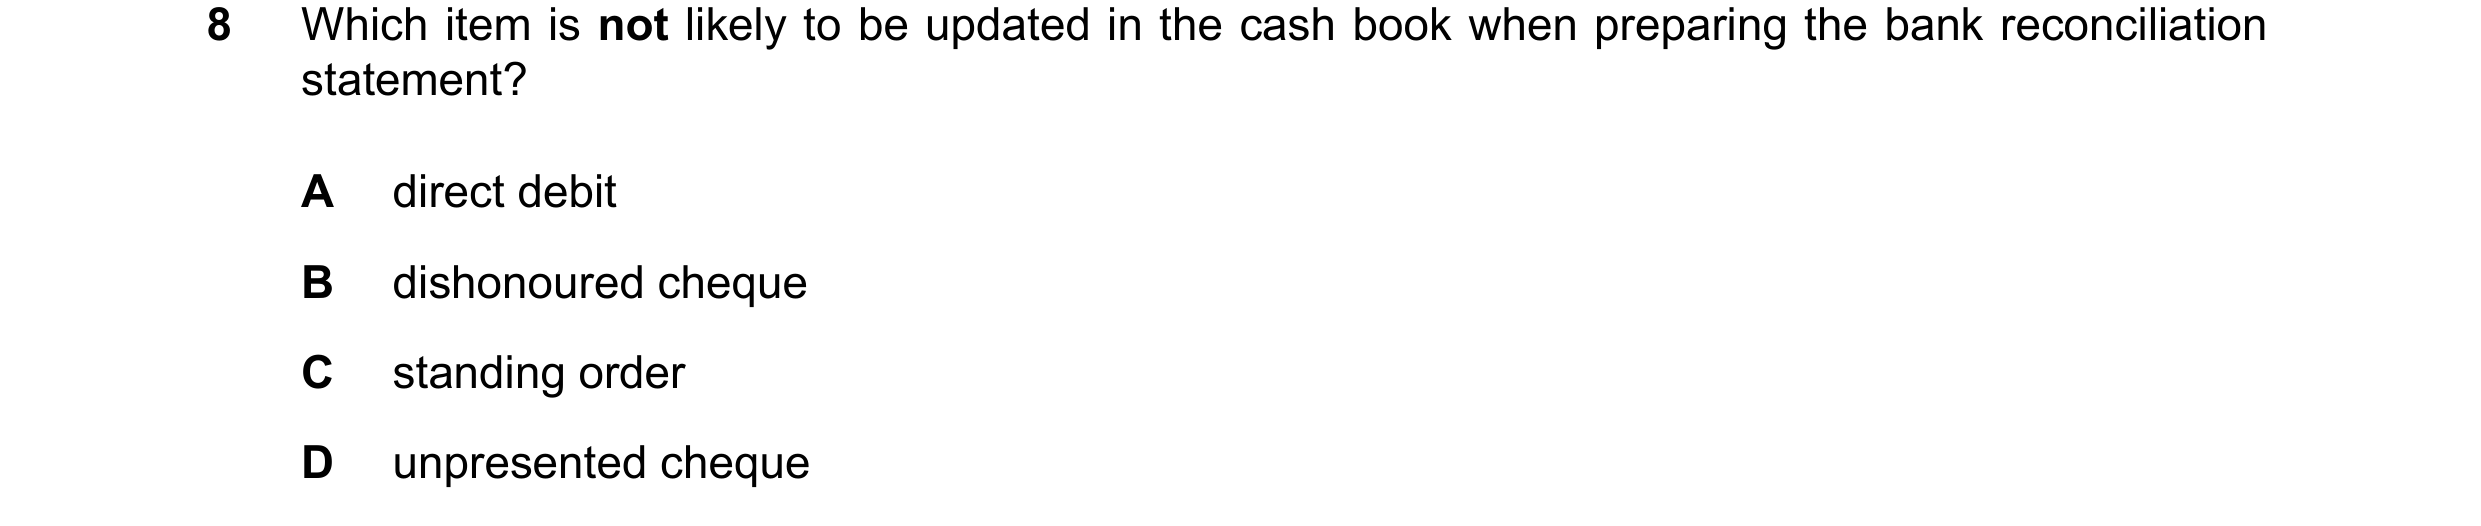 105 / 110
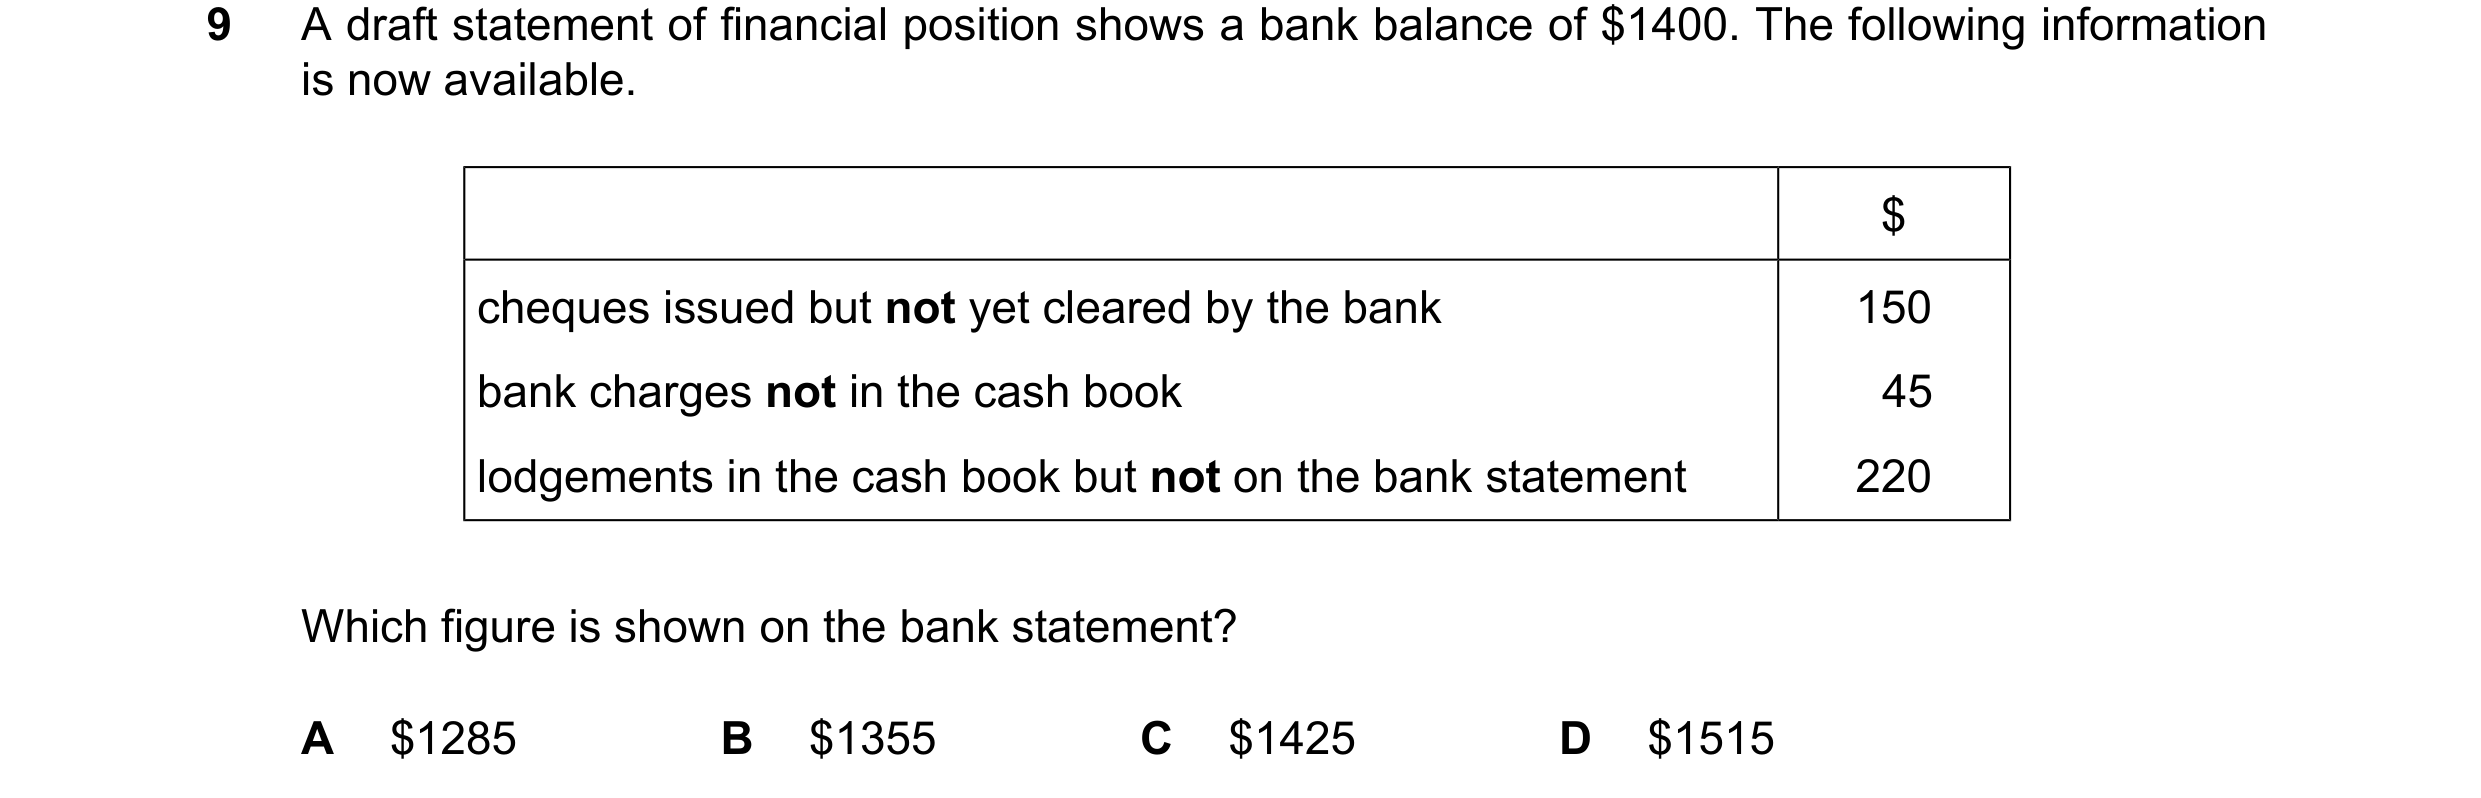
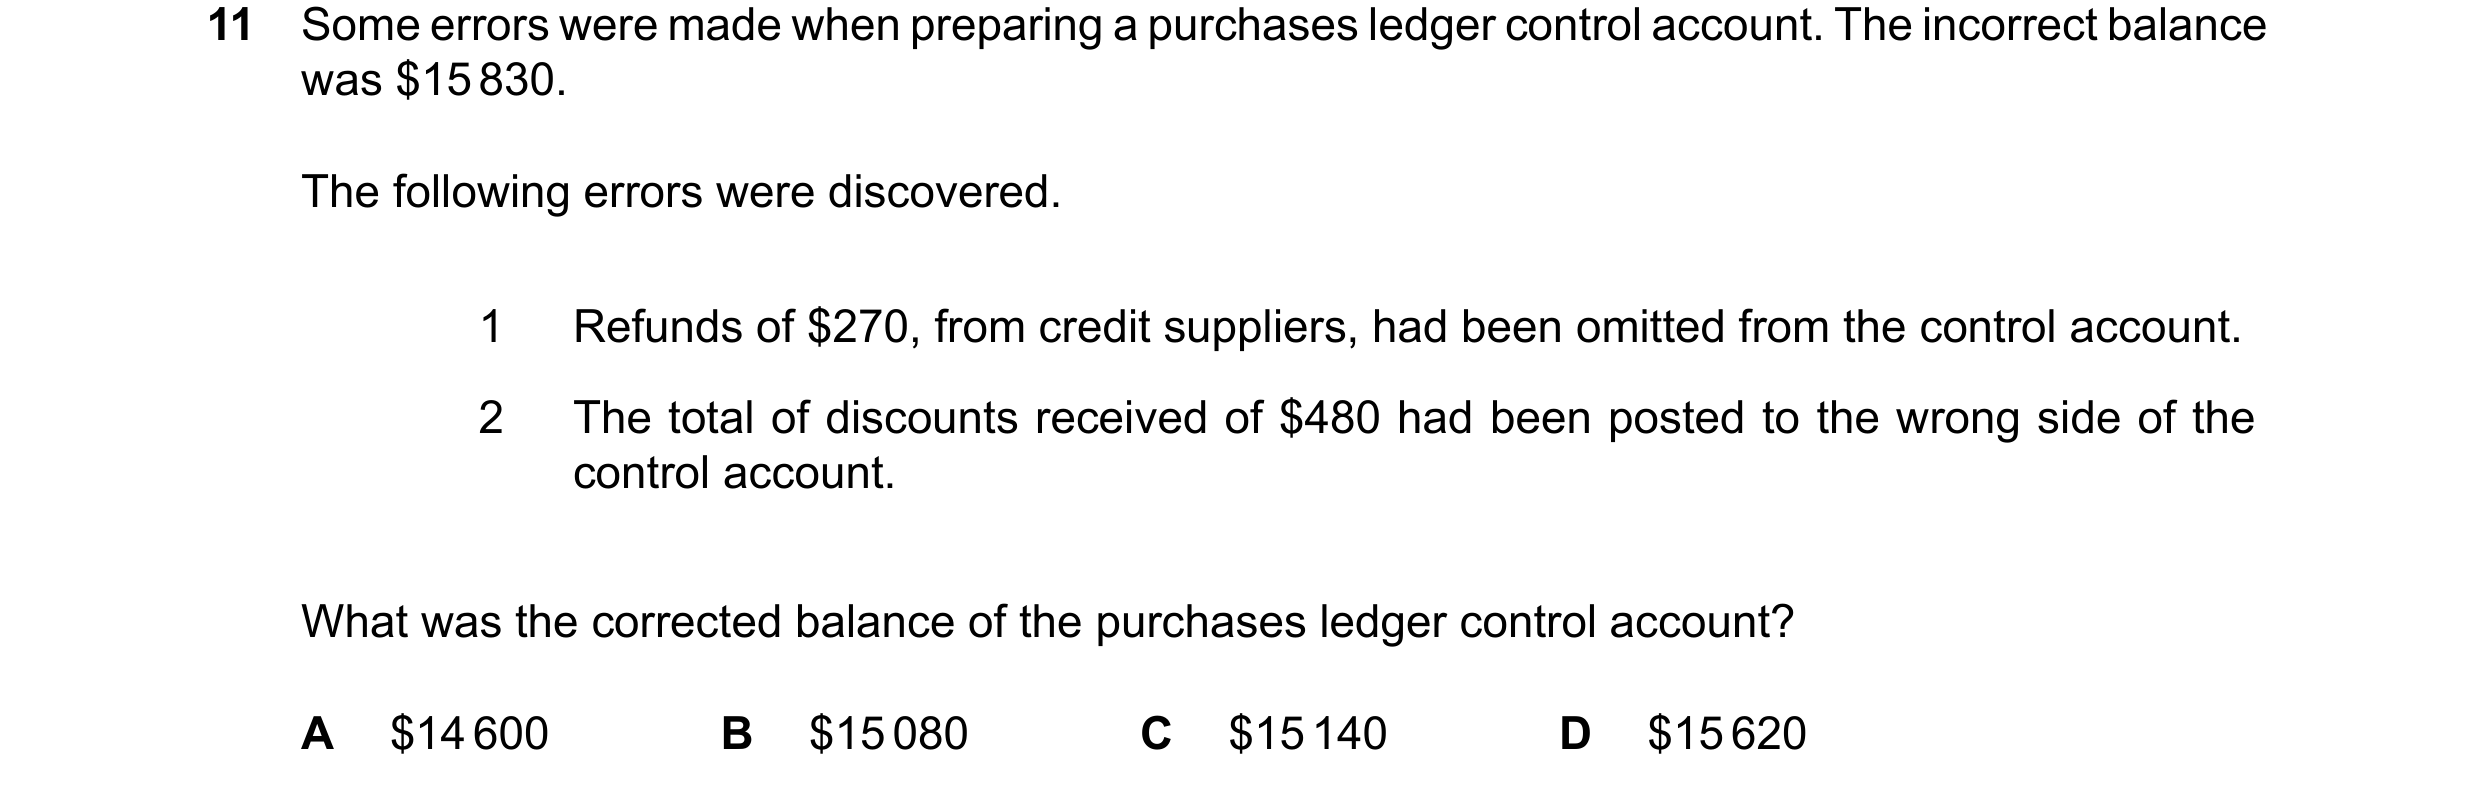
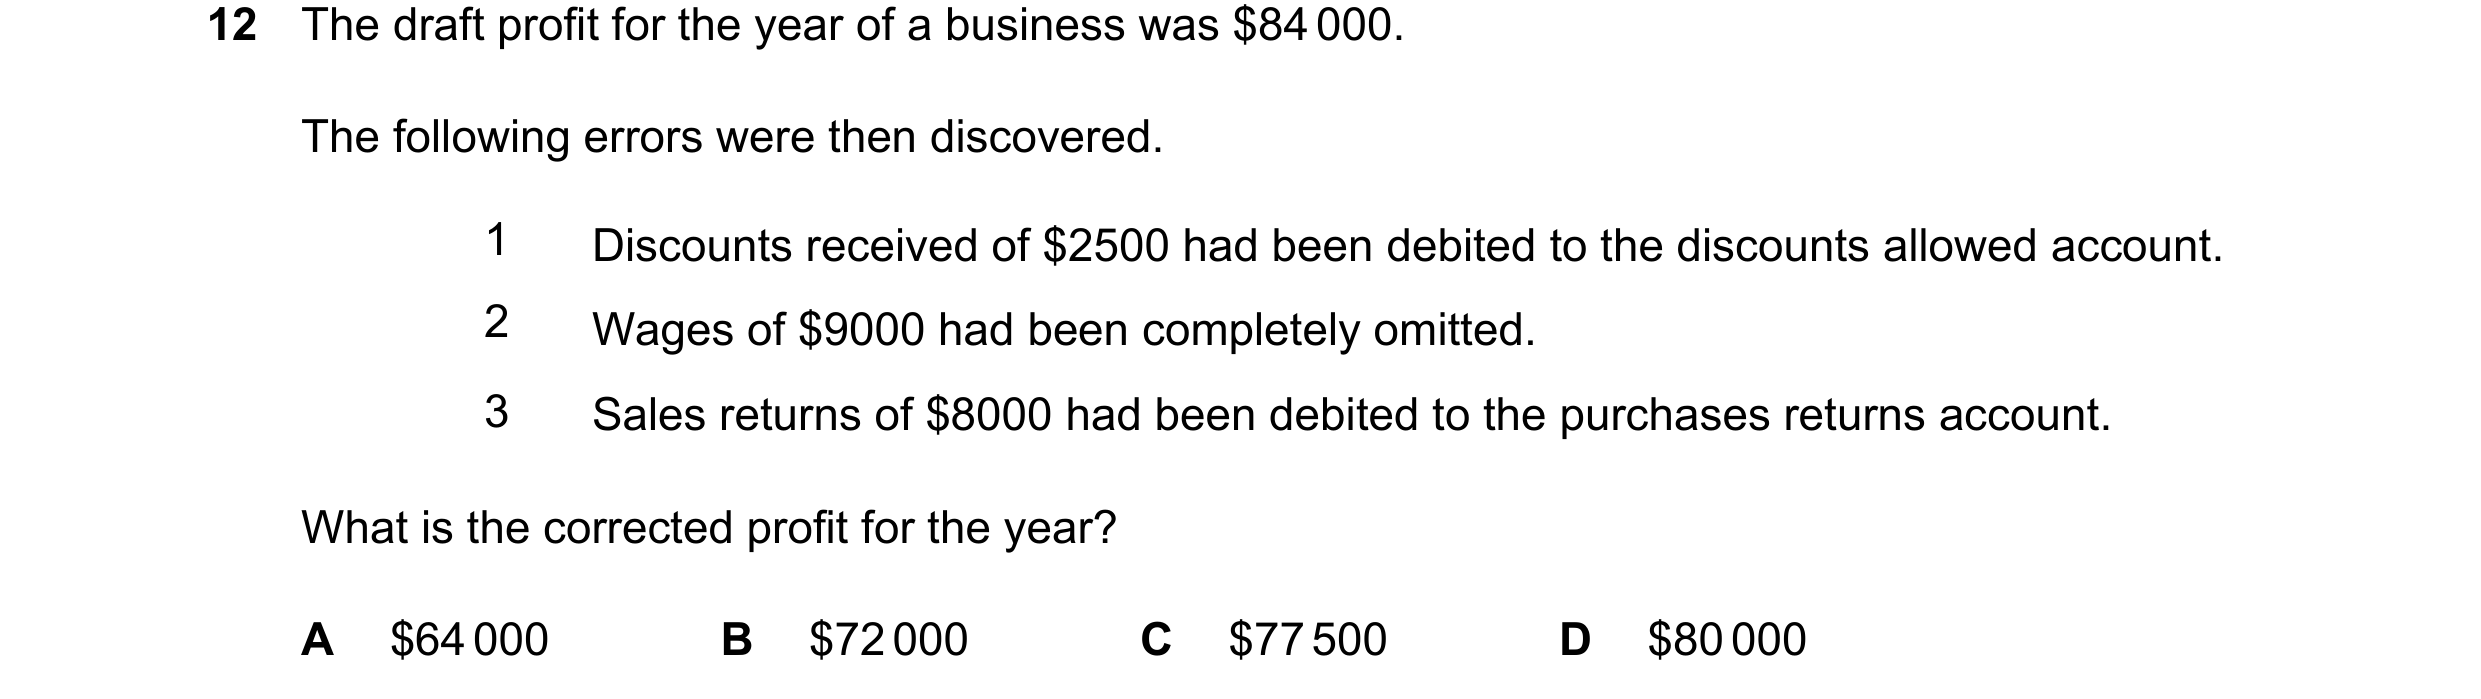 106 / 110
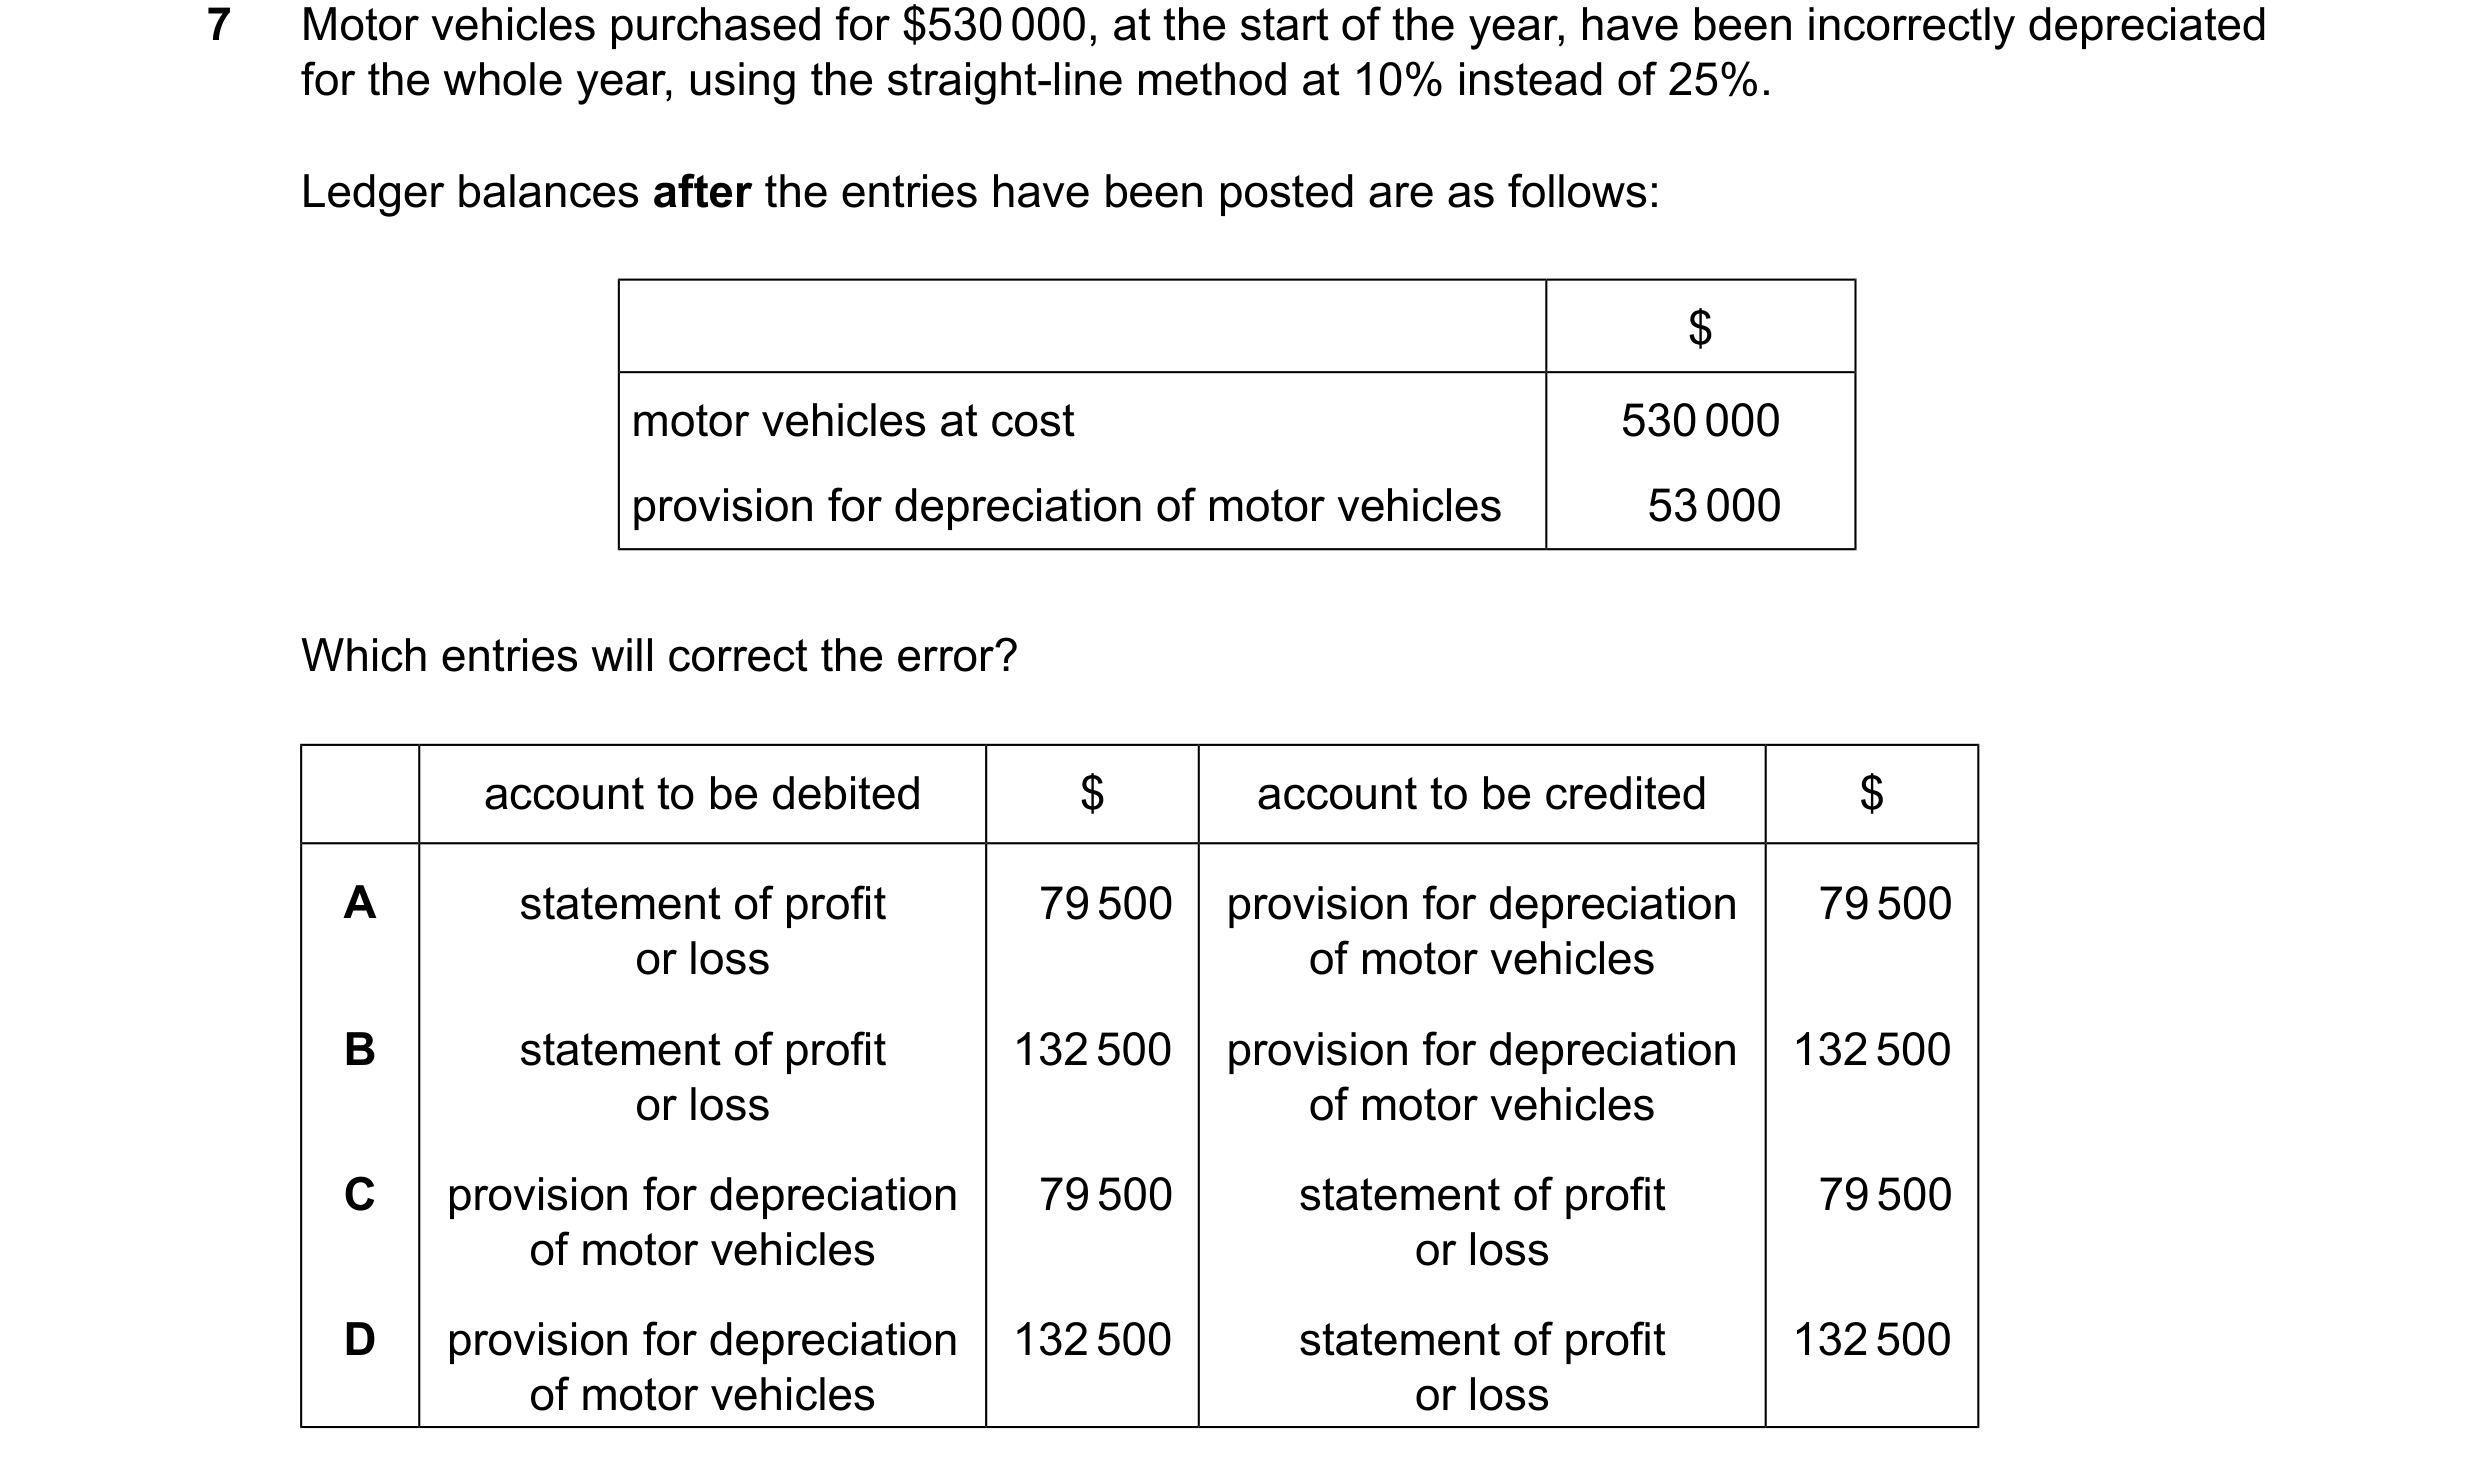
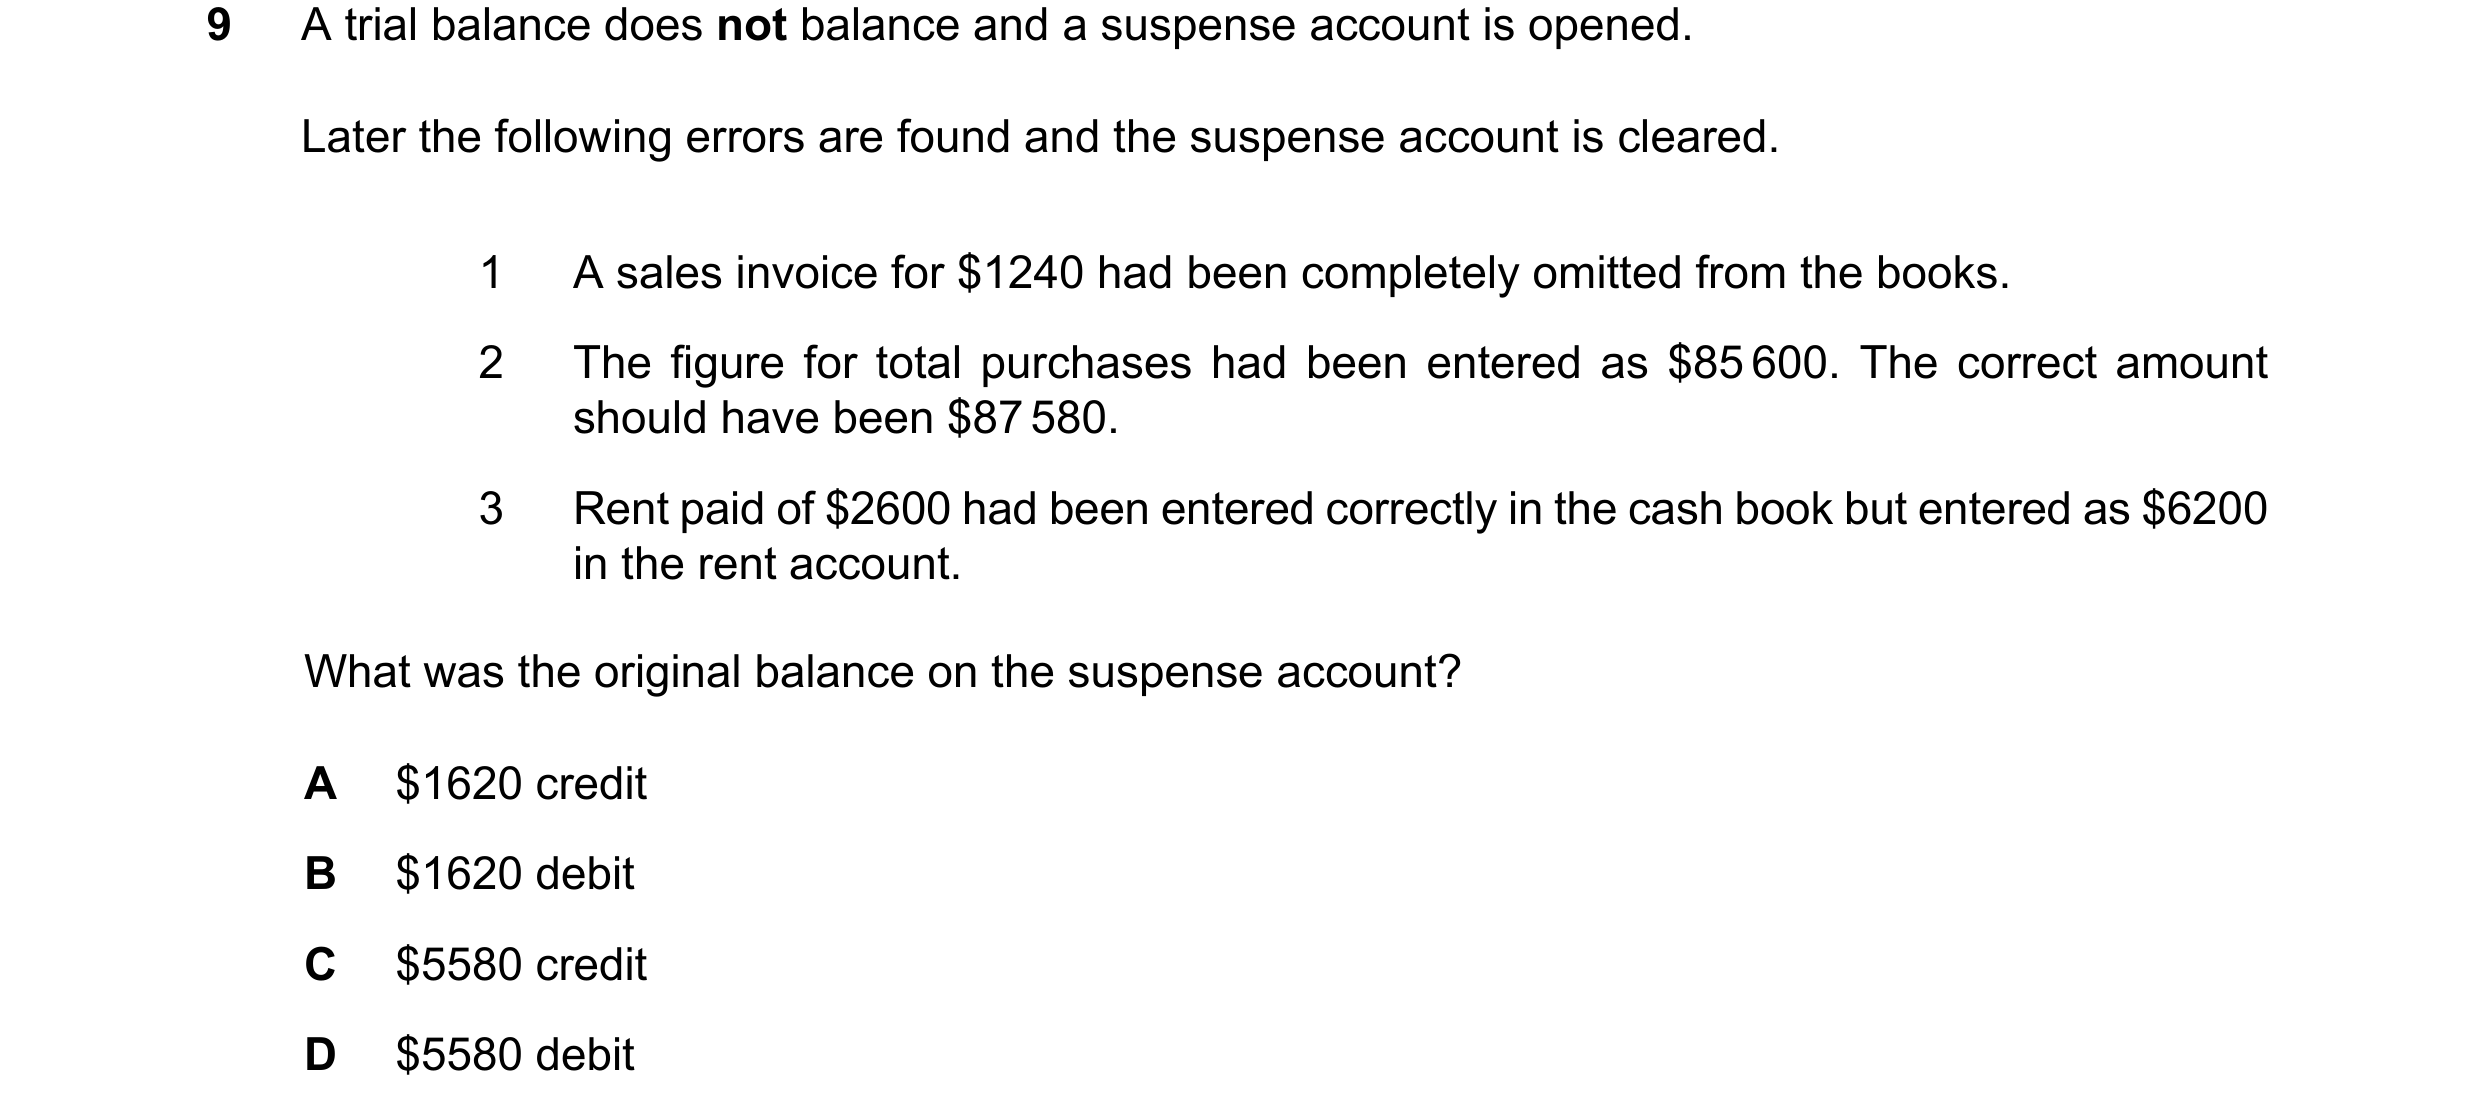
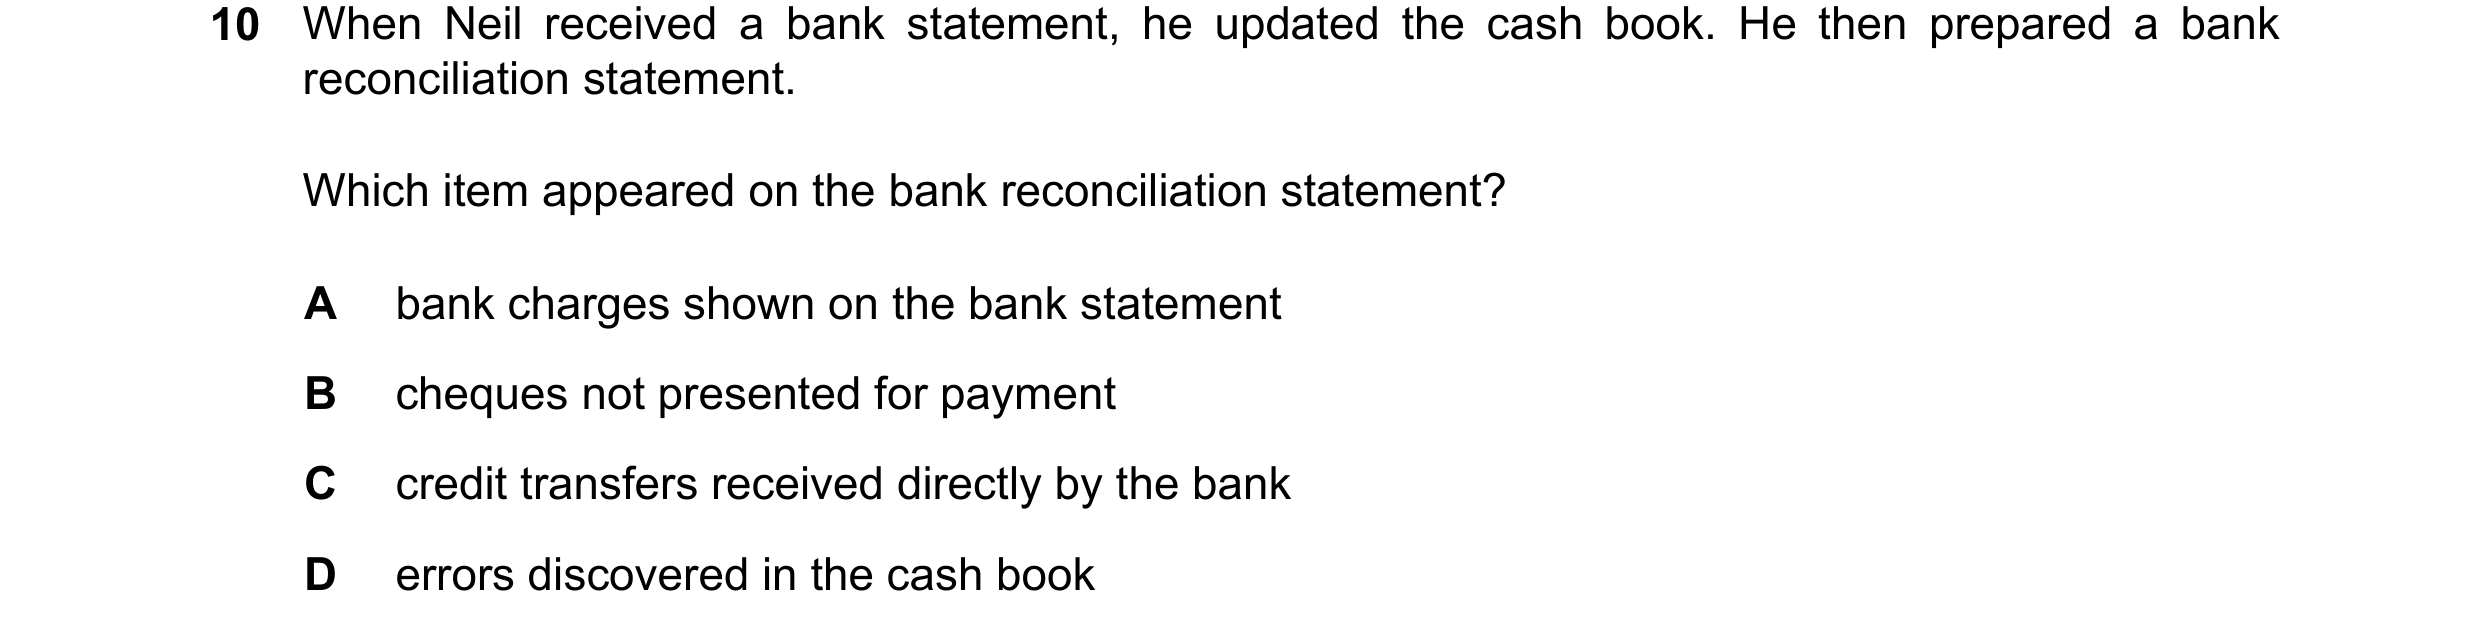 107 / 110
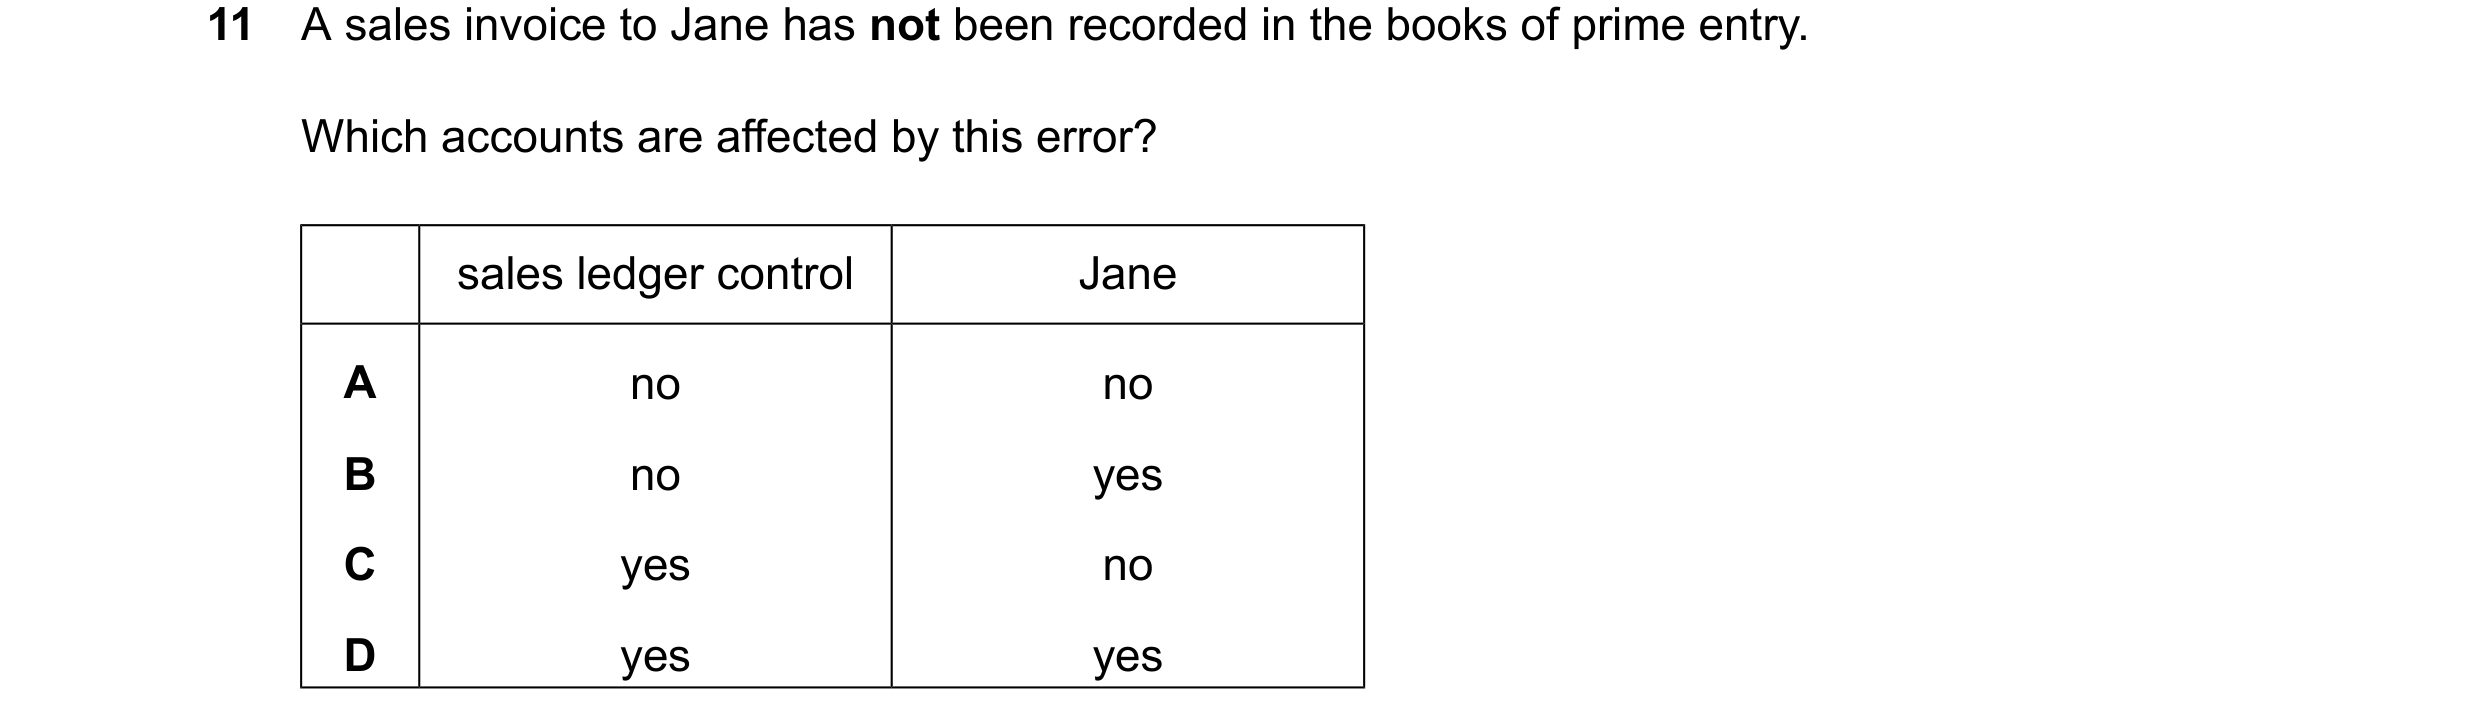
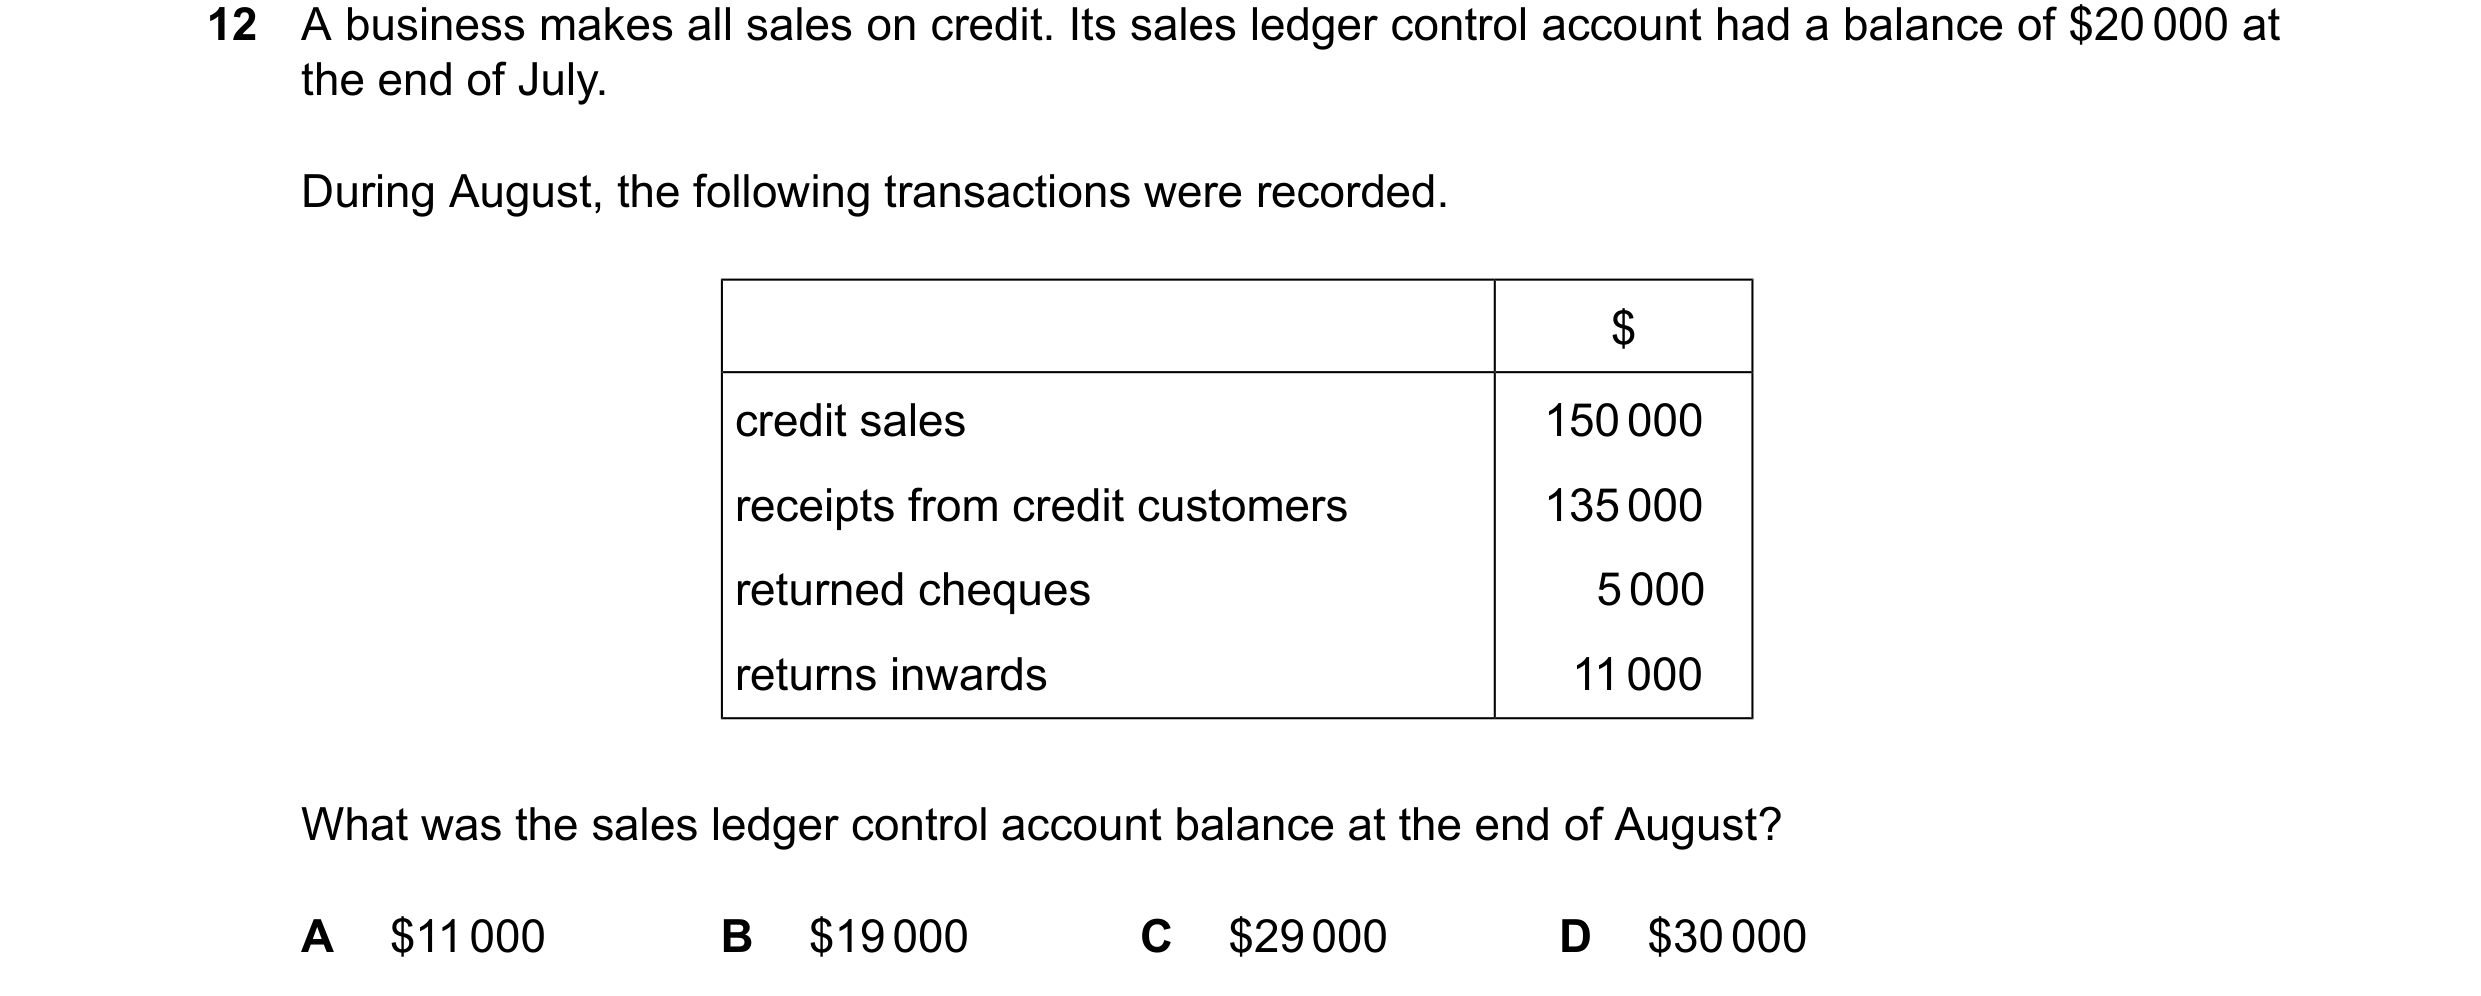
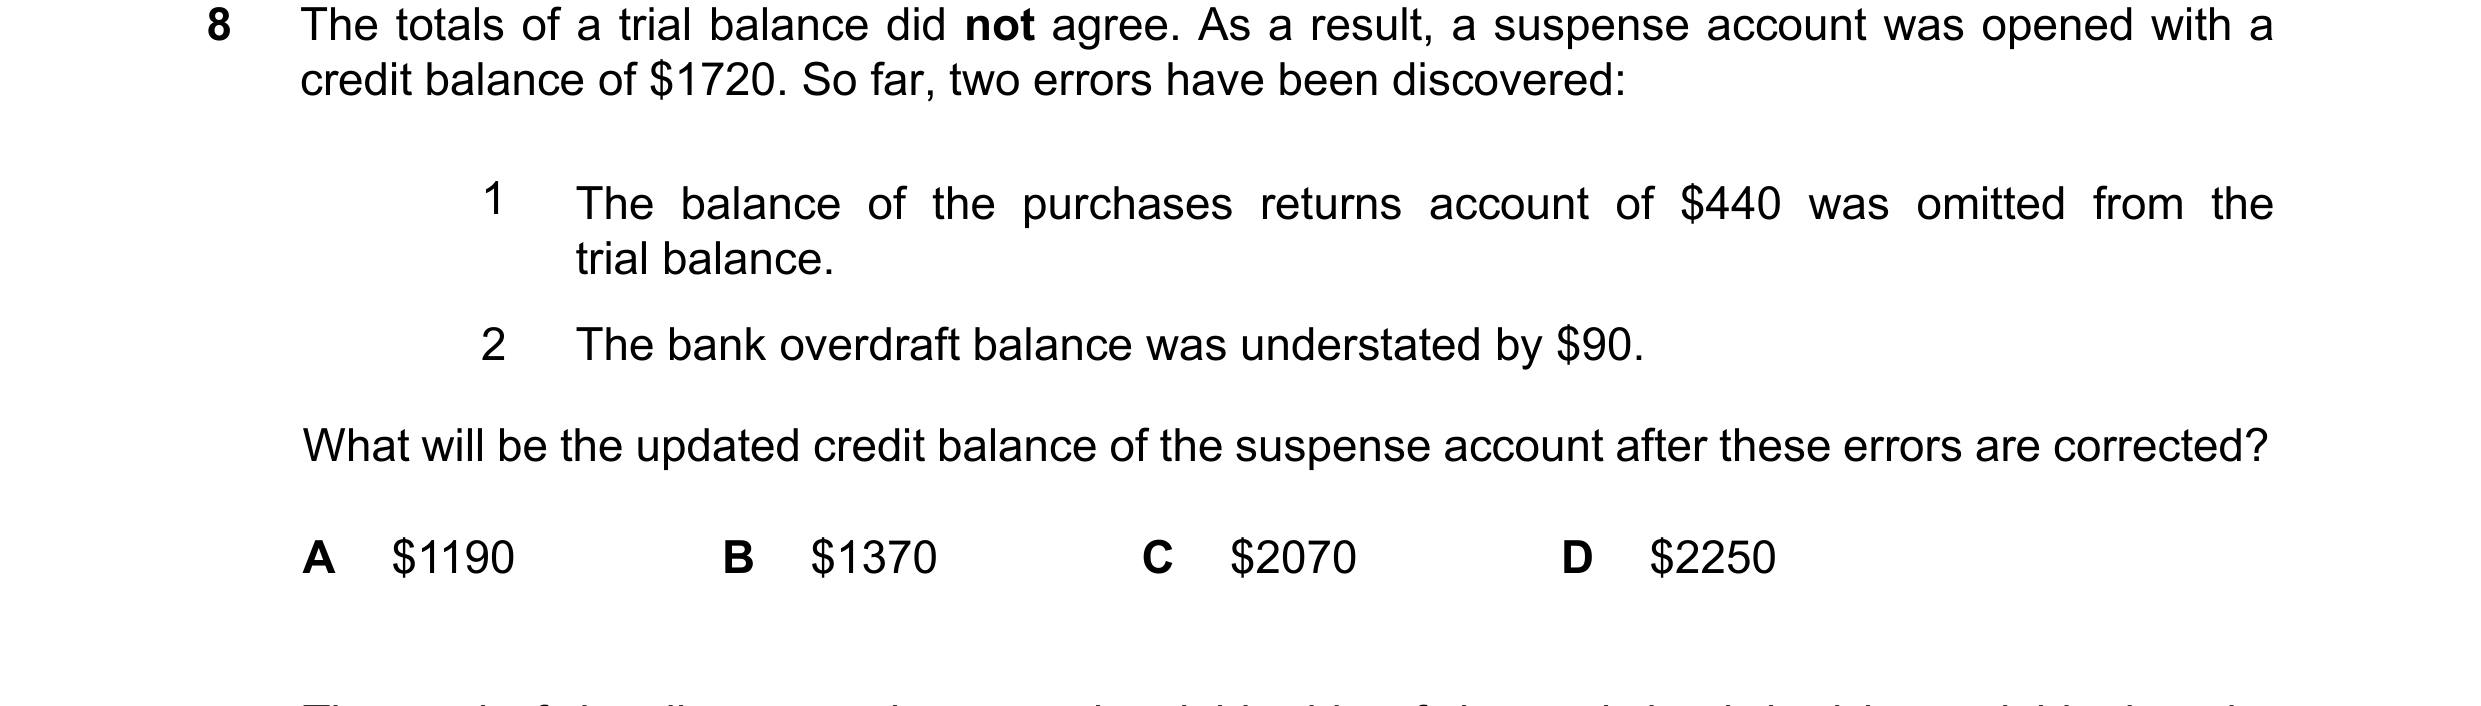
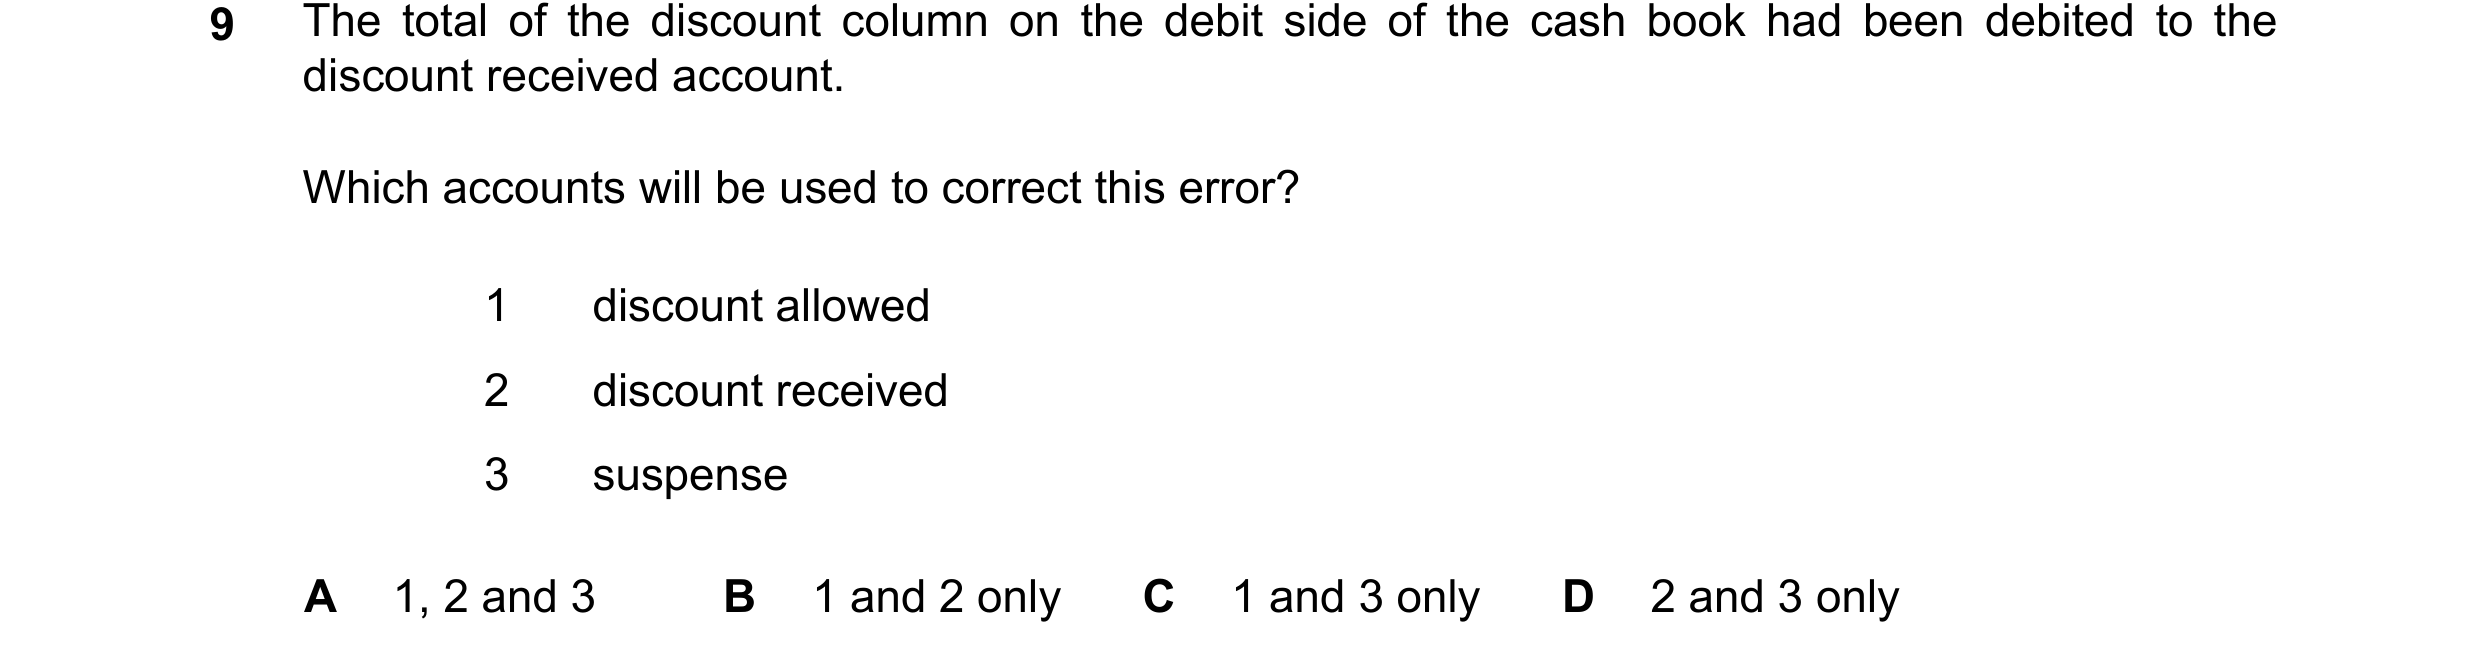 108 / 110
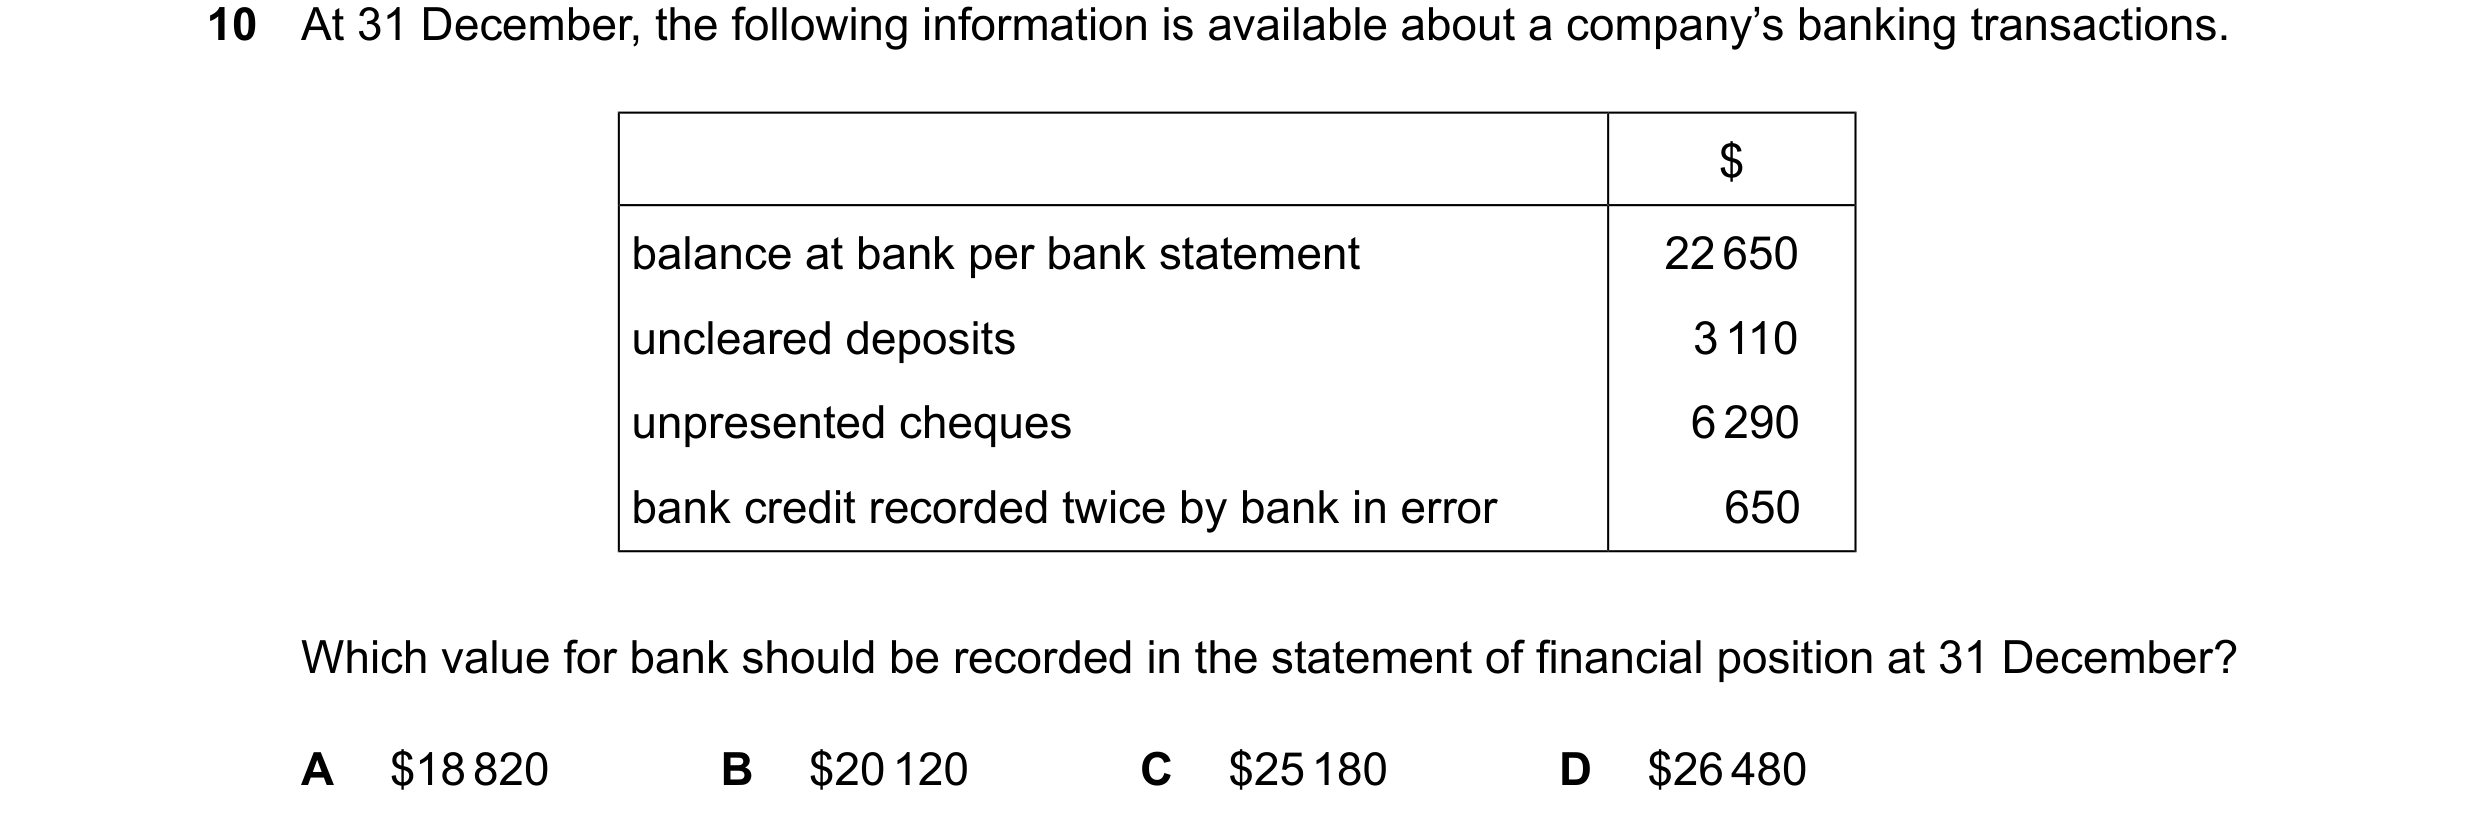
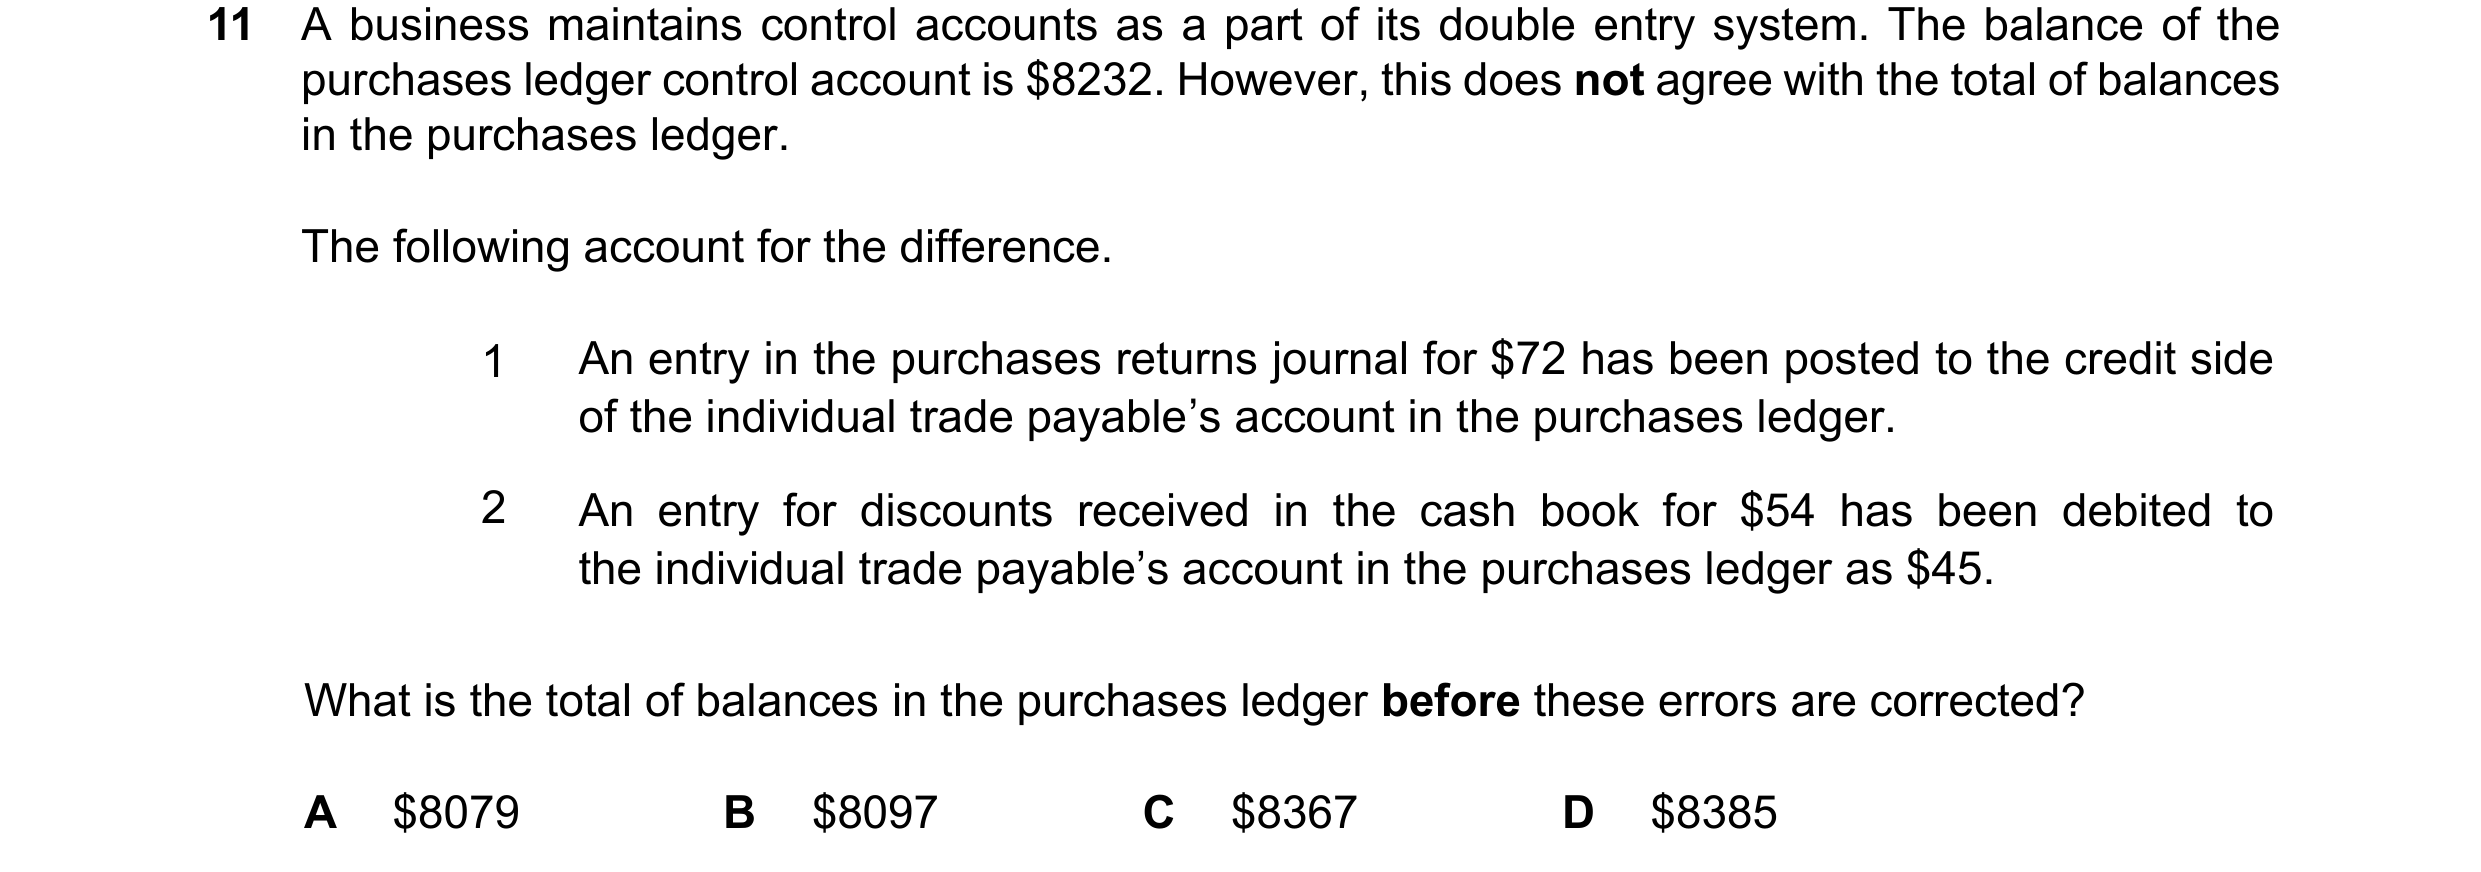
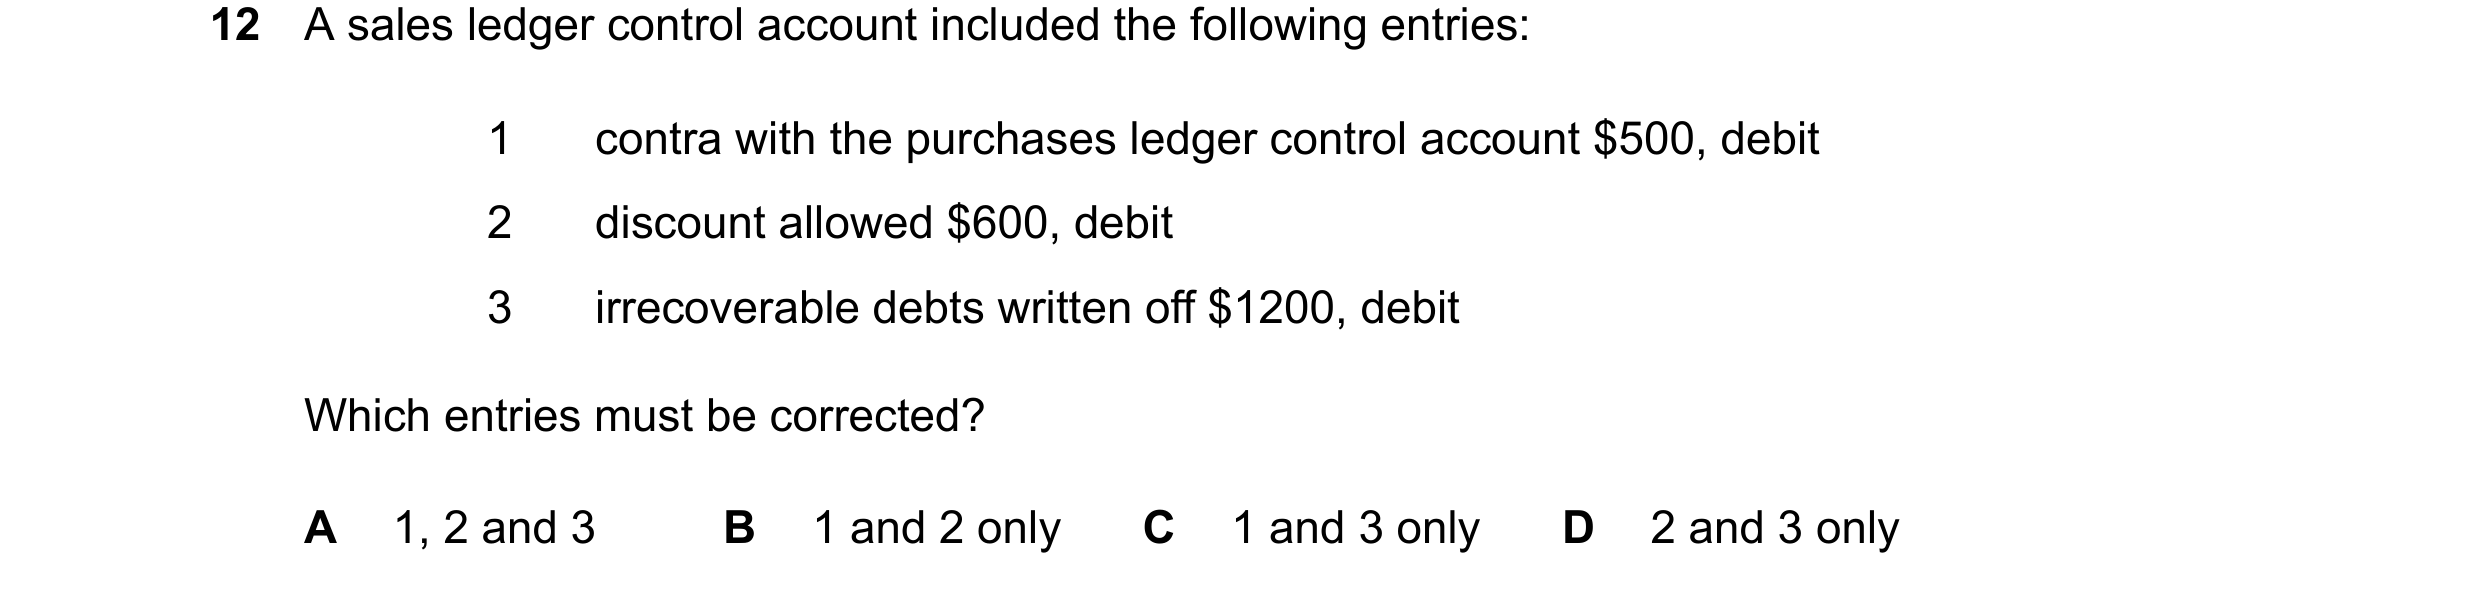
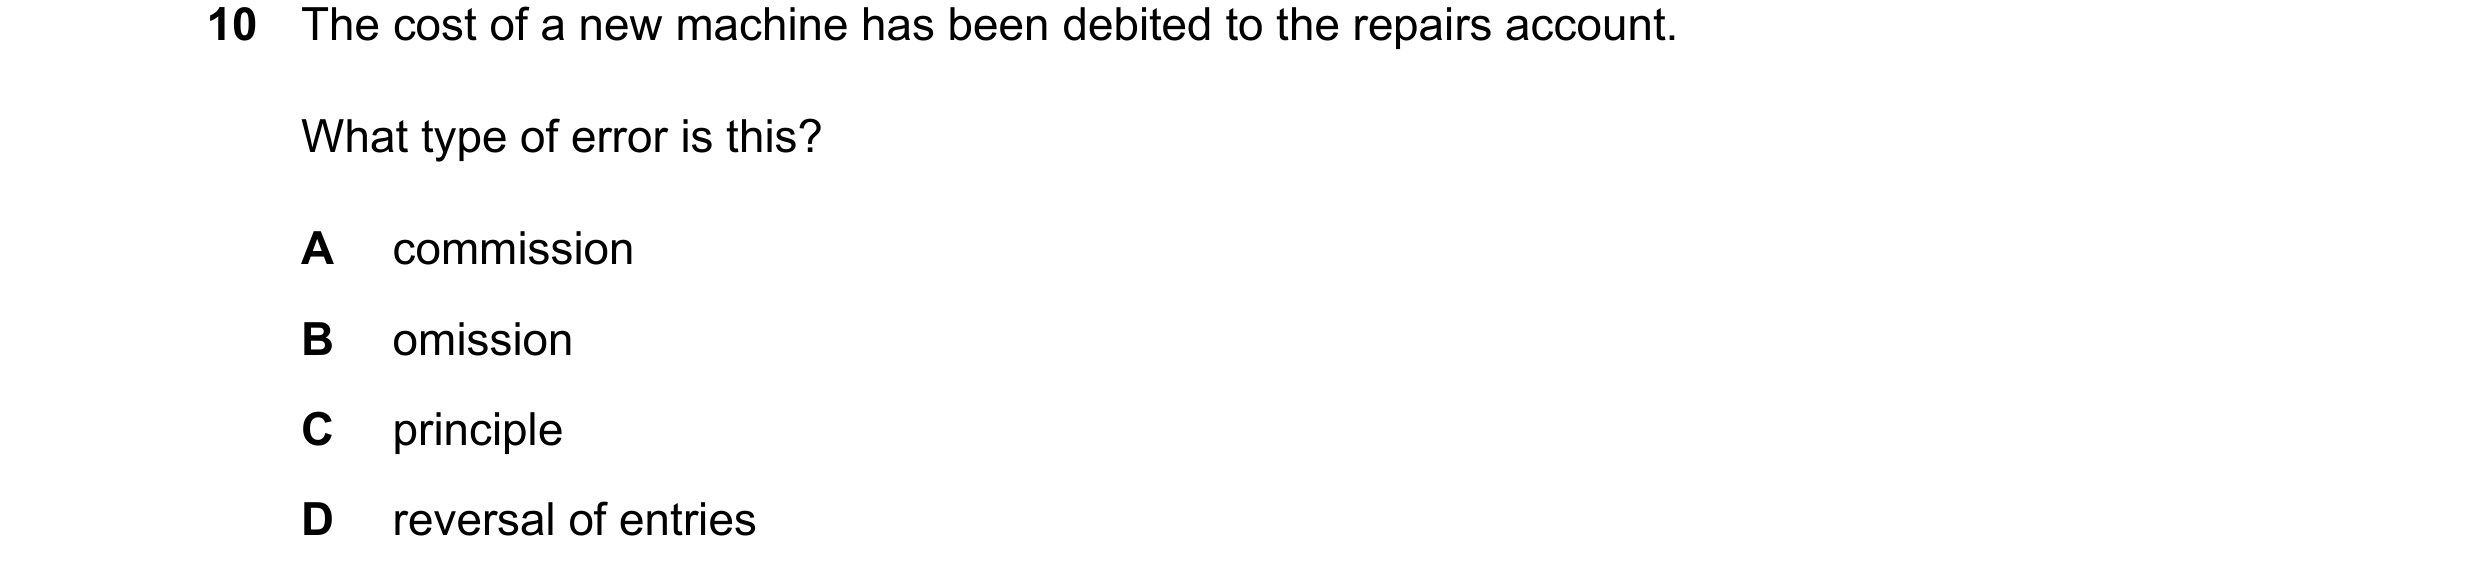 109 / 110
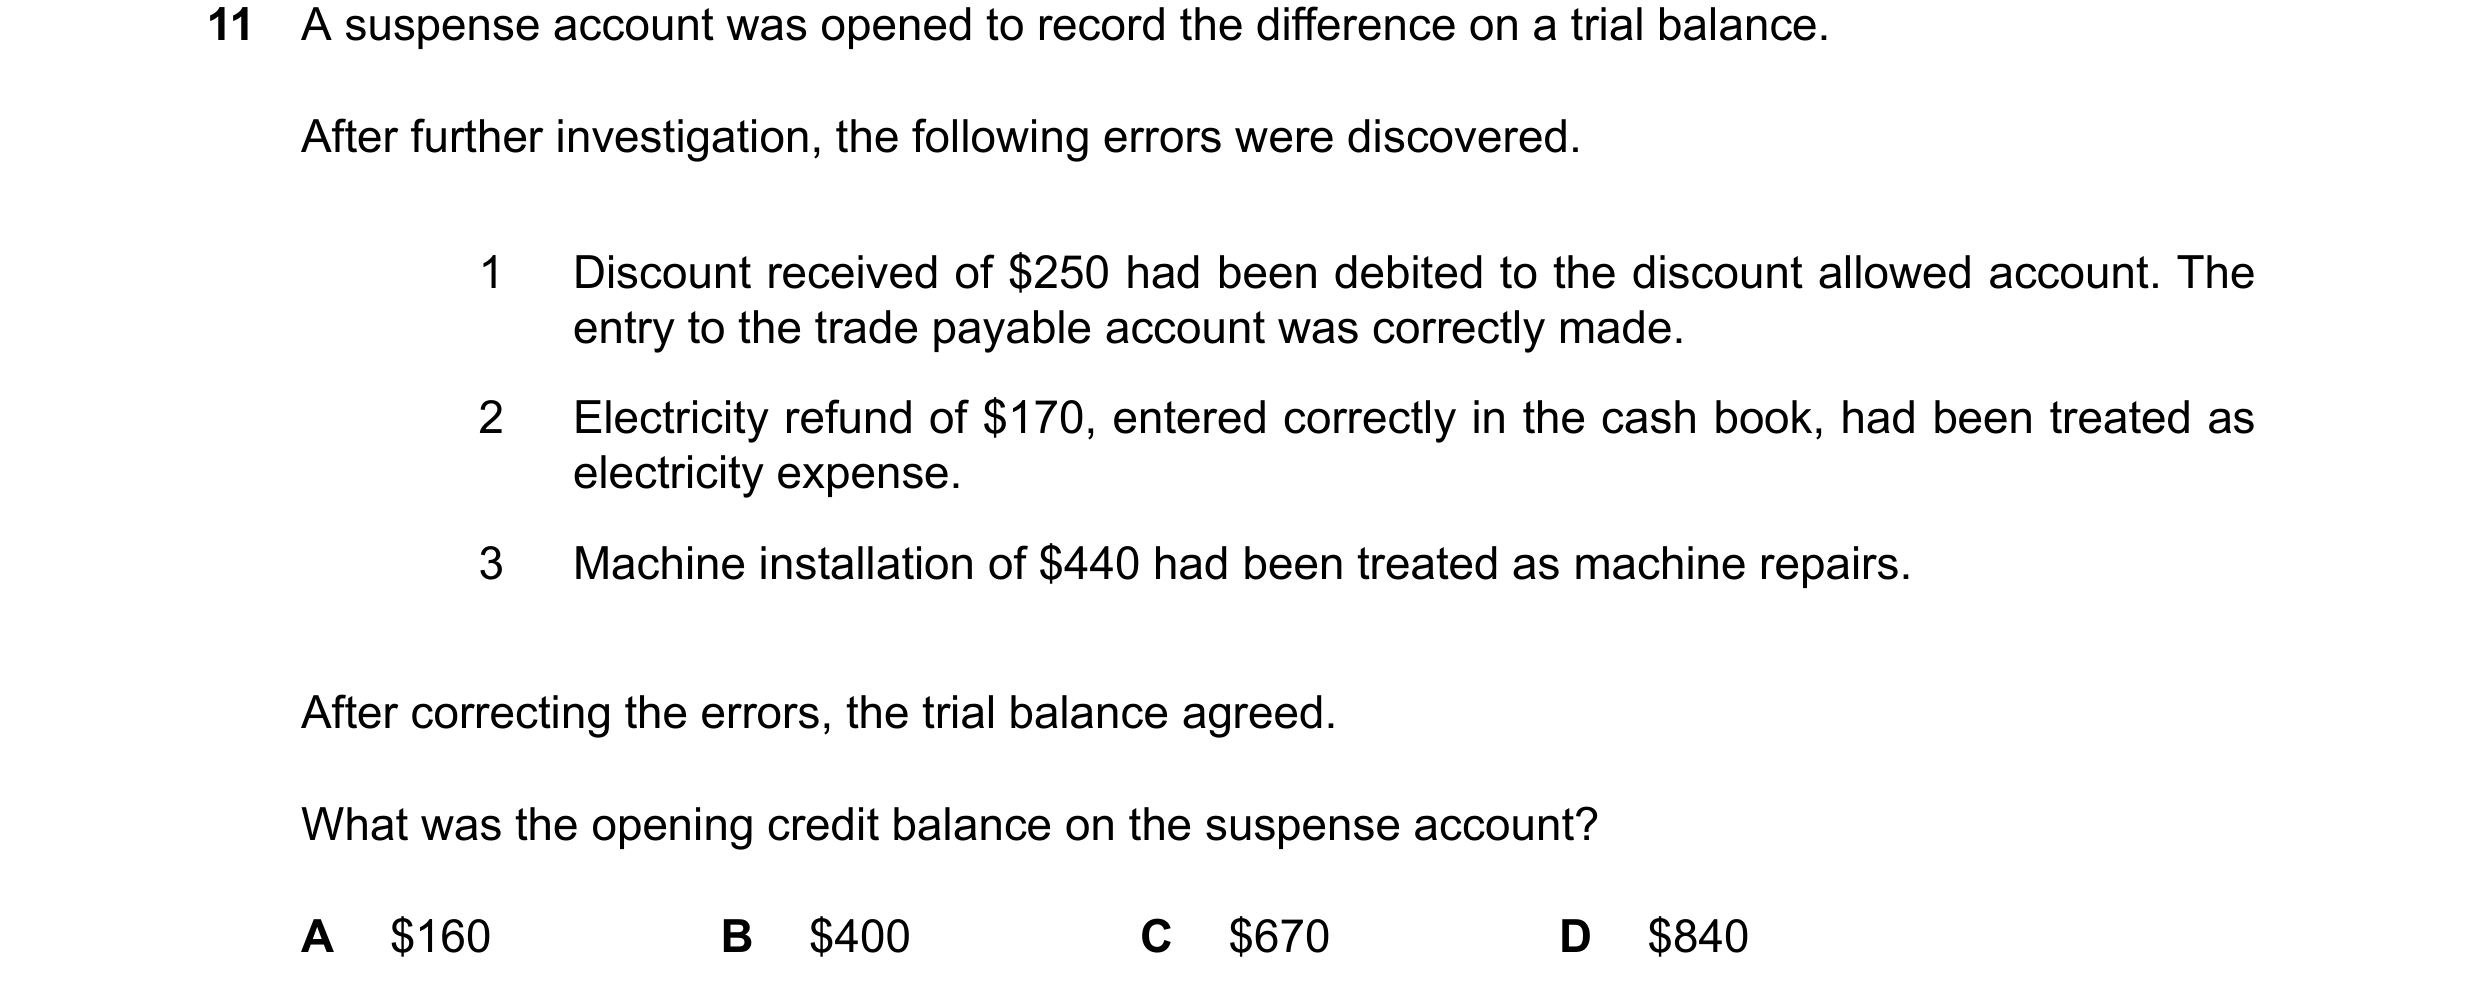
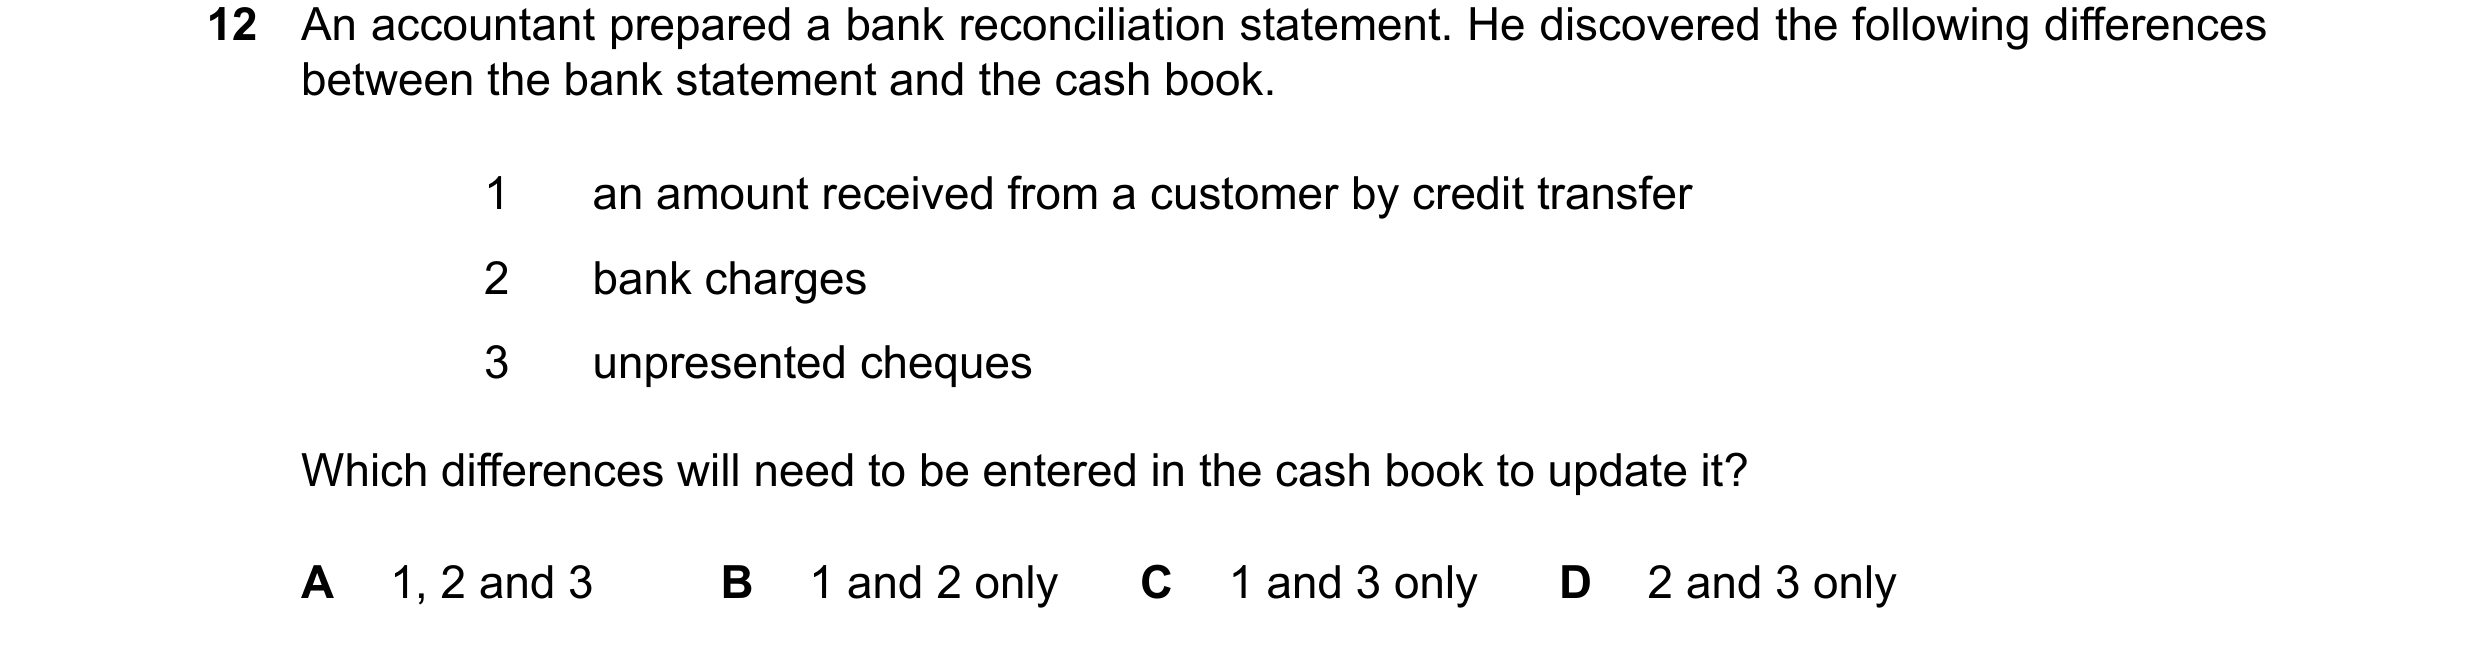
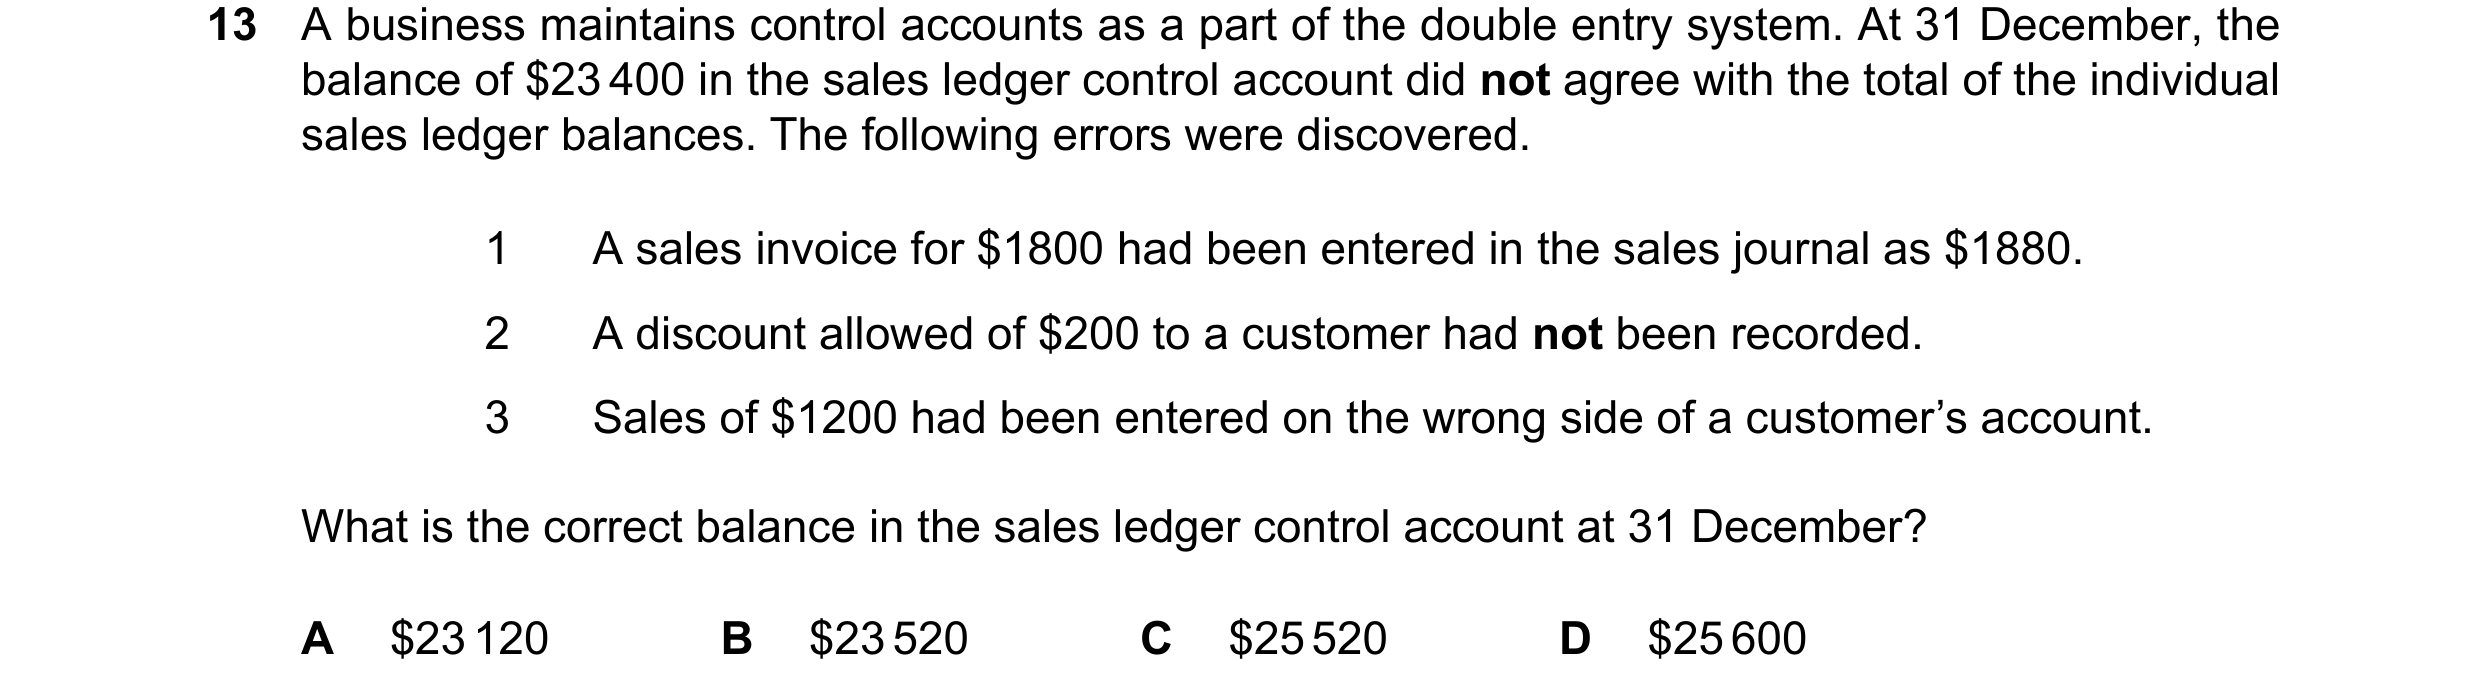 110 / 110