Questions as text
Q1 · The following balances appear in the internal accounts of a company 9706/32 Oct/Nov 2009
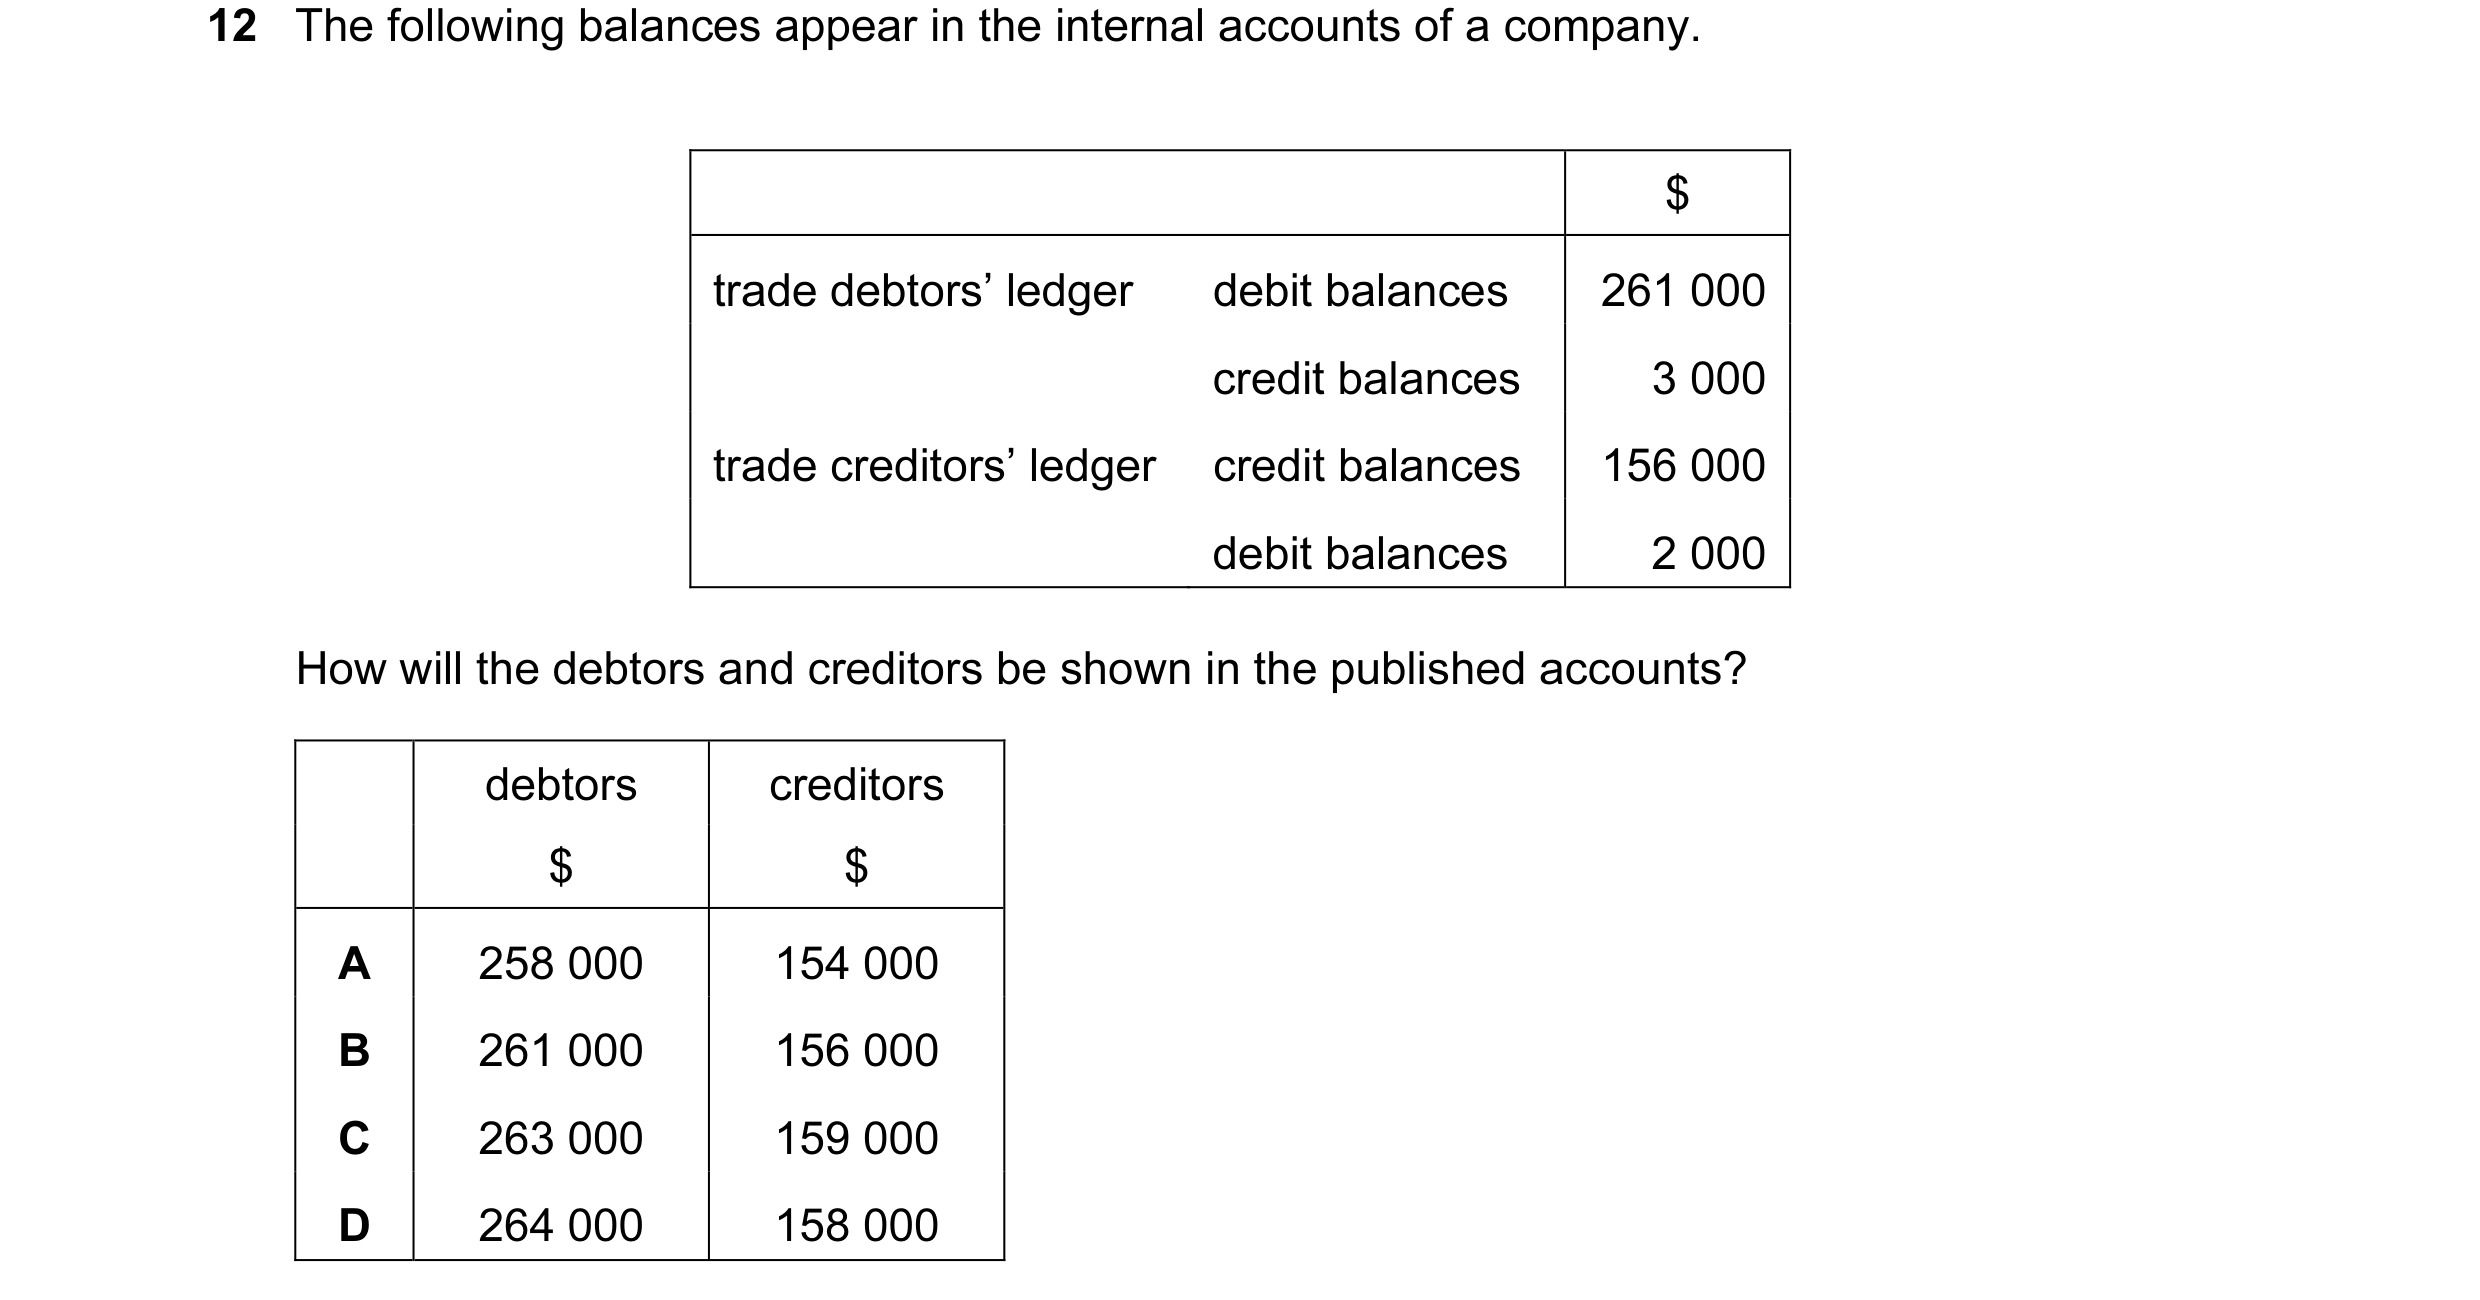
12 The following balances appear in the internal accounts of a company. $ trade debtors’ ledger debit balances 261 000 credit balances 3 000 trade creditors’ ledger credit balances 156 000 debit balances 2 000 How will the debtors and creditors be shown in the published accounts? debtors creditors $ $ A 258 000 154 000 B 261 000 156 000 C 263 000 159 000 D 264 000 158 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2009
Q2 · Which increases the net cash inflow from operating activities? 9706/33 May/June 2010
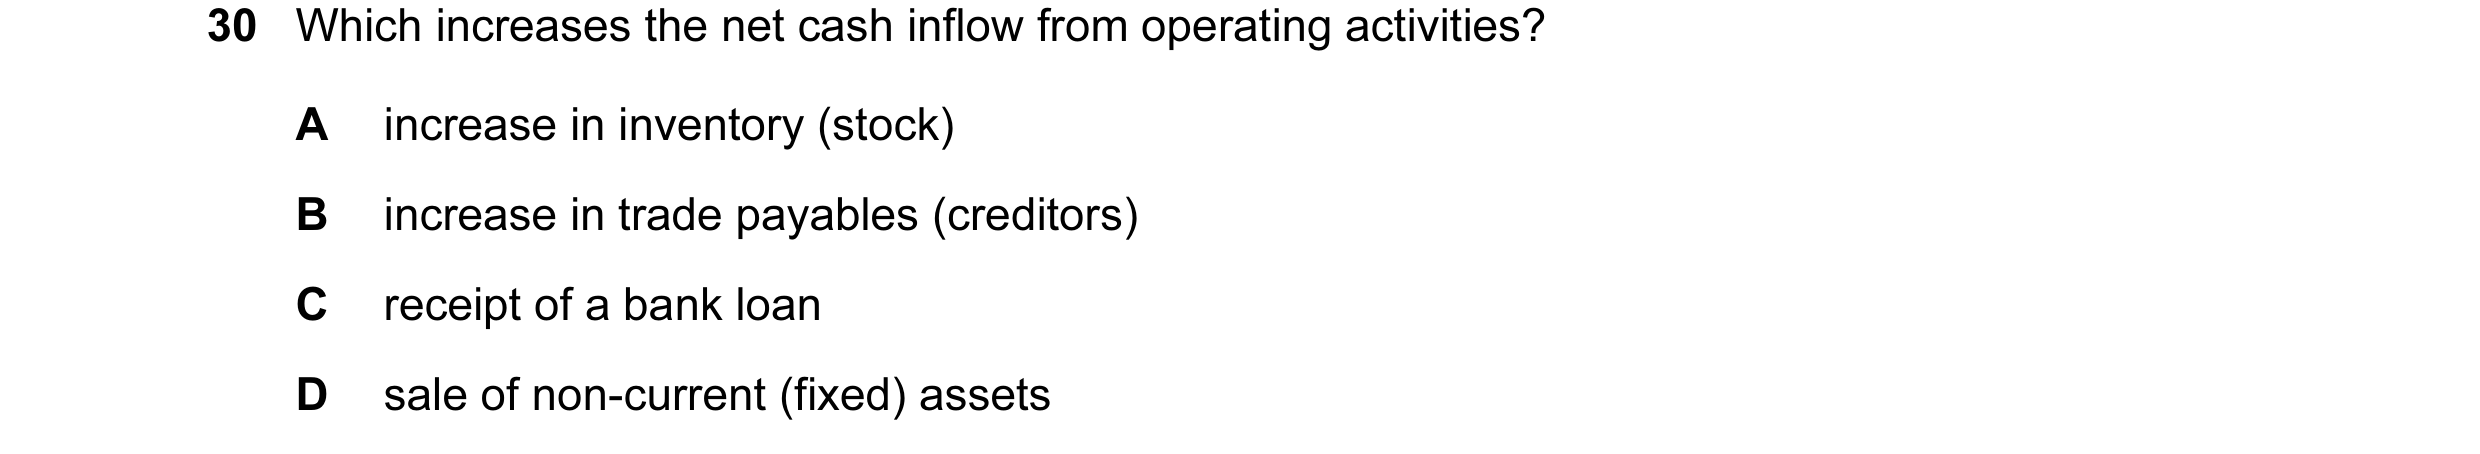
30 Which increases the net cash inflow from operating activities? A increase in inventory (stock) B increase in trade payables (creditors) C receipt of a bank loan D sale of non-current (fixed) assets
1 marks
Answer: B
This question in 9706/33 May/June 2010
Q3 · A company prepares internal accounts as follows 9706/31 Oct/Nov 2010
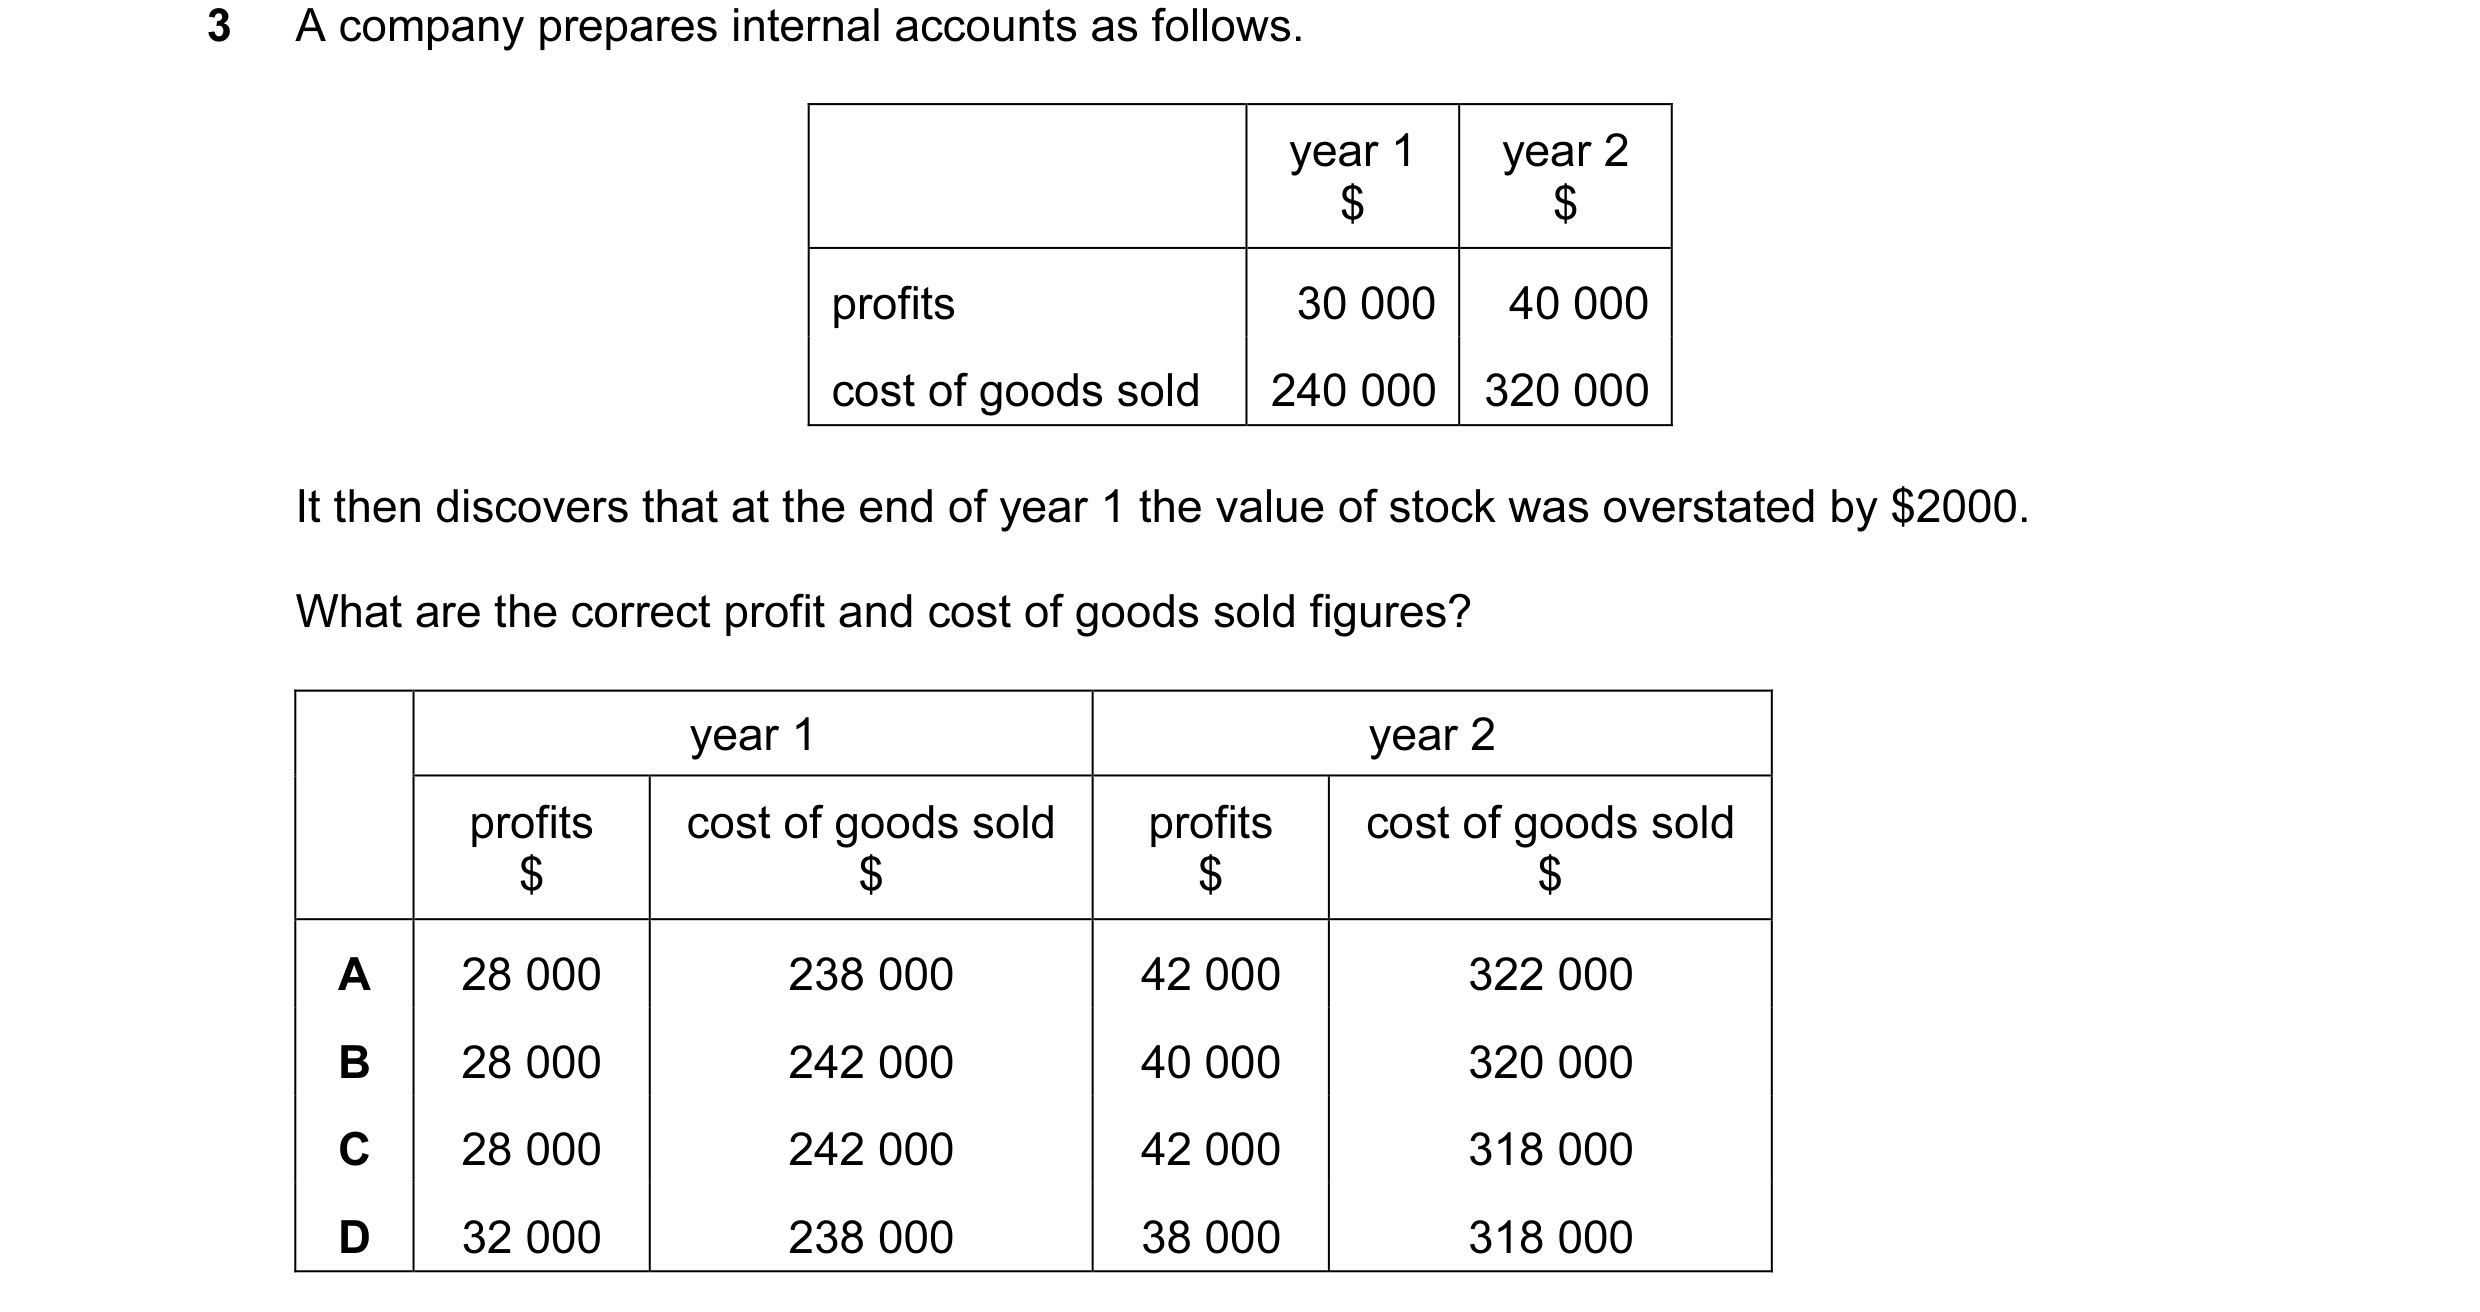
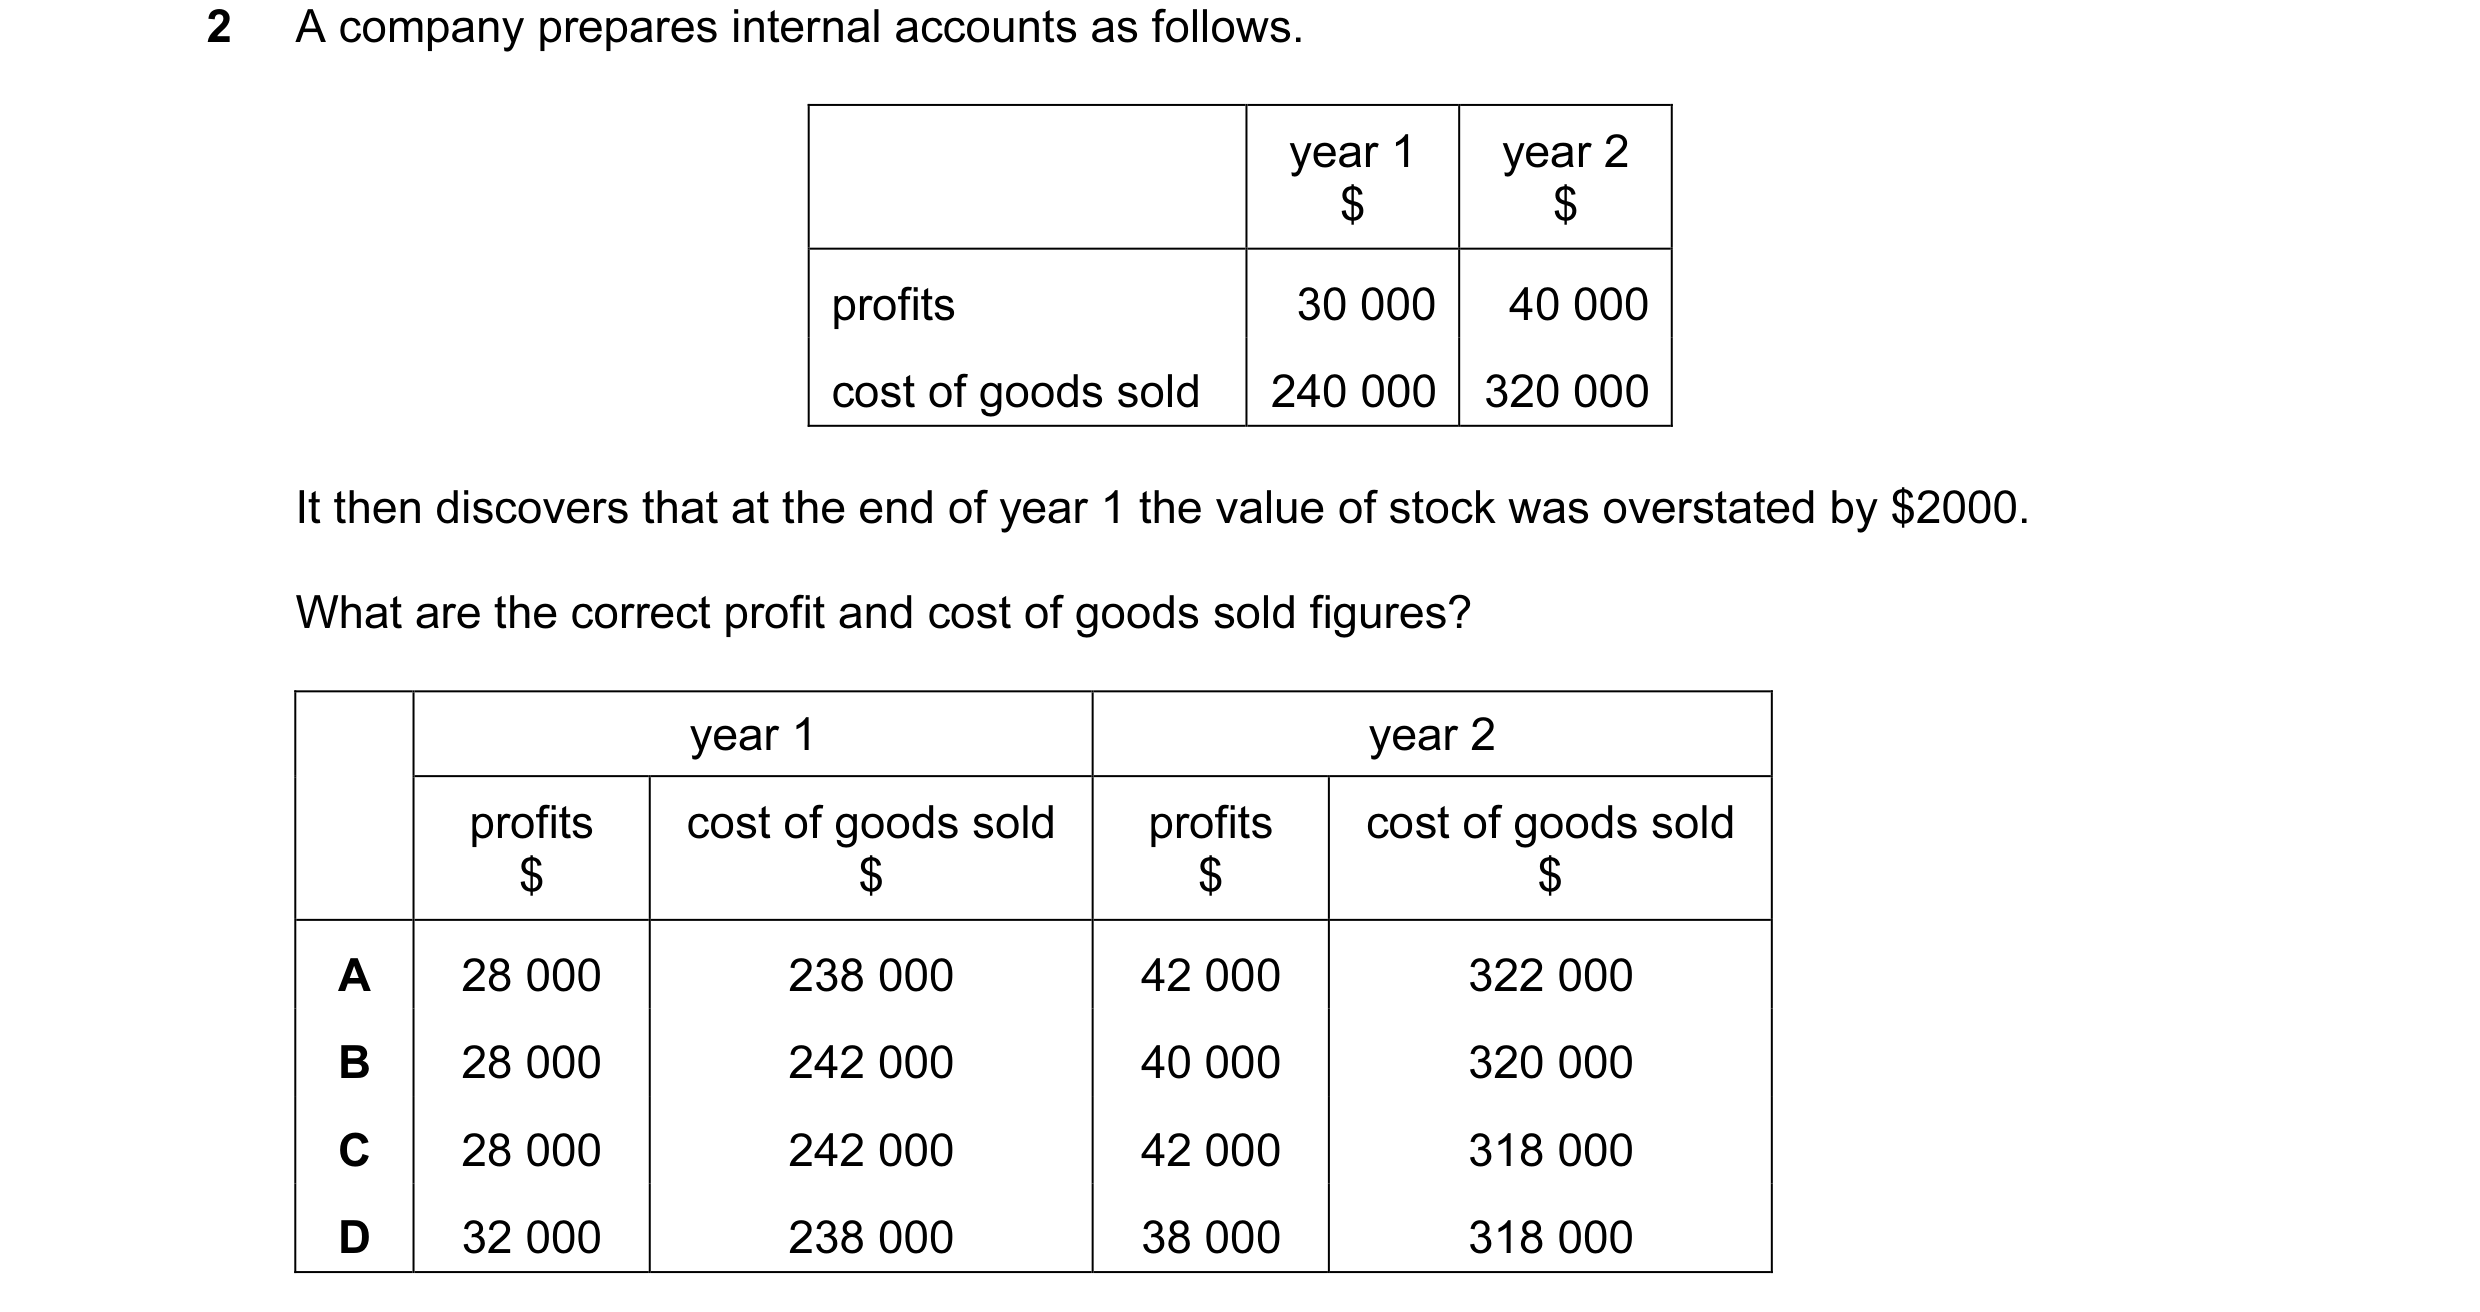
3 A company prepares internal accounts as follows. year 1 year 2 $ $ profits 30 000 40 000 cost of goods sold 240 000 320 000 It then discovers that at the end of year 1 the value of stock was overstated by $2000. What are the correct profit and cost of goods sold figures? year 1 year 2 profits cost of goods sold profits cost of goods sold $ $ $ $ A 28 000 238 000 42 000 322 000 B 28 000 242 000 40 000 320 000 C 28 000 242 000 42 000 318 000 D 32 000 238 000 38 000 318 000
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2010
Q4 · A company prepares internal accounts as follows 9706/32 Oct/Nov 2010
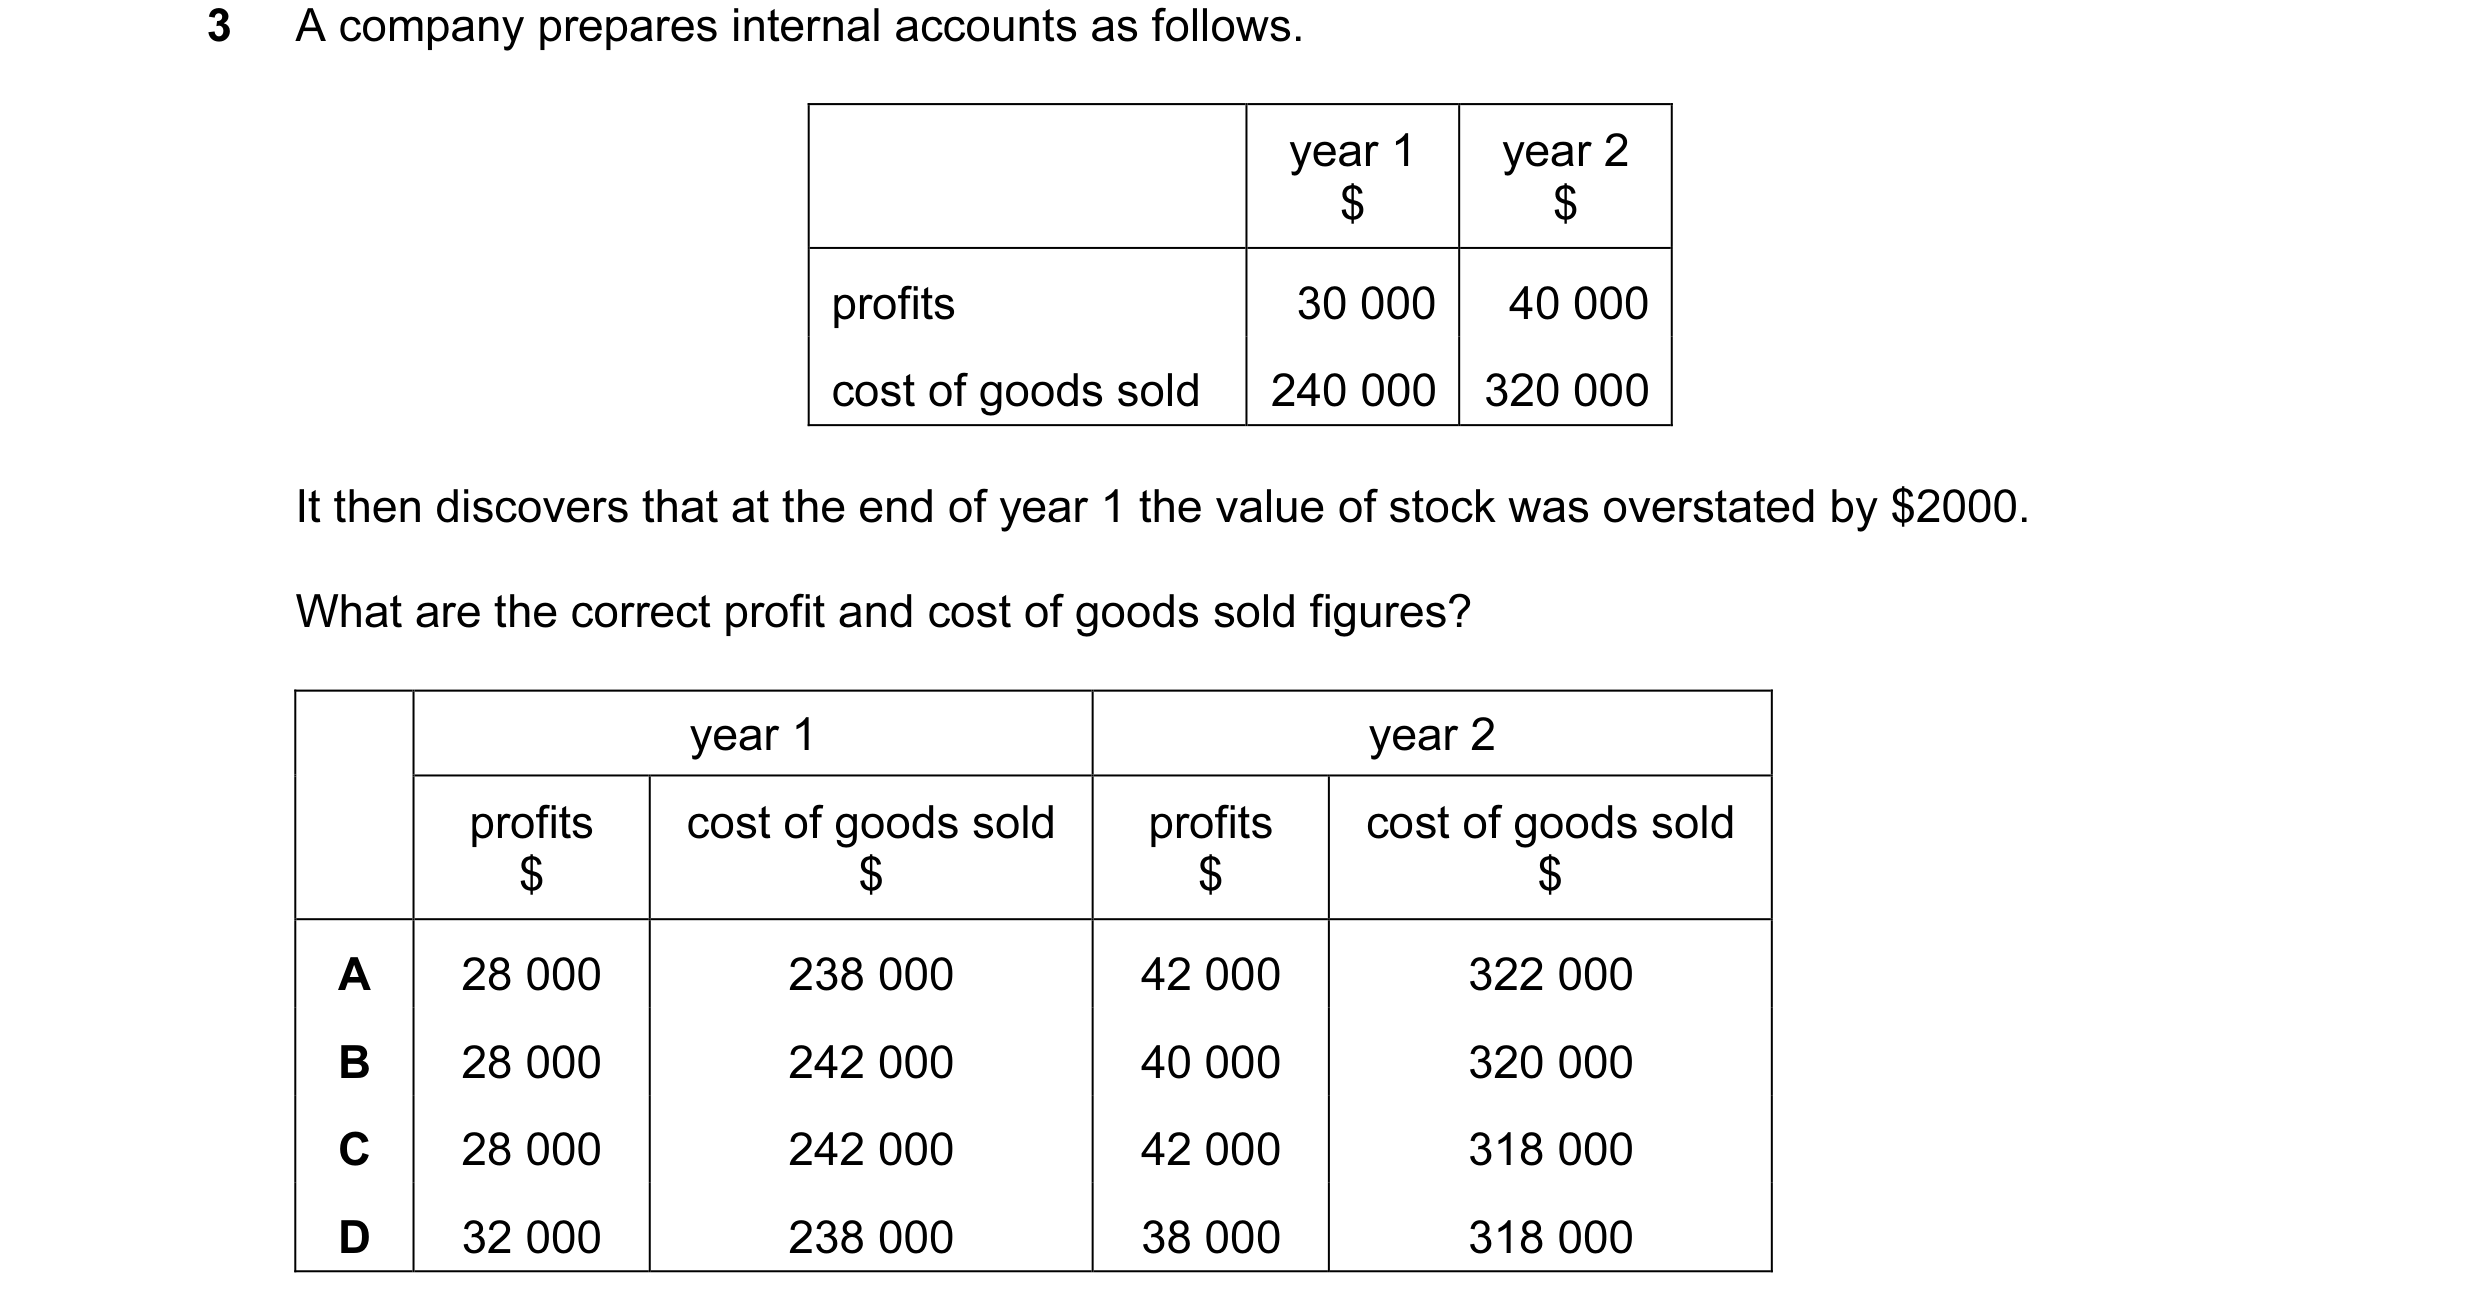
3 A company prepares internal accounts as follows. year 1 year 2 $ $ profits 30 000 40 000 cost of goods sold 240 000 320 000 It then discovers that at the end of year 1 the value of stock was overstated by $2000. What are the correct profit and cost of goods sold figures? year 1 year 2 profits cost of goods sold profits cost of goods sold $ $ $ $ A 28 000 238 000 42 000 322 000 B 28 000 242 000 40 000 320 000 C 28 000 242 000 42 000 318 000 D 32 000 238 000 38 000 318 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2010
Q5 · A company prepares internal accounts as follows 9706/33 Oct/Nov 2010
2 A company prepares internal accounts as follows. year 1 year 2 $ $ profits 30 000 40 000 cost of goods sold 240 000 320 000 It then discovers that at the end of year 1 the value of stock was overstated by $2000. What are the correct profit and cost of goods sold figures? year 1 year 2 profits cost of goods sold profits cost of goods sold $ $ $ $ A 28 000 238 000 42 000 322 000 B 28 000 242 000 40 000 320 000 C 28 000 242 000 42 000 318 000 D 32 000 238 000 38 000 318 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2010
Q6 · A market trader has not kept any books of account 9706/32 Oct/Nov 2013
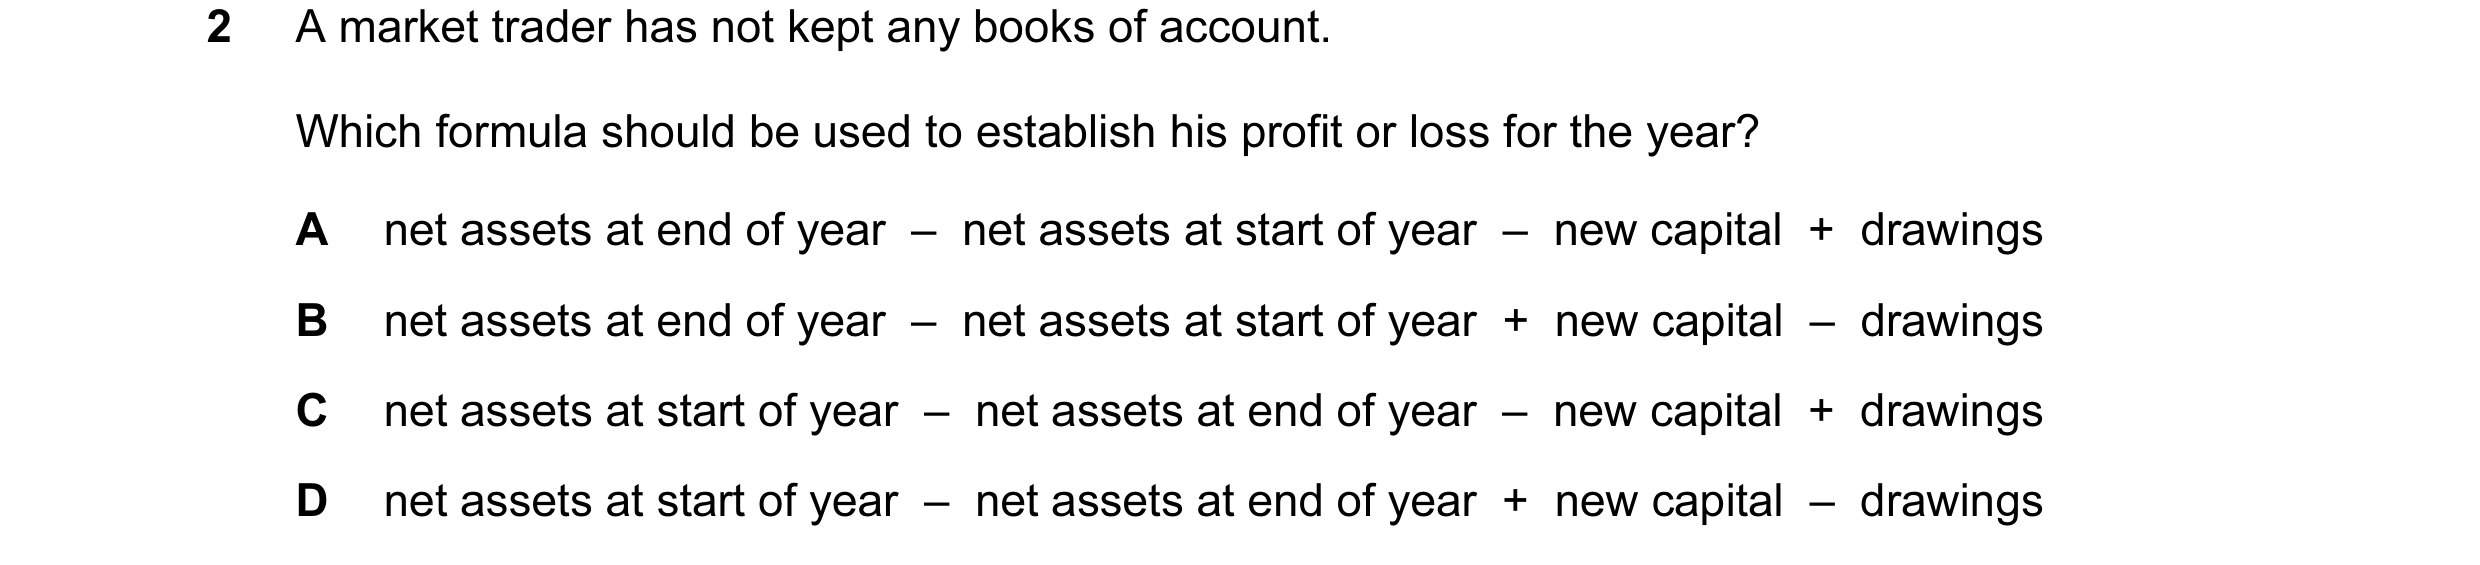
2 A market trader has not kept any books of account. Which formula should be used to establish his profit or loss for the year? A net assets at end of year – net assets at start of year – new capital + drawings B net assets at end of year – net assets at start of year + new capital – drawings C net assets at start of year – net assets at end of year – new capital + drawings D net assets at start of year – net assets at end of year + new capital – drawings
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2013
Q7 · A trade receivable’s balance of $720 has been set-off against the purchase ledger 9706/33 Oct/Nov 2013
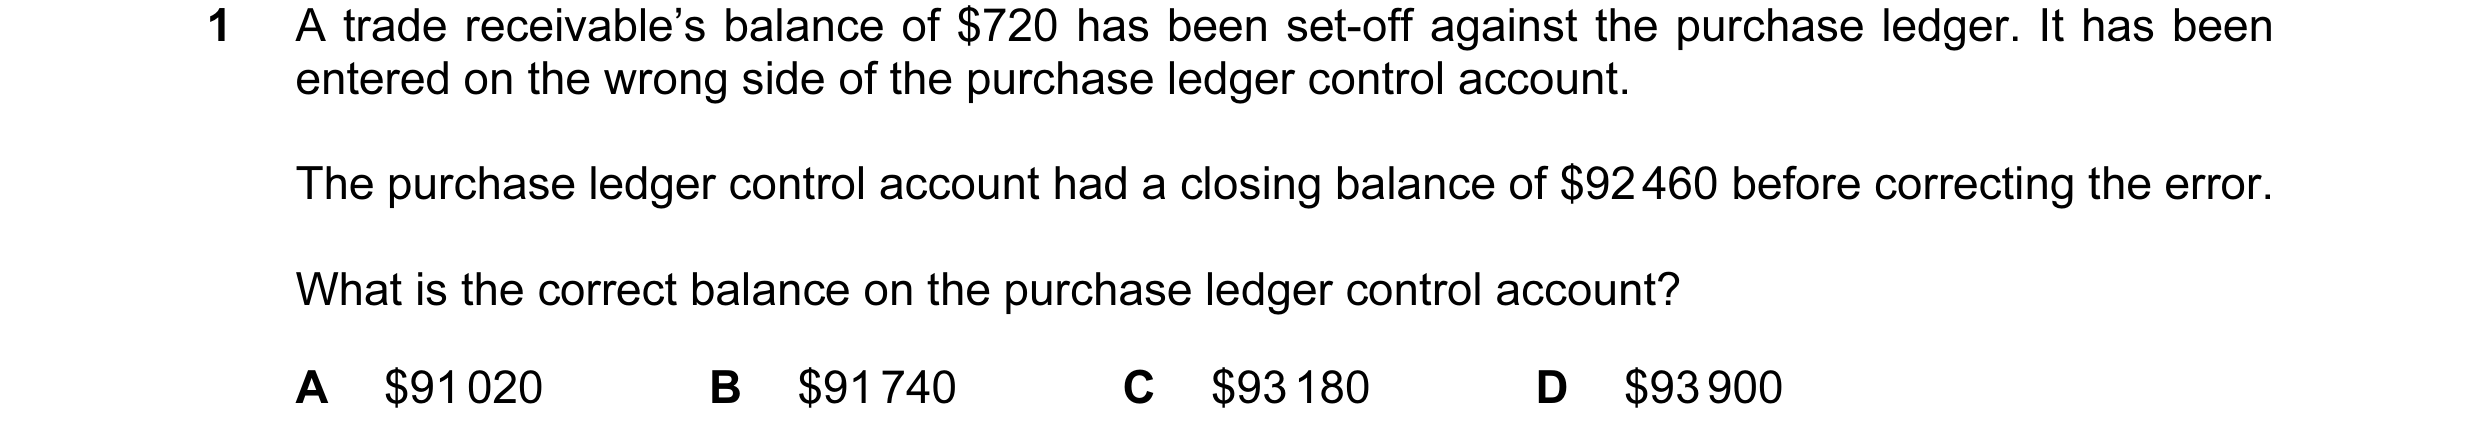
1 A trade receivable’s balance of $720 has been set-off against the purchase ledger. It has been entered on the wrong side of the purchase ledger control account. The purchase ledger control account had a closing balance of $92 460 before correcting the error. What is the correct balance on the purchase ledger control account? A $91 020 B $91 740 C $93 180 D $93 900
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2013
Q8 · The totals of the trial balance for a business were $536 300 debit and $519 800 credit 9706/33 May/June 2014
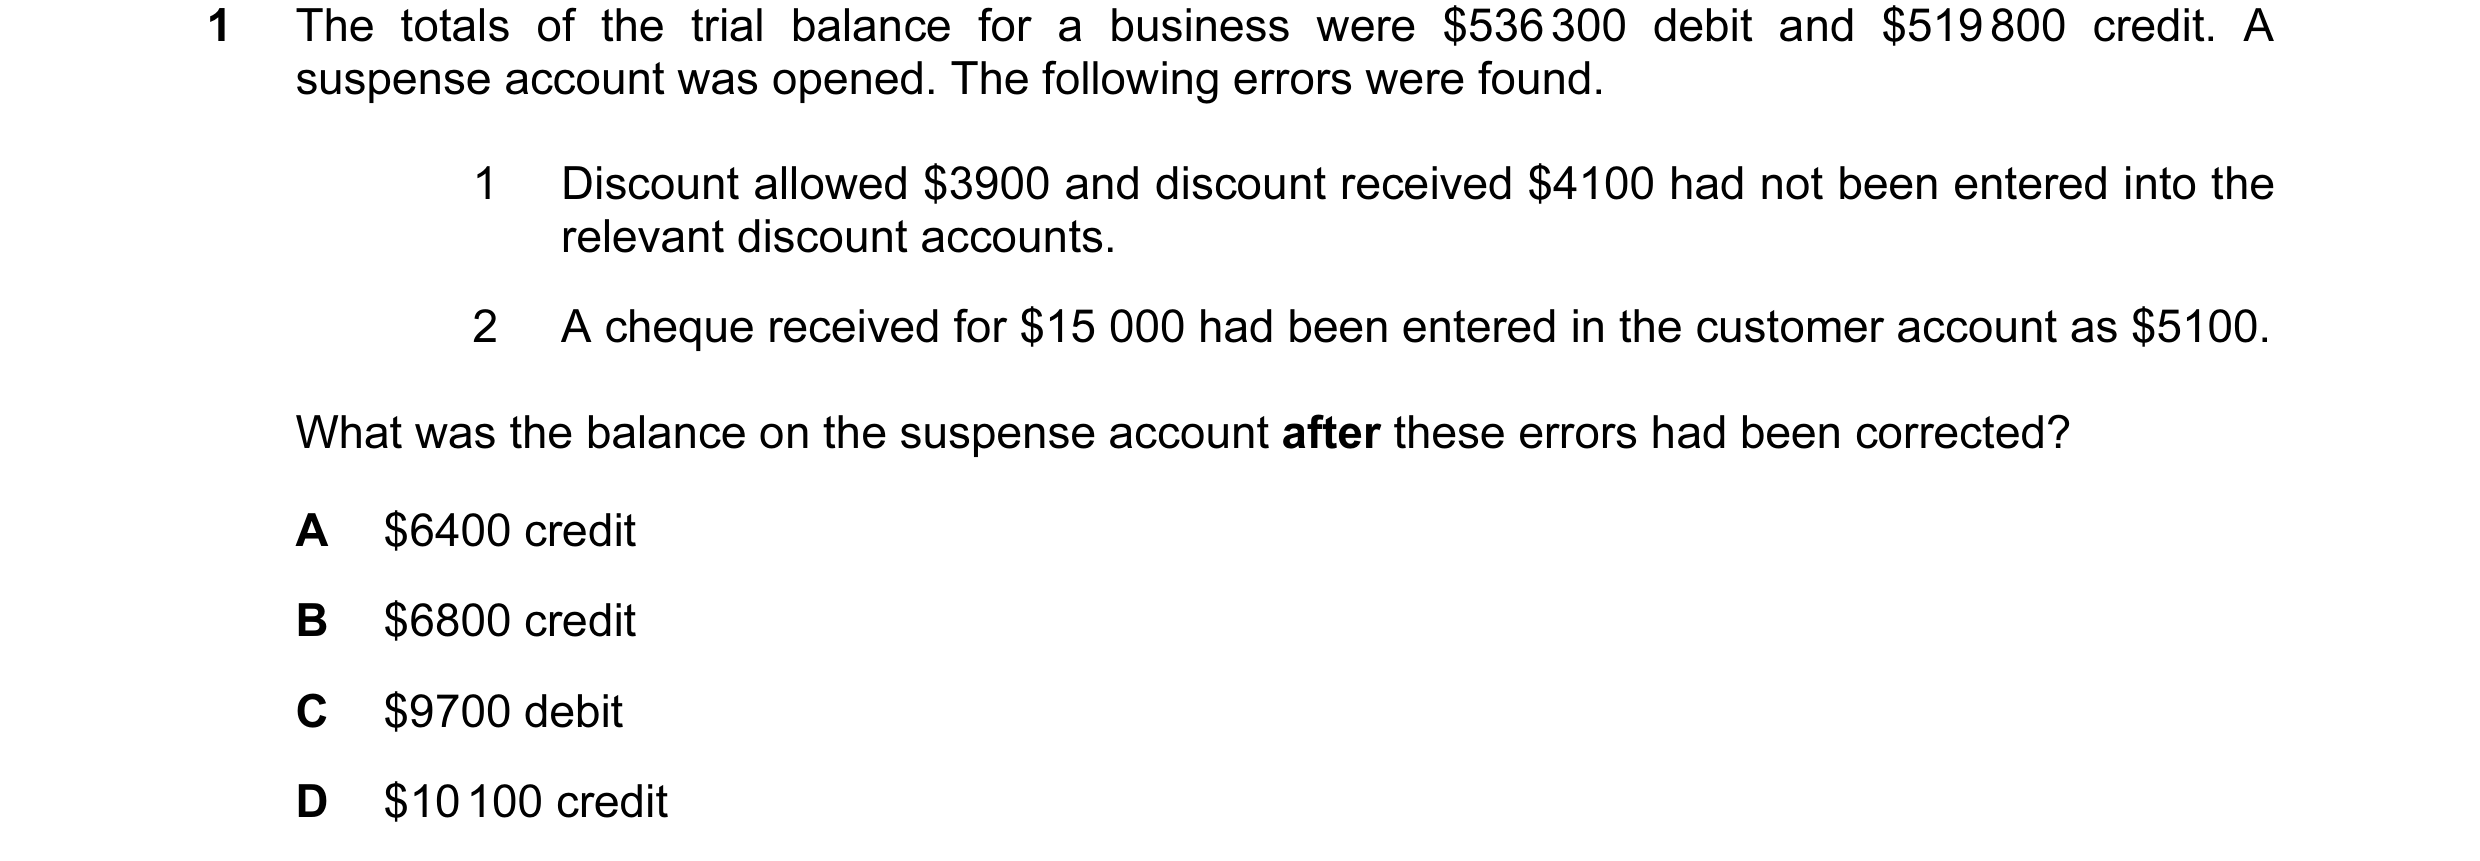
1 The totals of the trial balance for a business were $536 300 debit and $519 800 credit. A suspense account was opened. The following errors were found. 1 Discount allowed $3900 and discount received $4100 had not been entered into the relevant discount accounts. 2 A cheque received for $15 000 had been entered in the customer account as $5100. What was the balance on the suspense account after these errors had been corrected? A $6400 credit B $6800 credit C $9700 debit D $10 100 credit
1 marks
Answer: A
This question in 9706/33 May/June 2014
Q9 · A trial balance did not agree and a suspense account was opened 9706/31 Oct/Nov 2015
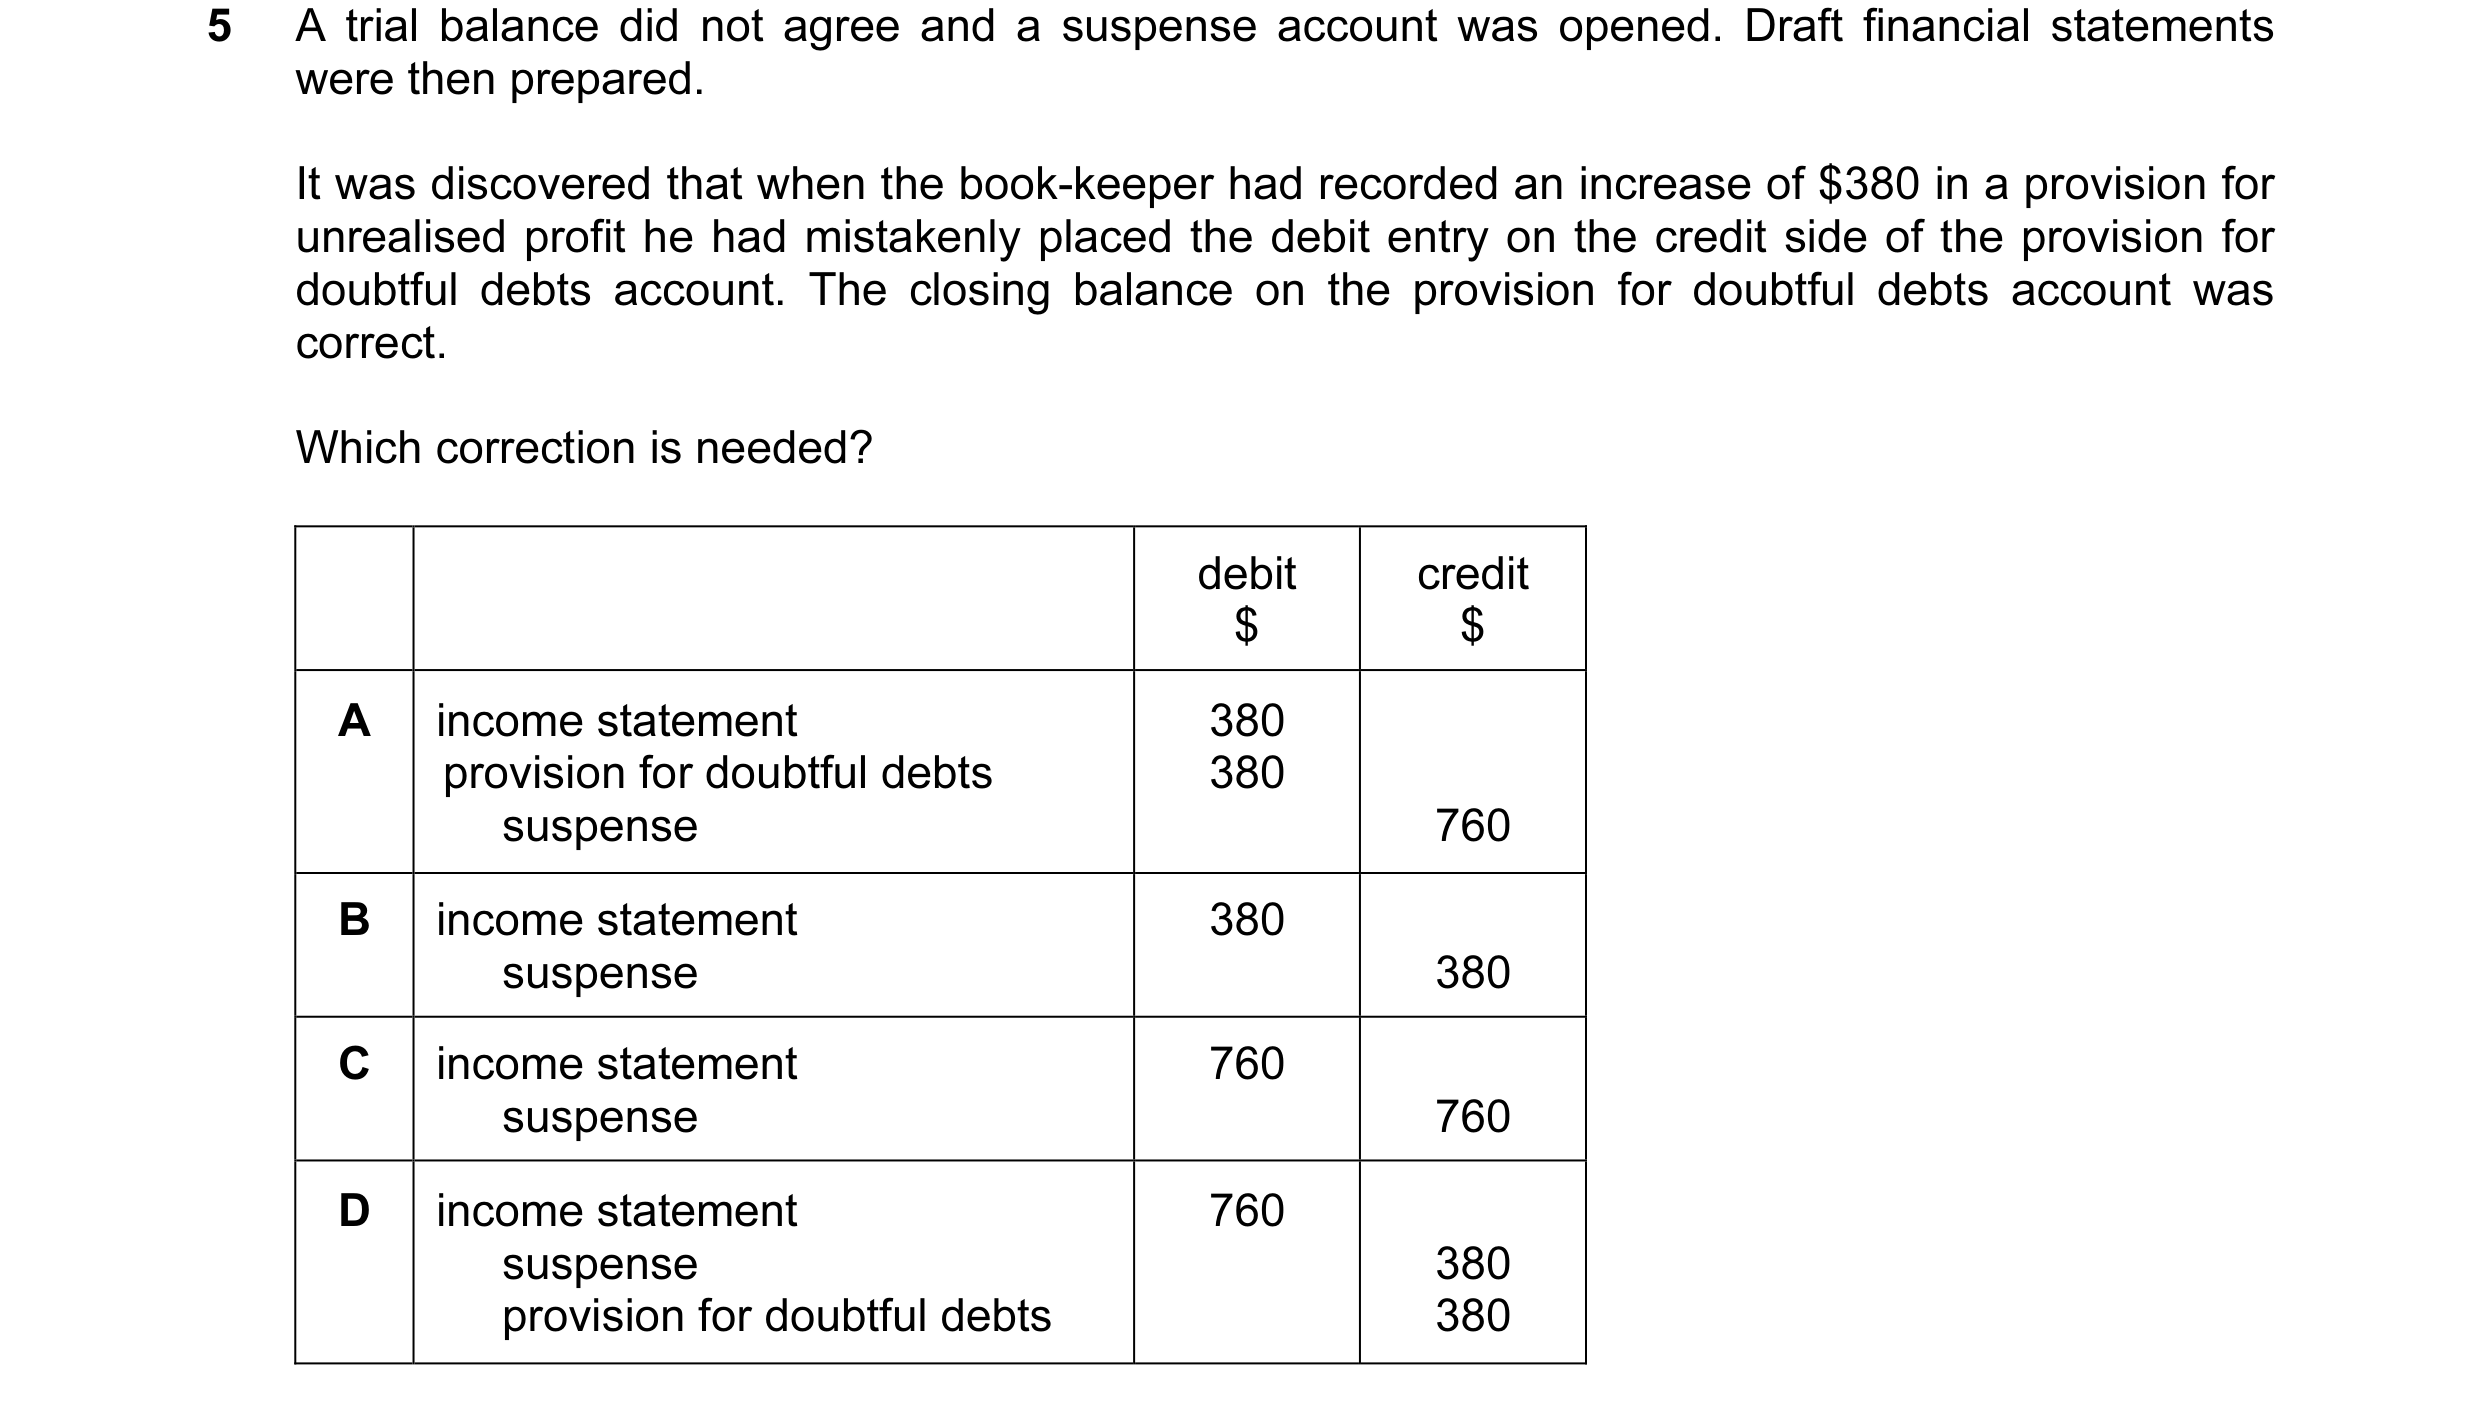
5 A trial balance did not agree and a suspense account was opened. Draft financial statements were then prepared. It was discovered that when the book-keeper had recorded an increase of $380 in a provision for unrealised profit he had mistakenly placed the debit entry on the credit side of the provision for doubtful debts account. The closing balance on the provision for doubtful debts account was correct. Which correction is needed? debit credit $ $ A income statement 380 provision for doubtful debts 380 suspense 760 B income statement 380 suspense 380 C income statement 760 suspense 760 D income statement 760 suspense 380 provision for doubtful debts 380
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2015
Q10 · Which error would result in a balance on a suspense account? 9706/32 Oct/Nov 2015
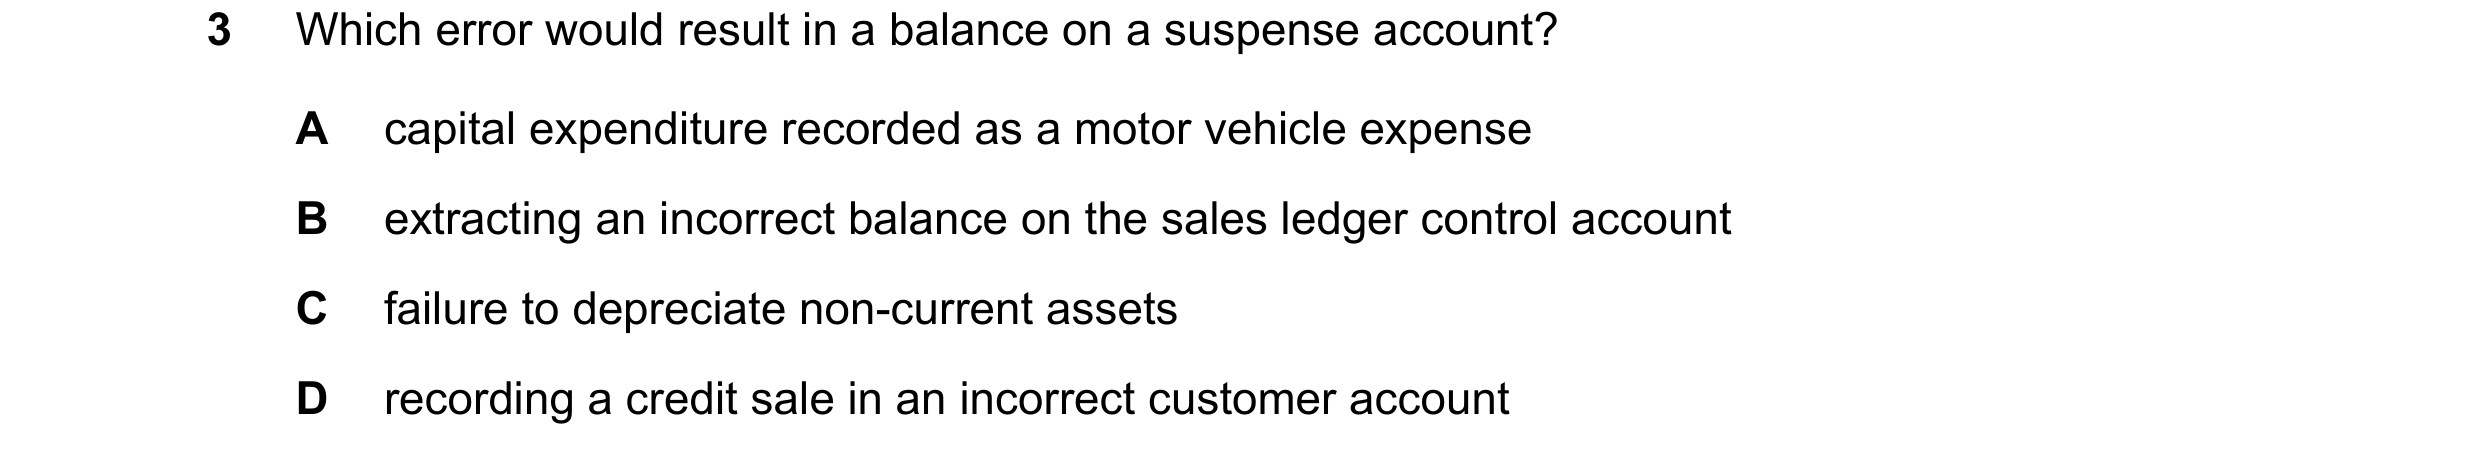
3 Which error would result in a balance on a suspense account? A capital expenditure recorded as a motor vehicle expense B extracting an incorrect balance on the sales ledger control account C failure to depreciate non-current assets D recording a credit sale in an incorrect customer account
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2015
 1 / 3
 2 / 3
 3 / 3