Questions as text
Q1 · The accounting year end of a business is 31 October 9706/11 May/June 2006
2 The accounting year end of a business is 31 October. On 1 April the business rents out part of its warehouse for an annual rent of $6000 receivable in equal instalments on 1 April, 1 July, 1 October and 1 January. At 31 October what would the final accounts show? Profit and Loss Account Balance Sheet $ $ A rental income 3500 current asset 1000 B rental income 3500 current liability 1000 C rental income 4500 current liability 1000 D rental income 6000 current asset 1500
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q2 · The following information is taken from the stationery account of a business 9706/11 May/June 2006
3 The following information is taken from the stationery account of a business. $ stock of stationery at beginning of the year 600 cash paid for stationery during the year 7000 invoice not yet received for stationery 480 stock of stationery at end of year 800 How much should be debited to the Profit and Loss Account for stationery? A $6680 B $6800 C $7280 D $8080
1 marks
Answer: C
This question in 9706/11 May/June 2006
Q3 · On 30 September 2005 a manufacturer’s current assets totalled $28 000 9706/11 May/June 2006
4 On 30 September 2005 a manufacturer’s current assets totalled $28 000. The next day only two transactions took place. 1 Stock bought for cash. The list price of $2000 was subject to a trade discount of 20 % and a cash discount of 5 %. Payment was made immediately. 2 A bad debt of $400 was written off. What was the total of current assets on 2 October 2005? A $27 680 B $28 080 C $29 520 D $29 600
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q4 · A business uses the straight line method to provide for depreciation of equipment 9706/11 May/June 2006
5 A business uses the straight line method to provide for depreciation of equipment. Why should it continue to use this method in subsequent years? A accounting principles never allow accounting methods to be changed B other methods of depreciation are unsuitable for depreciating equipment C to ensure that profits are stated on a consistent basis over time D to ensure that the Balance Sheet always shows the market value for equipment
1 marks
Answer: C
This question in 9706/11 May/June 2006
Q5 · Stock has been damaged 9706/11 May/June 2006
6 Stock has been damaged. The stock cost $1200. It would have sold for $1800 when perfect. It can be sold for $1700 if repairs are undertaken at a cost of $600. To replace the stock would cost $1000. At what value should the damaged stock be shown in the final accounts? A $1000 B $1100 C $1200 D $1800
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q6 · Which accounting policies illustrate the matching principle? 9706/11 May/June 2006
7 Which accounting policies illustrate the matching principle? 1 charging depreciation on fixed assets 2 revaluing fixed assets on a regular basis 3 using the reducing balance method of depreciation A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 2 and 3 only
1 marks
Answer: C
This question in 9706/11 May/June 2006
Q7 · The following information is extracted from the records of a business 9706/11 May/June 2006
8 The following information is extracted from the records of a business. $ At 31 December 2004: Rent paid in advance 4 000 During the year ended 31 December 2005: Rent paid 41 000 At 31 December 2005: Rent paid in advance 7 000 How much will be debited for rent in the Profit and Loss Account for the year ended 31 December 2005? A $34 000 B $38 000 C $41 000 D $44 000
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q8 · Stocks should be valued at the lower of cost and net realisable value 9706/11 May/June 2006
14 Stocks should be valued at the lower of cost and net realisable value. The table shows data about four products. W X Y Z product $ $ $ $ cost 18 19 17 23 realisable value 15 28 17 26 selling expenses 3 2 3 At how much should the total stocks be valued? A $72 B $77 C $78 D $86
1 marks
Answer: A
This question in 9706/11 May/June 2006
Q9 · At the end of a financial year the following information is available 9706/11 May/June 2006
16 At the end of a financial year the following information is available. $ sales 200 000 opening stock 15 000 closing stock 18 000 If the business makes a standard mark-up of 25 %, what were the purchases? A $147 000 B $153 000 C $157 000 D $163 000
1 marks
Answer: D
This question in 9706/11 May/June 2006
Q10 · A trader does not keep double-entry records 9706/11 May/June 2006
17 A trader does not keep double-entry records. At the beginning of a period, suppliers are owed $43 600. Payments of $197 320 were made in the period. Suppliers are owed $35 390 at the end of the period. What are the total purchases for the period? A $118 330 B $189 110 C $205 530 D $276 310
1 marks
Answer: B
This question in 9706/11 May/June 2006
Q11 · In the books of Y how could a credit entry of $500 in X’s account have arisen? 9706/11 Oct/Nov 2006
2 In the books of Y how could a credit entry of $500 in X’s account have arisen? A X bought goods from Y B X returned goods to Y C Y made a payment to X D Y returned goods to X
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2006
Q12 · A company’s net profit is $20 000 9706/11 Oct/Nov 2006
3 A company’s net profit is $20 000. Capital receipts of $5000 have been treated as revenue receipts. Capital expenditure of $4000 has been treated as revenue expenditure. What is the correct net profit figure? A $11 000 B $19 000 C $21 000 D $29 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2006
Q13 · A trader buys stock costing $6000 9706/11 Oct/Nov 2006
8 A trader buys stock costing $6000. He is entitled to trade discount at 10 % and cash discount of 5 %. On the same day he discovers that he can only sell the stock for $5000. Which amount should he record as the purchase price of the stock? A $5000 B $5130 C $5400 D $6000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2006
Q14 · A customer paid a deposit in advance for goods to be supplied at a later date 9706/11 May/June 2007
2 A customer paid a deposit in advance for goods to be supplied at a later date. How should this be recorded in the seller’s books? debit credit A cash customer B cash sales C customer prepayment D customer sales
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q15 · An item of stock originally cost $5000, but has deteriorated badly and is written down to… 9706/11 May/June 2007
5 An item of stock originally cost $5000, but has deteriorated badly and is written down to its estimated net realisable value of $2000. Which accounting principle has been applied? A consistency B materiality C prudence D substance over form
1 marks
Answer: C
This question in 9706/11 May/June 2007
Q16 · A company changes from the straight-line method of depreciation to the reducing balance… 9706/11 May/June 2007
6 A company changes from the straight-line method of depreciation to the reducing balance method. Which accounting principle has not been applied? A consistency B going concern C historic cost D materiality
1 marks
Answer: A
This question in 9706/11 May/June 2007
Q17 · Rent is paid by a business monthly in advance on the first day of each month 9706/11 May/June 2008
2 Rent is paid by a business monthly in advance on the first day of each month. The payments during this financial year have been as follows: – up to and including 1 June $500 per month – from 1 July thereafter $600 per month Which amount(s) will appear in the accounts for the year ended 31 October? profit and loss balance sheet expense A $6400 $600 prepayment B $6400 $600 accrual C $6400 - D $7000 -
1 marks
Answer: C
This question in 9706/11 May/June 2008
Q18 · A transport business owned by a sole proprietor purchases a motor vehicle 9706/11 May/June 2009
2 A transport business owned by a sole proprietor purchases a motor vehicle. This is charged to the Motor expenses account. What are the effects of this on the end-of-year balance sheet? A fixed assets understated current assets understated B fixed assets overstated current assets overstated C fixed assets overstated capital account overstated D fixed assets understated capital account understated
1 marks
Answer: D
This question in 9706/11 May/June 2009
Q19 · The following information is taken from the stationery account of a business 9706/11 May/June 2009
4 The following information is taken from the stationery account of a business. $ stock of stationery at beginning of the year 600 cash paid for stationery during the year 7000 amount owing for stationery at end of year 480 stock of stationery at end of year 800 How much should be debited to the profit and loss account for stationery? A $6680 B $6800 C $7280 D $8080
1 marks
Answer: C
This question in 9706/11 May/June 2009
Q20 · Development costs are capitalised 9706/11 May/June 2009
5 Development costs are capitalised. Which accounting principle is being applied? A business entity B historic cost C matching D materiality
1 marks
Answer: C
This question in 9706/11 May/June 2009
Q21 · In preparing the profit and loss account, only realised profits and not anticipated… 9706/11 May/June 2009
7 In preparing the profit and loss account, only realised profits and not anticipated profits must be brought into account. In addition, all possible losses must also be taken into account. Which accounting principle does this describe? A accruals B consistency C going concern D prudence
1 marks
Answer: D
This question in 9706/11 May/June 2009
Q22 · Who is most likely to use the creditors’ ledger? 9706/11 May/June 2009
10 Who is most likely to use the creditors’ ledger? A cashier B credit controller C creditors D purchases controller
1 marks
Answer: D
This question in 9706/11 May/June 2009
Q23 · A business sells some of its stock for $500 on credit to a customer 9706/11 May/June 2009
11 A business sells some of its stock for $500 on credit to a customer. The stock originally cost $600. What is the effect of this transaction on the balance sheet? current assets owner’s capital A decrease by $100 decrease by $100 B decrease by $100 increase by $100 C increase by $100 decrease by $100 D increase by $100 increase by $100
1 marks
Answer: A
This question in 9706/11 May/June 2009
Q24 · The accounting year end of a business is 31 October 9706/12 Oct/Nov 2009
1 The accounting year end of a business is 31 October. On 1 April the business rents out part of its warehouse for an annual rent of $6000. Payments were received in equal instalments on 1 April, 1 July, 1 October and 1 January. At 31 October what would the final accounts show? profit and loss account balance sheet $ $ A rental income 3500 current asset 1000 B rental income 3500 current liability 1000 C rental income 4500 current liability 1000 D rental income 6000 current asset 1500
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q25 · A business paid $15000 for electricity in the year 9706/12 Oct/Nov 2009
2 A business paid $15000 for electricity in the year. The opening prepayment was $1000 and the closing accrual was $2000. What was the charge for electricity for the year? A $15 000 B $16 000 C $17 000 D $18 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2009
Q26 · A business makes a provision for doubtful debts equal to 5 % of its debtors 9706/12 Oct/Nov 2009
3 A business makes a provision for doubtful debts equal to 5 % of its debtors. At 31 March 2008 the provision for doubtful debts was $850. At 31 March 2009 the debtors after the provision for doubtful debts were $17 100. How much is the increase in the provision for doubtful debts for the year ended 31 March 2009? A $45 B $50 C $850 D $900
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2009
Q27 · A business is separate from its owner 9706/12 Oct/Nov 2009
4 A business is separate from its owner. This results in only business transactions being recorded in the accounts. Which accounting principle applies? A business entity B materiality C money measurement D prudence
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2009
Q28 · At 31 March the balance sheet of a company included the following 9706/12 Oct/Nov 2009
5 At 31 March the balance sheet of a company included the following. $ trade debtors 23 000 provision for doubtful debts 1 200 During April credit sales were $64 000 and cash sales were $256 000. Credit customers paid $56 840 net of a 2 % cash discount. What will be the trade debtors at 30 April? A $27 800 B $28 960 C $29 000 D $30 160
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q29 · Which transaction would increase the current assets of a business? 9706/12 Oct/Nov 2009
18 Which transaction would increase the current assets of a business? A paying creditors $750 cash B purchasing a fixed asset on credit for $5000 C purchasing stock on credit for $1000 and selling immediately for $2000 cash D selling stock of $1000 at cost price on credit
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2009
Q30 · A business has a bank overdraft of $4800 9706/11 May/June 2010
3 A business has a bank overdraft of $4800. It pays for materials invoiced at $3000 less a trade discount of 20 % and a settlement discount of 5 %. A cheque for $500 is received from a debtor. What is the bank balance after these transactions? A $2020 overdraft B $6580 overdraft C $7150 overdraft D $7580 overdraft
1 marks
Answer: B
This question in 9706/11 May/June 2010
Q31 · Which of the following items will be debited to accounts in the purchases ledger? 9706/11 May/June 2010
4 Which of the following items will be debited to accounts in the purchases ledger? 1 discount allowed 2 payments to suppliers 3 purchases 4 purchases returns A 1 and 2 B 2 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: C
This question in 9706/11 May/June 2010
Q32 · A business has a bank overdraft of $4800 9706/12 May/June 2010
2 A business has a bank overdraft of $4800. It pays for materials invoiced at $3000 less a trade discount of 20 % and a settlement discount of 5 %. A cheque for $500 is received from a debtor. What is the bank balance after these transactions? A $2020 overdraft B $6580 overdraft C $7150 overdraft D $7580 overdraft
1 marks
Answer: B
This question in 9706/12 May/June 2010
Q33 · Which of the following items will be debited to accounts in the purchases ledger? 9706/12 May/June 2010
3 Which of the following items will be debited to accounts in the purchases ledger? 1 discount allowed 2 payments to suppliers 3 purchases 4 purchases returns A 1 and 2 B 2 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: C
This question in 9706/12 May/June 2010
Q34 · A business has a bank overdraft of $4800 9706/13 May/June 2010
1 A business has a bank overdraft of $4800. It pays for materials invoiced at $3000 less a trade discount of 20 % and a settlement discount of 5 %. A cheque for $500 is received from a debtor. What is the bank balance after these transactions? A $2020 overdraft B $6580 overdraft C $7150 overdraft D $7580 overdraft
1 marks
Answer: B
This question in 9706/13 May/June 2010
Q35 · Which of the following items will be debited to accounts in the purchases ledger? 9706/13 May/June 2010
2 Which of the following items will be debited to accounts in the purchases ledger? 1 discount allowed 2 payments to suppliers 3 purchases 4 purchases returns A 1 and 2 B 2 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: C
This question in 9706/13 May/June 2010
Q36 · The personal spending of the owner of a business is not recognised as a business expense 9706/13 May/June 2010
3 The personal spending of the owner of a business is not recognised as a business expense. Which accounting principle is being applied? A business entity B consistency C money measurement D prudence
1 marks
Answer: A
This question in 9706/13 May/June 2010
Q37 · A business obtained a machine by means of a hire purchase agreement 9706/13 May/June 2010
4 A business obtained a machine by means of a hire purchase agreement. It showed the machine in its balance sheet at the cash price of $30 000 although only $10 000 has been repaid. Which accounting principle is involved? A accruals B materiality C prudence D substance over form
1 marks
Answer: D
This question in 9706/13 May/June 2010
Q38 · The table shows information from the books of a business at 30 April 2010 9706/13 May/June 2010
5 The table shows information from the books of a business at 30 April 2010. details $ credit sales invoiced during financial year 79 000 goods sent to customers on 28 April 2010 and invoiced 4 May 2010 6 100 goods sent to customers during April 2010 on sale or return basis but 8 300 not sold by 30 April 2010 What is the amount of sales for the year ended 30 April 2010? A $76 800 B $85 100 C $85 300 D $93 400
1 marks
Answer: B
This question in 9706/13 May/June 2010
Q39 · An item of capital expenditure has been incorrectly treated as revenue expenditure in the… 9706/13 May/June 2010
30 An item of capital expenditure has been incorrectly treated as revenue expenditure in the accounts of a business. What is the effect of this error on the accounts of the business? assets profit A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: D
This question in 9706/13 May/June 2010
Q40 · On 1 January 2009 a business had prepaid rent of $50 9706/11 Oct/Nov 2010
1 On 1 January 2009 a business had prepaid rent of $50. During 2009, three rent payments were made of $250 each. On 31 December 2009, the business still owes $200 rent on account for 2009. The business owner has charged the rent payments made during 2009 in his income (profit and loss) account. What is the effect on net profit? A $200 too high B $200 too low C $250 too high D $250 too low
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2010
Q41 · A customer paid a deposit in advance for goods to be supplied at a later date 9706/11 Oct/Nov 2010
2 A customer paid a deposit in advance for goods to be supplied at a later date. How should this be recorded in the seller’s books? debit credit A cash customer B cash sales C customer prepayment D customer sales
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2010
Q42 · What does the application of the accounting principle of consistency ensure? 9706/11 Oct/Nov 2010
4 What does the application of the accounting principle of consistency ensure? A that all losses are provided for B that assets are recorded at their actual cost C that financial statements are produced annually D that profits are calculated the same way each year
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2010
Q43 · At 30 June the balance sheet of a business includes the following 9706/11 Oct/Nov 2010
5 At 30 June the balance sheet of a business includes the following. $ trade receivables (debtors) 46 000 provision for doubtful debts 5 % 2 300 During July, sales of $350 000 were made of which 20 % were in cash. Credit customers paid $303 800 after deducting a 2 % cash discount. How much did the trade receivables (debtors) owe to the business at 31 July? A $15 200 B $16 000 C $22 200 D $76 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2010
Q44 · An electricity accrual of $375 was treated as a prepayment in preparing a trader’s income… 9706/11 Oct/Nov 2010
9 An electricity accrual of $375 was treated as a prepayment in preparing a trader’s income (profit and loss) account. What was the effect on profit? A overstated by $375 B overstated by $750 C understated by $375 D understated by $750
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2010
Q45 · At the end of a financial year the following information is available 9706/11 Oct/Nov 2010
10 At the end of a financial year the following information is available. $ sales 200 000 opening inventory (stock) 15 000 closing inventory (stock) 18 000 If the business makes a standard mark-up of 25 %, what were the purchases? A $147 000 B $153 000 C $157 000 D $163 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2010
Q46 · On 1 January 2009 a business had prepaid rent of $50 9706/12 Oct/Nov 2010
1 On 1 January 2009 a business had prepaid rent of $50. During 2009, three rent payments were made of $250 each. On 31 December 2009, the business still owes $200 rent on account for 2009. The business owner has charged the rent payments made during 2009 in his income (profit and loss) account. What is the effect on net profit? A $200 too high B $200 too low C $250 too high D $250 too low
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2010
Q47 · A customer paid a deposit in advance for goods to be supplied at a later date 9706/12 Oct/Nov 2010
2 A customer paid a deposit in advance for goods to be supplied at a later date. How should this be recorded in the seller’s books? debit credit A cash customer B cash sales C customer prepayment D customer sales
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2010
Q48 · At 30 June the balance sheet of a business includes the following 9706/12 Oct/Nov 2010
5 At 30 June the balance sheet of a business includes the following. $ trade receivables (debtors) 46 000 provision for doubtful debts 5 % 2 300 During July, sales of $350 000 were made of which 20 % were in cash. Credit customers paid $303 800 after deducting a 2 % cash discount. How much did the trade receivables (debtors) owe to the business at 31 July? A $15 200 B $16 000 C $22 200 D $76 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2010
Q49 · An electricity accrual of $375 was treated as a prepayment in preparing a trader’s income… 9706/12 Oct/Nov 2010
9 An electricity accrual of $375 was treated as a prepayment in preparing a trader’s income (profit and loss) account. What was the effect on profit? A overstated by $375 B overstated by $750 C understated by $375 D understated by $750
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2010
Q50 · A customer paid a deposit in advance for goods to be supplied at a later date 9706/13 Oct/Nov 2010
1 A customer paid a deposit in advance for goods to be supplied at a later date. How should this be recorded in the seller’s books? debit credit A cash customer B cash sales C customer prepayment D customer sales
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2010
Q51 · What does the application of the accounting principle of consistency ensure? 9706/13 Oct/Nov 2010
3 What does the application of the accounting principle of consistency ensure? A that all losses are provided for B that assets are recorded at their actual cost C that financial statements are produced annually D that profits are calculated the same way each year
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2010
Q52 · A business paid $10 000 for waste disposal in the year 9706/11 May/June 2011
1 A business paid $10 000 for waste disposal in the year. The opening prepayment was $1500 and the closing accrual was $2000. What was the charge for waste disposal for the year? A $6500 B $9500 C $10 500 D $13 500
1 marks
Answer: D
This question in 9706/11 May/June 2011
Q53 · Which transaction would increase the current assets of a business? 9706/11 May/June 2011
3 Which transaction would increase the current assets of a business? A paying invoices $950, after receiving $50 cash discount B purchasing a machine on credit for $1200 C purchasing inventory for $1100 cash and selling it on credit for $1500 D selling inventory with an original cost of $800 at below cost price
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q54 · Accountants prefer the commercial reality of a transaction to a strictly legal approach 9706/11 May/June 2011
5 Accountants prefer the commercial reality of a transaction to a strictly legal approach. Which accounting principle is being applied? A consistency B materiality C prudence D substance over form
1 marks
Answer: D
This question in 9706/11 May/June 2011
Q55 · There is great uncertainty about the continuance of a business 9706/11 May/June 2011
6 There is great uncertainty about the continuance of a business. This has caused the proprietor to make a large reduction in the valuation of the year-end inventory. Which accounting principle does this illustrate? A going concern B matching C materiality D substance over form
1 marks
Answer: A
This question in 9706/11 May/June 2011
Q56 · Closing inventory has been overvalued 9706/11 May/June 2011
8 Closing inventory has been overvalued. What is the effect on the financial statements? net current assets profit from operations A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/11 May/June 2011
Q57 · At the year end a company discovers that some inventory is damaged 9706/11 May/June 2011
13 At the year end a company discovers that some inventory is damaged. This inventory originally cost $2000 and to replace it would now cost $1900. It would normally sell for $2400 but can now only be sold for $2200 if repairs costing $400 are undertaken. At what value should the damaged inventory be shown in the financial statements? A $1800 B $1900 C $2000 D $2200
1 marks
Answer: A
This question in 9706/11 May/June 2011
Q58 · A club charges each of its 100 members an annual subscription of $12 9706/11 May/June 2011
14 A club charges each of its 100 members an annual subscription of $12. At the end of a year four members had not paid their annual subscription. What will be the entries in the financial statements for subscriptions? income and expenditure account balance sheet $ A 1152 current asset $48 B 1152 current liability $48 C 1200 current asset $48 D 1200 current liability $48
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q59 · A business paid $10 000 for waste disposal in the year 9706/12 May/June 2011
10 A business paid $10 000 for waste disposal in the year. The opening prepayment was $1500 and the closing accrual was $2000. What was the charge for waste disposal for the year? A $6500 B $9500 C $10 500 D $13 500
1 marks
Answer: D
This question in 9706/12 May/June 2011
Q60 · Which transaction would increase the current assets of a business? 9706/12 May/June 2011
12 Which transaction would increase the current assets of a business? A paying invoices $950, after receiving $50 cash discount B purchasing a machine on credit for $1200 C purchasing inventory for $1100 cash and selling it on credit for $1500 D selling inventory with an original cost of $800 at below cost price
1 marks
Answer: C
This question in 9706/12 May/June 2011
Q61 · A business paid $10 000 for waste disposal in the year 9706/13 May/June 2011
2 A business paid $10 000 for waste disposal in the year. The opening prepayment was $1500 and the closing accrual was $2000. What was the charge for waste disposal for the year? A $6500 B $9500 C $10 500 D $13 500
1 marks
Answer: D
This question in 9706/13 May/June 2011
Q62 · Which transaction would increase the current assets of a business? 9706/13 May/June 2011
4 Which transaction would increase the current assets of a business? A paying invoices $950, after receiving $50 cash discount B purchasing a machine on credit for $1200 C purchasing inventory for $1100 cash and selling it on credit for $1500 D selling inventory with an original cost of $800 at below cost price
1 marks
Answer: C
This question in 9706/13 May/June 2011
Q63 · A company values its loose tools for inclusion in its balance sheet 9706/12 Oct/Nov 2011
6 A company values its loose tools for inclusion in its balance sheet. The tools are not very valuable and the company uses estimating when valuing them. Which accounting principle is being applied? A accruals B consistency C going concern D materiality
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2011
Q64 · Which statement is correct? 9706/11 May/June 2012
2 Which statement is correct? A Carriage inwards is a credit. B Carriage outwards is a debit. C Purchase returns is a debit. D Sales returns is a credit.
1 marks
Answer: B
This question in 9706/11 May/June 2012
Q65 · Which statement is correct? 9706/12 May/June 2012
1 Which statement is correct? A Carriage inwards is a credit. B Carriage outwards is a debit. C Purchase returns is a debit. D Sales returns is a credit.
1 marks
Answer: B
This question in 9706/12 May/June 2012
Q66 · The table shows opening and closing balances for the rent receivable account 9706/12 May/June 2012
2 The table shows opening and closing balances for the rent receivable account. start of year end of year $ $ rent received in advance 4200 1600 rent due in arrears 2000 2400 During the year, $111 000 rental income was received. What is the total rent receivable for the year? A $110 600 B $111 000 C $113 200 D $114 000
1 marks
Answer: D
This question in 9706/12 May/June 2012
Q67 · A business buys a machine on hire purchase for $50 000 9706/12 May/June 2012
4 A business buys a machine on hire purchase for $50 000. Although it will not own the machine until it has paid the final instalment, it has made the following entries: debit credit Machinery account $50 000 Bank account $5 000 Finance company account $45 000 Which accounting principle has been applied? A going concern B matching C prudence D substance over form
1 marks
Answer: D
This question in 9706/12 May/June 2012
Q68 · A sole trader owns a vehicle valued at $4000 for his own use and a vehicle valued at… 9706/12 May/June 2012
5 A sole trader owns a vehicle valued at $4000 for his own use and a vehicle valued at $2500 for business use. On 1 April 2012 he sold the business vehicle. On the same date he bought a new vehicle for $8000 for his own use and transferred his old vehicle to the business. What is the change in the value of vehicles in the business accounts? A $1500 B $4000 C $5500 D $6500
1 marks
Answer: A
This question in 9706/12 May/June 2012
Q69 · Which accounting principle means that a company’s financial statements are comparable… 9706/12 May/June 2012
6 Which accounting principle means that a company’s financial statements are comparable from one period to the next? A accruals B consistency C going concern D materiality
1 marks
Answer: B
This question in 9706/12 May/June 2012
Q70 · The inventory records of a business show the following information for product X 9706/12 May/June 2012
14 The inventory records of a business show the following information for product X. cost per unit units $ 1 January opening balance 100 3 3 January receipts into inventory 50 4 8 January inventory issued 120 – What is the value of the inventory issued on 8 January using the first in first out (FIFO) method? A $360 B $380 C $410 D $420
1 marks
Answer: B
This question in 9706/12 May/June 2012
Q71 · A business makes up its financial statements to 30 April each year 9706/11 Oct/Nov 2012
1 A business makes up its financial statements to 30 April each year. Included in the ledger account balances on 1 May 2011 was insurance (debit) $800. On 31 October 2011 an insurance premium of $2100 was paid for the year ending 31 October 2012. Which amount was charged for insurance in the income statement for the year ended 30 April 2012? A $1050 B $1850 C $2100 D $2900
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2012
Q72 · The dividends receivable account shows dividends of $7500 received during the year 9706/11 Oct/Nov 2012
3 The dividends receivable account shows dividends of $7500 received during the year. Dividends of $1200 are due at the year end. How will dividends be shown in the financial statements? statement of income statement $ $ financial position A credit 7500 other receivables 1200 B credit 8700 other receivables 1200 C debit 7500 other payables 1200 D debit 8700 other payables 1200
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2012
Q73 · A business has a good reputation 9706/11 Oct/Nov 2012
5 A business has a good reputation. The owner wishes to include goodwill in the financial statements. An accountant advises against it. Which accounting principle is the accountant applying? A business entity B going concern C matching D prudence
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2012
Q74 · What is an example of the substance over form concept? 9706/11 Oct/Nov 2012
7 What is an example of the substance over form concept? A accounting for assets on hire purchase B depreciating assets over their useful lives C using doubtful debt provisions D valuing inventory at the lower of cost and net realisable value
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2012
Q75 · A business sells a non-current asset for cash 9706/11 Oct/Nov 2012
17 A business sells a non-current asset for cash. The disposal account includes entries for the cost of the asset and the sales proceeds. Which books of prime entry are used? cost sales proceeds A cash book general journal B cash book sales journal C general journal cash book D purchases journal cash book
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2012
Q76 · Rent for premises is paid monthly in advance on the first day of each month 9706/12 Oct/Nov 2012
1 Rent for premises is paid monthly in advance on the first day of each month. The payments during the last financial year were as follows. up to and including 1 January $1000 per month from 1 February $1200 per month Which amount(s) will appear in the financial statements for the year ended 30 April? statement of income statement financial position A $12 400 – B $12 600 – C $12 600 $1200 accrual D $12 600 $1200 prepaid
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2012
Q77 · Which accounting principle attempts to deal with off-balance-sheet transactions? 9706/12 Oct/Nov 2012
5 Which accounting principle attempts to deal with off-balance-sheet transactions? A consistency B going concern C prudence D substance over form
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2012
Q78 · Draft financial statements show revenue of $106 000 and closing inventory of $2100 9706/12 Oct/Nov 2012
6 Draft financial statements show revenue of $106 000 and closing inventory of $2100. There were 100 items which had cost $10 an item but which were for sale at $6 an item. At the year end these were with a customer on a sale or return basis. These items were treated as having been sold although no sale had been agreed. What are the values of revenue and inventory when the principle of prudence is applied? revenue inventory $ $ A 105 000 2700 B 105 000 3100 C 105 400 2700 D 105 400 3100
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2012
Q79 · Inventory is valued at the lower of cost and net realisable value 9706/12 Oct/Nov 2012
7 Inventory is valued at the lower of cost and net realisable value. Which accounting principle is being applied? A going concern B matching C materiality D prudence
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2012
Q80 · A draft income statement shows a profit for the year of $360 000 9706/12 Oct/Nov 2012
10 A draft income statement shows a profit for the year of $360 000. Interest received for the year of $1200 has been treated as interest paid. What is the correct profit? A $357 600 B $358 800 C $361 200 D $362 400
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2012
Q81 · The table shows information relating to closing inventory 9706/12 Oct/Nov 2012
17 The table shows information relating to closing inventory. $ cost 50 000 realisable value 45 000 costs of realisation 5 000 replacement cost 35 000 What is the value of the closing inventory? A $35 000 B $40 000 C $45 000 D $50 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2012
Q82 · A business maintains a sales journal, a purchases journal, a cash book and a general… 9706/13 Oct/Nov 2012
1 A business maintains a sales journal, a purchases journal, a cash book and a general journal. Which items would be posted to the ledger accounts from the journal? 1 depreciation charge for the year 2 write off of a bad debt 3 discount allowed on settlement of a debt 4 interest on overdue accounts A 1, 2 and 4 B 1 and 4 only C 2, 3 and 4 D 2 and 3 only
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2012
Q83 · A company’s accounting year end is 31 December 9706/13 Oct/Nov 2012
2 A company’s accounting year end is 31 December. It always pays its insurance premiums annually, in advance, on the due date, 1 September. During the last few years the following premiums have been paid: Year 1 $2400 Year 2 $2760 Year 3 $3840 What will be the charge for insurance in the company’s income statement for Year 3? A $2760 B $3120 C $3480 D $3840
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2012
Q84 · The following payments have been made for property rates 9706/13 Oct/Nov 2012
6 The following payments have been made for property rates. $ 8 November 2011 paid rates for 6 months to 31 March 2012 1300 4 May 2012 paid rates for 6 months to 30 September 2012 1800 Which amount for rates is shown in the statement of financial position at 30 June 2012? A accrual $900 B accrual $1800 C prepayment $900 D prepayment $1800
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2012
Q85 · Which action is an application of the prudence principle? 9706/13 Oct/Nov 2012
7 Which action is an application of the prudence principle? A applying the same depreciation method each year B excluding the owner’s personal spending from the accounts C making an allowance for debts which may go bad D valuing assets on the assumption that the business will continue to trade
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2012
Q86 · X and Y are in partnership, sharing profits and losses in the ratio of 2:1 9706/13 Oct/Nov 2012
15 X and Y are in partnership, sharing profits and losses in the ratio of 2:1. X had taken goods costing $1500 from the business for his own use. The goods had been treated as a sale and credited to the sales account at their normal selling price of $2400. It was agreed that the goods should have been credited to the purchases account and not to sales and the records were corrected accordingly. Which entries should be made in the partners’ current accounts to make the correction? current accounts X Y $ $ A credit 300 debit 300 B debit 600 debit 300 C debit 1000 debit 500 D debit 1600 debit 800
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2012
Q87 · A trader made four transactions 9706/11 May/June 2013
1 A trader made four transactions. 1 paid for repairs to manufacturing equipment 2 purchased an item to be used by the business for more than 12 months 3 took goods for resale for his own use 4 transferred his own vehicle to the business Which items are capital expenditure? A 1 and 2 B 2 and 3 C 2 only D 3 and 4
1 marks
Answer: C
This question in 9706/11 May/June 2013
Q88 · Which transaction would increase the current assets of a business? 9706/11 May/June 2013
8 Which transaction would increase the current assets of a business? A paying credit suppliers $750 cash B purchasing a non-current asset on credit for $5000 C purchasing inventory on credit for $1000 and selling immediately for $2000 cash D selling inventory of $1000 at cost price on credit
1 marks
Answer: C
This question in 9706/11 May/June 2013
Q89 · A business has a bank balance of $4800 9706/11 May/June 2013
9 A business has a bank balance of $4800. It pays for materials invoiced at $3000 less trade discount of 30% and cash discount of 10%. A cheque for $450 is received from a customer. What is the bank balance after these transactions? A $2250 B $2460 C $3360 D $3450
1 marks
Answer: C
This question in 9706/11 May/June 2013
Q90 · A sole trader pays private expenses from the business bank account and records them as… 9706/11 May/June 2013
10 A sole trader pays private expenses from the business bank account and records them as drawings. Which accounting principle is applied? A business entity B going concern C matching D prudence
1 marks
Answer: A
This question in 9706/11 May/June 2013
Q91 · On which basis should inventory be valued? 9706/11 May/June 2013
18 On which basis should inventory be valued? A historical cost B lower of cost and net realisable value C lower of cost and replacement cost D replacement cost
1 marks
Answer: B
This question in 9706/11 May/June 2013
Q92 · In the books of account of Y, how could a credit entry of $500 in X’s account have arisen? 9706/12 May/June 2013
1 In the books of account of Y, how could a credit entry of $500 in X’s account have arisen? A X bought goods from Y. B X returned goods to Y. C Y made a payment to X. D Y returned goods to X.
1 marks
Answer: B
This question in 9706/12 May/June 2013
Q93 · What does the application of the accounting principle of consistency ensure? 9706/12 May/June 2013
5 What does the application of the accounting principle of consistency ensure? A that all losses are provided for B that assets are recorded at their actual cost C that financial statements are produced annually D that profits are calculated the same way each year
1 marks
Answer: D
This question in 9706/12 May/June 2013
Q94 · A trader recently purchased a non-current asset for his business at a cost of $6500 9706/12 May/June 2013
6 A trader recently purchased a non-current asset for his business at a cost of $6500. A friend told him he could buy a similar asset on-line for $5000. The trader is now unsure how to value the asset in the books of account. Which principle should the trader apply? A accruals B business entity C historical cost D materiality
1 marks
Answer: C
This question in 9706/12 May/June 2013
Q95 · Goods that had previously been purchased on credit have been returned to the supplier 9706/11 Oct/Nov 2013
2 Goods that had previously been purchased on credit have been returned to the supplier. How should this be recorded in the purchaser’s books of account? account to be debited account to be credited A bank purchases returns B trade payable bank C creditor purchases returns D purchases returns trade payable
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2013
Q96 · A company’s financial year ends on 31 December 9706/12 Oct/Nov 2013
7 A company’s financial year ends on 31 December. At 31 December Year 1 the company carried forward a debit balance of $36 200 on the rent account. During Year 2 payments made for 12 months’ rent, to 31 March Year 3, were $157 200. What is the amount of rent to be charged in the income statement in Year 2? A $121 000 B $154 100 C $160 300 D $193 400
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2013
Q97 · A trader buys inventory costing $6000 9706/12 Oct/Nov 2013
8 A trader buys inventory costing $6000. He is entitled to trade discount at 10% and cash discount of 5%. On the same day he discovers that he can only sell the inventory for $5000. Which amount should he record as the purchase price of the inventory? A $5000 B $5130 C $5400 D $6000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2013
Q98 · A customer paid a deposit in advance for goods to be supplied at a later date 9706/13 Oct/Nov 2013
1 A customer paid a deposit in advance for goods to be supplied at a later date. How should this be recorded in the seller’s books? debit credit A cash customer B cash sales C customer cash D customer sales
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2013
Q99 · A business wishes to record the following transactions in its books of account 9706/13 Oct/Nov 2013
4 A business wishes to record the following transactions in its books of account. contra between sales ledger control account and purchases ledger control account depreciation charge for the year increase in provision for doubtful debts purchase of non-current asset on credit How many transactions require an entry in the general journal? A 1 B 2 C 3 D 4
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2013
Q100 · Which items will be debited to accounts in the purchases ledger? 9706/11 May/June 2014
1 Which items will be debited to accounts in the purchases ledger? 1 discount allowed 2 payments to suppliers 3 purchases 4 purchases returns A 1 and 2 B 2 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: C
This question in 9706/11 May/June 2014
Q101 · When preparing a sole trader’s annual accounts, no adjustment was made for a prepayment… 9706/12 May/June 2014
2 When preparing a sole trader’s annual accounts, no adjustment was made for a prepayment at the end of the year. What is the effect of this omission? A current assets overstated owner’s capital overstated B current assets understated owner’s capital understated C profit for the year overstated trade payables understated D profit for the year understated trade payables understated
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q102 · Which statement is correct? 9706/12 May/June 2014
3 Which statement is correct? A The balance on the bad debts recovered account is carried down to the next accounting period. B The balance on the bad debts recovered account is credited to the income statement. C The balance on the provision for doubtful debts account is calculated before the deduction of bad debts. D The balance on the provision for doubtful debts account is not included in a trial balance.
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q103 · A trader took out a 6% bank loan of $30 000 on 1 November 2013, to be repaid in full in… 9706/12 May/June 2014
4 A trader took out a 6% bank loan of $30 000 on 1 November 2013, to be repaid in full in 10 years’ time. Interest is to be paid annually. No interest had been paid by 30 April 2014. How should this be recorded in the statement of financial position at 30 April 2014? current liabilities non-current liabilities $ $ A 0 30 000 B 900 30 000 C 1 800 30 000 D 30 900 0
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q104 · The bank column of a cash book showed a credit balance of $5000 9706/12 May/June 2014
8 The bank column of a cash book showed a credit balance of $5000. There were unpresented cheques amounting to $1500. The bank statement showed bank charges of $700 not in the cash book. What is the balance on the bank statement? A $3300 debit B $4200 debit C $4200 credit D $5800 credit
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q105 · X buys from and sells goods to Y 9706/12 May/June 2014
10 X buys from and sells goods to Y. At the end of the month, X owes Y $3200 and Y owes X $1941. Which double entry records the contra entry in X’s books? Dr Cr $ $ A purchases ledger control account 1259 sales ledger control account 1259 B purchases ledger control account 1941 sales ledger control account 1941 C sales ledger control account 1259 purchases ledger control account 1259 D sales ledger control account 1941 purchases ledger control account 1941
1 marks
Answer: B
This question in 9706/12 May/June 2014
Q106 · A business owner suspects a loss of cash has occurred 9706/12 May/June 2014
14 A business owner suspects a loss of cash has occurred. He provides the data shown. $ cash balance at the start of the month 150 cash balance at the end of the month 100 cash banked 10 200 cash sales for the month 10 500 How much cash has been lost? A $200 B $250 C $300 D $350
1 marks
Answer: D
This question in 9706/12 May/June 2014
Q107 · The provision for doubtful debts at 1 January 2013 was $1580 9706/13 Oct/Nov 2014
2 The provision for doubtful debts at 1 January 2013 was $1580. Trade receivables at 31 December 2013 were $44 750. An irrecoverable debt of $12 500 had not been written off. The provision for doubtful debts was 5%. Which entry for doubtful debts was included in the income statement for the year ended 31 December 2013? A credit $32.50 B credit $657.50 C debit $32.50 D debit $657.50
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q108 · On 1 January a business has prepaid $800 for four months’ motor insurance 9706/13 Oct/Nov 2014
4 On 1 January a business has prepaid $800 for four months’ motor insurance. It also has an outstanding invoice for fuel of $140. During January it pays the fuel invoice and a further $600 for fuel. At 31 January it has an outstanding fuel invoice of $160. What is the charge for motor expenses in the income statement for January? A $760 B $960 C $1100 D $1560
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2014
Q109 · A business values its inventory at the lower of cost and net realisable value 9706/13 Oct/Nov 2014
5 A business values its inventory at the lower of cost and net realisable value. Which accounting principle applies? A matching B materiality C prudence D substance over form
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2014
Q110 · During the financial year a business paid its trade payables $295 000 after taking a cash… 9706/13 Oct/Nov 2014
11 During the financial year a business paid its trade payables $295 000 after taking a cash discount of $15 000. At the start of the year the trade payables balance was $25 000. At the end of the year $32 000 was owed to trade payables. What was the amount of credit purchases made during the year? A $288 000 B $302 000 C $303 000 D $317 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2014
Q111 · A trader, whose year end was 31 December 2014, paid business rates of $3000 on 1 November… 9706/11 May/June 2015
2 A trader, whose year end was 31 December 2014, paid business rates of $3000 on 1 November 2014. The business rates were for the six months ending 31 March 2015, but no adjustment had been made for the prepayment. Which effect does this omission have on the profit for the year? A overstated $1500 B overstated $2000 C understated $1500 D understated $2000
1 marks
Answer: C
This question in 9706/11 May/June 2015
Q112 · An analysis of the cash account for a sole trader showed the following for the year 9706/11 May/June 2015
7 An analysis of the cash account for a sole trader showed the following for the year. $ capital introduced 300 cash takings banked 125 000 expenses paid 31 200 drawings 2 600 cash in hand at year-end 100 There were no credit sales. What was the revenue for the year? A $158 500 B $158 600 C $159 100 D $159 200
1 marks
Answer: B
This question in 9706/11 May/June 2015
Q113 · A business had the inventory receipts as shown 9706/11 May/June 2015
8 A business had the inventory receipts as shown. 1 April 2000 litres at $4.00 per litre 2 April 1000 litres at $5.50 per litre There was no opening inventory. On 3 April 2500 litres were issued to production. What is the value of the issue to production using FIFO? A $2 250 B $2 750 C $10 750 D $11 250
1 marks
Answer: C
This question in 9706/11 May/June 2015
Q114 · Which item incorrectly applies the matching principle? 9706/11 May/June 2015
10 Which item incorrectly applies the matching principle? A capitalising staff expertise and writing it off over the working life of the staff B including a value for unused stationery in statement of financial position C providing for doubtful debts in the year the sales took place D recording telephone costs incurred but not yet billed
1 marks
Answer: A
This question in 9706/11 May/June 2015
Q115 · A trader buys and sells two products for cash 9706/11 May/June 2015
12 A trader buys and sells two products for cash. The following information is available. product X product Y $ $ carriage outwards 3 700 – goods taken for own use at cost – 2 500 payments to suppliers 44 500 38 200 discount received 900 – What is the total value of ordinary goods purchased? A $80 200 B $81 100 C $83 600 D $84 800
1 marks
Answer: C
This question in 9706/11 May/June 2015
Q116 · Which statement contains the correct accounting treatment for accrued income? 9706/12 May/June 2015
1 Which statement contains the correct accounting treatment for accrued income? A added to income and shown as a current asset B added to income and shown as a current liability C deducted from income and shown as a current asset D deducted from income and shown as a current liability
1 marks
Answer: A
This question in 9706/12 May/June 2015
Q117 · A trader made the following transactions 9706/12 May/June 2015
2 A trader made the following transactions. $ cash withdrawn from bank for business use 200 cash banked 120 What was the total effect on ledger accounts? increase $ decrease $ A bank account 80 cash account 80 B bank account 320 cash account 320 C cash account 80 bank account 80 D cash account 320 bank account 320
1 marks
Answer: C
This question in 9706/12 May/June 2015
Q118 · Rent is paid by a business monthly in advance on the first day of each month 9706/12 May/June 2015
3 Rent is paid by a business monthly in advance on the first day of each month. The payments during this financial year have been as follows. up to and including 1 June $500 per month from 1 July $600 per month Which amount(s) will appear in the financial statements for the year ended 31 October? income statement statement of financial expense position A $6400 $600 other receivables B $6400 $600 other payables C $6400 – D $7000 –
1 marks
Answer: C
This question in 9706/12 May/June 2015
Q119 · A business started on 1 January 2013 9706/12 May/June 2015
4 A business started on 1 January 2013. At 31 December 2014 the following information is available. 31 December 2013 31 December 2014 $ $ trade receivables 80 000 100 000 increase in provision for doubtful 4 000 2 000 debts in income statement What is the rate for provision for doubtful debts in 2014? A 2% B 3.33% C 5% D 6%
1 marks
Answer: D
This question in 9706/12 May/June 2015
Q120 · A business receives a $50 000 deposit from a customer for a product which is to be… 9706/11 Oct/Nov 2015
1 A business receives a $50 000 deposit from a customer for a product which is to be delivered after the end of the financial year. How should this be shown in the statement of financial position at the year end? A current assets B current liabilities C non-current assets D non-current liabilities
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q121 · Derek places advertisements in monthly magazines 9706/11 Oct/Nov 2015
2 Derek places advertisements in monthly magazines. In September 2014 Derek paid $900 for advertisements to appear in the October 2014 to March 2015 editions of one magazine. In December 2014 he paid a further $880 for advertisements to appear in the January 2015 to April 2015 editions of another magazine. Which amount was shown for advertisements under other receivables in Derek’s statement of financial position at 31 January 2015? A $520 B $820 C $960 D $1260
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2015
Q122 · A business prepared its draft financial statements 9706/11 Oct/Nov 2015
3 A business prepared its draft financial statements. It was later discovered that an adjustment for prepaid rent was required. What is the effect of this adjustment? expenses current assets A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q123 · A trader purchased fixtures and fittings on credit from a supplier 9706/11 Oct/Nov 2015
4 A trader purchased fixtures and fittings on credit from a supplier. These were faulty and were returned to the supplier. Which entry in the trader’s books of account recorded the return? account to debit account to credit A fixtures and fittings supplier B purchases returns fixtures and fittings C supplier fixtures and fittings D supplier purchases returns
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2015
Q124 · Which entries are made to transfer cash discount obtained from suppliers to the financial… 9706/11 Oct/Nov 2015
6 Which entries are made to transfer cash discount obtained from suppliers to the financial statements at the end of the year? debit entry credit entry A trade payables account income statement B discount received account income statement C income statement trade payables account D income statement discount received account
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q125 · A trader adjusts his financial statements for a prepayment of $15 000 for three months’… 9706/11 Oct/Nov 2015
9 A trader adjusts his financial statements for a prepayment of $15 000 for three months’ property rental. Which accounting concept has he applied? A consistency B matching C materiality D prudence
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q126 · What is meant by the historical cost principle? 9706/11 Oct/Nov 2015
10 What is meant by the historical cost principle? A Each transaction must have a debit and credit of equal value. B Reported profits are realistic and not overstated. C Similar transactions should be recorded in the same way. D Transactions are recorded at actual cost.
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2015
Q127 · At the year end a company discovers that some inventory is damaged 9706/11 Oct/Nov 2015
15 At the year end a company discovers that some inventory is damaged. This inventory originally cost $2000 and to replace it would now cost $1900. It would normally sell for $2400 but can now only be sold for $2200 if repairs costing $400 are undertaken. At what value should the damaged inventory be shown in the financial statements? A $1800 B $1900 C $2000 D $2200
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2015
Q128 · Which entries are made to record interest on capital in partnership accounts? 9706/11 Oct/Nov 2015
16 Which entries are made to record interest on capital in partnership accounts? debit credit A appropriation account capital account B appropriation account current account C capital account appropriation account D current account appropriation account
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2015
Q129 · On 1 January a business had an inventory of 100 units at a cost of $10 each 9706/11 Oct/Nov 2015
20 On 1 January a business had an inventory of 100 units at a cost of $10 each. The following transactions then took place. units purchased units sold February 50 March 60 at $11 each April 70 at $12 each 100 May 30 All sales are made at $13 per unit. The business values its inventory on a FIFO basis. What is the value of the inventory at the end of May? A $390 B $550 C $600 D $650
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2015
Q130 · Why does a trader account for accrued income? 9706/12 Oct/Nov 2015
1 Why does a trader account for accrued income? A so that current liabilities are not overstated B so that current liabilities are not understated C so that profit is not overstated D so that profit is not understated
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2015
Q131 · A trader sends his staff on a training course costing $100 per person 9706/12 Oct/Nov 2015
2 A trader sends his staff on a training course costing $100 per person. 10 staff attended in April and 4 in May. Half the total cost had to be paid at the start of April and the balance at the end of May. Which entry for training was made in the statement of financial position on 30 April? A $300 accrual B $400 accrual C $600 prepayment D $700 prepayment
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2015
Q132 · A business paid $10 000 for motor expenses in the year 9706/12 Oct/Nov 2015
3 A business paid $10 000 for motor expenses in the year. The opening prepayment was $1500 and the closing accrual was $2000. What was the charge for motor expenses for the year? A $6500 B $9500 C $10 500 D $13 500
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2015
Q133 · At 1 January 2014 a business had prepaid rent of $700 9706/12 Oct/Nov 2015
8 At 1 January 2014 a business had prepaid rent of $700. In July it paid an invoice for $9300 and on 31 December it transferred an expense of $9000 to the income statement. Which value appeared in the statement of financial position at 31 December 2014? A $400 other payables B $400 other receivables C $1000 other payables D $1000 other receivables
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2015
Q134 · The creation of a provision for doubtful debts is an example of which accounting concept? 9706/12 Oct/Nov 2015
11 The creation of a provision for doubtful debts is an example of which accounting concept? A business entity B consistency C prudence D realisation
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2015
Q135 · Sanjay maintains a sales ledger in which Pardeep’s account has a debit balance of $850 9706/13 Oct/Nov 2015
1 Sanjay maintains a sales ledger in which Pardeep’s account has a debit balance of $850. What does this show? A Pardeep has paid Sanjay $850. B Pardeep owes Sanjay $850. C Sanjay has paid Pardeep $850. D Sanjay owes Pardeep $850.
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q136 · Which books of prime entry are used in preparing a disposal account? 9706/13 Oct/Nov 2015
4 Which books of prime entry are used in preparing a disposal account? A cash book and general journal B cash book and sales journal C cash book, general journal and sales journal D general journal and sales journal
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2015
Q137 · Peter, a credit customer of John, settles his account of $200 9706/13 Oct/Nov 2015
7 Peter, a credit customer of John, settles his account of $200. He pays by cheque and receives a cash discount of 5%. Which entries are made in John’s books of account to record this transaction? account to account to $ $ be debited be credited A bank 190 Peter 200 discount allowed 10 B bank 190 Peter 200 discount received 10 C Peter 200 bank 190 discount allowed 10 D Peter 200 bank 190 discount received 10
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2015
Q138 · What is the advantage of keeping a full set of double entry books of account? 9706/13 Oct/Nov 2015
11 What is the advantage of keeping a full set of double entry books of account? A Account balances are available through the year. B Business assets and owner’s assets can be kept separate. C It enables the book-keeper to check the bank statement for errors and omissions. D It stops the value of assets being overstated.
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2015
Q139 · A business started on 1 January 2014 9706/13 Oct/Nov 2015
30 A business started on 1 January 2014. The following balances are available at 31 December 2014. $ total sales 150 000 cash purchases 72 000 cash expenses 32 000 depreciation 4 000 trade receivables 18 000 What is the cash surplus for the year? A $24 000 B $28 000 C $42 000 D $46 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2015
Q140 · A computer used for demonstration to customers was treated as capital expenditure 9706/12 Feb/March 2016
10 A computer used for demonstration to customers was treated as capital expenditure. At the end of the year a customer purchased the computer in the ordinary course of business. Which entries are needed to adjust the cost of sales? account to be debited account to be credited A inventory demonstration equipment B purchases demonstration equipment C sales inventory D selling expenses sales
1 marks
Answer: B
This question in 9706/12 Feb/March 2016
Q141 · A business makes up its financial statements to 30 April each year 9706/12 Feb/March 2016
11 A business makes up its financial statements to 30 April each year. Included in the ledger account balances on 1 May 2014 was insurance (debit) $800. On 31 October 2014 an insurance premium of $2100 was paid for the year ended 31 October 2015. Which amount was charged for insurance in the income statement for the year ended 30 April 2015? A $1050 B $1850 C $2100 D $2900
1 marks
Answer: B
This question in 9706/12 Feb/March 2016
Q142 · Inventories are valued at the lower of cost and net realisable value in the statement of… 9706/11 May/June 2016
1 Inventories are valued at the lower of cost and net realisable value in the statement of financial position. Which accounting concept is being applied? A duality B historic cost C matching D prudence
1 marks
Answer: D
This question in 9706/11 May/June 2016
Q143 · A company calculates a draft profit for the year of $88 000 9706/11 May/June 2016
8 A company calculates a draft profit for the year of $88 000. This includes the profit margin of $3000 on goods sold on credit but not yet paid for. It also includes $500 profit taken on goods sold to a customer on a sale or return basis. What is the correct gross profit? A $84 500 B $85 000 C $87 500 D $91 000
1 marks
Answer: C
This question in 9706/11 May/June 2016
Q144 · A company received interest of $8800 during the financial year 9706/12 May/June 2016
9 A company received interest of $8800 during the financial year. Interest of $700 was due at the beginning of the year and $850 at the end of the year. Which entry appeared in the interest received account to make the transfer to the income statement? A $8650 credit B $8650 debit C $8950 credit D $8950 debit
1 marks
Answer: D
This question in 9706/12 May/June 2016
Q145 · The following information is available for rent and rates 9706/12 May/June 2016
11 The following information is available for rent and rates. $ prepaid rent at the start of the year 1250 accrued rates at the start of the year 1380 rent and rates income statement amount 8750 prepaid rent at the end of the year 1104 accrued rates at the end of the year 1000 What is the amount paid for rent and rates during the year? A $8516 B $8854 C $8880 D $8984
1 marks
Answer: D
This question in 9706/12 May/June 2016
Q146 · Inventories are valued at the lower of cost and net realisable value in the statement of… 9706/13 May/June 2016
1 Inventories are valued at the lower of cost and net realisable value in the statement of financial position. Which accounting concept is being applied? A duality B historic cost C matching D prudence
1 marks
Answer: D
This question in 9706/13 May/June 2016
Q147 · A company changes from the straight-line method of depreciation to the reducing balance… 9706/11 Oct/Nov 2016
1 A company changes from the straight-line method of depreciation to the reducing balance method. Which accounting principle has not been applied? A consistency B going concern C historic cost D materiality
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q148 · Ryan sells goods on credit to Sumit 9706/11 Oct/Nov 2016
4 Ryan sells goods on credit to Sumit. Sumit also supplies goods to Ryan. It is decided to make a set-off of the purchases ledger and sales ledger balances. In which books of prime entry is this set-off recorded? in Ryan’s books in Sumit’s books A general journal general journal B general journal purchases journal C sales journal general journal D sales journal sales journal
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2016
Q149 · Inventory costing $1200 has been damaged 9706/11 Oct/Nov 2016
7 Inventory costing $1200 has been damaged. It would normally be sold for $1800. It can be sold for $1700 if repairs are undertaken at a cost of $600. To replace the inventory would cost $1000. At which value should the damaged inventory be shown in the financial statements? A $1000 B $1100 C $1200 D $1800
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2016
Q150 · Which transaction applies the matching concept? 9706/12 Oct/Nov 2016
1 Which transaction applies the matching concept? A A machine acquired on long-term rental is included in non-current assets. B Computer equipment is depreciated over two years. C A building is revalued following a fall in property prices. D A waste-paper basket is treated as revenue expenditure.
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2016
Q151 · A trader did not keep full accounting records 9706/12 Oct/Nov 2016
11 A trader did not keep full accounting records. The following information was available for 2015. $ trade payables on 1 January 32 785 trade payables on 31 December 43 630 payments to suppliers during the year 72 830 discounts received during the year 3 450 What was the value of purchases? A $58 535 B $65 435 C $80 225 D $87 125
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2016
Q152 · Which item is entered in the general journal? 9706/13 Oct/Nov 2016
1 Which item is entered in the general journal? A A cash discount given to a customer B The correction of an error made in the ledger C The sale of an asset for cash D The withdrawal of cash for private use by the owner
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2016
Q153 · A calculator costs $9.50 and has a useful life of 5 years 9706/13 Oct/Nov 2016
2 A calculator costs $9.50 and has a useful life of 5 years. The book-keeper has decided to treat the purchase of the calculator as revenue expenditure. Which accounting principle has been applied? A accruals B materiality C prudence D substance over form
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2016
Q154 · On 1 January Ann owed Sam $400 9706/13 Oct/Nov 2016
4 On 1 January Ann owed Sam $400. She paid the amount due on 6 January after deducting a 2% cash discount. How did Ann record this? account debited account credited A bank 392 Sam 400 discount allowed 8 B bank 392 Sam 400 discount received 8 C Sam 400 bank 392 discount allowed 8 D Sam 400 bank 392 discount received 8
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2016
Q155 · Which accounting treatments illustrate the use of the matching concept? 9706/12 Feb/March 2017
1 Which accounting treatments illustrate the use of the matching concept? 1 comparing the receipts and payments in the cash book to obtain the balance of inventory at net realisable value rather than cost 2 using the FIFO method of inventory valuation each year 3 charging depreciation on non-current assets A 1, 2 and 3 B 1 and 3 only C 2 only D 3 only
1 marks
Answer: D
This question in 9706/12 Feb/March 2017
Q156 · A business’s year end is 31 March 9706/11 May/June 2017
1 A business’s year end is 31 March. On 31 March 2016 the business received an order from a credit customer. The goods were not sent to the customer until 5 April 2016. This sale was not included in the financial statements for the year ended 31 March 2016. Which accounting concept(s) are being applied? 1 business entity 2 realisation 3 substance over form A 1 and 2 B 1 only C 2 and 3 D 2 only
1 marks
Answer: D
This question in 9706/11 May/June 2017
Q157 · Trade receivable balances at the start of a period were $30 000 and were $38 000 at the… 9706/11 May/June 2017
8 Trade receivable balances at the start of a period were $30 000 and were $38 000 at the end. During that period: $ credit sales 60 000 irrecoverable debt written off 1 000 customer discounts allowed 2 000 How much did the company receive from its customers in the period? A $49 000 B $52 000 C $65 000 D $68 000
1 marks
Answer: A
This question in 9706/11 May/June 2017
Q158 · At the start of the year the provision for doubtful debts was $19 600 9706/11 May/June 2017
9 At the start of the year the provision for doubtful debts was $19 600. During the year irrecoverable debts of $12 300 were written off. The provision for doubtful debts at the year end was $15 500. What was the net effect of these items on the profit for the year? A $4100 decrease B $4100 increase C $8200 decrease D $8200 increase
1 marks
Answer: C
This question in 9706/11 May/June 2017
Q159 · The following information is extracted from the records of a business 9706/11 May/June 2017
11 The following information is extracted from the records of a business. $ at 1 January 2016 rent paid in advance 4 000 during the year ended 31 December 2016 rent paid 41 000 at 31 December 2016 rent paid in advance 7 000 How much will be charged for rent in the income statement for the year ended 31 December 2016? A $34 000 B $38 000 C $41 000 D $44 000
1 marks
Answer: B
This question in 9706/11 May/June 2017
Q160 · The following details are for the inventory of a company 9706/11 May/June 2017
21 The following details are for the inventory of a company. cost per kilo total cost kilos $ $ inventory 1 January 2016 100 100 10 000 purchased January 2016 200 105 21 000 purchased 1 February 2016 300 110 33 000 400 kilos remained as inventory at the end of February 2016. The company used FIFO to value its inventory. What was the value of inventory at the end of February? A $40 000 B $42 667 C $43 500 D $44 000
1 marks
Answer: C
This question in 9706/11 May/June 2017
Q161 · When a businessman introduces capital into his business, the transaction is debited in… 9706/12 May/June 2017
1 When a businessman introduces capital into his business, the transaction is debited in the cash book and credited to his capital account. Of which accounting concept is this an example? A business entity B going concern C matching D prudence
1 marks
Answer: A
This question in 9706/12 May/June 2017
Q162 · Which are examples of the accounting equation? 9706/12 May/June 2017
2 Which are examples of the accounting equation? 1 capital + assets = liabilities 2 capital = assets + liabilities 3 capital = assets – liabilities A 1 and 3 B 1 only C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/12 May/June 2017
Q163 · Which statements about the prudence concept are correct? 9706/13 Oct/Nov 2017
1 Which statements about the prudence concept are correct? 1 Assets should not be overstated. 2 Liabilities should be overstated. 3 Losses should only be provided for after they have occurred. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2017
Q164 · What would not be a purpose of ledger accounts? 9706/12 Feb/March 2018
1 What would not be a purpose of ledger accounts? A to assist in the preparation of the financial statements B to assist in the preparation of the trial balance C to record the double entry from the subsidiary books D to verify the accuracy of the book-keeping system
1 marks
Answer: D
This question in 9706/12 Feb/March 2018
Q165 · Adam records his inventory using the AVCO (perpetual inventory) to calculate its value 9706/12 Feb/March 2018
21 Adam records his inventory using the AVCO (perpetual inventory) to calculate its value. Which statement is correct? A He only values it at the end of the month. B He only values it at the year-end. C He values it at the same price throughout the year. D His inventory is valued after every purchase and issue.
1 marks
Answer: D
This question in 9706/12 Feb/March 2018
Q166 · A book-keeper enters a sales order in the sales journal 9706/11 May/June 2018
1 A book-keeper enters a sales order in the sales journal. Which accounting concept is not being applied? A matching B prudence C realisation D substance over form
1 marks
Answer: D
This question in 9706/11 May/June 2018
Q167 · A new business has several costs relating to its building 9706/11 May/June 2018
3 A new business has several costs relating to its building. Which costs are classified as revenue expenditure? 1 cost of an extension to the factory 2 legal fees on purchase of land 3 repairs to the warehouse roof A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/11 May/June 2018
Q168 · On 1 January a business has prepaid $800 for four months’ motor insurance 9706/11 May/June 2018
7 On 1 January a business has prepaid $800 for four months’ motor insurance. It also has an outstanding invoice for fuel of $140. During January it pays the fuel invoice and a further $600 for fuel. At 31 January it has an outstanding fuel invoice of $160. What is the charge for motor expenses in the income statement for January? A $760 B $960 C $1100 D $1560
1 marks
Answer: B
This question in 9706/11 May/June 2018
Q169 · The owner of a business has been told that work completed for a customer should be… 9706/12 May/June 2018
1 The owner of a business has been told that work completed for a customer should be recorded in the books of account although the invoice has not yet been sent to the customer. Which accounting concepts are being applied? 1 matching 2 materiality 3 realisation A 1 and 2 B 1 and 3 C 2 only D 2 and 3
1 marks
Answer: B
This question in 9706/12 May/June 2018
Q170 · The accounting year-end for a company is 31 October 9706/12 May/June 2018
4 The accounting year-end for a company is 31 October. The table shows the company’s telephone invoice received on 2 December for the three months ended 30 November. $ telephone calls to 30 November 1041 rental of equipment for the period from 1 September to 30 November 156 Which accrual should the company make in the financial statements for the year ended 31 October? A $399 B $798 C $1093 D $1197
1 marks
Answer: B
This question in 9706/12 May/June 2018
Q171 · A business created a provision for doubtful debts at 31 December 2016 9706/12 May/June 2018
5 A business created a provision for doubtful debts at 31 December 2016. The provision was calculated as a percentage of the trade receivables at each year end as follows. trade provision for year ended receivables doubtful debts $ % 31 December 2016 32 500 10 31 December 2017 34 300 5 Which entry in the provision for doubtful debts account for the year ended 31 December 2017 was required? A $1535 credit B $1535 debit C $1715 credit D $1715 debit
1 marks
Answer: B
This question in 9706/12 May/June 2018
Q172 · During the financial year a business paid $295 000 to its trade payables, after taking a… 9706/12 May/June 2018
9 During the financial year a business paid $295 000 to its trade payables, after taking a cash discount of $15 000. At the start of the year the trade payables balance was $25 000. At the end of the year $32 000 was owed to trade payables. What was the amount of credit purchases made during the year? A $288 000 B $302 000 C $303 000 D $317 000
1 marks
Answer: D
This question in 9706/12 May/June 2018
Q173 · A business does not keep complete accounting records 9706/12 May/June 2018
12 A business does not keep complete accounting records. All transactions are in cash. Which item will not be required in order to calculate the owner’s cash drawings? A non-current assets purchased B opening capital account C purchases D sales
1 marks
Answer: B
This question in 9706/12 May/June 2018
Q174 · A company does not include in the financial statements the value of skills gained by its… 9706/12 Oct/Nov 2018
1 A company does not include in the financial statements the value of skills gained by its employees from training programmes. Which accounting concept is being applied? A consistency B materiality C money measurement D substance over form
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2018
Q175 · A business sells a non-current asset for cash 9706/12 Oct/Nov 2018
5 A business sells a non-current asset for cash. The disposal account includes entries for the cost of the asset and the sales proceeds. Which books of prime entry are used? cost sales proceeds A cash book general journal B cash book sales journal C general journal cash book D purchases journal cash book
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2018
Q176 · Which items are revenue expenditure? 9706/13 Oct/Nov 2018
3 Which items are revenue expenditure? 1 cost of painting new office premises during construction 2 cost of repairs to factory plant and machinery 3 legal fees for the purchase of new factory premises A 1 and 2 B 2 only C 2 and 3 D 3 only
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2018
Q177 · A customer paid a deposit in advance for goods to be supplied at a later date 9706/13 Oct/Nov 2018
6 A customer paid a deposit in advance for goods to be supplied at a later date. How should this be recorded in the seller’s books? debit credit A cash customer B cash sales C customer cash D customer sales
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2018
Q178 · A business has a bank balance of $4800 9706/13 Oct/Nov 2018
7 A business has a bank balance of $4800. It pays for materials invoiced at $3000 less trade discount of 30% and cash discount of 10%. A cheque for $450 is received from a customer. What is the bank balance after these transactions? A $2250 B $2460 C $3360 D $3450
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2018
Q179 · An item is included in the financial statements because it affects their interpretation 9706/12 Feb/March 2019
1 An item is included in the financial statements because it affects their interpretation. Which accounting concept is being applied? A consistency B materiality C money measurement D substance over form
1 marks
Answer: B
This question in 9706/12 Feb/March 2019
Q180 · A business has a practice of not conducting a physical count of unused stationery at the… 9706/11 May/June 2019
1 A business has a practice of not conducting a physical count of unused stationery at the year end. Which accounting concept has been applied for this practice? A matching B materiality C money measurement D prudence
1 marks
Answer: B
This question in 9706/11 May/June 2019
Q181 · Which concept is identified by the accounting equation assets = capital + liabilities? 9706/12 May/June 2019
1 Which concept is identified by the accounting equation assets = capital + liabilities? A business entity B duality C going concern D realisation
1 marks
Answer: B
This question in 9706/12 May/June 2019
Q182 · When valuing inventory for inclusion in the financial statements, its selling price is… 9706/13 May/June 2019
1 When valuing inventory for inclusion in the financial statements, its selling price is ignored if it is higher than its cost price. Which concept is being applied in this situation? A business entity B consistency C duality D historic cost
1 marks
Answer: D
This question in 9706/13 May/June 2019
Q183 · Which concept requires that revenue is only recorded in a business’s books of account… 9706/11 Oct/Nov 2019
1 Which concept requires that revenue is only recorded in a business’s books of account when it is certain of being received? A business entity B going concern C materiality D realisation
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2019
Q184 · A trader sends his staff on a training course costing $100 per person 9706/11 Oct/Nov 2019
10 A trader sends his staff on a training course costing $100 per person. 10 staff attended in April and 4 in May. Half the total cost had to be paid at the start of April and the balance at the end of May. Which entry for training was made in the statement of financial position on 30 April? A $300 accrual B $400 accrual C $600 prepayment D $700 prepayment
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2019
Q185 · Which concept requires that profits should be based on recognising revenues and their… 9706/12 Oct/Nov 2019
1 Which concept requires that profits should be based on recognising revenues and their related expenses for an accounting period? A consistency B matching C materiality D prudence
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2019
Q186 · The employees of a company are skilled and efficient 9706/13 Oct/Nov 2019
1 The employees of a company are skilled and efficient. Although they are regarded as a human asset of the company, no value for them has been recorded in the financial statements. Which accounting concept has been applied? A duality B money measurement C realisation D substance over form
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2019
Q187 · A trader sells goods for $6600 to a customer on 31 March 2019, the last day of his… 9706/12 Feb/March 2020
1 A trader sells goods for $6600 to a customer on 31 March 2019, the last day of his financial year. He does not produce an invoice until three days later. He is advised that the sales of $6600 should be entered in the financial statements for the year ended 31 March 2019. Which accounting concepts are being applied? 1 consistency 2 prudence 3 realisation A 1 and 2 B 2 and 3 C 2 only D 3 only
1 marks
Answer: D
This question in 9706/12 Feb/March 2020
Q188 · The owner of a business purchased a camera to take some photographs of her family 9706/11 May/June 2020
1 The owner of a business purchased a camera to take some photographs of her family. She wishes to include it as an asset in the financial statements of the business. Her accountant says that she should not do this. Which accounting principle is the accountant applying? A business entity B consistency C going concern D realisation
1 marks
Answer: A
This question in 9706/11 May/June 2020
Q189 · The owner of a business purchased a camera to take some photographs of her family 9706/13 May/June 2020
1 The owner of a business purchased a camera to take some photographs of her family. She wishes to include it as an asset in the financial statements of the business. Her accountant says that she should not do this. Which accounting principle is the accountant applying? A business entity B consistency C going concern D realisation
1 marks
Answer: A
This question in 9706/13 May/June 2020
Q190 · Which accounting concept is being applied when calculating depreciation? 9706/11 Oct/Nov 2020
1 Which accounting concept is being applied when calculating depreciation? A business entity B matching C materiality D substance over form
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2020
Q191 · A business prepaid its rent 9706/11 Oct/Nov 2020
10 A business prepaid its rent. What is the effect of this on the current assets and the rent expense at the year end? current assets rent expense A decrease increase B increase decrease C increase no effect D no effect increase
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2020
Q192 · The inclusion of unpaid loan interest in financial statements is in accordance with which… 9706/12 Oct/Nov 2020
1 The inclusion of unpaid loan interest in financial statements is in accordance with which accounting concept? A consistency B going concern C matching D money measurement
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2020
Q193 · How could a credit entry of $500 in X’s account have arisen in the books of account of Y? 9706/12 Oct/Nov 2020
7 How could a credit entry of $500 in X’s account have arisen in the books of account of Y? A X bought goods from Y. B X returned goods to Y. C Y made a payment to X. D Y returned goods to X.
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2020
Q194 · A company decided not to capitalise the purchase of a stapler for use in its office 9706/13 Oct/Nov 2020
1 A company decided not to capitalise the purchase of a stapler for use in its office. Which accounting concept was the company applying? A consistency B duality C materiality D prudence
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2020
Q195 · Which book of prime entry is also used as a ledger account? 9706/13 Oct/Nov 2020
2 Which book of prime entry is also used as a ledger account? A cash book B purchases journal C sales journal D journal
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2020
Q196 · A business values its inventory at the lower of cost and net realisable value 9706/12 Feb/March 2021
1 A business values its inventory at the lower of cost and net realisable value. Which accounting concept is being applied? A business entity B duality C matching D prudence
1 marks
Answer: D
This question in 9706/12 Feb/March 2021
Q197 · On 1 May, Tom sold an old motor vehicle with a net book value of $10 000 to Arnold for… 9706/12 Feb/March 2021
2 On 1 May, Tom sold an old motor vehicle with a net book value of $10 000 to Arnold for $12 000. Arnold paid $7500 by cheque and agreed to pay the balance by instalments. What was the net effect of these transactions on Arnold’s accounting equation on 1 May? owner’s equity assets liabilities / capital $ $ $ A increase 2500 increase 2500 no effect B increase 2500 increase 4500 decrease 2000 C increase 4500 increase 2500 increase 2000 D increase 4500 increase 4500 no effect
1 marks
Answer: D
This question in 9706/12 Feb/March 2021
Q198 · The skill and efficiency of the workforce of a business has increased during the… 9706/11 May/June 2021
1 The skill and efficiency of the workforce of a business has increased during the financial period. The owner of the business wants to record a value for this in the financial statements. His accountant advises against this idea. Which accounting concept is the accountant applying? A business entity B matching C money measurement D prudence
1 marks
Answer: C
This question in 9706/11 May/June 2021
Q199 · An item of revenue expenditure is wrongly treated as capital expenditure 9706/11 May/June 2021
4 An item of revenue expenditure is wrongly treated as capital expenditure. What is the effect of this error? non-current profit for the assets year A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 9706/11 May/June 2021
Q200 · Which of these items require entries to be made in the general journal? 9706/12 May/June 2021
1 Which of these items require entries to be made in the general journal? 1 purchase of a non-current asset on credit 2 sale of inventory to a customer on credit 3 the owner taking drawings from their business in cash 4 writing off an irrecoverable debt A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: B
This question in 9706/12 May/June 2021
Q201 · A trader purchased fixtures and fittings on credit from a supplier 9706/12 May/June 2021
9 A trader purchased fixtures and fittings on credit from a supplier. These were faulty and were returned to the supplier. Which entry in the trader’s books of account recorded the return? account to debit account to credit A fixtures and fittings purchases returns B fixtures and fittings supplier C purchases returns fixtures and fittings D supplier fixtures and fittings
1 marks
Answer: D
This question in 9706/12 May/June 2021
Q202 · A business purchased a pocket calculator for the use of the book-keeper 9706/13 May/June 2021
1 A business purchased a pocket calculator for the use of the book-keeper. The accountant included it as an expense in the income statement. Which accounting concept is applied? A historic cost B materiality C realisation D substance over form
1 marks
Answer: B
This question in 9706/13 May/June 2021
Q203 · What is not a reason for a business to maintain a purchases journal? 9706/13 May/June 2021
2 What is not a reason for a business to maintain a purchases journal? A to assist in preparing the purchases ledger control account B to divide book-keeping duties between several people C to keep transactions of a similar nature in one place D to reduce the number of entries in the purchases ledger
1 marks
Answer: D
This question in 9706/13 May/June 2021
Q204 · John took goods from the business for his own use 9706/13 May/June 2021
12 John took goods from the business for his own use. These had cost $125, and $20 had been paid for their delivery to the business premises. How was this recorded in John’s books of account? debit accounts $ credit accounts $ A drawings 145 purchases 125 carriage inwards 20 B drawings 145 purchases 125 carriage outwards 20 C purchases 125 drawings 145 carriage inwards 20 D purchases 125 drawings 145 carriage outwards 20
1 marks
Answer: A
This question in 9706/13 May/June 2021
Q205 · A trader keeps a full set of accounting records 9706/11 Oct/Nov 2021
1 A trader keeps a full set of accounting records. Which statement is correct? A Credit notes issued are recorded in the sales journal. B Sales invoices are recorded in the general journal. C The sales account is kept in the general ledger. D The sales journal is prepared from entries in the sales ledger.
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2021
Q206 · The totals of the discount columns in a three-column cash book were debit side $320 and… 9706/11 Oct/Nov 2021
2 The totals of the discount columns in a three-column cash book were debit side $320 and credit side $140. What entries are made when these totals are posted to the nominal ledger? account debited $ account credited $ A discounts allowed 140 discounts received 320 B discounts allowed 320 discounts received 140 C discounts received 140 discounts allowed 320 D discounts received 320 discounts allowed 140
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2021
Q207 · A trader has prepared financial statements which include unpaid wages to her employees 9706/12 Oct/Nov 2021
1 A trader has prepared financial statements which include unpaid wages to her employees. Which accounting concept is being applied? A business entity B duality C matching D substance over form
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2021
Q208 · A trader maintains a full set of accounting records 9706/12 Oct/Nov 2021
8 A trader maintains a full set of accounting records. Each month she issues many sales invoices. Where does she record an individual sales invoice? A sales journal and sales ledger B sales journal and sales ledger control account C sales ledger and sales account D sales ledger and sales ledger control account
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2021
Q209 · A company does not include in the financial statements the value of skills gained by its… 9706/13 Oct/Nov 2021
1 A company does not include in the financial statements the value of skills gained by its employees from training programmes. Which accounting concept is being applied? A consistency B materiality C money measurement D substance over form
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2021
Q210 · The following transactions took place 9706/13 Oct/Nov 2021
2 The following transactions took place. 1 owner’s withdrawal of inventory for private use 2 purchase of new shop fixtures on credit 3 writing off an irrecoverable debt Which transactions would be recorded in the general journal? A 1, 2 and 3 B 1 and 2 only C 1 only D 2 and 3 only
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2021
Q211 · The following information is available for the telephone account for the year ended 31… 9706/13 Oct/Nov 2021
8 The following information is available for the telephone account for the year ended 31 December 2020. at at payments 1 Jan 2020 31 Dec 2020 and refund $ $ $ accrual 2000 5000 prepayment 1000 3000 payments made 19 000 amount refunded 500 What was the telephone expense for 2020? A $9500 B $17 500 C $19 500 D $21 500
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2021
Q212 · A trader did not keep full accounting records 9706/13 Oct/Nov 2021
12 A trader did not keep full accounting records. The following information was available for 2020. $ trade payables on 1 January 32 785 trade payables on 31 December 43 630 payments to suppliers during the year 72 830 discounts received during the year 3 450 What was the value of purchases? A $58 535 B $65 435 C $80 225 D $87 125
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2021
Q213 · Which actions are taken in respect of the totals of a three-column cash book at the end… 9706/12 Feb/March 2022
1 Which actions are taken in respect of the totals of a three-column cash book at the end of an accounting period? cash and bank discount columns columns A balanced balanced B balanced totalled C totalled balanced D totalled totalled
1 marks
Answer: B
This question in 9706/12 Feb/March 2022
Q214 · Which statements are correct? 9706/11 May/June 2022
1 Which statements are correct? 1 A book of prime entry is also part of the double entry system. 2 All sales made by the business are included in the sales ledger. 3 Ledger accounts for income and liabilities have credit balances. 4 Trade discounts appear in the income statement. A 1 and 2 B 1 and 3 only C 1, 3 and 4 D 3 and 4 only
1 marks
Answer: B
This question in 9706/11 May/June 2022
Q215 · Which accounting concept states that revenue can only be recognised after it has been… 9706/12 May/June 2022
1 Which accounting concept states that revenue can only be recognised after it has been earned? A consistency B going concern C money measurement D realisation
1 marks
Answer: D
This question in 9706/12 May/June 2022
Q216 · On what basis does a trading business produce an income statement? 9706/12 May/June 2022
11 On what basis does a trading business produce an income statement? 1 cash received and paid out by the business in the year 2 income earned less costs incurred by the business during the year 3 revenue received less any cash paid out by the business during the year A 1 and 2 B 1 and 3 C 2 and 3 D 2 only
1 marks
Answer: D
This question in 9706/12 May/June 2022
Q217 · Mia has agreed to supply goods to a customer on a sale or return basis 9706/13 May/June 2022
1 Mia has agreed to supply goods to a customer on a sale or return basis. At the end of her financial year, the customer has not indicated whether they will keep the goods. Which accounting concept should Mia apply to these items in her financial accounts? A matching B prudence C realisation D substance over form
1 marks
Answer: C
This question in 9706/13 May/June 2022
Q218 · The amount of the expense for rent and rates recorded in the income statement for the… 9706/13 May/June 2022
8 The amount of the expense for rent and rates recorded in the income statement for the year ended 31 December 2021 was $76 230. The following information was also available. balance brought forward balance carried forward 1 January 2021 31 December 2021 $ $ rent accrued 4000 6500 rates prepaid 770 820 How much was paid from the bank account for rent and rates during the year ended 31 December 2021? A $73 680 B $73 780 C $78 680 D $78 780
1 marks
Answer: B
This question in 9706/13 May/June 2022
Q219 · For which items does the cash book act as a book of prime entry? 9706/11 Oct/Nov 2022
1 For which items does the cash book act as a book of prime entry? 1 payments to suppliers 2 purchase of a non-current asset on credit 3 receipts from customers 4 returns outwards A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2022
Q220 · Which statements about accruals and prepayments are correct? 9706/11 Oct/Nov 2022
8 Which statements about accruals and prepayments are correct? 1 Accrued revenue at the end of an accounting period is recorded as a current asset. 2 Accrued revenue at the end of an accounting period is recorded as a current liability. 3 Prepaid expenses at the end of an accounting period are recorded as a current asset. 4 Prepaid expenses at the end of an accounting period are recorded as a current liability. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2022
Q221 · A business has a bank overdraft of $4800 9706/11 Oct/Nov 2022
9 A business has a bank overdraft of $4800. It pays for materials invoiced, $3000, less a trade discount of 20% and a settlement discount of 5%. A cheque for $500 is received from a credit customer. What is the bank balance after these transactions? A $2020 overdraft B $6580 overdraft C $7150 overdraft D $7580 overdraft
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2022
Q222 · Which items would be entered in the General Journal? 9706/12 Oct/Nov 2022
1 Which items would be entered in the General Journal? 1 goods taken by owner for personal use 2 goods purchased for resale 3 purchase of a non-current asset on credit 4 purchase of office stationery A 1 and 2 B 1 and 3 only C 1, 3 and 4 D 3 and 4 only
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2022
Q223 · Goods, $1200, sent to a customer on a sale or return basis have not been recorded in the… 9706/13 Oct/Nov 2022
1 Goods, $1200, sent to a customer on a sale or return basis have not been recorded in the sales journal. Which accounting concept has been applied? A going concern B matching C materiality D realisation
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2022
Q224 · A credit customer cleared her debt of $600 after deducting a cash discount of $12 9706/12 Feb/March 2023
2 A credit customer cleared her debt of $600 after deducting a cash discount of $12. How would the customer account appear in the books of the supplier after the payment has been recorded? debit $ credit $ A balance b / d 600 bank 588 discount allowed 12 B balance b / d 600 bank 588 discount received 12 C bank 588 balance b / d 600 discount allowed 12 D bank 588 balance b / d 600 discount received 12
1 marks
Answer: A
This question in 9706/12 Feb/March 2023
Q225 · What is the advantage of keeping a full set of double entry books of account? 9706/12 Feb/March 2023
3 What is the advantage of keeping a full set of double entry books of account? A Account balances are available through the year. B Business assets and owner’s assets can be kept separate. C It enables the book-keeper to check the bank statement for errors and omissions. D It stops the value of assets being overstated.
1 marks
Answer: A
This question in 9706/12 Feb/March 2023
Q226 · Which statement describes the purpose of preparing a trial balance? 9706/11 May/June 2023
1 Which statement describes the purpose of preparing a trial balance? A to assist in the preparation of financial statements B to calculate owner’s equity C to calculate profit for the year D to prove that ledger balances are free from errors
1 marks
Answer: A
This question in 9706/11 May/June 2023
Q227 · Where is discount allowed recorded? 9706/11 May/June 2023
10 Where is discount allowed recorded? discount allowed sales ledger cash book account control account A credit side credit side credit side B credit side debit side debit side C debit side debit side credit side D debit side credit side debit side
1 marks
Answer: C
This question in 9706/11 May/June 2023
Q228 · An asset is purchased on credit by a business 9706/12 May/June 2023
2 An asset is purchased on credit by a business. What is the effect of this transaction on the accounting equation? assets liabilities capital A increase decrease increase B increase decrease no change C increase increase decrease D increase increase no change
1 marks
Answer: D
This question in 9706/12 May/June 2023
Q229 · The accounting equation of a business was as shown 9706/13 May/June 2023
3 The accounting equation of a business was as shown. assets = liabilities + capital $ $ $ 48 000 = 7000 + 41 000 The assets included a bank balance of $1000. The following transactions occurred. 1 The owner took drawings of $2000 by cheque. 2 Goods for resale were purchased on credit; list price was $4000 less 25% trade discount. What was the accounting equation after these transactions? assets = liabilities + capital $ $ $ A 49 000 10 000 39 000 B 50 000 10 000 40 000 C 50 000 11 000 39 000 D 51 000 11 000 40 000
1 marks
Answer: C
This question in 9706/13 May/June 2023
Q230 · A sole trader settles an account payable in full with her own money 9706/11 Oct/Nov 2023
2 A sole trader settles an account payable in full with her own money. This transaction has not been recorded. What will be the effect when this is recorded? A asset decreased and liability decreased B asset increased and liability decreased C liability decreased and capital increased D liability increased and capital decreased
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2023
Q231 · Sally had $1000 in the bank when she paid $1500 to buy goods for resale 9706/11 Oct/Nov 2023
3 Sally had $1000 in the bank when she paid $1500 to buy goods for resale. The bank allowed the payment. How was this transaction recorded in Sally’s books of account? account account(s) $ $ debited credited A inventory 1500 bank 1500 B inventory 1500 bank 1000 bank overdraft 500 C purchases 1500 bank 1500 D purchases 1500 bank 1000 bank overdraft 500
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2023
Q232 · Which items identify revenue expenditure and a capital receipt? 9706/11 Oct/Nov 2023
4 Which items identify revenue expenditure and a capital receipt? revenue expenditure capital receipt A carriage inward on a non-current asset issue of debentures B commission received proceeds from sale of non-current asset C discounts allowed cash drawings D repair of motor vehicle receipt of loan from lender
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2023
Q233 · Which statements describe advantages of maintaining full accounting records? 9706/12 Oct/Nov 2023
2 Which statements describe advantages of maintaining full accounting records? 1 A more complete assessment of business performance is possible. 2 Book-keeping costs are minimised. 3 Business managers can make more informed decisions. 4 Financial statements will be free from errors and inaccuracies. A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2023
Q234 · At a business’s financial year-end there were expenses owing, expenses prepaid, income… 9706/12 Oct/Nov 2023
13 At a business’s financial year-end there were expenses owing, expenses prepaid, income owing and income received in advance. How will the ledger account balances brought down at the start of the new financial year appear in the general ledger? debit balances credit balances A expenses owing expenses prepaid income owing income received in advance B expenses owing expenses prepaid income received in advance income owing C expenses prepaid expenses owing income owing income received in advance D expenses prepaid expenses owing income received in advance income owing
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2023
Q235 · Inventories are valued at the lower of cost and net realisable value in the statement of… 9706/13 Oct/Nov 2023
1 Inventories are valued at the lower of cost and net realisable value in the statement of financial position. Which accounting concept is being applied? A duality B historic cost C matching D prudence
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2023
Q236 · On 1 January, Ann owed Sam $400 9706/13 Oct/Nov 2023
3 On 1 January, Ann owed Sam $400. She paid the amount due on 6 January after deducting a 2% cash discount. How did Ann record this? account debited $ account credited $ A bank 392 Sam 400 discount allowed 8 B bank 392 Sam 400 discount received 8 C Sam 400 bank 392 discount allowed 8 D Sam 400 bank 392 discount received 8
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2023
Q237 · Which items will be debited to accounts in the purchases ledger? 9706/12 Feb/March 2024
3 Which items will be debited to accounts in the purchases ledger? 1 discount allowed 2 payments to suppliers 3 purchases 4 purchases returns A 1 and 2 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: D
This question in 9706/12 Feb/March 2024
Q238 · Tom bought goods costing $100 on credit from Sam 9706/12 Feb/March 2024
4 Tom bought goods costing $100 on credit from Sam. He returned goods costing $20 as faulty. He deducted a cash discount and paid $76 by cheque in full settlement. Which amounts were recorded in Tom’s books of prime entry? purchases purchases three-column journal returns journal cash book (bank column) $ $ $ A 80 0 76 B 80 0 80 C 100 20 76 D 100 20 80
1 marks
Answer: C
This question in 9706/12 Feb/March 2024
Q239 · The owner of a business paid for business stationery using her personal funds 9706/11 May/June 2024
2 The owner of a business paid for business stationery using her personal funds. Which ledger account will be credited? A capital B cash C drawings D stationery
1 marks
Answer: A
This question in 9706/11 May/June 2024
Q240 · What is not a purpose of ledger accounts? 9706/13 May/June 2024
2 What is not a purpose of ledger accounts? A to assist in the preparation of the financial statements B to assist in the preparation of the trial balance C to record the double entry from the subsidiary books D to verify the accuracy of the bookkeeping system
1 marks
Answer: D
This question in 9706/13 May/June 2024
Q241 · An item is included in a financial statement because it affects the interpretation of… 9706/13 May/June 2024
3 An item is included in a financial statement because it affects the interpretation of financial statements. Which accounting concept is being applied? A consistency B materiality C money measurement D substance over form A business acquired new factory machinery costing of $120 000. This amount was included in
1 marks
Answer: B
This question in 9706/13 May/June 2024
Q242 · Which statements are true of a bank overdraft? 9706/11 Oct/Nov 2024
1 Which statements are true of a bank overdraft? 1 it is long-term finance 2 it is short-term finance 3 it is of fixed amount 4 it is of variable amount up to a limit A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2024
Q243 · A business sells a non-current asset for cash 9706/11 Oct/Nov 2024
3 A business sells a non-current asset for cash. The disposal account includes entries for the cost of the asset and the sales proceeds. Which books of prime entry are used? cost of asset sales proceeds A cash book general journal B cash book sales journal C general journal cash book D purchases journal cash book
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2024
Q244 · The owner of a business received an order from a customer on the last day of the… 9706/11 Oct/Nov 2024
4 The owner of a business received an order from a customer on the last day of the financial year, 31 December, and despatched the goods on the same day. The goods were invoiced to the customer a few days later, on 3 January. Which accounting concept should be applied when deciding whether to record the sale on 31 December or 3 January? A consistency B objectivity C prudence D realisation
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2024
Q245 · A business uses the weighted average cost (AVCO) method of inventory valuation 9706/11 Oct/Nov 2024
24 A business uses the weighted average cost (AVCO) method of inventory valuation. During March the following transactions took place. 1 March opening inventory 200 units at $6.00 per unit 14 March received 300 units at $6.50 per unit 20 March issued 250 units to production at $7.00 per unit 28 March received 100 units at $6.70 per unit What is the value of inventory at 31 March? A $2195 B $2245 C $2295 D $2450
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2024
Q246 · A business sells computers 9706/12 Oct/Nov 2024
1 A business sells computers. When it values its inventory it excludes the value of the inventory that is more than one year old. This is because it may be obsolete. Which accounting principle does this demonstrate? A going concern B historical cost C prudence D realisation
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2024
Q247 · Peter is a credit customer of John 9706/12 Oct/Nov 2024
3 Peter is a credit customer of John. He settles his account of $200. He pays by cheque and receives a cash discount of 5%. Which entries are made in John’s books of account to record this transaction? account to account to $ $ be debited be credited A bank 190 Peter 200 discount allowed 10 B bank 190 Peter 200 discount received 10 C Peter 200 bank 190 discount allowed 10 D Peter 200 bank 190 discount received 10
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2024
Q248 · Which book of prime entry is used to record the sale of a non-current asset on credit? 9706/13 Oct/Nov 2024
1 Which book of prime entry is used to record the sale of a non-current asset on credit? A cash book B general journal C sales journal D sales returns journal
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2024
Q249 · Which accounting concepts are applied when a business makes an annual charge for… 9706/13 Oct/Nov 2024
3 Which accounting concepts are applied when a business makes an annual charge for depreciation of non-current assets? 1 consistency 2 matching/accruals 3 prudence 4 realisation A 1, 2 and 3 B 1 and 4 C 2 and 3 only D 3 and 4
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2024
Q250 · A sole trader uses the double entry system to record their business transactions 9706/11 May/June 2025
3 A sole trader uses the double entry system to record their business transactions. Which transaction does not follow the double entry rules? A An expense account is debited at the end of the year when there is an expense prepaid on that date. B The capital account is credited when the sole trader introduces their personal computer to the business. C The provision for motor vehicles depreciation account is debited when a motor vehicle is sold. D The purchases account is credited when the sole trader draws goods from the business.
1 marks
Answer: A
This question in 9706/11 May/June 2025
Q251 · What is the correct double entry to record goods taken for own use by the owner of a… 9706/12 May/June 2025
2 What is the correct double entry to record goods taken for own use by the owner of a business? debit credit A drawings inventory B drawings purchases C inventory drawings D purchases drawings
1 marks
Answer: B
This question in 9706/12 May/June 2025
Q252 · Which account balance will be in the credit column of a trial balance? 9706/12 May/June 2025
4 Which account balance will be in the credit column of a trial balance? A carriage inwards B carriage outwards C purchases returns D sales returns
1 marks
Answer: C
This question in 9706/12 May/June 2025
Q253 · A sole trader uses the double entry system to record their business transactions 9706/13 May/June 2025
3 A sole trader uses the double entry system to record their business transactions. Which transaction does not follow the double entry rules? A An expense account is debited at the end of the year when there is an expense prepaid on that date. B The capital account is credited when the sole trader introduces their personal computer to the business. C The provision for motor vehicles depreciation account is debited when a motor vehicle is sold. D The purchases account is credited when the sole trader draws goods from the business.
1 marks
Answer: A
This question in 9706/13 May/June 2025
Q254 · What are the documents to verify the existence of a sales transaction? 9706/11 Oct/Nov 2025
3 What are the documents to verify the existence of a sales transaction? 1 delivery note 2 price quotation 3 sales invoice 4 sales order A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2025
Q255 · Which items appear in the credit column of a trial balance? 9706/12 Oct/Nov 2025
2 Which items appear in the credit column of a trial balance? A discounts allowed, returns inwards B discounts allowed, returns outwards C discounts received, returns inwards D discounts received, returns outwards
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2025
Q256 · A trader sells goods for $6600 to a customer on 31 March 2025, the last day of his… 9706/12 Oct/Nov 2025
3 A trader sells goods for $6600 to a customer on 31 March 2025, the last day of his financial year. He does not produce an invoice until three days later. He is advised that the sales of $6600 should be entered in the financial statements for the year ended 31 March 2025. Which accounting concepts are being applied? 1 consistency 2 prudence 3 realisation A 1 and 2 B 2 and 3 C 2 only D 3 only
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2025
Q257 · A business acquired a non-current asset 9706/13 Oct/Nov 2025
2 A business acquired a non-current asset. One half of the purchase consideration was paid by cheque on the date of the purchase. The balance was paid to the supplier three months later. What was the credit entry to record this acquisition on the date of purchase? A bank B bank and loan C bank and other payables D bank and other receivables
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2025
Q258 · Which statements about the prudence concept are correct? 9706/13 Oct/Nov 2025
3 Which statements about the prudence concept are correct? 1 Assets should not be overstated. 2 Liabilities should be overstated. 3 Losses should only be provided for after they have occurred. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2025
Q259 · Arya sells one type of product at a unit price of $100 and with a credit period of one… 9706/13 Oct/Nov 2025
4 Arya sells one type of product at a unit price of $100 and with a credit period of one month. Customers’ purchases in excess of 80 units are allowed a discount of 5%. Roy purchased 100 units but returned 10 units two weeks later. How should Arya record the sales returns? account to be debited account to be credited A sales returns $950 bank $950 B sales returns $1000 bank $1000 C sales returns $950 trade receivables – Roy $950 D sales returns $1000 trade receivables – Roy $1000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2025
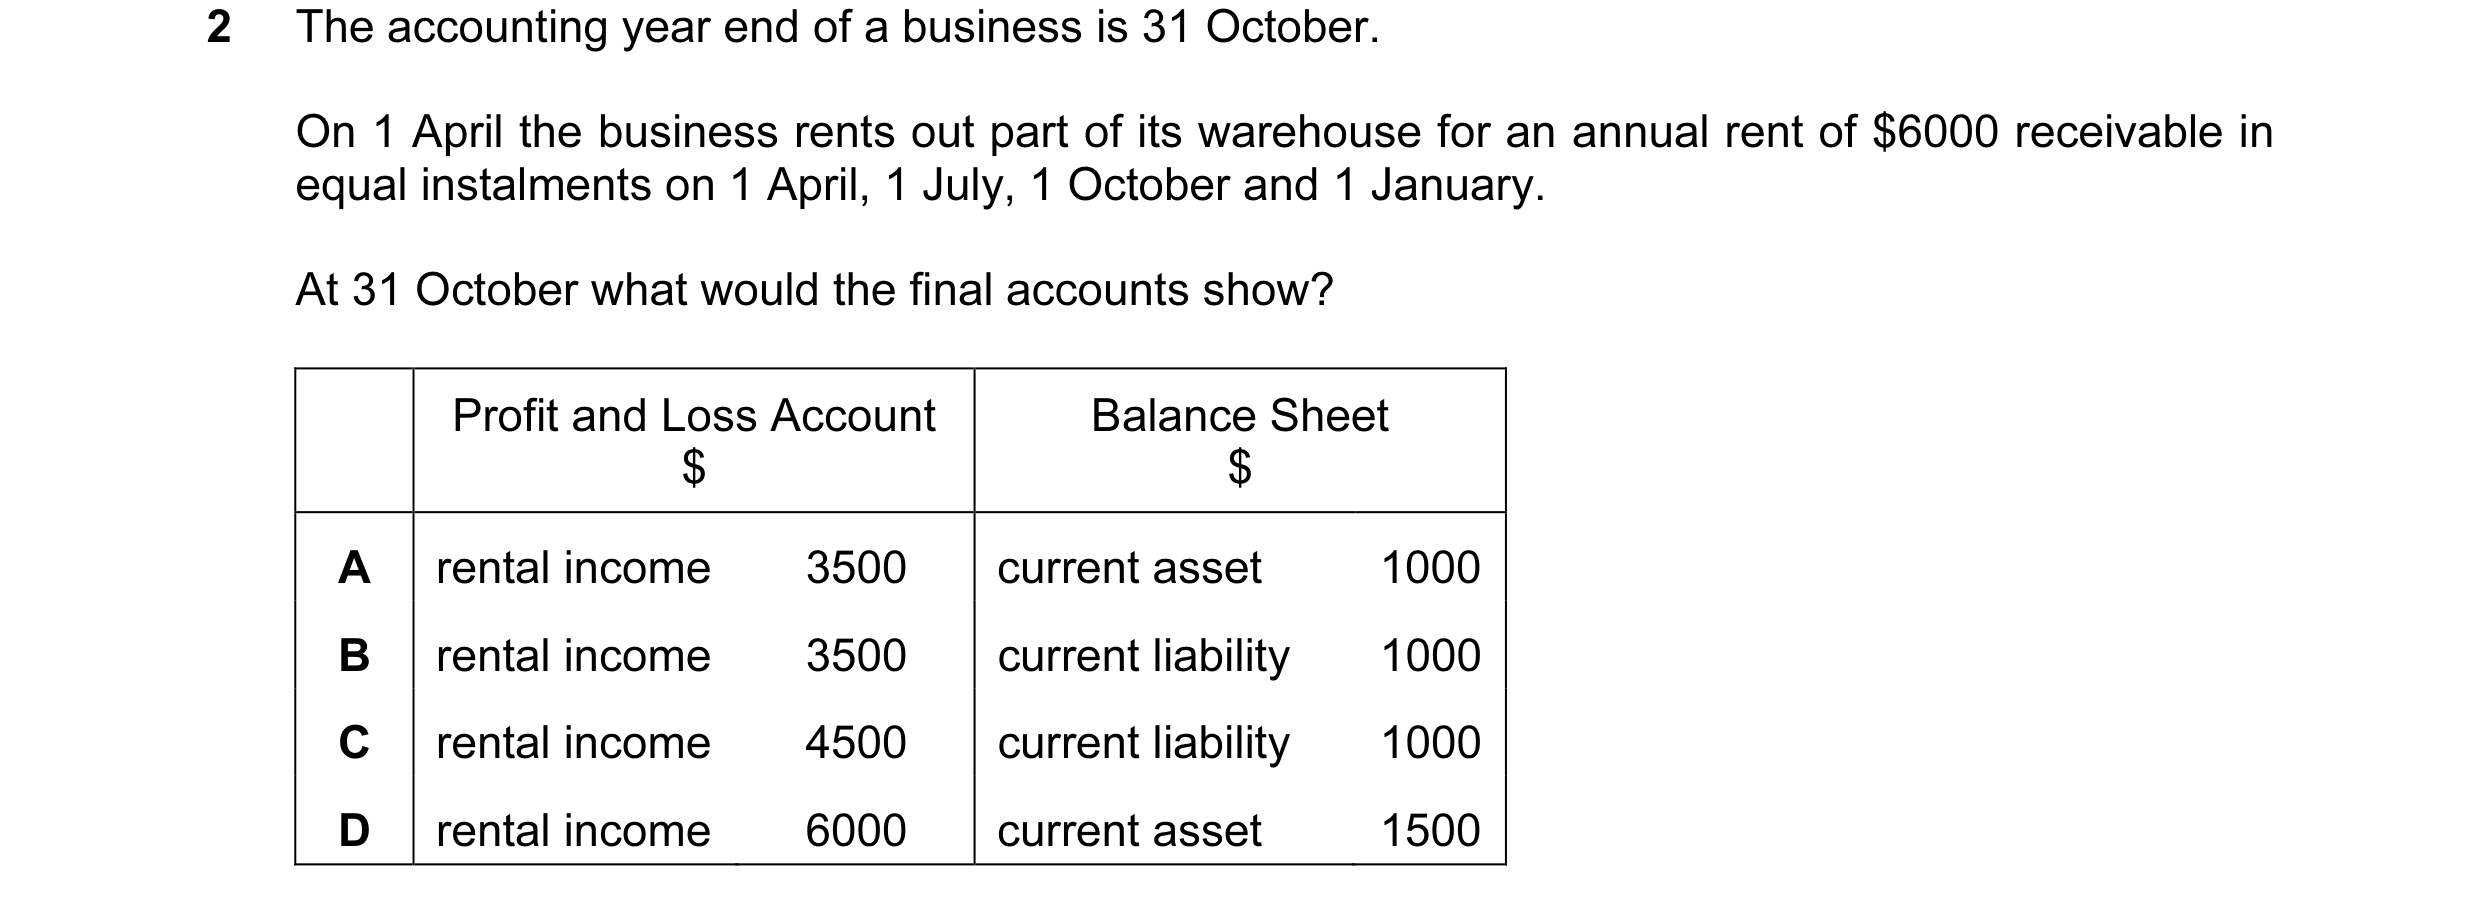
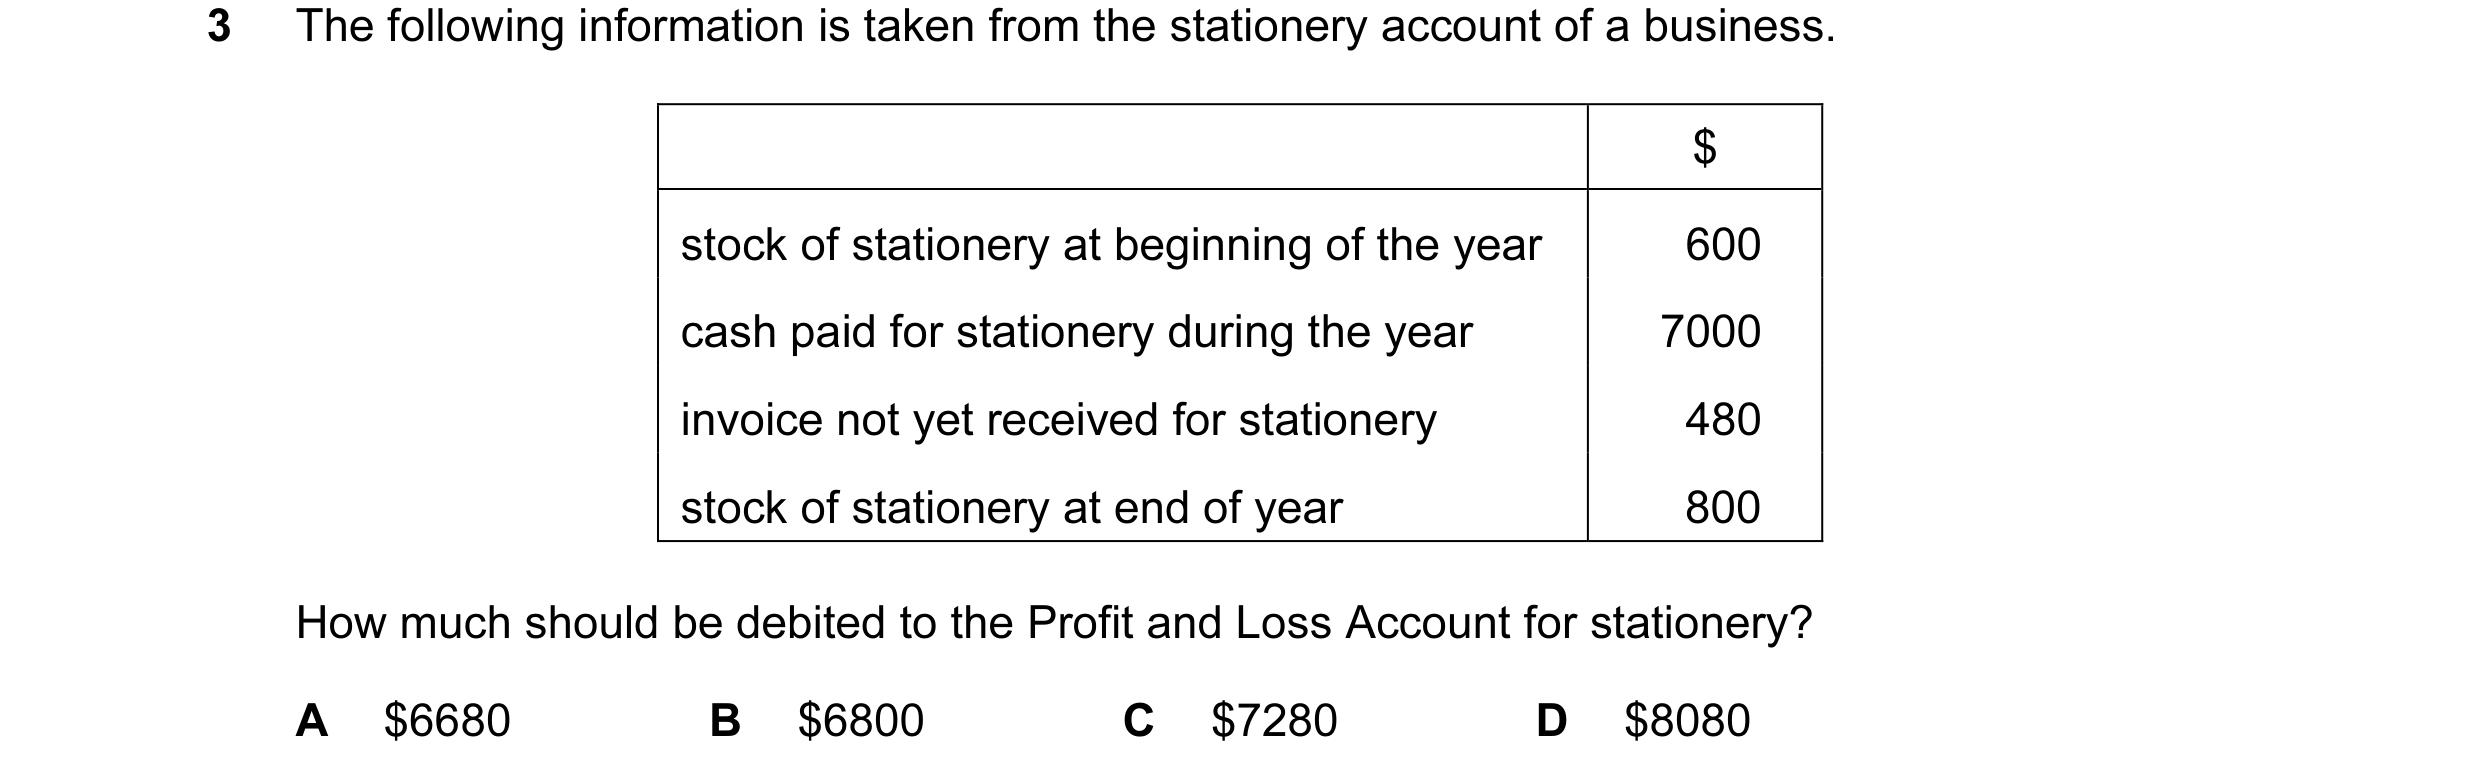
 1 / 58
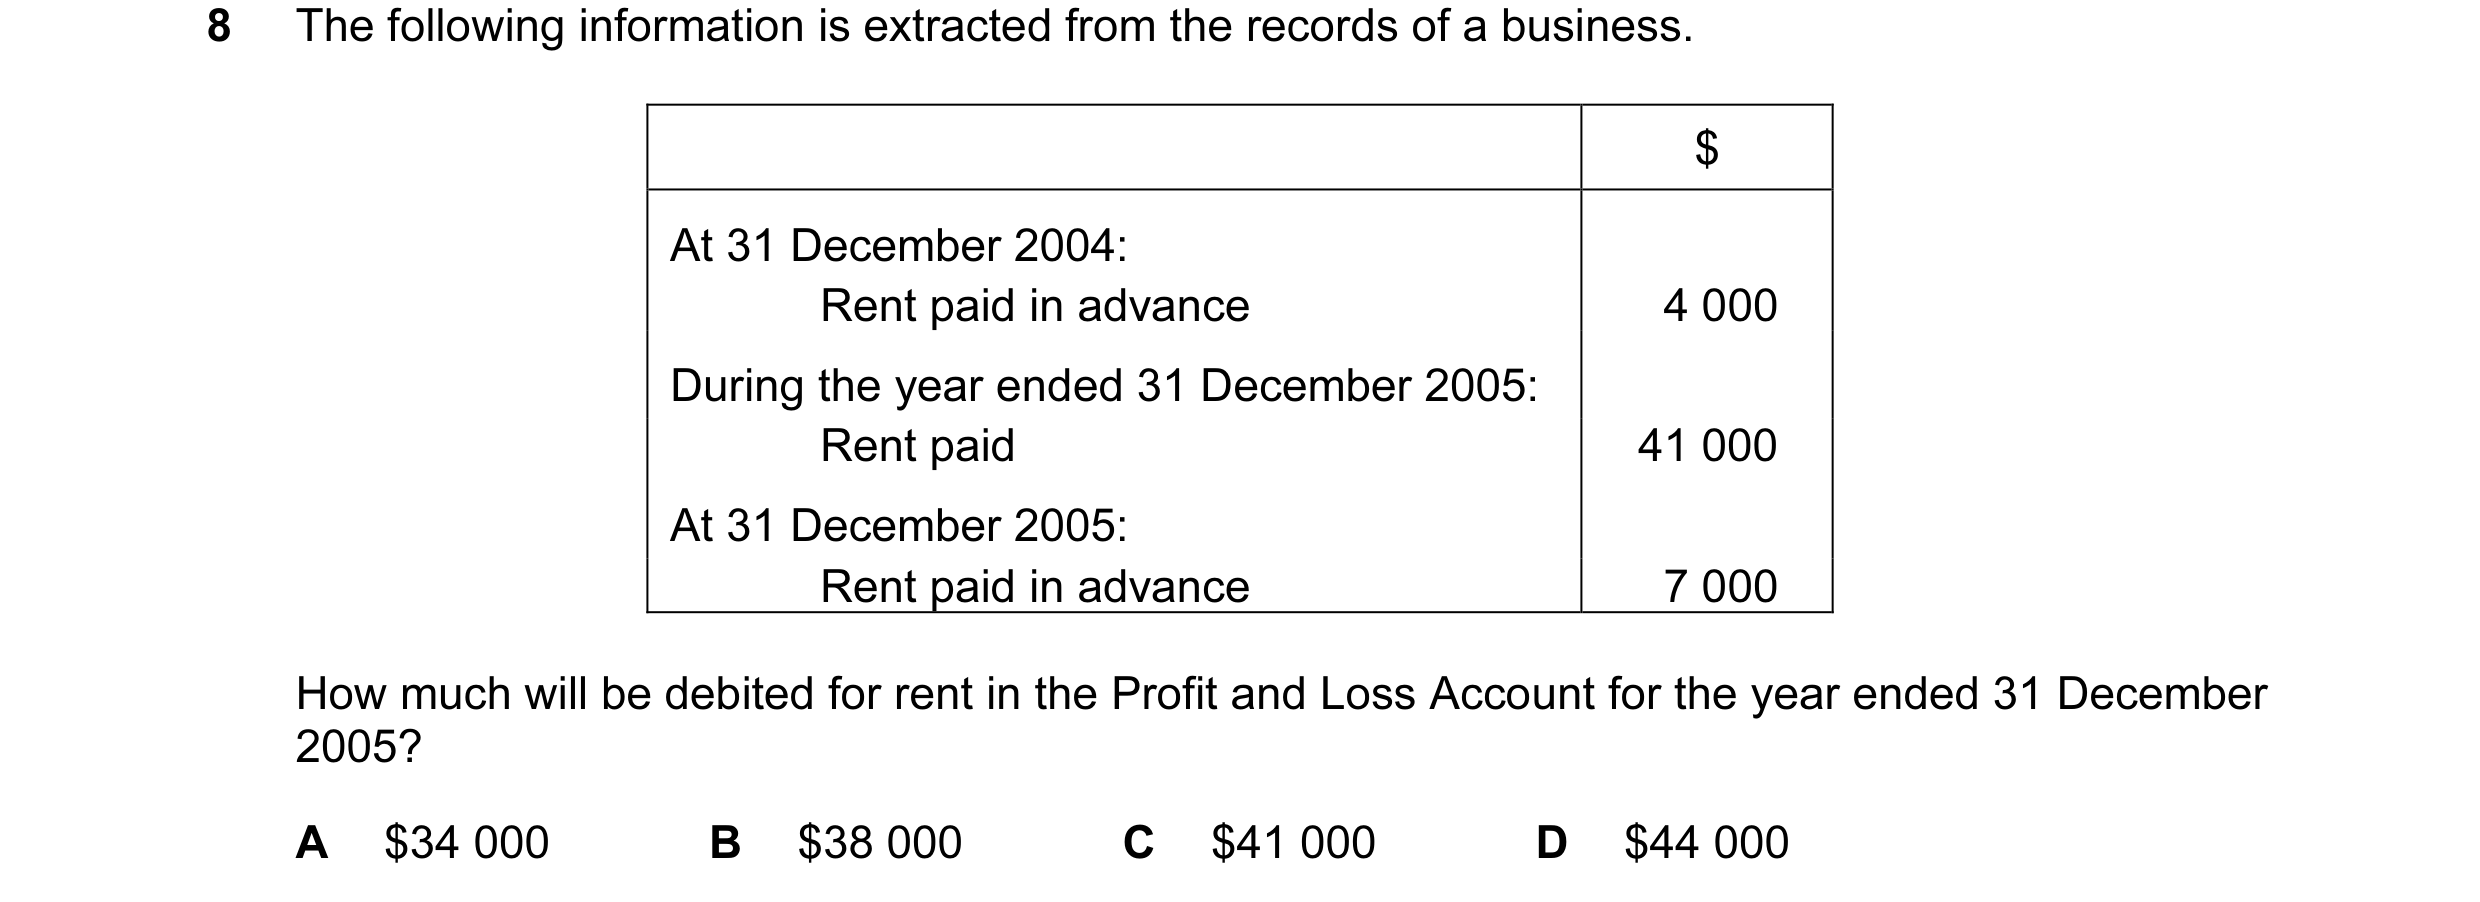
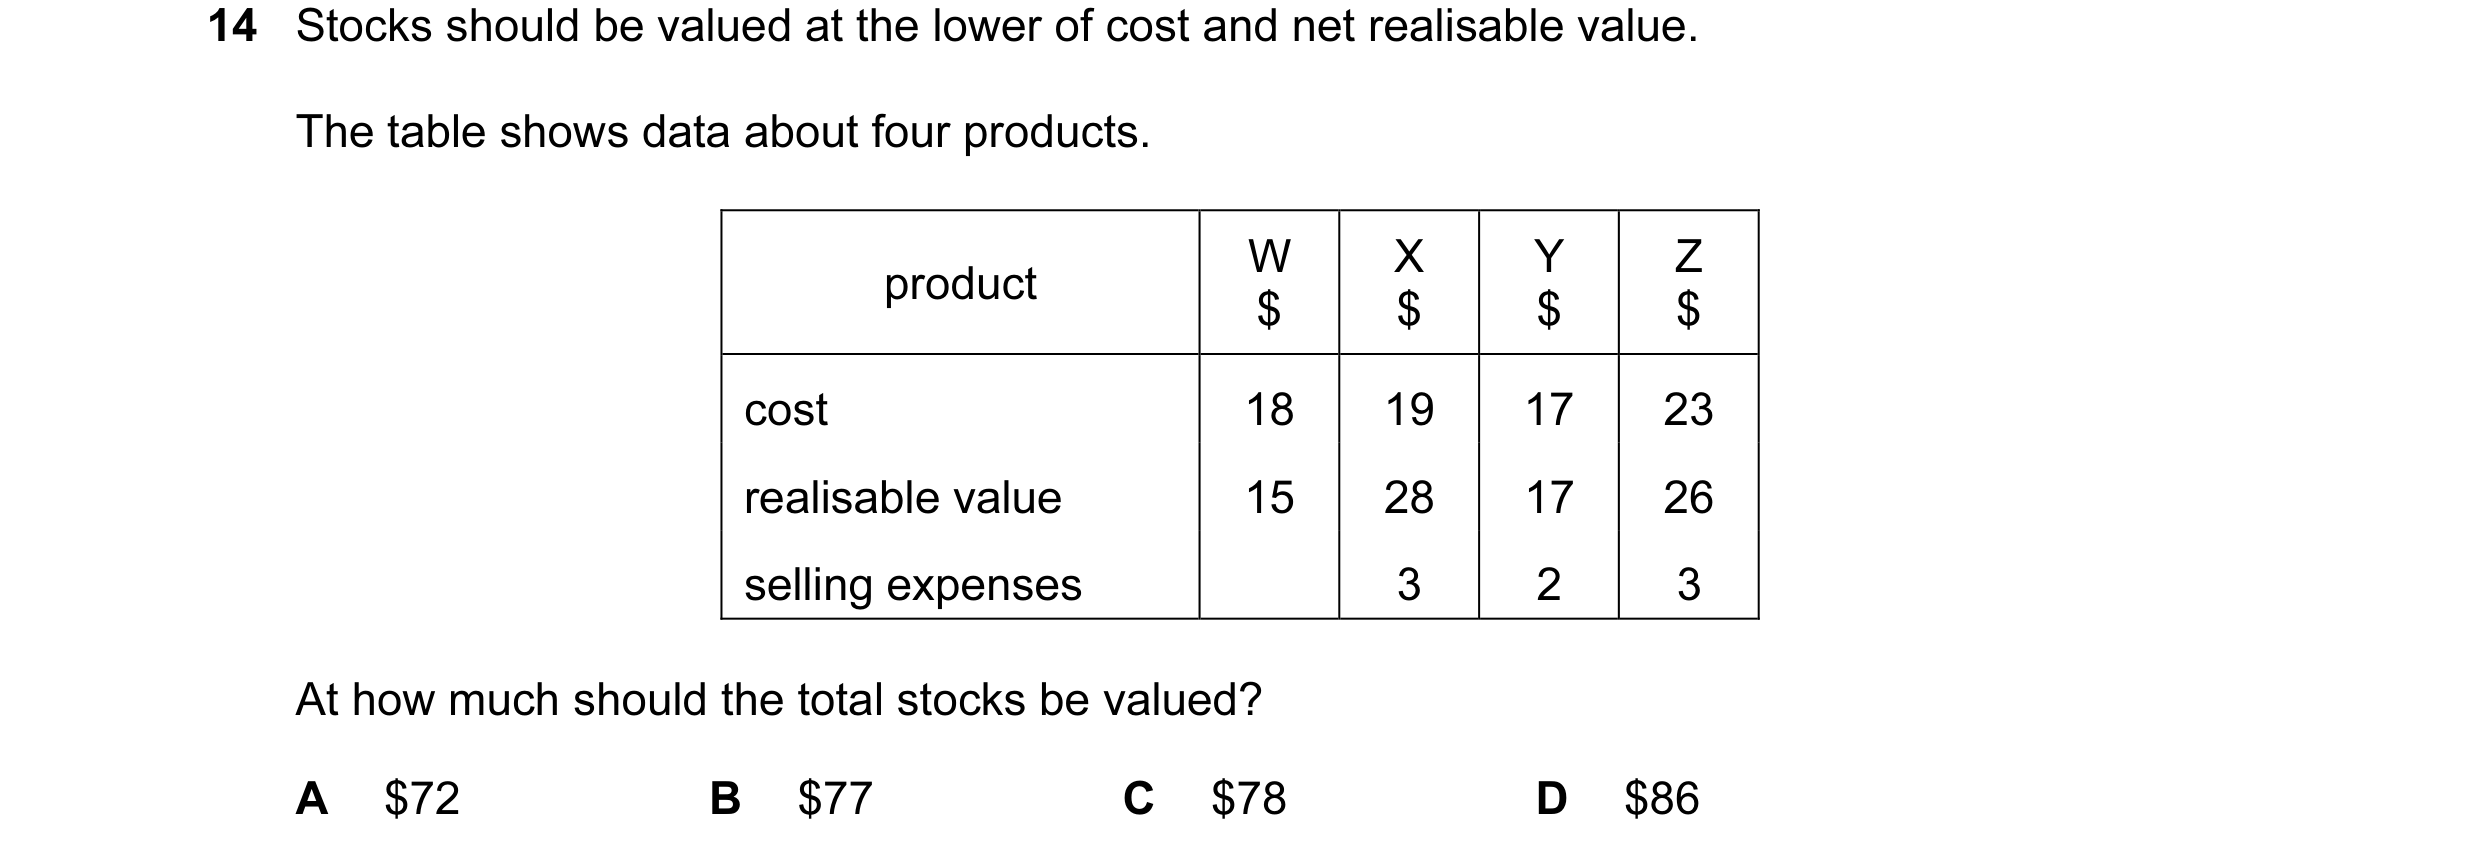 2 / 58
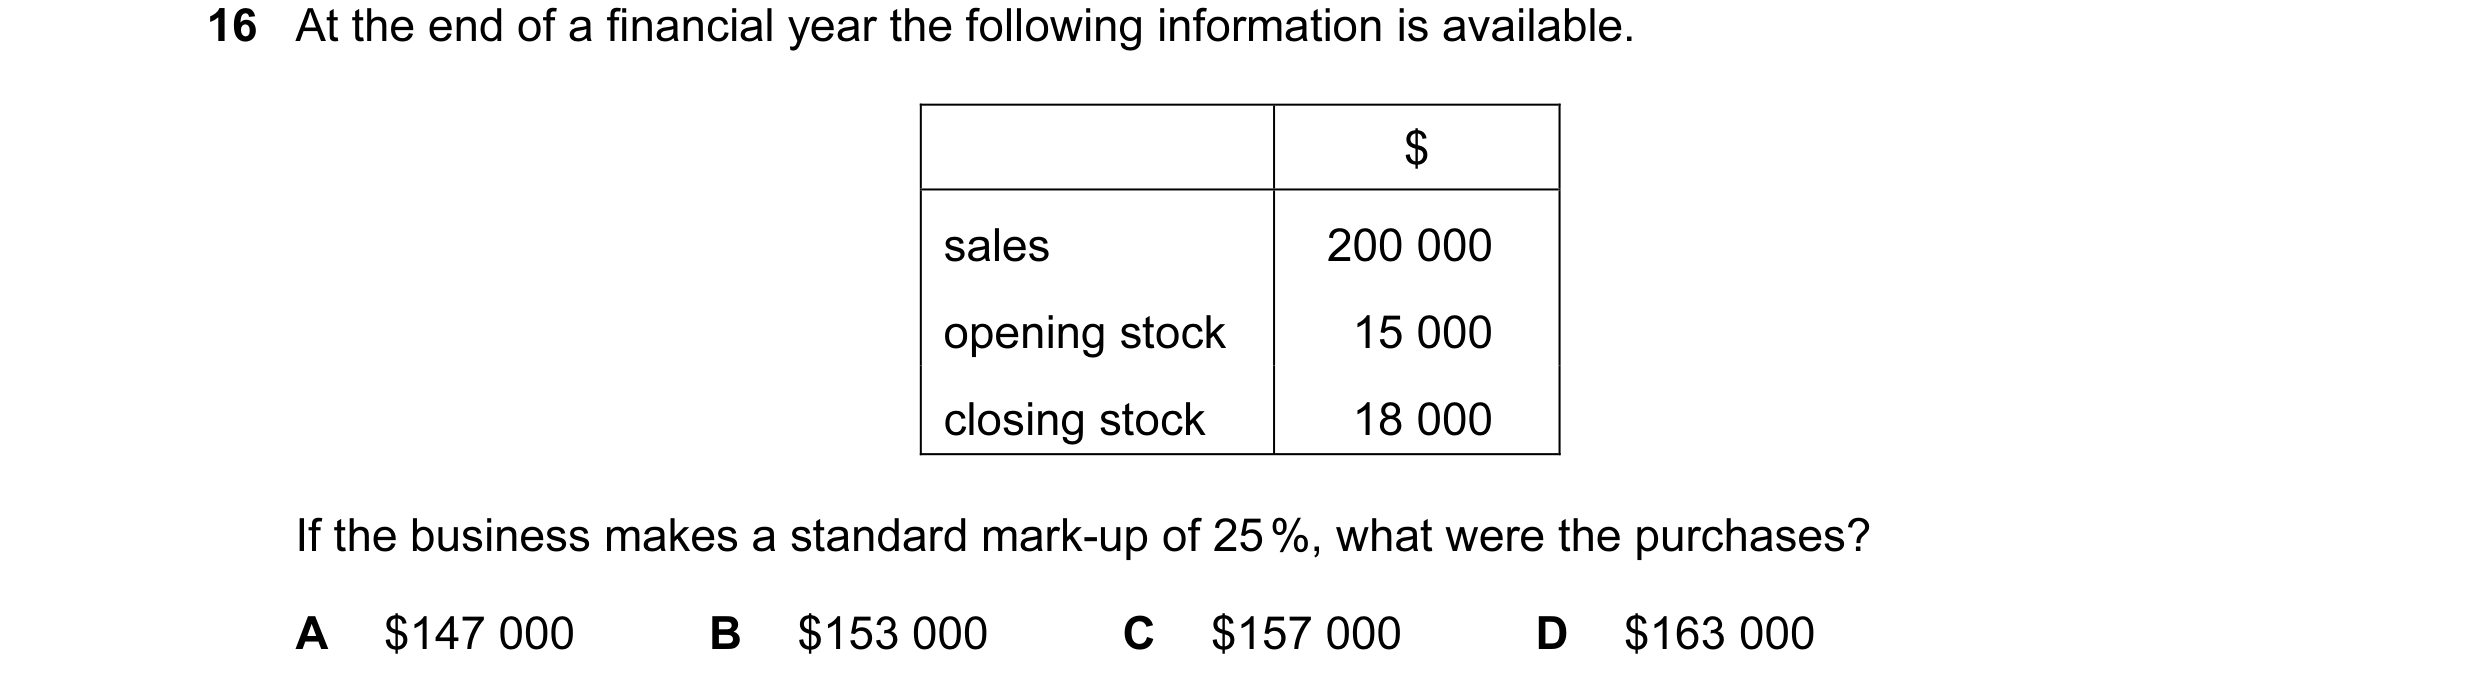
 3 / 58
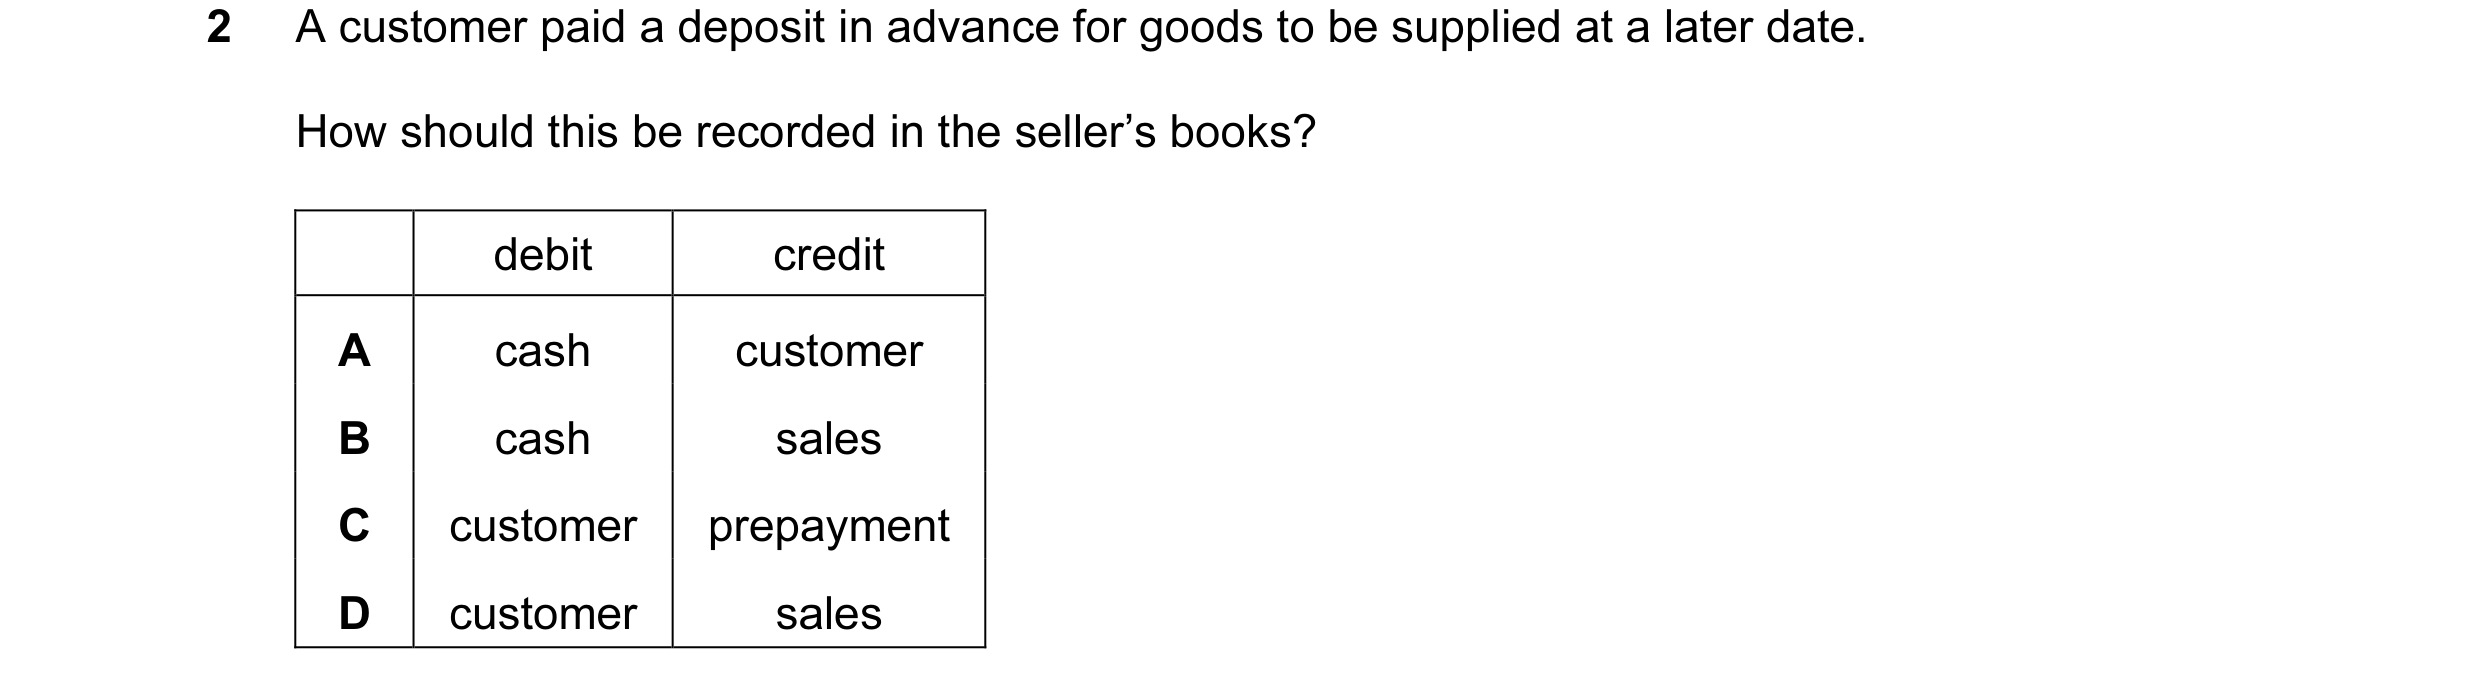
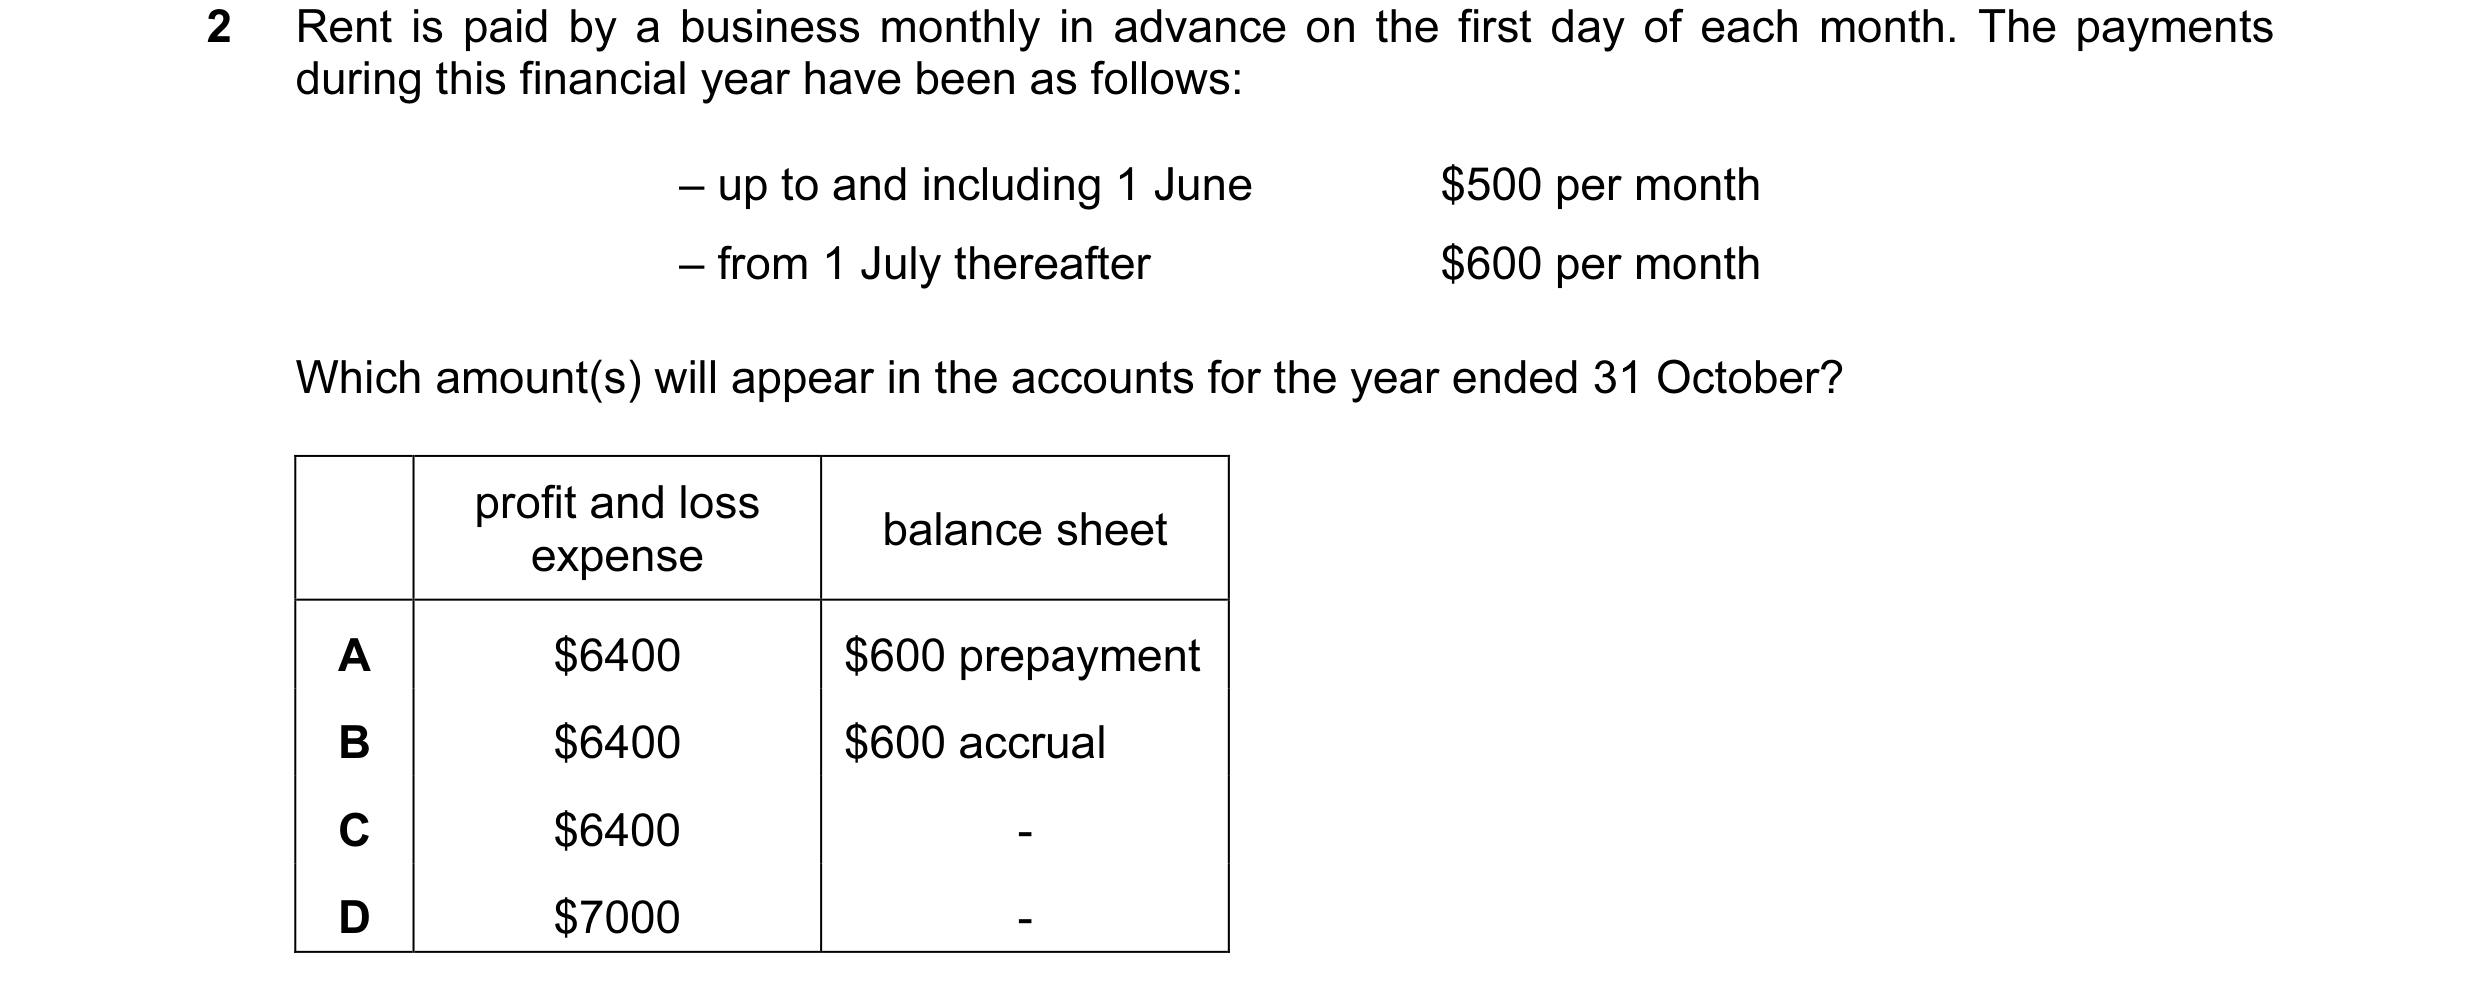 4 / 58
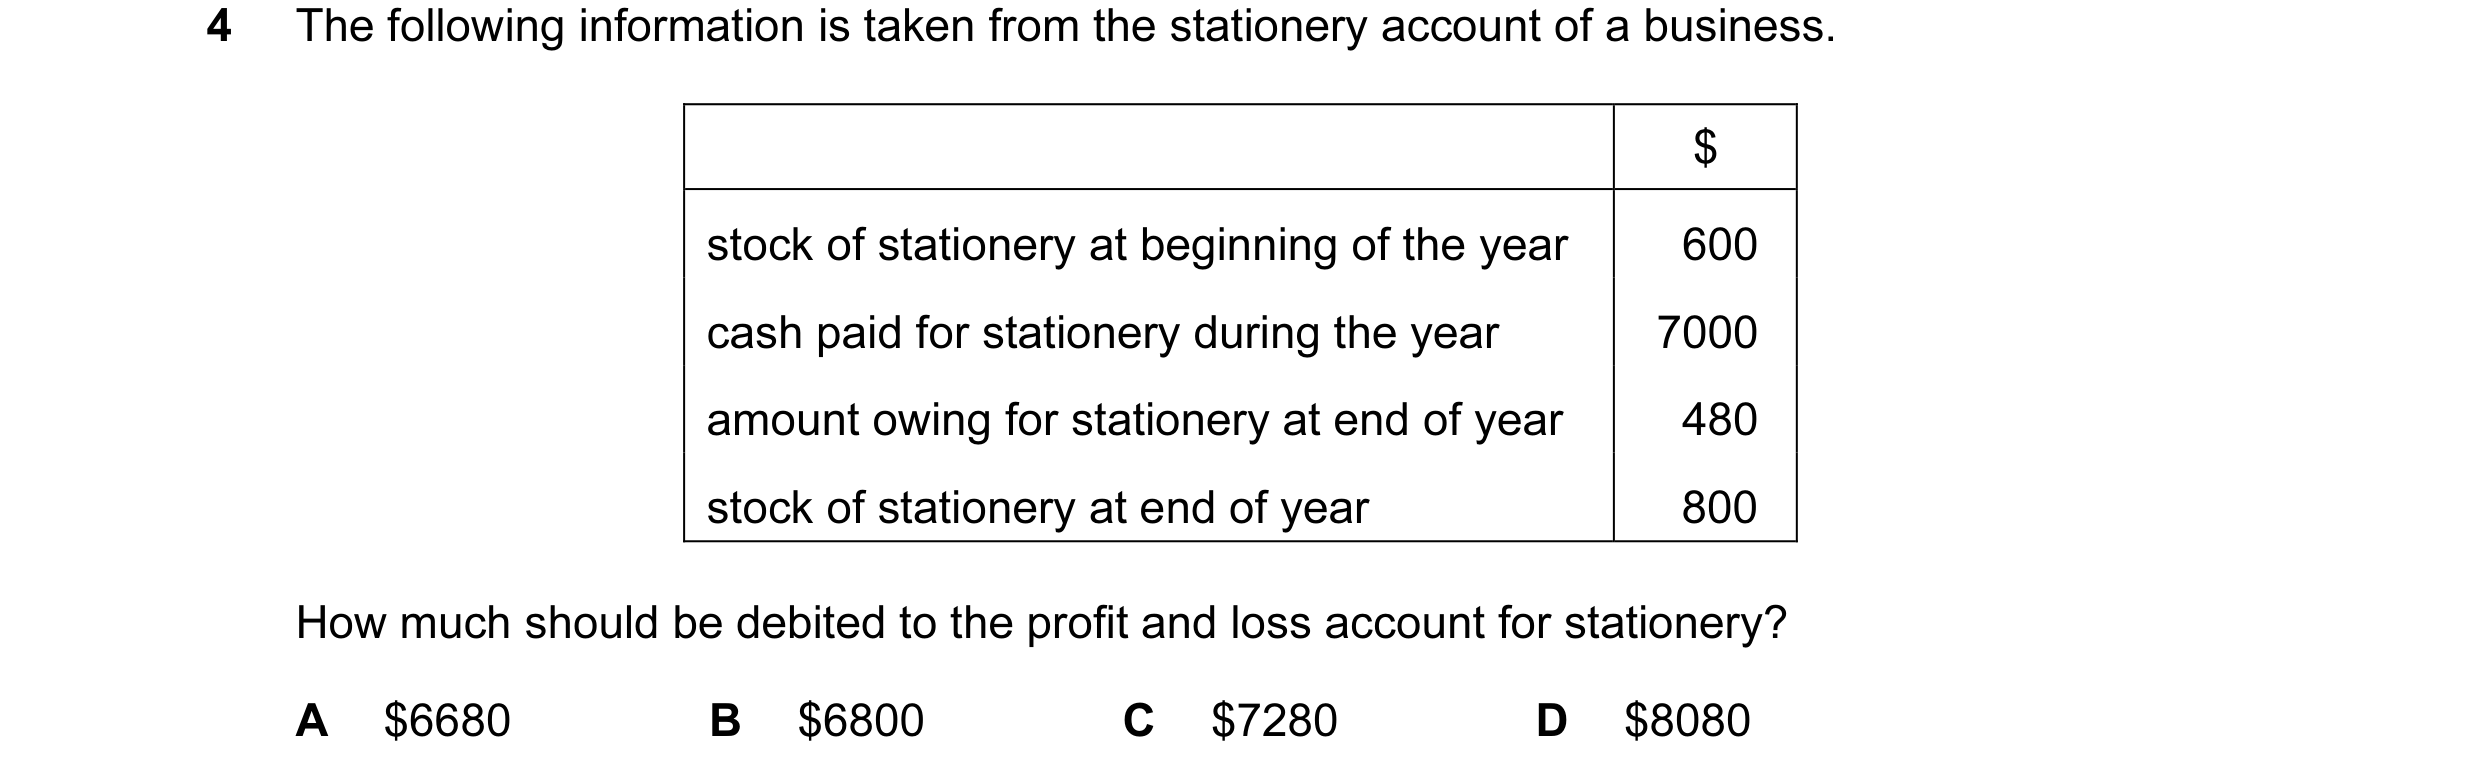
 5 / 58
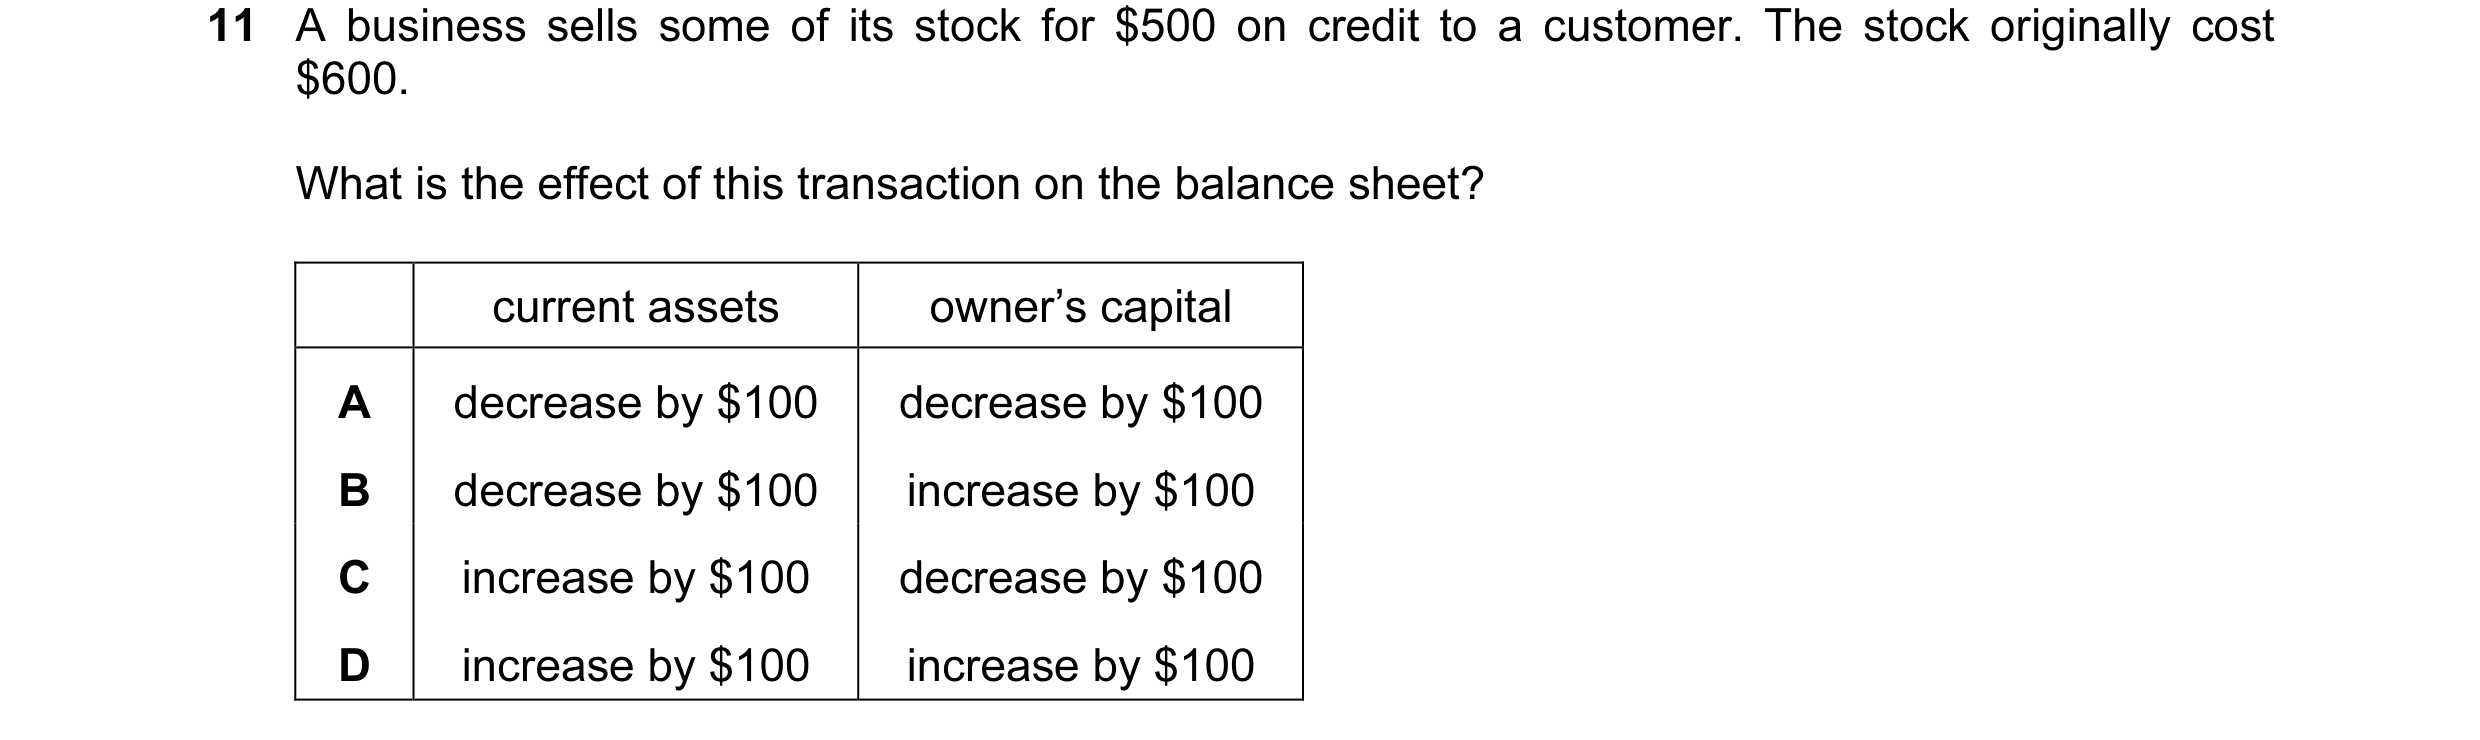
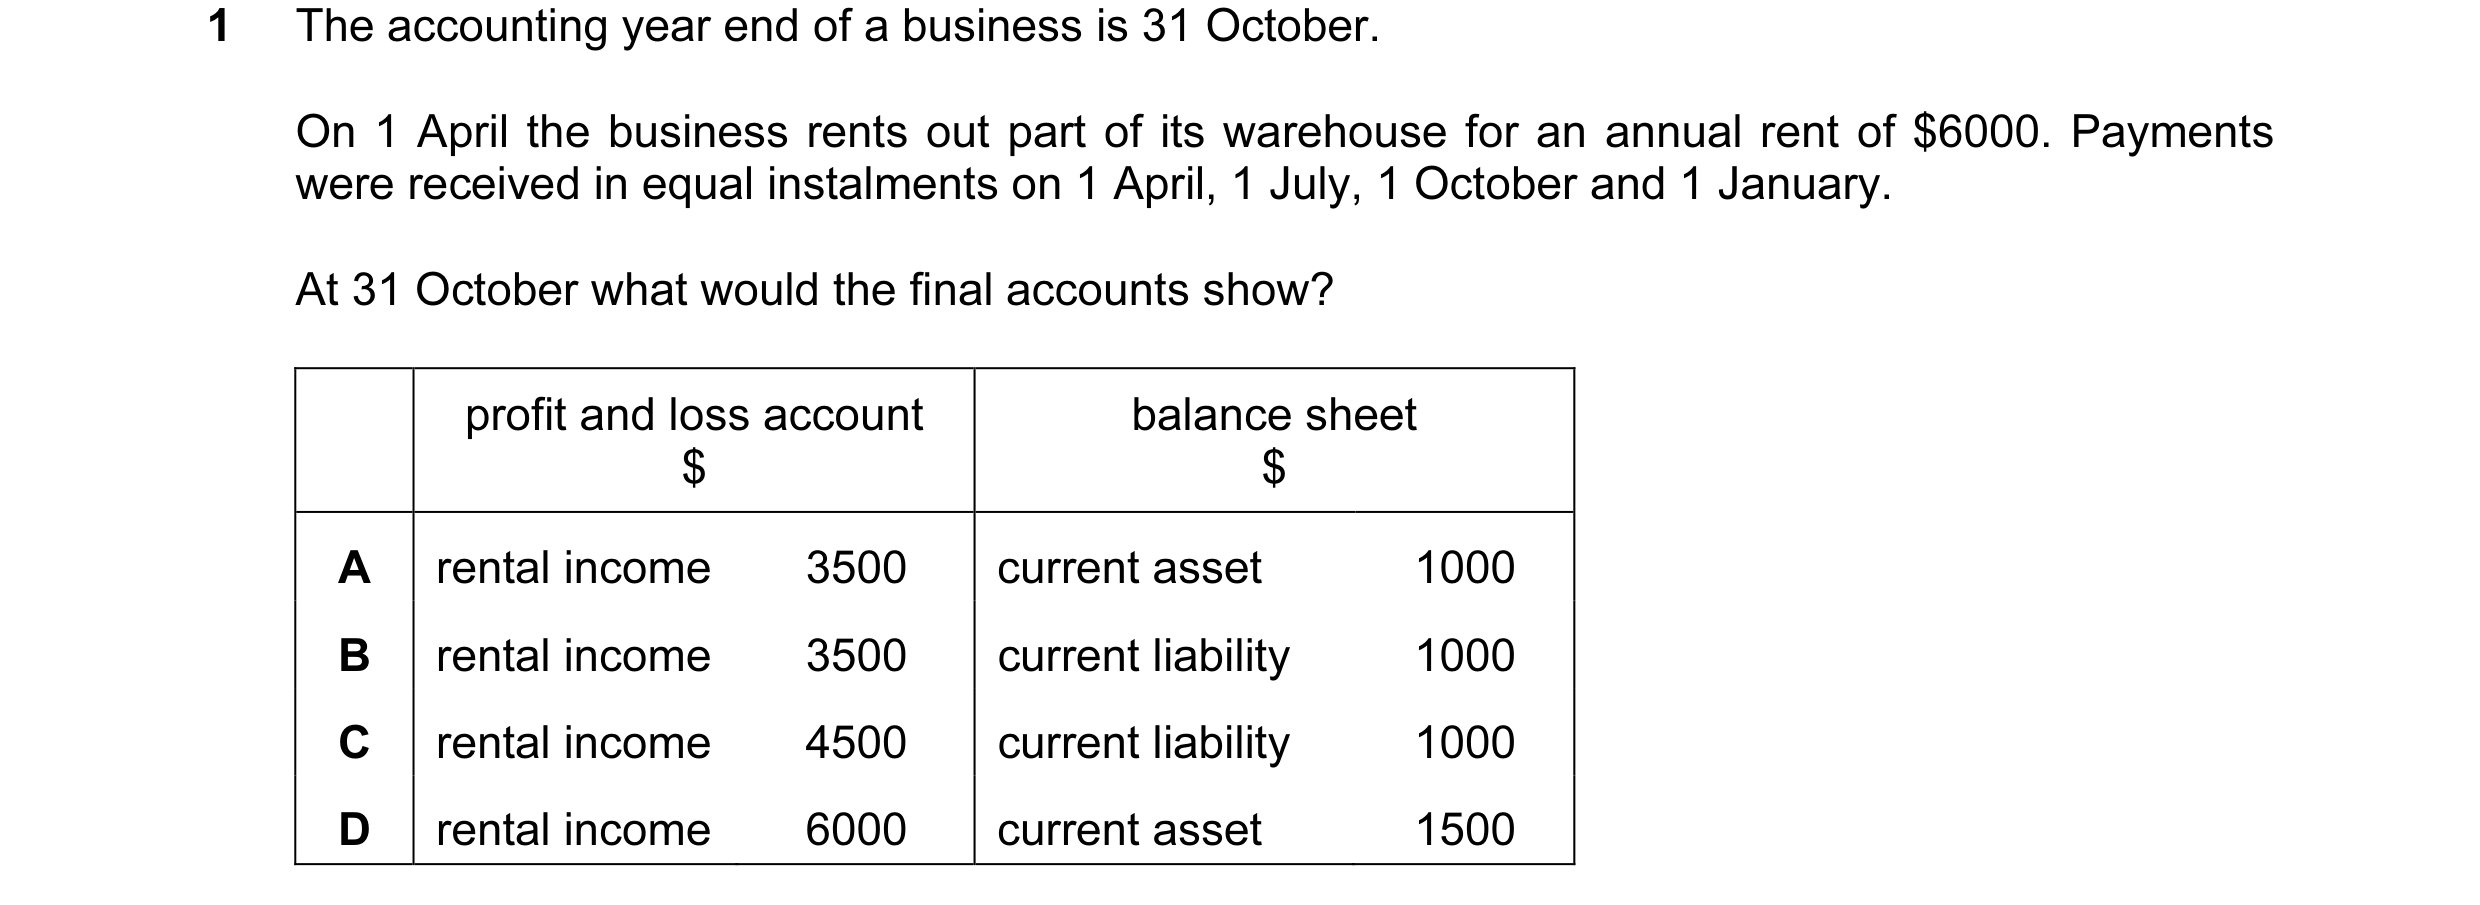
 6 / 58
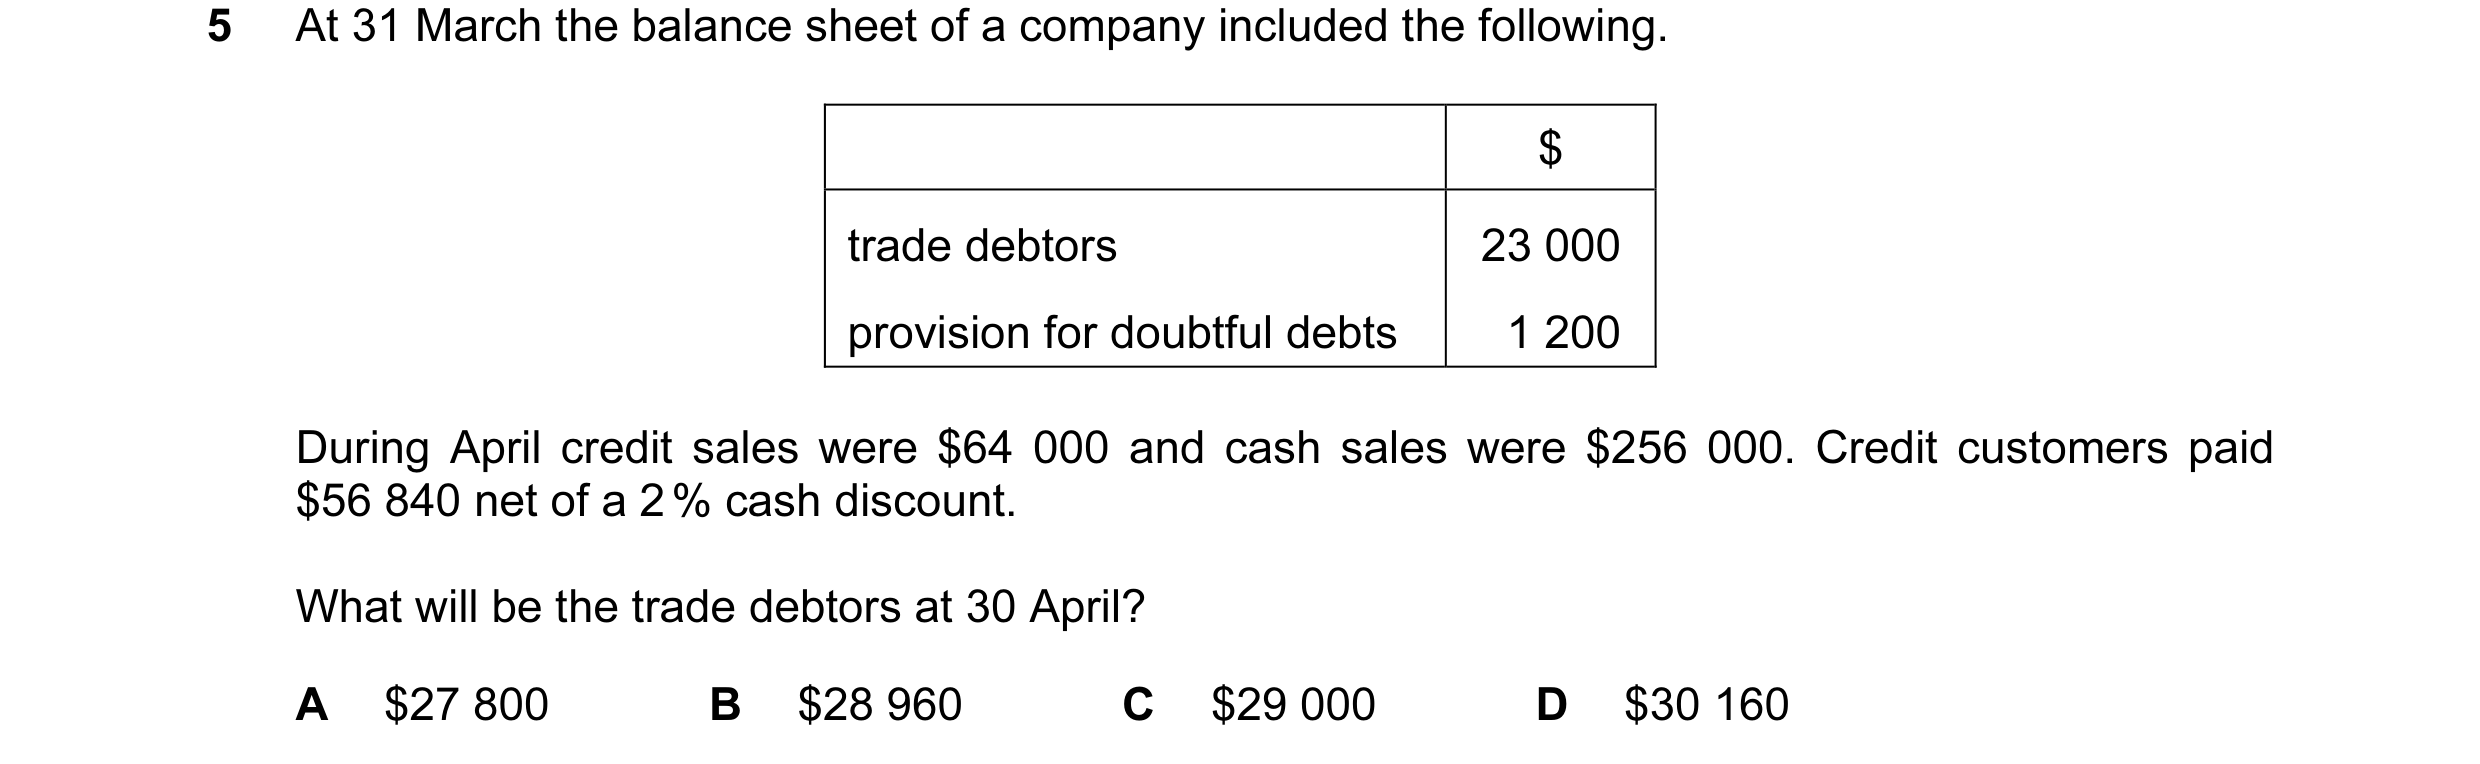
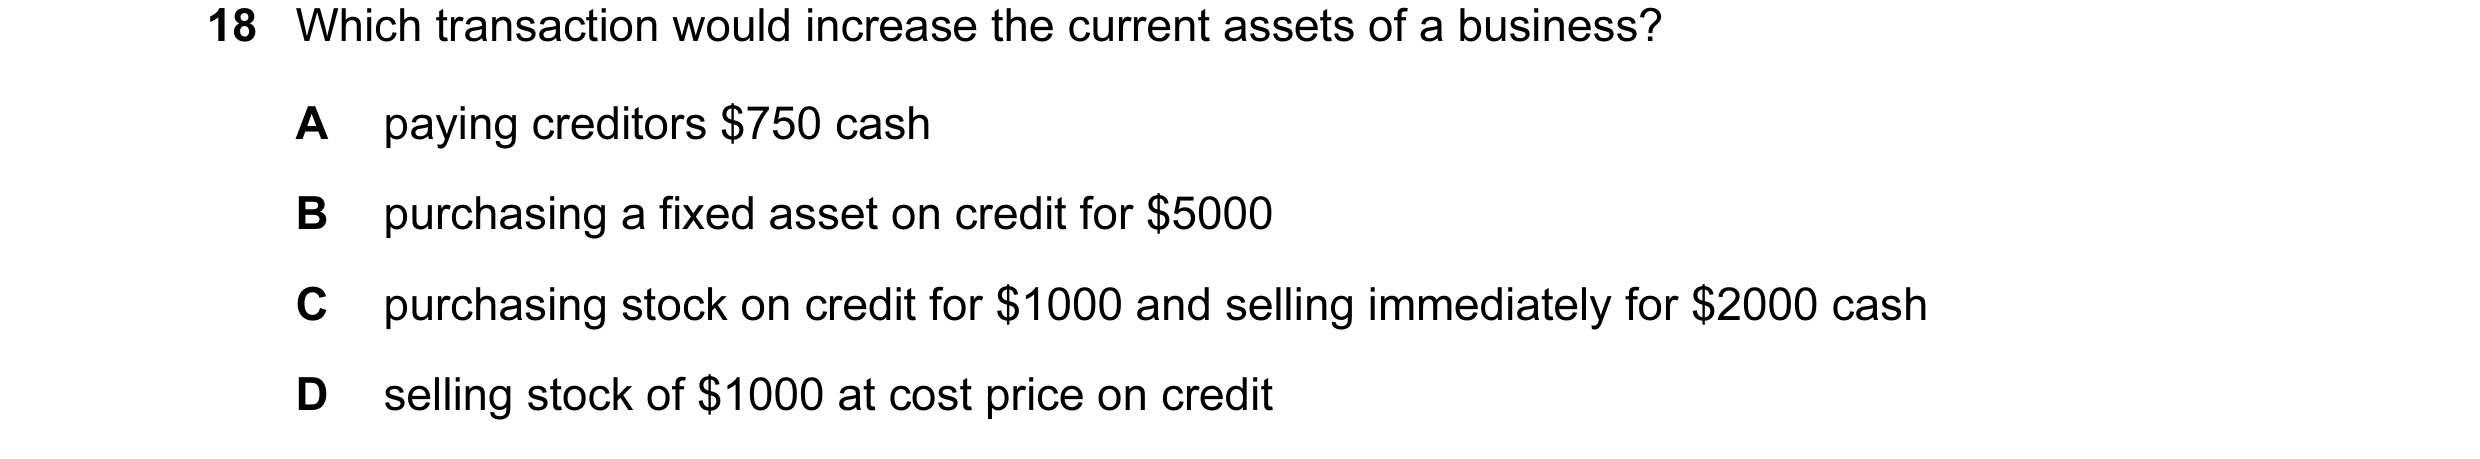
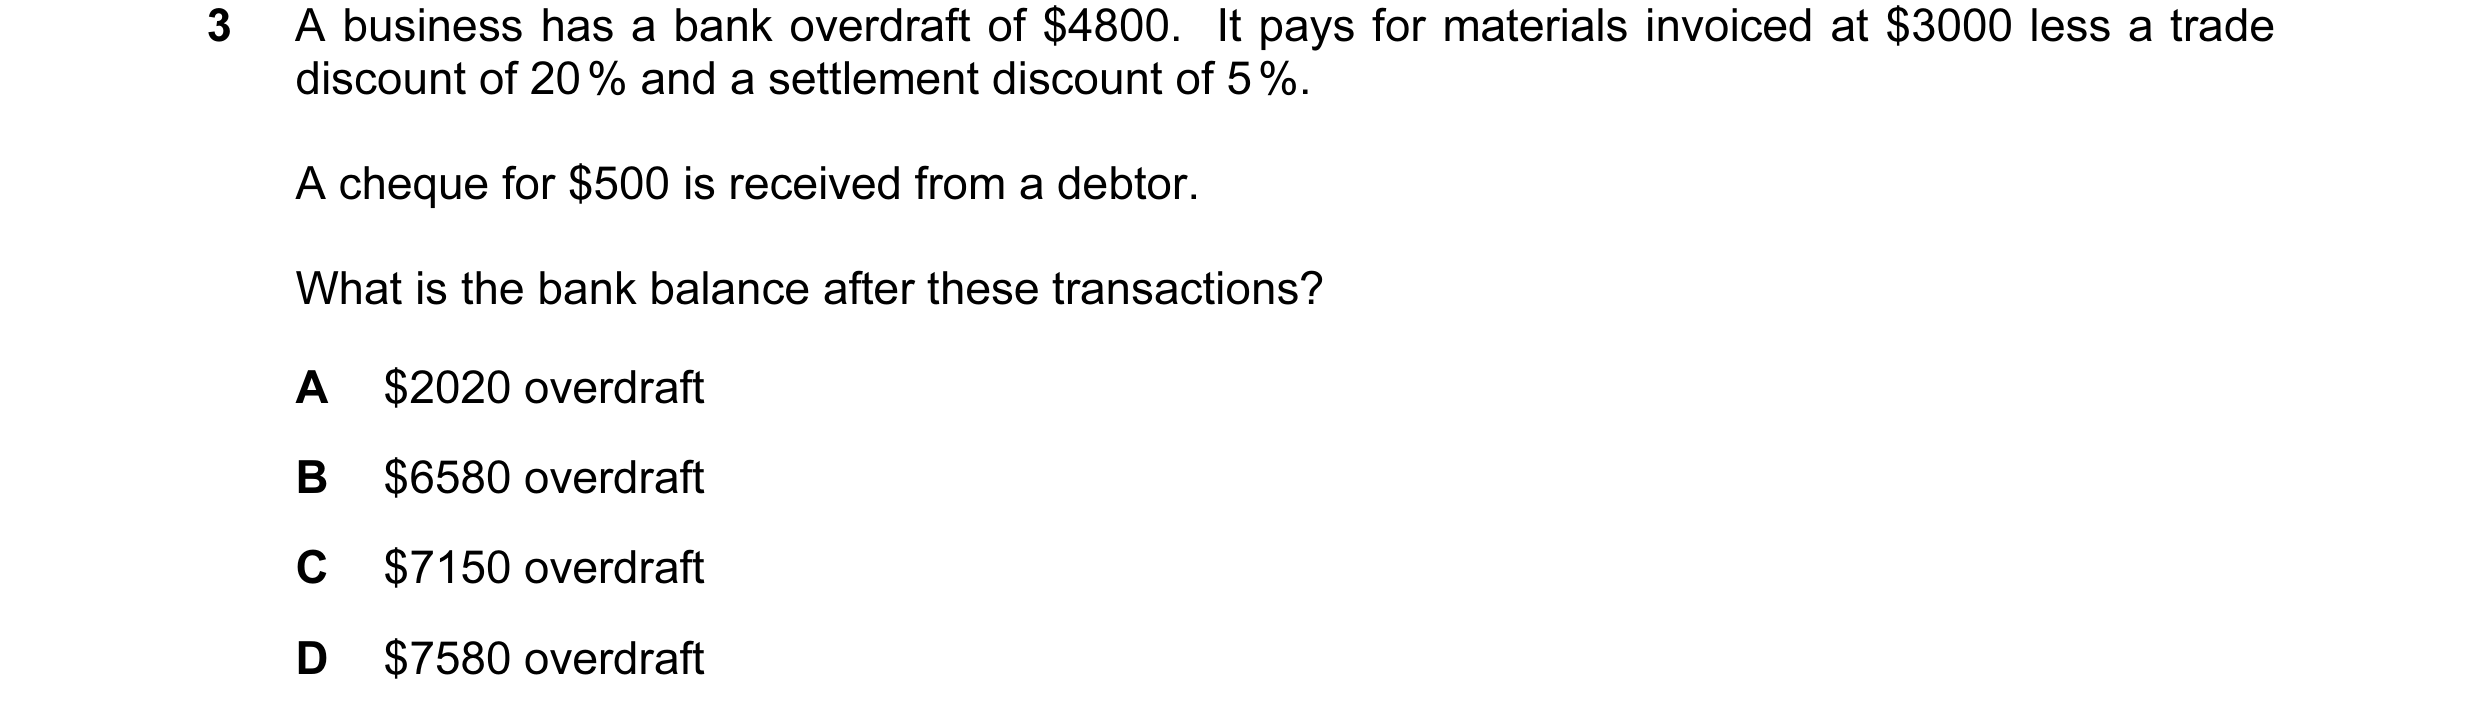
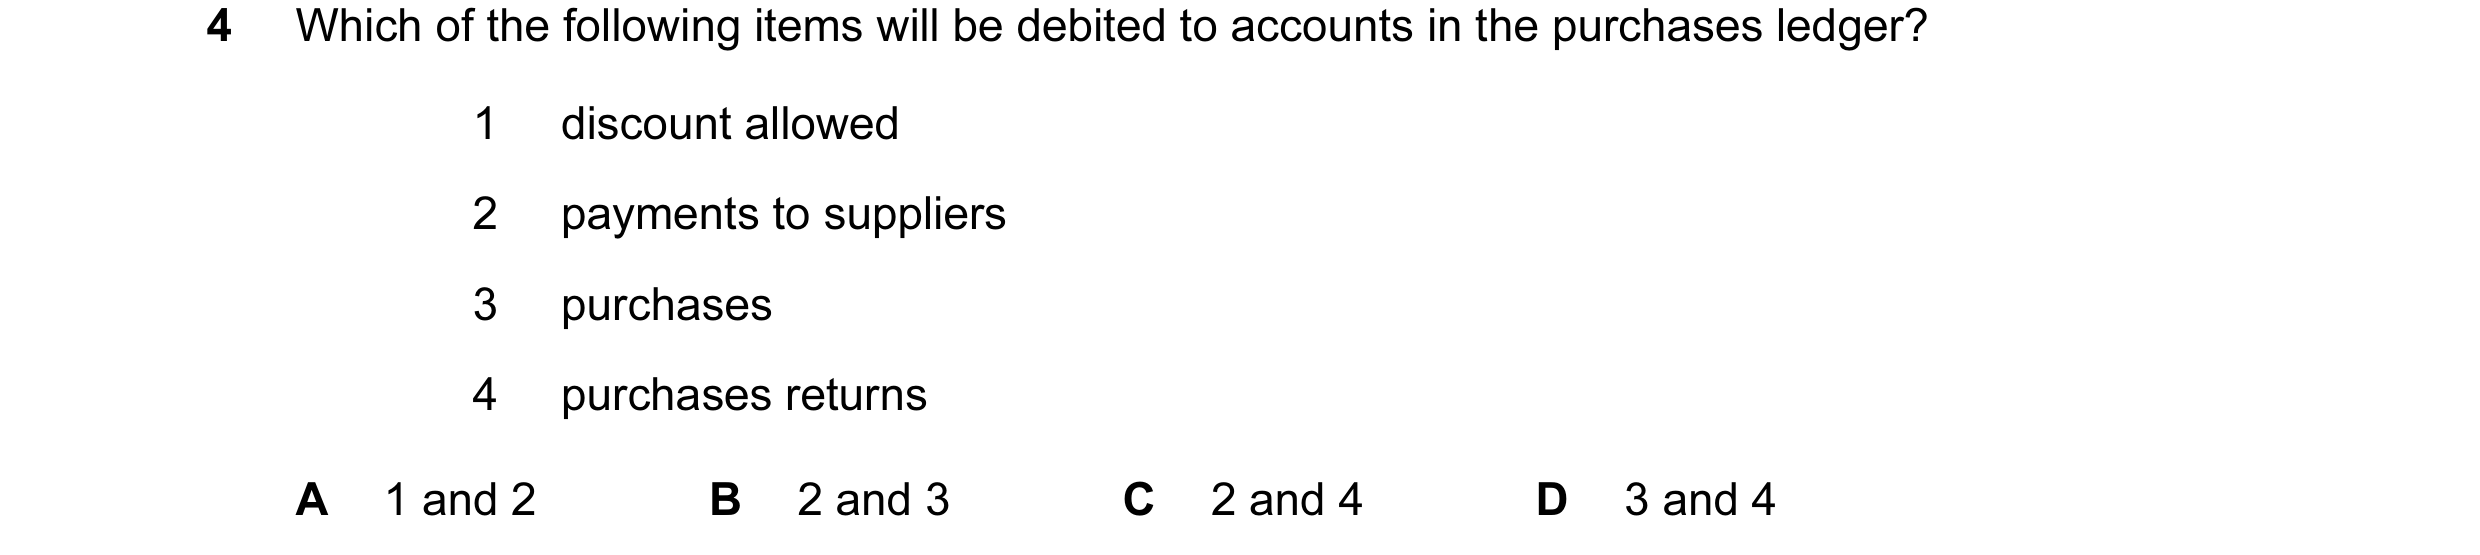
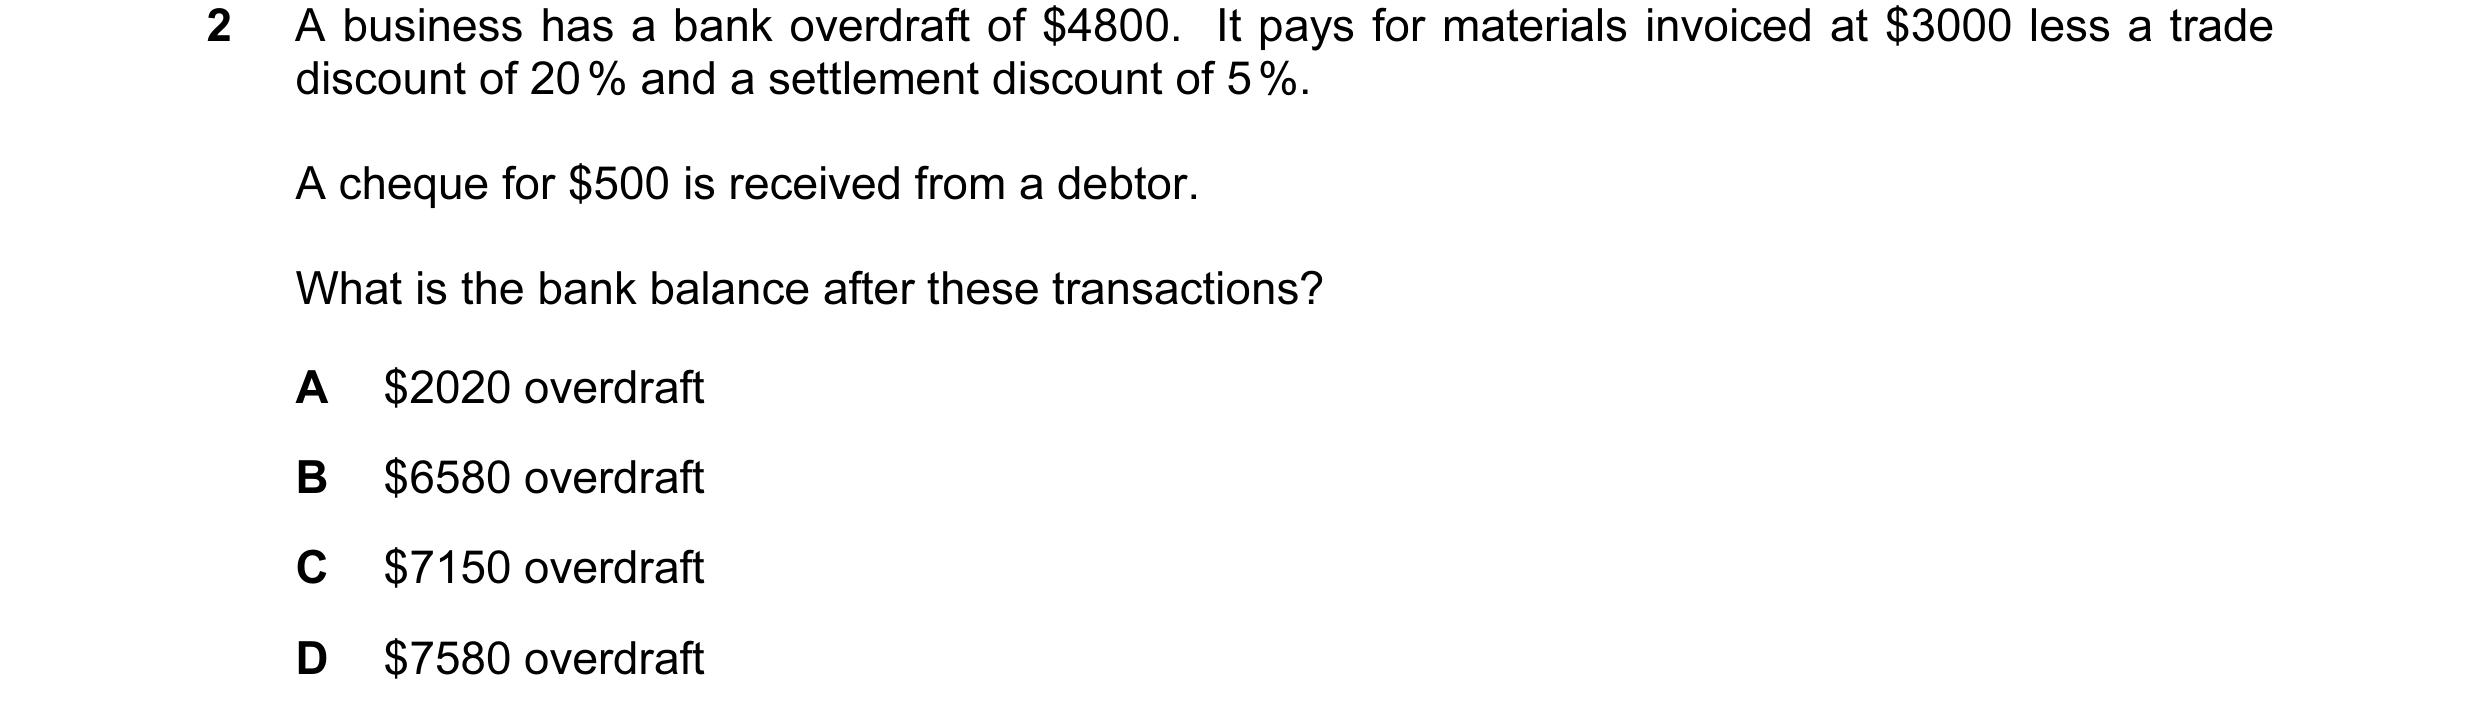 7 / 58
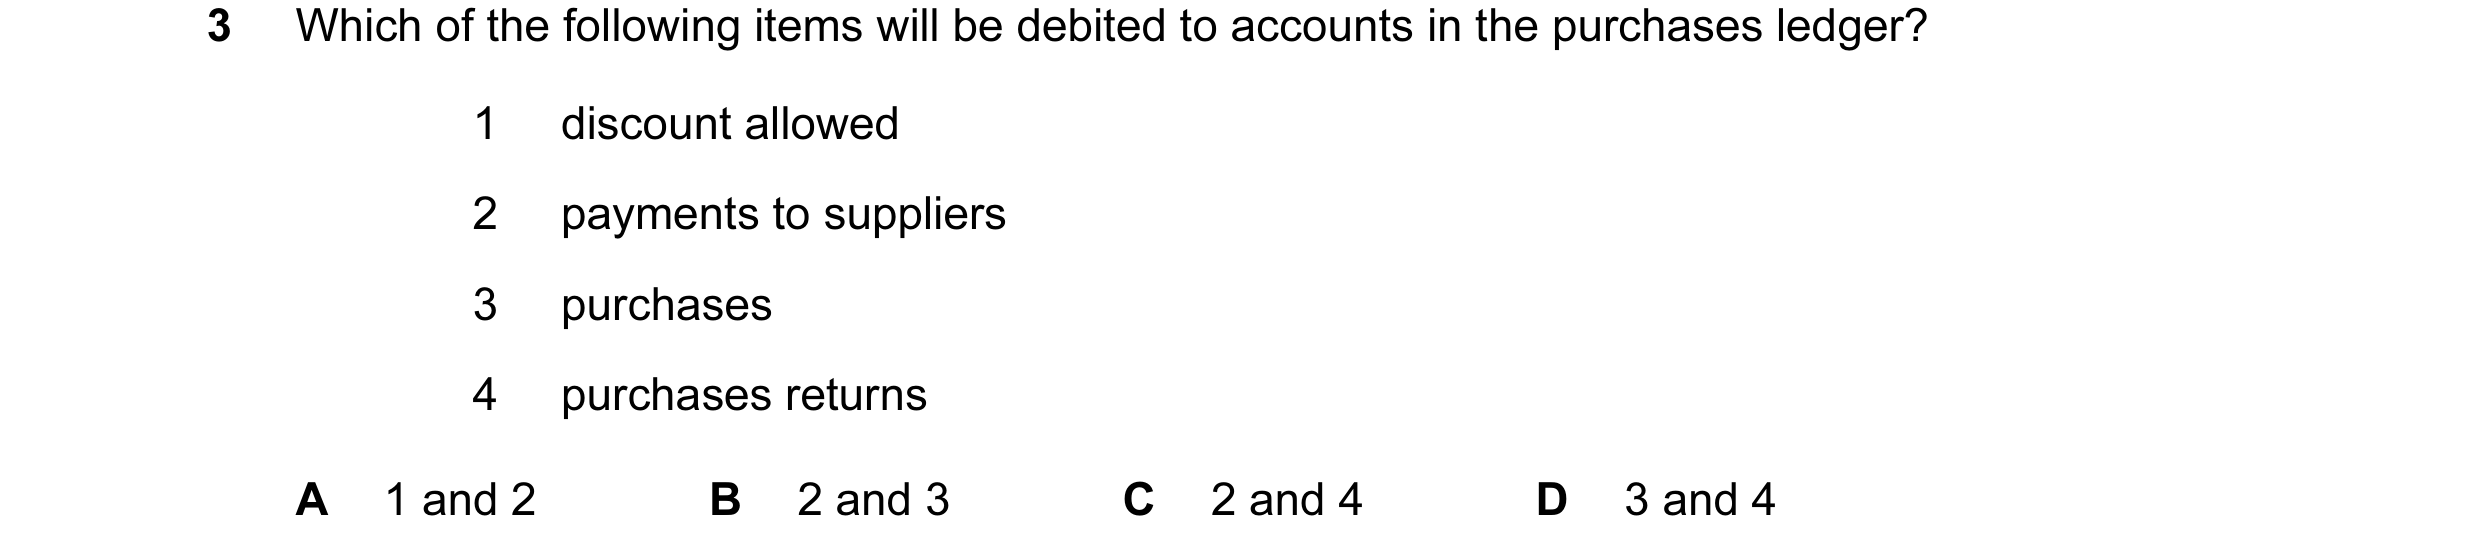
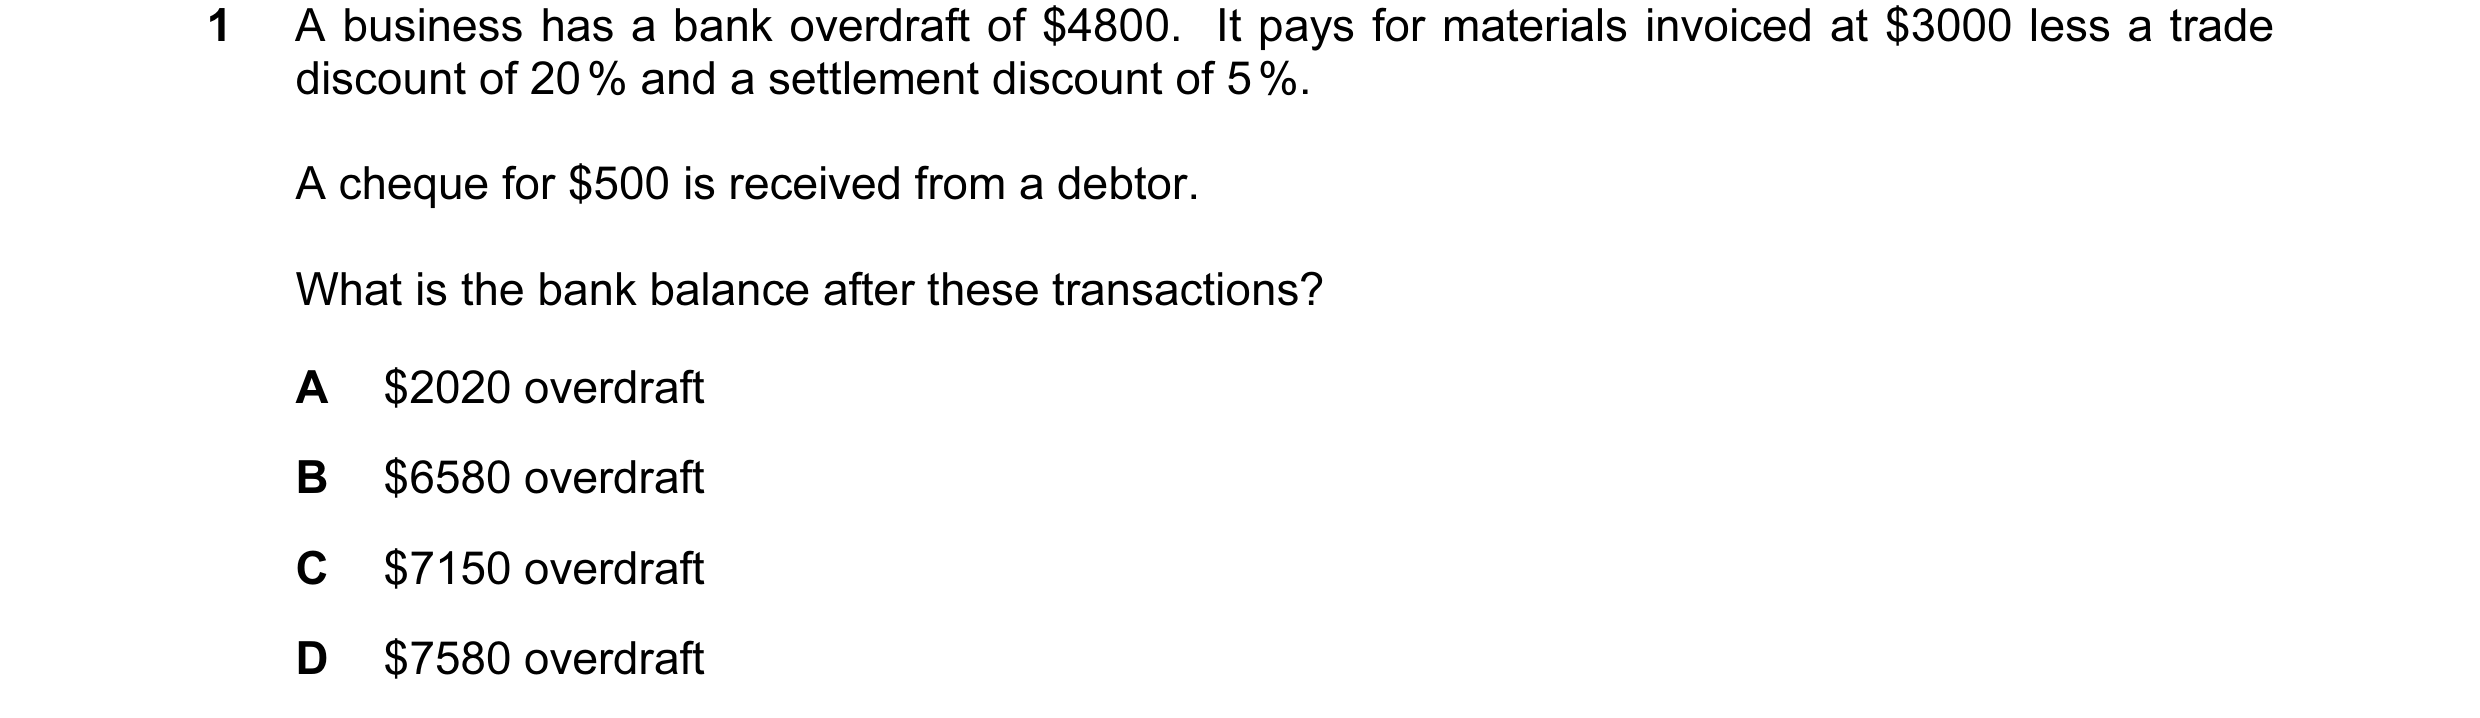
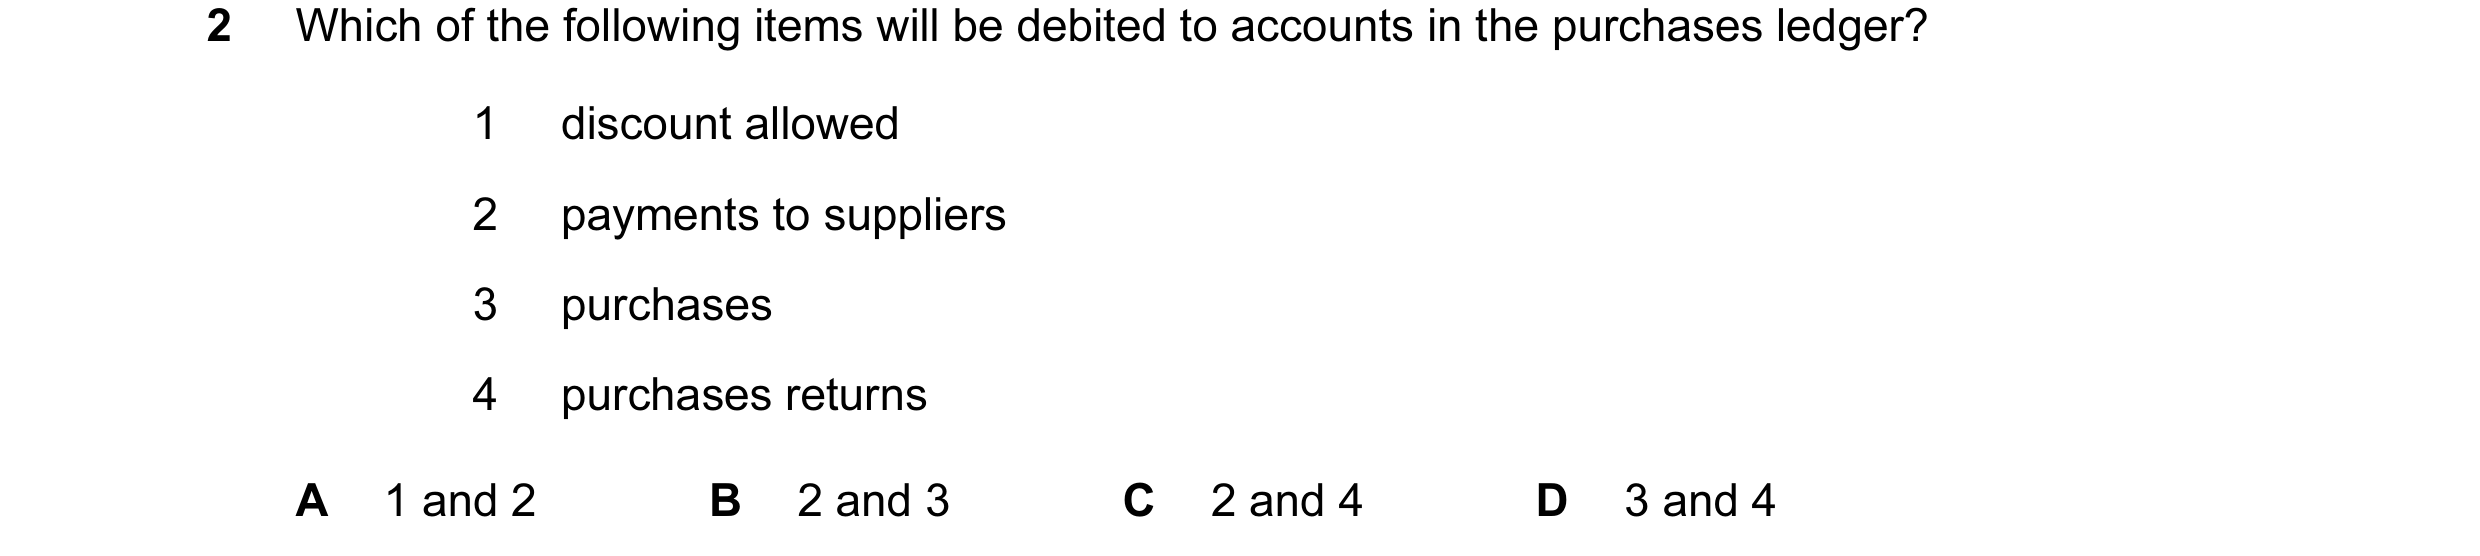
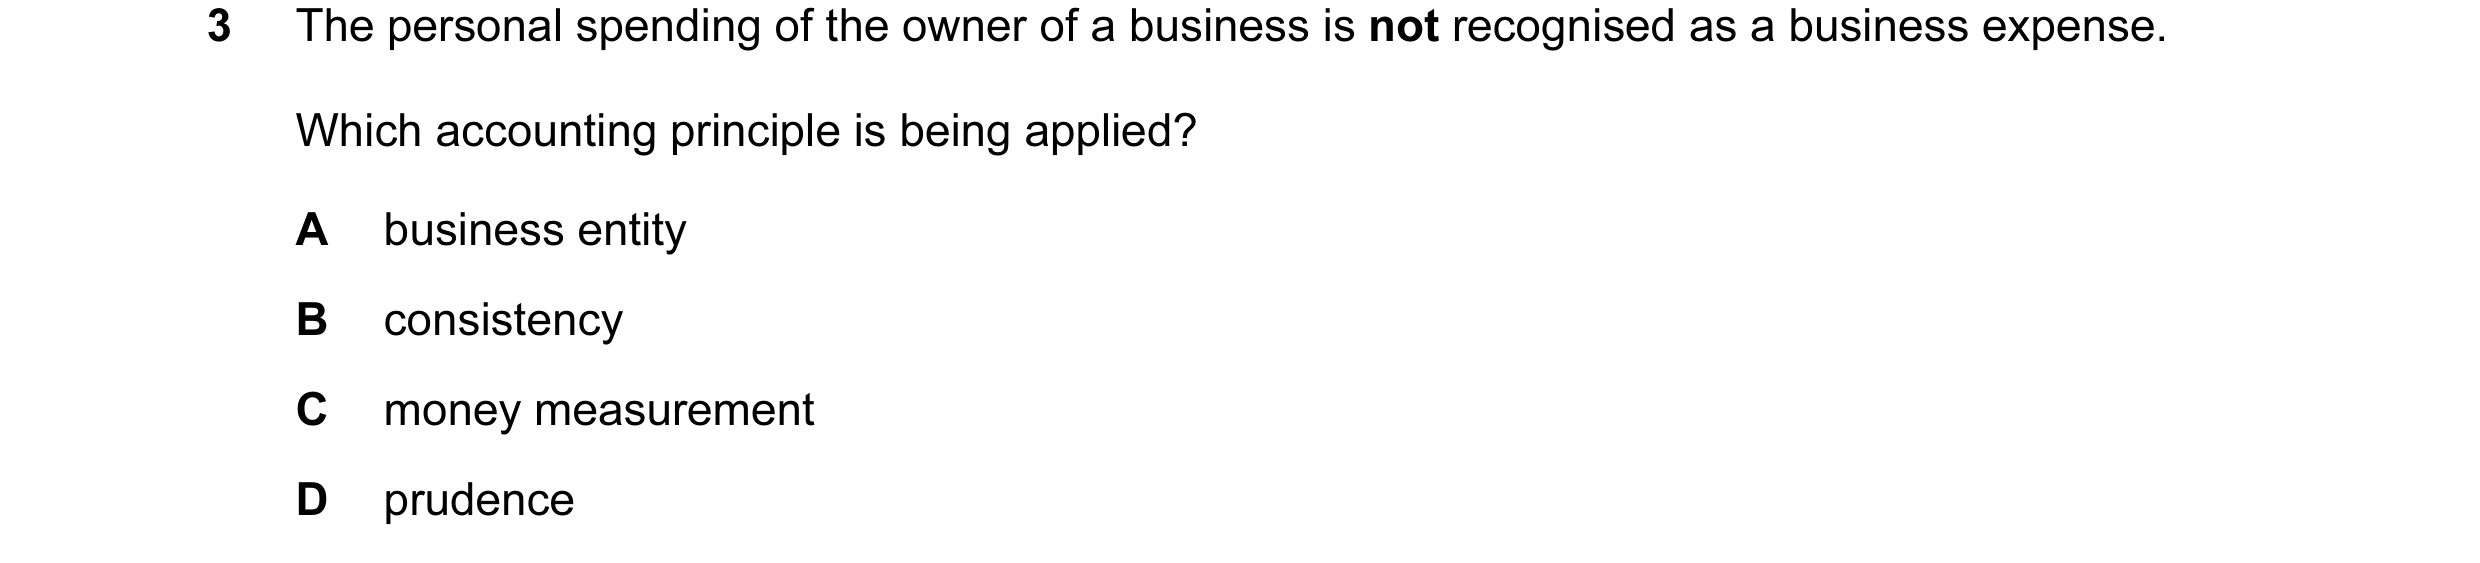
 8 / 58
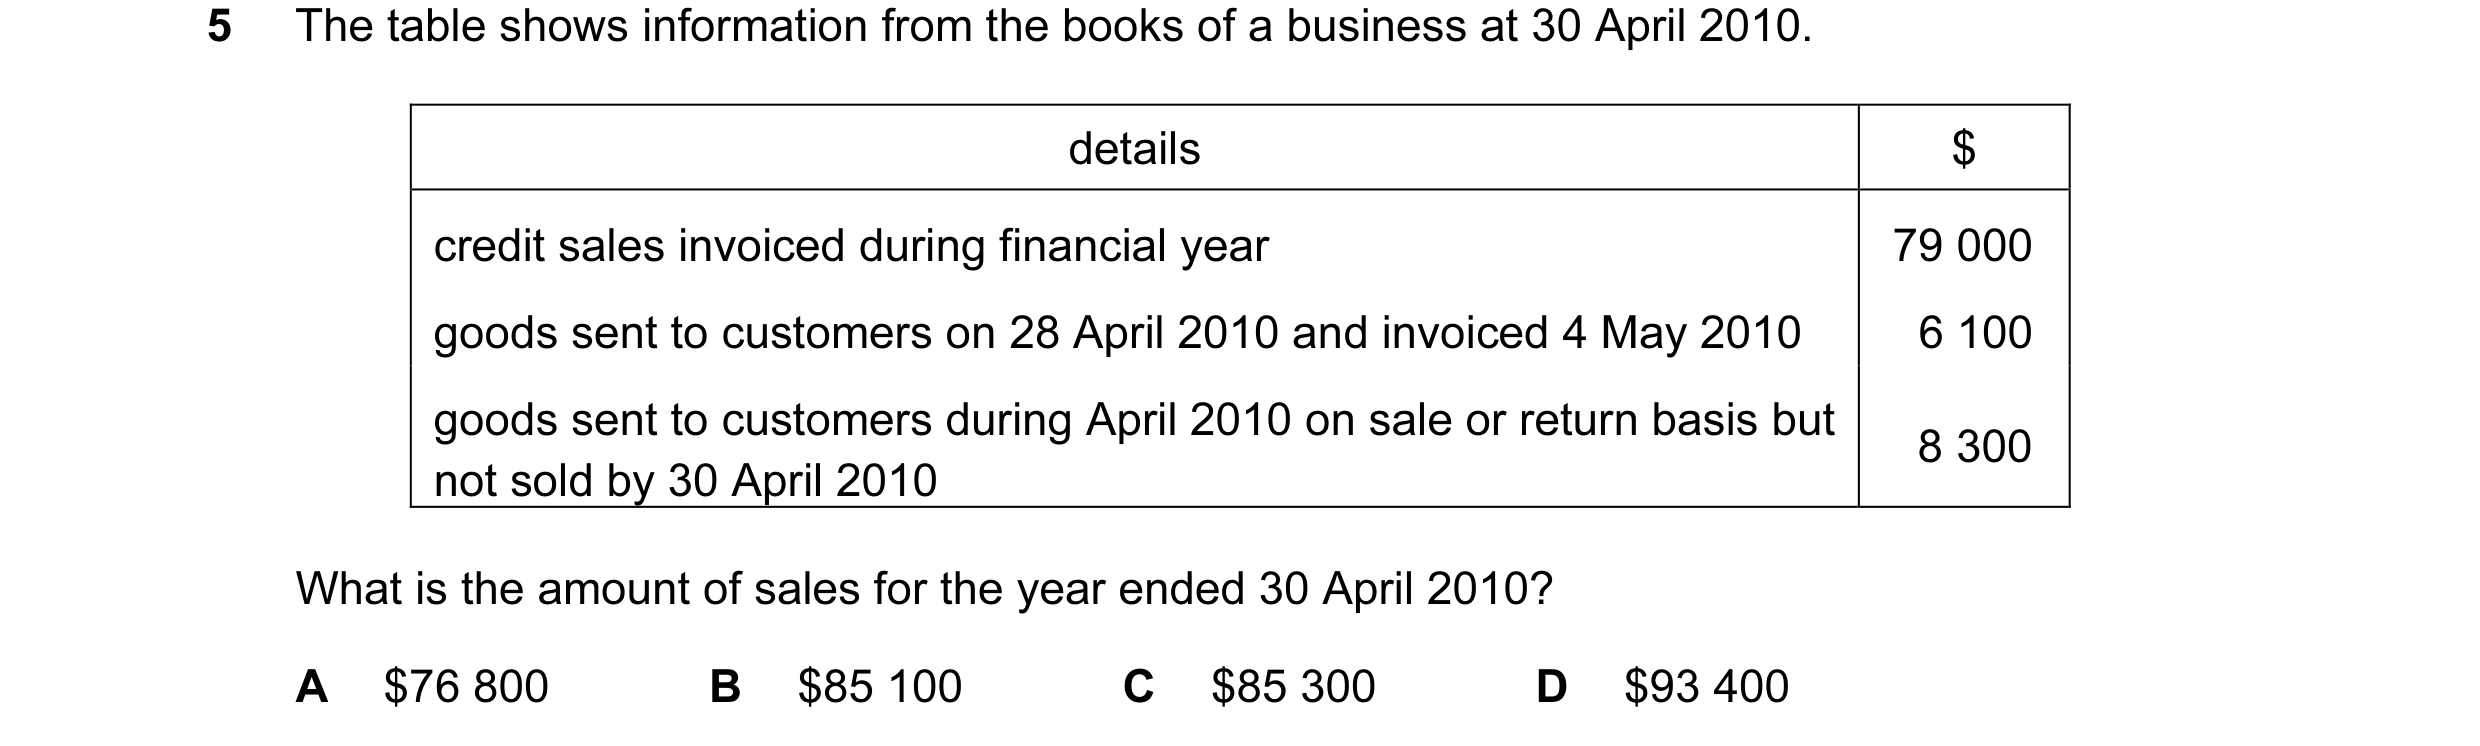
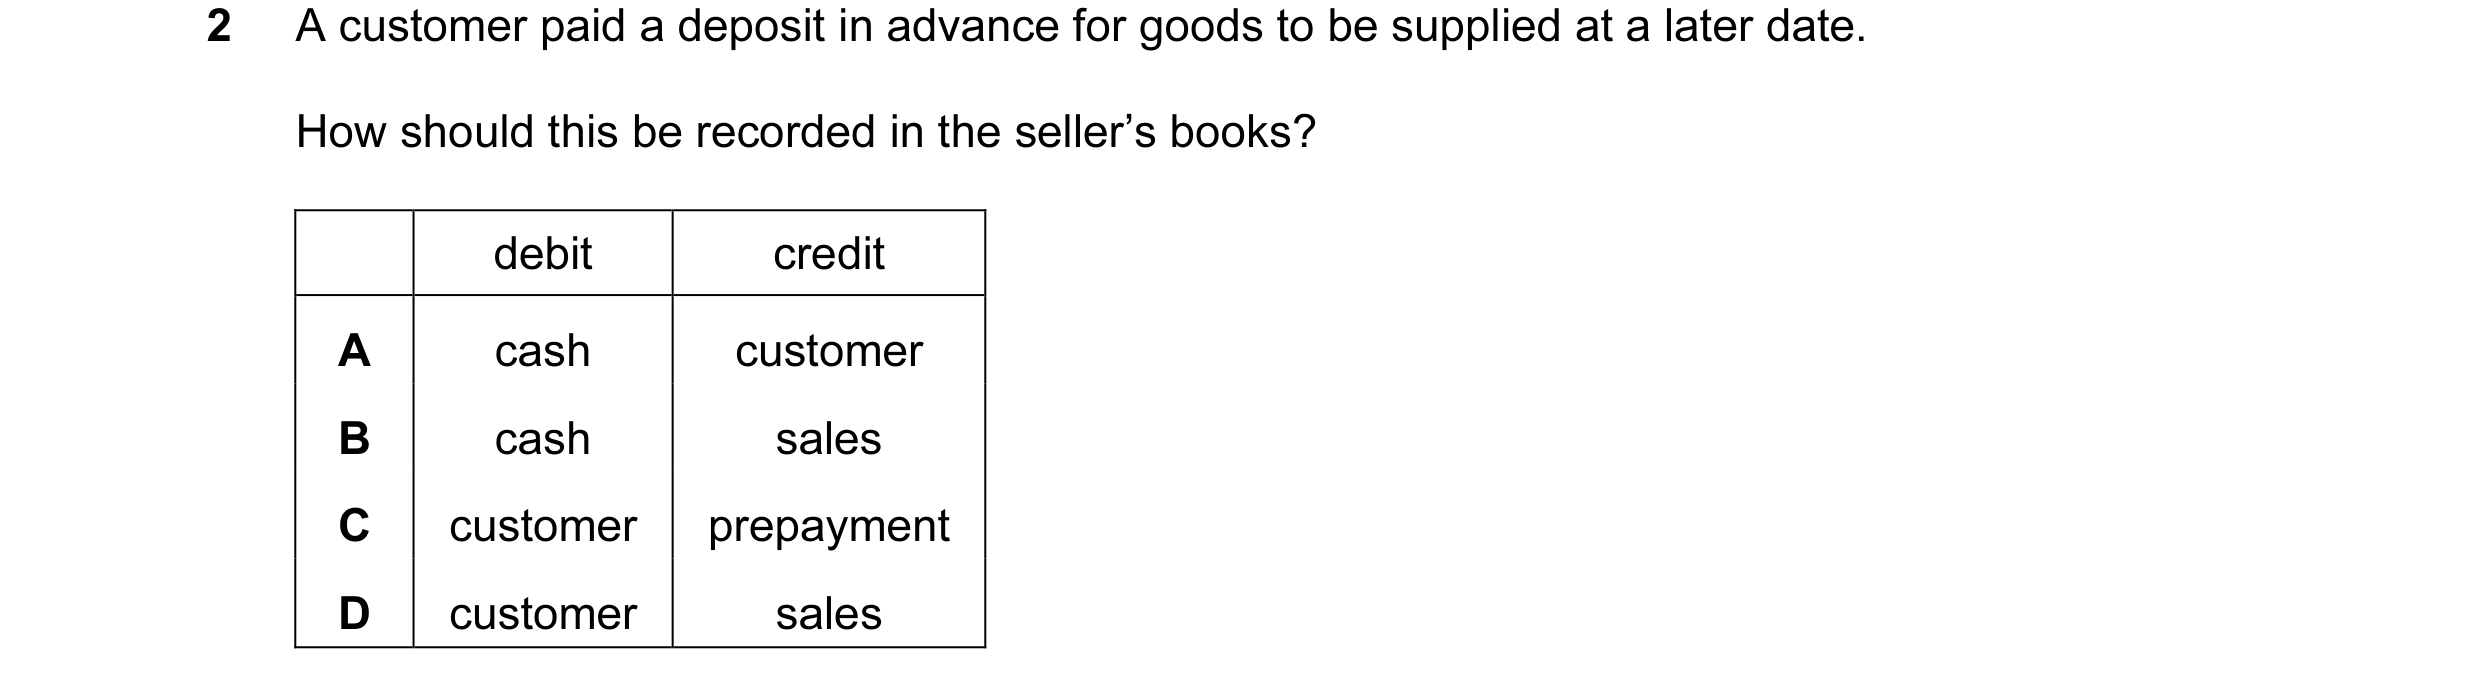 9 / 58
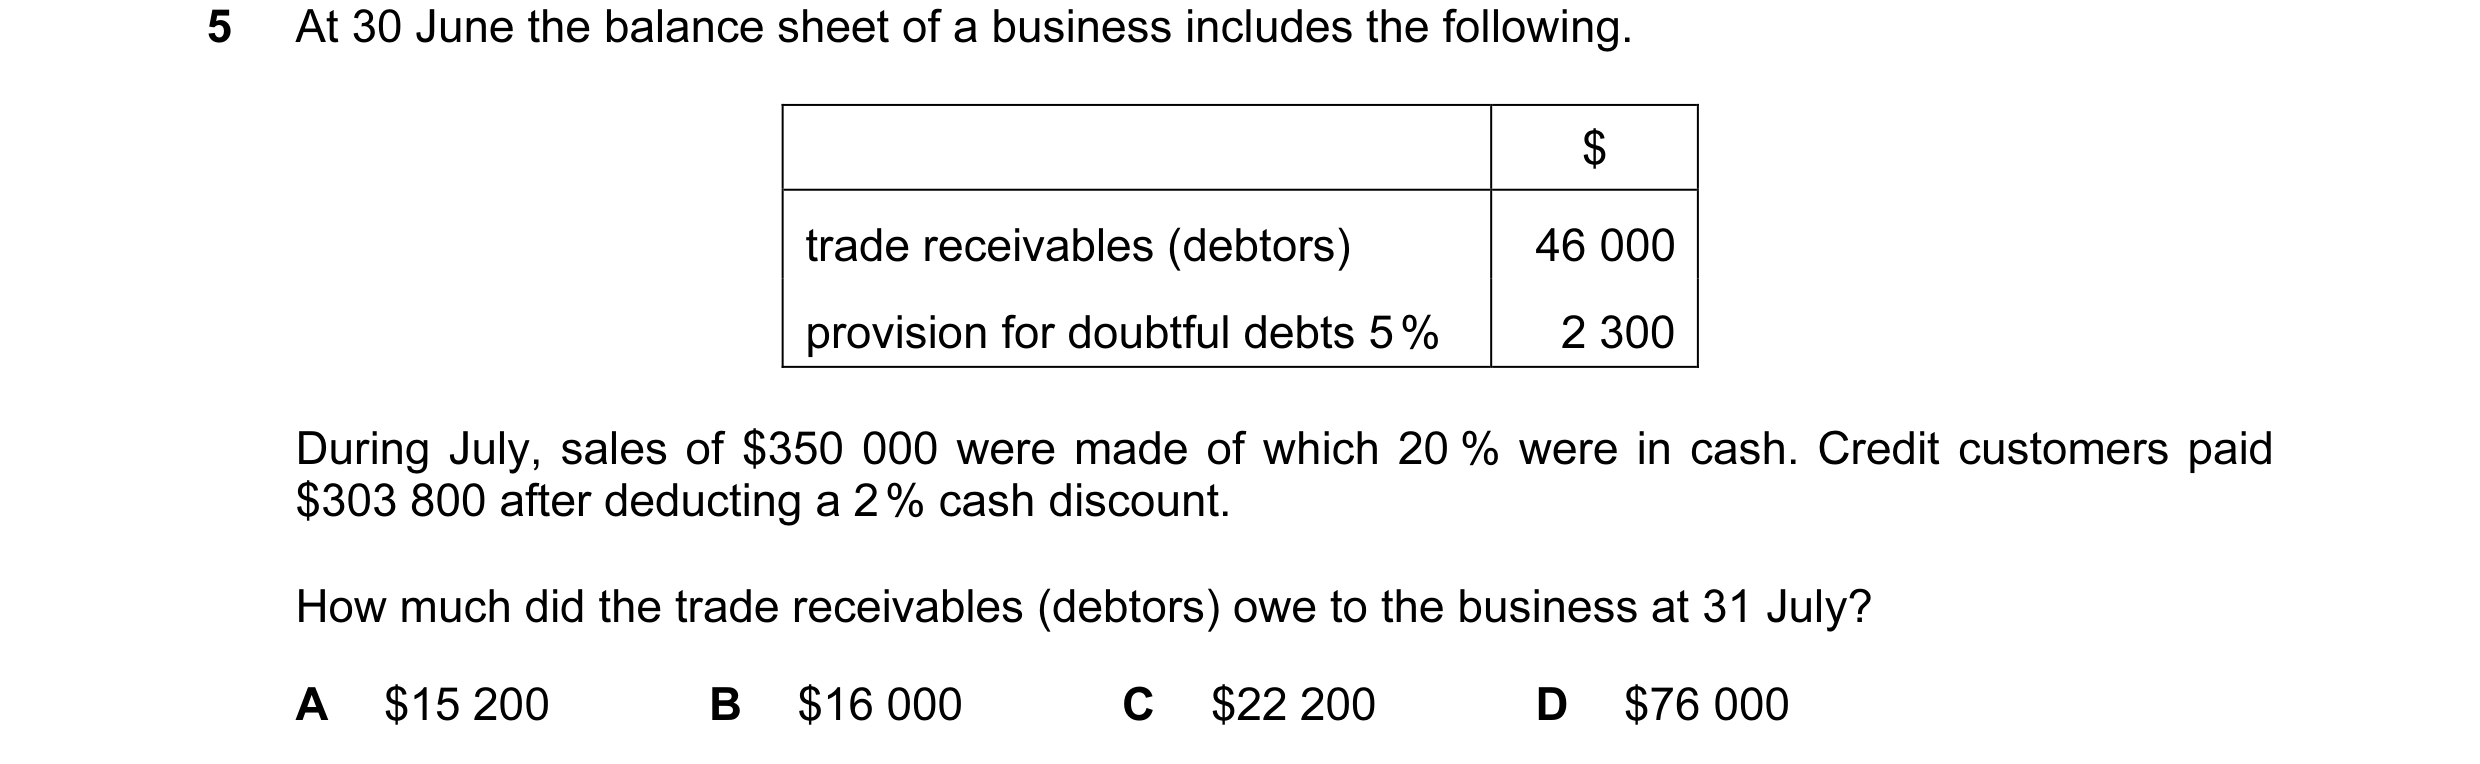
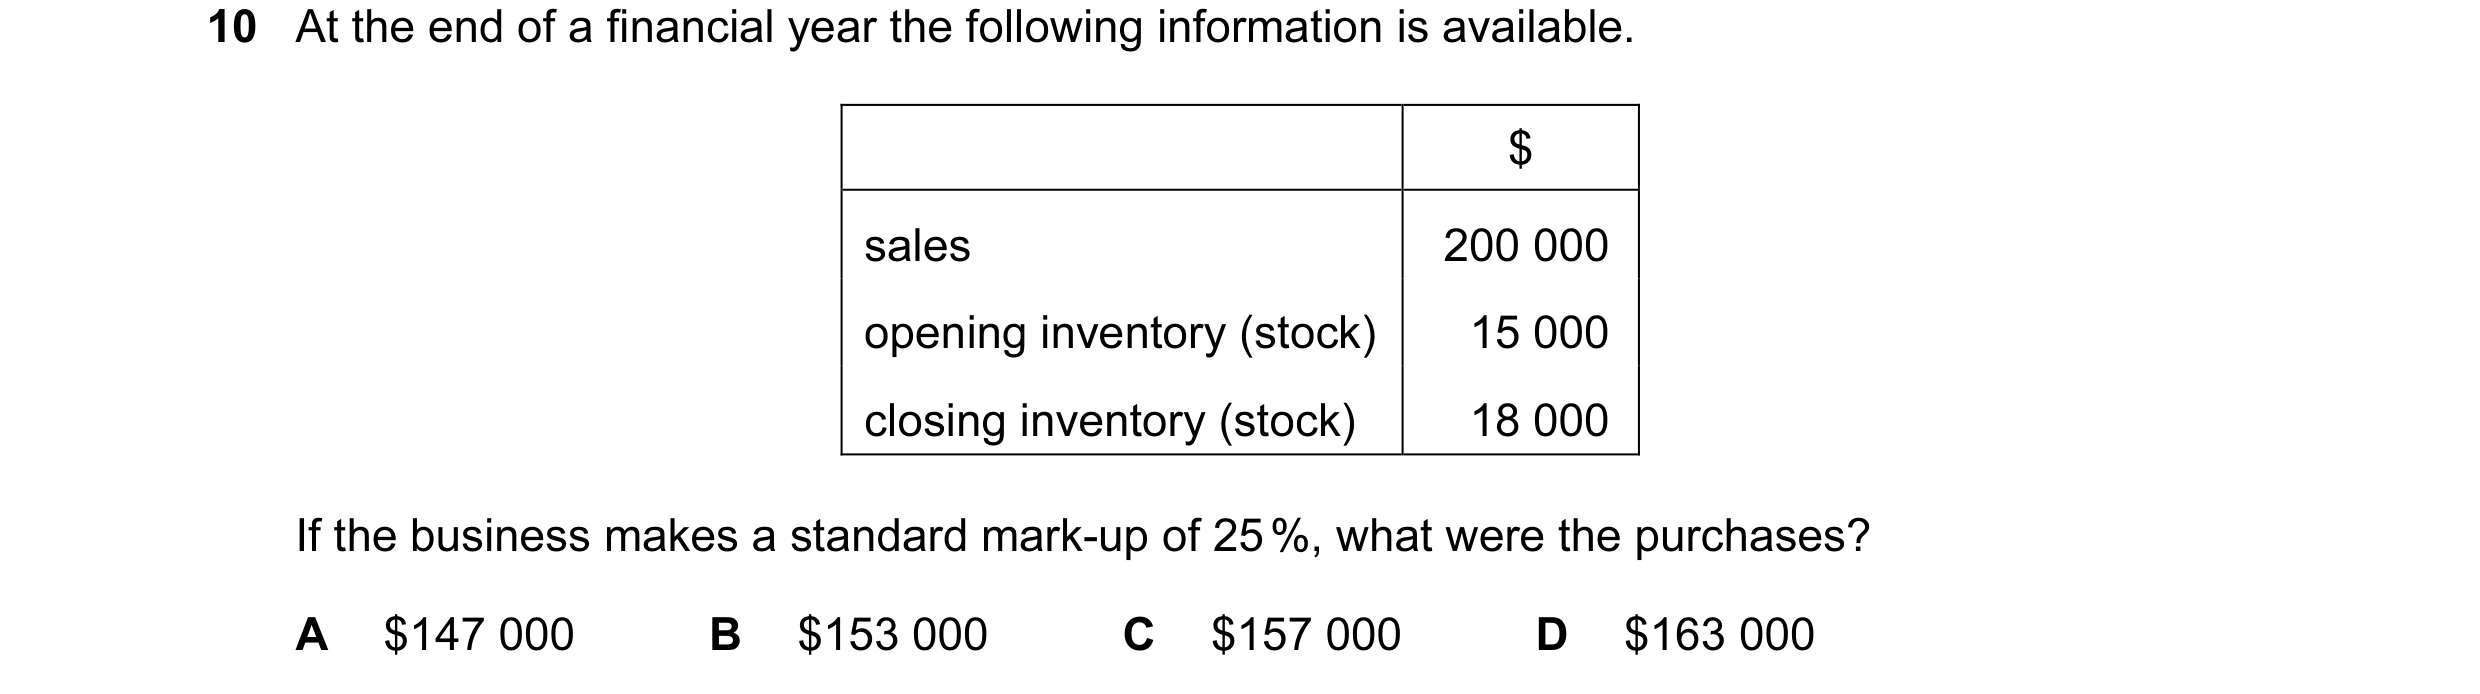 10 / 58
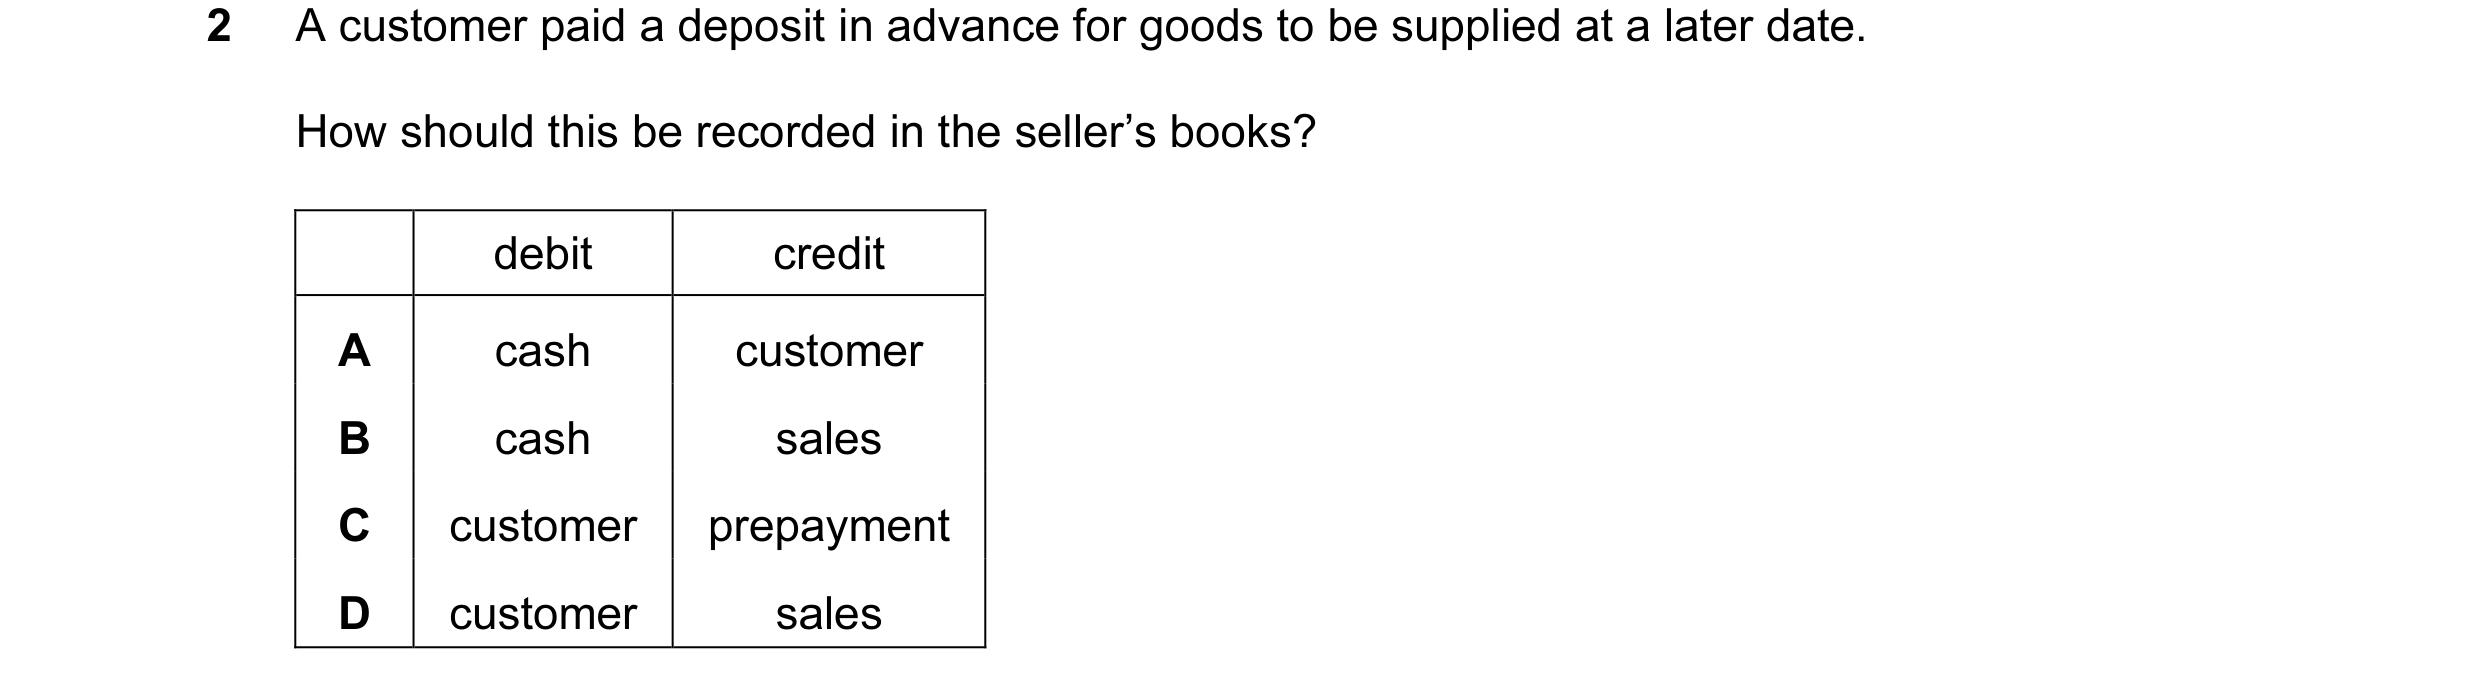
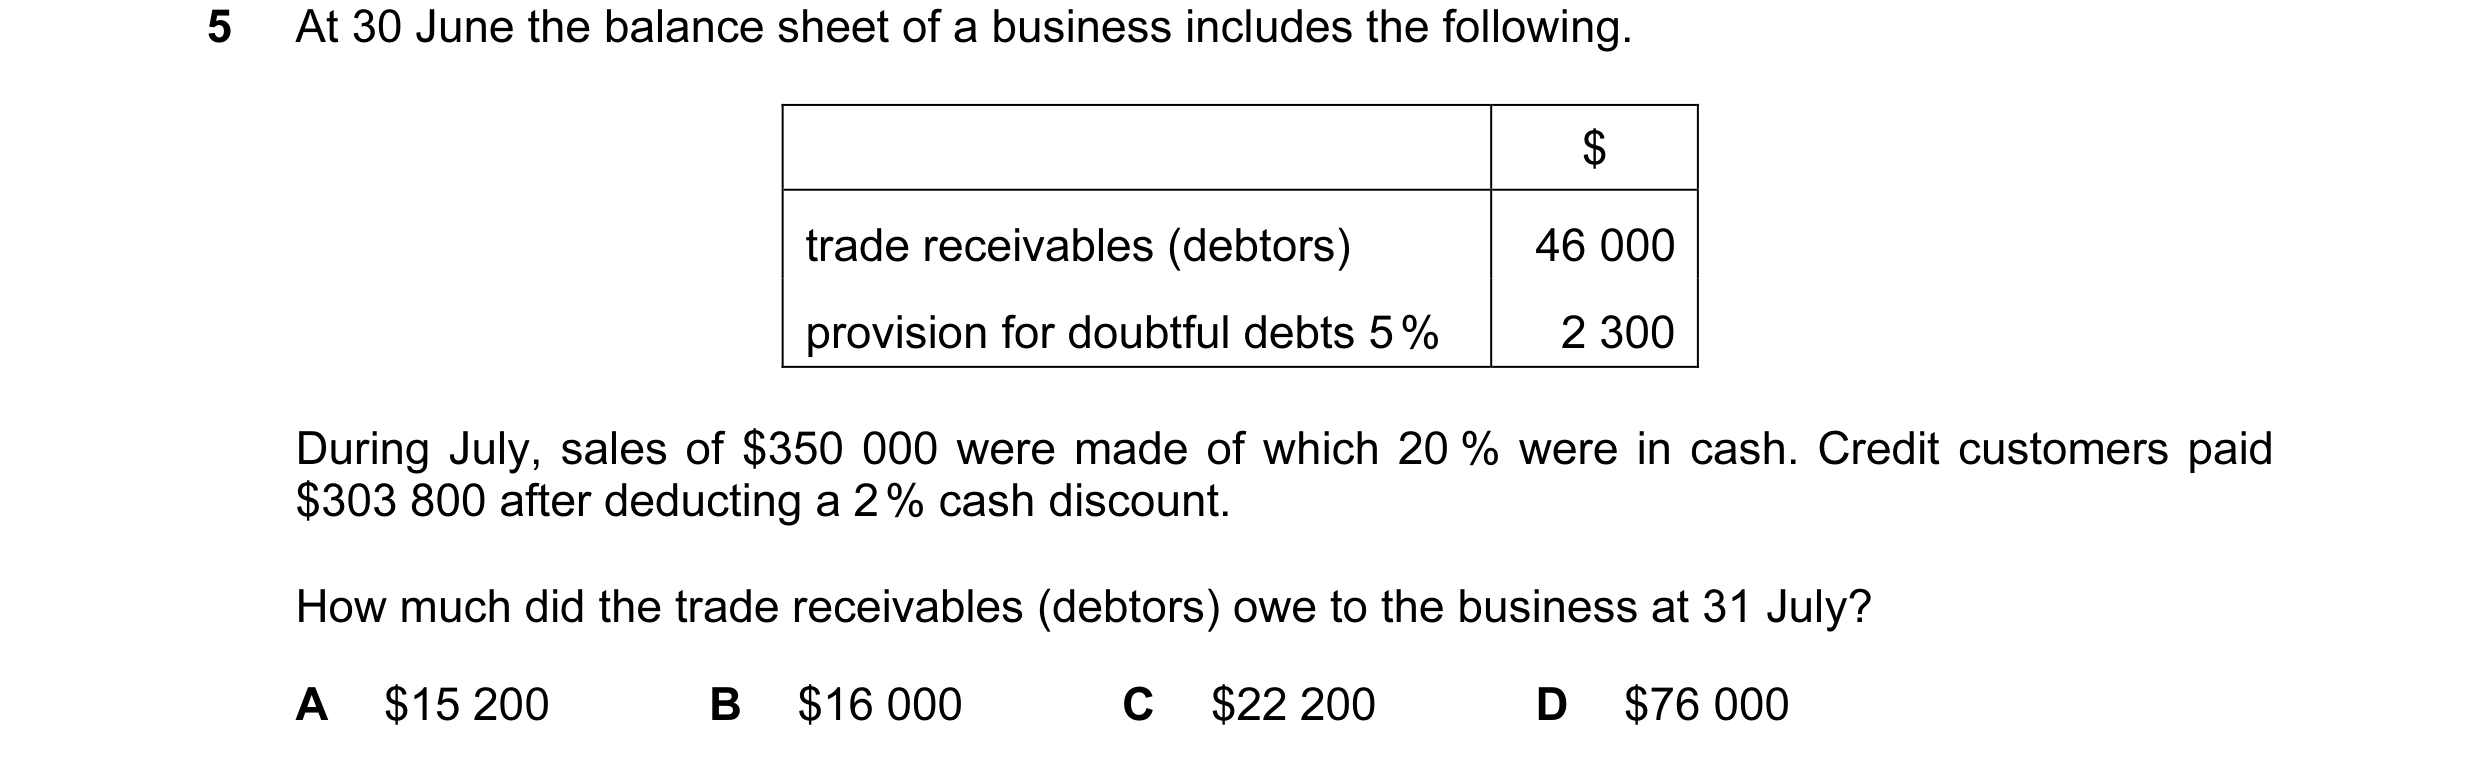
 11 / 58
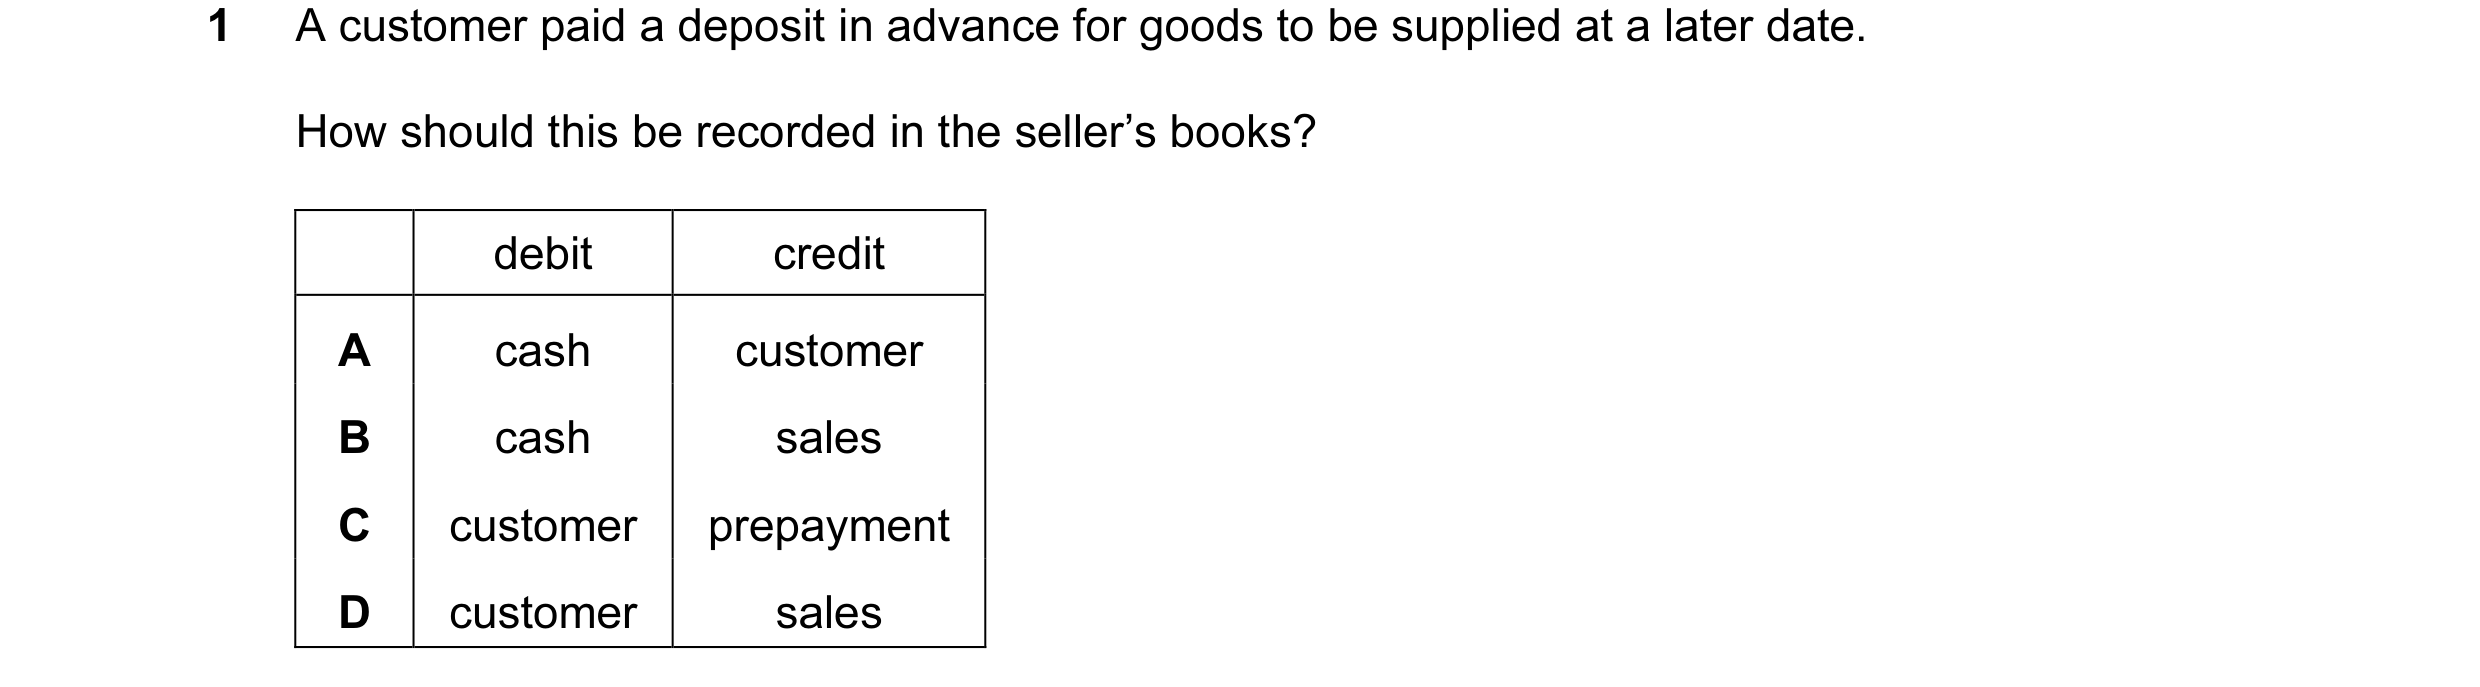
 12 / 58
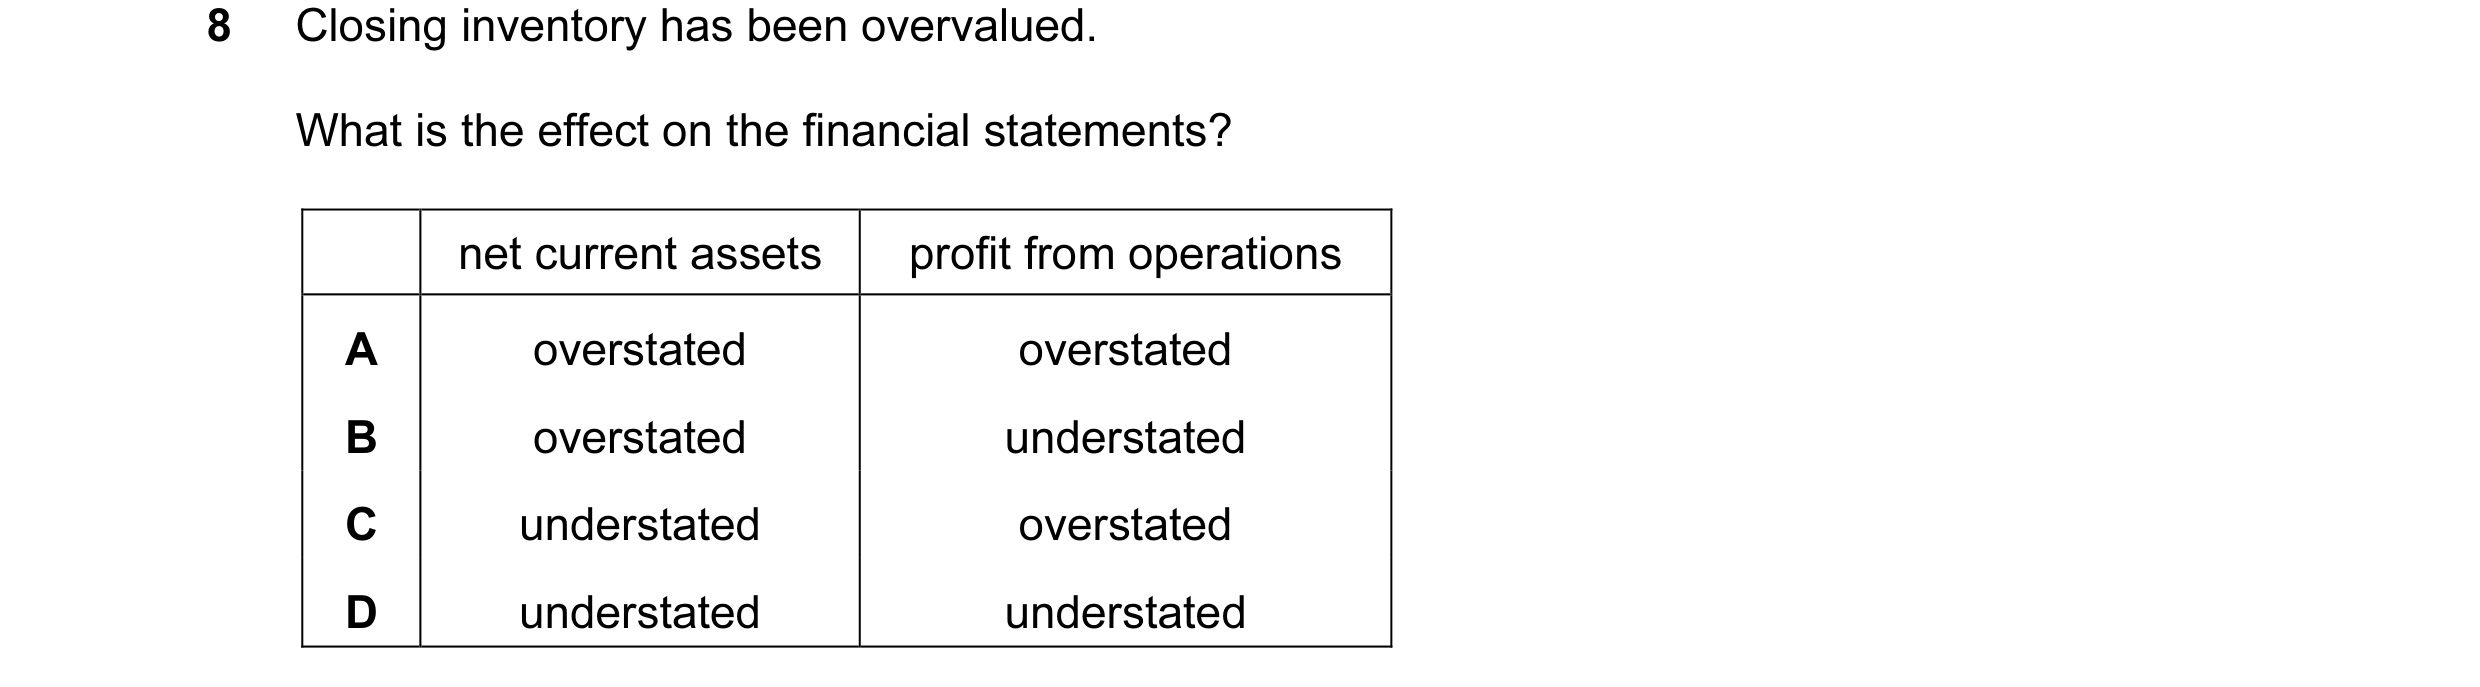
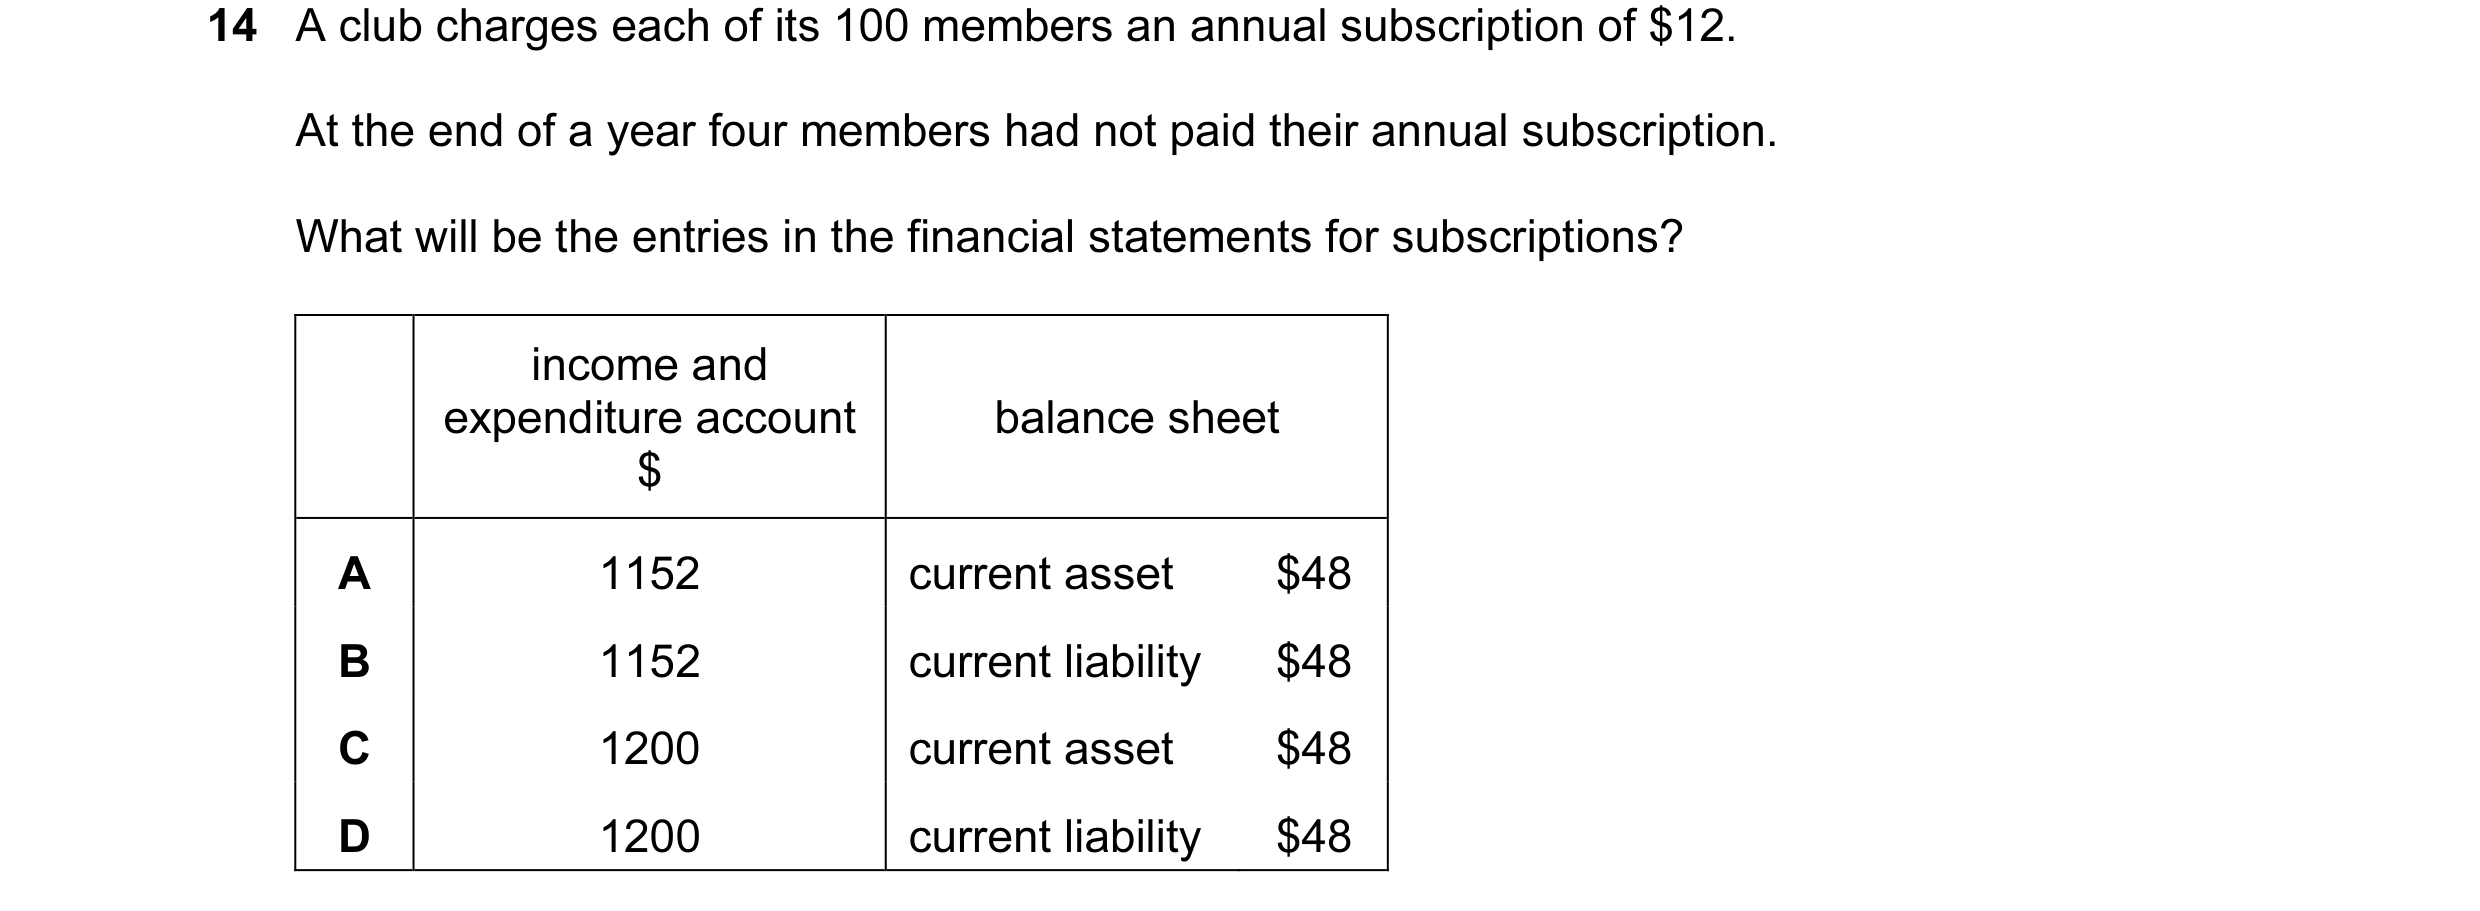
 13 / 58
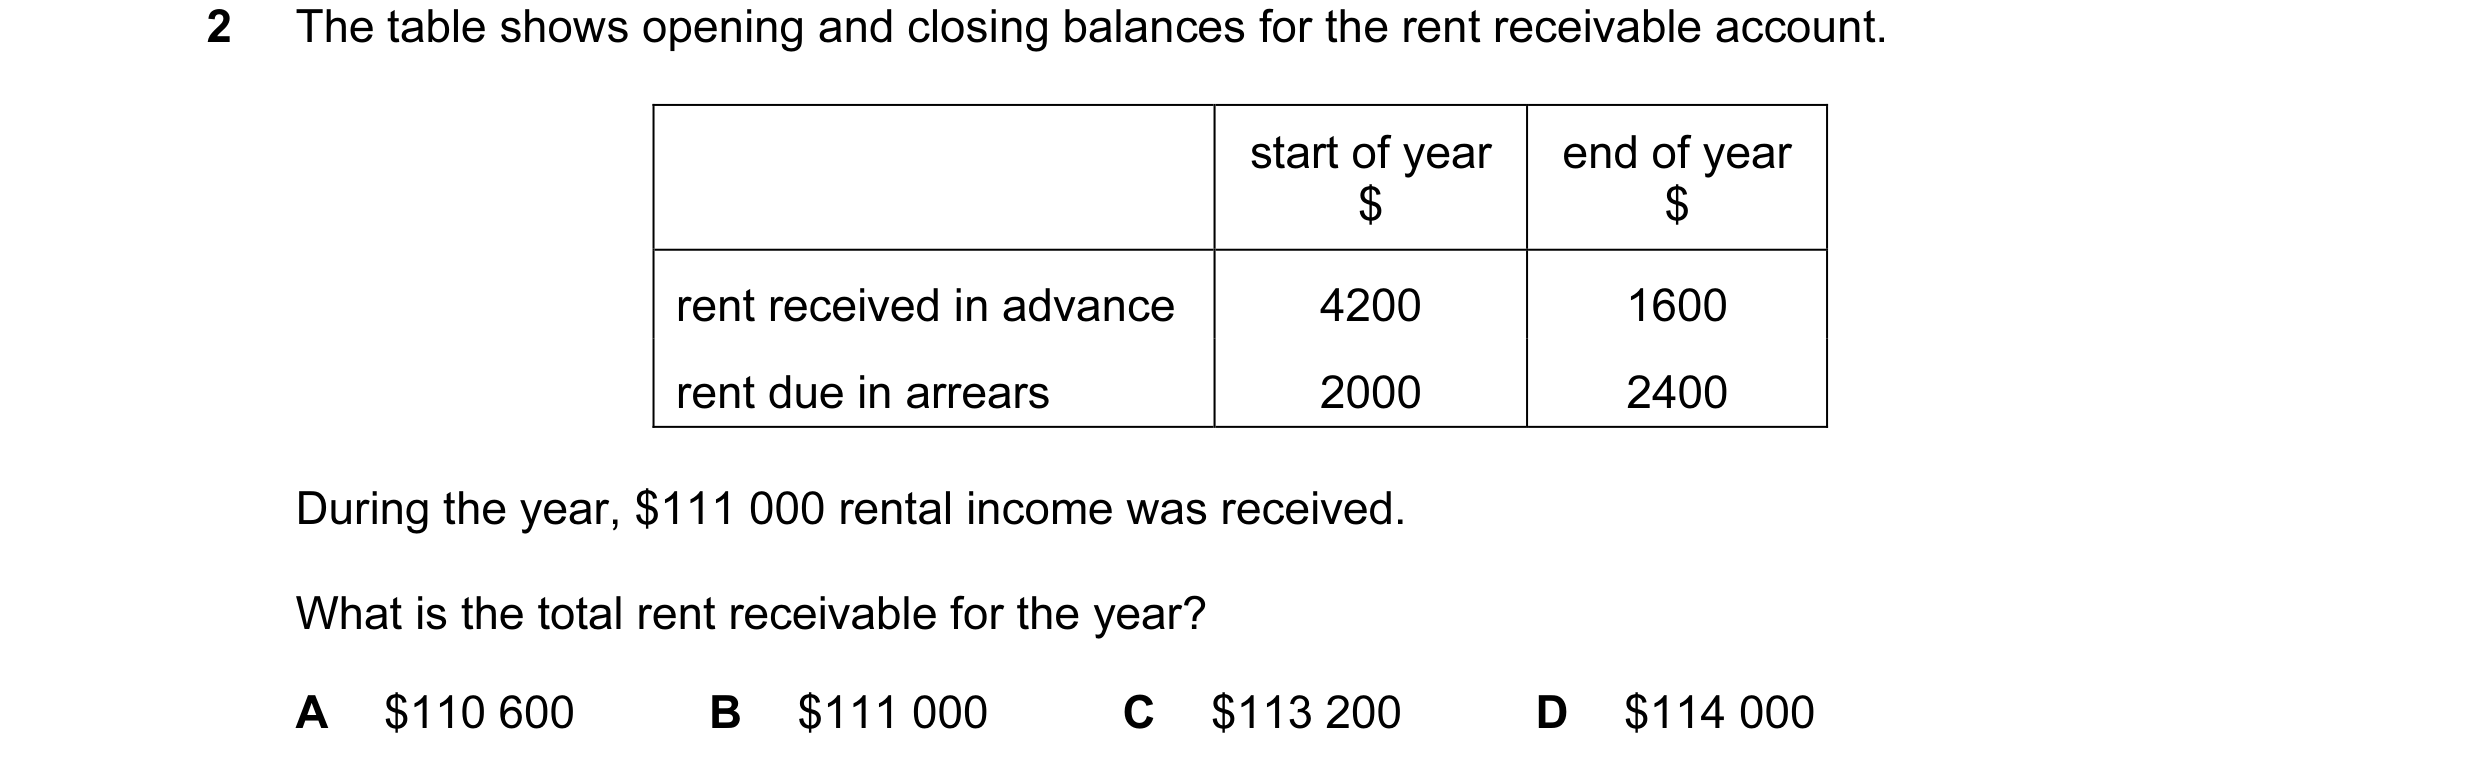 14 / 58
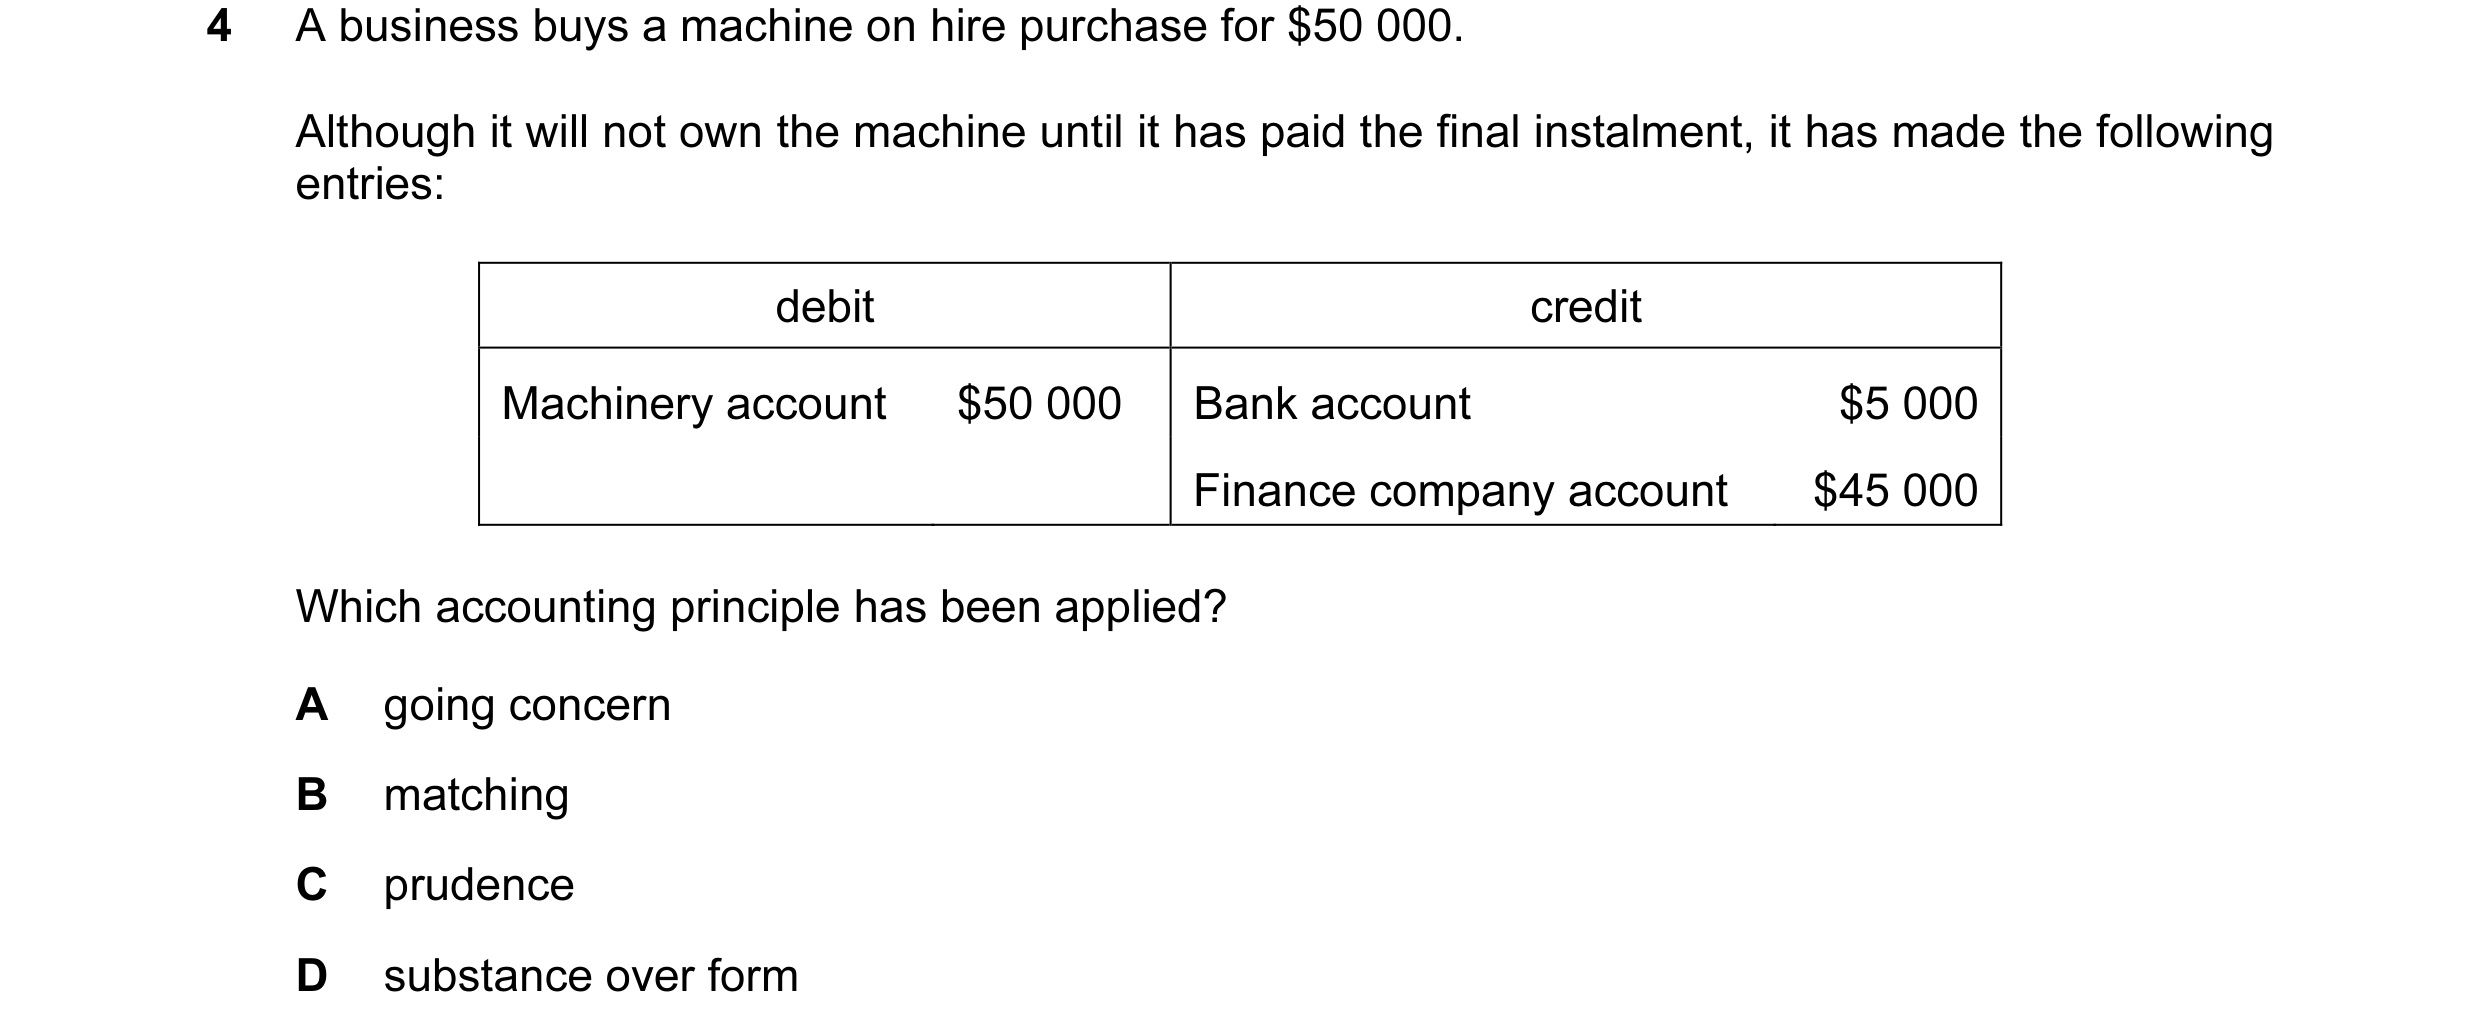
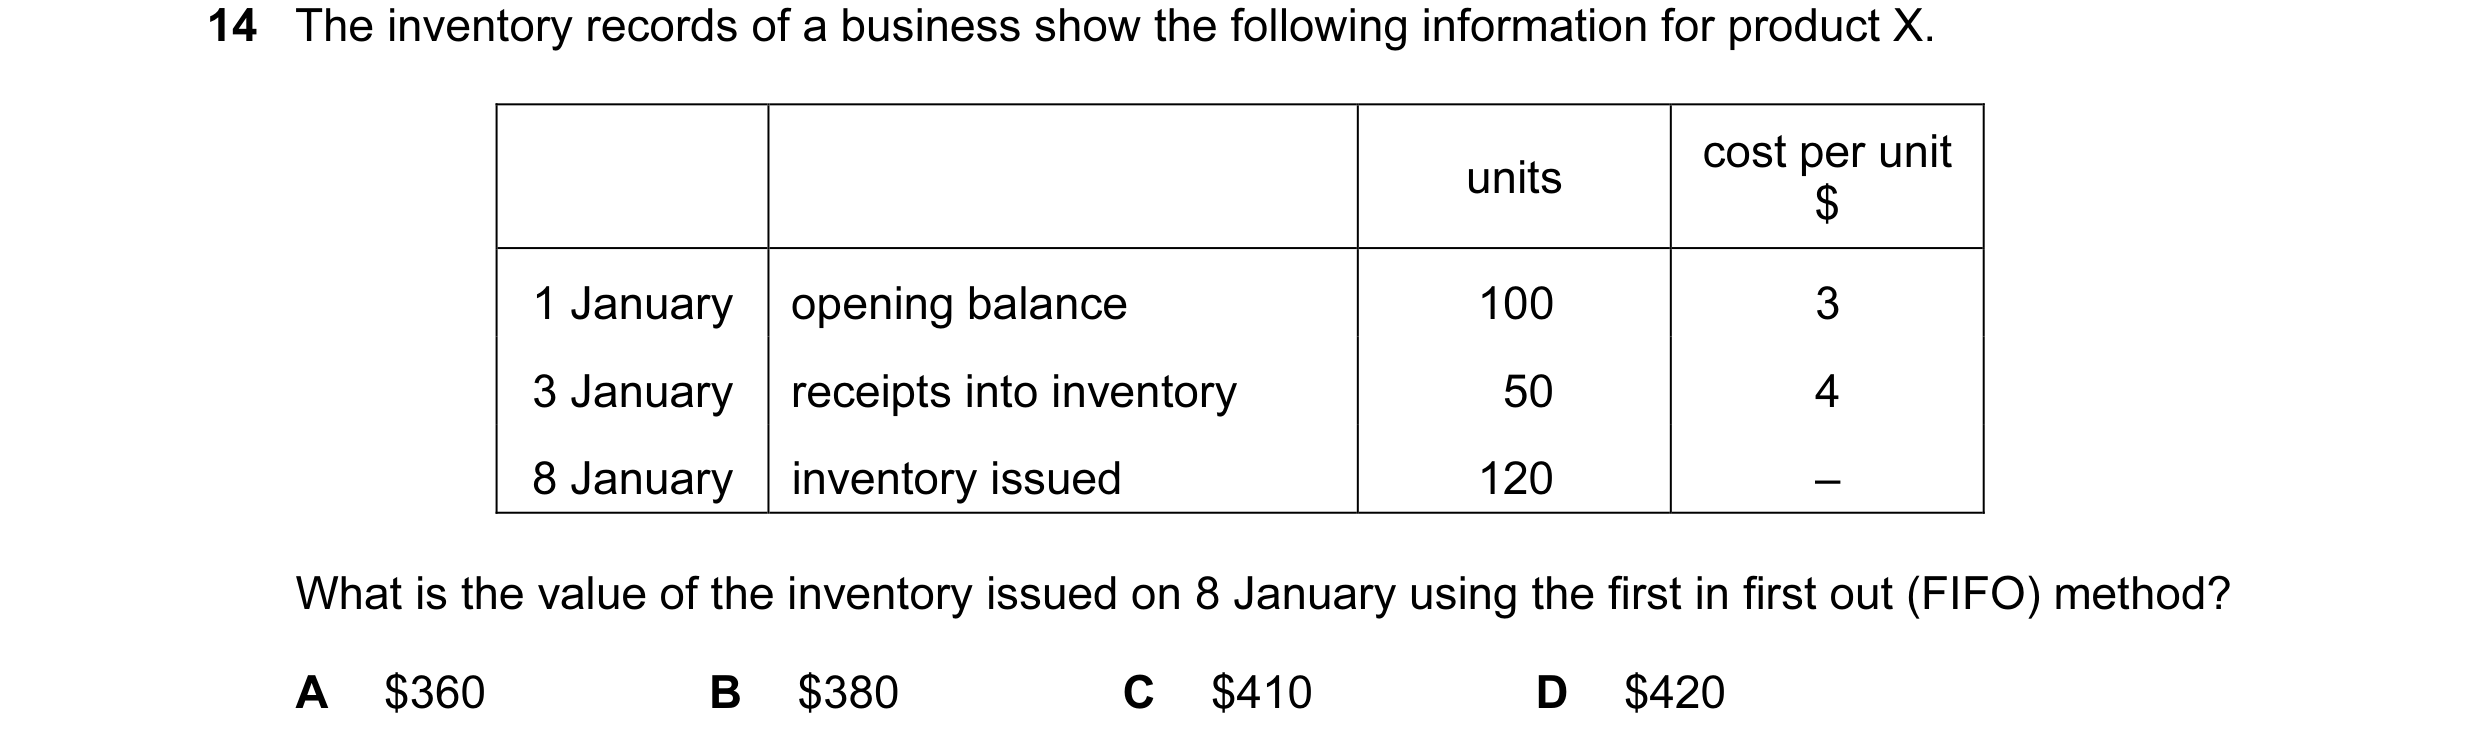 15 / 58
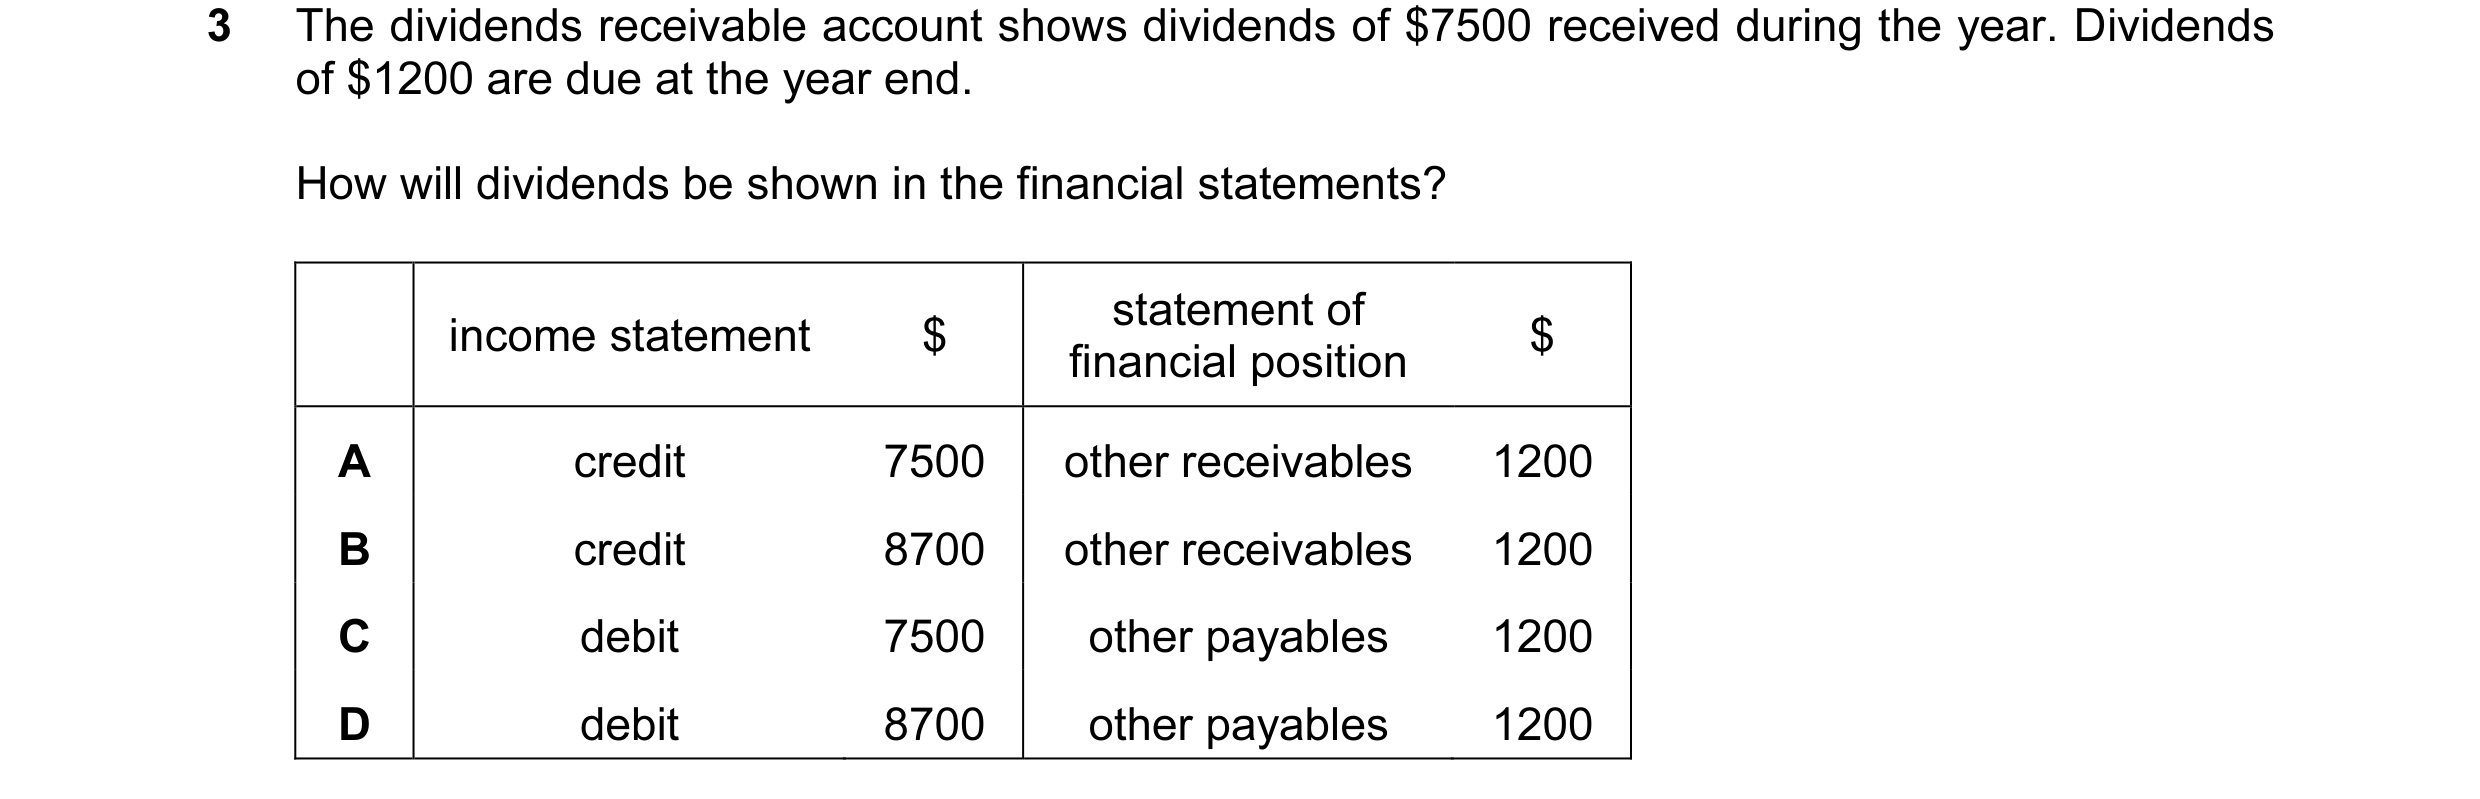
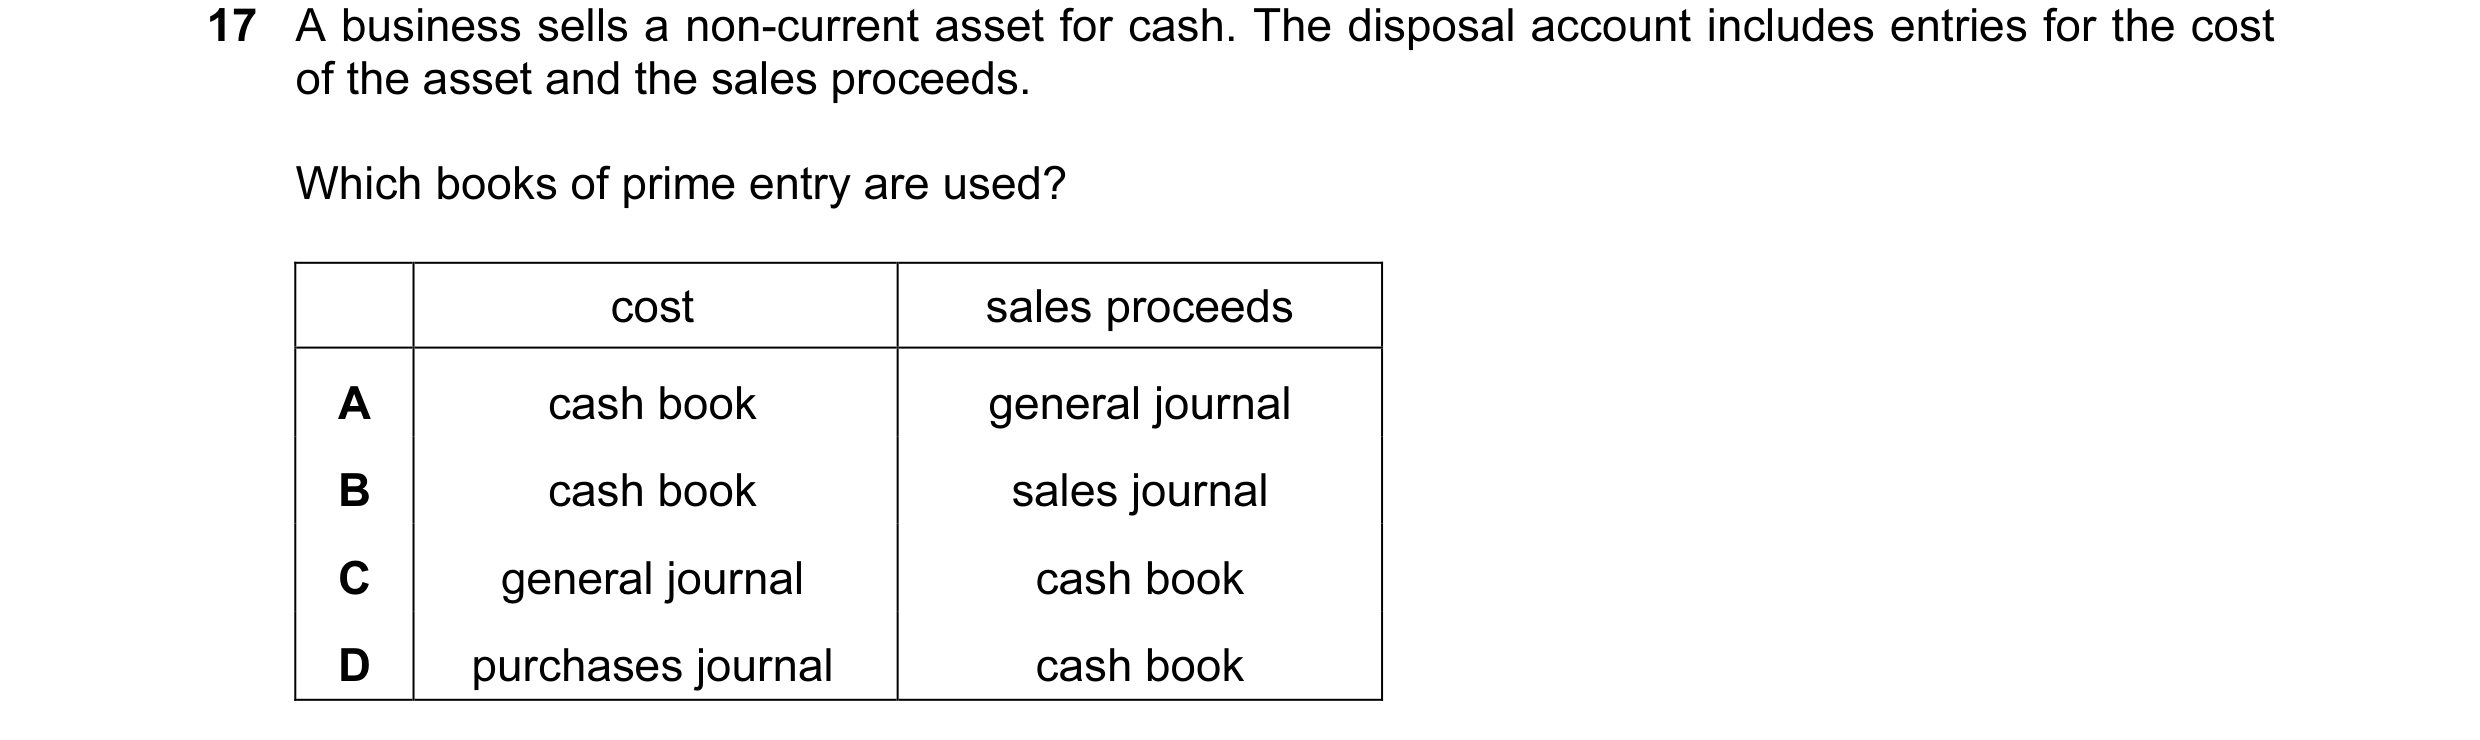 16 / 58
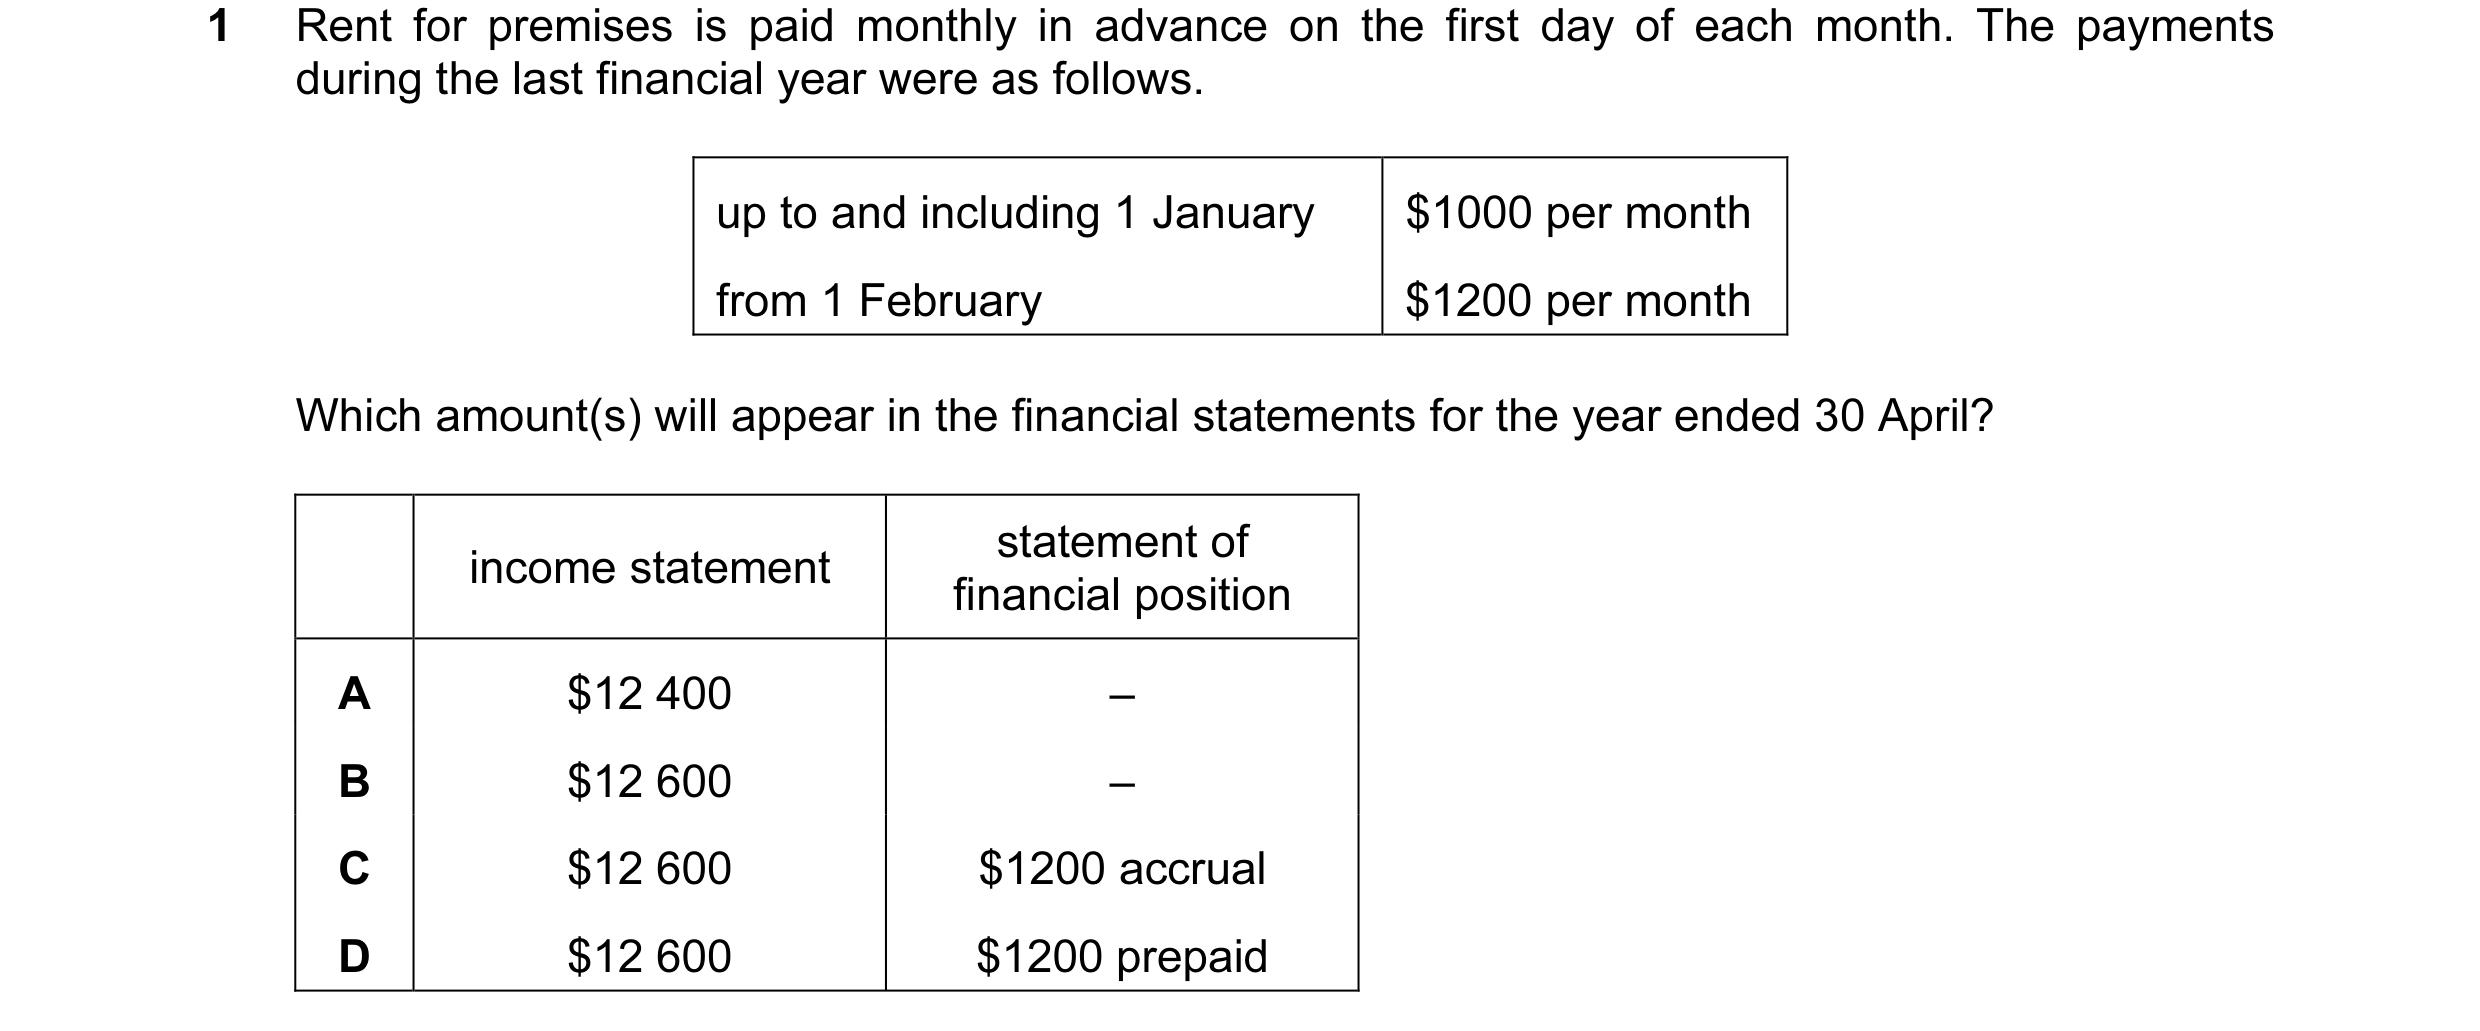
 17 / 58
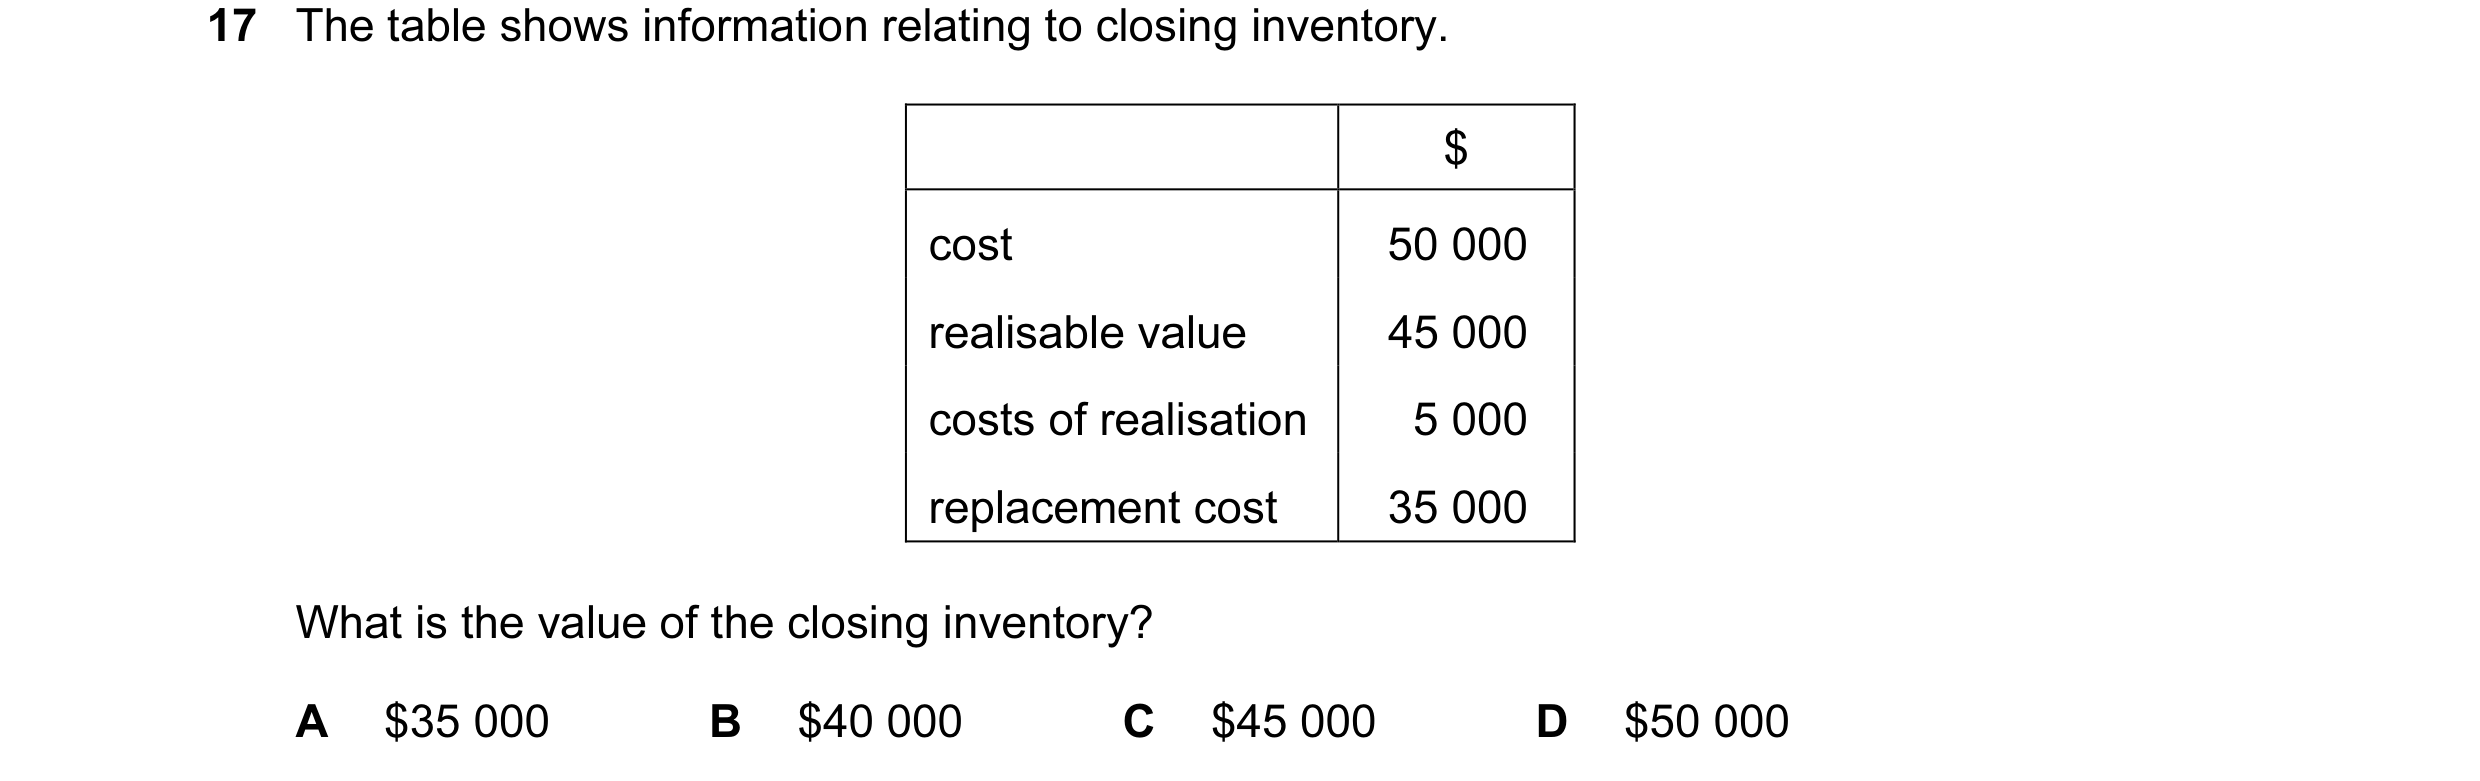
 18 / 58
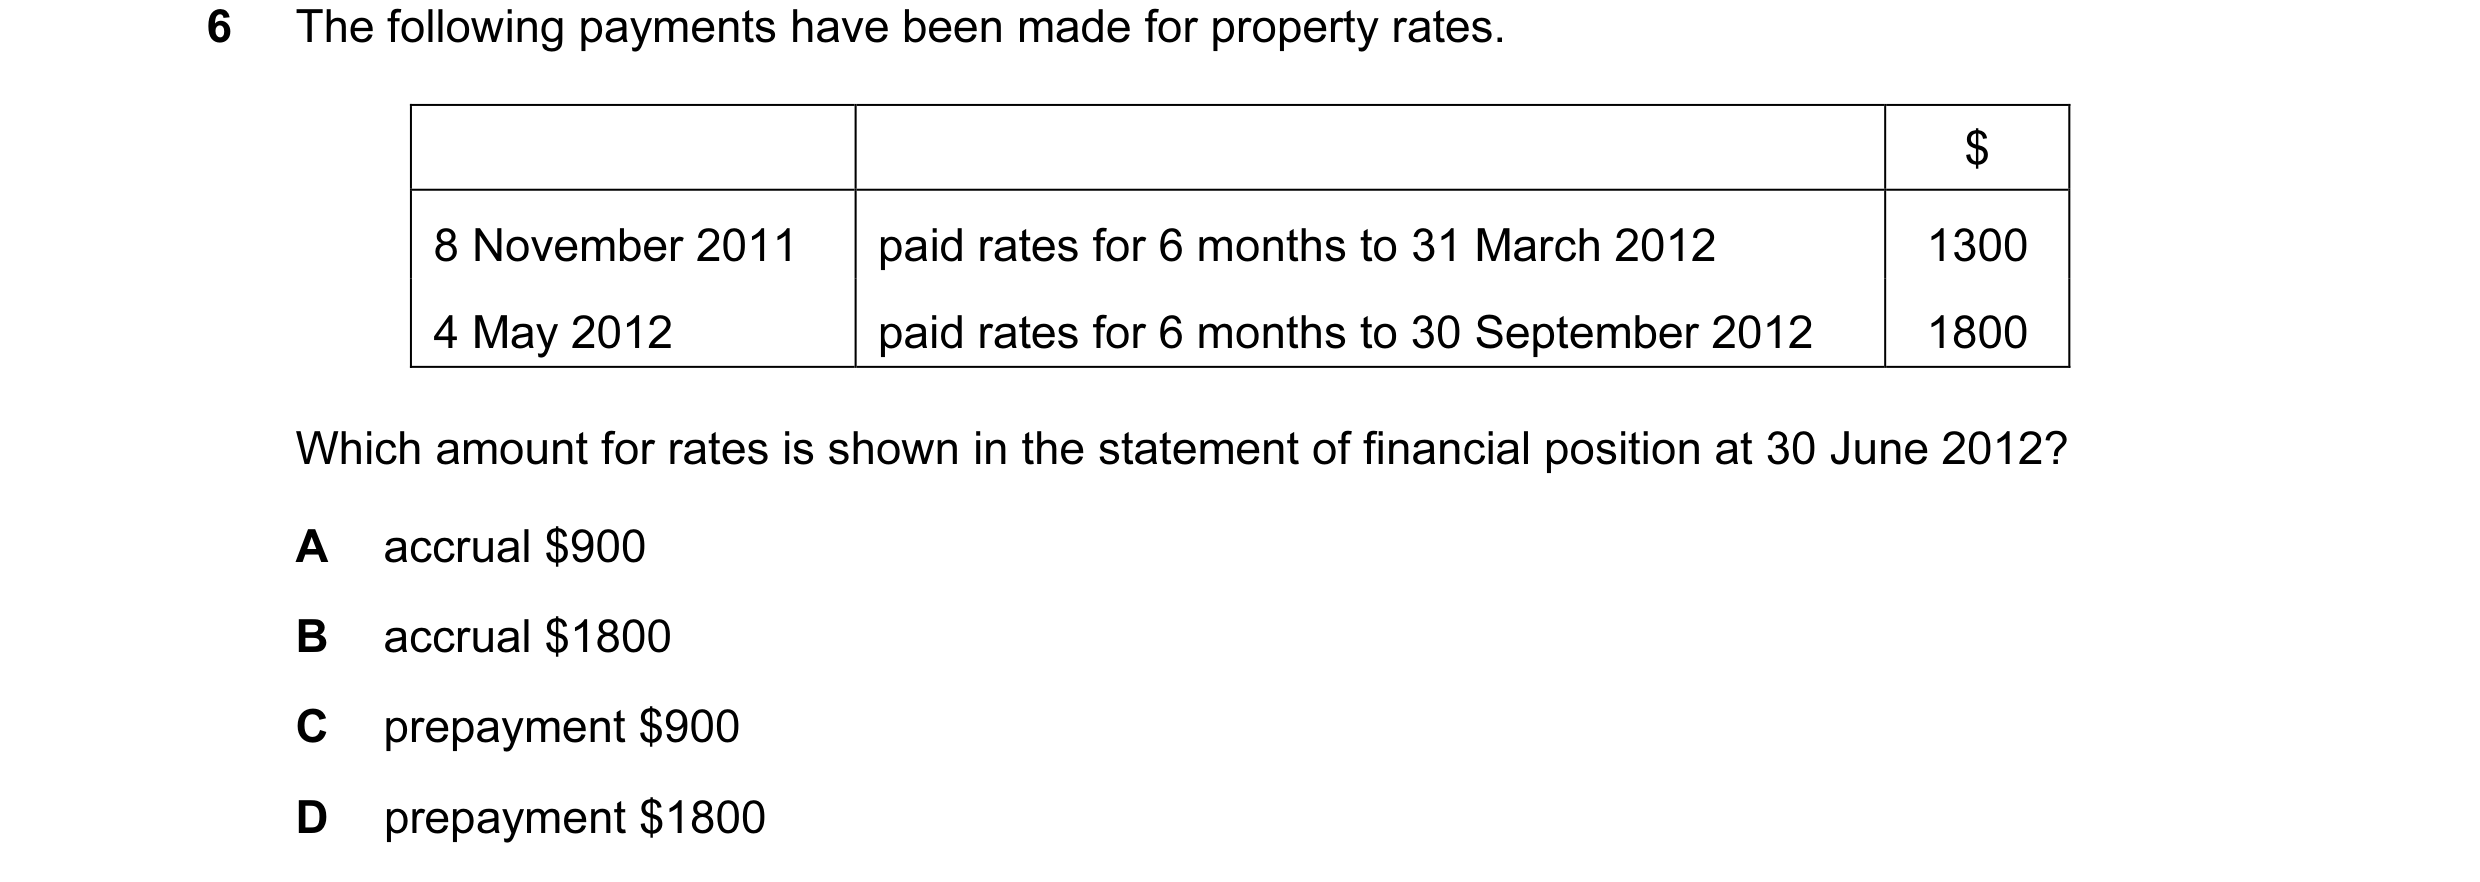
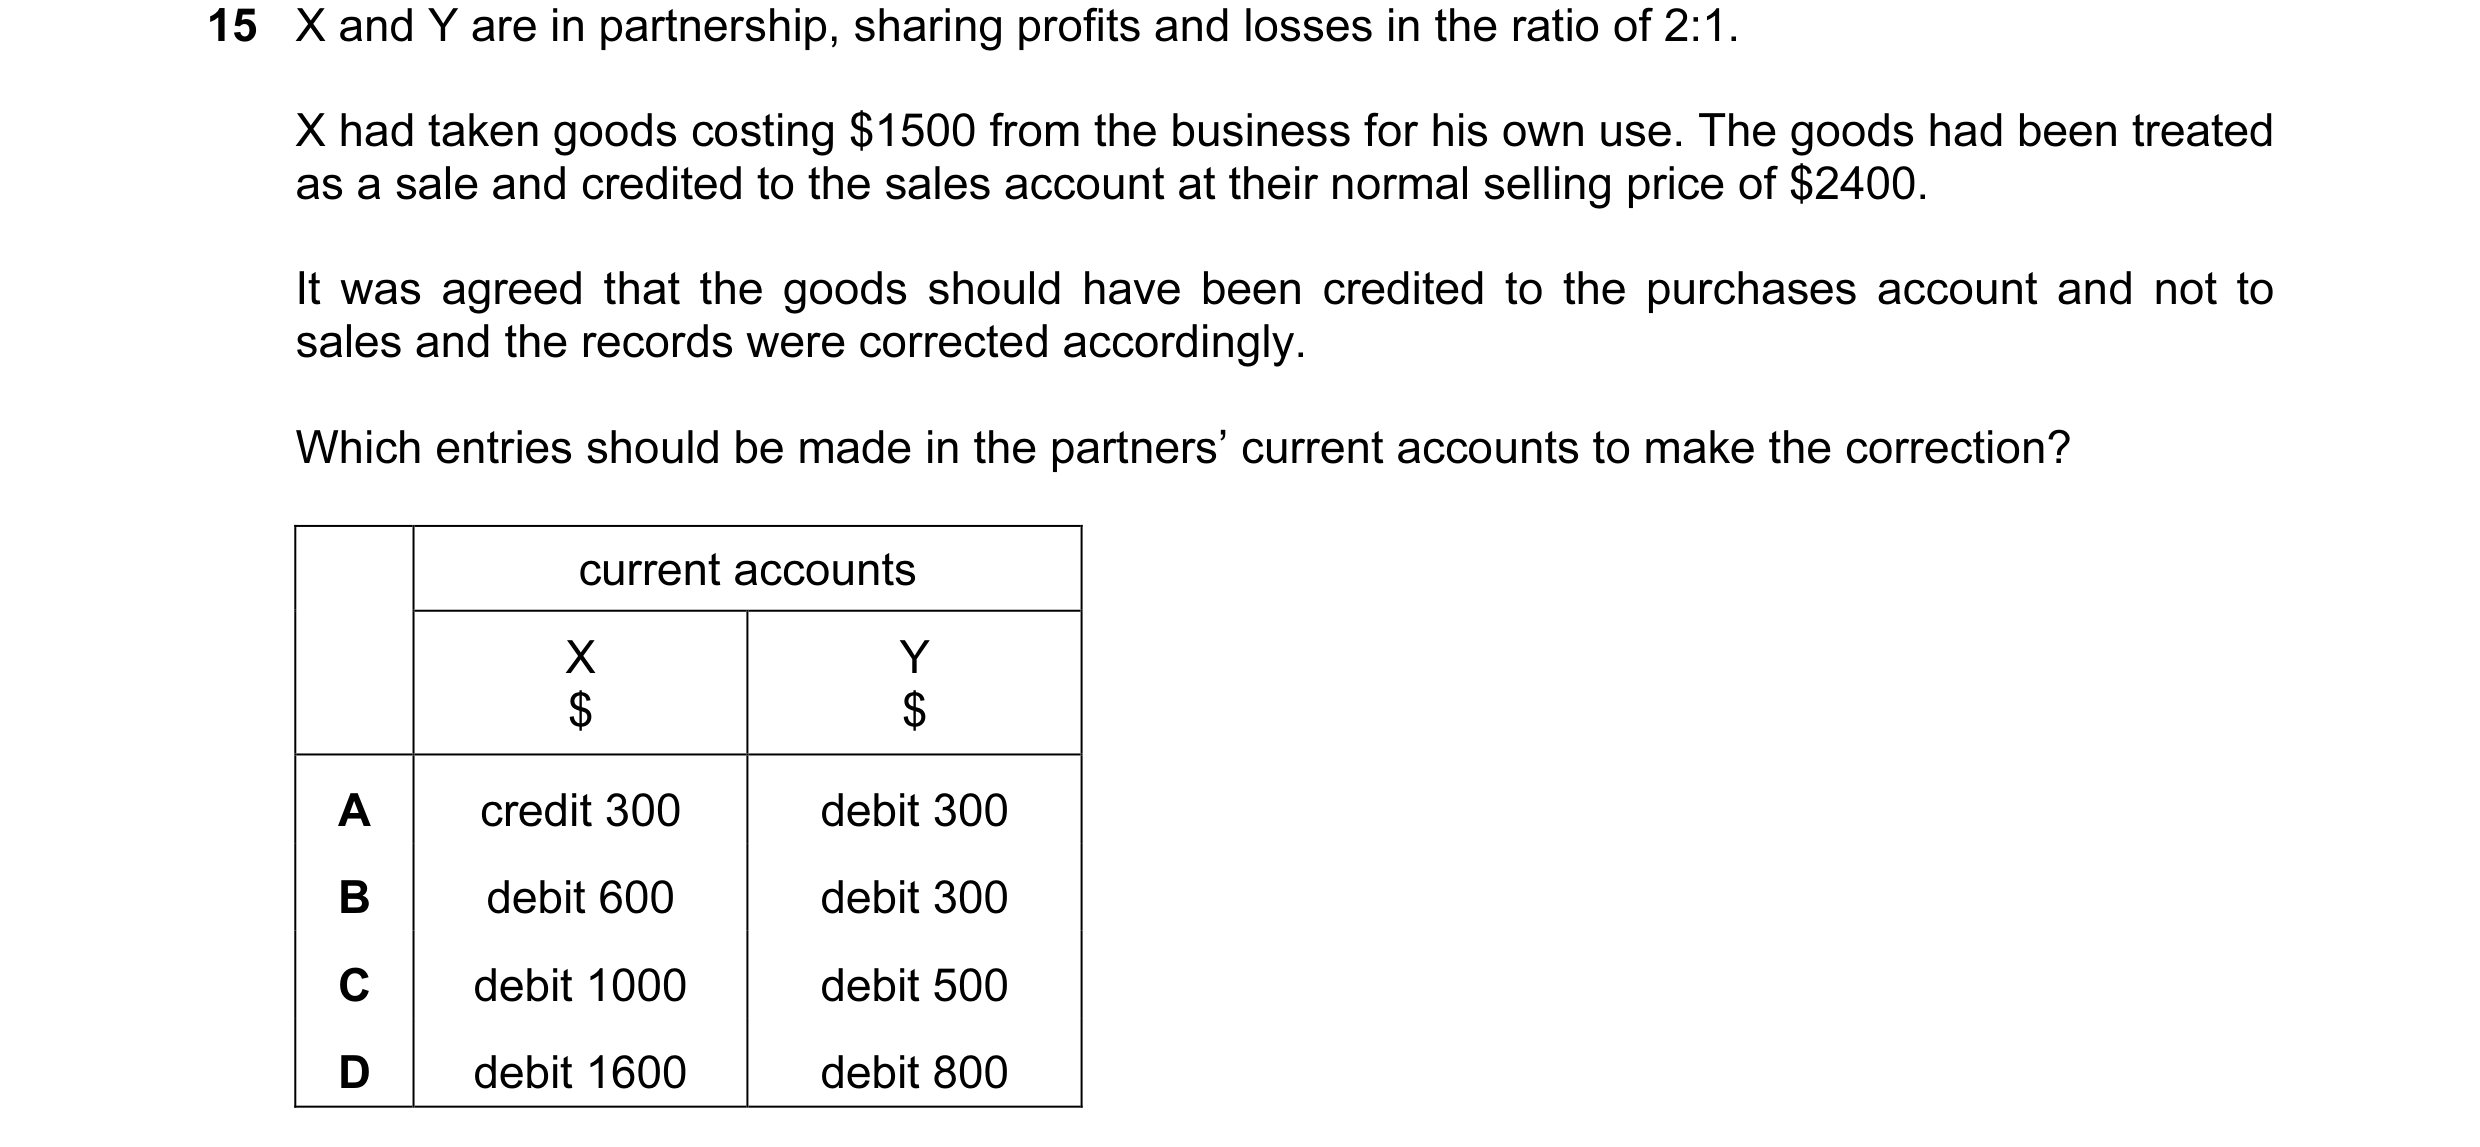
 19 / 58
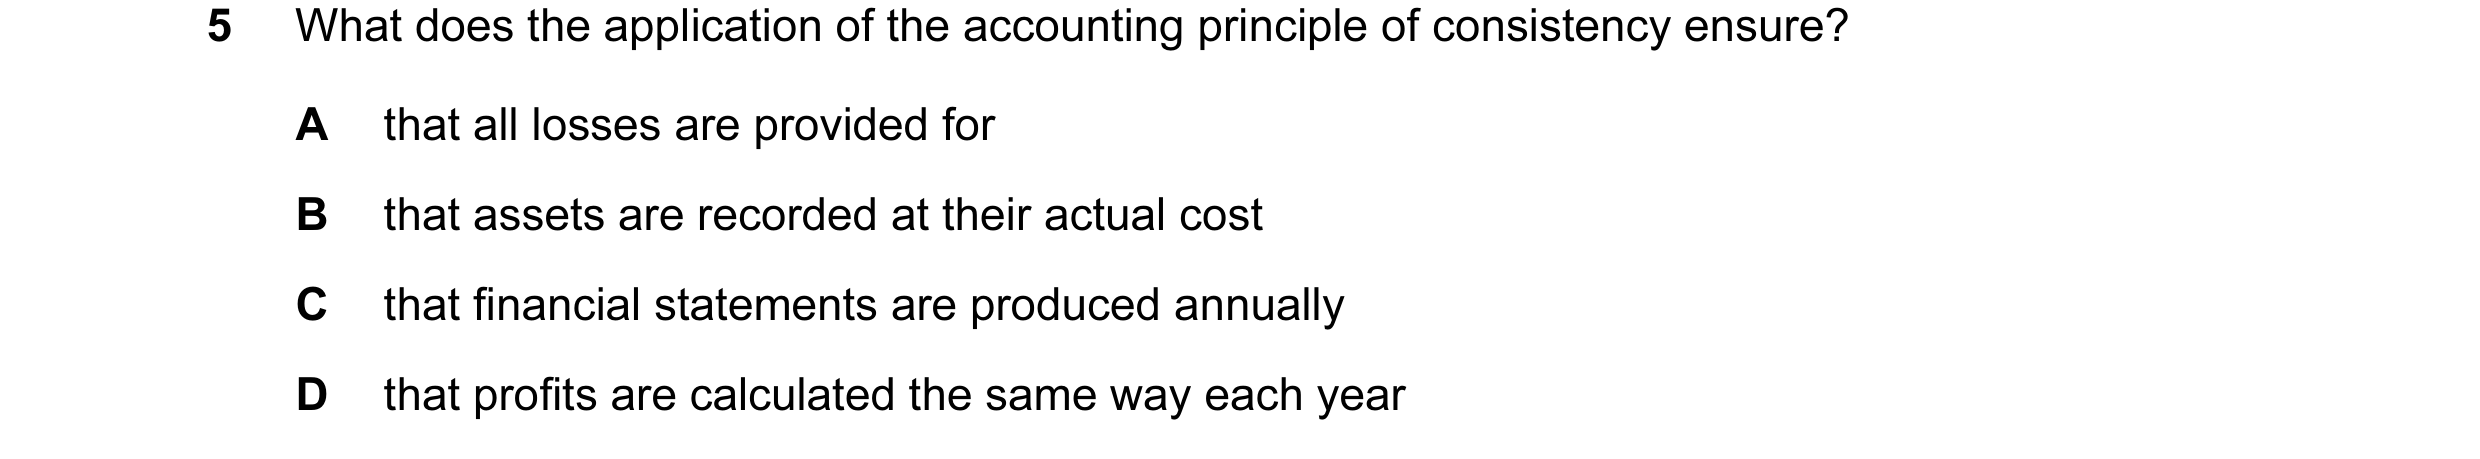 20 / 58
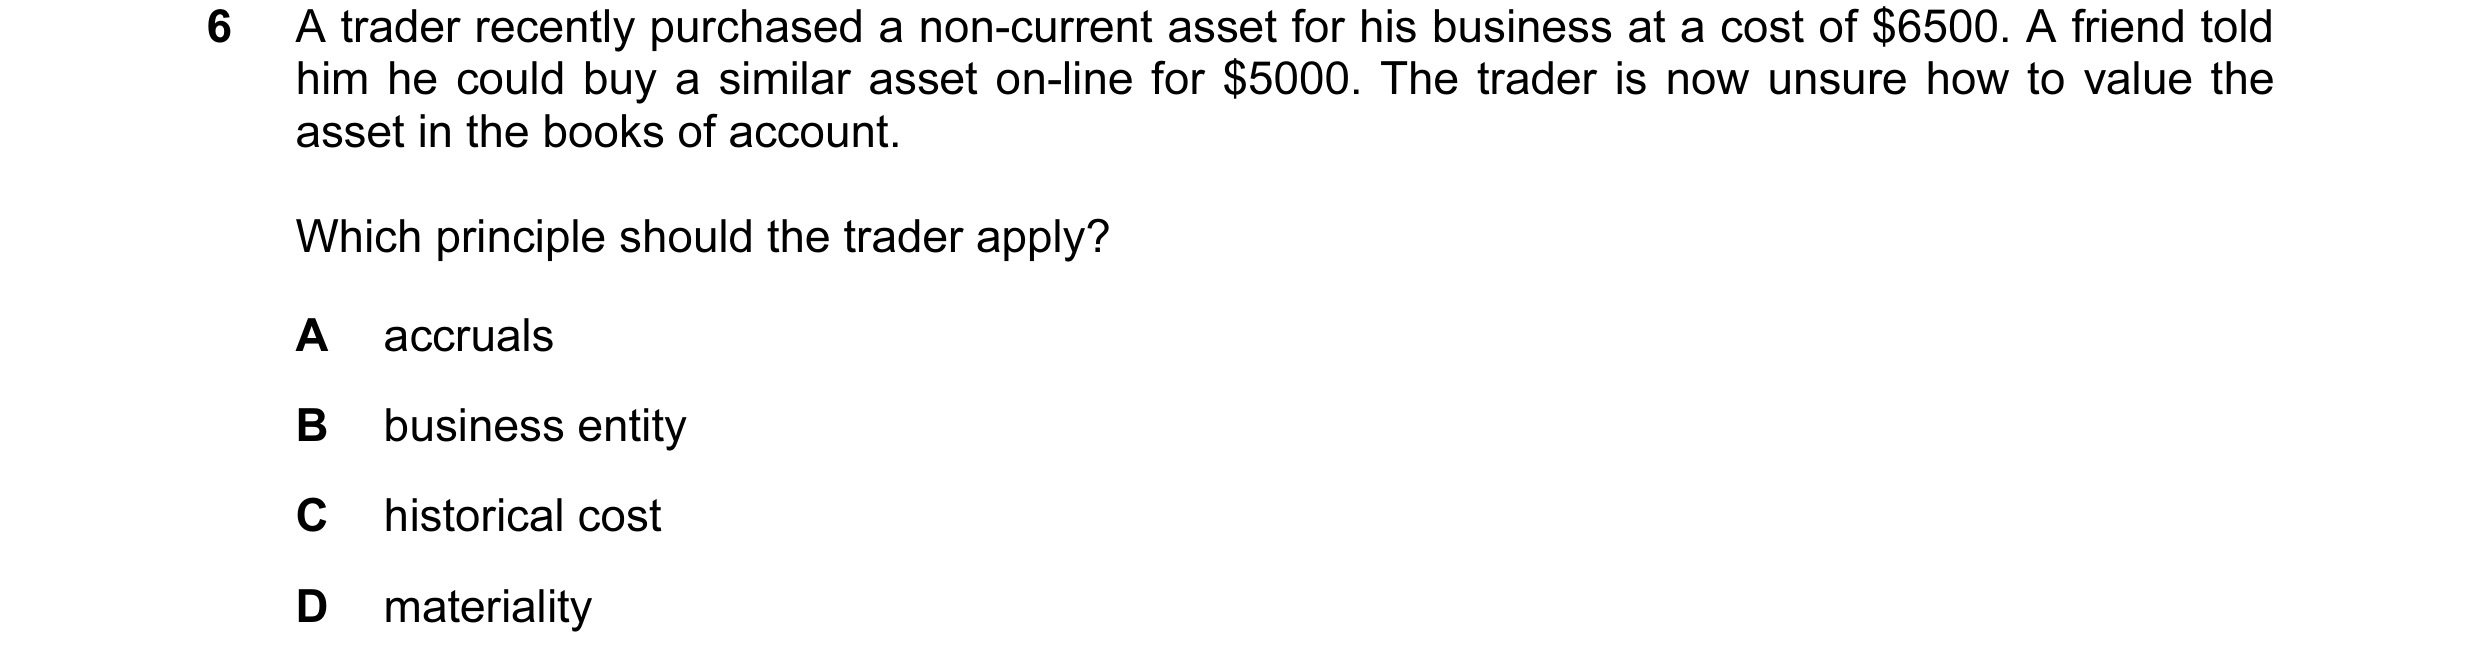
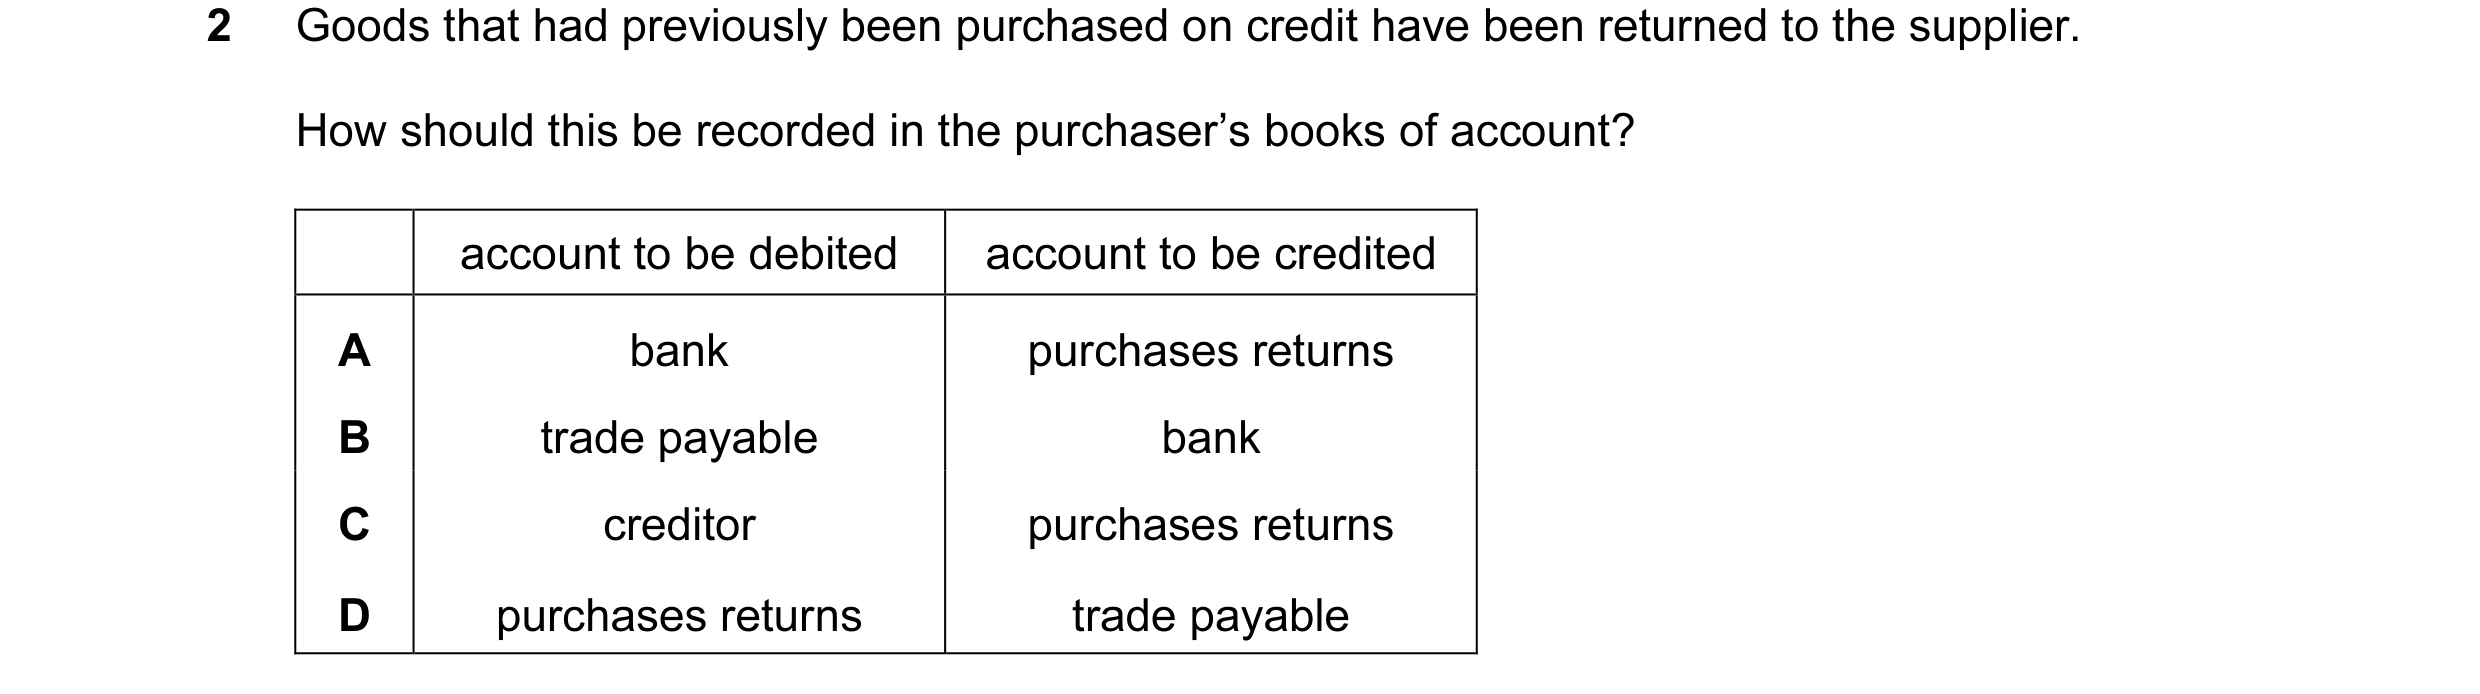
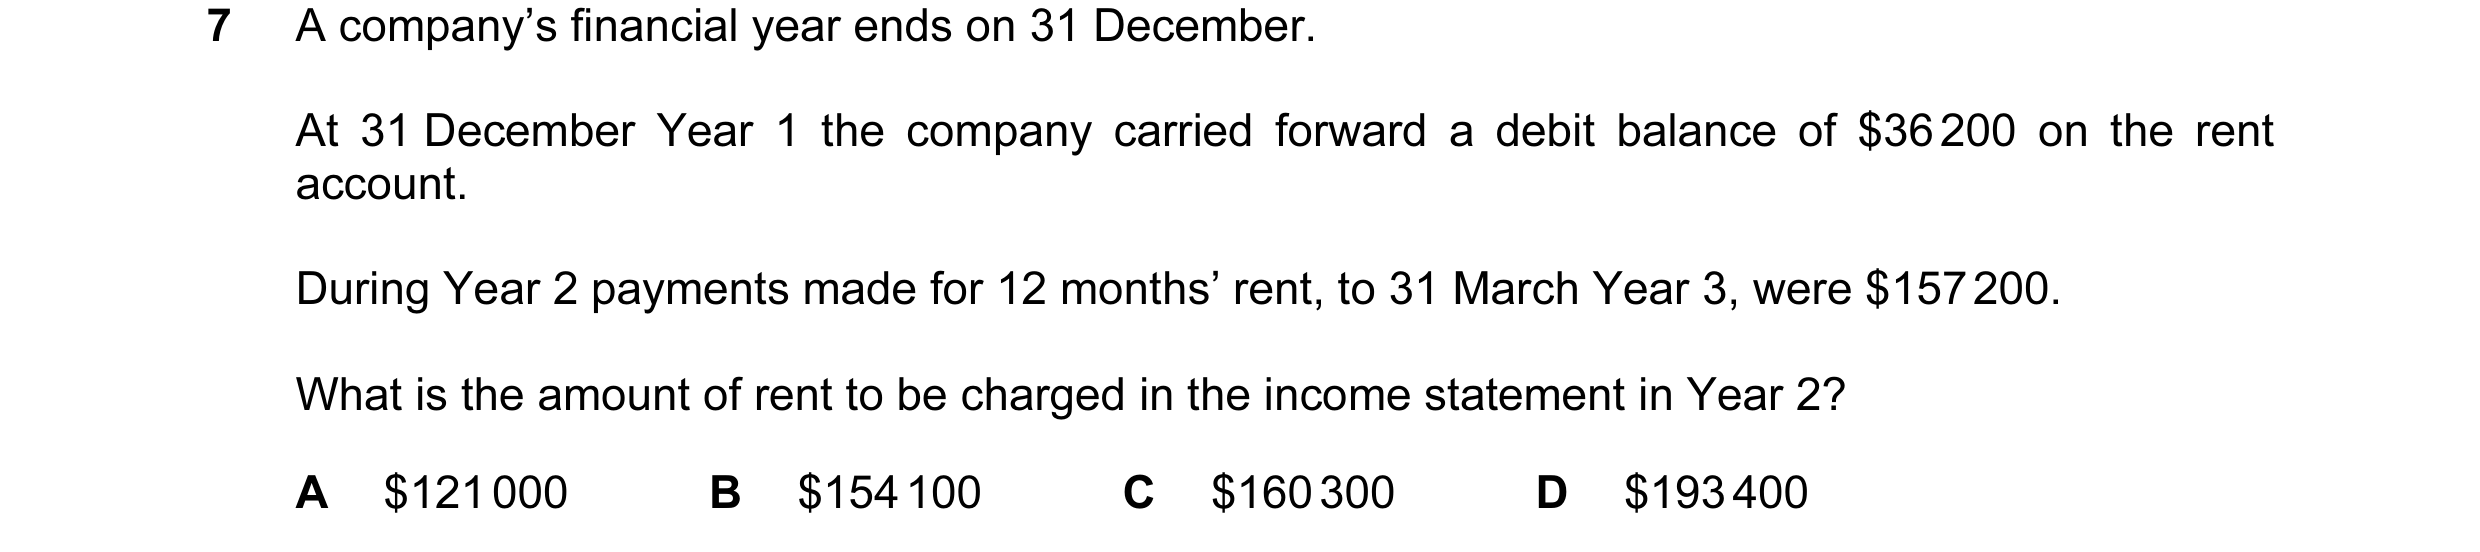
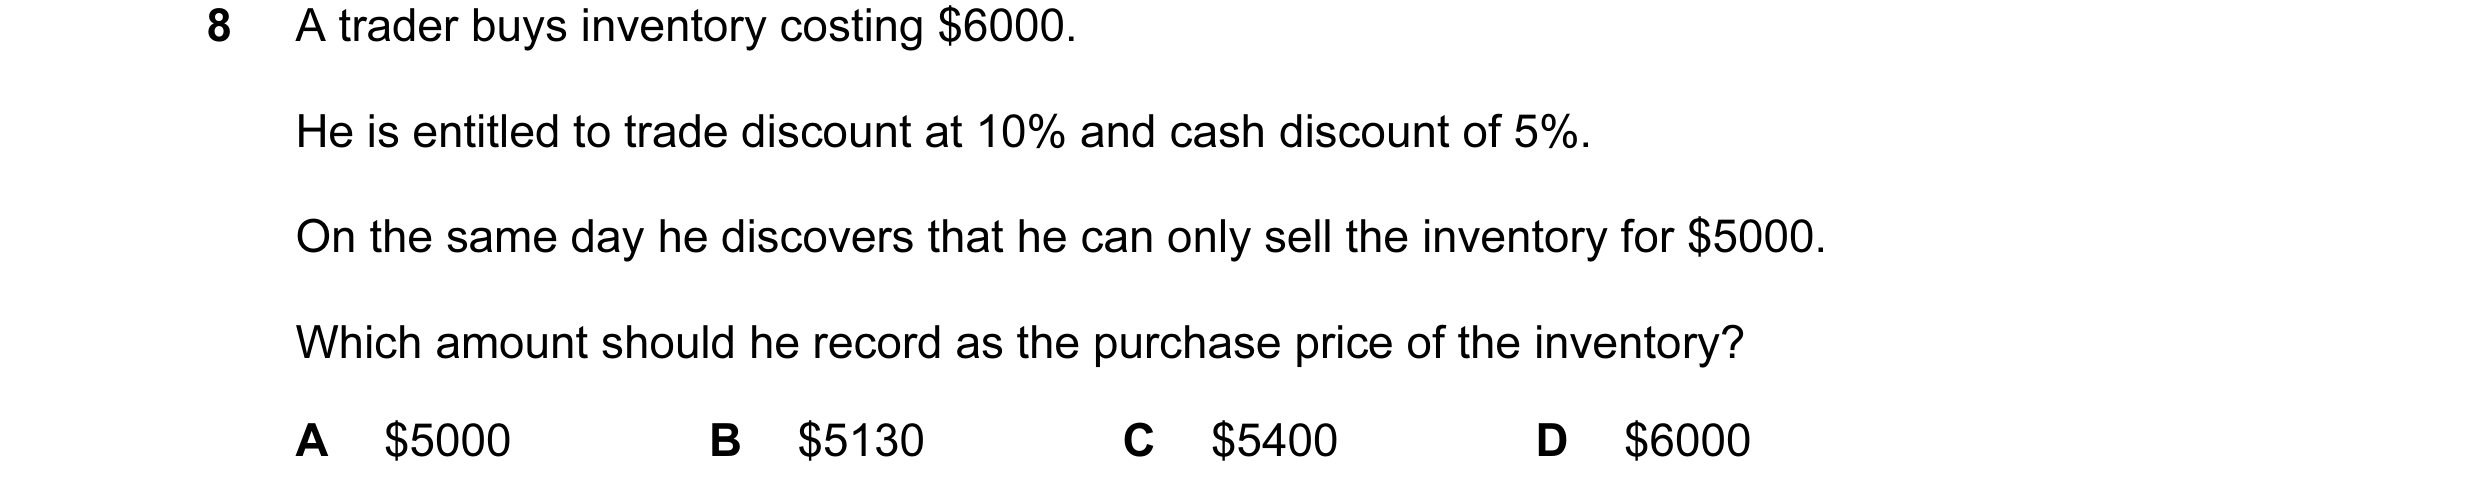
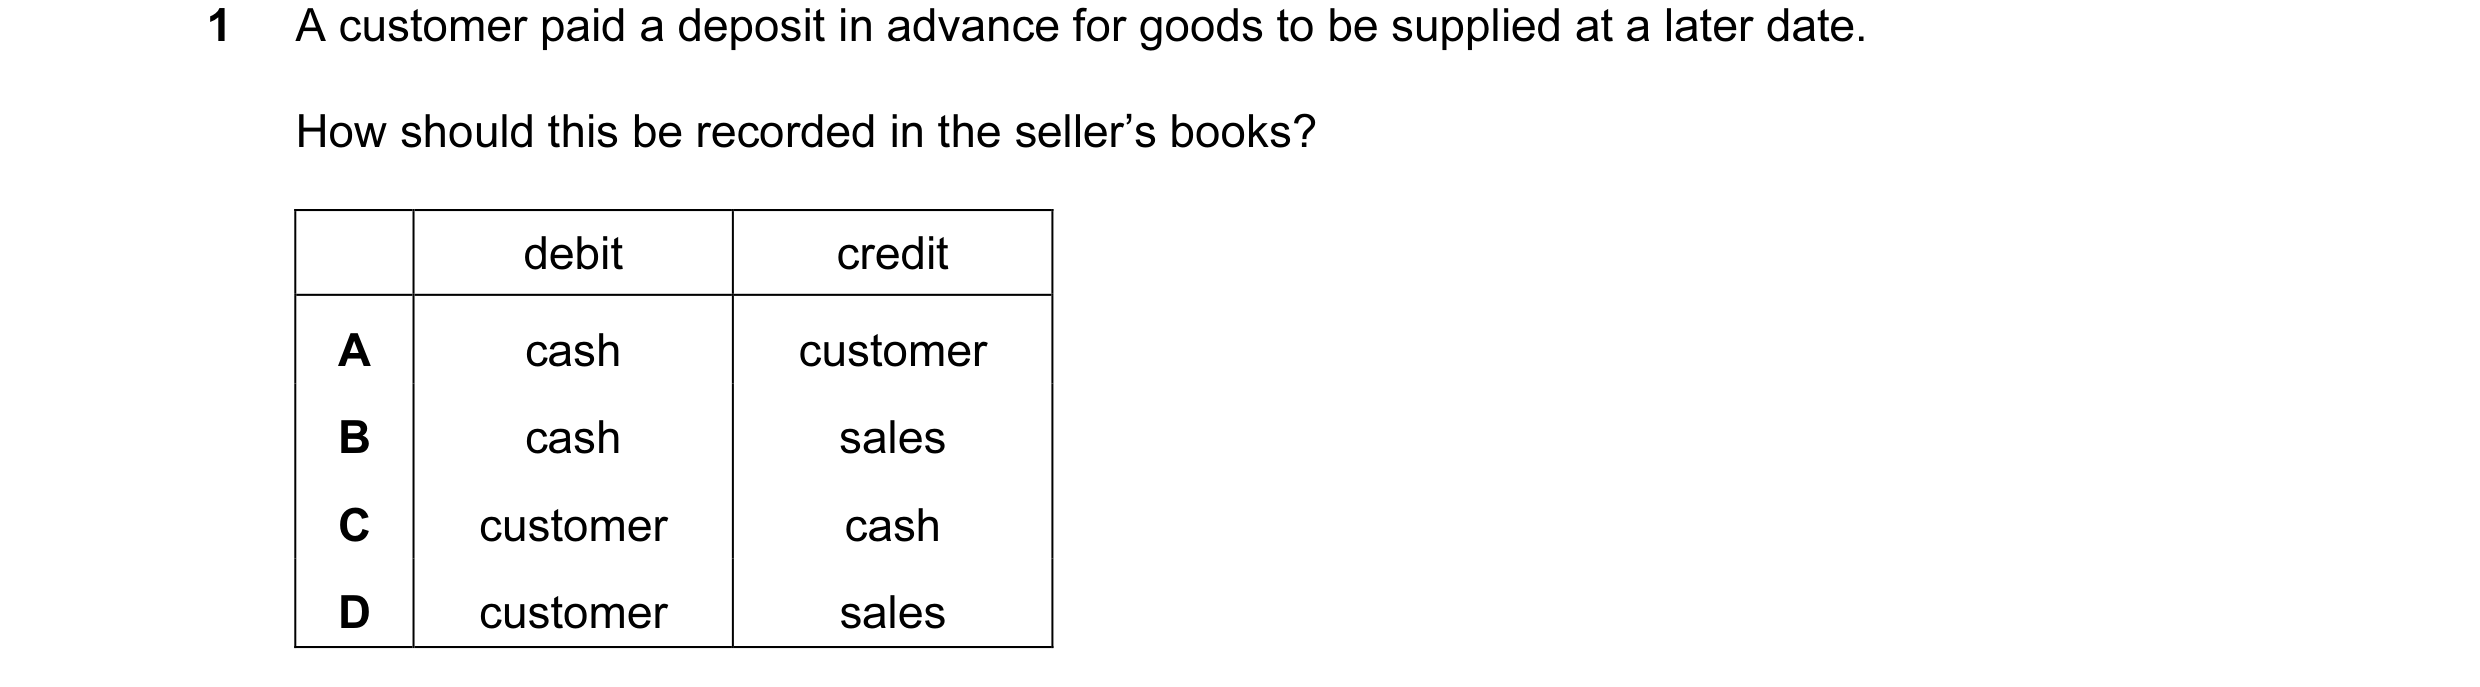 21 / 58
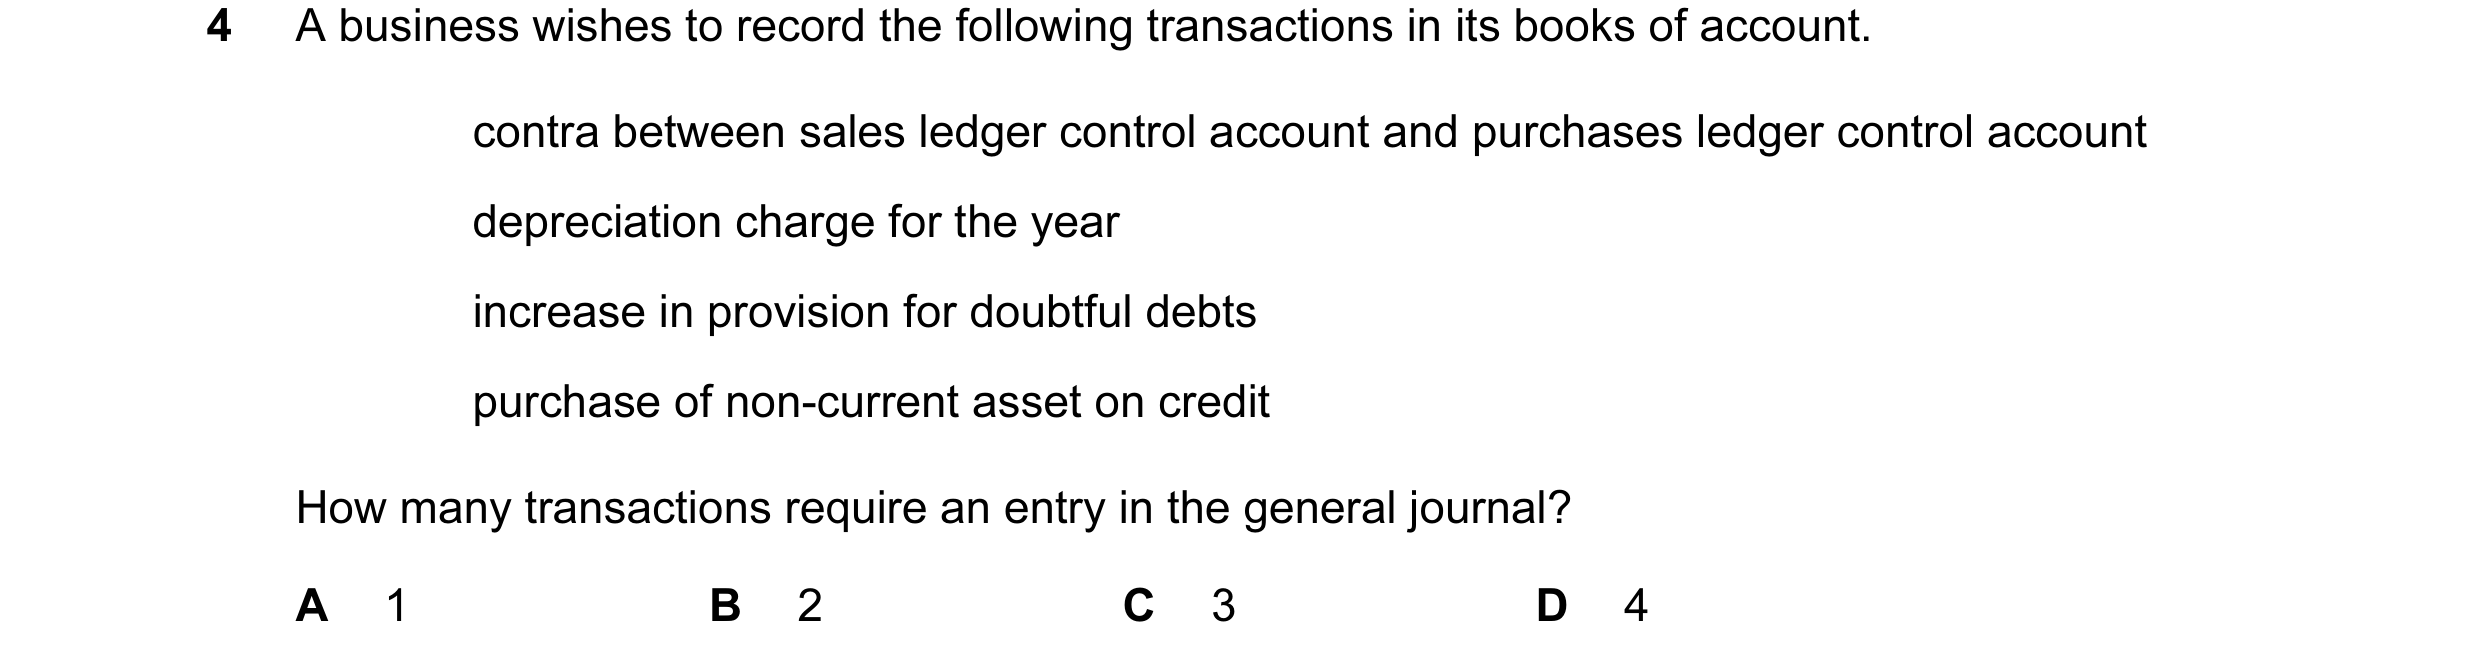
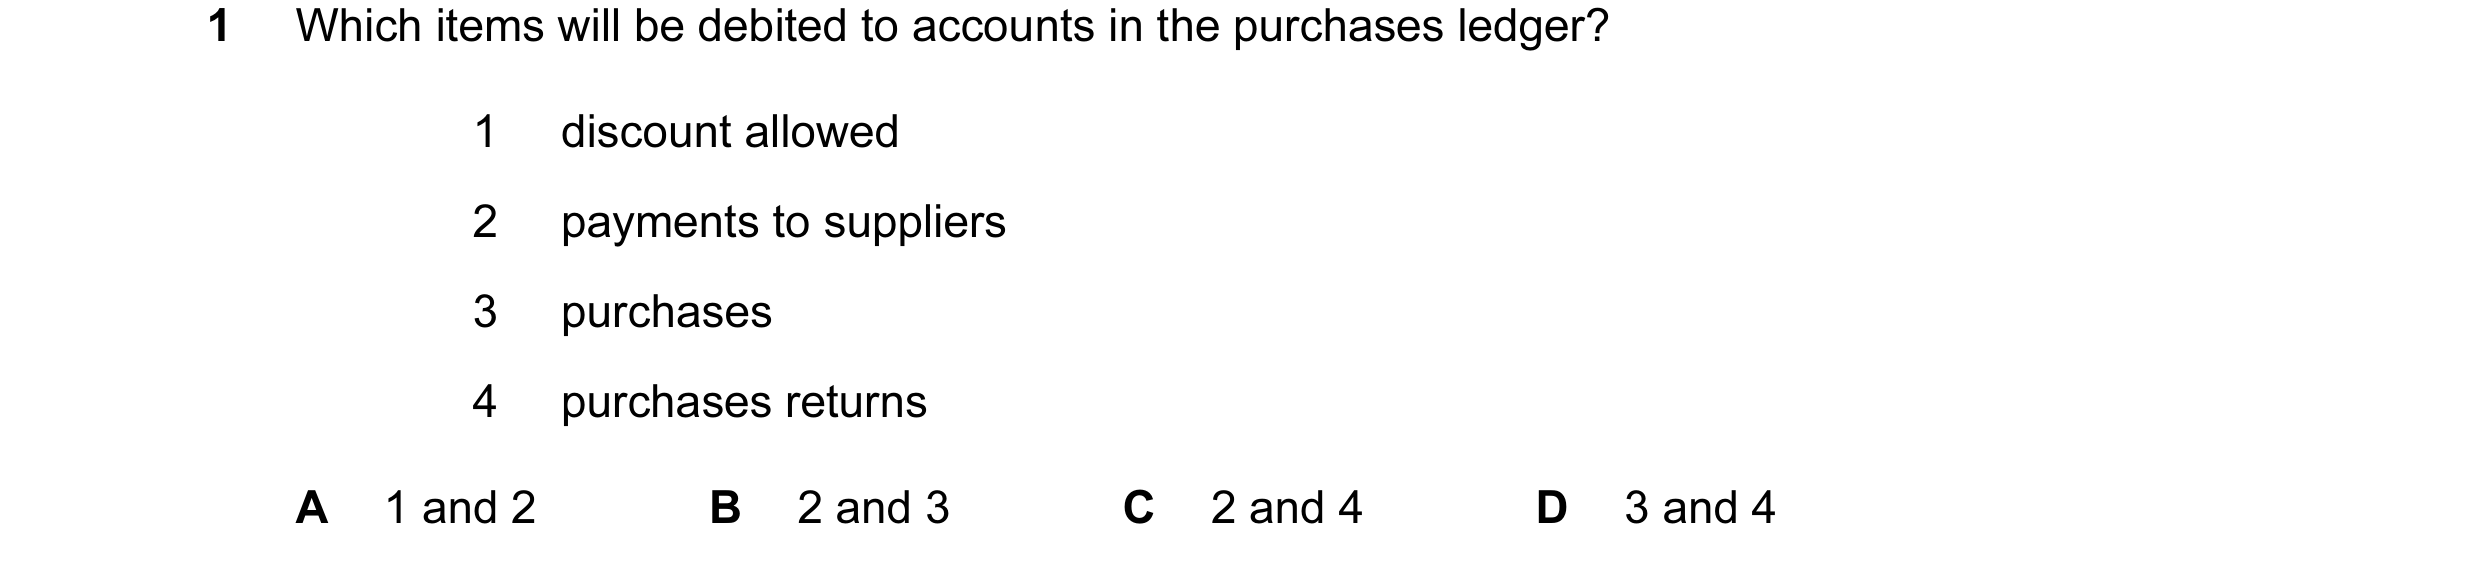
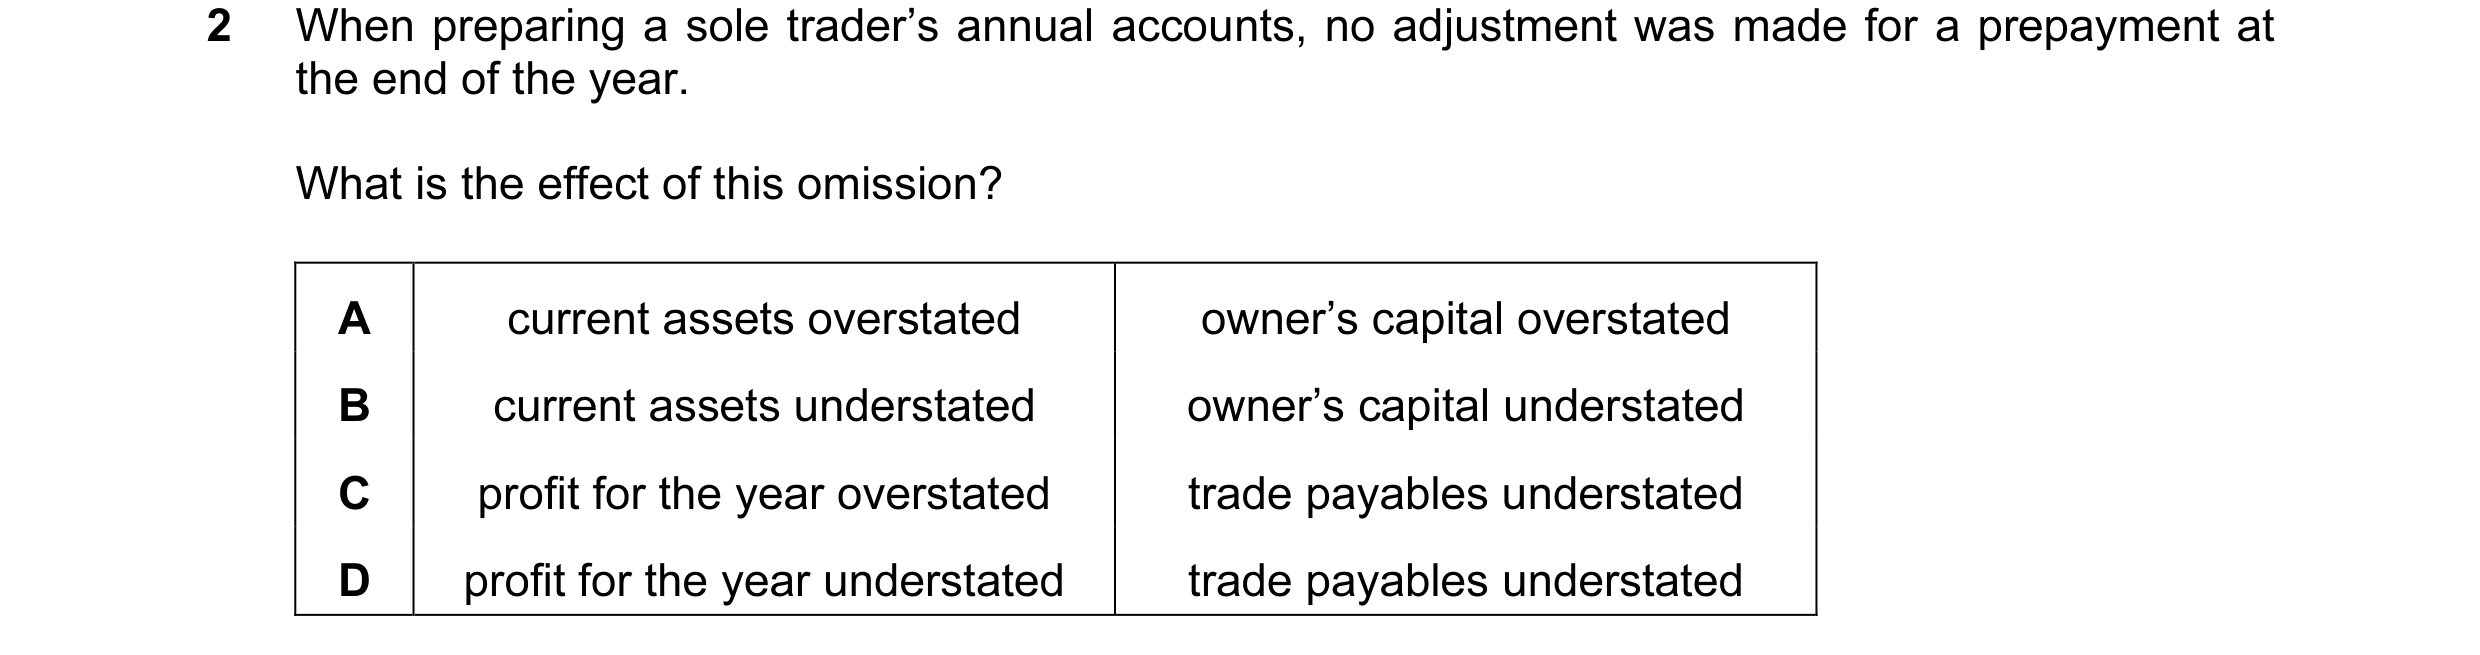
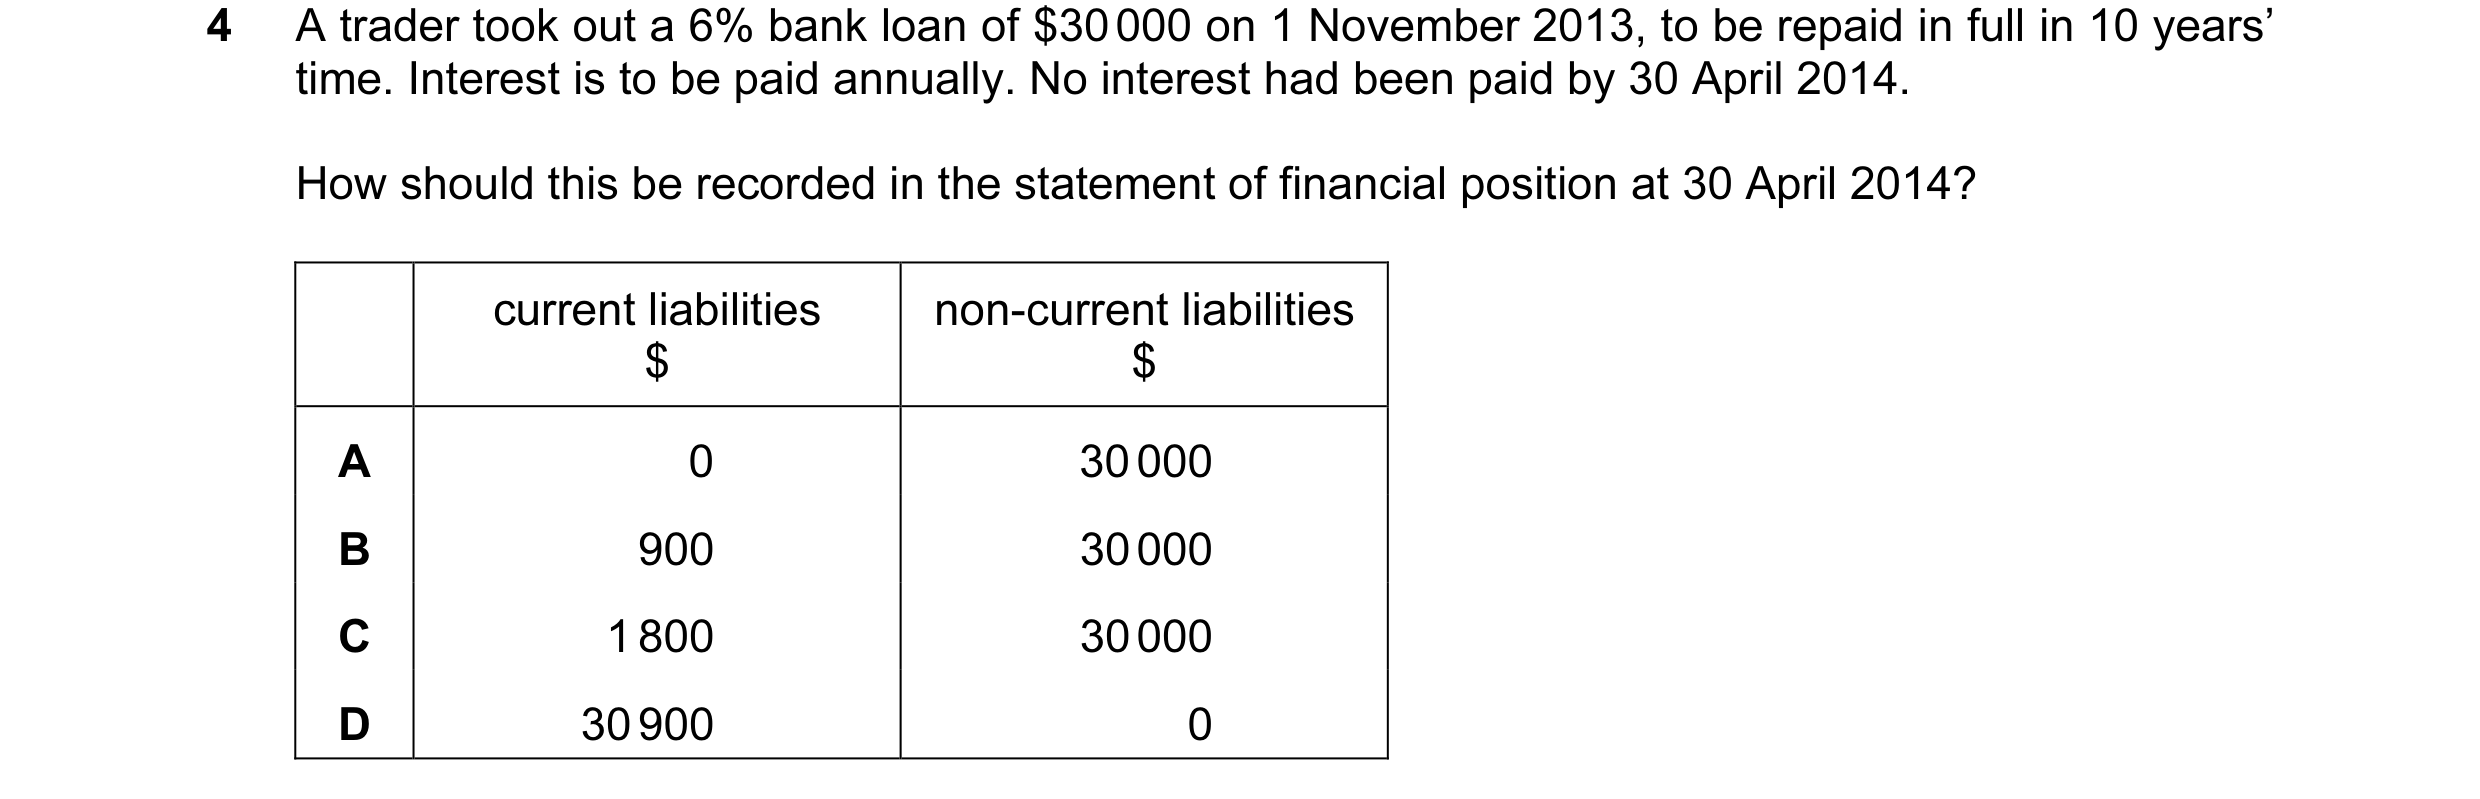 22 / 58
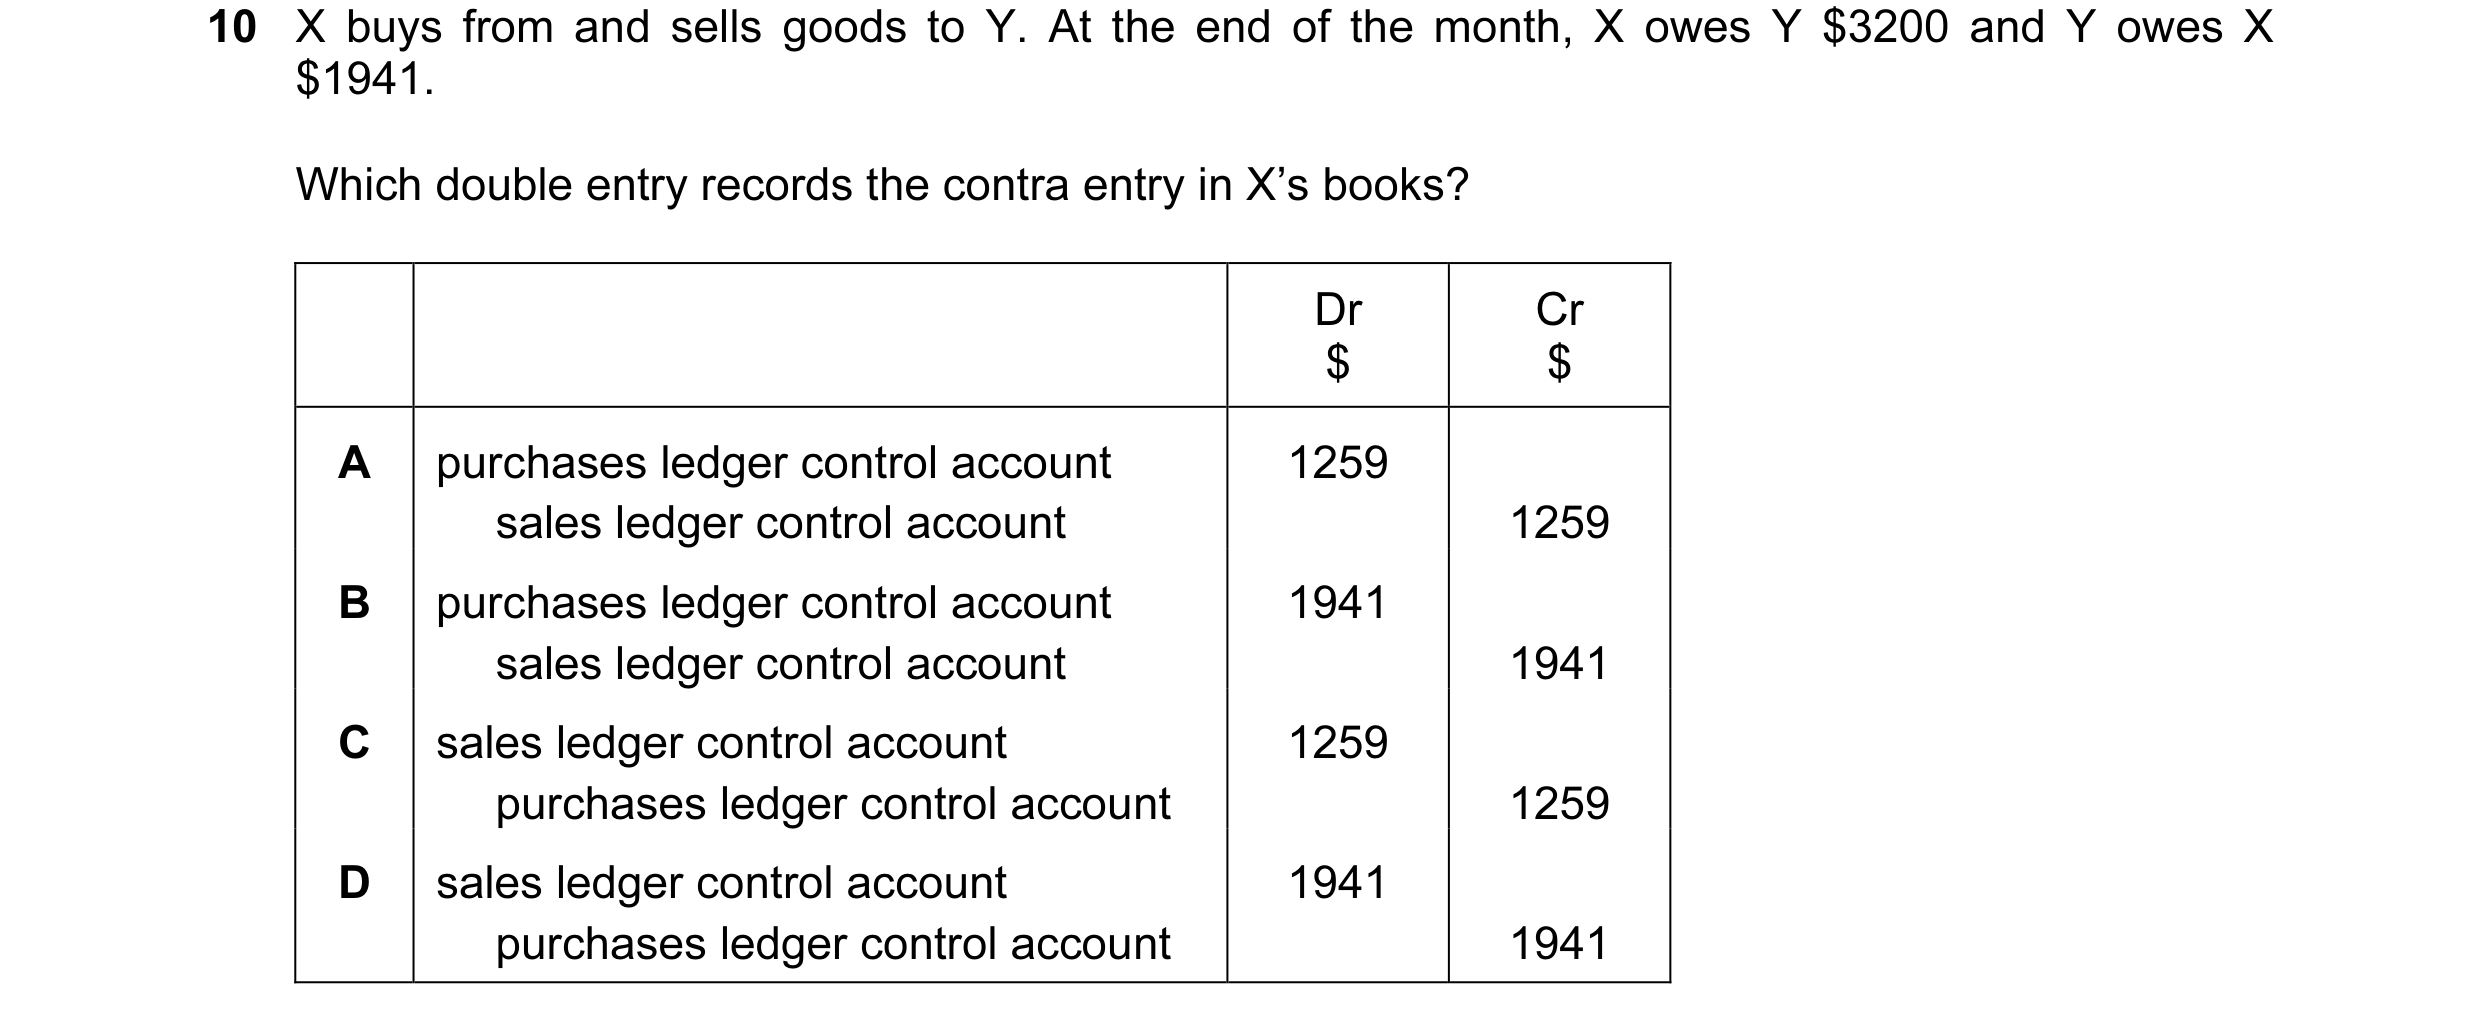
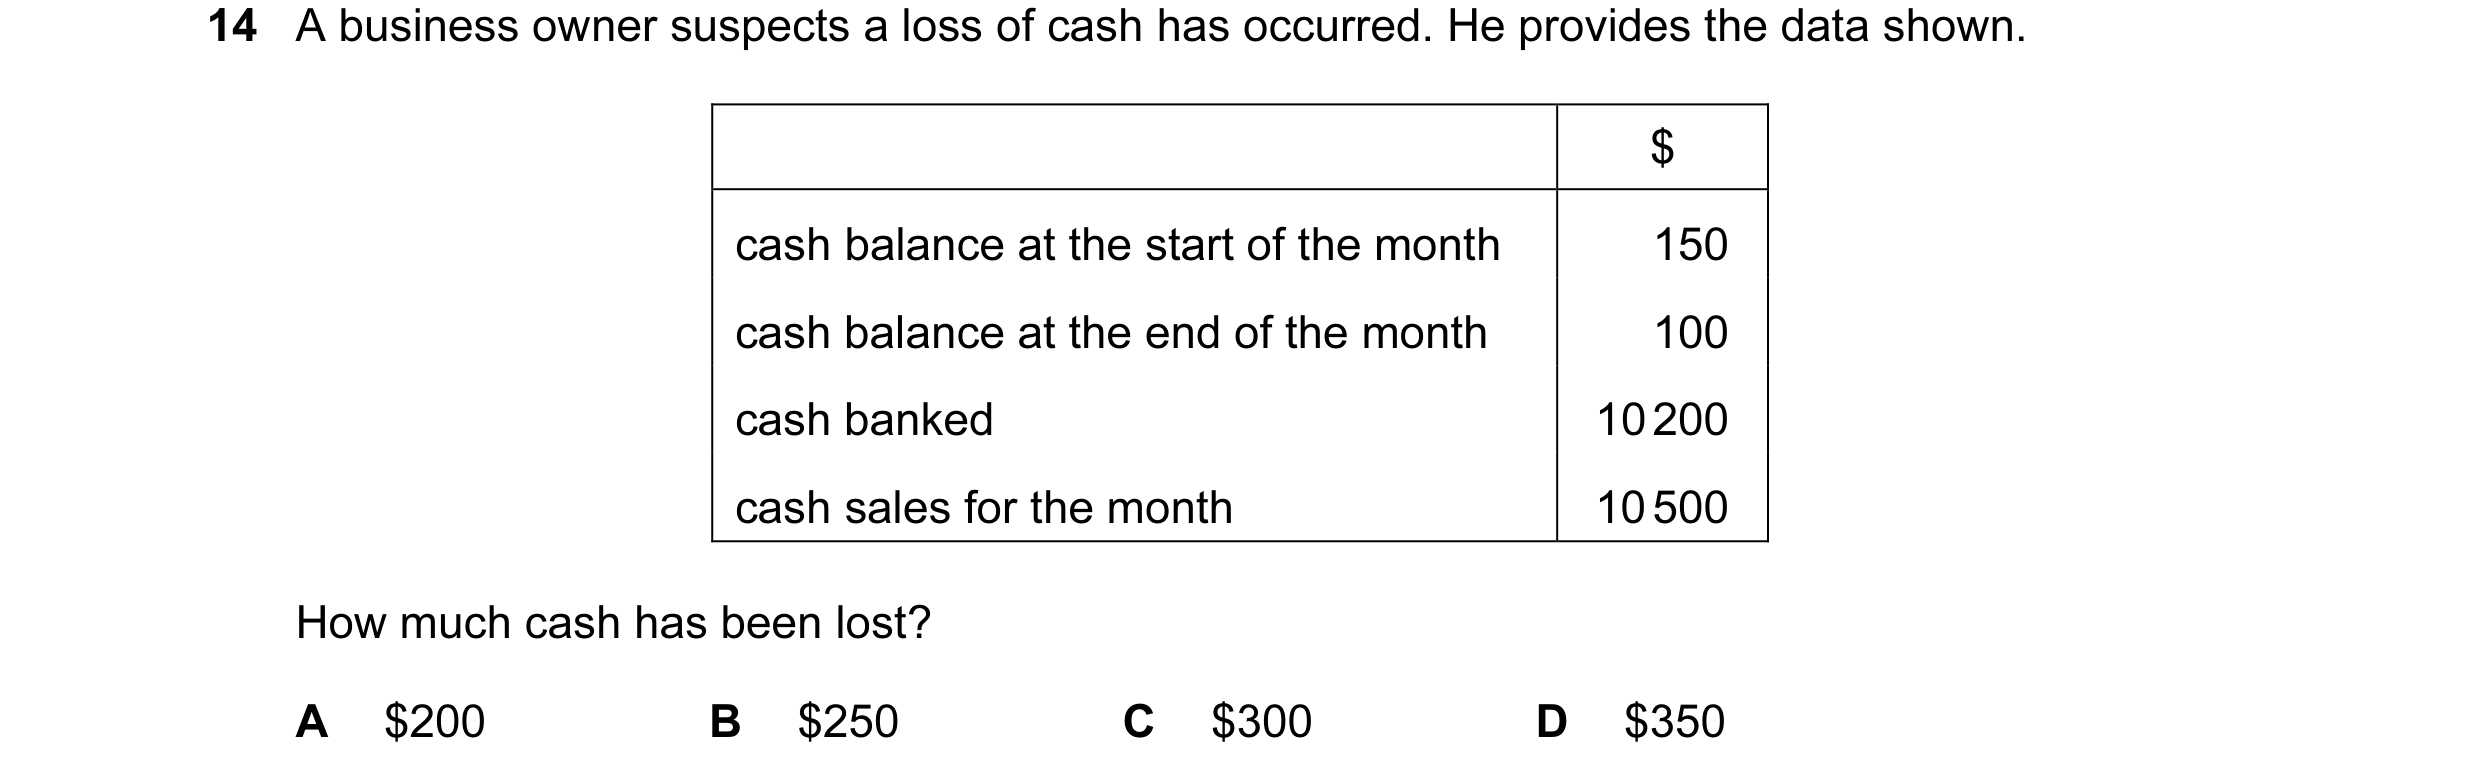 23 / 58
 24 / 58
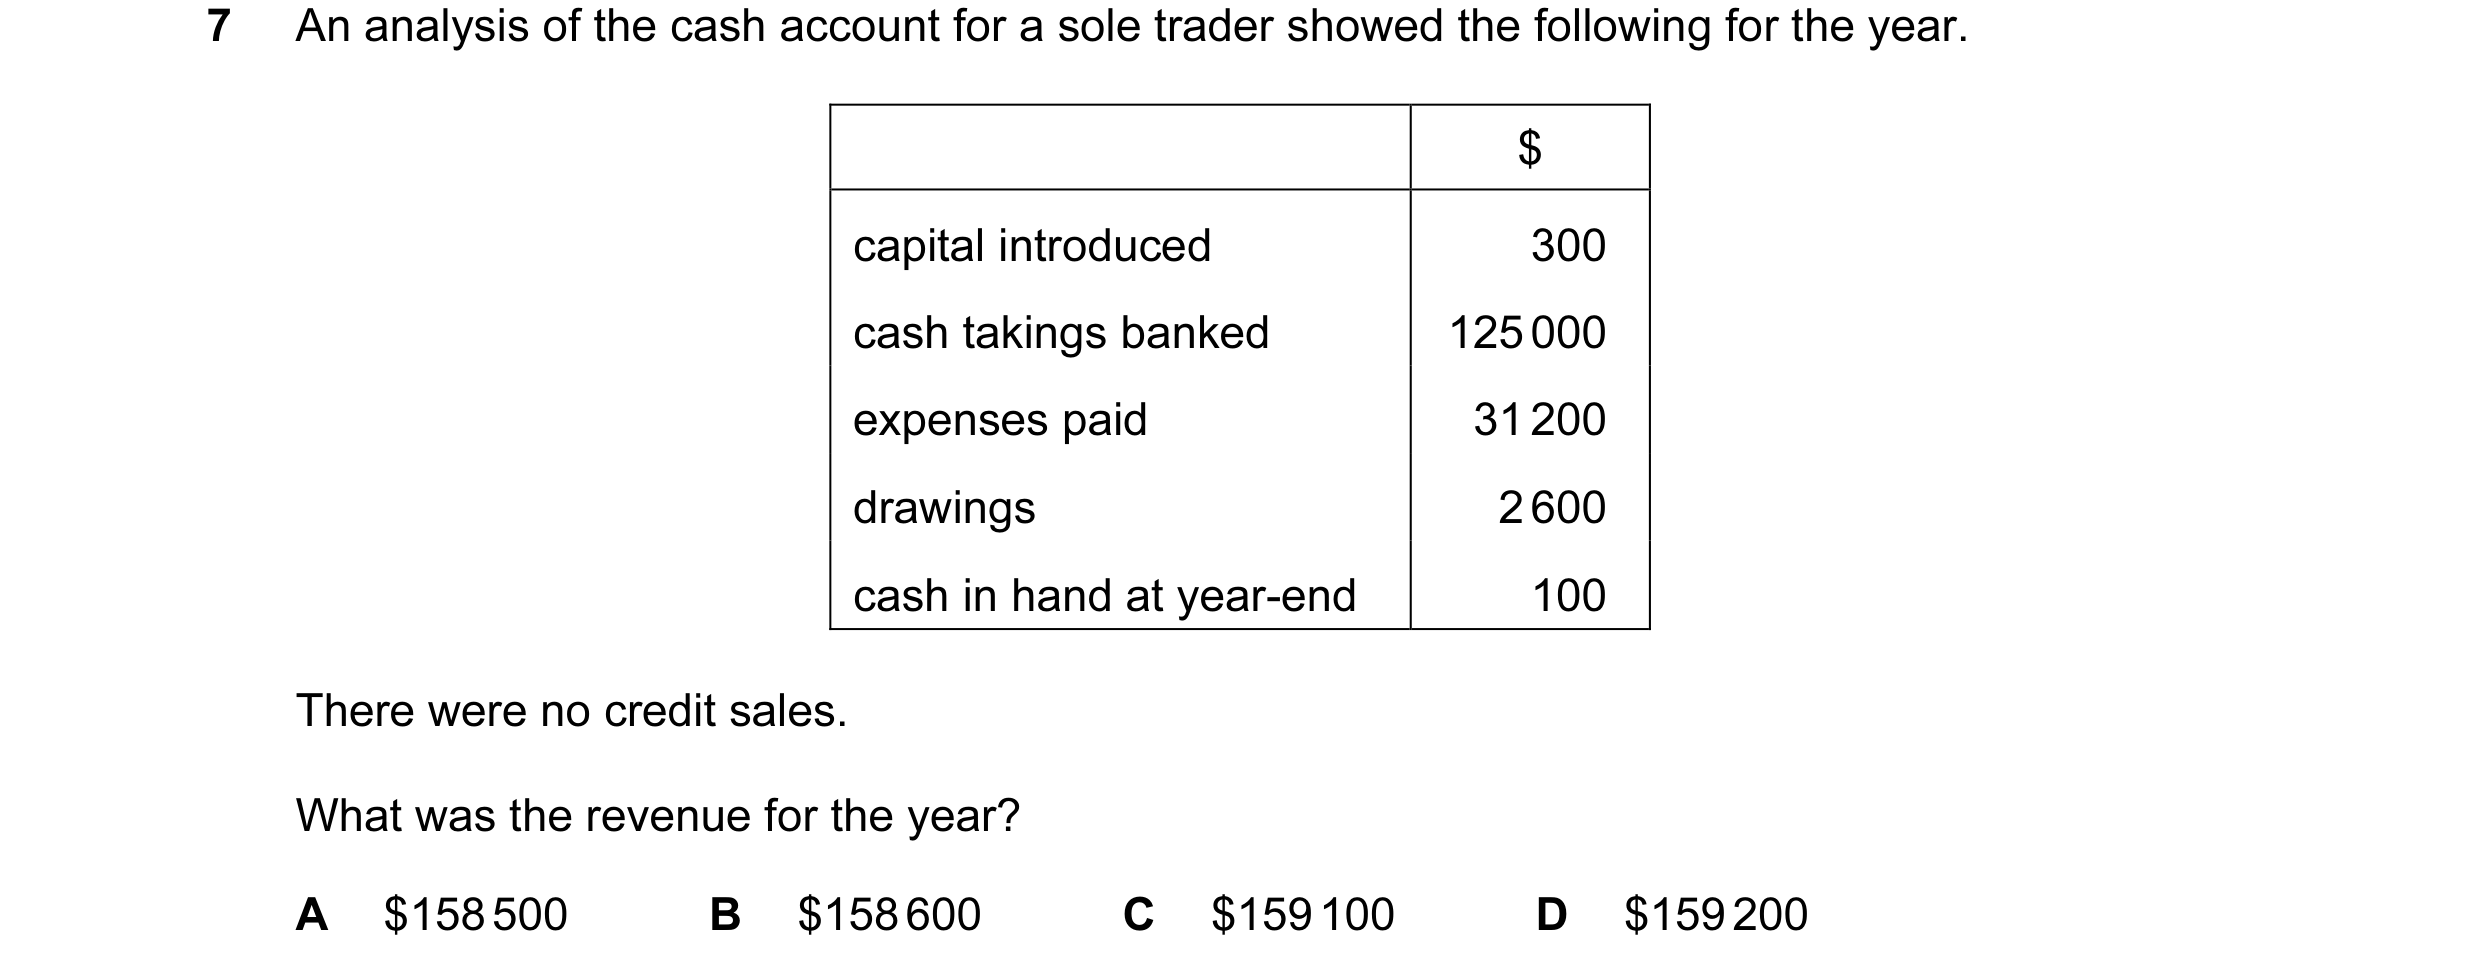
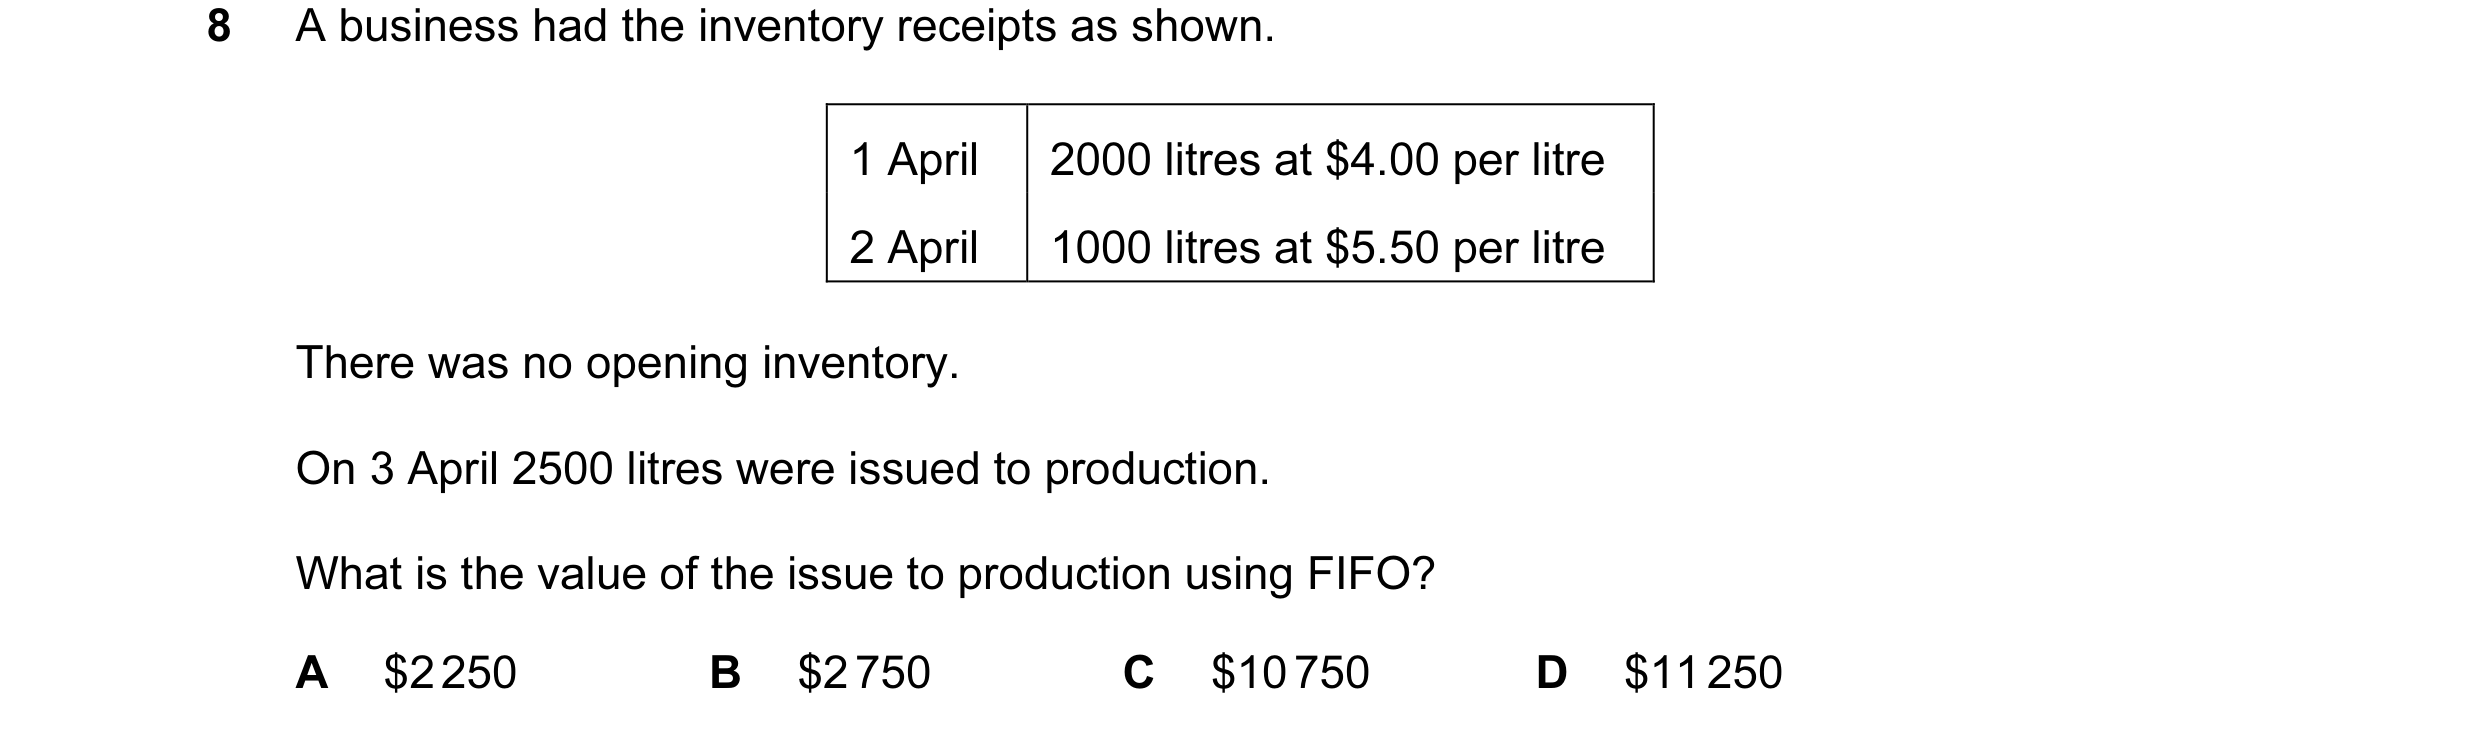
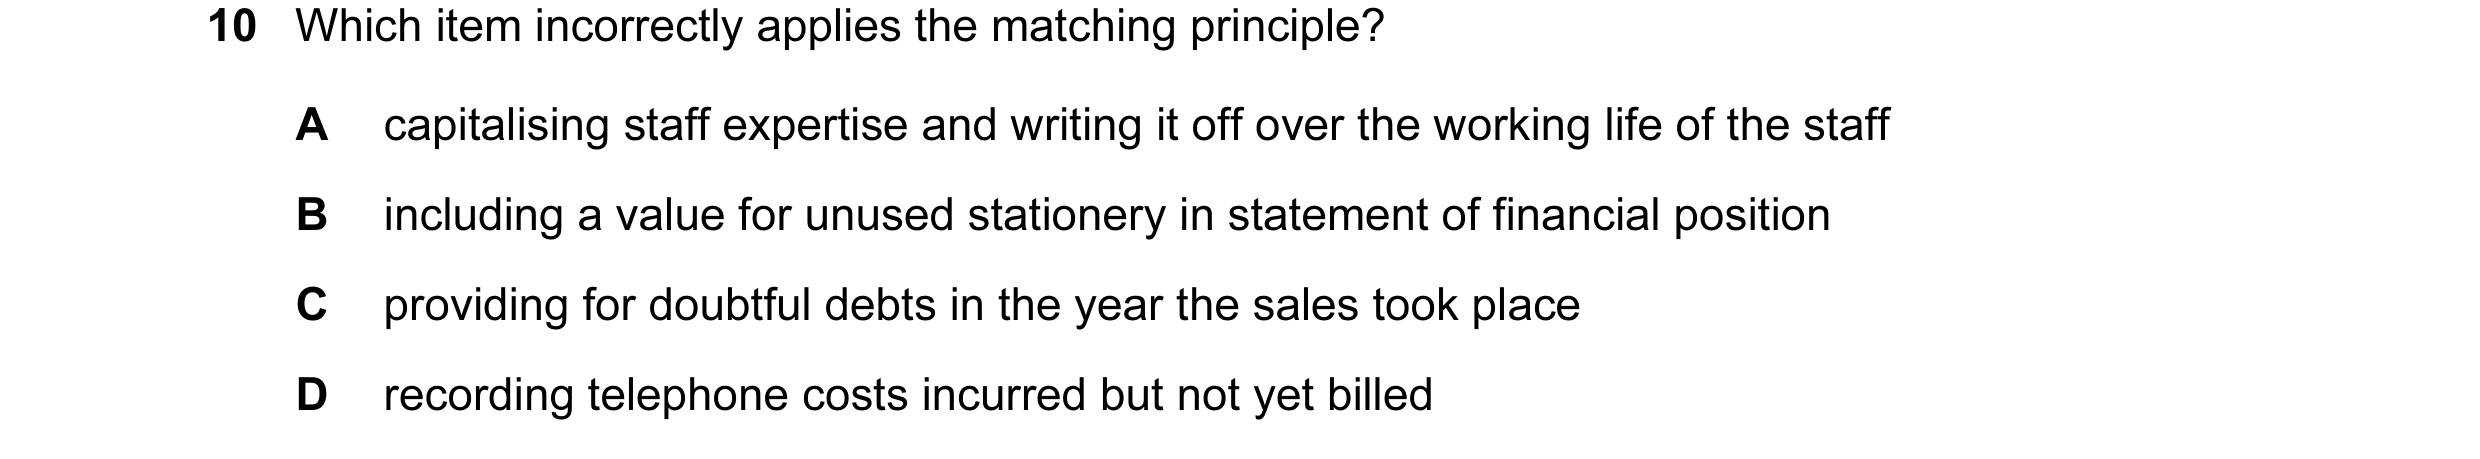
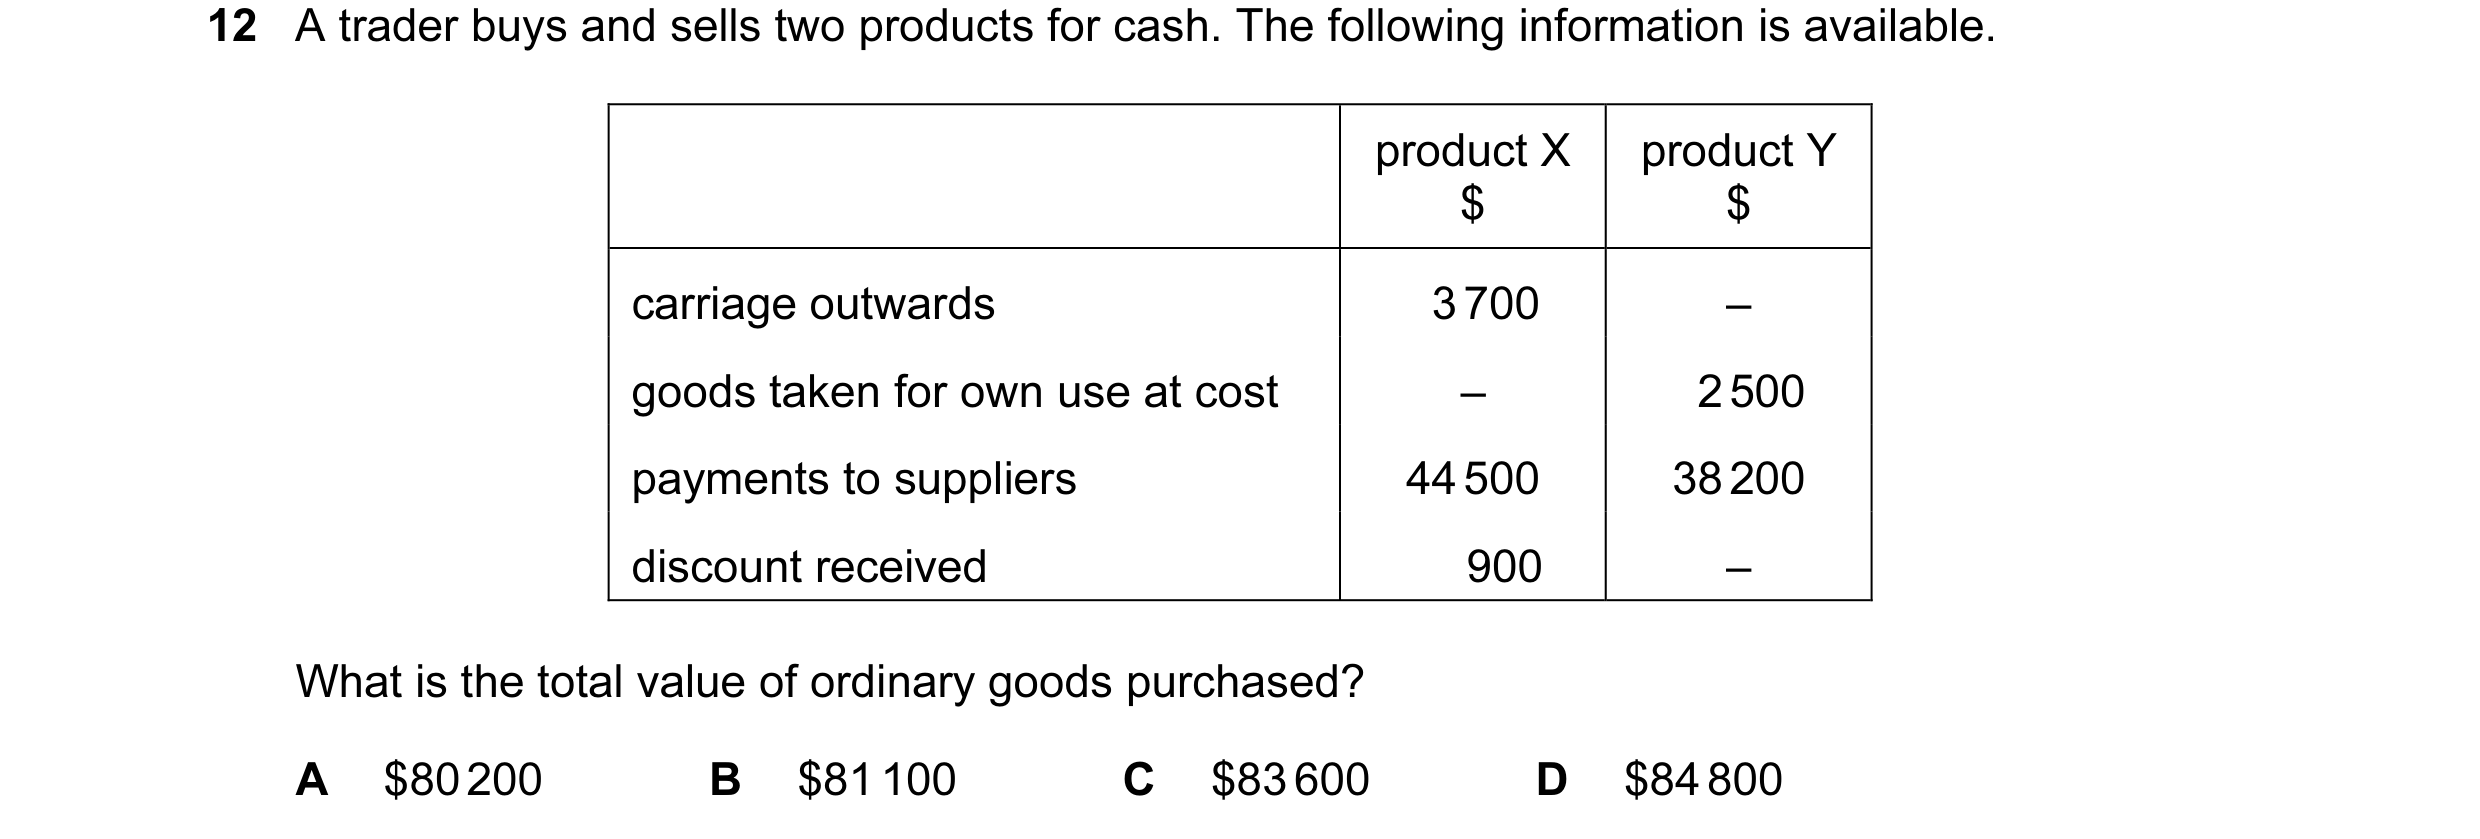 25 / 58
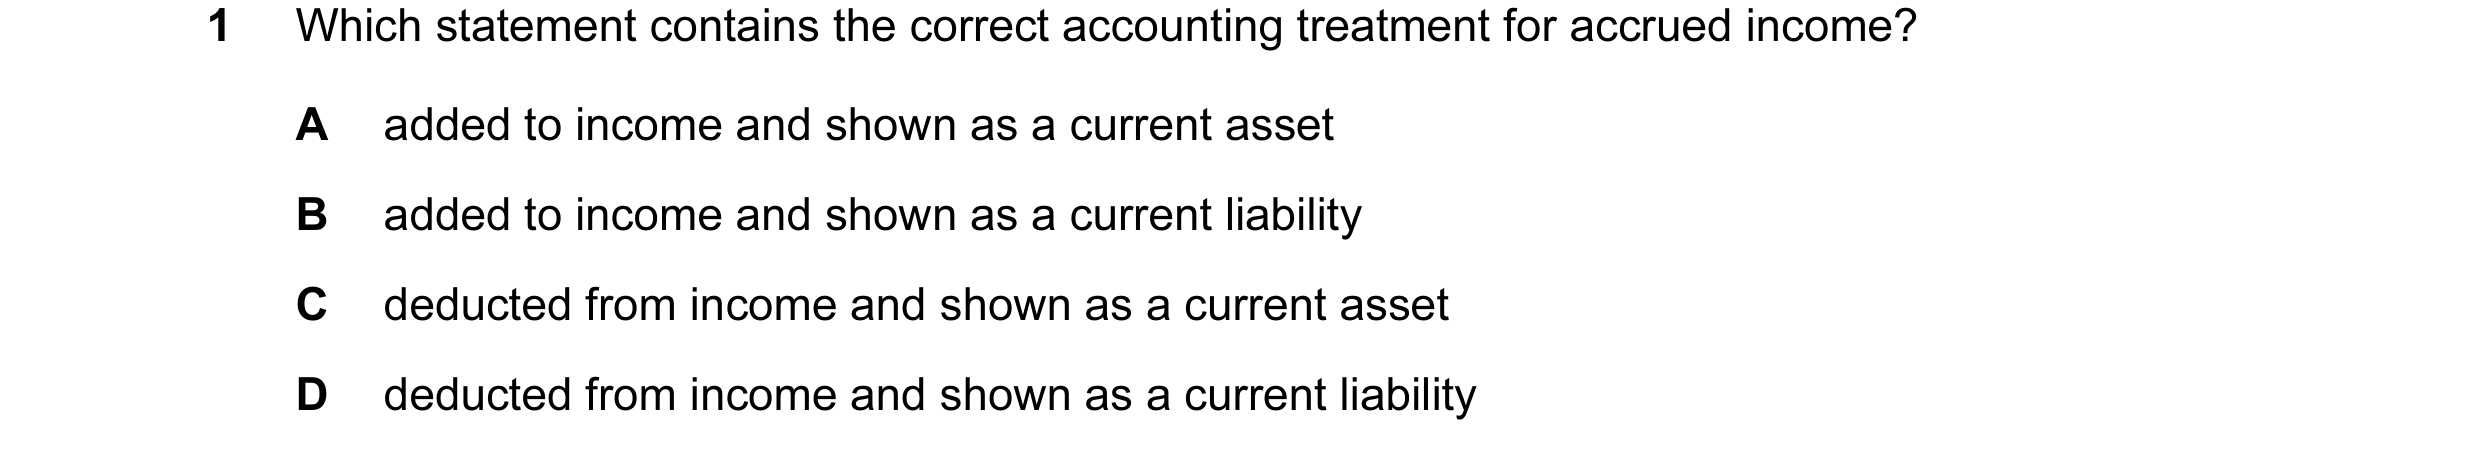
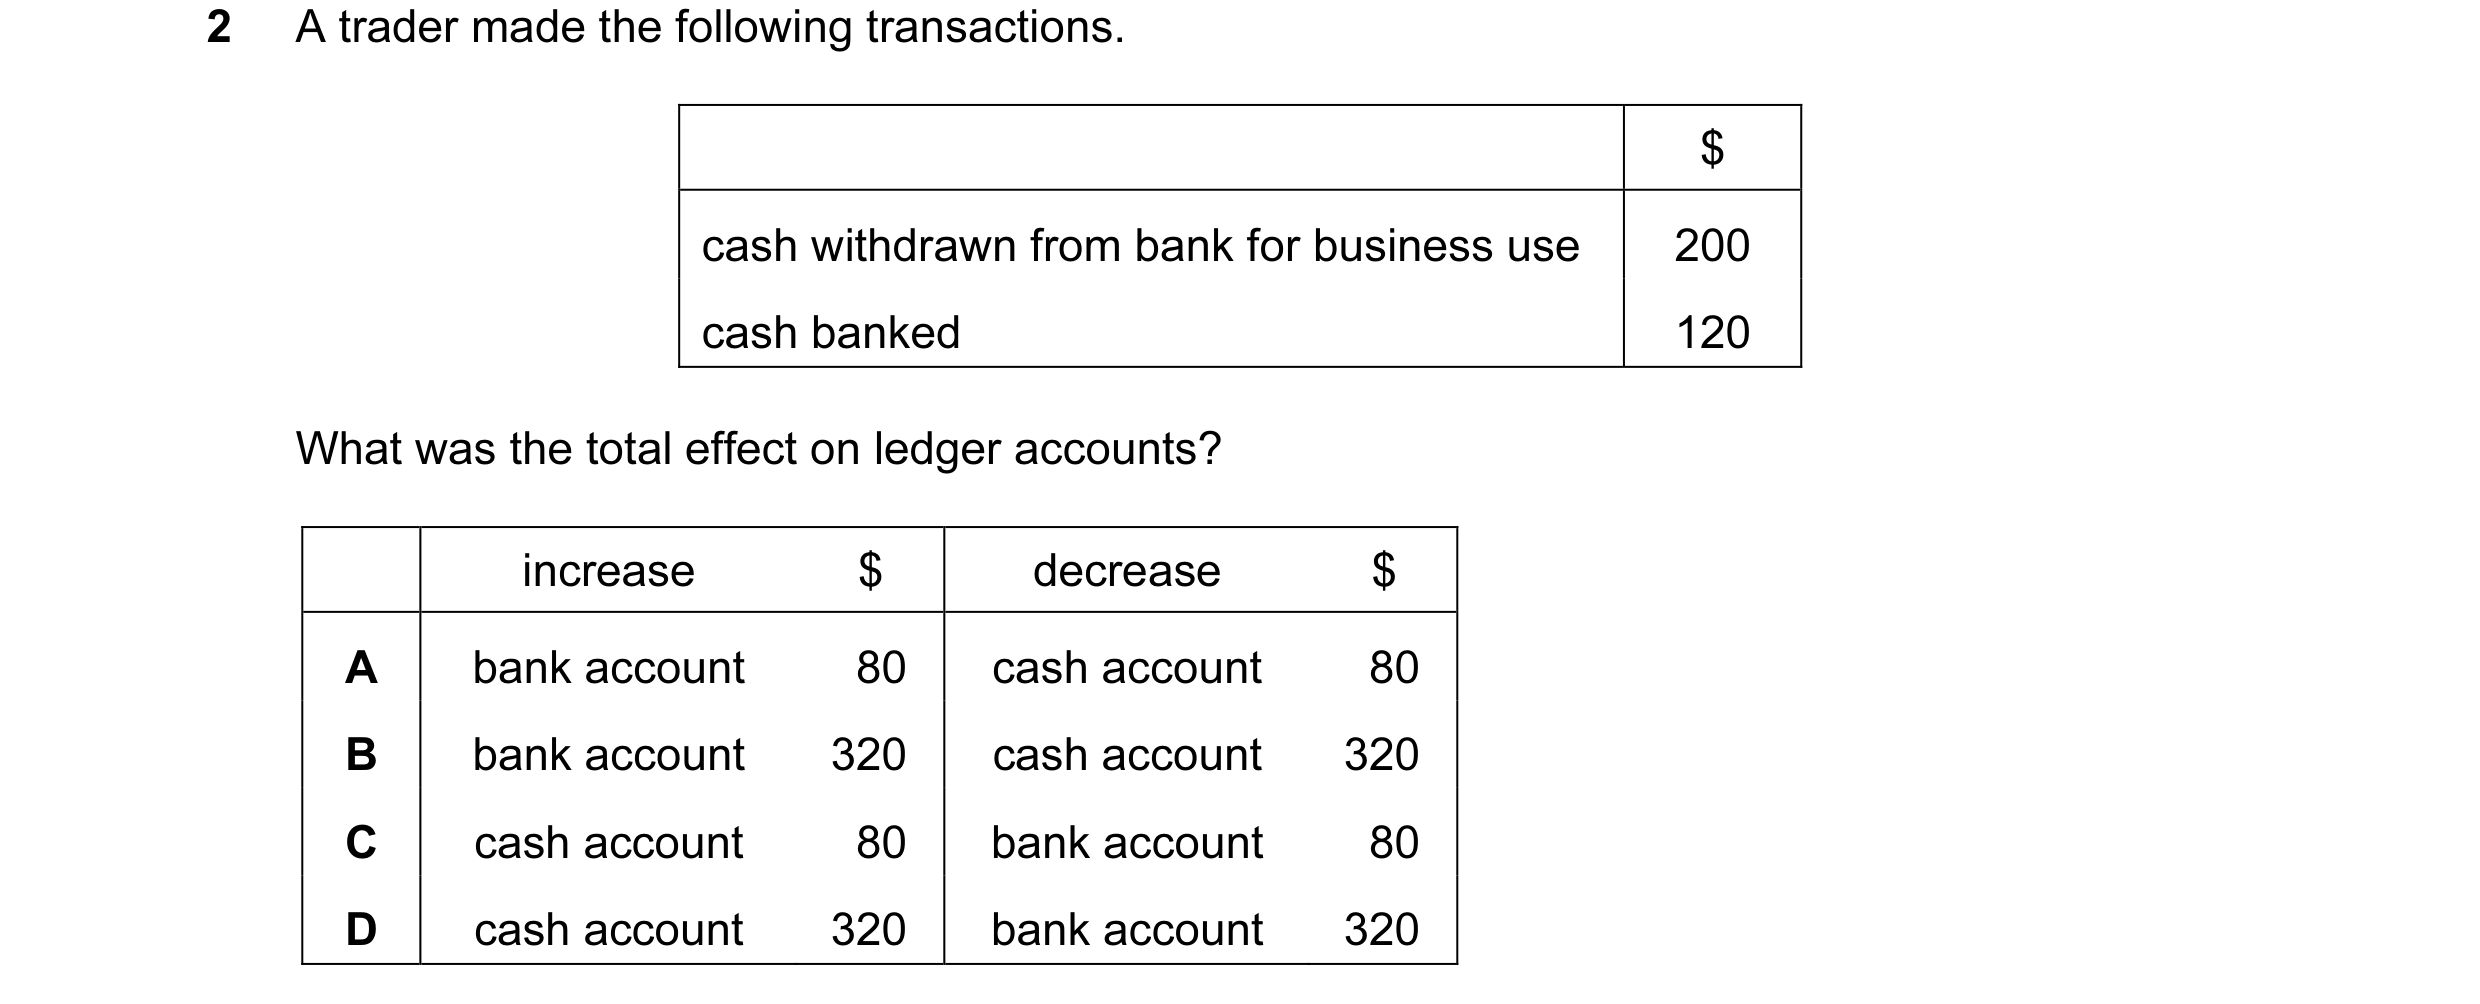
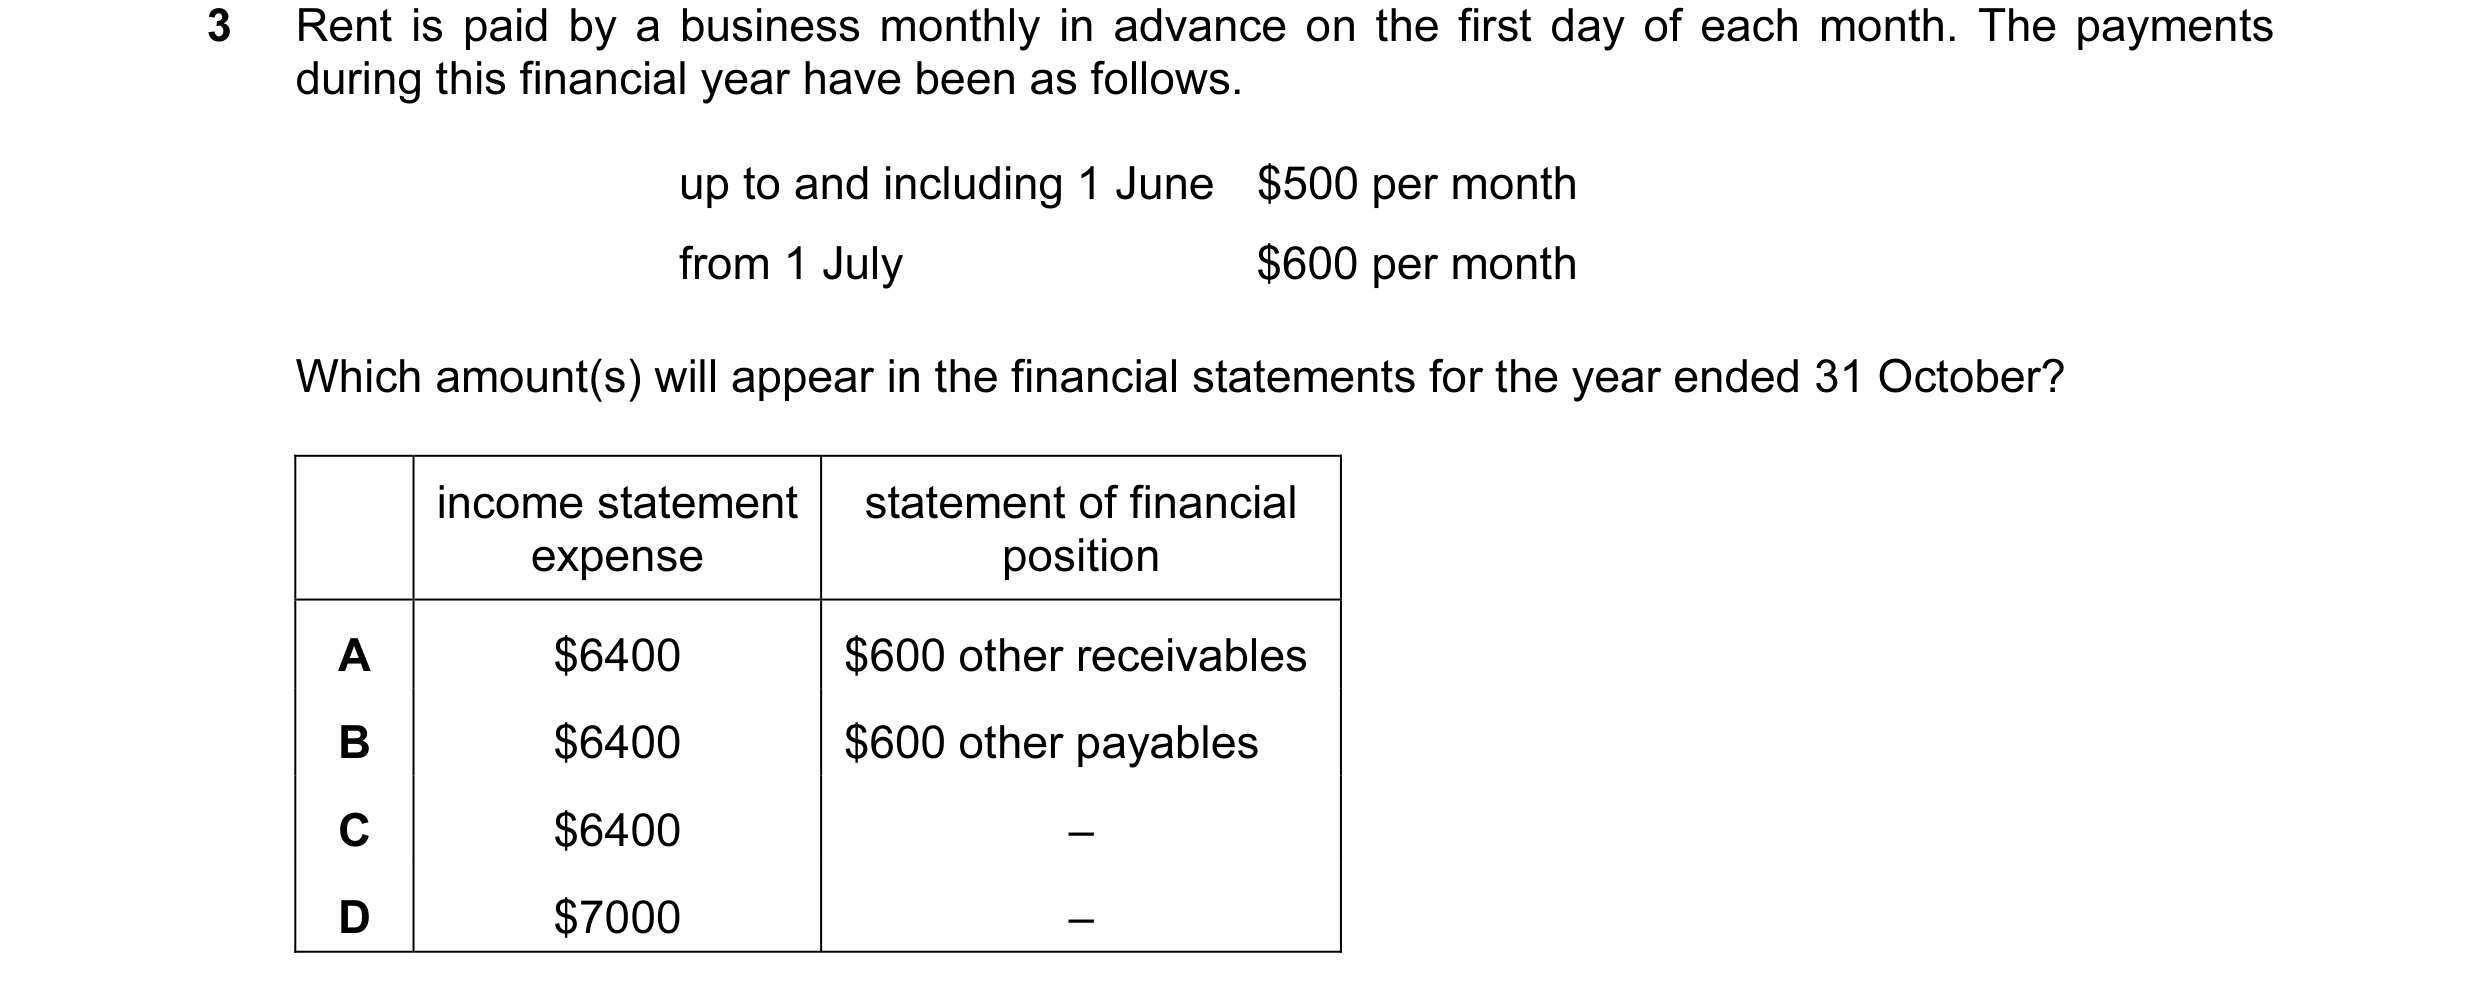
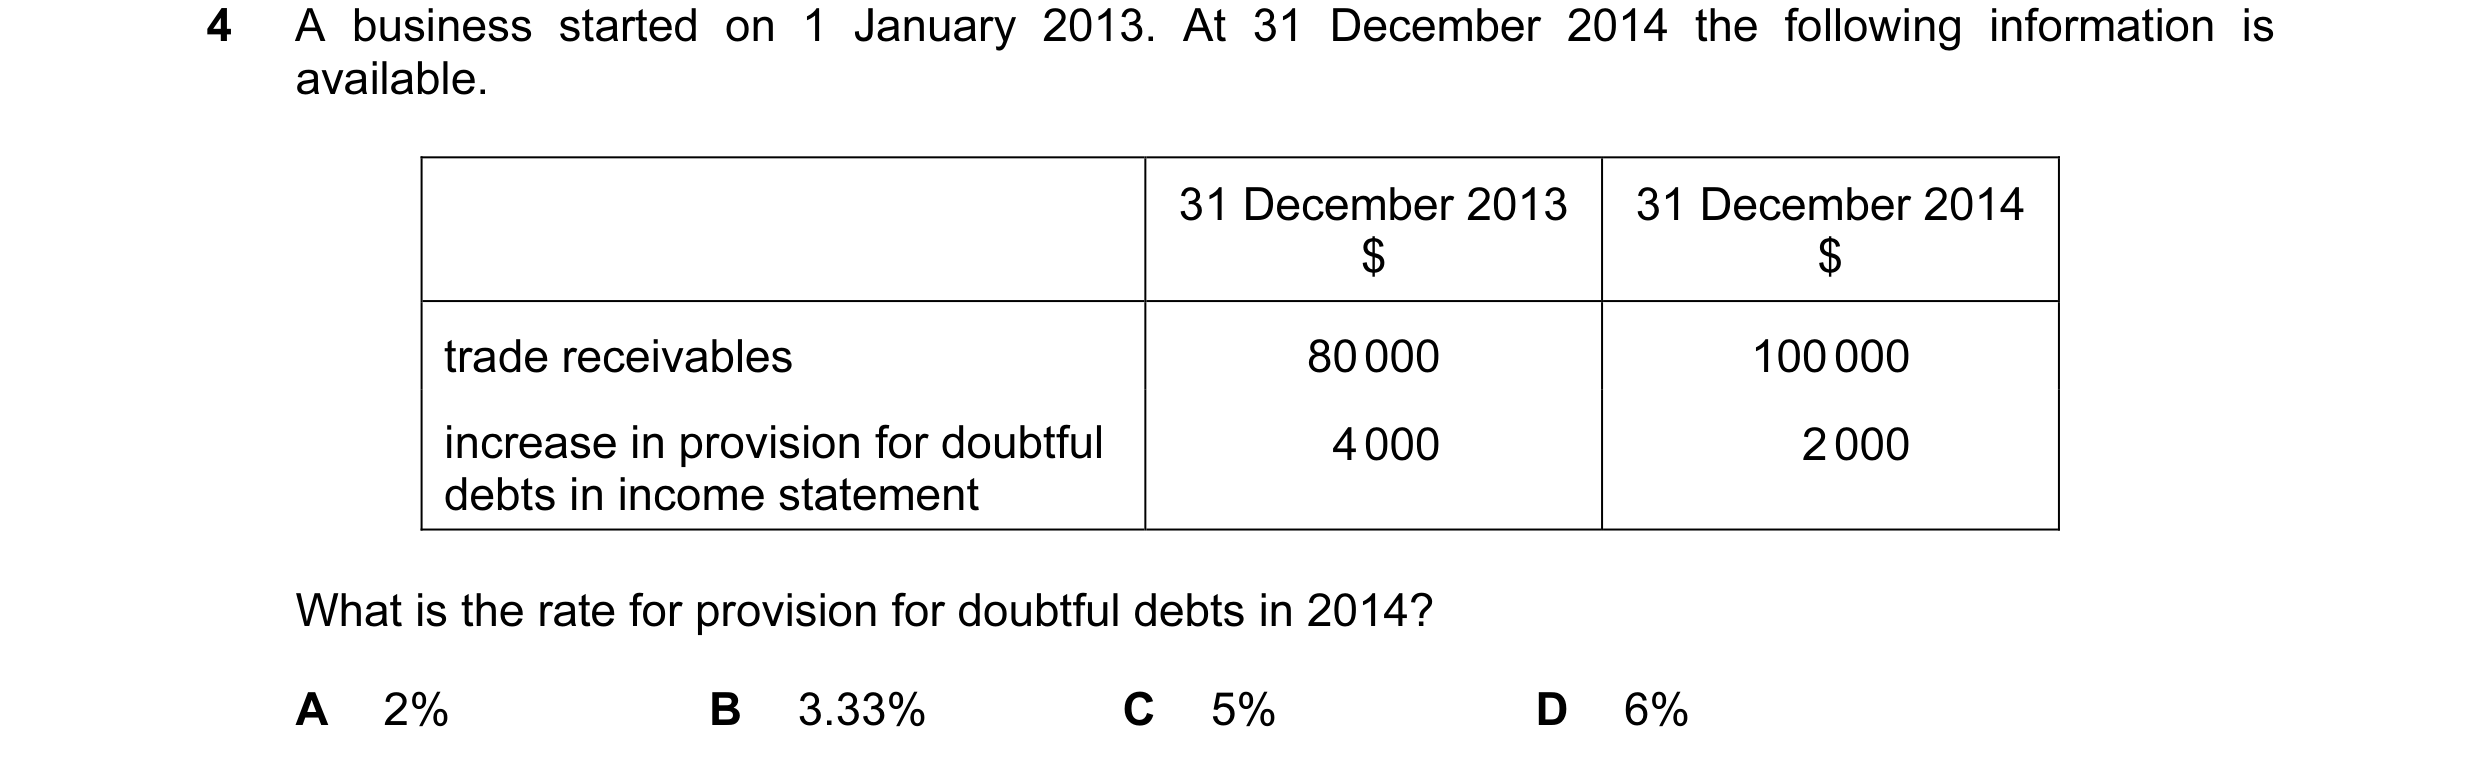 26 / 58
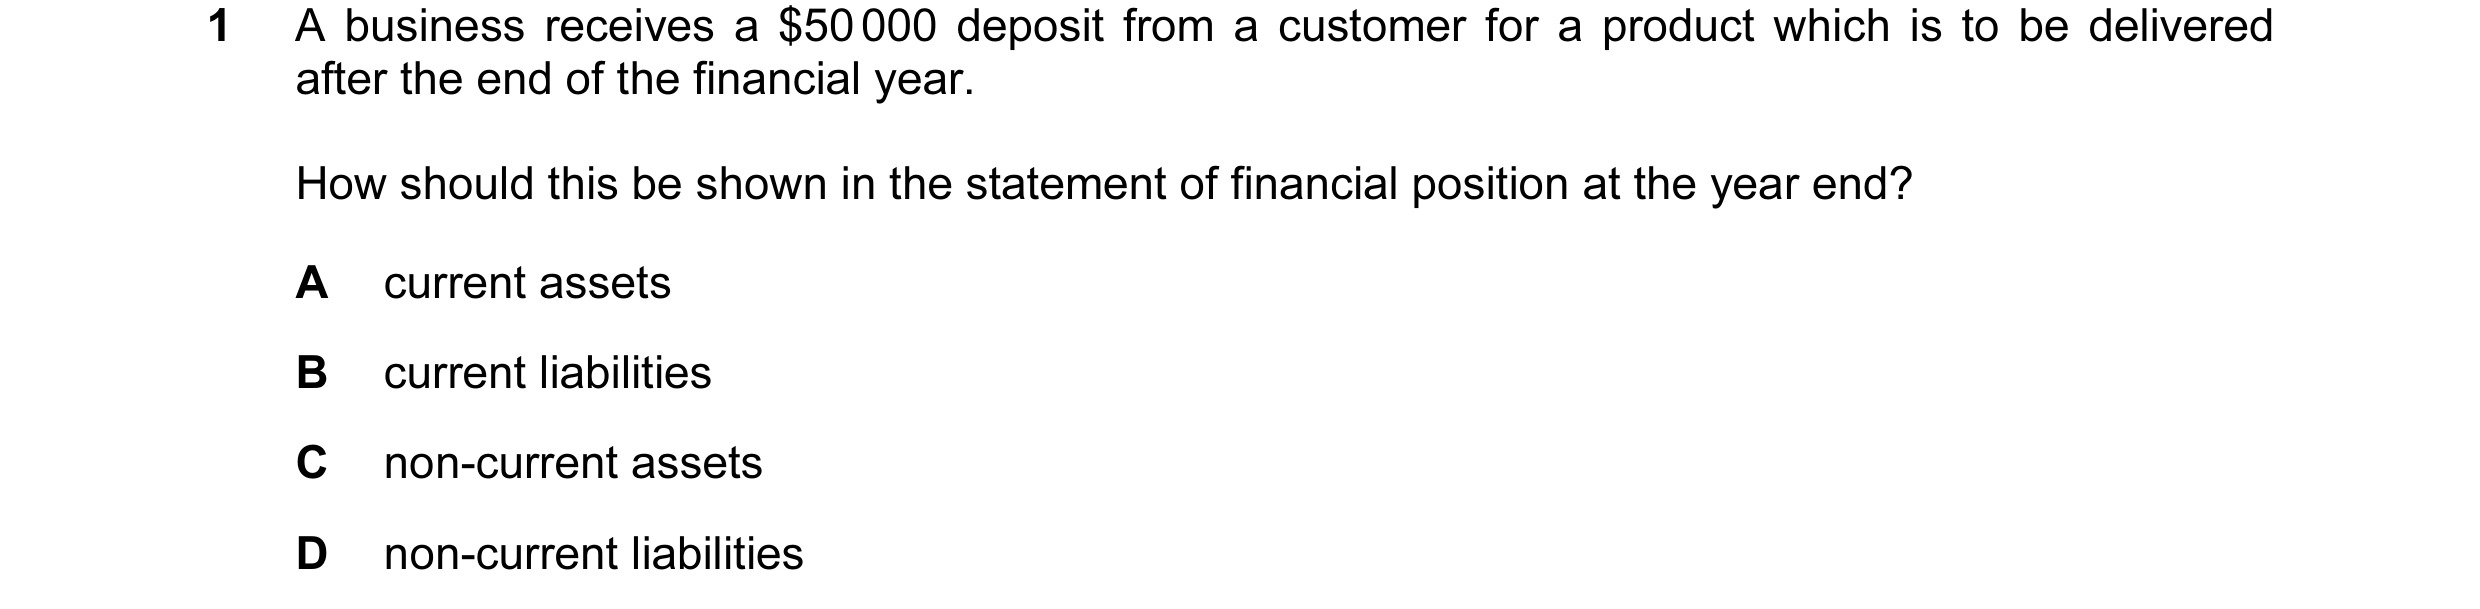
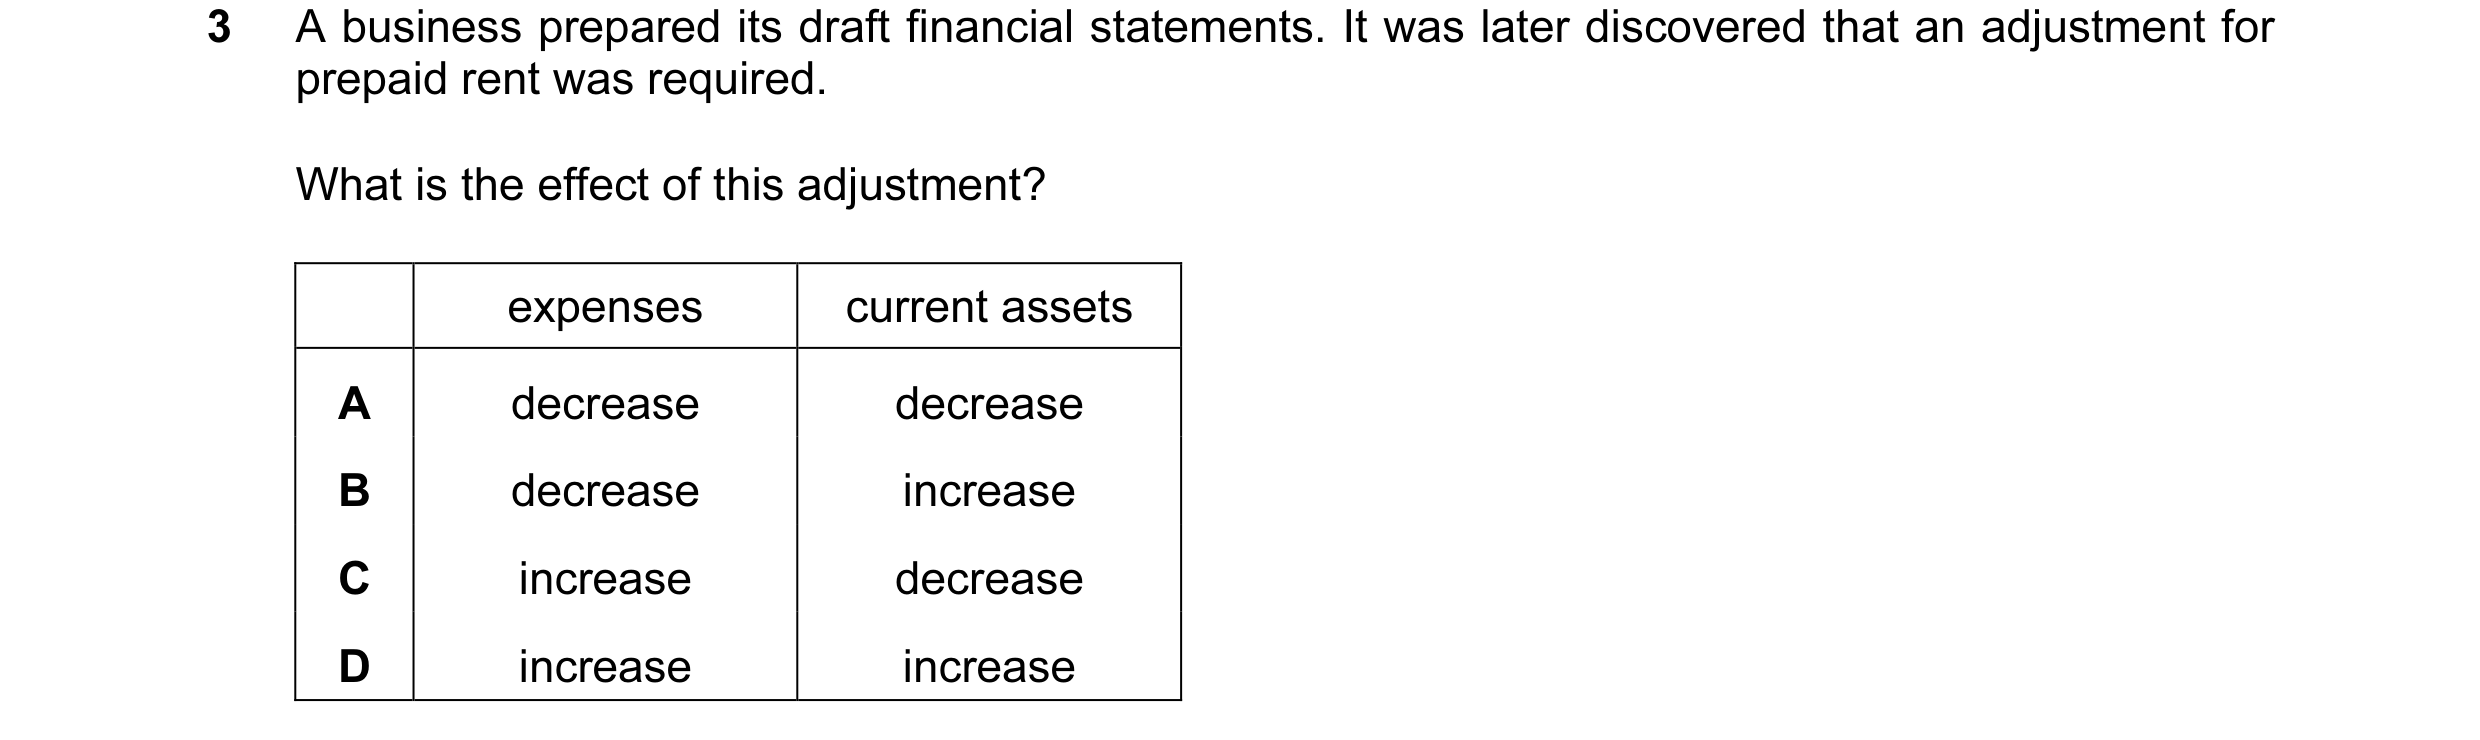
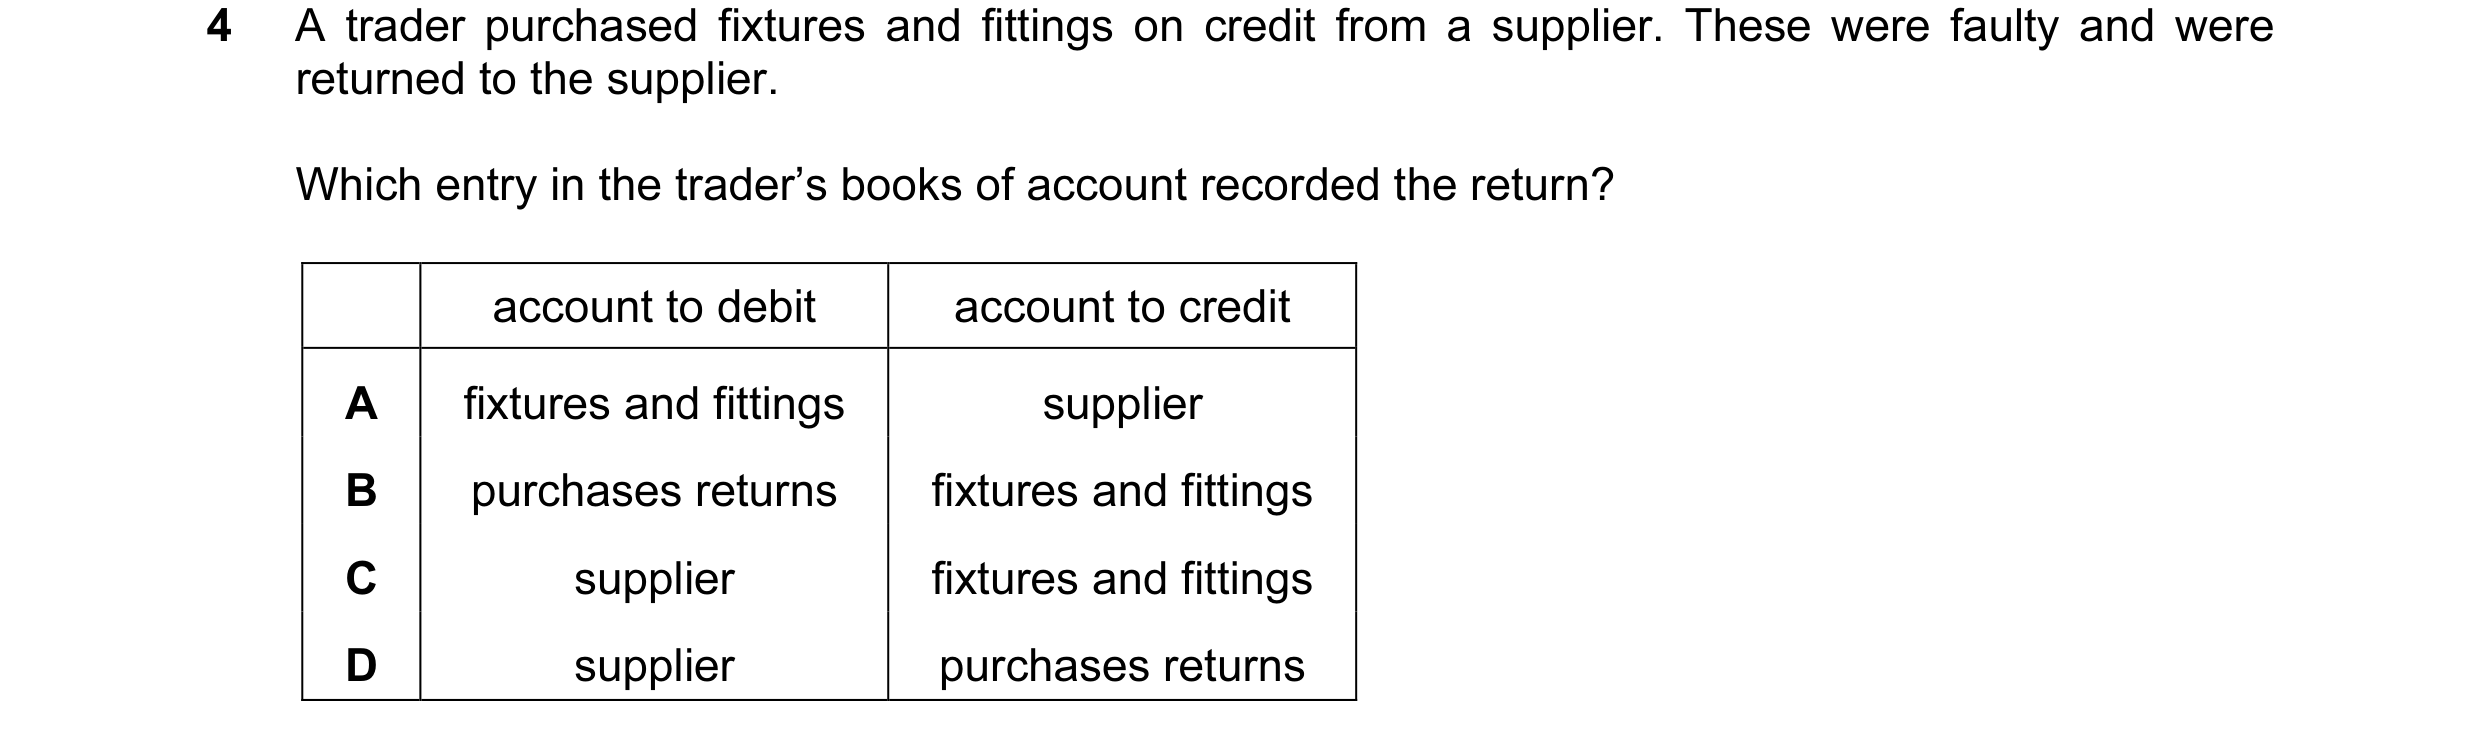 27 / 58
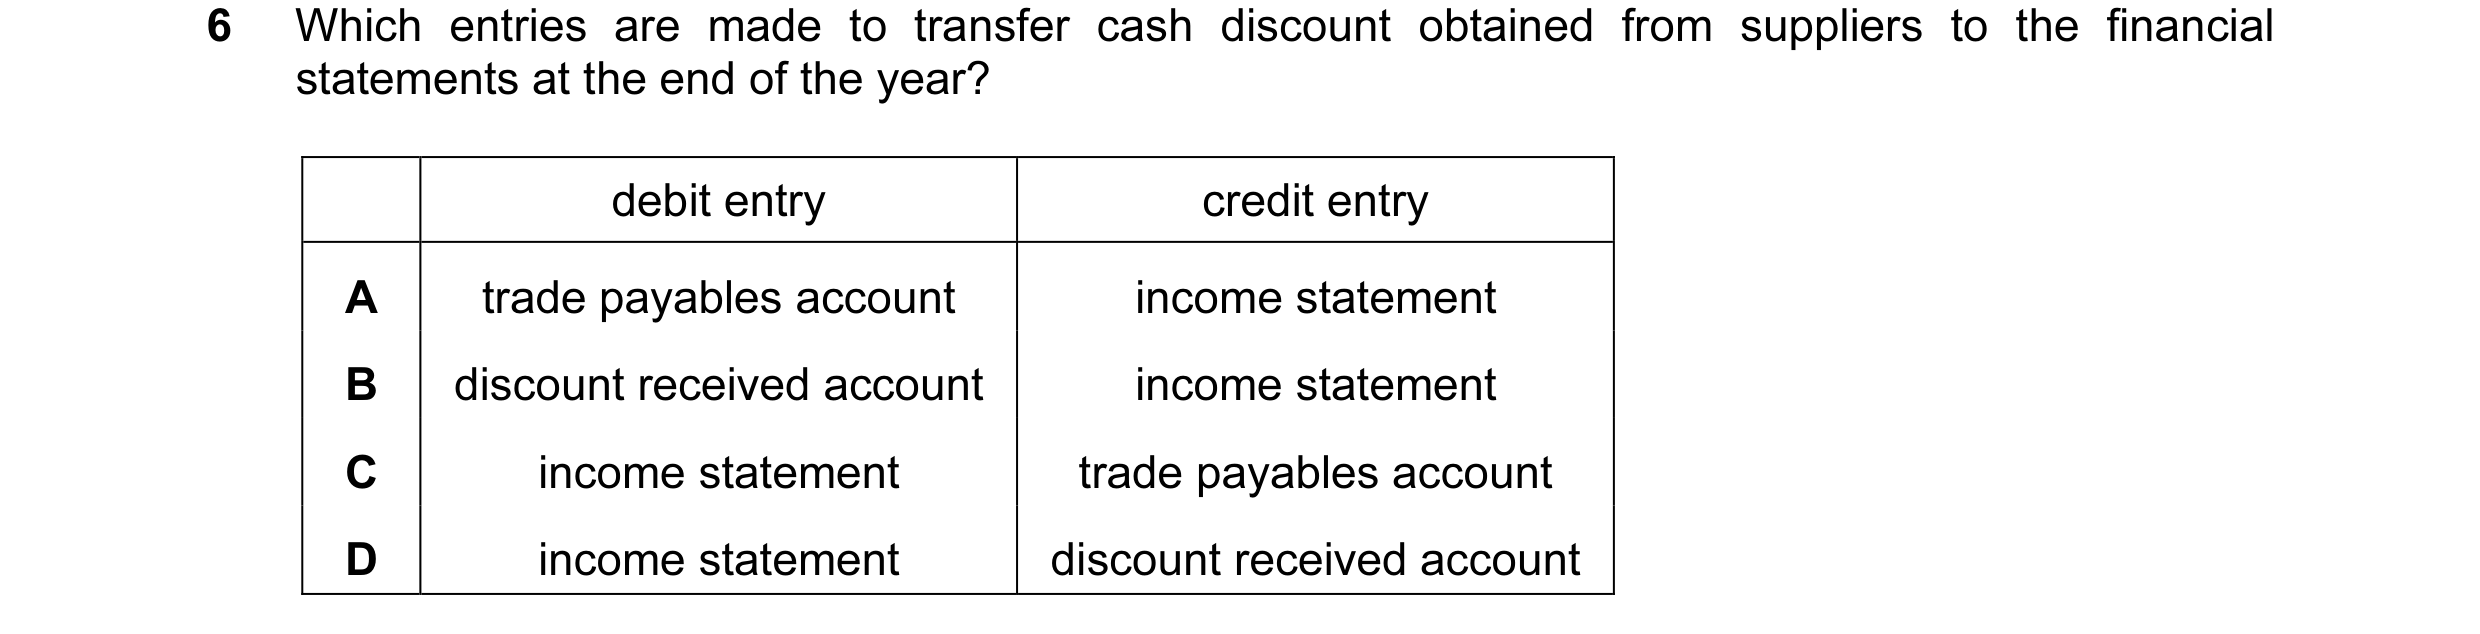
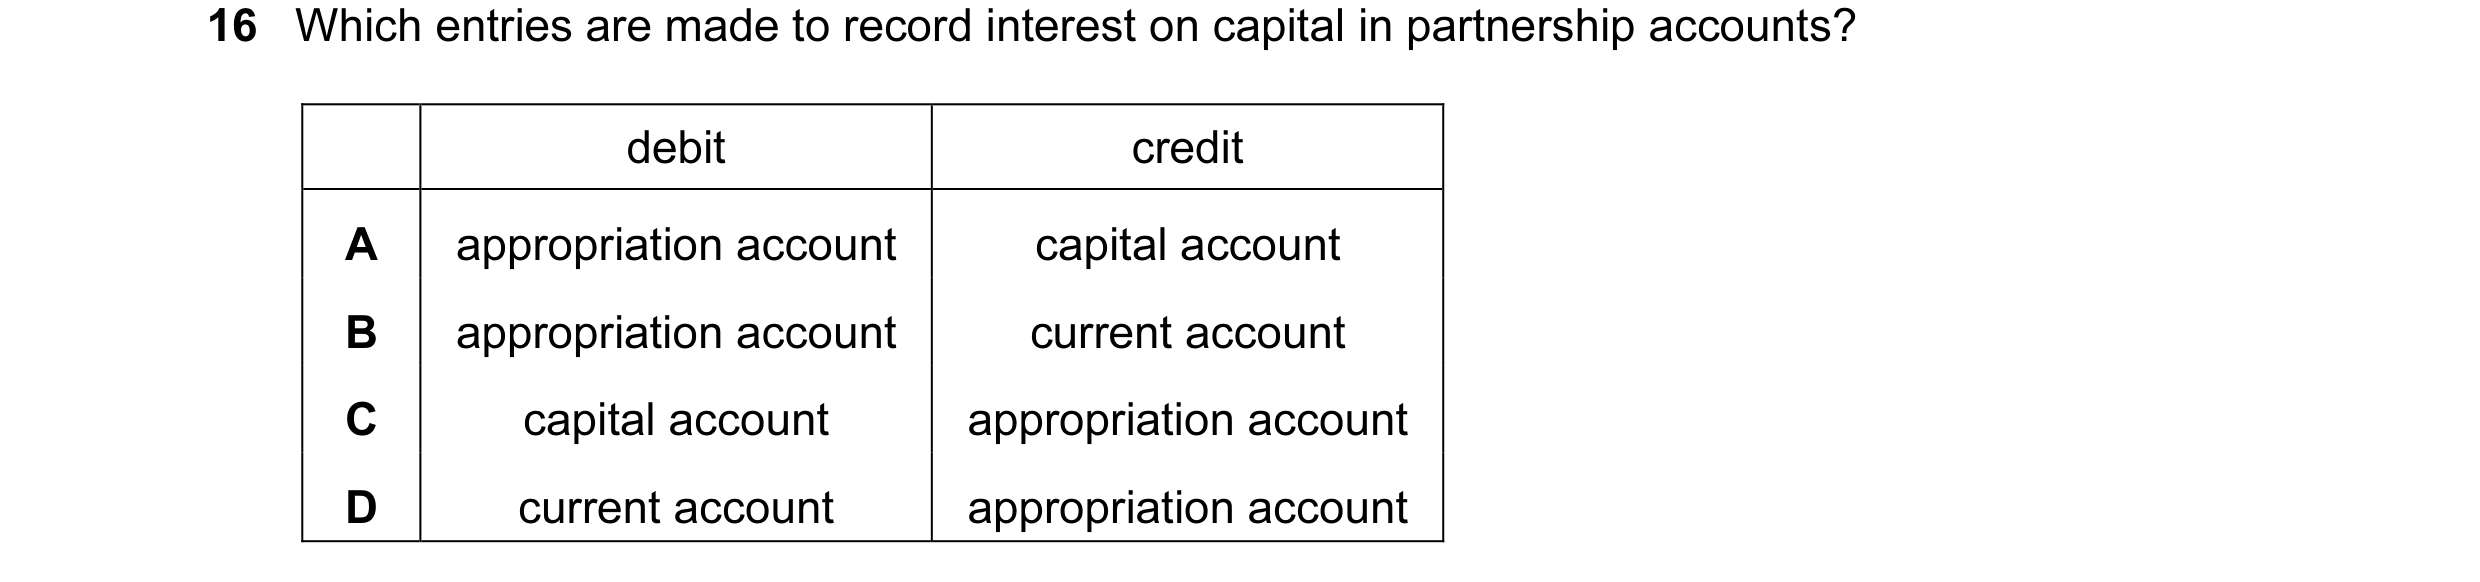 28 / 58
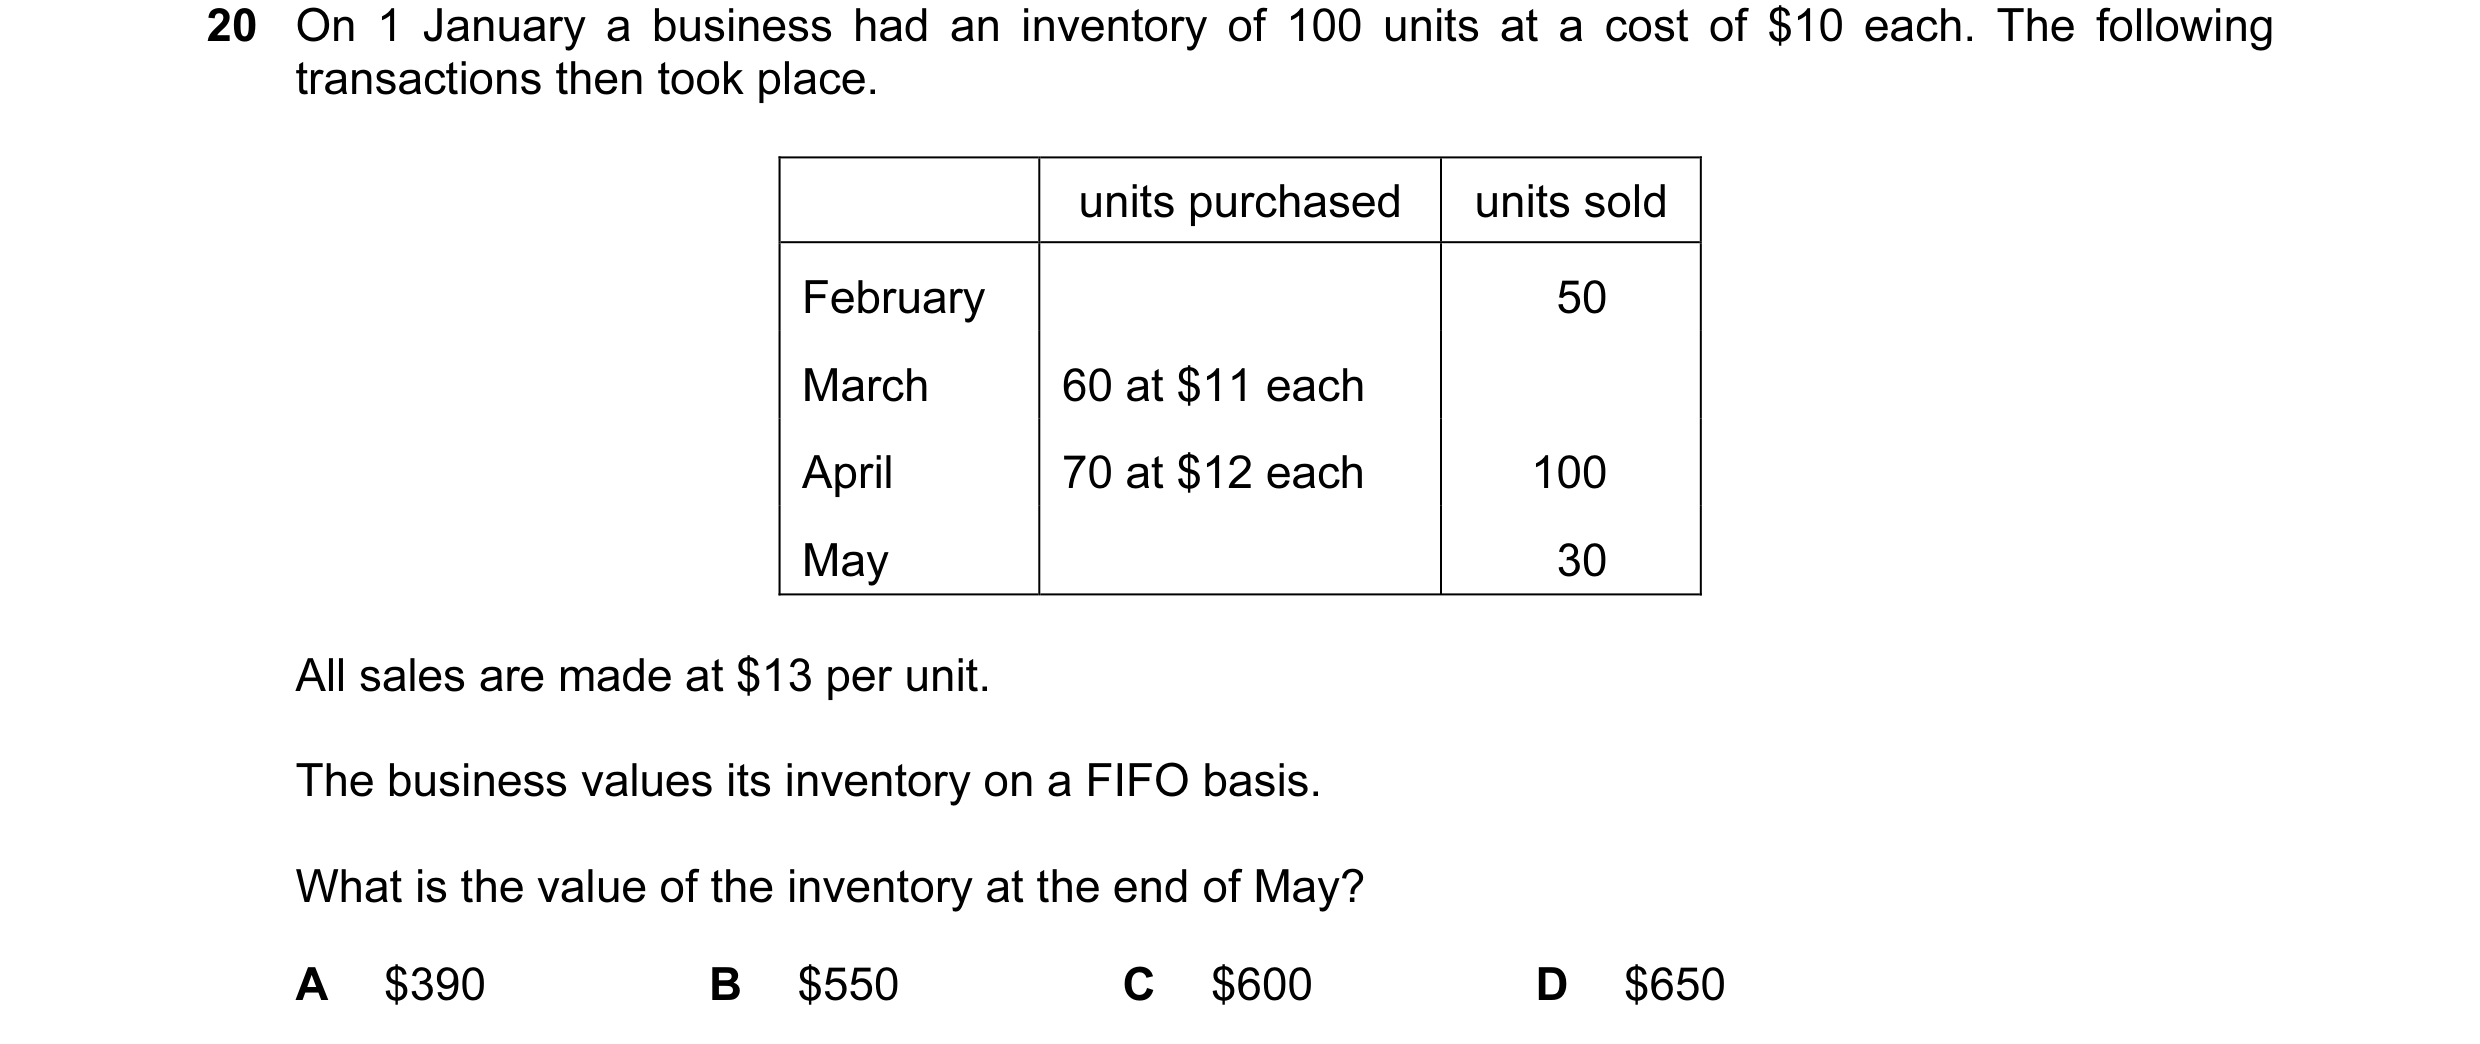
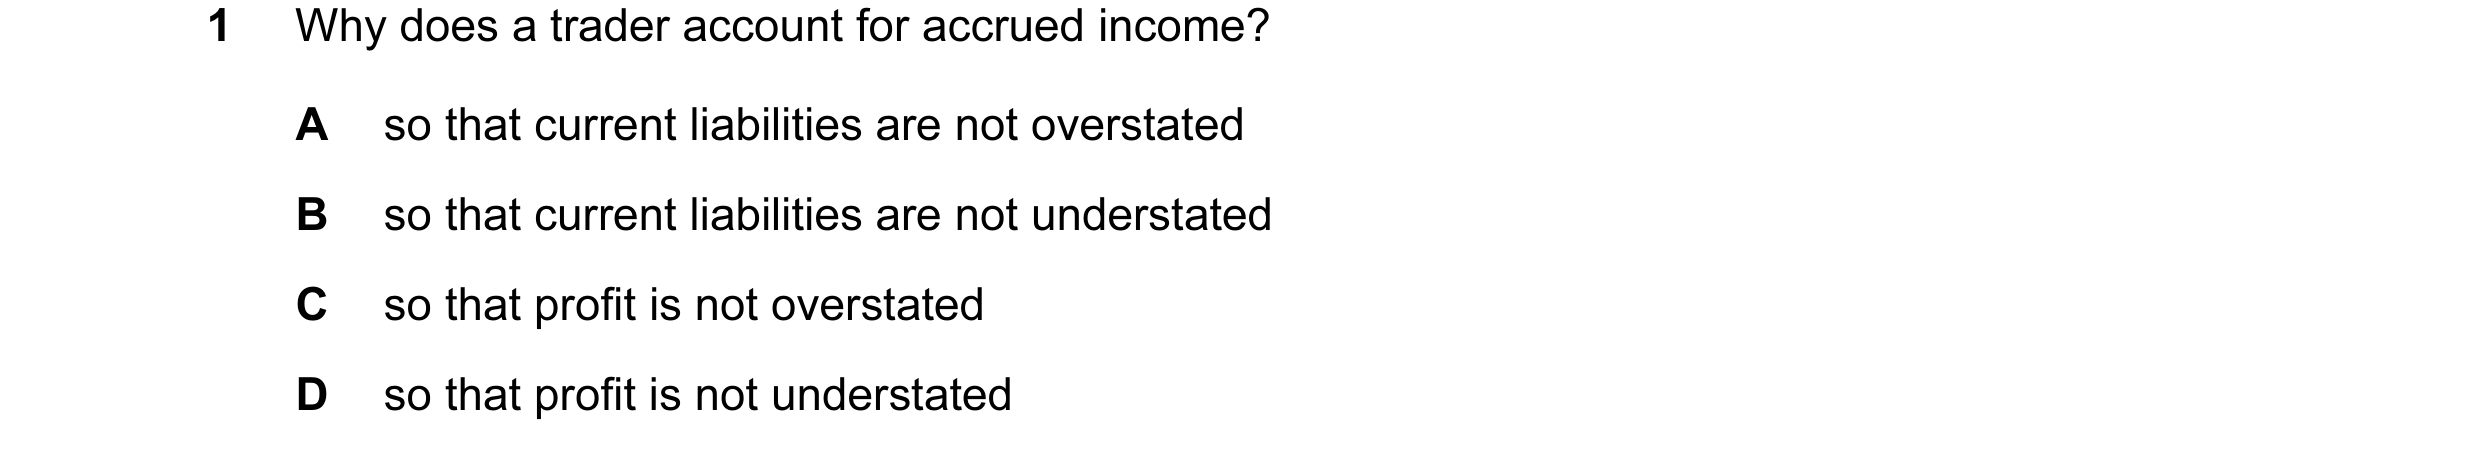
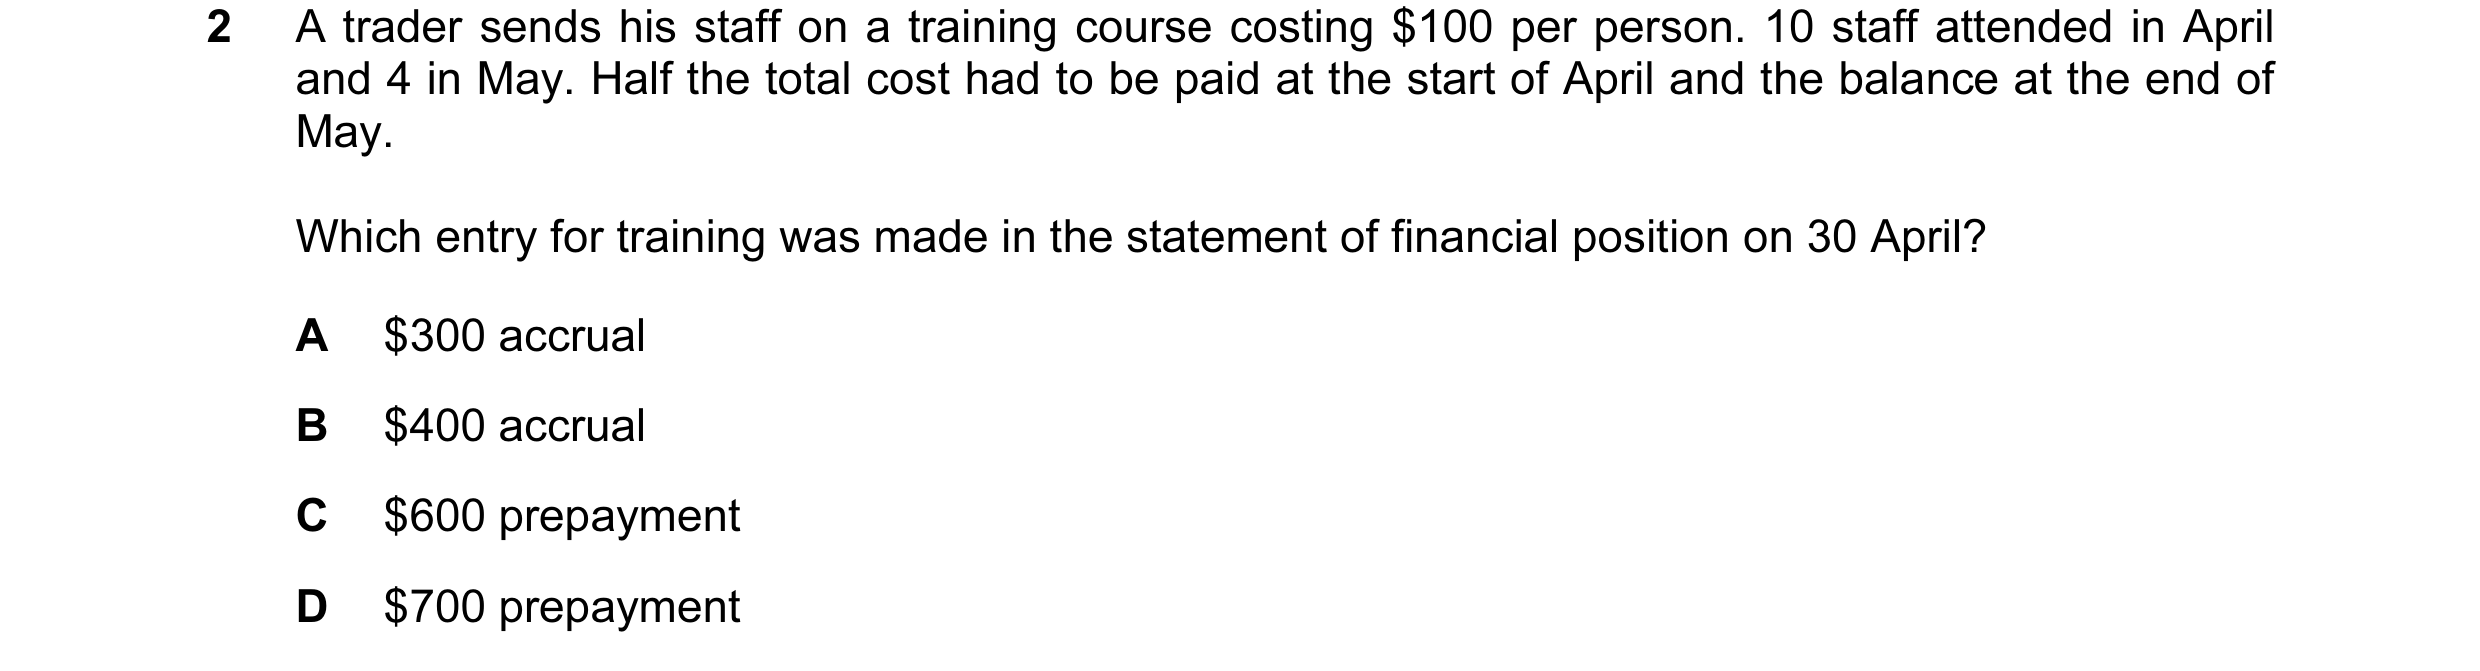
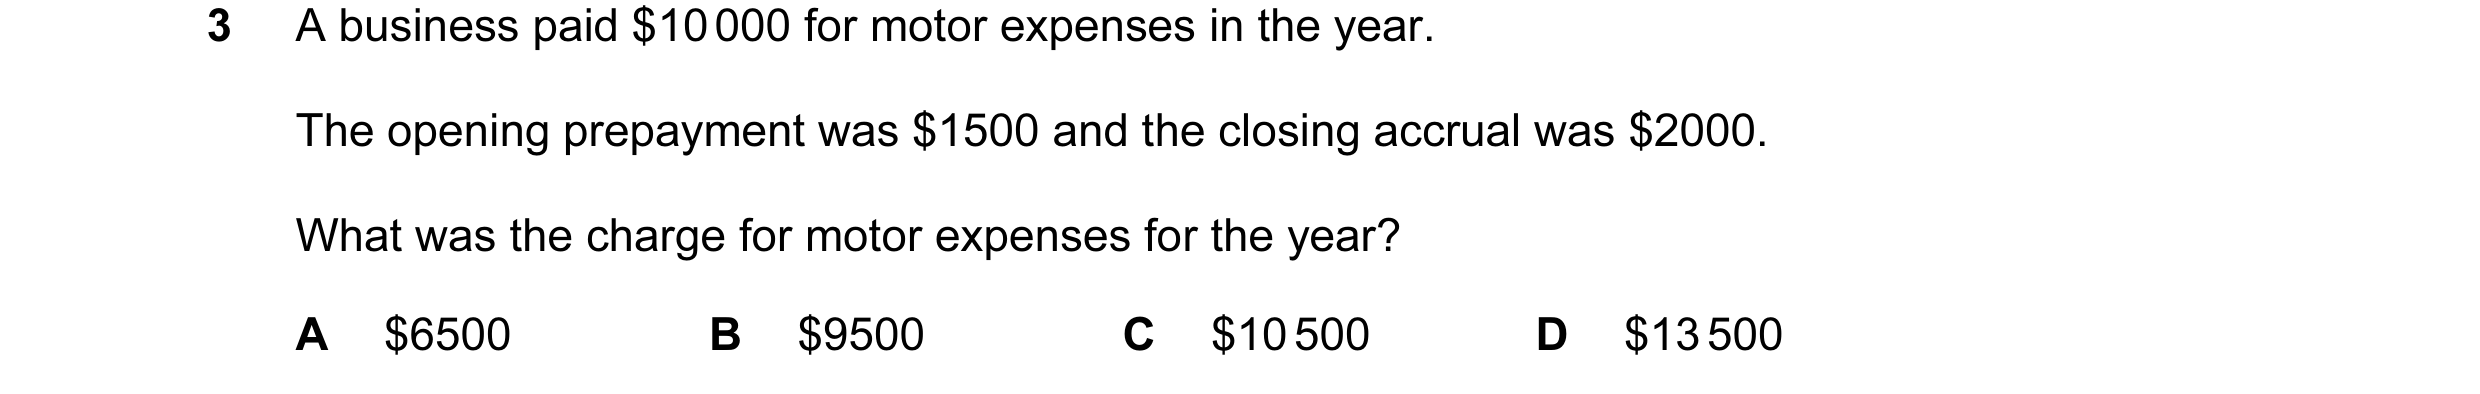
 29 / 58
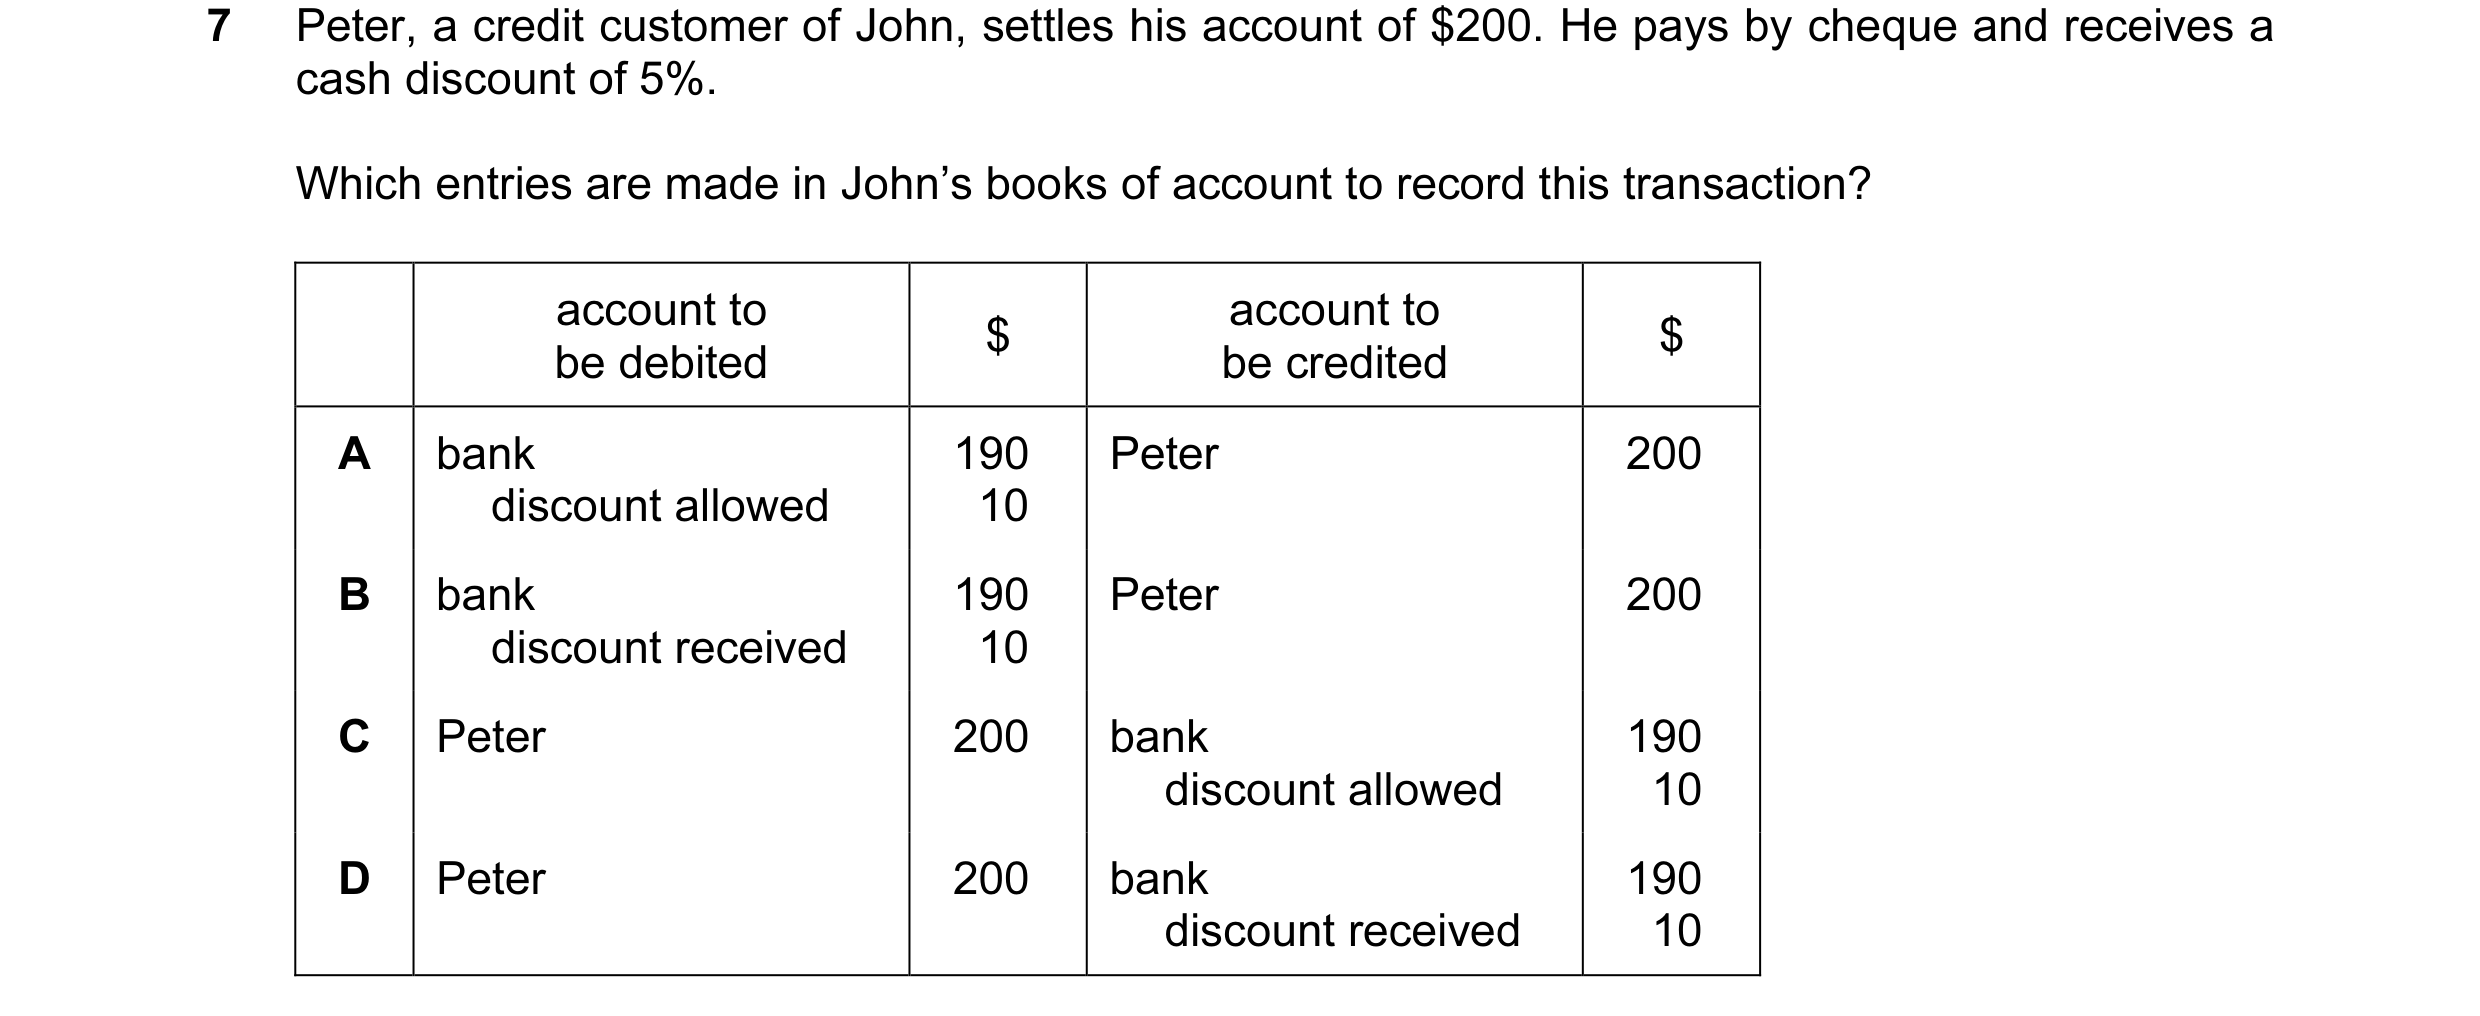
 30 / 58
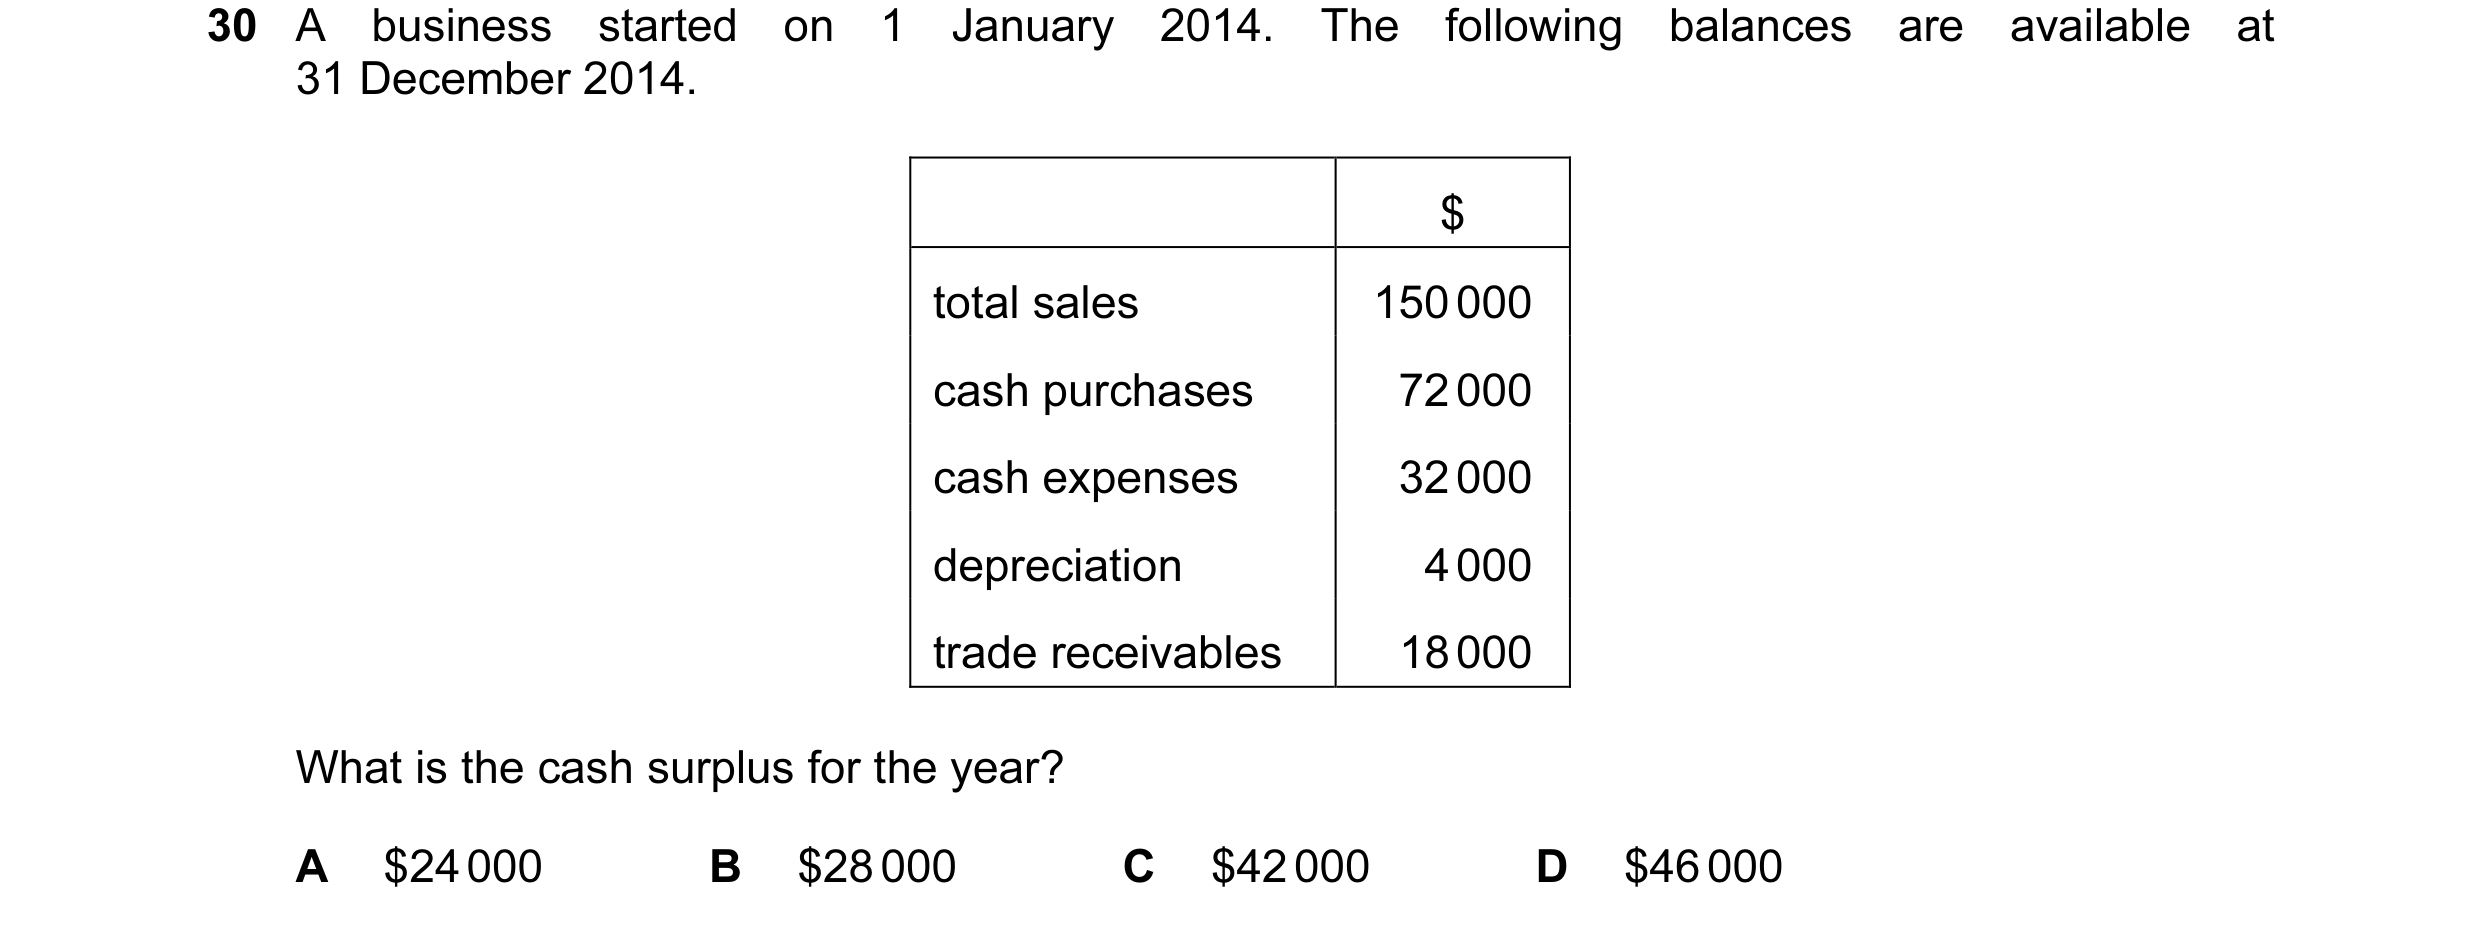
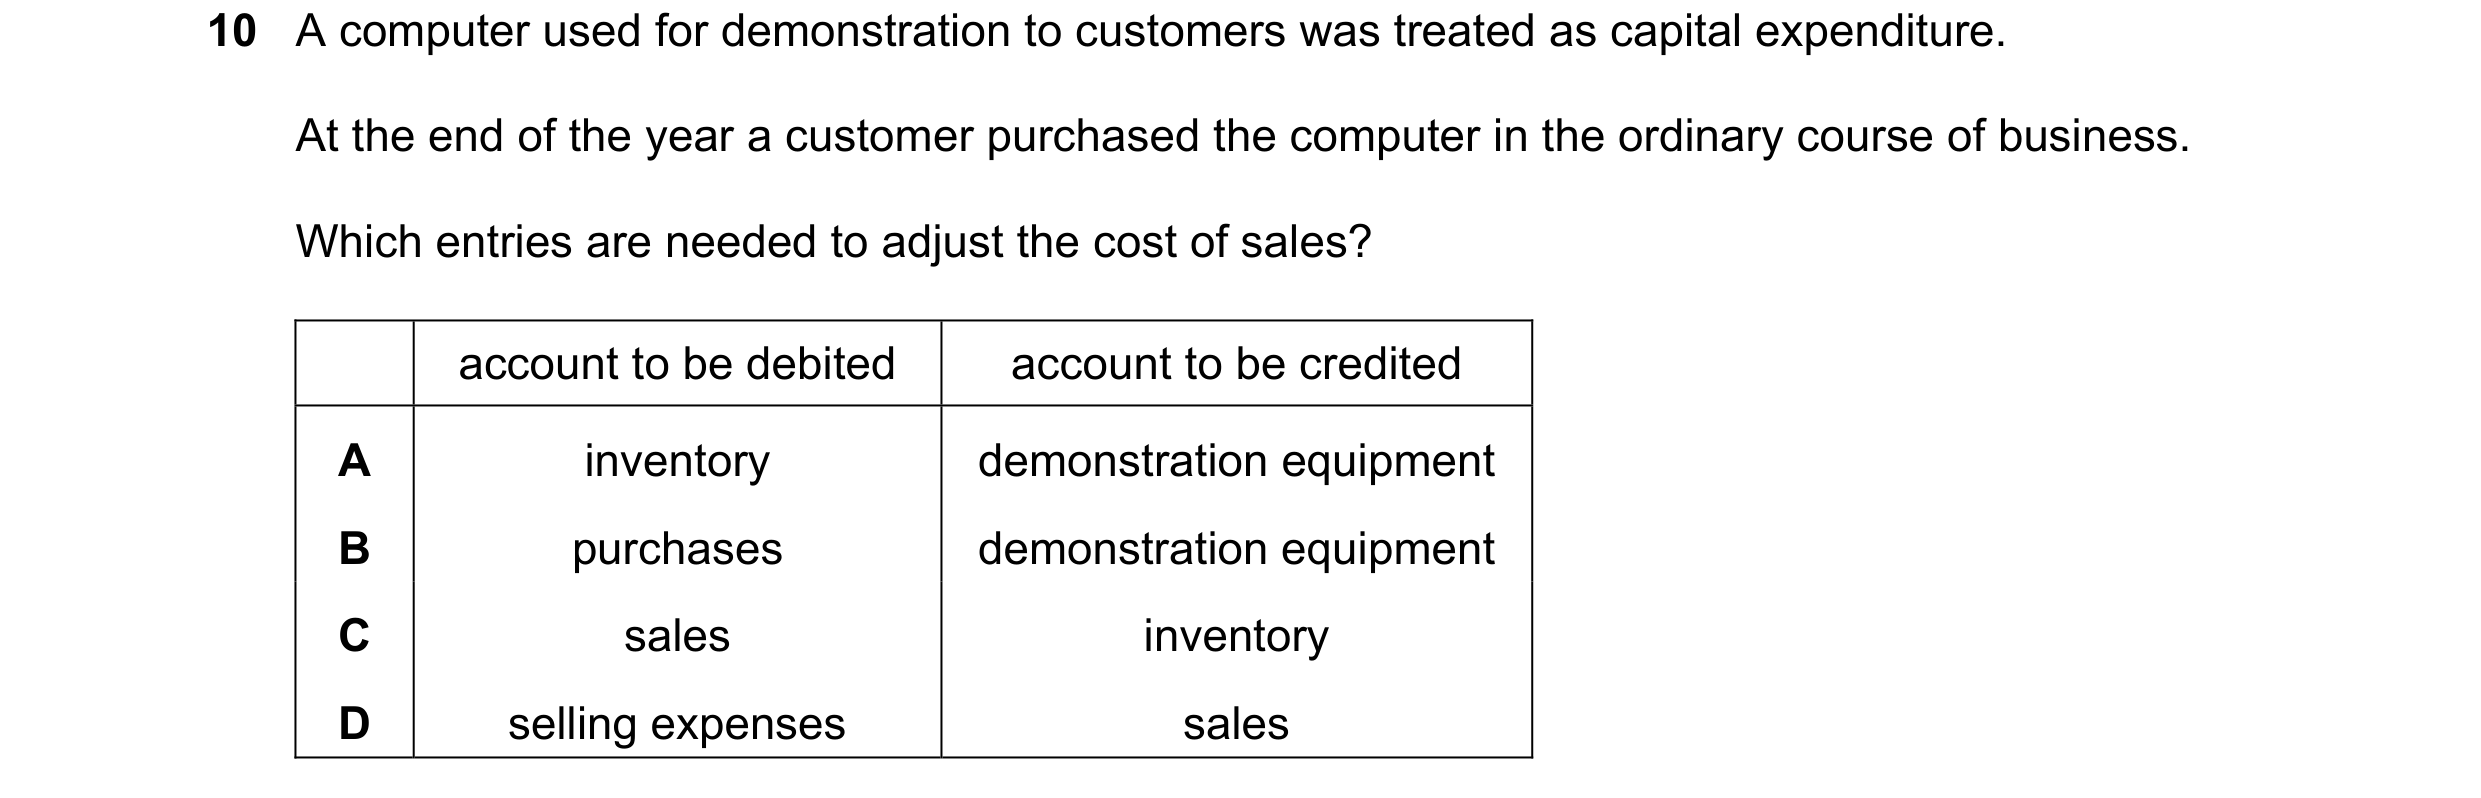
 31 / 58
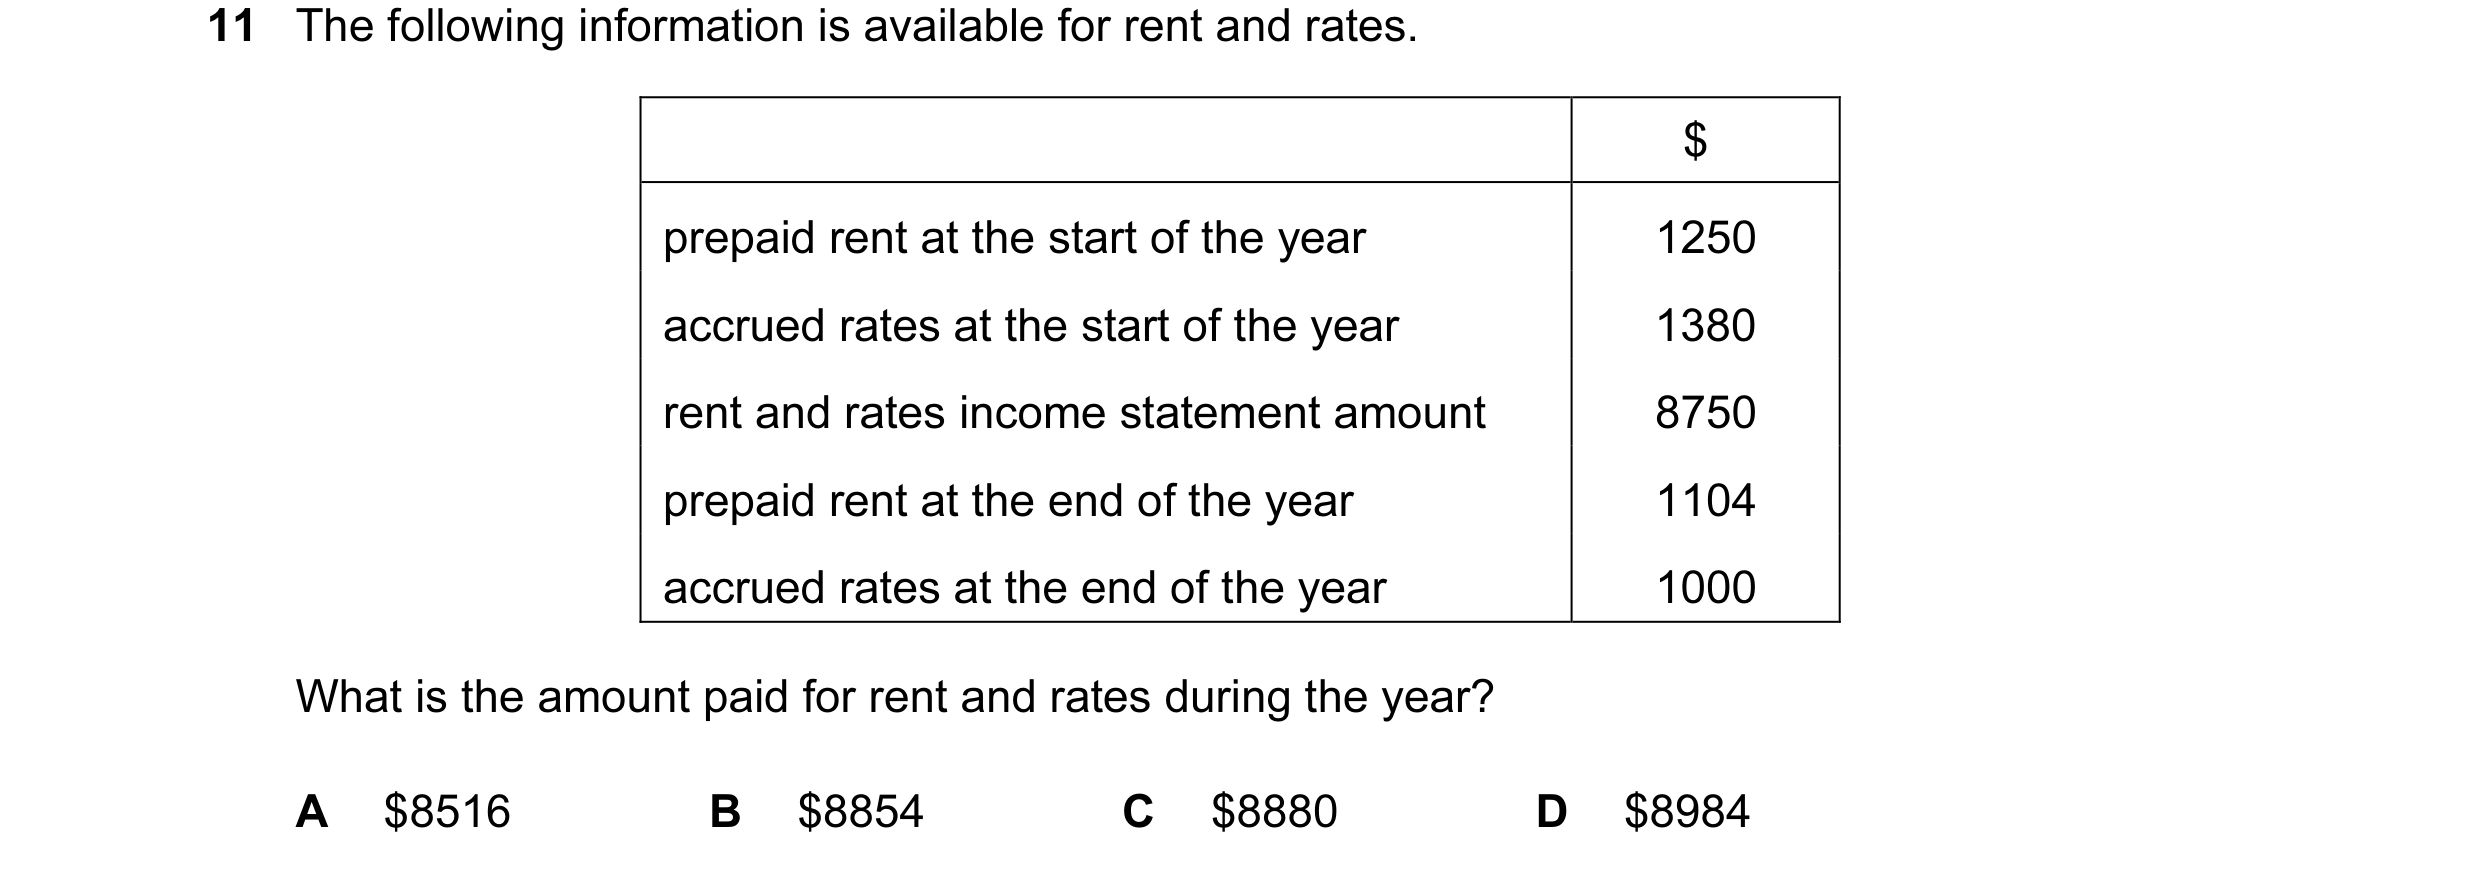
 32 / 58
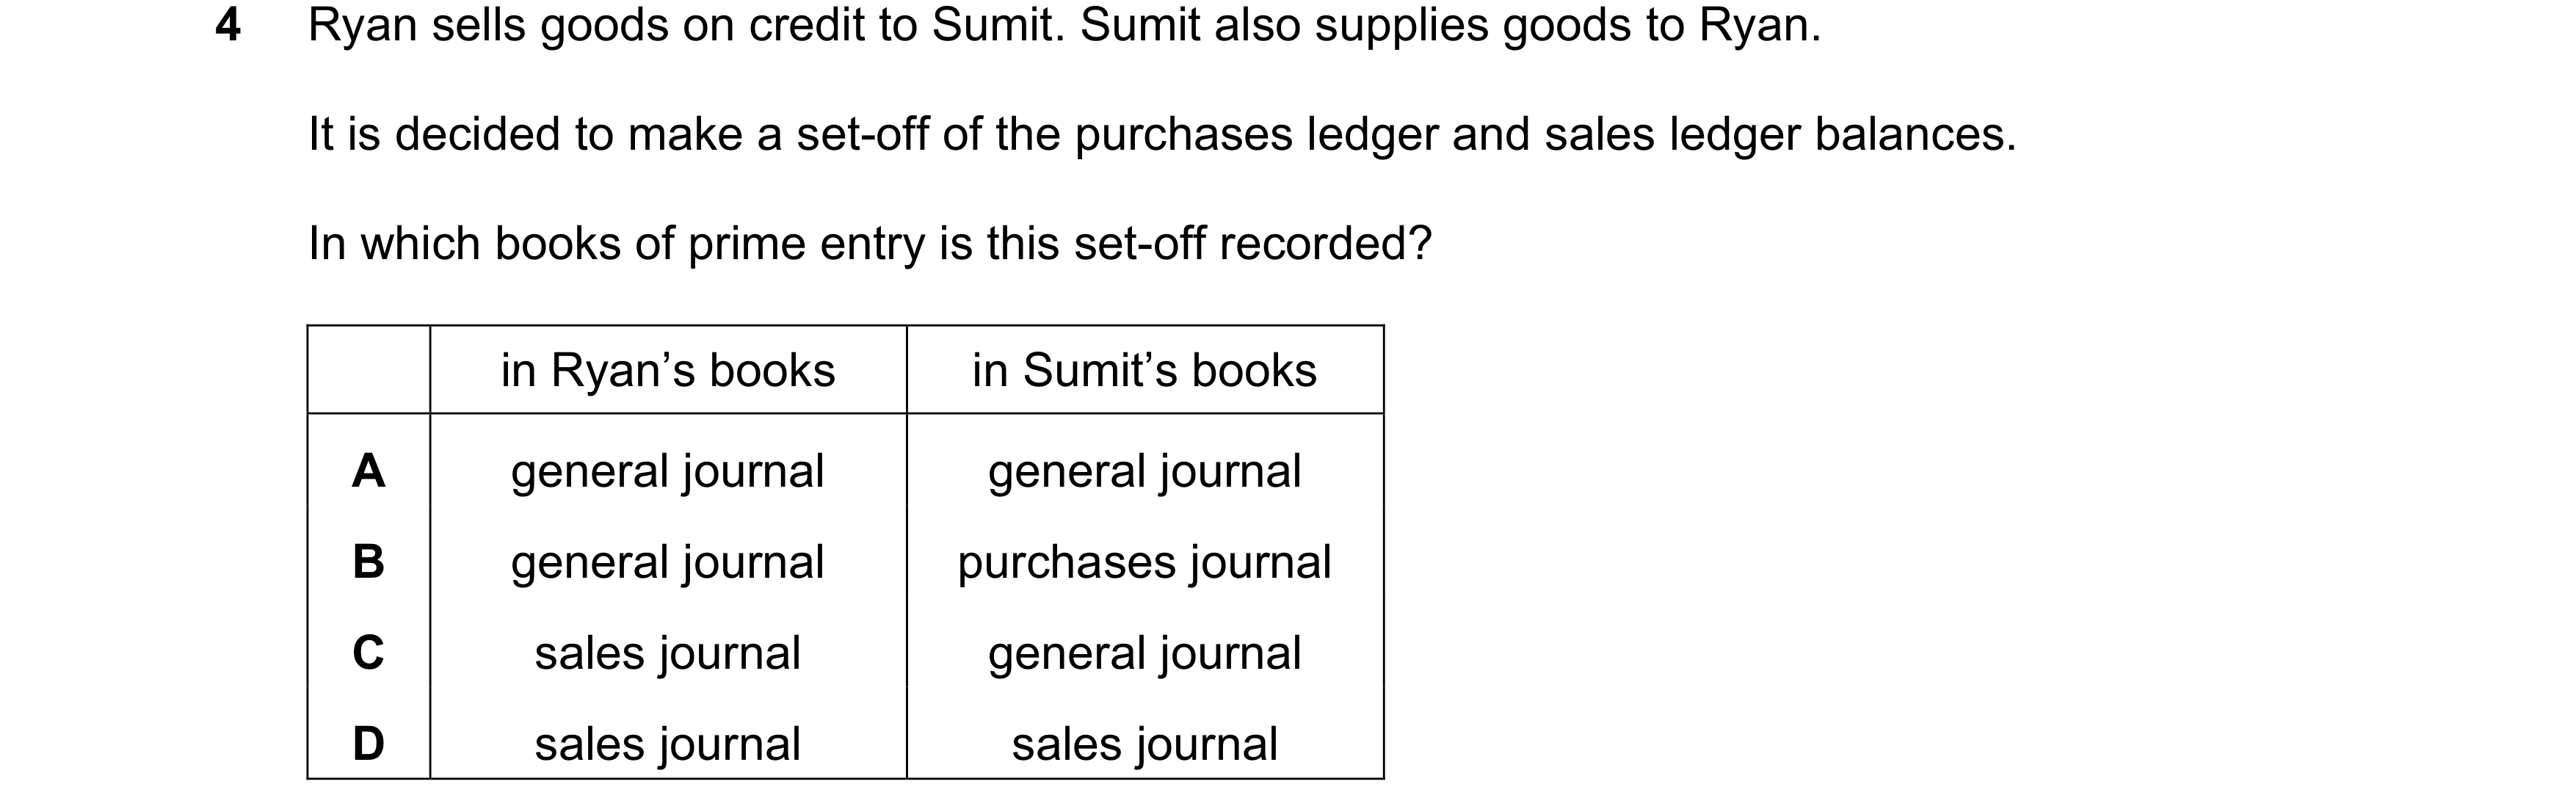
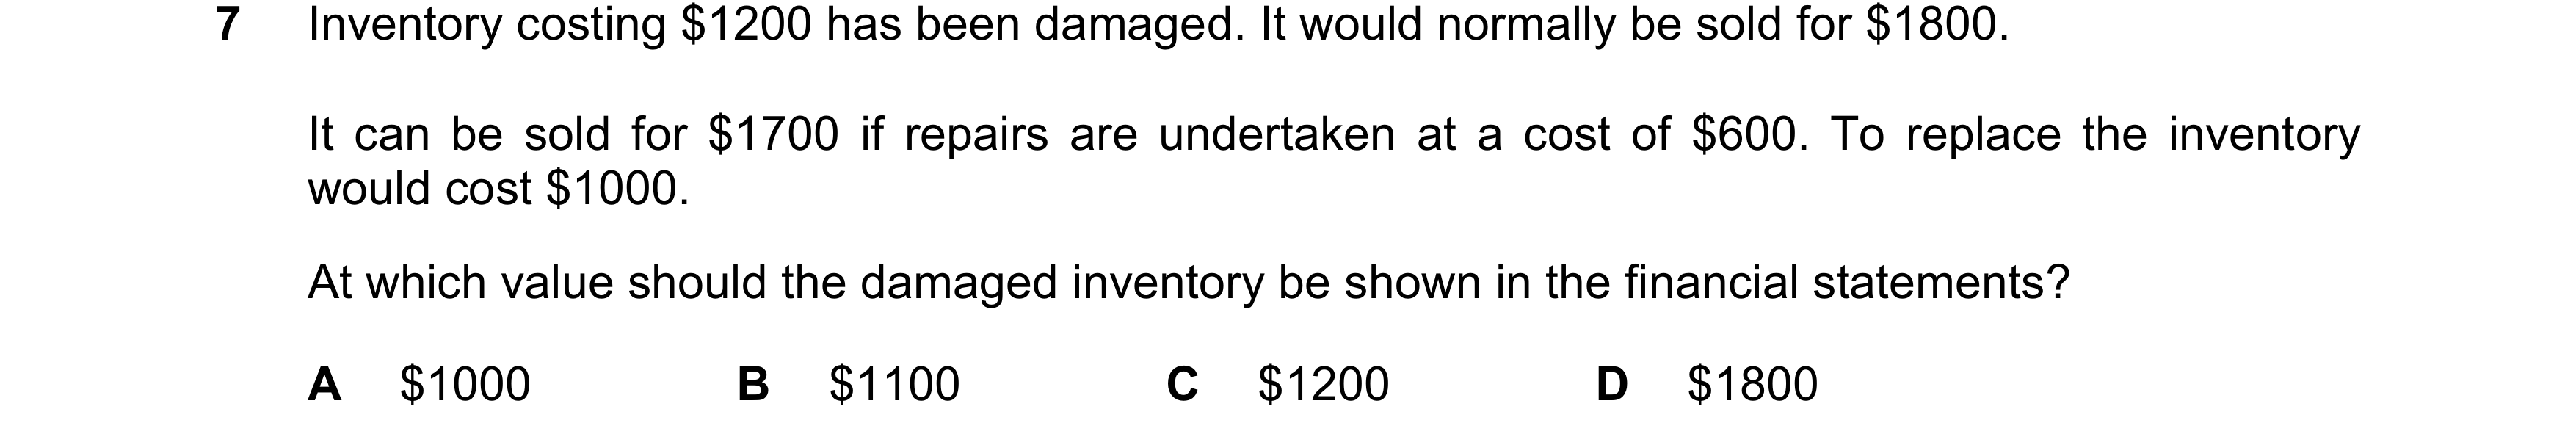
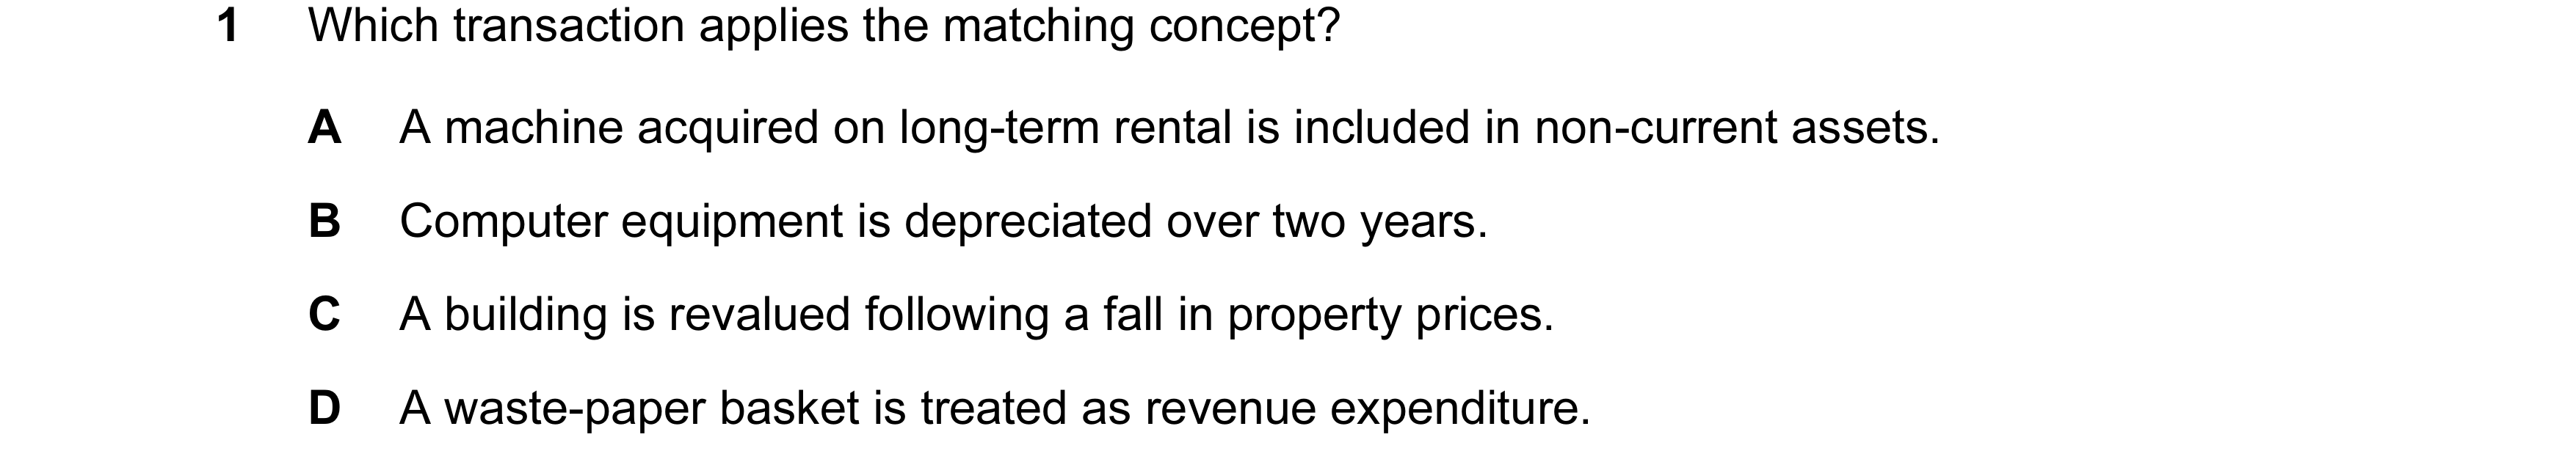
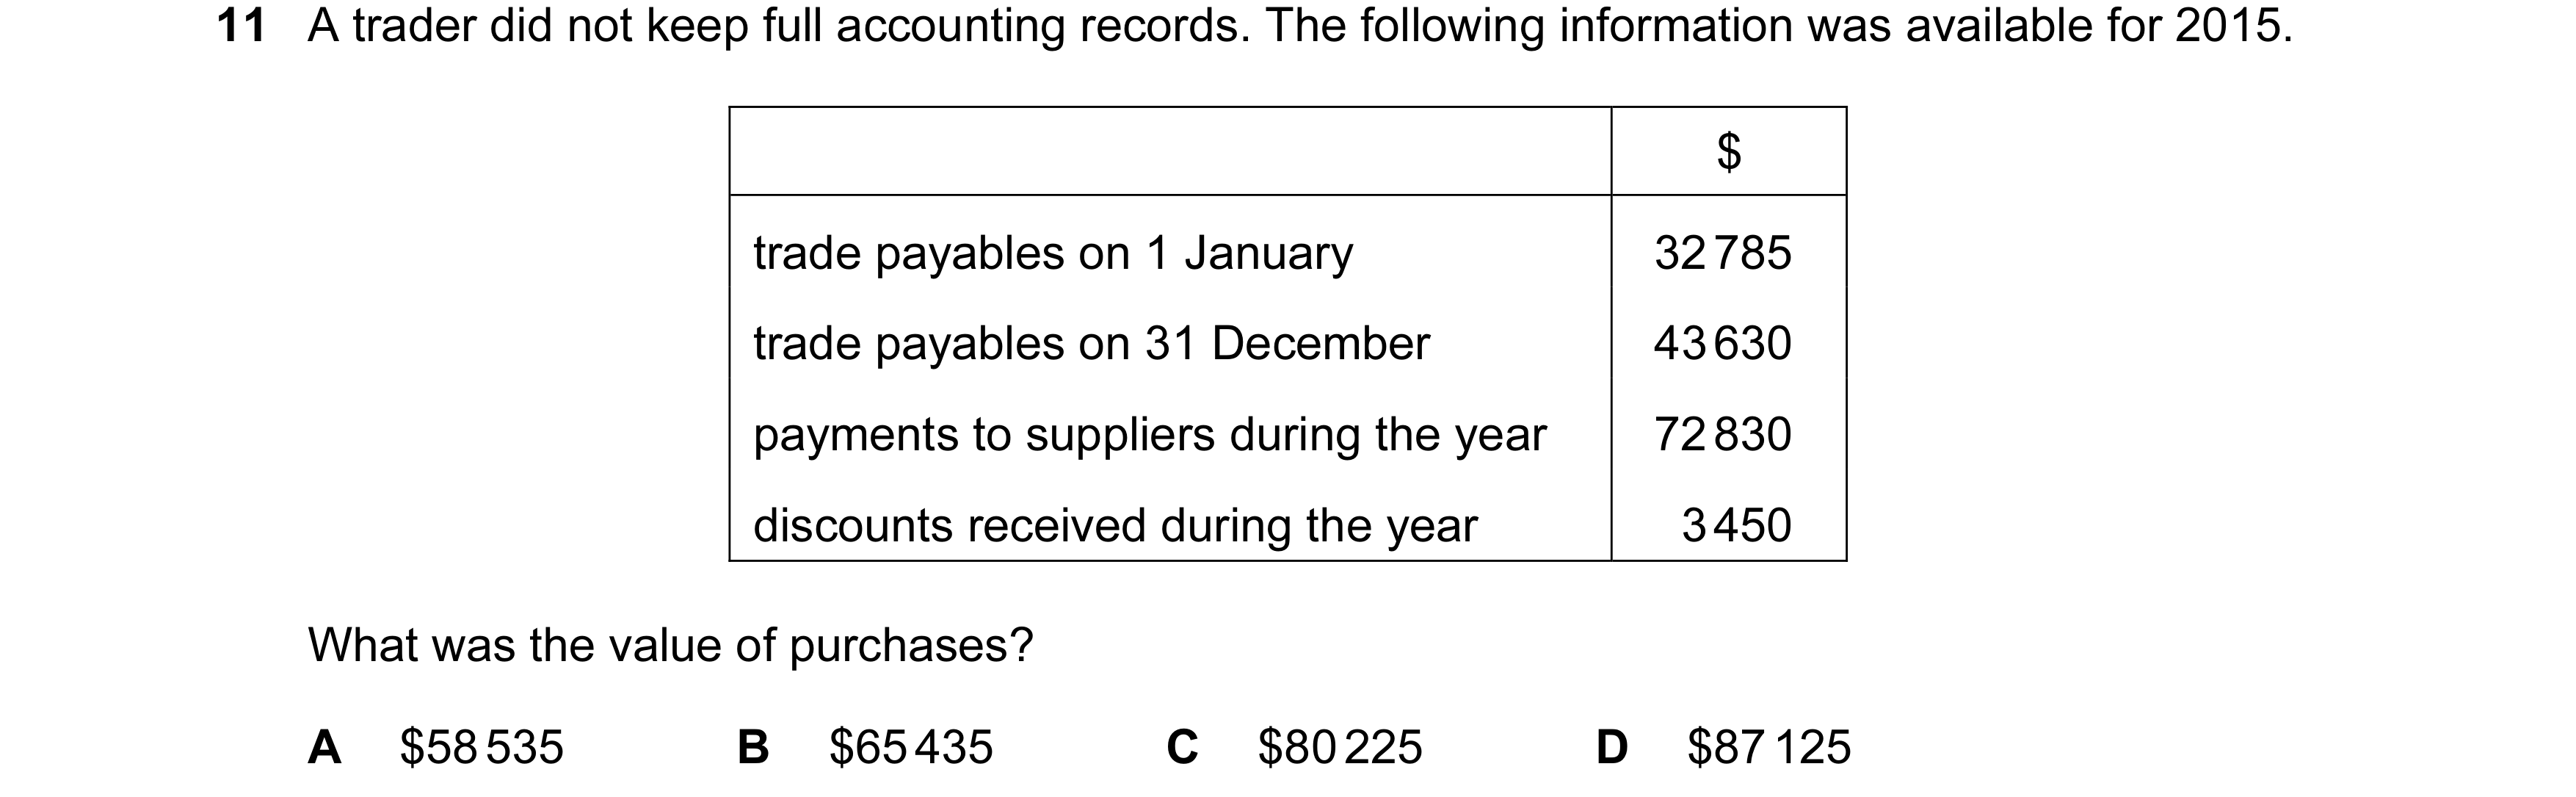
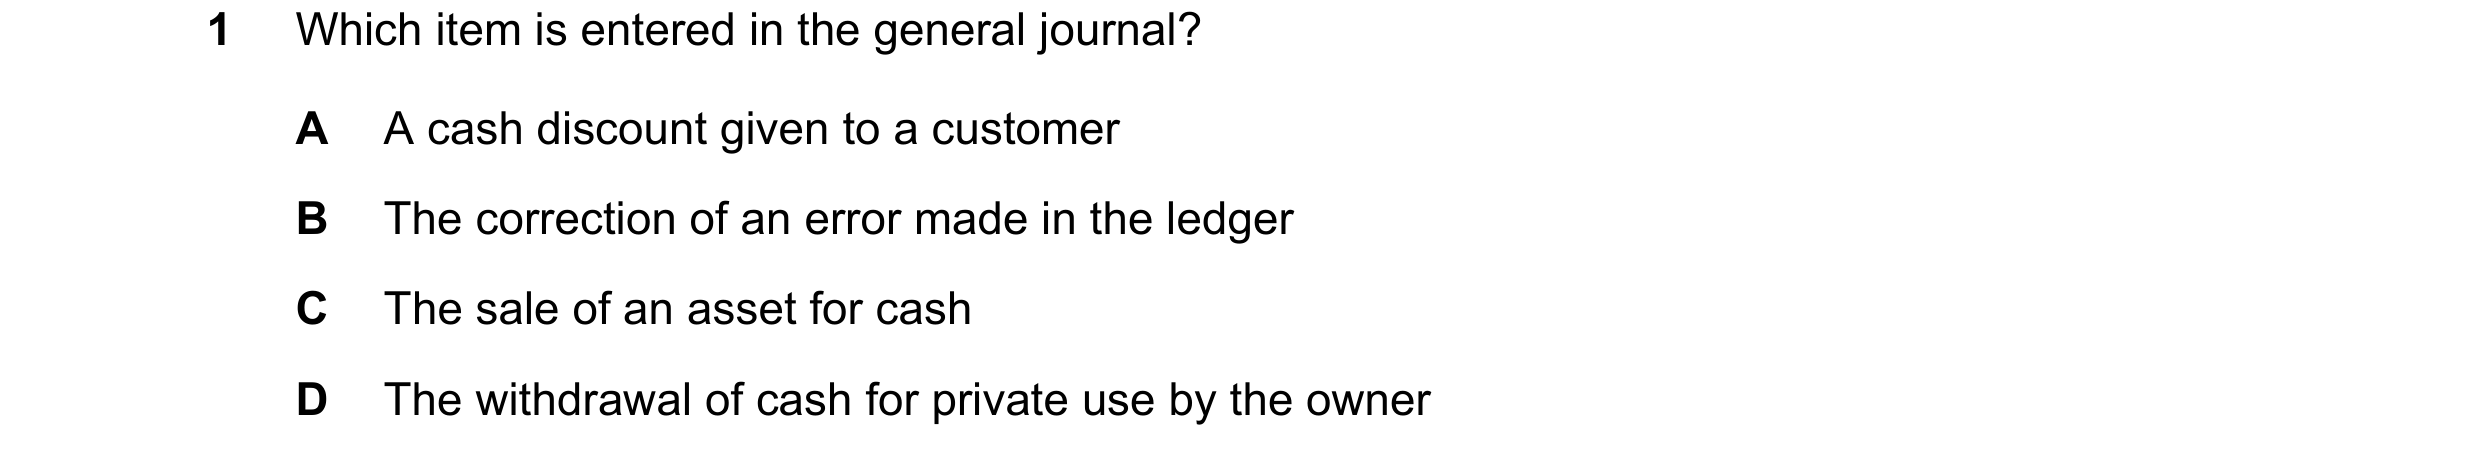 33 / 58
 34 / 58
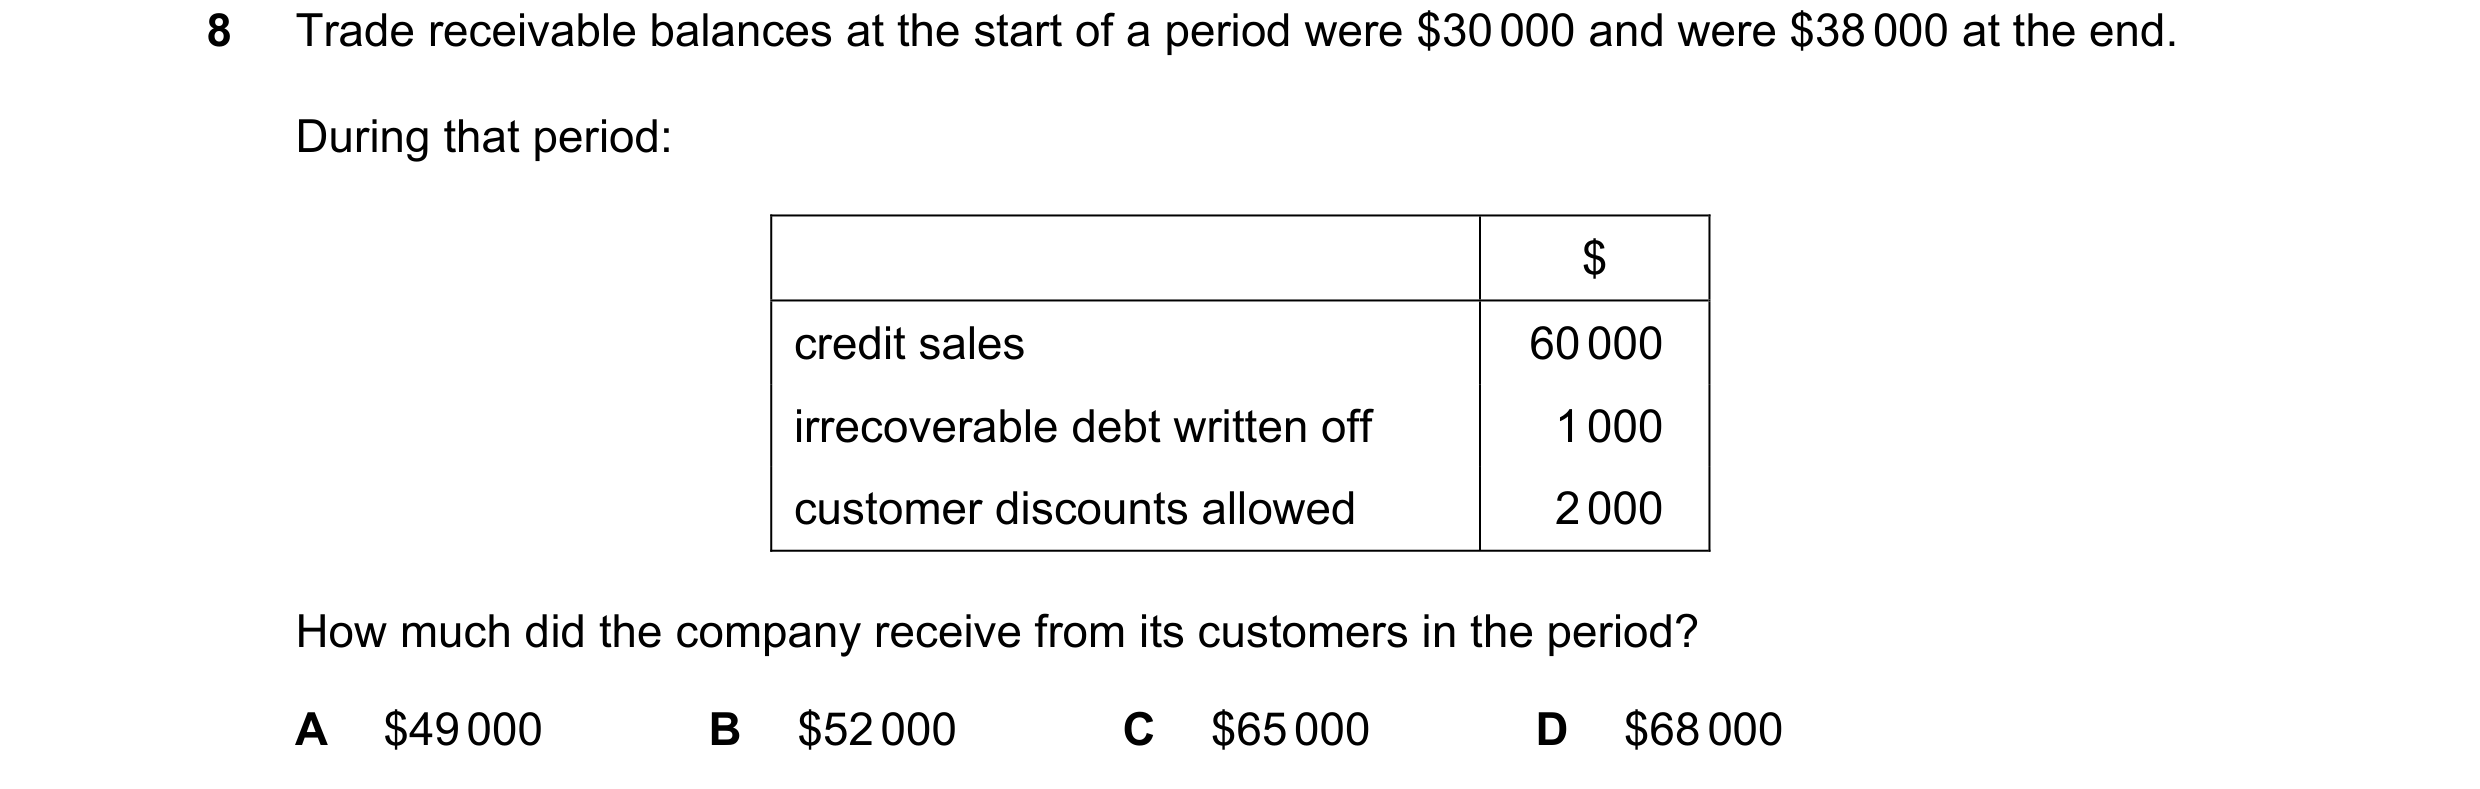
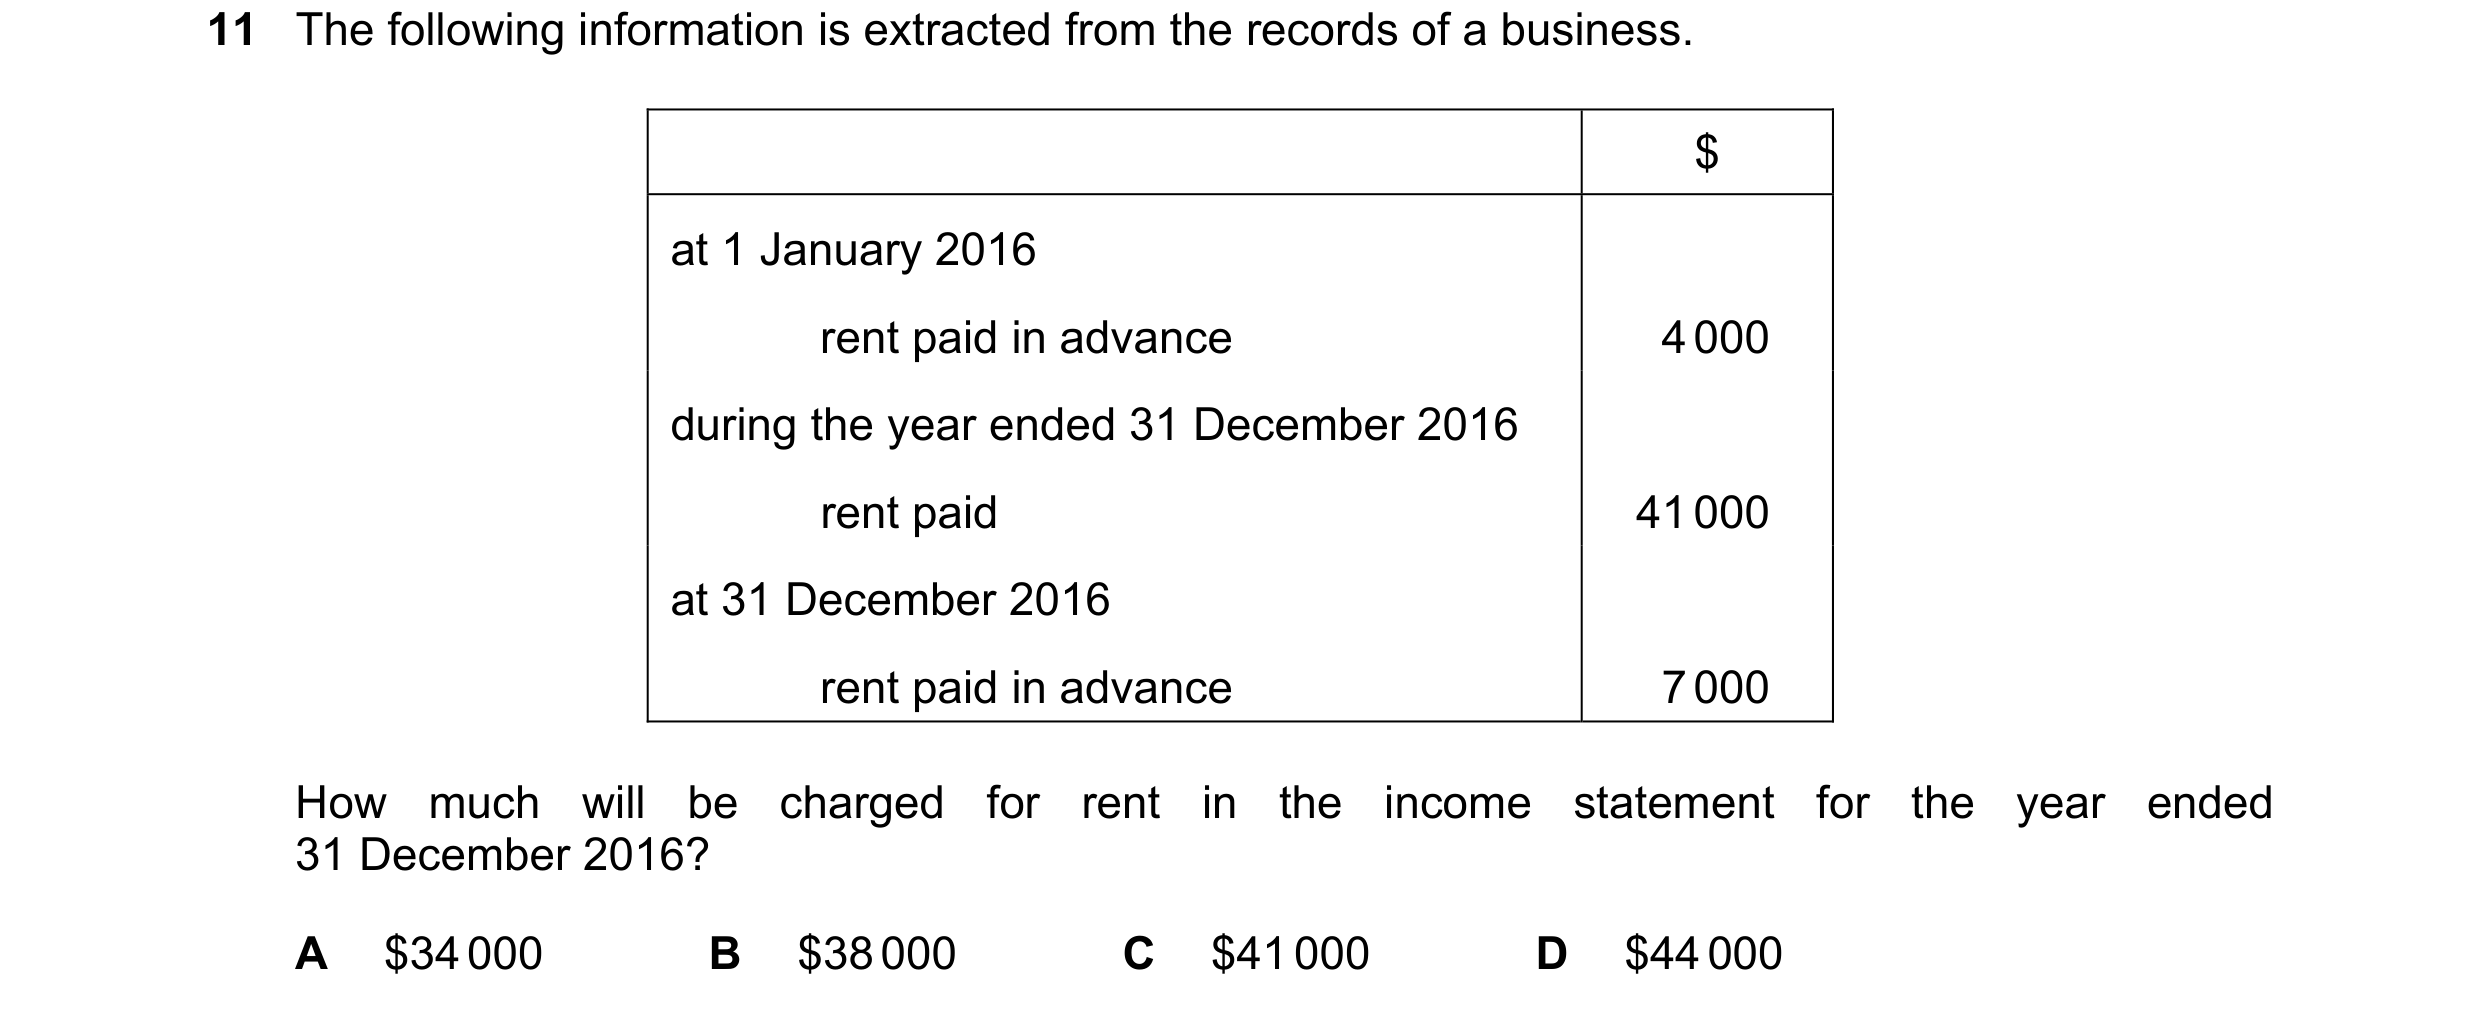 35 / 58
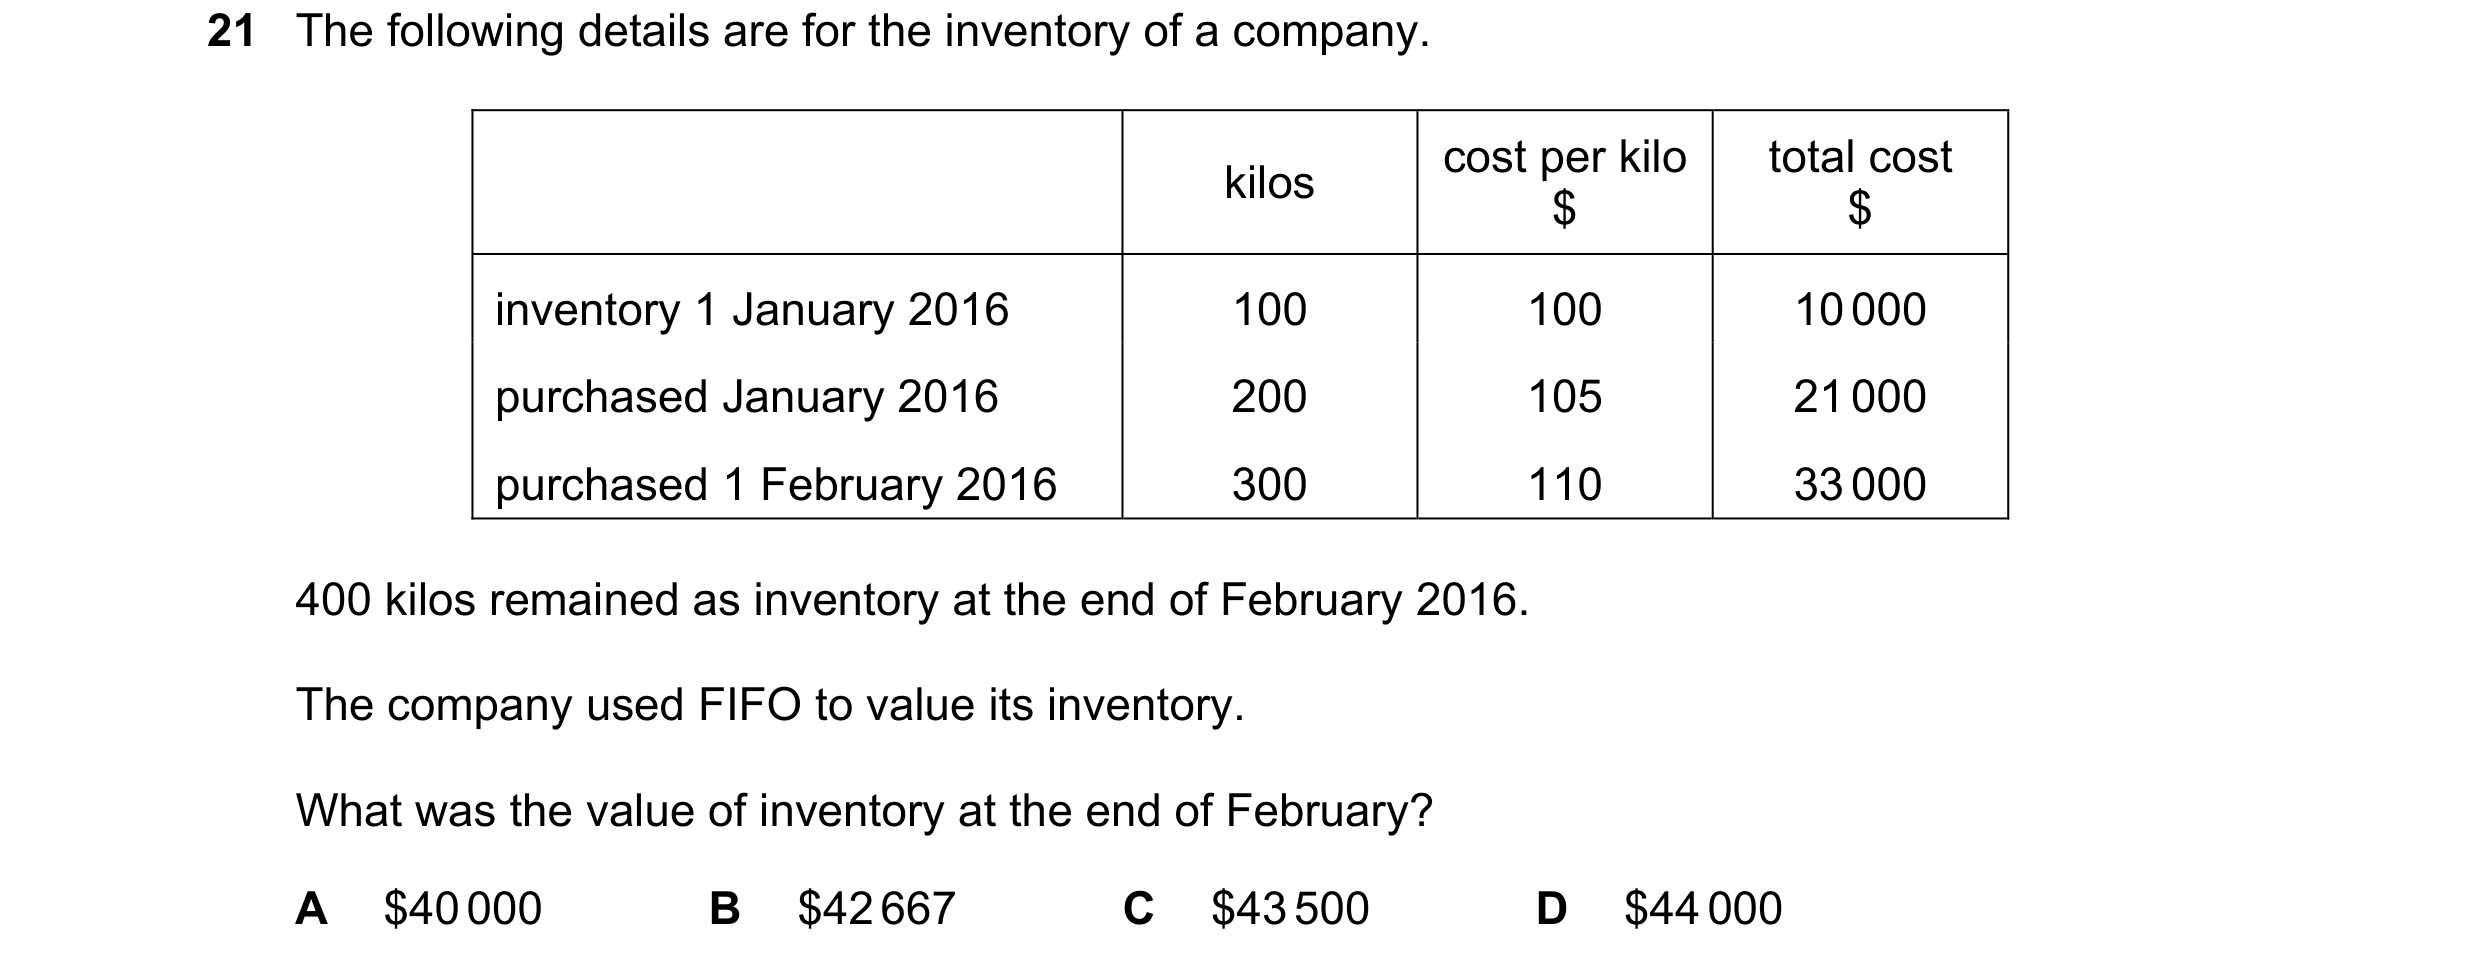
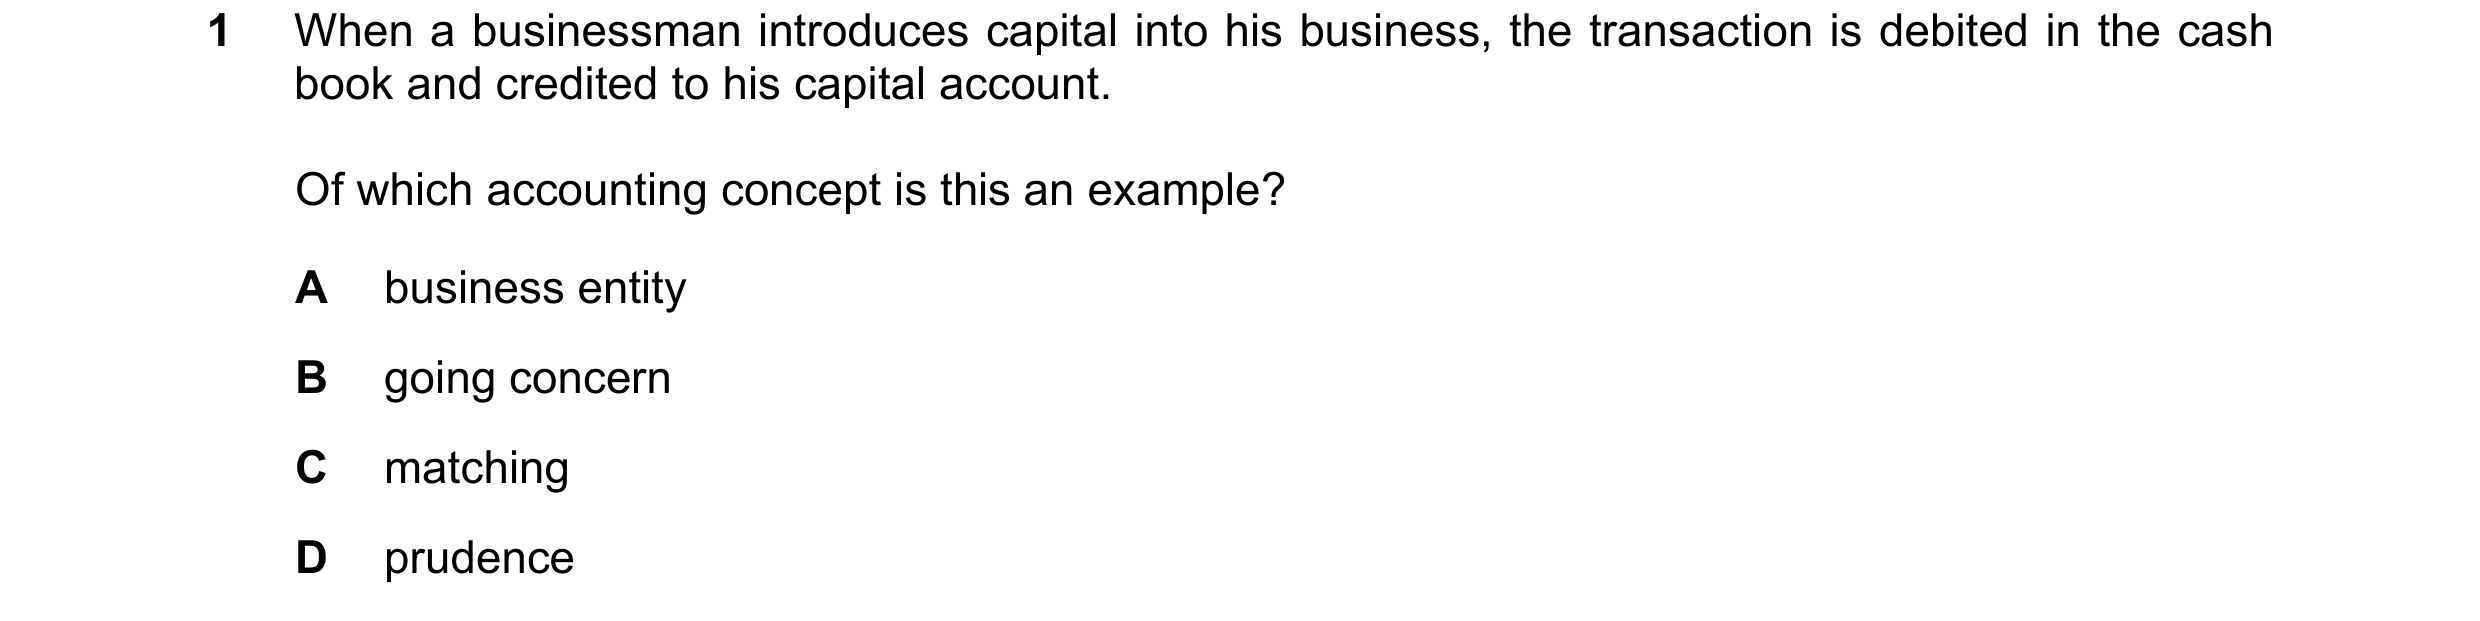
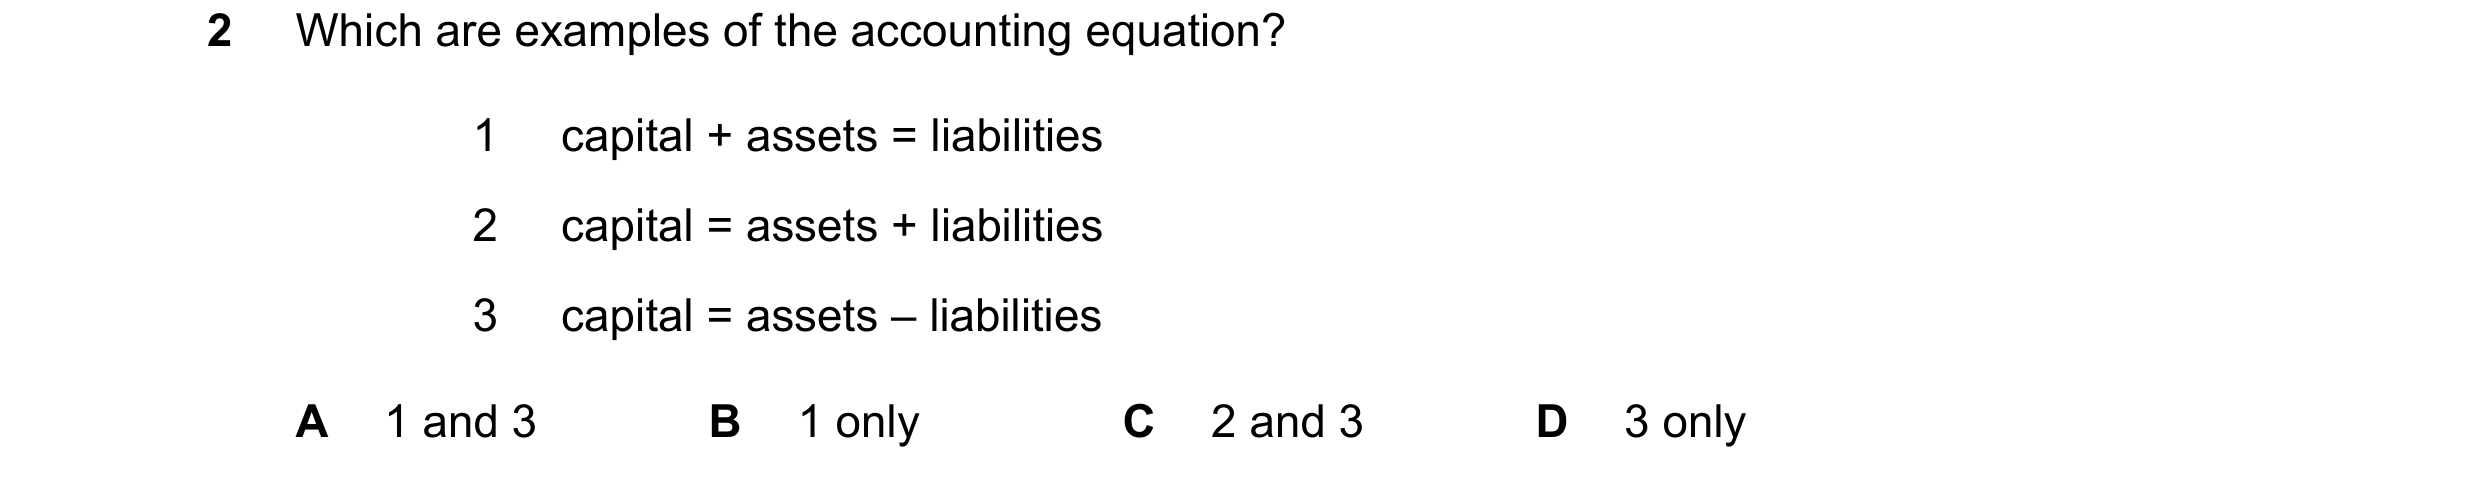
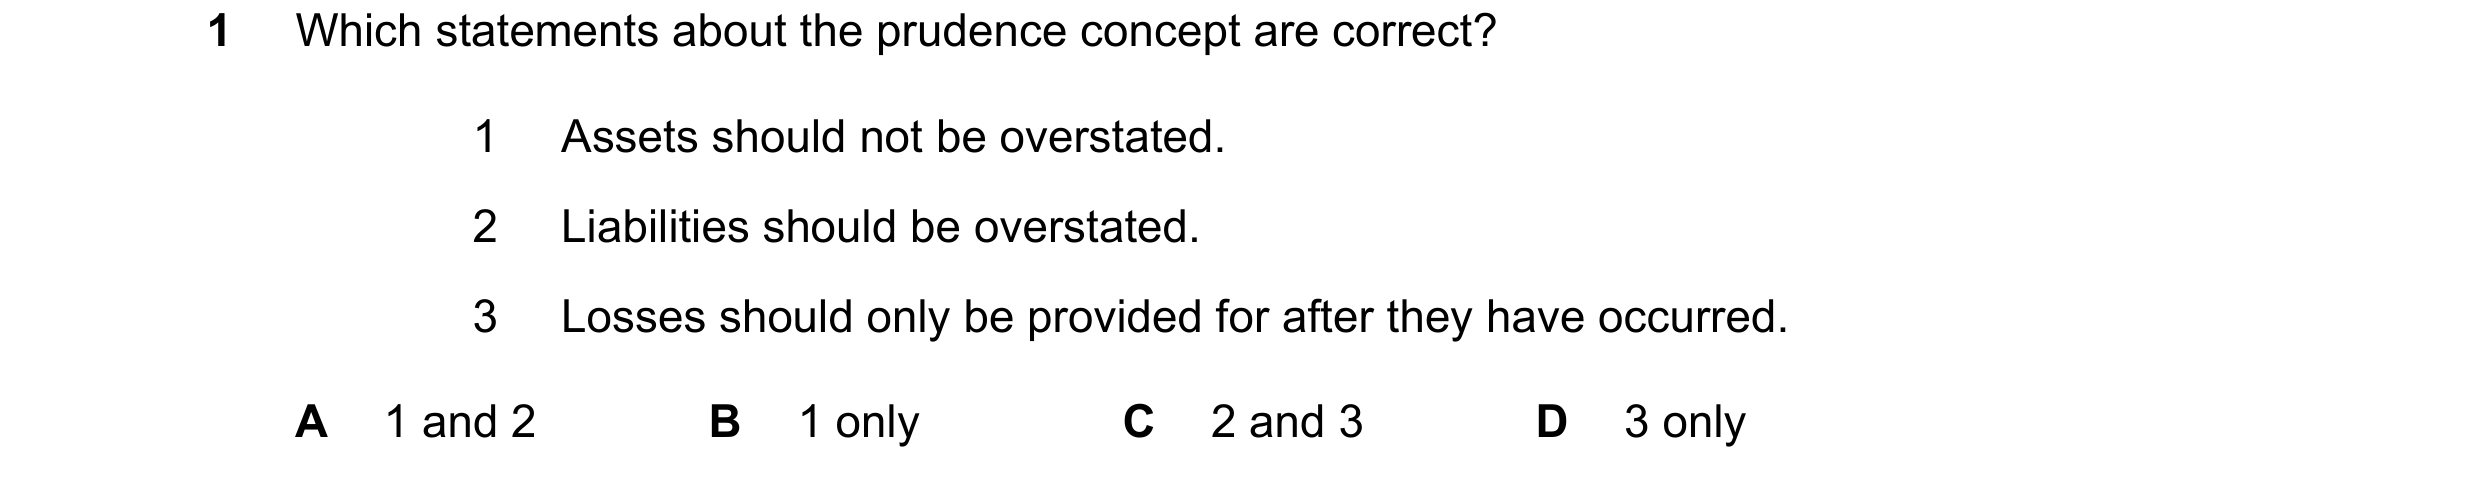
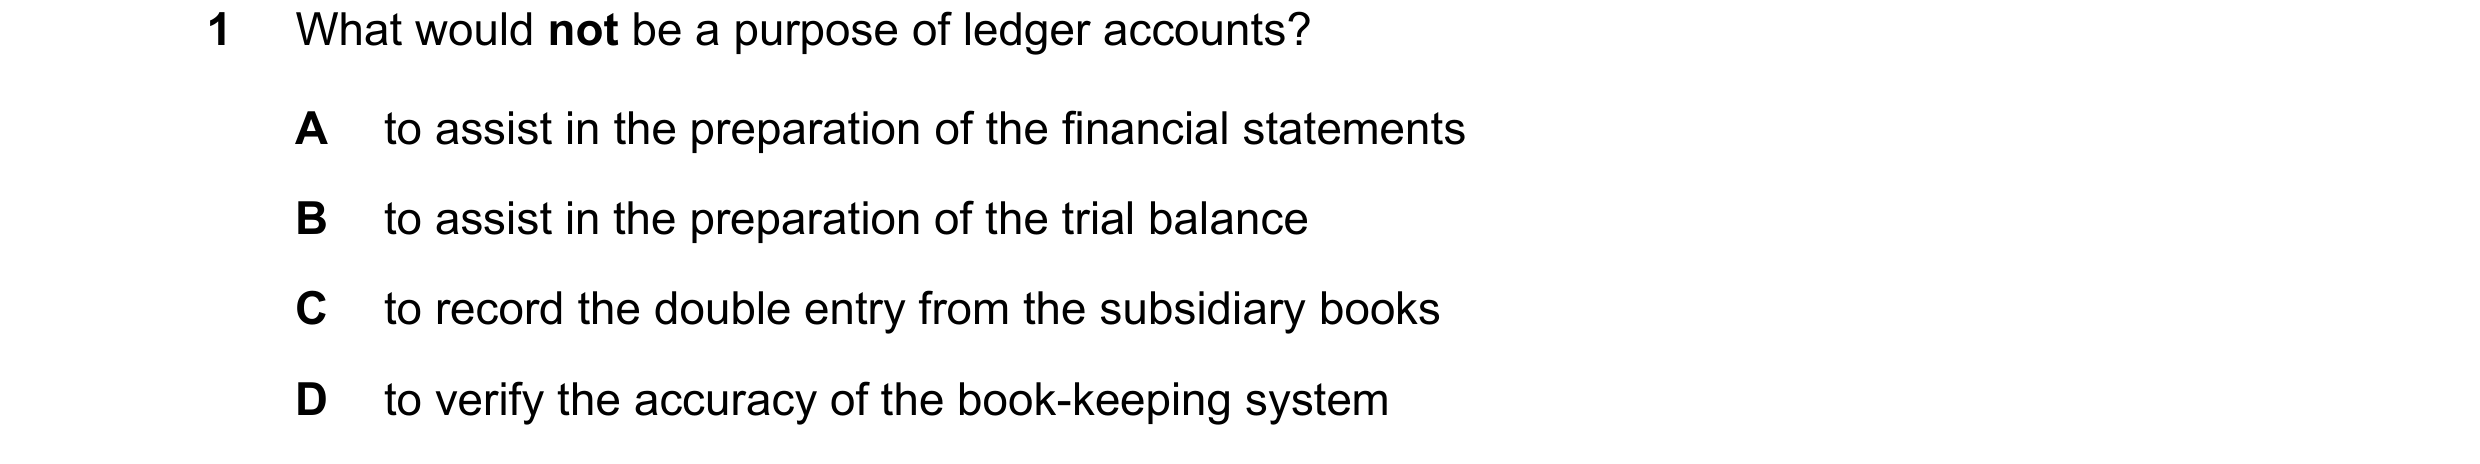 36 / 58
 37 / 58
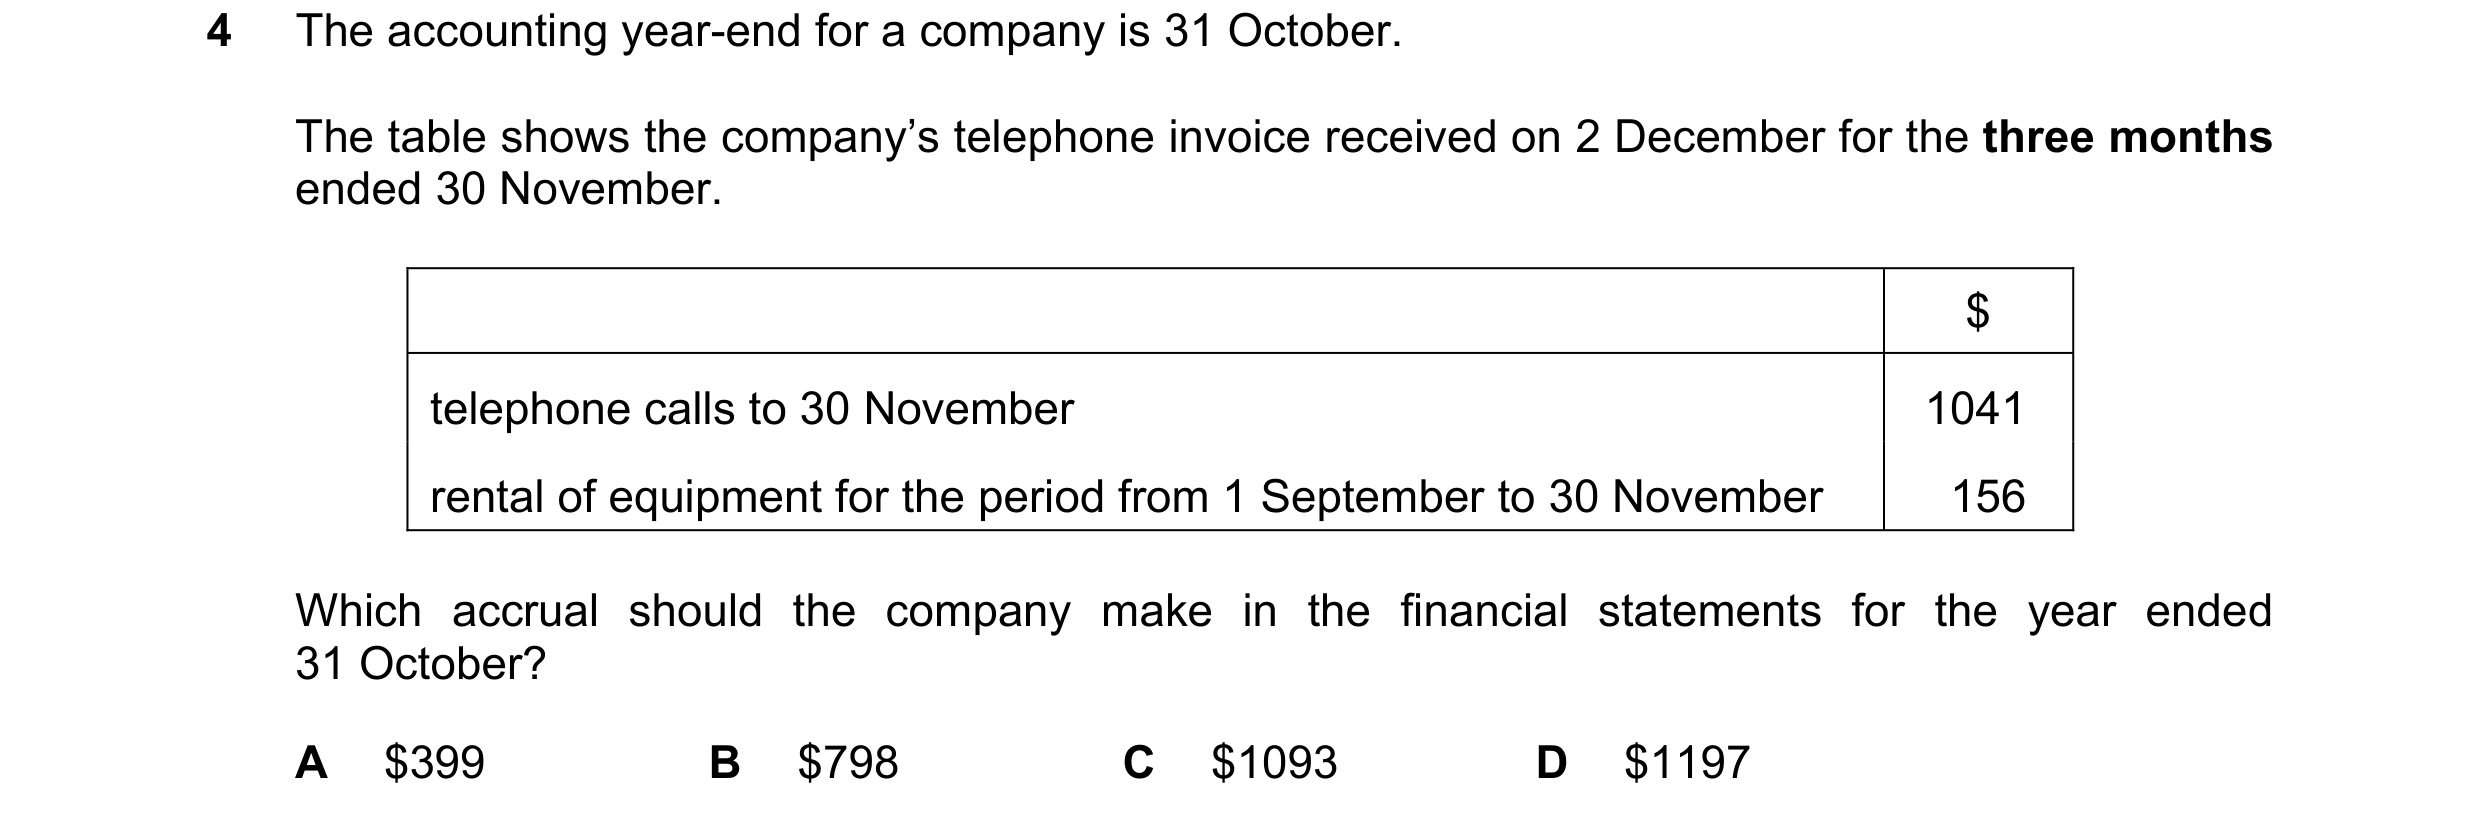
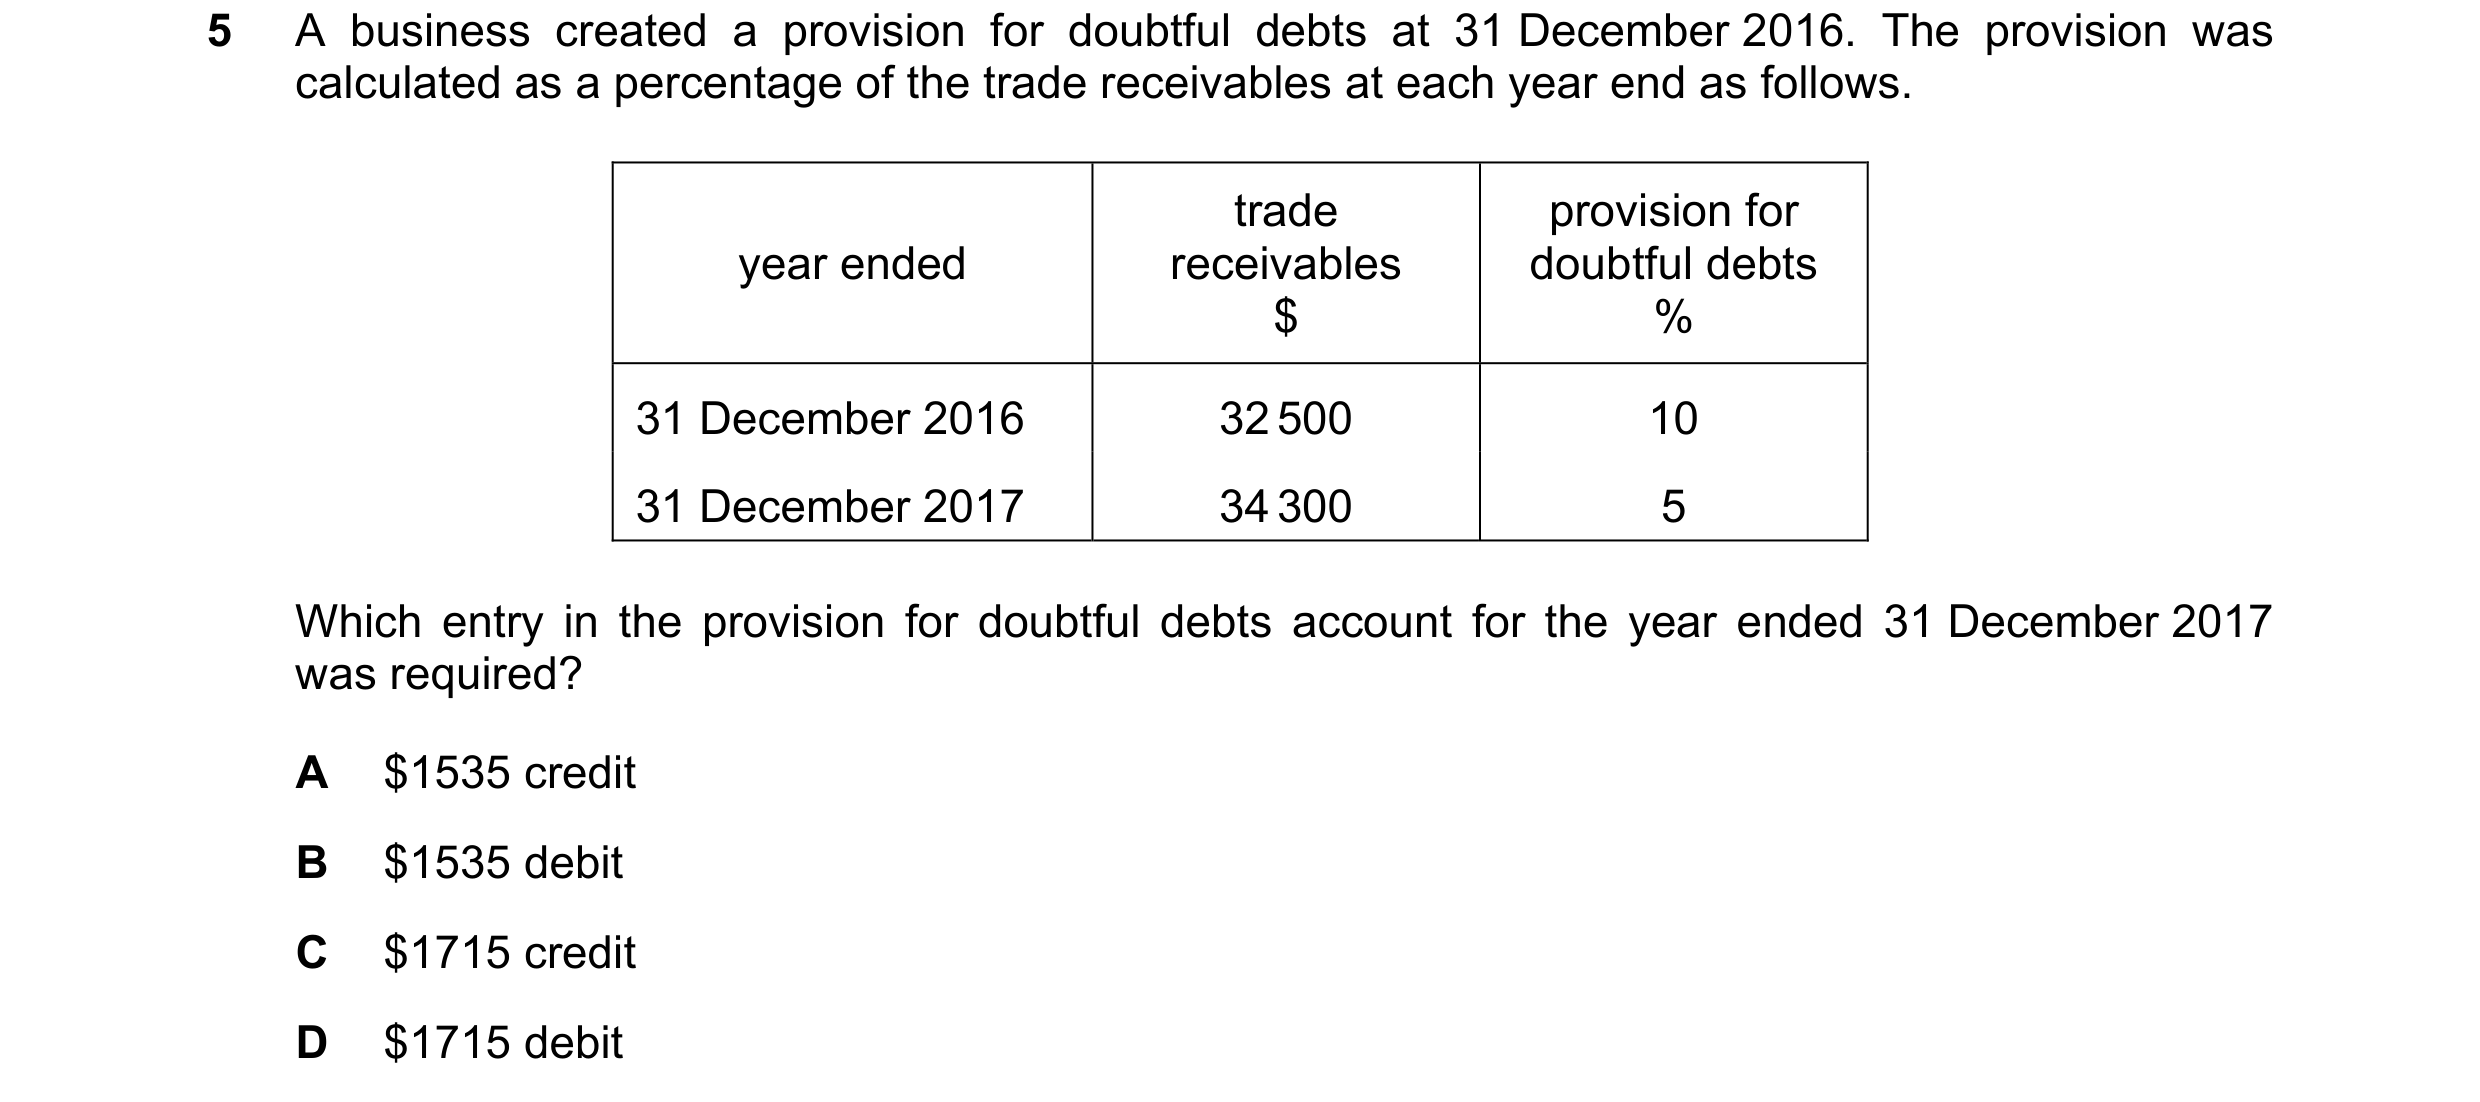
 38 / 58
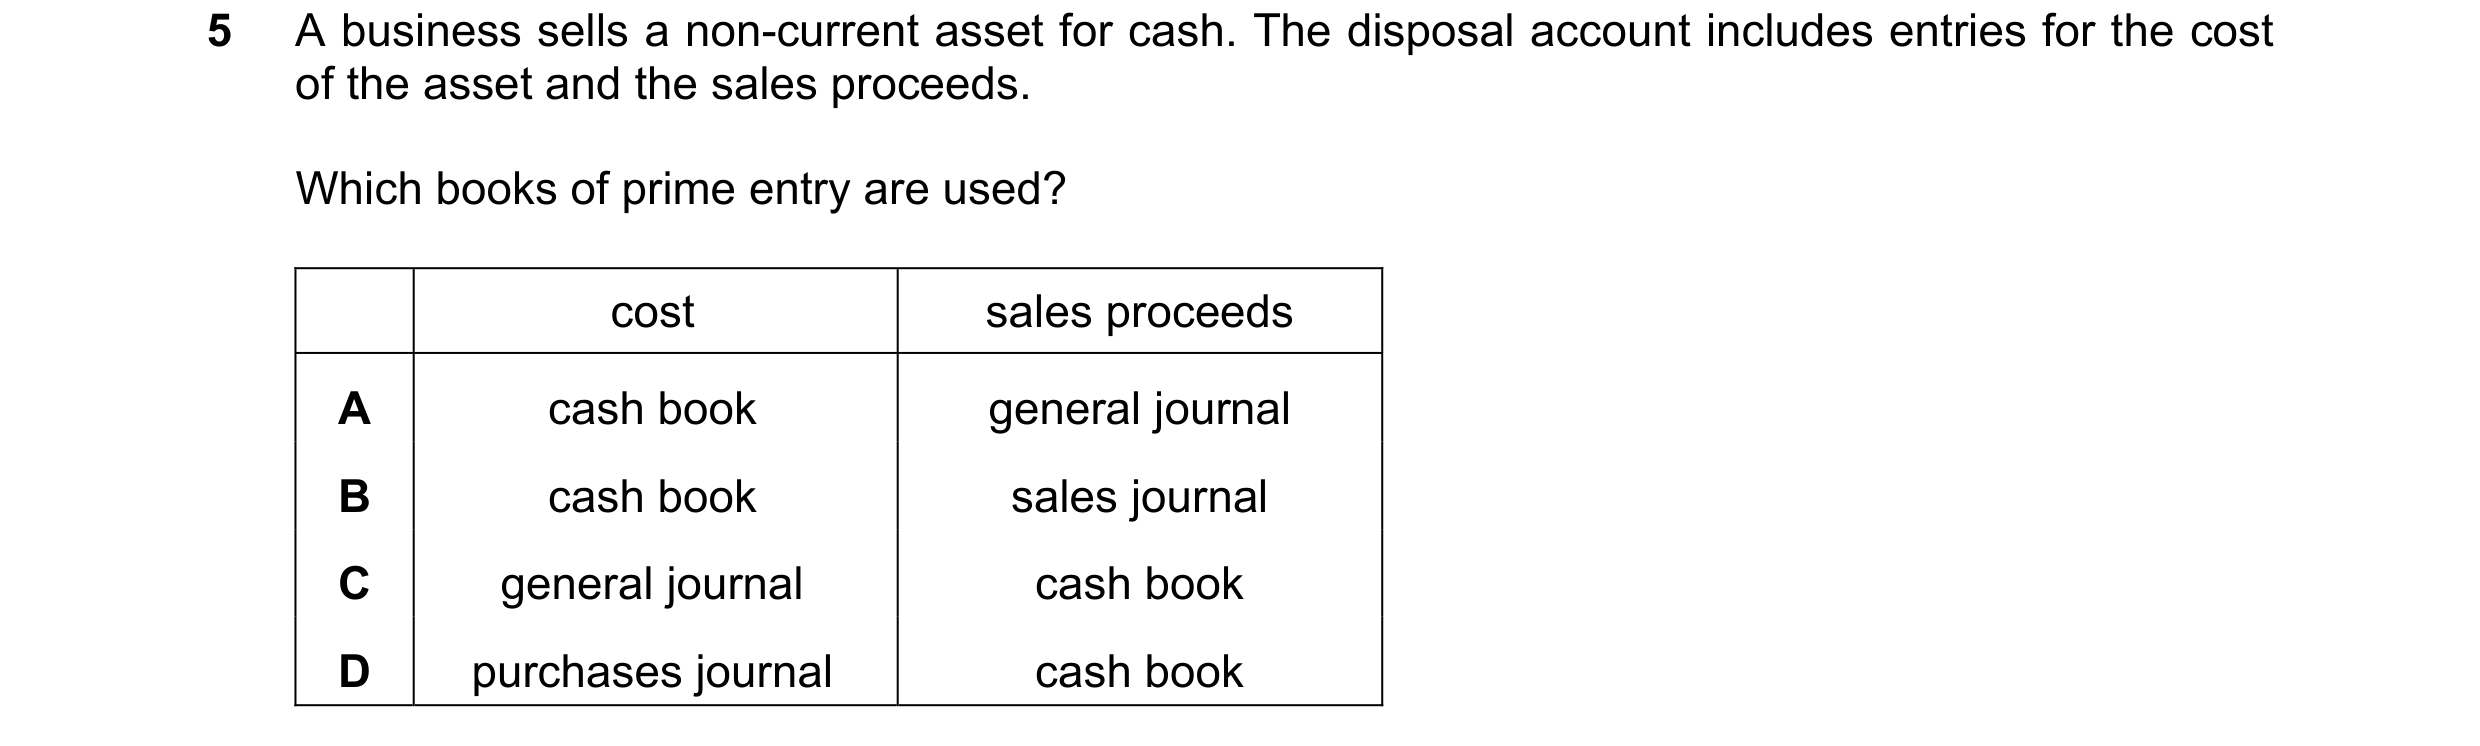
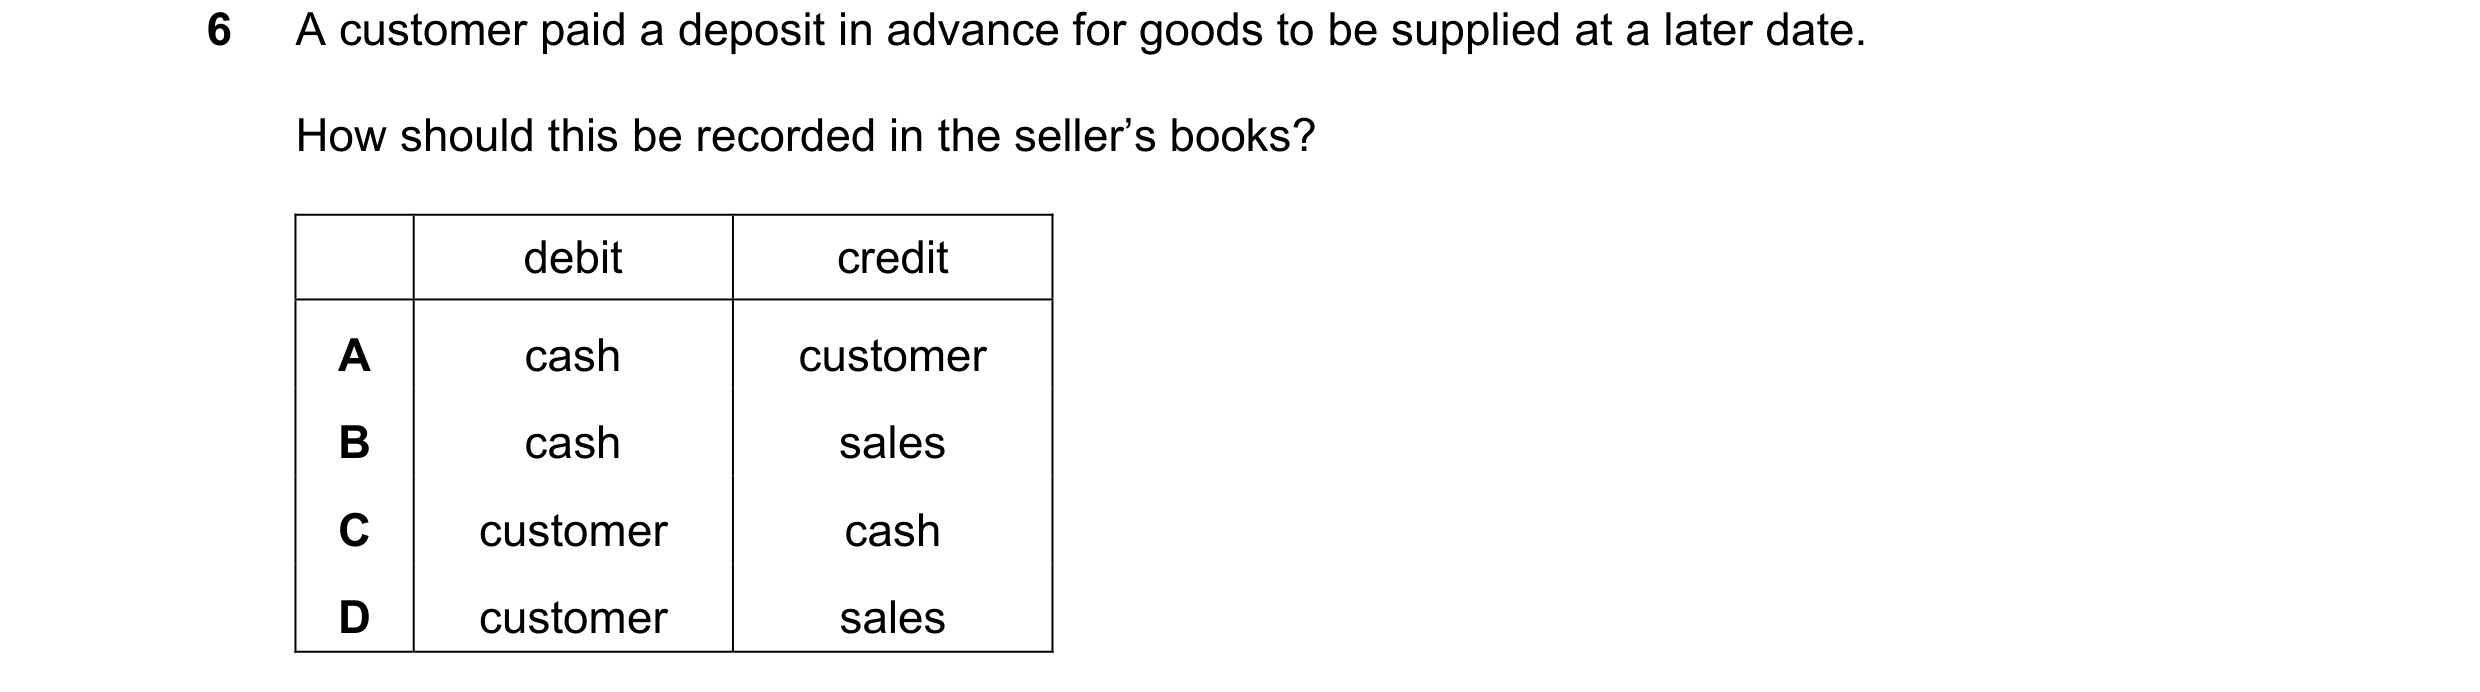
 39 / 58
 40 / 58
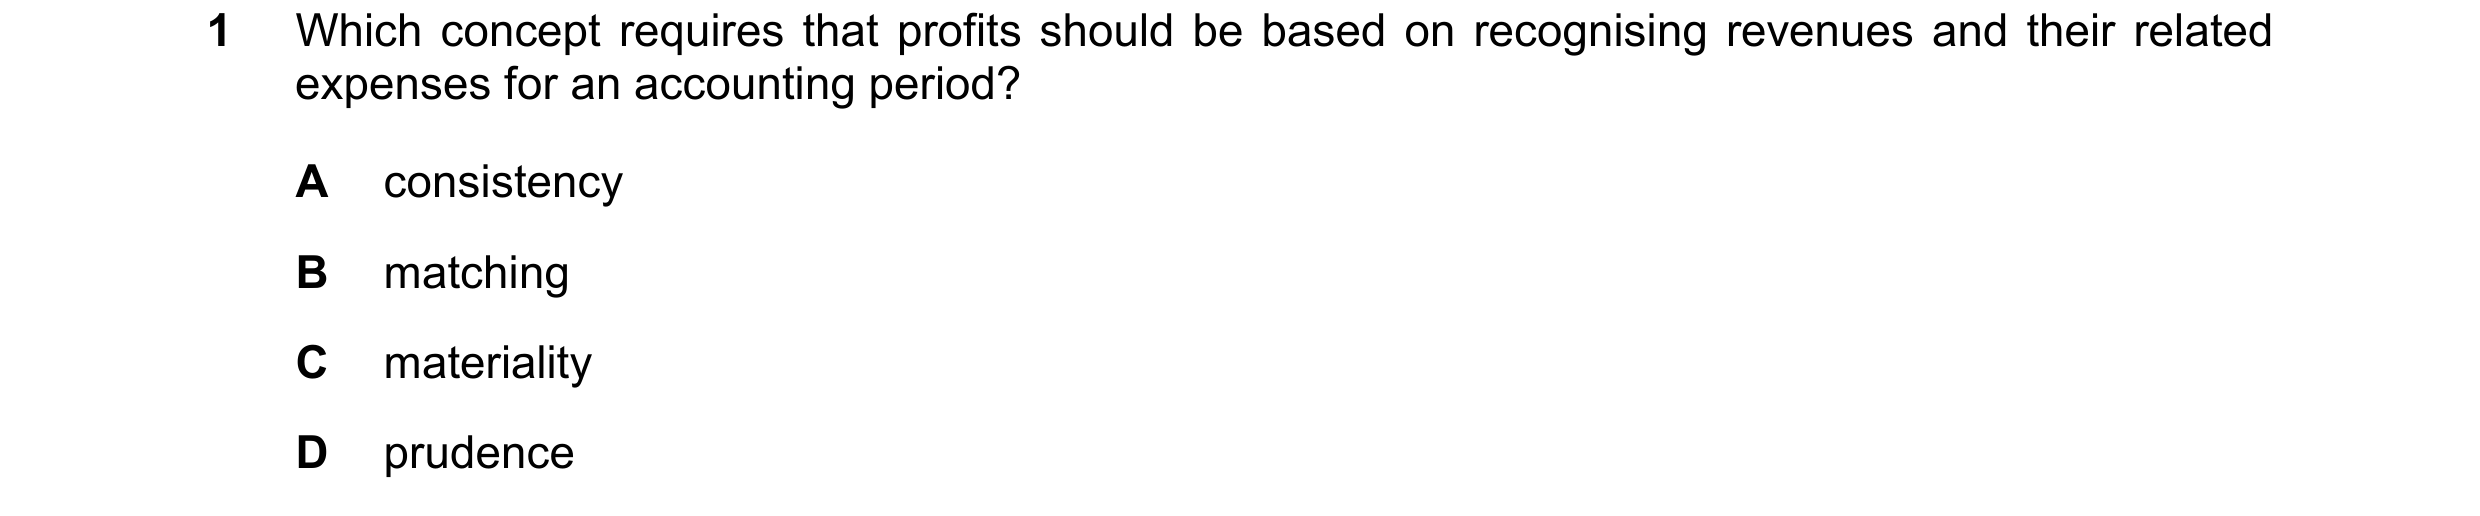
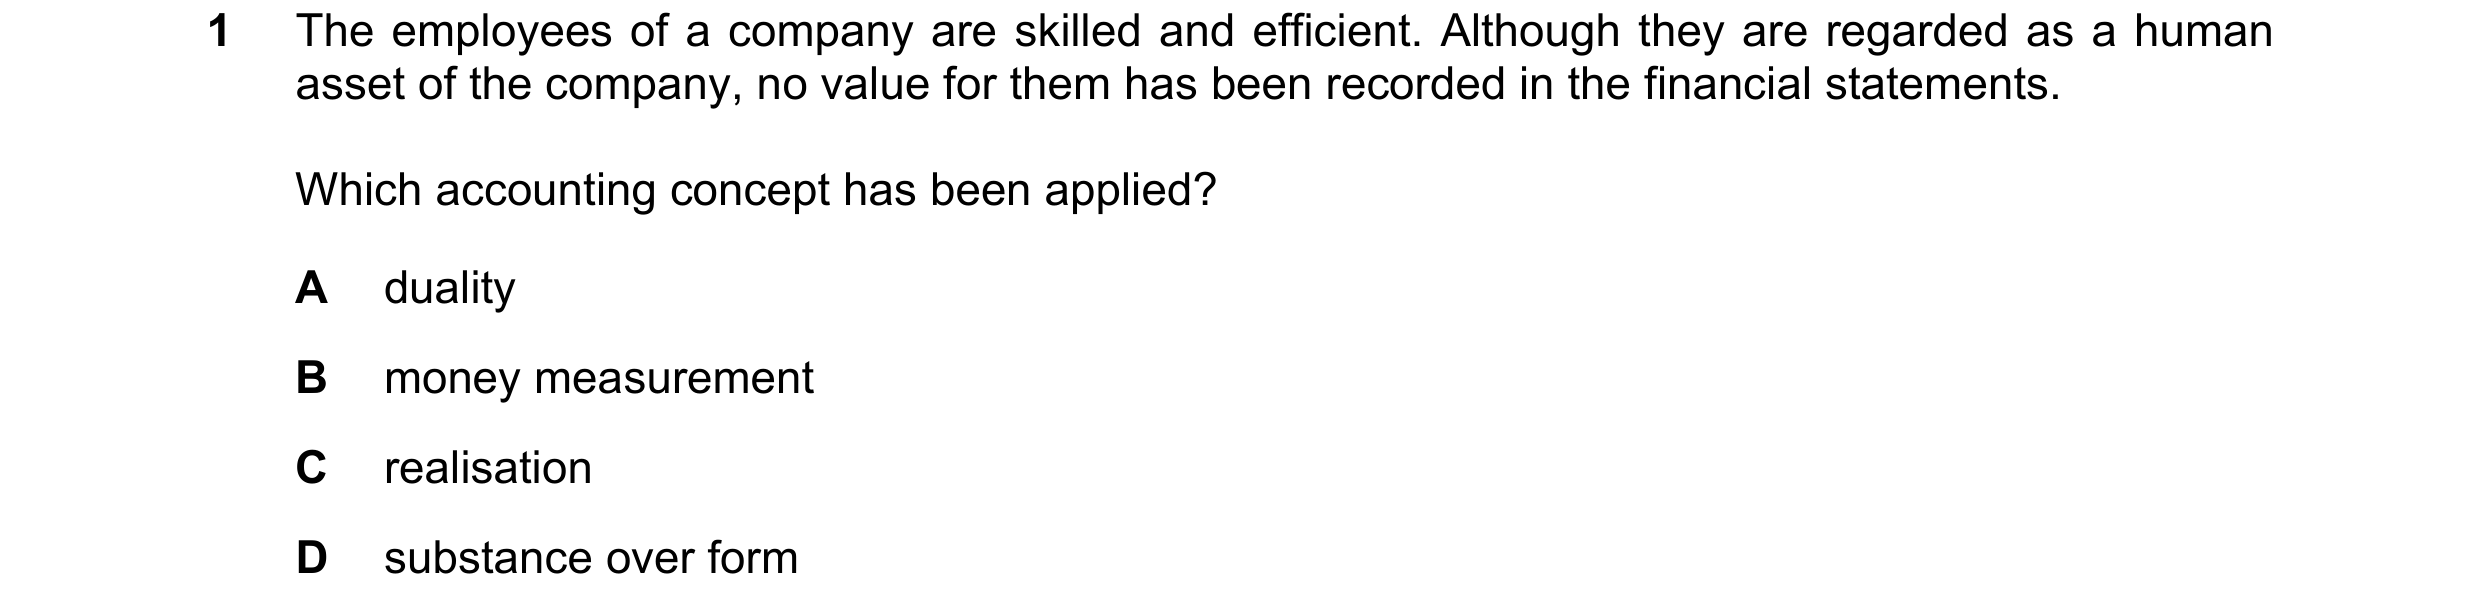
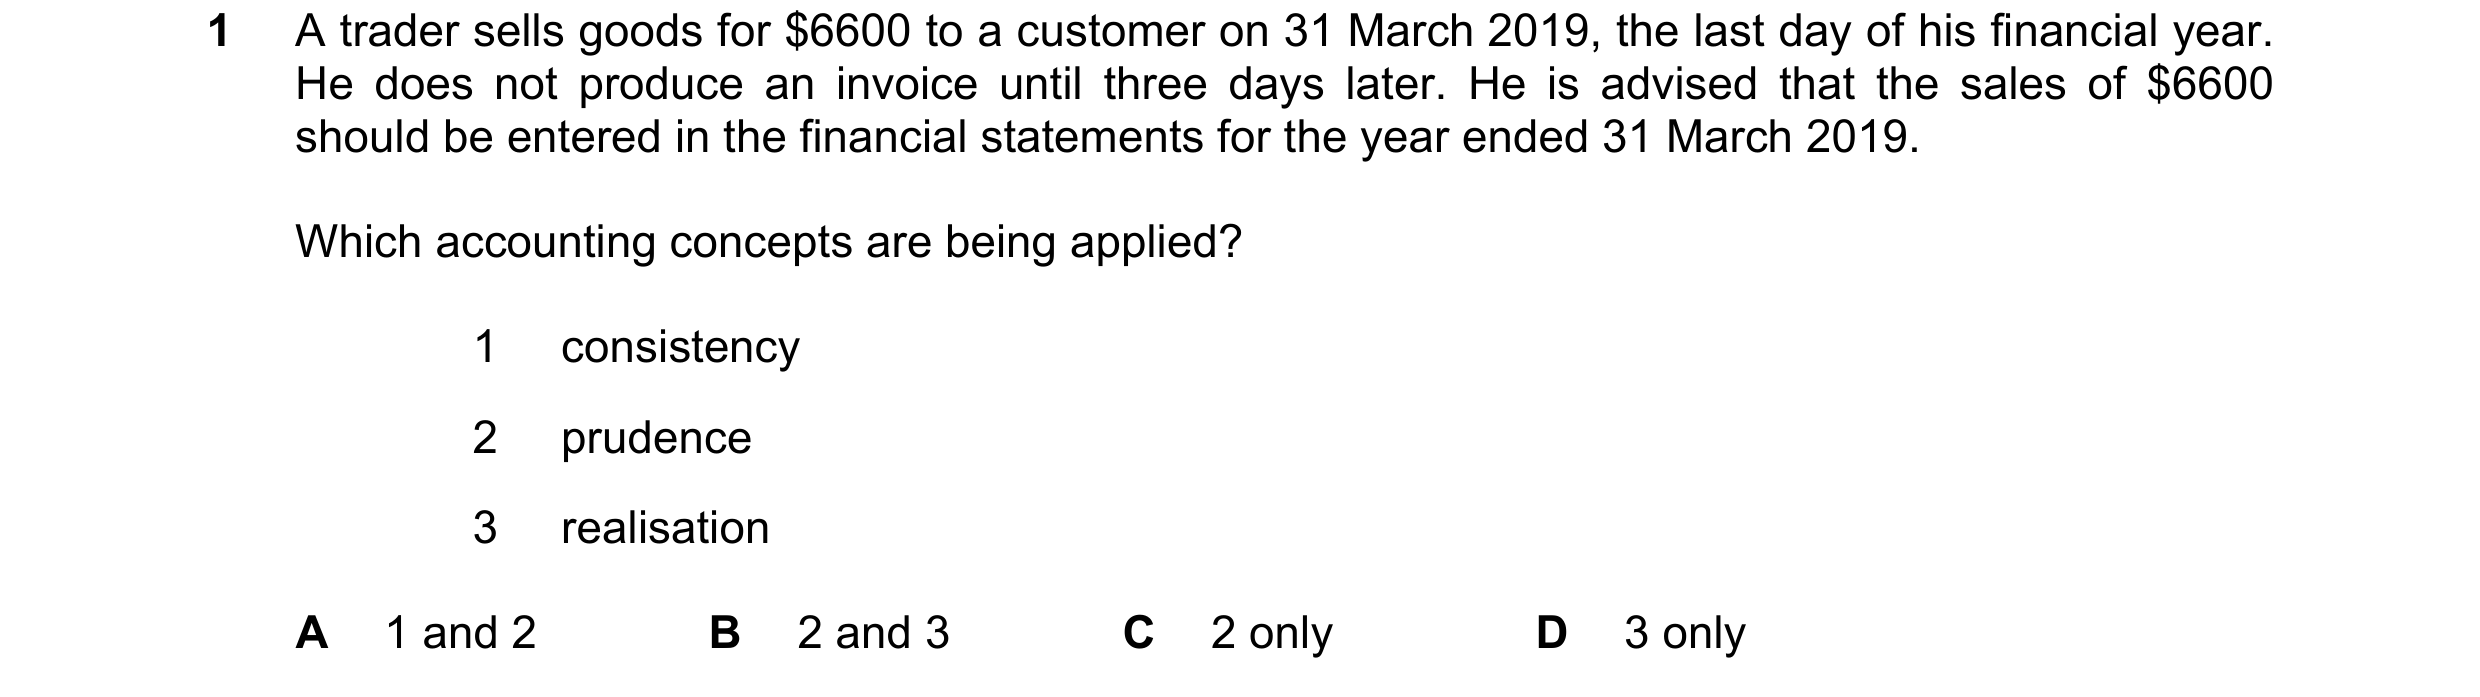
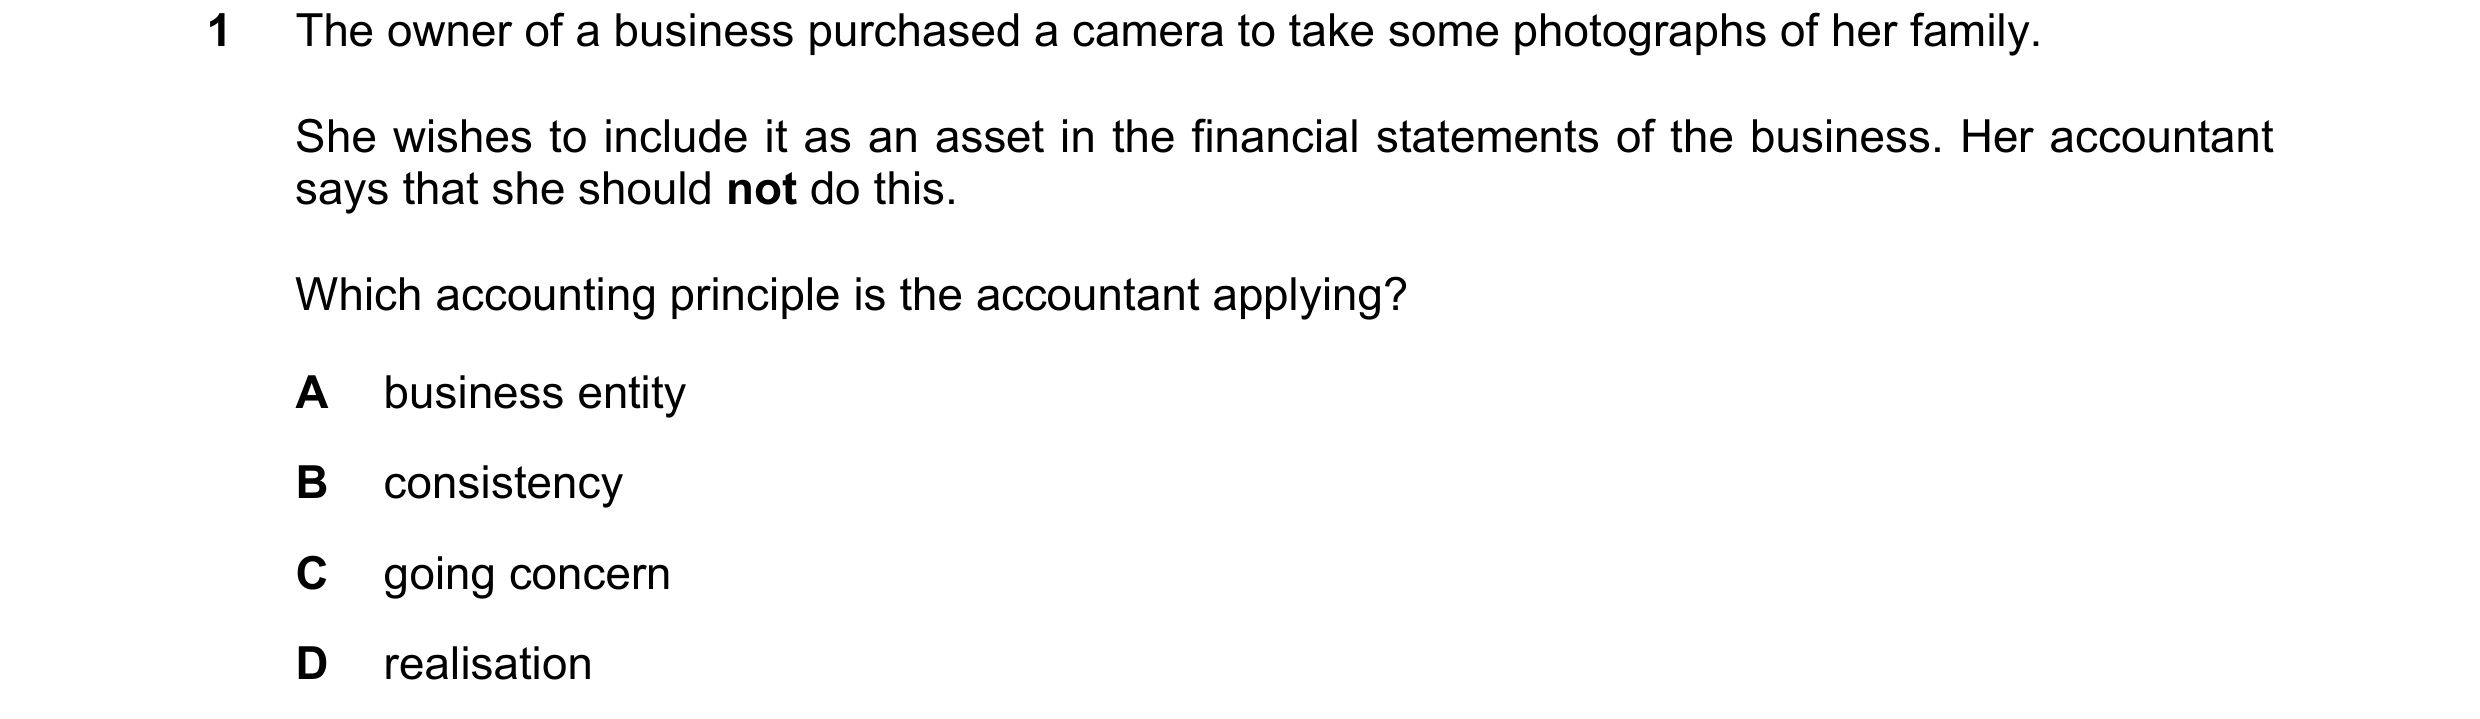 41 / 58
 42 / 58
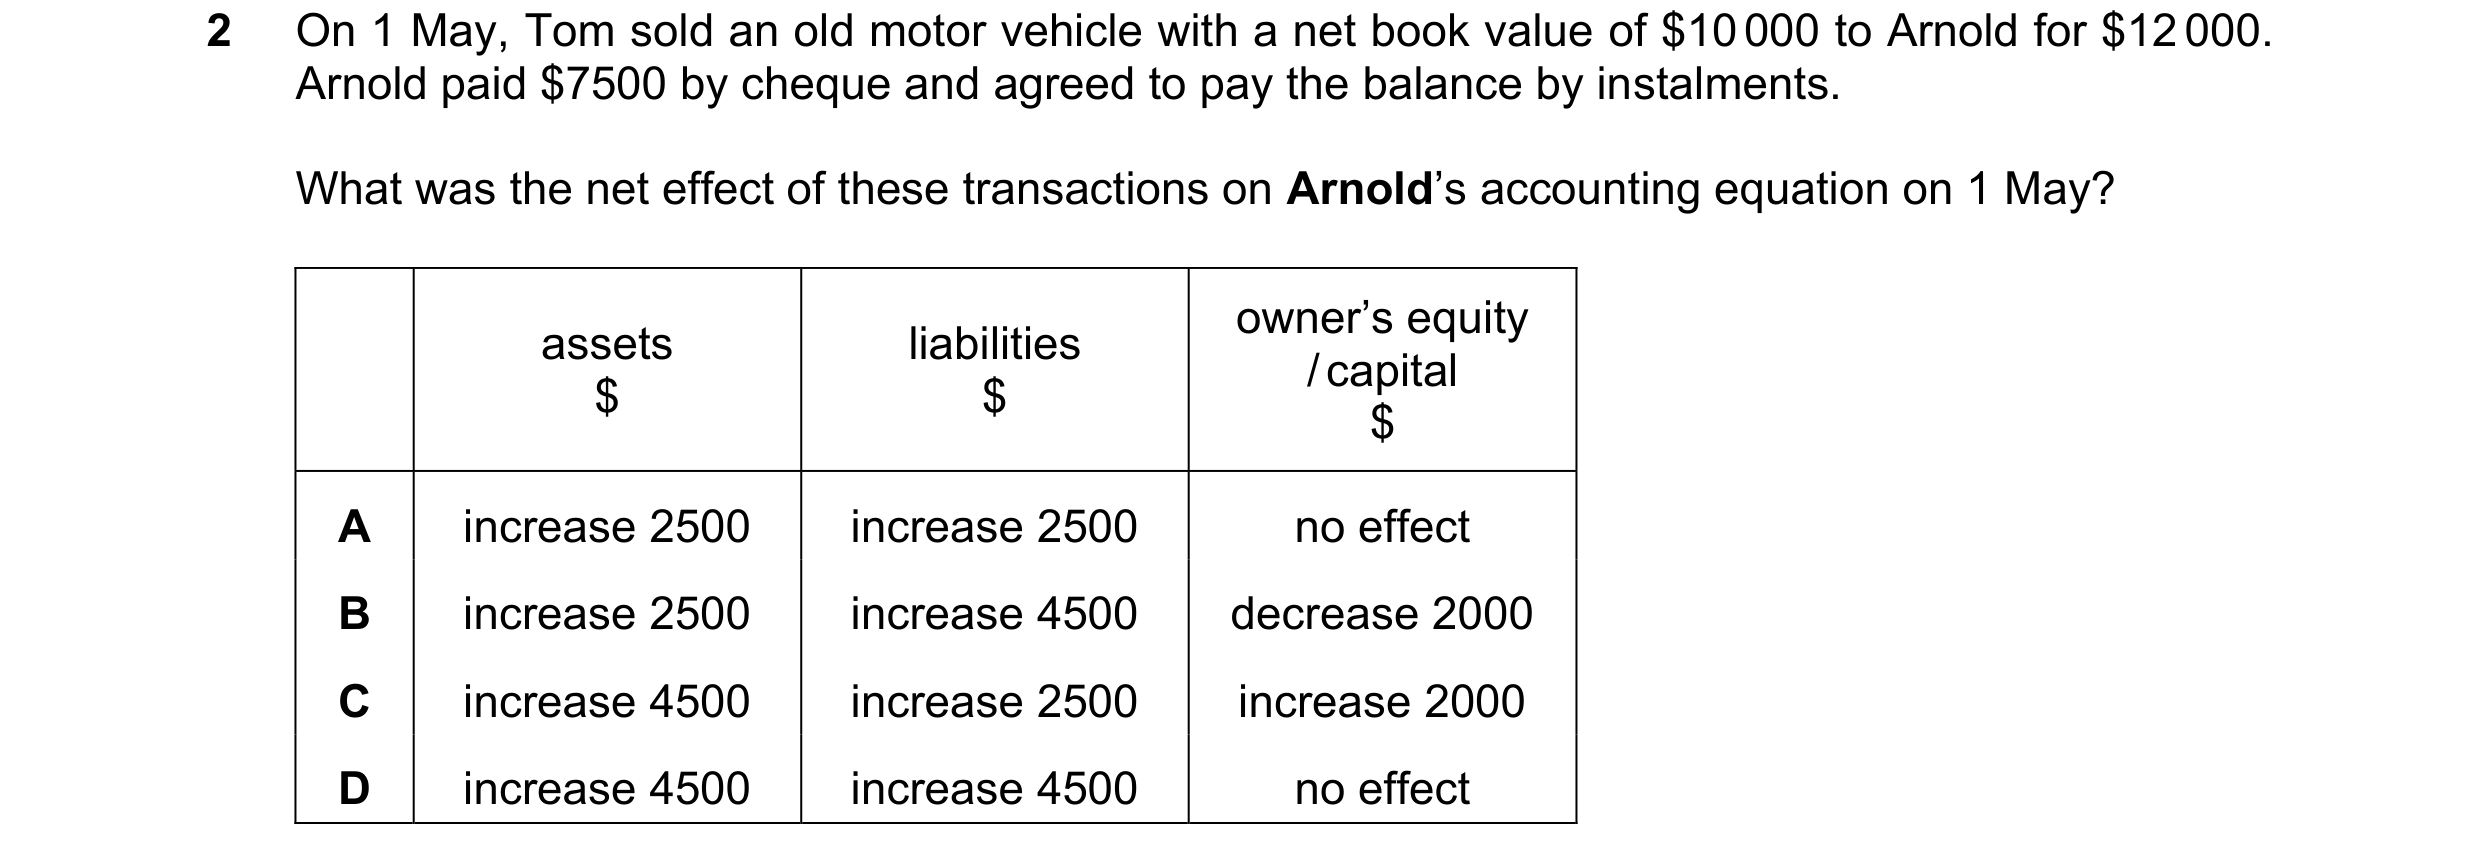
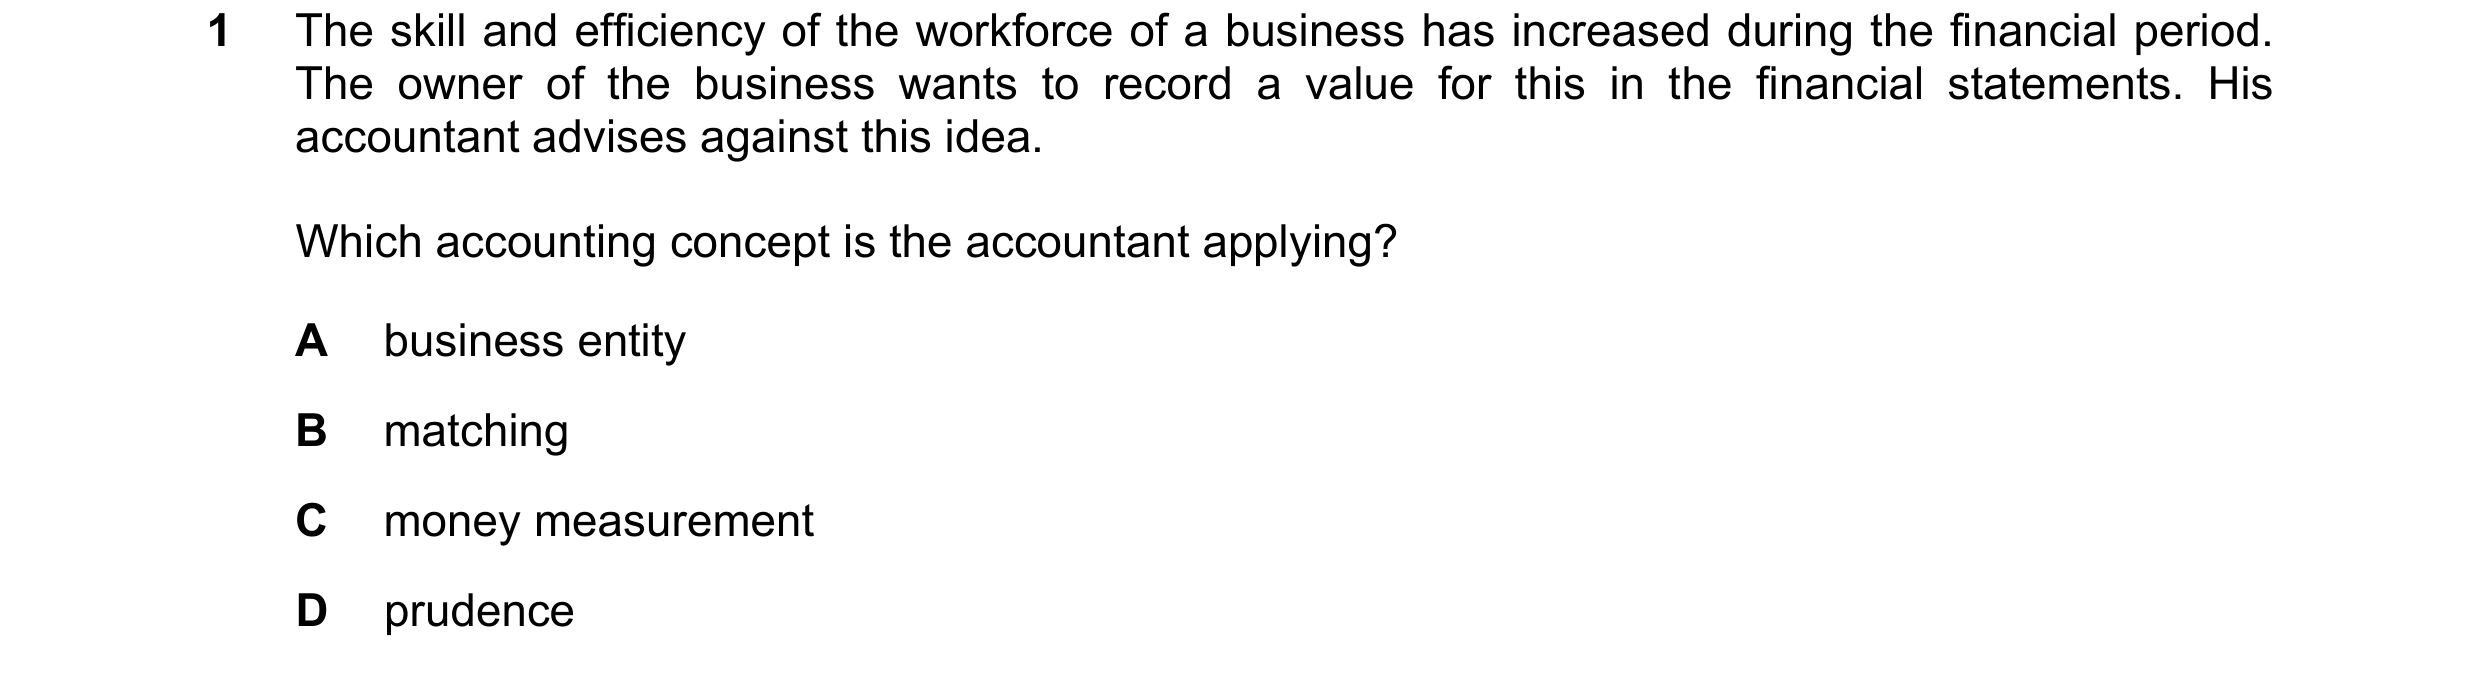 43 / 58
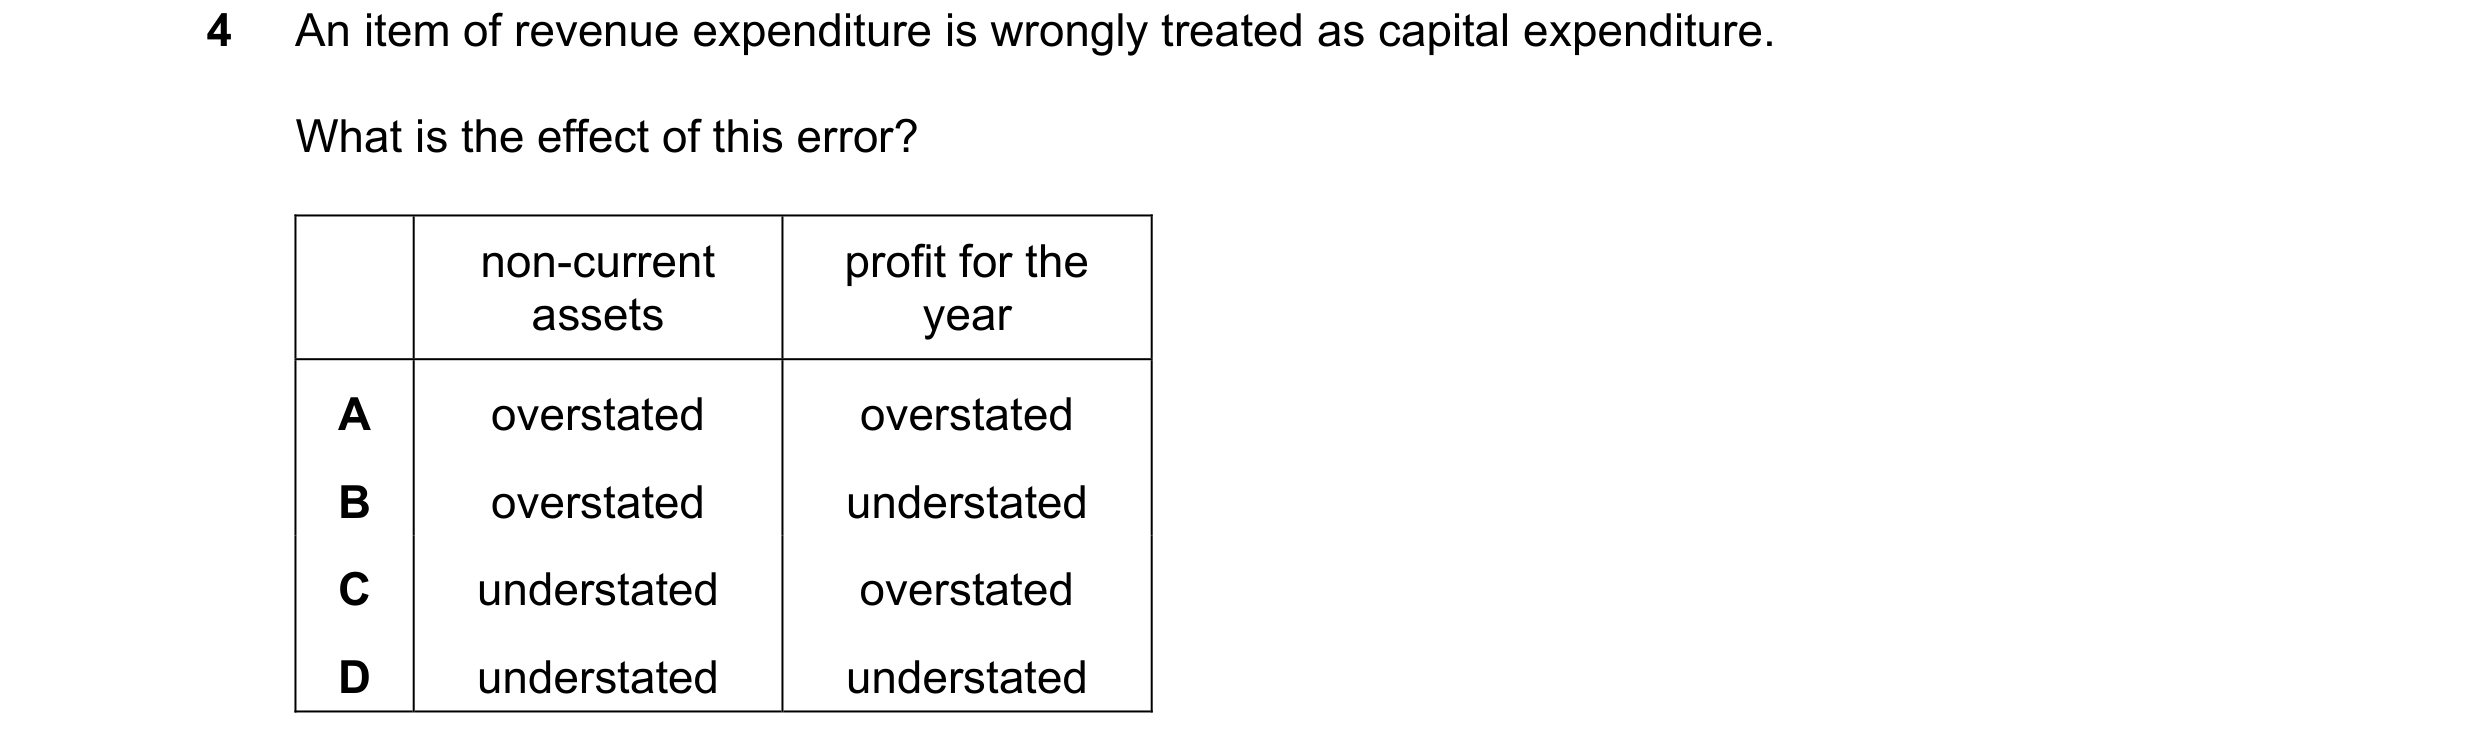
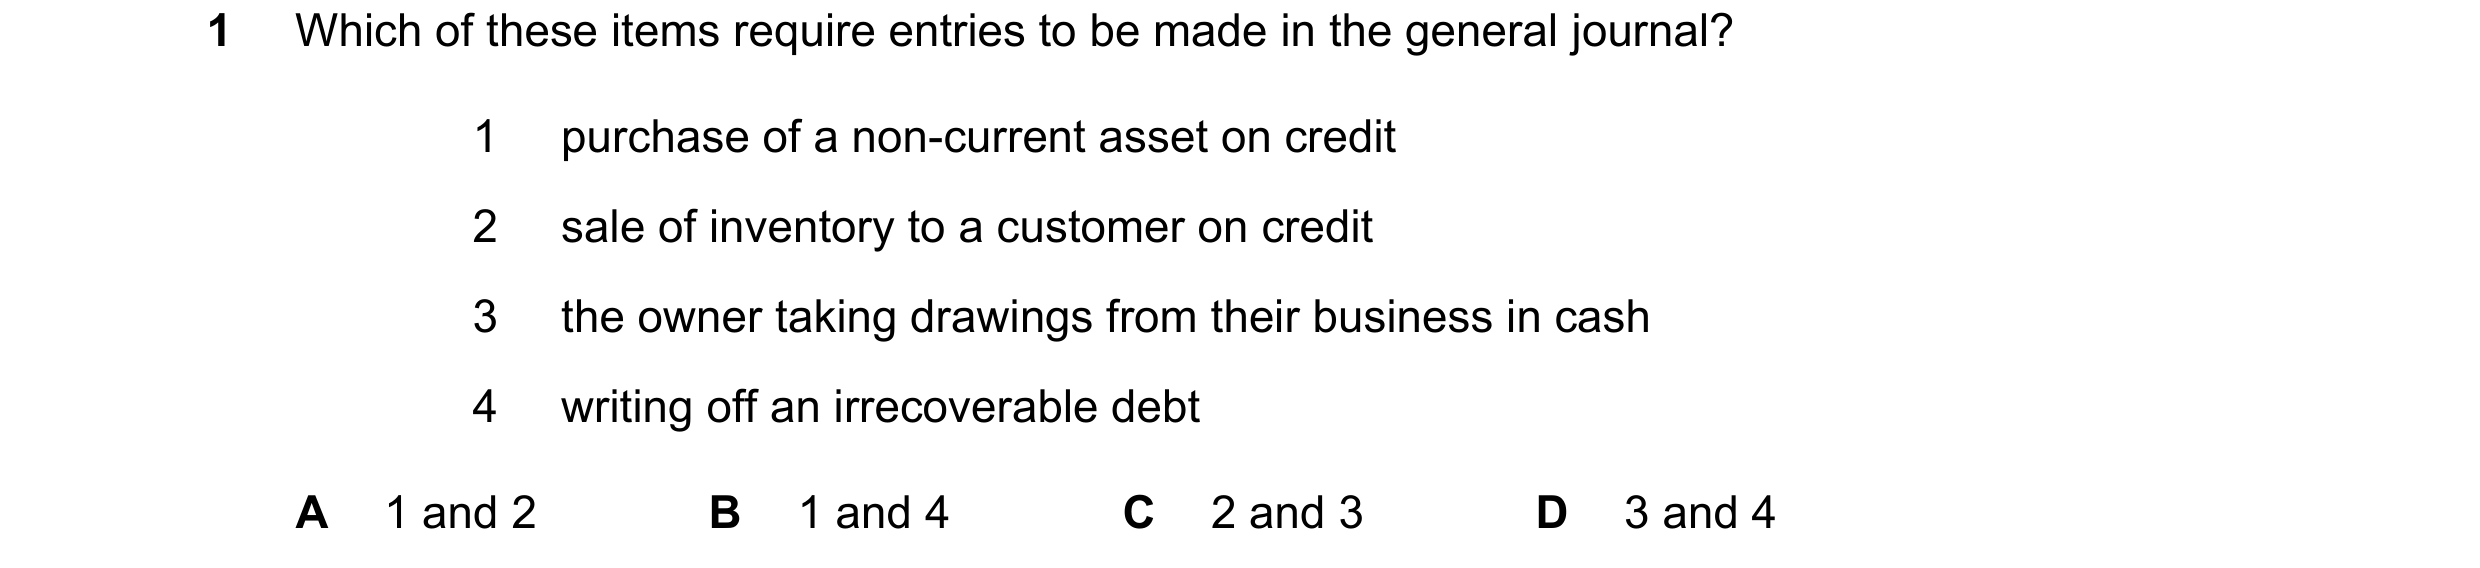
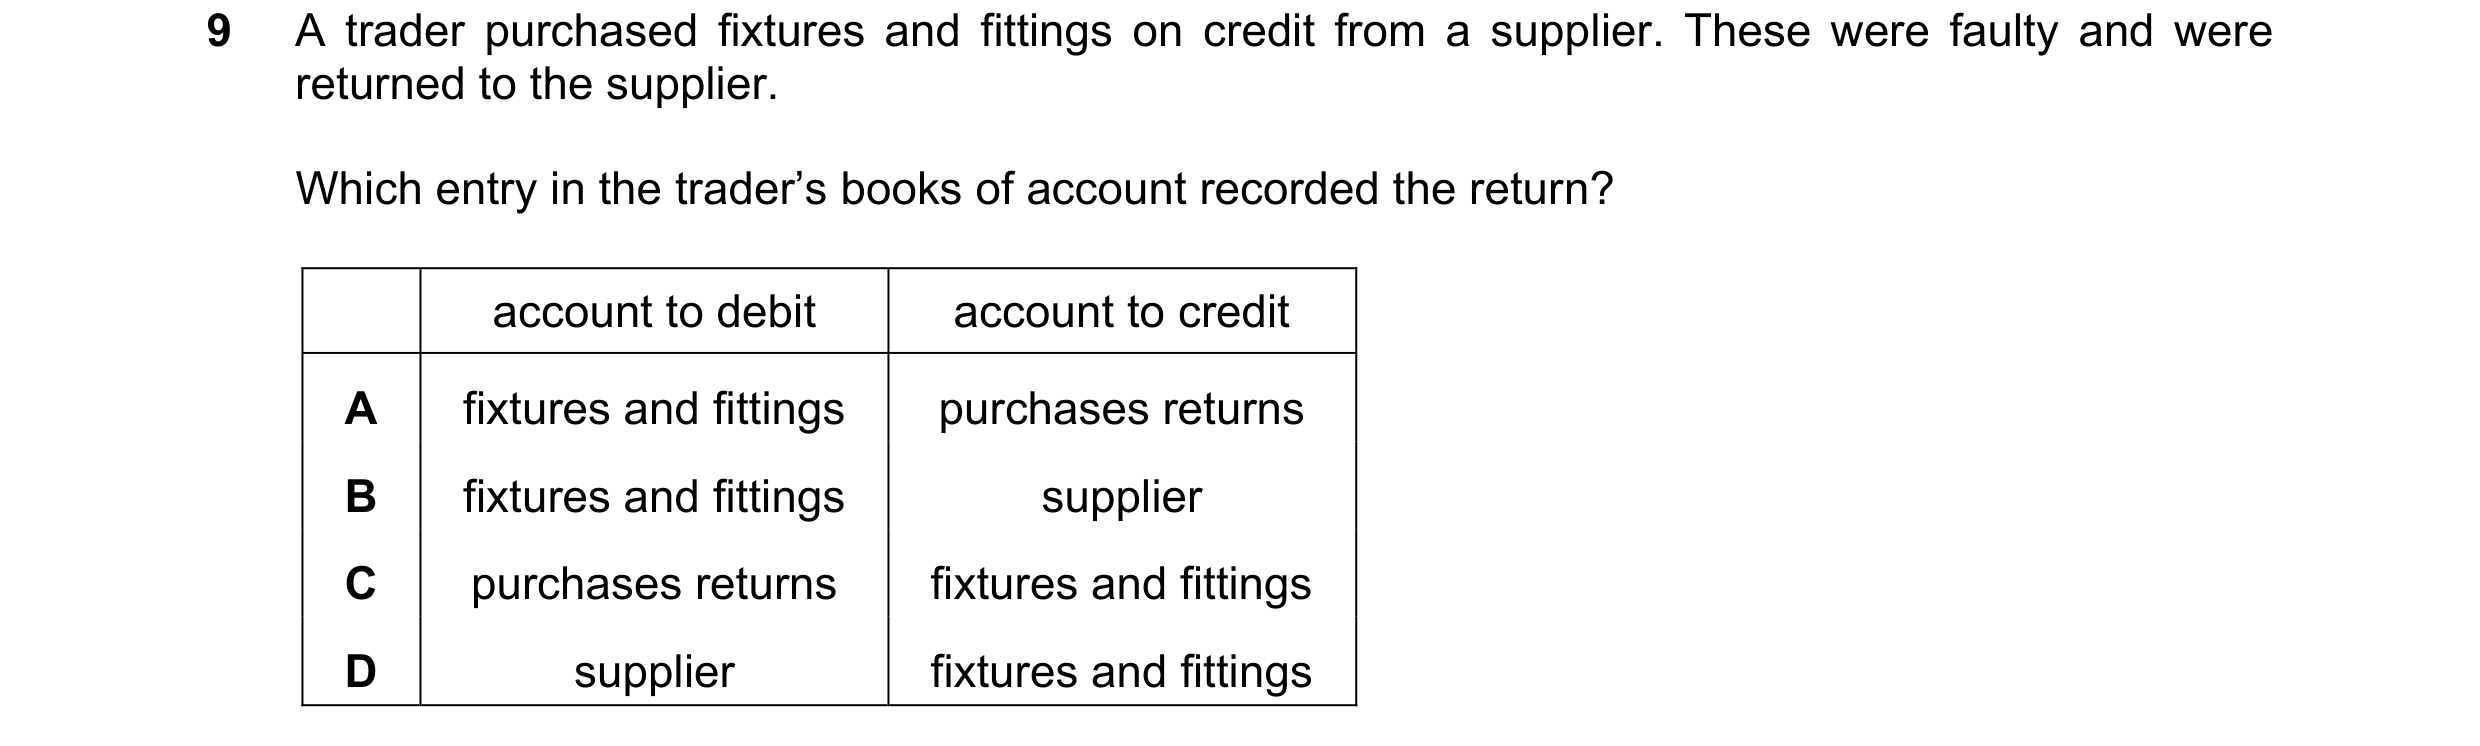
 44 / 58
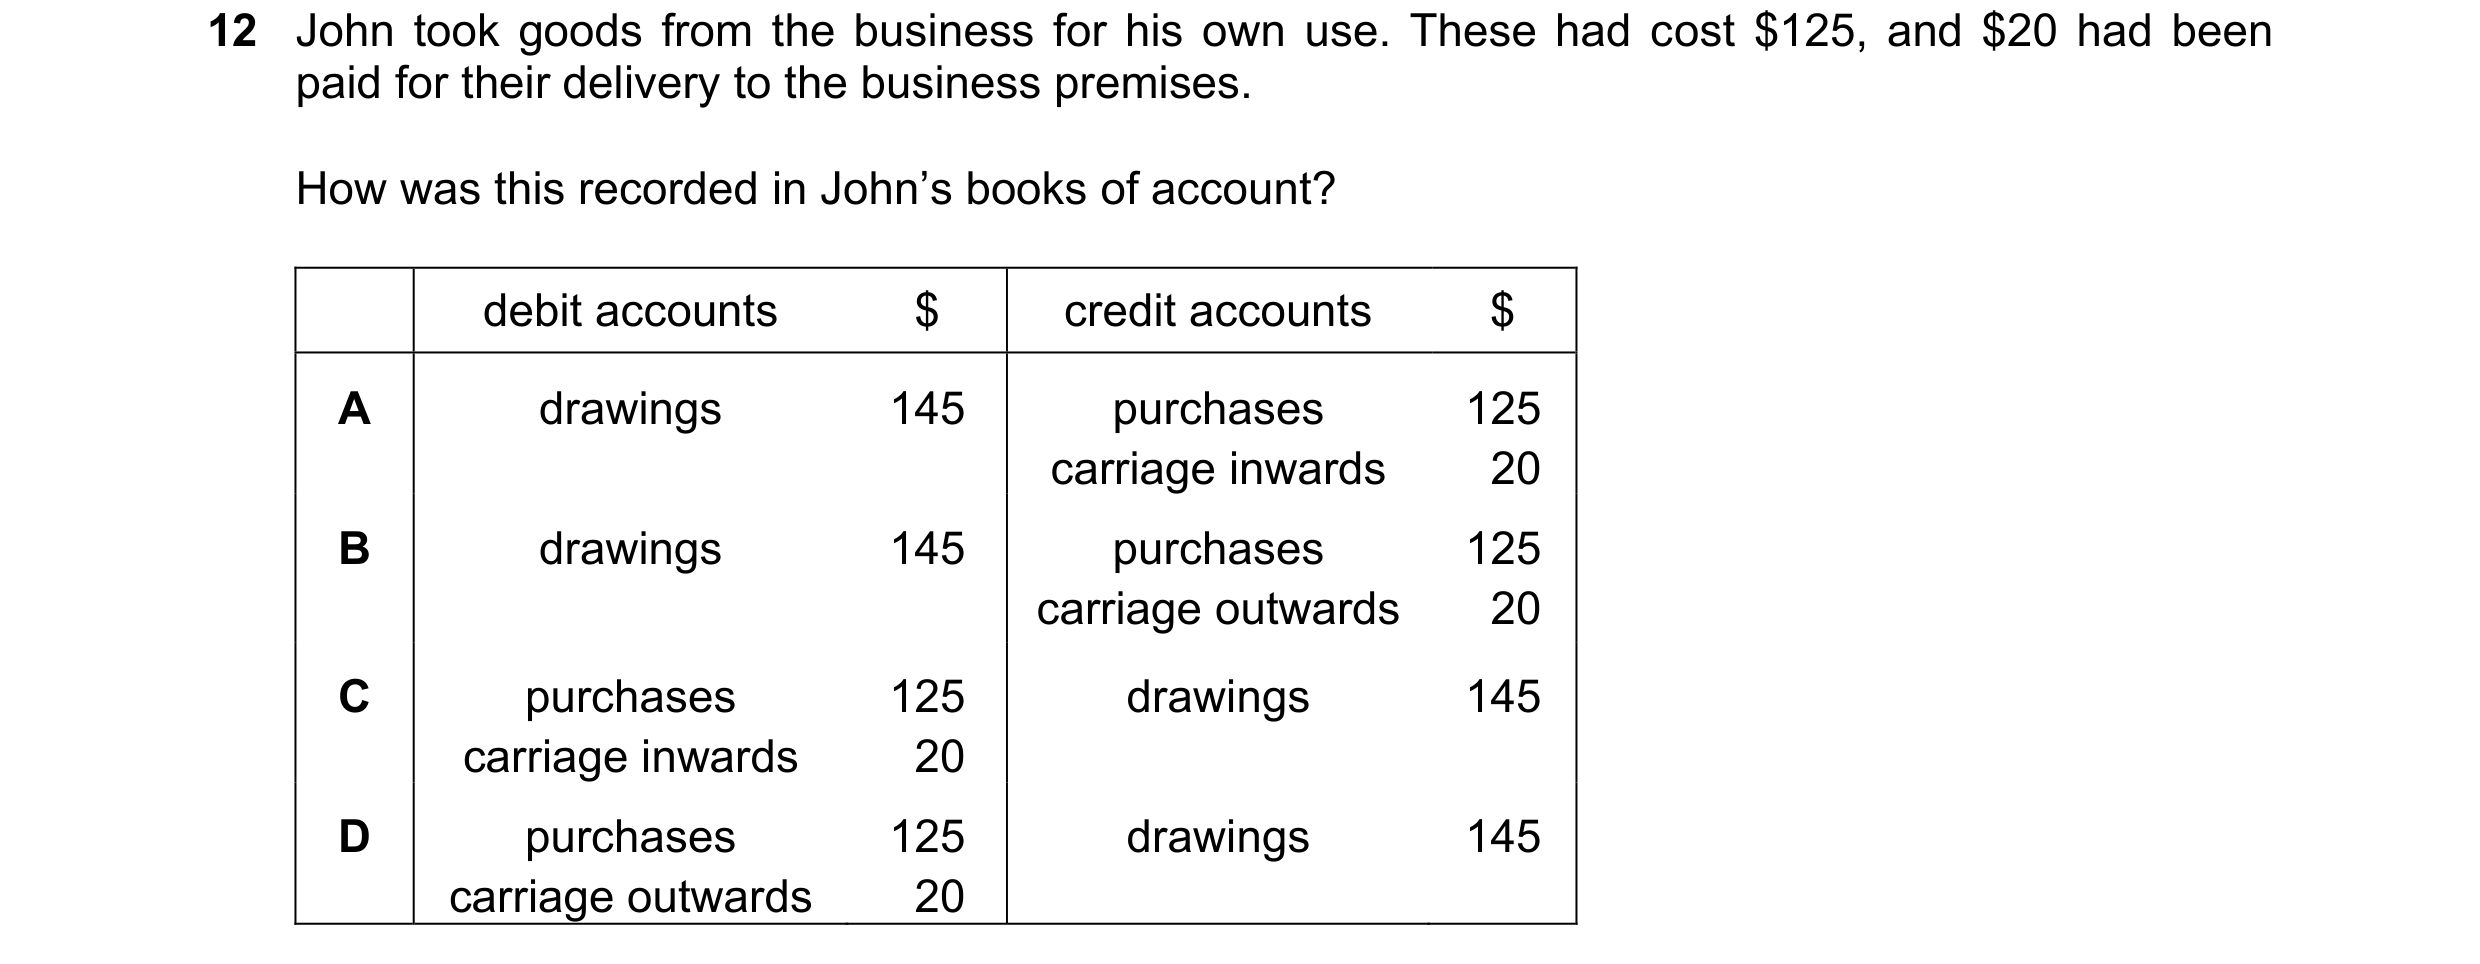
 45 / 58
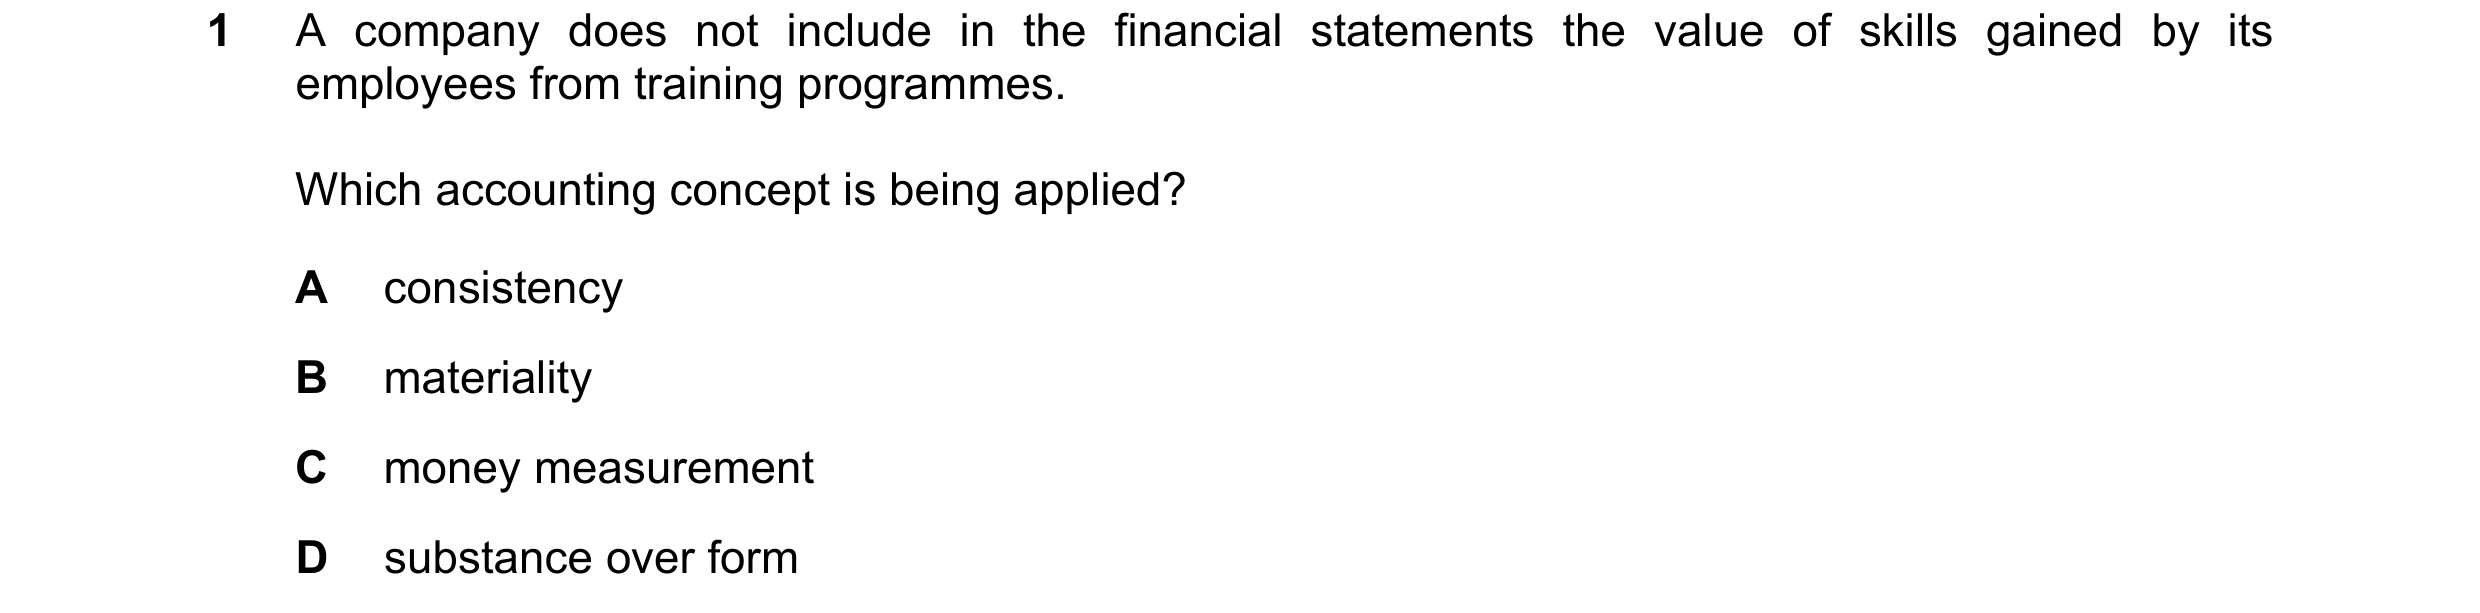
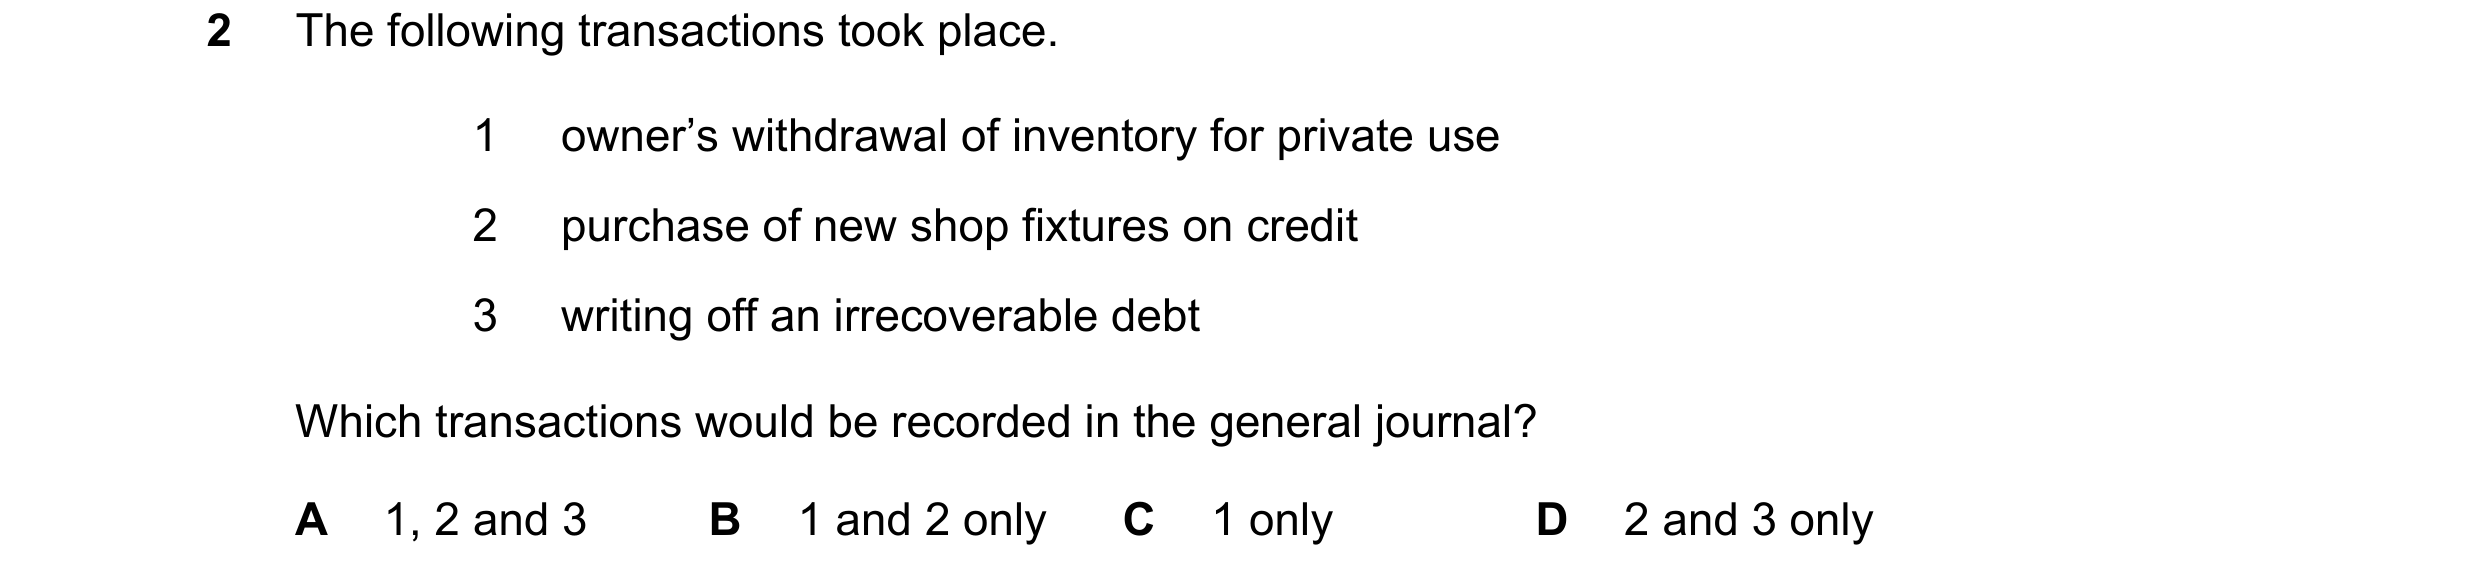
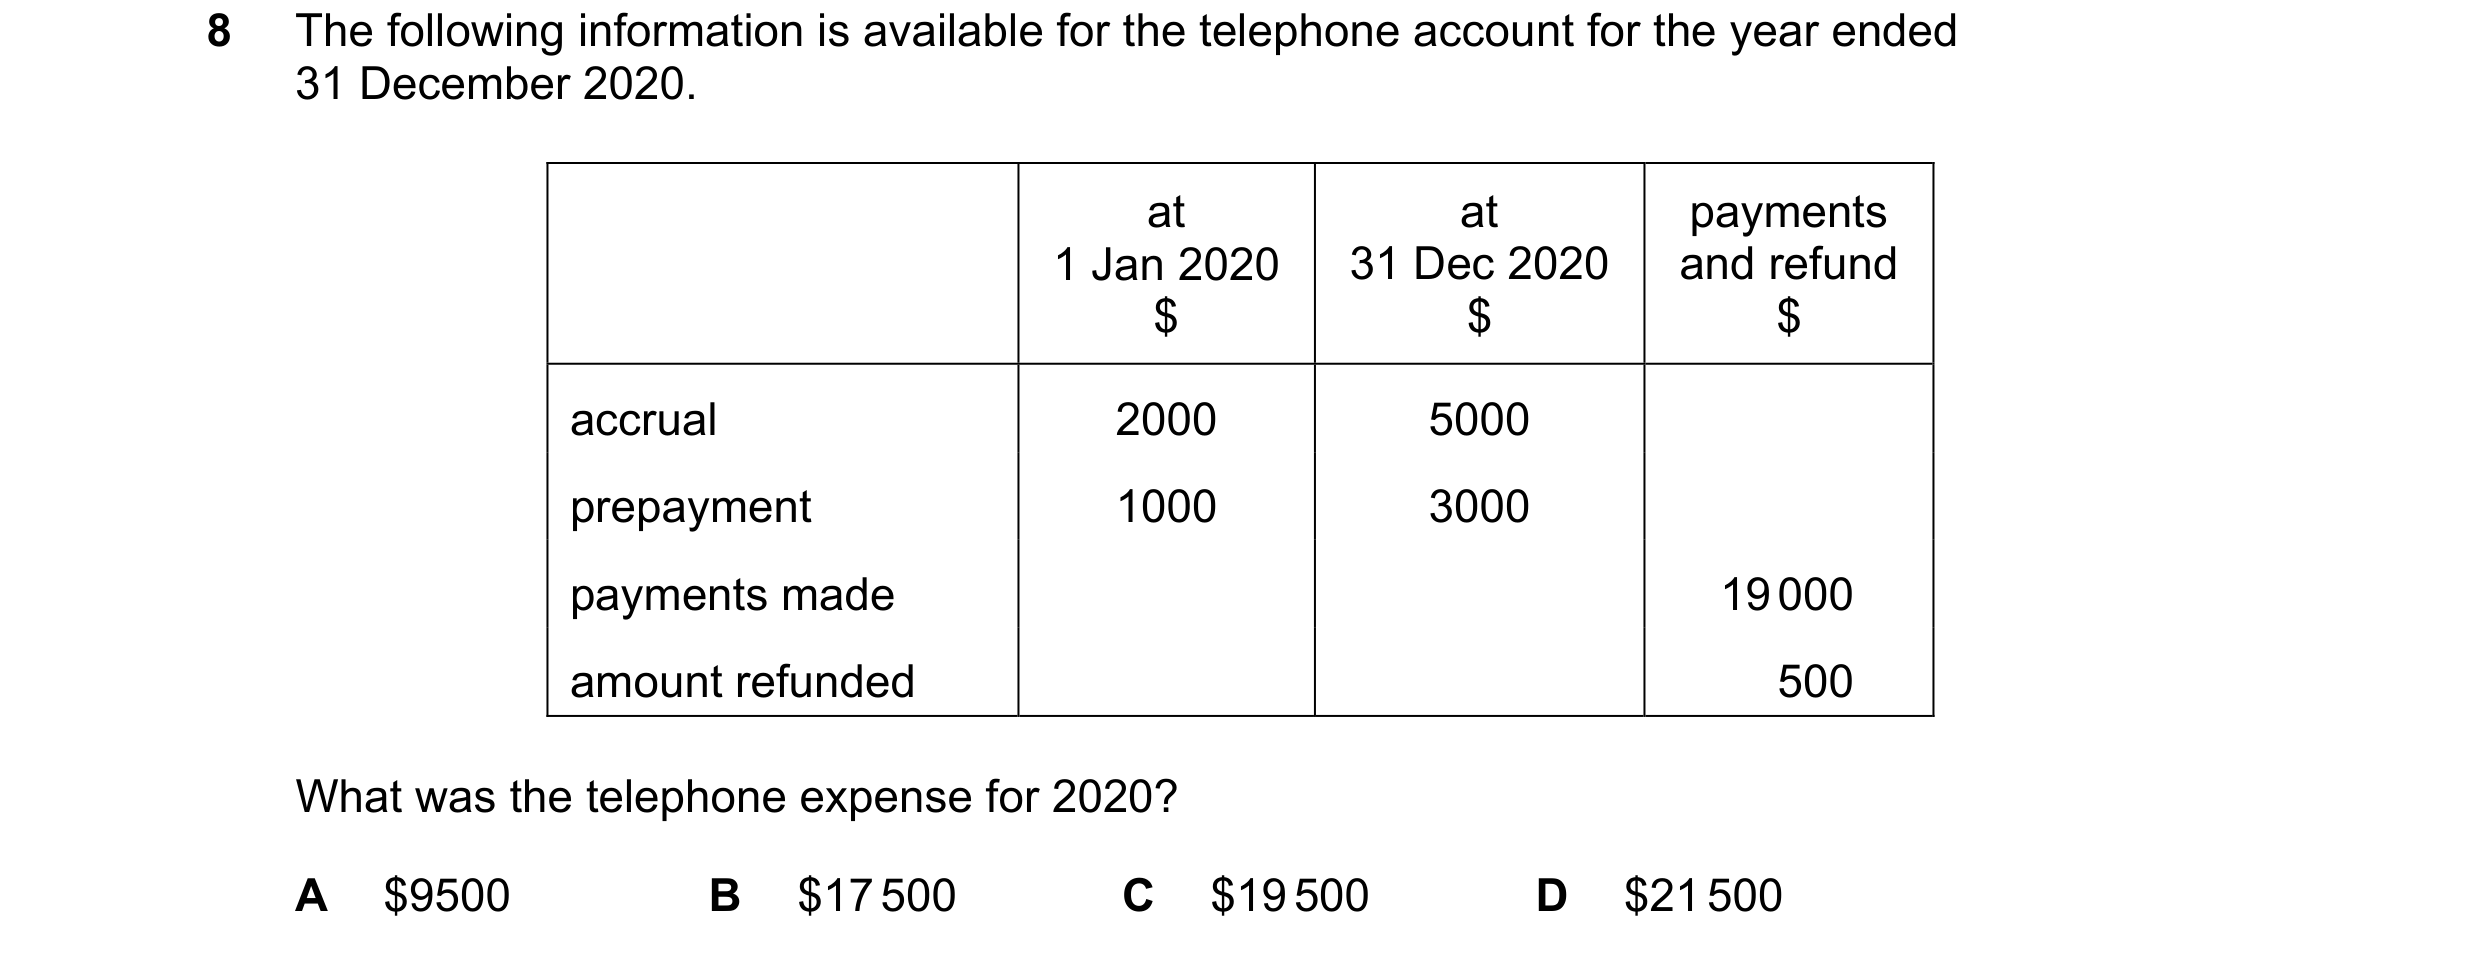 46 / 58
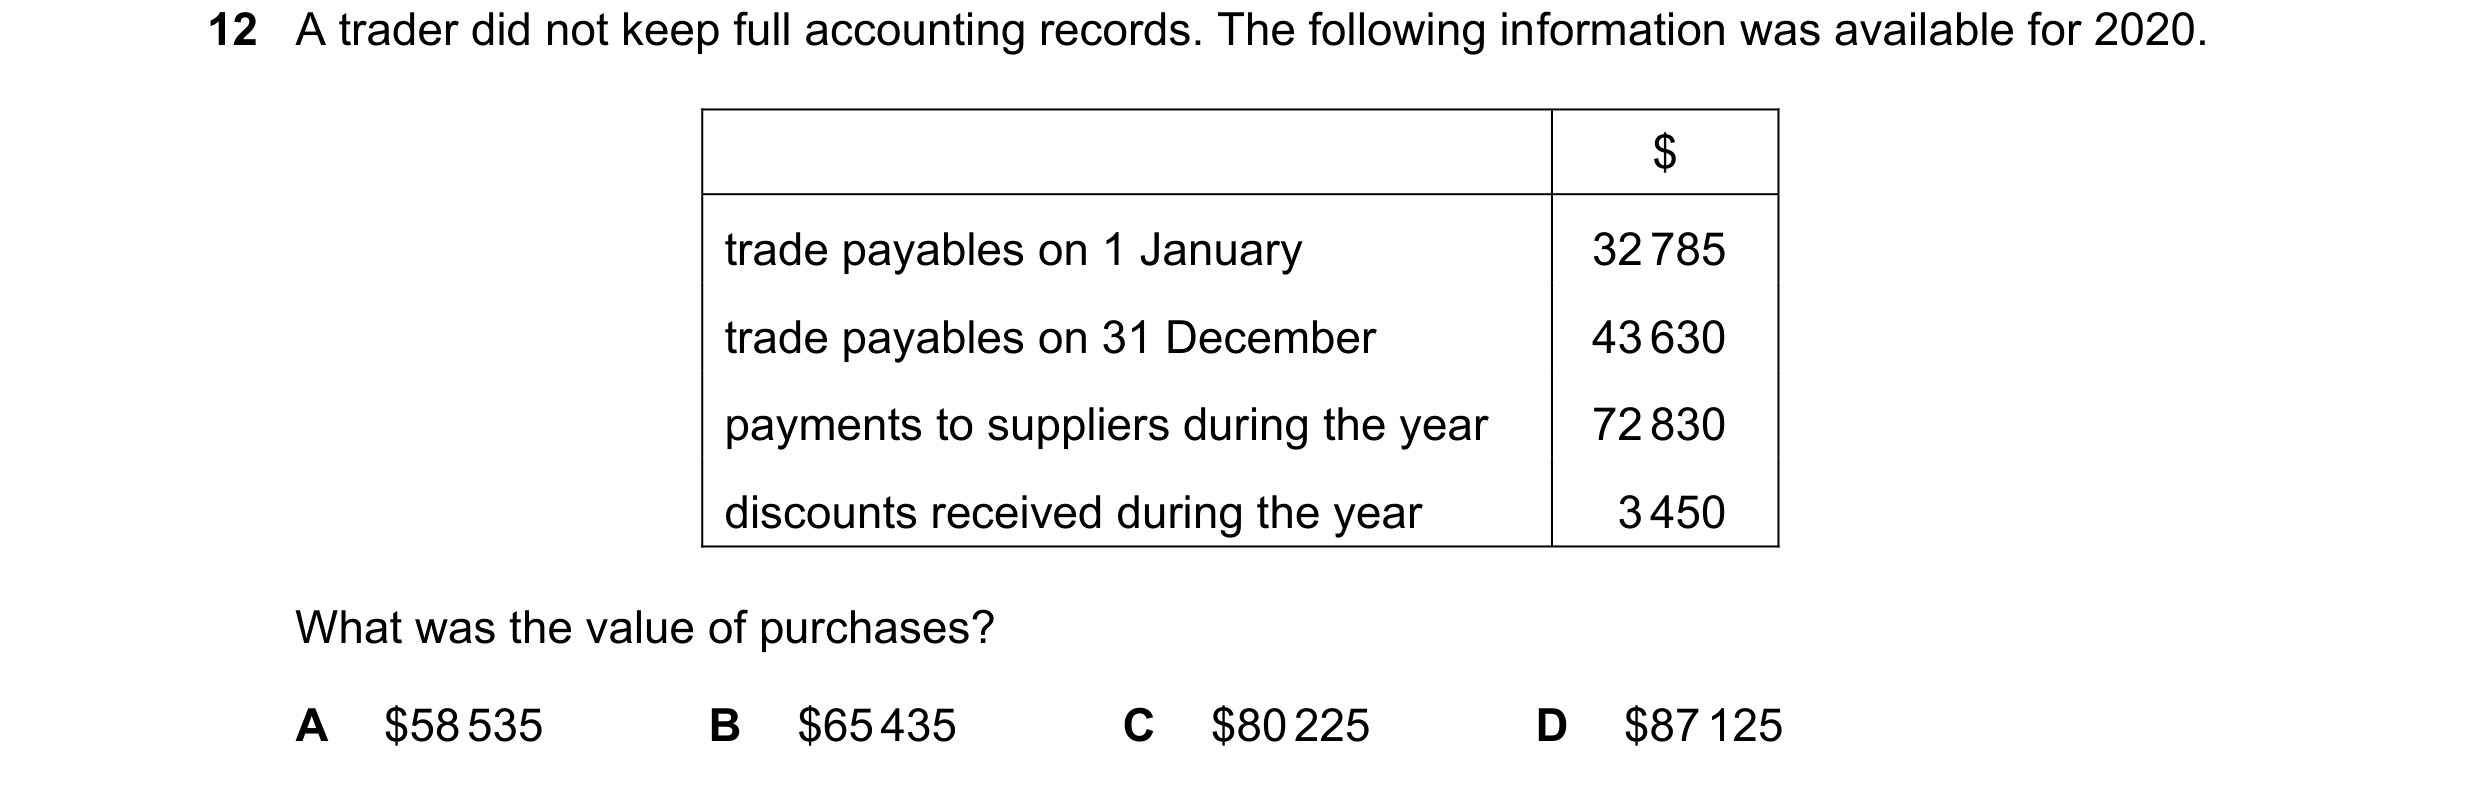
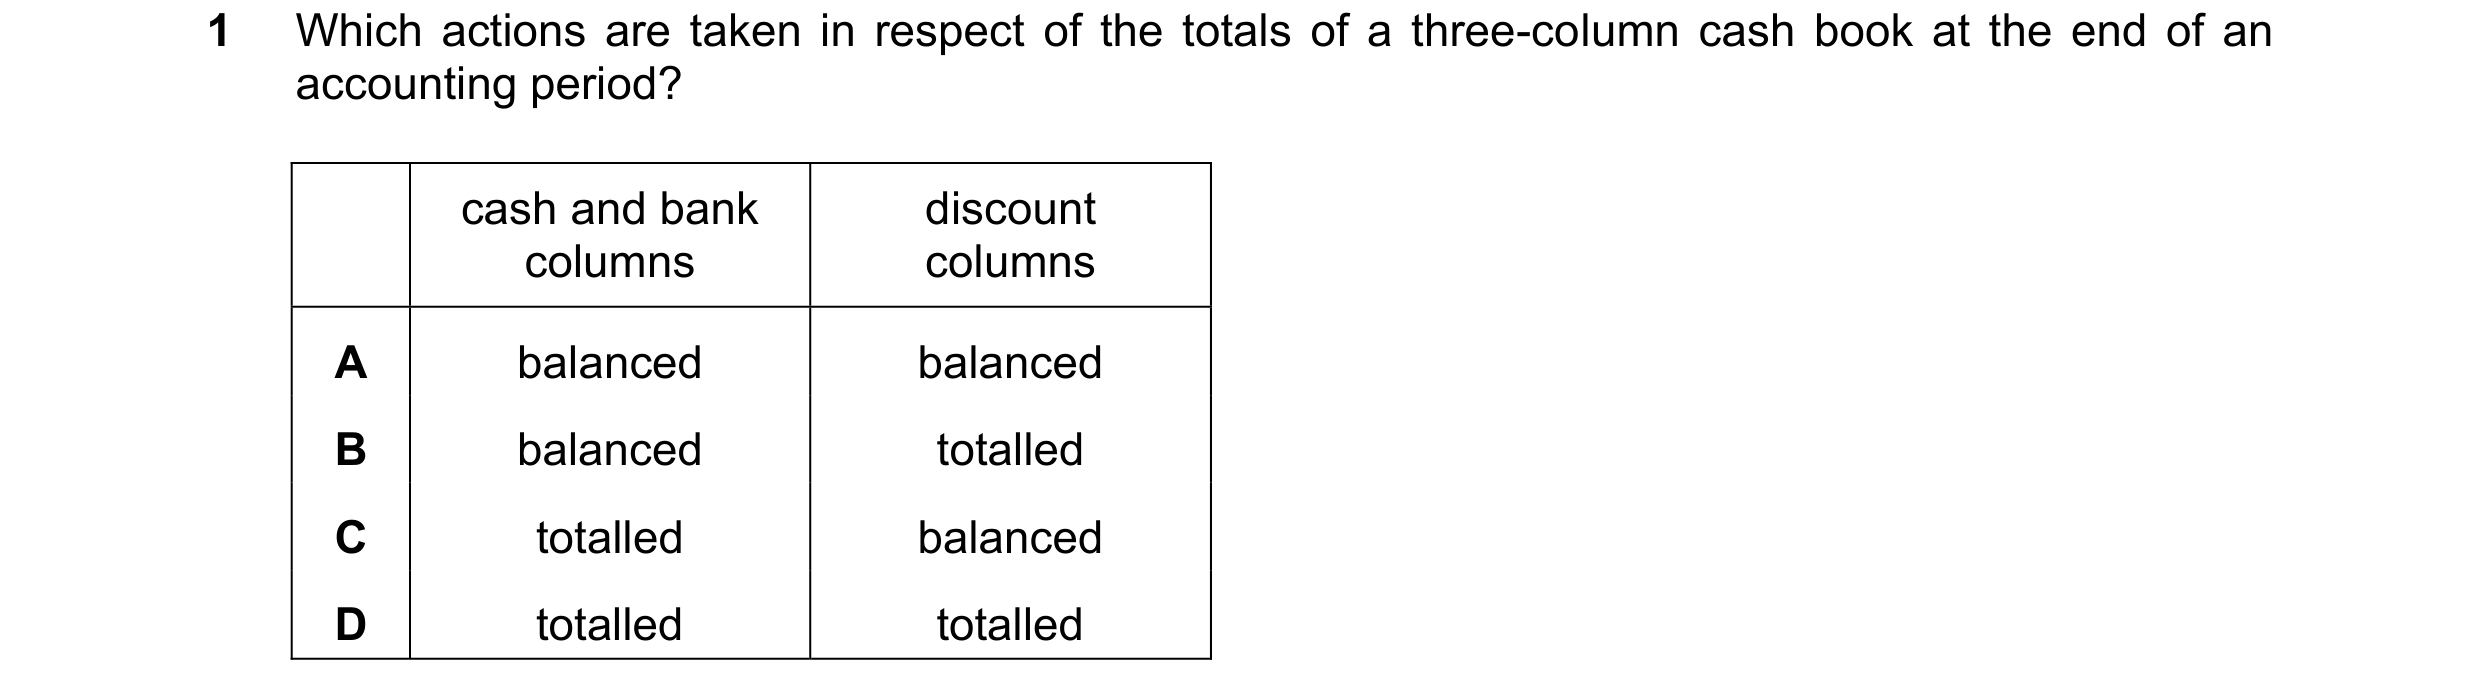
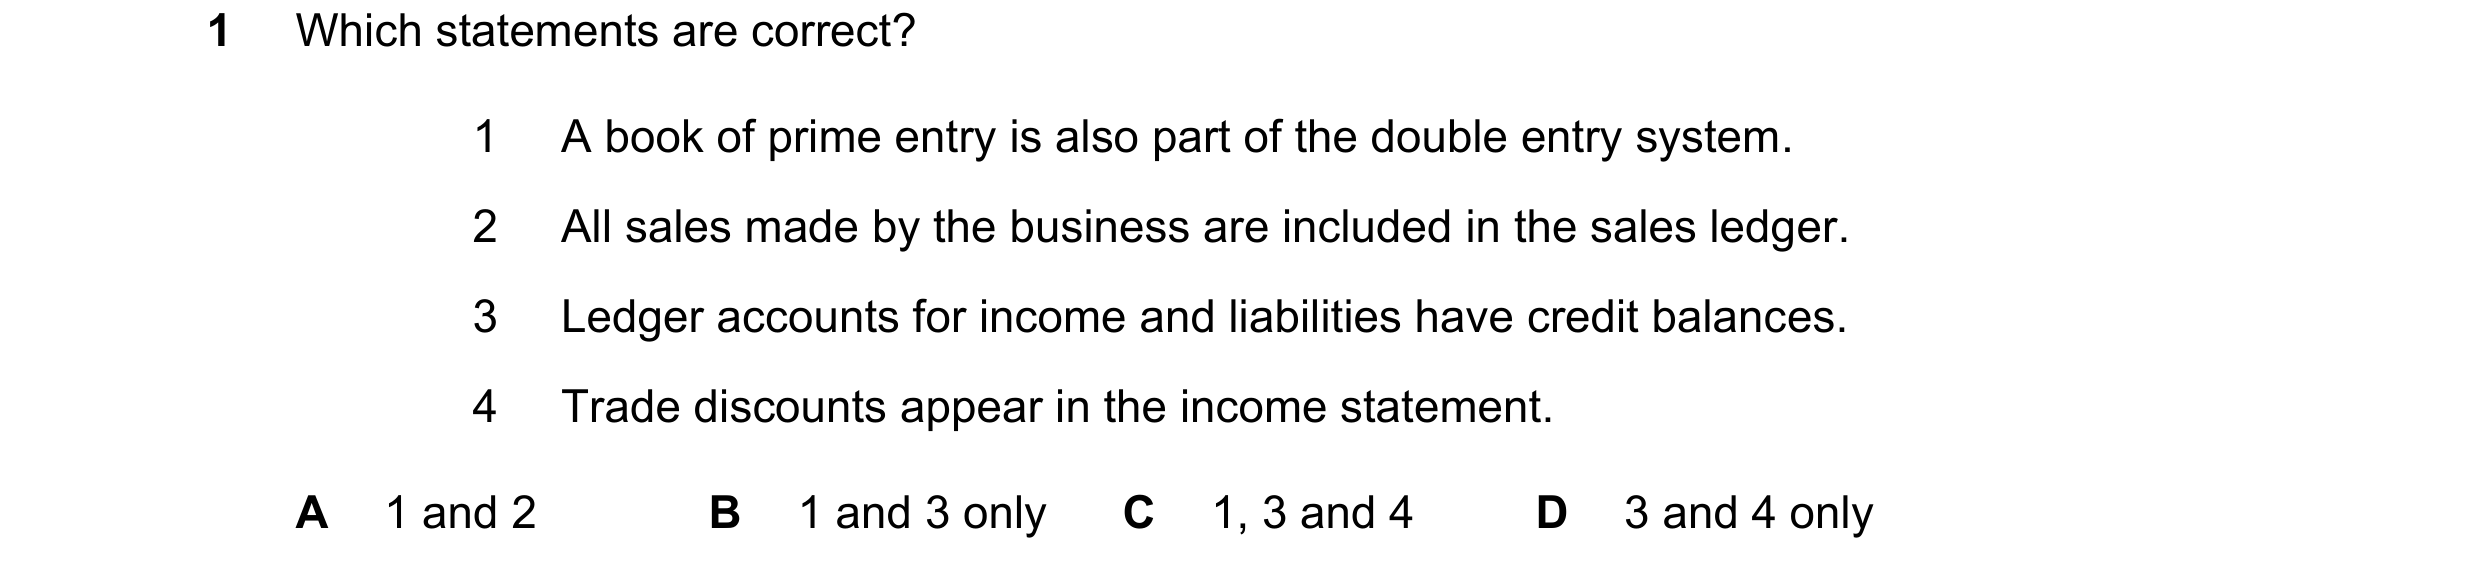
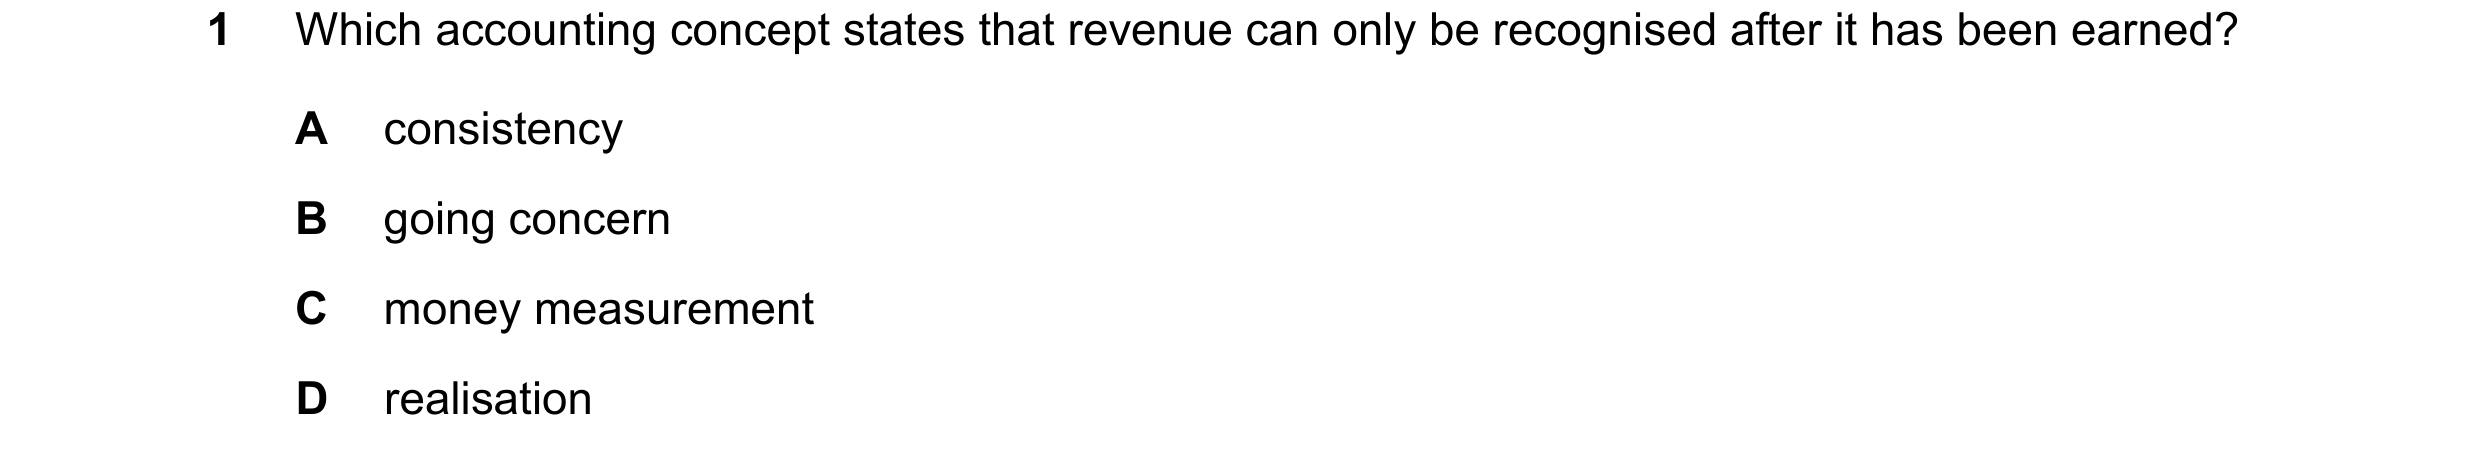
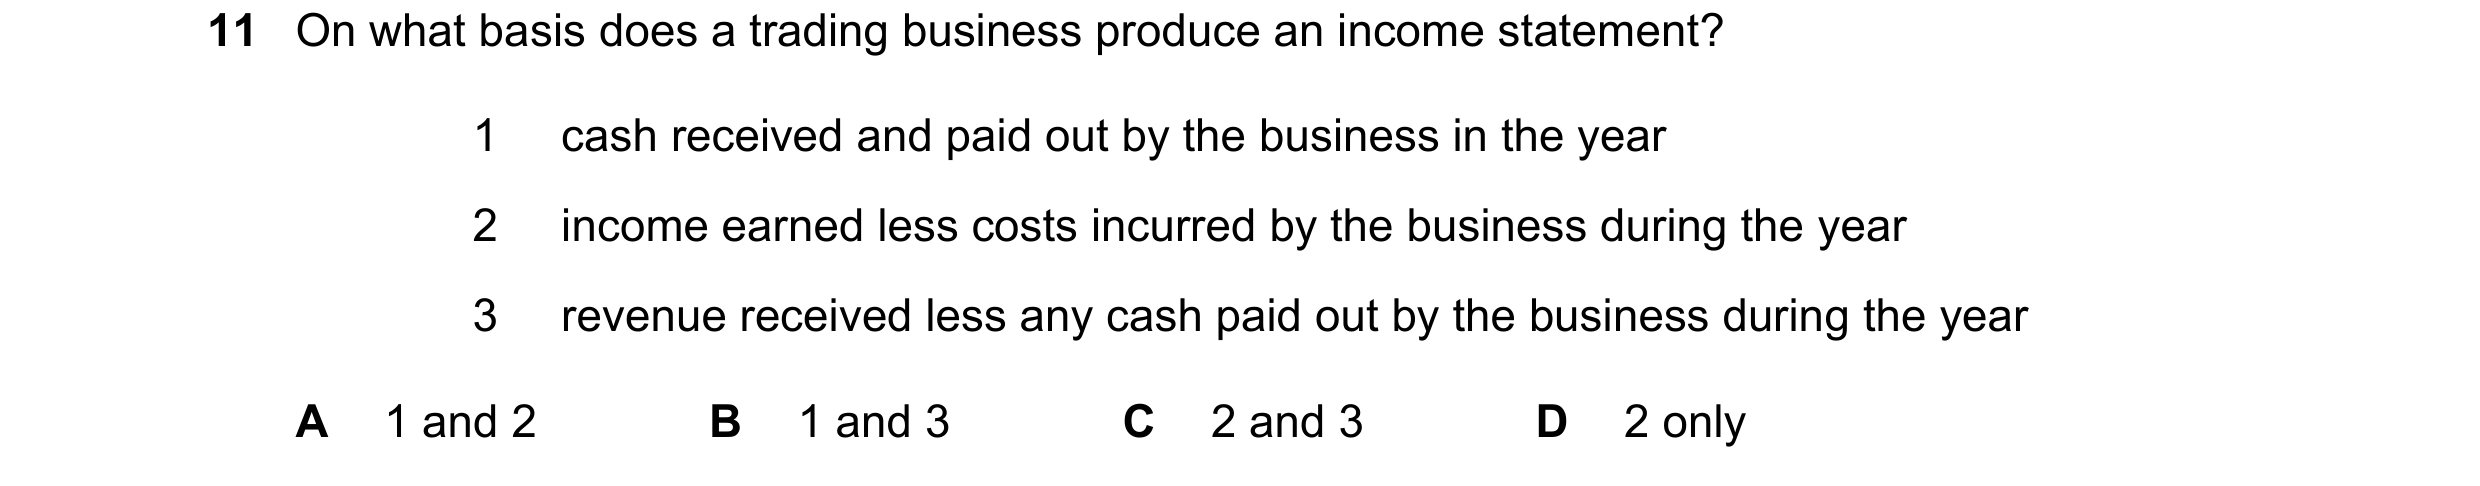 47 / 58
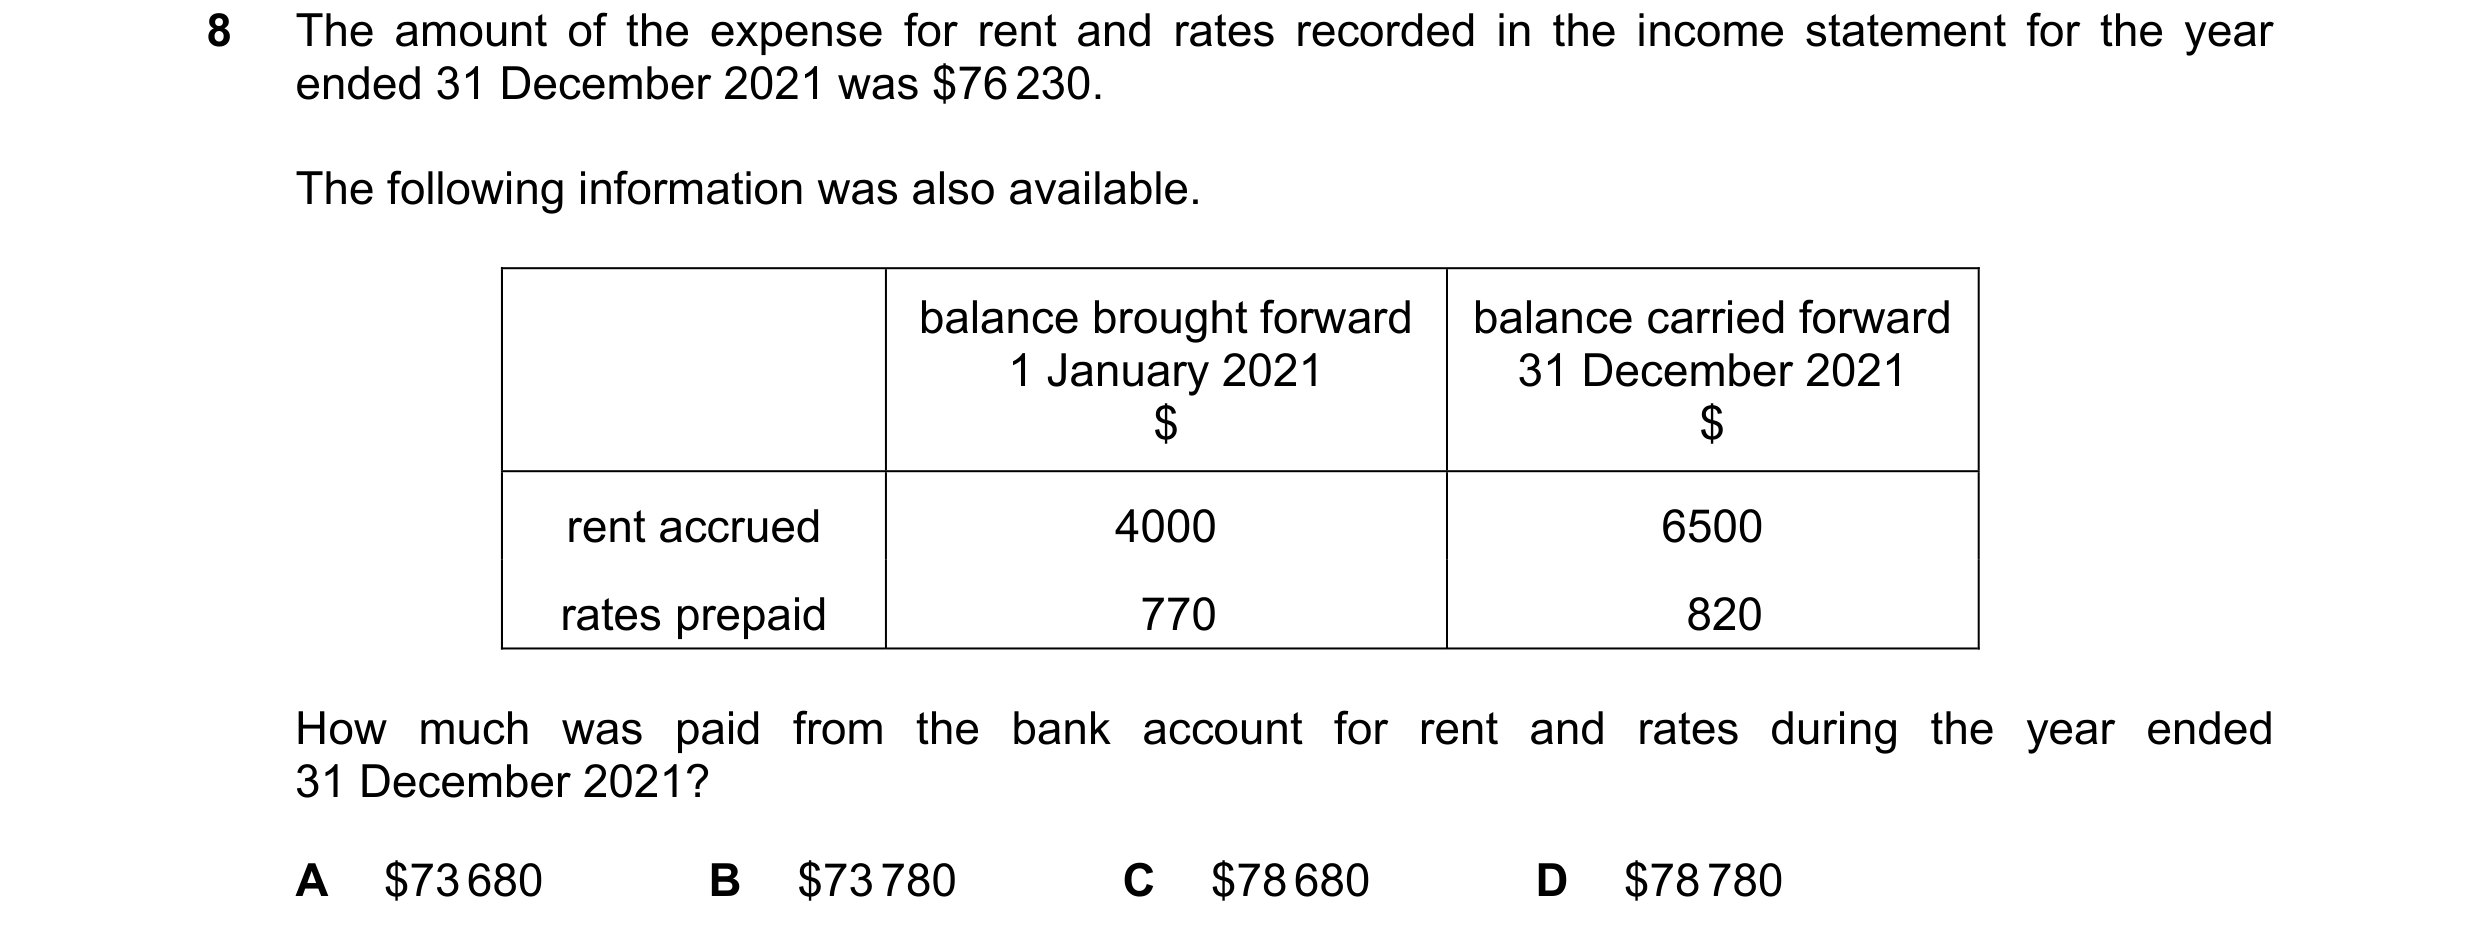
 48 / 58
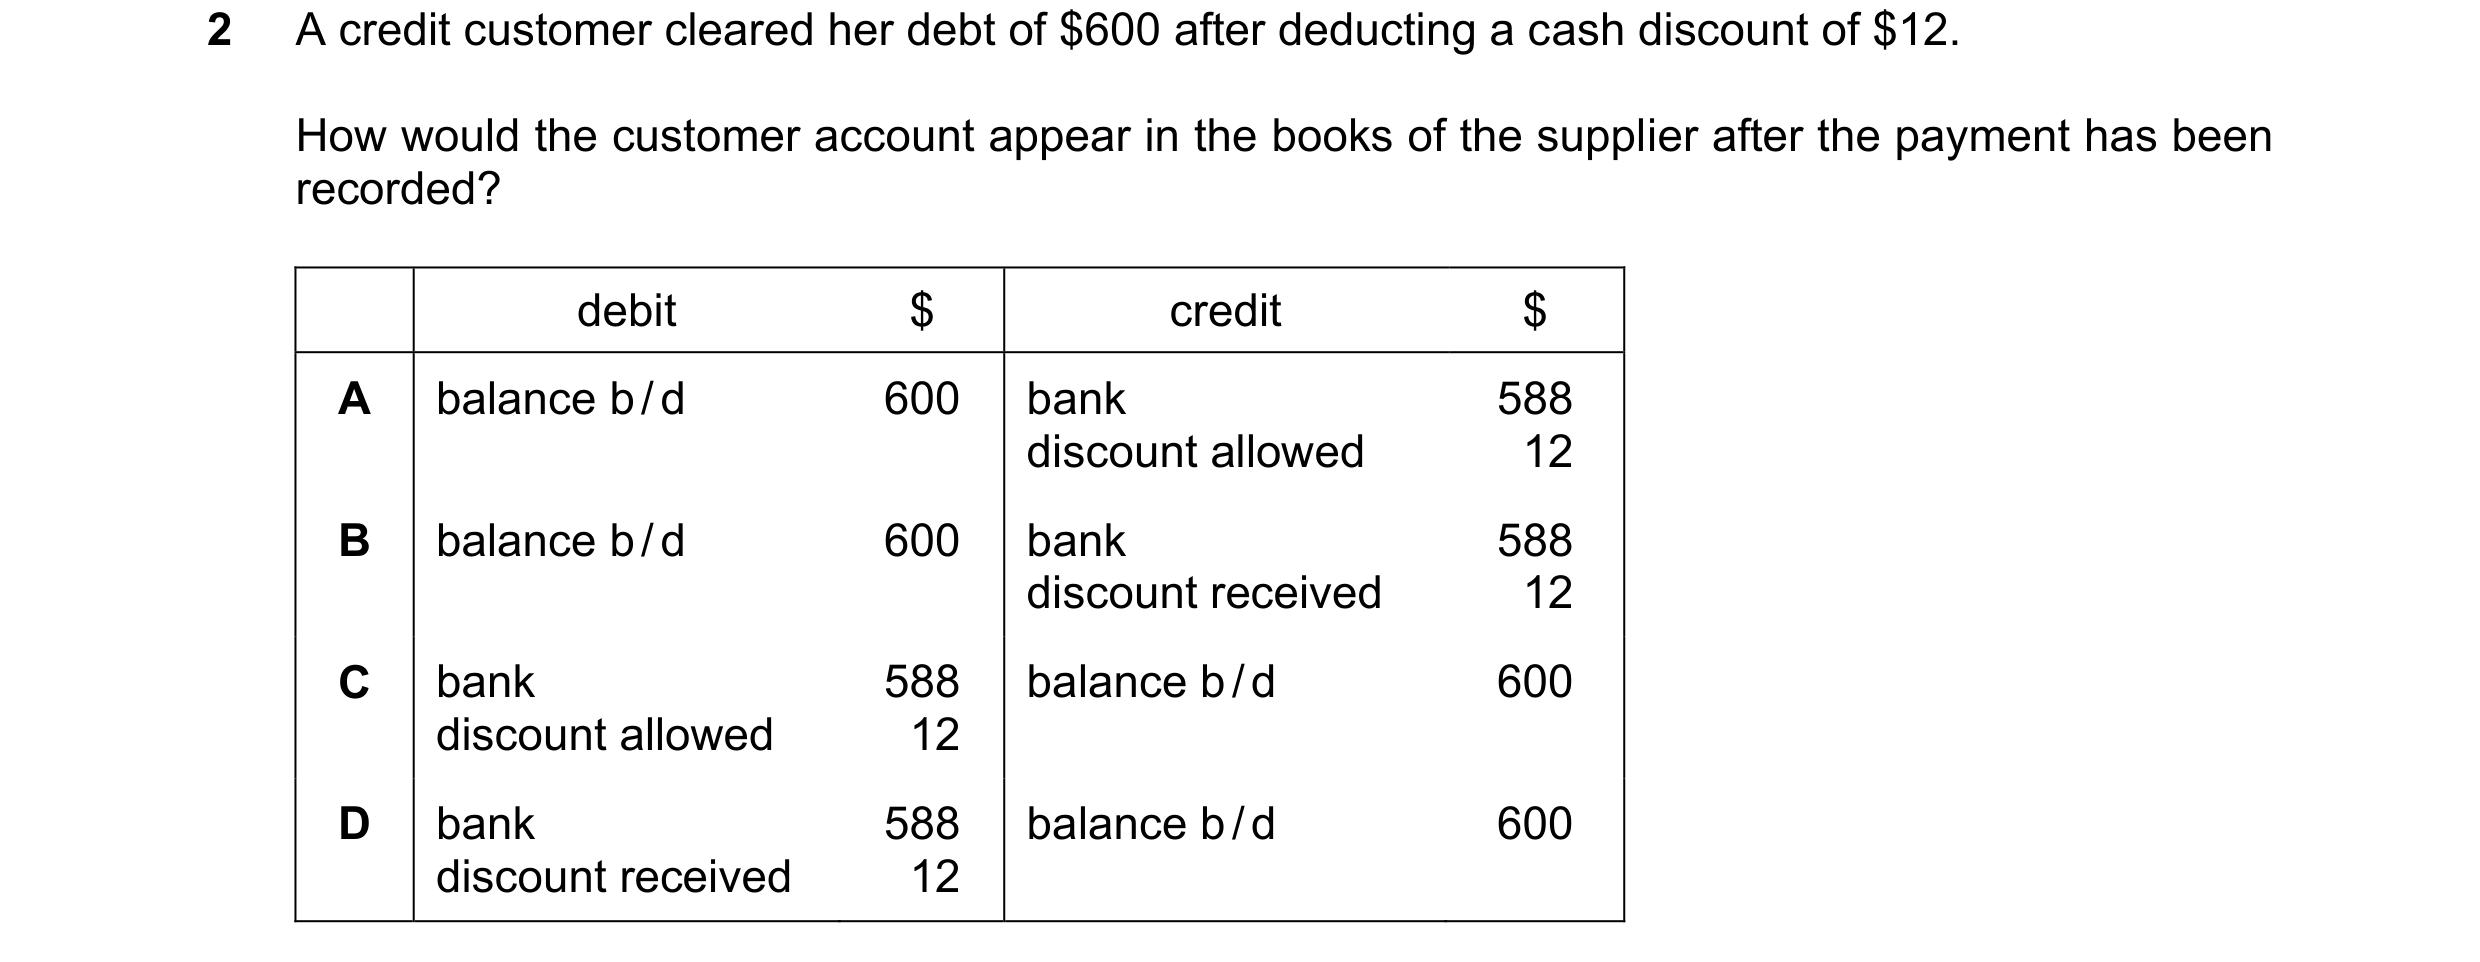 49 / 58
 50 / 58
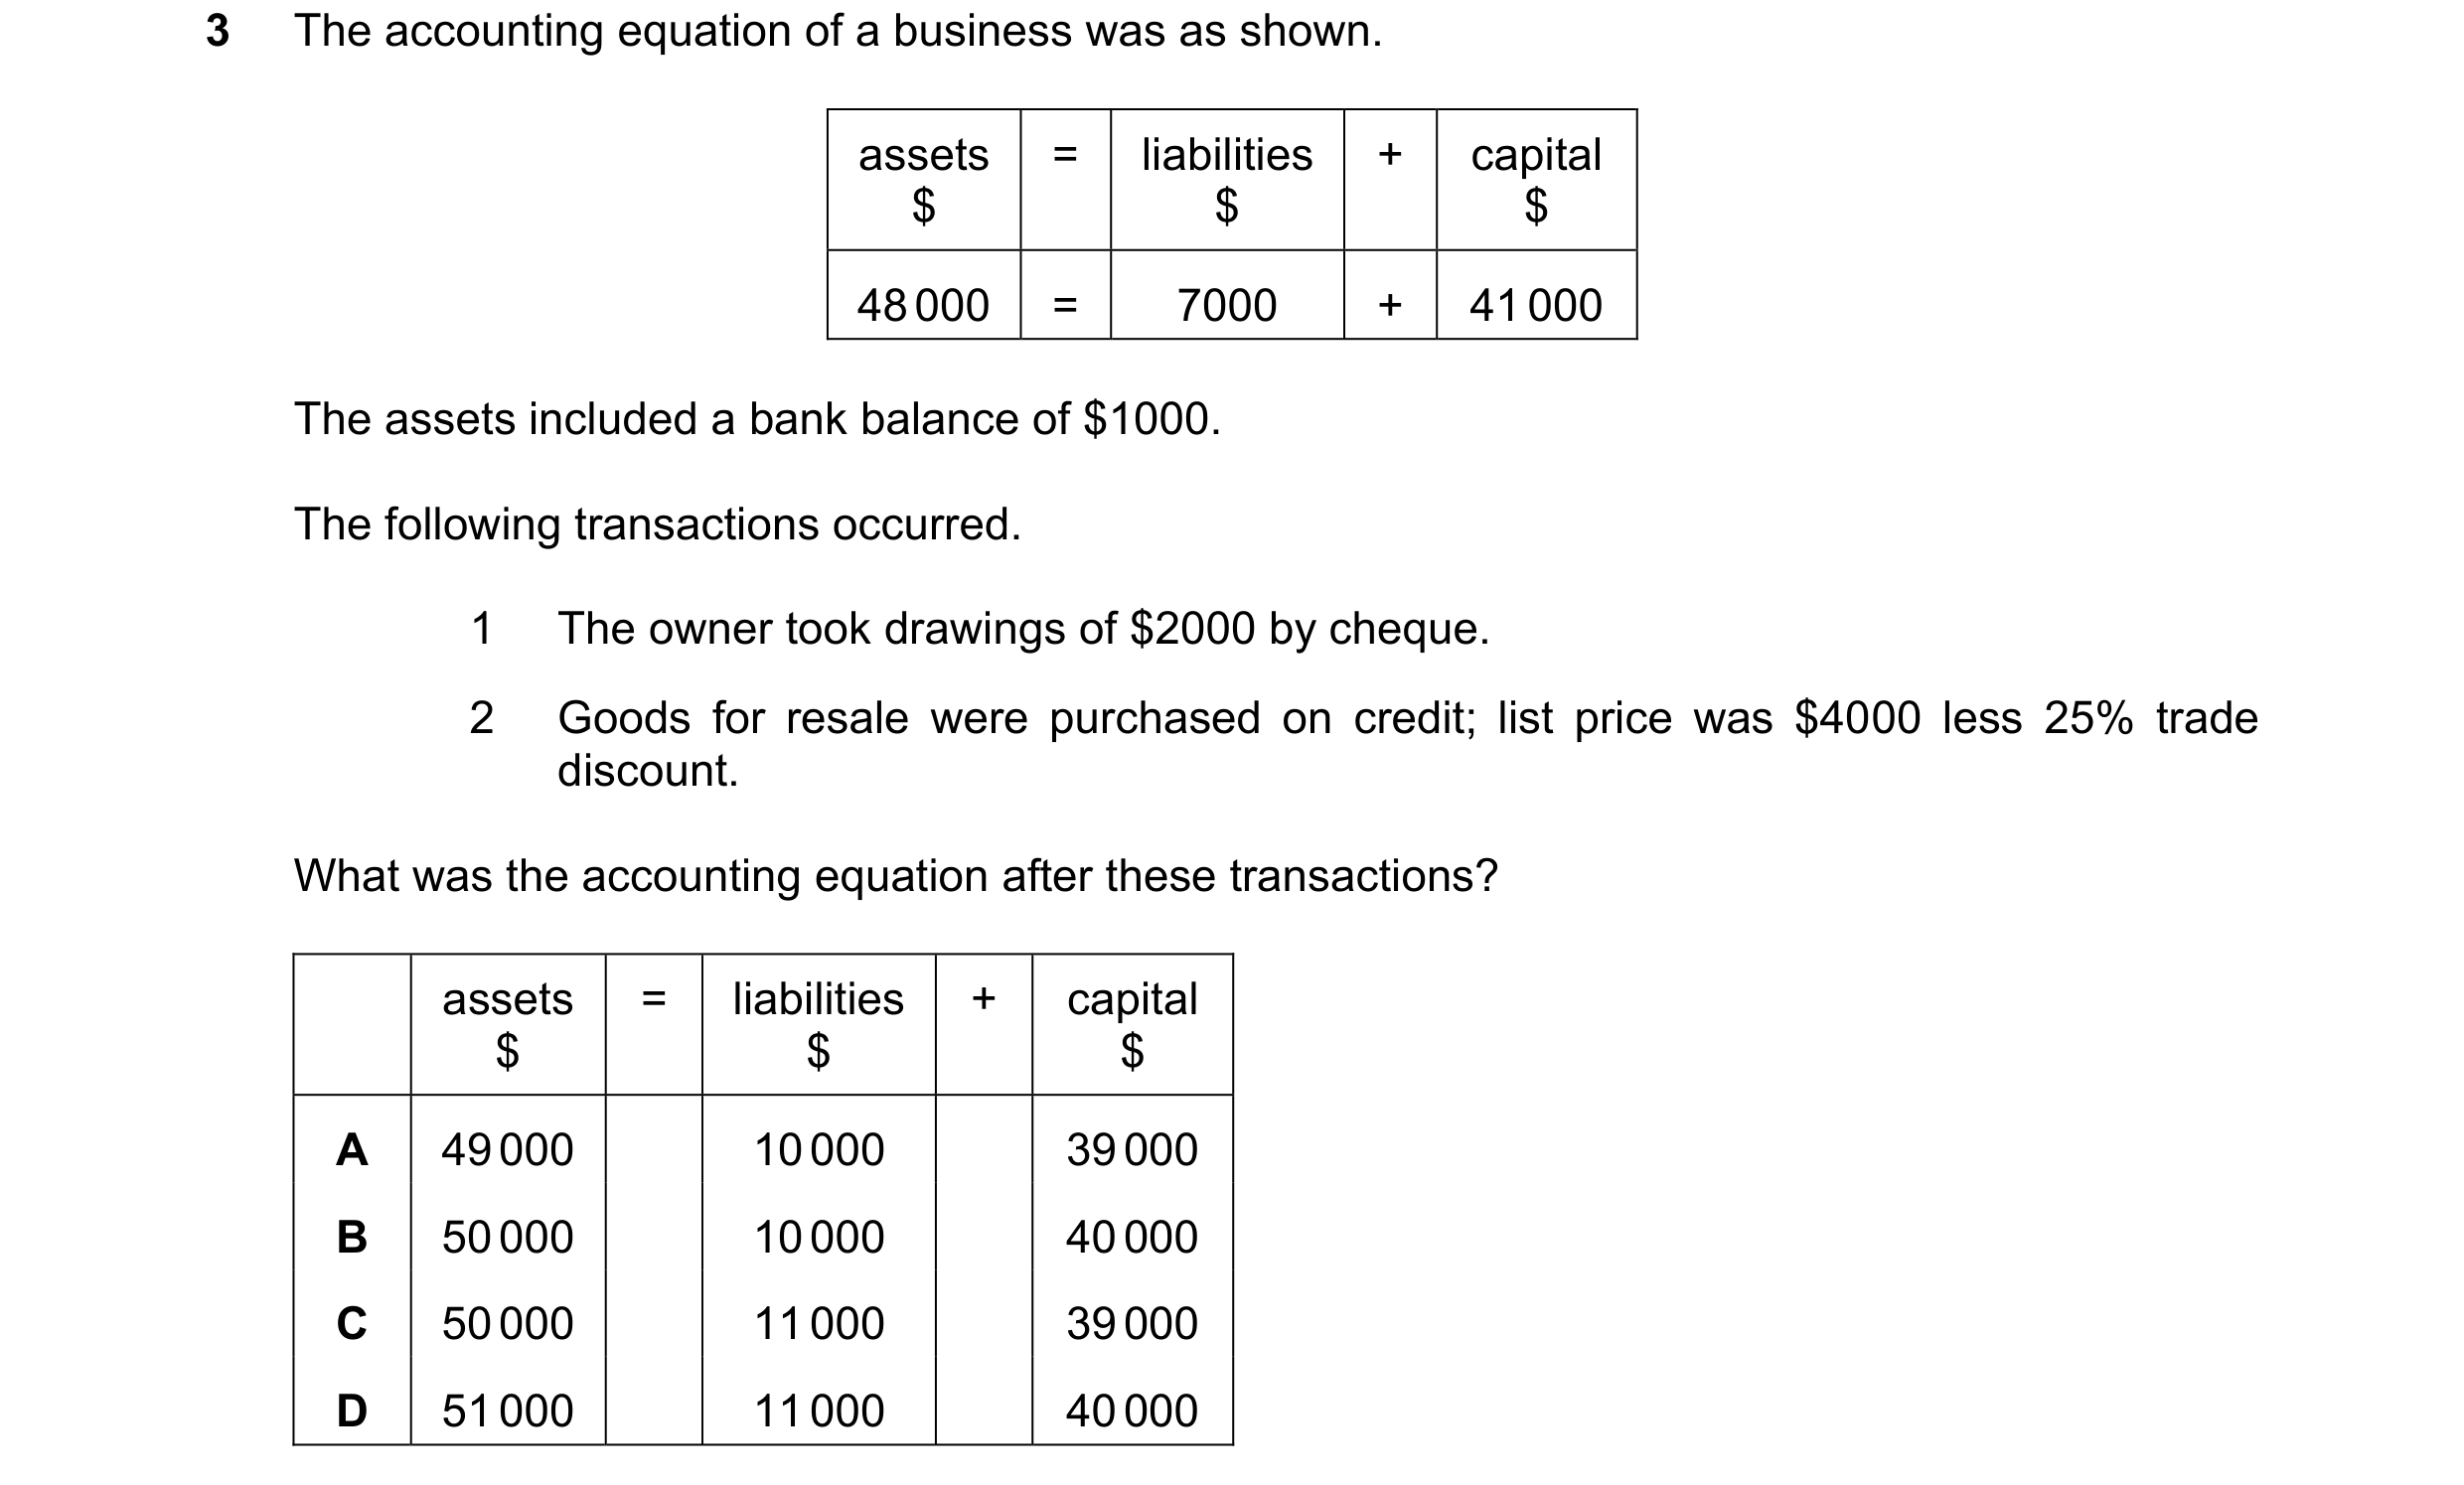
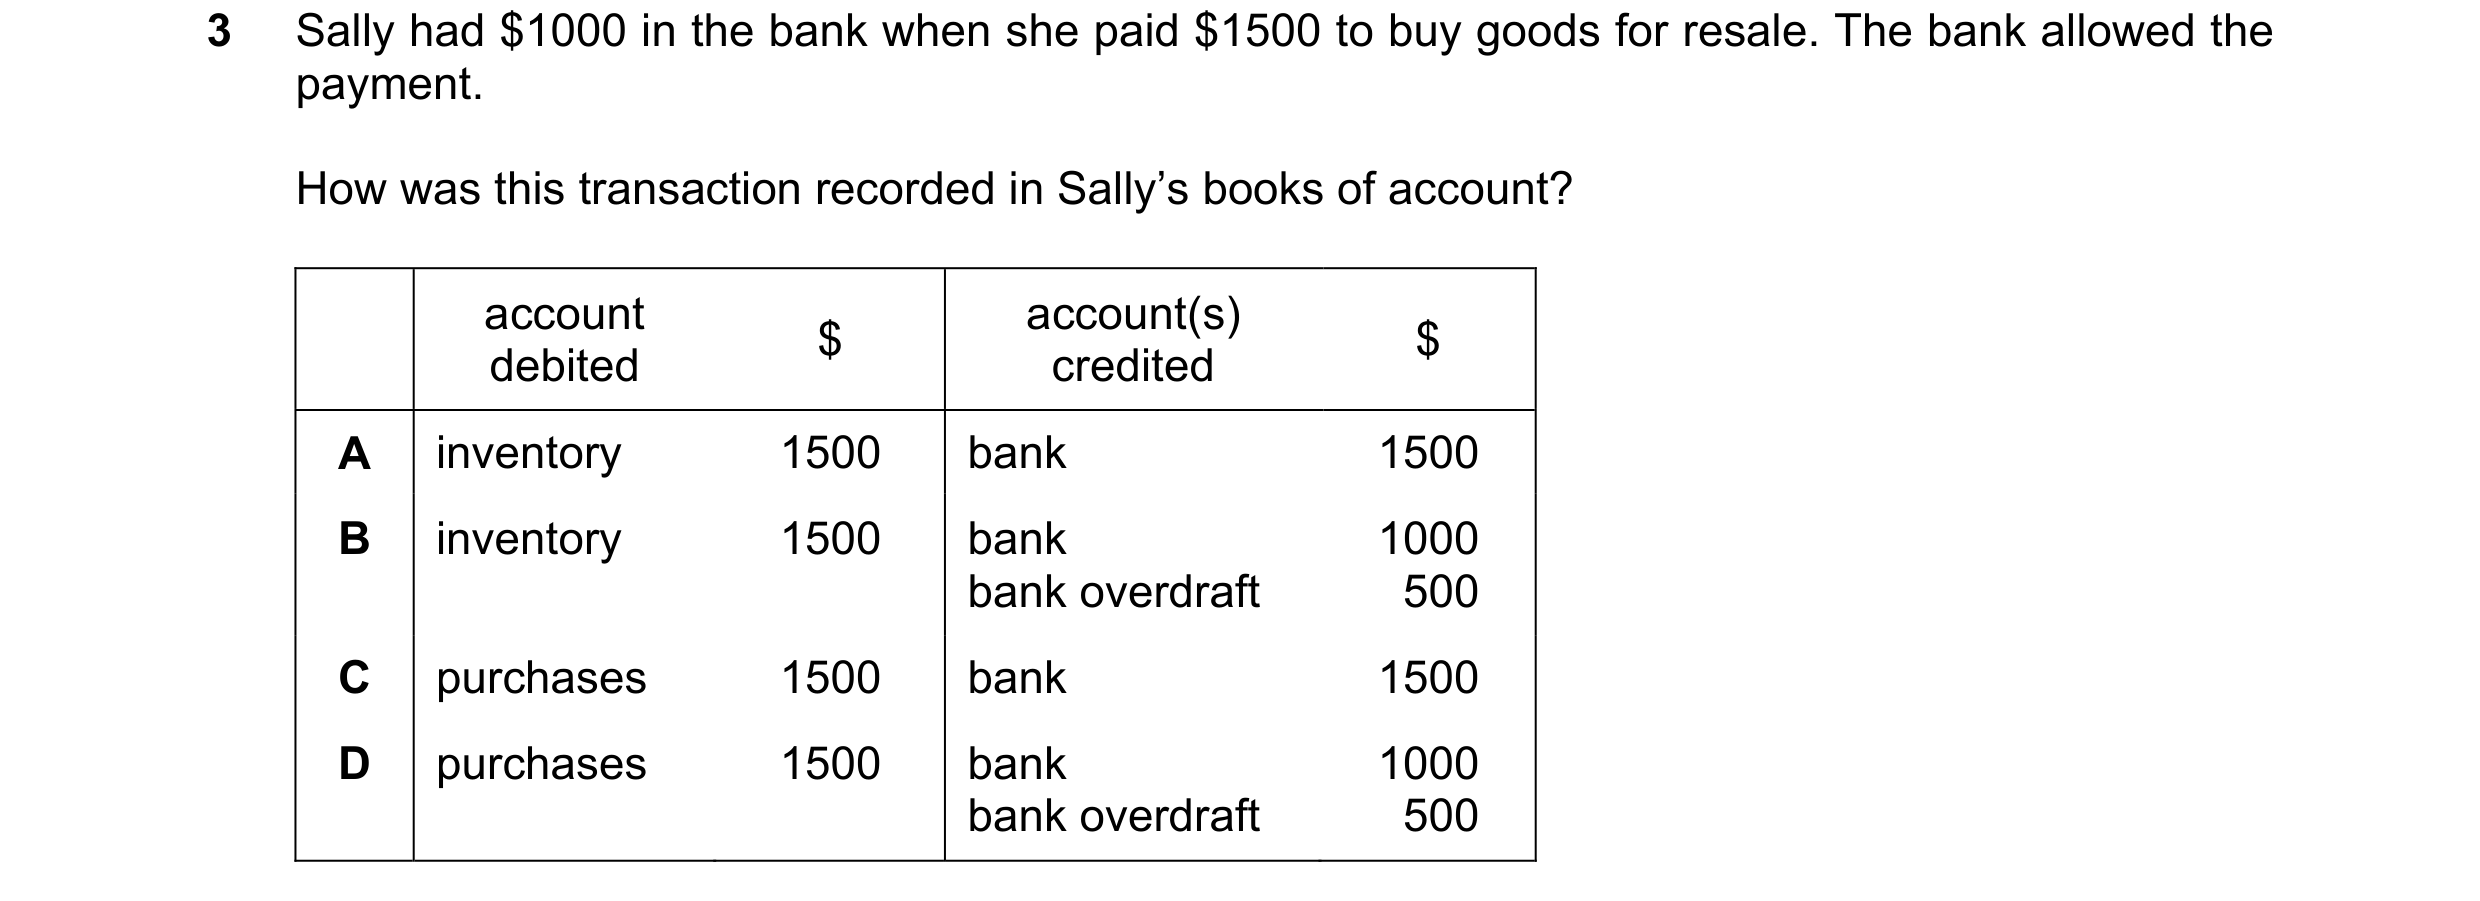 51 / 58
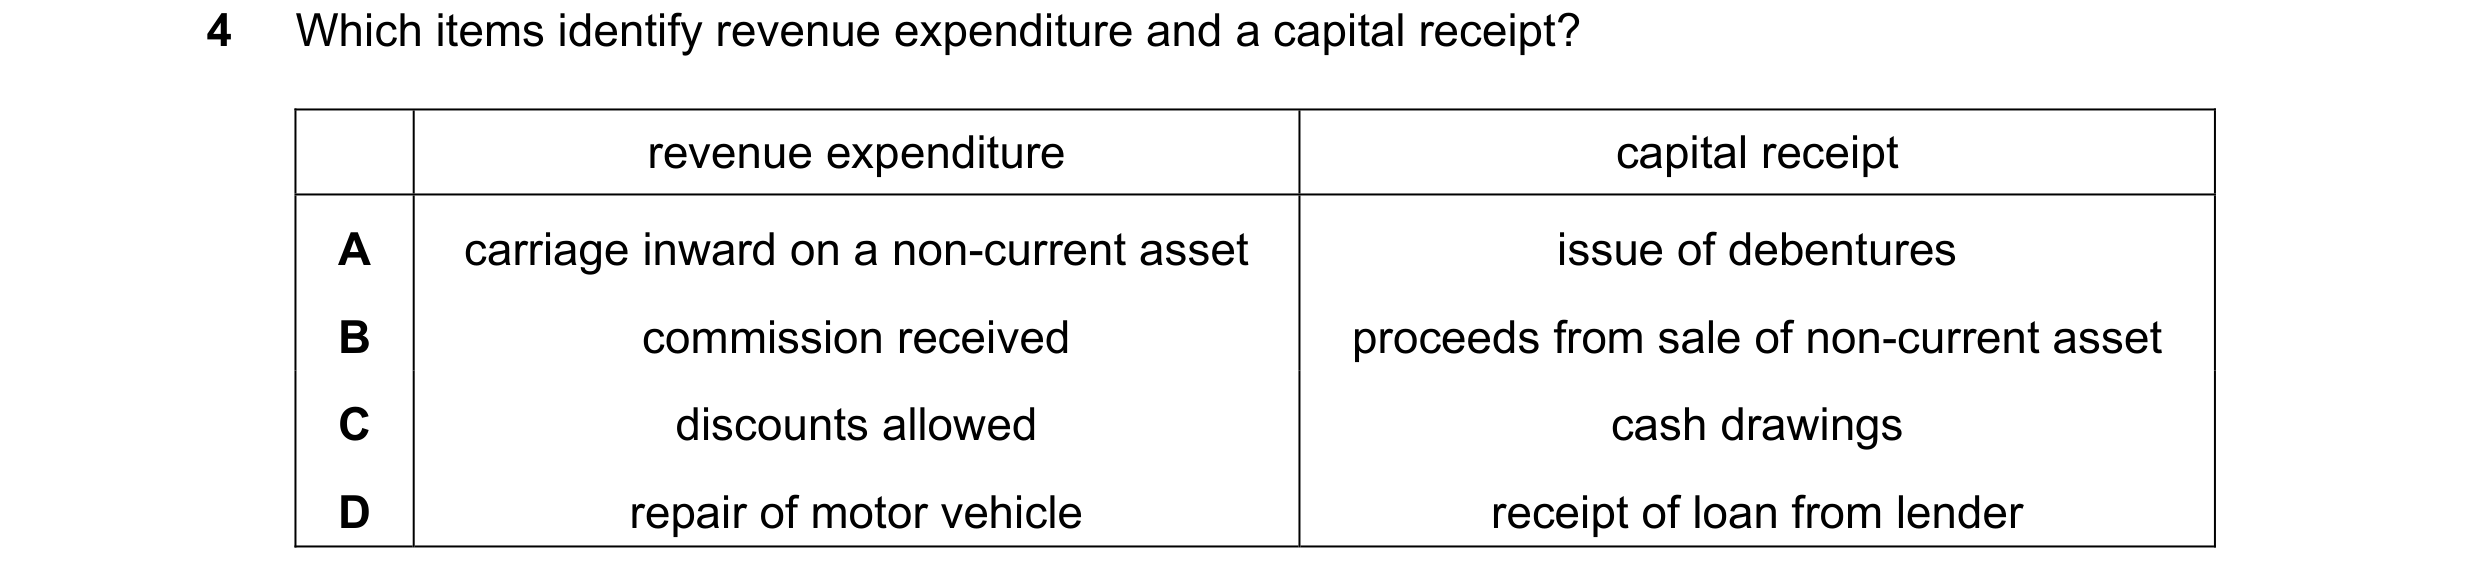
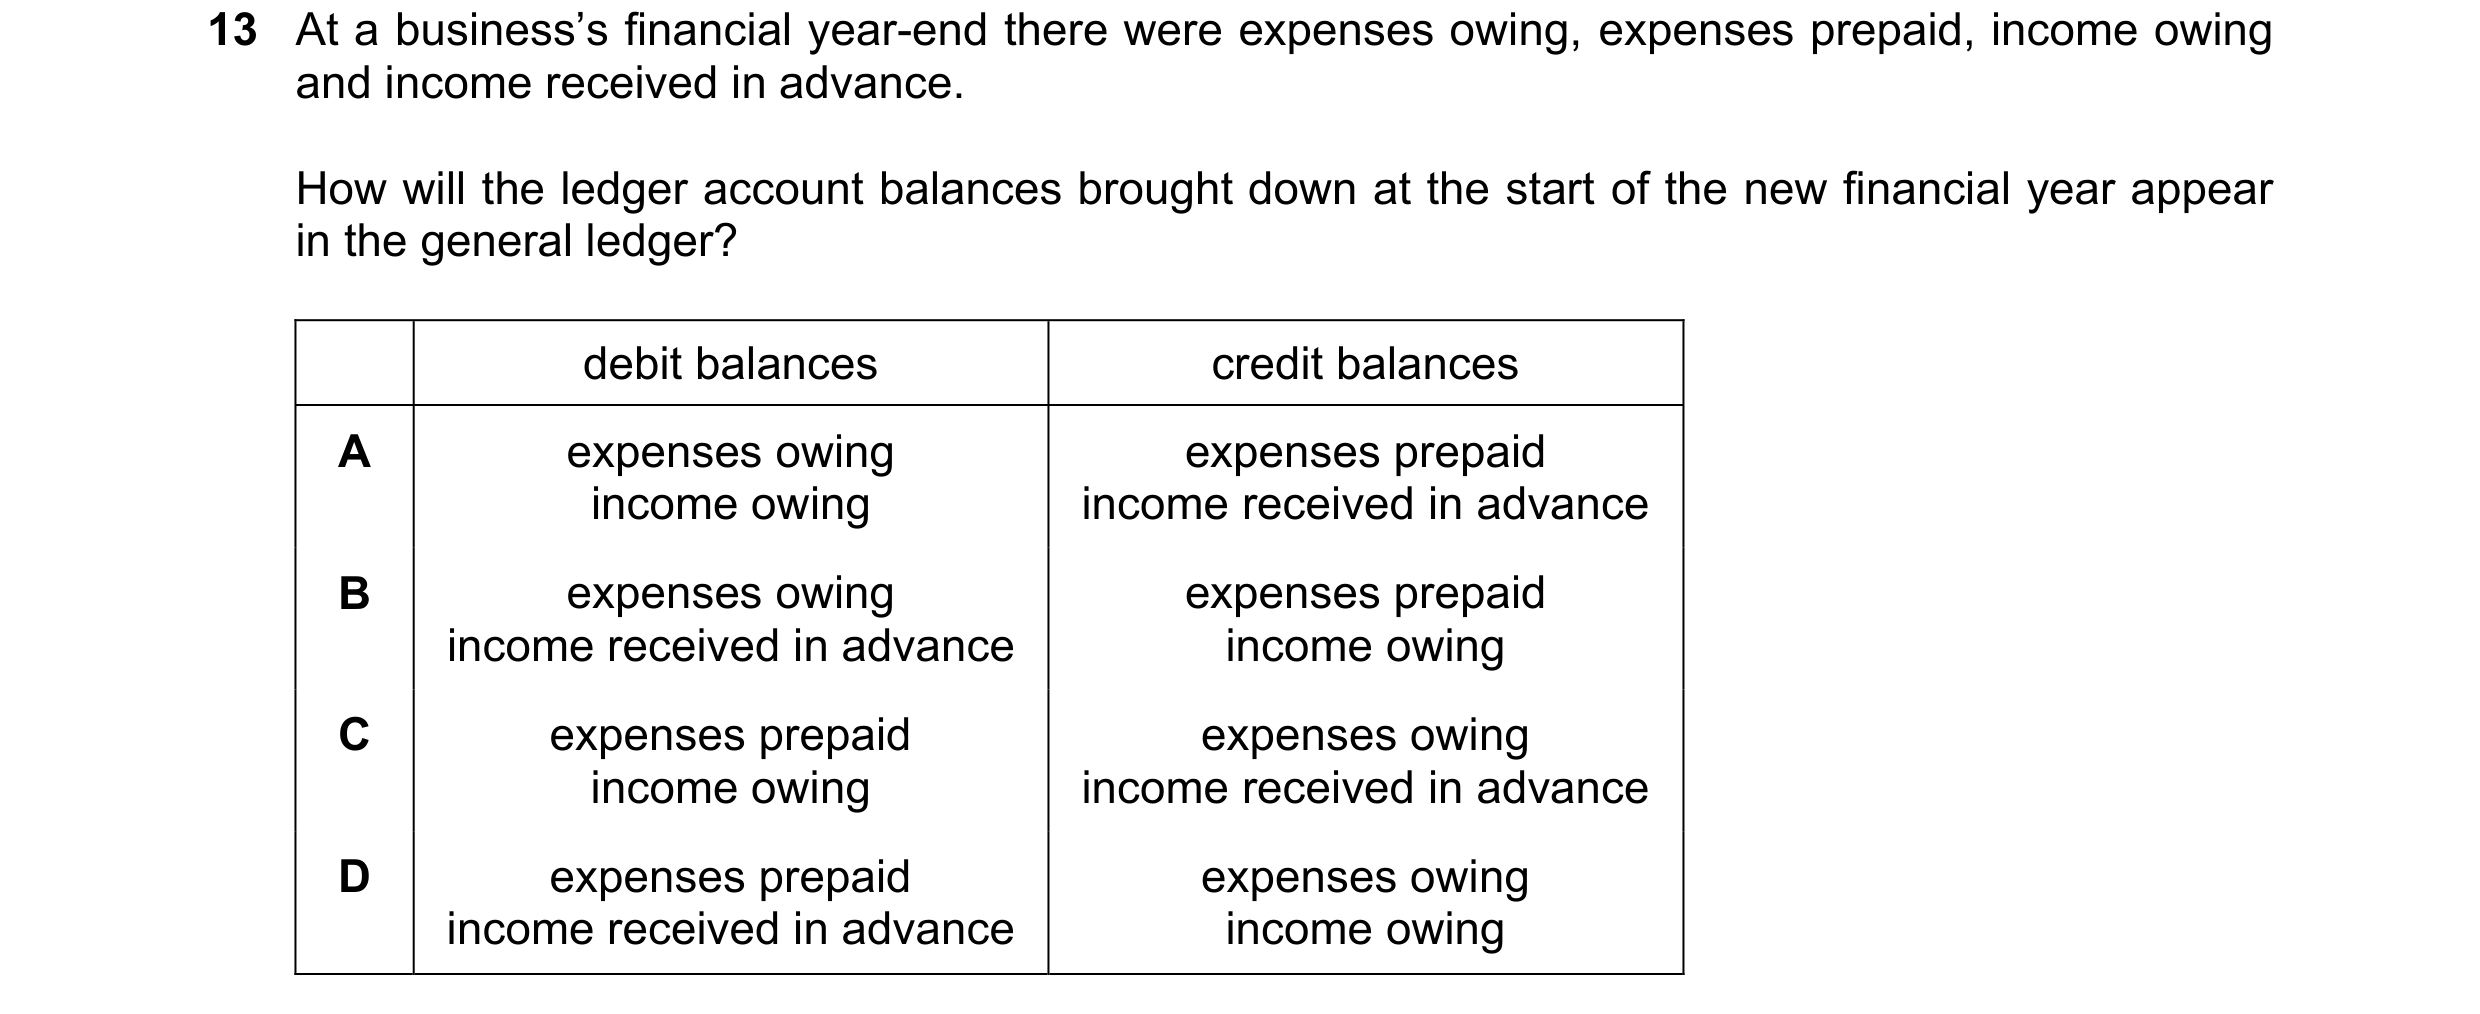
 52 / 58
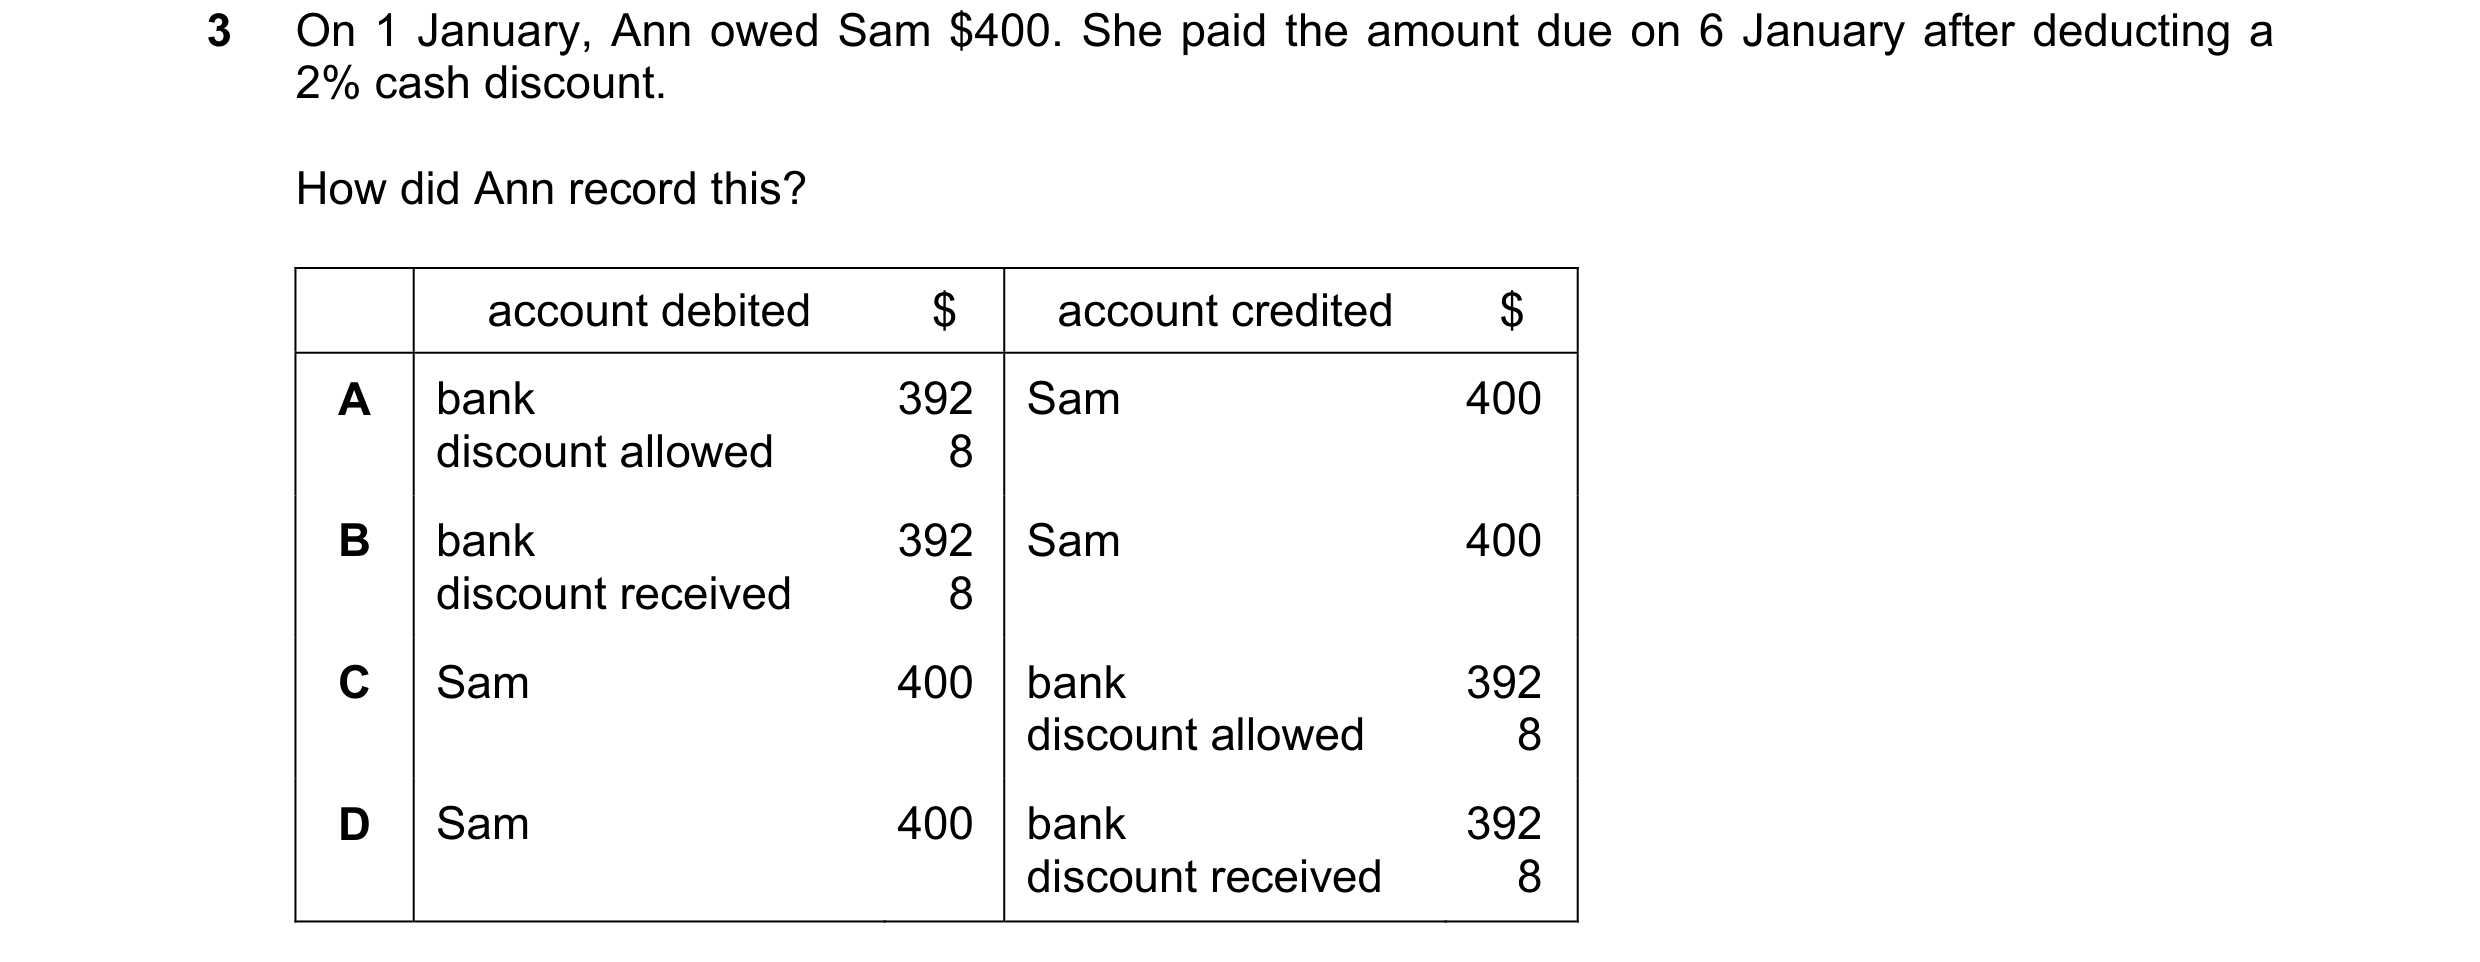
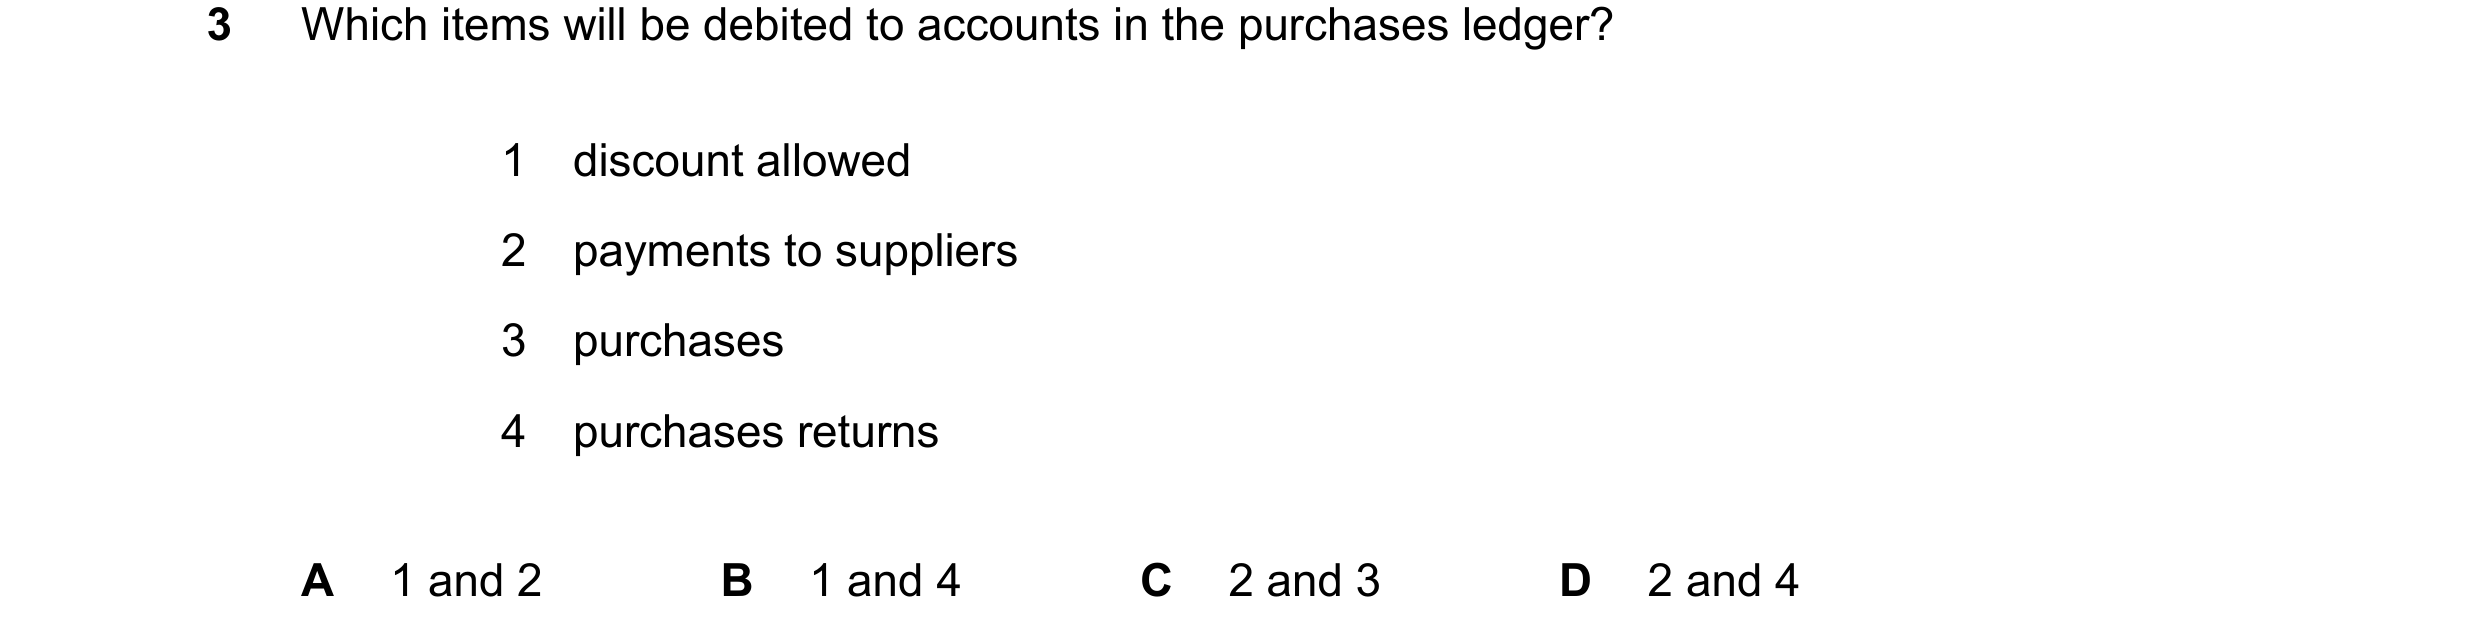
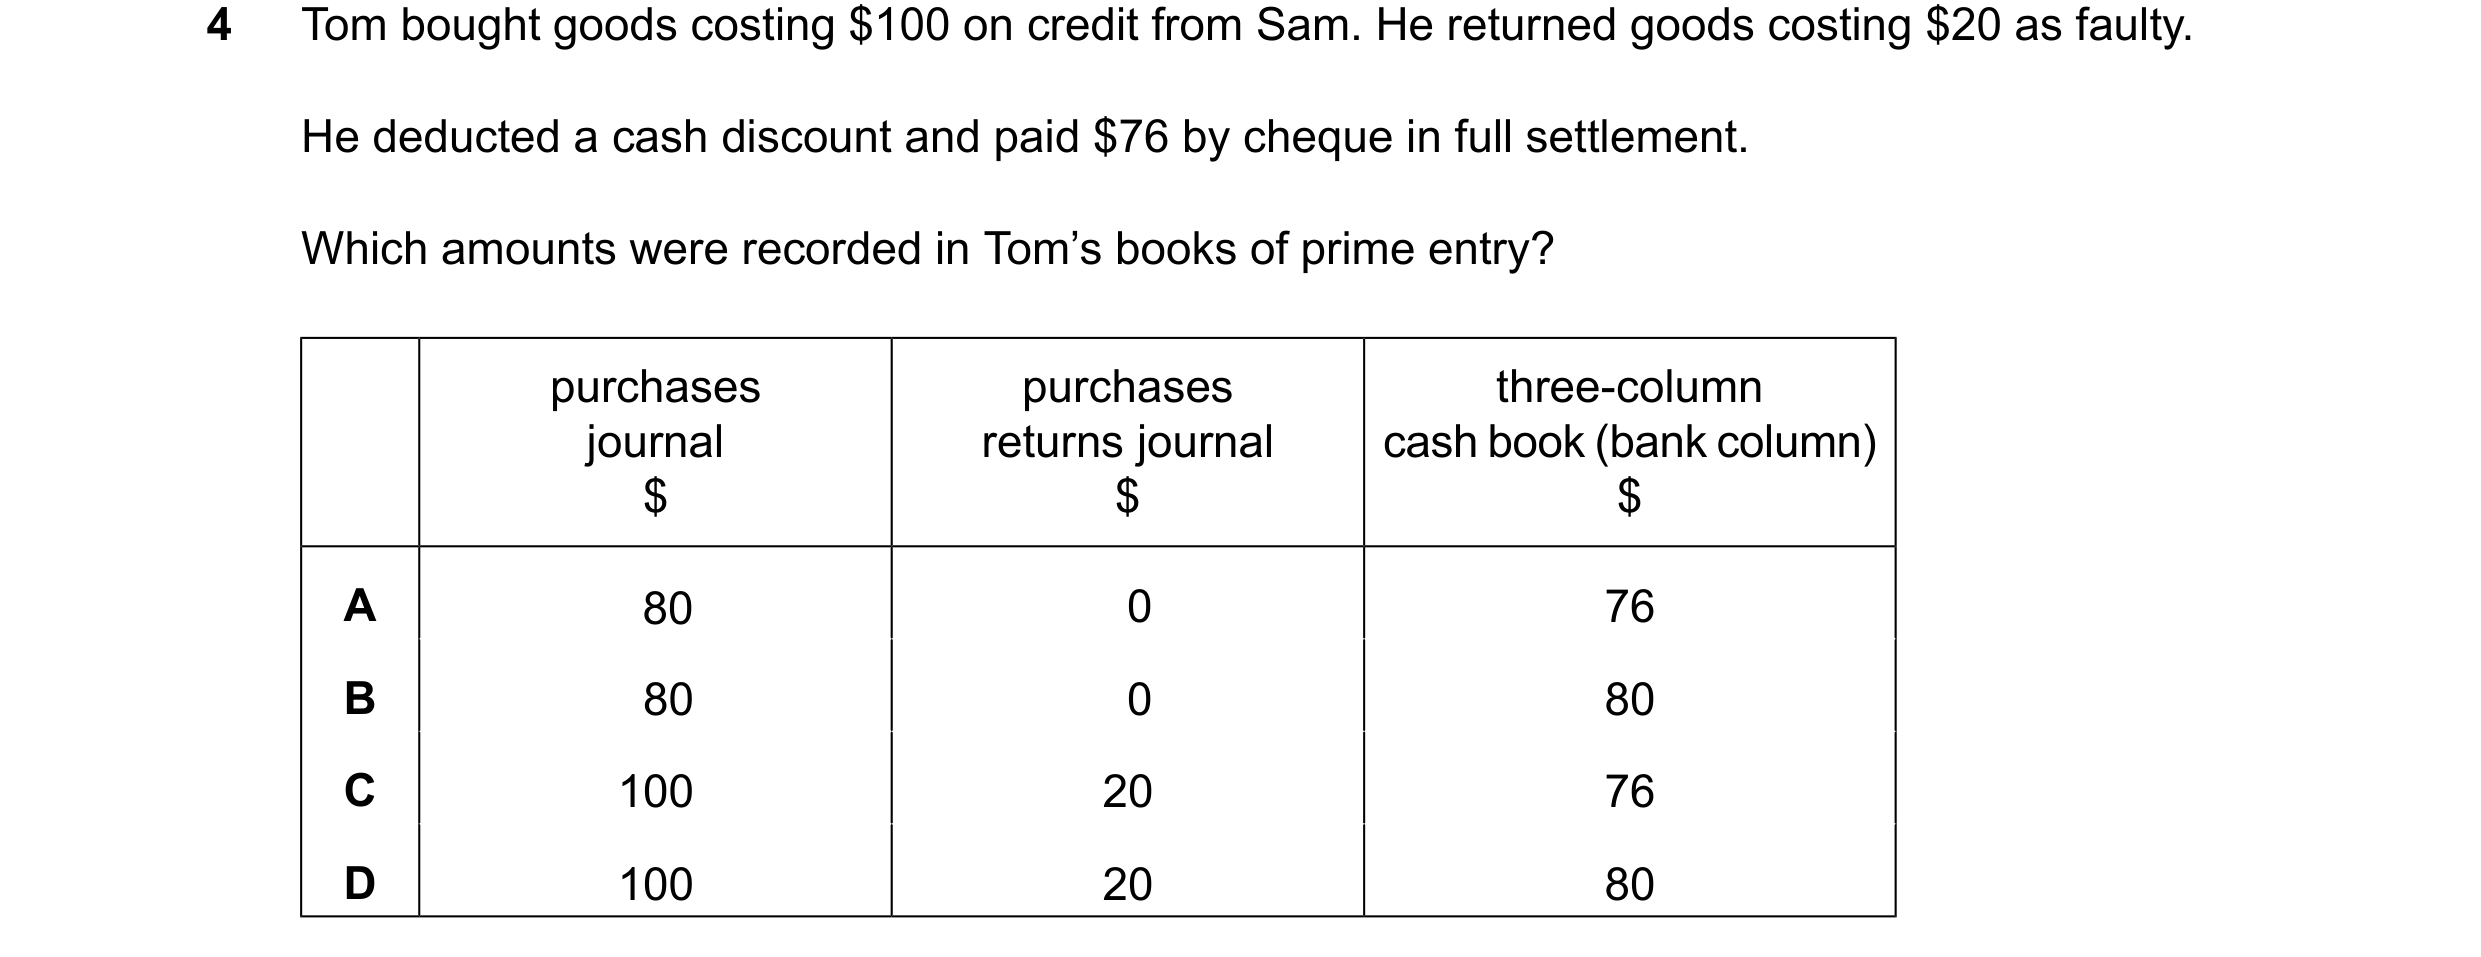
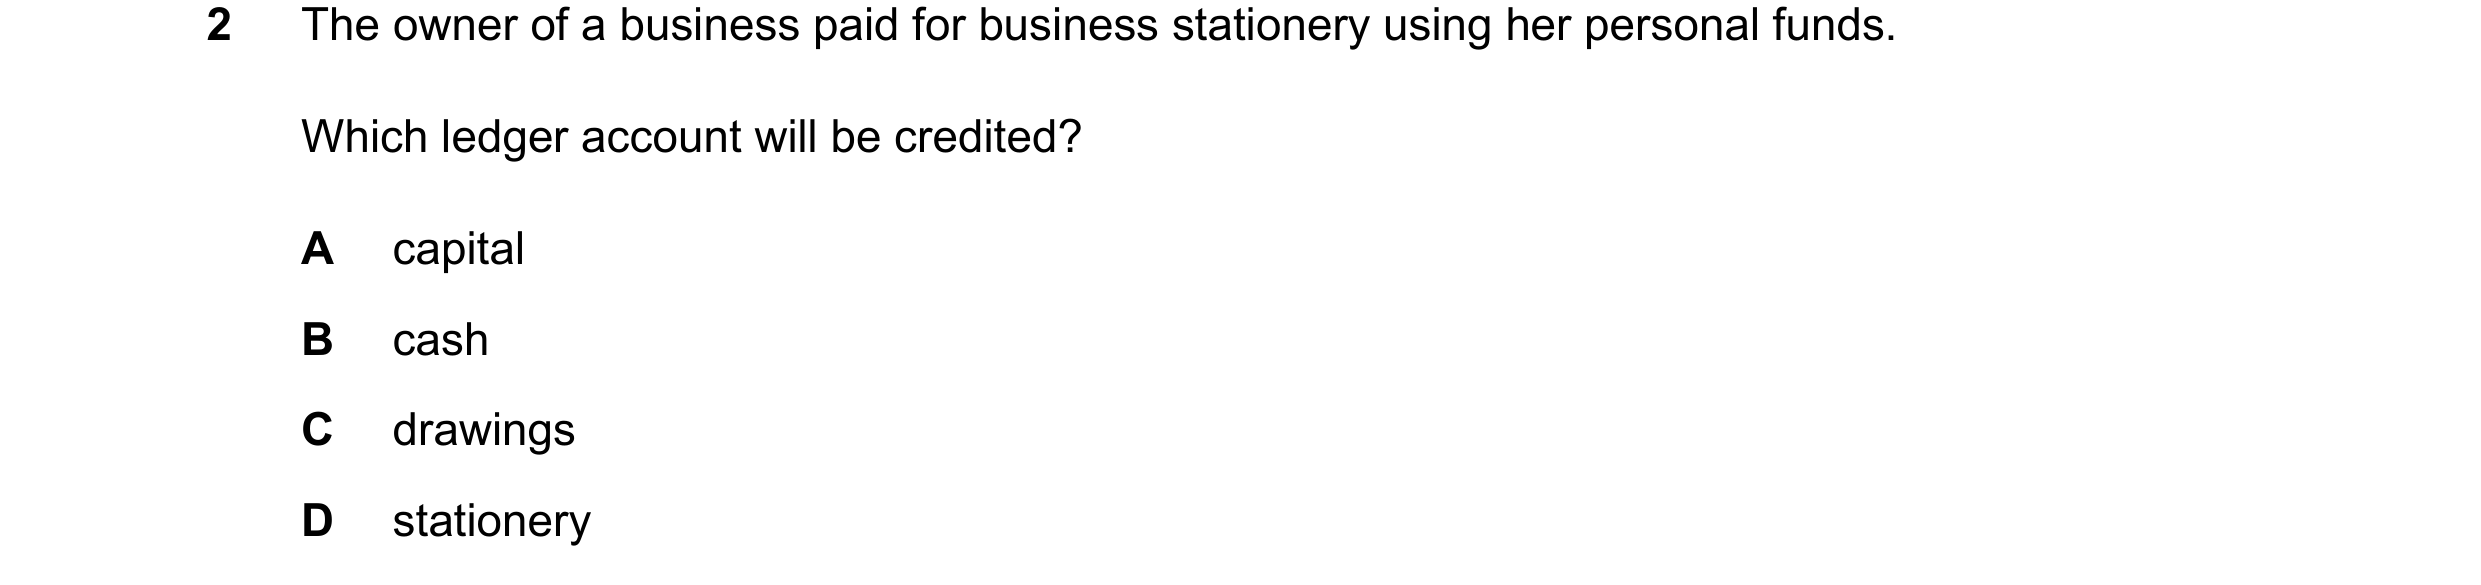 53 / 58
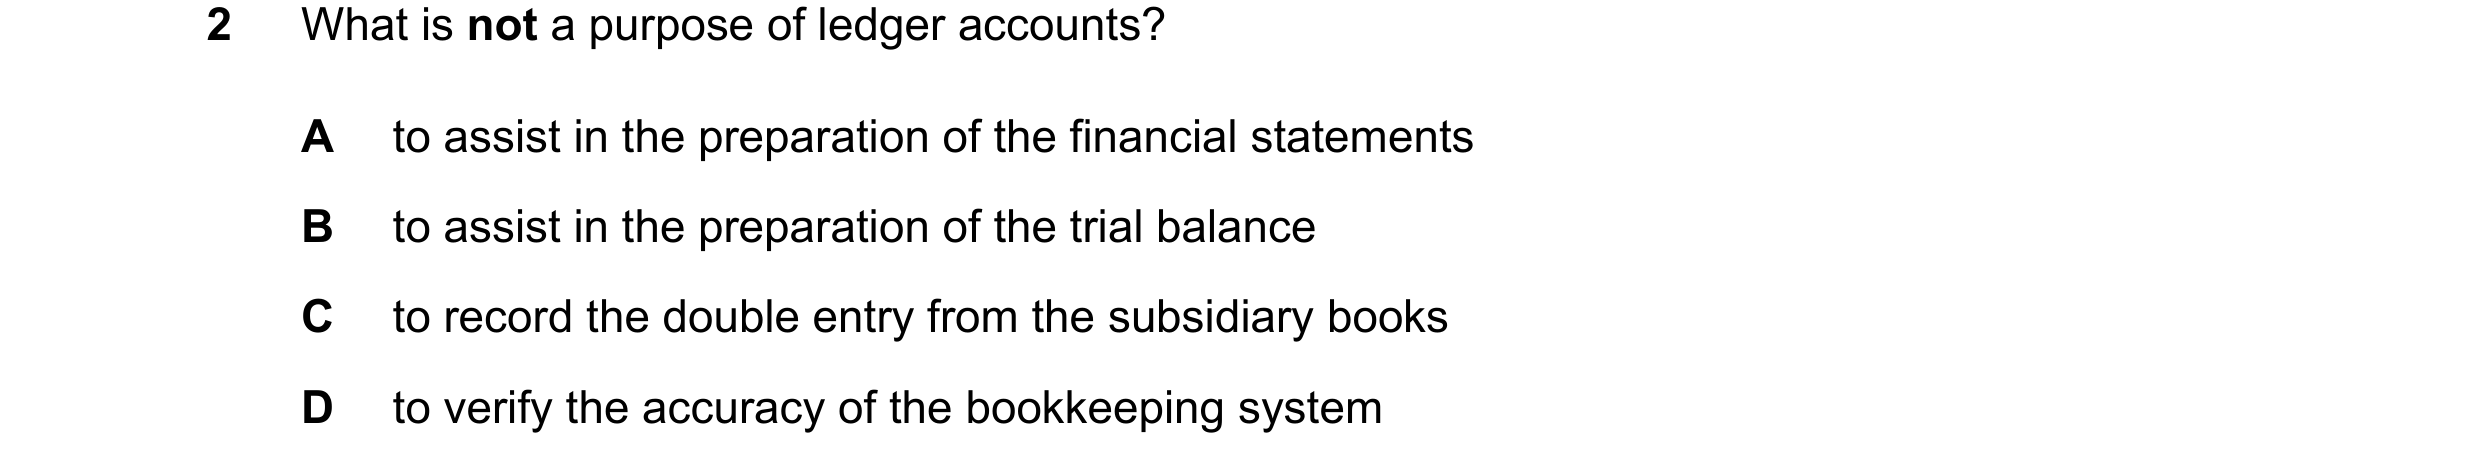
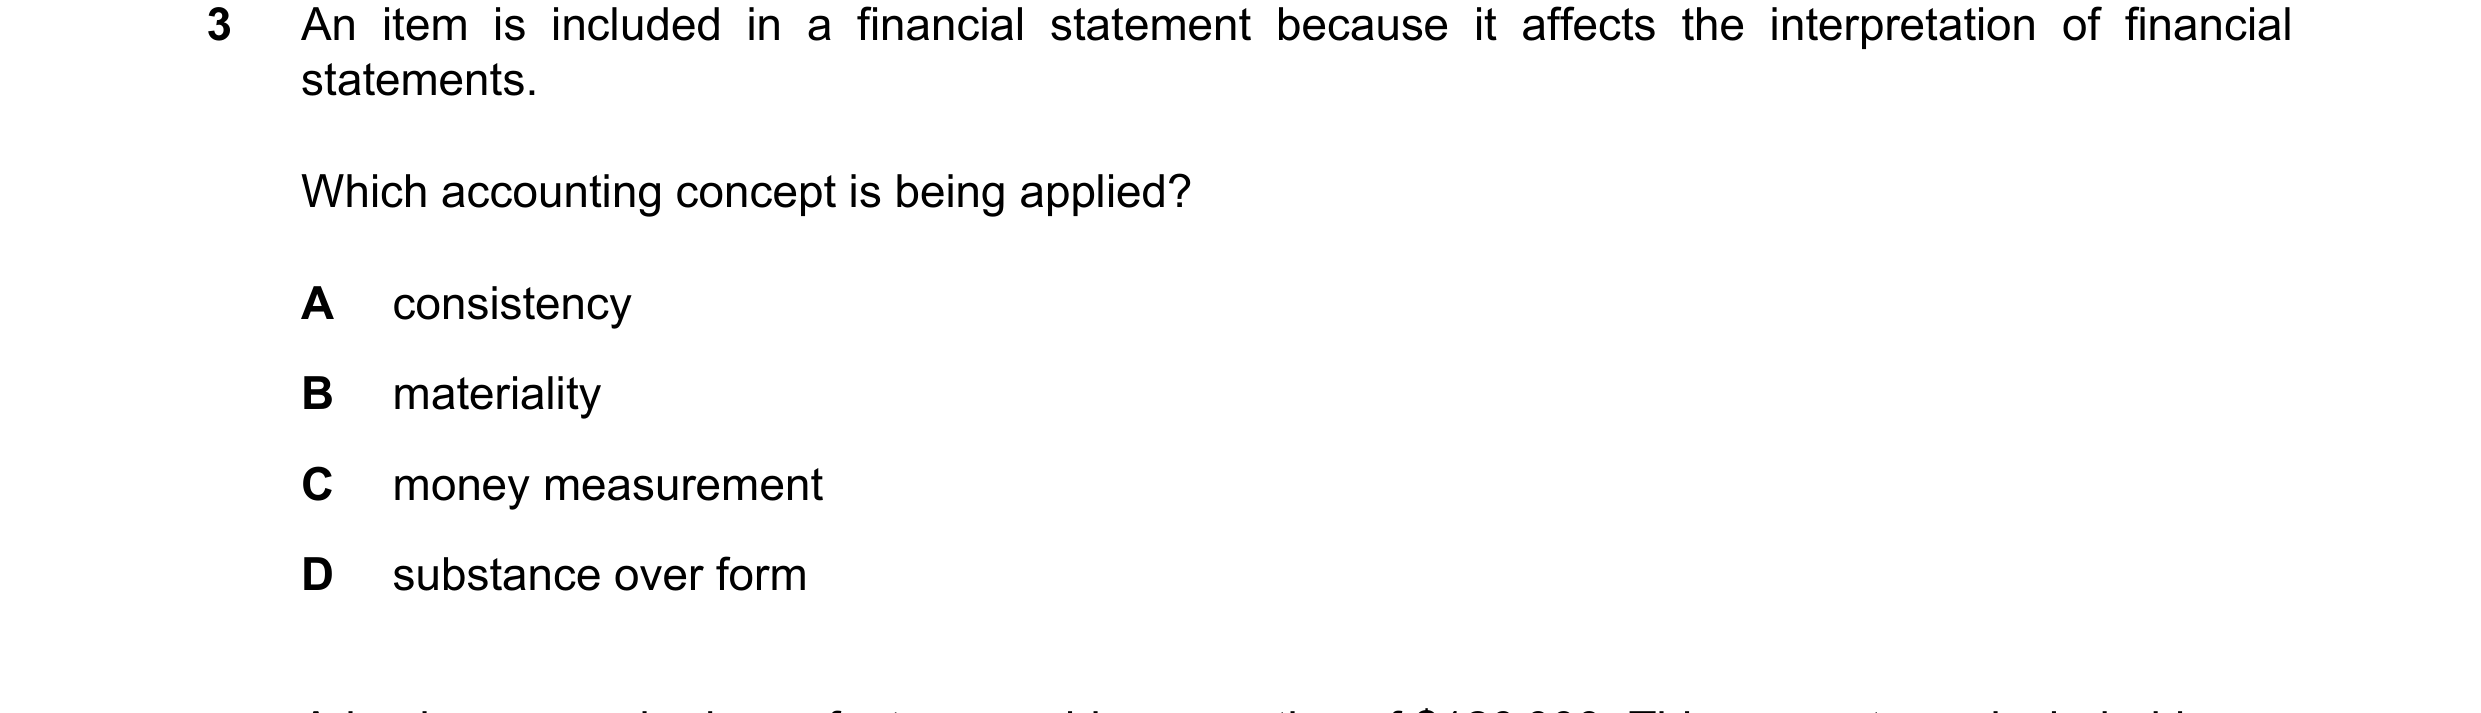
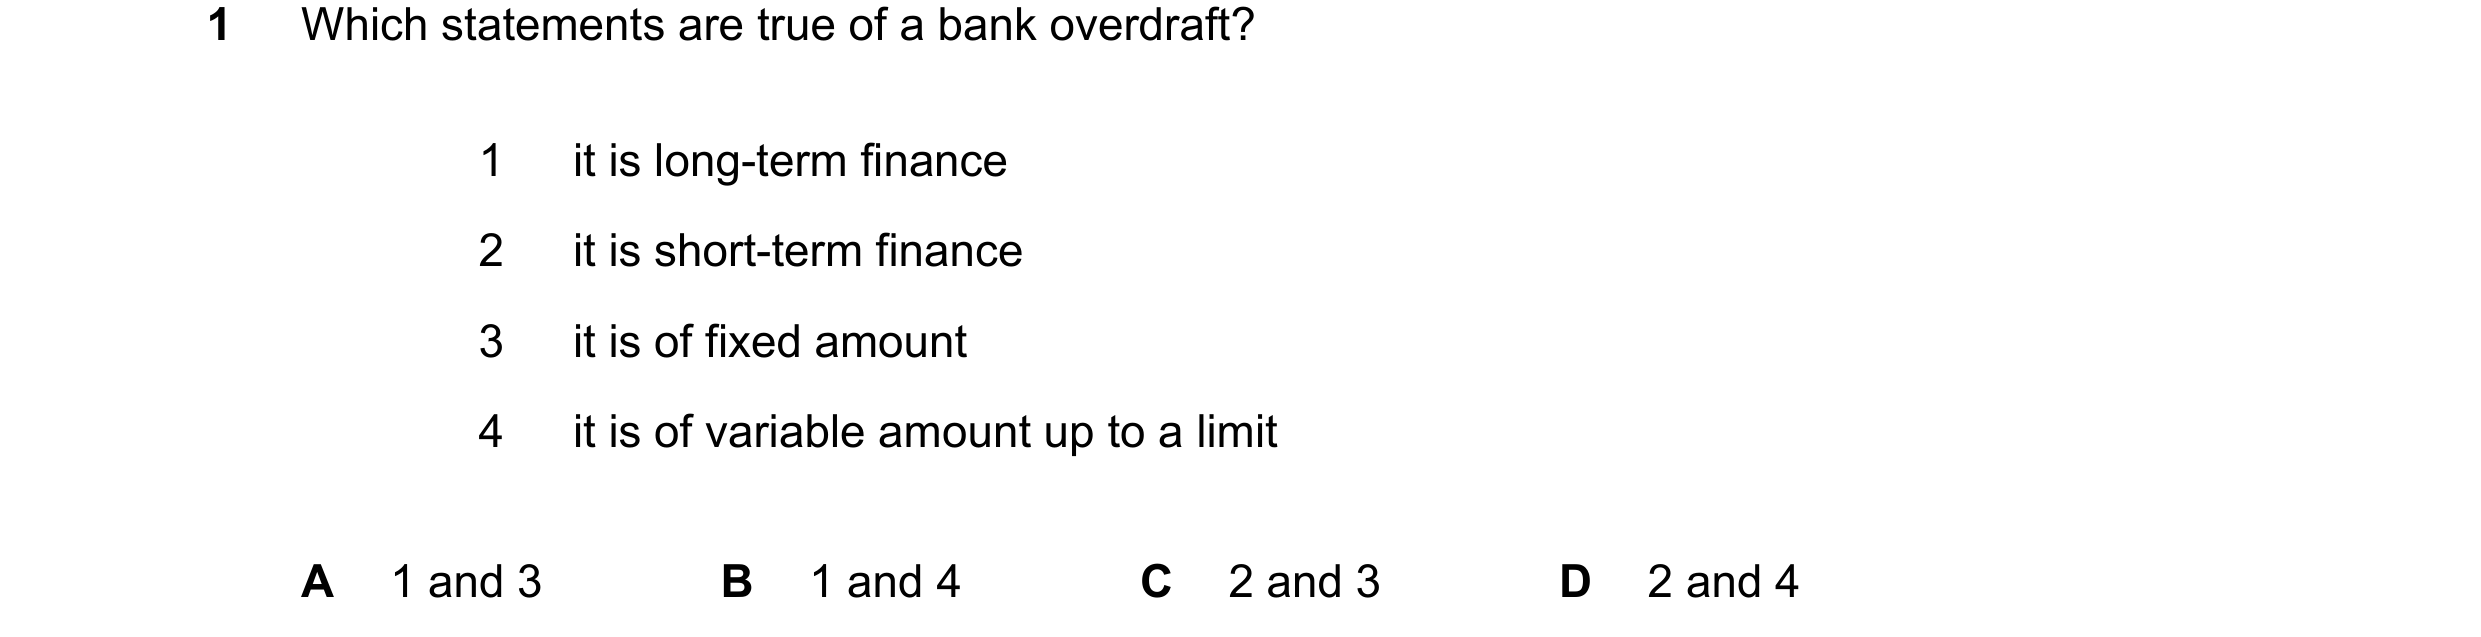
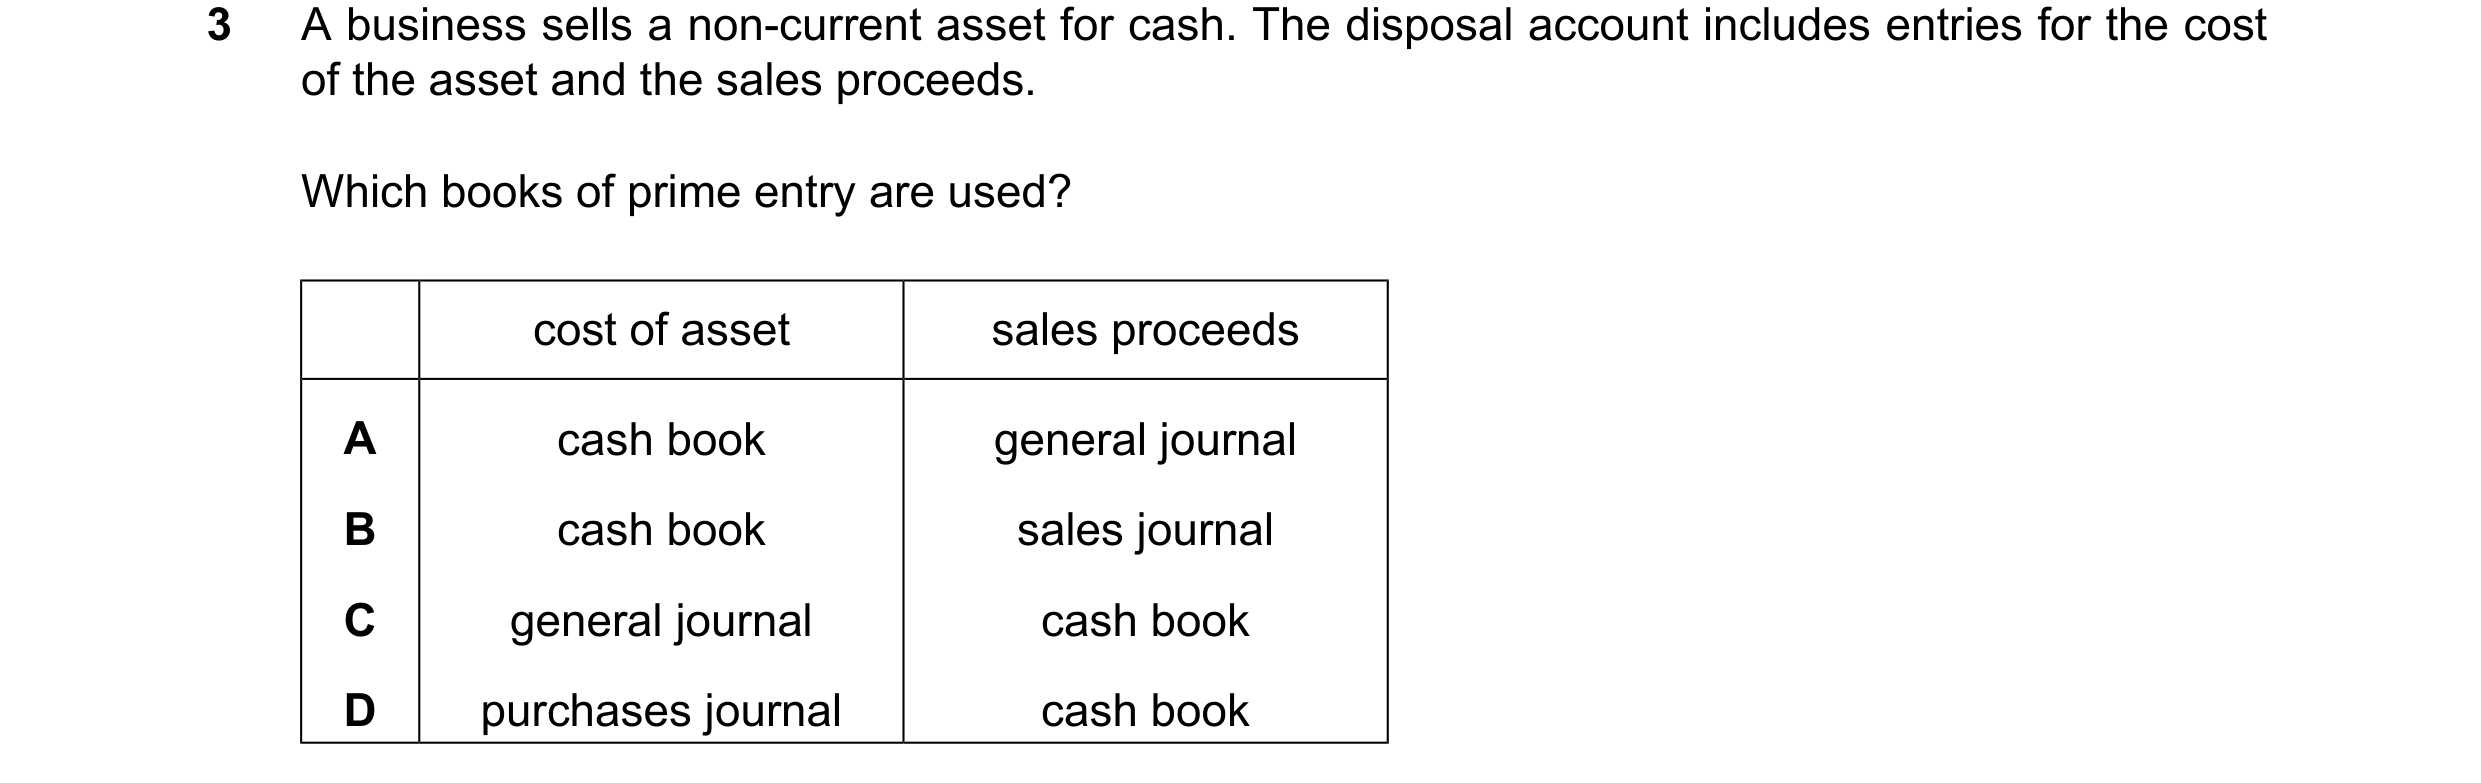 54 / 58
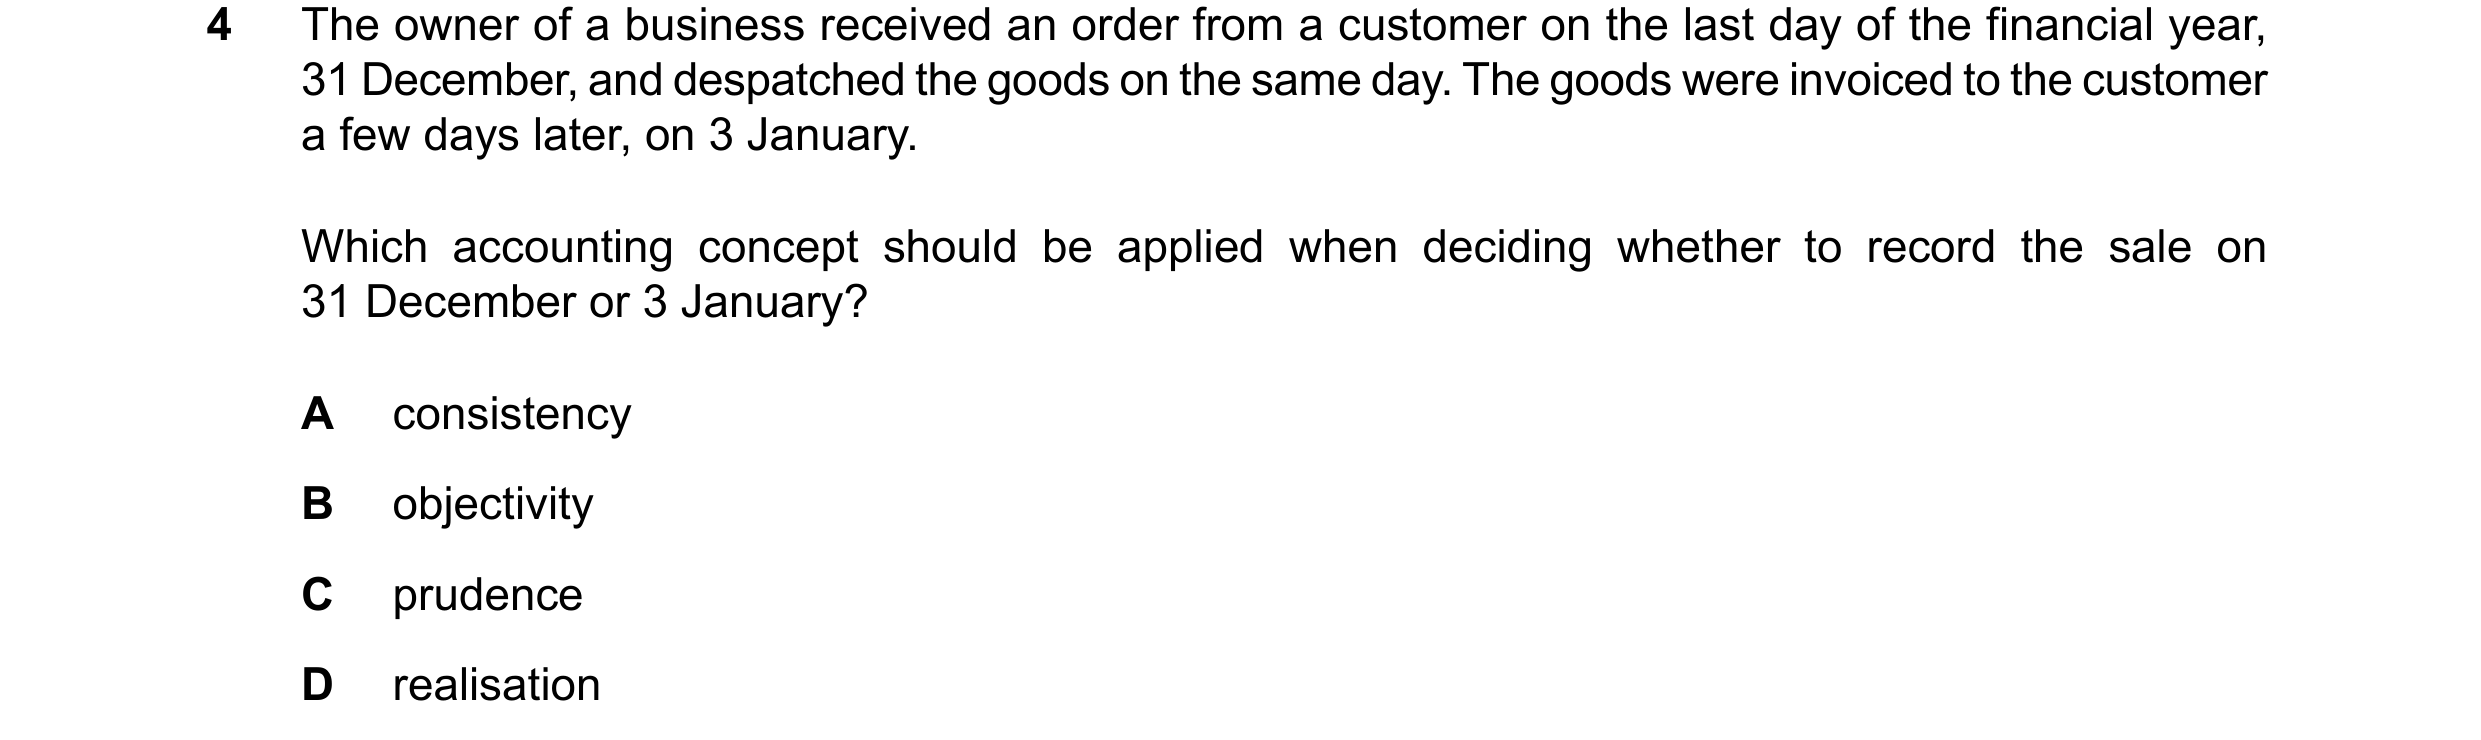
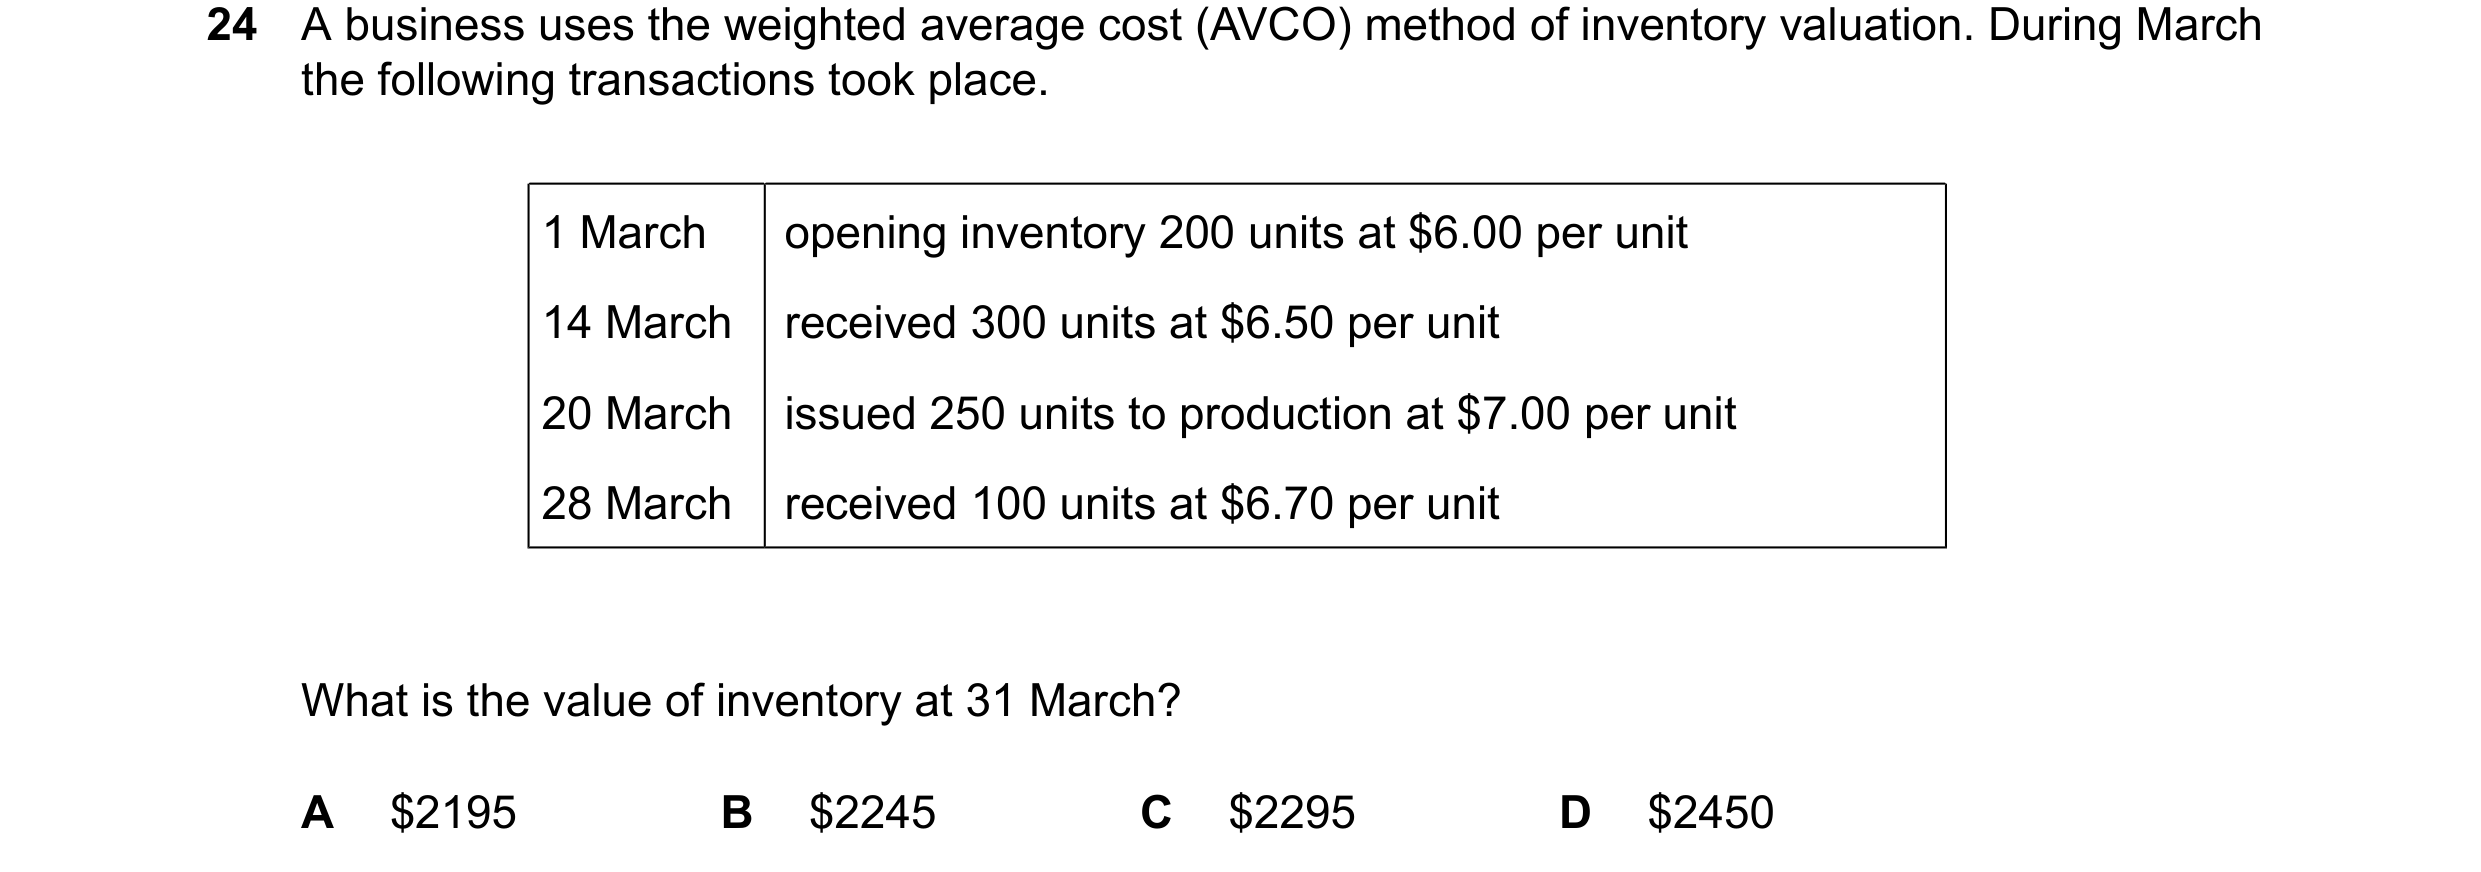
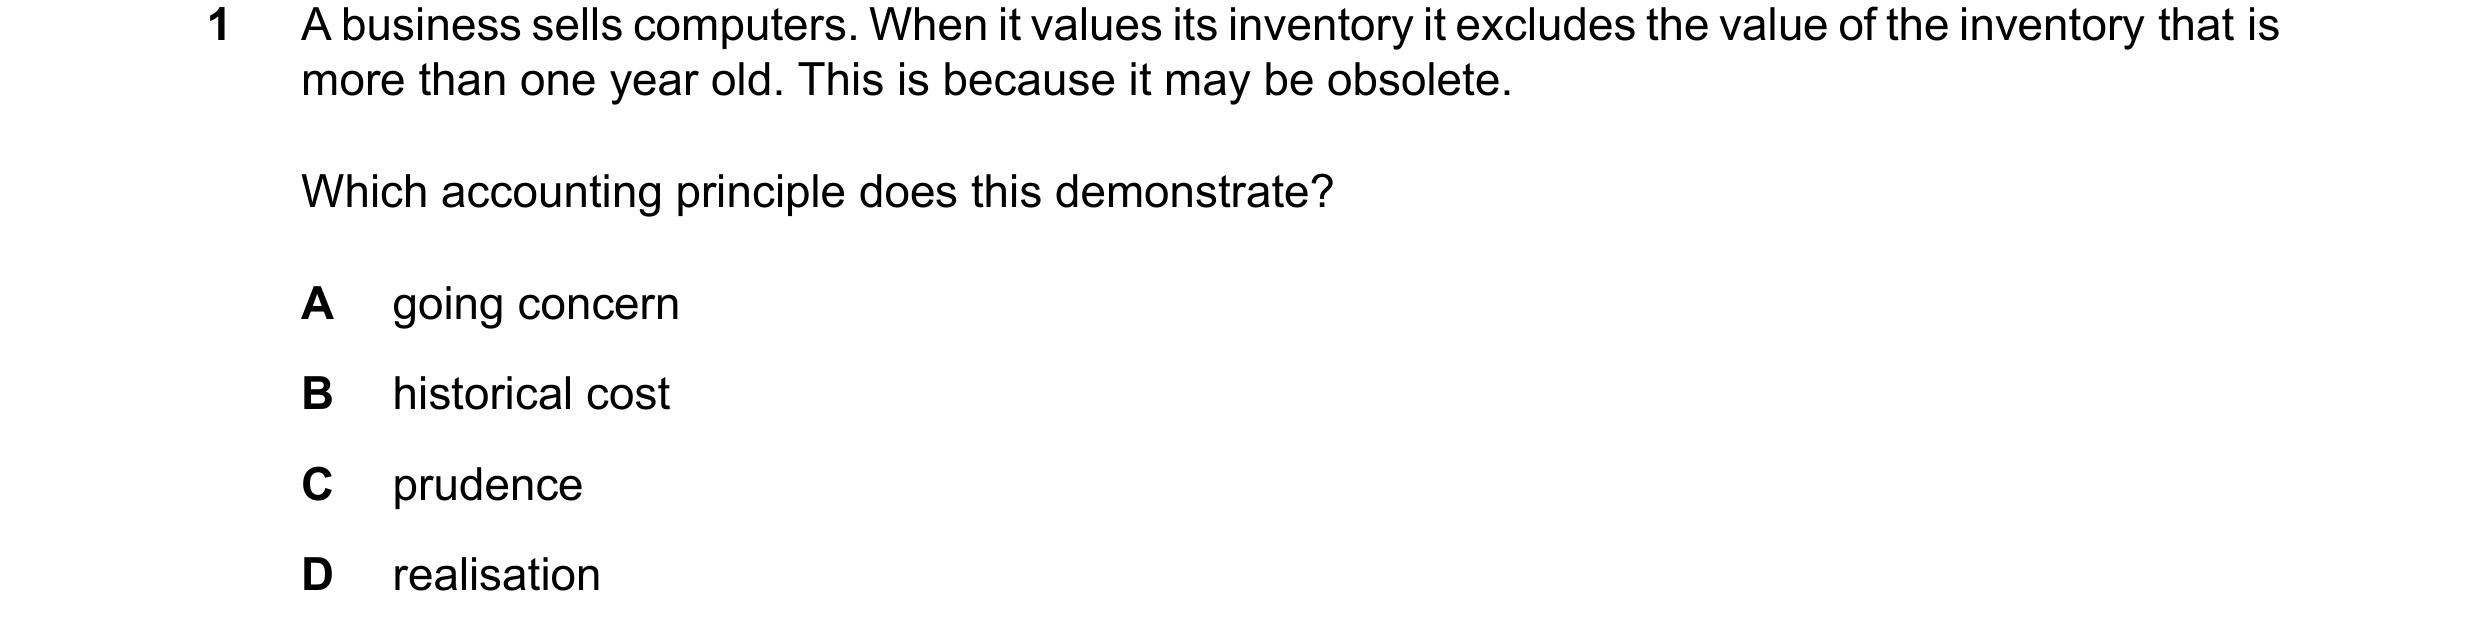
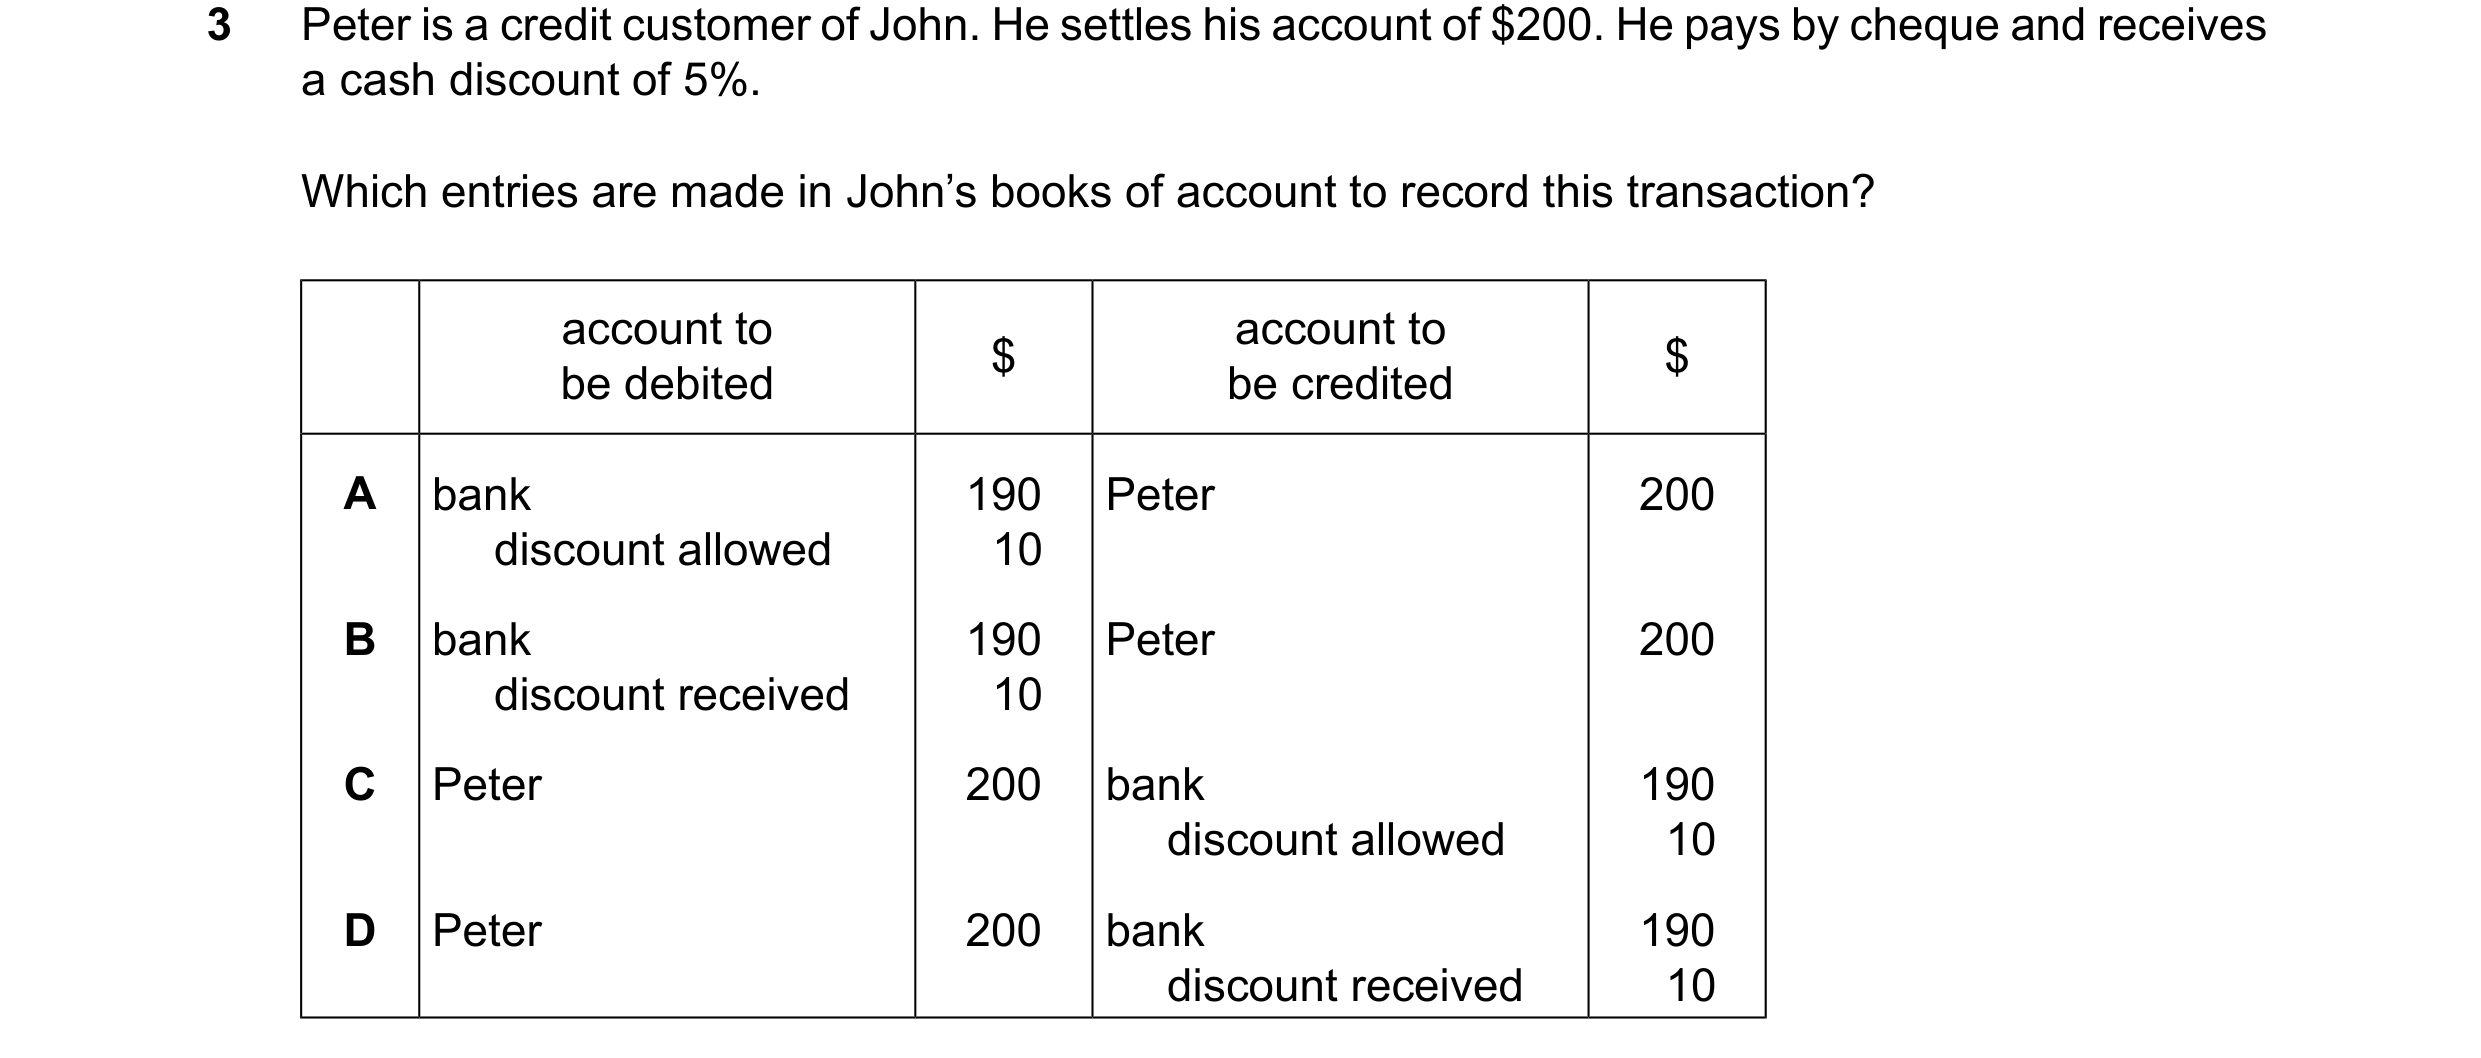 55 / 58
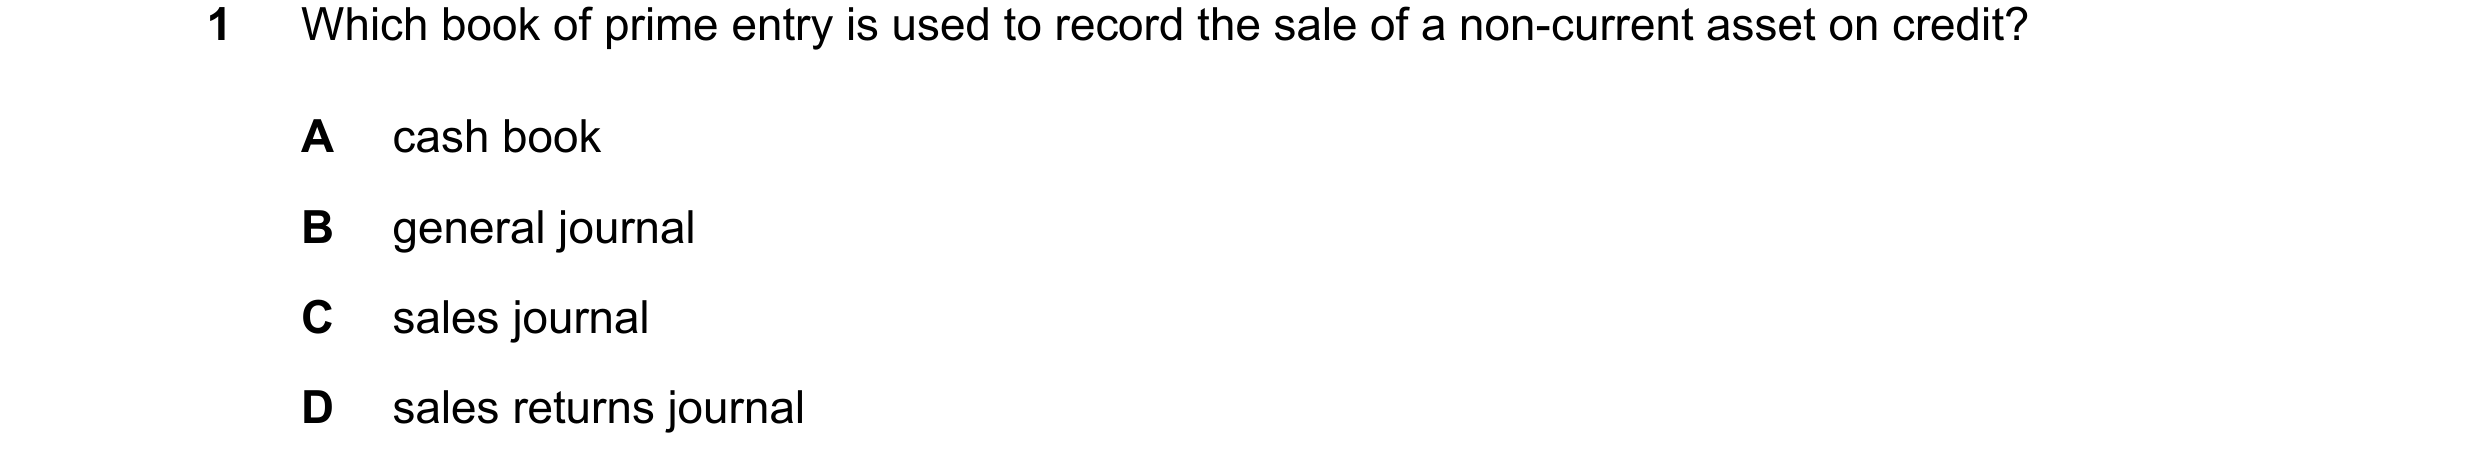
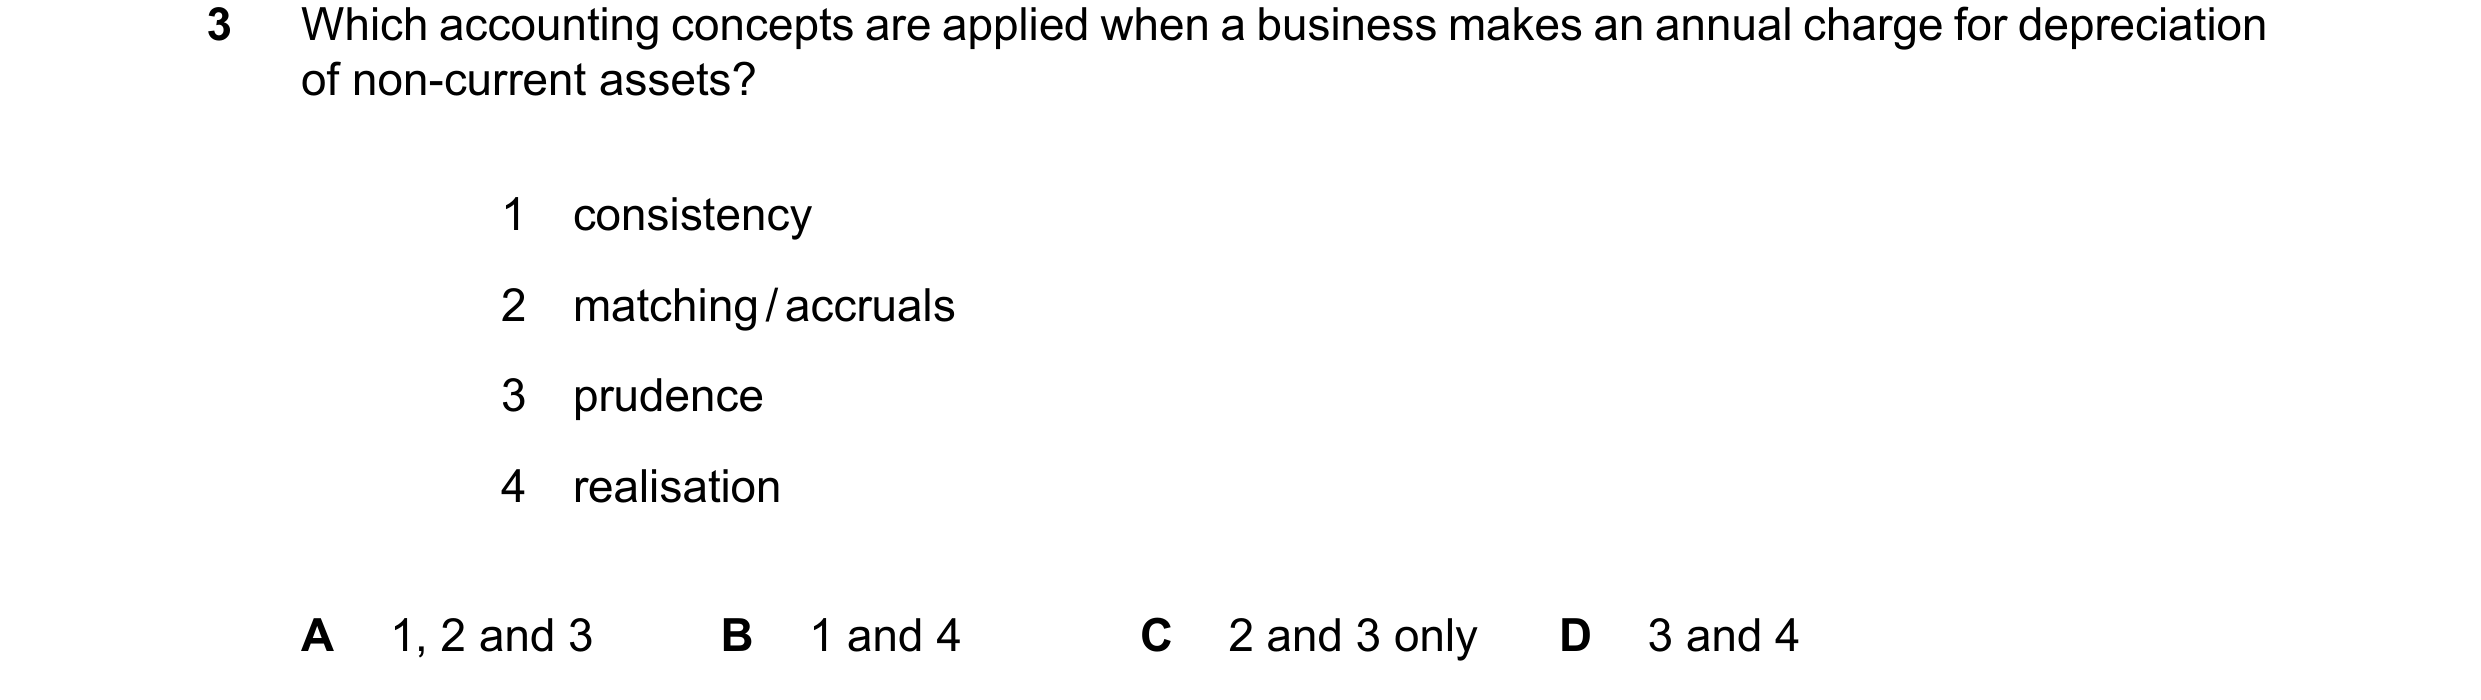
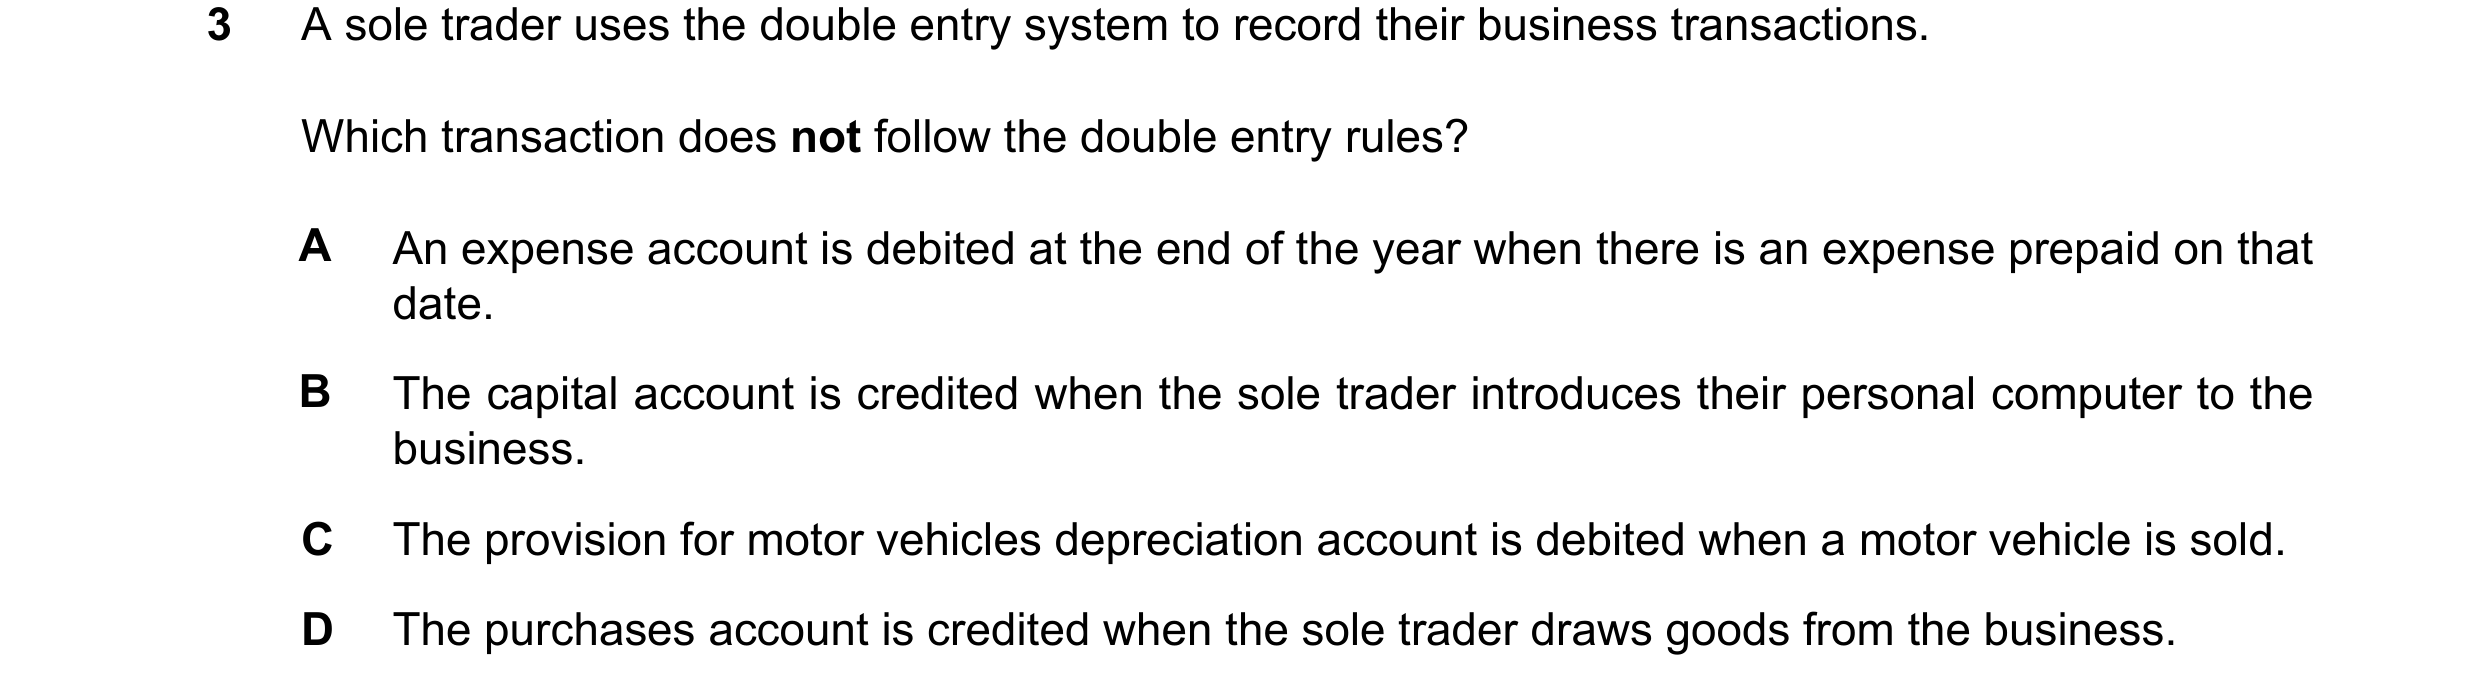
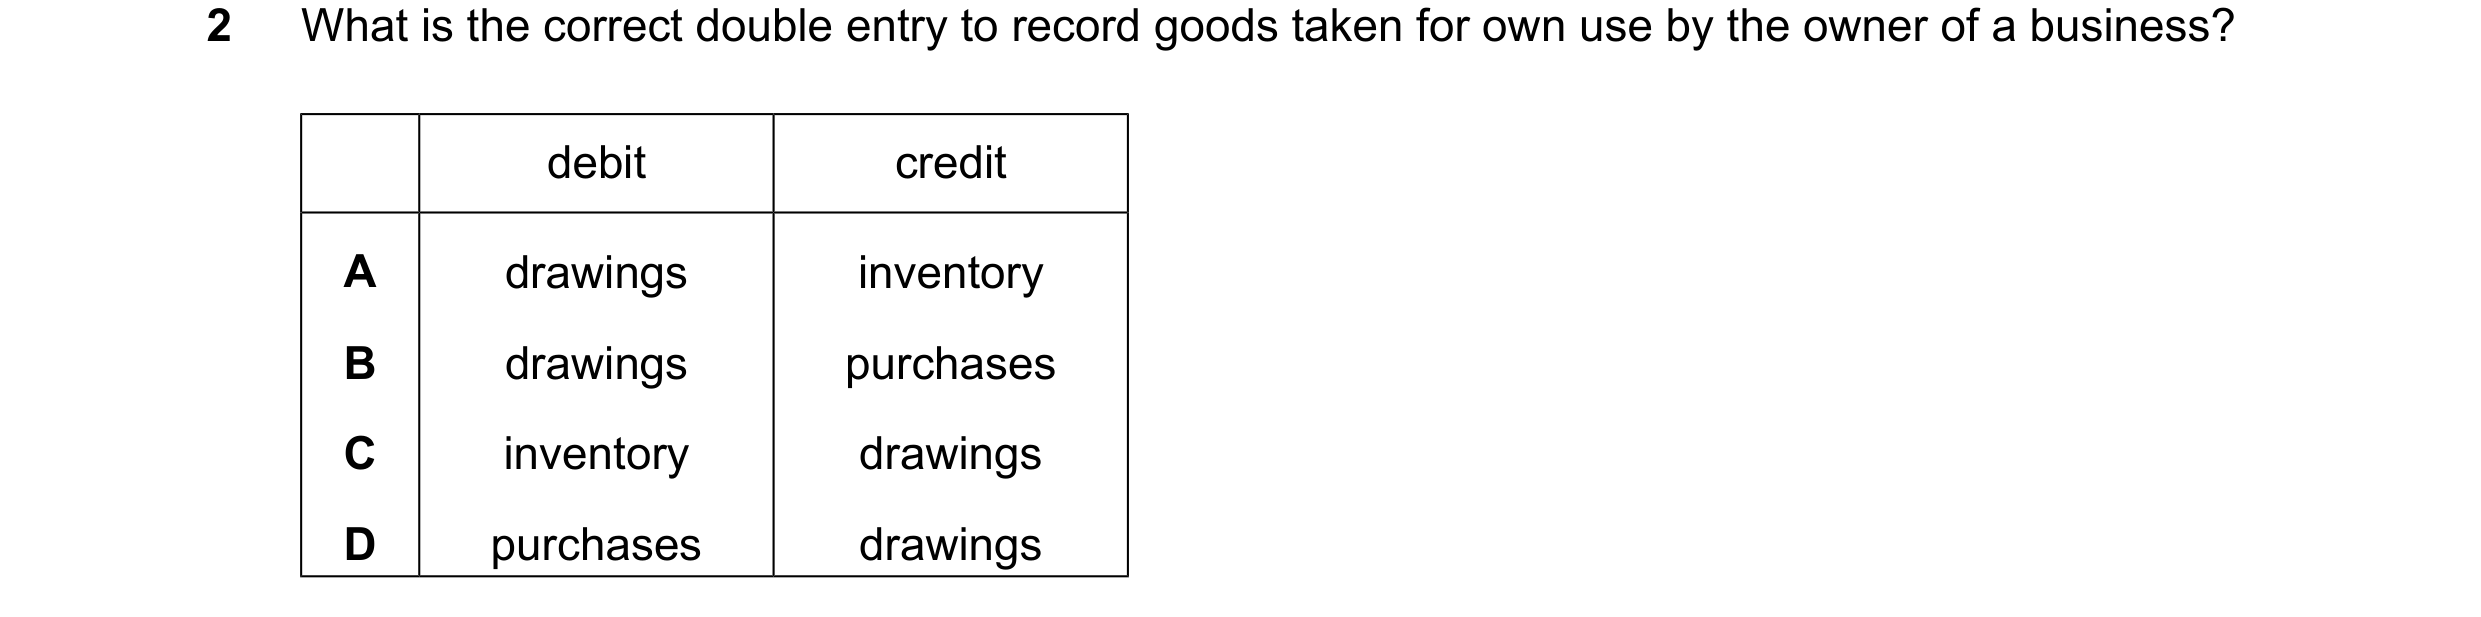
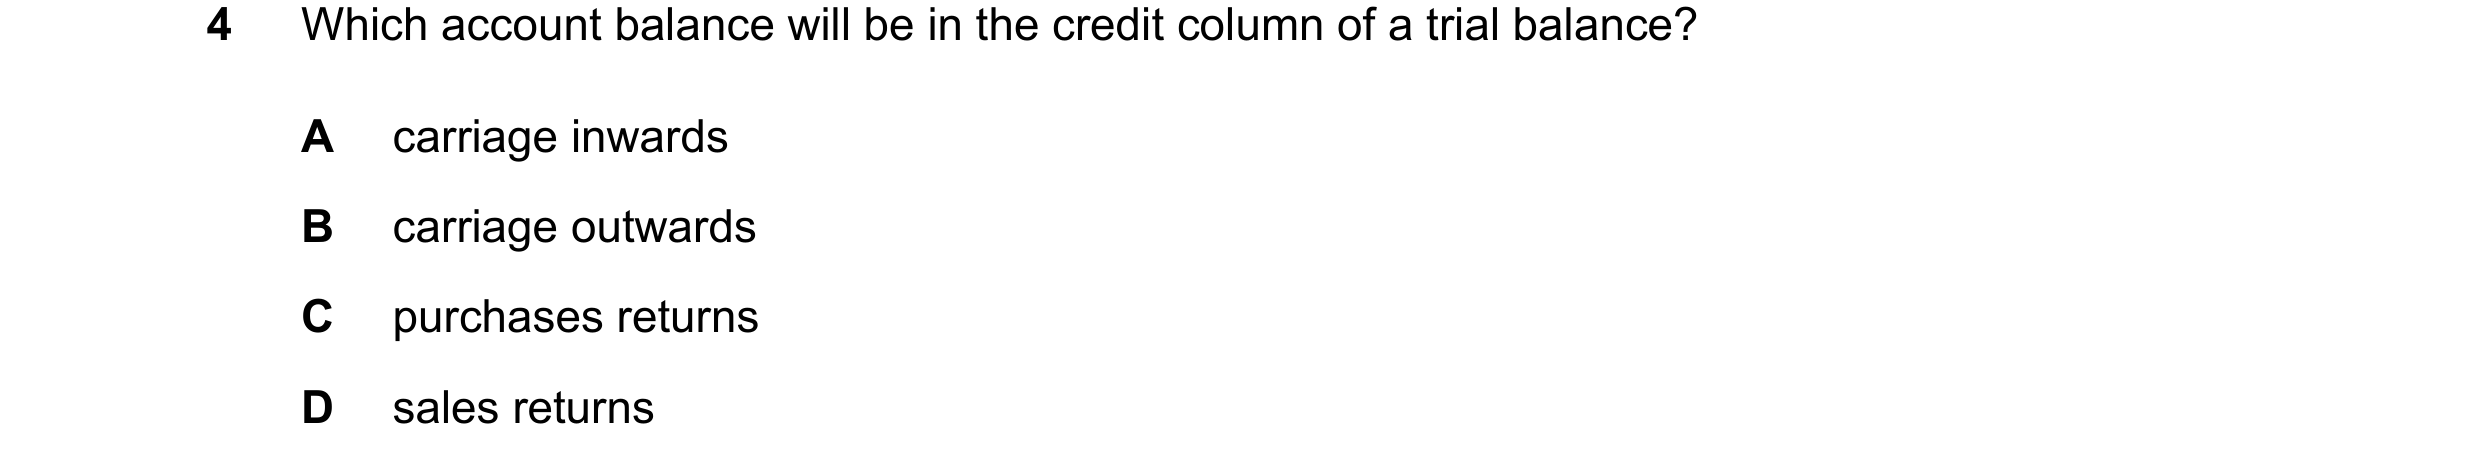 56 / 58
 57 / 58
 58 / 58