Questions as text
Q1 · A company makes a bonus issue of shares 9706/11 Oct/Nov 2010
18 A company makes a bonus issue of shares. What is the effect on the net assets and the reserves in the balance sheet? net assets reserves A increase decrease B increase unchanged C unchanged decrease D unchanged increase
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2010
Q2 · A company’s share capital and reserves are: $ non current (fixed) assets 250 000 net… 9706/11 Oct/Nov 2010
20 A company’s share capital and reserves are: $ non current (fixed) assets 250 000 net current assets 125 000 375 000 share capital and reserves 150 000 shares $1 each 150 000 share premium 75 000 general reserve 125 000 profits retained 25 000 375 000 The directors propose to issue bonus shares on the basis of one $1 share for every three already held. Following this the directors intend to make a rights issue on the basis of one new $1 share for every four shares held, at a premium of $0.20 per share. What will the total net assets of the company be after the share issues? A $425 000 B $435 000 C $475 000 D $485 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2010
Q3 · A company makes a bonus issue of shares 9706/12 Oct/Nov 2010
18 A company makes a bonus issue of shares. What is the effect on the net assets and the reserves in the balance sheet? net assets reserves A increase decrease B increase unchanged C unchanged decrease D unchanged increase
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2010
Q4 · The table shows extracts from the trial balance of a company at 31 December 2009 9706/12 Oct/Nov 2010
19 The table shows extracts from the trial balance of a company at 31 December 2009. $ ordinary share capital 750 000 8 % preference shares 250 000 6 % debentures (2015) 150 000 bank loan repayable (2012) 75 000 bank overdraft 110 000 mortgage on buildings (repayable 2010) 120 000 What is the total of non current liabilities in the balance sheet at 31 December 2009? A $195 000 B $225 000 C $345 000 D $595 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2010
Q5 · A company’s share capital and reserves are: $ non current (fixed) assets 250 000 net… 9706/12 Oct/Nov 2010
20 A company’s share capital and reserves are: $ non current (fixed) assets 250 000 net current assets 125 000 375 000 share capital and reserves 150 000 shares $1 each 150 000 share premium 75 000 general reserve 125 000 profits retained 25 000 375 000 The directors propose to issue bonus shares on the basis of one $1 share for every three already held. Following this the directors intend to make a rights issue on the basis of one new $1 share for every four shares held, at a premium of $0.20 per share. What will the total net assets of the company be after the share issues? A $425 000 B $435 000 C $475 000 D $485 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2010
Q6 · How should goodwill be treated by a limited company? 9706/11 May/June 2011
15 How should goodwill be treated by a limited company? A Goodwill should always be written off immediately. B Non-purchased goodwill is shown in the balance sheet. C Purchased goodwill is shown in the balance sheet and written off over its useful life. D Purchased goodwill remains on the balance sheet as a permanent item.
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q7 · A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000… 9706/11 May/June 2011
16 A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000 4 % debentures. By what amount will the net assets of the company increase? A $250 000 B $550 000 C $1 000 000 D $1 300 000
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q8 · An extract from Bumble Ltd's balance sheet shows the following 9706/11 May/June 2011
17 An extract from Bumble Ltd's balance sheet shows the following. $000 ordinary shares of $0.25 each 500 share premium 100 retained earnings 300 The company makes a rights issue of 1 share for each 4 held at a price of $0.30 per share. All shares are taken up. What will the new balance sheet show? A B C D $000 $000 $000 $000 ordinary shares of $0.25 each 625 500 625 625 rights issue – 125 – – share premium 100 125 125 100 retained earnings 300 275 300 325
1 marks
Answer: C
This question in 9706/11 May/June 2011
Q9 · How should goodwill be treated by a limited company? 9706/12 May/June 2011
7 How should goodwill be treated by a limited company? A Goodwill should always be written off immediately. B Non-purchased goodwill is shown in the balance sheet. C Purchased goodwill is shown in the balance sheet and written off over its useful life. D Purchased goodwill remains on the balance sheet as a permanent item.
1 marks
Answer: C
This question in 9706/12 May/June 2011
Q10 · A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000… 9706/12 May/June 2011
8 A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000 4 % debentures. By what amount will the net assets of the company increase? A $250 000 B $550 000 C $1 000 000 D $1 300 000
1 marks
Answer: C
This question in 9706/12 May/June 2011
Q11 · An extract from Bumble Ltd's balance sheet shows the following 9706/12 May/June 2011
9 An extract from Bumble Ltd's balance sheet shows the following. $000 ordinary shares of $0.25 each 500 share premium 100 retained earnings 300 The company makes a rights issue of 1 share for each 4 held at a price of $0.30 per share. All shares are taken up. What will the new balance sheet show? A B C D $000 $000 $000 $000 ordinary shares of $0.25 each 625 500 625 625 rights issue – 125 – – share premium 100 125 125 100 retained earnings 300 275 300 325
1 marks
Answer: C
This question in 9706/12 May/June 2011
Q12 · How should goodwill be treated by a limited company? 9706/13 May/June 2011
16 How should goodwill be treated by a limited company? A Goodwill should always be written off immediately. B Non-purchased goodwill is shown in the balance sheet. C Purchased goodwill is shown in the balance sheet and written off over its useful life. D Purchased goodwill remains on the balance sheet as a permanent item.
1 marks
Answer: C
This question in 9706/13 May/June 2011
Q13 · A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000… 9706/13 May/June 2011
17 A company issues for cash 50 000 shares of $5 each at a premium of $15 each and $300 000 4 % debentures. By what amount will the net assets of the company increase? A $250 000 B $550 000 C $1 000 000 D $1 300 000
1 marks
Answer: C
This question in 9706/13 May/June 2011
Q14 · An extract from Bumble Ltd's balance sheet shows the following 9706/13 May/June 2011
18 An extract from Bumble Ltd's balance sheet shows the following. $000 ordinary shares of $0.25 each 500 share premium 100 retained earnings 300 The company makes a rights issue of 1 share for each 4 held at a price of $0.30 per share. All shares are taken up. What will the new balance sheet show? A B C D $000 $000 $000 $000 ordinary shares of $0.25 each 625 500 625 625 rights issue – 125 – – share premium 100 125 125 100 retained earnings 300 275 300 325
1 marks
Answer: C
This question in 9706/13 May/June 2011
Q15 · What could be used to fund a bonus issue of shares? 9706/11 Oct/Nov 2011
16 What could be used to fund a bonus issue of shares? 1 asset revaluation reserve 2 general reserve 3 retained earnings 4 share premium A 1 and 2 only B 1, 2 and 3 only C 1, 2, 3 and 4 D 2 and 3 only
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2011
Q16 · An investor owns 10 000 5 % preference shares in Howdo Limited 9706/11 Oct/Nov 2011
17 An investor owns 10 000 5 % preference shares in Howdo Limited. One year Howdo does not have enough profits to pay the preference dividend. The investor is not too worried as he expects the profits to improve and he thinks the directors will pay the missed dividend the following year. Which type of preference shares does the investor own? A cumulative B non-cumulative C participating D redeemable
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2011
Q17 · A balance sheet shows the following information 9706/11 Oct/Nov 2011
18 A balance sheet shows the following information. $ 100 000 ordinary shares of $0.50 each 50 000 50 000 5 % preference shares of $0.10 each 5 000 share premium 10 000 revaluation reserve 20 000 retained earnings 35 000 120 000 What is the balance sheet value of one ordinary share? A $0.50 B $1.00 C $1.15 D $1.20
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2011
Q18 · What could be used to fund a bonus issue of shares? 9706/13 Oct/Nov 2011
15 What could be used to fund a bonus issue of shares? 1 asset revaluation reserve 2 general reserve 3 retained earnings 4 share premium A 1 and 2 only B 1, 2 and 3 only C 1, 2, 3 and 4 D 2 and 3 only
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2011
Q19 · An investor owns 10 000 5 % preference shares in Howdo Limited 9706/13 Oct/Nov 2011
16 An investor owns 10 000 5 % preference shares in Howdo Limited. One year Howdo does not have enough profits to pay the preference dividend. The investor is not too worried as he expects the profits to improve and he thinks the directors will pay the missed dividend the following year. Which type of preference shares does the investor own? A cumulative B non-cumulative C participating D redeemable
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2011
Q20 · A balance sheet shows the following information 9706/13 Oct/Nov 2011
17 A balance sheet shows the following information. $ 100 000 ordinary shares of $0.50 each 50 000 50 000 5 % preference shares of $0.10 each 5 000 share premium 10 000 revaluation reserve 20 000 retained earnings 35 000 120 000 What is the balance sheet value of one ordinary share? A $0.50 B $1.00 C $1.15 D $1.20
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2011
Q21 · The following is an extract from the statement of financial position of a company 9706/13 May/June 2013
20 The following is an extract from the statement of financial position of a company. $ ordinary shares of $0.25 each 35 000 6% cumulative preference shares 40 000 No dividend was paid on the preference shares last year but the directors propose to pay a dividend this year. The directors also propose a final ordinary share dividend of $0.05 per share. What is the amount of dividends to be paid? cumulative ordinary shares preference shares $ $ A 1750 2400 B 1750 4800 C 7000 2400 D 7000 4800
1 marks
Answer: D
This question in 9706/13 May/June 2013
Q22 · A shareholder in a company sells his shares to another person 9706/13 May/June 2013
21 A shareholder in a company sells his shares to another person. What is the effect on the share capital account of the company? A It is increased by any premium paid for the shares. B It is increased by the selling price of the shares. C It is reduced by the value of shares sold. D It remains unaltered.
1 marks
Answer: D
This question in 9706/13 May/June 2013
Q23 · X and Y are in partnership, sharing profits and losses equally 9706/13 Oct/Nov 2017
12 X and Y are in partnership, sharing profits and losses equally. They agree to admit Z as an equal partner. Z is to introduce $100 000 as capital and his share of goodwill. The partnership’s goodwill is $60 000 and all adjustments are to be made in the capital accounts. What is the balance on Z’s capital account after his admission to the partnership? A credit $80 000 B credit $160 000 C debit $20 000 D debit $60 000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2017
Q24 · There were three partners in a partnership 9706/13 Oct/Nov 2017
13 There were three partners in a partnership. The total of their current accounts at the start of the year was $18 000 and at the end of the year was $32 000. Drawings for the year amounted to $22 000 and partners’ salaries were $13 000. What was the profit for the year? A $5000 B $14 000 C $23 000 D $36 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2017
Q25 · Which items would appear in a partnership’s appropriation account, in the absence of a… 9706/13 Oct/Nov 2017
14 Which items would appear in a partnership’s appropriation account, in the absence of a partnership agreement? 1 profit for the year 2 partners’ interest on drawings 3 partners’ salaries 4 partners’ share of profits A 1 and 4 B 1 only C 2 and 3 D 4 only
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2017
Q26 · Which event does not require entries in a company’s ledger accounts? 9706/13 Oct/Nov 2017
15 Which event does not require entries in a company’s ledger accounts? A a bonus issue of shares B a rights issue of shares at a price above nominal value C a sale by a shareholder of shares at a price above nominal value D an issue of the company’s shares at par value
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2017
Q27 · An extract from a statement of changes in equity for the year ended 31 December 2016 is… 9706/13 Oct/Nov 2017
16 An extract from a statement of changes in equity for the year ended 31 December 2016 is shown. ordinary share retained share capital premium earnings $ $ $ balance at start of year 50 000 3000 35 000 profit for the year 9 000 During the year 2016 the following occurred, but had not yet been entered. 1 10 000 ordinary shares of $1 each were issued at $1.50. 2 An interim dividend of $2000 was paid. 3 A final dividend of $3000 was proposed. What are the final balances at 31 December 2016? ordinary share retained share capital premium earnings $ $ $ A 60 000 8000 39 000 B 60 000 8000 42 000 C 65 000 3000 39 000 D 65 000 3000 42 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2017
Q28 · The following information has been extracted from the statement of financial position of… 9706/13 Oct/Nov 2017
17 The following information has been extracted from the statement of financial position of a limited company. $ 6% debenture (2020–2022) 20 000 400 000 ordinary shares of $1 each 400 000 5-year bank loan 200 000 share premium account 50 000 retained earnings 75 000 What is the value of the total equity? A $525 000 B $545 000 C $695 000 D $725 000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2017
Q29 · A company issues 50 000 ordinary shares of $5 each at a premium of $15 9706/12 Feb/March 2018
13 A company issues 50 000 ordinary shares of $5 each at a premium of $15. It also issues a 4% debenture, $300 000. By which amount do the net assets of the company increase? A $250 000 B $550 000 C $1 000 000 D $1 300 000
1 marks
Answer: C
This question in 9706/12 Feb/March 2018
Q30 · Which statements describe a capital reserve? 9706/12 Feb/March 2018
14 Which statements describe a capital reserve? 1 It is a reserve arising from a gain which is not yet realised. 2 It is a reserve created by transferring an amount from profit for the year. 3 It is a reserve which can be credited back to retained earnings if not used. A 1, 2 and 3 B 1 and 2 only C 1 only D 2 and 3 only
1 marks
Answer: C
This question in 9706/12 Feb/March 2018
Q31 · The following is an extract from a statement of changes in equity 9706/12 Feb/March 2018
15 The following is an extract from a statement of changes in equity. ordinary share general retained share capital premium reserve earnings $ $ $ $ balance at the 75 000 15 000 3000 45 000 start of the year During the year the following occurred. 1 An interim dividend of $4875 was paid. 2 A final dividend of $6000 was proposed. 3 $2500 was transferred to the general reserve. What was the balance of retained earnings at the end of the year? A $31 625 B $36 625 C $37 625 D $42 625
1 marks
Answer: C
This question in 9706/12 Feb/March 2018
Q32 · Which item will not be affected by the issue of shares at a premium? 9706/11 May/June 2018
16 Which item will not be affected by the issue of shares at a premium? A capital reserves B net assets C profit for the year D working capital
1 marks
Answer: C
This question in 9706/11 May/June 2018
Q33 · A company has the following capital and reserves 9706/11 May/June 2018
17 A company has the following capital and reserves. $000 ordinary shares of $1 each, fully paid 1250 share premium account 100 revaluation reserve 200 general reserve 150 retained earnings 210 It is company policy to maintain reserves in their most flexible form. The company makes a 1-for-5 bonus issue. What is the maximum amount of distributable reserves after the bonus issue? A $110 000 B $310 000 C $360 000 D $410 000
1 marks
Answer: C
This question in 9706/11 May/June 2018
Q34 · P Limited has an ordinary share capital of 100 000 shares of $1 each 9706/11 May/June 2018
18 P Limited has an ordinary share capital of 100 000 shares of $1 each. The market value per share is $1.20. Which entries could record a 1-for-10 bonus issue of ordinary shares? debit credit $ $ A dividend 10 000 ordinary shares 10 000 B dividend 12 000 ordinary shares 10 000 share premium 2 000 C retained earnings 10 000 ordinary shares 10 000 D retained earnings 12 000 ordinary shares 10 000 share premium 2 000
1 marks
Answer: C
This question in 9706/11 May/June 2018
Q35 · Which company reserves may not be used to pay dividends? 9706/12 May/June 2018
15 Which company reserves may not be used to pay dividends? 1 general reserve 2 retained earnings 3 revaluation reserves 4 share premium A 1, 2 and 3 B 1 and 2 only C 2 and 3 only D 3 and 4
1 marks
Answer: D
This question in 9706/12 May/June 2018
Q36 · A company issued 50 000 ordinary shares of $0.50 each at a price of $0.60 each 9706/12 May/June 2018
16 A company issued 50 000 ordinary shares of $0.50 each at a price of $0.60 each. What were the accounting entries for the issue? debit $ credit $ A bank 30 000 share capital 25 000 share premium 5 000 B bank 25 000 share capital 30 000 share premium 5 000 C share capital 30 000 bank 30 000 D share capital 25 000 bank 30 000 share premium 5 000
1 marks
Answer: A
This question in 9706/12 May/June 2018
Q37 · What could be used to fund a bonus issue of shares? 9706/12 May/June 2018
17 What could be used to fund a bonus issue of shares? 1 general reserve 2 retained earnings 3 share premium A 1, 2 and 3 B 1 and 2 only C 1 and 3 only D 3 only
1 marks
Answer: A
This question in 9706/12 May/June 2018
Q38 · The total equity of a company on 1 January 2017 was $400 000 9706/13 May/June 2018
15 The total equity of a company on 1 January 2017 was $400 000. The following information is available for the year ended 31 December 2017. 1 There was a rights issue of 20 000 ordinary shares of $1 each at $1.50 in June 2017. All of these were taken up. 2 The profit for the year was $45 000. 3 Dividends paid during the year were $8000 and dividends proposed at the year end were $15 000. 4 A transfer to the general reserve of $10 000 was made. What was the total equity at 31 December 2017? A $442 000 B $452 000 C $467 000 D $477 000
1 marks
Answer: C
This question in 9706/13 May/June 2018
Q39 · A company makes a bonus issue of shares 9706/13 May/June 2018
16 A company makes a bonus issue of shares. What is the correct effect on the statement of financial position? share capital total assets A decrease decrease B decrease no change C increase increase D increase no change
1 marks
Answer: D
This question in 9706/13 May/June 2018
Q40 · Which statements about limited companies are correct? 9706/11 Oct/Nov 2018
15 Which statements about limited companies are correct? 1 Debenture interest is recorded in the income statement. 2 Director’s remuneration is recorded in the statement of changes in equity. 3 Share premium is a revenue reserve. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2018
Q41 · A company has the following capital and reserves 9706/11 Oct/Nov 2018
16 A company has the following capital and reserves. $ ordinary shares of $1 each 400 000 share premium account 60 000 revaluation reserve 120 000 general reserve 300 000 retained earnings 90 000 970 000 The company plans to make a bonus issue of one share for every four held. What will be the maximum amount of distributable reserves for the company after the bonus issue? A $290 000 B $300 000 C $350 000 D $390 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2018
Q42 · Which items would not appear in the income statement? 9706/11 Oct/Nov 2018
18 Which items would not appear in the income statement? 1 finance costs 2 loss on sale of non-current assets 3 ordinary share dividends A 1 only B 1 and 2 C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2018
Q43 · Which items would not be in the appropriation account for a partnership? 9706/12 Oct/Nov 2018
13 Which items would not be in the appropriation account for a partnership? 1 interest on capital 2 interest on a partner’s loan 3 share of profit on revaluation of assets 4 share of residual profit A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2018
Q44 · X and Y had been in partnership sharing profit and losses in the ratio of 1 : 2… 9706/12 Oct/Nov 2018
14 X and Y had been in partnership sharing profit and losses in the ratio of 1 : 2 respectively. Z was later admitted to the partnership. It was agreed that the goodwill is valued at $120 000. No goodwill account is to be retained in the books of account. Profit and losses were to be shared between X, Y and Z in the ratio of 2 : 1 : 1 respectively. What was the effect of the goodwill adjustment in X’s capital account? A decreased by $20 000 B decreased by $60 000 C increased by $20 000 D increased by $60 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2018
Q45 · J and K shared profits equally 9706/12 Oct/Nov 2018
15 J and K shared profits equally. Their capital account balances were J $400 000 and K $160 000. L was admitted as a partner. The three partners then shared profits equally. On admission of L as a partner, assets were increased in value by $210 000. L paid in capital equal to the average new capital balances of J and K. What was the capital paid in by L? A $175 000 B $280 000 C $350 000 D $385 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2018
Q46 · The statement of financial position of a business on 31 December 2017 showed the following 9706/12 Oct/Nov 2018
16 The statement of financial position of a business on 31 December 2017 showed the following. $ retained earnings 136 000 general reserves 28 000 share premium 55 000 During the year ended 31 December 2017 the business had made a profit for the year of $25 000 and had transferred $10 000 to the general reserve. What was the total of revenue reserves on 1 January 2017? A $101 000 B $139 000 C $149 000 D $194 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2018
Q47 · A company provides the following information 9706/12 Oct/Nov 2018
17 A company provides the following information. $ ordinary shares of $0.50 each 84 000 retained earnings 50 000 134 000 The following transactions then take place. 1 The company makes a rights issue of one new ordinary share for every two held, at $1.30. The issue was fully subscribed. 2 A bonus issue of two new ordinary shares for every three held was then made. What is the maximum possible balance of the retained earnings after these transactions? A $8400 B $16 800 C $33 200 D $41 600
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2018
Q48 · What is the effect of a company issuing bonus shares? 9706/13 Oct/Nov 2018
17 What is the effect of a company issuing bonus shares? A increases liquidity B increases profitability C reduces gearing D reduces reserves
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2018
Q49 · During the year a business issued $1 ordinary shares at $1.20 each 9706/12 Feb/March 2019
16 During the year a business issued $1 ordinary shares at $1.20 each. The directors proposed a
final dividend at the end of the year.
Which balances in the statement of changes in equity were affected by these transactions?
ordinary share general retained
share capital premium reserve earnings
A Jv Jv
B Jv Jv J
Cc Jv J
D Jv J
1 marks
Answer: A
This question in 9706/12 Feb/March 2019
Q50 · A company has ordinary share capital of $250 000 9706/12 Feb/March 2019
17 A company has ordinary share capital of $250 000. The ordinary shares have a nominal value of $0.25 each. A rights issue is made on the basis of 2 shares for every 5 shares held at a premium of $0.15. What is the total amount of capital raised from the rights issue of shares? A $15 000 B $40 000 C $60 000 D $160 000
1 marks
Answer: D
This question in 9706/12 Feb/March 2019
Q51 · A shareholder sells some shares for less than he paid for them 9706/12 Feb/March 2019
18 A shareholder sells some shares for less than he paid for them. What happens to the share capital of the company? A decreases by the nominal value of the shares sold B decreases by the sales proceeds of the shares sold C increases by the amount received from the sale of the shares D remains the same as before
1 marks
Answer: D
This question in 9706/12 Feb/March 2019
Q52 · A company issued $1 ordinary shares for $1.20 each 9706/11 May/June 2019
15 A company issued $1 ordinary shares for $1.20 each. The total proceeds were recorded in the ordinary share capital account. Which journal entry completes the entries for the share issue? account to debit account to credit A suspense ordinary share capital B ordinary share capital suspense C ordinary share capital share premium D share premium ordinary share capital
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q53 · An extract from a company’s statement of financial position showed the following… 9706/11 May/June 2019
16 An extract from a company’s statement of financial position showed the following information. $000 issued capital: 2 million ordinary shares of $0.50 each 1000 share premium 600 retained earnings 2400 The directors have agreed to make a bonus issue of 3 ordinary shares for 4 shares held. They wish to maintain reserves in their most flexible form. Which debit entry should be made in the retained earnings account? A $150 000 B $750 000 C $900 000 D $1 500 000
1 marks
Answer: A
This question in 9706/11 May/June 2019
Q54 · A company issues 500 000 $1 ordinary shares for $3 each and $250 000 debentures of 6% 9706/11 May/June 2019
17 A company issues 500 000 $1 ordinary shares for $3 each and $250 000 debentures of 6%. By which amount will the net assets of the company increase? A $750 000 B $1 250 000 C $1 500 000 D $1 750 000
1 marks
Answer: C
This question in 9706/11 May/June 2019
Q55 · X and Y are in partnership sharing profits and losses in the ratio 2 : 1 9706/12 May/June 2019
11 X and Y are in partnership sharing profits and losses in the ratio 2 : 1. Z will be admitted with the following new arrangements. Profit and loss sharing ratio will be 2 : 1 : 2 respectively. Goodwill is valued at $90 000. Z will pay the partners for his share of the goodwill. How much will Z pay X? A $18 000 B $24 000 C $45 000 D $60 000
1 marks
Answer: B
This question in 9706/12 May/June 2019
Q56 · D, E and F are in partnership, sharing profits in the ratio 2 : 2 : 1 9706/12 May/June 2019
12 D, E and F are in partnership, sharing profits in the ratio 2 : 2 : 1. D is allowed an annual salary of $10 000. E has made a loan to the partnership on which the partnership pays interest of $5000 each year. Profit for the year before appropriation was $150 000. What was F’s total share of profit for the year? A $27 000 B $28 000 C $29 000 D $30 000
1 marks
Answer: B
This question in 9706/12 May/June 2019
Q57 · L and M had been in partnership sharing profits and losses equally 9706/12 May/June 2019
13 L and M had been in partnership sharing profits and losses equally. P was admitted to the partnership and the partners continued to share profits and losses equally. Goodwill was valued at $48 000 but the partners agreed that no goodwill account would be retained in the books of account. What were the accounting entries to record the goodwill? A debit L capital account $16 000, debit M capital account $16 000, credit P capital account $32 000 B debit P capital account $32 000, credit L capital account $16 000, credit M capital account $16 000 C debit L capital account $8000, debit M capital account $8000, credit P capital account $16 000 D debit P capital account $16 000, credit L capital account $8000, credit M capital account $8000
1 marks
Answer: D
This question in 9706/12 May/June 2019
Q58 · Which items do not appear in a statement of changes in equity? 9706/12 May/June 2019
14 Which items do not appear in a statement of changes in equity? 1 dividend paid 2 dividend proposed 3 loan interest A 1 and 2 only B 1, 2 and 3 C 1 only D 2 and 3 only
1 marks
Answer: D
This question in 9706/12 May/June 2019
Q59 · On 1 January a company’s equity included 100 000 $1 ordinary shares 9706/12 May/June 2019
15 On 1 January a company’s equity included 100 000 $1 ordinary shares. The directors of the company then did the following: 1 March Made a rights issue of 20 000 ordinary shares at $1.25 each. The rights issue was fully subscribed. 1 June Made a bonus issue of 5000 ordinary shares. 1 July Paid an interim dividend of $0.10 on all of the shares in issue at that date. By how much did the bank account increase as a result of these transactions? A $12 500 B $17 500 C $30 000 D $37 000
1 marks
Answer: A
This question in 9706/12 May/June 2019
Q60 · The following balances are extracted from the books of J Limited 9706/12 May/June 2019
16 The following balances are extracted from the books of J Limited. 30 April 2019 30 April 2018 $ $ ordinary shares of $0.50 each 700 000 500 000 share premium 90 000 50 000 How many ordinary shares have been issued during the year ended 30 April 2019? A 200 000 B 240 000 C 400 000 D 480 000
1 marks
Answer: C
This question in 9706/12 May/June 2019
Q61 · Goodwill is adjusted in partners’ accounts when there is a change in the profit sharing… 9706/13 May/June 2019
12 Goodwill is adjusted in partners’ accounts when there is a change in the profit sharing ratio. How is this recorded? debit credit A capital accounts in new profit sharing ratio capital accounts in old profit sharing ratio B capital accounts in old profit sharing ratio capital accounts in new profit sharing ratio C current accounts in new profit sharing ratio current accounts in old profit sharing ratio D current accounts in old profit sharing ratio current accounts in new profit sharing ratio
1 marks
Answer: A
This question in 9706/13 May/June 2019
Q62 · X, Y and Z were in partnership sharing profits and losses in the ratio 5 : 3 : 2… 9706/13 May/June 2019
13 X, Y and Z were in partnership sharing profits and losses in the ratio 5 : 3 : 2 respectively. The capital account balances before any adjustments were $40 000, $30 000 and $20 000 respectively. Z retired from the partnership. X and Y continued in partnership, sharing the profits and losses in the ratio 3 : 2 respectively. Net assets were to be revalued upwards by $10 000. What was the capital account balance for partner X following Z’s retirement? A $35 000 B $39 000 C $41 000 D $45 000
1 marks
Answer: D
This question in 9706/13 May/June 2019
Q63 · L and M are business partners sharing profits and losses in the ratio 2 : 1 9706/13 May/June 2019
14 L and M are business partners sharing profits and losses in the ratio 2 : 1. On 31 December 2018, their capital and current accounts showed the following credit balances. L M $ $ capital account 200 000 100 000 current account 40 000 30 000 At 1 January 2019, M transferred his private motor vehicle to the partnership. This motor vehicle originally cost $15 000. Its current market value is $8000. Both partners made drawings of $20 000 each. What was the total of each partner’s capital and current accounts after the changes? L M capital current capital current account account account account $ $ $ $ A 180 000 40 000 88 000 30 000 B 200 000 20 000 100 000 18 000 C 200 000 20 000 108 000 10 000 D 200 000 20 000 115 000 10 000
1 marks
Answer: C
This question in 9706/13 May/June 2019
Q64 · Which items may be recorded in a Statement of Changes in Equity? 9706/13 May/June 2019
15 Which items may be recorded in a Statement of Changes in Equity? 1 issue of debentures 2 profit for the year 3 proposed dividends A 1 and 2 B 1 only C 2 and 3 D 2 only
1 marks
Answer: D
This question in 9706/13 May/June 2019
Q65 · The equity of a company included the following: $ ordinary shares of $1 each 1 500 000… 9706/13 May/June 2019
16 The equity of a company included the following: $ ordinary shares of $1 each 1 500 000 share premium account 600 000 The market price of one share was $1.50. The company made a fully subscribed rights issue of 500 000 ordinary shares at $1.20 per share. What was the balance on the ordinary share capital account and share premium account after the issue? ordinary share share premium capital account account $ $ A 2 000 000 700 000 B 2 000 000 850 000 C 2 100 000 600 000 D 2 250 000 600 000
1 marks
Answer: A
This question in 9706/13 May/June 2019
Q66 · A company provides the following financial information at the end of the financial year 9706/13 May/June 2019
17 A company provides the following financial information at the end of the financial year. $000 retained earnings at the start of the year 50 profit for the year 120 ordinary dividends paid during the year 70 ordinary dividends proposed payable in the next financial year 30 transfer to general reserve 20 What is the amount of retained earnings at the end of the financial year? A $50 000 B $70 000 C $80 000 D $100 000
1 marks
Answer: C
This question in 9706/13 May/June 2019
Q67 · Which statement is not correct? 9706/11 Oct/Nov 2019
15 Which statement is not correct? A Bonus shares can be issued from capital reserves. B Bonus shares can be issued from revenue reserves. C Dividends can be paid from capital reserves. D Dividends can be paid from revenue reserves.
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2019
Q68 · During the year ended 31 December 2018 a business made a profit of $31 000 9706/11 Oct/Nov 2019
16 During the year ended 31 December 2018 a business made a profit of $31 000. A dividend of 8% was paid on the 200 000 ordinary shares of $0.50 each, and $12 000 was transferred to general reserve. The retained earnings of the business on 31 December 2018 amounted to $68 000. What was the balance of retained earnings on 1 January 2018? A $41 000 B $57 000 C $65 000 D $79 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2019
Q69 · A company had an issued share capital of $400 000 made up of ordinary shares of $0.50… 9706/11 Oct/Nov 2019
17 A company had an issued share capital of $400 000 made up of ordinary shares of $0.50 fully paid. The following transactions took place. 1 An issue of bonus shares on the basis of one ordinary share for every four ordinary shares already held was made. 2 Later, a rights issue of ordinary shares of one new share for every two already held at a premium of $0.15 per share was made. This issue was fully subscribed. By how much will the company’s bank account be increased? A $125 000 B $162 500 C $250 000 D $325 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2019
Q70 · The directors of a limited company recently made a rights issue of one ordinary share for… 9706/12 Oct/Nov 2019
17 The directors of a limited company recently made a rights issue of one ordinary share for every three held at a premium of $0.50 per share. The rights issue was fully subscribed. The statement of financial position showed the following information after the rights issue was made. $000 issued share capital: (shares of $1 each) 1200 share premium 300 Which amount was debited to the company’s bank account when the rights issue was made? A $300 000 B $400 000 C $450 000 D $600 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2019
Q71 · A company’s year end is 31 December 9706/12 Oct/Nov 2019
18 A company’s year end is 31 December. During the year ended 31 December 2018 it paid the following dividends: $ final dividend for the year ended 31 December 2017 15 000 interim dividend for the year ended 31 December 2018 8 000 On 1 February 2019 it declared a final dividend of $10 000 for the year ended 31 December 2018. How much should be recorded for dividends in the statement of changes in equity for the year ended 31 December 2018? A $8000 B $18 000 C $23 000 D $33 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2019
Q72 · Which items are capital reserves? 9706/13 Oct/Nov 2019
15 Which items are capital reserves? 1 debentures 2 retained earnings 3 revaluation reserve 4 share premium A 1 and 2 B 1 only C 3 and 4 D 4 only
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2019
Q73 · A company's statement of financial position showed the total equity of $300 000 on 1 July… 9706/13 Oct/Nov 2019
16 A company's statement of financial position showed the total equity of $300 000 on 1 July 2018. The following took place during the year ended 30 June 2019. 1 Profit for the year was $77 500. 2 An interim dividend of $9000 was paid. A final dividend of $16 000 was proposed. 3 A transfer of $8000 to the general reserve was made. What was the total equity at 30 June 2019? A $344 500 B $352 500 C $368 500 D $376 500
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2019
Q74 · The table shows an extract from the financial statements of a limited company 9706/13 Oct/Nov 2019
17 The table shows an extract from the financial statements of a limited company. $ ordinary share capital 500 000 ($1 shares) share premium 150 000 revaluation reserve 200 000 retained earnings 250 000 What is the maximum dividend per share that can be paid? A $0.50 B $0.80 C $0.90 D $1.20
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2019
Q75 · Which item is shown in the statement of changes in equity? 9706/12 Feb/March 2020
15 Which item is shown in the statement of changes in equity? A dividend proposed B interest on long-term loan C issue of debenture D revaluation gain on non-current assets
1 marks
Answer: D
This question in 9706/12 Feb/March 2020
Q76 · Which statement about bonus shares is correct? 9706/12 Feb/March 2020
16 Which statement about bonus shares is correct? A They may be issued as repayment of debentures. B They may be issued at a premium. C They may be issued to the holders of preference shares. D They may be issued using the share premium account.
1 marks
Answer: D
This question in 9706/12 Feb/March 2020
Q77 · The equity of P Limited at 1 January 2019 was $668 000 9706/12 Feb/March 2020
17 The equity of P Limited at 1 January 2019 was $668 000. Profit for the year ended 31 December 2019 was $120 000. During the year ended 31 December 2019, the following also took place: 1 April Paid an interim dividend of $40 000 1 July Transferred $50 000 from retained earnings to general reserve 1 October Issued 5% debentures for $200 000 31 December Proposed a final dividend of $30 000 What was the total equity of P Limited at 31 December 2019? A $698 000 B $718 000 C $748 000 D $948 000
1 marks
Answer: C
This question in 9706/12 Feb/March 2020
Q78 · What would be recorded in a partnership appropriation account? 9706/11 May/June 2020
13 What would be recorded in a partnership appropriation account? 1 interest on capital 2 interest on drawings 3 interest on loan by partner to partnership 4 interest on bank overdraft A 1, 2 and 3 B 1 and 2 only C 2, 3 and 4 D 3 and 4 only
1 marks
Answer: B
This question in 9706/11 May/June 2020
Q79 · X and Y were in partnership and shared their profits equally 9706/11 May/June 2020
14 X and Y were in partnership and shared their profits equally. On 1 March 2019, Z is admitted as a partner. In future they will share profits in the ratio X, Y and Z, 3 : 2 : 1. The net assets valued at $20 000 have lost $8000 in value. Goodwill is valued at $9000 but will not be retained in the books of account. What will the entries in the capital accounts of Y be to record these changes? debit credit $ $ A 4500 9000 B 4500 7000 C 6000 4500 D 7000 4500
1 marks
Answer: D
This question in 9706/11 May/June 2020
Q80 · The statement of financial position showed the following balances at 31 December 2019 9706/11 May/June 2020
15 The statement of financial position showed the following balances at 31 December 2019. L M $ $ capital accounts 20 000 10 000 current accounts 1 000 debit 2 500 credit Net assets at 1 January 2019 were $14 000. Property had been revalued upwards by $12 000 during the year ended 31 December 2019. No drawings had been made during the year. What was the profit for the year ended 31 December 2019? A $2500 B $5500 C $14 500 D $17 500
1 marks
Answer: B
This question in 9706/11 May/June 2020
Q81 · ‘Shareholders are entitled to a fixed annual dividend with any unpaid dividends being… 9706/11 May/June 2020
16 ‘Shareholders are entitled to a fixed annual dividend with any unpaid dividends being paid out of future profits.’ What does this statement describe? A cumulative preference shares B debentures C ordinary shares D participating preference shares
1 marks
Answer: A
This question in 9706/11 May/June 2020
Q82 · Which statements about a bonus issue of ordinary shares are correct? 9706/11 May/June 2020
17 Which statements about a bonus issue of ordinary shares are correct? 1 It will generate extra funds for the company. 2 The company’s liquidity is not affected. 3 Shareholders can sell their bonus shares. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: C
This question in 9706/11 May/June 2020
Q83 · The following information is available for T Limited 9706/11 May/June 2020
18 The following information is available for T Limited. 30 June 2018 30 June 2019 $ $ retained earnings 94 000 148 000 general reserve 50 000 65 000 accrued loan interest 3 000 1 000 During the year ended 30 June 2019, T Limited made the following payments. $ dividend 60 000 loan interest 27 000 What was the profit from operations for the year ended 30 June 2019? A $104 000 B $114 000 C $129 000 D $154 000
1 marks
Answer: D
This question in 9706/11 May/June 2020
Q84 · How should interest charged on a partner’s drawings account be treated? 9706/12 May/June 2020
12 How should interest charged on a partner’s drawings account be treated? A credited to the appropriation account B credited to the income statement C debited to the appropriation account D debited to the income statement
1 marks
Answer: A
This question in 9706/12 May/June 2020
Q85 · X, Y and Z were in partnership, sharing profits equally 9706/12 May/June 2020
13 X, Y and Z were in partnership, sharing profits equally. When Z retired from the business the assets were revalued. Goodwill was also valued but was not retained in the books of accounts. Which statement about Z’s retirement is correct? A Only X and Y’s capital accounts will be adjusted for the revaluation. B Only X and Y’s capital accounts will be adjusted for goodwill. C The balance on Z’s current account will form part of her retirement settlement. D Z may only be paid in cash for her share on retirement.
1 marks
Answer: C
This question in 9706/12 May/June 2020
Q86 · L and M are in partnership, sharing profits and losses in the ratio of 3 : 2 9706/12 May/June 2020
14 L and M are in partnership, sharing profits and losses in the ratio of 3 : 2. They have the following current account balances. L M $ $ 31 March 2019 3 000 credit 4500 debit 31 March 2020 14 200 credit 6200 debit The balances at 31 March 2020 are after taking into account the following. L M $ $ interest on drawings 1 000 1 500 interest on capital 3 000 2 000 drawings 10 000 15 000 What was the residual profit to be shared between L and M for the year ended 31 March 2020? A $24 000 B $27 000 C $29 000 D $32 000
1 marks
Answer: D
This question in 9706/12 May/June 2020
Q87 · How is unpaid debenture interest recorded in the financial statements of a company at the… 9706/12 May/June 2020
15 How is unpaid debenture interest recorded in the financial statements of a company at the year end? 1 a current liability in the statement of financial position 2 a non-current liability in the statement of financial position 3 an expense in the income statement 4 an item in the statement of changes in equity A 1 and 3 B 1 only C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/12 May/June 2020
Q88 · On 1 December 2019 a company’s statement of financial position included the following 9706/12 May/June 2020
16 On 1 December 2019 a company’s statement of financial position included the following. $ ordinary shares of $5 each 2 500 000 share premium 850 000 retained earnings 710 000 2019 15 December paid an ordinary share interim dividend of $0.15 per share 23 December made a bonus issue of 25 000 ordinary shares Reserves were kept in their most flexible form. What were the balances on the revenue reserves and capital reserves accounts after these transactions? revenue reserves capital reserves $ $ A 335 000 725 000 B 335 000 825 000 C 635 000 725 000 D 635 000 825 000
1 marks
Answer: C
This question in 9706/12 May/June 2020
Q89 · What would be recorded in a partnership appropriation account? 9706/13 May/June 2020
13 What would be recorded in a partnership appropriation account? 1 interest on capital 2 interest on drawings 3 interest on loan by partner to partnership 4 interest on bank overdraft A 1, 2 and 3 B 1 and 2 only C 2, 3 and 4 D 3 and 4 only
1 marks
Answer: B
This question in 9706/13 May/June 2020
Q90 · X and Y were in partnership and shared their profits equally 9706/13 May/June 2020
14 X and Y were in partnership and shared their profits equally. On 1 March 2019, Z is admitted as a partner. In future they will share profits in the ratio X, Y and Z, 3 : 2 : 1. The net assets valued at $20 000 have lost $8000 in value. Goodwill is valued at $9000 but will not be retained in the books of account. What will the entries in the capital accounts of Y be to record these changes? debit credit $ $ A 4500 9000 B 4500 7000 C 6000 4500 D 7000 4500
1 marks
Answer: D
This question in 9706/13 May/June 2020
Q91 · The statement of financial position showed the following balances at 31 December 2019 9706/13 May/June 2020
15 The statement of financial position showed the following balances at 31 December 2019. L M $ $ capital accounts 20 000 10 000 current accounts 1 000 debit 2 500 credit Net assets at 1 January 2019 were $14 000. Property had been revalued upwards by $12 000 during the year ended 31 December 2019. No drawings had been made during the year. What was the profit for the year ended 31 December 2019? A $2500 B $5500 C $14 500 D $17 500
1 marks
Answer: B
This question in 9706/13 May/June 2020
Q92 · ‘Shareholders are entitled to a fixed annual dividend with any unpaid dividends being… 9706/13 May/June 2020
16 ‘Shareholders are entitled to a fixed annual dividend with any unpaid dividends being paid out of future profits.’ What does this statement describe? A cumulative preference shares B debentures C ordinary shares D participating preference shares
1 marks
Answer: A
This question in 9706/13 May/June 2020
Q93 · Which statements about a bonus issue of ordinary shares are correct? 9706/13 May/June 2020
17 Which statements about a bonus issue of ordinary shares are correct? 1 It will generate extra funds for the company. 2 The company’s liquidity is not affected. 3 Shareholders can sell their bonus shares. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: C
This question in 9706/13 May/June 2020
Q94 · The following information is available for T Limited 9706/13 May/June 2020
18 The following information is available for T Limited. 30 June 2018 30 June 2019 $ $ retained earnings 94 000 148 000 general reserve 50 000 65 000 accrued loan interest 3 000 1 000 During the year ended 30 June 2019, T Limited made the following payments. $ dividend 60 000 loan interest 27 000 What was the profit from operations for the year ended 30 June 2019? A $104 000 B $114 000 C $129 000 D $154 000
1 marks
Answer: D
This question in 9706/13 May/June 2020
Q95 · X and Y were in partnership sharing profits and losses equally 9706/11 Oct/Nov 2020
12 X and Y were in partnership sharing profits and losses equally. Z joined the partnership and profit continued to be shared equally between the three partners. Goodwill was valued but no goodwill account was to remain in the books of account. Which entries were made to record the goodwill adjustment? debit account credit account 1 goodwill X and Y 2 goodwill X, Y and Z 3 X and Y goodwill 4 X, Y and Z goodwill A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2020
Q96 · Which are not appropriations of partnership profit? 9706/11 Oct/Nov 2020
13 Which are not appropriations of partnership profit? 1 interest on capital 2 interest on drawings 3 interest on loan from partner 4 partner’s drawings A 1 and 3 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2020
Q97 · L, M and N were in partnership sharing profits and losses in the ratio 3 : 2 : 1 9706/11 Oct/Nov 2020
14 L, M and N were in partnership sharing profits and losses in the ratio 3 : 2 : 1. The partnership was dissolved on 31 December 2019. After all assets had been realised and all liabilities paid, the following balances remained in the books of account. L M N total ($) ($) ($) ($) partners’ capital accounts 30 000 20 000 10 000 60 000 partners’ current accounts 4 000 8 000 (3 000) 9 000 cash at bank (debit) 60 000 realisation account (debit) 9 000 How much cash did N receive when the dissolution was complete? A $5500 B $7000 C $10 000 D $11 500
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2020
Q98 · Which items will be shown in the equity and reserves section of the statement of… 9706/11 Oct/Nov 2020
15 Which items will be shown in the equity and reserves section of the statement of financial position? 1 debentures 2 finance charges 3 retained earnings 4 share premium A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2020
Q99 · The following information was taken from the accounting records of a company at 1 January… 9706/11 Oct/Nov 2020
17 The following information was taken from the accounting records of a company at 1 January 2020. $ non-current assets at cost 250 000 accumulated depreciation 120 000 trade receivables 42 000 bank overdraft 25 000 cash & cash equivalents 9 000 prepaid expenses 2 000 inventory 17 000 5% debenture (2025) 7 000 What was the total capital employed? A $164 000 B $168 000 C $171 000 D $175 000
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2020
Q100 · A company issued 100 000 ordinary shares of $1 each at a premium of $2 9706/12 Oct/Nov 2020
15 A company issued 100 000 ordinary shares of $1 each at a premium of $2. The market value was $4 per share. Which statement is not correct? A Capital reserves increased by $200 000. B Cash and cash equivalents increased by $300 000. C Ordinary share capital increased by $100 000. D Revenue reserves increased by $400 000.
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2020
Q101 · Which item has no effect on the total equity of a limited company? 9706/12 Oct/Nov 2020
16 Which item has no effect on the total equity of a limited company? A bonus issue of shares B dividends paid C rights issue of shares D upward revaluation of non-current assets
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2020
Q102 · Information relating to W Limited for the year ended 31 December 2019 was as follows: $… 9706/12 Oct/Nov 2020
17 Information relating to W Limited for the year ended 31 December 2019 was as follows: $ retained earnings at 1 January 2019 22 000 profit from operations 83 000 dividend paid 20 000 dividend proposed 15 000 bank loan interest 16 000 What was the amount of retained earnings at 31 December 2019? A $32 000 B $47 000 C $54 000 D $69 000
1 marks
Answer: D
This question in 9706/12 Oct/Nov 2020
Q103 · On the dissolution of a partnership, one of the partners takes a motor vehicle in part… 9706/13 Oct/Nov 2020
13 On the dissolution of a partnership, one of the partners takes a motor vehicle in part settlement of the amount due to him. How is this entered in the books of account? debit account credit account A capital motor vehicle B capital realisation C realisation capital D motor vehicle capital
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2020
Q104 · At 31 December 2019 X, Y and Z were in partnership sharing profits and losses equally 9706/13 Oct/Nov 2020
14 At 31 December 2019 X, Y and Z were in partnership sharing profits and losses equally. At that date the net assets of the partnership were valued at $300 000 and X’s capital account balance was $70 000. On 1 January 2020 X retired. The net assets were then revalued upwards by $90 000. X left half of the amount due to him on retirement as a loan to the partnership. What was the value of the partnership’s net assets remaining after X’s retirement? A $220 000 B $230 000 C $290 000 D $350 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2020
Q105 · Which items would appear in a partnership’s appropriation account? 9706/13 Oct/Nov 2020
15 Which items would appear in a partnership’s appropriation account? 1 partners’ interest on capital 2 partners’ introduction of new capital 3 salaries of employees 4 salaries of partners A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2020
Q106 · Which item will affect the total equity of a limited company? 9706/13 Oct/Nov 2020
16 Which item will affect the total equity of a limited company? A bonus issue of shares B issue of debentures C proposed dividend D rights issue of shares
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2020
Q107 · A company makes a fully subscribed rights issue of 100 000 ordinary shares of $1 each at… 9706/13 Oct/Nov 2020
17 A company makes a fully subscribed rights issue of 100 000 ordinary shares of $1 each at $1.20. The market value of a share at that date was $1.30. Half of the rights issue proceeds were used to repay a long-term loan. By how much did the company’s capital employed increase? A $60 000 B $65 000 C $120 000 D $130 000
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2020
Q108 · Where are dividends paid during the year recorded in the financial statements of a… 9706/13 Oct/Nov 2020
18 Where are dividends paid during the year recorded in the financial statements of a limited company? 1 income statement 2 statement of changes in equity 3 statement of financial position A 1 and 2 B 1 only C 2 and 3 D 2 only
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2020
Q109 · X and Y were in partnership sharing profits and losses equally 9706/12 Feb/March 2021
13 X and Y were in partnership sharing profits and losses equally. Z was admitted as a partner and the profit and loss sharing ratio for X, Y and Z will be 2 : 2 : 1 respectively. On the date of admission, the value of non-current assets was increased by $48 000. Goodwill was valued at $30 000 but would not be retained in the books of account. What was the effect on X’s capital account? A increased by $19 200 B increased by $24 000 C increased by $27 000 D increased by $31 200
1 marks
Answer: C
This question in 9706/12 Feb/March 2021
Q110 · Which items would appear in a partnership’s appropriation account, in the absence of a… 9706/12 Feb/March 2021
14 Which items would appear in a partnership’s appropriation account, in the absence of a partnership agreement? 1 profit for the year 2 partners’ interest on drawings 3 partners’ salaries 4 partners’ share of profits A 1 and 4 B 1 only C 2 and 3 D 4 only
1 marks
Answer: A
This question in 9706/12 Feb/March 2021
Q111 · Annie and Bernie have been in partnership for some years, sharing profits and losses in… 9706/12 Feb/March 2021
15 Annie and Bernie have been in partnership for some years, sharing profits and losses in the ratio 2 : 1. On 1 January 2020, they decided to introduce interest on drawings. The annual interest on drawings for the year ended 31 December 2020 was $1300 for Annie and $800 for Bernie. Which effect did this change have on the balance on Annie’s current account at 31 December 2020? A decrease of $100 B decrease of $500 C increase of $100 D increase of $500
1 marks
Answer: C
This question in 9706/12 Feb/March 2021
Q112 · The total of shareholders’ equity at 31 December 2019 was $45 500 9706/12 Feb/March 2021
16 The total of shareholders’ equity at 31 December 2019 was $45 500. During the year ended 31 December 2020, the following took place. 1 An issue of 10 000 ordinary shares of $1 each at a premium of $0.25 was made. 2 A bonus issue of 5000 shares of $1 each was made. 3 Buildings were revalued from $250 000 to $265 000. 4 The profit for the year was $20 400. 5 There was a transfer to the general reserve of $6000. 6 The directors proposed a final dividend of $8000. What was the balance of the shareholders’ equity at 31 December 2020? A $85 400 B $87 400 C $93 400 D $98 400
1 marks
Answer: C
This question in 9706/12 Feb/March 2021
Q113 · The following relates to a limited company during a year 9706/12 Feb/March 2021
17 The following relates to a limited company during a year. $ repayment of a debenture 200 000 receipt from issue of ordinary shares 500 000 non-current assets purchased by cheque 300 000 net book value of disposals 50 000 disposal proceeds 60 000 revaluation surplus 20 000 What was the total net cash inflow arising from these? A $60 000 B $70 000 C $80 000 D $110 000
1 marks
Answer: A
This question in 9706/12 Feb/March 2021
Q114 · What is included in the reserves of a limited company? 9706/12 Feb/March 2021
18 What is included in the reserves of a limited company? A debentures B ordinary shares C preference shares D share premium
1 marks
Answer: D
This question in 9706/12 Feb/March 2021
Q115 · L, M and N are in partnership, sharing profits and losses equally 9706/11 May/June 2021
13 L, M and N are in partnership, sharing profits and losses equally. On 31 December 2020 N retired. At that date: 1 N’s capital account balance was $30 000 and his current account had a debit balance of $5400. 2 Profit for the year was $21 000 before paying L’s salary of $6000. 3 The goodwill was valued at $18 000 but is not to remain in the books of account. 4 Other assets are to be revalued upwards by $6000. How much will N be entitled to on his retirement? A $30 600 B $37 600 C $41 400 D $42 400
1 marks
Answer: B
This question in 9706/11 May/June 2021
Q116 · Charlie and Daphne are in partnership, sharing profits and losses in the ratio 2 : 1 9706/11 May/June 2021
14 Charlie and Daphne are in partnership, sharing profits and losses in the ratio 2 : 1. Their fixed capital account balances at 31 December 2019 were $20 000 and $13 000 respectively. They changed the terms of the partnership on 1 January 2020 to introduce interest on capital at the rate of 10% per annum. Which effect did this change have on Charlie’s total share of profit for the year ended 31 December 2020? A decrease of $200 B decrease of $700 C increase of $200 D increase of $700
1 marks
Answer: A
This question in 9706/11 May/June 2021
Q117 · What will be debited in the appropriation account of a partnership? 9706/11 May/June 2021
15 What will be debited in the appropriation account of a partnership? 1 interest on partners’ drawings 2 interest on the partner’s loan 3 salaries of partners 4 partners’ share of goodwill written off A 1 and 3 B 2 and 3 C 2 and 4 D 3 only
1 marks
Answer: D
This question in 9706/11 May/June 2021
Q118 · A company made a rights issue of ordinary shares at a premium 9706/11 May/June 2021
16 A company made a rights issue of ordinary shares at a premium. How will this be treated in the financial statements? 1 as equity in the statement of financial position 2 as a movement in the statement of changes in equity 3 as a non-current liability in the statement of financial position A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: A
This question in 9706/11 May/June 2021
Q119 · The income statement of X Limited for 2020 showed an incorrect profit figure because $10… 9706/11 May/June 2021
17 The income statement of X Limited for 2020 showed an incorrect profit figure because $10 000 of goods had been counted twice when closing inventory was valued. This incorrect inventory value was carried forward as the opening inventory for 2021. In February 2021 the directors paid a dividend equal to 40% of the profit for 2020. What were the effects of the error in inventory valuation? retained earnings at dividend paid in 2021 31 December 2021 A decrease of $4000 decrease of $4000 B decrease of $4000 increase of $14 000 C increase of $4000 decrease of $4000 D increase of $4000 decrease of $14 000
1 marks
Answer: C
This question in 9706/11 May/June 2021
Q120 · A company has the following items in its statement of financial position 9706/11 May/June 2021
18 A company has the following items in its statement of financial position. $ ordinary shares of $0.50 each 900 000 retained earnings 450 000 long-term bank loan 30 000 The company then issues 100 000 bonus shares of $0.50 each to its shareholders. What is the total equity after the issue of the bonus shares? A $1 300 000 B $1 350 000 C $1 380 000 D $1 400 000
1 marks
Answer: B
This question in 9706/11 May/June 2021
Q121 · Which statements apply when a bonus issue of ordinary shares is made by a company? 9706/12 May/June 2021
15 Which statements apply when a bonus issue of ordinary shares is made by a company? 1 It will be made to existing shareholders. 2 The issue can be at a premium. 3 They can be issued at lower than market price. A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: B
This question in 9706/12 May/June 2021
Q122 · At the start of the year a limited company’s equity was as follows 9706/12 May/June 2021
16 At the start of the year a limited company’s equity was as follows. $ ordinary shares of $1 each 200 000 retained earnings 120 000 During the year the following took place. 1 Non-current assets were revalued upwards by $70 000. 2 An interim dividend of $30 000 was paid. 3 A 10% debenture (2030) of $10 000 was issued. The profit for the year was $80 000. What was the total equity at the end of the year? A $380 000 B $390 000 C $440 000 D $480 000
1 marks
Answer: C
This question in 9706/12 May/June 2021
Q123 · The financial year of a limited company ends on 30 June 9706/12 May/June 2021
17 The financial year of a limited company ends on 30 June. The following information is available regarding ordinary dividends. for the year dividend proposed ended $ 30 June 2019 12 000 30 June 2020 19 000 During the year ended 30 June 2020, the company paid last year’s proposed dividend in full together with an interim dividend of $4300. What is the amount of dividends shown in the financial statements for the year ended 30 June 2020? statement of statement of income statement changes in equity financial position $ $ $ A nil 16 300 nil B nil 23 300 23 300 C 19 000 16 300 nil D 23 300 19 000 19 000
1 marks
Answer: A
This question in 9706/12 May/June 2021
Q124 · P and Q were in partnership, sharing profits and losses equally 9706/13 May/June 2021
13 P and Q were in partnership, sharing profits and losses equally. R was admitted to the partnership. The terms of R’s admission were as follows. 1 R introduced capital of $20 000 cash and a vehicle valued at $6000. 2 Non-current assets were revalued upwards by $14 000. 3 Goodwill was valued at $10 000, but will not be retained in the books of account. 4 The new future profit-sharing ratio will be P, Q, R, 2 : 2 : 1. What was the opening balance on R’s capital account? A $21 200 B $24 000 C $28 000 D $28 800
1 marks
Answer: B
This question in 9706/13 May/June 2021
Q125 · H and D are in partnership 9706/13 May/June 2021
14 H and D are in partnership. They are charged 5% interest on their annual drawings. Their appropriation account for the year ended 30 April 2021 showed the following. H D $ $ interest on drawings 2 080 1 520 interest on capital 2 000 1 000 salaries 20 000 15 000 share of profits 63 000 42 000 On 1 May 2020 the balance on H’s current account was $3300 debit. What was the credit balance on H’s current account on 30 April 2021? A $38 020 B $40 100 C $79 620 D $81 700
1 marks
Answer: A
This question in 9706/13 May/June 2021
Q126 · L and M are in partnership 9706/13 May/June 2021
15 L and M are in partnership. The following information about the partnership relates to 2020. $ profit before appropriation 88 000 interest on drawings: L 1 000 M 1 000 interest on capital: L 3 000 M 1 000 Profits are shared in the same ratio as partners’ capital account balances. What is L’s share of the residual profit? A $41 000 B $43 000 C $61 500 D $64 500
1 marks
Answer: D
This question in 9706/13 May/June 2021
Q127 · A company’s statement of financial position shows the following balances 9706/13 May/June 2021
16 A company’s statement of financial position shows the following balances. $ ordinary shares of $1 each 100 000 share premium 10 000 retained earnings 48 000 bank (debit) 50 000 A bonus issue of one ordinary share for every four ordinary shares held takes place. Reserves are kept in their most flexible form. What are the new account balances? retained share premium bank (debit) earnings $ $ $ A nil 33 000 50 000 B nil 33 000 75 000 C 10 000 23 000 50 000 D 10 000 23 000 75 000
1 marks
Answer: A
This question in 9706/13 May/June 2021
Q128 · What are shown in the statement of changes in equity? 9706/13 May/June 2021
17 What are shown in the statement of changes in equity? A bonus issue, debenture interest paid, profit for the year B bonus issue, dividends proposed, loss for the year C rights issue, dividends paid, profit for the year D rights issue, debenture interest paid, loss for the year
1 marks
Answer: C
This question in 9706/13 May/June 2021
Q129 · The following information is available for a limited company at 31 December 2020 9706/13 May/June 2021
18 The following information is available for a limited company at 31 December 2020. $ non-current assets 200 000 shareholders’ equity 170 000 5% debentures (2028) 40 000 bank loan 150 000 The bank loan is repayable in five annual equal instalments with the first payment due on 1 June 2021. What was the total working capital at 31 December 2020? A $120 000 B $130 000 C $160 000 D $190 000
1 marks
Answer: B
This question in 9706/13 May/June 2021
Q130 · A shareholder sells some ordinary shares for more than he paid for them 9706/11 Oct/Nov 2021
15 A shareholder sells some ordinary shares for more than he paid for them. What is the effect on the company statement of financial position? ordinary share capital share premium account A decrease decrease B decrease increase C no effect decrease D no effect no effect
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2021
Q131 · The equity of X Limited at 30 June 2021 was as follows 9706/11 Oct/Nov 2021
16 The equity of X Limited at 30 June 2021 was as follows. $ share capital 600 000 share premium 100 000 revaluation reserve 90 000 general reserve 50 000 retained earnings 80 000 What was the maximum total dividend that could be paid to shareholders? A $80 000 B $130 000 C $220 000 D $320 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2021
Q132 · The value of inventory for a limited company at 31 May 2020 was overstated by $20 000 9706/11 Oct/Nov 2021
17 The value of inventory for a limited company at 31 May 2020 was overstated by $20 000. What was the effect of this error on retained earnings? retained earnings at retained earnings at 31 May 2020 31 May 2021 A overstated by $20 000 no effect B overstated by $20 000 understated by $20 000 C understated by $20 000 no effect D understated by $20 000 overstated by $20 000
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2021
Q133 · X and Y are in partnership sharing profits and losses equally 9706/12 Oct/Nov 2021
15 X and Y are in partnership sharing profits and losses equally. They have combined capital account balances of $200 000. Z was admitted as a partner. Non-current assets were revalued upwards by $30 000. Goodwill was valued at $20 000 but was not to be retained in the books of account. Following Z’s admission the total of the partners’ capital accounts was $270 000. How much capital did Z contribute? A $20 000 B $40 000 C $50 000 D $70 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2021
Q134 · A company’s statement of financial position at 1 January 2020 included the following… 9706/12 Oct/Nov 2021
16 A company’s statement of financial position at 1 January 2020 included the following amounts. $ ordinary shares of $5 each 800 000 general reserve 80 000 retained earnings 120 000 The following transactions took place during the year ended 31 December 2020. 1 The company issued a further 50 000 ordinary shares at a premium of $1 per share. 2 The company’s land was revalued upwards by $130 000. 3 The company paid a final dividend of $60 000. What were the total revenue reserves and capital reserves at 31 December 2020 after these three transactions? total revenue total capital reserves reserves $ $ A 140 000 180 000 B 190 000 130 000 C 200 000 180 000 D 250 000 130 000
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2021
Q135 · A company revalued its premises upwards 9706/12 Oct/Nov 2021
17 A company revalued its premises upwards. Which statement about the increase in value is correct? A It is an unrealised profit. B It is debited to the revaluation reserve. C It is recorded in the income statement. D It can be used to pay cash dividends.
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2021
Q136 · The table shows equity and liabilities of a company at 31 December 2020 9706/12 Oct/Nov 2021
18 The table shows equity and liabilities of a company at 31 December 2020. $ ordinary share capital 750 000 6% debentures (2030) 150 000 bank loan (repayable 2024) 75 000 bank overdraft 110 000 mortgage on buildings (repayable 2021) 120 000 What is the total of non-current liabilities in the statement of financial position at 31 December 2020? A $195 000 B $225 000 C $270 000 D $345 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2021
Q137 · A partner is retiring from a partnership business 9706/13 Oct/Nov 2021
14 A partner is retiring from a partnership business. What is the correct accounting treatment for goodwill if no goodwill is retained in the books of account? old partners’ new partners’ capital accounts capital accounts A credit in old debit in new profit-sharing ratio profit-sharing ratio B credit in old debit in old profit-sharing ratio profit-sharing ratio C debit in new credit in new profit-sharing ratio profit-sharing ratio D debit in old credit in new profit-sharing ratio profit-sharing ratio
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2021
Q138 · X, Y and Z are in partnership sharing profits and losses equally 9706/13 Oct/Nov 2021
15 X, Y and Z are in partnership sharing profits and losses equally. At 31 December 2020, X had a capital account balance of $100 000 and a current account credit balance of $80 000. On 1 January 2021 X retired. Non-current assets and goodwill were revalued upwards by a total of $60 000. X left half the amount due to her on retirement as a loan to the partnership. The balance was paid to her by cheque. How much was X paid? A $40 000 B $60 000 C $100 000 D $120 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2021
Q139 · A company had share capital of 100 000 ordinary shares of $1 each at the start of its… 9706/13 Oct/Nov 2021
16 A company had share capital of 100 000 ordinary shares of $1 each at the start of its financial year. The following transactions took place during the year. 1 An issue of 50 000 ordinary shares at $1.40 each was made. 2 A bonus issue of 15 000 ordinary shares of $1 each was then made. 3 A 12% debenture of $100 000 was issued. 4 A bank loan of $75 000 was repaid. What was the net cash inflow from these transactions? A $75 000 B $95 000 C $110 000 D $210 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2021
Q140 · A company paid an ordinary share dividend of $15 000 in the year 9706/13 Oct/Nov 2021
17 A company paid an ordinary share dividend of $15 000 in the year. Where would it appear in the financial statements? A as a finance cost in the income statement B as an administrative expense in the income statement C under retained earnings in the statement of changes in equity D under share capital in the statement of changes in equity
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2021
Q141 · The equity of a limited company is shown 9706/13 Oct/Nov 2021
18 The equity of a limited company is shown. start of the year end of the year $ $ ordinary shares of $1 each 200 000 250 000 retained earnings 77 000 112 000 total equity 277 000 362 000 During the year the following transactions took place. 1 A bonus issue of one ordinary share for every four ordinary shares held was made. 2 Debenture interest of $18 000 was paid. 3 An interim dividend of $22 000 was paid. What was the profit for the year? A $57 000 B $107 000 C $125 000 D $157 000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2021
Q142 · P and Q are in partnership sharing profits and losses equally 9706/12 Feb/March 2022
15 P and Q are in partnership sharing profits and losses equally. On 1 January 2021, the partnership had net assets of $410 000. At that date, R was admitted into the business on the following terms. 1 Net assets to be revalued to $480 000. 2 Goodwill was valued at $50 000 but will not be retained in the books of account. 3 Profits and losses will now be shared P 40%, Q 40% and R 20%. What was the change in Q’s capital immediately after R’s admission? A decrease by $33 000 B decrease by $40 000 C increase by $33 000 D increase by $40 000
1 marks
Answer: D
This question in 9706/12 Feb/March 2022
Q143 · X and Y are in partnership, sharing residual profits and losses equally 9706/12 Feb/March 2022
16 X and Y are in partnership, sharing residual profits and losses equally. Partners are charged 2% interest on their drawings. Y is entitled to a salary of $10 000. The partners’ drawings for the year were as shown. $ X 12 000 Y 8 000 The profit for the year was $52 000. How much did each partner receive as a share of residual profits? A $10 800 B $11 200 C $20 800 D $21 200
1 marks
Answer: D
This question in 9706/12 Feb/March 2022
Q144 · Which statements are correct? 9706/12 Feb/March 2022
17 Which statements are correct? 1 Dividends can be paid out of the general reserve. 2 Rights issues can be made from the share premium account. 3 The general reserve can be created from retained earnings. A 1 and 2 B 1 and 3 C 1 only D 2 and 3
1 marks
Answer: B
This question in 9706/12 Feb/March 2022
Q145 · A limited company had the following balances on 1 January 2021 9706/12 Feb/March 2022
18 A limited company had the following balances on 1 January 2021. $ revaluation reserve 20 000 retained earnings 142 000 Profit for the year ended 31 December 2021 was $105 000. The revaluation reserve, $20 000, was created two years ago from a revaluation of a property. The same property was revalued on 31 December 2021 with a revaluation loss of $35 000. On 1 August 2021 an interim dividend, $40 000, was paid. On 31 December 2021 a final dividend, $55 000, was proposed. What was the value of retained earnings at 31 December 2021? A $117 000 B $137 000 C $172 000 D $192 000
1 marks
Answer: D
This question in 9706/12 Feb/March 2022
Q146 · The bank balance of a limited company was $390 000 before the following transactions took… 9706/12 Feb/March 2022
19 The bank balance of a limited company was $390 000 before the following transactions took place. 1 An issue of 500 000 new shares of $0.50 each was made at a premium of $0.25 per share. 2 A debenture for $100 000 was repaid. 3 A bonus issue of 100 000 shares of $0.50 each was made. What was the bank balance after these transactions? A $540 000 B $665 000 C $715 000 D $865 000
1 marks
Answer: B
This question in 9706/12 Feb/March 2022
Q147 · X and Y were in partnership sharing profits and losses equally 9706/11 May/June 2022
14 X and Y were in partnership sharing profits and losses equally. On 1 January, P was admitted into the partnership. He contributed $20 000 cash and $10 000 other assets. The non-current assets were revalued upwards by $12 000 on this date. There was no adjustment for goodwill. Profits and losses continued to be shared equally. What was the balance on P’s capital account after all relevant entries had been made? A $20 000 B $26 000 C $30 000 D $34 000
1 marks
Answer: C
This question in 9706/11 May/June 2022
Q148 · Daisy, Freddie and Harry, who shared profits equally, had been in partnership for some… 9706/11 May/June 2022
15 Daisy, Freddie and Harry, who shared profits equally, had been in partnership for some years. Harry decided to retire. Harry’s capital and current accounts had credit balances of $40 000 and $8000 respectively. The total assets of the partnership had a book value of $98 000 but a realisable value of $116 000. There was no adjustment for goodwill. Which amount did Harry receive from the partnership on his retirement? A $38 000 B $42 000 C $48 000 D $54 000
1 marks
Answer: D
This question in 9706/11 May/June 2022
Q149 · A company made a bonus issue of one ordinary share for every five ordinary shares held 9706/11 May/June 2022
16 A company made a bonus issue of one ordinary share for every five ordinary shares held. What is the effect on share capital and reserves and net assets? share capital and net assets reserves A increase increase B increase no change C no change increase D no change no change
1 marks
Answer: D
This question in 9706/11 May/June 2022
Q150 · At the end of its first year of trading, a company provided the following information 9706/11 May/June 2022
17 At the end of its first year of trading, a company provided the following information. paid during at the year end the year $ $ dividends 3 000 5 800 proposed debenture interest 4 000 1 600 accrued directors’ salaries 10 800 nil By how much do these items reduce the profit for the year? A $13 200 B $14 400 C $16 400 D $19 400
1 marks
Answer: C
This question in 9706/11 May/June 2022
Q151 · M Limited has the following balances at 1 January 2021 9706/11 May/June 2022
18 M Limited has the following balances at 1 January 2021. $ ordinary share capital 500 000 shares of $0.50 each 250 000 share premium 10 000 general reserve 40 000 retained earnings 50 000 During the year ended 31 December 2021: 1 an interim dividend of $0.02 per share was paid 2 there was a transfer of $20 000 to the general reserve. For the year ended 31 December 2021, the company made a profit for the year of $80 000. What is the maximum additional dividend payable per ordinary share for the year ended 31 December 2021? A $0.20 B $0.22 C $0.32 D $0.34
1 marks
Answer: C
This question in 9706/11 May/June 2022
Q152 · Dua and Noor are in partnership sharing profits and losses equally 9706/12 May/June 2022
15 Dua and Noor are in partnership sharing profits and losses equally. They admitted Zee and now share profits and losses in the ratio Dua : Noor : Zee, 2 : 2 : 1. On admission of Zee, tangible assets were reduced in value by $20 000 and goodwill was valued at $60 000, but was not retained in the books of account. What was the net decrease on Noor’s capital account? A $4000 B $8000 C $10 000 D $14 000
1 marks
Answer: A
This question in 9706/12 May/June 2022
Q153 · The following information is available for a partnership 9706/12 May/June 2022
16 The following information is available for a partnership. $ profit for the year before interest 15 000 interest on partner’s loan to the firm 1 000 interest on capital 2 000 drawings 10 000 Which profit figure is to be appropriated between the partners? A $3000 B $13 000 C $14 000 D $15 000
1 marks
Answer: C
This question in 9706/12 May/June 2022
Q154 · Which item should not be recorded in a statement of changes in equity? 9706/12 May/June 2022
17 Which item should not be recorded in a statement of changes in equity? A bonus issue of ordinary shares B dividends paid on ordinary shares C profit from operations for the year D transfer to general reserve
1 marks
Answer: C
This question in 9706/12 May/June 2022
Q155 · The following information has been extracted from the statement of financial position of… 9706/12 May/June 2022
18 The following information has been extracted from the statement of financial position of a limited company. $ 6% debenture (2026–2028) 20 000 400 000 ordinary shares of $1 each 400 000 5-year bank loan 200 000 share premium account 50 000 retained earnings 75 000 What is the value of the total equity? A $525 000 B $545 000 C $695 000 D $725 000
1 marks
Answer: A
This question in 9706/12 May/June 2022
Q156 · On 1 January, X Limited had share capital of 100 000 ordinary shares which had been… 9706/12 May/June 2022
19 On 1 January, X Limited had share capital of 100 000 ordinary shares which had been issued at their par value of $1 each. There was no share premium account. On 1 March, a bonus issue of one new ordinary share for every five ordinary shares held was made from retained earnings. On 1 June, the company made a rights issue of one new ordinary share for every four ordinary shares held at a price of $1.50 each. All the rights were taken up. How much was recorded in the share premium account? A $12 500 B $15 000 C $30 000 D $45 000
1 marks
Answer: B
This question in 9706/12 May/June 2022
Q157 · Which factors may cause a partnership to revalue its tangible non-current assets? 9706/13 May/June 2022
14 Which factors may cause a partnership to revalue its tangible non-current assets? 1 admission of a new partner 2 change in the profit-sharing ratios 3 retirement of a partner A 1 and 2 B 1 and 3 C 1 only D 2 and 3
1 marks
Answer: B
This question in 9706/13 May/June 2022
Q158 · L and M were in partnership sharing profits and losses in the ratio of 2 : 1 9706/13 May/June 2022
15 L and M were in partnership sharing profits and losses in the ratio of 2 : 1. At 31 December 2021, the assets and liabilities of the partnership were as follows. $ non-current assets at net book value 600 000 inventory 50 000 trade receivables 40 000 bank 5 000 debit trade payables 20 000 capital and current account L 350 000 capital and current account M 325 000 The partnership closed on 31 December 2021. At that date the following took place. 1 The non-current assets were sold for $654 000. 2 Inventory was sold for $80 000. 3 All trade receivables were collected and trade payables were settled at their book values. 4 Realisation expenses were $6000. What was L’s share of the profit on realisation? A $50 000 B $52 000 C $56 000 D $60 000
1 marks
Answer: B
This question in 9706/13 May/June 2022
Q159 · X, Y and Z are in partnership sharing profits and losses in the ratio 5 : 2 : 3 9706/13 May/June 2022
16 X, Y and Z are in partnership sharing profits and losses in the ratio 5 : 2 : 3. Y is entitled to a salary of $18 000 per annum. Partners receive interest at 6% per annum on their capital account balances at the beginning of the year. At the beginning of the year, capital account balances were as follows. $ X 30 000 Y 22 000 Z 20 000 The profit for the year before Y’s salary and partners’ interest on capital is $140 000. What is Y’s share of the total profits? A $23 536 B $28 000 C $42 856 D $46 000
1 marks
Answer: C
This question in 9706/13 May/June 2022
Q160 · During the year, a business issued $1 ordinary shares at $1.20 each 9706/13 May/June 2022
17 During the year, a business issued $1 ordinary shares at $1.20 each. The directors proposed a
final dividend at the end of the year.
Which balances in the statement of changes in equity were affected by these transactions?
ordinary share general retained
share capital premium reserve earnings
A J J
B J J Jv
Cc J Jv
D J Jv
1 marks
Answer: A
This question in 9706/13 May/June 2022
Q161 · The following items were taken from the bank transactions of a company for a period 9706/13 May/June 2022
18 The following items were taken from the bank transactions of a company for a period. $ share issue proceeds 30 000 sale of non-current assets 5 000 dividend paid 9 000 increase in bank loan 6 000 What was the net increase in the company’s bank balance as a result of these? A $28 000 B $32 000 C $38 000 D $40 000
1 marks
Answer: B
This question in 9706/13 May/June 2022
Q162 · On 1 January 2021, W Limited had total revenue reserves of $122 000 9706/13 May/June 2022
19 On 1 January 2021, W Limited had total revenue reserves of $122 000. During the year ended 31 December 2021, the following took place. 1 A dividend of $7500 was paid. 2 An amount of $10 000 was transferred from retained earnings to general reserve. 3 Premises were revalued upwards by $19 800. For the year ended 31 December 2021, W Limited made a profit for the year of $32 000. What was the total of revenue reserves at 31 December 2021? A $136 500 B $141 800 C $146 500 D $156 300
1 marks
Answer: C
This question in 9706/13 May/June 2022
Q163 · L, M and N share profits equally 9706/11 Oct/Nov 2022
15 L, M and N share profits equally. N is retiring and net assets at net book value of $27 000 are revalued at $36 000. Goodwill is valued at $18 000 but will not be recorded in the books of account. After N retires, L and M will share profits in the ratio 3 : 2. What will be the change to L’s capital account? A $1800 decrease B $1800 increase C $7800 decrease D $7800 increase
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2022
Q164 · Dele and Iyabo are partners and share profits in the ratio of 3 : 1 9706/11 Oct/Nov 2022
16 Dele and Iyabo are partners and share profits in the ratio of 3 : 1. Their profit for the year is $80 000. The following information is available. Dele Iyabo $ $ interest on capital 3000 2500 interest on drawings 500 1000 How will the residual profit be shared? Dele Iyabo $ $ A 57 000 19 000 B 57 500 18 500 C 62 500 21 500 D 63 000 21 000
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2022
Q165 · W Limited made a loss for the year 9706/11 Oct/Nov 2022
17 W Limited made a loss for the year. The directors wish to increase the balance on the retained earnings account. How can they do this? 1 increase dividends paid 2 issue new ordinary shares at a premium 3 make a transfer from general reserve A 1 and 2 B 1 only C 2 and 3 D 3 only
1 marks
Answer: D
This question in 9706/11 Oct/Nov 2022
Q166 · The following items were taken from the financial statements of a limited company during… 9706/11 Oct/Nov 2022
18 The following items were taken from the financial statements of a limited company during a period. $ increase in trade receivables 6 000 increase in trade payables 4 000 loan repaid 10 000 What was the effect of these items on the net cash inflow or outflow for the period? A $8000 outflow B $12 000 inflow C $12 000 outflow D $20 000 outflow
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2022
Q167 · The following information is available for a limited company 9706/11 Oct/Nov 2022
19 The following information is available for a limited company. At 1 April 2021 the balance of the retained earnings account was $858 000. for the year ended 31 March 2022 $ profit from operations 978 000 debenture interest paid for the year 100 000 ordinary share dividends paid 150 000 On 31 March 2022 the directors transferred $280 000 to a general reserve. They also issued 250 000 bonus shares of $1 each using the general reserve. What was the balance of the retained earnings account at 31 March 2022? A $1 056 000 B $1 306 000 C $1 406 000 D $1 586 000
1 marks
Answer: B
This question in 9706/11 Oct/Nov 2022
Q168 · Where is the dividend received by a company shown in its financial statements? 9706/12 Oct/Nov 2022
17 Where is the dividend received by a company shown in its financial statements? A income statement only B income statement and statement of changes in equity C statement of changes in equity only D statement of financial position and income statement
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2022
Q169 · On 1 January a company had 300 000 ordinary shares of $1 each and a 10% bank loan of $100… 9706/12 Oct/Nov 2022
18 On 1 January a company had 300 000 ordinary shares of $1 each and a 10% bank loan of $100 000. On 1 July the company issued a 6% debenture of $800 000. The profit from operations for the year ended 31 December was $120 000. The company paid a dividend of $0.05 per ordinary share during the year. What was the profit for the year ended 31 December? A $71 000 B $86 000 C $96 000 D $110 000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2022
Q170 · X Limited recorded the following information in its books of account 9706/12 Oct/Nov 2022
19 X Limited recorded the following information in its books of account. 1 issue of 10 000 ordinary shares of $1 each at a price of $1.80 2 payment of dividends, $6200 3 transfer to general reserve, $7500 What was the effect on total revenue reserves? A $6200 decrease B $6700 increase C $8000 increase D $13 700 decrease
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2022
Q171 · Which items would appear on the debit side of the dissolution account for a partnership? 9706/13 Oct/Nov 2022
14 Which items would appear on the debit side of the dissolution account for a partnership? 1 costs of dissolution 2 net book value of the assets 3 proceeds of sales of assets 4 profit on dissolution A 1 and 2 only B 1, 2 and 4 C 1, 3 and 4 D 2, 3 and 4
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2022
Q172 · L and M were in partnership sharing profits and losses equally 9706/13 Oct/Nov 2022
15 L and M were in partnership sharing profits and losses equally. They admitted a new partner, P. The partners do not have a partnership agreement. The terms of P’s admission were as follows: 1 Assets were revalued downwards by $60 000. 2 Goodwill was valued at $30 000 but was not retained in the books of account. What will be the effect on L’s capital account balance on the admission of P? effect due to effect due to revaluation goodwill A decrease increase B decrease decrease C increase increase D increase decrease
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2022
Q173 · J and K are in partnership sharing residual profits and losses in the ratio 7 : 3 9706/13 Oct/Nov 2022
16 J and K are in partnership sharing residual profits and losses in the ratio 7 : 3. Their fixed capital accounts have balances of J $40 000, K $60 000. Interest is allowed on these at the rate of 10% per year. J is paid a salary of $40 000 per year. Profit for the year was $200 000. What was each partner’s total share of the profit for the year? J K $ $ A 137 000 63 000 B 140 000 60 000 C 149 000 51 000 D 152 000 48 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2022
Q174 · X, Y and Z were in partnership sharing profits and losses equally 9706/13 Oct/Nov 2022
17 X, Y and Z were in partnership sharing profits and losses equally. Z retired from the partnership on 31 March 2022. The balances on his capital account and current account were $85 000 and $7000 debit respectively. After Z’s retirement, X and Y would share profits and losses equally. Goodwill was valued at $24 000 and would not remain in the books of accounts. As part of the amount due to him, Z took a motor vehicle at an agreed valuation of $4000. The other non-current assets were revalued downwards by $15 000. The remaining amount due to Z would be paid equally by X and Y. How much would X pay to Z? A $36 500 B $37 500 C $38 500 D $45 500
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2022
Q175 · Draft financial statements for a company showed a balance of retained earnings of $170… 9706/13 Oct/Nov 2022
18 Draft financial statements for a company showed a balance of retained earnings of $170 000 at the year end. The following information was then discovered. 1 An irrecoverable debt of $25 000 should have been written off. 2 An ordinary share dividend, $30 000, had been paid but not recorded. 3 Closing inventory was undervalued by $15 000. What was the correct balance of retained earnings at the year end? A $100 000 B $125 000 C $130 000 D $185 000
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2022
Q176 · A company provided the following information 9706/13 Oct/Nov 2022
19 A company provided the following information. at 1 January $ ordinary shares of $1 each 100 000 retained earnings 95 000 The following actions took place during the year ended 31 December. 1 A bonus issue of one ordinary share for every two ordinary shares held on 1 January. 2 A rights issue of 50 000 ordinary shares at $1.25 each. The issue was fully subscribed. 3 A transfer, $25 000, to create a general reserve. 4 A dividend, $11 250, was paid. The profit for the year ended 31 December was $68 500. What was the total shareholders’ equity at 31 December? A $289 750 B $314 750 C $364 750 D $389 750
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2022
Q177 · A limited company intends to issue shares at a price above the par value 9706/12 Feb/March 2023
18 A limited company intends to issue shares at a price above the par value. Which items, apart from the bank balance, will be affected by the share issue? A share capital, capital reserves and revenue reserves B share capital and capital reserves only C share capital and revenue reserves only D share capital only
1 marks
Answer: B
This question in 9706/12 Feb/March 2023
Q178 · The following information is available for a limited company for a financial year ended… 9706/12 Feb/March 2023
19 The following information is available for a limited company for a financial year ended on 31 December. $ total equity on 1 January 492 000 profit for the year 70 500 dividends paid 24 000 dividends proposed 12 000 On 30 June, there was a bonus issue of 20 000 ordinary shares of $1 each. On 31 December, the following decisions were made. 1 The buildings are to be revalued at $250 000. These had cost $200 000 and the accumulated depreciation was $50 000. 2 There is to be a transfer of $5000 to the general reserve. What is the total equity on 31 December after these adjustments have been made? A $588 500 B $613 500 C $618 500 D $638 500
1 marks
Answer: D
This question in 9706/12 Feb/March 2023
Q179 · The following actions took place in respect of a limited company 9706/11 May/June 2023
18 The following actions took place in respect of a limited company. 1 A transfer of $50 000 was made from retained earnings to general reserve. 2 An issue of 200 000 ordinary shares of $1 each at a price of $2.50 each was made. 3 Non-current assets with a carrying value of $1 250 000 were revalued at $1 500 000. 4 Ordinary dividends of $100 000 were proposed. What was the increase in the company’s total equity? A $450 000 B $500 000 C $650 000 D $750 000
1 marks
Answer: D
This question in 9706/11 May/June 2023
Q180 · A company had sufficient balances in each of the share premium, general reserve and… 9706/12 May/June 2023
17 A company had sufficient balances in each of the share premium, general reserve and retained earnings accounts to issue bonus shares. During the year, bonus shares were issued. The directors decided to keep the reserves in their most flexible form. Which ledger account will be debited on the issue of the bonus shares? A bank B general reserve C retained earnings D share premium
1 marks
Answer: D
This question in 9706/12 May/June 2023
Q181 · X Limited had the following equity on 1 January 9706/12 May/June 2023
18 X Limited had the following equity on 1 January. $ ordinary share capital ($1 shares) 400 000 share premium 30 000 general reserve 10 000 retained earnings 70 000 During the year ended 31 December, the following transactions took place. 1 January a bonus issue of 1 ordinary share for every 8 ordinary shares; it is the company’s policy to keep its reserves in the most flexible form 1 July an issue of debentures for $150 000 1 December a rights issue of 1 ordinary share for every 15 ordinary shares at a price of $1.60 per share; the rights issue was fully taken up 31 December profit for the year ended 31 December was $120 000 What was the total equity at 31 December? A $678 000 B $728 000 C $828 000 D $878 000
1 marks
Answer: A
This question in 9706/12 May/June 2023
Q182 · Which item would not be included on the statement of financial position for a limited… 9706/13 May/June 2023
17 Which item would not be included on the statement of financial position for a limited company? A issued share capital B proposed final dividends C revaluation reserve D share premium account
1 marks
Answer: B
This question in 9706/13 May/June 2023
Q183 · The equity section of the statement of financial position of a limited company at 1… 9706/13 May/June 2023
18 The equity section of the statement of financial position of a limited company at 1 January is shown. $ ordinary shares of $2 each 450 000 retained earnings 150 000 600 000 On 28 February, the company made a rights issue of 1 new share for every 3 existing shares held at a premium of $1.50 per share. The rights issue was fully subscribed. How much cash was received from the rights issue? A $112 500 B $225 000 C $262 500 D $525 000
1 marks
Answer: C
This question in 9706/13 May/June 2023
Q184 · Which reserves are revenue reserves? 9706/12 Oct/Nov 2023
19 Which reserves are revenue reserves? 1 general reserve 2 retained earnings 3 revaluation reserve 4 share premium account A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2023
Q185 · A limited company has the following in its statement of financial position at 31 March 9706/12 Oct/Nov 2023
20 A limited company has the following in its statement of financial position at 31 March. equity $ ordinary share capital 200 000 retained earnings 82 500 share premium 80 000 Ordinary shares have a par value of $0.40 each. A bonus issue is made on the basis of 3 shares for every 8 shares held at 31 March. The issue is made so that reserves are kept in their most flexible form. What are the balances on the reserve accounts after the bonus issue has been made? retained share earnings premium $ $ A 7 500 80 000 B 52 500 80 000 C 82 500 5 000 D 82 500 80 000
1 marks
Answer: C
This question in 9706/12 Oct/Nov 2023
Q186 · Which items will not form part of the equity of a limited company? 9706/13 Oct/Nov 2023
19 Which items will not form part of the equity of a limited company? 1 long-term bank loan 2 share premium 3 retained earnings 4 revaluation reserve A 1, 3 and 4 B 1 only C 2, 3 and 4 D 2 only
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2023
Q187 · Why is a statement of changes in equity prepared? 9706/12 Feb/March 2024
18 Why is a statement of changes in equity prepared? A to calculate profit when incomplete records have been kept B to match the dividends paid to profit for the year C to show the change in capital employed D to show the movements in the shareholders’ stake in the business
1 marks
Answer: D
This question in 9706/12 Feb/March 2024
Q188 · The trial balance of a company at 31 December at the end of year 1 included the following… 9706/12 Feb/March 2024
19 The trial balance of a company at 31 December at the end of year 1 included the following amounts. $ Ordinary share capital 800 000 ($0.50 shares) Share premium 200 000 Retained earnings 1 000 000 On 1 January in year 2 the company made a rights issue of 400 000 shares at a premium of $0.70 per share. This was fully taken up. On 1 July in year 2 the company issued bonus shares at the rate of one new share for every four held. The policy is to maintain reserves in their most flexible form. What is the balance on the share premium account after these transactions? A $230 000 B $330 000 C $355 000 D $480 000
1 marks
Answer: A
This question in 9706/12 Feb/March 2024
Q189 · Which statements about debenture interest are correct? 9706/11 May/June 2024
17 Which statements about debenture interest are correct? 1 Interest percentage rate will always be higher than dividend per share. 2 Interest will be deducted in the statement of changes in equity. 3 Interest will be paid before ordinary shareholder dividends. 4 Interest will be paid even if the company records a loss. A 1, 2 and 3 B 1, 3 and 4 C 2 and 3 only D 3 and 4 only
1 marks
Answer: D
This question in 9706/11 May/June 2024
Q190 · A company has the following reserves 9706/11 May/June 2024
18 A company has the following reserves. $ share premium 60 000 revaluation reserve 75 000 general reserve 10 000 retained earnings 21 500 The directors wish to make a bonus issue of ordinary shares of $1 each. What is the maximum number of bonus shares which the company could possibly issue? A 31 500 B 91 500 C 135 000 D 166 500
1 marks
Answer: B
This question in 9706/11 May/June 2024
Q191 · A company is planning to invest funds in a project 9706/13 May/June 2024
18 A company is planning to invest funds in a project. Current interest rates are high and the company wishes to avoid a change in the control of shareholders. Which method should the company use to fund the project? A a bonus issue B a fully subscribed rights issue C an issue of debentures D a new issue of shares
1 marks
Answer: B
This question in 9706/13 May/June 2024
Q192 · A company’s statement of financial position at the beginning of the financial year on 1… 9706/13 May/June 2024
19 A company’s statement of financial position at the beginning of the financial year on 1 January is shown. $ issued share capital 2 000 000 share premium 500 000 revaluation reserve 300 000 general reserve 150 000 retained earnings 1 600 000 The profit for the year ended 31 December was $680 000. During the year, the following took place: • an issue of 500 000 ordinary shares of $1 each at a price of $2.50 each • an upward revaluation of non-current assets of $250 000 • a transfer of $100 000 from retained earnings to general reserve • a payment of ordinary dividends of $125 000. What was the increase in the company’s equity and reserves for the financial year ended 31 December? A $1 305 000 B $1 955 000 C $2 055 000 D $2 180 000
1 marks
Answer: C
This question in 9706/13 May/June 2024
Q193 · A company issued shares at a premium 9706/12 Oct/Nov 2024
18 A company issued shares at a premium. In which financial statements would the share premium appear? A statement of changes in equity and statement of financial position B statement of financial position only C statement of profit or loss and statement of financial position D statement of profit or loss only
1 marks
Answer: A
This question in 9706/12 Oct/Nov 2024
Q194 · The statement of financial position of a company at 31 December showed the following: $… 9706/12 Oct/Nov 2024
19 The statement of financial position of a company at 31 December showed the following: $ issued share capital: 200000 ordinary shares at $1 per share 200000 During the following year, the company carried out the following: 1 On 1 January made a rights issue of one ordinary share for every five ordinary shares held. The share issue price was $1.50 per ordinary share and the issue was fully subscribed. 2 On 1 July made a bonus issue of one ordinary share for every four ordinary shares held at that date. What was the amount of cash received by the company in respect of these transactions? A $40000 B $60000 C $110000 D $135000
1 marks
Answer: B
This question in 9706/12 Oct/Nov 2024
Q195 · Which of these are revenue reserves? 9706/13 Oct/Nov 2024
18 Which of these are revenue reserves? 1 general reserve 2 retained earnings 3 revaluation reserve 4 share premium account A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2024
Q196 · A company made a bonus issue of ordinary shares 9706/13 Oct/Nov 2024
19 A company made a bonus issue of ordinary shares. Where would this appear in the financial statements? A statement of changes in equity and statement of financial position B statement of financial position only C statement of profit or loss and statement of changes in equity D statement of profit or loss and statement of financial position
1 marks
Answer: A
This question in 9706/13 Oct/Nov 2024
Q197 · A company provided the following information for the financial year ended 31 December 9706/13 Oct/Nov 2024
20 A company provided the following information for the financial year ended 31 December. 1 January 31 December $ $ ordinary share capital 500000 600000 ($1 shares) share premium 50000 − general reserve − 25000 retained earnings 240000 280000 During the year a bonus issue of one ordinary share for every five ordinary shares was made. It is the company’s policy to keep its reserves in the most flexible form. A dividend of $0.15 per share was paid during the year on all ordinary shares held on 1 January. What was the profit for the year? A $115 000 B $140 000 C $165 000 D $190 000
1 marks
Answer: D
This question in 9706/13 Oct/Nov 2024
Q198 · Which statement is correct in relation to the financial statements of limited companies? 9706/11 May/June 2025
19 Which statement is correct in relation to the financial statements of limited companies? A Debentures are presented as part of the total equity. B Dividend paid is shown in the statement of changes in equity. C Proposed dividend reduces the balance of retained earnings. D The gain from revaluation of non-current assets is added to retained earnings.
1 marks
Answer: B
This question in 9706/11 May/June 2025
Q199 · A company provides the following information about its equity 9706/11 May/June 2025
20 A company provides the following information about its equity. $ 150000 shares $1 each 150000 share premium 75000 general reserve 125000 retained earnings 25000 The directors propose to issue bonus shares on the basis of one $1 share for every three already held. Following this, the directors intend to make a rights issue on the basis of one new $1 share for every four shares held, at a premium of $0.20 per share. What will be the total equity of the company after the share issues? A $425000 B $435000 C $475000 D $485000
1 marks
Answer: B
This question in 9706/11 May/June 2025
Q200 · Which items will be shown in a company’s statement of changes in equity? 9706/12 May/June 2025
19 Which items will be shown in a company’s statement of changes in equity? 1 a bonus issue of ordinary shares 2 an issue of debentures 3 a proposed dividend on ordinary shares 4 an upwards revaluation of the company’s non-current assets A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: B
This question in 9706/12 May/June 2025
Q201 · The table shows a company’s equity 9706/12 May/June 2025
20 The table shows a company’s equity. $ ordinary shares of $1.00 each 200000 share premium account 80000 revenue reserves 160000 Changes now to be made to the equity (in the order given) are as follows: • a one-for-one bonus issue of ordinary shares • a rights issue of 100000 ordinary shares of $1.00 each at $1.40 per share. The company wishes to maintain reserves in the most flexible form. What will be the equity of the company? ordinary share capital share premium revenue reserves $ $ $ A 500000 40000 40000 B 500000 80000 nil C 540000 nil 40000 D 540000 40000 40000
1 marks
Answer: A
This question in 9706/12 May/June 2025
Q202 · Which statement is correct in relation to the financial statements of limited companies? 9706/13 May/June 2025
19 Which statement is correct in relation to the financial statements of limited companies? A Debentures are presented as part of the total equity. B Dividend paid is shown in the statement of changes in equity. C Proposed dividend reduces the balance of retained earnings. D The gain from revaluation of non-current assets is added to retained earnings.
1 marks
Answer: B
This question in 9706/13 May/June 2025
Q203 · A company provides the following information about its equity 9706/13 May/June 2025
20 A company provides the following information about its equity. $ 150000 shares $1 each 150000 share premium 75000 general reserve 125000 retained earnings 25000 The directors propose to issue bonus shares on the basis of one $1 share for every three already held. Following this, the directors intend to make a rights issue on the basis of one new $1 share for every four shares held, at a premium of $0.20 per share. What will be the total equity of the company after the share issues? A $425000 B $435000 C $475000 D $485000
1 marks
Answer: B
This question in 9706/13 May/June 2025
Q204 · Which list shows entries that should be credited to a partner’s current account? 9706/11 Oct/Nov 2025
16 Which list shows entries that should be credited to a partner’s current account? A interest on partner’s loan, partner’s salary, share of profits B interest on drawings, negative opening balance, share of loss C interest on drawings, positive opening balance, share of loss D interest on partner’s capital, interest on drawings, share of profits
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2025
Q205 · X and Y are in partnership, sharing profits and losses in the ratio of 3 : 2 respectively 9706/11 Oct/Nov 2025
17 X and Y are in partnership, sharing profits and losses in the ratio of 3 : 2 respectively. Interest on drawings is 5%. During the year ended 31 December, the amount that X and Y each drew was the same as their respective partner’s salary. X and Y were charged interest on drawings of $550 and $450 respectively. Profit for the year was $94 000, and loan interest paid to X was $3000. What was Y’s share of residual profit? A $28800 B $29200 C $30000 D $38000
1 marks
Answer: C
This question in 9706/11 Oct/Nov 2025
Q206 · How is any premium on an issue of shares treated? 9706/11 Oct/Nov 2025
18 How is any premium on an issue of shares treated? A added to a capital reserve B added to a revenue reserve C deducted from a capital reserve D deducted from a revenue reserve
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2025
Q207 · The table shows a company’s capital 9706/11 Oct/Nov 2025
19 The table shows a company’s capital. $ ordinary shares of $1.00 each 200000 share premium account 80000 revenue reserves 160000 The following changes are now required to be made (in the order given): • a one-for-one bonus issue • a rights issue of 100 000 ordinary shares of $1.00 each at $1.40 per share The company wishes to maximise the amounts available to pay dividends. What will be the ordinary share capital, share premium and revenue reserves of the company? ordinary share capital share premium revenue reserves $ $ $ A 500000 40000 40000 B 500000 80000 nil C 540000 nil 40000 D 540000 40000 40000
1 marks
Answer: A
This question in 9706/11 Oct/Nov 2025
Q208 · A company provides the following information 9706/13 Oct/Nov 2025
19 A company provides the following information. $ ordinary shares of $0.50 each 84000 retained earnings 50000 total equity 134000 The following transactions then take place. 1 The company makes a rights issue of one new ordinary share for every two held, at $1.30. The issue is fully subscribed. 2 A bonus issue of two ordinary shares for every three held is then made. What is the maximum possible balance of the retained earnings after these transactions? A $8400 B $16800 C $33200 D $41600
1 marks
Answer: C
This question in 9706/13 Oct/Nov 2025
Q209 · A company has an ordinary share capital of $400000 made up of ordinary shares of $0.50… 9706/13 Oct/Nov 2025
20 A company has an ordinary share capital of $400000 made up of ordinary shares of $0.50 each. The following information is available about dividends for the year ended 31 December. dividends paid during the year $0.10 per share proposed dividends at year end $60000 Which entry should be made for dividends in the statement of changes in equity for the year ended 31 December? A $40000 B $80000 C $100000 D $140000
1 marks
Answer: B
This question in 9706/13 Oct/Nov 2025
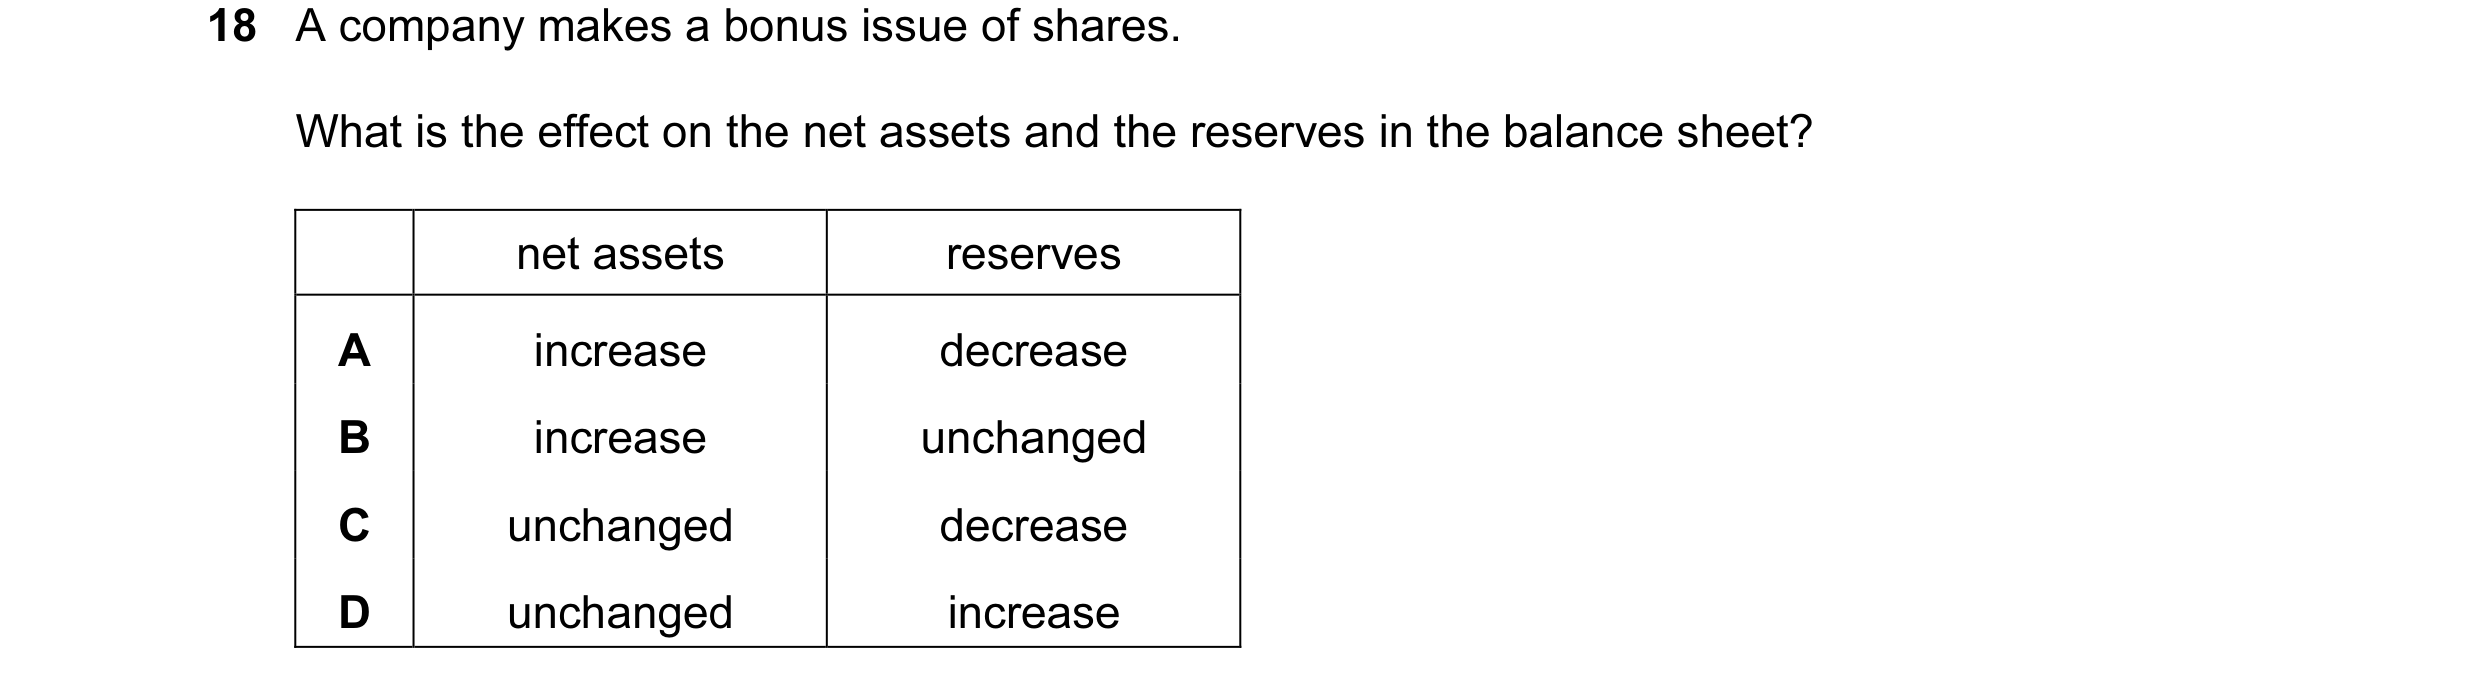
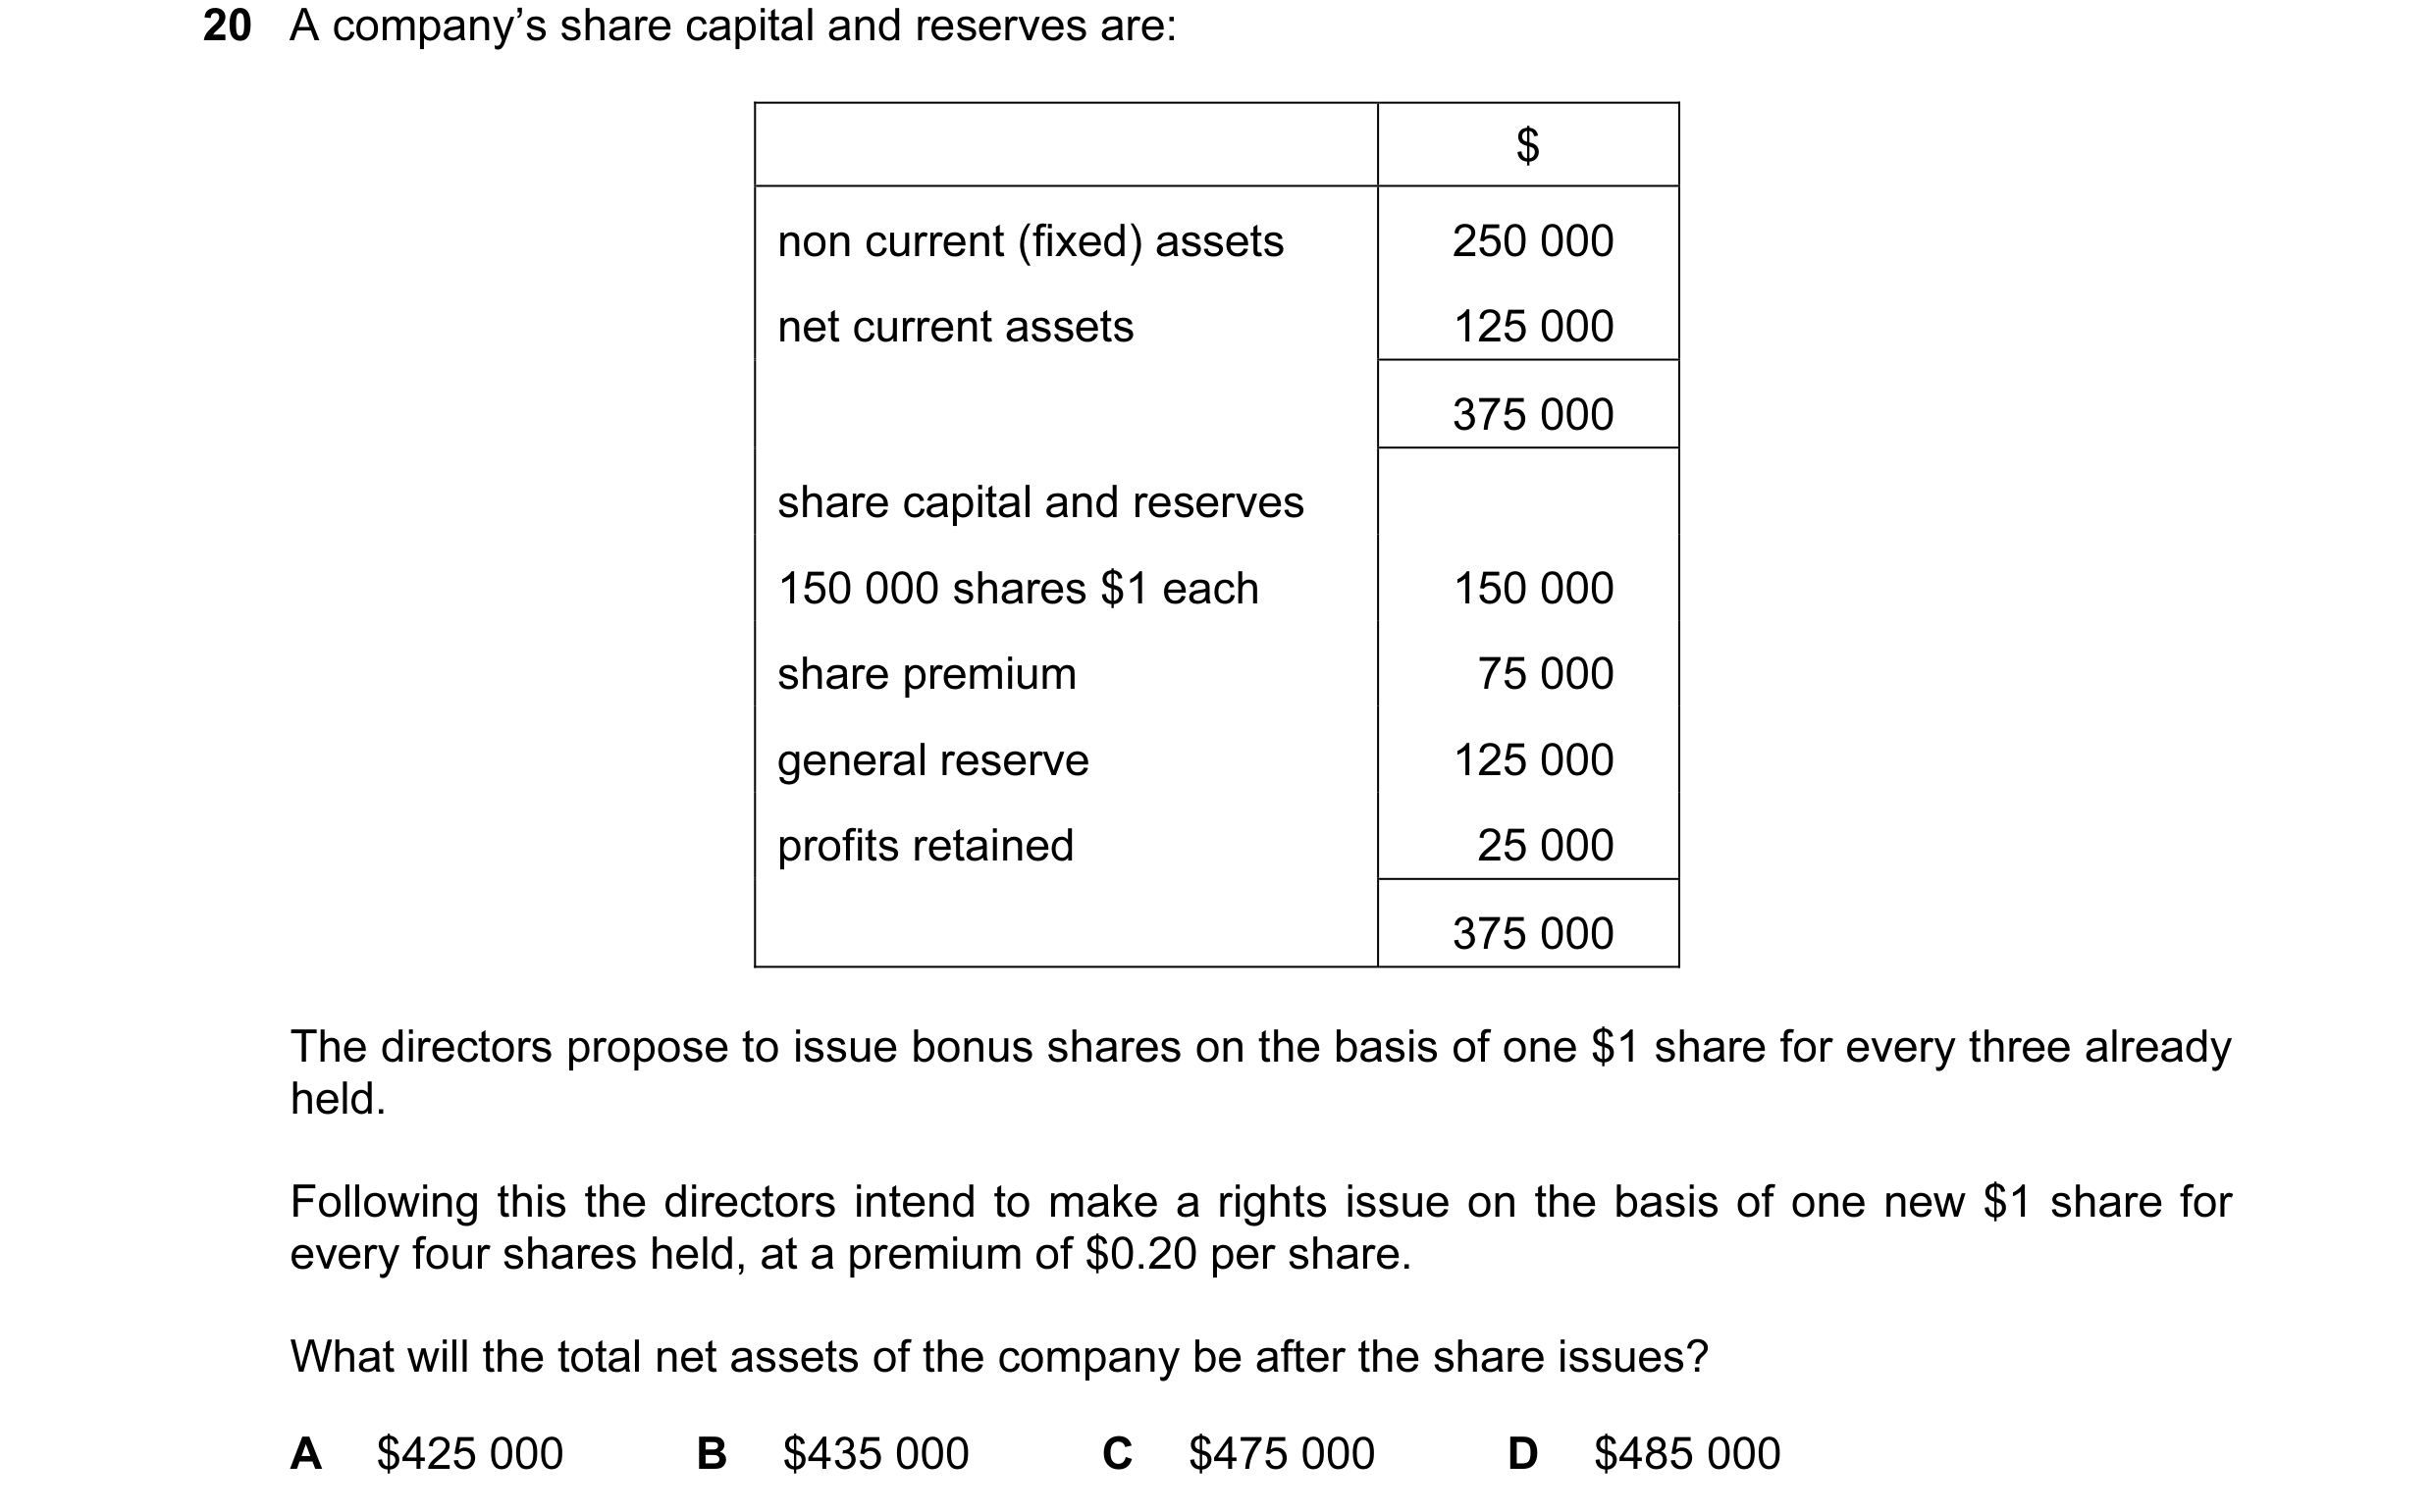
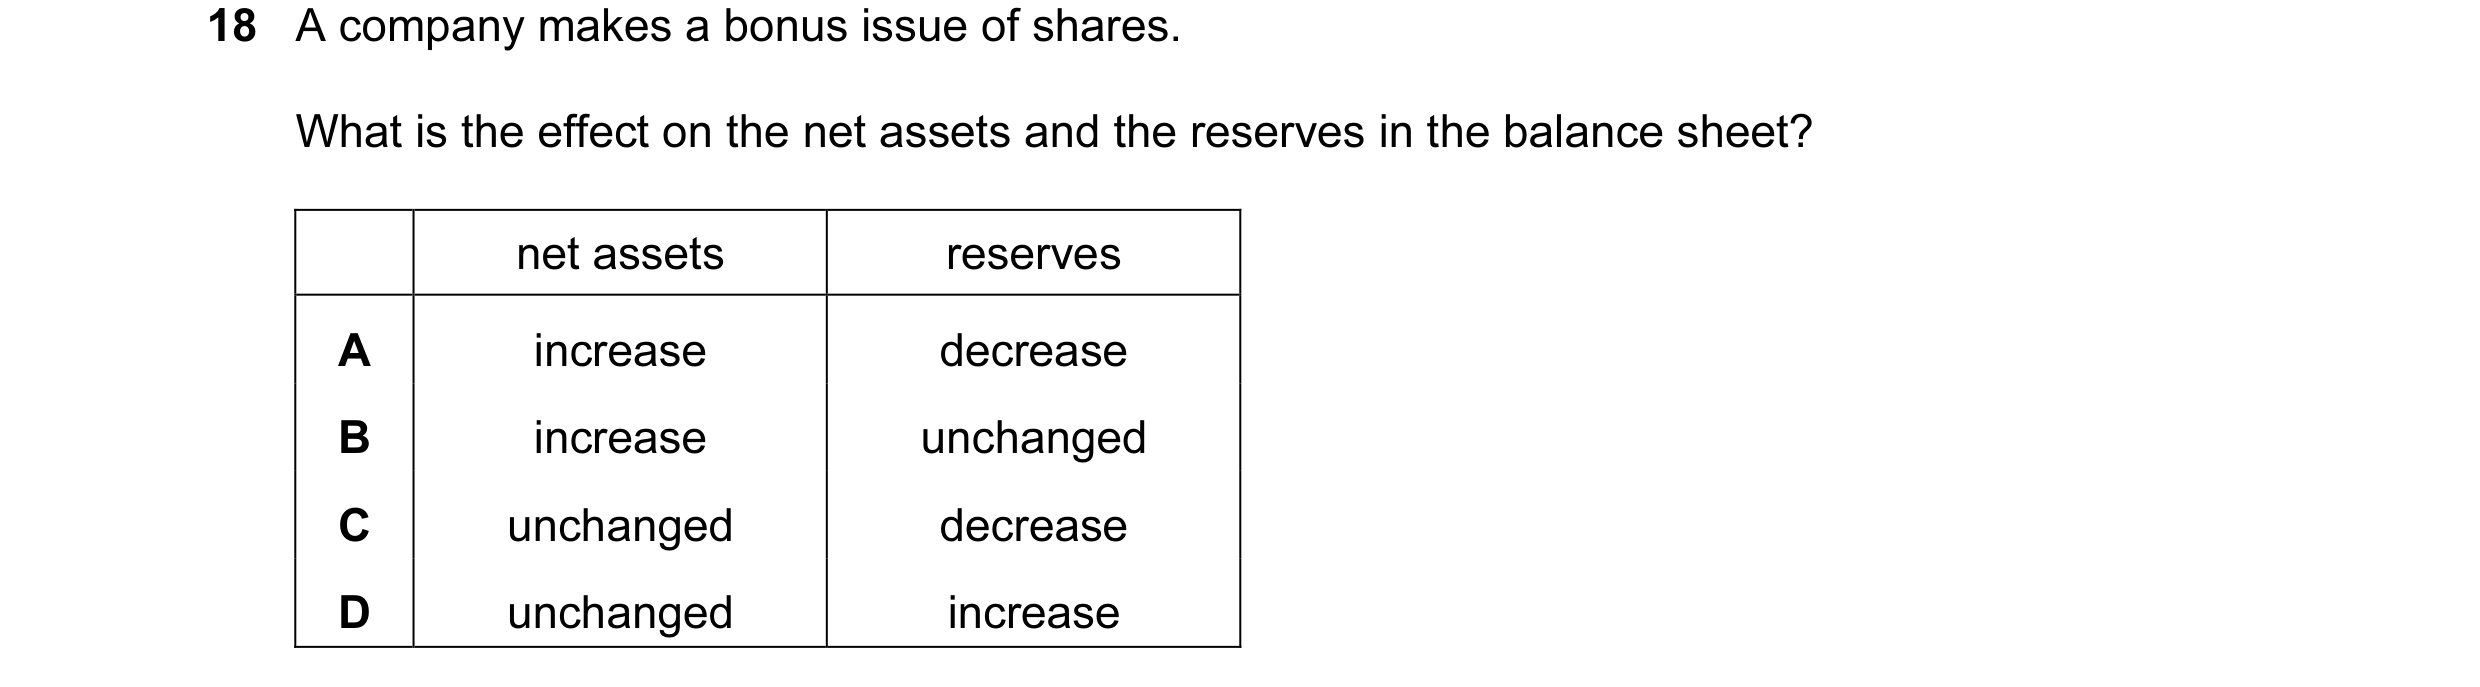 1 / 60
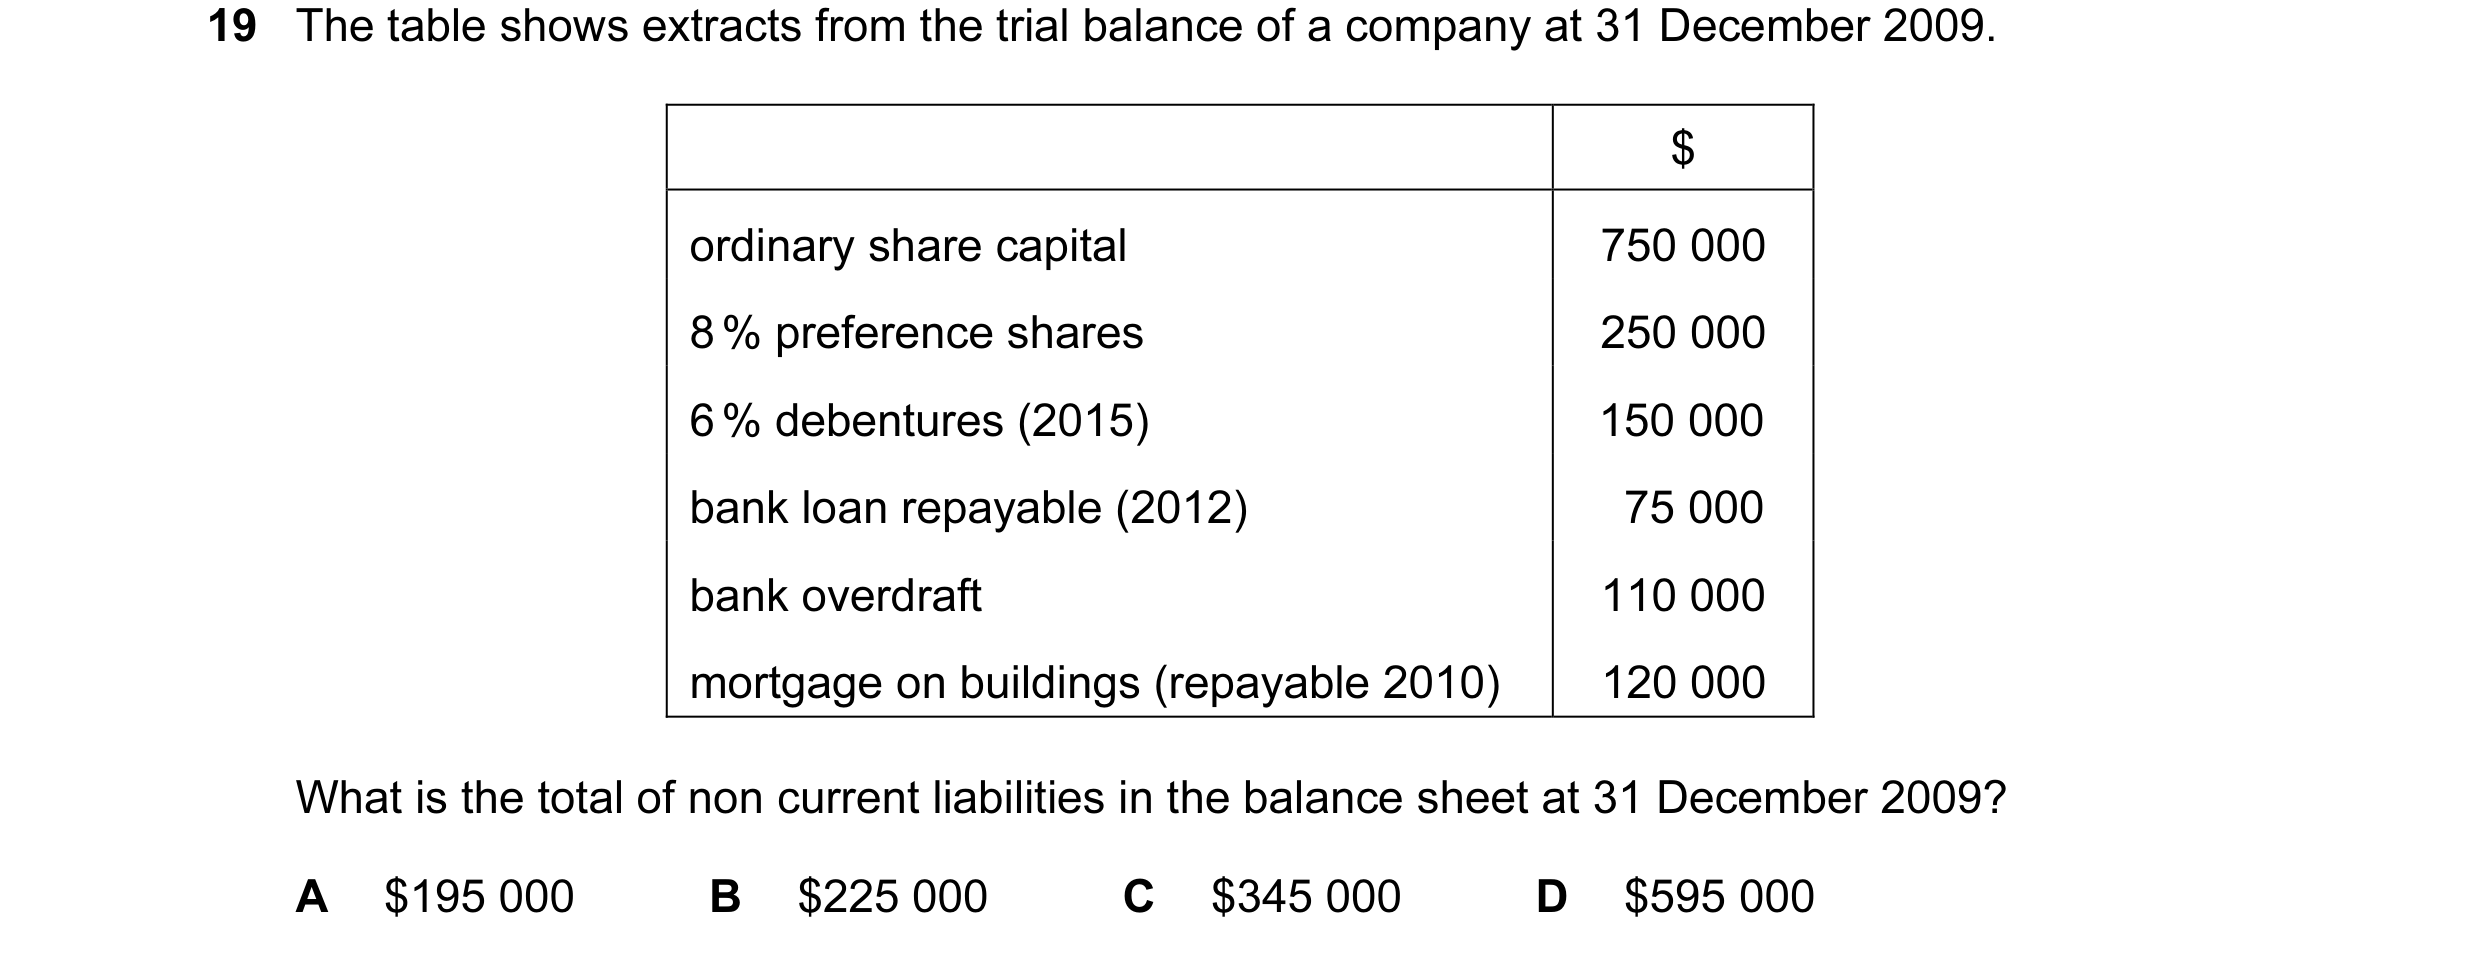
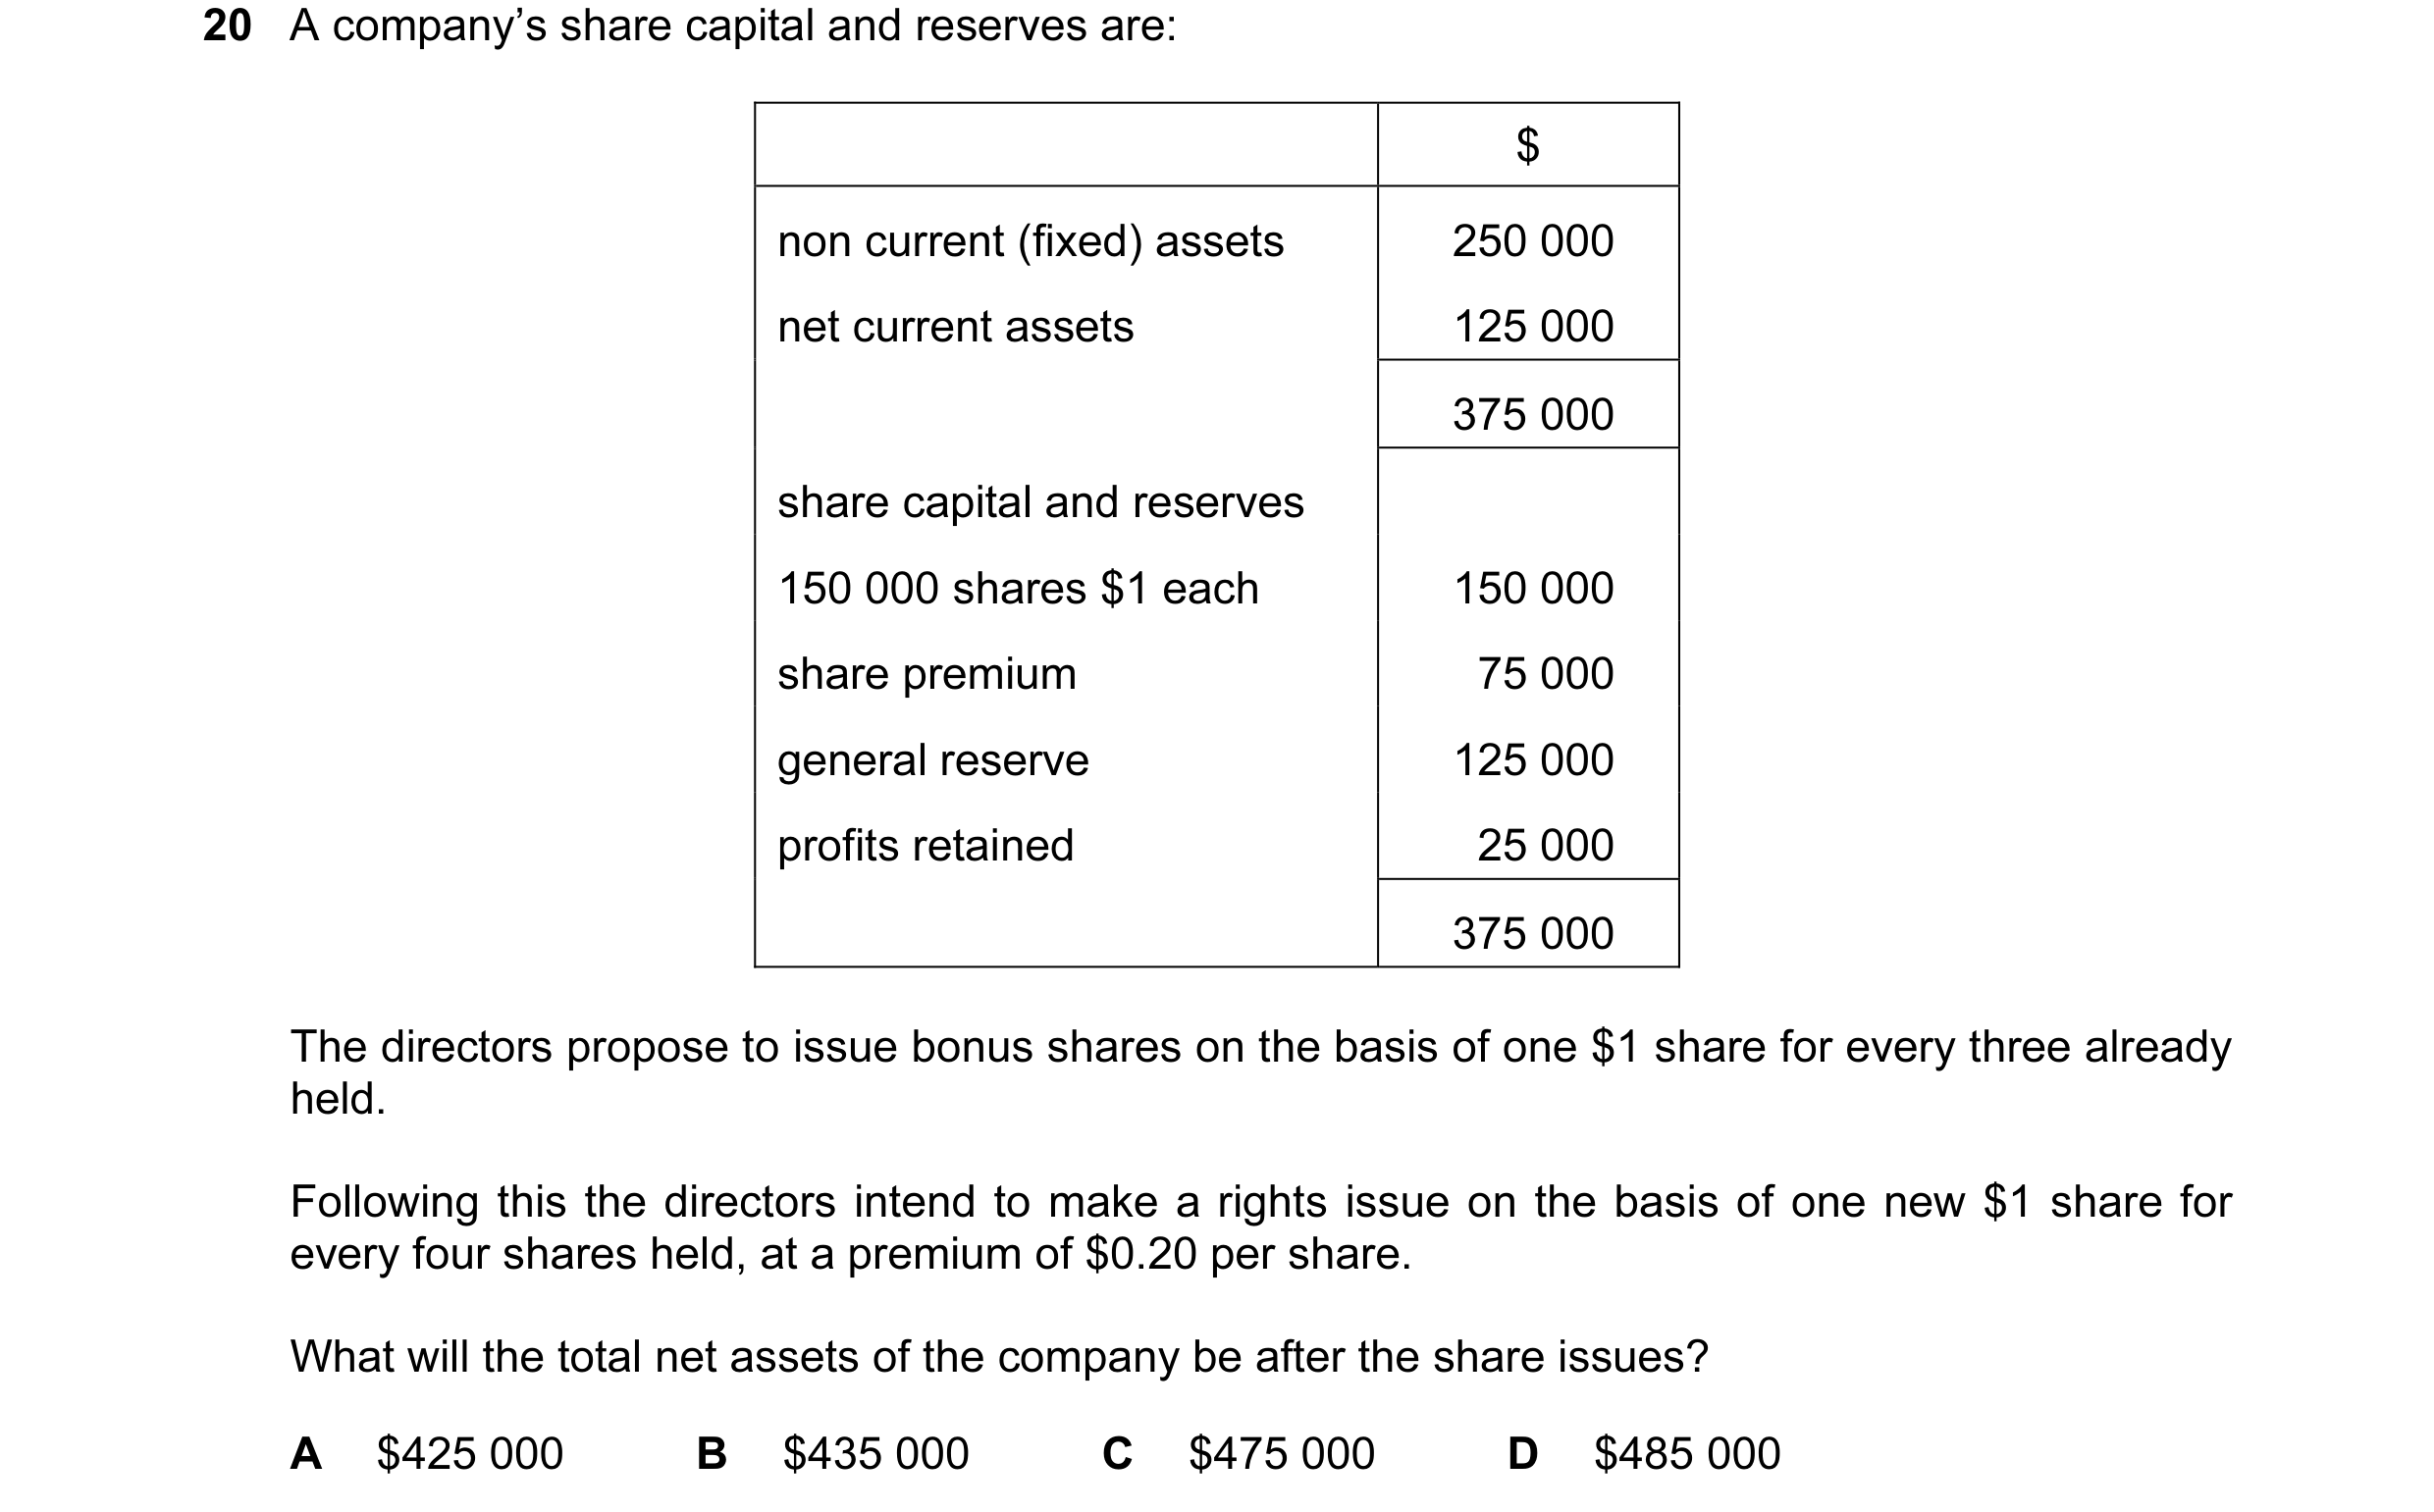
 2 / 60
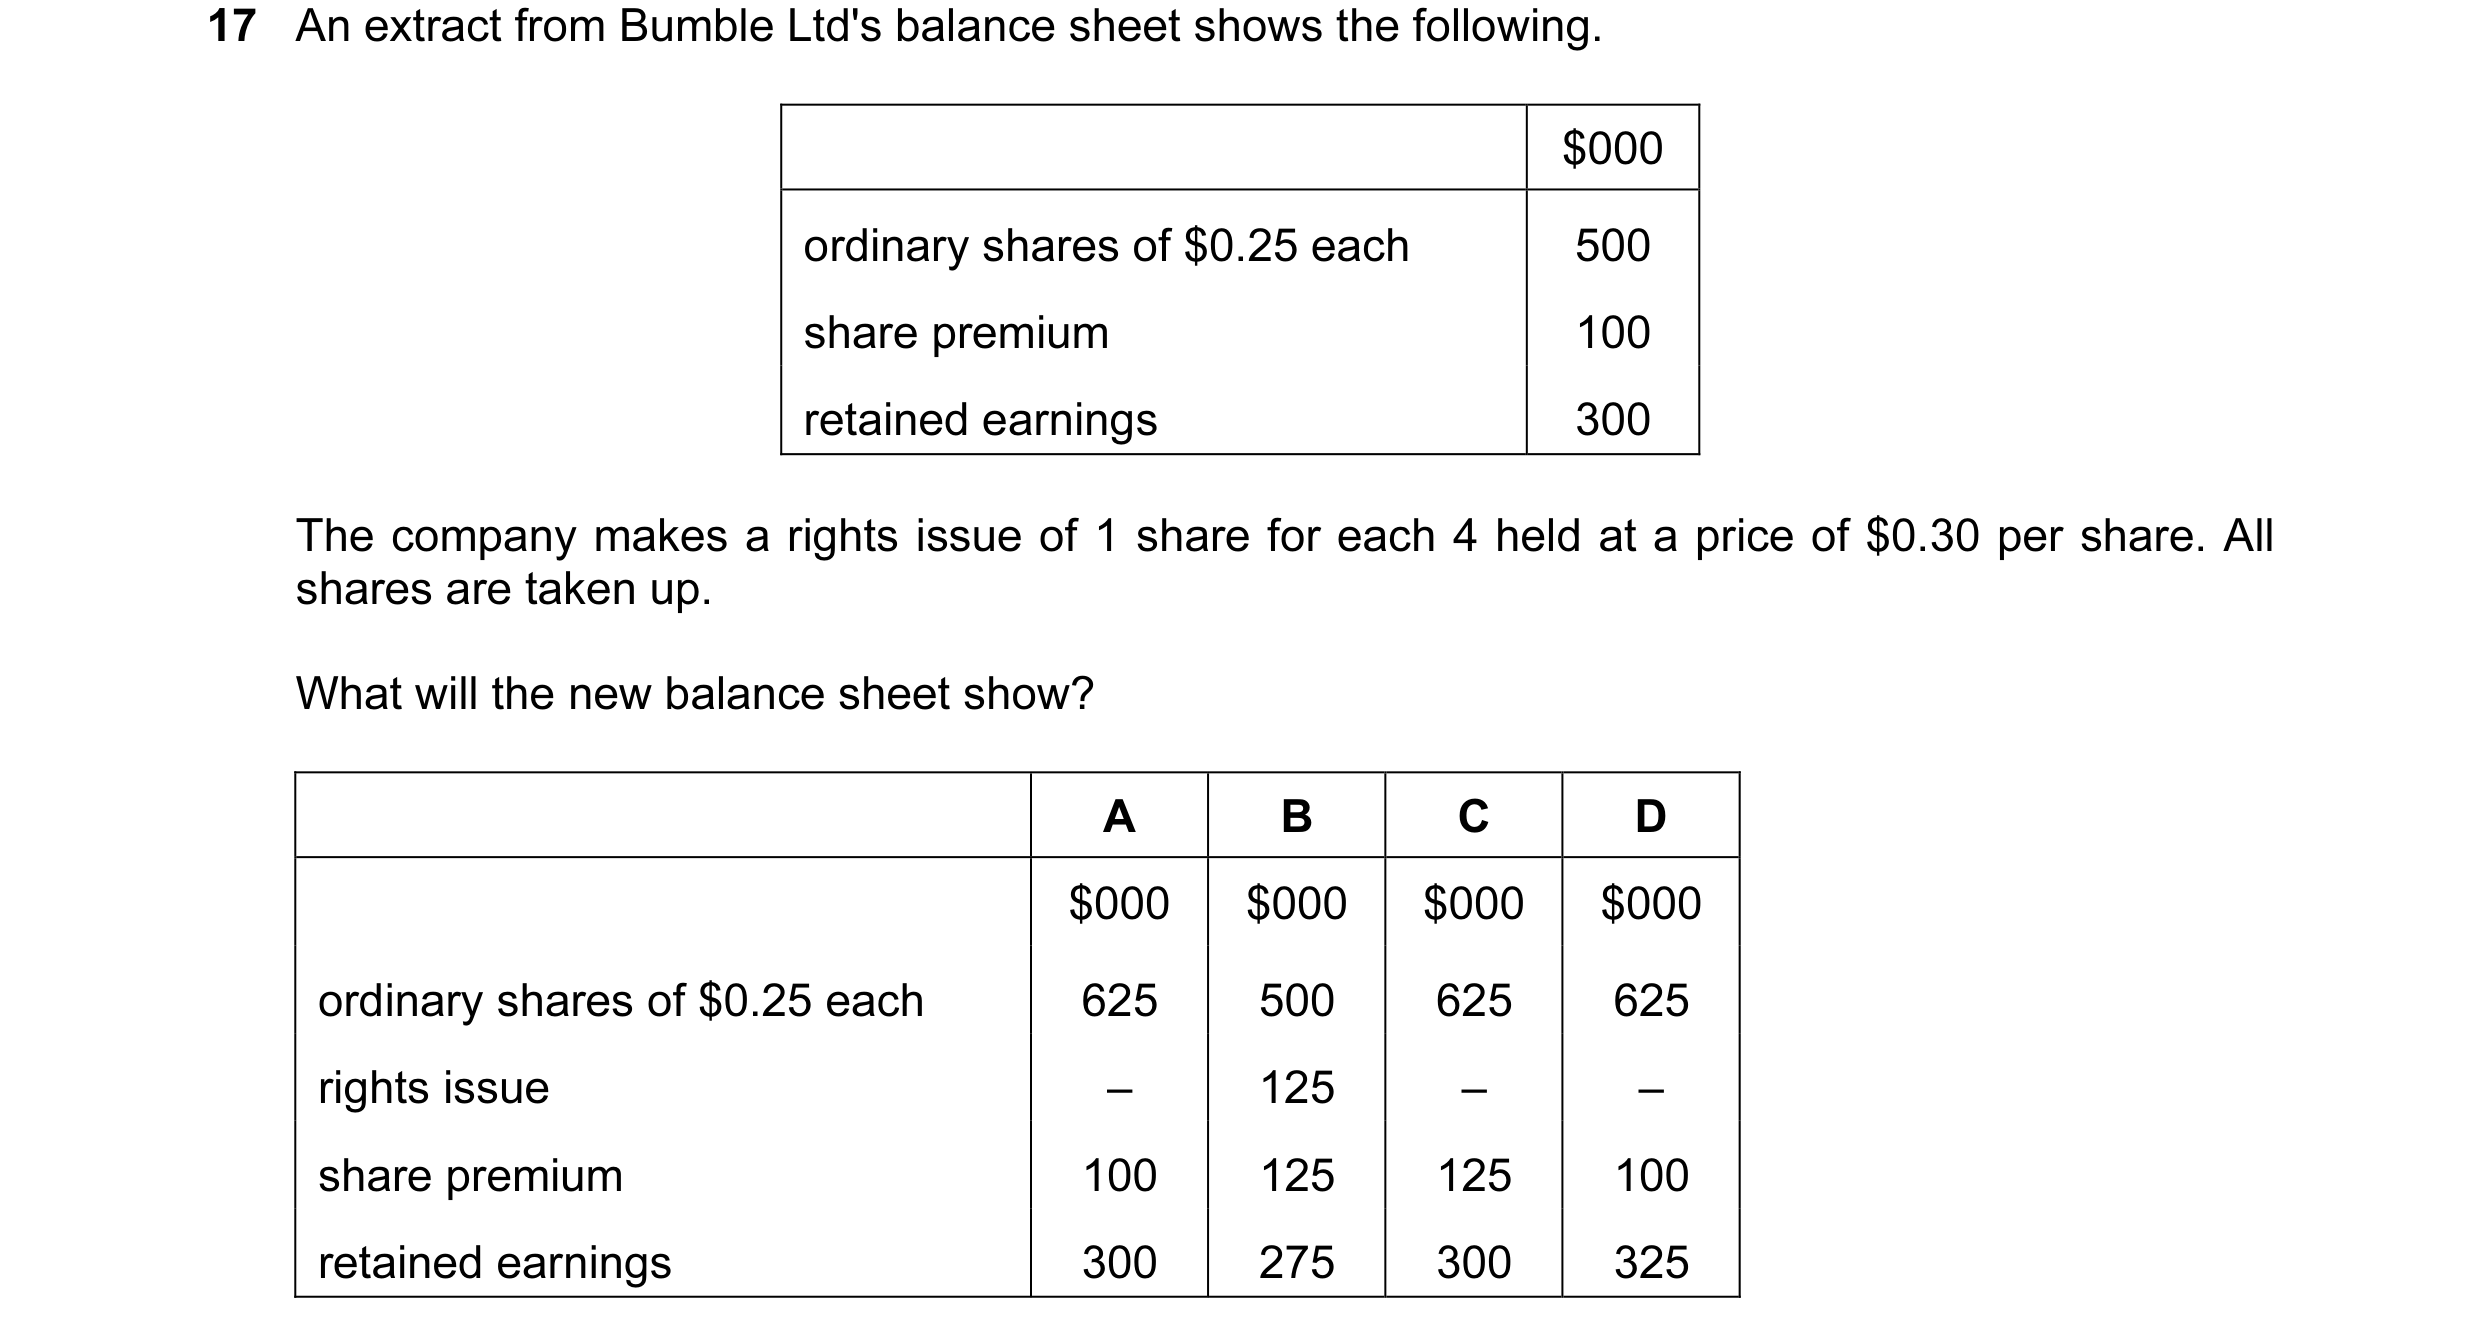
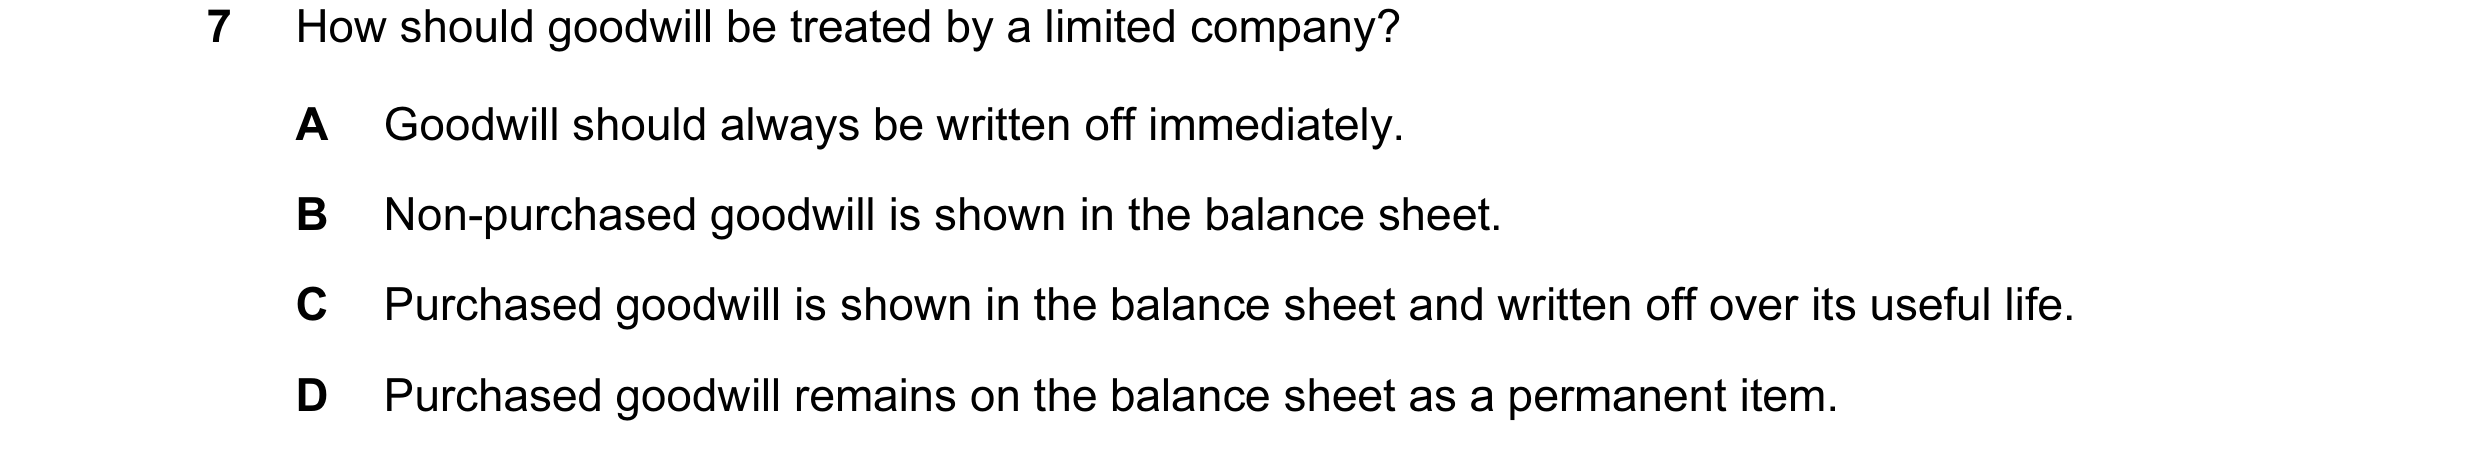
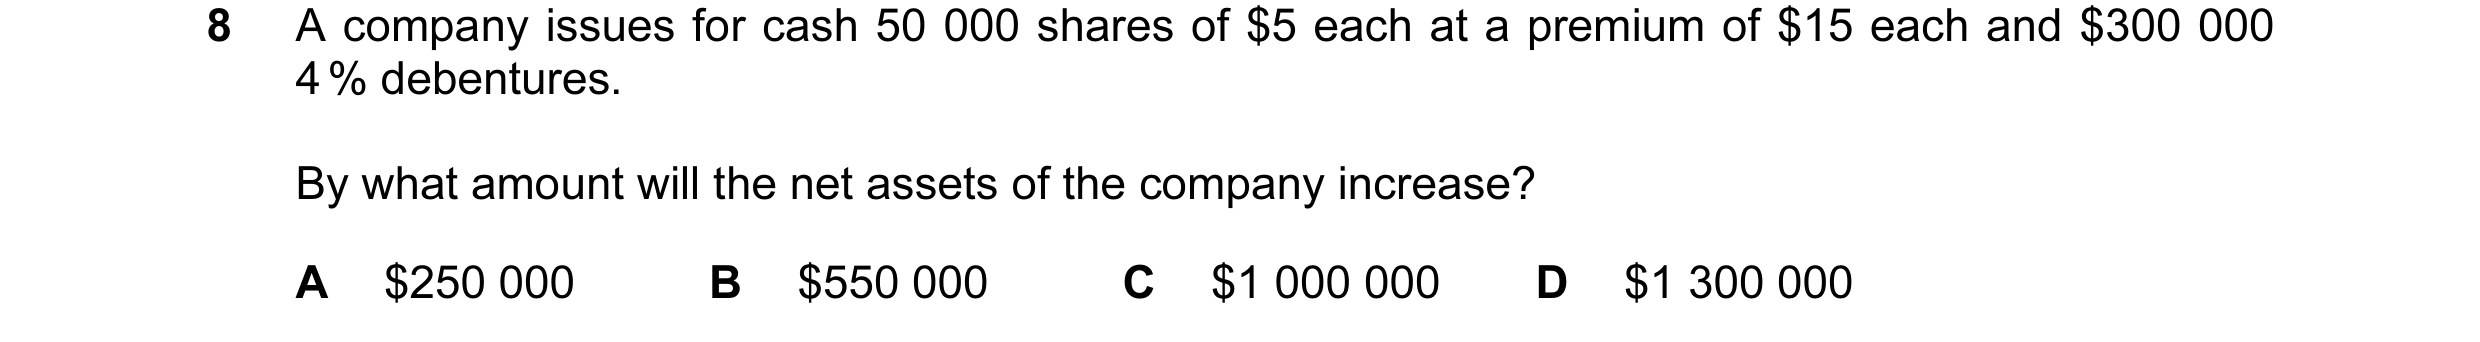 3 / 60
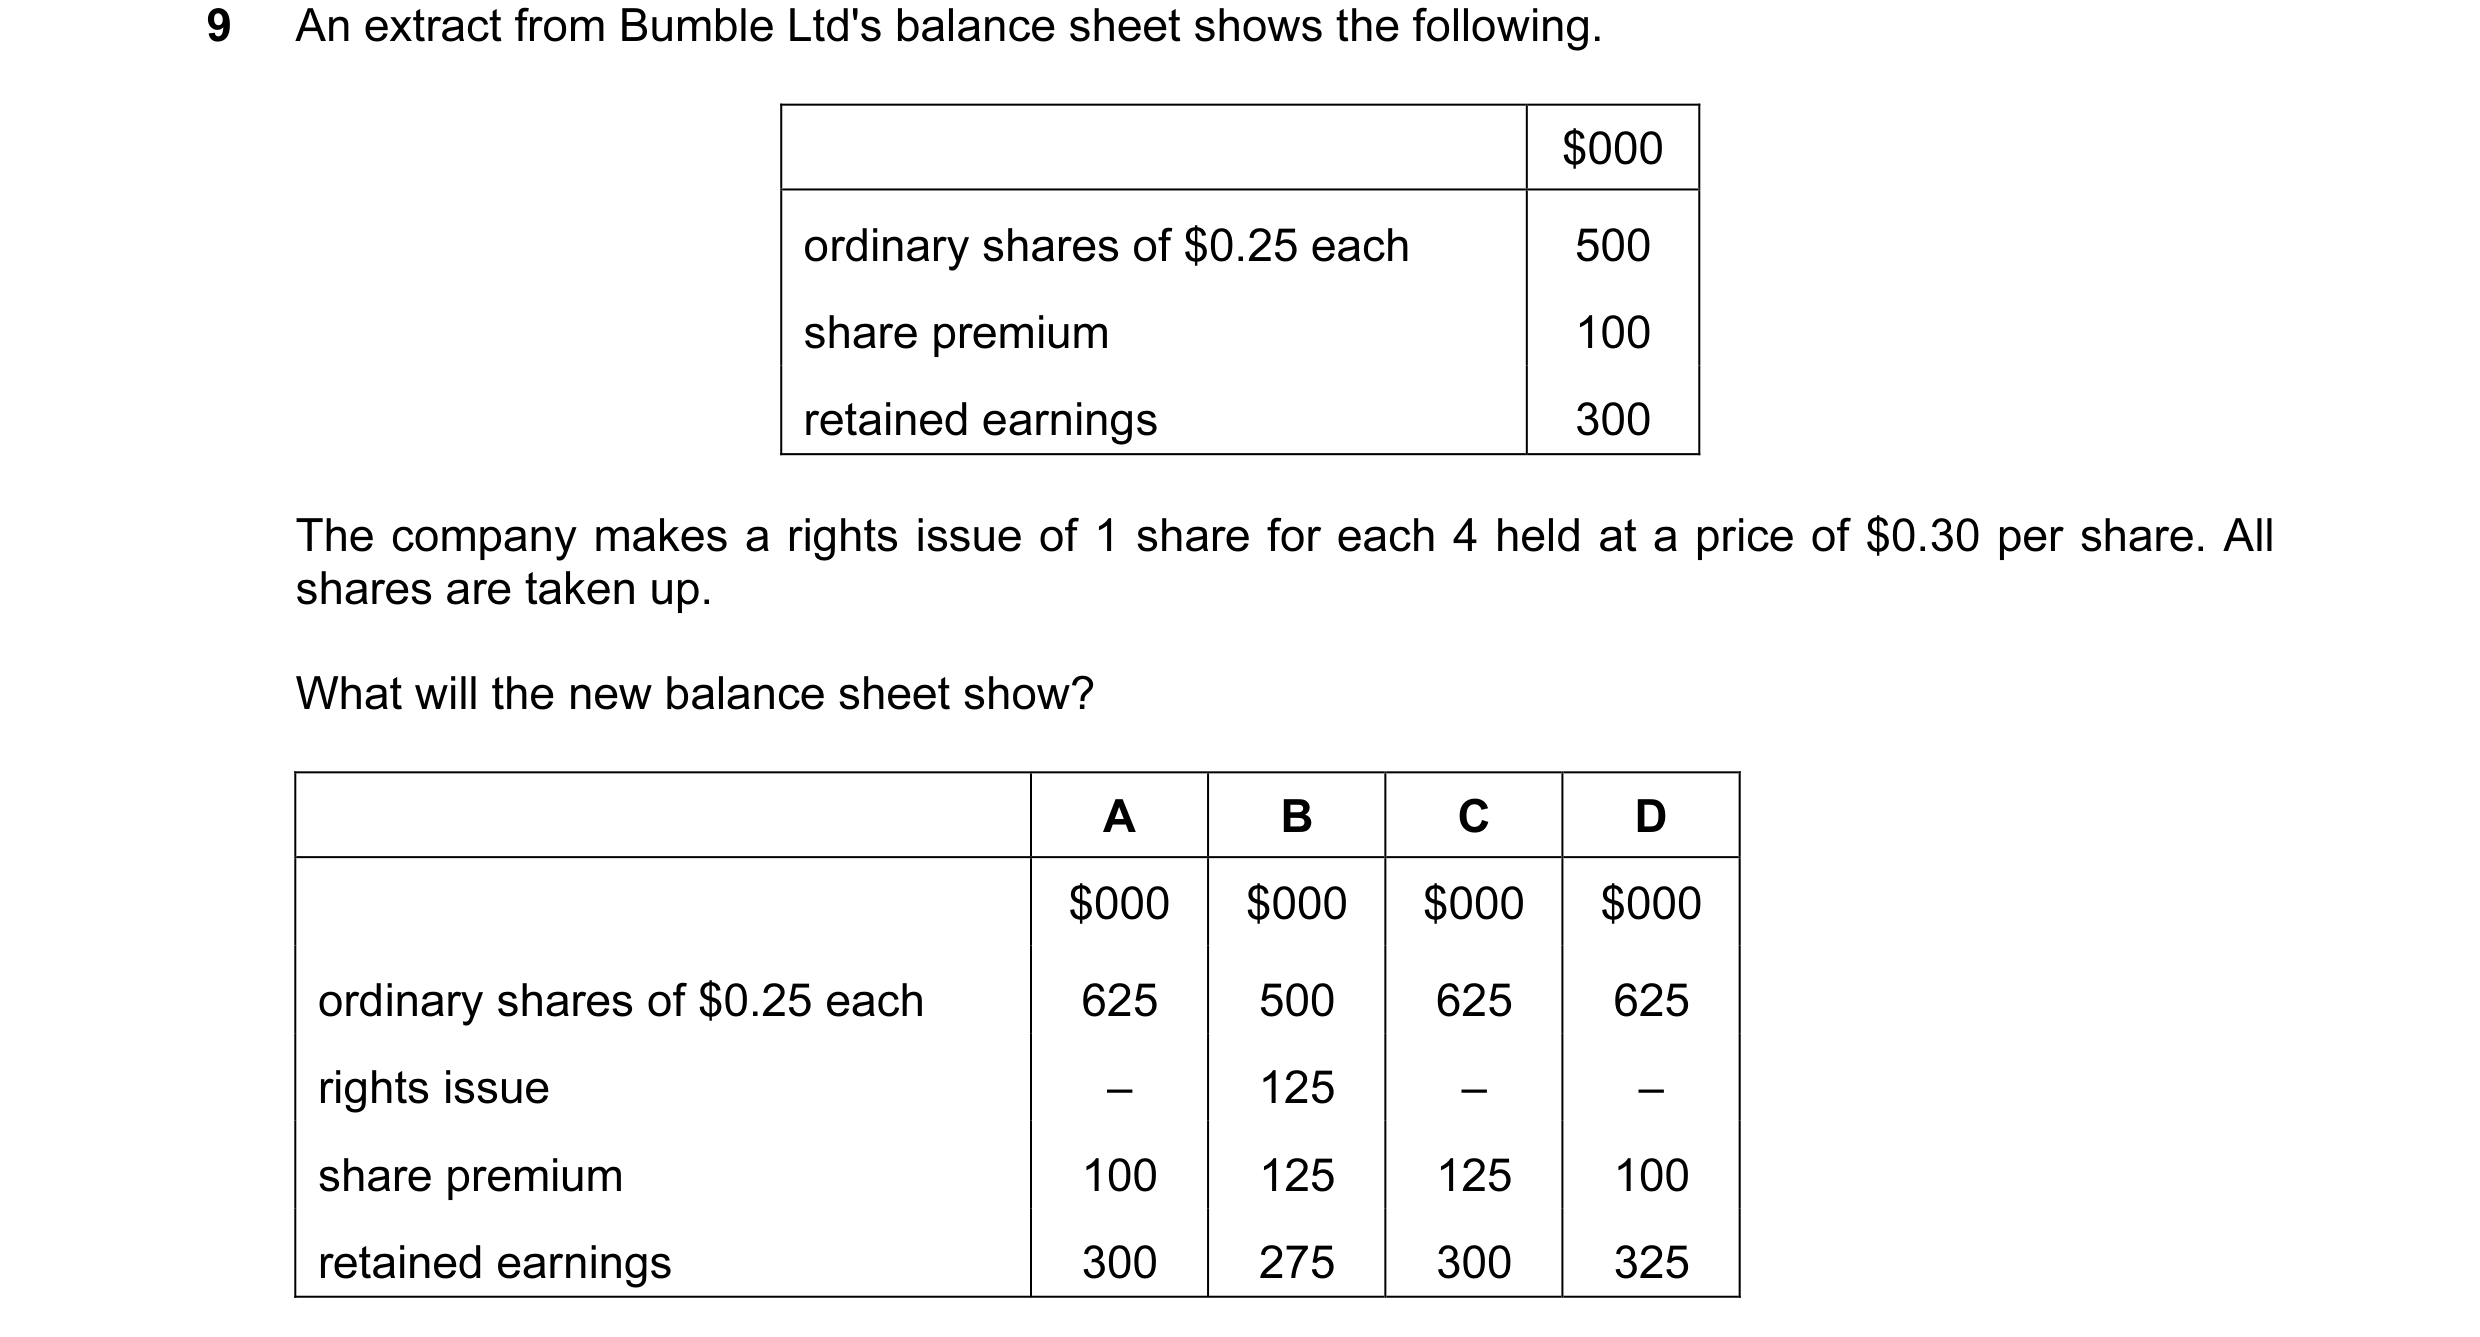
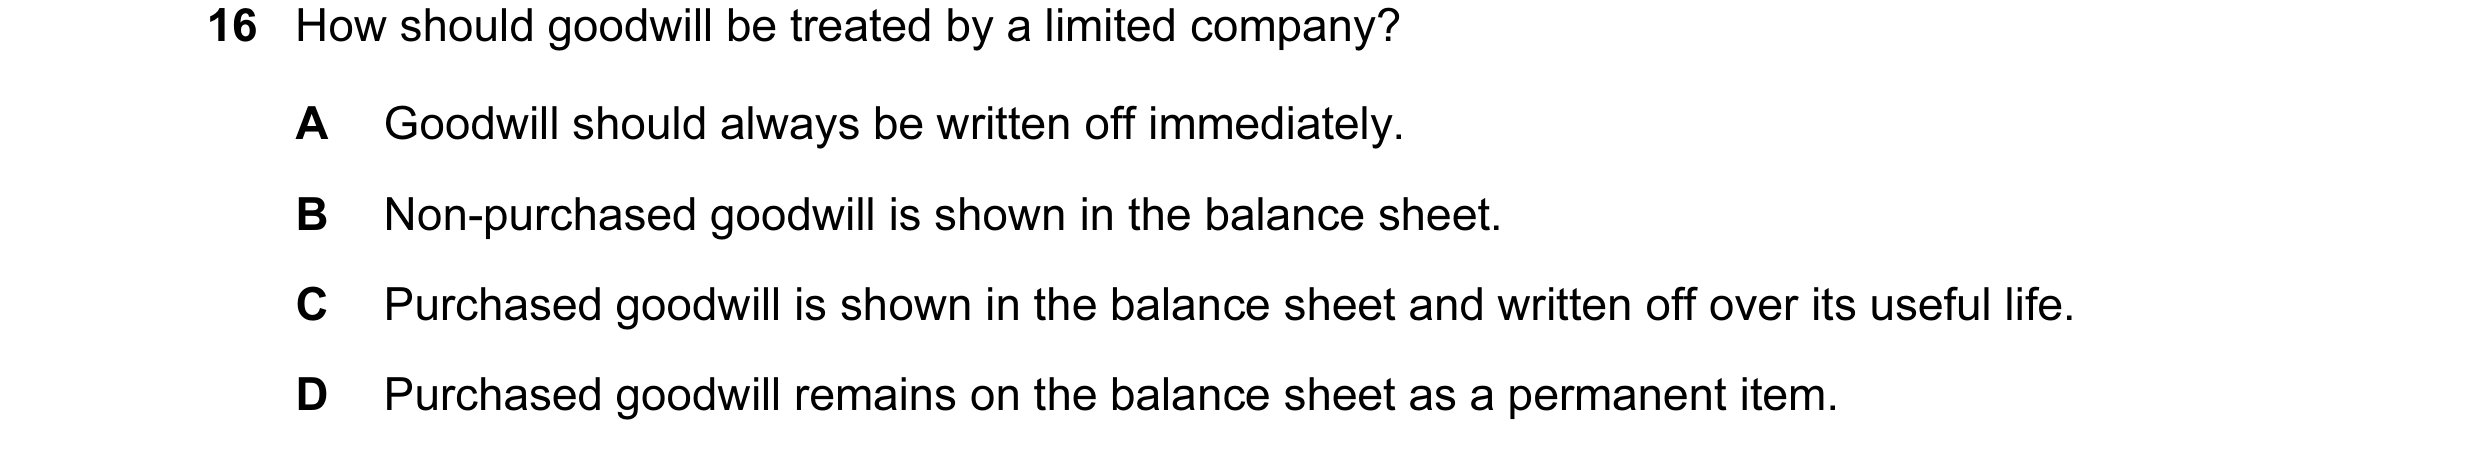
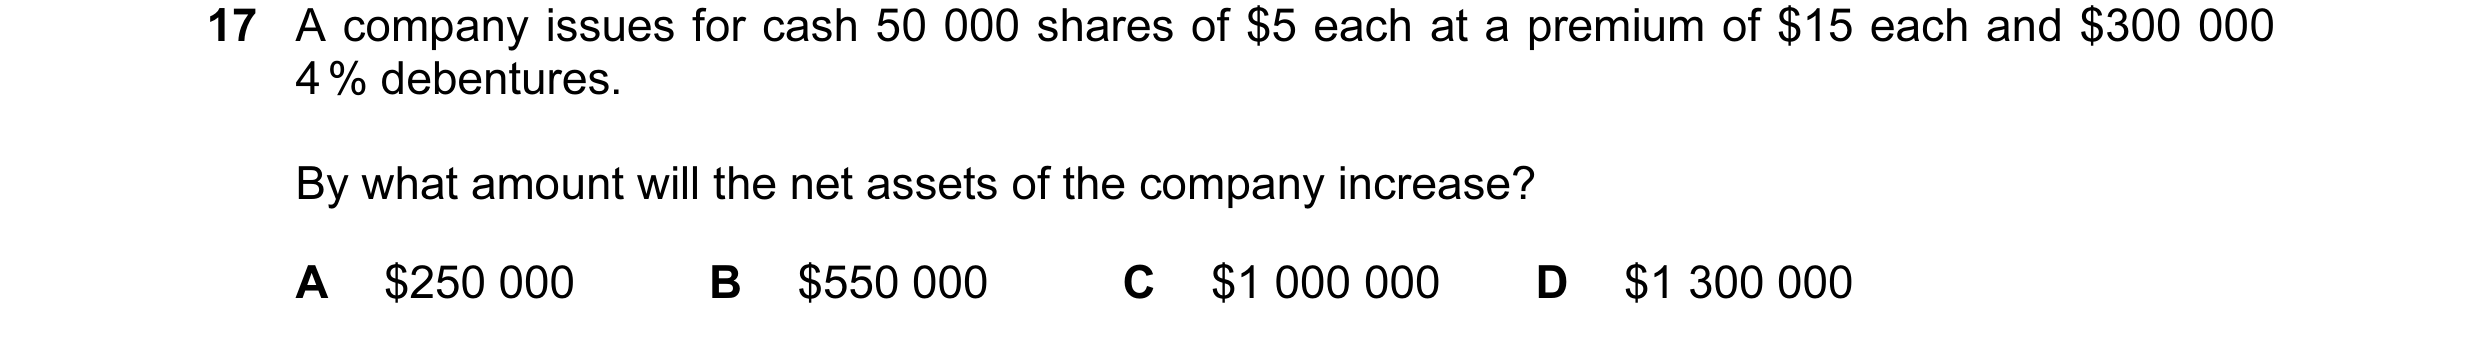 4 / 60
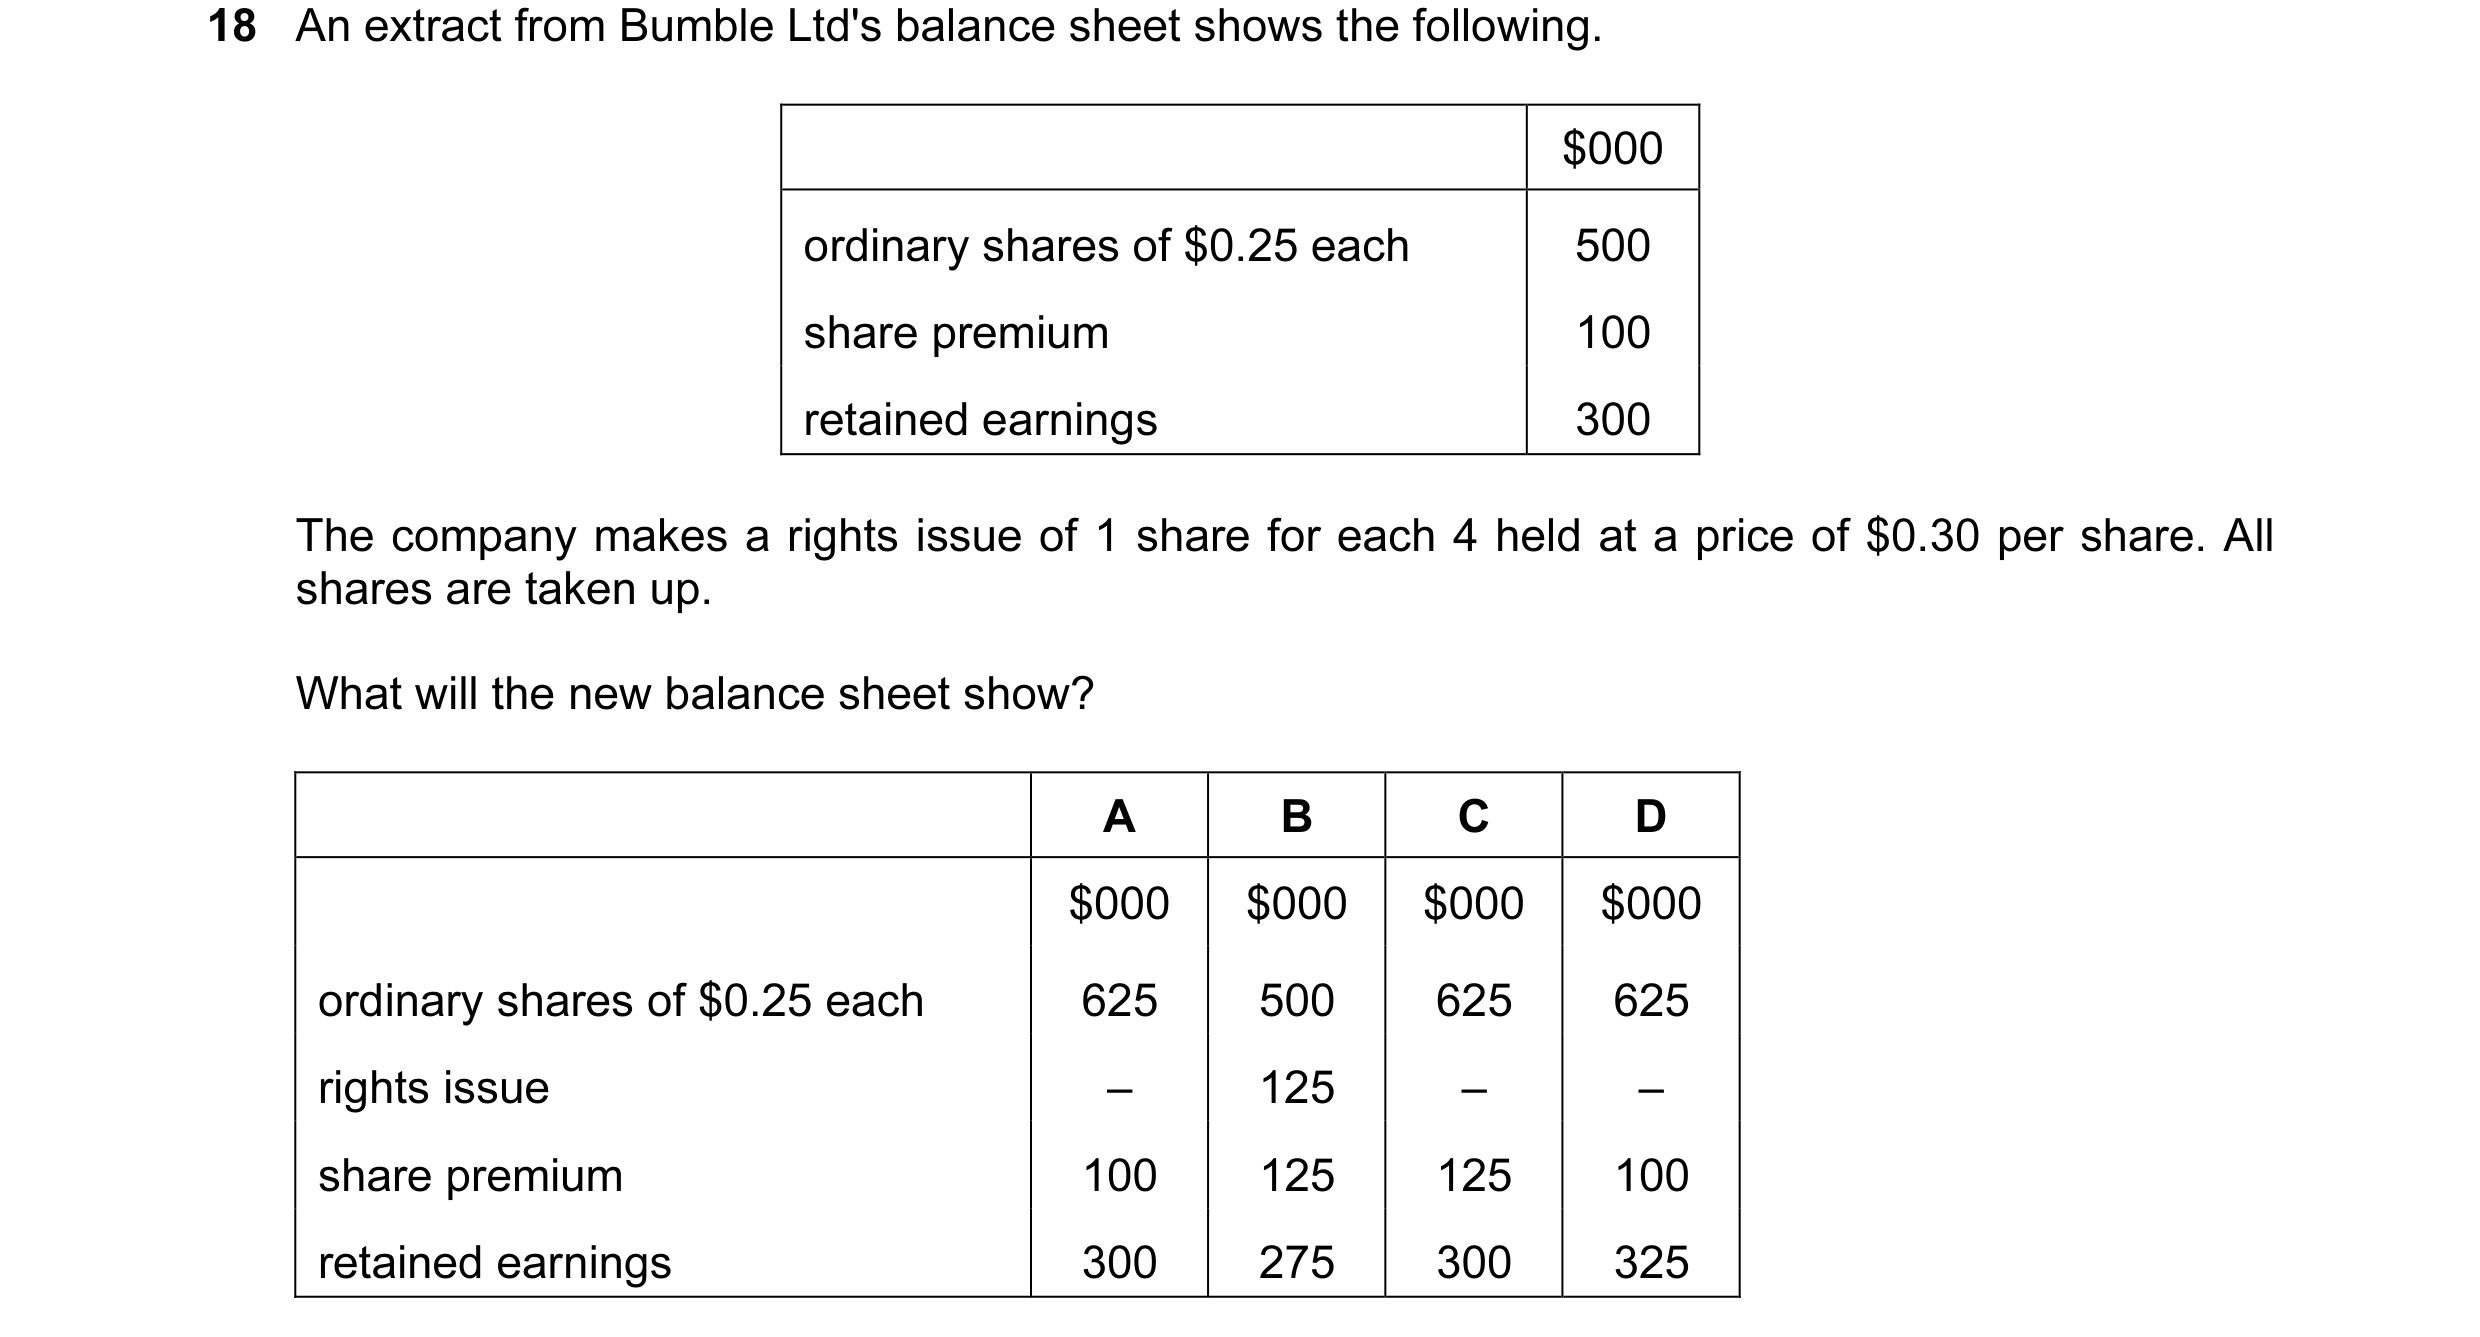
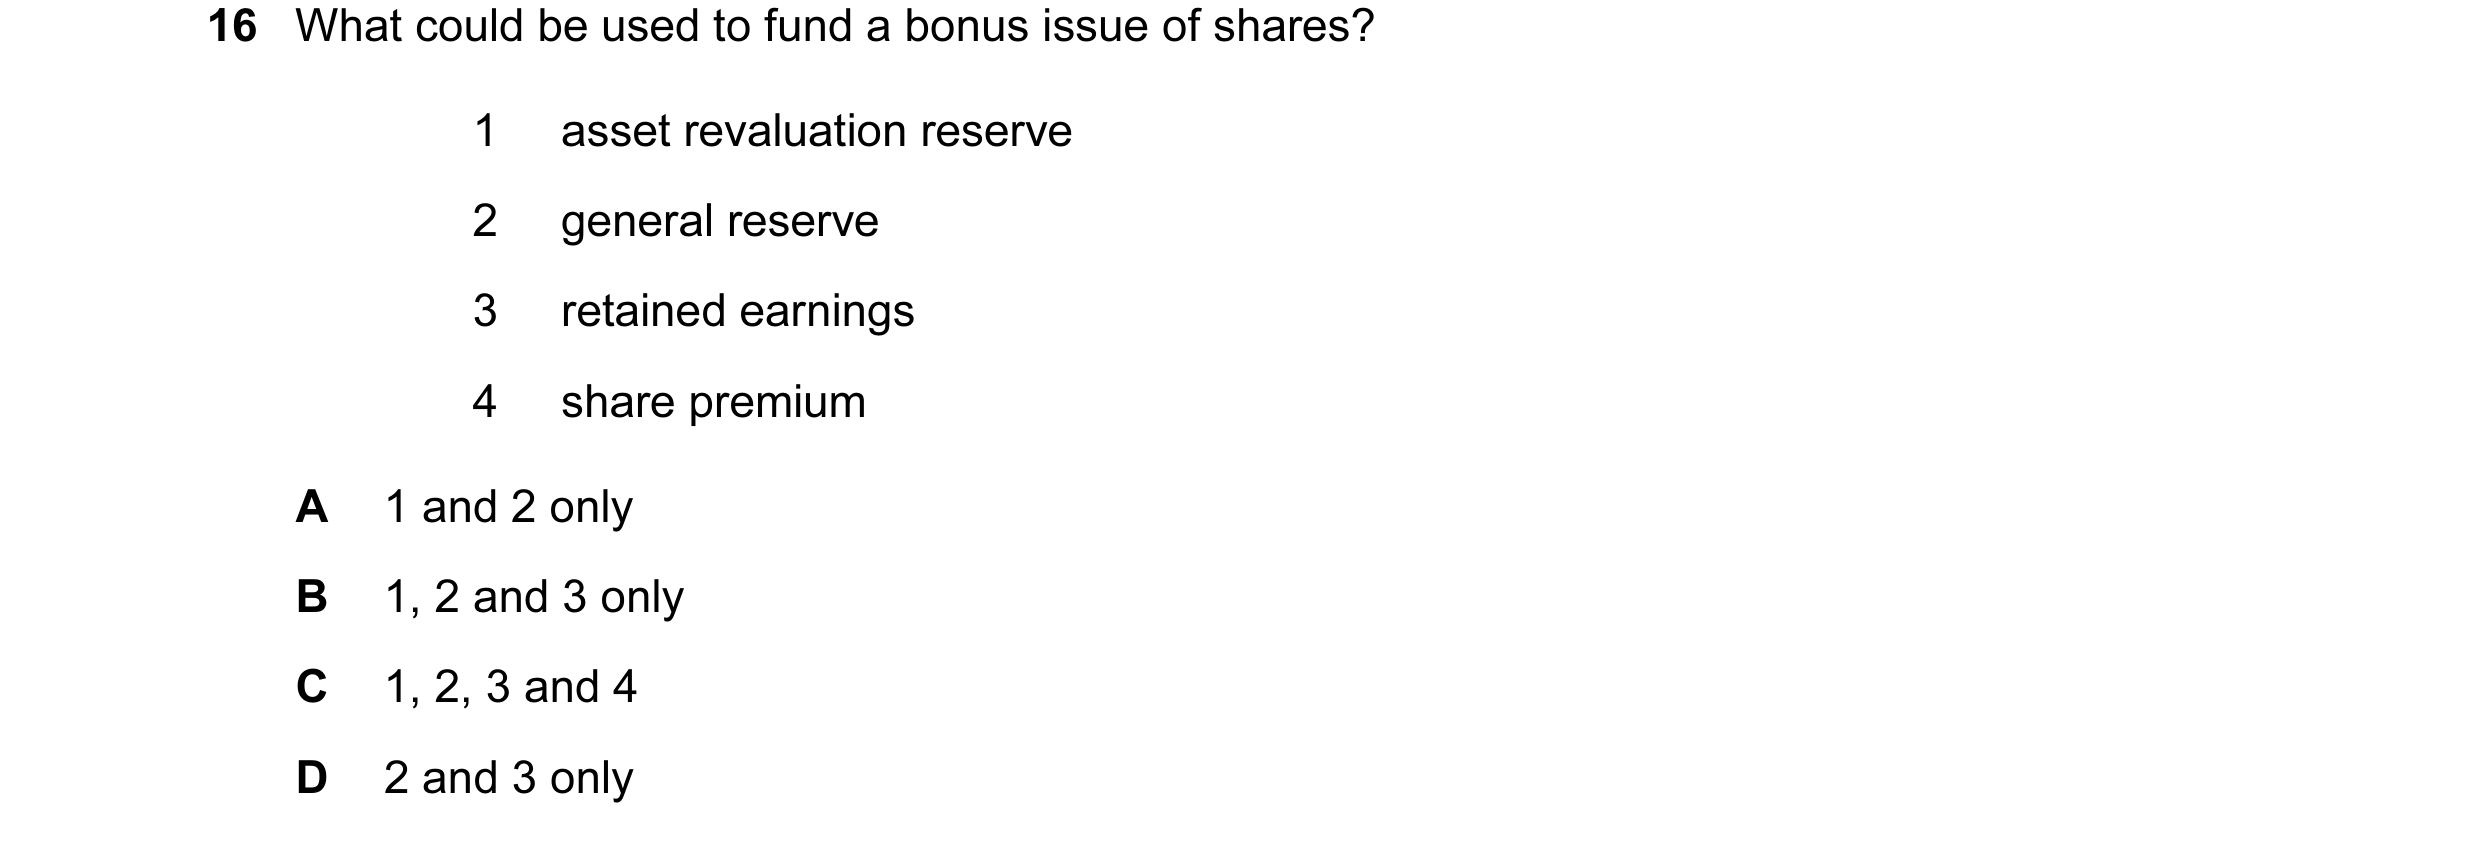
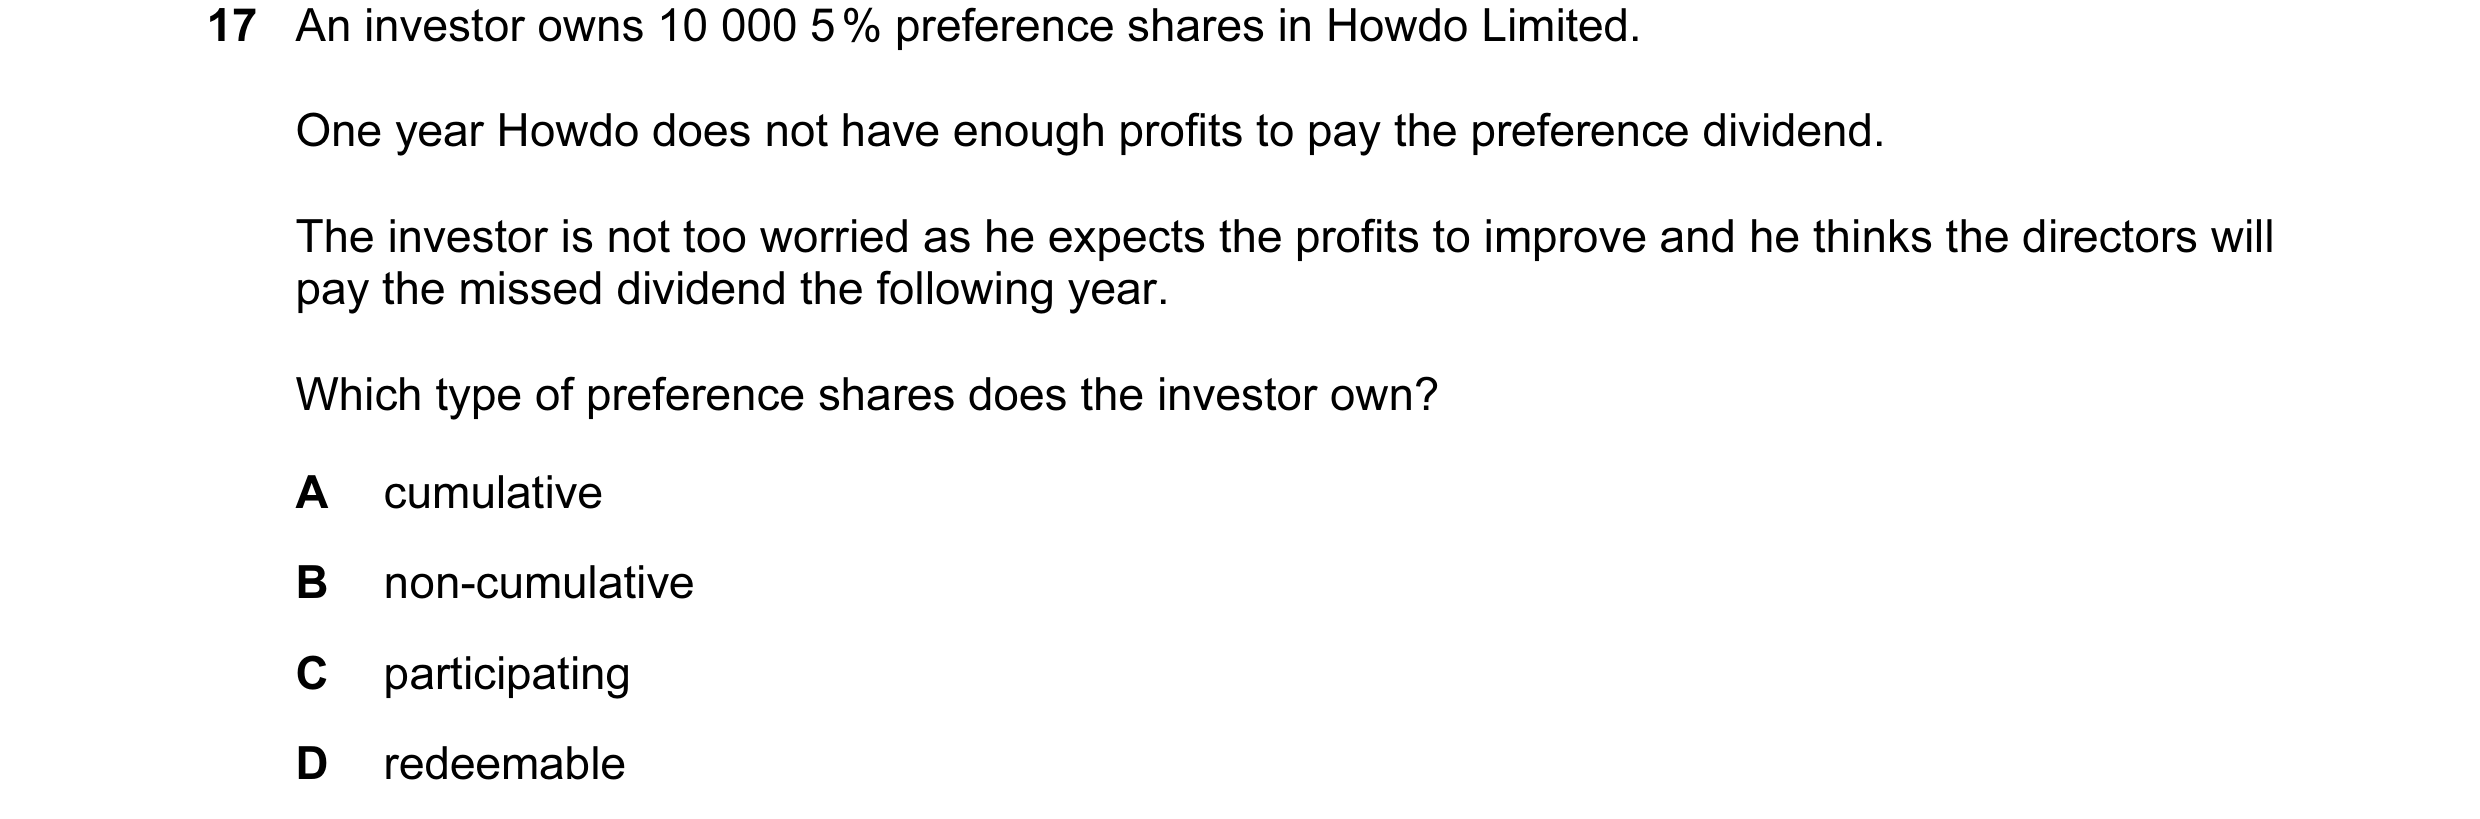 5 / 60
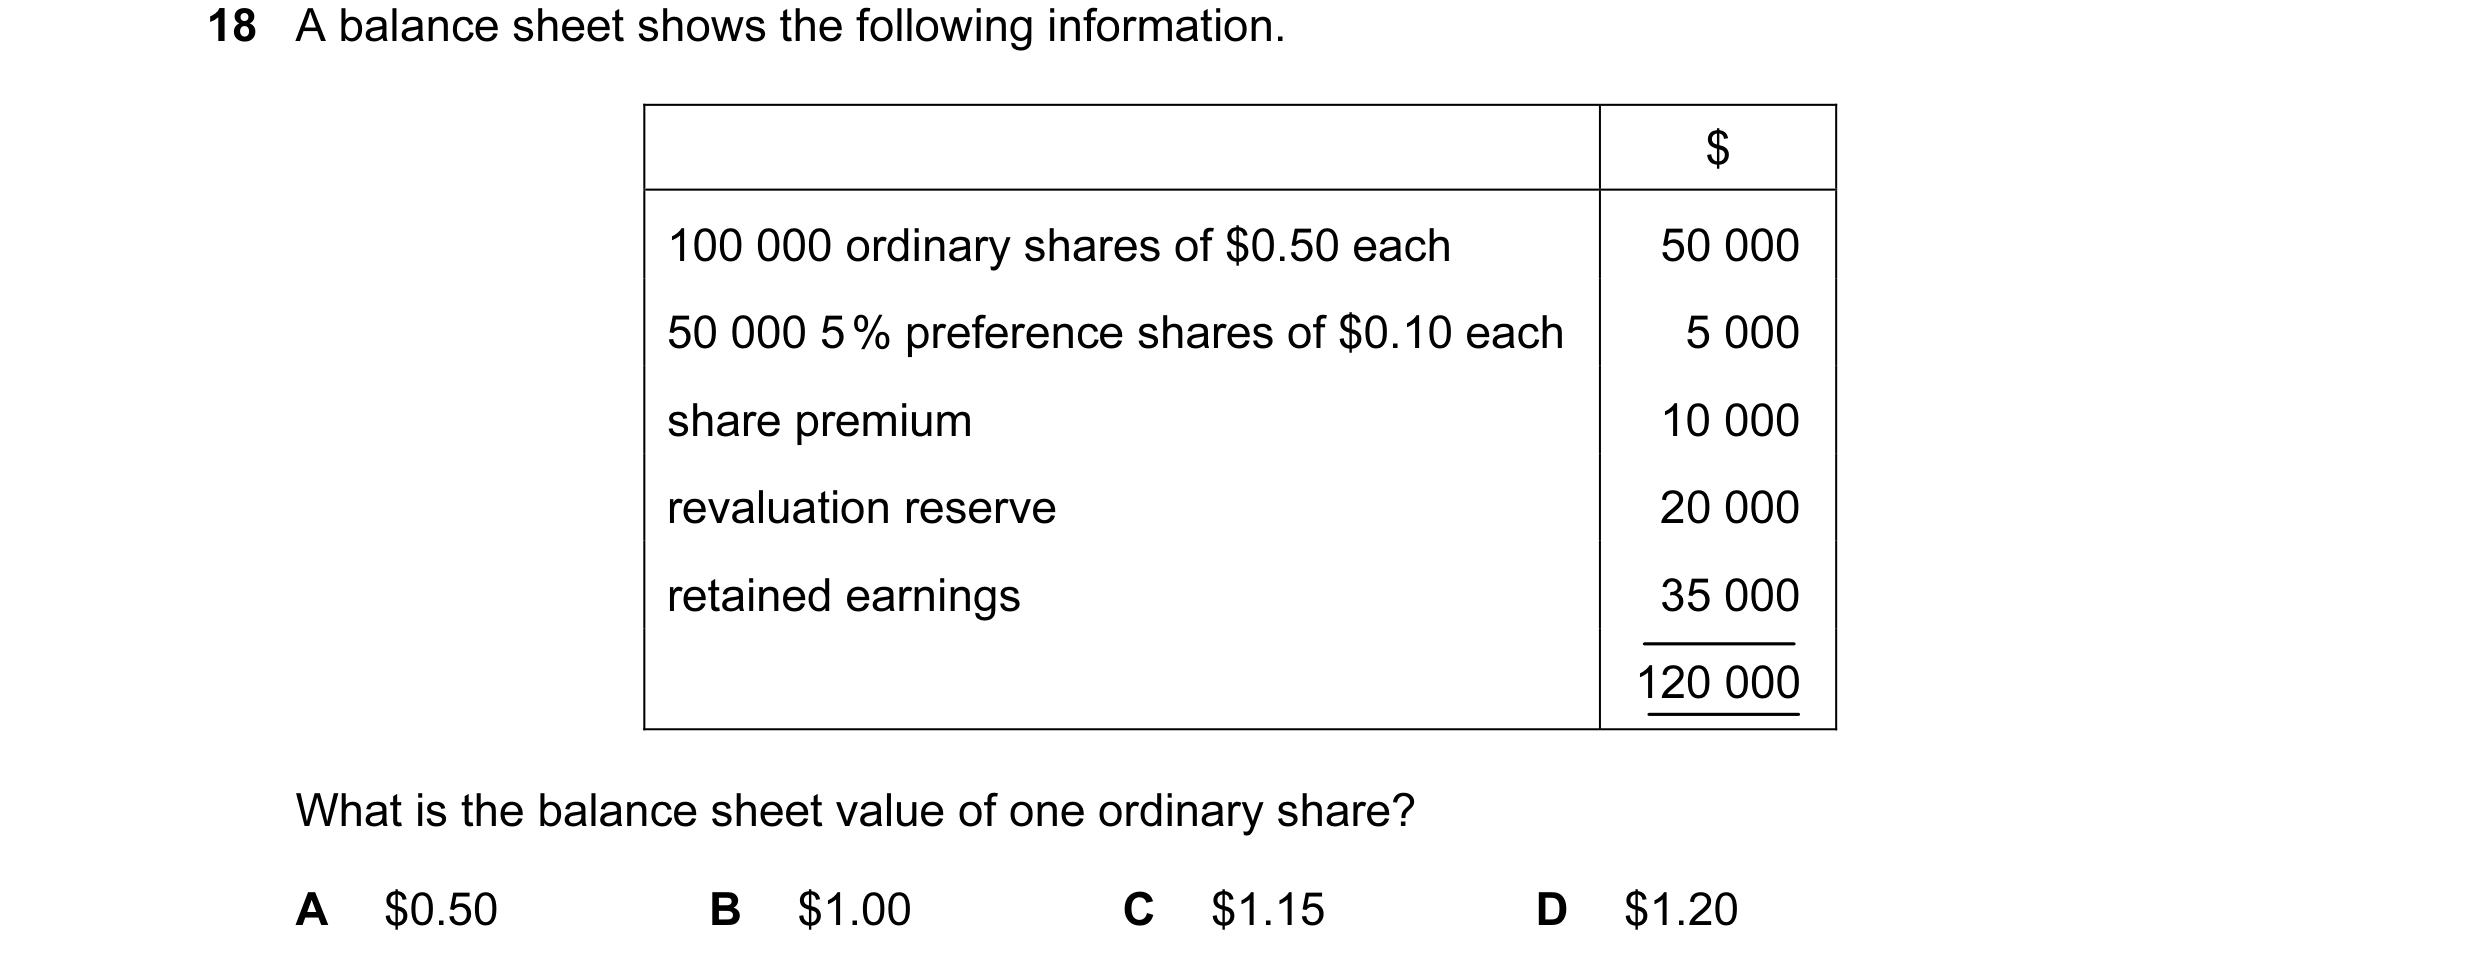
 6 / 60
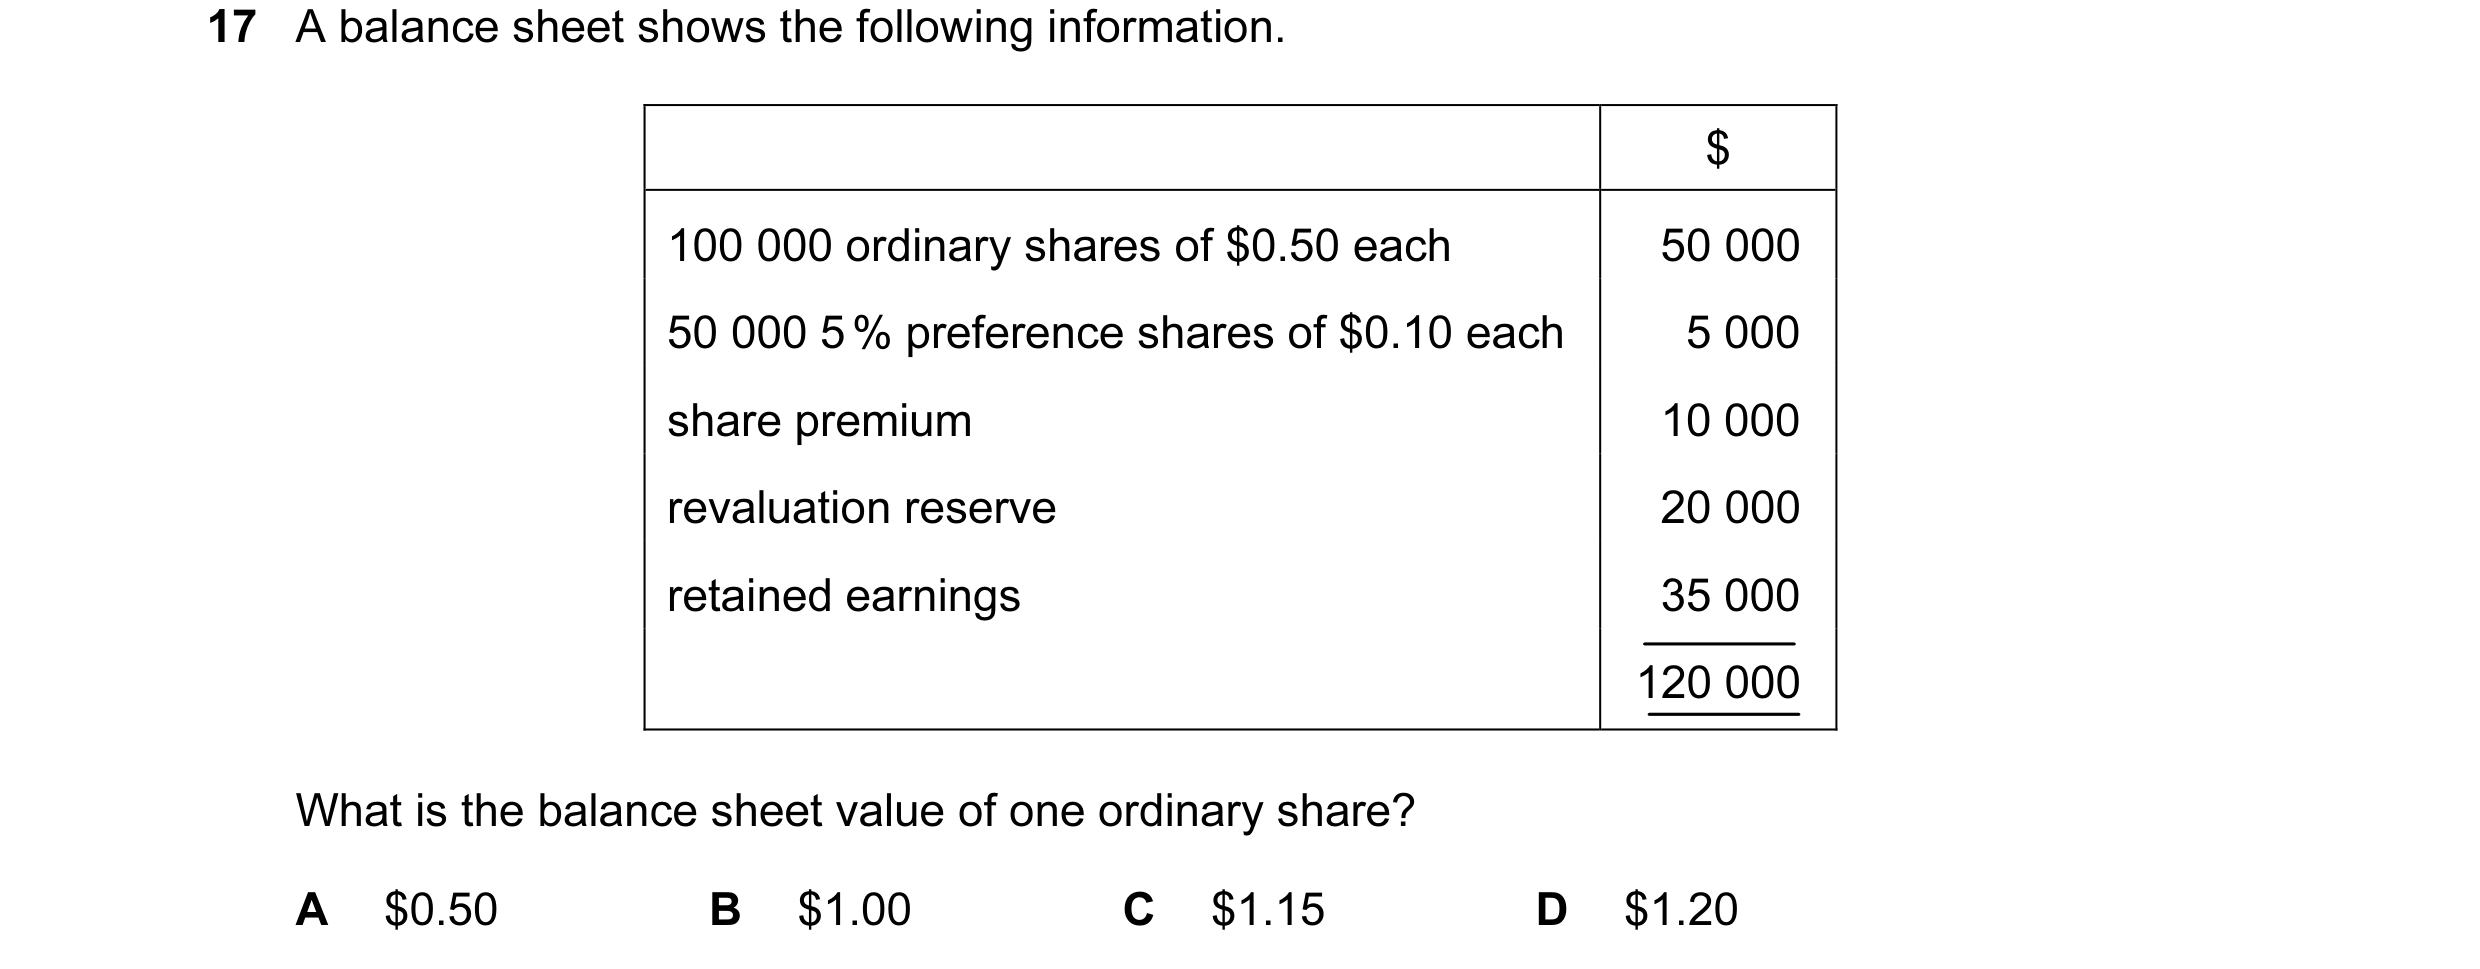
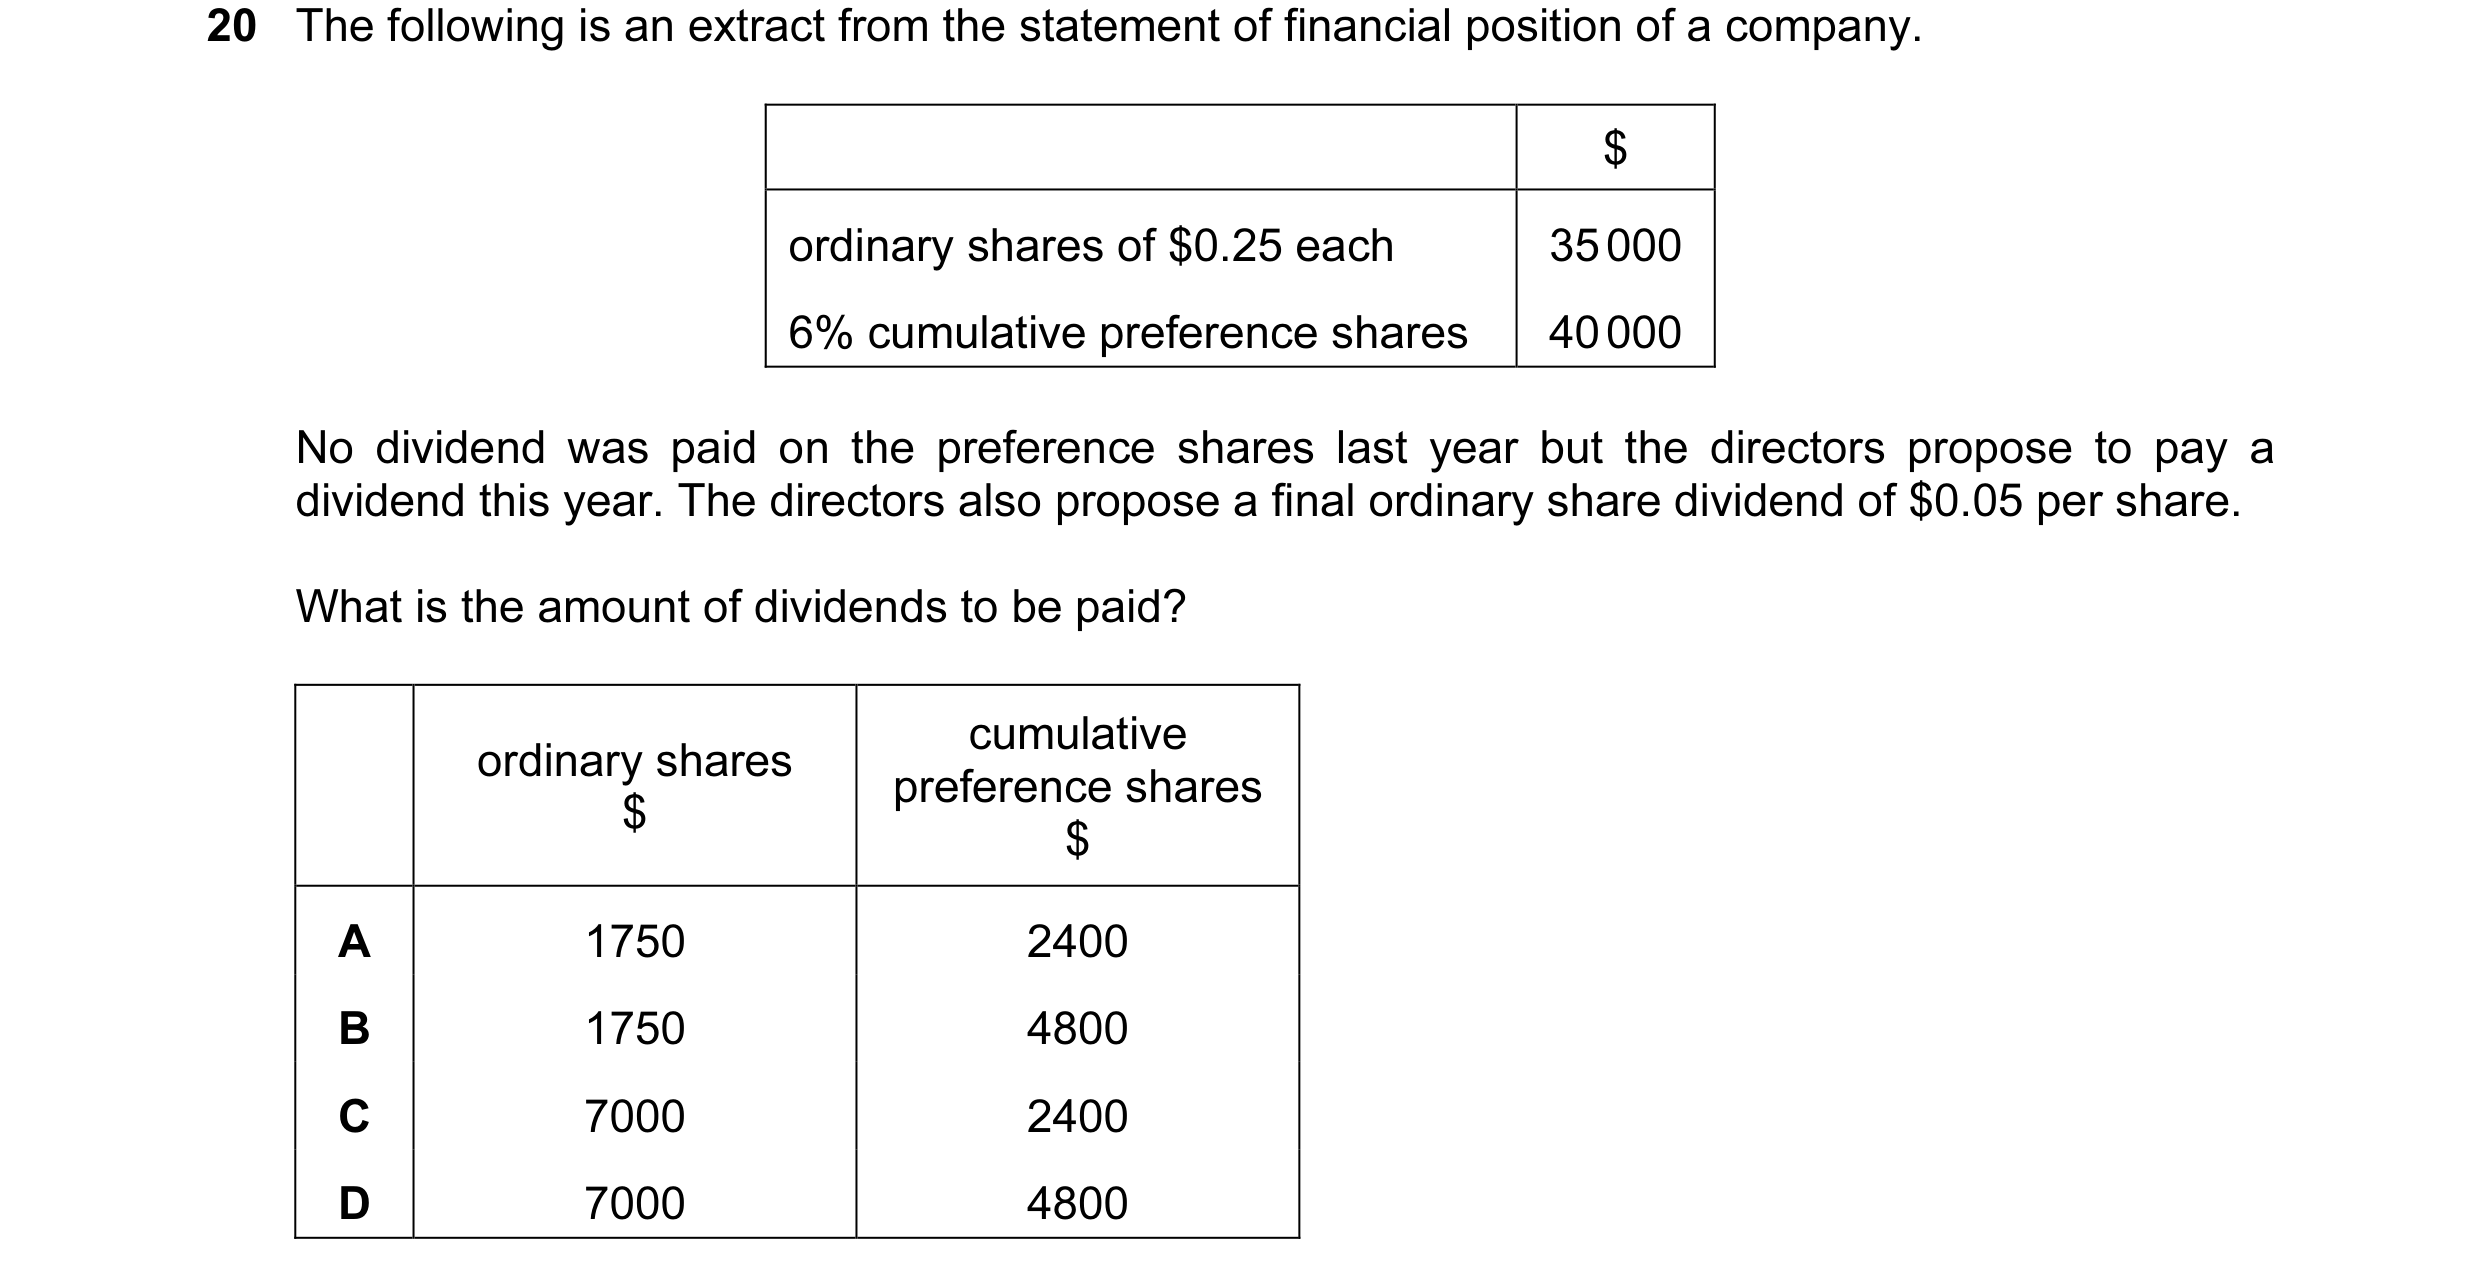
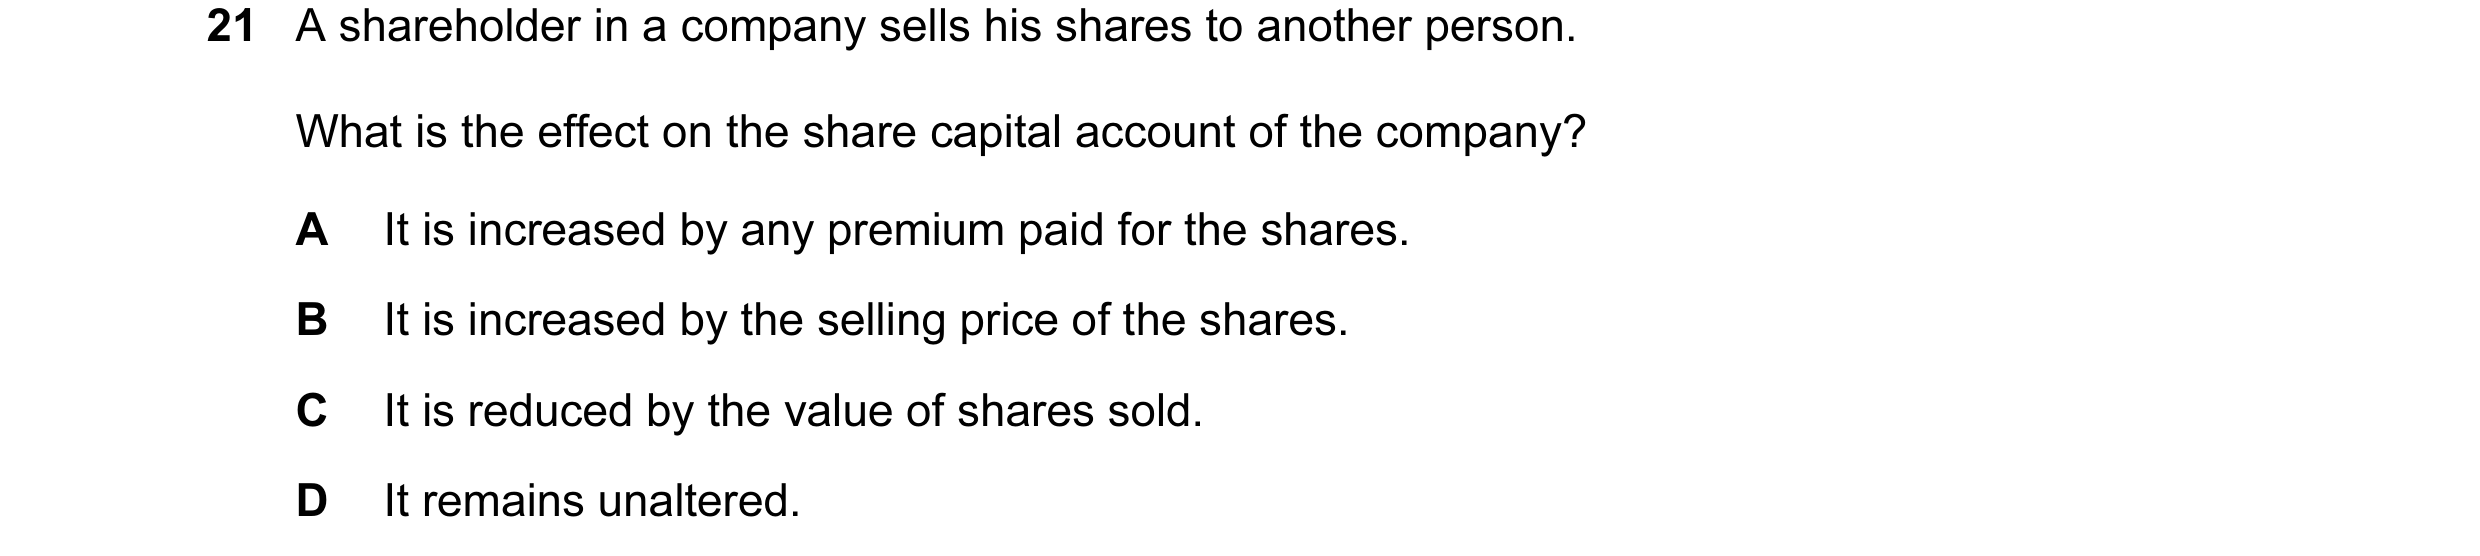 7 / 60
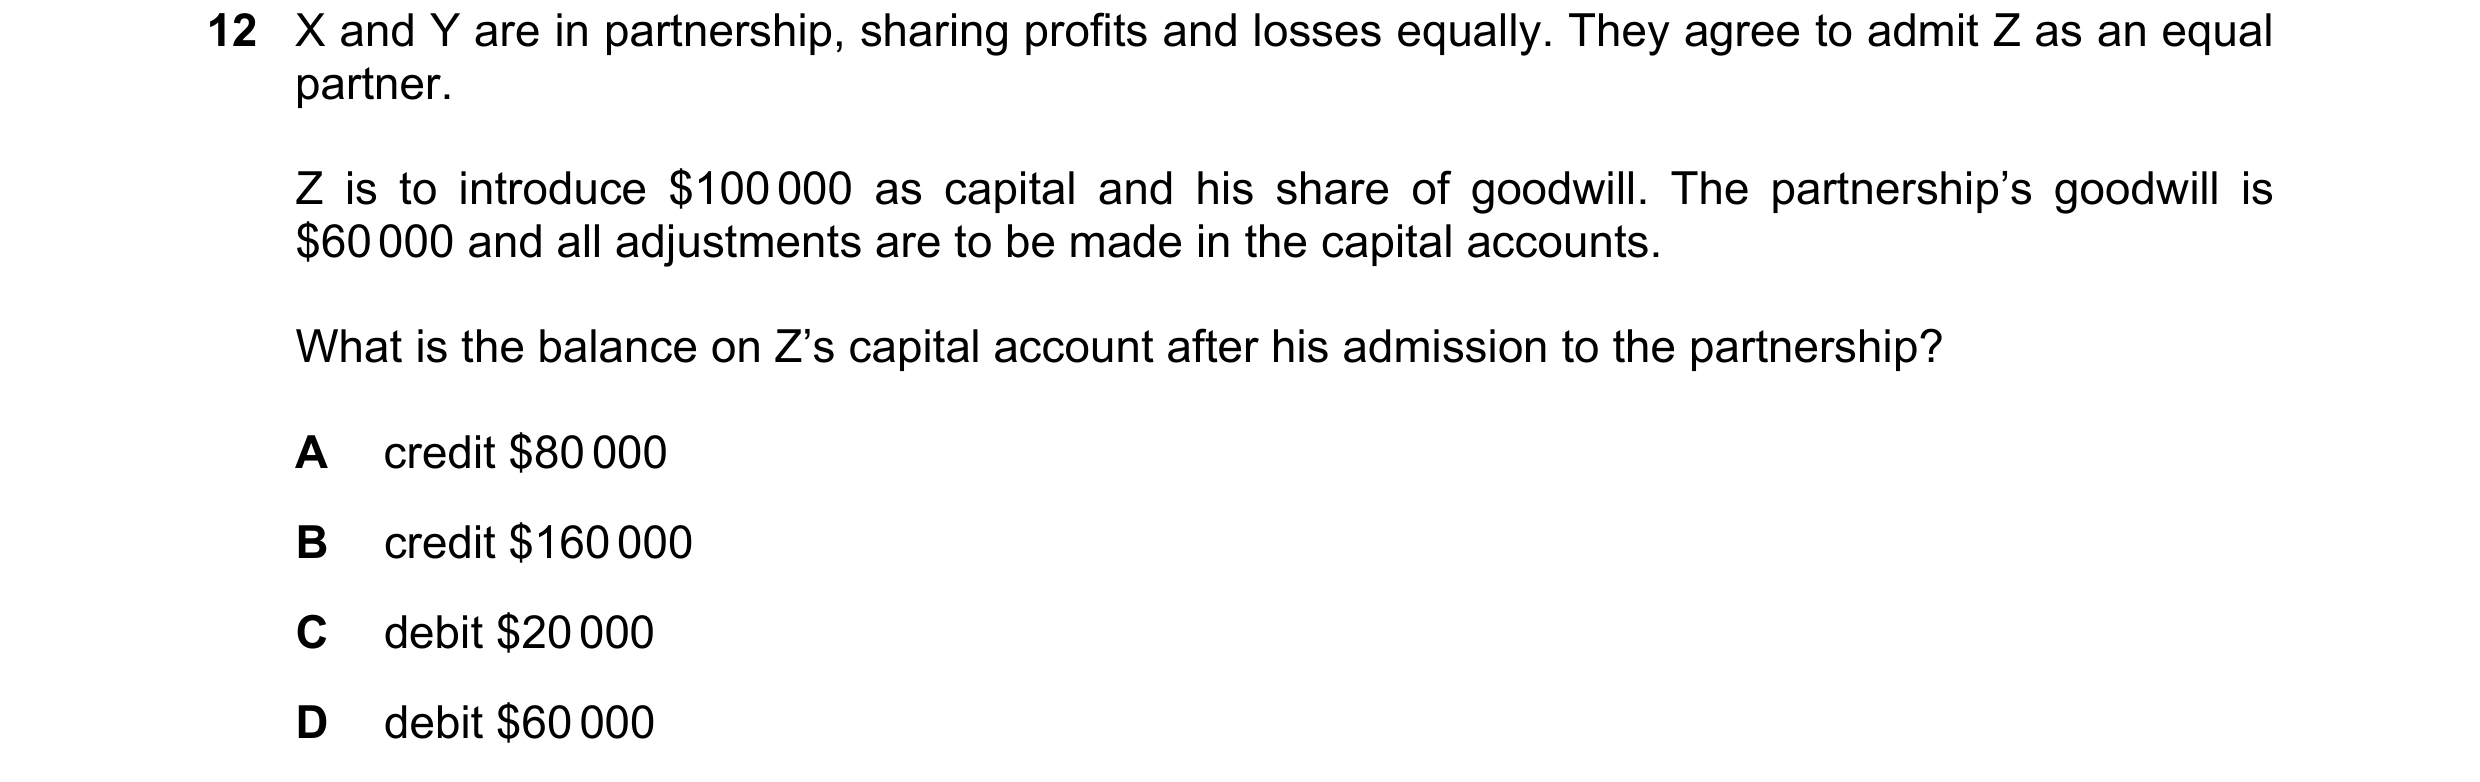
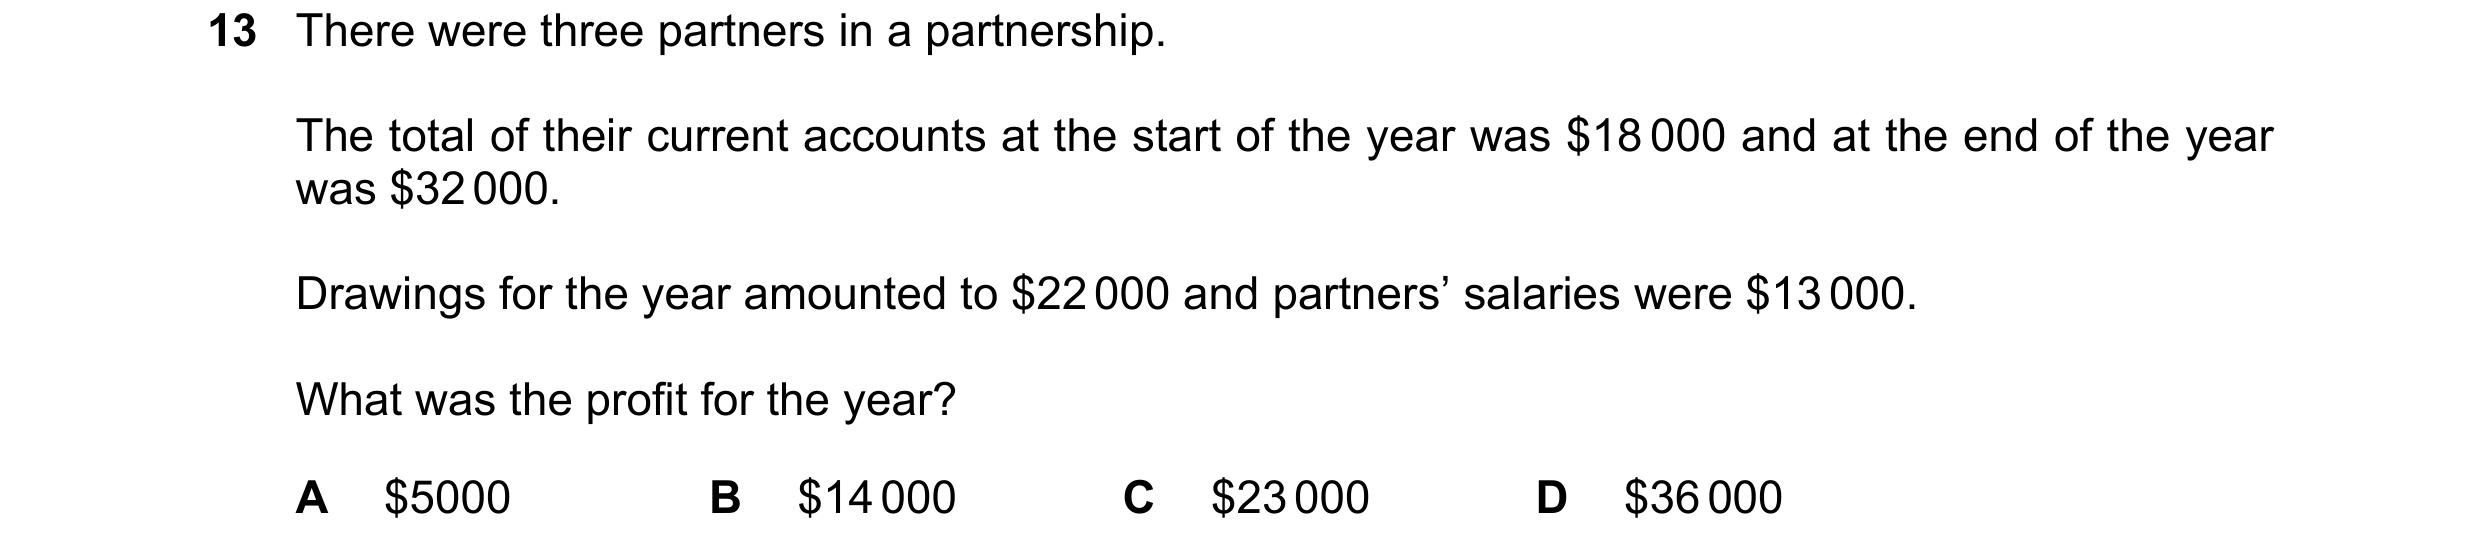
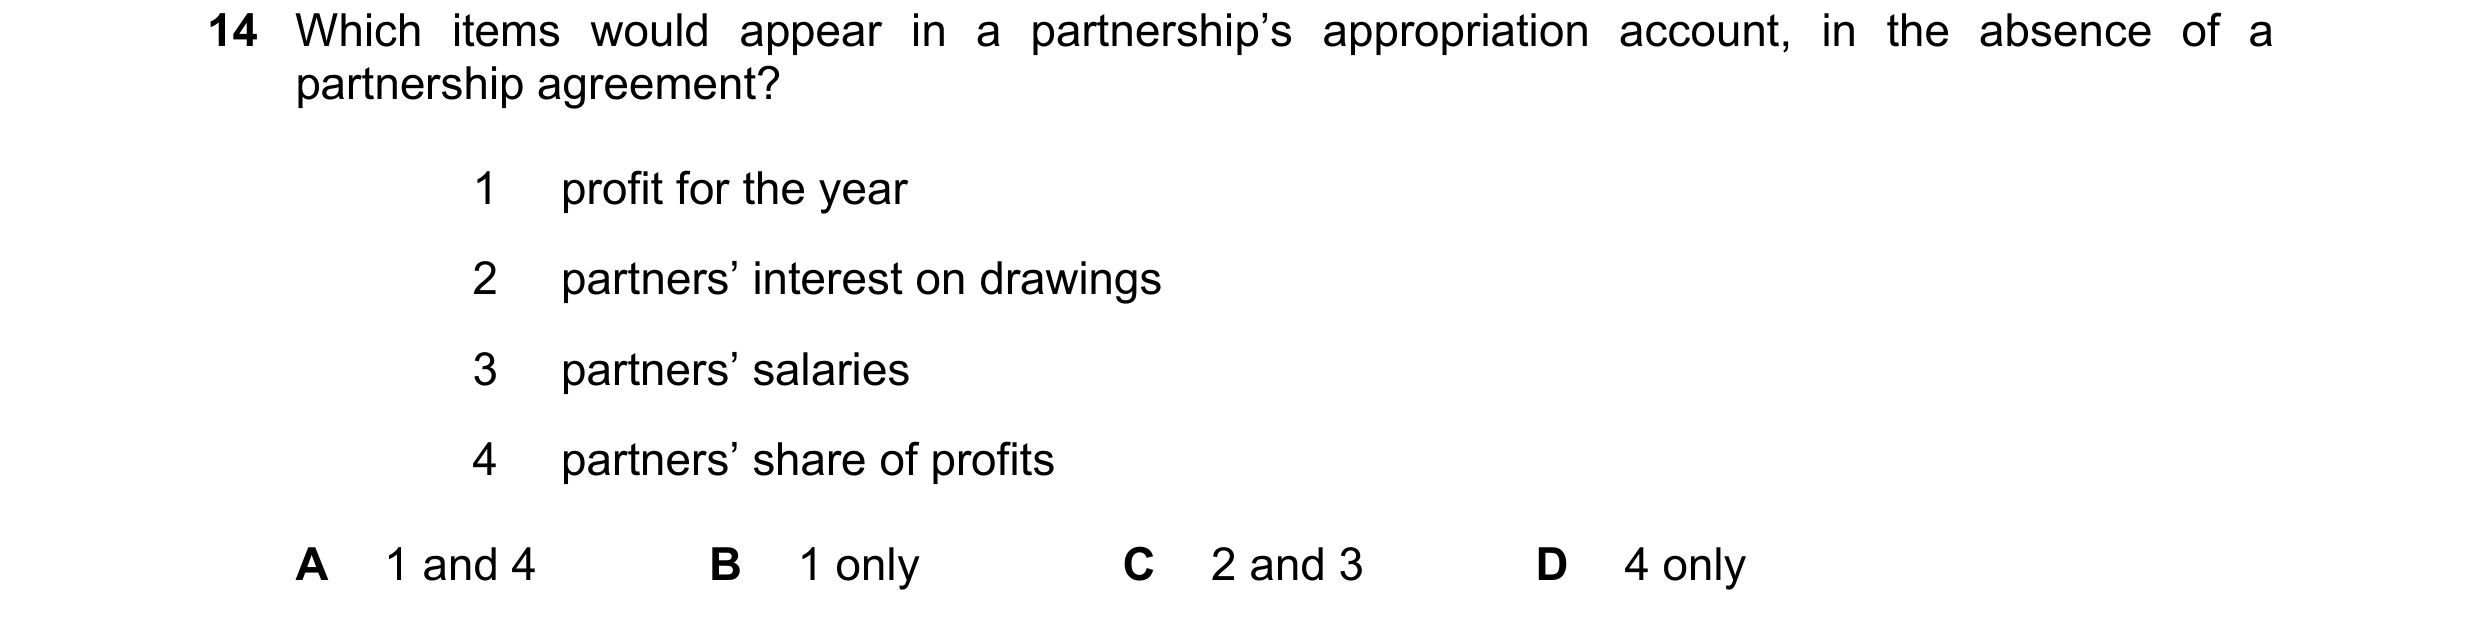
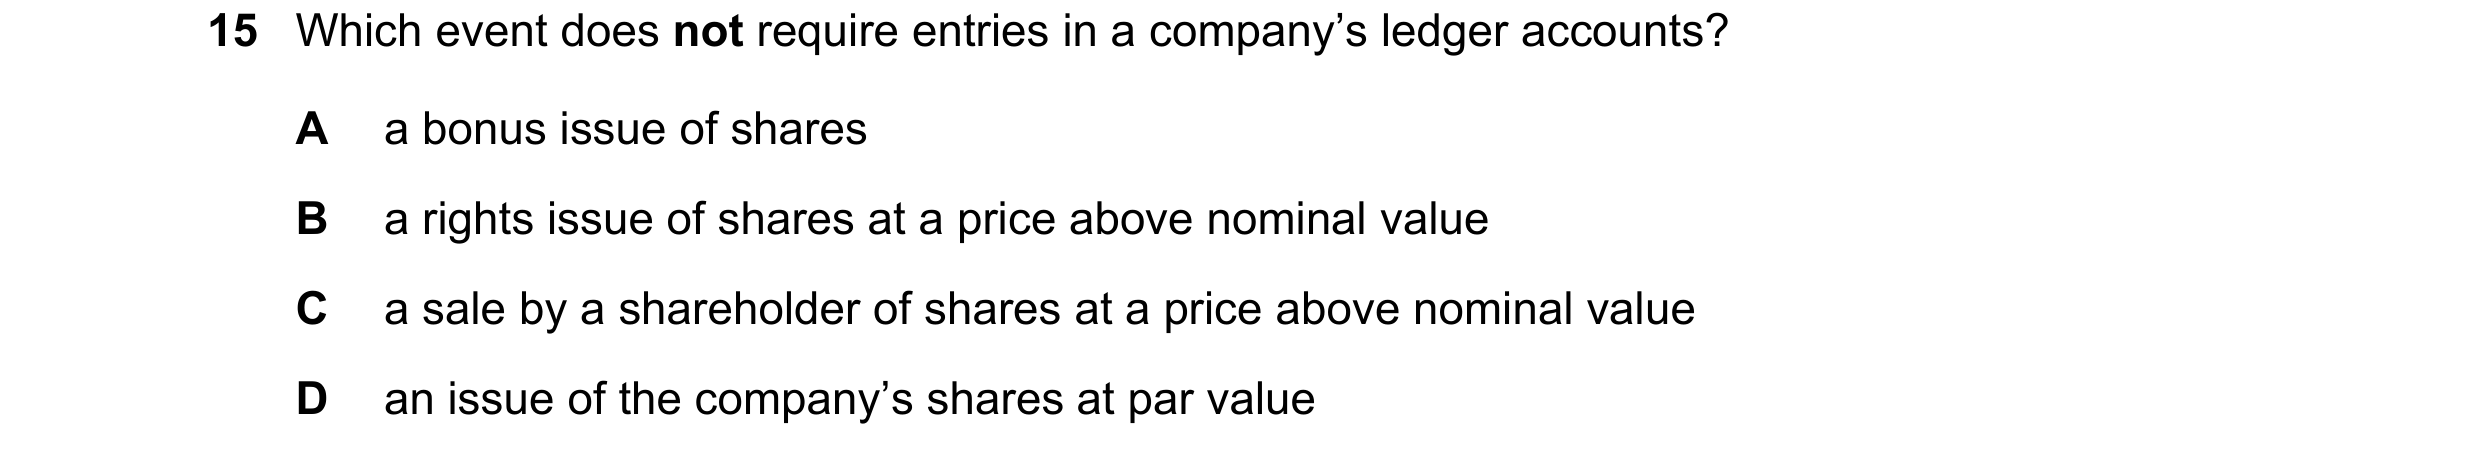 8 / 60
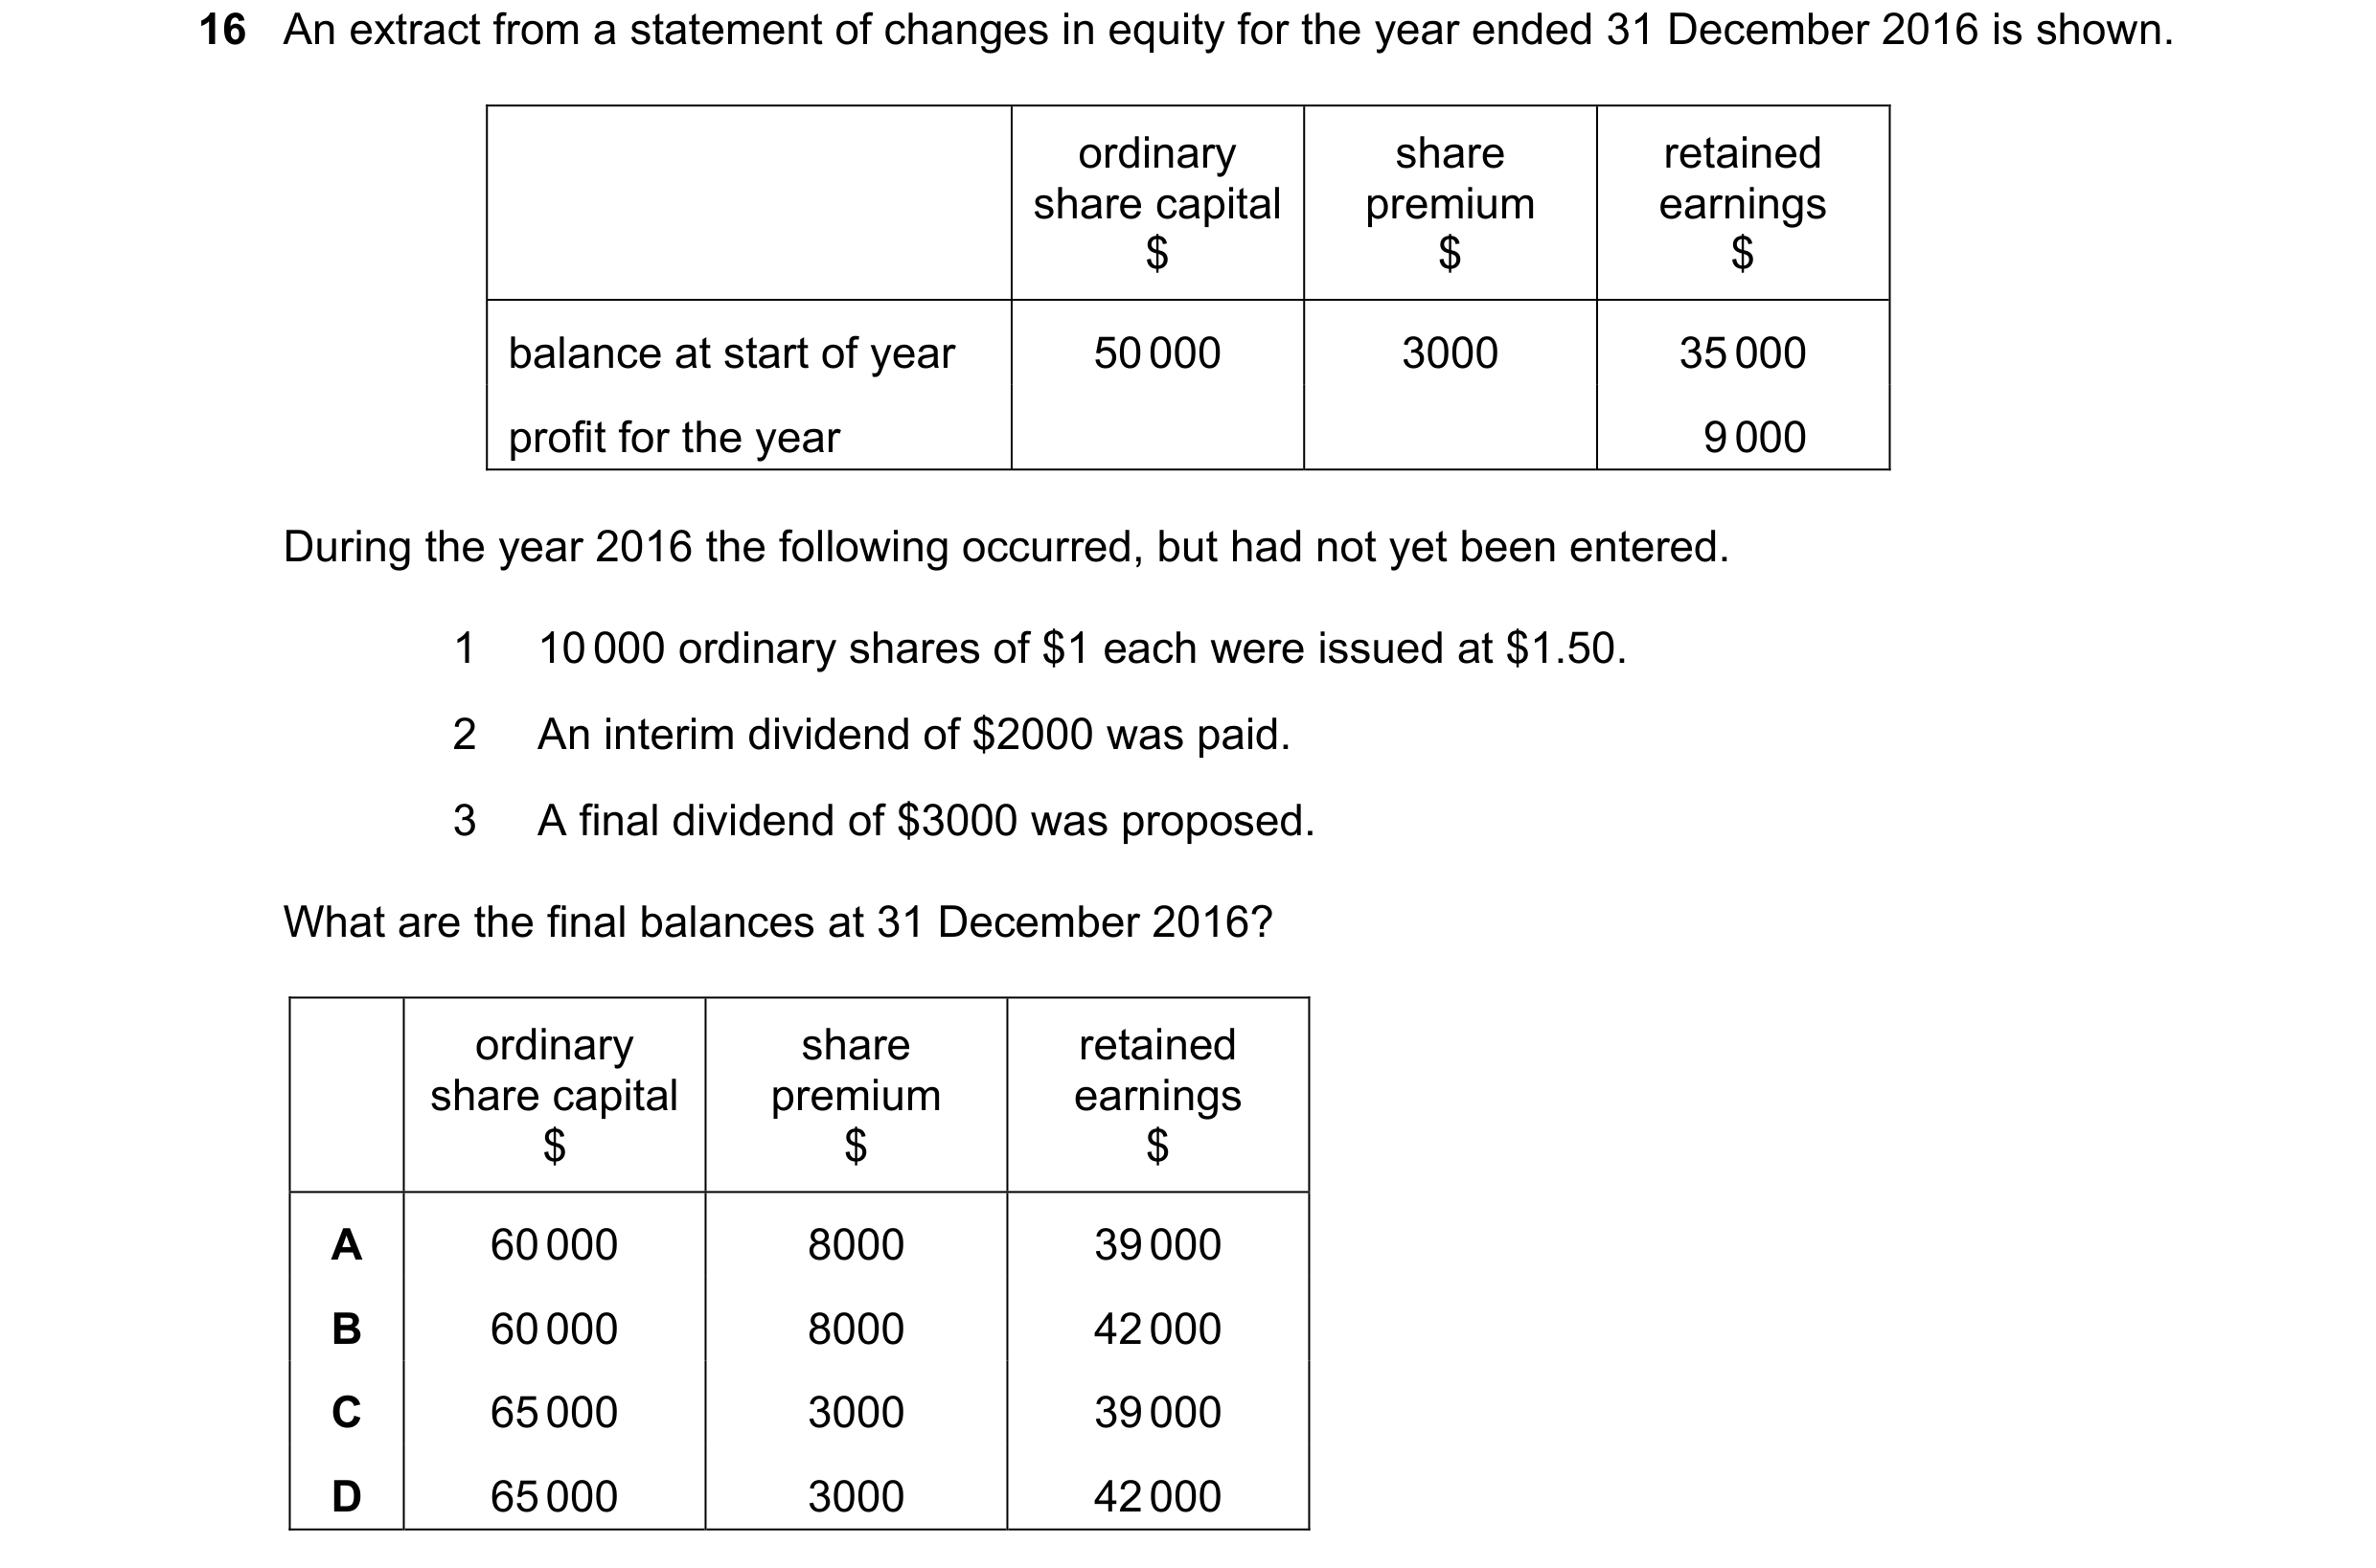
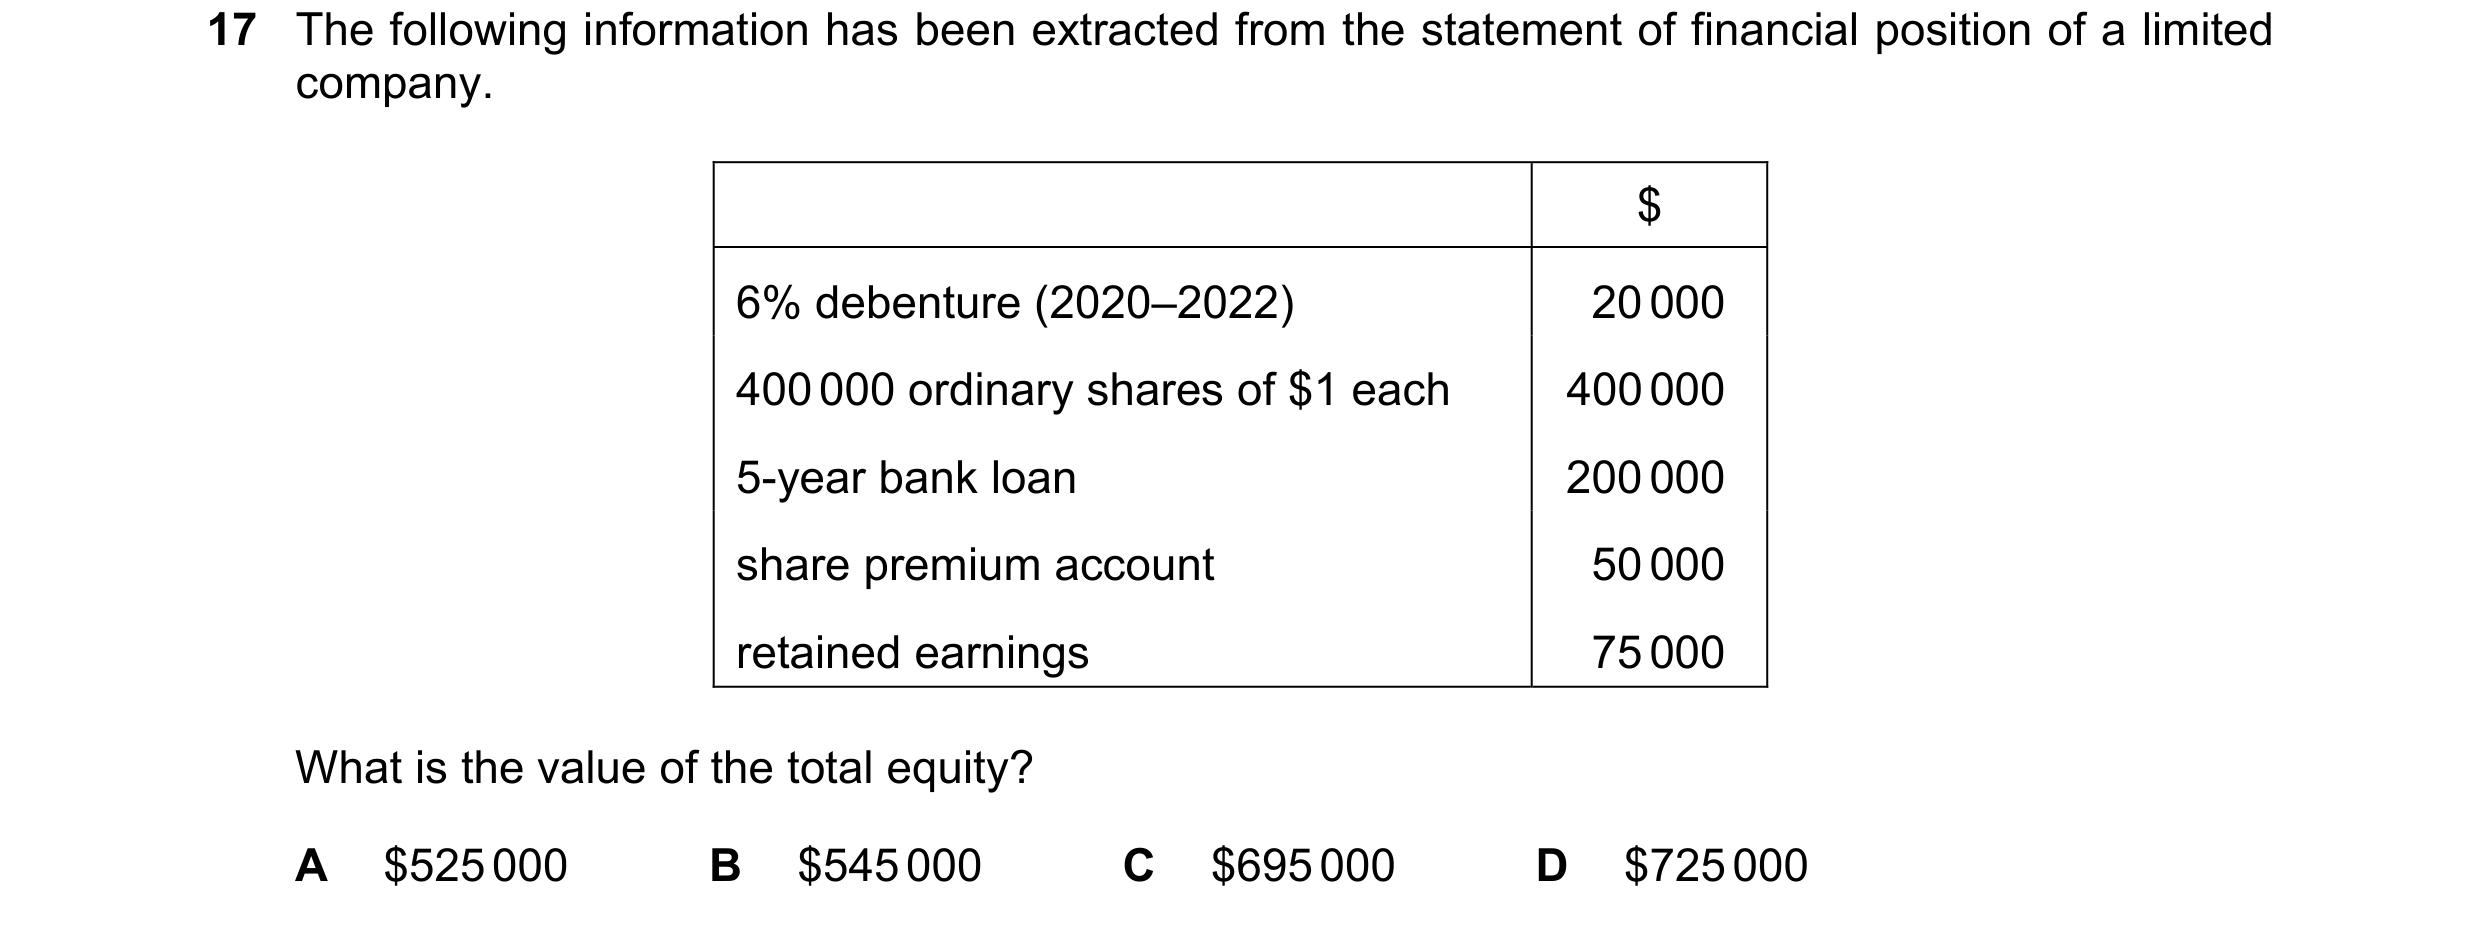
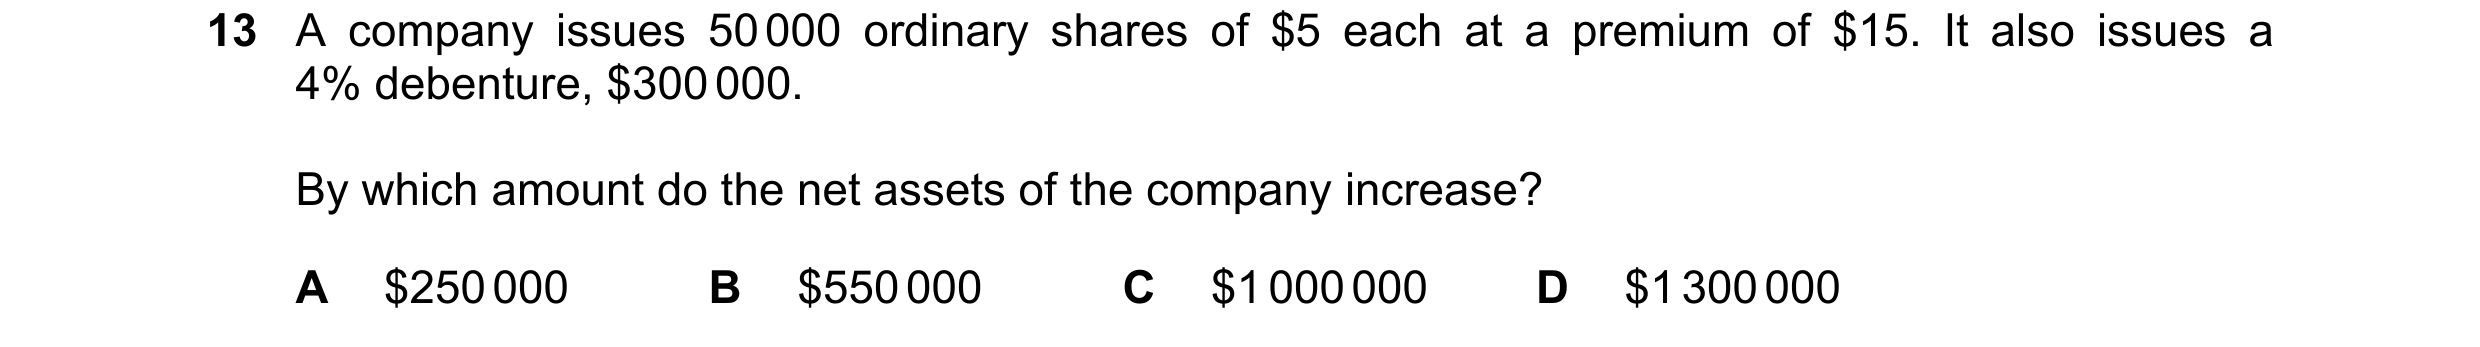 9 / 60
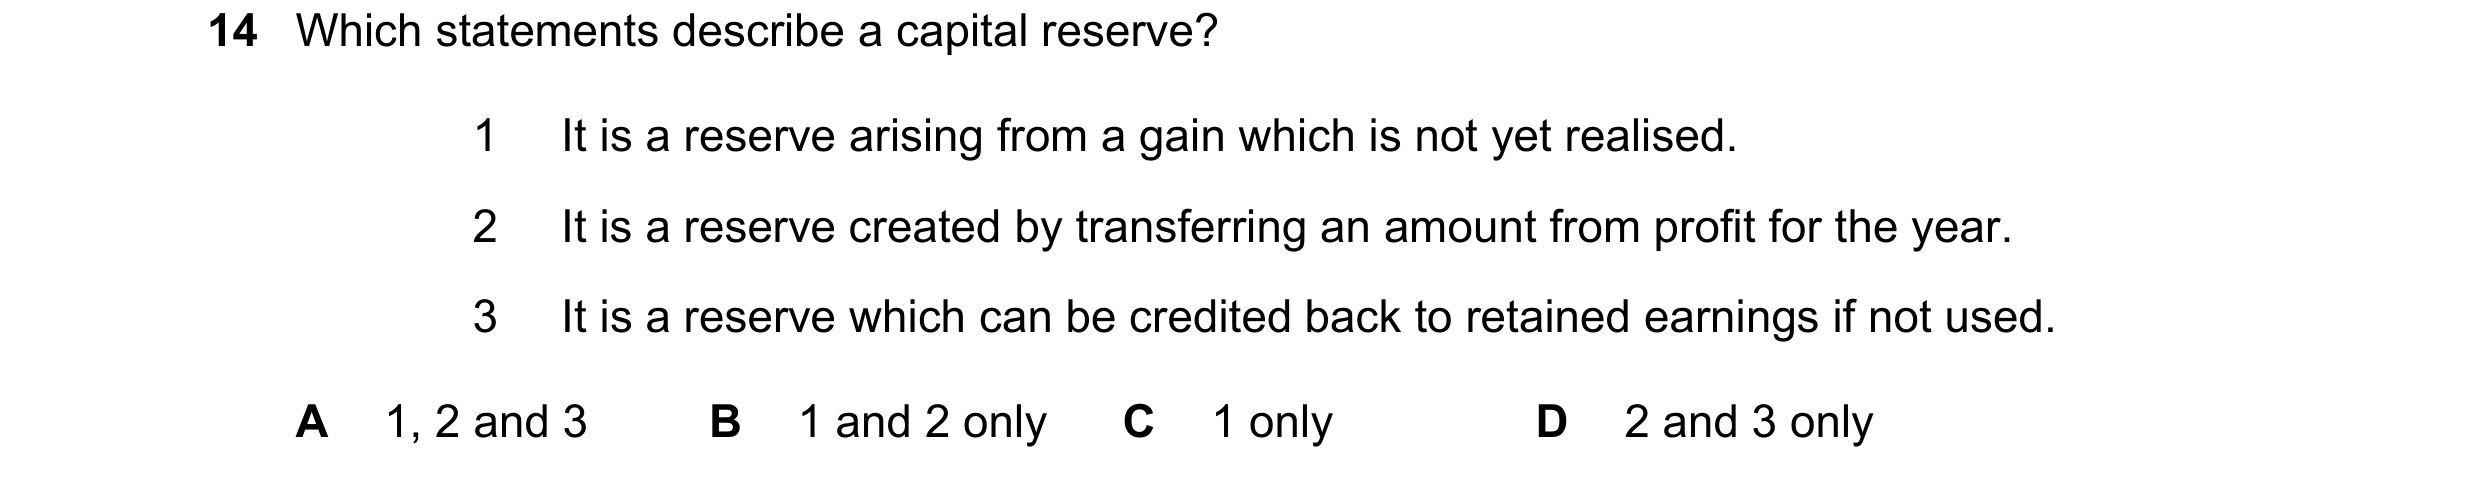
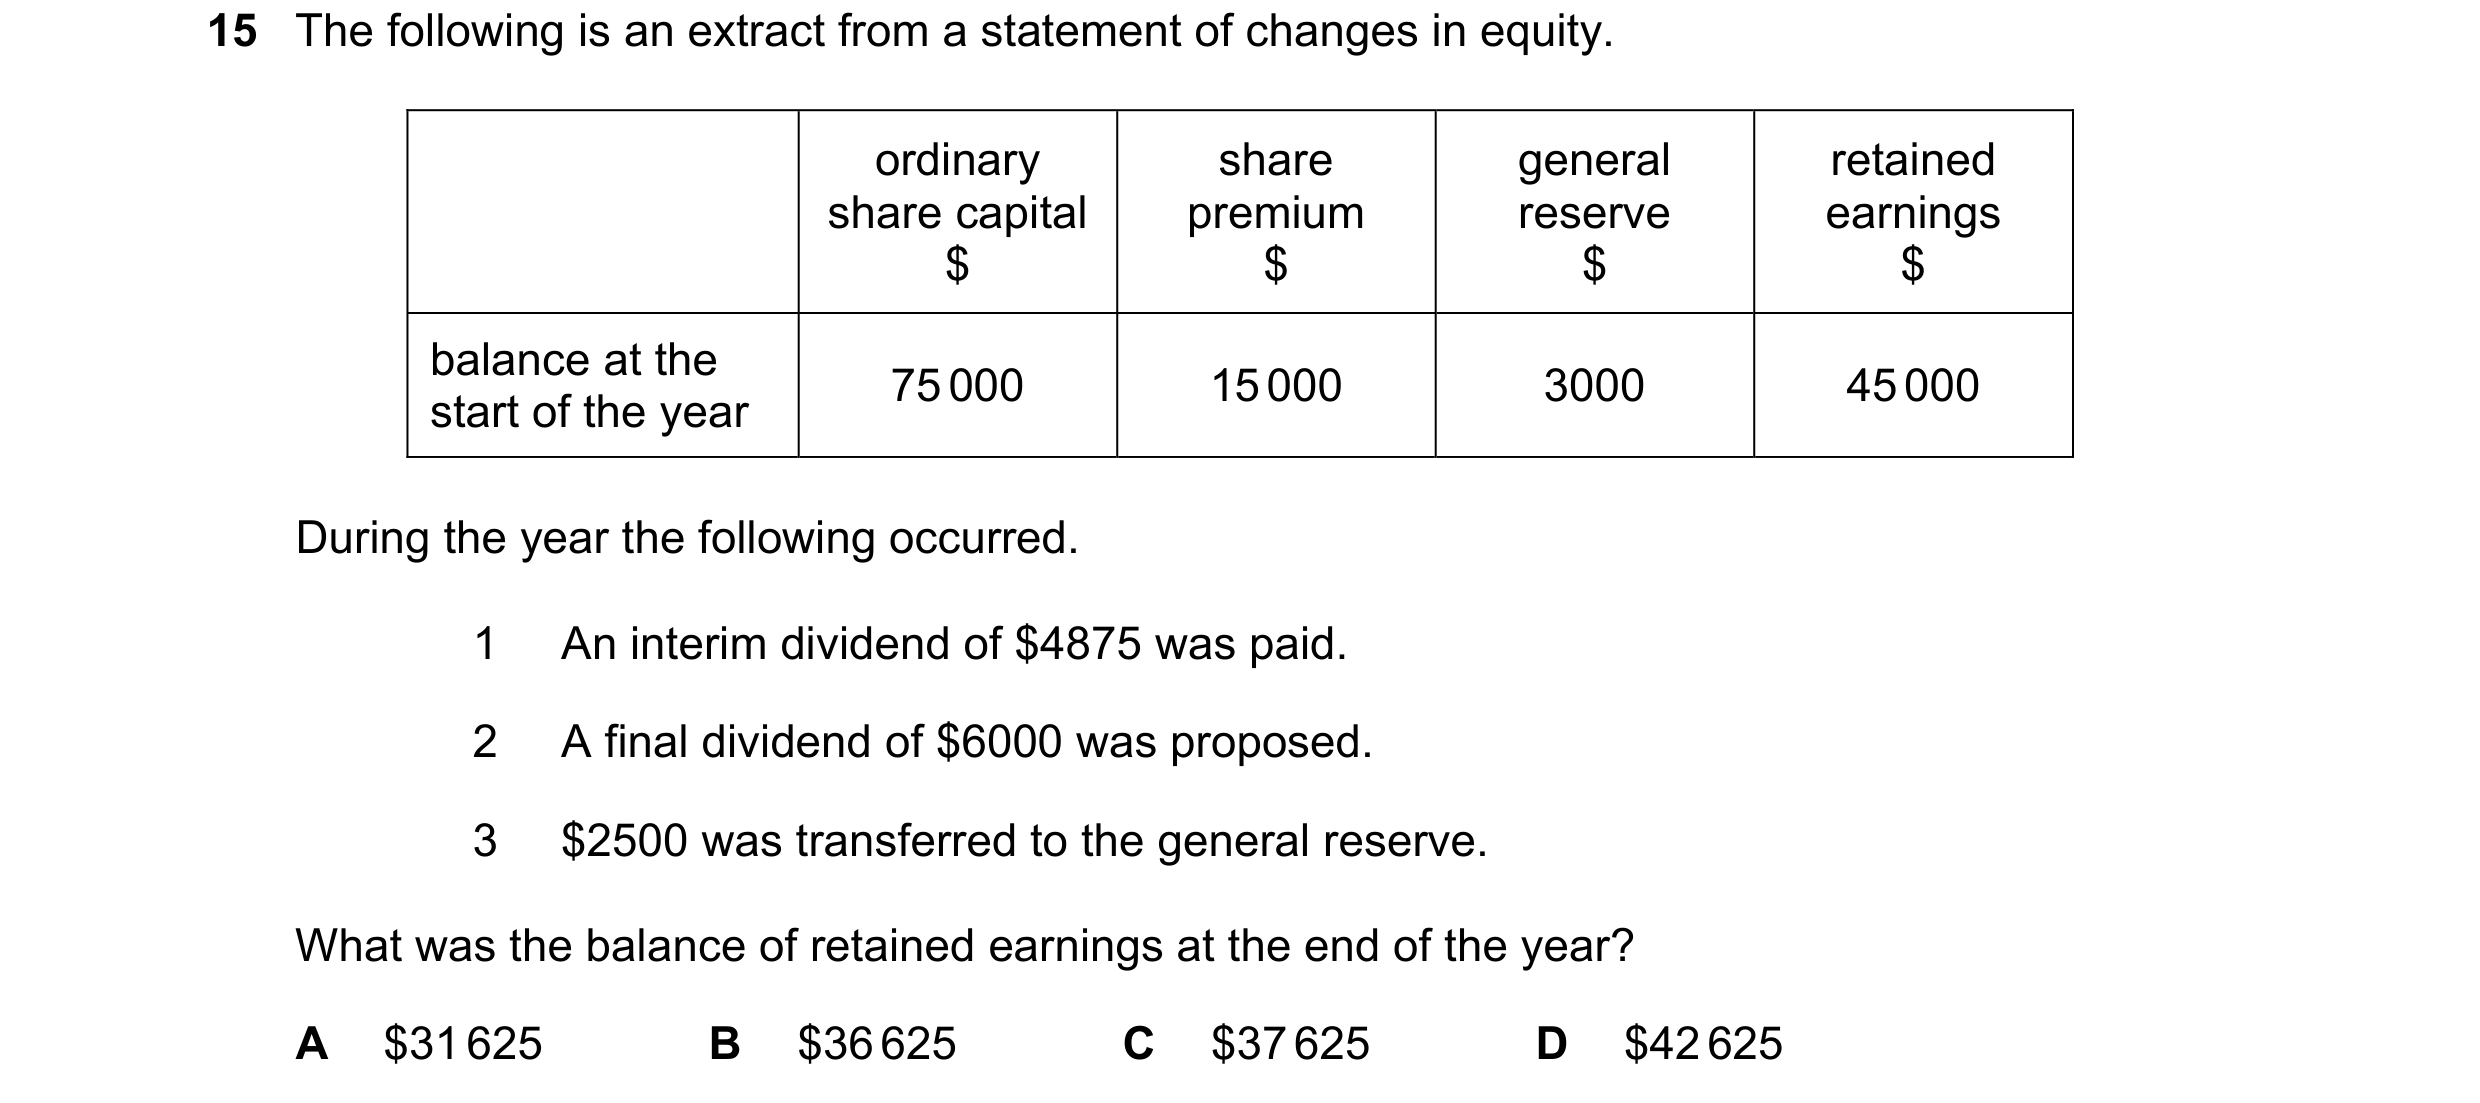
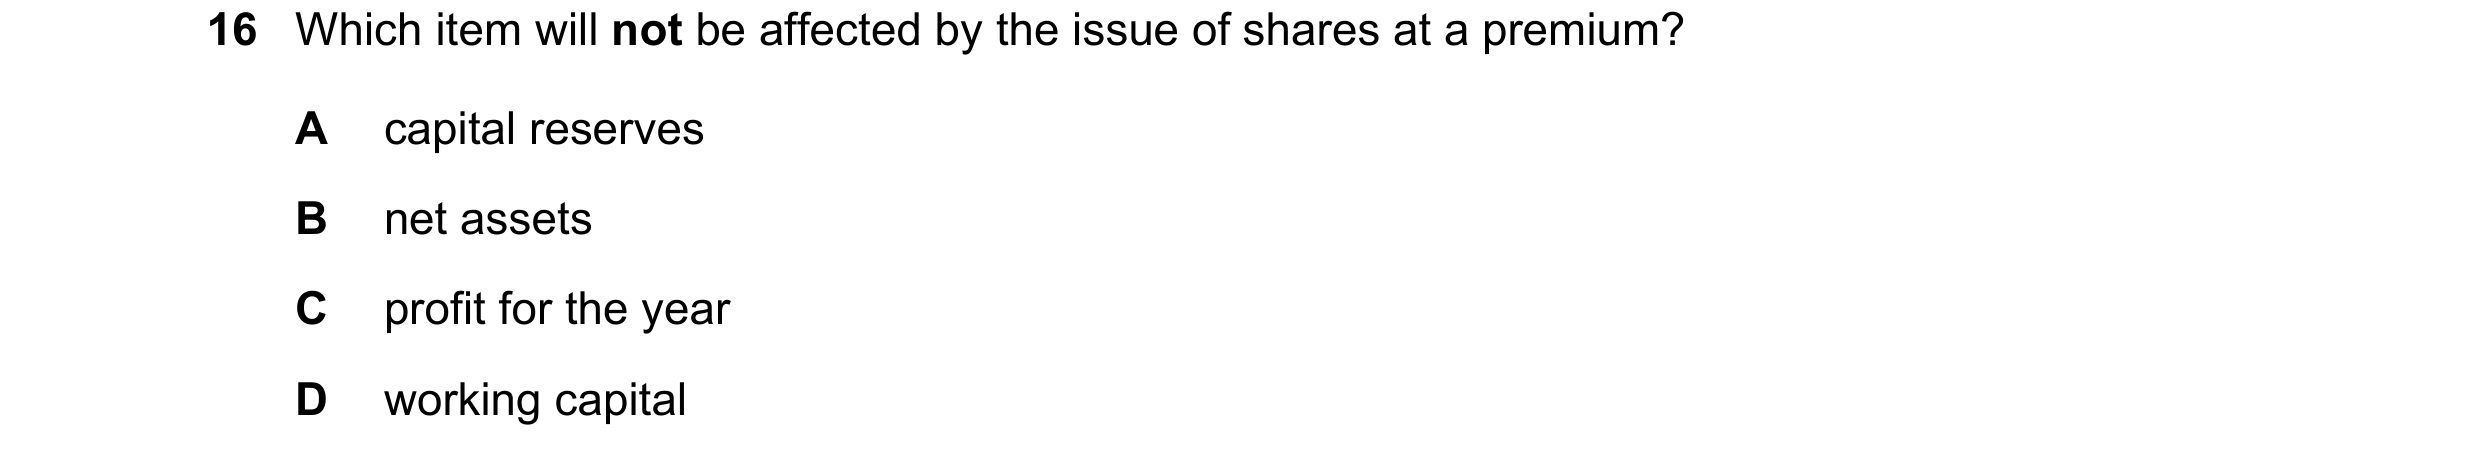
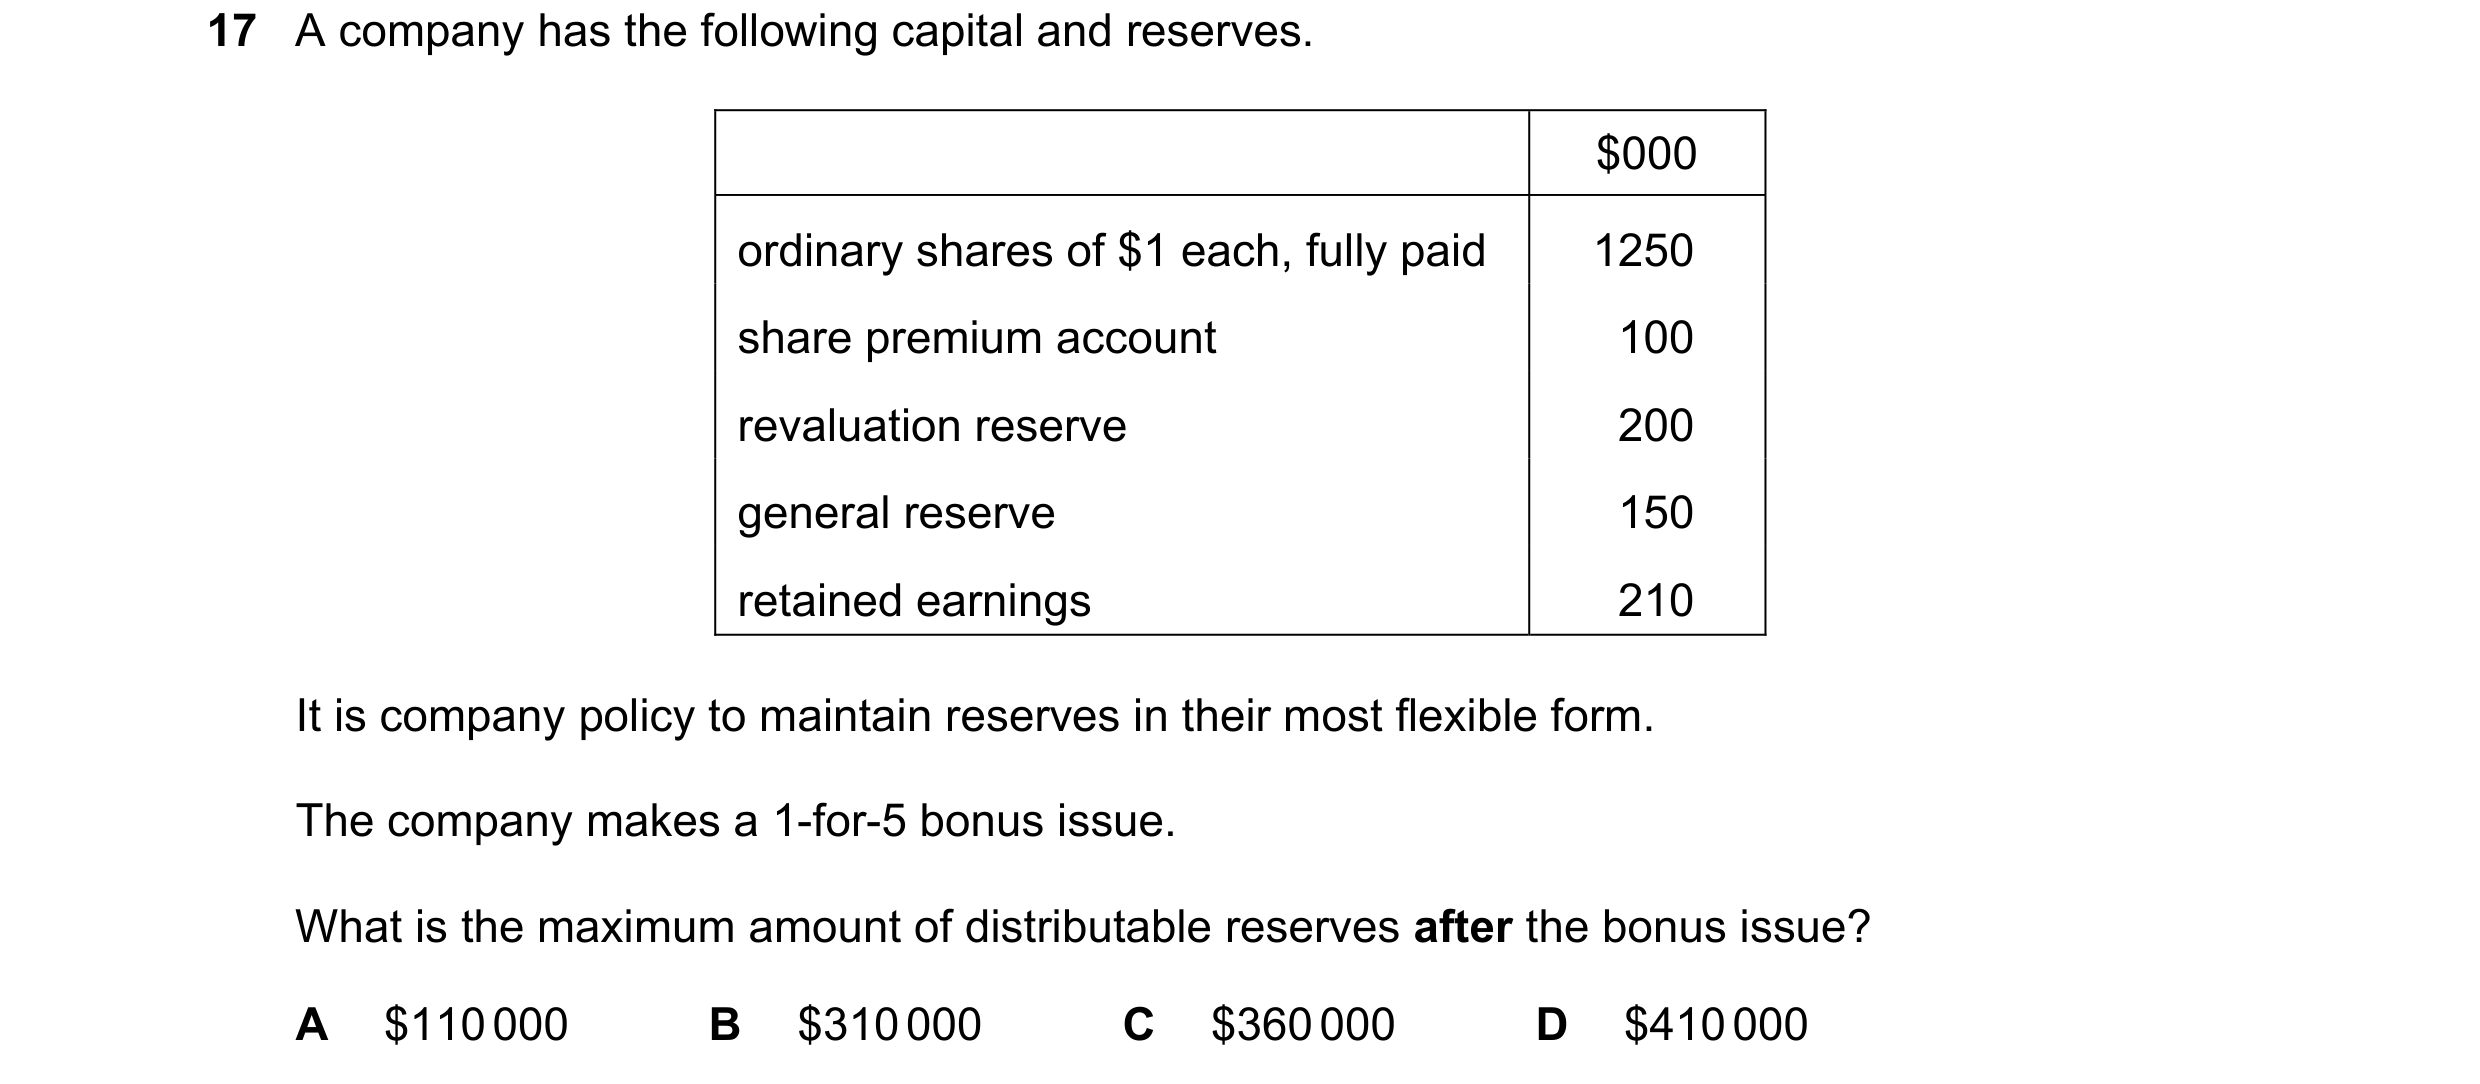 10 / 60
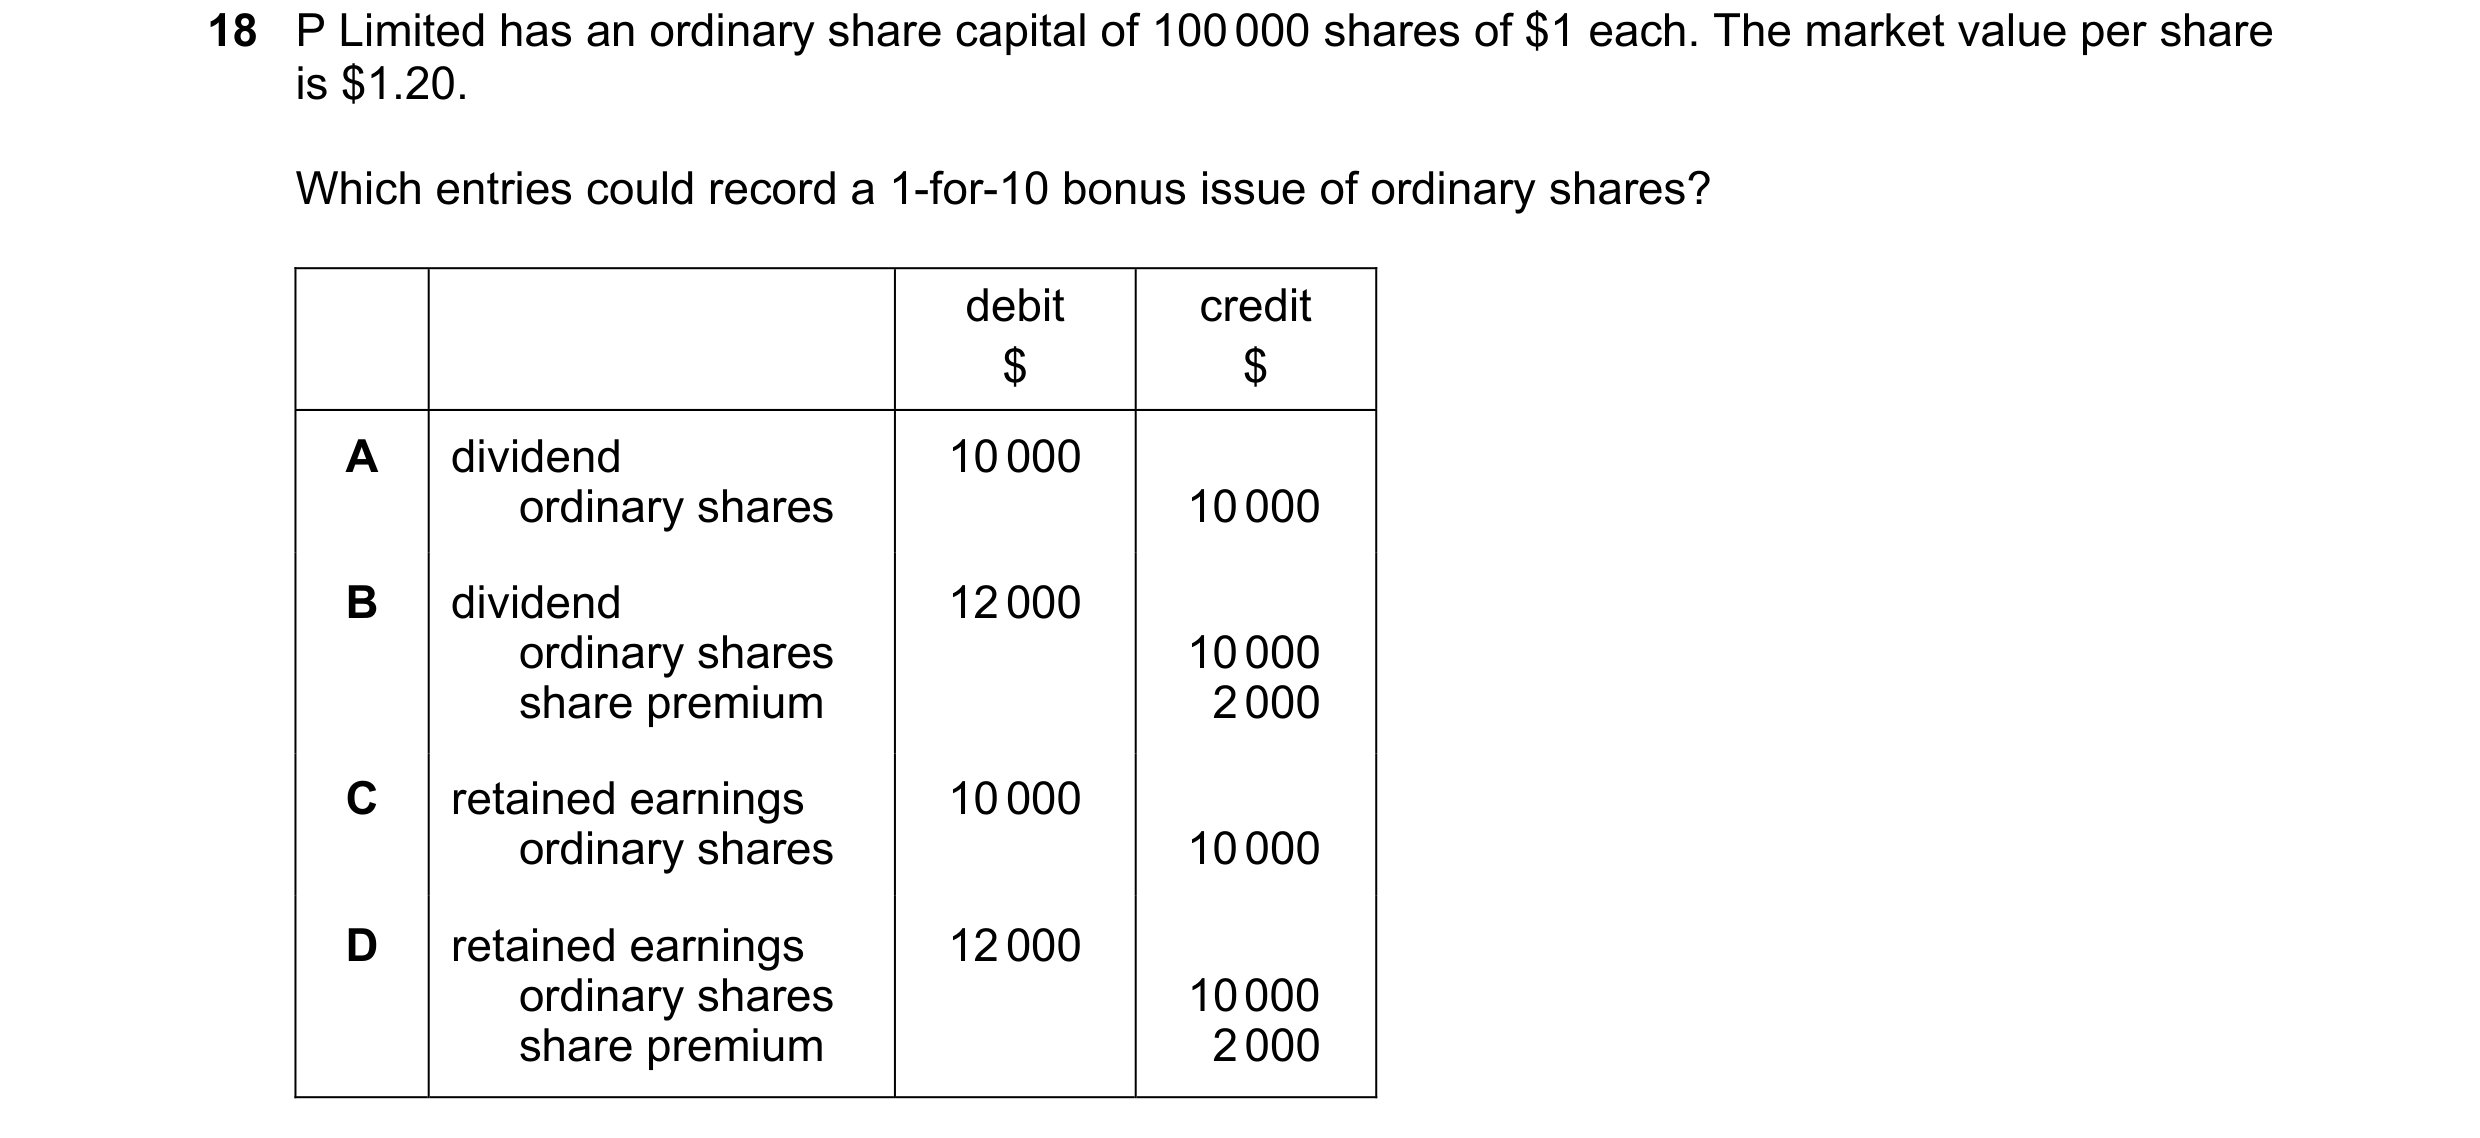
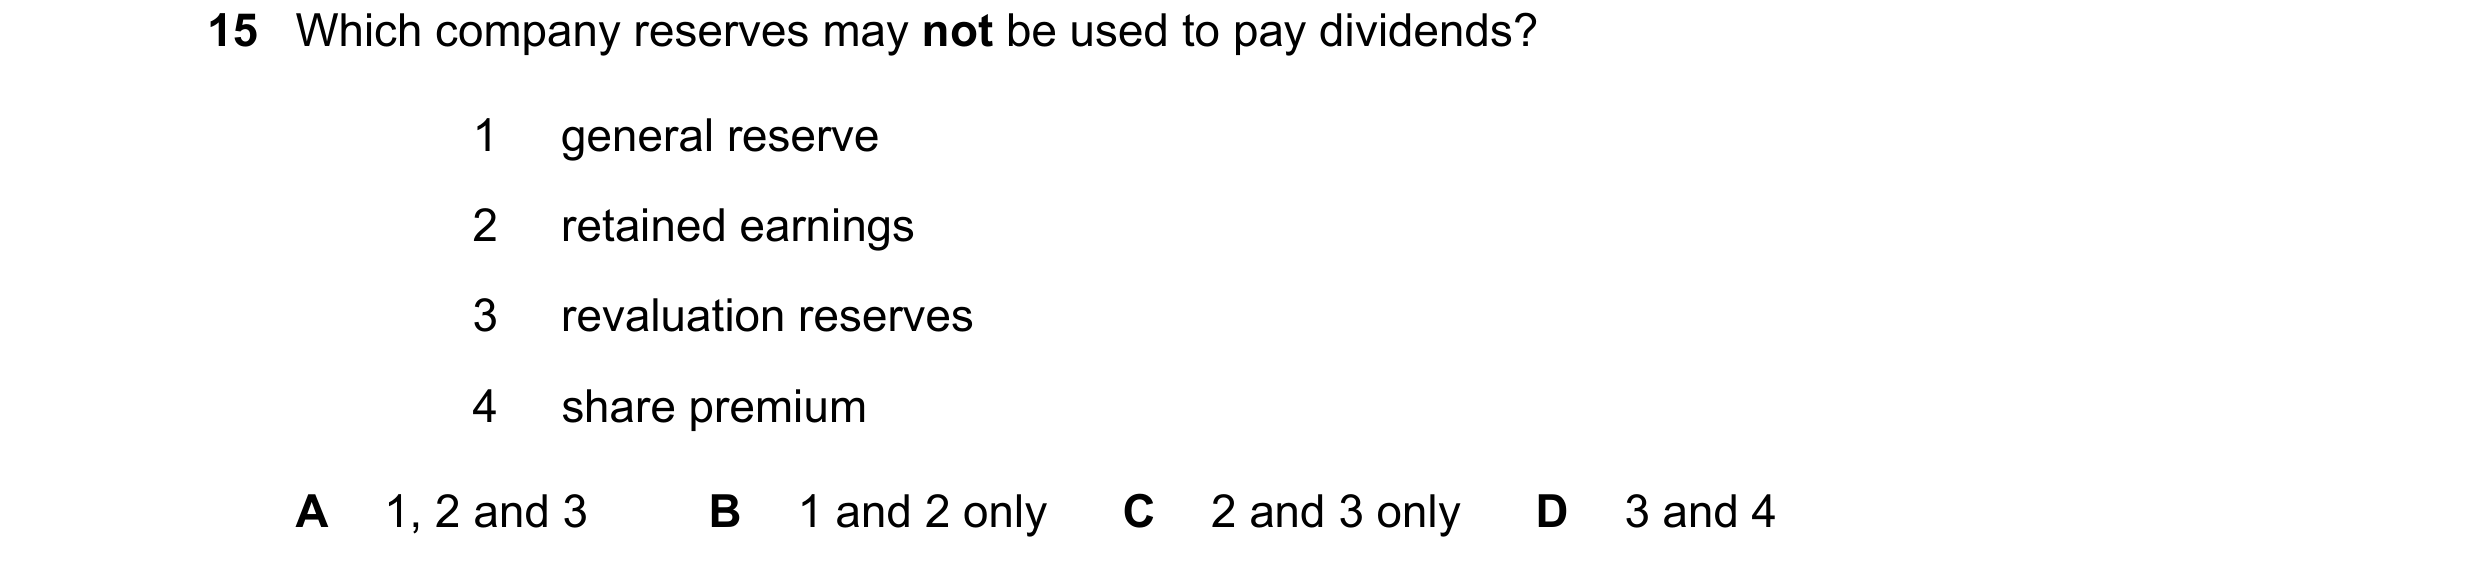
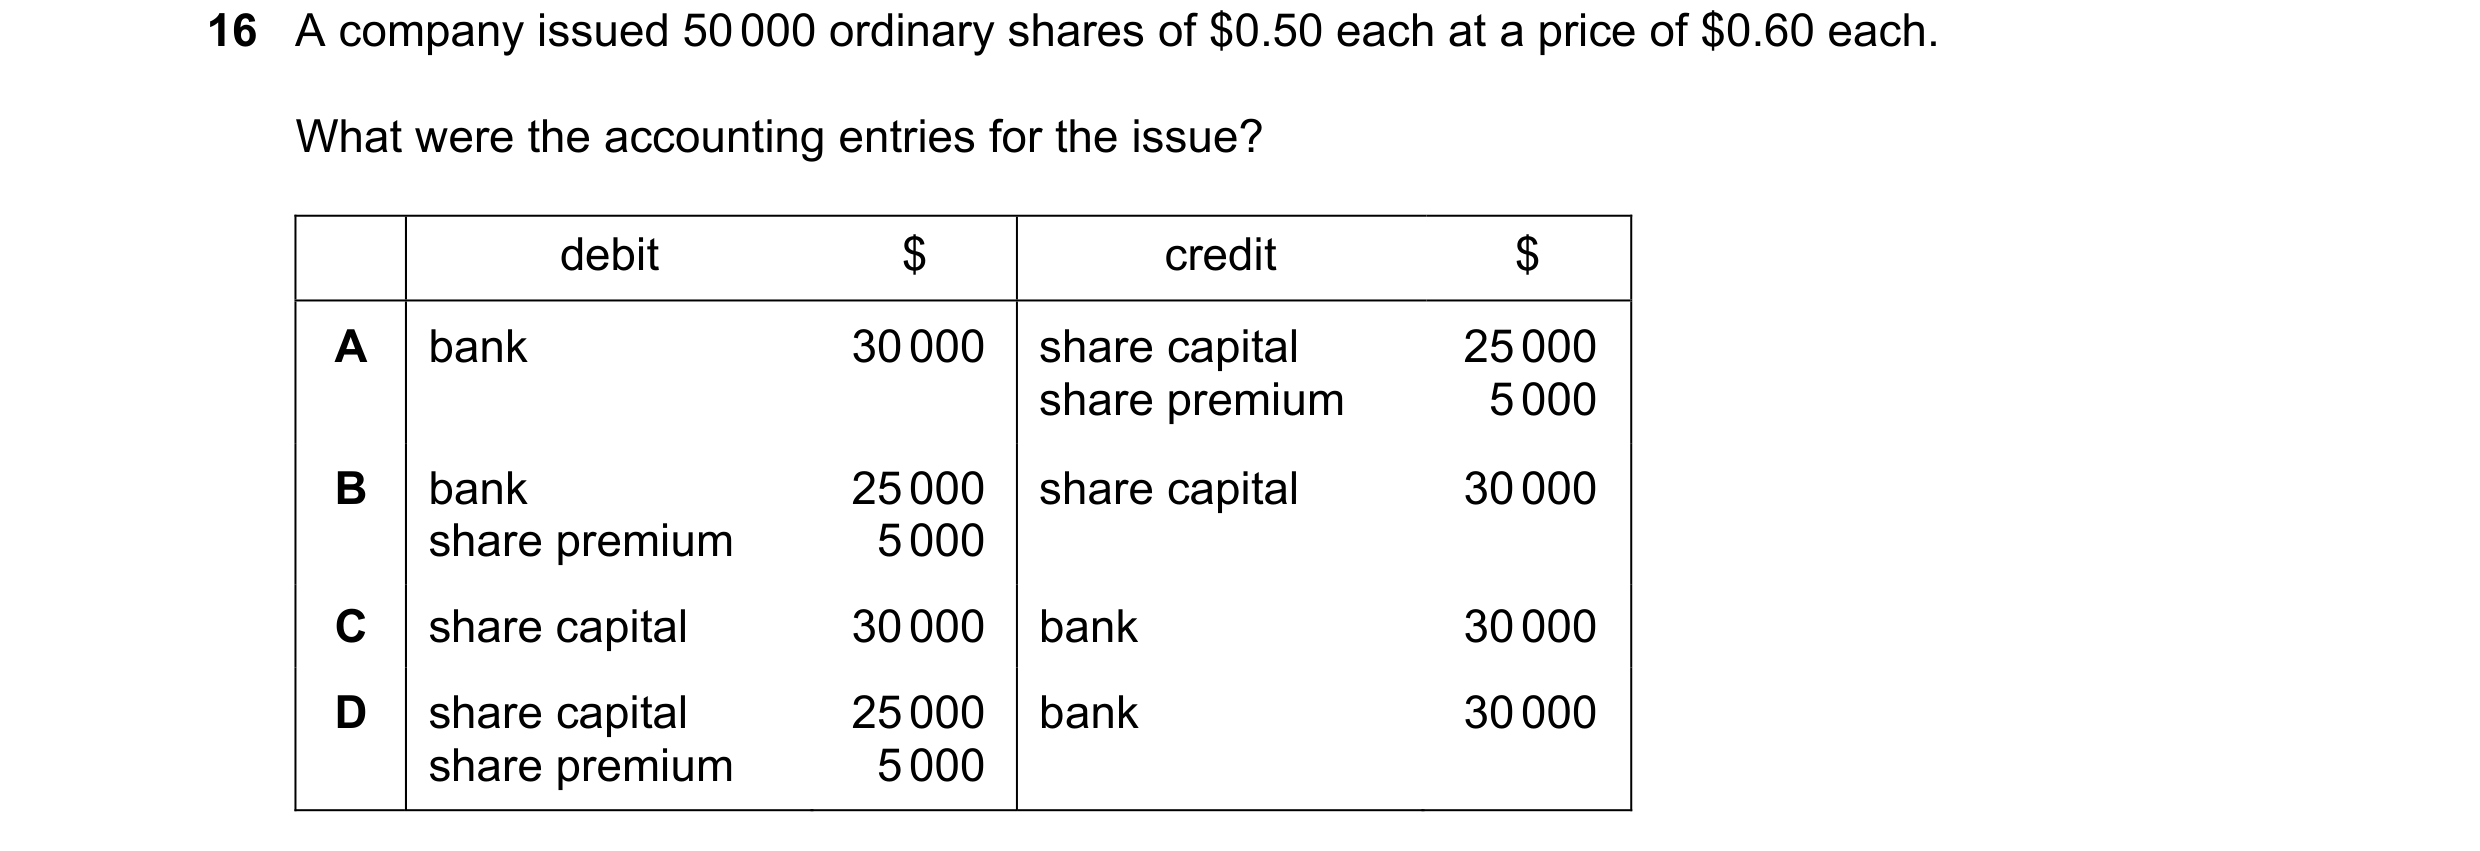
 11 / 60
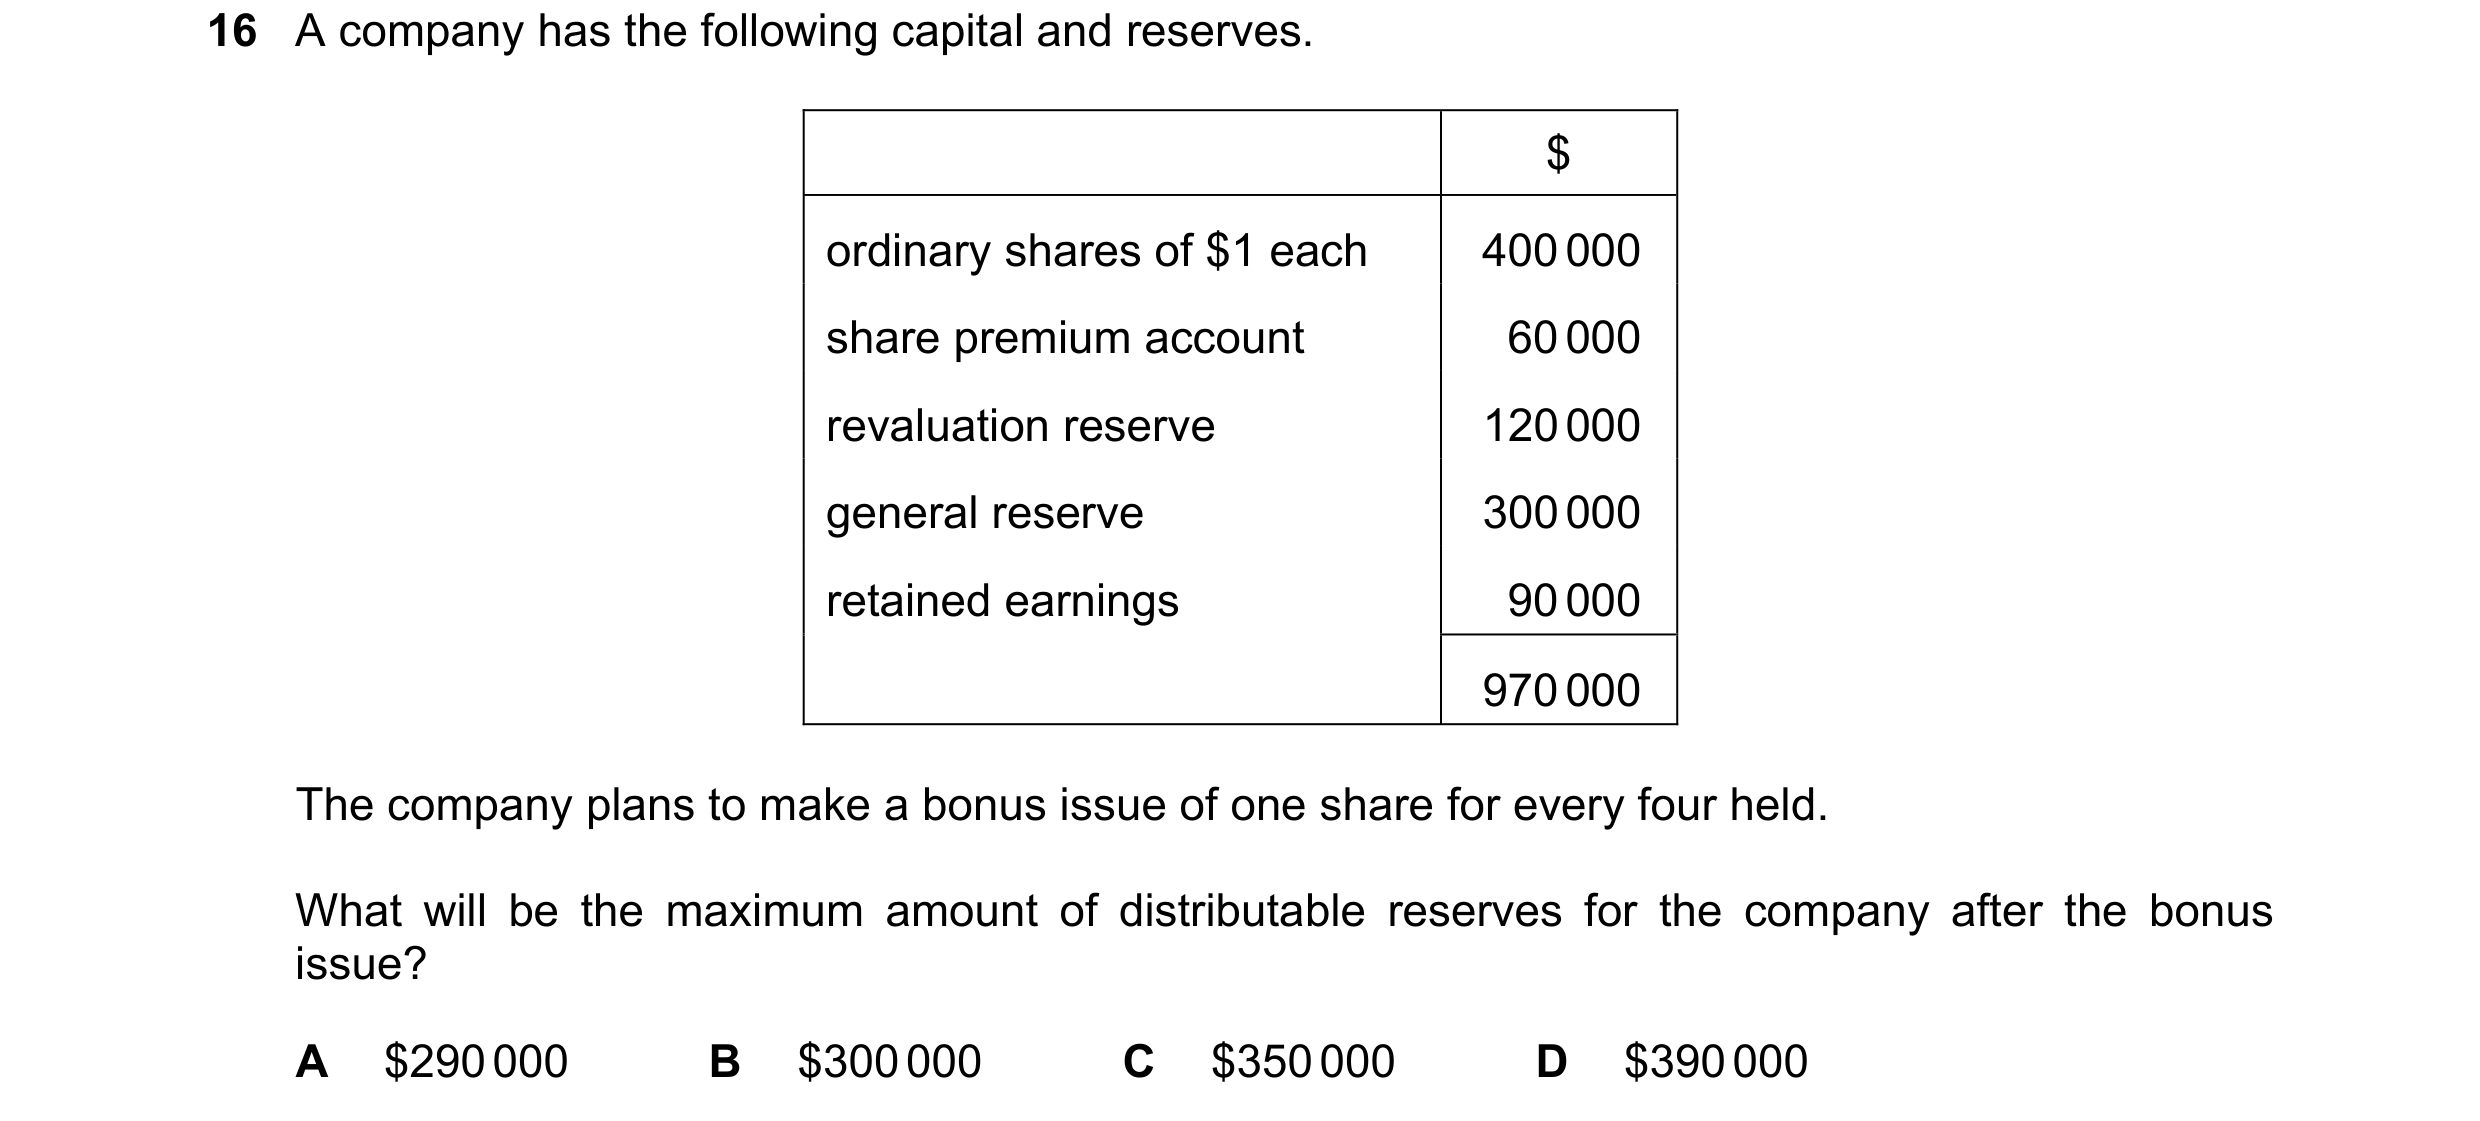 12 / 60
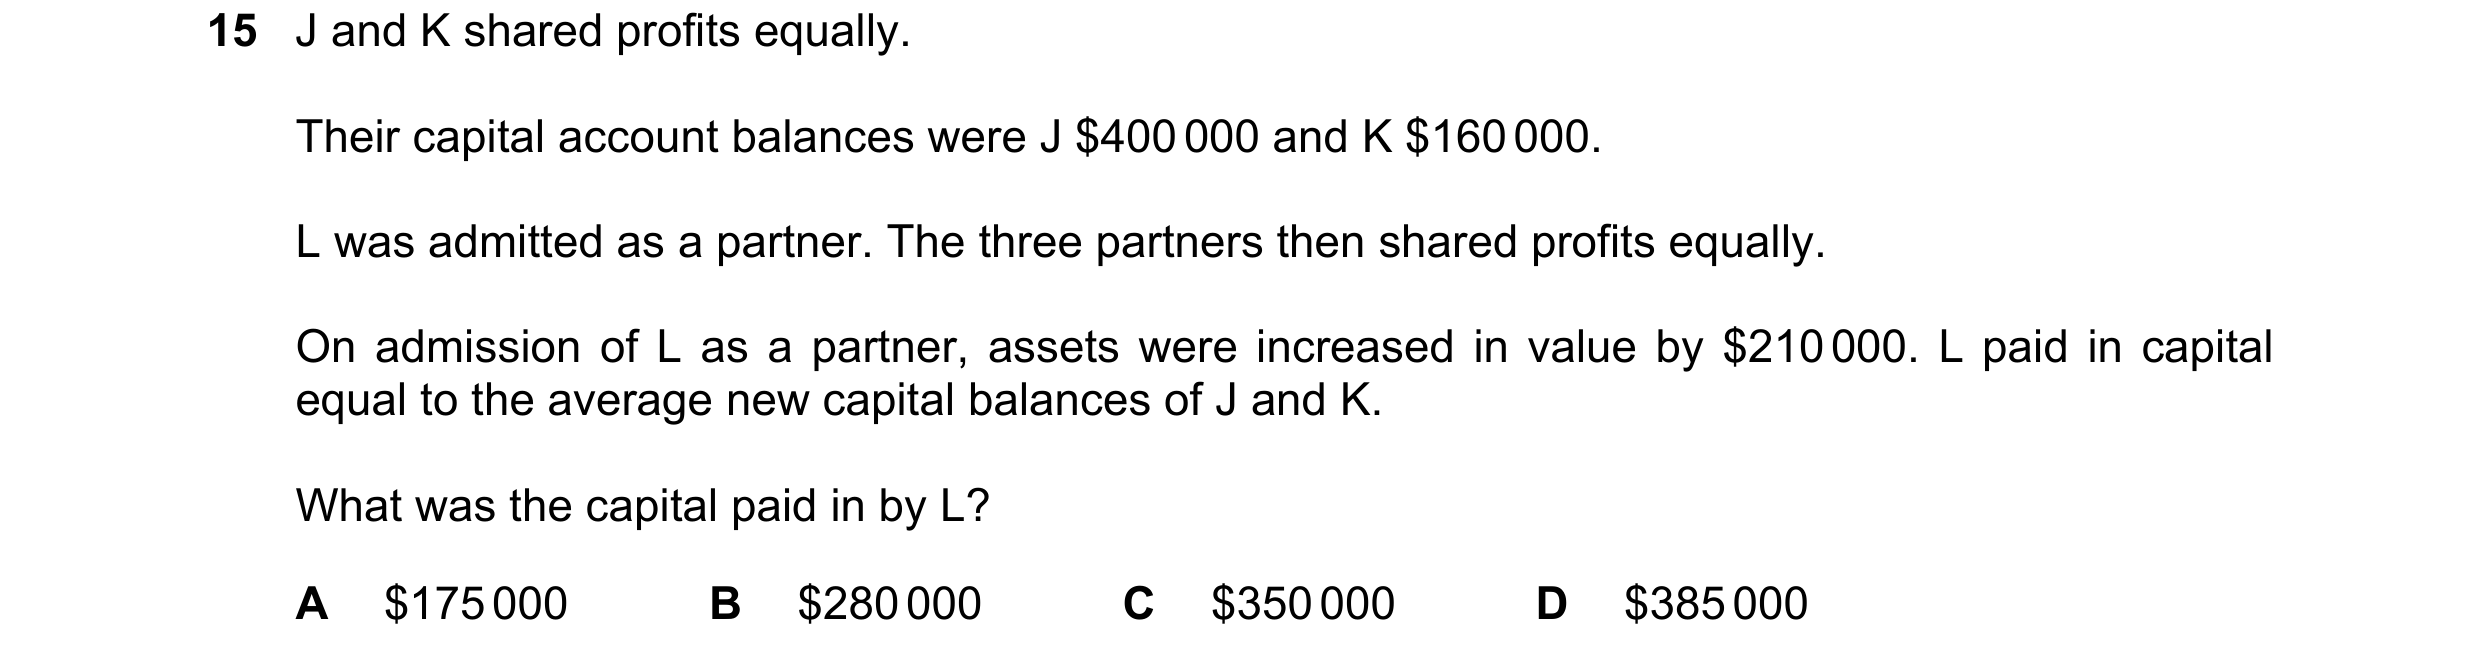 13 / 60
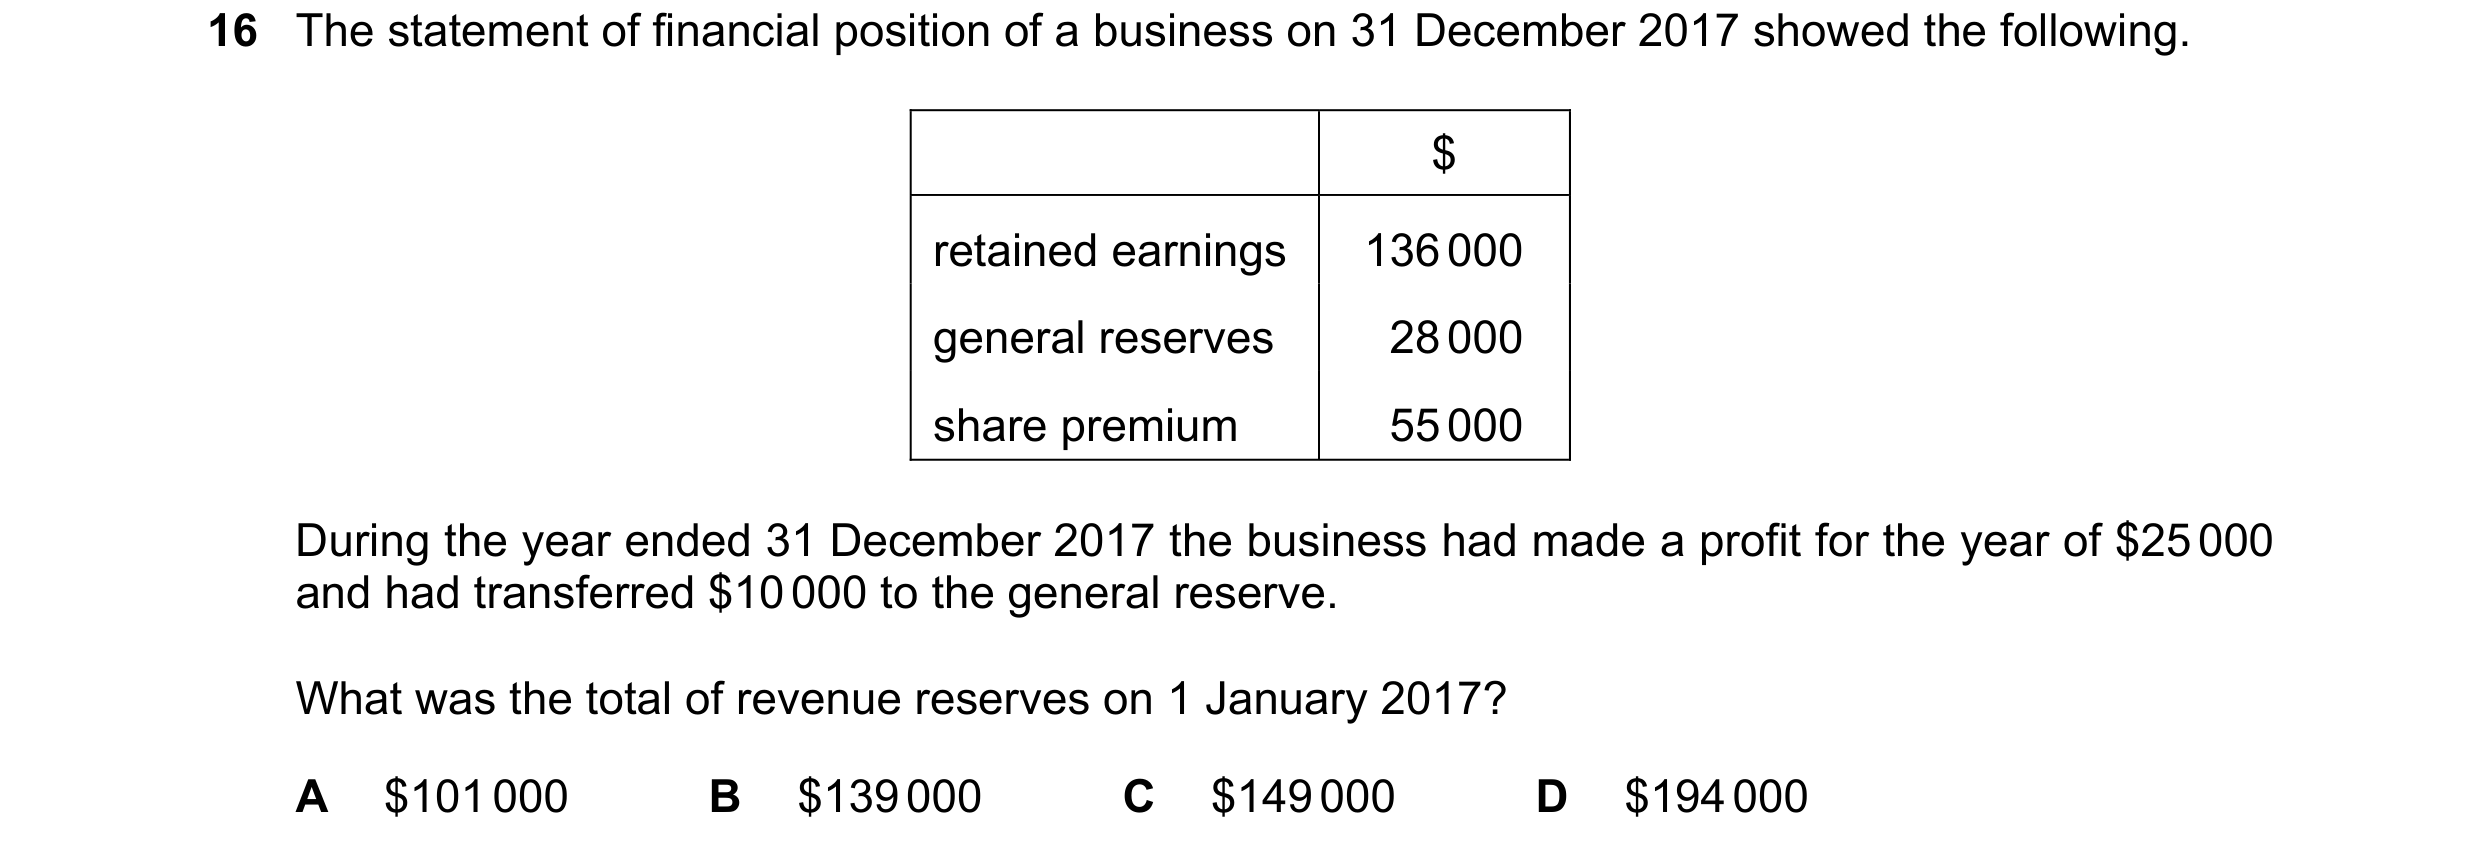
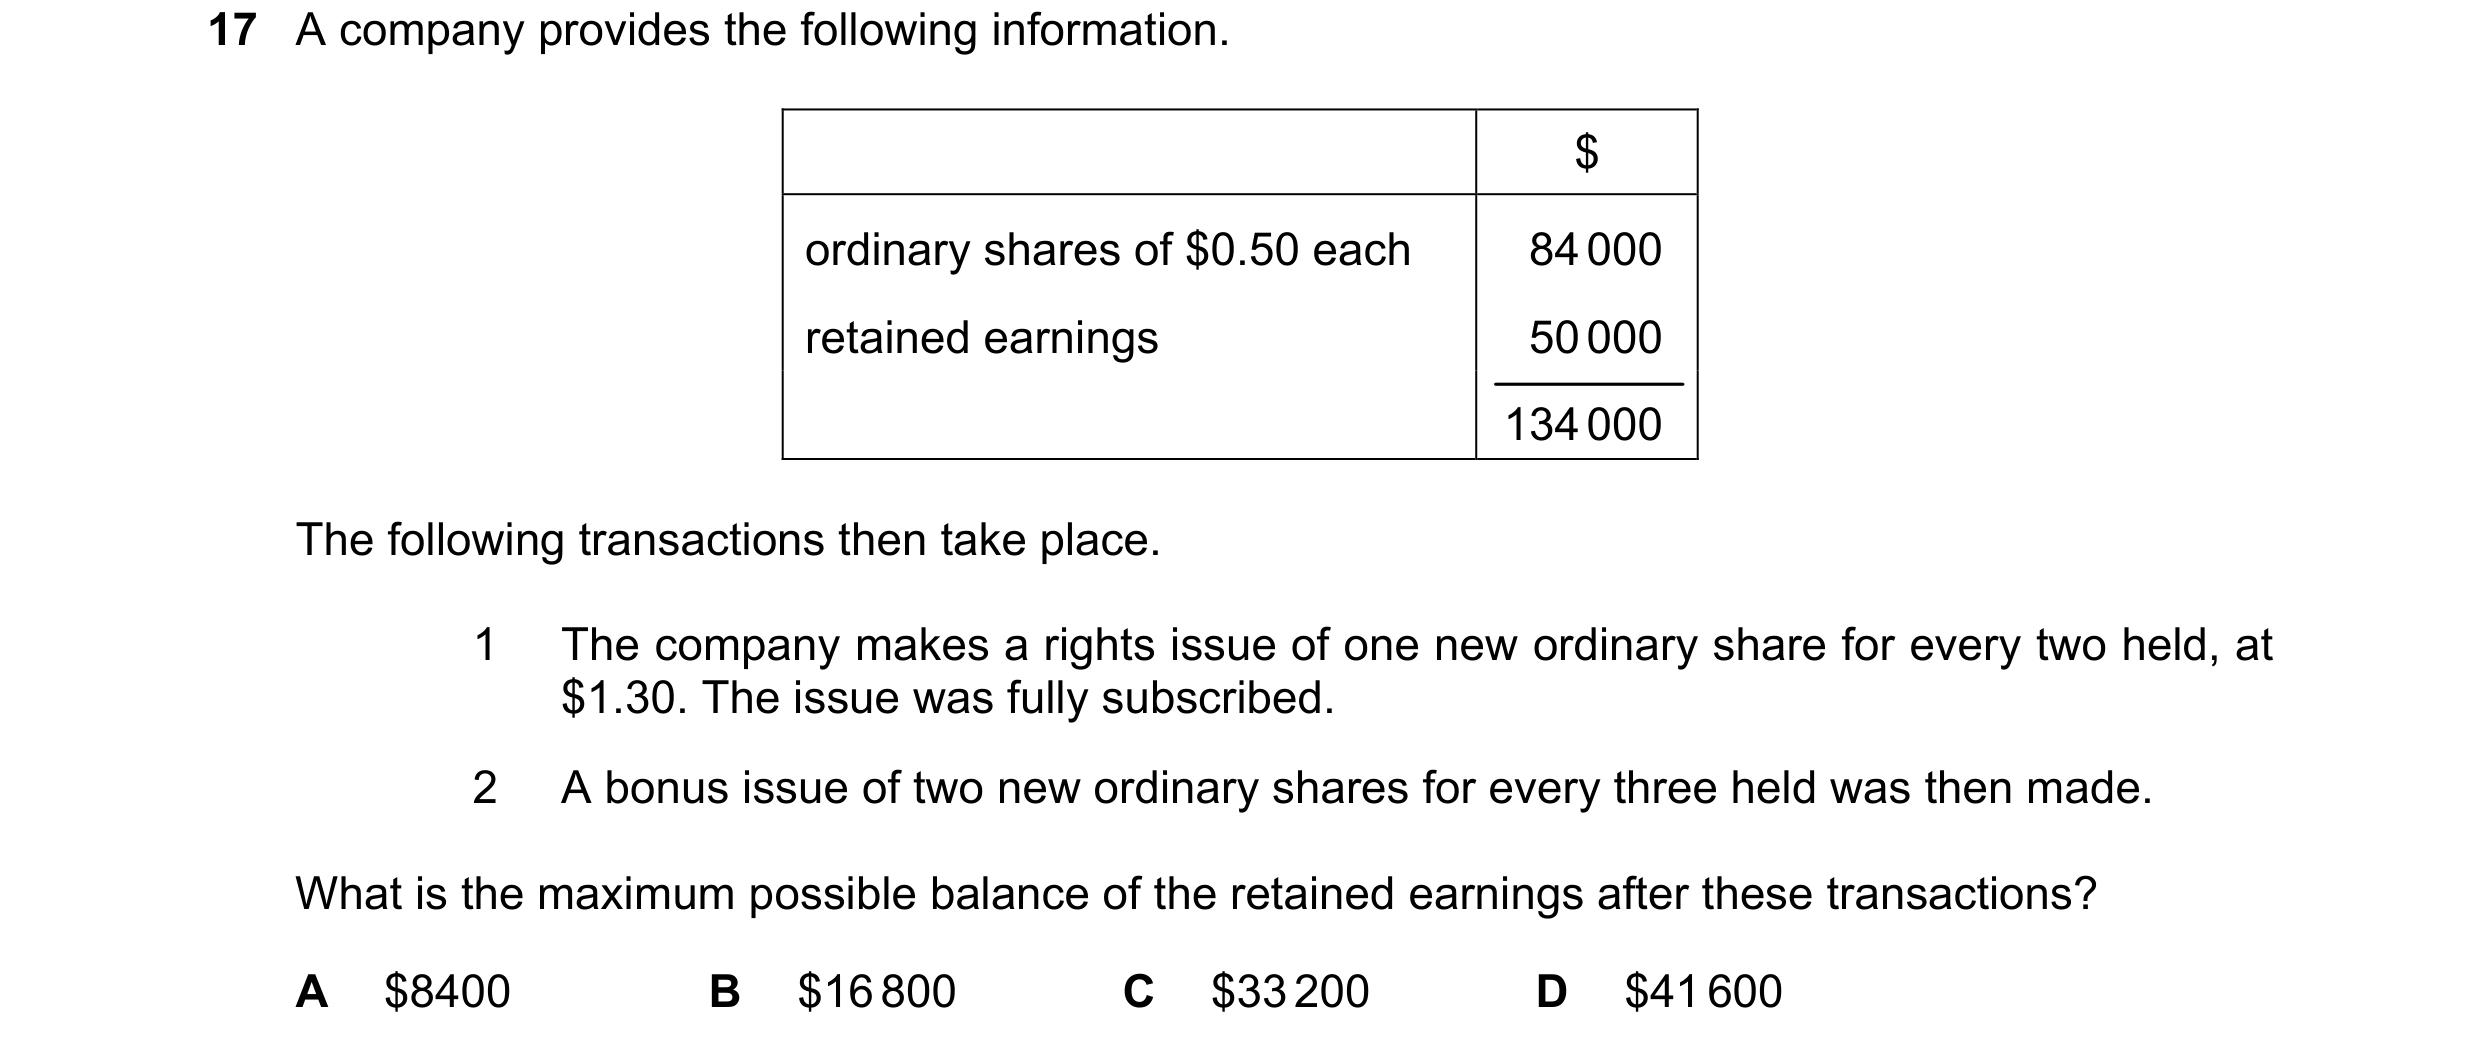
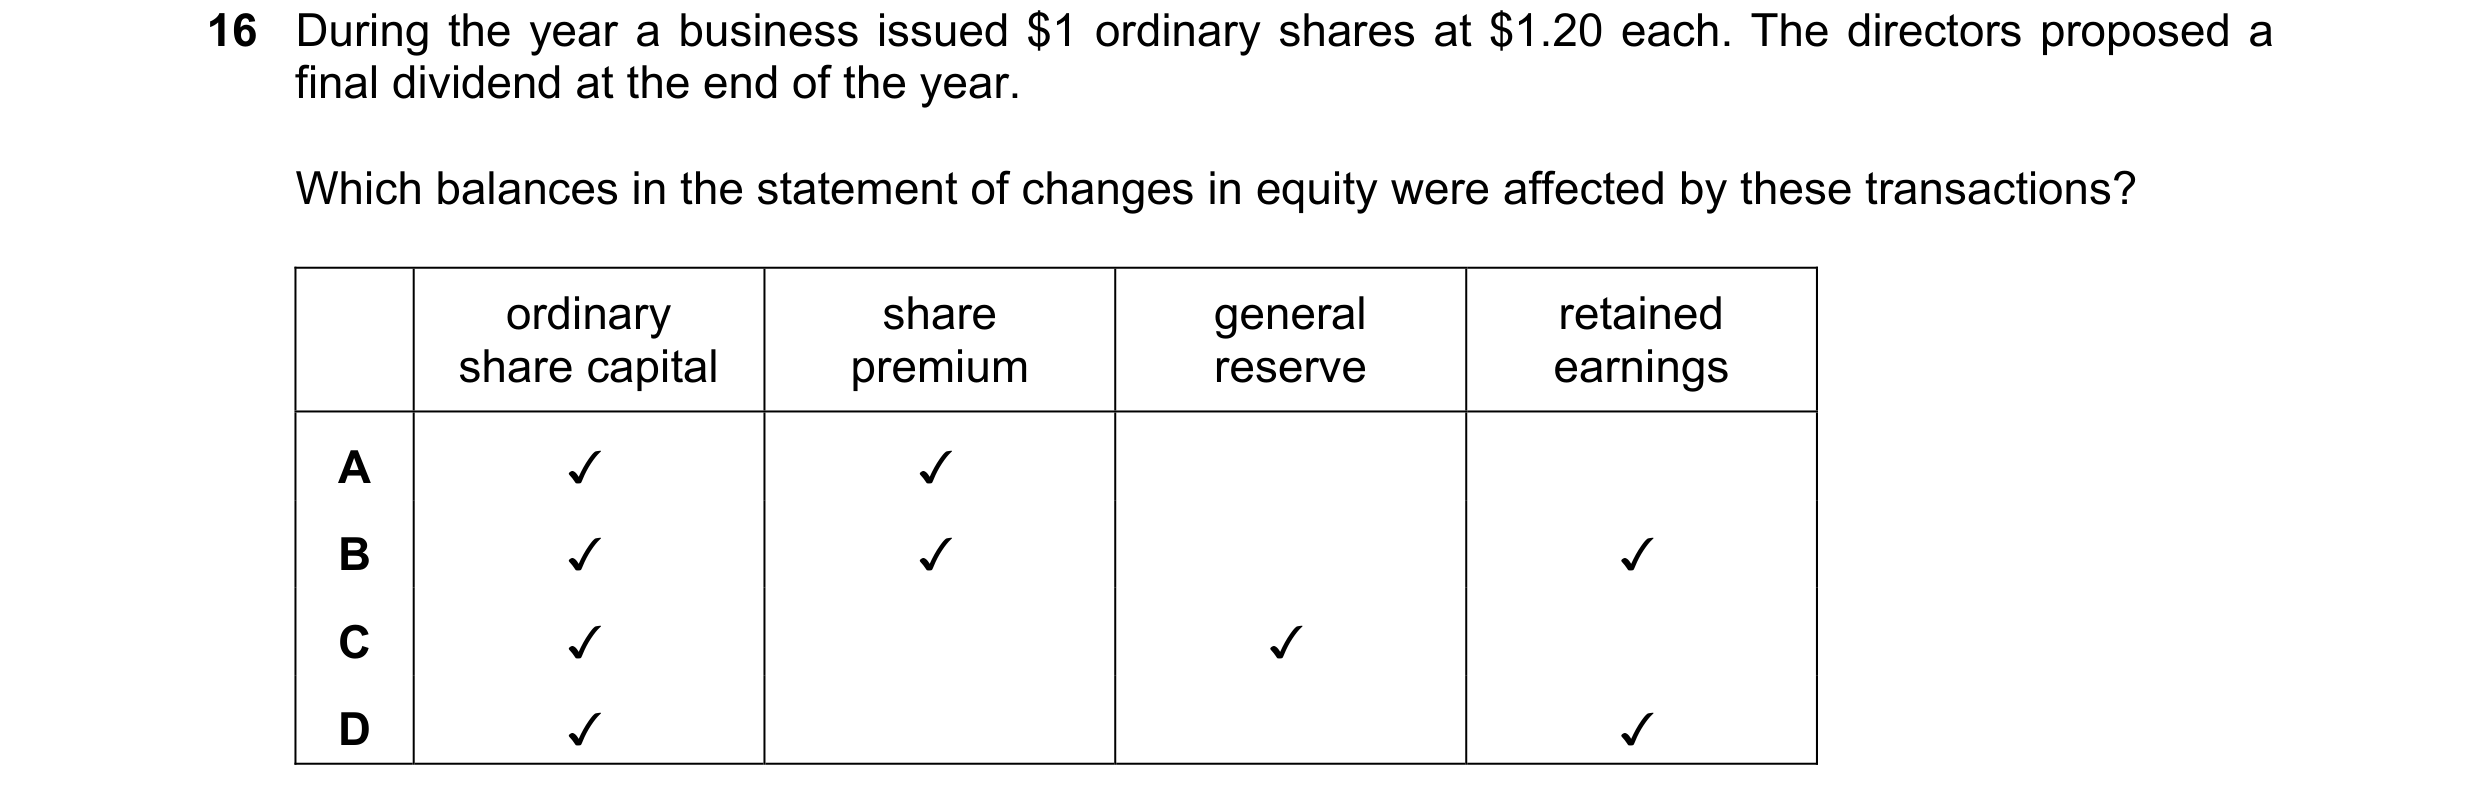 14 / 60
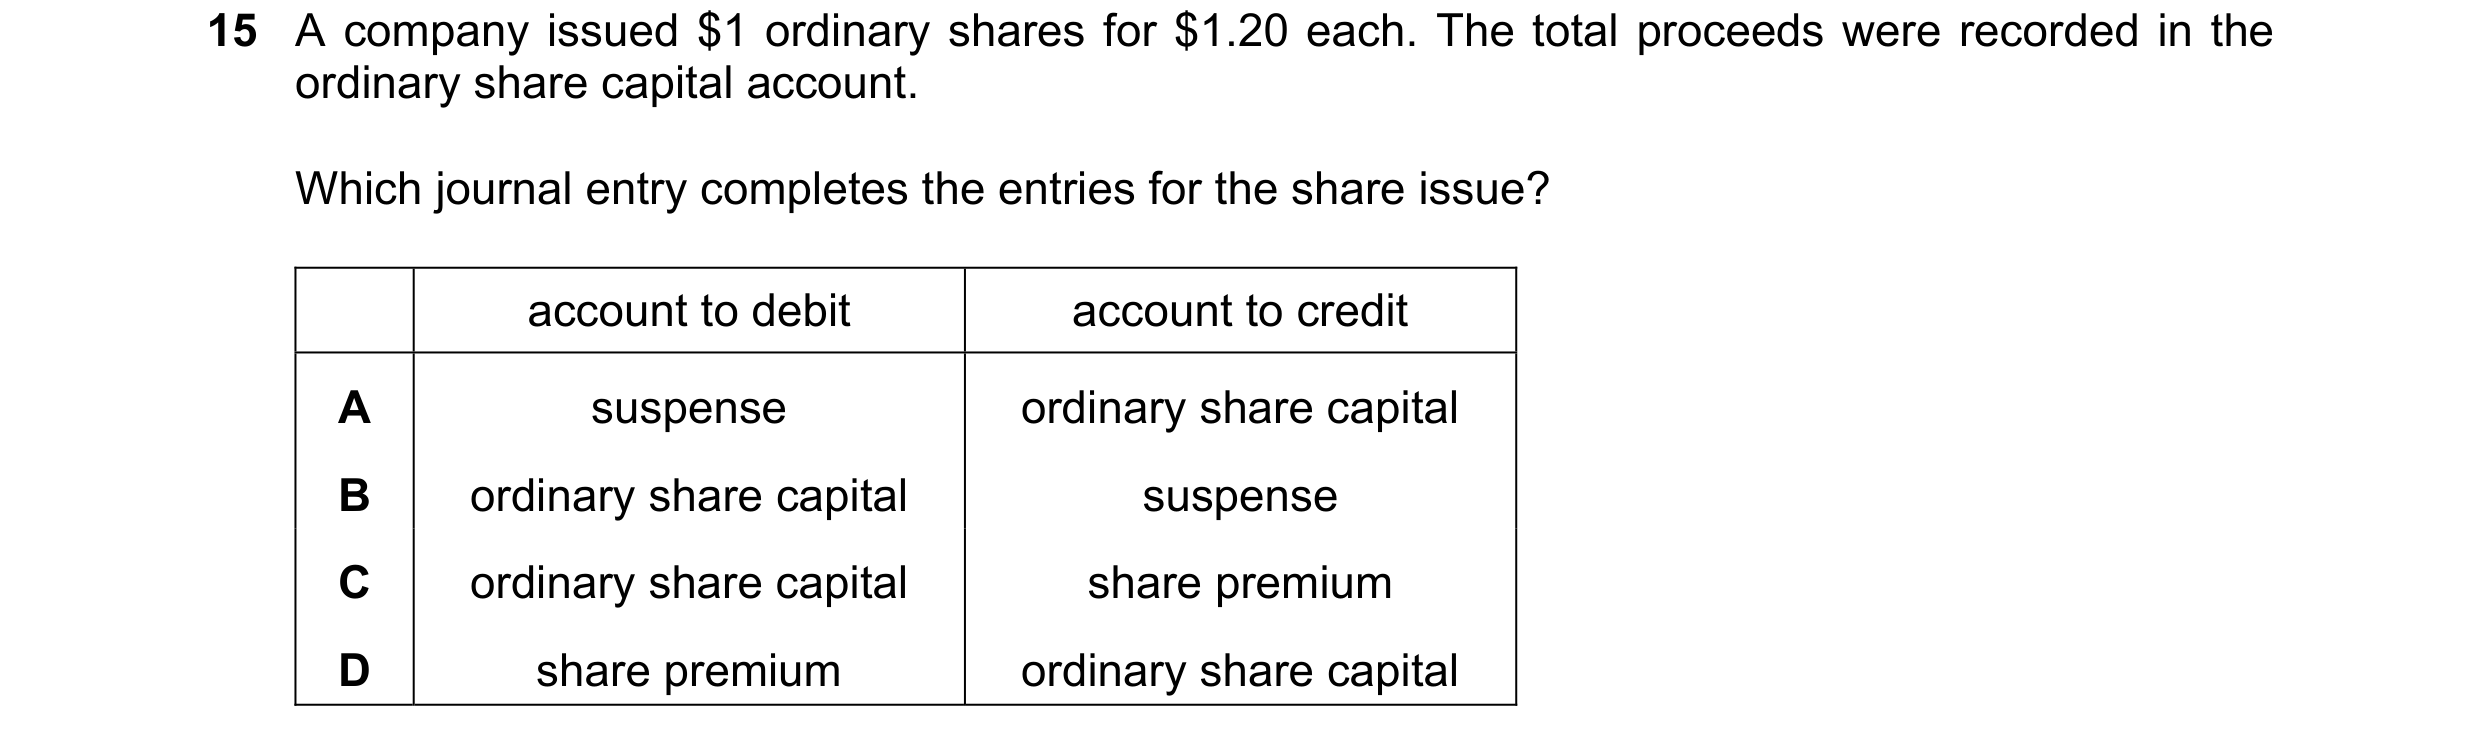
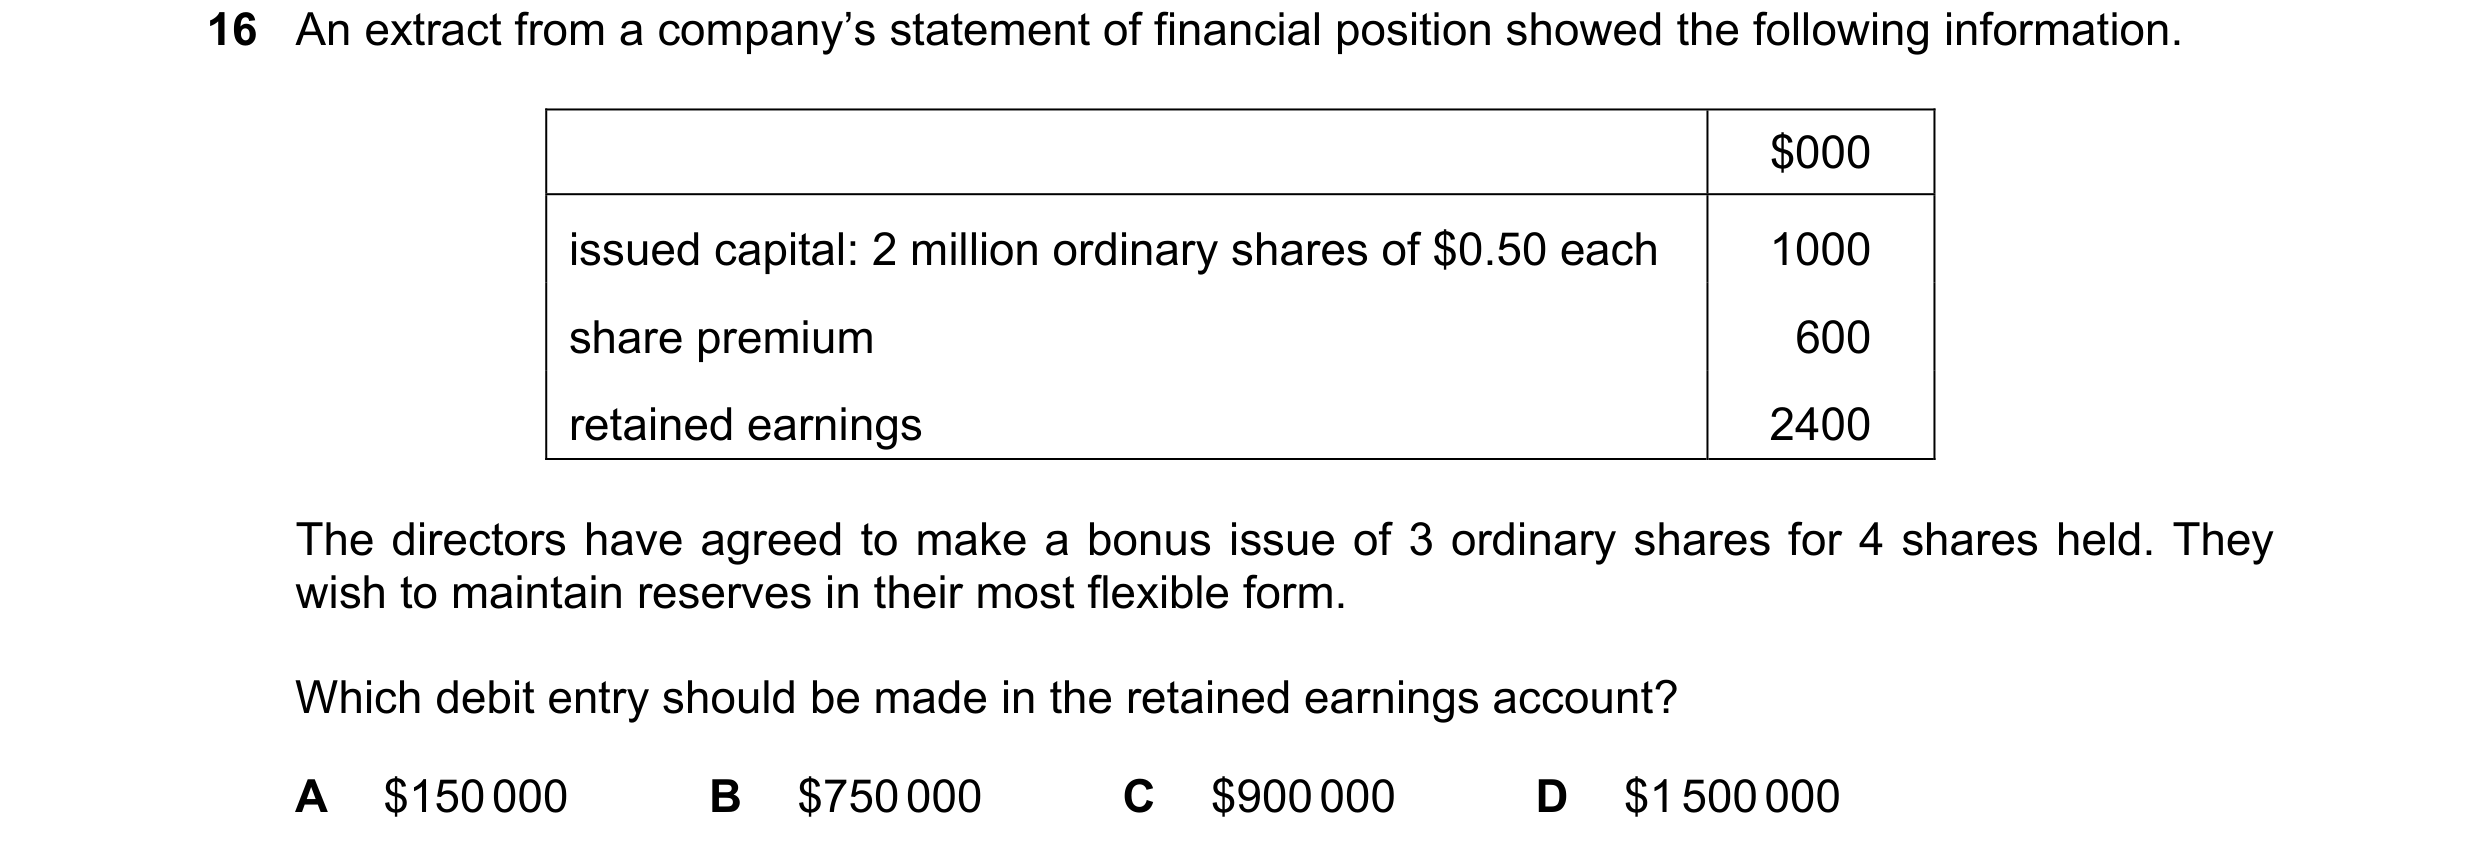
 15 / 60
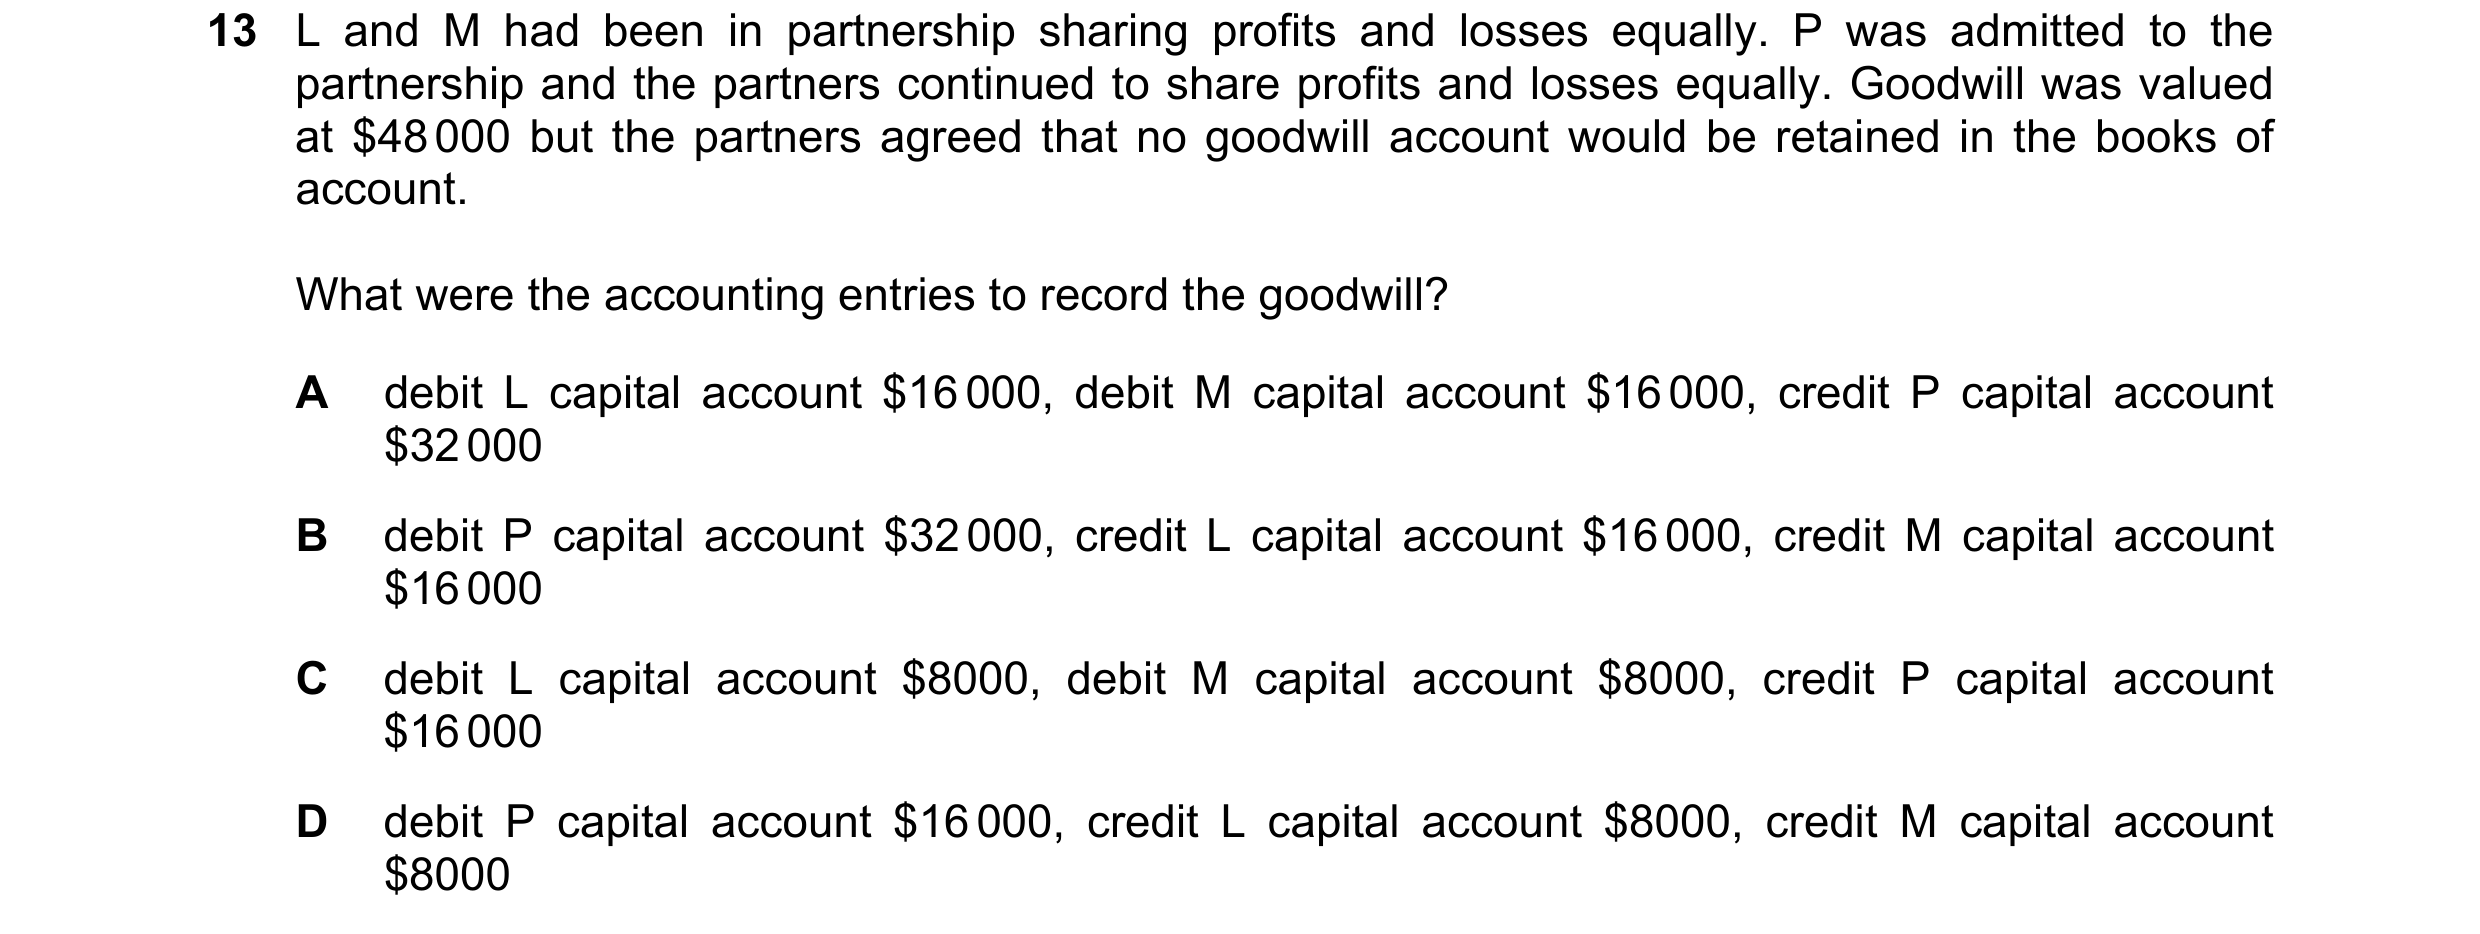
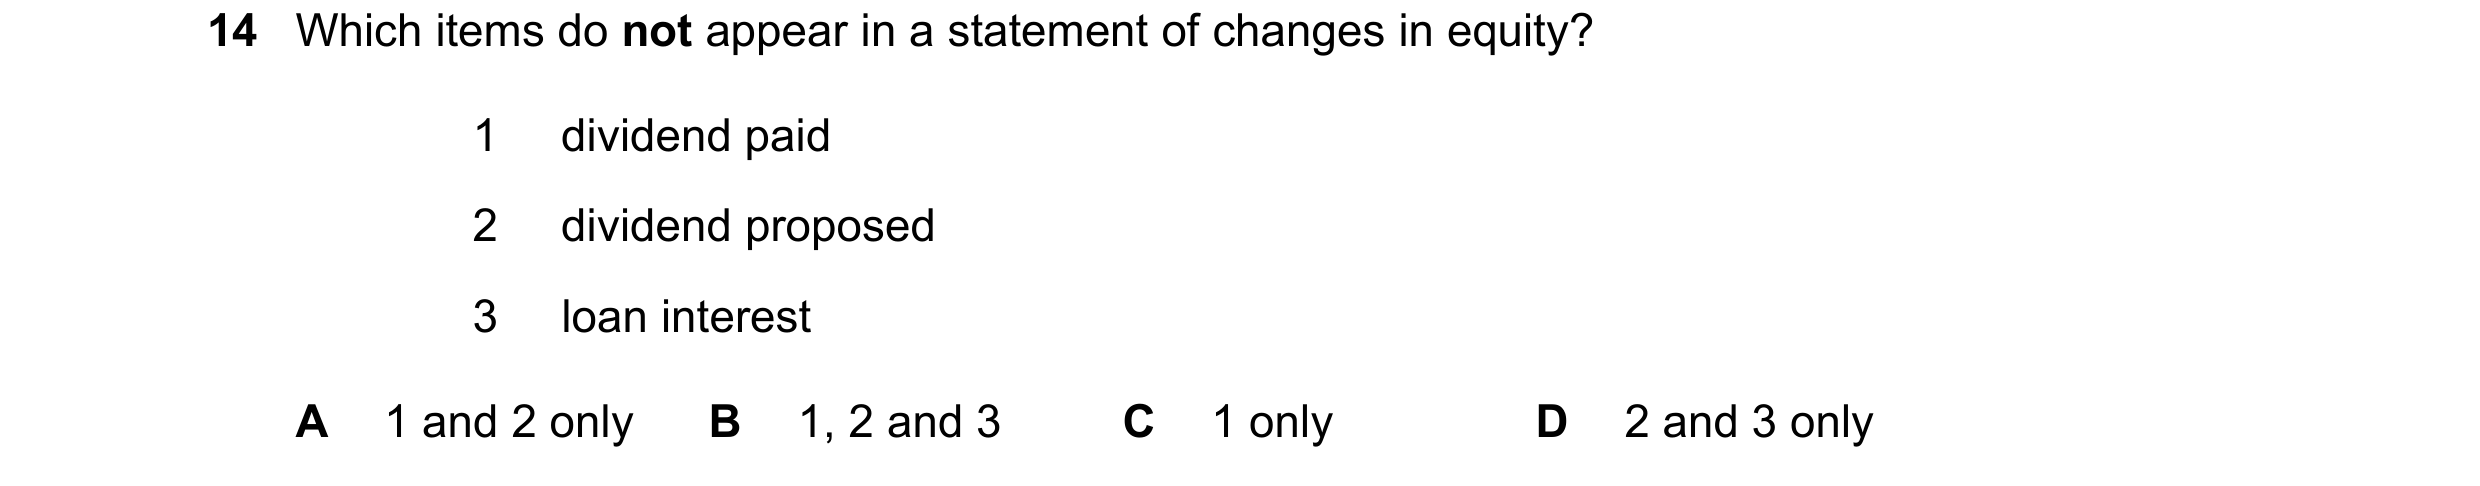 16 / 60
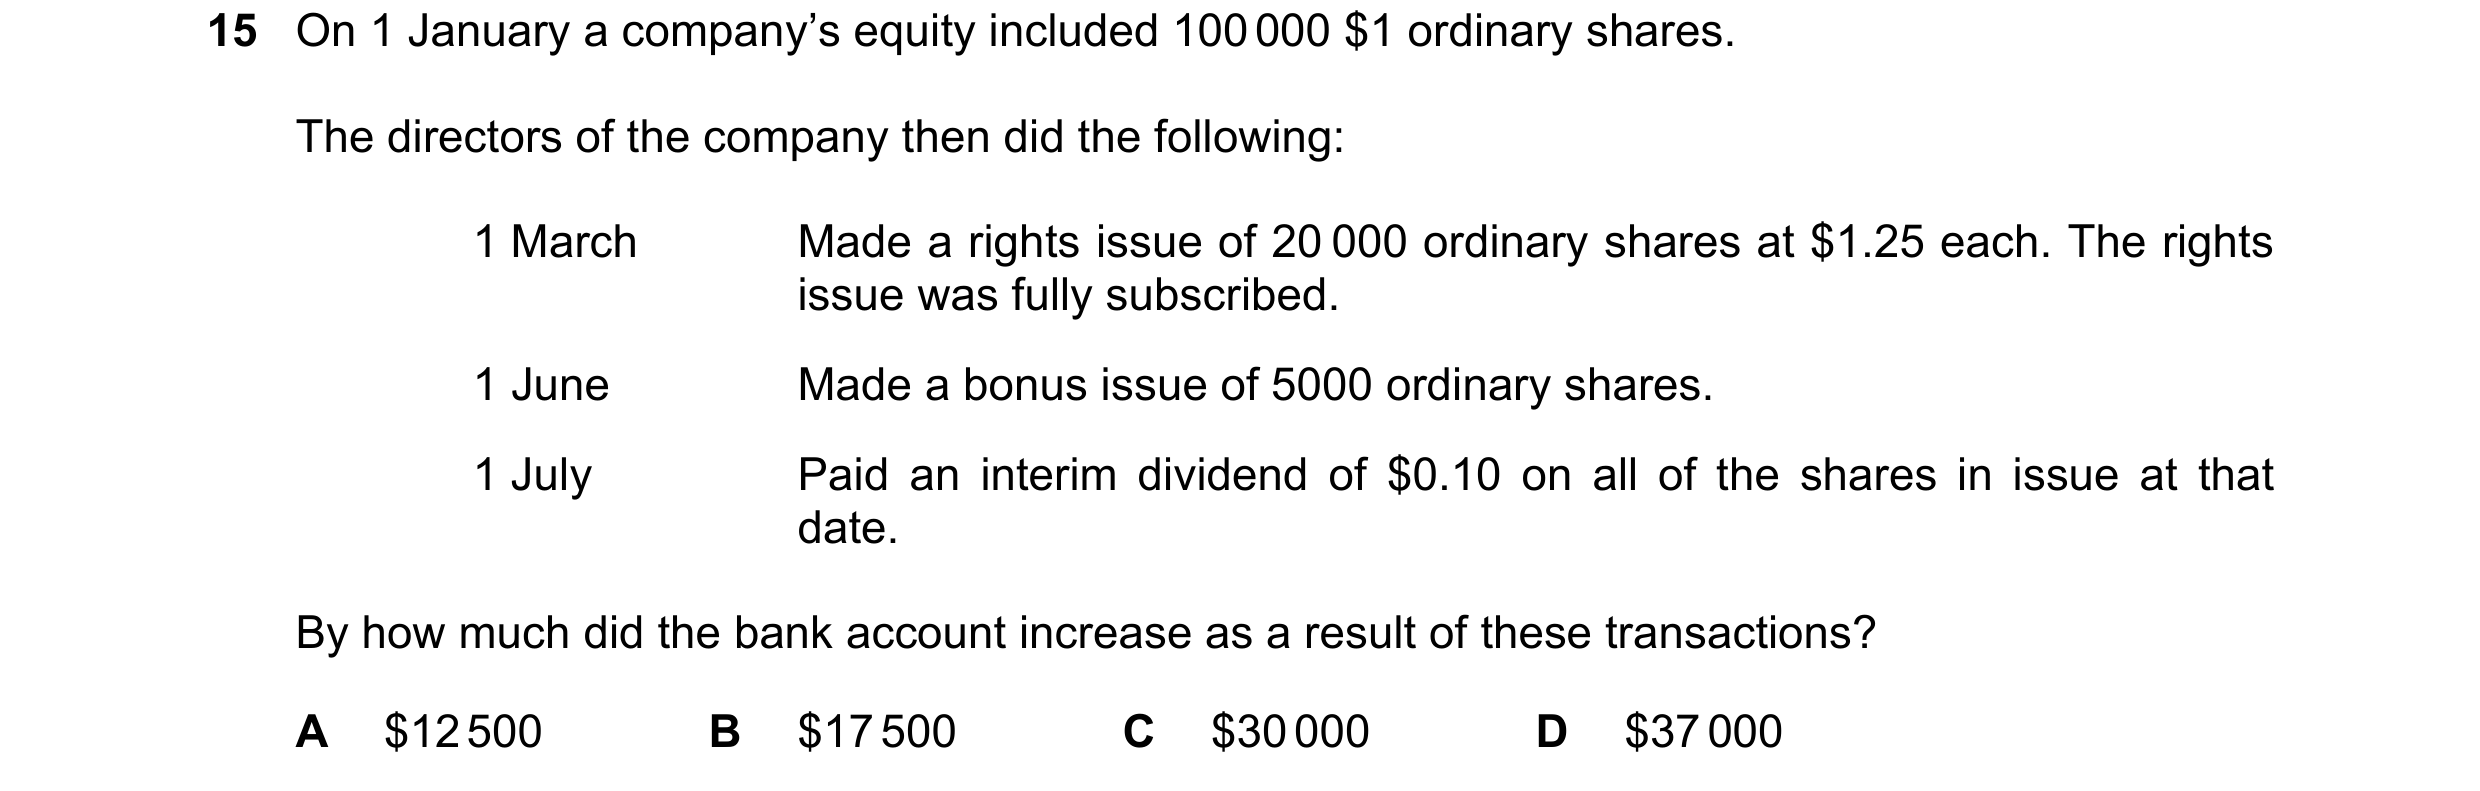
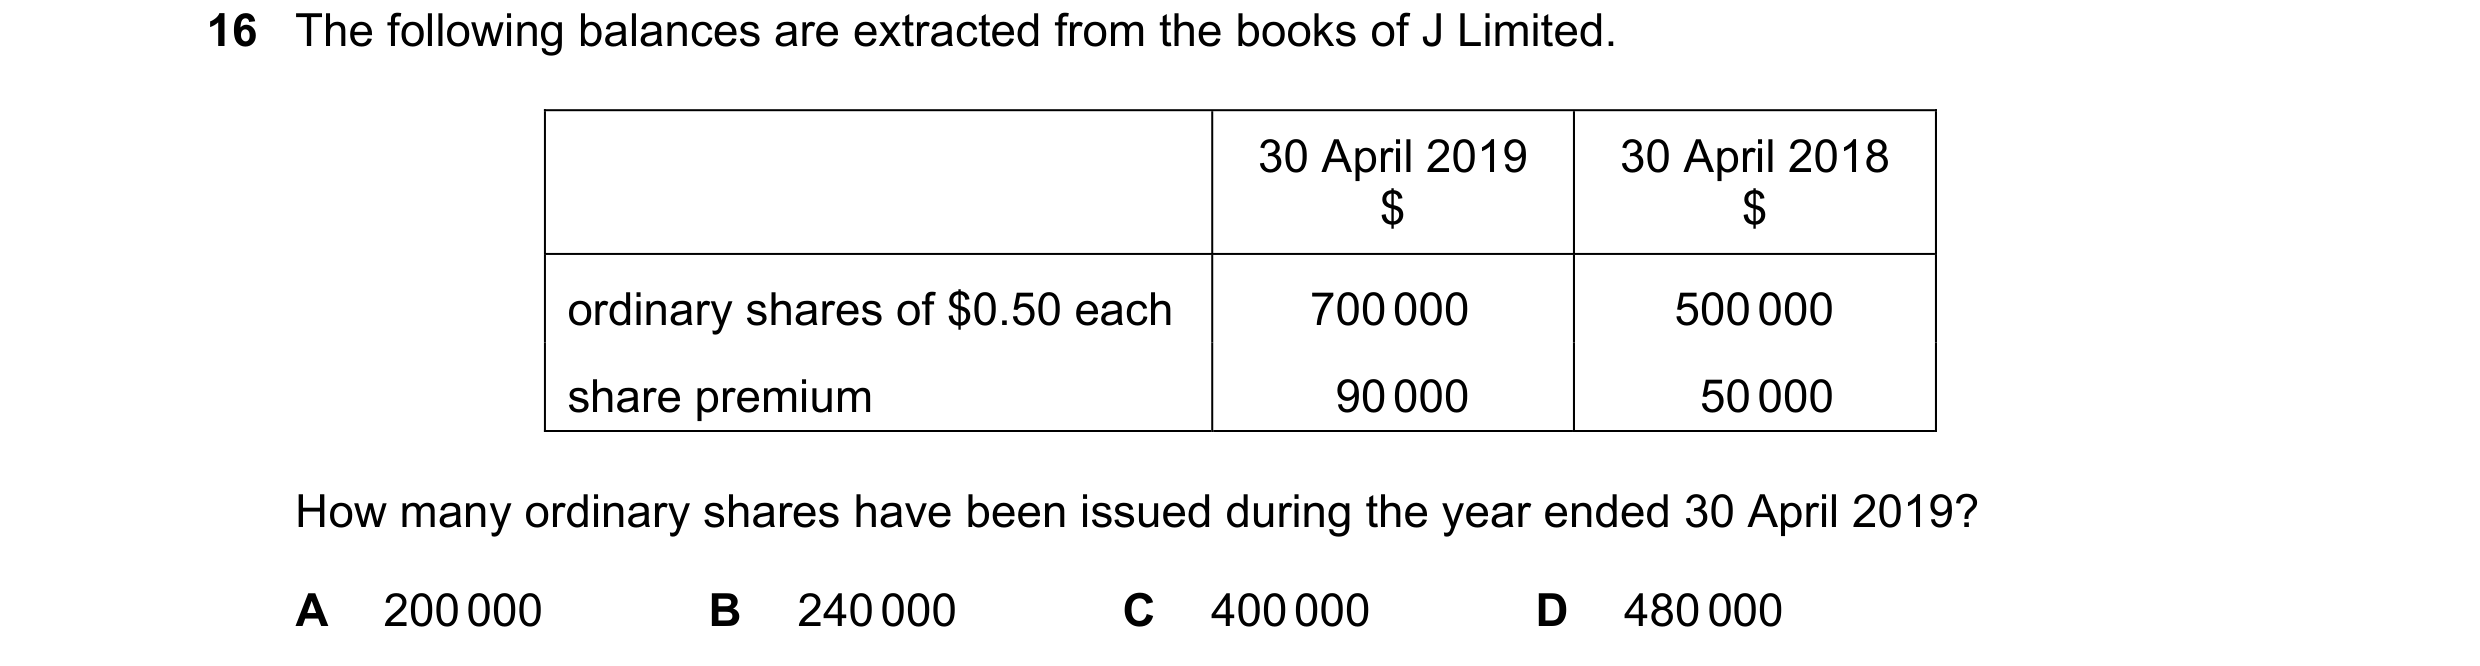
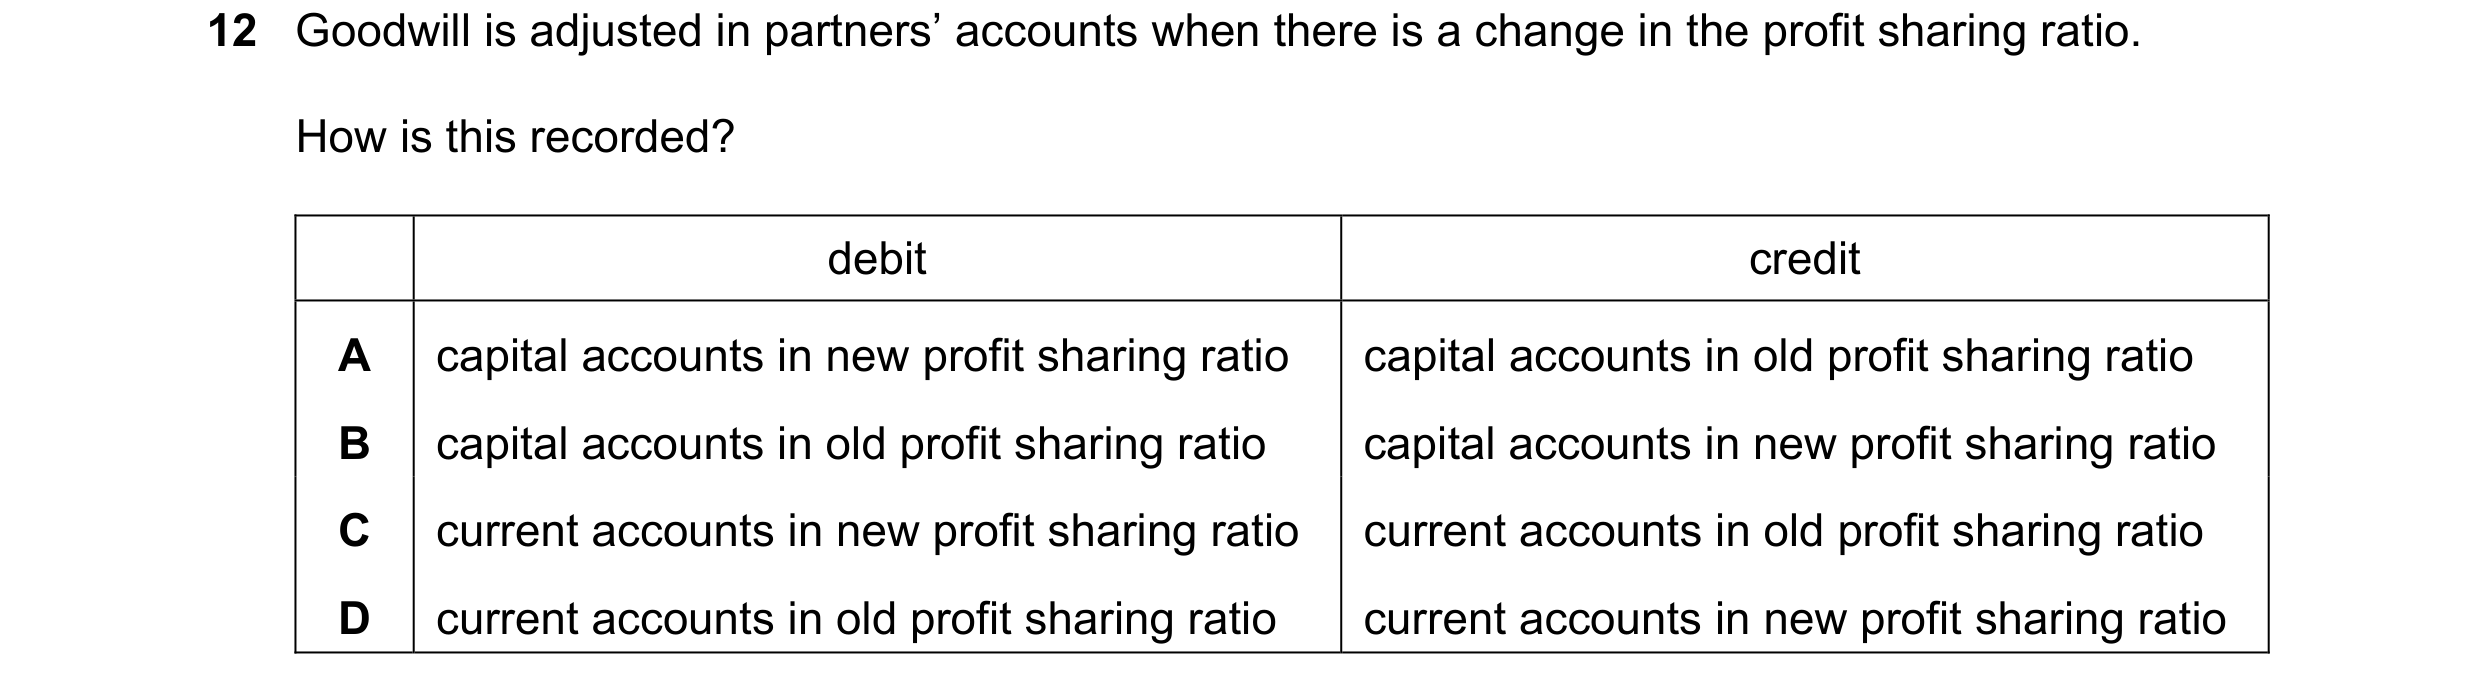
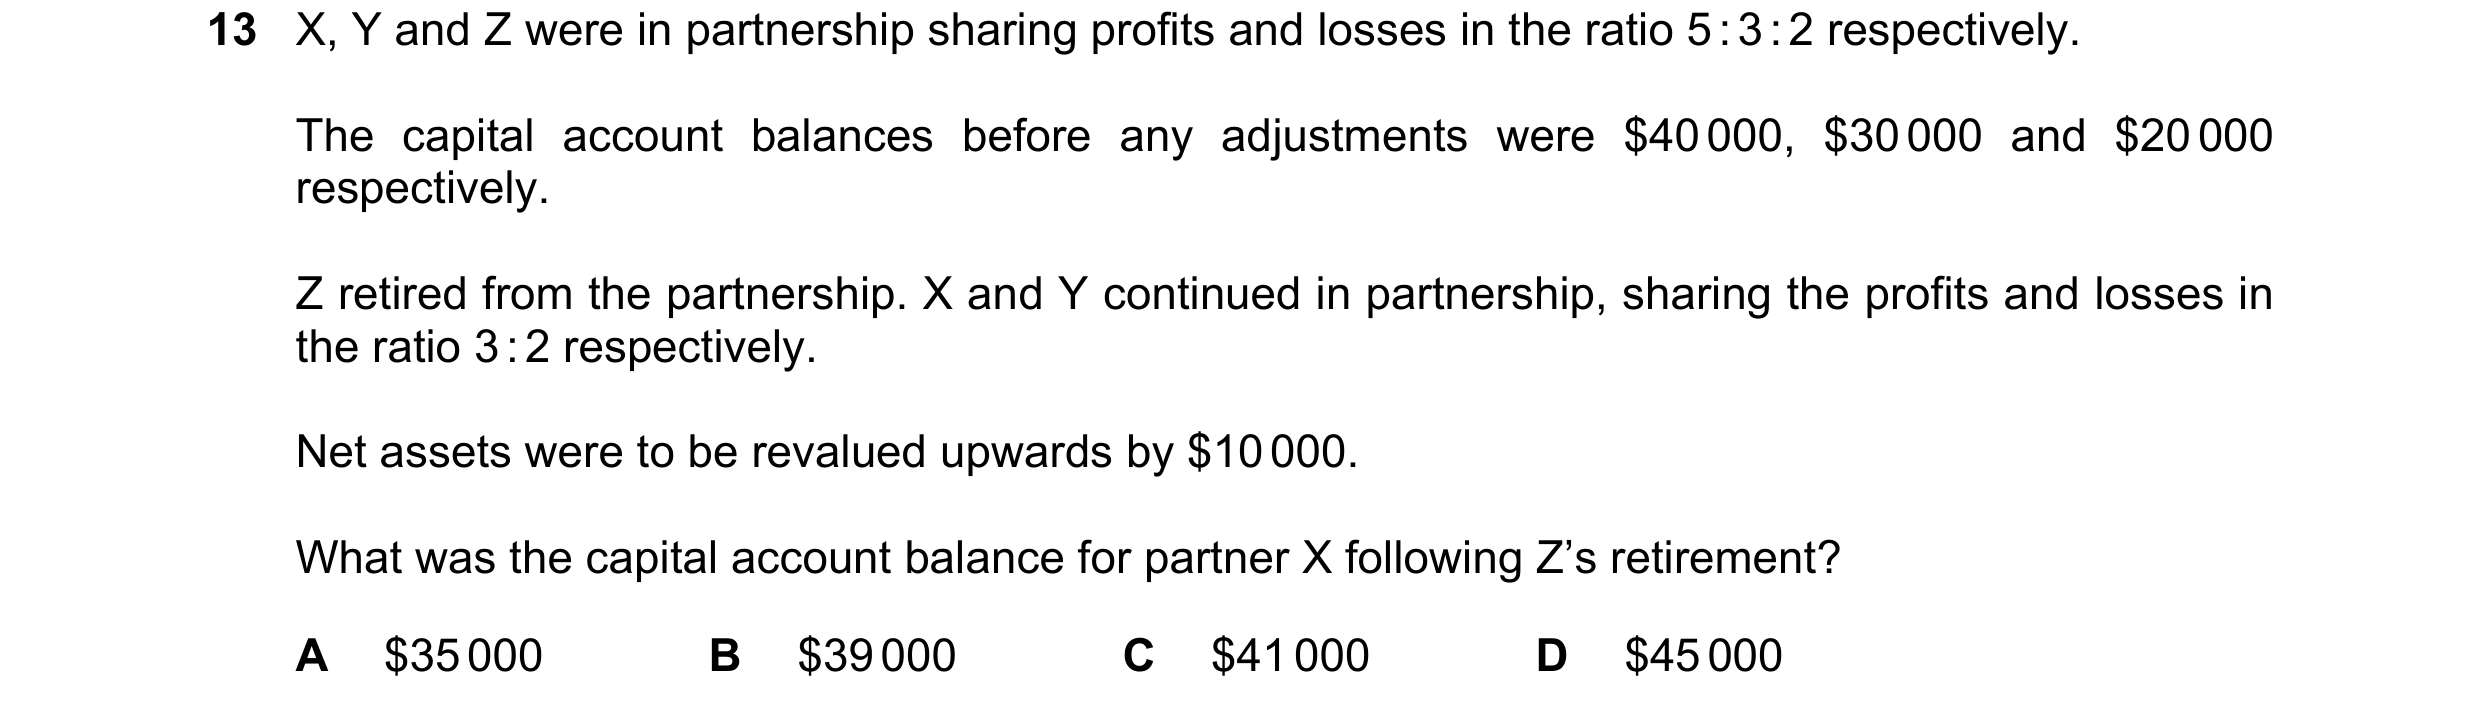 17 / 60
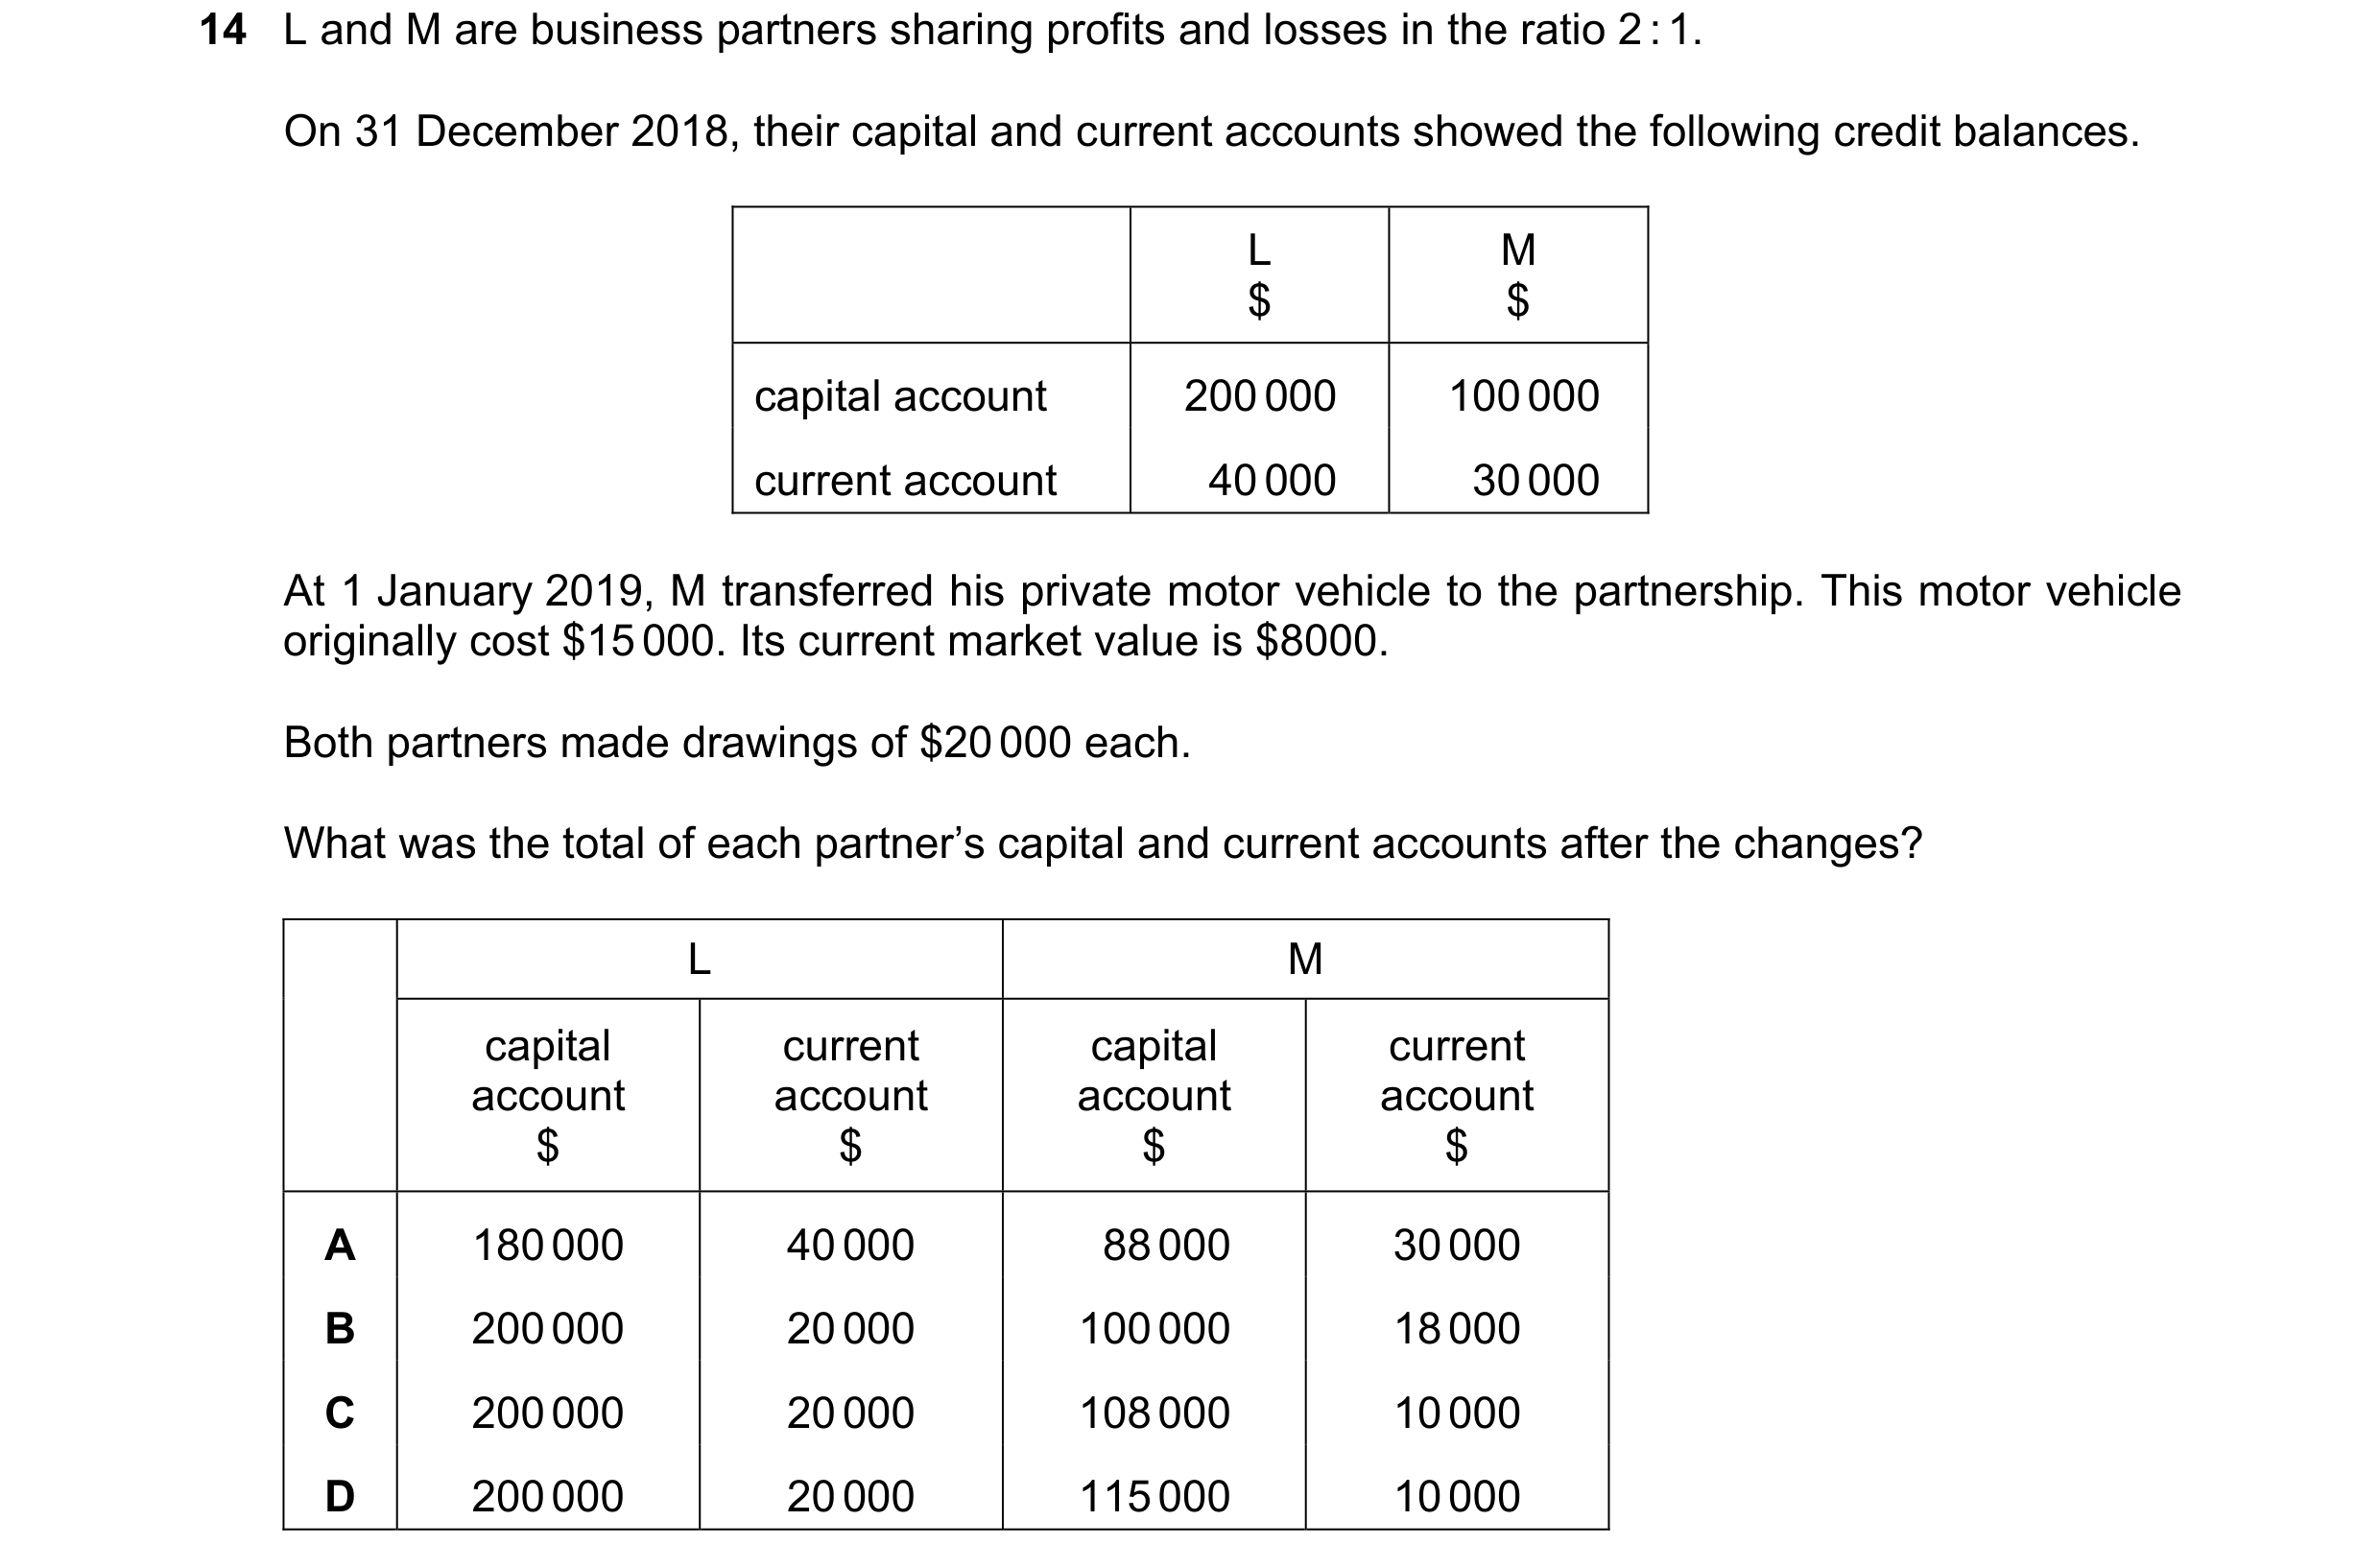
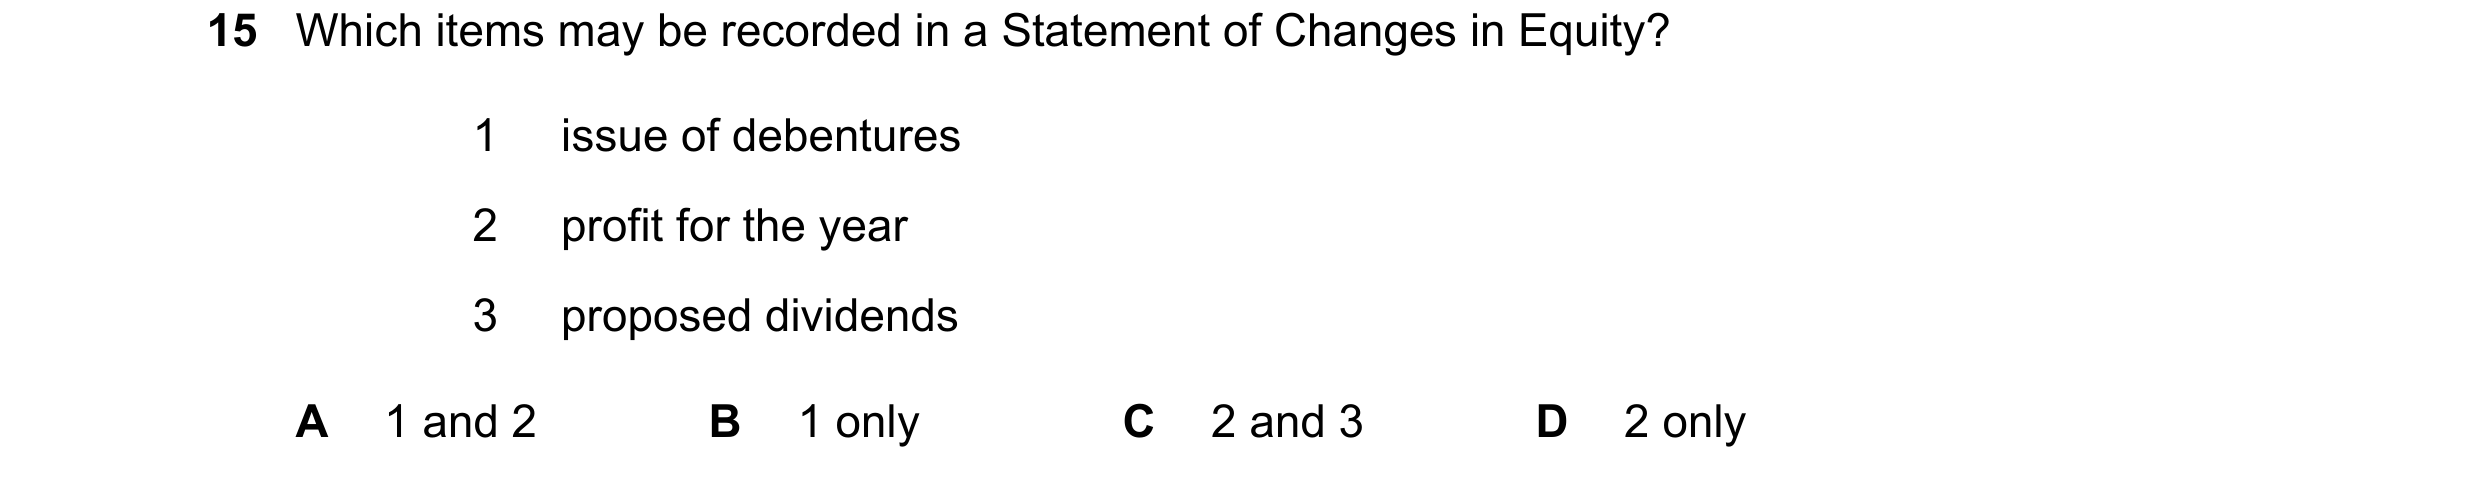 18 / 60
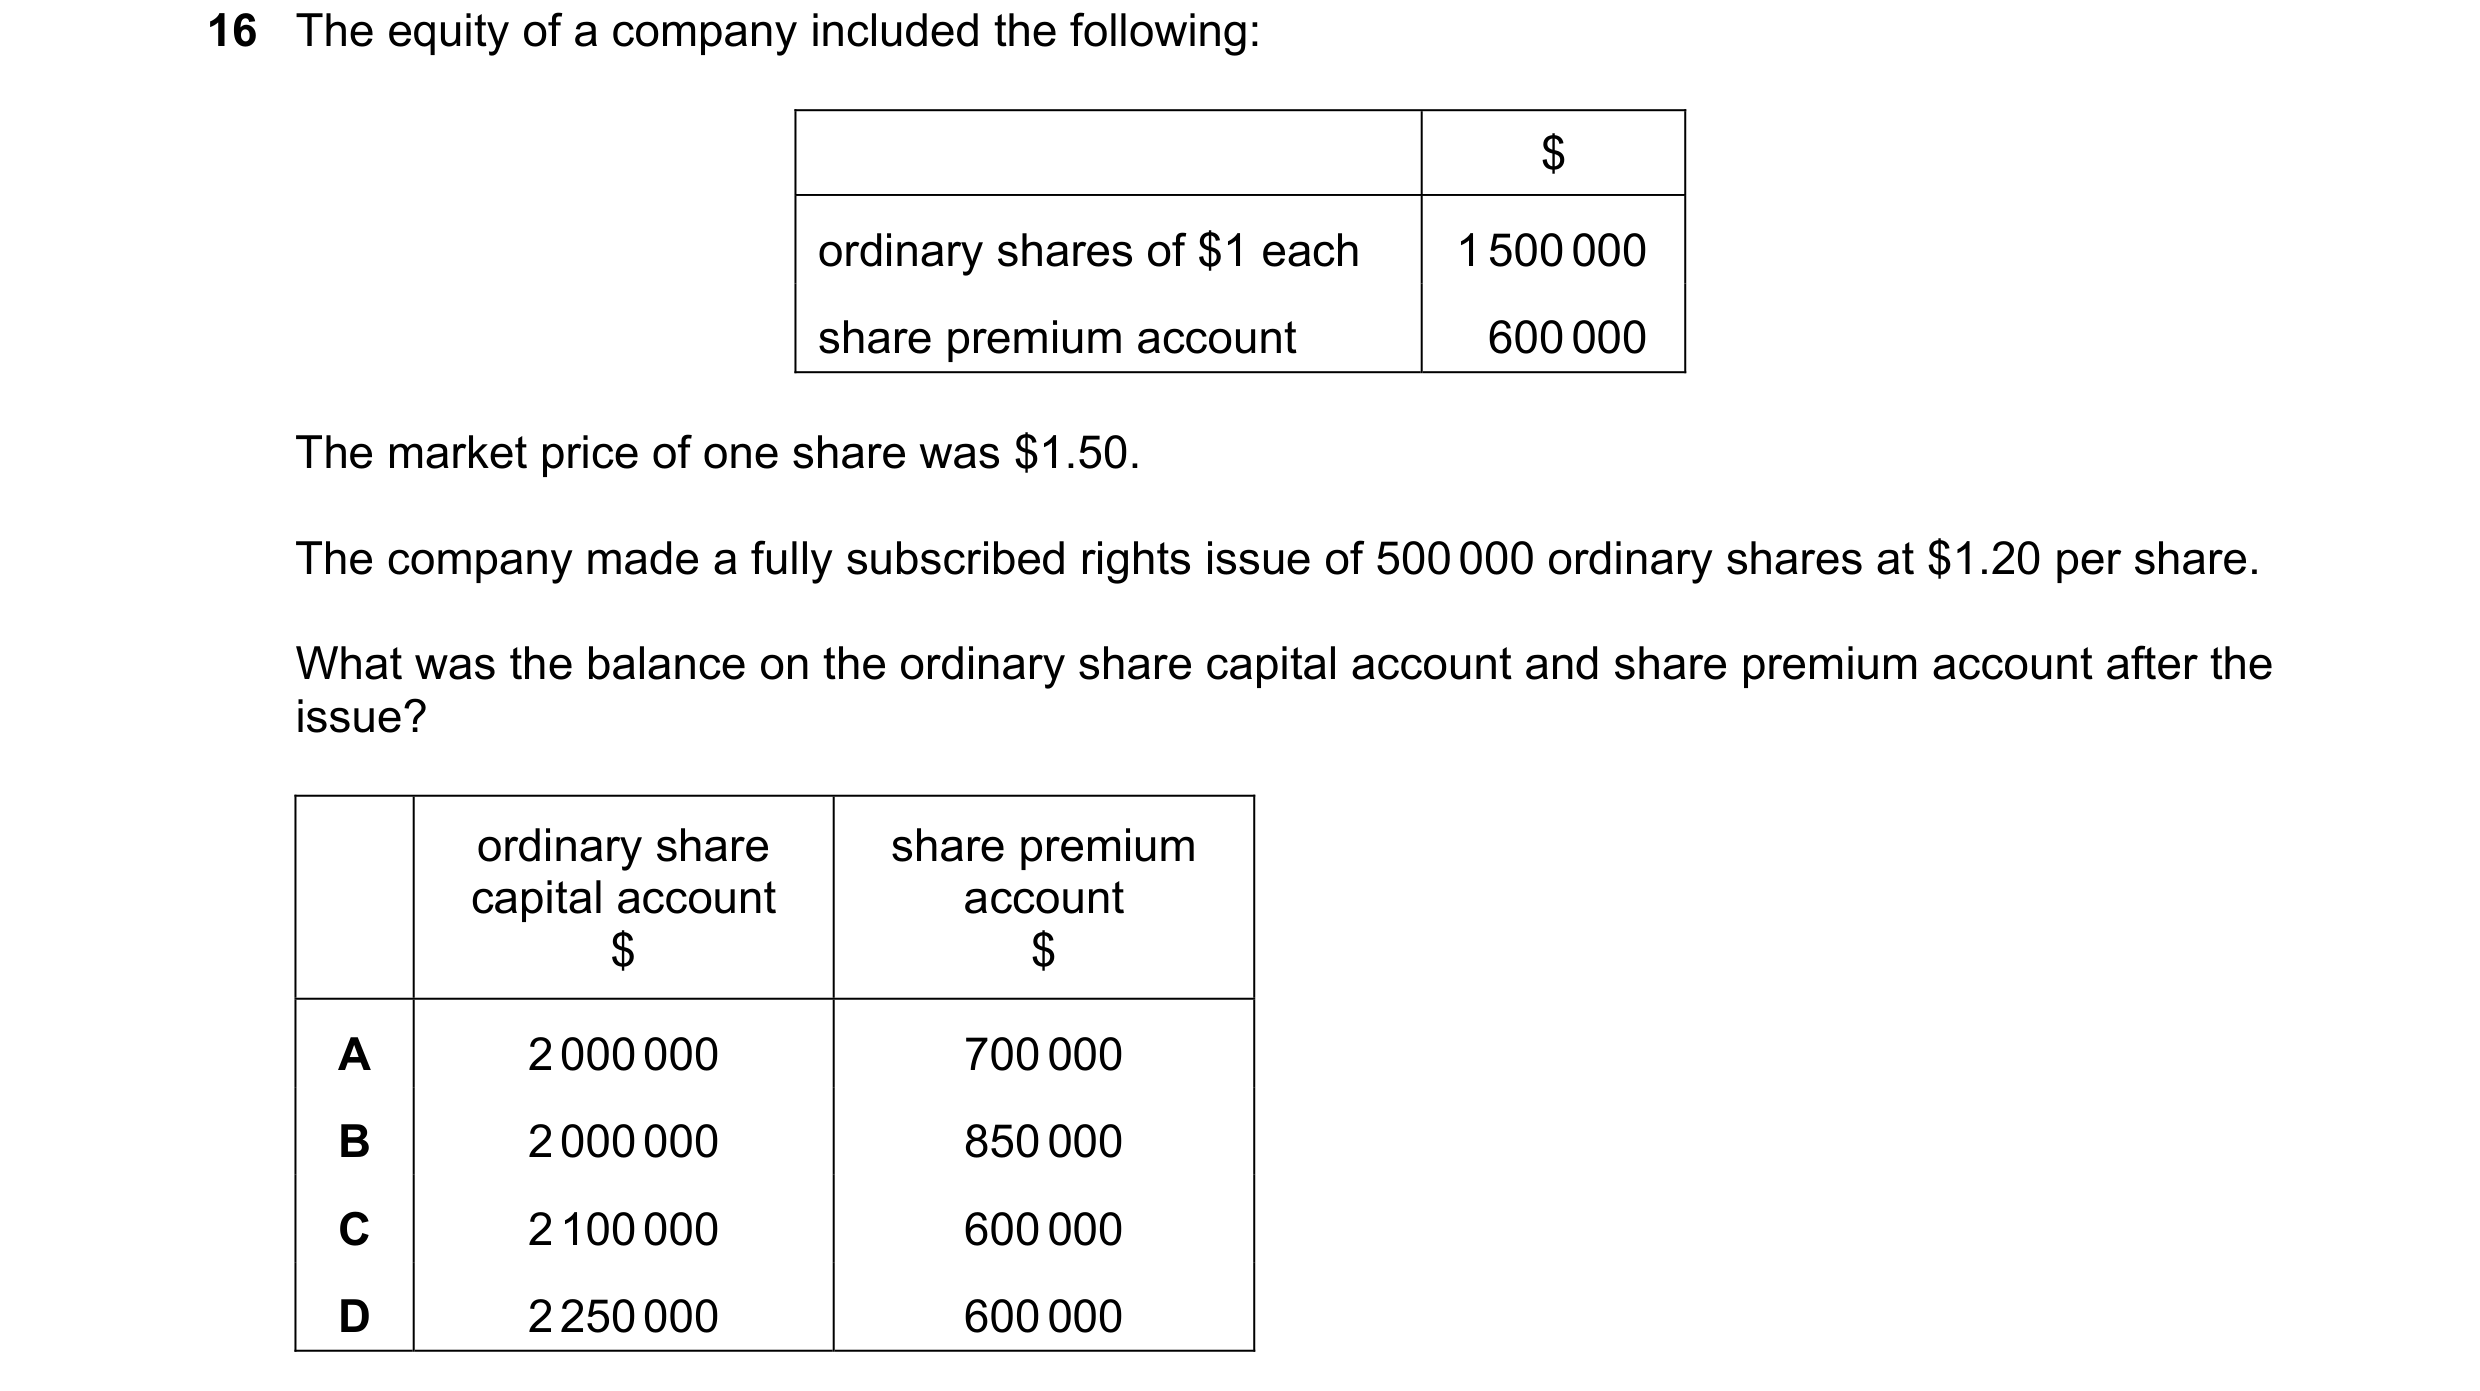
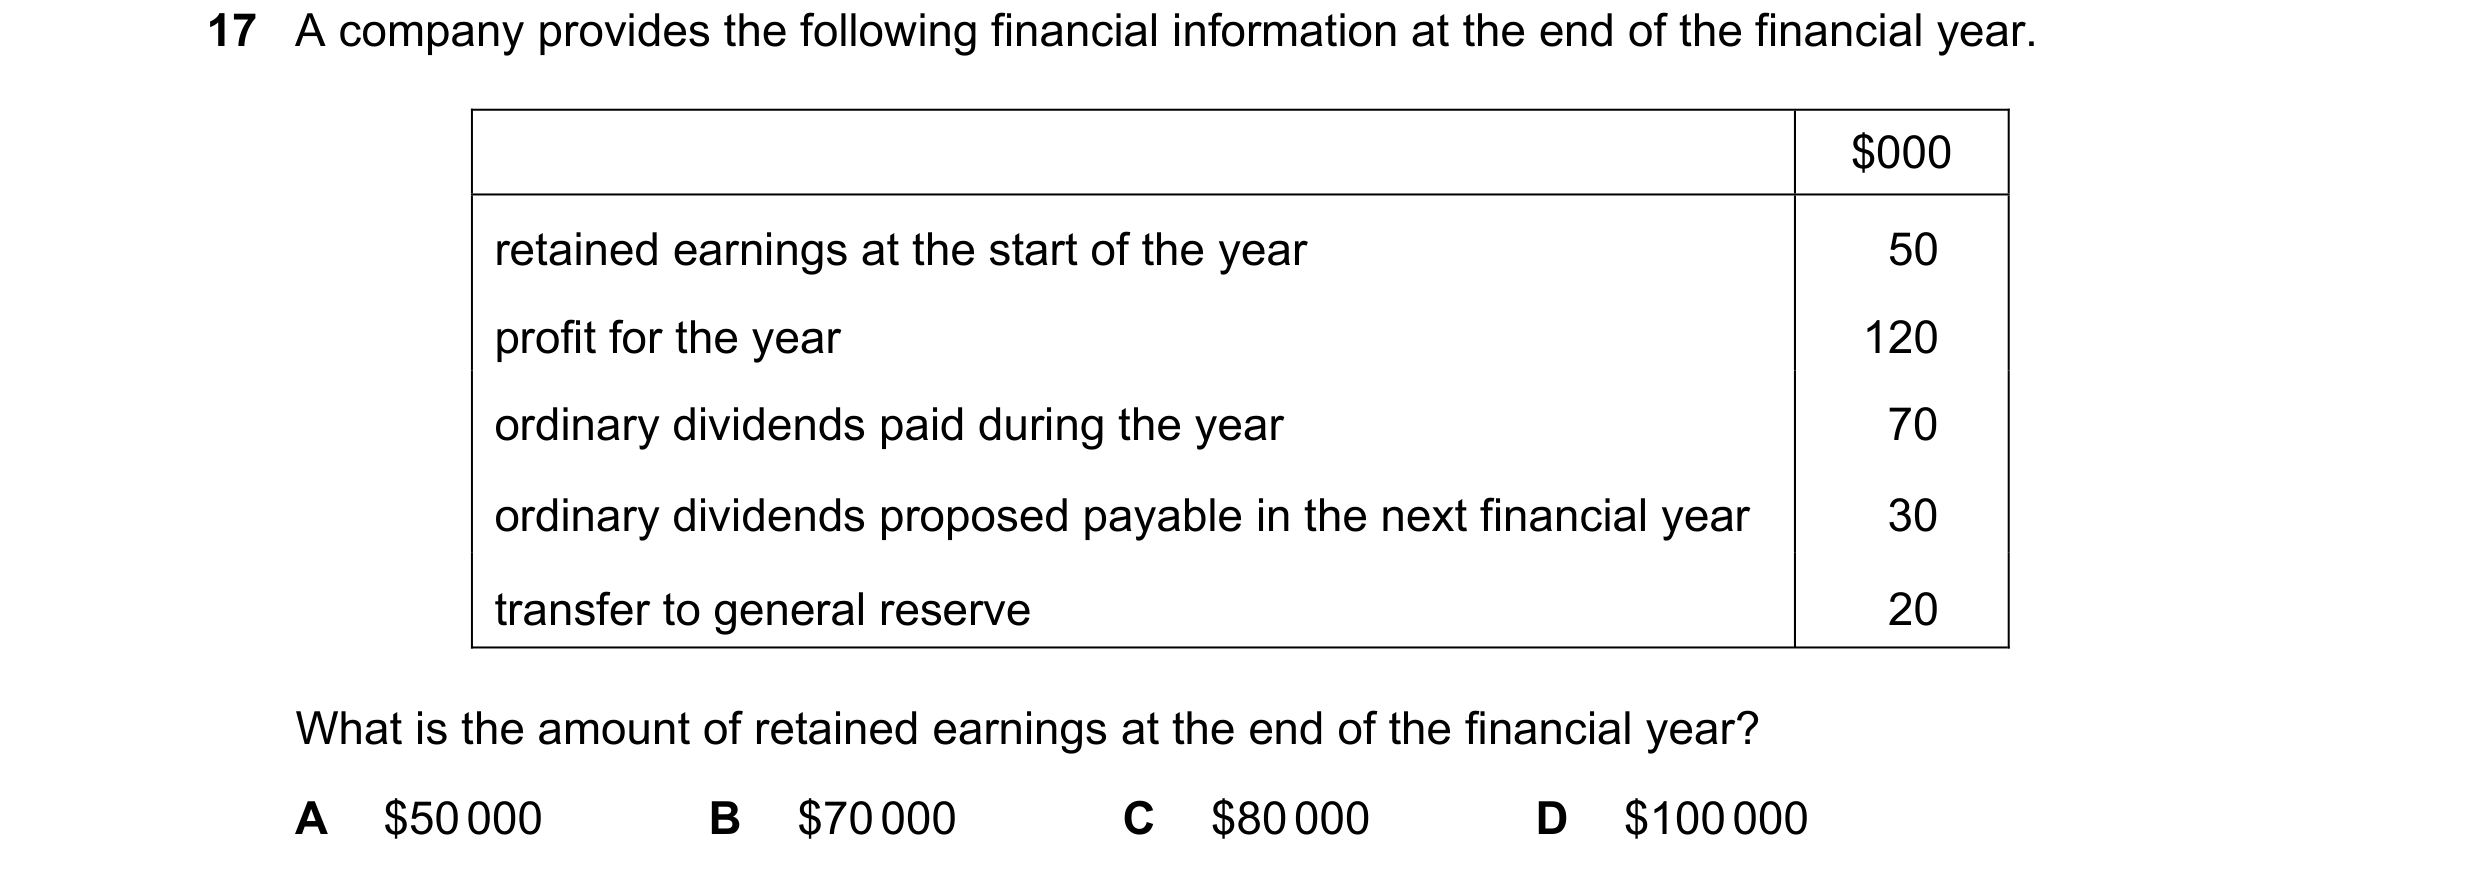
 19 / 60
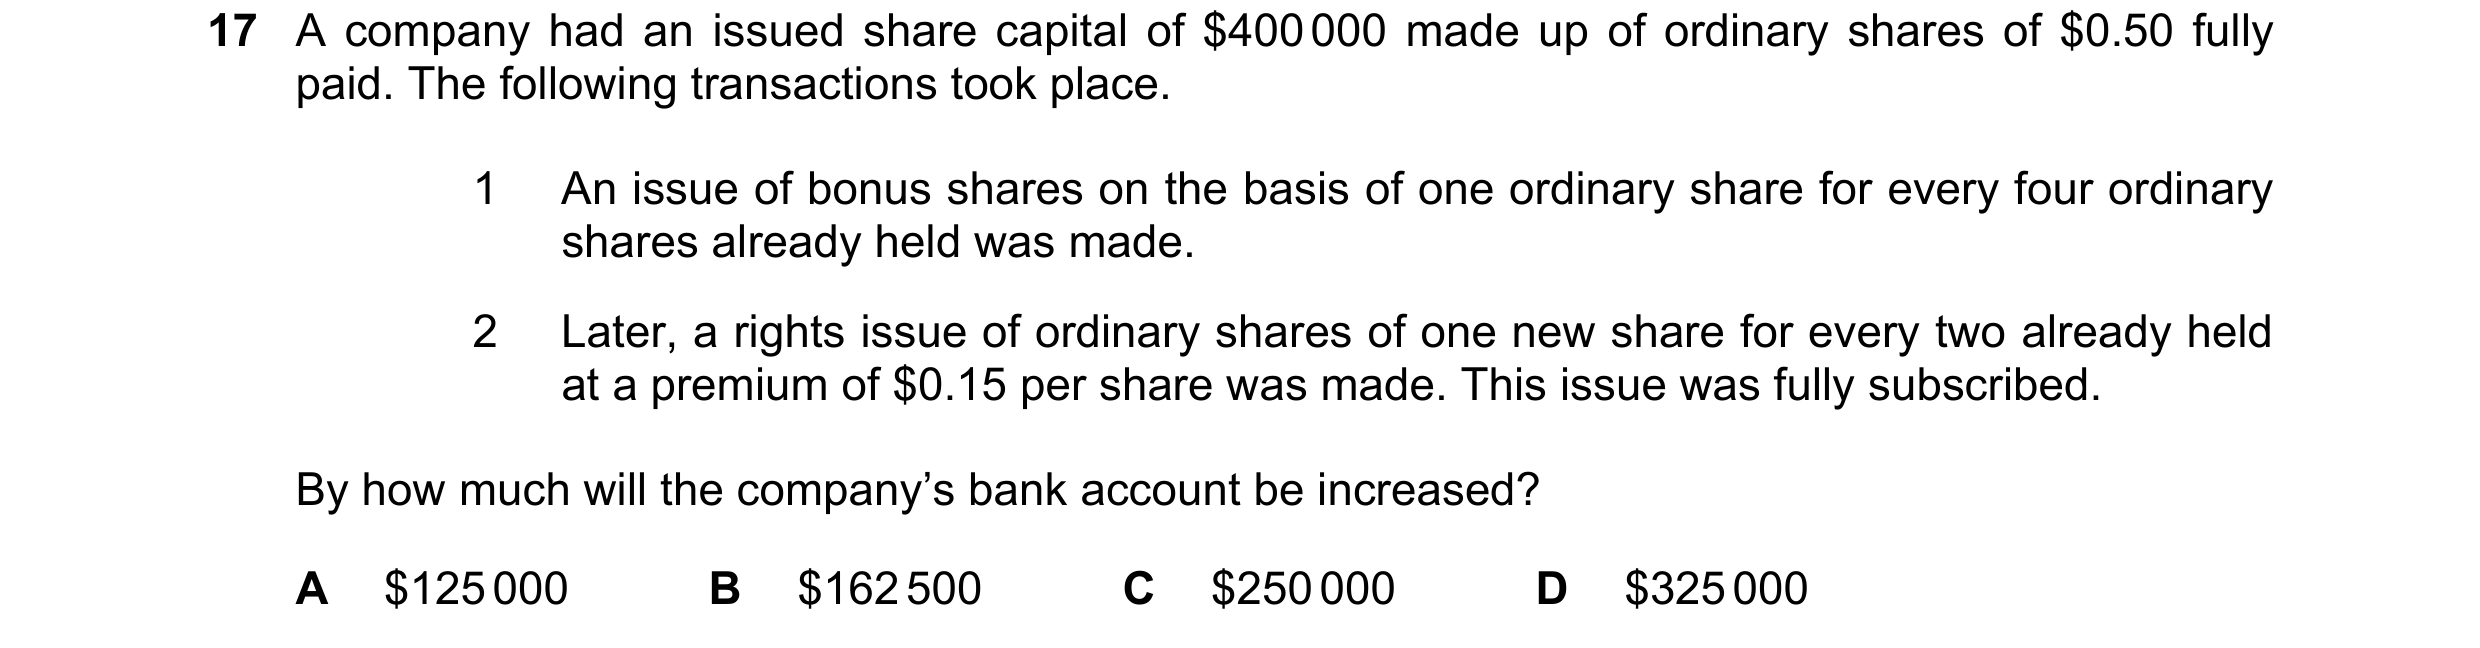
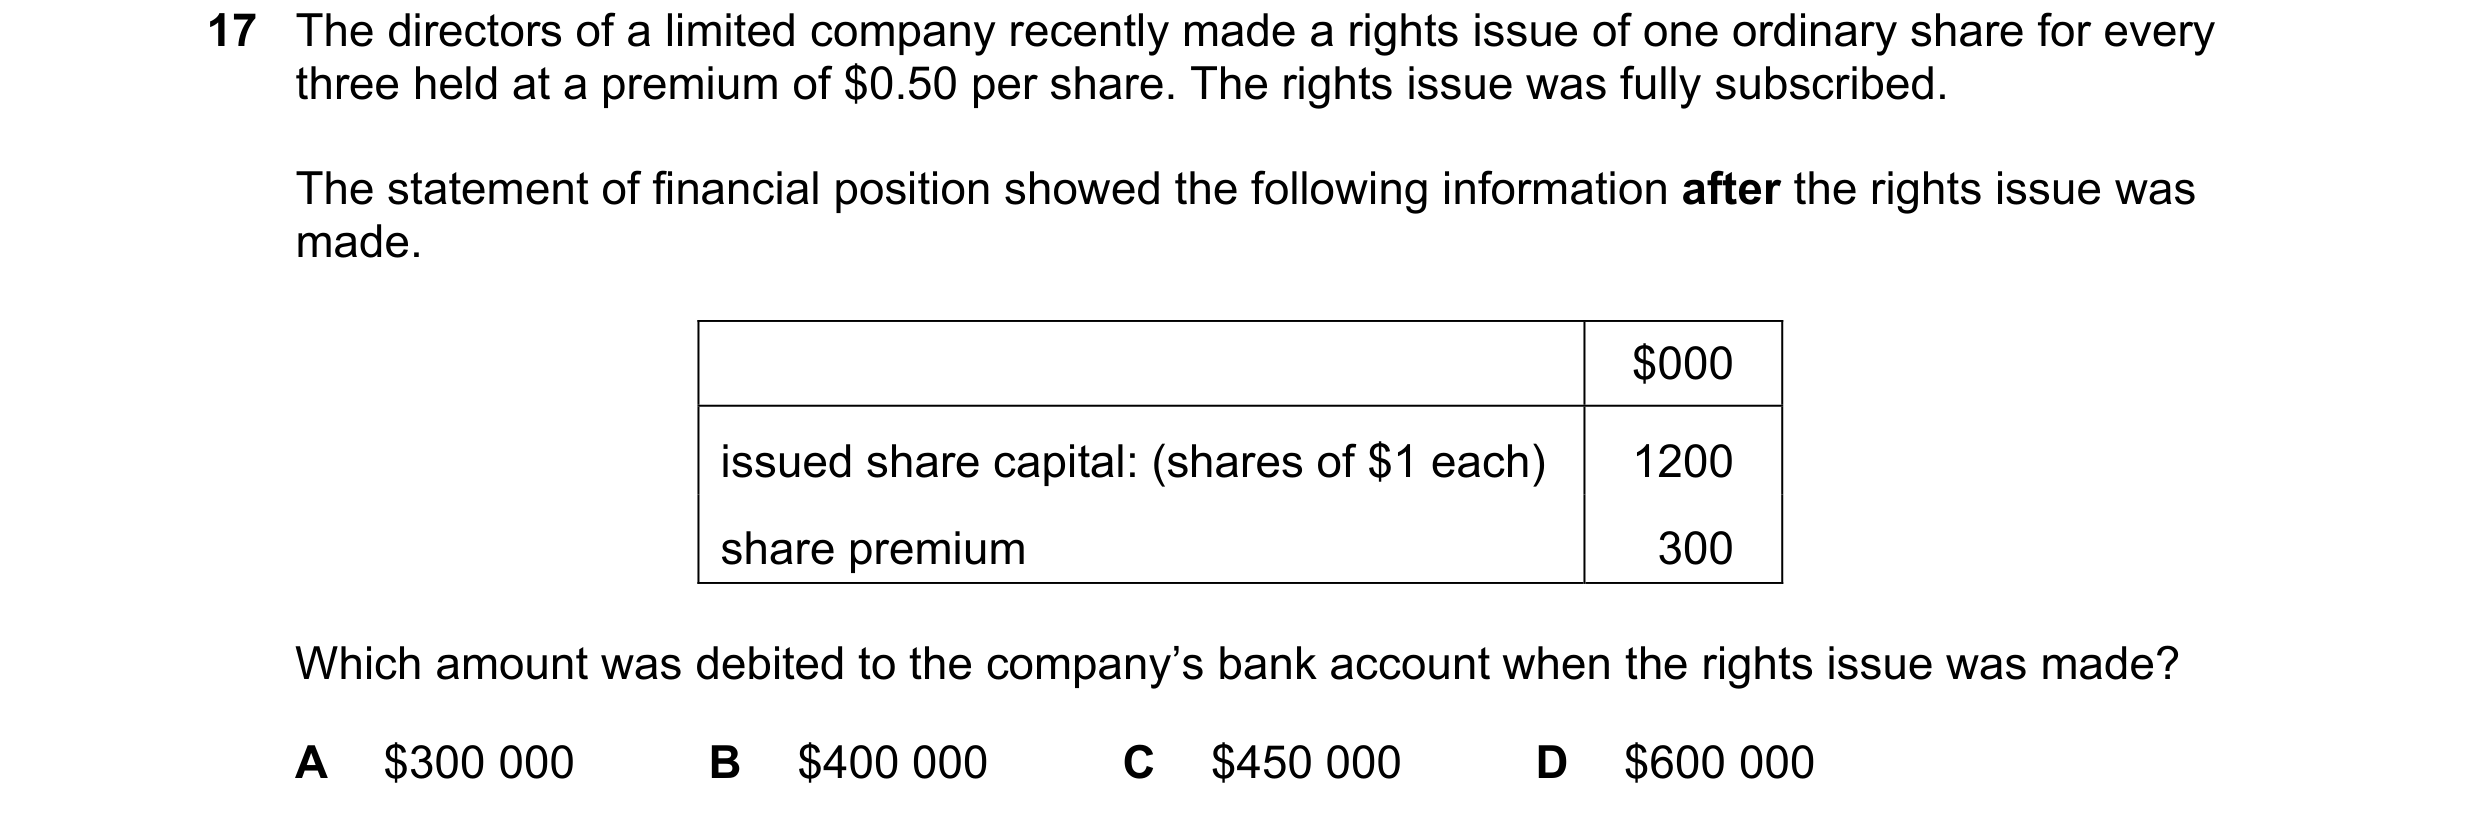
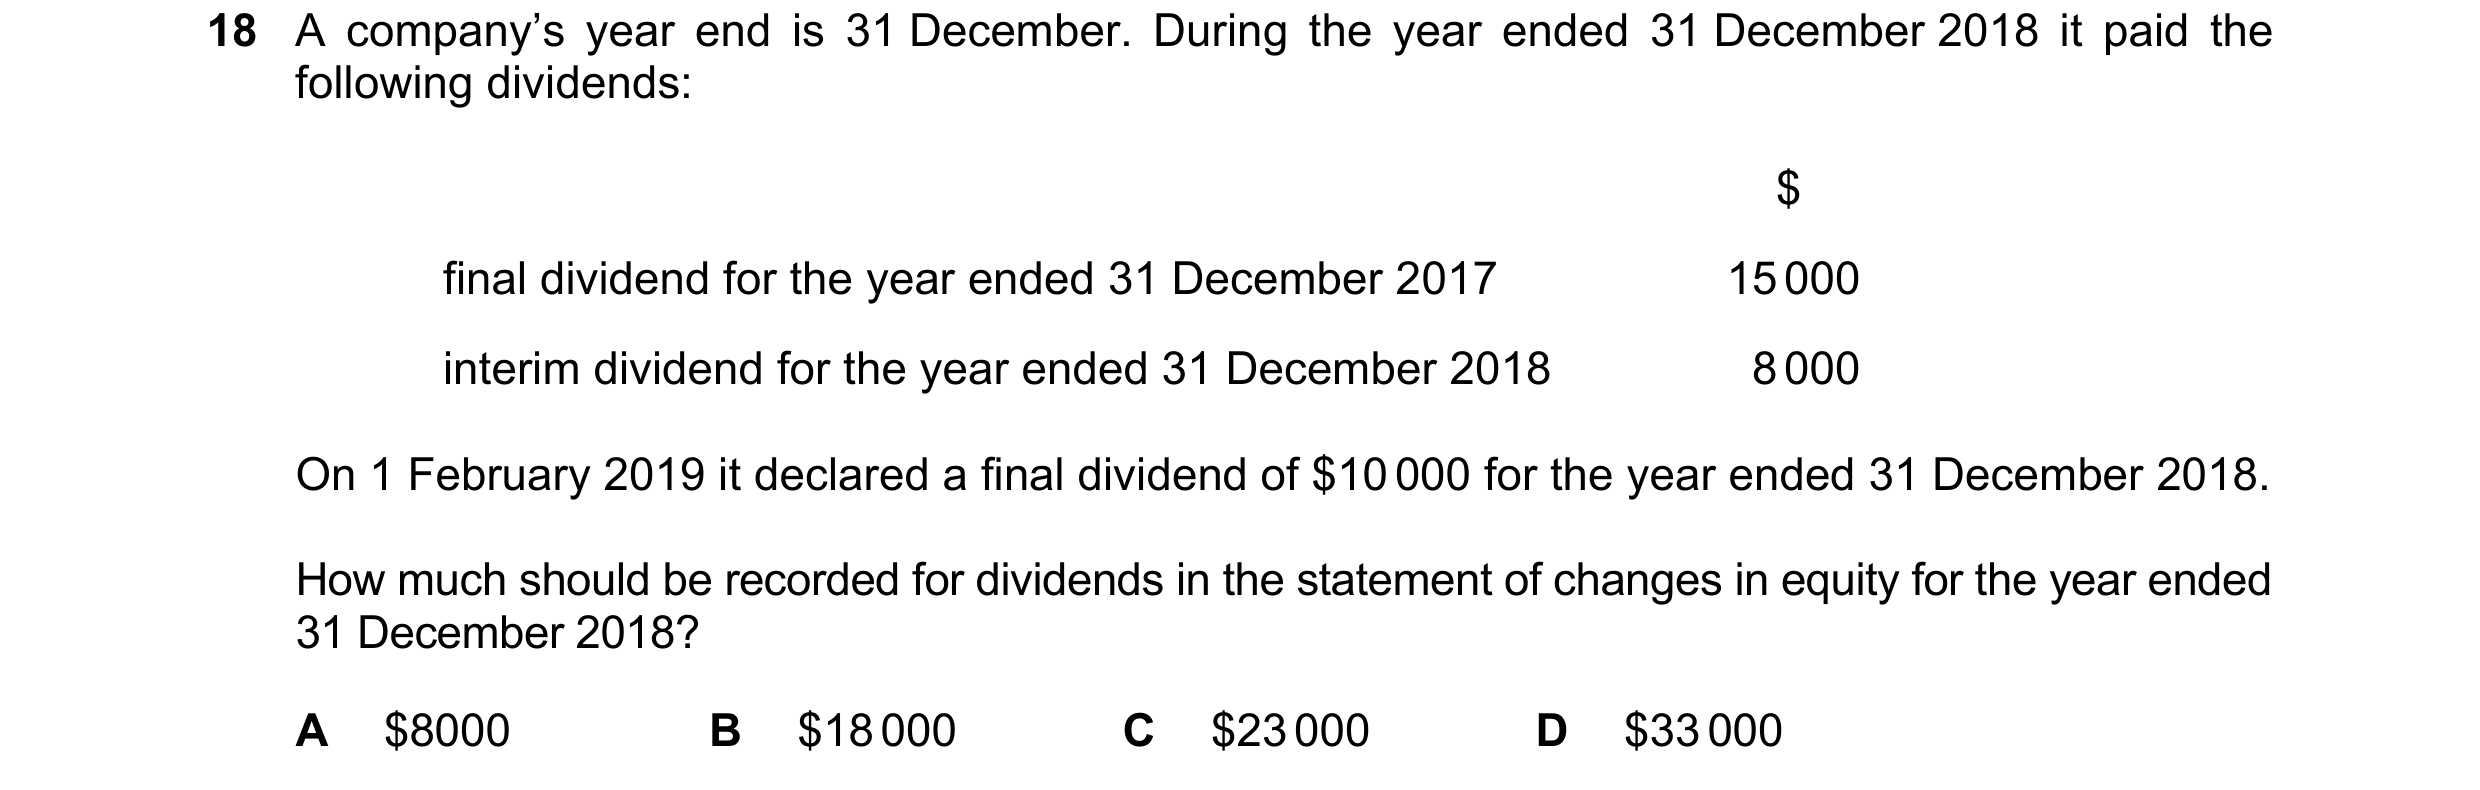
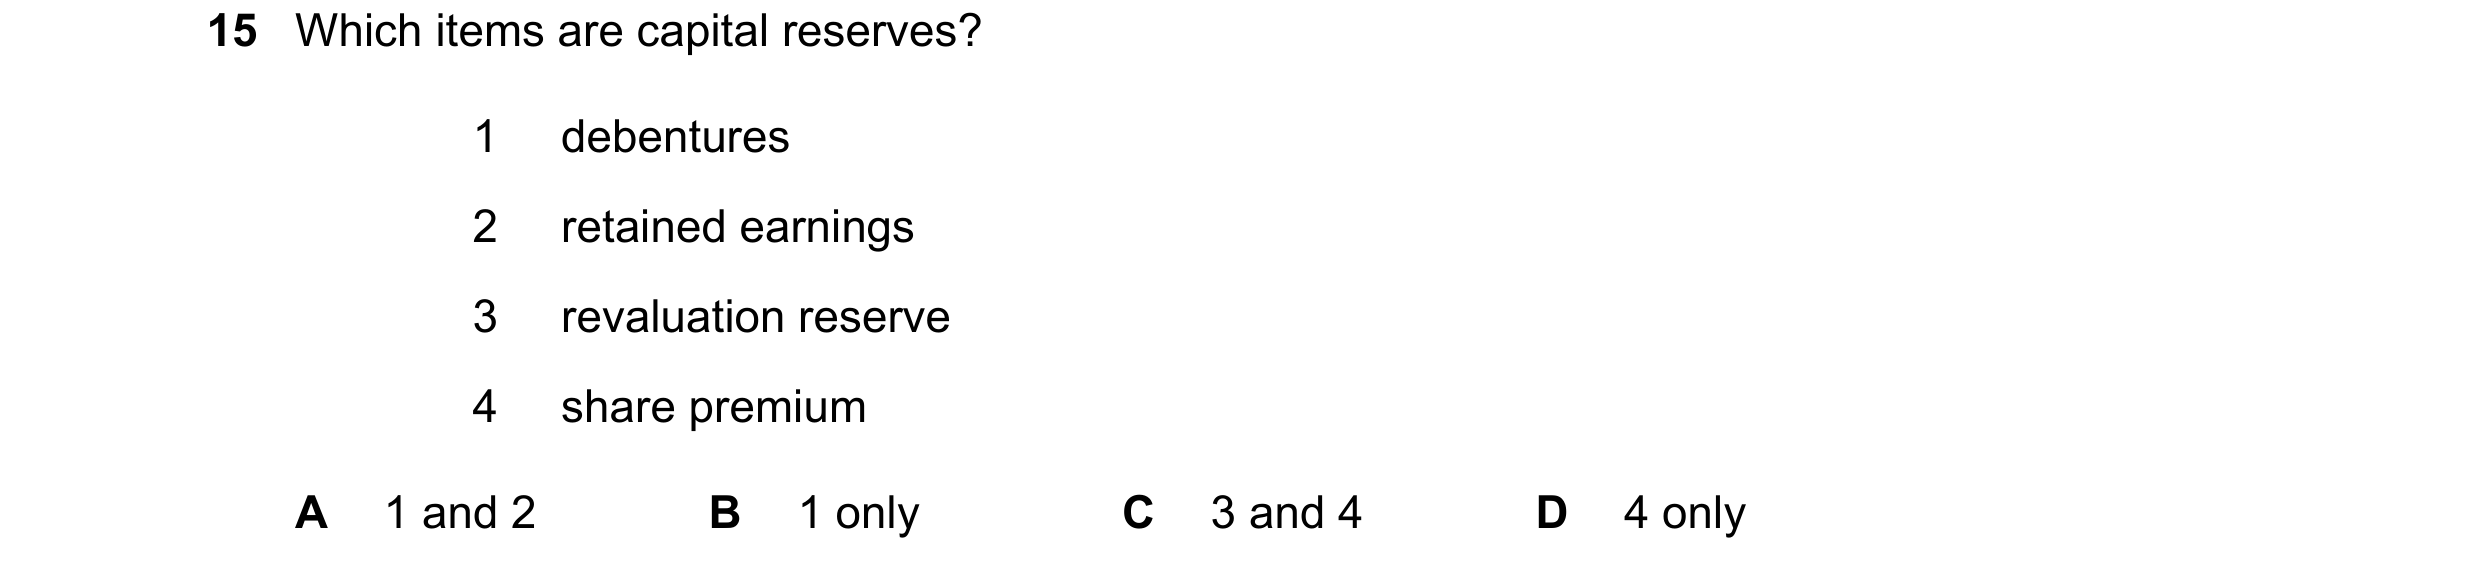 20 / 60
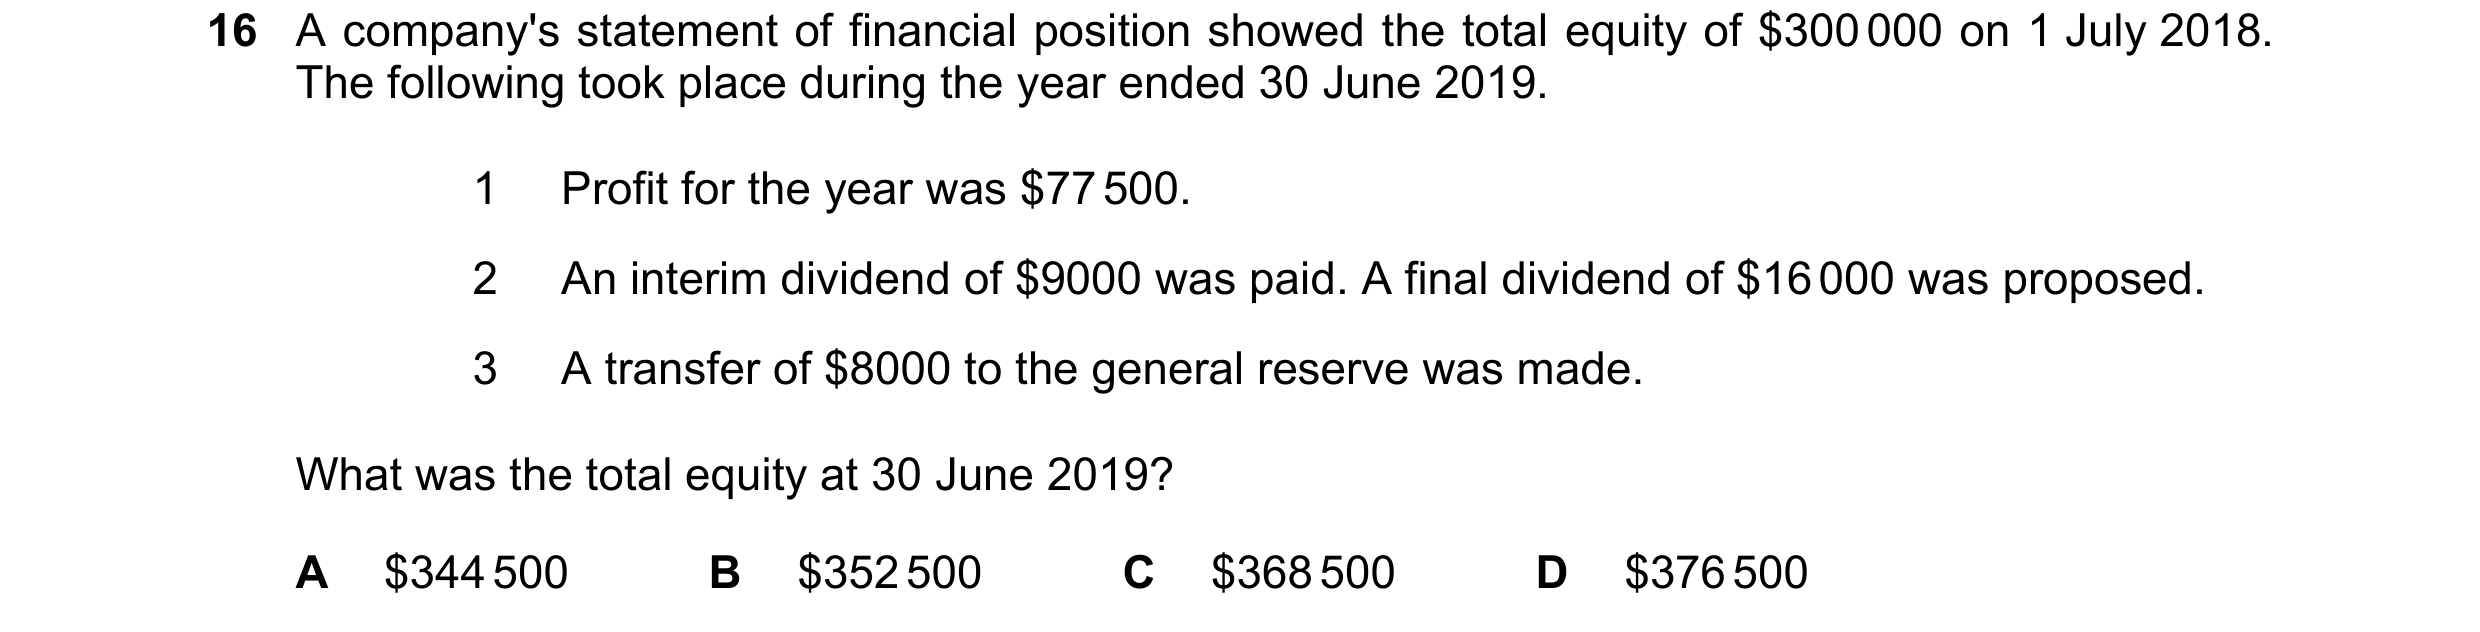
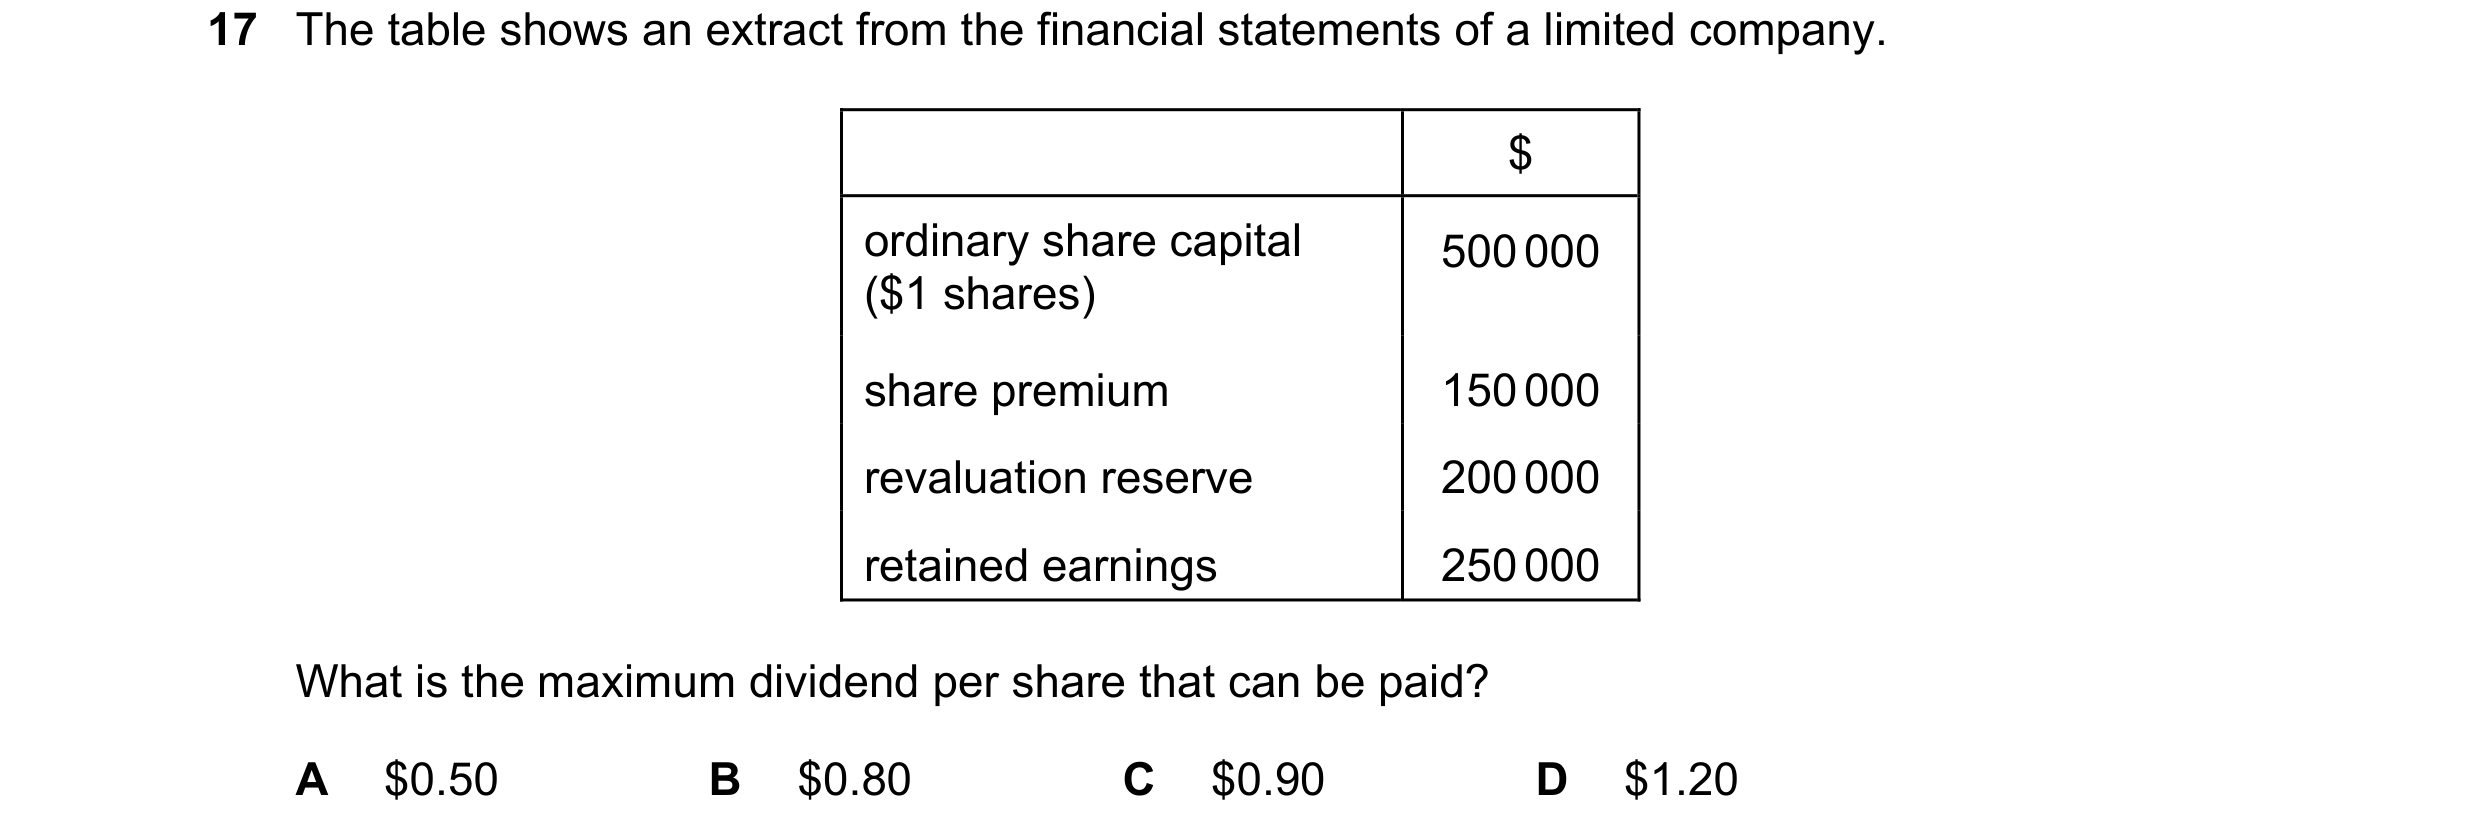
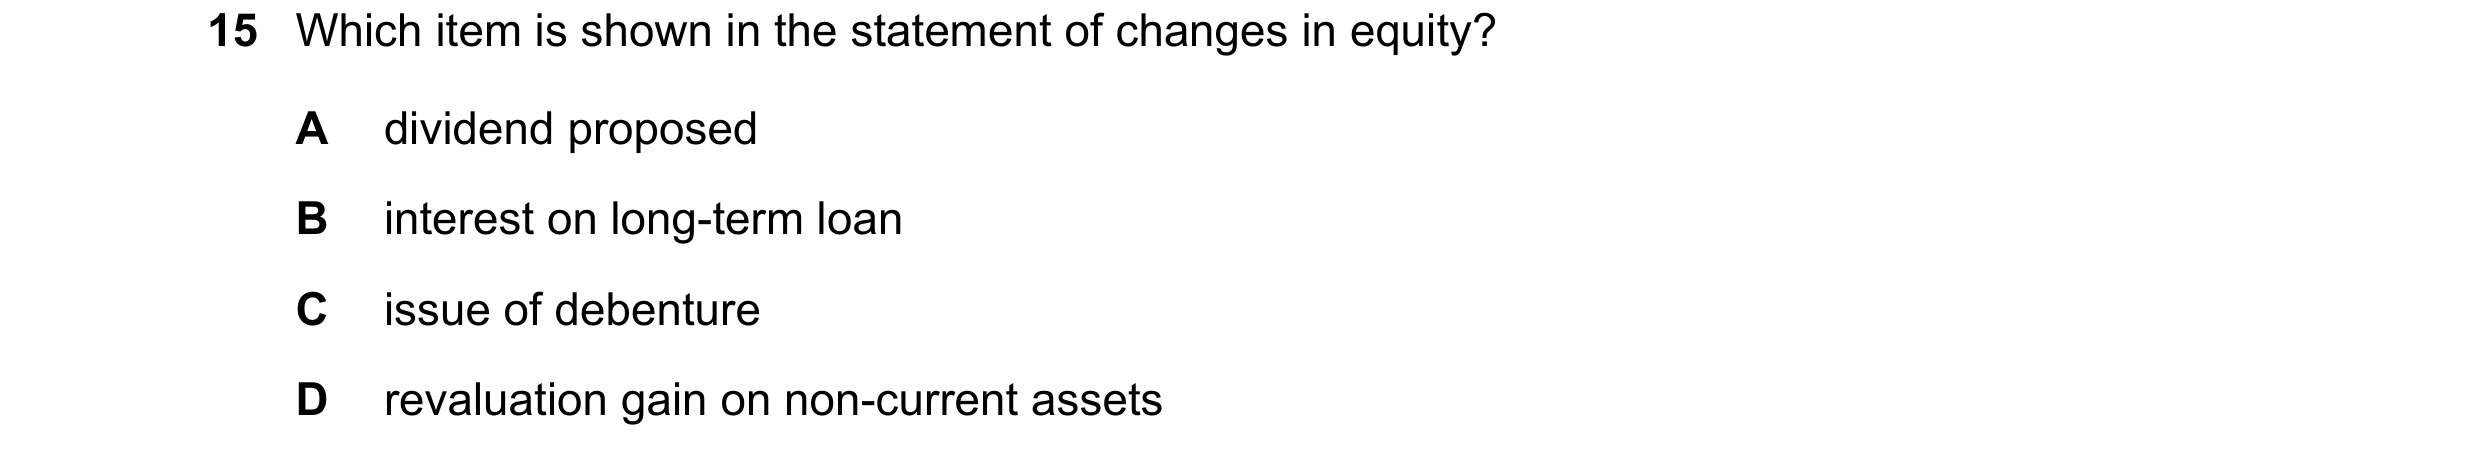
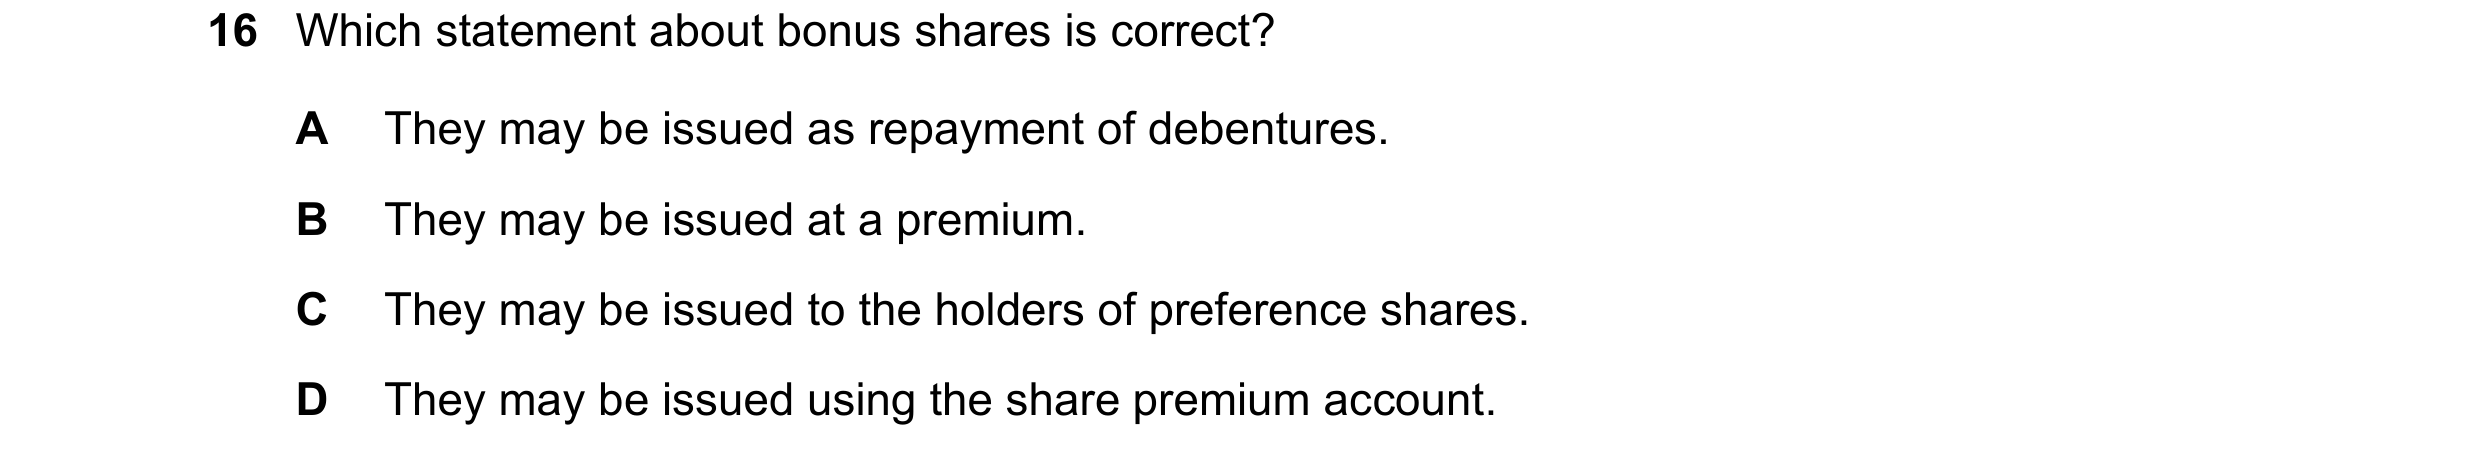
 21 / 60
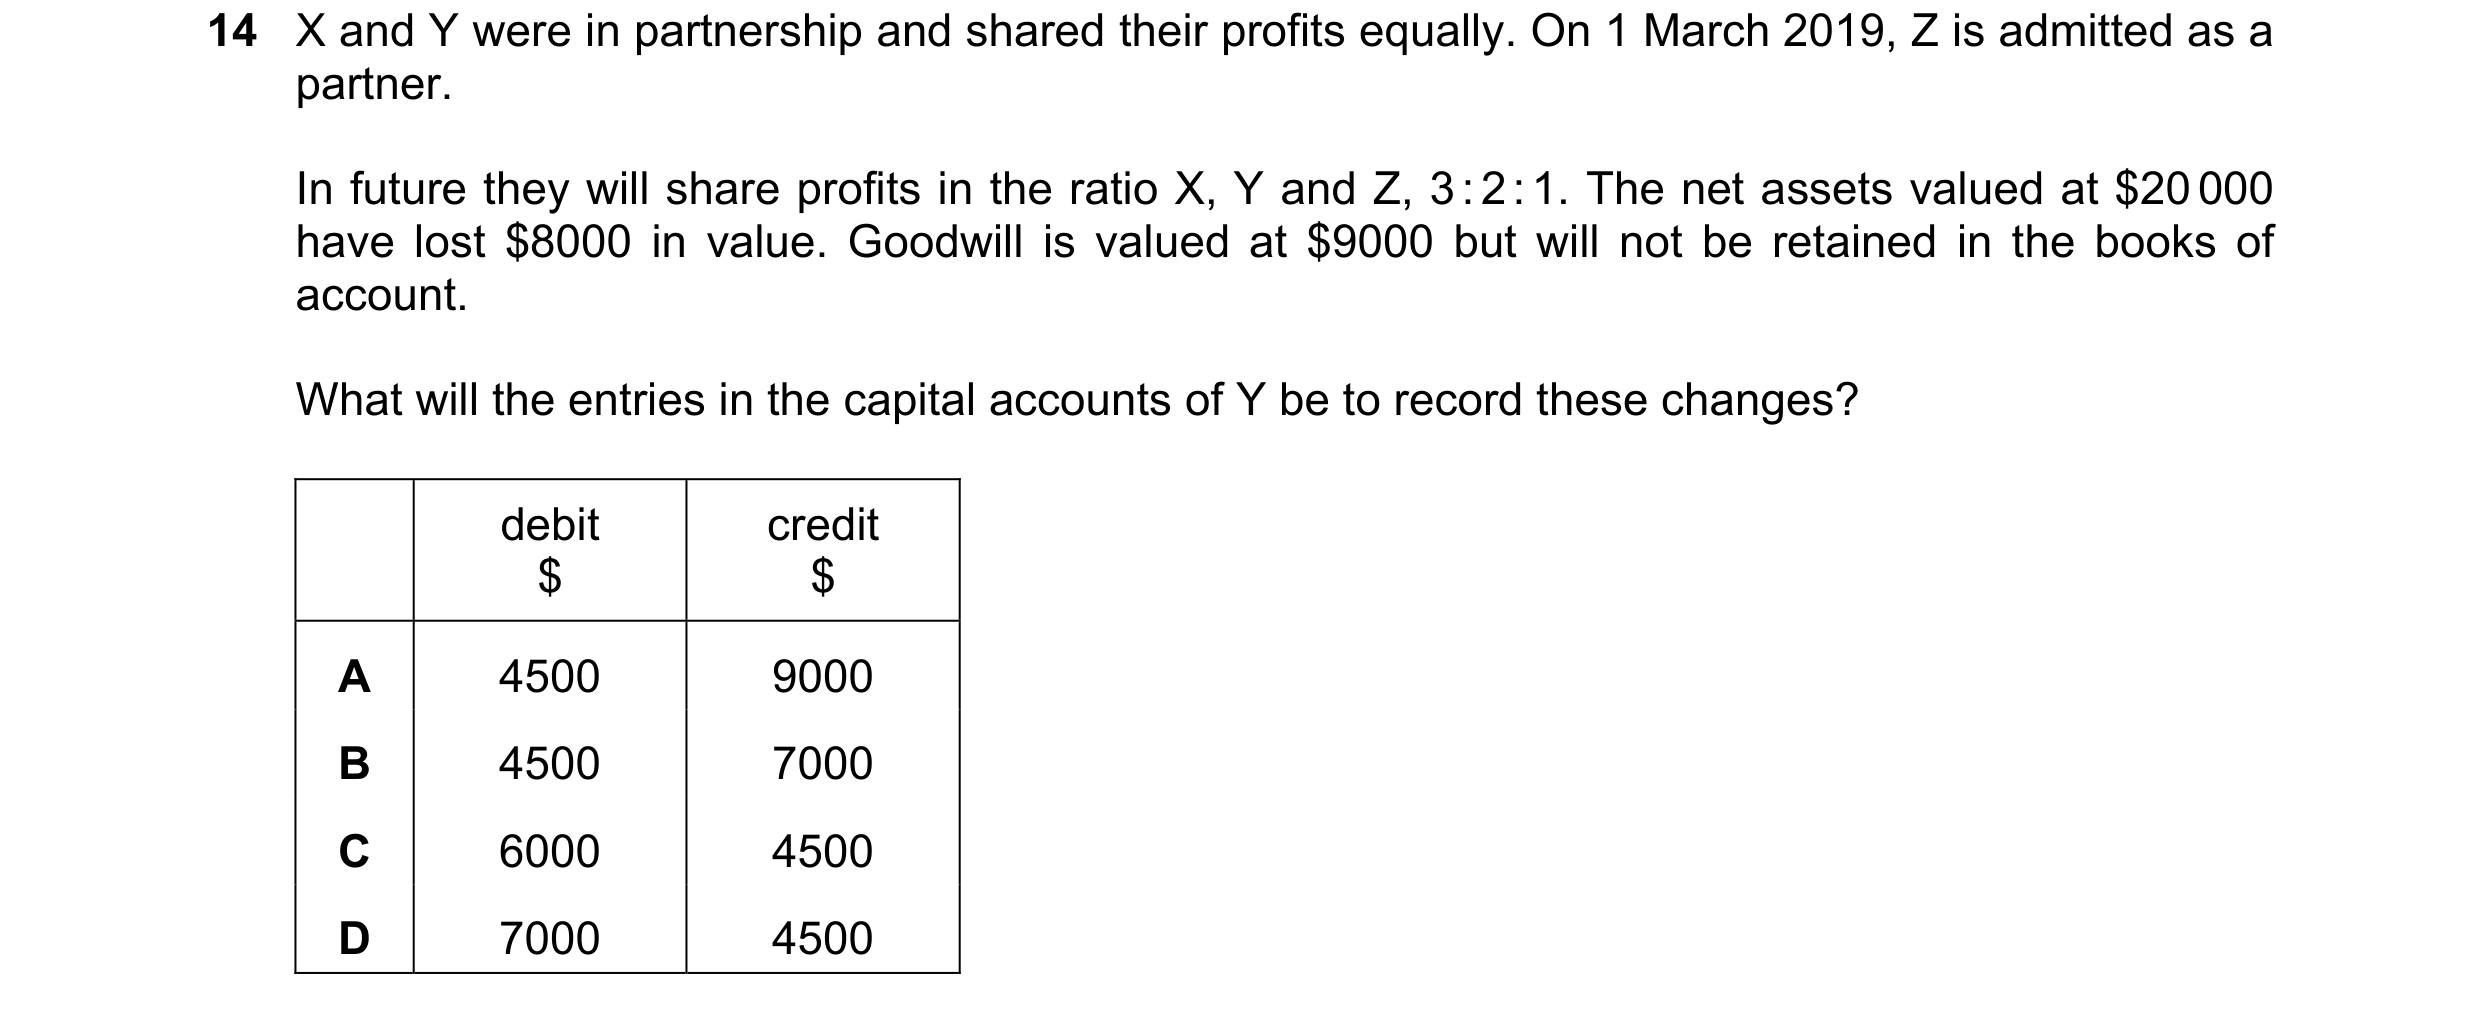
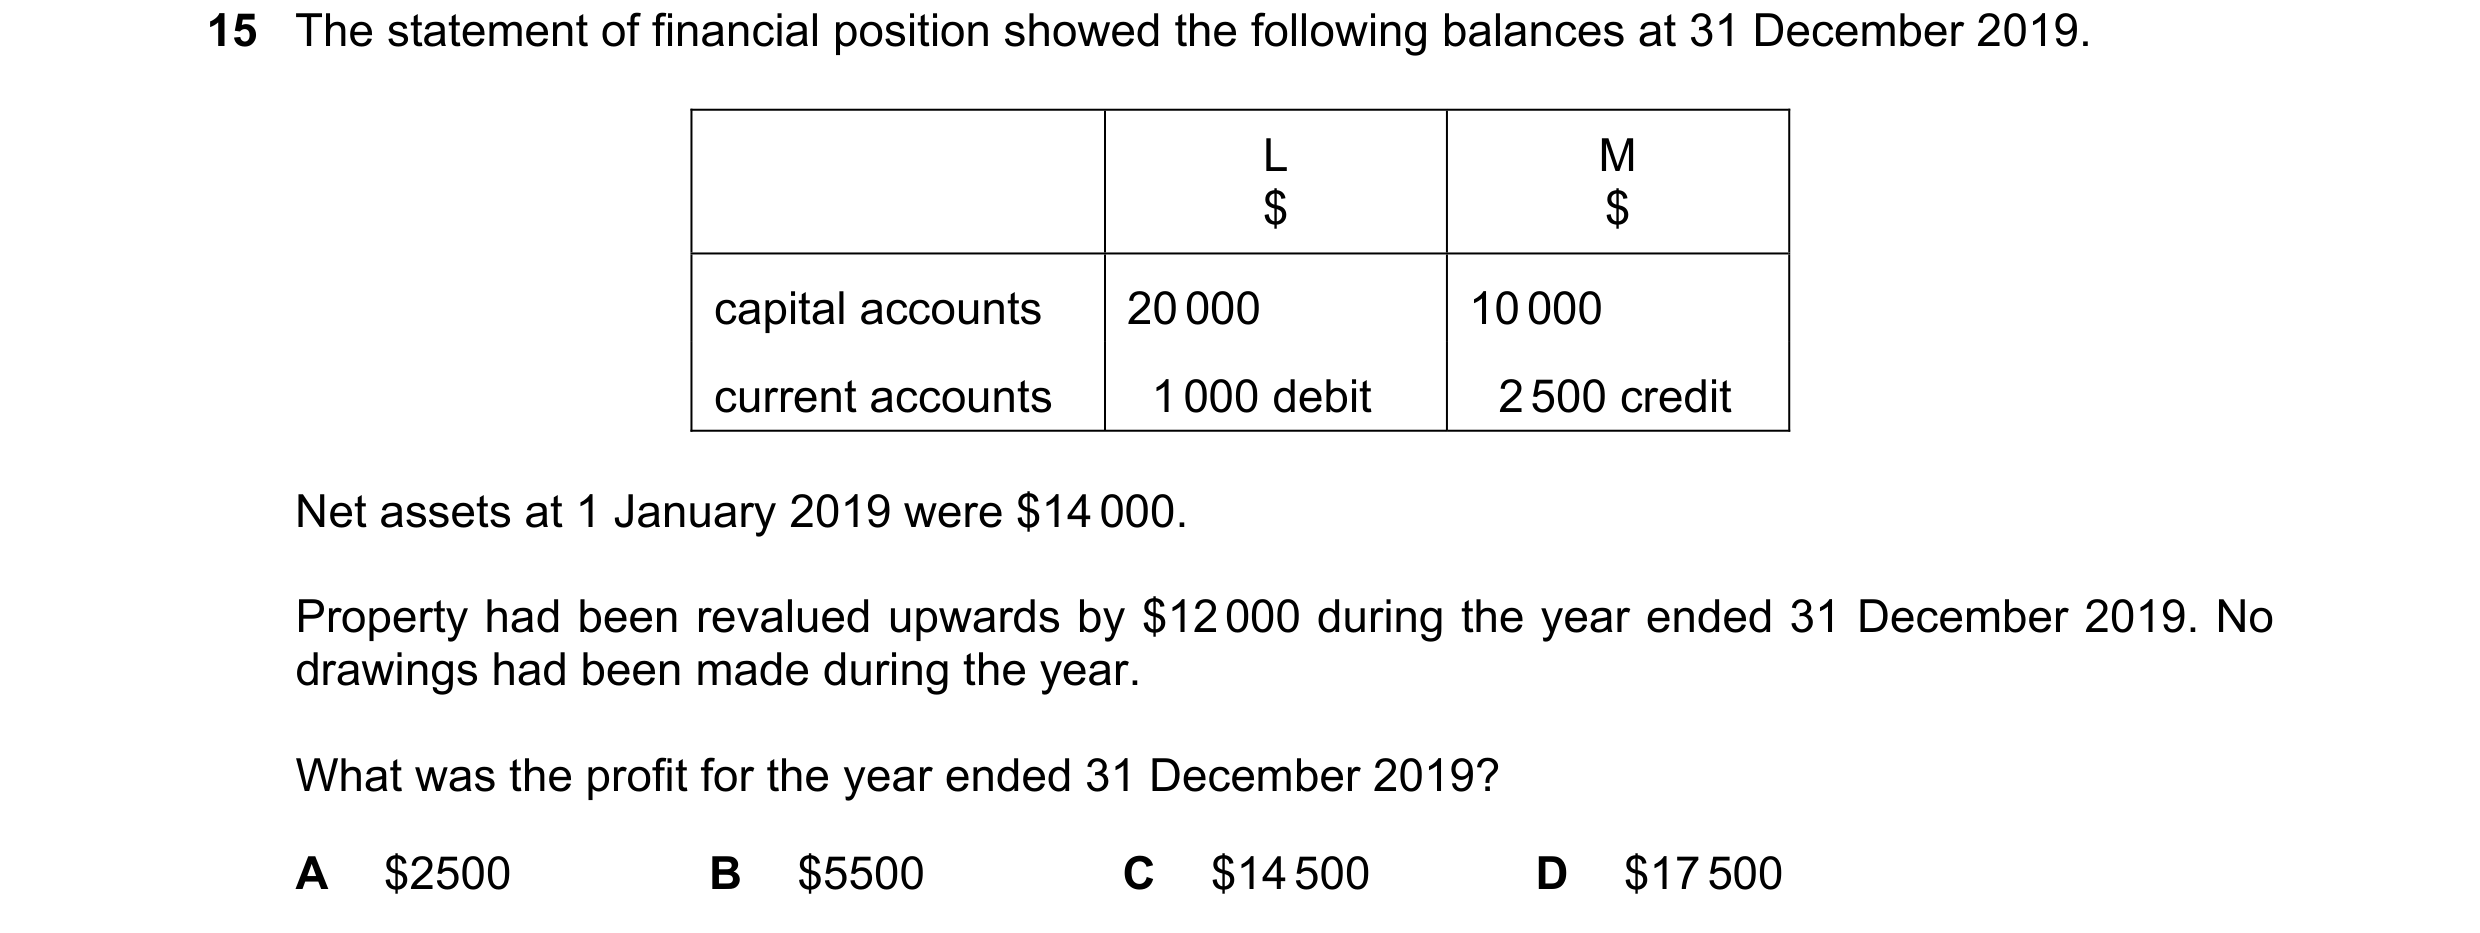
 22 / 60
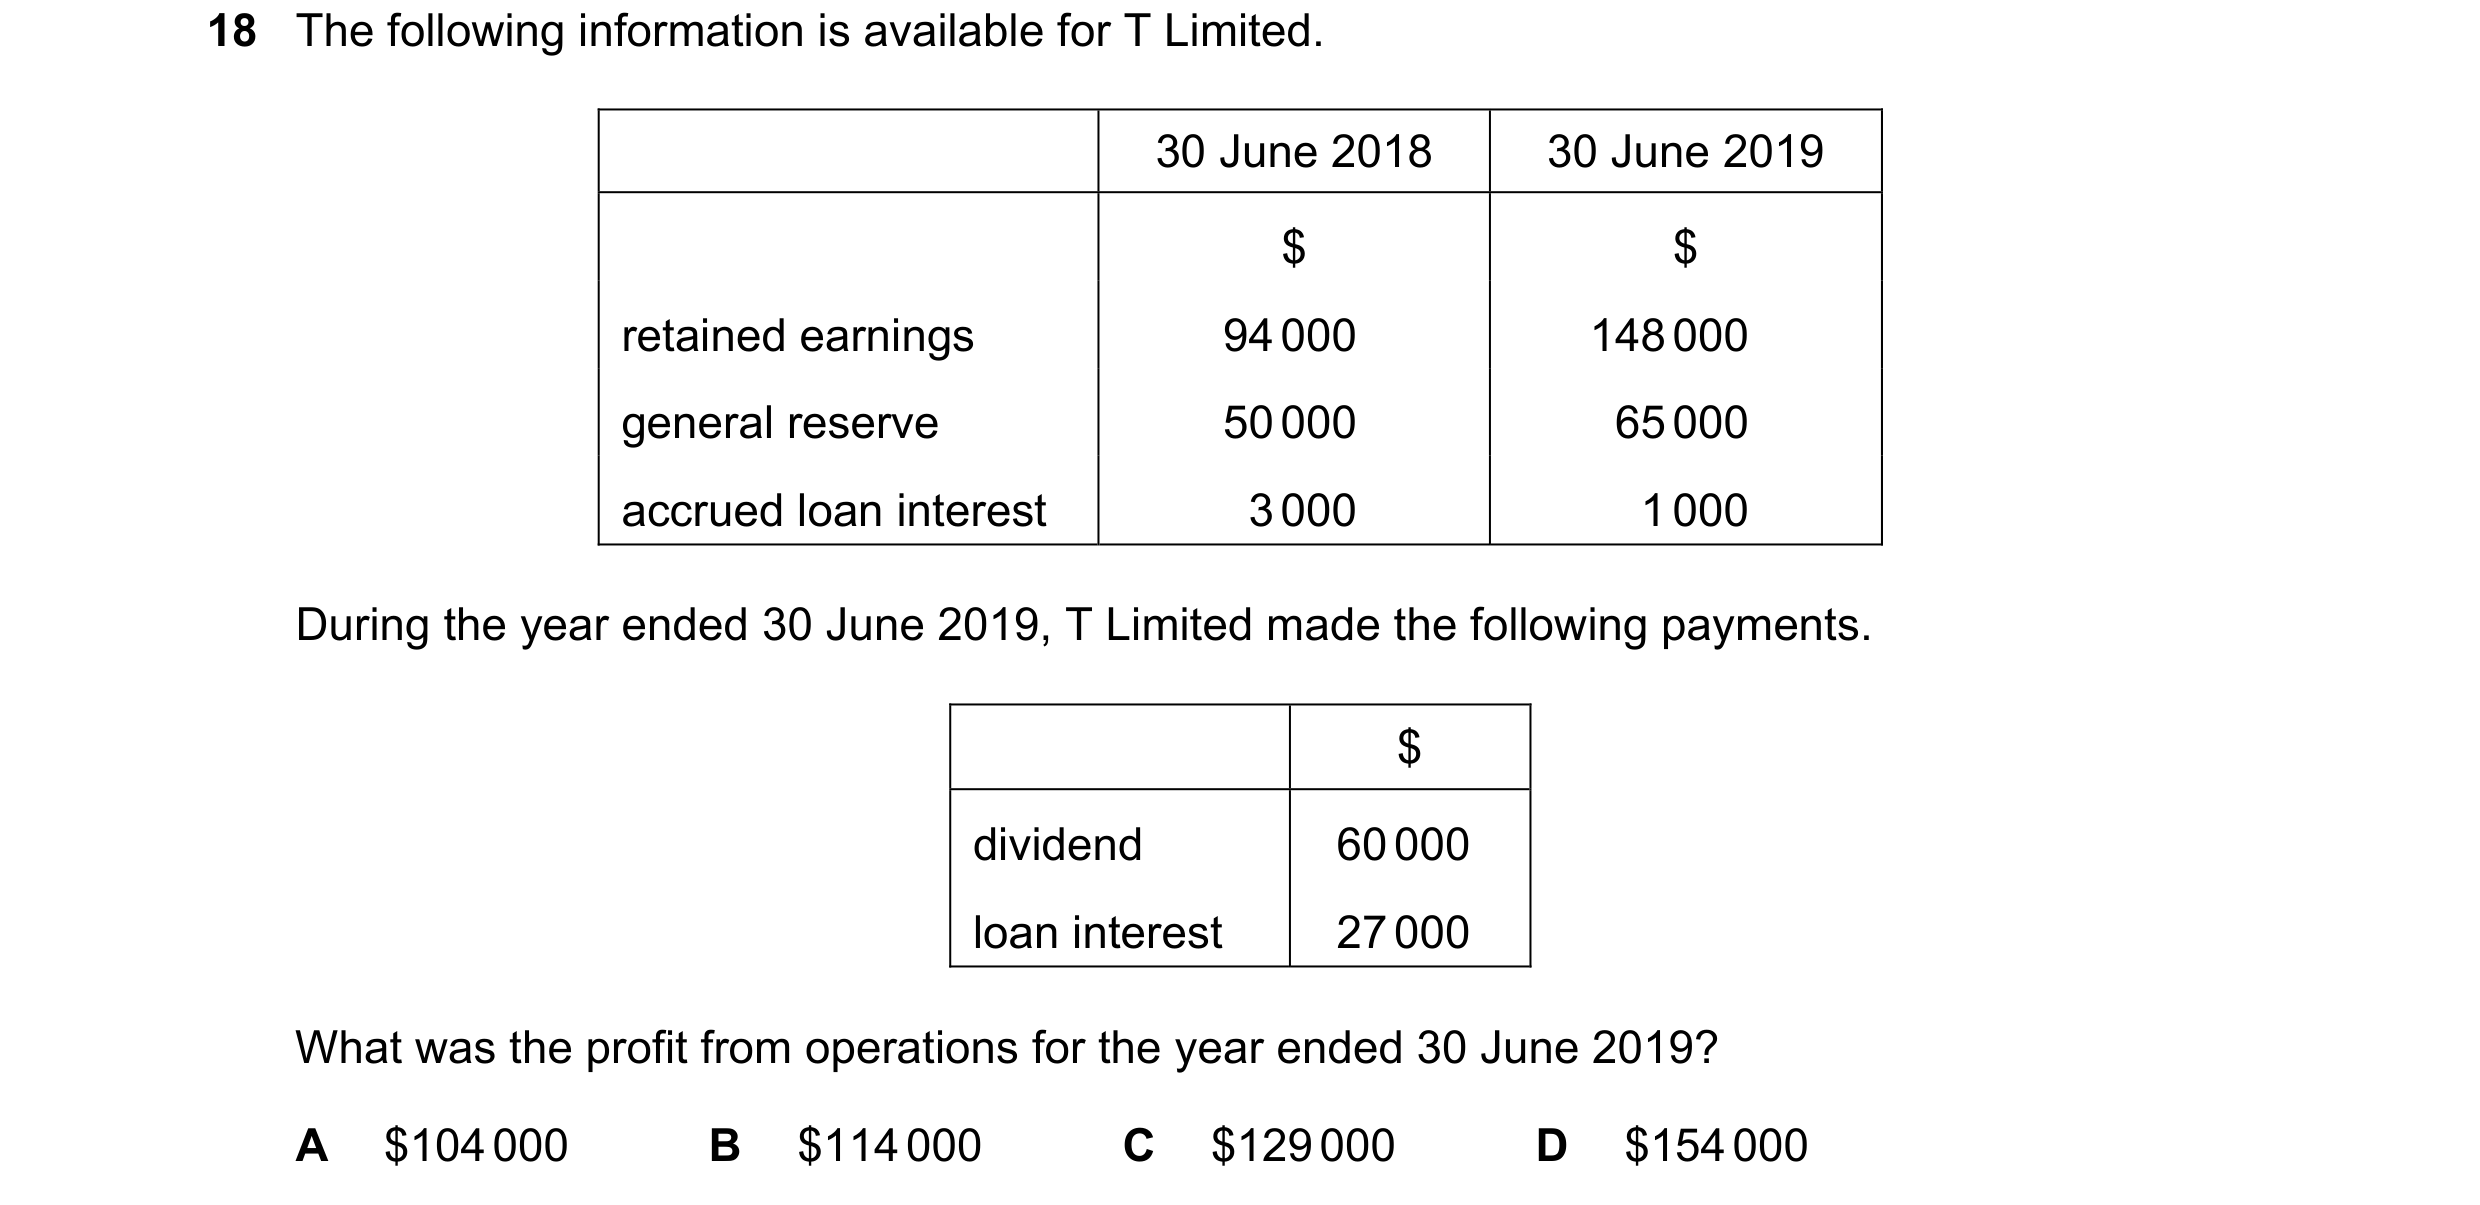
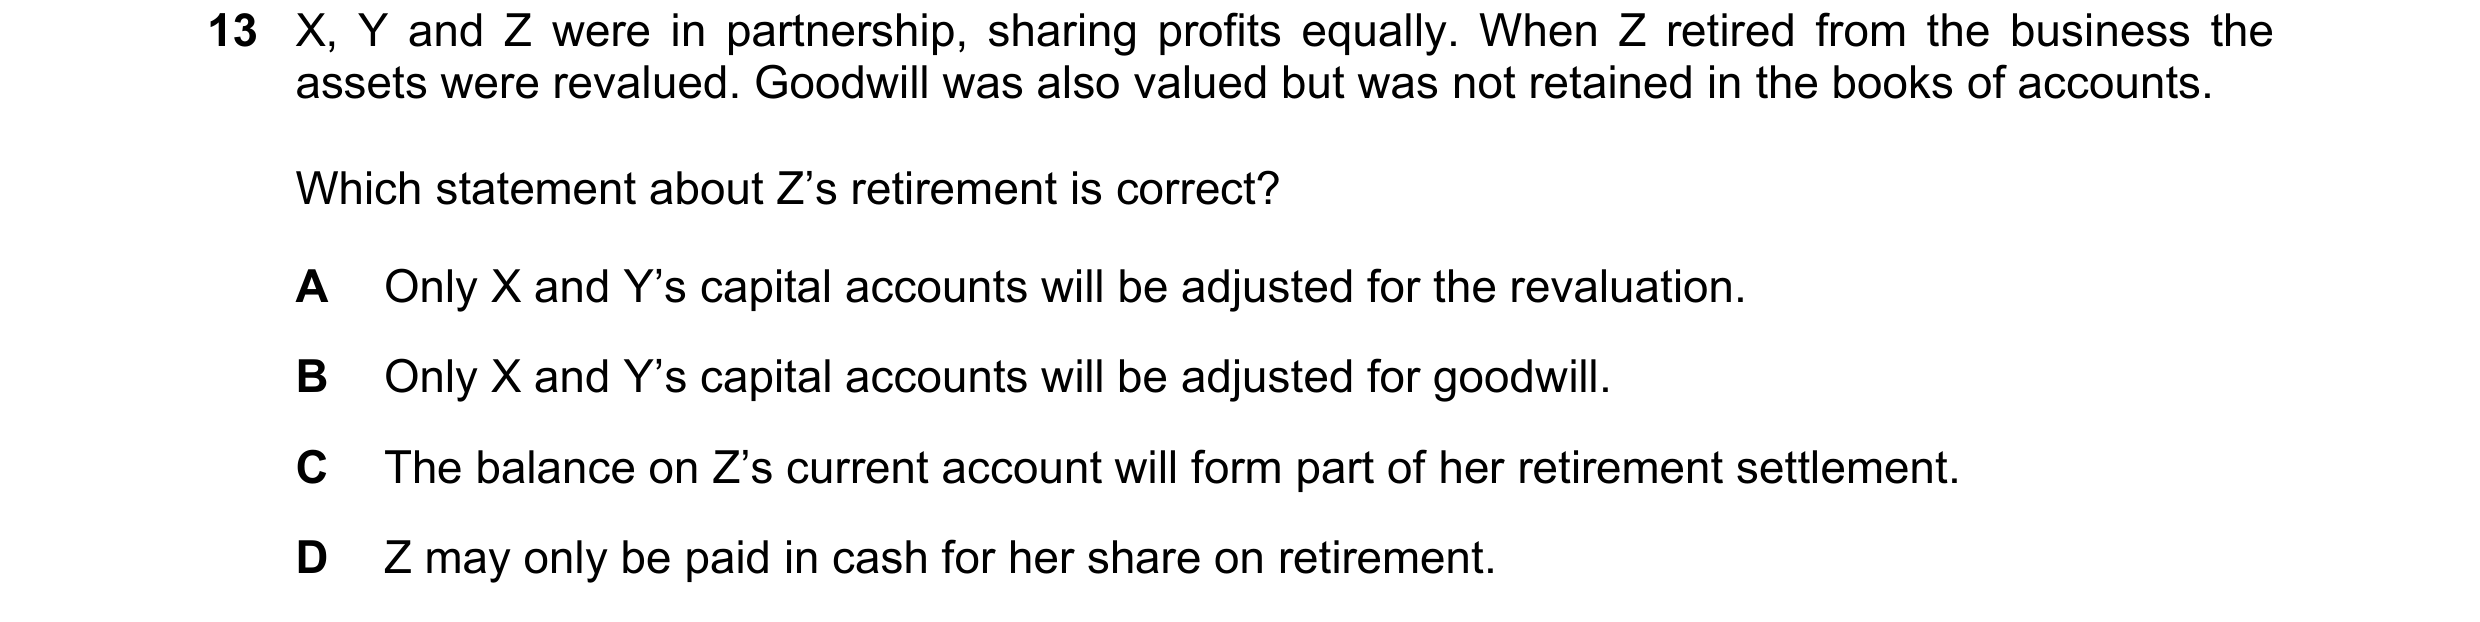 23 / 60
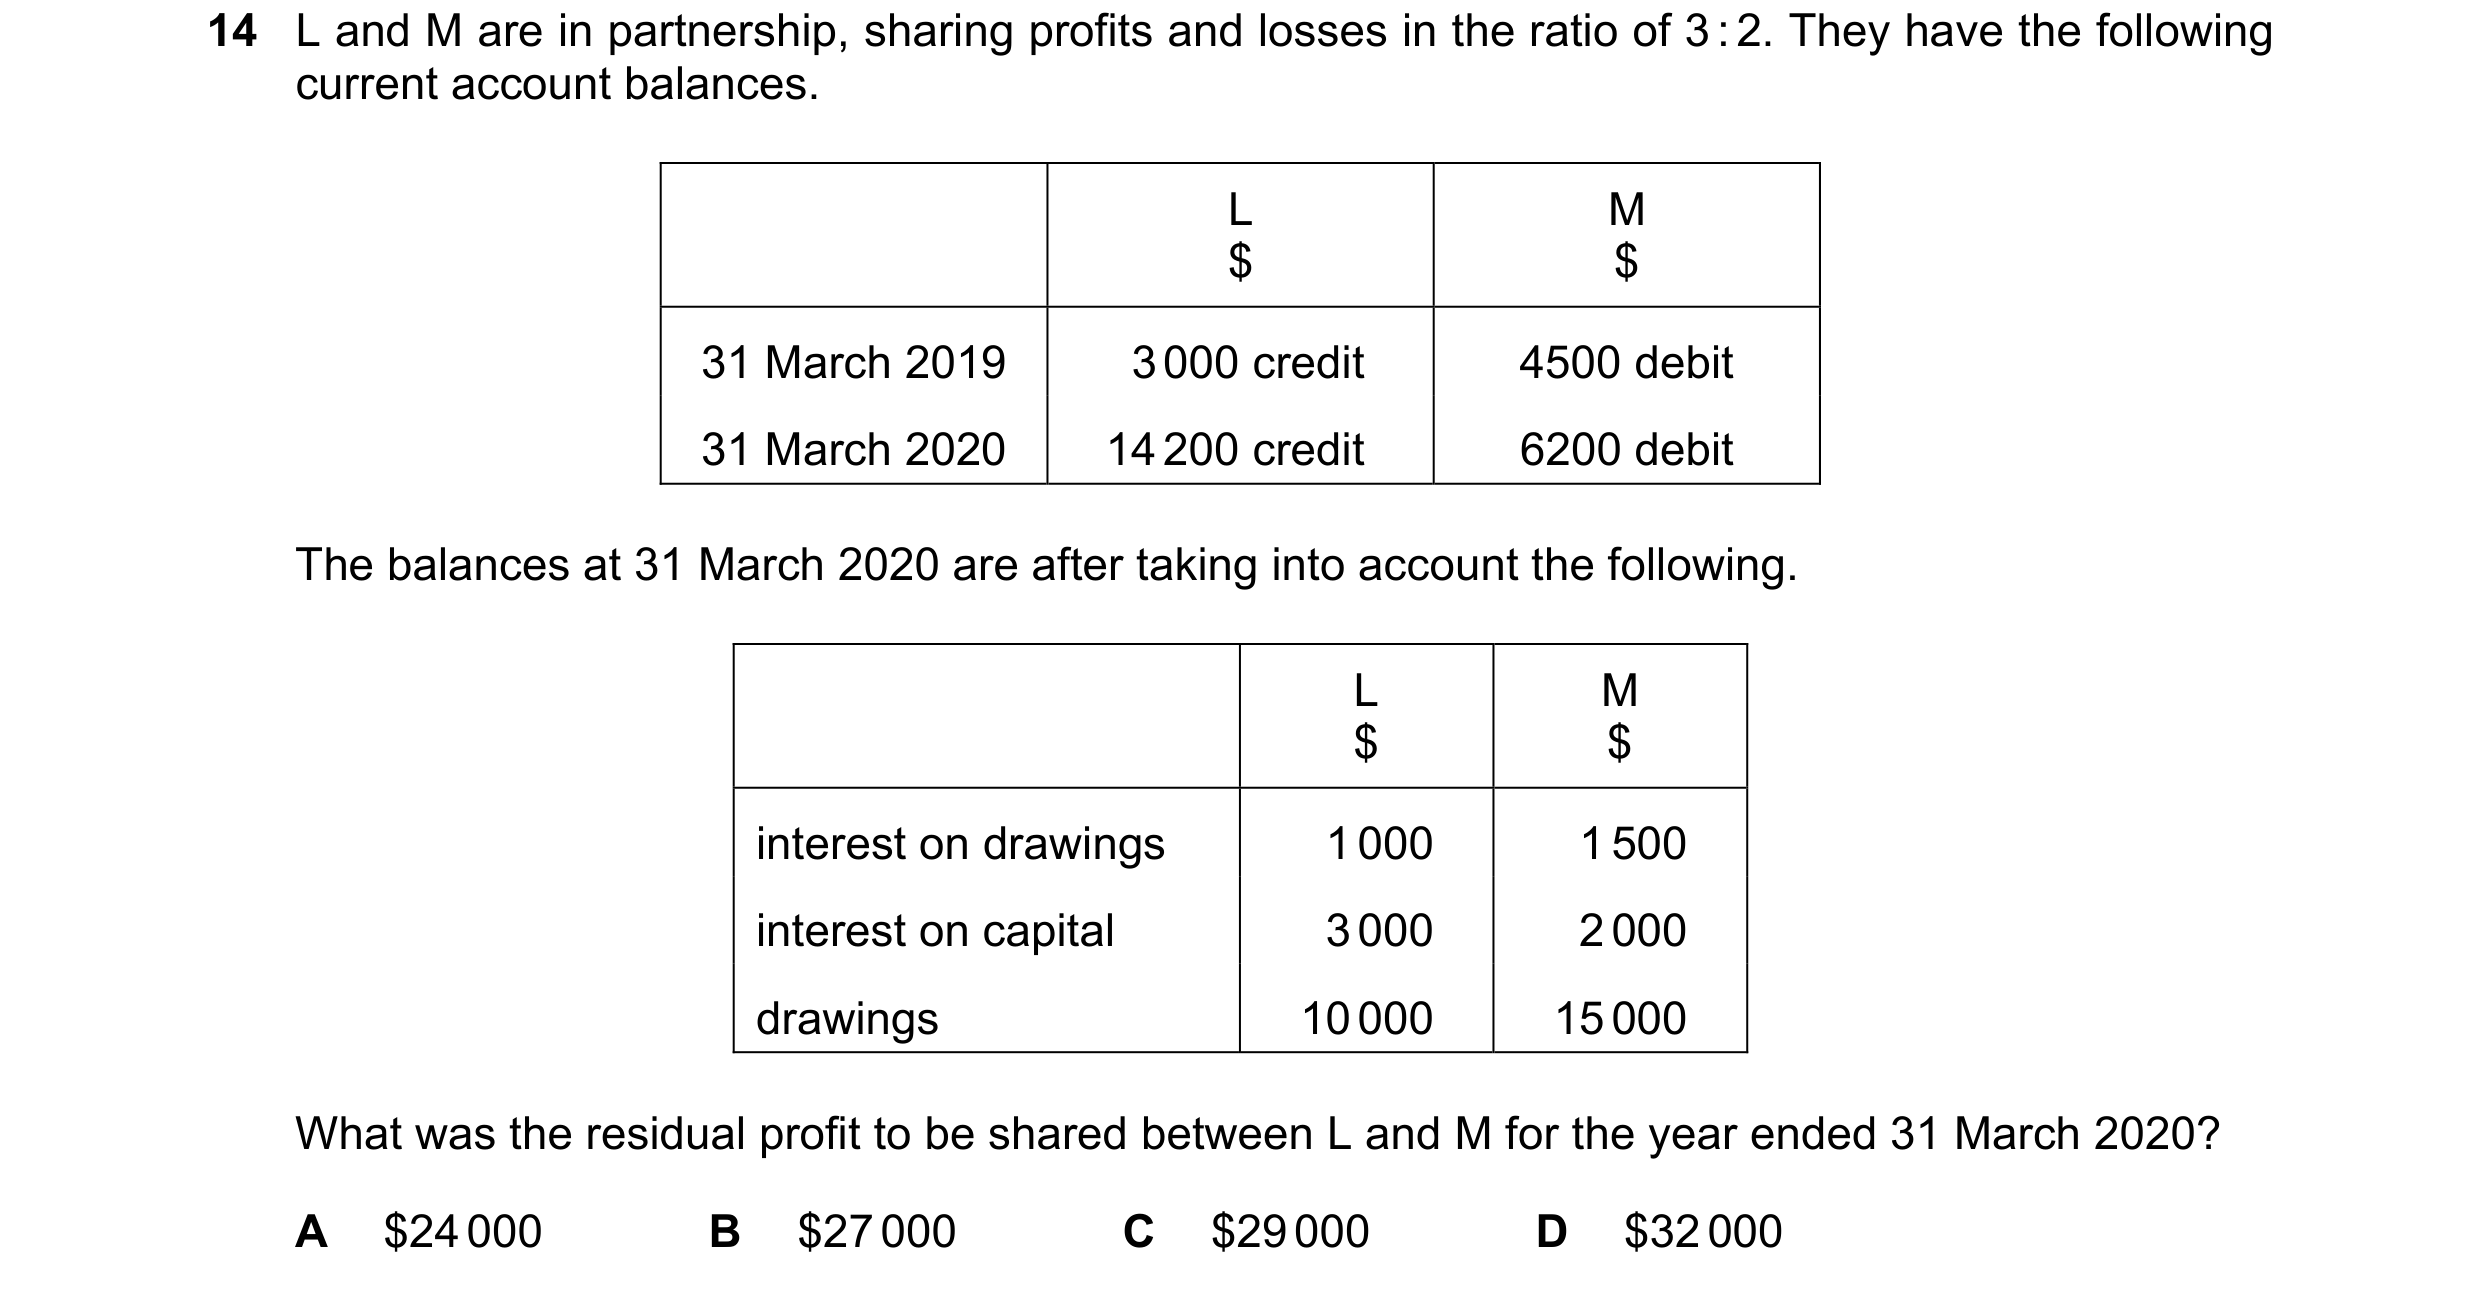
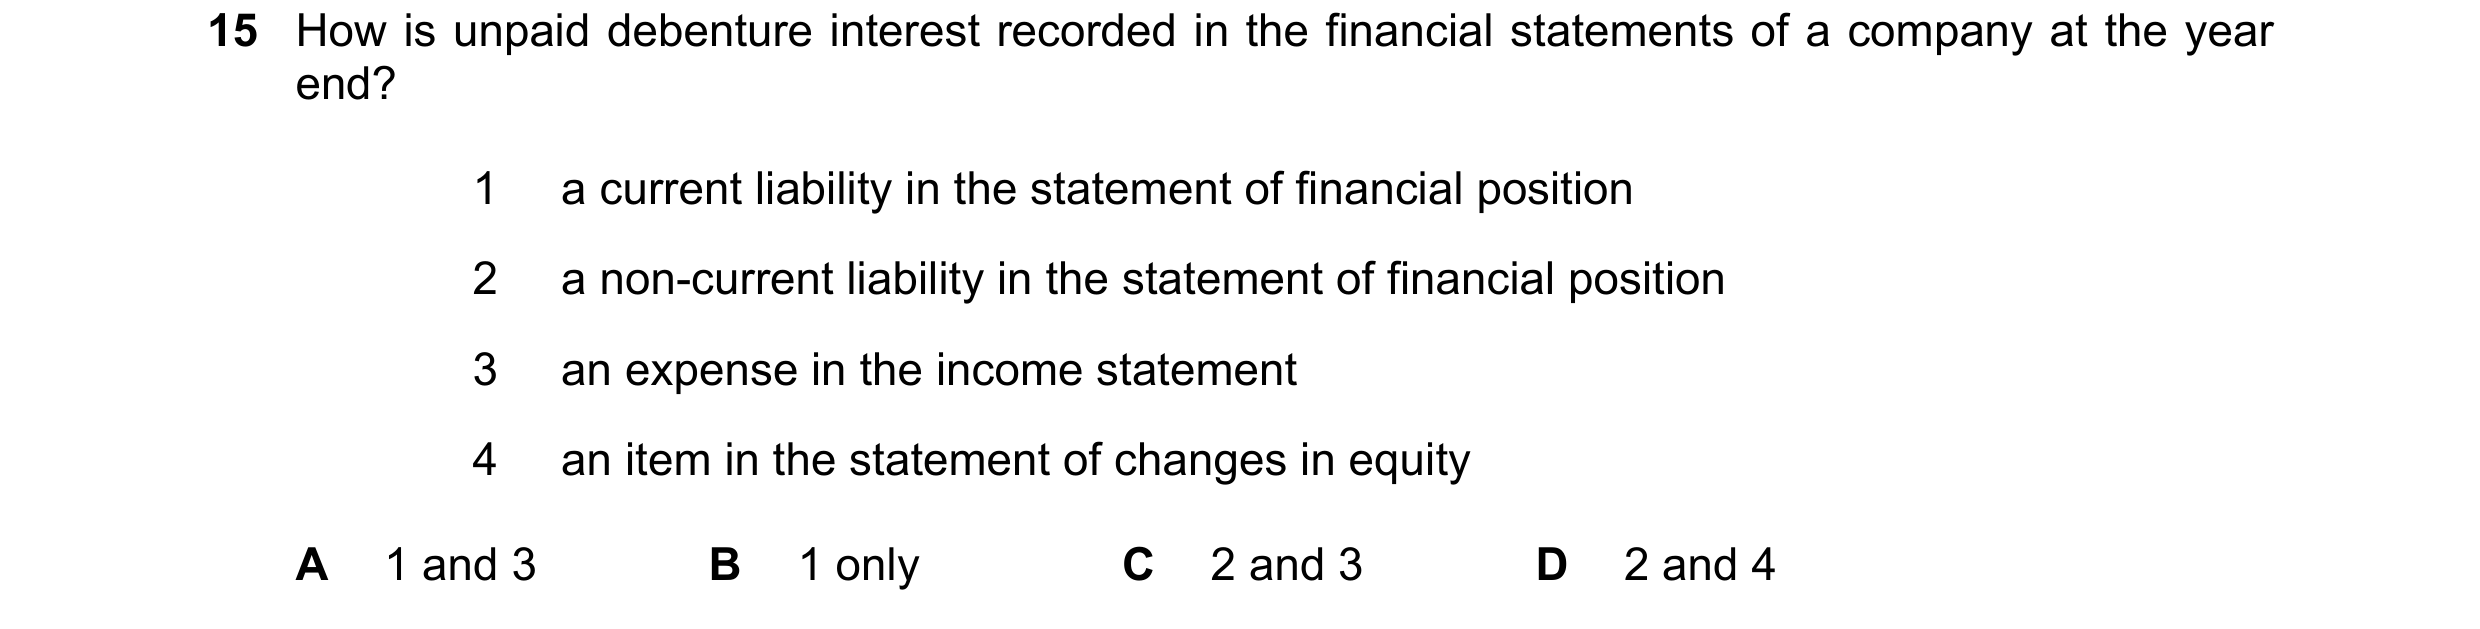 24 / 60
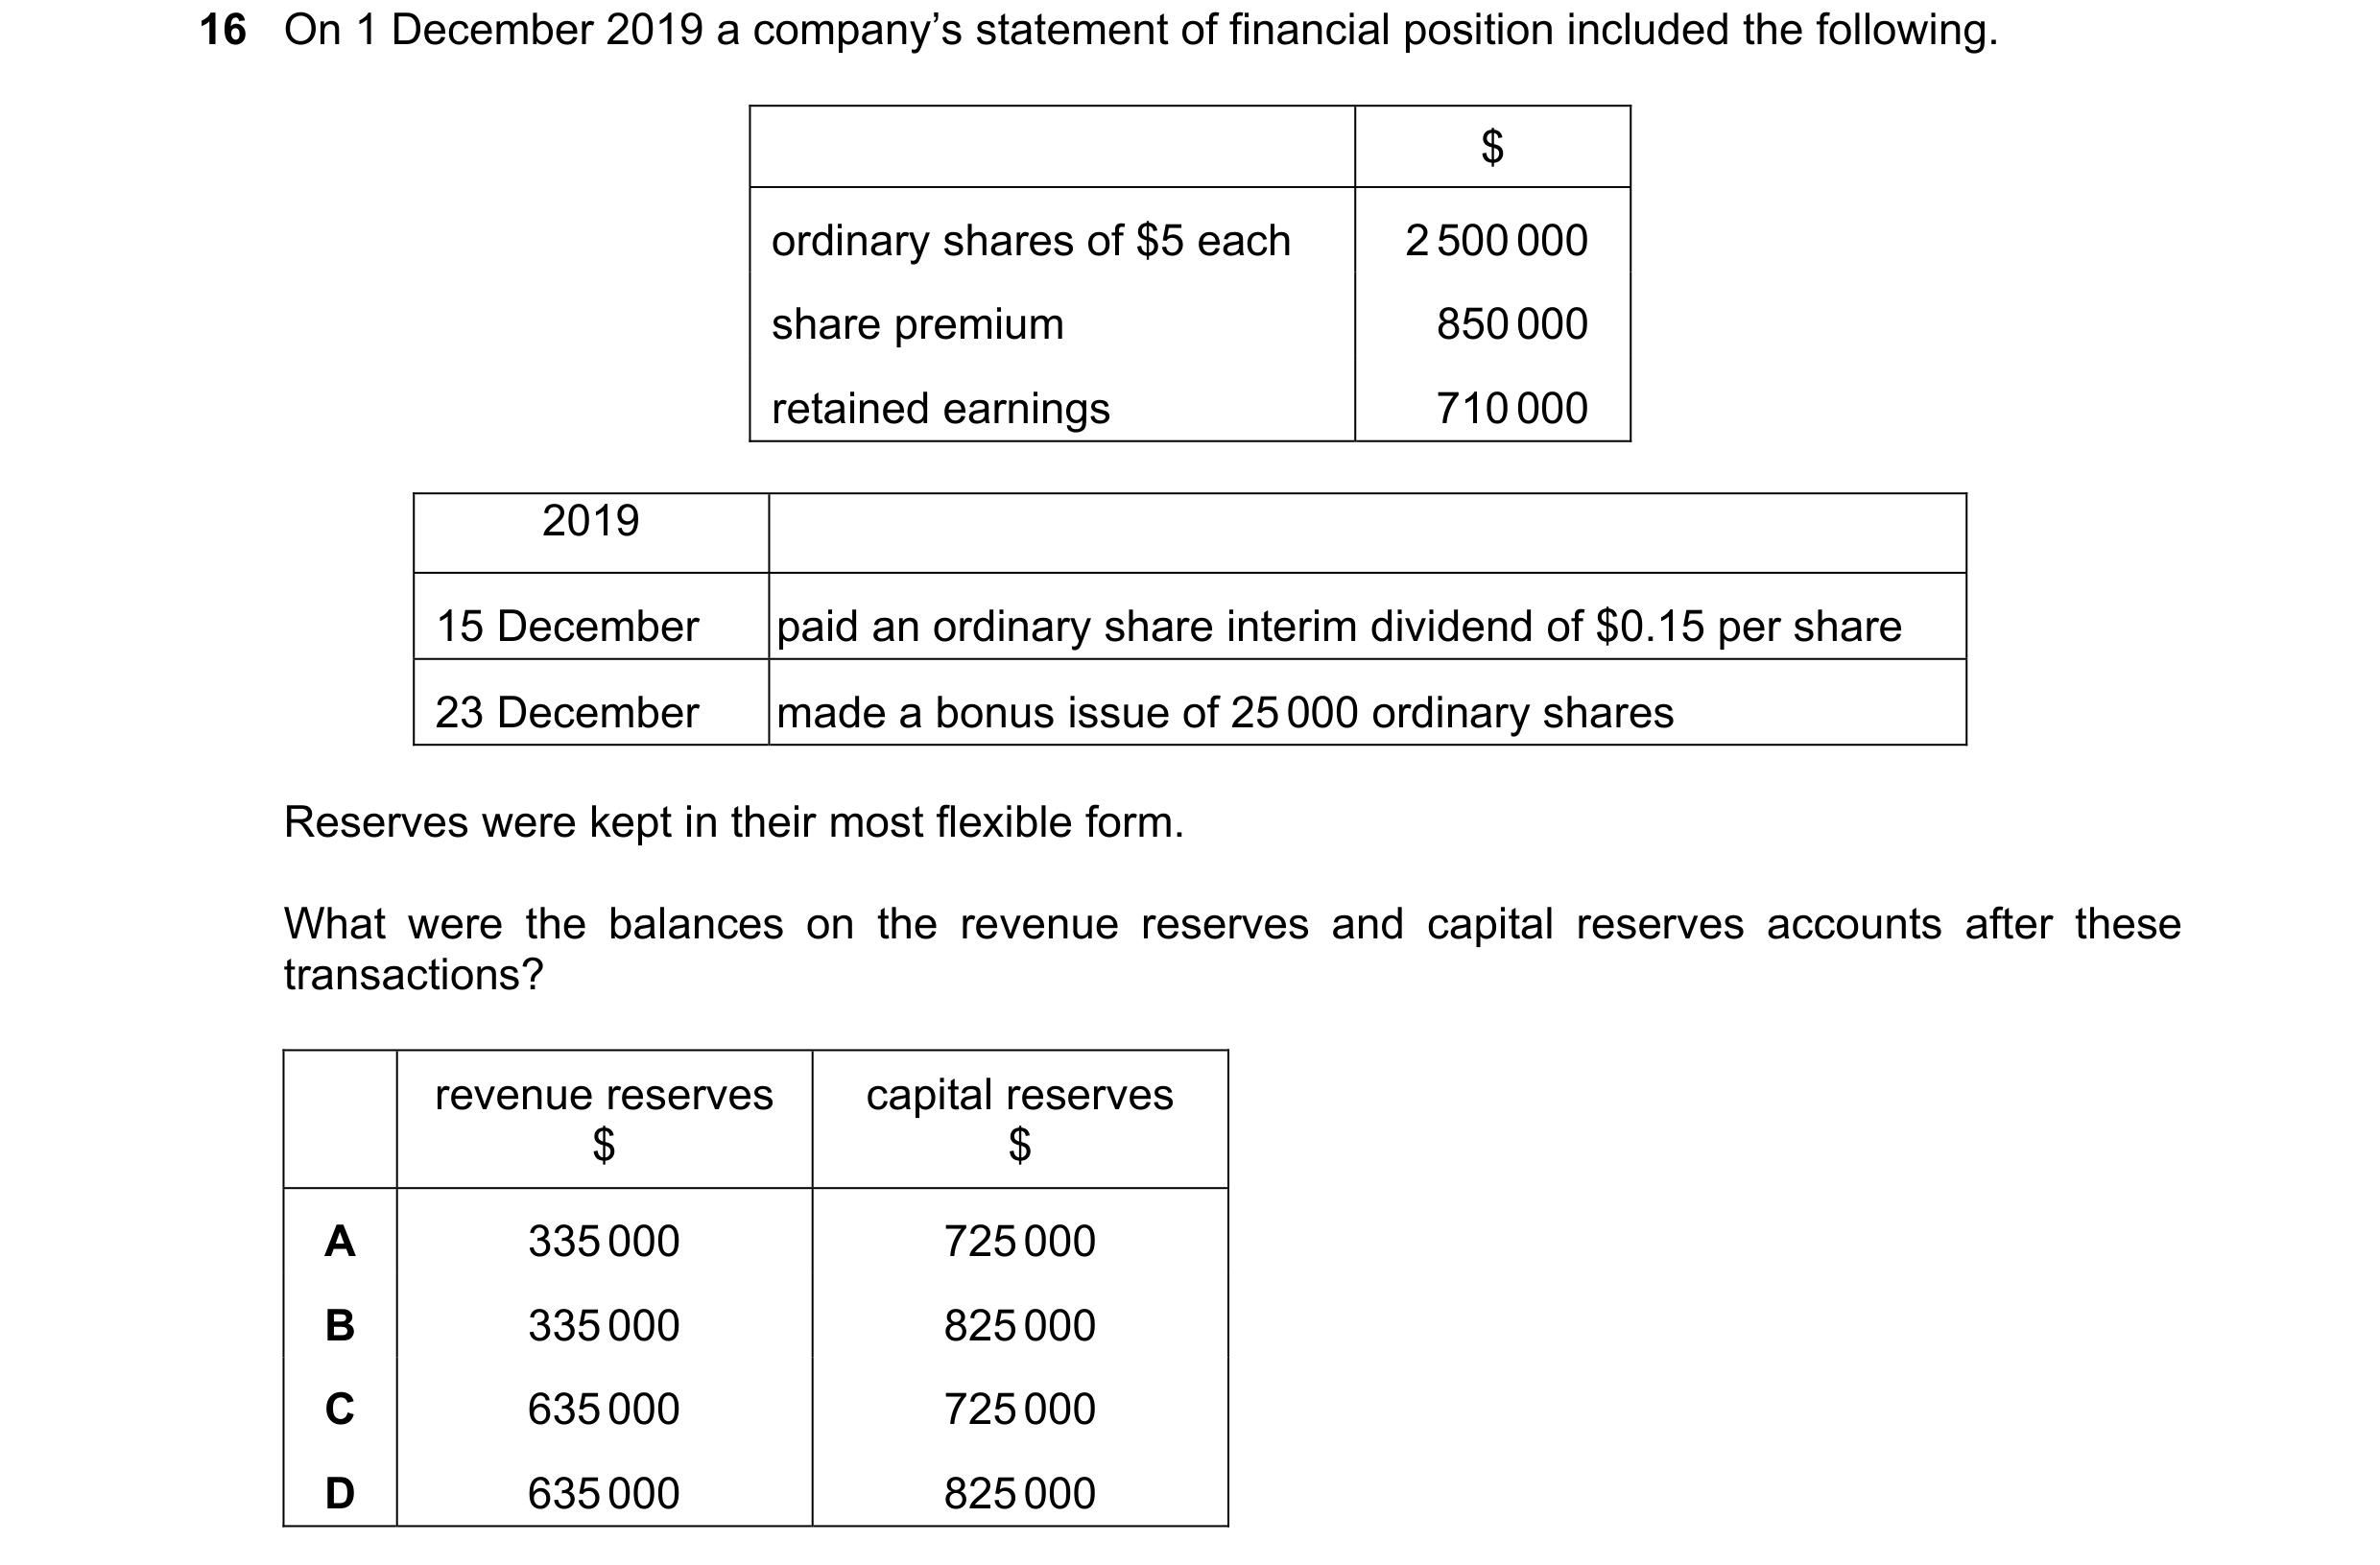
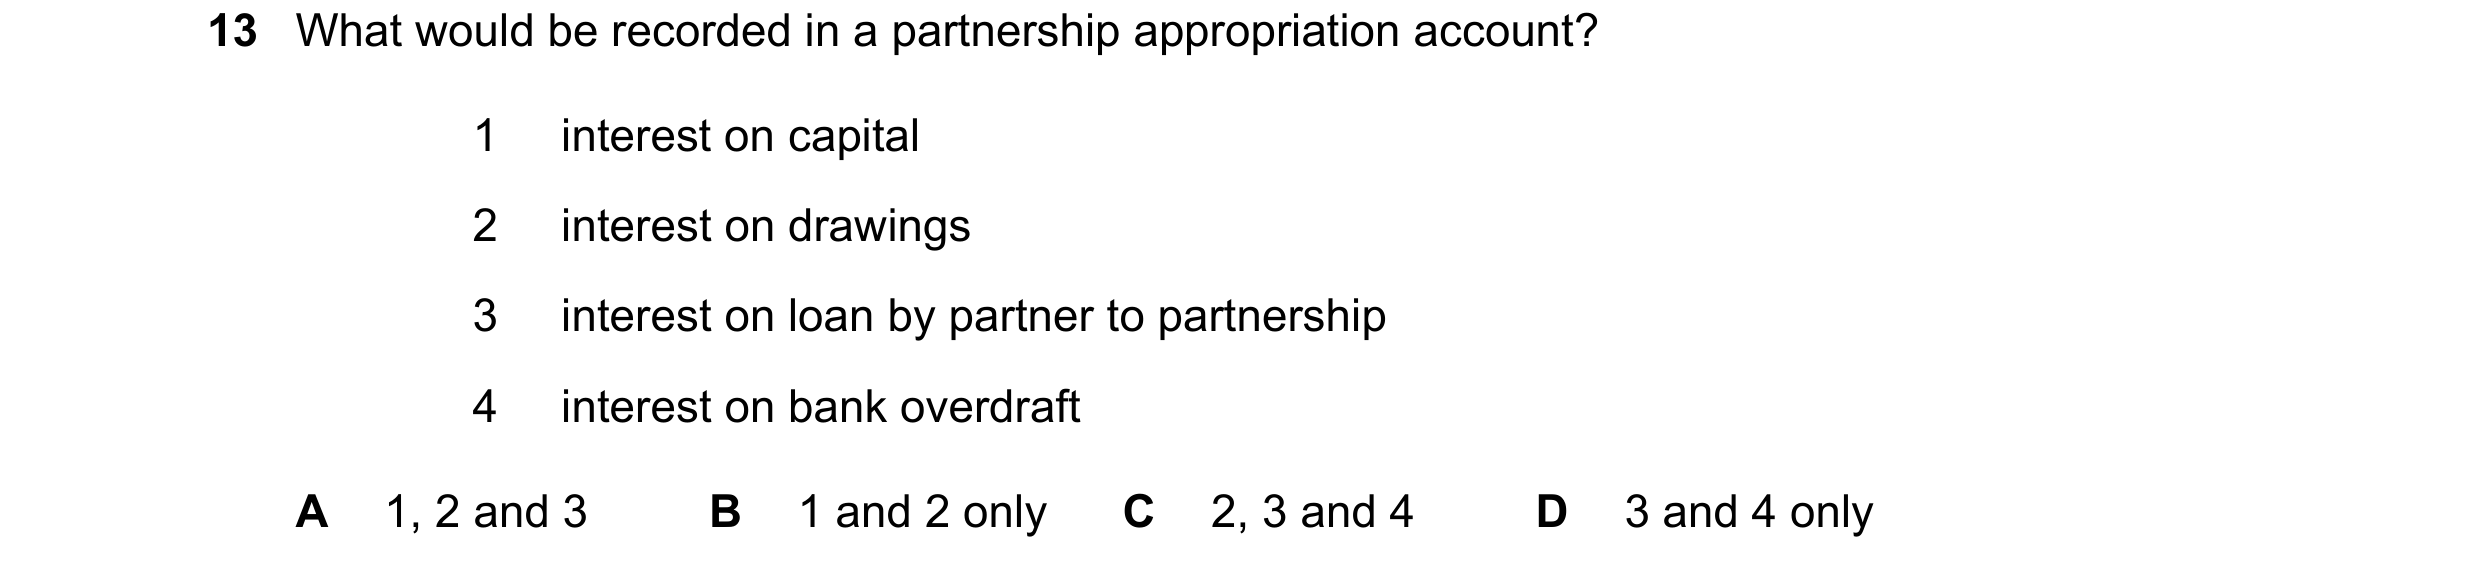
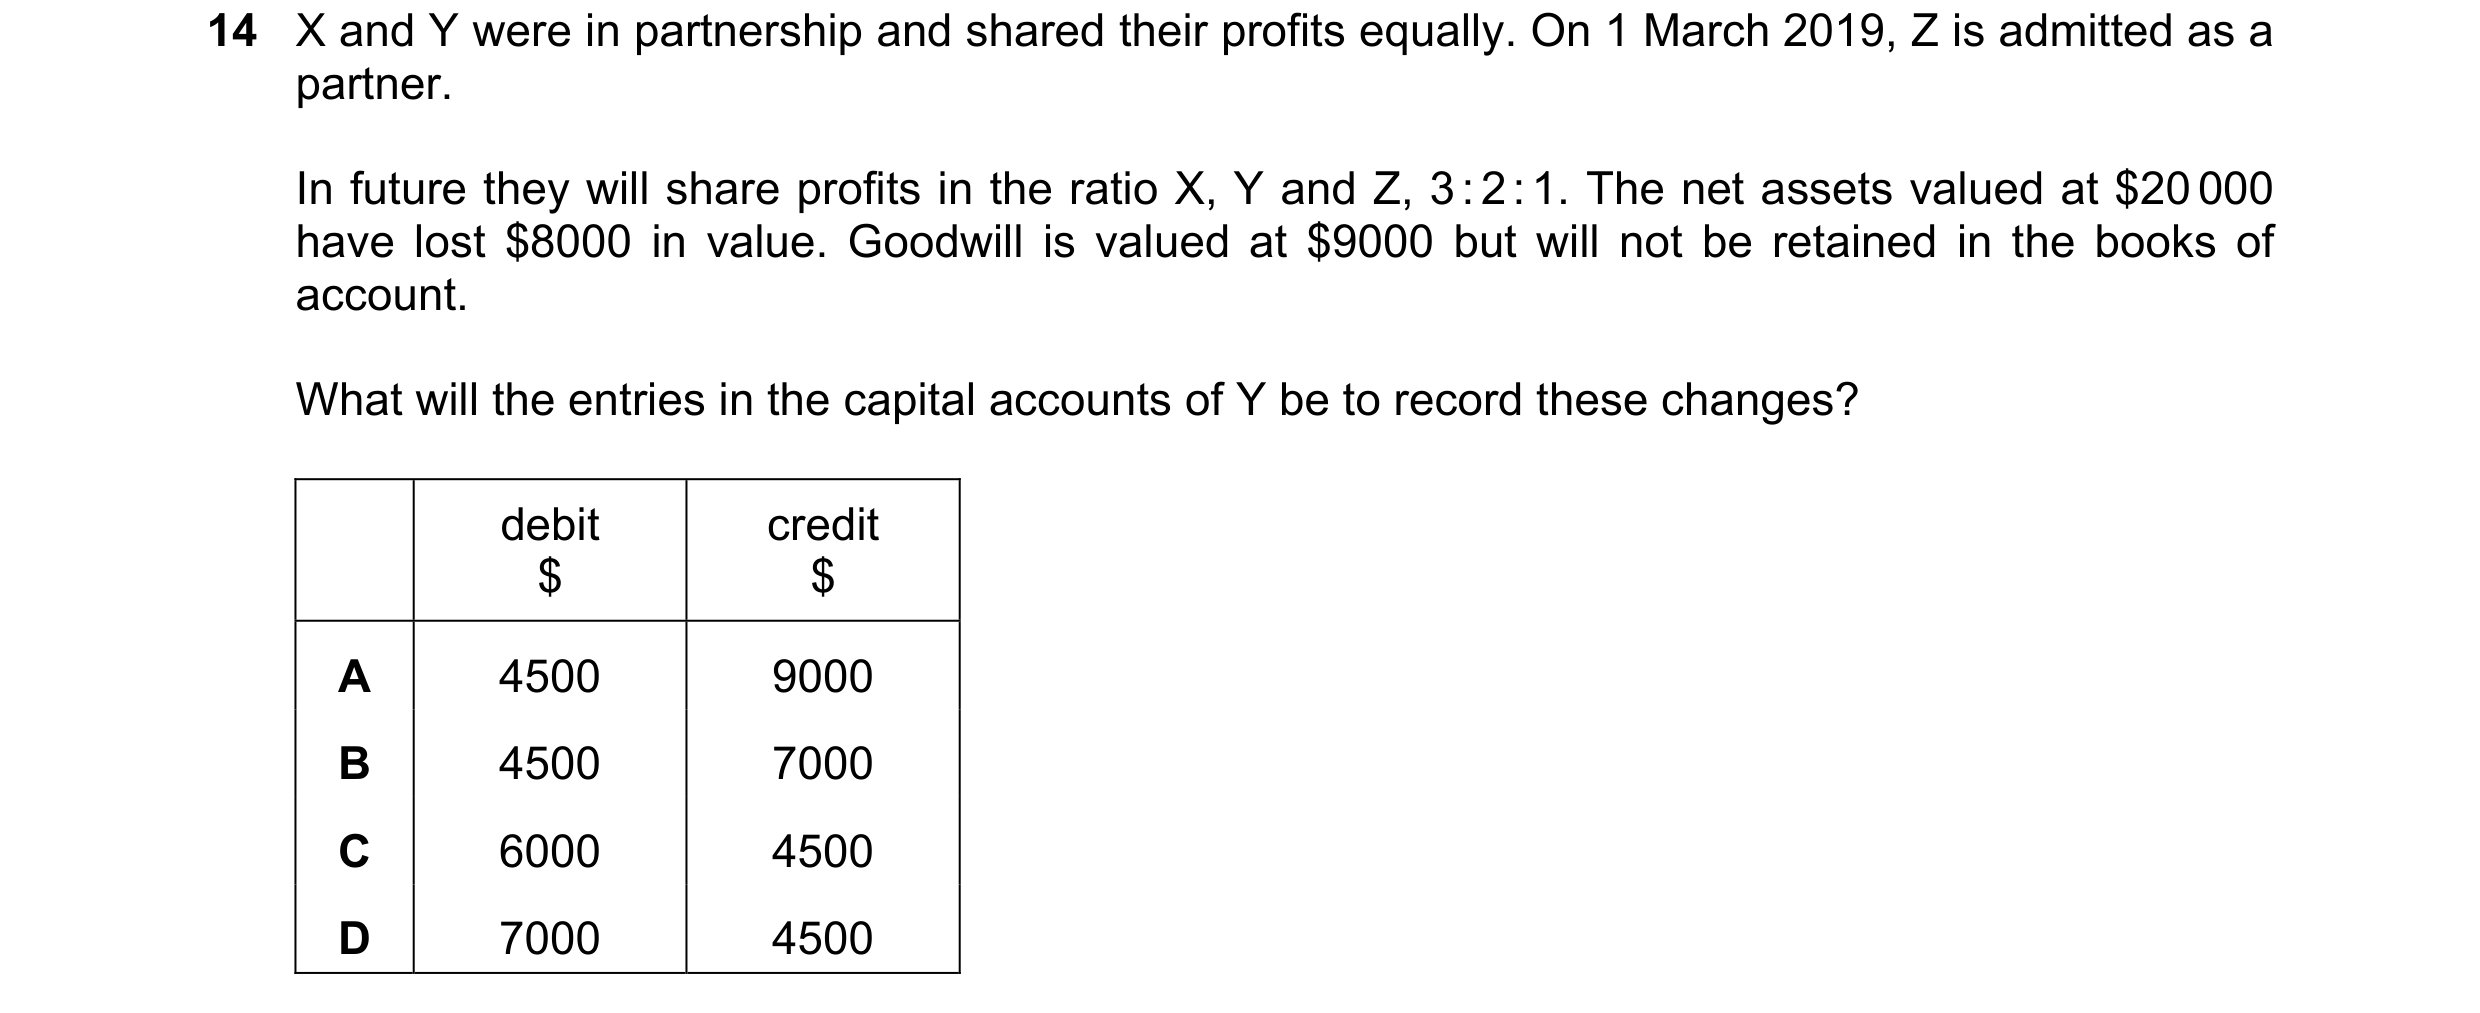 25 / 60
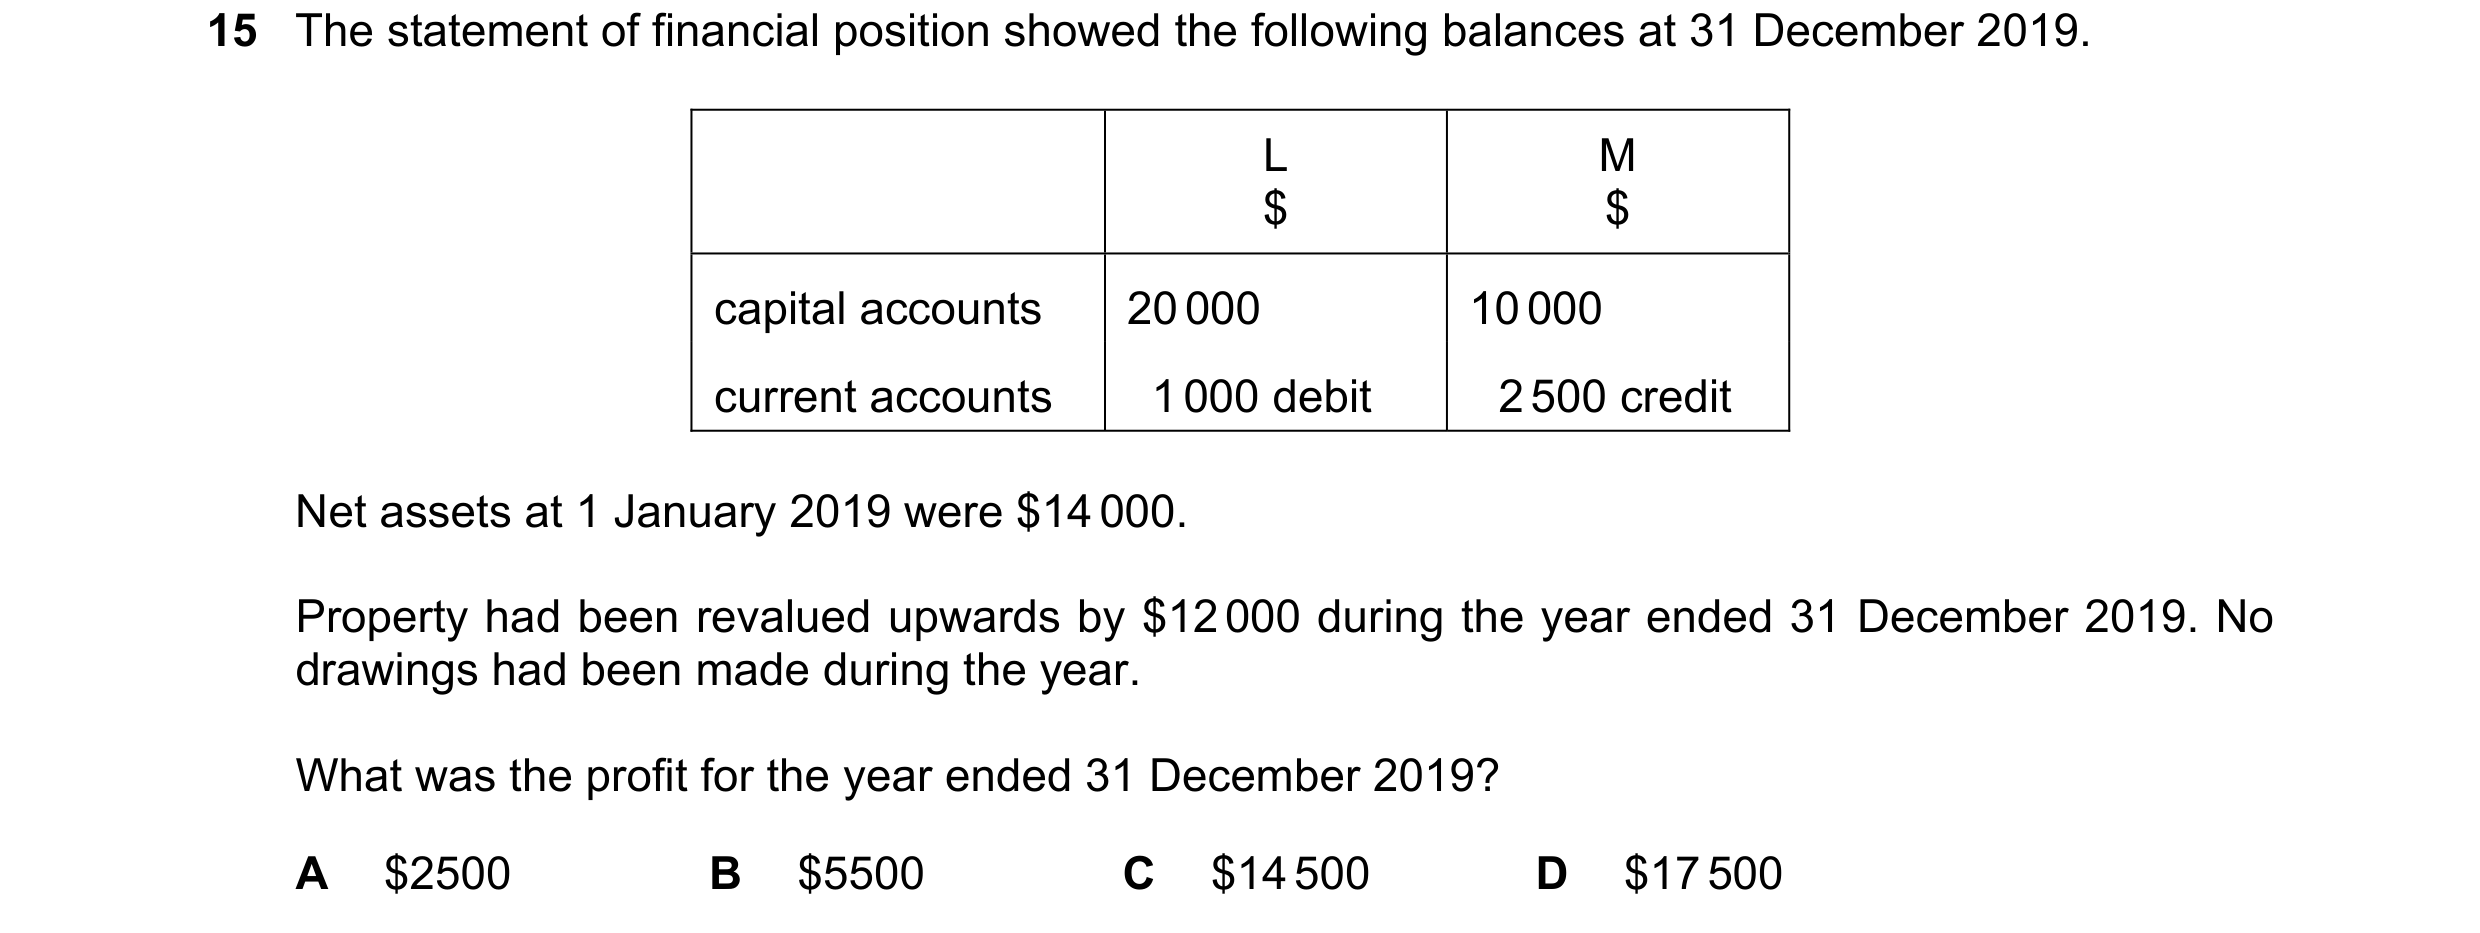
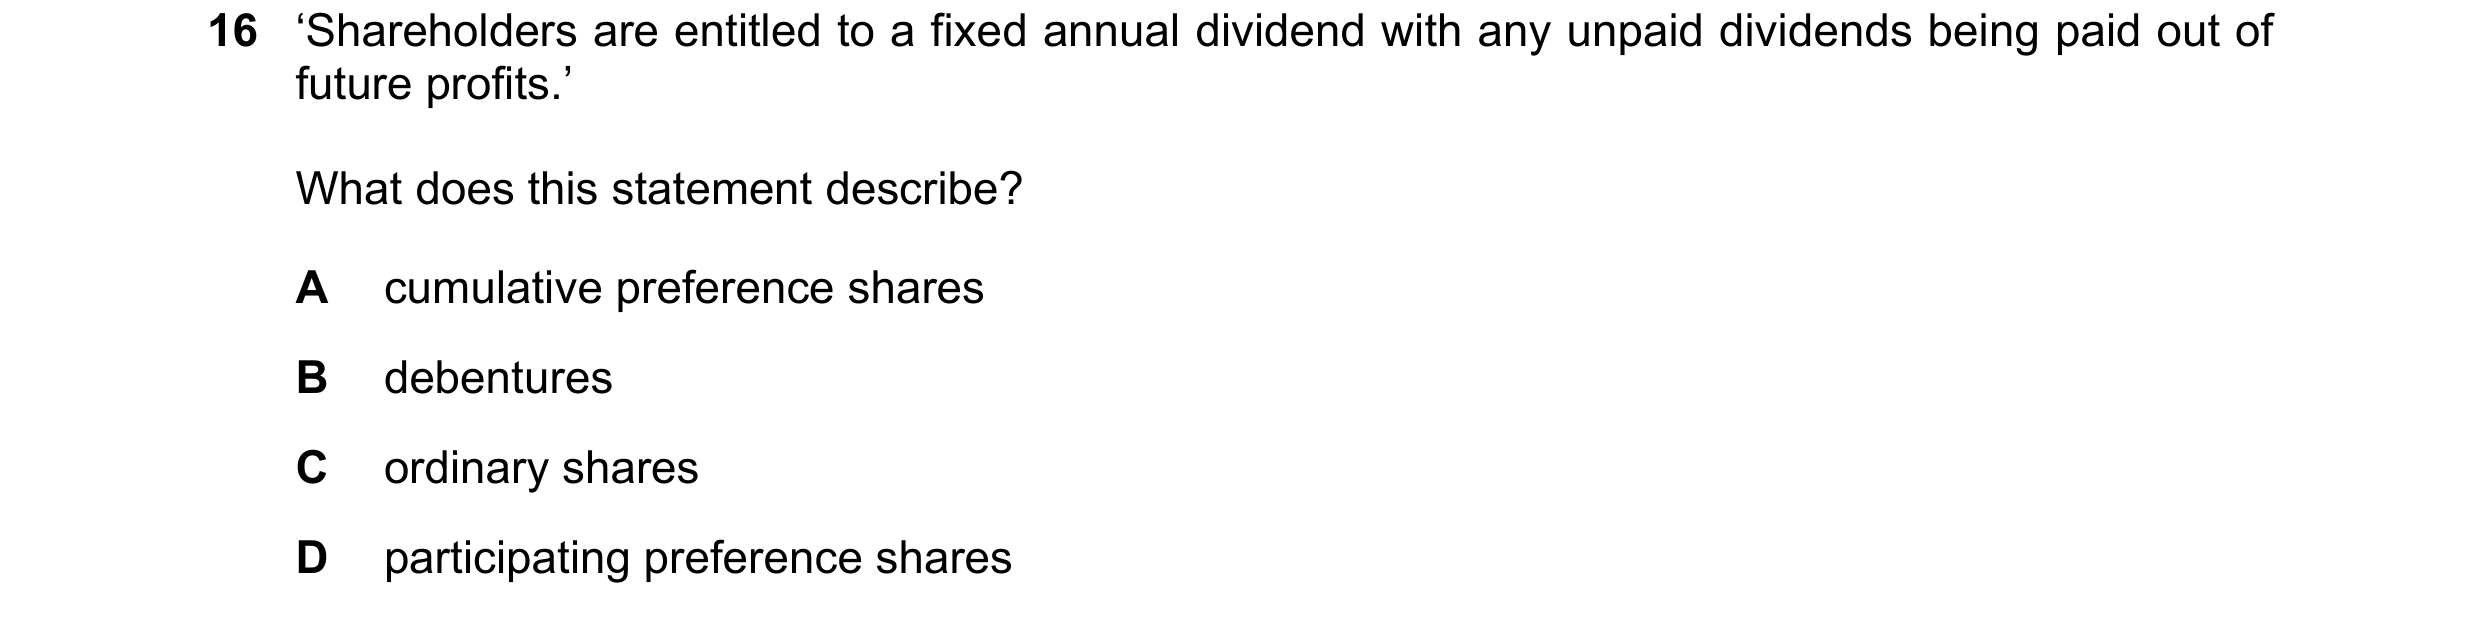
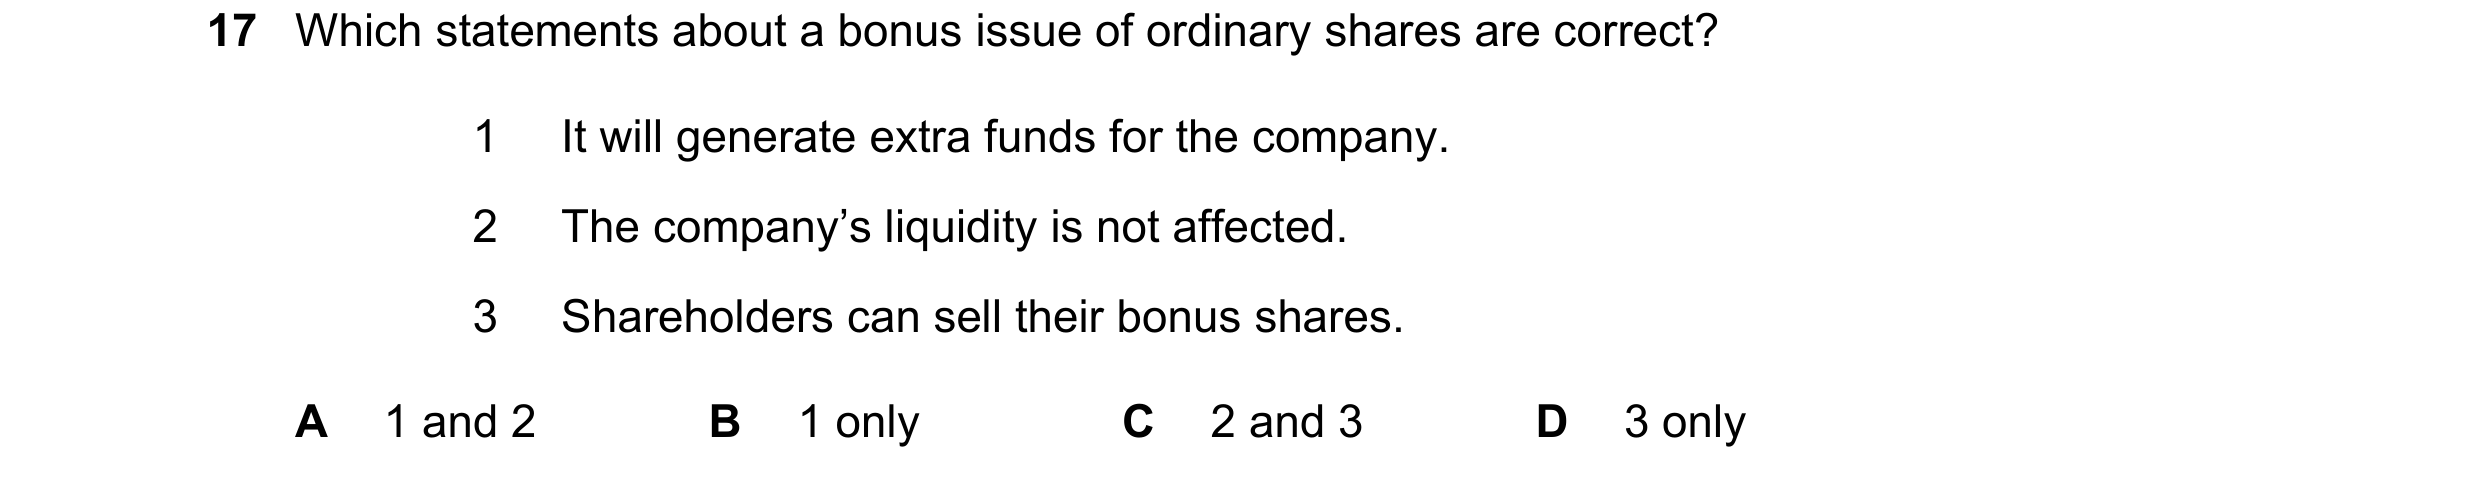
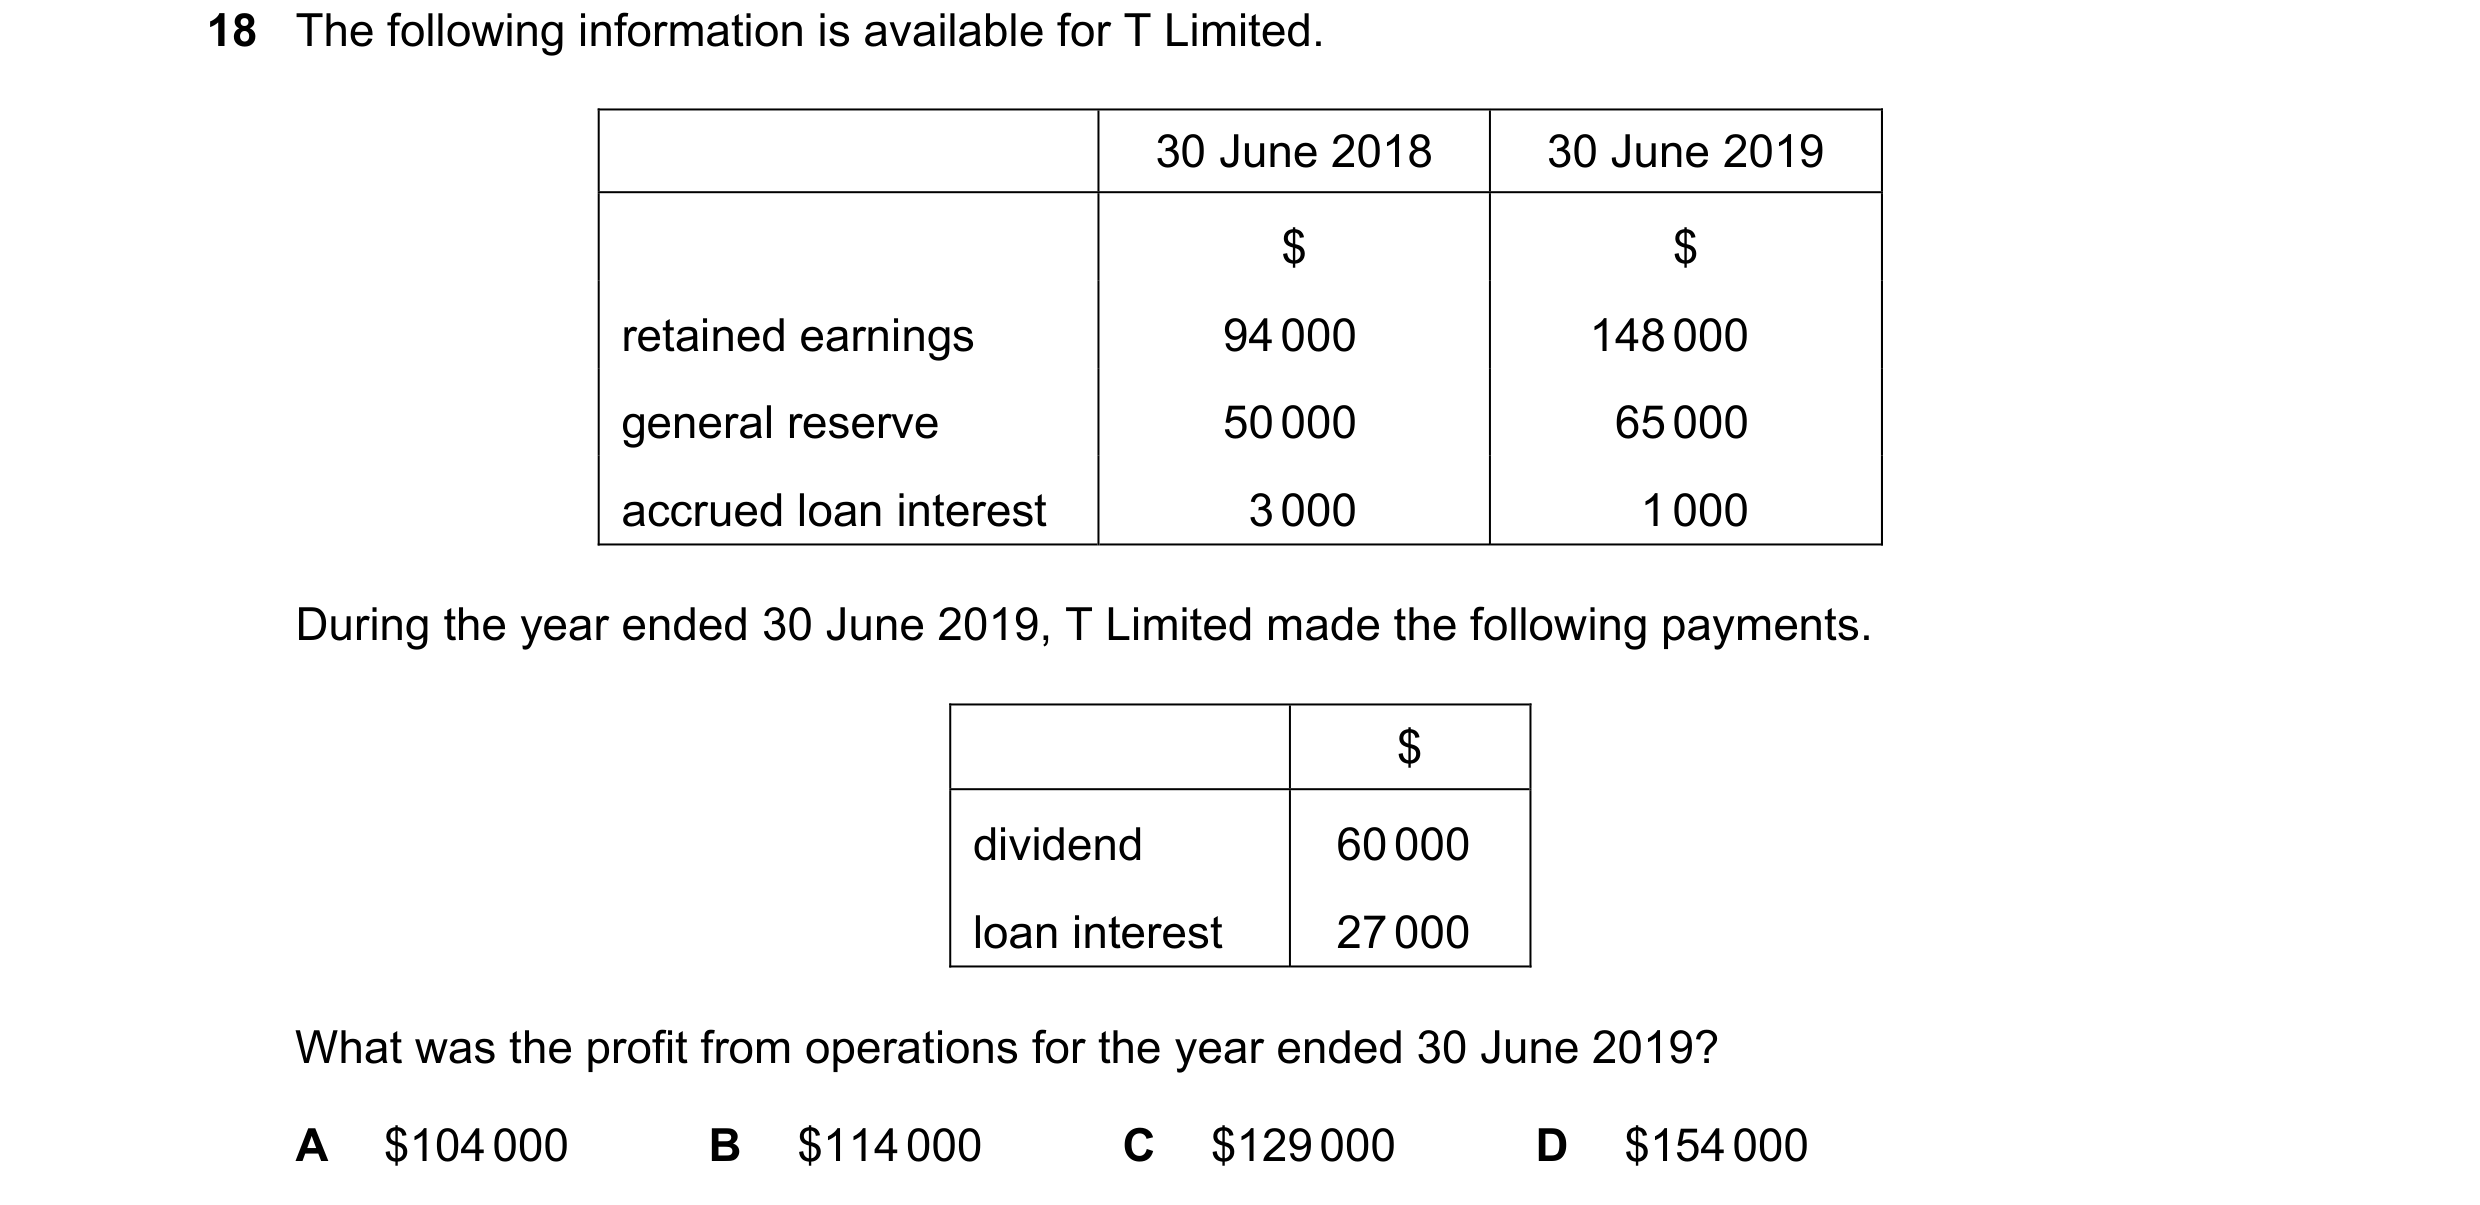 26 / 60
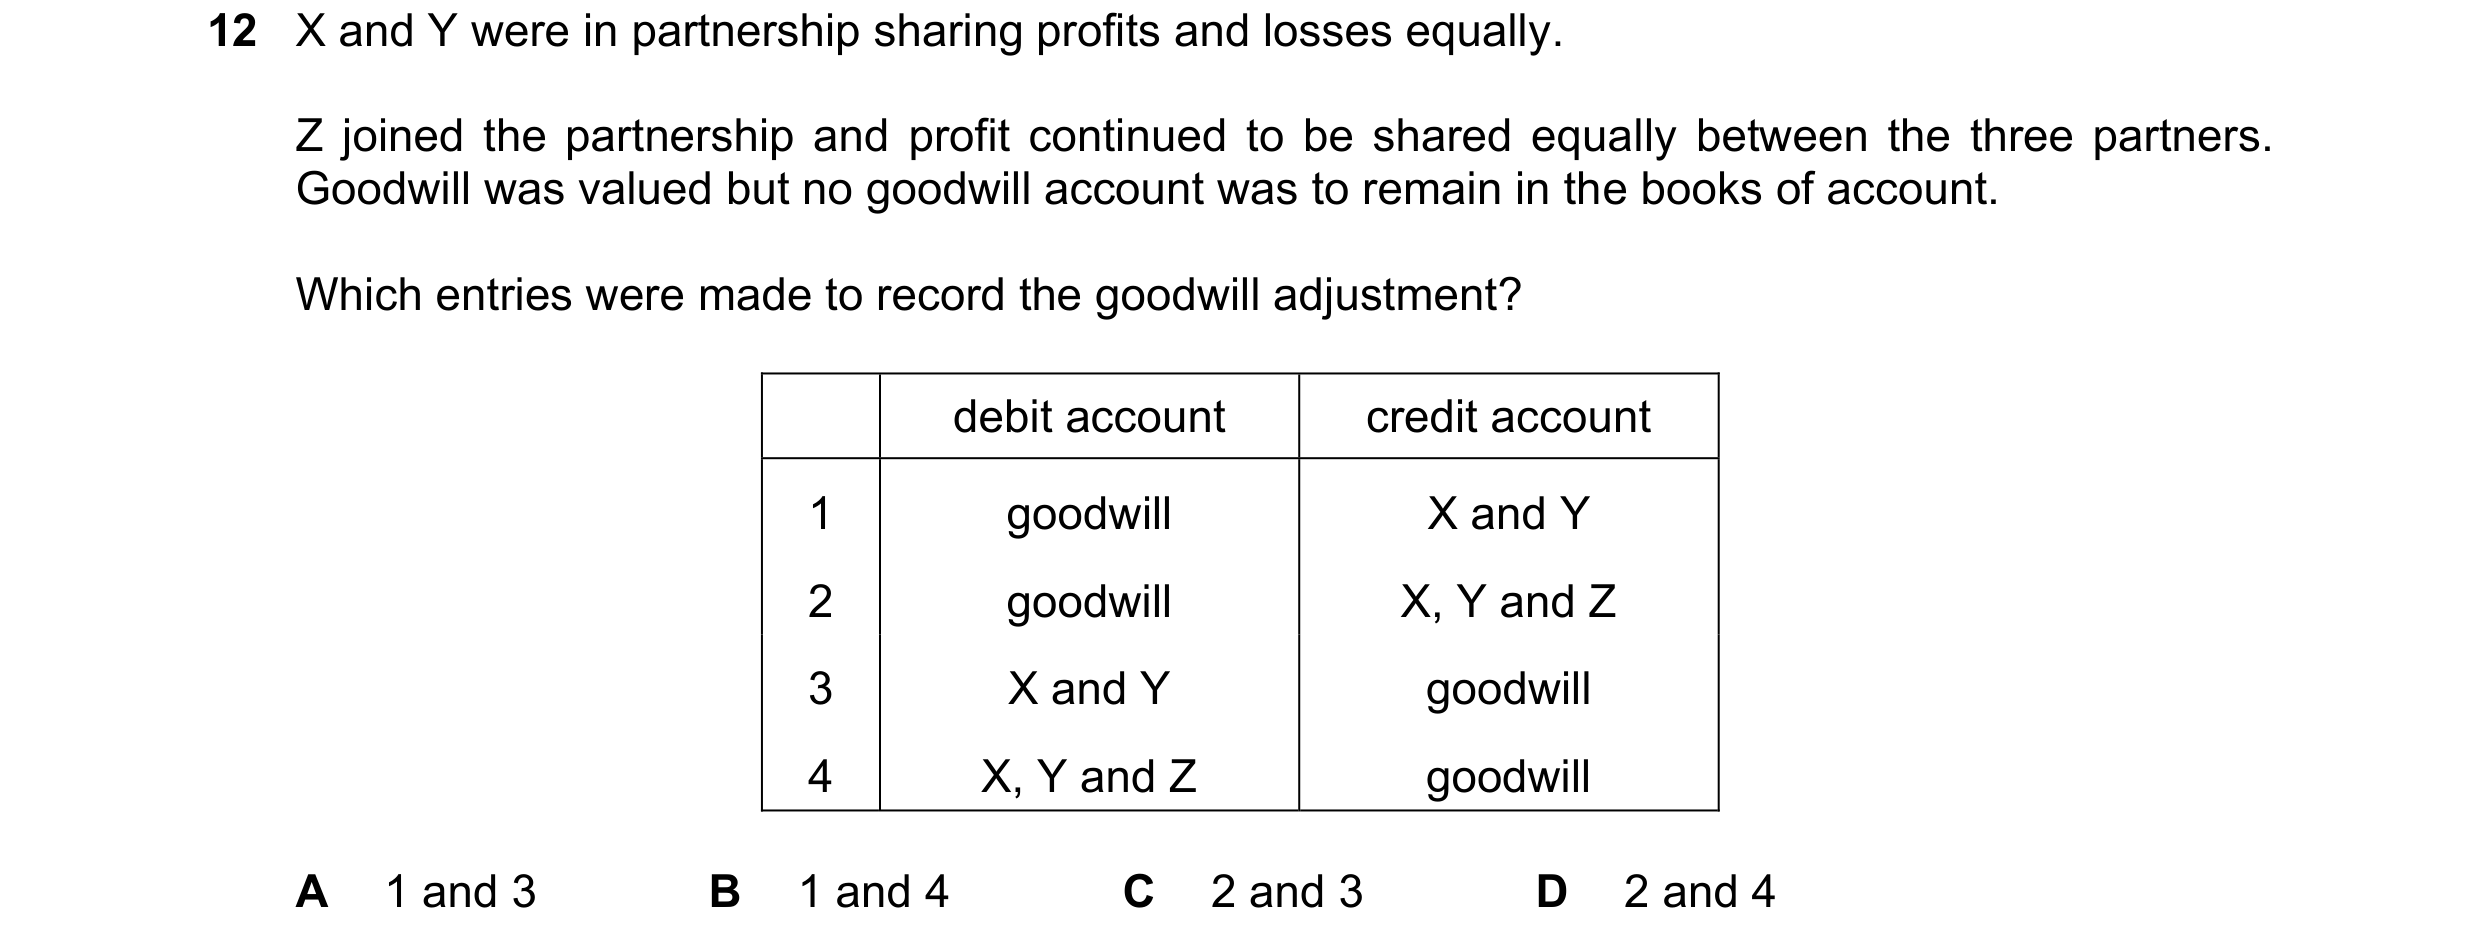
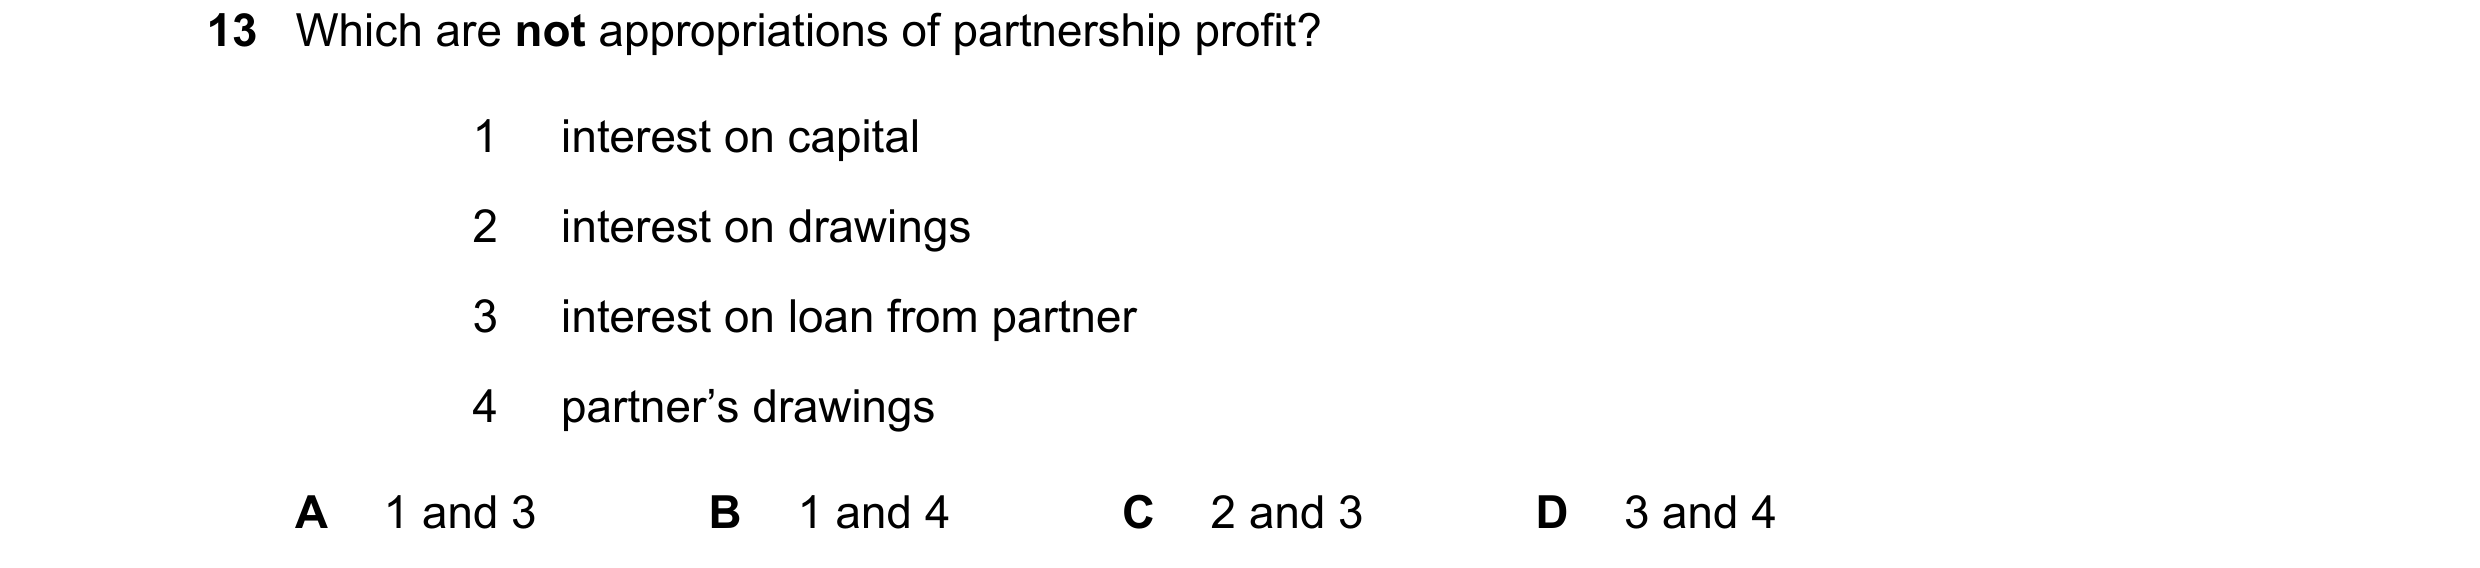
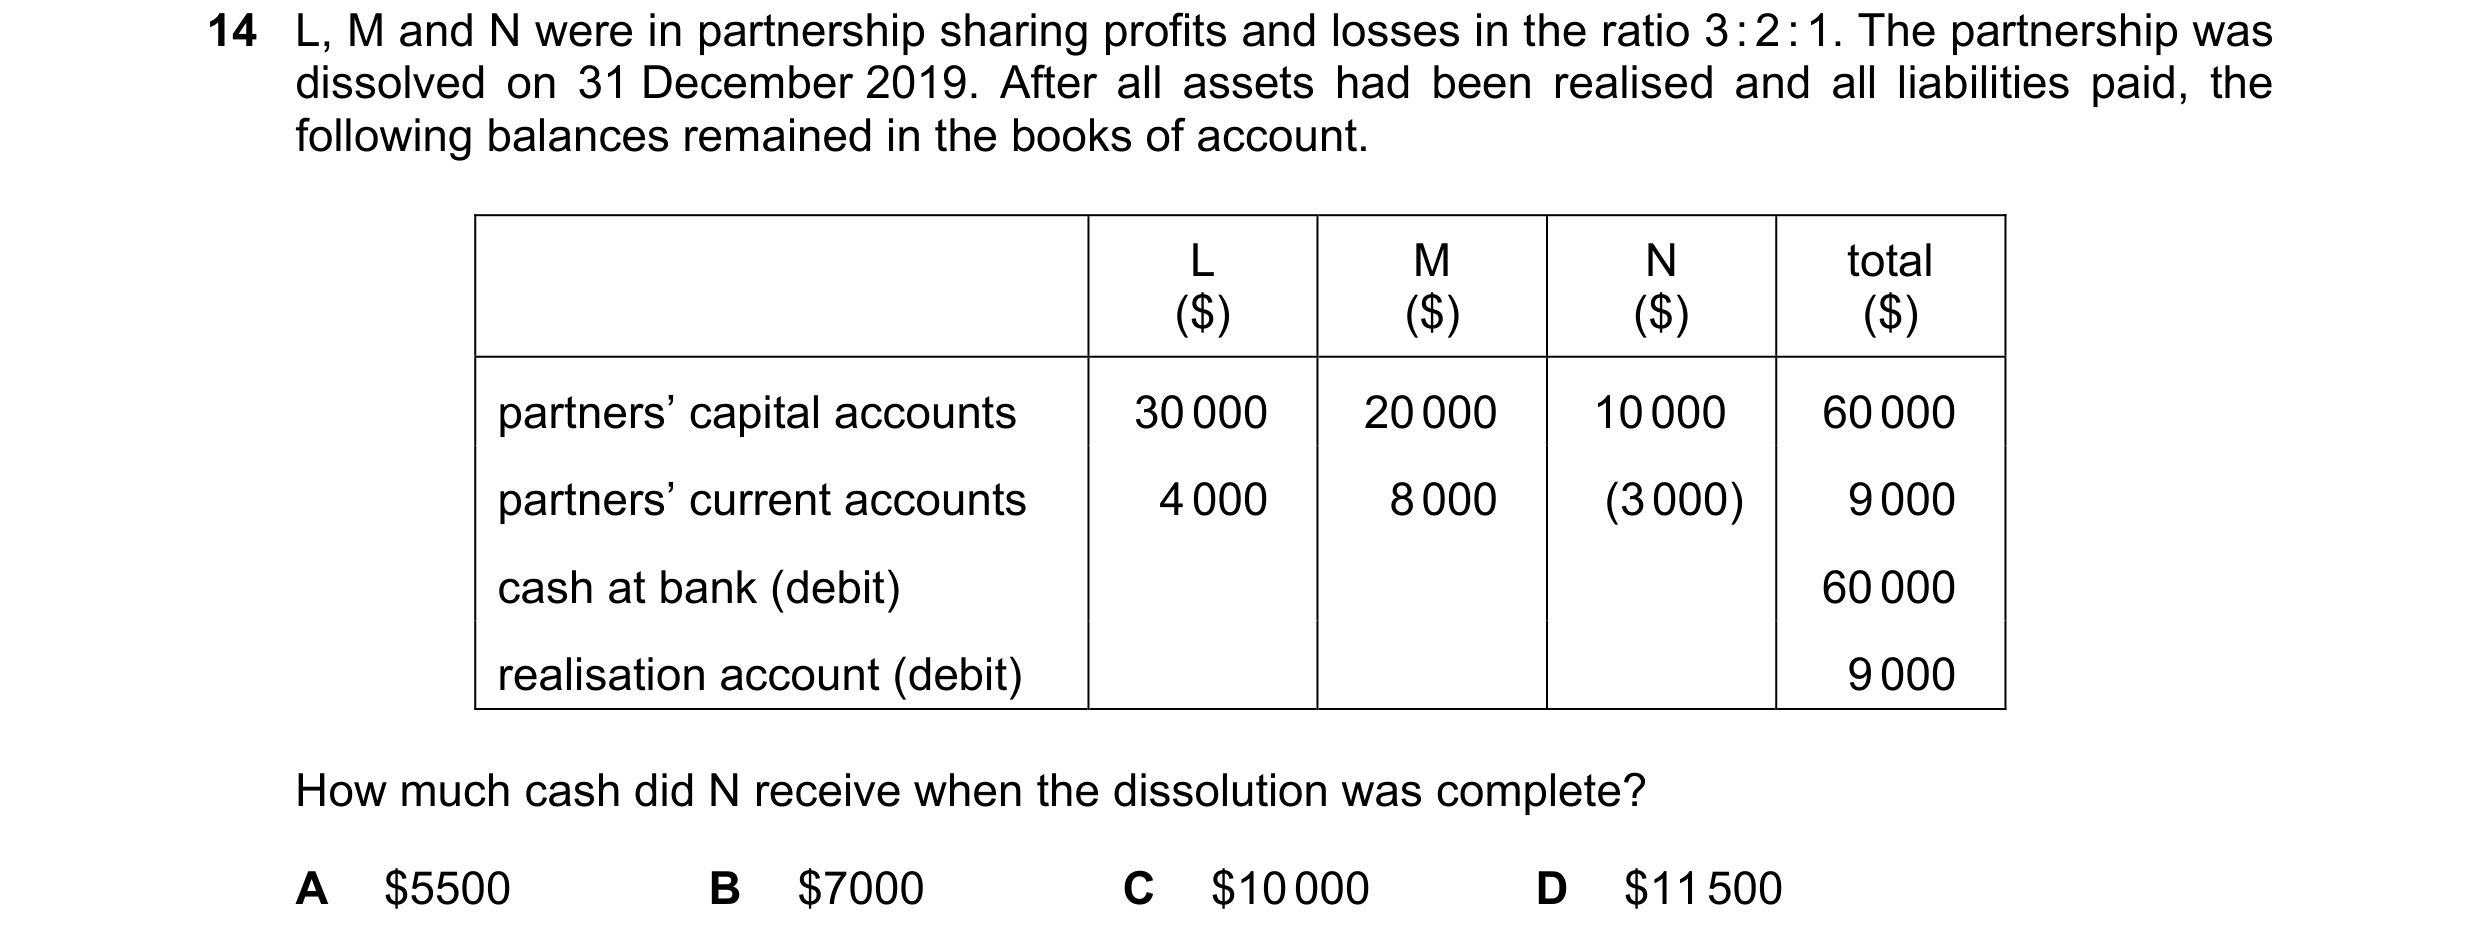
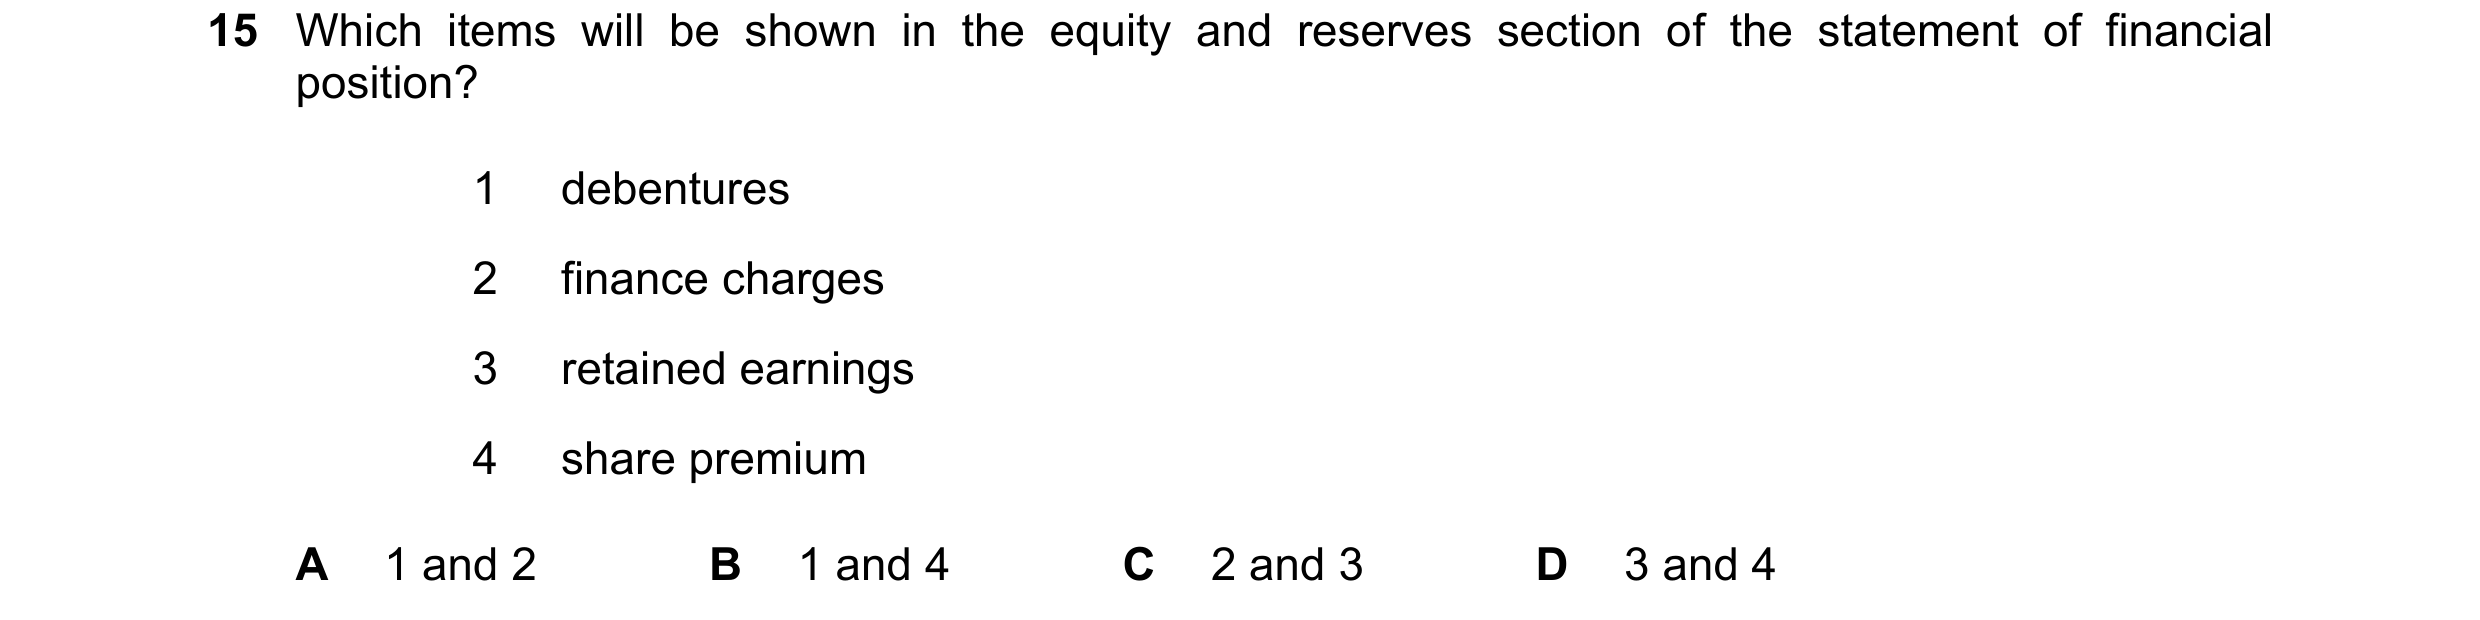 27 / 60
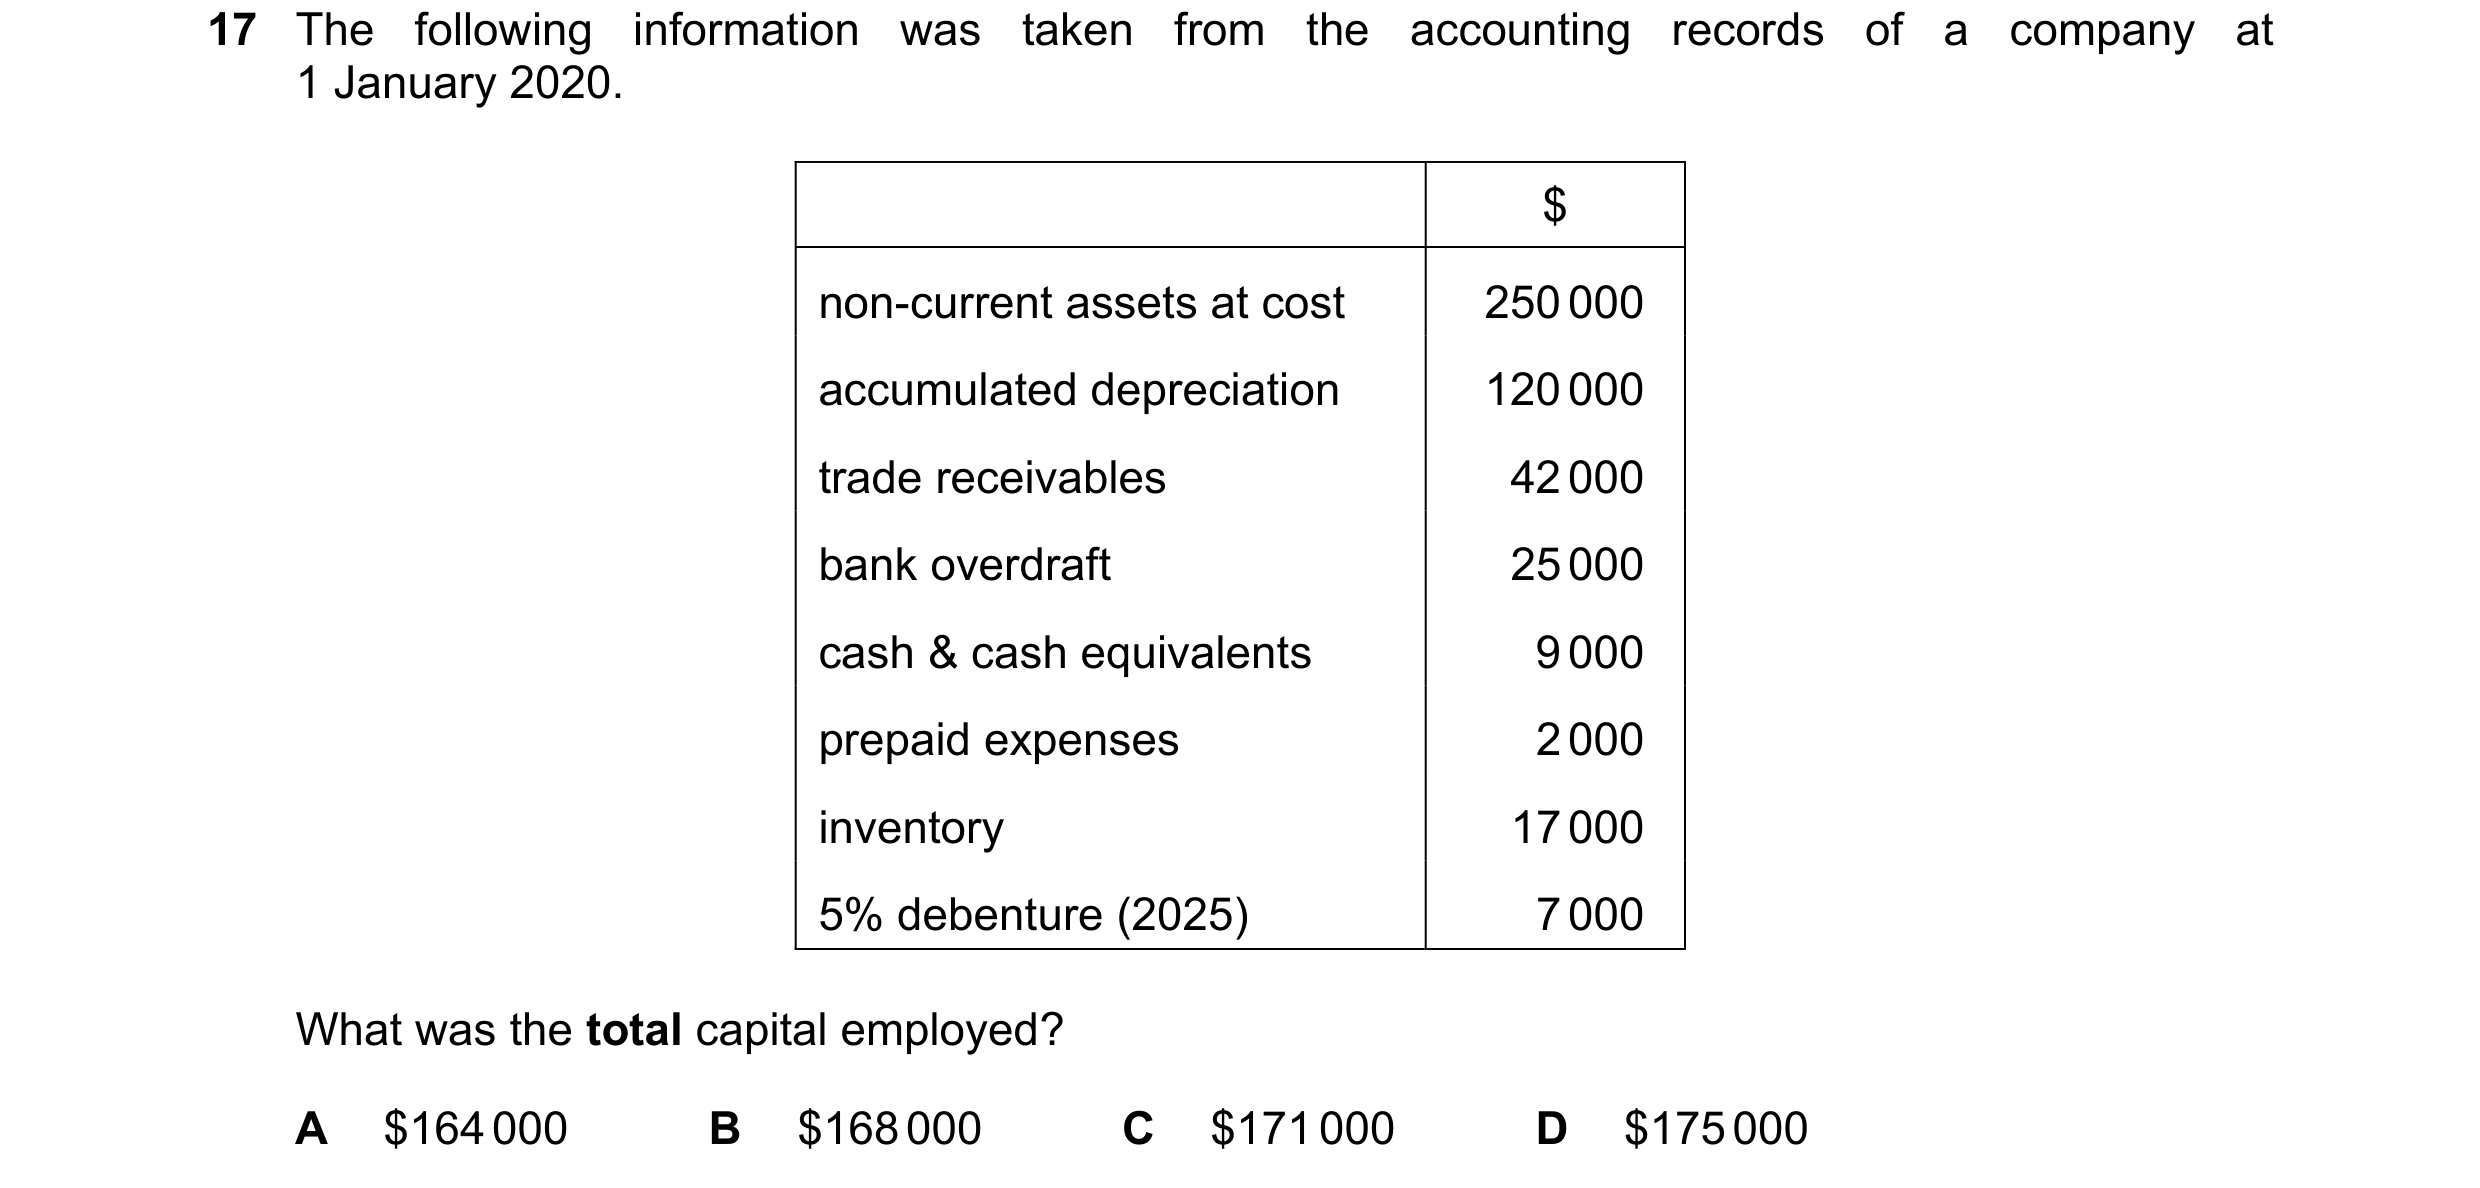
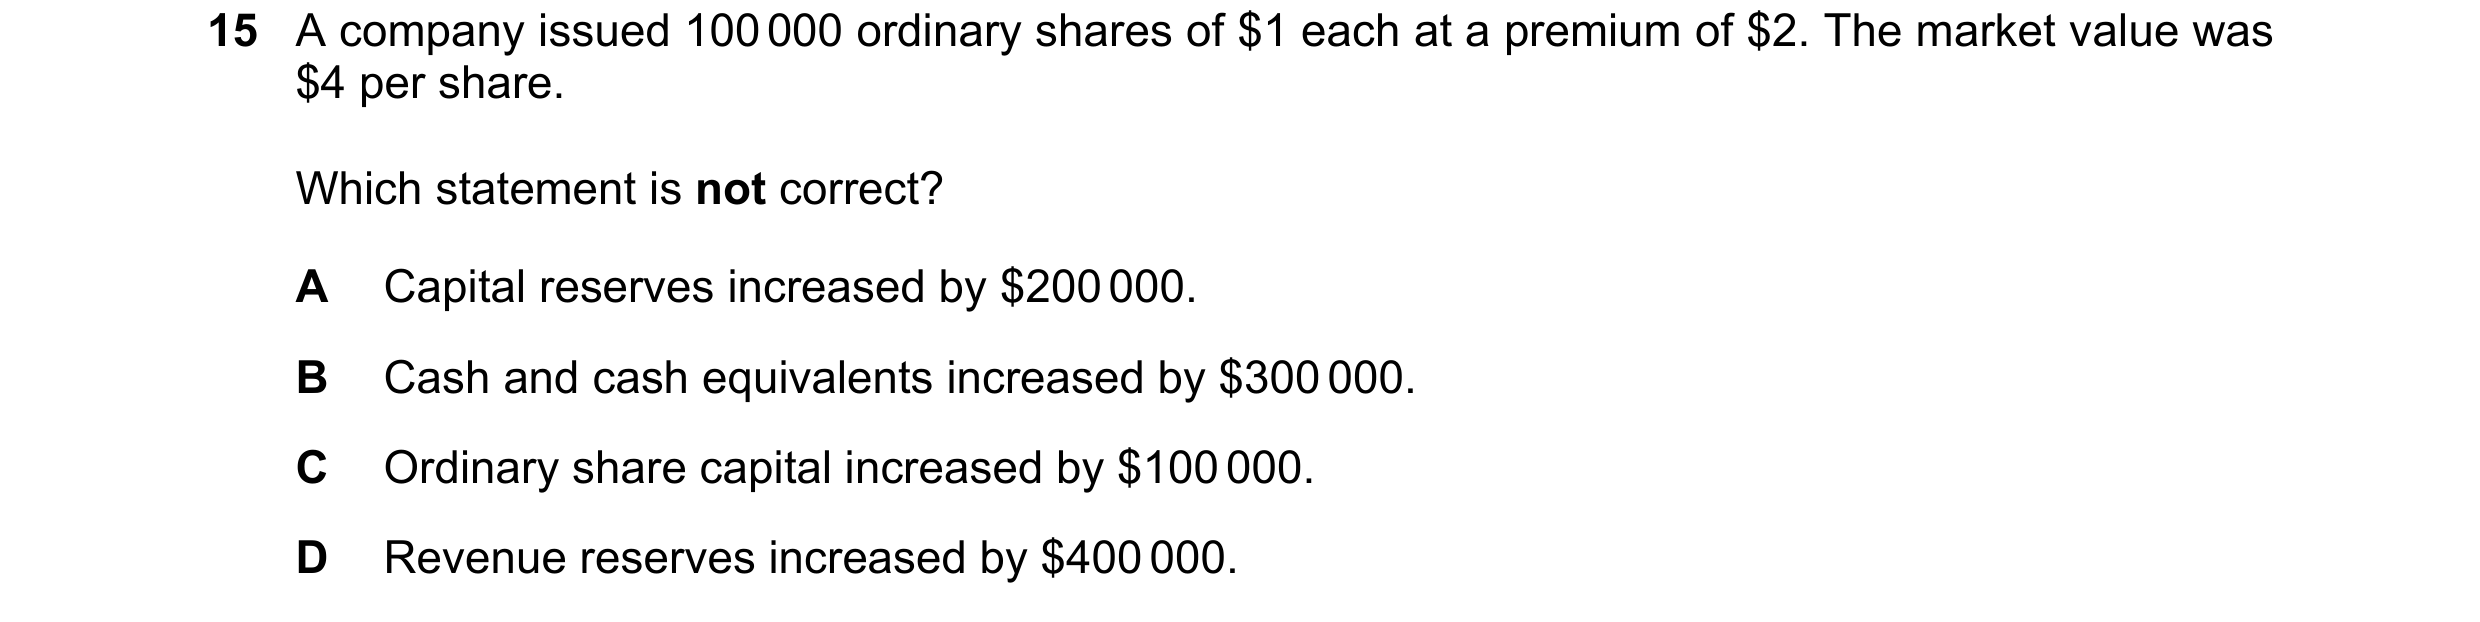
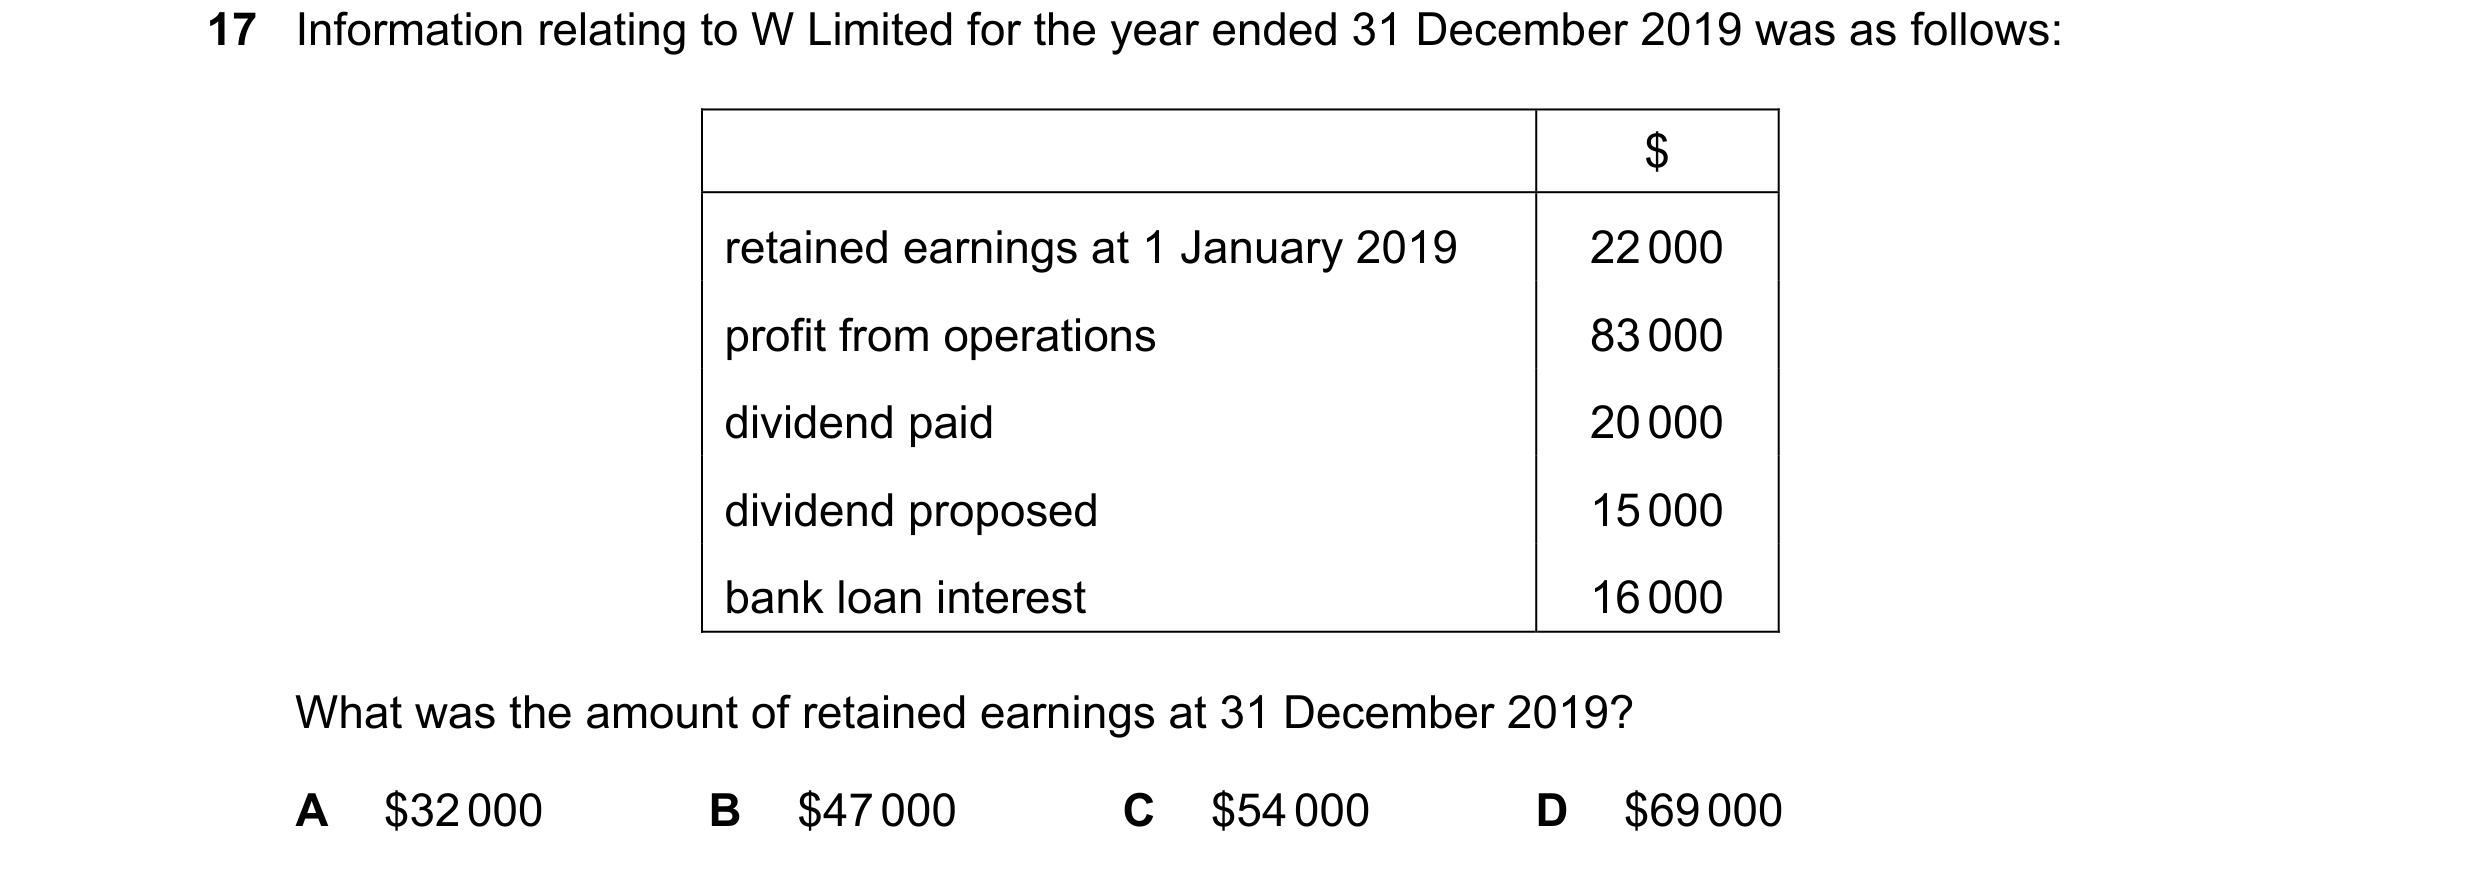 28 / 60
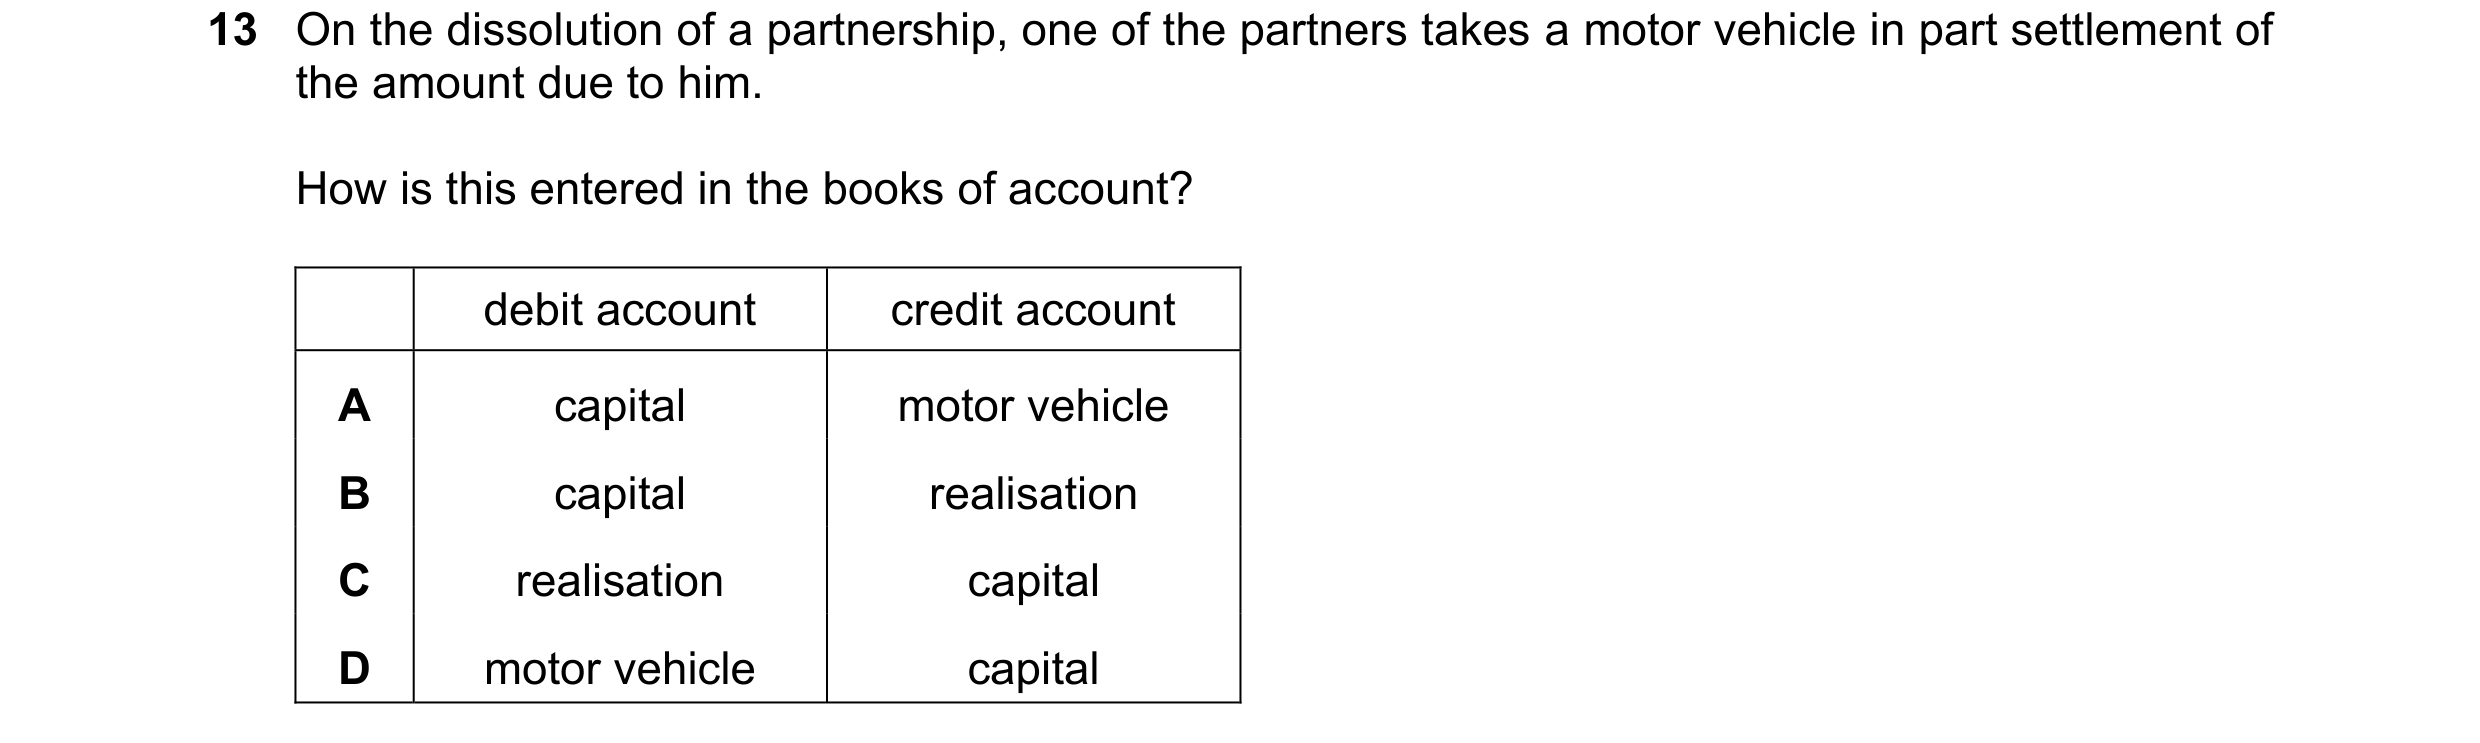
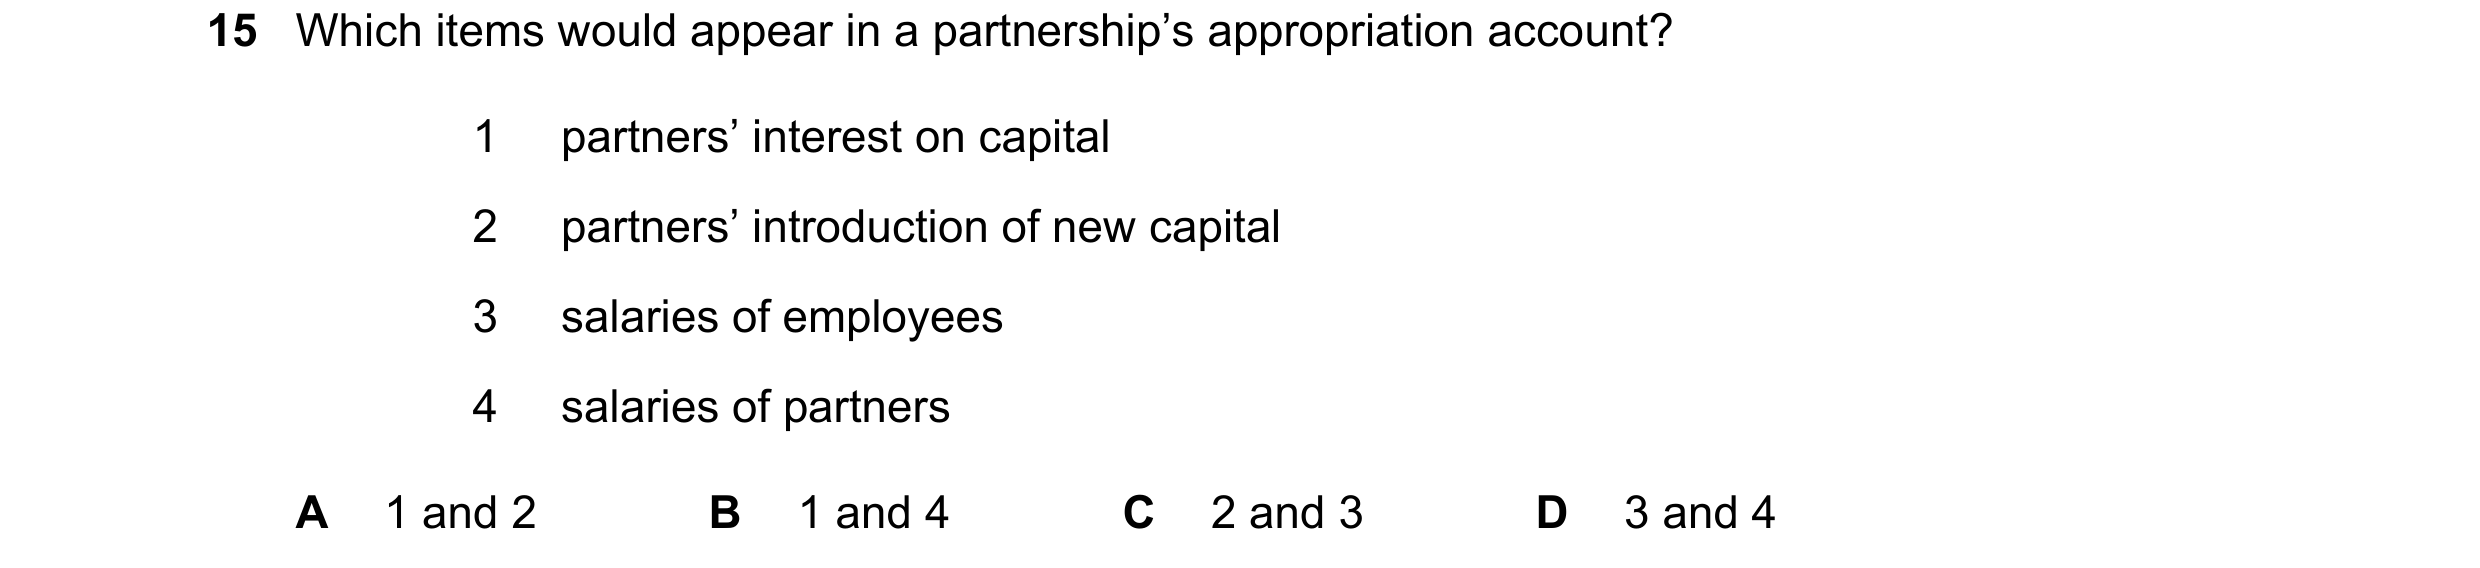
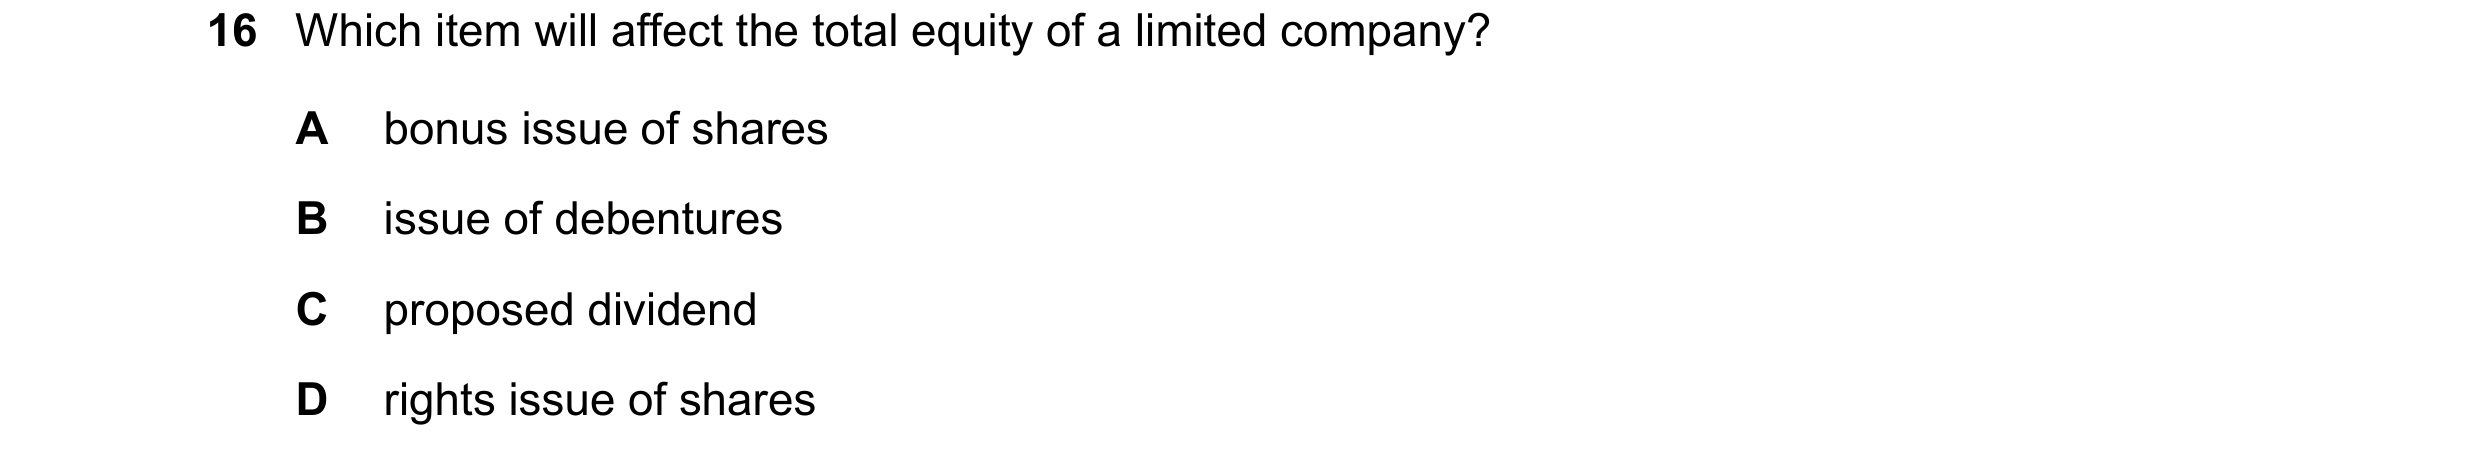
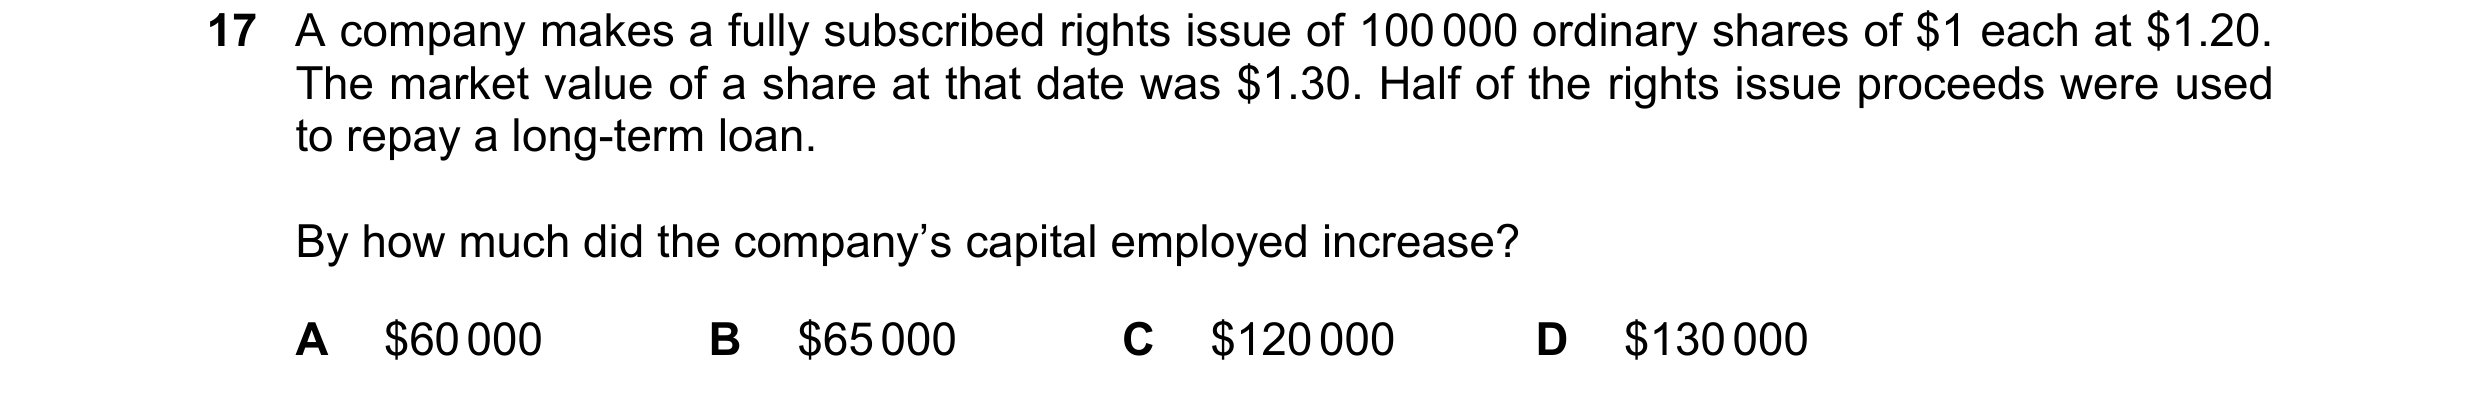 29 / 60
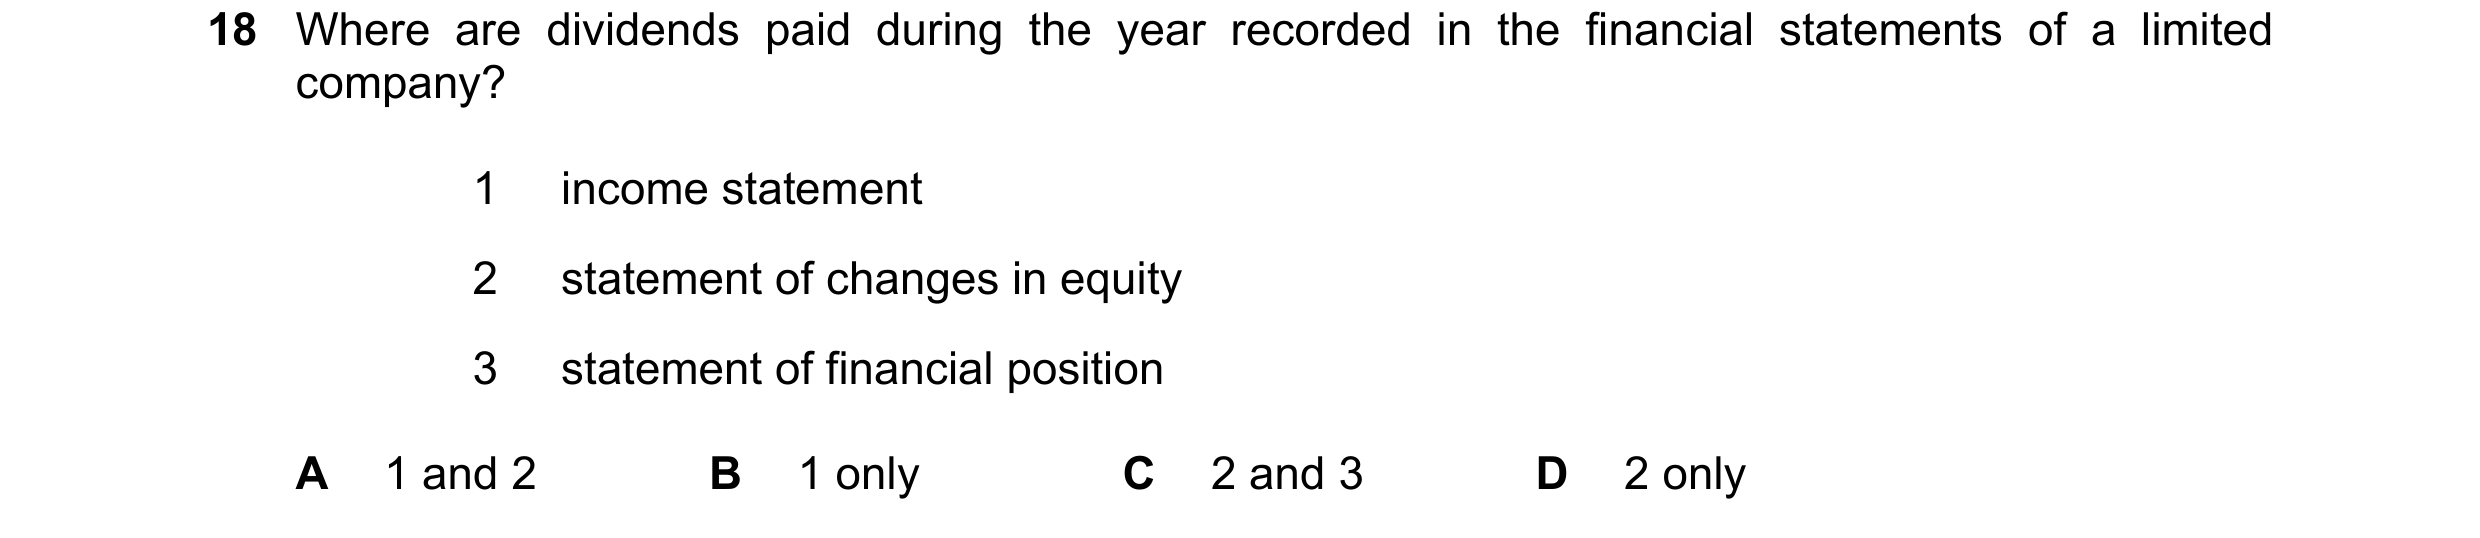
 30 / 60
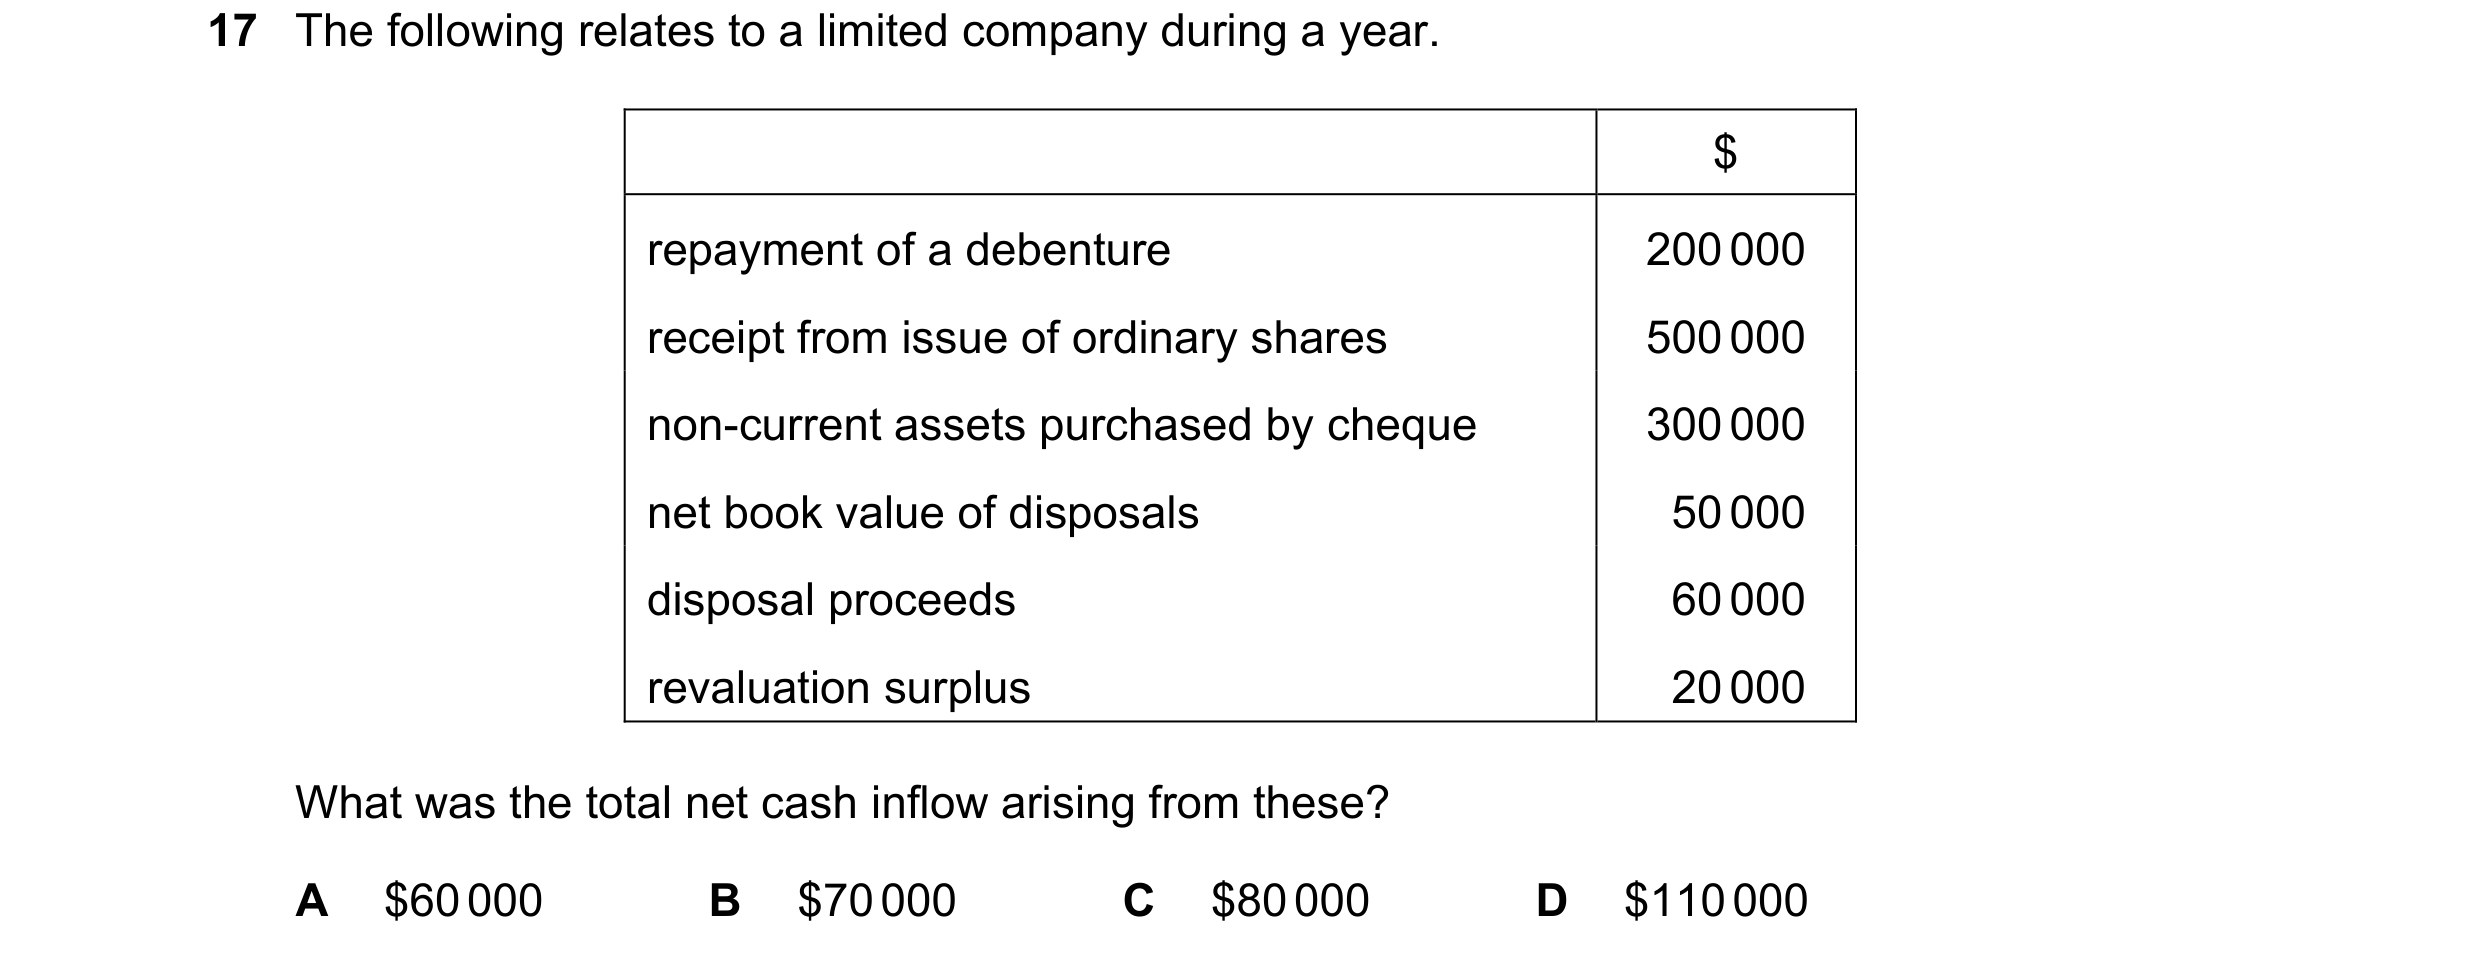
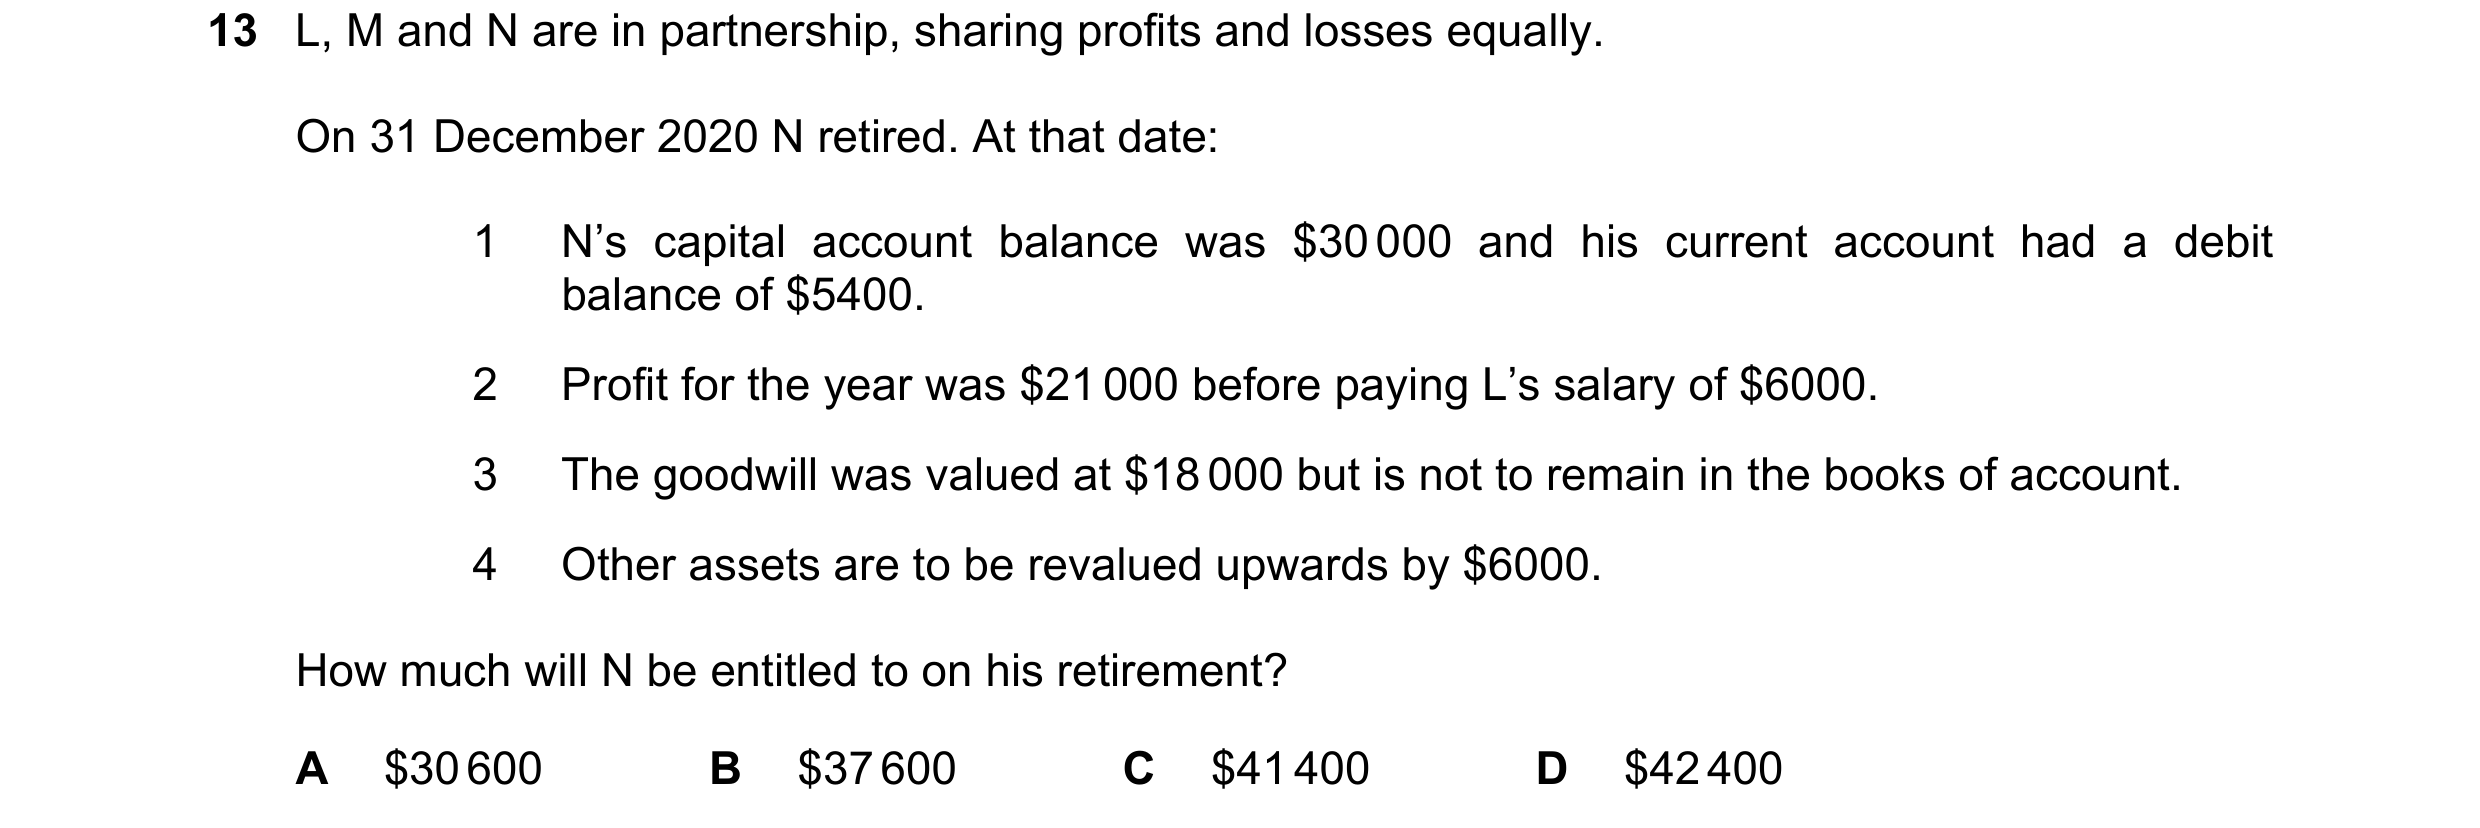 31 / 60
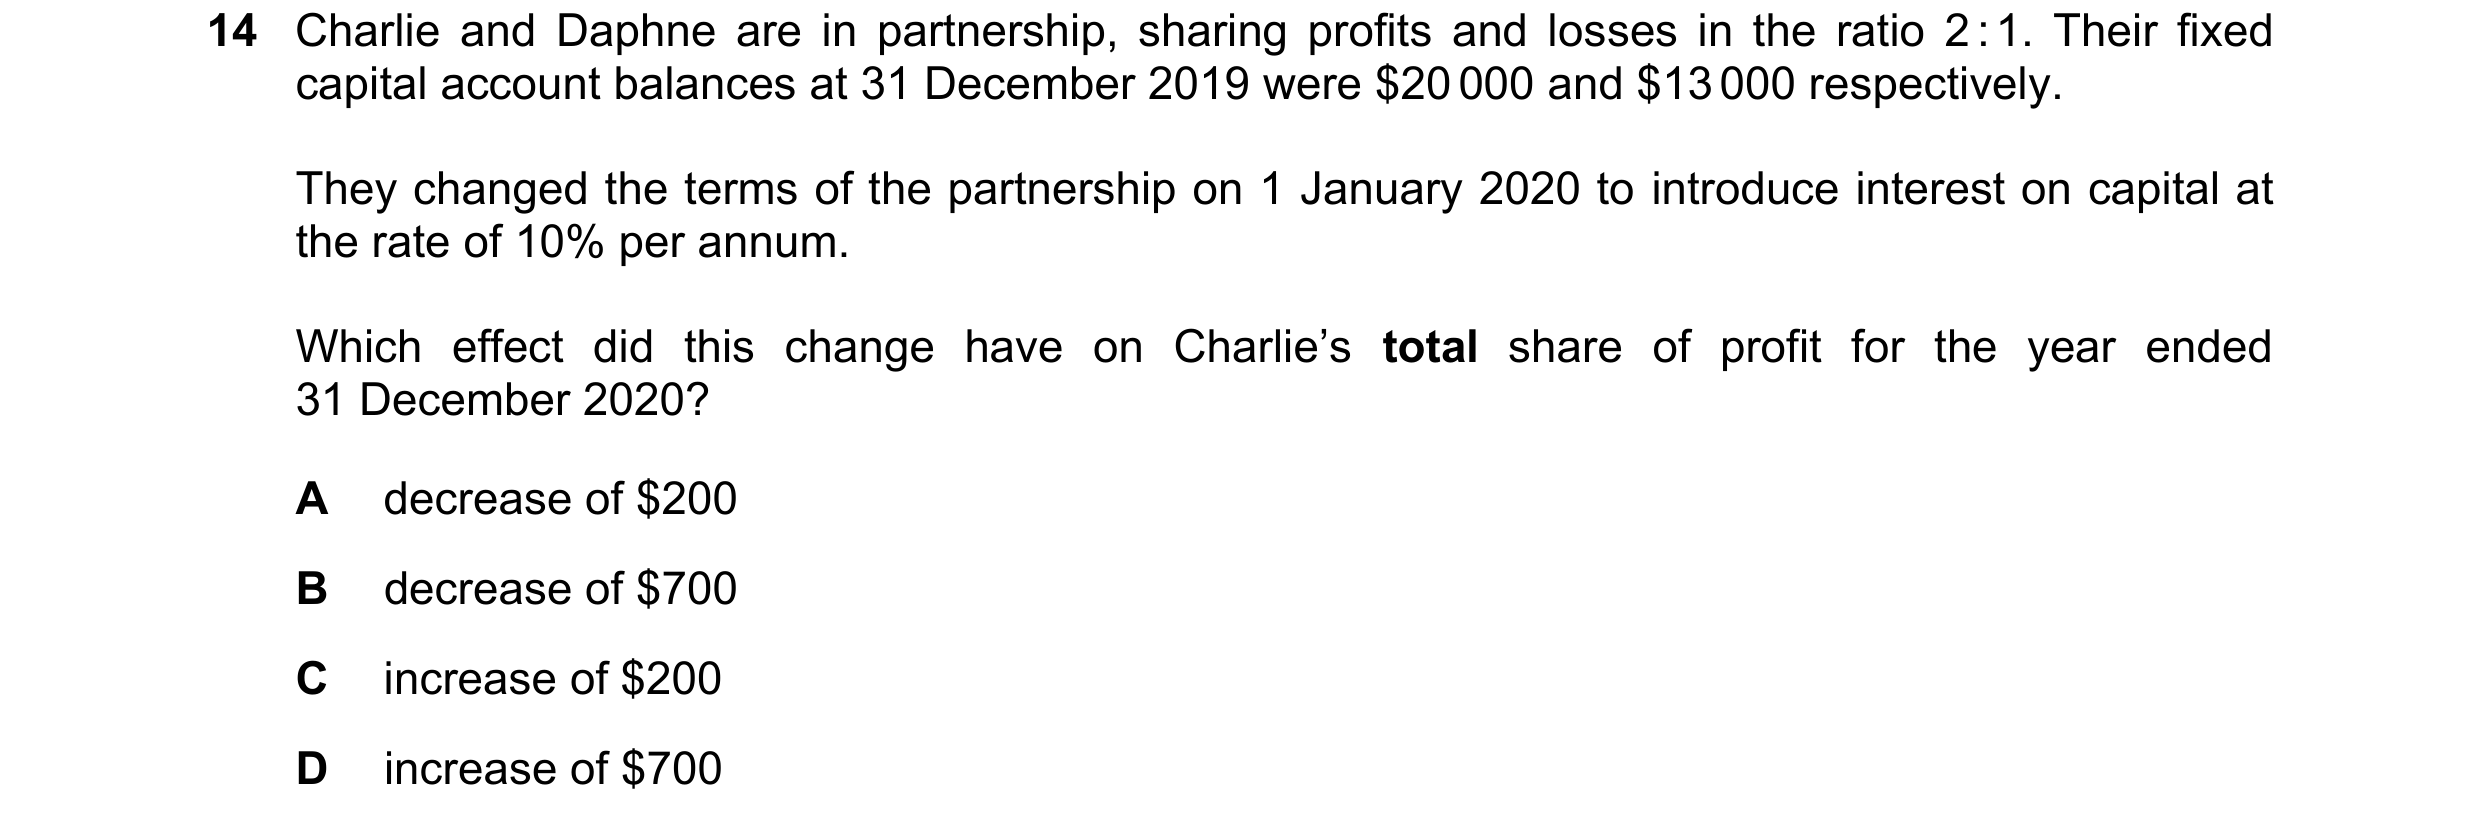
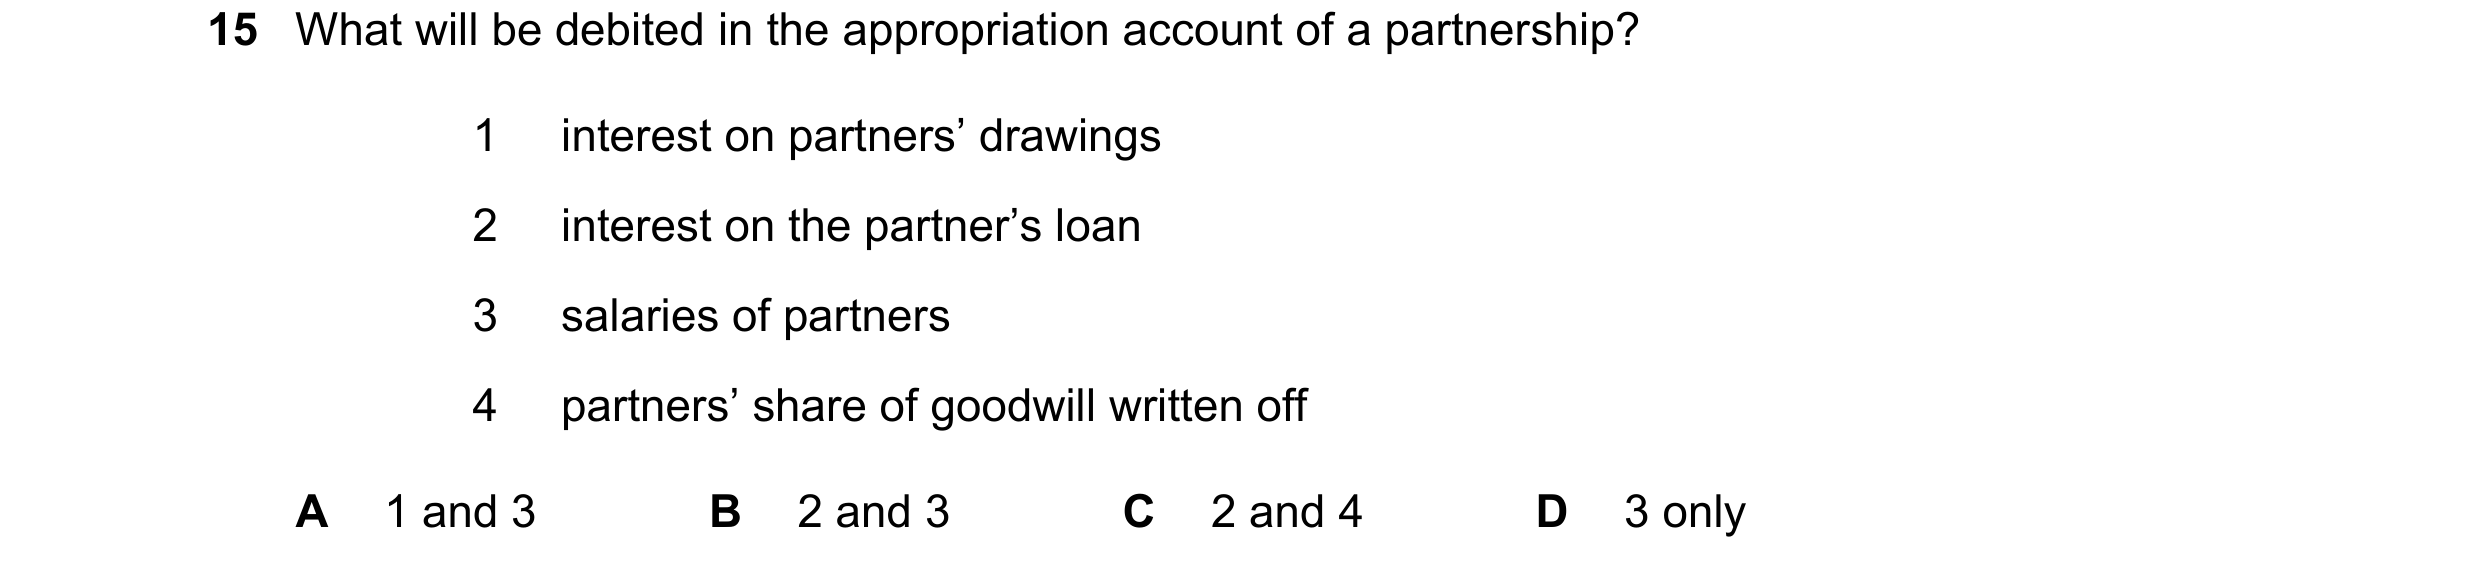
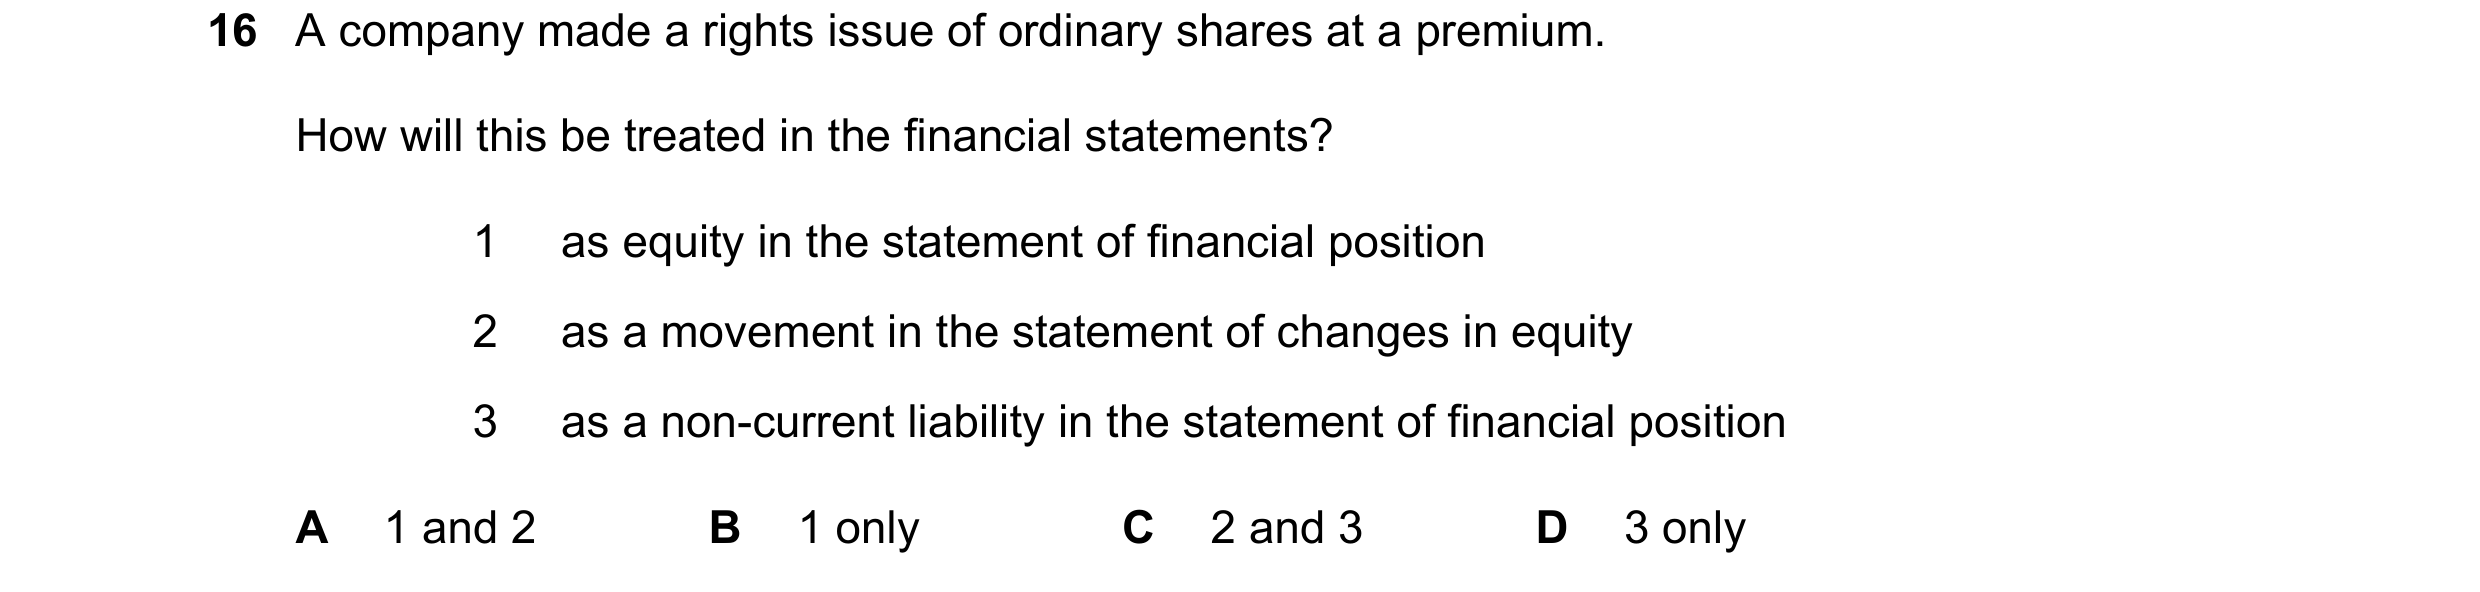
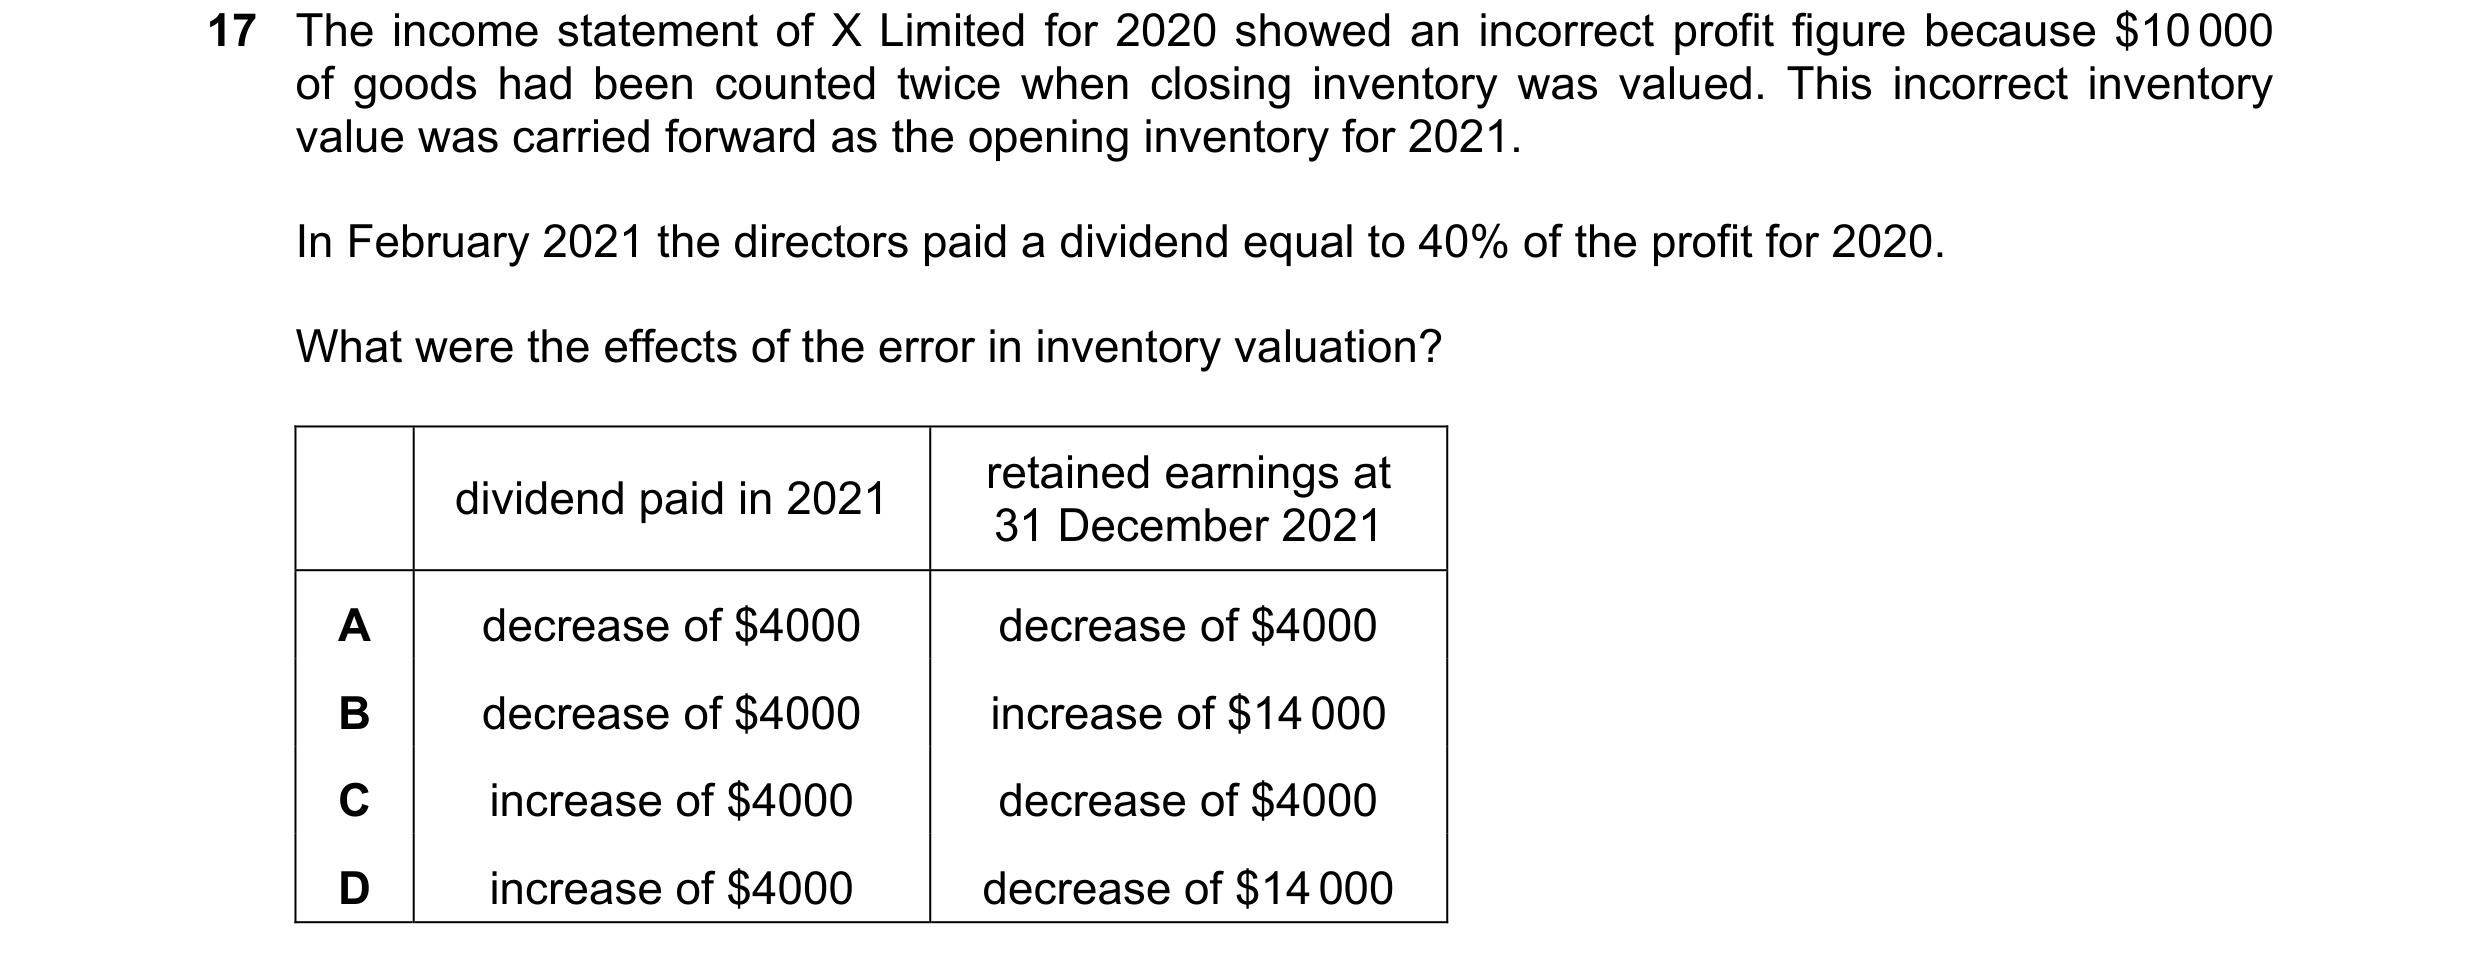 32 / 60
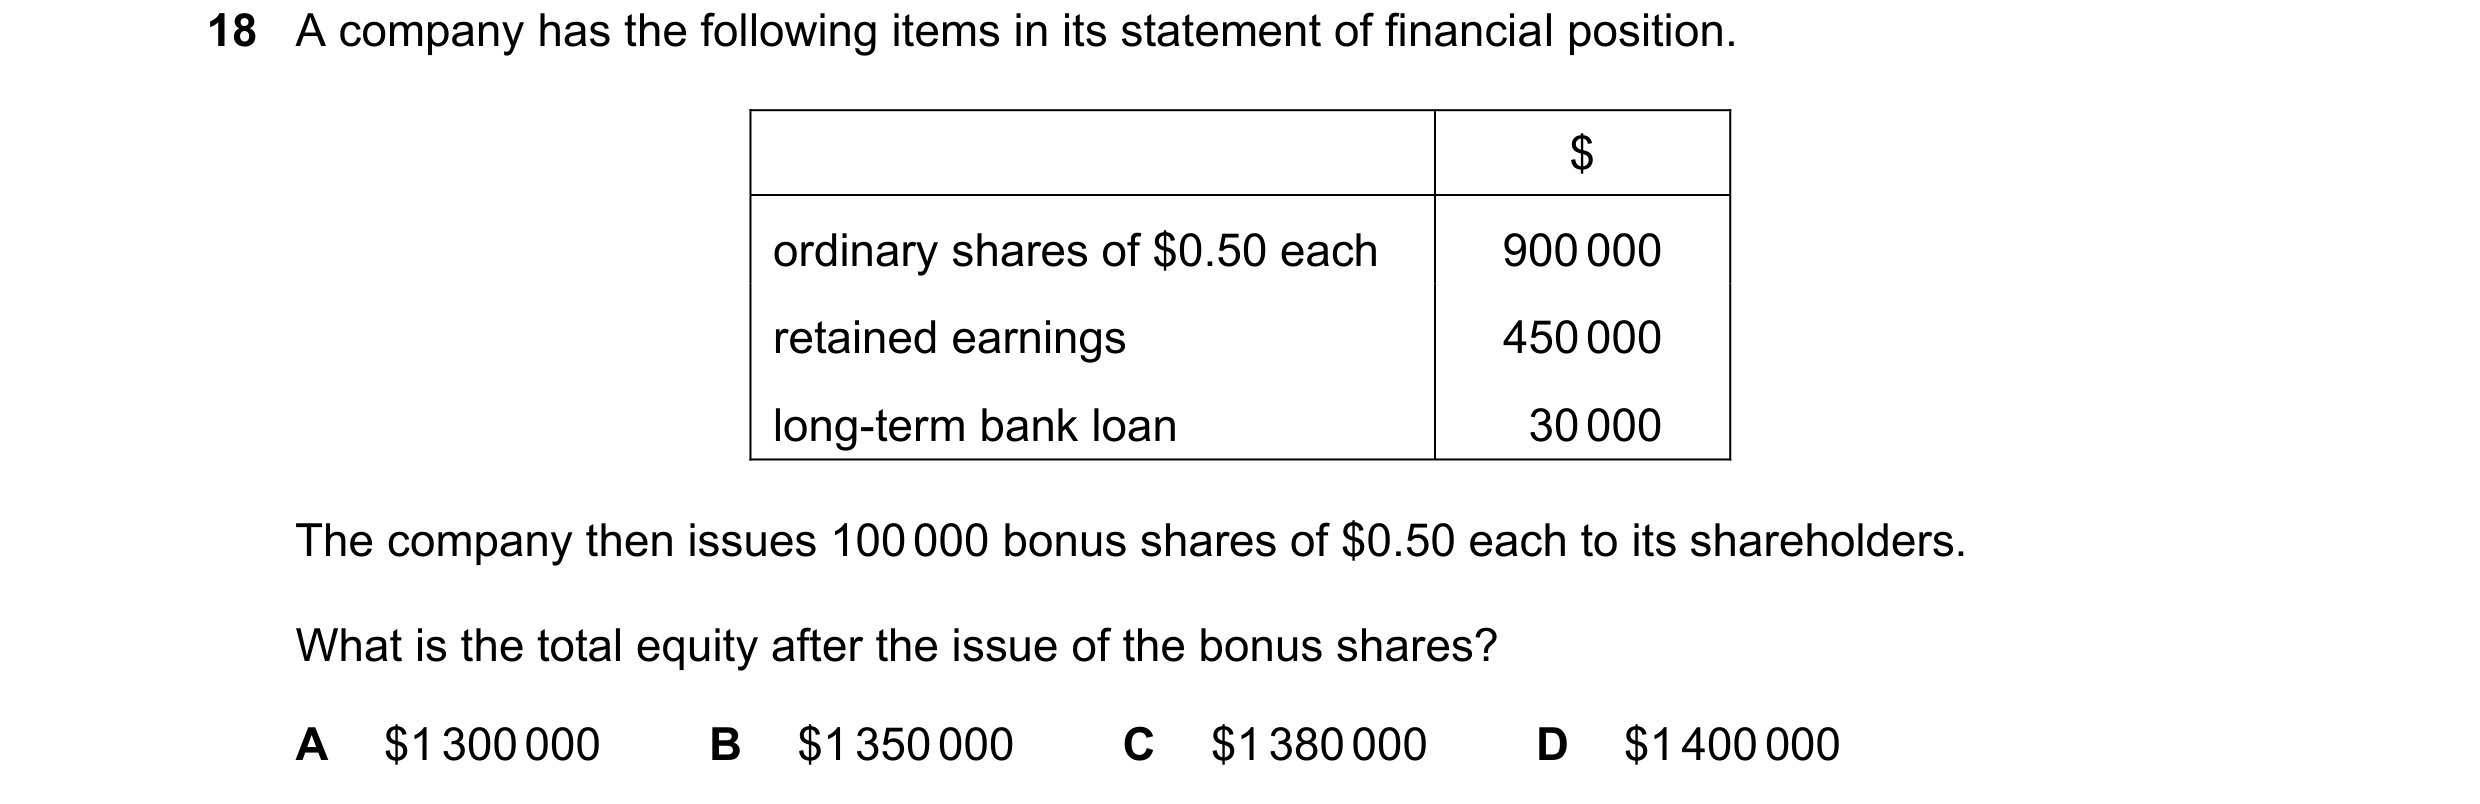
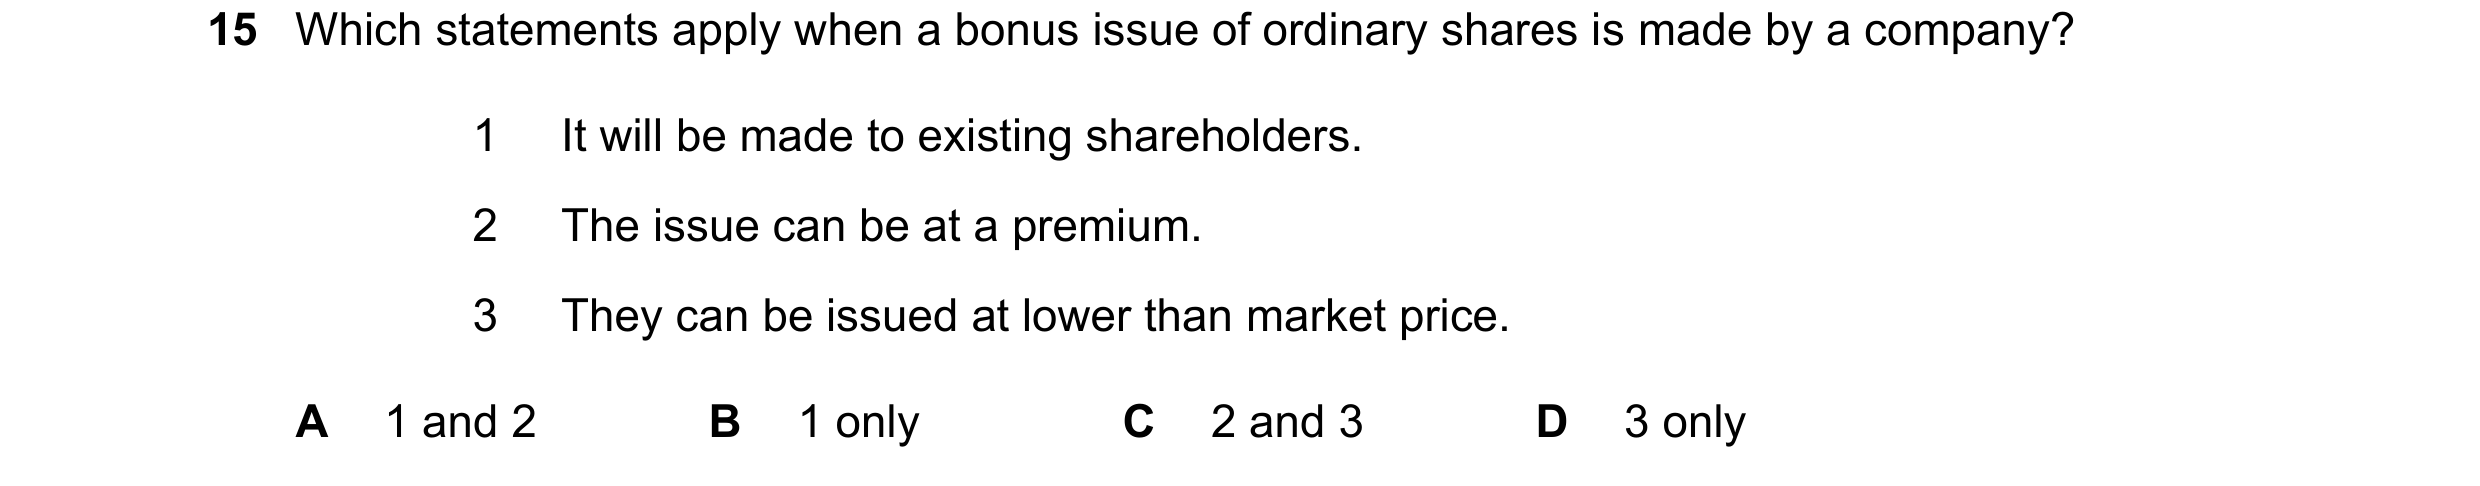
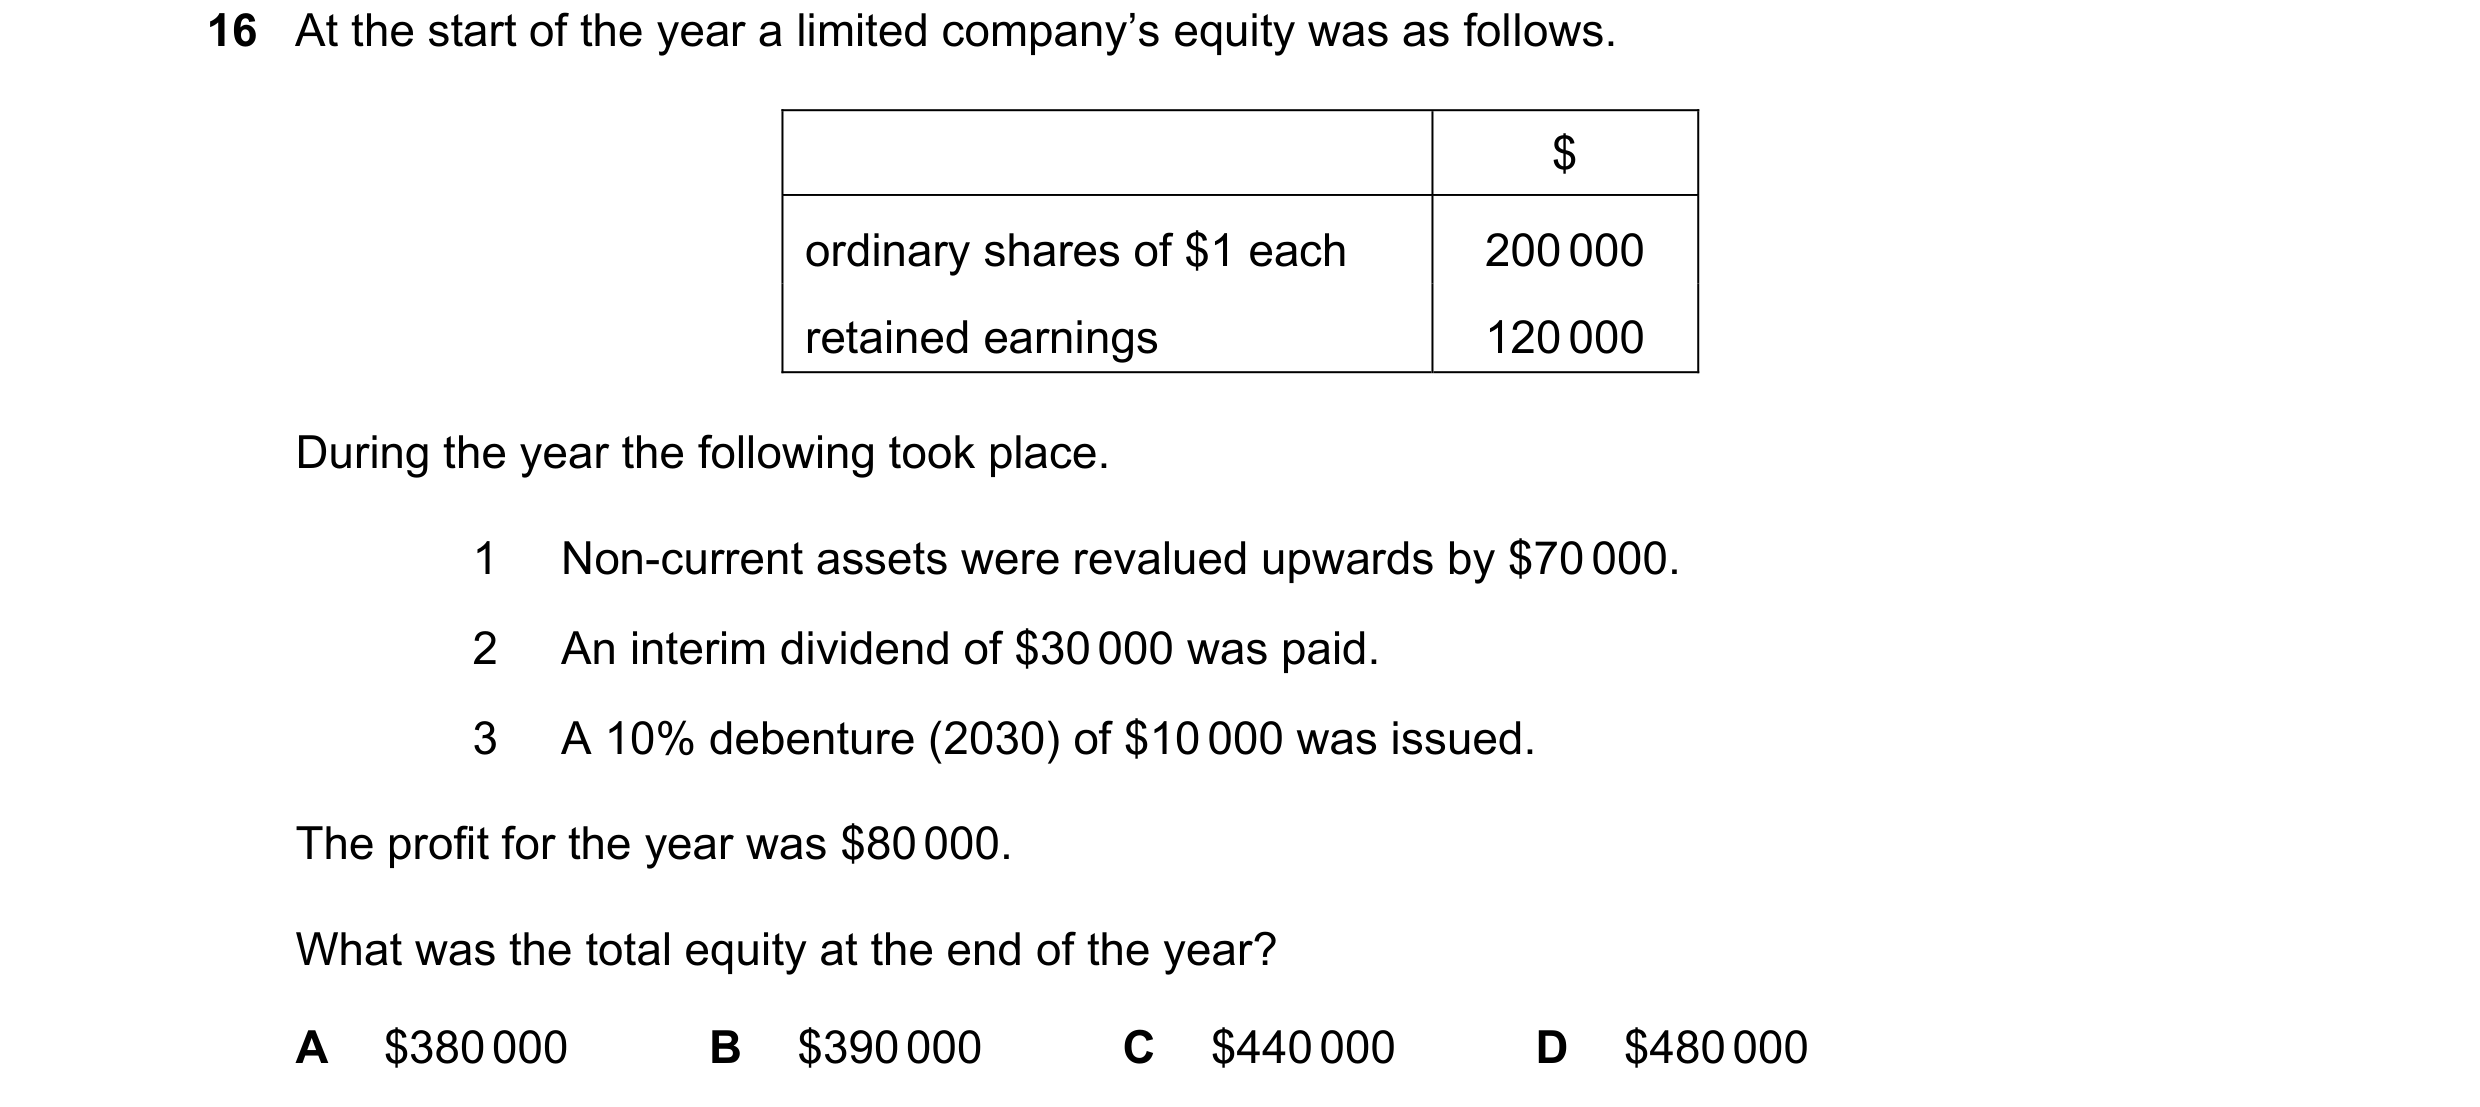 33 / 60
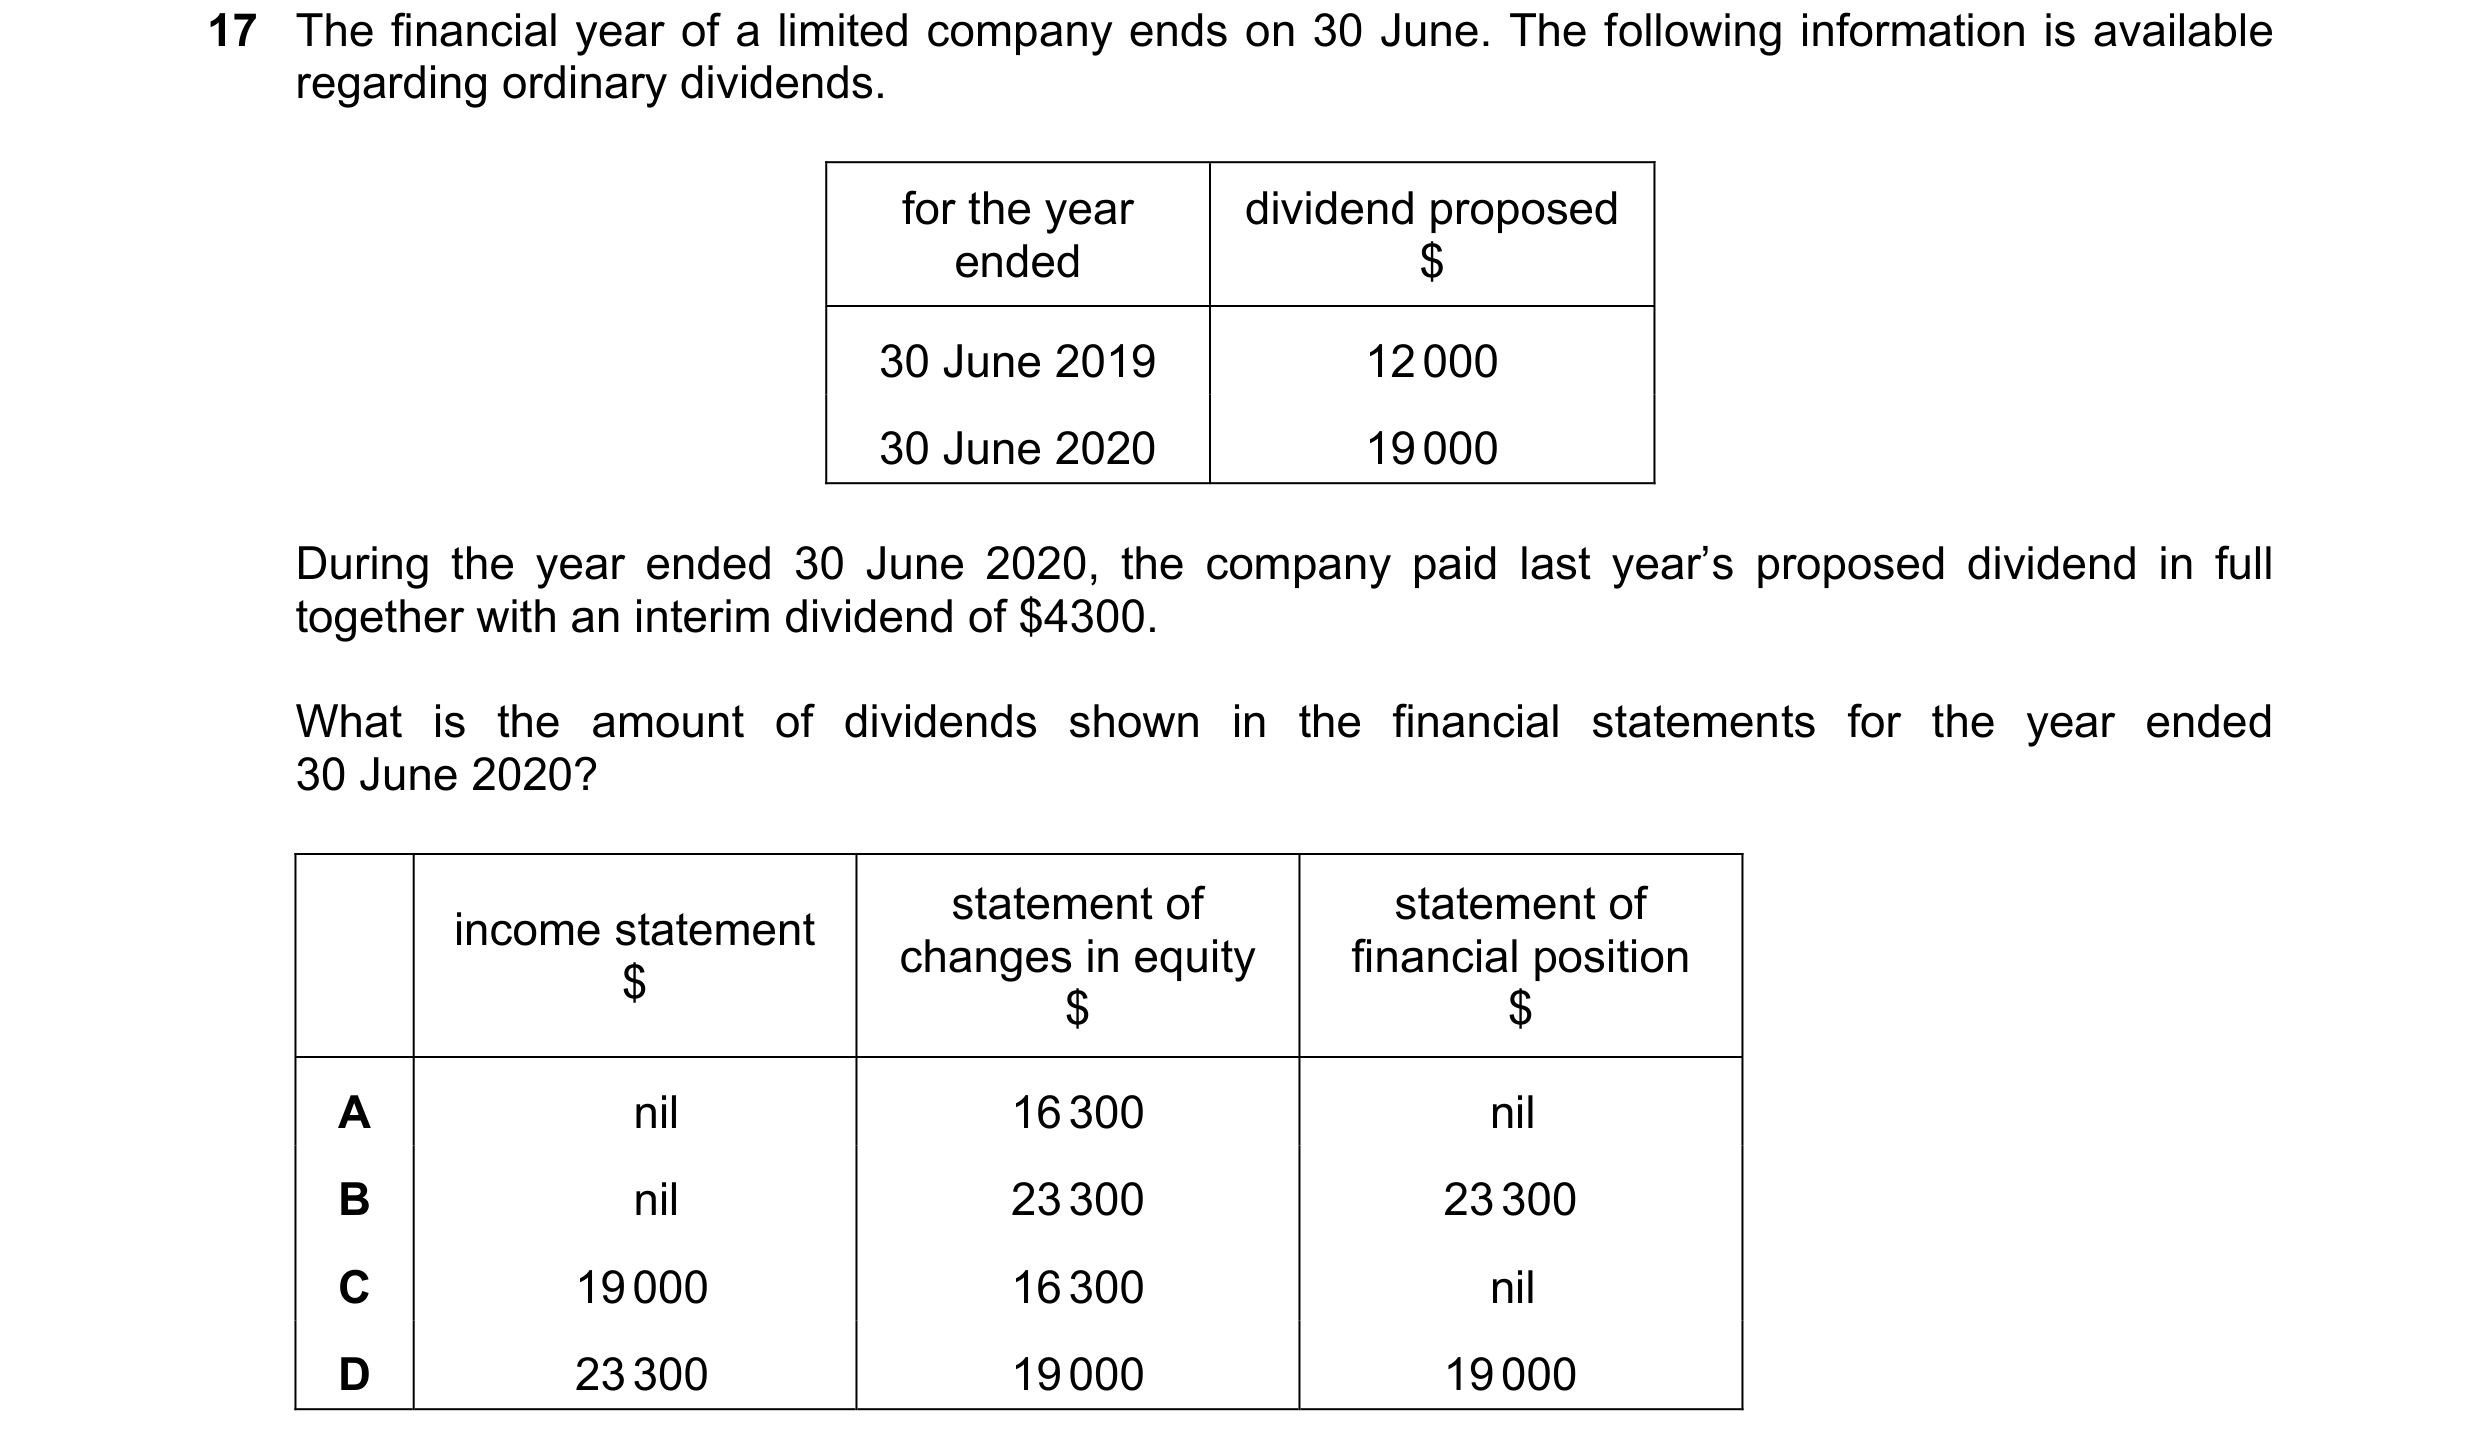
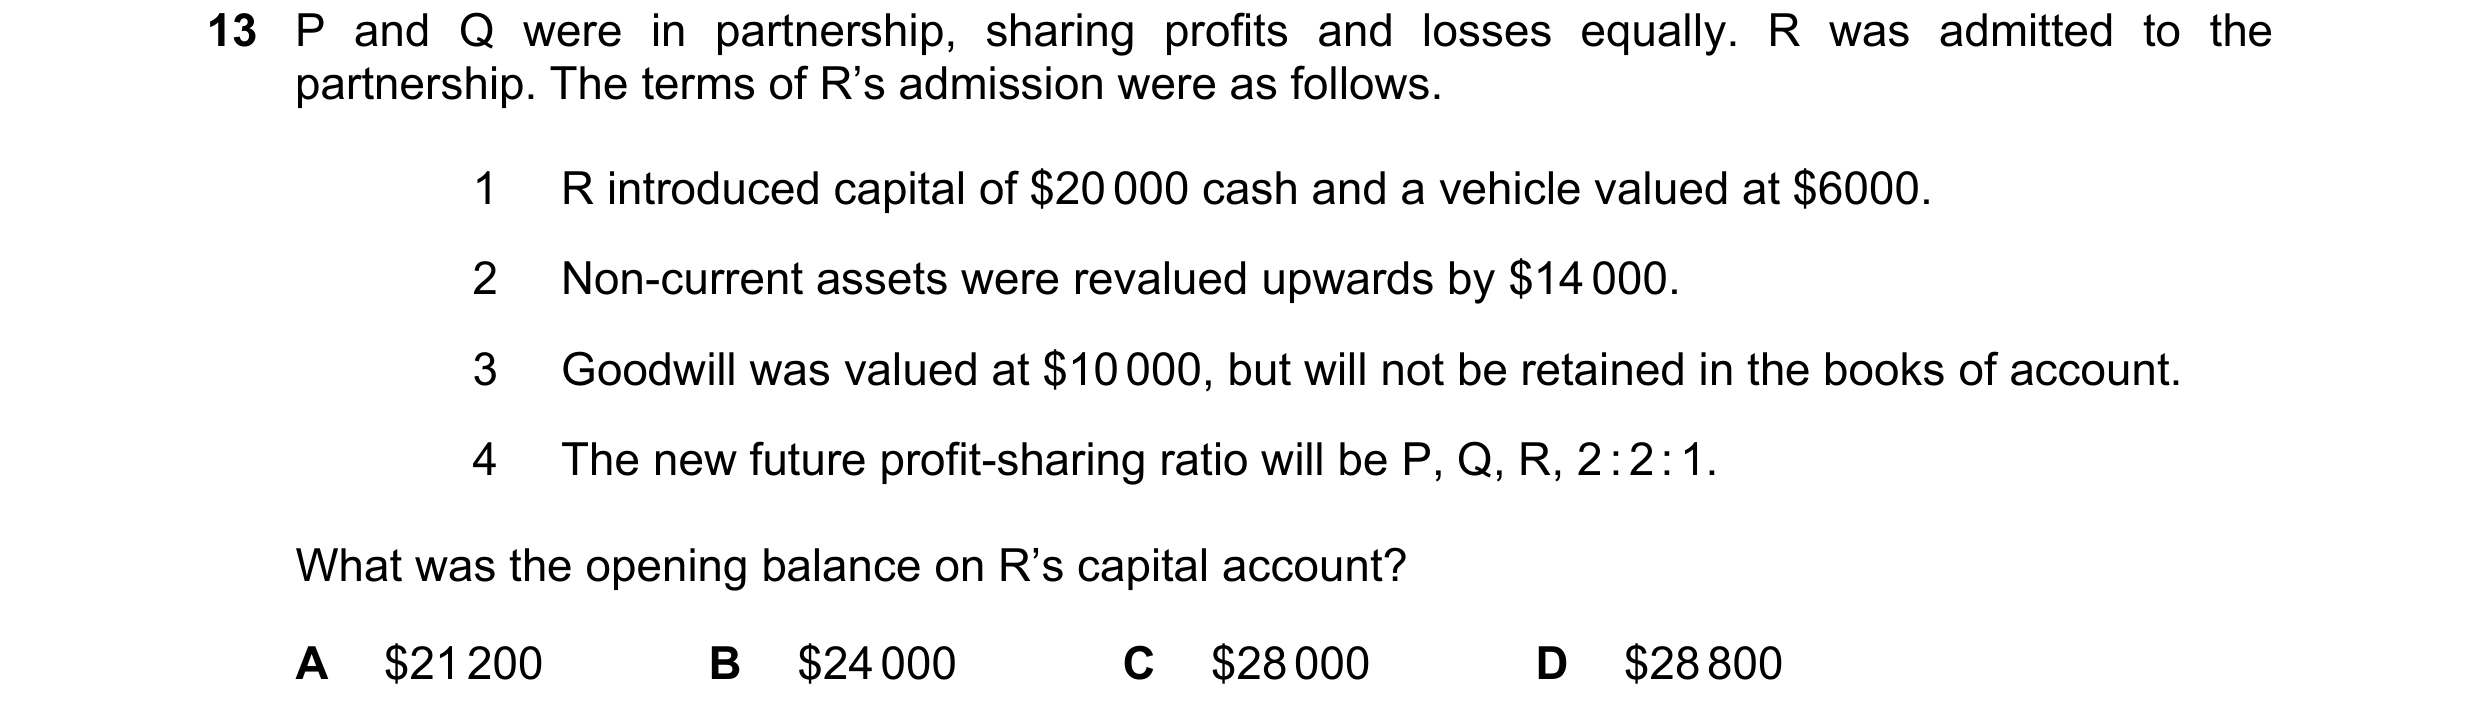
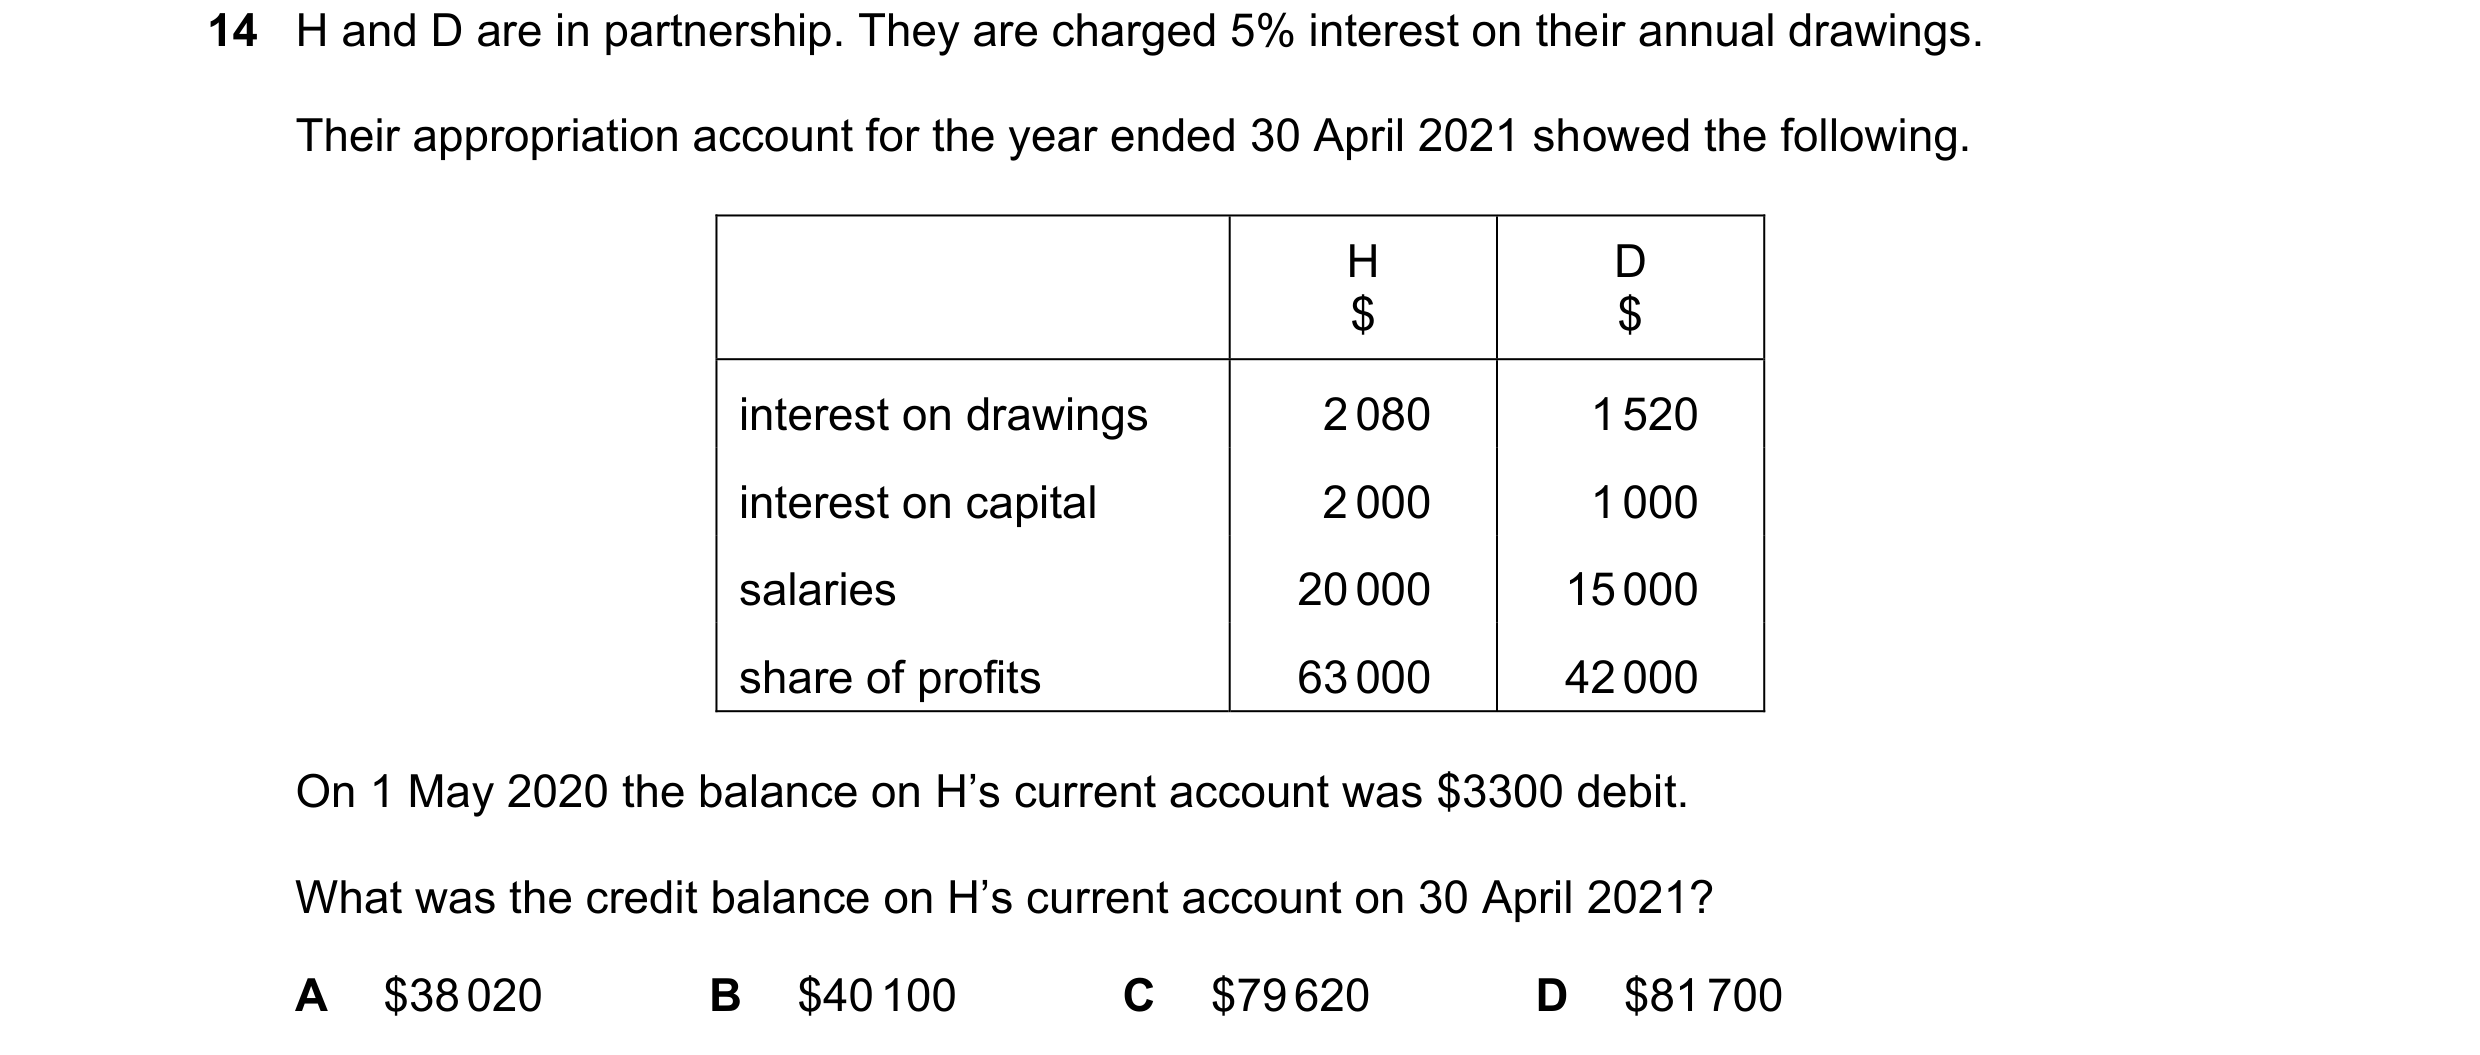 34 / 60
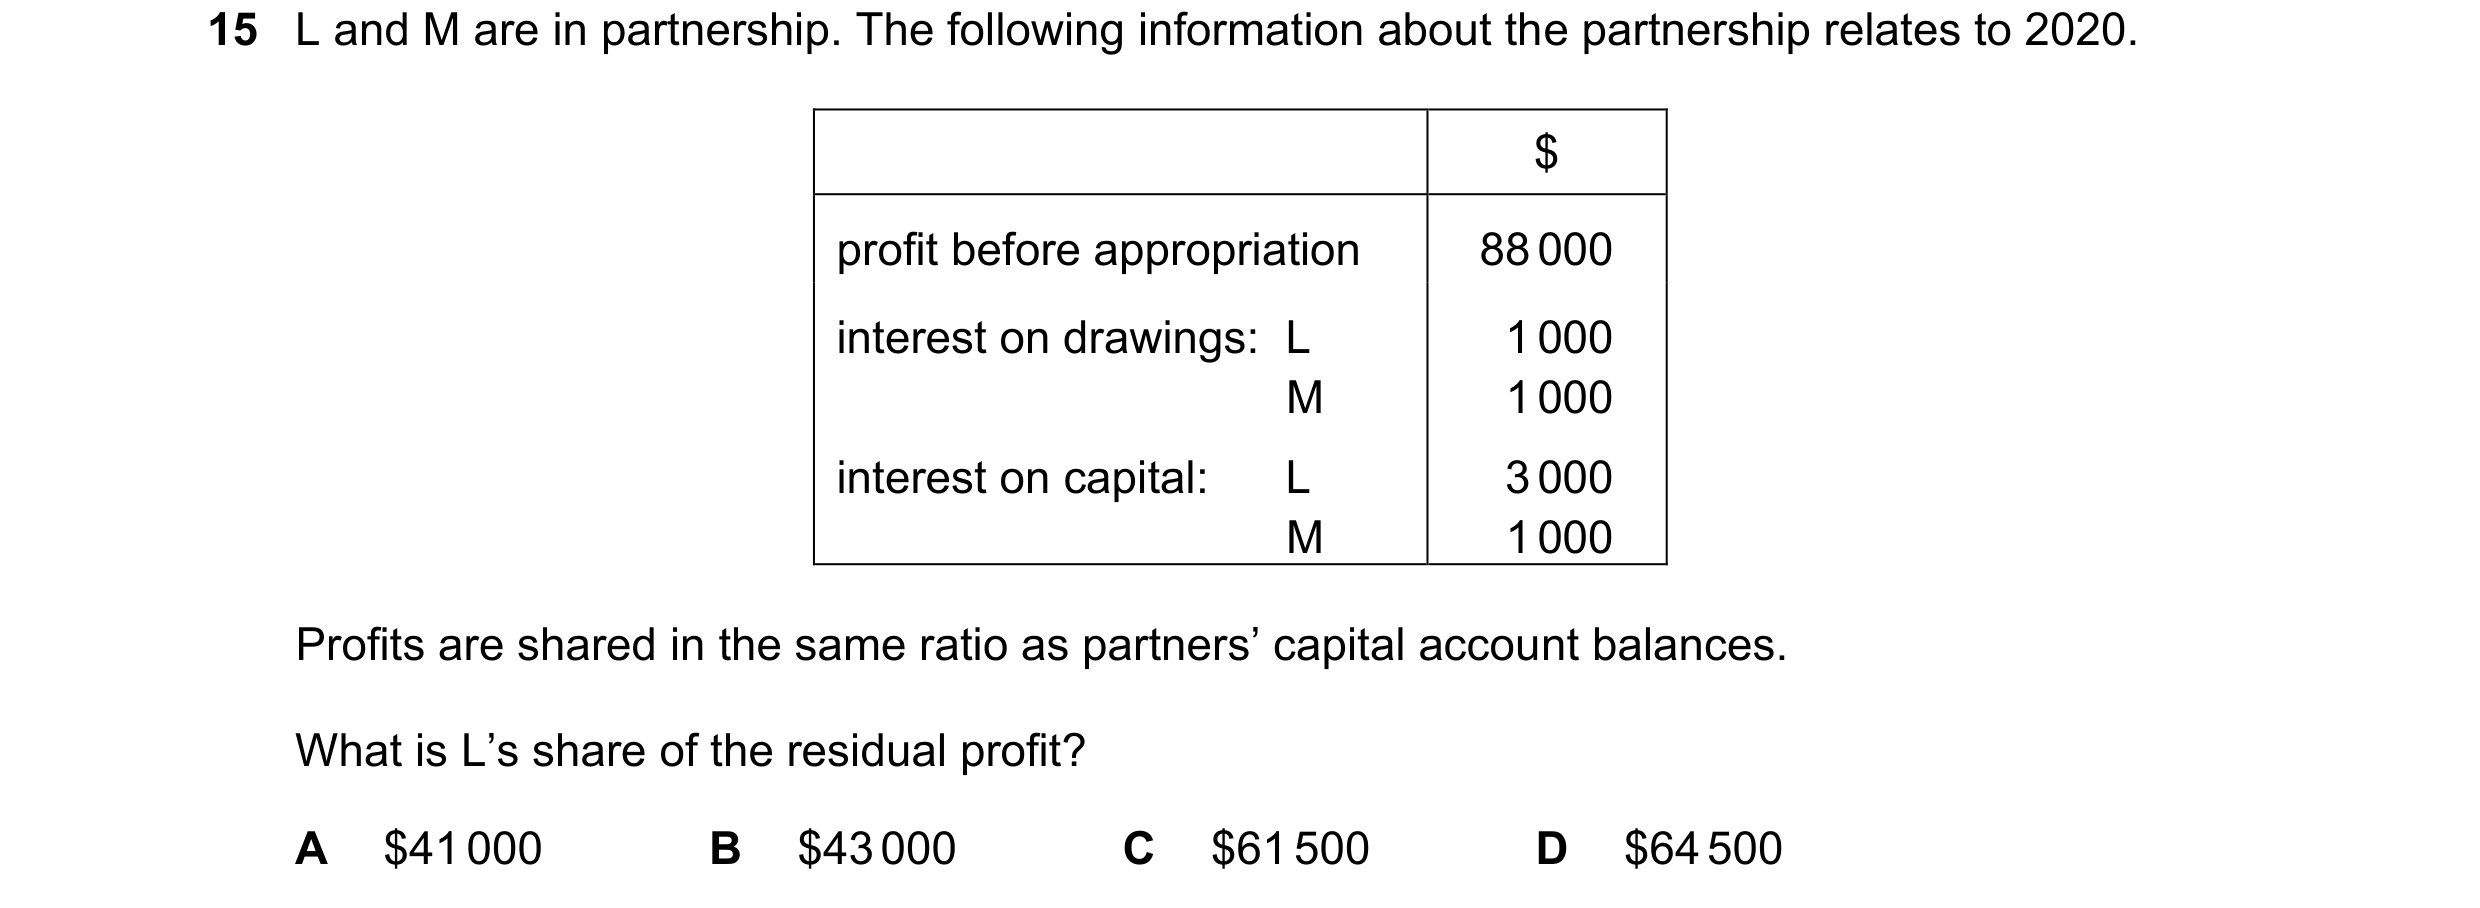
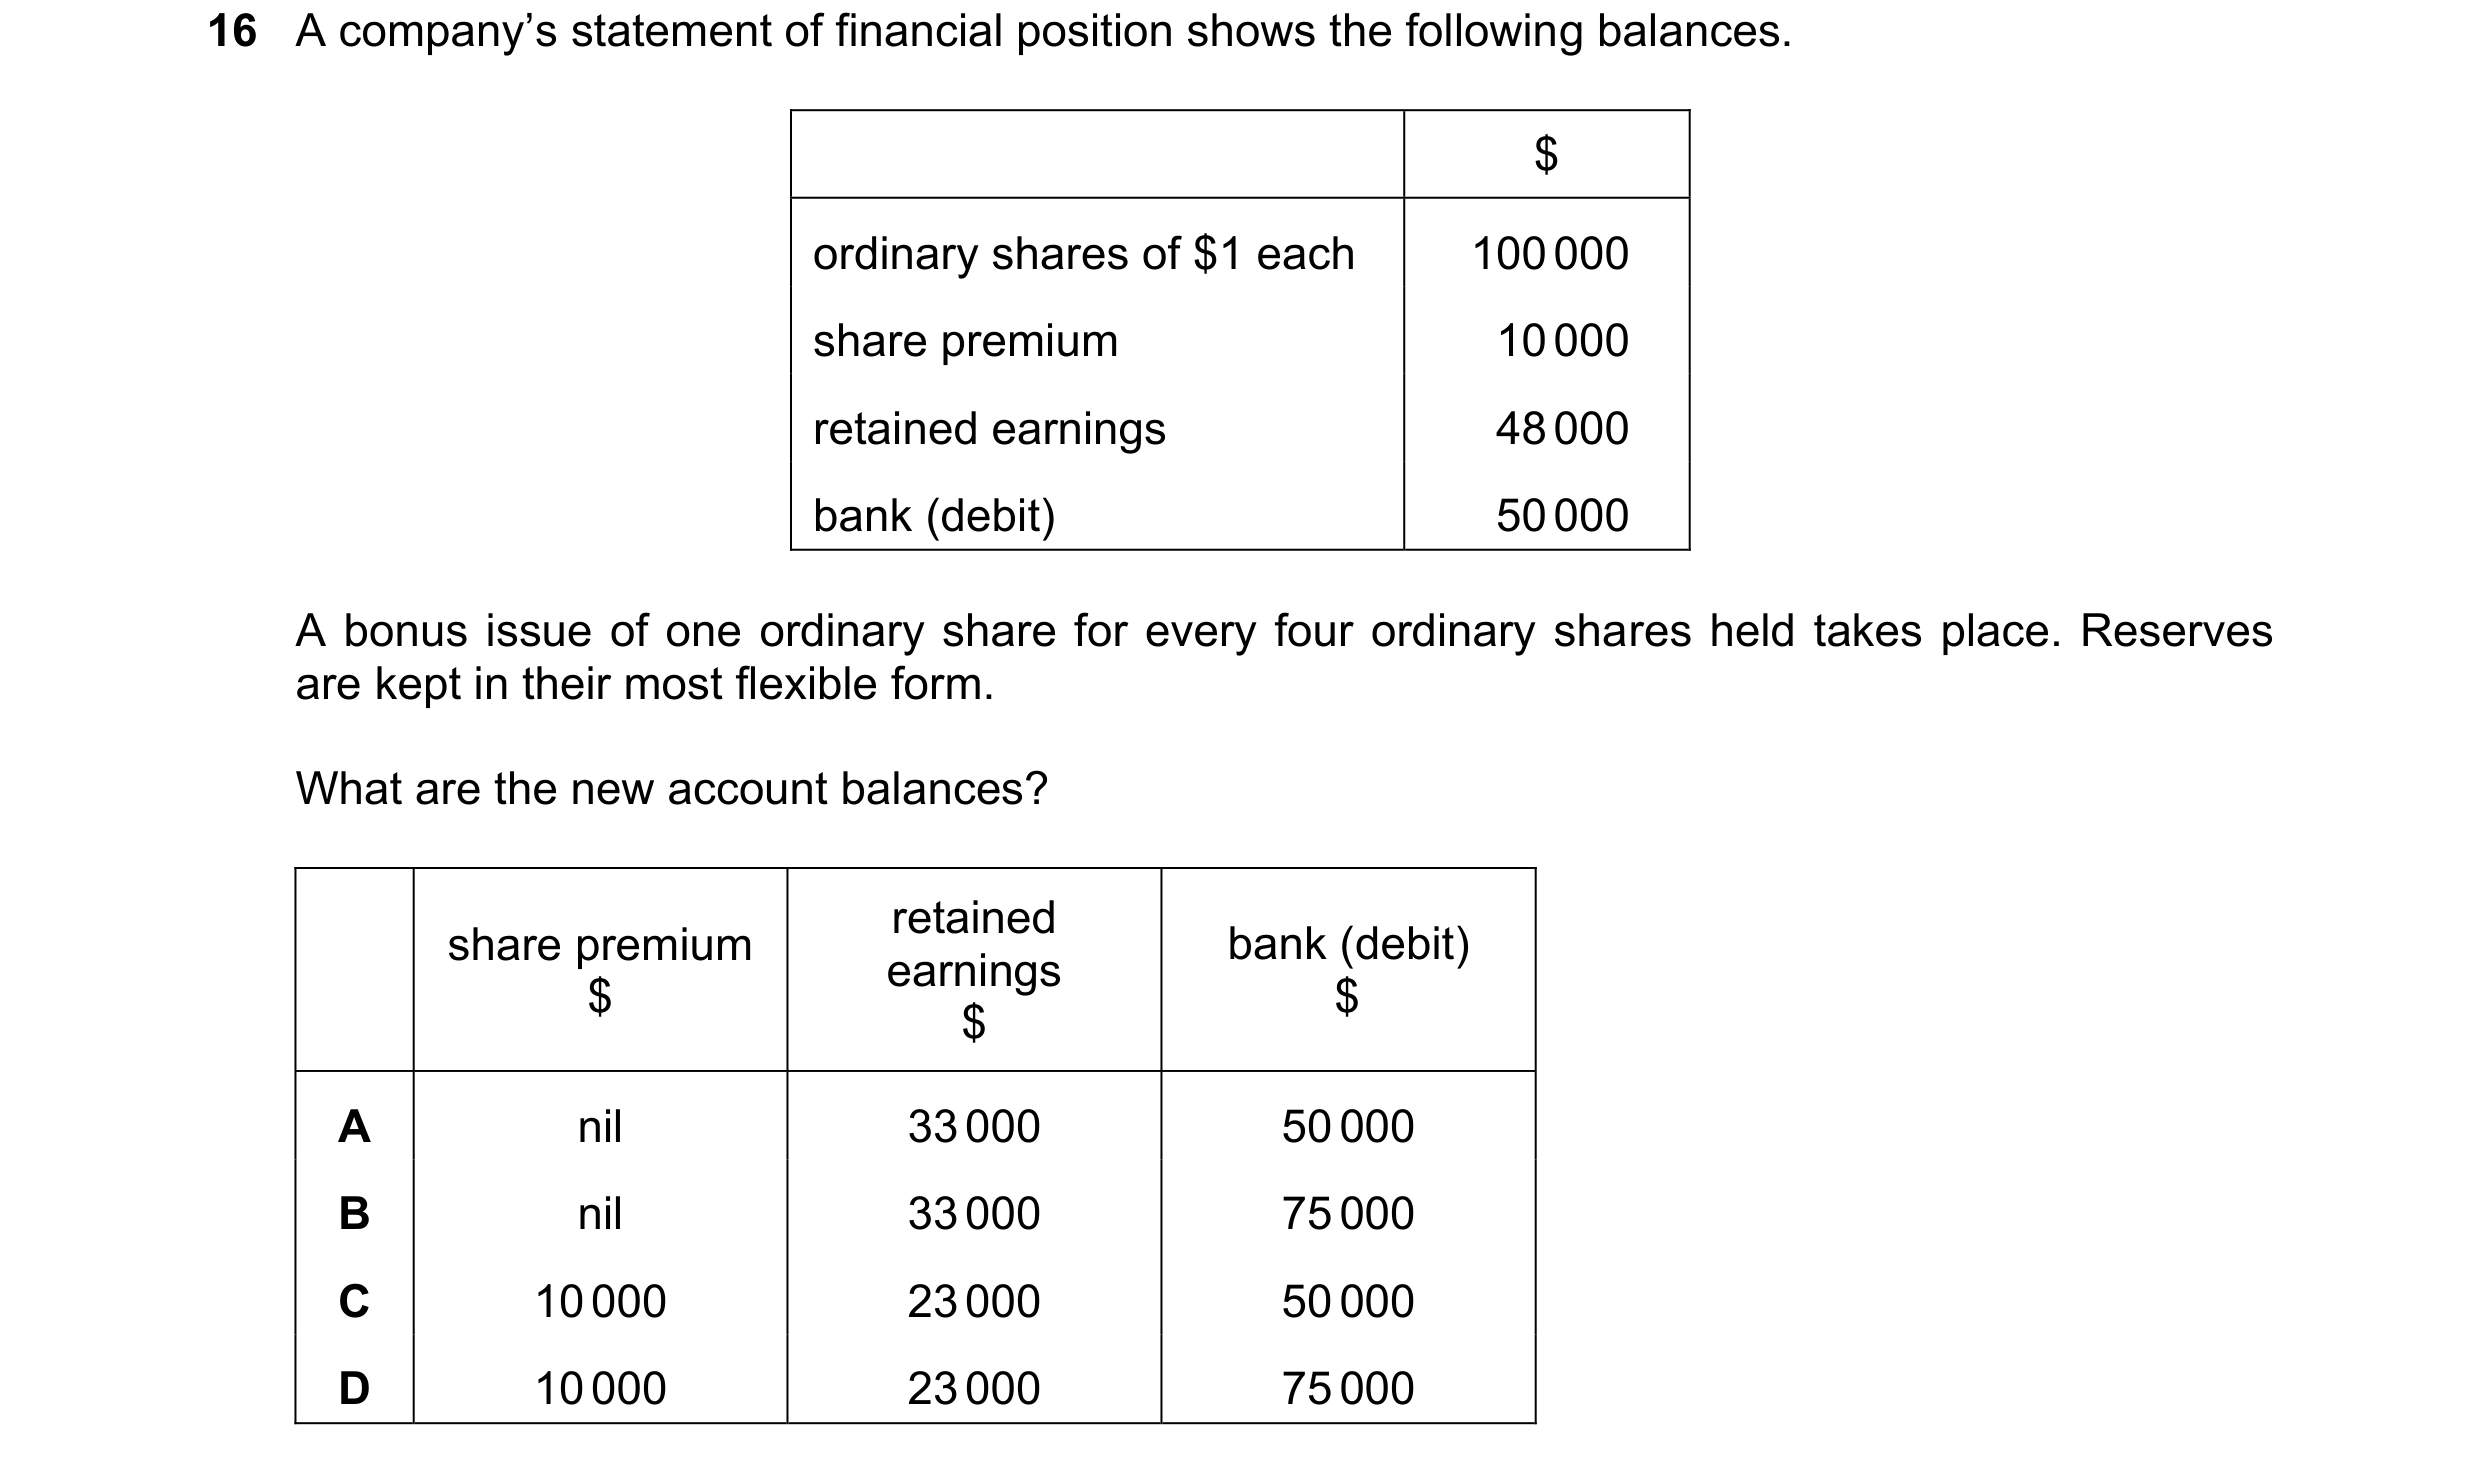
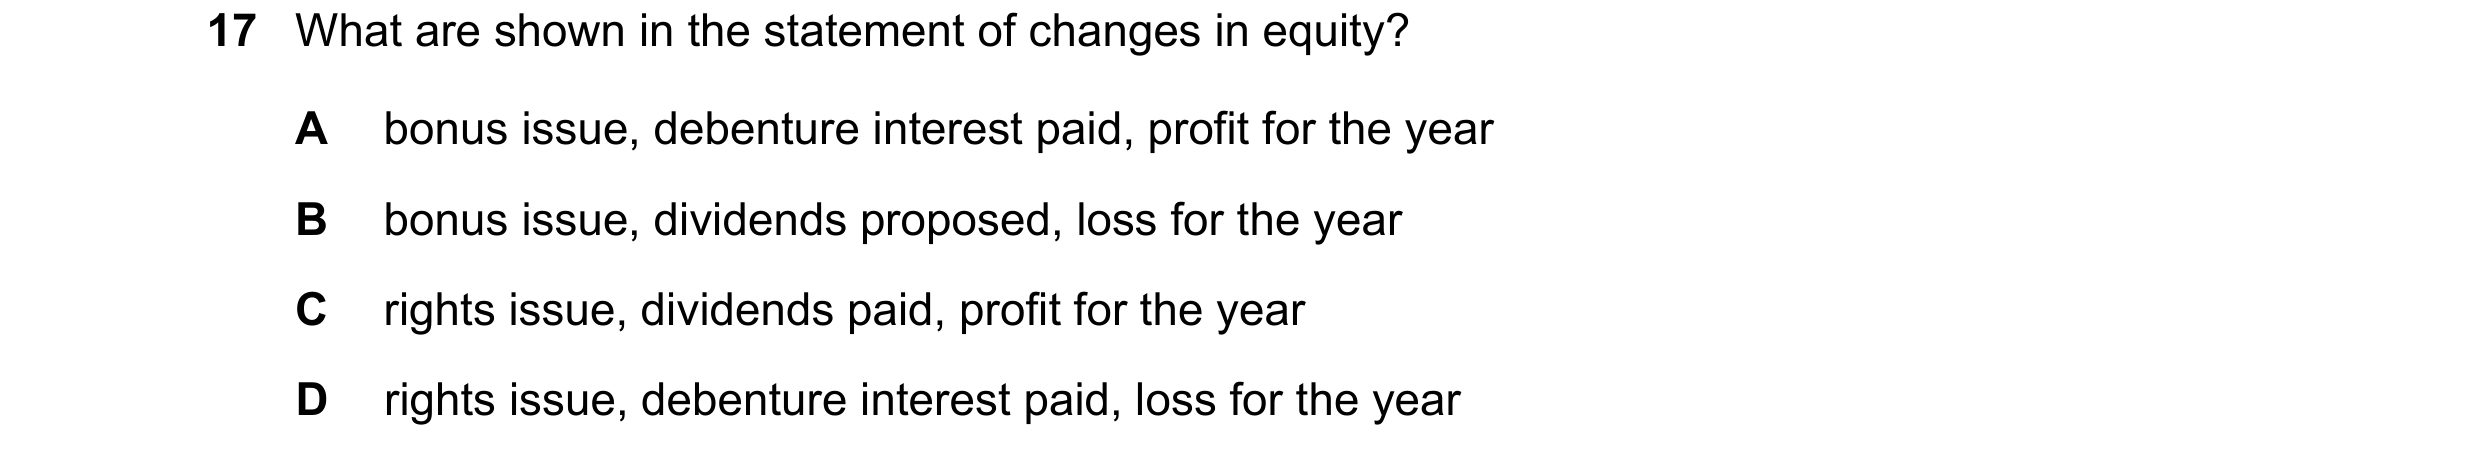 35 / 60
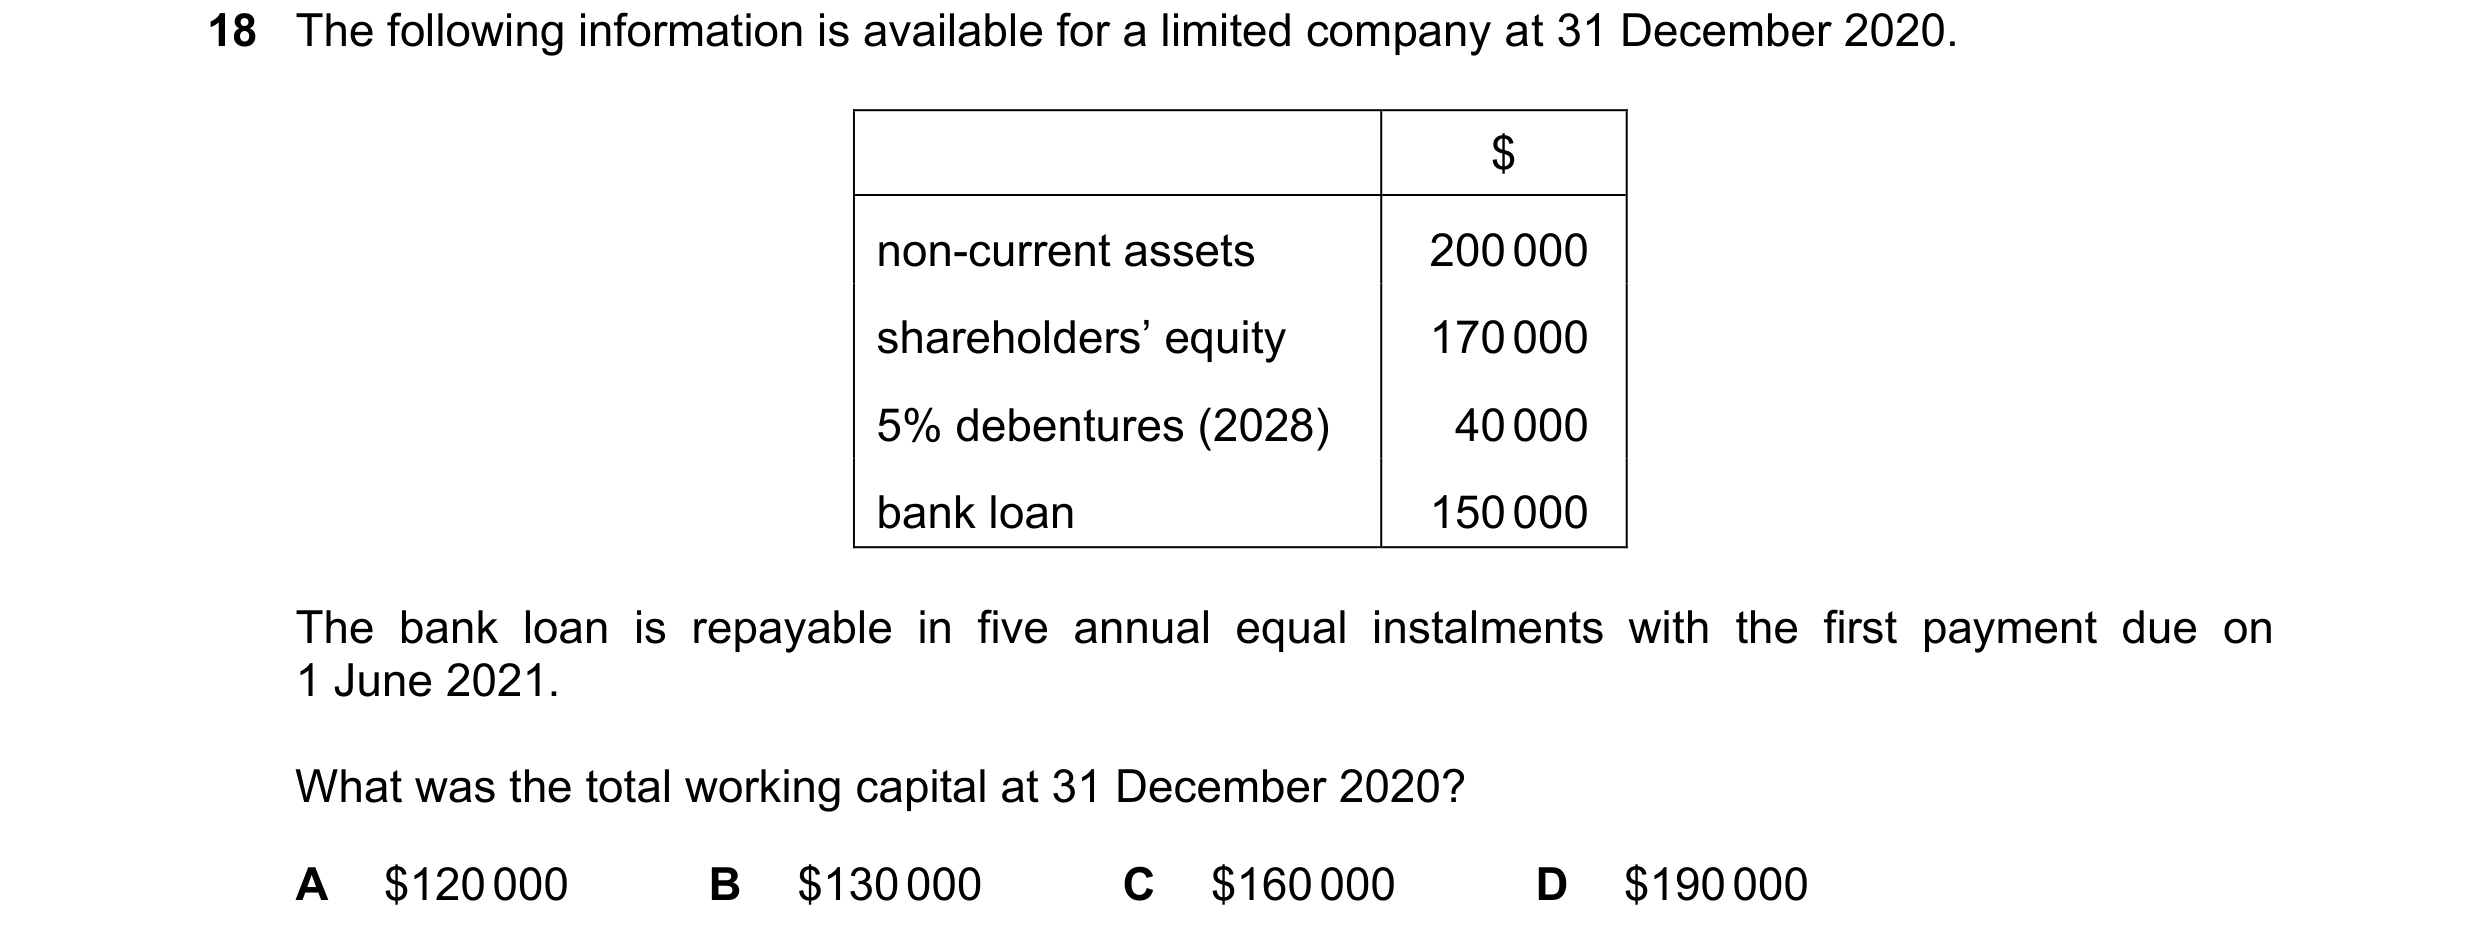
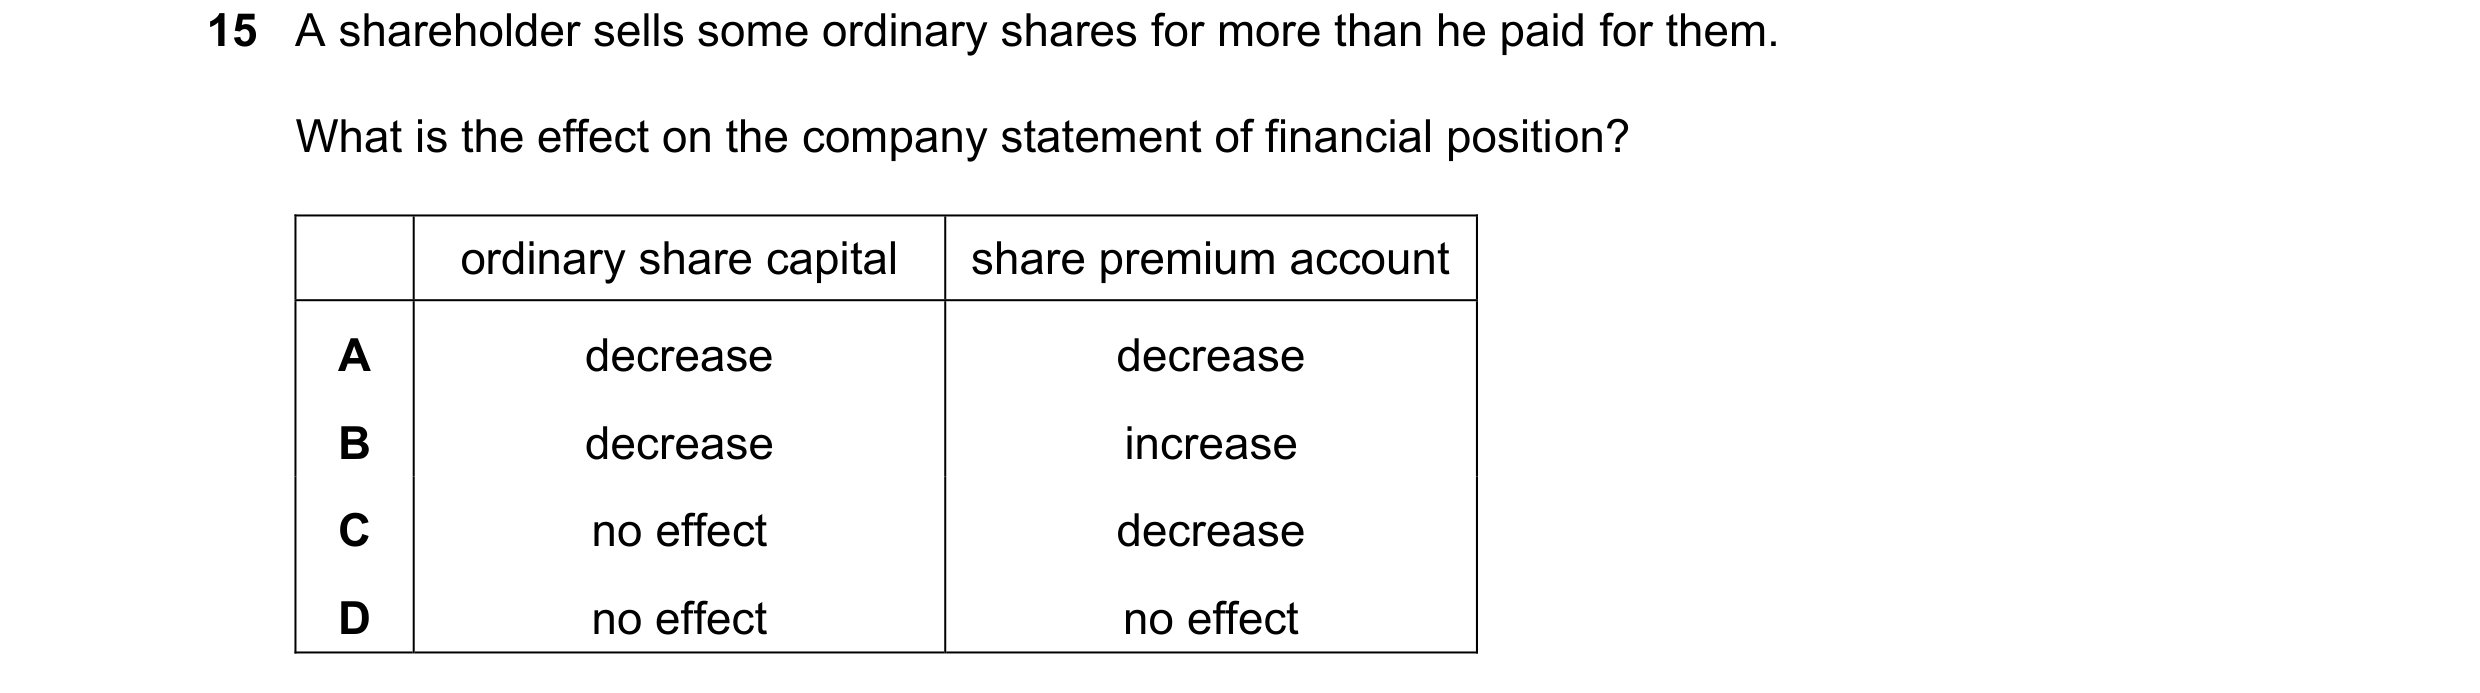
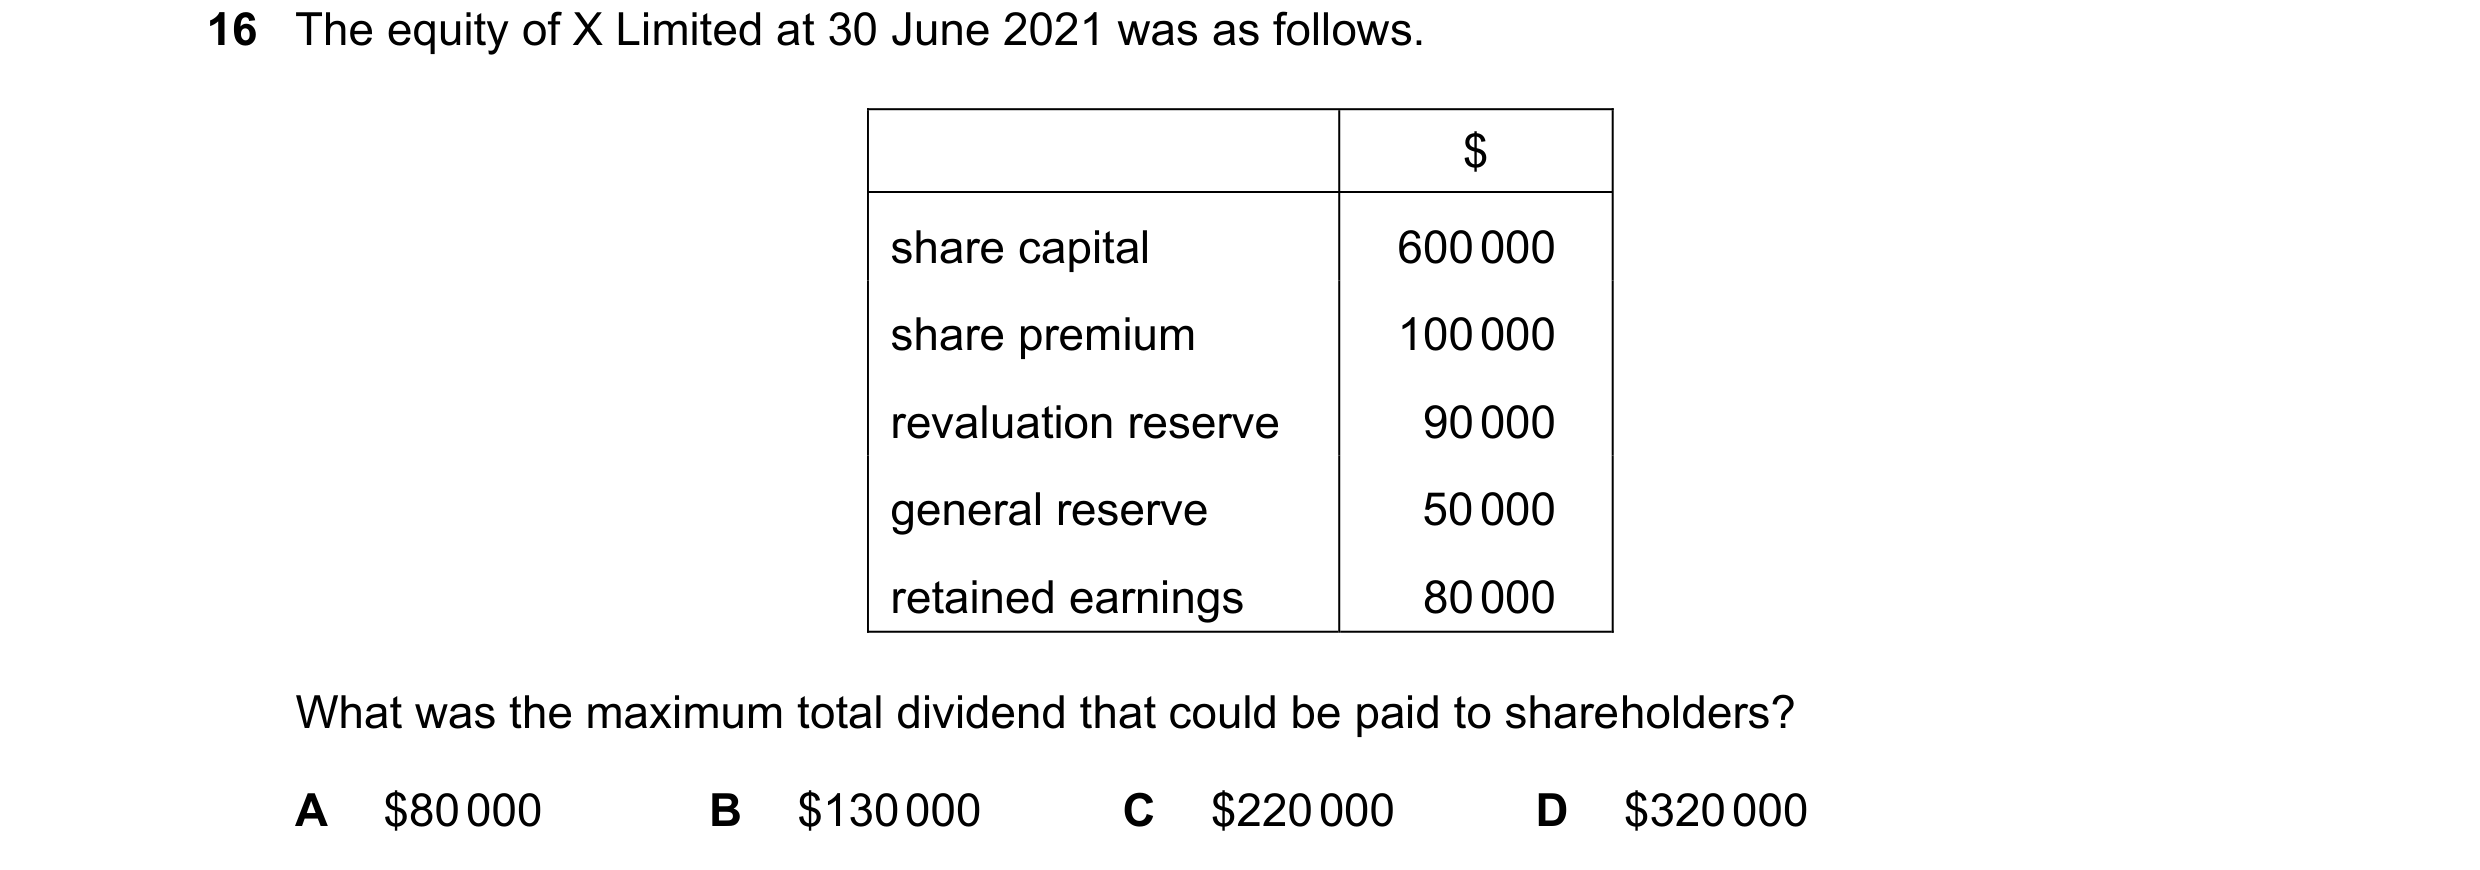
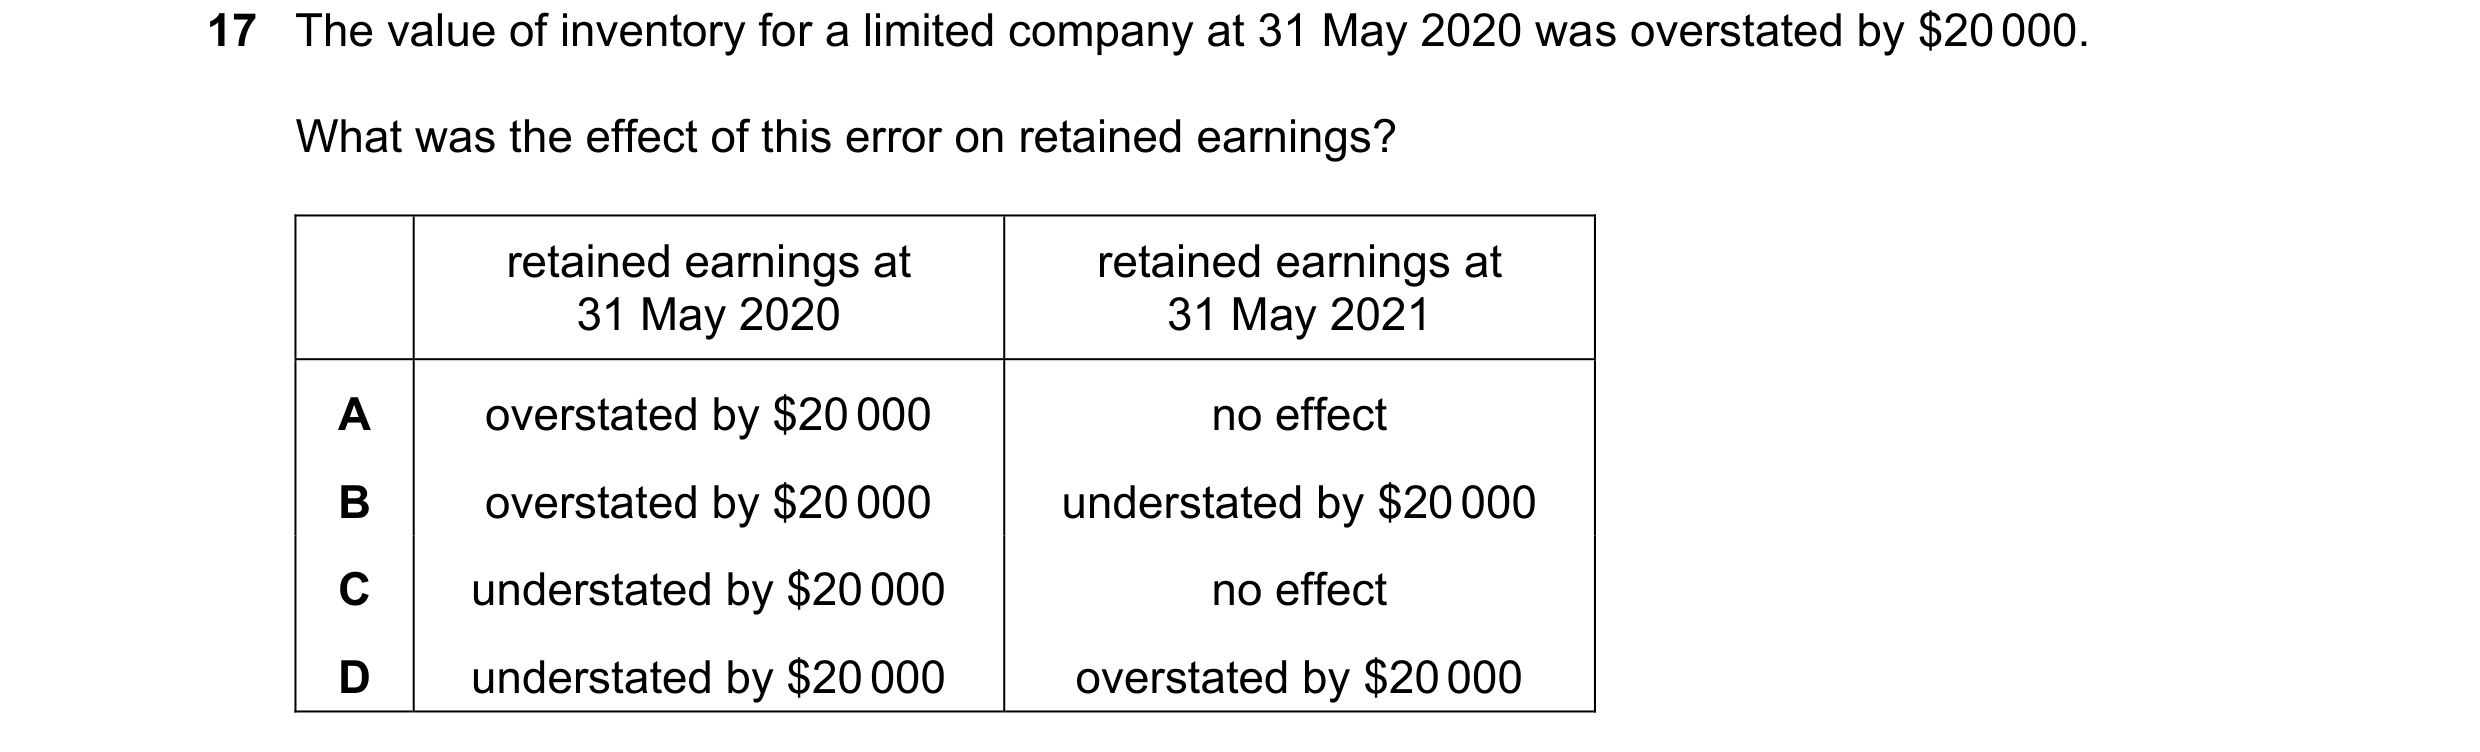 36 / 60
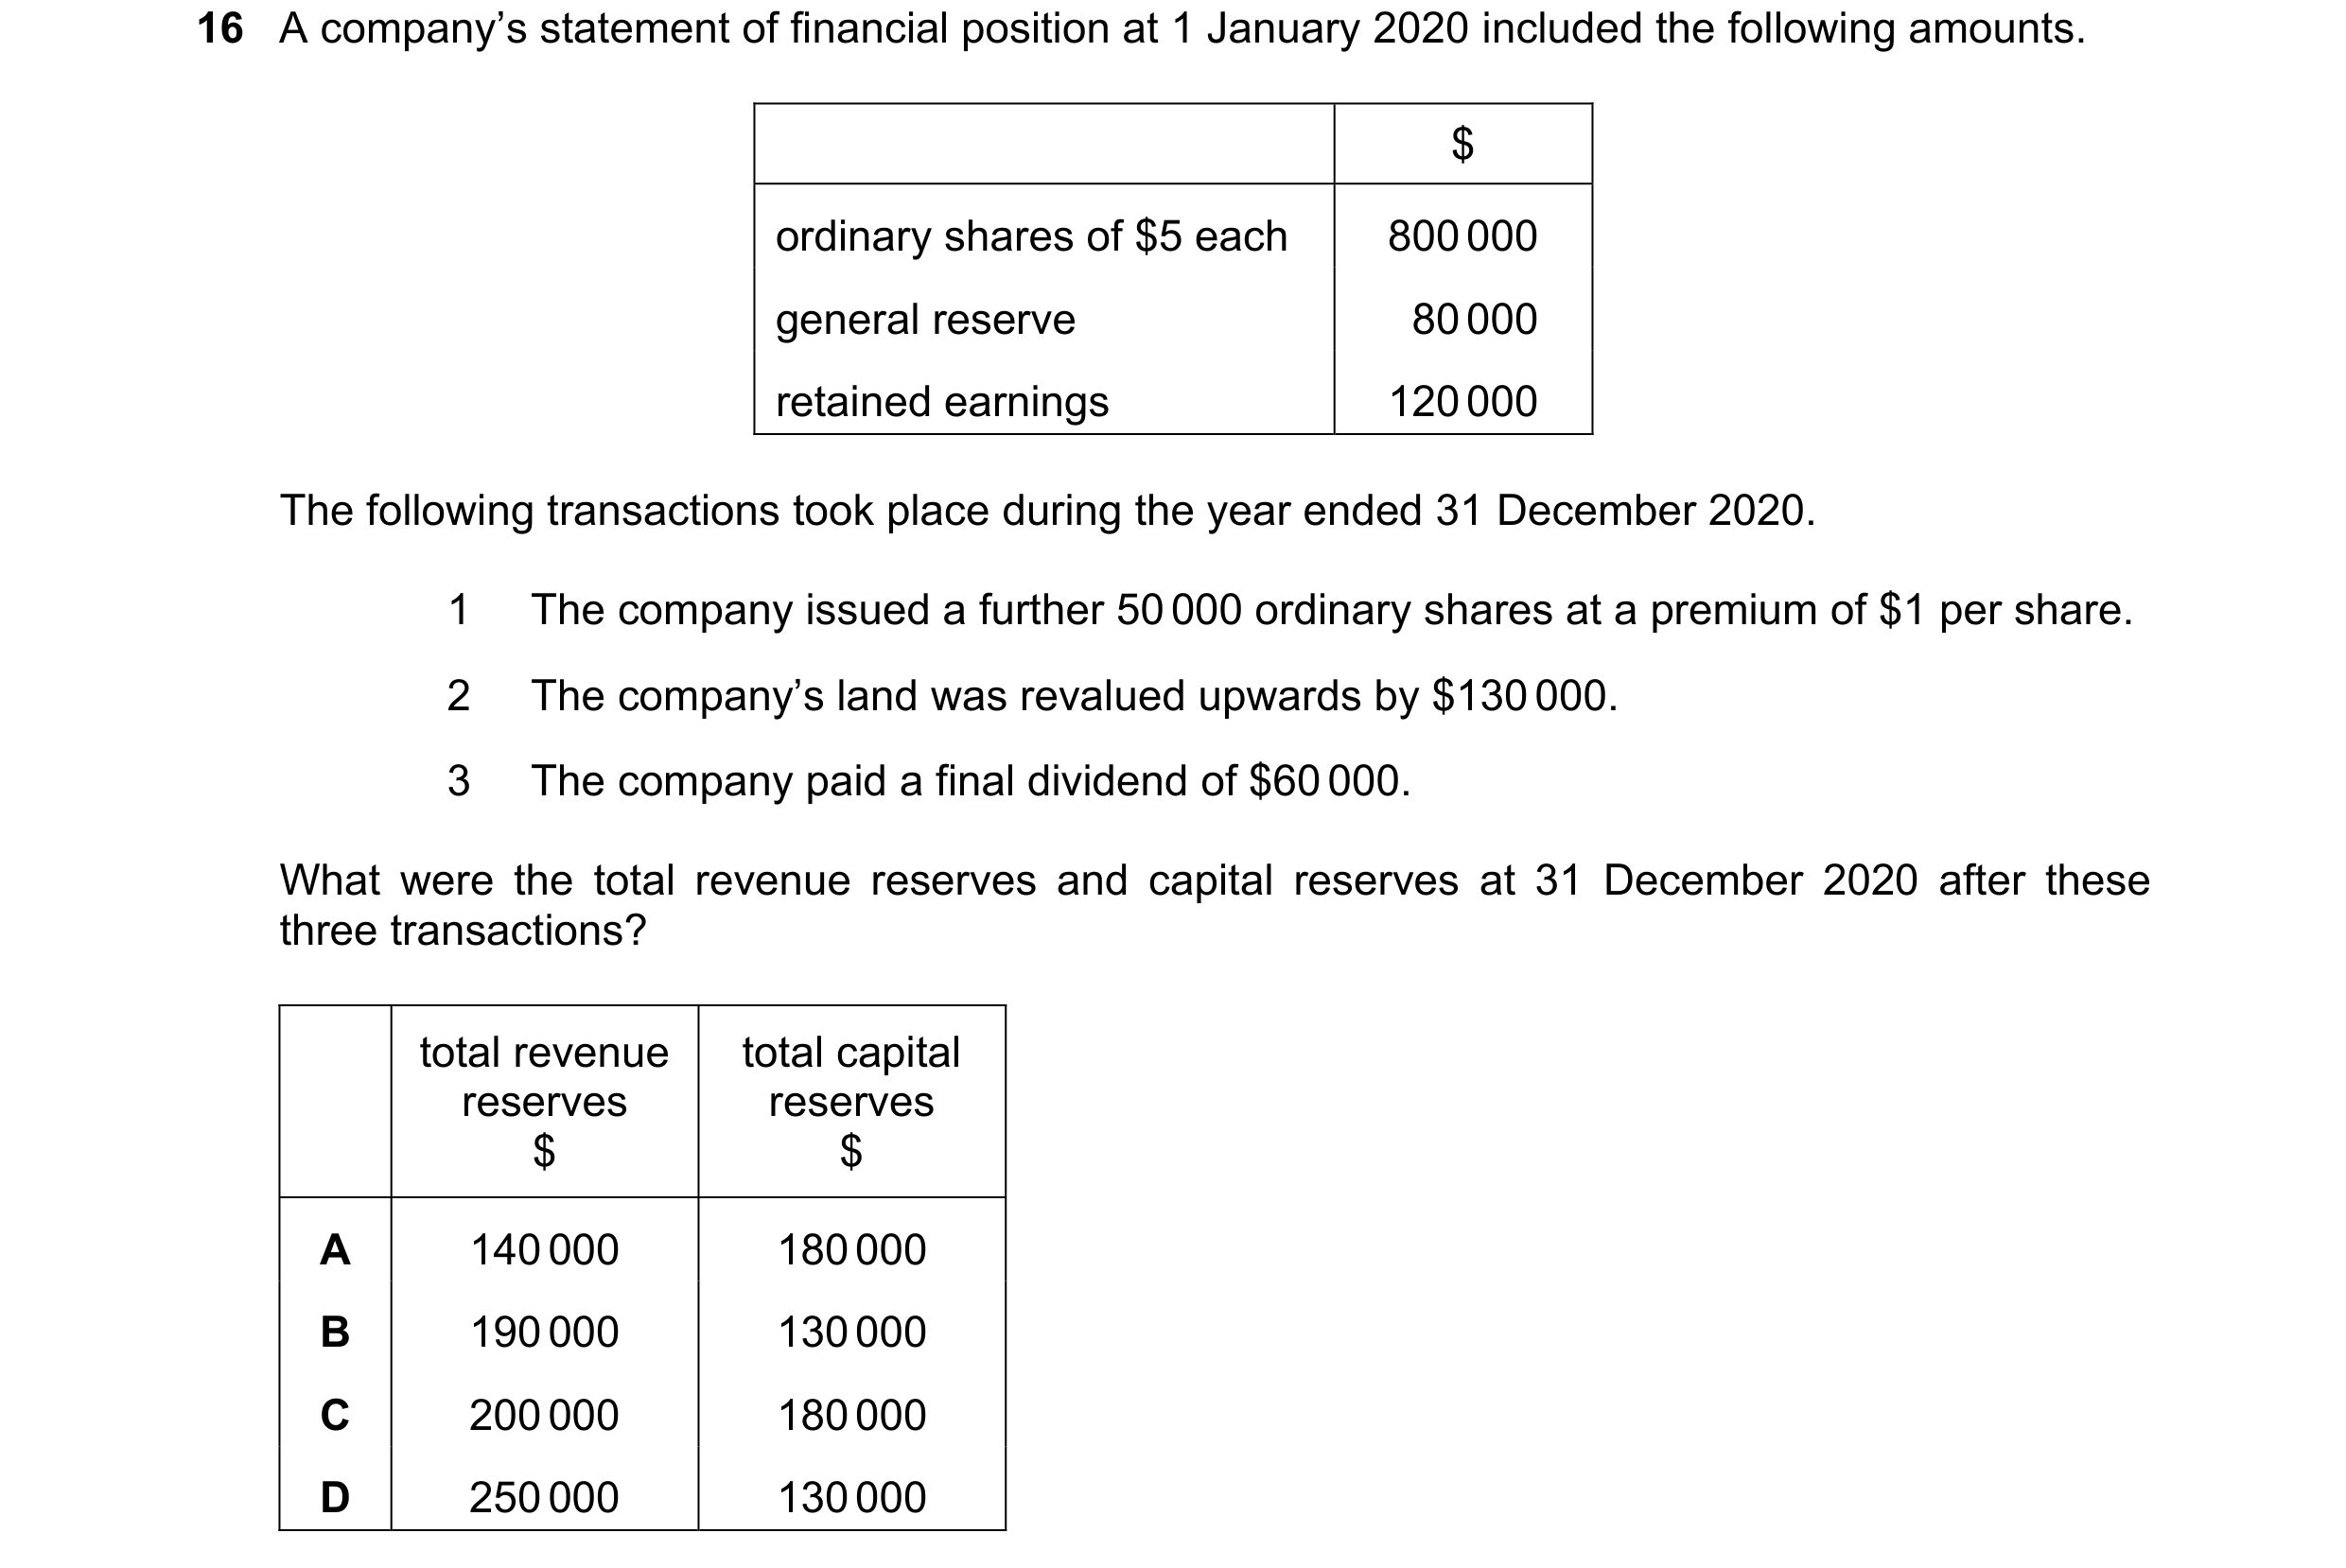
 37 / 60
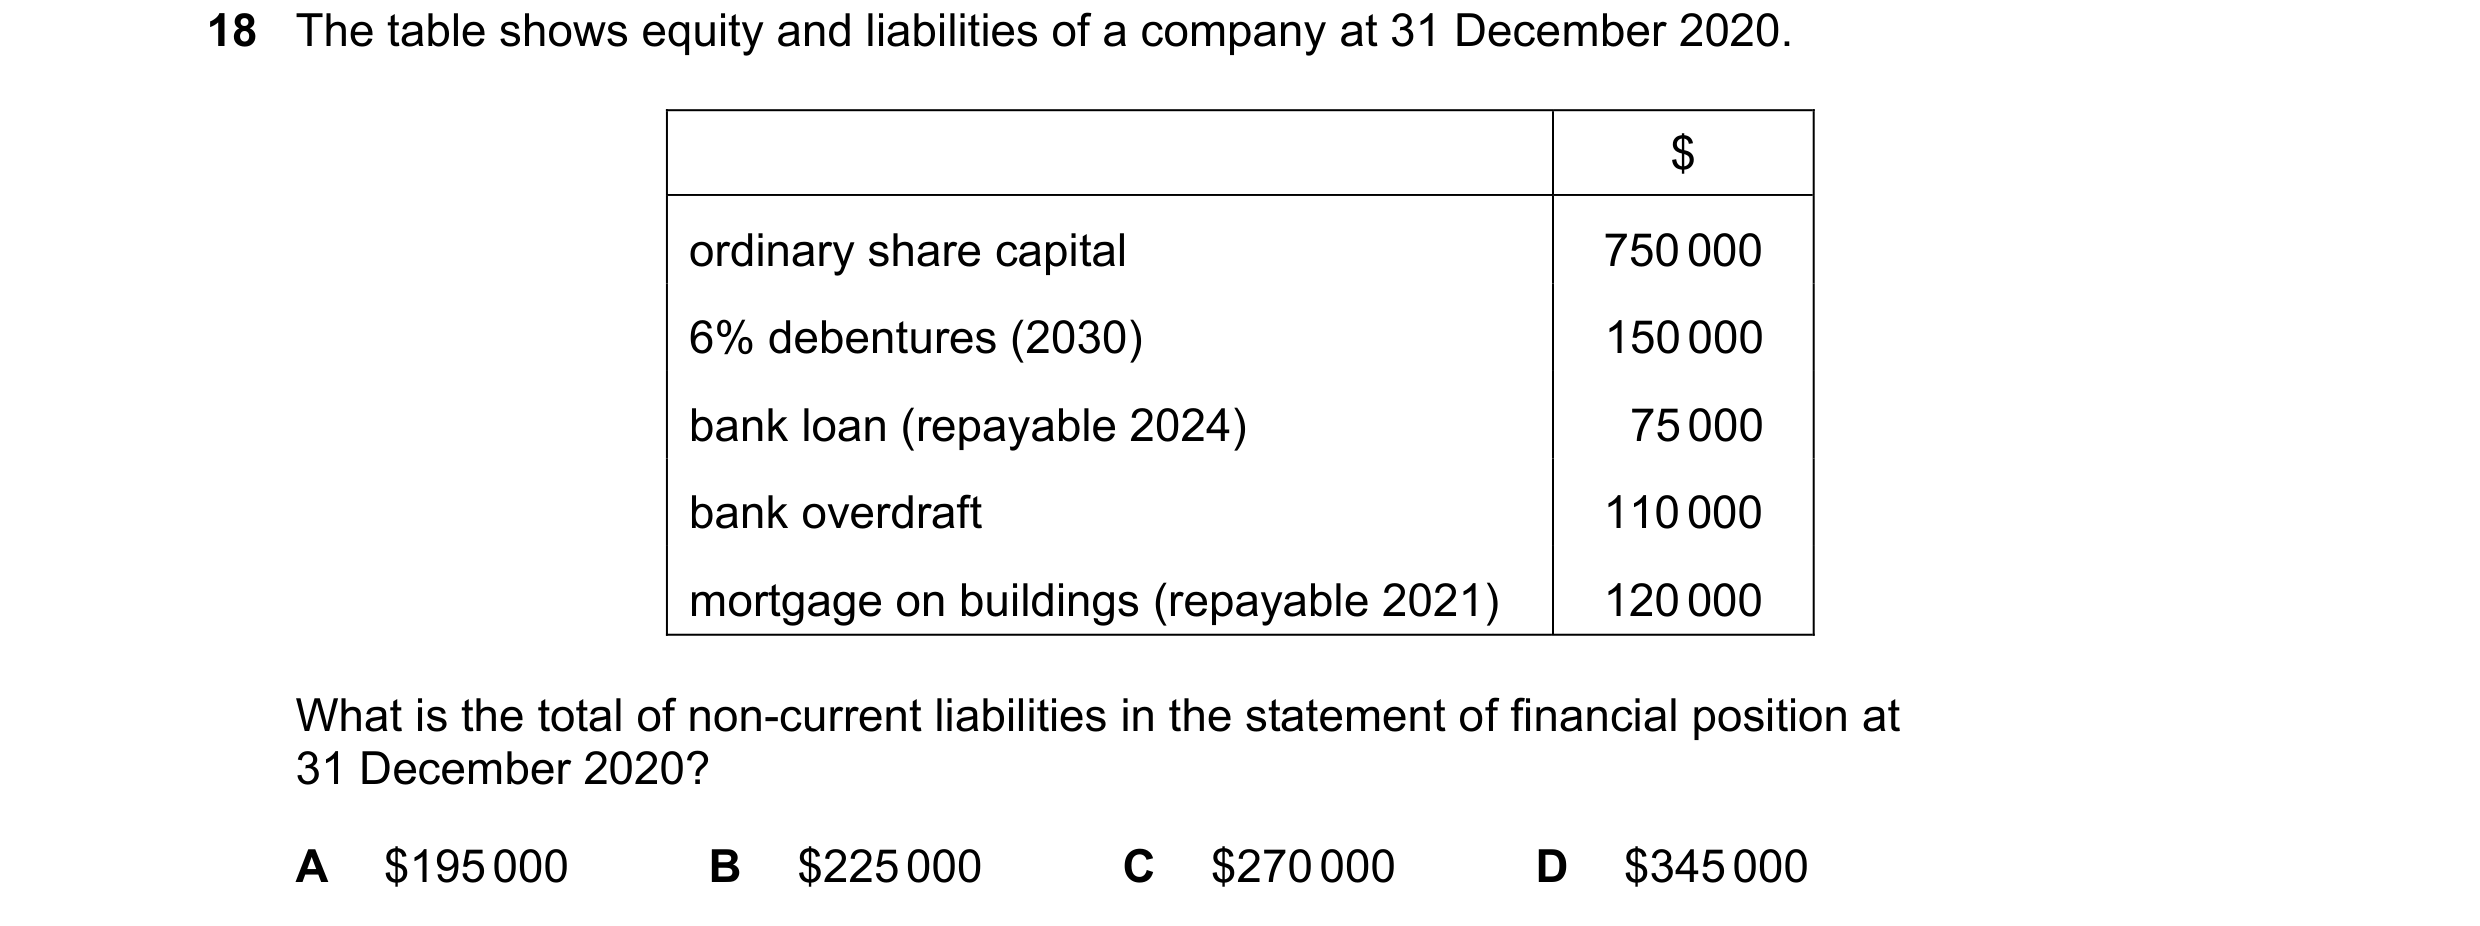
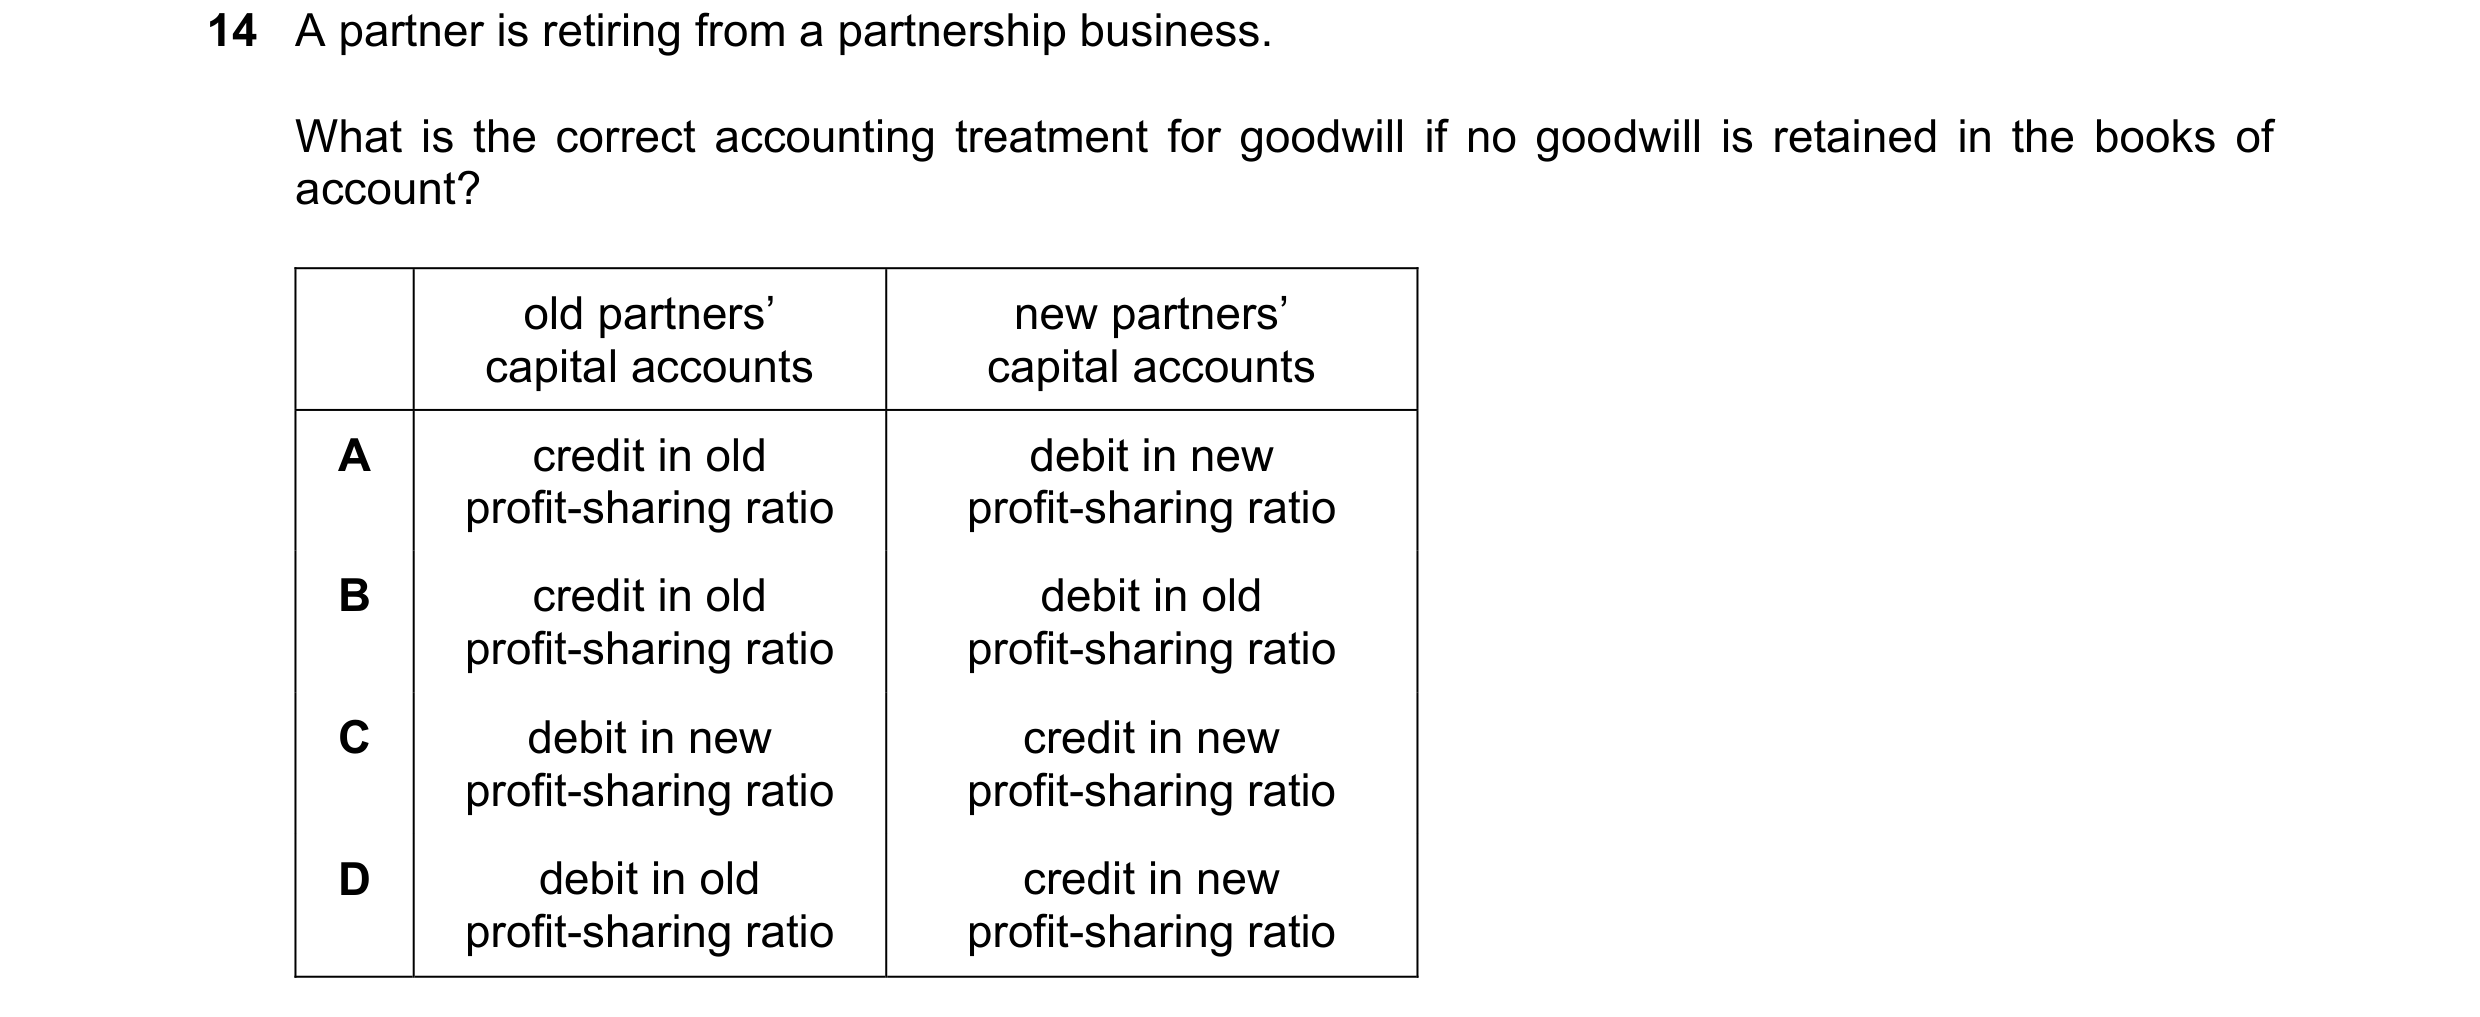
 38 / 60
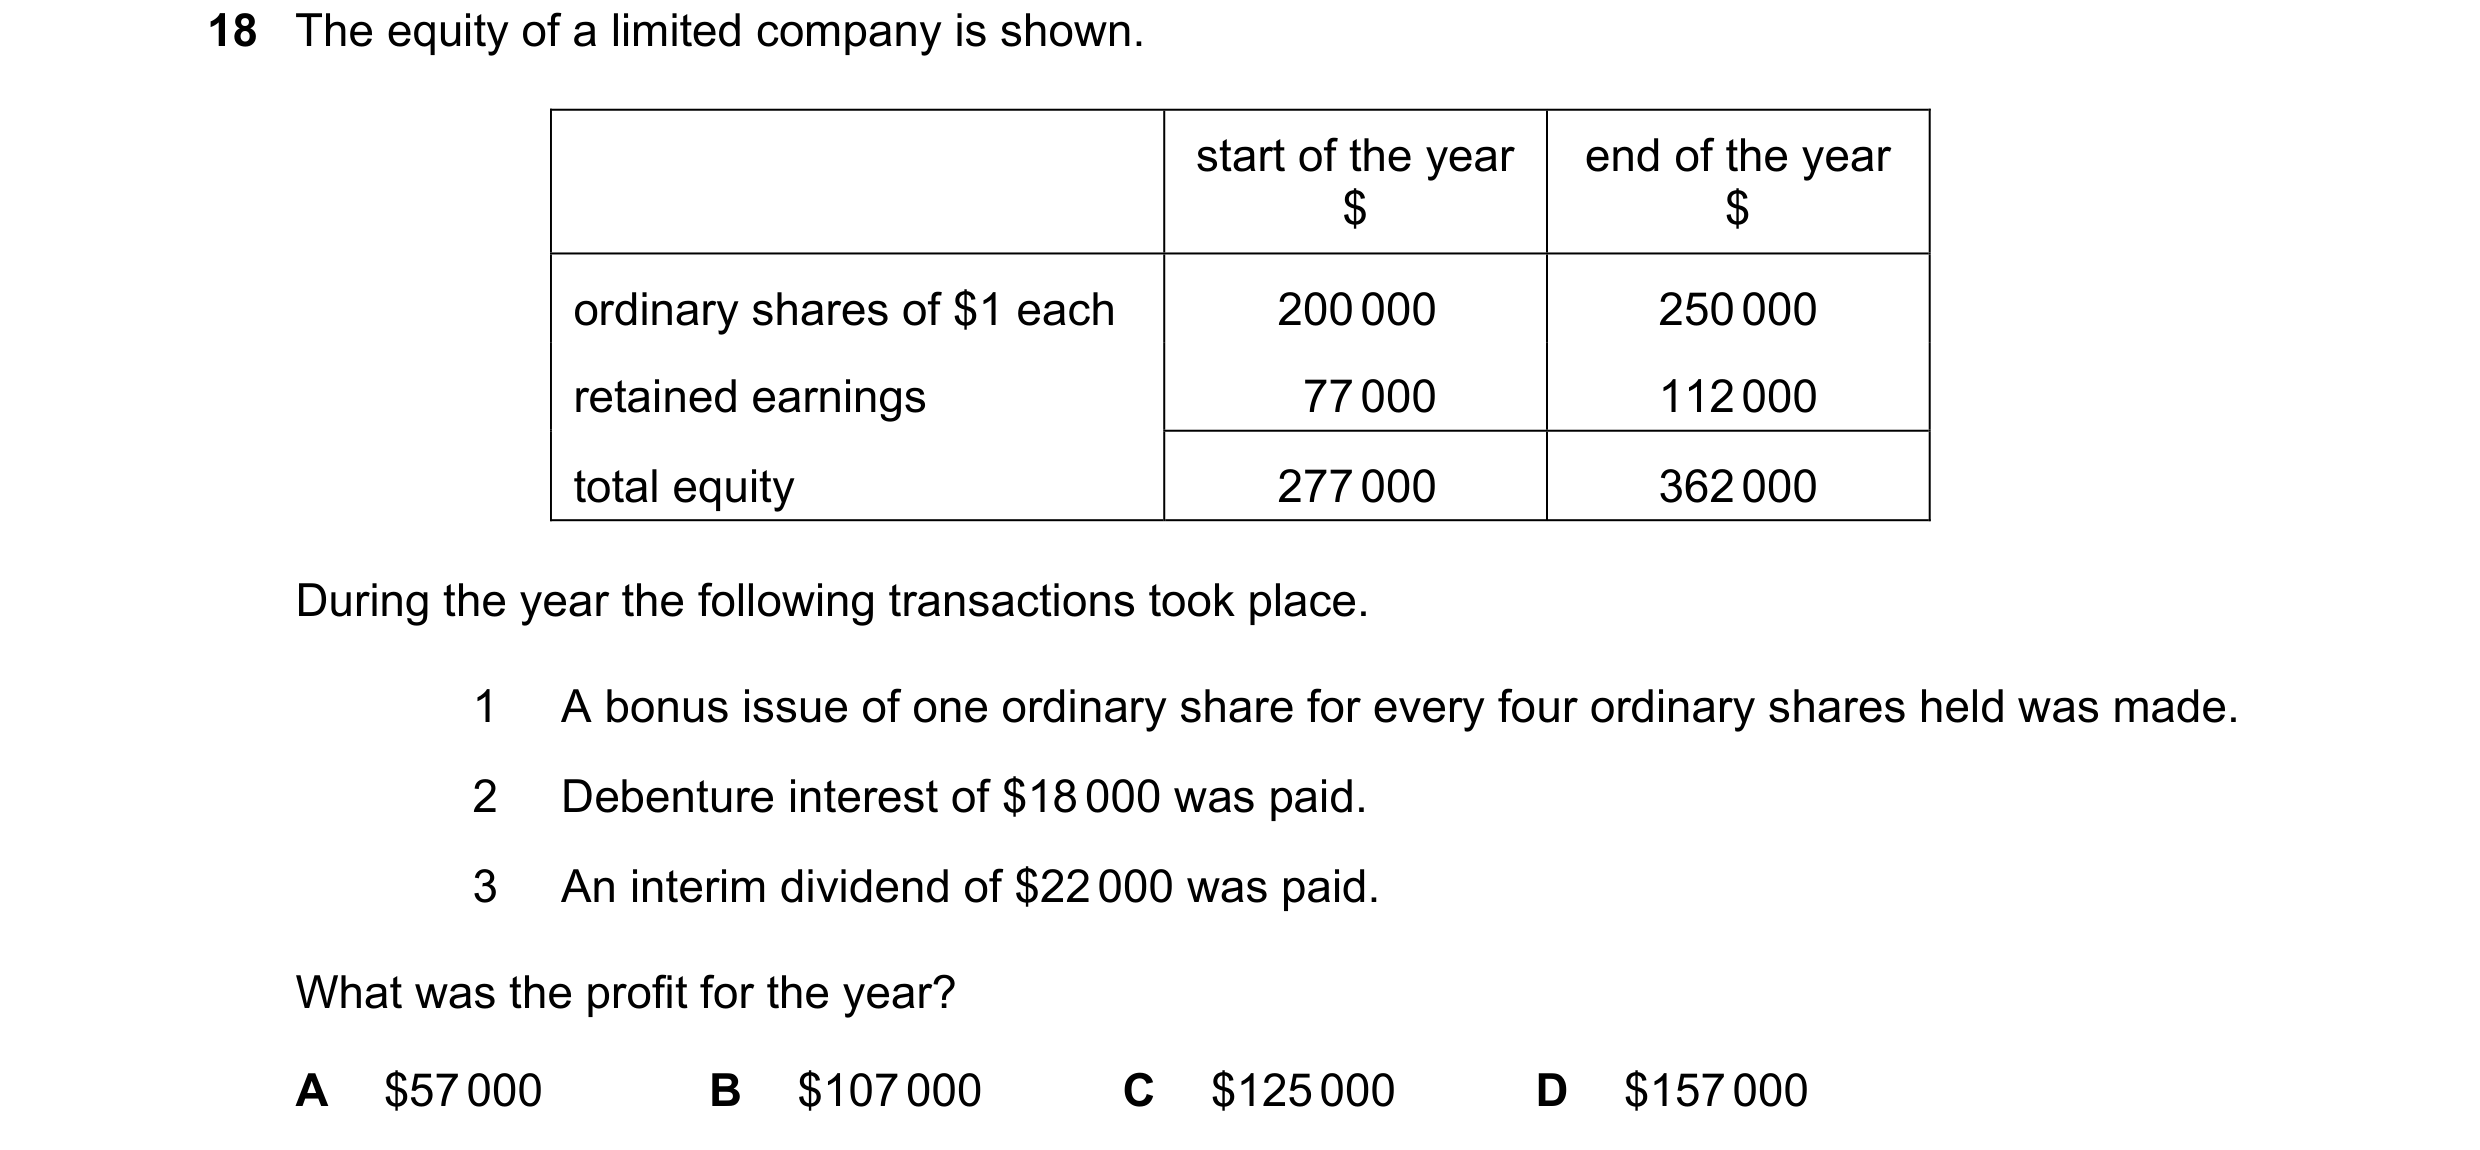 39 / 60
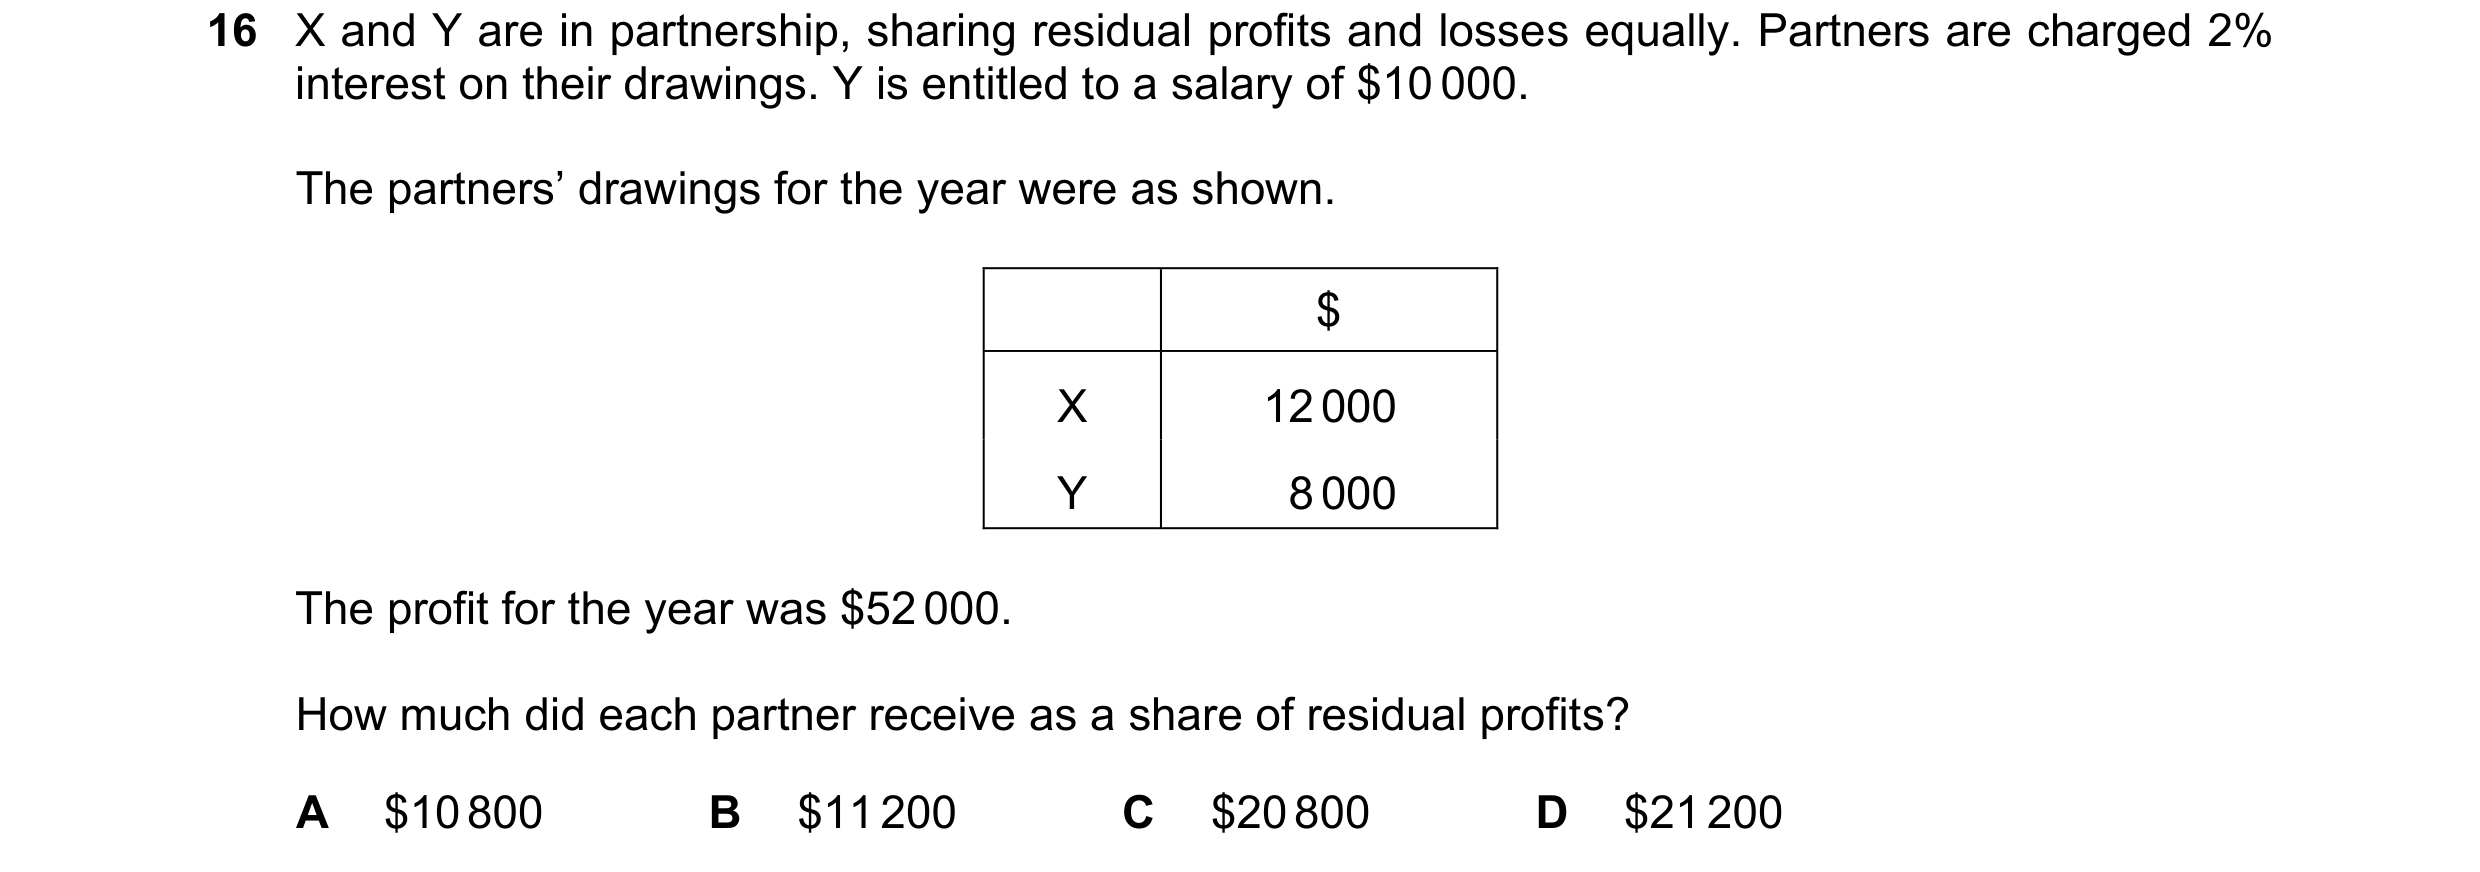
 40 / 60
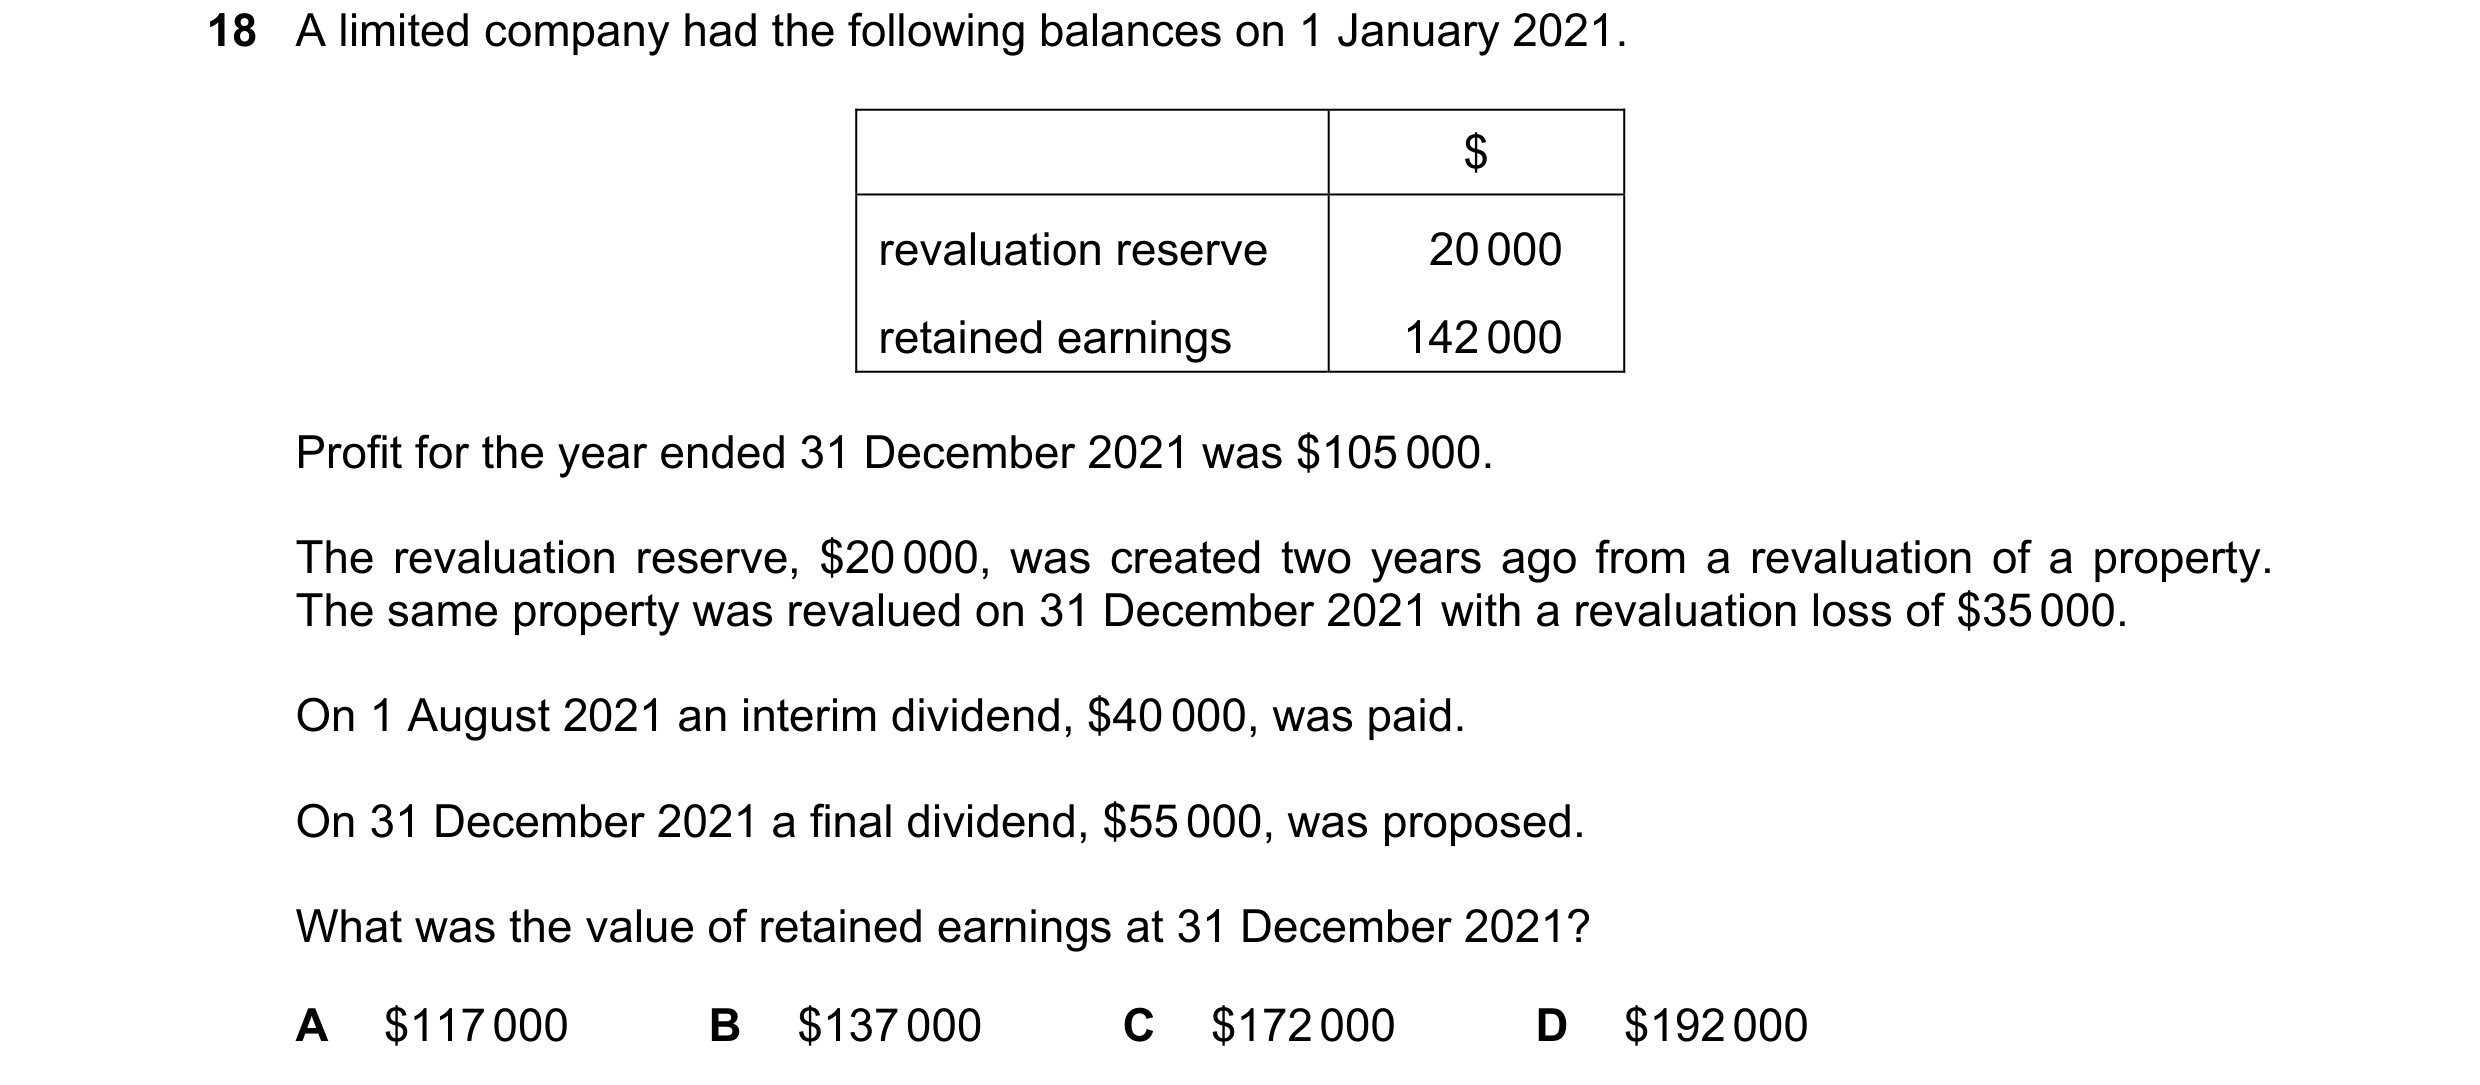
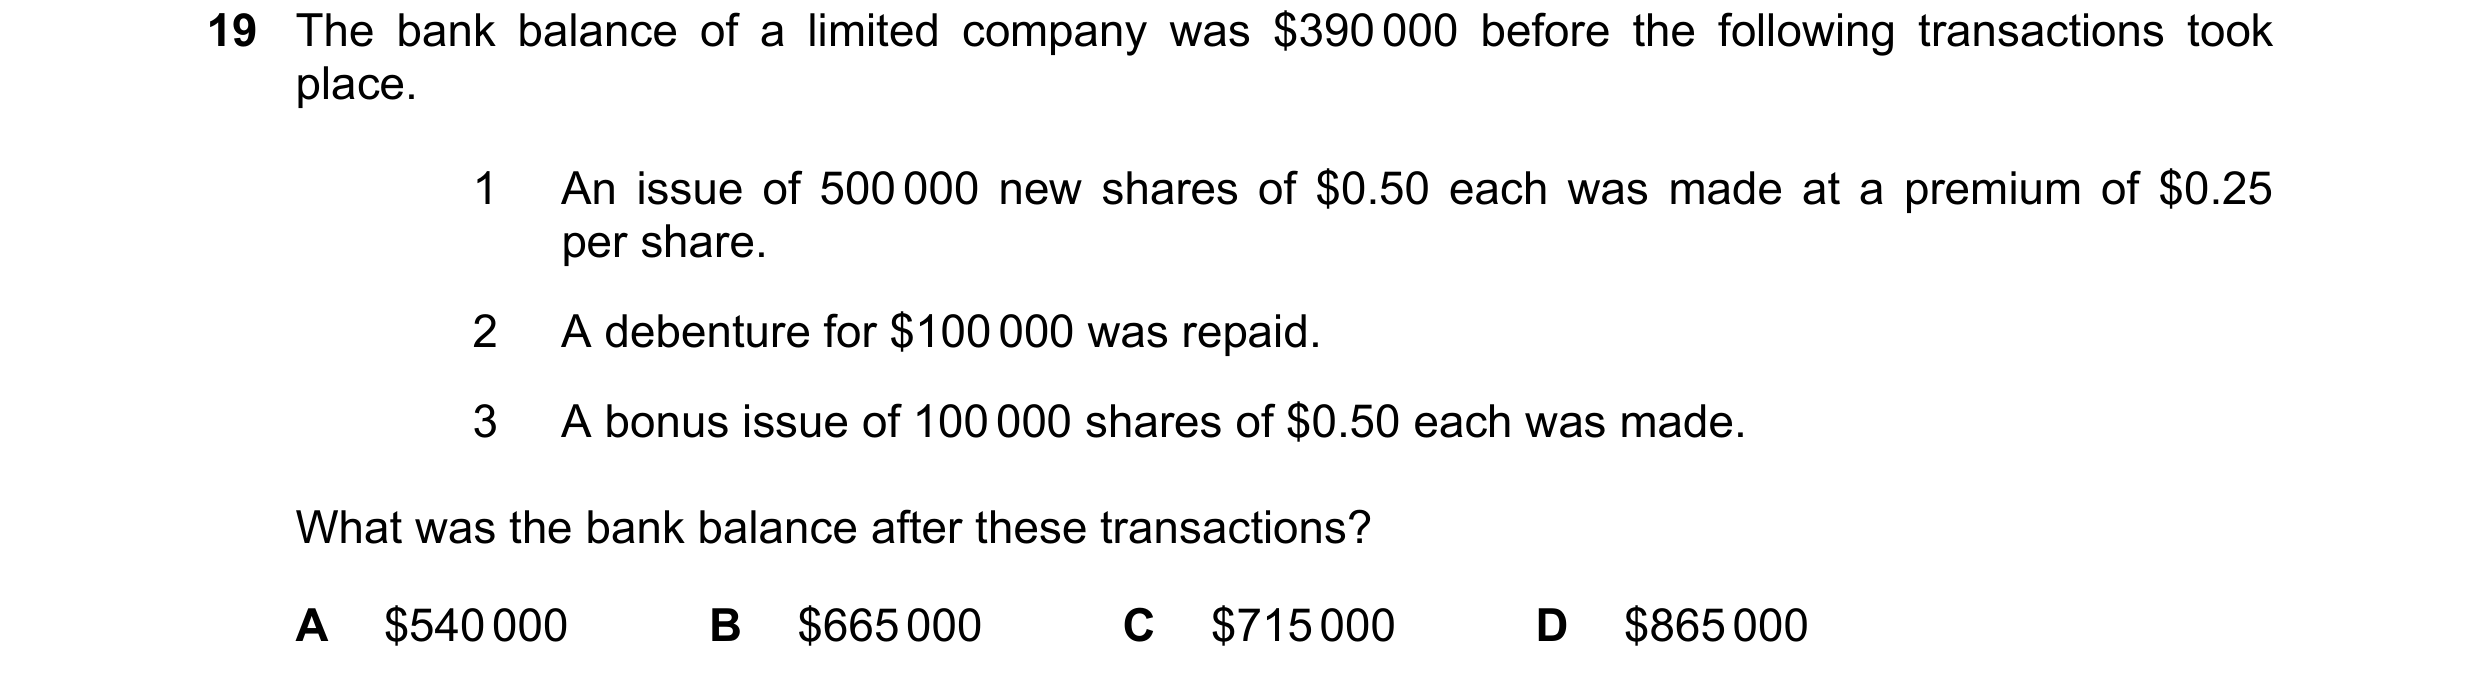
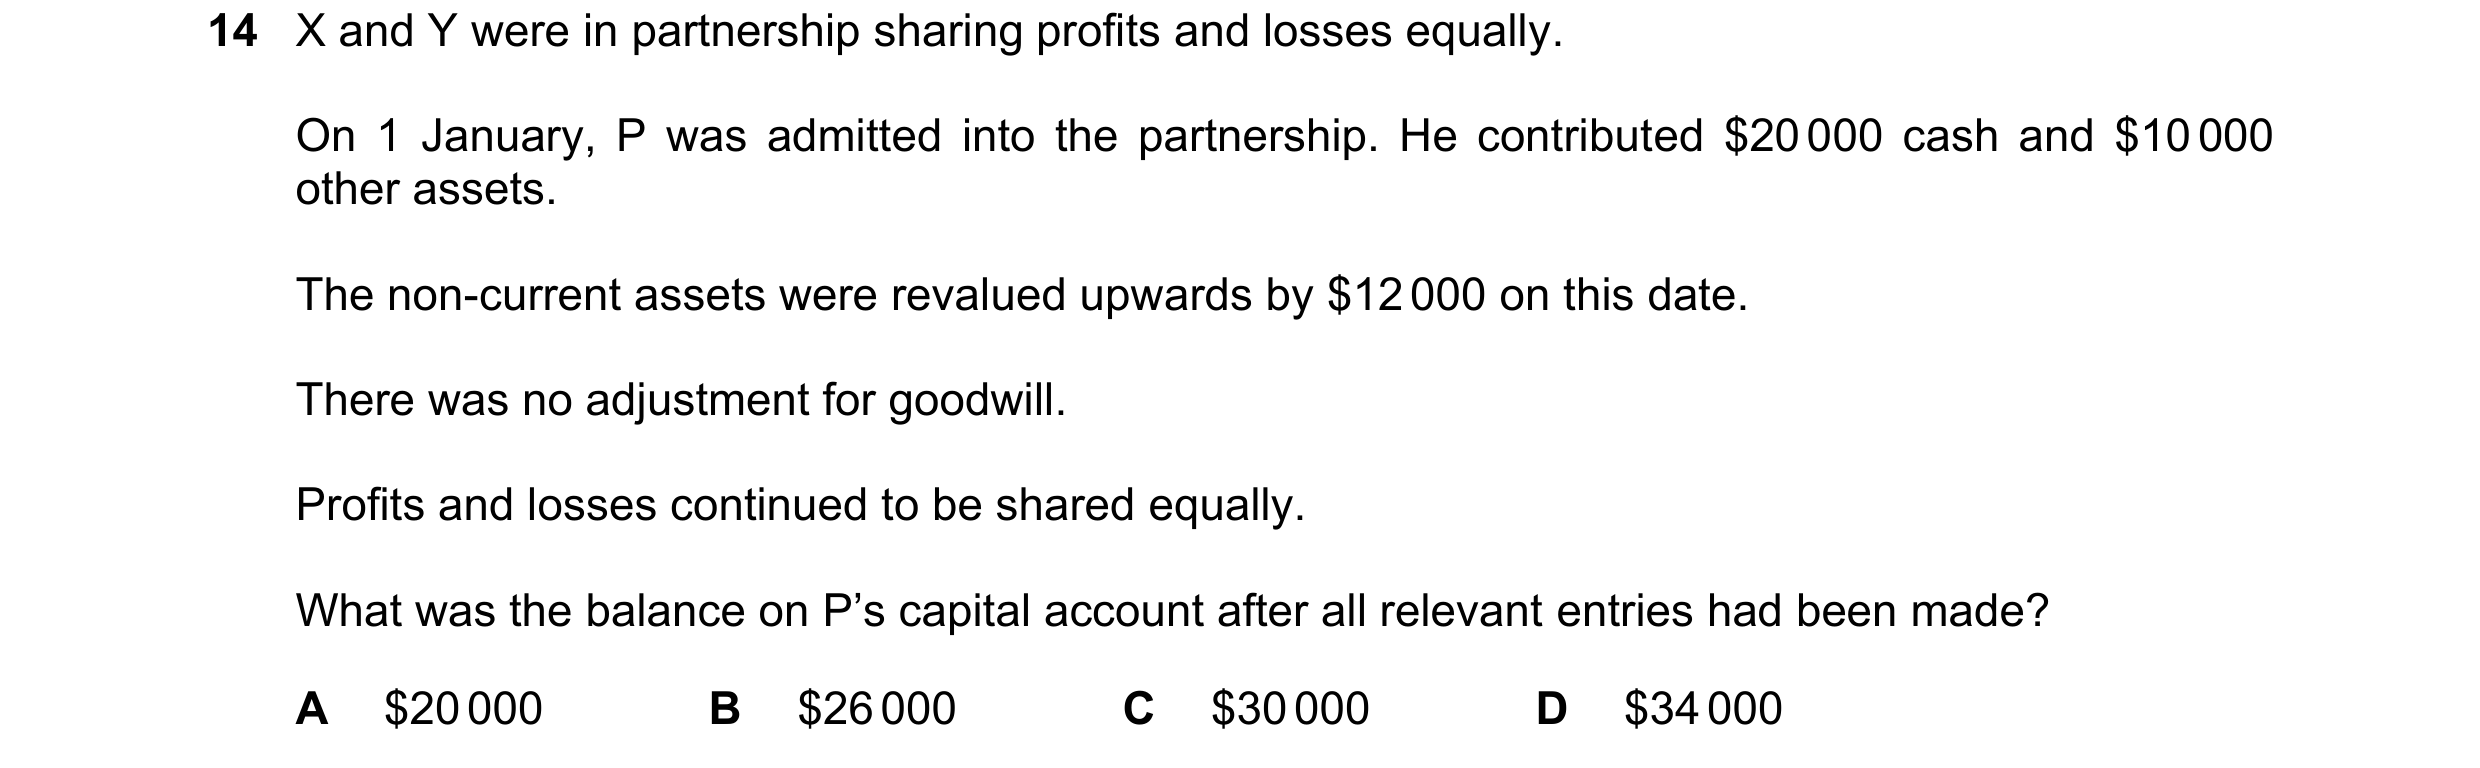
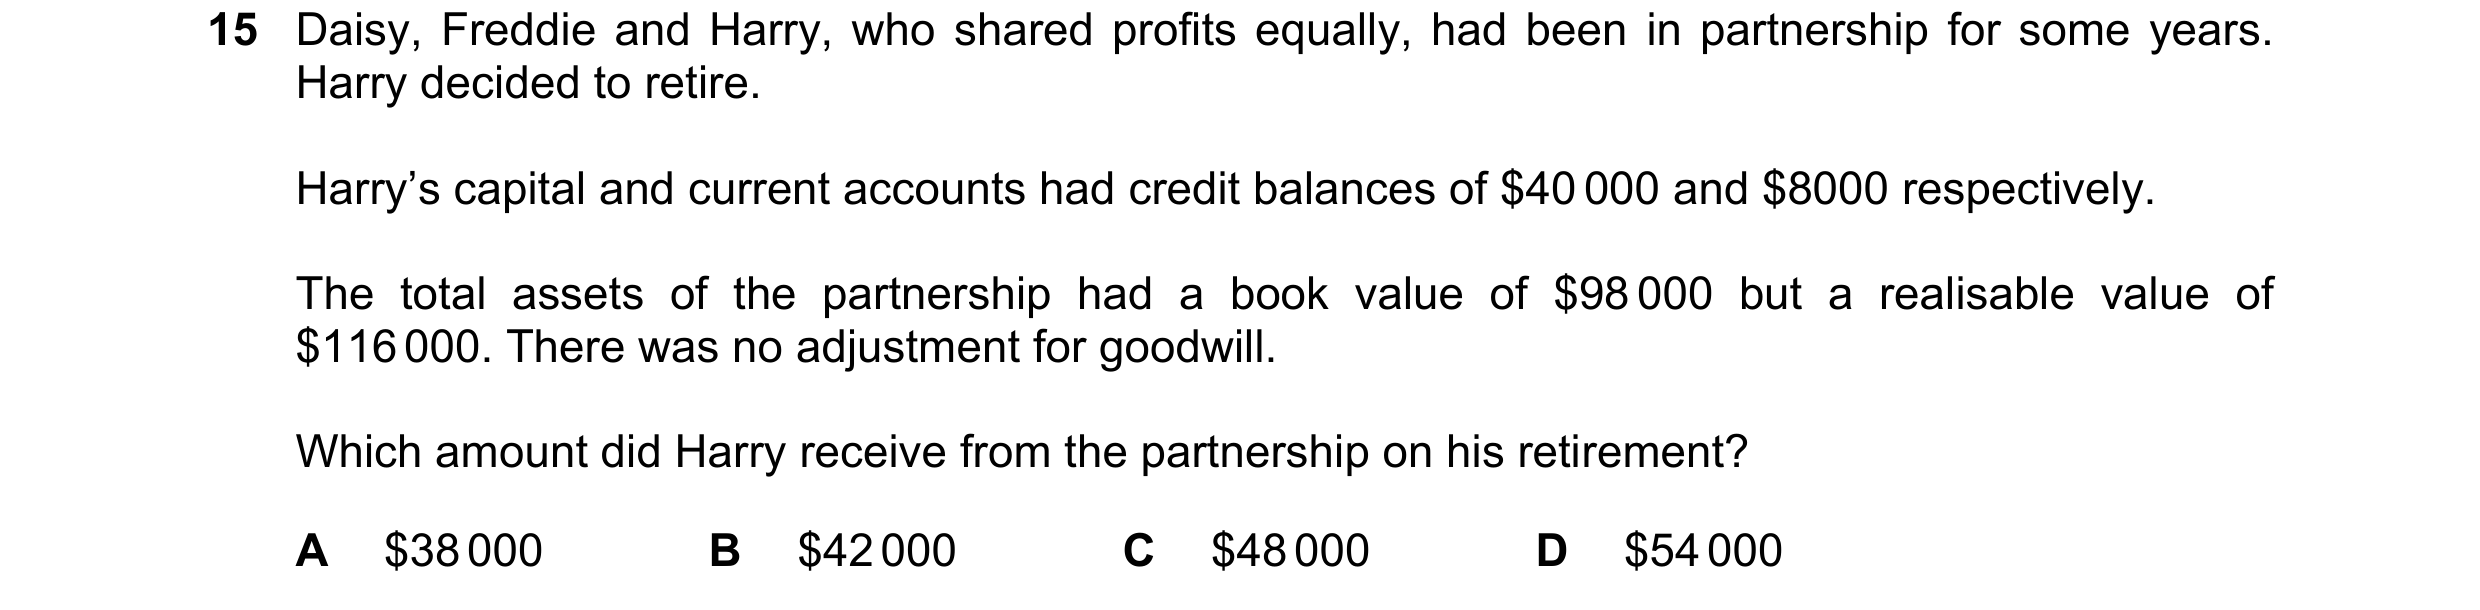 41 / 60
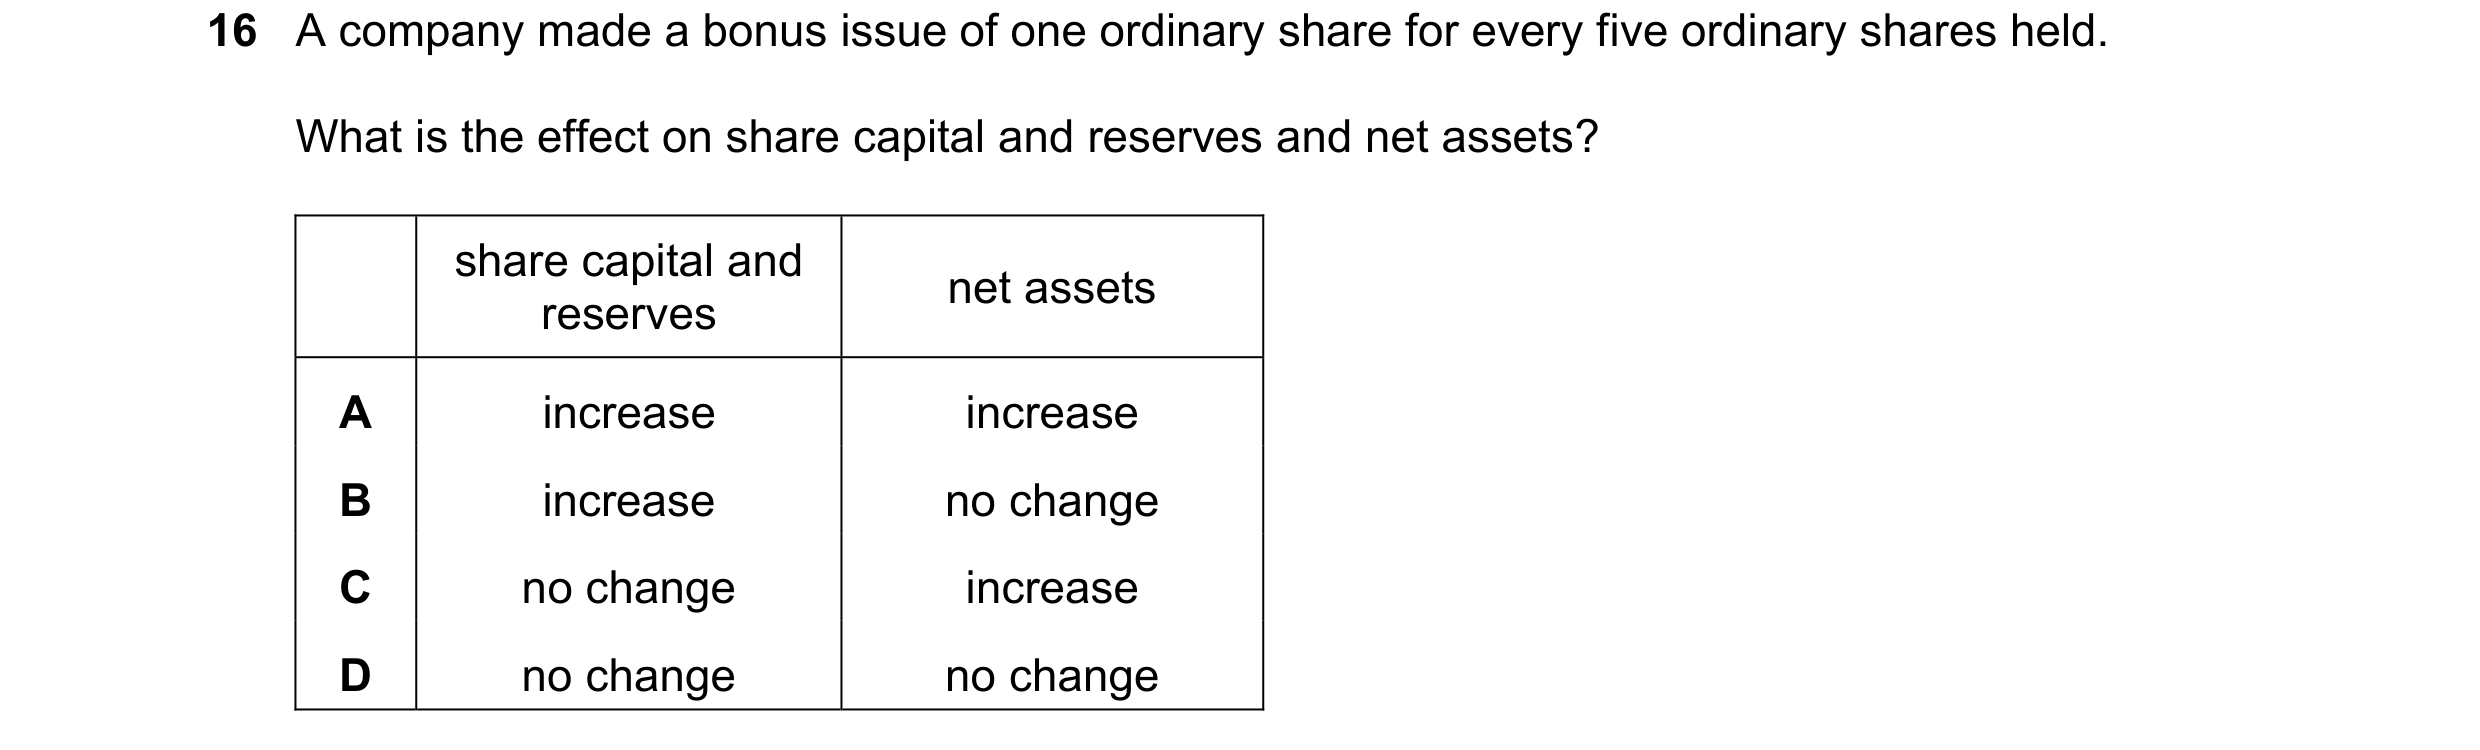
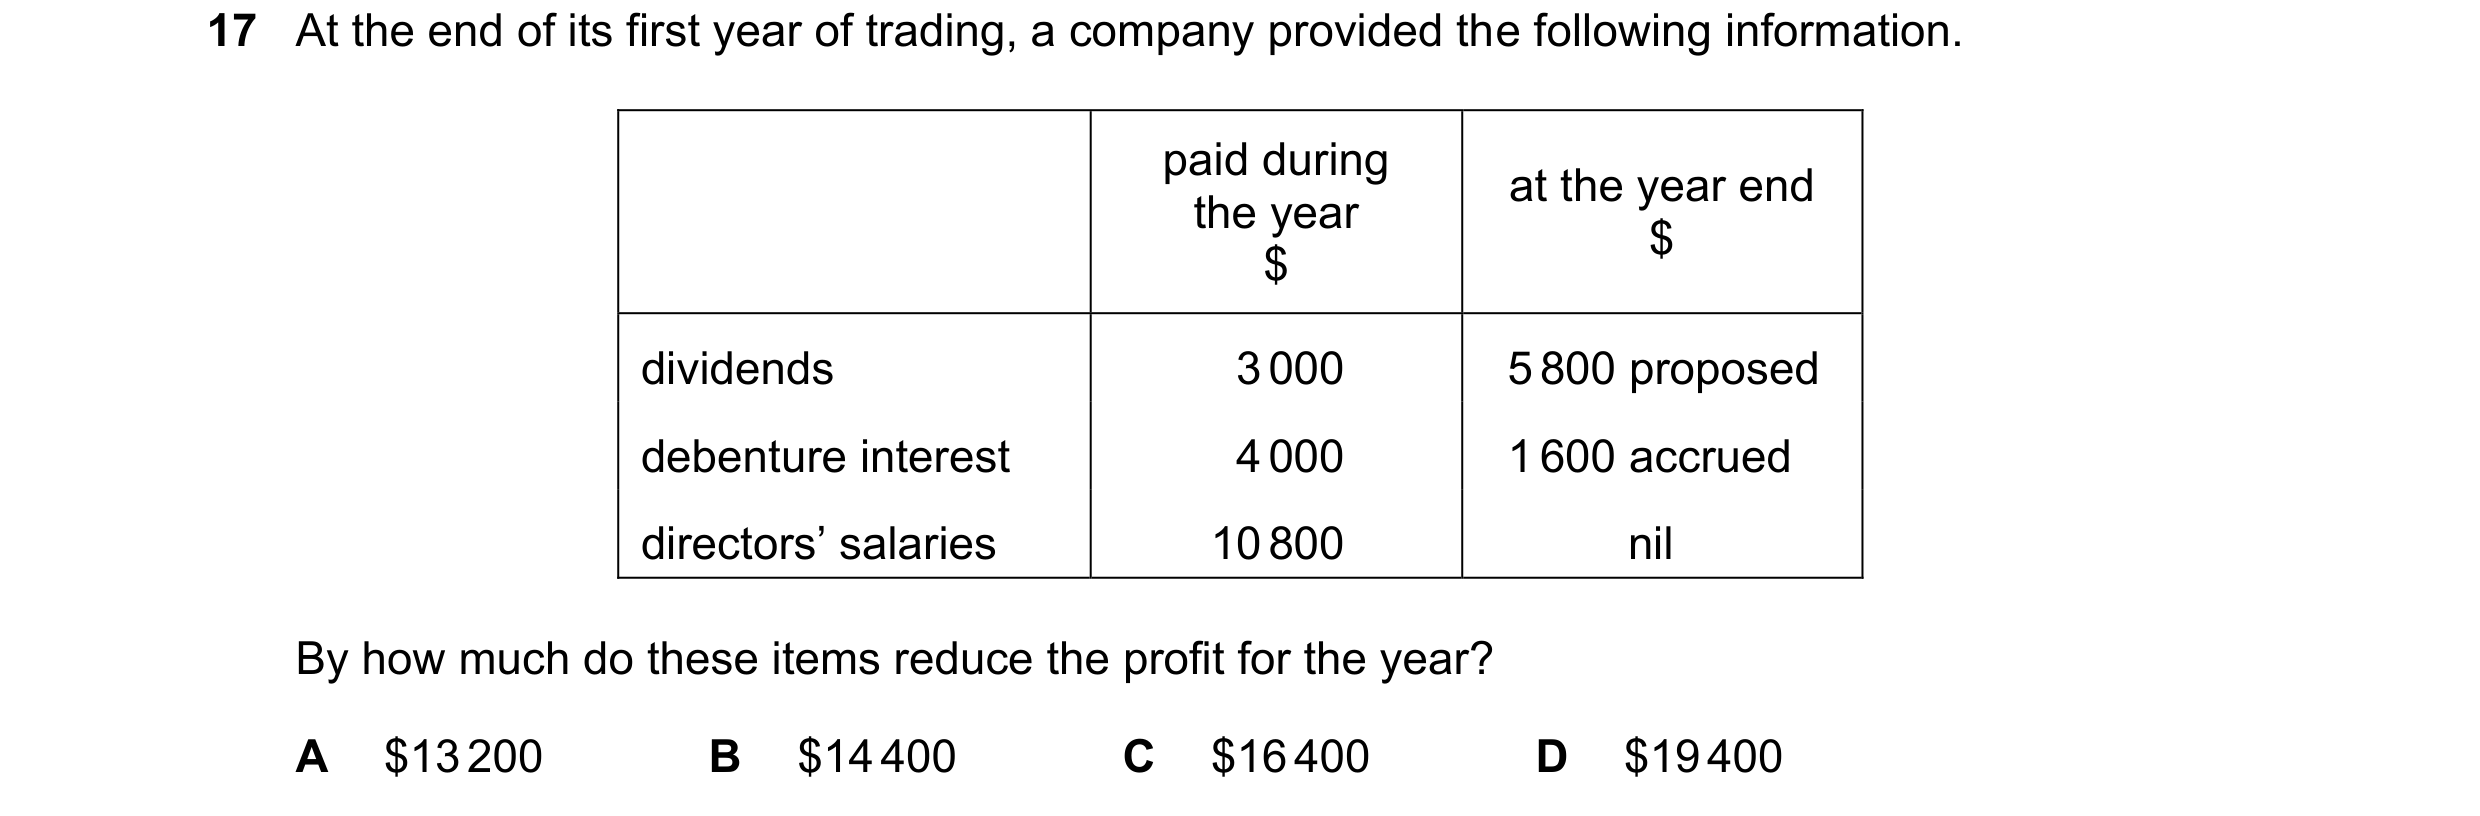
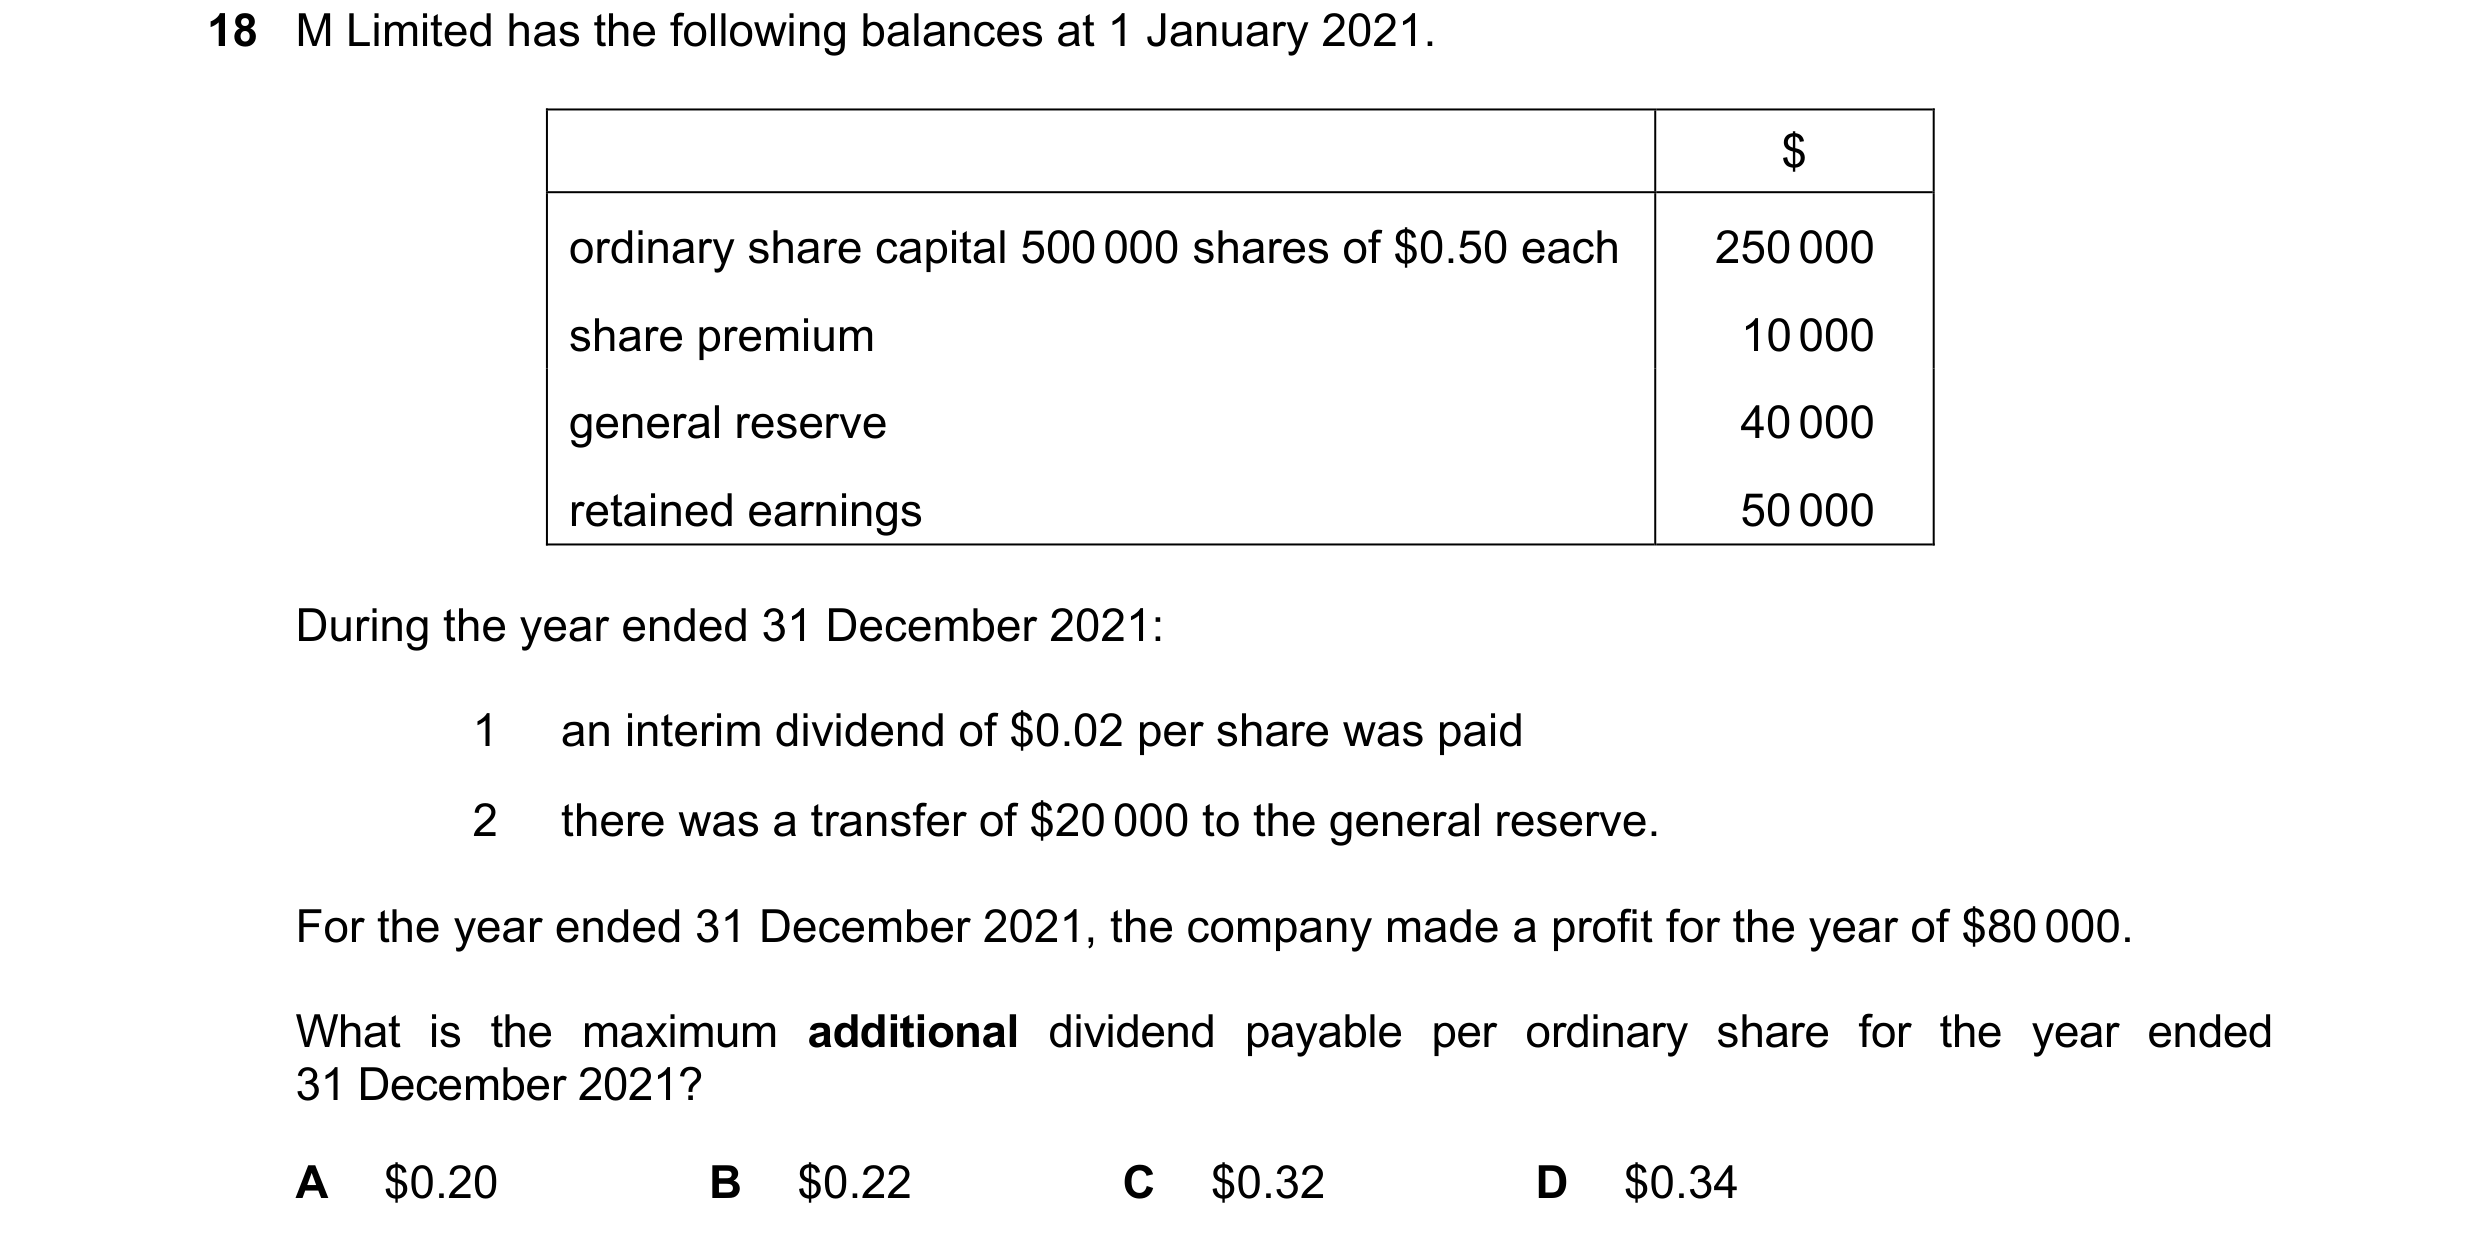 42 / 60
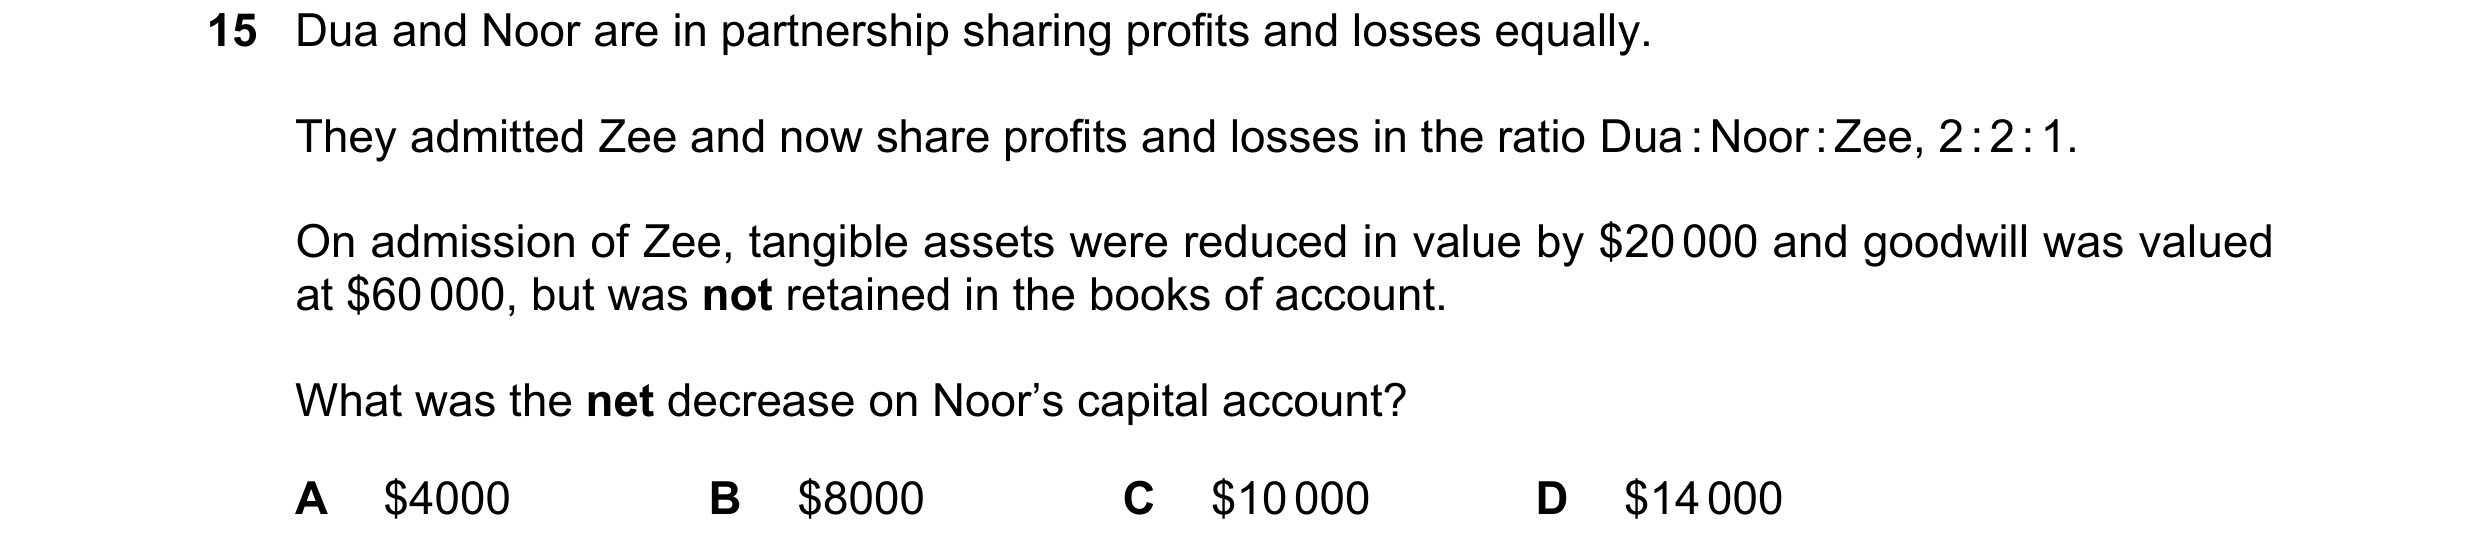
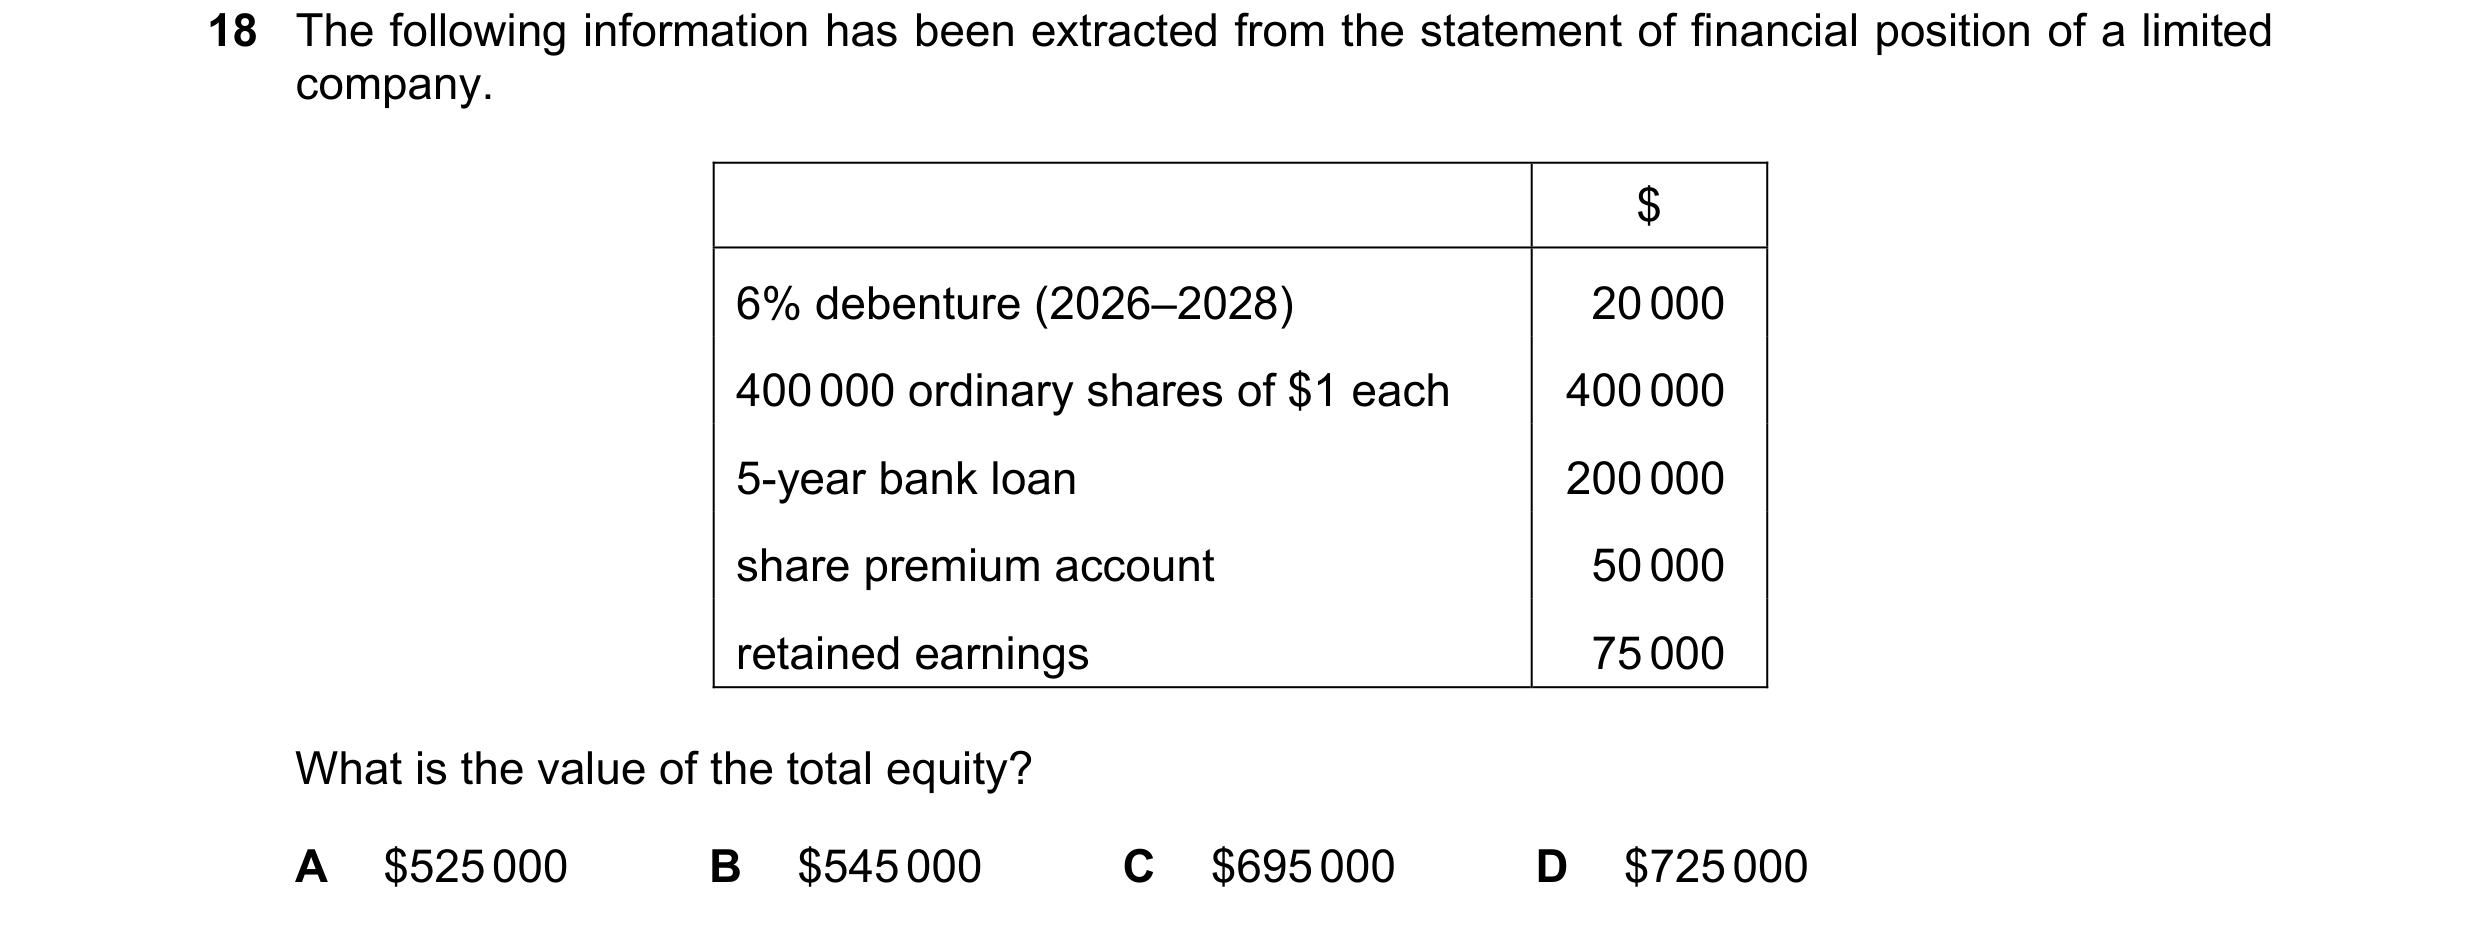 43 / 60
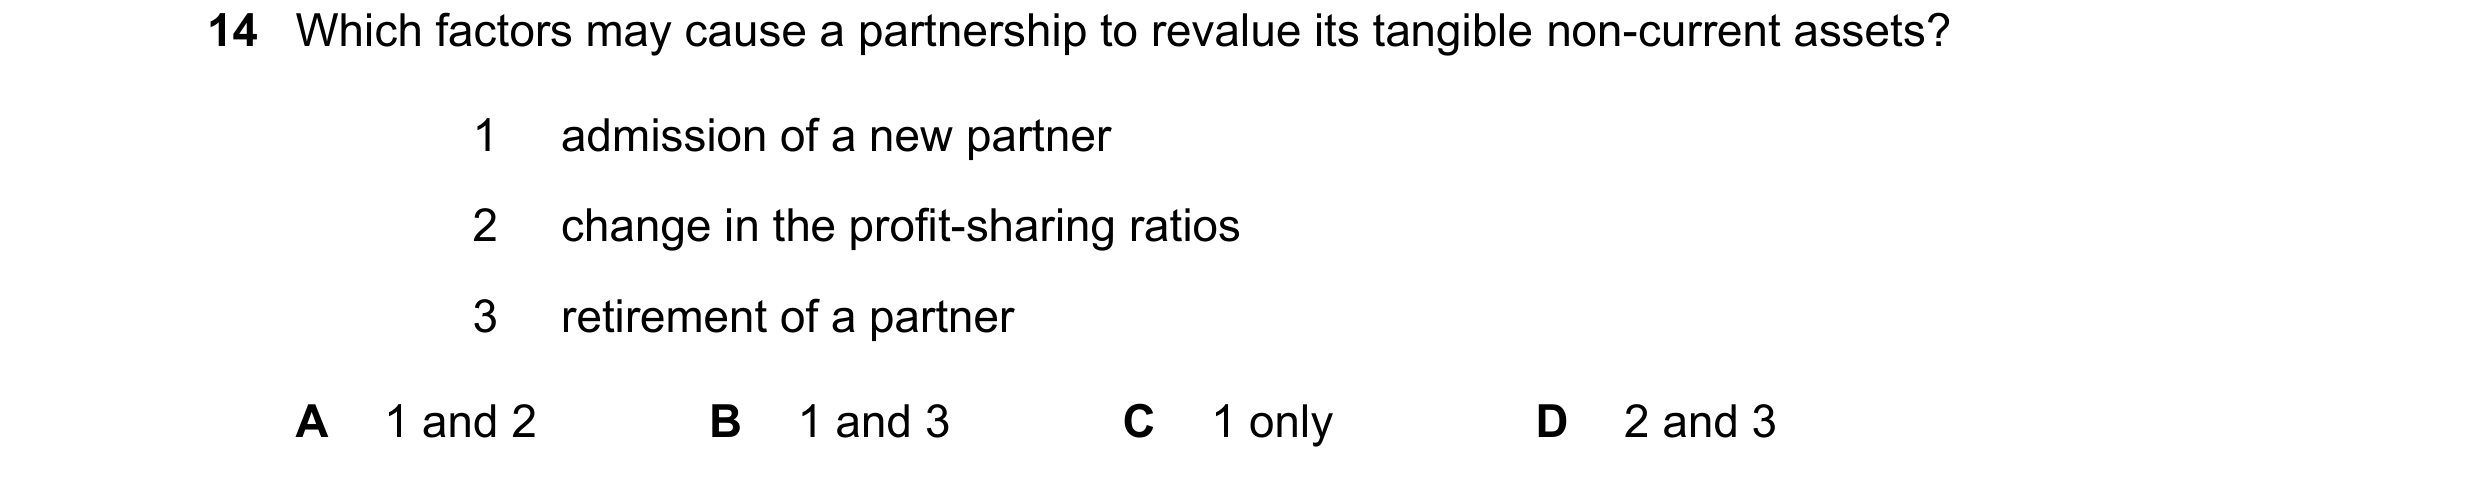
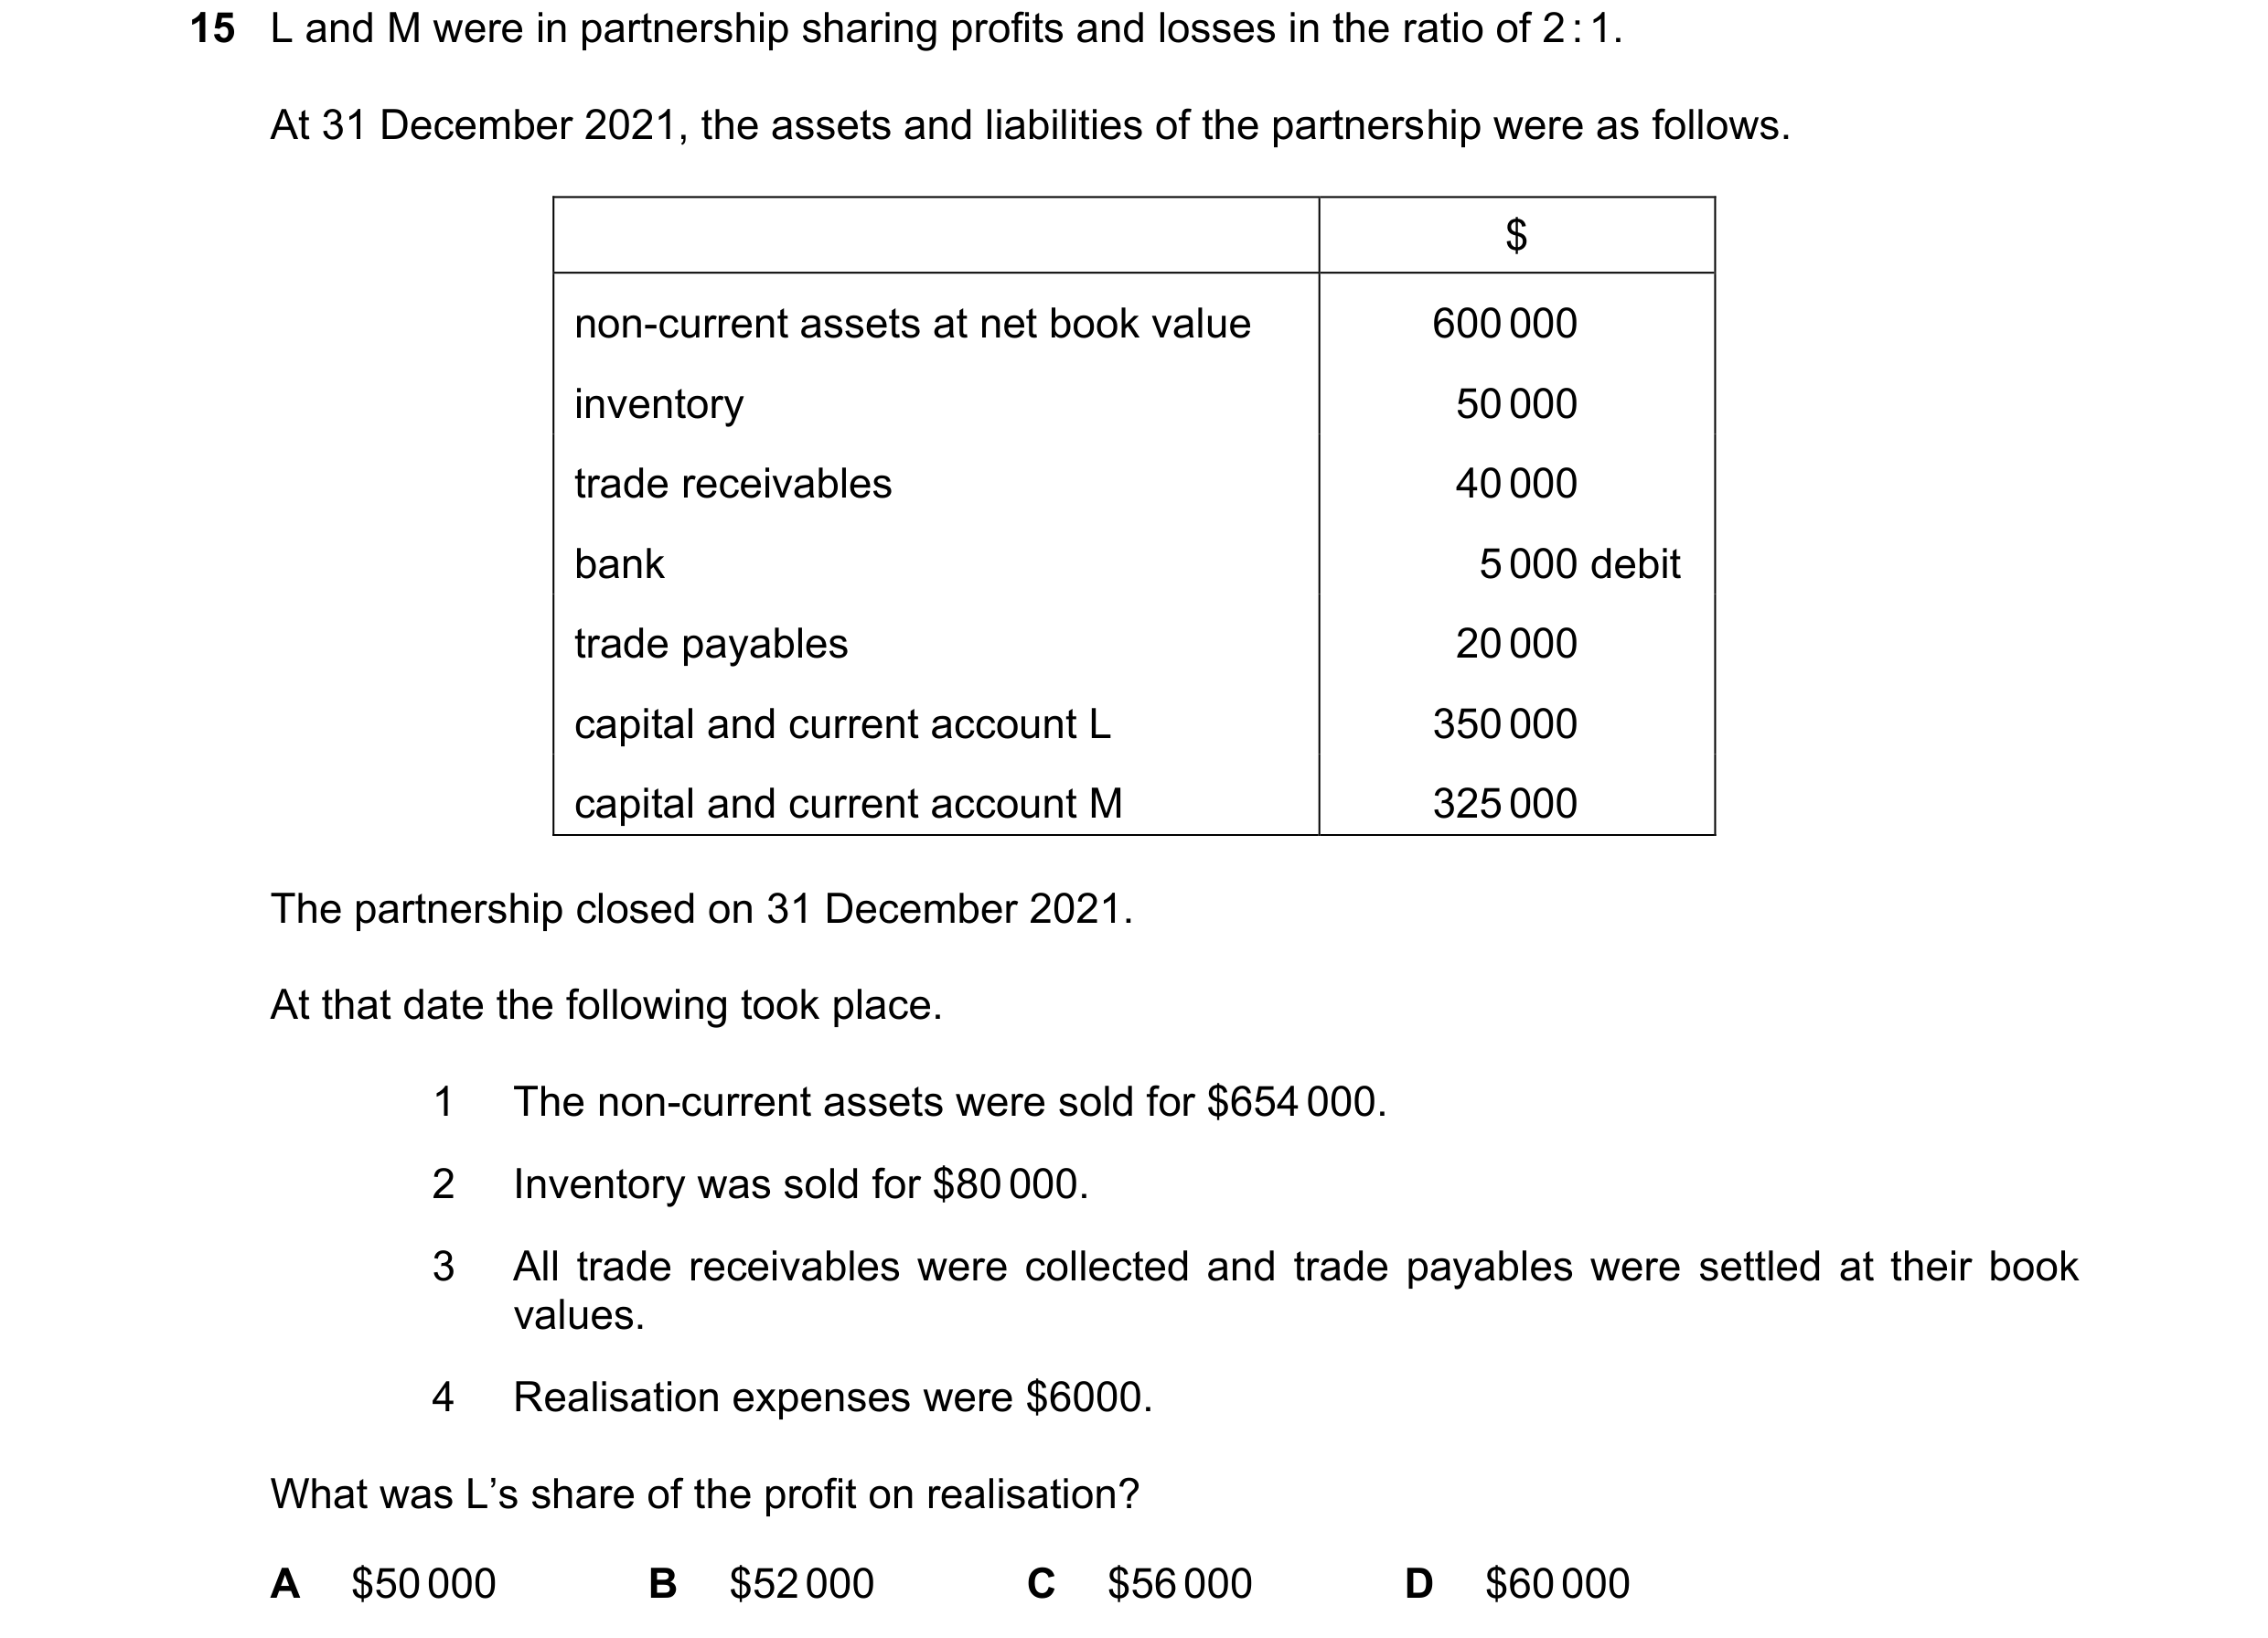 44 / 60
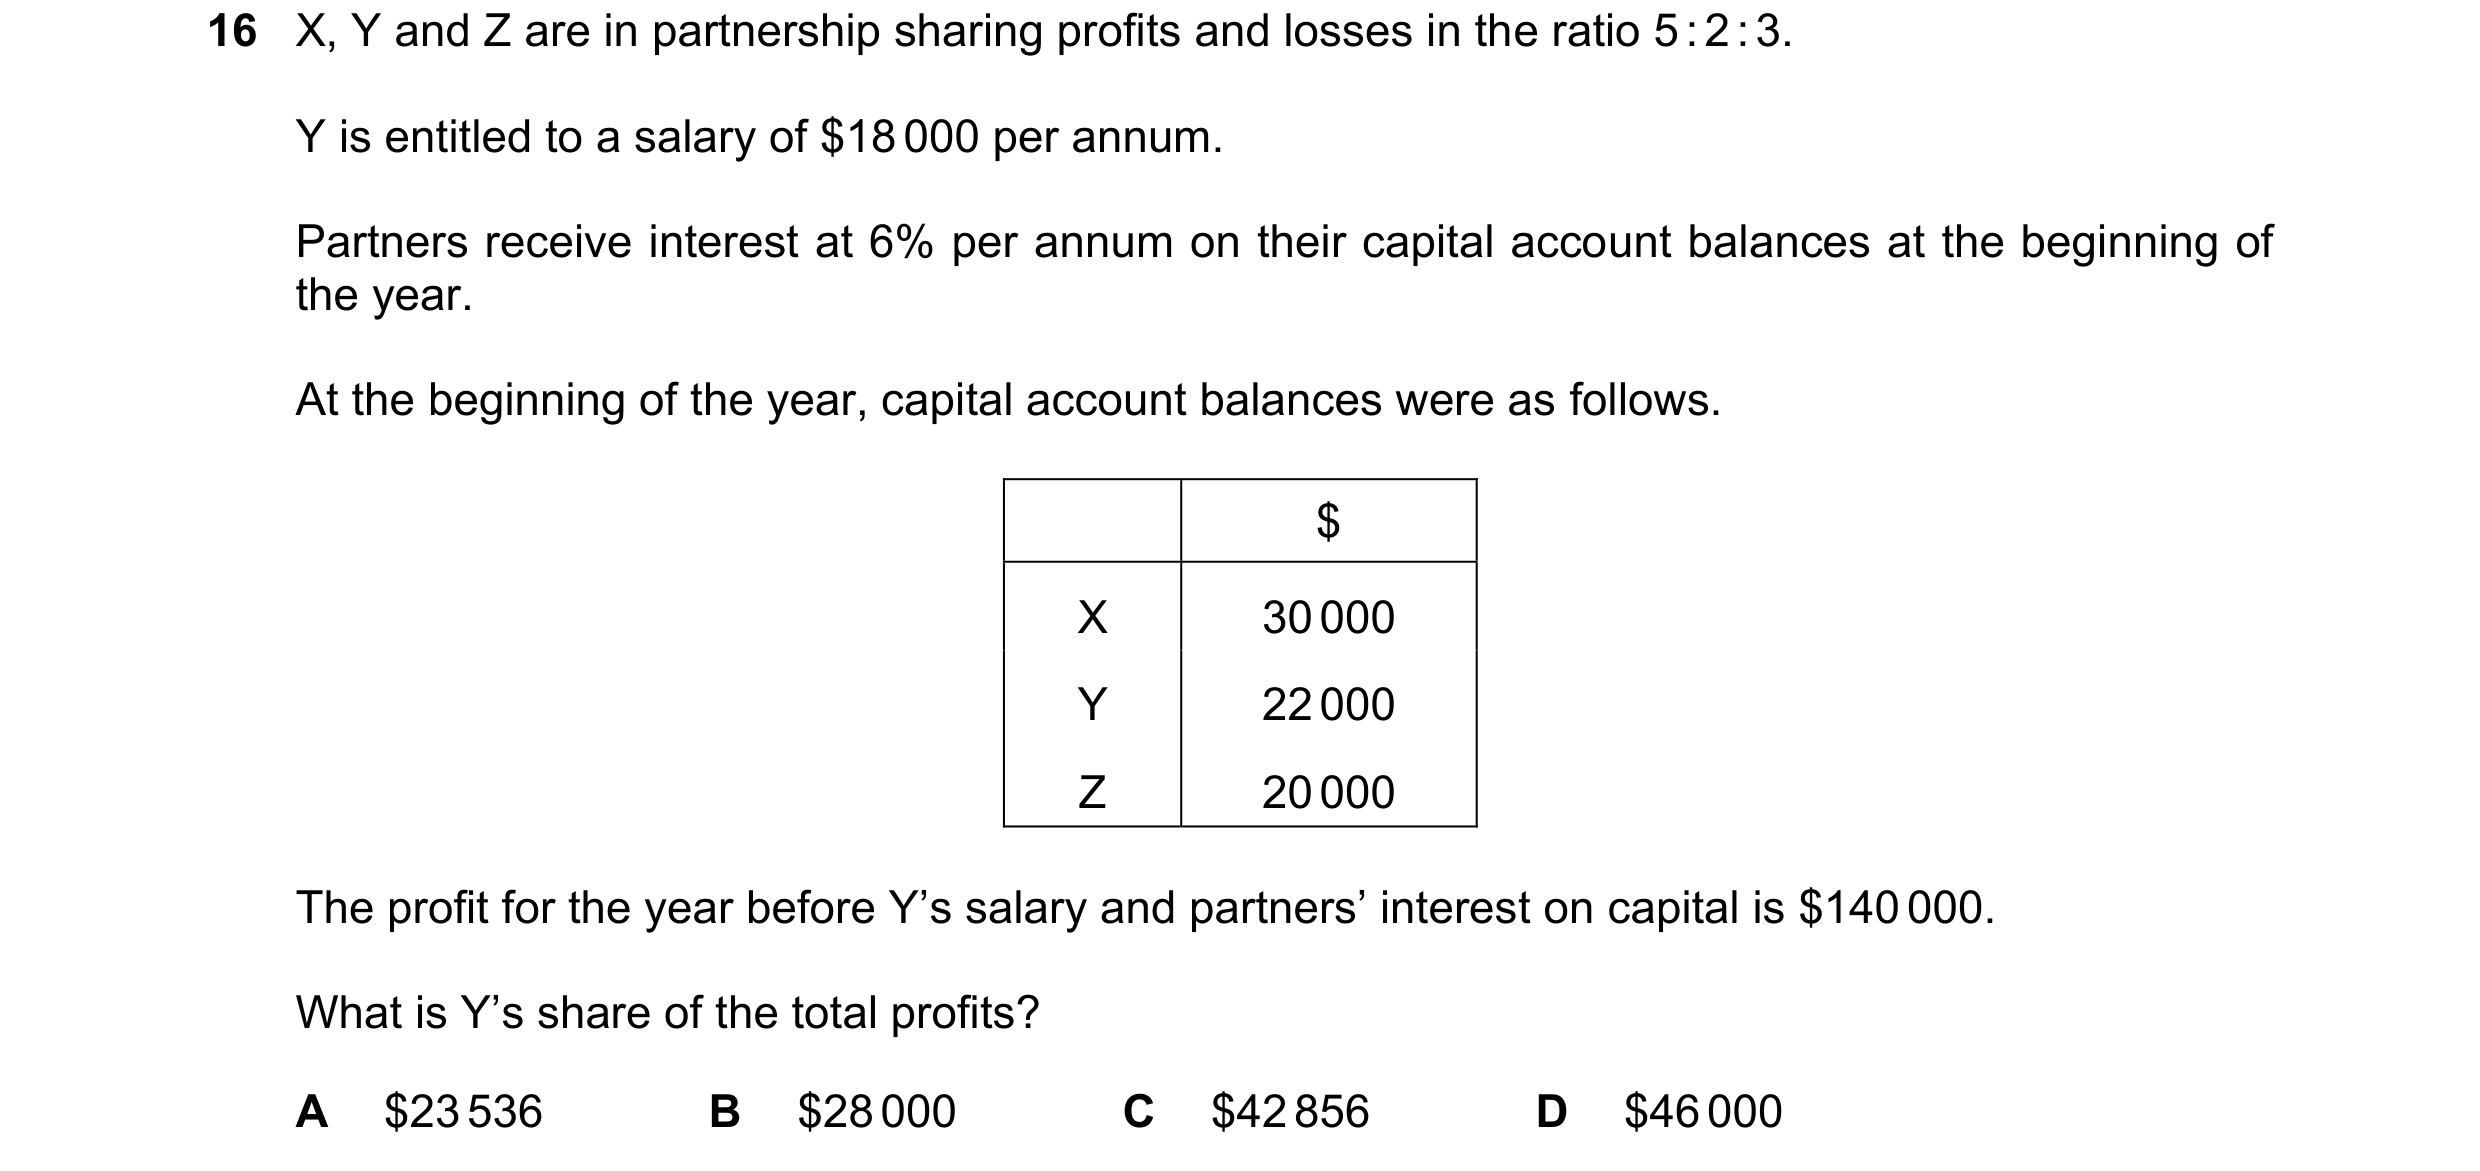
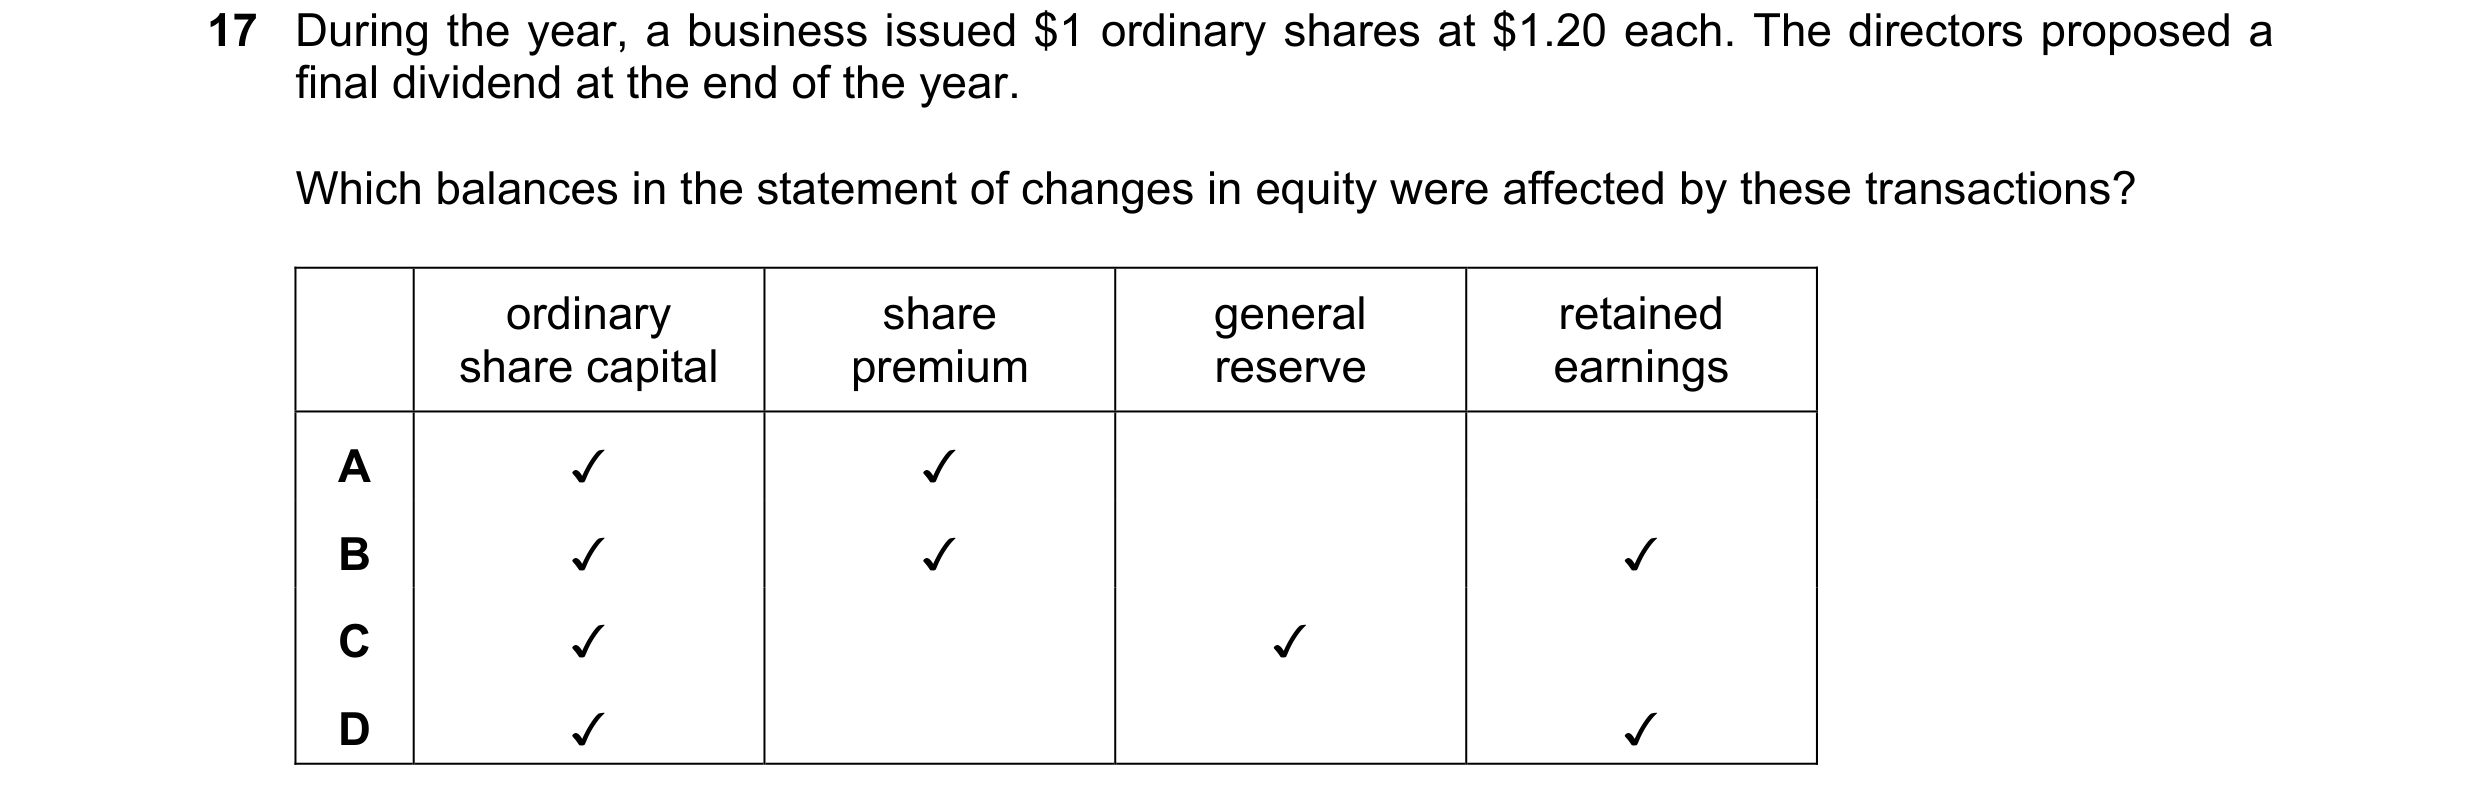
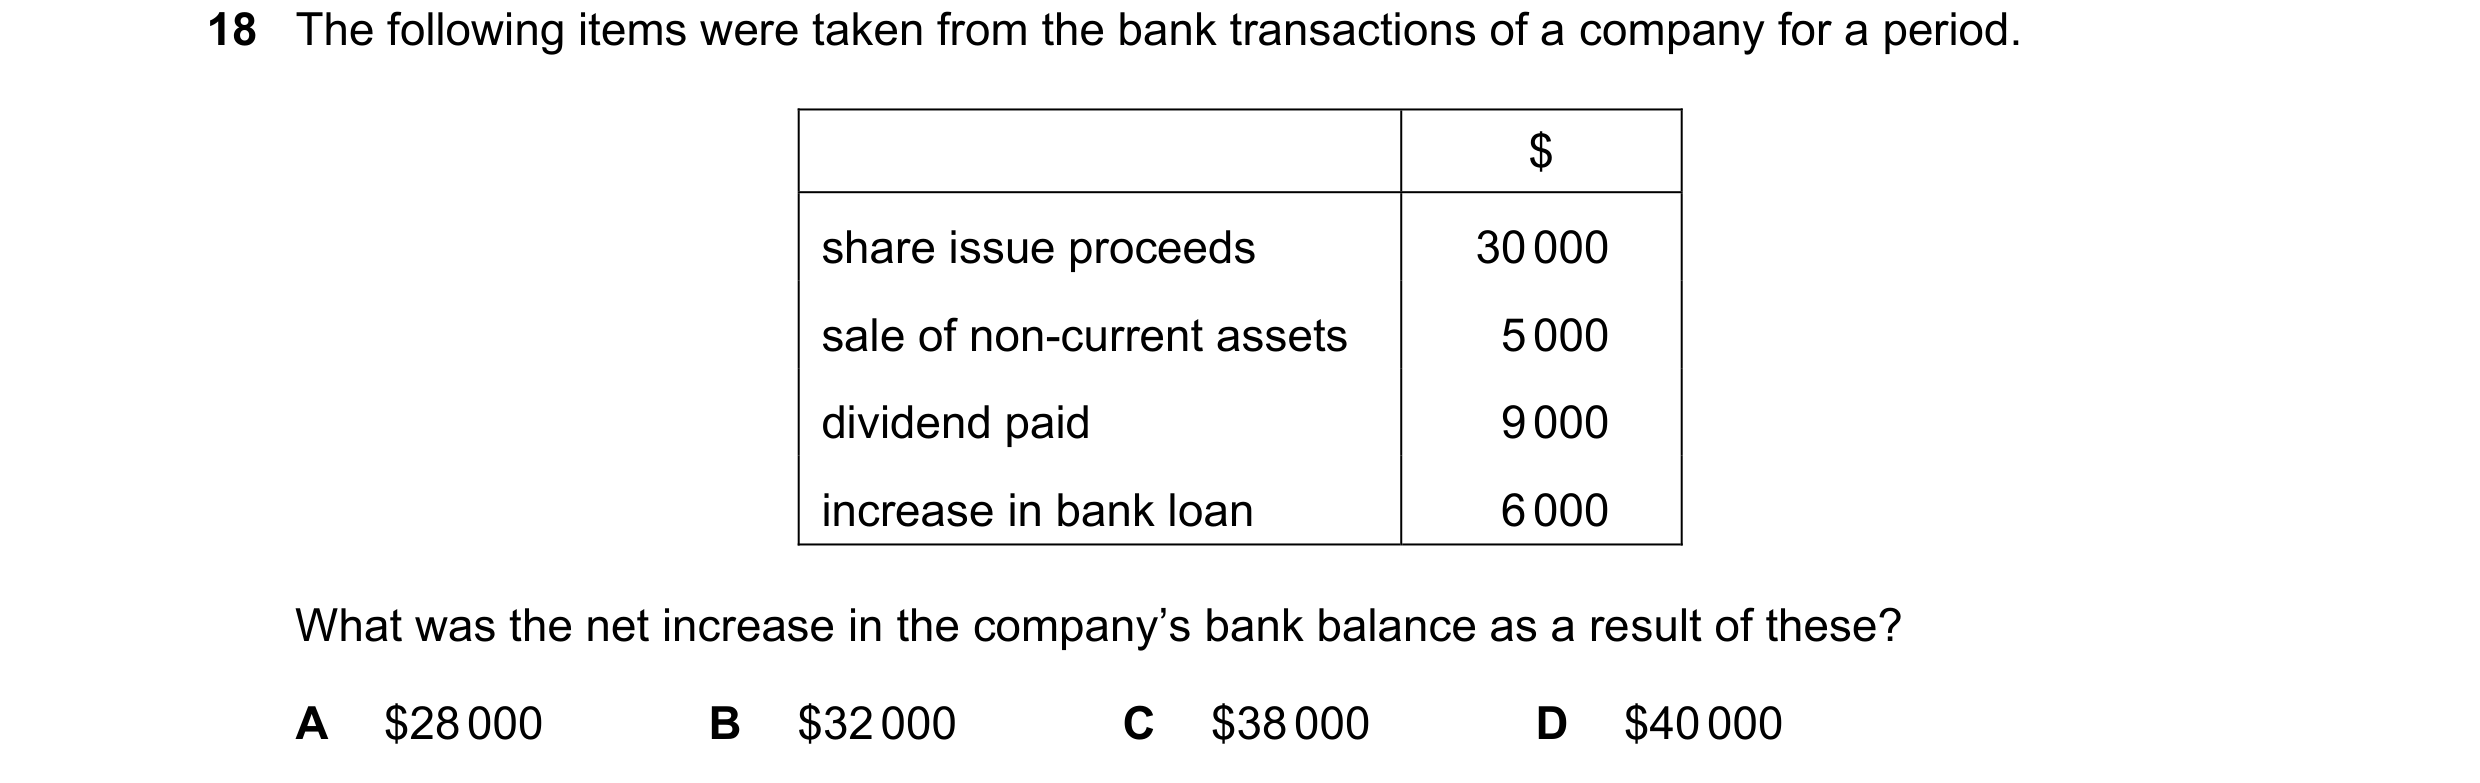 45 / 60
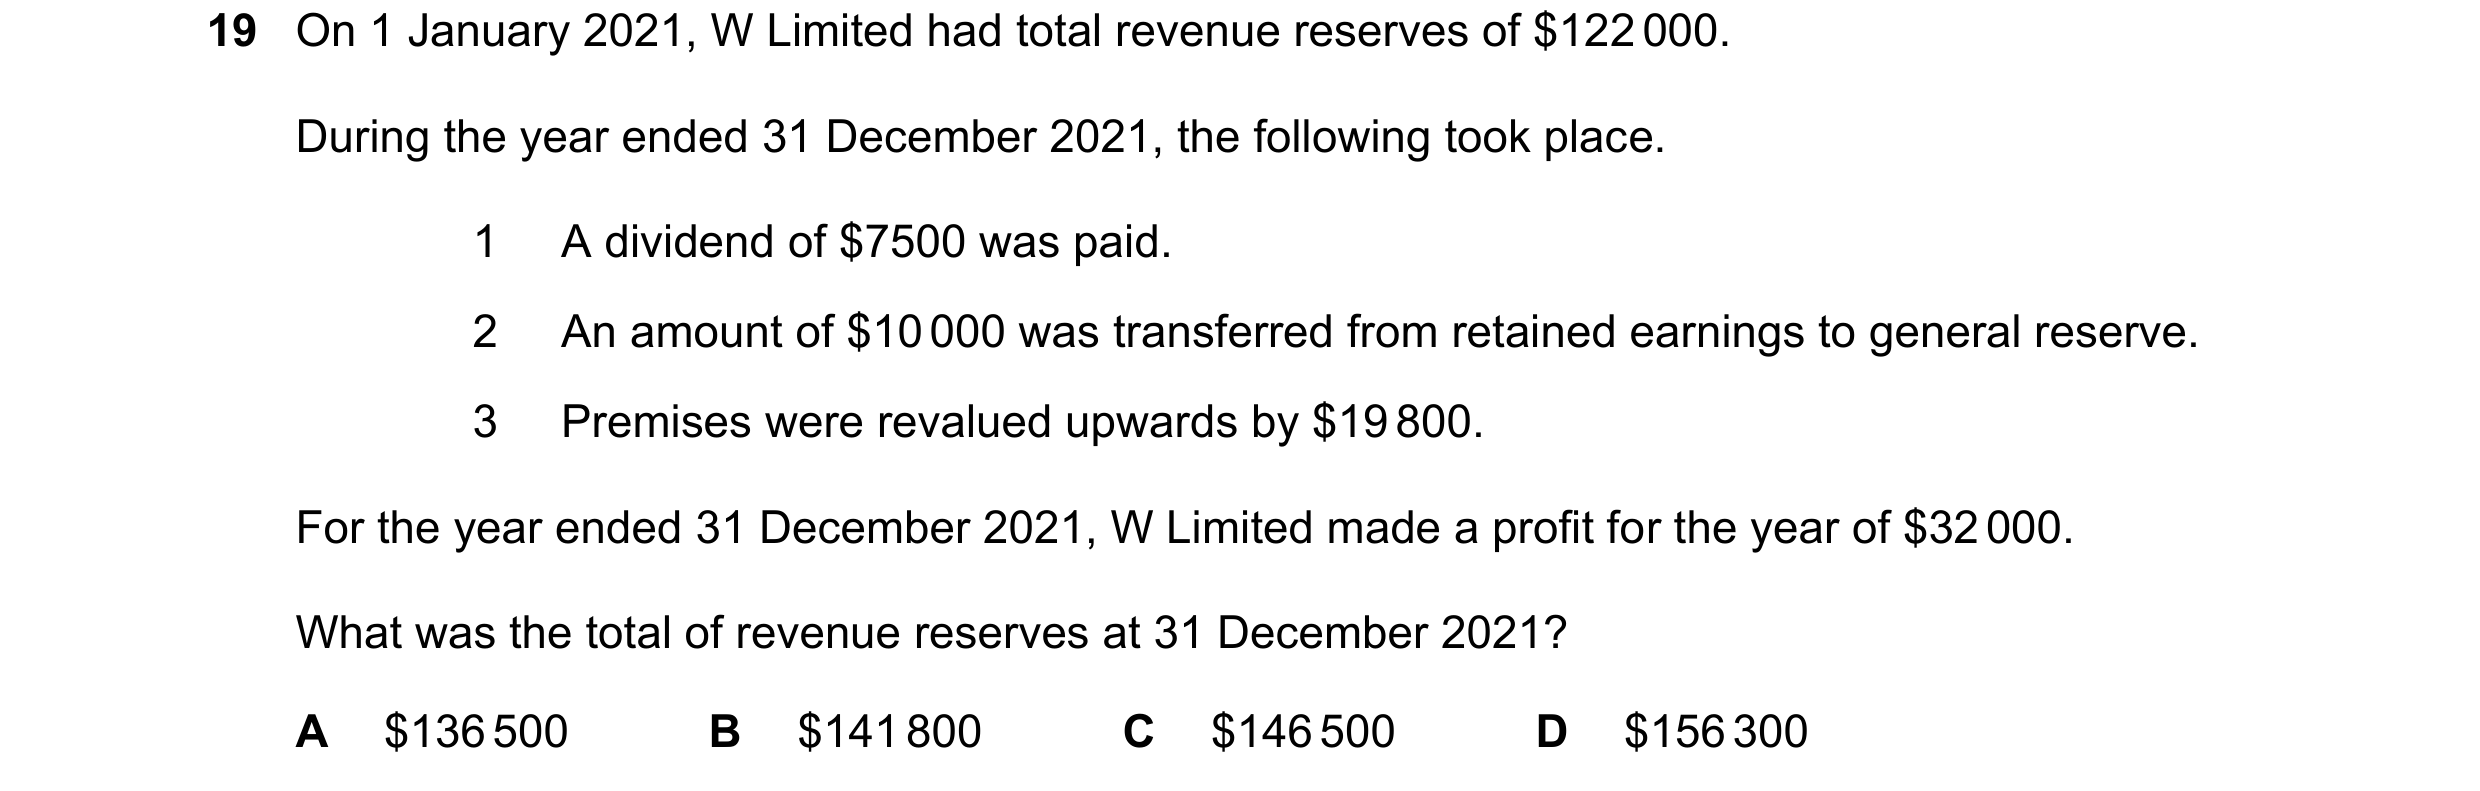
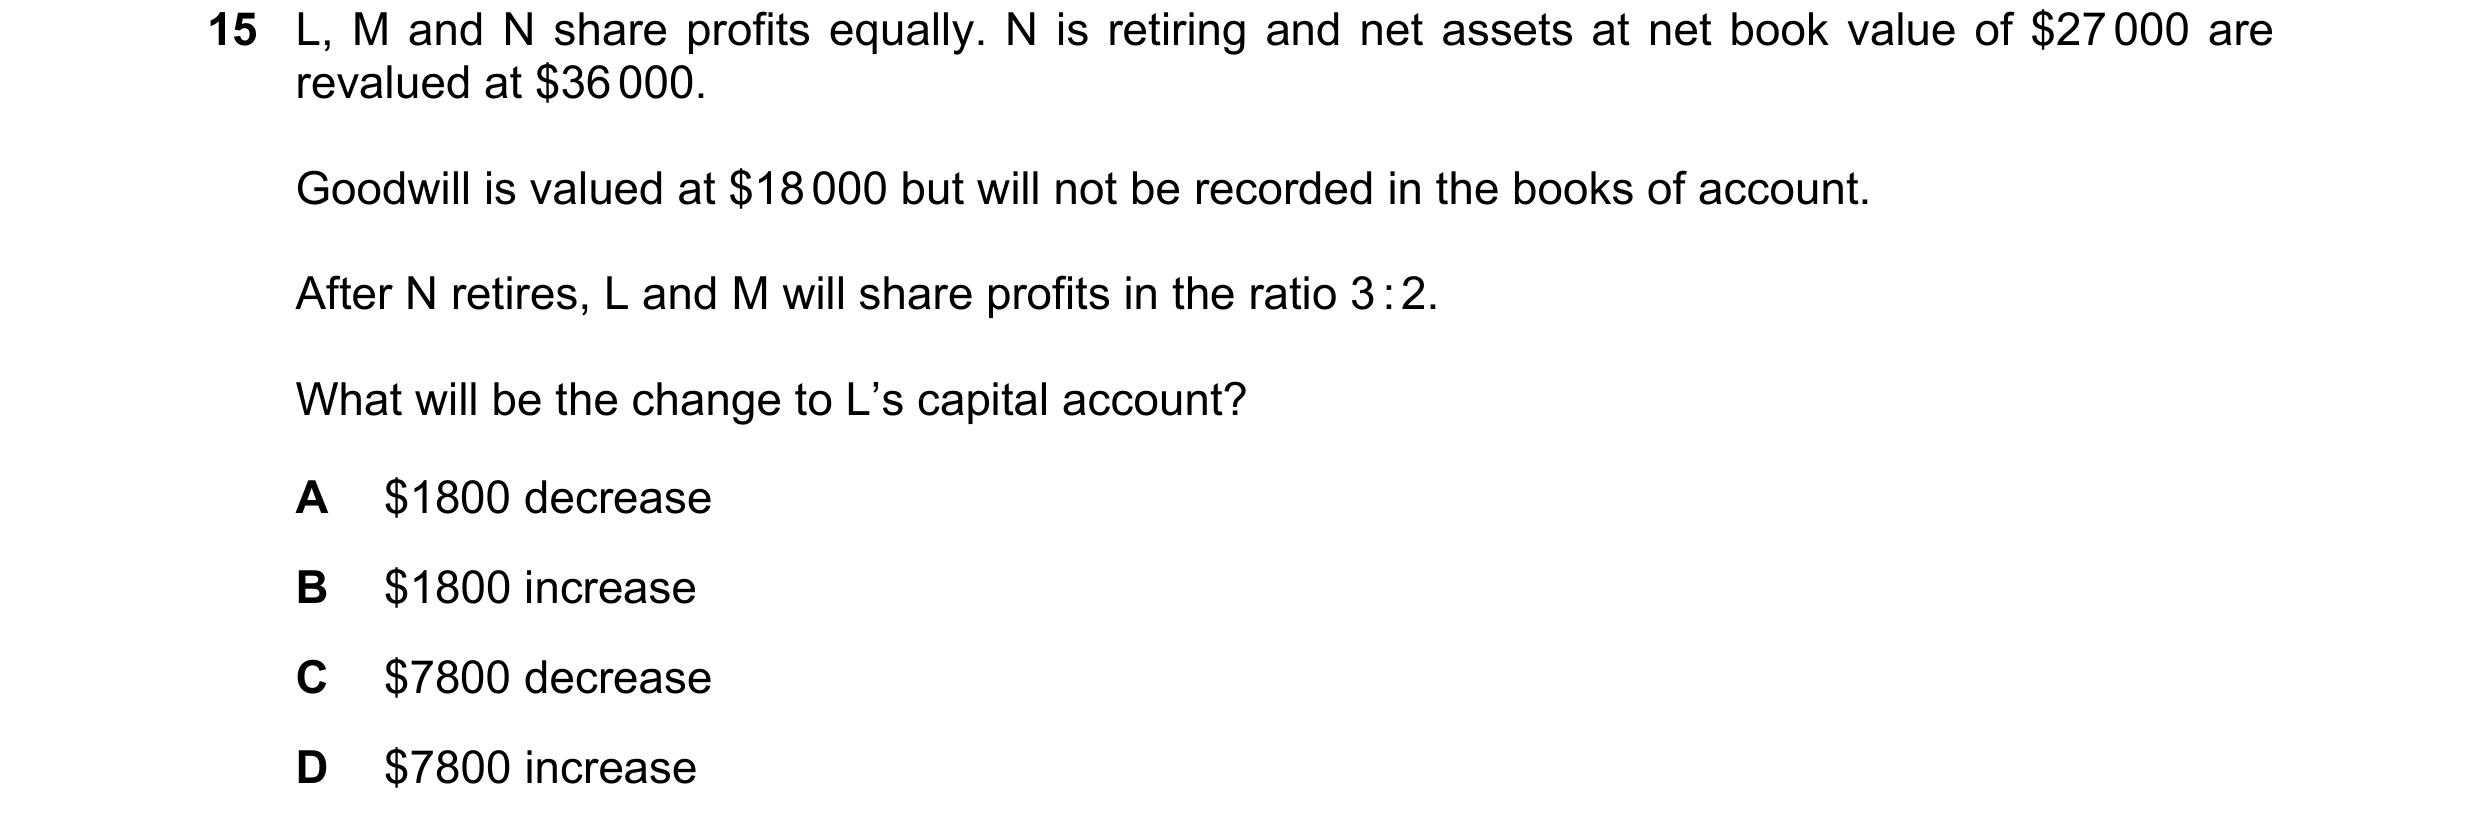
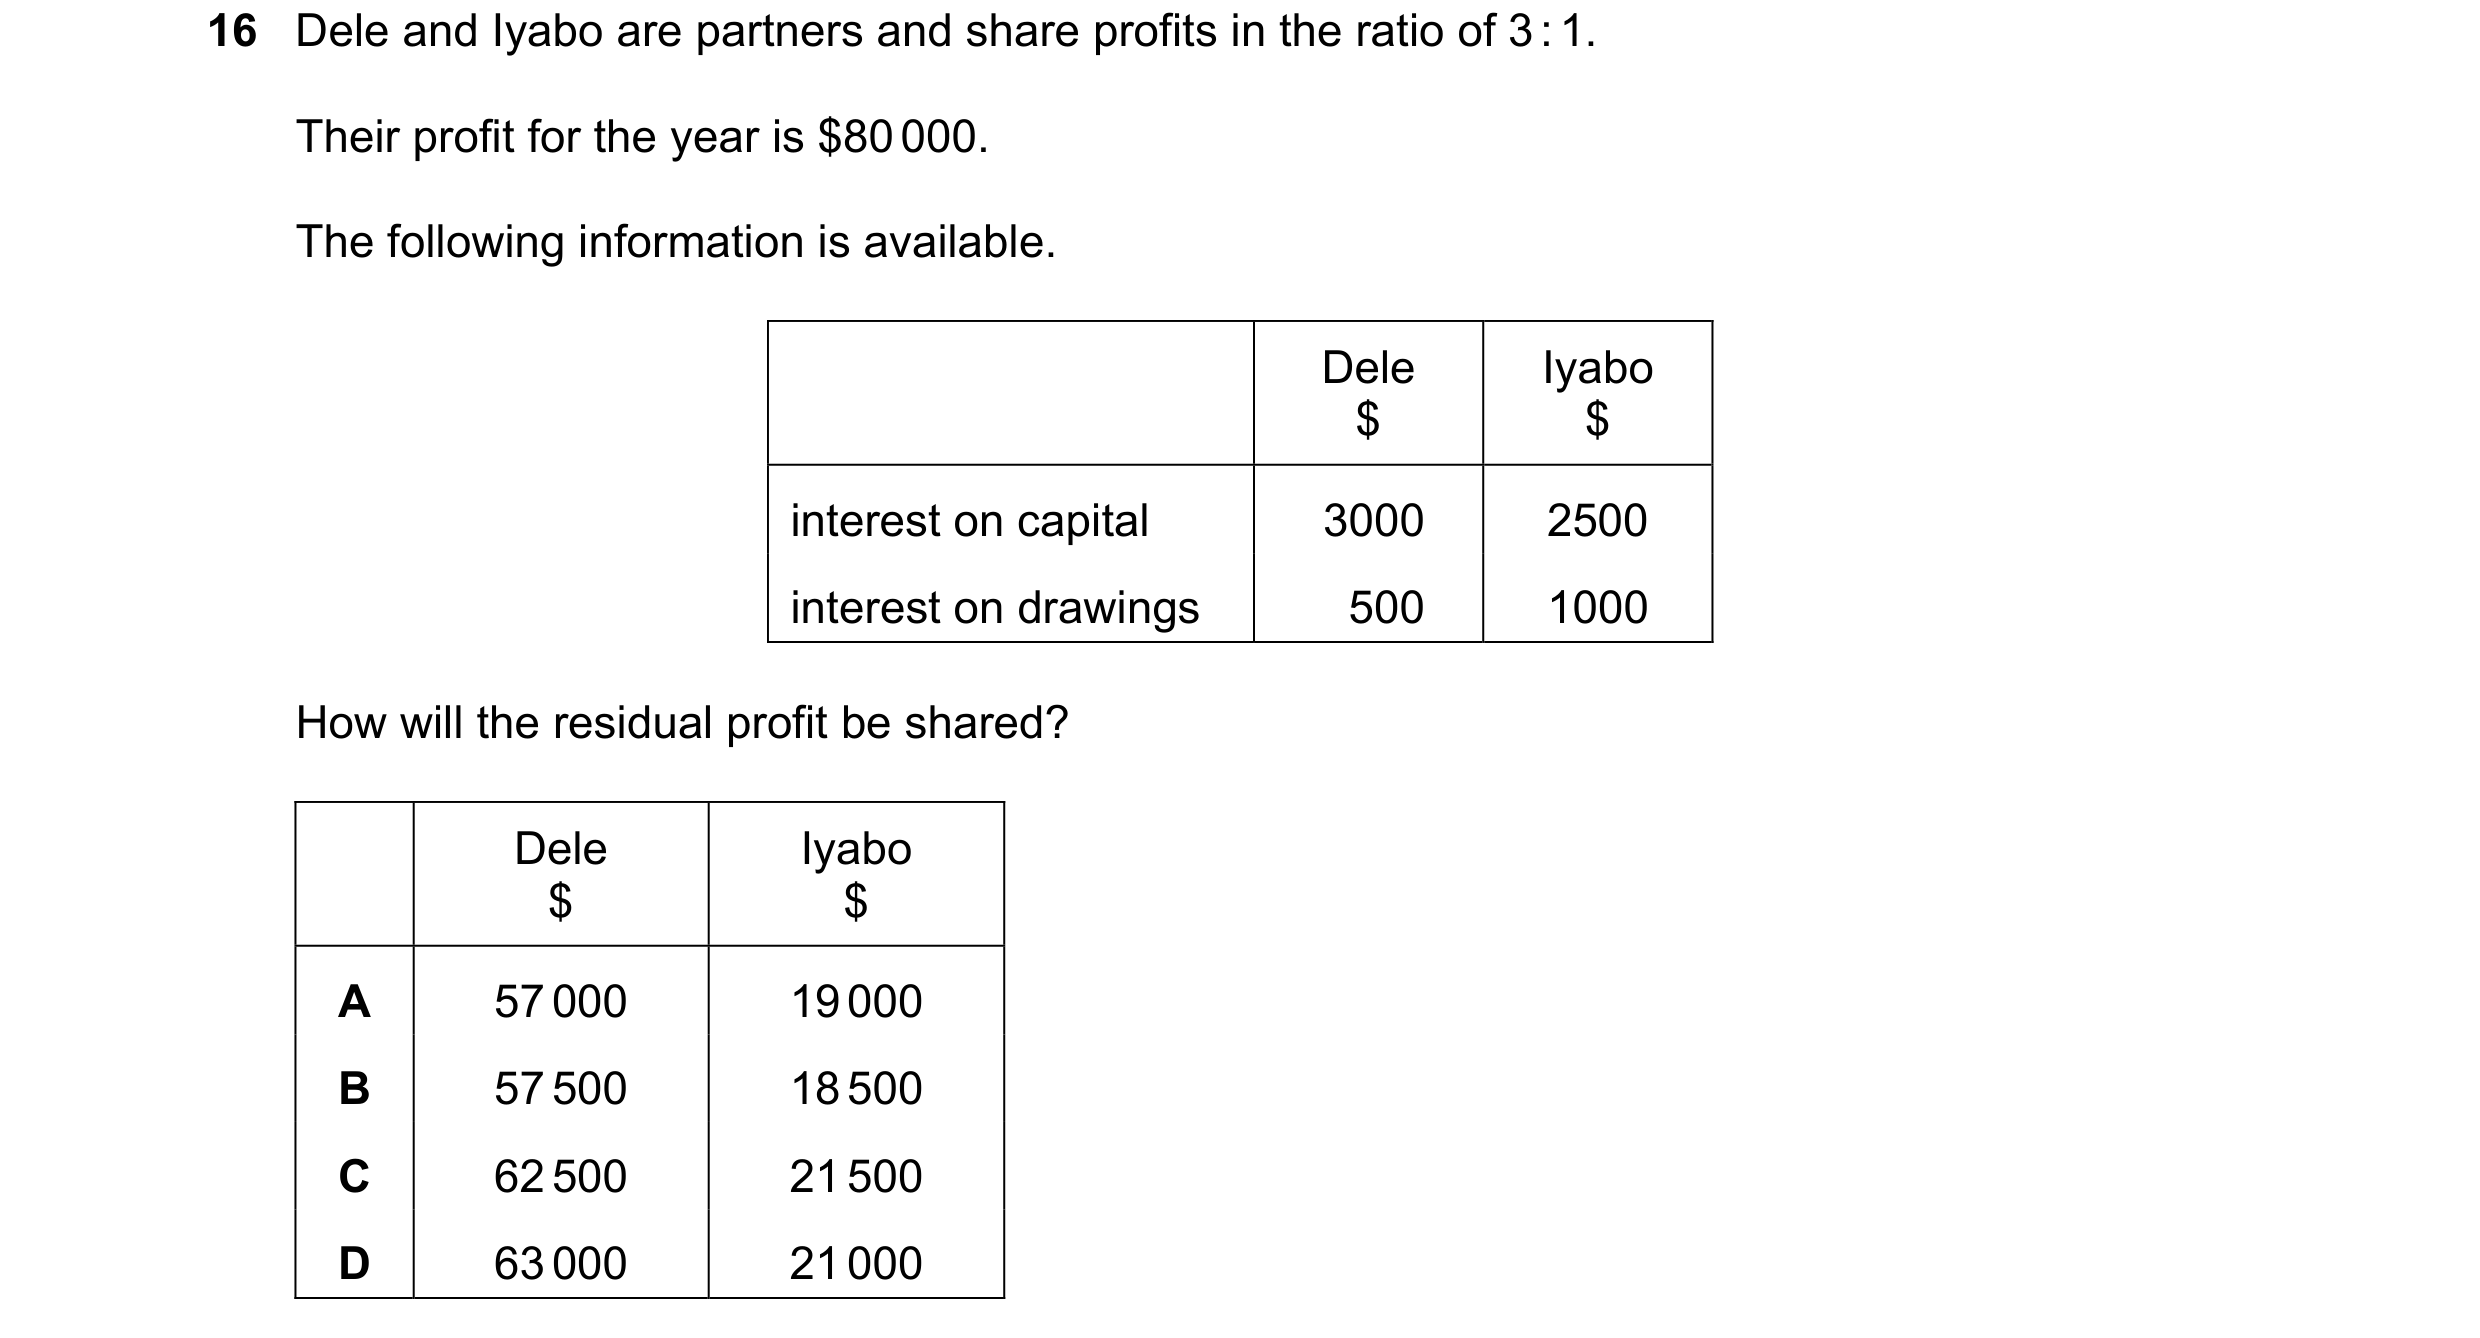 46 / 60
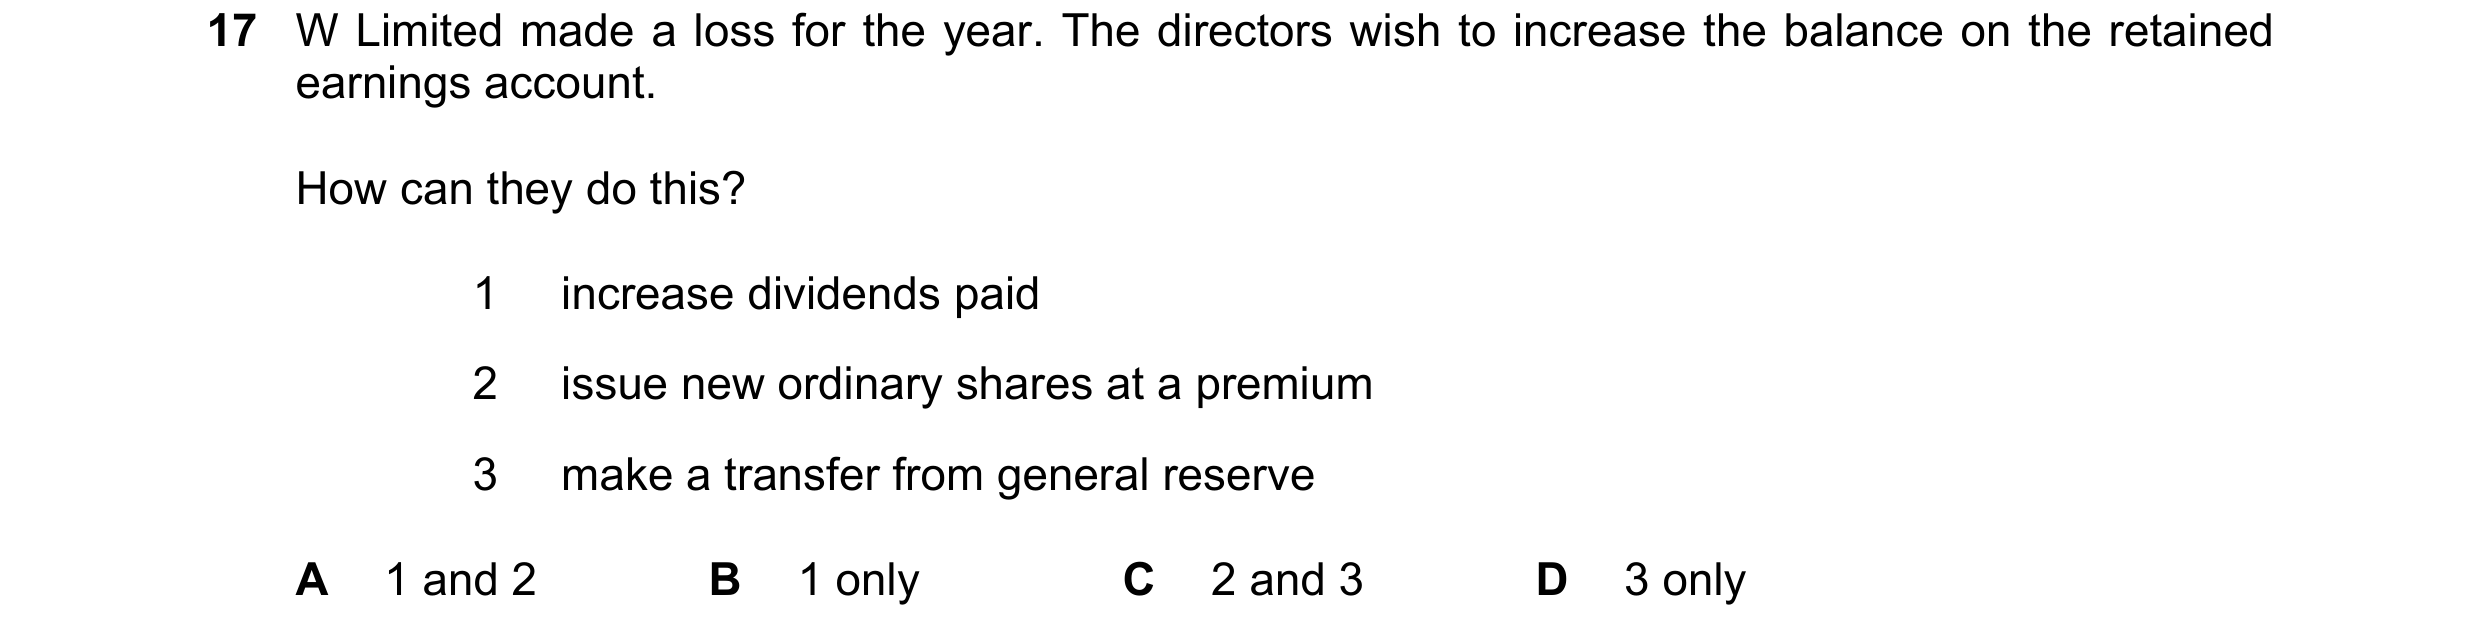
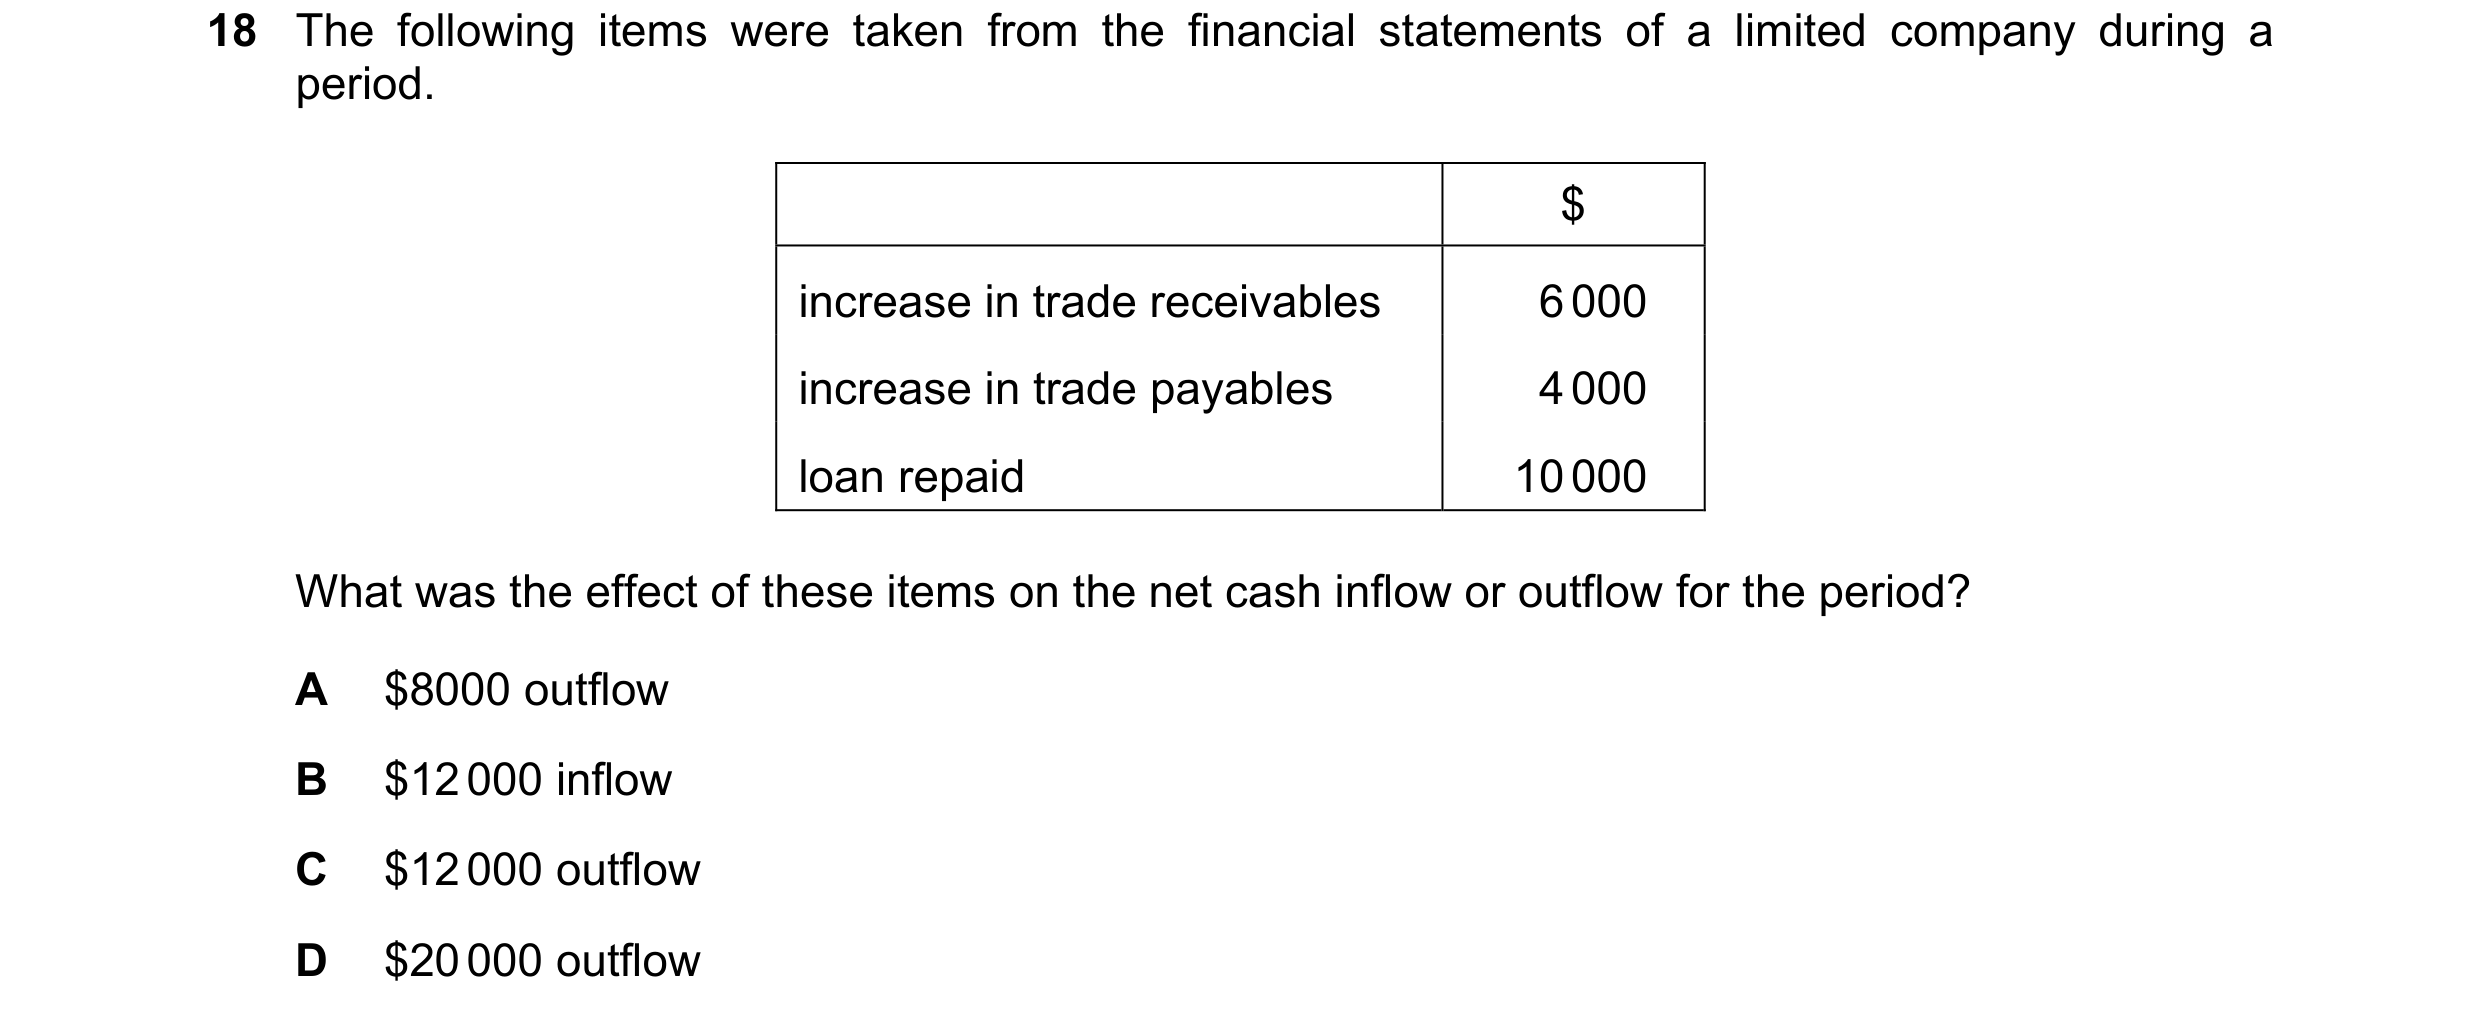
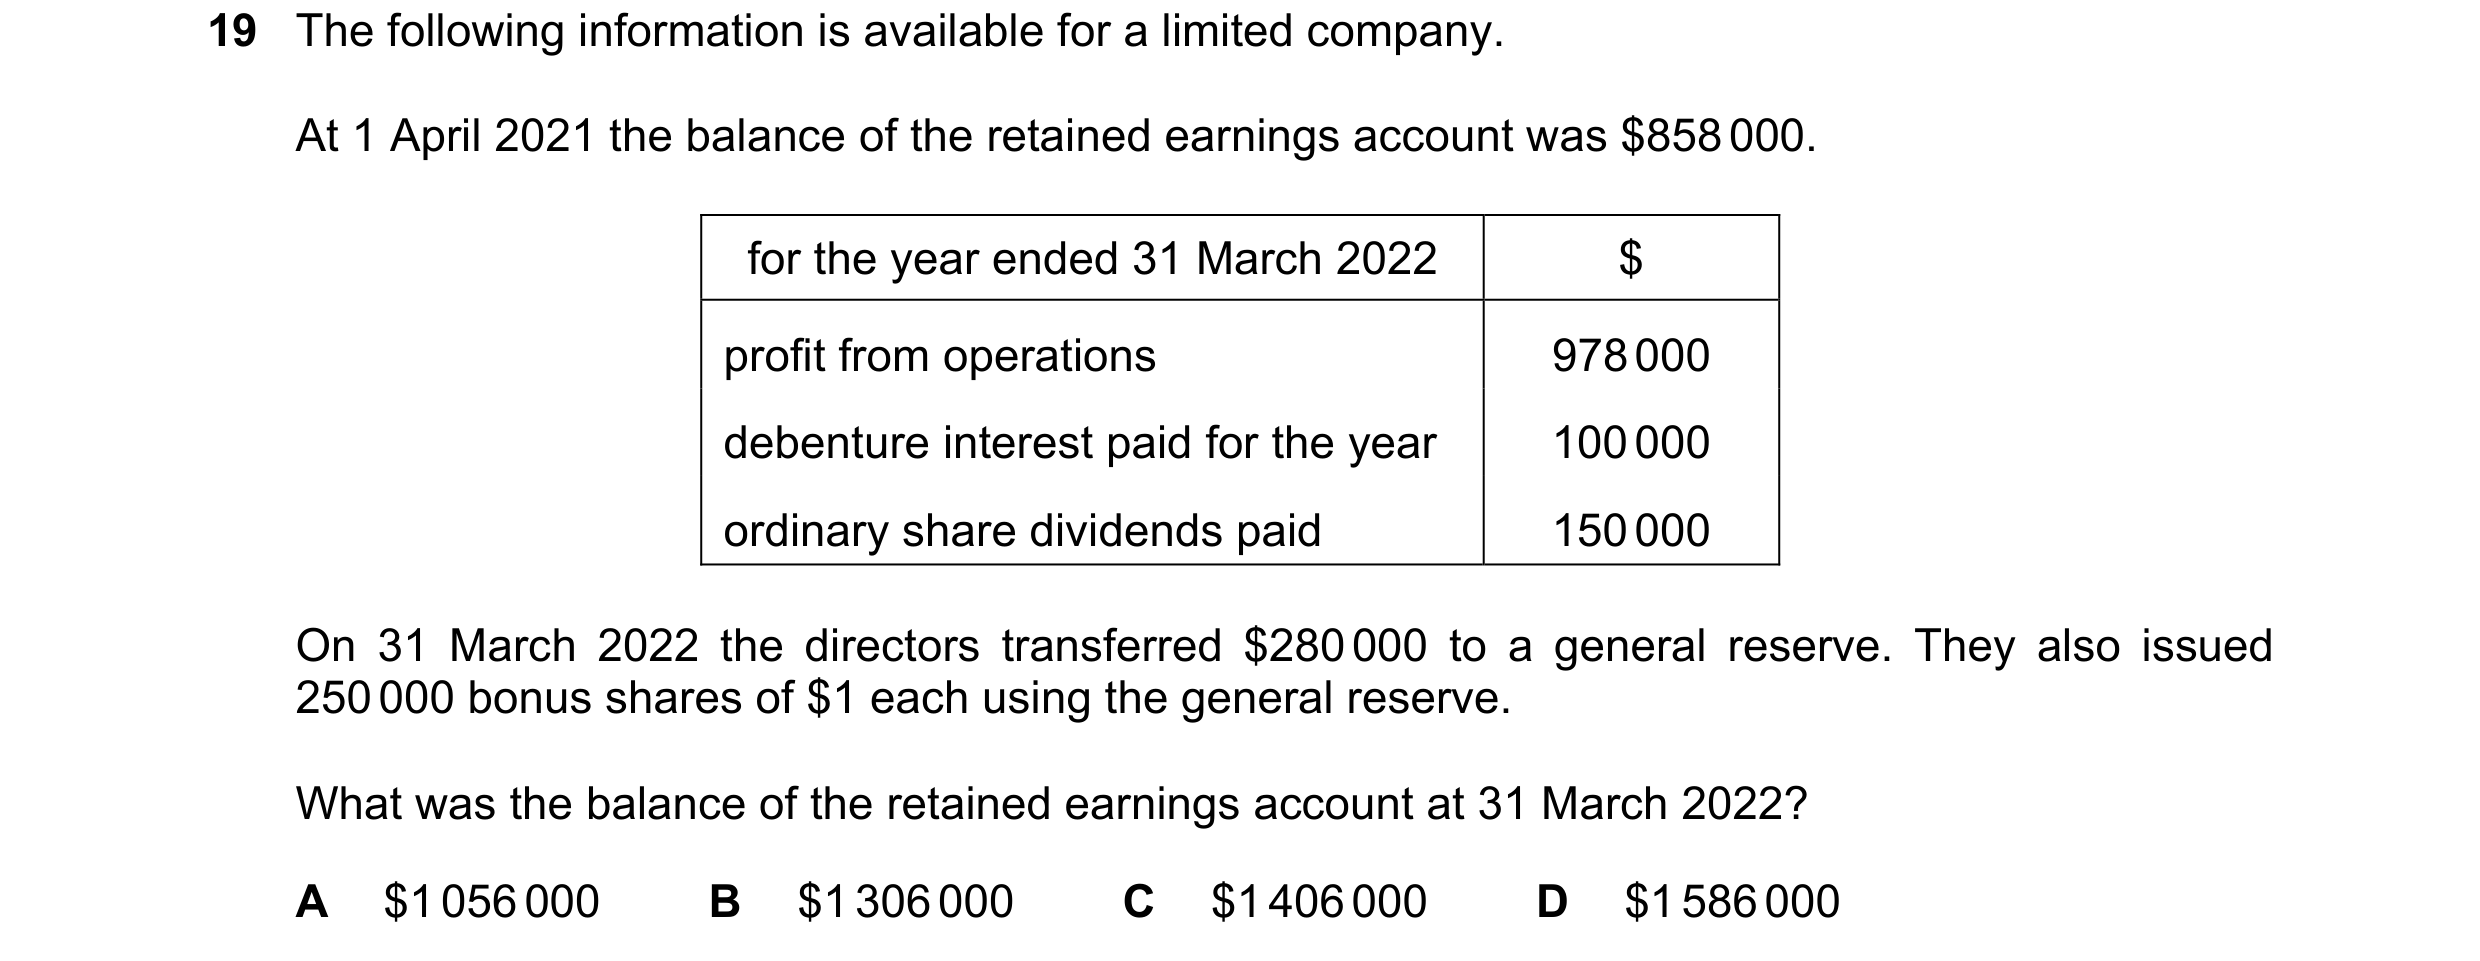
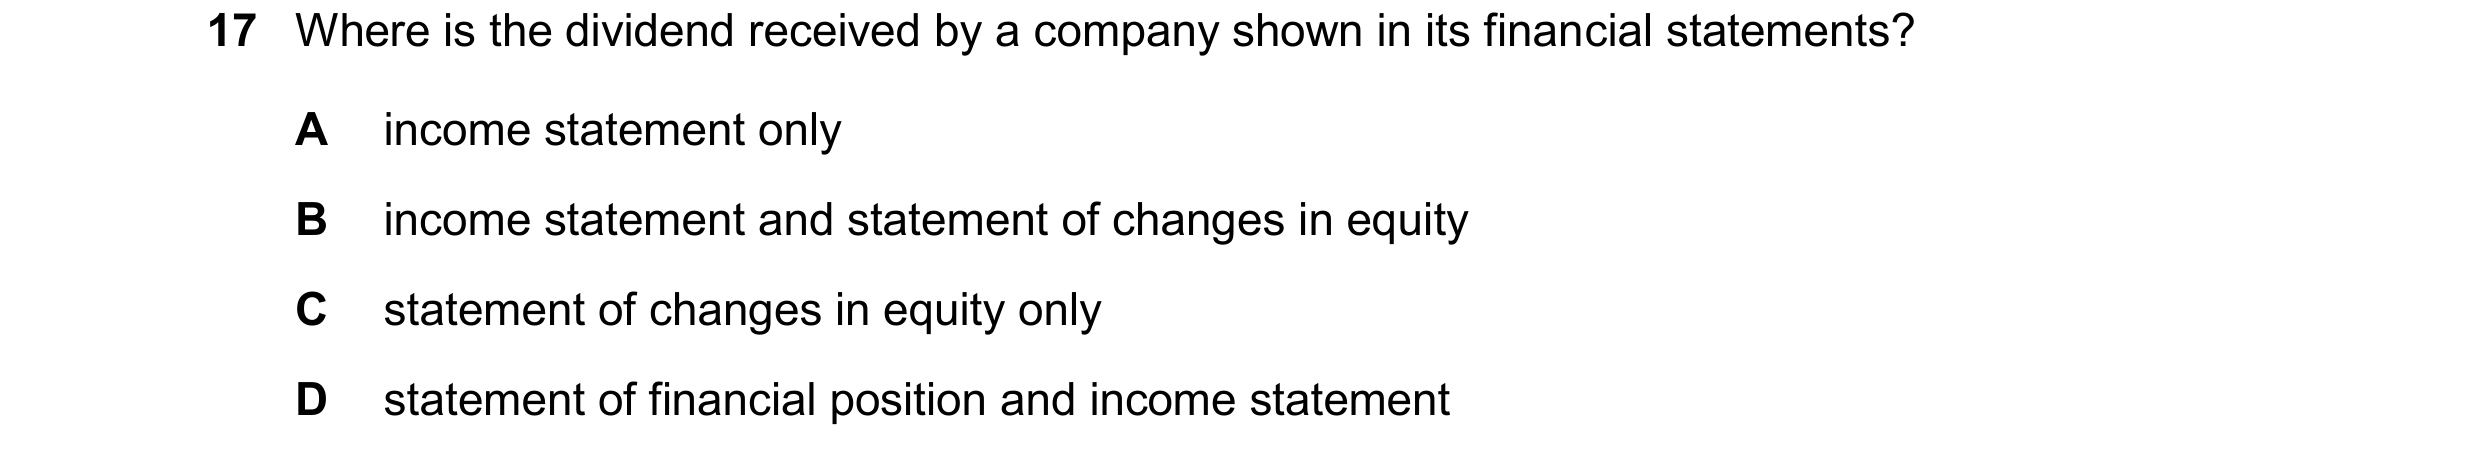 47 / 60
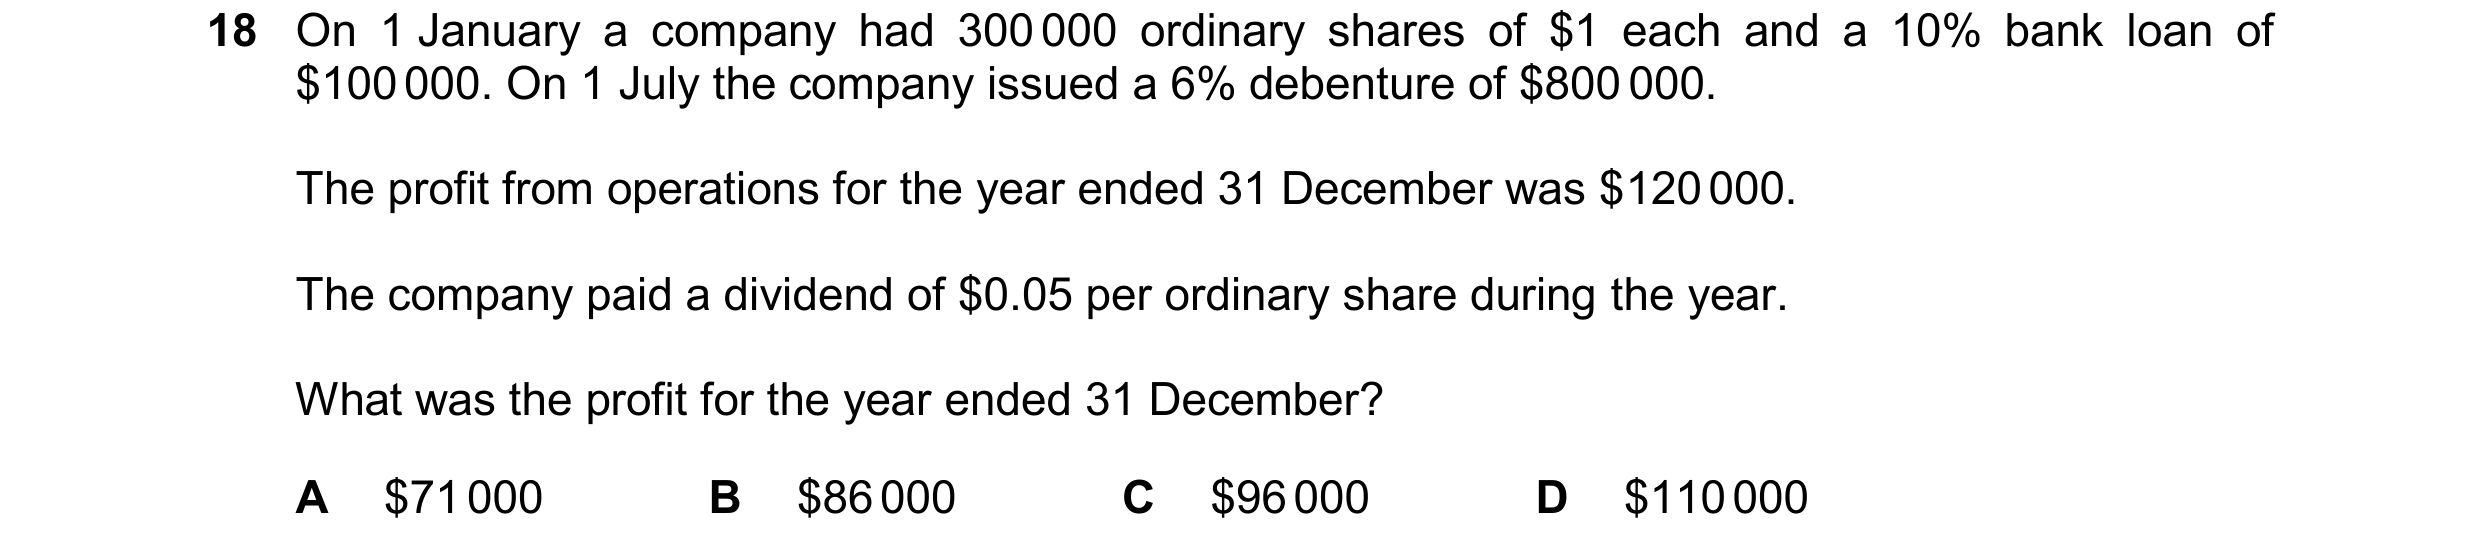
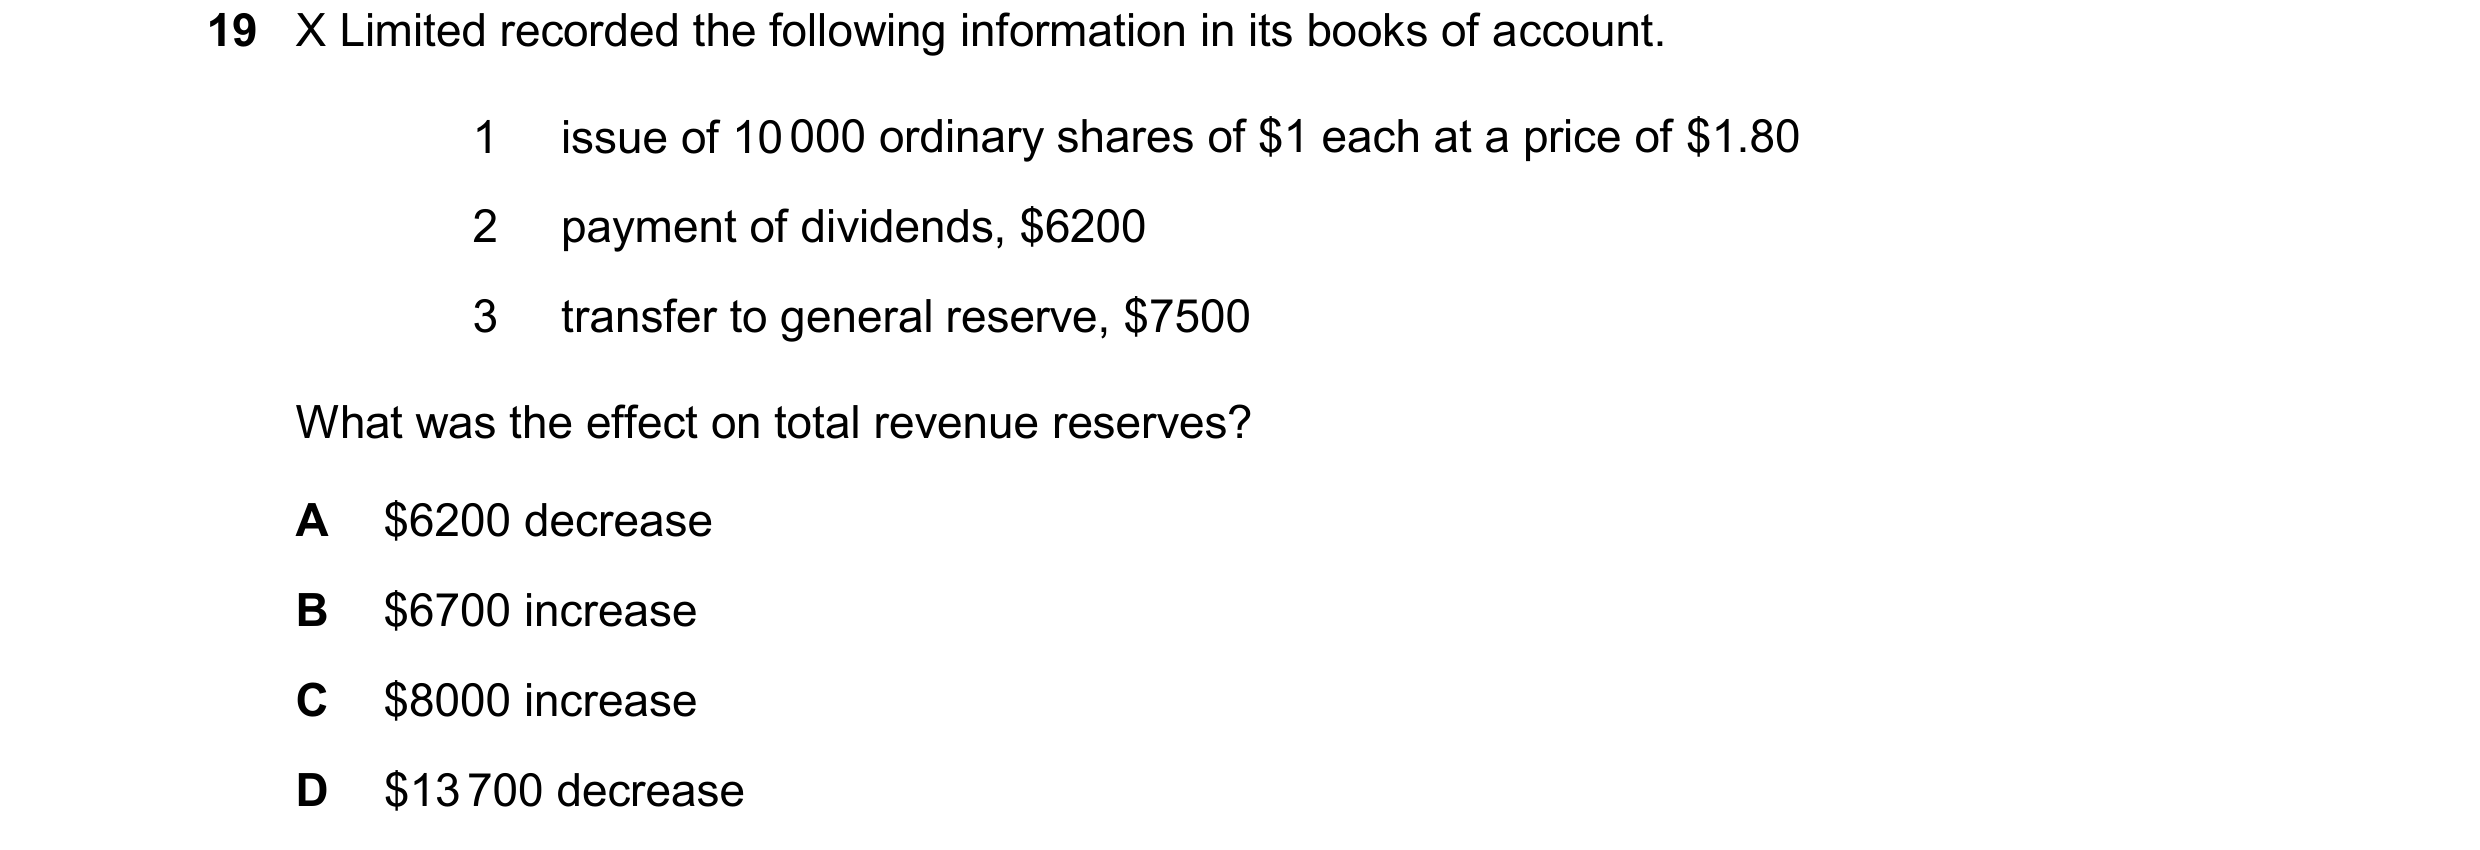
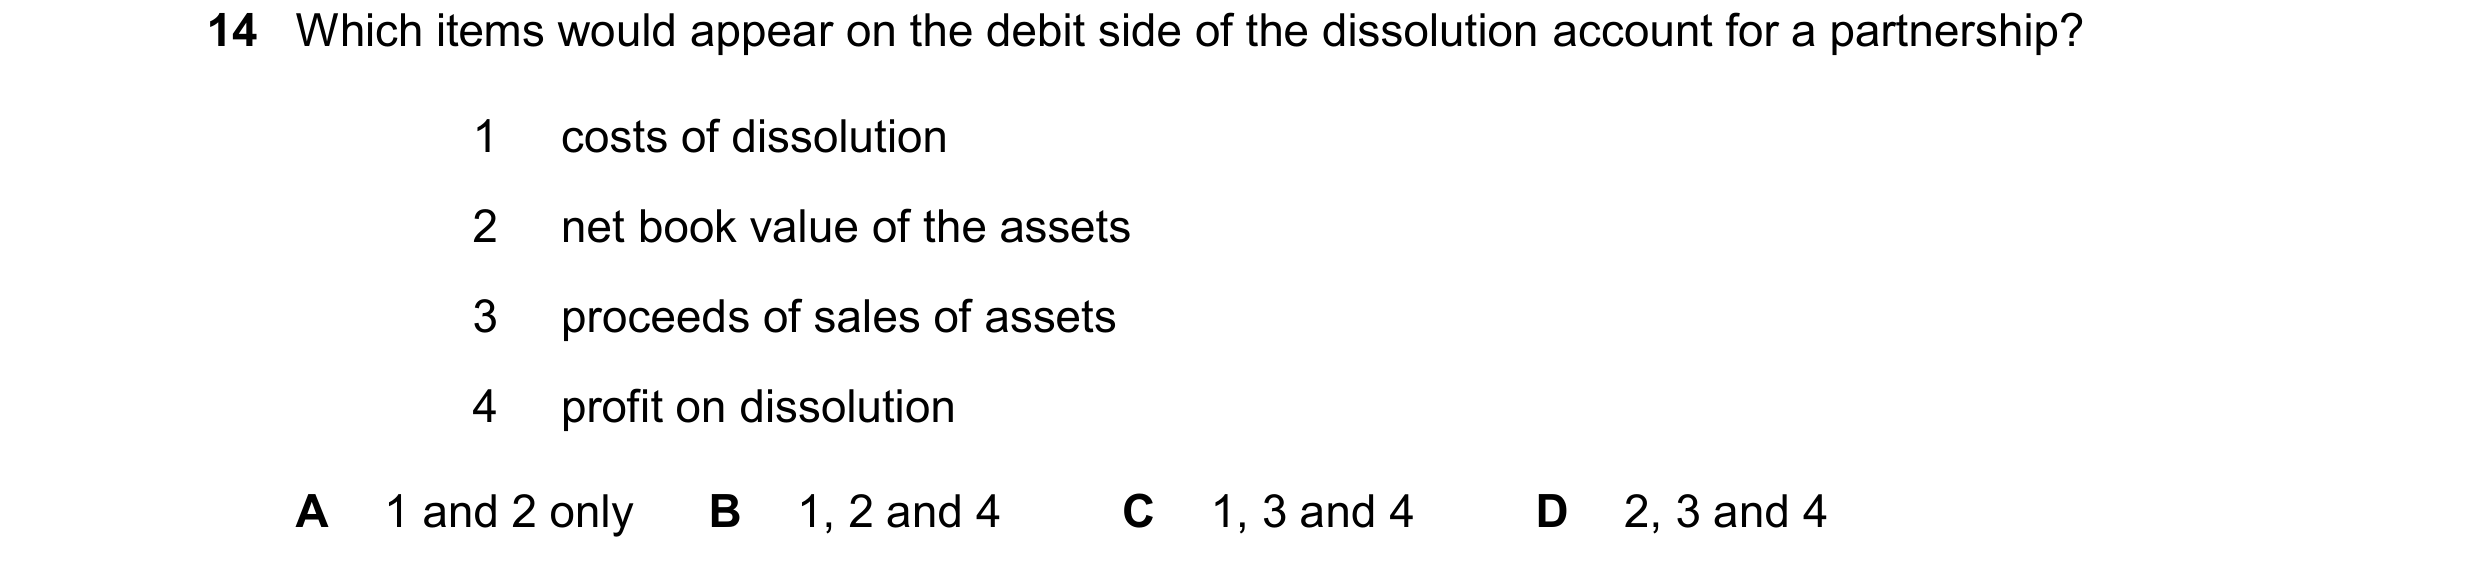
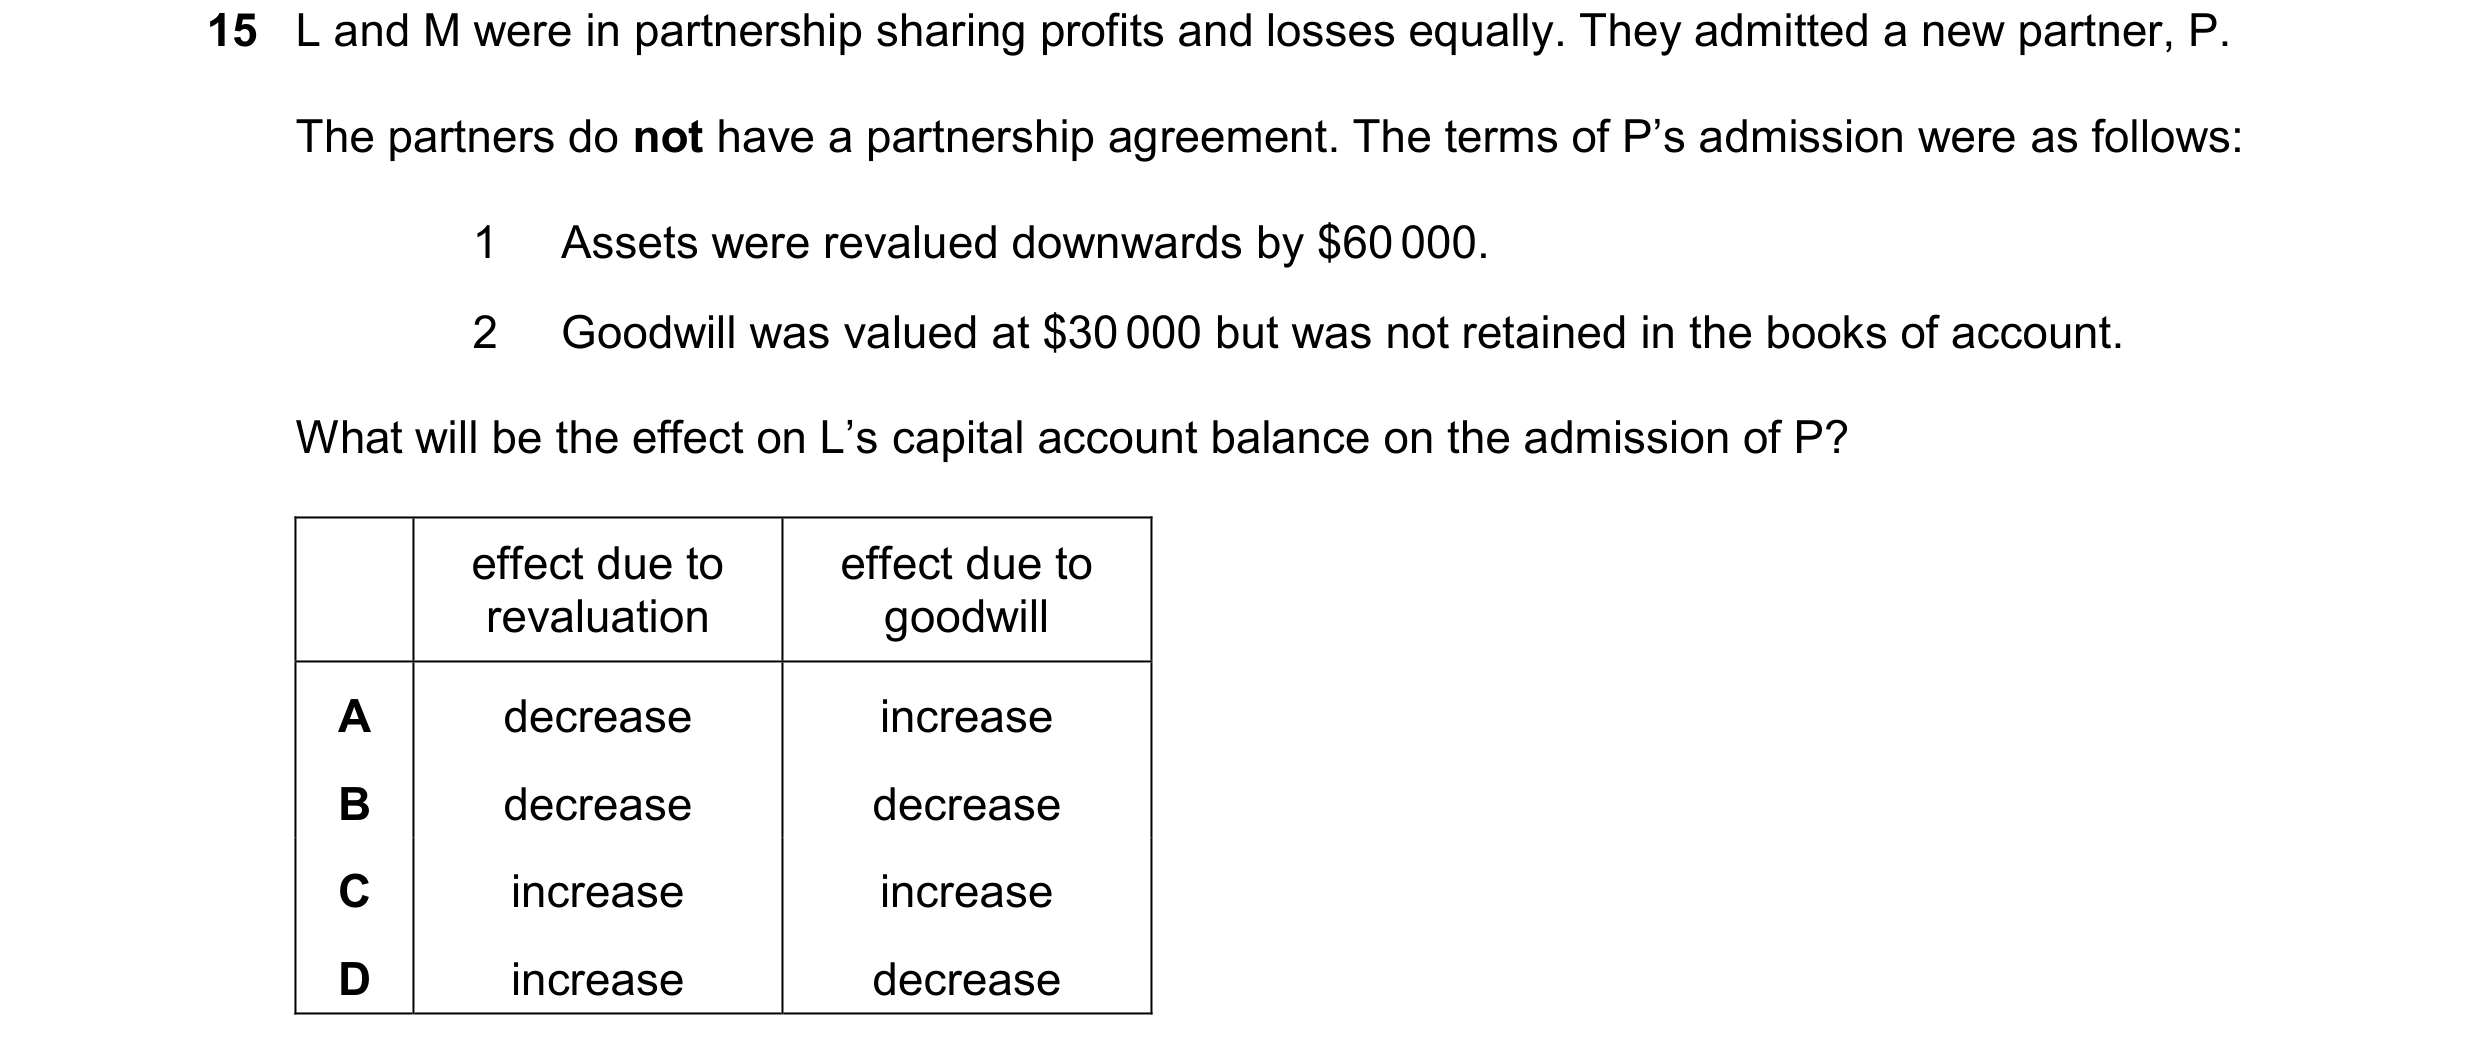 48 / 60
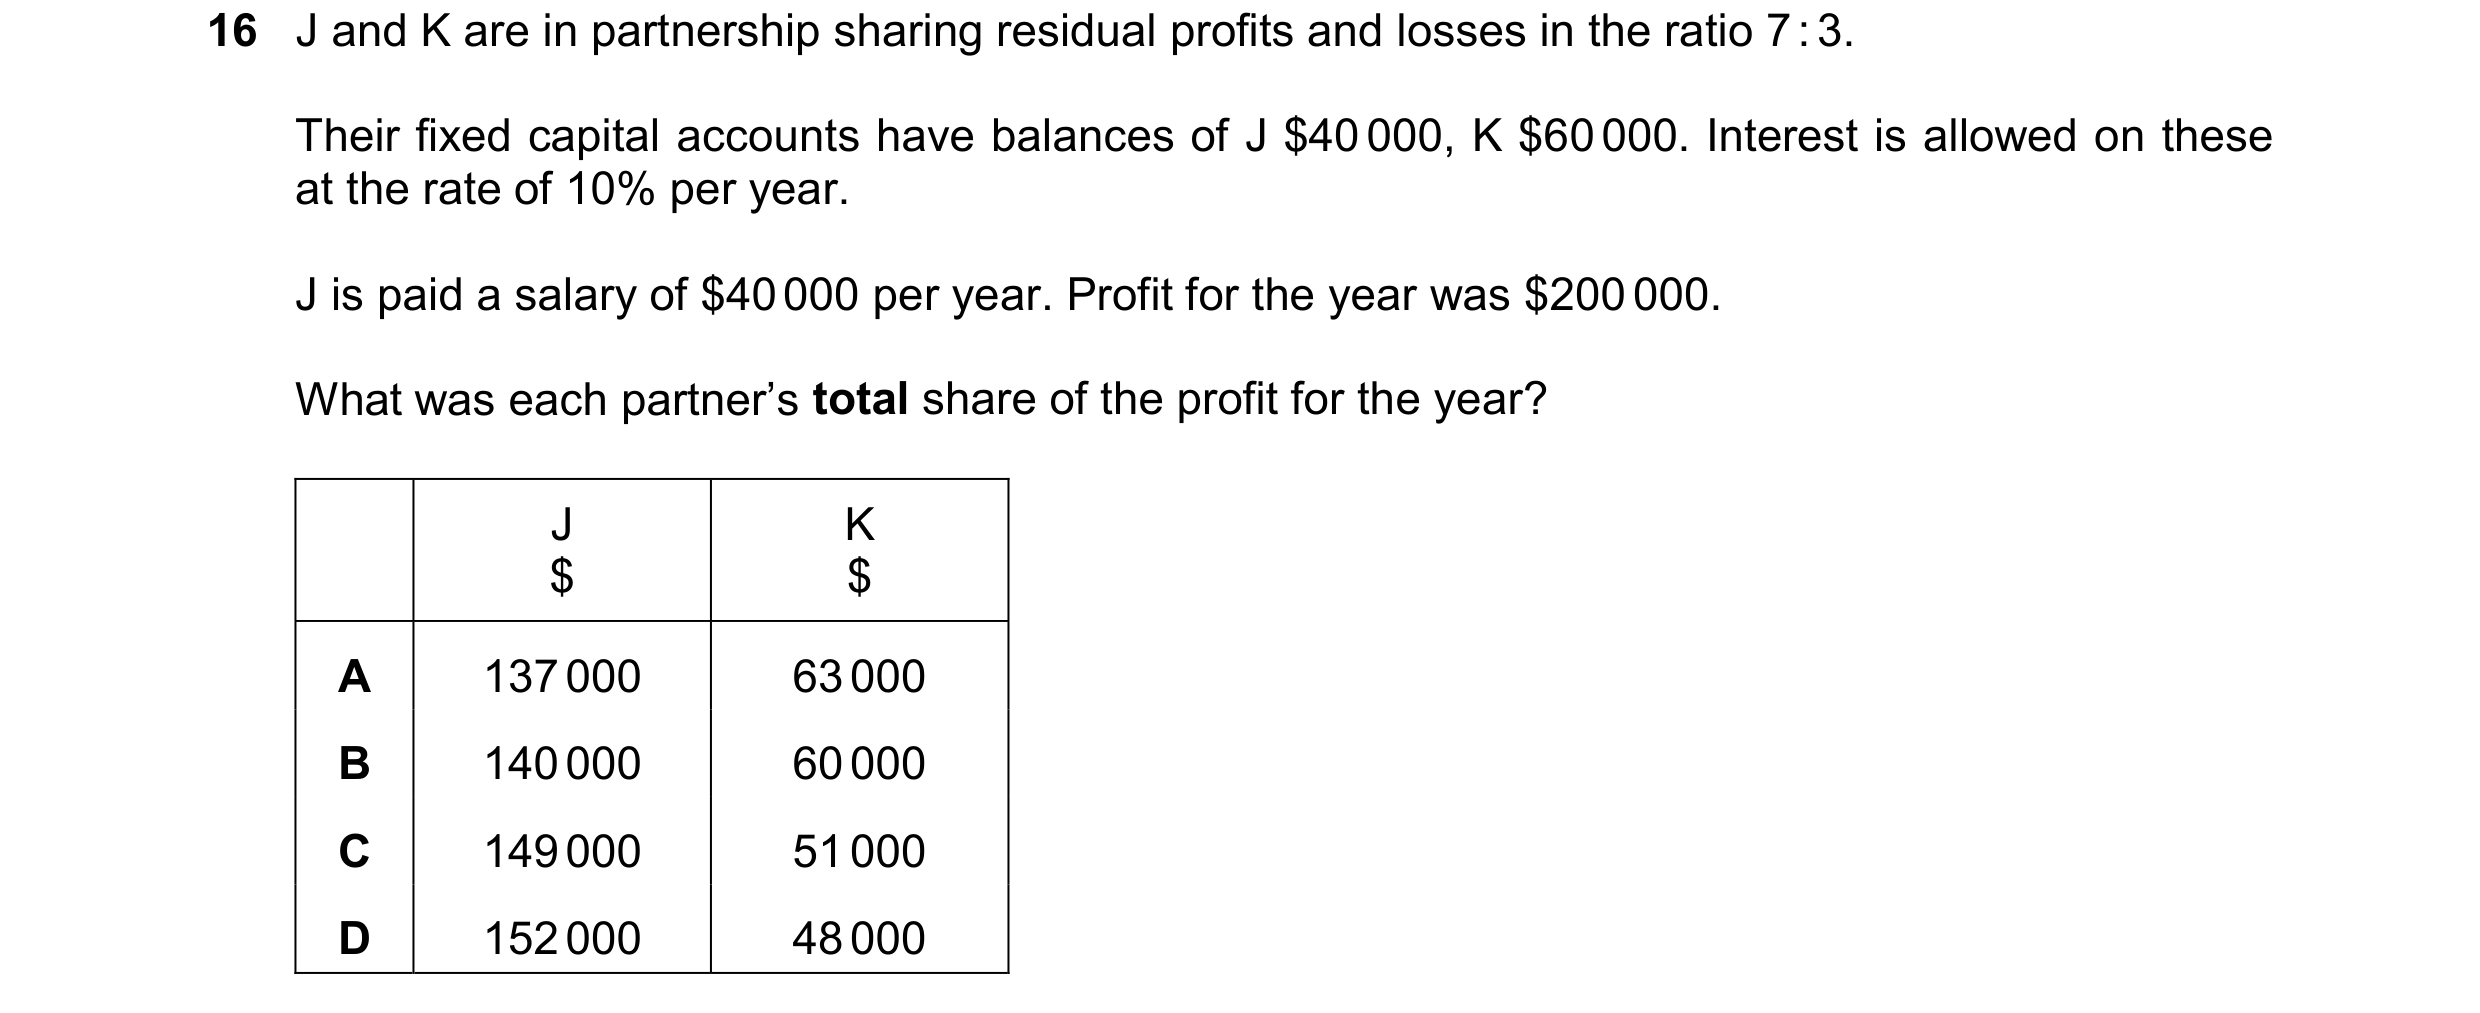
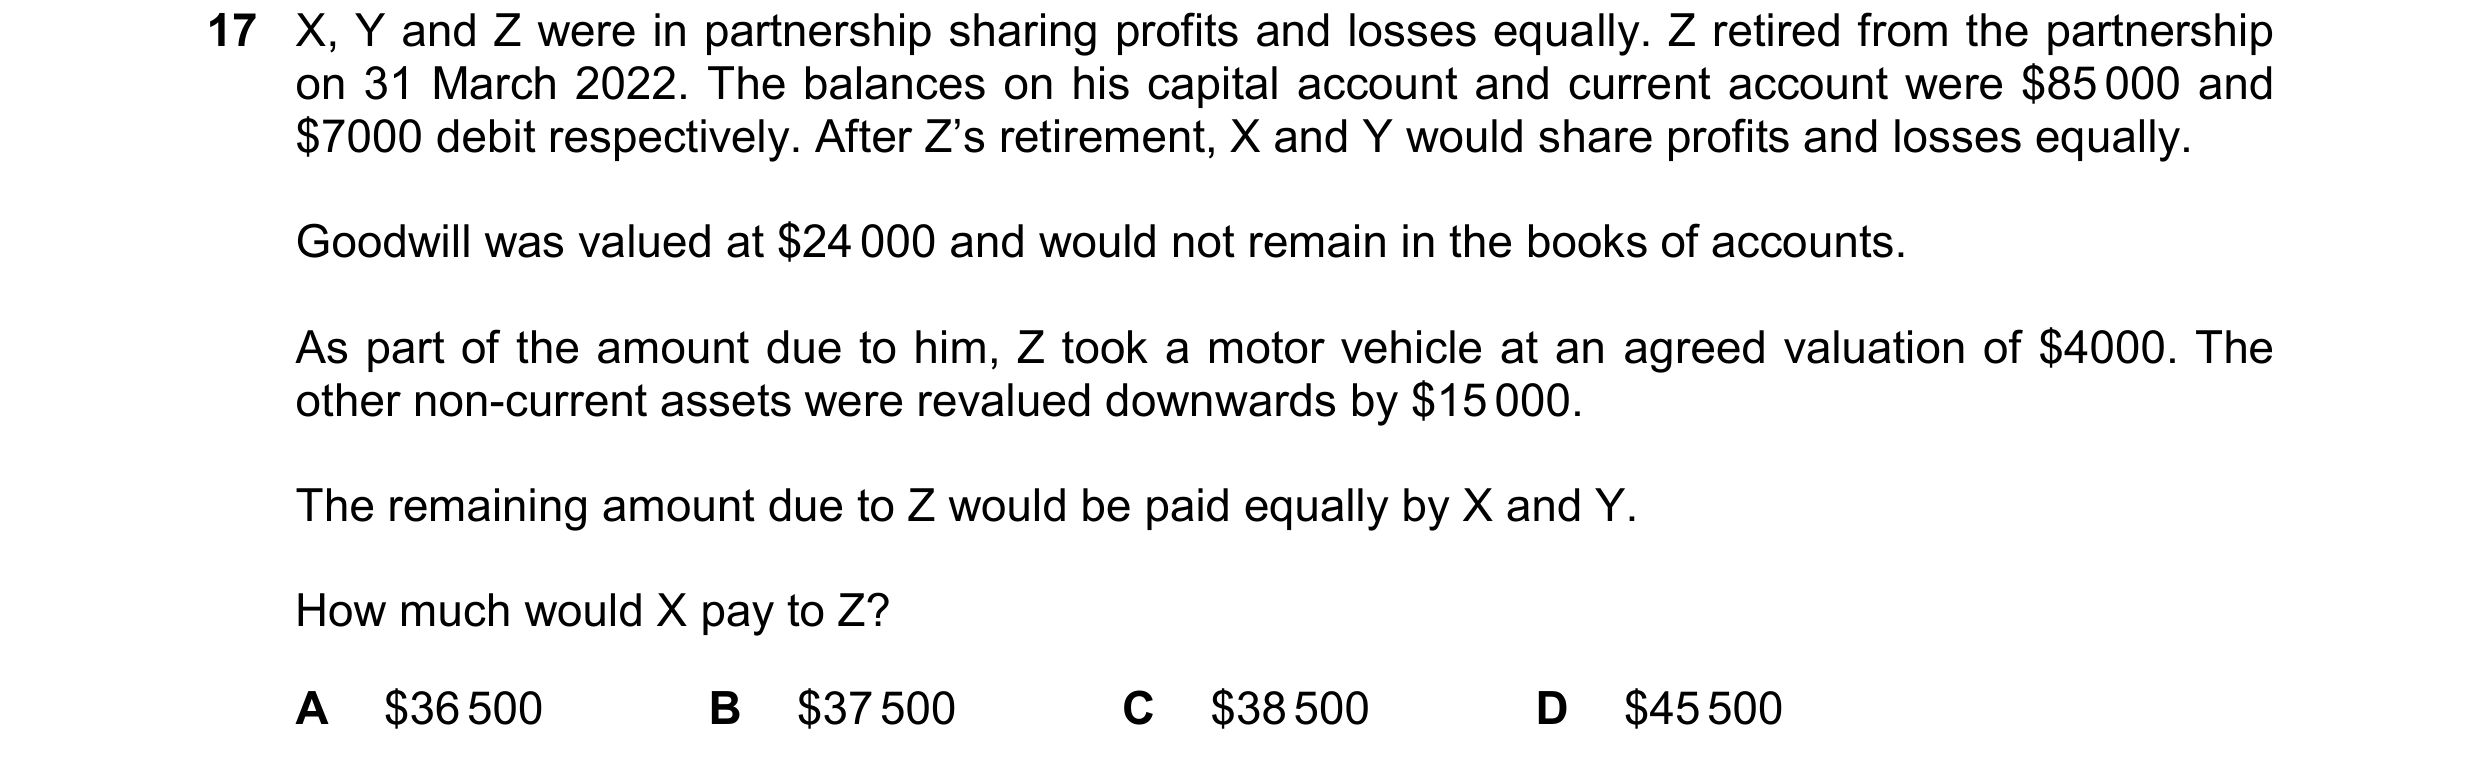
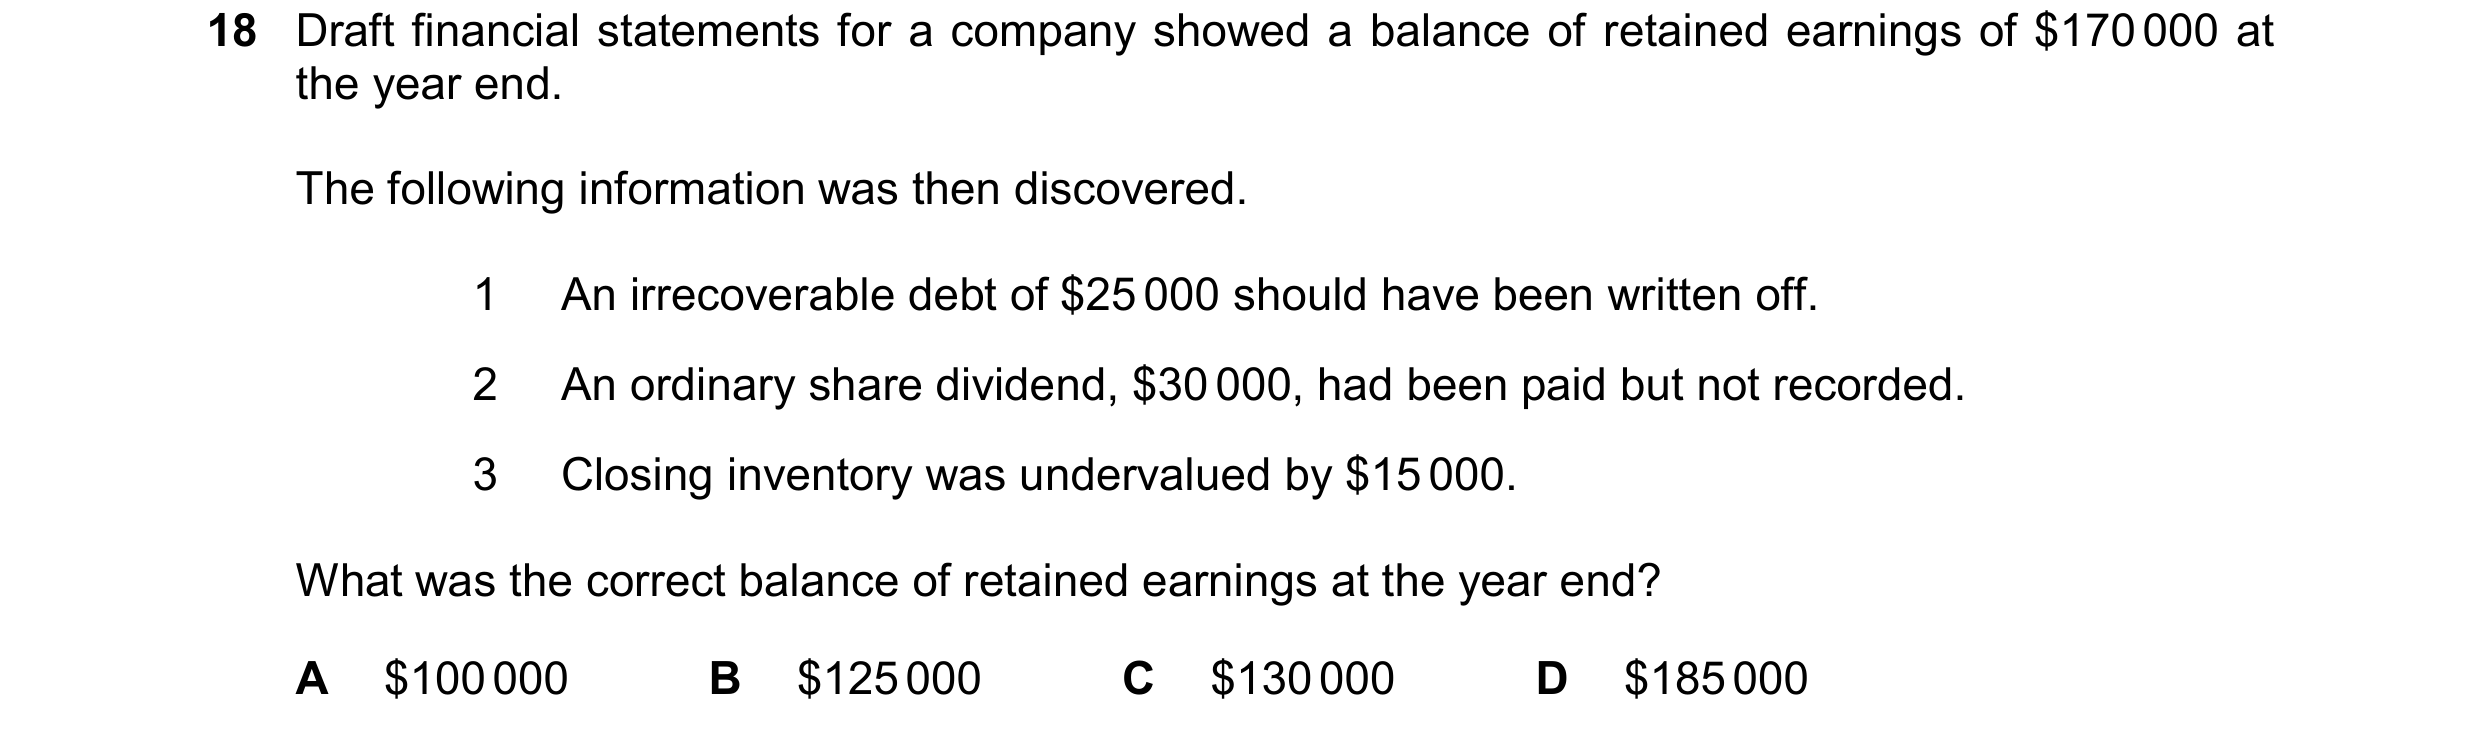 49 / 60
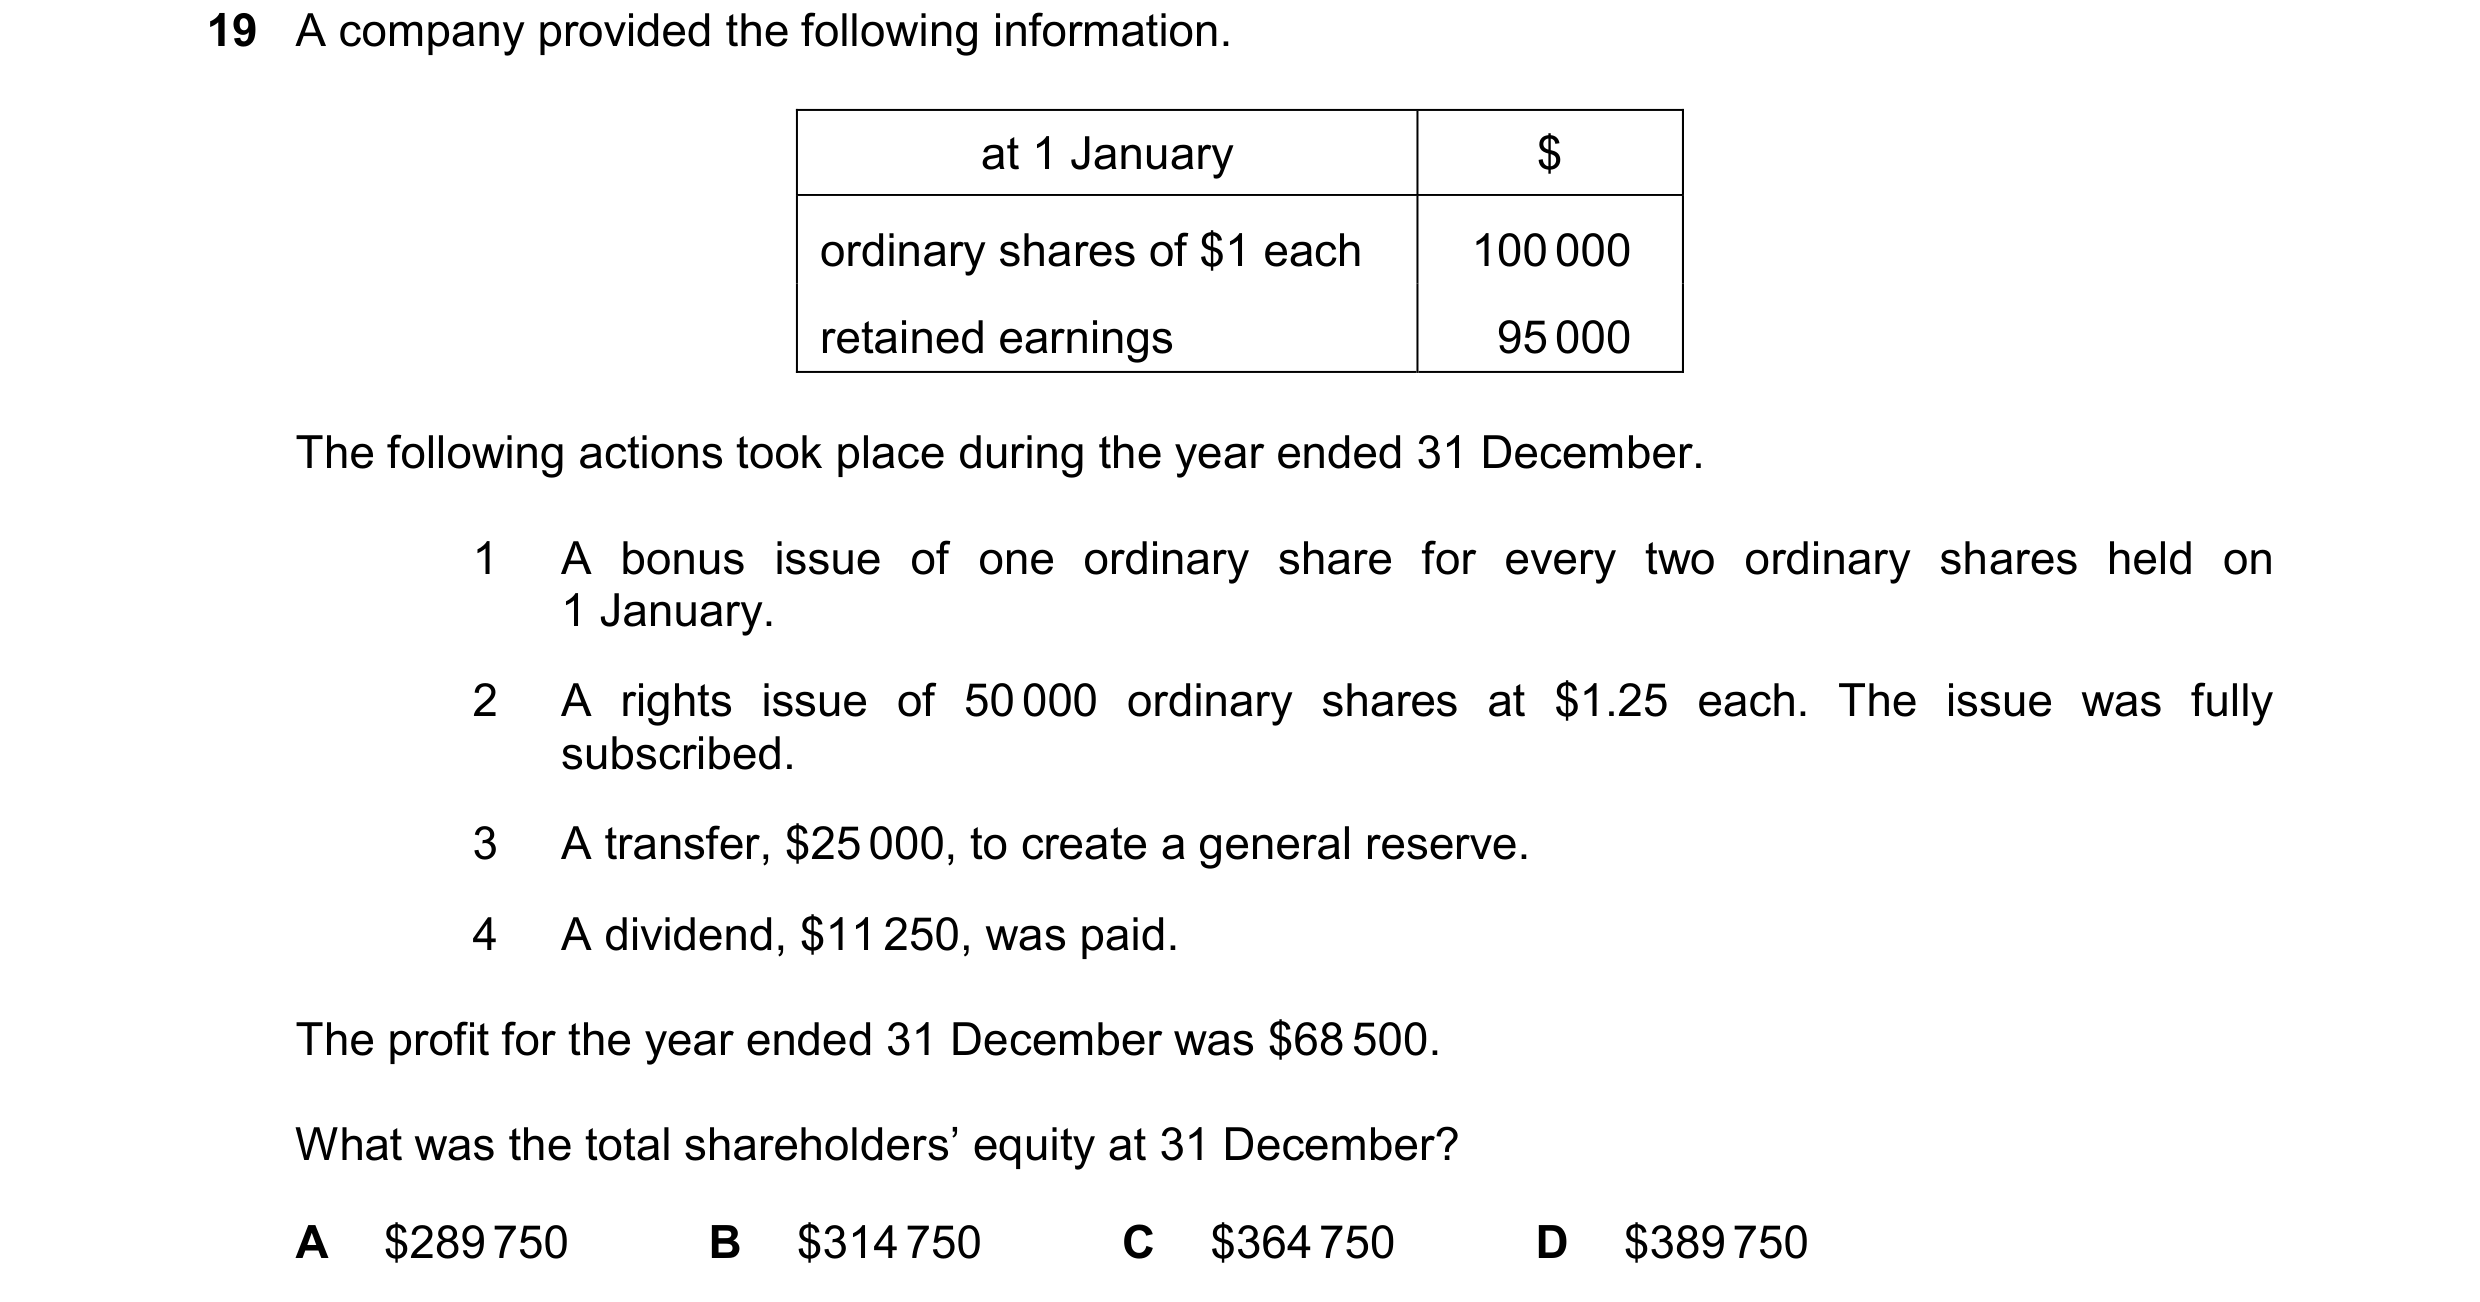
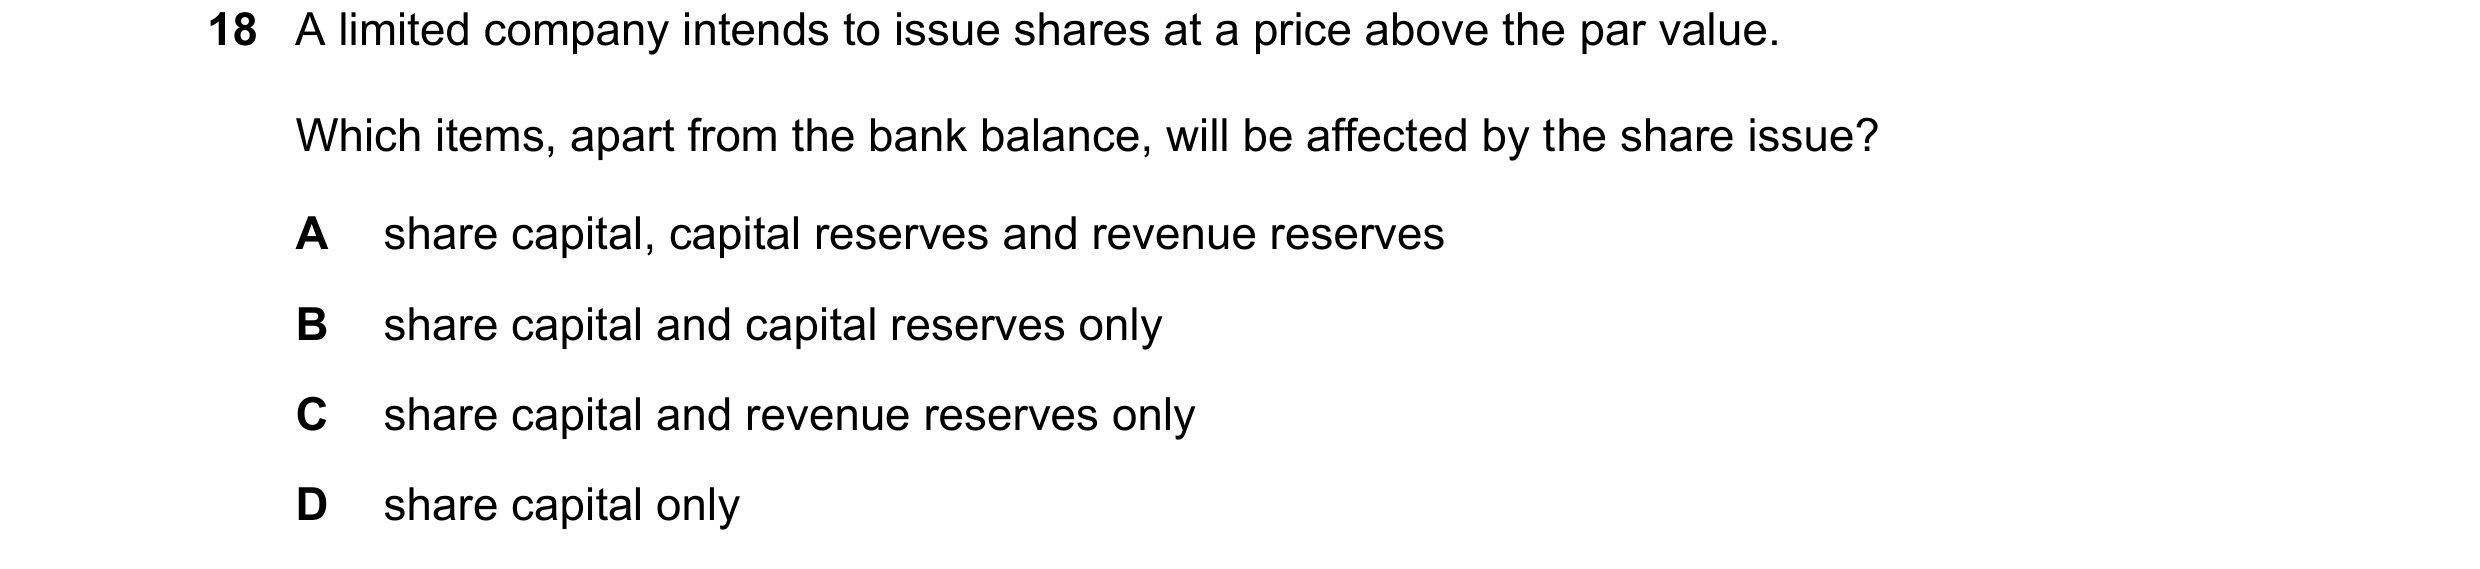
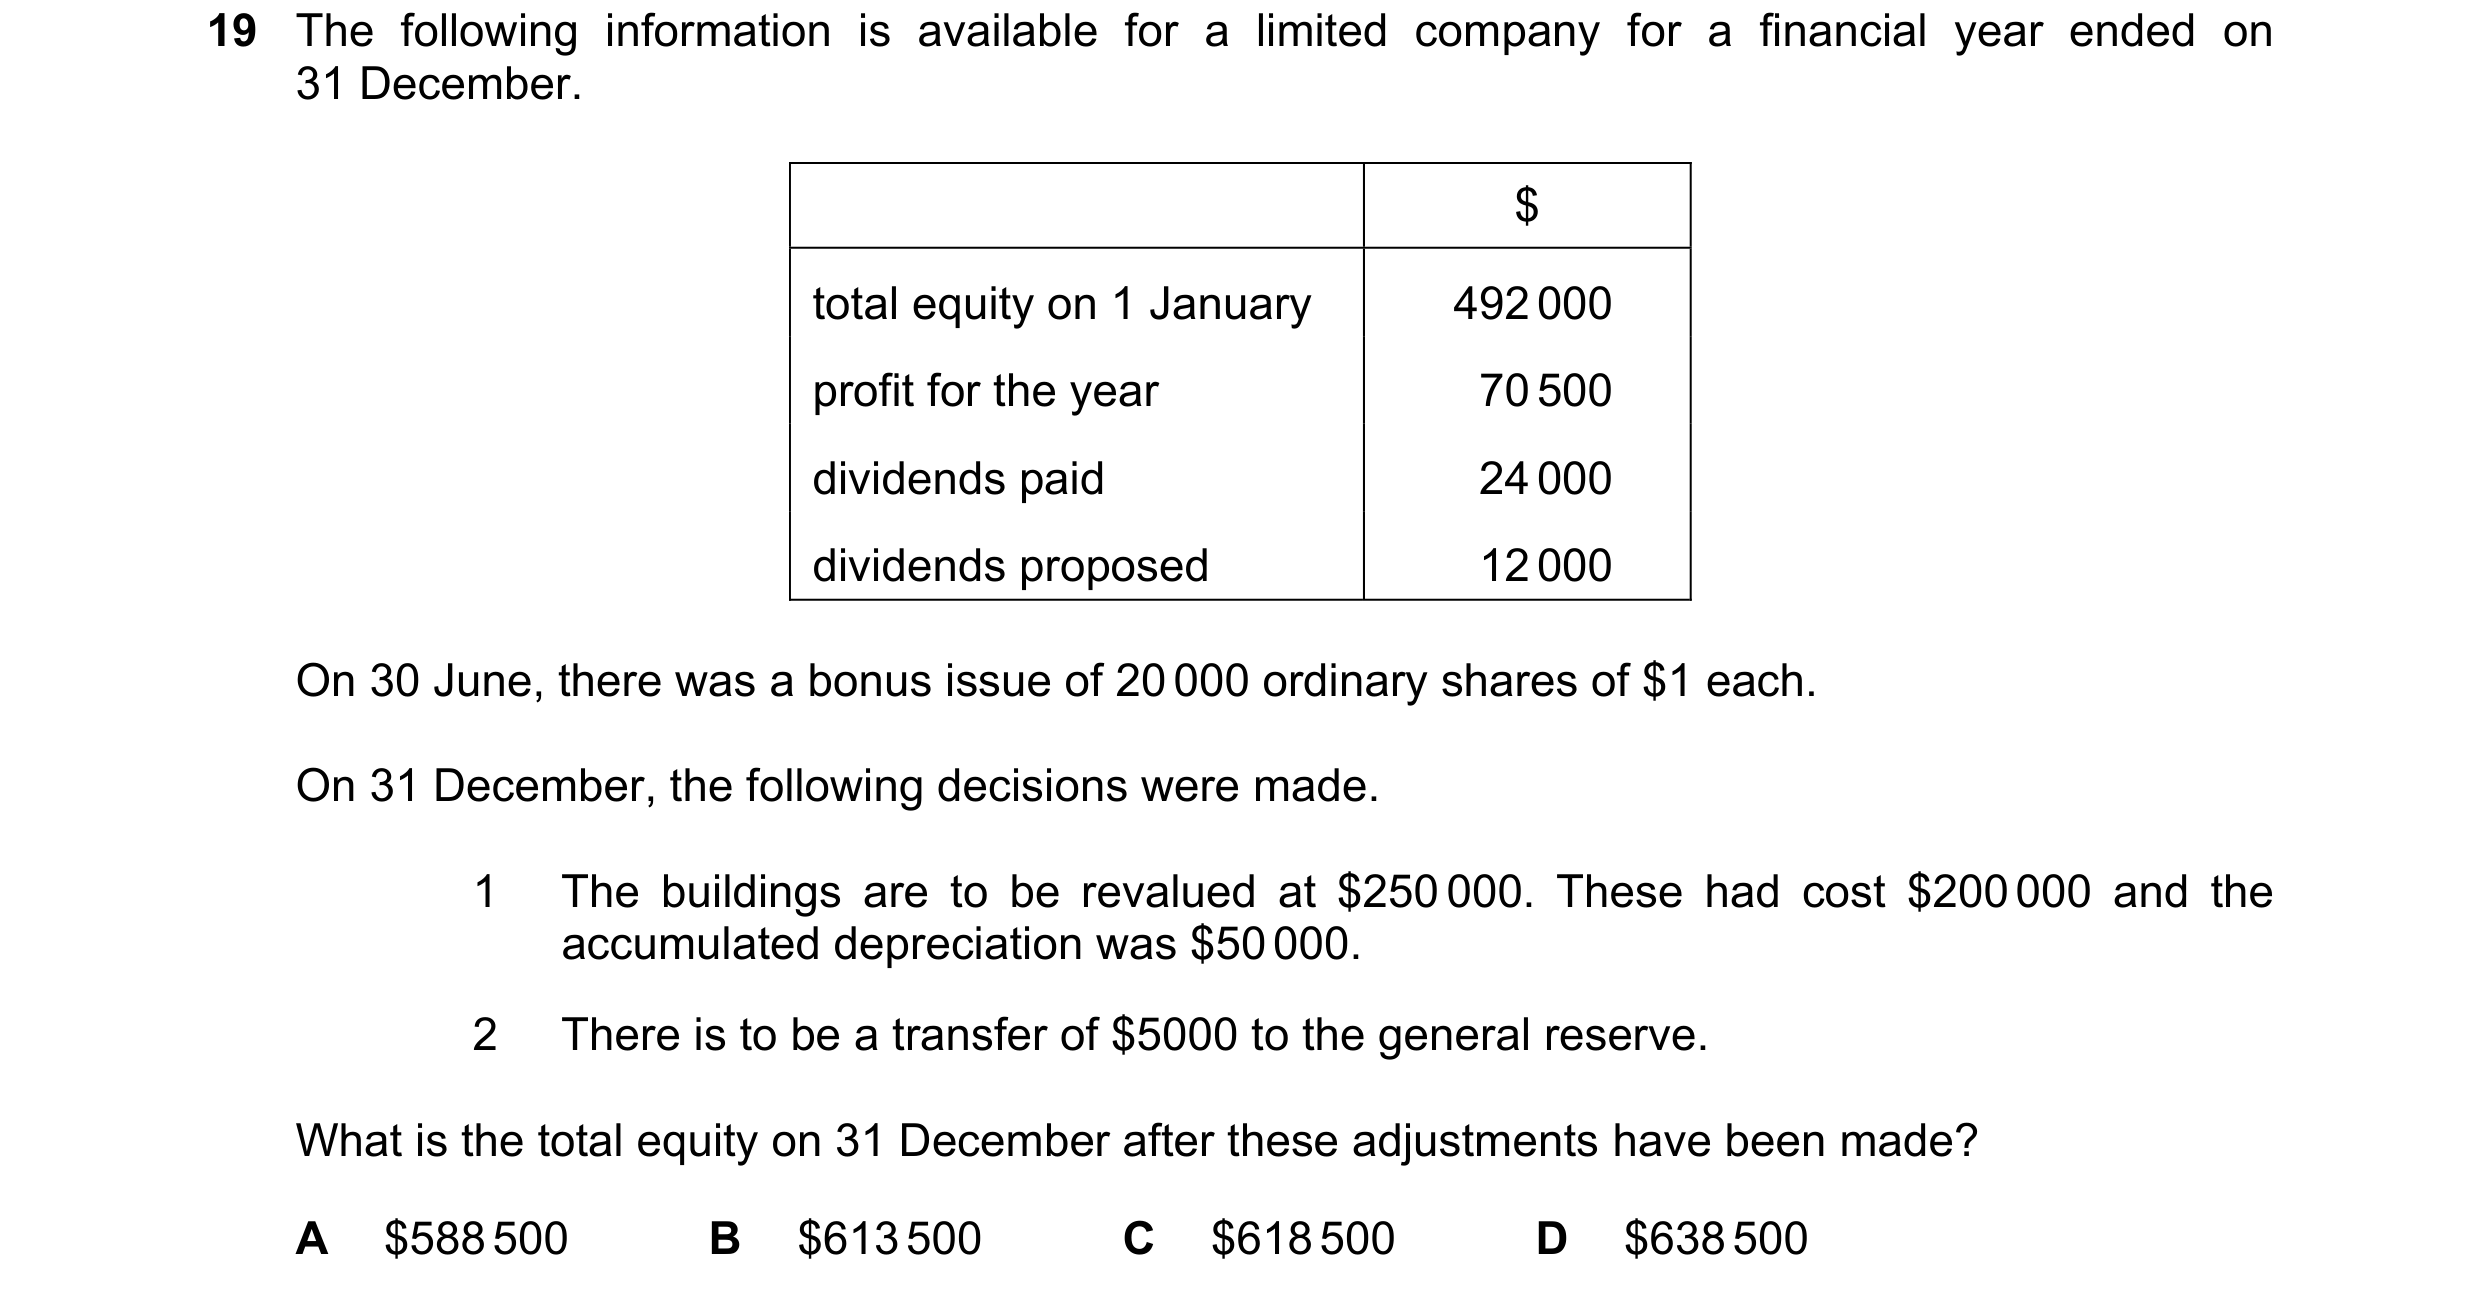 50 / 60
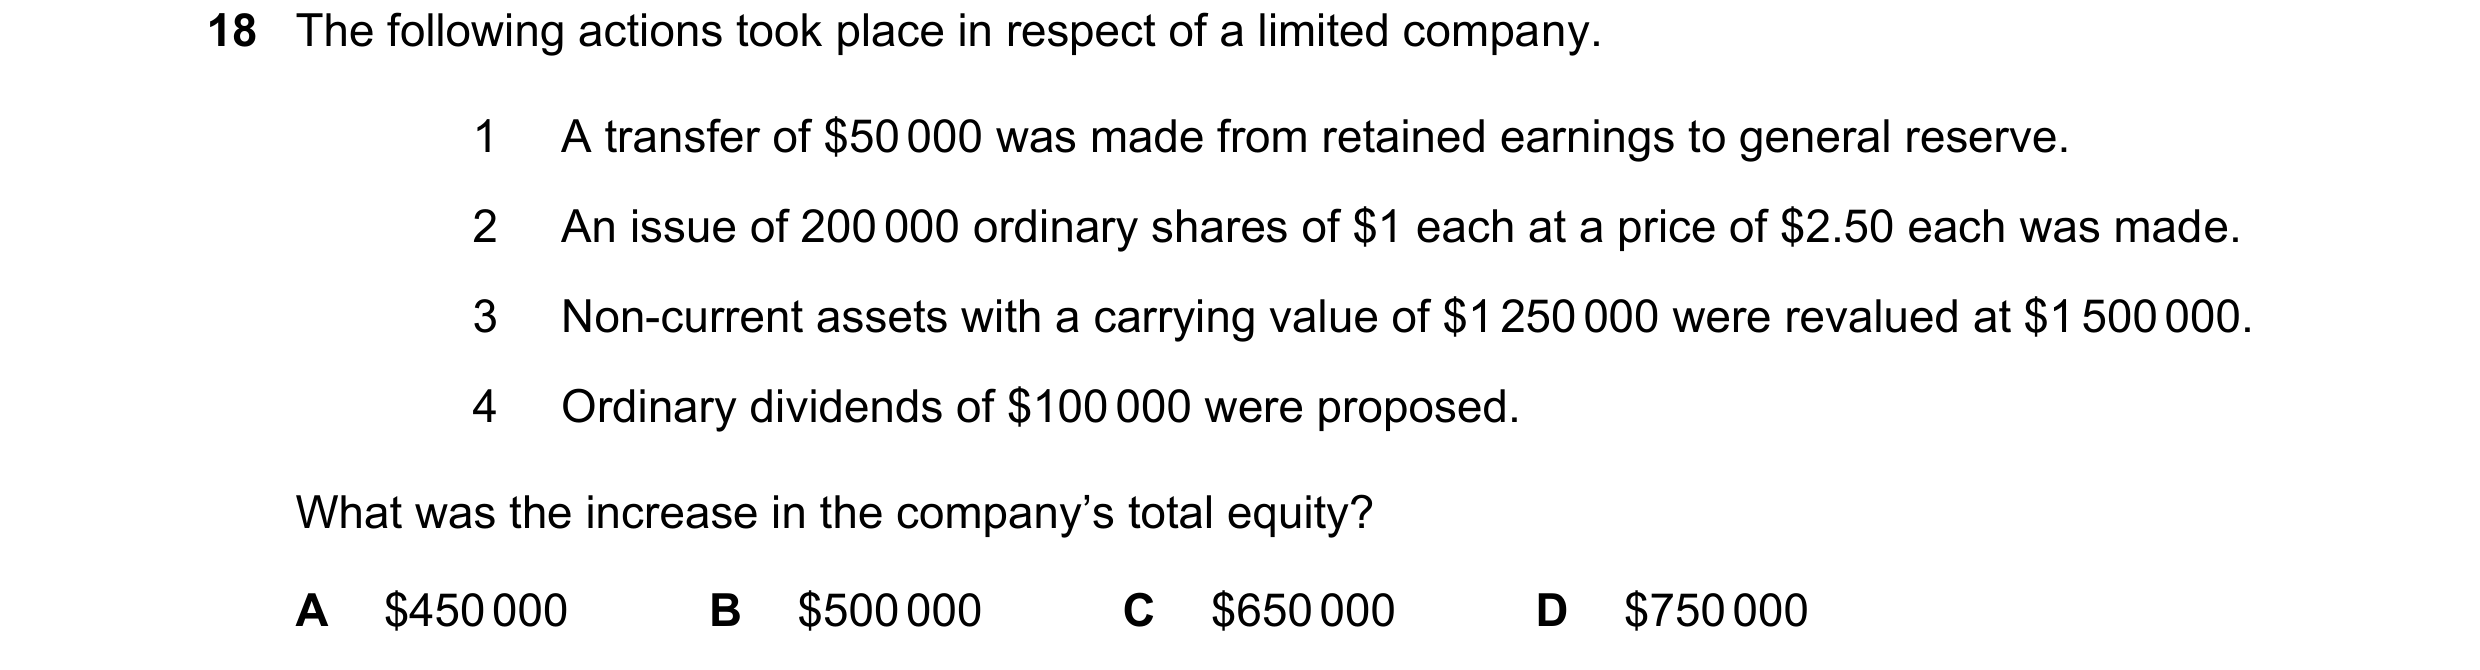
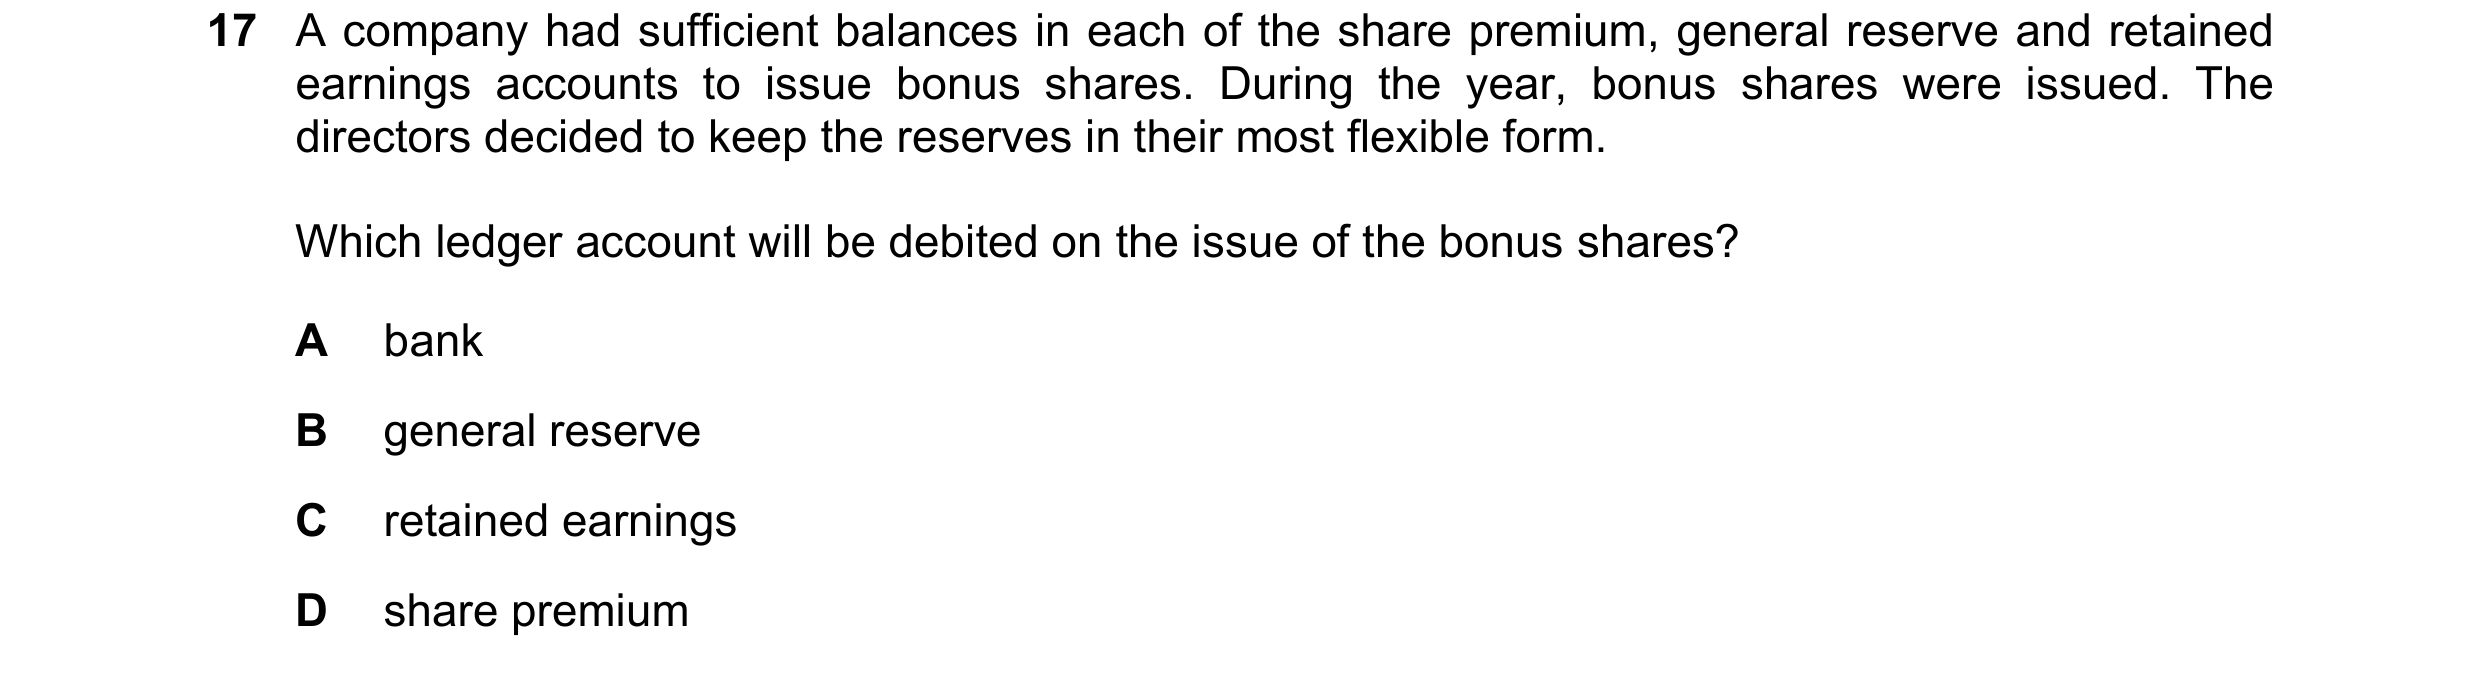
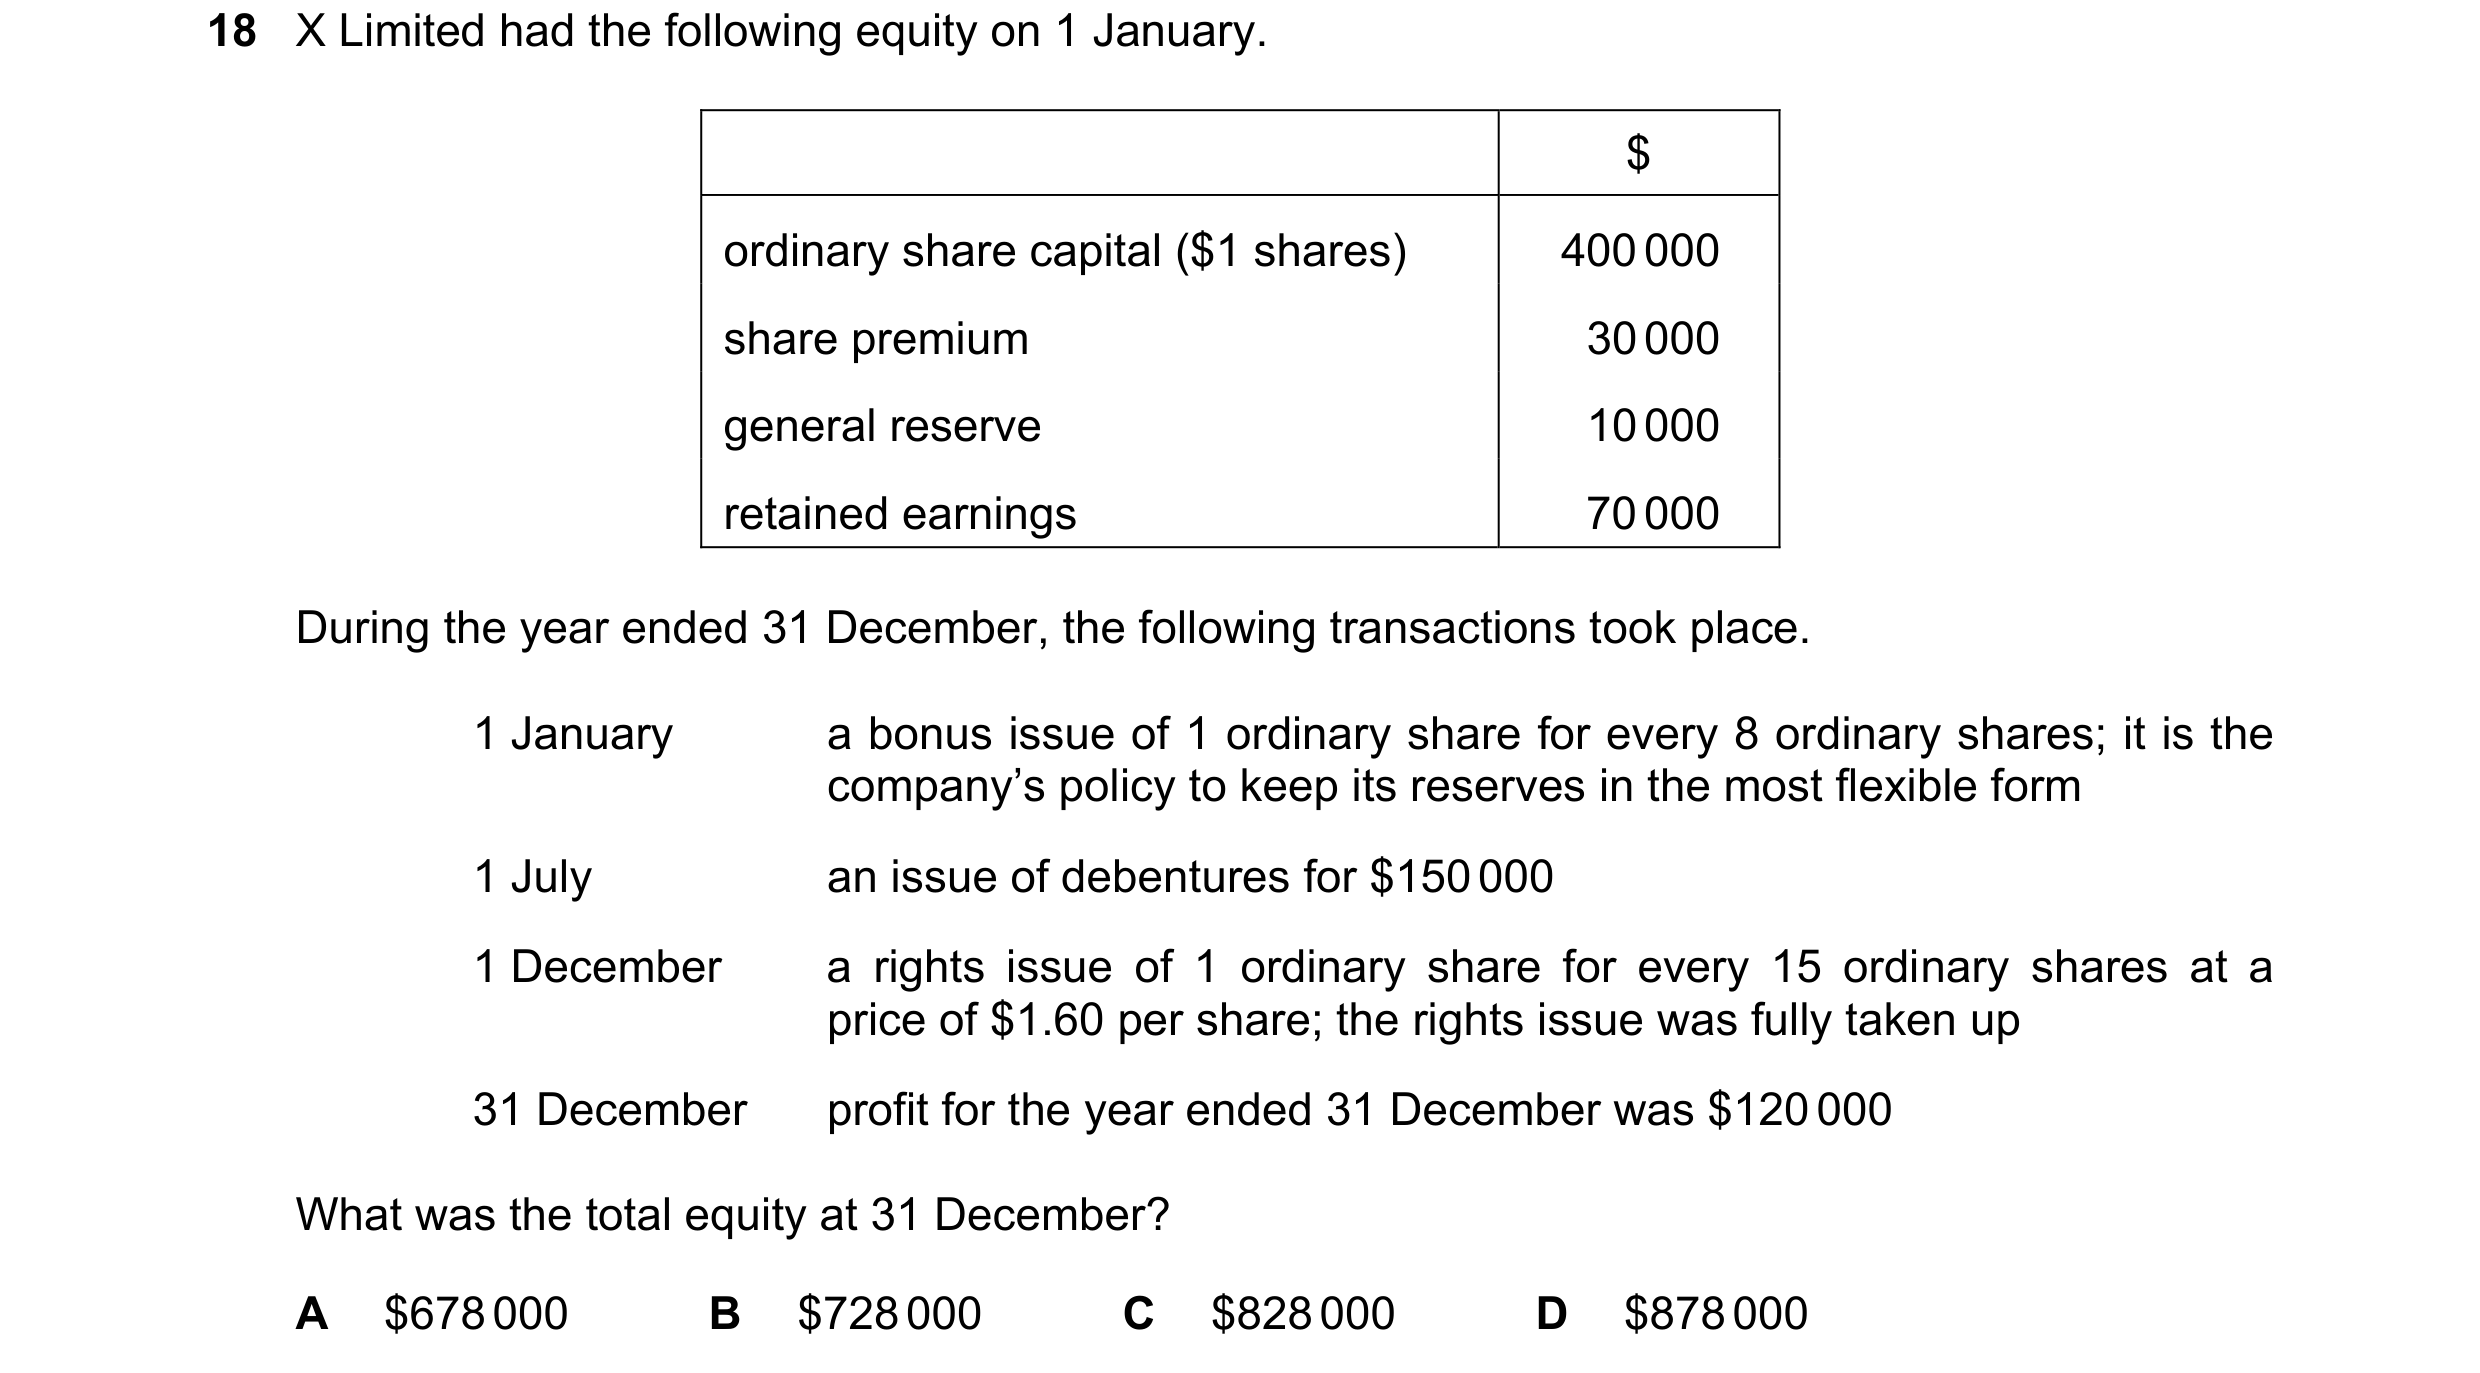
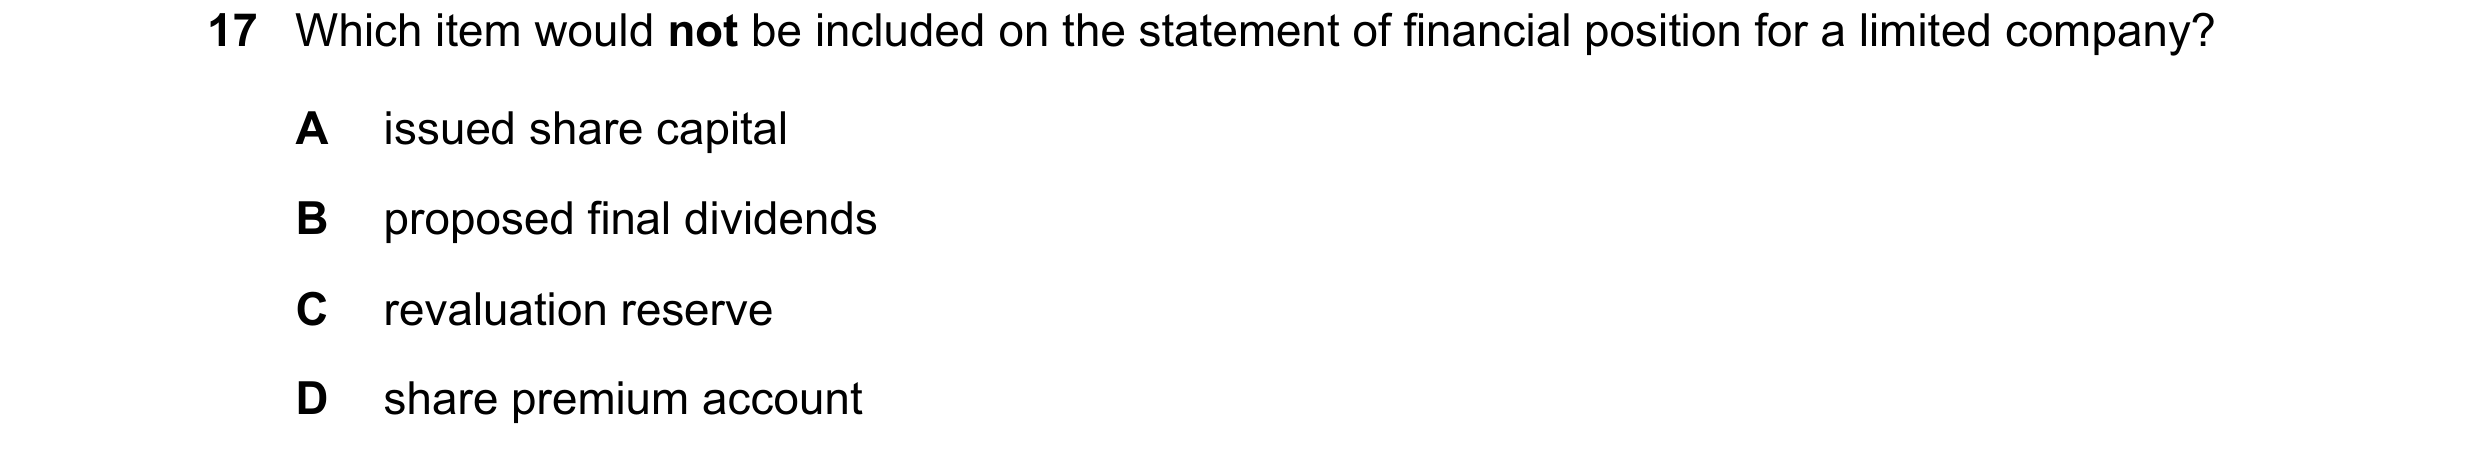 51 / 60
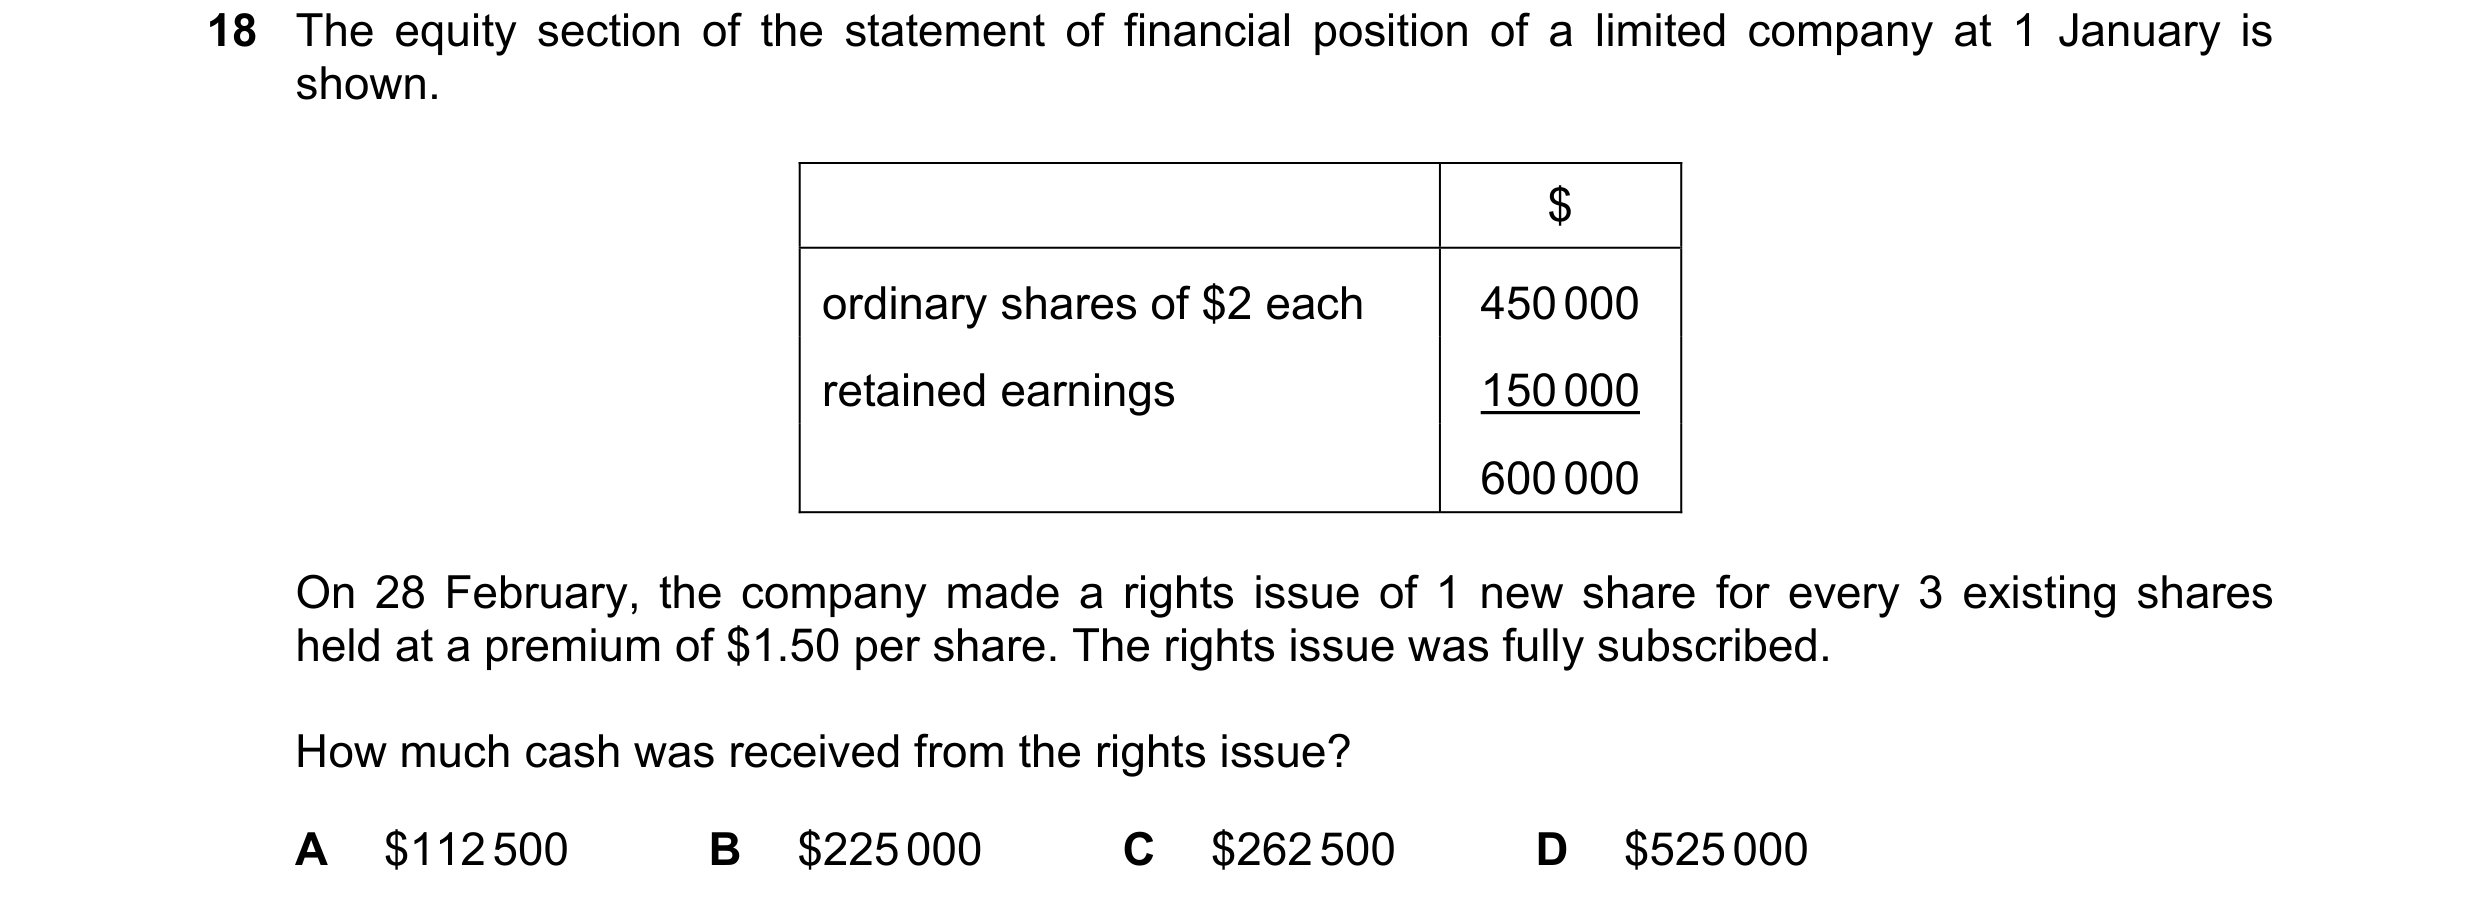
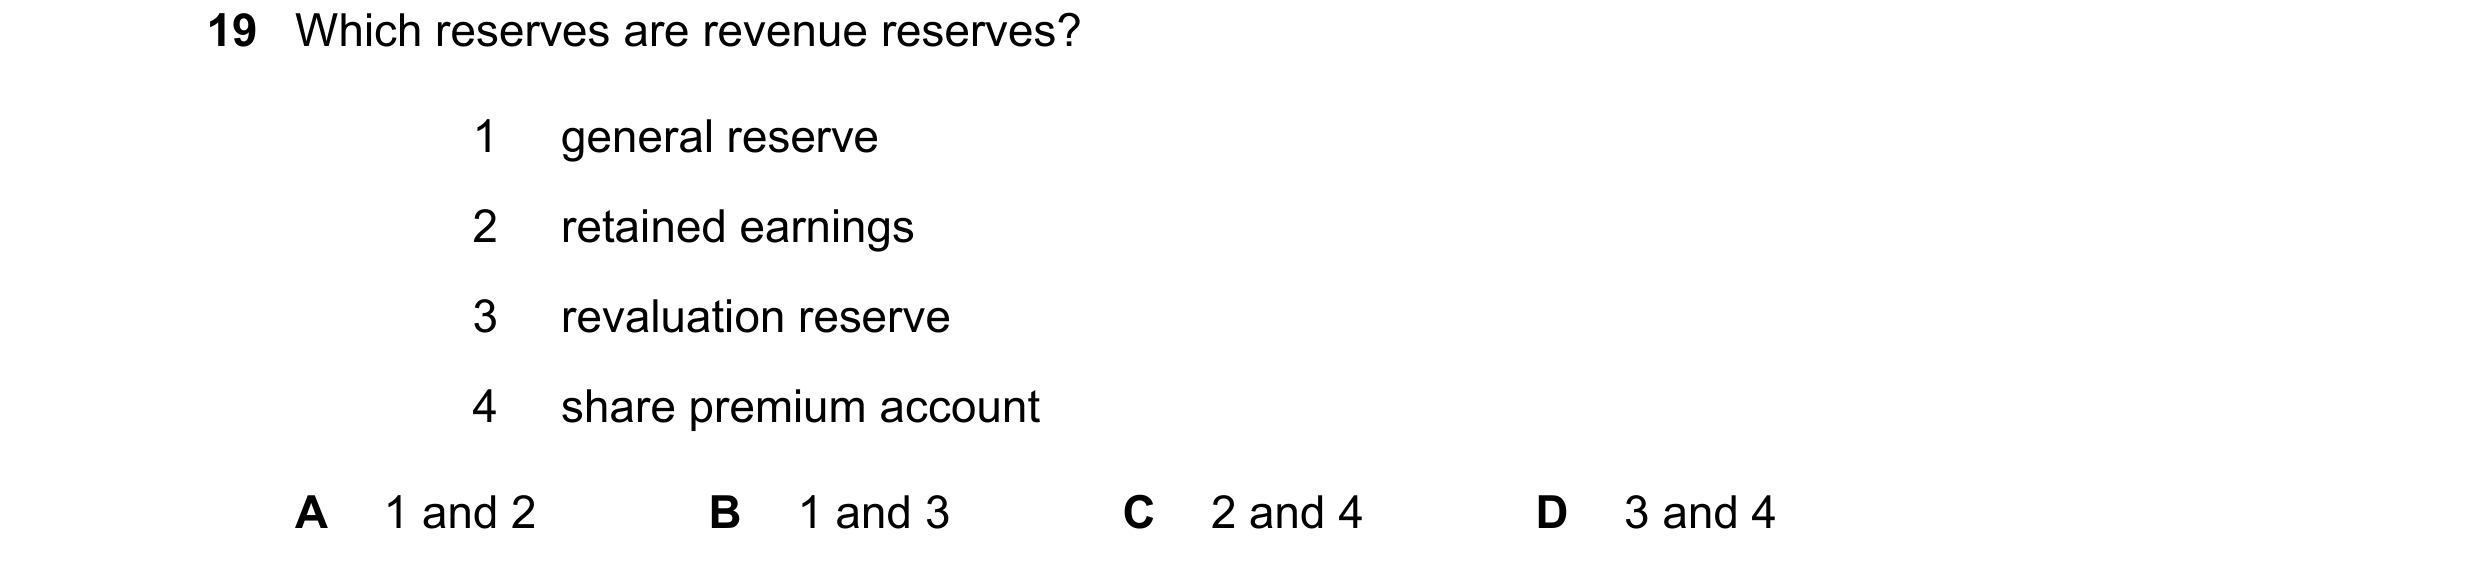
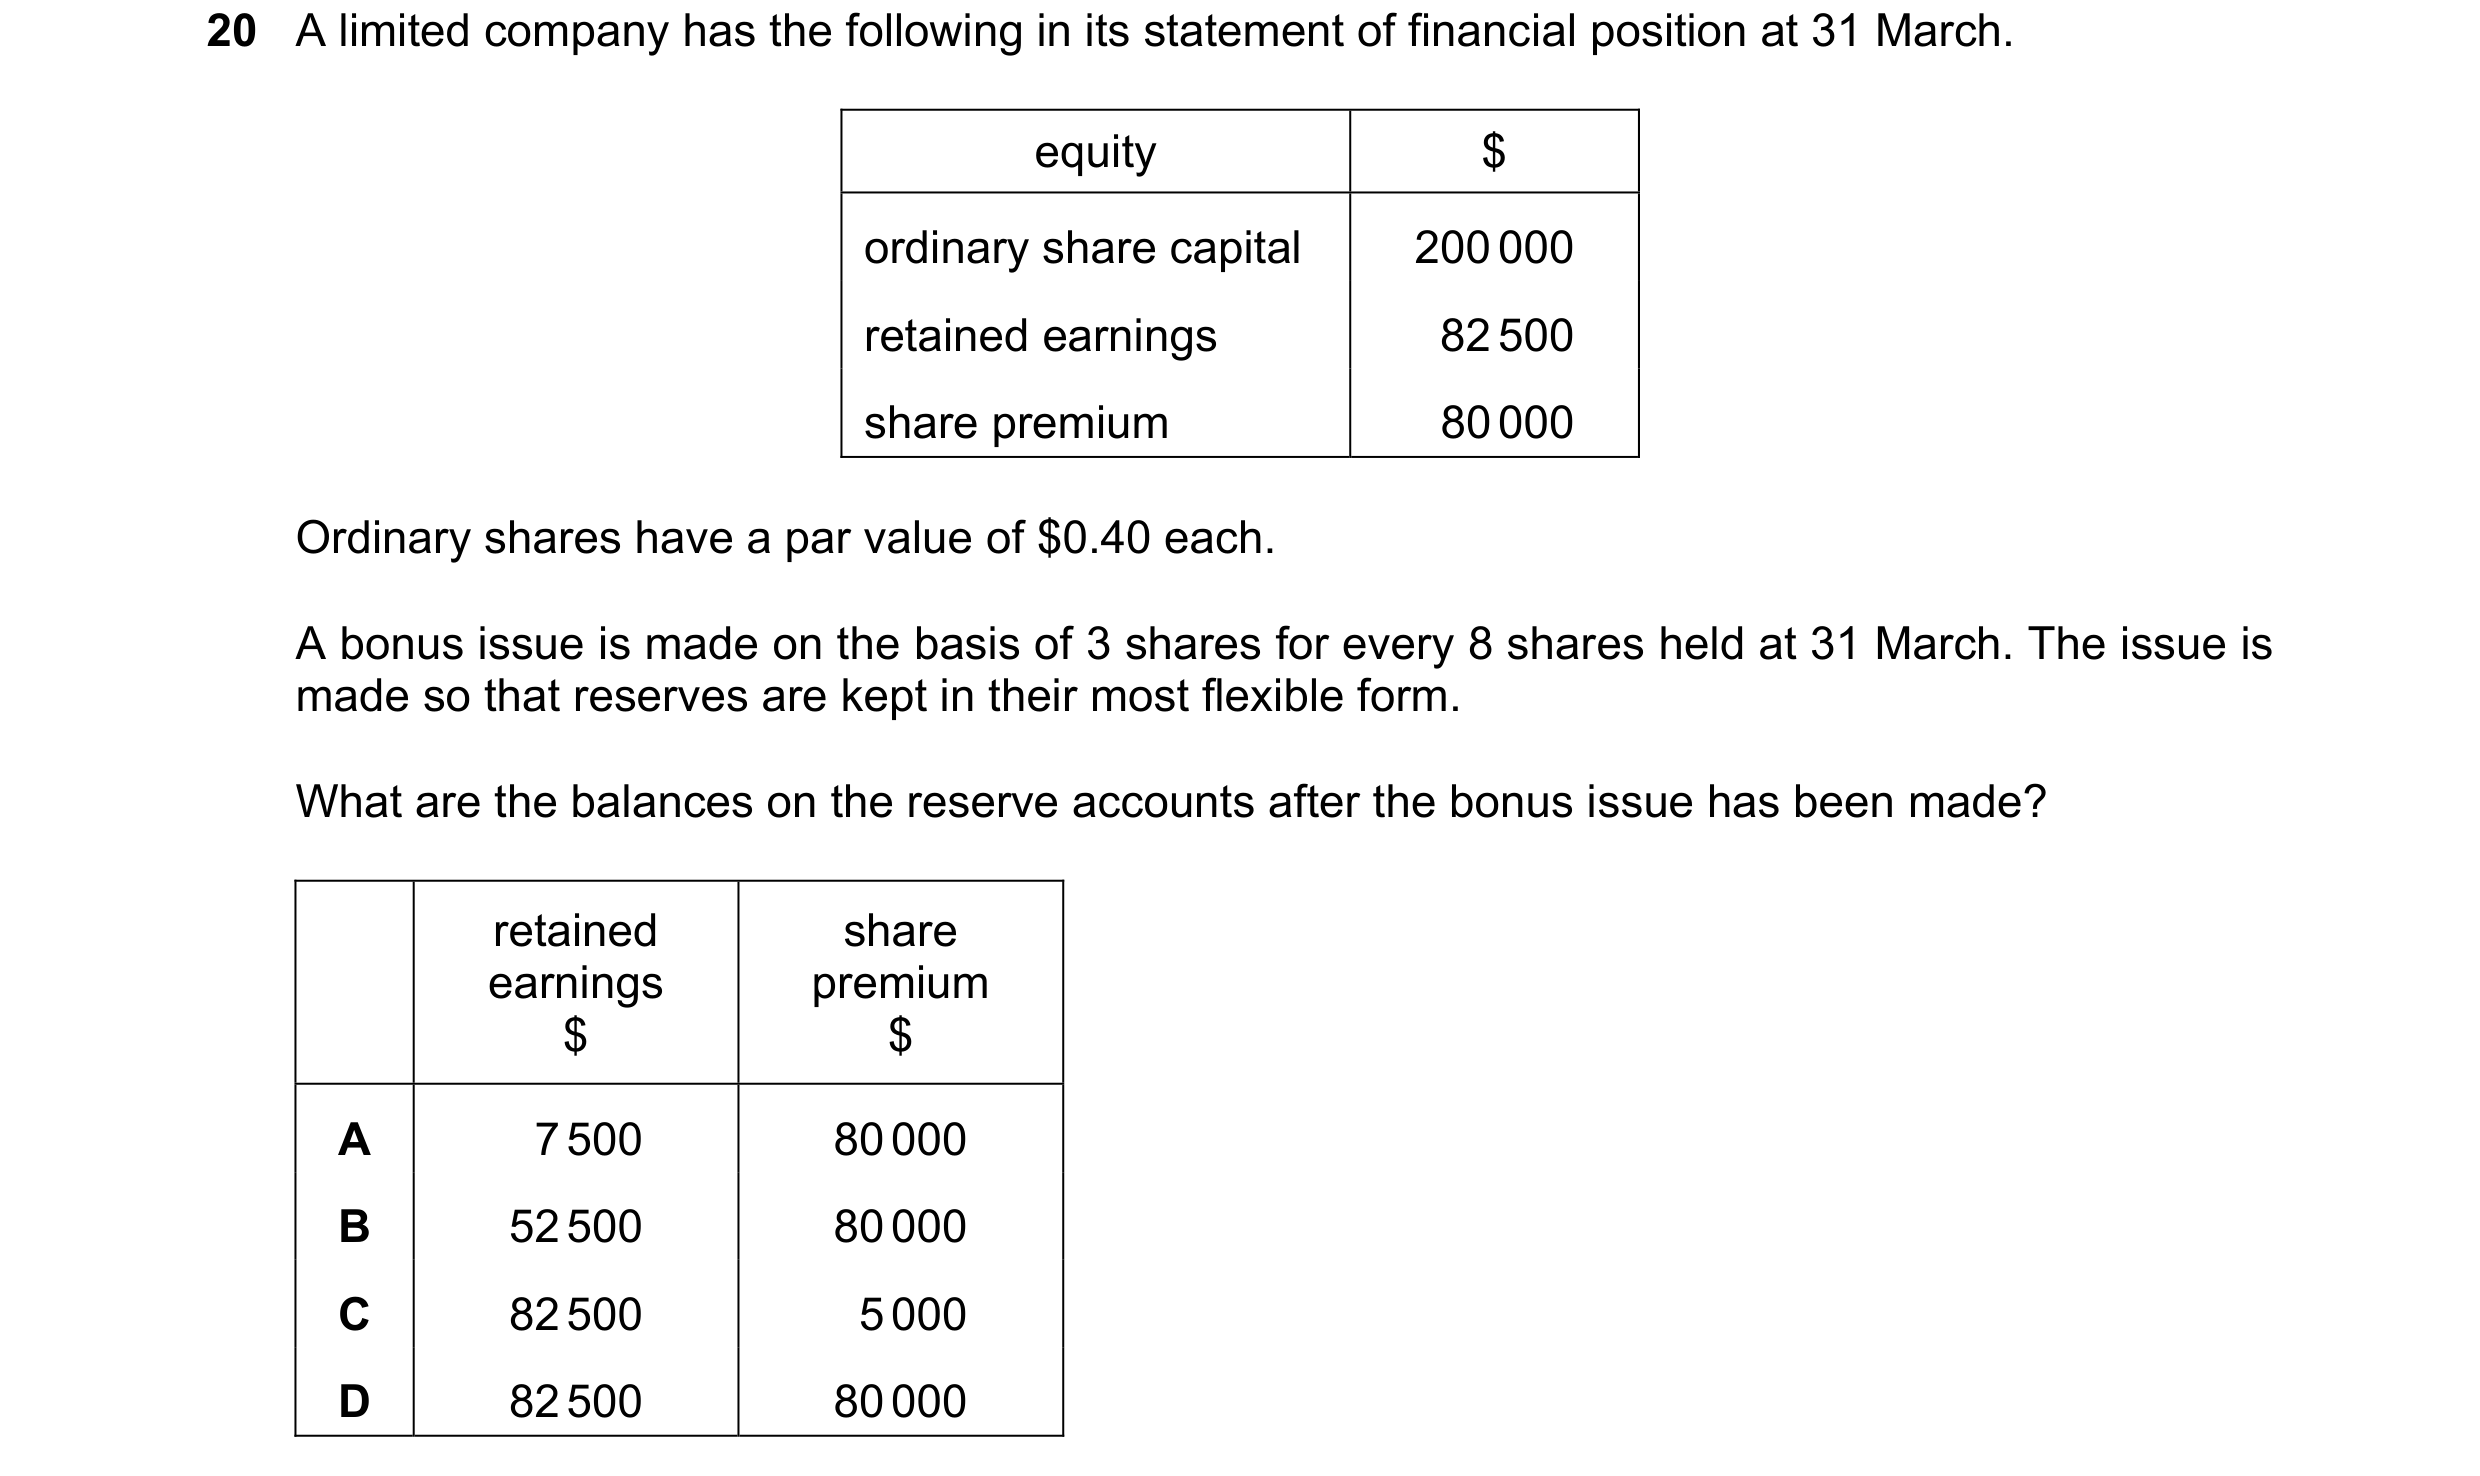 52 / 60
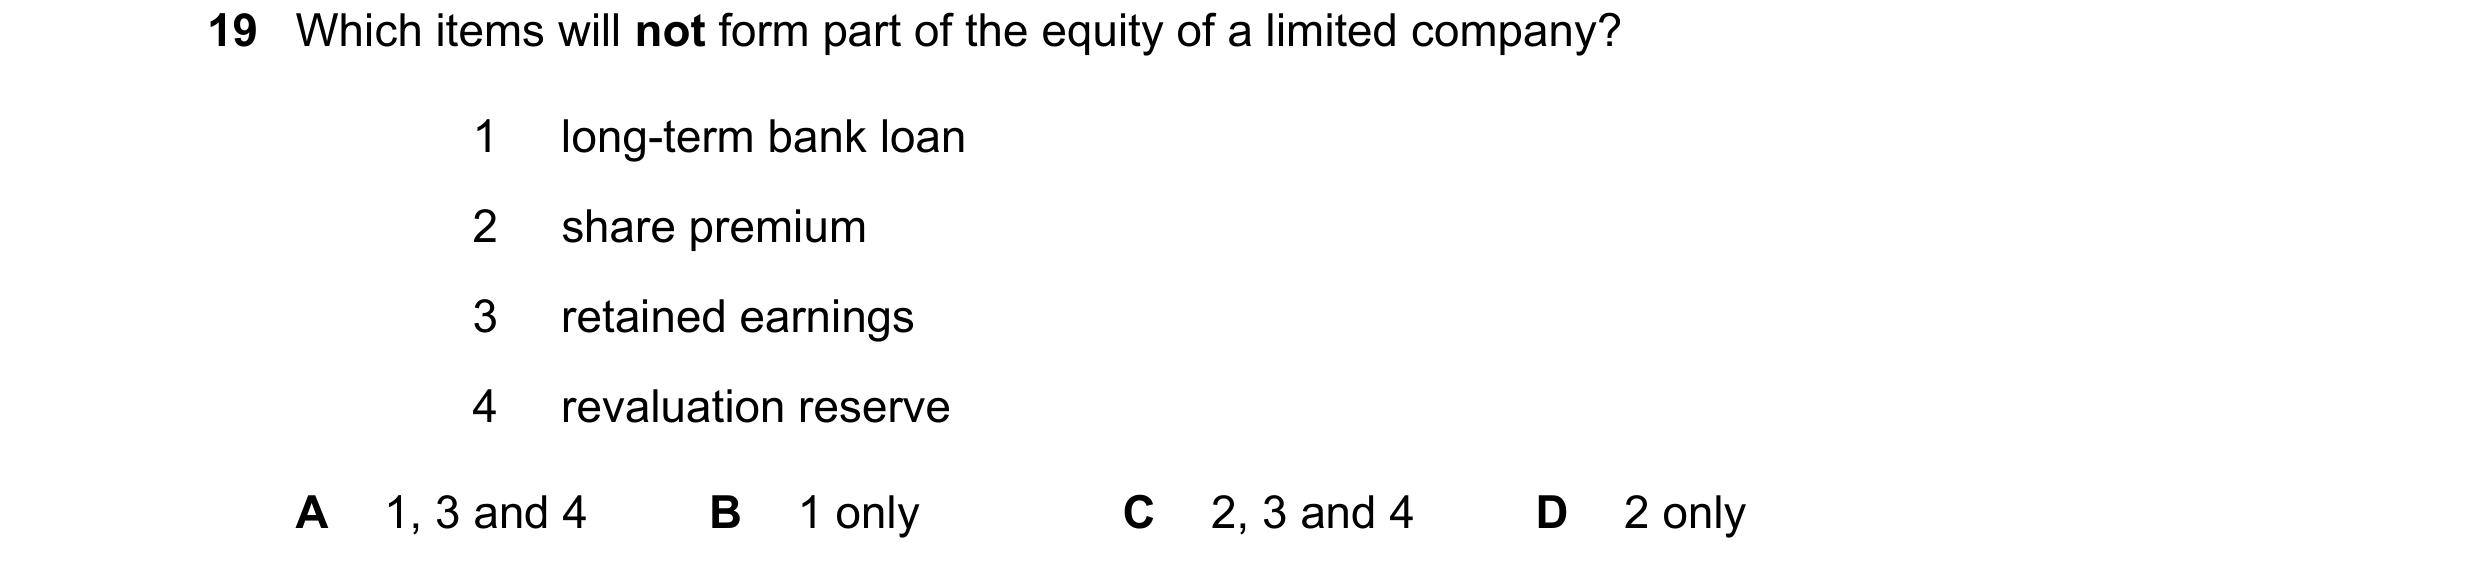
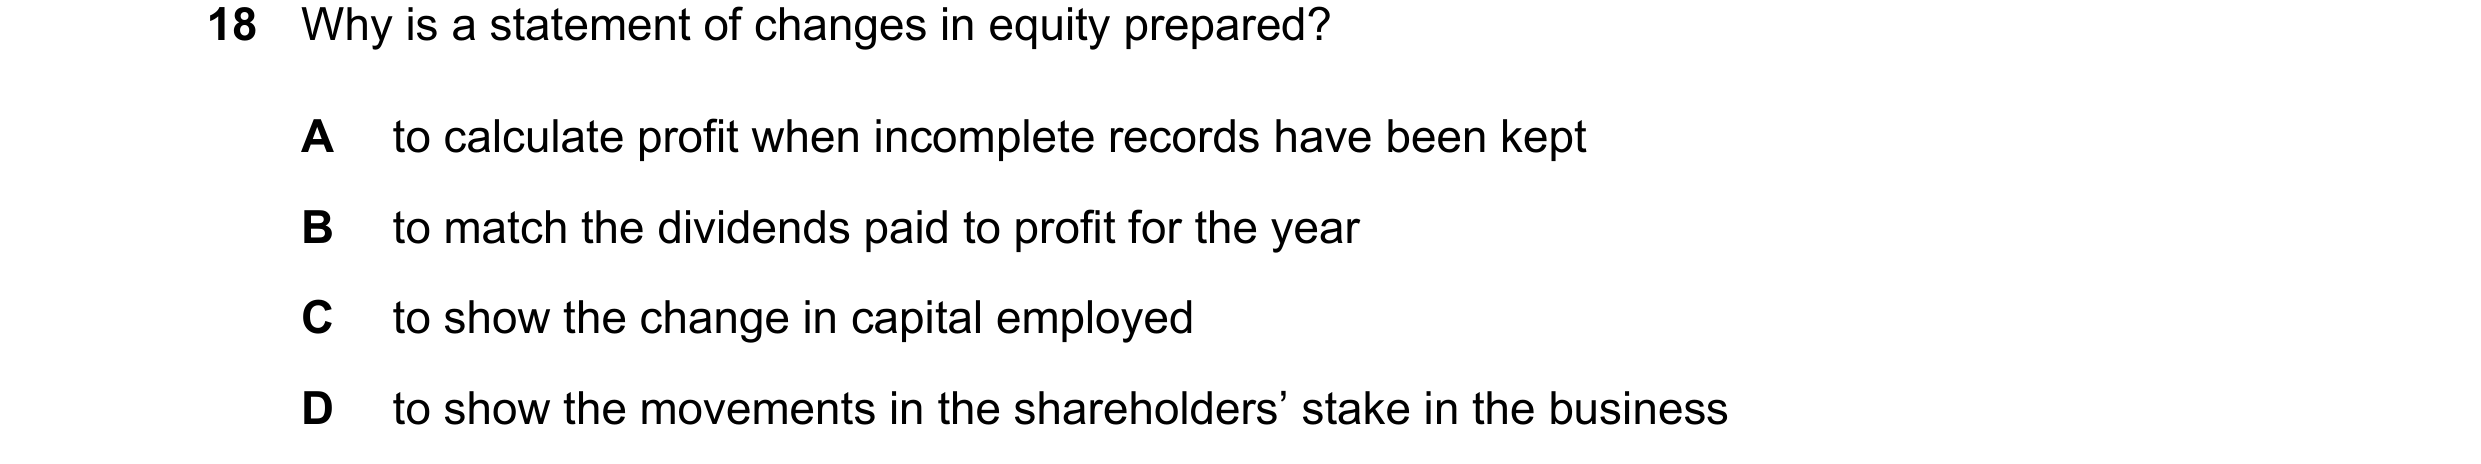
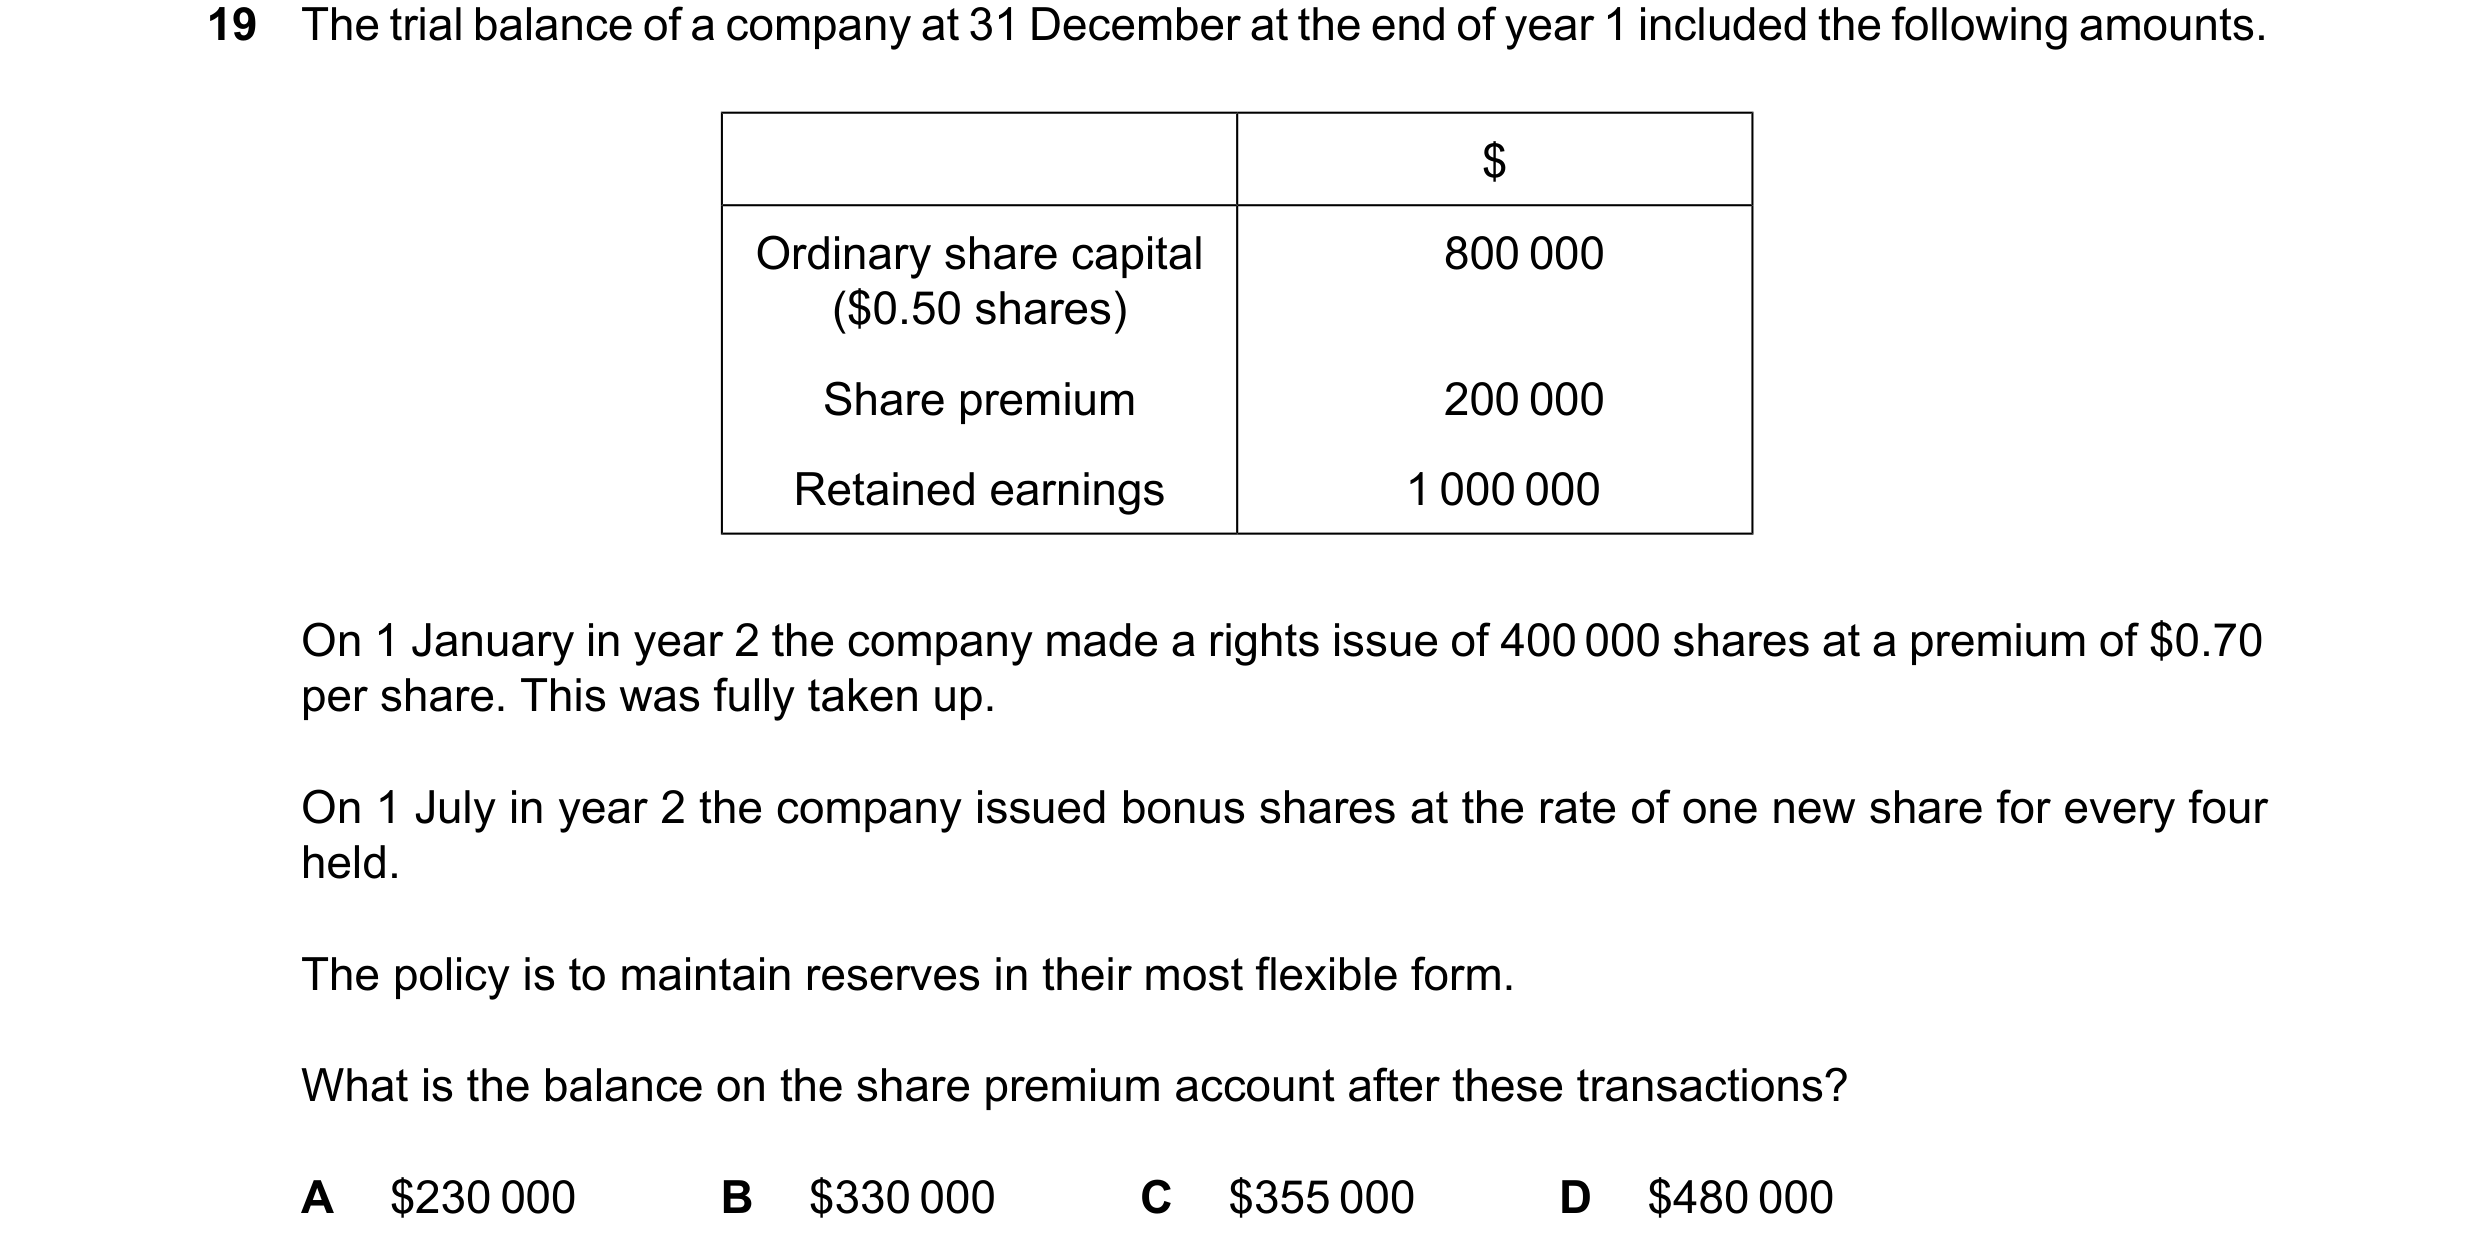
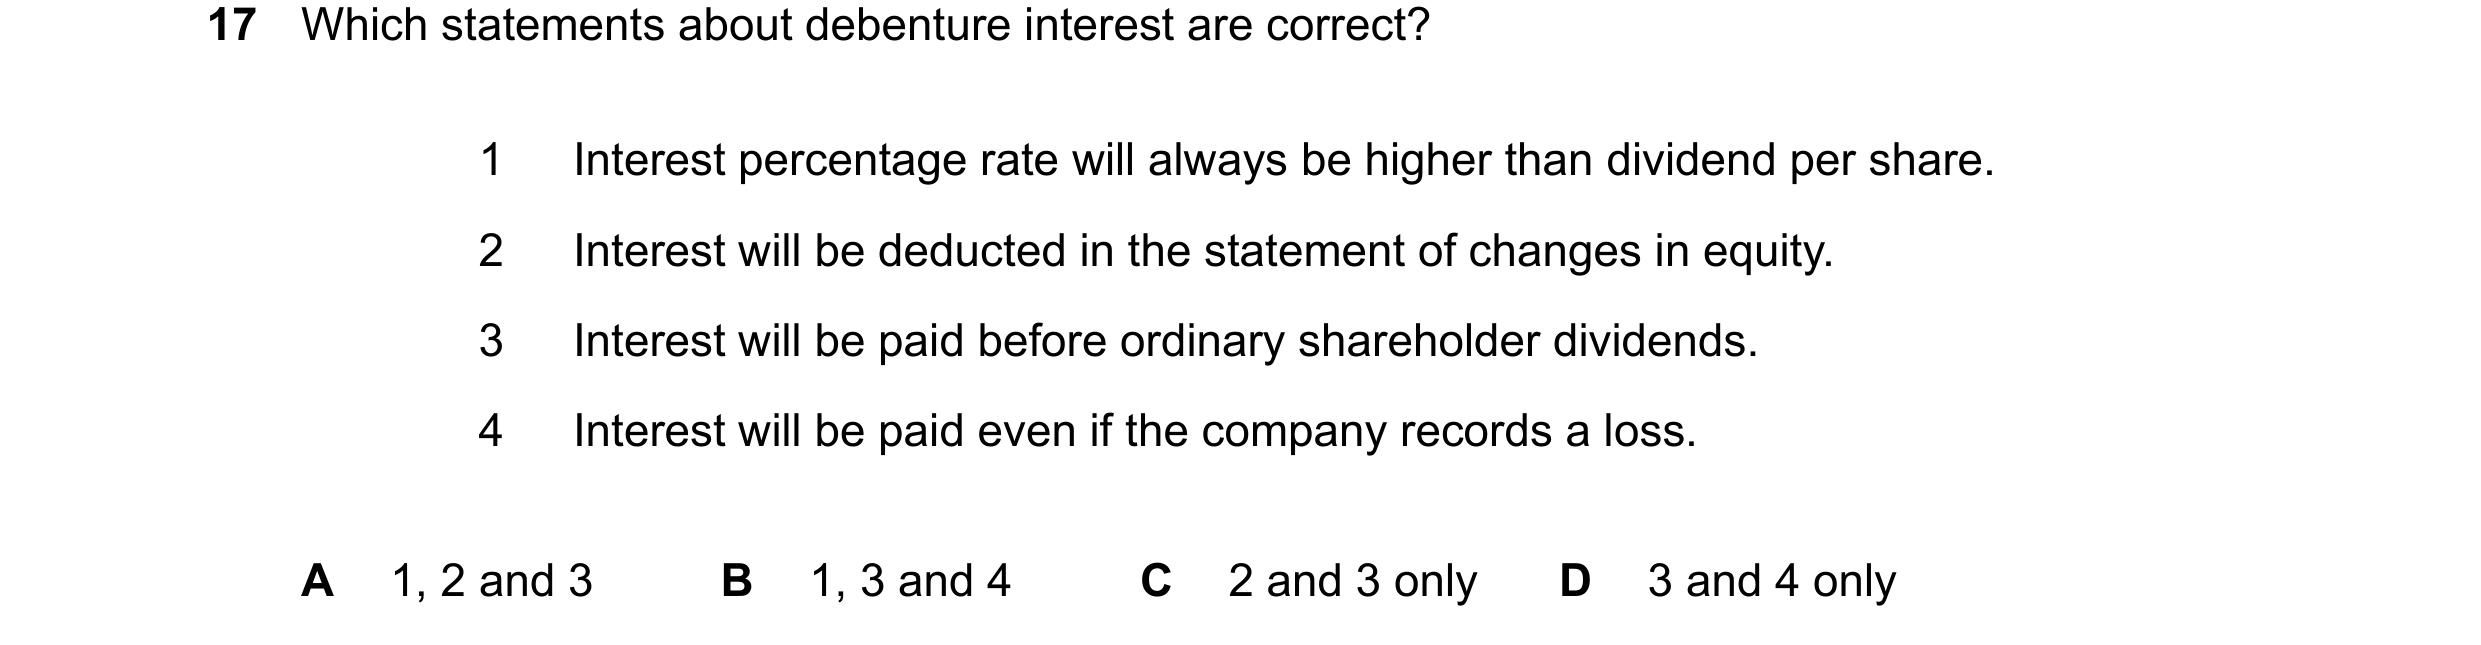 53 / 60
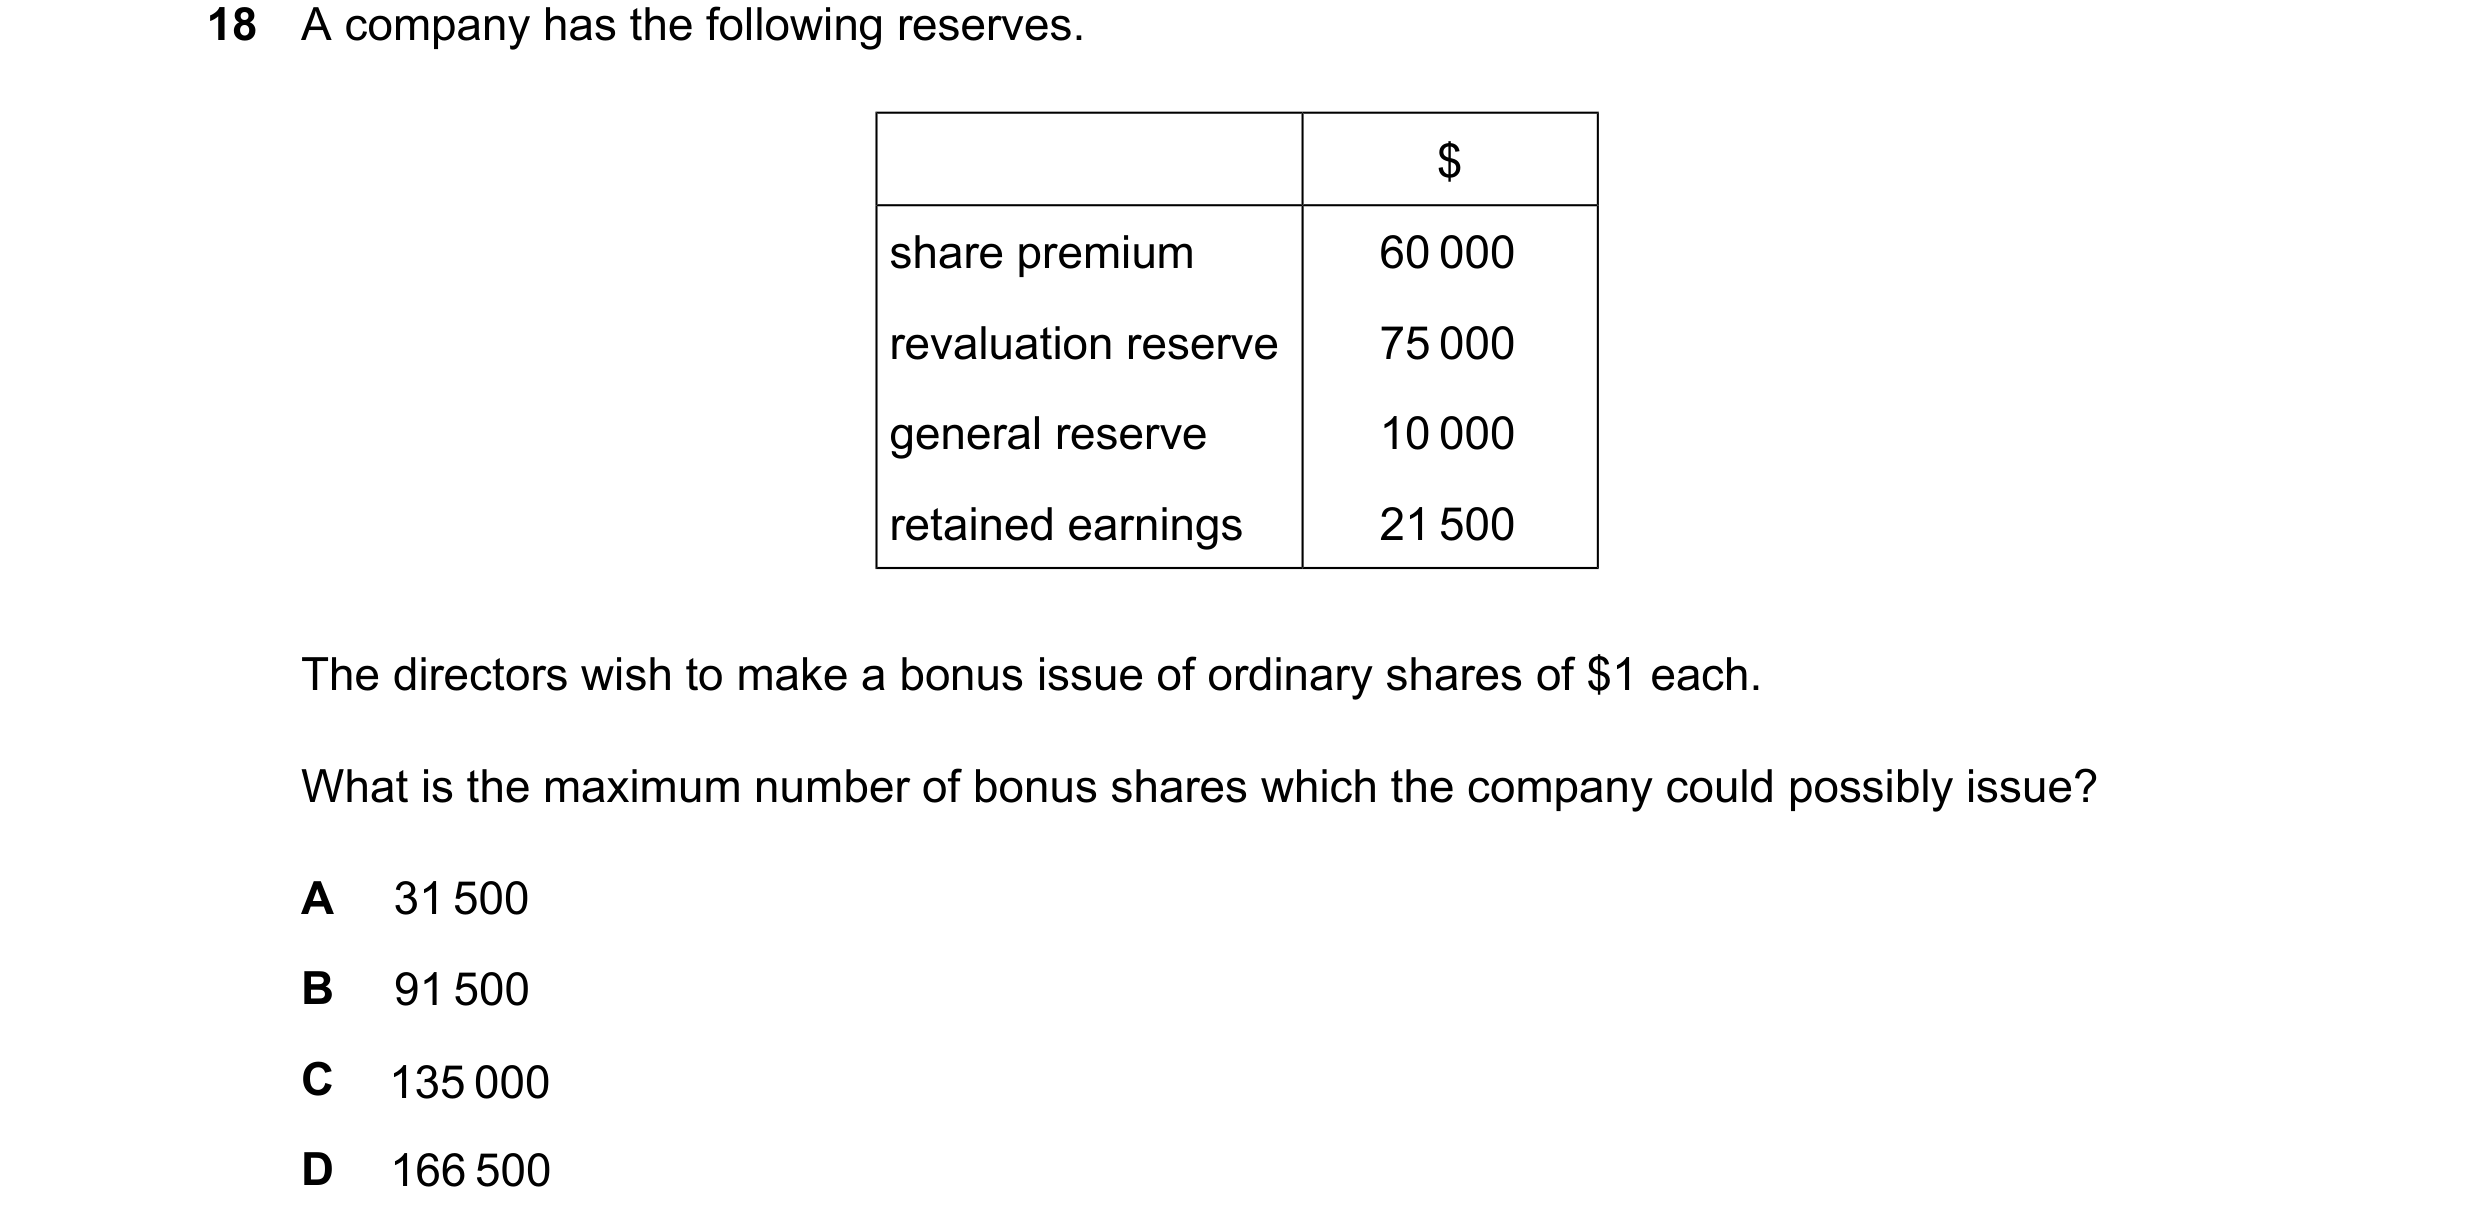
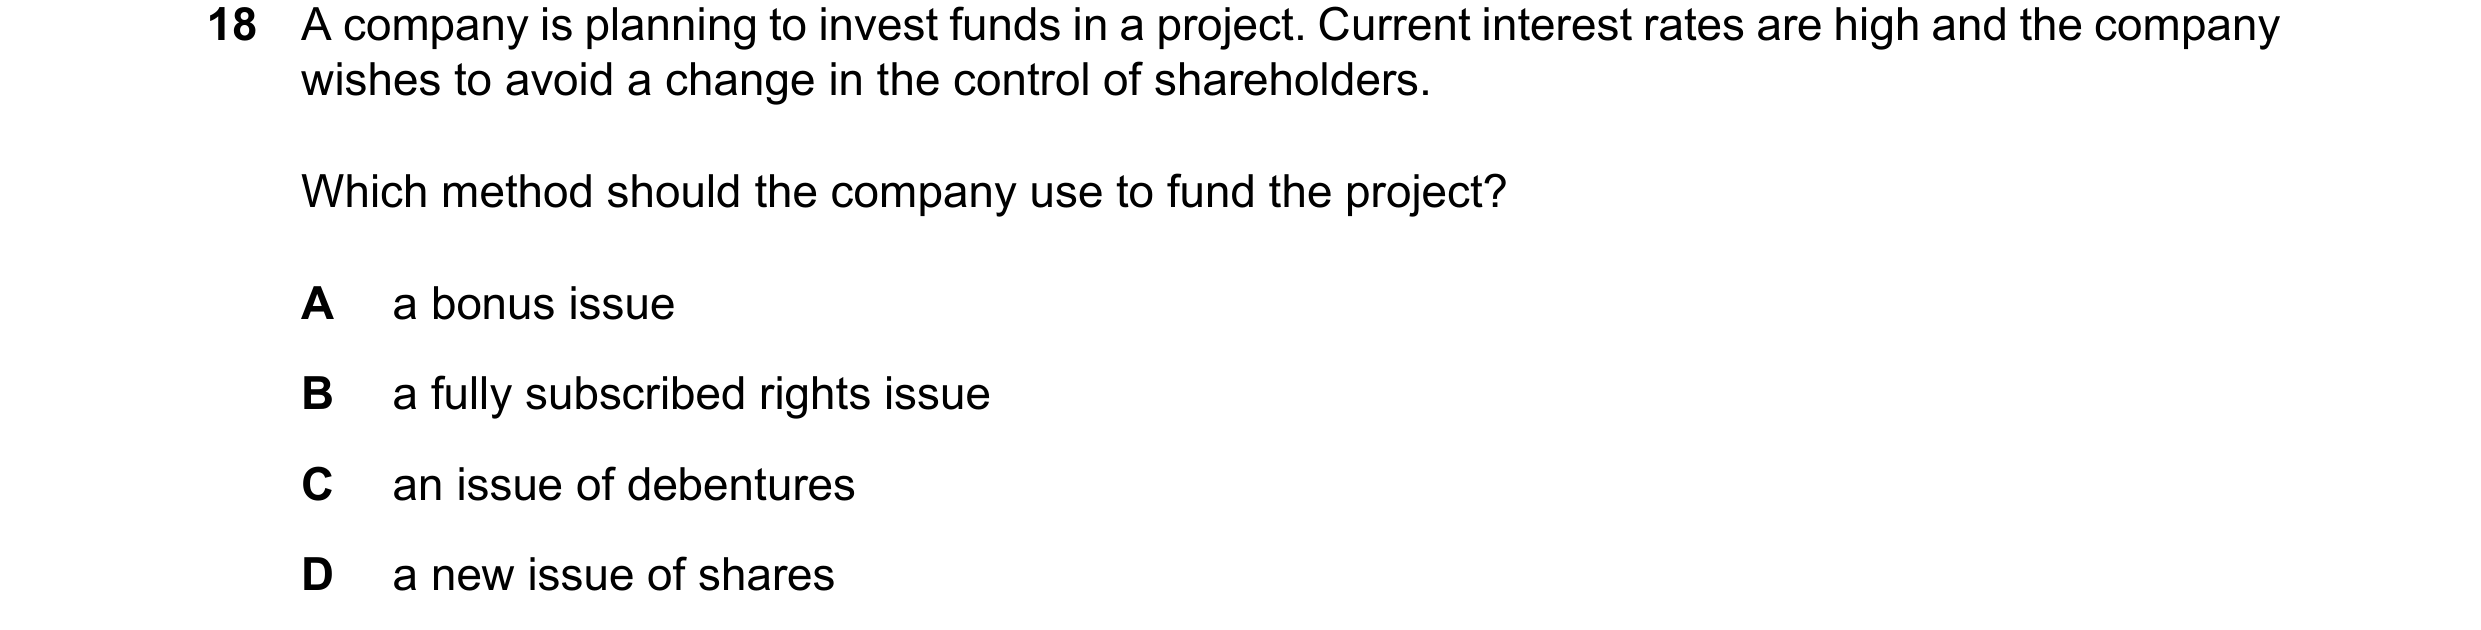 54 / 60
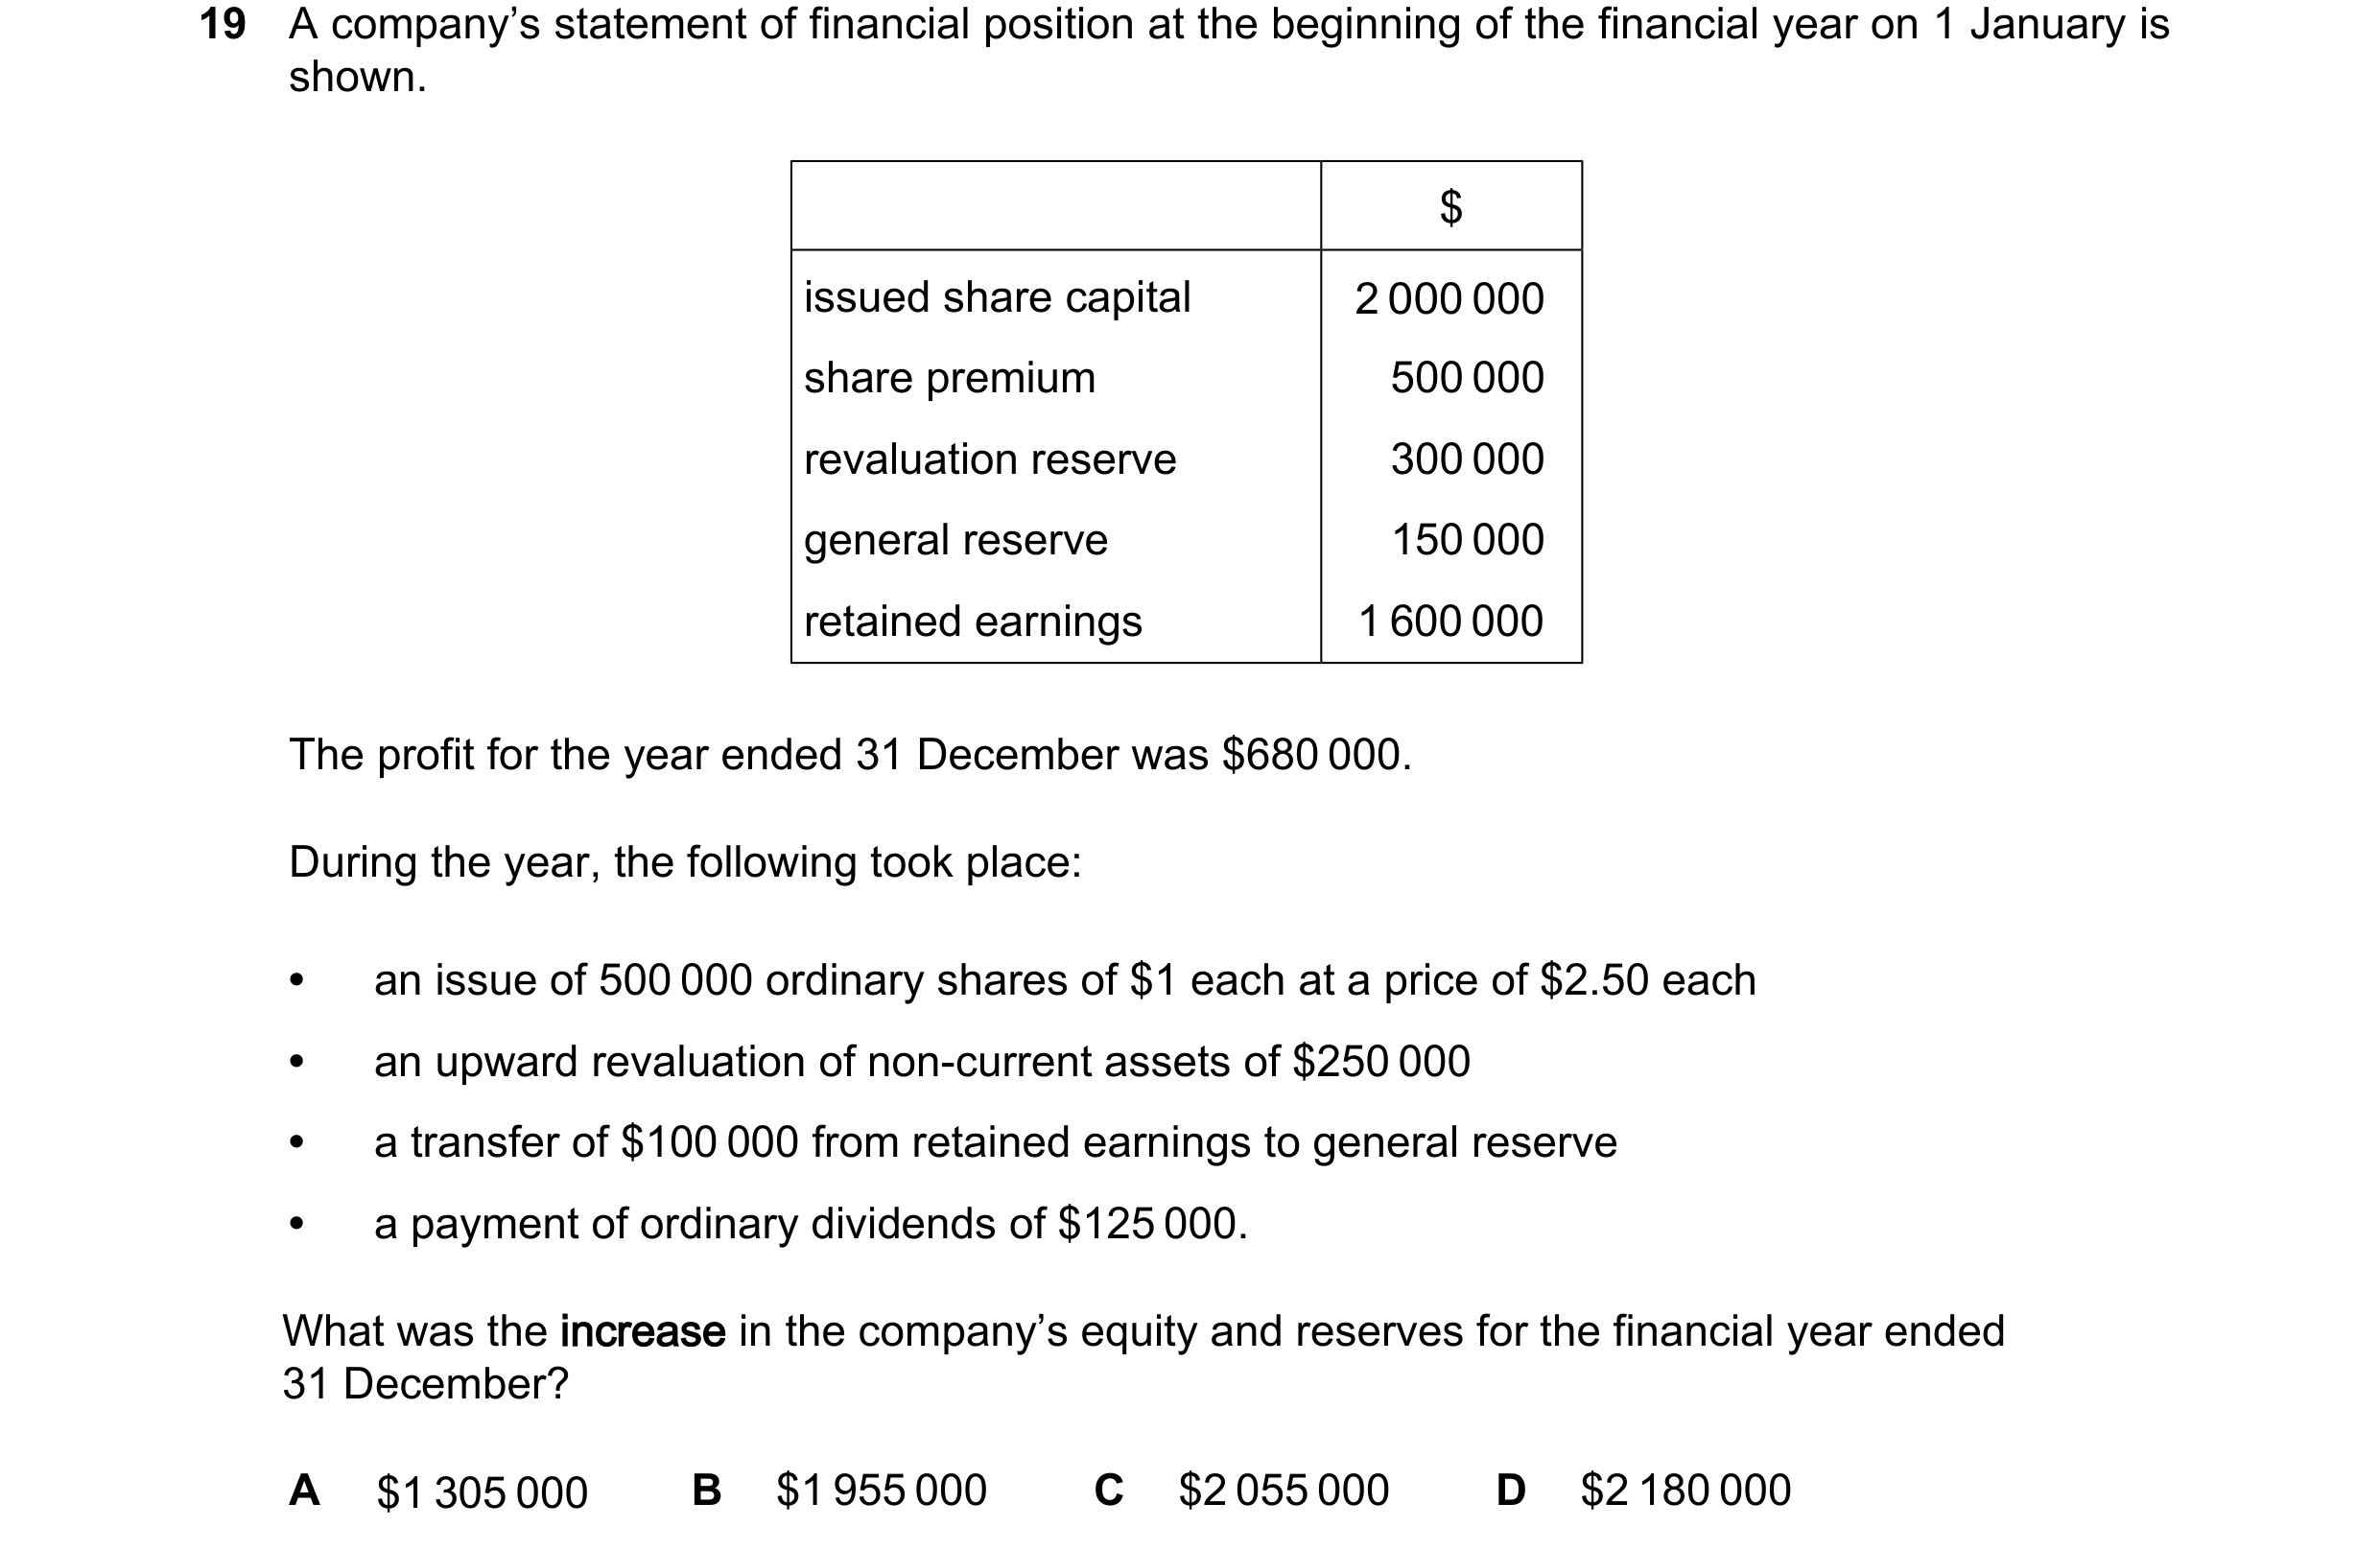
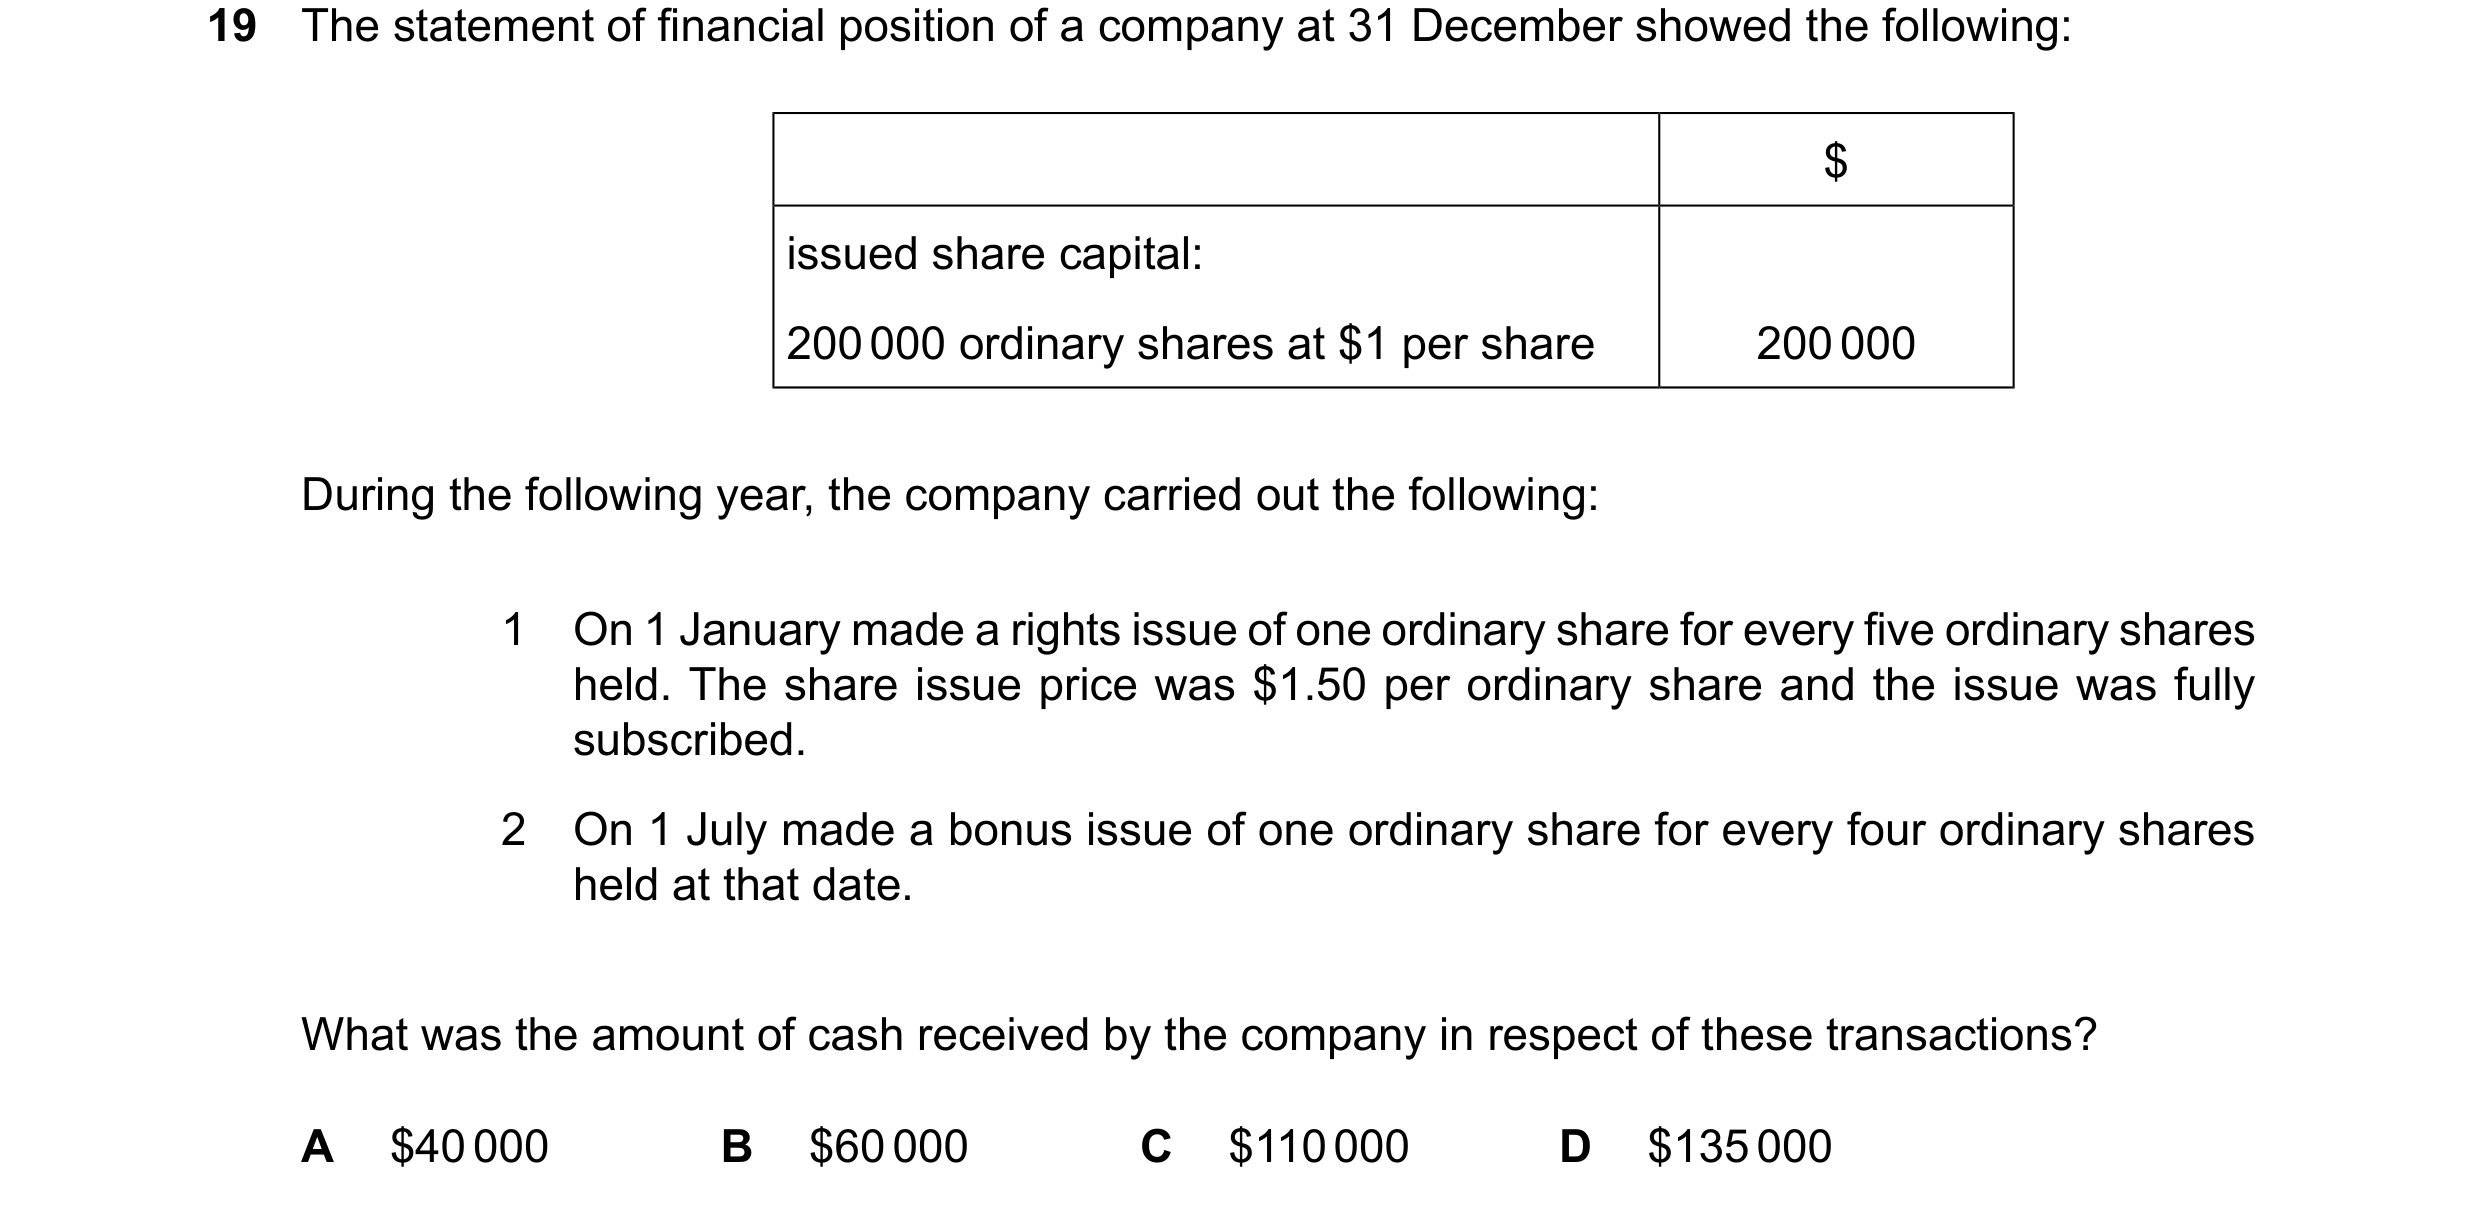 55 / 60
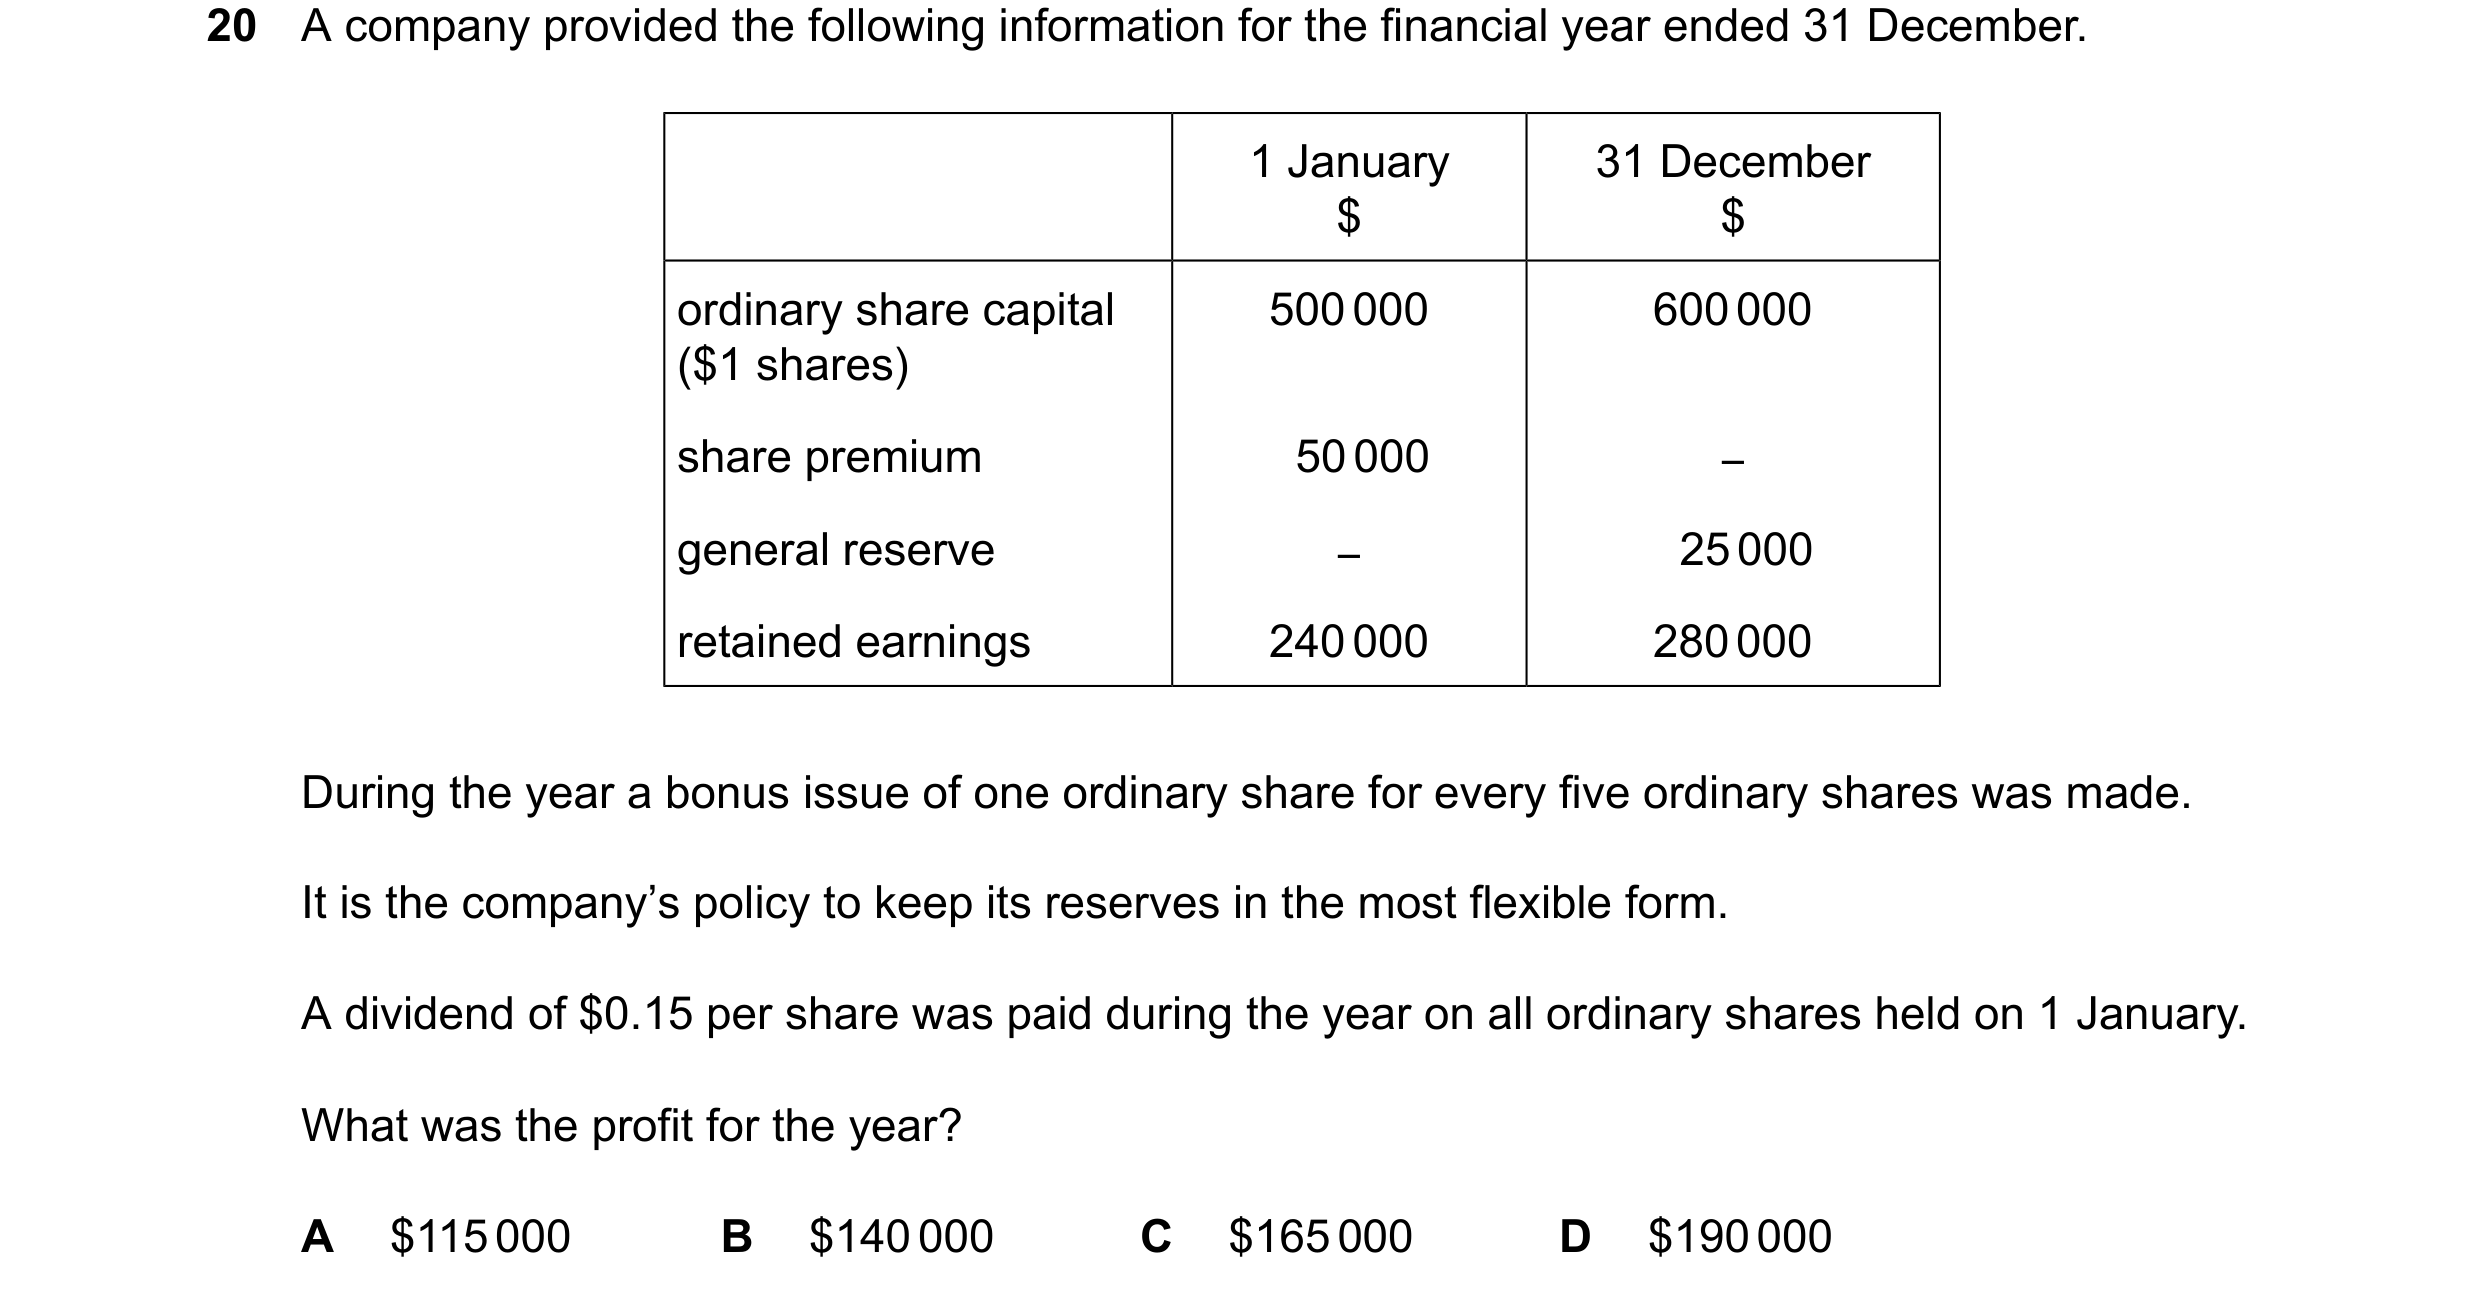
 56 / 60
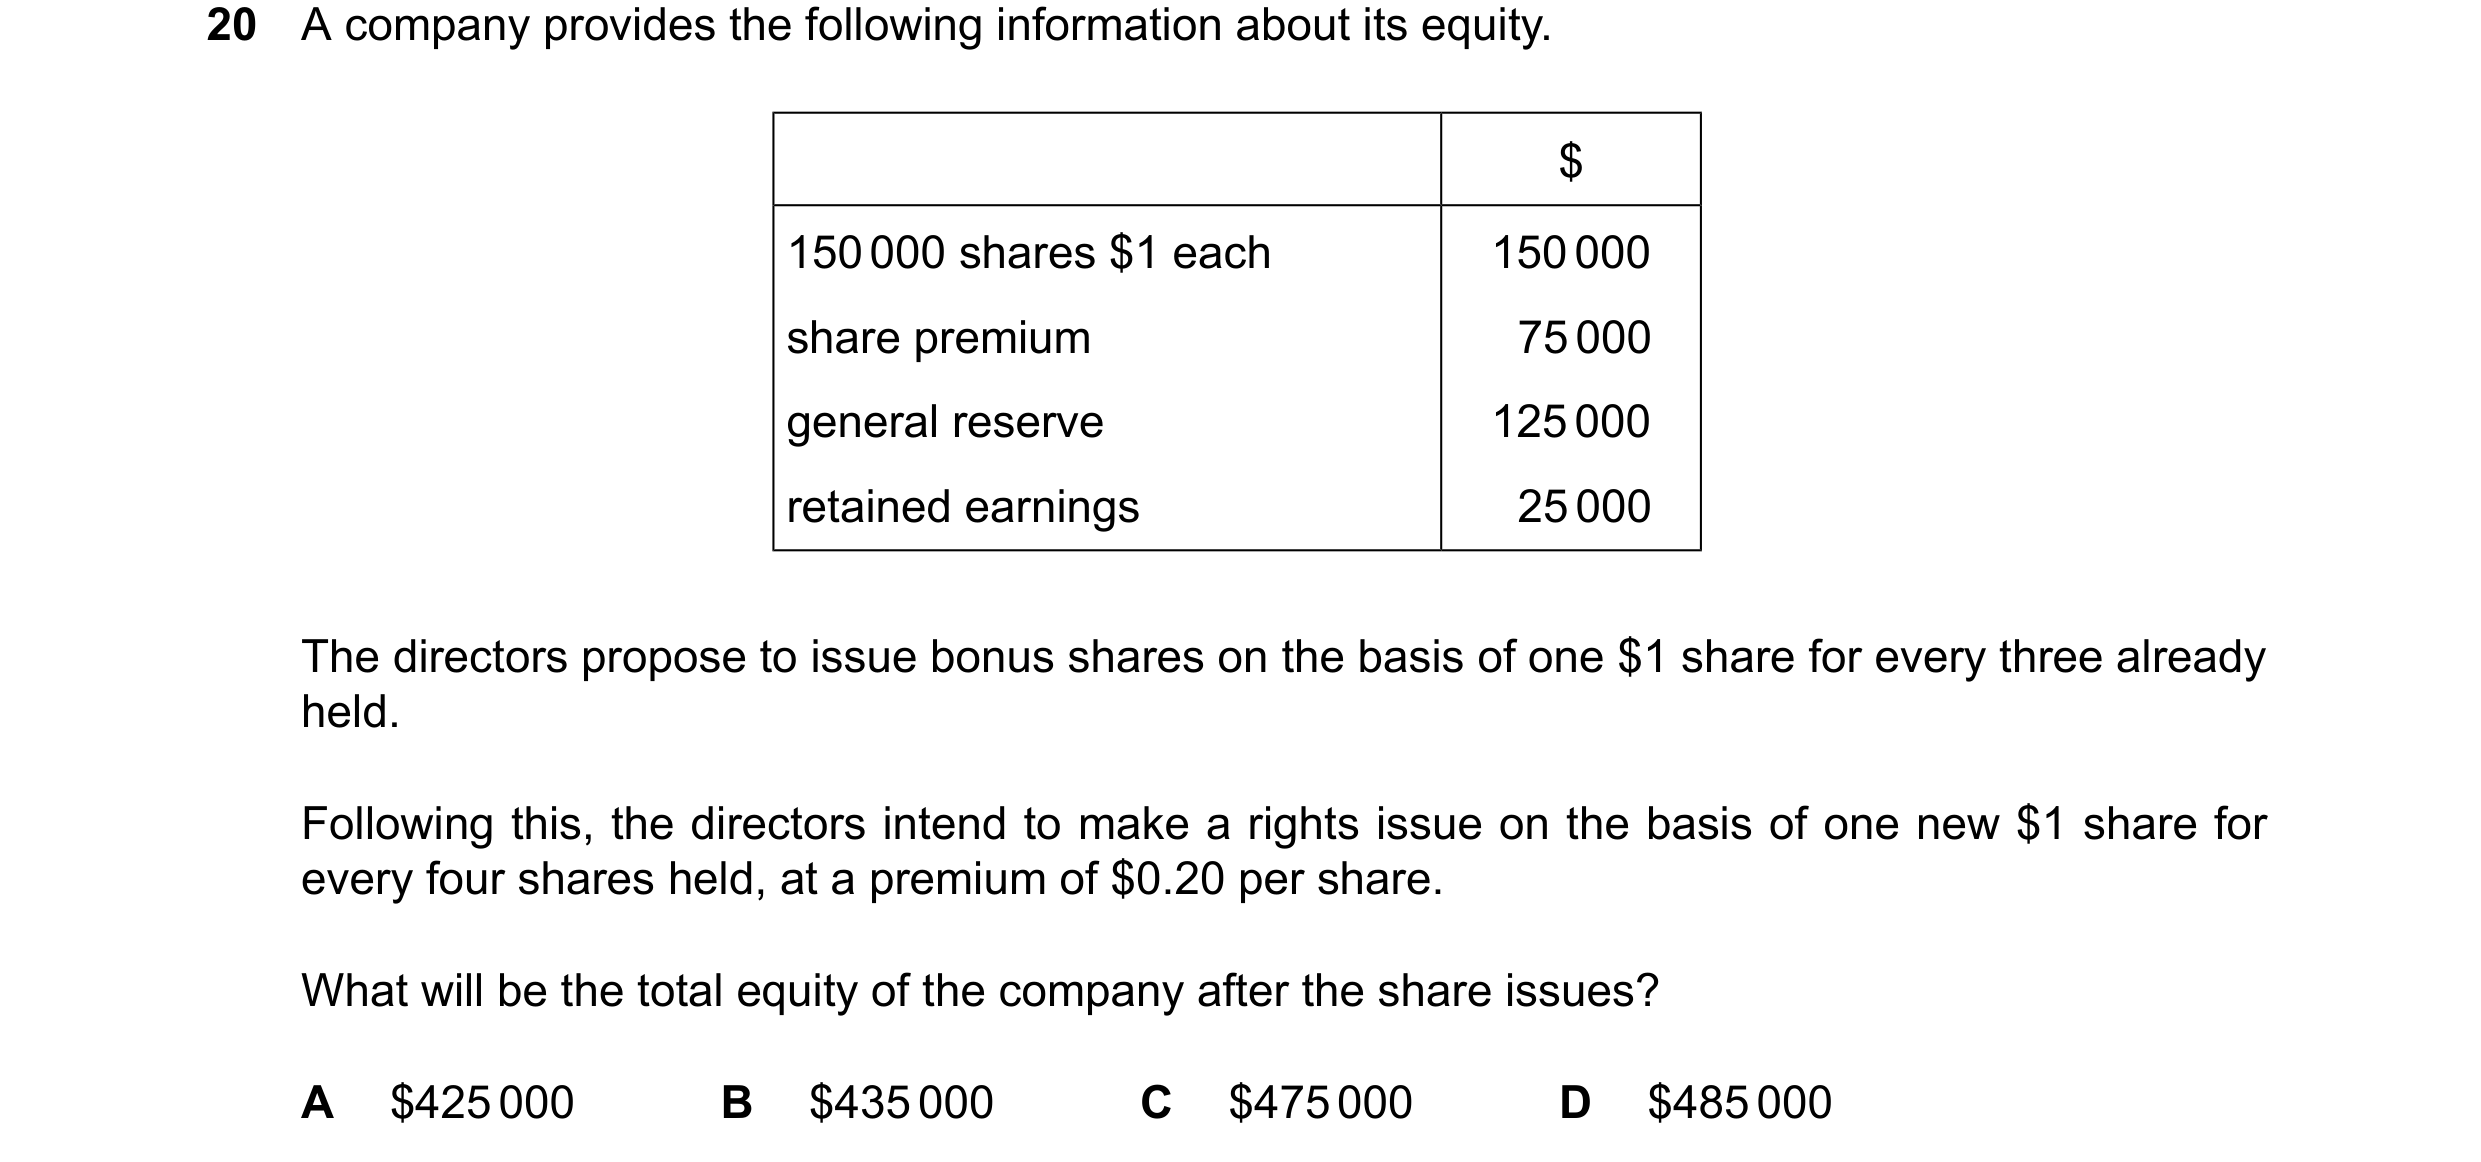
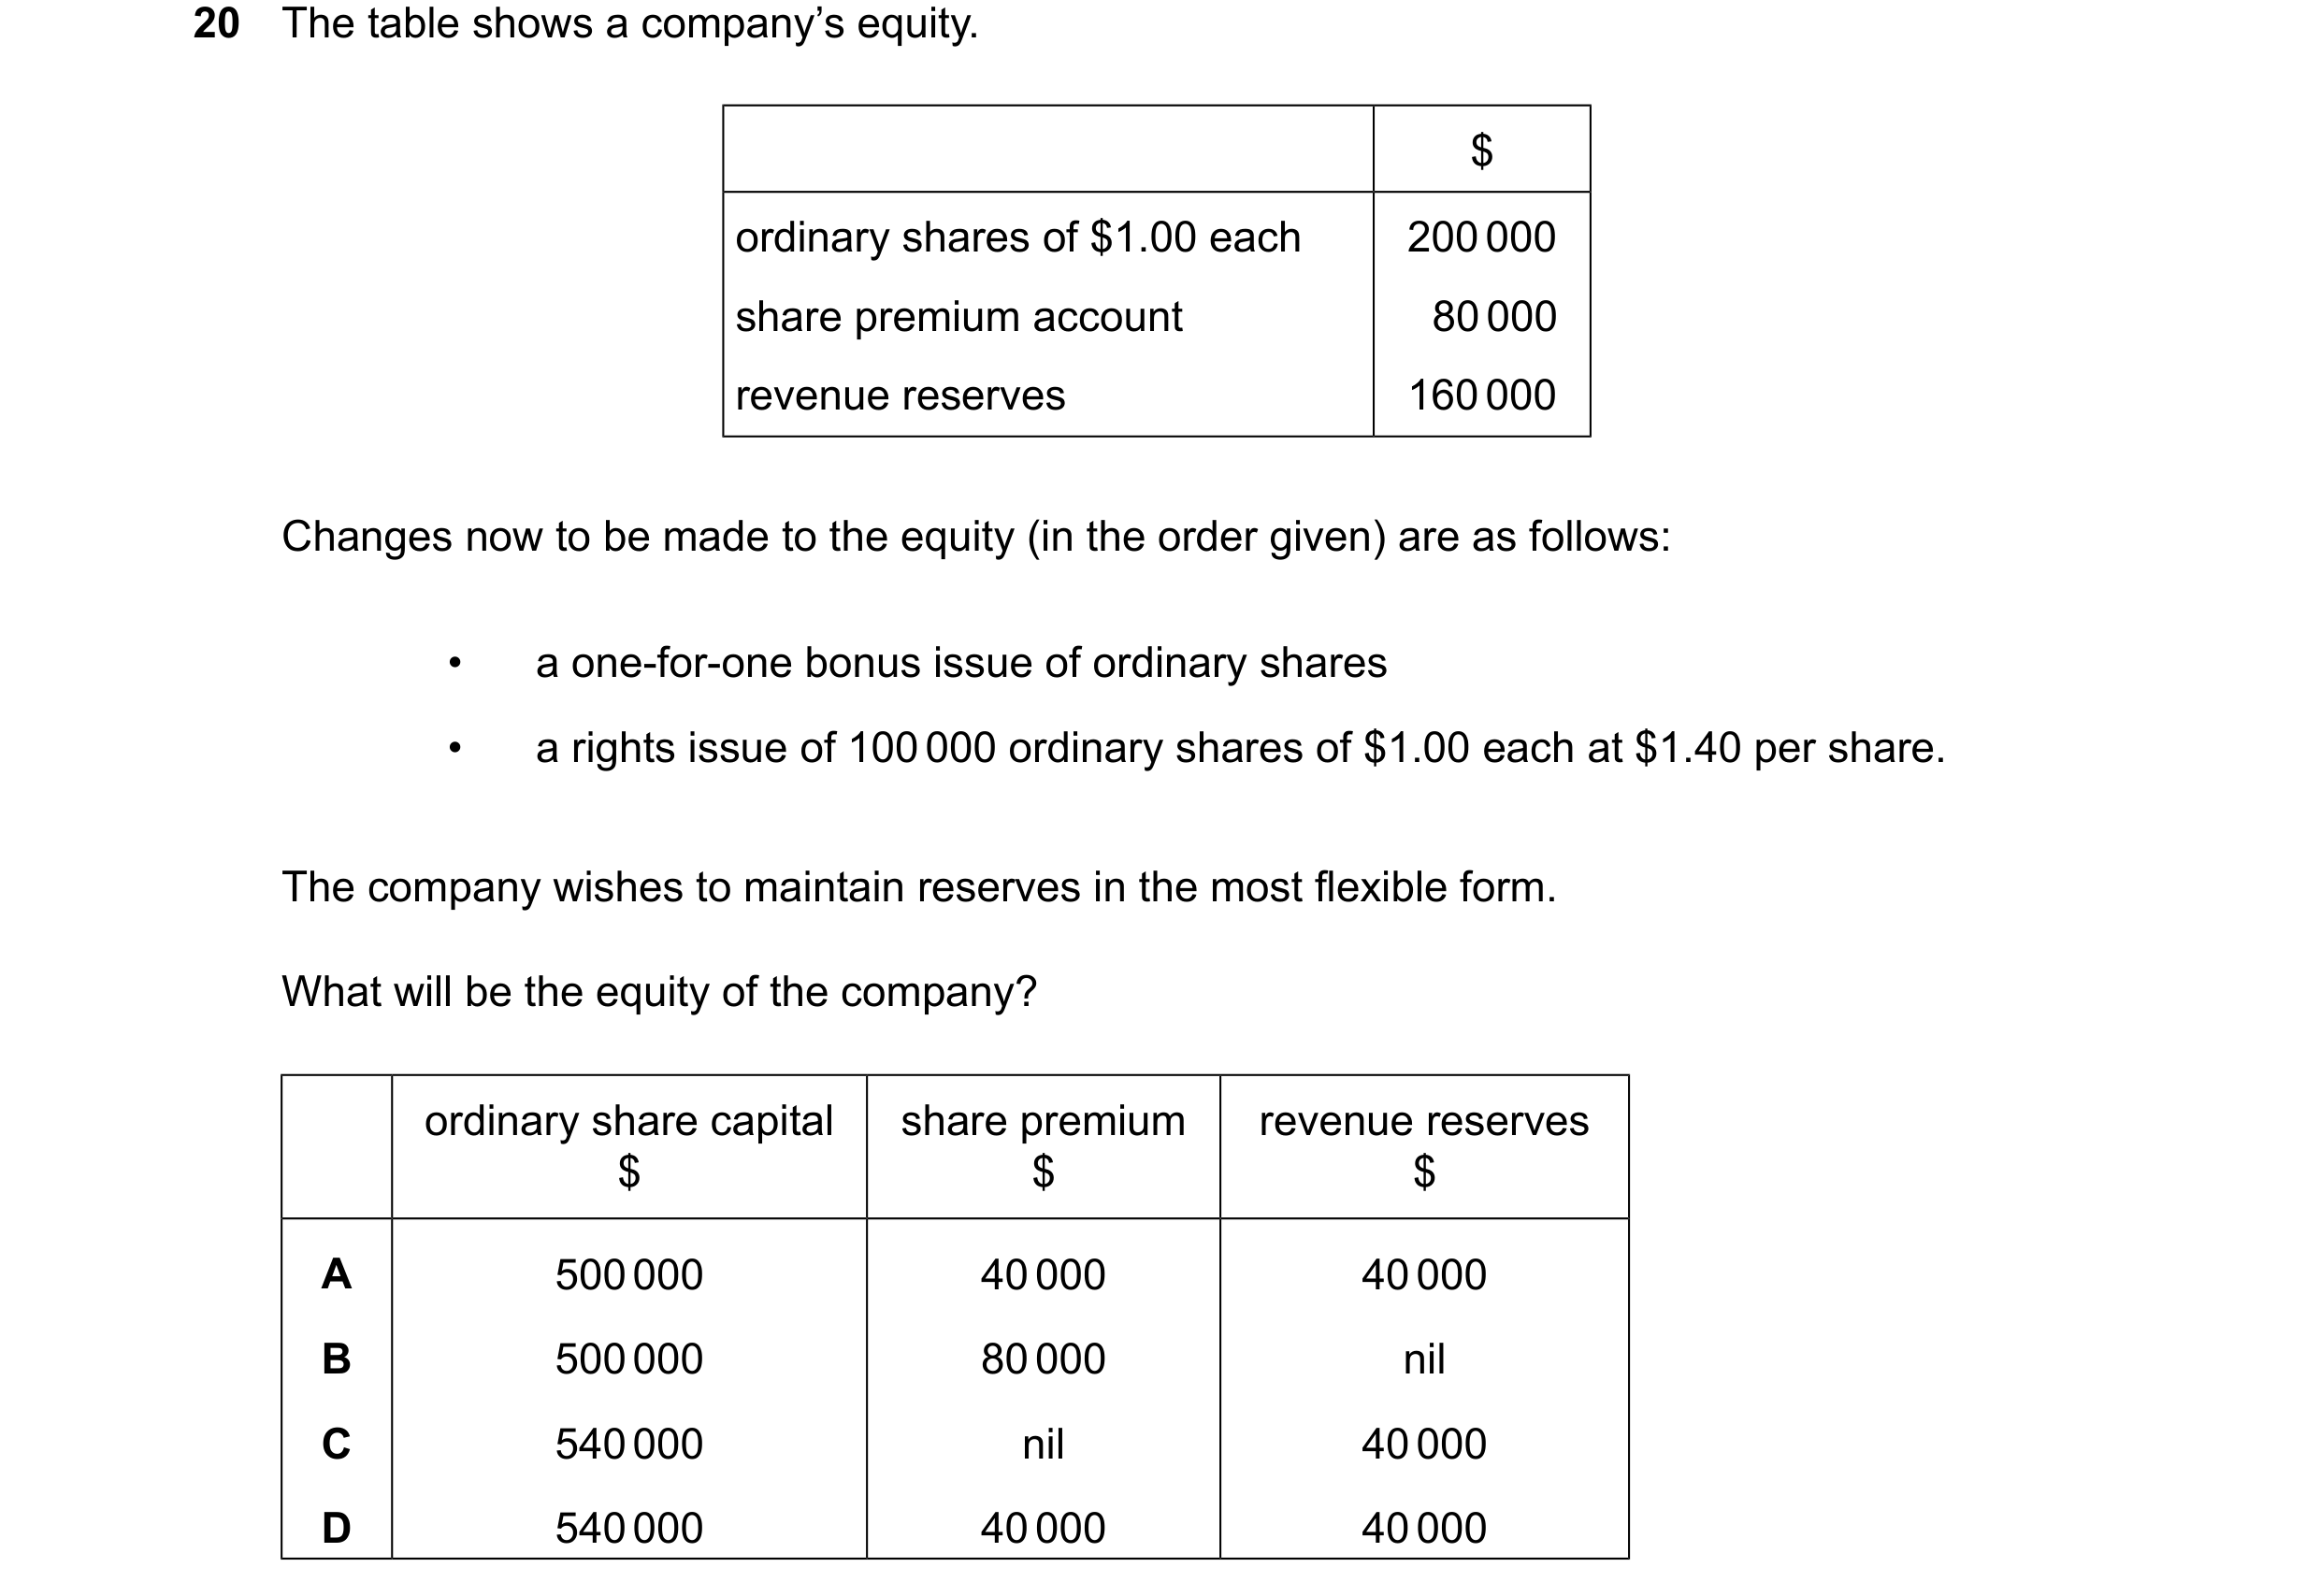 57 / 60
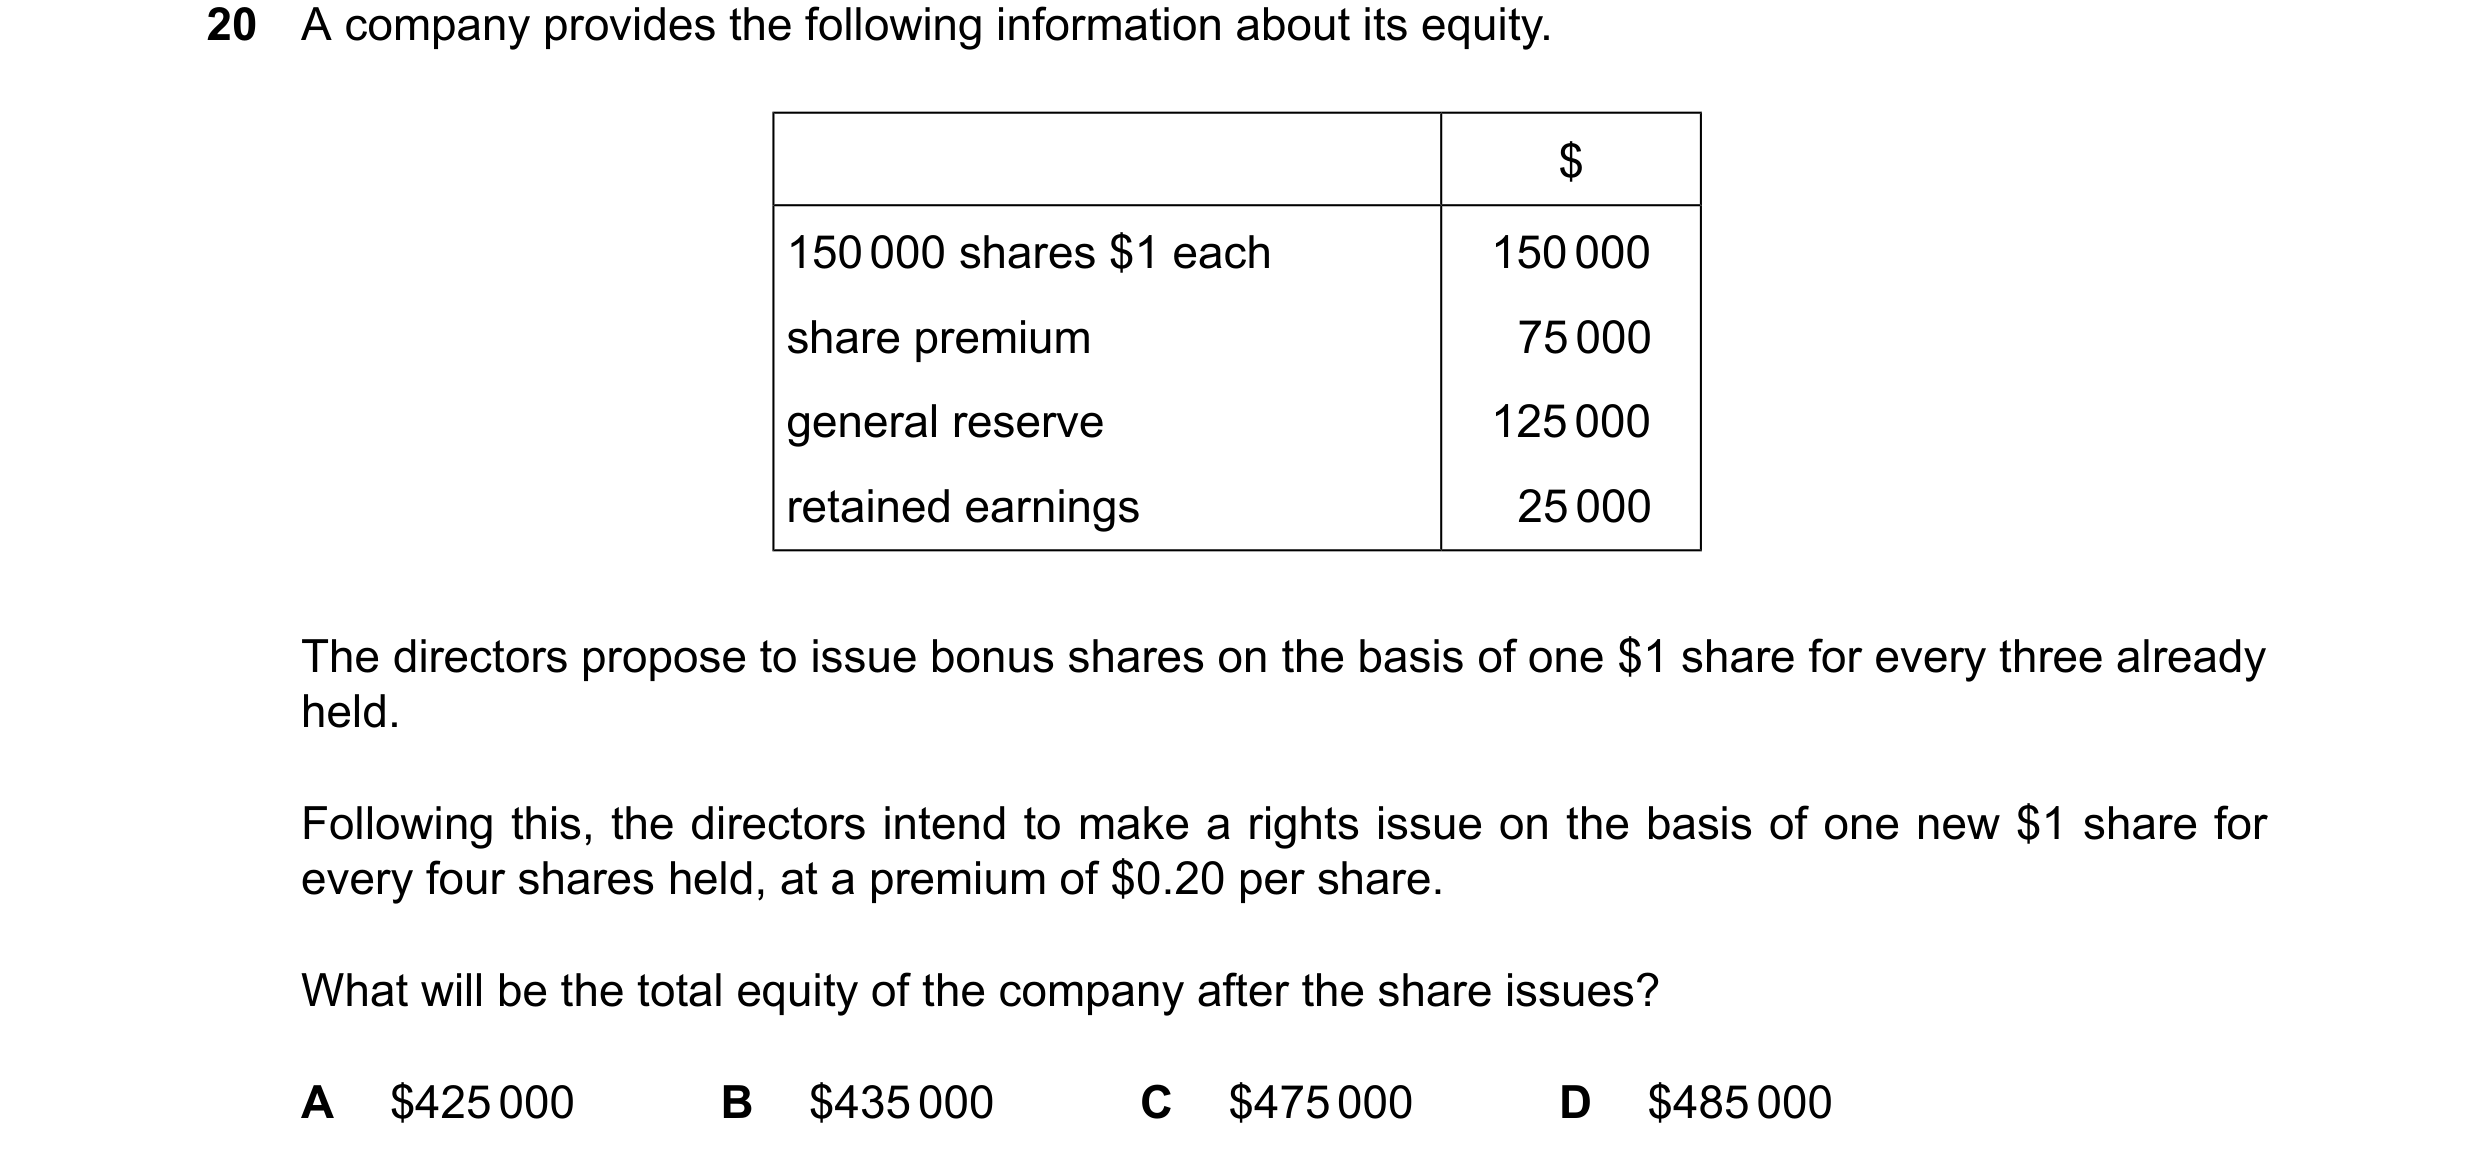
 58 / 60
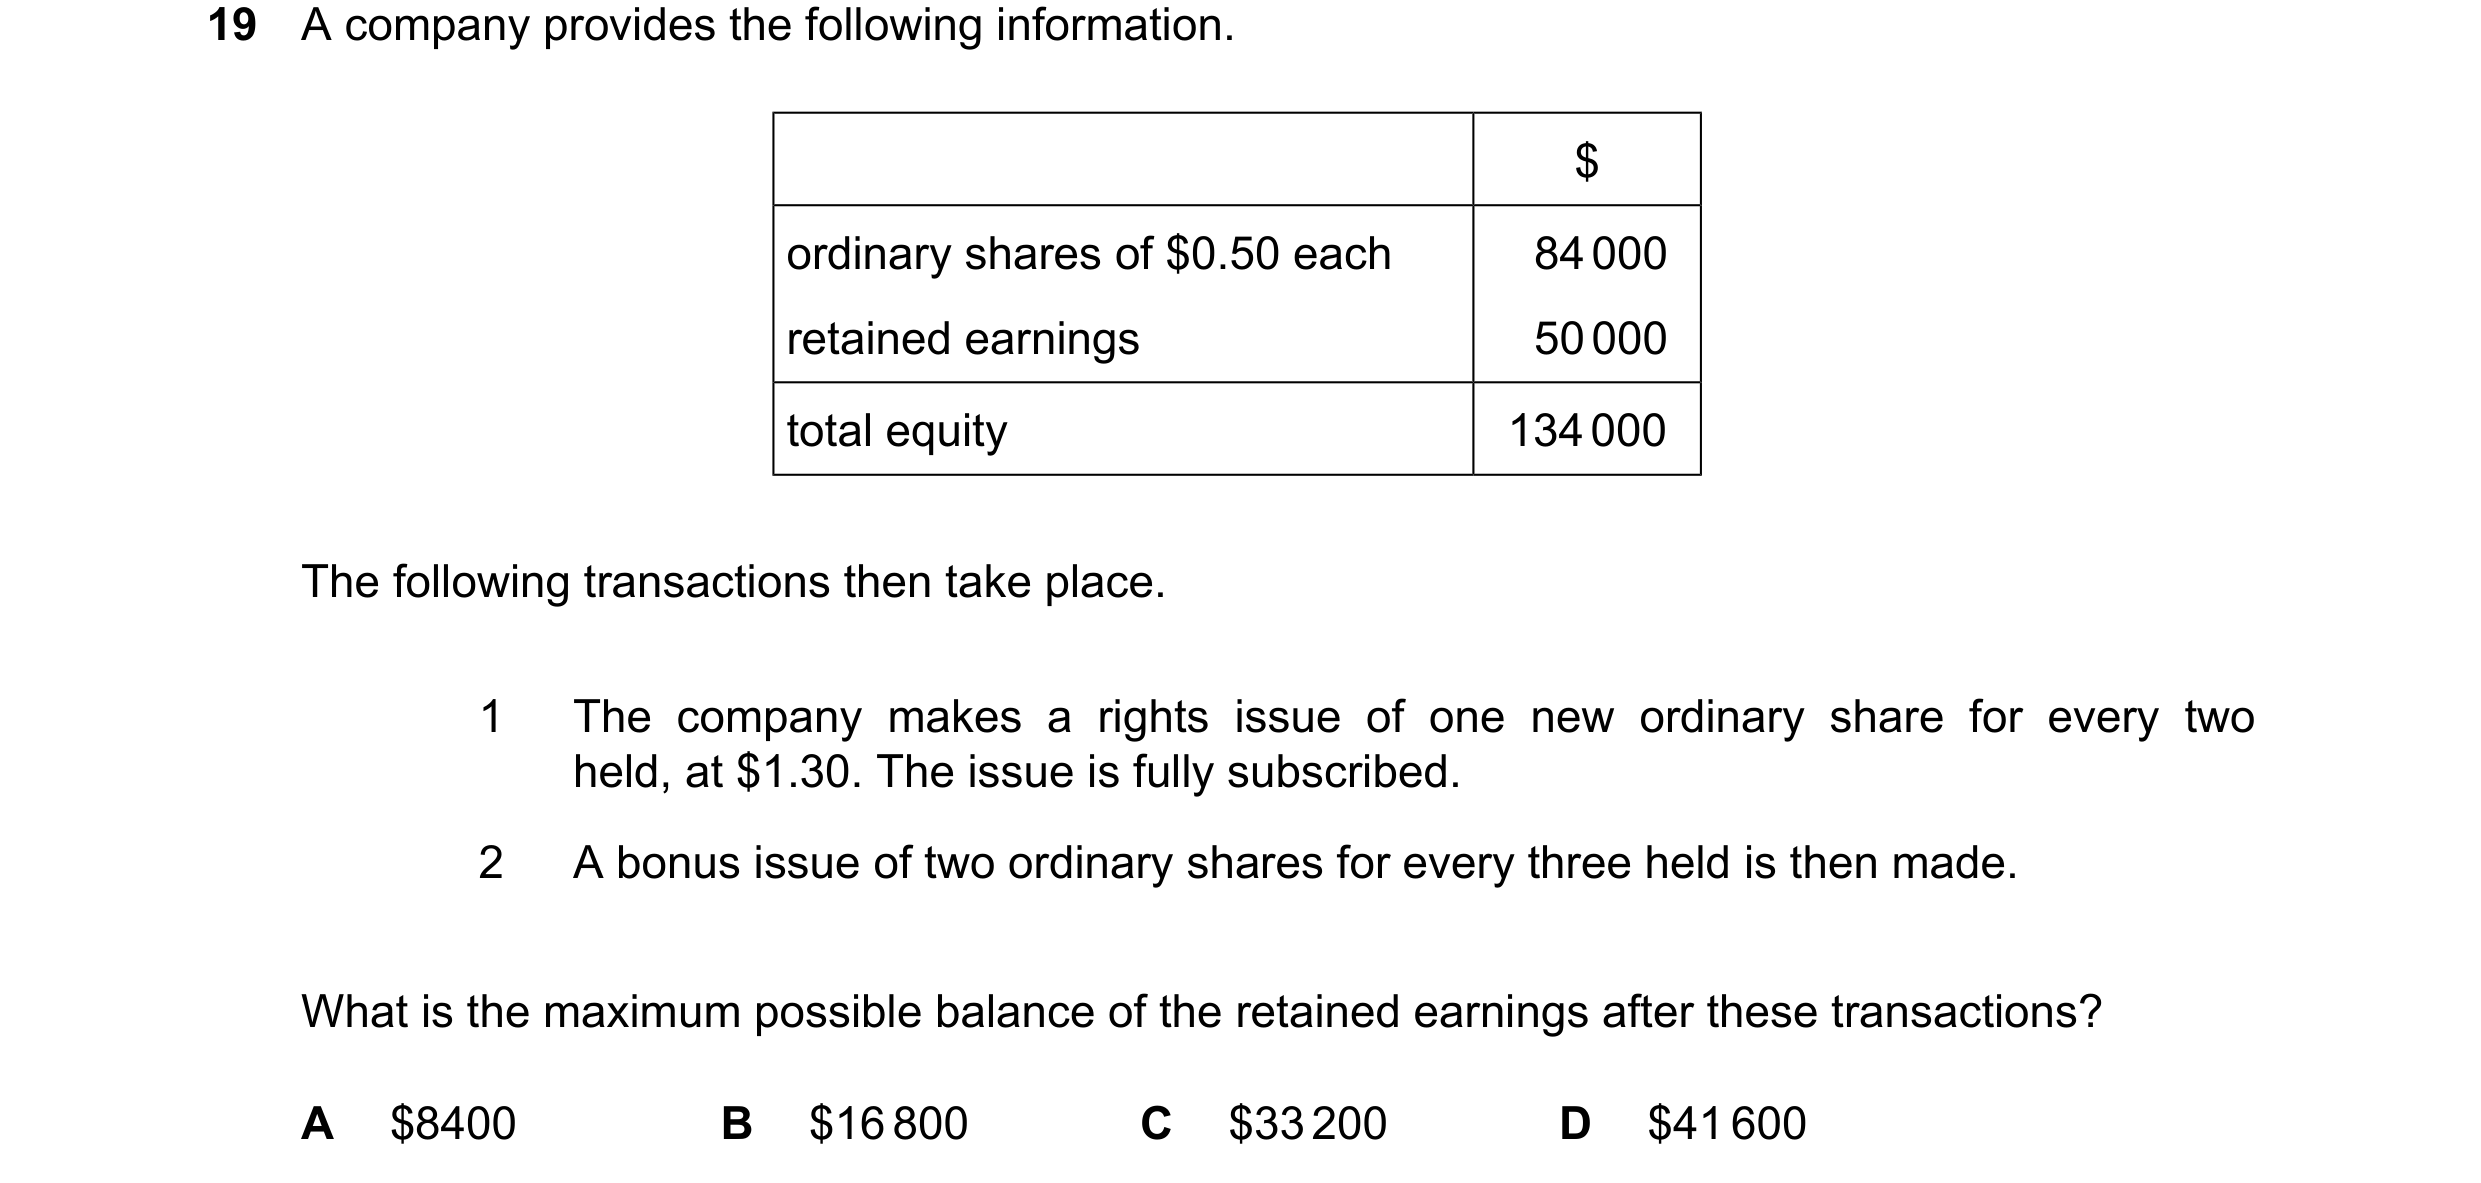 59 / 60
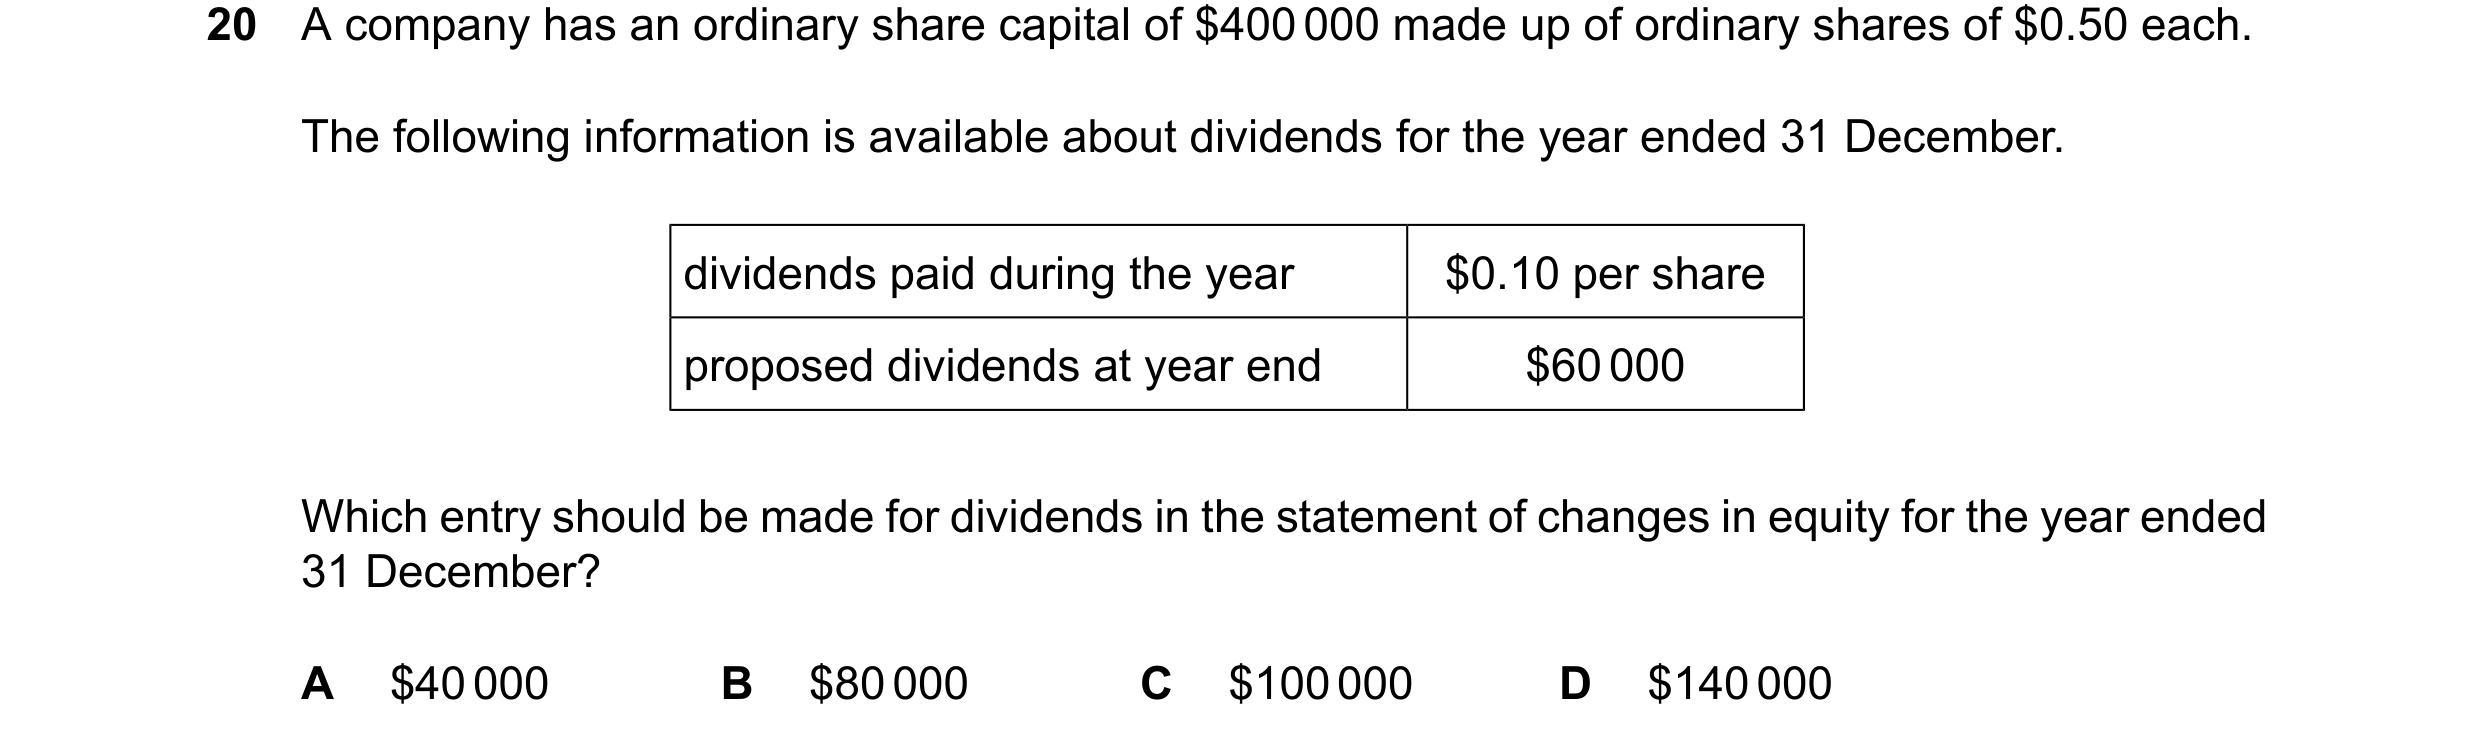 60 / 60