Questions as text
Q1 · On 31 May 2016 an interim ordinary share dividend of 3% was paid on all shares in issue… 9706/23 Oct/Nov 2017
3 On 31 May 2016 an interim ordinary share dividend of 3% was paid on all shares in issue at that date.
0 marks
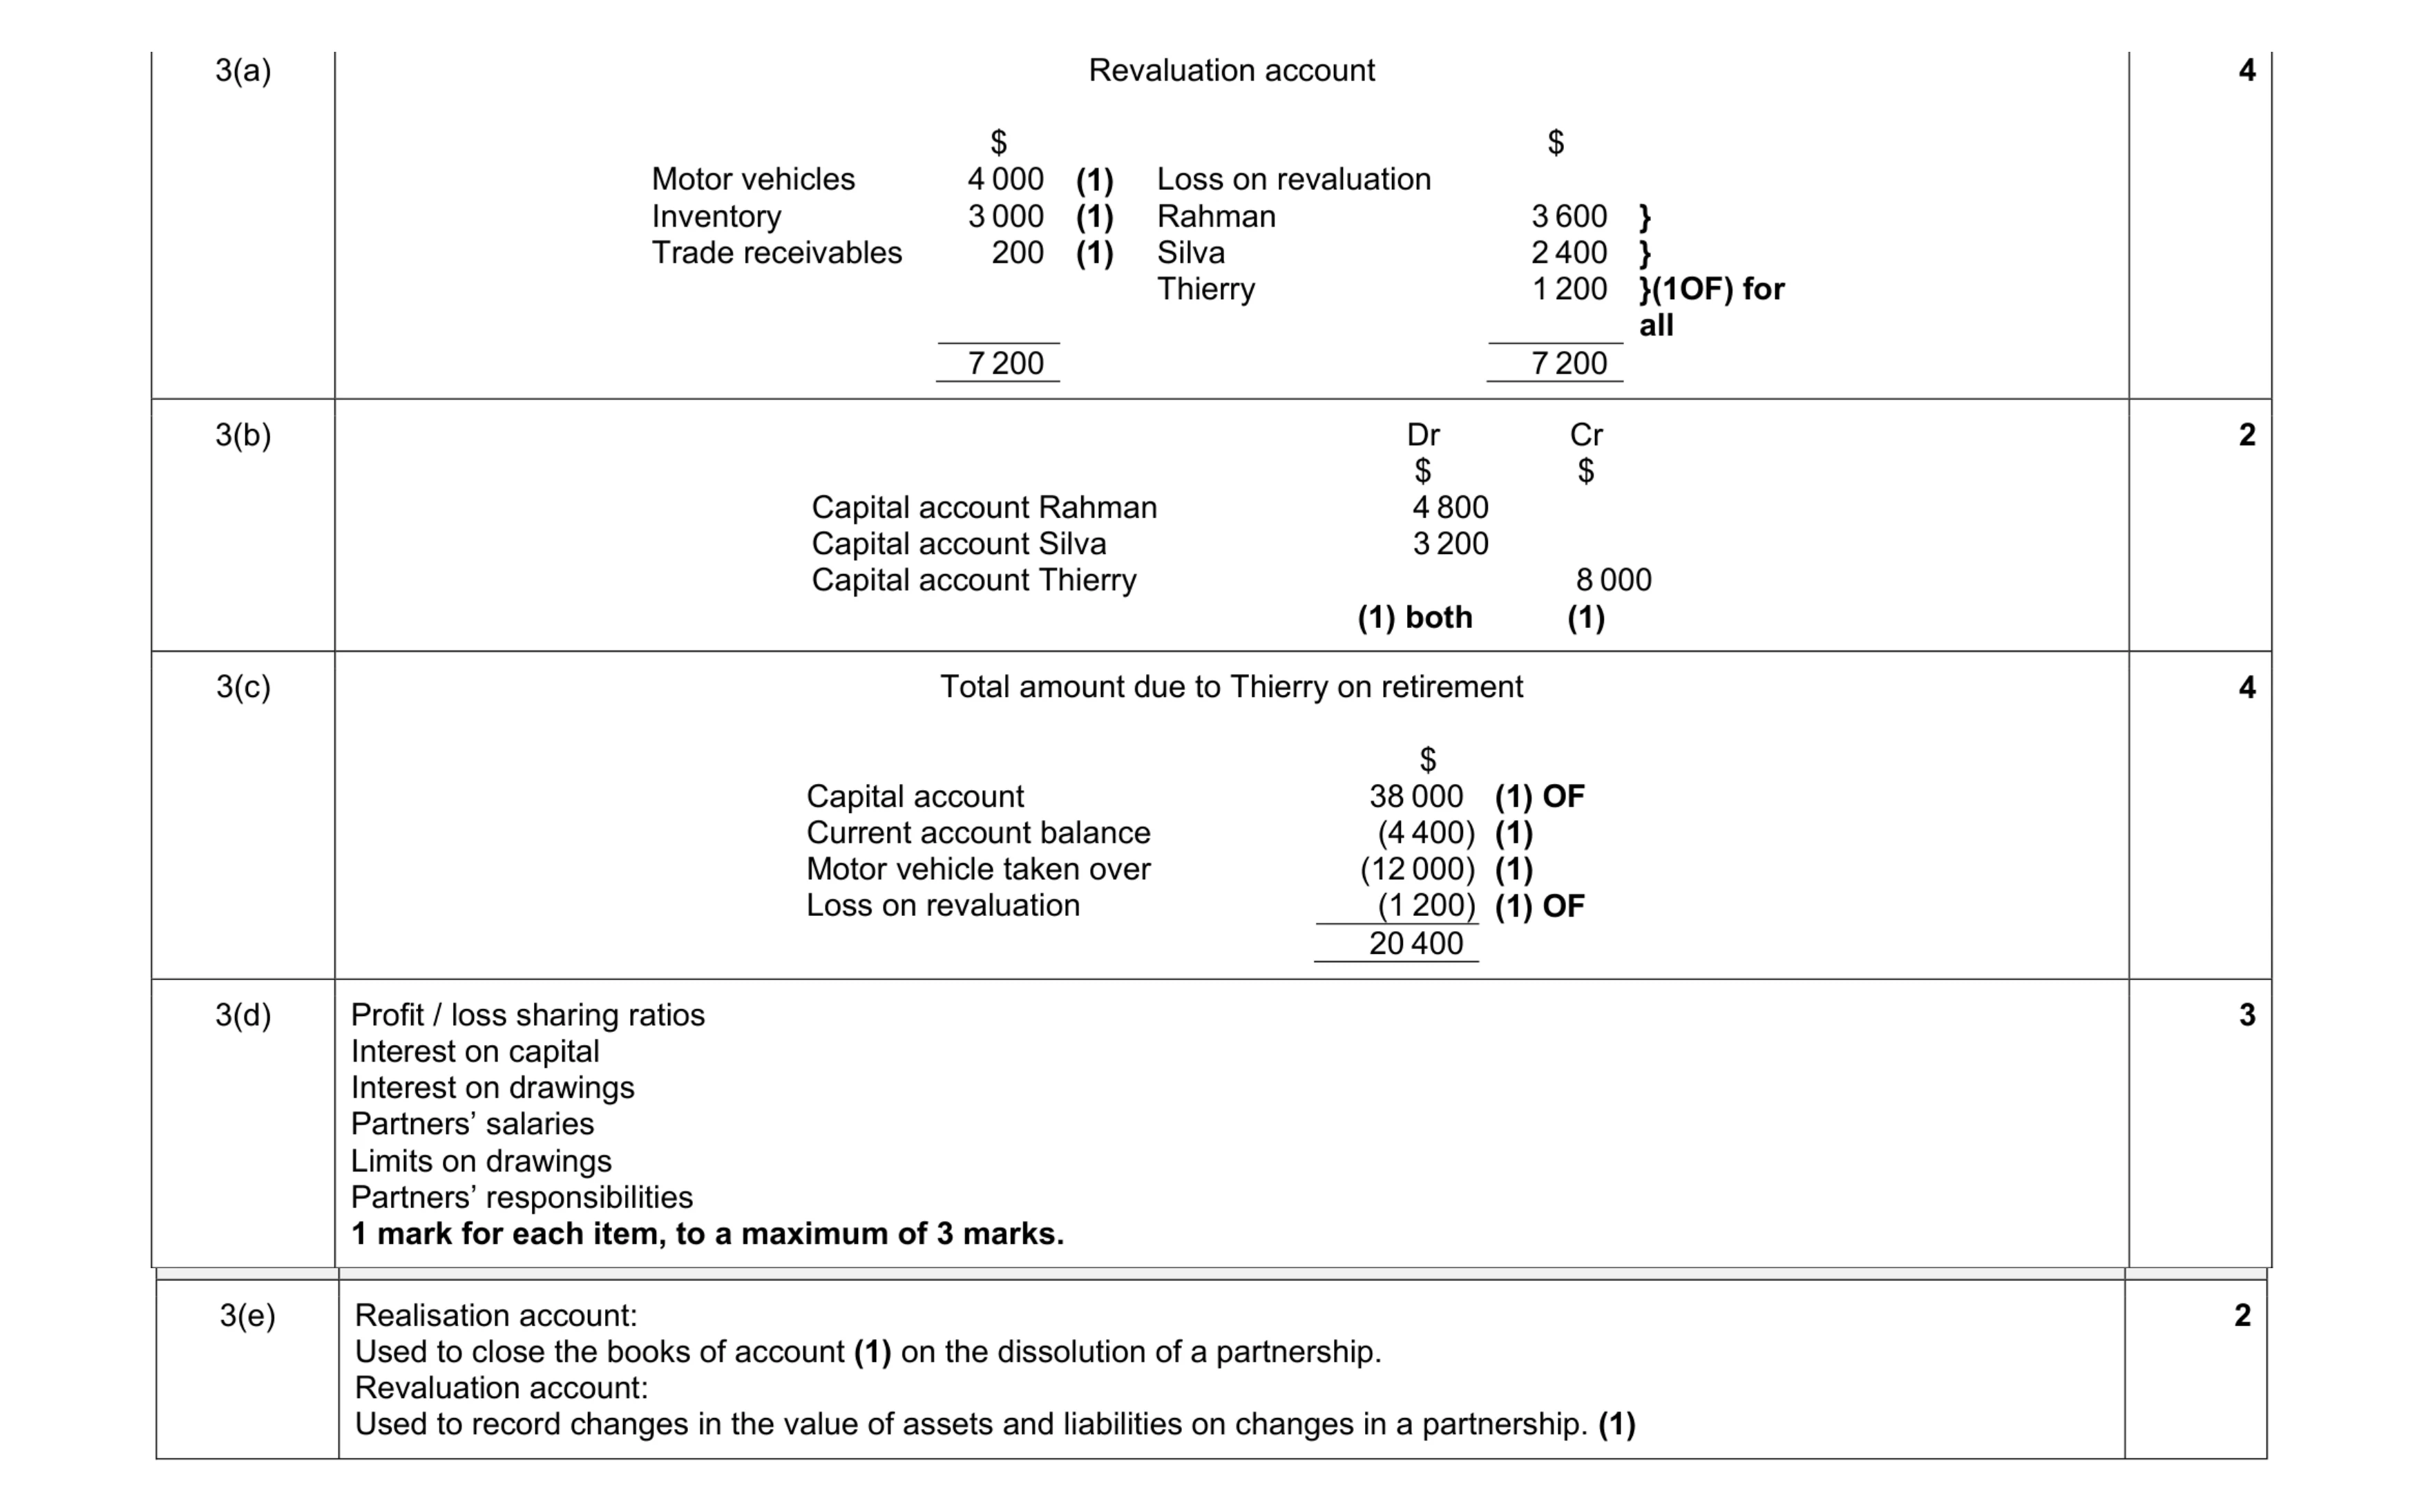
Mark scheme: 3(a) Revaluation account $ $ Motor vehicles 4 000 (1) Loss on revaluation Inventory 3 000 (1) Rahman 3 600 } Trade receivables 200 (1) Silva 2 400 } Thierry 1 200 }(1OF) for all 7 200 7 200 4 3(b) Dr $ Cr $ Capital account Rahman 4 800 Capital account Silva 3 200 Capital account Thierry 8 000 (1) both (1) 2 3(c) Total amount due to Thierry on retirement $ Capital account 38 000 (1) OF Current account balance (4 400) (1) Motor vehicle taken over (12 000) (1) Loss on revaluation (1 200) (1) OF 20 400 4 3(d) Profit / loss sharing ratios Interest on capital Interest on drawings Partners’ salaries Limits on drawings Partners’ responsibilities 1 mark for each item, to a maximum of 3 marks. 3 Question Answer Marks 3(e) Realisation account: Used to close the books of account (1) on the dissolution of a partnership. Revaluation account: Used to record changes in the value of assets and liabilities on changes in a partnership. (1) 2
This question in 9706/23 Oct/Nov 2017
Q2 · REQUIRED (e) Prepare the income statement for the year ended 31 December 2017 9706/22 Oct/Nov 2018
REQUIRED (e) Prepare the income statement for the year ended 31 December 2017. [9] (f) Advise Finn whether or not he should employ a book-keeper at a cost of $500 a month. Justify your answer. [4] (g) State two reasons why a trader might maintain a provision for doubtful debts. 1 2 [2] [Total: 30] PLEASE TURN OVER 2 Jack and Kelly are in partnership. They share profits and losses in the ratio of 2 : 5 respectively. The partners decided to admit Liam as a partner with effect from 1 July 2018. The partnership’s statement of financial position immediately prior to Liam’s admission was as follows. Jack and Kelly Summarised statement of financial position at 30 June 2018 $ Assets Non-current assets 91 400 Current assets 21 700 Total assets 113 100 Capital and liabilities Capital accounts Jack 33 000 Kelly 71 000 Current liabilities 9 100 Total capital and liabilities 113 100 The partners do not maintain separate current accounts. The following was agreed. 1 Assets were revalued upwards by $21 000. 2 Goodwill was valued at $52 500. No goodwill account was to be maintained in the partnership’s books of account. 3 In the future profits and losses would be shared in the ratio Jack : Kelly : Liam, 2 : 5 : 3 respectively. 4 The balances of the partners’ capital accounts immediately after Liam’s admission should total $120 000 and be in the same ratio as the profit sharing ratio. Each partner would either pay funds into, or withdraw funds from, the business bank account in order to achieve this requirement. REQUIRED (a) Prepare the partners’ capital accounts to record Liam’s admission as a partner on the next page. [6] $ Liam $ Kelly $ Jack Accounts Capital $ Partners’ Liam $ Kelly $ Jack (b) State what is meant by the term ‘goodwill’. [1] (c) Explain why a partnership may make an adjustment for goodwill when they admit a new partner. [2] (d) Explain why partners may agree not to maintain a goodwill account in the books of the partnership on the admission of a new partner. [2] Additional information The partners forecast that profit for the year ending 30 June 2019 will be $60 000. This is an increase of 25% on the current year’s profit. The partners believe that Liam’s admission will result in an improved return on capital employed. REQUIRED (e) Advise the partners whether or not they are correct in believing that Liam’s admission will result in an improved return on capital employed in the year ending 30 June 2019. Support your answer with calculations. [4] [Total: 15] 3 Part of the equity of a limited company consists of ordinary shares. REQUIRED (a) (i) Explain two reasons why a company may make a bonus share issue. 1 2 [4] (ii) State three uses of the share premium account, other than the issue of bonus shares. 1 2 3 [3] Additional information On 1 January 2017 the issued share capital of S Limited consists of ordinary shares of $0.40 each. The following information is available for the year ended 31 December 2017: 1 On 1 April 2017 the company issued a 6% debenture of $300 000. 2 On 1 May 2017 the company paid a final dividend of $0.04 per ordinary share. 3 On 1 October 2017 the company made a rights issue of 1 ordinary share for every 4 held. The shares were offered at a 20% discount on the market price of $1.45. The rights issue was fully subscribed. 4 On 15 October 2017 the company paid an interim dividend of $0.015 per share to the shareholders who were on the share register at 1 August 2017.
37 marks
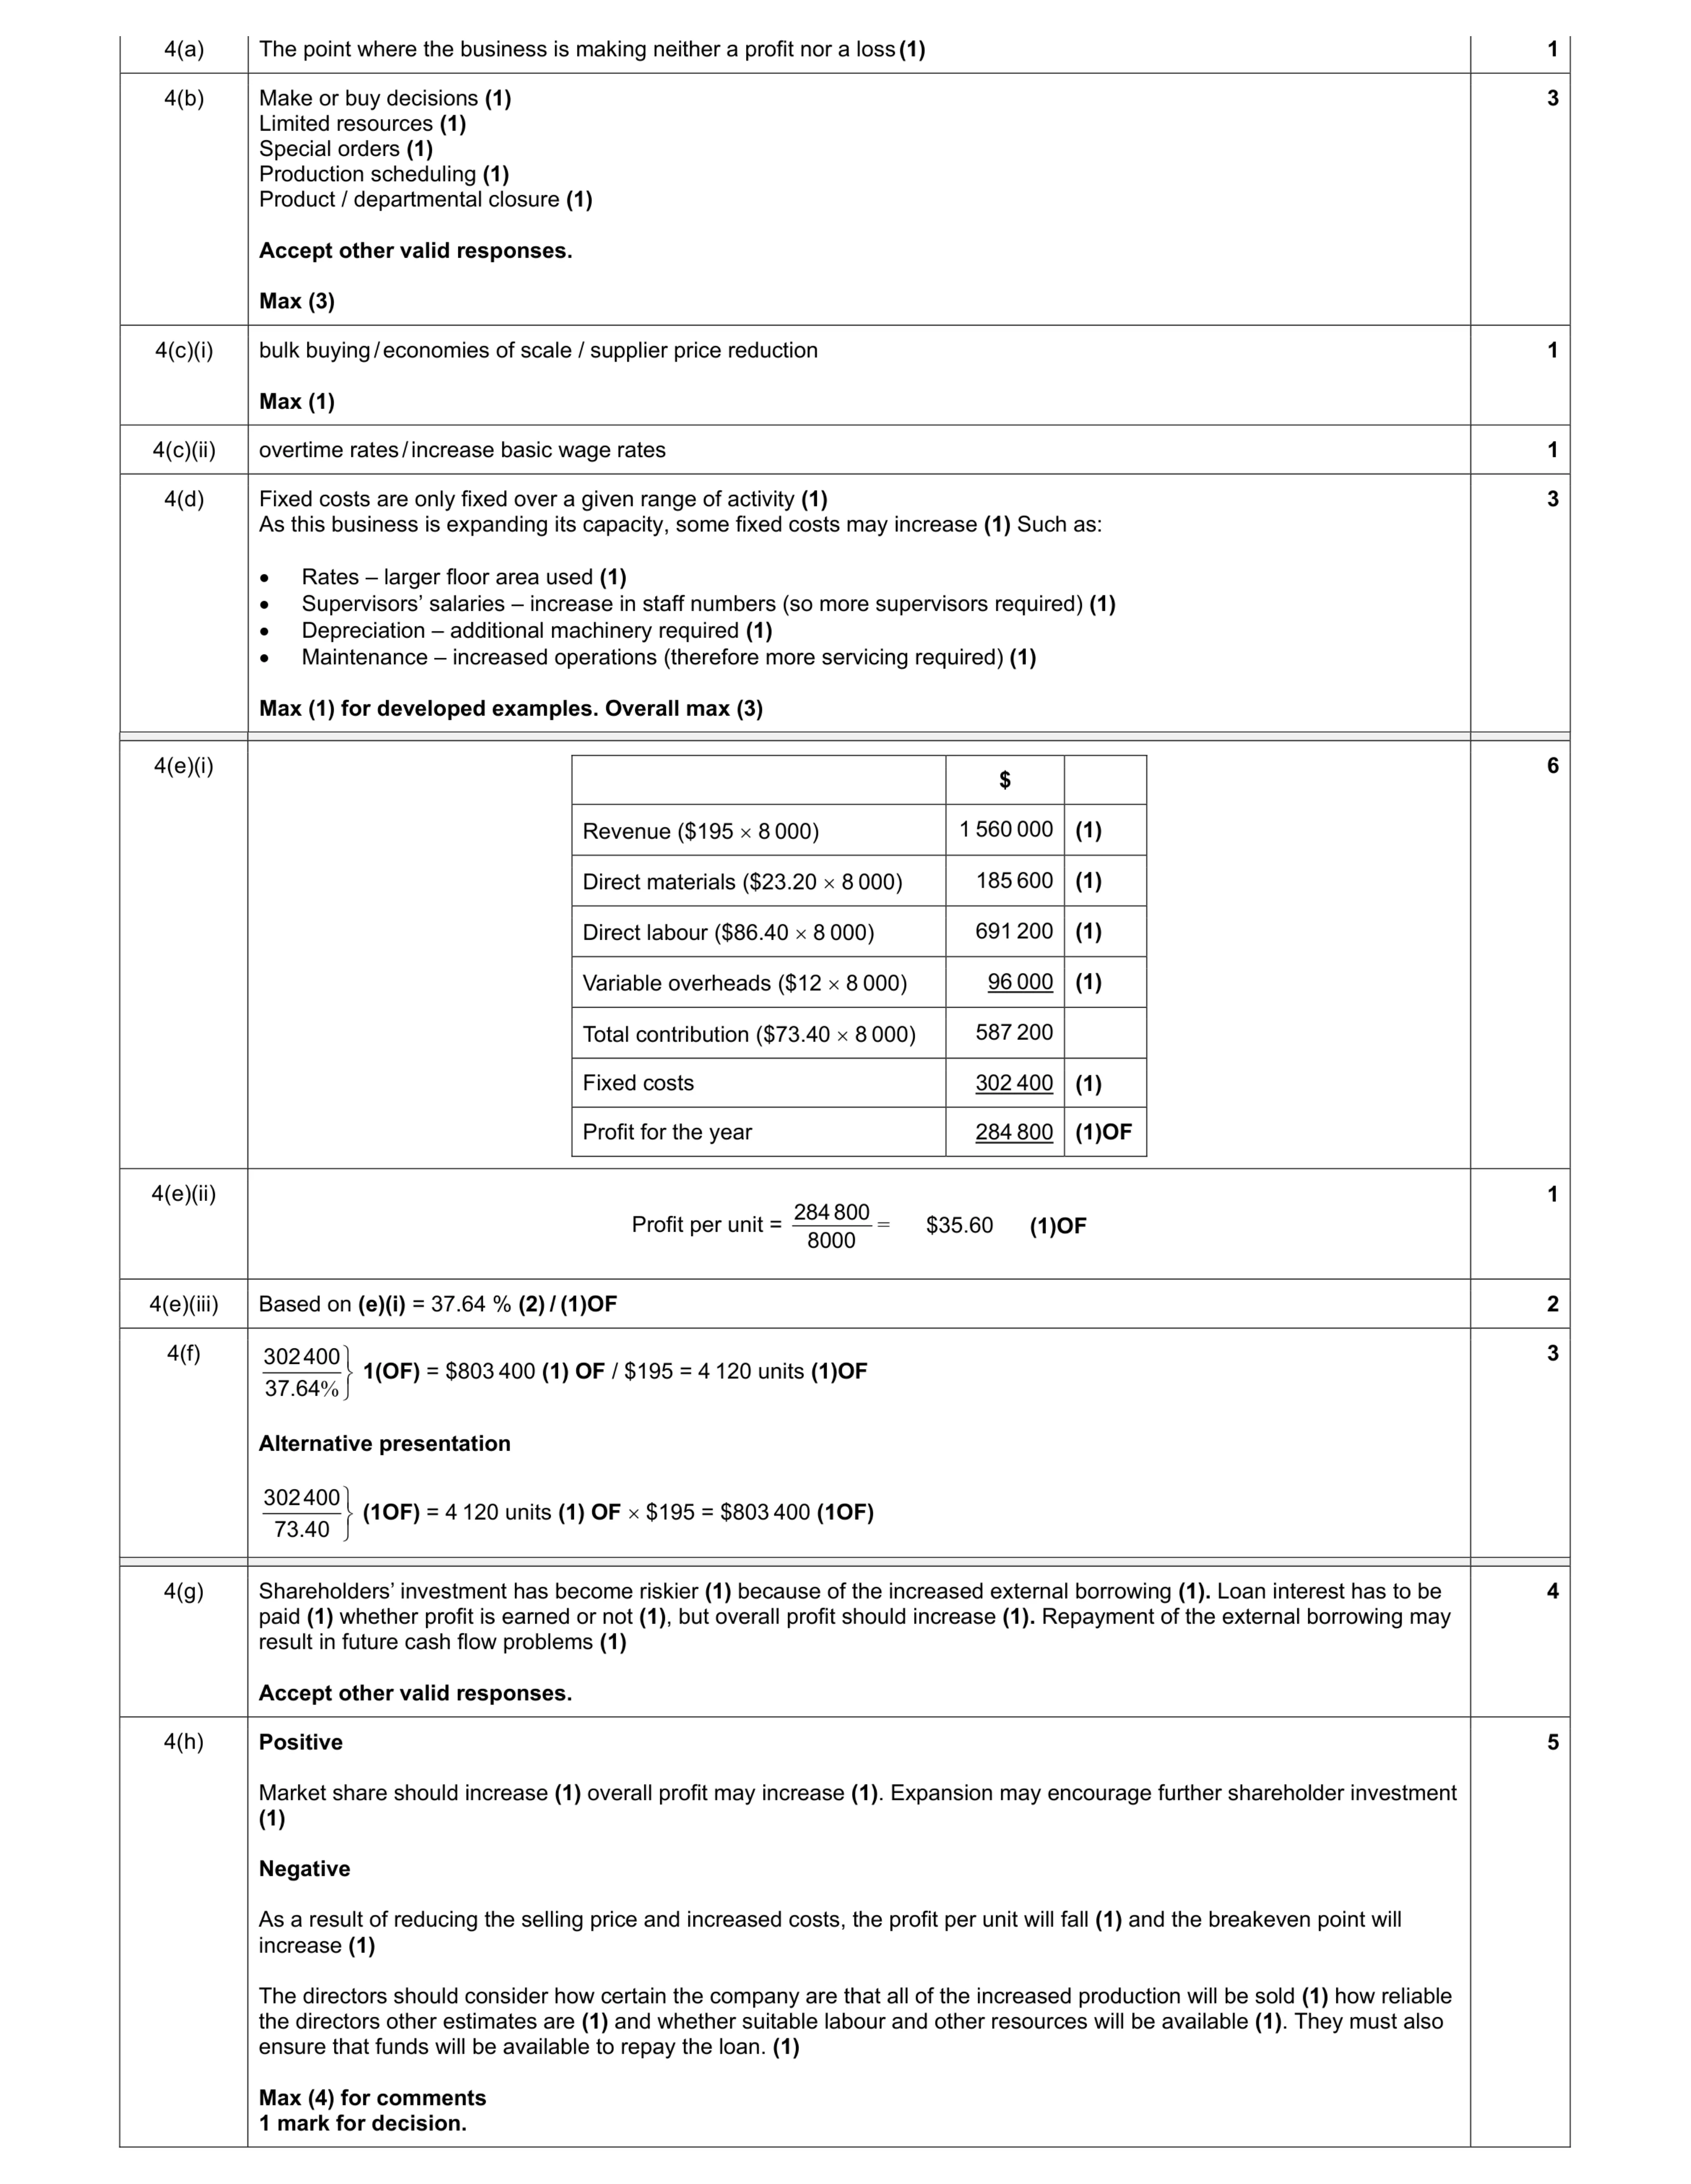
Mark scheme: 4(a) The point where the business is making neither a profit nor a loss (1) 1 4(b) Make or buy decisions (1) Limited resources (1) Special orders (1) Production scheduling (1) Product / departmental closure (1) Accept other valid responses. Max (3) 3 4(c)(i) bulk buying / economies of scale / supplier price reduction Max (1) 1 4(c)(ii) overtime rates / increase basic wage rates 1 4(d) Fixed costs are only fixed over a given range of activity (1) As this business is expanding its capacity, some fixed costs may increase (1) Such as: • Rates – larger floor area used (1) • Supervisors’ salaries – increase in staff numbers (so more supervisors required) (1) • Depreciation – additional machinery required (1) • Maintenance – increased operations (therefore more servicing required) (1) Max (1) for developed examples. Overall max (3) 3 Question Answer Marks 4(e)(i) $ Revenue ($195 × 8 000) 1 560 000 (1) Direct materials ($23.20 × 8 000) 185 600 (1) Direct labour ($86.40 × 8 000) 691 200 (1) Variable overheads ($12 × 8 000) 96 000 (1) Total contribution ($73.40 × 8 000) 587 200 Fixed costs 302 400 (1) Profit for the year 284 800 (1)OF 6 4(e)(ii) Profit per unit = 8000 800 284 = $35.60 (1)OF 1 4(e)(iii) Based on (e)(i) = 37.64 % (2) / (1)OF 2 4(f) 302400 37.64 % 1(OF) = $803 400 (1) OF / $195 = 4 120 units (1)OF Alternative presentation 302400 73.40 (1OF) = 4 120 units (1) OF × $195 = $803 400 (1OF) 3 Question Answer Marks 4(g) Shareholders’ investment has become riskier (1) because of the increased external borrowing (1). Loan interest has to be paid (1) whether profit is earned or not (1), but overall profit should increase (1). Repayment of the external borrowing may result in future cash flow problems (1) Accept other valid responses. 4 4(h) Positive Market share should increase (1) overall profit may increase (1). Expansion may encourage further shareholder investment (1) Negative As a result of reducing the selling price and increased costs, the profit per unit will fall (1) and the breakeven point will increase (1) The directors should consider how certain the company are that all of the increased production will be sold (1) how reliable the directors other estimates are (1) and whether suitable labour and other resources will be available (1). They must also ensure that funds will be available to repay the loan. (1) Max (4) for comments 1 mark for decision. 5
This question in 9706/22 Oct/Nov 2018
Q3 · A bonus issue of one ordinary share for every four shares held was made on 31 October 2019 9706/22 Feb/March 2020
2 A bonus issue of one ordinary share for every four shares held was made on 31 October 2019. Reserves were maintained in their most flexible form.
0 marks
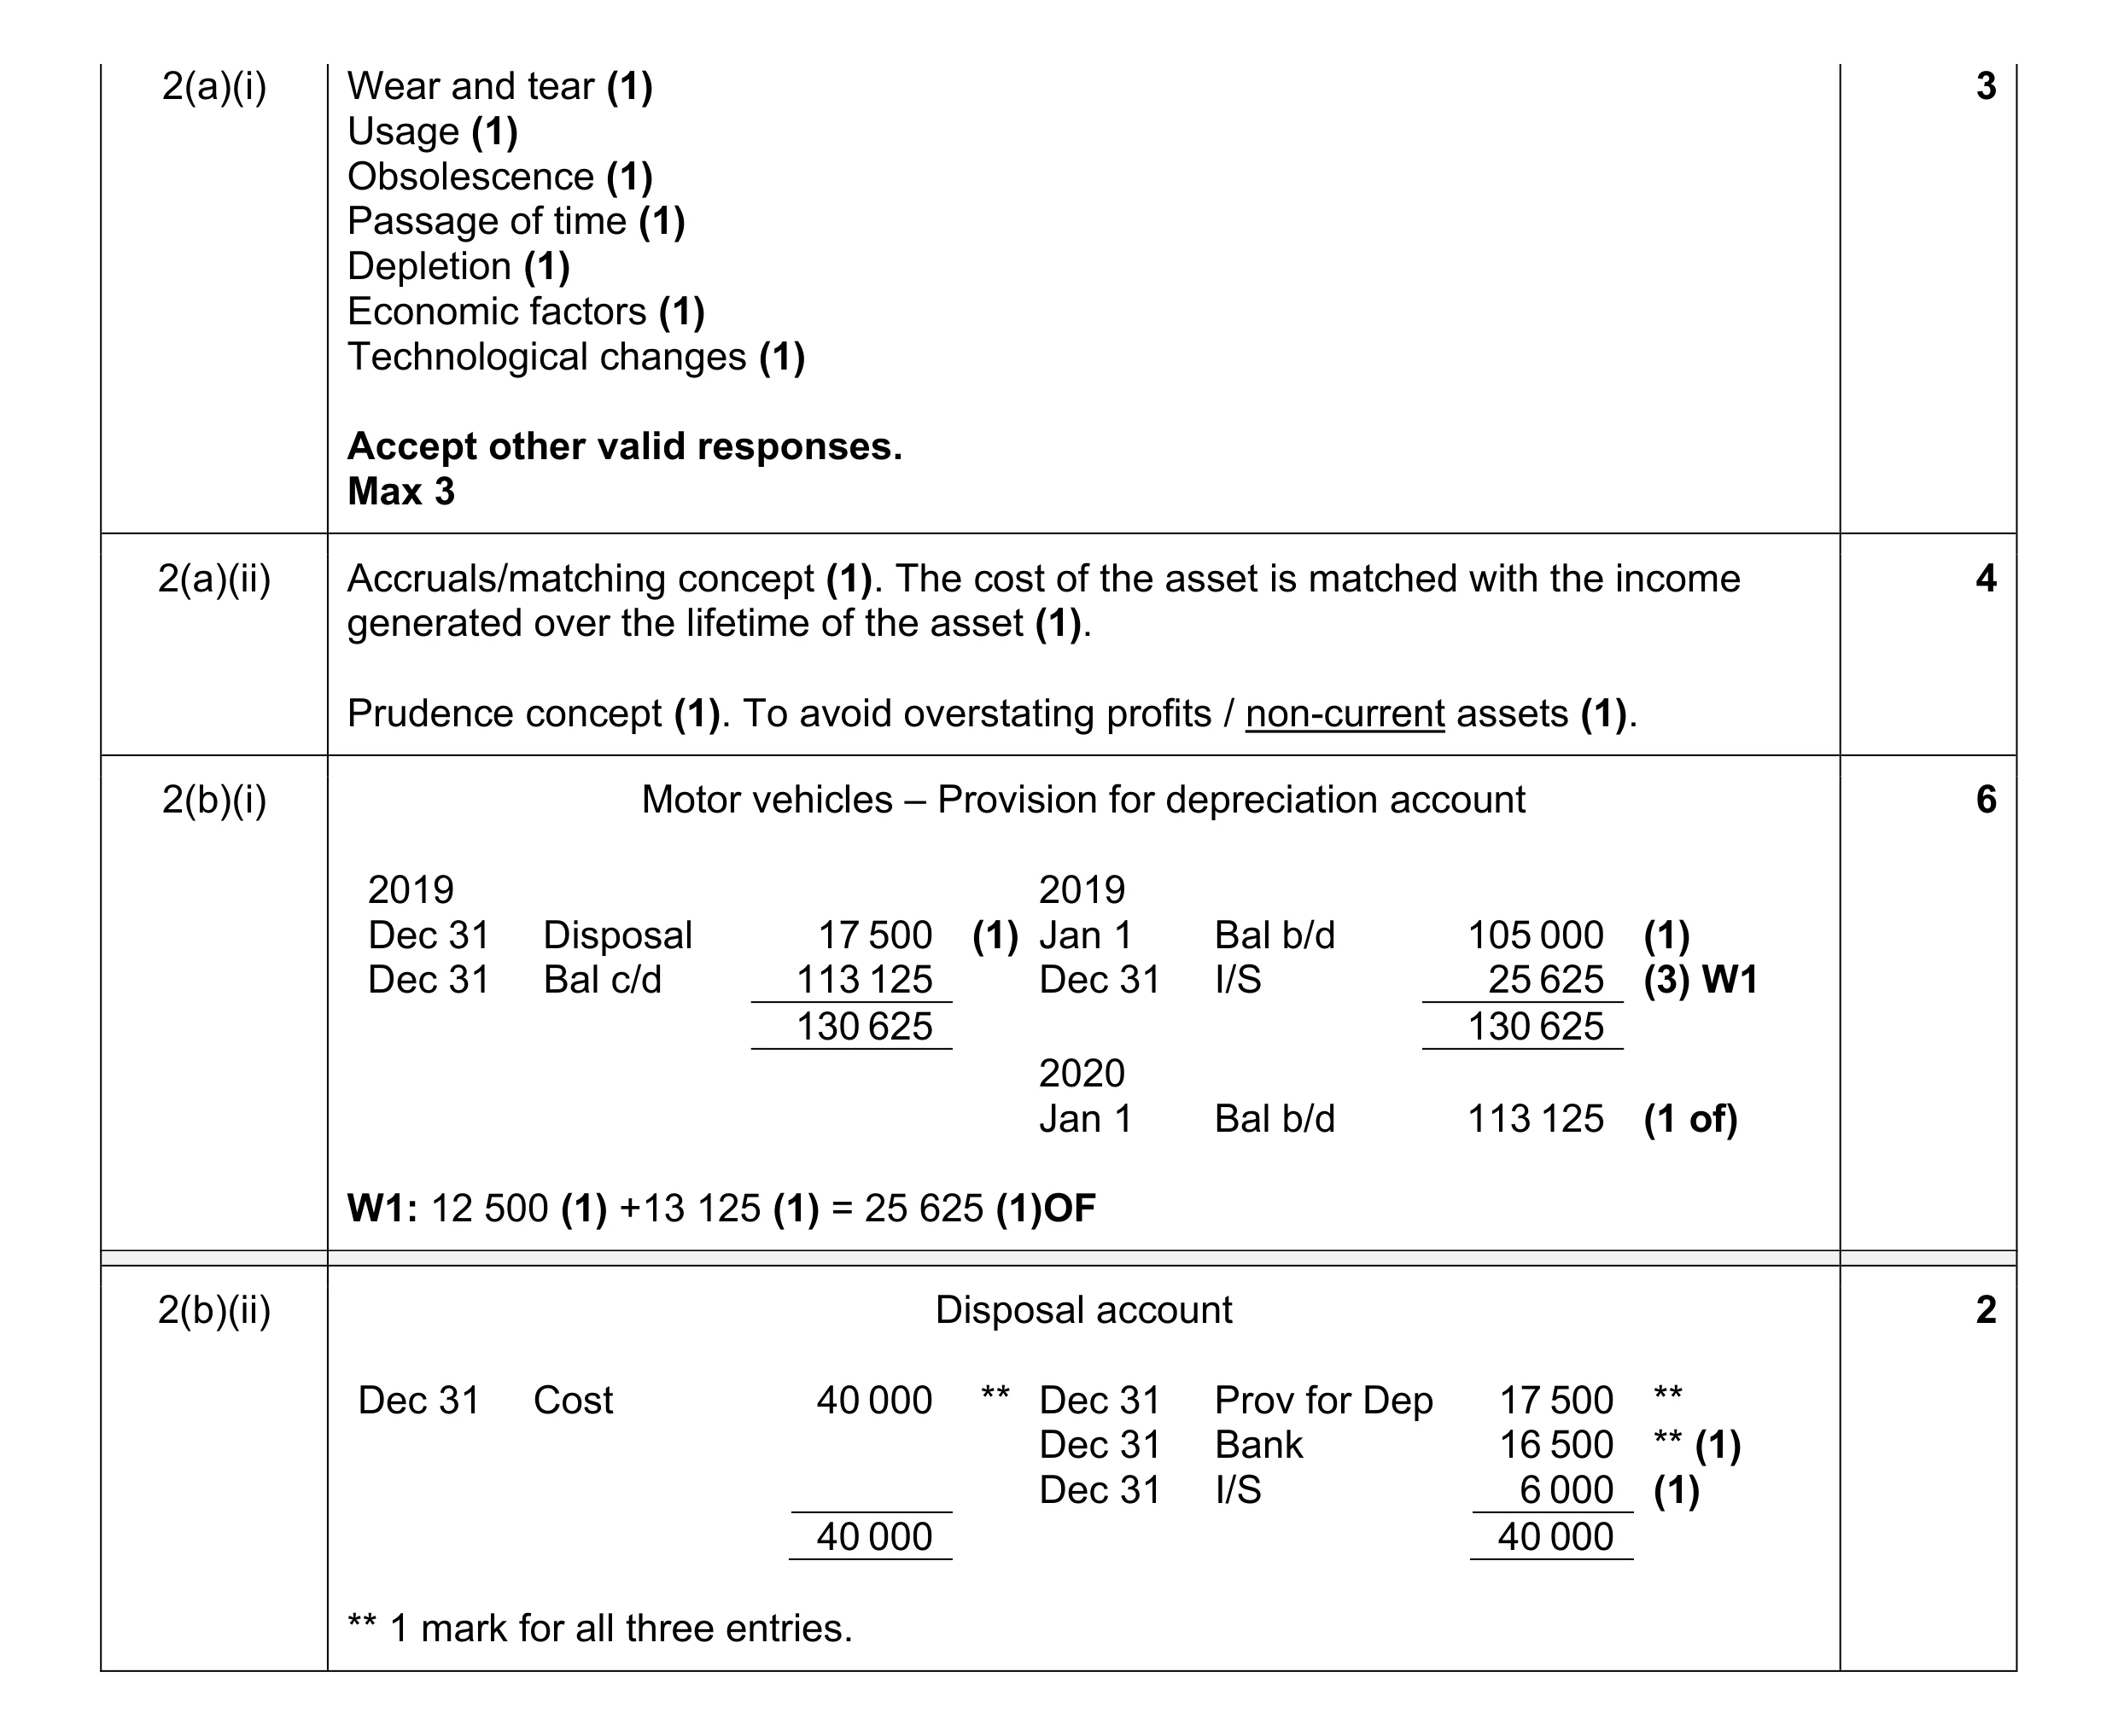
Mark scheme: 2(a)(i) Wear and tear (1) 3 Usage (1) Obsolescence (1) Passage of time (1) Depletion (1) Economic factors (1) Technological changes (1) Accept other valid responses. Max 3 2(a)(ii) Accruals/matching concept (1). The cost of the asset is matched with the income 4 generated over the lifetime of the asset (1). Prudence concept (1). To avoid overstating profits / non-current assets (1). 2(b)(i) Motor vehicles – Provision for depreciation account 6 2019 2019 Dec 31 Disposal 17 500 (1) Jan 1 Bal b/d 105 000 (1) Dec 31 Bal c/d 113 125 Dec 31 I/S 25 625 (3) W1 130 625 130 625 2020 Jan 1 Bal b/d 113 125 (1 of) W1: 12 500 (1) +13 125 (1) = 25 625 (1)OF 2(b)(ii) Disposal account 2 Dec 31 Cost 40 000 ** Dec 31 Prov for Dep 17 500 ** Dec 31 Bank 16 500 ** (1) Dec 31 I/S 6 000 (1) 40 000 40 000 ** 1 mark for all three entries.
This question in 9706/22 Feb/March 2020
Question 4 9706/21 May/June 2021
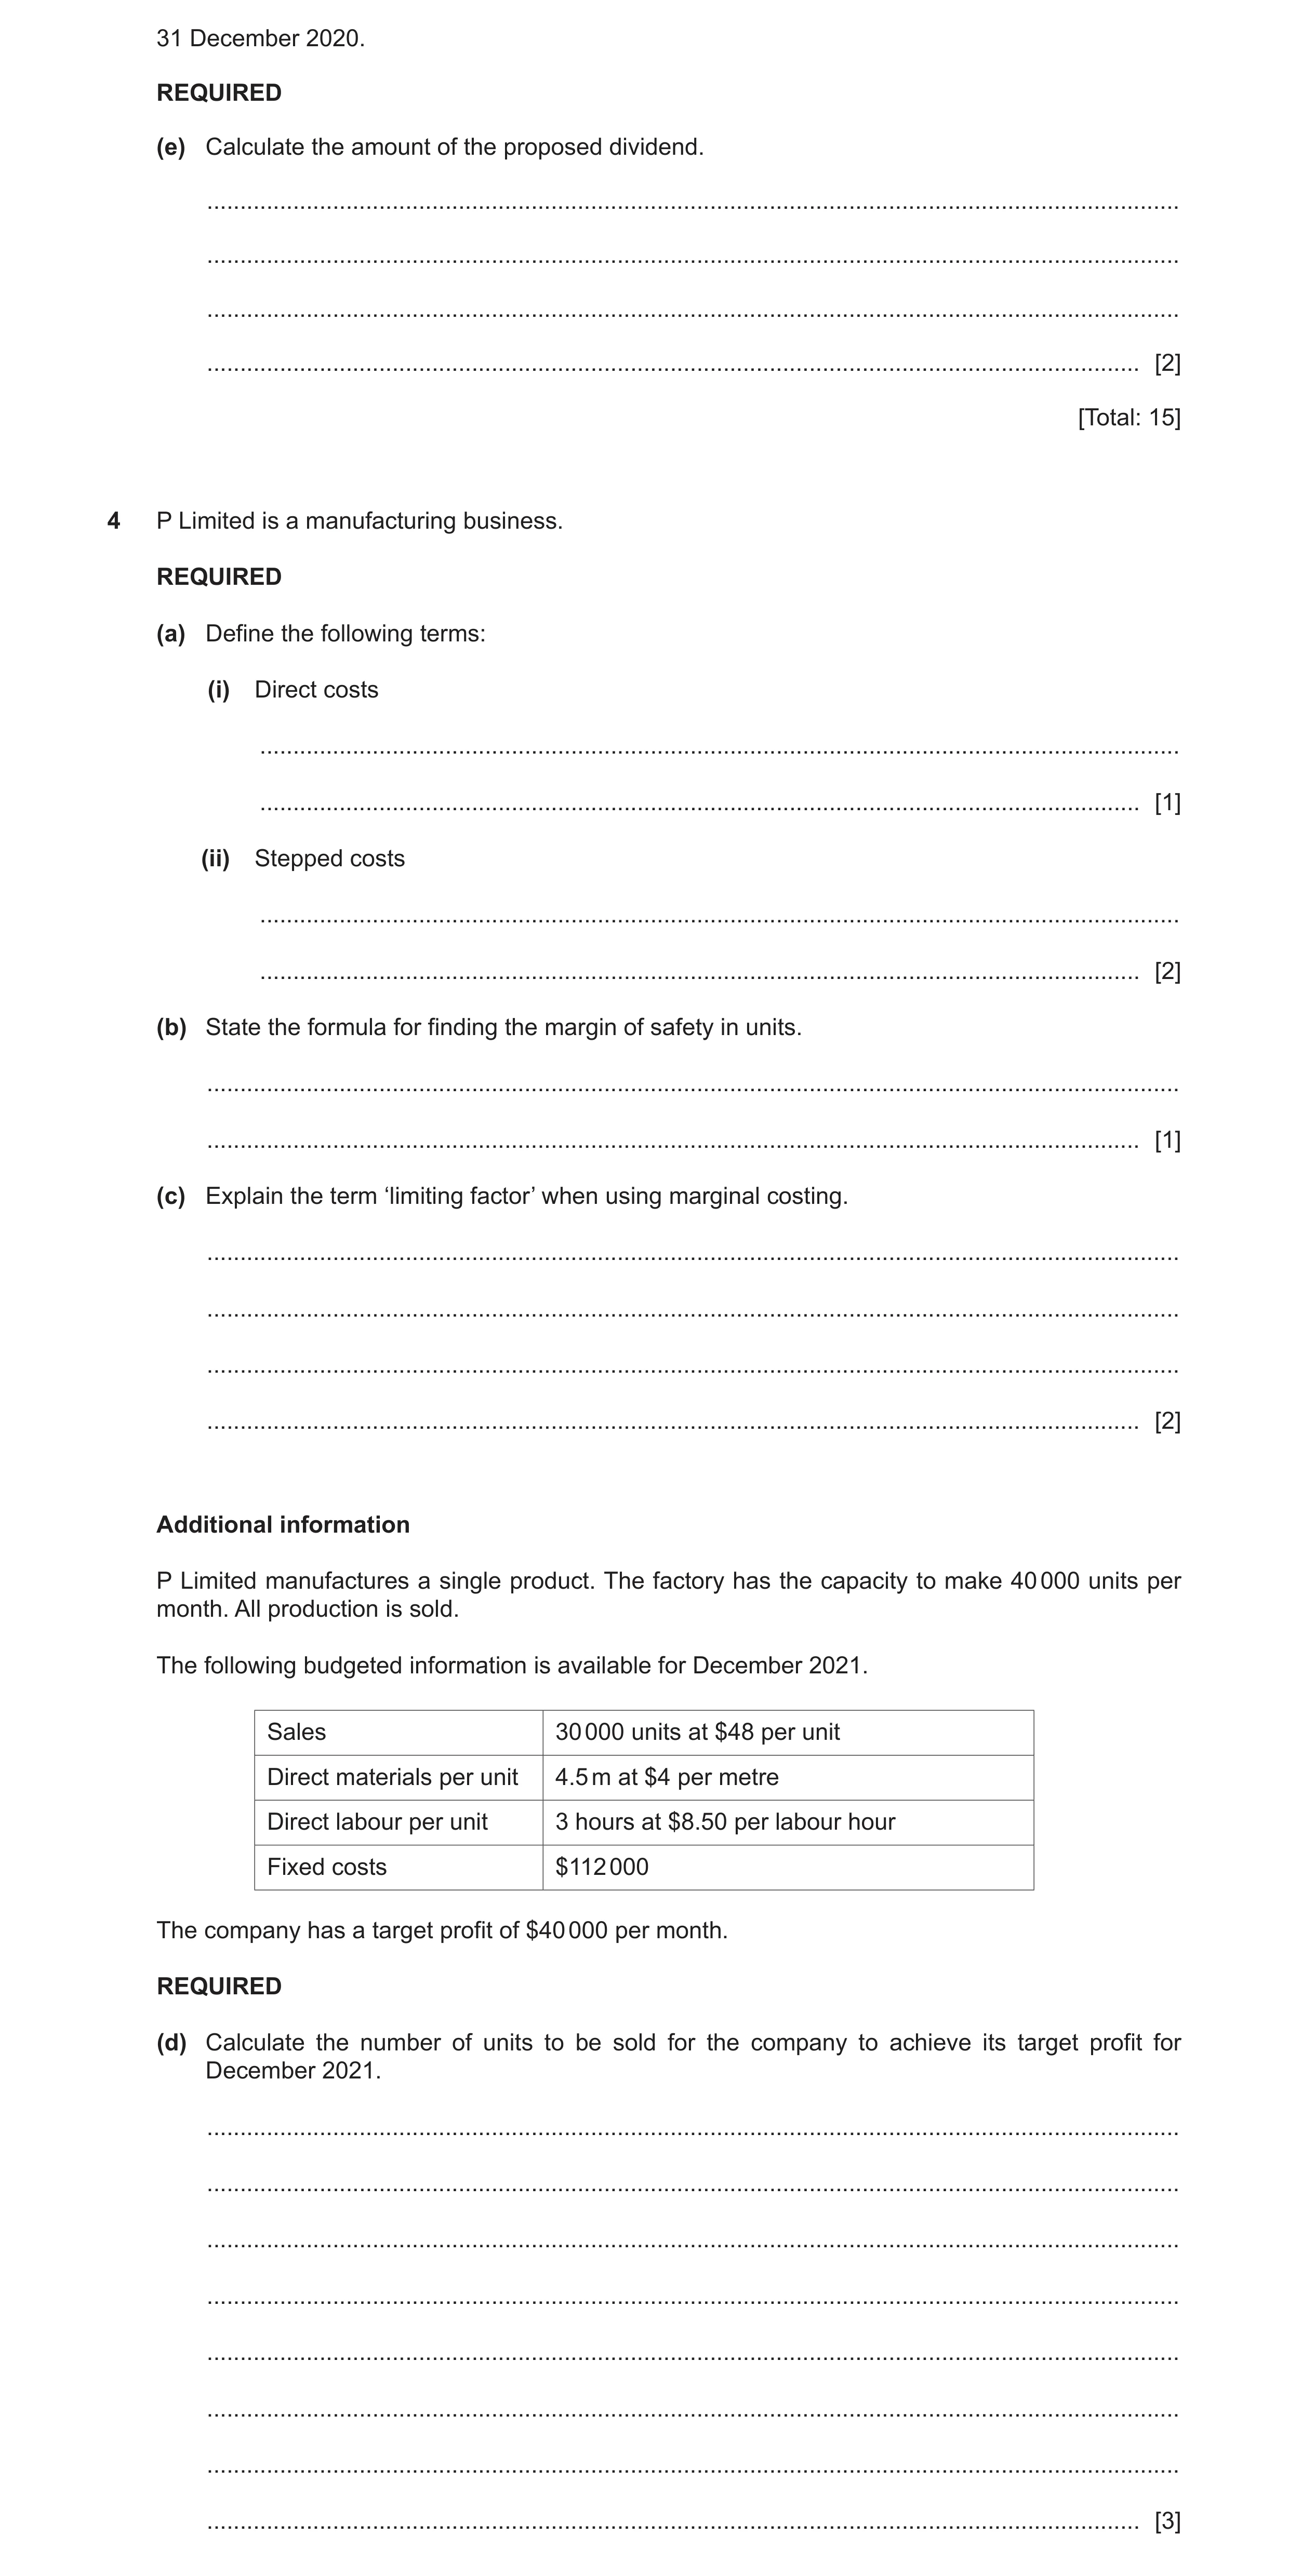
31 December 2020. REQUIRED (e) Calculate the amount of the proposed dividend. … … … … [2] [Total: 15] 4 P Limited is a manufacturing business. REQUIRED (a) Define the following terms: (i) Direct costs … … [1] (ii) Stepped costs … … [2] (b) State the formula for finding the margin of safety in units. … … [1] (c) Explain the term ‘limiting factor’ when using marginal costing. … … … … [2] Additional information P Limited manufactures a single product. The factory has the capacity to make 40 000 units per month. All production is sold. The following budgeted information is available for December 2021. Sales 30 000 units at $48 per unit Direct materials per unit 4.5 m at $4 per metre Direct labour per unit 3 hours at $8.50 per labour hour Fixed costs $112 000 The company has a target profit of $40 000 per month. REQUIRED (d) Calculate the number of units to be sold for the company to achieve its target profit for December 2021. … … … … … … … … [3]
11 marks
This question in 9706/21 May/June 2021
Q5 · The following information has been extracted from the financial statements of D Limited… 9706/22 Oct/Nov 2021
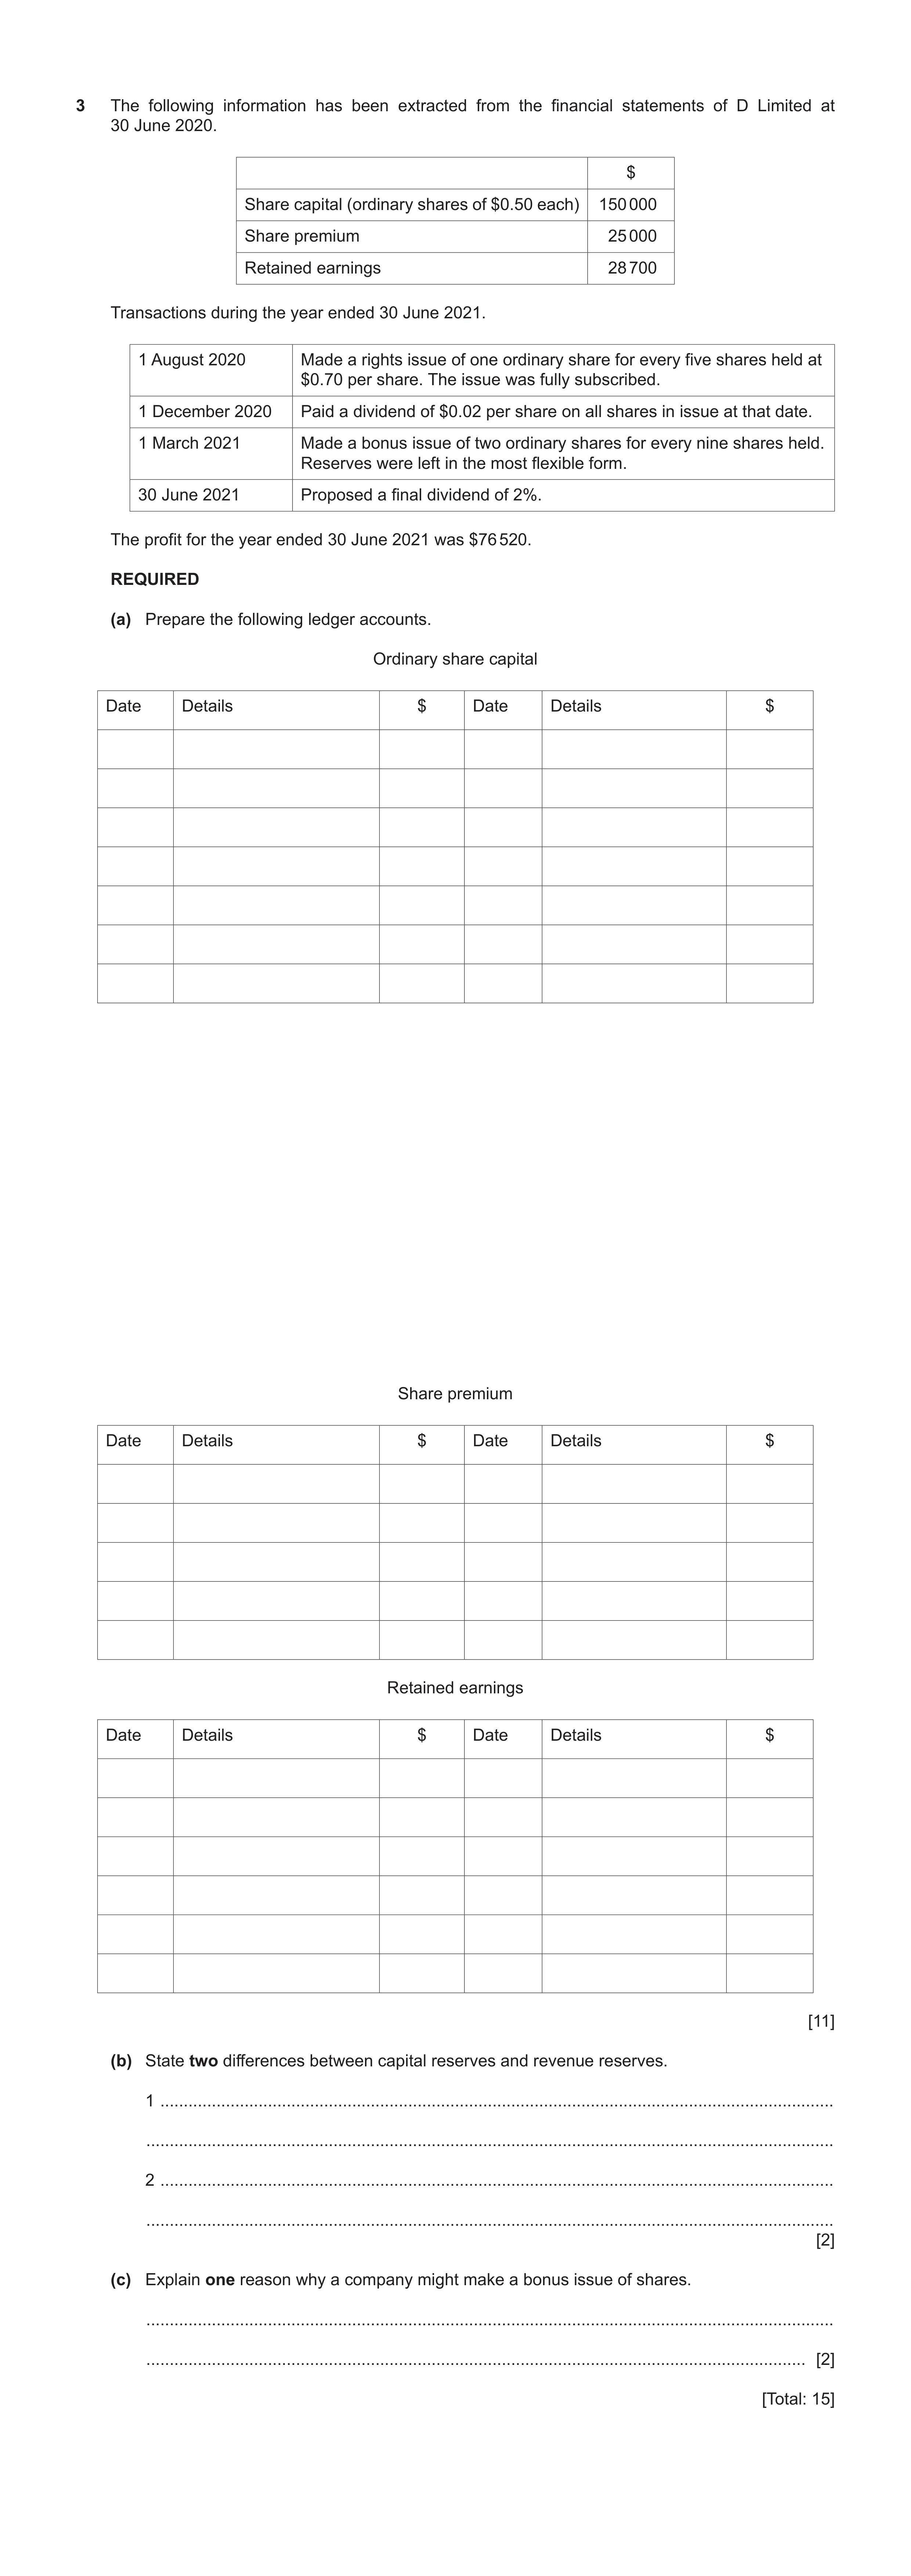
3 The following information has been extracted from the financial statements of D Limited at 30 June 2020. $ Share capital (ordinary shares of $0.50 each) 150 000 Share premium 25 000 Retained earnings 28 700 Transactions during the year ended 30 June 2021. 1 August 2020 Made a rights issue of one ordinary share for every five shares held at $0.70 per share. The issue was fully subscribed. 1 December 2020 Paid a dividend of $0.02 per share on all shares in issue at that date. 1 March 2021 Made a bonus issue of two ordinary shares for every nine shares held. Reserves were left in the most flexible form. 30 June 2021 Proposed a final dividend of 2%. The profit for the year ended 30 June 2021 was $76 520. REQUIRED (a) Prepare the following ledger accounts. Ordinary share capital Date Details $ Date Details $ Share premium Date Details $ Date Details $ Retained earnings Date Details $ Date Details $ [11] (b) State two differences between capital reserves and revenue reserves. 1 … … 2 … … [2] (c) Explain one reason why a company might make a bonus issue of shares. … … [2] [Total: 15]
15 marks
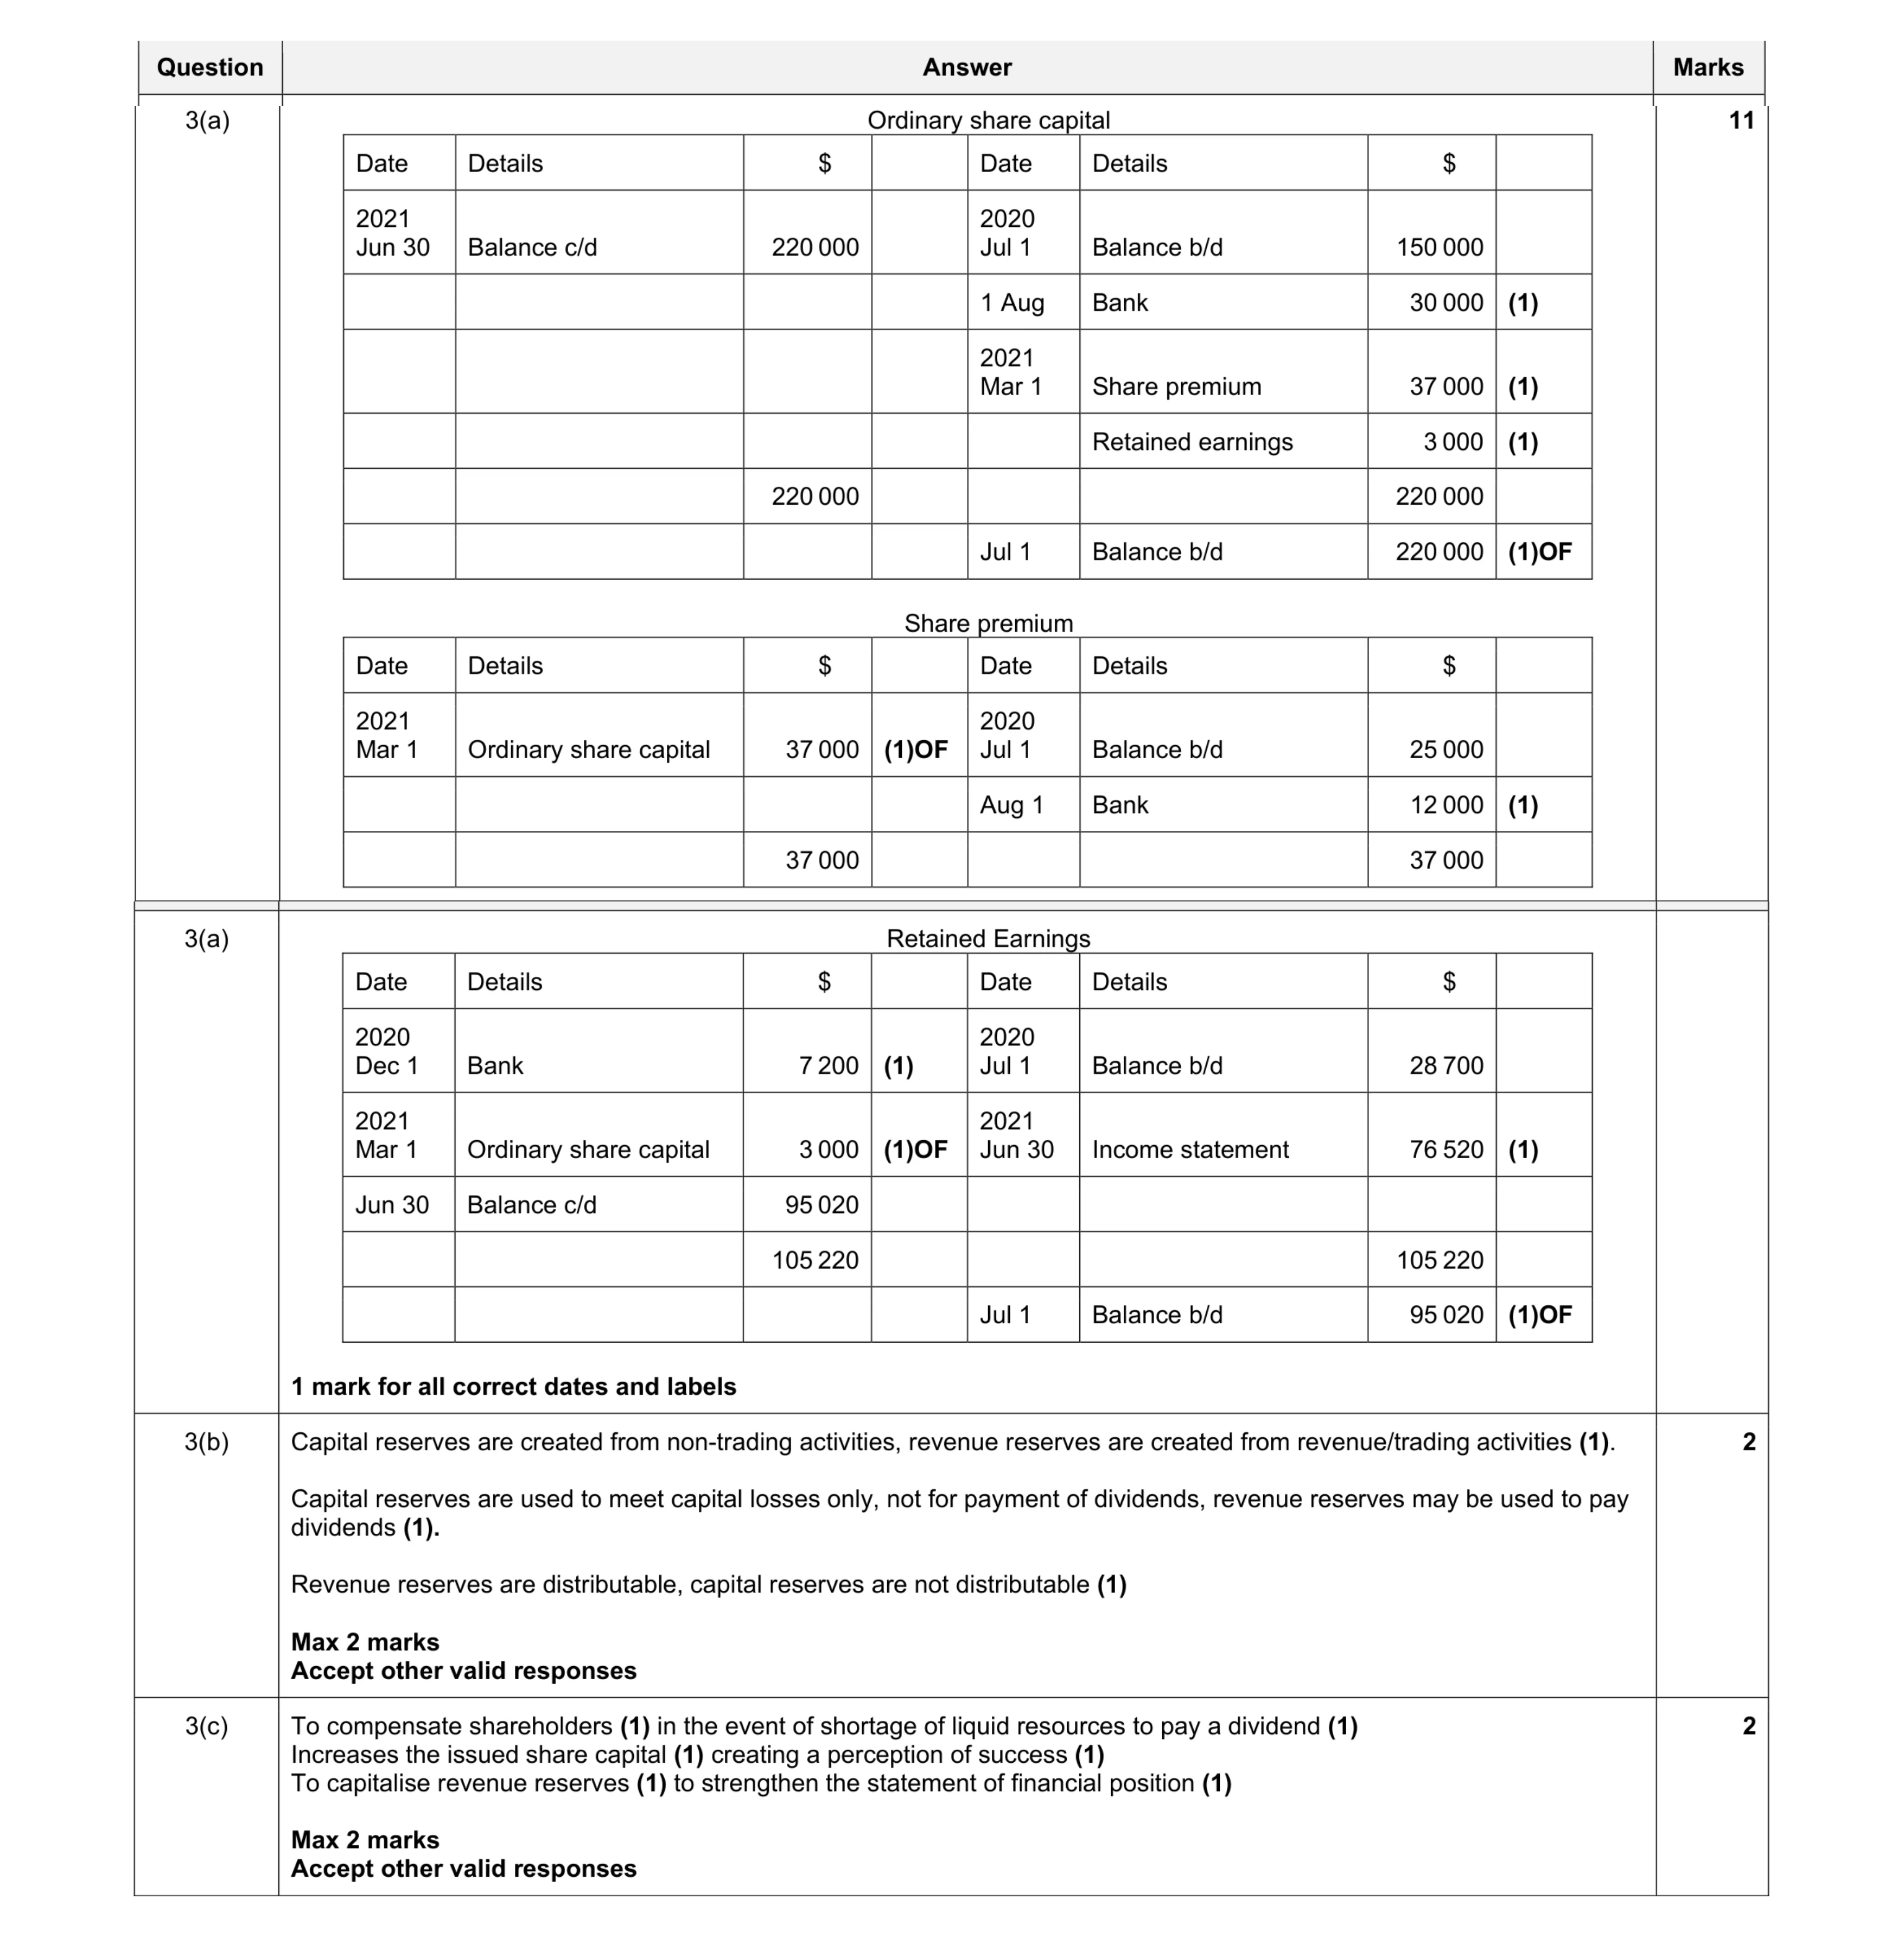
Mark scheme: 3(a) Ordinary share capital Date Details $ Date Details $ 2021 Jun 30 Balance c/d 220 000 2020 Jul 1 Balance b/d 150 000 1 Aug Bank 30 000 (1) 2021 Mar 1 Share premium 37 000 (1) Retained earnings 3 000 (1) 220 000 220 000 Jul 1 Balance b/d 220 000 (1)OF Share premium Date Details $ Date Details $ 2021 Mar 1 Ordinary share capital 37 000 (1)OF 2020 Jul 1 Balance b/d 25 000 Aug 1 Bank 12 000 (1) 37 000 37 000 11 Question Answer Marks 3(a) Retained Earnings Date Details $ Date Details $ 2020 Dec 1 Bank 7 200 (1) 2020 Jul 1 Balance b/d 28 700 2021 Mar 1 Ordinary share capital 3 000 (1)OF 2021 Jun 30 Income statement 76 520 (1) Jun 30 Balance c/d 95 020 105 220 105 220 Jul 1 Balance b/d 95 020 (1)OF 1 mark for all correct dates and labels 3(b) Capital reserves are created from non-trading activities, revenue reserves are created from revenue/trading activities (1). Capital reserves are used to meet capital losses only, not for payment of dividends, revenue reserves may be used to pay dividends (1). Revenue reserves are distributable, capital reserves are not distributable (1) Max 2 marks Accept other valid responses 2 3(c) To compensate shareholders (1) in the event of shortage of liquid resources to pay a dividend (1) Increases the issued share capital (1) creating a perception of success (1) To capitalise revenue reserves (1) to strengthen the statement of financial position (1) Max 2 marks Accept other valid responses 2
This question in 9706/22 Oct/Nov 2021
Q6 · R Limited is a retail company 9706/23 Oct/Nov 2022
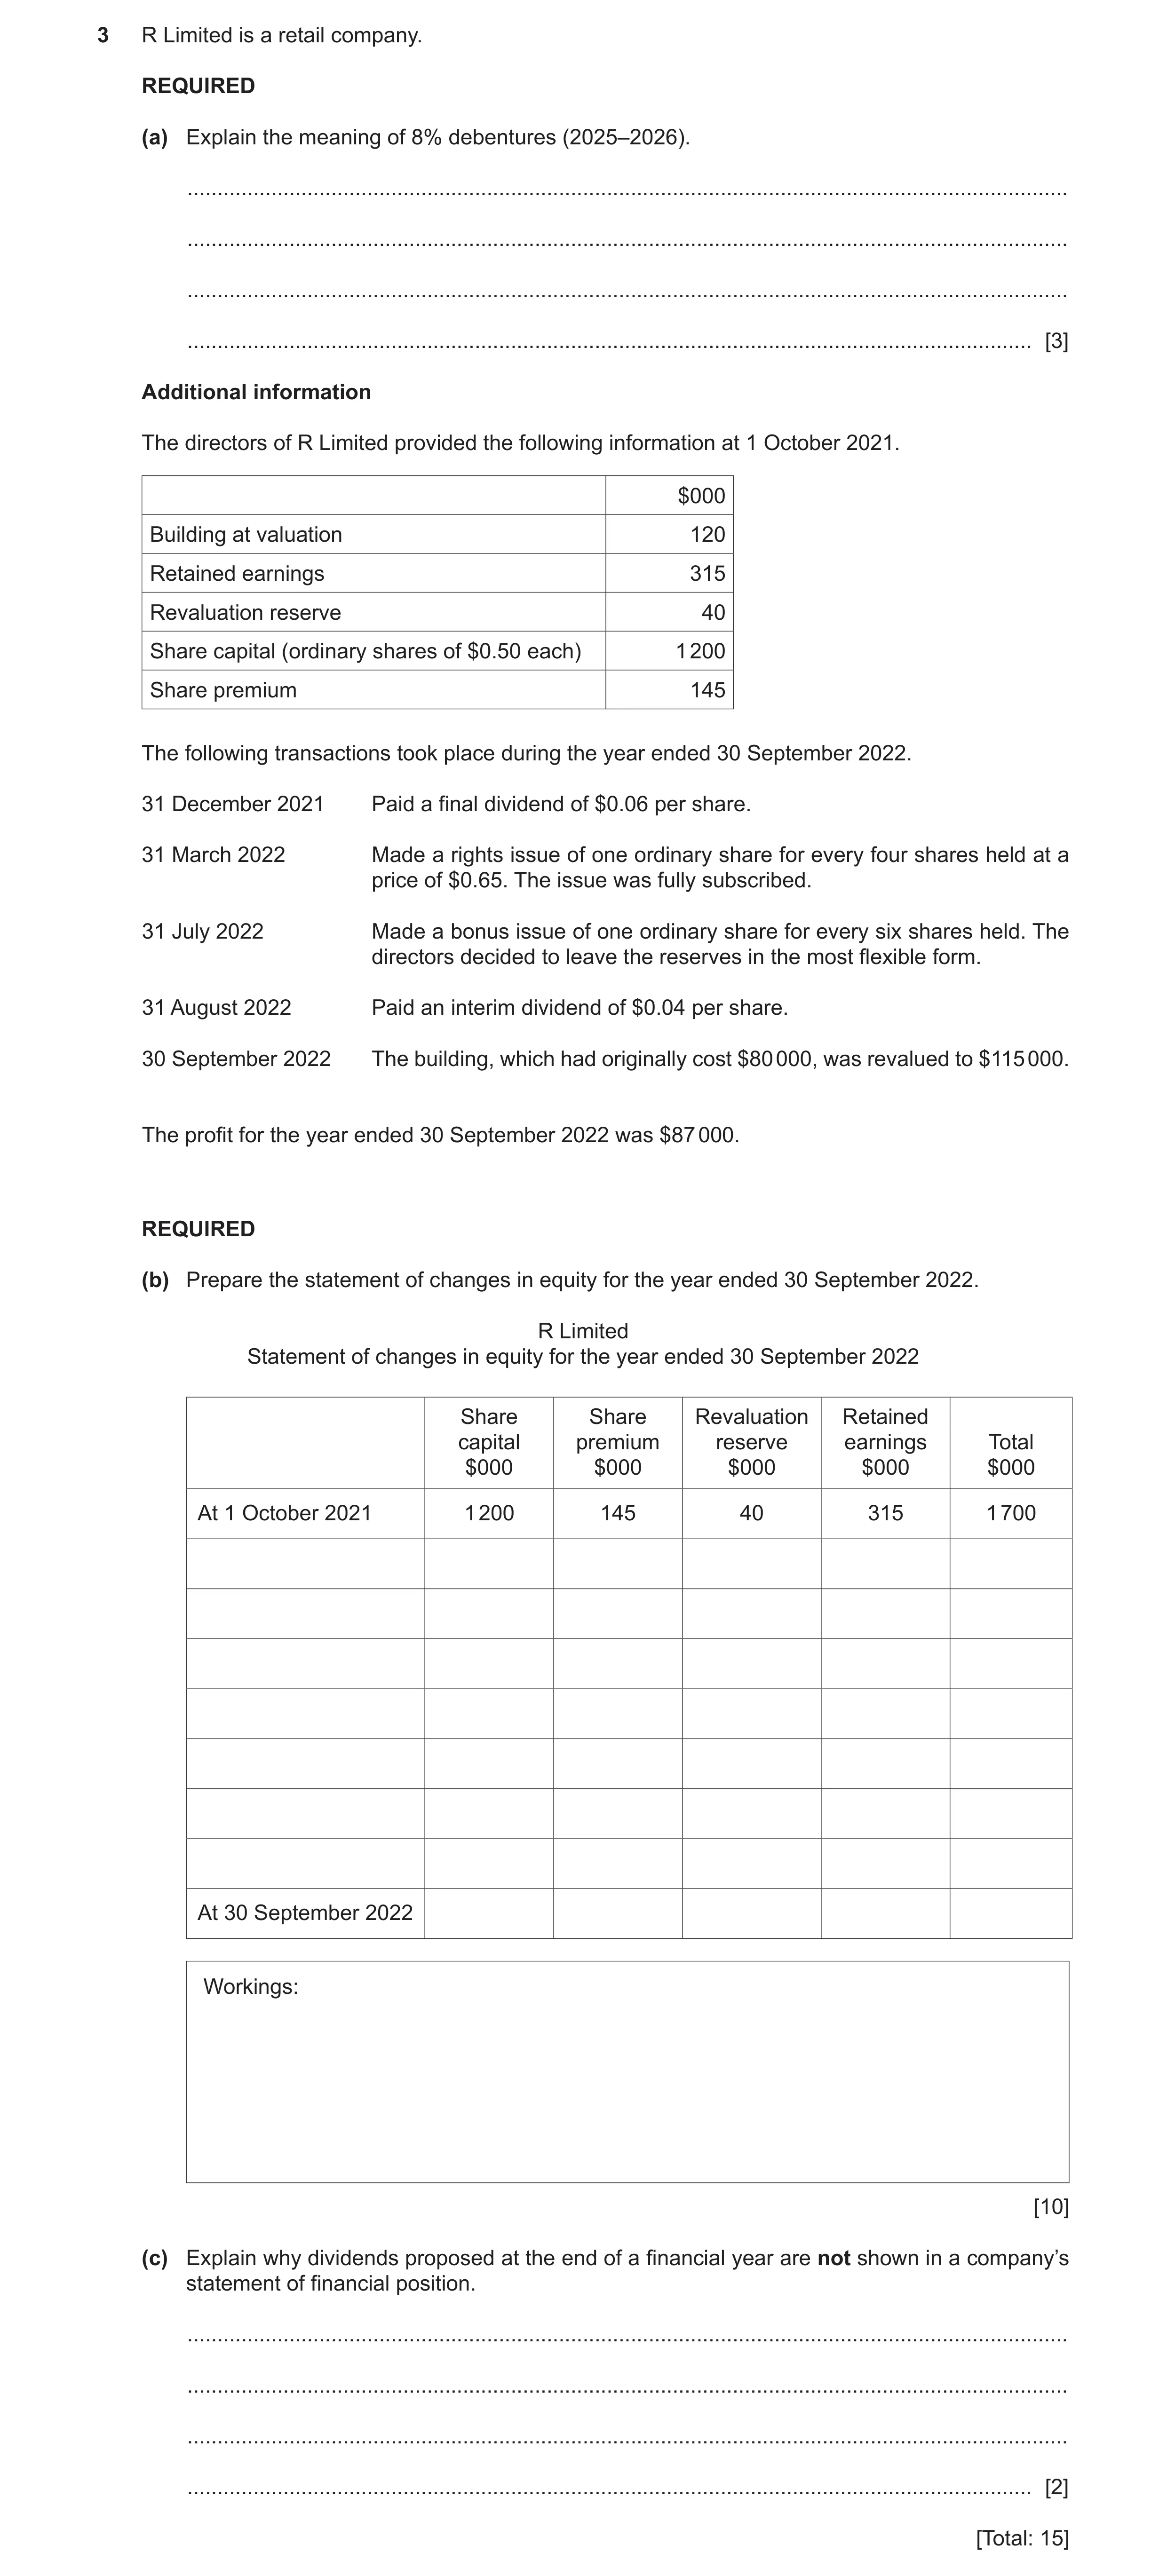
3 R Limited is a retail company. REQUIRED (a) Explain the meaning of 8% debentures (2025–2026). … … … … [3] Additional information The directors of R Limited provided the following information at 1 October 2021. $000 Building at valuation 120 Retained earnings 315 Revaluation reserve 40 Share capital (ordinary shares of $0.50 each) 1 200 Share premium 145 The following transactions took place during the year ended 30 September 2022. 31 December 2021 Paid a final dividend of $0.06 per share. 31 March 2022 Made a rights issue of one ordinary share for every four shares held at a price of $0.65. The issue was fully subscribed. 31 July 2022 Made a bonus issue of one ordinary share for every six shares held. The directors decided to leave the reserves in the most flexible form. 31 August 2022 Paid an interim dividend of $0.04 per share. 30 September 2022 The building, which had originally cost $80 000, was revalued to $115 000. The profit for the year ended 30 September 2022 was $87 000. REQUIRED (b) Prepare the statement of changes in equity for the year ended 30 September 2022. R Limited Statement of changes in equity for the year ended 30 September 2022 Share Share Revaluation Retained capital premium reserve earnings Total $000 $000 $000 $000 $000 At 1 October 2021 1 200 145 40 315 1 700 At 30 September 2022 Workings: [10] (c) Explain why dividends proposed at the end of a financial year are not shown in a company’s statement of financial position. … … … … [2] [Total: 15]
15 marks
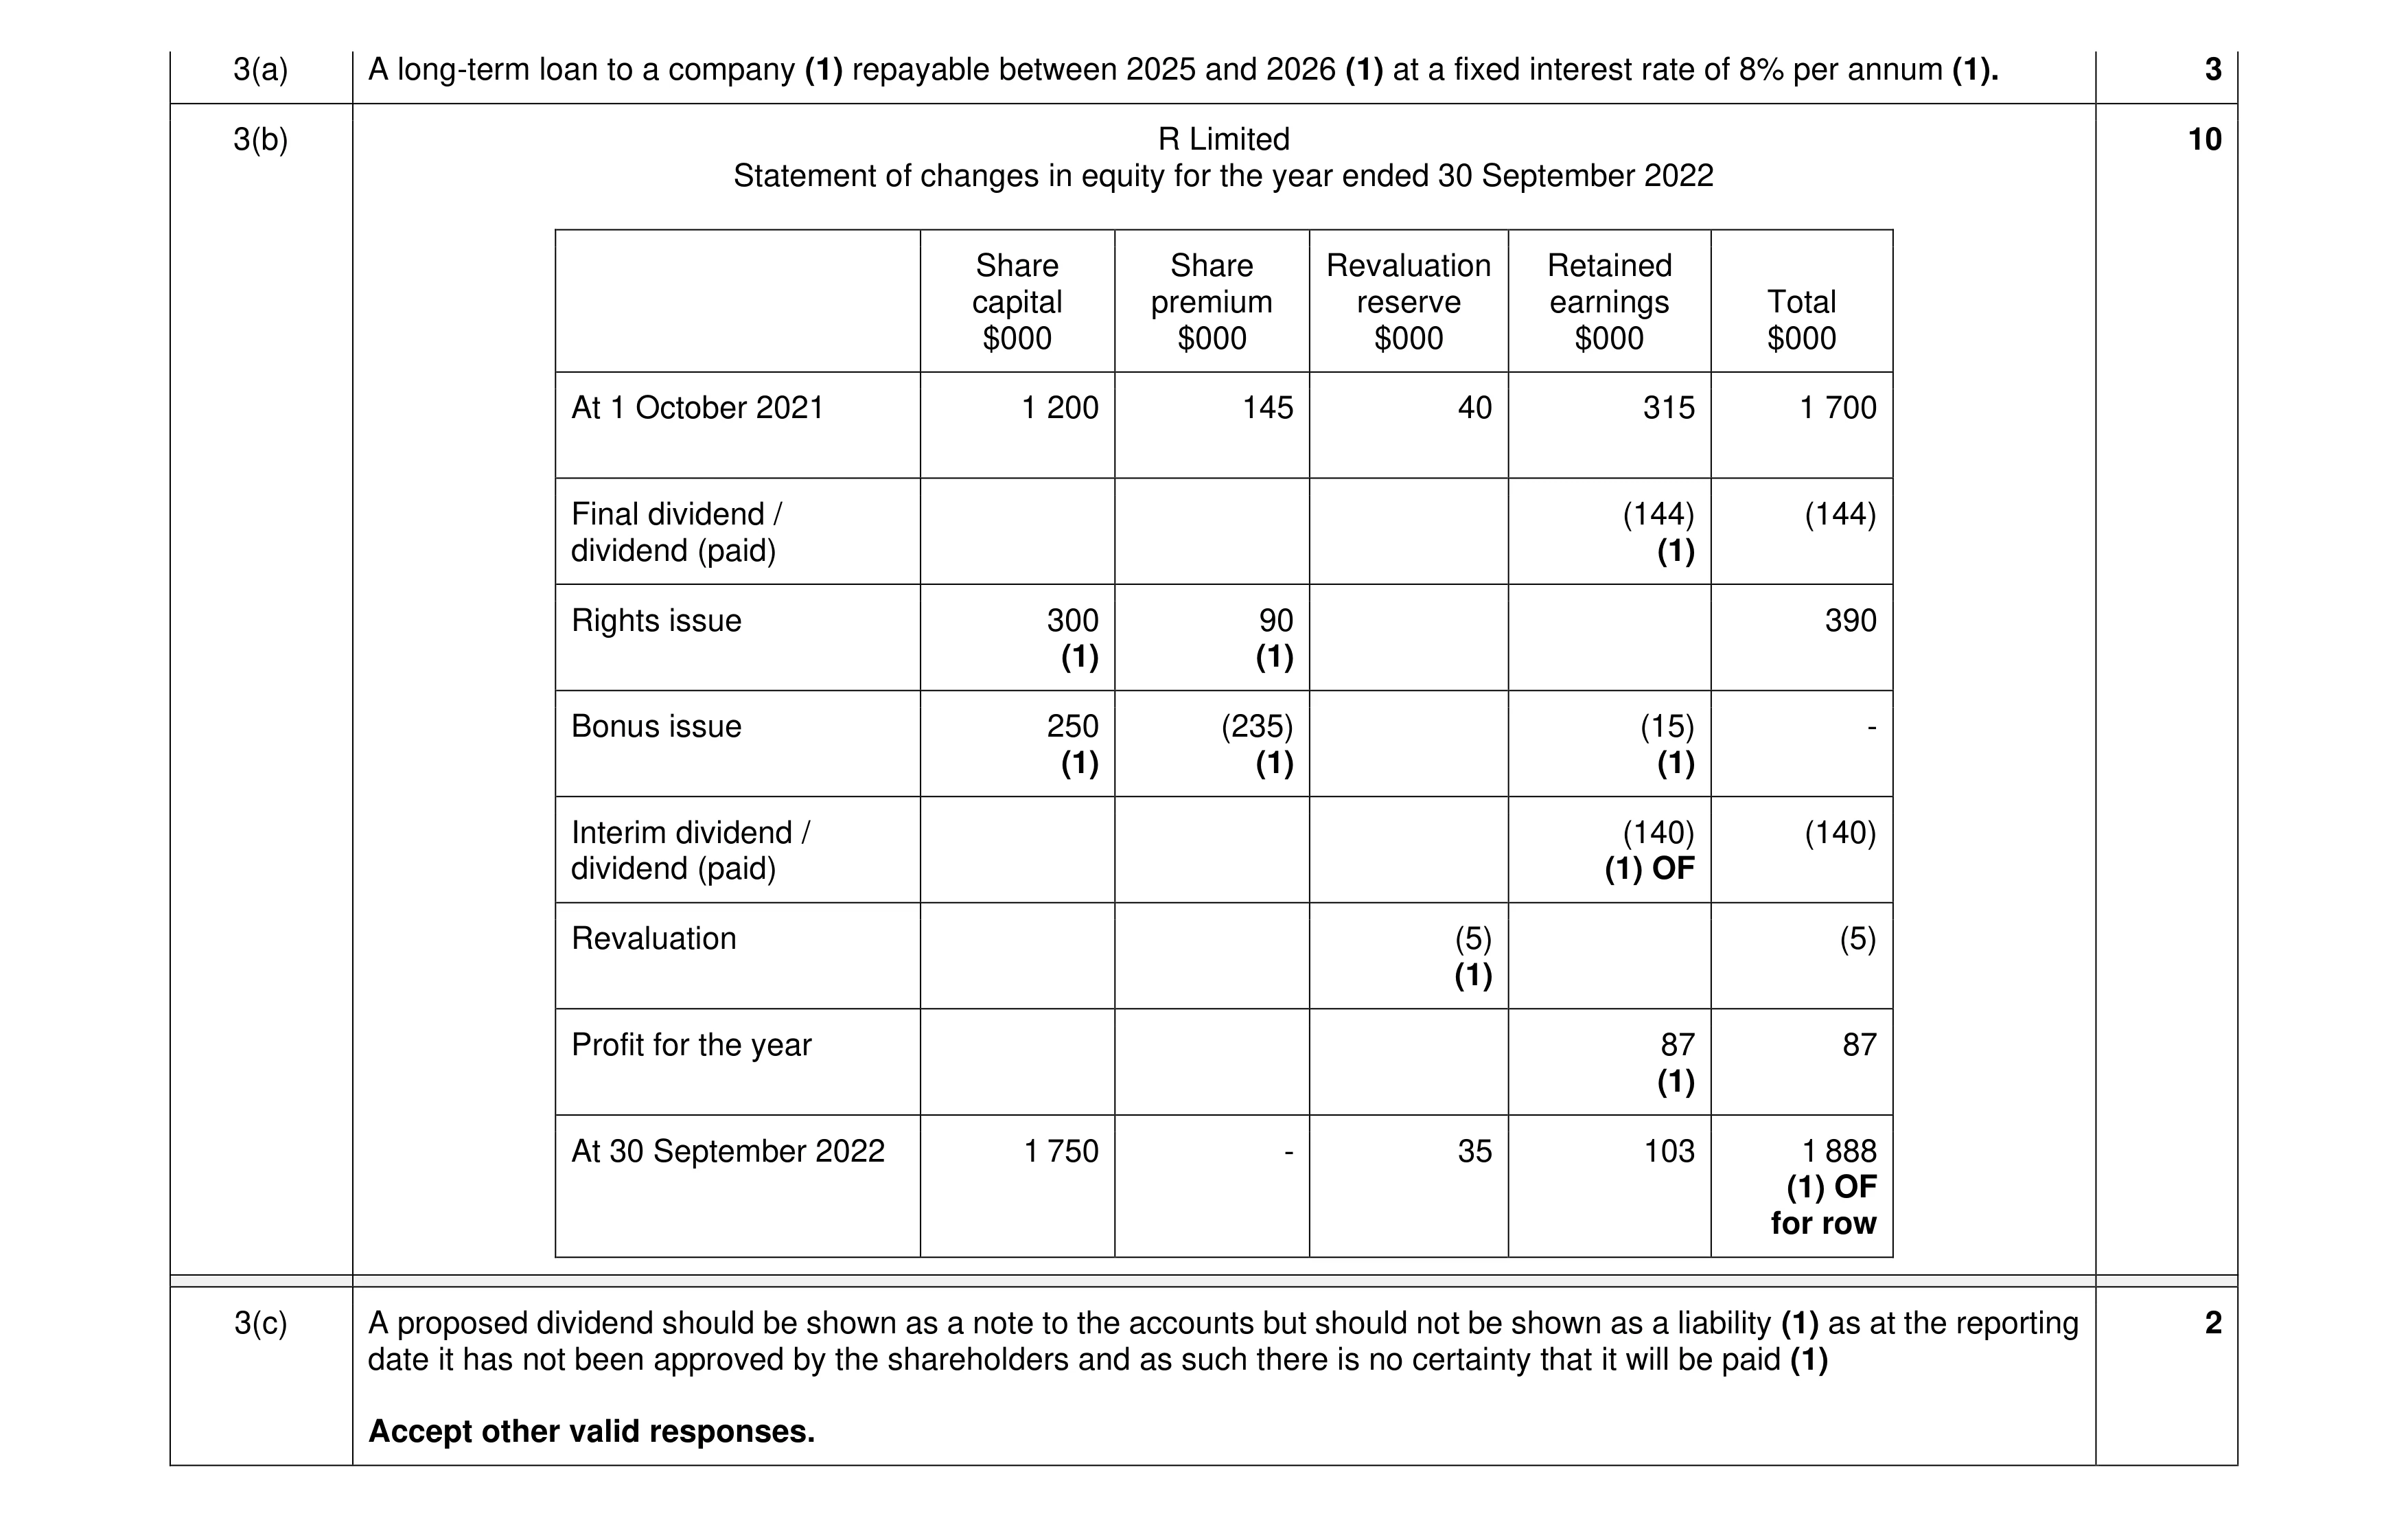
Mark scheme: 3(a) A long-term loan to a company (1) repayable between 2025 and 2026 (1) at a fixed interest rate of 8% per annum (1). 3 3(b) R Limited 10 Statement of changes in equity for the year ended 30 September 2022 Share Share Revaluation Retained capital premium reserve earnings Total $000 $000 $000 $000 $000 At 1 October 2021 1 200 145 40 315 1 700 Final dividend / (144) (144) dividend (paid) (1) Rights issue 300 90 390 (1) (1) Bonus issue 250 (235) (15) - (1) (1) (1) Interim dividend / (140) (140) dividend (paid) (1) OF Revaluation (5) (5) (1) Profit for the year 87 87 (1) At 30 September 2022 1 750 - 35 103 1 888 (1) OF for row 3(c) A proposed dividend should be shown as a note to the accounts but should not be shown as a liability (1) as at the reporting 2 date it has not been approved by the shareholders and as such there is no certainty that it will be paid (1) Accept other valid responses.
This question in 9706/23 Oct/Nov 2022
Q7 · REQUIRED (c) Prepare the statement of profit or loss for the year ended 31 December 2022 9706/21 May/June 2023
REQUIRED (c) Prepare the statement of profit or loss for the year ended 31 December 2022. Use the space provided on the next page to show your workings. Mima Supplies Statement of profit or loss for the year ended 31 December 2022 … … … … … … … … … … … … … … … … … … … … … … Workings: [13] (d) Explain the importance of making an allowance for irrecoverable debts in a business’s financial statements. … … … … … [2] Additional information Mima would like to assess her business’s liquidity position at 31 December 2022. REQUIRED (e) Identify two ratios which could be used to assess a business’s liquidity position. 1 … 2 … [2] Additional information Mima has noticed that her business’s rate of inventory turnover has decreased since last year. She is considering two options to increase the rate of inventory turnover. Option A: reduce inventory levels. Option B: reduce selling prices by 2% and increase the annual advertising budget by 5%. REQUIRED (f) Advise Mima which option she should choose. Justify your choice by considering both options. … … … … … … … … … … … … … … … [7] [Total: 30] 2 Param uses control accounts to verify the accuracy of his business’s sales and purchases ledgers. He provided the following information for the month ended 30 April 2023 relating to trade receivables. $ Sales ledger balances, 1 April 2023 Debit 14 890 Credit 610 Contra entries with the purchases ledger 1 850 Credit sales 153 480 Credit customers’ cheques returned 880 Discounts allowed 4 830 Interest charged on overdue accounts 540 Irrecoverable debts written off 1 830 Receipts from credit customers 148 200 Returns inwards 2 790 There were no credit balances in the sales ledger on 30 April 2023. REQUIRED (a) Prepare the sales ledger control account for April 2023. Dates are not required. Sales ledger control account $ $ [6] (b) Identify the books of prime entry for each of the following: (i) discounts allowed … [1] (ii) irrecoverable debts written off. … [1] (c) State three benefits of maintaining control accounts. 1 … … 2 … … 3 … … [3] Additional information The balance of the sales ledger control account at 30 April 2023 did not agree with the total of the individual customer account balances at this date. The following errors were discovered, some of which affected the sales ledger control account and some of which affected the customer account balances. 1 Returns inwards of $720 had been credited to the account of Rafiq Stores instead of Raif Stores. 2 A sales invoice for $820 had been omitted from the books of account. 3 The balance of a credit customer’s account, $430, had been brought down as $340. 4 The total of the returns inwards journal had been understated by $470. 5 Interest of $40 charged on an overdue account had been correctly entered in the journal but had been credited to the customer’s account. REQUIRED (d) Calculate the revised sales ledger control account balance at 30 April 2023. … … … … … … … … [4] [Total: 15] 3 The following extract from J Limited’s statement of financial position at 1 January 2022 is available. $ Equity Issued capital: ordinary shares of $0.25 each 600 000 Share premium 175 000 Retained earnings 54 000 Total equity 829 000 Non‑current liabilities 7% Debentures (2028) 200 000 REQUIRED (a) State two features of revenue reserves which do not apply to capital reserves. 1 … … … 2 … … … [2] Additional information The directors wished to raise additional finance. On 1 April 2022 the company made a rights issue of 2 ordinary shares for every 3 shares held at a price of $0.35 per share. The issue was fully subscribed. REQUIRED (b) Calculate the amount raised by the rights issue of shares. … … … … … … [3] Additional information The directors had considered making an issue of debentures rather than a rights issue. (c) Identify two reasons why the directors of J Limited might prefer to raise additional finance through a rights issue rather than by issuing debentures. 1 … … 2 … … [2] Additional information The directors paid an interim dividend of $0.12 per share on 1 July 2022. REQUIRED (d) Calculate the total amount of the interim dividend. … … … … [2] Additional information The company made a profit of $535 000 for the year ended 31 December 2022. REQUIRED (e) Prepare the statement of changes in equity for the year ended 31 December 2022. J Limited Statement of changes in equity at 31 December 2022 Share capital Share Retained Total premium earnings $ $ $ $ [6] [Total: 15] 4 D Limited has two production departments and two service departments at one of its factories where absorption costing is used. Some forecast factory overheads have already been allocated and apportioned as follows: Production departments Service departments Cutting Assembly Maintenance Canteen $ $ $ $ Factory overheads 223 480 217 980 45 270 36 260 The following forecast factory overheads are still to be apportioned. $ Depreciation of machinery 48 000 Power 40 200 Canteen department overheads should be reapportioned on the basis of the number of employees. Maintenance department overheads should be reapportioned on the basis of the number of machines in production departments. The following data is available. Production departments Service departments Cutting Assembly Maintenance Canteen Machinery at carrying value $90 000 $66 000 $18 000 $6 000 Number of machines 43 27 Kilowatt hours 1 800 1 500 100 200 Number of employees 27 18 5 Budgeted machine hours 40 000 33 500 Budgeted direct labour hours 23 000 62 500 REQUIRED (a) Complete the following table to show the apportionment of factory overheads and the reapportionment of service department overheads. Production departments Service departments Cutting Assembly Maintenance Canteen $ $ $ $ Factory overheads 223 480 217 980 45 270 36 260 Depreciation of machinery Power Total overheads Reapportionment Subtotal Reapportionment Total overheads [5] (b) Calculate, to two decimal places, an overhead absorption rate for each production department, using a suitable basis. … … … … … … [2] Additional information The following information is available. Cutting department Assembly department Direct labour rate per hour $10.90 $8.20 Machine hours per unit 8 6 Labour hours per unit 3 4 Direct materials cost $6.95 per unit. Selling prices are set to achieve a profit margin of 25%. A customer has placed an order for 40 units. REQUIRED (c) Calculate the selling price to be quoted for this order of 40 units. … … … … … … … … … … … … [5] (d) State two causes of under absorption of overheads. 1 … … 2 … … [2] Additional information At the other factory a single product, Product Exe, is currently being made. Marginal costing is used at this factory. The following information is available. Selling price per unit $48 Contribution per unit $13 Direct labour 2.5 hours per unit at $10 per hour Fixed costs $96 000 per annum Factory capacity 28 000 labour hours per year Current production level 80% of factory capacity All units produced are sold. REQUIRED (e) Calculate the profit made each year from Product Exe. … … … … … … [4] Additional information The directors plan to make a new product, Product Wye, at this factory at the request of an important customer. The following details are available. 1 The factory will be able to operate at full capacity. 2 All units produced will be sold. 3 Product Wye will have a selling price of $64 per unit and a contribution of $8 per unit. 4 Product Wye will require direct labour at $10 per hour for 1.5 hours per unit. 5 The customer requires 10 000 units of Product Wye each year. The customer will only accept this quantity each year. 6 In order to complete the customer’s order, production of Product Exe will be reduced. 7 Some new machinery will be required costing $36 000. Machinery is depreciated by 20% per annum.
72 marks
This question in 9706/21 May/June 2023
Q8 · On 1 September 2022, a bonus issue of shares was made of one ordinary share for every six… 9706/22 Oct/Nov 2023
2 On 1 September 2022, a bonus issue of shares was made of one ordinary share for every six shares held. Reserves were maintained in their most flexible form.
0 marks
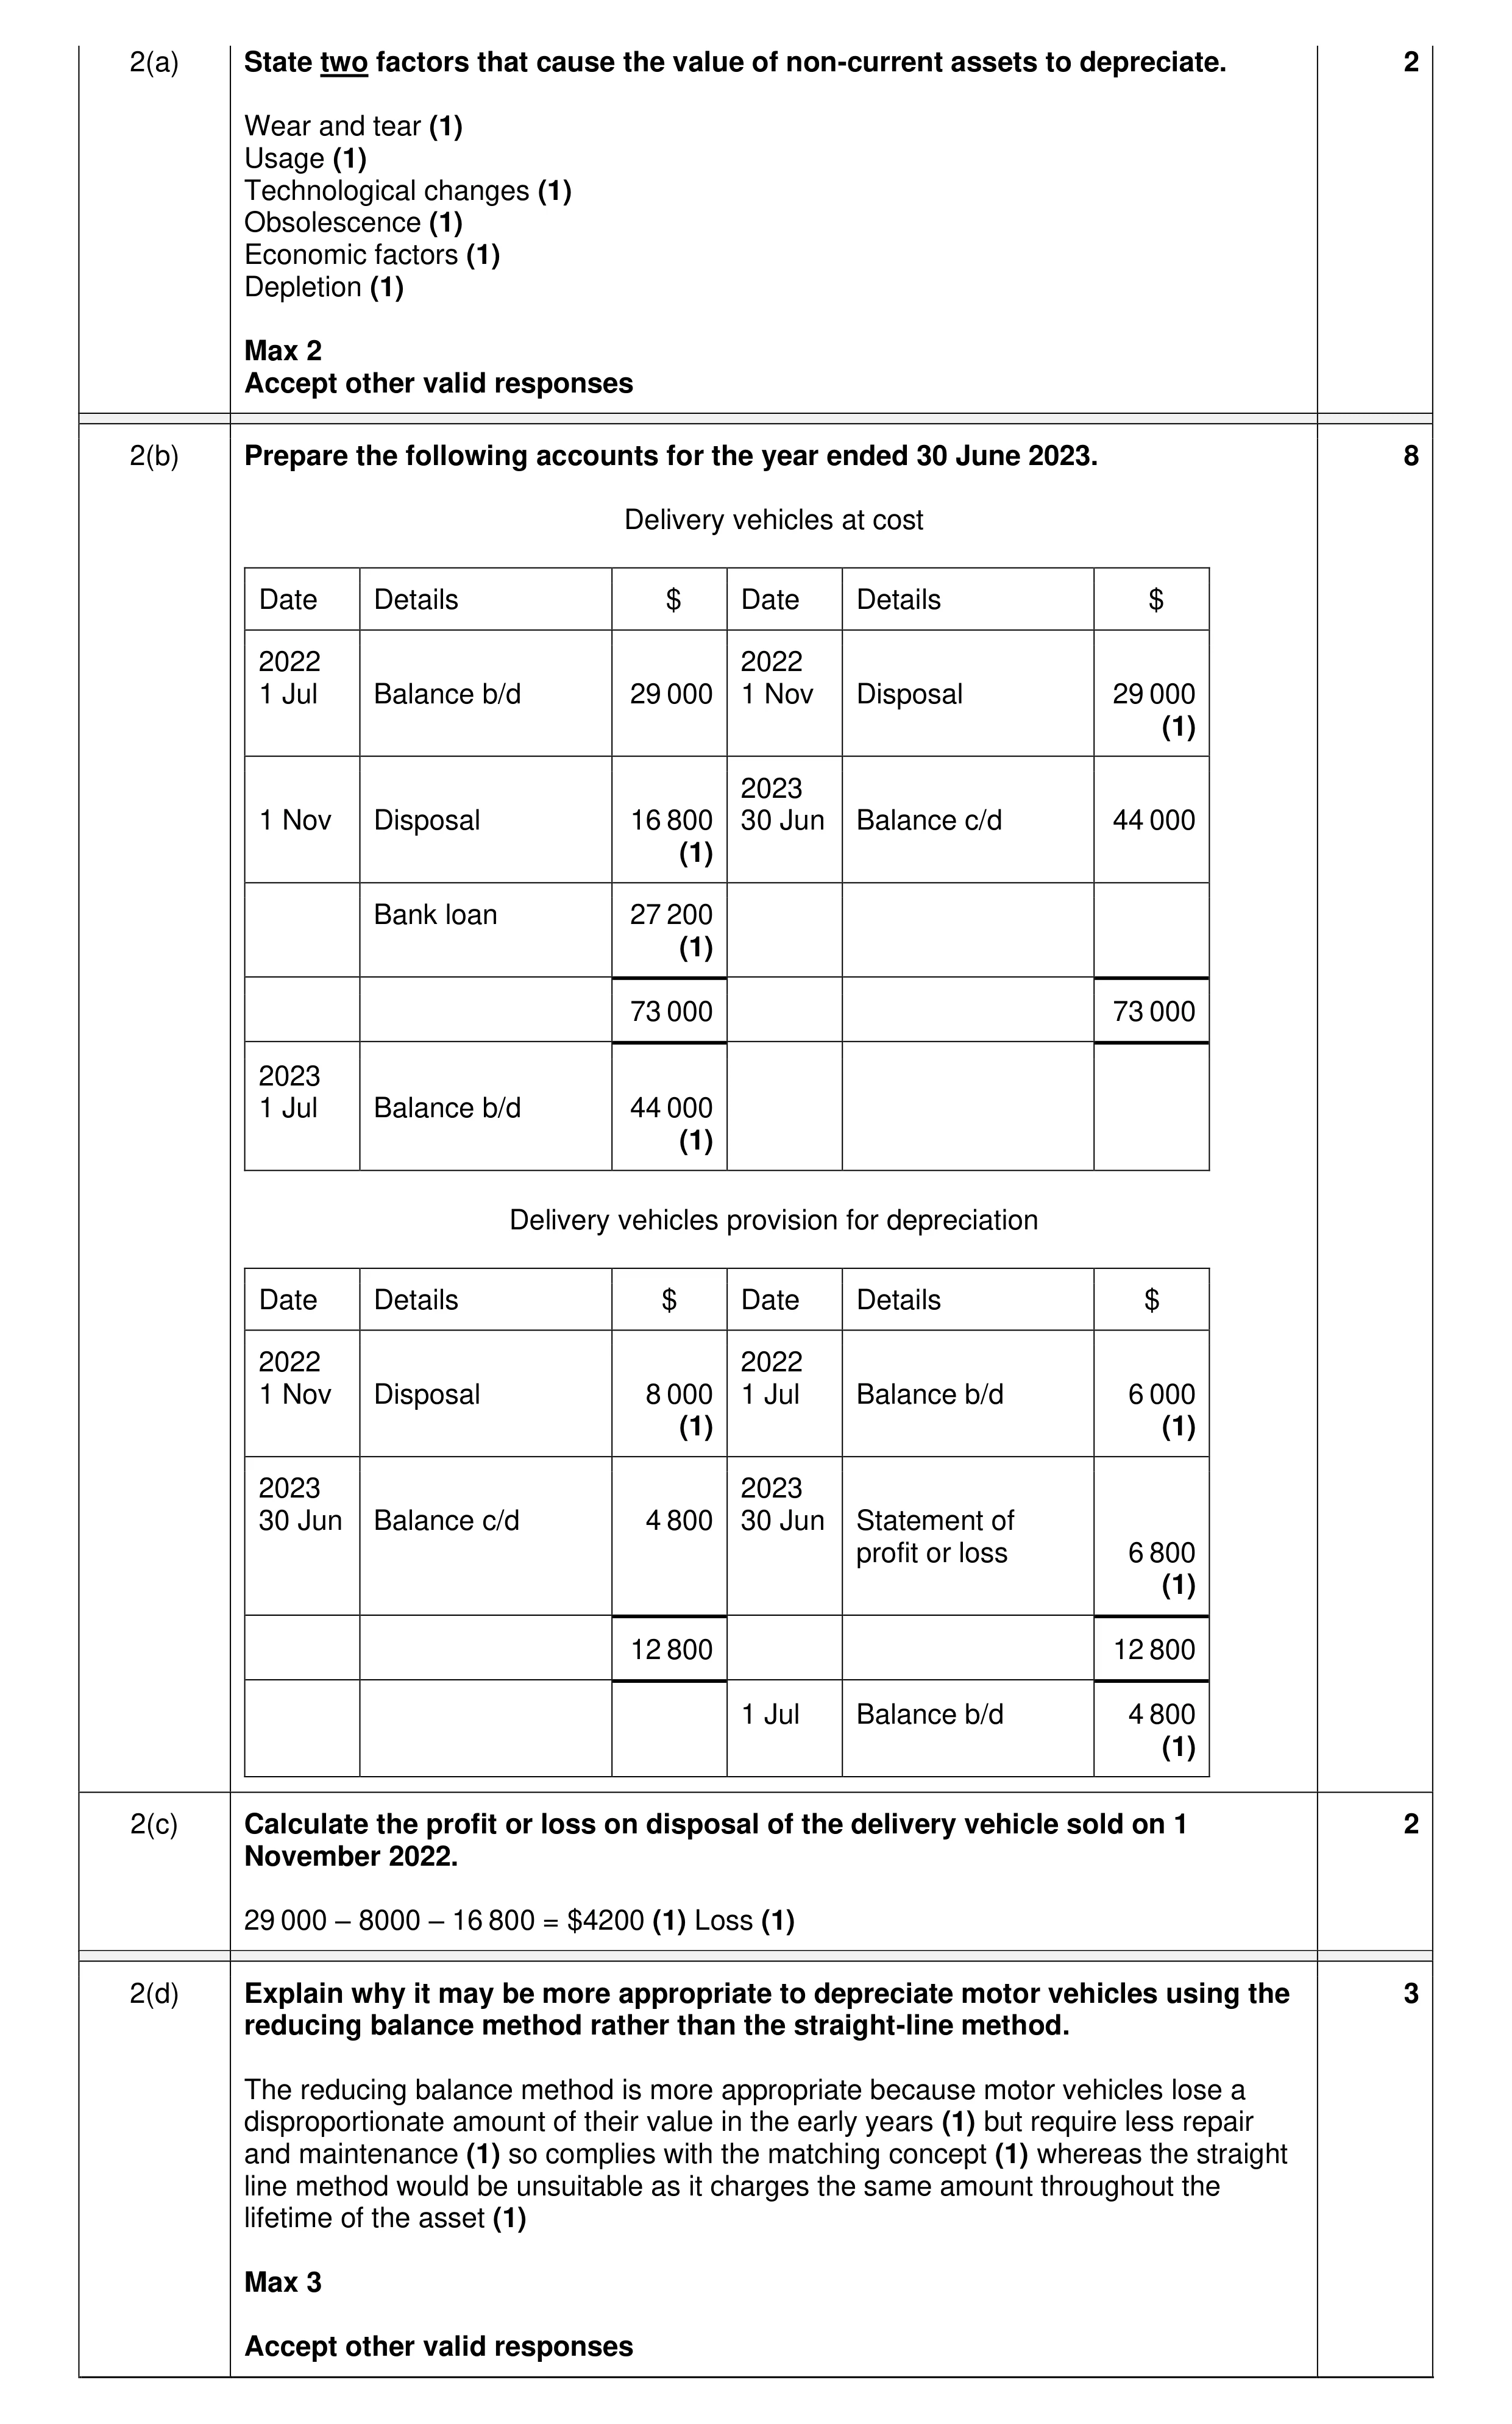
Mark scheme: 2(a) State two factors that cause the value of non-current assets to depreciate. 2 Wear and tear (1) Usage (1) Technological changes (1) Obsolescence (1) Economic factors (1) Depletion (1) Max 2 Accept other valid responses 2(b) Prepare the following accounts for the year ended 30 June 2023. 8 Delivery vehicles at cost Date Details $ Date Details $ 2022 2022 1 Jul Balance b/d 29 000 1 Nov Disposal 29 000 (1) 2023 1 Nov Disposal 16 800 30 Jun Balance c/d 44 000 (1) Bank loan 27 200 (1) 73 000 73 000 2023 1 Jul Balance b/d 44 000 (1) Delivery vehicles provision for depreciation Date Details $ Date Details $ 2022 2022 1 Nov Disposal 8 000 1 Jul Balance b/d 6 000 (1) (1) 2023 2023 30 Jun Balance c/d 4 800 30 Jun Statement of profit or loss 6 800 (1) 12 800 12 800 1 Jul Balance b/d 4 800 (1) 2(c) Calculate the profit or loss on disposal of the delivery vehicle sold on 1 2 November 2022. 29 000 – 8000 – 16 800 = $4200 (1) Loss (1) 2(d) Explain why it may be more appropriate to depreciate motor vehicles using the 3 reducing balance method rather than the straight-line method. The reducing balance method is more appropriate because motor vehicles lose a disproportionate amount of their value in the early years (1) but require less repair and maintenance (1) so complies with the matching concept (1) whereas the straight line method would be unsuitable as it charges the same amount throughout the lifetime of the asset (1) Max 3 Accept other valid responses
This question in 9706/22 Oct/Nov 2023
Q9 · On 1 May 2023 a rights issue of shares was made 9706/23 May/June 2024
8 On 1 May 2023 a rights issue of shares was made. Shareholders were offered three ordinary shares for every five ordinary shares held at 1 January 2023. The shares were issued at a premium of $0.20 per share. The rights issue was fully subscribed.
0 marks
This question in 9706/23 May/June 2024
Q10 · On 1 October 2024, the directors had paid a dividend of $0.03 per share on all shares in… 9706/21 Oct/Nov 2025
2 On 1 October 2024, the directors had paid a dividend of $0.03 per share on all shares in issue at this date.
0 marks
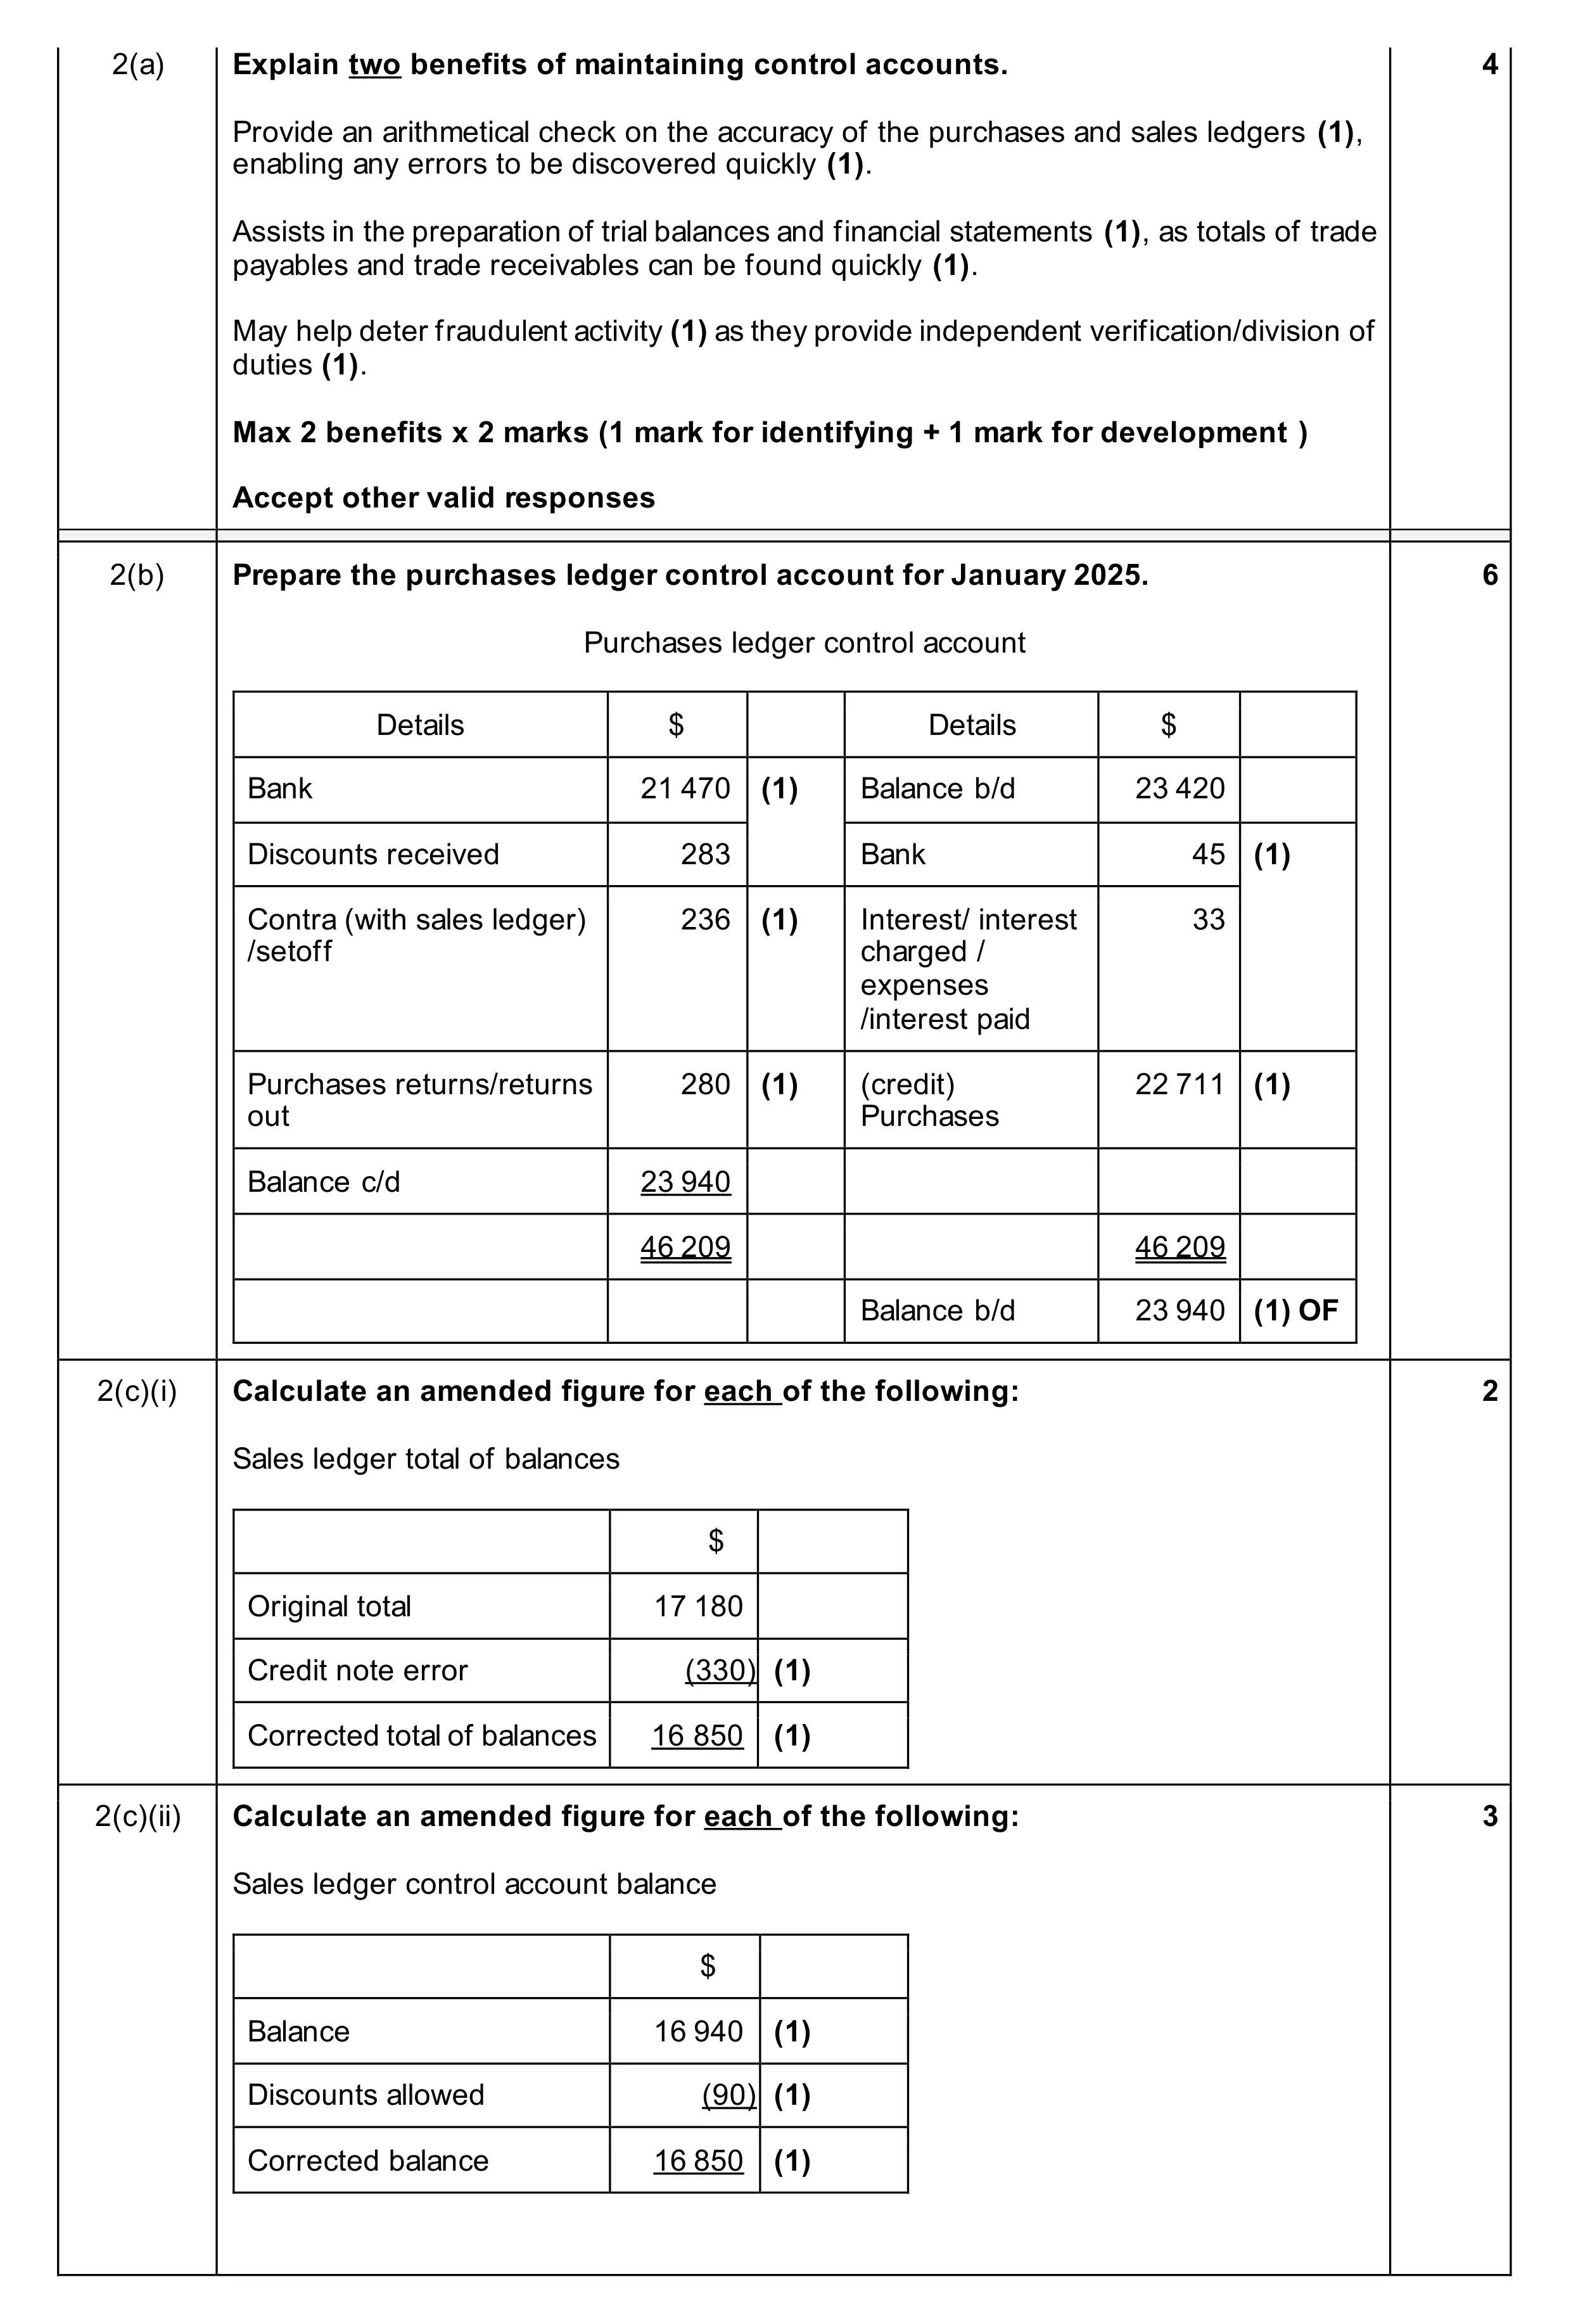
Mark scheme: 2(a) Explain two benefits of maintaining control accounts. 4 Provide an arithmetical check on the accuracy of the purchases and sales ledgers (1), enabling any errors to be discovered quickly (1). Assists in the preparation of trial balances and financial statements (1), as totals of trade payables and trade receivables can be found quickly (1). May help deter fraudulent activity (1) as they provide independent verification/division of duties (1). Max 2 benefits x 2 marks (1 mark for identifying + 1 mark for development ) Accept other valid responses 2(b) Prepare the purchases ledger control account for January 2025. 6 Purchases ledger control account Details $ Details $ Bank 21 470 (1) Balance b/d 23 420 Discounts received 283 Bank 45 (1) Contra (with sales ledger) 236 (1) Interest/ interest 33 /setoff charged / expenses /interest paid Purchases returns/returns 280 (1) (credit) 22 711 (1) out Purchases Balance c/d 23 940 46 209 46 209 Balance b/d 23 940 (1) OF 2(c)(i) Calculate an amended figure for each of the following: 2 Sales ledger total of balances $ Original total 17 180 Credit note error (330) (1) Corrected total of balances 16 850 (1) 2(c)(ii) Calculate an amended figure for each of the following: 3 Sales ledger control account balance $ Balance 16 940 (1) Discounts allowed (90) (1) Corrected balance 16 850 (1)
This question in 9706/21 Oct/Nov 2025
 1 / 26
 8 / 26


 26 / 26
 0
 37
 0
 15
 15
 0
 0