Questions as text
Q1 · The balance sheet of a company includes the following 9706/31 Oct/Nov 2009
3 The balance sheet of a company includes the following. $ 000 ordinary share capital 600 share premium account 200 retained profit 100 900 10 % debenture stock 120 The company has decided to redeem all its debenture stock at a premium of 5 %. Which is true? A The company must create a capital redemption reserve. B The debenture stock must have been issued at a premium. C The premium may be debited to the share premium account. D The premium must be debited in the profit and loss account.
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2009
Q2 · A public company has the following summarised balance sheet 9706/31 Oct/Nov 2009
4 A public company has the following summarised balance sheet. $ ordinary share capital ($5 shares) 750 000 share premium 150 000 profit and loss 100 000 The company decides to purchase 60 000 of its own shares for $400 000. What is the position after this transaction? share capital profit and loss account $ $ A 350 000 100 000 B 450 000 nil C 450 000 50 000 D 450 000 100 000
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2009
Q3 · At the end of a financial year a company redeemed $50 000 of 8 % debentures at a premium… 9706/31 Oct/Nov 2009
5 At the end of a financial year a company redeemed $50 000 of 8 % debentures at a premium of 4 %. What was the total paid to debenture holders during that year? A $52 000 B $54 000 C $56 000 D $56 160
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2009
Q4 · A company shows the following figures in its balance sheet 9706/31 Oct/Nov 2009
9 A company shows the following figures in its balance sheet. $ 000 goodwill 35 equipment, at cost, less depreciation 70 bank overdraft 17 loan repayable over 5 years 100 (current liability portion $20 000) stocks for resale 95 trade creditors 54 6 month deposit account 125 What is the figure for capital and reserves? A $29 000 B $84 000 C $99 000 D $154 000
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2009
Q5 · A company has the following items in its accounts for the year ended 31 August 2009 9706/31 Oct/Nov 2009
11 A company has the following items in its accounts for the year ended 31 August 2009. 1 Research expenditure $30 000. 2 A completed development project, which cost $100 000. Sales commenced on 1 September 2008. The project has a commercial life of 5 years. 3 A development project in progress, eligible for capitalisation $50 000. What is the correct accounting treatment for these items at 31 August 2009? profit and loss expense balance sheet asset $ $ A 0 180 000 B 30 000 150 000 C 50 000 130 000 D 100 000 80 000
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2009
Q6 · The following balances appear in the internal accounts of a company 9706/31 Oct/Nov 2009
13 The following balances appear in the internal accounts of a company. $ trade debtors’ ledger debit balances 261 000 credit balances 3 000 trade creditors’ ledger credit balances 156 000 debit balances 2 000 How will the debtors and creditors be shown in the published accounts? debtors creditors $ $ A 258 000 154 000 B 261 000 156 000 C 263 000 159 000 D 264 000 158 000
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2009
Q7 · The balance sheet of a company includes the following 9706/32 Oct/Nov 2009
2 The balance sheet of a company includes the following. $ 000 ordinary share capital 600 share premium account 200 retained profit 100 900 10 % debenture stock 120 The company has decided to redeem all its debenture stock at a premium of 5 %. Which is true? A The company must create a capital redemption reserve. B The debenture stock must have been issued at a premium. C The premium may be debited to the share premium account. D The premium must be debited in the profit and loss account.
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2009
Q8 · A public company has the following summarised balance sheet 9706/32 Oct/Nov 2009
3 A public company has the following summarised balance sheet. $ ordinary share capital ($5 shares) 750 000 share premium 150 000 profit and loss 100 000 The company decides to purchase 60 000 of its own shares for $400 000. What is the position after this transaction? share capital profit and loss account $ $ A 350 000 100 000 B 450 000 nil C 450 000 50 000 D 450 000 100 000
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2009
Q9 · At the end of a financial year a company redeemed $50 000 of 8 % debentures at a premium… 9706/32 Oct/Nov 2009
4 At the end of a financial year a company redeemed $50 000 of 8 % debentures at a premium of 4 %. What was the total paid to debenture holders during that year? A $52 000 B $54 000 C $56 000 D $56 160
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2009
Q10 · A company shows the following figures in its balance sheet 9706/32 Oct/Nov 2009
8 A company shows the following figures in its balance sheet. $ 000 goodwill 35 equipment, at cost, less depreciation 70 bank overdraft 17 loan repayable over 5 years 100 (current liability portion $20 000) stocks for resale 95 trade creditors 54 6 month deposit account 125 What is the figure for capital and reserves? A $29 000 B $84 000 C $99 000 D $154 000
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2009
Q11 · A company has the following items in its accounts for the year ended 31 August 2009 9706/32 Oct/Nov 2009
10 A company has the following items in its accounts for the year ended 31 August 2009. 1 Research expenditure $30 000. 2 A completed development project, which cost $100 000. Sales commenced on 1 September 2008. The project has a commercial life of 5 years. 3 A development project in progress, eligible for capitalisation $50 000. What is the correct accounting treatment for these items at 31 August 2009? profit and loss expense balance sheet asset $ $ A 0 180 000 B 30 000 150 000 C 50 000 130 000 D 100 000 80 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2009
Q12 · The following balances appear in the internal accounts of a company 9706/32 Oct/Nov 2009
12 The following balances appear in the internal accounts of a company. $ trade debtors’ ledger debit balances 261 000 credit balances 3 000 trade creditors’ ledger credit balances 156 000 debit balances 2 000 How will the debtors and creditors be shown in the published accounts? debtors creditors $ $ A 258 000 154 000 B 261 000 156 000 C 263 000 159 000 D 264 000 158 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2009
Q13 · Which increases the net cash inflow from operating activities? 9706/31 May/June 2010
1 Which increases the net cash inflow from operating activities? A increase in inventory (stock) B increase in trade payables (creditors) C receipt of a bank loan D sale of non-current (fixed) assets
1 marks
Answer: B
This question in 9706/31 May/June 2010
Q14 · The following information has been extracted from the accounts of a company 9706/31 May/June 2010
2 The following information has been extracted from the accounts of a company. at 31 May year 1 year 2 $ $ operating profit 700 000 880 000 depreciation 54 000 62 000 (loss) profit on disposal of non-current (fixed) assets (8 000) 17 000 working capital (excluding cash and bank) 107 000 123 000 What is the cash flow from operating activities in the year ended 31 May, year 2? A $909 000 B $941 000 C $943 000 D $975 000
1 marks
Answer: A
This question in 9706/31 May/June 2010
Q15 · A partnership has been dissolved and $15 000 is left in the bank 9706/31 May/June 2010
3 A partnership has been dissolved and $15 000 is left in the bank. How should this be distributed between the partners? A according to the last agreed balances on their capital accounts B according to the last agreed profit sharing ratio C according to the last agreed total balances on their capital and current accounts D equally
1 marks
Answer: B
This question in 9706/31 May/June 2010
Q16 · X and Y are equal partners 9706/31 May/June 2010
4 X and Y are equal partners. They agree to admit Z as an equal partner. Z agrees to pay $33 000 for his share of the goodwill. Goodwill is not to appear in the accounts. The partnership offices are to be revalued at $60 000 more than their present book value. What changes are needed in the partners’ capital accounts to record these events? X Y Z $ $ $ A + 16 500 + 16 500 − 33 000 B + 30 000 + 30 000 + 33 000 C + 33 000 + 33 000 + 33 000 D + 46 500 + 46 500 nil
1 marks
Answer: D
This question in 9706/31 May/June 2010
Q17 · When is a capital redemption reserve created? 9706/31 May/June 2010
5 When is a capital redemption reserve created? A when a non-current asset is revalued B when a redemption of shares is not covered by a new issue of shares C when debentures are redeemed without a new issue of shares D when the authorised share capital is increased
1 marks
Answer: B
This question in 9706/31 May/June 2010
Q18 · A company makes a 1-for-3 bonus issue of shares 9706/31 May/June 2010
6 A company makes a 1-for-3 bonus issue of shares. The book value of its shareholders’ funds immediately before the issue are as follows. $ ordinary share capital 300 000 share premium account 120 000 profit and loss account 100 000 The costs of the bonus issue are $10 000. What will be the book value of shareholders funds after the bonus issue? A $510 000 B $520 000 C $610 000 D $620 000
1 marks
Answer: A
This question in 9706/31 May/June 2010
Q19 · A business makes a profit for the financial year to 31 March 2010 of $100 000 9706/31 May/June 2010
9 A business makes a profit for the financial year to 31 March 2010 of $100 000. After the balance sheet date the following three events occurred: an adjusting event of $40 000 profit a non-adjusting event of $30 000 profit a dividend declared of $20 000. What is the adjusted profit? A $140 000 B $160 000 C $170 000 D $190 000
1 marks
Answer: A
This question in 9706/31 May/June 2010
Q20 · A company is preparing its statement of changes in equity for the year ended 31 August 9706/31 May/June 2010
10 A company is preparing its statement of changes in equity for the year ended 31 August. The following information is available. $000 balance of retained earnings (profits) at start of year 350 net profit for the year 140 final dividend paid in respect of previous year 60 interim dividend paid 30 proposed final dividend for the current year 70 transfer to capital redemption reserve 100 What is the balance of retained earnings (profits) to transfer to the balance sheet at 31 August? A $230 000 B $290 000 C $300 000 D $390 000
1 marks
Answer: C
This question in 9706/31 May/June 2010
Q21 · Which statement about the issue by a company of bonus shares is correct? 9706/31 May/June 2010
15 Which statement about the issue by a company of bonus shares is correct? A They can be issued at a premium. B They can be issued by using both capital and revenue reserves. C They can only be issued from capital reserves. D They can only be issued from revenue reserves.
1 marks
Answer: B
This question in 9706/31 May/June 2010
Q22 · When is a capital redemption reserve created? 9706/32 May/June 2010
5 When is a capital redemption reserve created? A when a non-current asset is revalued B when a redemption of shares is not covered by a new issue of shares C when debentures are redeemed without a new issue of shares D when the authorised share capital is increased
1 marks
Answer: B
This question in 9706/32 May/June 2010
Q23 · A company makes a 1-for-3 bonus issue of shares 9706/32 May/June 2010
6 A company makes a 1-for-3 bonus issue of shares. The book value of its shareholders’ funds immediately before the issue are as follows. $ ordinary share capital 300 000 share premium account 120 000 profit and loss account 100 000 The costs of the bonus issue are $10 000. What will be the book value of shareholders funds after the bonus issue? A $510 000 B $520 000 C $610 000 D $620 000
1 marks
Answer: A
This question in 9706/32 May/June 2010
Q24 · A company is preparing its statement of changes in equity for the year ended 31 August 9706/32 May/June 2010
10 A company is preparing its statement of changes in equity for the year ended 31 August. The following information is available. $000 balance of retained earnings (profits) at start of year 350 net profit for the year 140 final dividend paid in respect of previous year 60 interim dividend paid 30 proposed final dividend for the current year 70 transfer to capital redemption reserve 100 What is the balance of retained earnings (profits) to transfer to the balance sheet at 31 August? A $230 000 B $290 000 C $300 000 D $390 000
1 marks
Answer: C
This question in 9706/32 May/June 2010
Q25 · Which statement about the issue by a company of bonus shares is correct? 9706/32 May/June 2010
15 Which statement about the issue by a company of bonus shares is correct? A They can be issued at a premium. B They can be issued by using both capital and revenue reserves. C They can only be issued from capital reserves. D They can only be issued from revenue reserves.
1 marks
Answer: B
This question in 9706/32 May/June 2010
Q26 · The following information has been extracted from the accounts of a company 9706/33 May/June 2010
1 The following information has been extracted from the accounts of a company. at 31 May year 1 year 2 $ $ operating profit 700 000 880 000 depreciation 54 000 62 000 (loss) profit on disposal of non-current (fixed) assets (8 000) 17 000 working capital (excluding cash and bank) 107 000 123 000 What is the cash flow from operating activities in the year ended 31 May, year 2? A $909 000 B $941 000 C $943 000 D $975 000
1 marks
Answer: A
This question in 9706/33 May/June 2010
Q27 · When is a capital redemption reserve created? 9706/33 May/June 2010
4 When is a capital redemption reserve created? A when a non-current asset is revalued B when a redemption of shares is not covered by a new issue of shares C when debentures are redeemed without a new issue of shares D when the authorised share capital is increased
1 marks
Answer: B
This question in 9706/33 May/June 2010
Q28 · A company makes a 1-for-3 bonus issue of shares 9706/33 May/June 2010
5 A company makes a 1-for-3 bonus issue of shares. The book value of its shareholders’ funds immediately before the issue are as follows. $ ordinary share capital 300 000 share premium account 120 000 profit and loss account 100 000 The costs of the bonus issue are $10 000. What will be the book value of shareholders funds after the bonus issue? A $510 000 B $520 000 C $610 000 D $620 000
1 marks
Answer: A
This question in 9706/33 May/June 2010
Q29 · A company had the following capital and reserves 9706/33 May/June 2010
7 A company had the following capital and reserves. $ ordinary shares of $1 each 100 000 share premium 20 000 income statement (profit and loss account) 10 000 It purchased a business for $125 000 by means of a cash payment of $50 000 a debenture loan of $15 000 an issue of 30 000 $1 ordinary shares at a premium of 100 % What will be the shareholders’ funds following the acquisition? A $130 000 B $160 000 C $180 000 D $190 000
1 marks
Answer: D
This question in 9706/33 May/June 2010
Q30 · A business makes a profit for the financial year to 31 March 2010 of $100 000 9706/33 May/June 2010
8 A business makes a profit for the financial year to 31 March 2010 of $100 000. After the balance sheet date the following three events occurred: an adjusting event of $40 000 profit a non-adjusting event of $30 000 profit a dividend declared of $20 000. What is the adjusted profit? A $140 000 B $160 000 C $170 000 D $190 000
1 marks
Answer: A
This question in 9706/33 May/June 2010
Q31 · A company is preparing its statement of changes in equity for the year ended 31 August 9706/33 May/June 2010
9 A company is preparing its statement of changes in equity for the year ended 31 August. The following information is available. $000 balance of retained earnings (profits) at start of year 350 net profit for the year 140 final dividend paid in respect of previous year 60 interim dividend paid 30 proposed final dividend for the current year 70 transfer to capital redemption reserve 100 What is the balance of retained earnings (profits) to transfer to the balance sheet at 31 August? A $230 000 B $290 000 C $300 000 D $390 000
1 marks
Answer: C
This question in 9706/33 May/June 2010
Q32 · The financial statements of a company for the year to 30 June includes the following 9706/33 May/June 2010
10 The financial statements of a company for the year to 30 June includes the following. Income (profit and loss) account $m operating profits 109 interest payable 14 profit before tax 95 taxation 25 profit after tax 70 dividends paid 38 retained profit for year 32 Balance sheet $m ordinary shares ($0.50 each) in issue 150 income statement (profit and loss account) 160 shareholders funds 310 What are the earnings per share for the year? A 22.6 cents B 23.3 cents C 31.7 cents D 46.7 cents
1 marks
Answer: B
This question in 9706/33 May/June 2010
Q33 · Which statement about the issue by a company of bonus shares is correct? 9706/33 May/June 2010
14 Which statement about the issue by a company of bonus shares is correct? A They can be issued at a premium. B They can be issued by using both capital and revenue reserves. C They can only be issued from capital reserves. D They can only be issued from revenue reserves.
1 marks
Answer: B
This question in 9706/33 May/June 2010
Q34 · Which increases the net cash inflow from operating activities? 9706/33 May/June 2010
30 Which increases the net cash inflow from operating activities? A increase in inventory (stock) B increase in trade payables (creditors) C receipt of a bank loan D sale of non-current (fixed) assets
1 marks
Answer: B
This question in 9706/33 May/June 2010
Q35 · A plc company redeemed 50 000 ordinary shares of $5 each at par 9706/31 Oct/Nov 2010
6 A plc company redeemed 50 000 ordinary shares of $5 each at par. The redemption was in part financed by a new issue of 80 000 preference shares of $1 each, issued at a premium of $1 per share. By what amount will distributable reserves be reduced? A $90 000 B $160 000 C $170 000 D $250 000
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2010
Q36 · The equity section of a company’s balance sheet is as follows 9706/31 Oct/Nov 2010
18 The equity section of a company’s balance sheet is as follows. $ ordinary shares of $0.50 each 200 000 preference shares of $1 each 100 000 share premium 50 000 retained earnings 120 000 The following items have not yet been adjusted. 1 purchase returns of $10 000 have been credited to the sales returns account 2 a long term loan of $40 000 has not been recorded 3 a rights issue during the year of 200 000 ordinary shares at a premium of $0.10 each What will the total of equity be after the above adjustments have been made? A $590 000 B $600 000 C $630 000 D $640 000
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2010
Q37 · A plc company redeemed 50 000 ordinary shares of $5 each at par 9706/32 Oct/Nov 2010
6 A plc company redeemed 50 000 ordinary shares of $5 each at par. The redemption was in part financed by a new issue of 80 000 preference shares of $1 each, issued at a premium of $1 per share. By what amount will distributable reserves be reduced? A $90 000 B $160 000 C $170 000 D $250 000
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2010
Q38 · The equity section of a company’s balance sheet is as follows 9706/32 Oct/Nov 2010
18 The equity section of a company’s balance sheet is as follows. $ ordinary shares of $0.50 each 200 000 preference shares of $1 each 100 000 share premium 50 000 retained earnings 120 000 The following items have not yet been adjusted. 1 purchase returns of $10 000 have been credited to the sales returns account 2 a long term loan of $40 000 has not been recorded 3 a rights issue during the year of 200 000 ordinary shares at a premium of $0.10 each What will the total of equity be after the above adjustments have been made? A $590 000 B $600 000 C $630 000 D $640 000
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2010
Q39 · A plc company redeemed 50 000 ordinary shares of $5 each at par 9706/33 Oct/Nov 2010
5 A plc company redeemed 50 000 ordinary shares of $5 each at par. The redemption was in part financed by a new issue of 80 000 preference shares of $1 each, issued at a premium of $1 per share. By what amount will distributable reserves be reduced? A $90 000 B $160 000 C $170 000 D $250 000
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2010
Q40 · The equity section of a company’s balance sheet is as follows 9706/33 Oct/Nov 2010
17 The equity section of a company’s balance sheet is as follows. $ ordinary shares of $0.50 each 200 000 preference shares of $1 each 100 000 share premium 50 000 retained earnings 120 000 The following items have not yet been adjusted. 1 purchase returns of $10 000 have been credited to the sales returns account 2 a long term loan of $40 000 has not been recorded 3 a rights issue during the year of 200 000 ordinary shares at a premium of $0.10 each What will the total of equity be after the above adjustments have been made? A $590 000 B $600 000 C $630 000 D $640 000
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2010
Q41 · Which is not included in a statement of cash flows? 9706/31 May/June 2011
1 Which is not included in a statement of cash flows? A dividends received B investments sold C provision for depreciation D purchase of non-current assets
1 marks
Answer: C
This question in 9706/31 May/June 2011
Q42 · Why might a company repay part of its share capital? 9706/31 May/June 2011
2 Why might a company repay part of its share capital? A Its cash reserves exceed its requirements for the foreseeable future. B Its shareholders need the cash. C Its shares are valued below their nominal value on the open market. D It wishes to decrease its gearing.
1 marks
Answer: A
This question in 9706/31 May/June 2011
Q43 · A company redeems 1000 ordinary shares of $1.00 each at a premium of 10 % 9706/31 May/June 2011
3 A company redeems 1000 ordinary shares of $1.00 each at a premium of 10 %. The shares were originally issued at par and there is no share premium account. How much will be charged to retained earnings? A $100 B $900 C $1000 D $1100
1 marks
Answer: D
This question in 9706/31 May/June 2011
Q44 · A company has redeemed ordinary shares without issuing any new shares 9706/31 May/June 2011
6 A company has redeemed ordinary shares without issuing any new shares. What is the effect on the balance sheet? ordinary share capital redemption retained earnings capital reserve A decrease decrease no change B decrease increase decrease C no change increase decrease D no change no change increase
1 marks
Answer: B
This question in 9706/31 May/June 2011
Q45 · A company is preparing its statement of changes in equity 9706/31 May/June 2011
10 A company is preparing its statement of changes in equity. It produces the following information. $000 retained earnings at start of year 40 profit for the year attributable to equity holders 30 transfer to reserves 15 dividends paid during the year 10 proposed dividends 5 What is the retained earnings figure at the end of the year? A $40 000 B $45 000 C $55 000 D $60 000
1 marks
Answer: B
This question in 9706/31 May/June 2011
Q46 · The reserves of a company are as follows: $ share premium 60 000 property revaluation… 9706/31 May/June 2011
11 The reserves of a company are as follows: $ share premium 60 000 property revaluation reserve 120 000 general reserve 80 000 retained earnings 160 000 420 000 The company has in issue 15 000 shares which have a book value of $50 each in the financial statements. What is the nominal (or par) value of one ordinary share? A $22 B $24 C $28 D $50
1 marks
Answer: A
This question in 9706/31 May/June 2011
Q47 · A company’s year end is 31 May 9706/31 May/June 2011
12 A company’s year end is 31 May. The following table shows dividends paid and proposed by it. $ proposed final dividend for year ended 31 May 2009, 100 000 payable September 2009 interim dividend for year ended 31 May 2010, 50 000 payable March 2010 proposed final dividend for year ended 31 May 2010, 120 000 payable September 2010 Which figure will be shown as dividends in the note to the accounts for the year ended 31 May 2010? A $120 000 B $150 000 C $170 000 D $270 000
1 marks
Answer: B
This question in 9706/31 May/June 2011
Q48 · Zachary plc has the following summary balance sheet at 31 Dec 2009 9706/31 May/June 2011
17 Zachary plc has the following summary balance sheet at 31 Dec 2009. $ million ordinary shares of $1 each 50 retained earnings 70 net assets 120 Zachary plc made a bonus issue (1 for 2) of ordinary shares on 1 January 2010 and a rights issue (1 for 5) of ordinary shares on 31 December 2010 at $2 per share. The share issue was fully subscribed. Retained earnings were $12 million for 2010. What were the net assets at 31 December 2010? A $112 million B $150 million C $162 million D $187 million
1 marks
Answer: C
This question in 9706/31 May/June 2011
Q49 · Why might a company repay part of its share capital? 9706/32 May/June 2011
1 Why might a company repay part of its share capital? A Its cash reserves exceed its requirements for the foreseeable future. B Its shareholders need the cash. C Its shares are valued below their nominal value on the open market. D It wishes to decrease its gearing.
1 marks
Answer: A
This question in 9706/32 May/June 2011
Q50 · Why would convertible loan stock be issued by a company? 9706/32 May/June 2011
3 Why would convertible loan stock be issued by a company? A to increase the equity of the company at the issue date B to increase gearing on conversion C to increase the market value of the company’s equity at the issue date D to obtain low-cost finance when equity market conditions are unfavourable
1 marks
Answer: D
This question in 9706/32 May/June 2011
Q51 · A company redeems 1000 ordinary shares of $1.00 each at a premium of 10 % 9706/32 May/June 2011
4 A company redeems 1000 ordinary shares of $1.00 each at a premium of 10 %. The shares were originally issued at par and there is no share premium account. How much will be charged to retained earnings? A $100 B $900 C $1000 D $1100
1 marks
Answer: D
This question in 9706/32 May/June 2011
Q52 · A company has redeemed ordinary shares without issuing any new shares 9706/32 May/June 2011
8 A company has redeemed ordinary shares without issuing any new shares. What is the effect on the balance sheet? ordinary share capital redemption retained earnings capital reserve A decrease decrease no change B decrease increase decrease C no change increase decrease D no change no change increase
1 marks
Answer: B
This question in 9706/32 May/June 2011
Q53 · The reserves of a company are as follows: $ share premium 60 000 property revaluation… 9706/32 May/June 2011
10 The reserves of a company are as follows: $ share premium 60 000 property revaluation reserve 120 000 general reserve 80 000 retained earnings 160 000 420 000 The company has in issue 15 000 shares which have a book value of $50 each in the financial statements. What is the nominal (or par) value of one ordinary share? A $22 B $24 C $28 D $50
1 marks
Answer: A
This question in 9706/32 May/June 2011
Q54 · A company is preparing its statement of changes in equity 9706/32 May/June 2011
11 A company is preparing its statement of changes in equity. It produces the following information. $000 retained earnings at start of year 40 profit for the year attributable to equity holders 30 transfer to reserves 15 dividends paid during the year 10 proposed dividends 5 What is the retained earnings figure at the end of the year? A $40 000 B $45 000 C $55 000 D $60 000
1 marks
Answer: B
This question in 9706/32 May/June 2011
Q55 · A company’s year end is 31 May 9706/32 May/June 2011
12 A company’s year end is 31 May. The following table shows dividends paid and proposed by it. $ proposed final dividend for year ended 31 May 2009, 100 000 payable September 2009 interim dividend for year ended 31 May 2010, 50 000 payable March 2010 proposed final dividend for year ended 31 May 2010, 120 000 payable September 2010 Which figure will be shown as dividends in the note to the accounts for the year ended 31 May 2010? A $120 000 B $150 000 C $170 000 D $270 000
1 marks
Answer: B
This question in 9706/32 May/June 2011
Q56 · Zachary plc has the following summary balance sheet at 31 Dec 2009 9706/32 May/June 2011
18 Zachary plc has the following summary balance sheet at 31 Dec 2009. $ million ordinary shares of $1 each 50 retained earnings 70 net assets 120 Zachary plc made a bonus issue (1 for 2) of ordinary shares on 1 January 2010 and a rights issue (1 for 5) of ordinary shares on 31 December 2010 at $2 per share. The share issue was fully subscribed. Retained earnings were $12 million for 2010. What were the net assets at 31 December 2010? A $112 million B $150 million C $162 million D $187 million
1 marks
Answer: C
This question in 9706/32 May/June 2011
Q57 · Why might a company repay part of its share capital? 9706/33 May/June 2011
1 Why might a company repay part of its share capital? A Its cash reserves exceed its requirements for the foreseeable future. B Its shareholders need the cash. C Its shares are valued below their nominal value on the open market. D It wishes to decrease its gearing.
1 marks
Answer: A
This question in 9706/33 May/June 2011
Q58 · A company redeems 1000 ordinary shares of $1.00 each at a premium of 10 % 9706/33 May/June 2011
2 A company redeems 1000 ordinary shares of $1.00 each at a premium of 10 %. The shares were originally issued at par and there is no share premium account. How much will be charged to retained earnings? A $100 B $900 C $1000 D $1100
1 marks
Answer: D
This question in 9706/33 May/June 2011
Q59 · Why would convertible loan stock be issued by a company? 9706/33 May/June 2011
4 Why would convertible loan stock be issued by a company? A to increase the equity of the company at the issue date B to increase gearing on conversion C to increase the market value of the company’s equity at the issue date D to obtain low-cost finance when equity market conditions are unfavourable
1 marks
Answer: D
This question in 9706/33 May/June 2011
Q60 · A company has redeemed ordinary shares without issuing any new shares 9706/33 May/June 2011
5 A company has redeemed ordinary shares without issuing any new shares. What is the effect on the balance sheet? ordinary share capital redemption retained earnings capital reserve A decrease decrease no change B decrease increase decrease C no change increase decrease D no change no change increase
1 marks
Answer: B
This question in 9706/33 May/June 2011
Q61 · A company is preparing its statement of changes in equity 9706/33 May/June 2011
9 A company is preparing its statement of changes in equity. It produces the following information. $000 retained earnings at start of year 40 profit for the year attributable to equity holders 30 transfer to reserves 15 dividends paid during the year 10 proposed dividends 5 What is the retained earnings figure at the end of the year? A $40 000 B $45 000 C $55 000 D $60 000
1 marks
Answer: B
This question in 9706/33 May/June 2011
Q62 · The reserves of a company are as follows: $ share premium 60 000 property revaluation… 9706/33 May/June 2011
10 The reserves of a company are as follows: $ share premium 60 000 property revaluation reserve 120 000 general reserve 80 000 retained earnings 160 000 420 000 The company has in issue 15 000 shares which have a book value of $50 each in the financial statements. What is the nominal (or par) value of one ordinary share? A $22 B $24 C $28 D $50
1 marks
Answer: A
This question in 9706/33 May/June 2011
Q63 · A company’s year end is 31 May 9706/33 May/June 2011
11 A company’s year end is 31 May. The following table shows dividends paid and proposed by it. $ proposed final dividend for year ended 31 May 2009, 100 000 payable September 2009 interim dividend for year ended 31 May 2010, 50 000 payable March 2010 proposed final dividend for year ended 31 May 2010, 120 000 payable September 2010 Which figure will be shown as dividends in the note to the accounts for the year ended 31 May 2010? A $120 000 B $150 000 C $170 000 D $270 000
1 marks
Answer: B
This question in 9706/33 May/June 2011
Q64 · Zachary plc has the following summary balance sheet at 31 Dec 2009 9706/33 May/June 2011
16 Zachary plc has the following summary balance sheet at 31 Dec 2009. $ million ordinary shares of $1 each 50 retained earnings 70 net assets 120 Zachary plc made a bonus issue (1 for 2) of ordinary shares on 1 January 2010 and a rights issue (1 for 5) of ordinary shares on 31 December 2010 at $2 per share. The share issue was fully subscribed. Retained earnings were $12 million for 2010. What were the net assets at 31 December 2010? A $112 million B $150 million C $162 million D $187 million
1 marks
Answer: C
This question in 9706/33 May/June 2011
Q65 · Which is not included in a statement of cash flows? 9706/33 May/June 2011
30 Which is not included in a statement of cash flows? A dividends received B investments sold C provision for depreciation D purchase of non-current assets
1 marks
Answer: C
This question in 9706/33 May/June 2011
Q66 · The following are extracts from the financial statements of a company for the two years… 9706/31 Oct/Nov 2011
1 The following are extracts from the financial statements of a company for the two years ended 30 September. Year 2 Year 1 $000 $000 profit from operations 61 040 57 200 depreciation 12 200 10 400 inventory 29 200 26 400 trade receivables 17 430 15 230 cash and cash equivalents 1 020 840 trade payables 11 100 9 750 What is the net cash from operating activities for the year to 30 September Year 2? A $59 190 B $66 890 C $69 590 D $76 890
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2011
Q67 · 600 000 shares are issued at $5.00 per share 9706/31 Oct/Nov 2011
2 600 000 shares are issued at $5.00 per share. A bank loan of $1 500 000 is repaid and non-current assets which cost $900 000 are sold for $250 000. How will these transactions affect the following headings in the company’s statement of cash flows? financing activities investing activities net change in cash $000 $000 $000 A –1500 –250 –1750 B +1500 +250 +1750 C +1500 +650 +2150 D +3000 –1250 +1750
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2011
Q68 · A limited company with an issued share capital of $300 000 in $1 ordinary shares makes a… 9706/31 Oct/Nov 2011
3 A limited company with an issued share capital of $300 000 in $1 ordinary shares makes a 1 for 4 bonus issue followed by a 1 for 5 rights issue. What will be the balance on the share capital account following these transactions? A $75 000 B $150 000 C $375 000 D $450 000
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2011
Q69 · A balance sheet extract shows the following 9706/31 Oct/Nov 2011
4 A balance sheet extract shows the following. $ ordinary shares of $1 each 1000 10 % convertible loan stock 400 retained earnings 140 (dr) net assets 1800 net liabilities 540 All the loan stock is to be converted to ordinary shares in the proportion of $1 loan stock to one new ordinary share. After the conversion, what will be the net asset value per share? A $0.80 B $0.90 C $1.00 D $1.29
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2011
Q70 · The following data relates to a company at 31 December 9706/31 Oct/Nov 2011
15 The following data relates to a company at 31 December. details of a non-current asset $ million historic cost 15 accumulated depreciation 10 value in use 4 fair value less costs to sell 3 What would be the impairment loss for the non-current asset to be recognised at 31 December? A $1 million B $3 million C $4 million D $5 million
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2011
Q71 · A company has 500 000 ordinary shares in issue and the following reserves 9706/31 Oct/Nov 2011
17 A company has 500 000 ordinary shares in issue and the following reserves. $ share premium 20 000 revaluation reserve 50 000 general reserve 80 000 retained earnings 40 000 What is the maximum dividend per share? A $0.08 B $0.24 C $0.34 D $0.38
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2011
Q72 · A company has the following items in its statement of financial position 9706/32 Oct/Nov 2011
3 A company has the following items in its statement of financial position. $ ordinary share capital, shares of $0.50 each 900 000 retained earnings 450 000 long-term bank loan 30 000 The company issues 100 000 bonus shares of $0.50 each to its shareholders. What is the total amount of shareholders’ funds after the issue of the bonus shares? A $1 300 000 B $1 350 000 C $1 380 000 D $1 400 000
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2011
Q73 · The capital structure of a company is: $ $1 ordinary shares 40 000 convertible loan stock… 9706/32 Oct/Nov 2011
4 The capital structure of a company is: $ $1 ordinary shares 40 000 convertible loan stock 20 000 share premium 10 000 The loan stock conversion is made on the basis of 1 new ordinary share for every $4 of convertible stock held. What is the capital structure after the conversion? ordinary shares share premium $ $ A 40 000 30 000 B 45 000 25 000 C 50 000 20 000 D 60 000 10 000
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2011
Q74 · A company has the following summarised statement of financial position at 31 December 9706/32 Oct/Nov 2011
5 A company has the following summarised statement of financial position at 31 December. $ ordinary share capital ($1 shares) 500 000 share premium 100 000 retained earnings 150 000 750 000 The company decides to purchase 50 000 of its own shares for $80 000. What reflects the correct position after the purchase? share capital retained earnings $ $ A 420 000 70 000 B 420 000 100 000 C 450 000 70 000 D 450 000 100 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2011
Q75 · What would not appear in the income statement of a limited company? 9706/32 Oct/Nov 2011
10 What would not appear in the income statement of a limited company? 1 finance costs 2 revenue 3 ordinary dividends paid 4 ordinary dividends payable A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2011
Q76 · At the start of the year a company has plant and machinery valued at $20 000 9706/32 Oct/Nov 2011
11 At the start of the year a company has plant and machinery valued at $20 000. Depreciation policy is to depreciate plant and machinery at 25 % using the reducing balance method. Following an impairment review the fair value of plant and machinery is $16 000 and its value in use is $25 000. At which value should plant and machinery be shown in the year end statement of financial position? A $15 000 B $16 000 C $20 000 D $25 000
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2011
Q77 · A company’s statement of financial position shows the following information 9706/32 Oct/Nov 2011
12 A company’s statement of financial position shows the following information. $000 ordinary shares of $10 each 120 7 % non-redeemable preference shares of $1 each 80 share premium account 50 general reserve 70 retained earnings 210 530 What is the book value of one ordinary share? A $27.50 B $37.50 C $44.20 D $53.00
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2011
Q78 · Which effect will a bonus issue of shares have on a company’s gearing ratio and earnings… 9706/32 Oct/Nov 2011
18 Which effect will a bonus issue of shares have on a company’s gearing ratio and earnings per share? gearing earnings per share A no effect increase B increase decrease C decrease increase D no effect decrease
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2011
Q79 · 600 000 shares are issued at $5.00 per share 9706/33 Oct/Nov 2011
1 600 000 shares are issued at $5.00 per share. A bank loan of $1 500 000 is repaid and non-current assets which cost $900 000 are sold for $250 000. How will these transactions affect the following headings in the company’s statement of cash flows? financing activities investing activities net change in cash $000 $000 $000 A –1500 –250 –1750 B +1500 +250 +1750 C +1500 +650 +2150 D +3000 –1250 +1750
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2011
Q80 · A limited company with an issued share capital of $300 000 in $1 ordinary shares makes a… 9706/33 Oct/Nov 2011
2 A limited company with an issued share capital of $300 000 in $1 ordinary shares makes a 1 for 4 bonus issue followed by a 1 for 5 rights issue. What will be the balance on the share capital account following these transactions? A $75 000 B $150 000 C $375 000 D $450 000
1 marks
Answer: D
This question in 9706/33 Oct/Nov 2011
Q81 · A balance sheet extract shows the following 9706/33 Oct/Nov 2011
3 A balance sheet extract shows the following. $ ordinary shares of $1 each 1000 10 % convertible loan stock 400 retained earnings 140 (dr) net assets 1800 net liabilities 540 All the loan stock is to be converted to ordinary shares in the proportion of $1 loan stock to one new ordinary share. After the conversion, what will be the net asset value per share? A $0.80 B $0.90 C $1.00 D $1.29
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2011
Q82 · A company’s year end is 31 December 9706/33 Oct/Nov 2011
9 A company’s year end is 31 December. During the year ended 31 December 2010 it pays the following dividends. Final dividend for the year ended 31 December 2009 $15 000 Interim dividend for the year ended 31 December 2010 $8 000 On 1 February 2011 it declares a final dividend of $10 000 for the year ended 31 December 2010. How much should be recorded in the accounts as dividends for the year ended 31 December 2010? A $8000 B $18 000 C $23 000 D $33 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2011
Q83 · The following data relates to a company at 31 December 9706/33 Oct/Nov 2011
14 The following data relates to a company at 31 December. details of a non-current asset $ million historic cost 15 accumulated depreciation 10 value in use 4 fair value less costs to sell 3 What would be the impairment loss for the non-current asset to be recognised at 31 December? A $1 million B $3 million C $4 million D $5 million
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2011
Q84 · A company has 500 000 ordinary shares in issue and the following reserves 9706/33 Oct/Nov 2011
16 A company has 500 000 ordinary shares in issue and the following reserves. $ share premium 20 000 revaluation reserve 50 000 general reserve 80 000 retained earnings 40 000 What is the maximum dividend per share? A $0.08 B $0.24 C $0.34 D $0.38
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2011
Q85 · The following are extracts from the financial statements of a company for the two years… 9706/33 Oct/Nov 2011
30 The following are extracts from the financial statements of a company for the two years ended 30 September. Year 2 Year 1 $000 $000 profit from operations 61 040 57 200 depreciation 12 200 10 400 inventory 29 200 26 400 trade receivables 17 430 15 230 cash and cash equivalents 1 020 840 trade payables 11 100 9 750 What is the net cash from operating activities for the year to 30 September Year 2? A $59 190 B $66 890 C $69 590 D $76 890
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2011
Q86 · A company redeems 10 000 preference shares of $5 each at a premium of 5 % 9706/31 May/June 2012
4 A company redeems 10 000 preference shares of $5 each at a premium of 5 %. The shares were originally issued at a premium of 10 % but the share premium account has been fully utilised. How much will be debited to the income statement? A $2500 B $50 000 C $52 500 D $55 000
1 marks
Answer: C
This question in 9706/31 May/June 2012
Q87 · A company provides the following financial information at the end of the financial year 9706/31 May/June 2012
5 A company provides the following financial information at the end of the financial year. $ 000 Retained earnings at the start of the year 50 Profit for the year attributable to equity holders 120 Ordinary dividends paid during the year 70 Ordinary dividends proposed payable in the next financial year 30 Transfer to general reserve 20 What is the amount of retained earnings at the end of the financial year? A $50 000 B $70 000 C $80 000 D $100 000
1 marks
Answer: C
This question in 9706/31 May/June 2012
Q88 · Which pair of statements about the reserves of a limited company is correct? 9706/31 May/June 2012
6 Which pair of statements about the reserves of a limited company is correct? revenue reserves capital reserves A can be credited back to retained created from retained earnings earnings if no longer needed B can be used to issue bonus shares can be credited back to retained earnings if no longer needed C can be used to pay cash dividends can be used to issue bonus shares D reduces the amount available can be used to pay cash dividends to pay dividends when created
1 marks
Answer: C
This question in 9706/31 May/June 2012
Q89 · A company makes a 1 for 2 bonus issue 9706/31 May/June 2012
7 A company makes a 1 for 2 bonus issue. What effect will this have? A improve cash flow B increase shareholders’ funds C reduce an ordinary shareholder’s percentage holding D reduce the value of an ordinary share
1 marks
Answer: D
This question in 9706/31 May/June 2012
Q90 · The table shows the capital structure of a company 9706/31 May/June 2012
10 The table shows the capital structure of a company. $ 100 000 ordinary shares of $1 each 100 000 10 % debentures 50 000 reserves 100 000 It increases the debentures by $50 000 and makes a bonus issue of one share for every two held. It then makes a rights issue of a further 100 000 shares at $1 each. How will these transactions affect the statement of financial position? gearing reserves bank A decrease decrease decrease B increase decrease decrease C increase decrease increase D decrease increase increase
1 marks
Answer: C
This question in 9706/31 May/June 2012
Q91 · At the end of the year, the following information has been extracted from a company’s… 9706/31 May/June 2012
13 At the end of the year, the following information has been extracted from a company’s statement of cash flows. $ total cash from operating activities 200 net cash used by investing activities (300) net cash used by financing activities (150) closing cash and cash equivalents (50) What was the opening figure for cash and cash equivalents? A $(200) B $(300) C $200 D $300
1 marks
Answer: C
This question in 9706/31 May/June 2012
Q92 · Which items are part of the published accounts of a limited company? 9706/31 May/June 2012
14 Which items are part of the published accounts of a limited company? 1 chairman’s statement 2 income statement 3 report of the directors 4 statement of cash flows A 1 only B 1 and 2 only C 1, 2 and 3 D 2, 3 and 4
1 marks
Answer: D
This question in 9706/31 May/June 2012
Q93 · The following information is taken from the financial statements of a limited company 9706/31 May/June 2012
16 The following information is taken from the financial statements of a limited company. $000 retained earnings at the start of the year 50 profit attributable to equity holders 30 dividends paid during the year 15 dividends proposed payable in the next financial year 10 surplus on revaluation of land during the year 20 What are the retained earnings at the end of the year? A $55 000 B $65 000 C $80 000 D $100 000
1 marks
Answer: B
This question in 9706/31 May/June 2012
Q94 · Which ratio can be calculated from the statement of financial position of a limited… 9706/31 May/June 2012
20 Which ratio can be calculated from the statement of financial position of a limited company? A the dividend yield per ordinary share B the earnings per ordinary share C the market value of an ordinary share D the net asset value per ordinary share
1 marks
Answer: D
This question in 9706/31 May/June 2012
Q95 · The table shows an extract from the financial statements of a limited company 9706/32 May/June 2012
4 The table shows an extract from the financial statements of a limited company. $ ordinary share capital 500 000 (500 000 × $1 shares) share premium account 150 000 revaluation reserve 200 000 retained earnings 250 000 What is the maximum dividend per share that can be paid? A $0.50 B $0.80 C $0.90 D $1.20
1 marks
Answer: A
This question in 9706/32 May/June 2012
Q96 · An extract from a company’s statement of financial position is shown below 9706/32 May/June 2012
5 An extract from a company’s statement of financial position is shown below. $ ordinary shares at $0.50 500 000 share premium account 100 000 retained earnings 300 000 900 000 The day after this statement was prepared the company made a 1 for 4 rights issue at a price that was at 20 % below the current market price of $1 per share. What was the balance on the share premium account after the rights issue? A $100 000 B $137 500 C $175 000 D $200 000
1 marks
Answer: C
This question in 9706/32 May/June 2012
Q97 · A company makes a 1 for 2 bonus issue 9706/32 May/June 2012
6 A company makes a 1 for 2 bonus issue. What effect will this have? A improve cash flow B increase shareholders’ funds C reduce an ordinary shareholder’s percentage holding D reduce the value of an ordinary share
1 marks
Answer: D
This question in 9706/32 May/June 2012
Q98 · A company has three non-current assets in use 9706/32 May/June 2012
13 A company has three non-current assets in use. At the end of its financial year, details of their valuations are as shown. carrying fair value less value in use asset amount costs to sell $ $ $ 1 20 000 25 000 28 000 2 30 000 26 000 24 000 3 25 000 32 000 20 000 How much should the total non-current assets be shown in the statement of financial position? A $64 000 B $66 000 C $71 000 D $75 000
1 marks
Answer: C
This question in 9706/32 May/June 2012
Q99 · The following information is taken from the financial statements of a limited company 9706/32 May/June 2012
15 The following information is taken from the financial statements of a limited company. $000 retained earnings at the start of the year 50 profit attributable to equity holders 30 dividends paid during the year 15 dividends proposed payable in the next financial year 10 surplus on revaluation of land during the year 20 What are the retained earnings at the end of the year? A $55 000 B $65 000 C $80 000 D $100 000
1 marks
Answer: B
This question in 9706/32 May/June 2012
Q100 · A company redeems its preference shares and makes a bonus issue of one ordinary share for… 9706/32 May/June 2012
18 A company redeems its preference shares and makes a bonus issue of one ordinary share for every four held. How will these transactions affect the statement of financial position? ordinary shares reserves bank A decrease no effect increase B increase decrease decrease C increase decrease no effect D increase increase decrease
1 marks
Answer: B
This question in 9706/32 May/June 2012
Q101 · A company redeems 10 000 preference shares of $5 each at a premium of 5 % 9706/33 May/June 2012
3 A company redeems 10 000 preference shares of $5 each at a premium of 5 %. The shares were originally issued at a premium of 10 % but the share premium account has been fully utilised. How much will be debited to the income statement? A $2500 B $50 000 C $52 500 D $55 000
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q102 · A company provides the following financial information at the end of the financial year 9706/33 May/June 2012
4 A company provides the following financial information at the end of the financial year. $ 000 Retained earnings at the start of the year 50 Profit for the year attributable to equity holders 120 Ordinary dividends paid during the year 70 Ordinary dividends proposed payable in the next financial year 30 Transfer to general reserve 20 What is the amount of retained earnings at the end of the financial year? A $50 000 B $70 000 C $80 000 D $100 000
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q103 · Which pair of statements about the reserves of a limited company is correct? 9706/33 May/June 2012
5 Which pair of statements about the reserves of a limited company is correct? revenue reserves capital reserves A can be credited back to retained created from retained earnings earnings if no longer needed B can be used to issue bonus shares can be credited back to retained earnings if no longer needed C can be used to pay cash dividends can be used to issue bonus shares D reduces the amount available can be used to pay cash dividends to pay dividends when created
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q104 · An extract from a company’s financial statements is as follows $ ordinary share capital… 9706/33 May/June 2012
6 An extract from a company’s financial statements is as follows $ ordinary share capital (shares of $1.00) 1 000 000 retained earnings (300 000) 700 000 The directors have decided to write off the debit balance on the retained earnings account together with goodwill of $100 000. The shareholders agreed to exchange their shares for new ordinary shares of $0.50. How many shares will the directors have to issue to the shareholders? A 600 000 B 700 000 C 1 200 000 D 1 400 000
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q105 · A company has the following capital and reserves: $000 ordinary shares of $1 each, fully… 9706/33 May/June 2012
7 A company has the following capital and reserves: $000 ordinary shares of $1 each, fully paid 1250 share premium account 100 revaluation reserve 200 general reserve 150 retained earnings 210 It is company policy to maintain reserves in their most flexible form. The company makes a 1-for-5 bonus issue. What is the maximum amount of distributable reserves after the bonus issue? A $110 000 B $310 000 C $360 000 D $410 000
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q106 · The table shows the capital structure of a company 9706/33 May/June 2012
9 The table shows the capital structure of a company. $ 100 000 ordinary shares of $1 each 100 000 10 % debentures 50 000 reserves 100 000 It increases the debentures by $50 000 and makes a bonus issue of one share for every two held. It then makes a rights issue of a further 100 000 shares at $1 each. How will these transactions affect the statement of financial position? gearing reserves bank A decrease decrease decrease B increase decrease decrease C increase decrease increase D decrease increase increase
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q107 · At the end of the year, the following information has been extracted from a company’s… 9706/33 May/June 2012
12 At the end of the year, the following information has been extracted from a company’s statement of cash flows. $ total cash from operating activities 200 net cash used by investing activities (300) net cash used by financing activities (150) closing cash and cash equivalents (50) What was the opening figure for cash and cash equivalents? A $(200) B $(300) C $200 D $300
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q108 · Which items are part of the published accounts of a limited company? 9706/33 May/June 2012
13 Which items are part of the published accounts of a limited company? 1 chairman’s statement 2 income statement 3 report of the directors 4 statement of cash flows A 1 only B 1 and 2 only C 1, 2 and 3 D 2, 3 and 4
1 marks
Answer: D
This question in 9706/33 May/June 2012
Q109 · To which asset is impairment normally applied each year? 9706/33 May/June 2012
14 To which asset is impairment normally applied each year? A goodwill B inventory C plant and machinery D trade receivables
1 marks
Answer: A
This question in 9706/33 May/June 2012
Q110 · A company owns three non-current assets 9706/33 May/June 2012
16 A company owns three non-current assets. An impairment review reveals the following. fair value less carrying value value in use asset costs to sell $ $ $ 1 40 000 50 000 30 000 2 30 000 25 000 27 000 3 20 000 22 000 24 000 What total value of non-current assets will be shown in the statement of financial position? A $75 000 B $79 000 C $87 000 D $90 000
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q111 · An extract from a company’s statement of financial position shows the following 9706/31 Oct/Nov 2012
4 An extract from a company’s statement of financial position shows the following. $000 issued ordinary shares of $0.25 each 600 share premium account 150 retained earnings 300 The company makes a rights issue of one new ordinary share for each three held, at a price of $0.30 per share. All shares are taken up. What does the new statement of financial position show? issued ordinary share premium share capital $000 $000 A 600 120 B 800 150 C 800 190 D 800 600
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2012
Q112 · A company would begin a capital reduction scheme in order to achieve which objective? 9706/31 Oct/Nov 2012
5 A company would begin a capital reduction scheme in order to achieve which objective? A to allow a company to cease trading B to allow loan interest to be paid C to eliminate accumulated trading losses D to expand the current business
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2012
Q113 · A limited company has the following capital and reserves 9706/31 Oct/Nov 2012
6 A limited company has the following capital and reserves. $ ordinary share capital 200 000 capital reserves 80 000 revenue reserves 100 000 What is the maximum amount that can be distributed to shareholders by way of dividends? A $80 000 B $100 000 C $180 000 D $380 000
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2012
Q114 · A company’s statement of financial position shows the following 9706/31 Oct/Nov 2012
7 A company’s statement of financial position shows the following. $ share capital ordinary shares of $10 each 100 000 general reserve 60 000 retained earnings 210 000 The following transactions take place. 1 The company pays a dividend of $70 000. 2 The company makes a bonus issue of 5000 ordinary shares. 3 The company issues a debenture of $120 000. What will be the total of share capital and reserves after these transactions are completed? A $250 000 B $300 000 C $350 000 D $420 000
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2012
Q115 · An extract from a company’s statement of financial position is as follows 9706/31 Oct/Nov 2012
8 An extract from a company’s statement of financial position is as follows. $000 ordinary shares of $1.00 600 10 % redeemable preference shares 400 share premium 160 retained earnings 900 The company has decided to redeem its preference shares at a premium of $0.20. No new shares are issued. Which row shows the effect of the redemption? capital redemption share retained reserve premium earnings $000 $000 $000 A – 160 – B 400 – 900 C 400 80 500 D – 160 500
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2012
Q116 · A company has 1 million ordinary shares in issue and the following reserves 9706/31 Oct/Nov 2012
19 A company has 1 million ordinary shares in issue and the following reserves. $ share premium 40 000 revaluation reserve 20 000 general reserve 80 000 retained earnings 30 000 What is the maximum dividend per share? A $0.03 B $0.11 C $0.13 D $0.17
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2012
Q117 · The summary statement of financial position for a limited company is shown below 9706/32 Oct/Nov 2012
4 The summary statement of financial position for a limited company is shown below. $ net assets 1 600 000 $1 ordinary shares 2 000 000 retained earnings (1 600 000) debentures 1 200 000 1 600 000 The company proposes a capital reconstruction scheme with the following terms. 1 Losses will be eliminated. 2 Net asset values will be reduced to $1 400 000. 3 All existing shares and debentures will be cancelled. 4 2 400 000 new $0.25 ordinary shares and $800 000 debentures will be issued at par to existing stakeholders. What is the value of the capital employed of the company immediately after the reconstruction? A $600 000 B $1 400 000 C $1 600 000 D $3 000 000
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2012
Q118 · A company has issued shares at a premium 9706/32 Oct/Nov 2012
5 A company has issued shares at a premium. For what purpose may the balance on the share premium account be used? A to write off a loss on the revaluation of non-current assets B to write off the discount on a new issue of shares C to write off the losses on a capital reduction D to write off the preliminary expenses incurred in forming the company
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2012
Q119 · A company’s statement of financial position at 31 December 2011 includes the following 9706/32 Oct/Nov 2012
6 A company’s statement of financial position at 31 December 2011 includes the following. $ ordinary shares of $1.00 12 000 retained earnings 4 000 In January 2012, the company made a bonus issue of one share for every four held. In June 2012, the company made a rights issue at $1.60 of one share for every two held. By how much did these transactions increase the company’s bank balance? A $9 600 B $12 000 C $12 800 D $19 200
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2012
Q120 · A business has the following capital structure 9706/32 Oct/Nov 2012
7 A business has the following capital structure. $ million ordinary shares of $1.00 each 20 retained earnings 25 capital employed 45 The company makes a bonus issue of one share for every 10 held. After this, the company makes a rights issue at par of one share for every 5 held. What is the capital employed after these transactions take place? A $47.2 million B $49.2 million C $49.4 million D $51.4 million
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2012
Q121 · A statement of financial position for a company shows the following 9706/32 Oct/Nov 2012
8 A statement of financial position for a company shows the following. $000 $1 ordinary shares 40 $1 redeemable preference shares 10 capital redemption reserve 10 retained profits 140 200 The preference shares are redeemed at a cost of $30 000. What is the resulting final capital redemption reserve balance? A $0 B $10 000 C $20 000 D $40 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2012
Q122 · The following information is available for a limited company for years 1 and 2 9706/32 Oct/Nov 2012
11 The following information is available for a limited company for years 1 and 2. year 1 year 2 $ $ dividends proposed 90 000 110 000 interim dividend 20 000 30 000 What is the amount to be entered as cash flow from financing activities in the statement of cash flow for year 2? A $110 000 B $120 000 C $130 000 D $140 000
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2012
Q123 · In a set of limited company accounts, which item would be included in the statement of… 9706/32 Oct/Nov 2012
12 In a set of limited company accounts, which item would be included in the statement of changes in equity? A accountant’s fees B debenture interest C directors’ remuneration D interim dividend payment
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2012
Q124 · The following is an extract from the statement of financial position of a limited company… 9706/32 Oct/Nov 2012
14 The following is an extract from the statement of financial position of a limited company at the start of the financial year. $000 ordinary shares of $1 each 50 convertible 10 % loan stock 30 retained earnings 120 total equity 200 During the year, the following took place. 1 The company made a profit from operations of $40 000. 2 The interest on the convertible loan stock was paid. 3 The loan stock was converted to an equal number of ordinary shares. 4 A dividend of 10 % was paid on the new total share capital. What was the total of the total equity at the end of the financial year? A $229 000 B $232 000 C $237 000 D $240 000
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2012
Q125 · What is a reason for a company issuing bonus shares? 9706/32 Oct/Nov 2012
19 What is a reason for a company issuing bonus shares? A to increase liquidity B to increase profitability C to reduce gearing D to reduce reserves
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2012
Q126 · Which statement about bonus shares is correct? 9706/33 Oct/Nov 2012
5 Which statement about bonus shares is correct? A They may be issued as repayment of debentures. B They may be issued at a premium. C They may be issued to the holders of preference shares. D They may be issued using the share premium account.
1 marks
Answer: D
This question in 9706/33 Oct/Nov 2012
Q127 · A company makes a 1 for 4 bonus issue of ordinary shares 9706/33 Oct/Nov 2012
6 A company makes a 1 for 4 bonus issue of ordinary shares. What will happen to share capital and shareholders’ funds? share capital shareholders’ funds A increase decrease B increase increase C increase no change D no change increase
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
Q128 · A company’s capital reduction scheme is as follows 9706/33 Oct/Nov 2012
7 A company’s capital reduction scheme is as follows. 1 reducing the $1.00 non-redeemable preference shares by $0.60. 2 reducing the $1.00 ordinary shares to shares of $0.05. The statement of financial position of the company immediately before the approval of the scheme is shown below. $ non-redeemable preference shares 100 000 ordinary shares 400 000 500 000 net assets 500 000 What will be the issued share capital after the capital reduction? A $20 000 B $60 000 C $80 000 D $260 000
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2012
Q129 · A company’s statement of financial position at the start of the year is shown below 9706/33 Oct/Nov 2012
8 A company’s statement of financial position at the start of the year is shown below. $ ordinary shares of $1.00 12 000 retained earnings 4 000 During the year, the company made a bonus issue of one share for every four held. Immediately afterwards, the company made a rights issue at $1.60 of one share for every two held. By how much did these transactions increase the company’s bank balance? A $9600 B $12 000 C $12 800 D $19 200
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2012
Q130 · A company purchases a business with net assets of $110 000 9706/33 Oct/Nov 2012
9 A company purchases a business with net assets of $110 000. In addition, the goodwill of the business is valued at $10 000. The purchase price of the business is settled by the issue of 80 000 $1 ordinary shares in the company. What will be the entry in the company’s share premium account? A credit $30 000 B debit $30 000 C credit $40 000 D debit $40 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
Q131 · A company purchases the business of a sole trader for $250 000 9706/33 Oct/Nov 2012
10 A company purchases the business of a sole trader for $250 000. The fair value of the net assets is $230 000. The purchase price is made up as follows: 1 the issue of 80 000 ordinary shares of $1 each in the company, at a price of $2 each 2 the issue of $50 000 6 % debenture stock at par in the company 3 the balance of the purchase price in cash. What is the amount of cash to be paid? A $40 000 B $90 000 C $100 000 D $120 000
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2012
Q132 · The following items appear in a company’s statement of financial position 9706/33 Oct/Nov 2012
11 The following items appear in a company’s statement of financial position. $000 goodwill 35 equipment, net book value 70 bank overdraft 17 loan repayable over 5 years 100 inventory 95 trade payables 54 three month deposit account 125 What is the figure for net current assets? A $24 000 B $109 000 C $129 000 D $149 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
Q133 · A company’s statement of financial position at 31 December 2010 included the following 9706/33 Oct/Nov 2012
12 A company’s statement of financial position at 31 December 2010 included the following. long-term liabilities $ loan (repayable on 30 June 2012) 120 000 8 % debentures (2010-2013) 70 000 The company intends to redeem half the debentures on 31 December 2012 and the remainder on 1 June 2013. How were these liabilities shown in the statement of financial position at 31 December 2011? current liabilities $ non-current liabilities $ A debentures 35 000 loan 120 000 debentures 35 000 B debentures 70 000 loan 120 000 C loan 120 000 debentures 35 000 debentures 35 000 D loan 120 000 – debentures 35 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
Q134 · A company’s financial statements show the following 9706/33 Oct/Nov 2012
13 A company’s financial statements show the following. $000 profit from operations 300 depreciation charges 80 increase in inventory 16 decrease in trade receivables 12 decrease in trade payables 10 What is the net cash from operating activities? A $366 000 B $374 000 C $398 000 D $418 000
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2012
Q135 · At the start of the year, a company’s total equity was as follows 9706/33 Oct/Nov 2012
14 At the start of the year, a company’s total equity was as follows. $000 ordinary share capital 1000 share premium 100 general reserve 500 retained earnings 300 1900 During the year, the following took place. 1 The company made a net profit attributable to equity holders of $120 000. 2 The company paid a dividend of $30 000. 3 The company proposed a final dividend of $40 000. 4 The company made a transfer of $60 000 to the general reserve. What was the company’s total equity at the end of the year? A $1 890 000 B $1 950 000 C $1 990 000 D $2 050 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
Q136 · How should proposed ordinary dividends be accounted for when preparing statements of cash… 9706/31 May/June 2013
3 How should proposed ordinary dividends be accounted for when preparing statements of cash flows? A as part of the cash from operating activities B as part of the financing activities C as part of the investing activities D not included in the statement
1 marks
Answer: D
This question in 9706/31 May/June 2013
Q137 · Which item will not appear on the income statement of a company? 9706/31 May/June 2013
4 Which item will not appear on the income statement of a company? A finance costs B impairment costs C ordinary share dividends paid D taxation
1 marks
Answer: C
This question in 9706/31 May/June 2013
Q138 · Which item would be included as equity in a company’s statement of financial position? 9706/31 May/June 2013
5 Which item would be included as equity in a company’s statement of financial position? A debenture stock B loan from a director C retained earnings D trade payables
1 marks
Answer: C
This question in 9706/31 May/June 2013
Q139 · A company has prepared its financial statements for the year ended 31 December 2012 9706/31 May/June 2013
9 A company has prepared its financial statements for the year ended 31 December 2012. The following items occurred in January 2013 before they were authorised for issue. 1 A major customer was declared bankrupt. He owed $11 000 on 31 December 2012. No provision for this had been made in the accounts. 2 There was a fire at the company’s premises resulting in uninsured losses of $15 000. 3 An impairment review identified the carrying value of non-current assets exceeded their recoverable amount by $20 000. 4 A court case was settled which resulted in the company being liable to pay damages of $18 000. In accordance with IAS 10, by which amount should the profit for the year be reduced? A $44 000 B $46 000 C $49 000 D $53 000
1 marks
Answer: C
This question in 9706/31 May/June 2013
Q140 · A company is preparing the statement of changes in equity for the year 9706/31 May/June 2013
10 A company is preparing the statement of changes in equity for the year. The following information is available. $ retained earnings at the beginning of the year 420 000 interest paid on debentures 45 000 interim dividends paid 20 000 proposed dividends for the year 35 000 issue of shares 40 000 profit for the year attributable to equity holders 145 000 What is the balance of retained earnings at the end of the year? A $465 000 B $505 000 C $545 000 D $550 000
1 marks
Answer: C
This question in 9706/31 May/June 2013
Q141 · The following information is for two non-current assets 9706/31 May/June 2013
16 The following information is for two non-current assets. fair value less net book value value in use costs to sell $ $ $ asset 1 50 000 45 000 48 000 asset 2 20 000 18 000 21 000 What is the total impairment loss? A $2000 B $4000 C $5000 D $7000
1 marks
Answer: A
This question in 9706/31 May/June 2013
Q142 · The financial statements of a company shows the following 9706/31 May/June 2013
18 The financial statements of a company shows the following. $ ordinary shares of $1 each 1 200 000 share premium 100 000 retained earnings 150 000 10% debenture 150 000 The directors of the company carry out the following actions. 1 issue 50 000 ordinary shares of $1 each at a premium of $0.20 2 repay $100 000 of the debenture at a premium of 20% What is the equity of the company after these transactions have taken place? A $1 490 000 B $1 500 000 C $1 510 000 D $1 540 000
1 marks
Answer: A
This question in 9706/31 May/June 2013
Q143 · The directors of a company carry out the following transactions 9706/31 May/June 2013
19 The directors of a company carry out the following transactions. 1 A debenture of $10 000 is redeemed at par. 2 A long term loan of $25 000 is obtained. 3 The property is sold for $50 000. What will be the improvement in working capital? A $15 000 B $25 000 C $65 000 D $75 000
1 marks
Answer: C
This question in 9706/31 May/June 2013
Q144 · A company applies a 20% factory profit to manufacturing cost 9706/33 May/June 2013
2 A company applies a 20% factory profit to manufacturing cost. Details of its inventory at transfer price are as follows. $ inventory at 31 May 2012 24 000 inventory at 31 May 2013 36 600 What is the correct treatment of unrealised profit in the income statement for the year ended 31 May 2013? A $2100 expense B $2100 income C $6100 expense D $6100 income
1 marks
Answer: A
This question in 9706/33 May/June 2013
Q145 · The following information is taken from the statement of financial position of a company 9706/33 May/June 2013
3 The following information is taken from the statement of financial position of a company. $ 5% debenture 2019 / 2020 50 000 asset revaluation reserve 10 000 goodwill 20 000 issued ordinary share capital 80 000 long-term loan (repayable 2018) 45 000 tangible non-current assets (at nbv) 116 000 retained earnings 36 000 share premium 16 000 What is the figure for equity to be included in the statement of financial position? A $142 000 B $162 000 C $182 000 D $202 000
1 marks
Answer: A
This question in 9706/33 May/June 2013
Q146 · What is the effect on a company’s statement of financial position of issuing bonus shares? 9706/33 May/June 2013
4 What is the effect on a company’s statement of financial position of issuing bonus shares? A The bank balance will be increased. B The non-current liabilities will be increased. C The reserves will be reduced. D The share capital will be reduced.
1 marks
Answer: C
This question in 9706/33 May/June 2013
Q147 · At the start of the year a company had plant and machinery with a net book value of $160… 9706/33 May/June 2013
5 At the start of the year a company had plant and machinery with a net book value of $160 000. During the year a machine which had cost $50 000 was disposed of. The sale proceeds were $60 000 and this resulted in a profit on disposal of $20 000. The remaining plant and machinery was then revalued at $190 000. What was the balance on the revaluation reserve at the year end? A $40 000 B $70 000 C $80 000 D $90 000
1 marks
Answer: B
This question in 9706/33 May/June 2013
Q148 · The directors of a company carry out the following actions 9706/33 May/June 2013
6 The directors of a company carry out the following actions. 1 make an issue of 50 000 ordinary shares of $1 each at par 2 make an issue of 20 000 bonus shares of $1 each at par 3 make a repayment of a debenture of $60 000 Which row shows the effect of these actions on the capital of the company? issued share capital non-current liabilities working capital A increase decrease decrease B increase decrease no effect C increase increase increase D no effect decrease increase
1 marks
Answer: A
This question in 9706/33 May/June 2013
Q149 · A company with 36 000 shares of $0.50 each in issue has, as its only reserve, a retained… 9706/33 May/June 2013
18 A company with 36 000 shares of $0.50 each in issue has, as its only reserve, a retained profit of $25 000. The directors then recommend a bonus issue of 1 for 4. What is the balance on the profit and loss account after the bonus issue? A $4500 B $7000 C $20 500 D $25 000
1 marks
Answer: C
This question in 9706/33 May/June 2013
Q150 · A company’s statement of financial position at 1 January included the following 9706/31 Oct/Nov 2013
9 A company’s statement of financial position at 1 January included the following. $ million ordinary share capital 500 retained earnings 200 The company results for the year to 31 December included the following. $ million profit before taxation 50 taxation 15 dividends proposed 10 revaluation surplus on land 12 What are the retained earnings at 31 December? A $225 million B $235 million C $237 million D $247 million
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2013
Q151 · Which items will be shown in the statement of changes in equity? 9706/31 Oct/Nov 2013
10 Which items will be shown in the statement of changes in equity? 1 dividends proposed 2 interest paid on debentures 3 issues of share capital 4 transfers to reserves A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2013
Q152 · At the year end a company had total net assets of $230 000 9706/31 Oct/Nov 2013
11 At the year end a company had total net assets of $230 000. The financial statements have not yet been approved by the directors and the following matters have come to light. There is an unpaid legal charge of $10 000 which will have to be paid if the case is lost. The inventory at the year end was valued at $45 000 but it is now discovered that, due to damage, it should have been $38 000. What will be the value of the net assets after any necessary adjustments have been made? A $175 000 B $185 000 C $213 000 D $223 000
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2013
Q153 · The equity section of the statement of financial position of a company at 1 May 2013 is… 9706/31 Oct/Nov 2013
19 The equity section of the statement of financial position of a company at 1 May 2013 is as follows. $ ordinary shares of $0.50 each fully paid 220 000 share premium 110 250 retained earnings 44 000 374 250 On 31 May 2013, the directors made a bonus issue of ordinary shares on the basis of six new shares for every eleven existing shares held. What is the number of bonus shares issued? A 60 000 B 120 000 C 240 000 D 806 667
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2013
Q154 · A company transfers manufactured items from factory to warehouse at cost plus 10% 9706/32 Oct/Nov 2013
3 A company transfers manufactured items from factory to warehouse at cost plus 10%. This year the transfer value was $93 500 and at the end of the year the closing inventory was 20% of the year’s production. How will the inventory of finished goods be shown? statement of trading account financial position $ $ A 17 000 17 000 B 18 700 16 830 C 18 700 17 000 D 18 700 18 700
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2013
Q155 · A company’s statement of financial position shows the following 9706/32 Oct/Nov 2013
5 A company’s statement of financial position shows the following. $000 $1 ordinary shares 500 retained earnings 400 10% debentures 300 1 200 net assets 1 200 A fully subscribed 1 for 4 rights issue at $2 per share is made and 50% of the debentures are repaid at par. What are the net assets following these changes? A $1 100 000 B $1 175 000 C $1 225 000 D $1 300 000
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2013
Q156 · When must a capital redemption reserve be set up? 9706/32 Oct/Nov 2013
6 When must a capital redemption reserve be set up? A ordinary shares are issued at a premium B ordinary shares are redeemed without a new issue of shares C preference shares are issued at a premium D preference shares are redeemed from the proceeds of a new issue of shares
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2013
Q157 · A company is carrying out an impairment review of its plant and machinery 9706/32 Oct/Nov 2013
9 A company is carrying out an impairment review of its plant and machinery. The following information is revealed. 1 Original cost of plant and machinery $50 000. Accumulated depreciation $15 000. 2 Undiscounted value of future cash flows from using the machinery $60 000. Present value of future cash flows from using the machinery $40 000. 3 Sales proceeds from disposing of the plant and machinery $48 000. Cost of disposing of the plant and machinery $10 000. At what value should the plant and machinery be shown in the statement of financial position? A $35 000 B $38 000 C $40 000 D $50 000
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2013
Q158 · How is inventory valued under IAS2? 9706/32 Oct/Nov 2013
17 How is inventory valued under IAS2? A purchase cost B purchase cost + carriage in C purchase cost + carriage in + conversion costs D purchase cost + carriage in + conversion costs + storage costs
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2013
Q159 · A company installing a new machine has the following costs 9706/32 Oct/Nov 2013
18 A company installing a new machine has the following costs. $ purchase price 200 000 delivery charges 5 000 preparing the site 35 000 training the workers 4 500 assembly and testing 8 000 advertising the new product 10 000 What is the total cost of the asset under IAS16? A $240 000 B $248 000 C $252 500 D $262 500
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2013
Q160 · A manufacturing company’s income statement shows a profit from operations of $9000 9706/33 Oct/Nov 2013
3 A manufacturing company’s income statement shows a profit from operations of $9000. The following errors are then discovered. 1 Opening inventory of finished goods has been valued at transfer price of $12 000. 2 Closing inventory of finished goods has been valued at transfer price of $6000. 3 Goods at transfer price have been entered in the income statement at their transfer value of $120 000. No adjustment has been made in respect of factory profit. 4 The company transfers goods from the factory to finished goods at cost plus 20%. What is the correct profit from operations? A $28 000 B $29 000 C $30 000 D $31 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2013
Q161 · The financial statements of a public limited company includes the following information 9706/33 Oct/Nov 2013
4 The financial statements of a public limited company includes the following information. $000 retained earnings at the start of the year 43 profit from operations 14 ordinary dividends paid during the year 5 dividends on redeemable preference shares paid during the year 2 proposed final dividend on ordinary shares 8 What is the figure for retained earnings at the end of the year? A $42 000 B $50 000 C $52 000 D $57 000
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2013
Q162 · The statement of financial position of a company is as follows 9706/33 Oct/Nov 2013
6 The statement of financial position of a company is as follows. $ non-current assets 85 000 bank 14 000 other net current assets 24 000 8% debentures (4 000) 119 000 ordinary share capital 100 000 share premium 2 000 retained earnings 17 000 119 000 The 8% debentures are redeemed at a premium of 20%. What is the total equity balance after the redemption? A $114 200 B $115 000 C $118 200 D $119 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2013
Q163 · A company purchases the non-current assets, inventory and trade receivables of another… 9706/33 Oct/Nov 2013
8 A company purchases the non-current assets, inventory and trade receivables of another business. It pays more than the book value for these items. The purchase price is paid partly by a debenture. The balance is paid by the issue of ordinary shares of $1 each at a premium of $0.20. Which row shows the effect of these transactions in the financial statements of the purchaser? non-current assets working capital equity A decrease decrease decrease B increase decrease increase C increase increase increase D increase no effect decrease
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2013
Q164 · A company agrees to purchase the assets and liabilities of another business 9706/33 Oct/Nov 2013
9 A company agrees to purchase the assets and liabilities of another business. The book value of the net assets acquired was: $ non-current assets 140 000 current assets 50 000 current liabilities 15 000 It is agreed that the fair value of the non-current assets is $155 000 and goodwill is valued at $20 000. The purchase price of the business is to be settled as follows. $ cash 40 000 5% debenture 20 000 The balance of the purchase price is to be settled by the issue of $1 ordinary shares at a premium of 25%. By how much will the company’s share premium account increase as a result of the purchase? A $23 000 B $30 000 C $37 500 D $42 000
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2013
Q165 · Which item will not be shown in the statement of changes in equity? 9706/33 Oct/Nov 2013
11 Which item will not be shown in the statement of changes in equity? A debenture interest paid B ordinary share dividends paid C profit for the year D revaluation surplus
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2013
Q166 · The information relates to a company 9706/33 Oct/Nov 2013
16 The information relates to a company. $ share premium account 240 000 10% debentures 100 000 retained earnings 180 000 The company redeems the debentures at a premium of 10%. Which values will the statement of financial position show after this transaction? retained share premium earnings account $ $ A 70 000 240 000 B 80 000 230 000 C 170 000 240 000 D 180 000 230 000
1 marks
Answer: D
This question in 9706/33 Oct/Nov 2013
Q167 · The following are extracts from the statement of financial position of a company 9706/33 Oct/Nov 2013
17 The following are extracts from the statement of financial position of a company. $ bank 8 500 issued ordinary shares of $1 each 50 000 share premium 20 000 The company makes a bonus issue of one share for every five held. How will this affect the following accounts? ordinary share bank share capital premium A increase decrease no effect B increase increase increase C increase no effect increase D no effect decrease no effect
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2013
Q168 · During the year ended 31 December, a company bought a new motor vehicle 9706/31 May/June 2014
1 During the year ended 31 December, a company bought a new motor vehicle. The cost price was $43 000. The company paid $37 000 by cheque and also traded in an old vehicle for which it was allowed $6000. The depreciated book value of the old vehicle was $4200. The company sold another vehicle for $3750 cash. This vehicle had a net book value of $4925. What is the effect of these transactions on the cash flow of the company? cash inflow cash outflow $ $ A 4 925 33 250 B 3 750 37 000 C 9 750 43 000 D 10 925 43 000
1 marks
Answer: B
This question in 9706/31 May/June 2014
Q169 · A statement of cash flows must be analysed between operating, investing and financing… 9706/31 May/June 2014
3 A statement of cash flows must be analysed between operating, investing and financing activities. What is a financing activity? A acquisition of non-current assets B issue of shares C sale of goods D sale of non-current assets
1 marks
Answer: B
This question in 9706/31 May/June 2014
Q170 · In 2013 a manufacturing company added factory profit of 20% to its cost of production 9706/31 May/June 2014
4 In 2013 a manufacturing company added factory profit of 20% to its cost of production. The following information is available. 2012 2013 $ $ provision for unrealised profit 12 100 ? closing inventory of finished goods at transfer price 63 000 75 000 What was the adjustment required to the provision for unrealised profit at the end of 2013? A $400 credit B $400 debit C $2900 credit D $2900 debit
1 marks
Answer: A
This question in 9706/31 May/June 2014
Q171 · The table shows an extract from the draft statement of financial position 9706/31 May/June 2014
5 The table shows an extract from the draft statement of financial position. accumulated cost net book value non-current assets depreciation $ $ $ freehold buildings 700 000 200 000 500 000 plant and machinery 450 000 100 000 350 000 Freehold buildings are to be revalued to $950 000. Plant and machinery is to be written down to $250 000. How much will be credited to the asset revaluation reserve? A $50 000 B $150 000 C $250 000 D $450 000
1 marks
Answer: D
This question in 9706/31 May/June 2014
Q172 · A company’s statement of financial position showed the following on 31 December 2012 9706/31 May/June 2014
6 A company’s statement of financial position showed the following on 31 December 2012. $ ordinary shares of $1 each 200 000 share premium 30 000 retained earnings 150 000 380 000 During the year ended 31 December 2013 it made a profit of $90 000. It also made the following share issues. 1 a rights issue of one share at $1.40 for every four held 2 a bonus issue of one share for every ten held What was the total of equity at 31 December 2013? A $520 000 B $540 000 C $565 000 D $575 000
1 marks
Answer: B
This question in 9706/31 May/June 2014
Q173 · A company has both a share premium account and retained earnings 9706/31 May/June 2014
7 A company has both a share premium account and retained earnings. It now redeems debentures paying a premium over their nominal value. Which statement is correct? A The debentures must have been issued at a discount. B The debentures must have been issued at a premium. C The premium can be debited to the share premium account. D The premium may be debited in the income statement.
1 marks
Answer: C
This question in 9706/31 May/June 2014
Q174 · Alan, Brian and Colin are in partnership sharing profits and losses in the ratio 3 : 2 : 1 9706/31 May/June 2014
8 Alan, Brian and Colin are in partnership sharing profits and losses in the ratio 3 : 2 : 1. Colin is to retire from the partnership on 30 June 2014. From that date, Alan and Brian are to share profits and losses in the ratio 2 : 1. The summarised statement of financial position at 30 June 2014 before Colin’s retirement is as follows. $ net assets 107 500 capital account – Alan 45 200 capital account – Brian 38 800 capital account – Colin 23 500 107 500 Goodwill is to be valued at $24 000 and is to remain in the books of account. Non-current assets with a net book value of $62 000 are to be revalued at $53 000. What is the new balance on Alan’s capital account? A $26 000 B $43 800 C $52 700 D $57 200
1 marks
Answer: C
This question in 9706/31 May/June 2014
Q175 · The statement of financial position of X showed the following 9706/31 May/June 2014
9 The statement of financial position of X showed the following. $ non-current assets 300 000 current assets 100 000 Y limited acquired X for a cash payment of $600 000, valuing the non-current assets of X at $400 000. What was the effect of the acquisition of X on the statement of financial position of Y limited? non-current assets current assets A decrease no change B increase decrease C increase increase D increase no change
1 marks
Answer: B
This question in 9706/31 May/June 2014
Q176 · A company has 100 000 ordinary shares of $1 each 9706/31 May/June 2014
12 A company has 100 000 ordinary shares of $1 each. During the year the following takes place. 1 The company pays an interim dividend of $0.10 per share. 2 The directors declare a final dividend of $0.20 per share to be paid after the end of the financial year. How are these reported in the financial statements? income statement of statement of statement cash flows changes in equity $ $ $ A – (10 000) (10 000) B – (30 000) (30 000) C (10 000) (10 000) – D (30 000) (30 000) (30 000)
1 marks
Answer: A
This question in 9706/31 May/June 2014
Q177 · The following information is available for a company preparing its statement of changes… 9706/31 May/June 2014
14 The following information is available for a company preparing its statement of changes in equity for 2014. $ retained earnings at start of year 118 000 retained earnings at end of year 80 000 transfers to general reserves 20 000 debenture interest paid 10 000 taxation 70 000 How much is profit from operations? A $52 000 B $62 000 C $98 000 D $108 000
1 marks
Answer: B
This question in 9706/31 May/June 2014
Q178 · A company has 500 000 ordinary shares in issue and the following reserves 9706/31 May/June 2014
19 A company has 500 000 ordinary shares in issue and the following reserves. $ share premium 20 000 revaluation reserve 50 000 general reserve 80 000 retained earnings 40 000 What is the maximum dividend per share that could be paid? A $0.08 B $0.24 C $0.34 D $0.38
1 marks
Answer: B
This question in 9706/31 May/June 2014
Q179 · The following information relates to a company’s non-current assets 9706/31 May/June 2014
20 The following information relates to a company’s non-current assets. carrying value fair value less value in use costs to sell $ $ $ machinery 35 000 32 000 40 000 motor vehicles 20 200 8 000 16 000 office equipment 12 000 10 000 8 000 What is the total value of non-current assets to be included in the statement of financial position? A $48 000 B $50 000 C $61 000 D $67 200
1 marks
Answer: C
This question in 9706/31 May/June 2014
Q180 · How is the closing balance of unrealised factory profit shown in the statement of… 9706/31 May/June 2014
21 How is the closing balance of unrealised factory profit shown in the statement of financial position? A as a deduction from the value of inventory of finished goods B as a deduction from the value of inventory of work in progress C as an addition to the value of inventory of finished goods D as an addition to the value of inventory of work in progress
1 marks
Answer: A
This question in 9706/31 May/June 2014
Q181 · During the year ended 31 December, a company bought a new motor vehicle 9706/32 May/June 2014
1 During the year ended 31 December, a company bought a new motor vehicle. The cost price was $43 000. The company paid $37 000 by cheque and also traded in an old vehicle for which it was allowed $6000. The depreciated book value of the old vehicle was $4200. The company sold another vehicle for $3750 cash. This vehicle had a net book value of $4925. What is the effect of these transactions on the cash flow of the company? cash inflow cash outflow $ $ A 4 925 33 250 B 3 750 37 000 C 9 750 43 000 D 10 925 43 000
1 marks
Answer: B
This question in 9706/32 May/June 2014
Q182 · After the date of the statement of financial position, but before the financial… 9706/32 May/June 2014
2 After the date of the statement of financial position, but before the financial statements were approved, certain events took place. Which event will require a note to the accounts? A discovery of fraud revealing that the financial statements are inaccurate B insolvency of a major debtor included in trade receivables at the statement of financial position date C loss in value of a non-current asset as a result of an impairment review D proposed final dividend declared by the directors
1 marks
Answer: D
This question in 9706/32 May/June 2014
Q183 · A statement of cash flows must be analysed between operating, investing and financing… 9706/32 May/June 2014
3 A statement of cash flows must be analysed between operating, investing and financing activities. What is a financing activity? A acquisition of non-current assets B issue of shares C sale of goods D sale of non-current assets
1 marks
Answer: B
This question in 9706/32 May/June 2014
Q184 · In 2013 a manufacturing company added factory profit of 20% to its cost of production 9706/32 May/June 2014
4 In 2013 a manufacturing company added factory profit of 20% to its cost of production. The following information is available. 2012 2013 $ $ provision for unrealised profit 12 100 ? closing inventory of finished goods at transfer price 63 000 75 000 What was the adjustment required to the provision for unrealised profit at the end of 2013? A $400 credit B $400 debit C $2900 credit D $2900 debit
1 marks
Answer: A
This question in 9706/32 May/June 2014
Q185 · The table shows an extract from the draft statement of financial position 9706/32 May/June 2014
5 The table shows an extract from the draft statement of financial position. accumulated cost net book value non-current assets depreciation $ $ $ freehold buildings 700 000 200 000 500 000 plant and machinery 450 000 100 000 350 000 Freehold buildings are to be revalued to $950 000. Plant and machinery is to be written down to $250 000. How much will be credited to the asset revaluation reserve? A $50 000 B $150 000 C $250 000 D $450 000
1 marks
Answer: D
This question in 9706/32 May/June 2014
Q186 · A company’s statement of financial position showed the following on 31 December 2012 9706/32 May/June 2014
6 A company’s statement of financial position showed the following on 31 December 2012. $ ordinary shares of $1 each 200 000 share premium 30 000 retained earnings 150 000 380 000 During the year ended 31 December 2013 it made a profit of $90 000. It also made the following share issues. 1 a rights issue of one share at $1.40 for every four held 2 a bonus issue of one share for every ten held What was the total of equity at 31 December 2013? A $520 000 B $540 000 C $565 000 D $575 000
1 marks
Answer: B
This question in 9706/32 May/June 2014
Q187 · A company has both a share premium account and retained earnings 9706/32 May/June 2014
7 A company has both a share premium account and retained earnings. It now redeems debentures paying a premium over their nominal value. Which statement is correct? A The debentures must have been issued at a discount. B The debentures must have been issued at a premium. C The premium can be debited to the share premium account. D The premium may be debited in the income statement.
1 marks
Answer: C
This question in 9706/32 May/June 2014
Q188 · Alan, Brian and Colin are in partnership sharing profits and losses in the ratio 3 : 2 : 1 9706/32 May/June 2014
8 Alan, Brian and Colin are in partnership sharing profits and losses in the ratio 3 : 2 : 1. Colin is to retire from the partnership on 30 June 2014. From that date, Alan and Brian are to share profits and losses in the ratio 2 : 1. The summarised statement of financial position at 30 June 2014 before Colin’s retirement is as follows. $ net assets 107 500 capital account – Alan 45 200 capital account – Brian 38 800 capital account – Colin 23 500 107 500 Goodwill is to be valued at $24 000 and is to remain in the books of account. Non-current assets with a net book value of $62 000 are to be revalued at $53 000. What is the new balance on Alan’s capital account? A $26 000 B $43 800 C $52 700 D $57 200
1 marks
Answer: C
This question in 9706/32 May/June 2014
Q189 · A company has 100 000 ordinary shares of $1 each 9706/32 May/June 2014
12 A company has 100 000 ordinary shares of $1 each. During the year the following takes place. 1 The company pays an interim dividend of $0.10 per share. 2 The directors declare a final dividend of $0.20 per share to be paid after the end of the financial year. How are these reported in the financial statements? income statement of statement of statement cash flows changes in equity $ $ $ A – (10 000) (10 000) B – (30 000) (30 000) C (10 000) (10 000) – D (30 000) (30 000) (30 000)
1 marks
Answer: A
This question in 9706/32 May/June 2014
Q190 · The following information is available for a company preparing its statement of changes… 9706/32 May/June 2014
14 The following information is available for a company preparing its statement of changes in equity for 2014. $ retained earnings at start of year 118 000 retained earnings at end of year 80 000 transfers to general reserves 20 000 debenture interest paid 10 000 taxation 70 000 How much is profit from operations? A $52 000 B $62 000 C $98 000 D $108 000
1 marks
Answer: B
This question in 9706/32 May/June 2014
Q191 · The following information relates to a company’s non-current assets 9706/32 May/June 2014
20 The following information relates to a company’s non-current assets. carrying value fair value less value in use costs to sell $ $ $ machinery 35 000 32 000 40 000 motor vehicles 20 200 8 000 16 000 office equipment 12 000 10 000 8 000 What is the total value of non-current assets to be included in the statement of financial position? A $48 000 B $50 000 C $61 000 D $67 200
1 marks
Answer: C
This question in 9706/32 May/June 2014
Q192 · How is the closing balance of unrealised factory profit shown in the statement of… 9706/32 May/June 2014
21 How is the closing balance of unrealised factory profit shown in the statement of financial position? A as a deduction from the value of inventory of finished goods B as a deduction from the value of inventory of work in progress C as an addition to the value of inventory of finished goods D as an addition to the value of inventory of work in progress
1 marks
Answer: A
This question in 9706/32 May/June 2014
Q193 · A company is redeeming $50 000 redeemable ordinary shares of $1 each at a premium of $0.10 9706/33 May/June 2014
6 A company is redeeming $50 000 redeemable ordinary shares of $1 each at a premium of $0.10. The shares were originally issued for $1. Which account must be debited with the premium? A capital redemption reserve B ordinary share capital C retained earnings D share premium
1 marks
Answer: C
This question in 9706/33 May/June 2014
Q194 · What is the effect of a bonus issue of shares on the share capital and net assets of a… 9706/33 May/June 2014
7 What is the effect of a bonus issue of shares on the share capital and net assets of a company? share capital net assets A increase increase B increase no effect C increase decrease D no effect no effect
1 marks
Answer: B
This question in 9706/33 May/June 2014
Q195 · A company’s convertible loan stock will be converted into ordinary shares on 1 January… 9706/33 May/June 2014
11 A company’s convertible loan stock will be converted into ordinary shares on 1 January 2020. Where would the company show this in the statement of financial position at 31 December 2013? A current liabilities B equity C non-current assets D non-current liabilities
1 marks
Answer: D
This question in 9706/33 May/June 2014
Q196 · Which item appears in the statement of changes in equity? 9706/33 May/June 2014
12 Which item appears in the statement of changes in equity? A issue of a debenture B profit on revaluation C proposed dividends D repayment of long term loan
1 marks
Answer: B
This question in 9706/33 May/June 2014
Q197 · A company’s financial information is as follows 9706/33 May/June 2014
13 A company’s financial information is as follows. $ loss for the year attributable to equity holders 220 000 loss on revaluation of property 240 000 surplus on revaluation of plant and machinery 80 000 What is the reduction in total equity for the year? A $140 000 B $220 000 C $380 000 D $460 000
1 marks
Answer: A
This question in 9706/33 May/June 2014
Q198 · A company provides the following 9706/33 May/June 2014
14 A company provides the following. $ profit from operations 280 000 loss on investments held as non-current assets 40 000 gain on revaluation of property 220 000 How much is the profit for the year? A $240 000 B $280 000 C $460 000 D $500 000
1 marks
Answer: A
This question in 9706/33 May/June 2014
Q199 · The following information is available for a limited company 9706/33 May/June 2014
20 The following information is available for a limited company. $ ordinary share capital of $0.50 each 200 000 share premium account 48 000 The directors intend to redeem the shares at par on the basis of two for every five shares issued. How much cash will be required to finance the share redemption? A $40 000 B $59 200 C $80 000 D $99 200
1 marks
Answer: C
This question in 9706/33 May/June 2014
Q200 · Which item would appear in the financing section in a statement of cash flows? 9706/31 Oct/Nov 2015
1 Which item would appear in the financing section in a statement of cash flows? A bonus issue of shares B increase in inventory C redemption of share capital D sale of non-current assets
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2015
Q201 · The statement of cash flows for a company included the following 9706/31 Oct/Nov 2015
2 The statement of cash flows for a company included the following. $ net increase in cash and cash equivalents 155 000 net cash inflow from operating activities 300 000 net cash outflow from investing activities (350 000) In addition, the company raised $420 000 by issuing debentures. There were no other financing cash flows apart from dividends paid. How much was the dividend payment? A $215 000 B $265 000 C $315 000 D $525 000
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2015
Q202 · When can a company issue redeemable shares? 9706/31 Oct/Nov 2015
6 When can a company issue redeemable shares? A when all preference shares have been redeemed B when no debentures are in issue C when no shares have been issued at a premium D when there are some non-redeemable shares in issue
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2015
Q203 · A company issues non-cumulative preference shares 9706/31 Oct/Nov 2015
7 A company issues non-cumulative preference shares. Which rights do the holders of these shares have? A dividends will be paid before debenture interest B dividends will be paid before those to ordinary shareholders C arrears of dividends will be paid in future years D voting rights at the annual general meeting
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2015
Q204 · A company has ordinary share capital of $1 000 000 in shares of $0.40 each 9706/31 Oct/Nov 2015
9 A company has ordinary share capital of $1 000 000 in shares of $0.40 each. The company proposes to make a rights issue of new ordinary shares on the basis of one new ordinary share for each five existing ordinary shares held, at a price of $1.20 per share. The company expects members holding 90% of the ordinary shares to take up the issue. How much cash will the company receive? A $216 000 B $240 000 C $540 000 D $600 000
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2015
Q205 · Which item will appear in a company’s statement of changes in equity? 9706/31 Oct/Nov 2015
11 Which item will appear in a company’s statement of changes in equity? A amortisation of intangible assets B an impairment loss C inventory written off D revaluation surplus
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2015
Q206 · The equity of a company at 1 January 2014 is as follows 9706/31 Oct/Nov 2015
12 The equity of a company at 1 January 2014 is as follows. $ ordinary shares of $1 each 400 000 share premium 180 000 The following events take place in 2014. issue of 100 000 ordinary shares for $2.20 each rights issue of 50 000 ordinary shares at $1.80 each, fully subscribed issue of 30 000 bonus shares payment of $165 000 ordinary dividend What is the balance on the share premium account at 31 December 2014? A $145 000 B $175 000 C $310 000 D $340 000
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2015
Q207 · The following information is available at the end of the first year of trading for a… 9706/31 Oct/Nov 2015
13 The following information is available at the end of the first year of trading for a limited company. $000 ordinary shares of $0.50 each 200 5% preference shares of $1 each 100 10% debentures 40 profit from operations 80 amount transferred to general reserve 21 After making the transfer to the general reserve, the company paid the remaining profit as dividends to its ordinary shareholders. What was the dividend per ordinary share? A $0.125 B $0.196 C $0.250 D $0.400
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2015
Q208 · A limited company’s financial statements for the year ended 30 June showed the following 9706/31 Oct/Nov 2015
14 A limited company’s financial statements for the year ended 30 June showed the following. $ ordinary share capital of $0.25 each 160 000 share premium account 32 000 A final dividend is proposed at $0.06 per share. What is the value of proposed dividends to be included in the Directors’ Report? A $2400 B $9600 C $38 400 D $40 320
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2015
Q209 · Which item is not part of the owner’s equity? 9706/32 Oct/Nov 2015
1 Which item is not part of the owner’s equity? A capital redemption reserve B ordinary share capital C proposed ordinary share dividend D revaluation reserve
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2015
Q210 · At the end of last year, a company's equity was as follows 9706/32 Oct/Nov 2015
7 At the end of last year, a company's equity was as follows. $ ordinary shares of $1 each 100 000 retained earnings 30 000 130 000 In the current financial year, the company makes a bonus issue of one ordinary share for every ten shares held previously. The bonus issue is followed by a fully subscribed rights issue of two shares at $1.30 per share for every eleven shares already held. By how much do these transactions increase the company's cash resources? A $10 000 B $20 000 C $26 000 D $46 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2015
Q211 · Which statement about debentures and preference shares is correct? 9706/32 Oct/Nov 2015
9 Which statement about debentures and preference shares is correct? A Both debentures and preference shares increase the gearing ratio. B Both debenture holders and preference shareholders can vote at the annual general meeting. C Capital employed includes preference shares but not debentures. D When the company ceases to trade, preference shareholders are repaid before debenture holders.
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2015
Q212 · The following information is available for a limited company 9706/32 Oct/Nov 2015
11 The following information is available for a limited company. $000 retained earnings (opening balance) 238 dividend paid 120 dividend proposed 150 revaluation gain from properties 72 profit for the year 184 What is the retained earnings balance at the end of the year? A $152 000 B $224 000 C $302 000 D $374 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2015
Q213 · Which items might appear in a statement of changes in equity? 9706/32 Oct/Nov 2015
12 Which items might appear in a statement of changes in equity? 1 issue of bonus shares 2 proposed dividend 3 purchase of non-current assets 4 revaluation of property during the year A 1 and 2 B 1 and 4 C 2 and 3 D 3 and 4
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2015
Q214 · What is shown in the statement of financial position? 9706/32 Oct/Nov 2015
13 What is shown in the statement of financial position? A dividends paid to shareholders B profit attributable to ordinary shareholders C revaluation reserve created for buildings D transfers to the general reserves for the year
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2015
Q215 · A company is proposing to purchase a new machine which will have a payback of five years 9706/32 Oct/Nov 2015
21 A company is proposing to purchase a new machine which will have a payback of five years. The following sources of finance are available. 1 an issue of convertible loan stock 2 an issue of debentures 3 an issue of ordinary shares to new shareholders Which source(s) would ensure that control is not lost? A 1 only B 1 and 2 C 2 only D 2 and 3
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2015
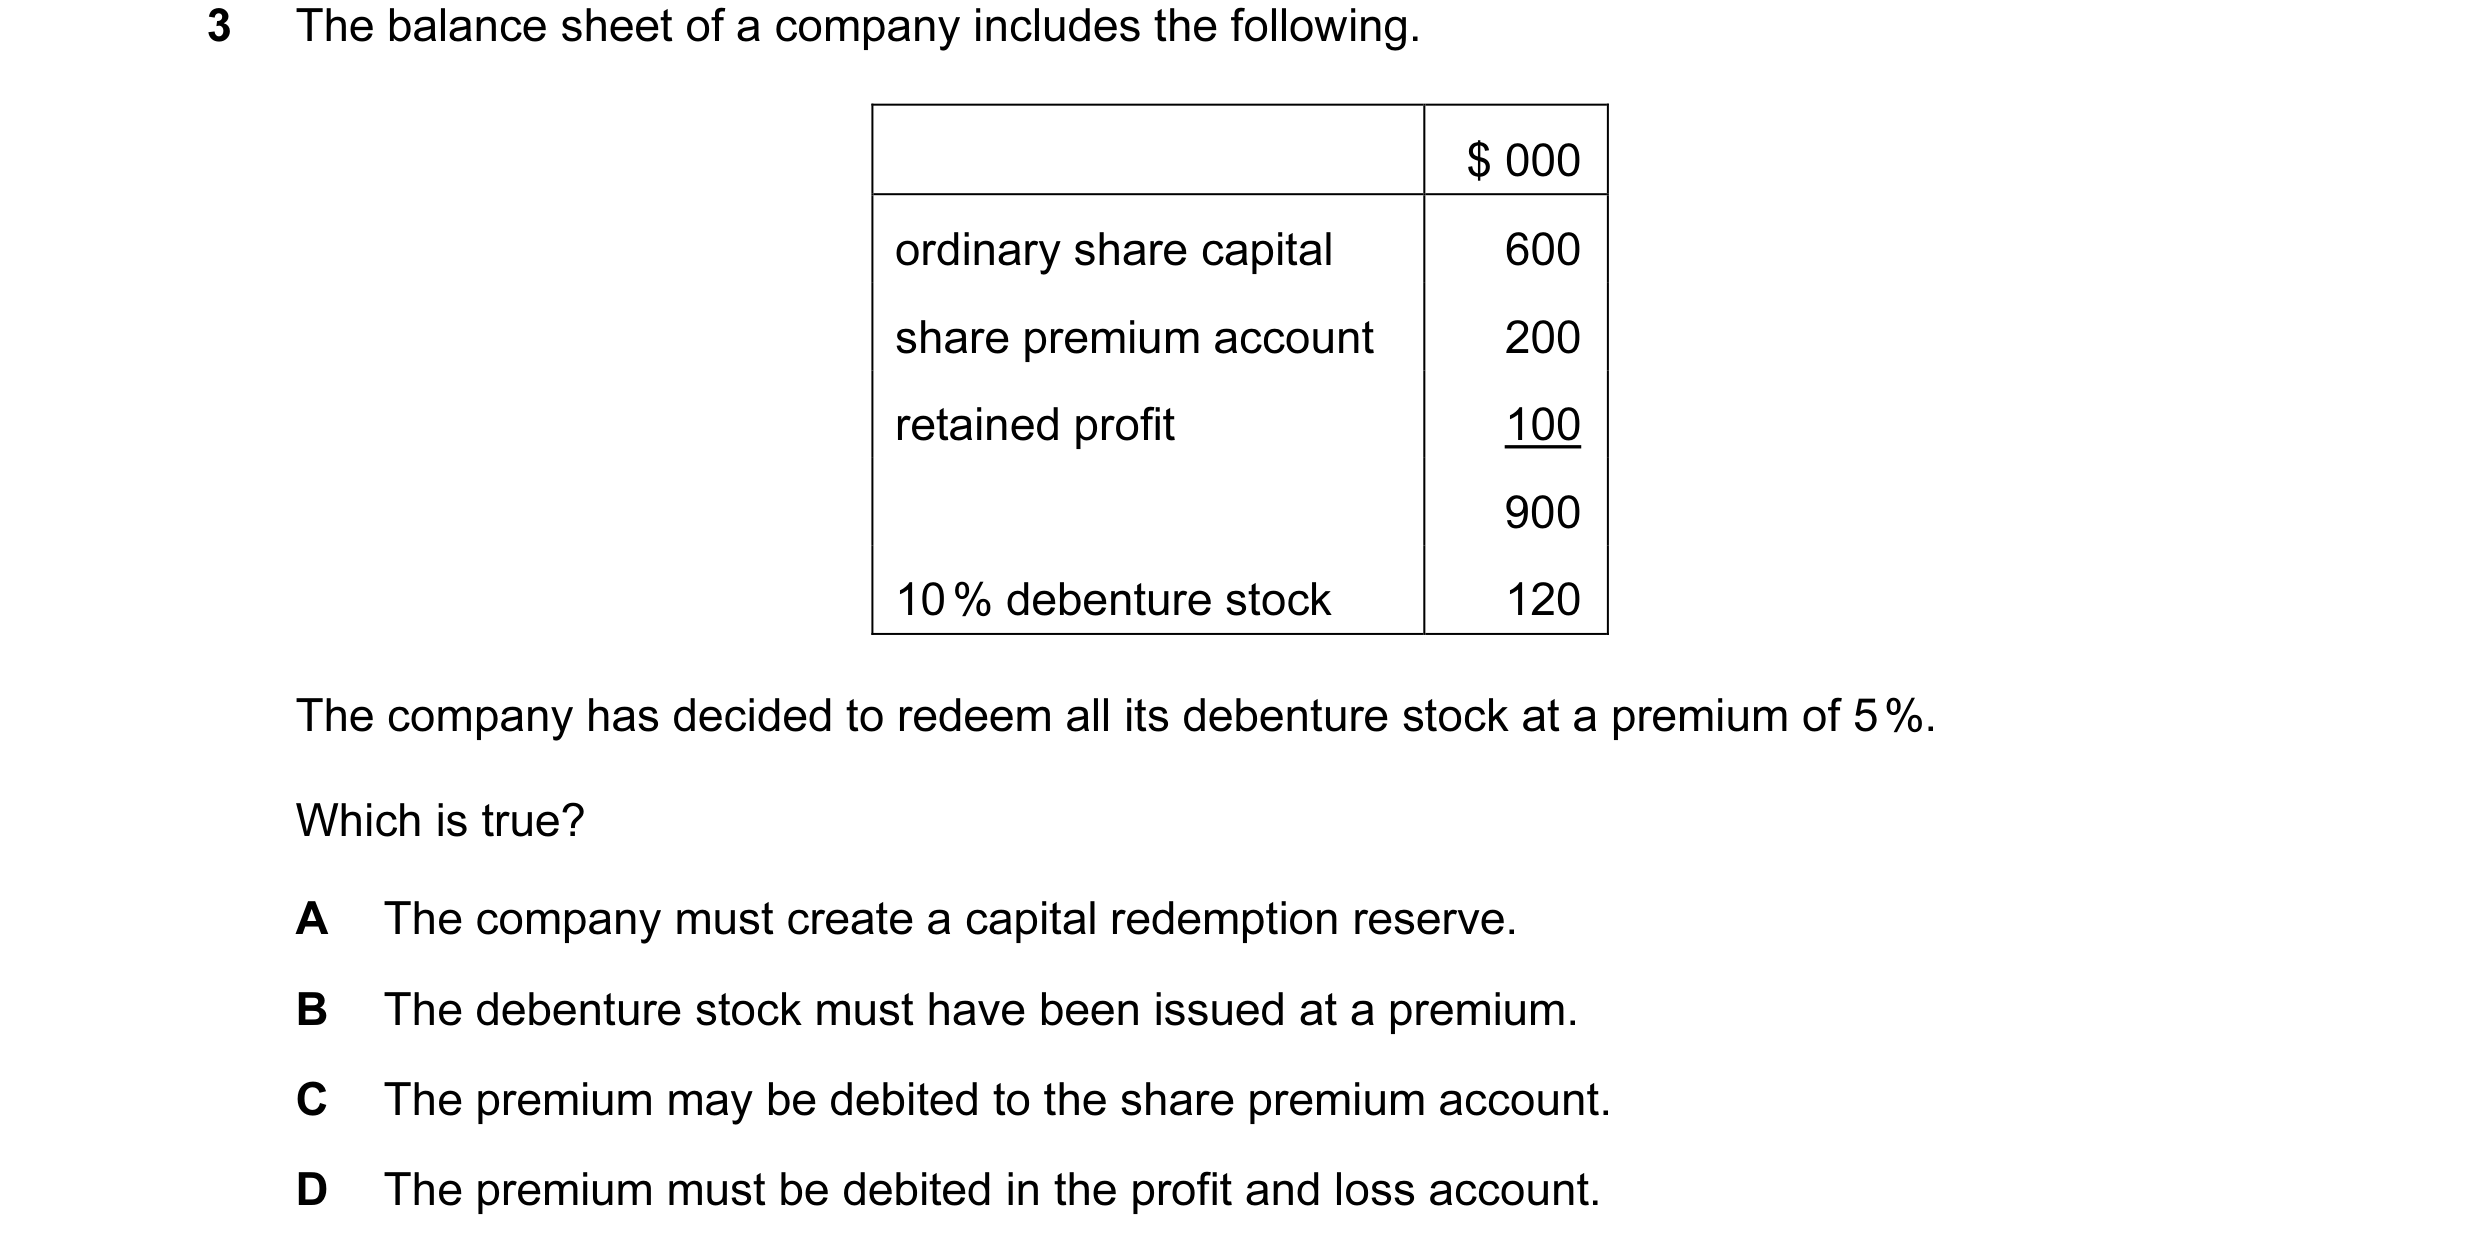
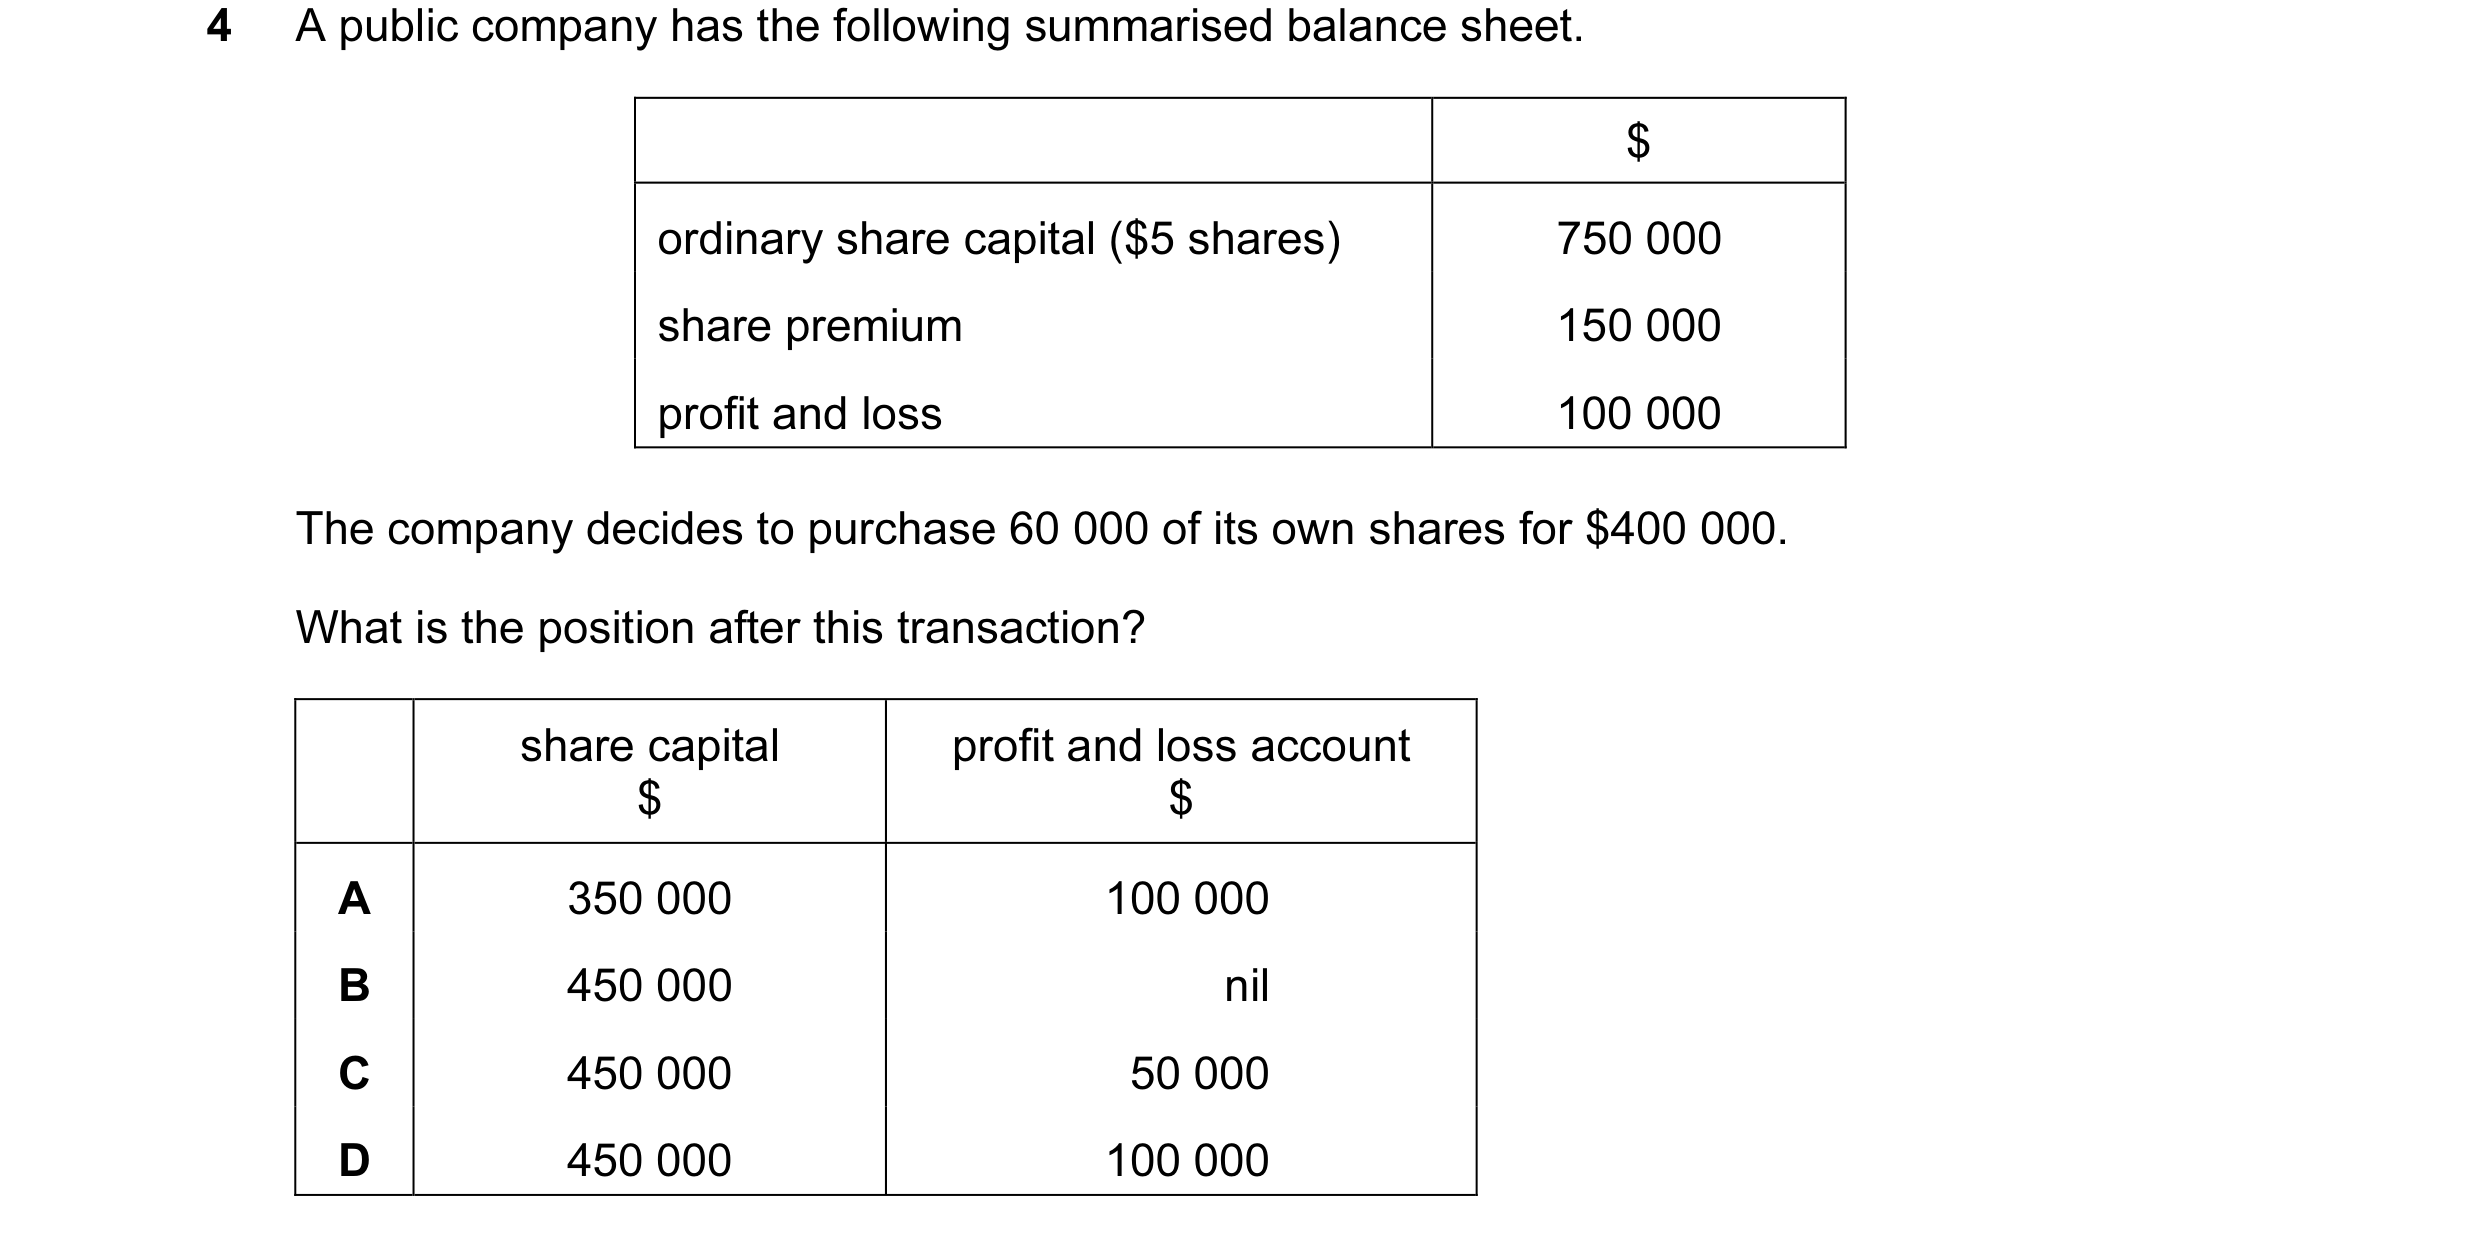
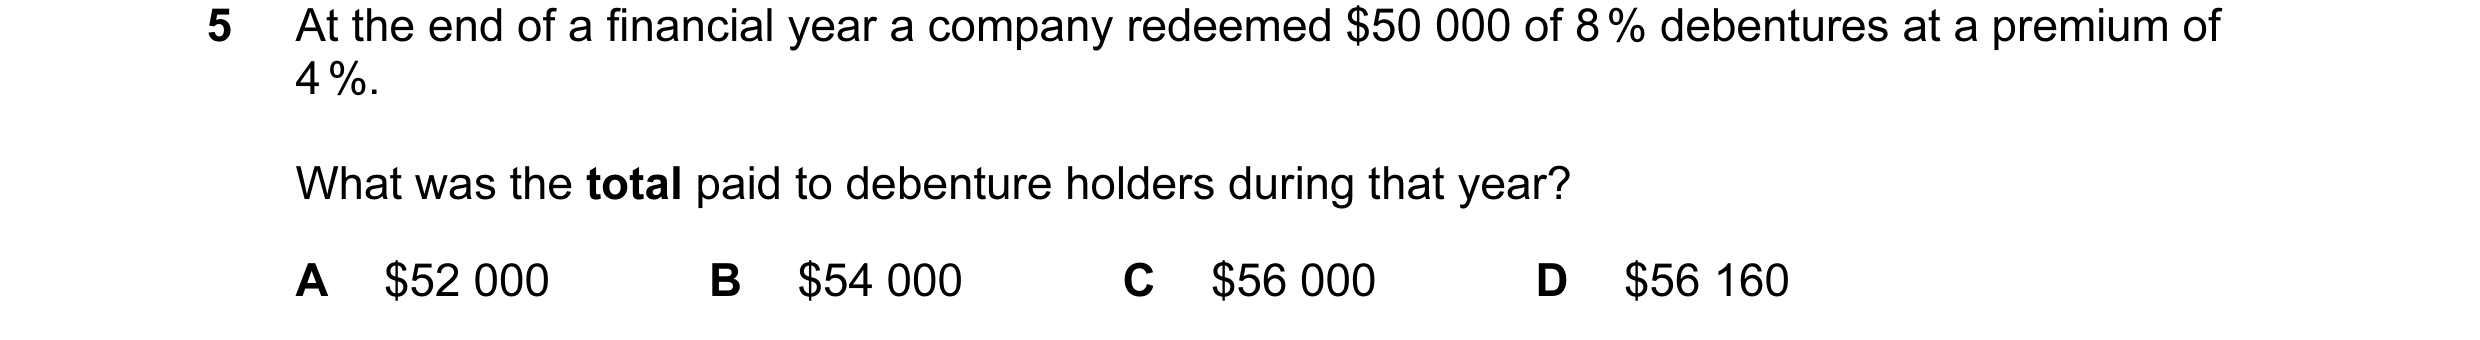 1 / 62
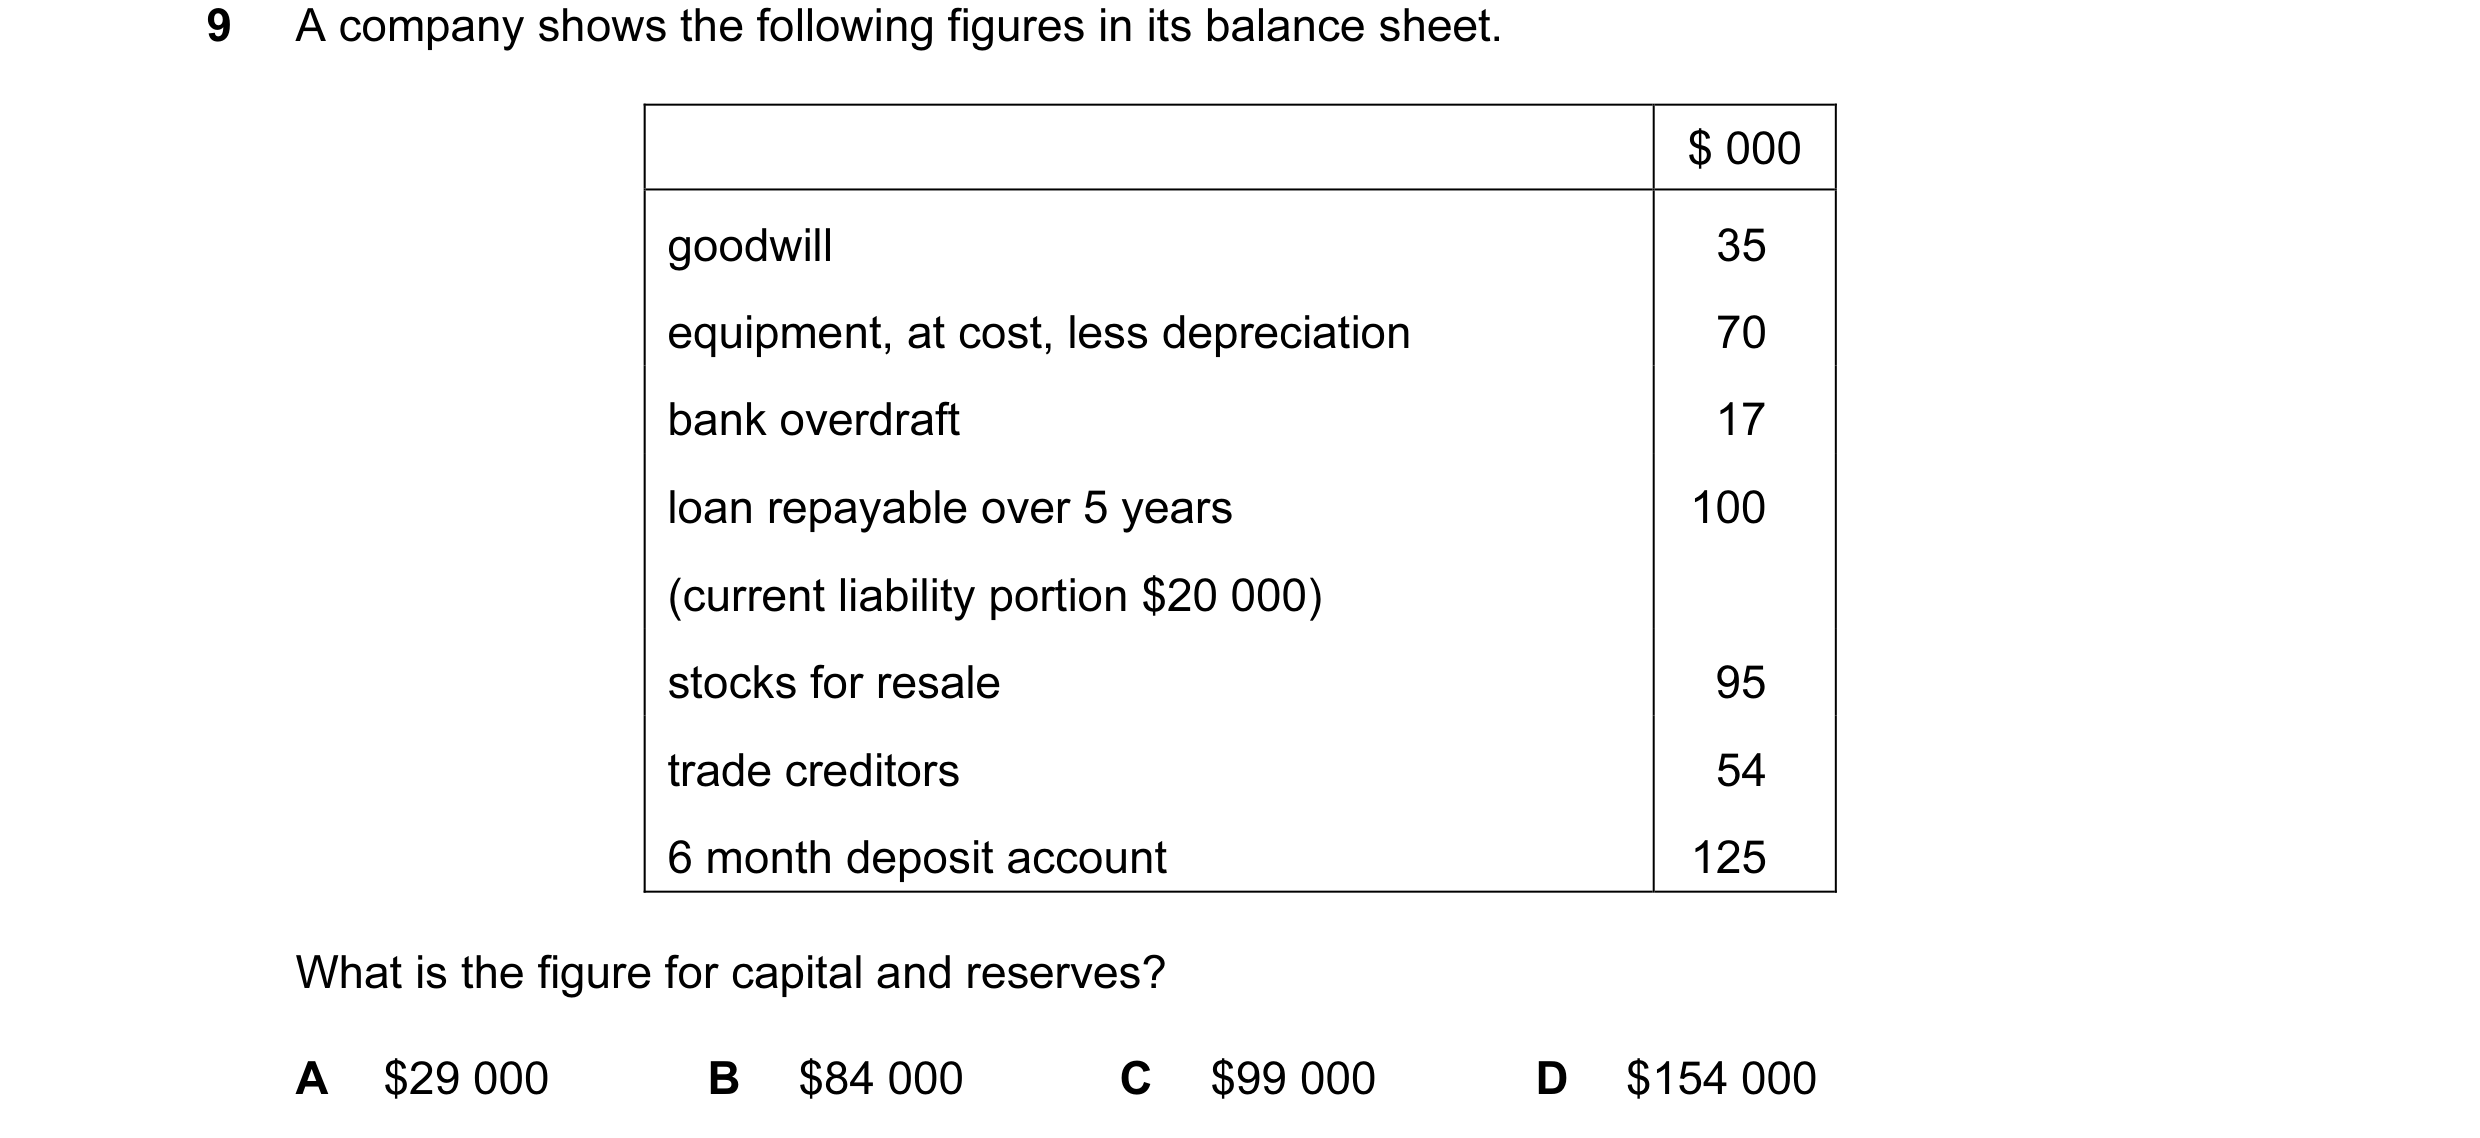
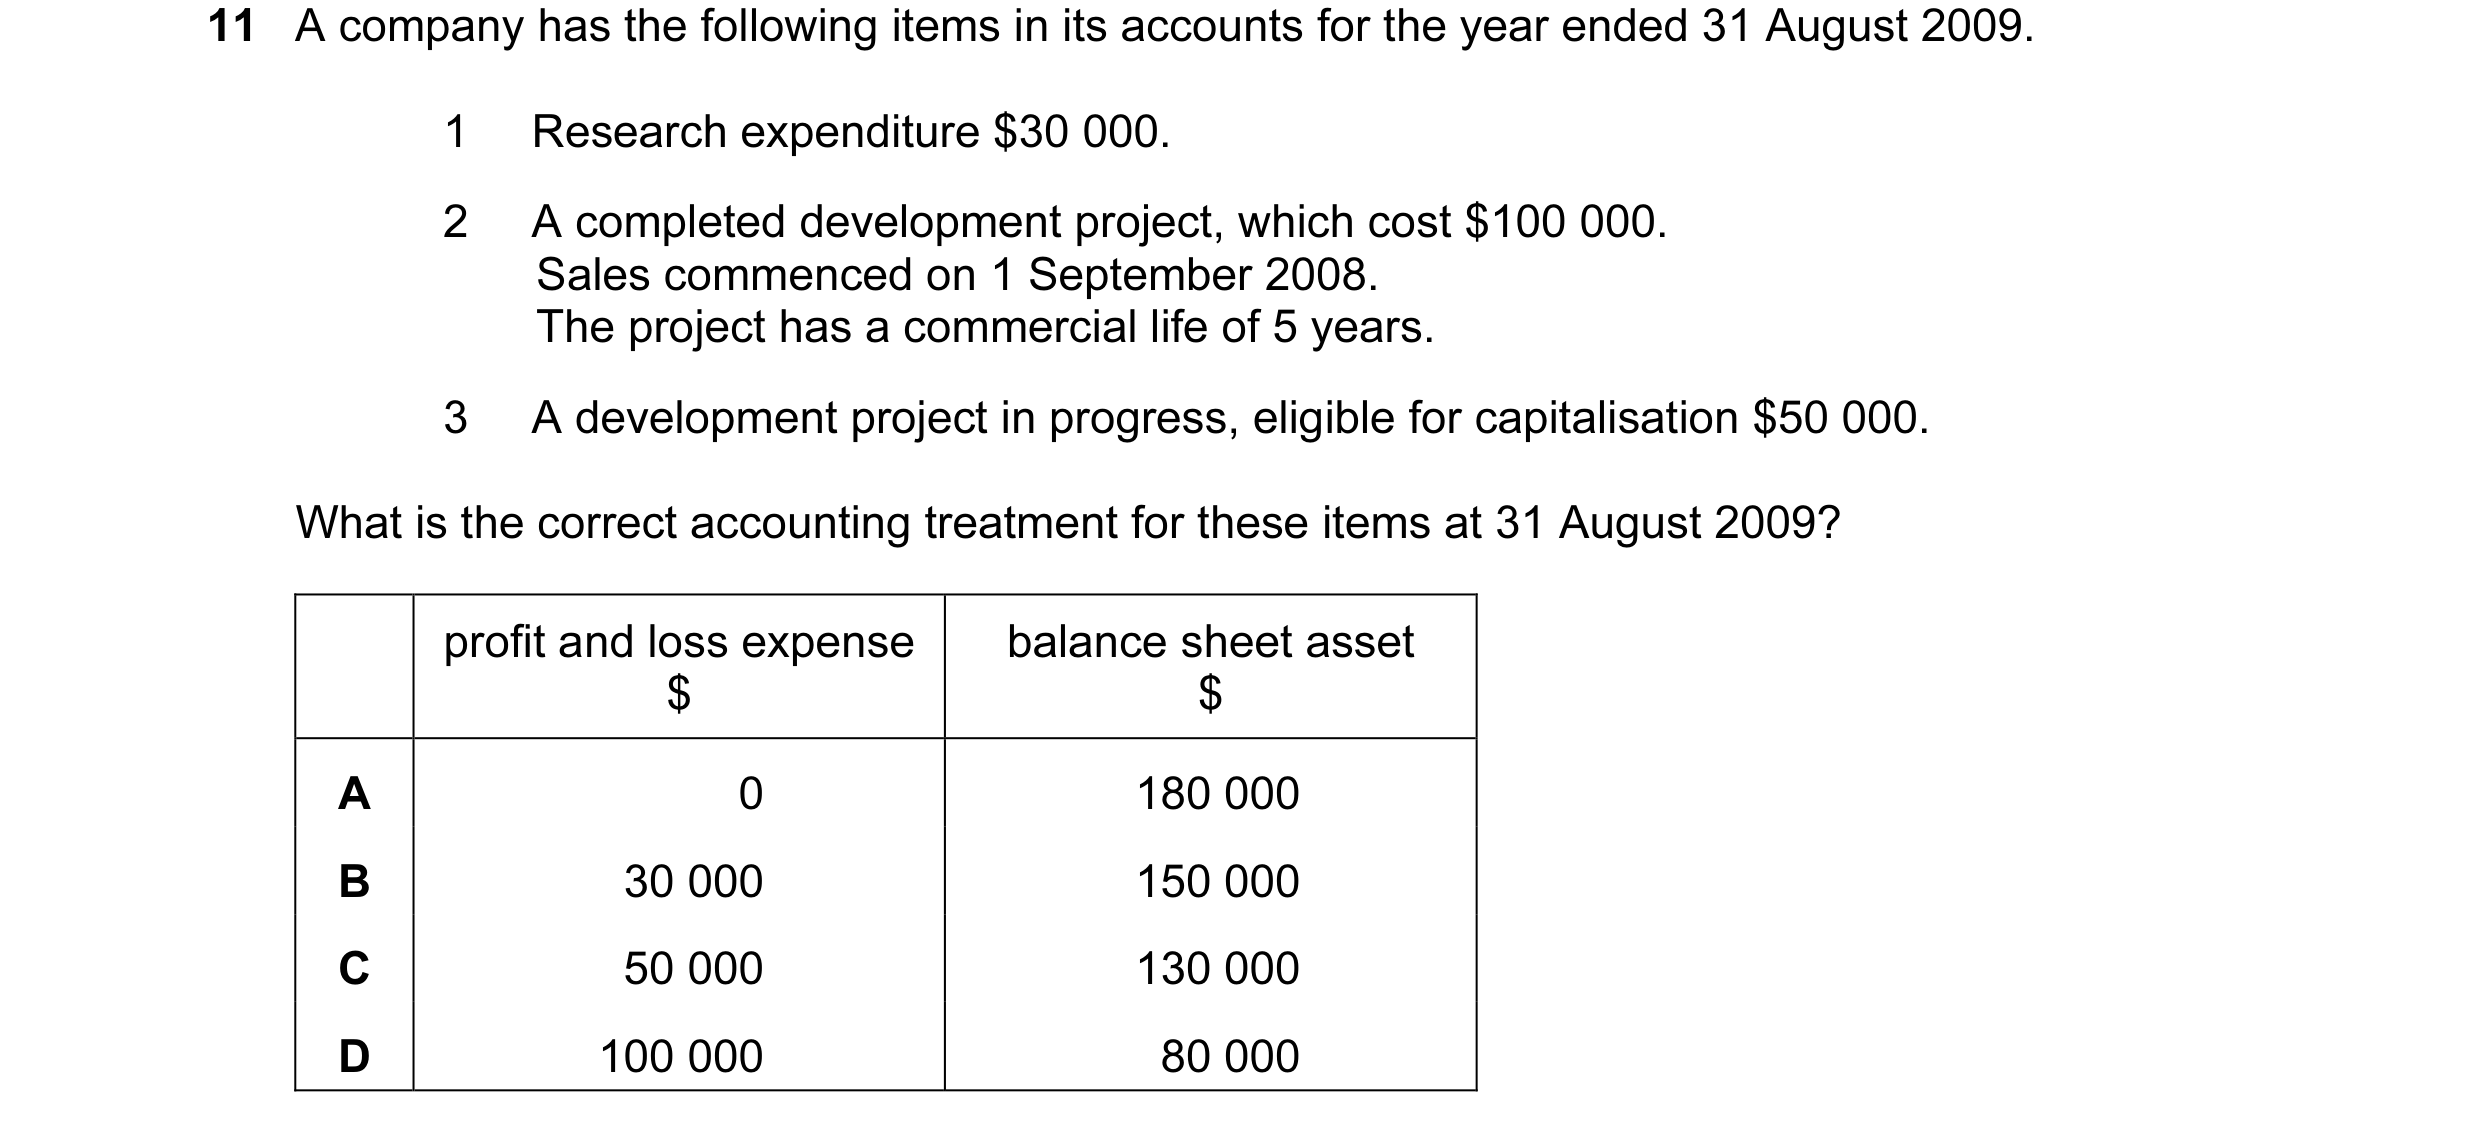 2 / 62
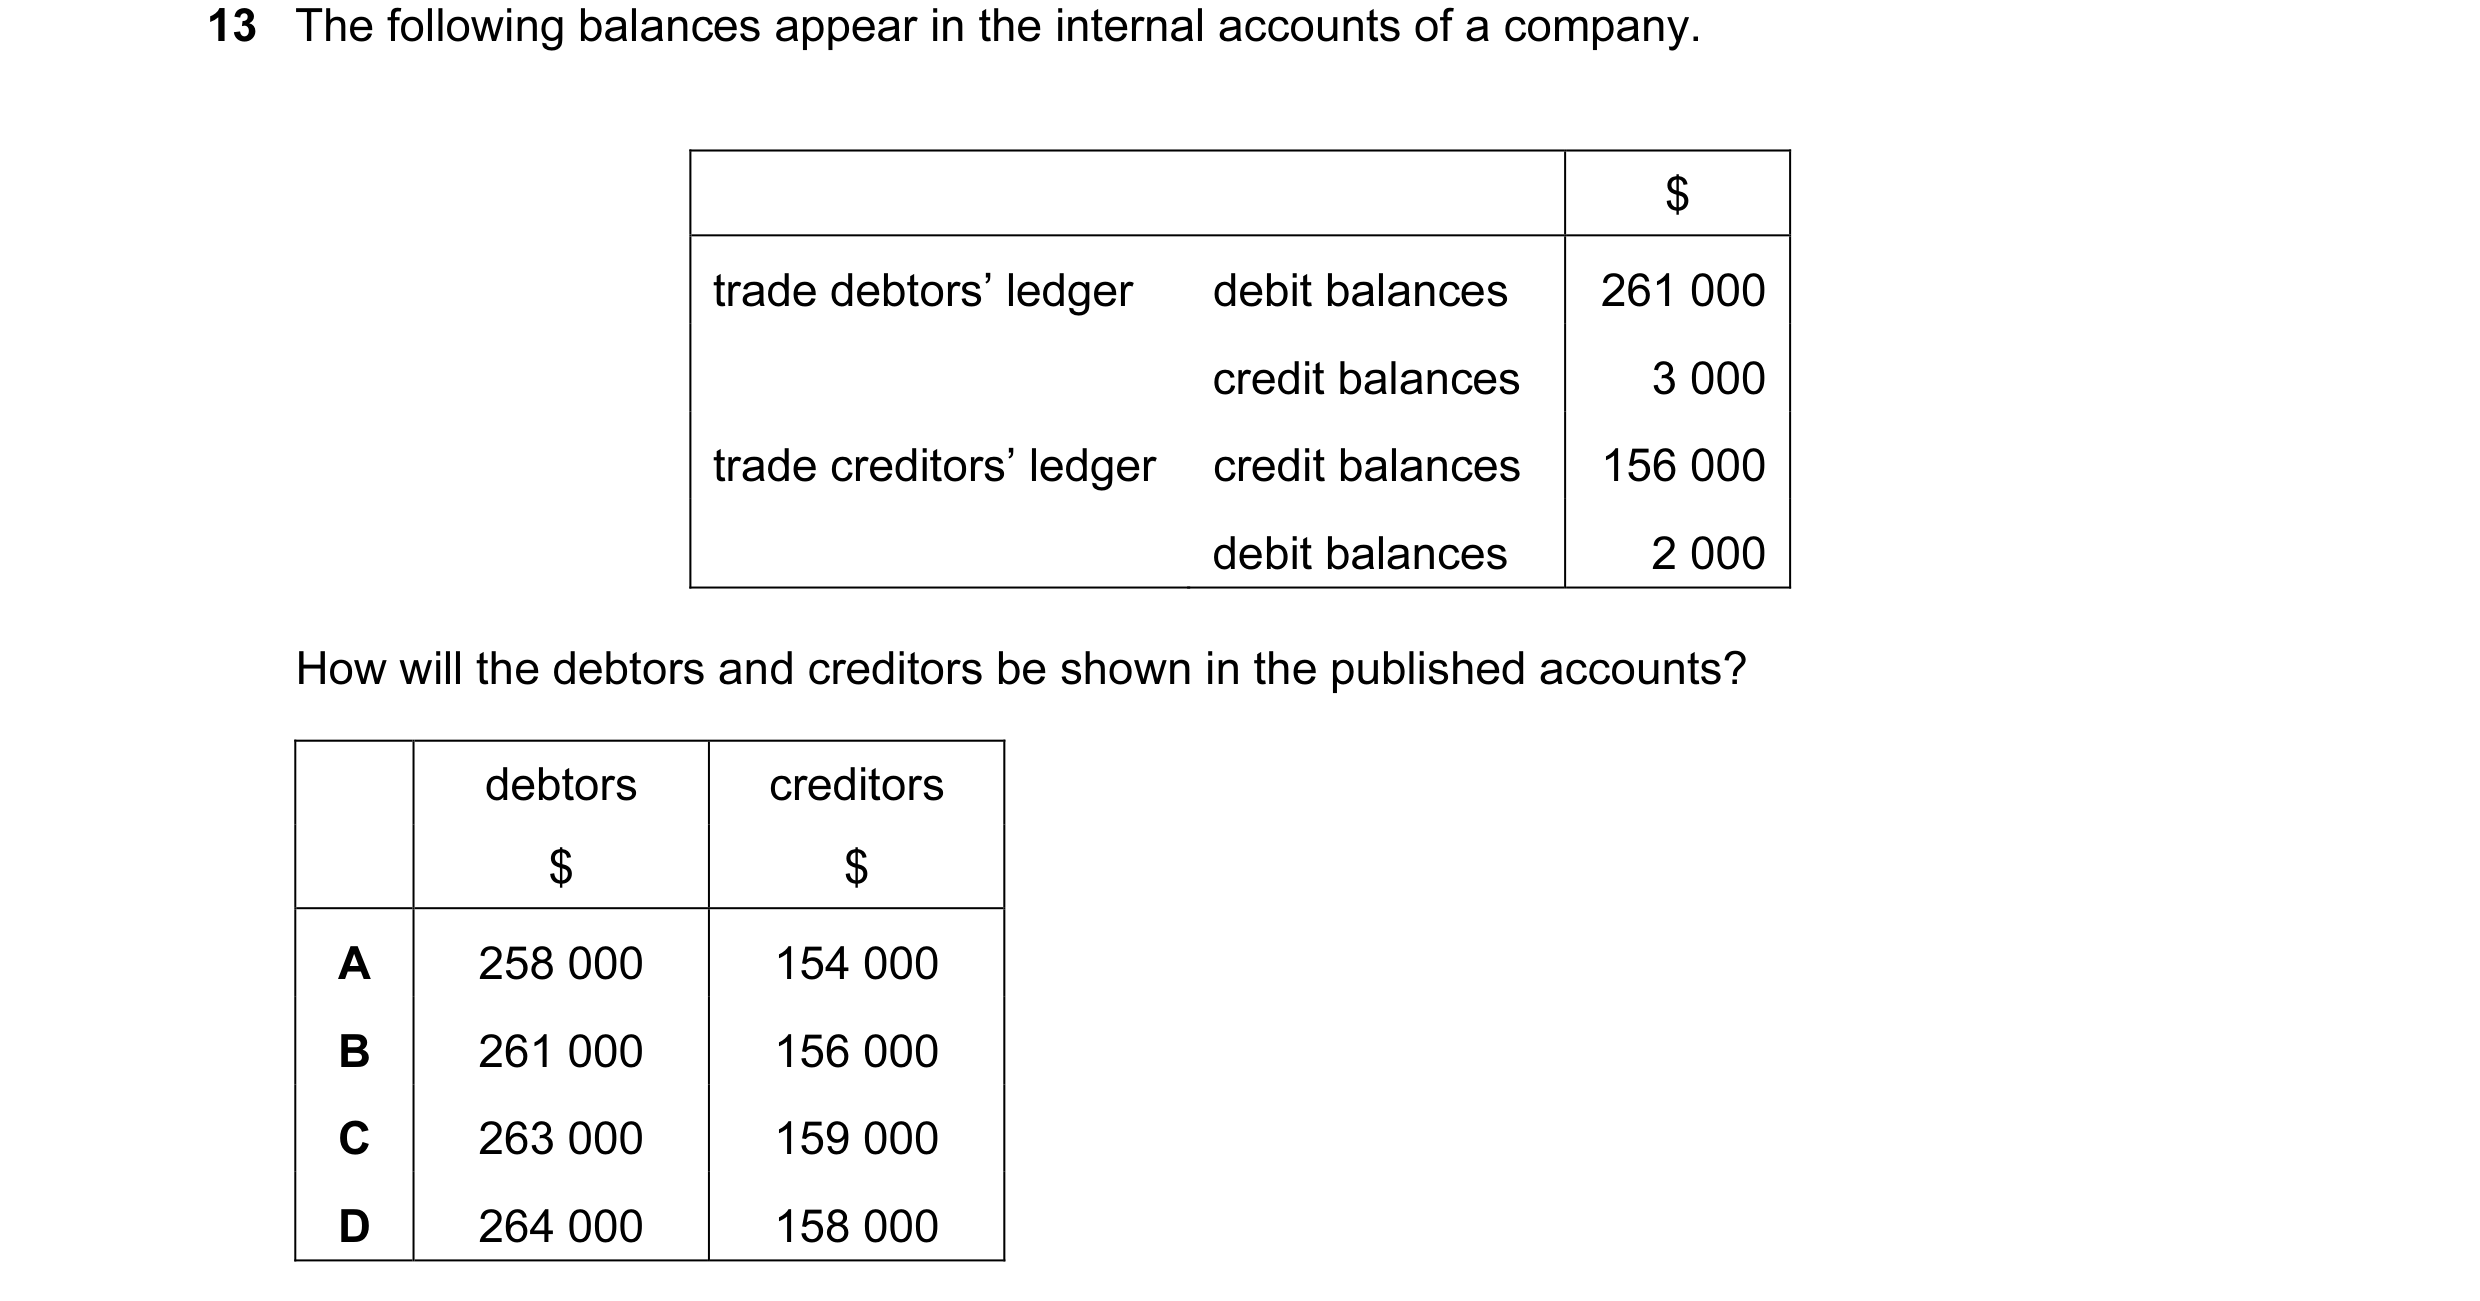
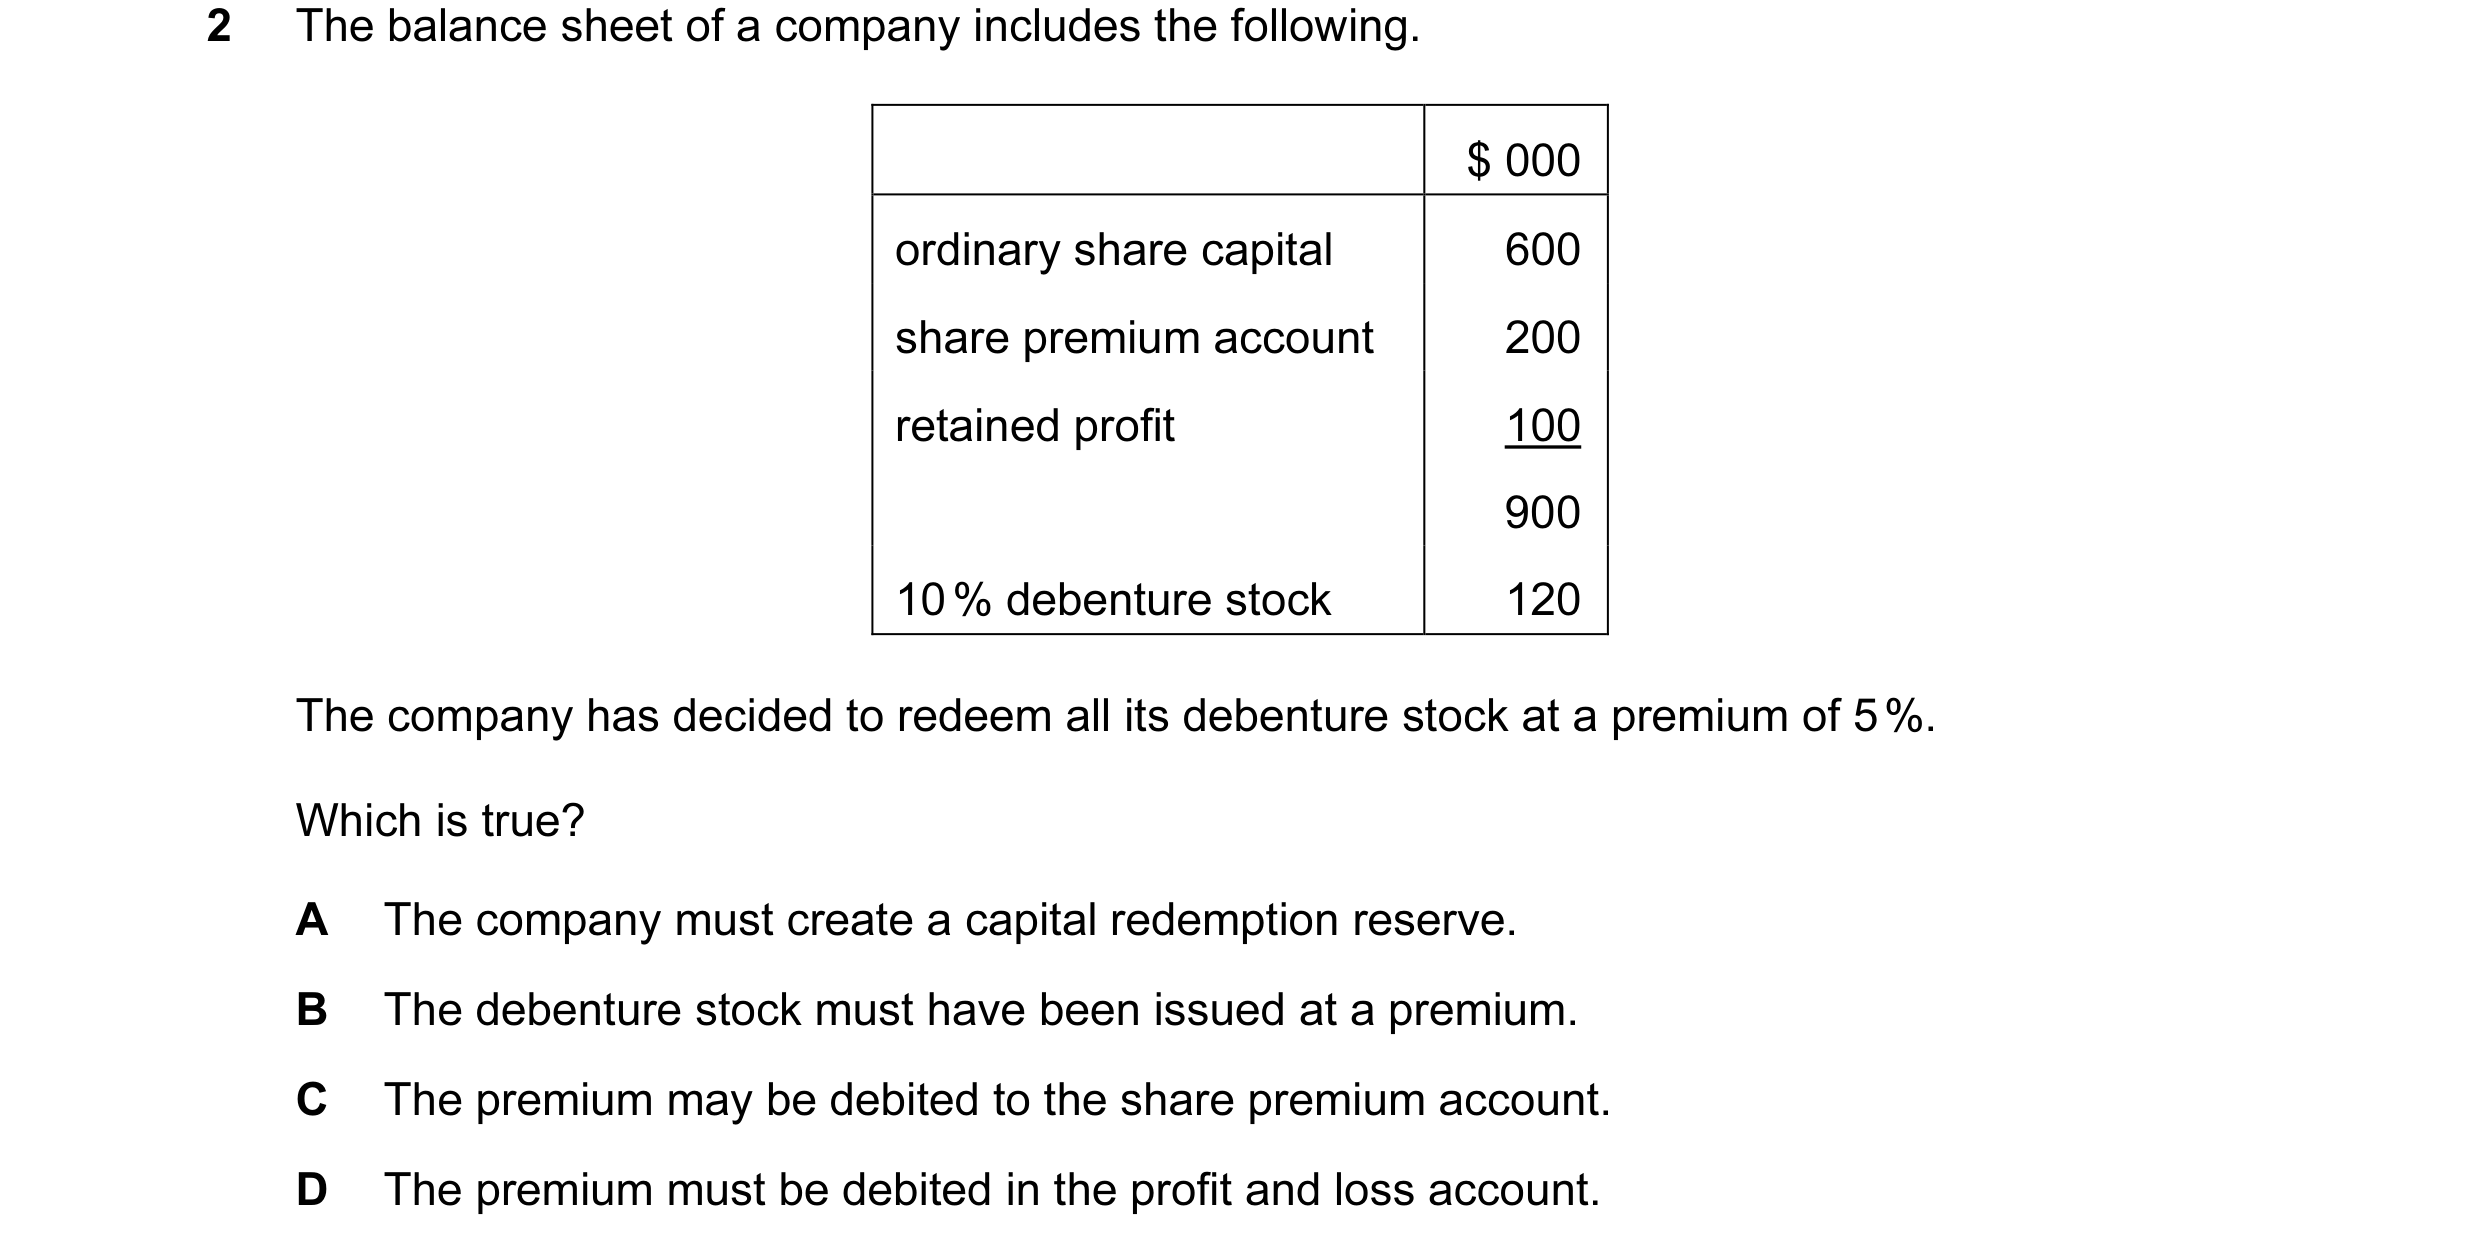 3 / 62
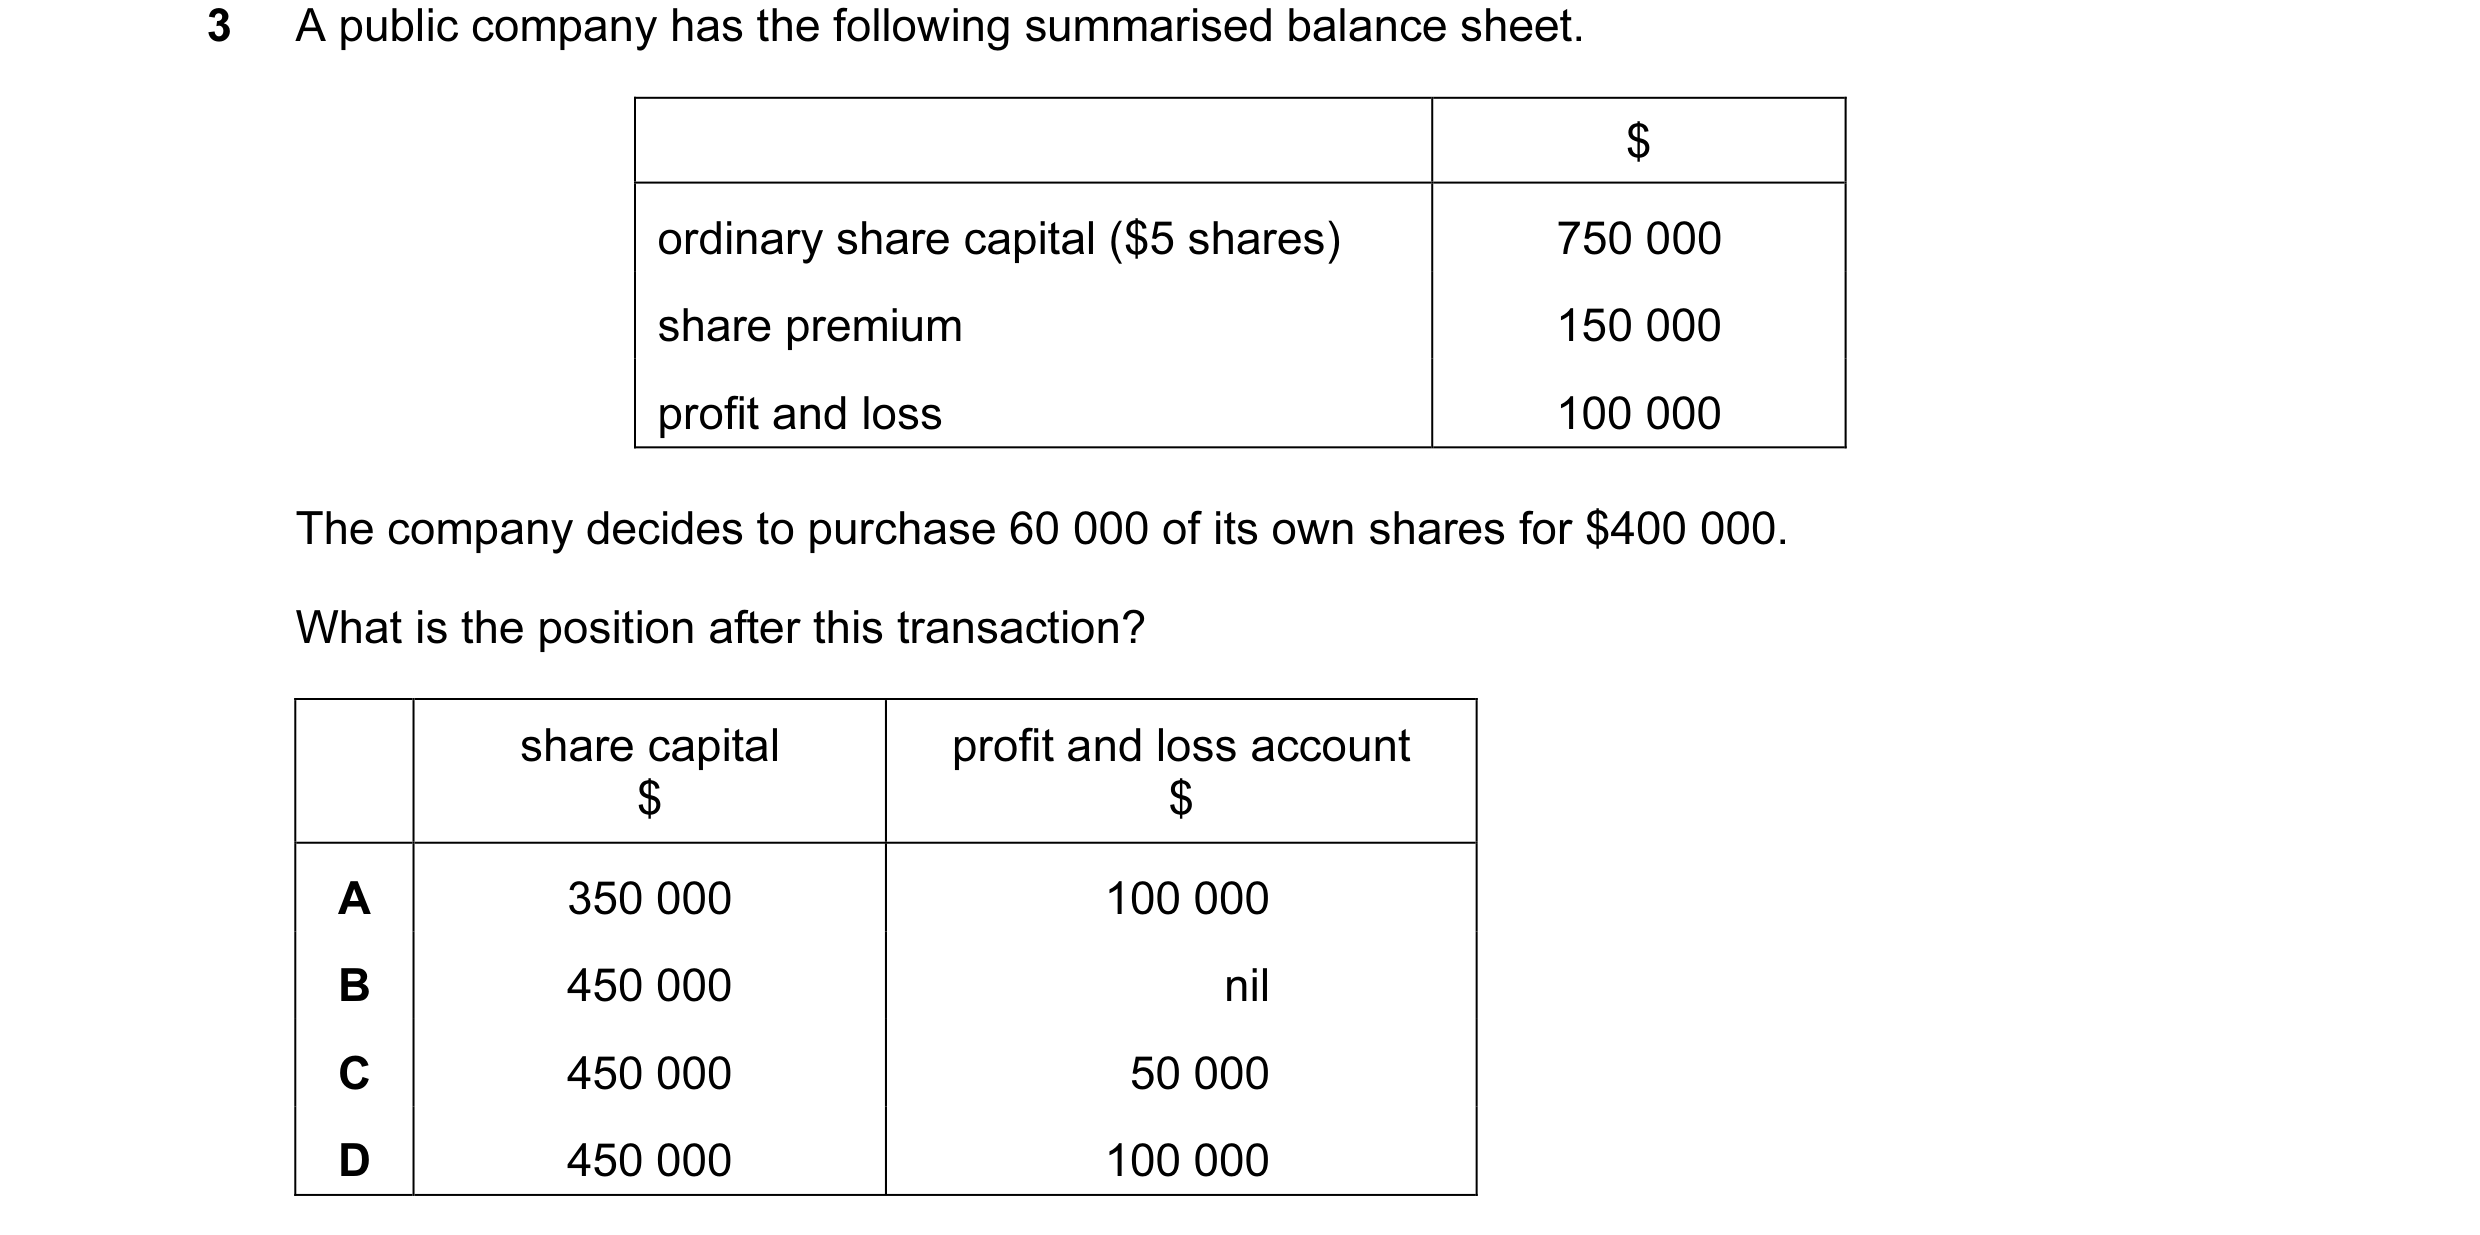
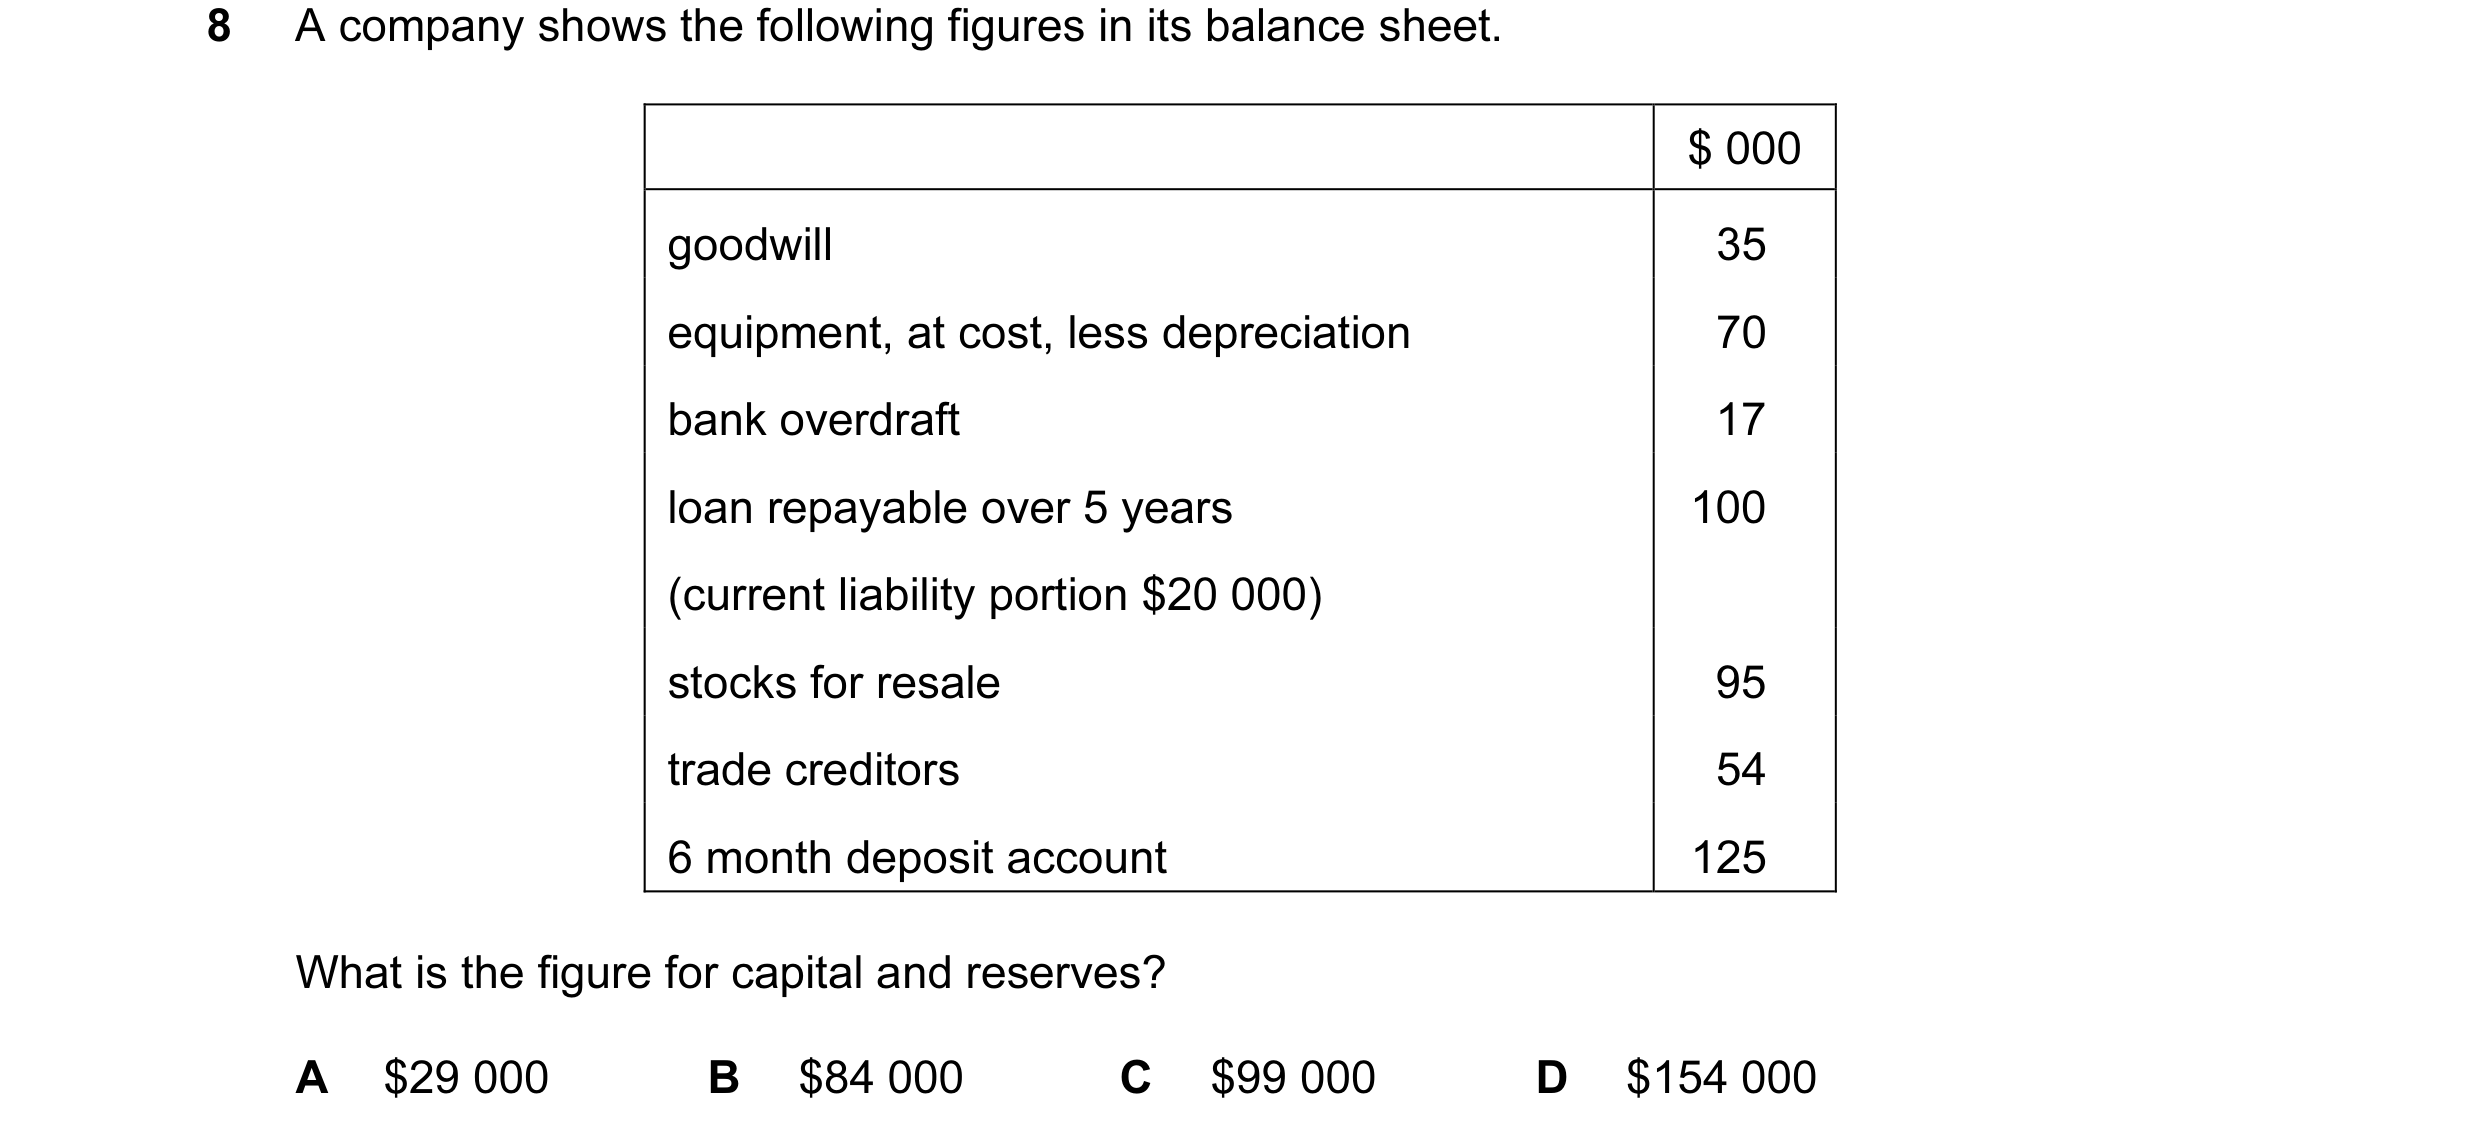 4 / 62
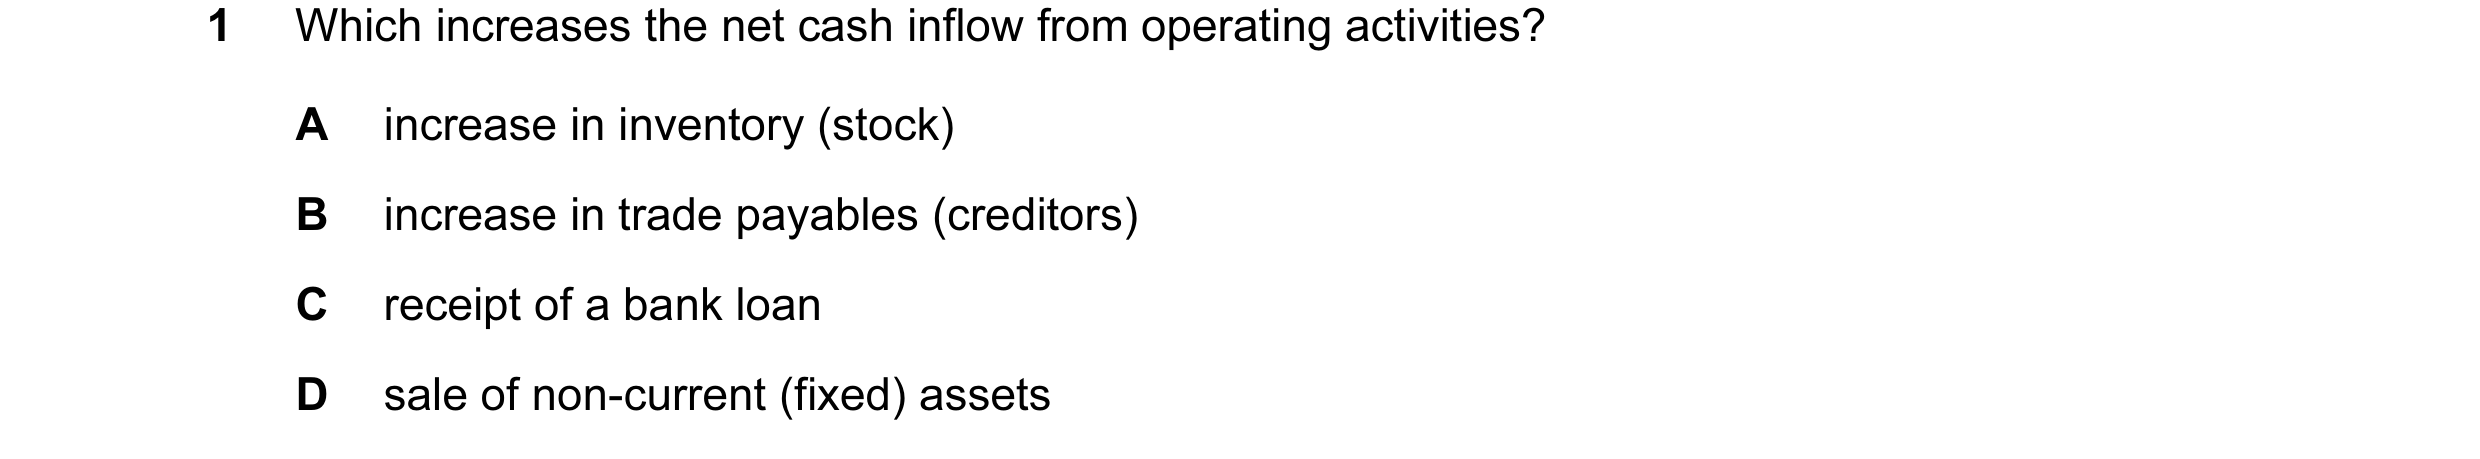 5 / 62
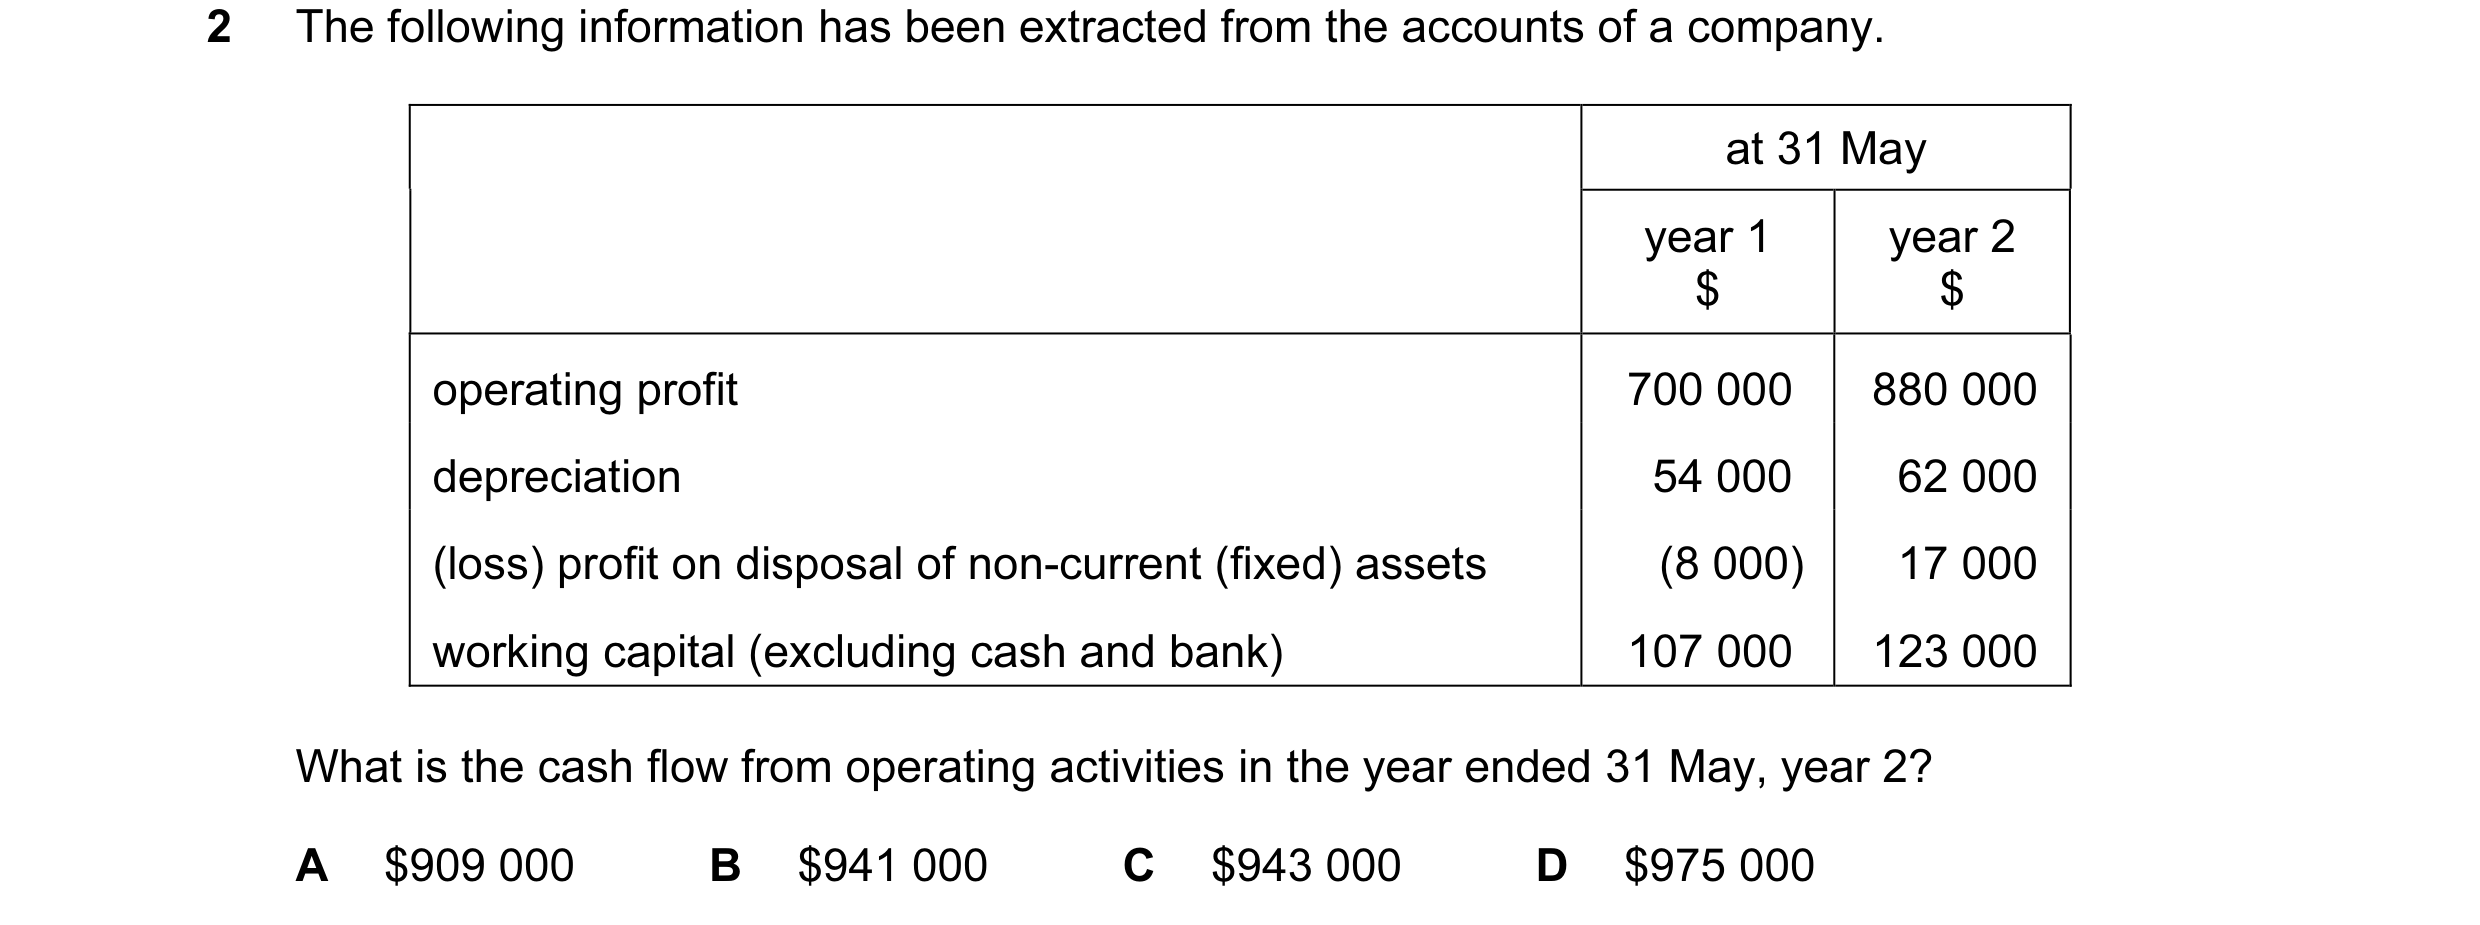
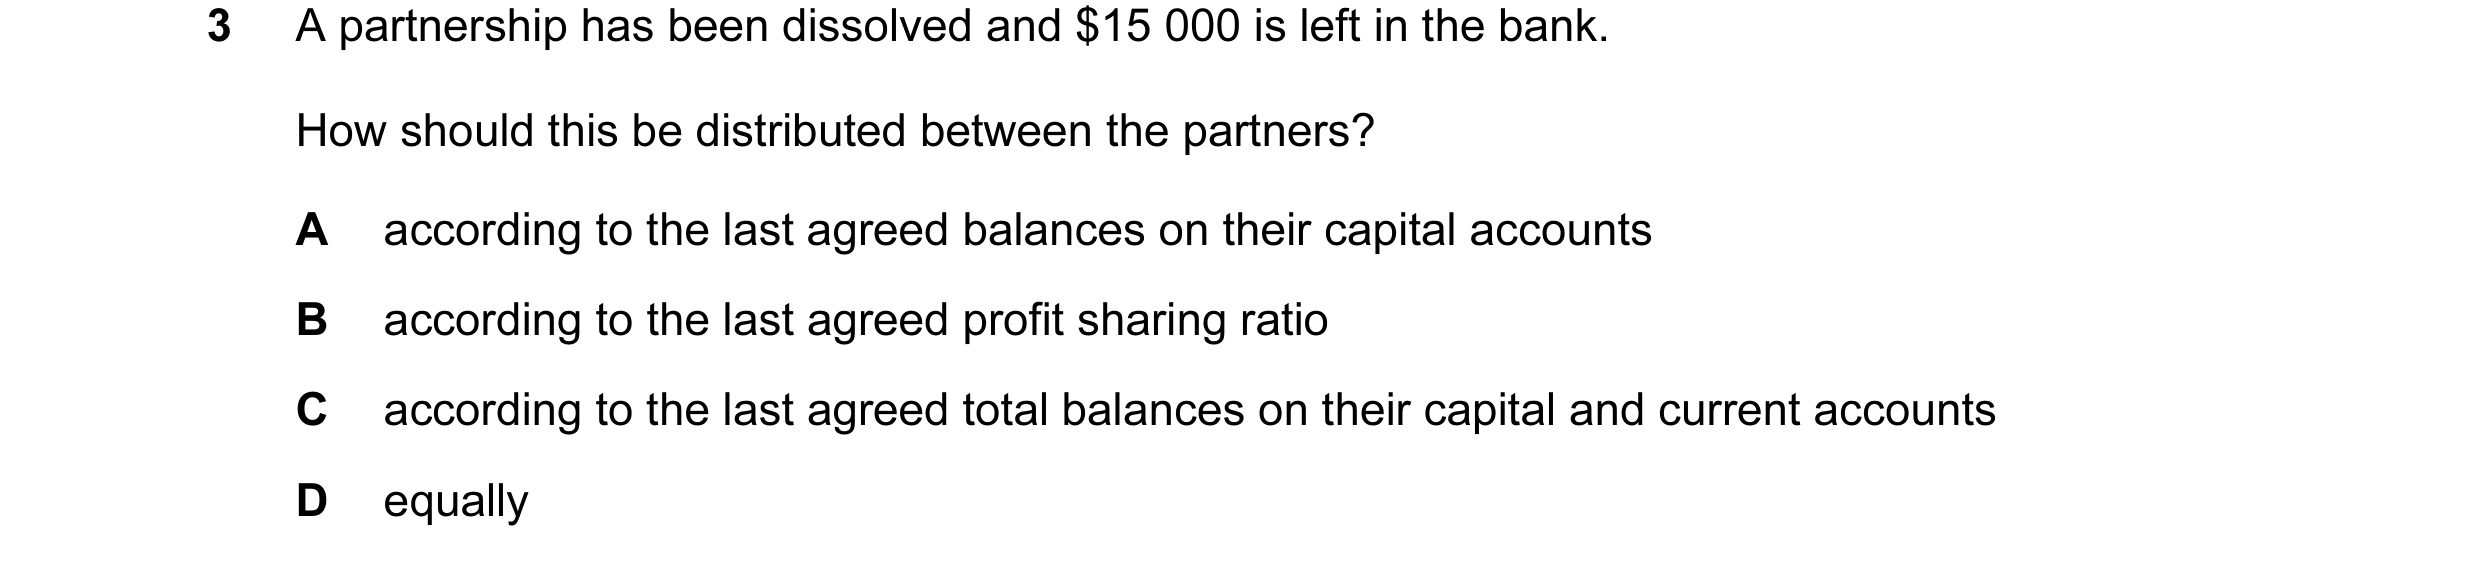
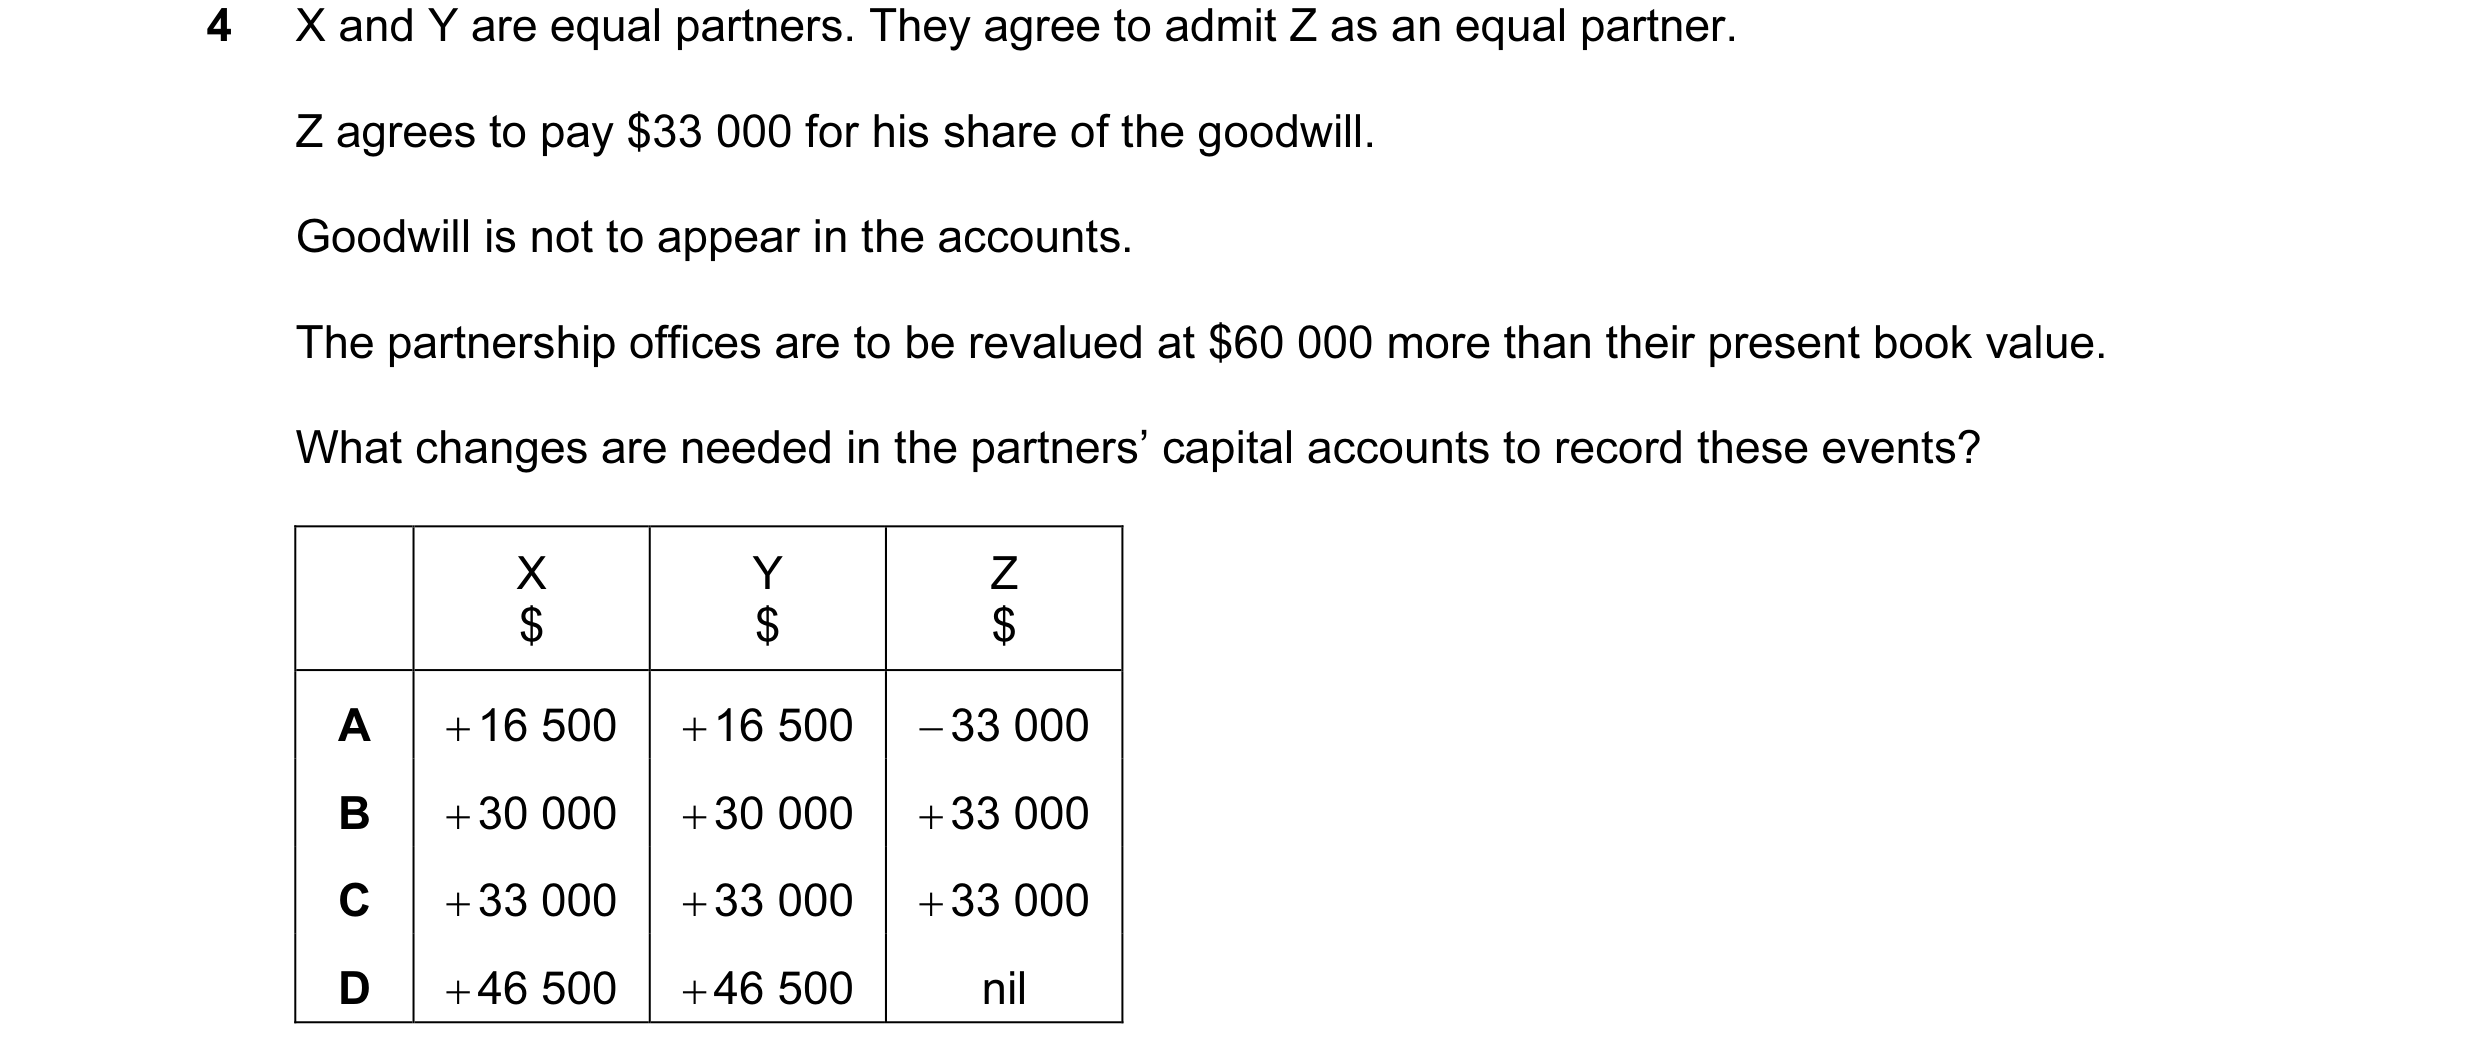
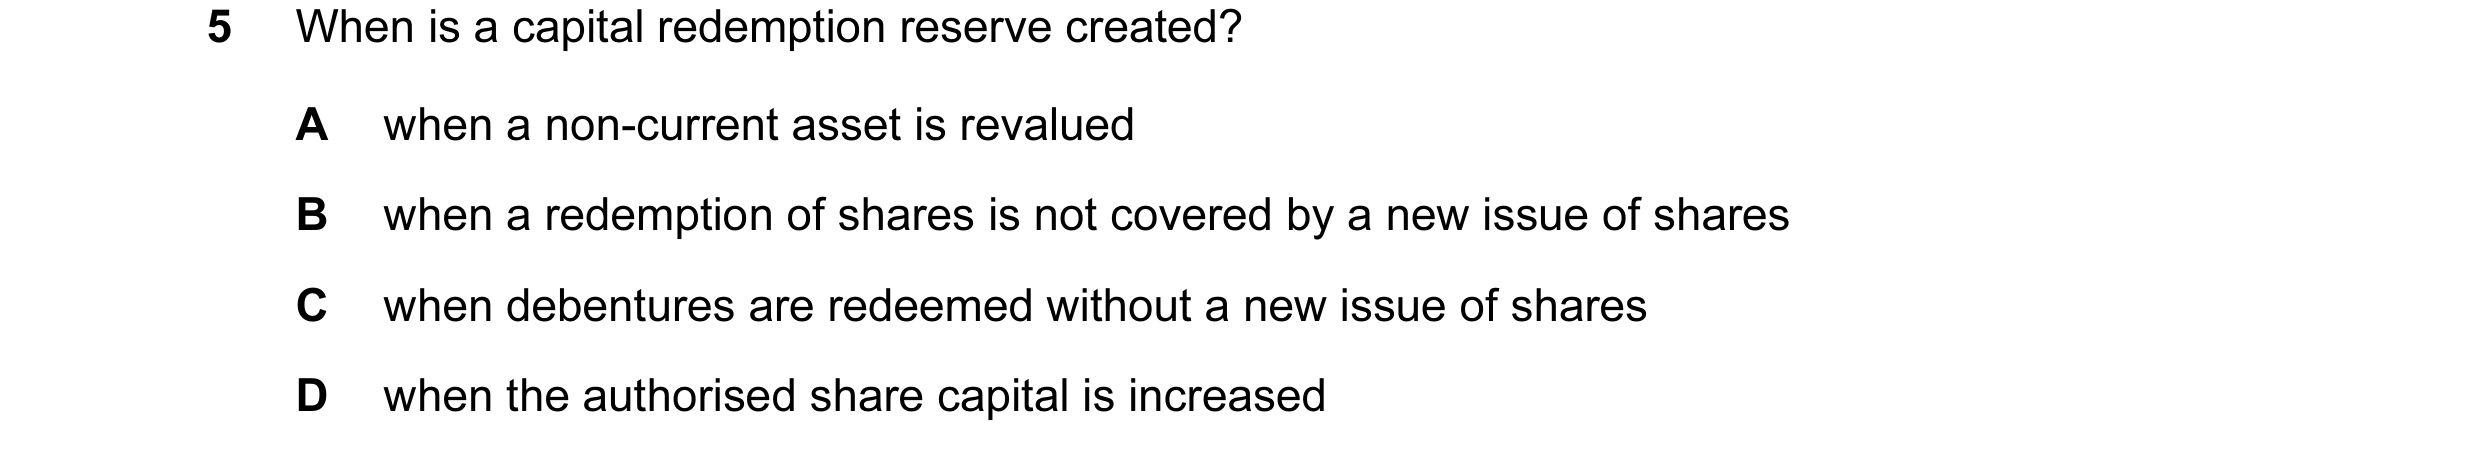 6 / 62
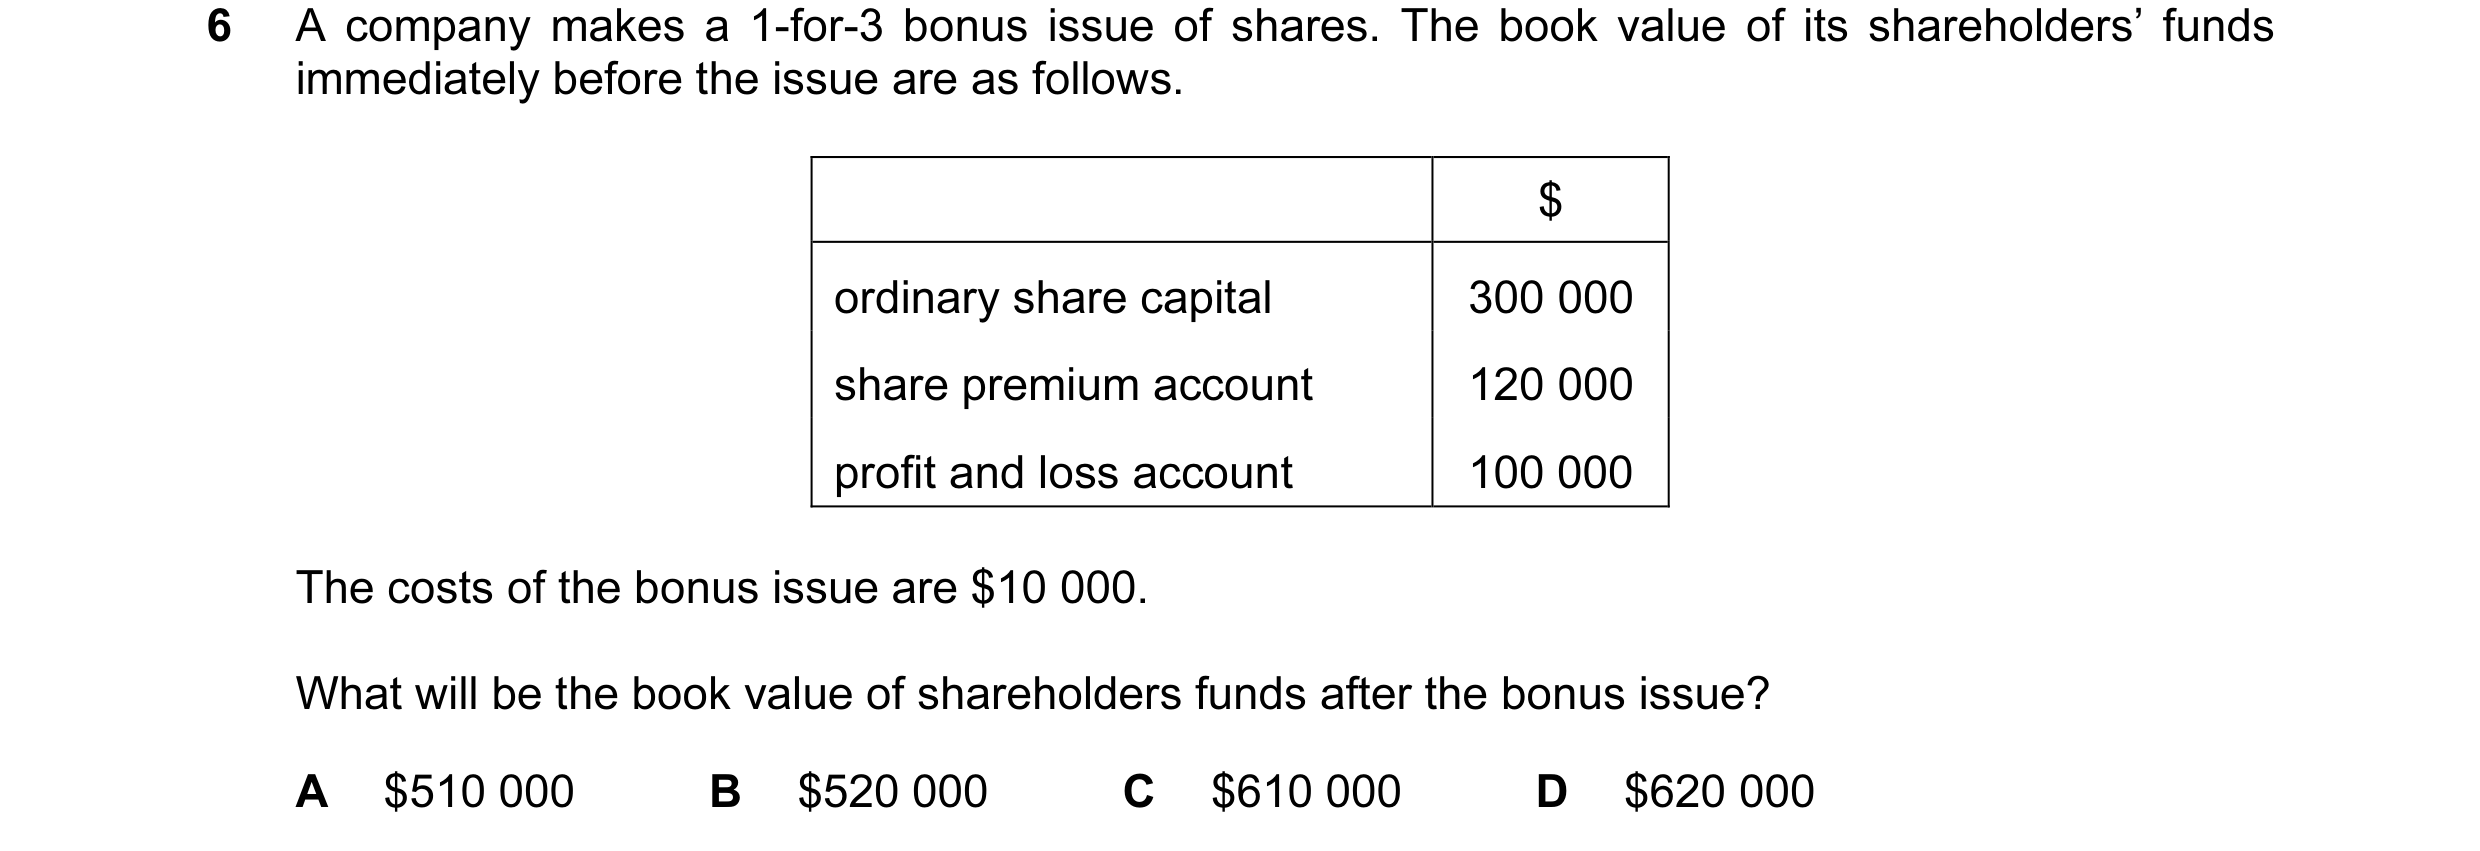
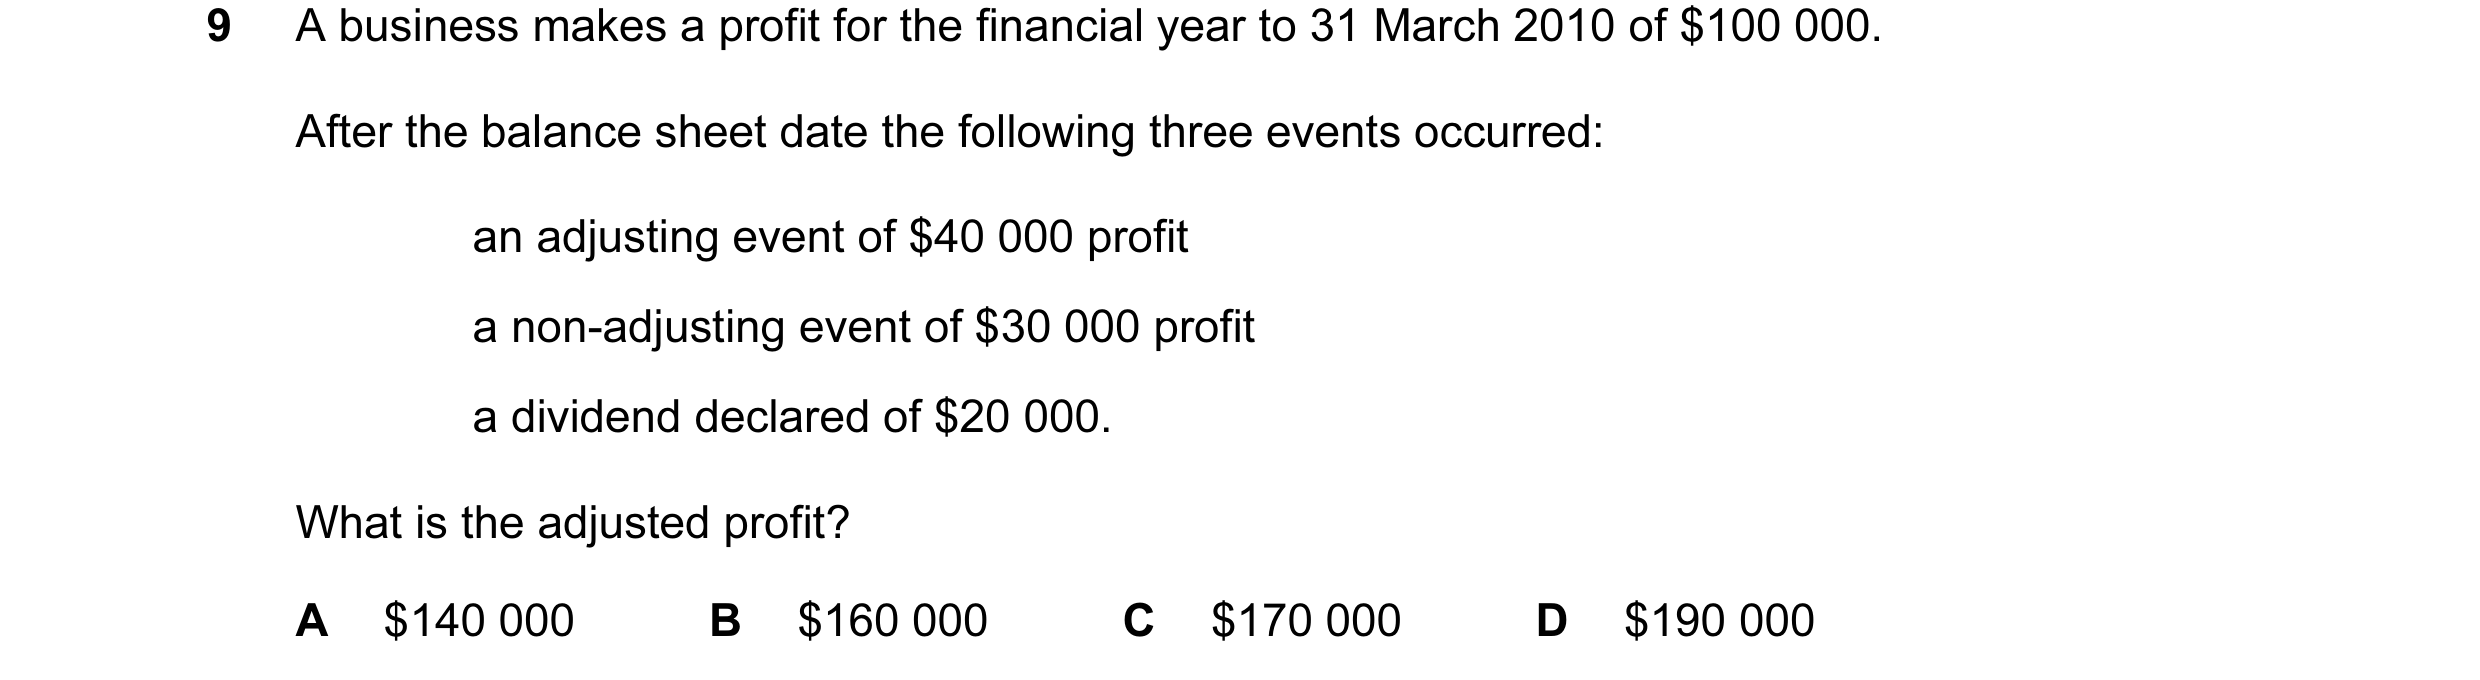
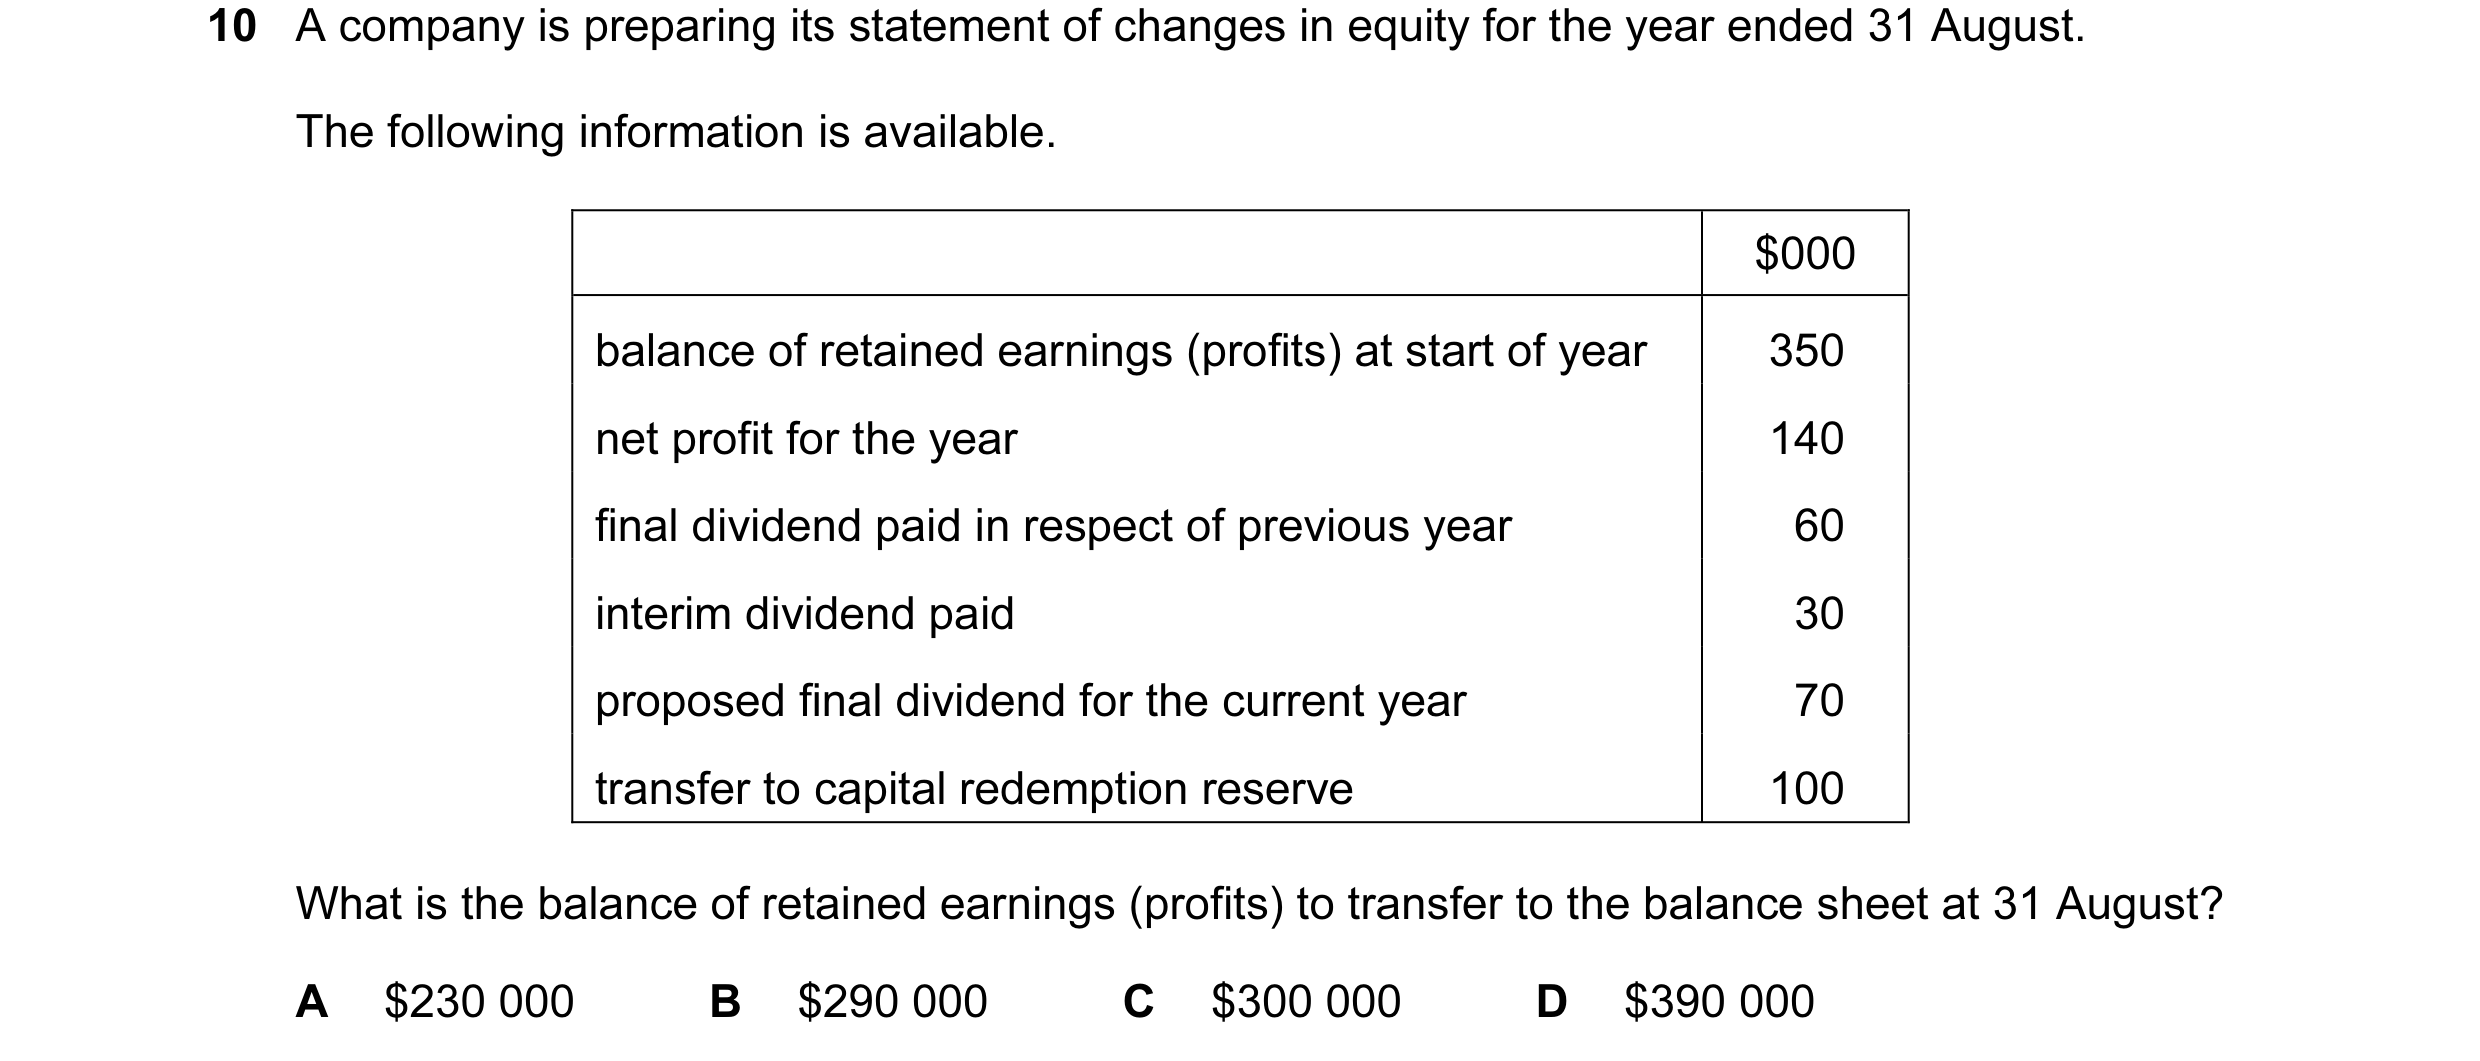
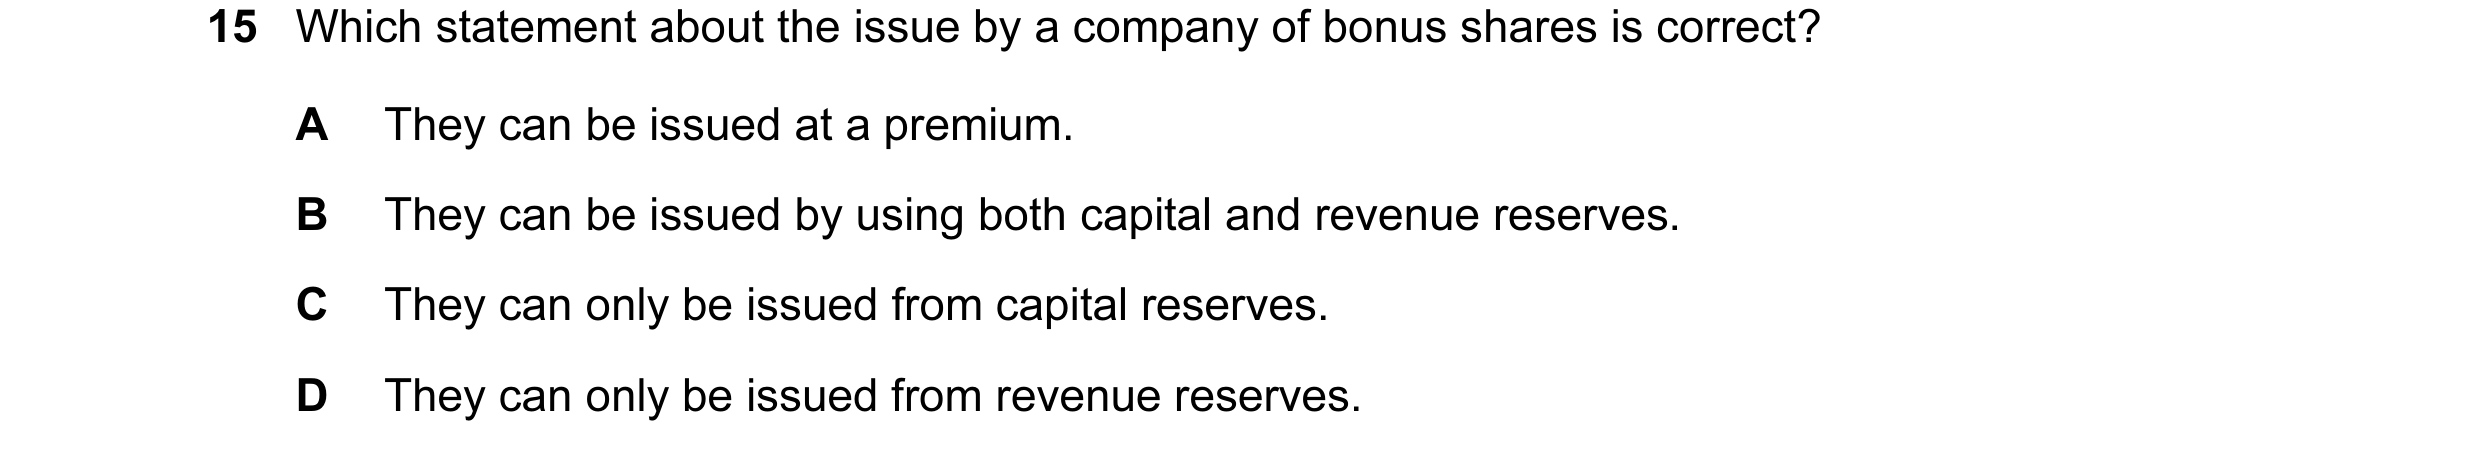 7 / 62
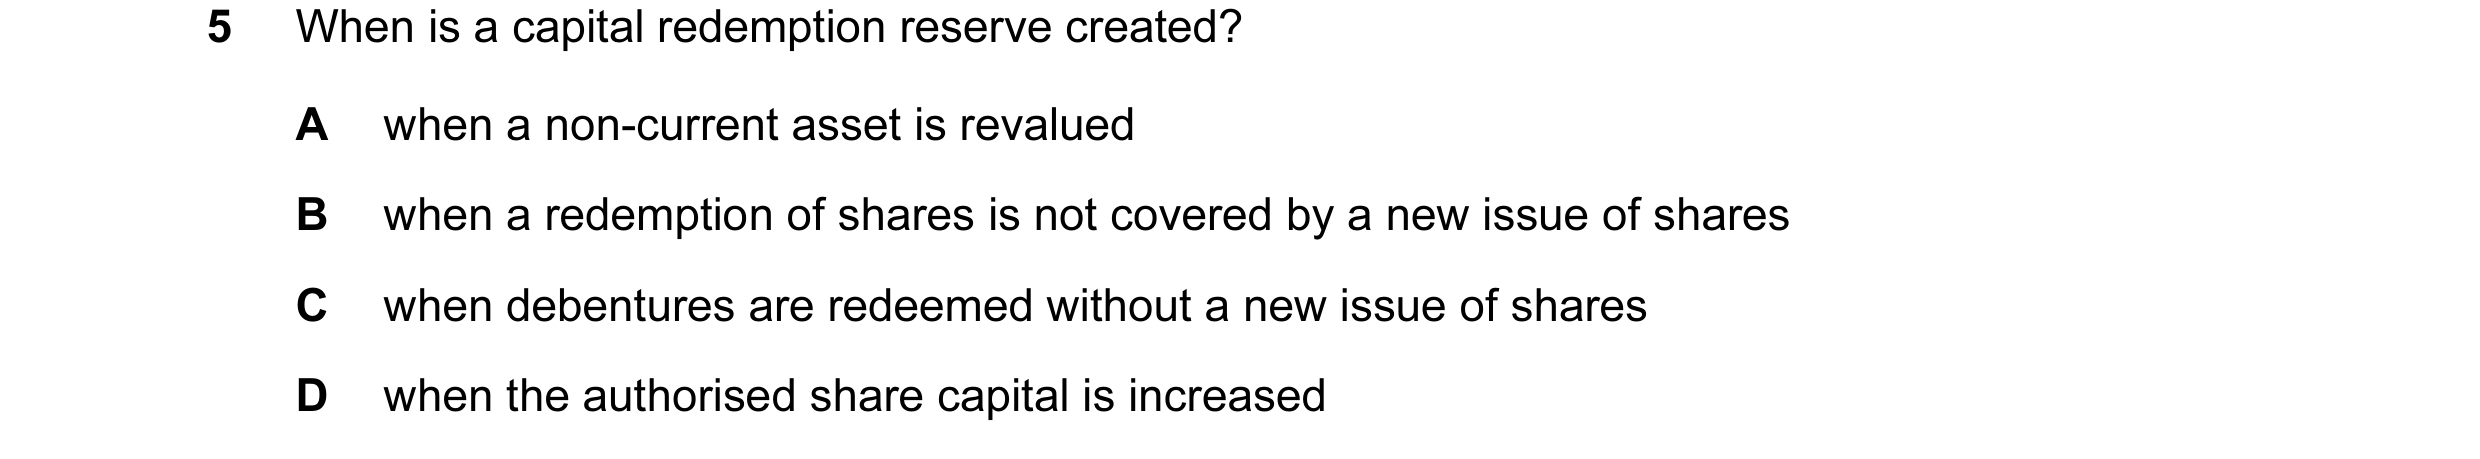
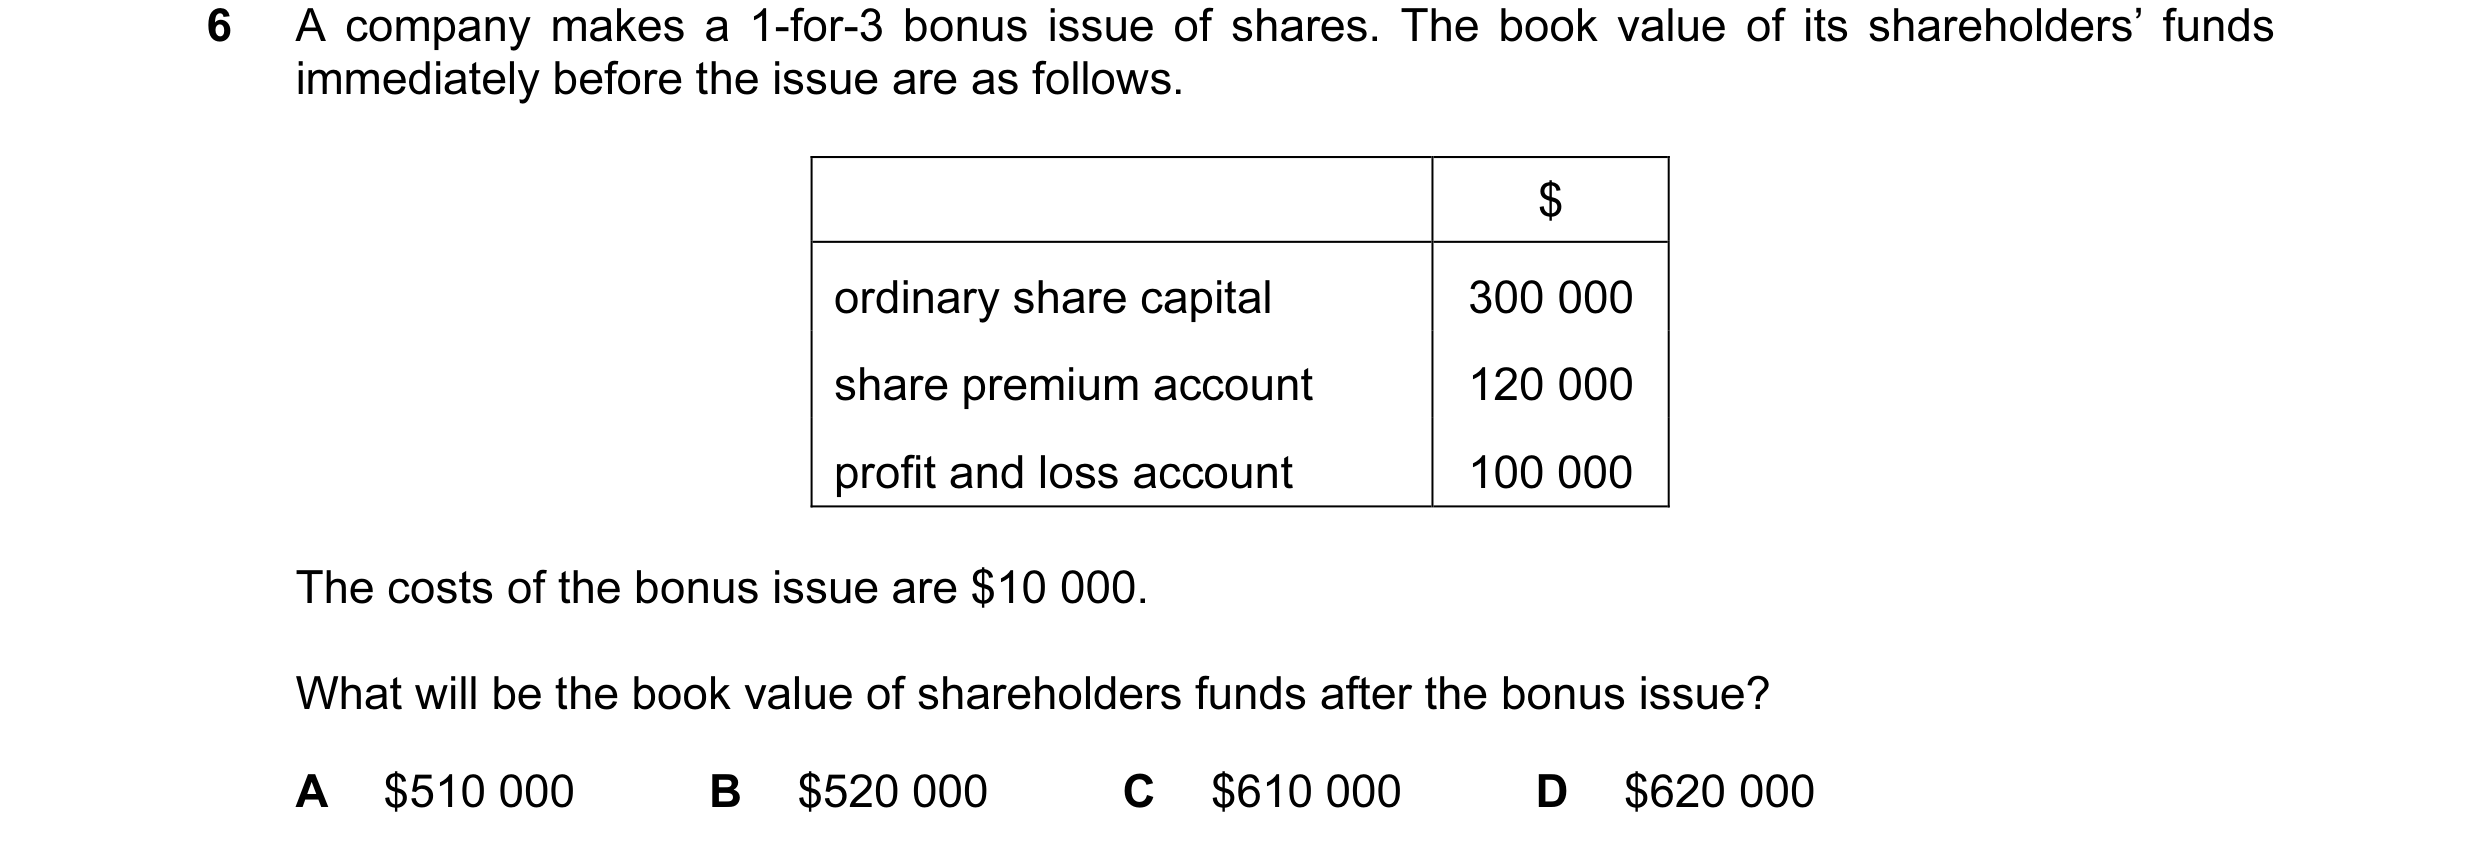
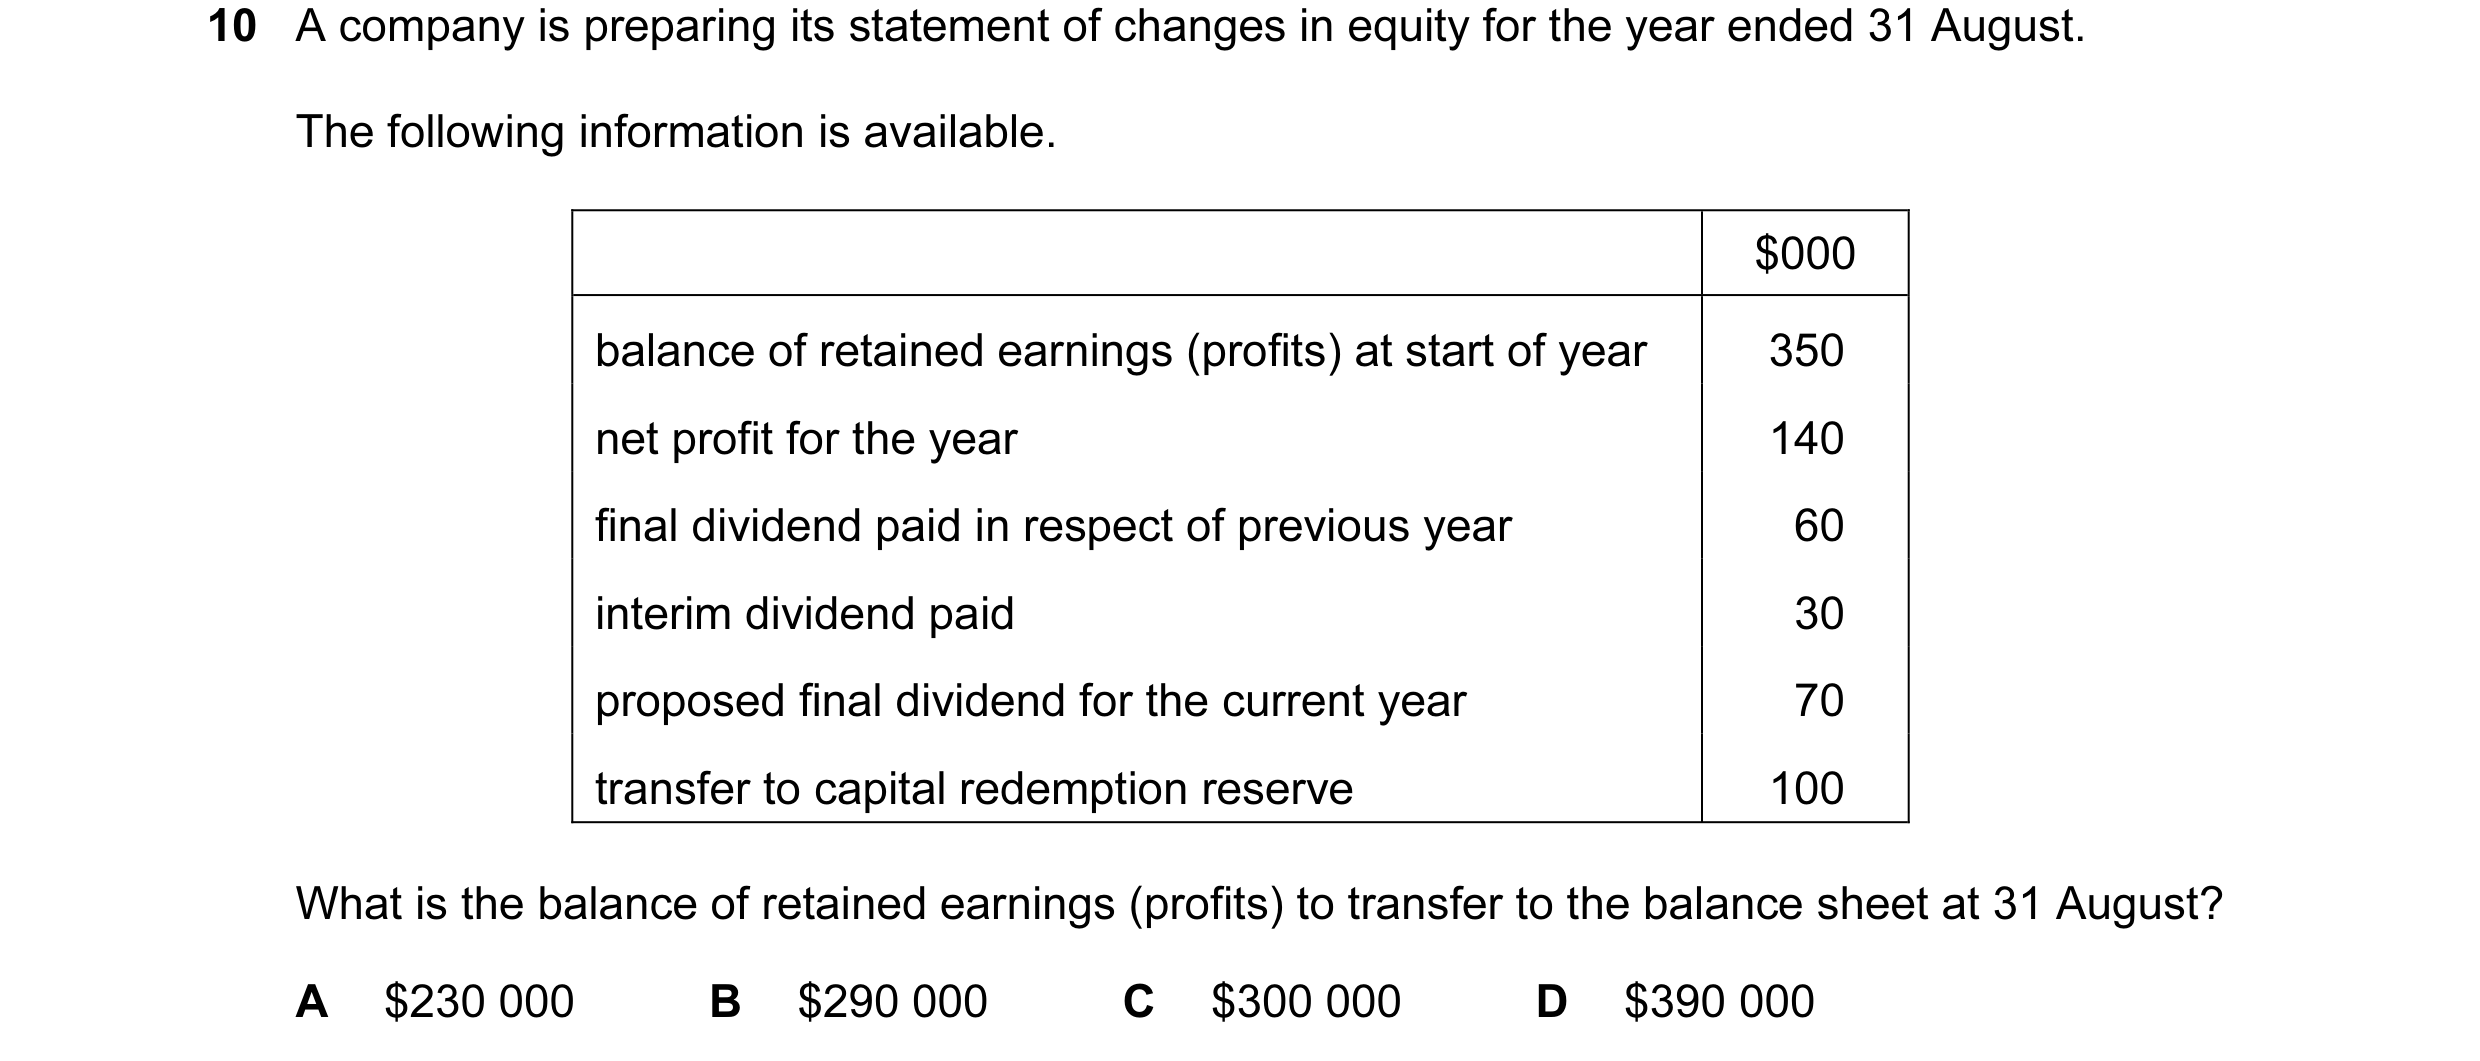
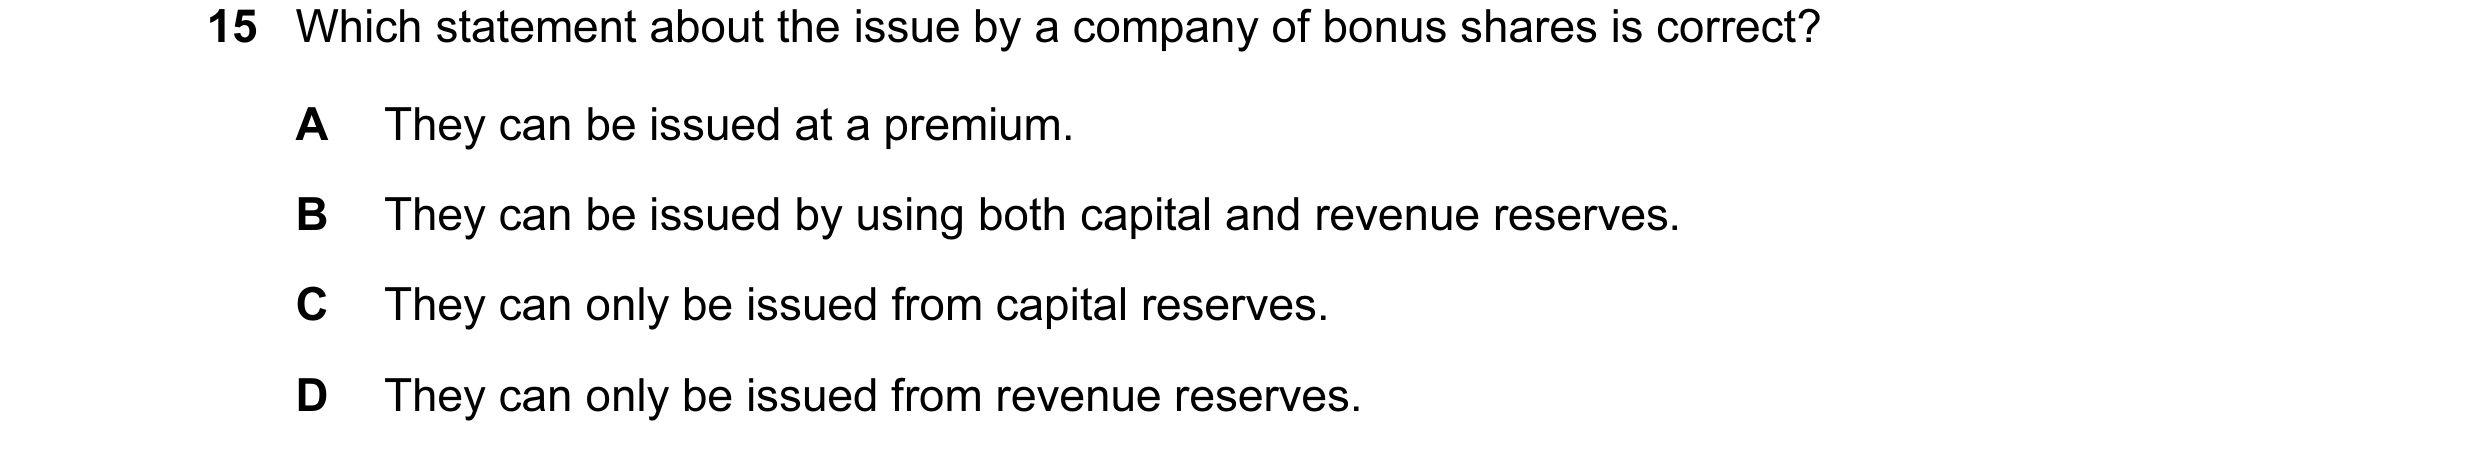 8 / 62
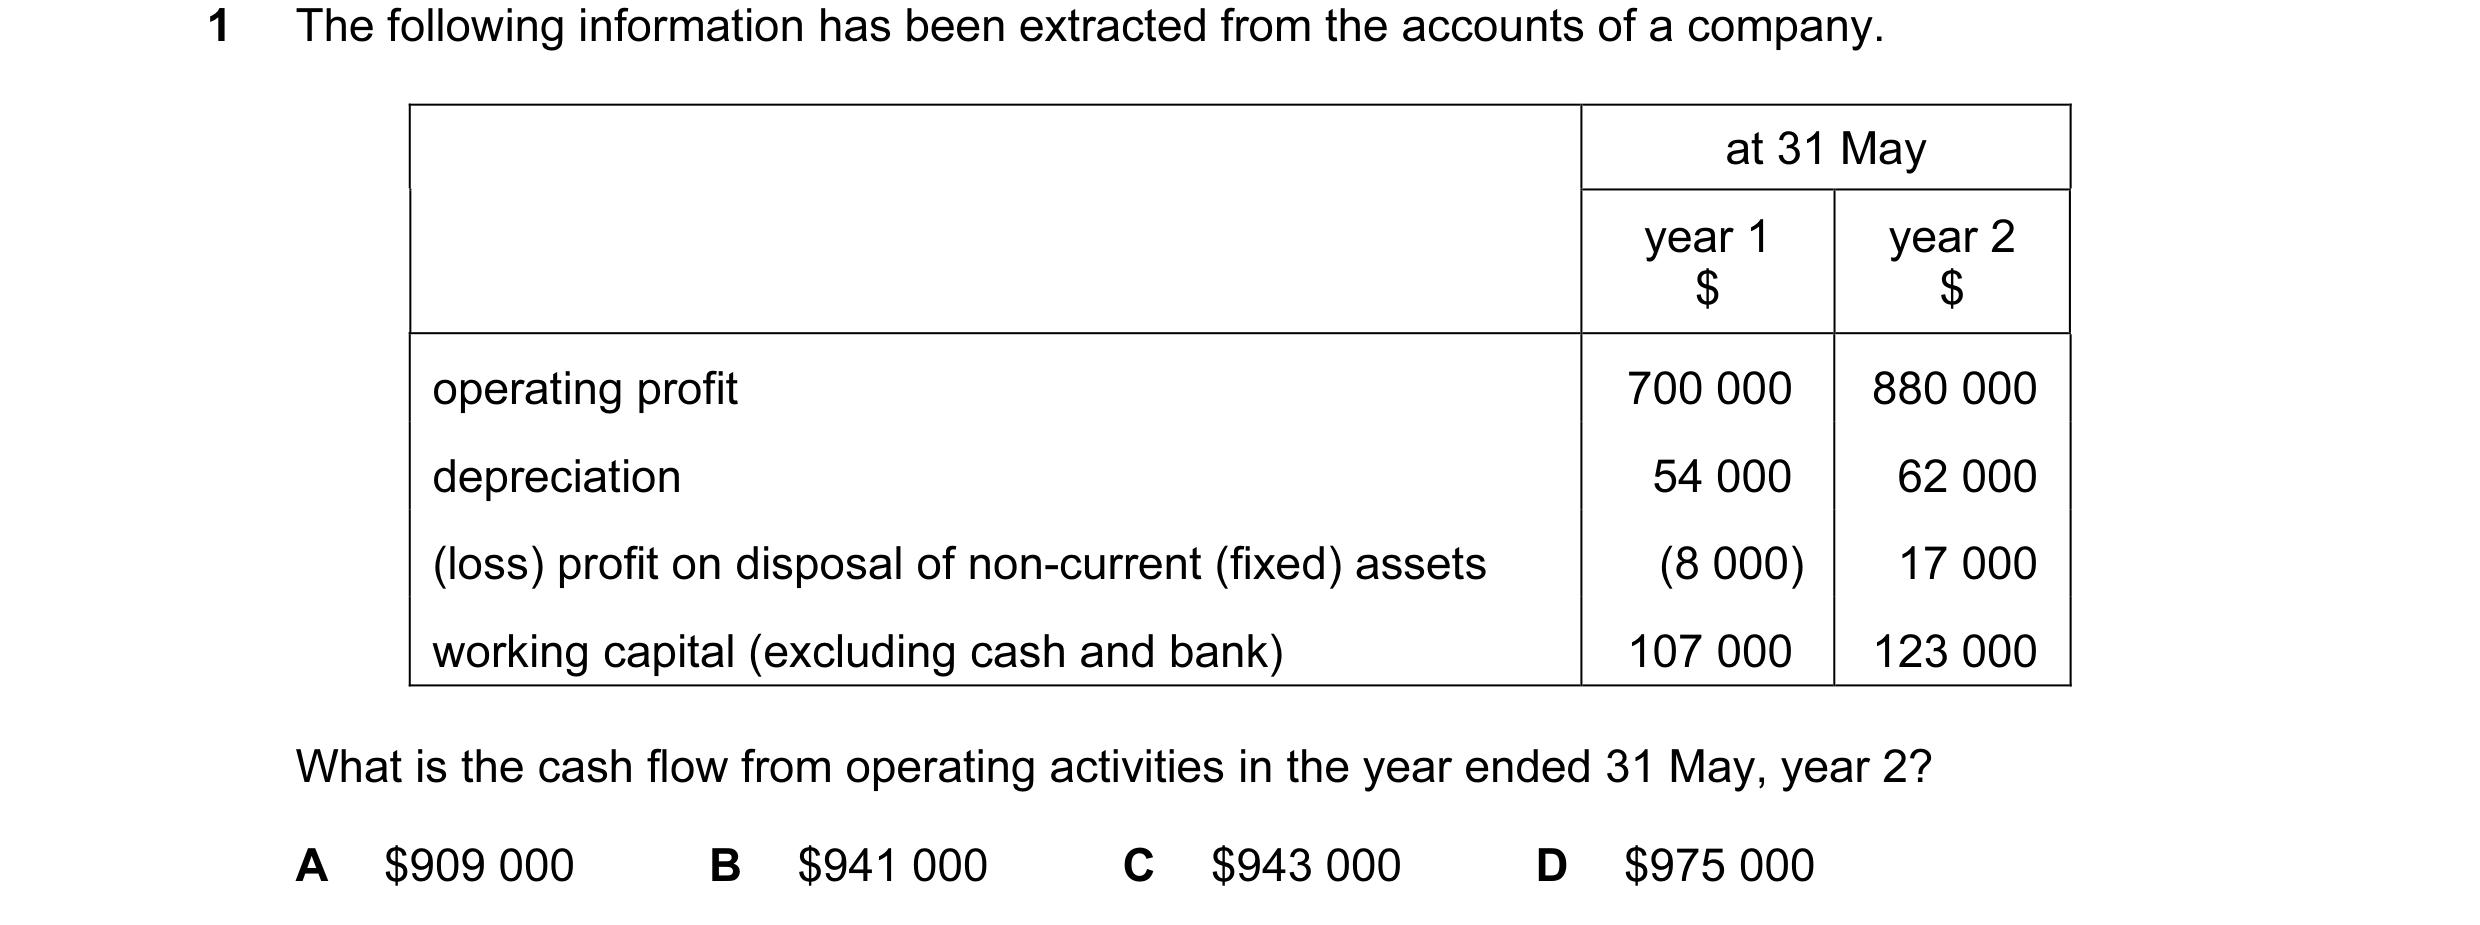
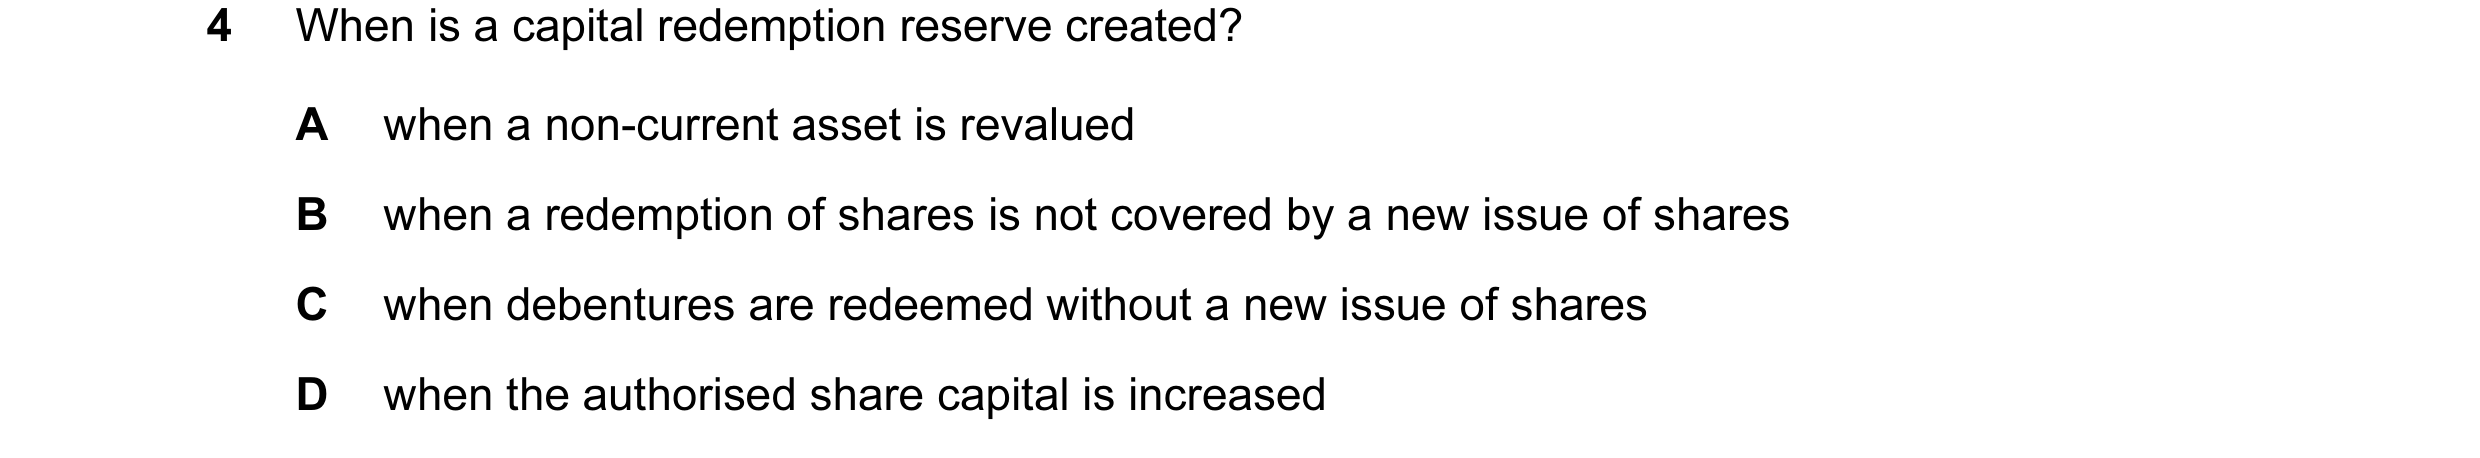
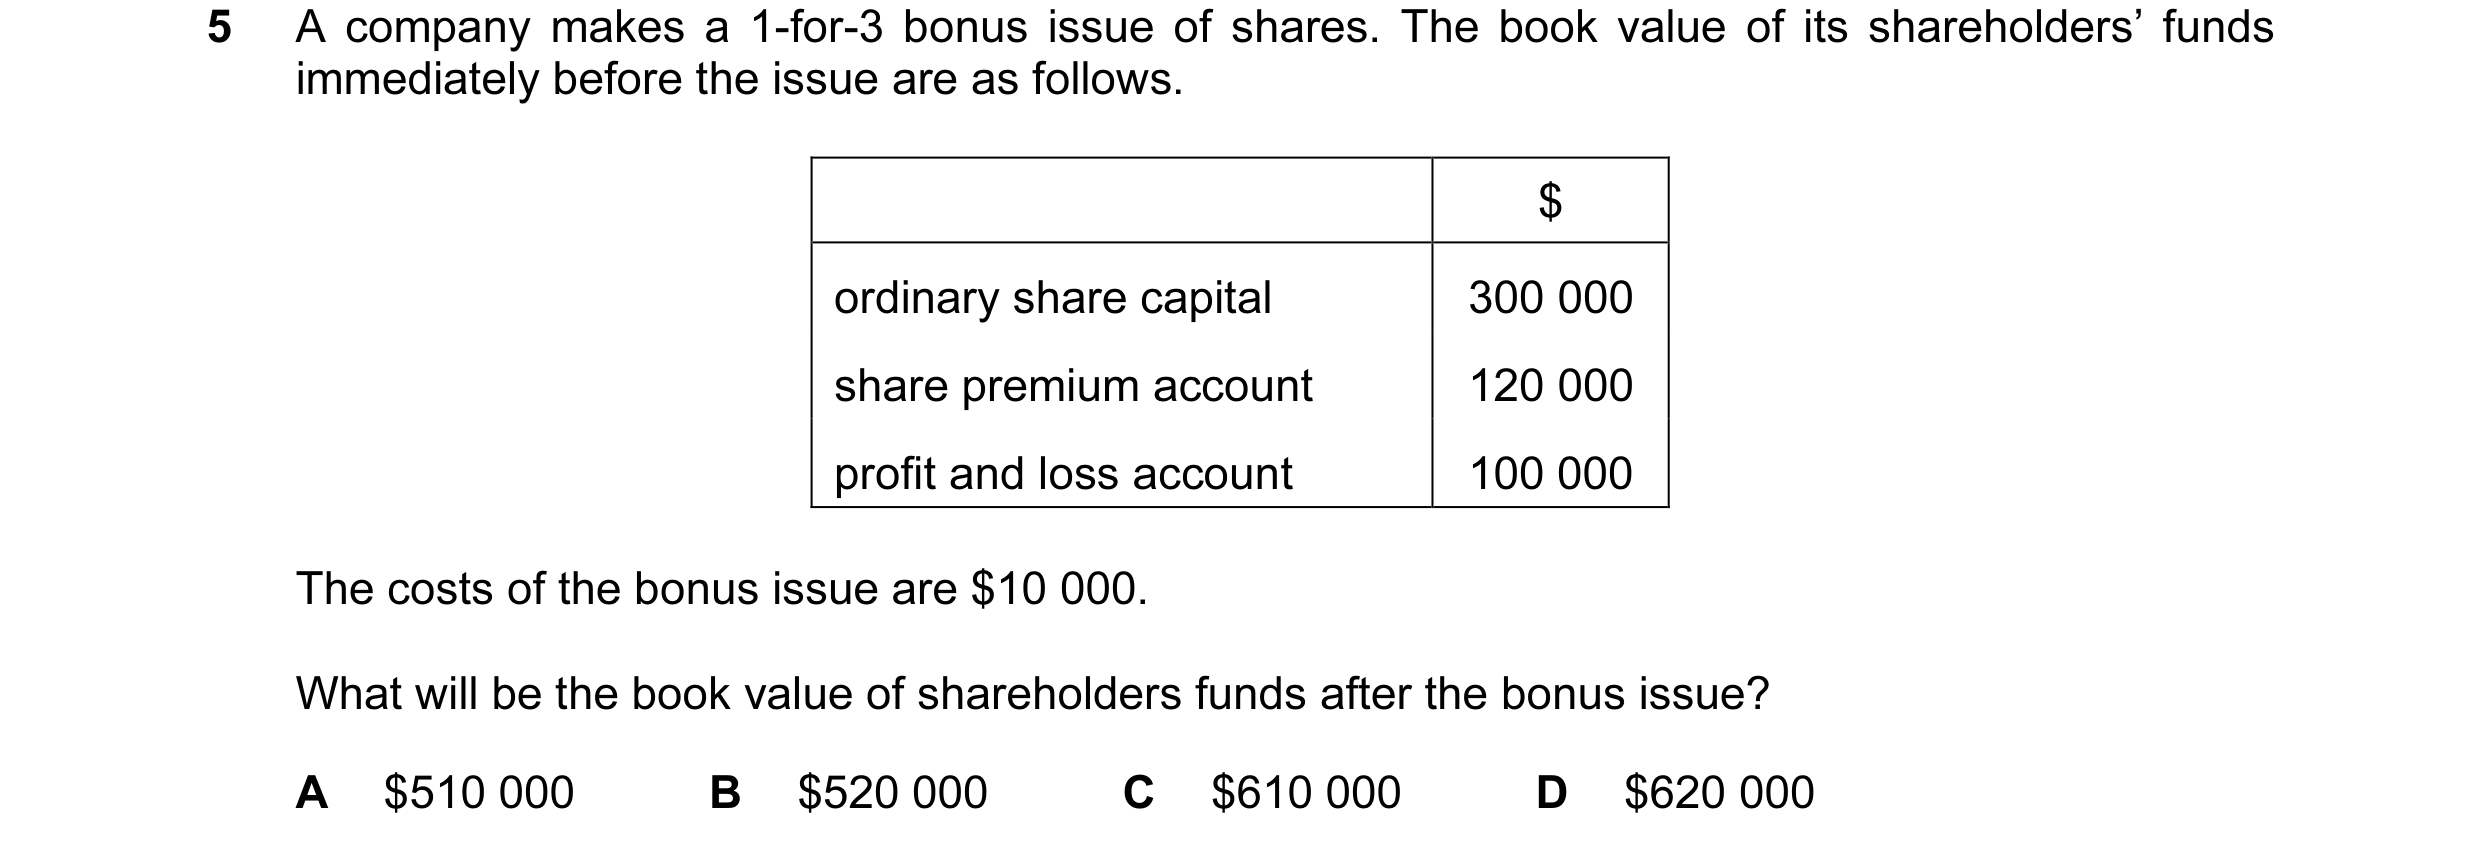
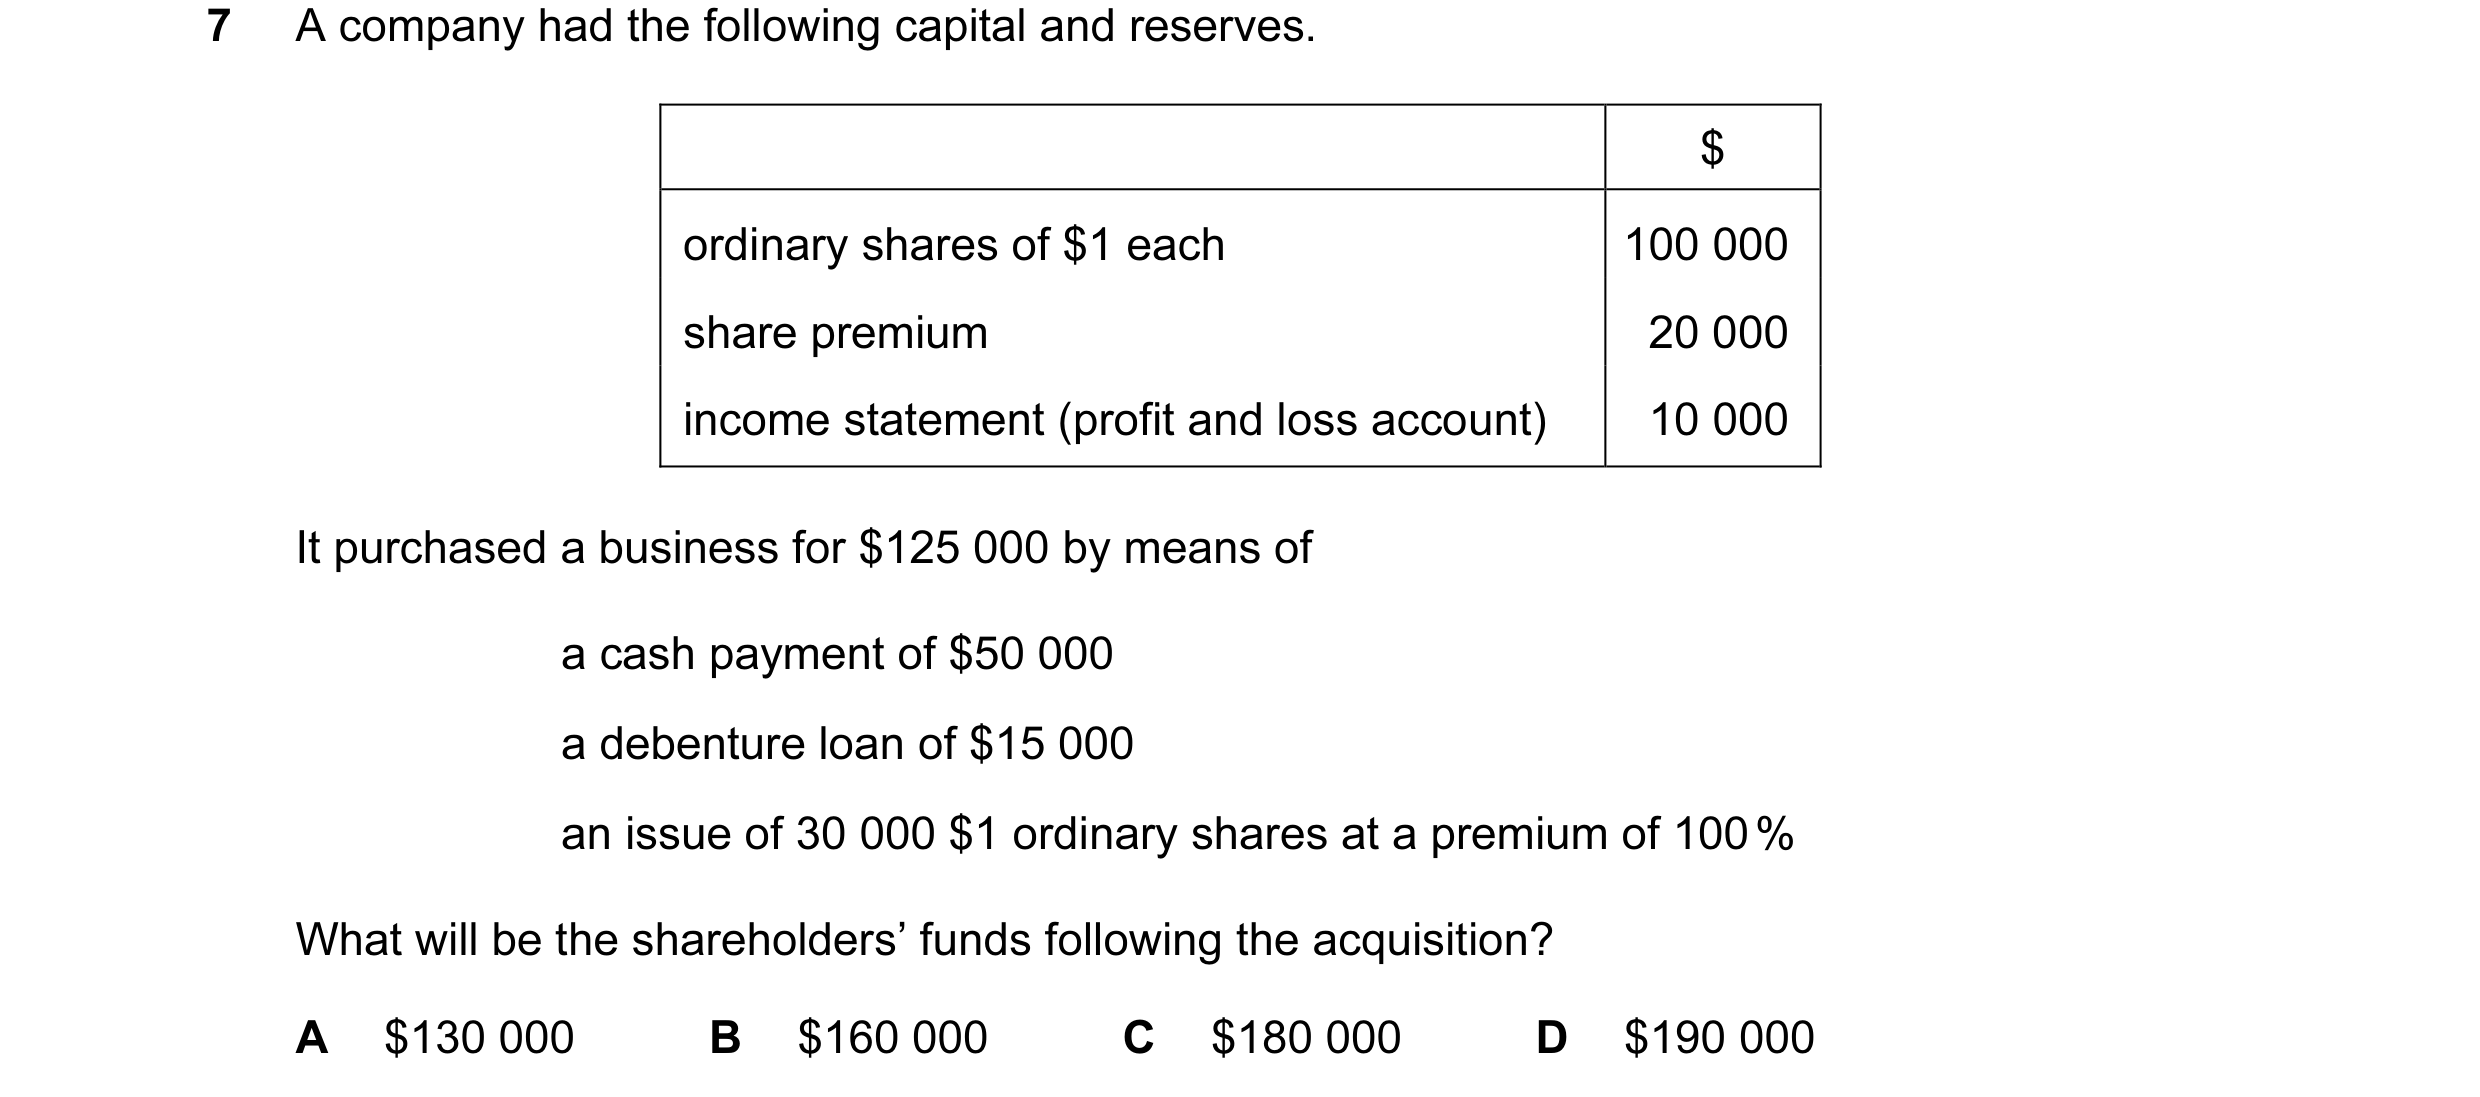 9 / 62
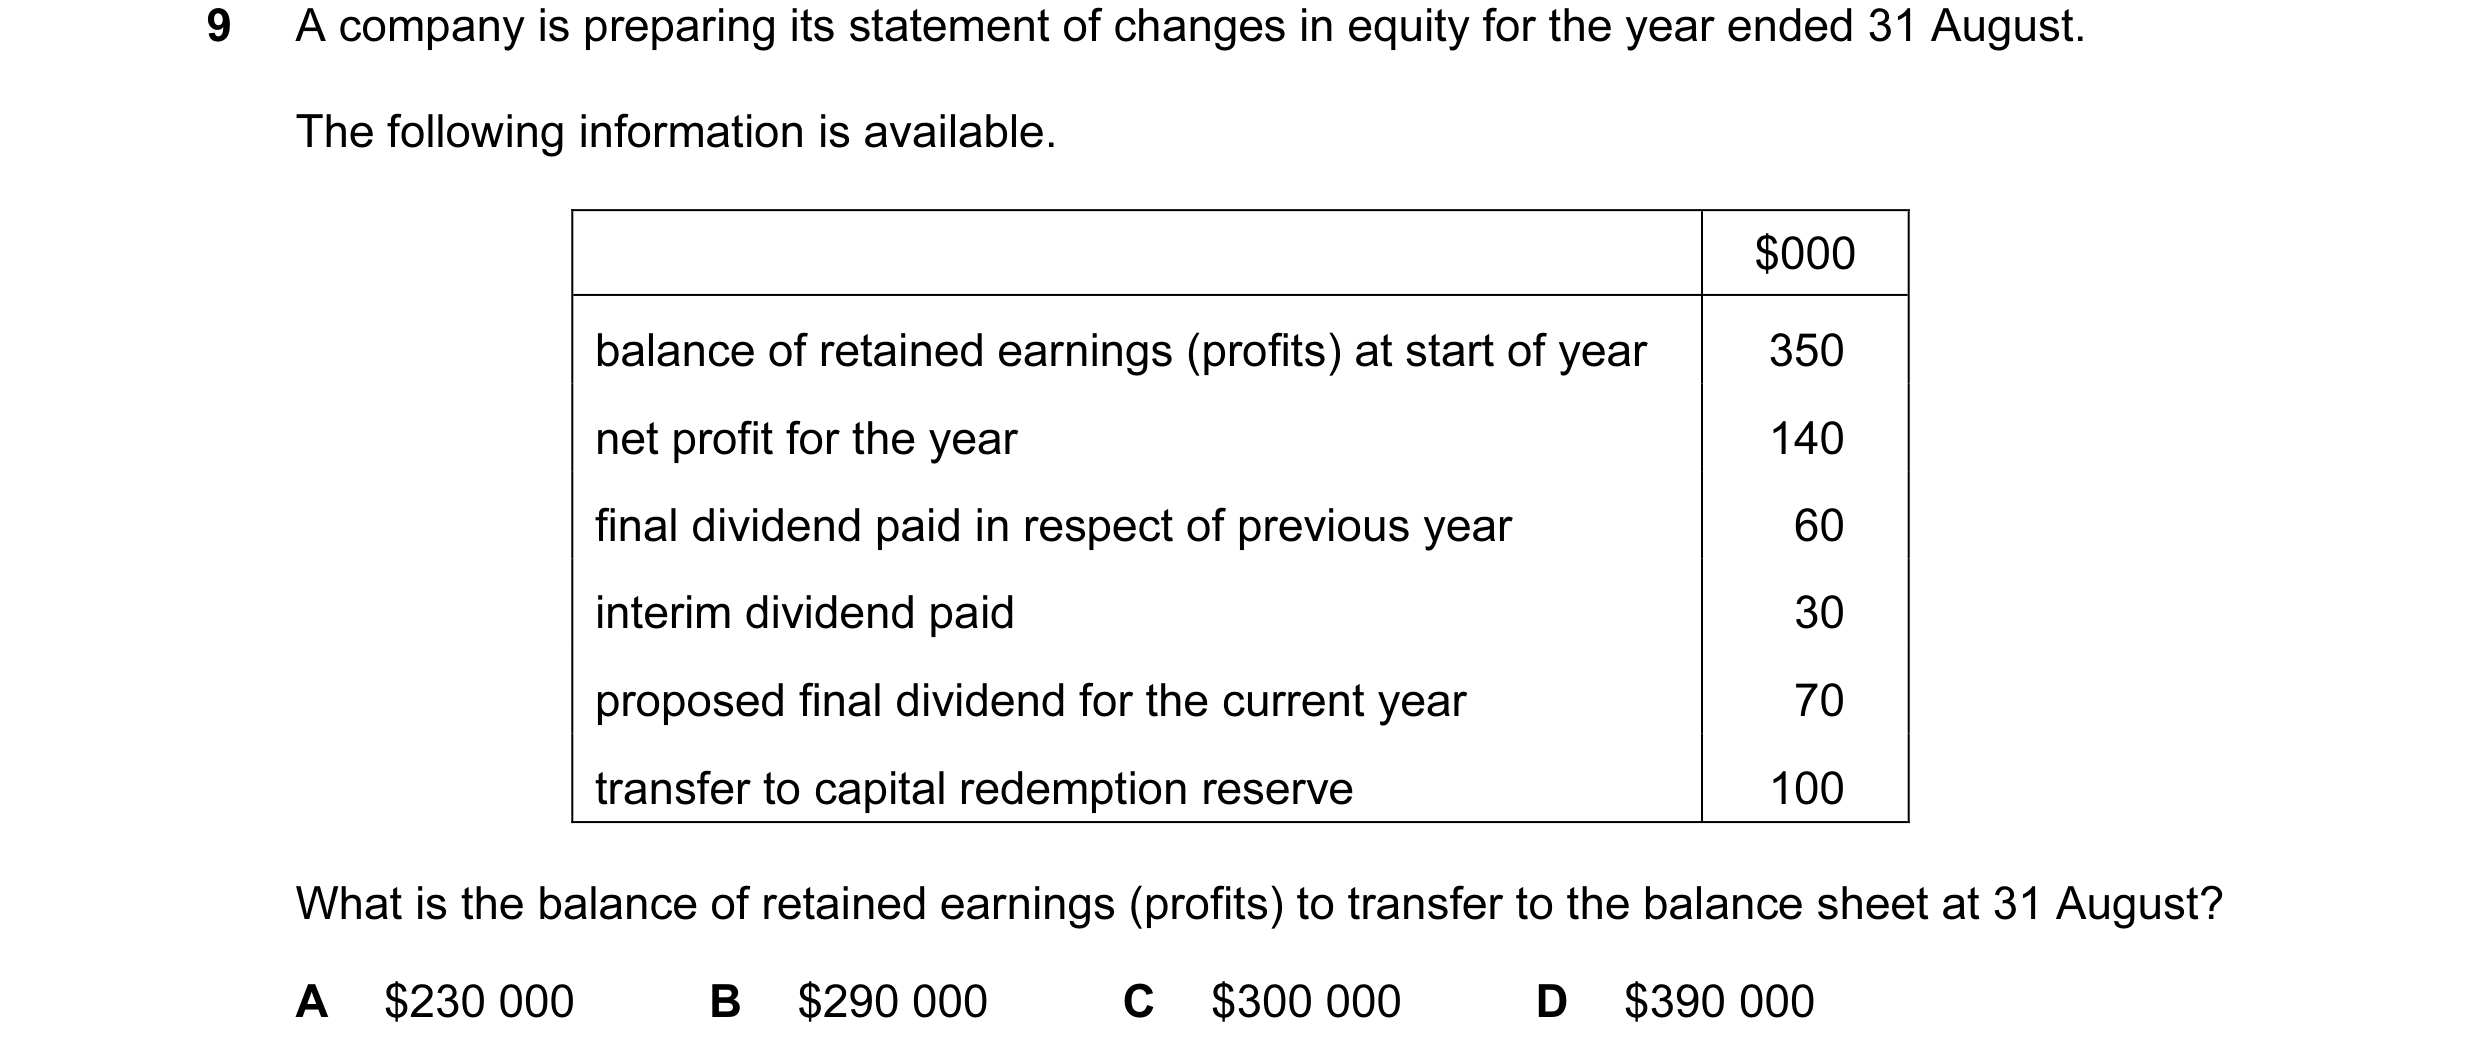
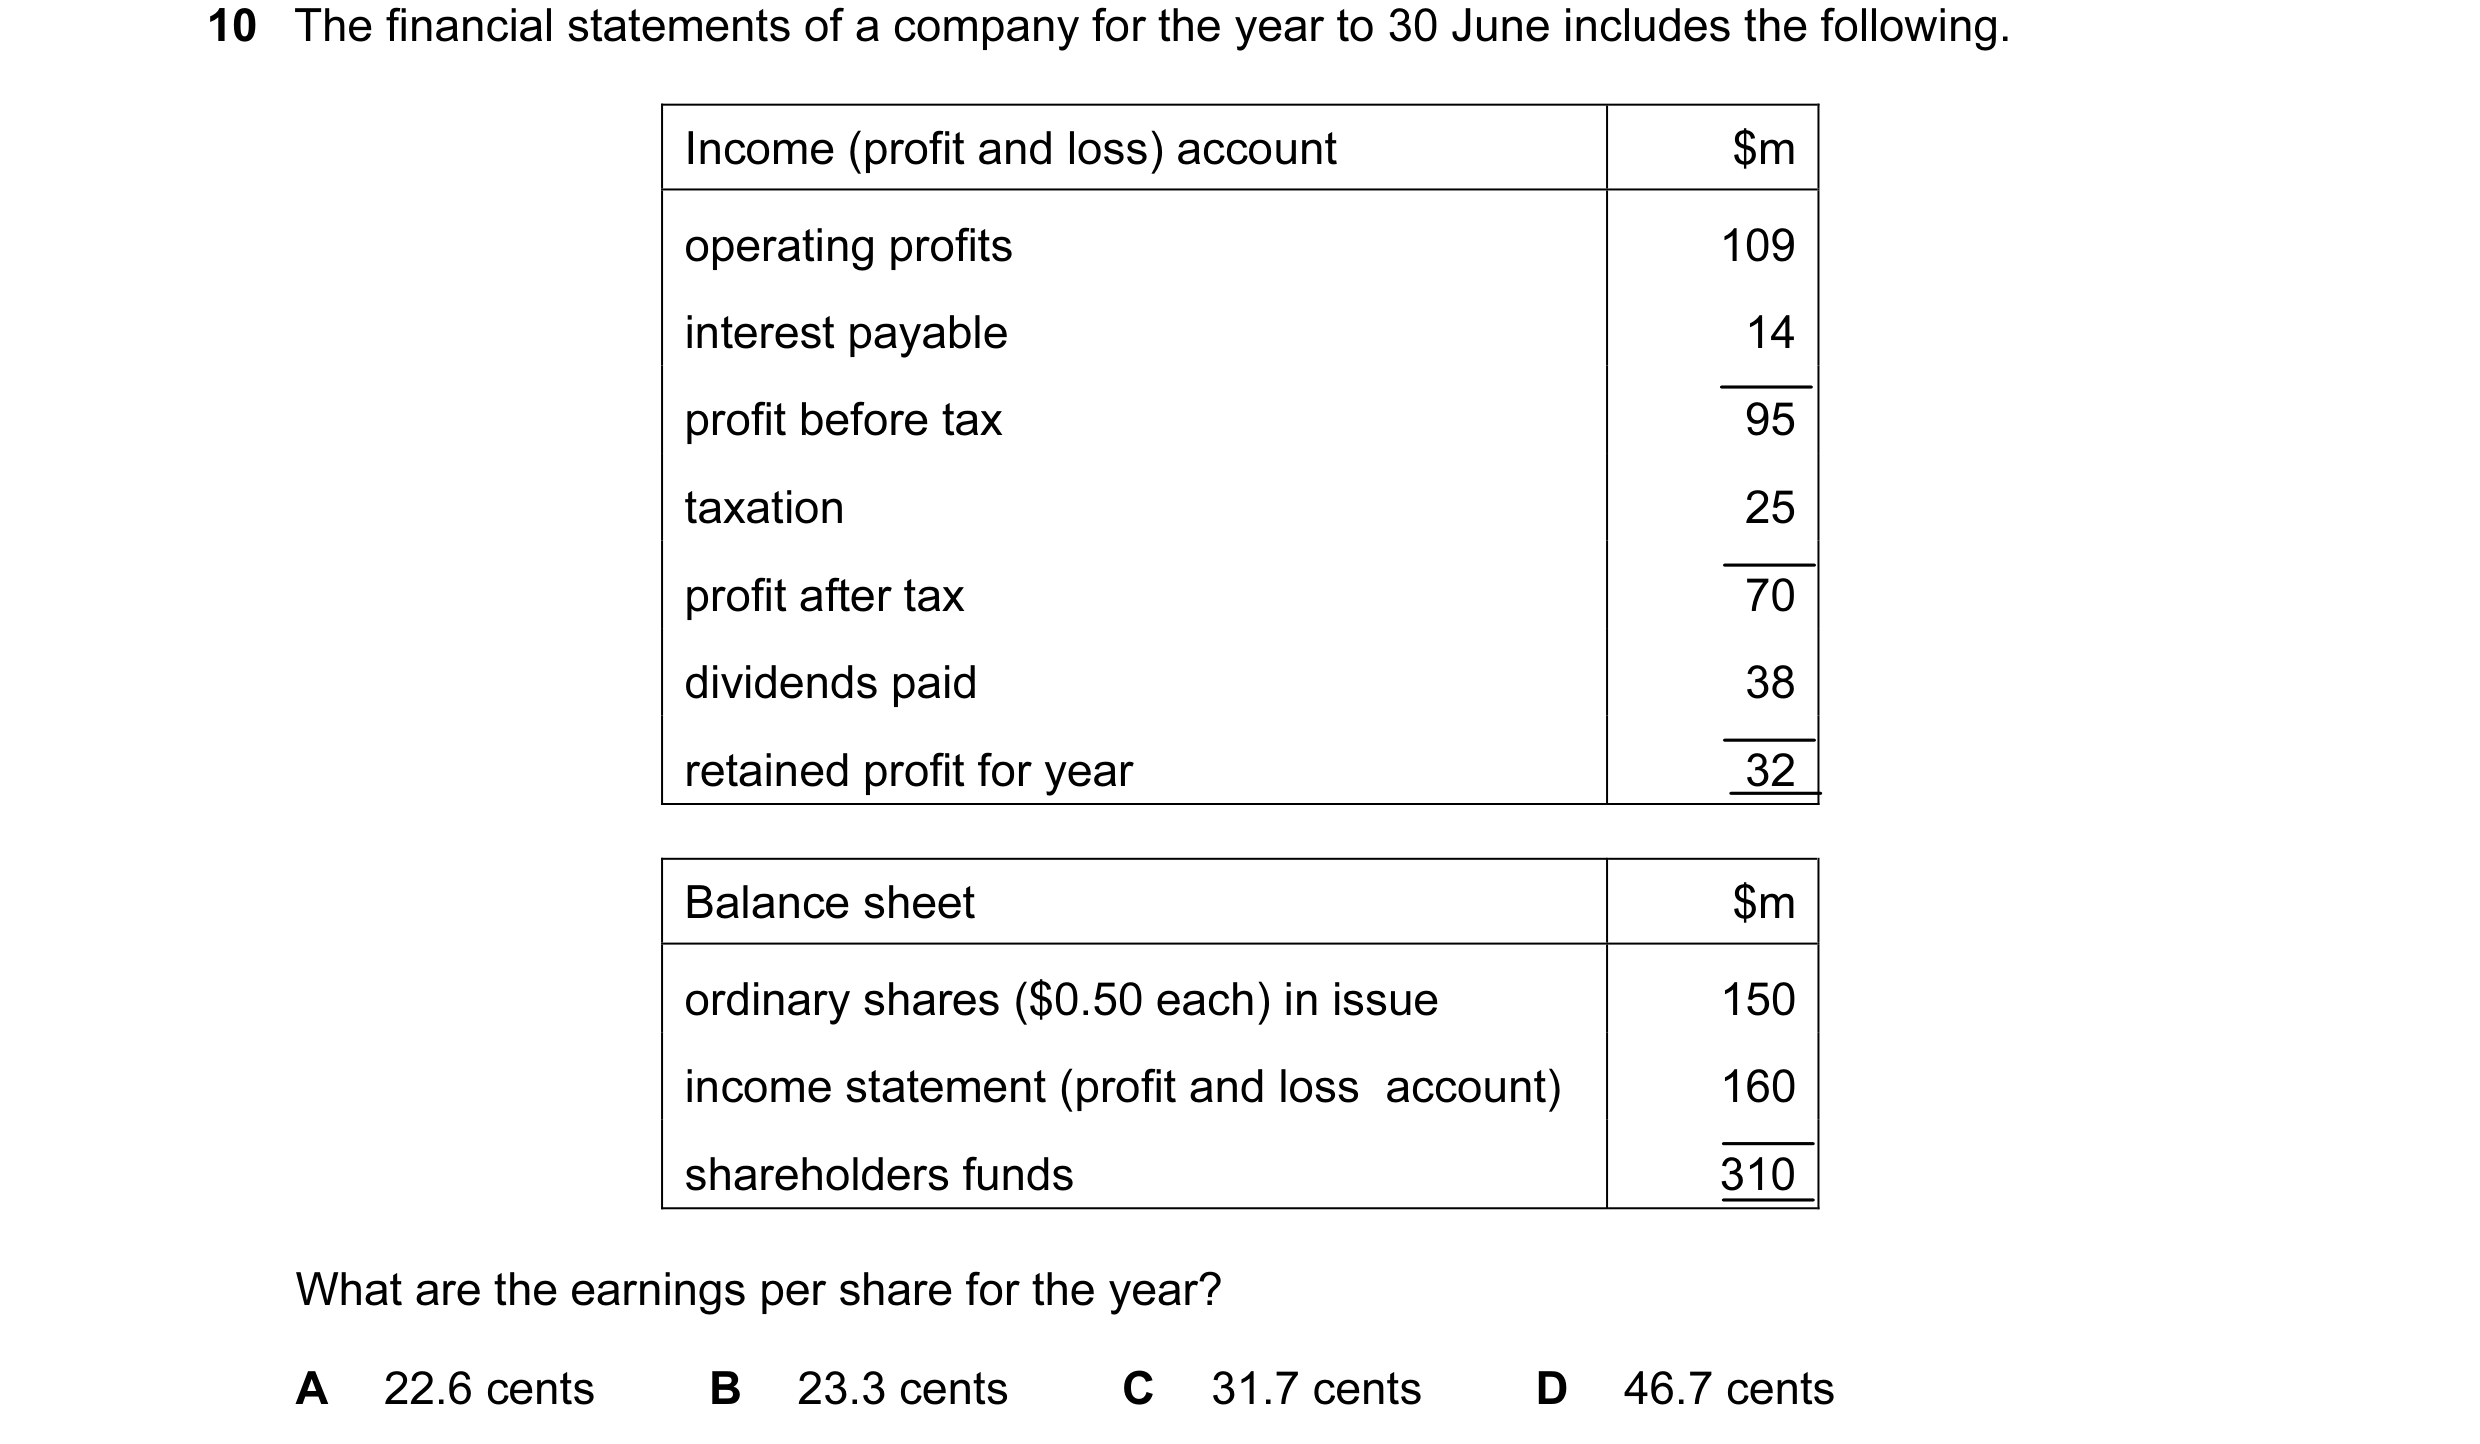 10 / 62
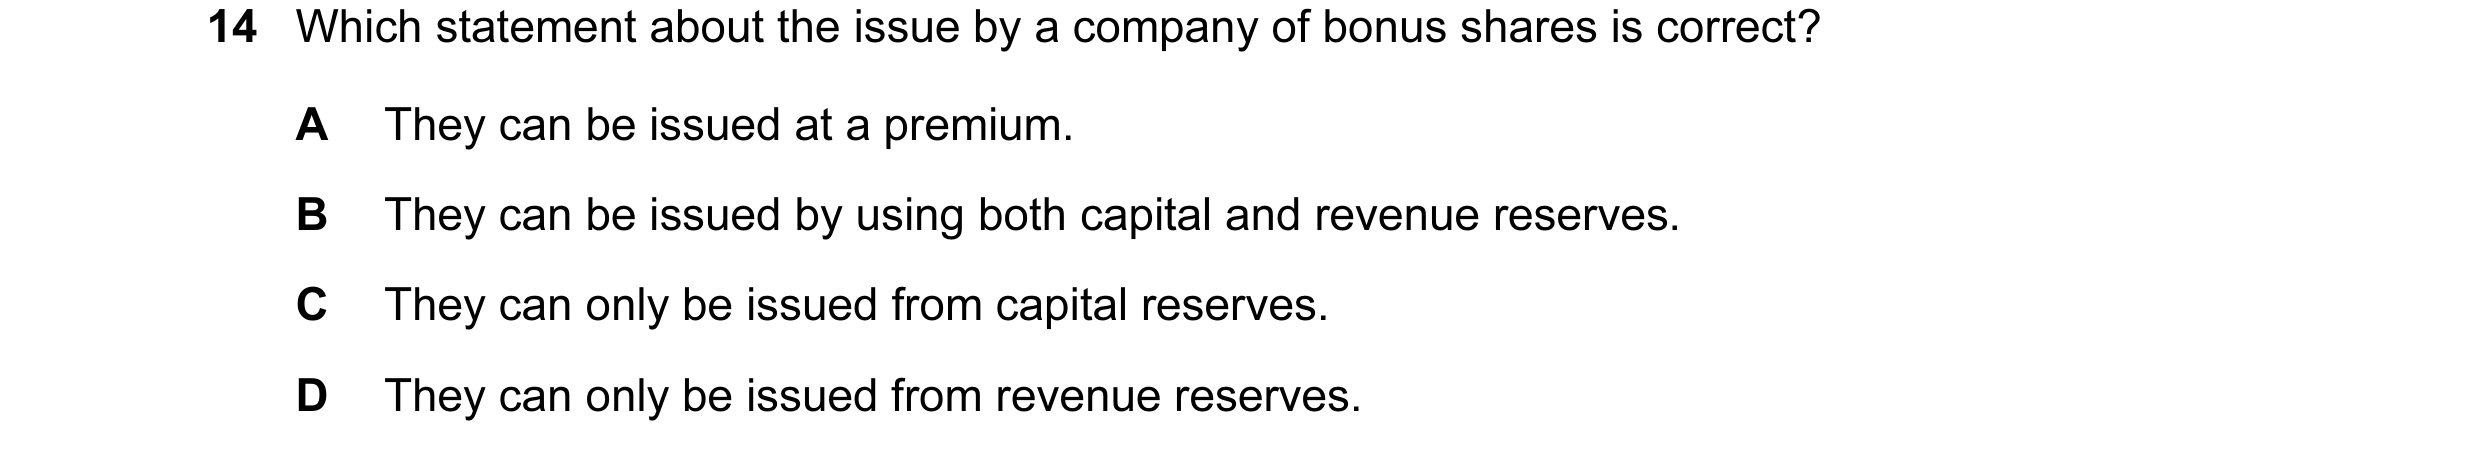
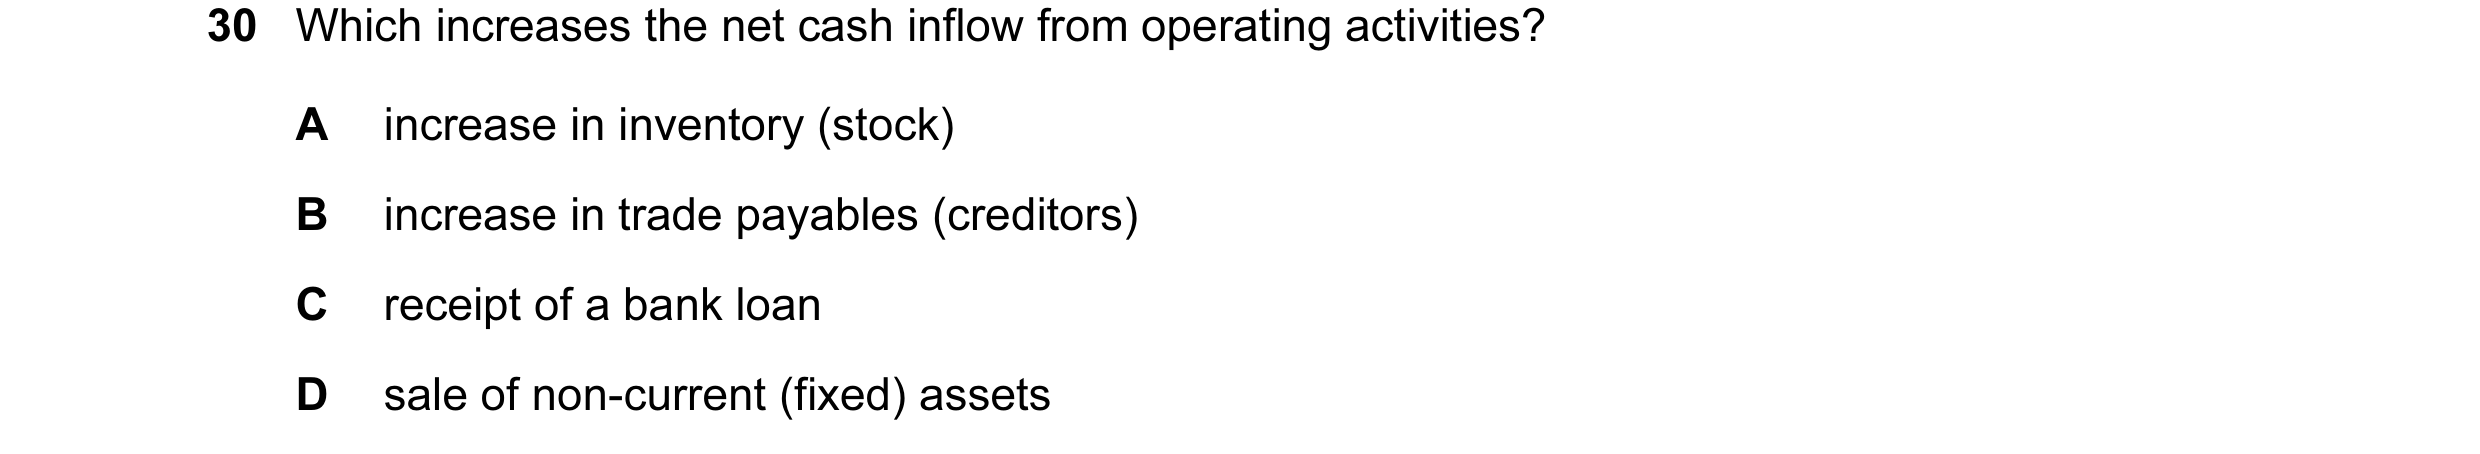
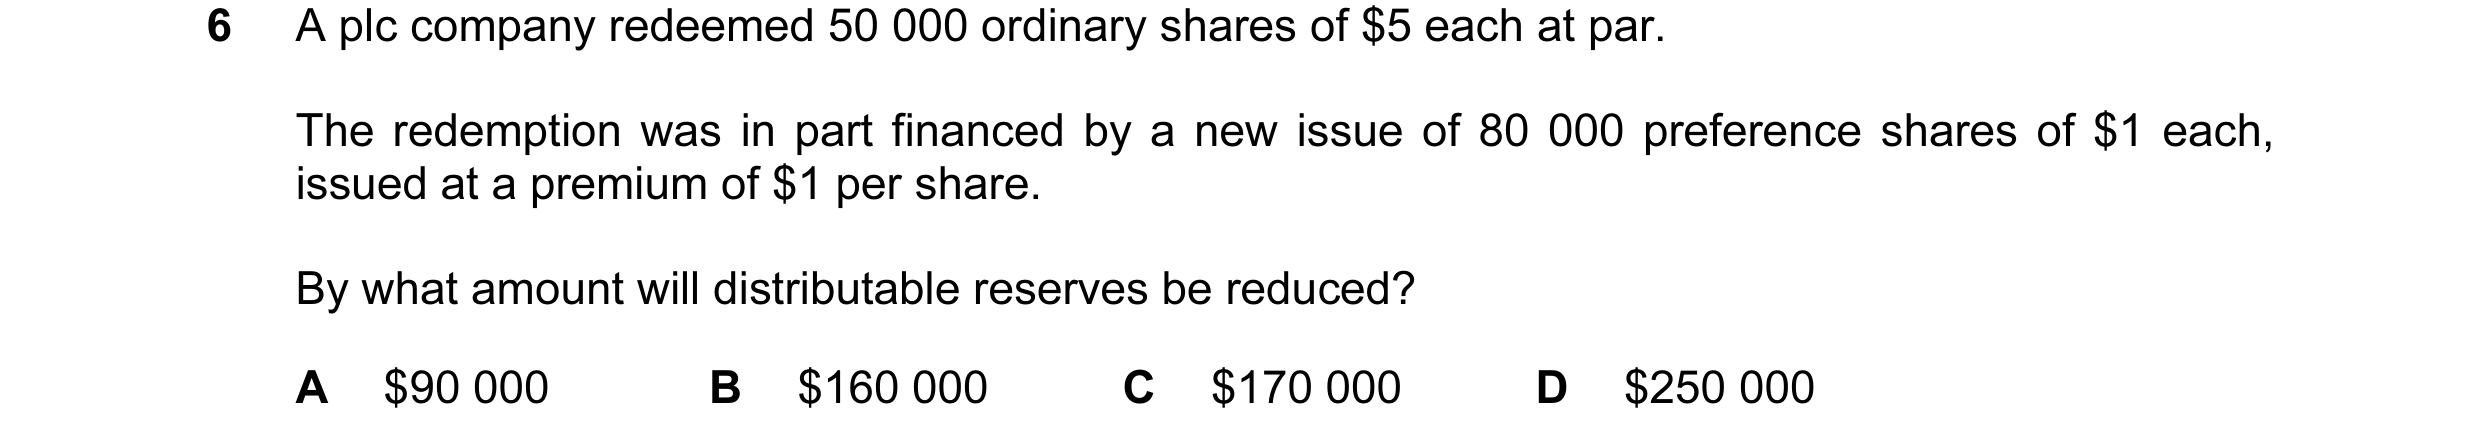
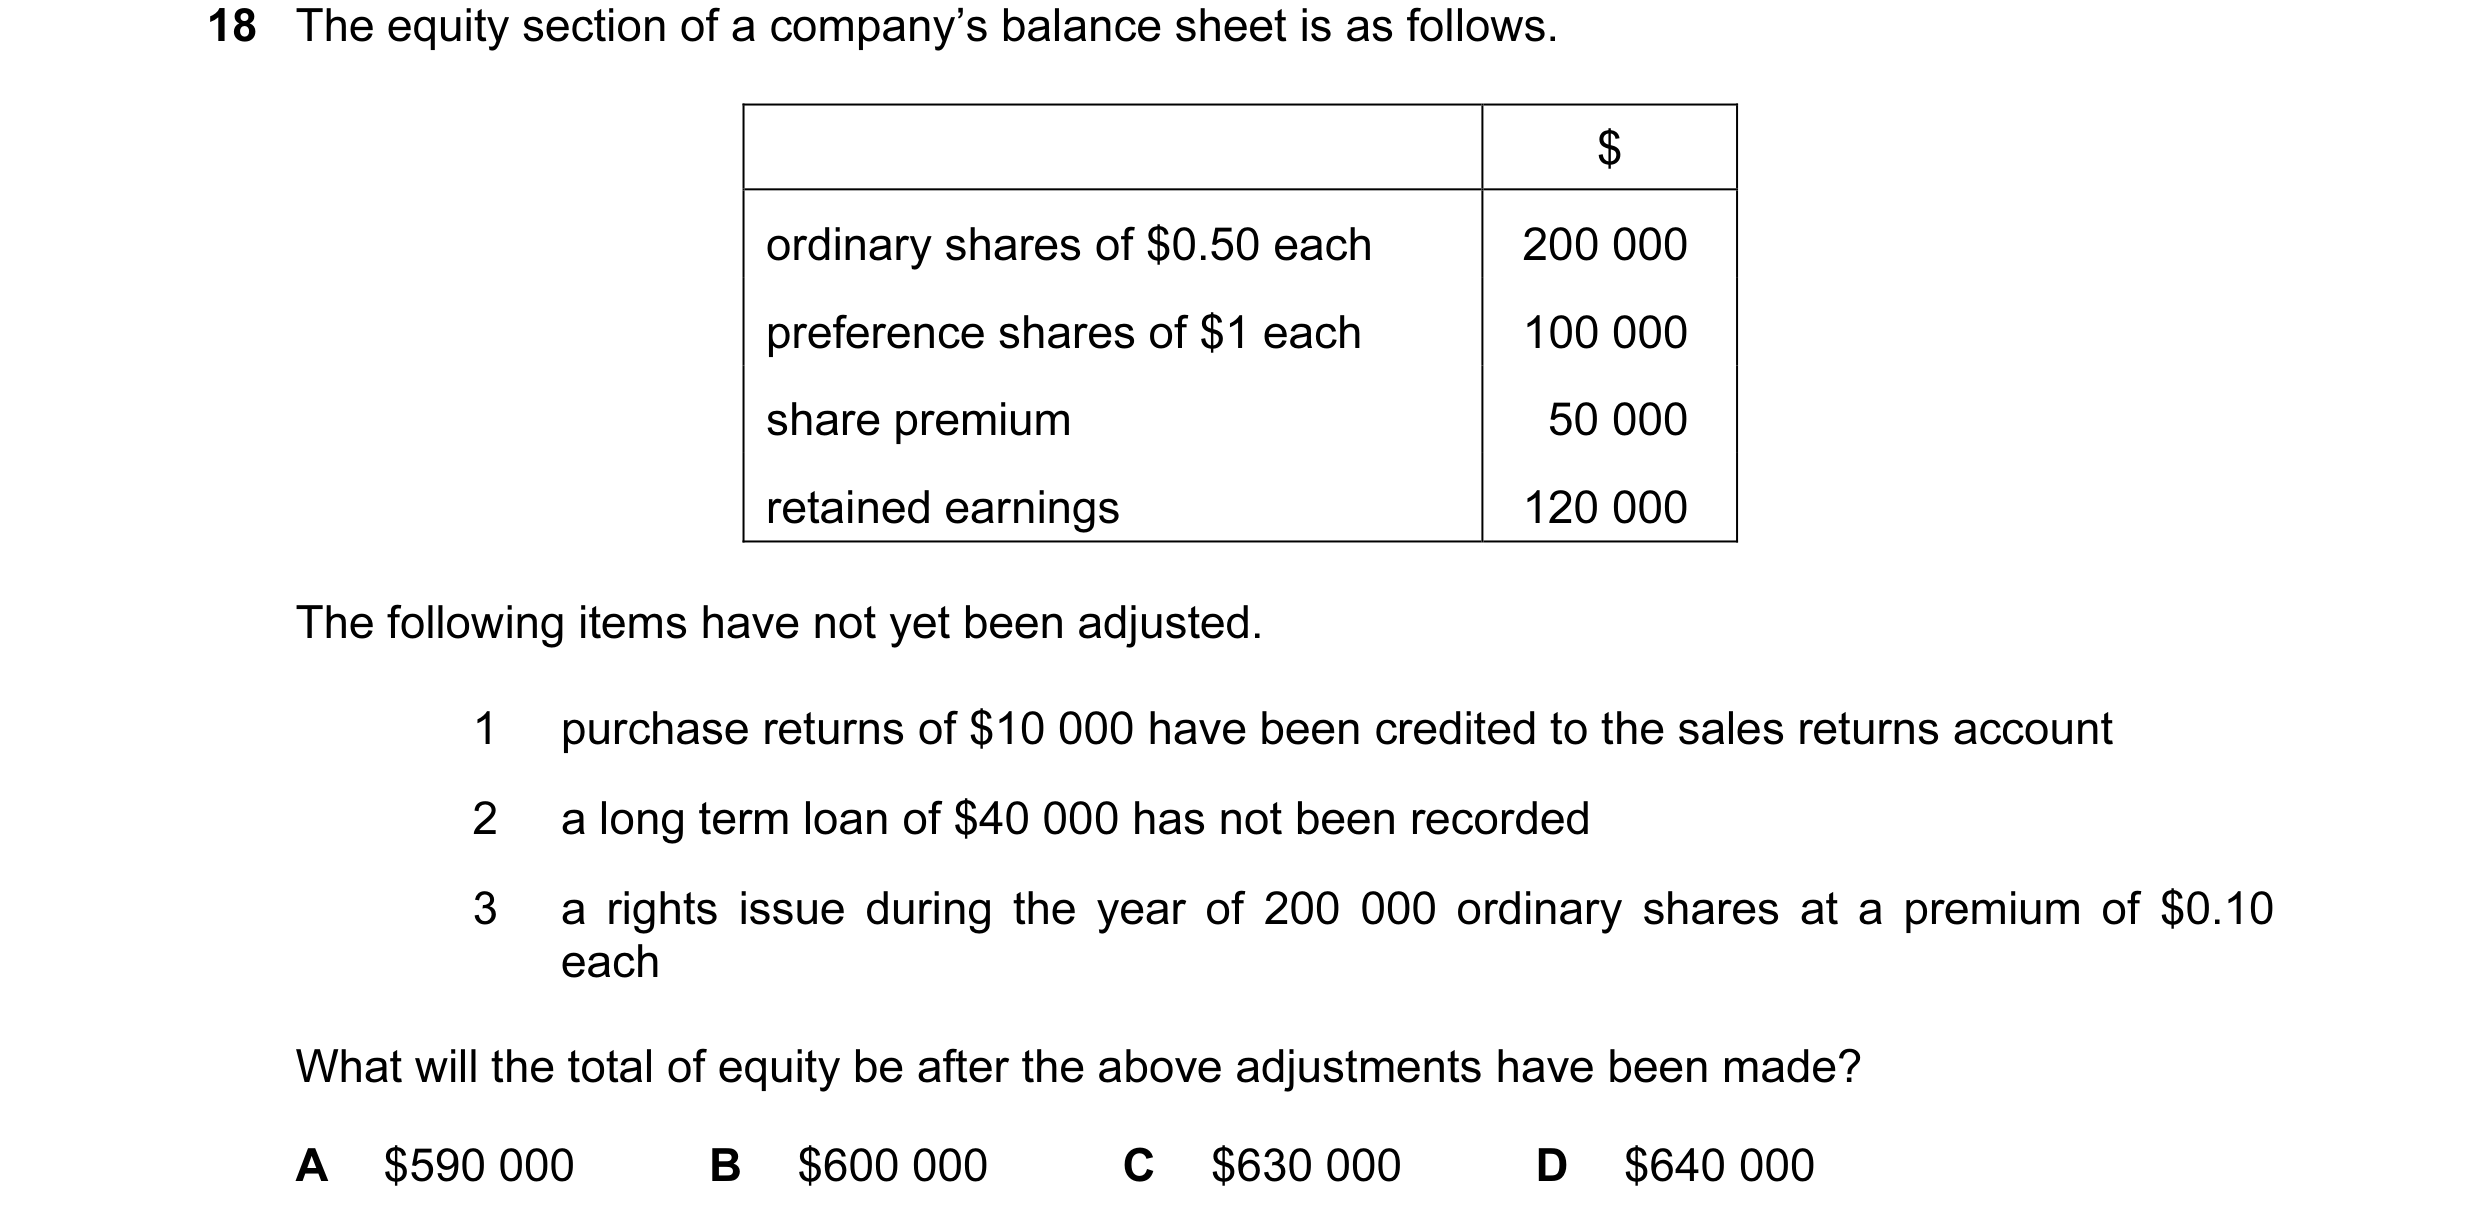
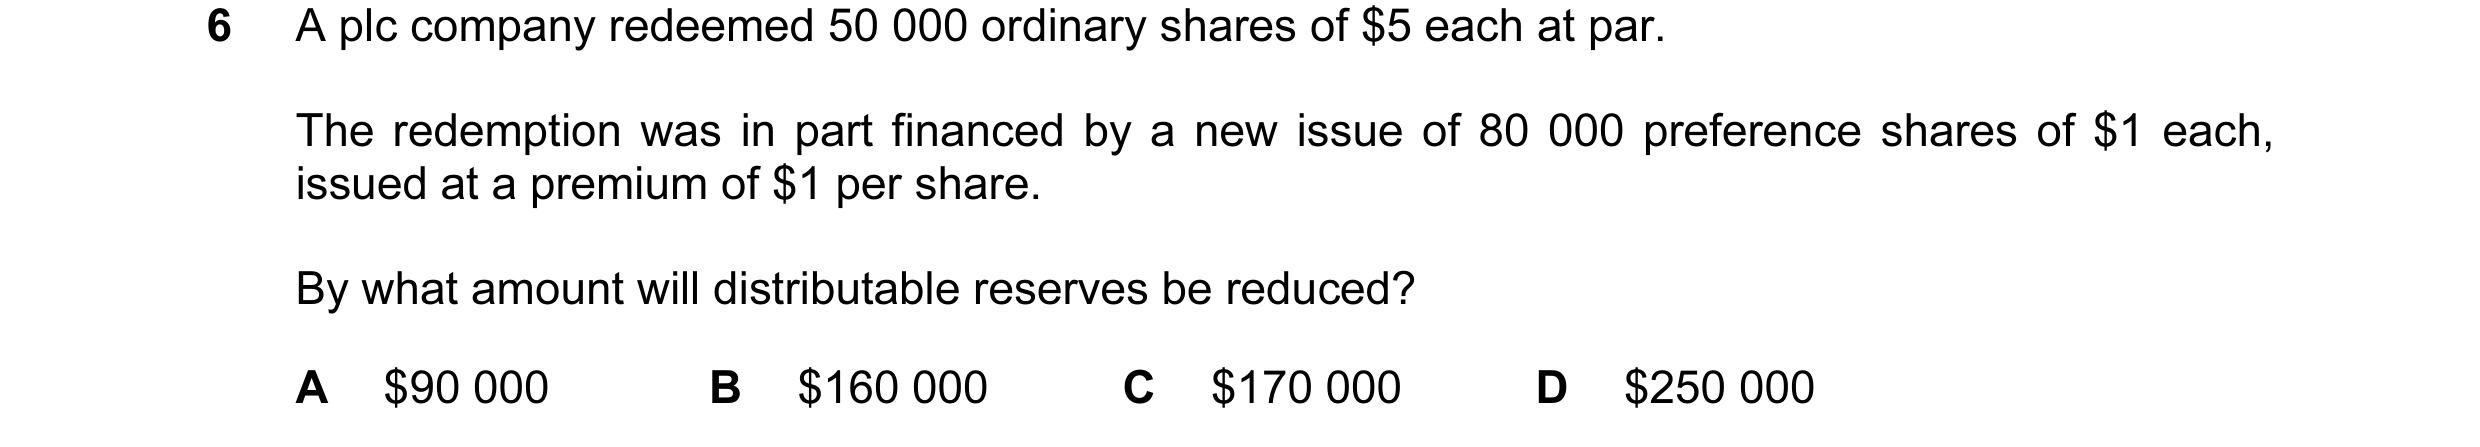 11 / 62
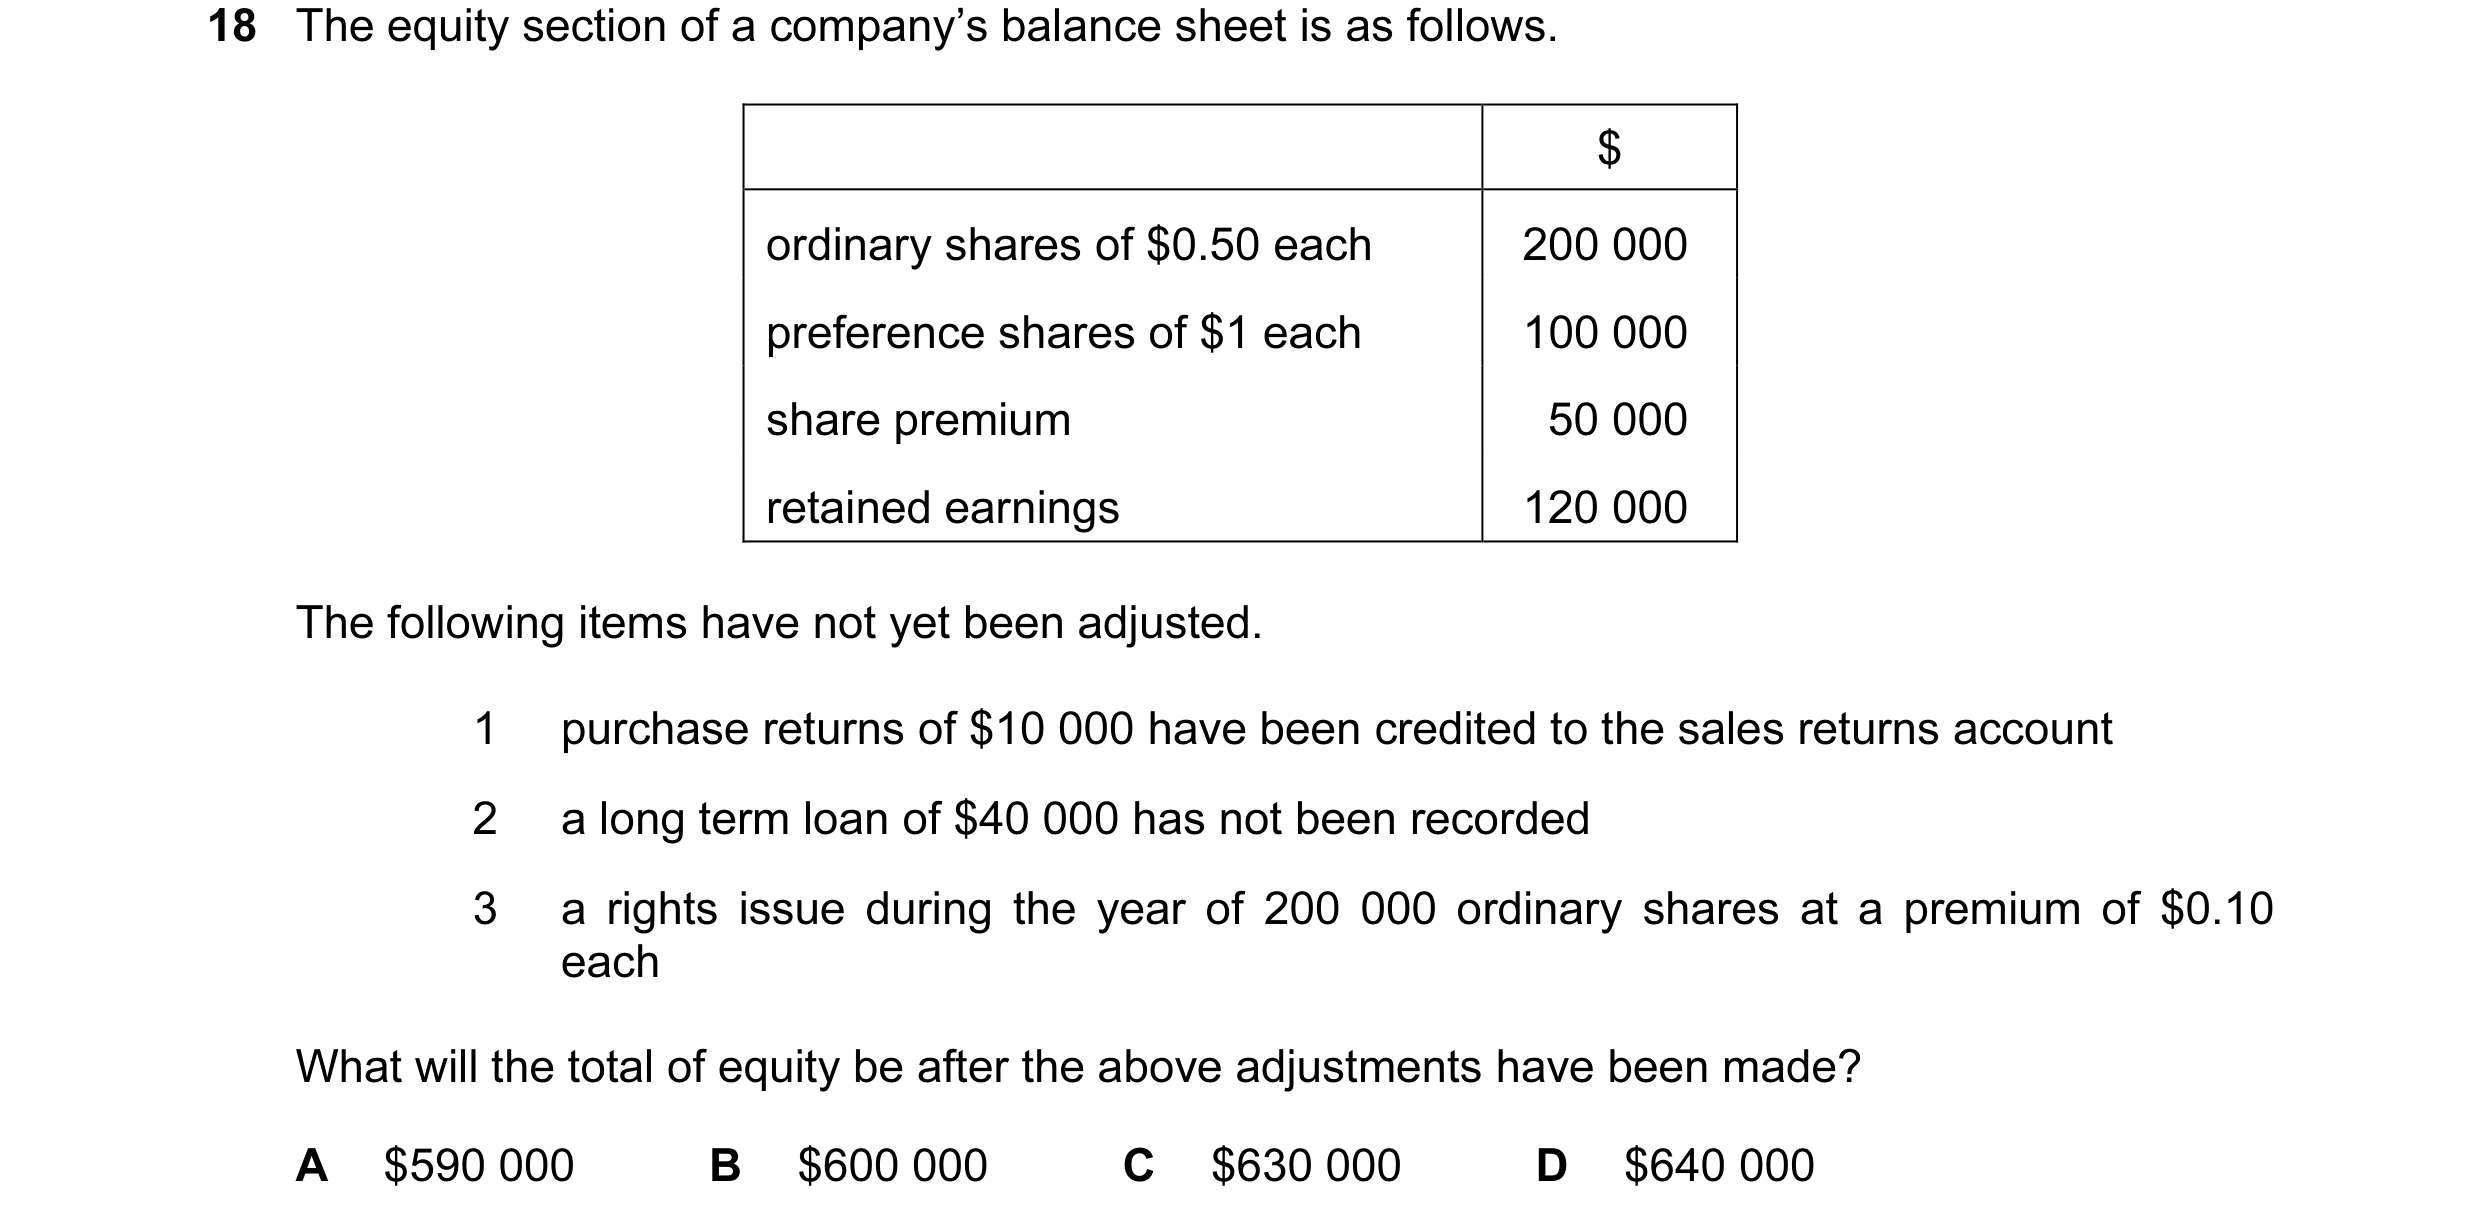
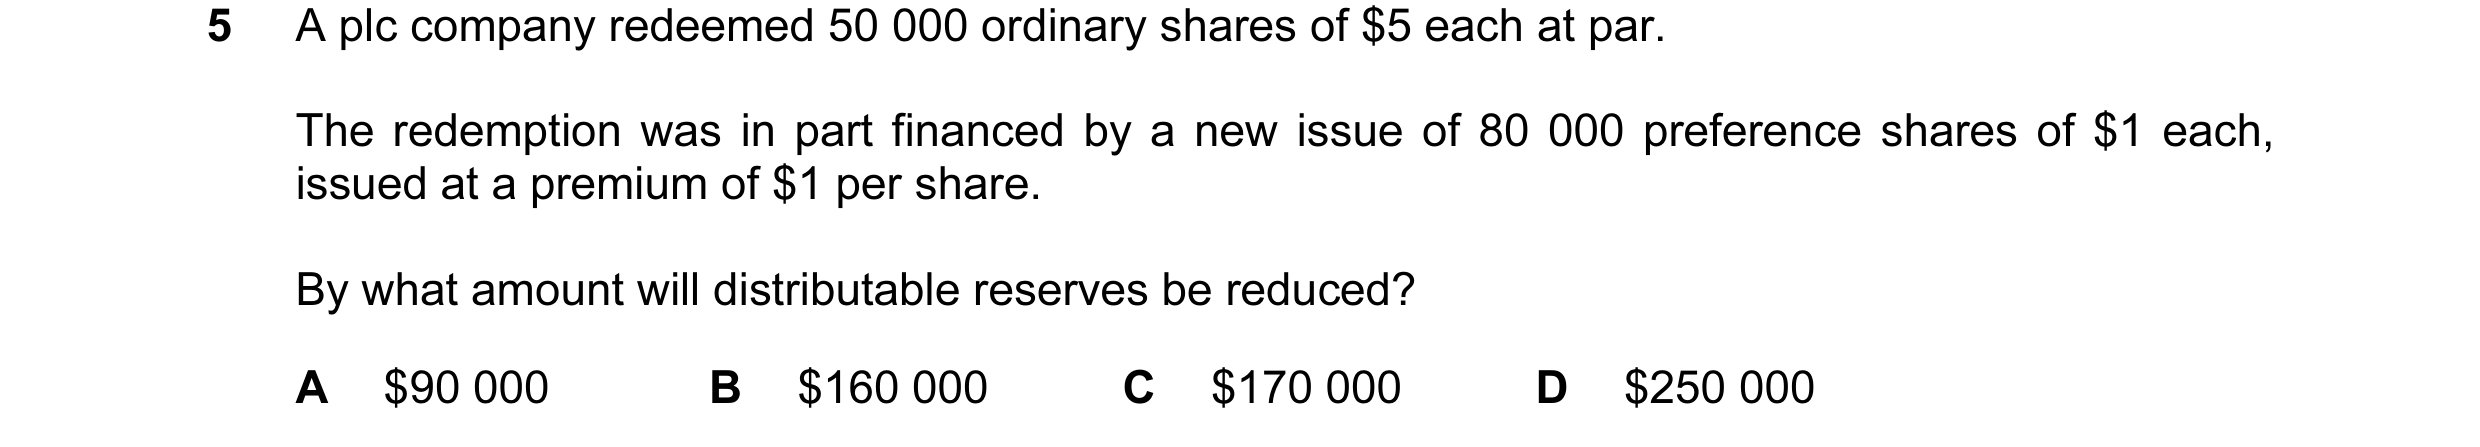
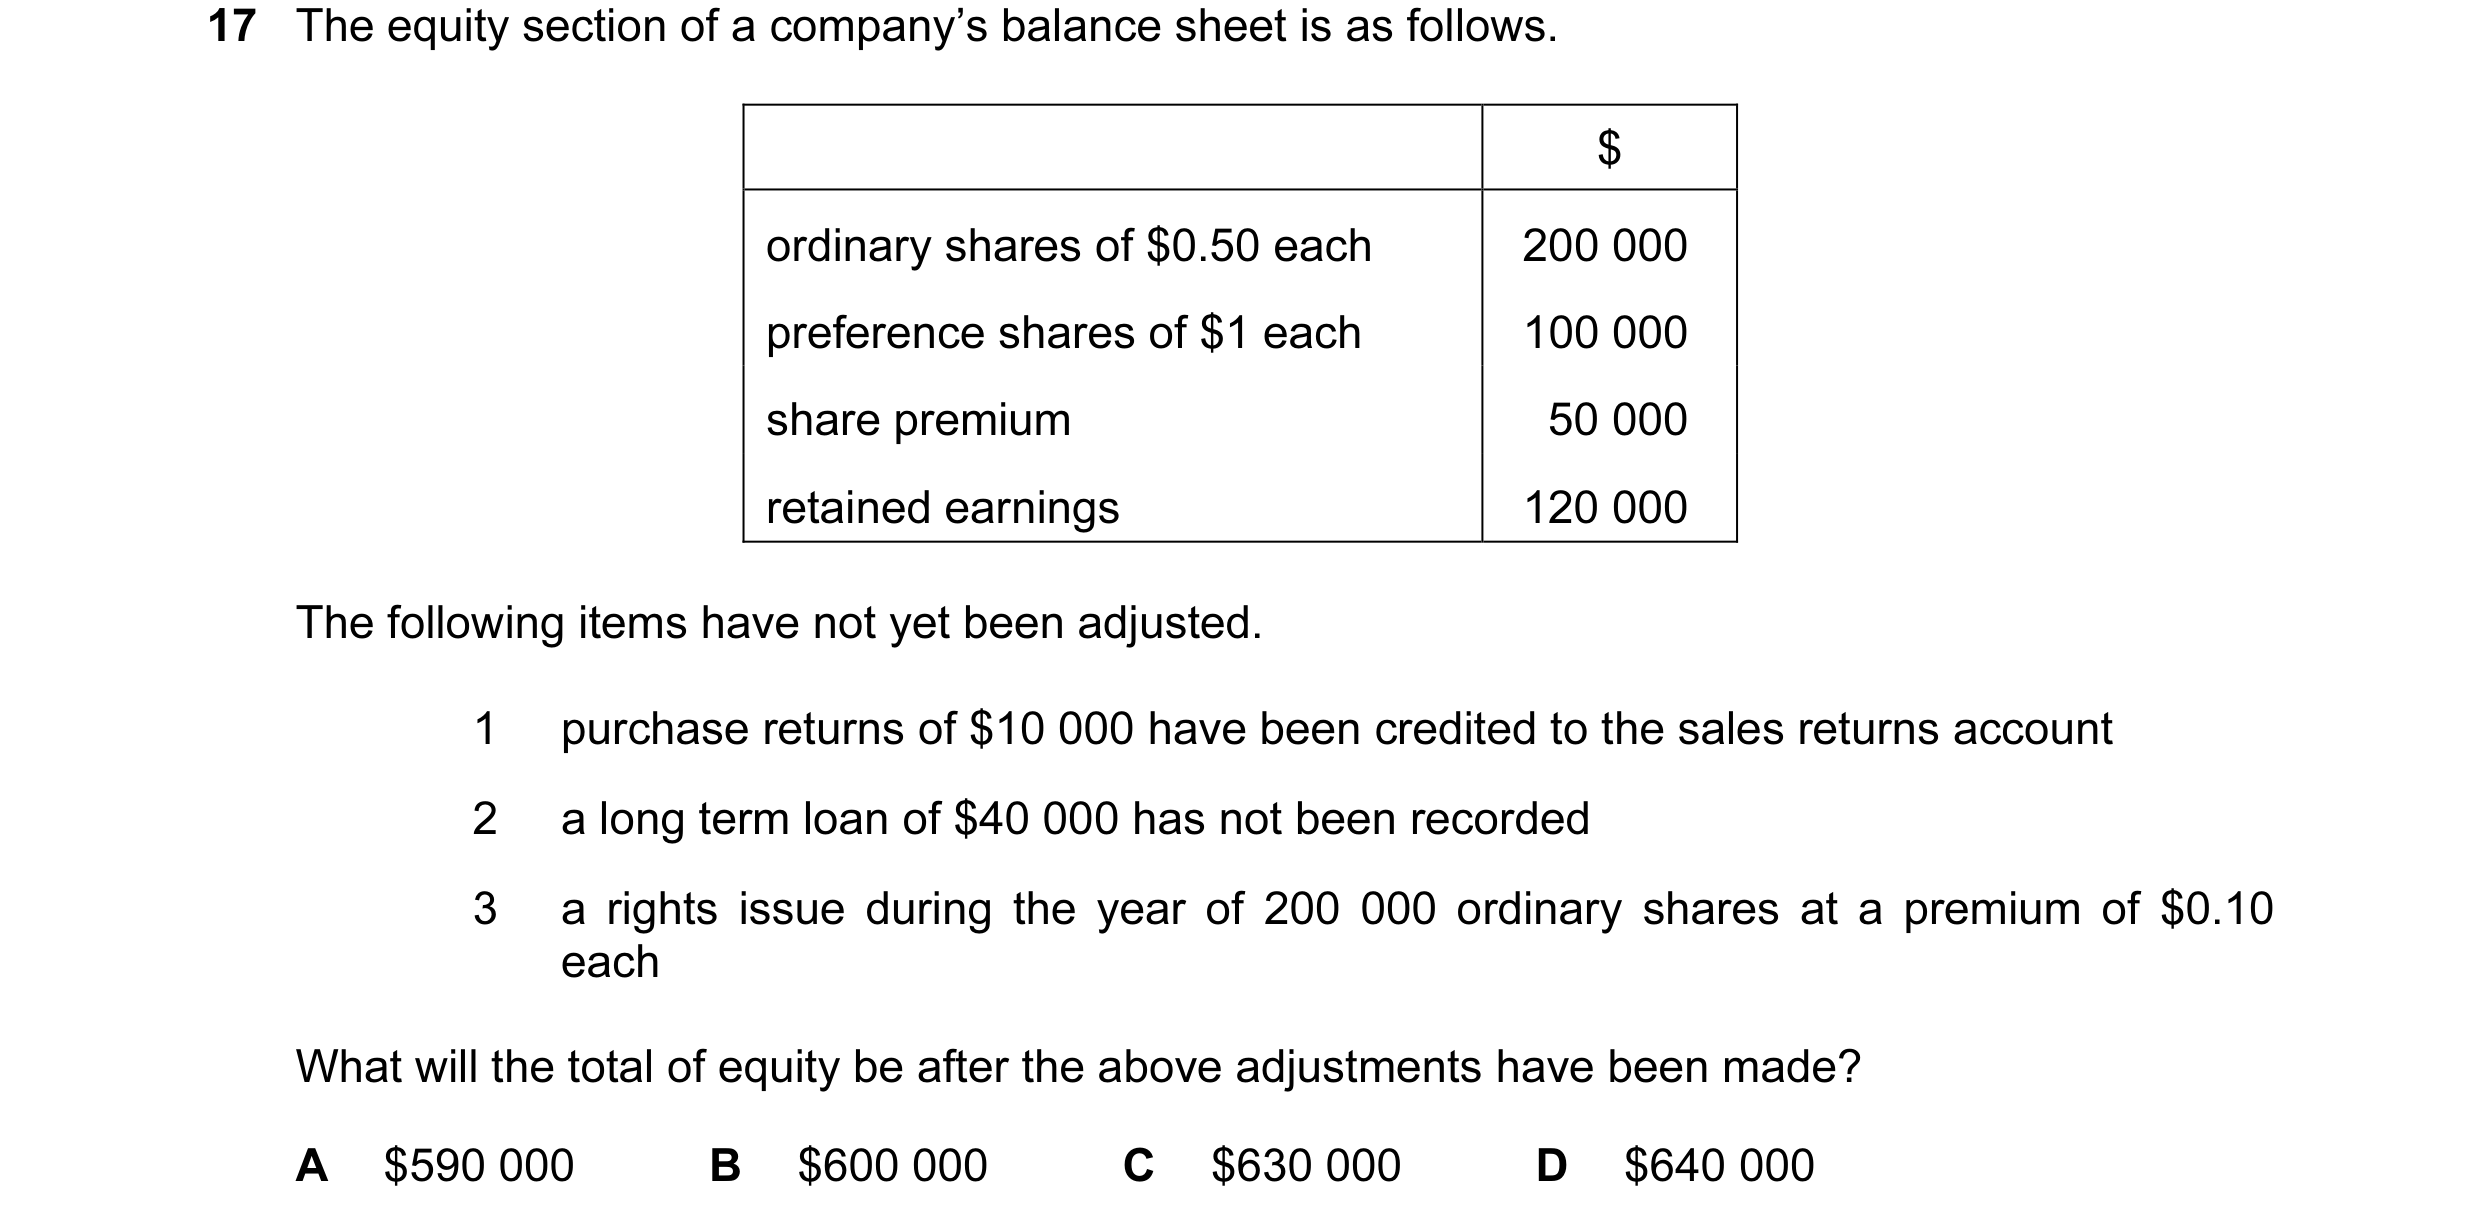
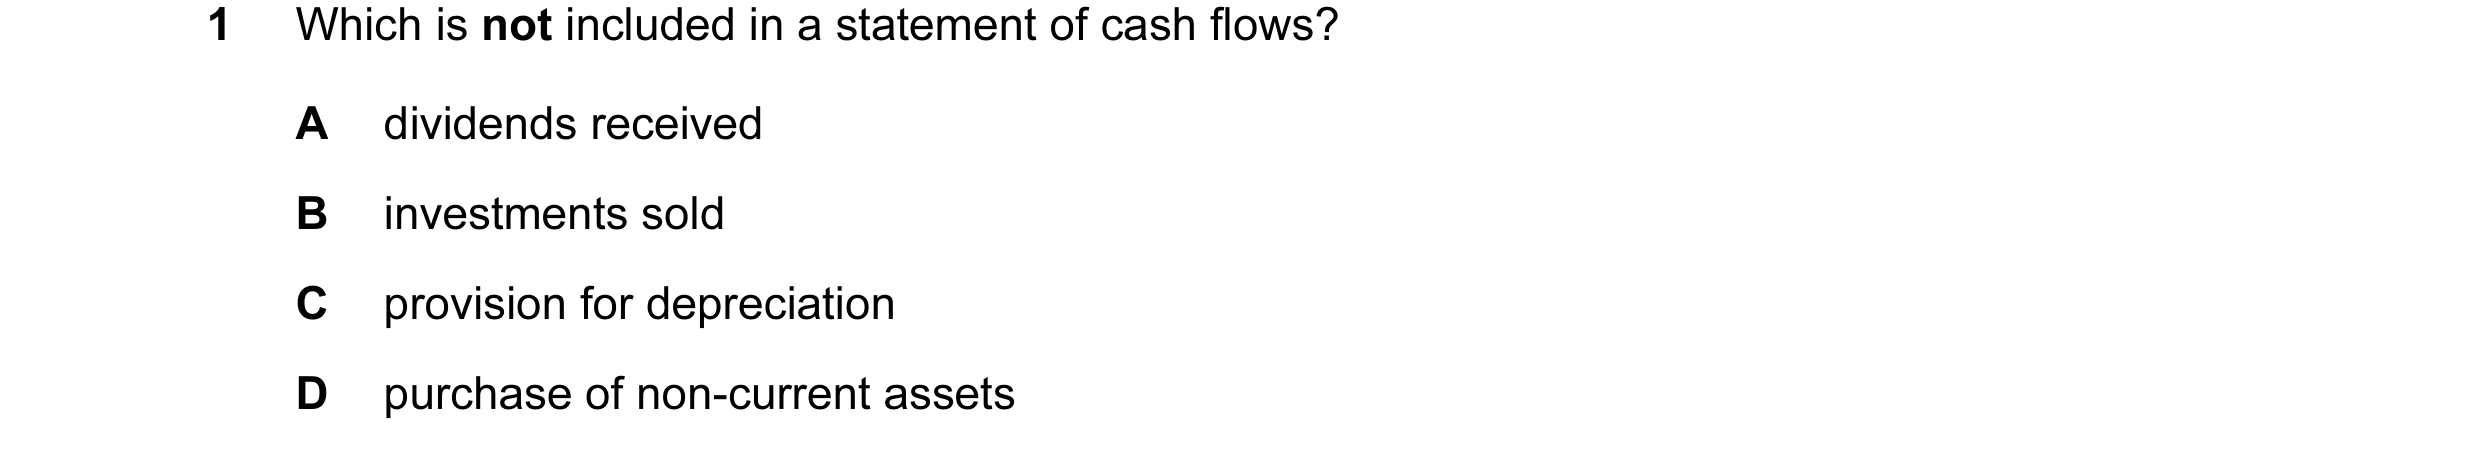 12 / 62
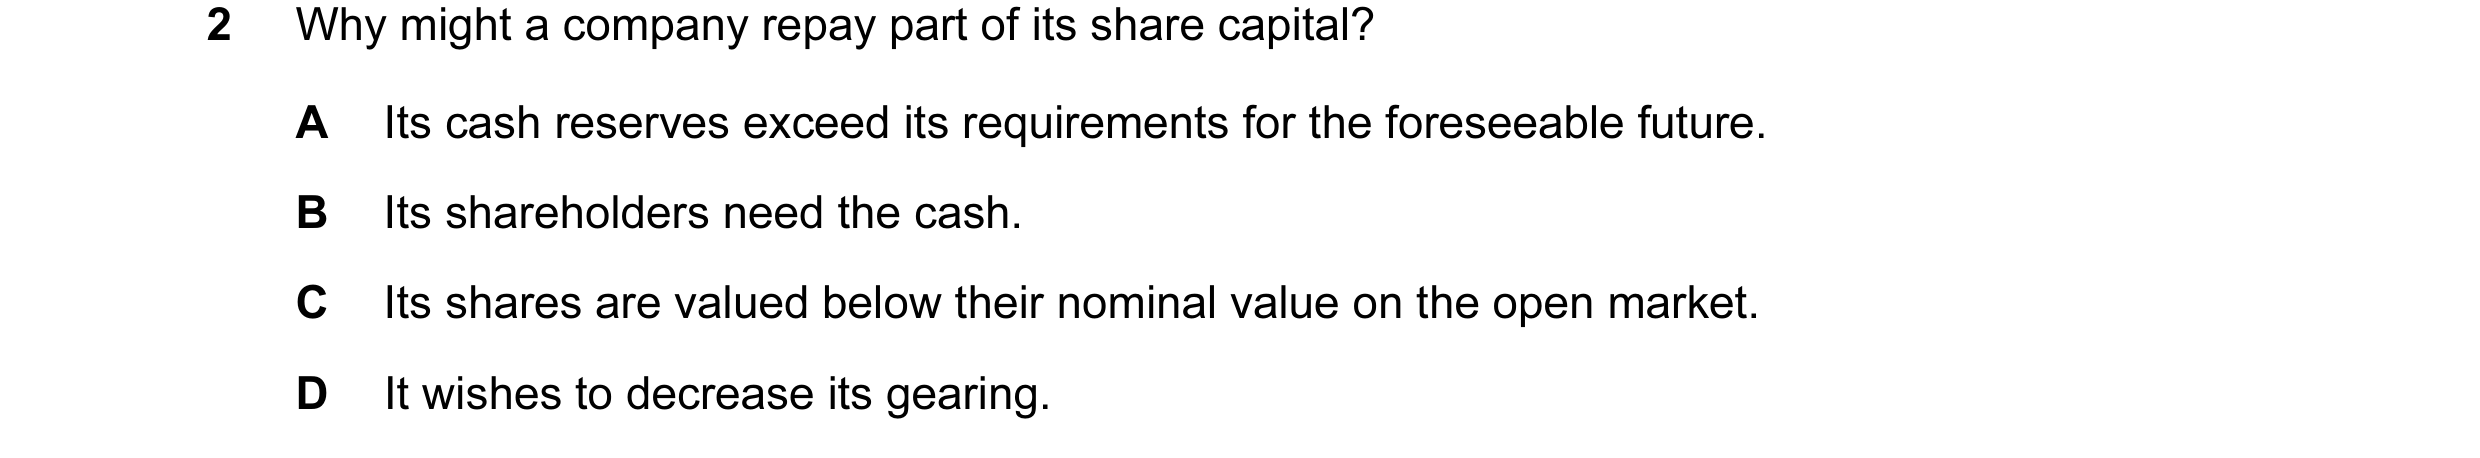
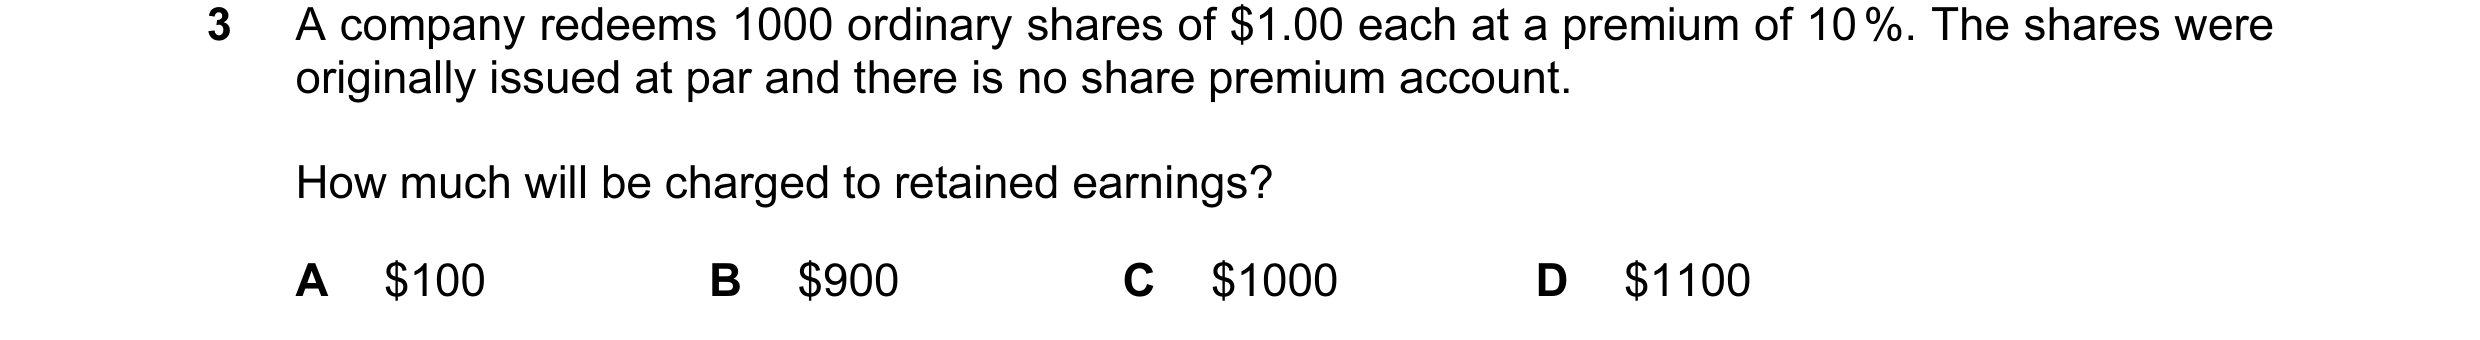
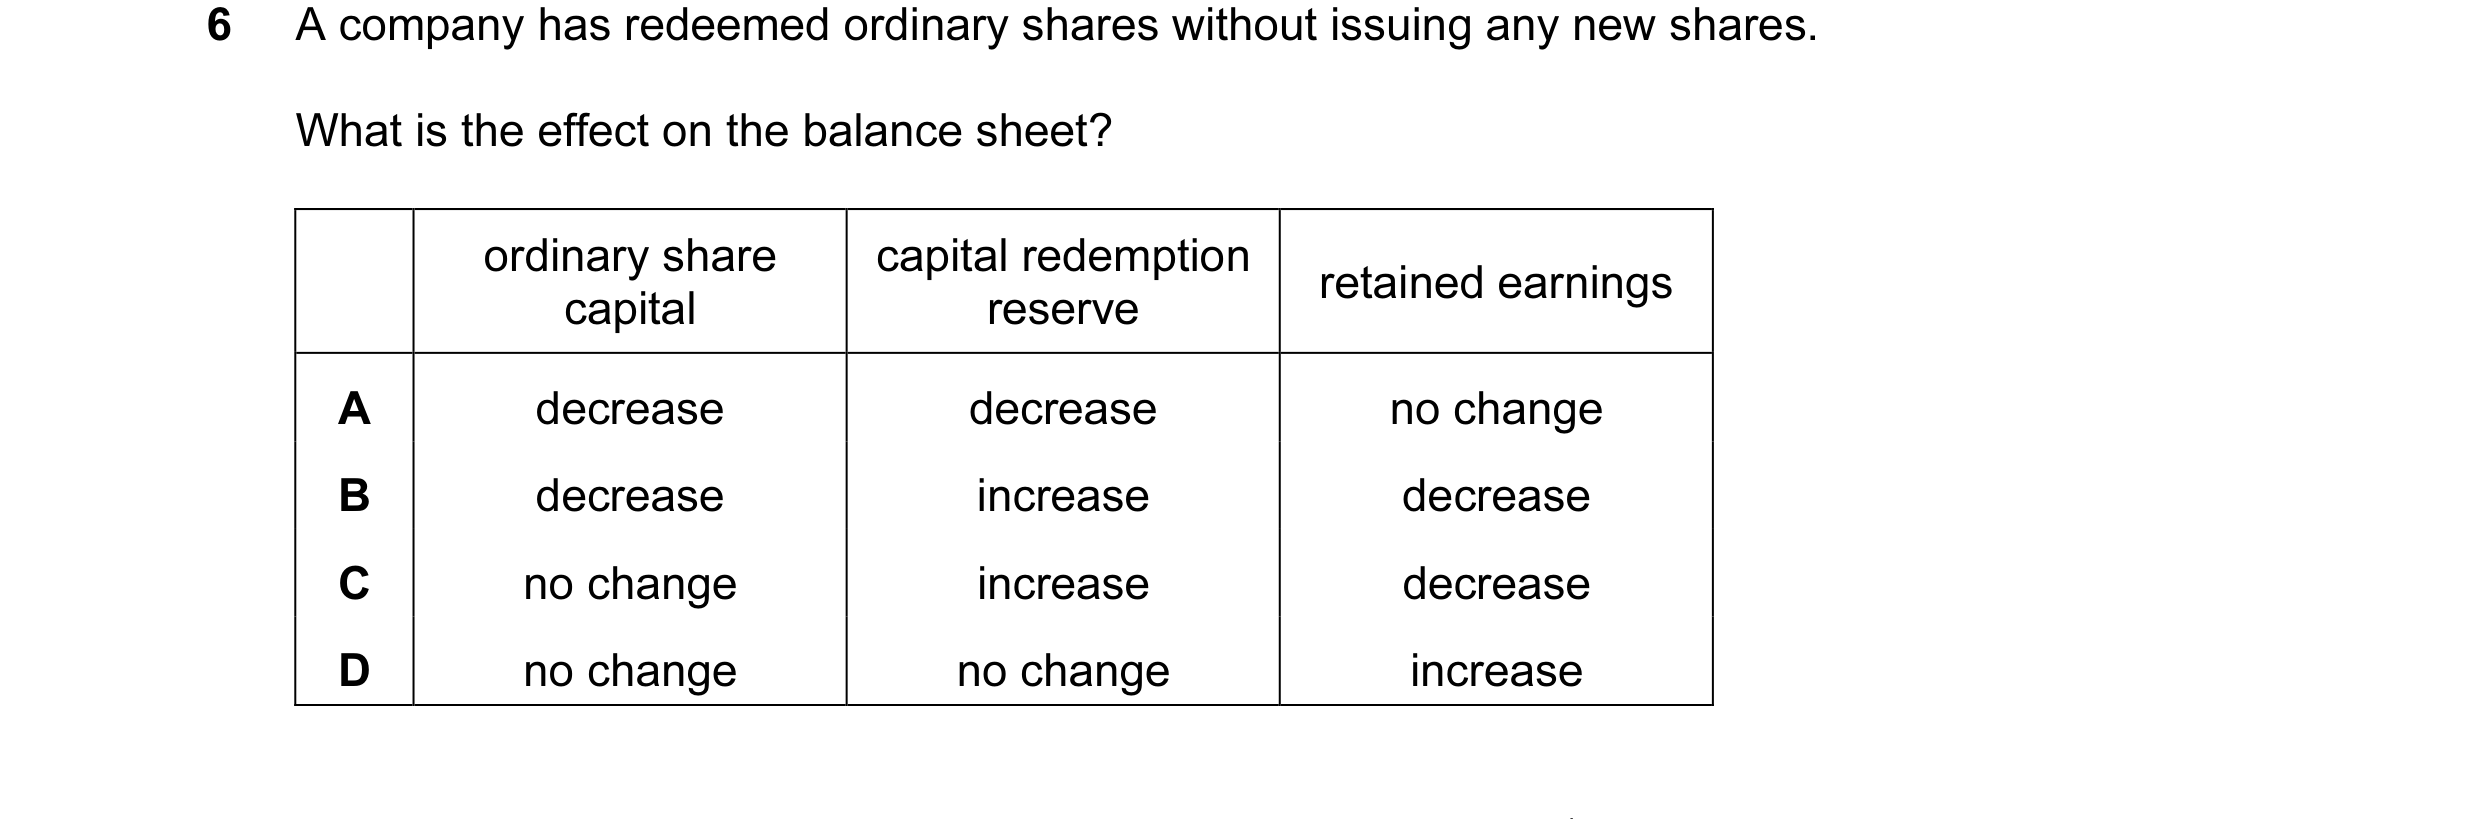
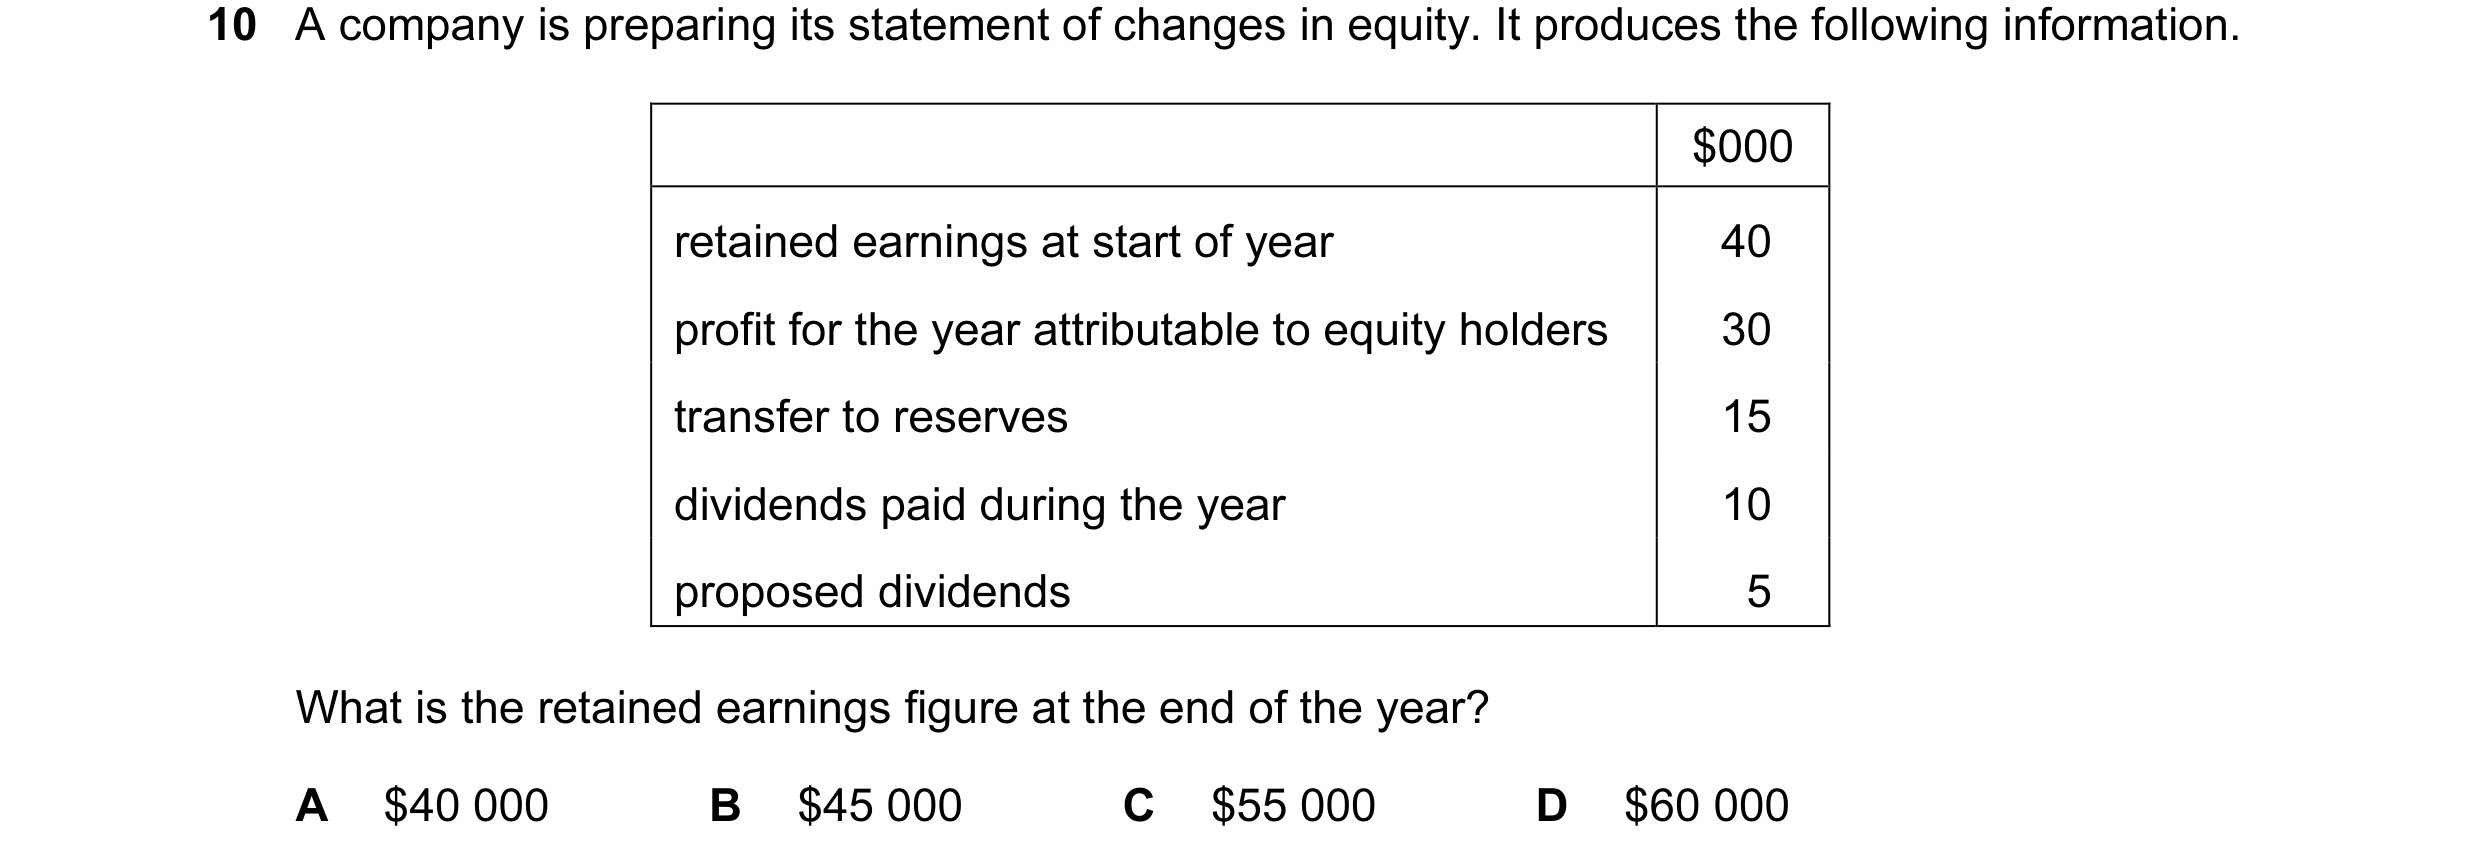 13 / 62
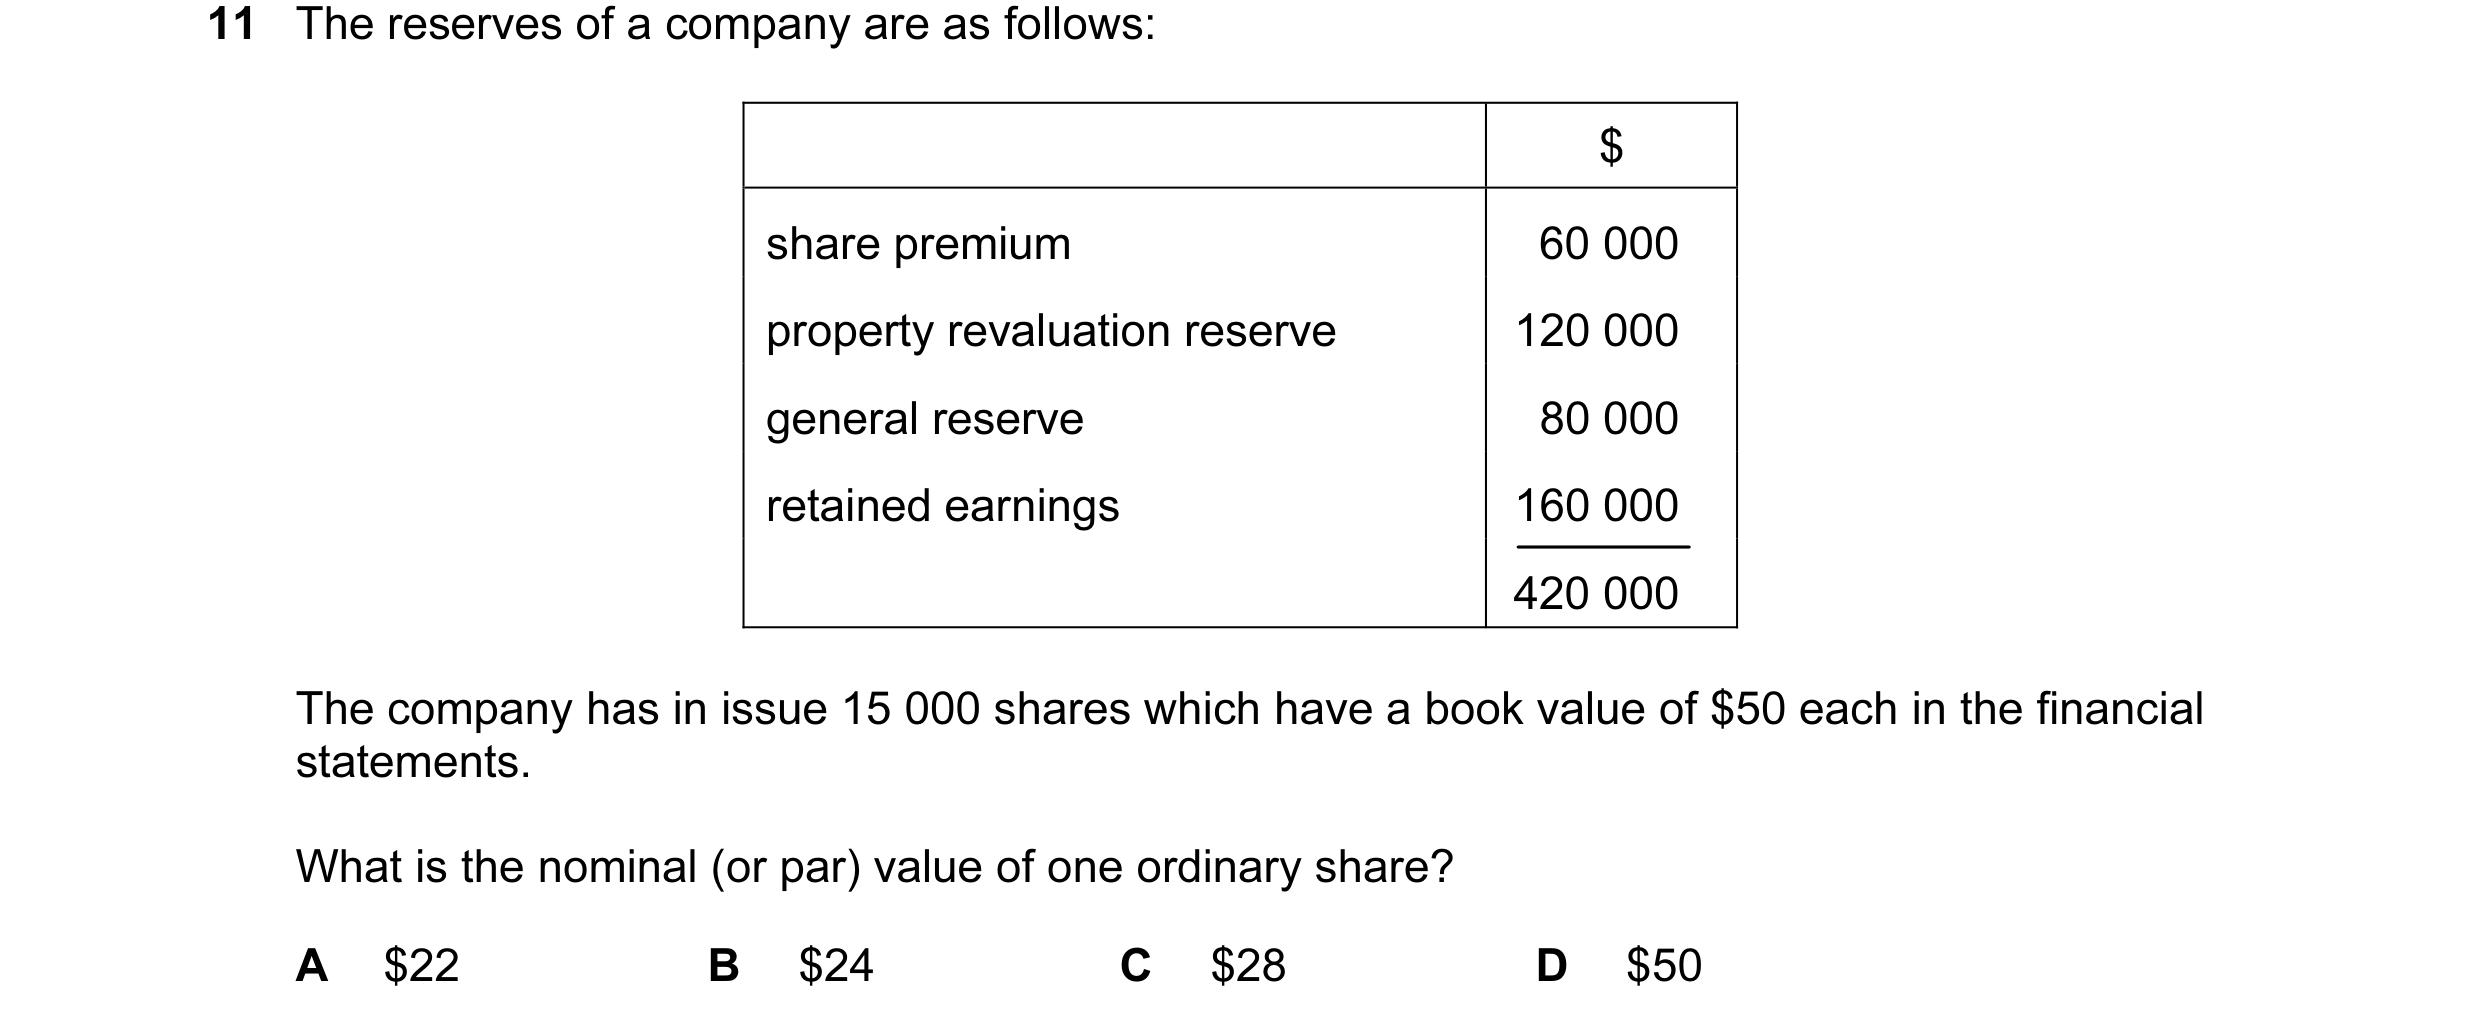
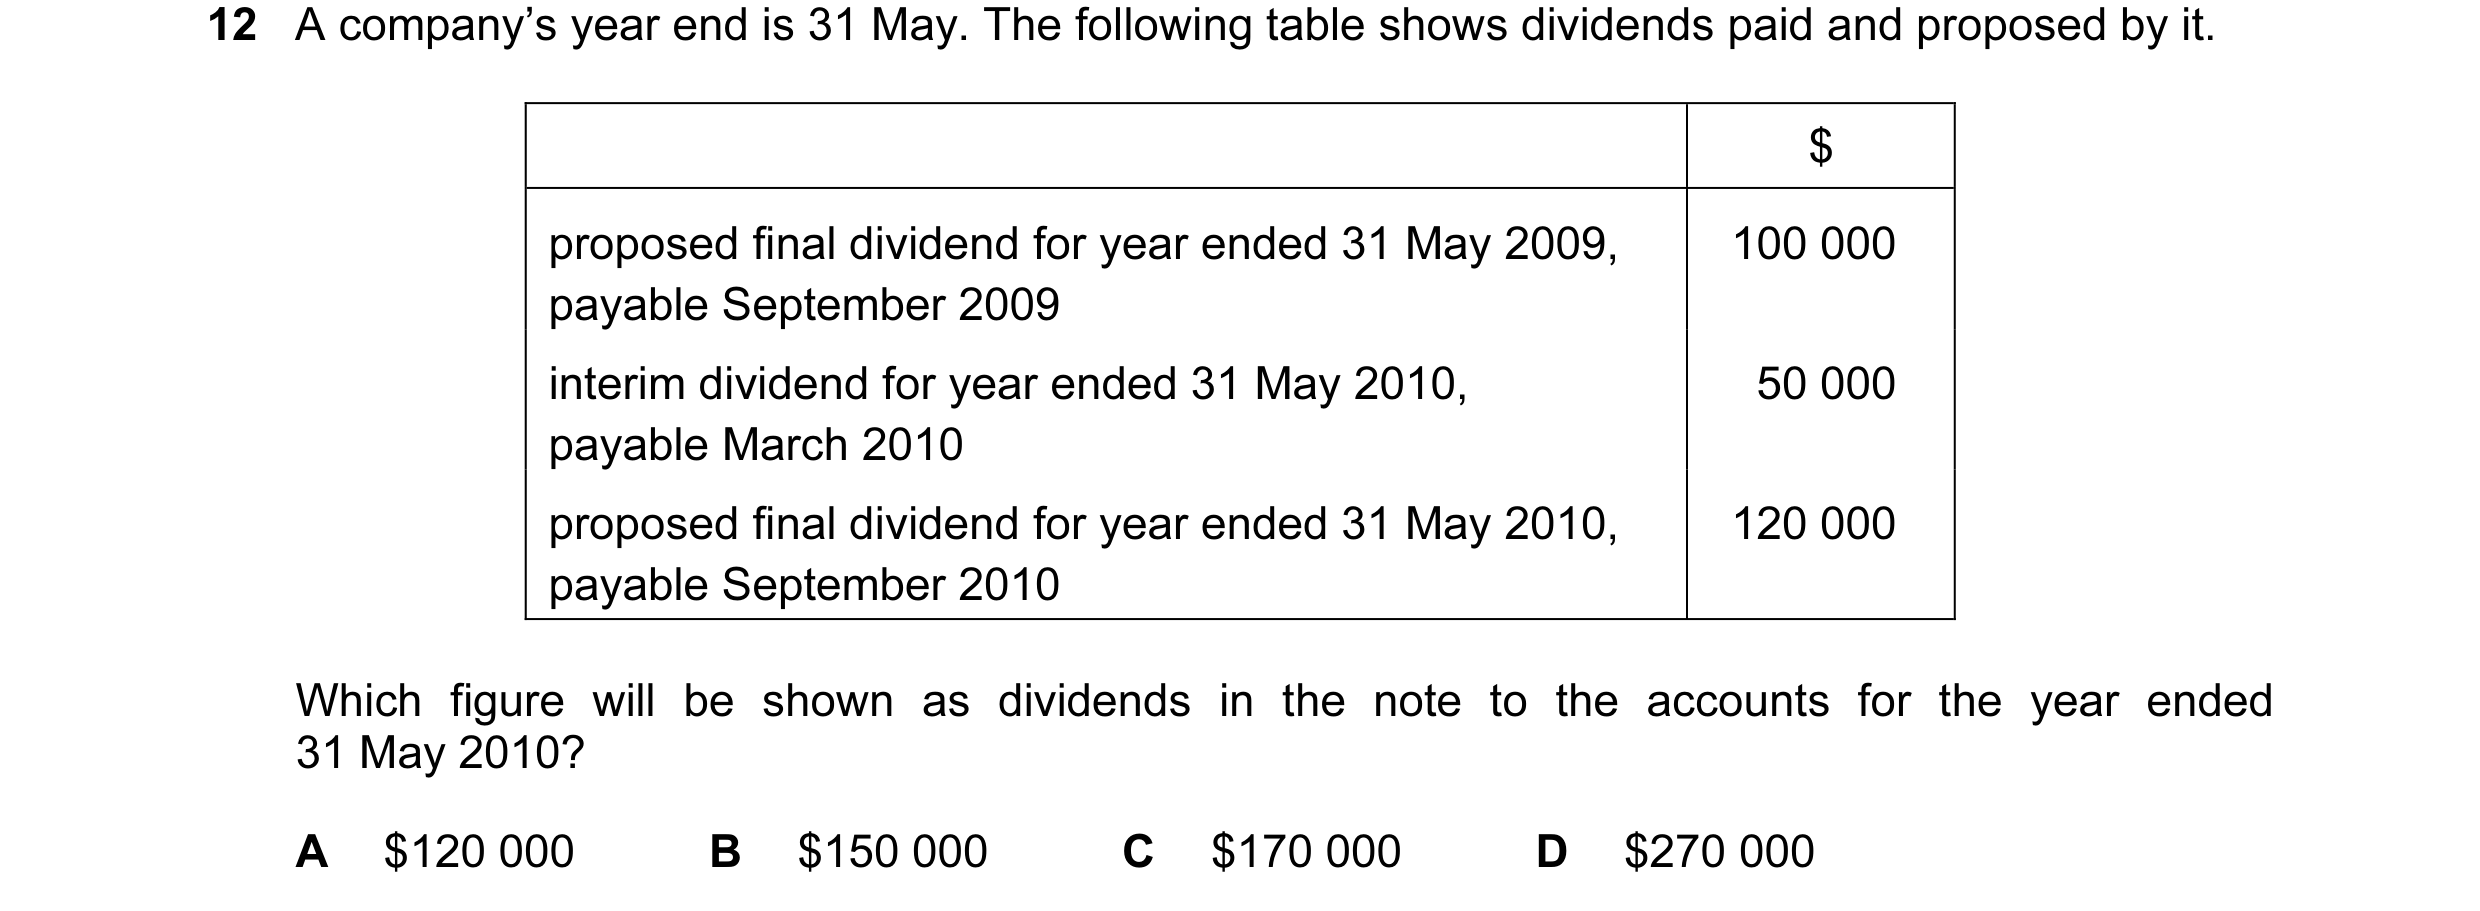
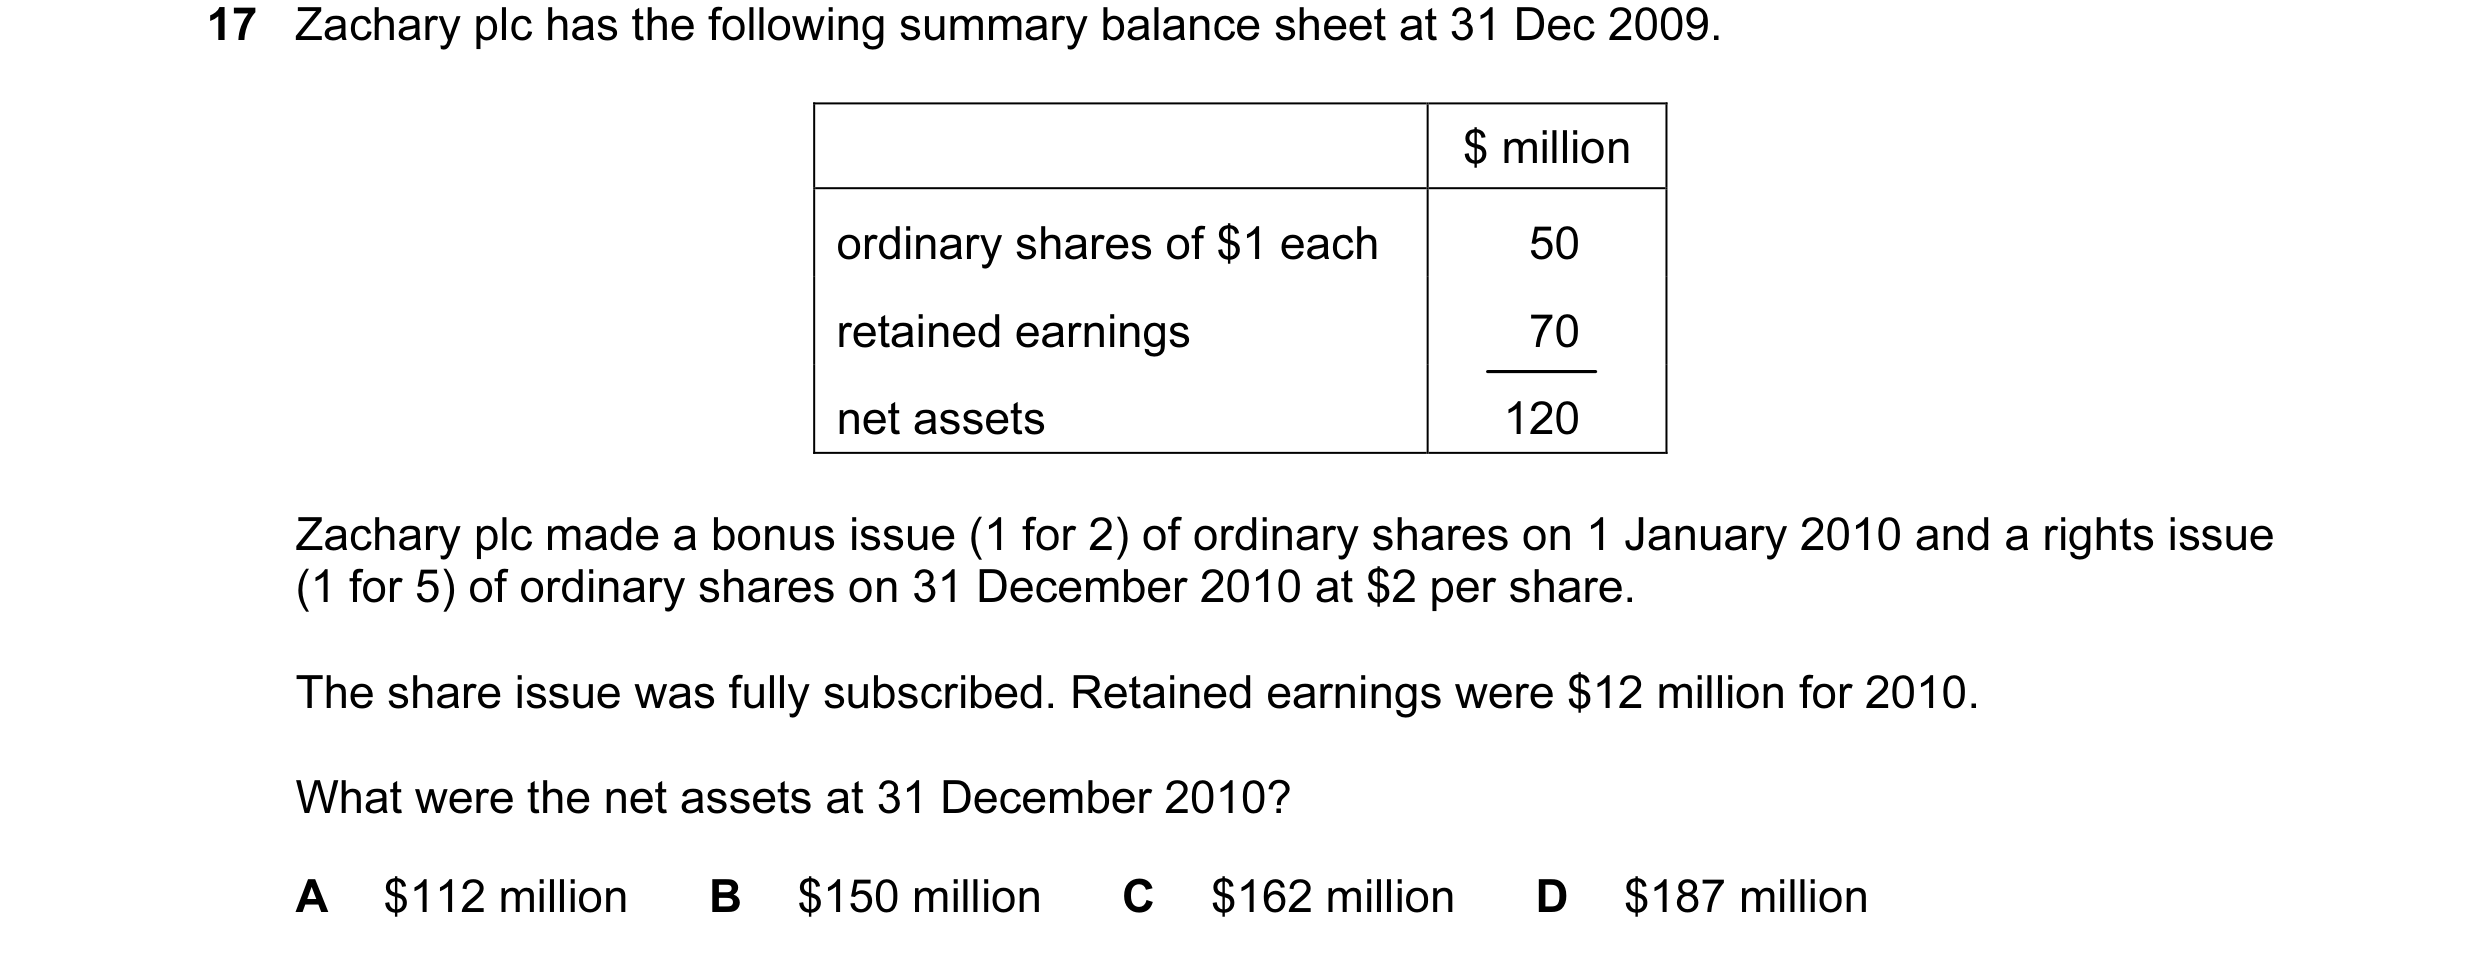
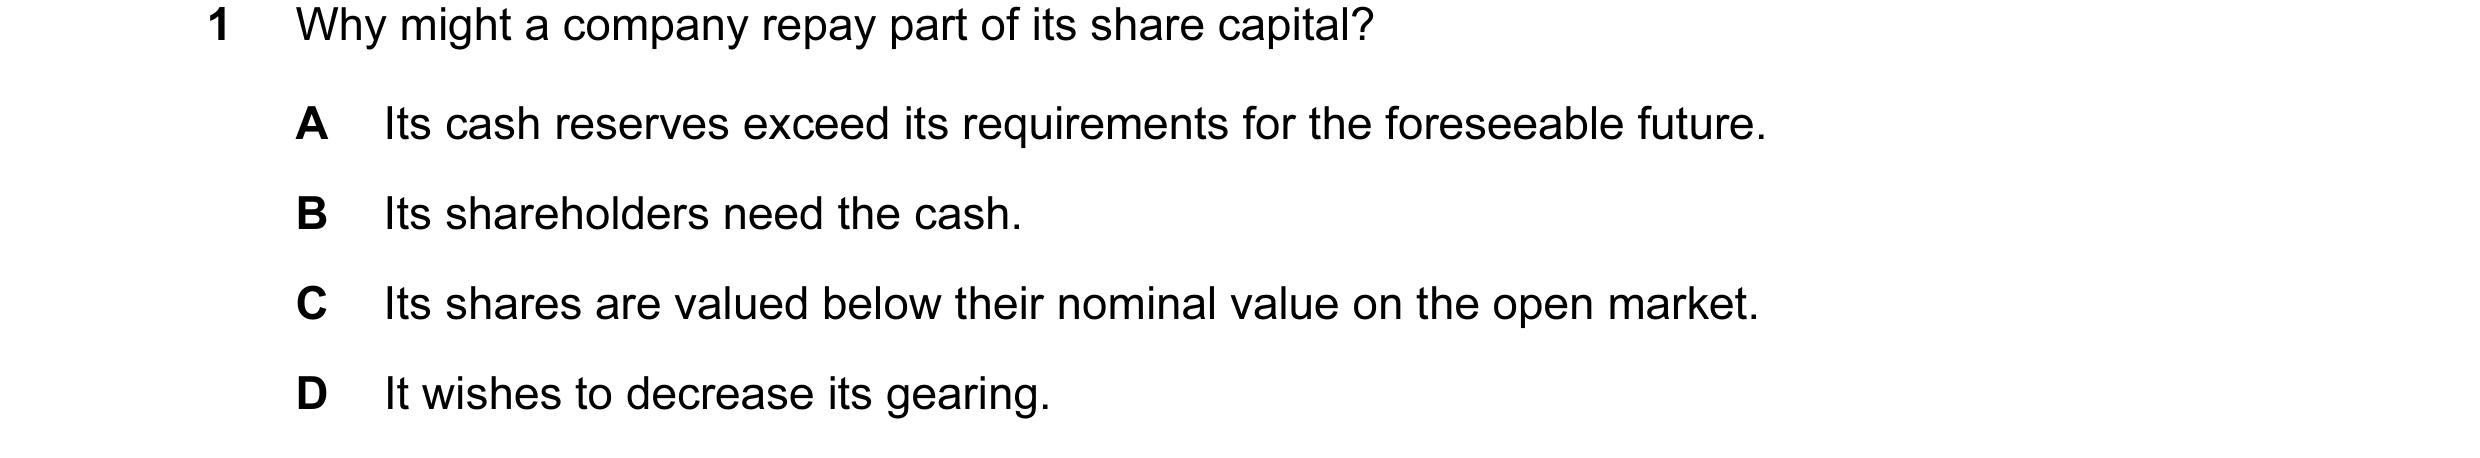 14 / 62
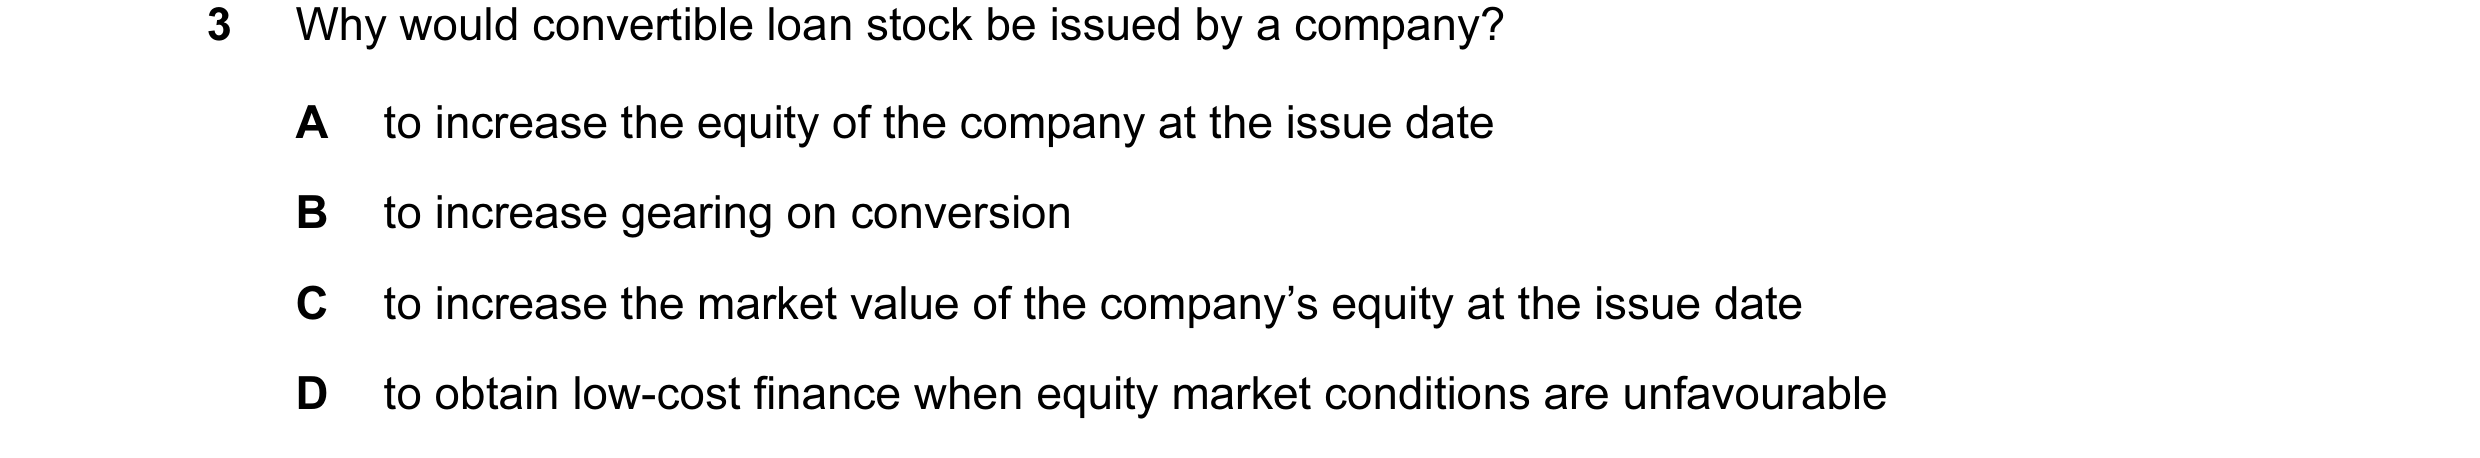
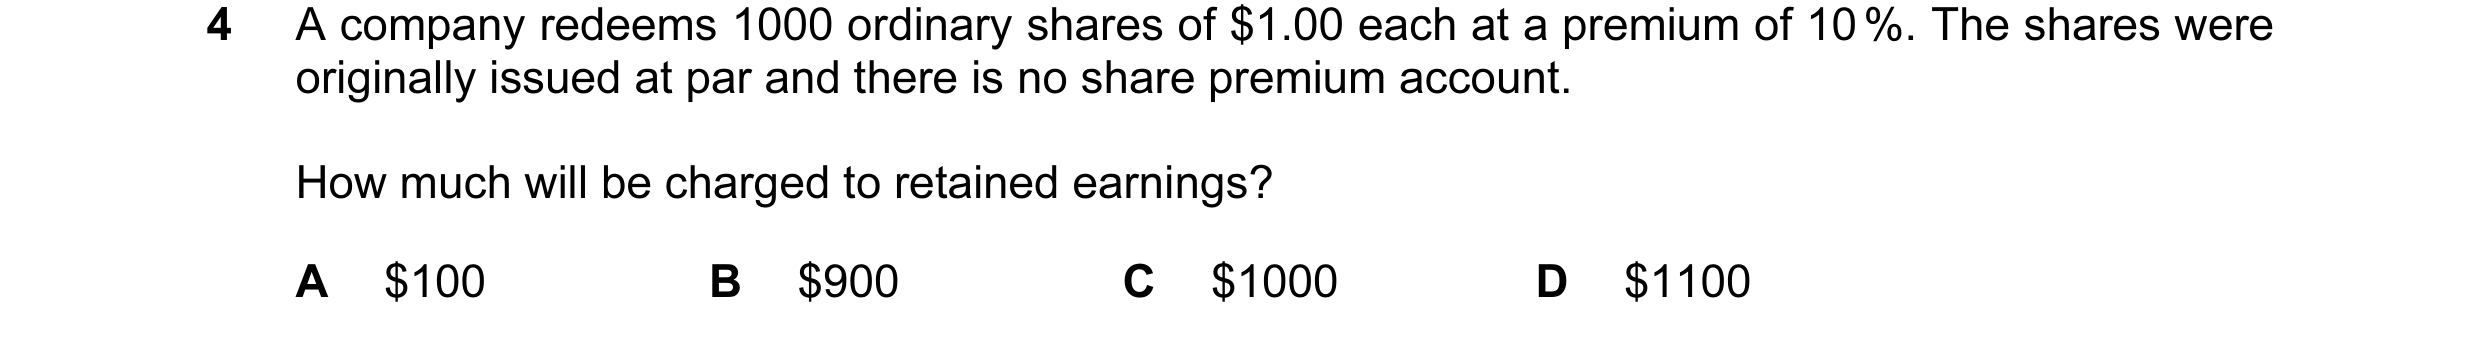
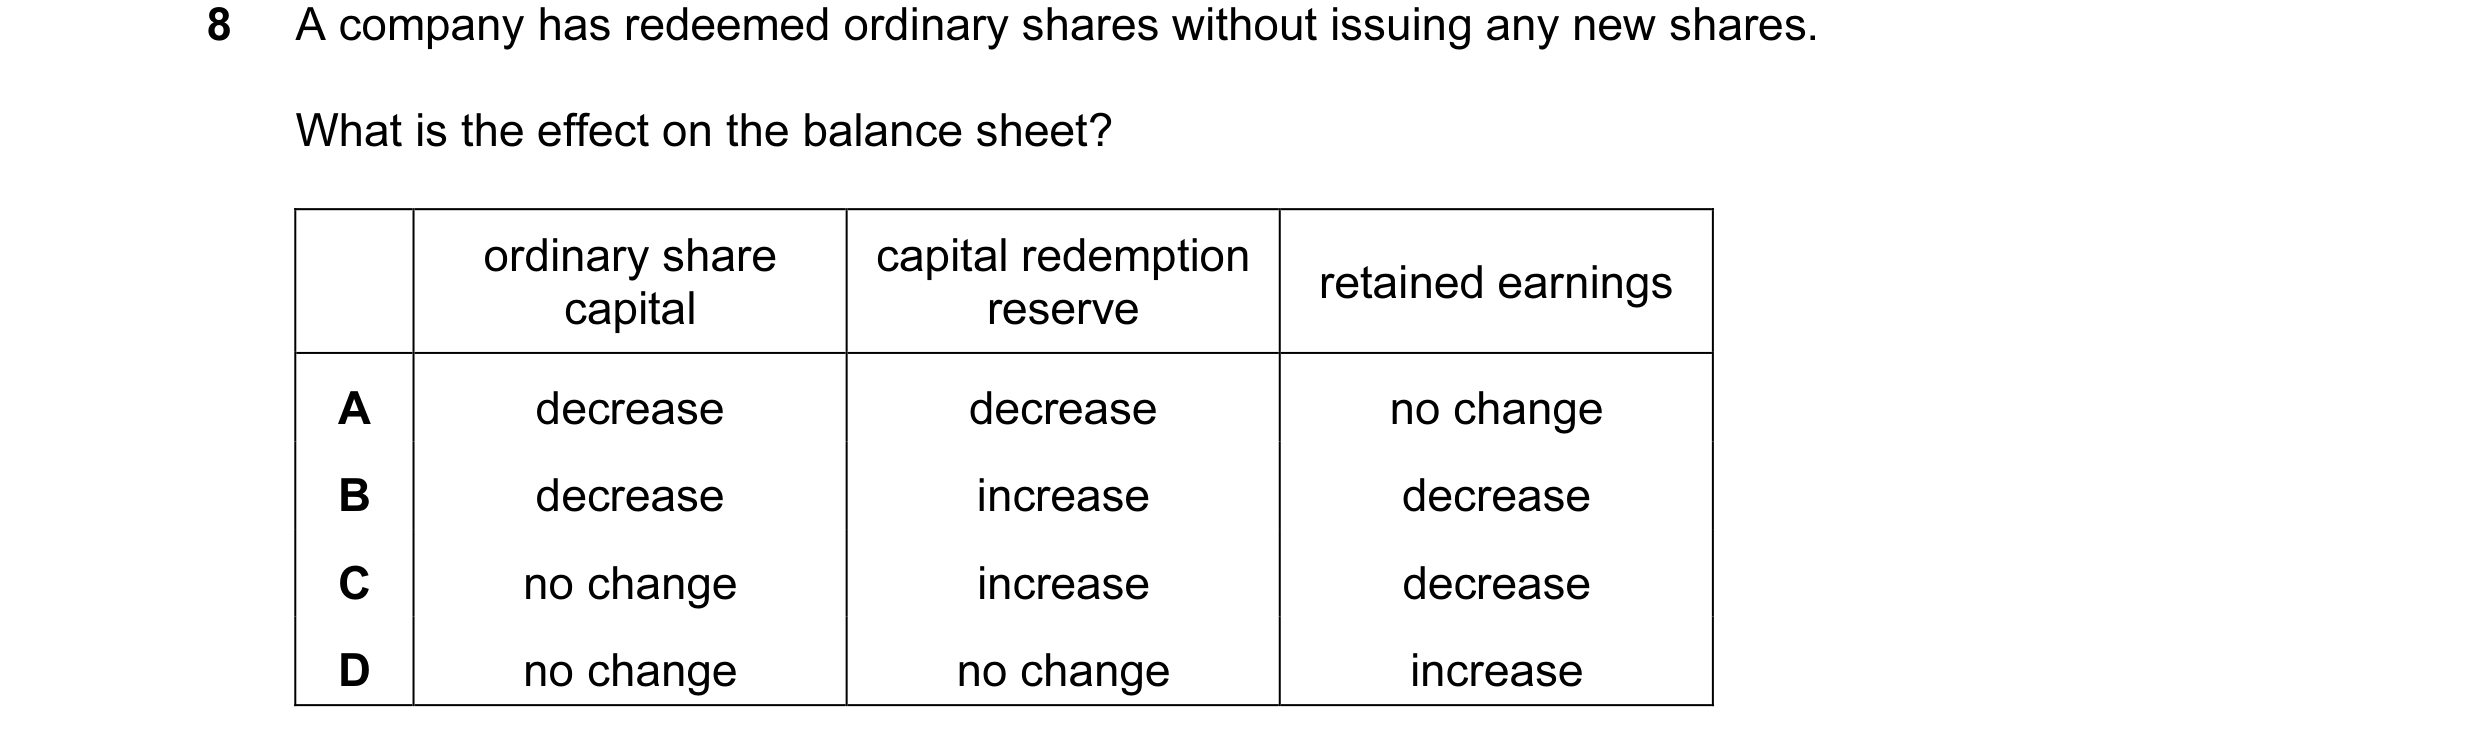
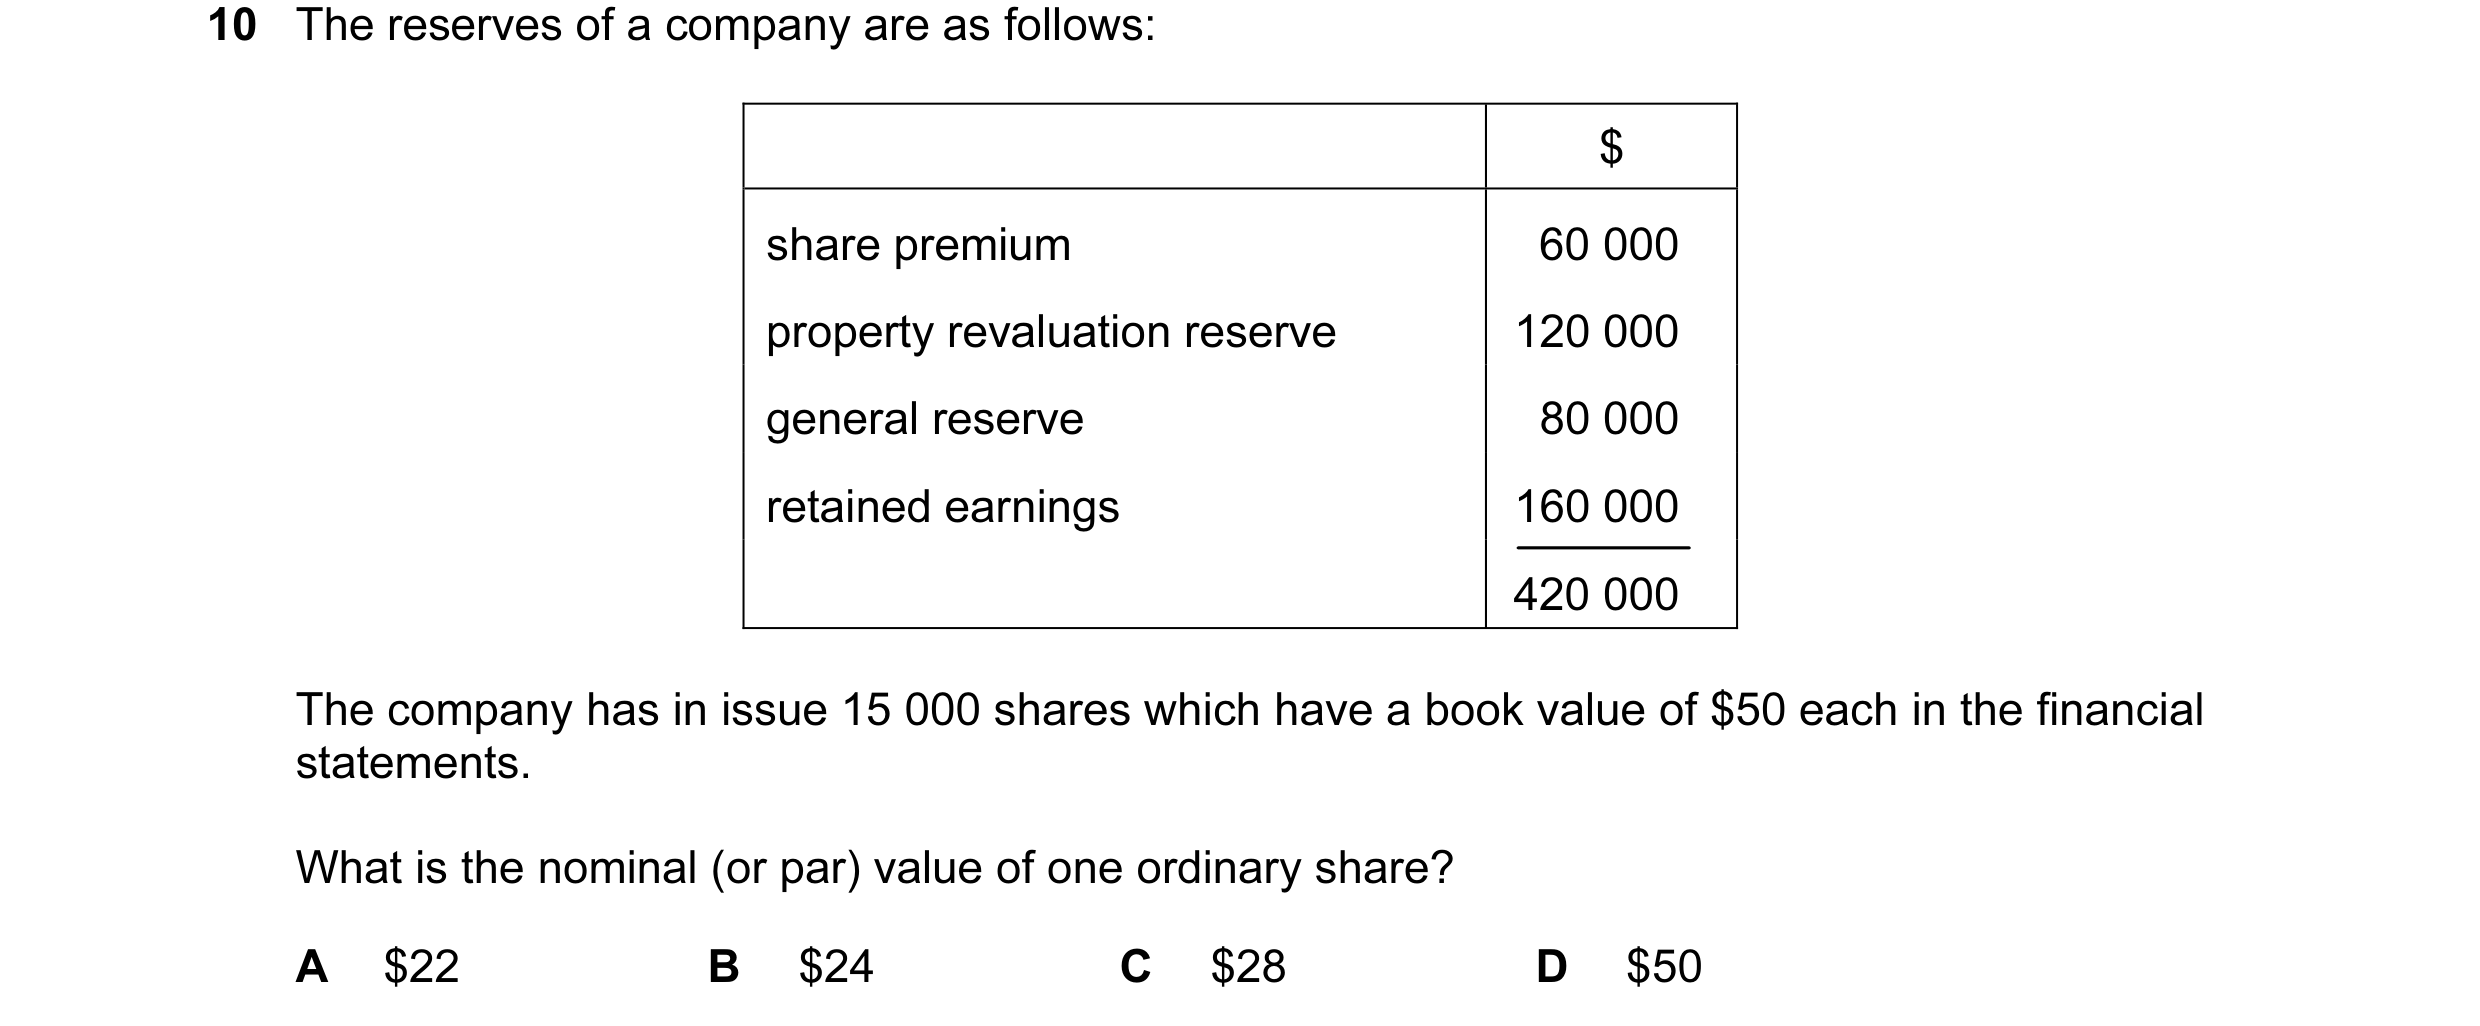 15 / 62
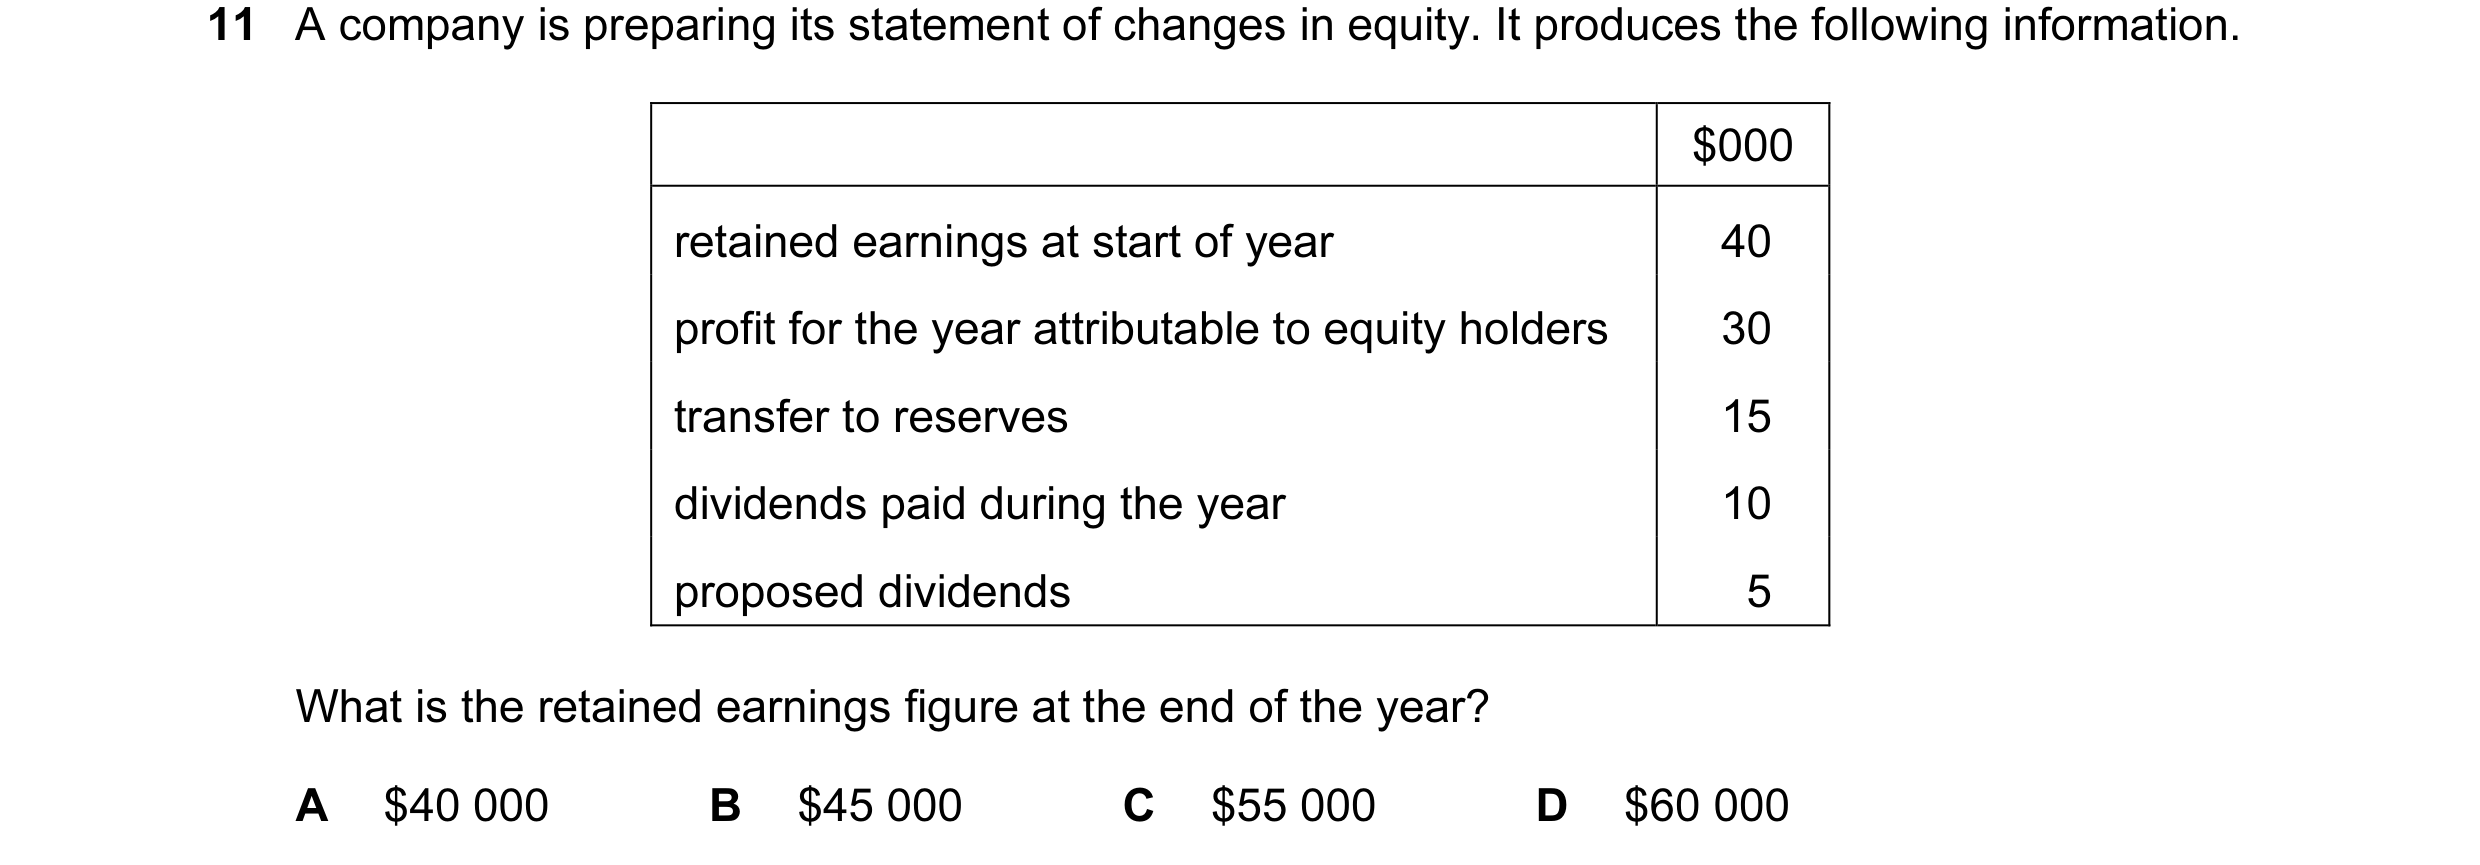
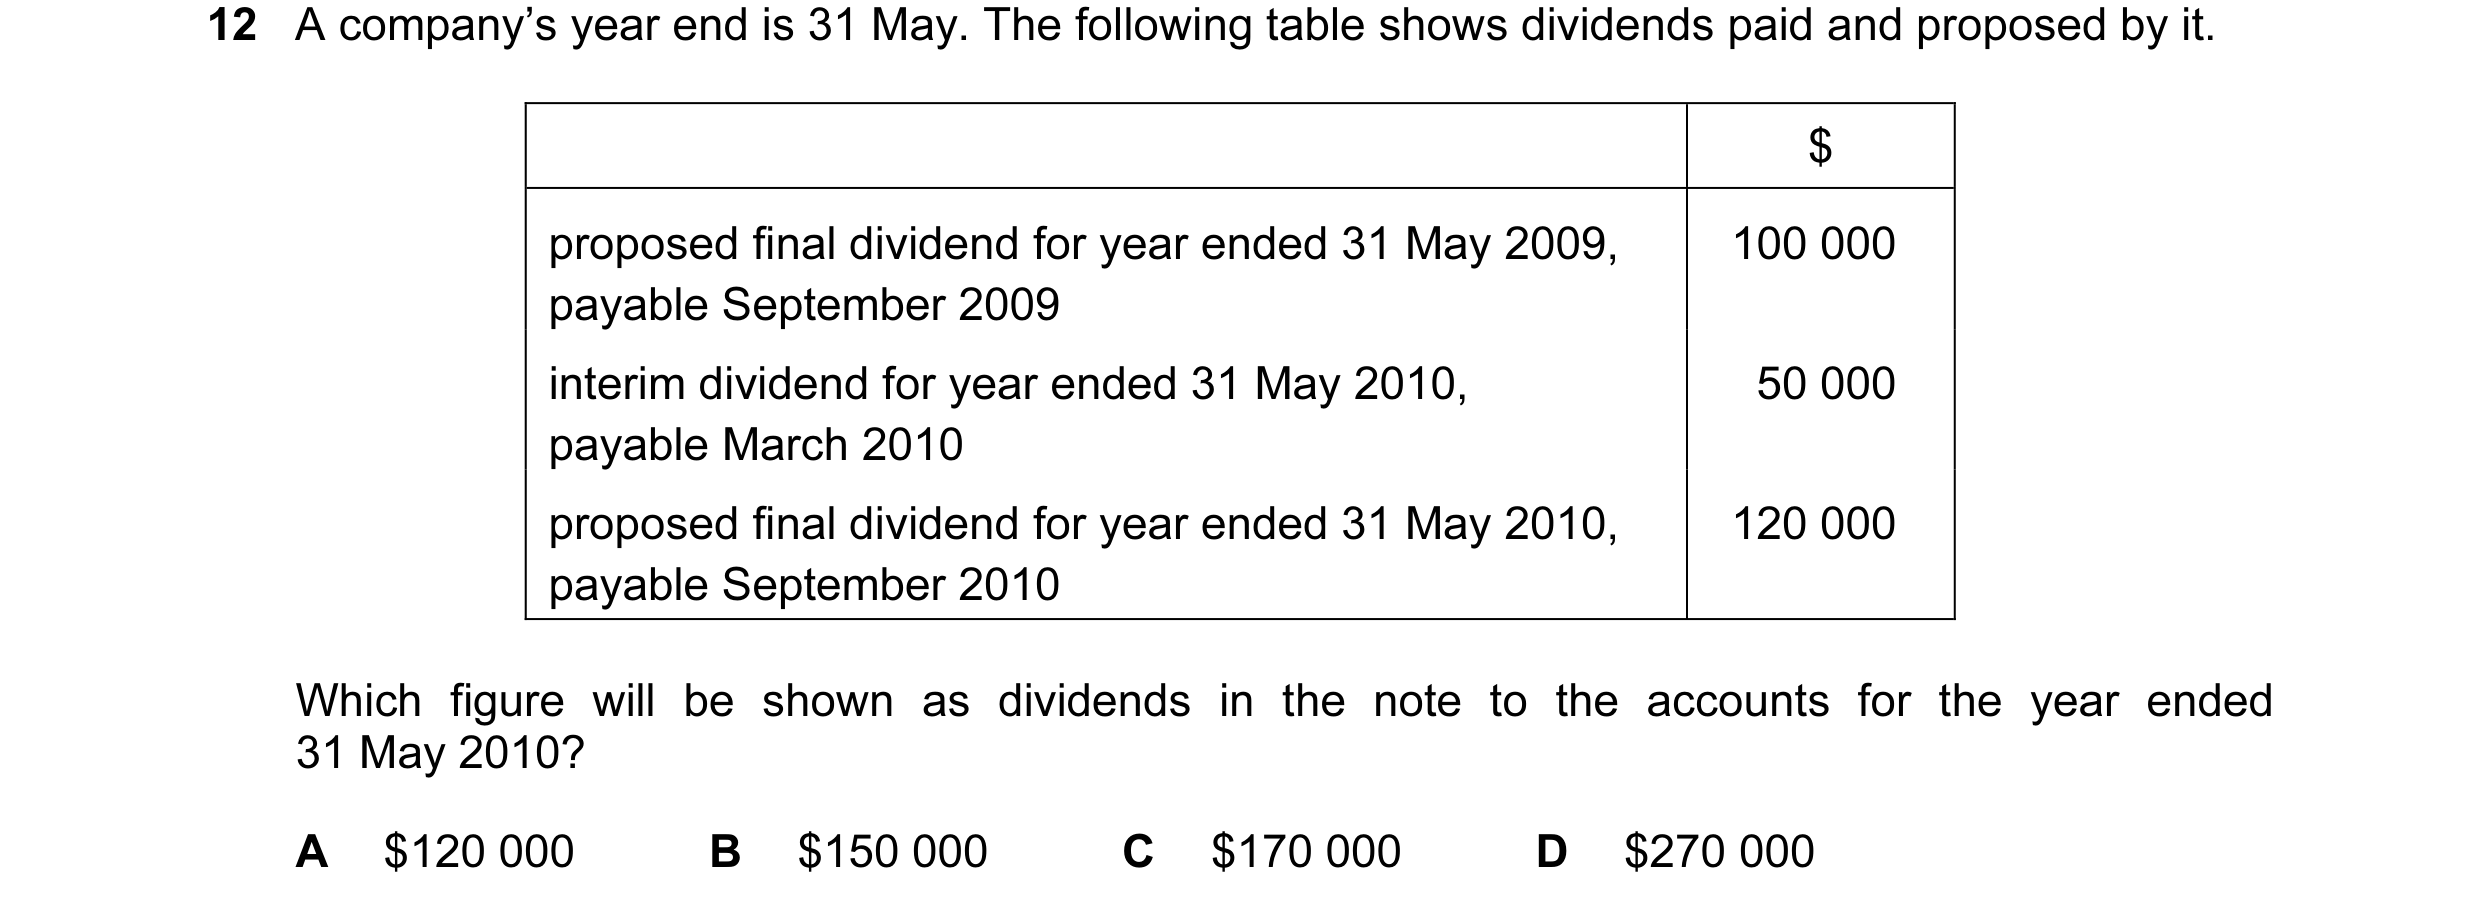
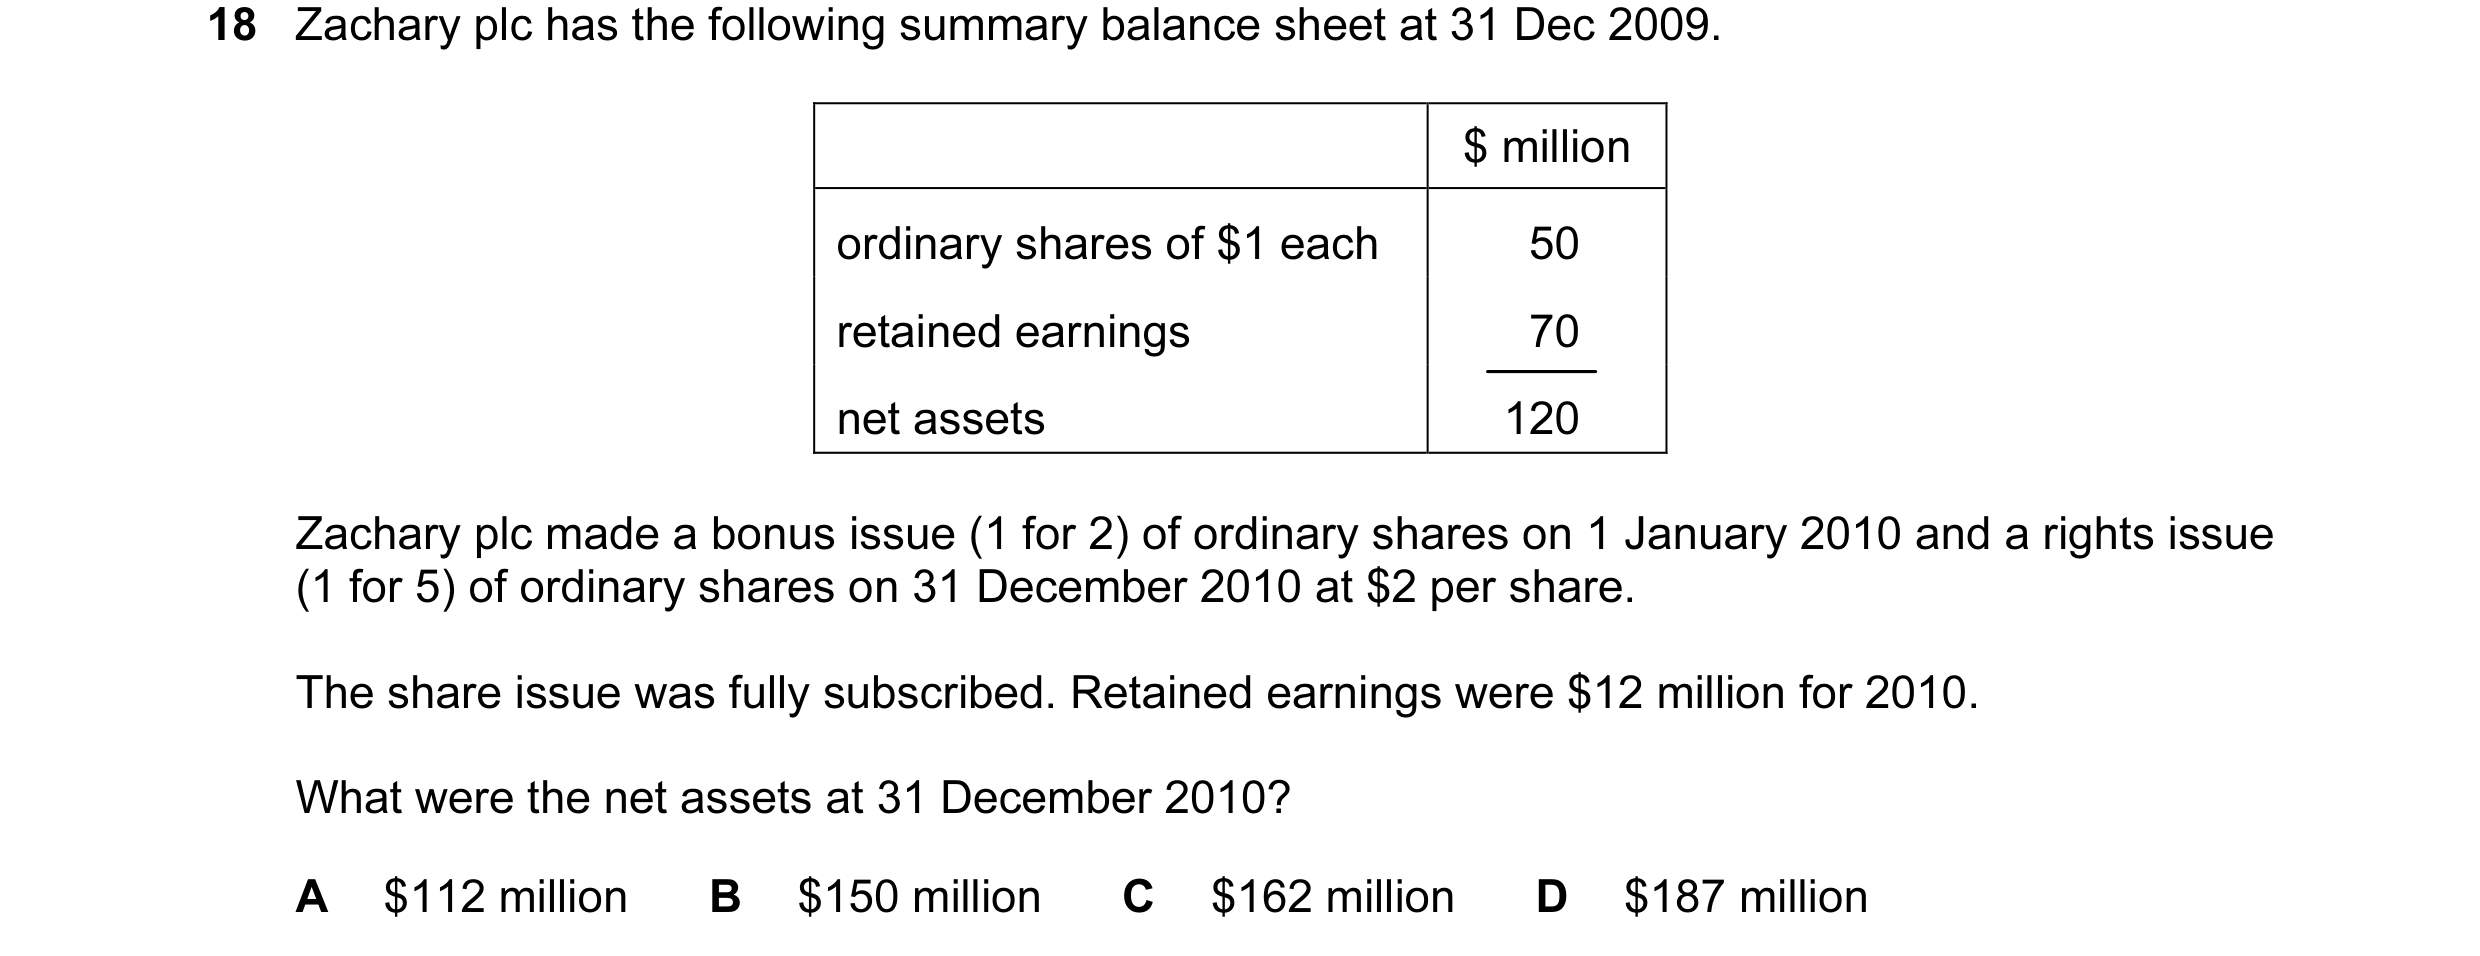
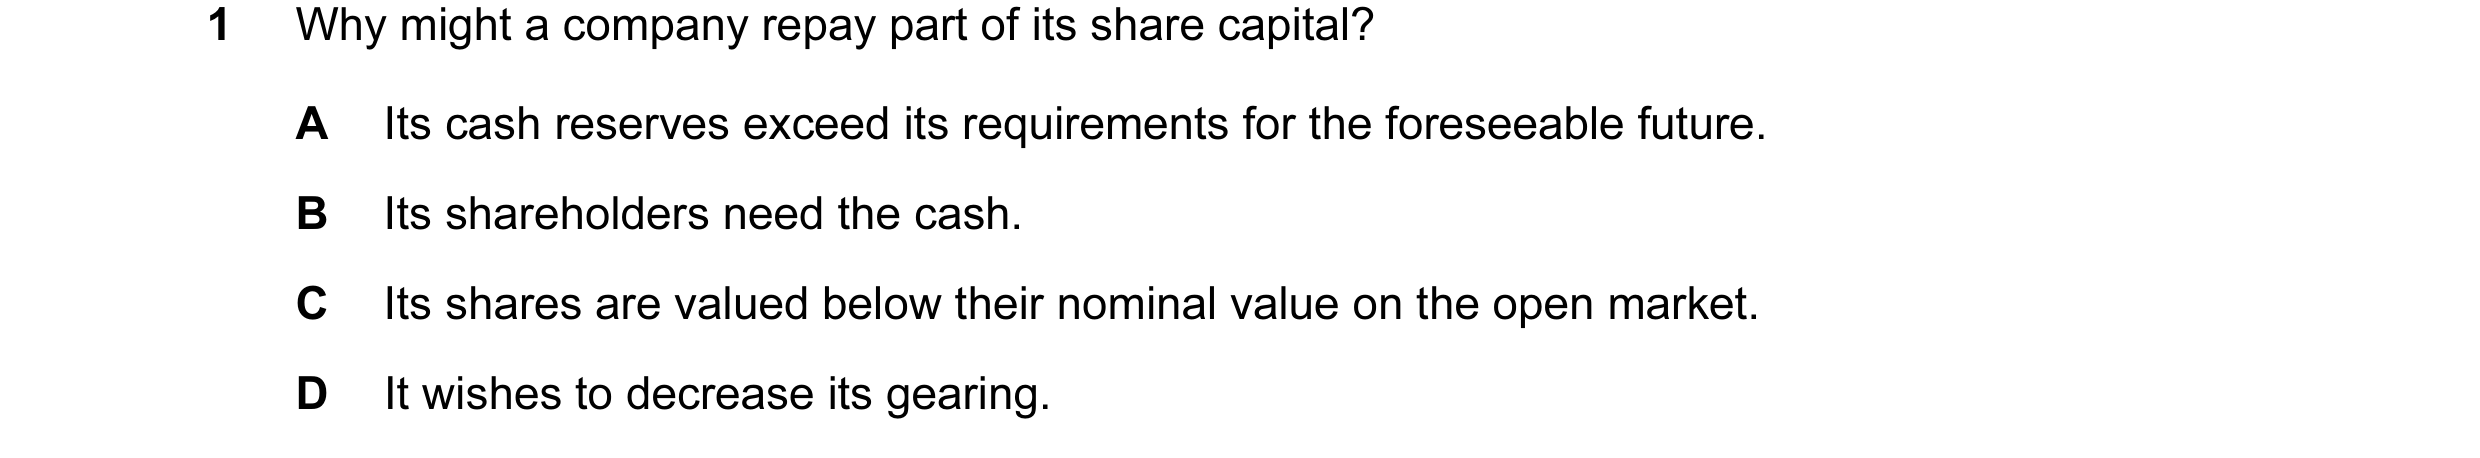 16 / 62
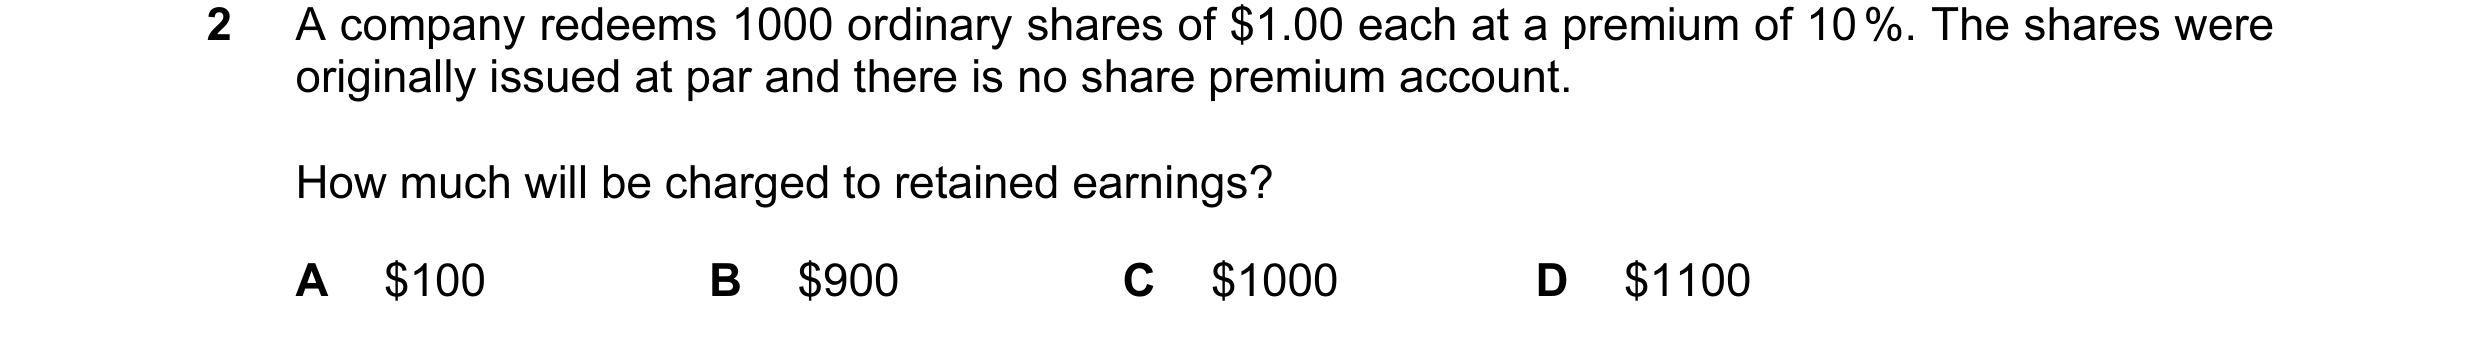
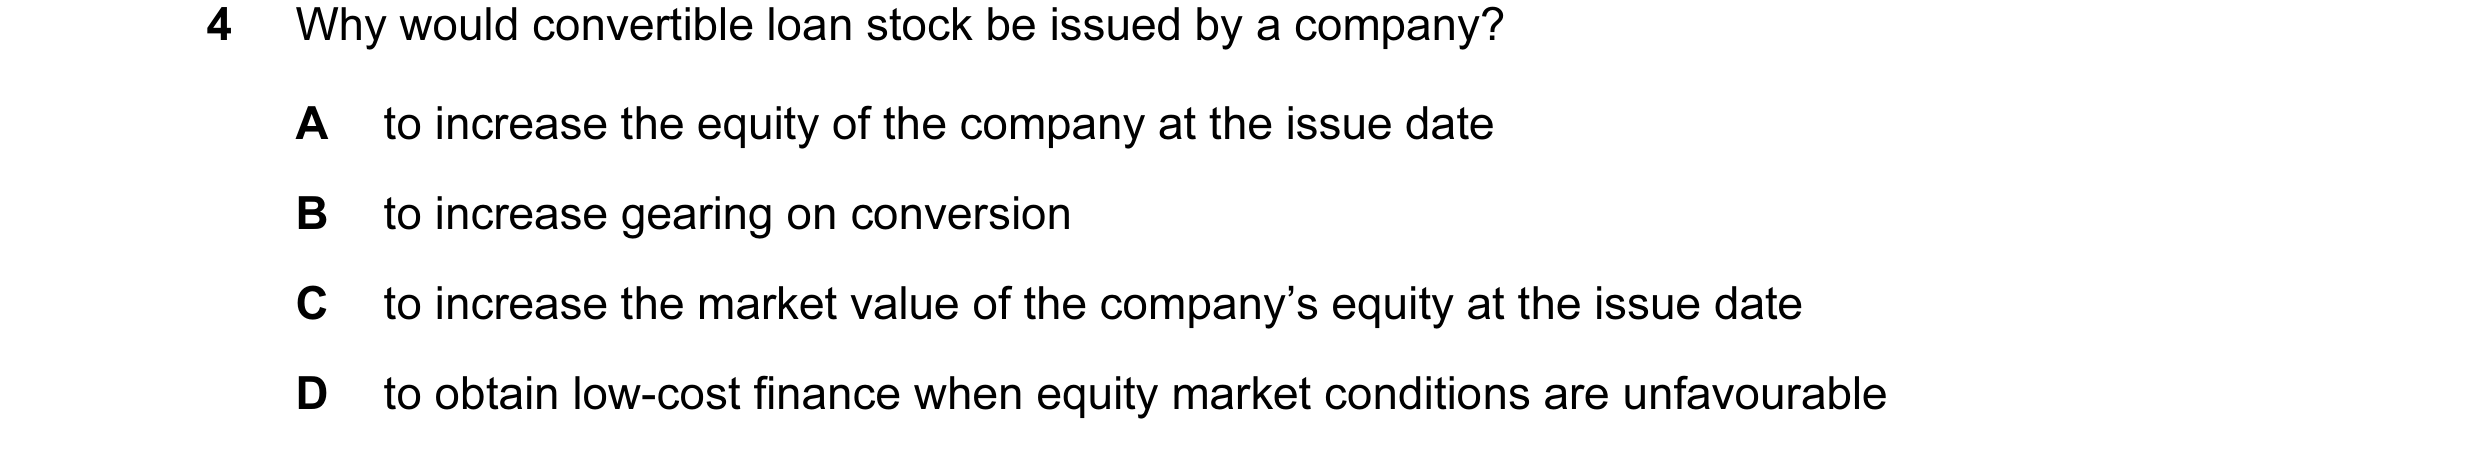
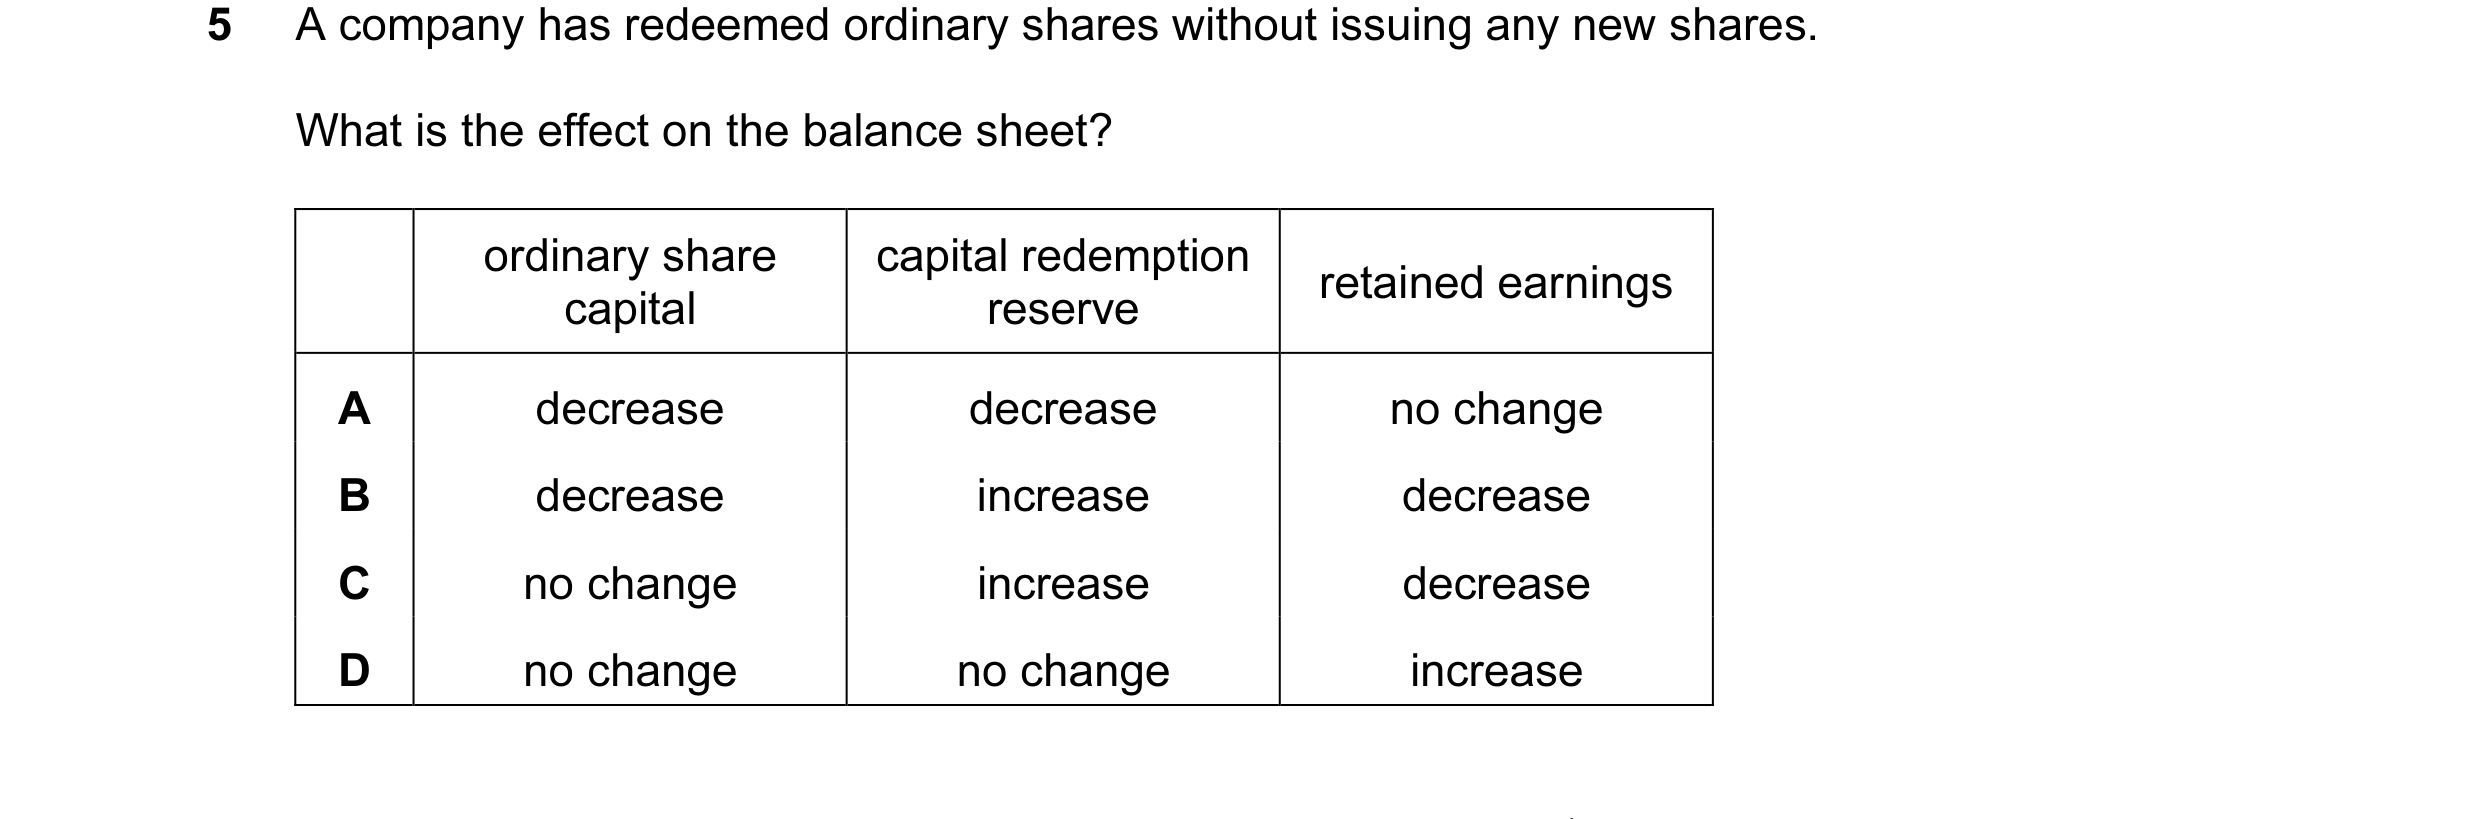
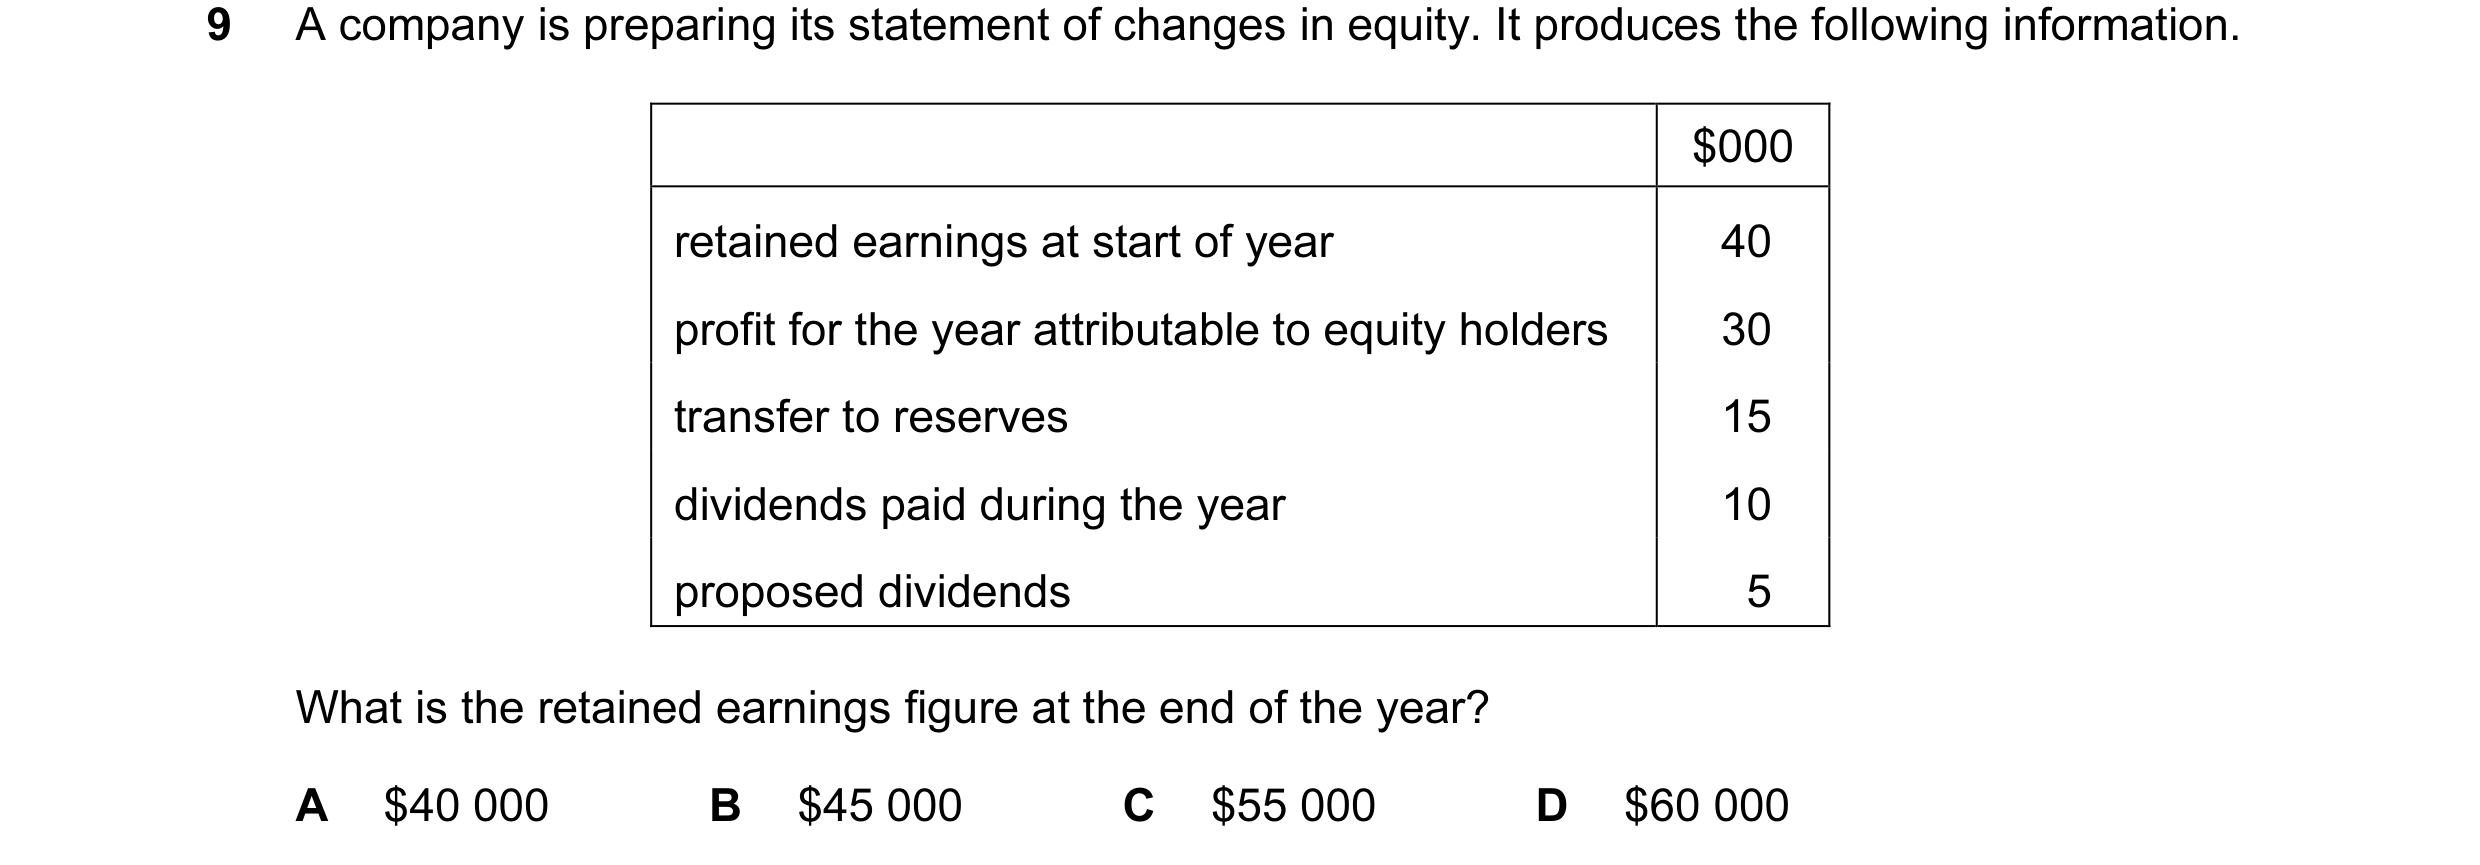 17 / 62
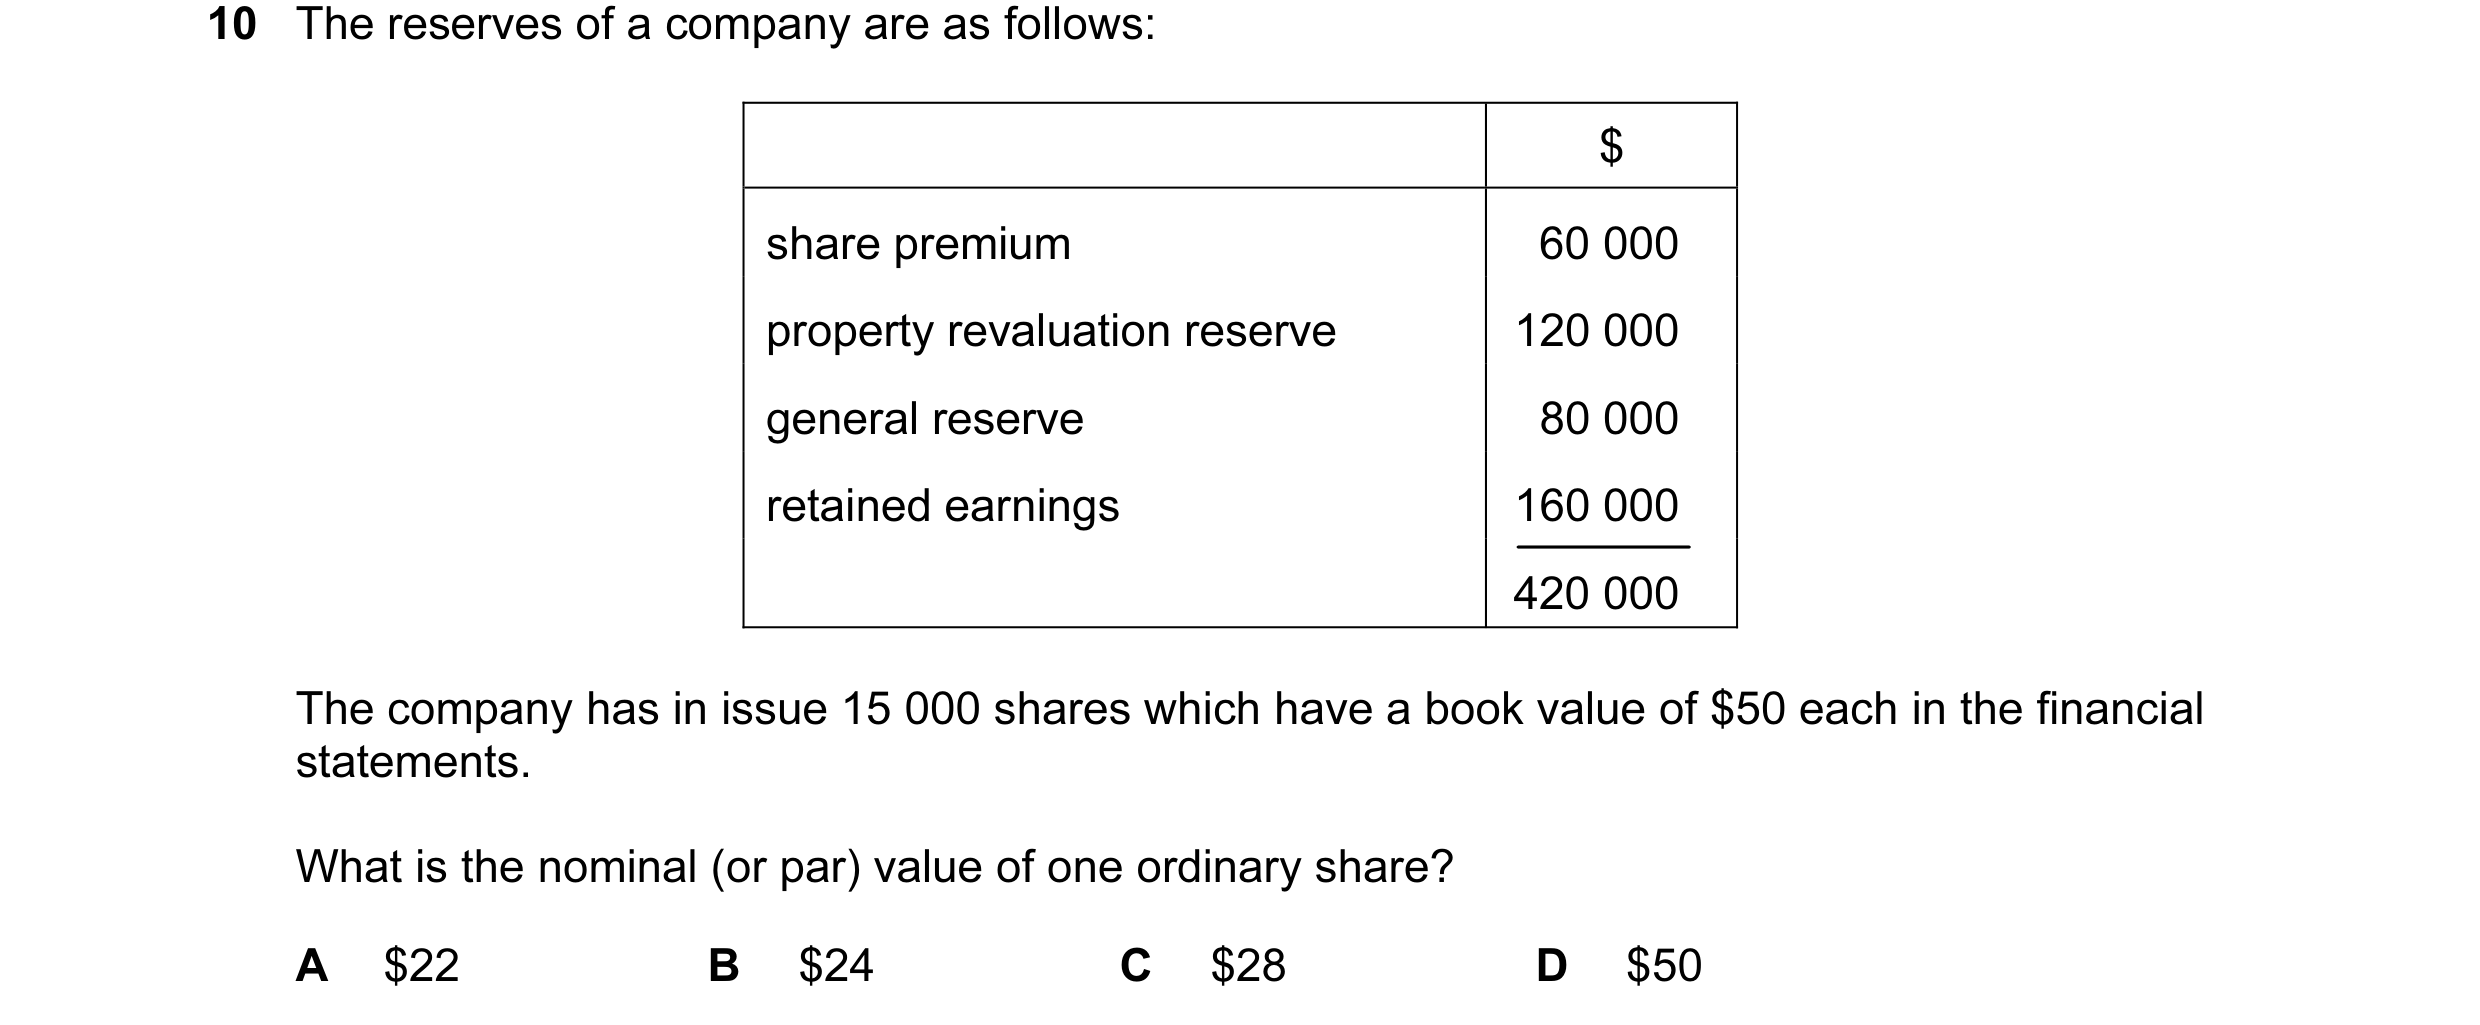
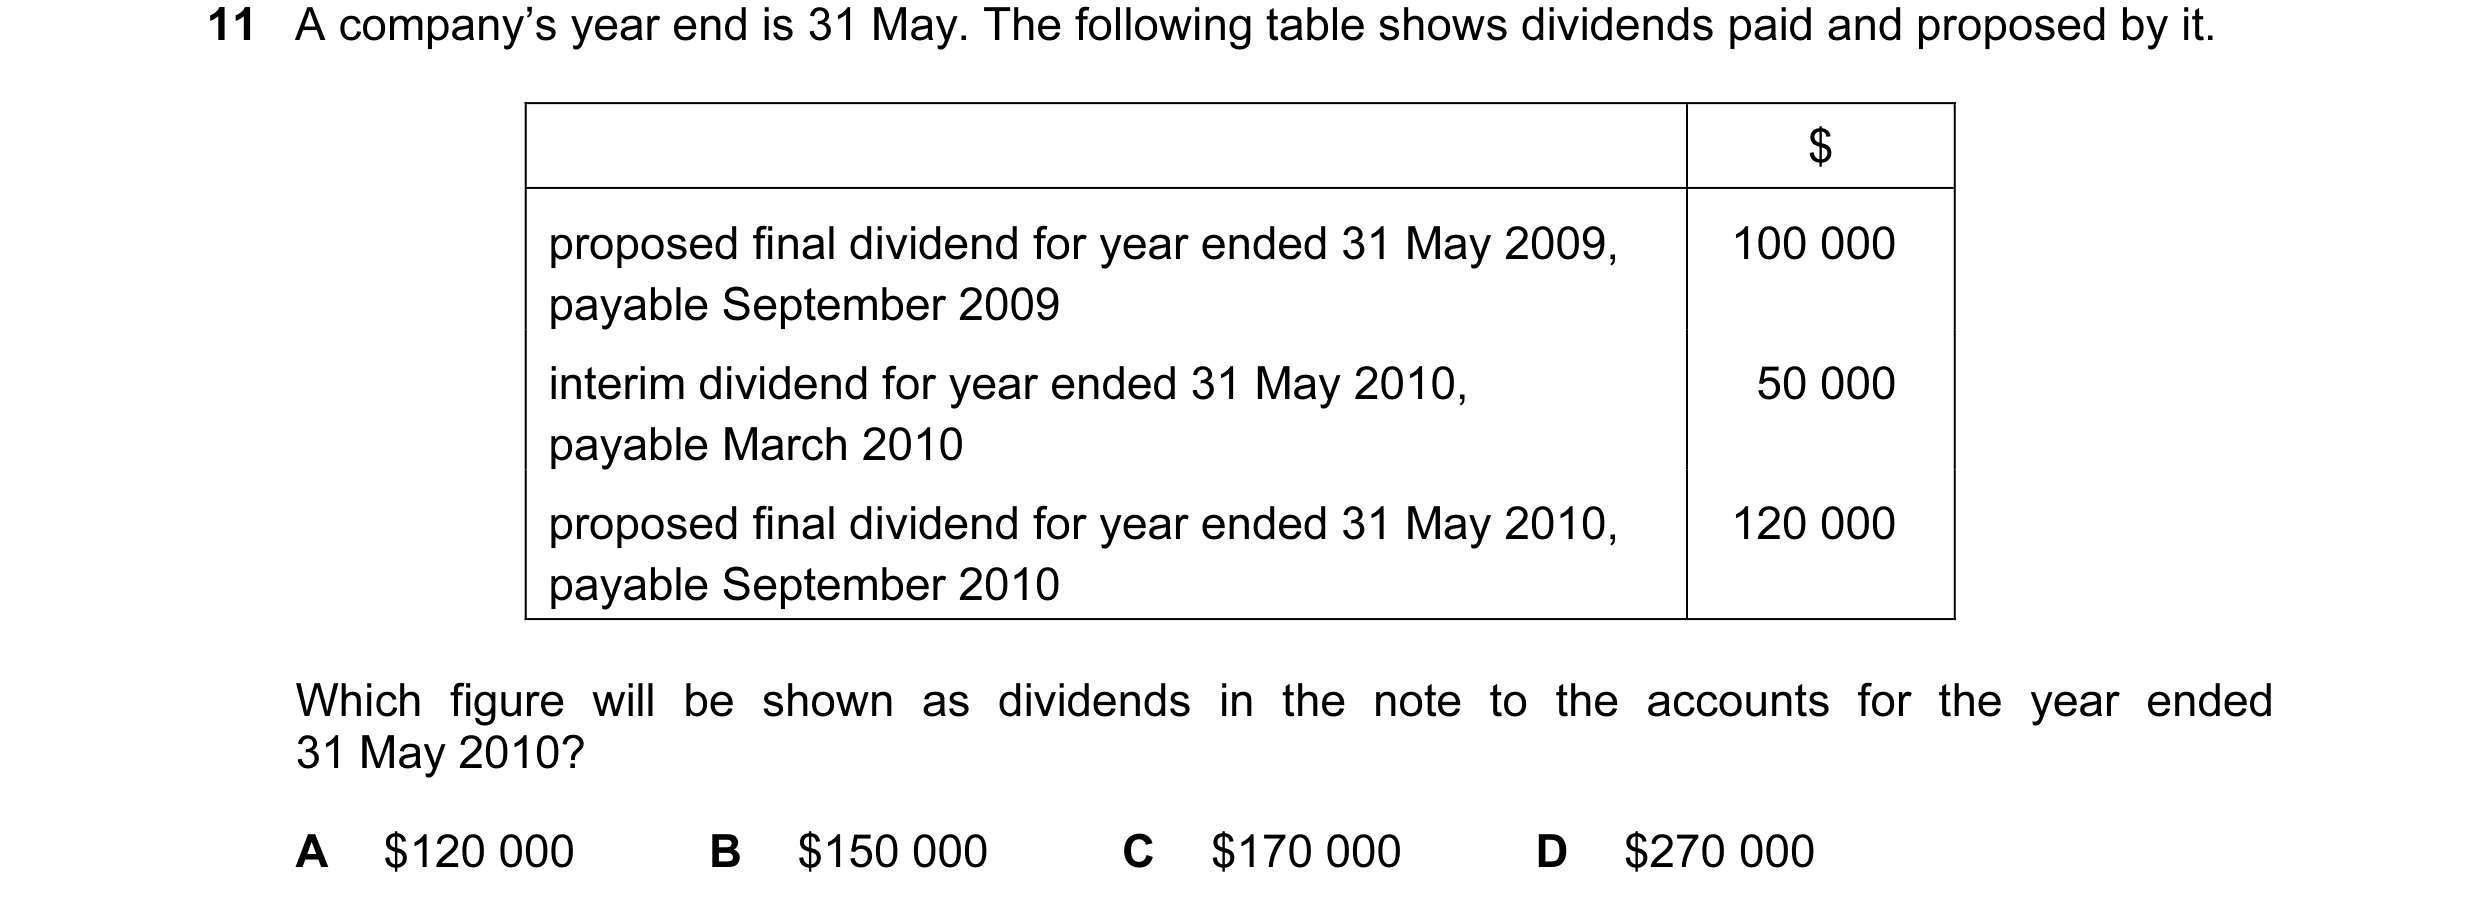
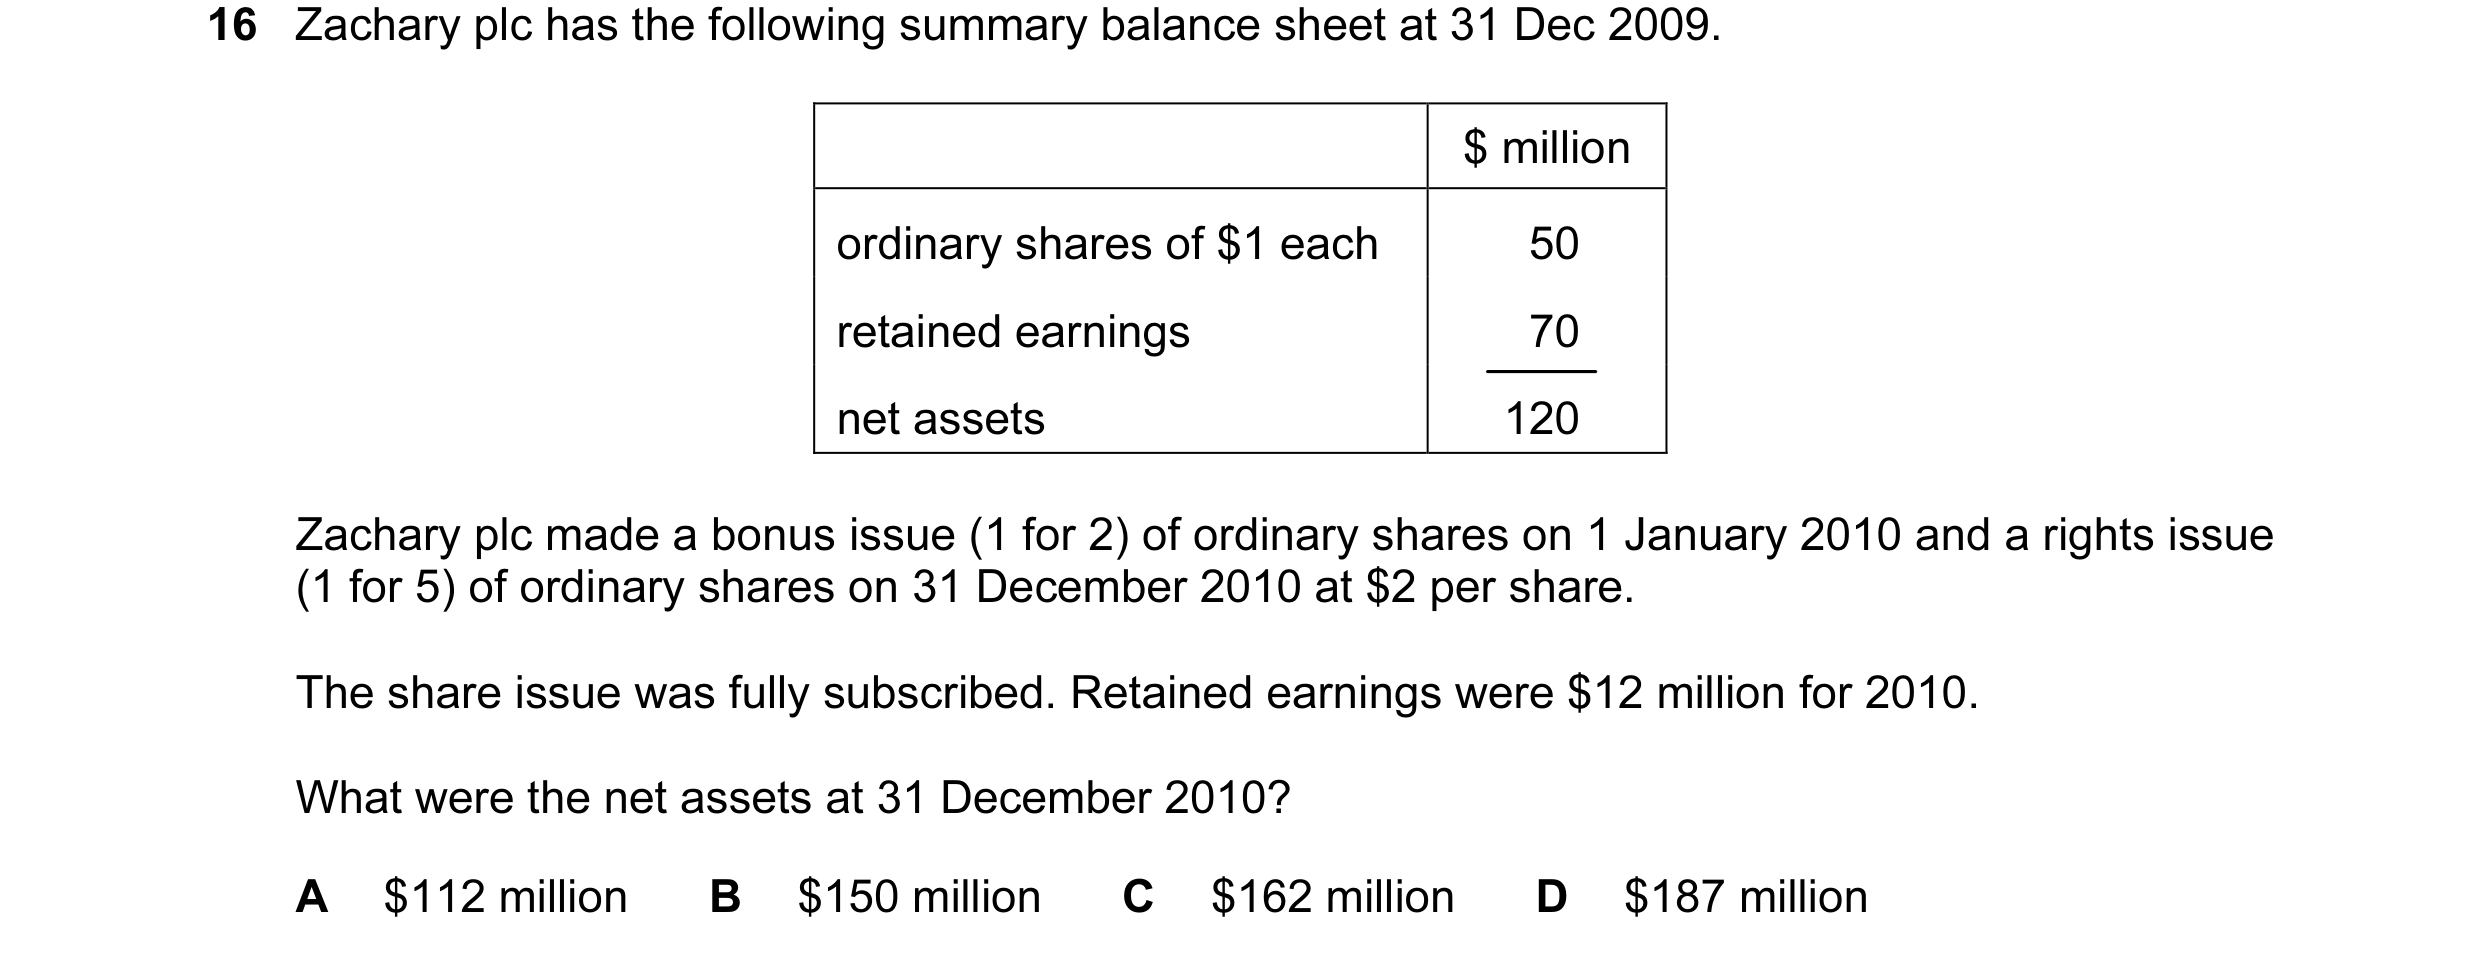
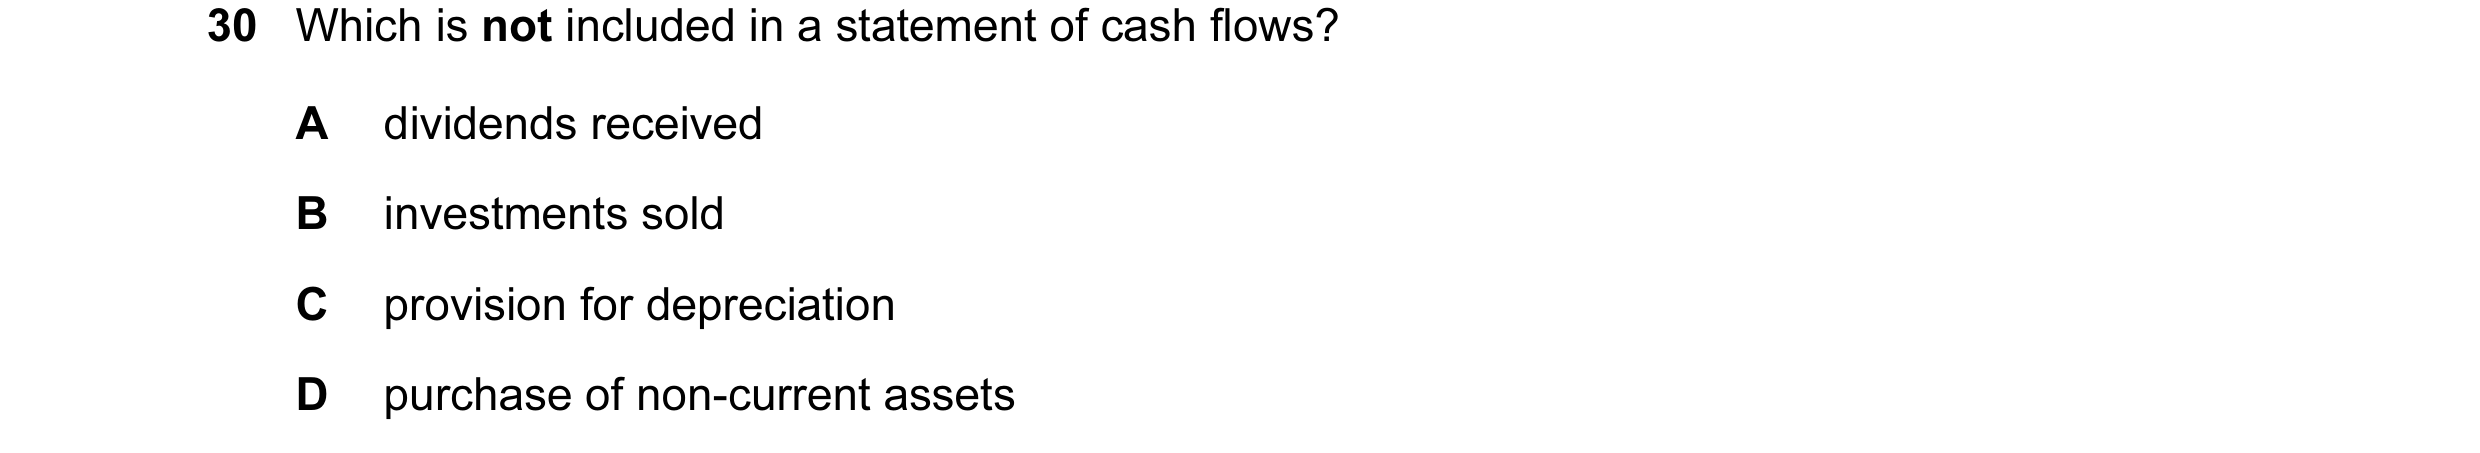 18 / 62
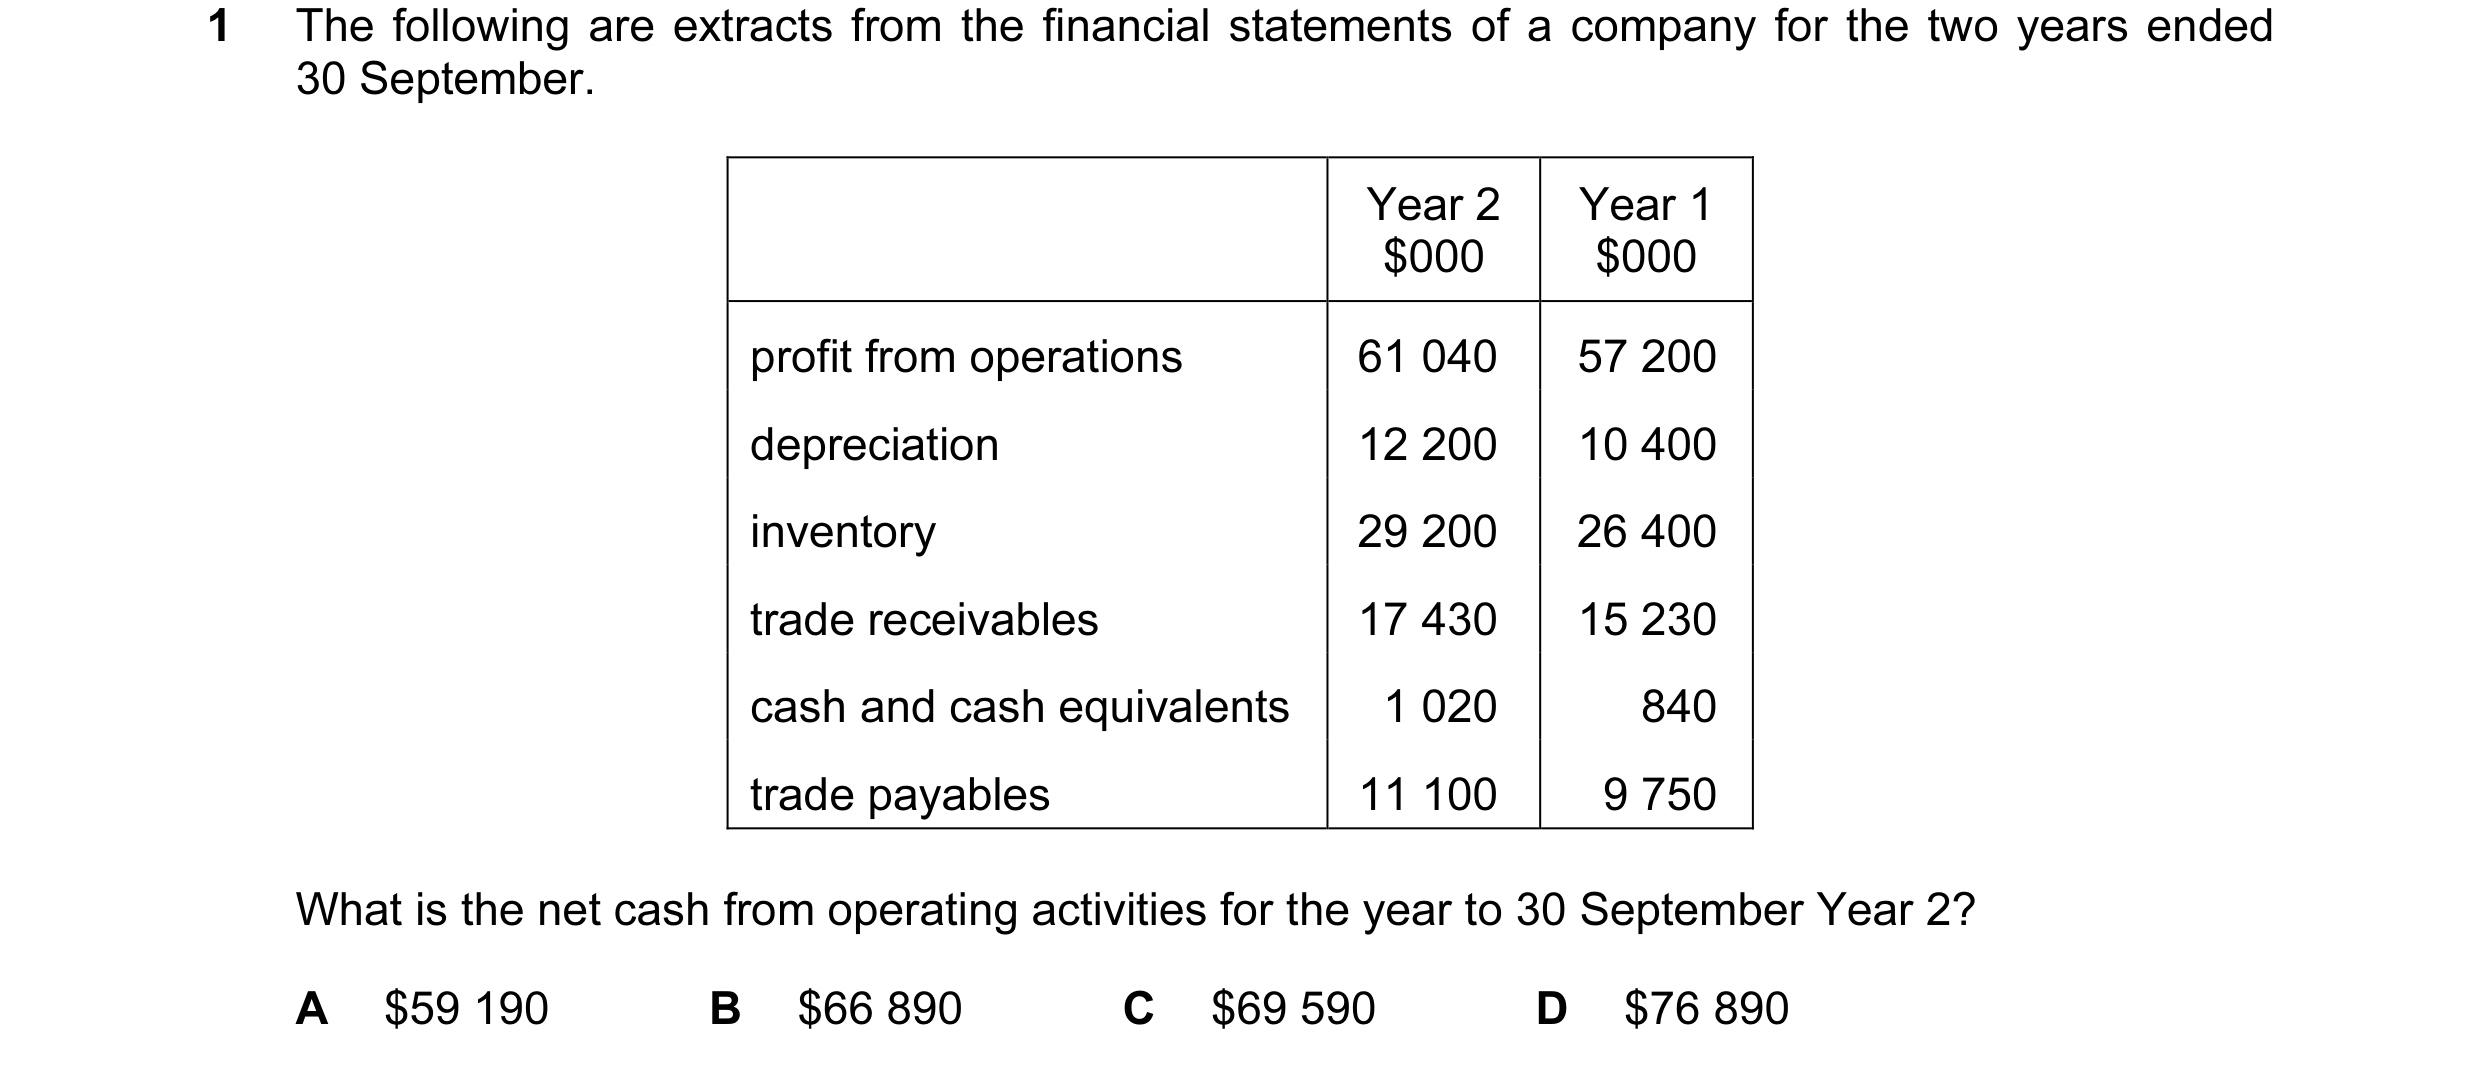
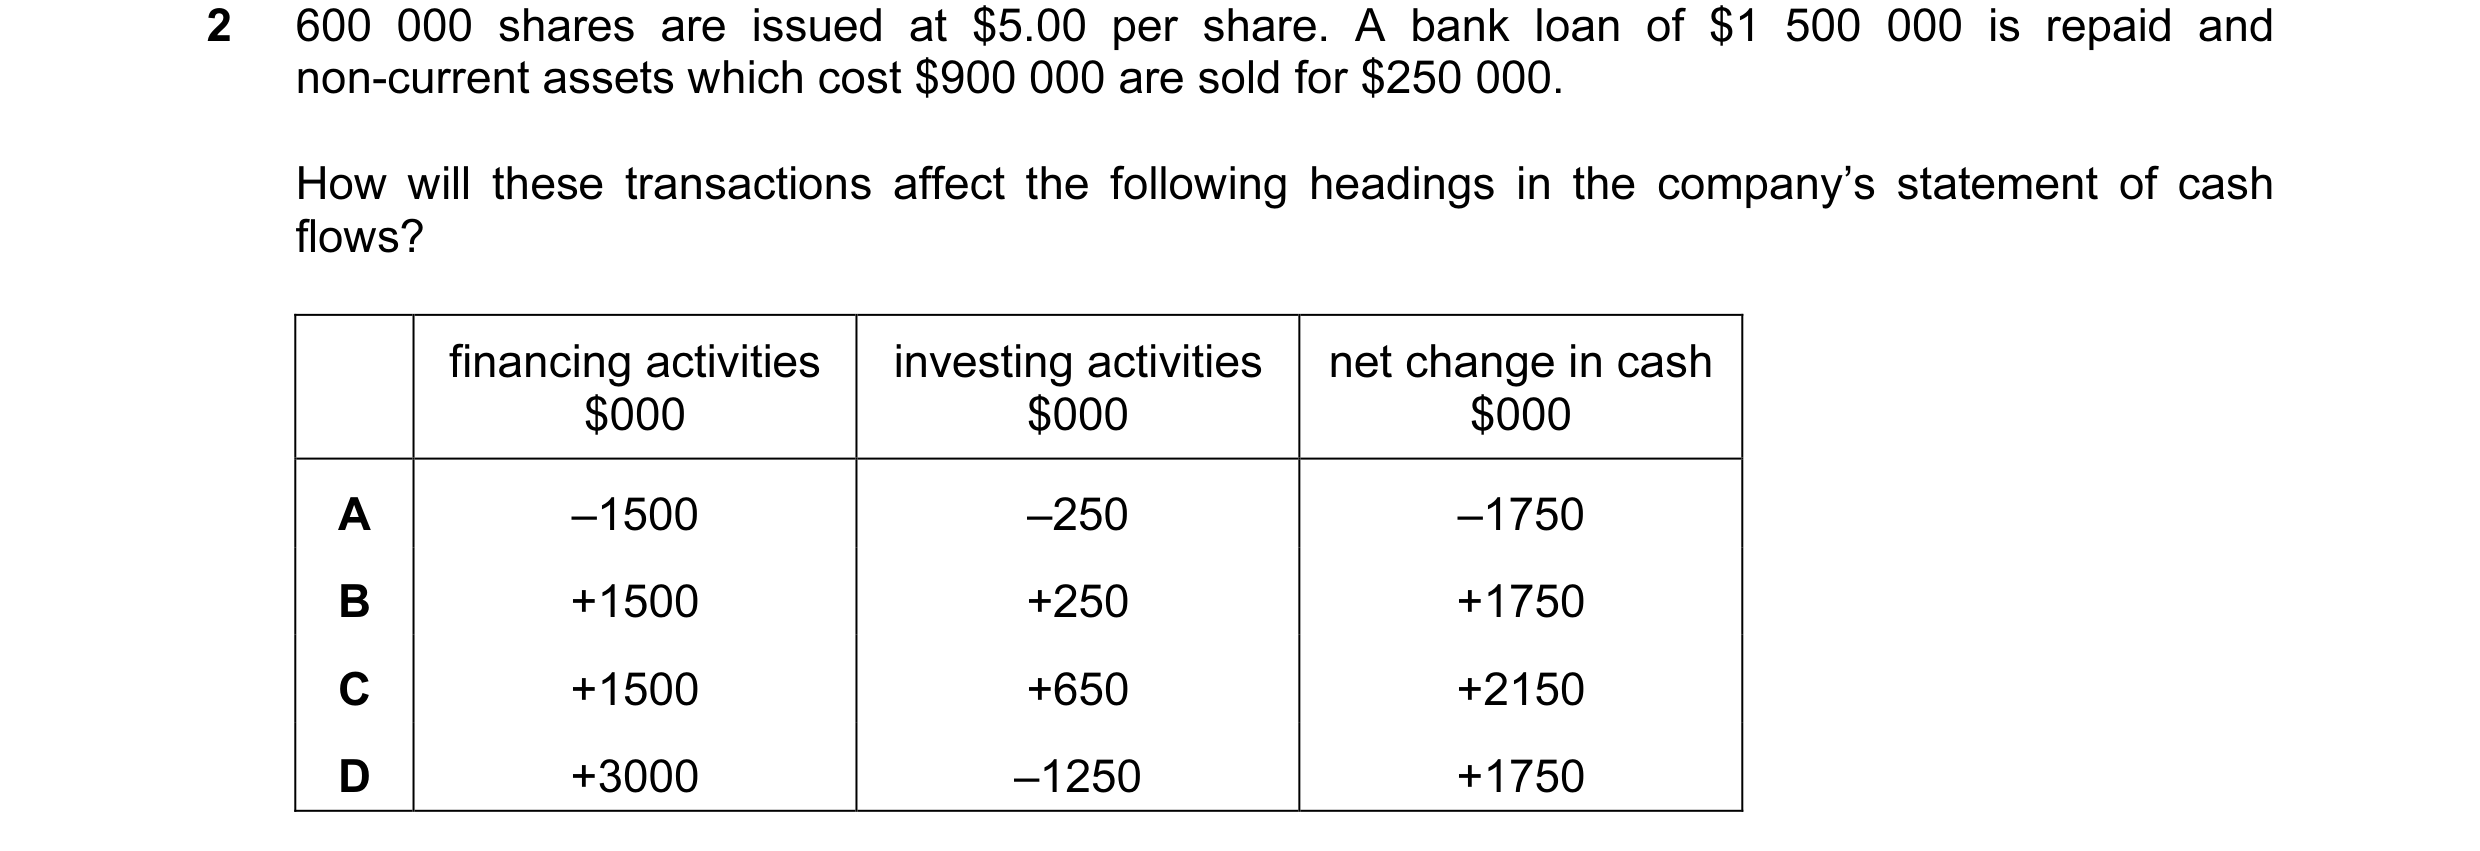
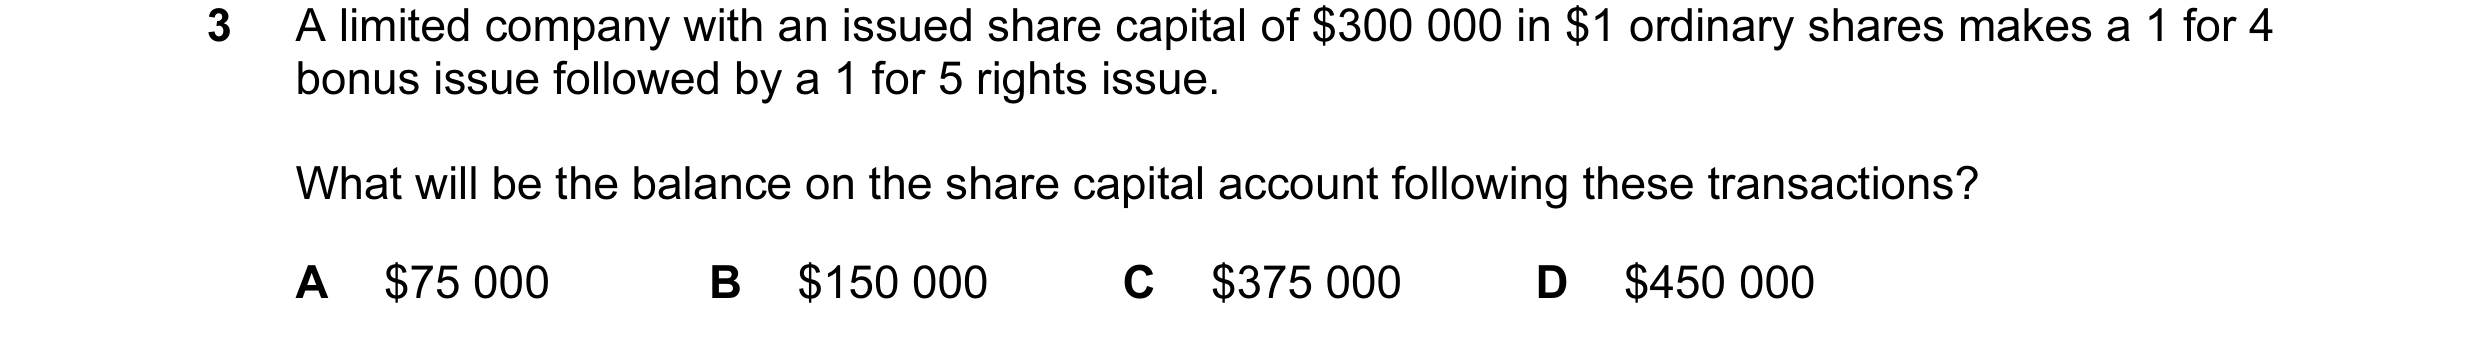
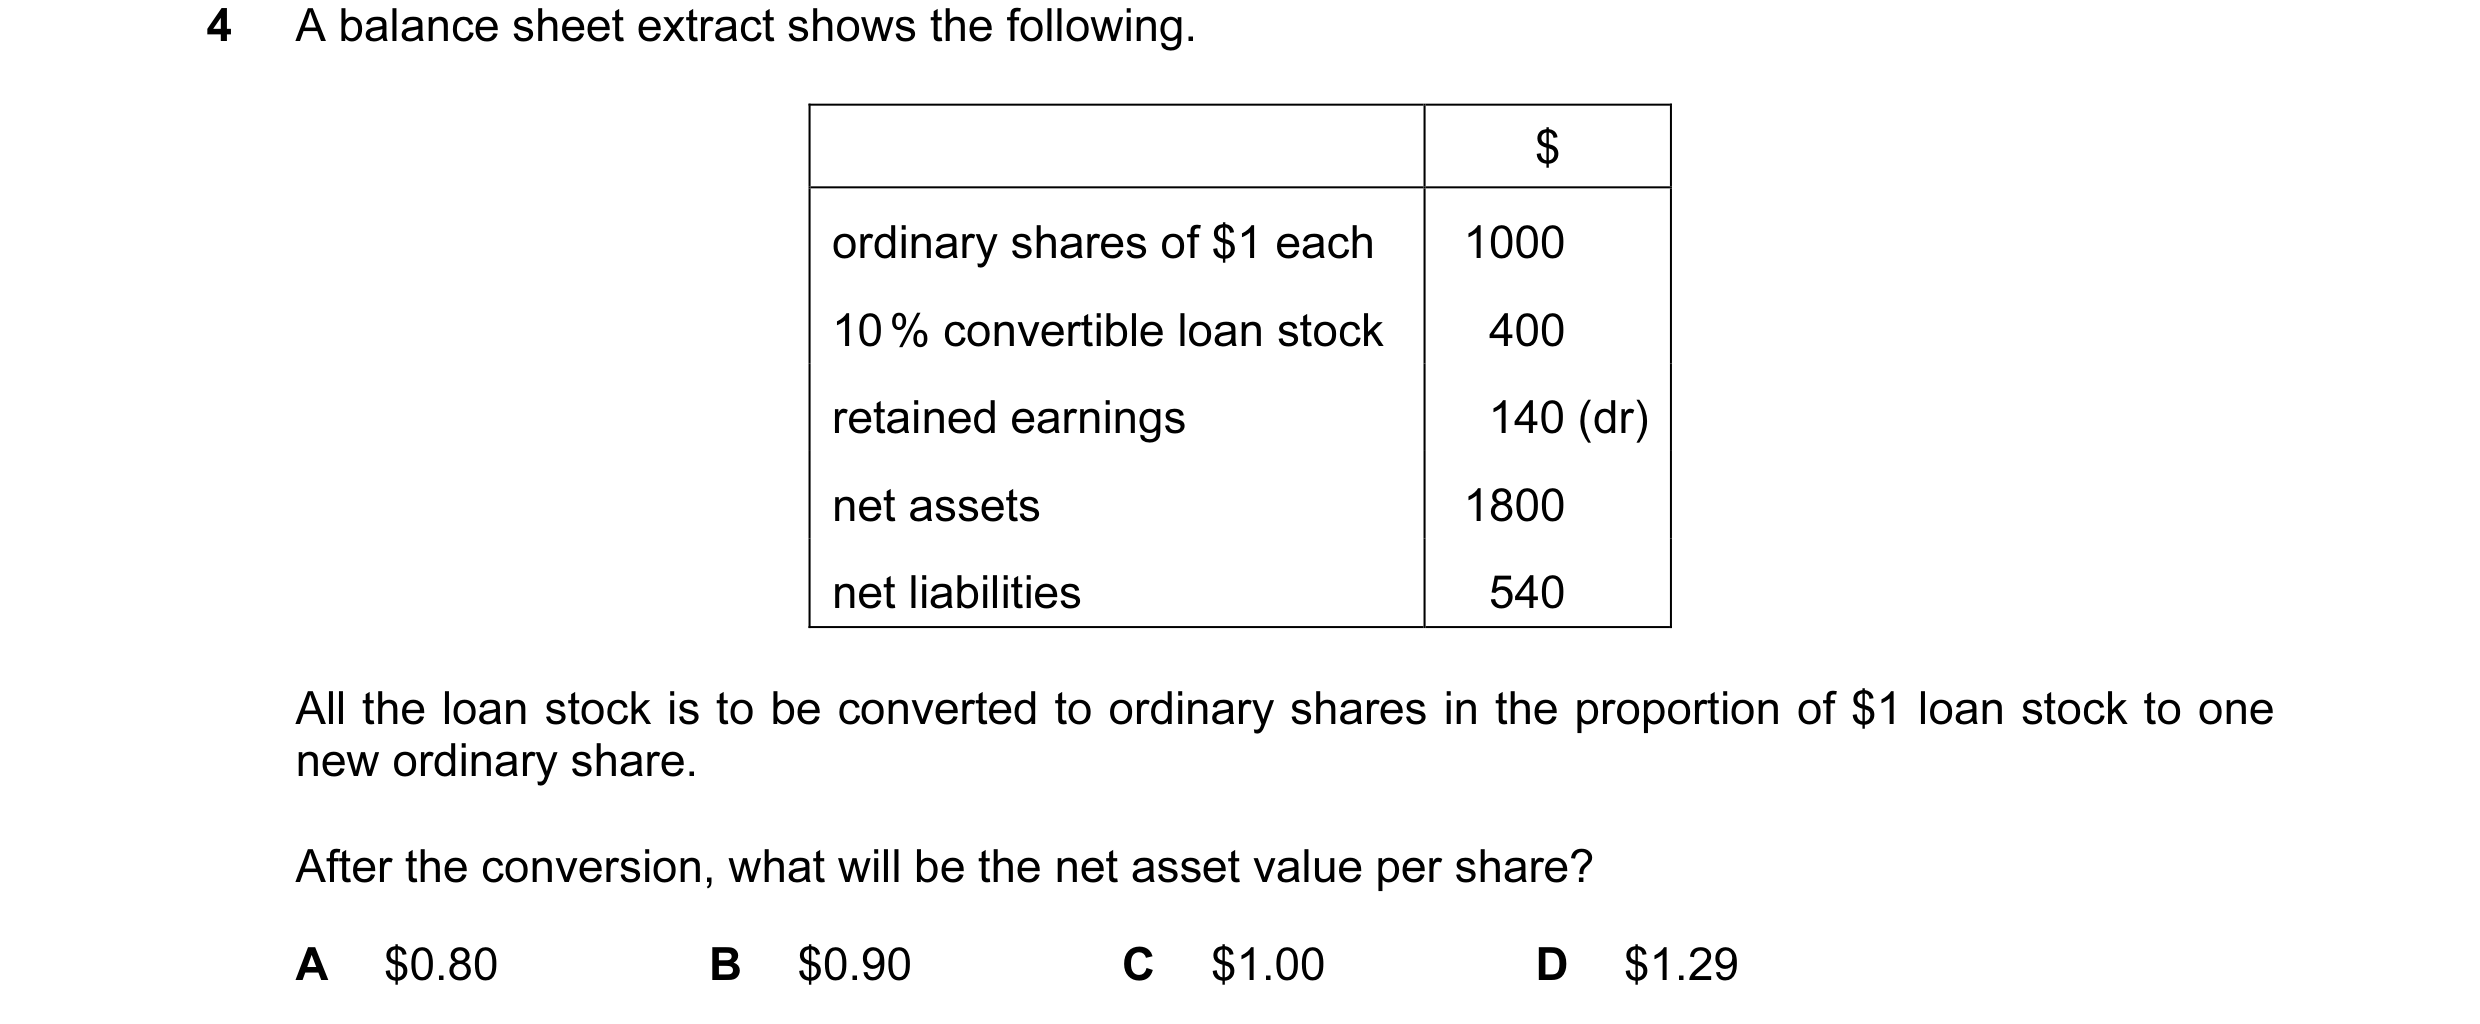 19 / 62
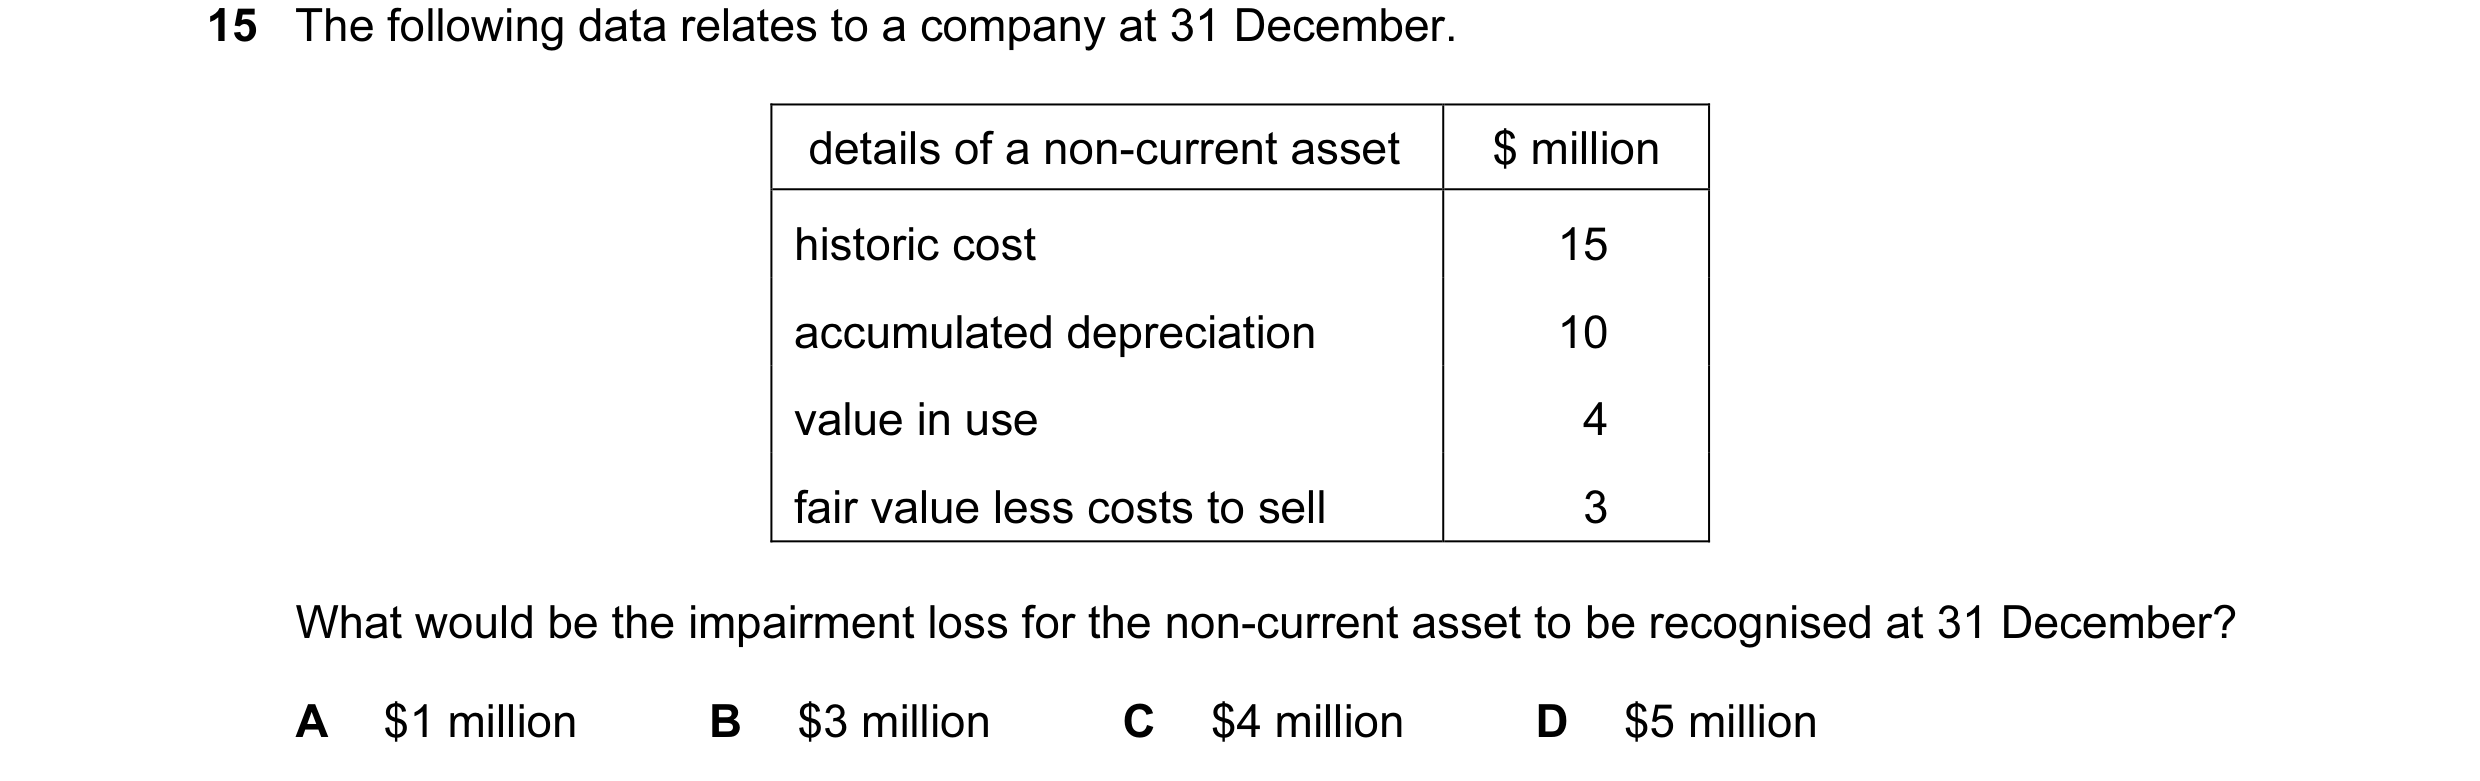
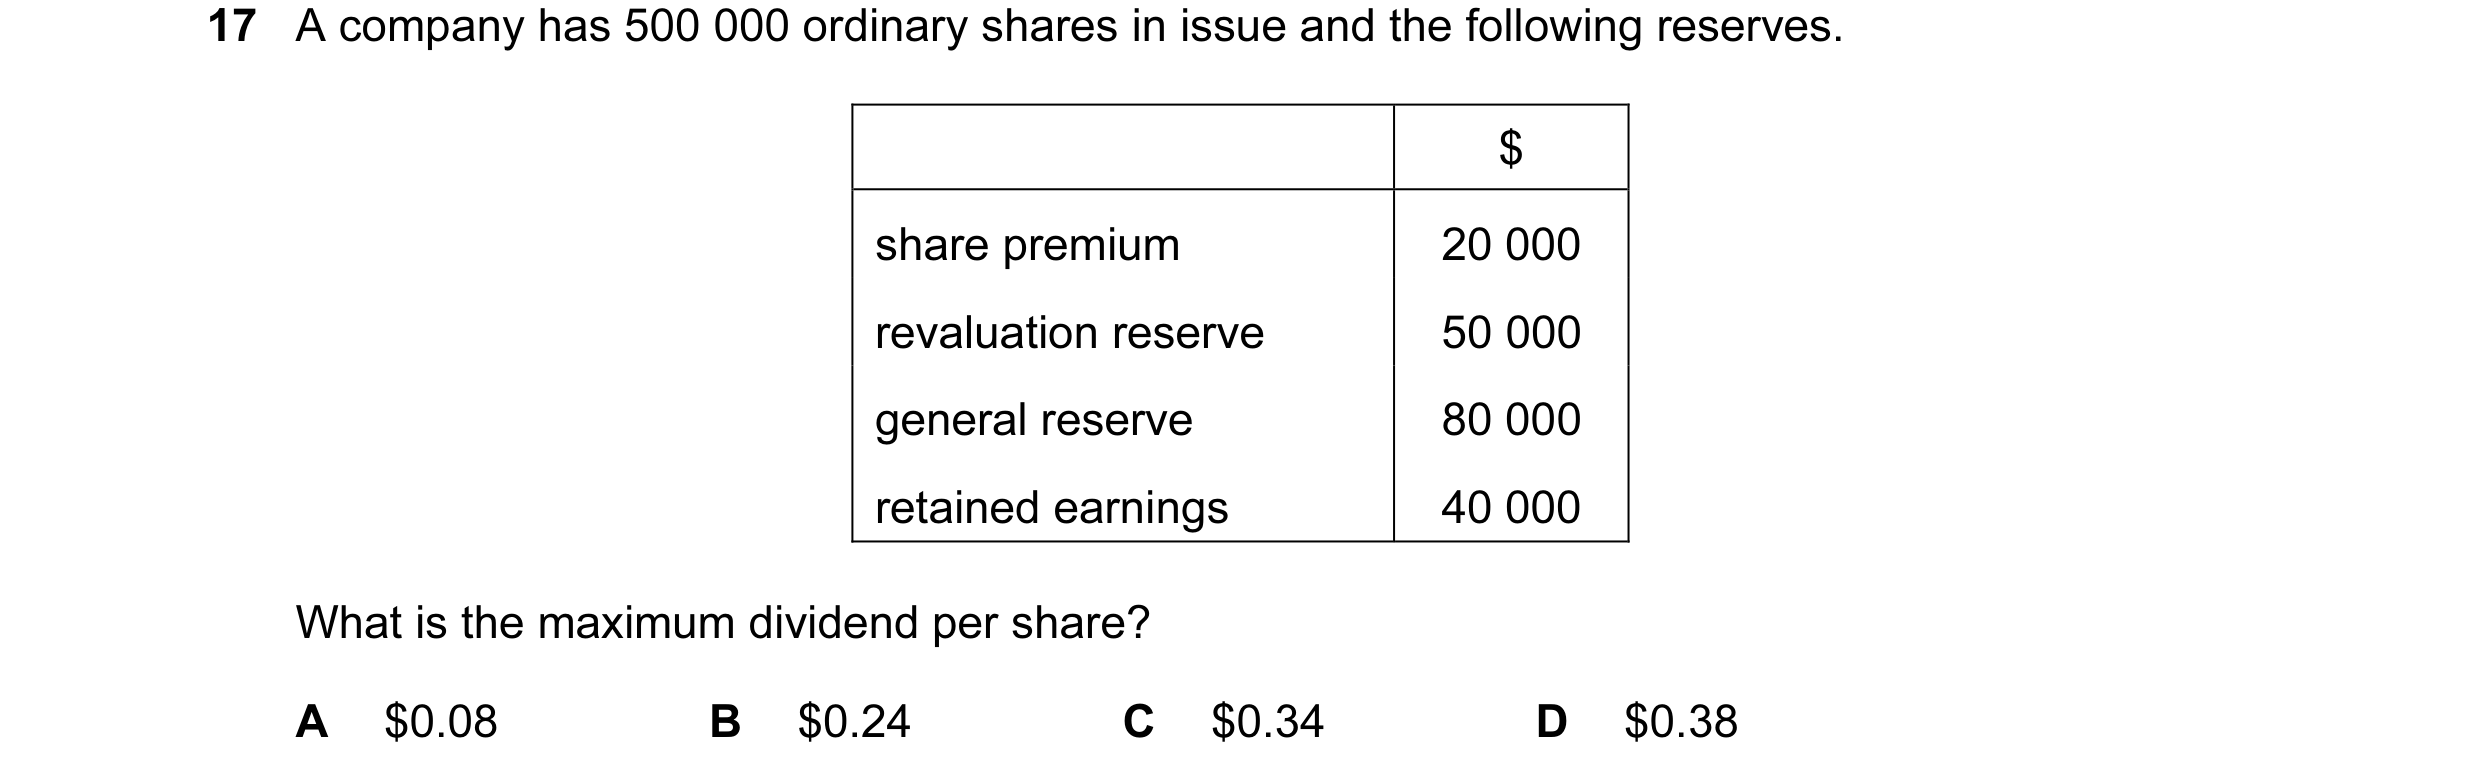
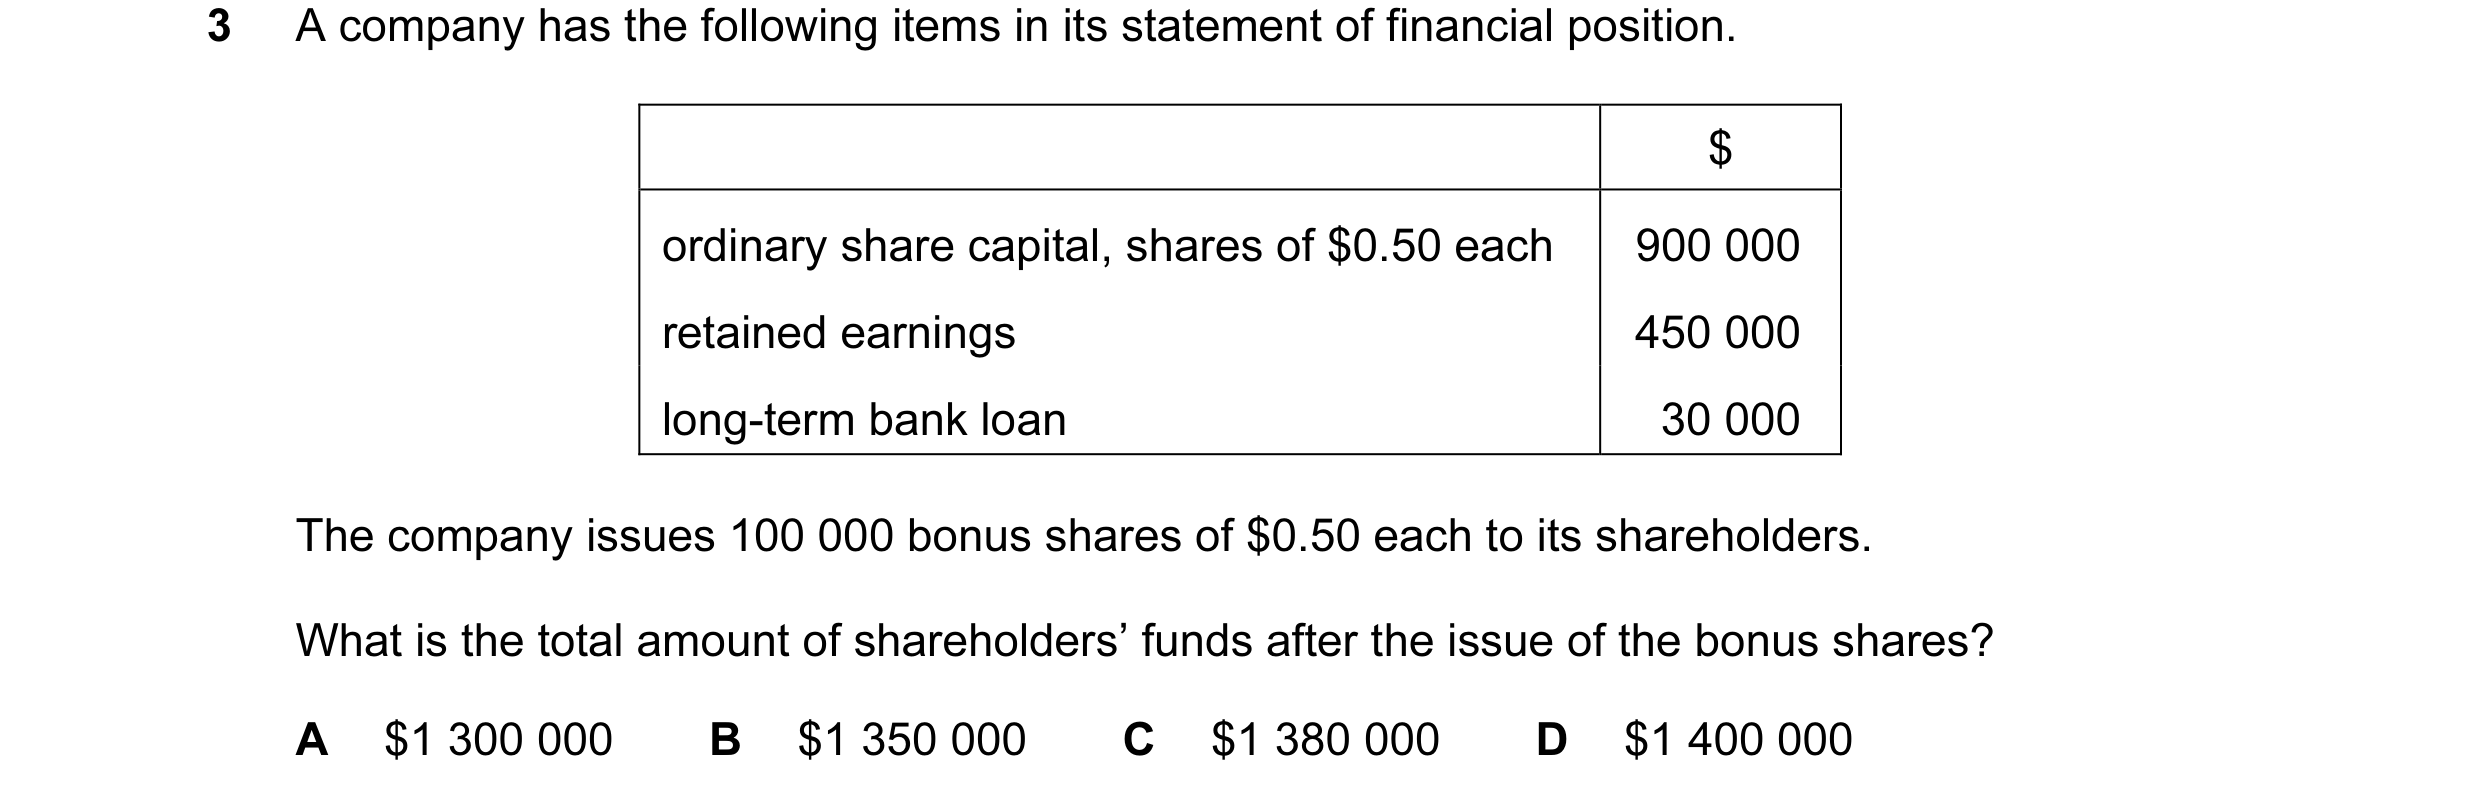 20 / 62
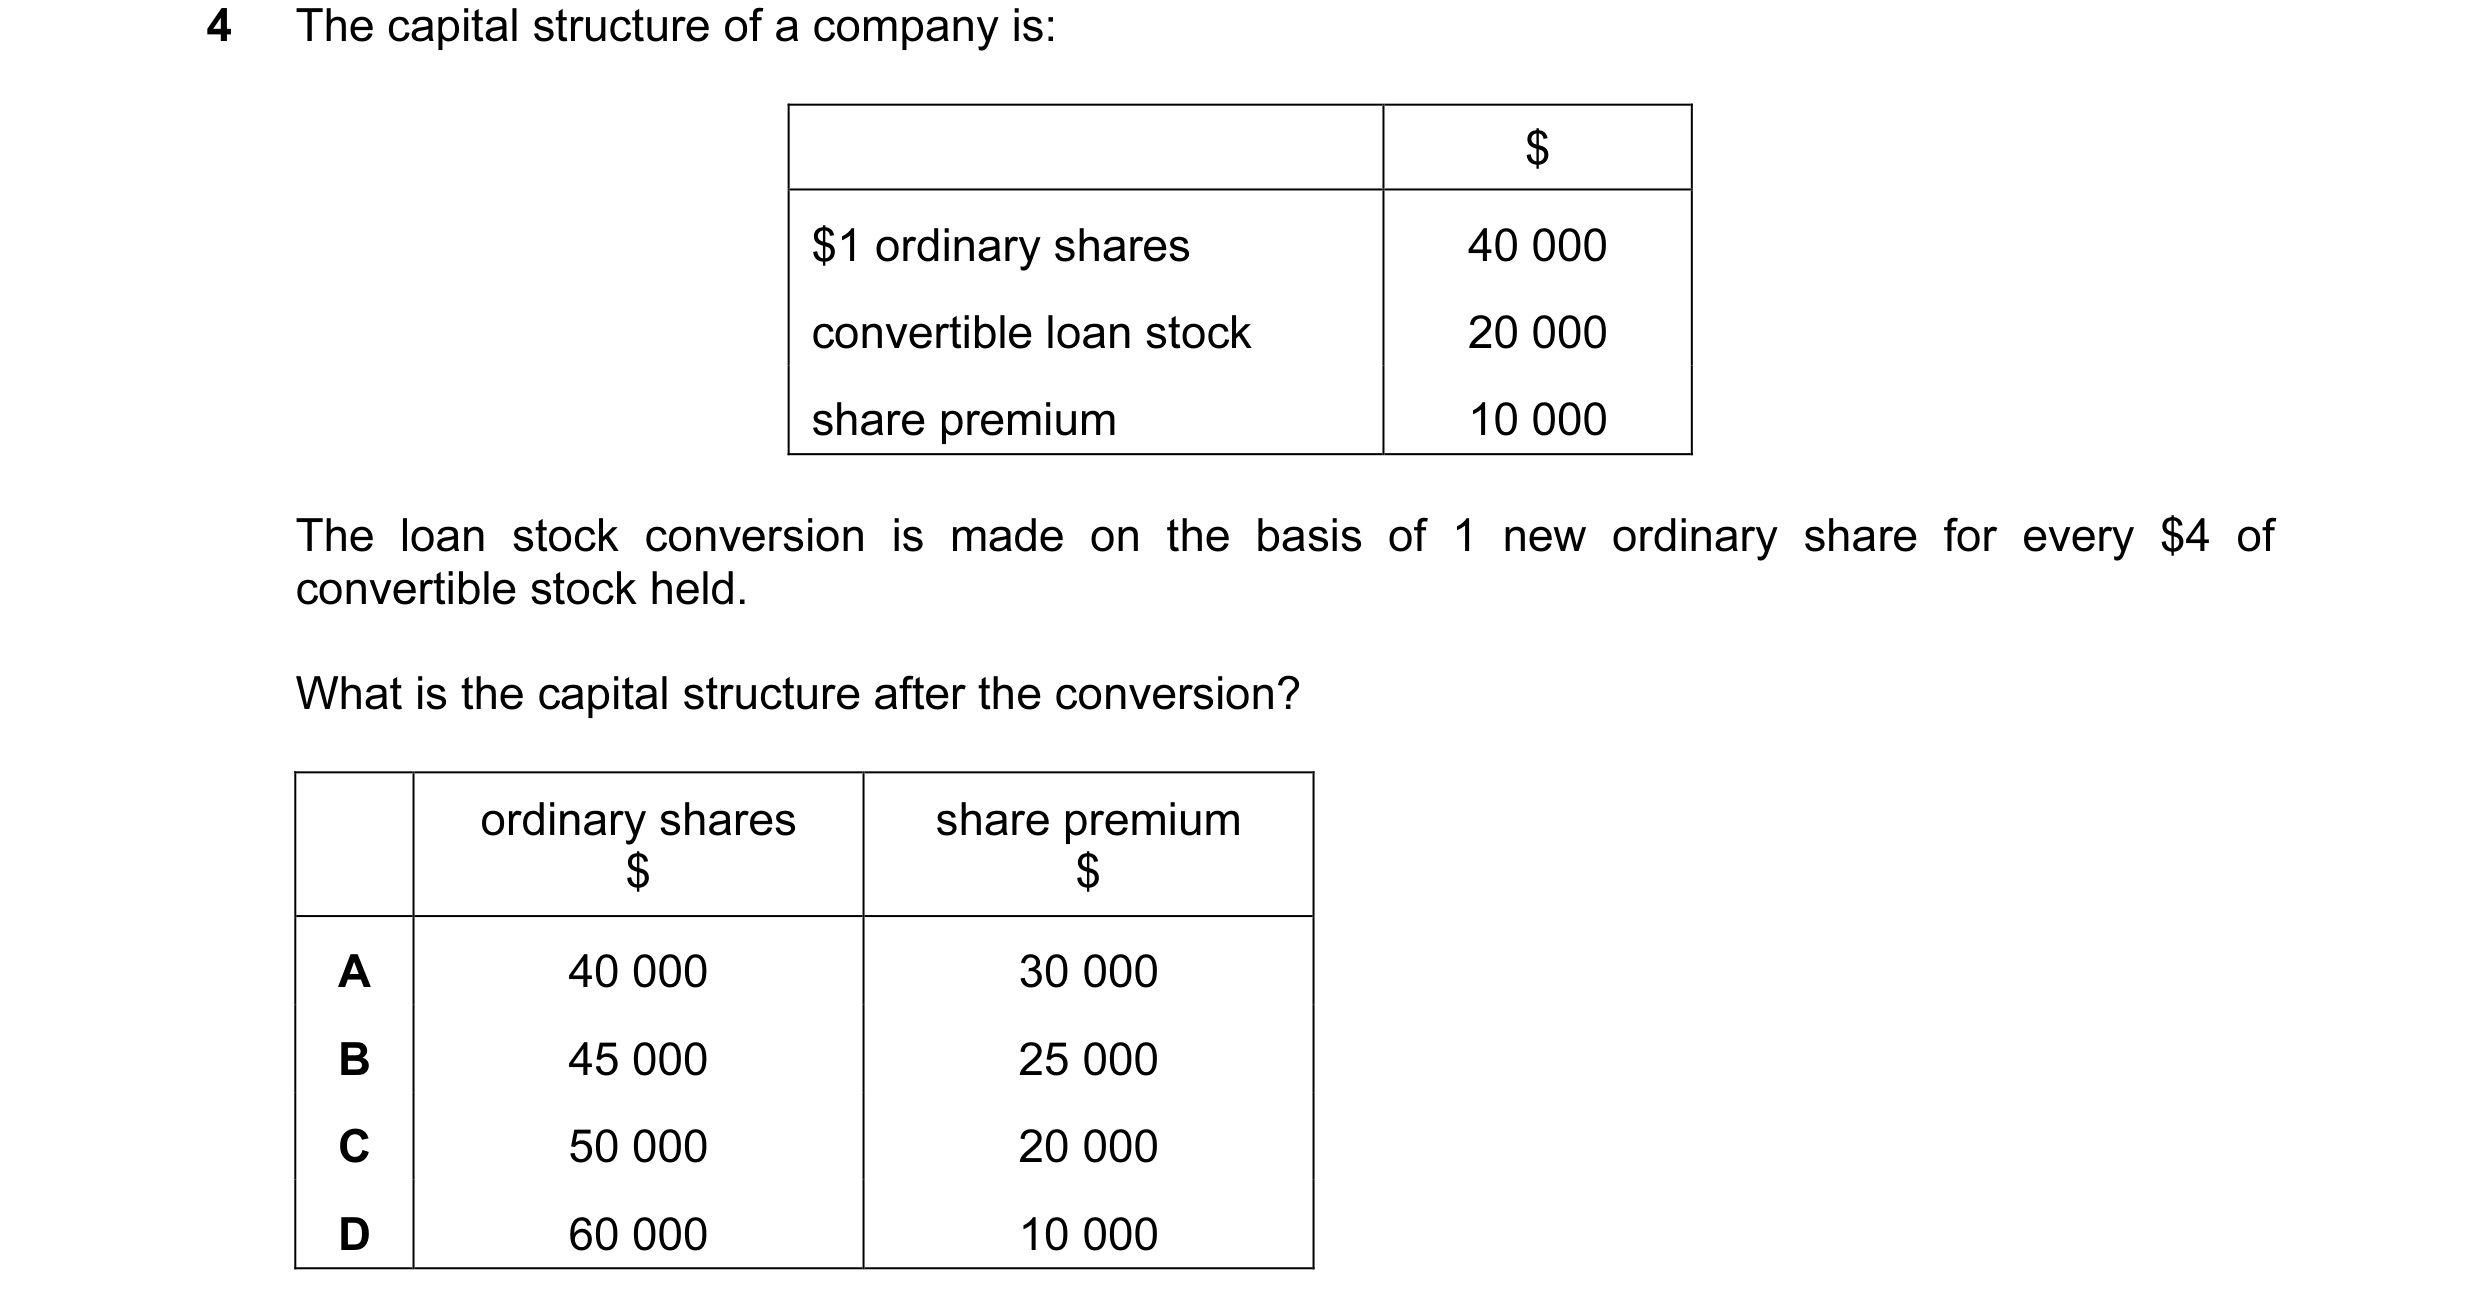
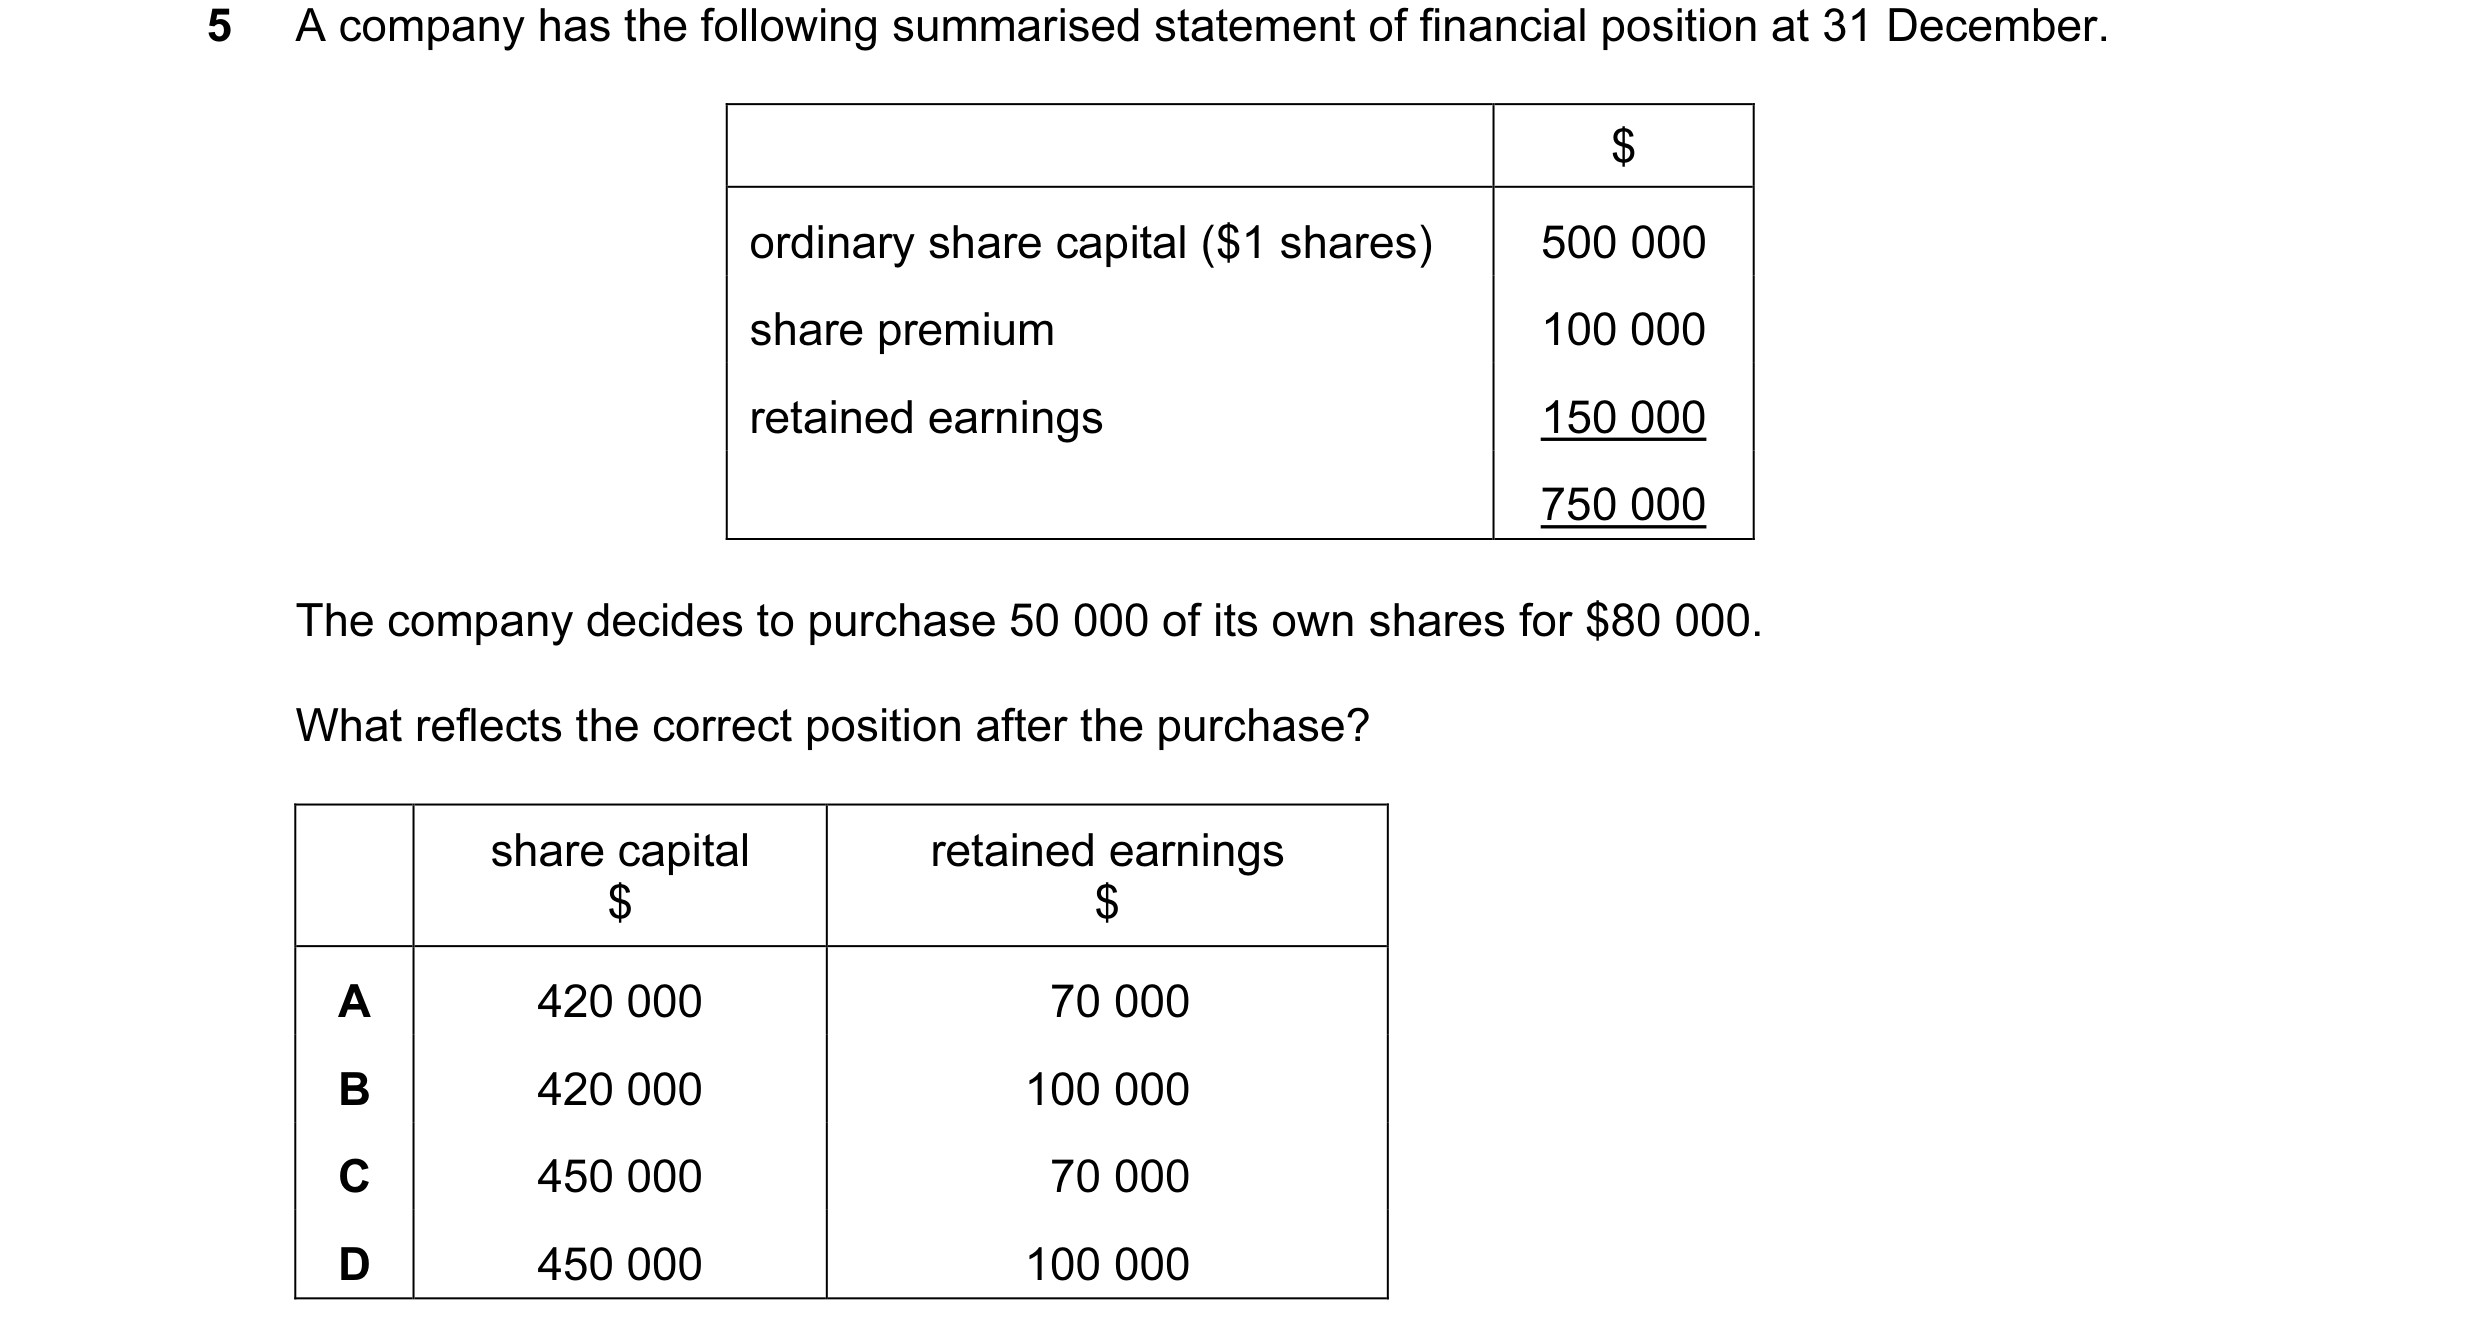
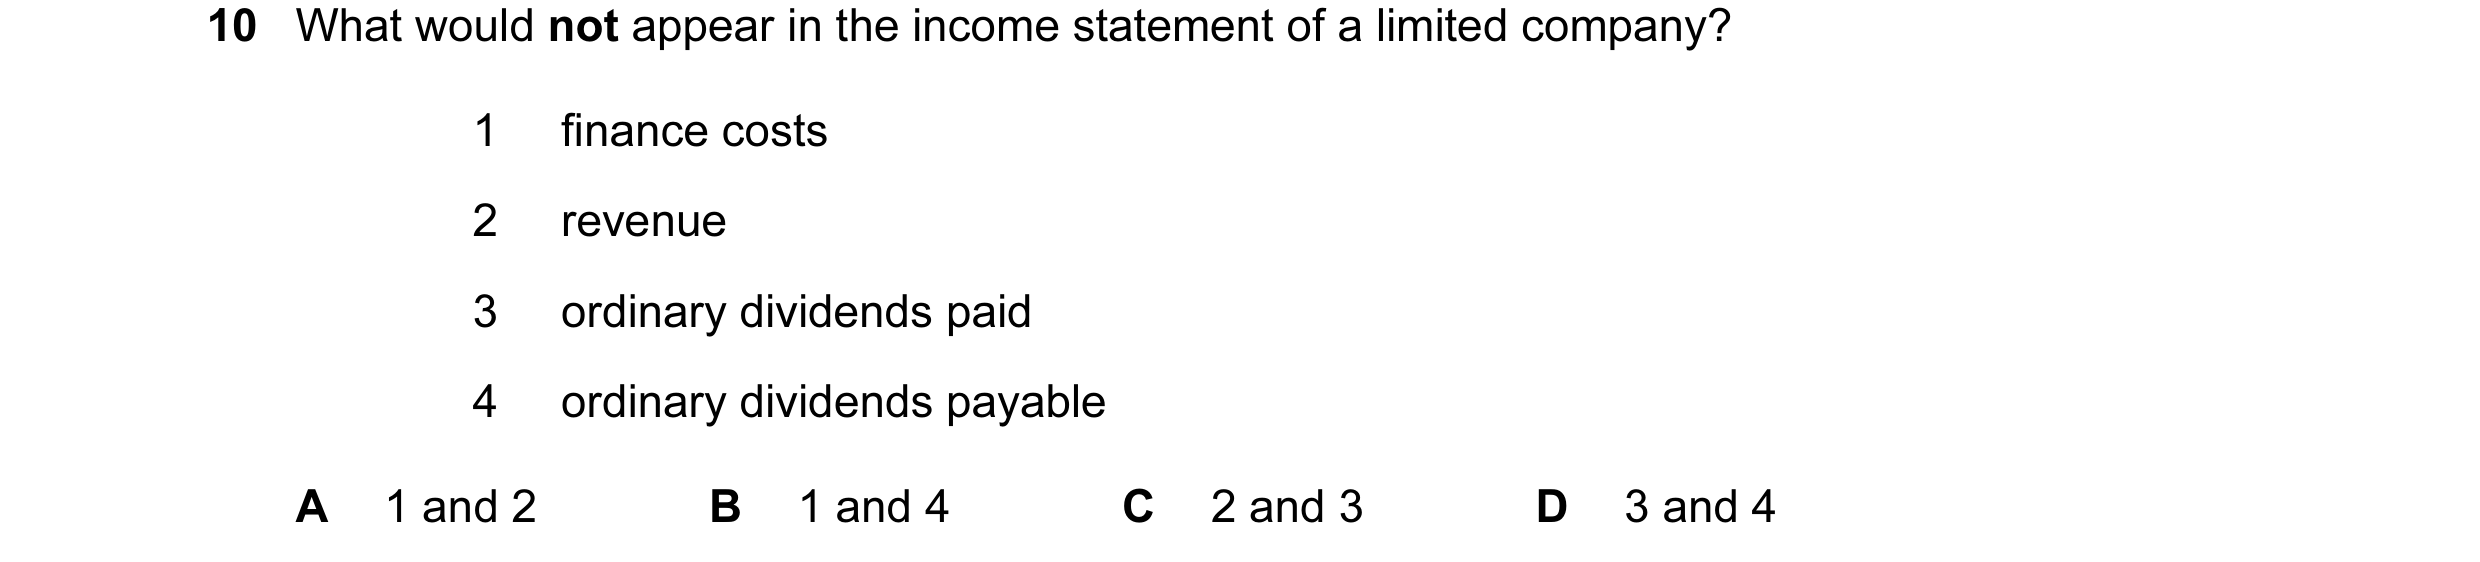 21 / 62
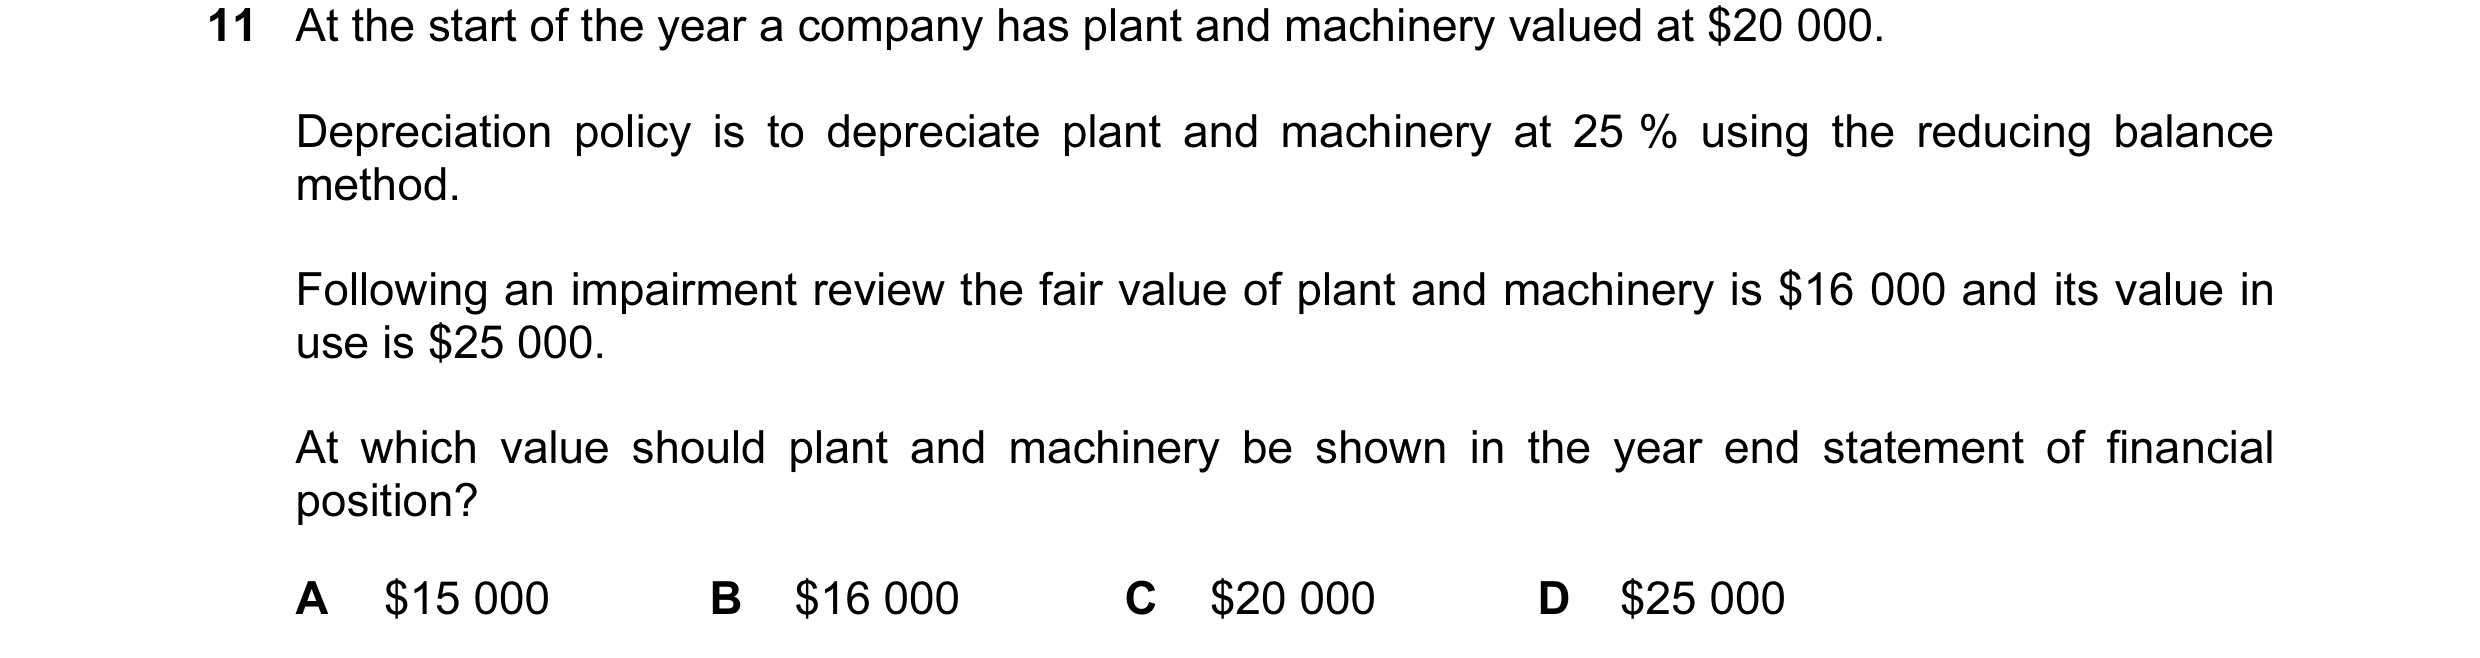
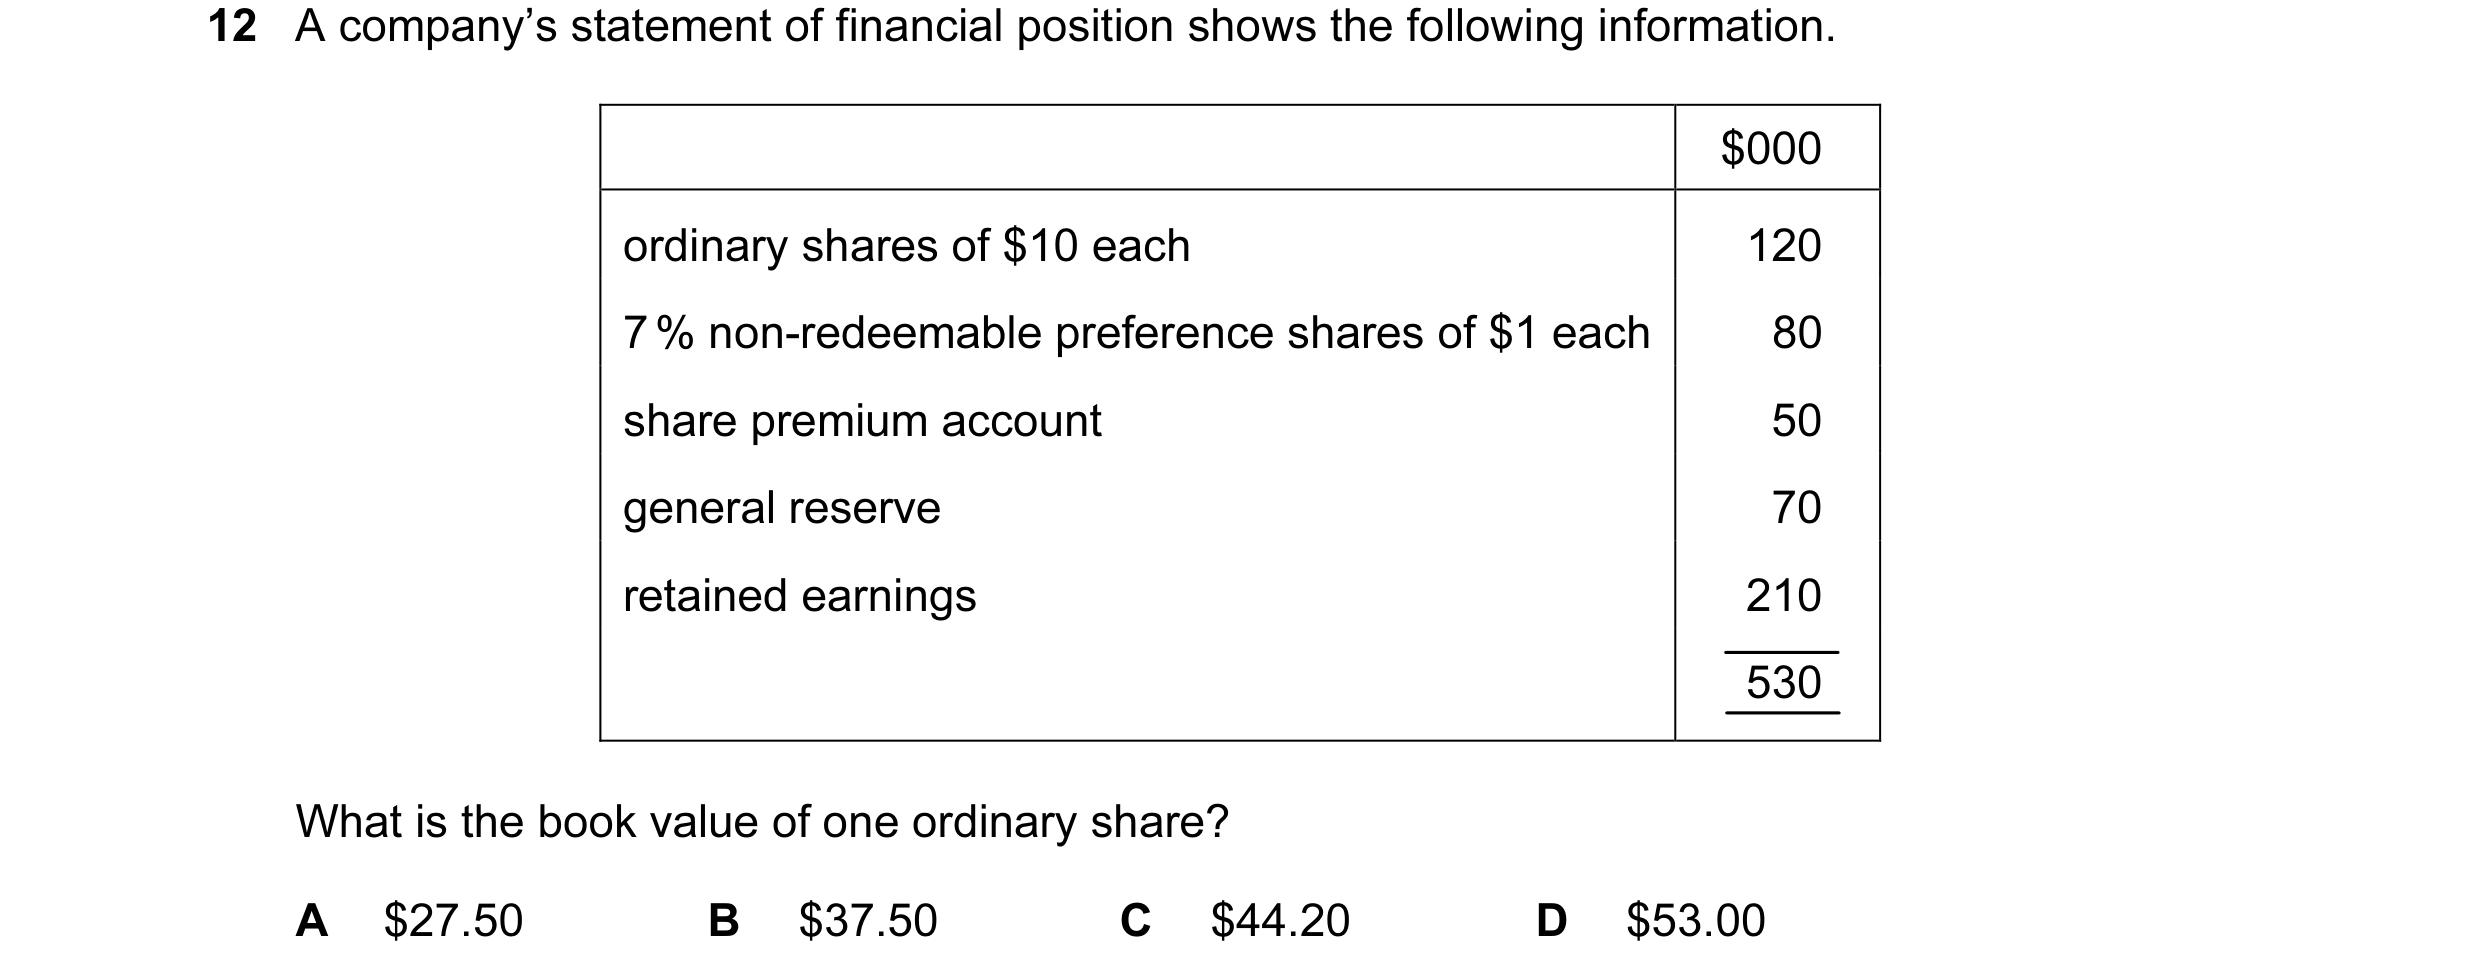
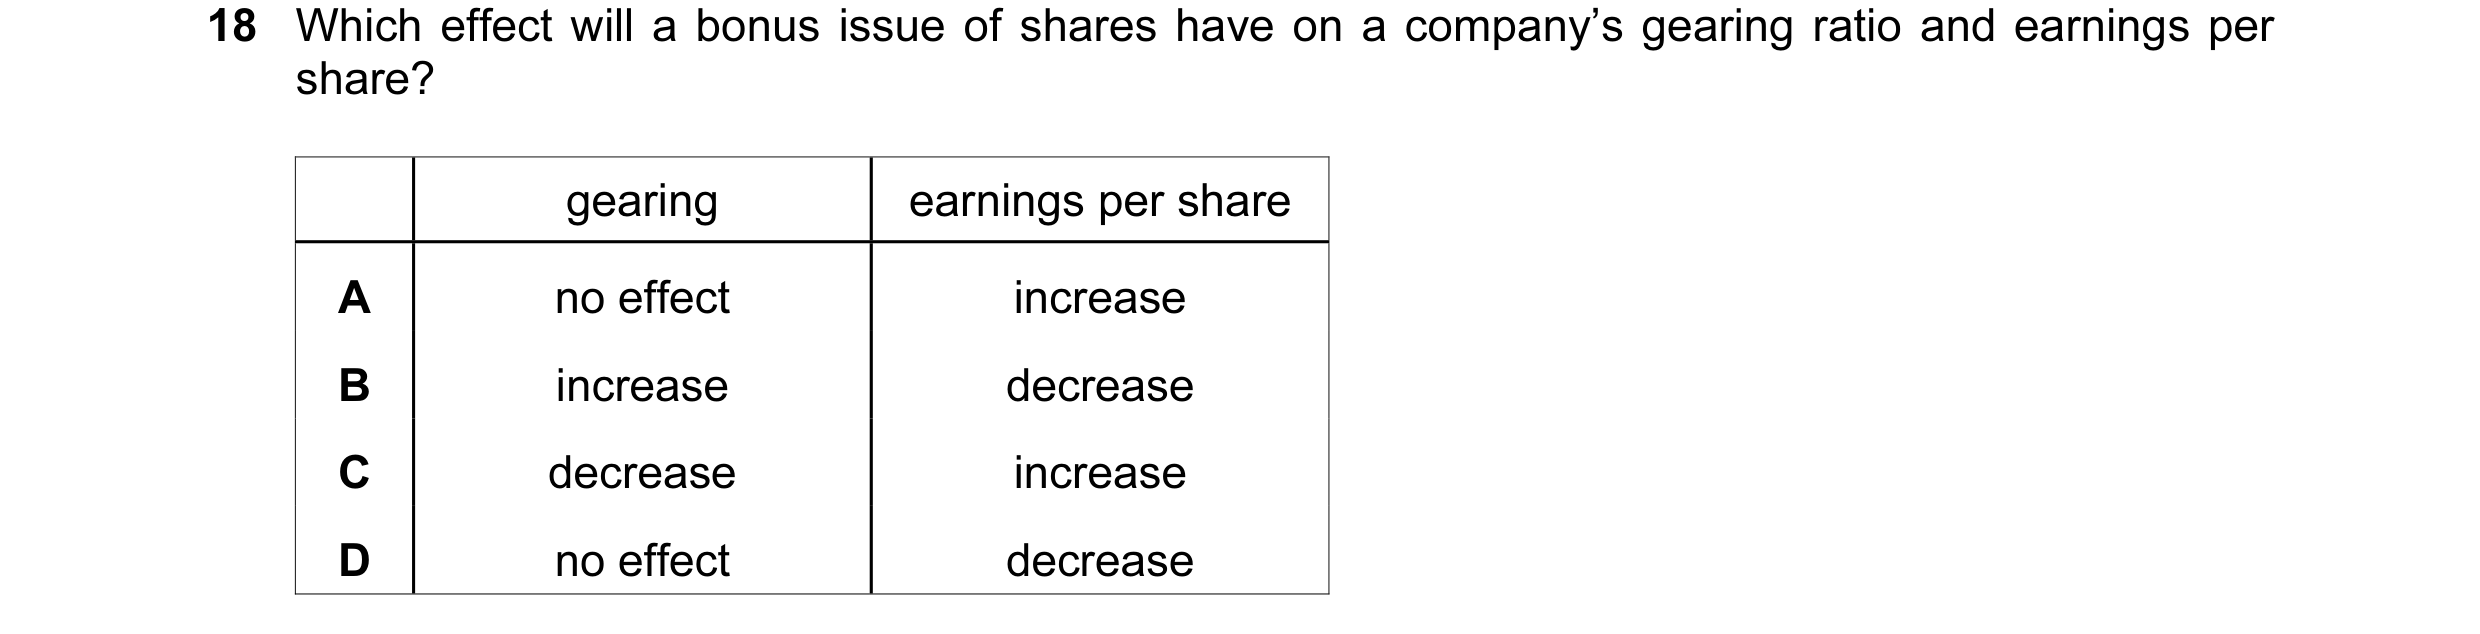
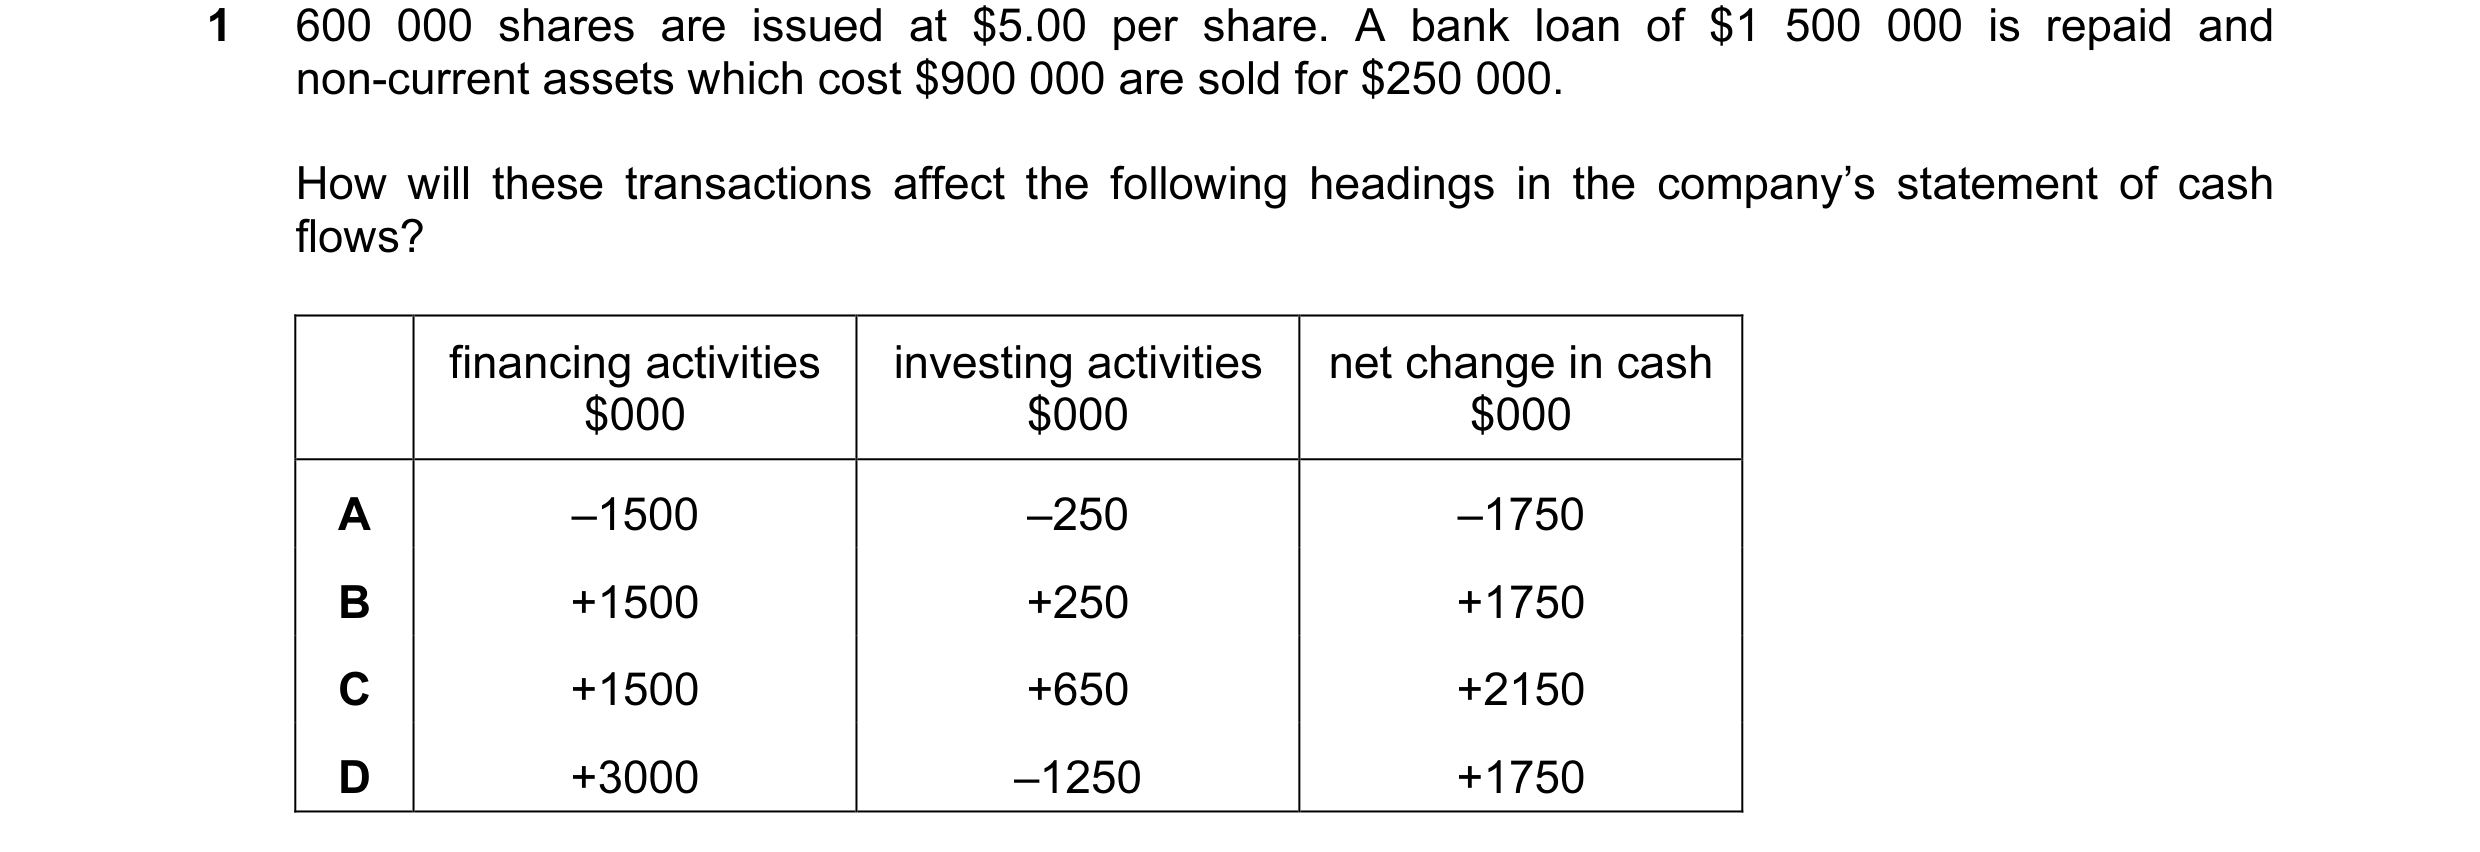 22 / 62
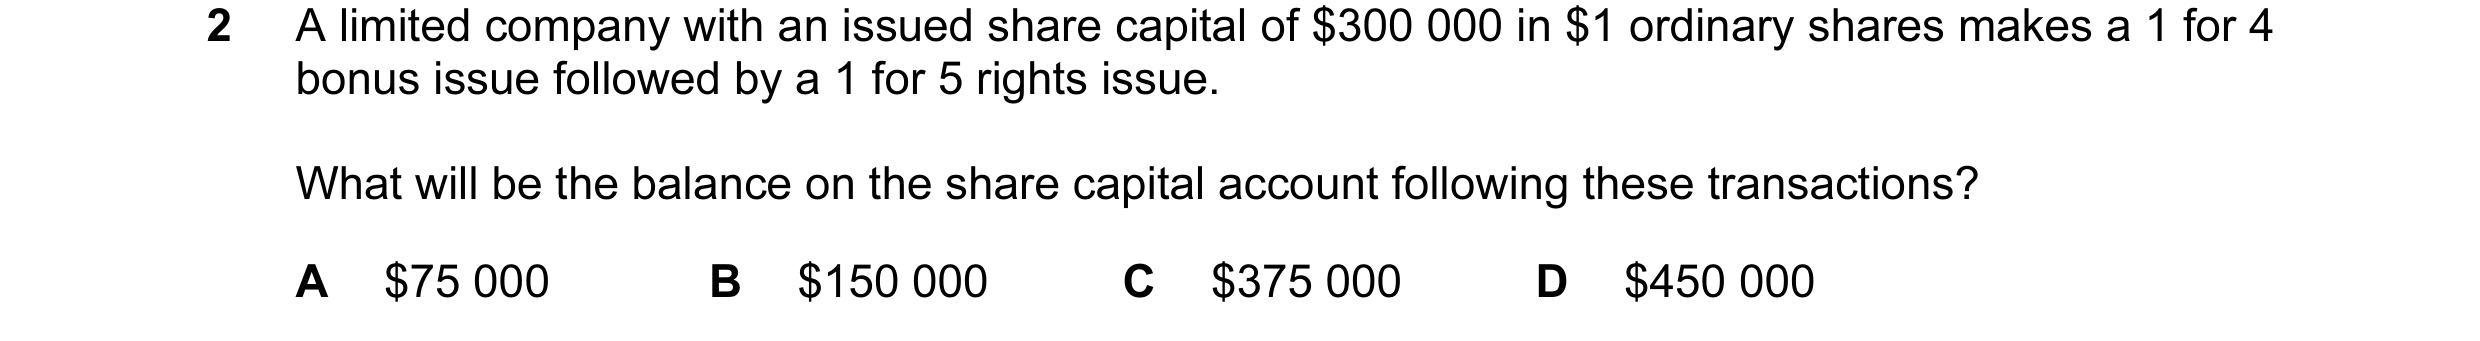
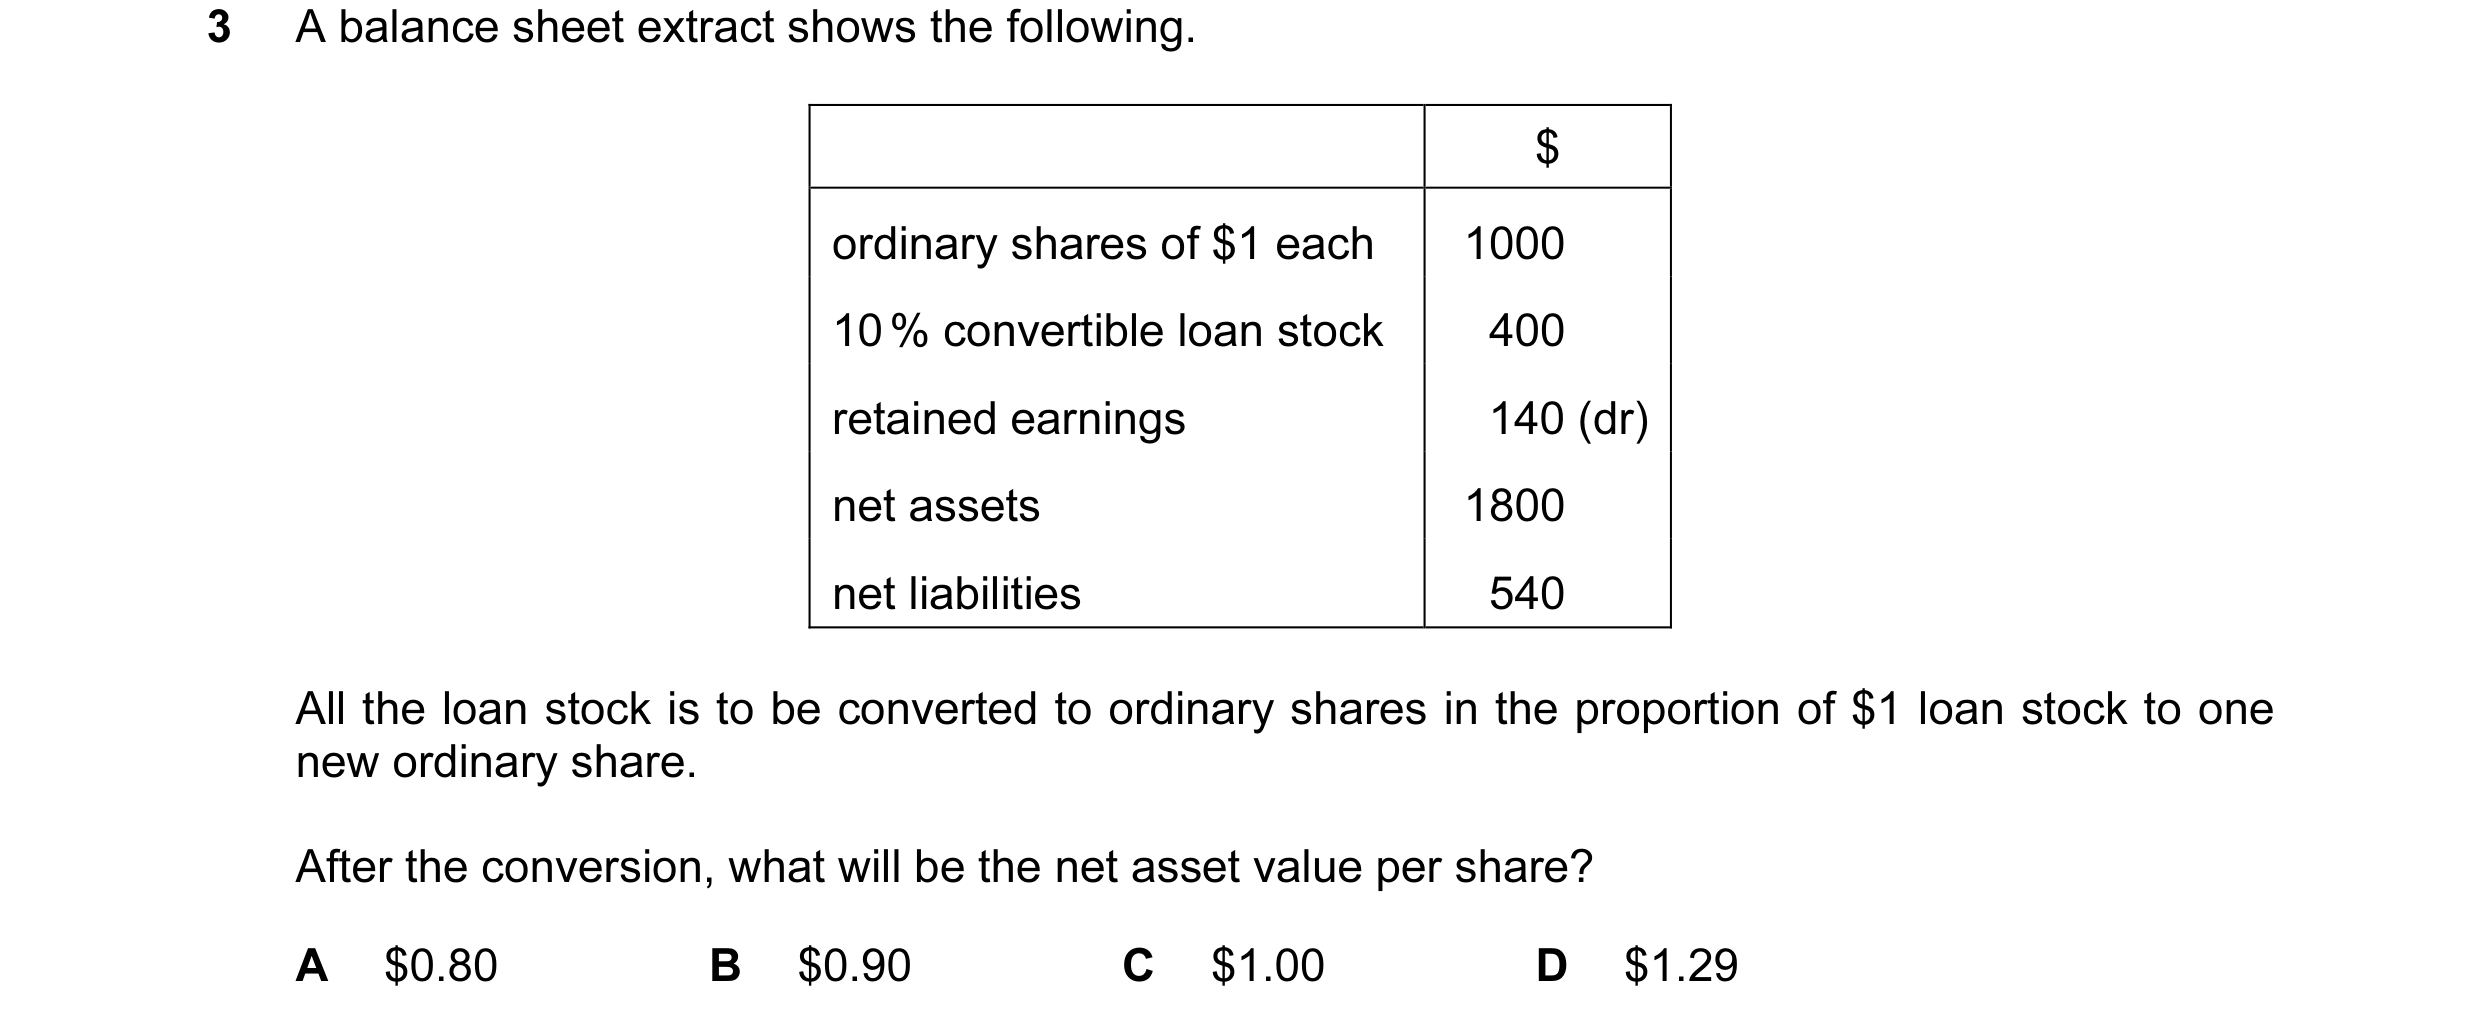
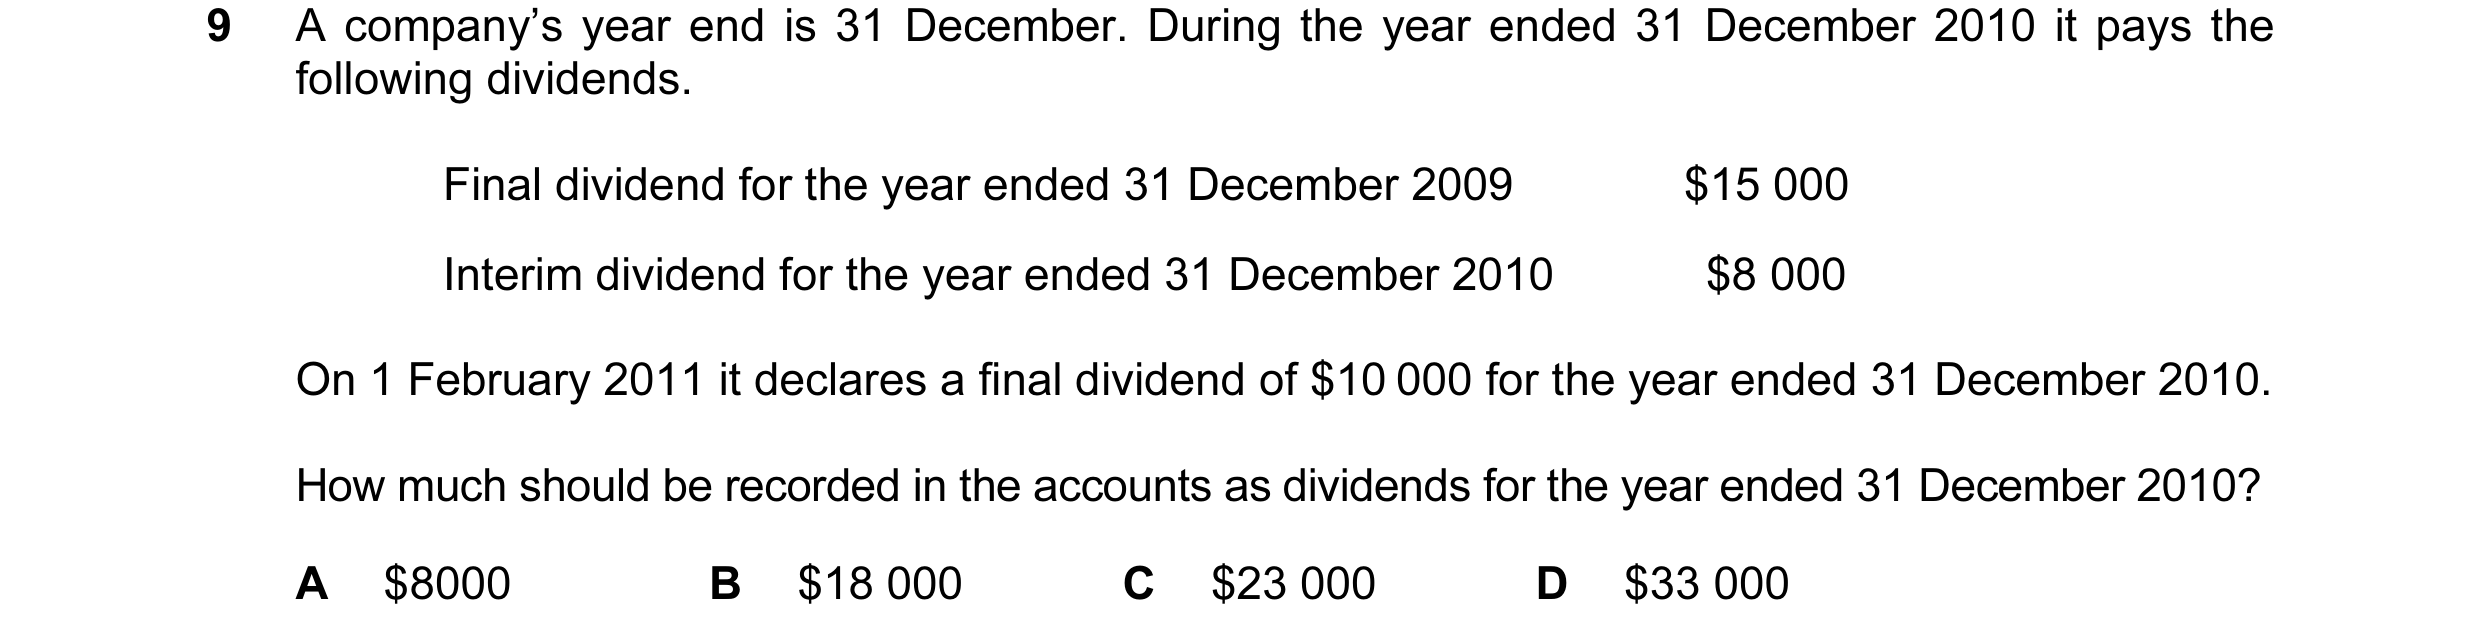
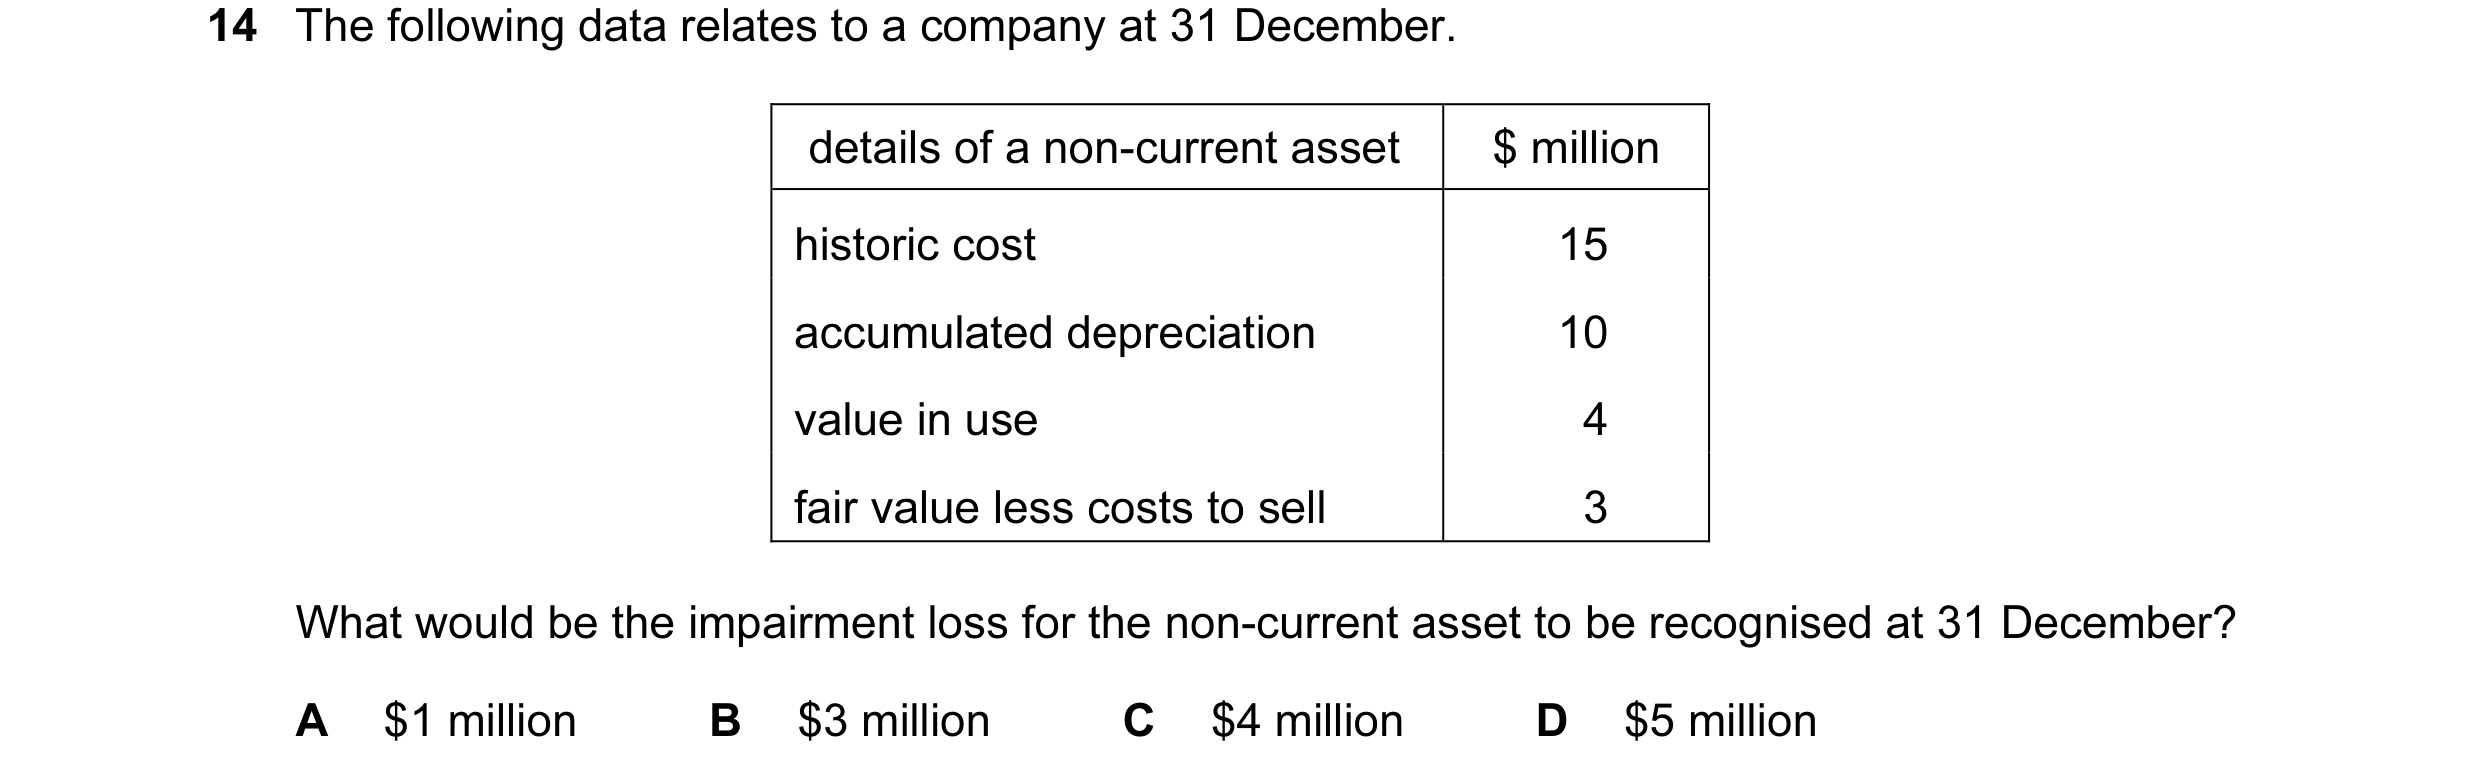 23 / 62
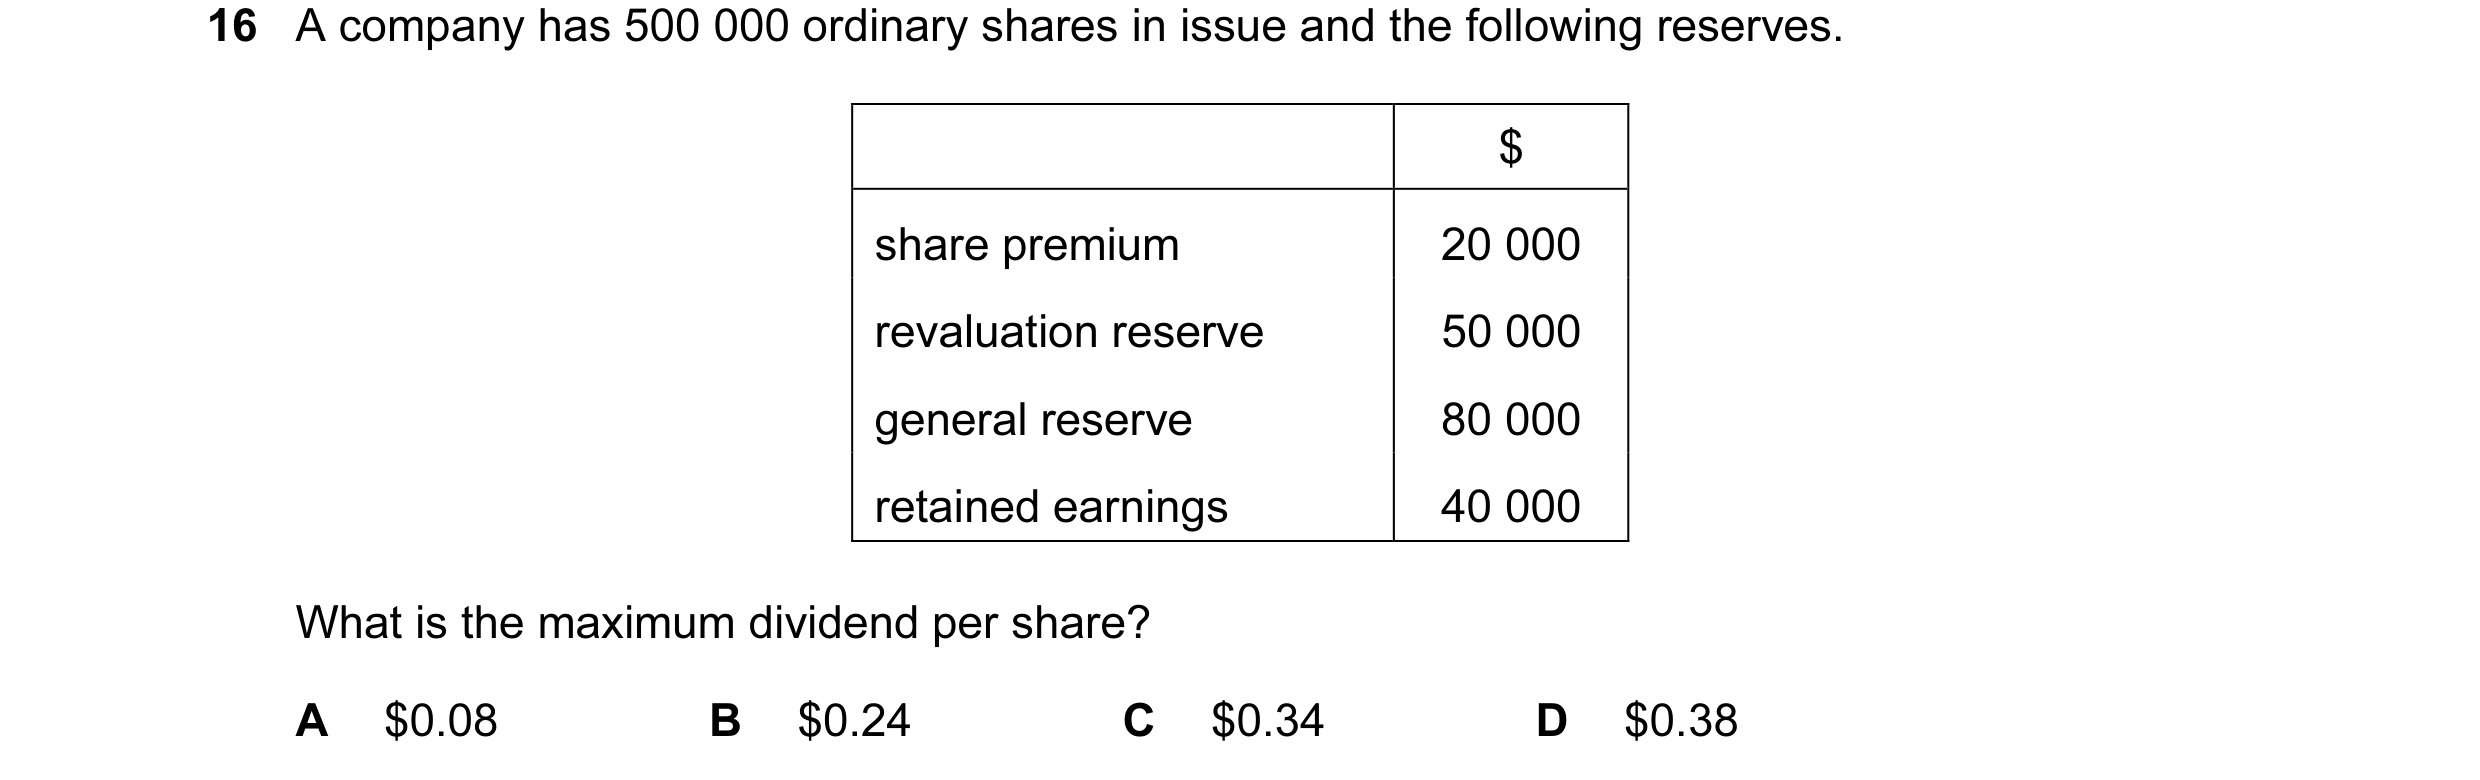
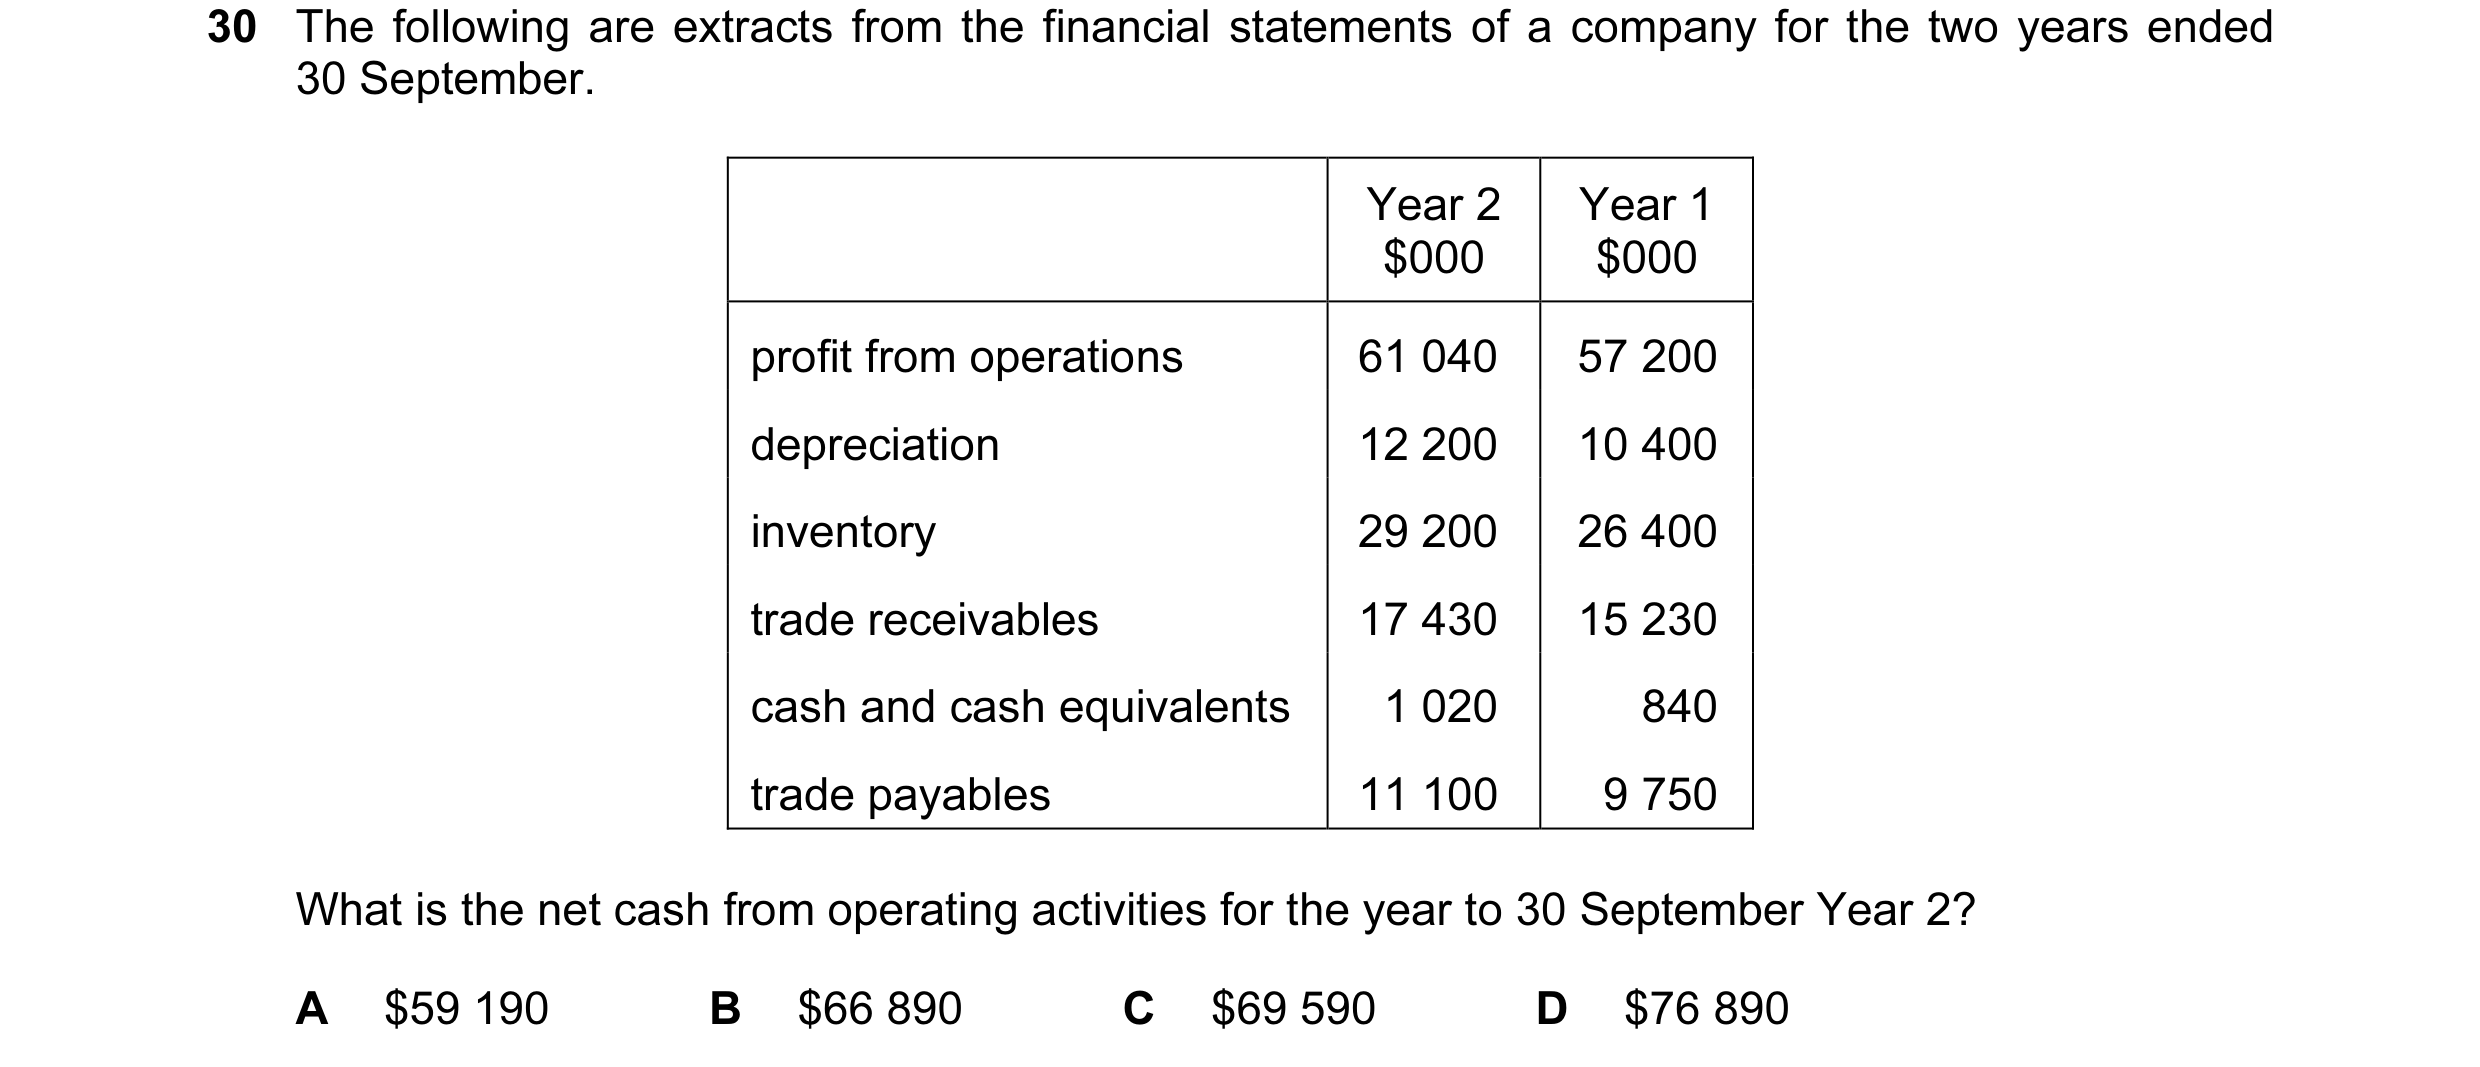
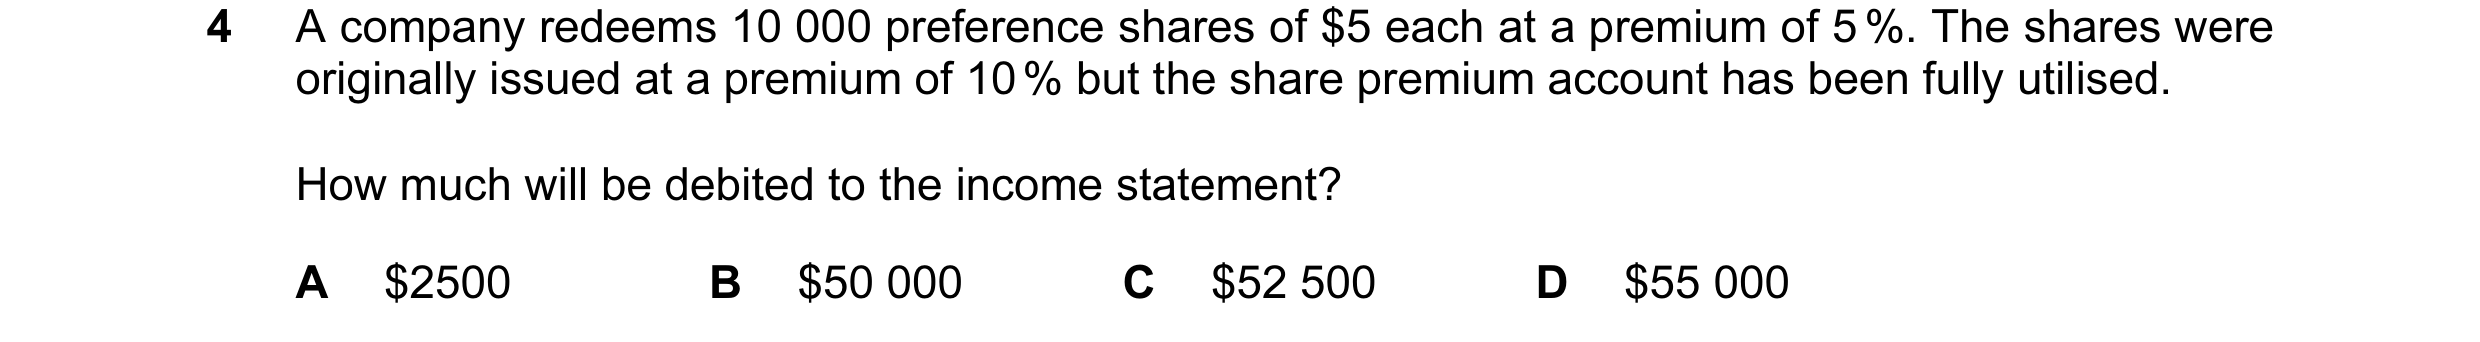
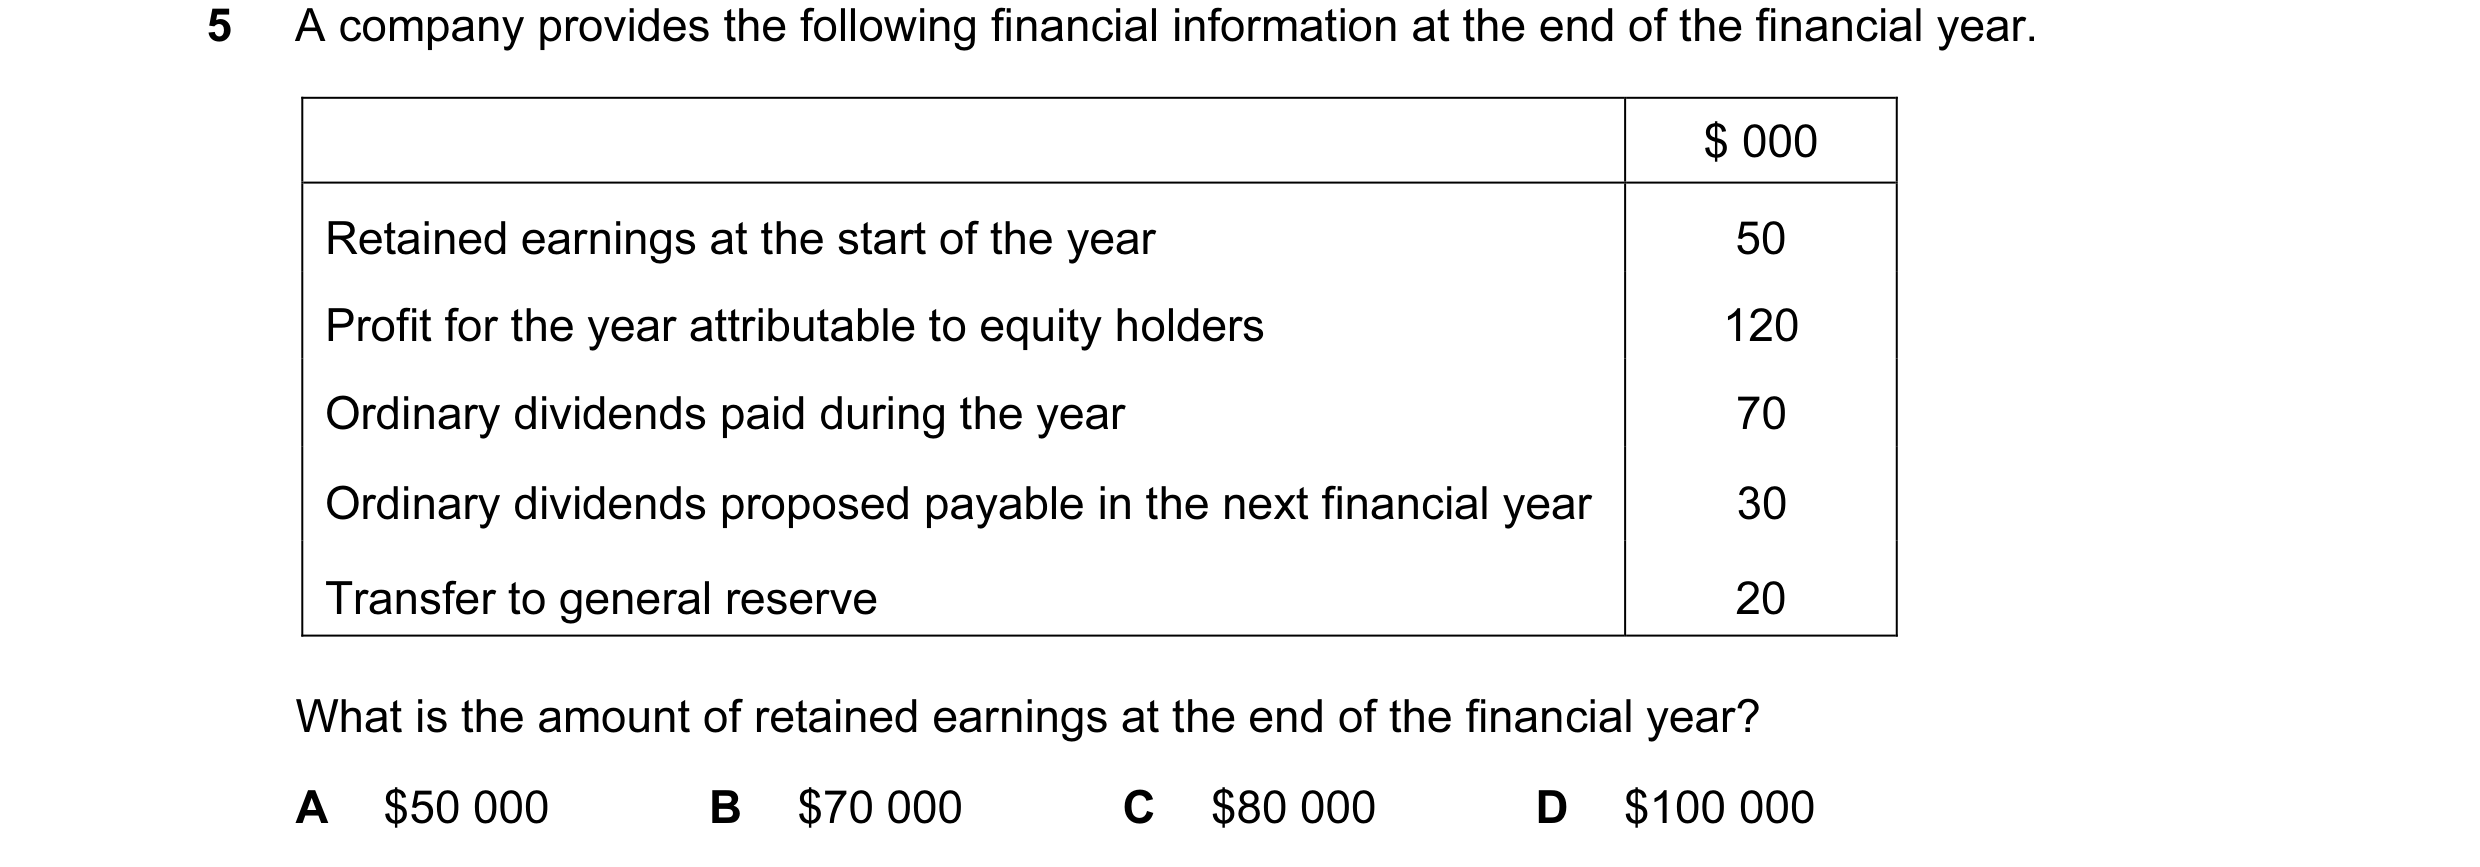 24 / 62
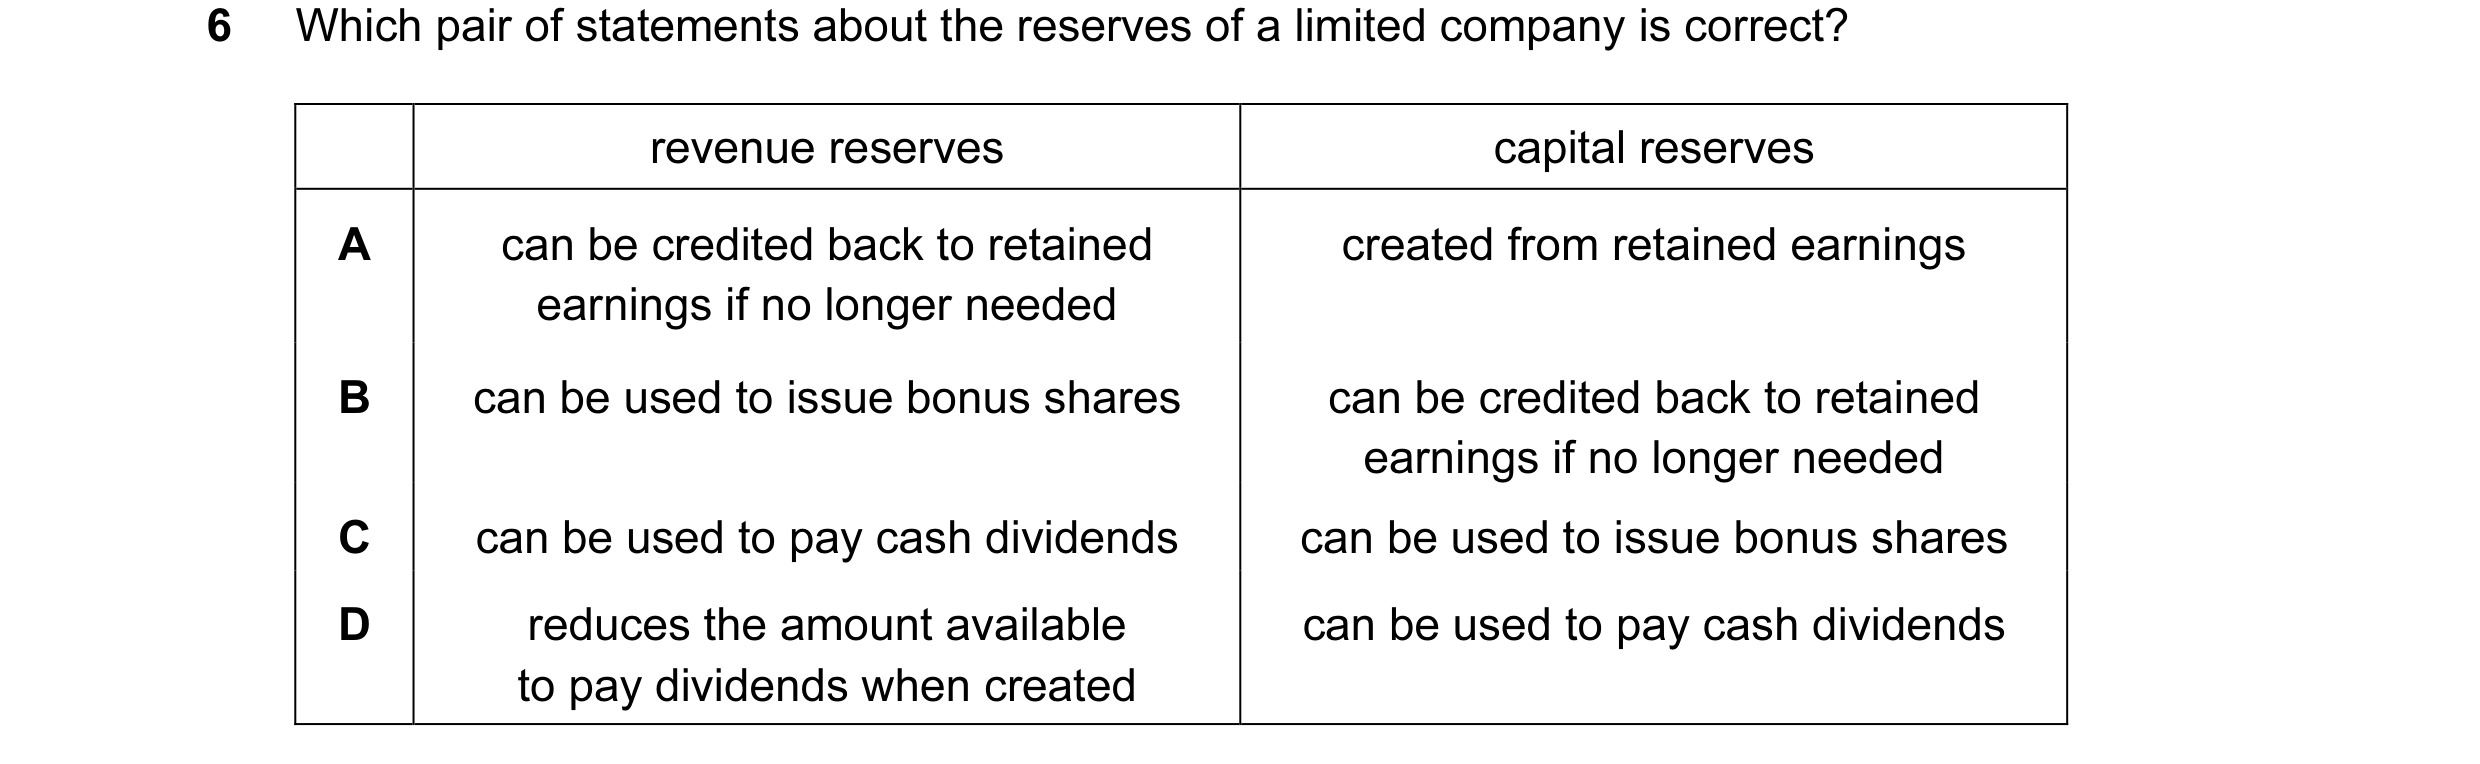
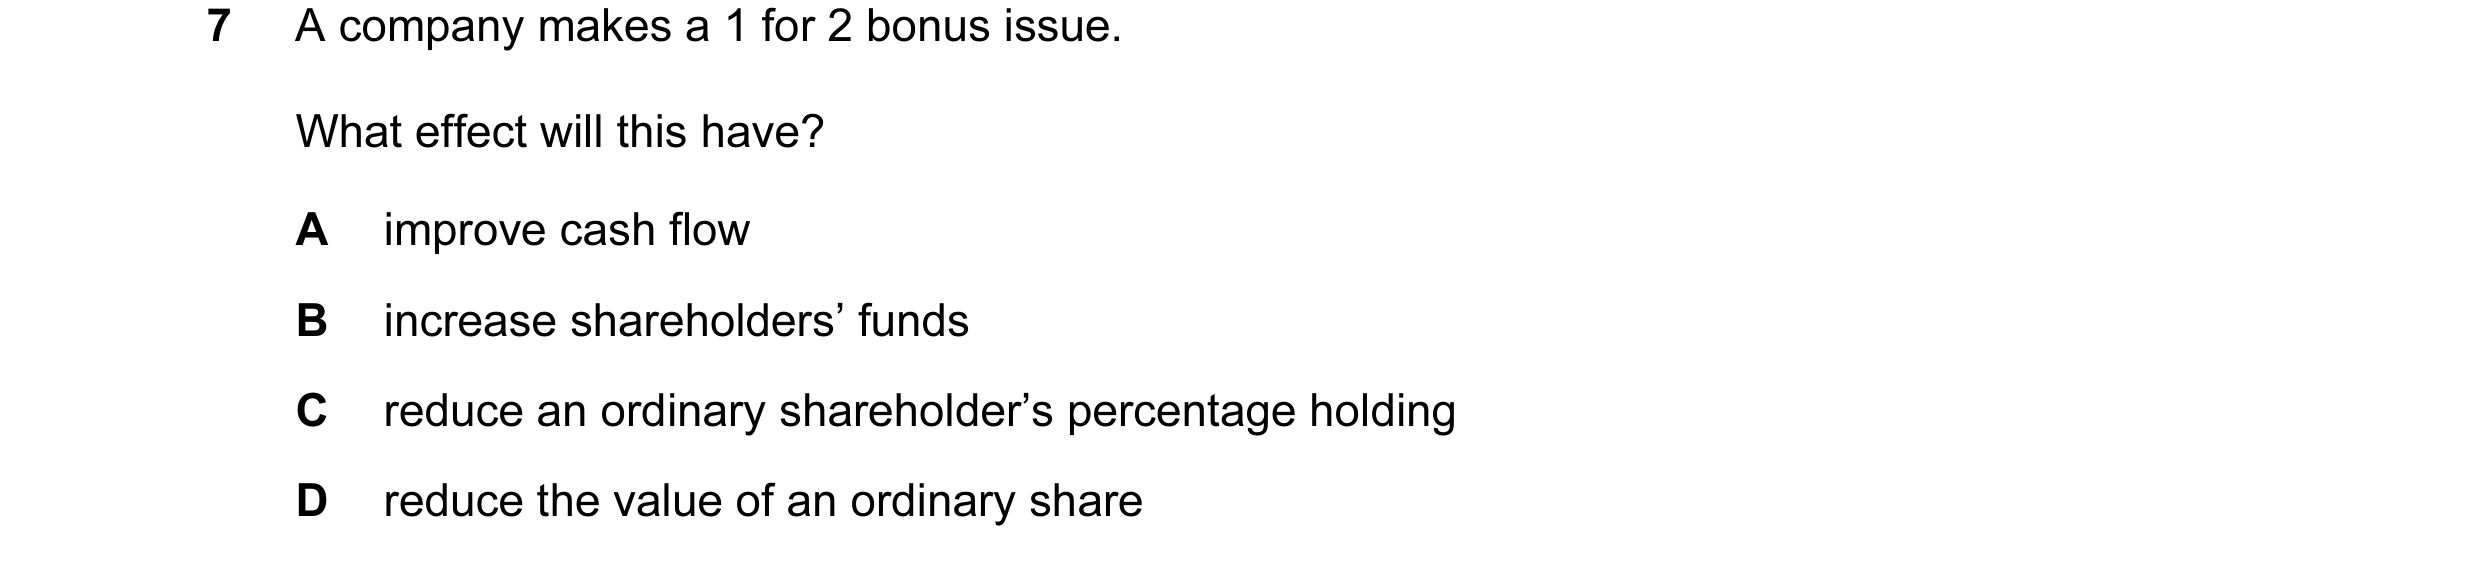
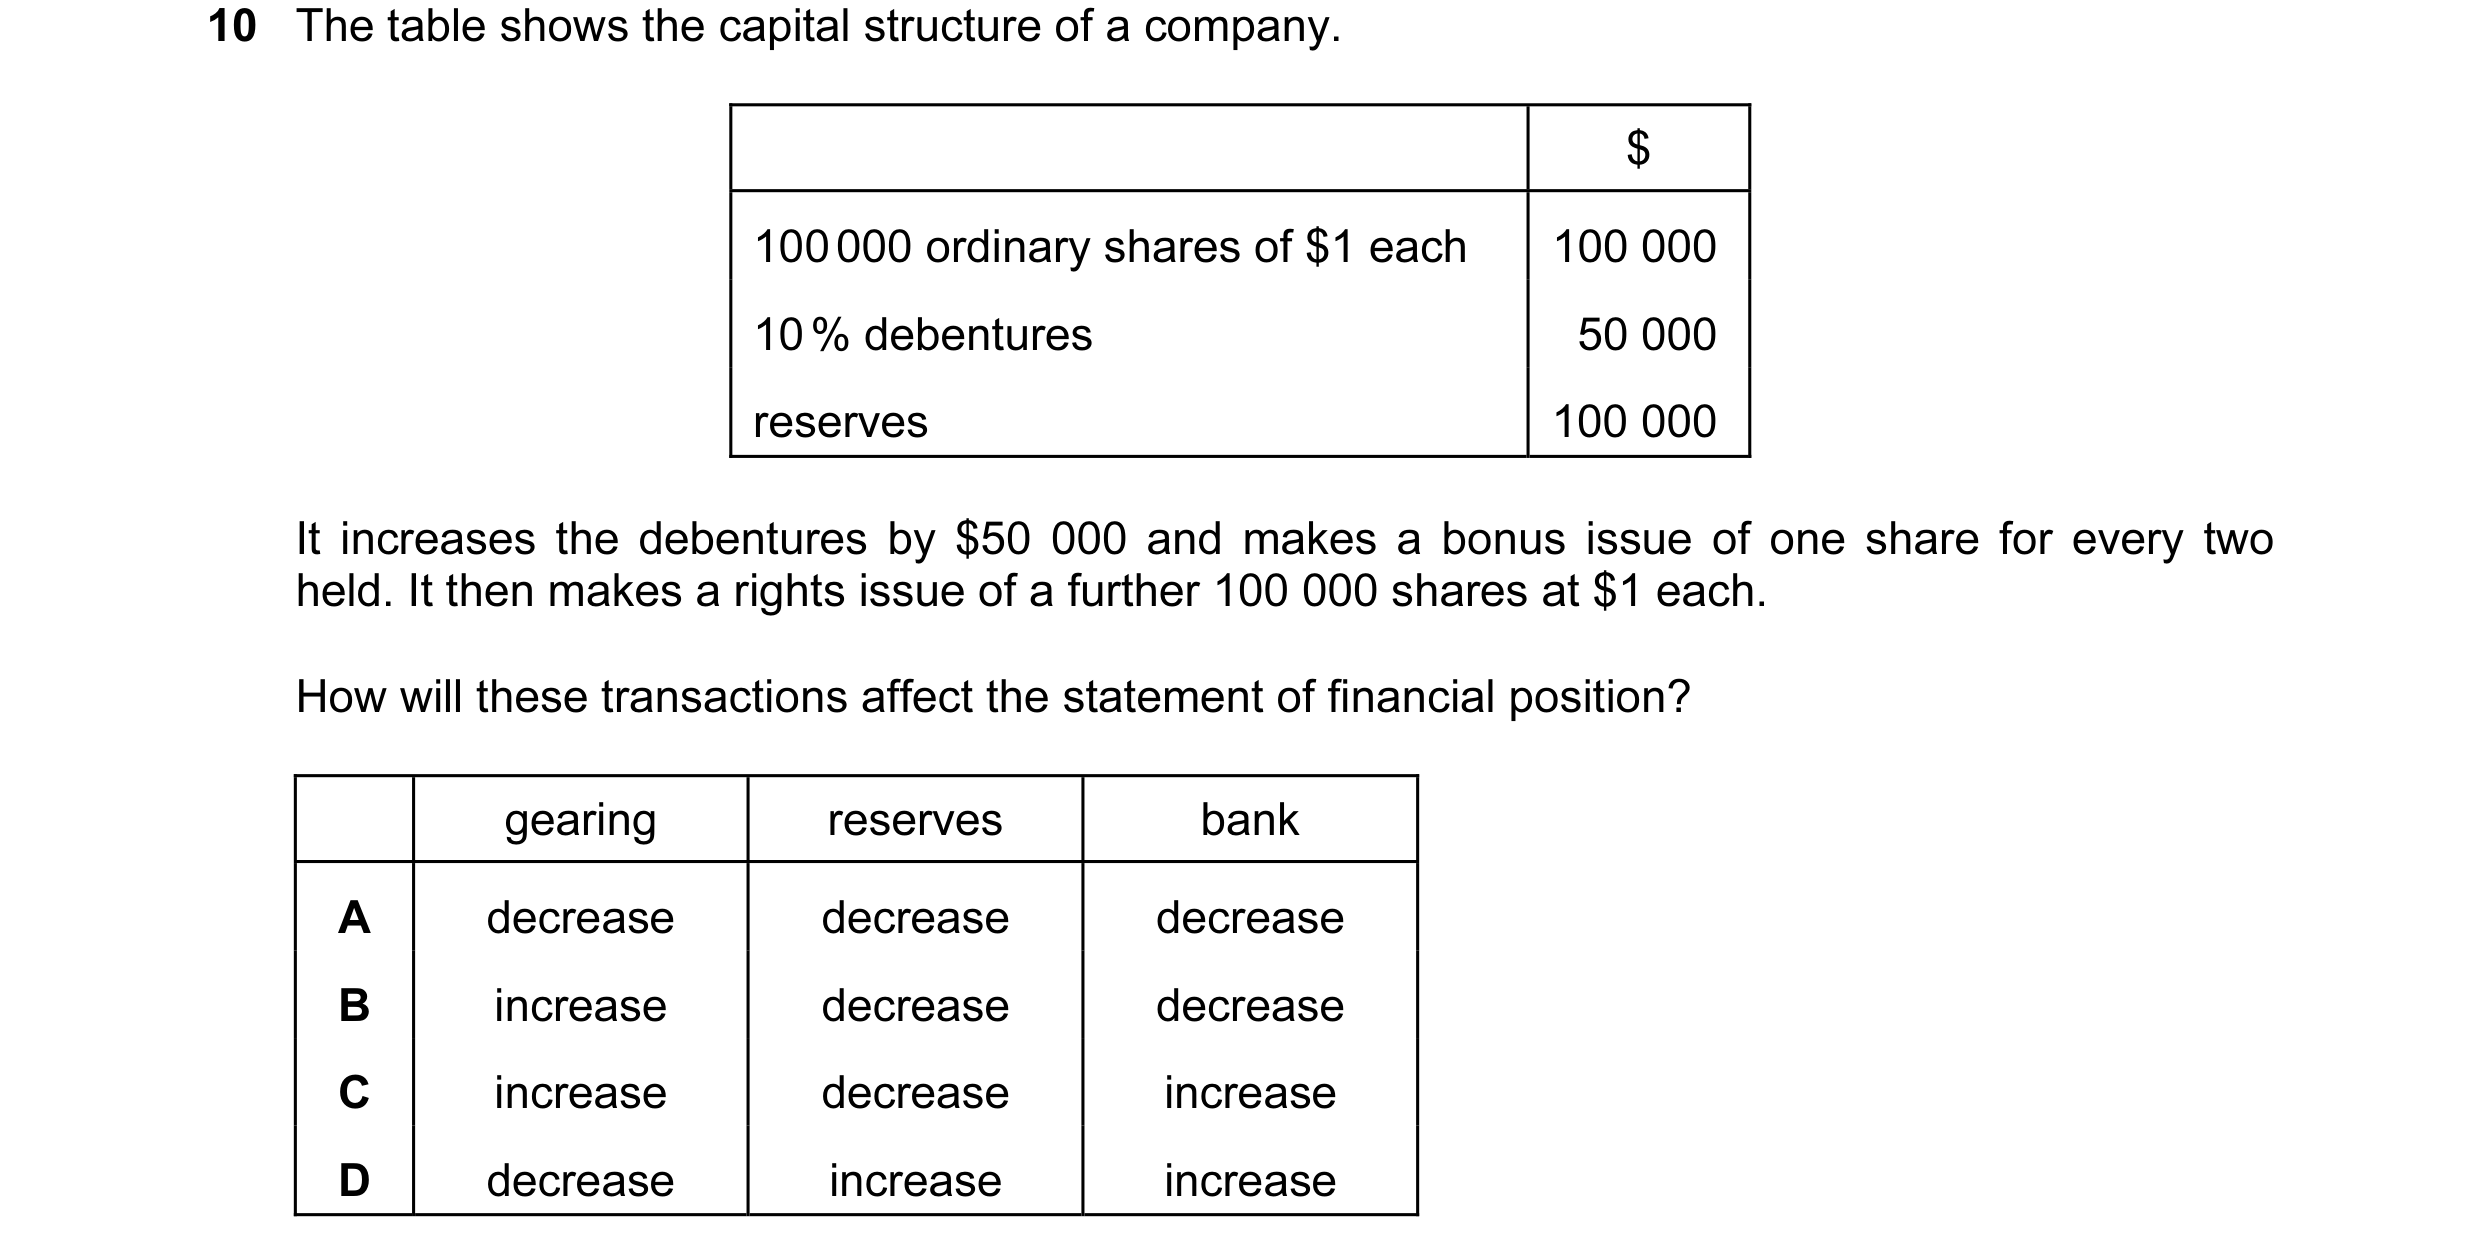 25 / 62
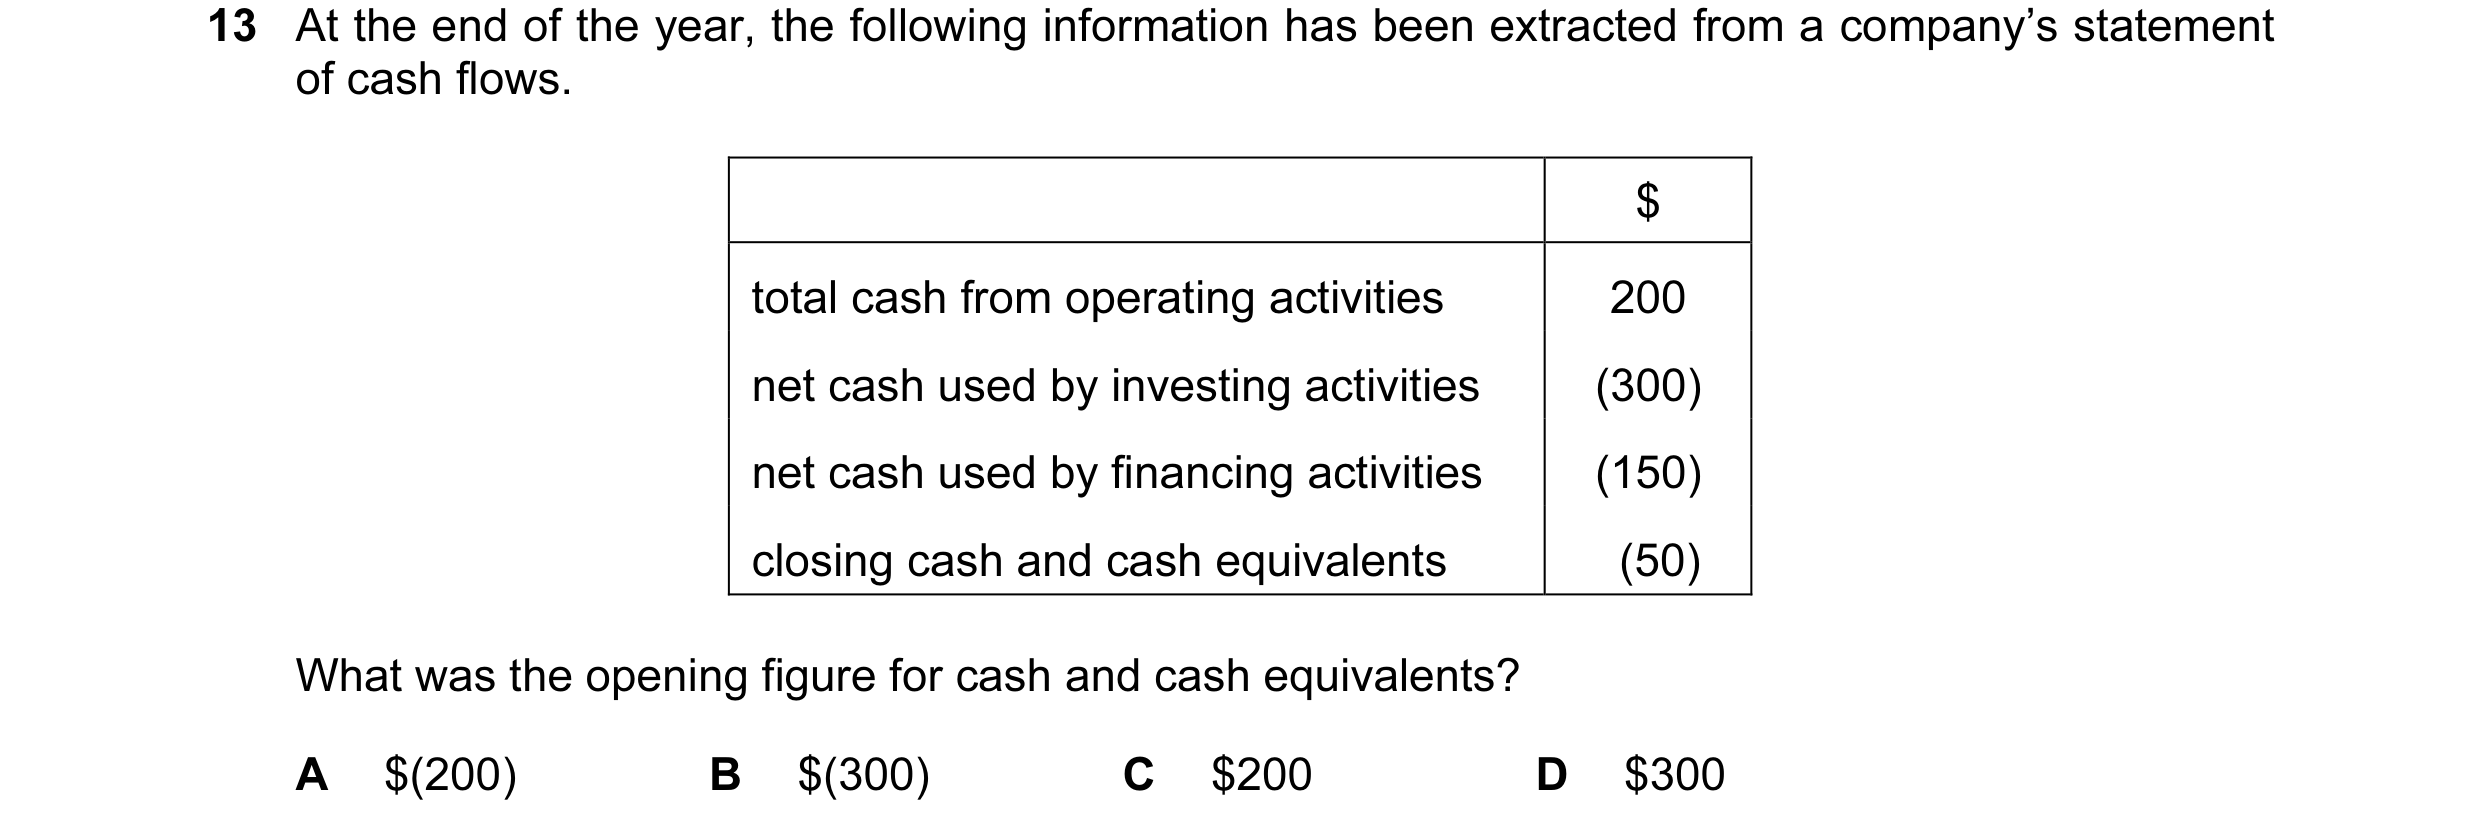
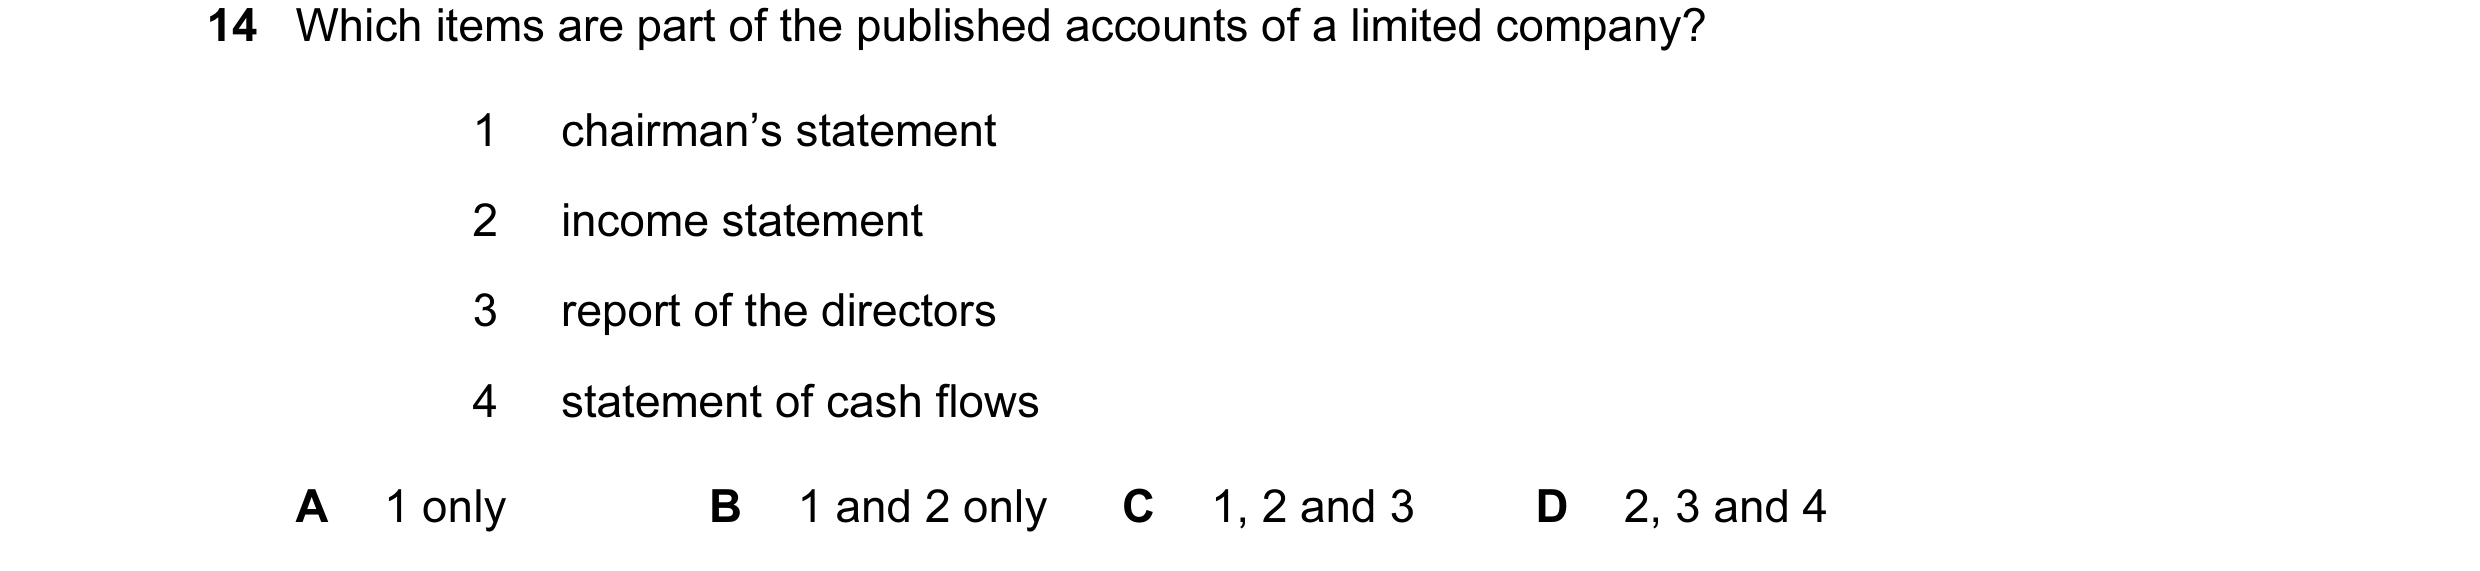
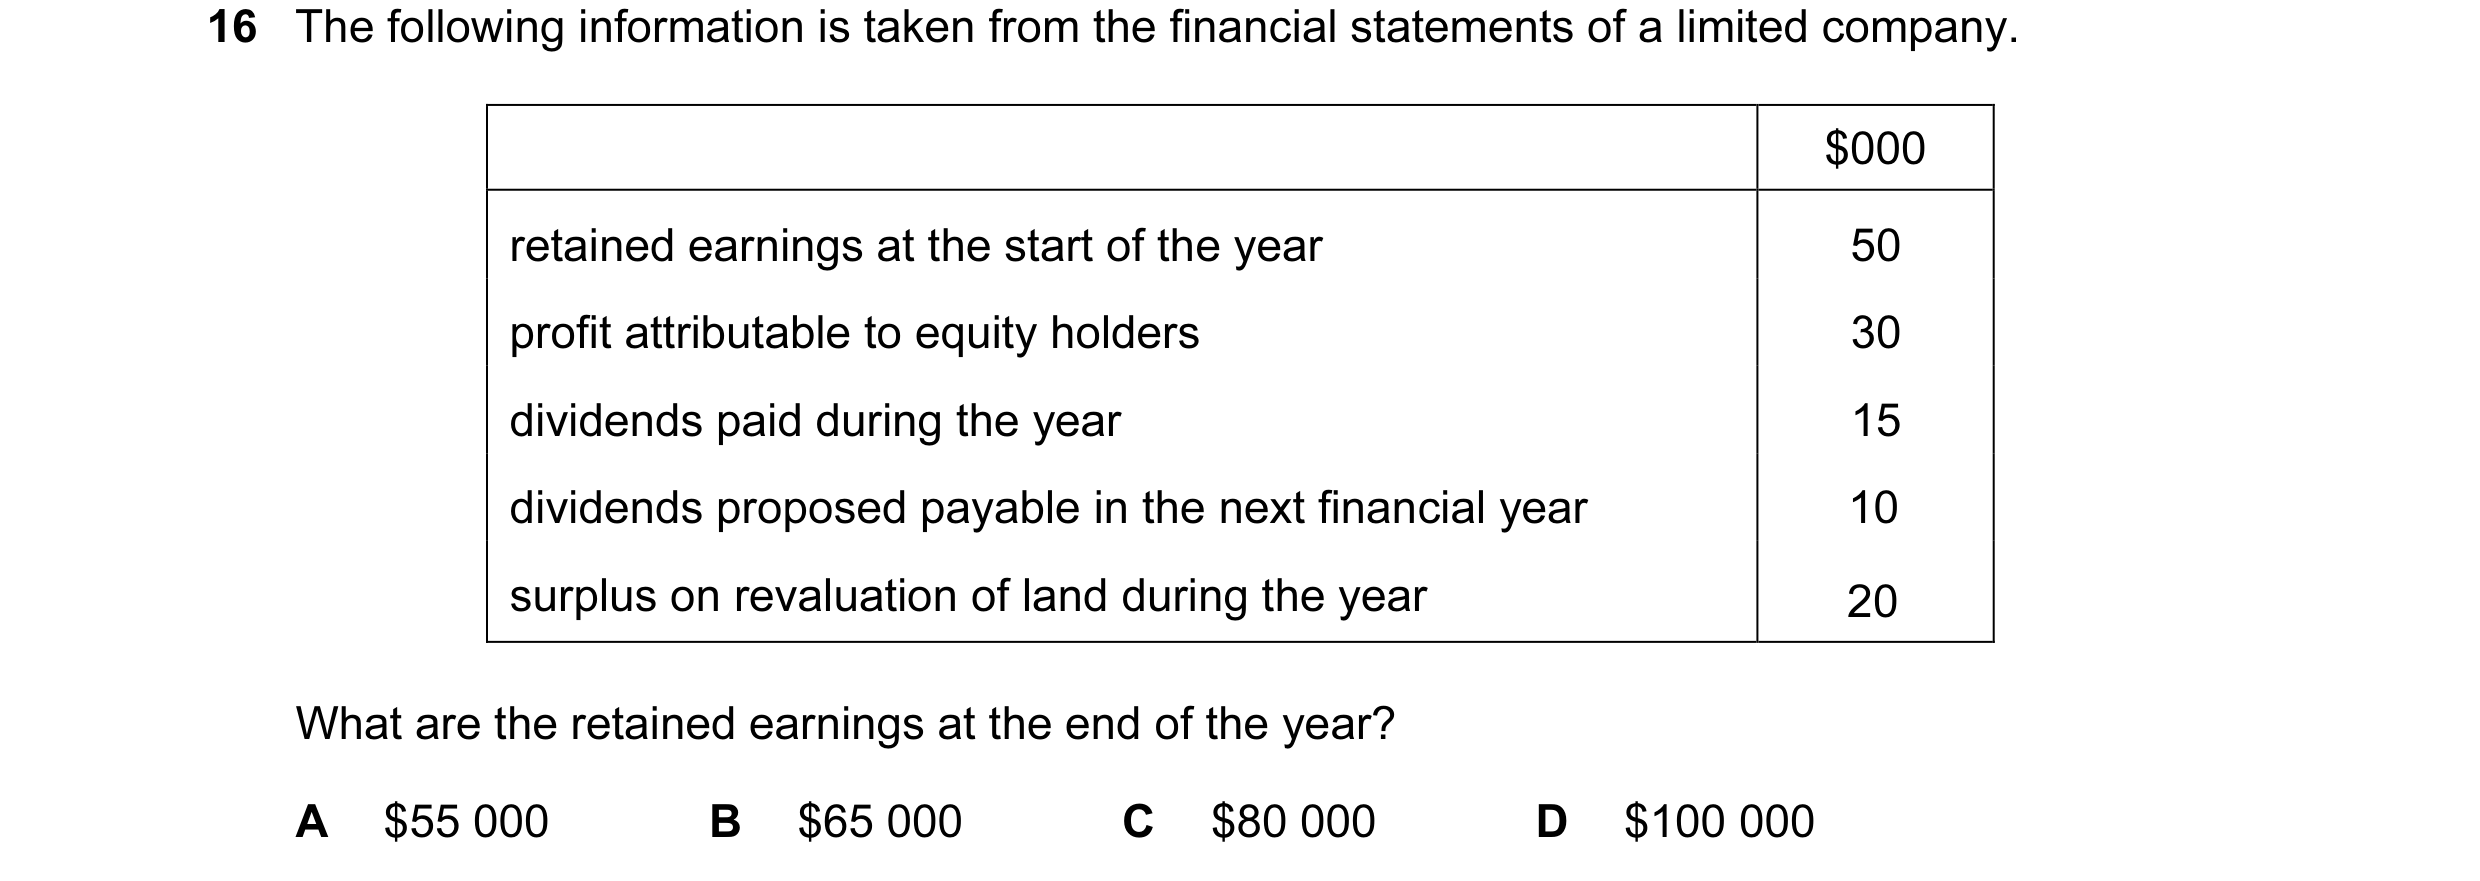
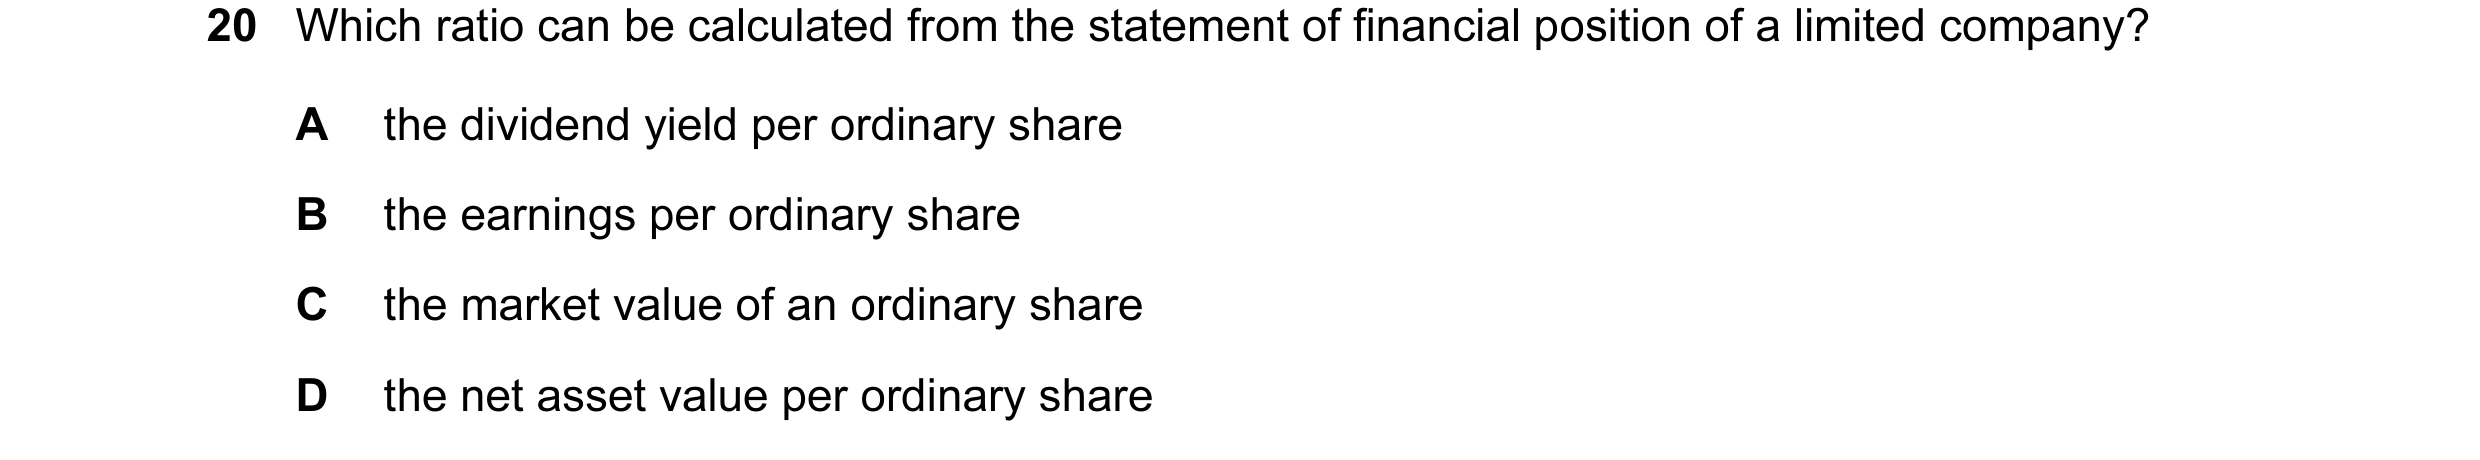 26 / 62
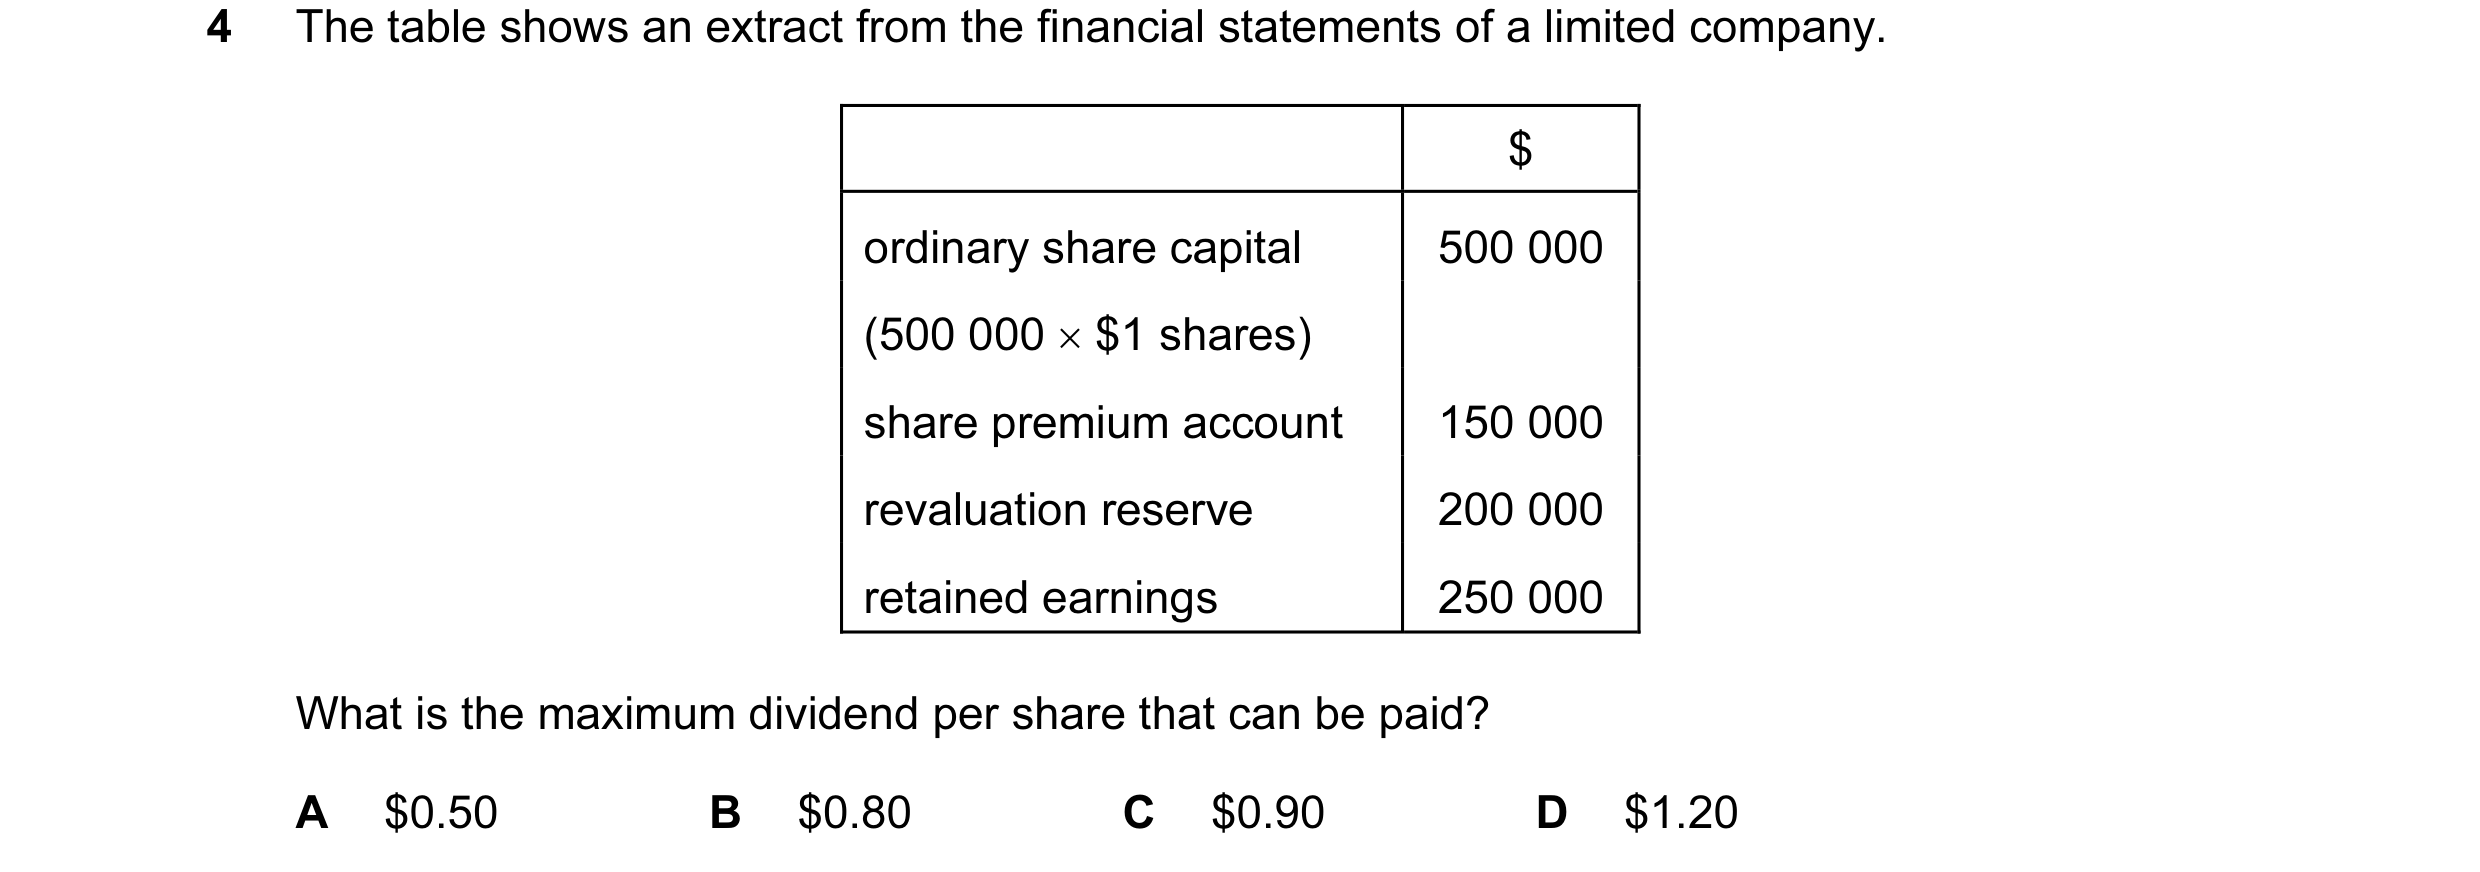
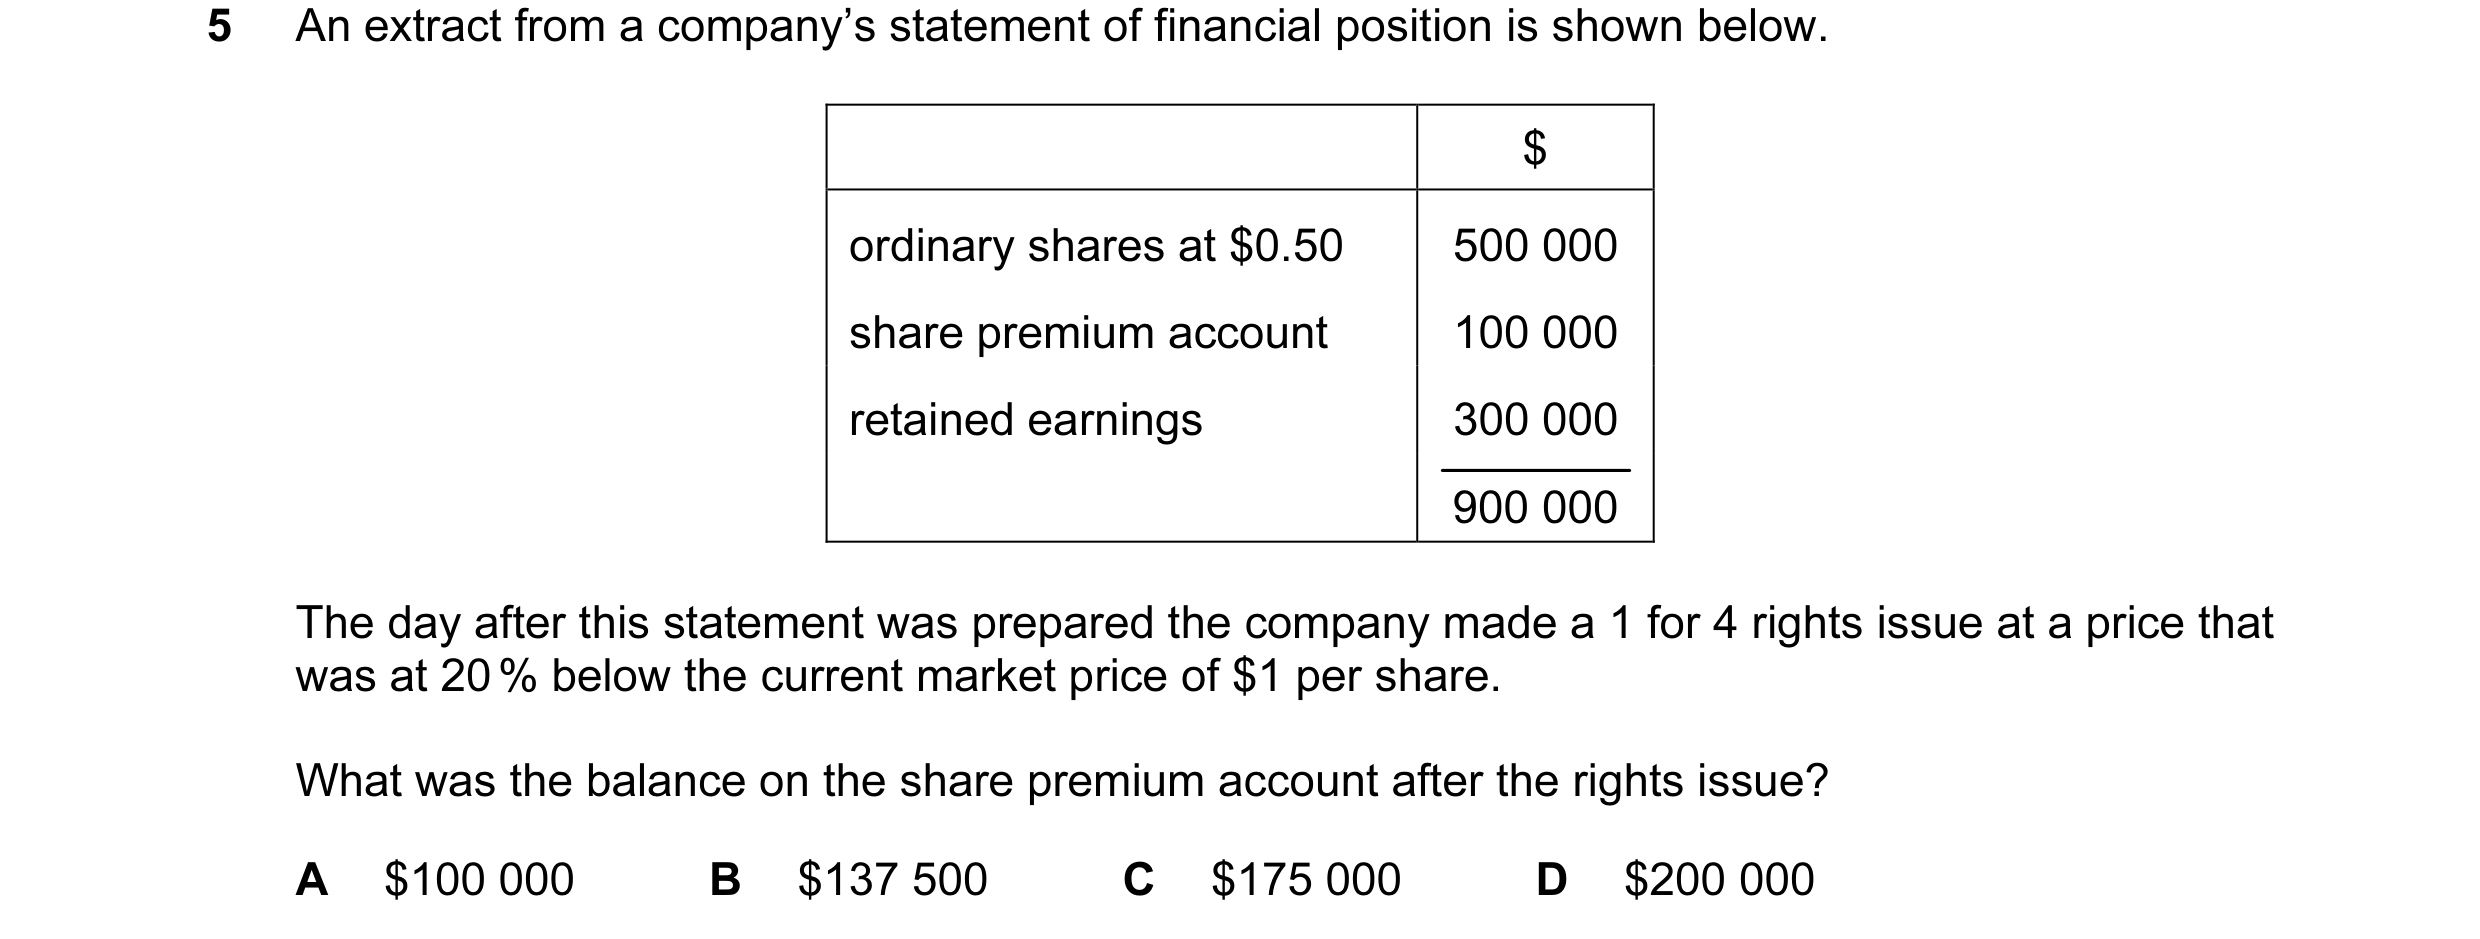
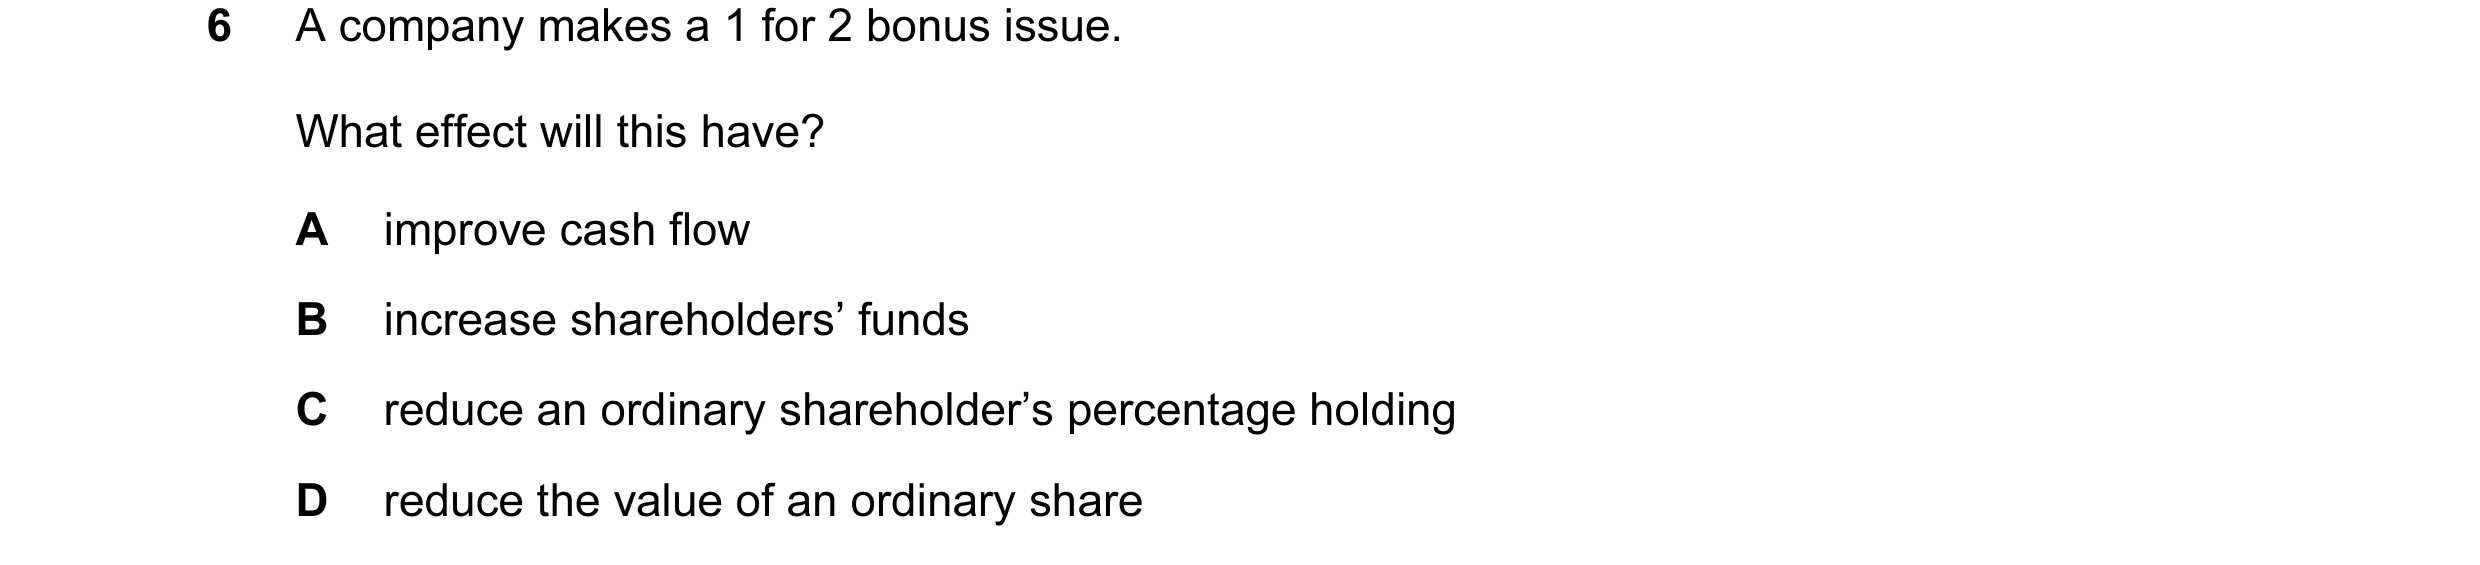
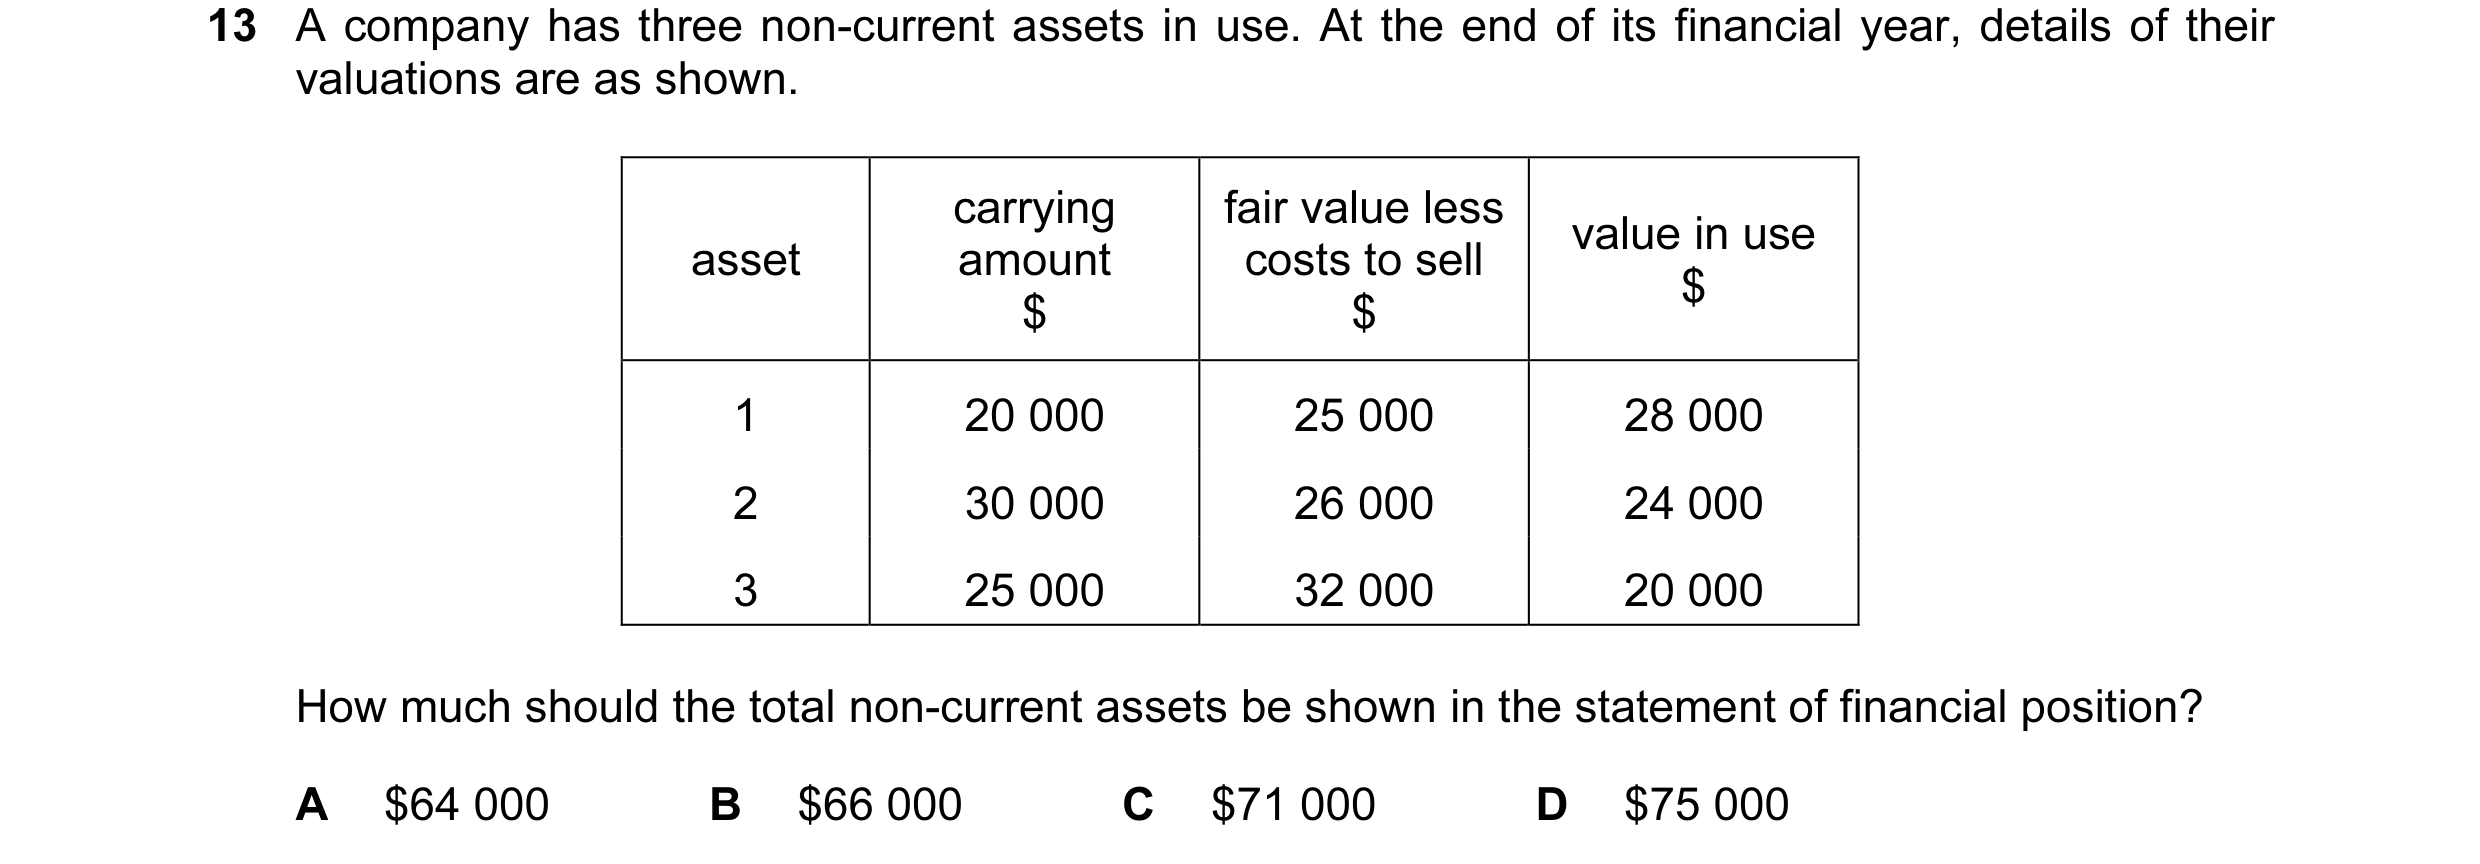 27 / 62
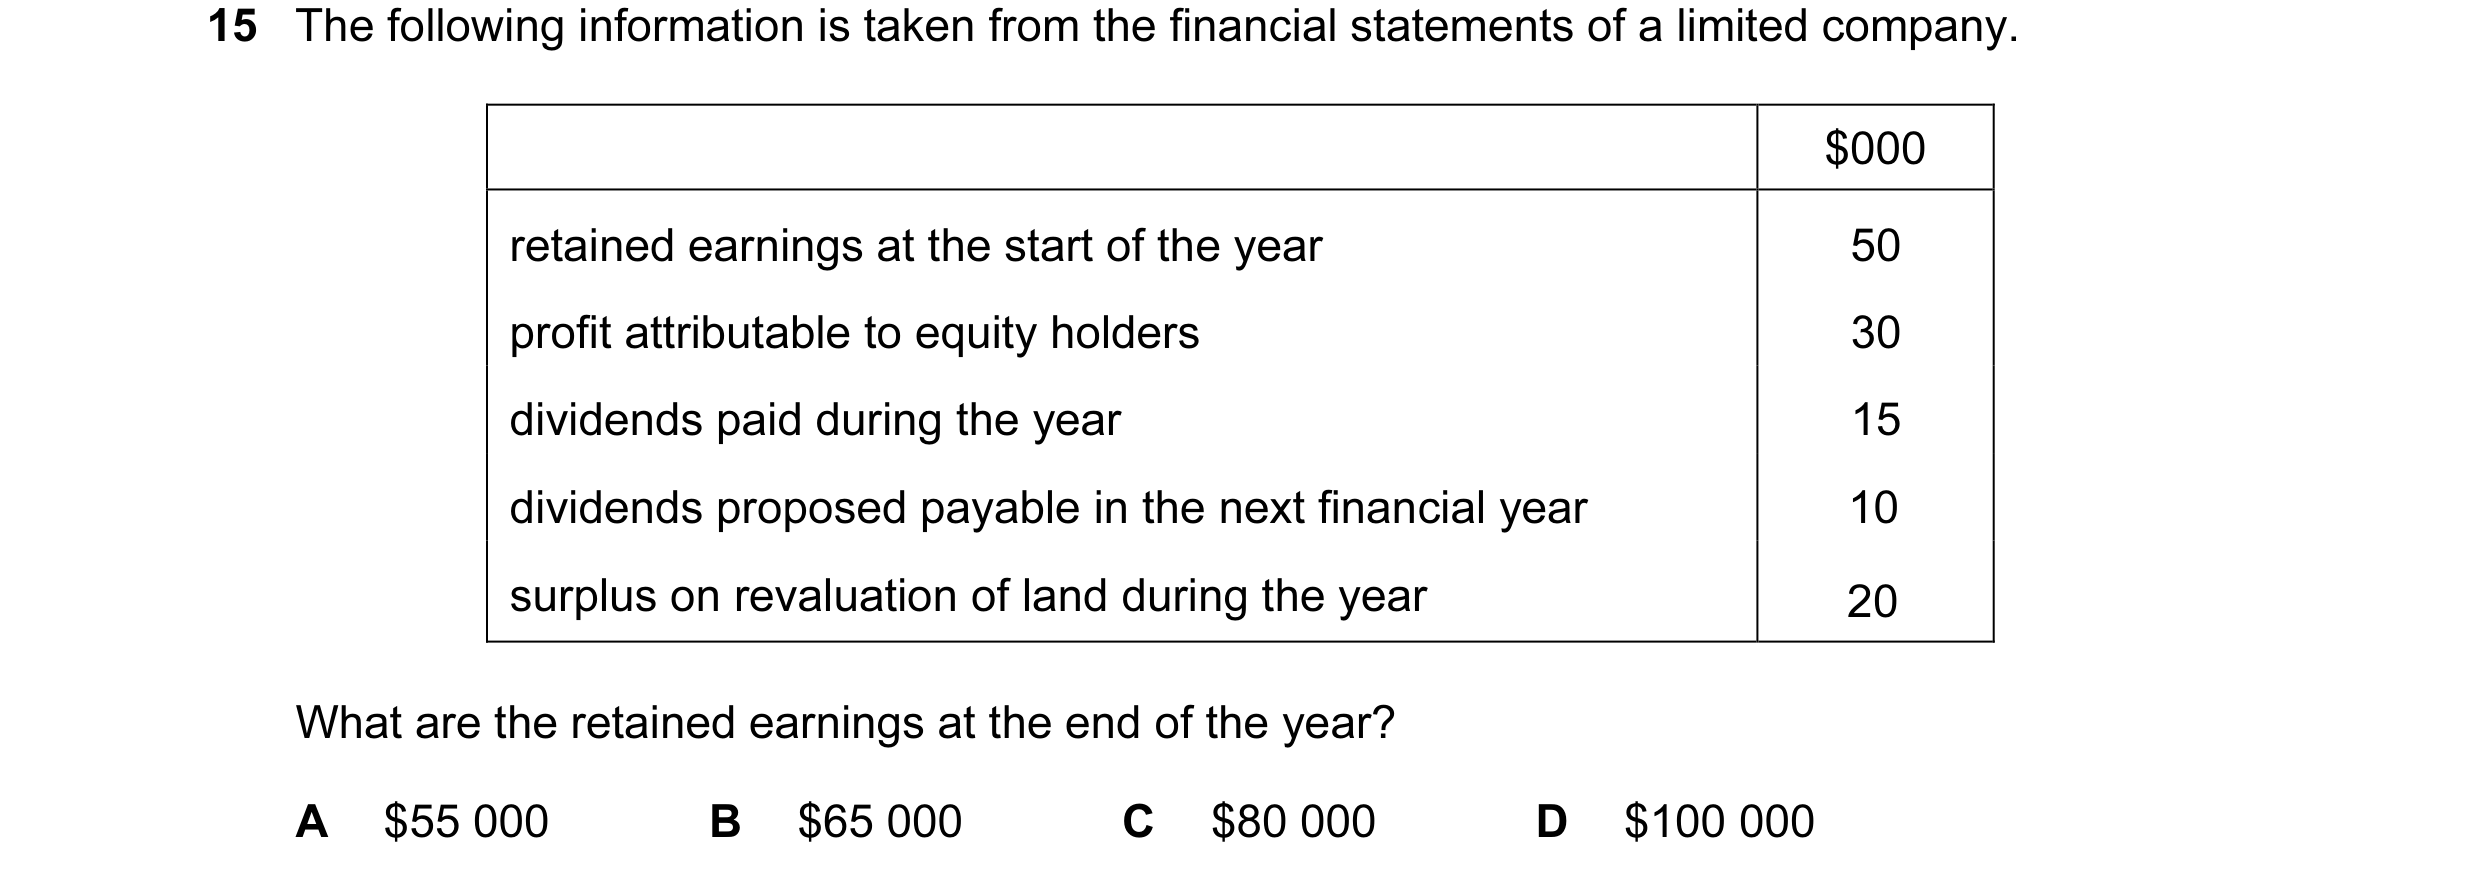
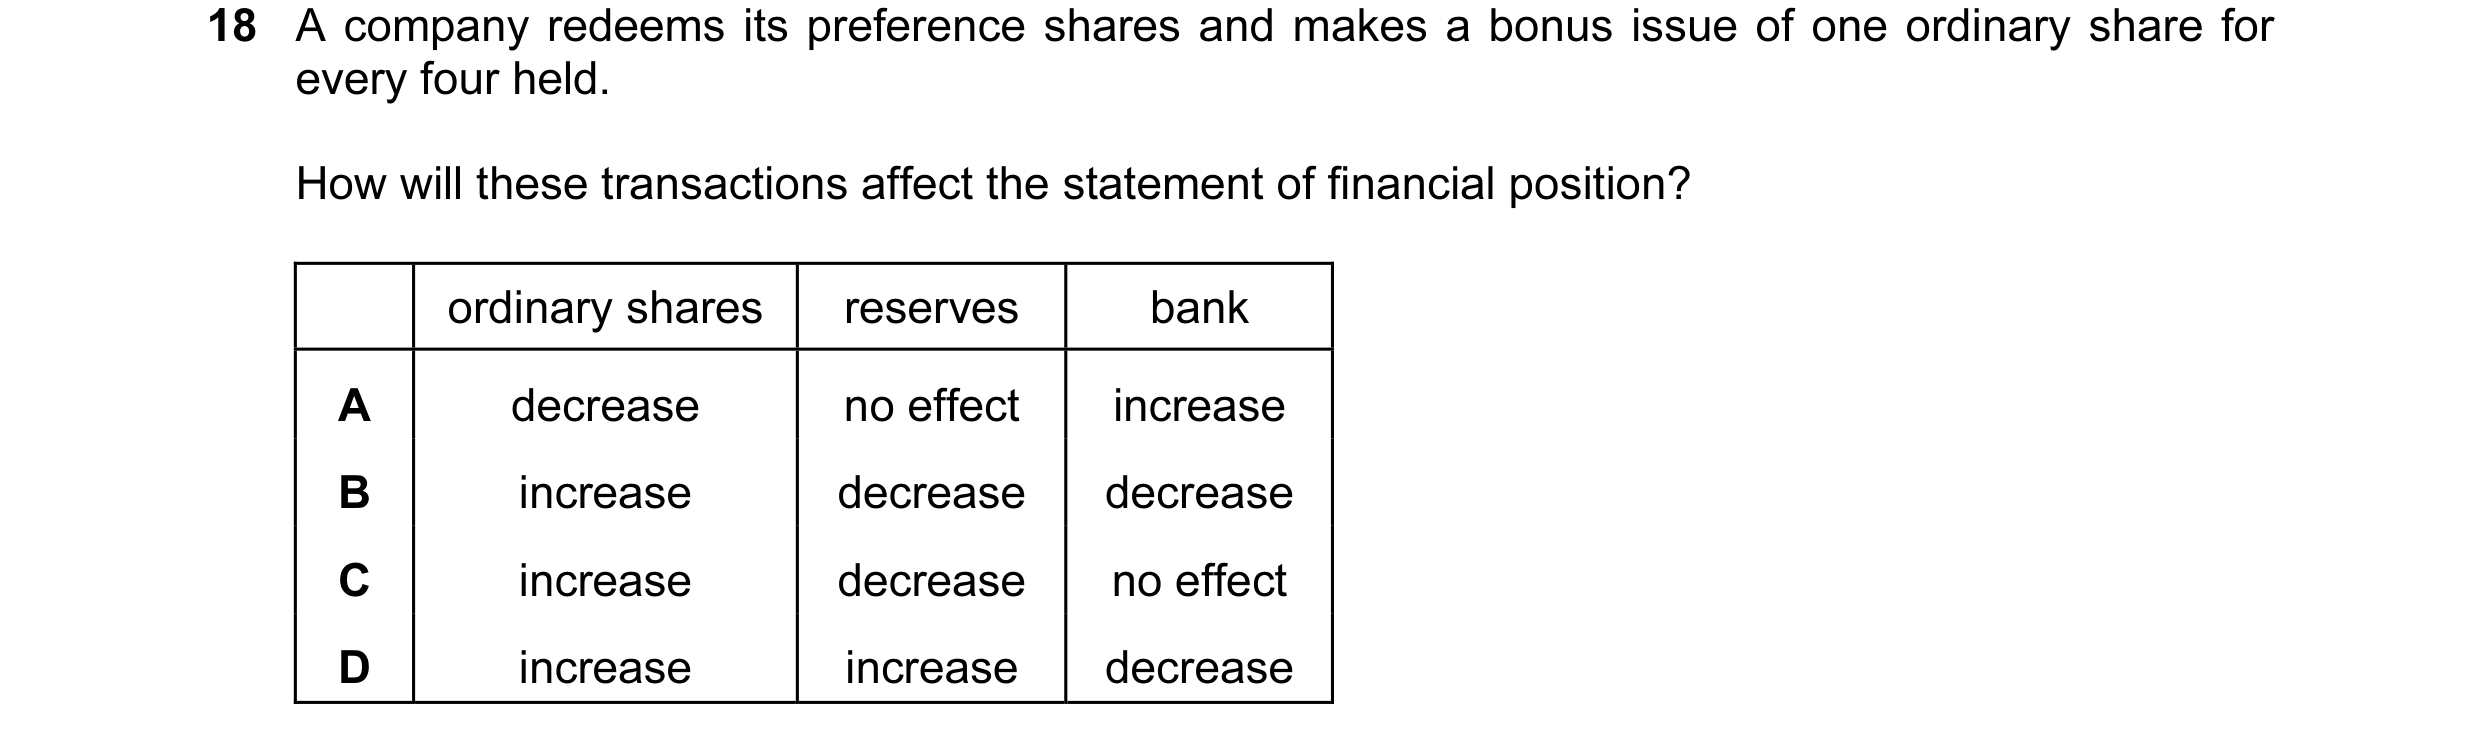
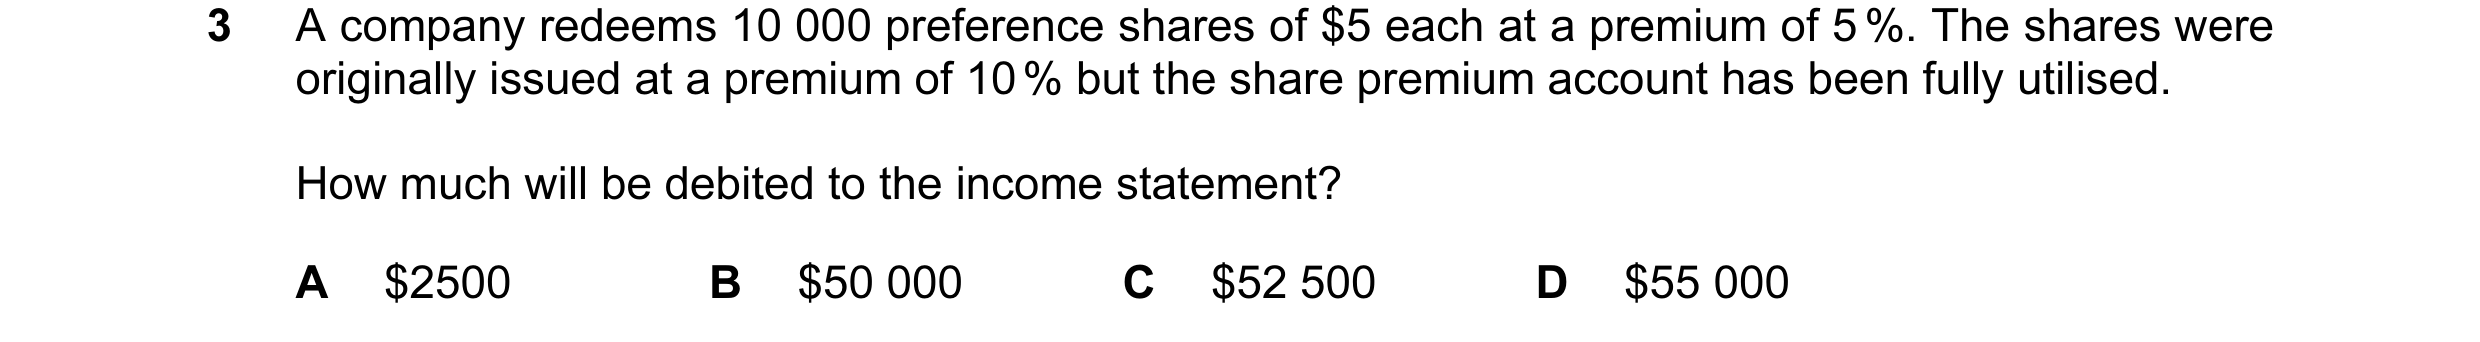
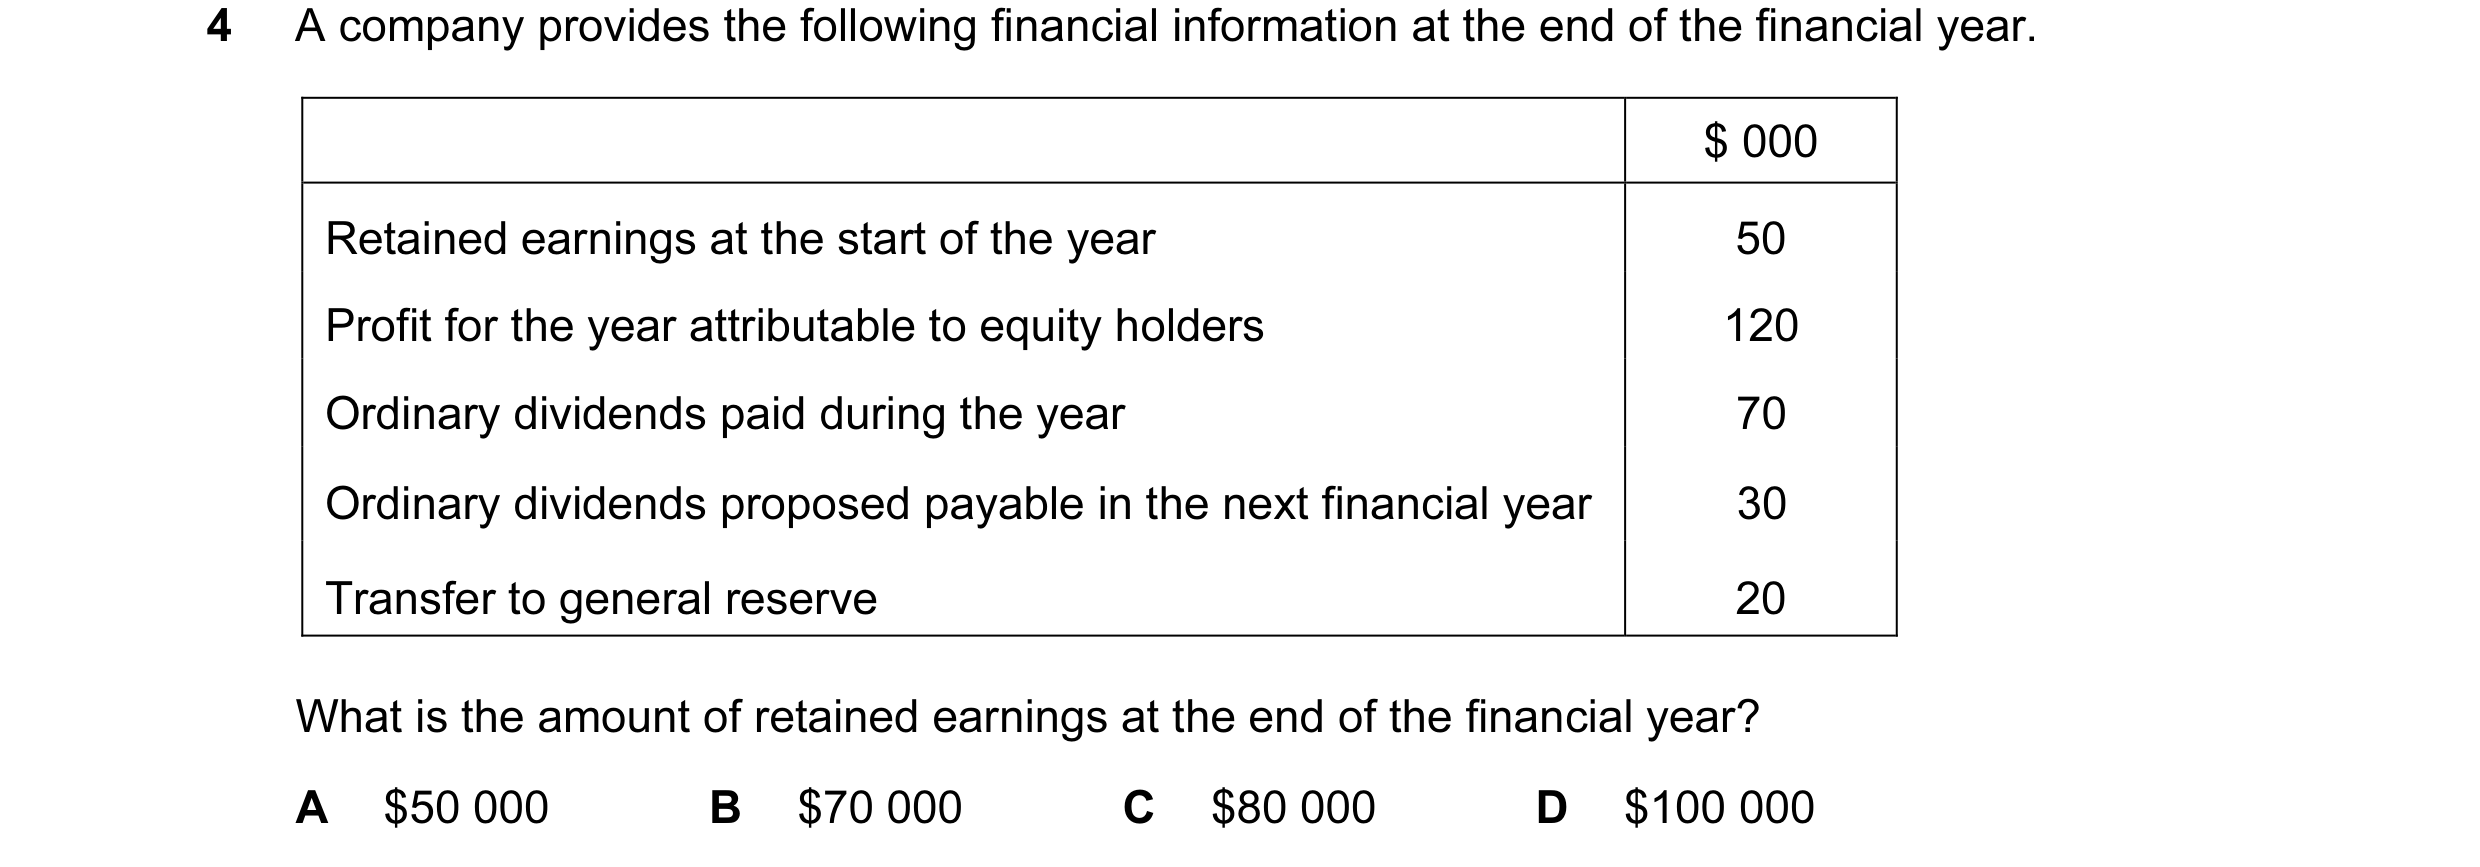 28 / 62
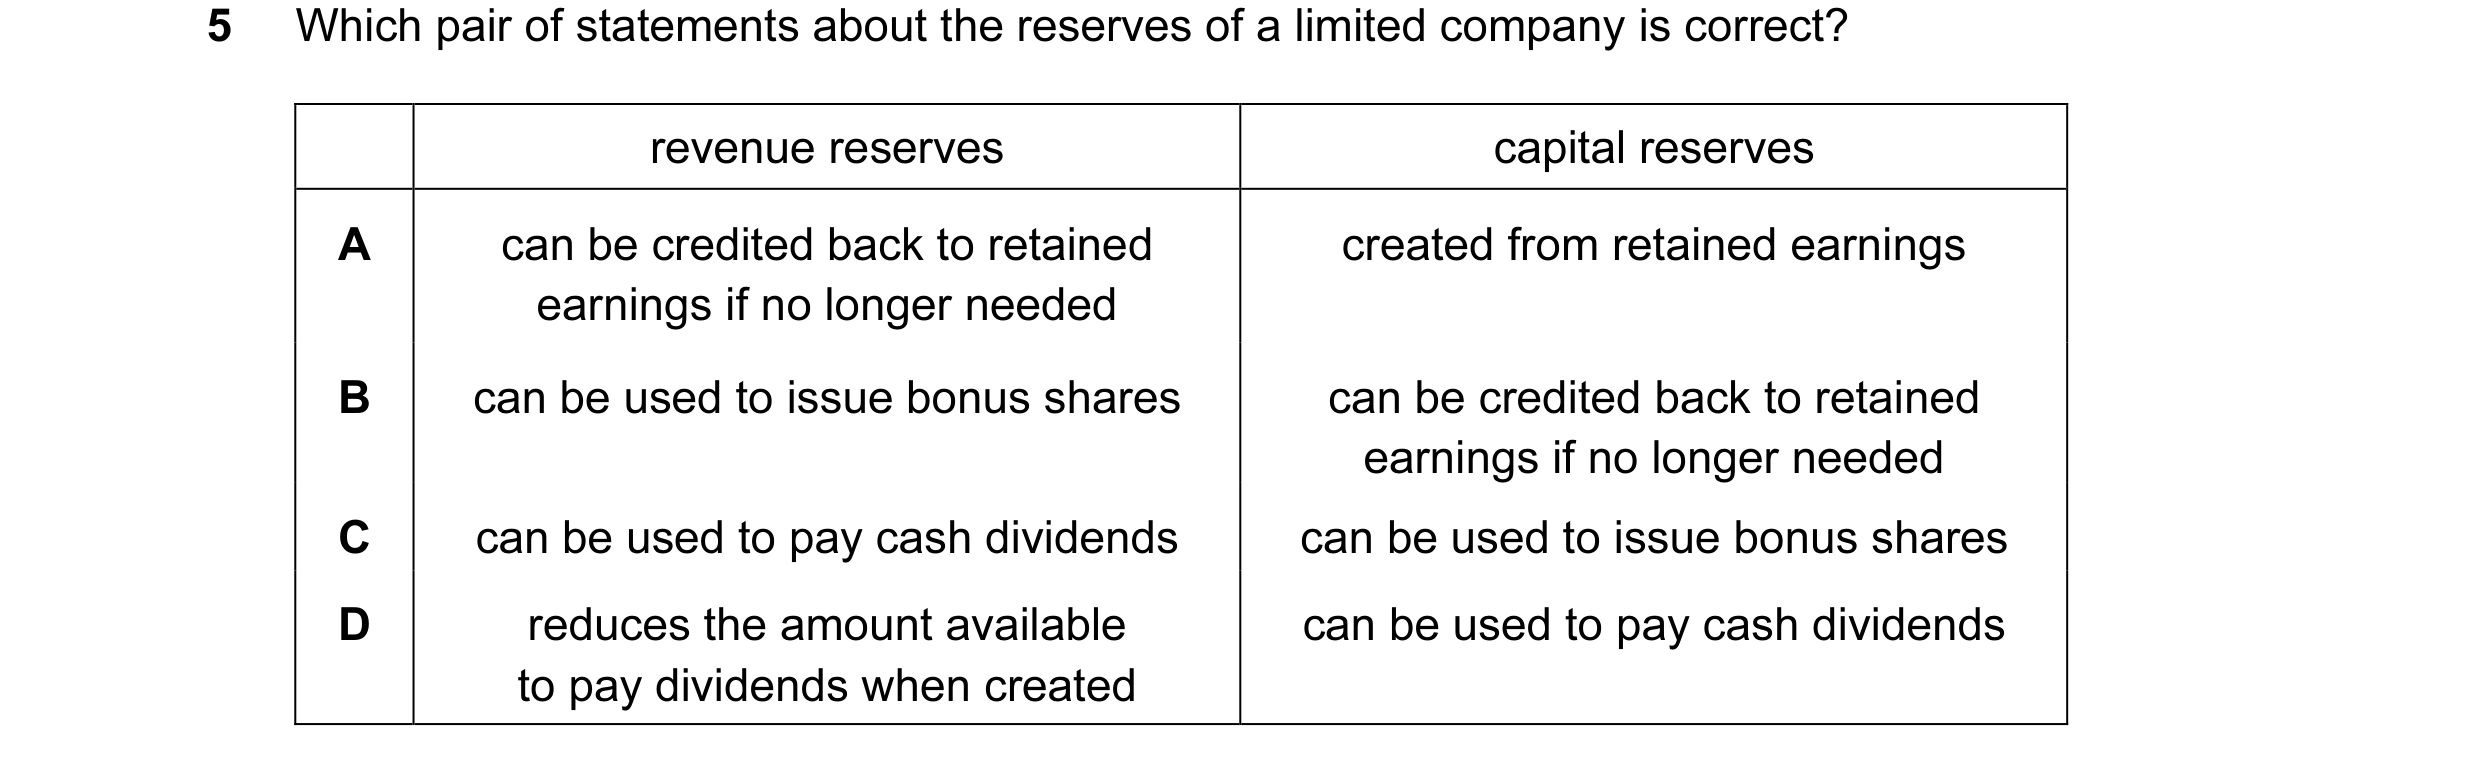
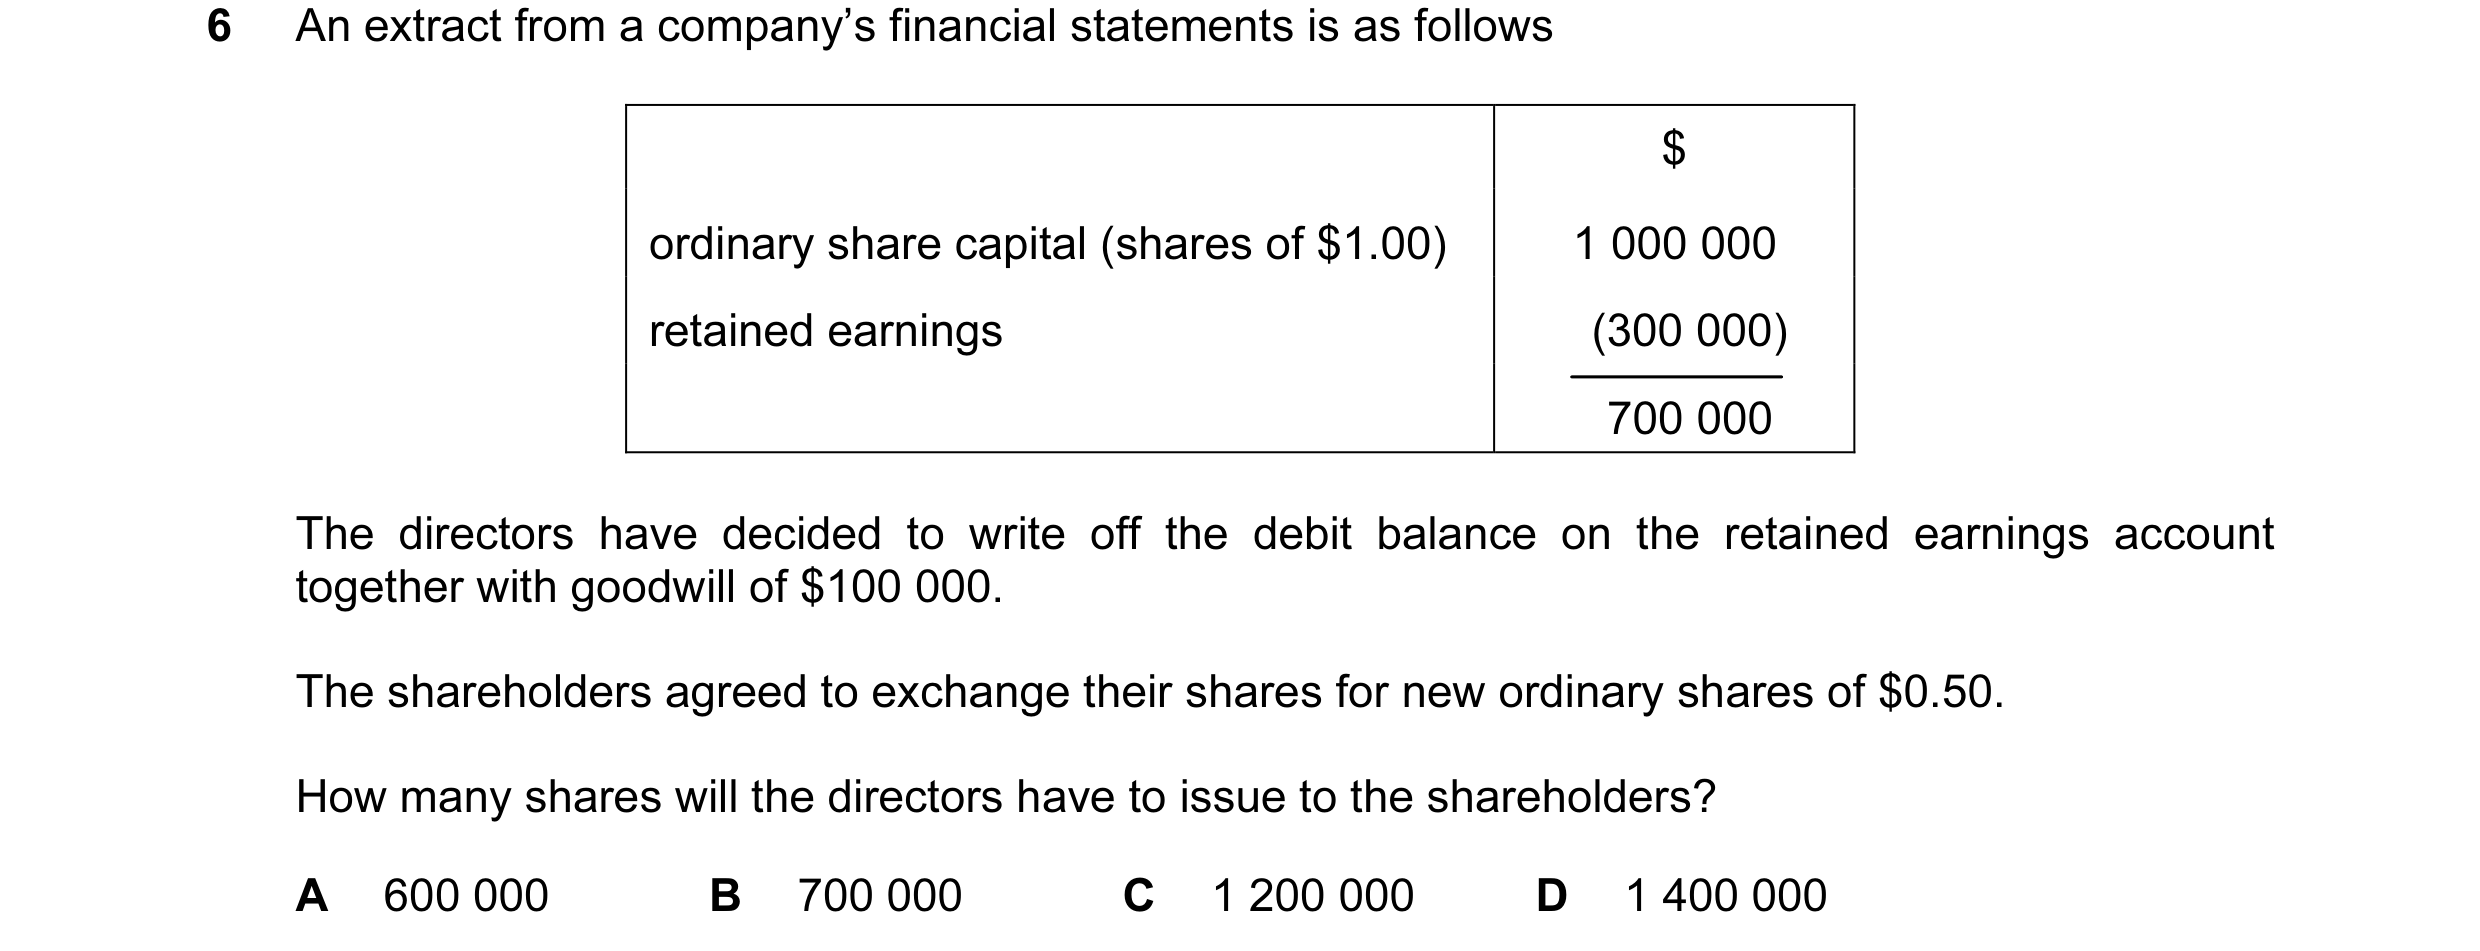
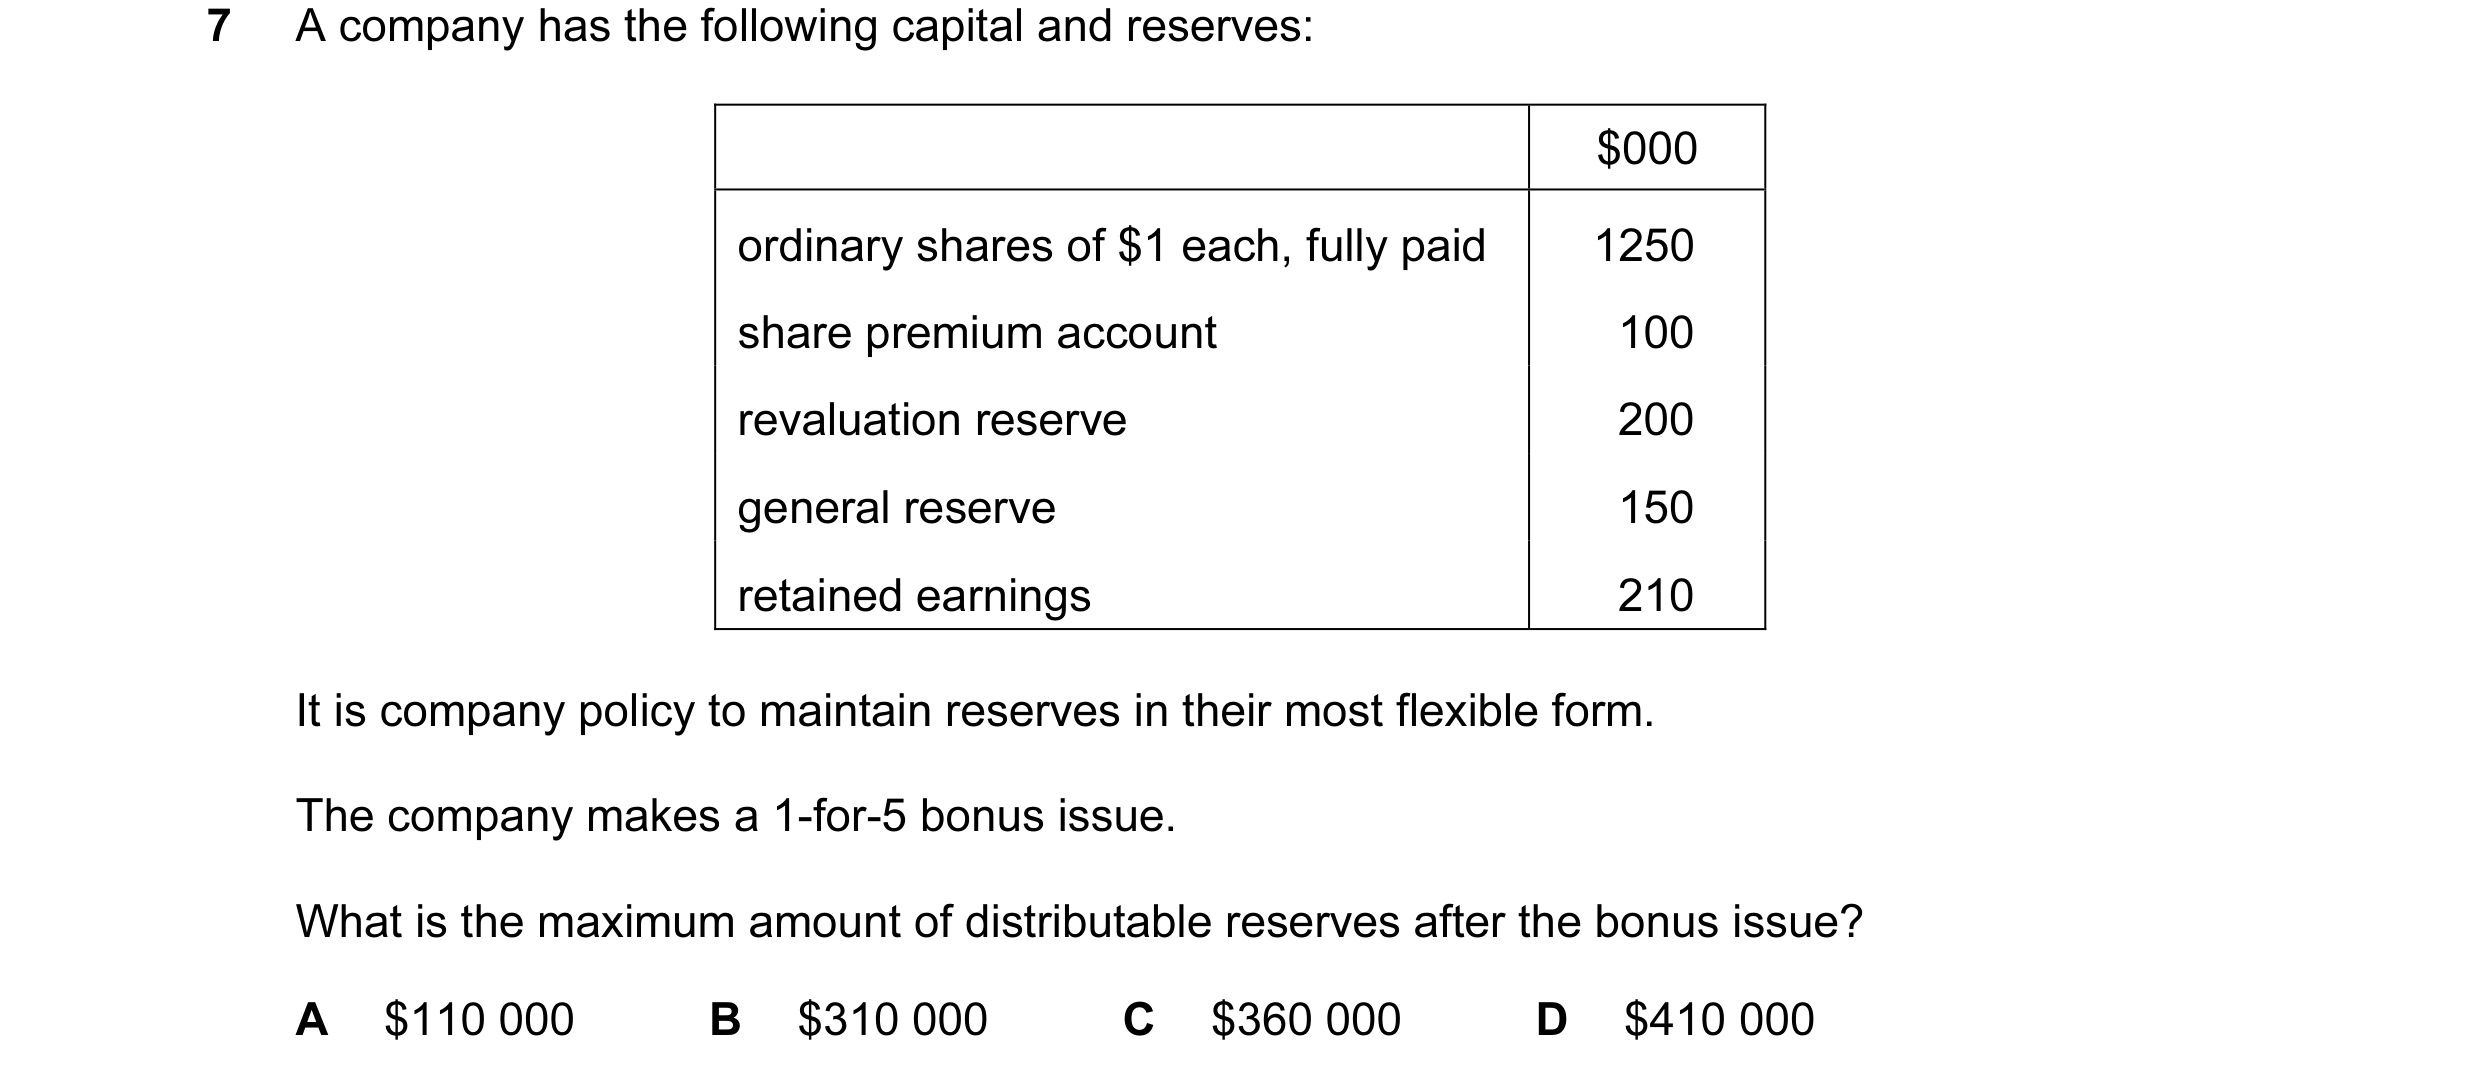 29 / 62
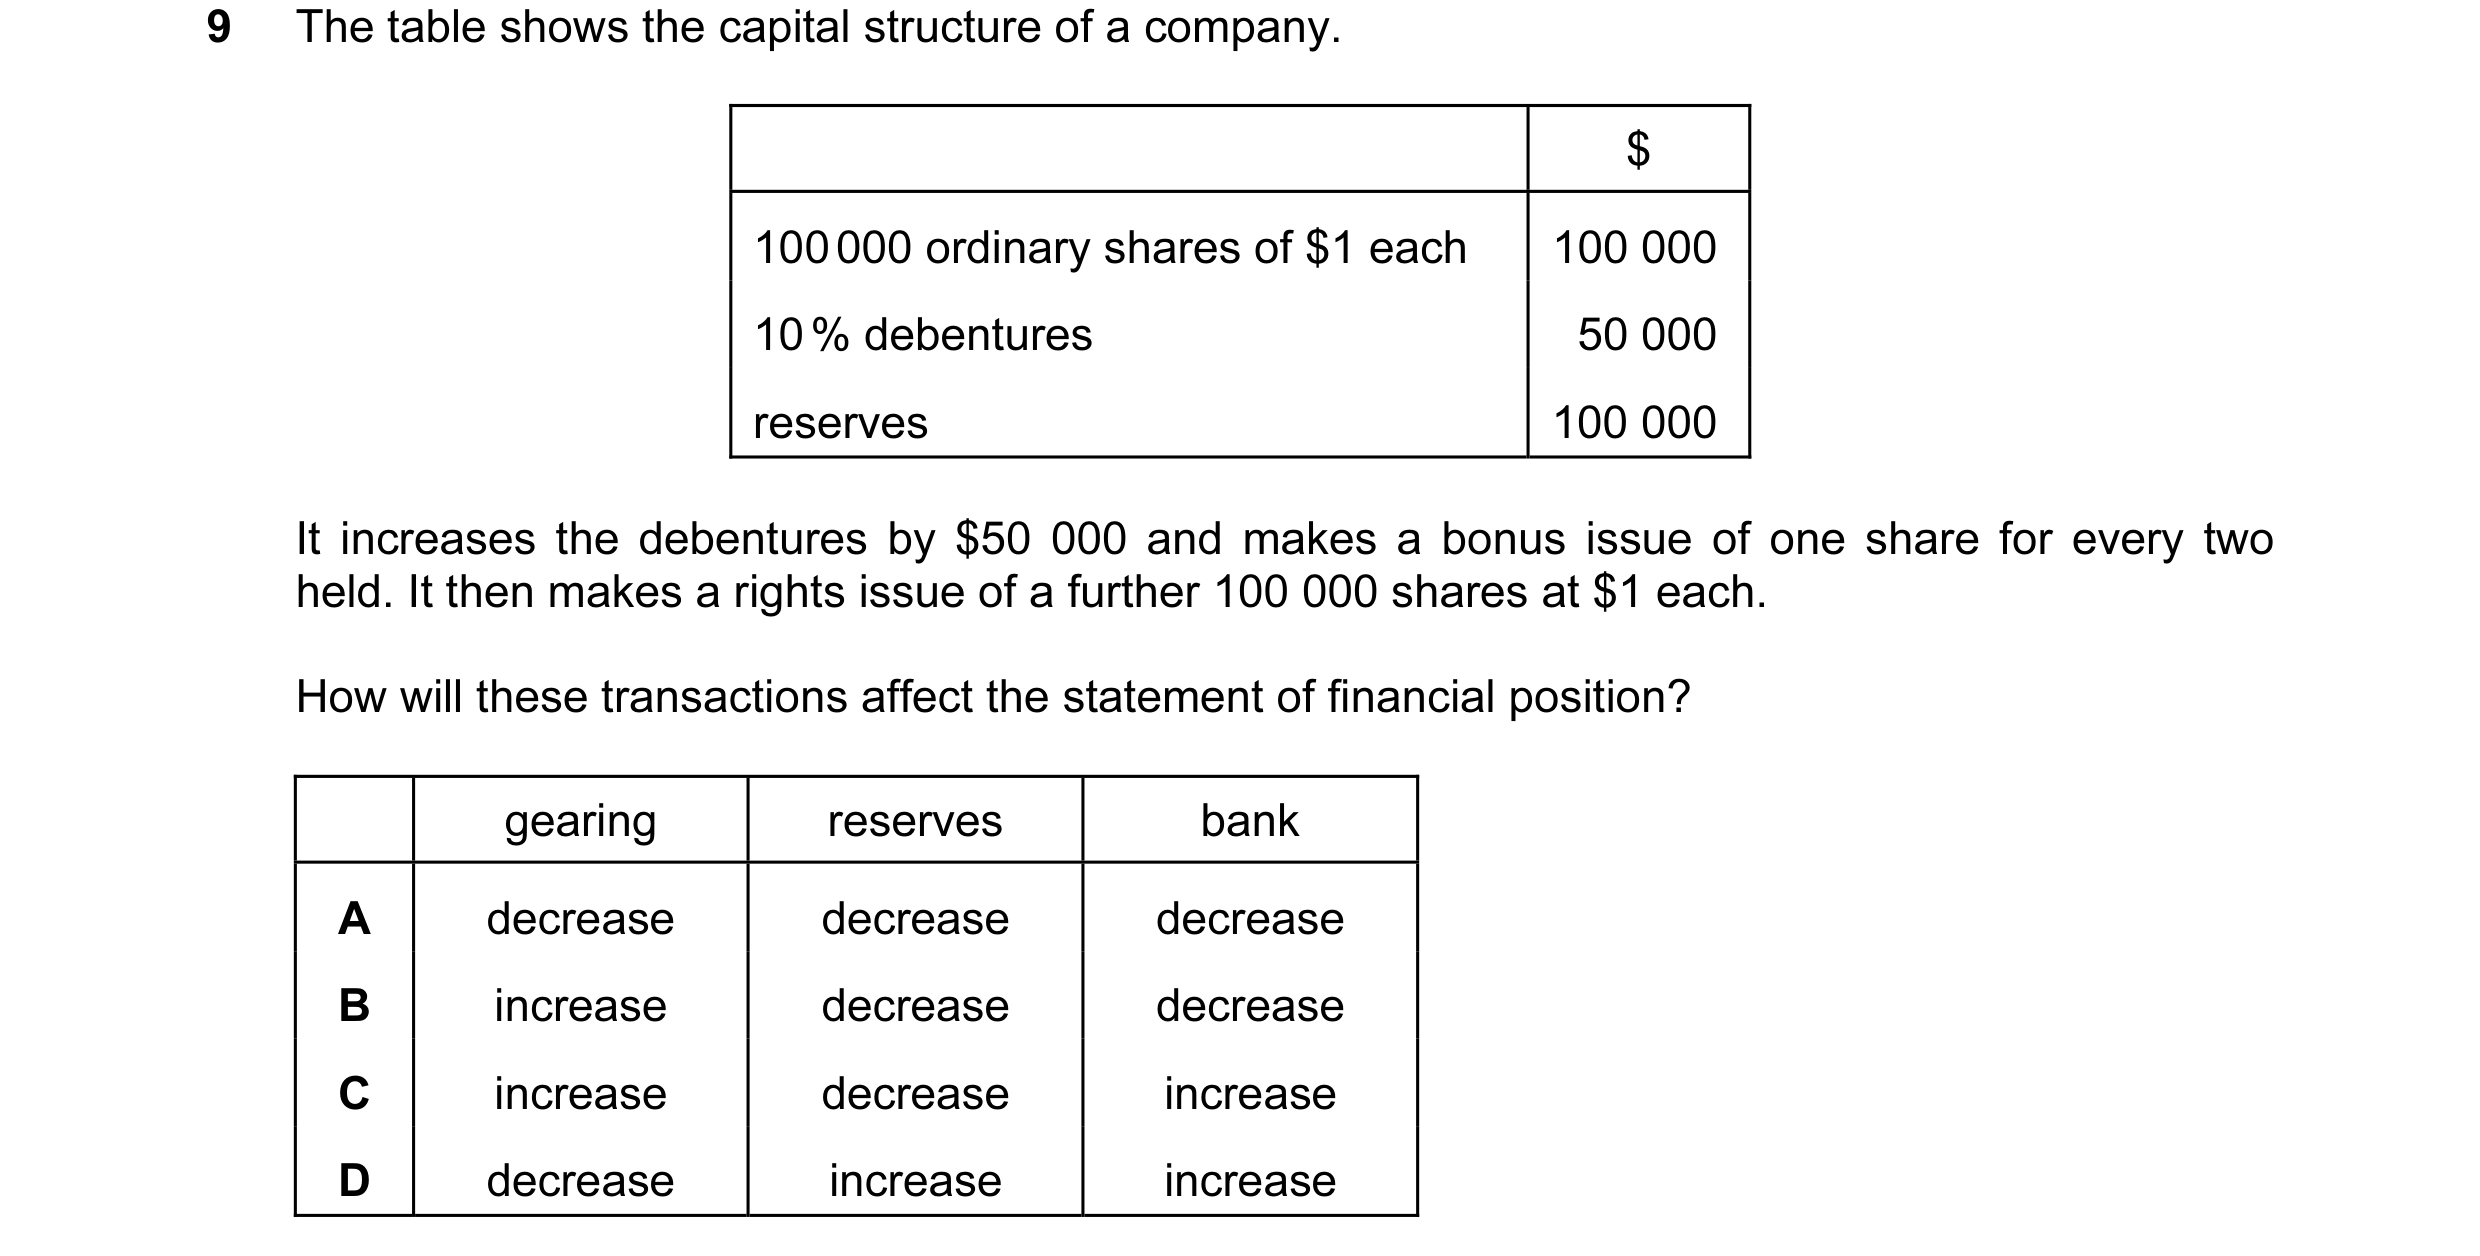
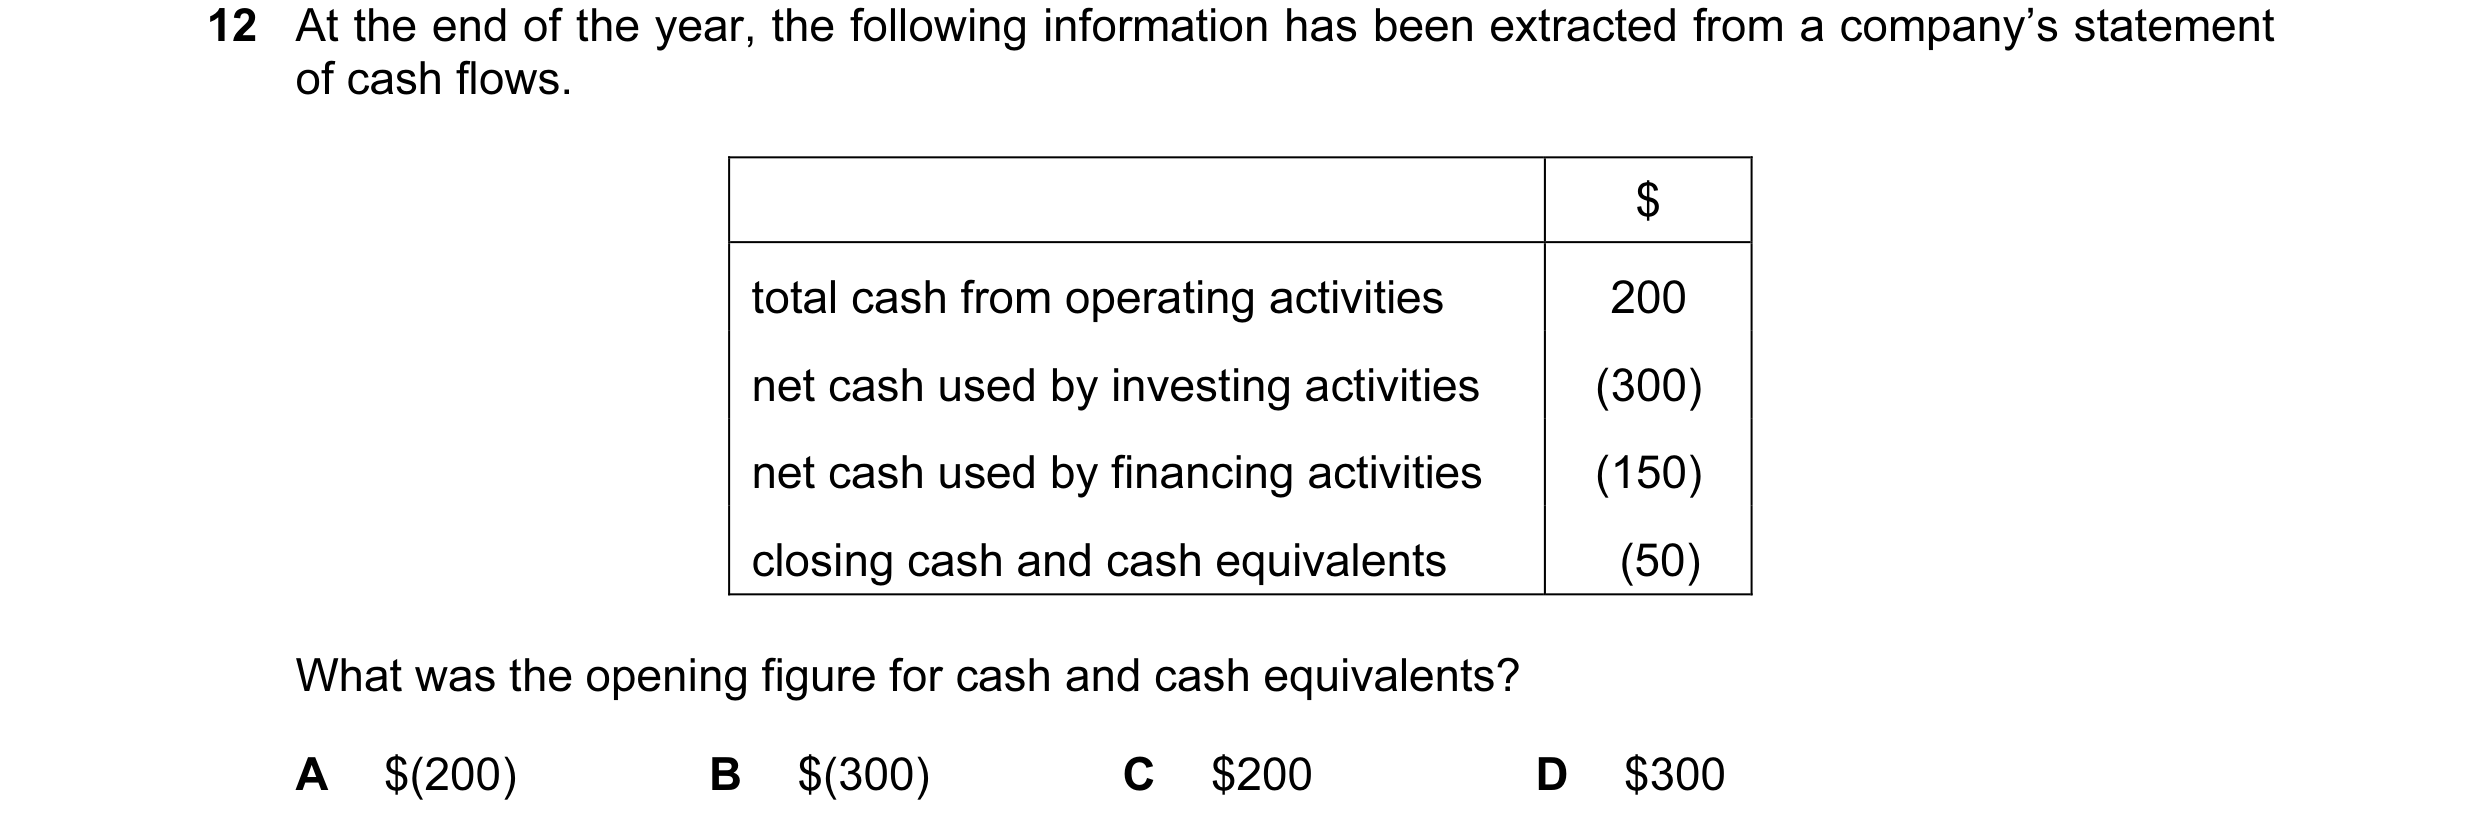
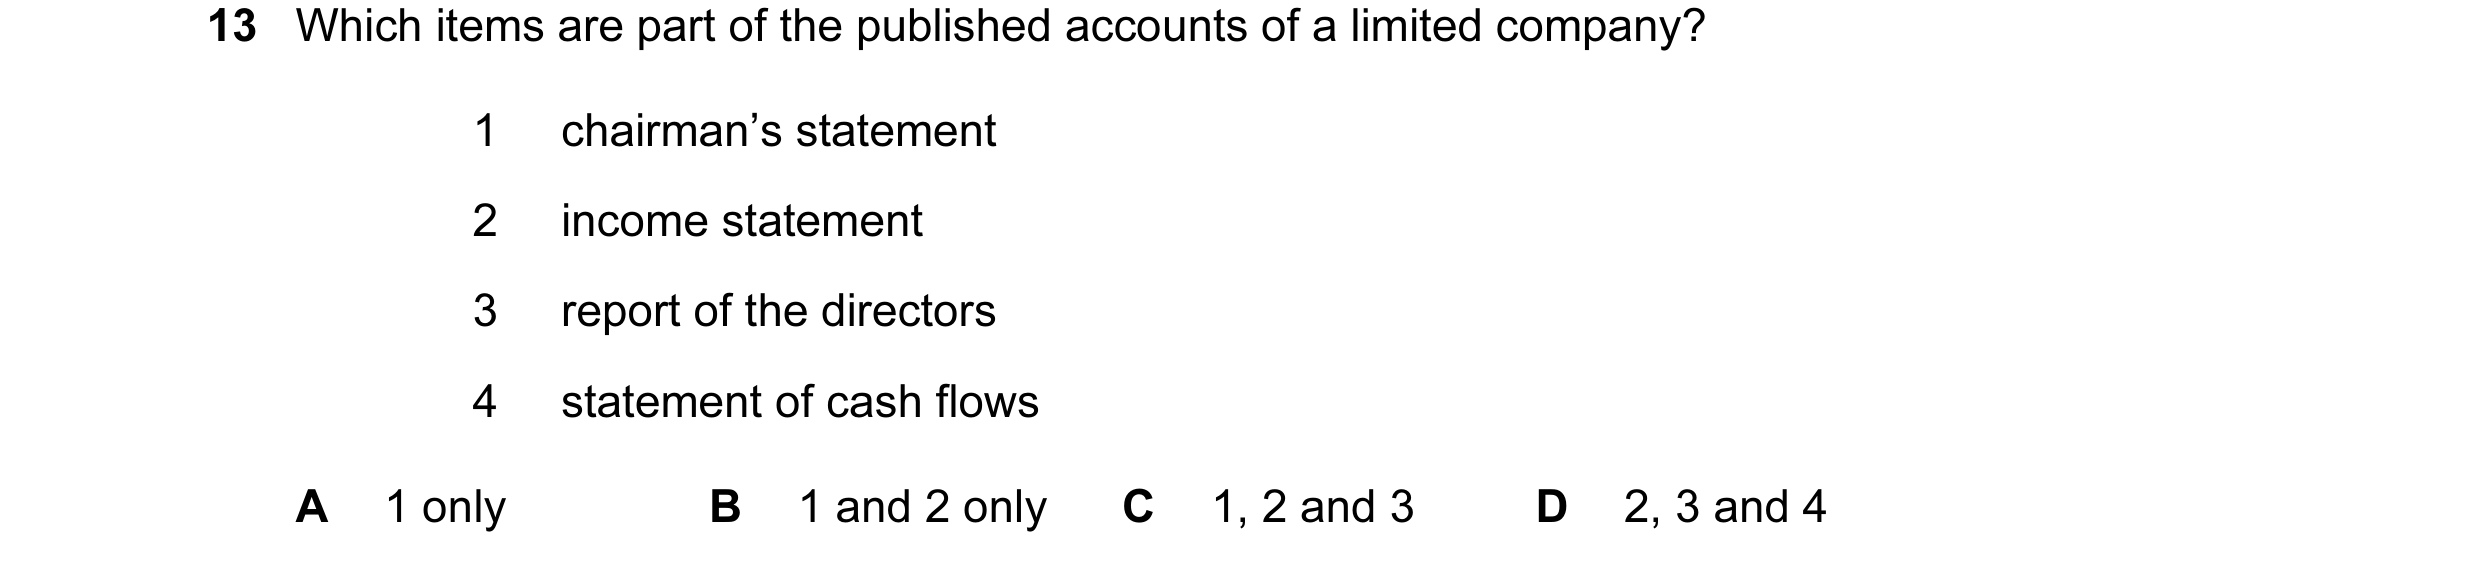
 30 / 62
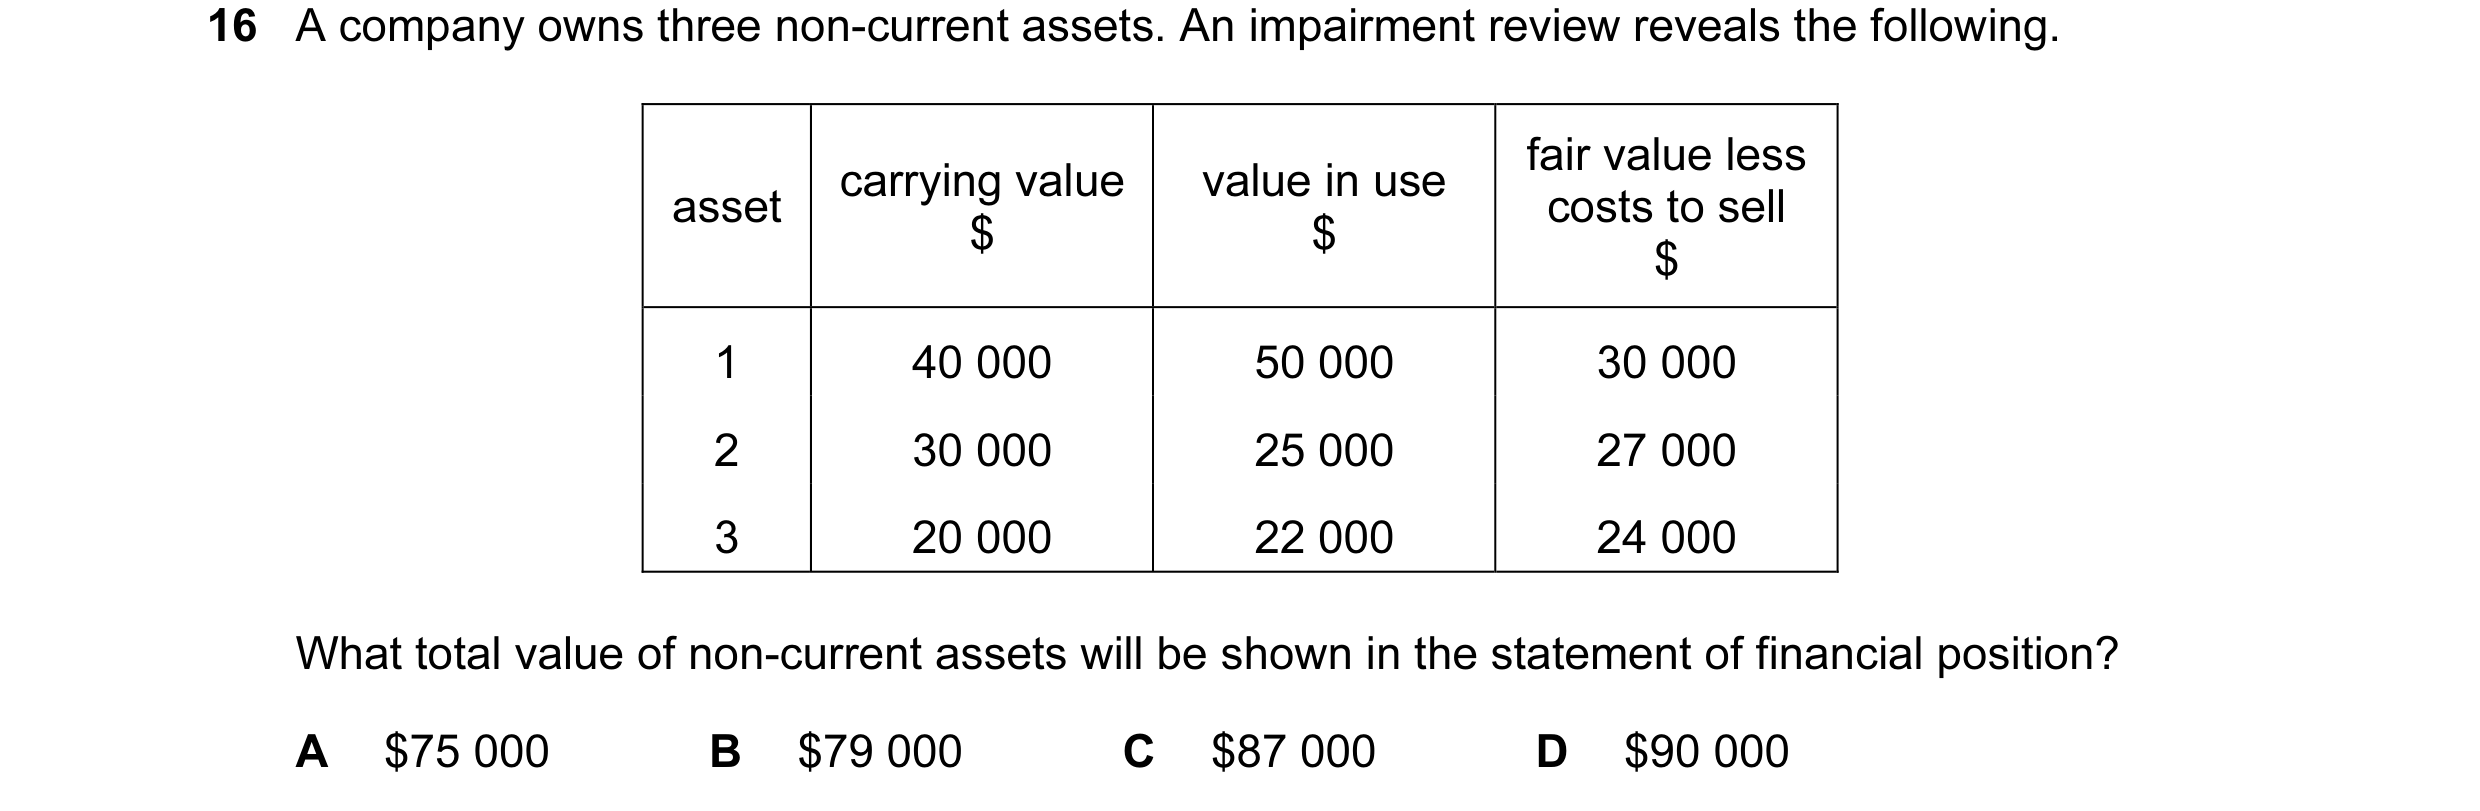
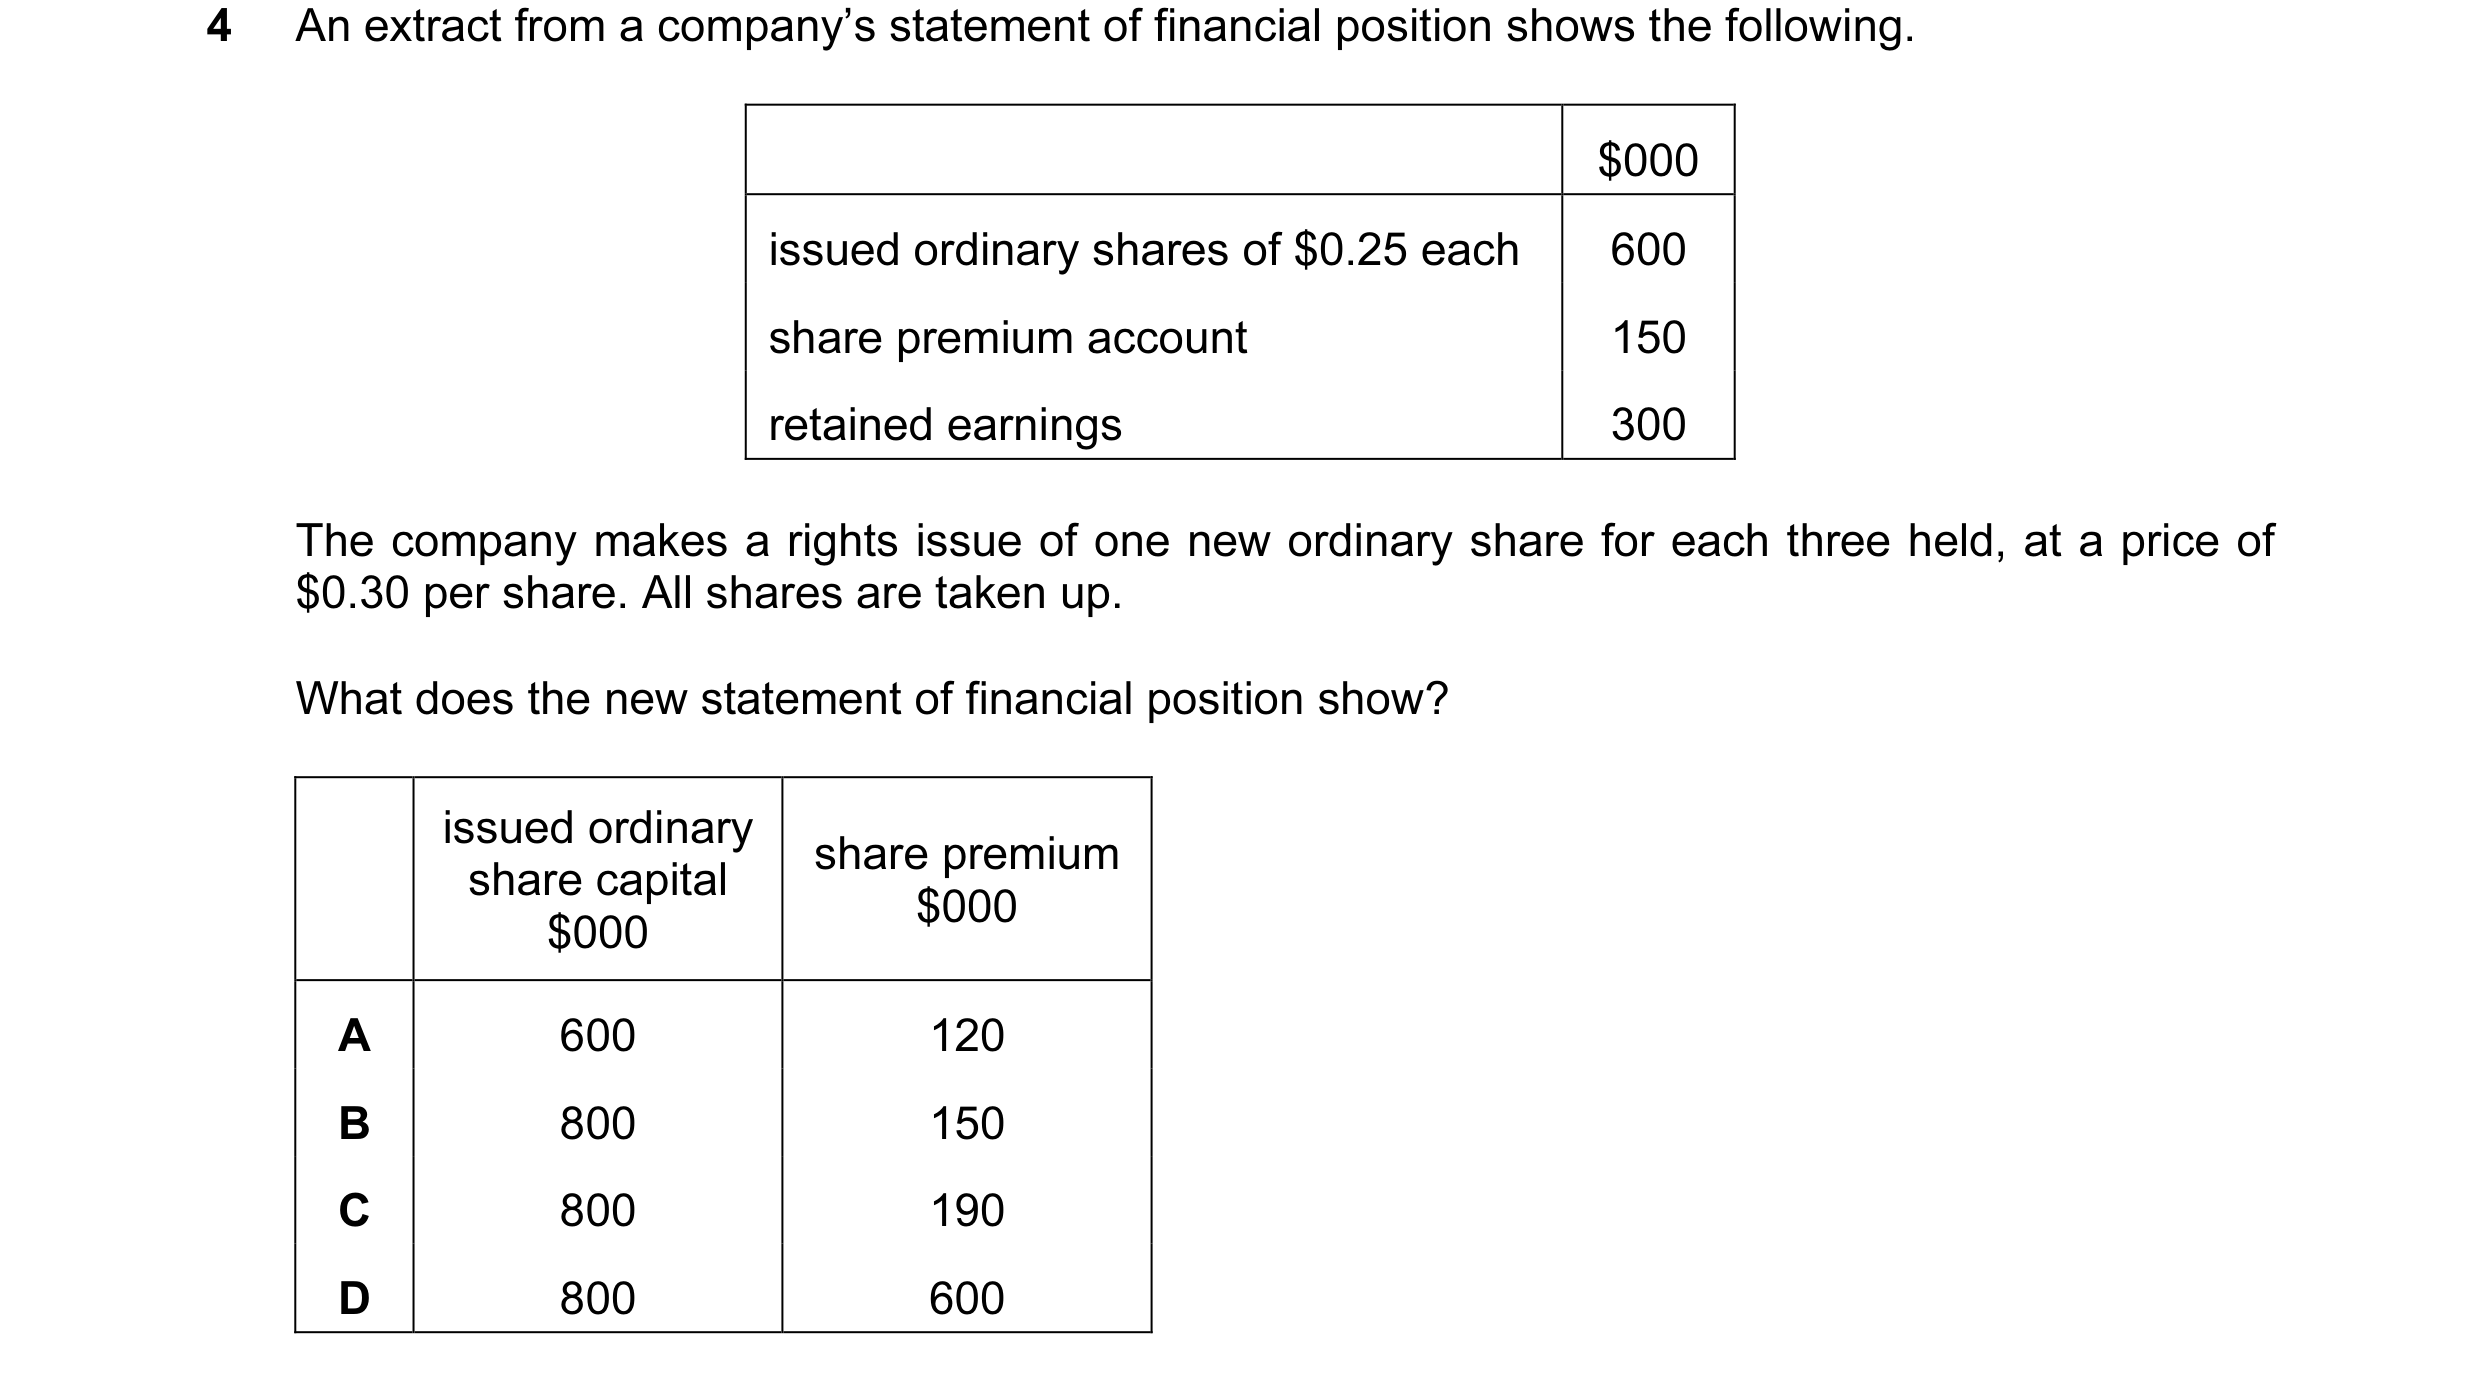
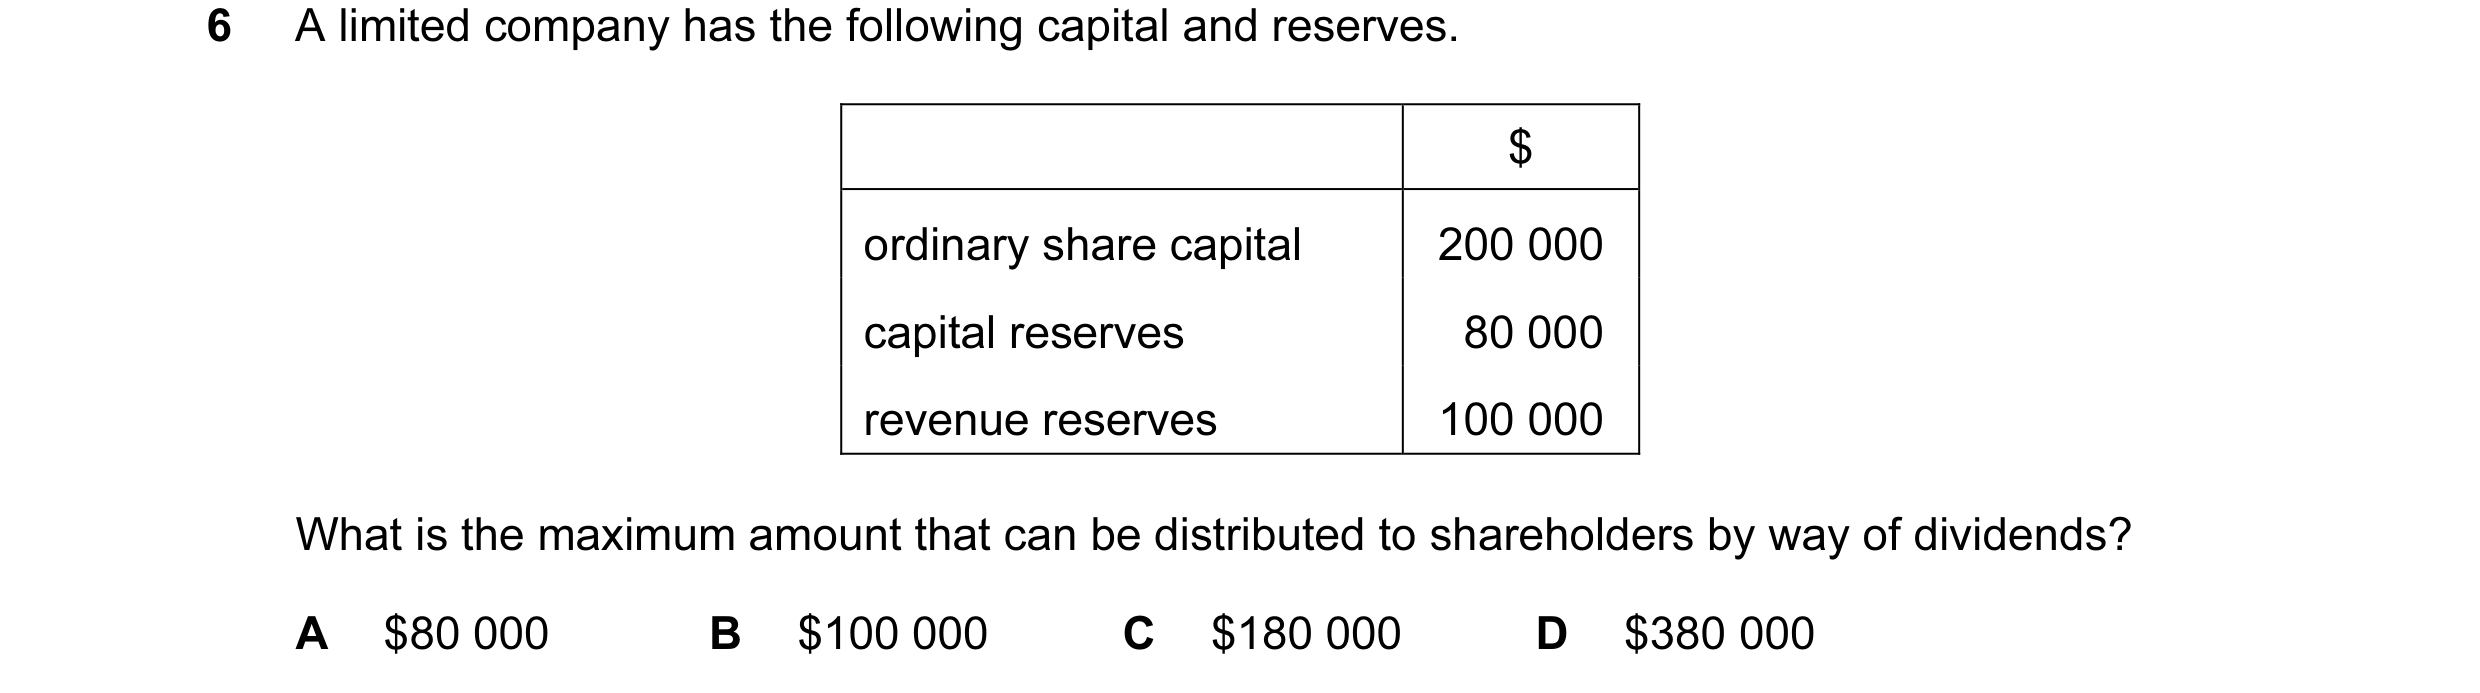 31 / 62
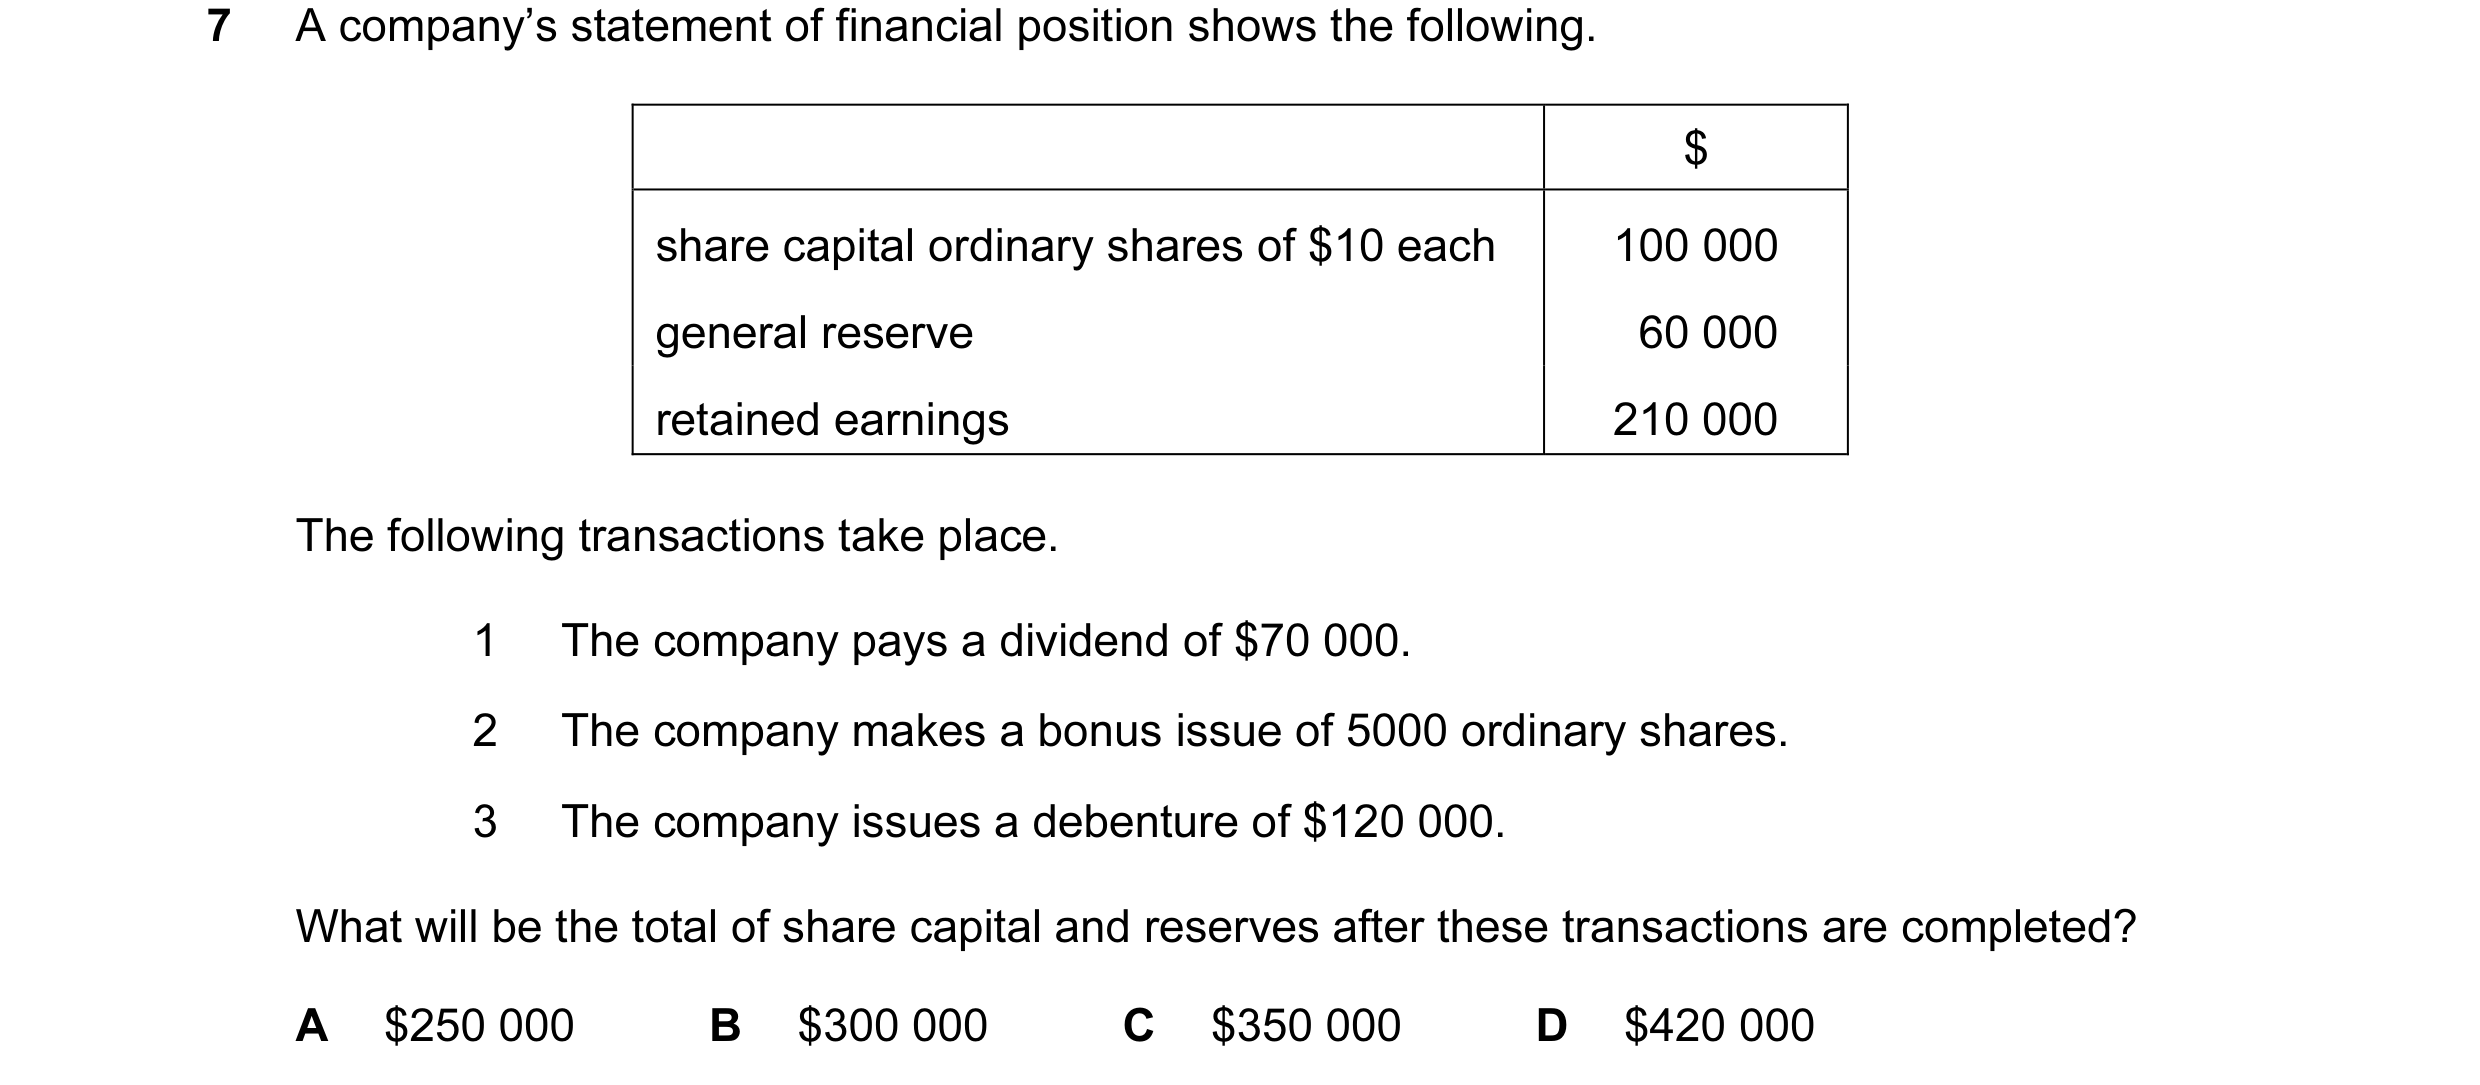
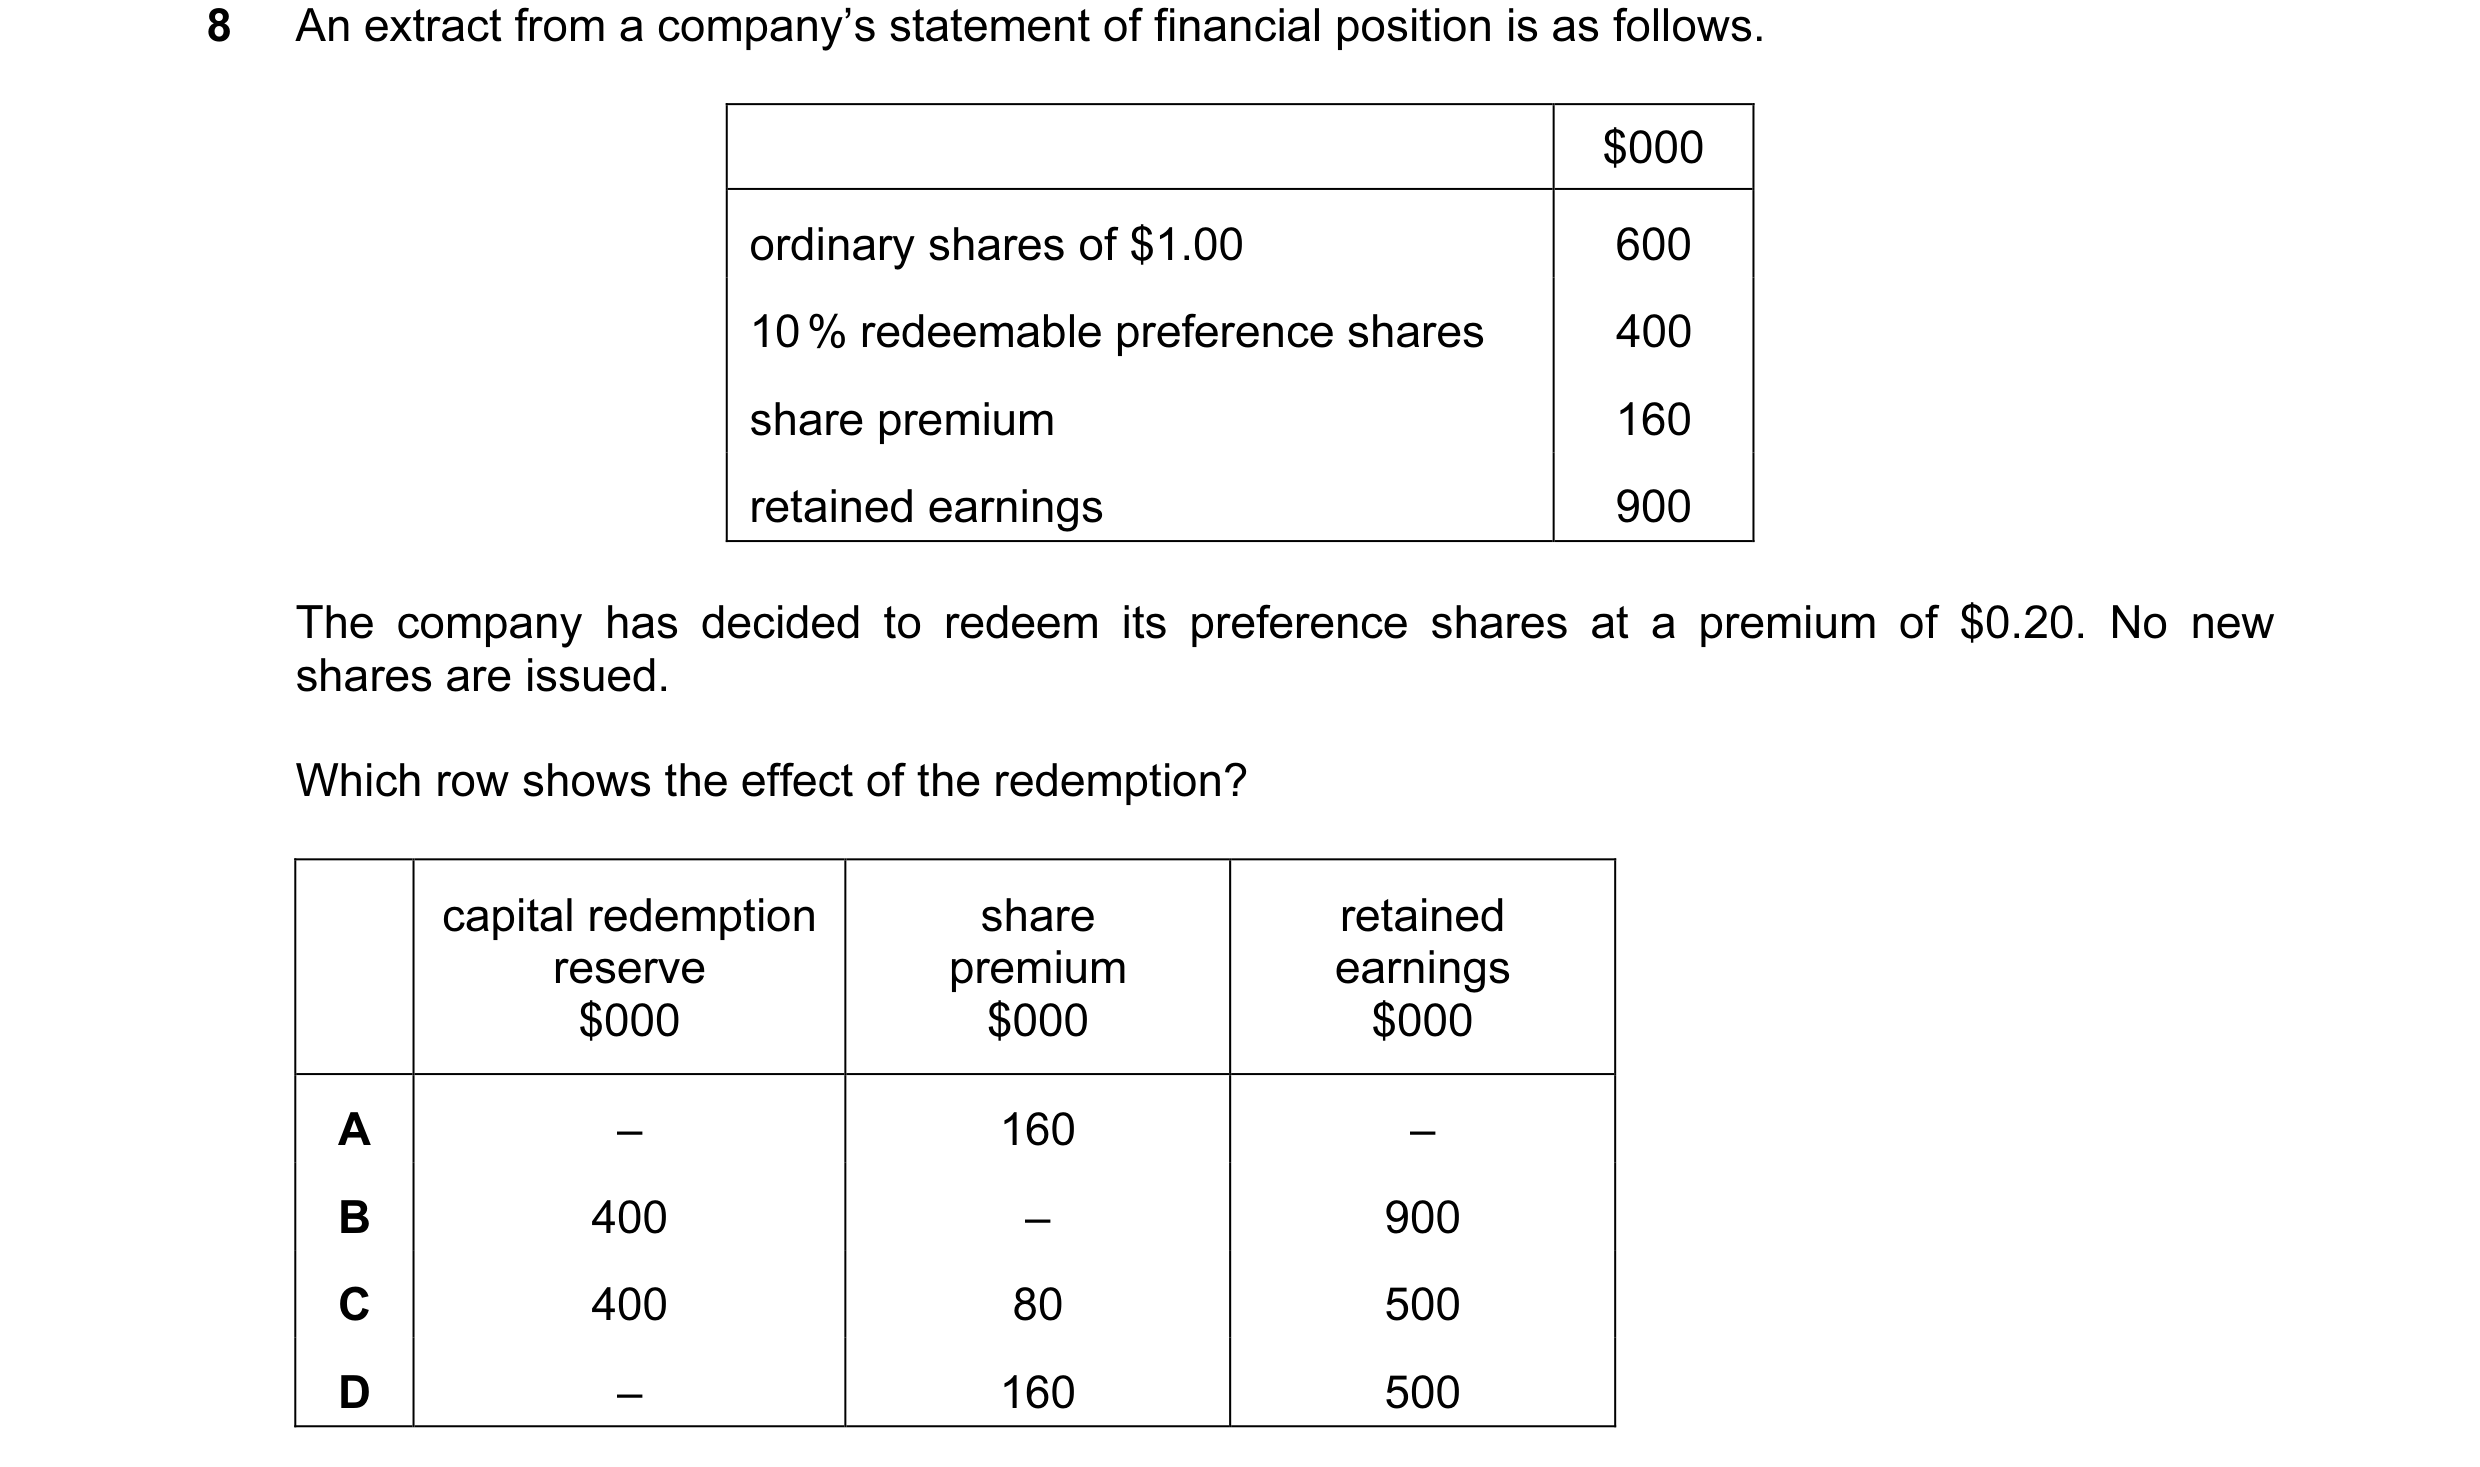
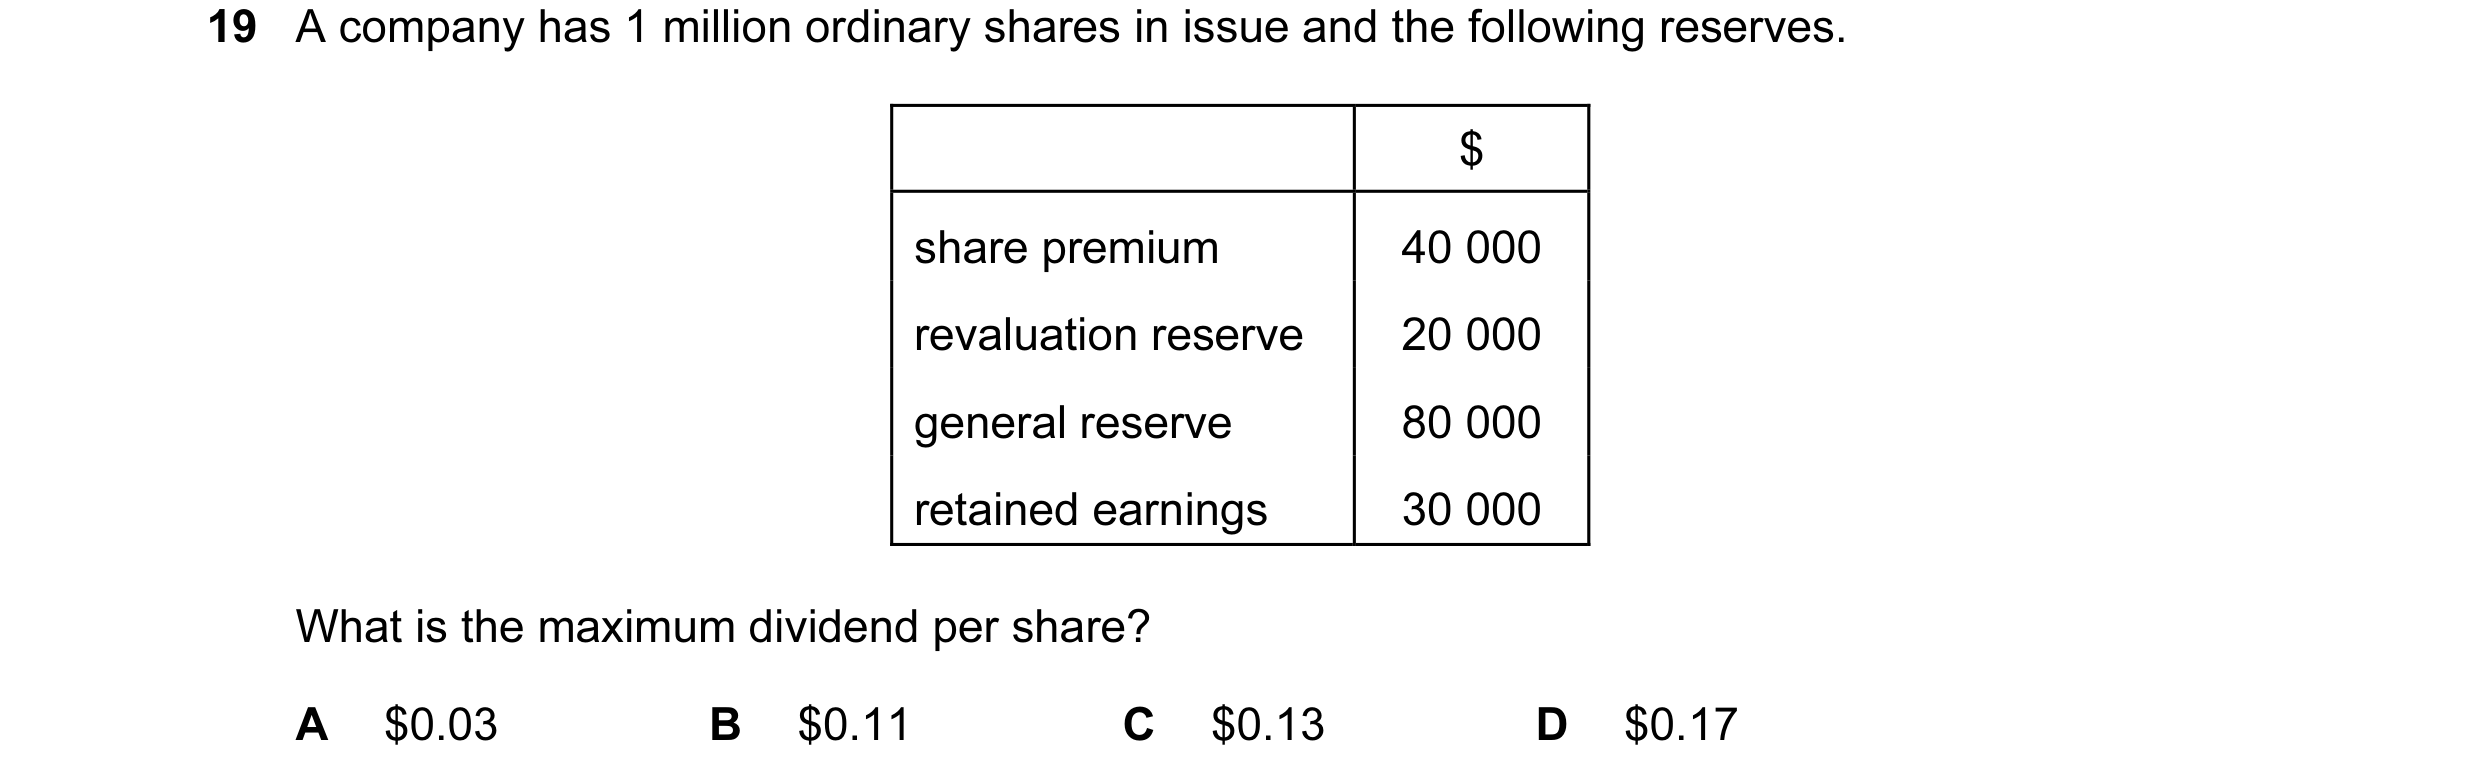 32 / 62
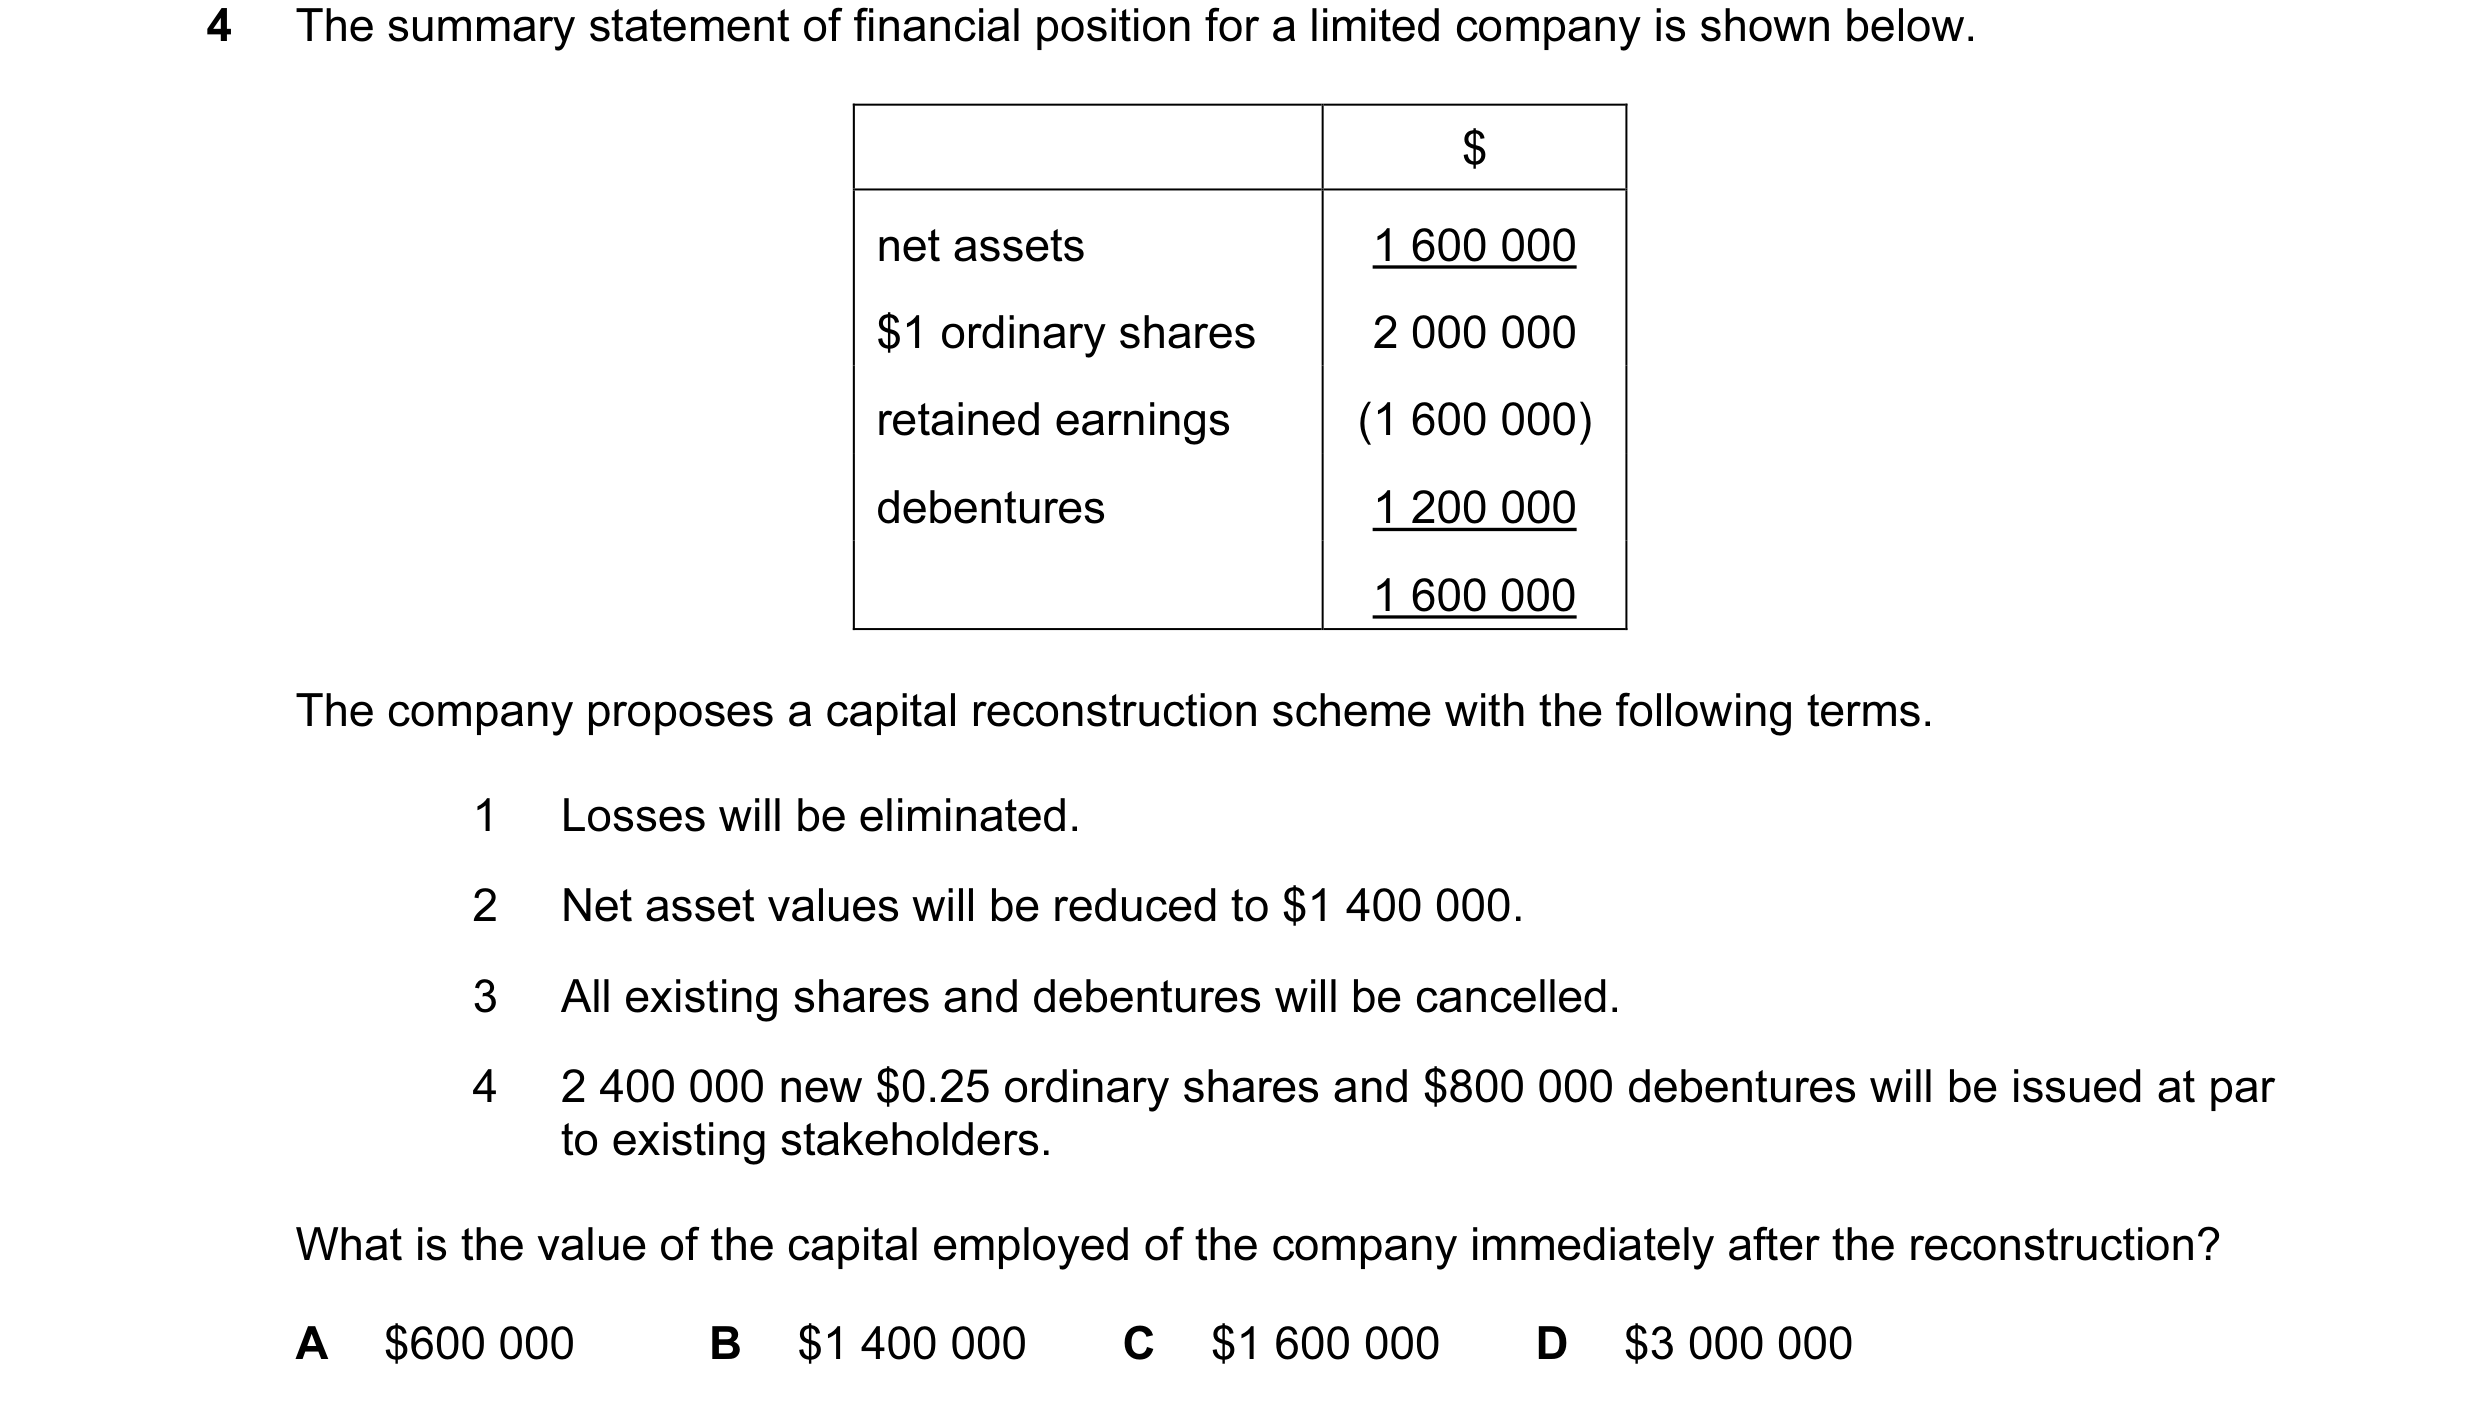
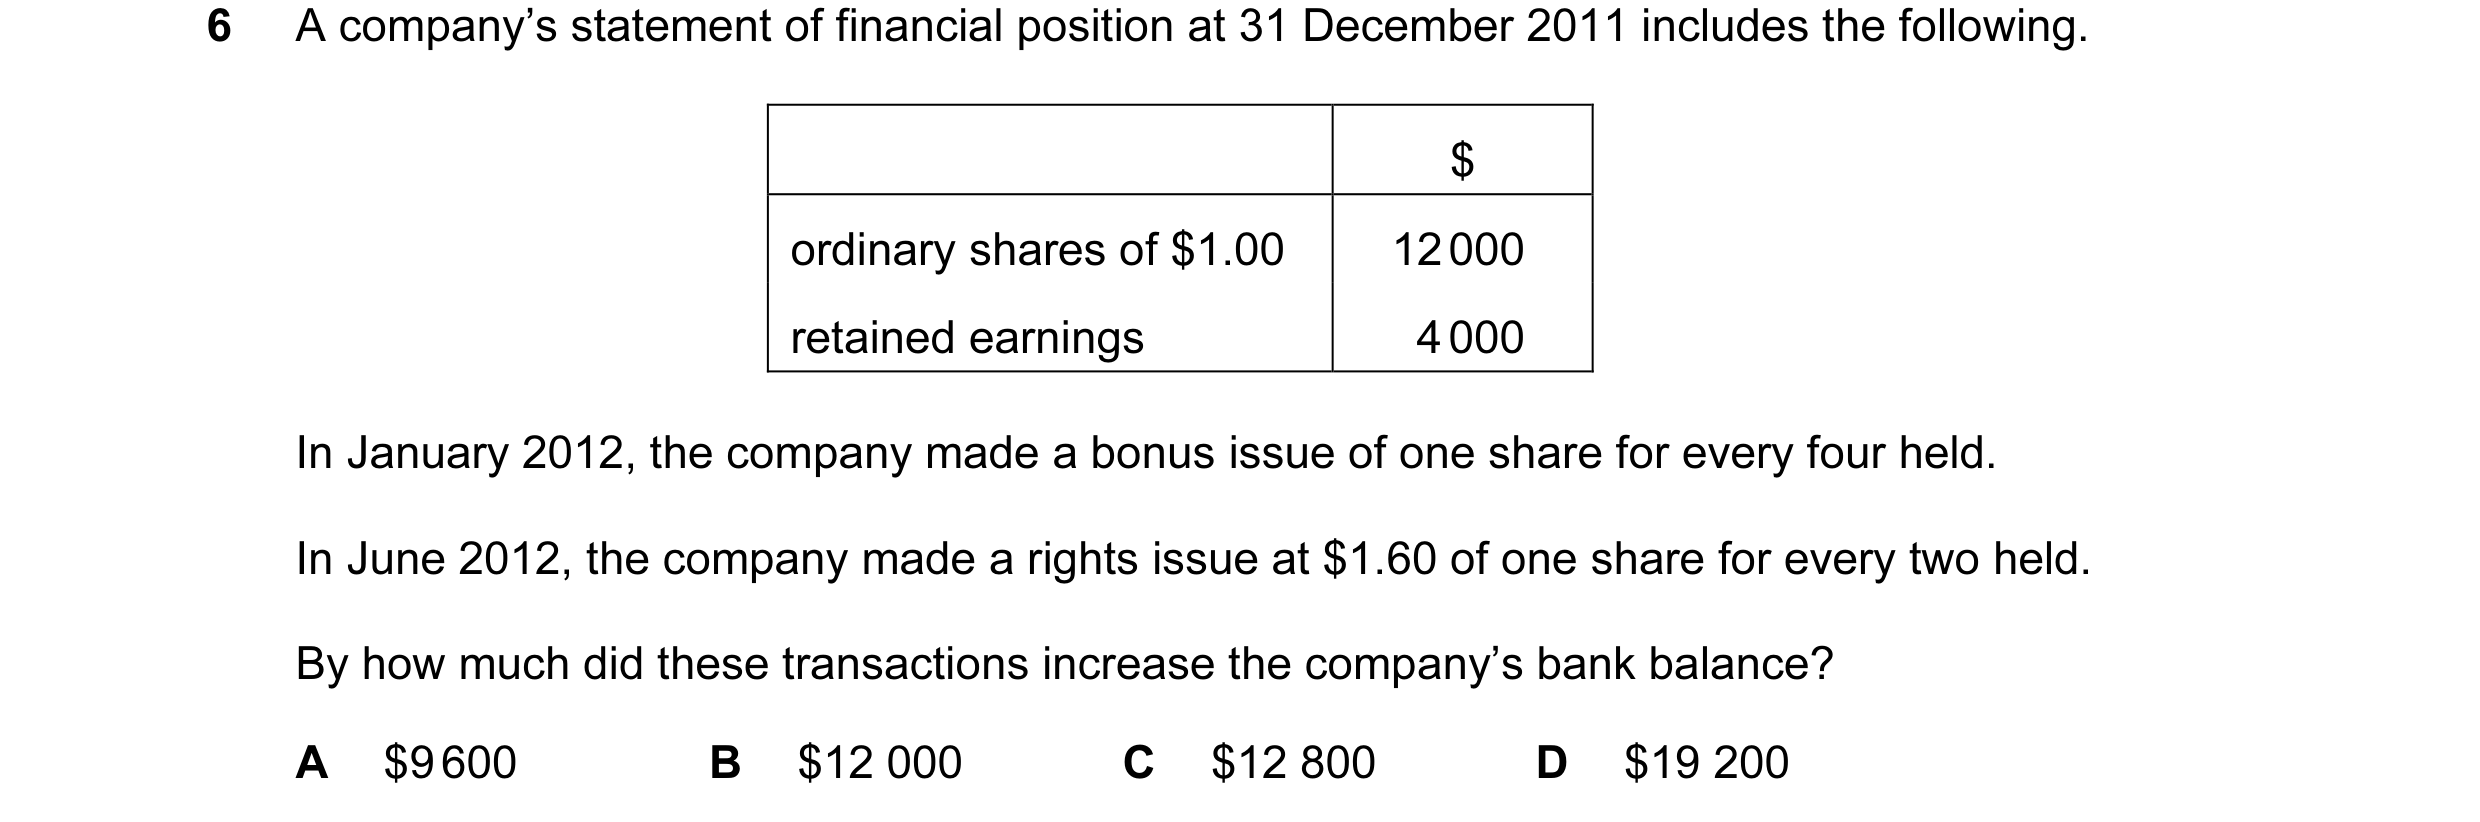 33 / 62
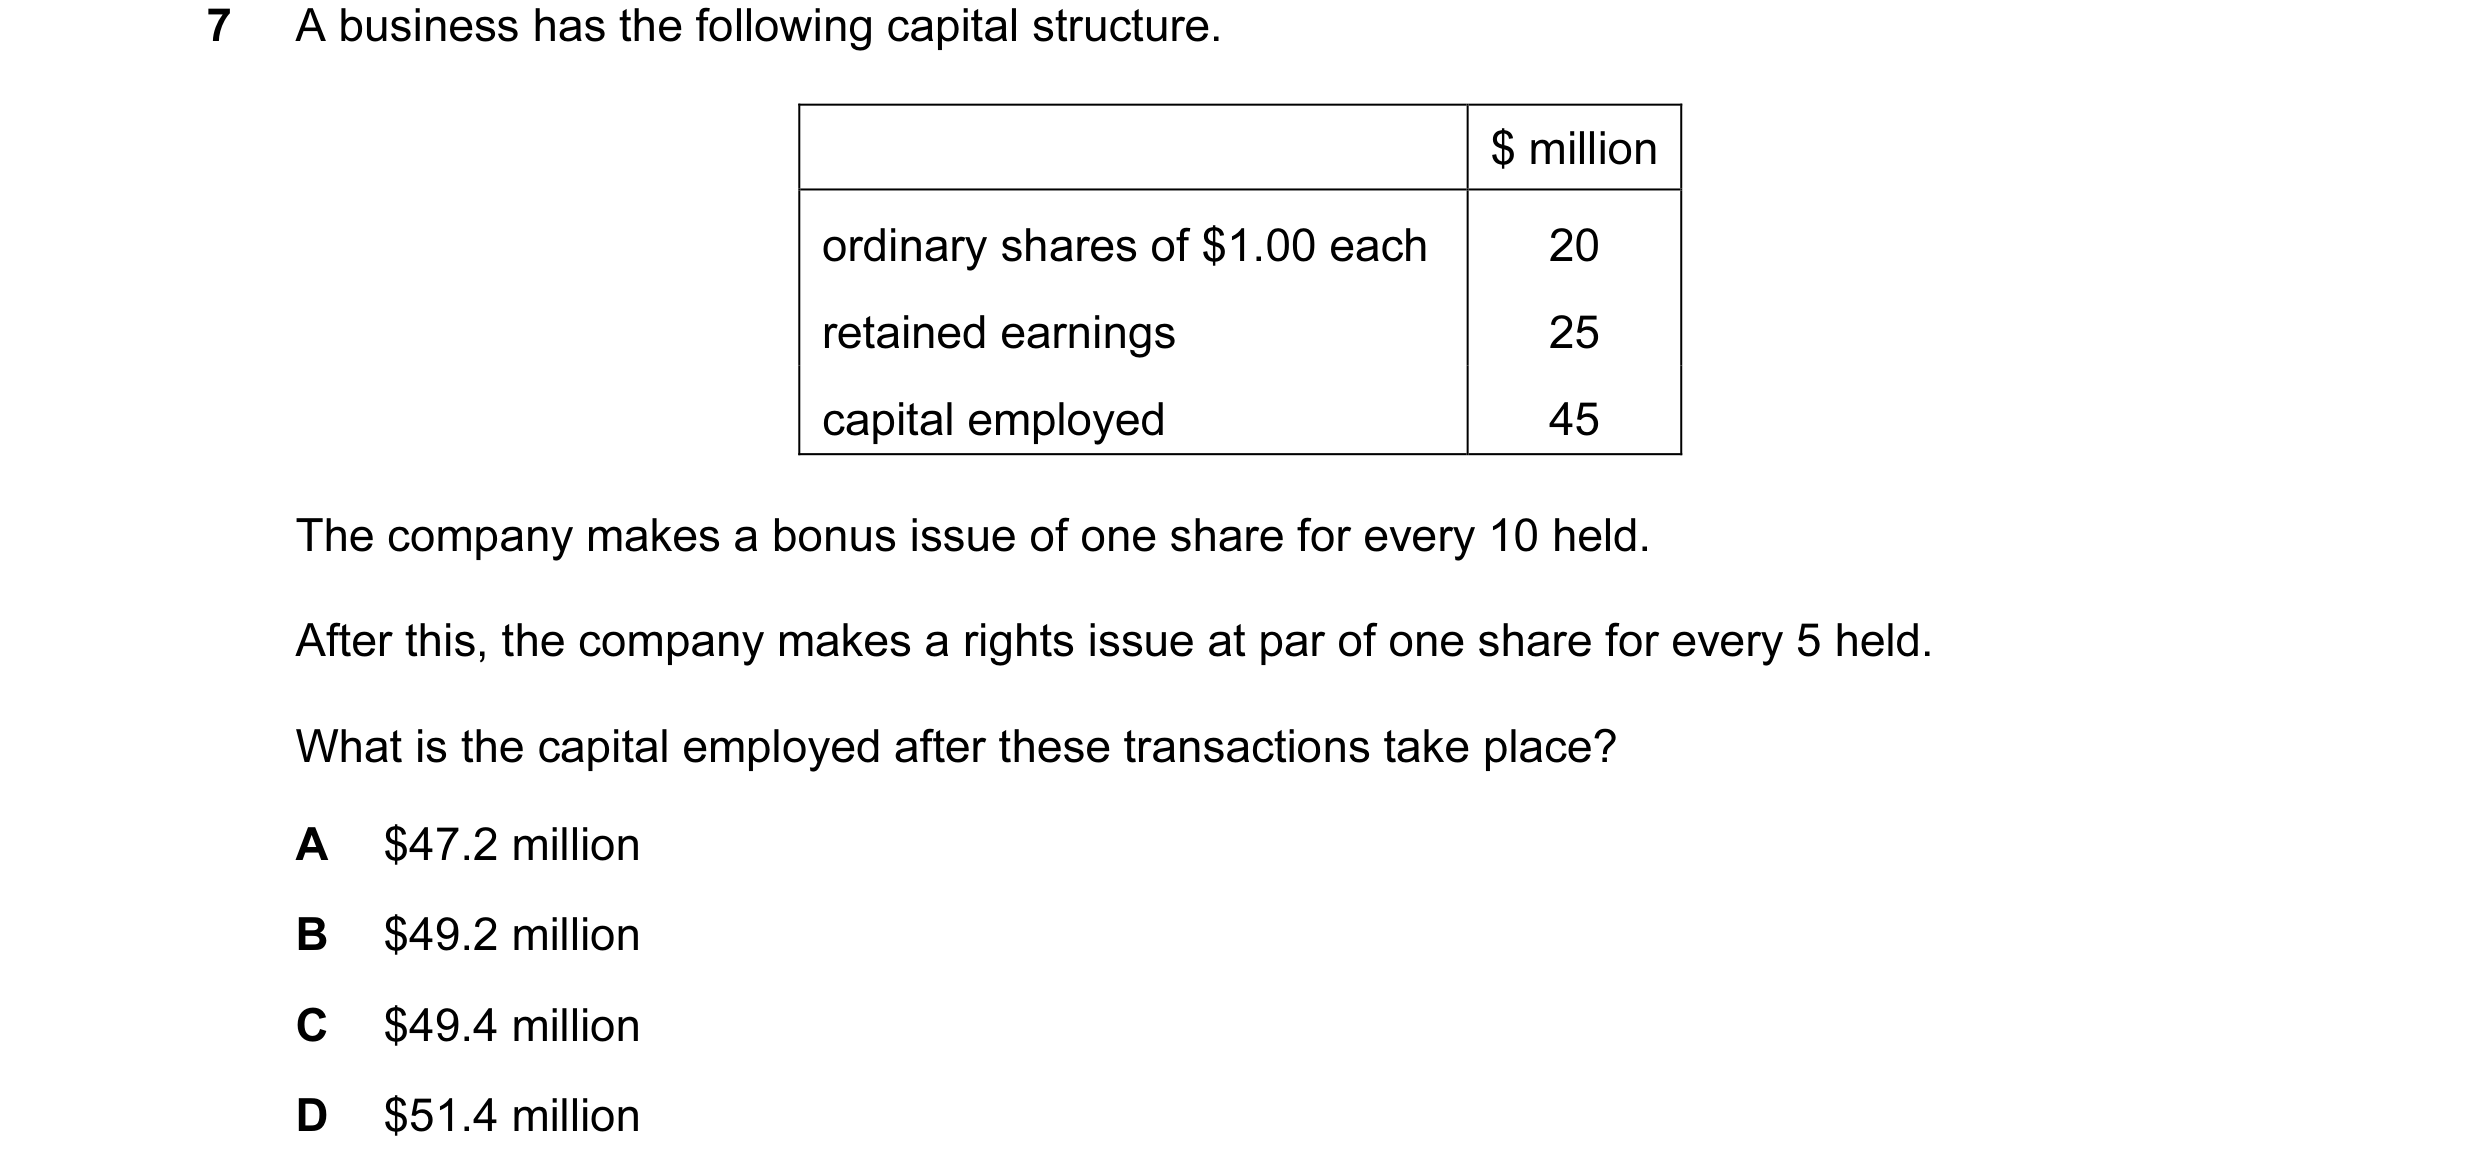
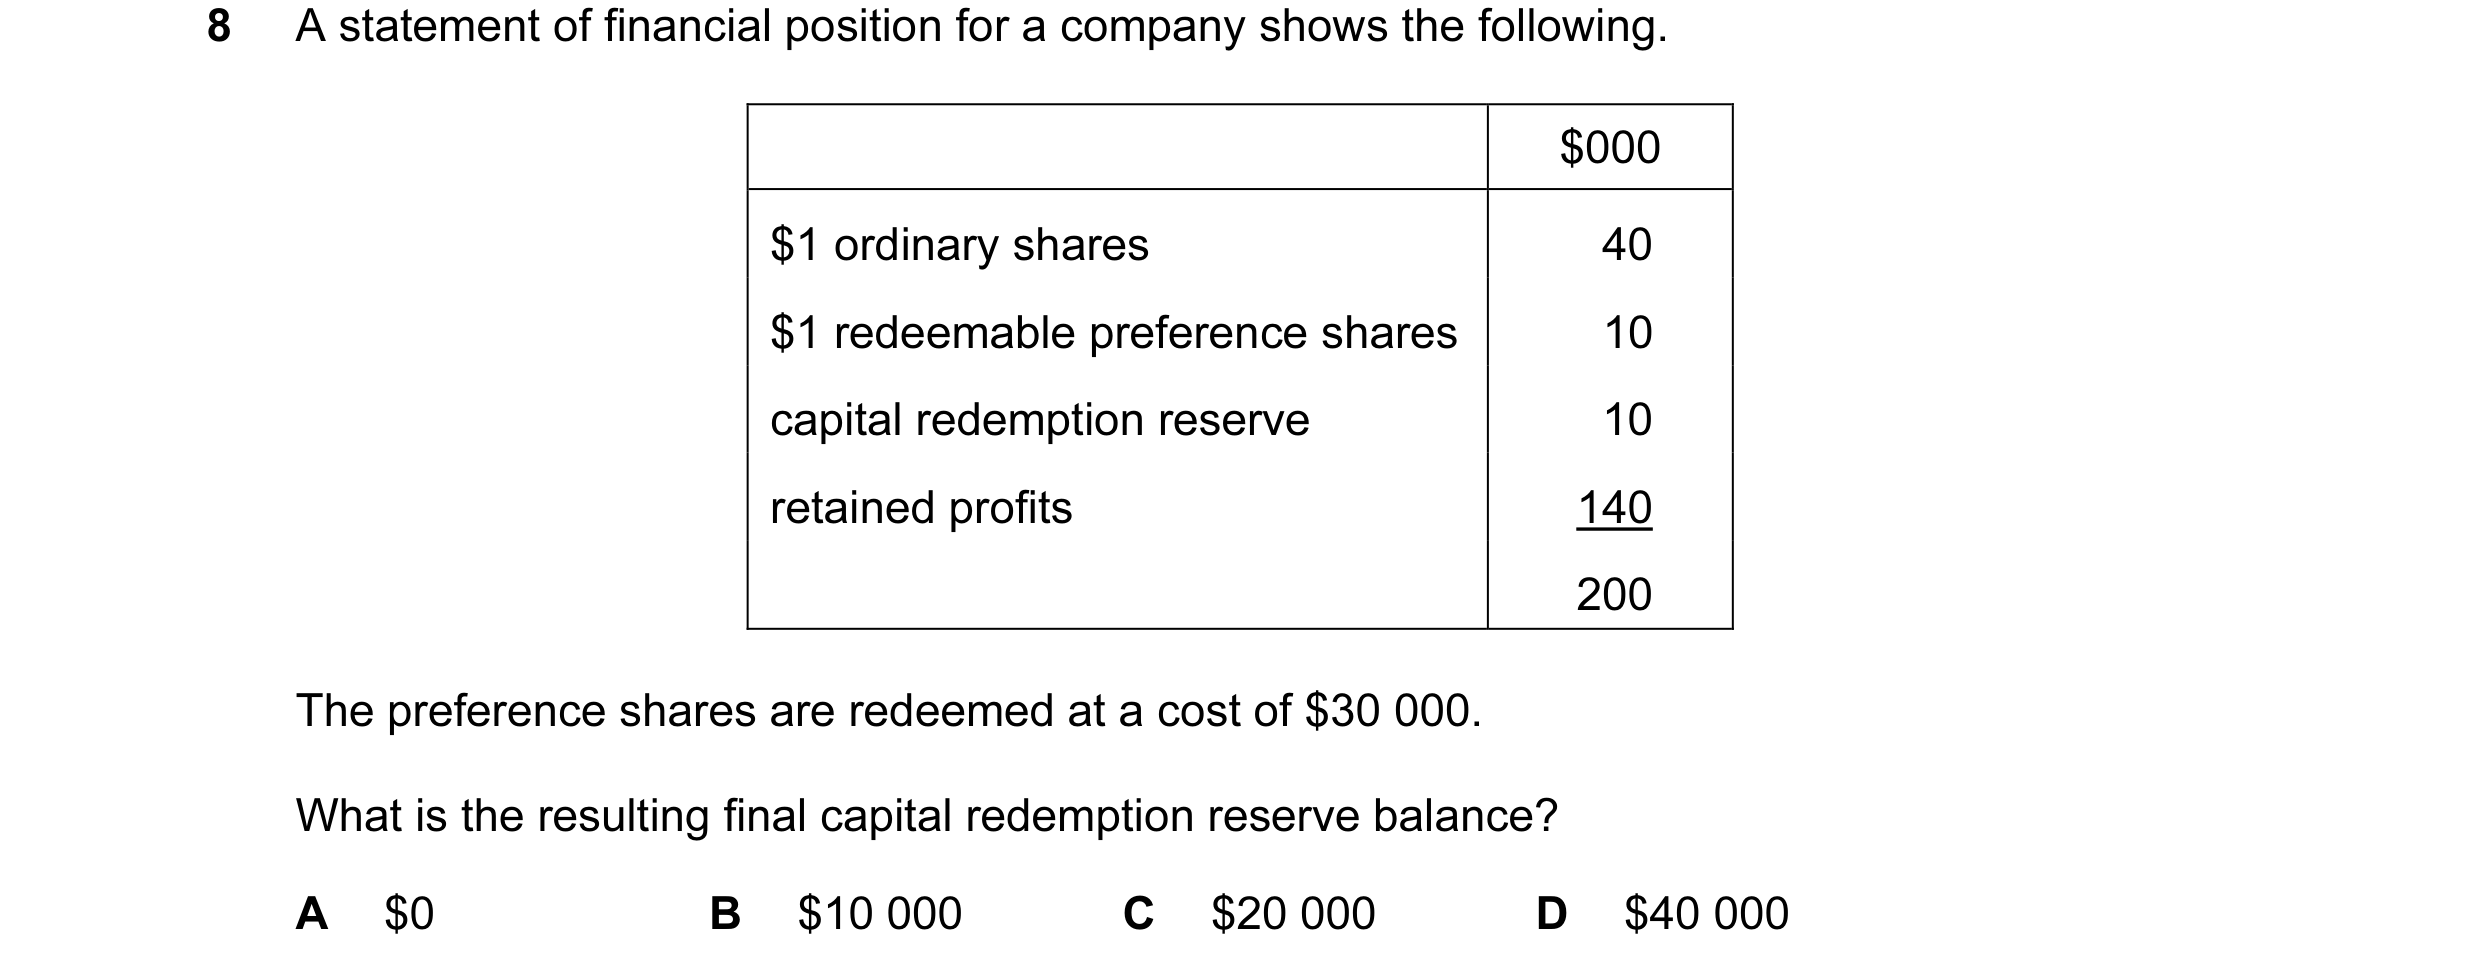
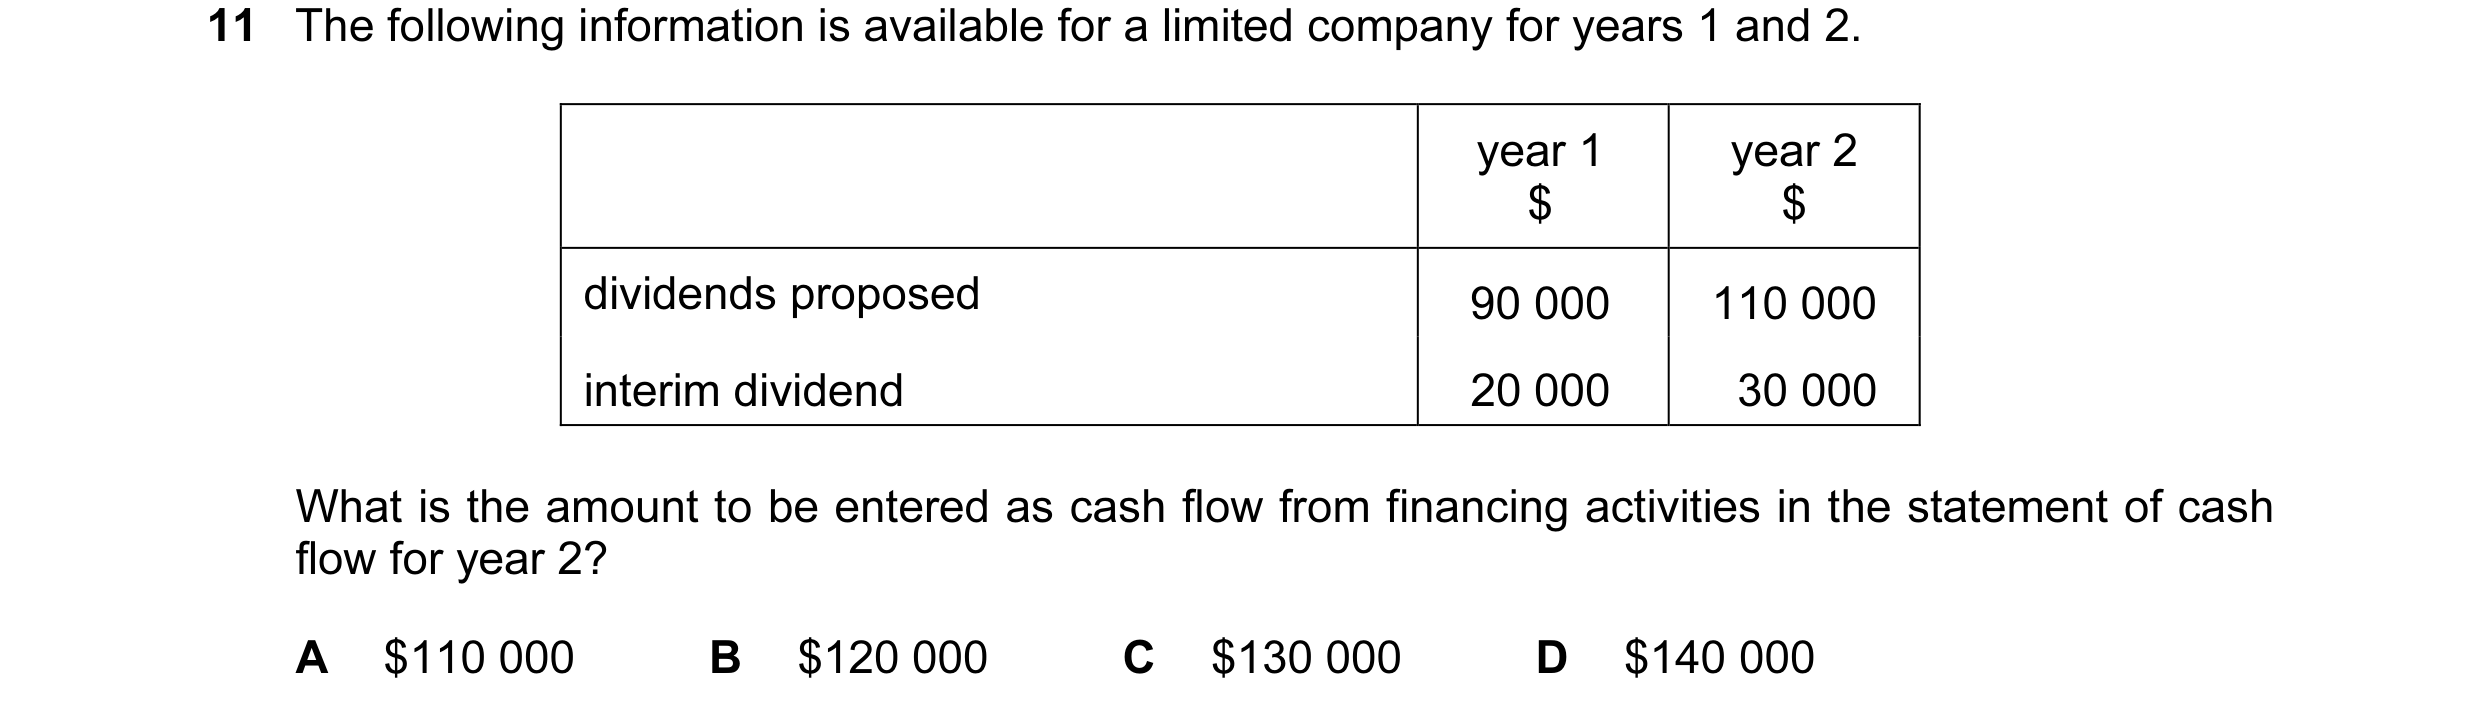 34 / 62
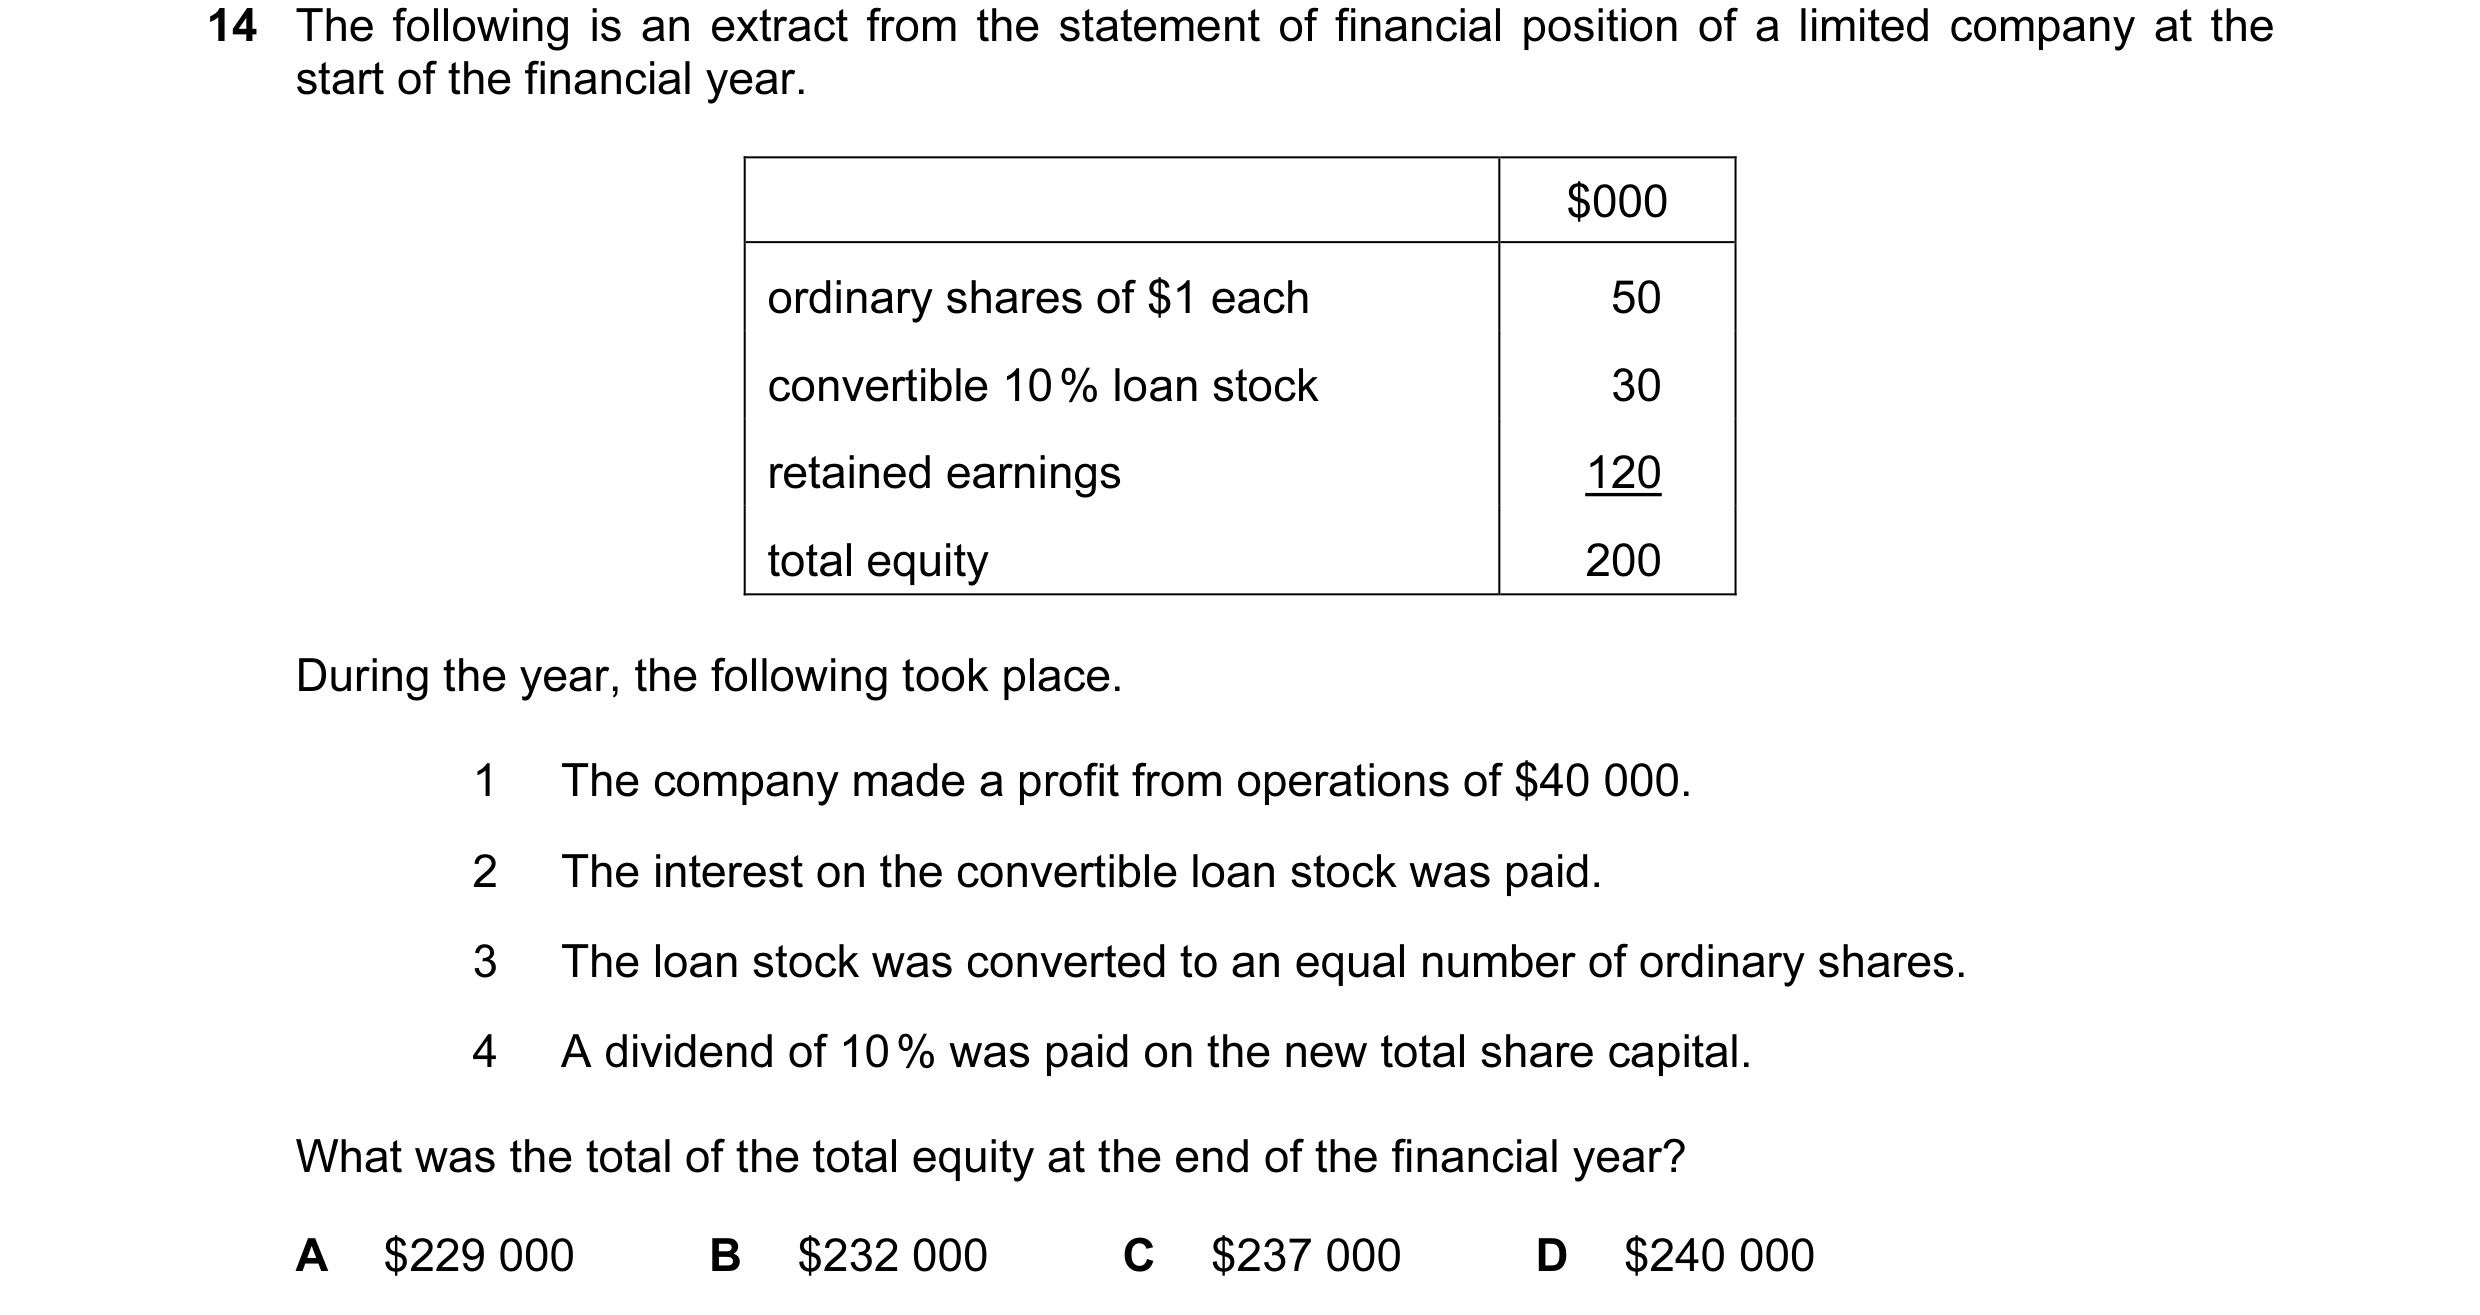
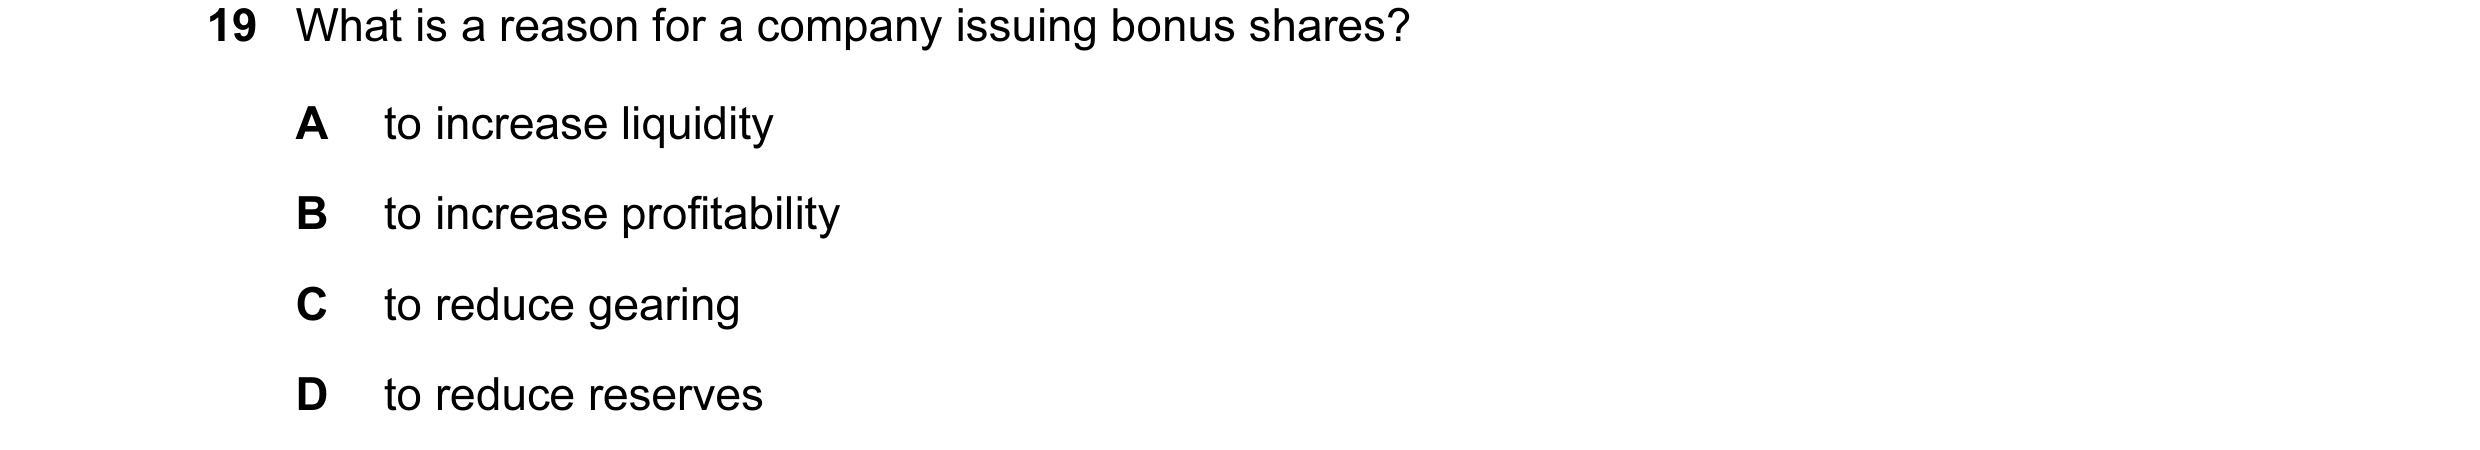
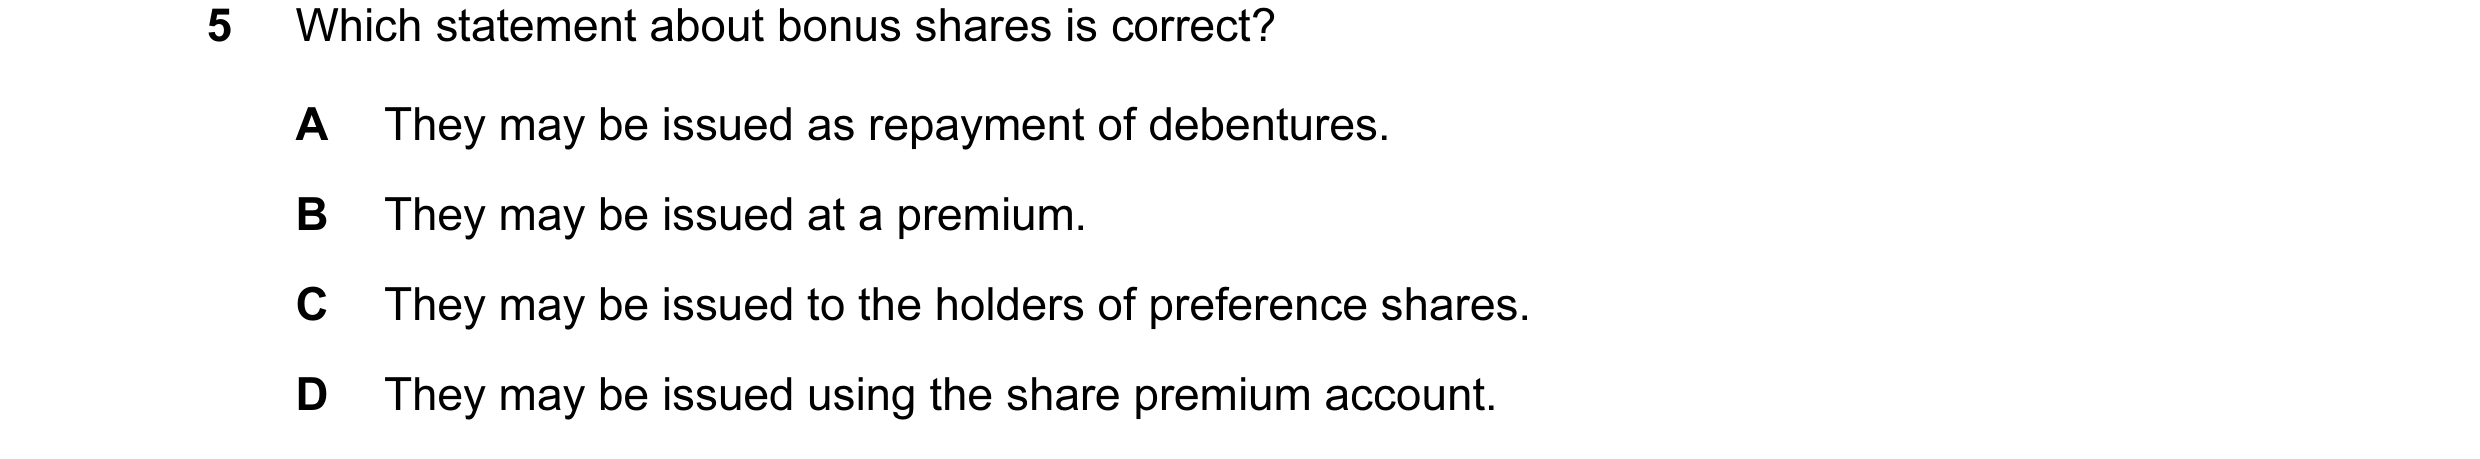 35 / 62
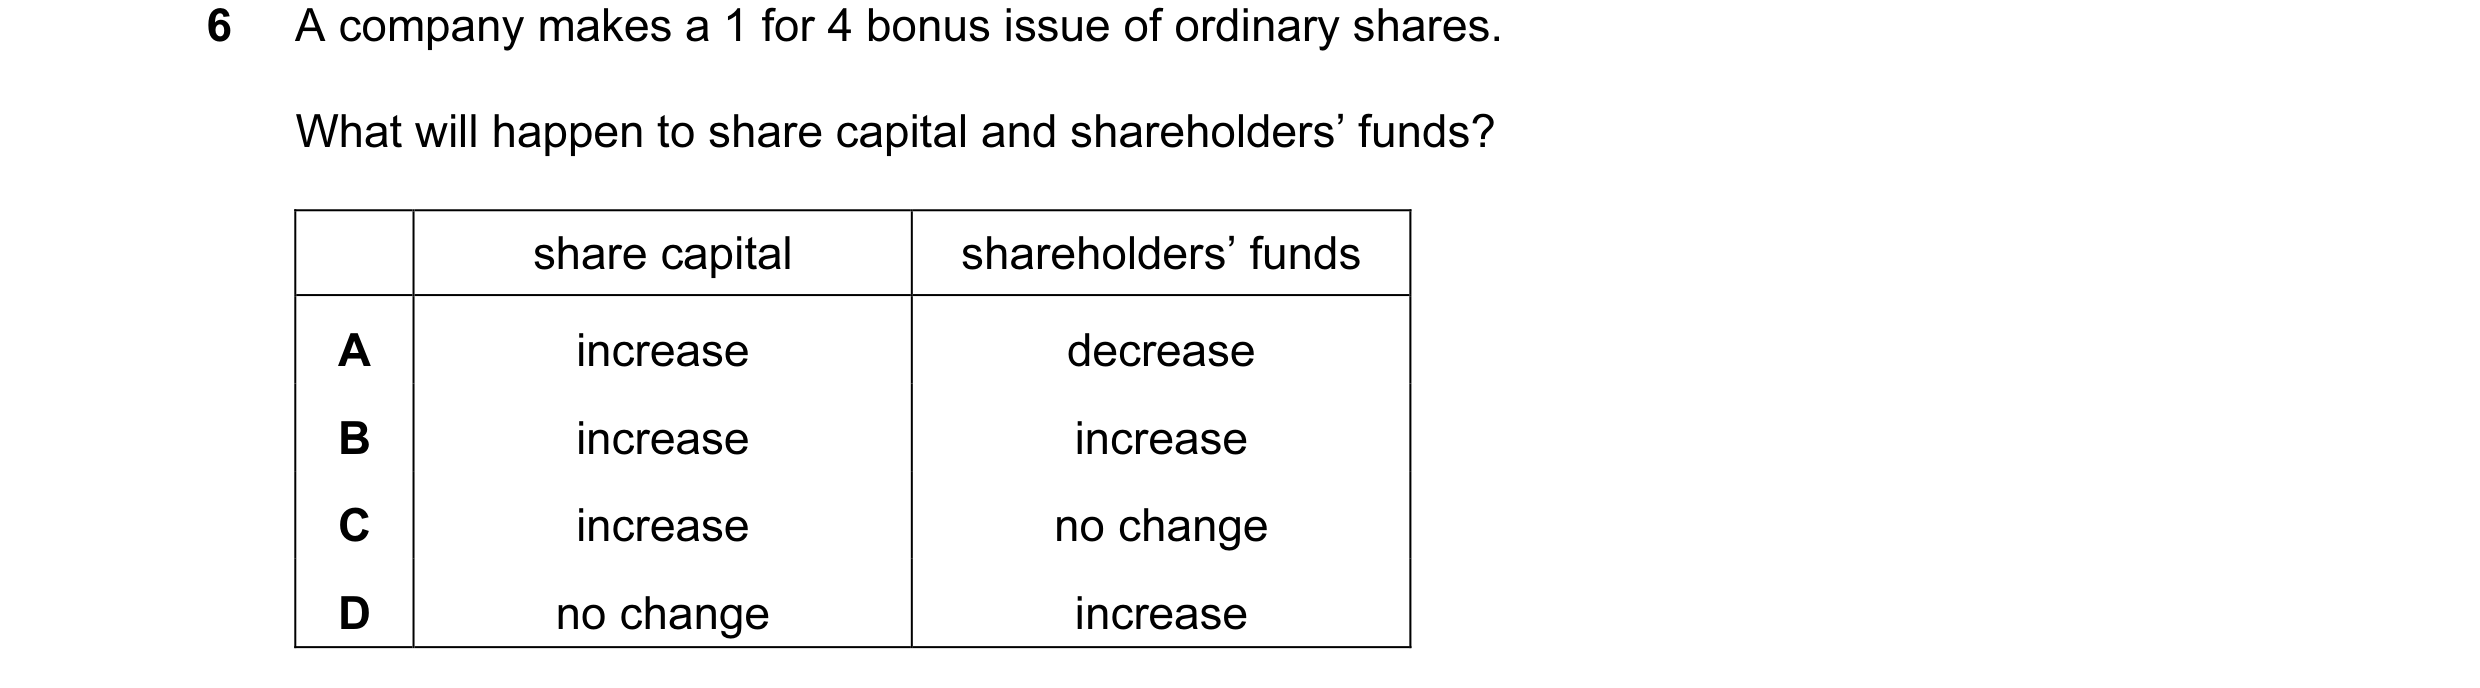
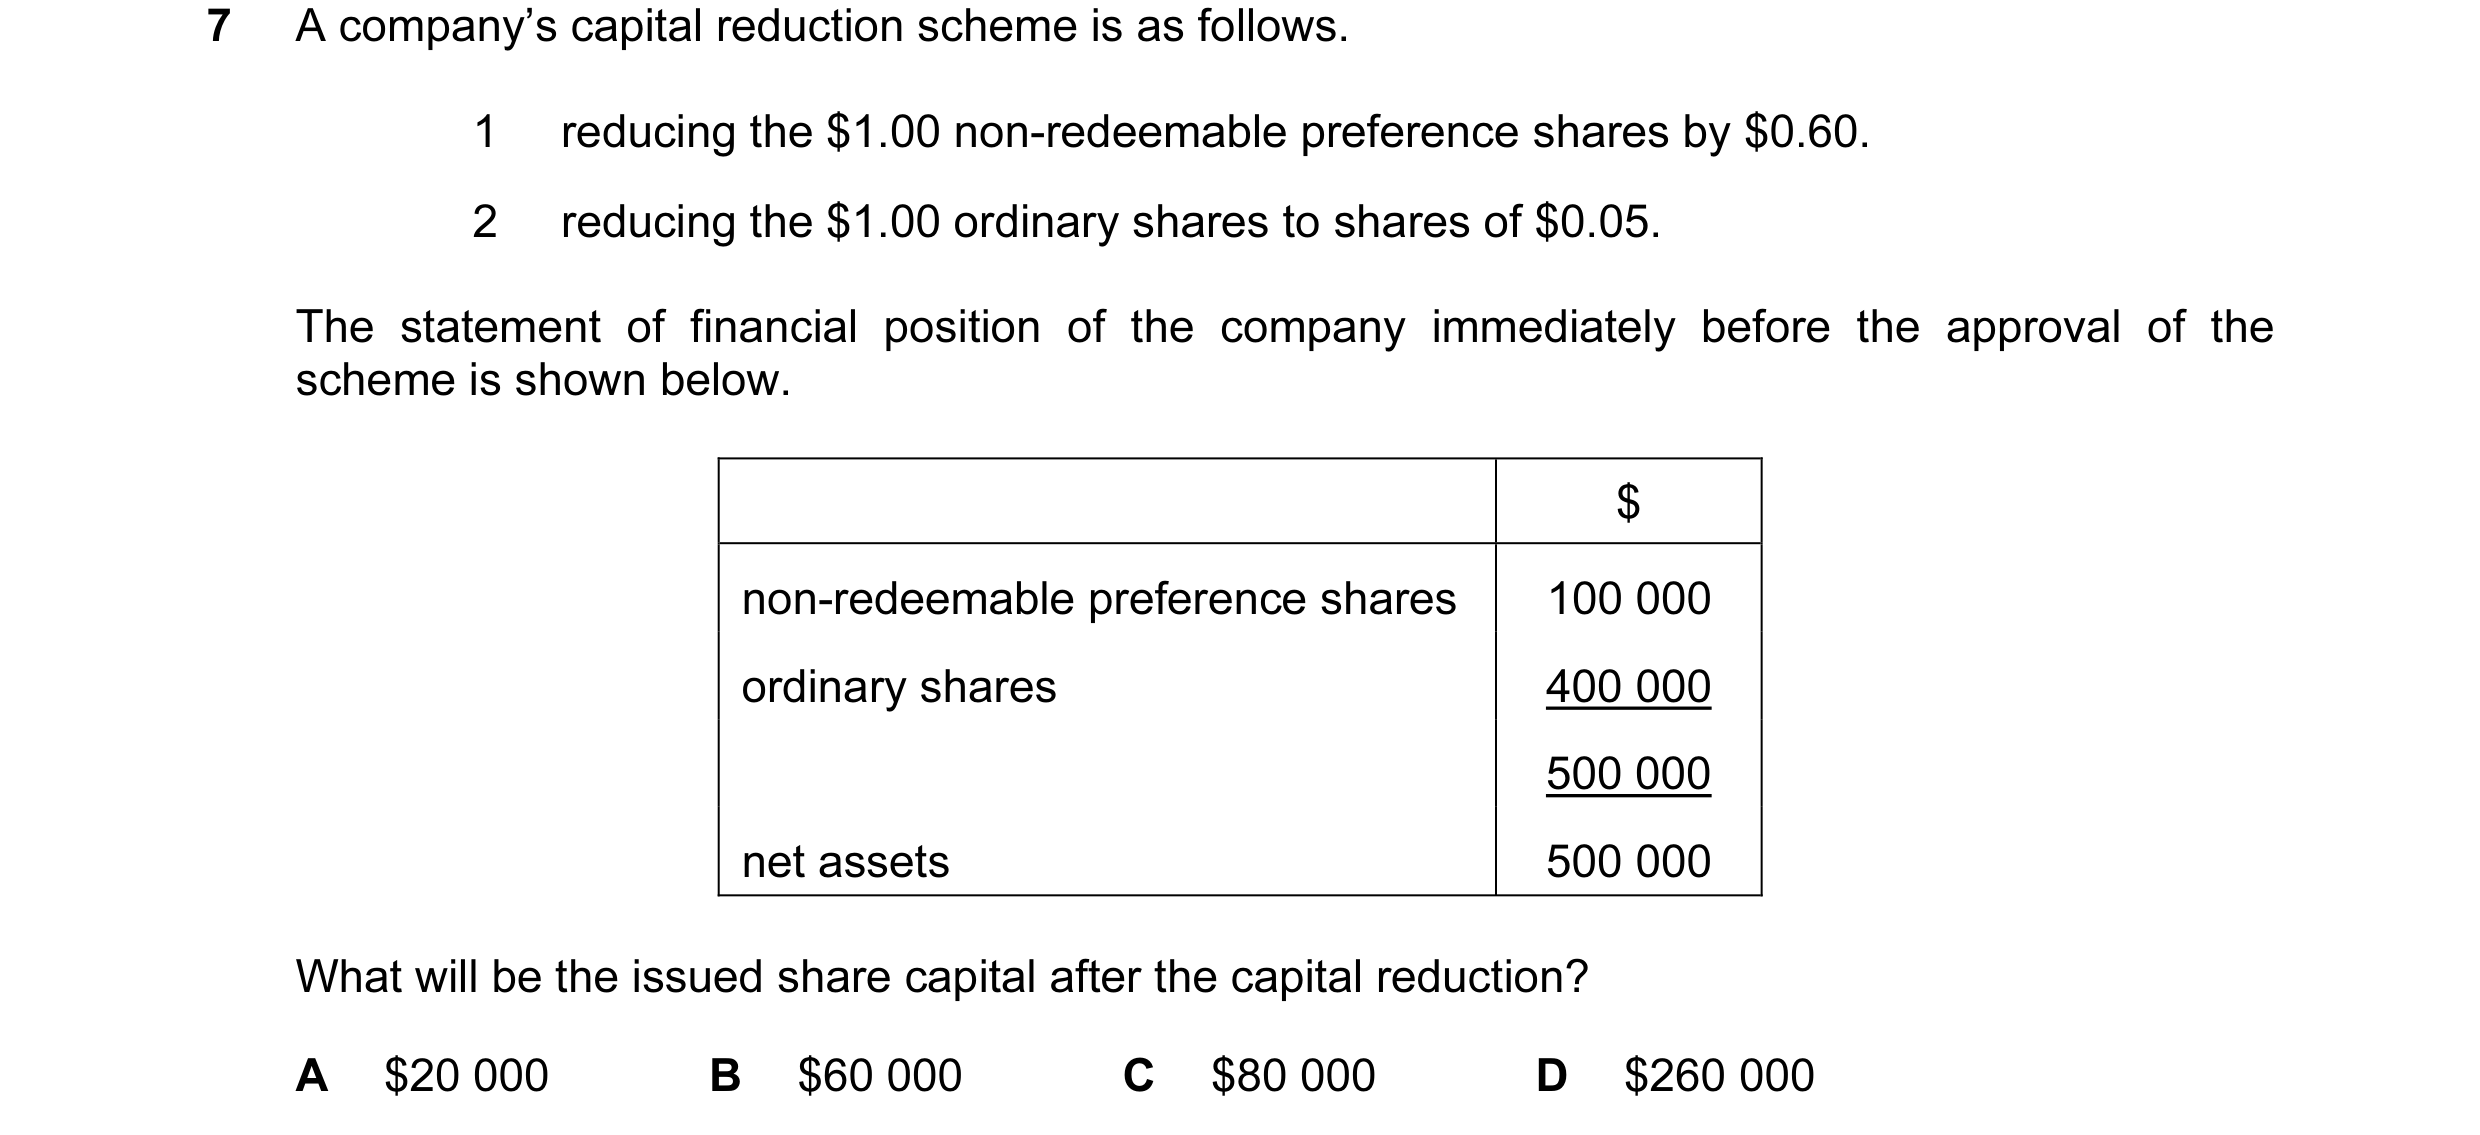
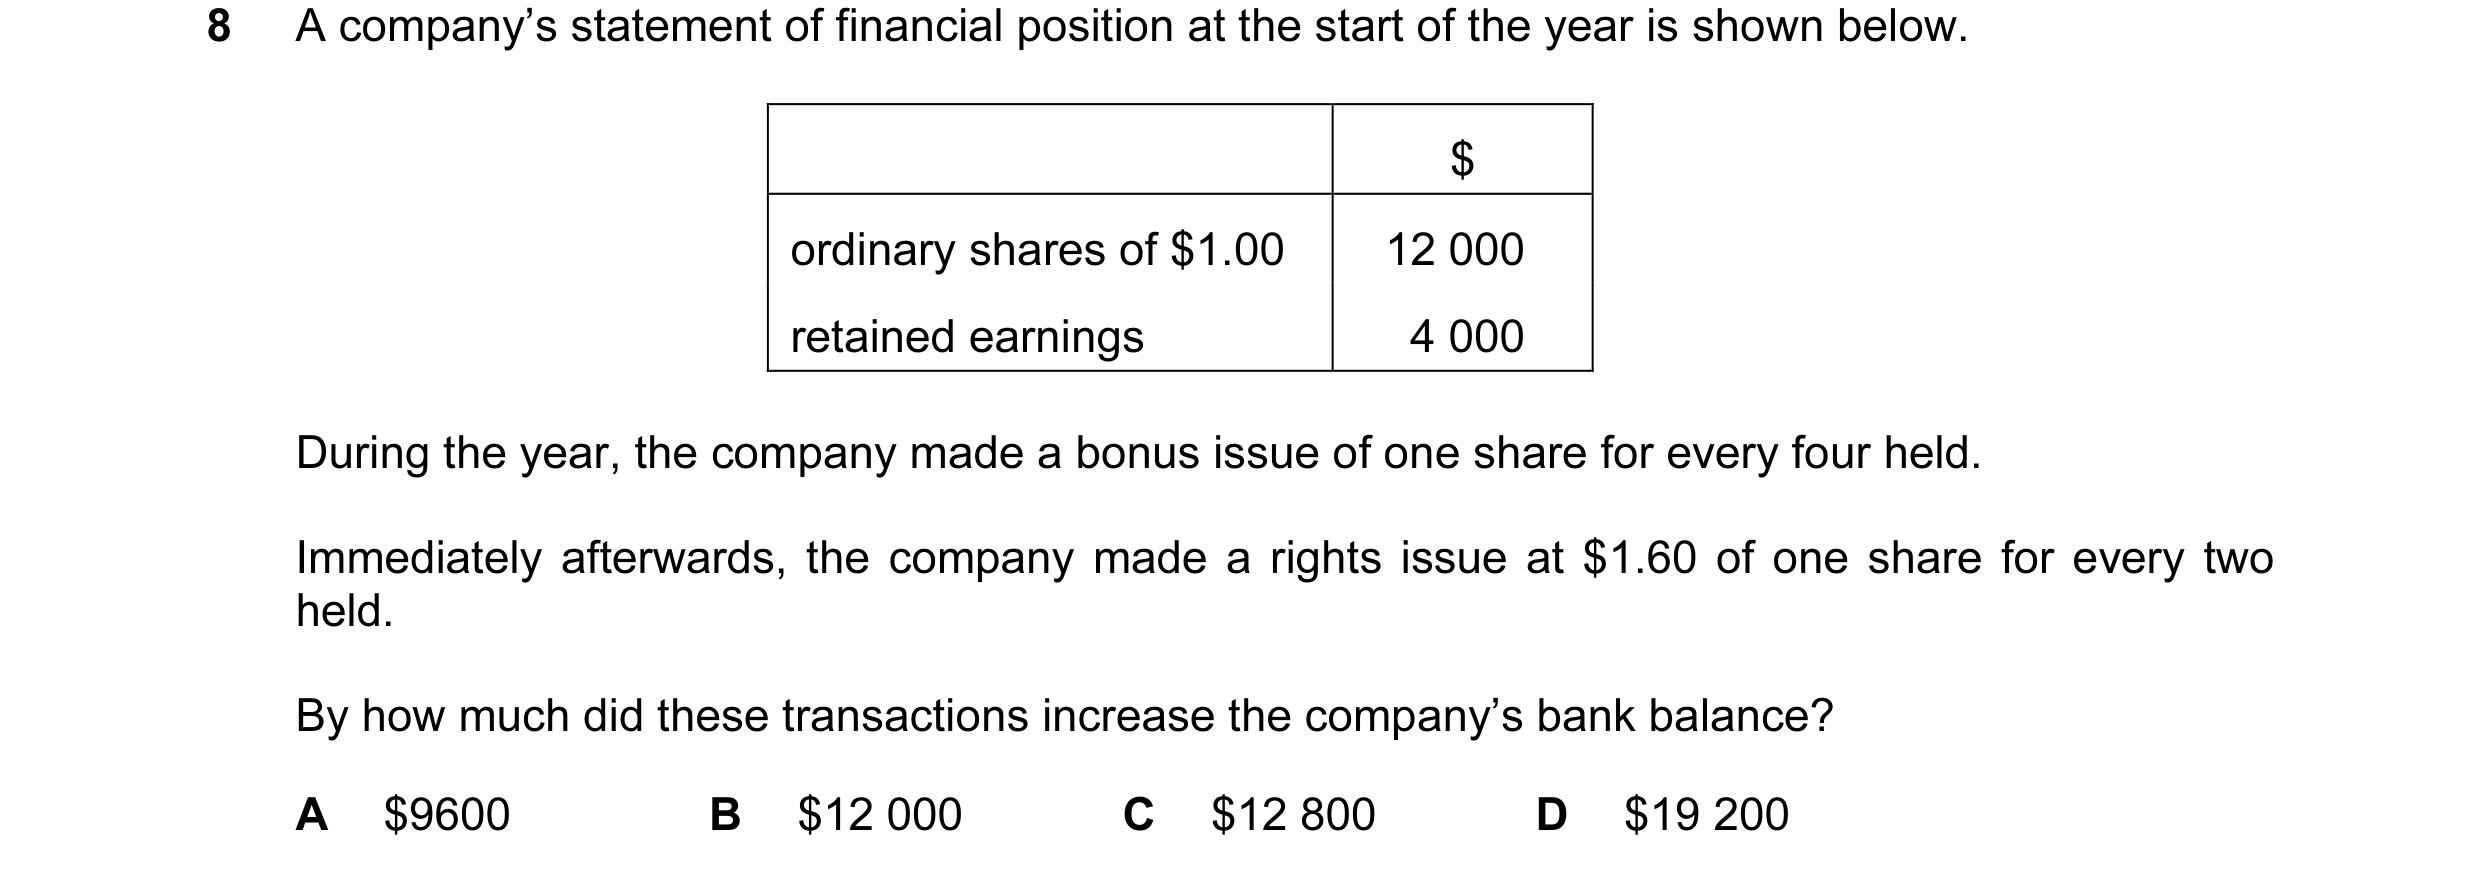 36 / 62
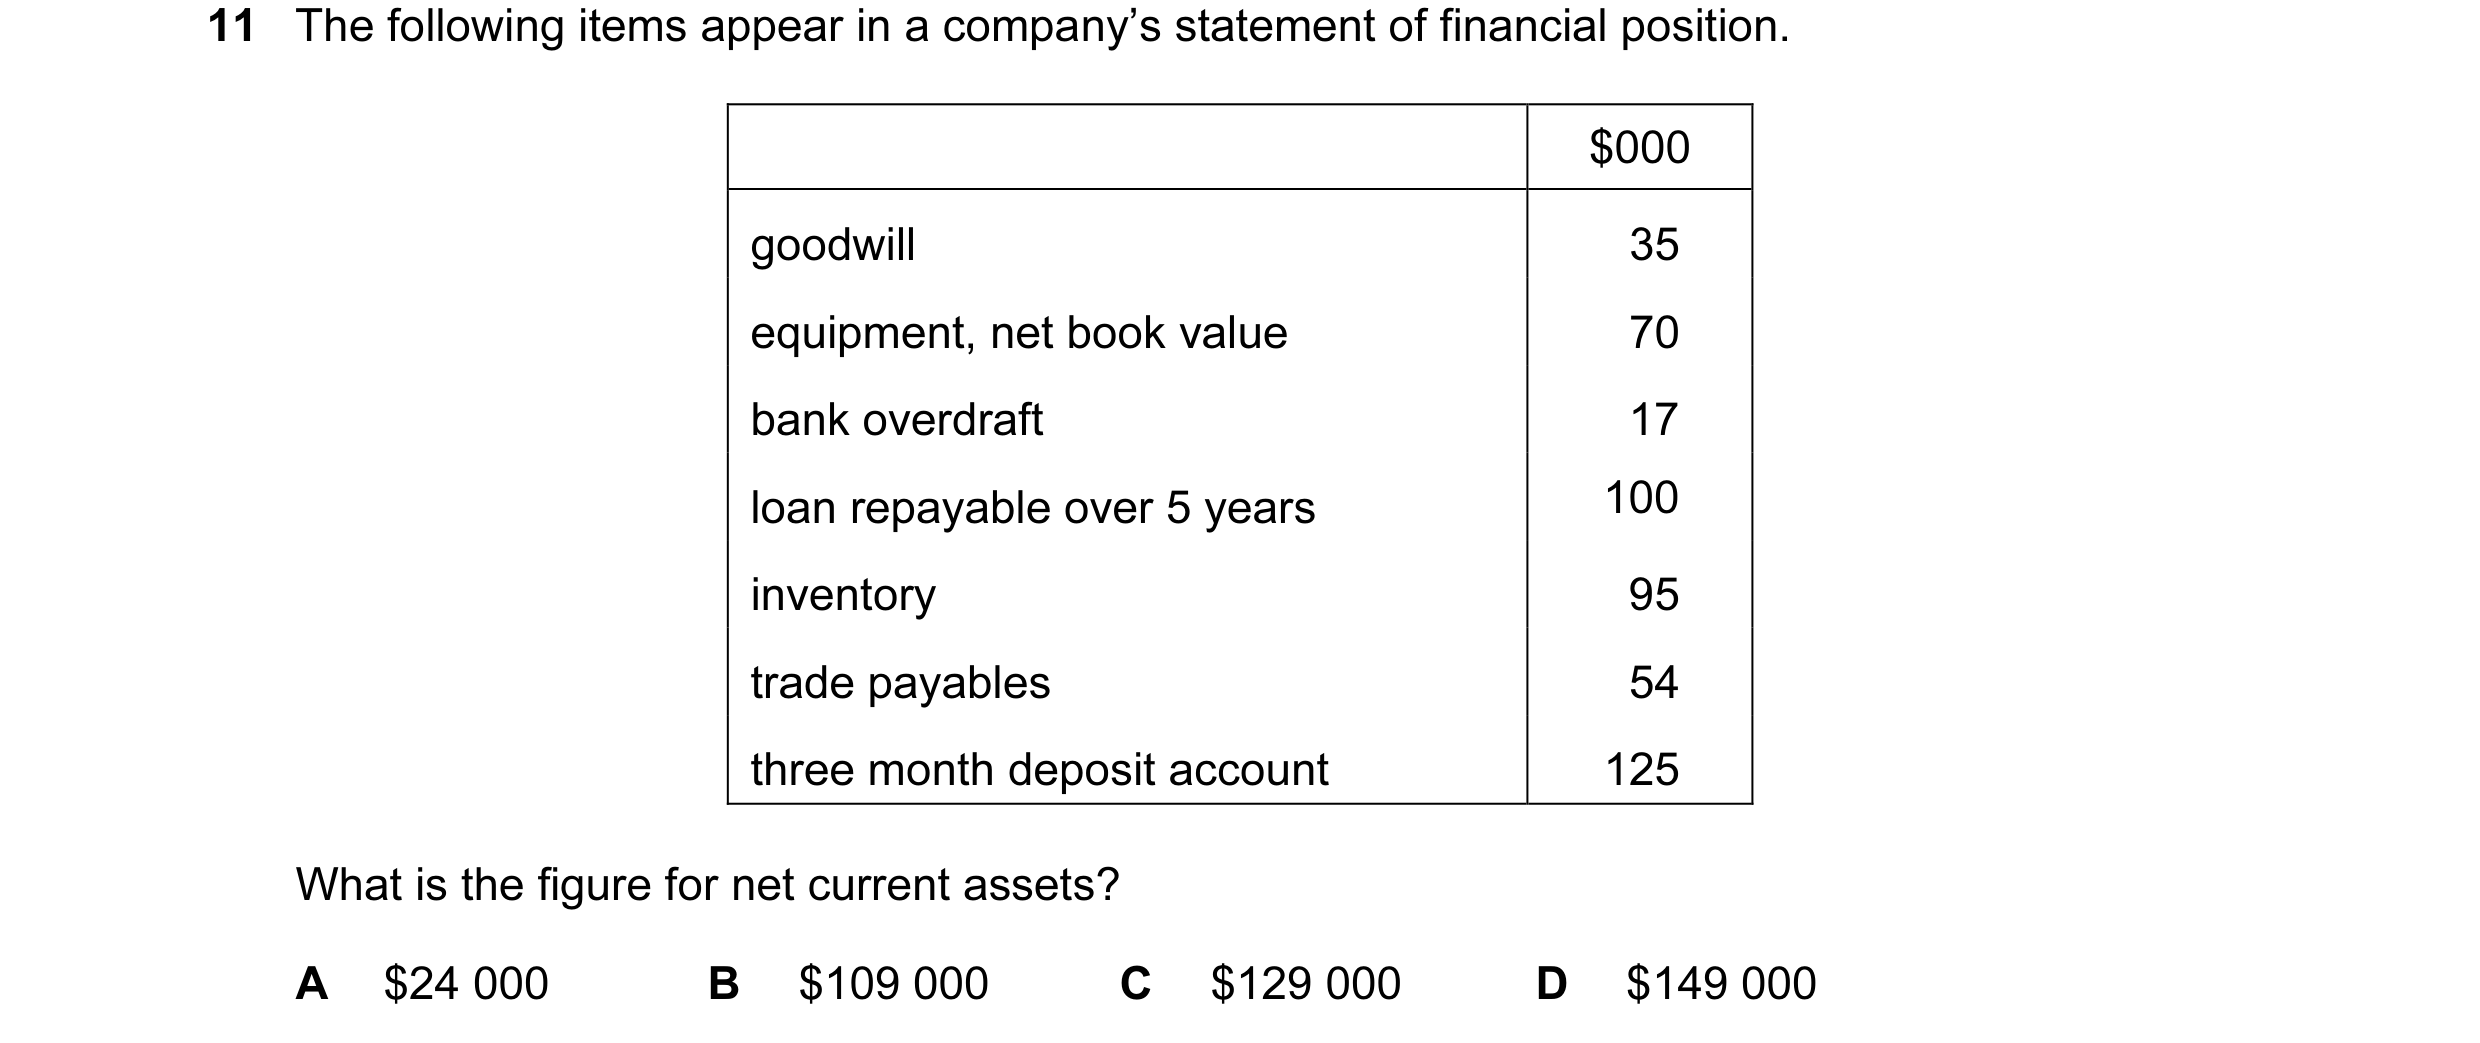 37 / 62
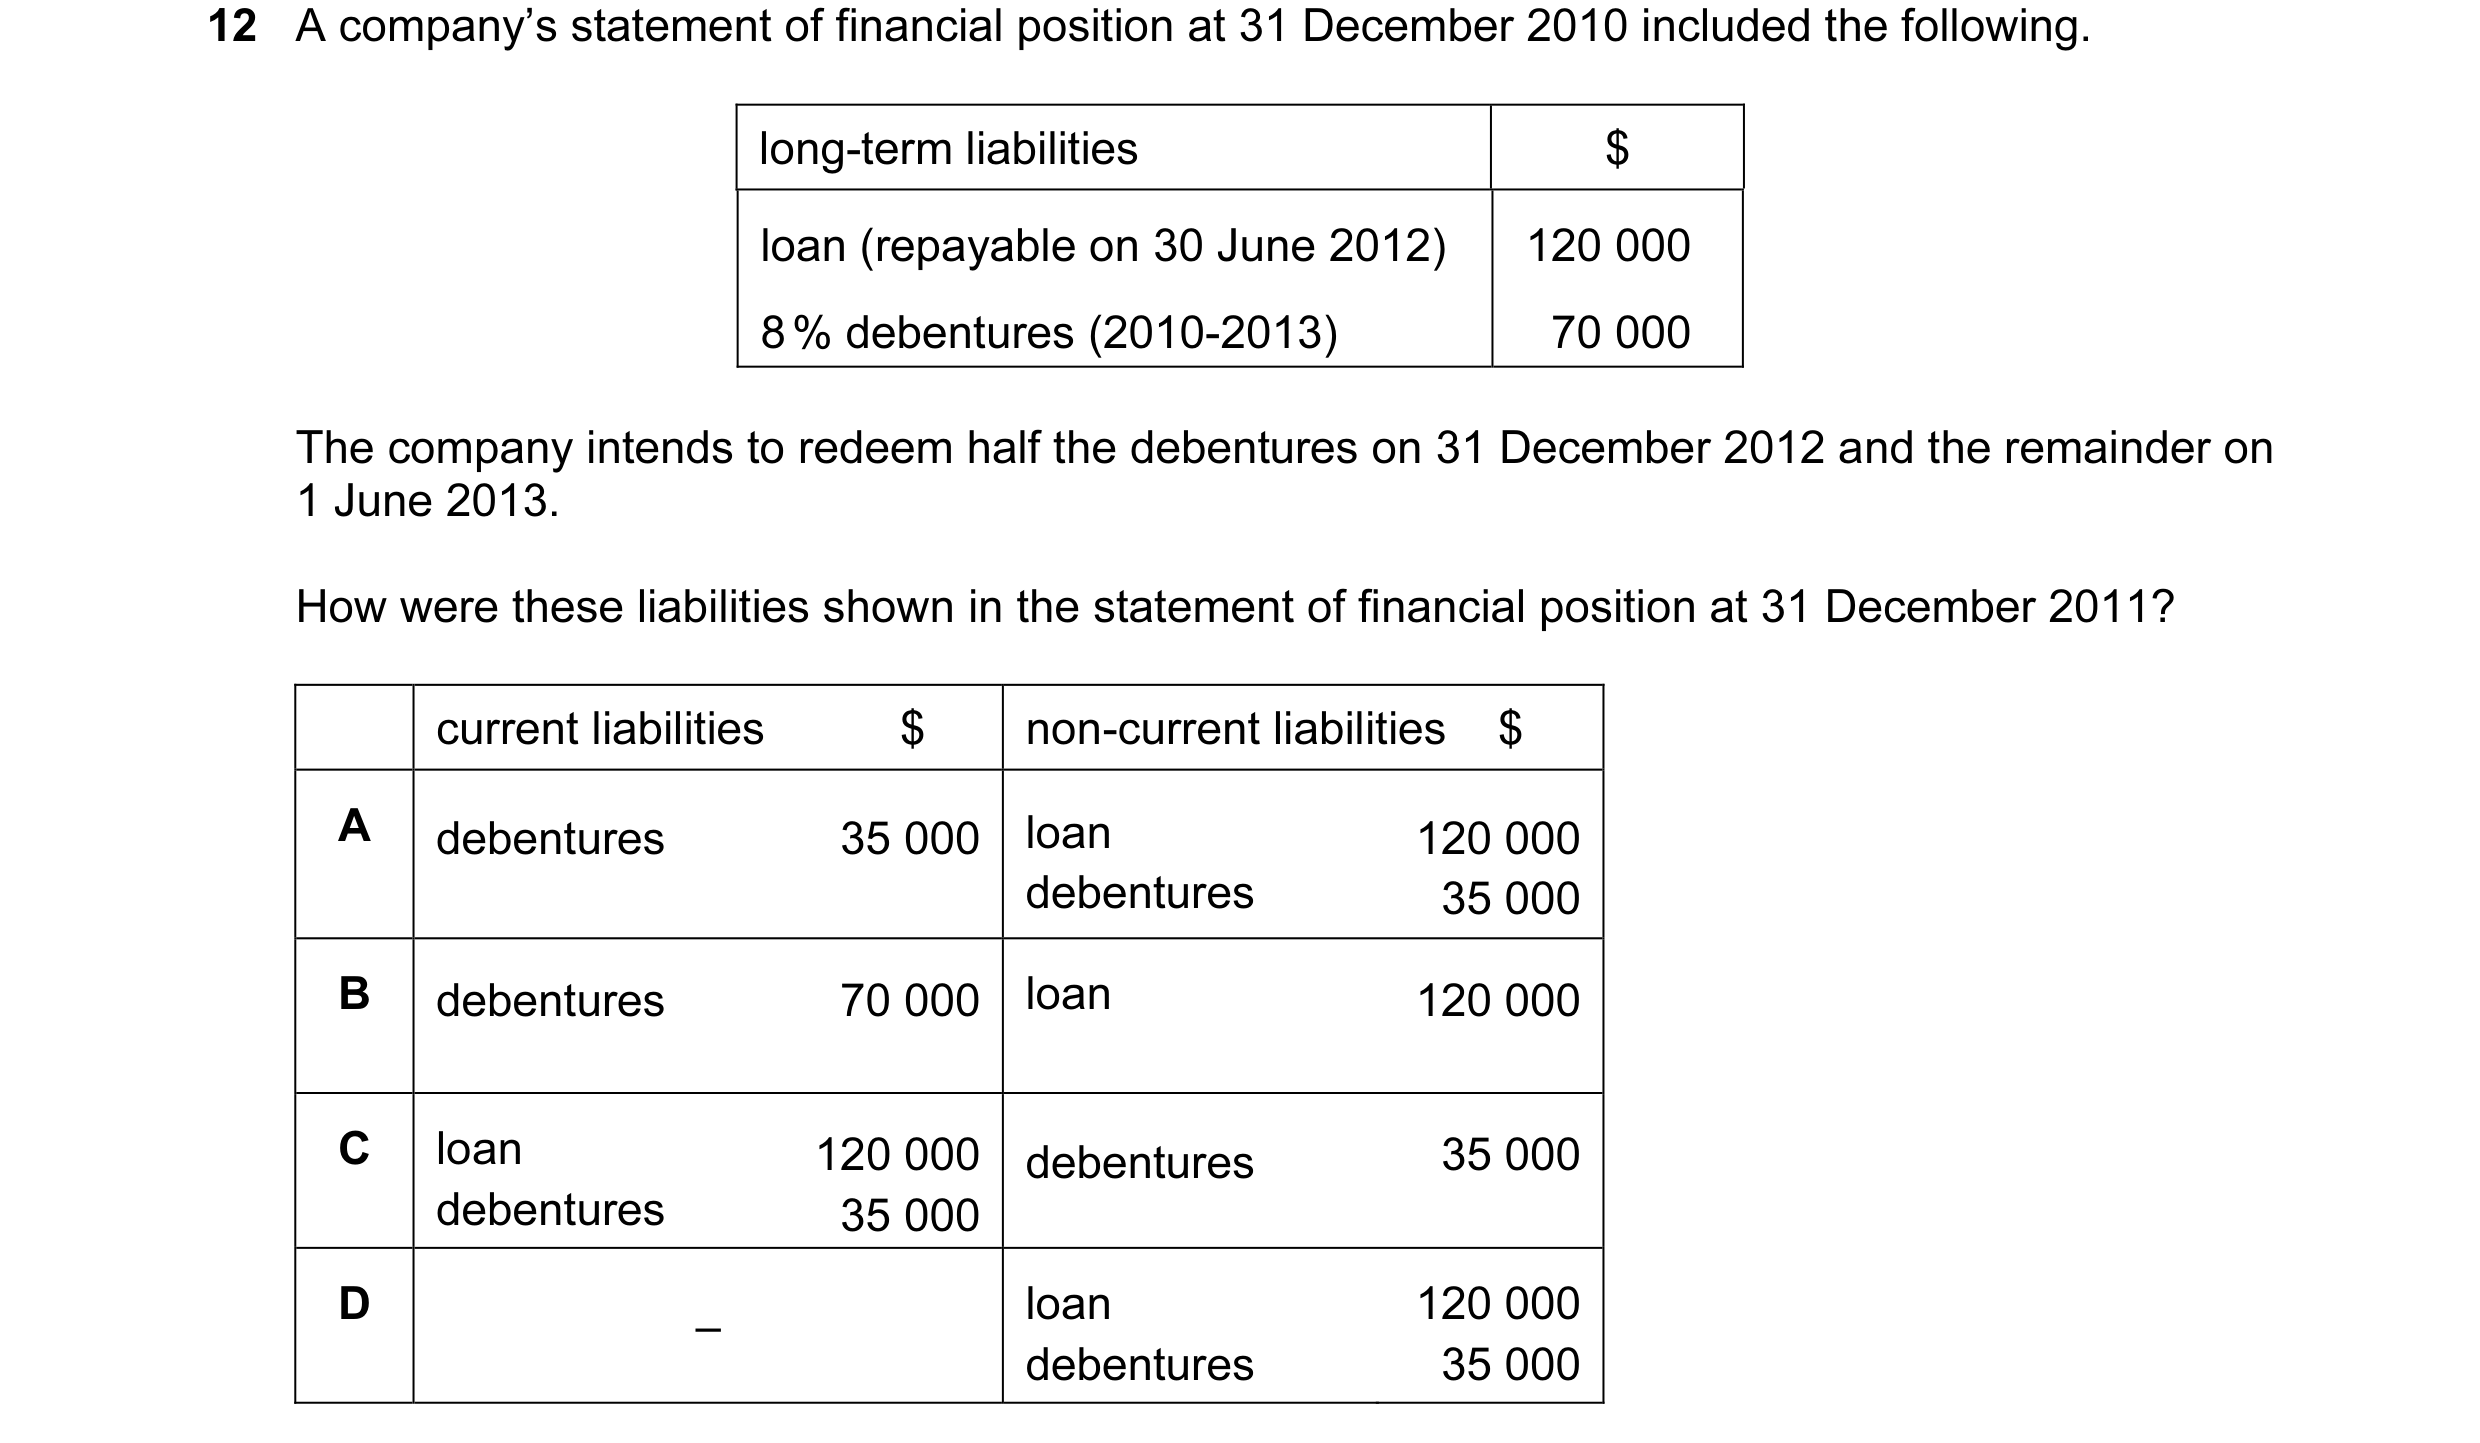
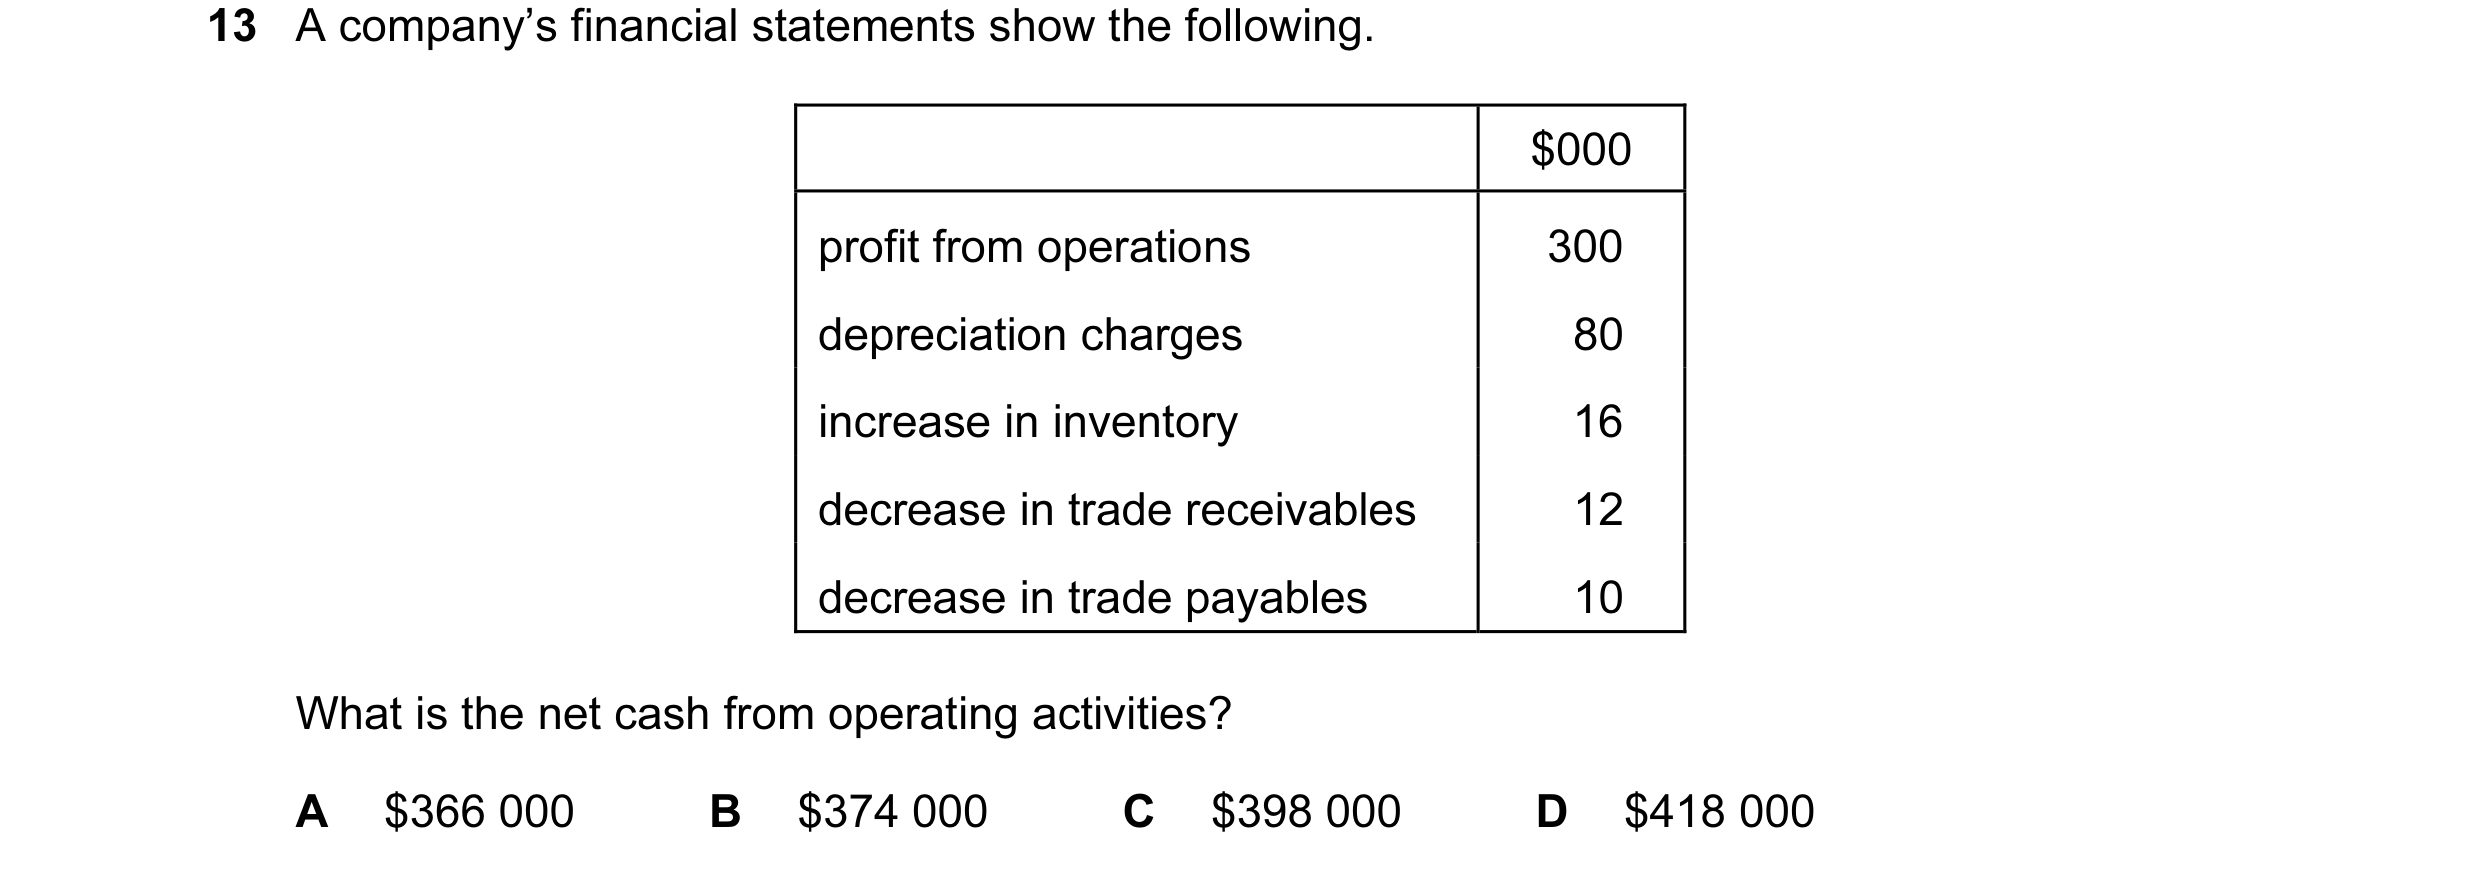 38 / 62
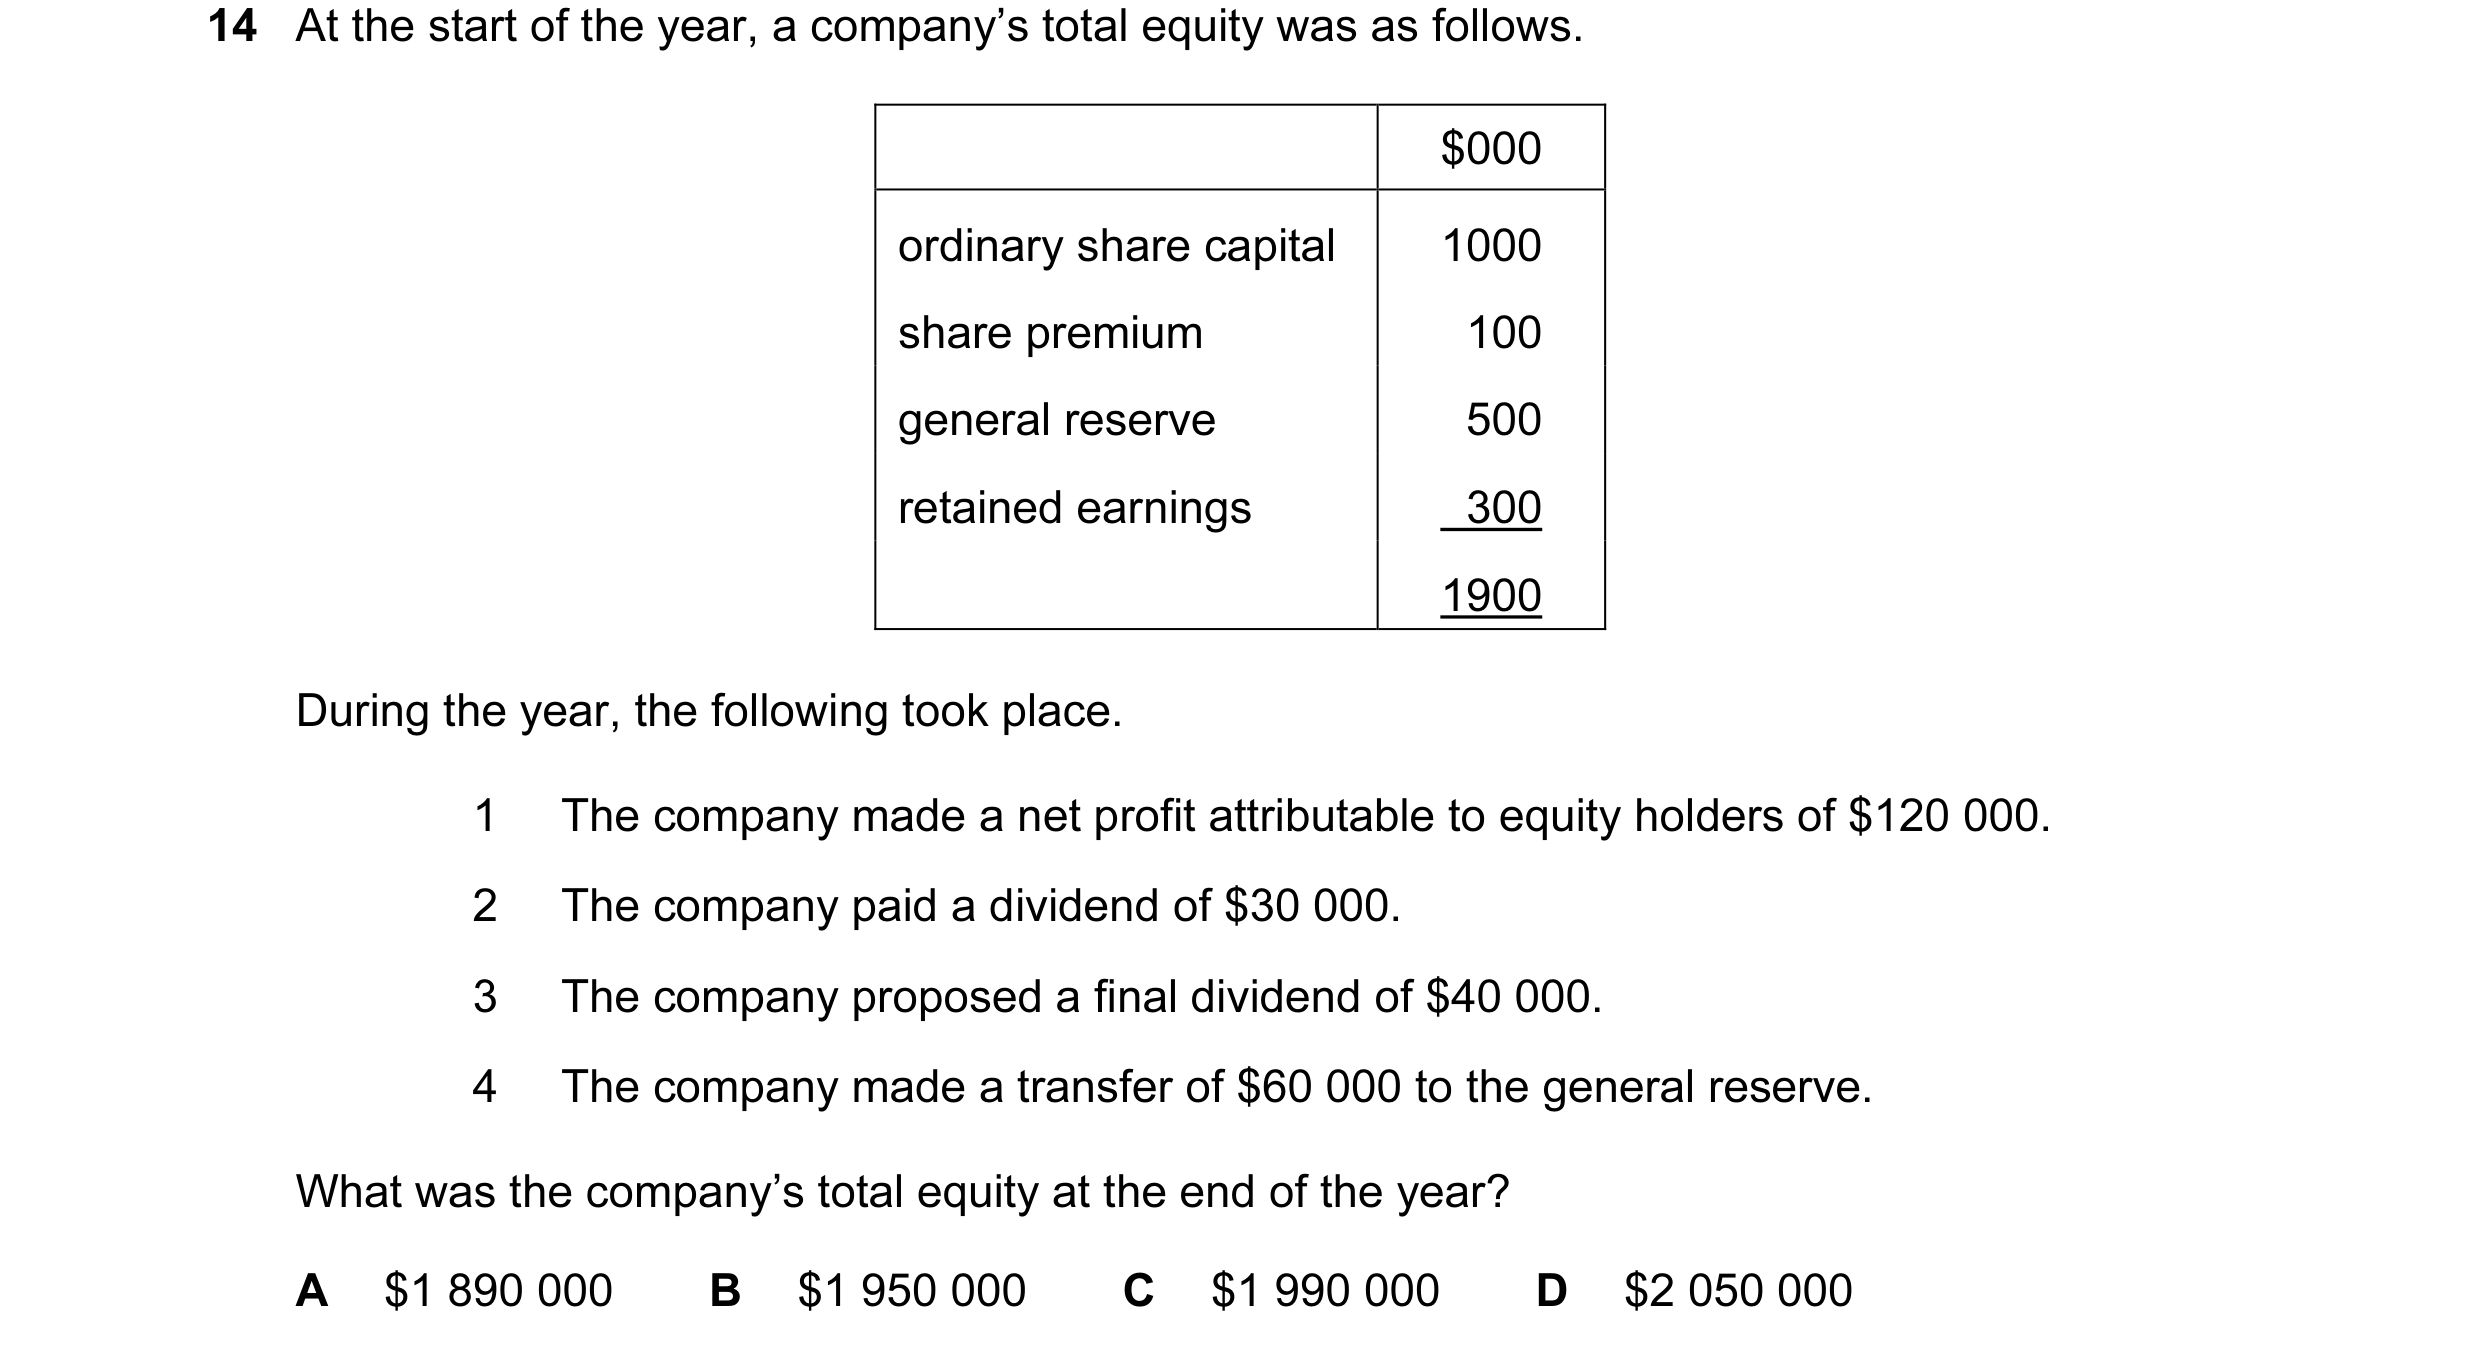
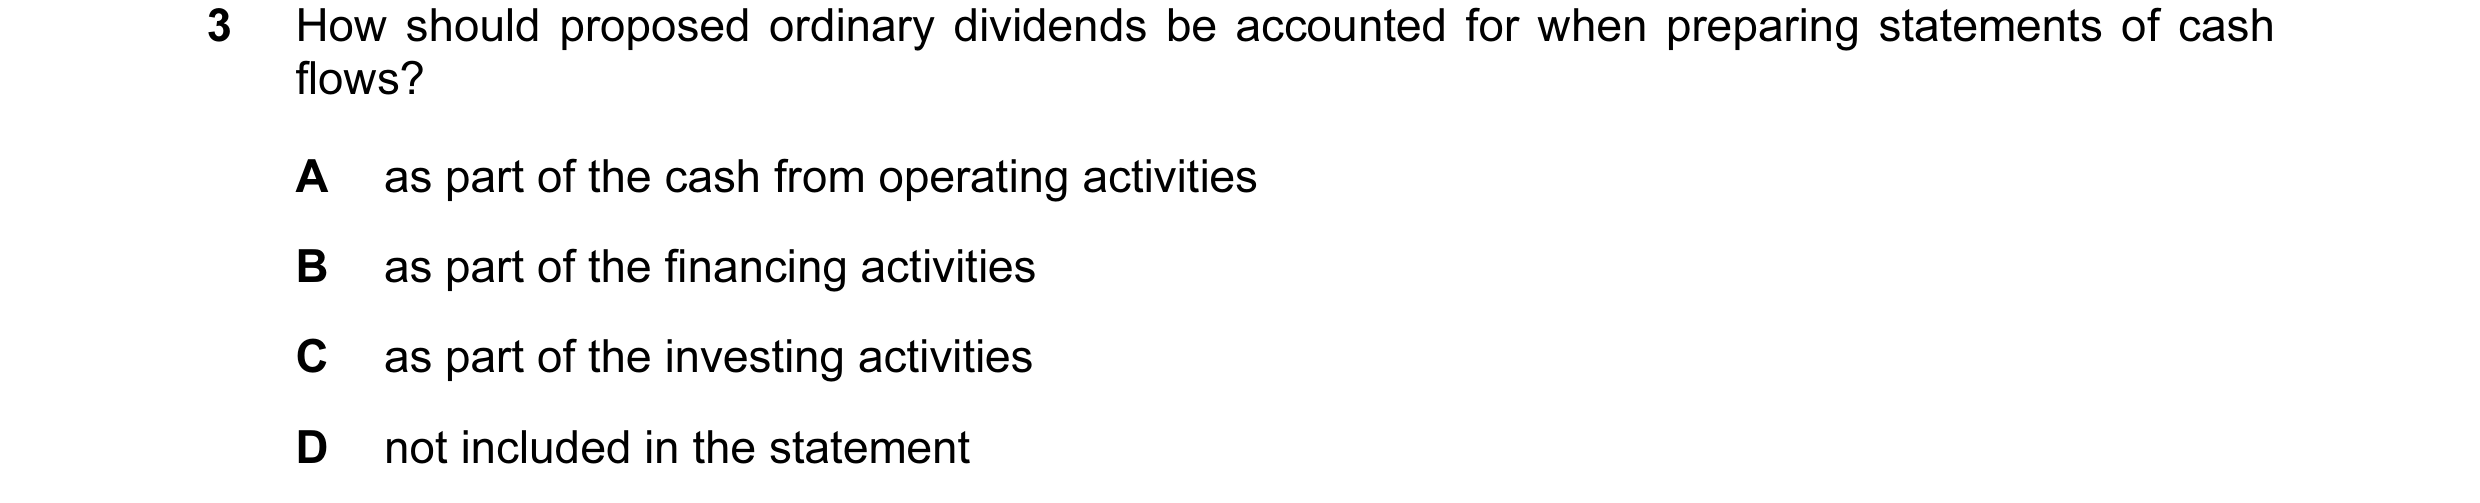
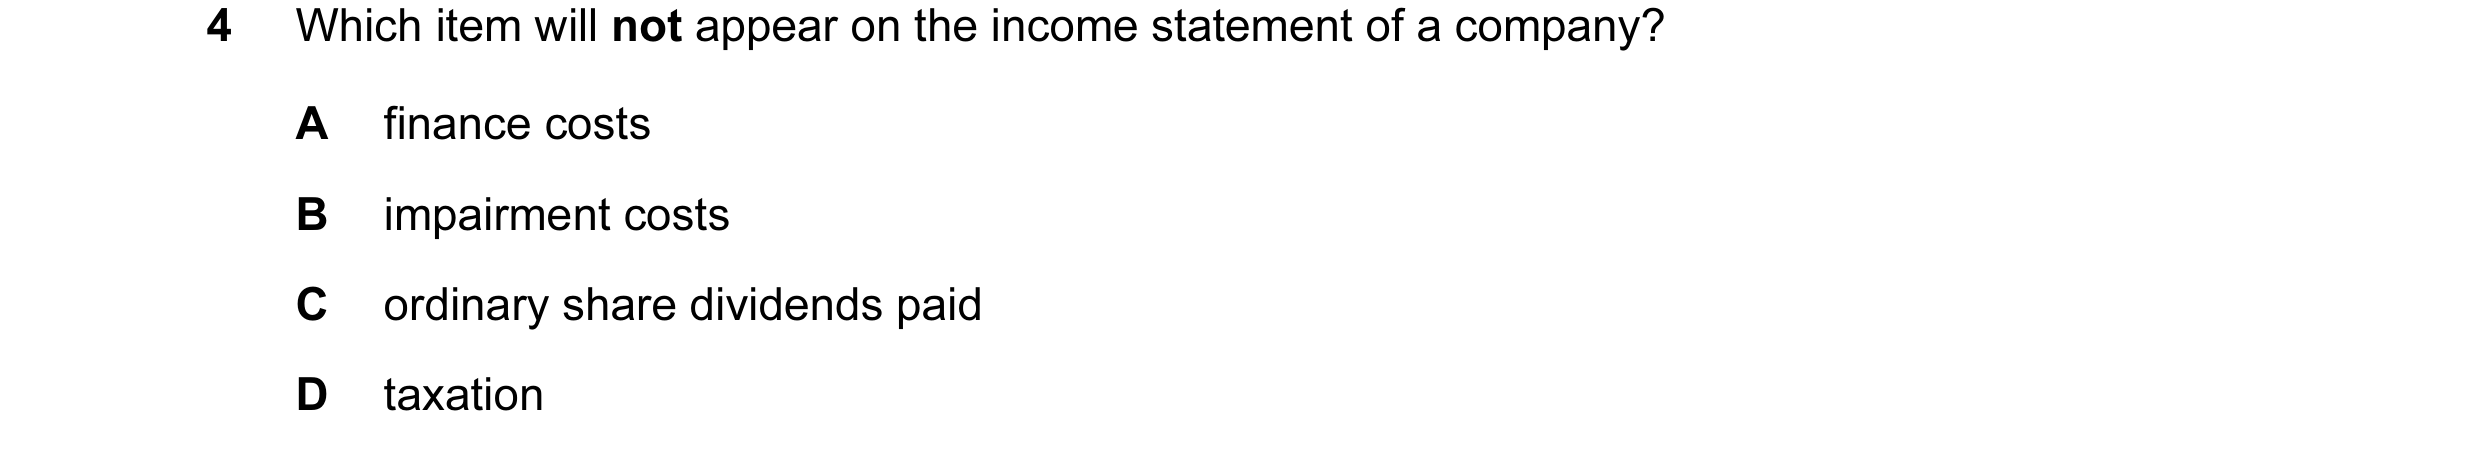
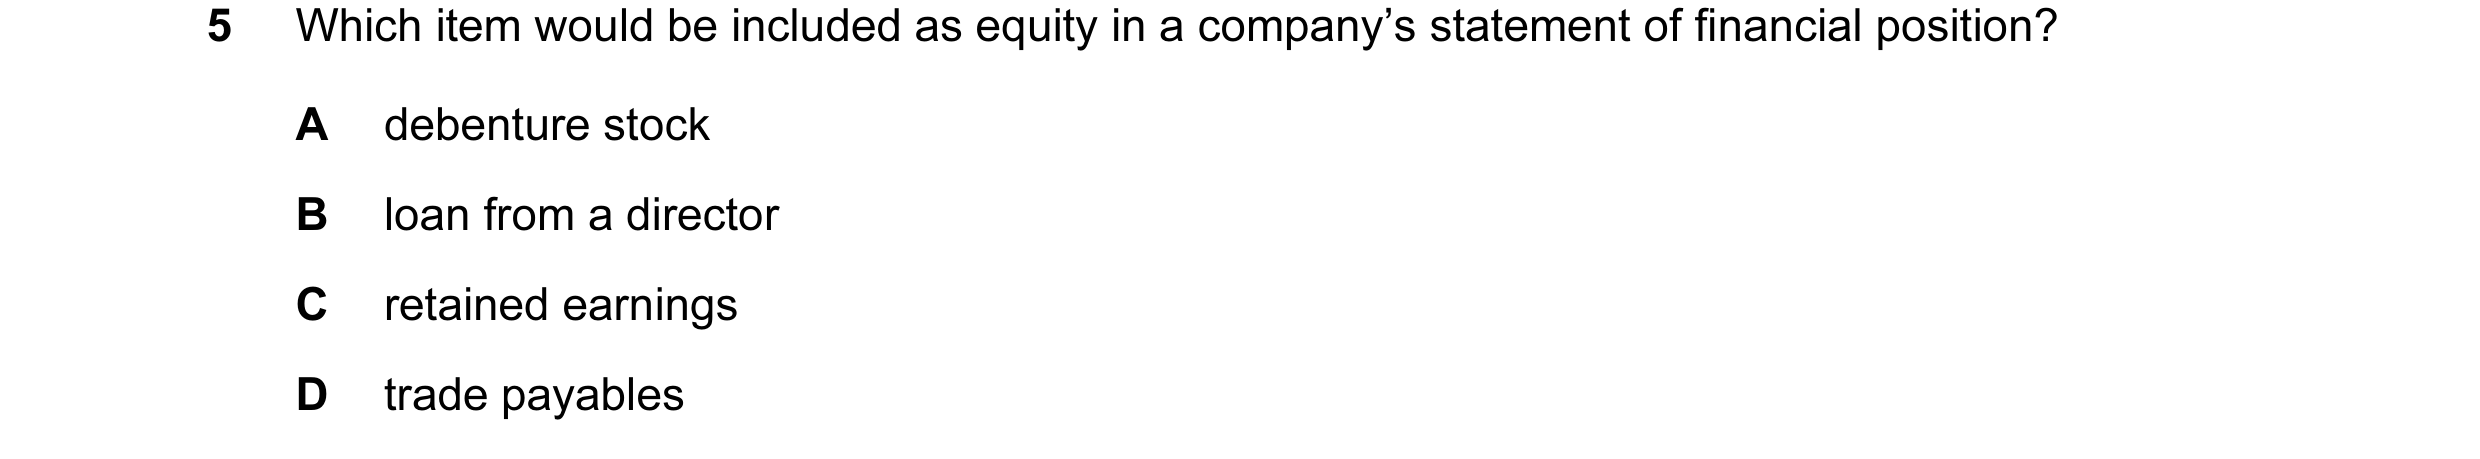 39 / 62
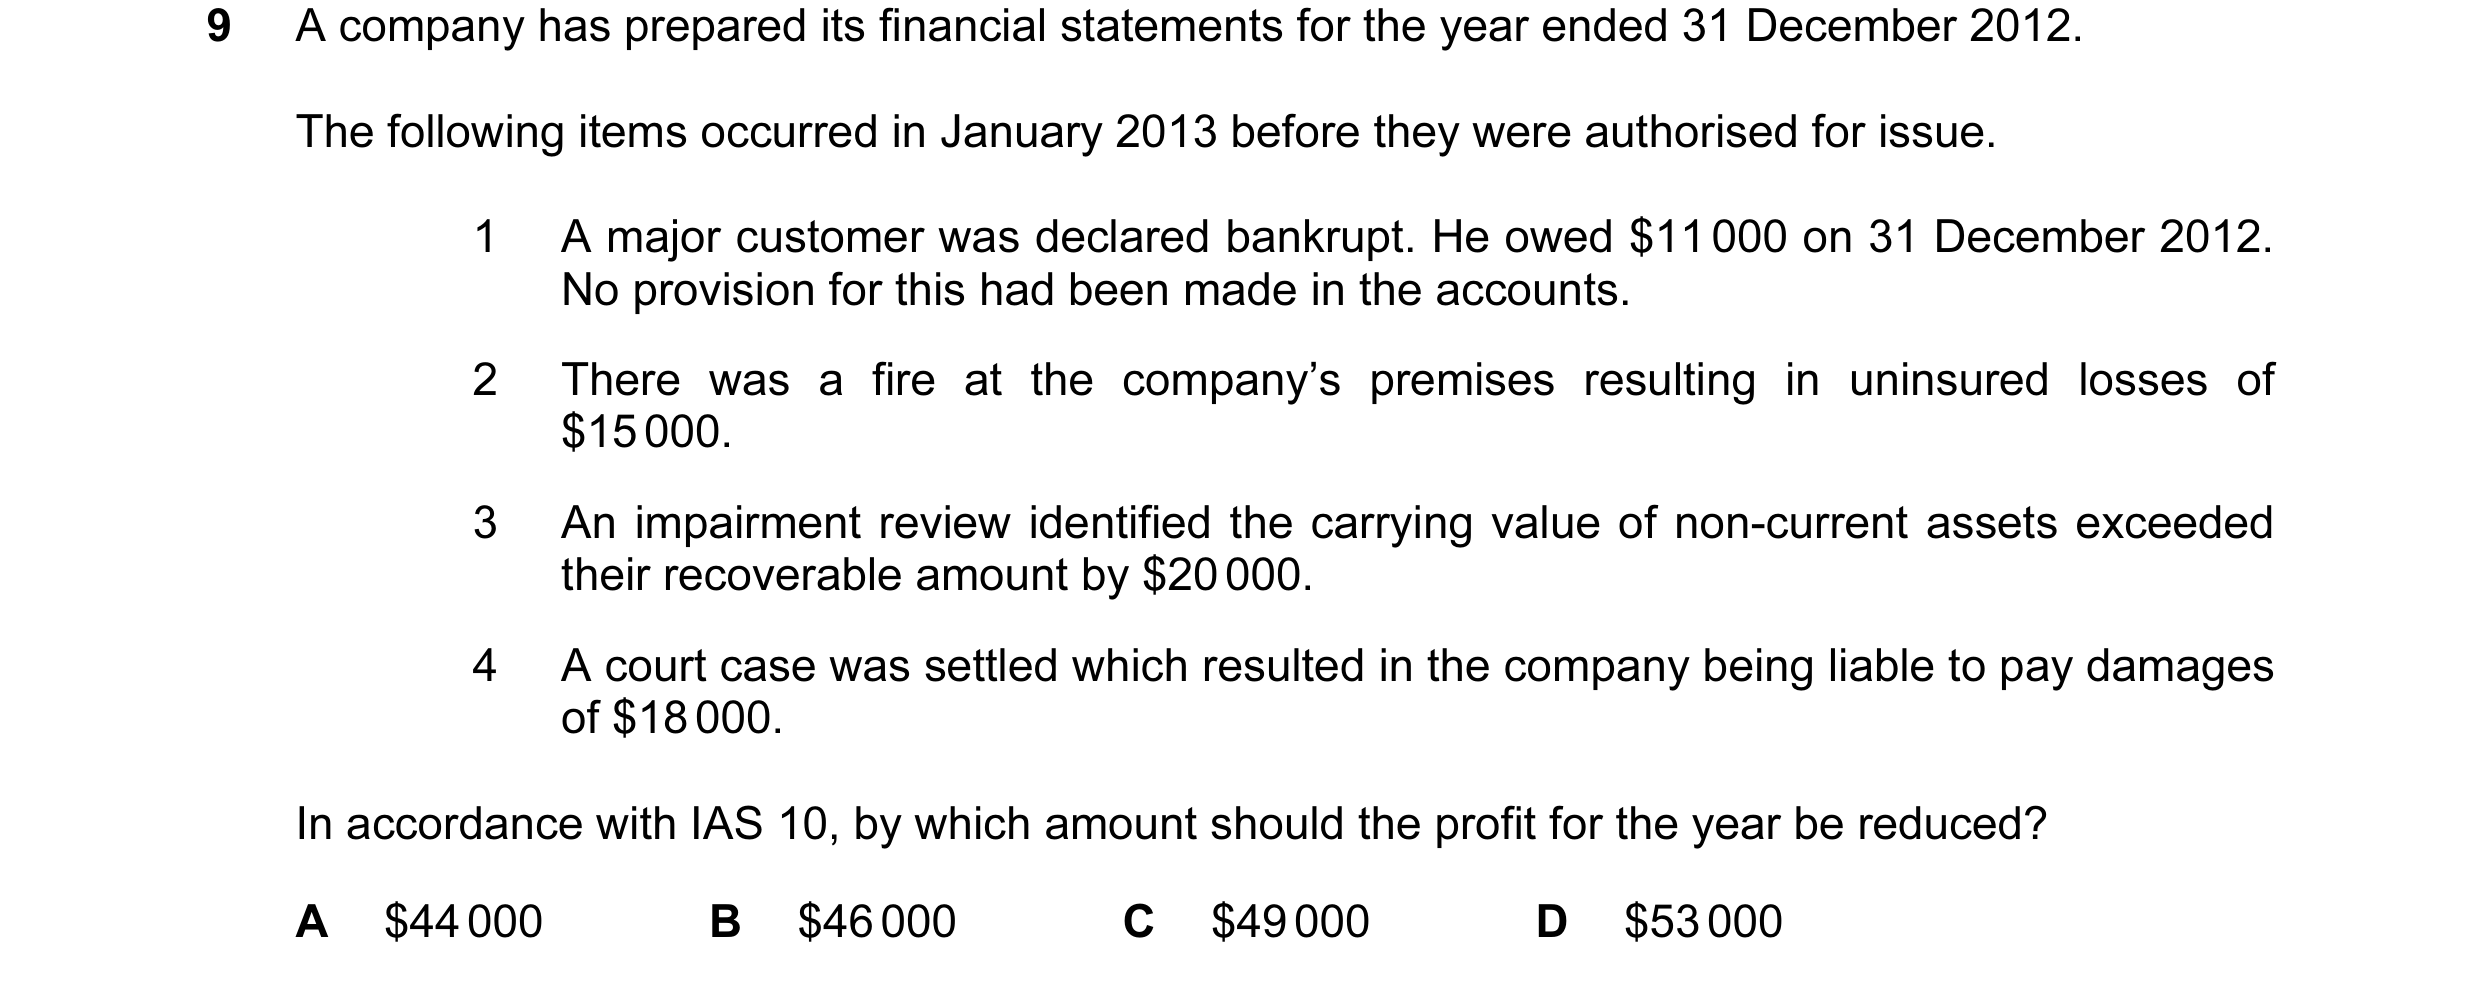
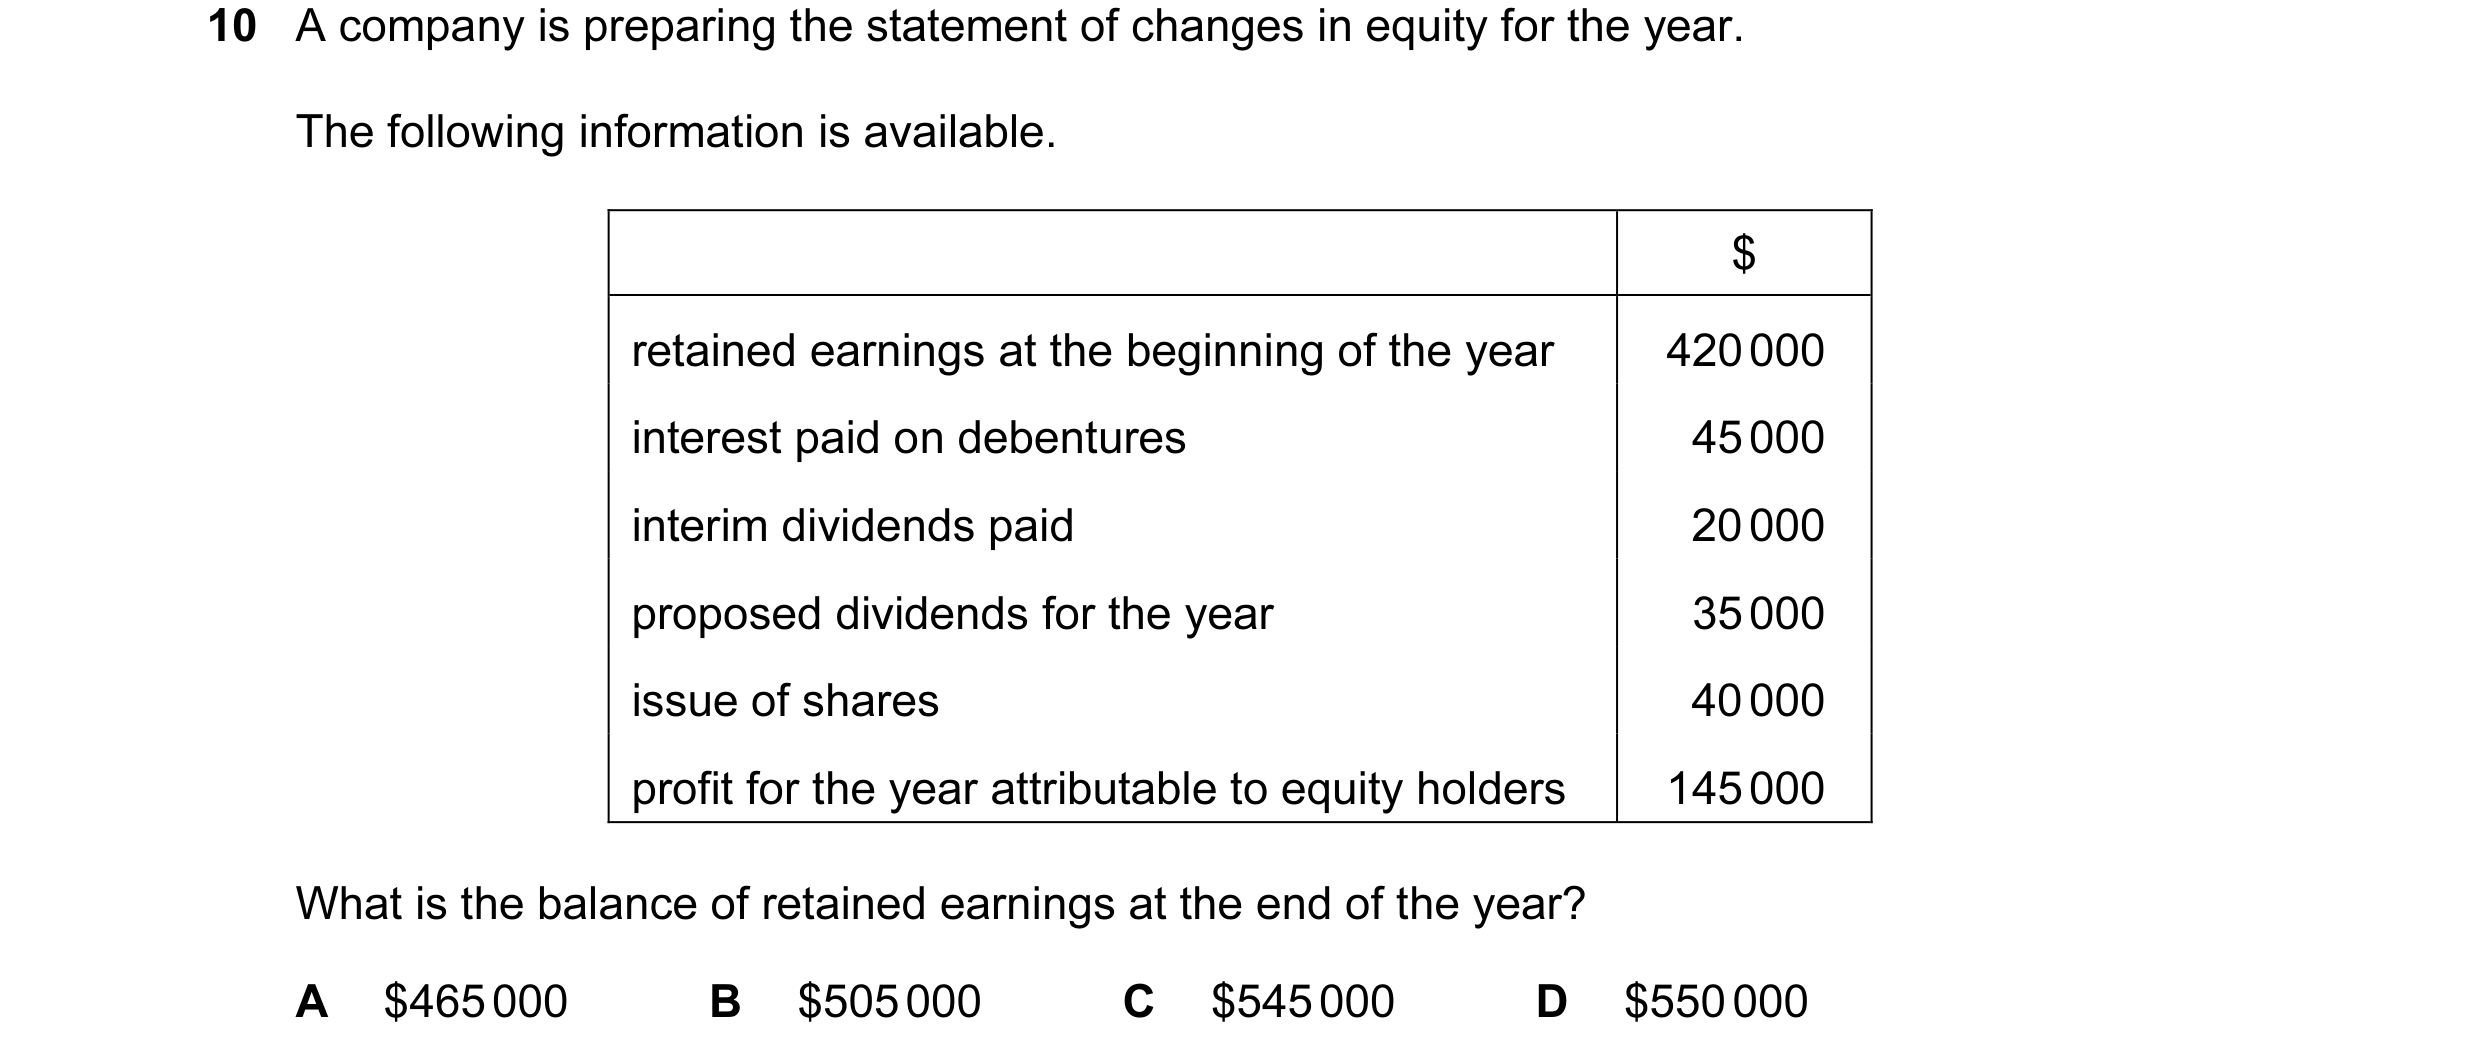
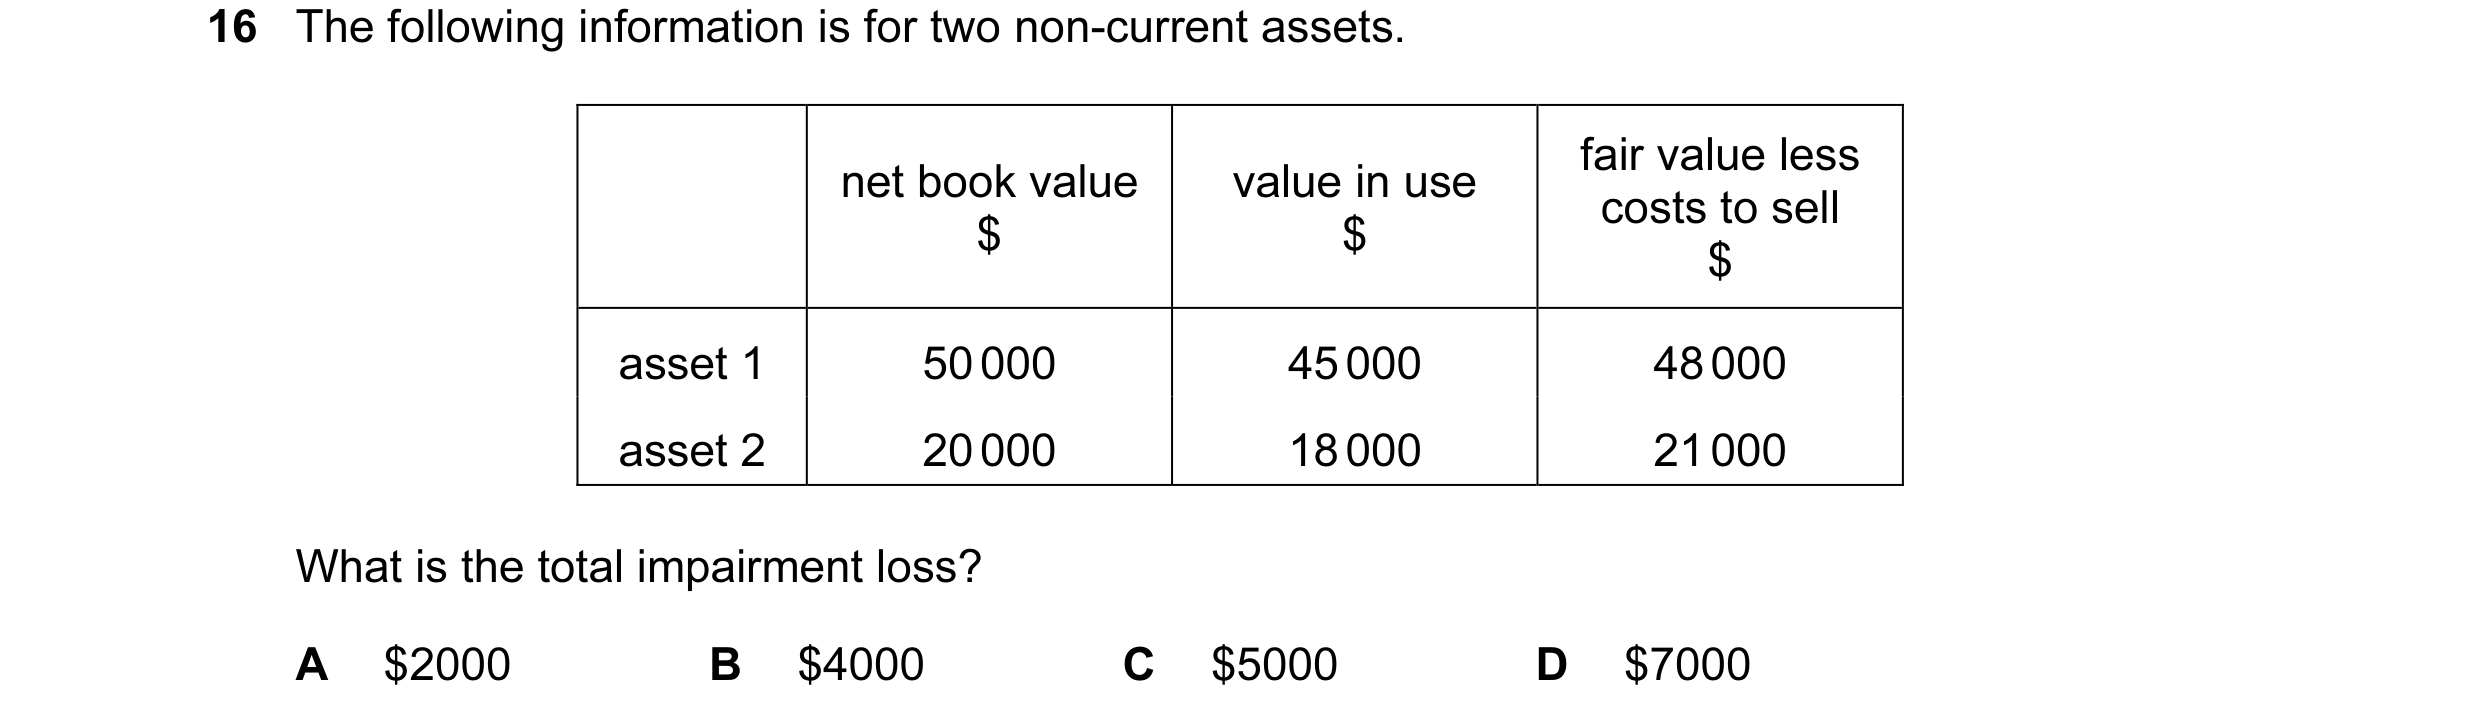 40 / 62
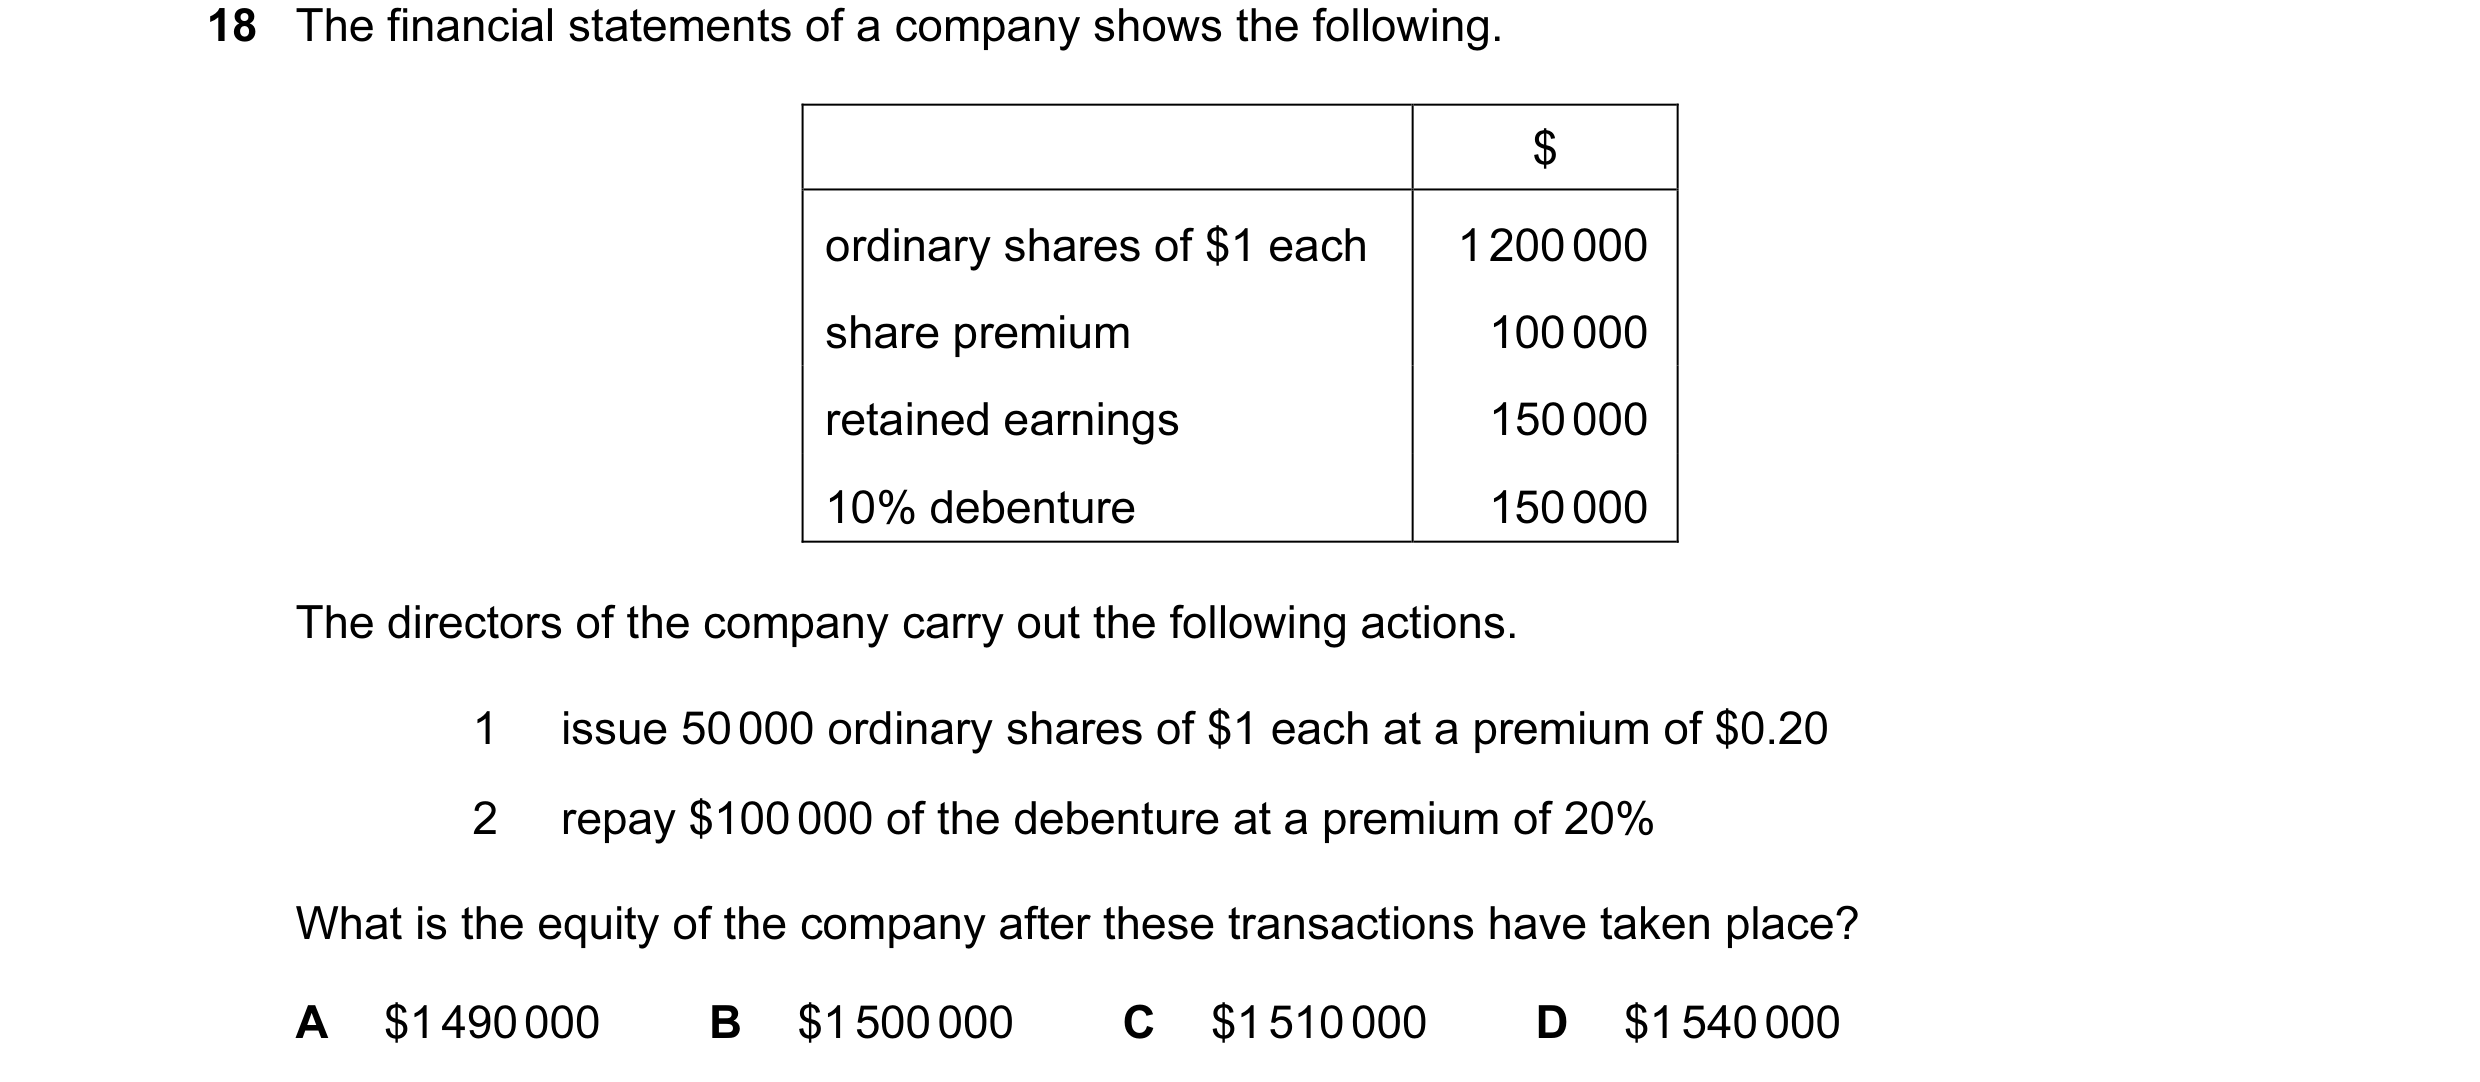
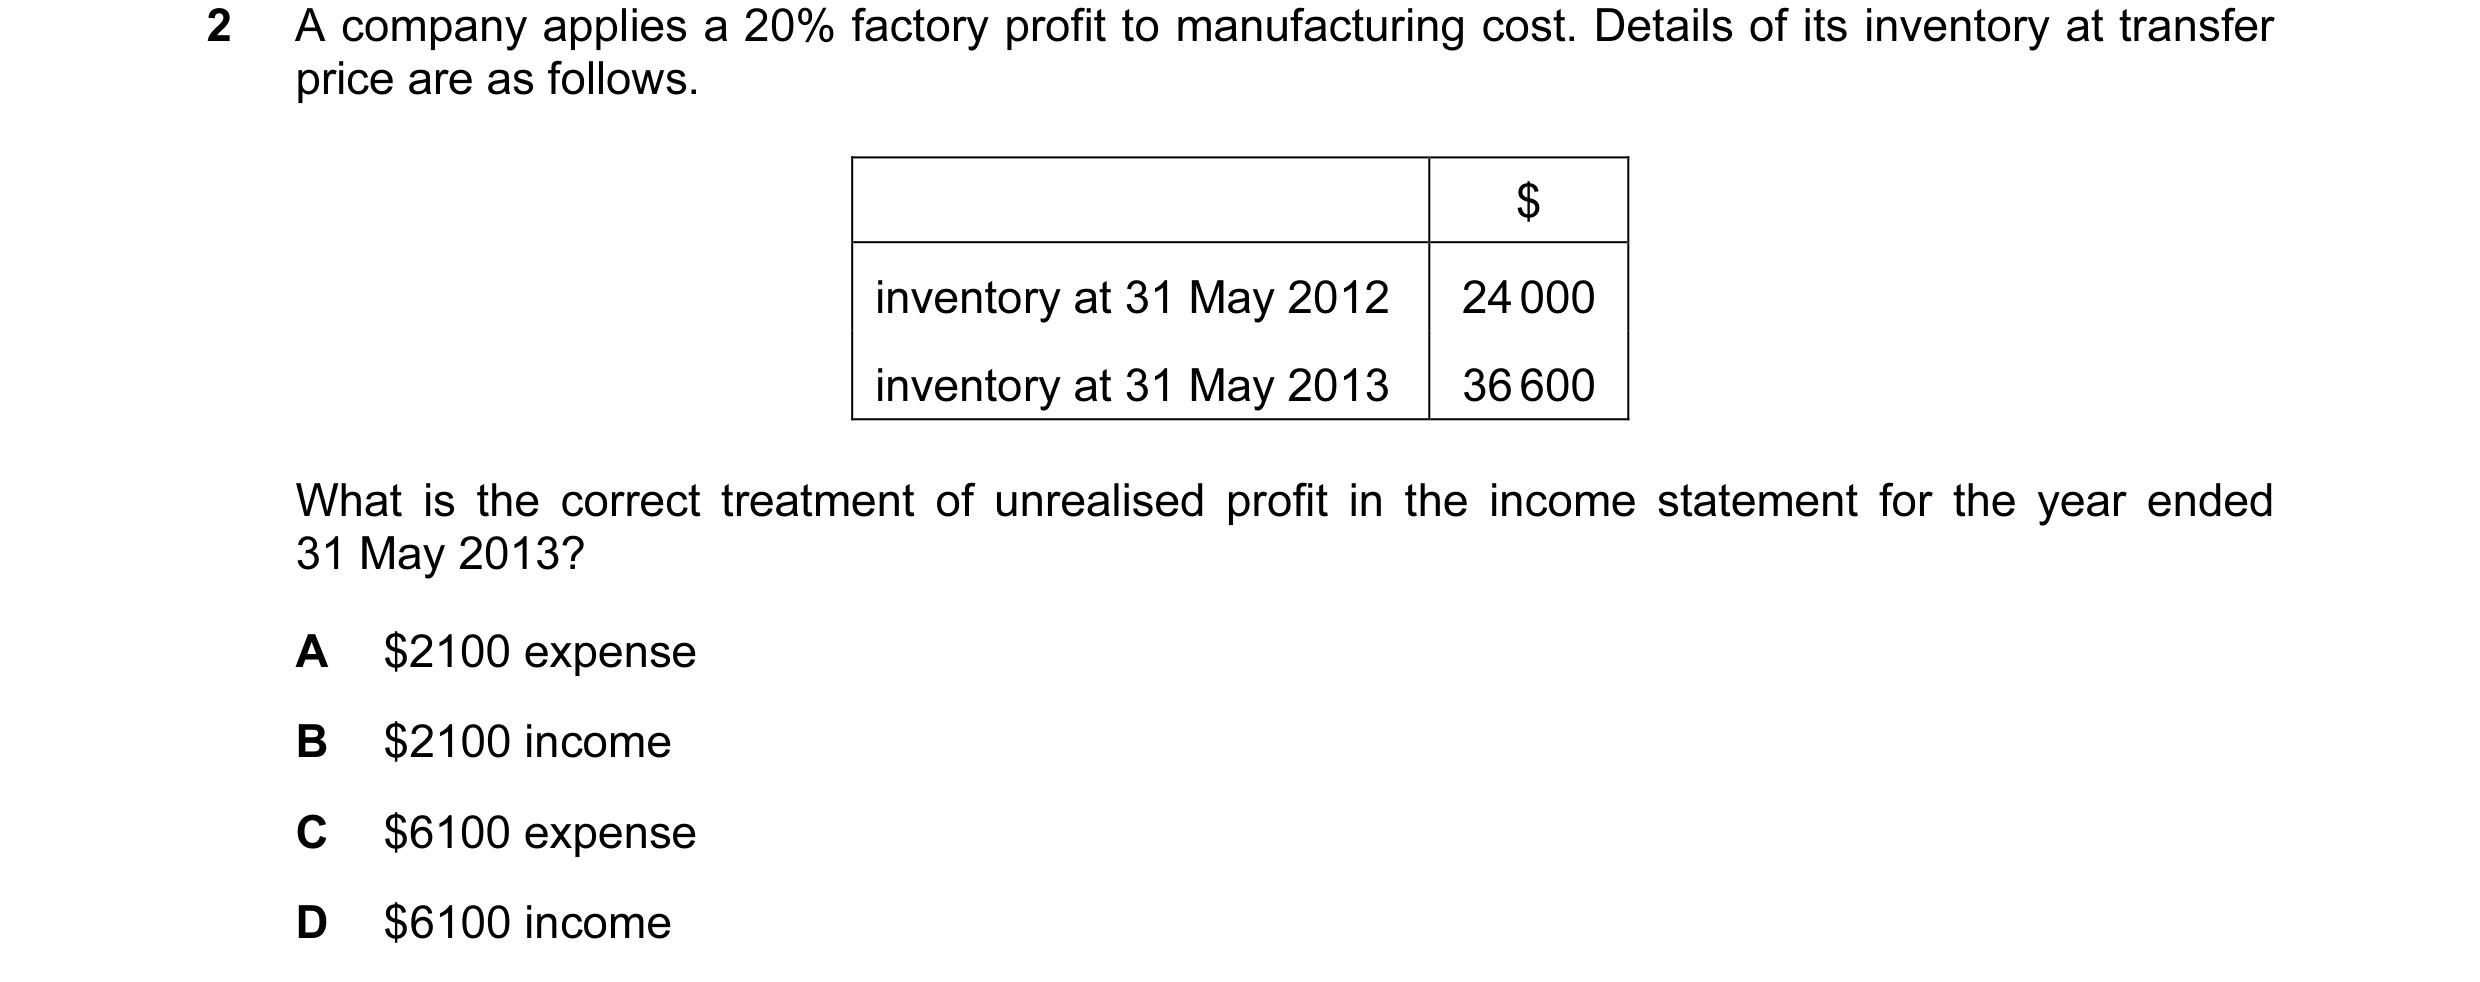 41 / 62
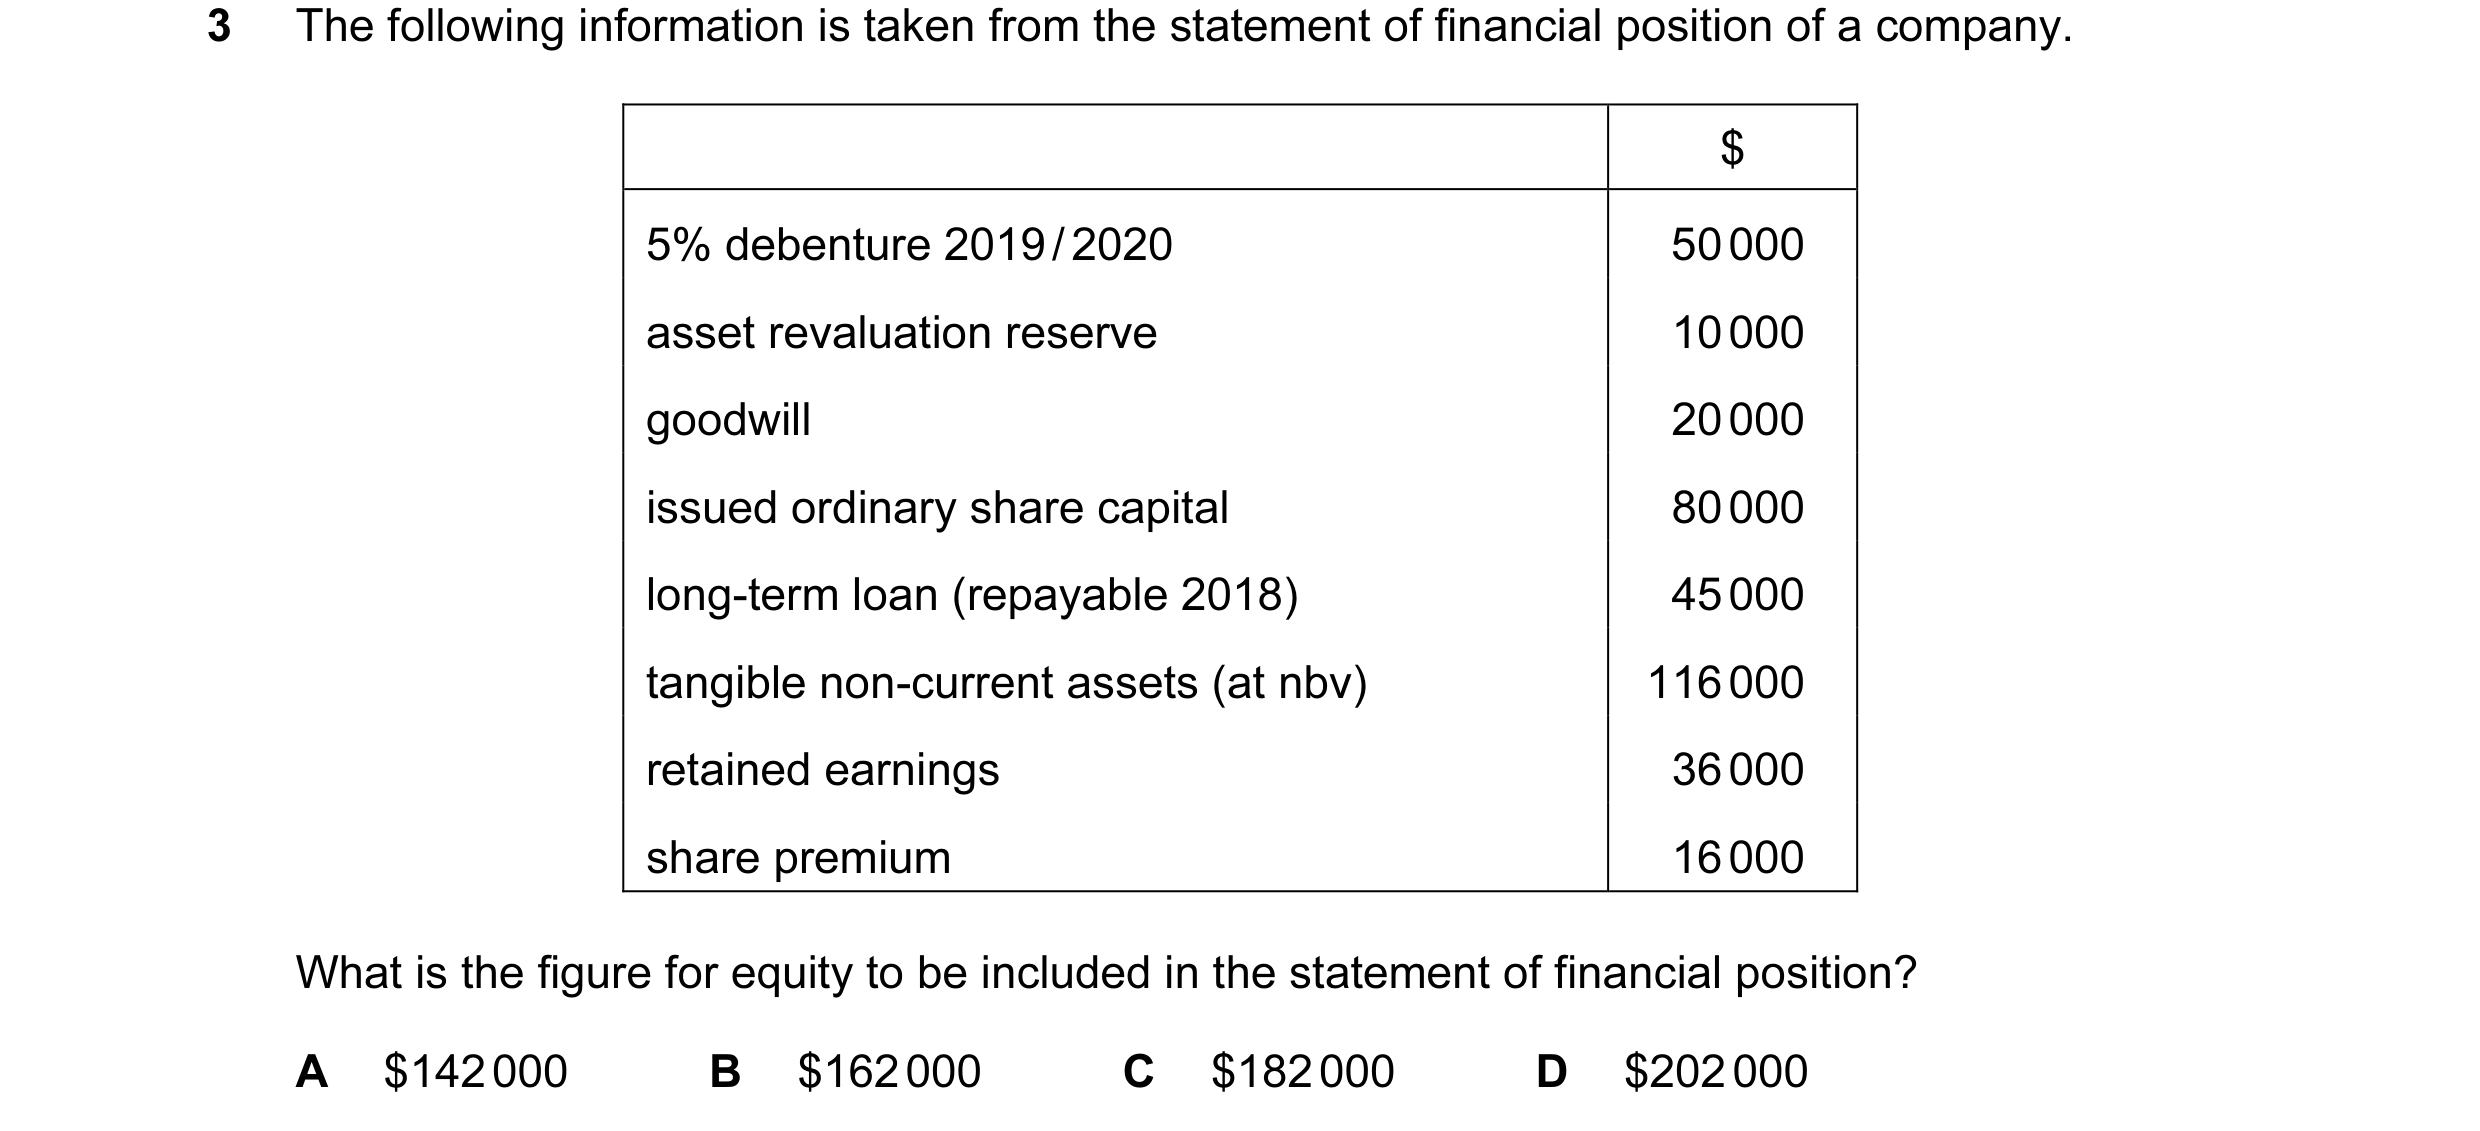
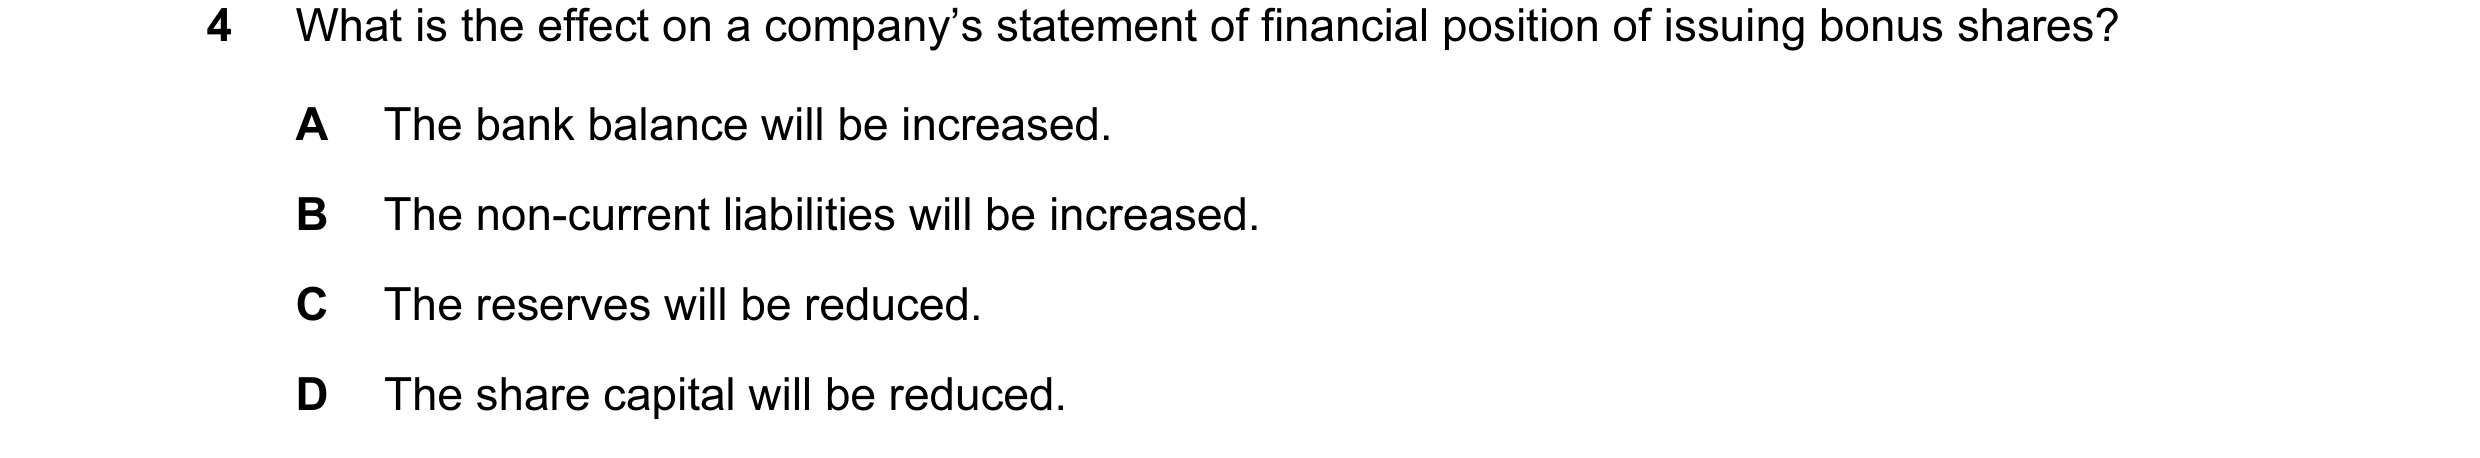
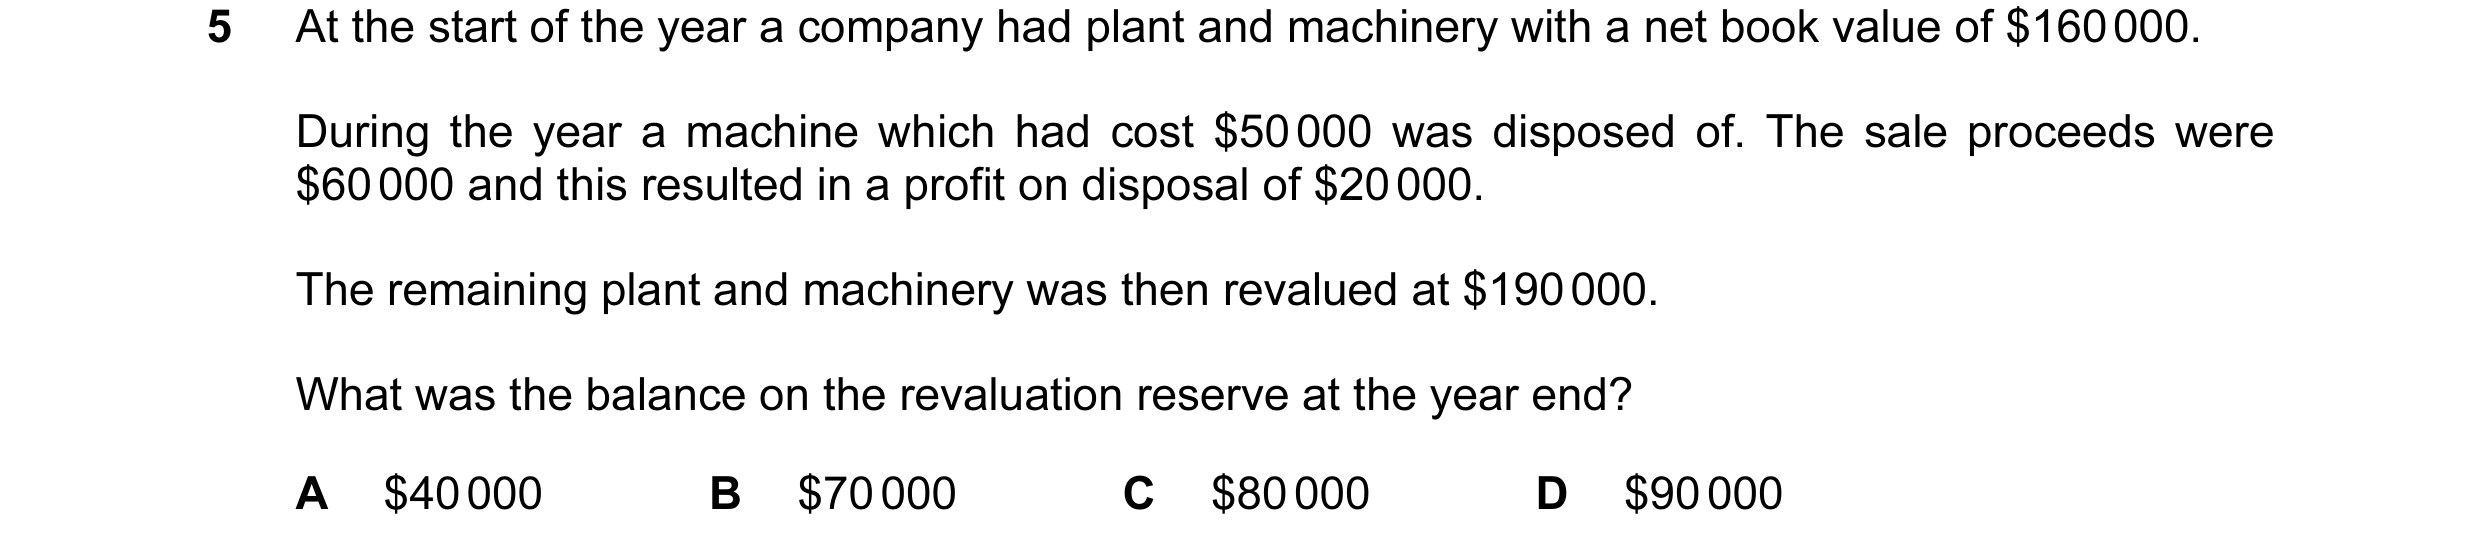
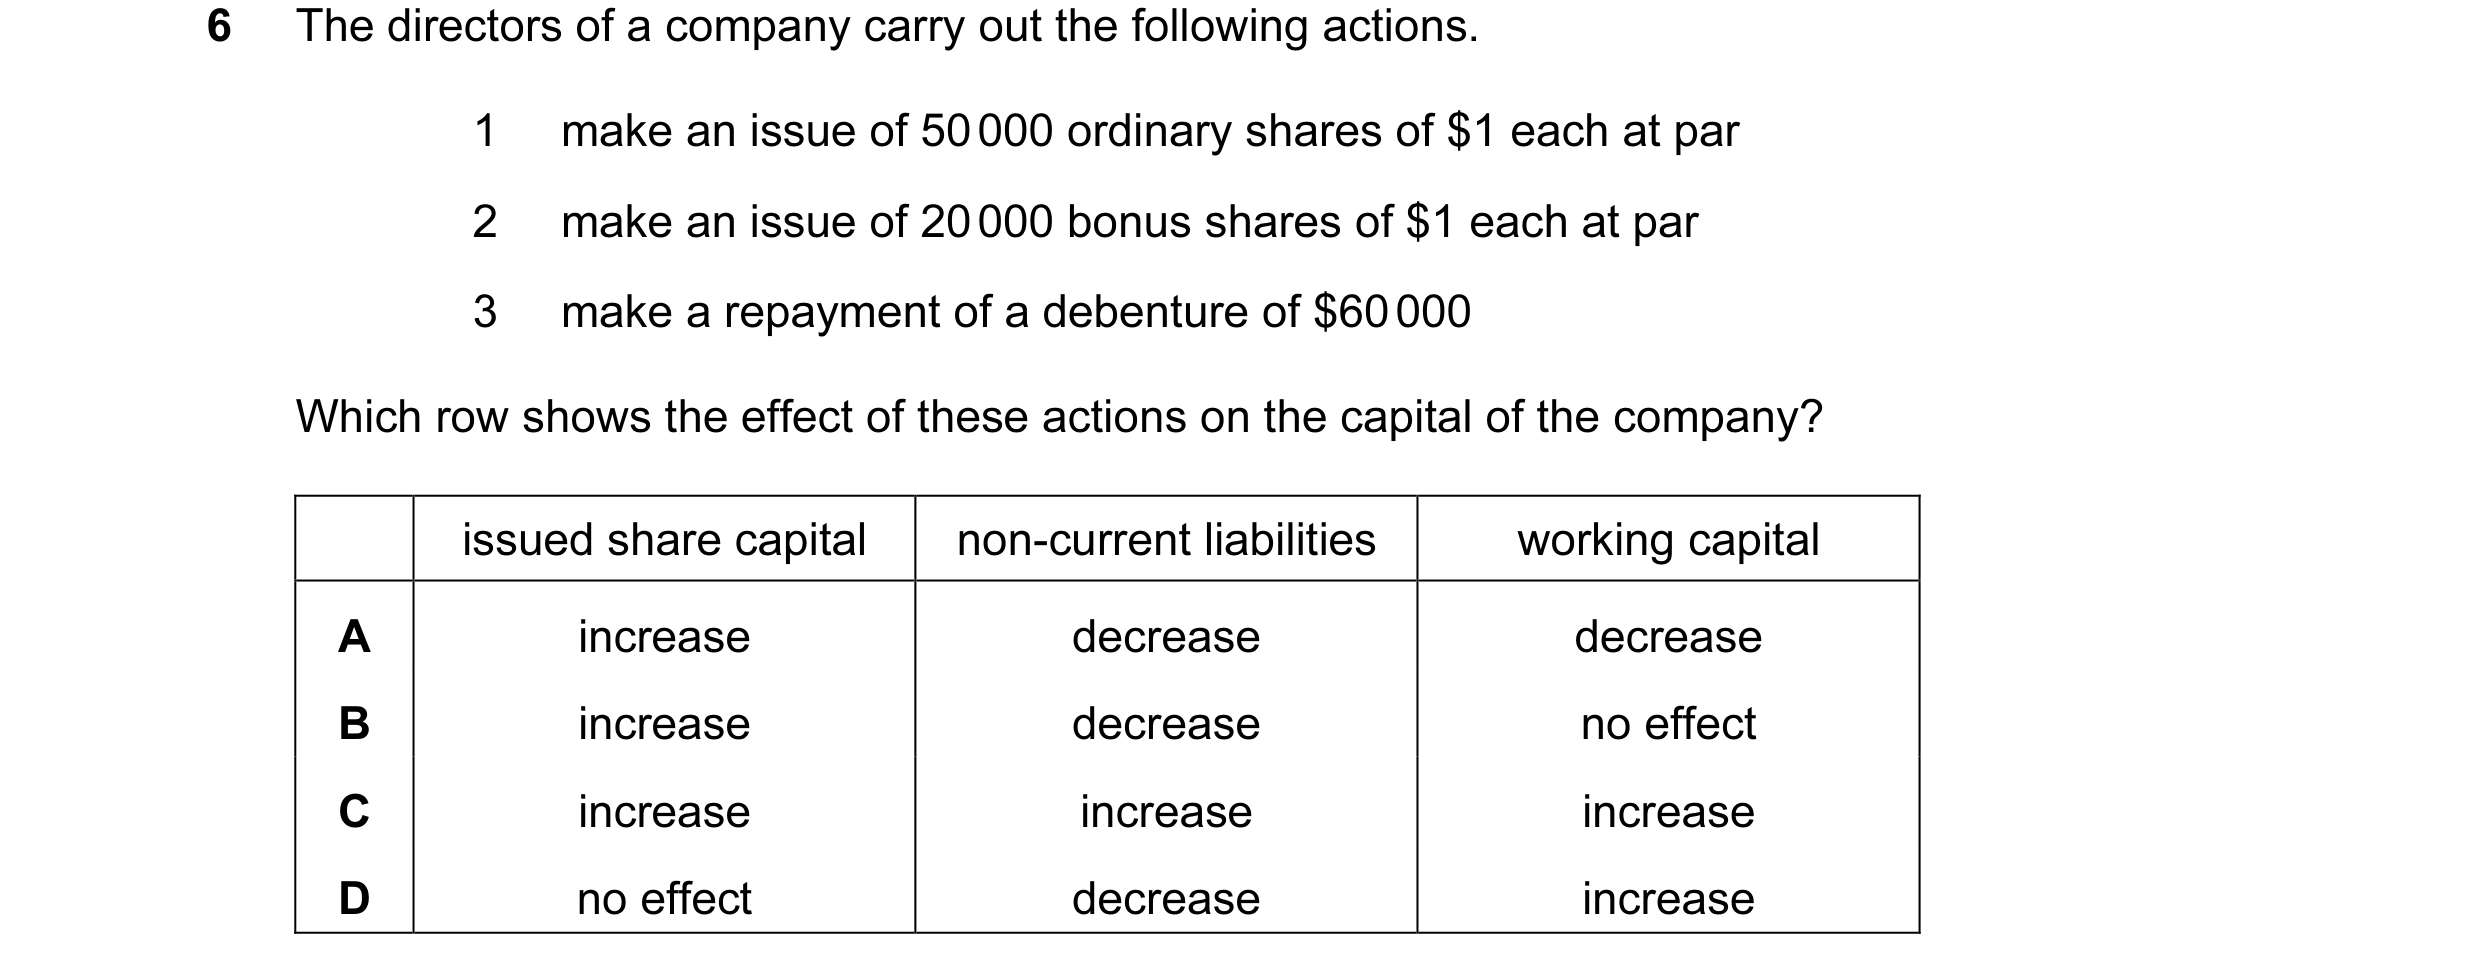 42 / 62
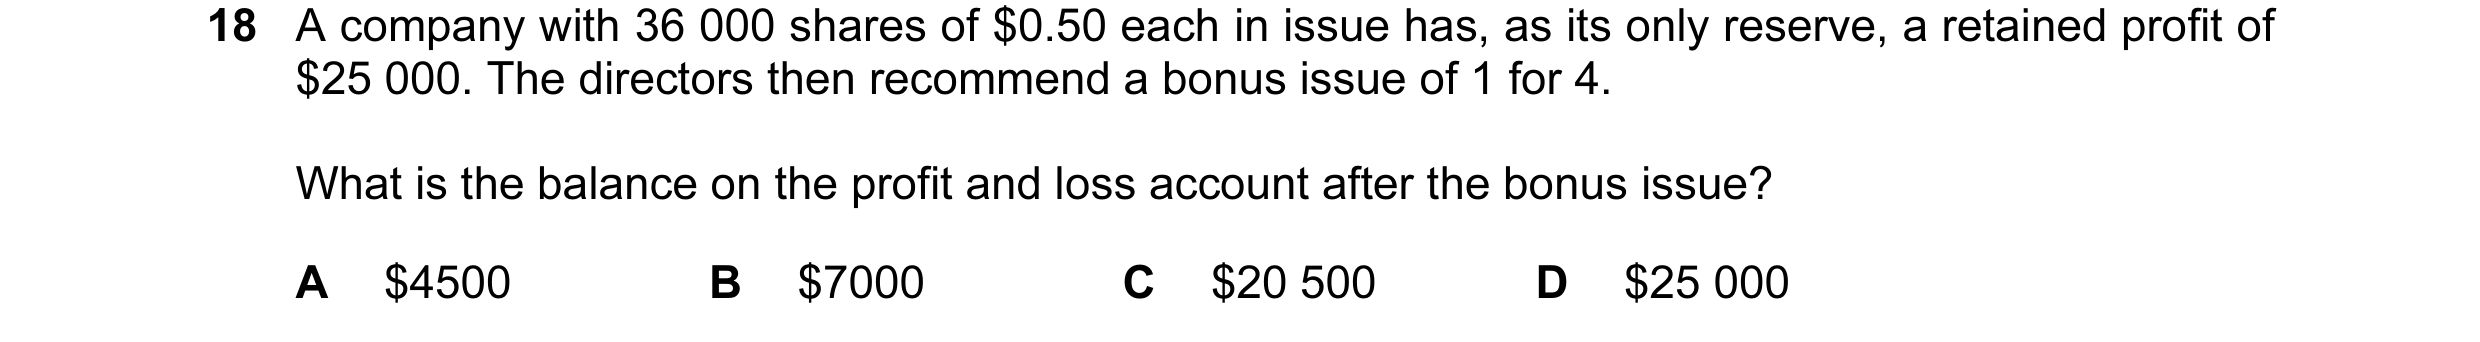
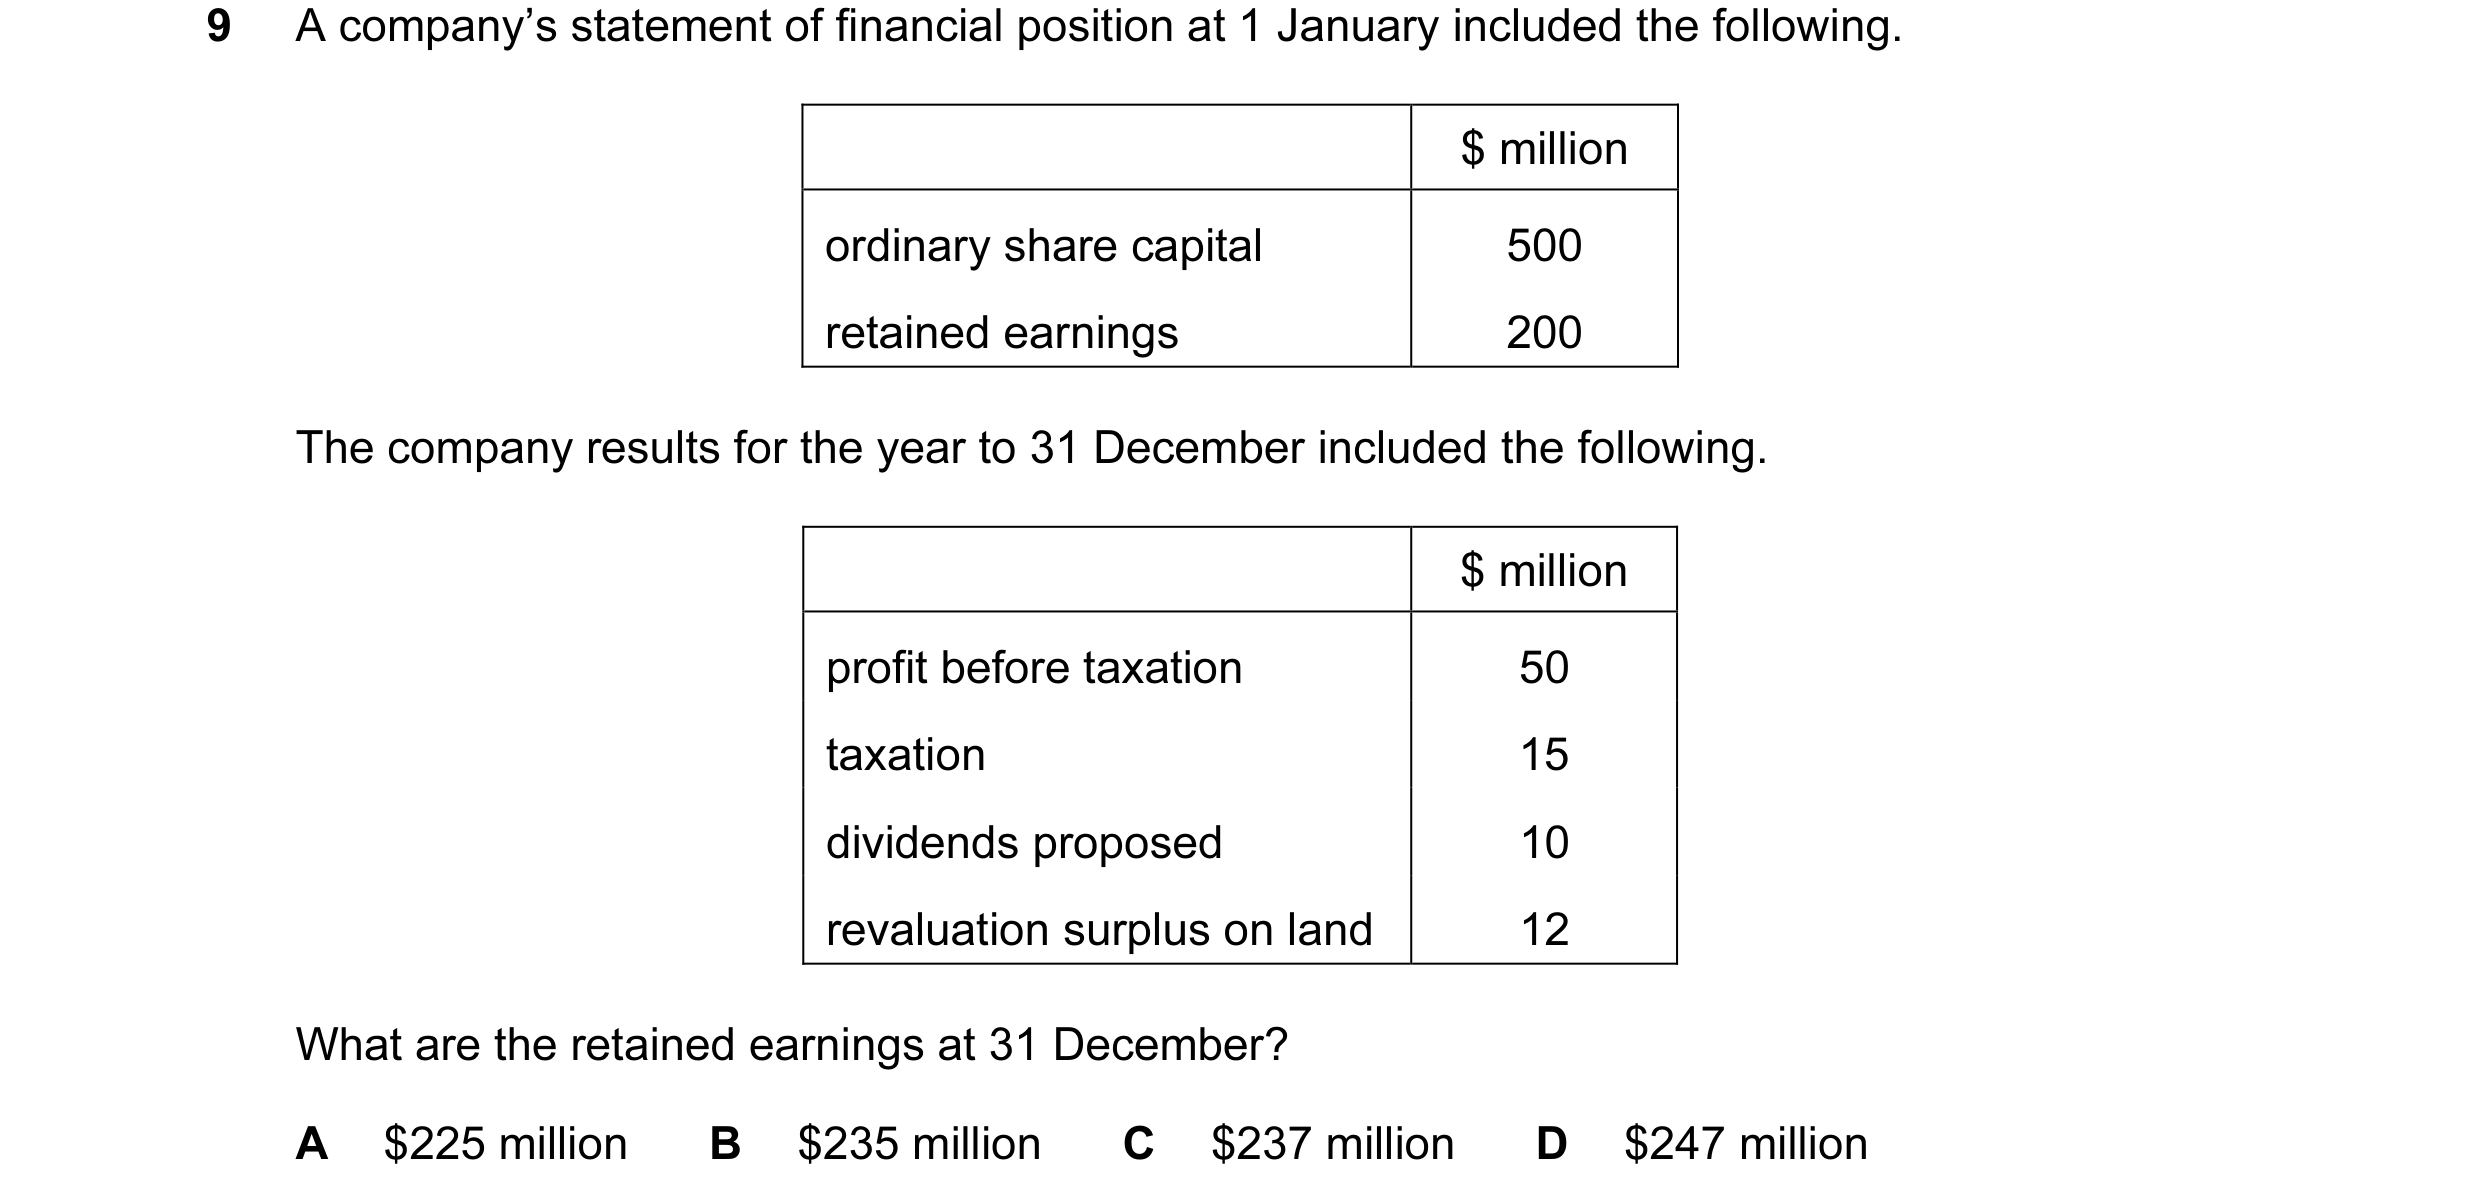
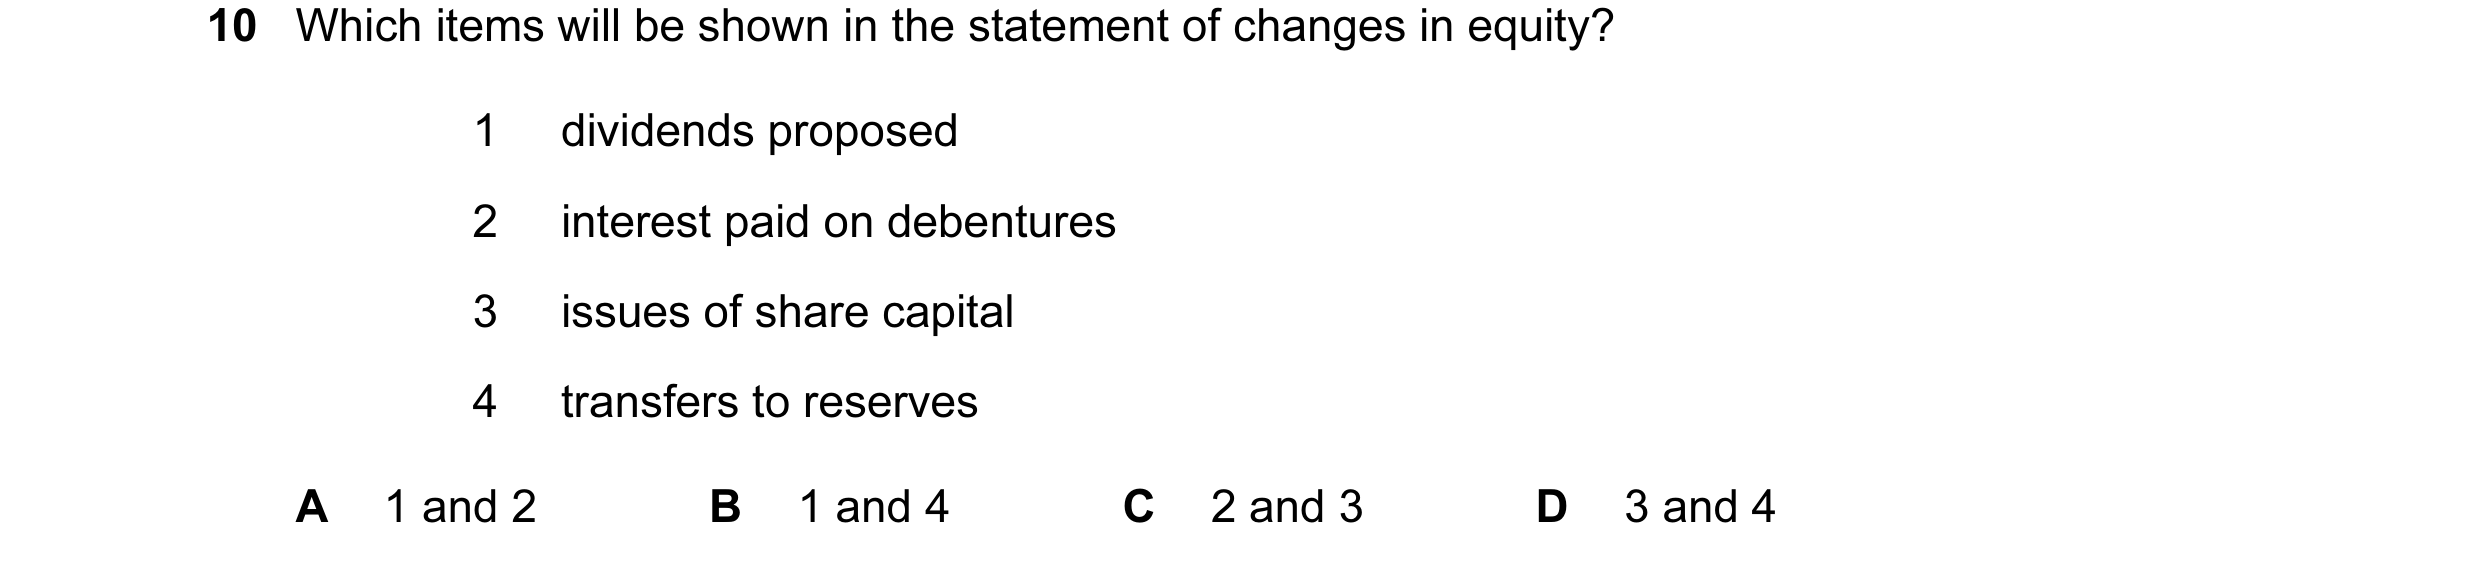
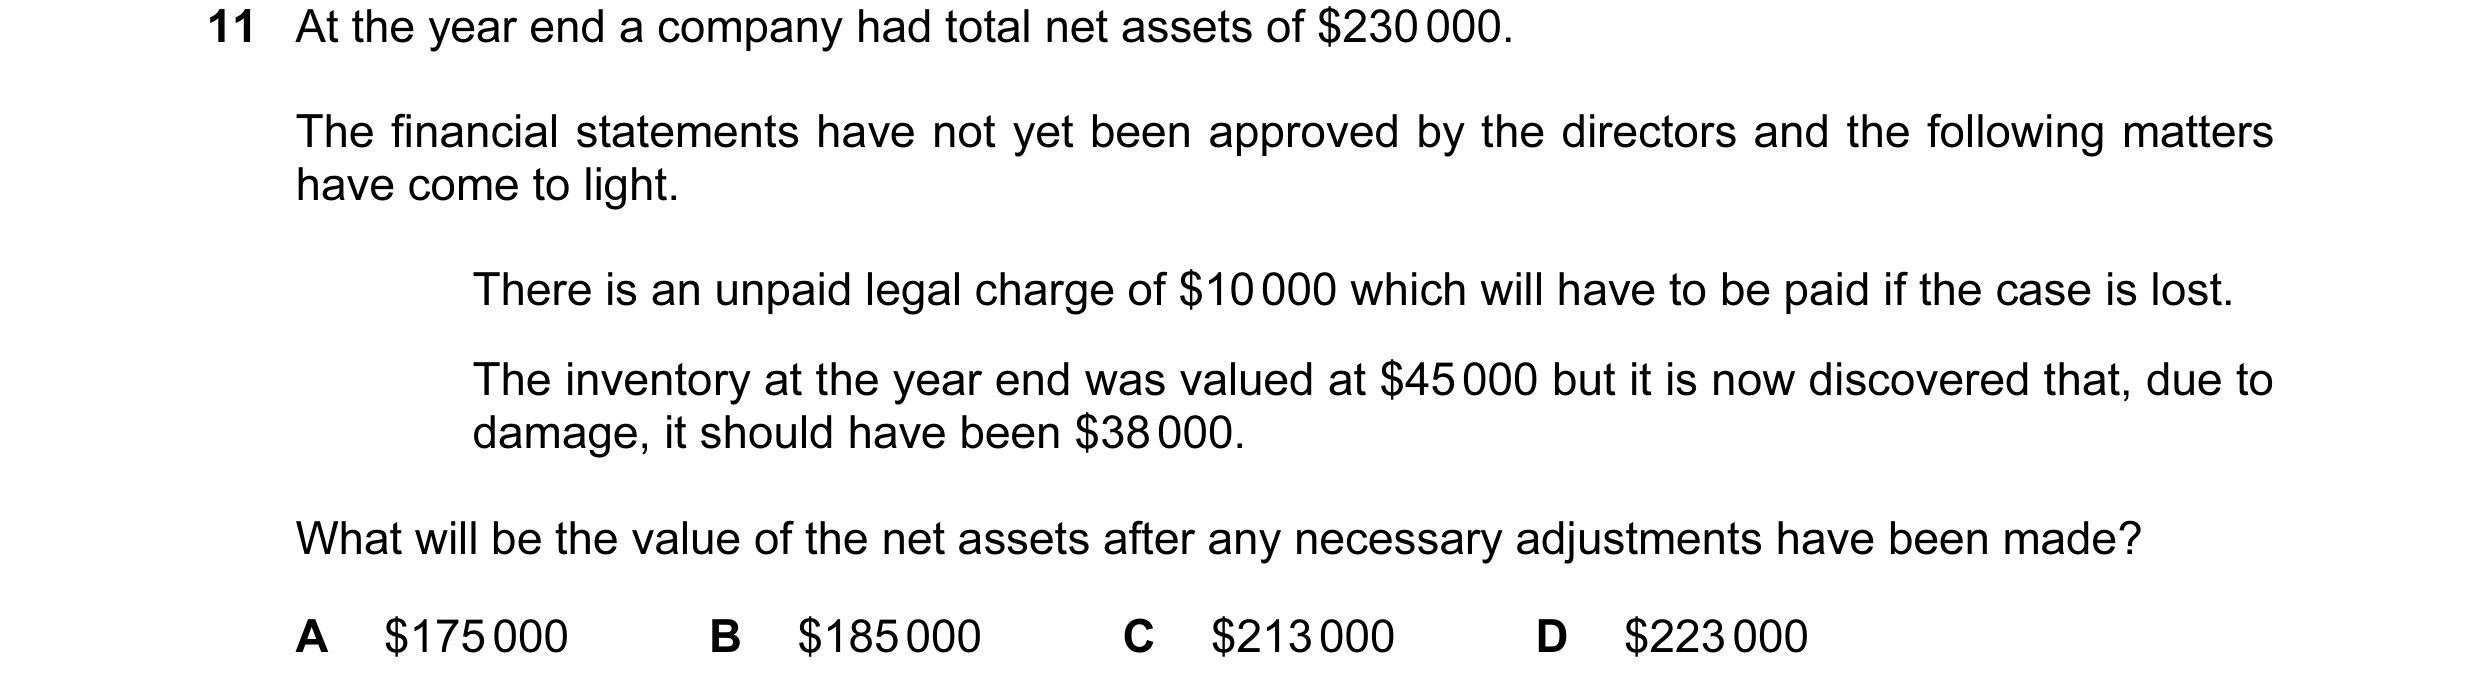 43 / 62
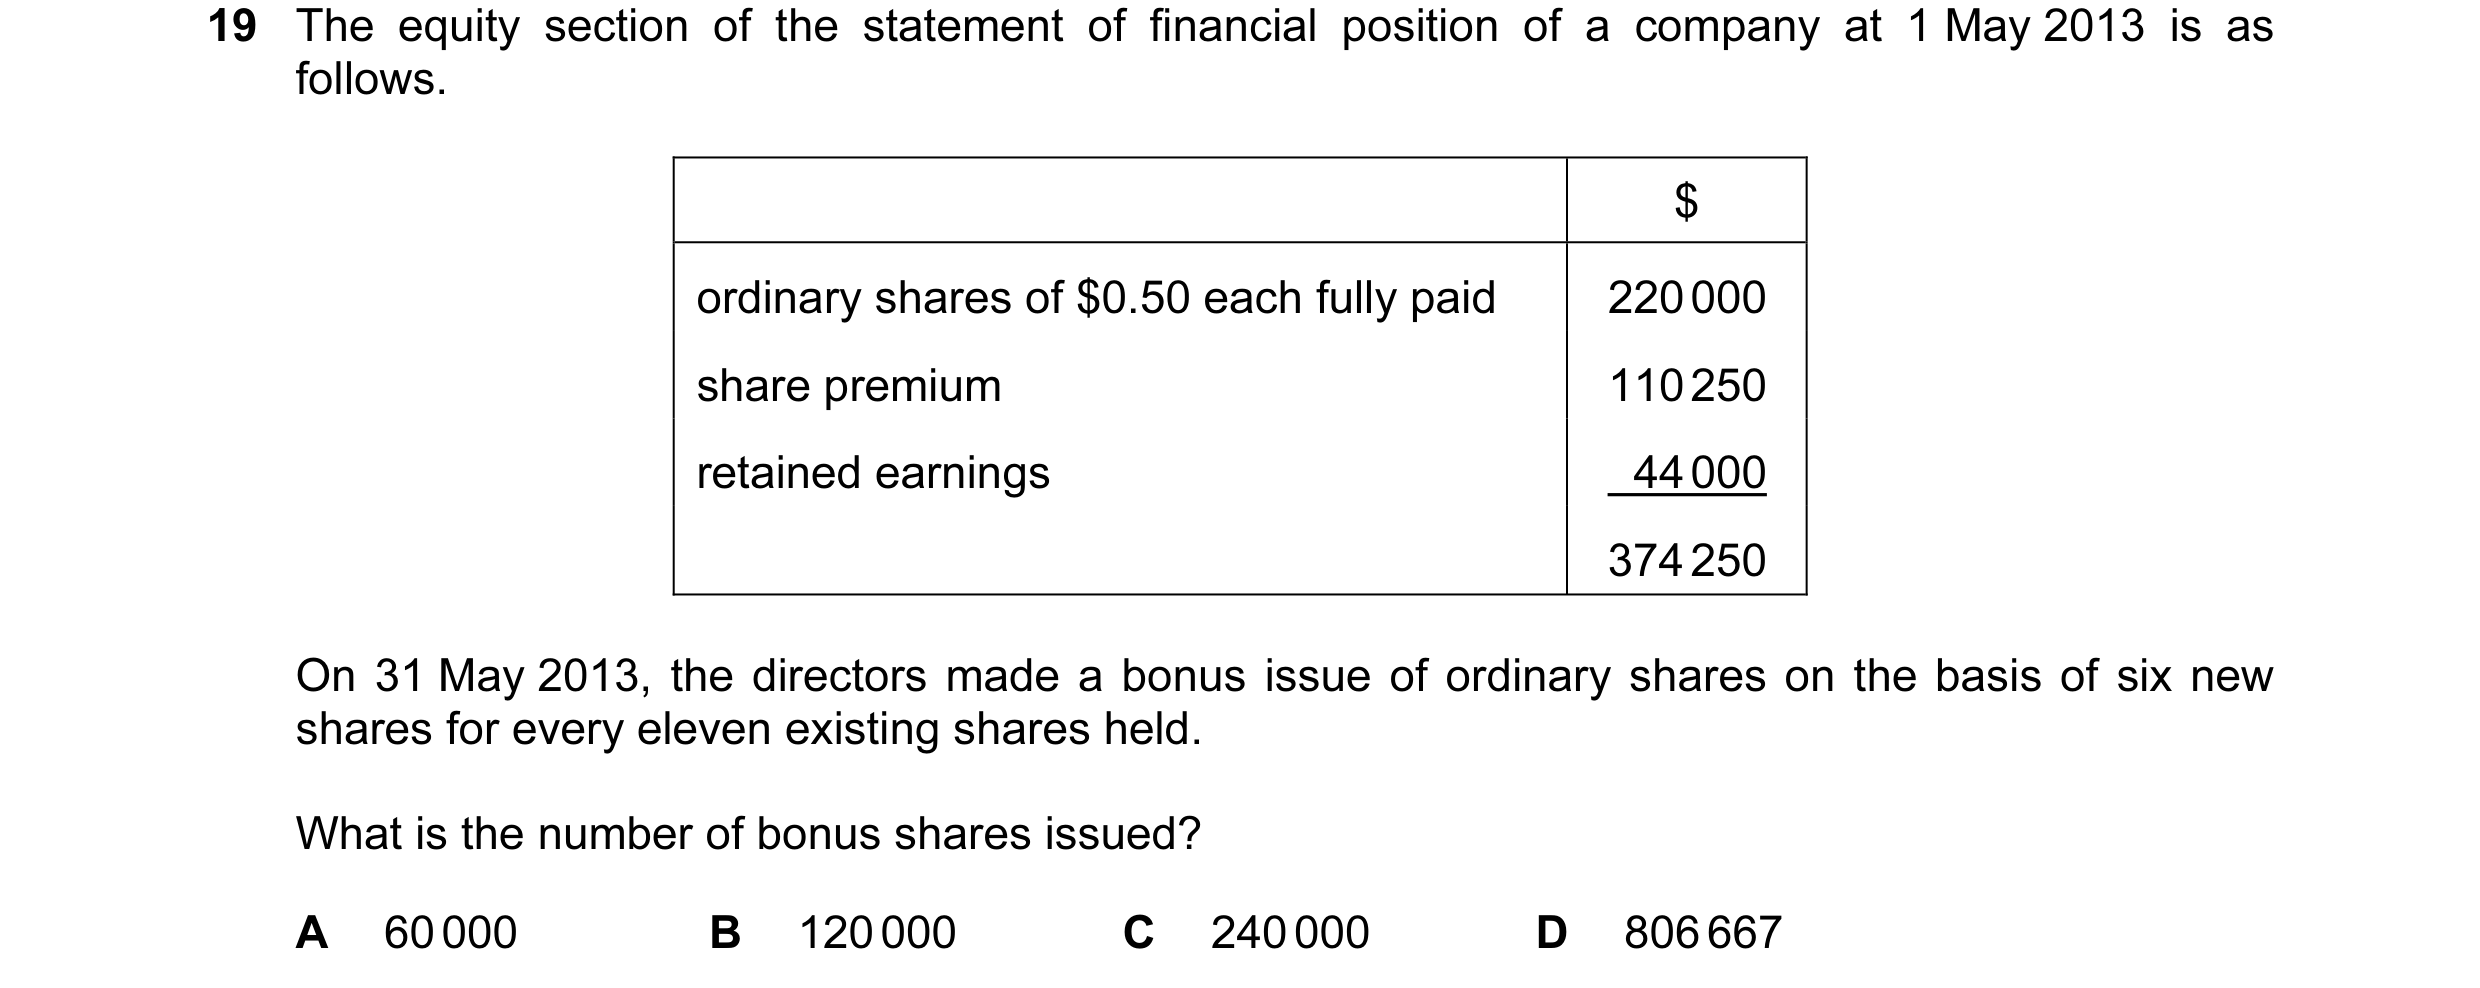
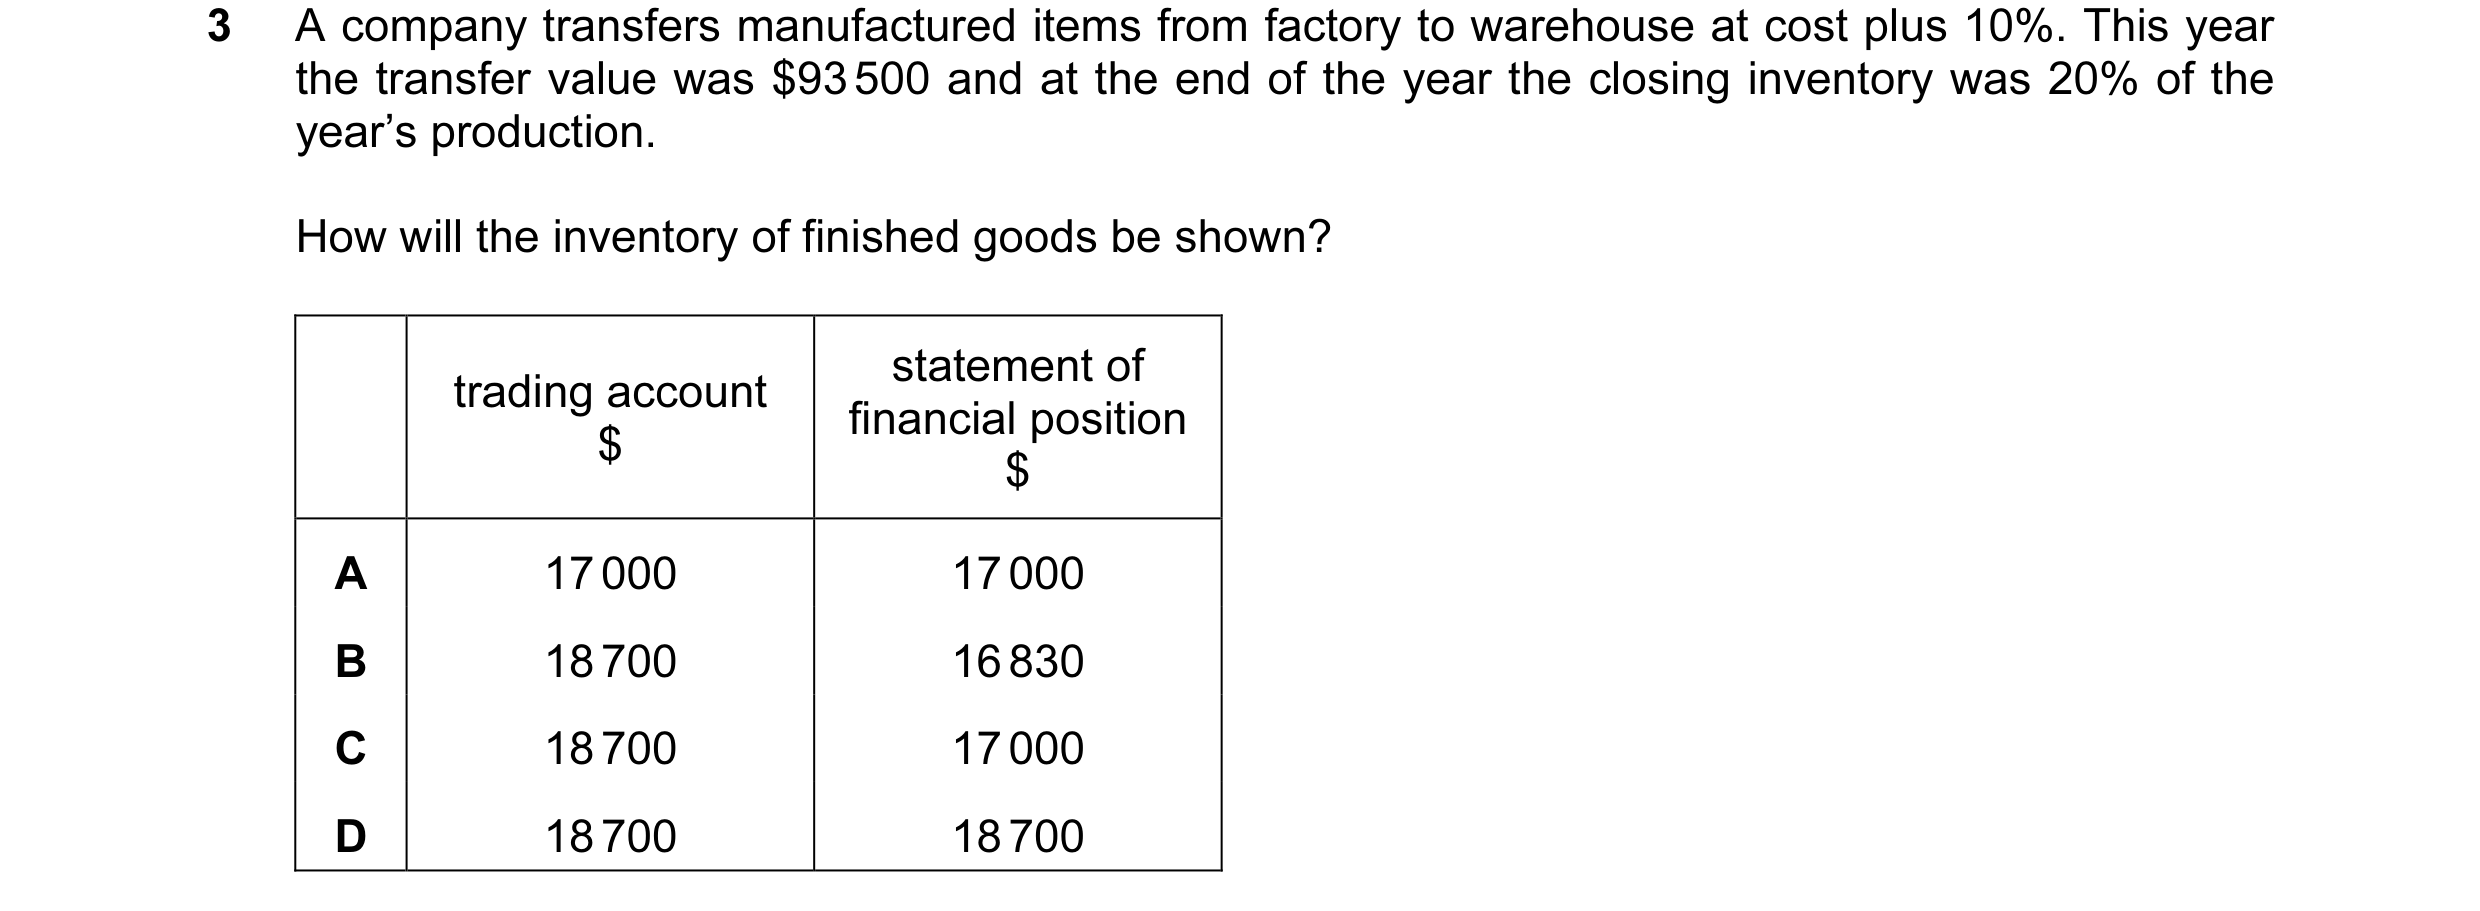
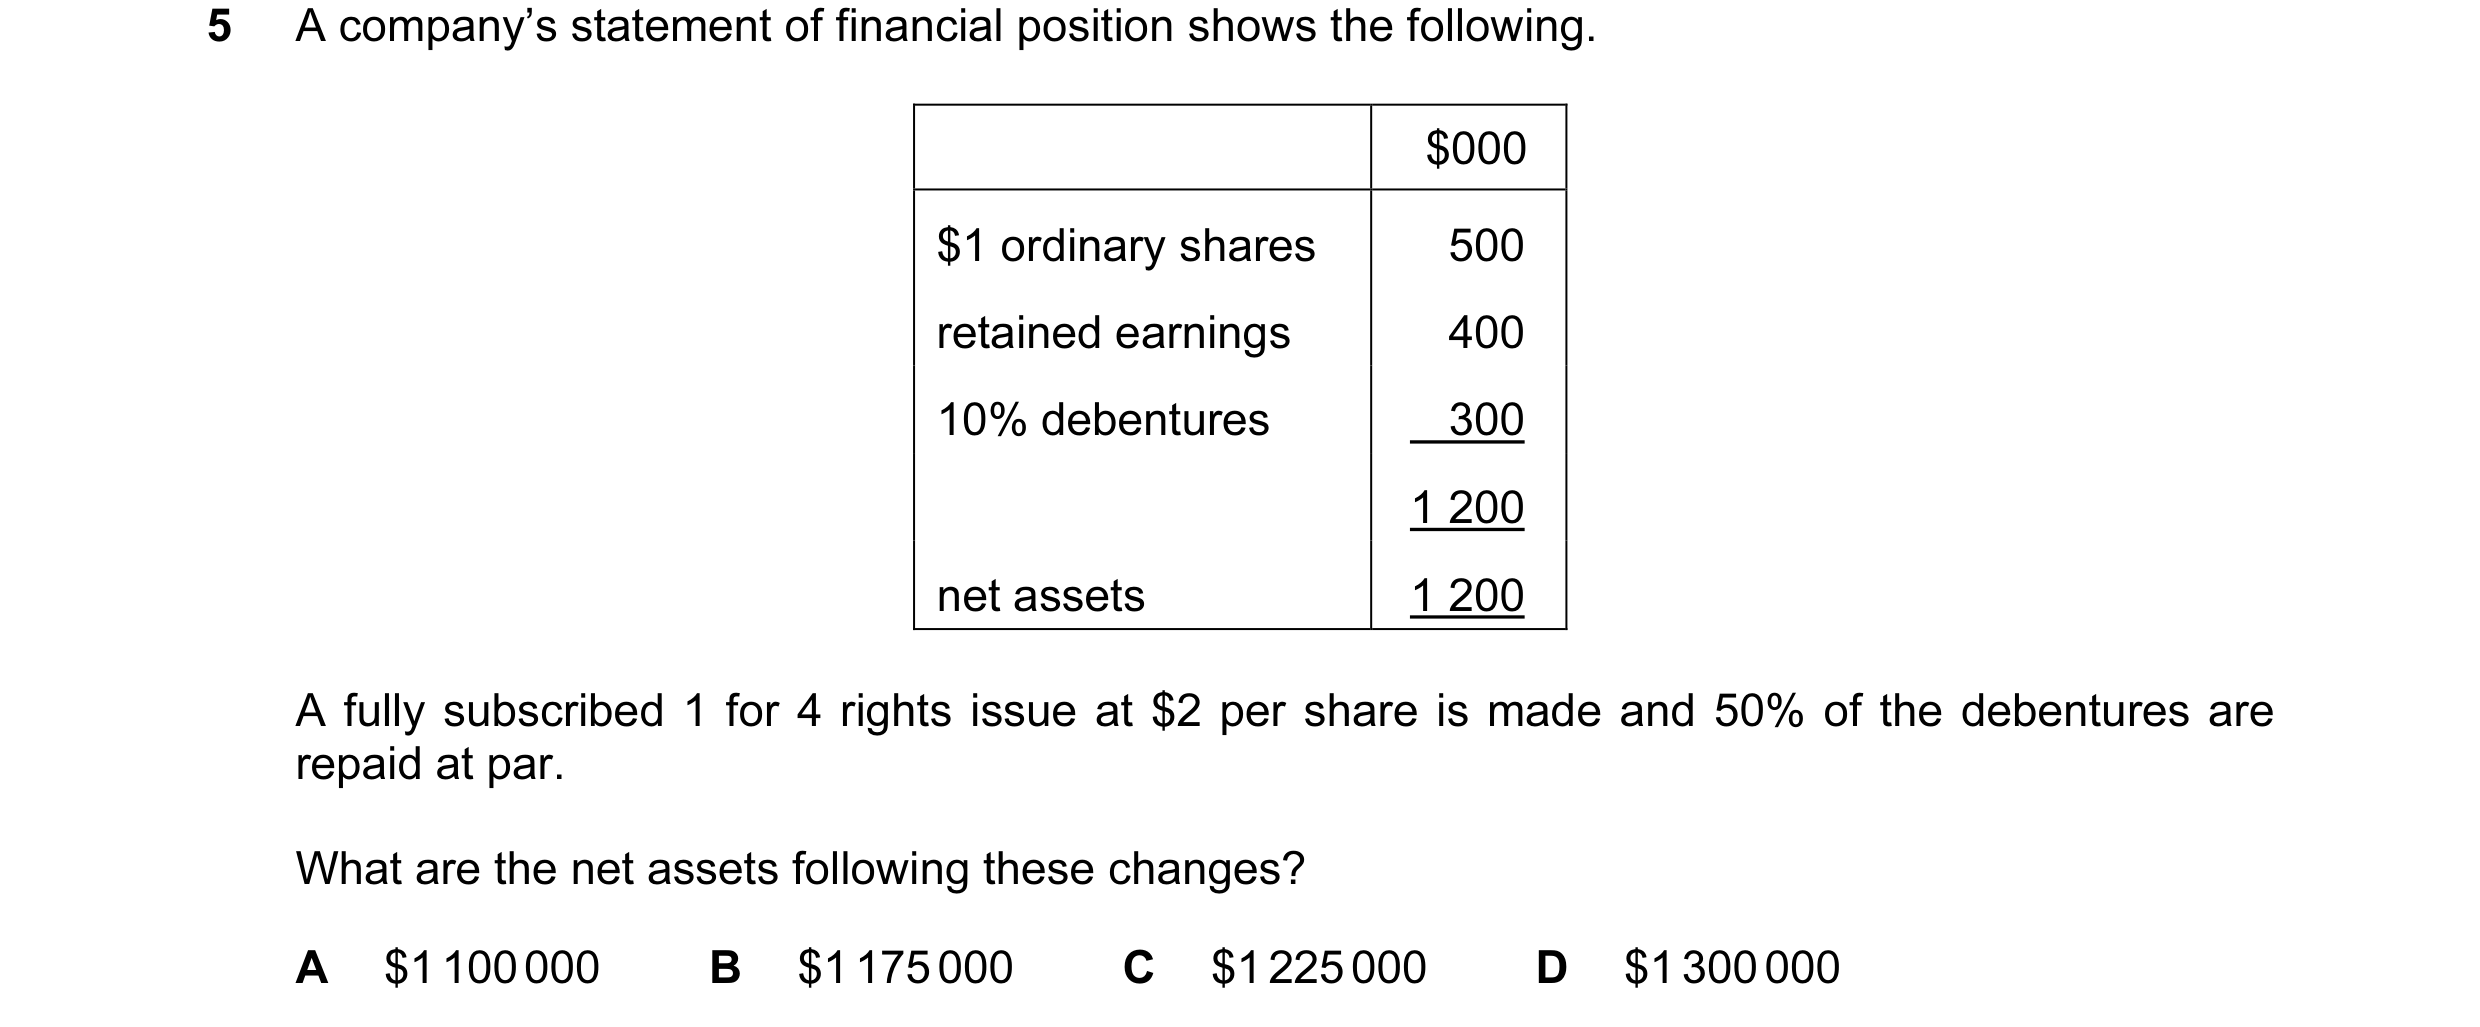 44 / 62
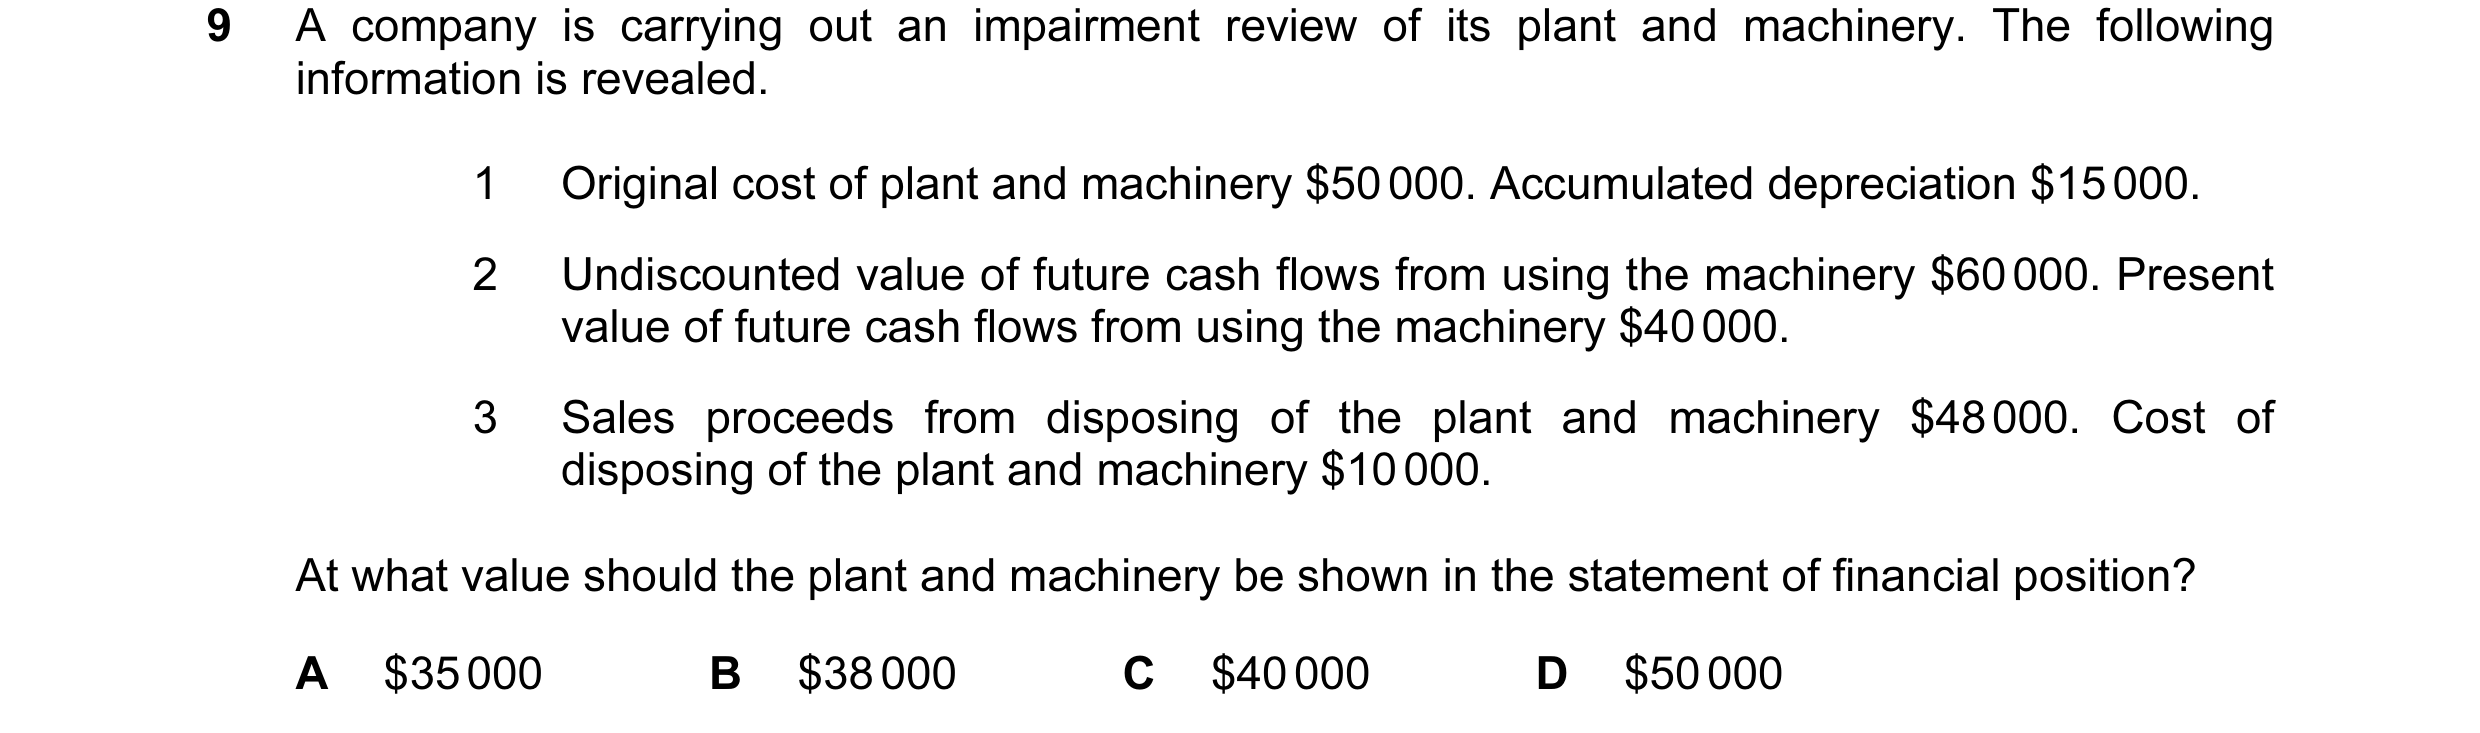
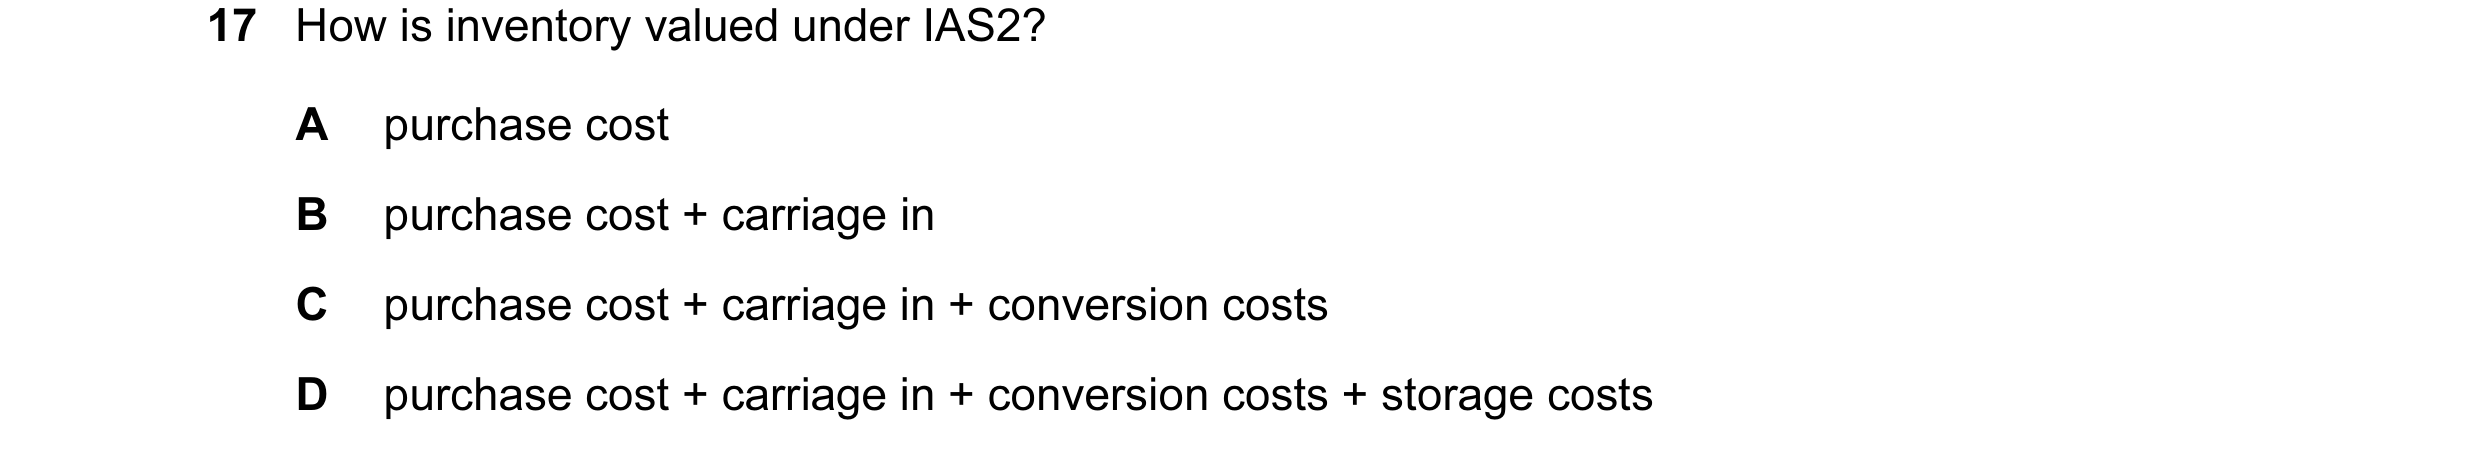
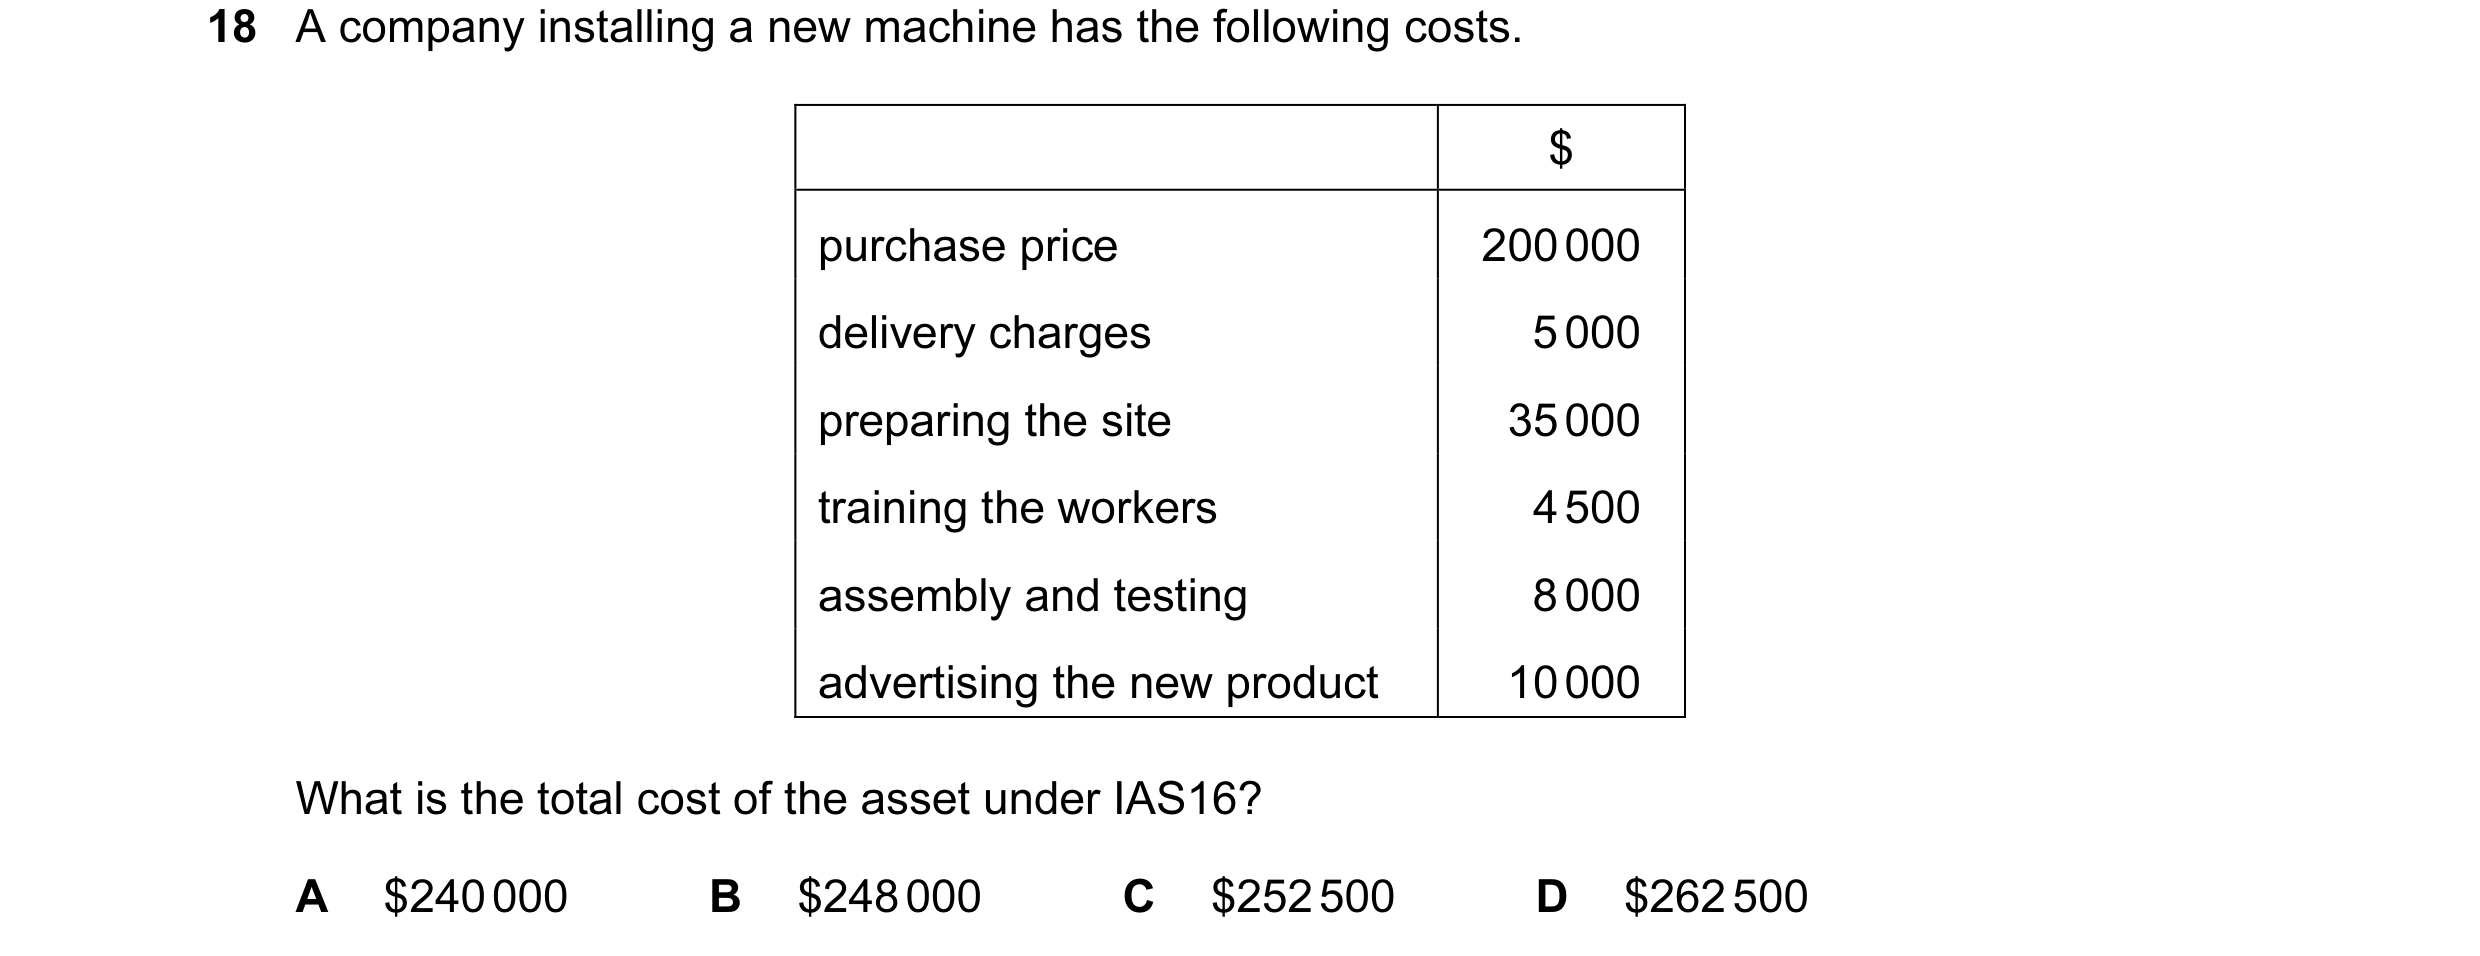 45 / 62
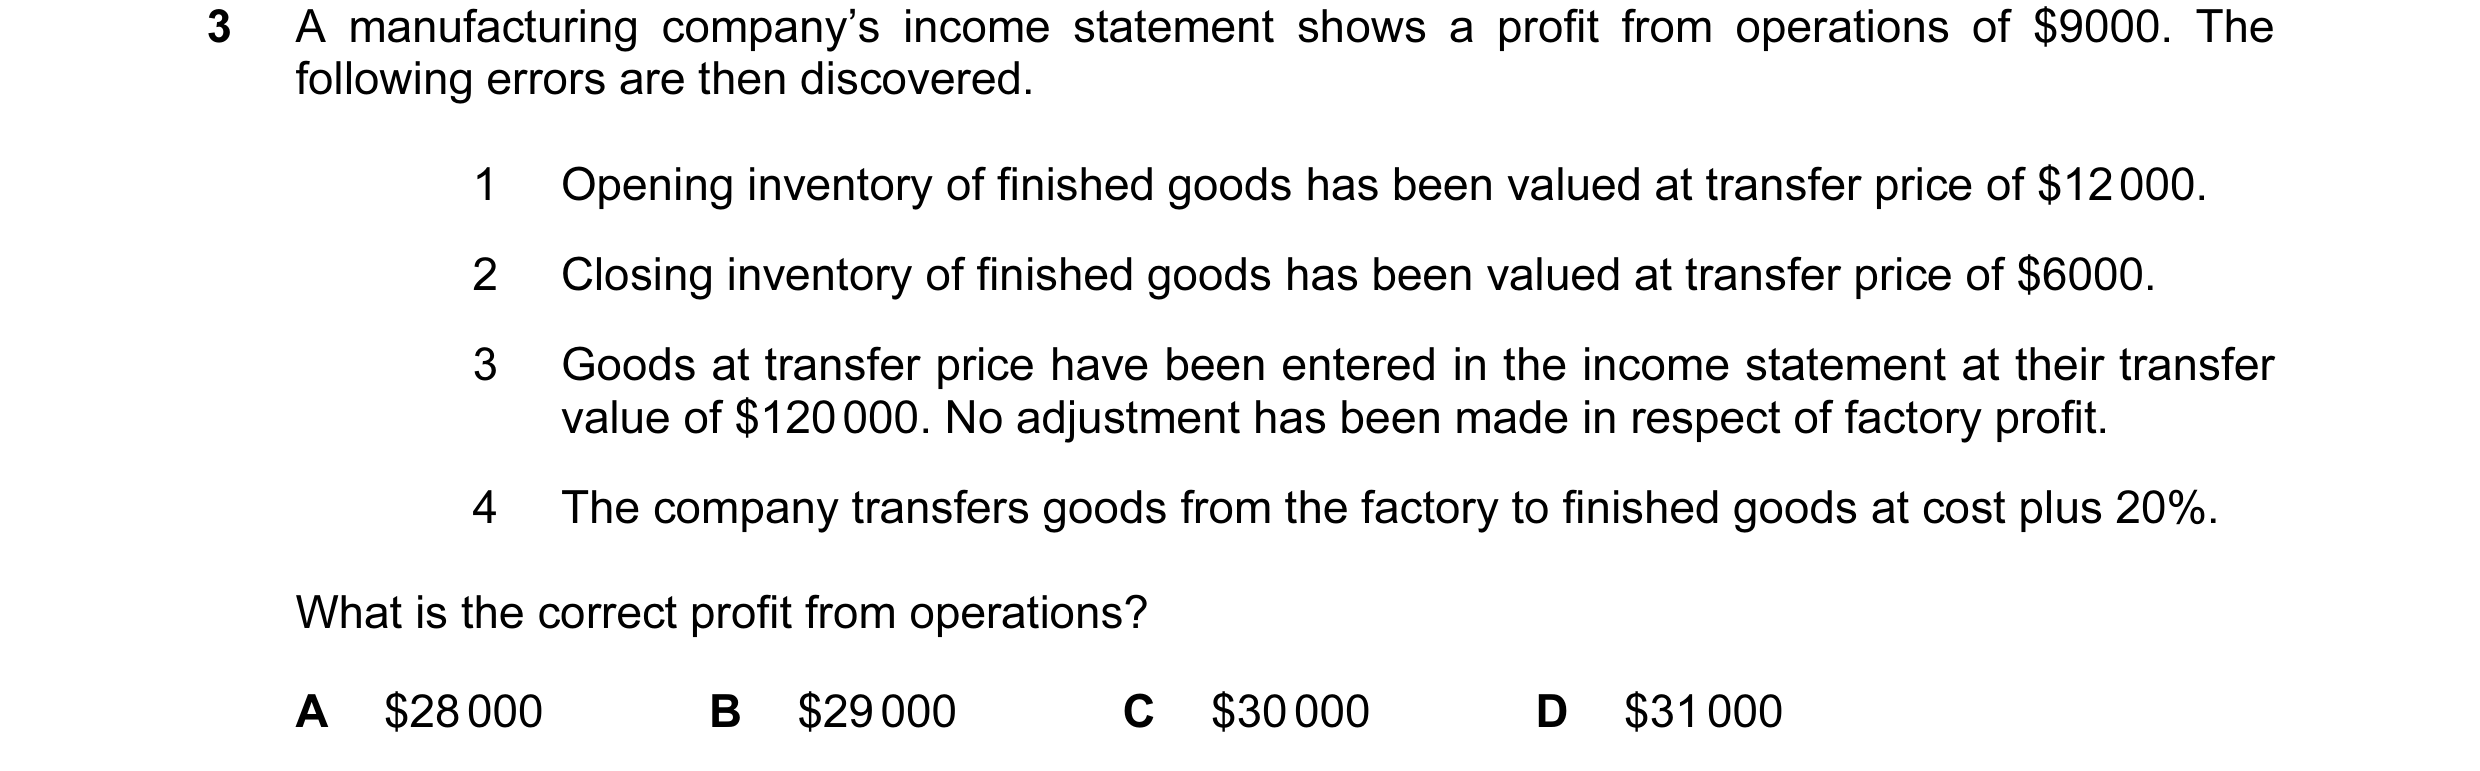
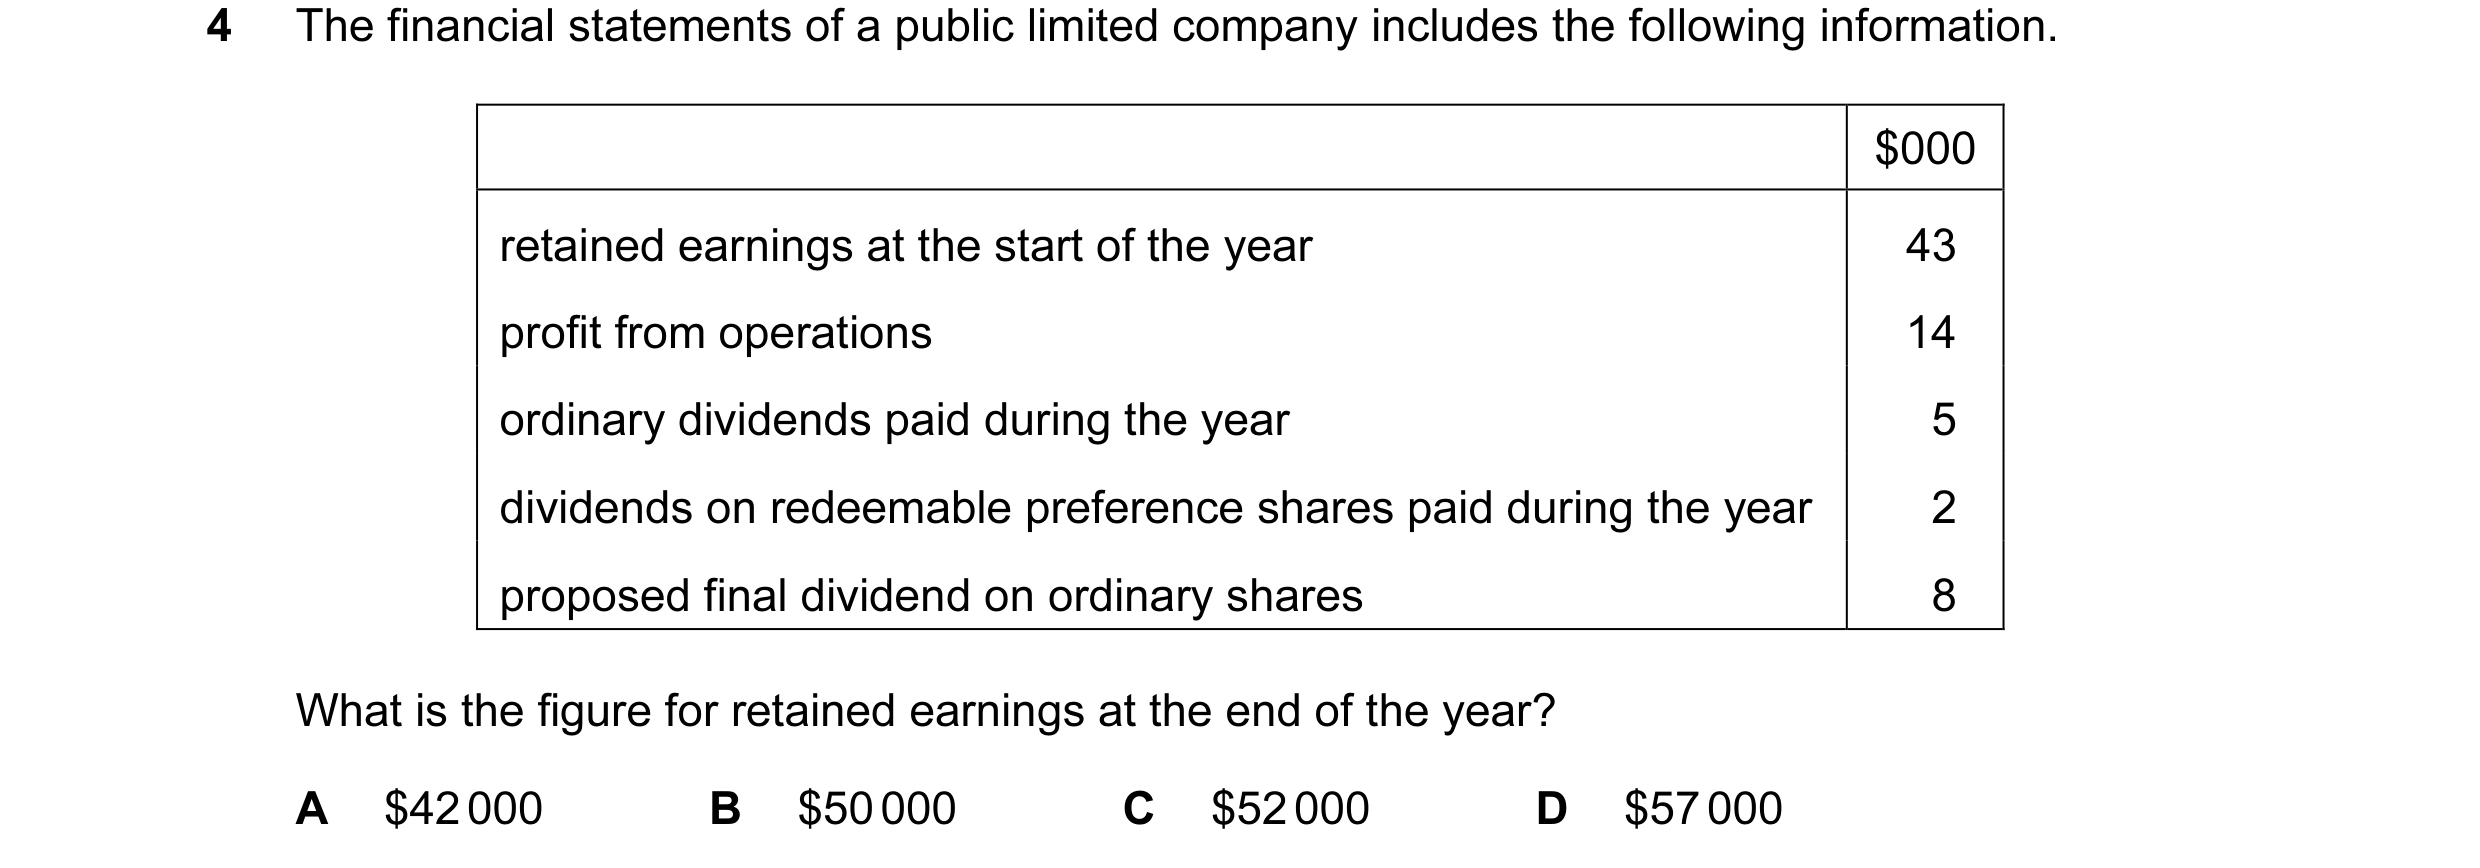
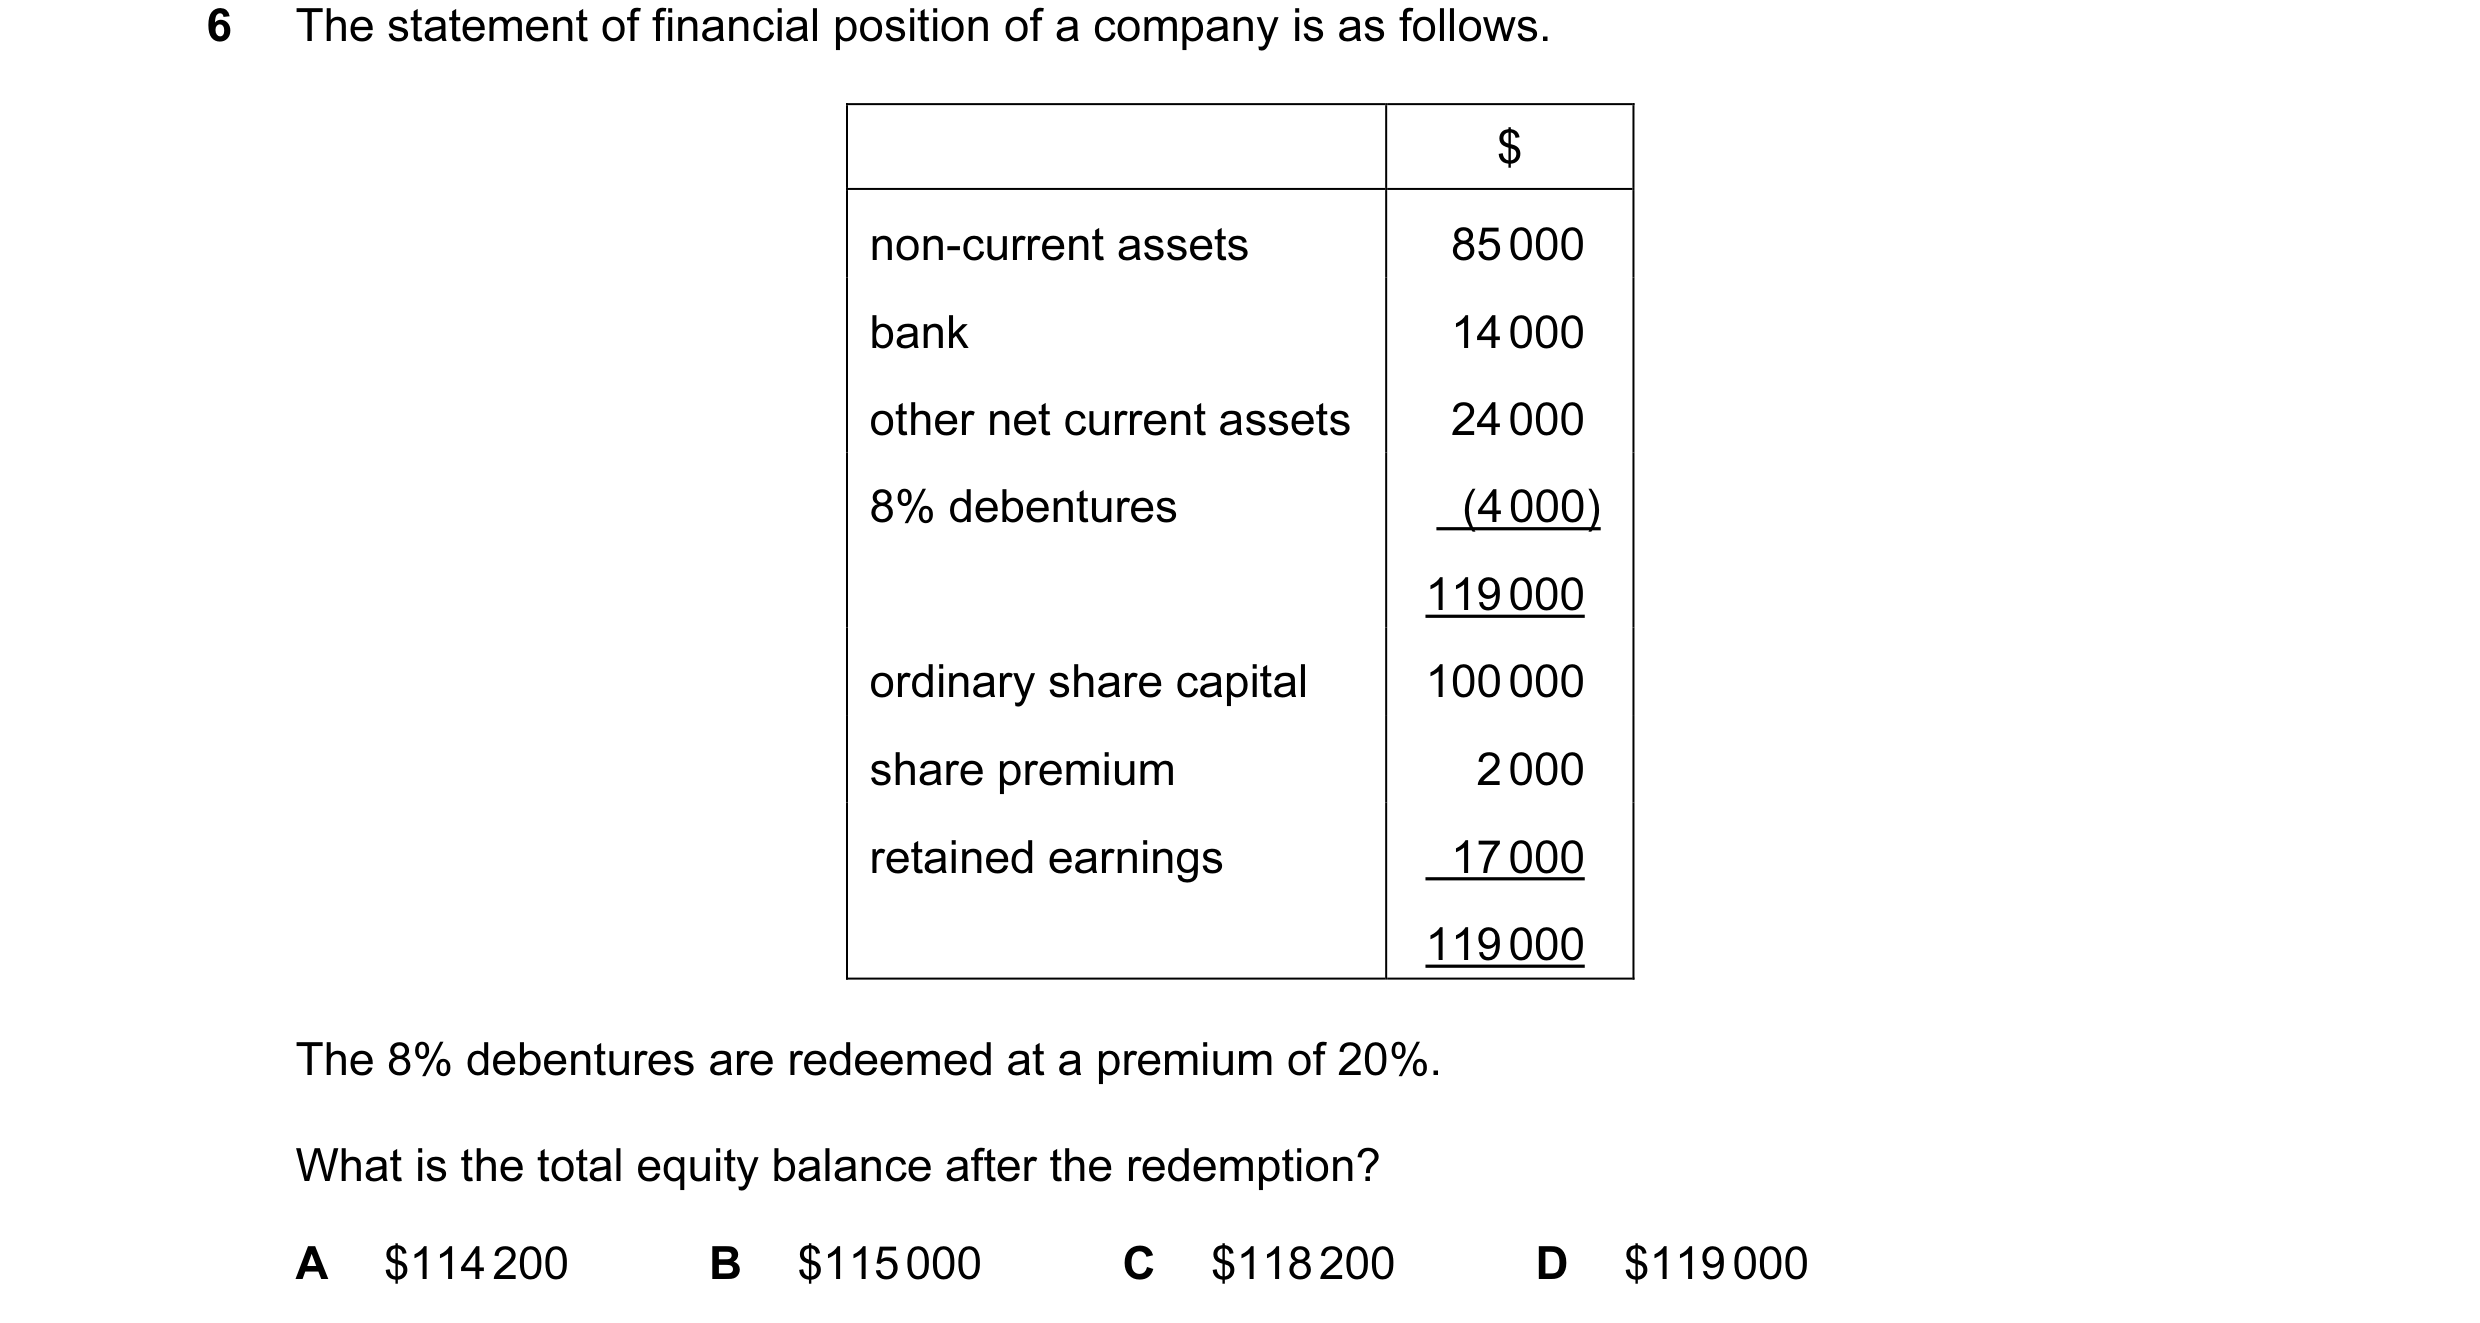 46 / 62
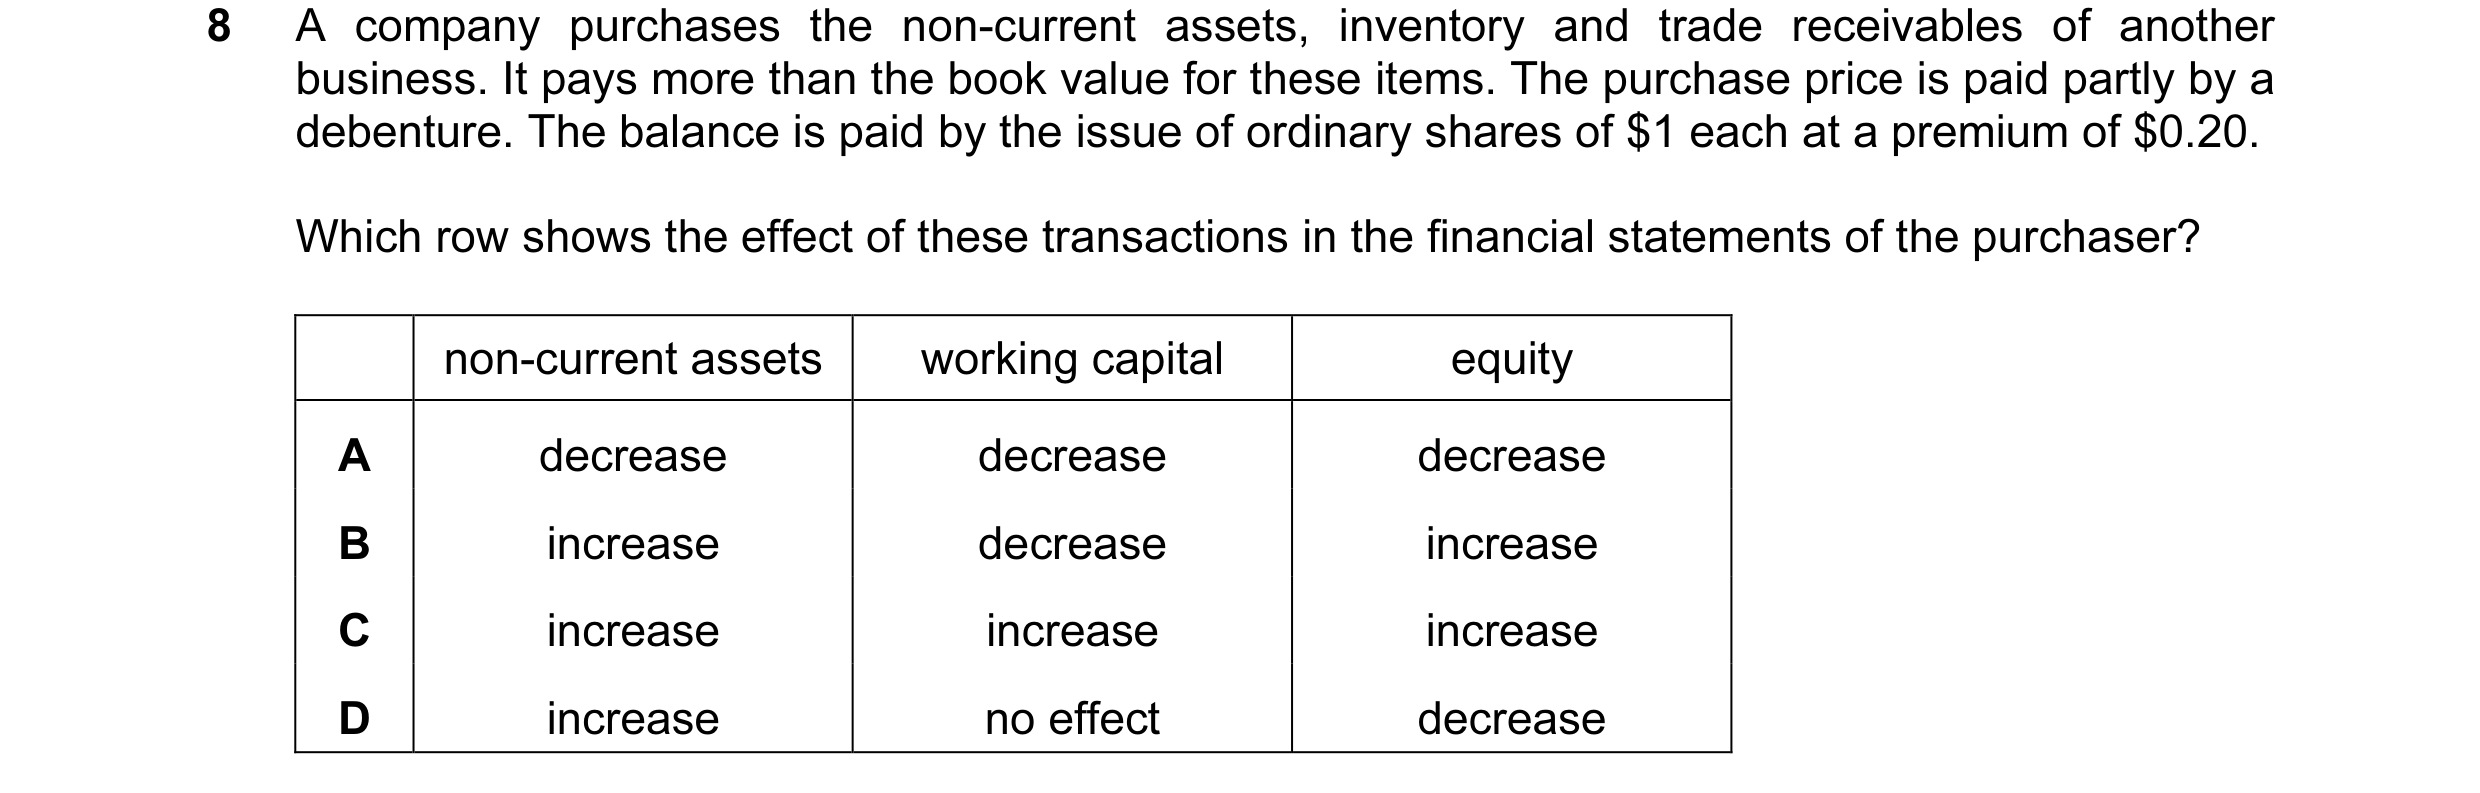
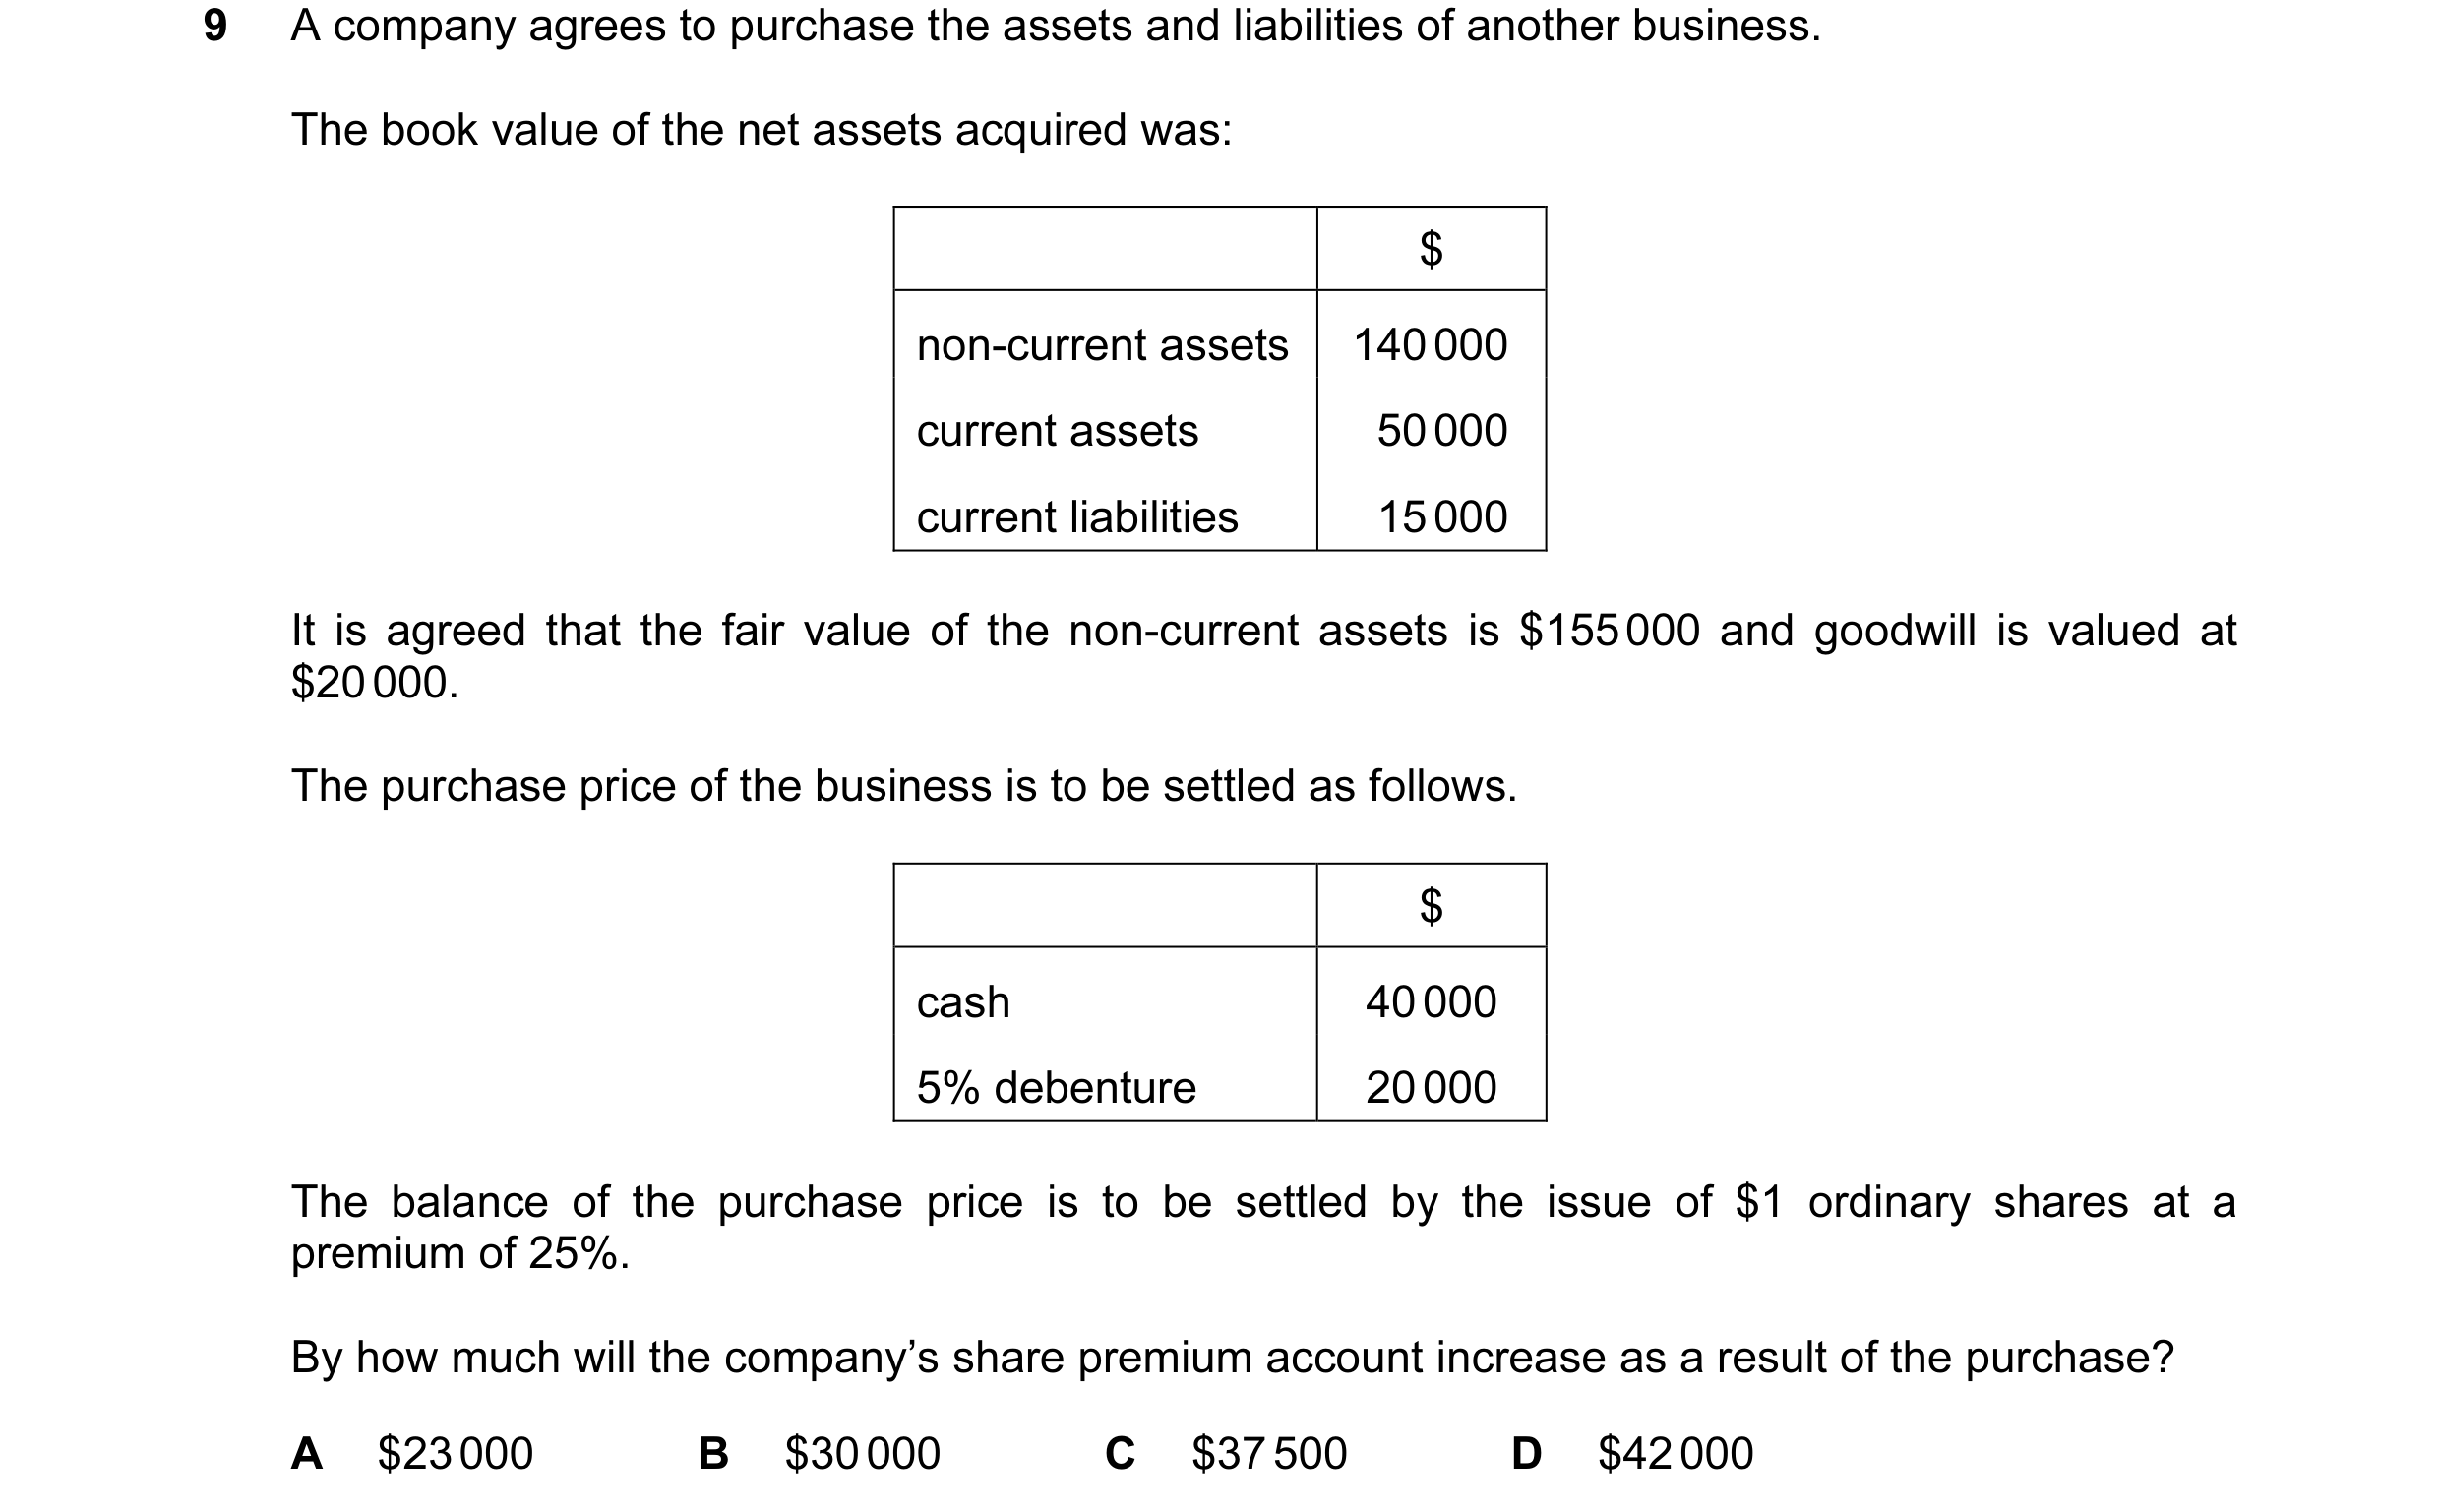
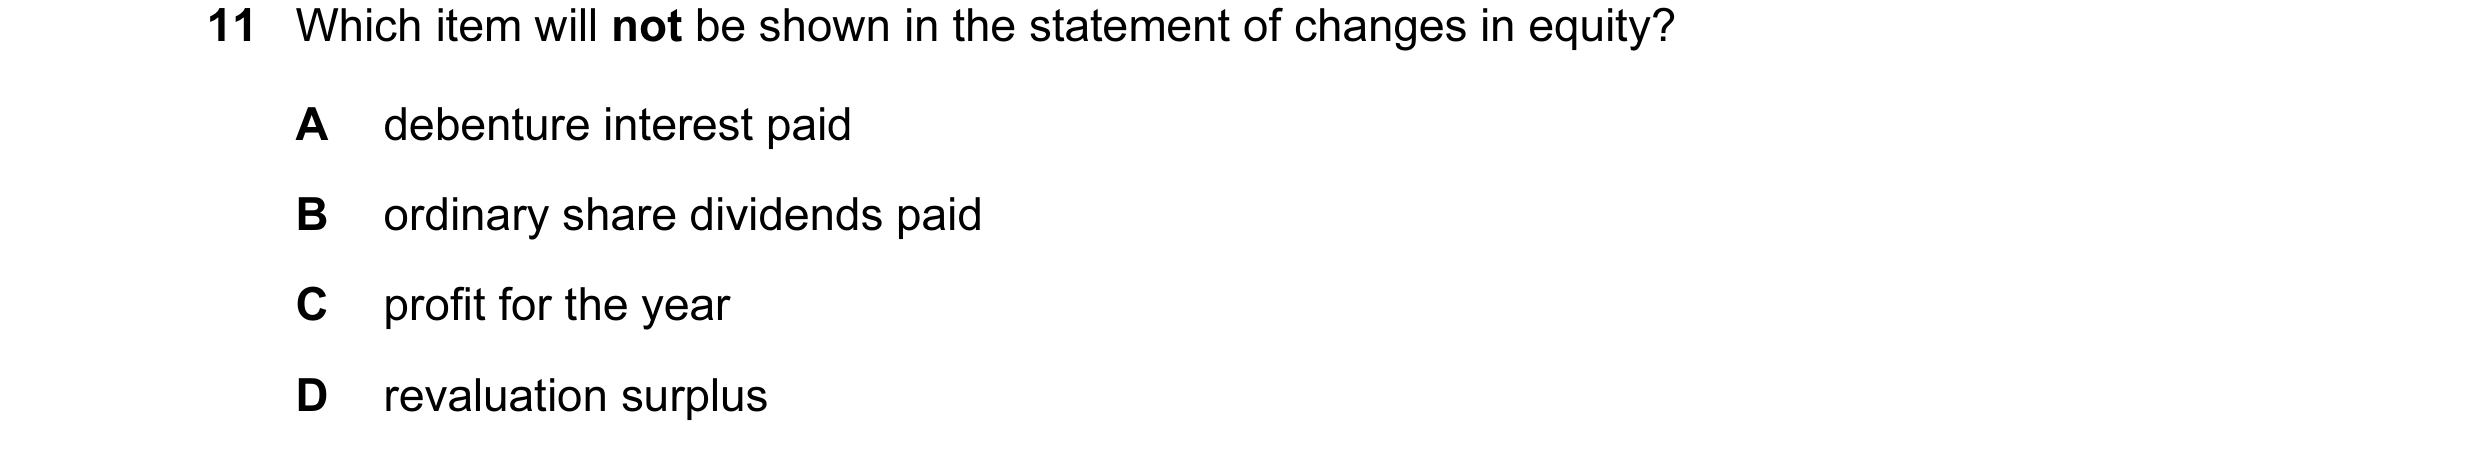 47 / 62
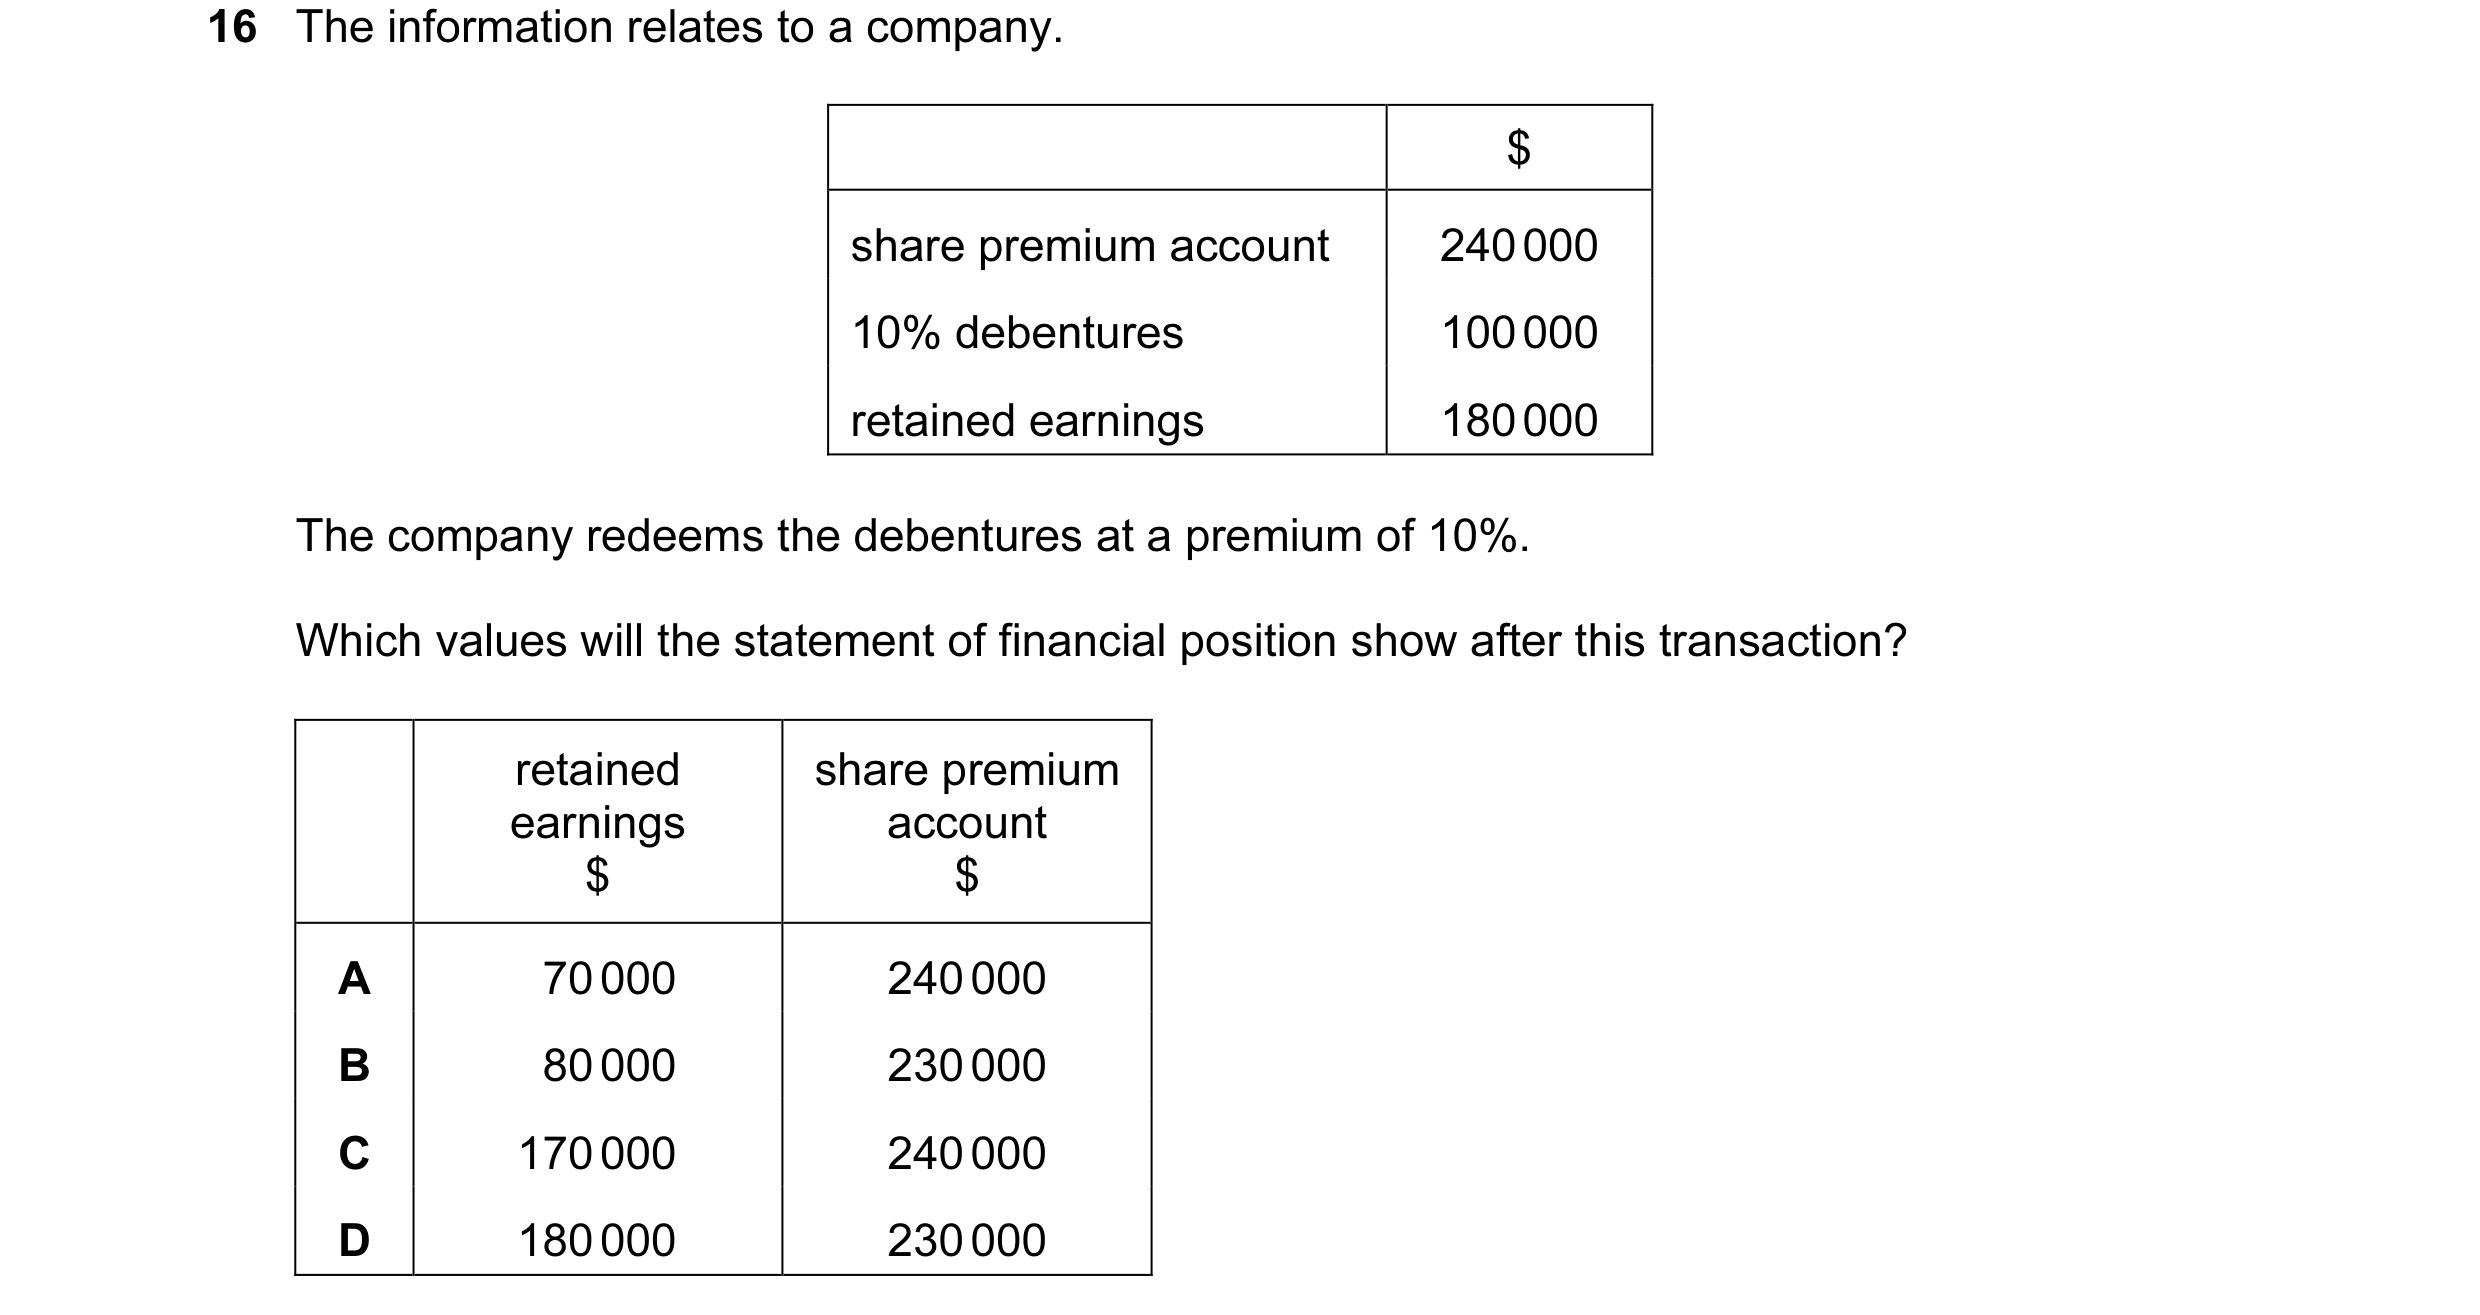
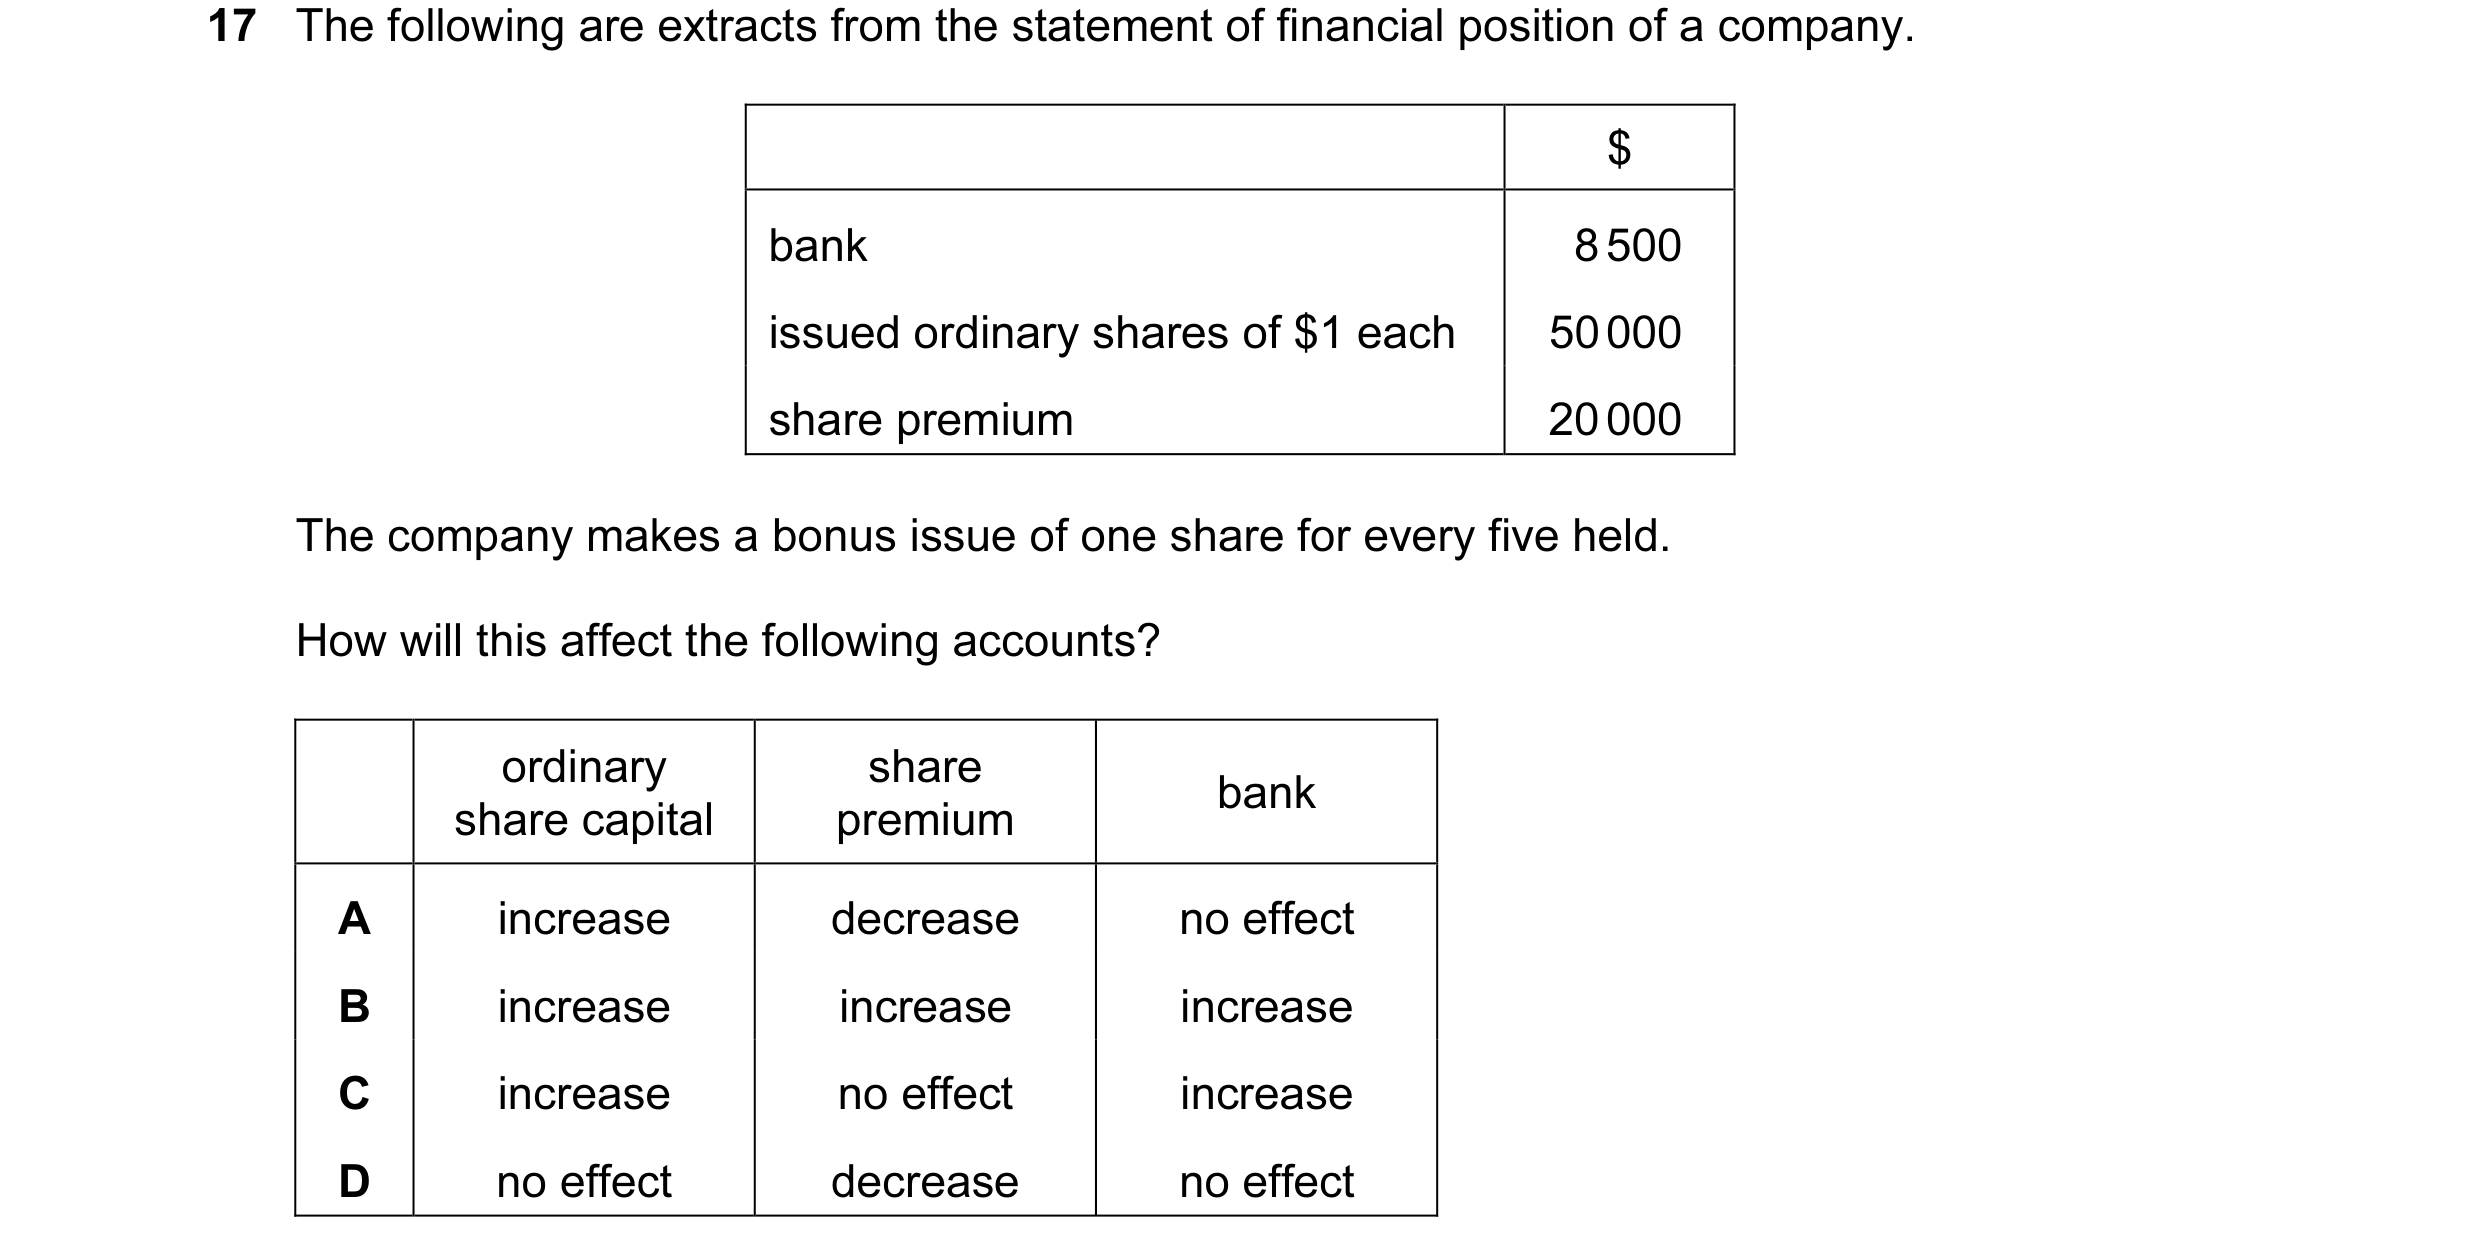 48 / 62
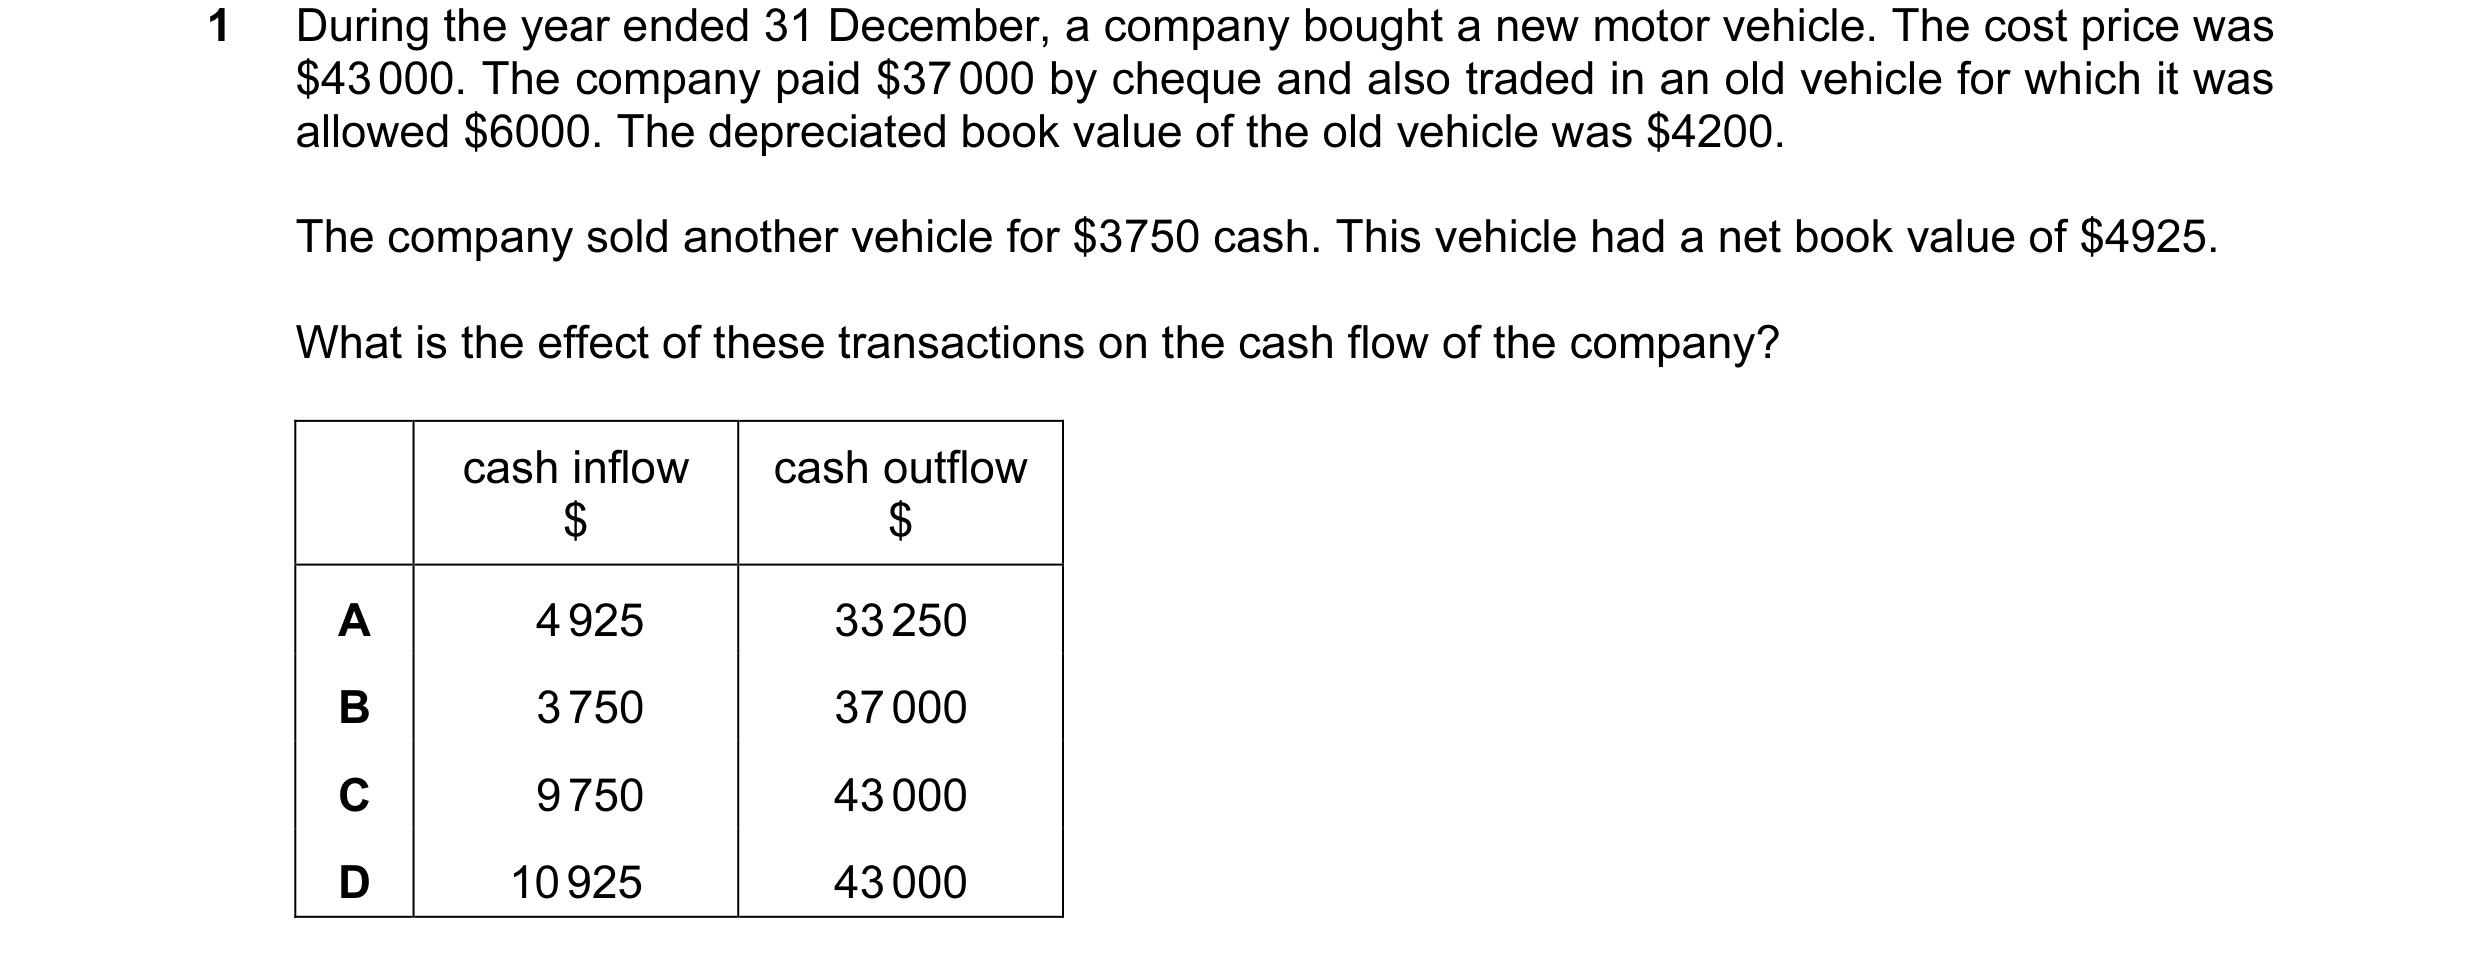
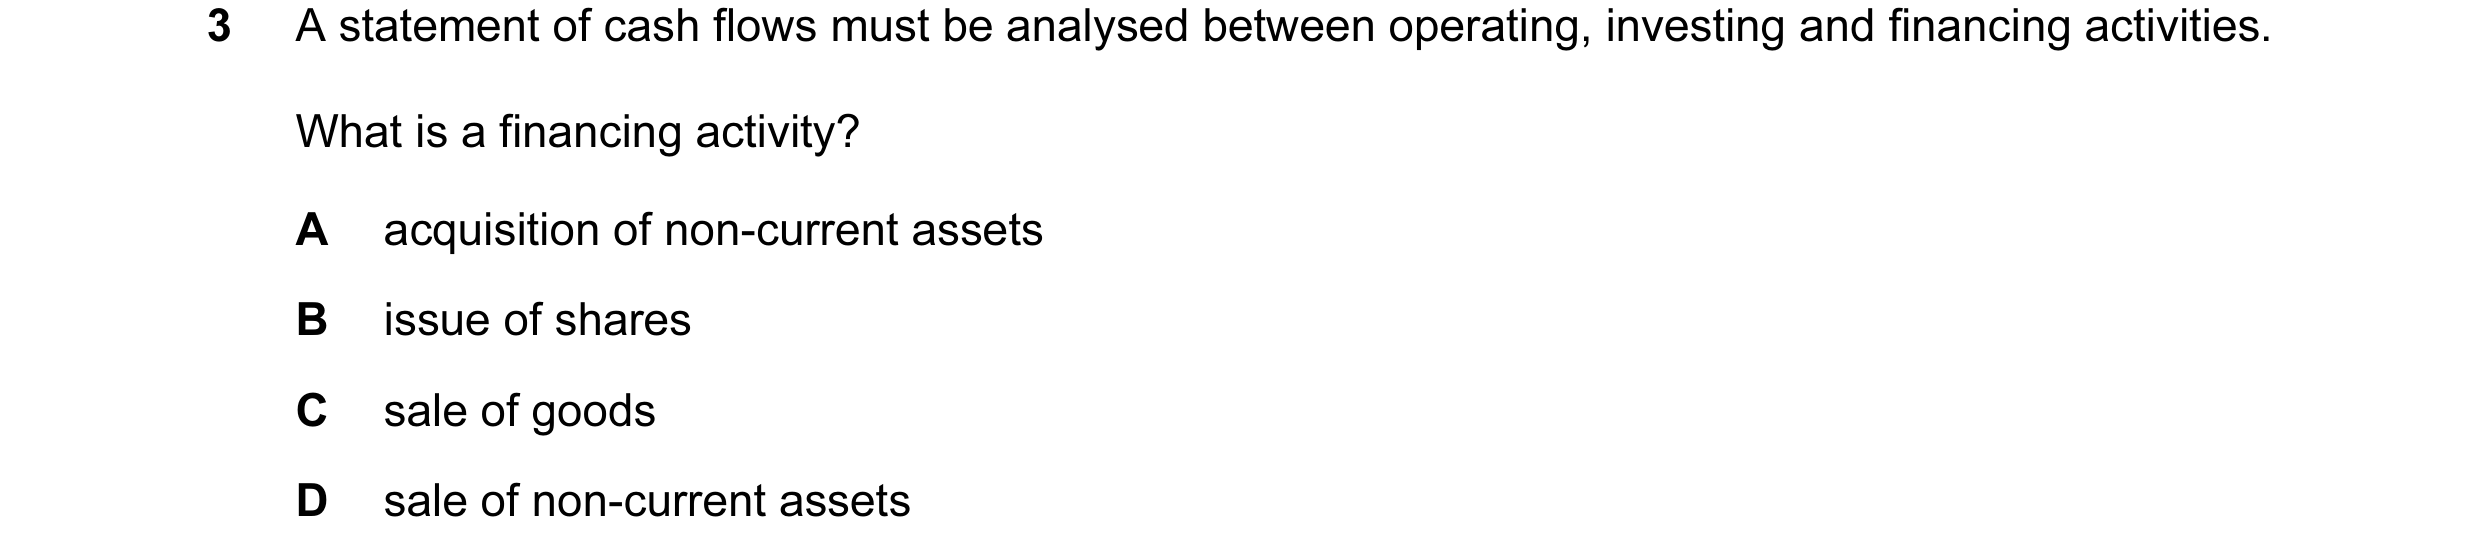
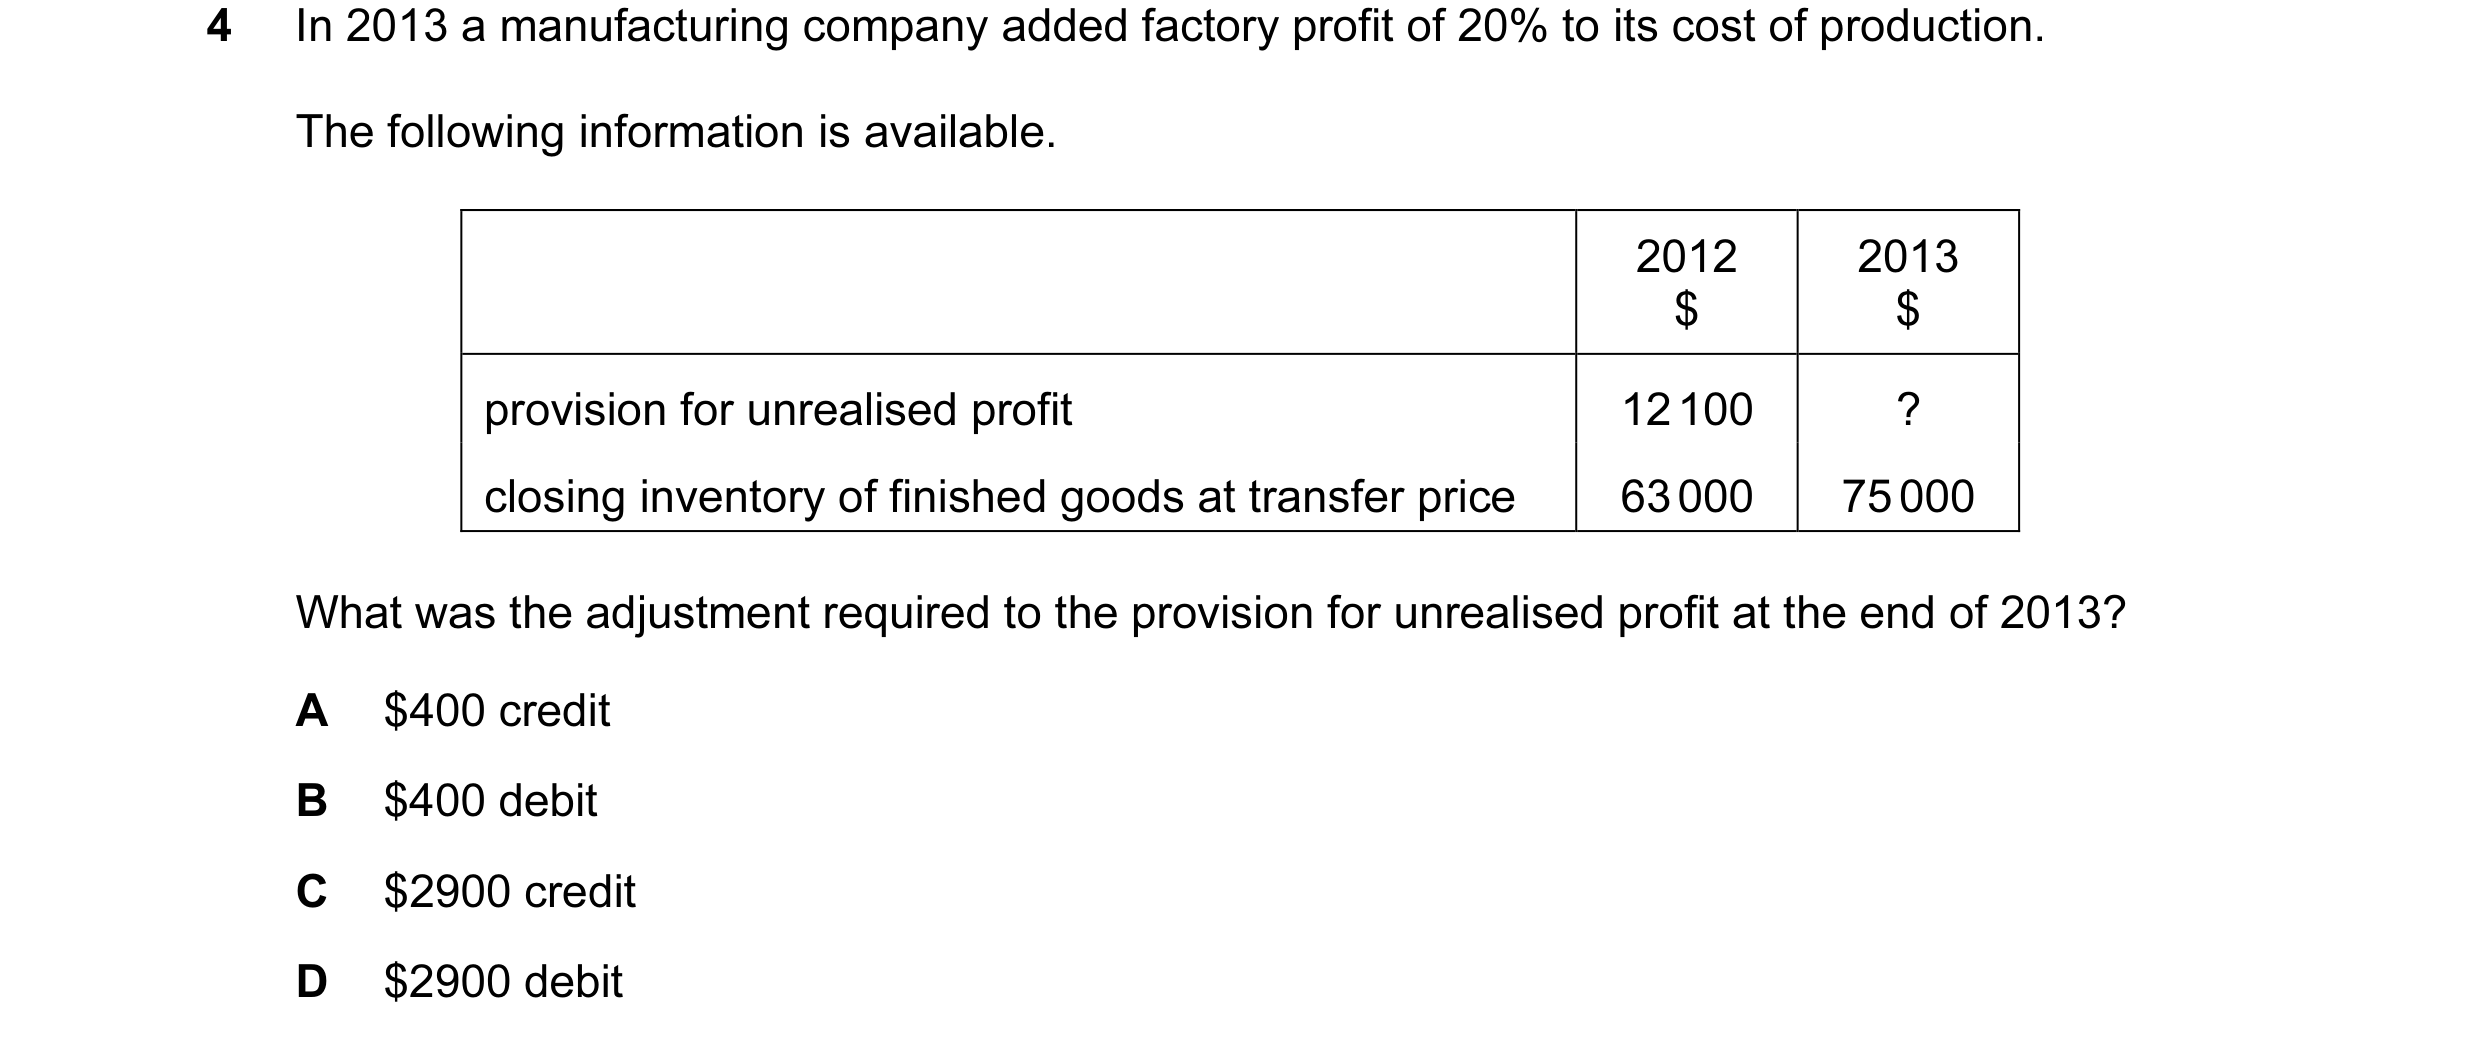 49 / 62
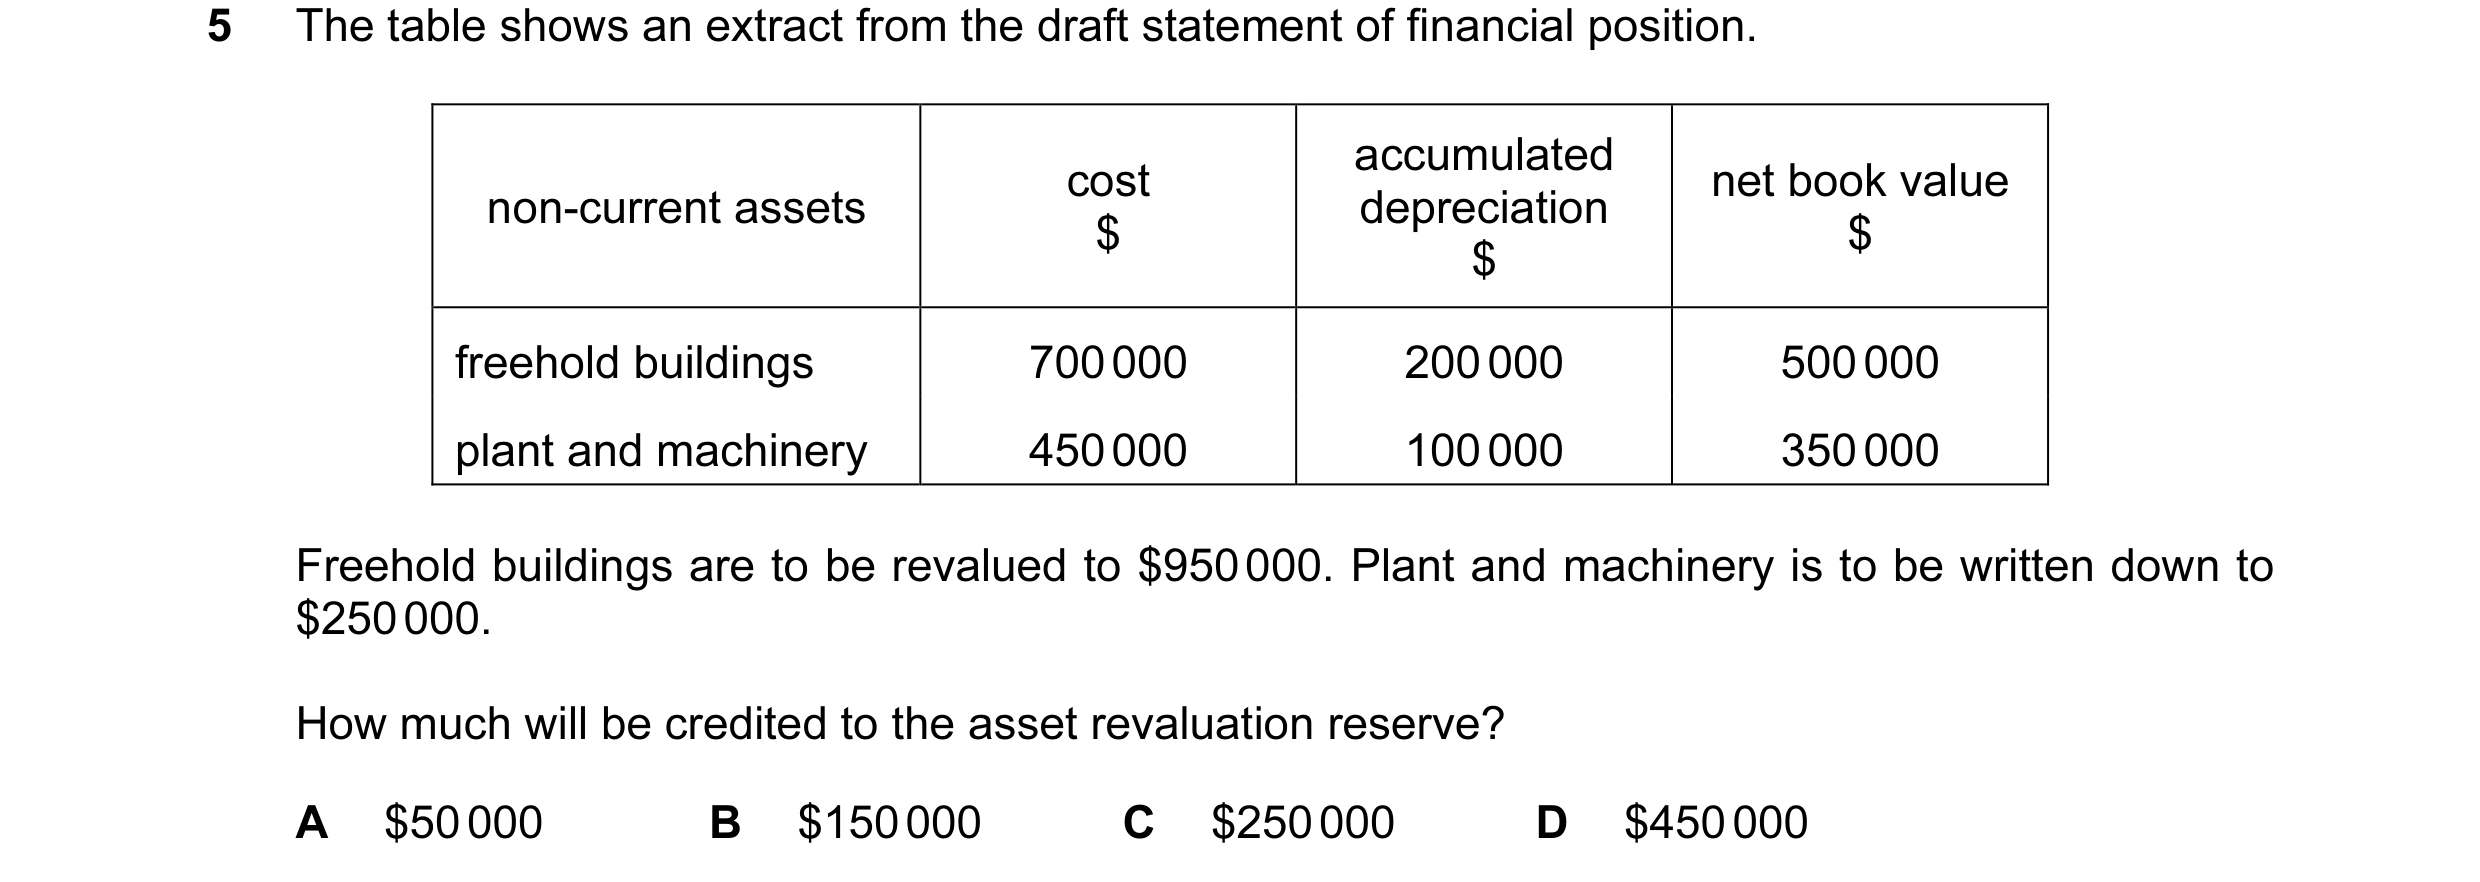
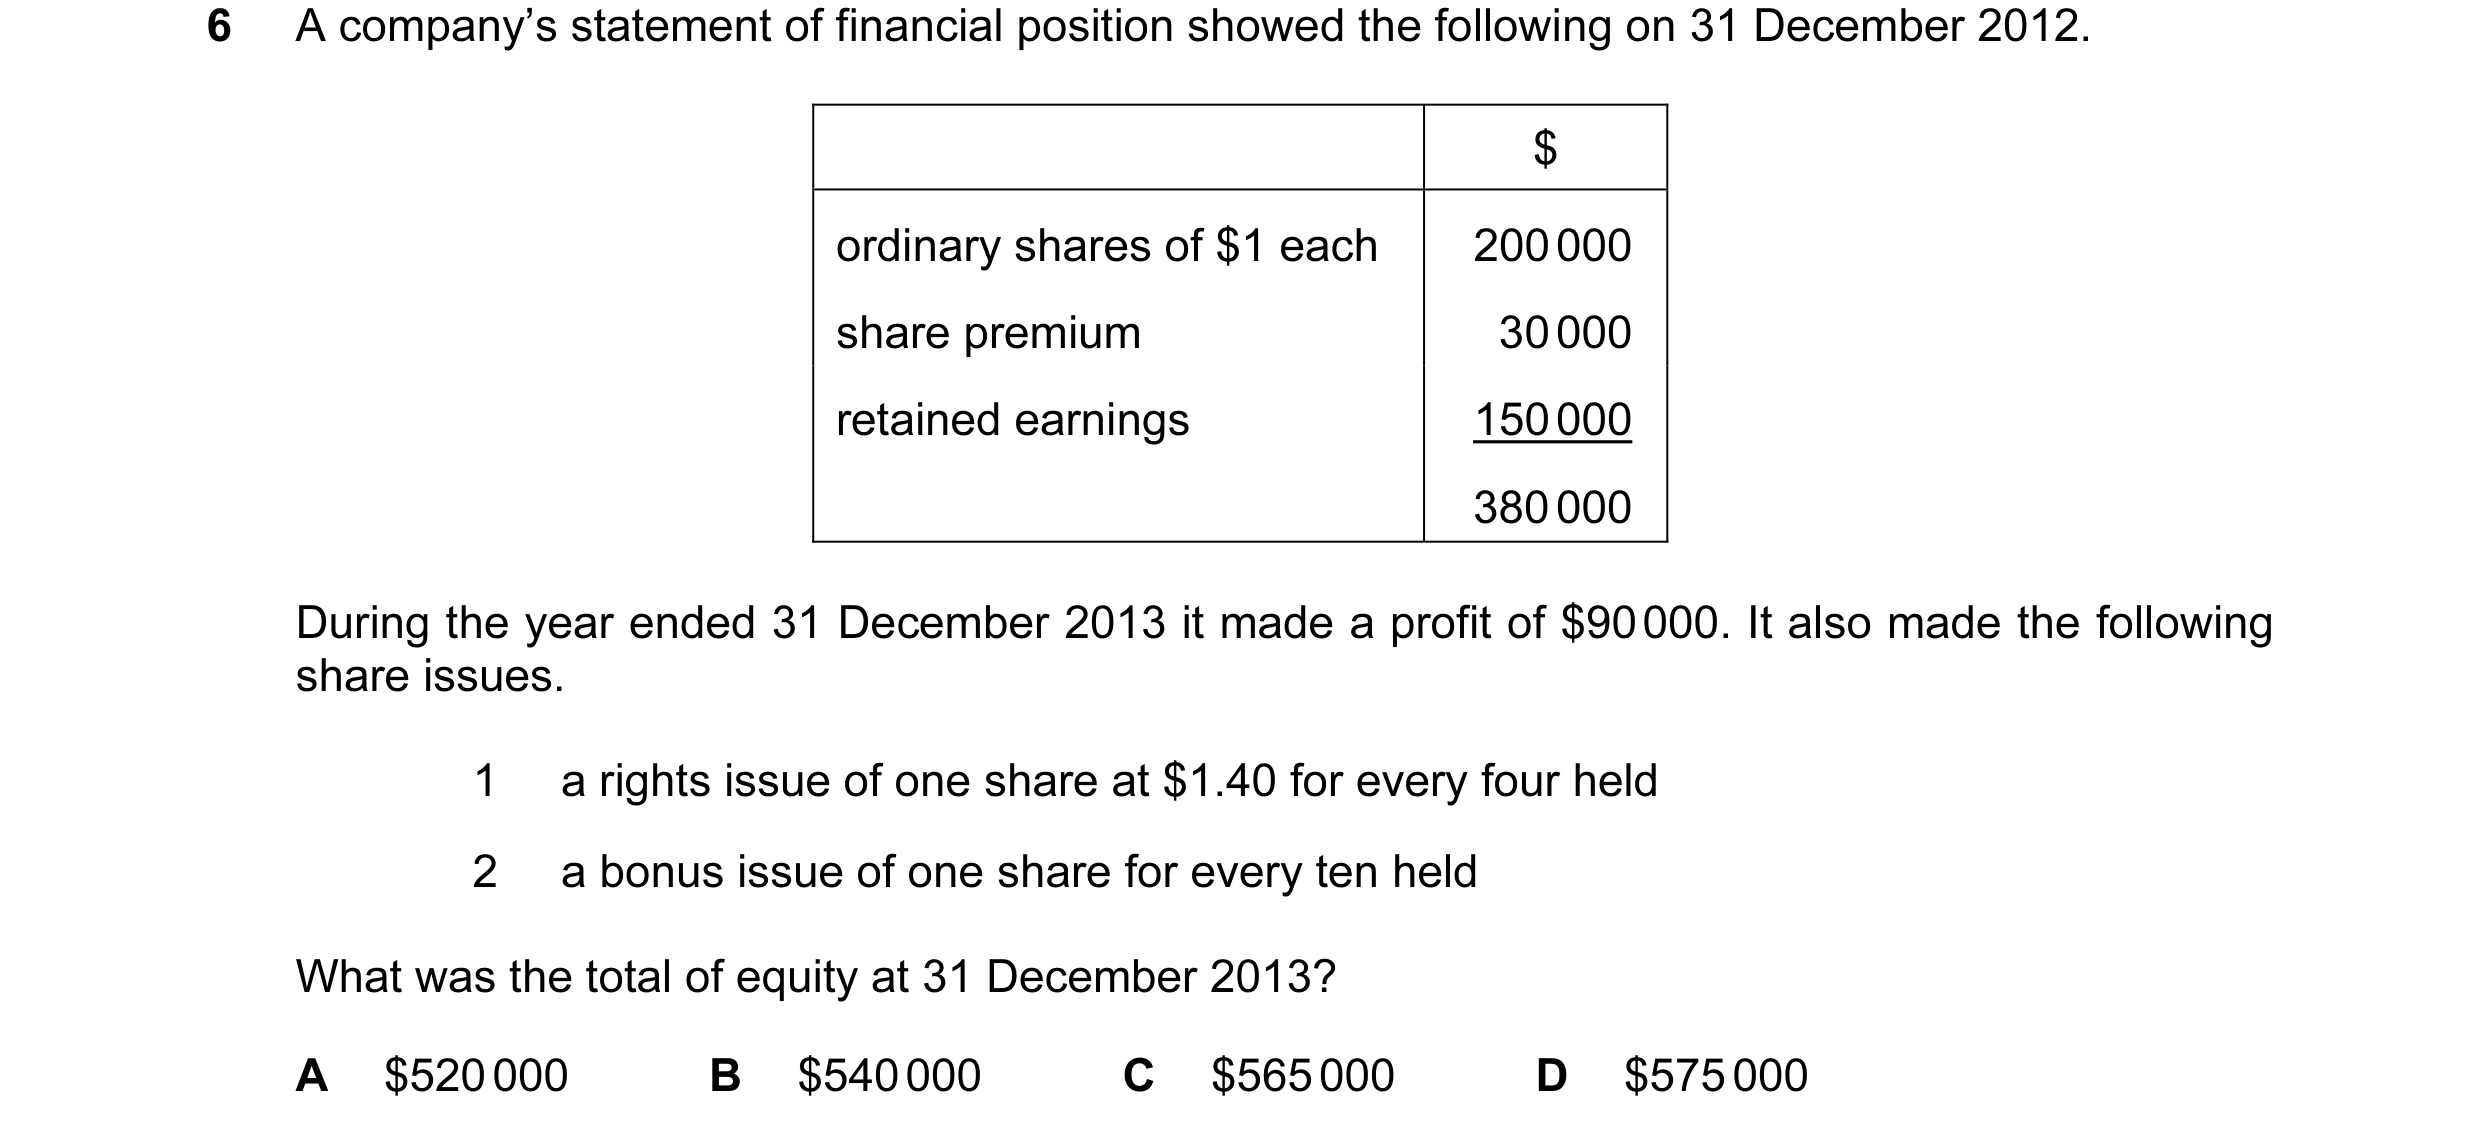
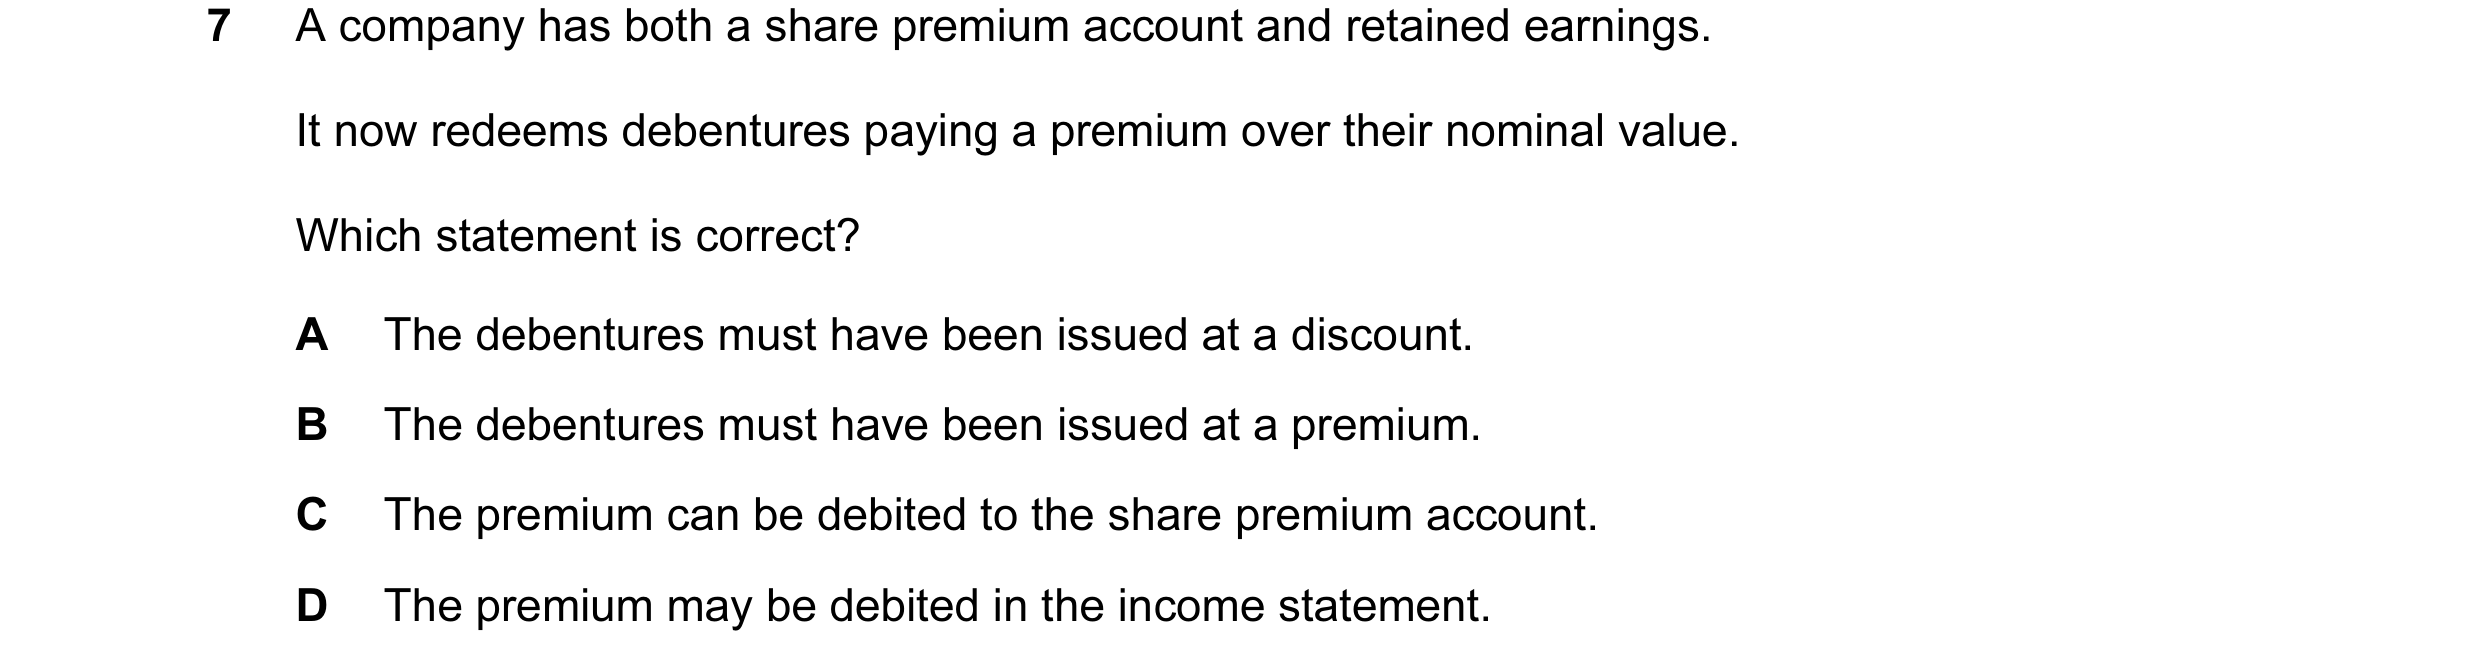 50 / 62
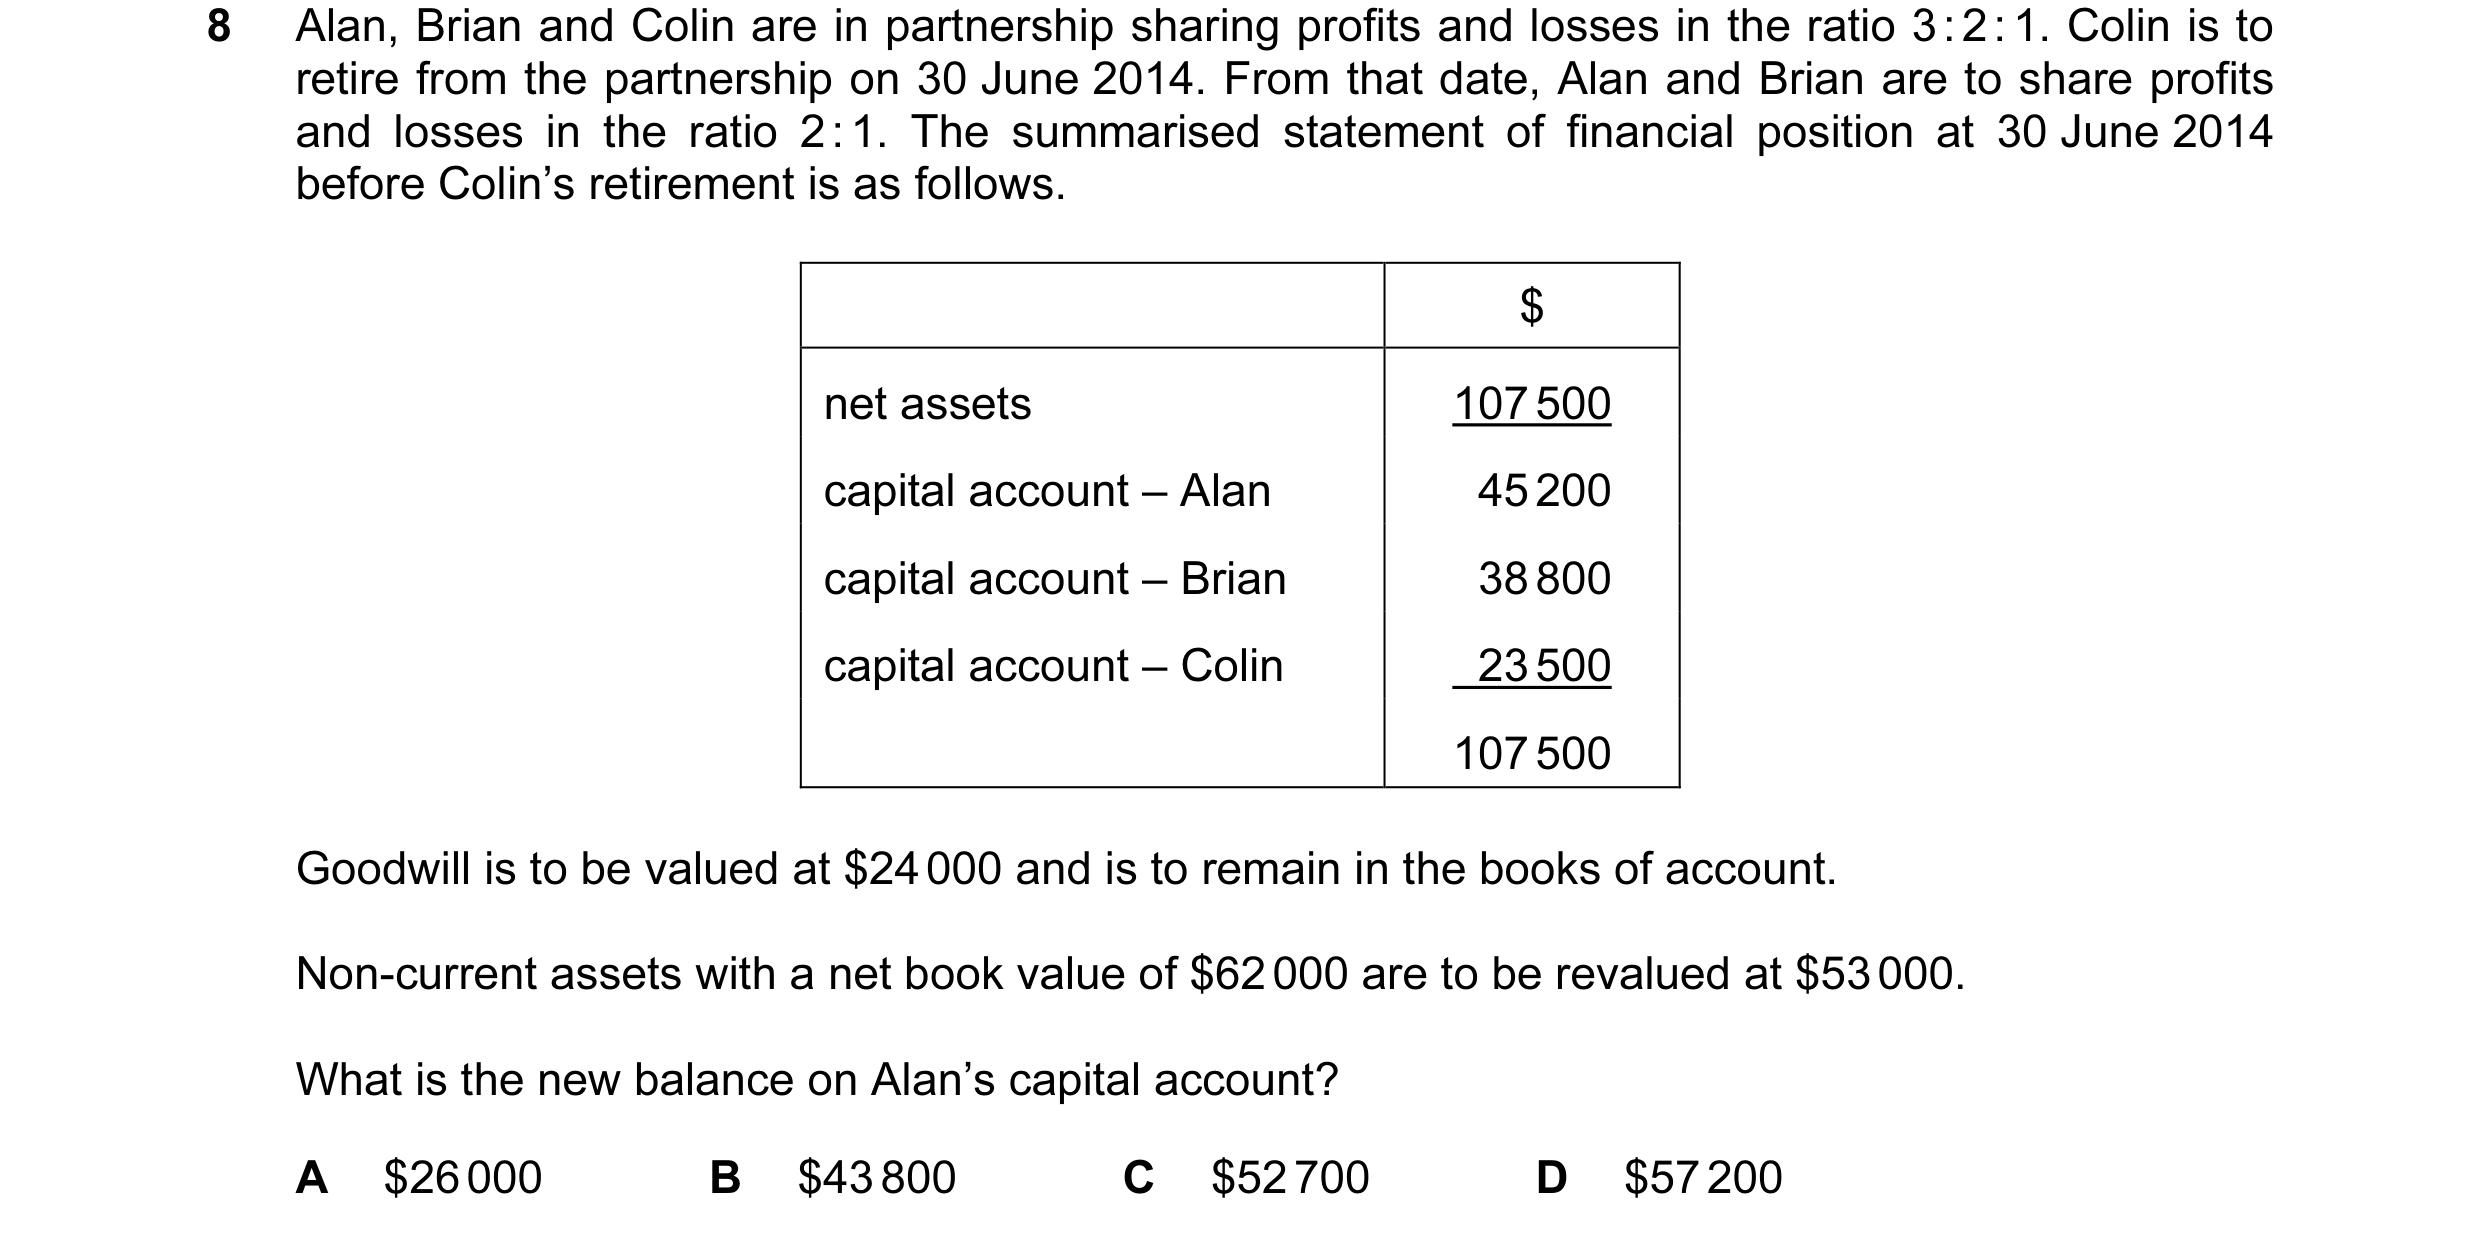
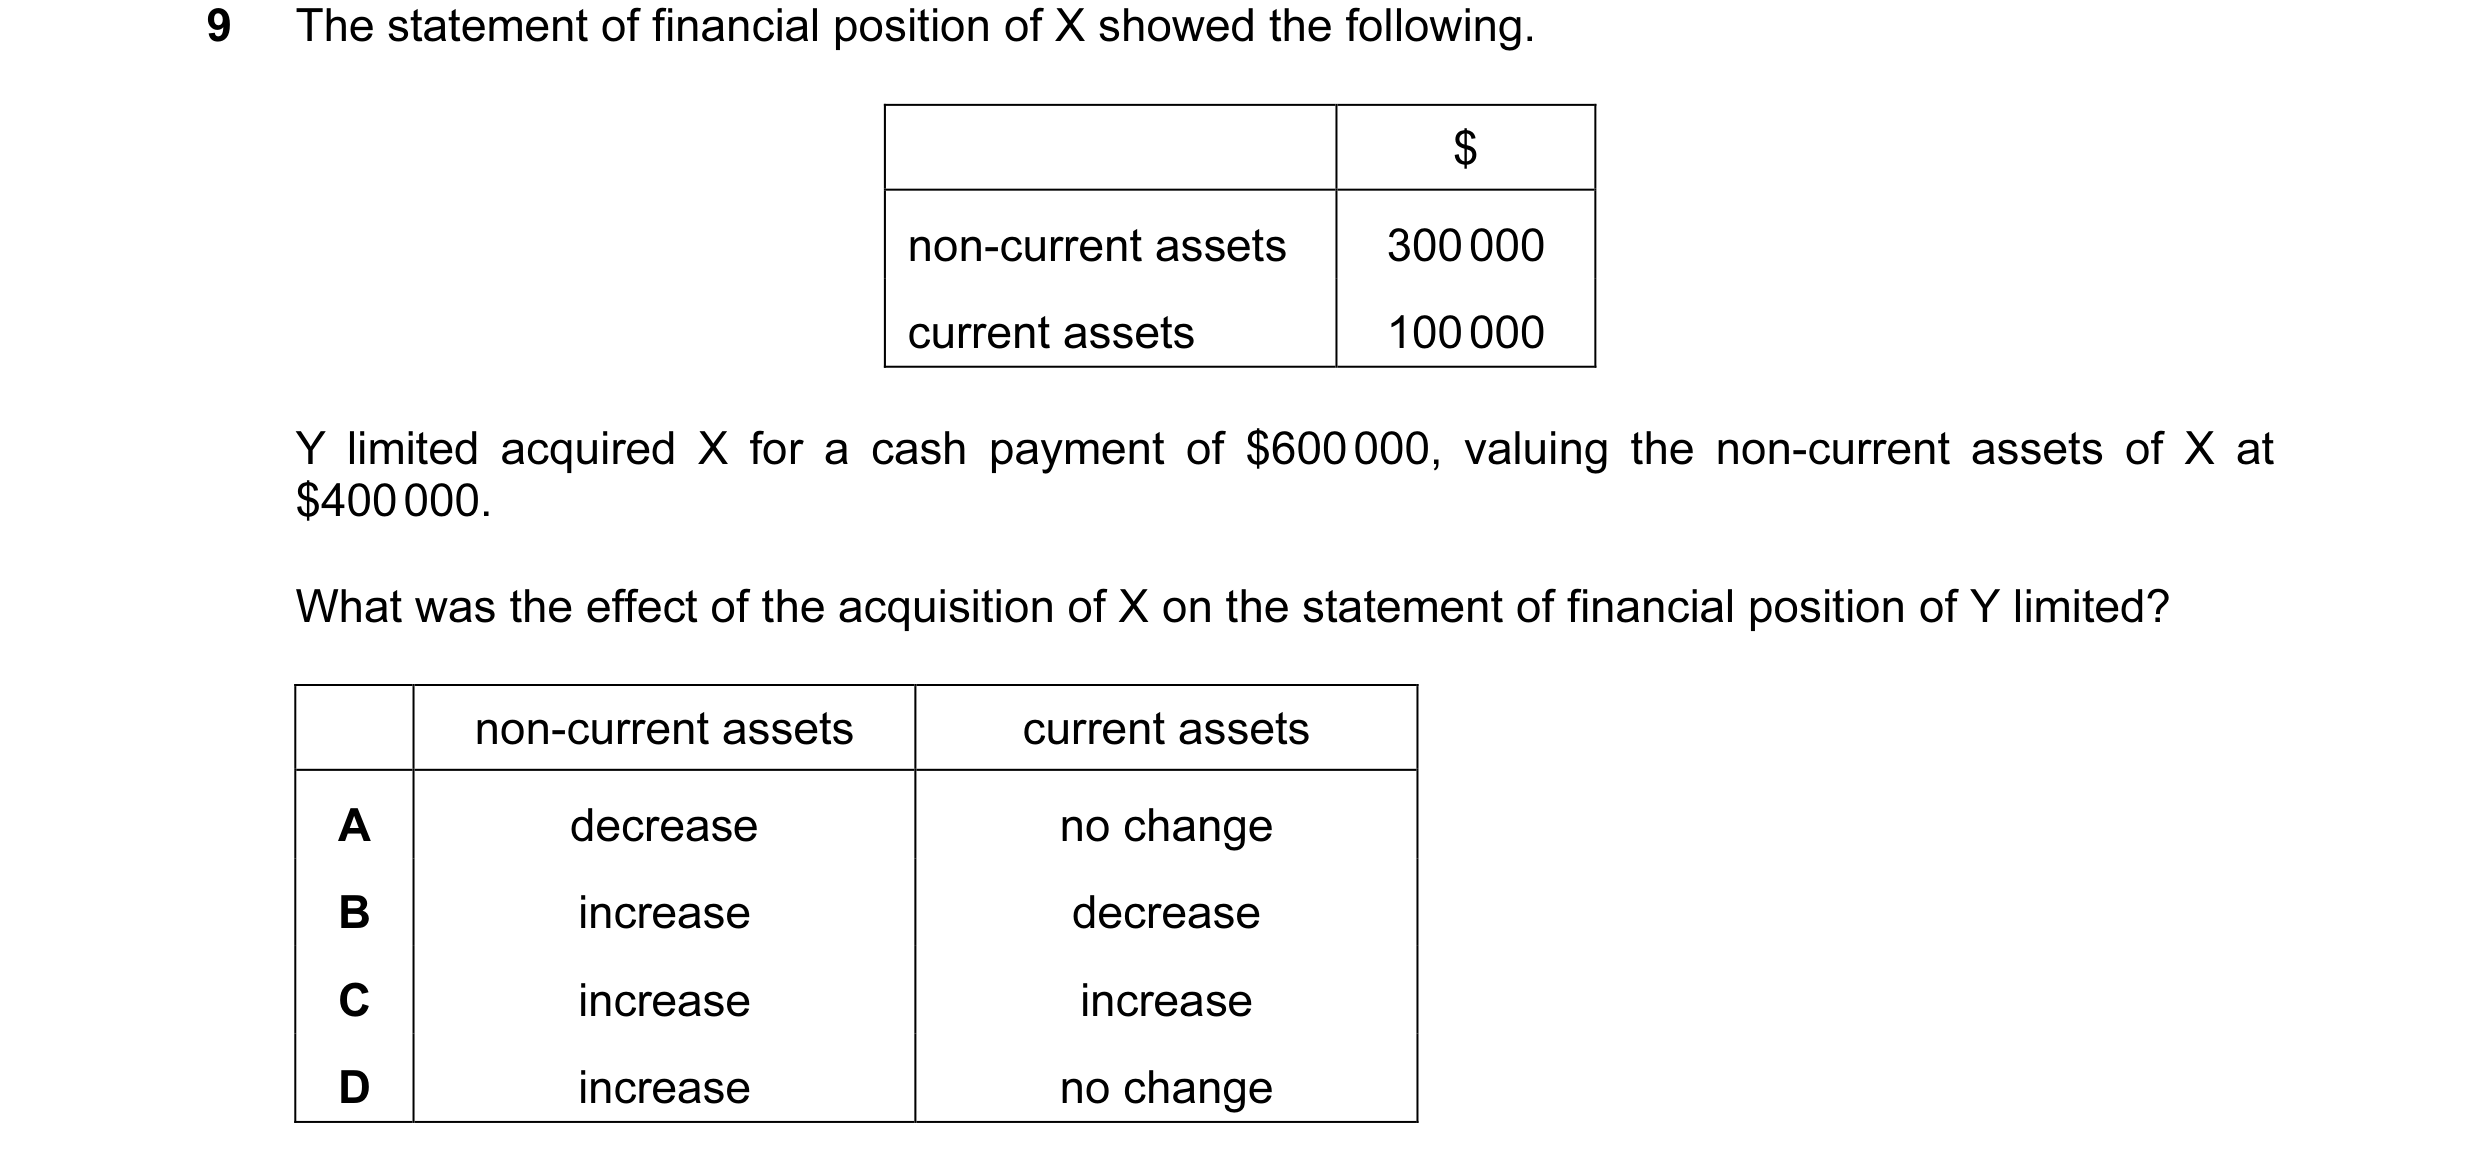 51 / 62
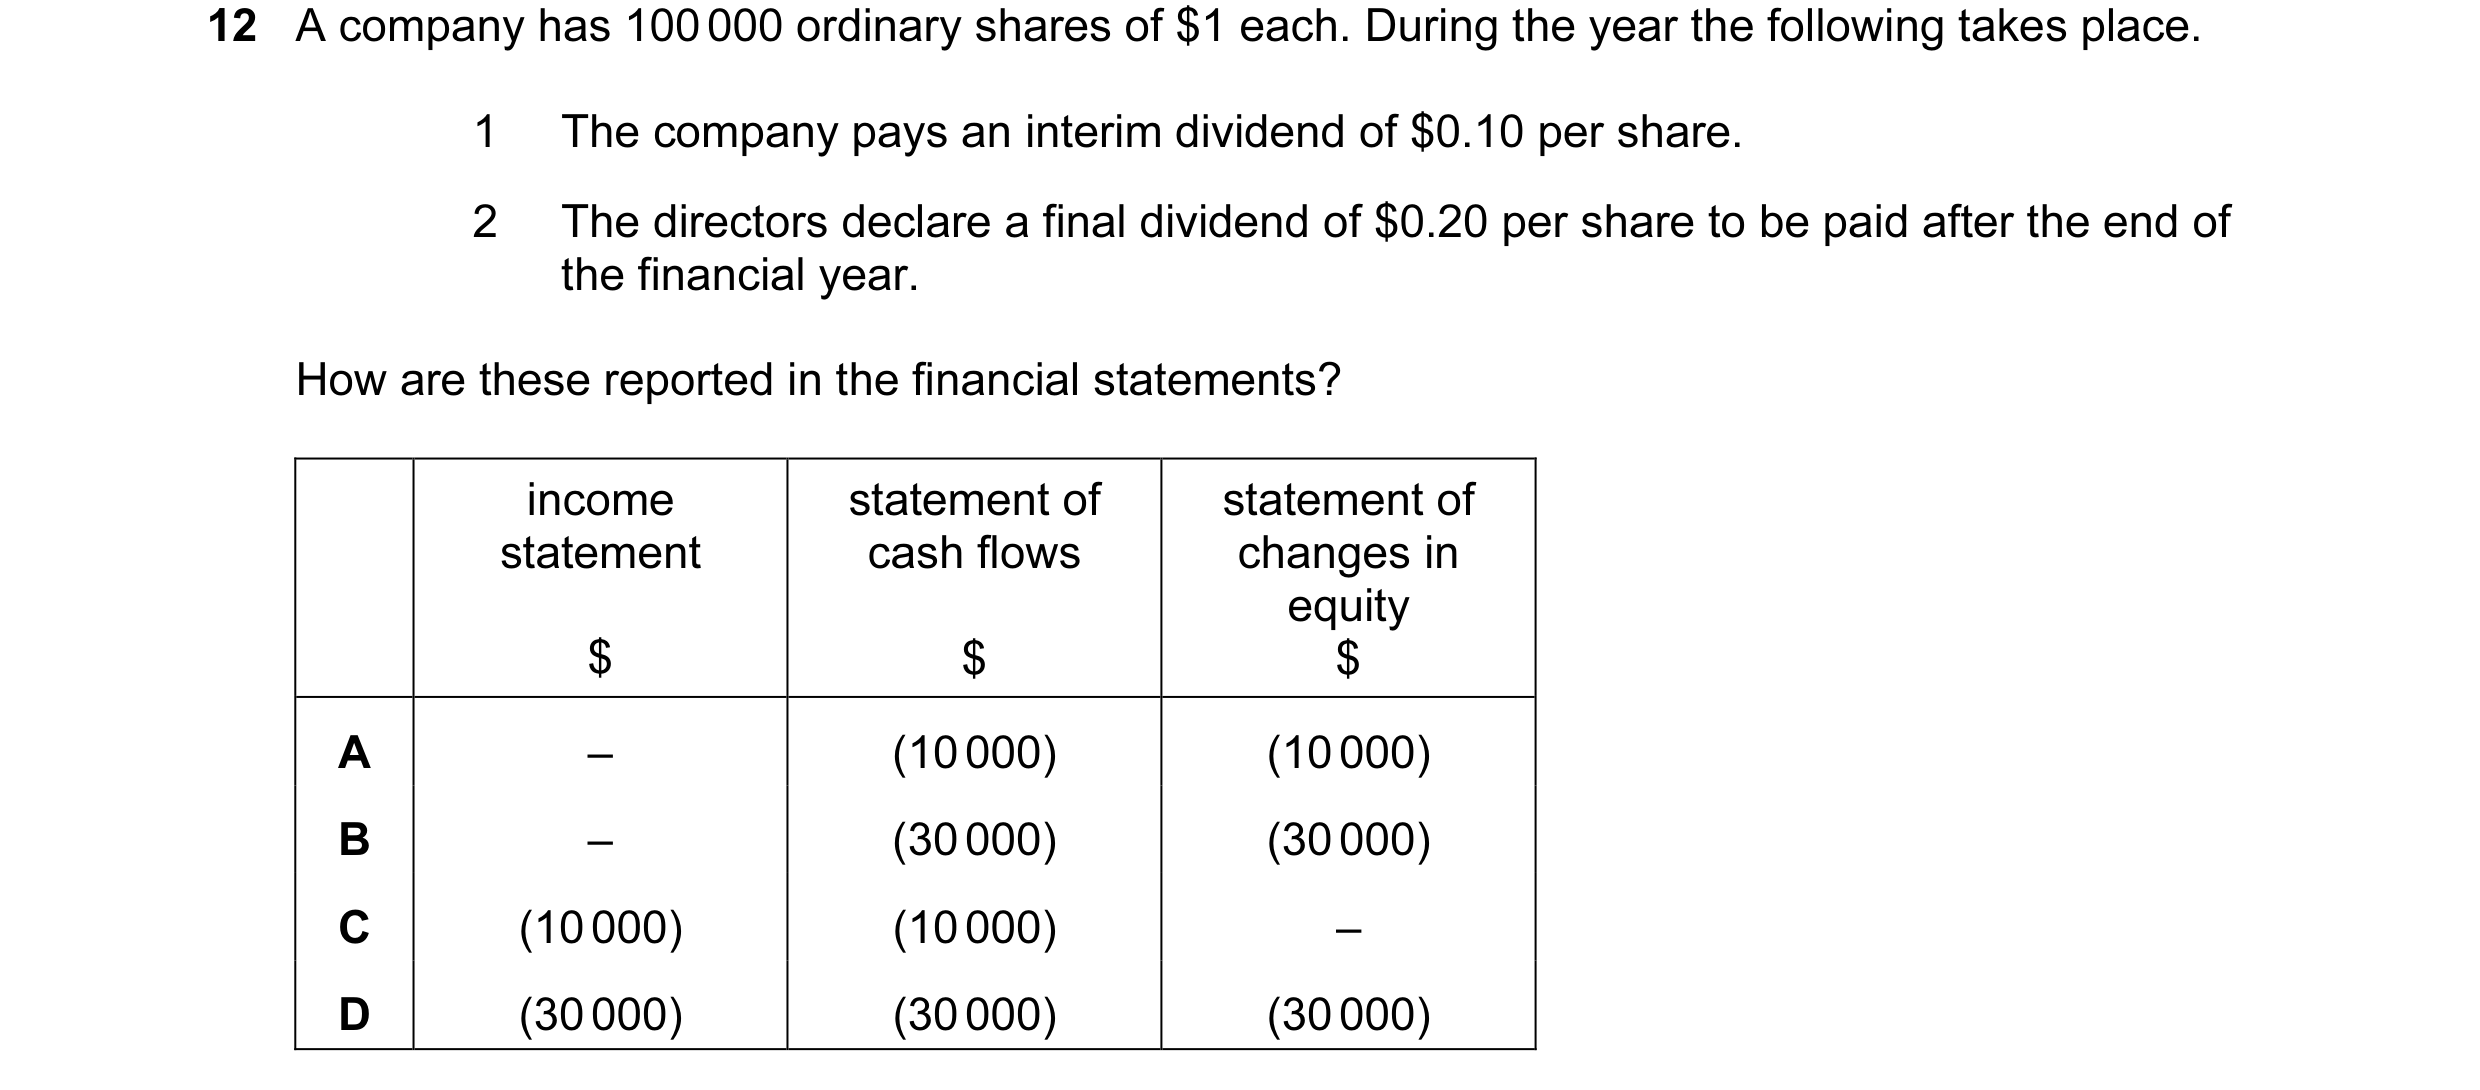
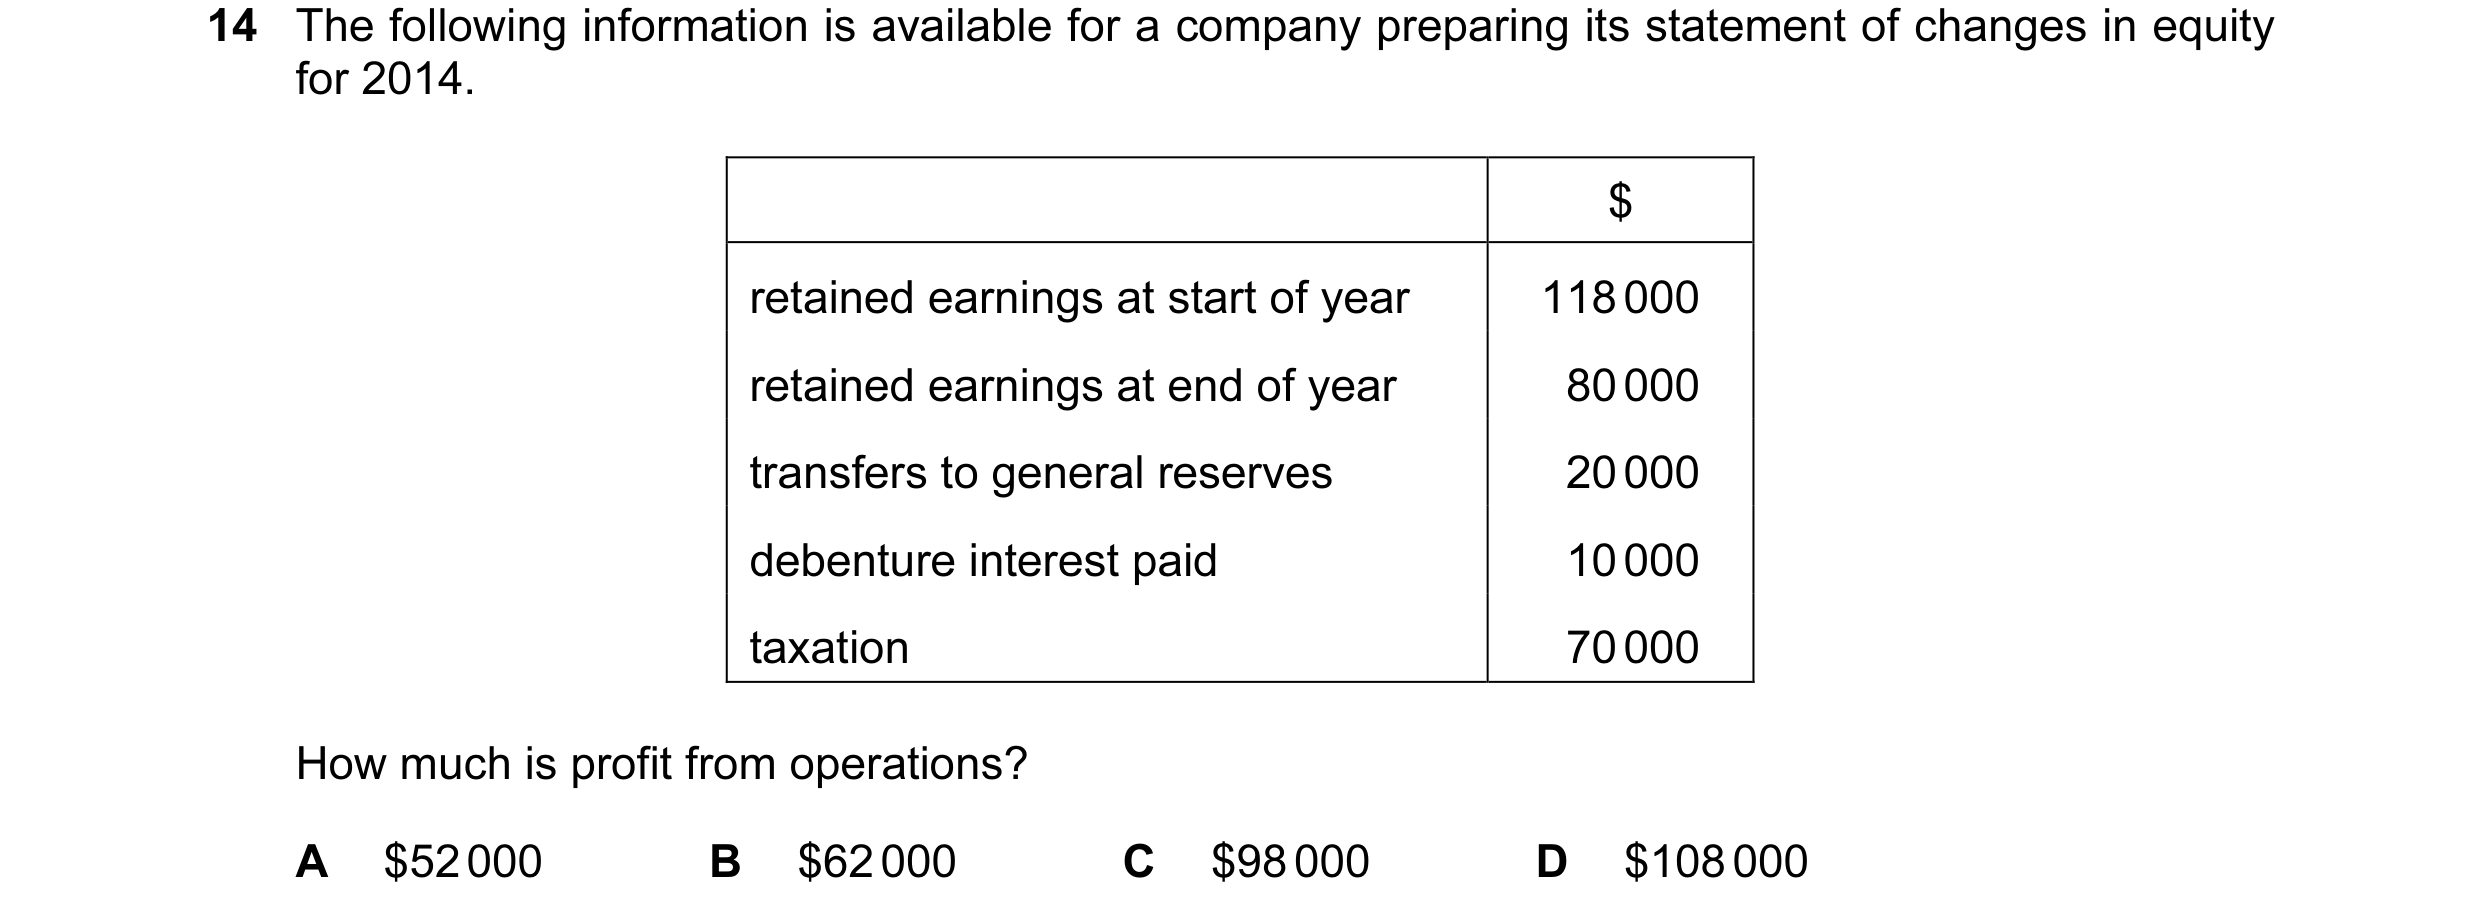
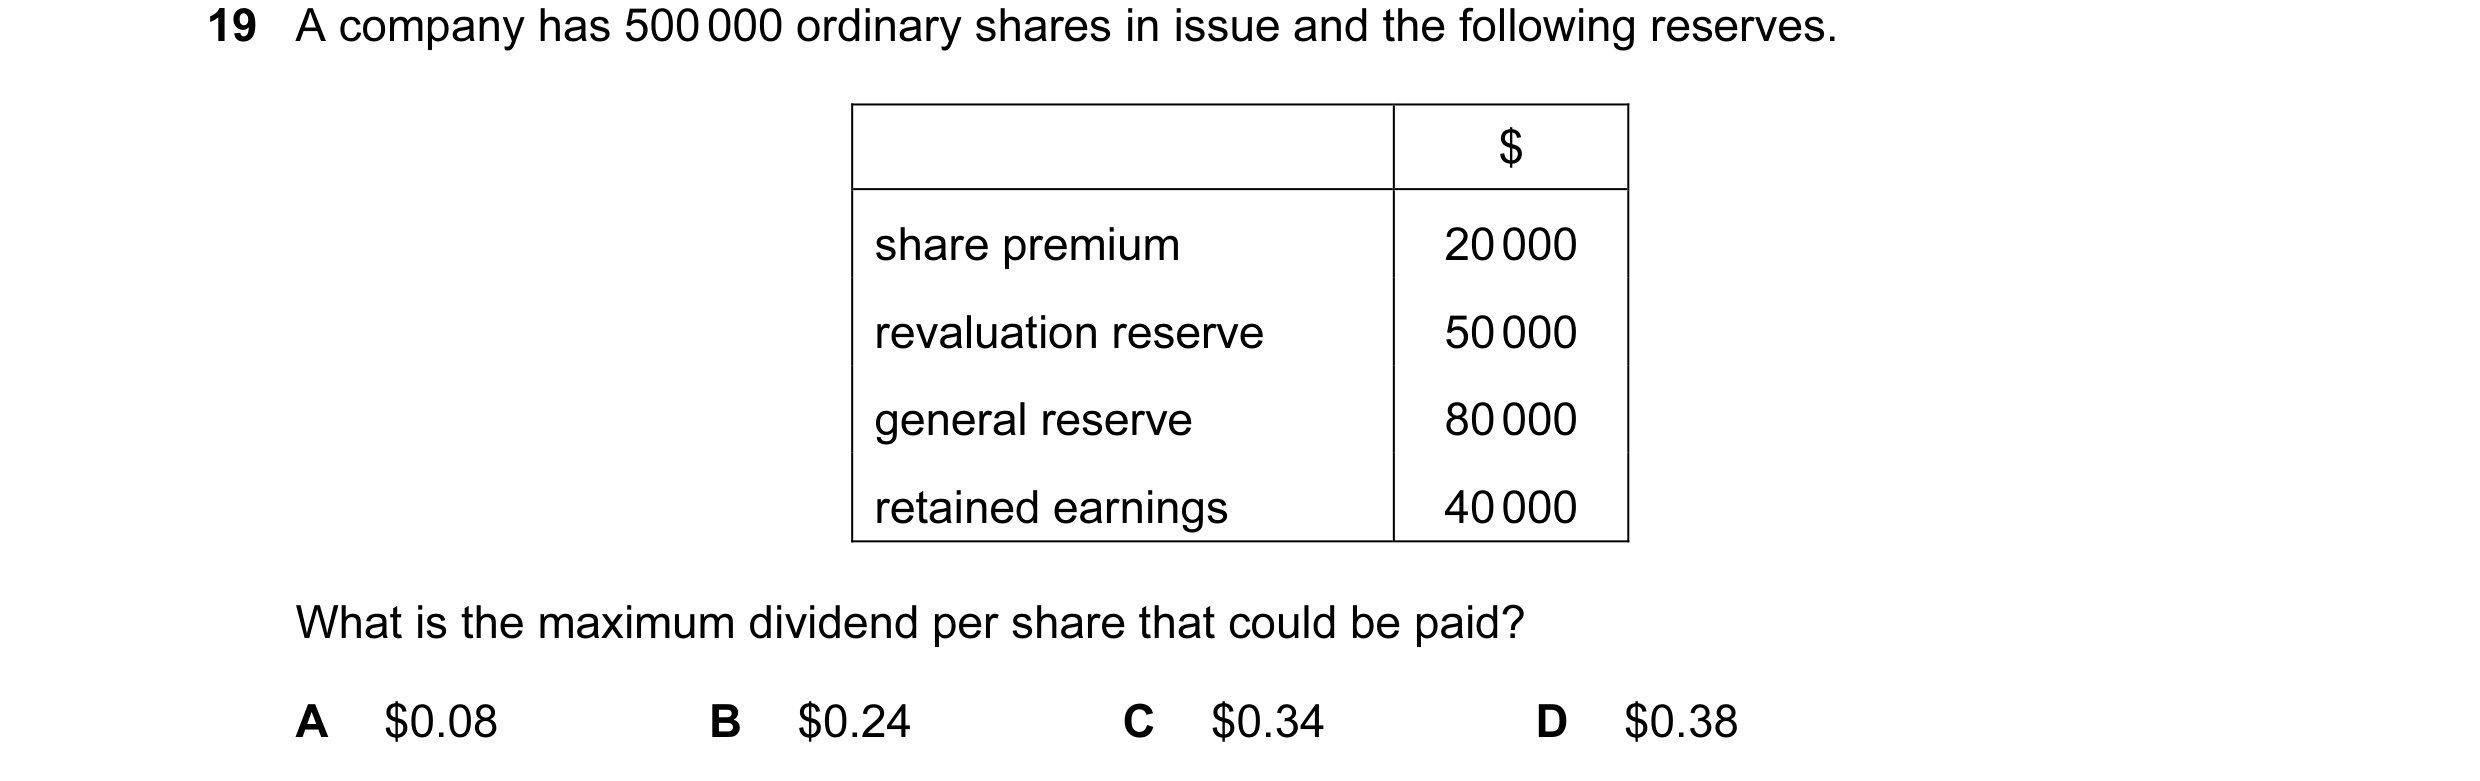 52 / 62
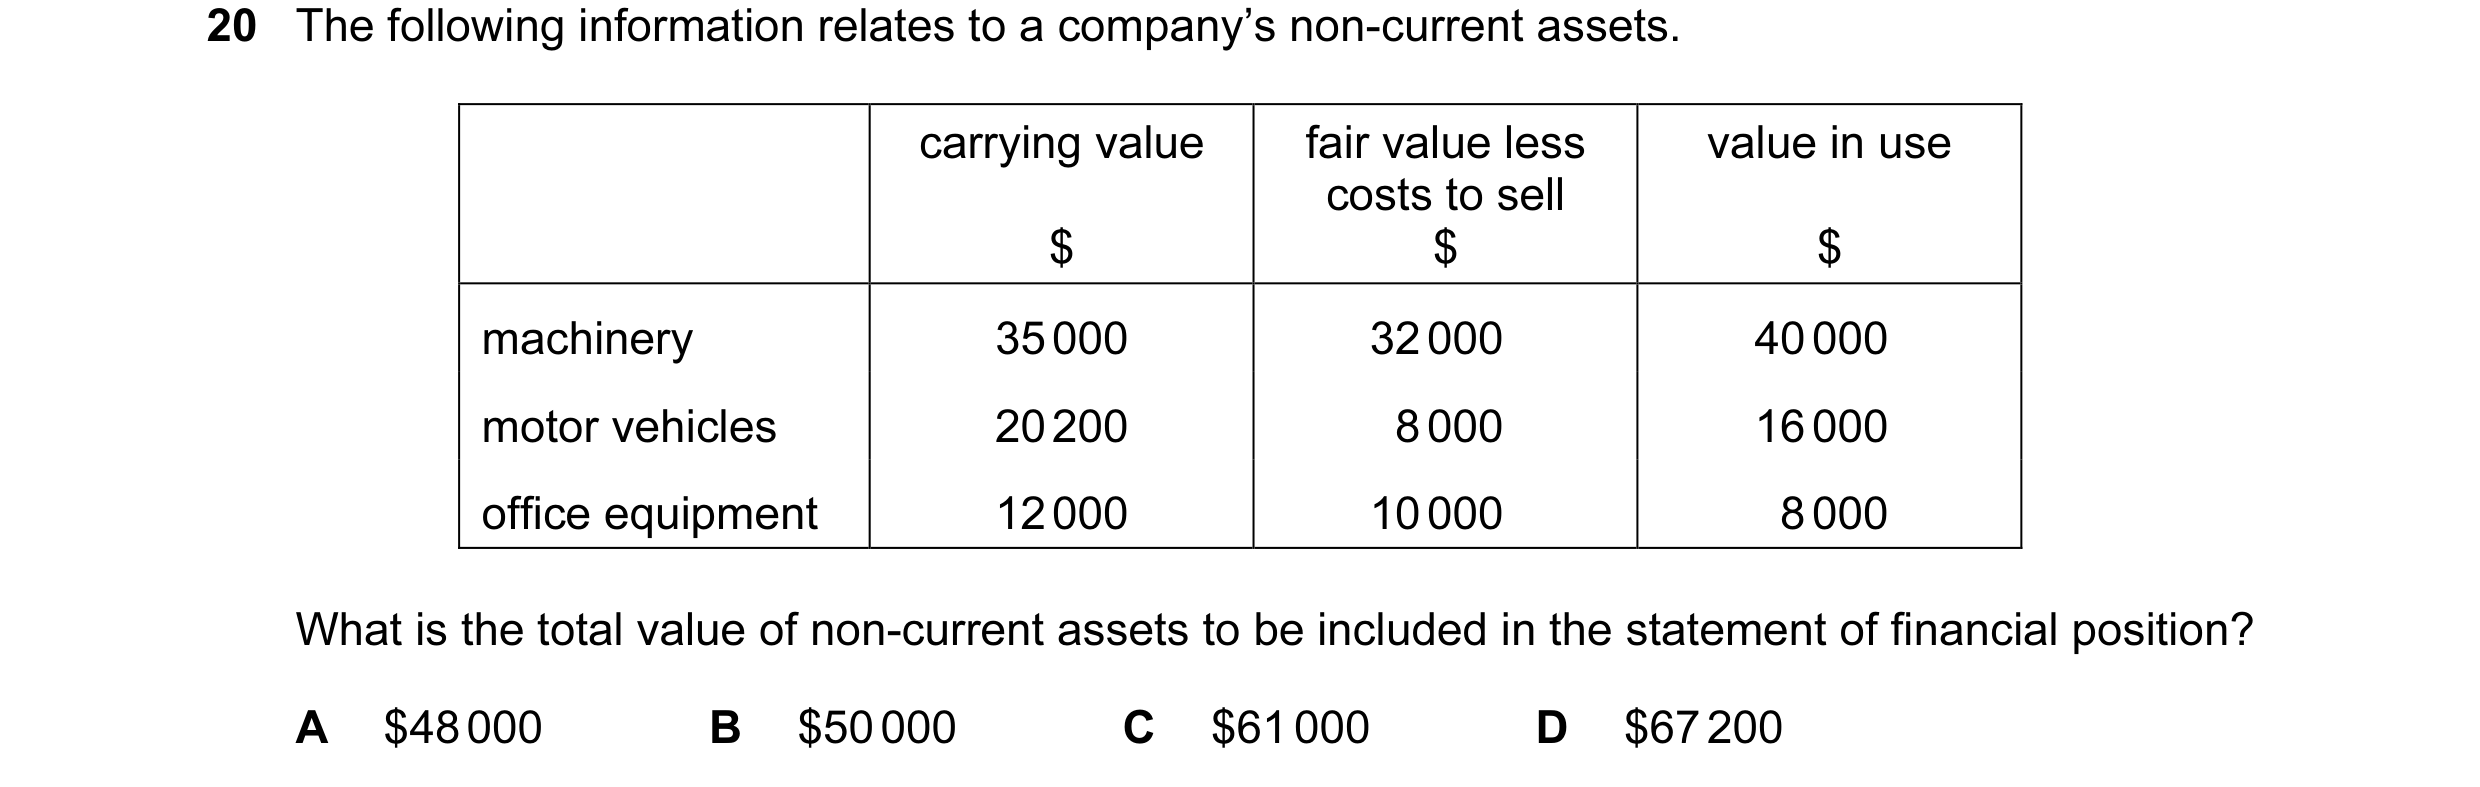
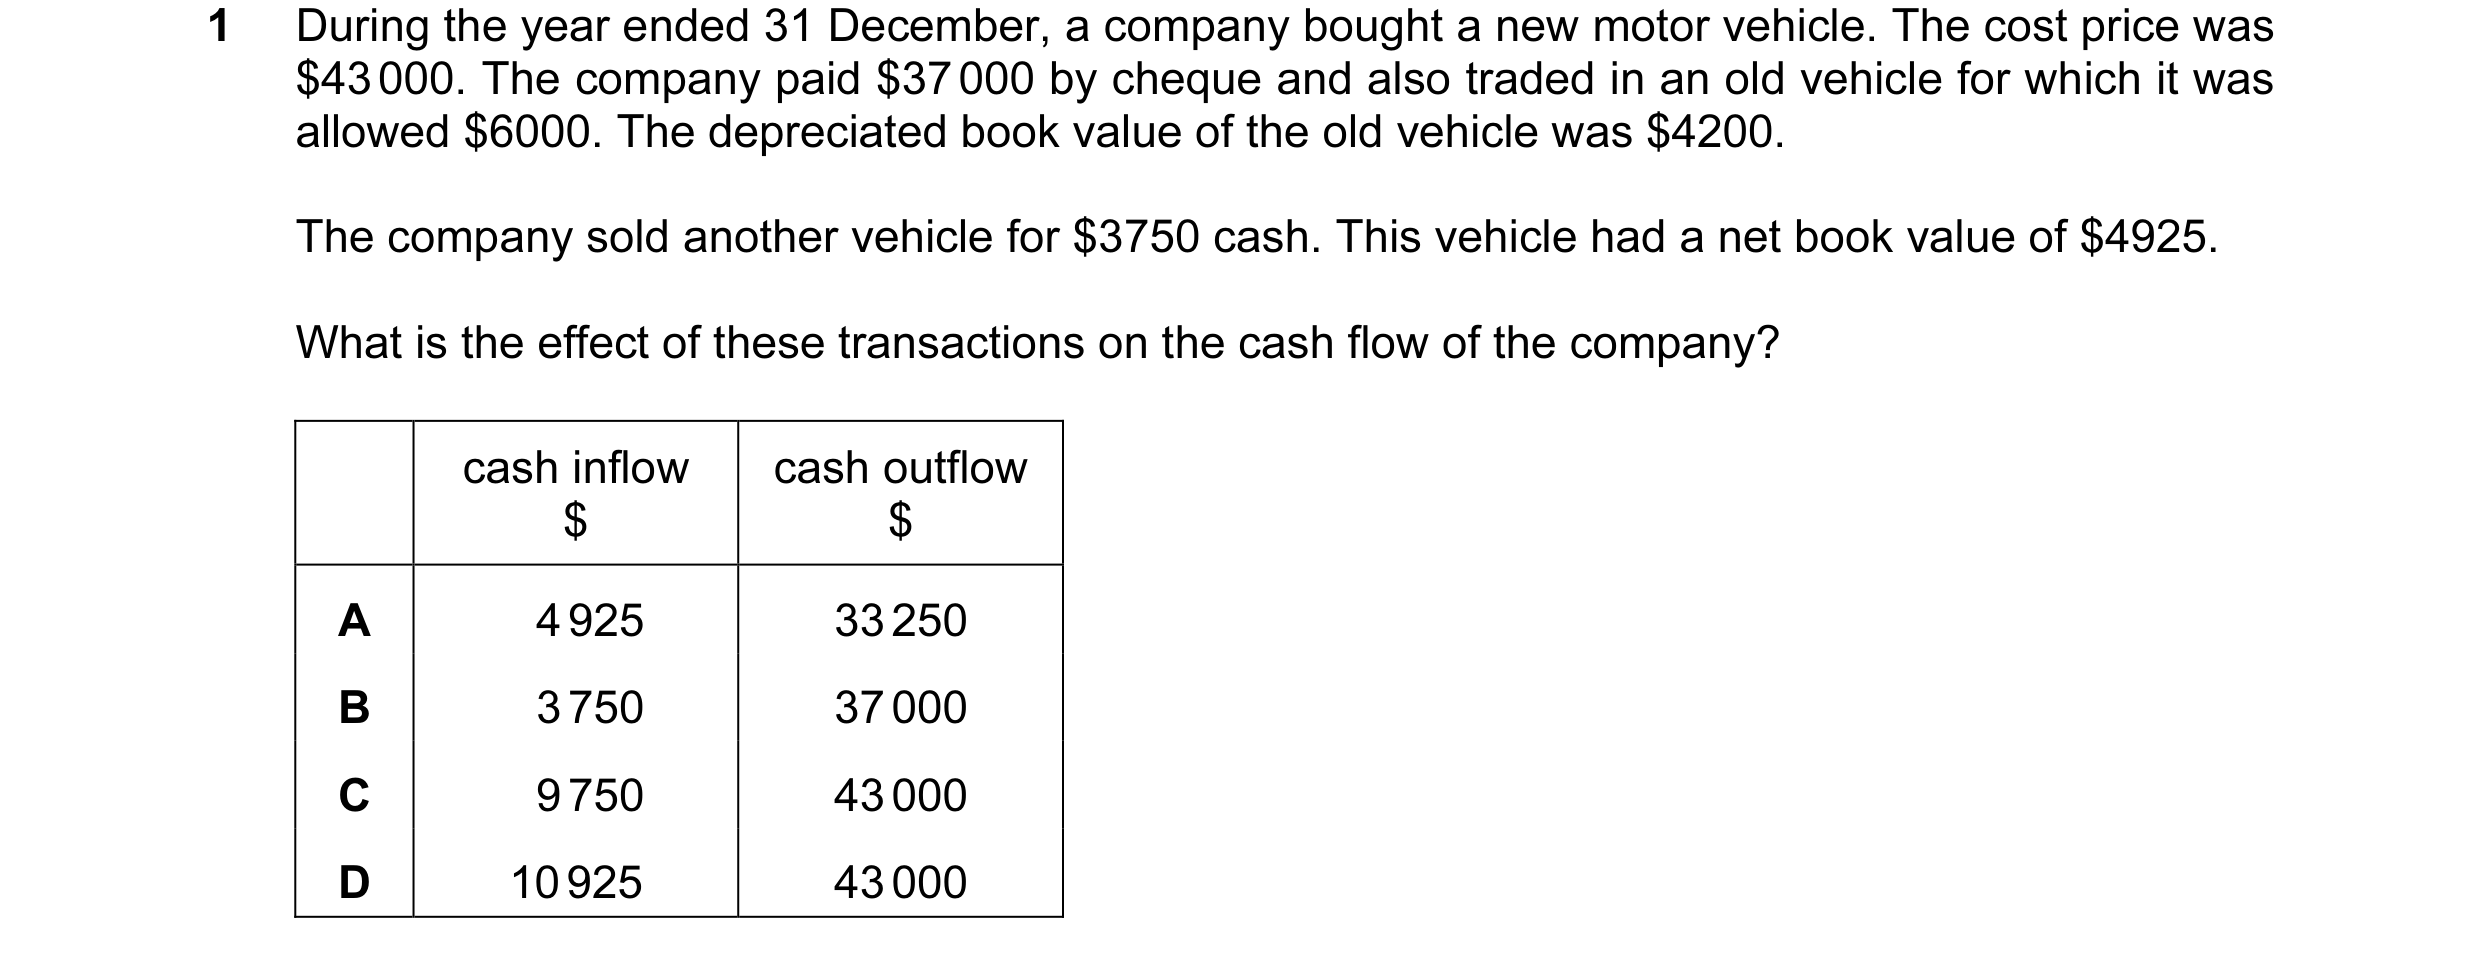
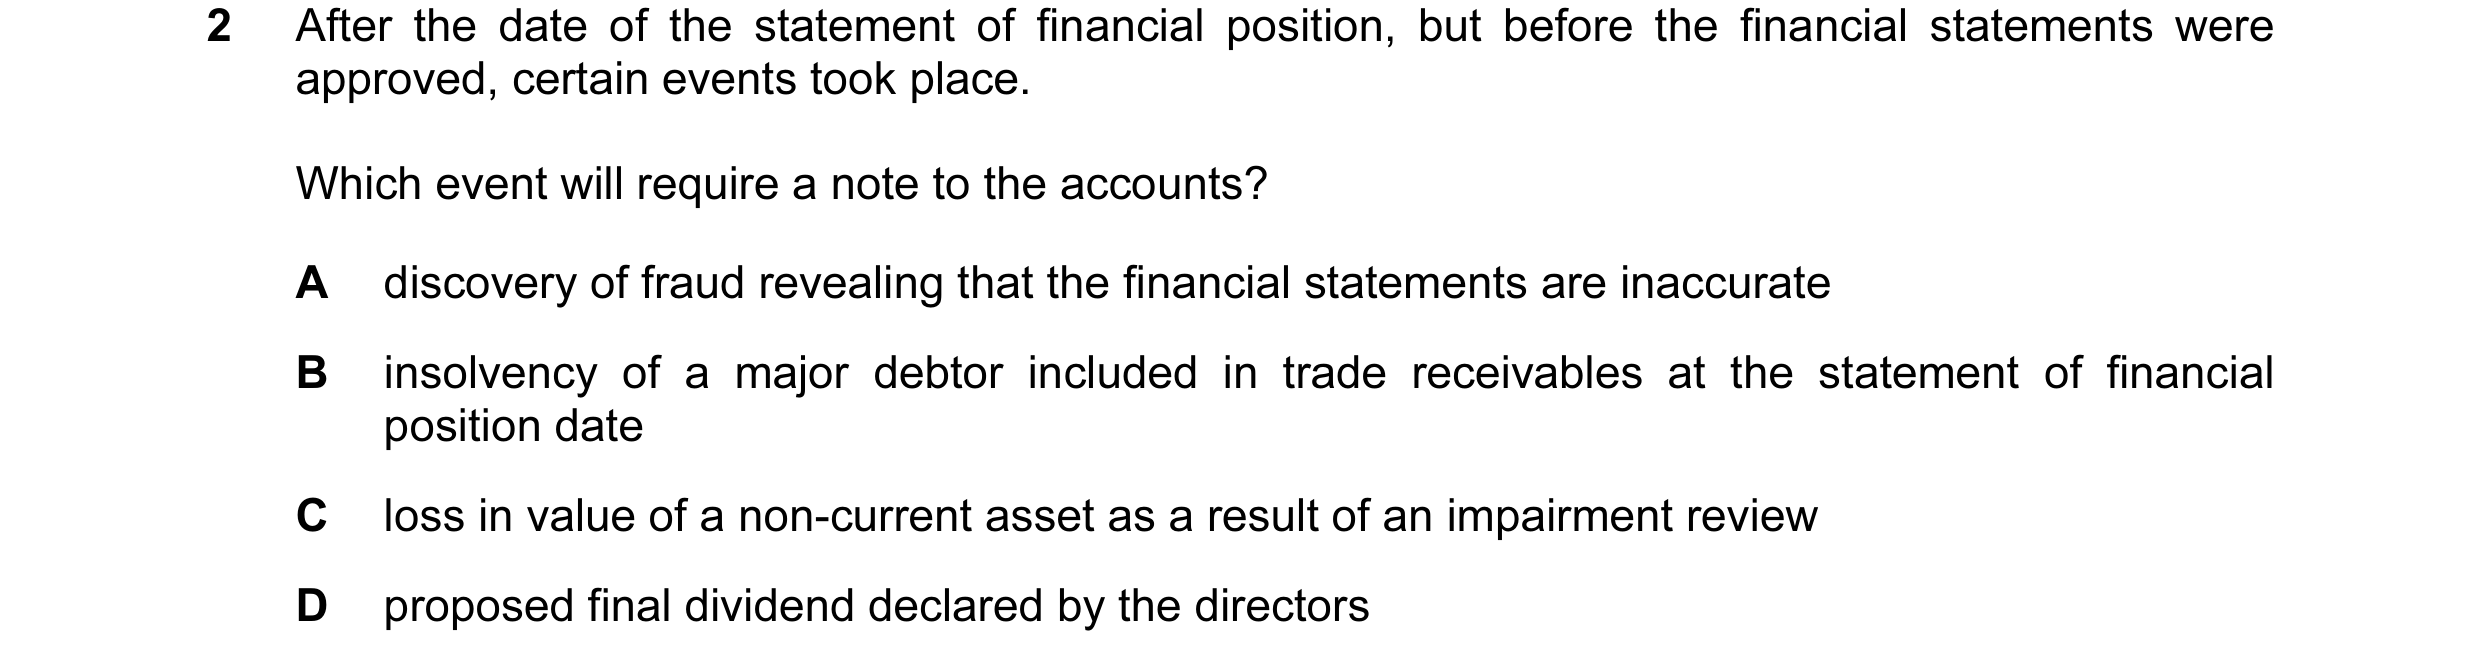 53 / 62
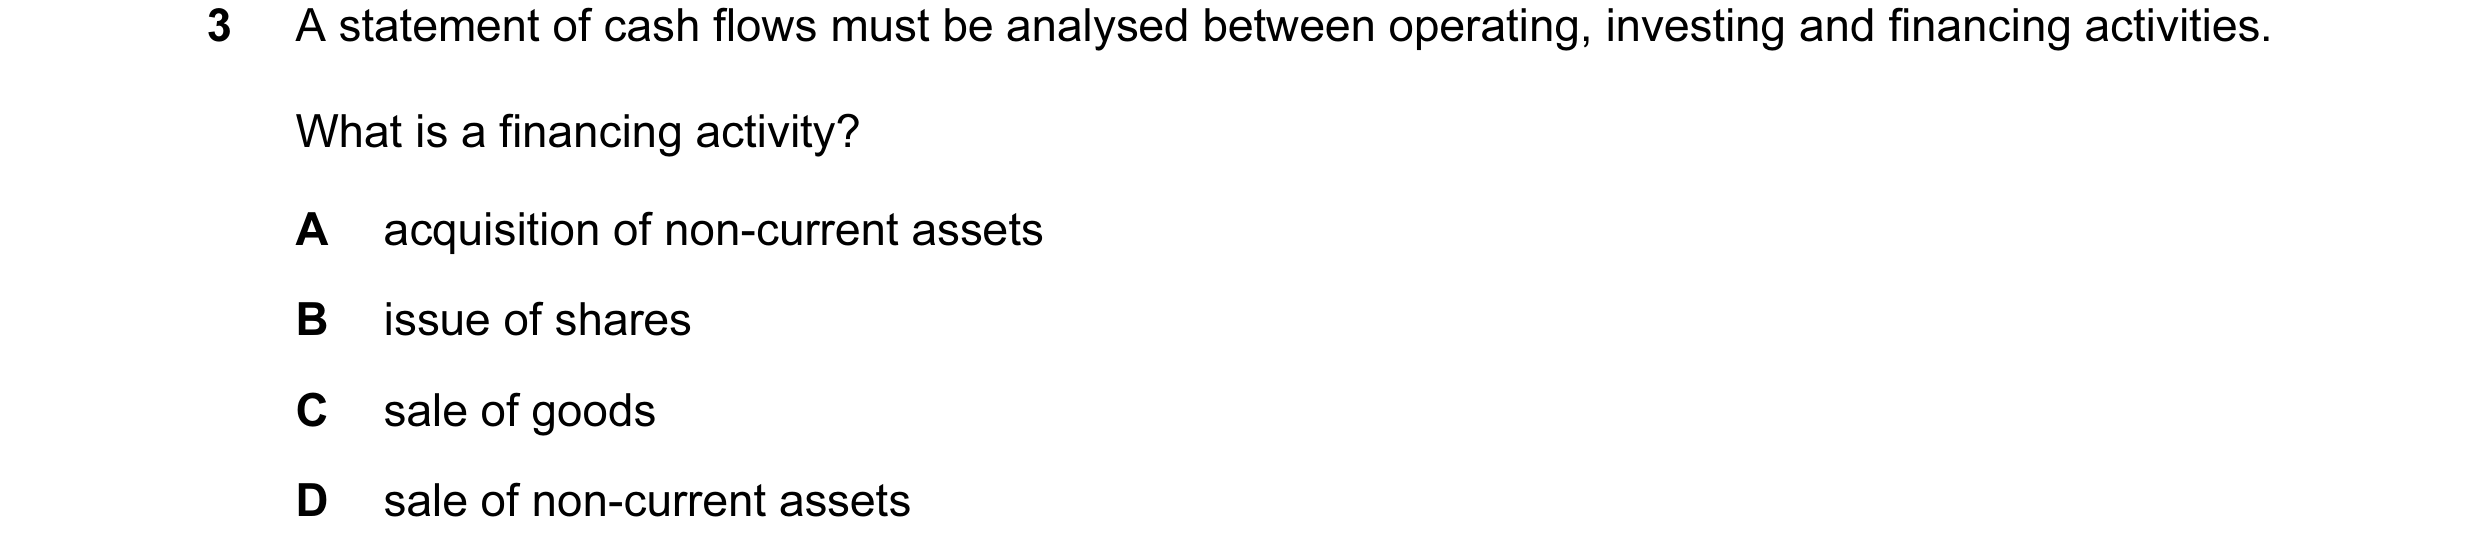
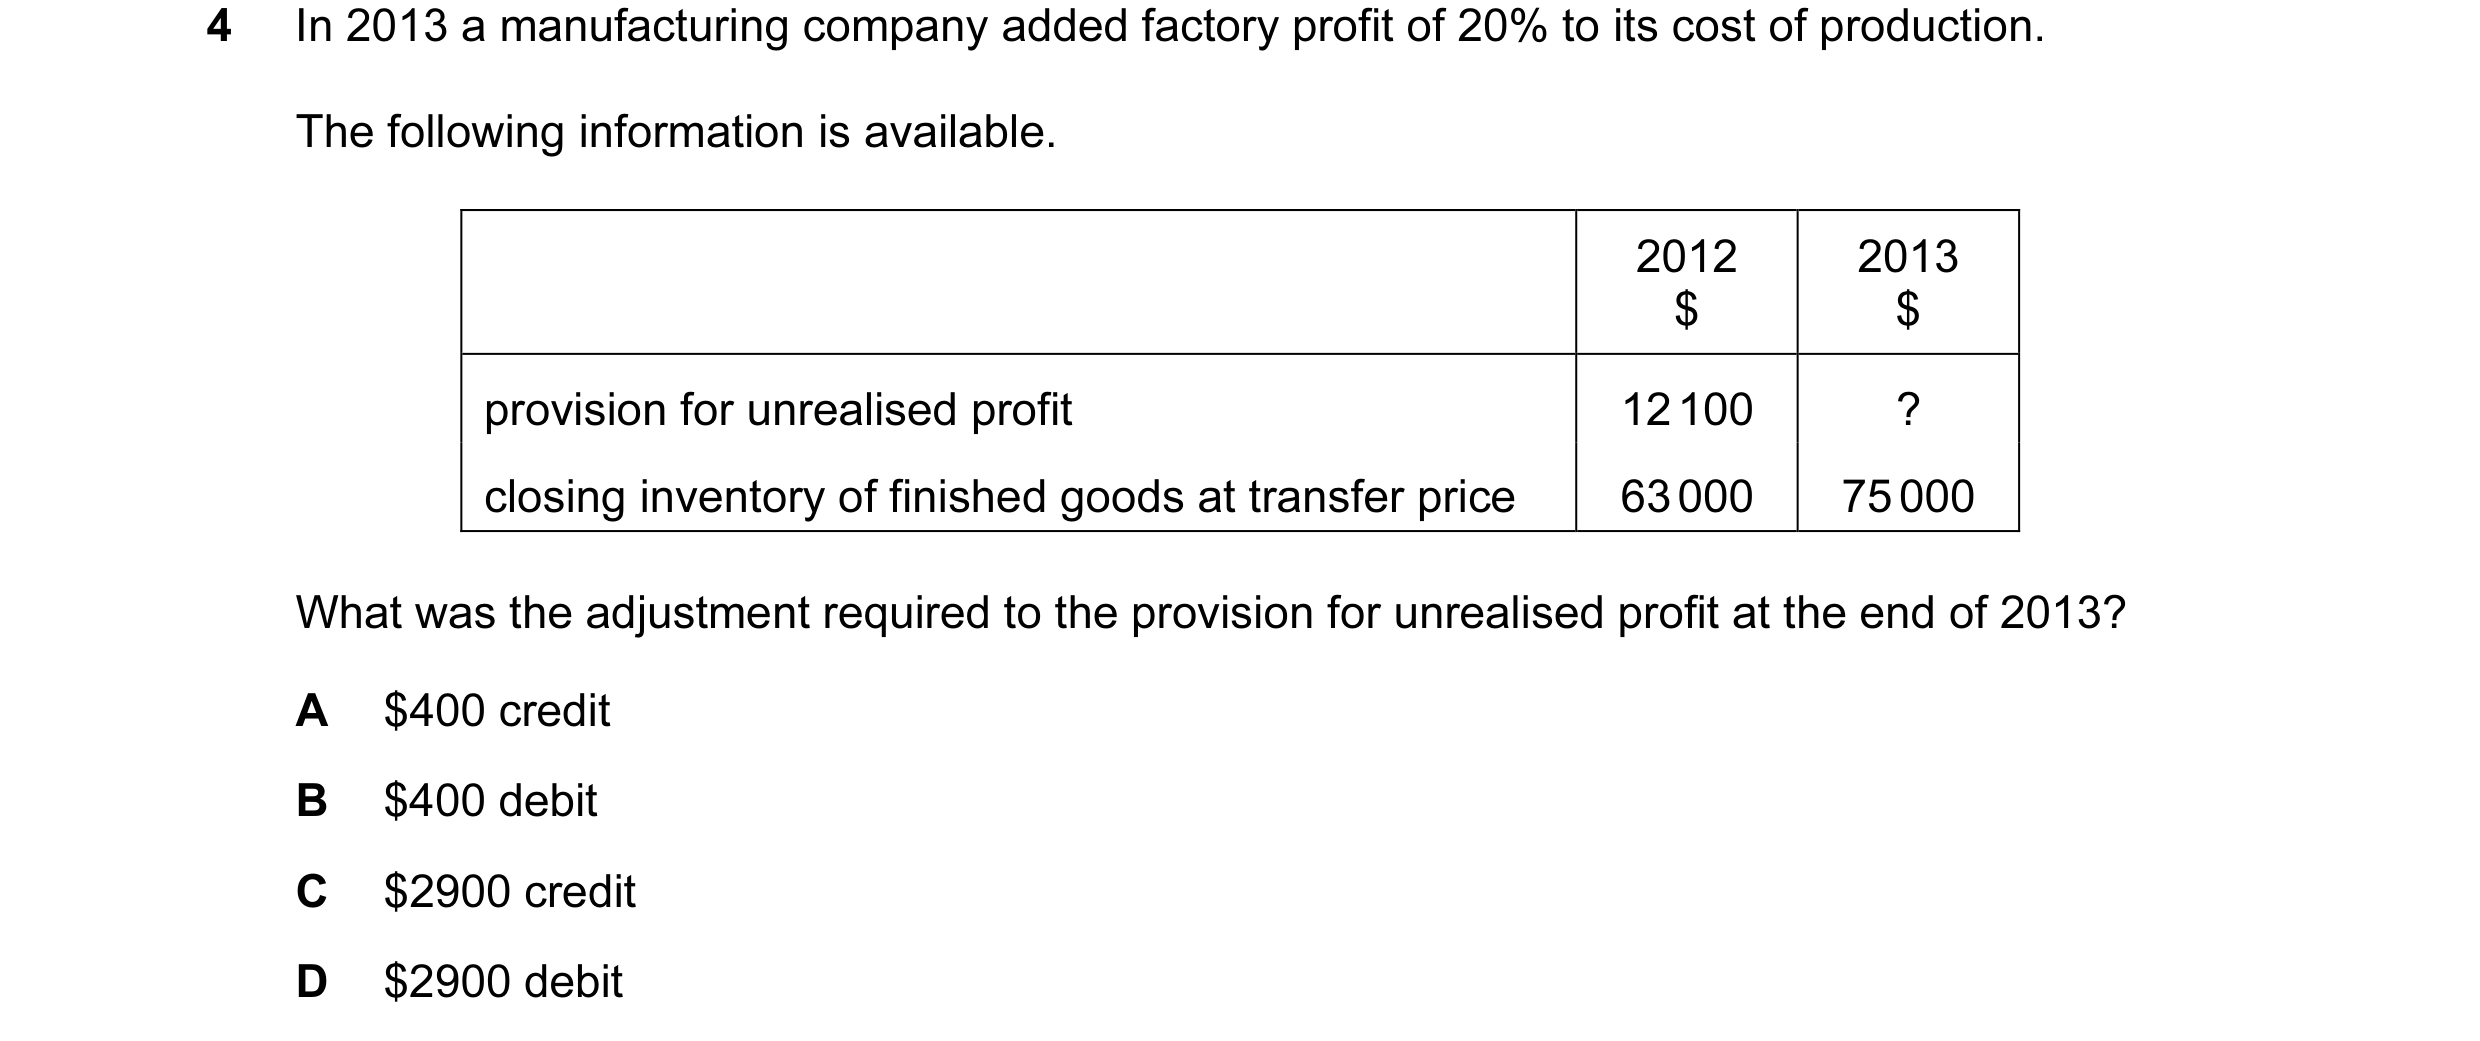
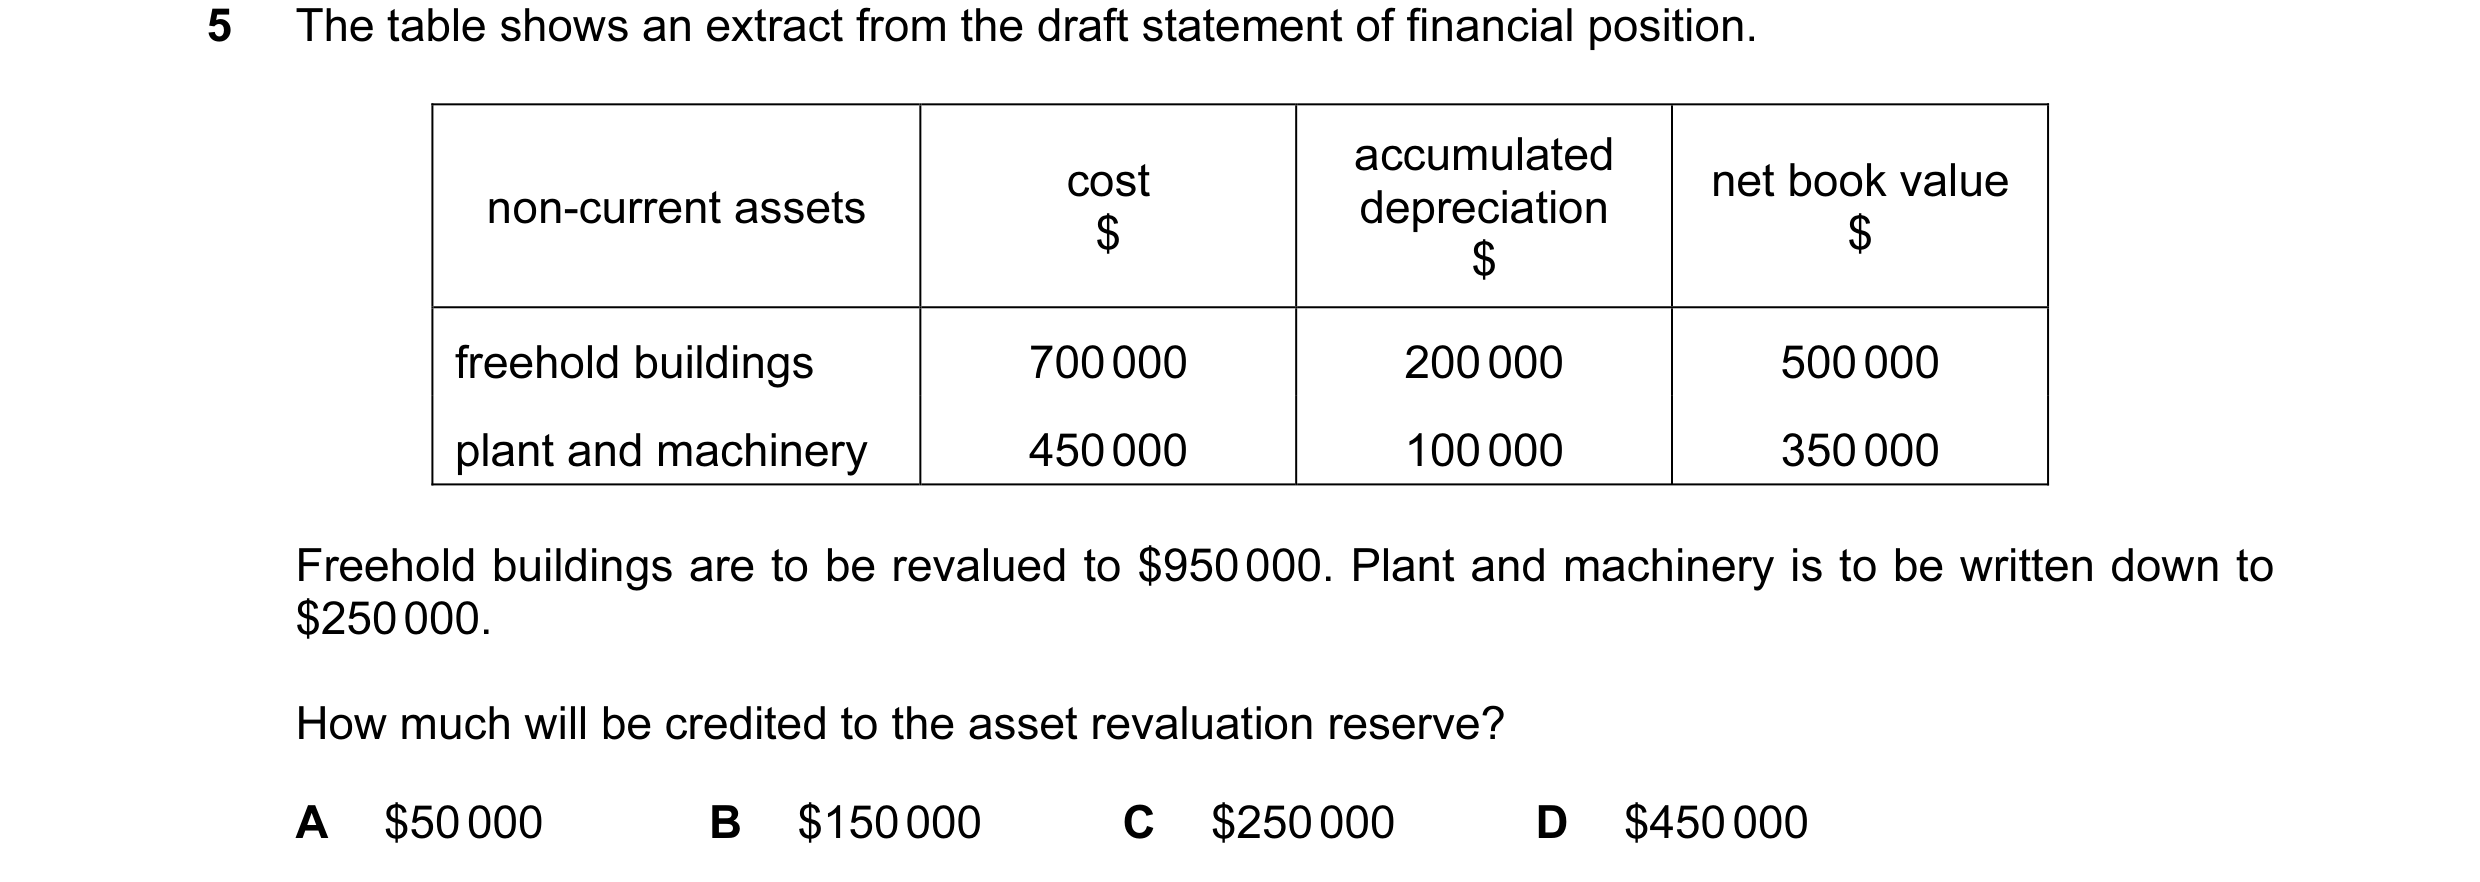 54 / 62
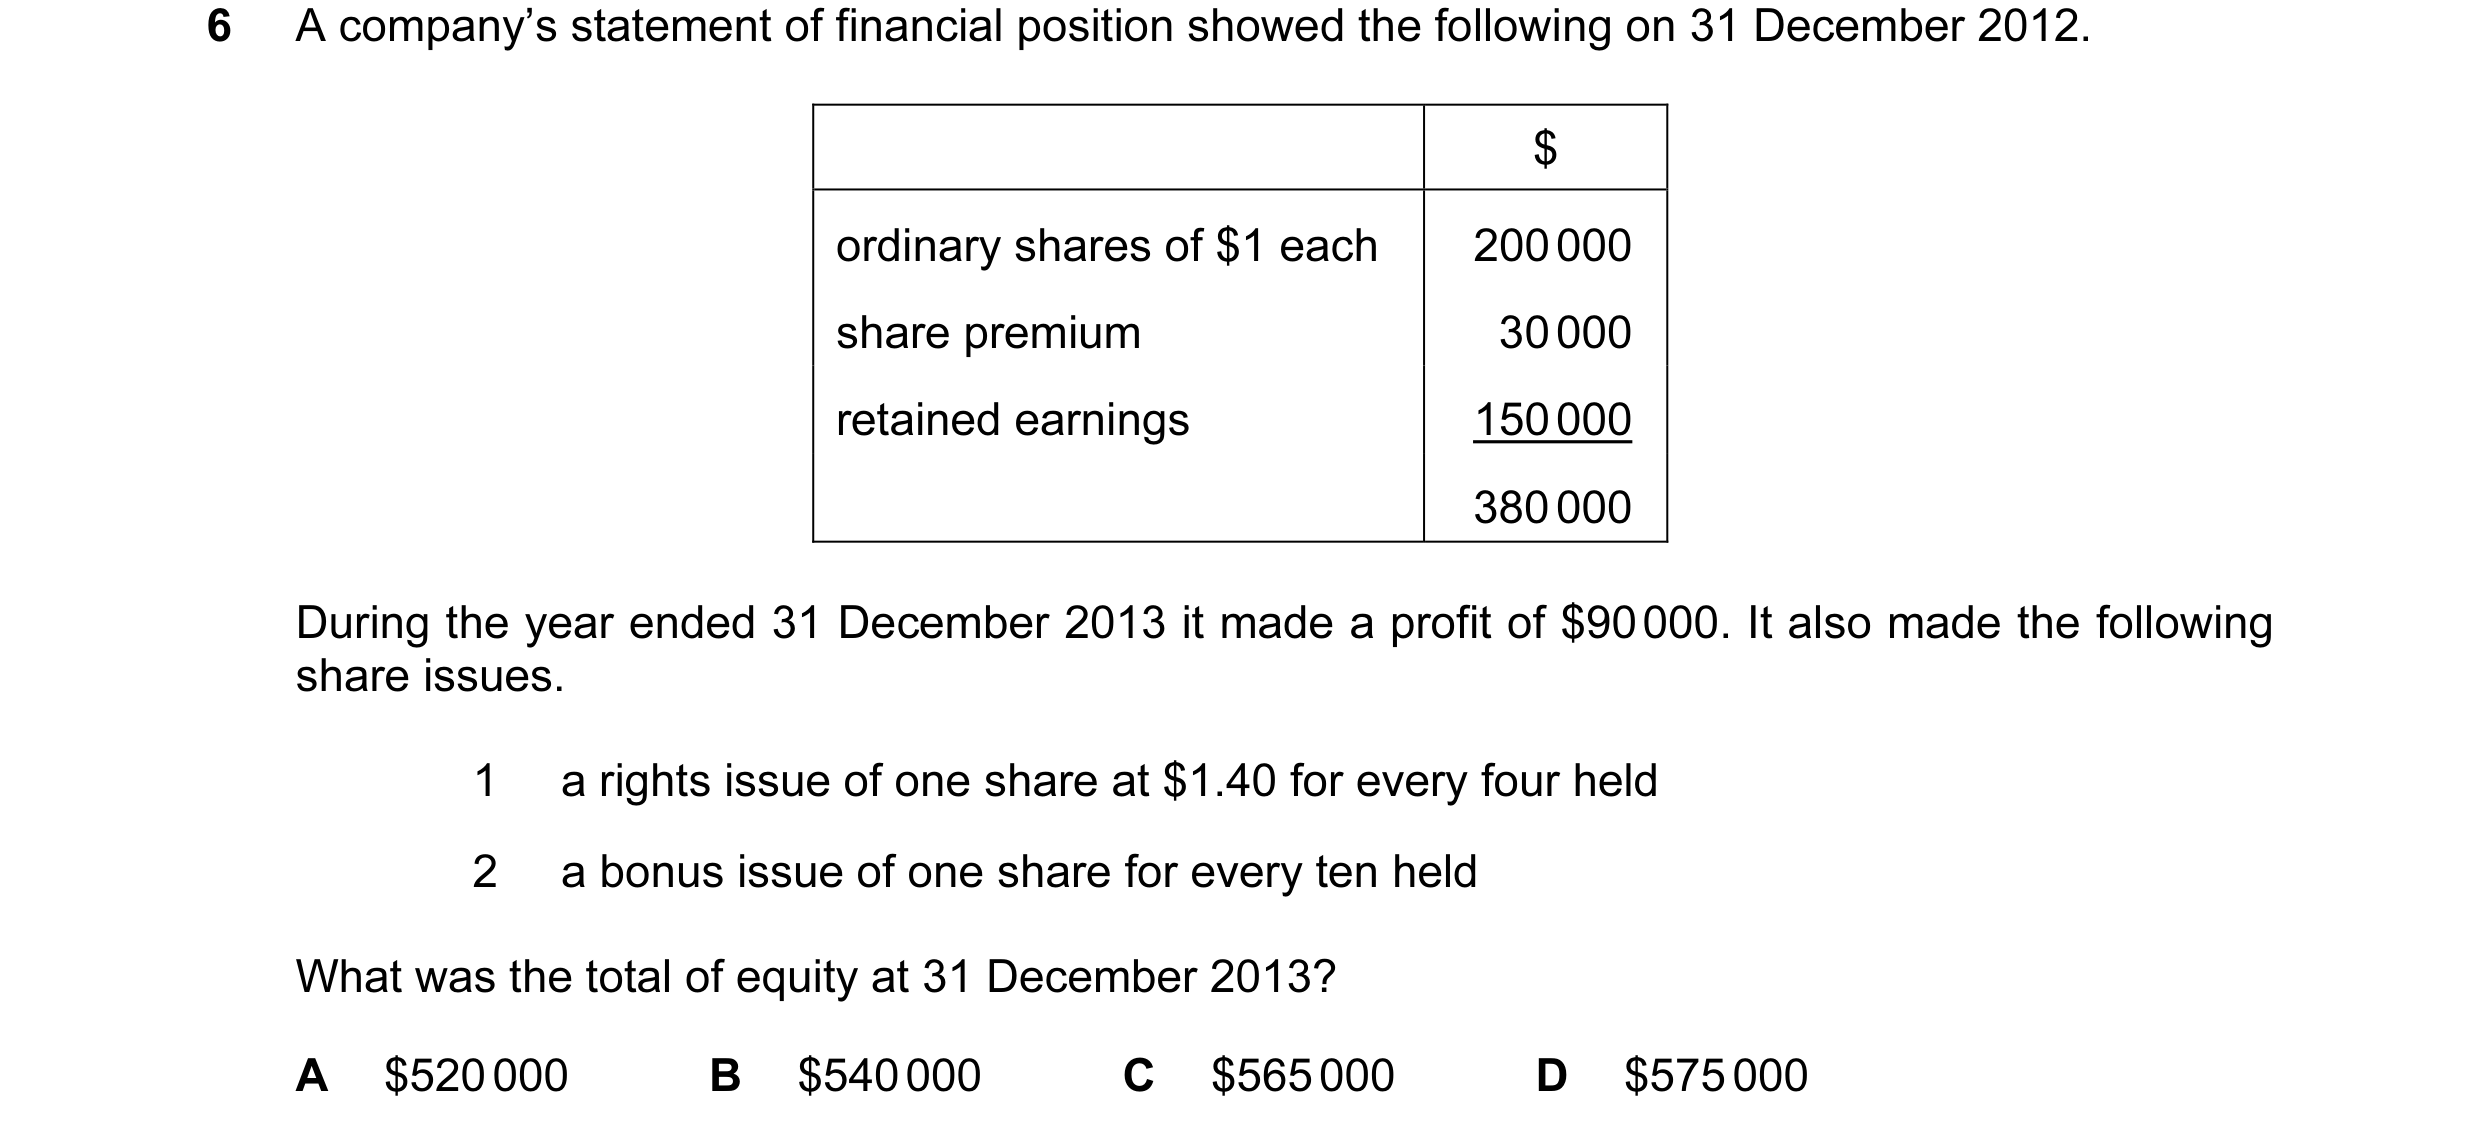
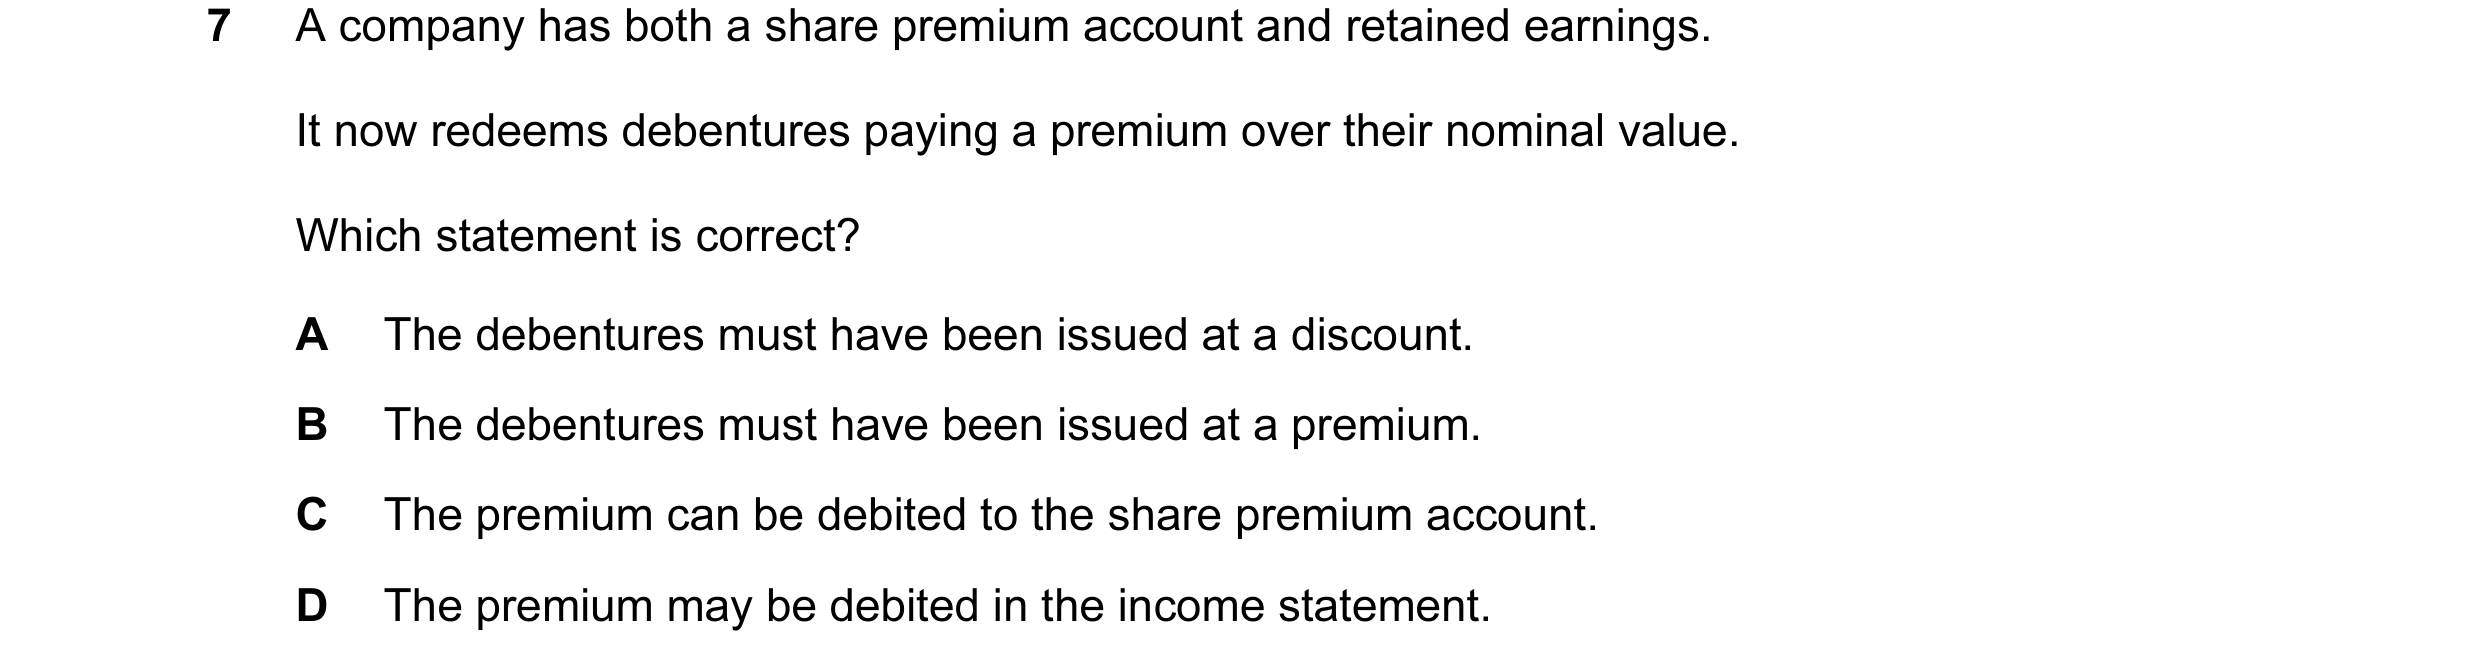
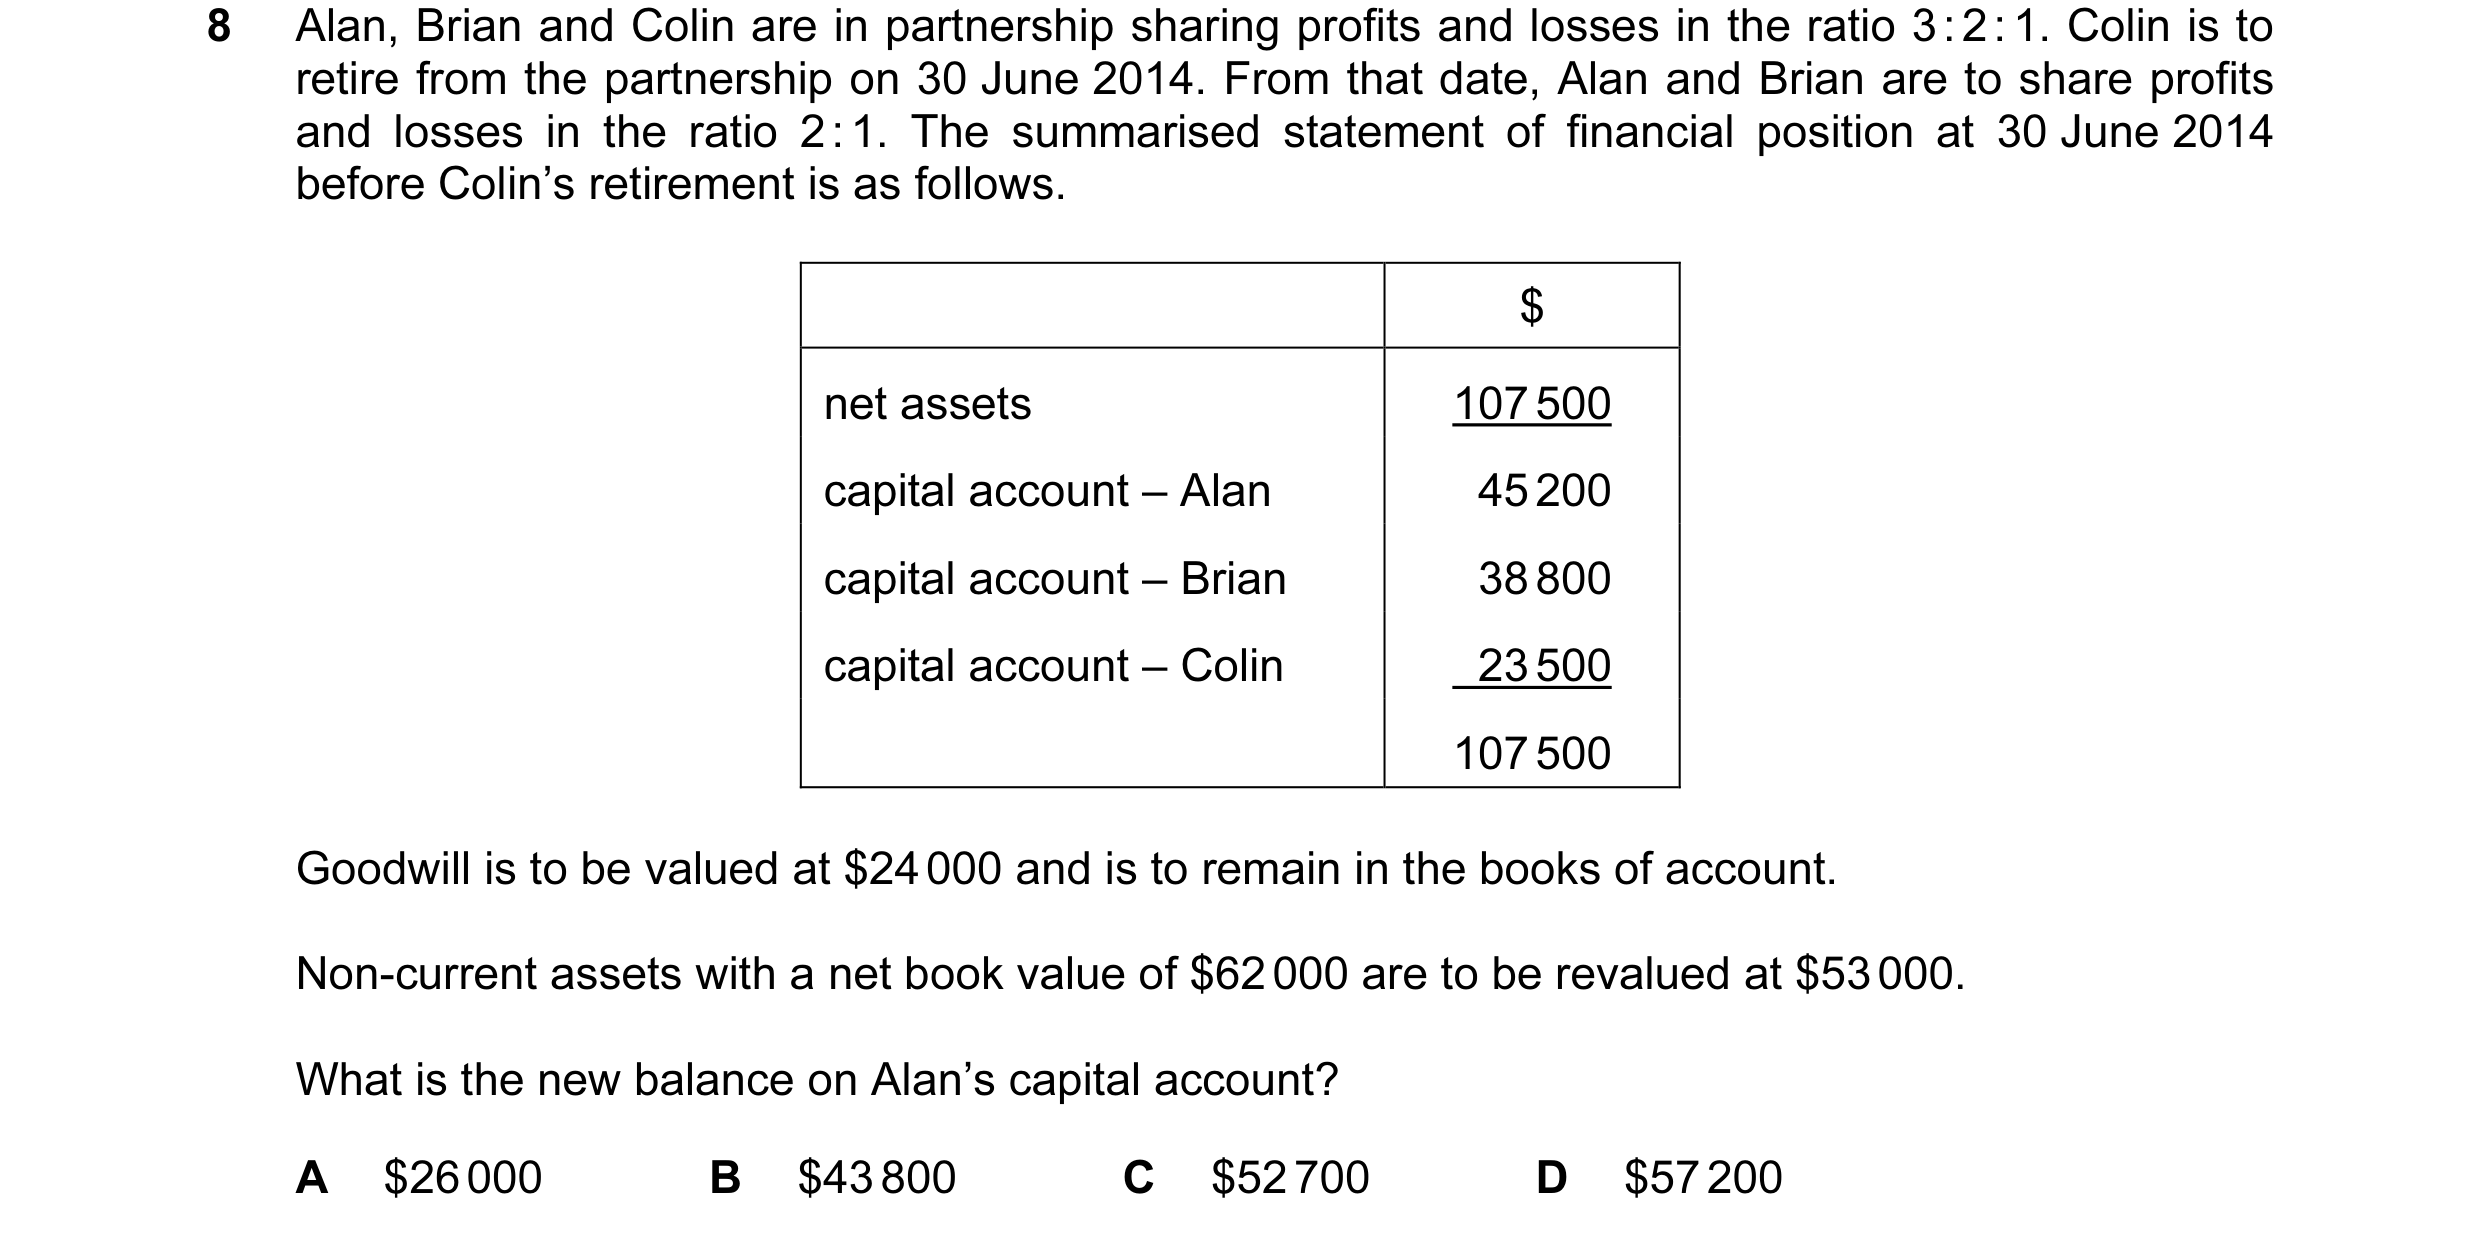 55 / 62
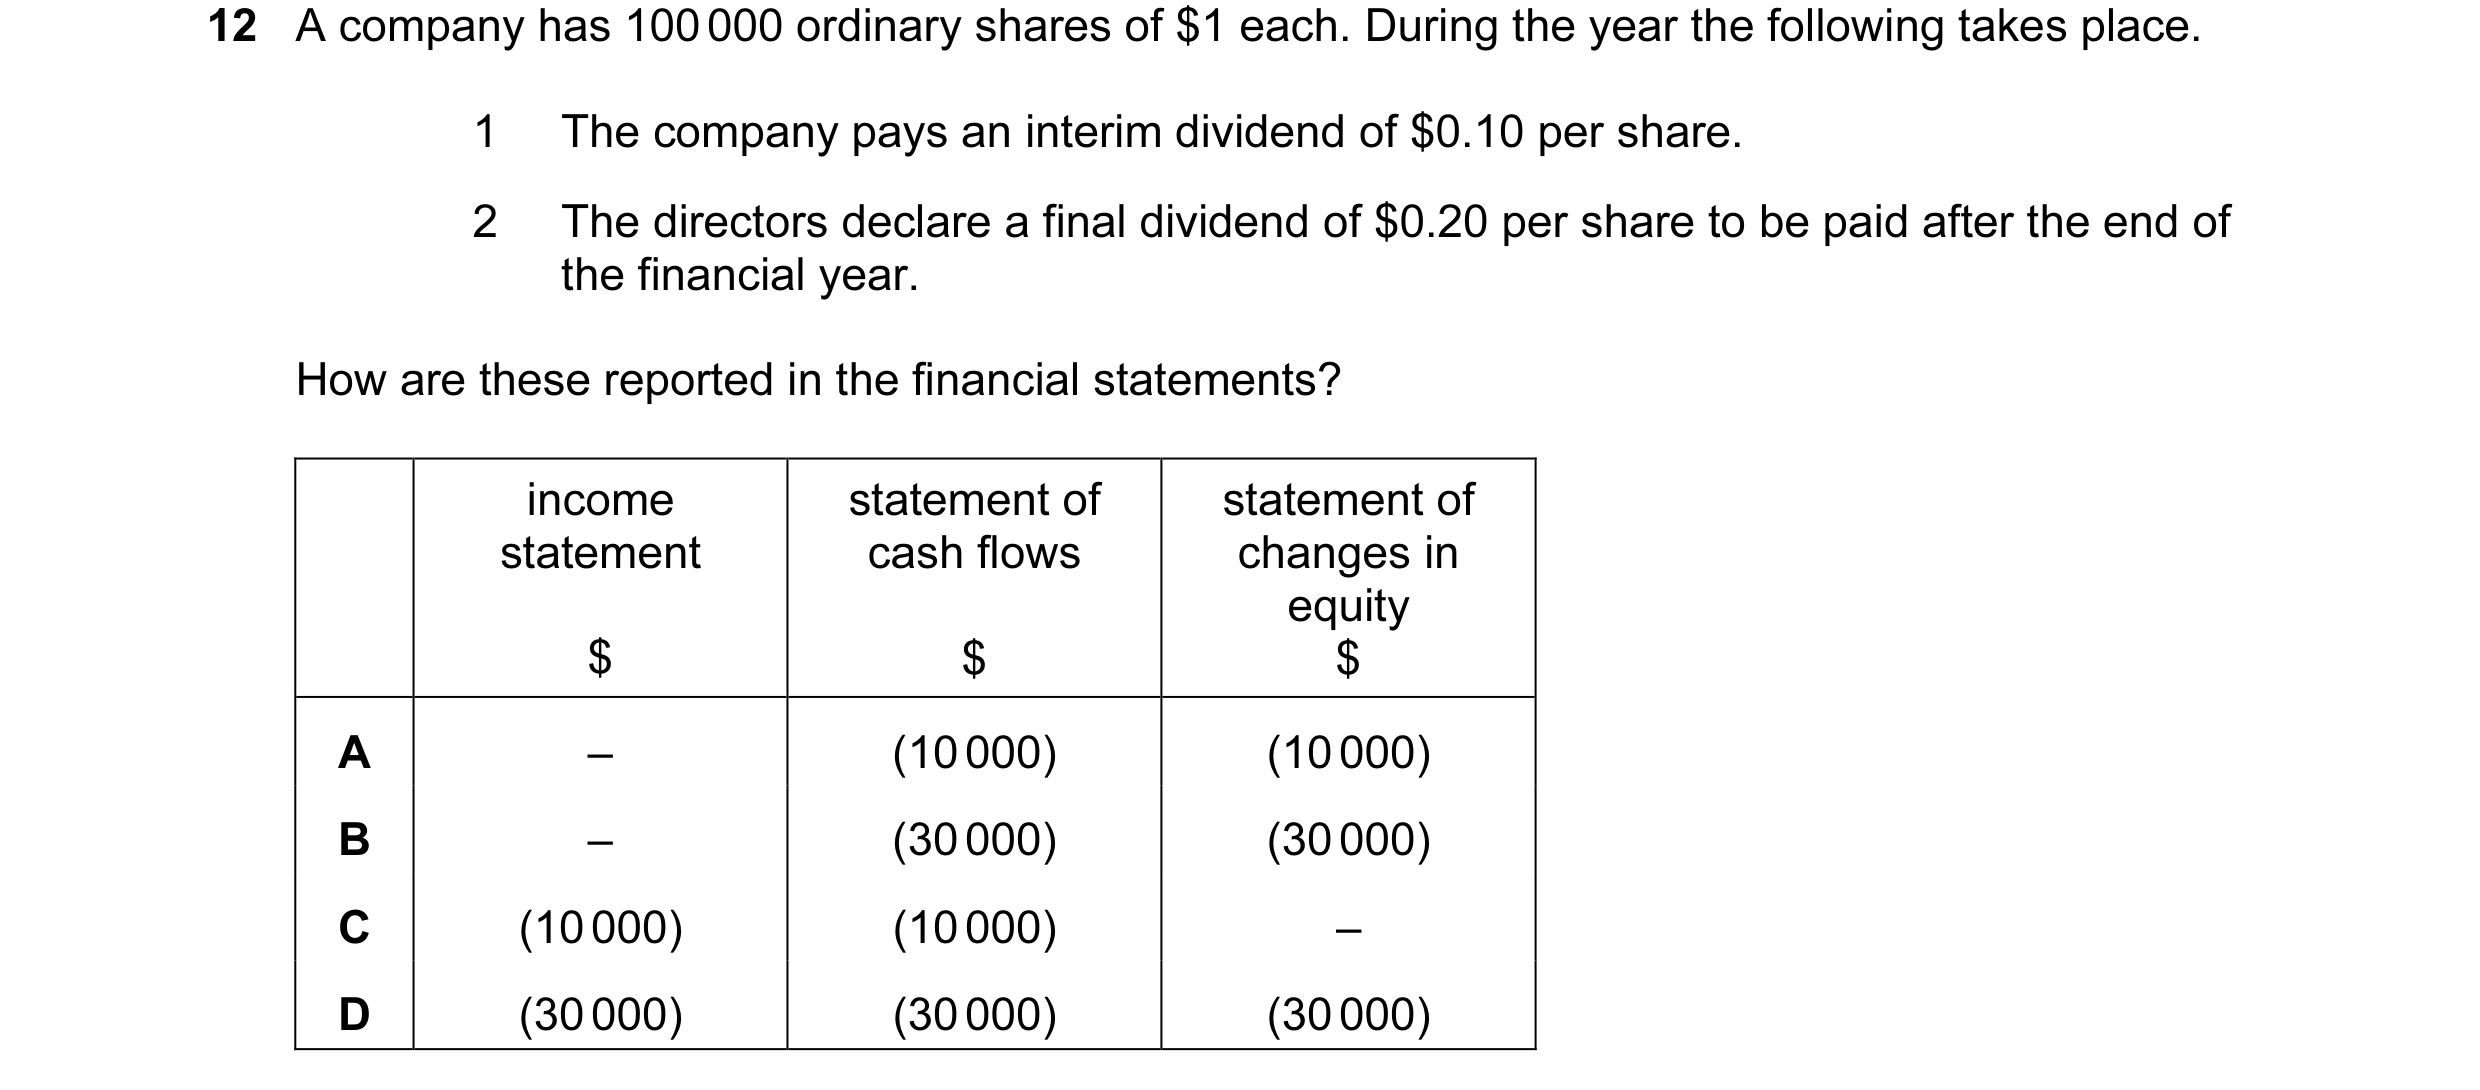
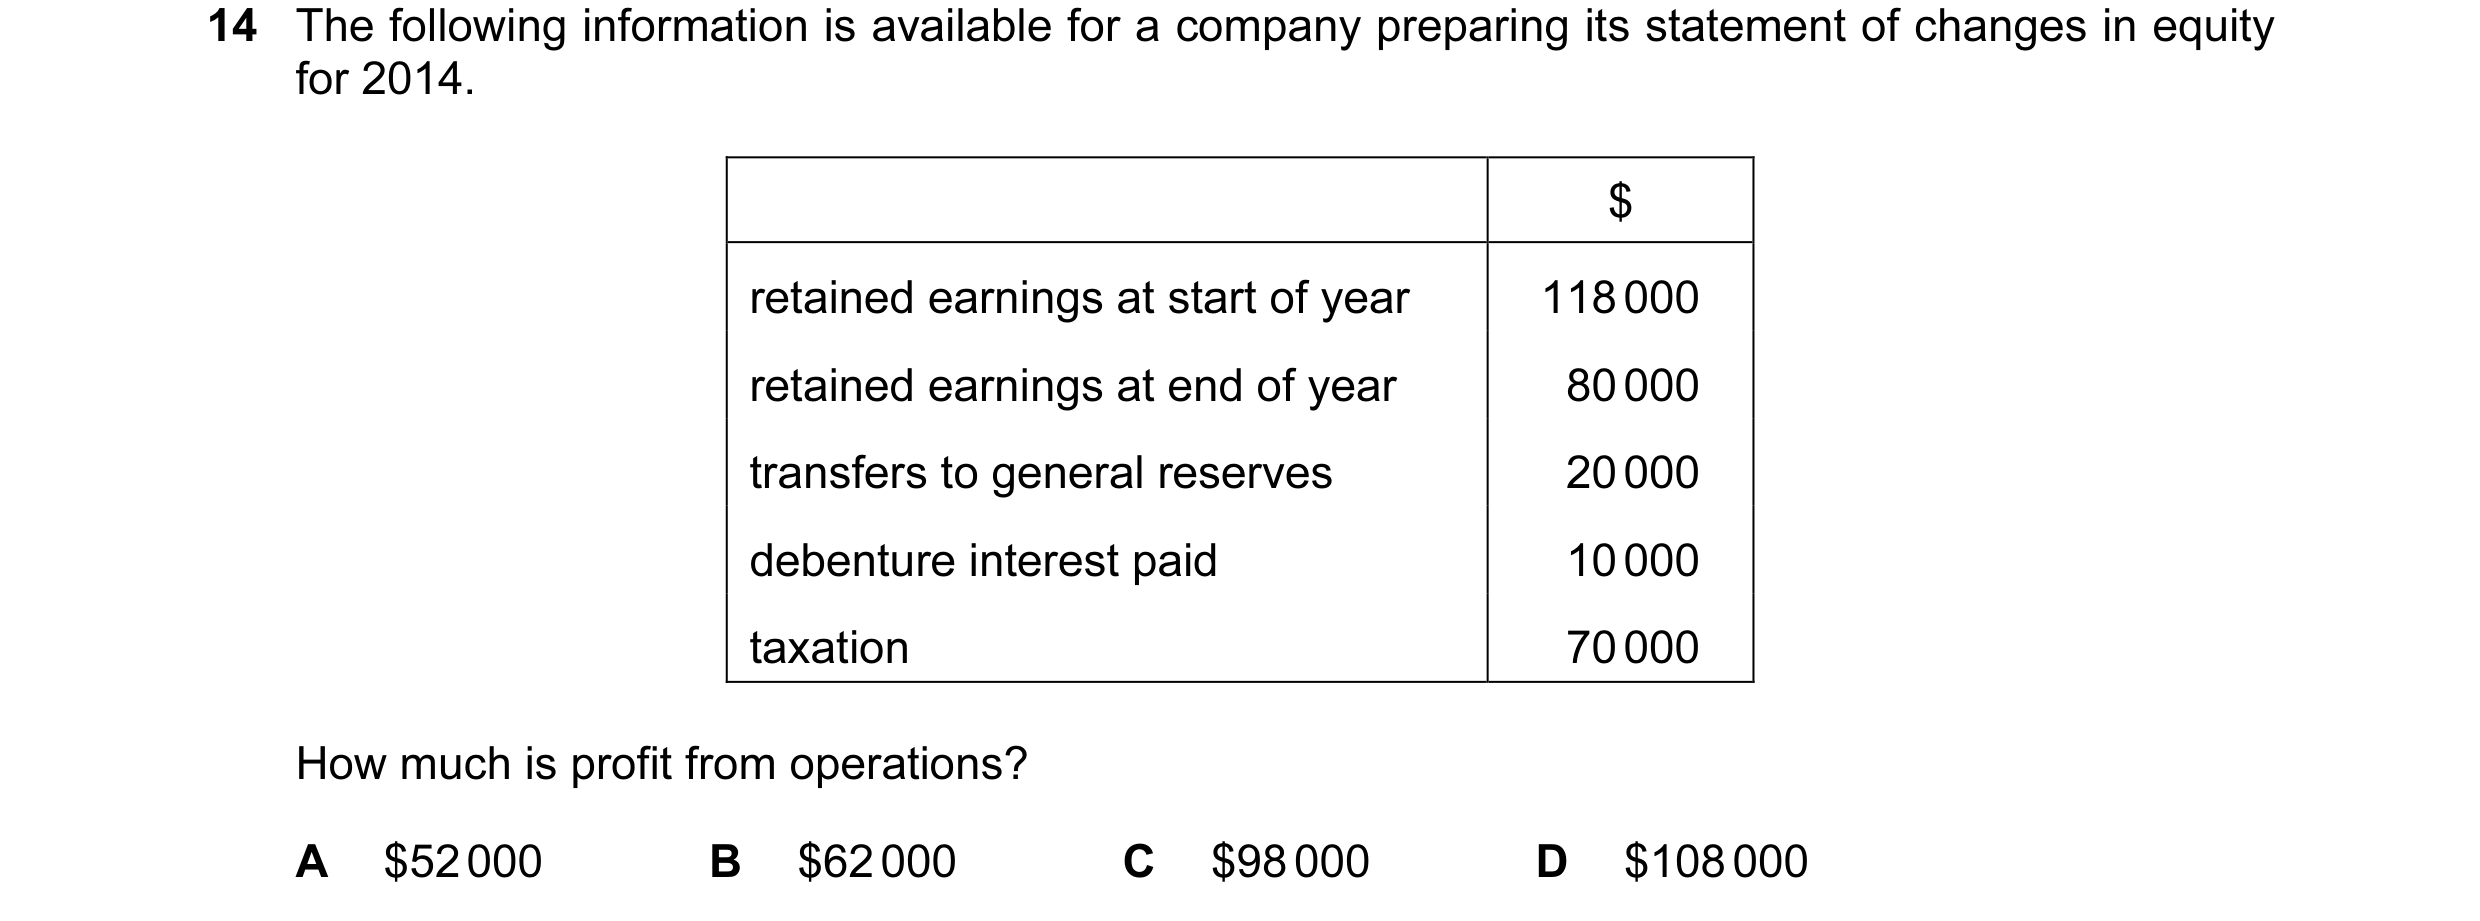
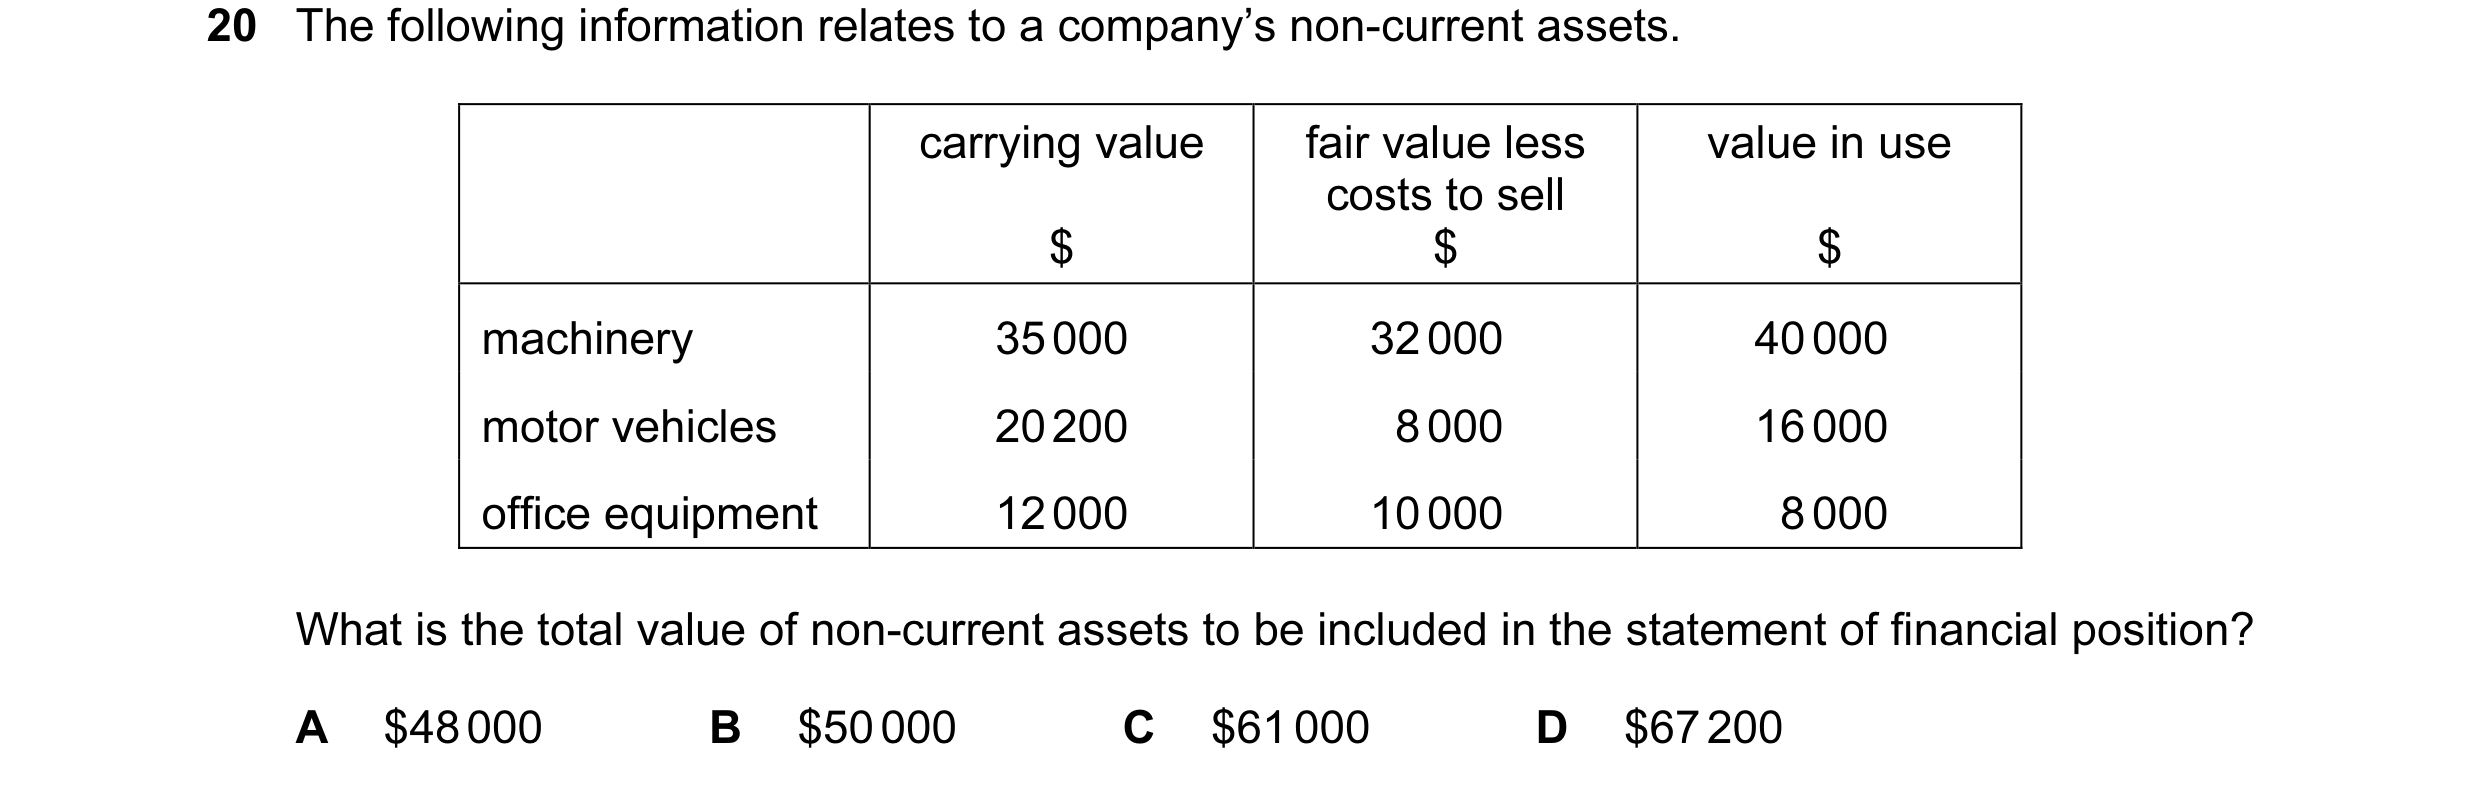
 56 / 62
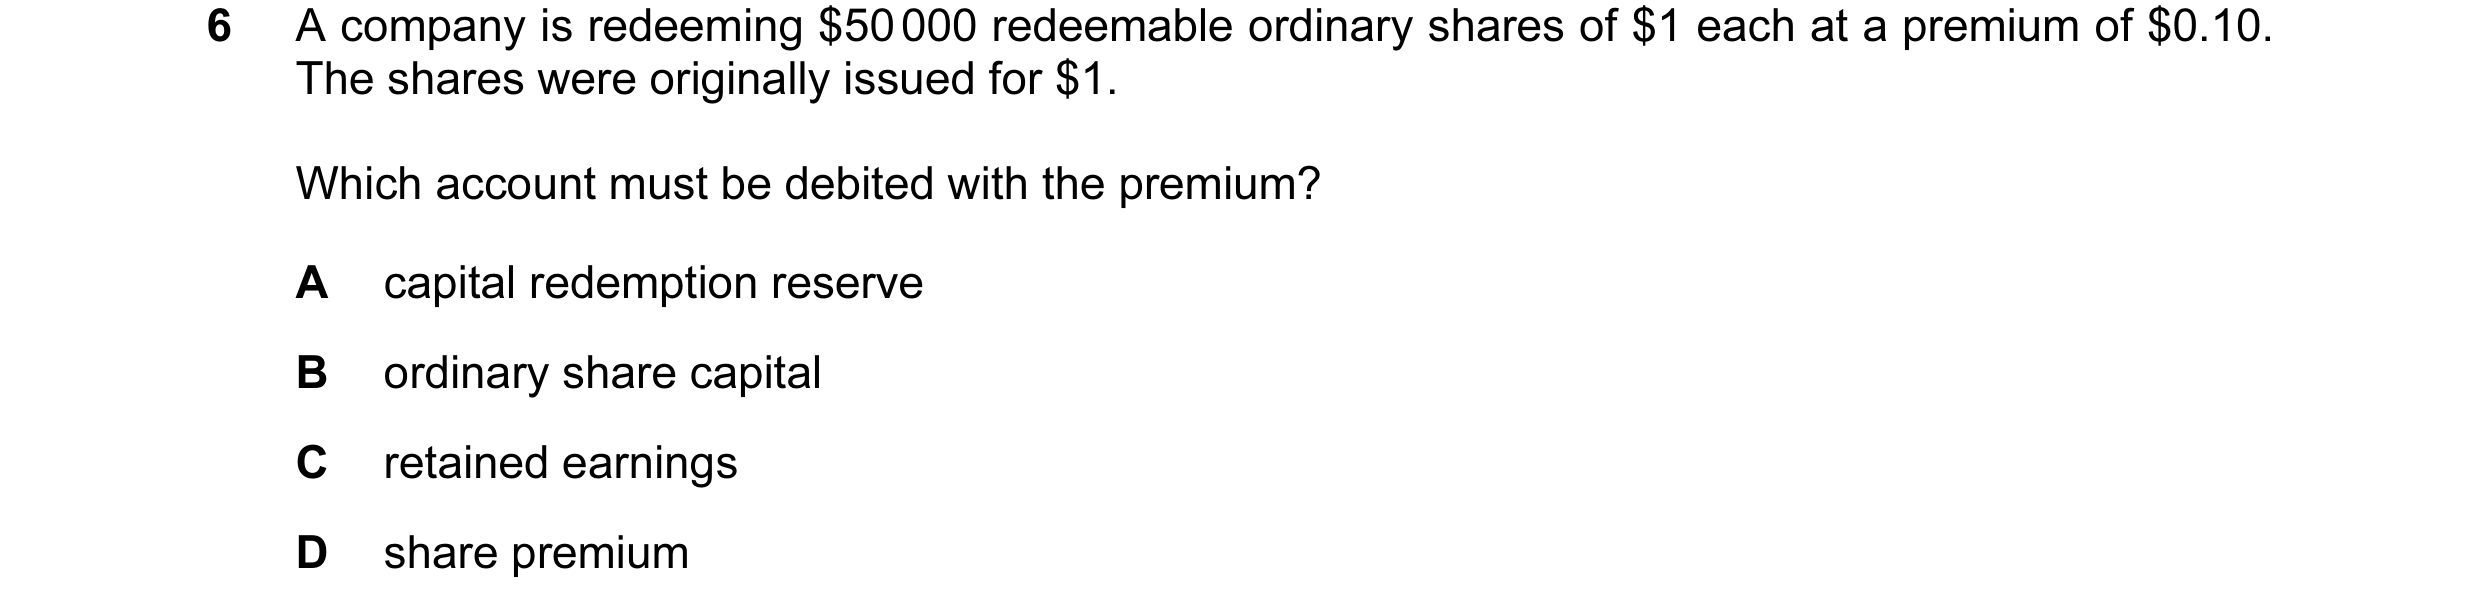
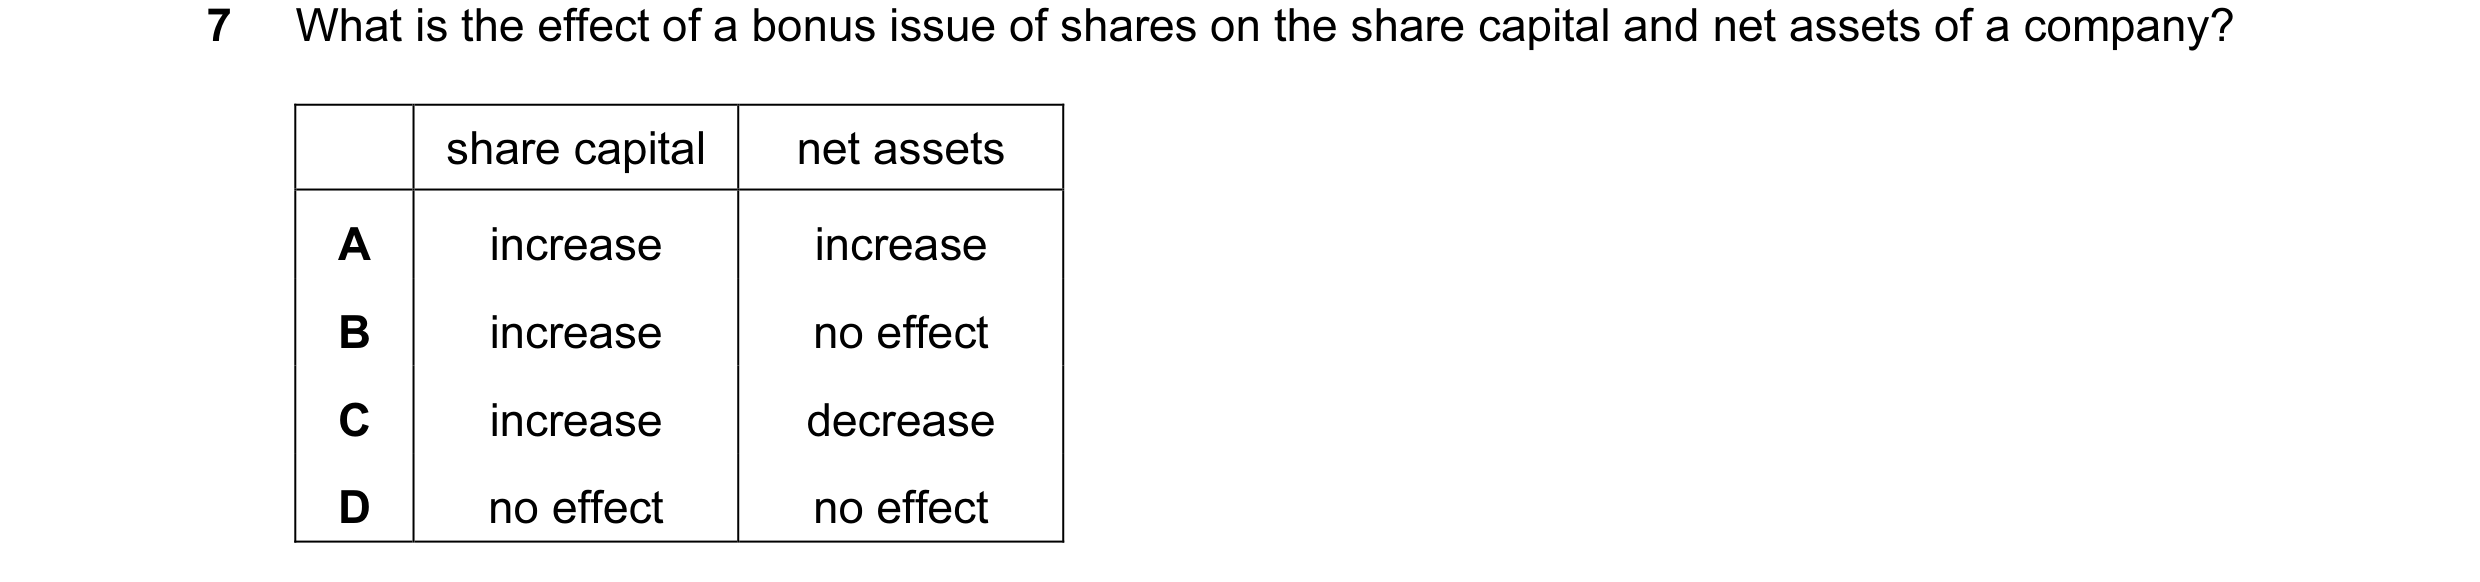
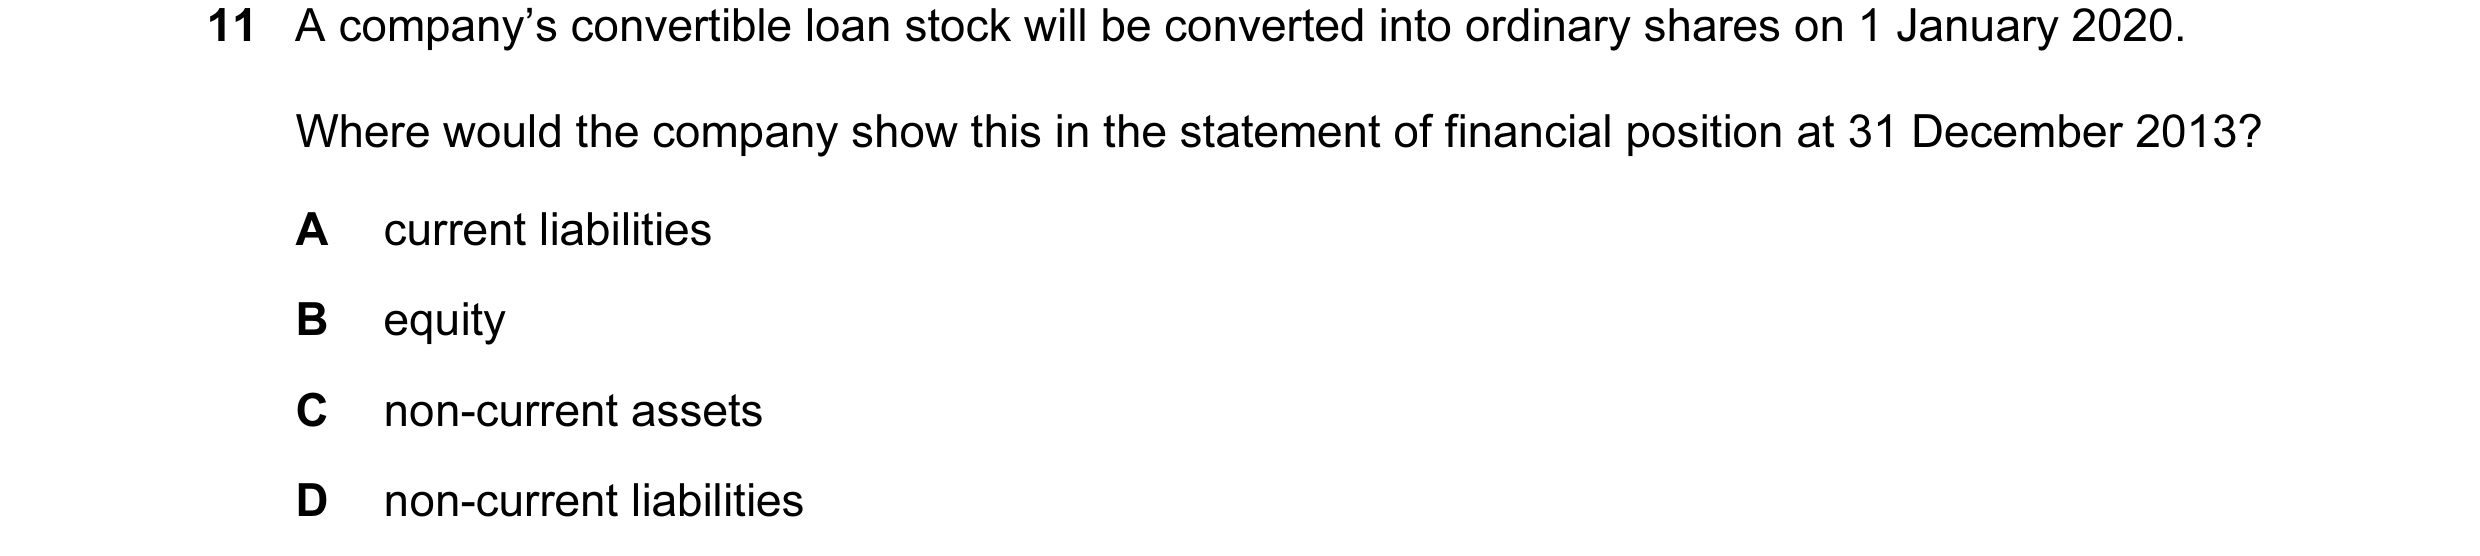
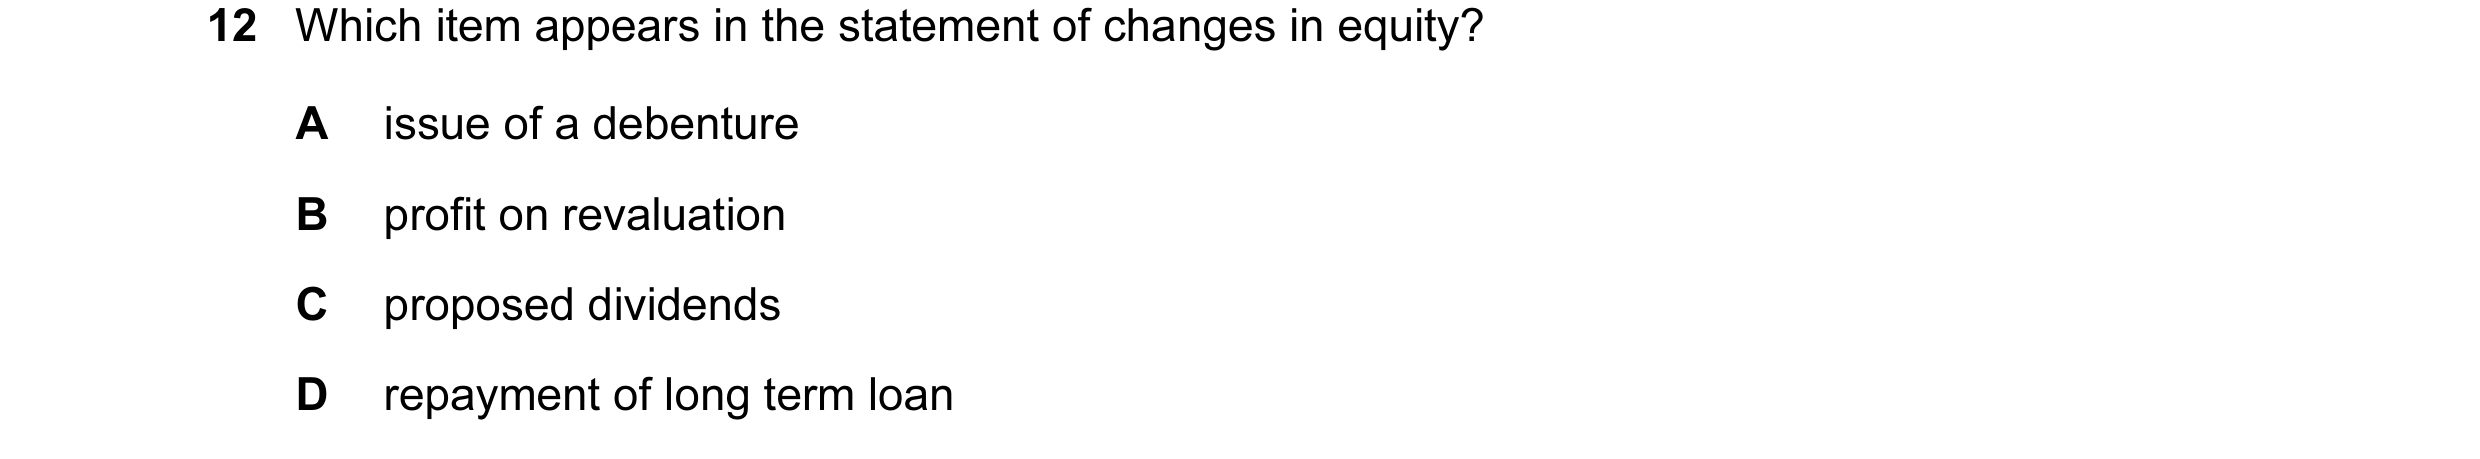
 57 / 62
 58 / 62
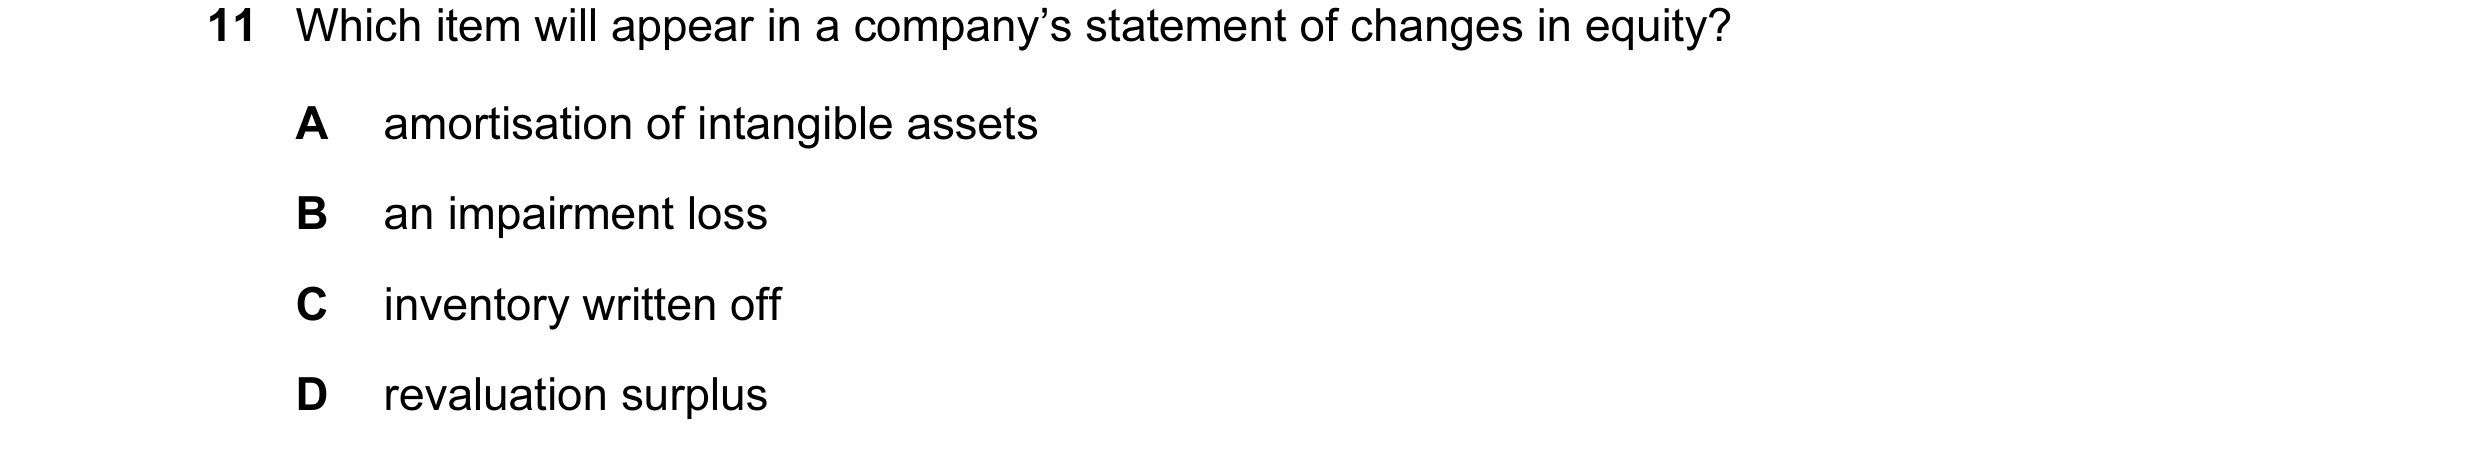
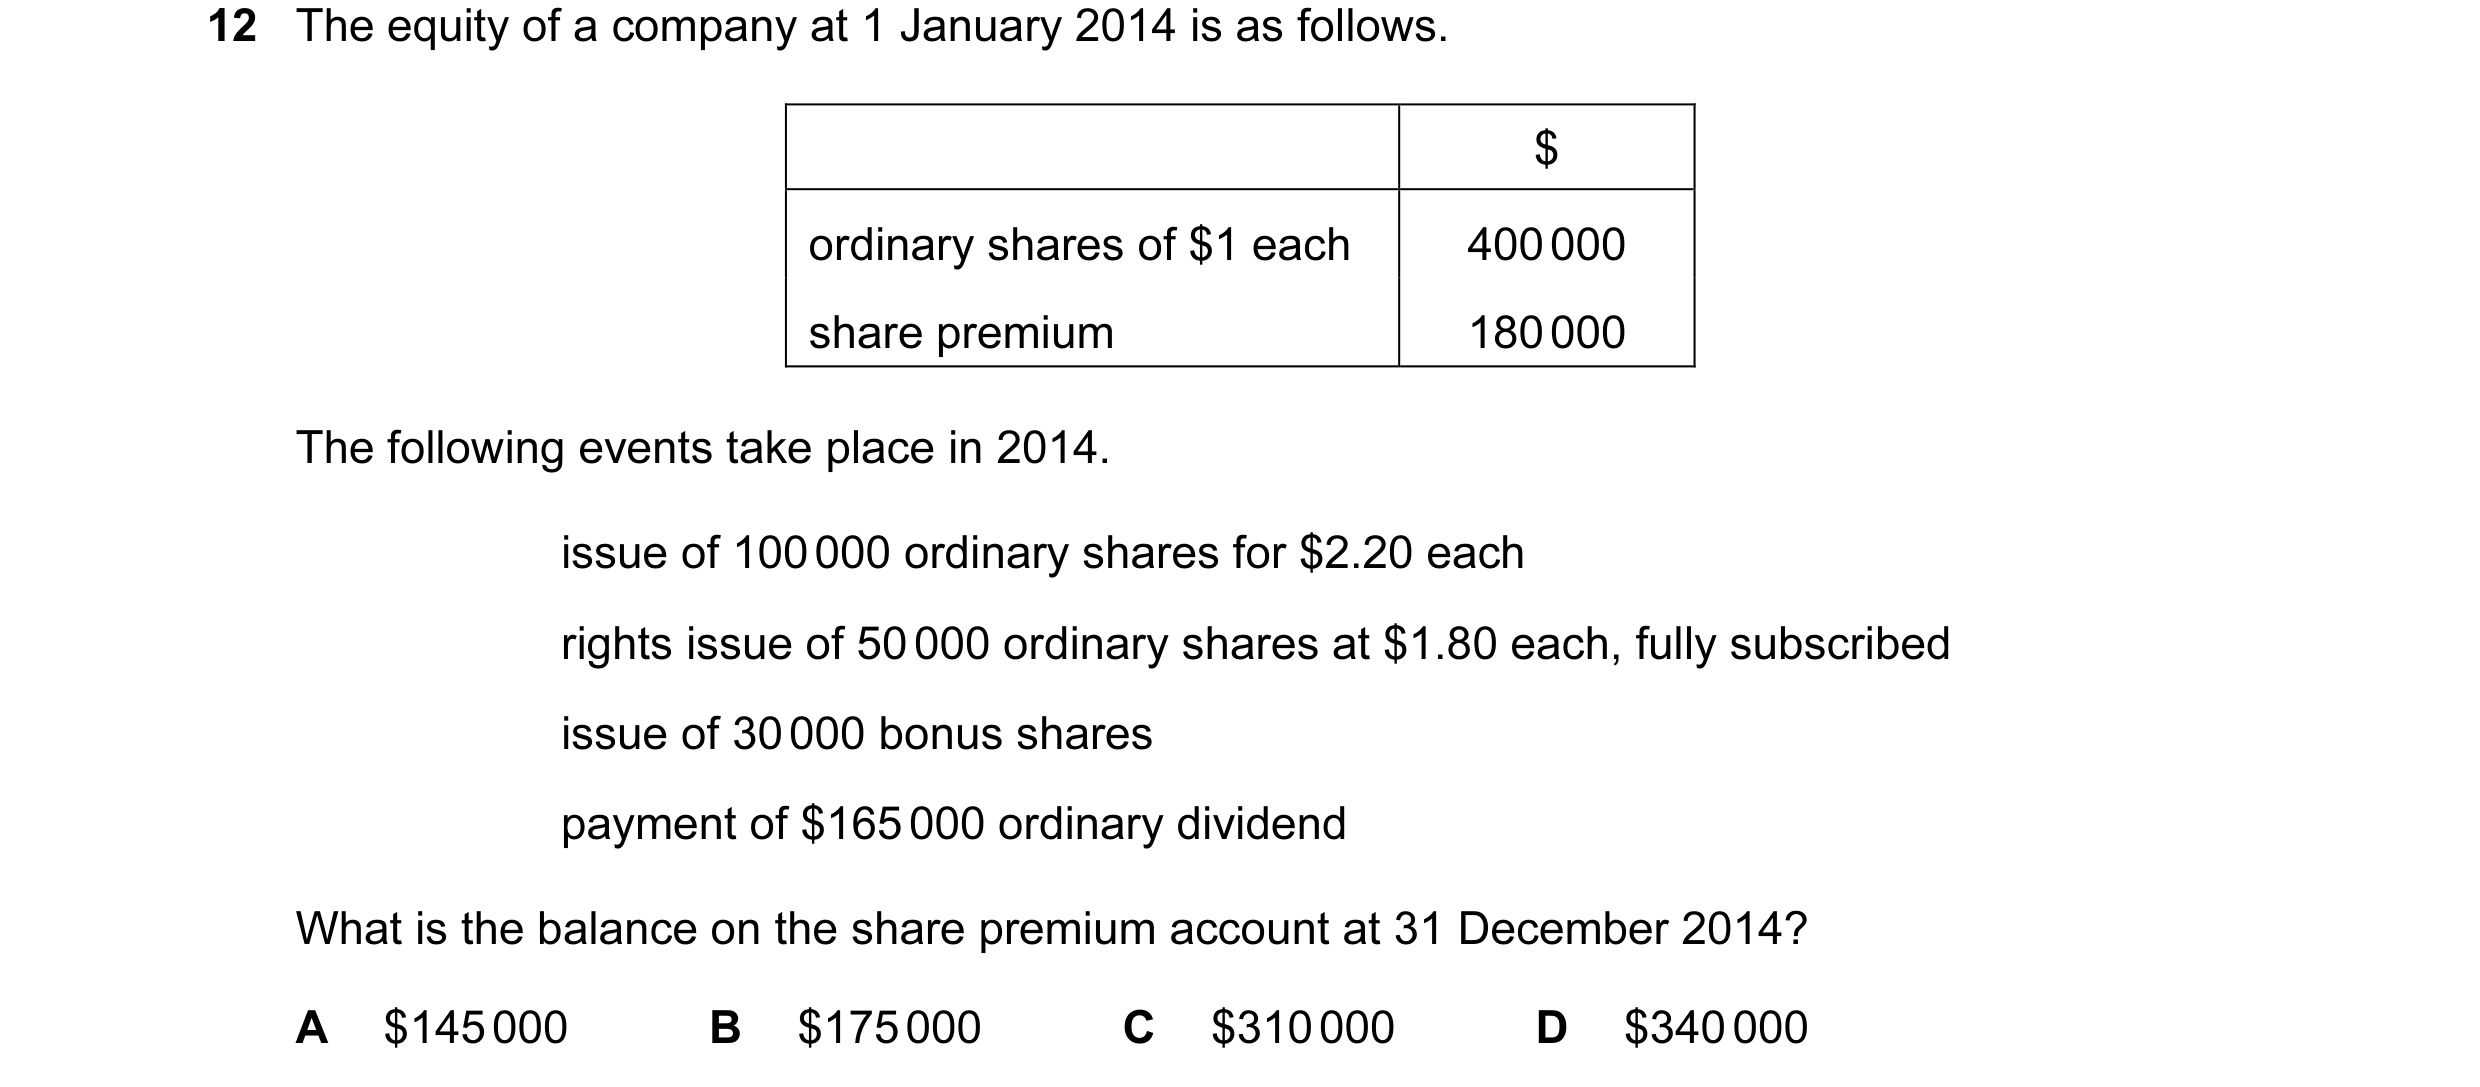 59 / 62
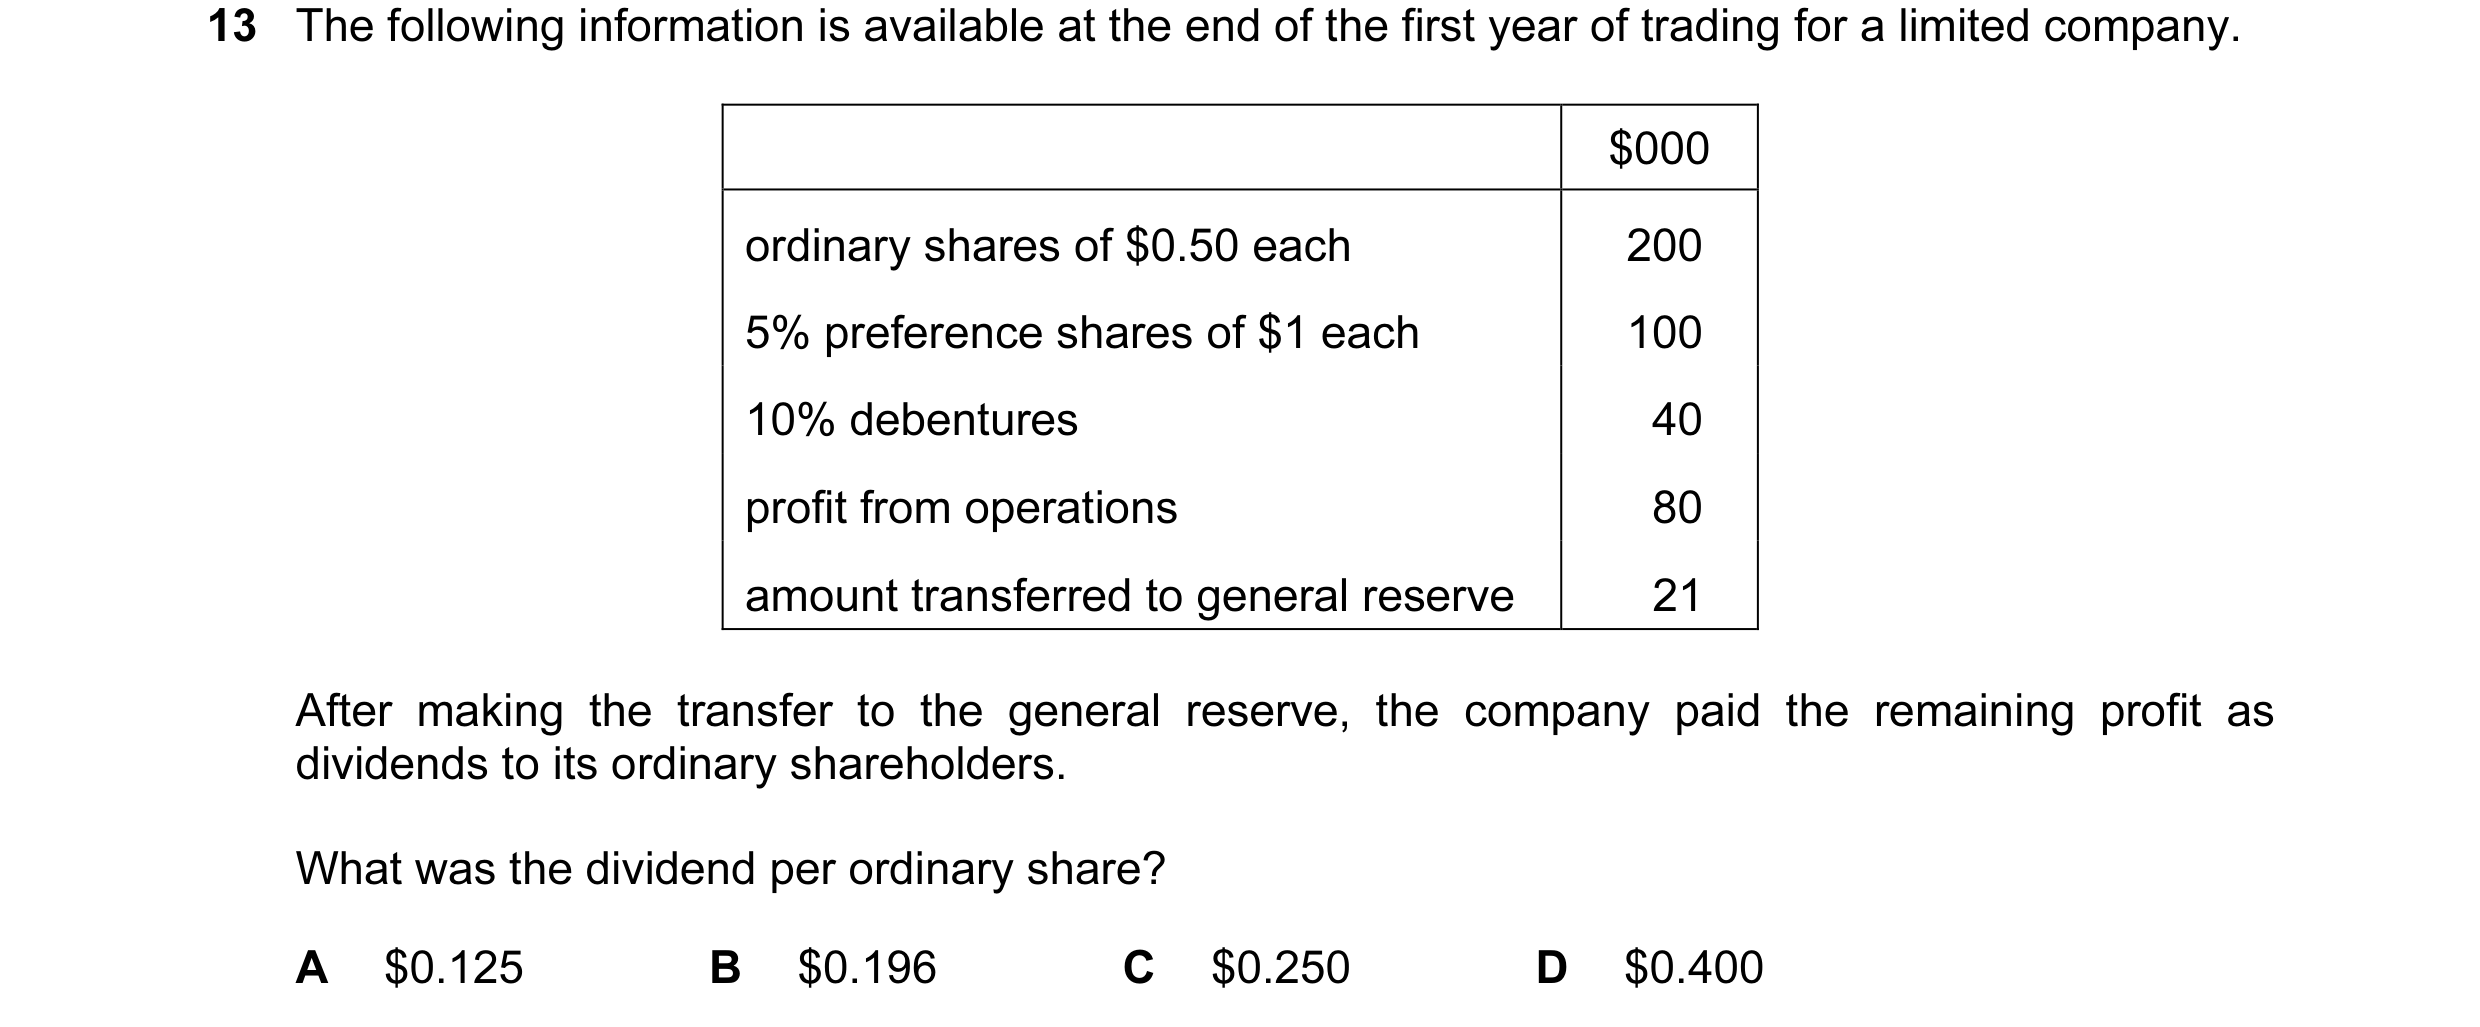
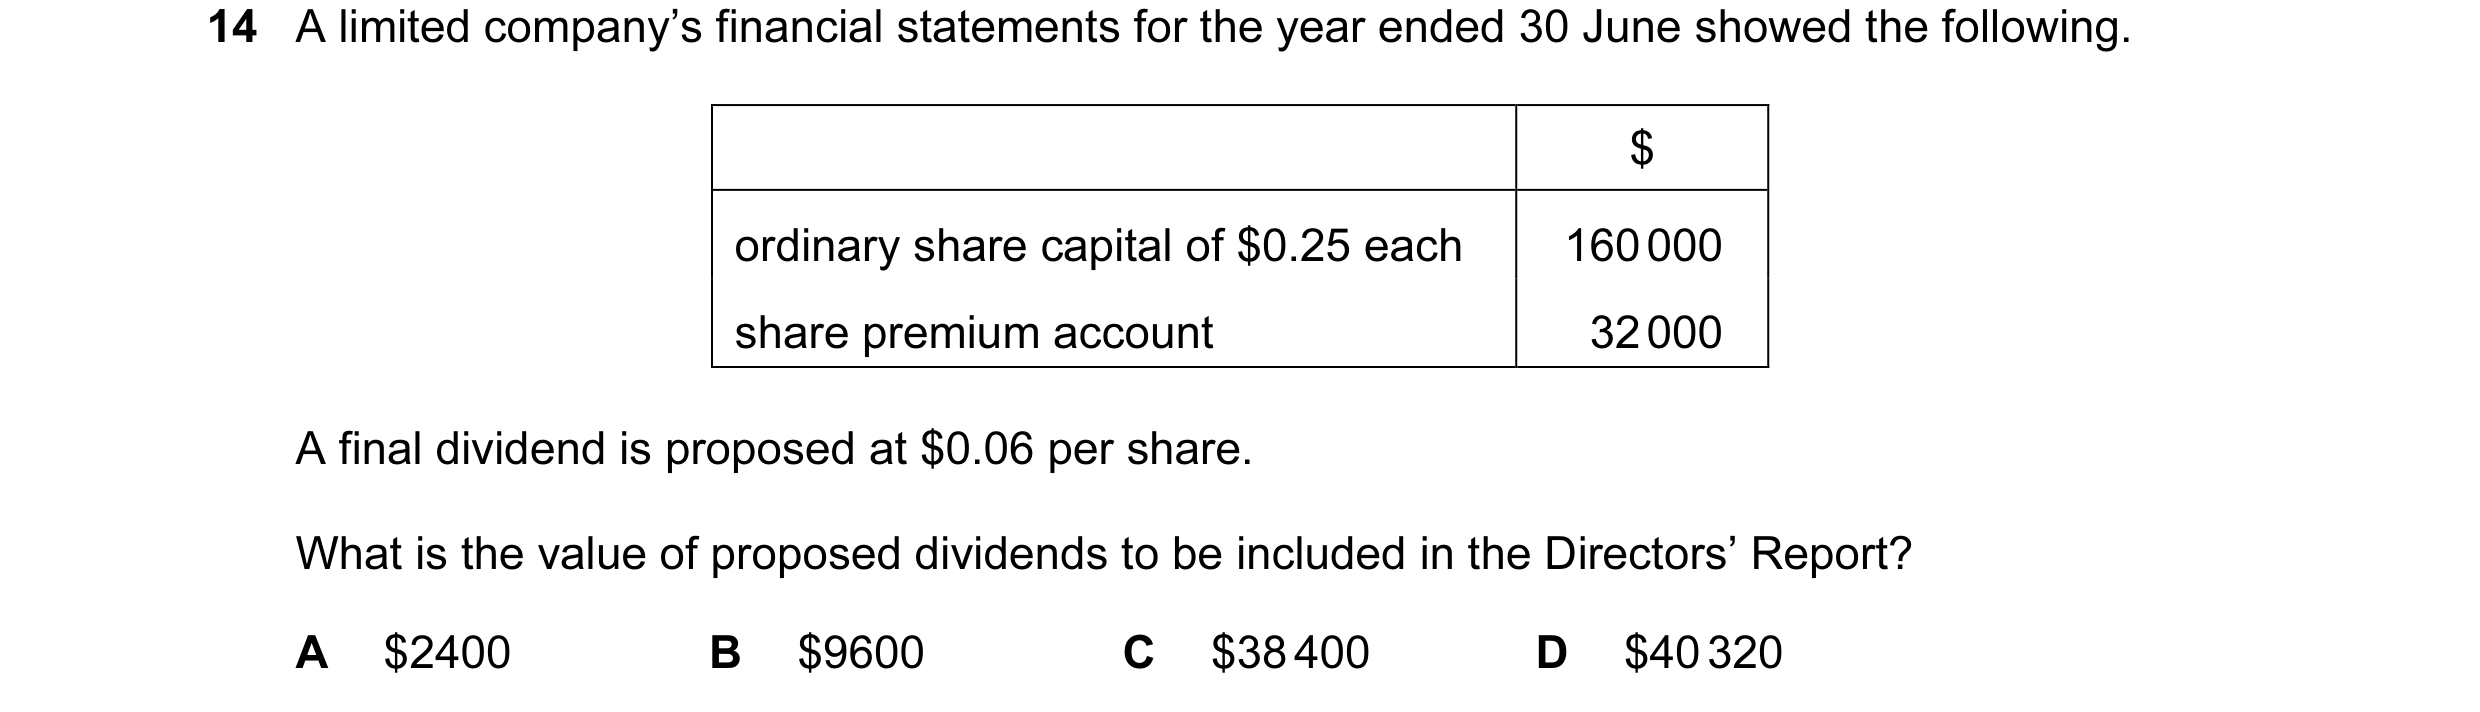
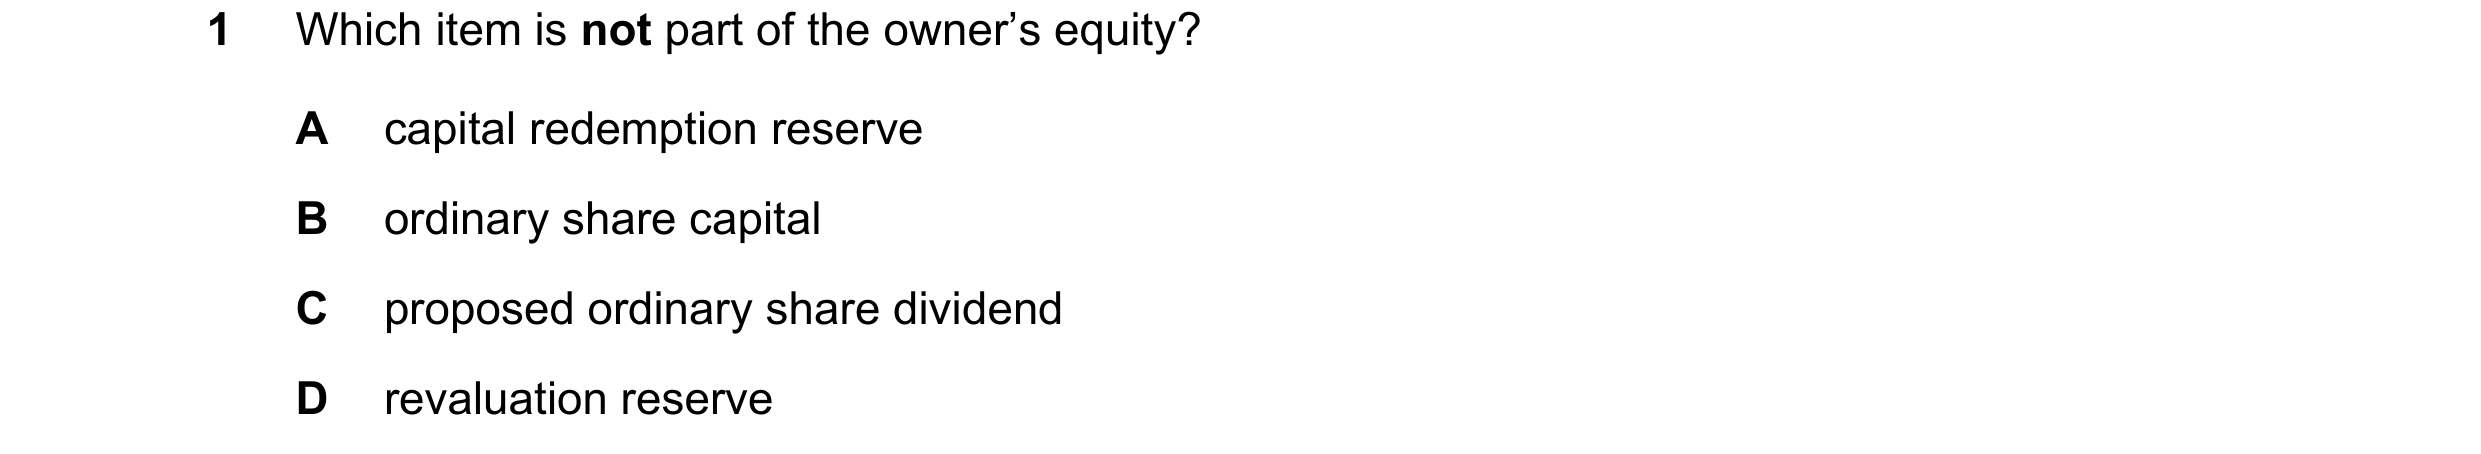 60 / 62
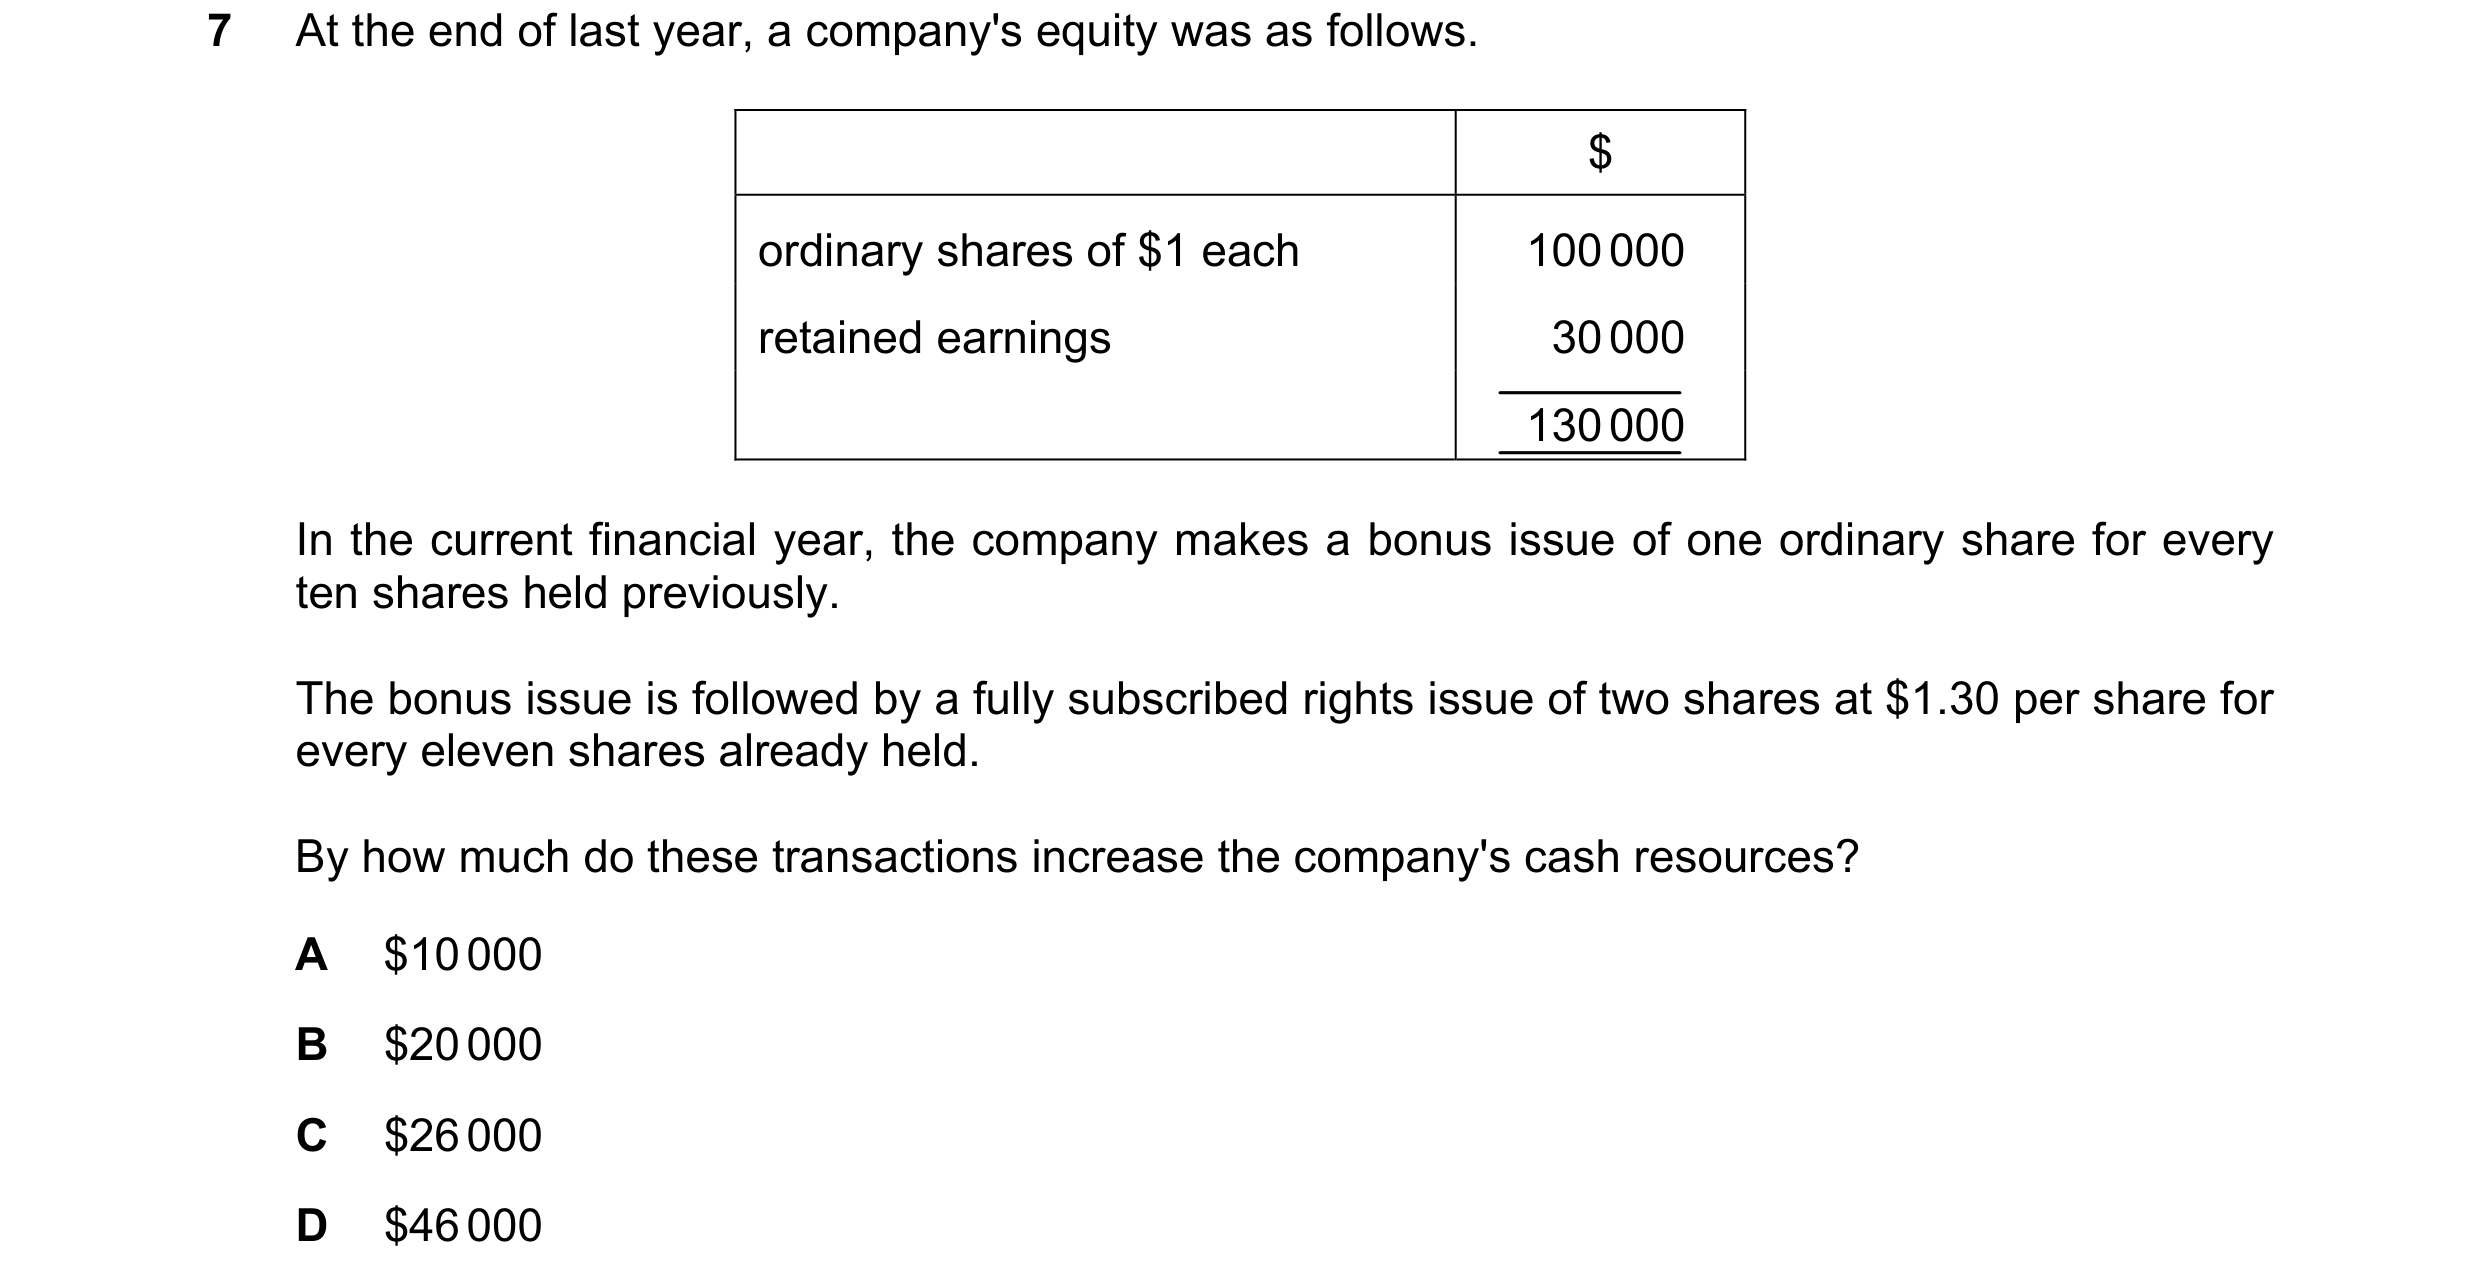
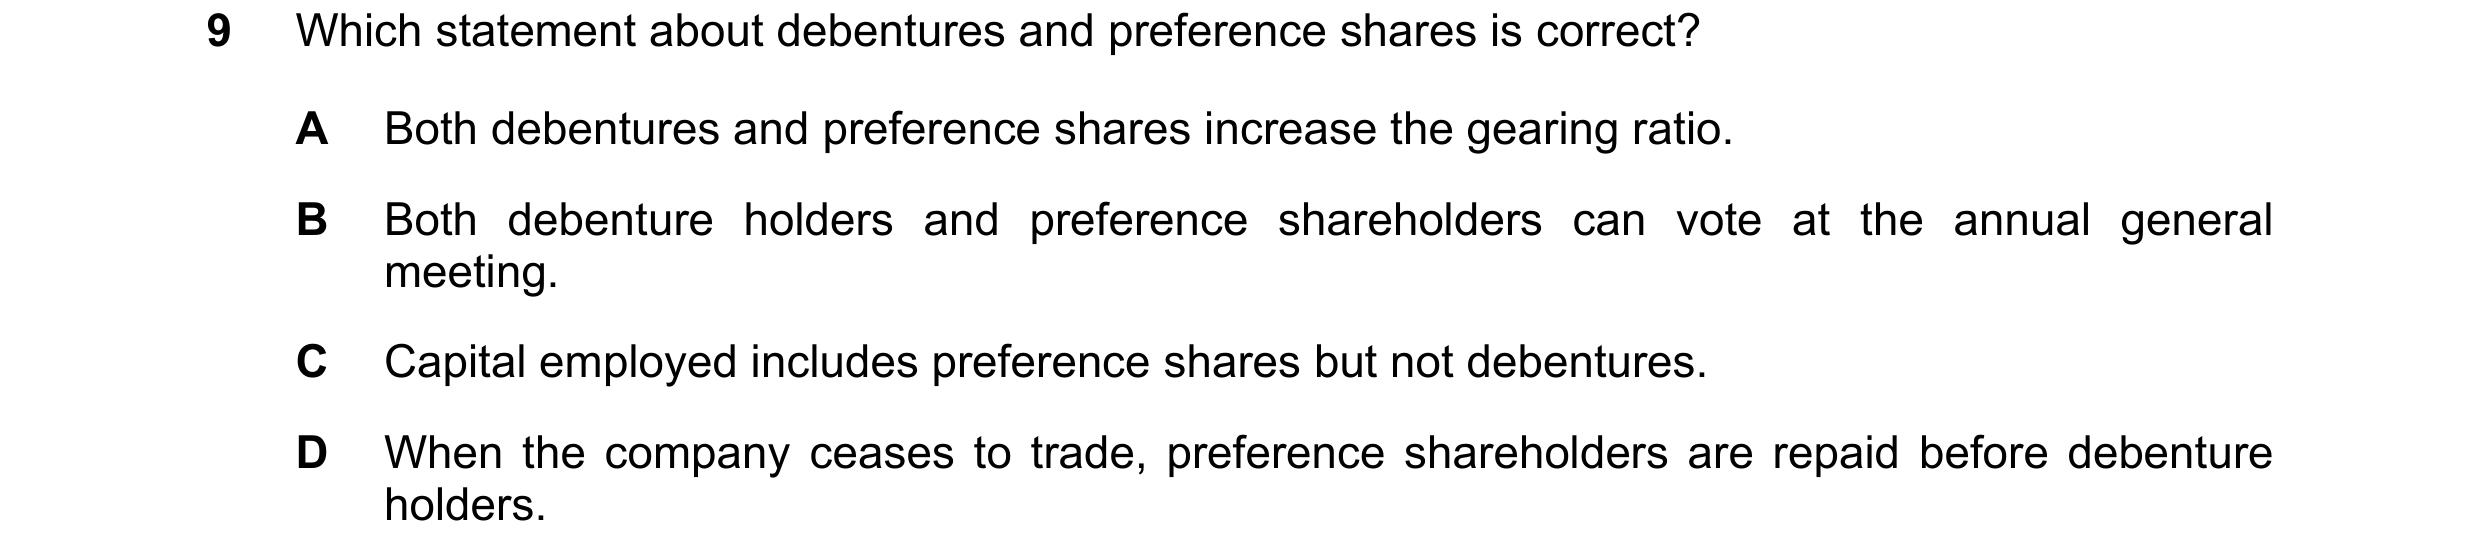
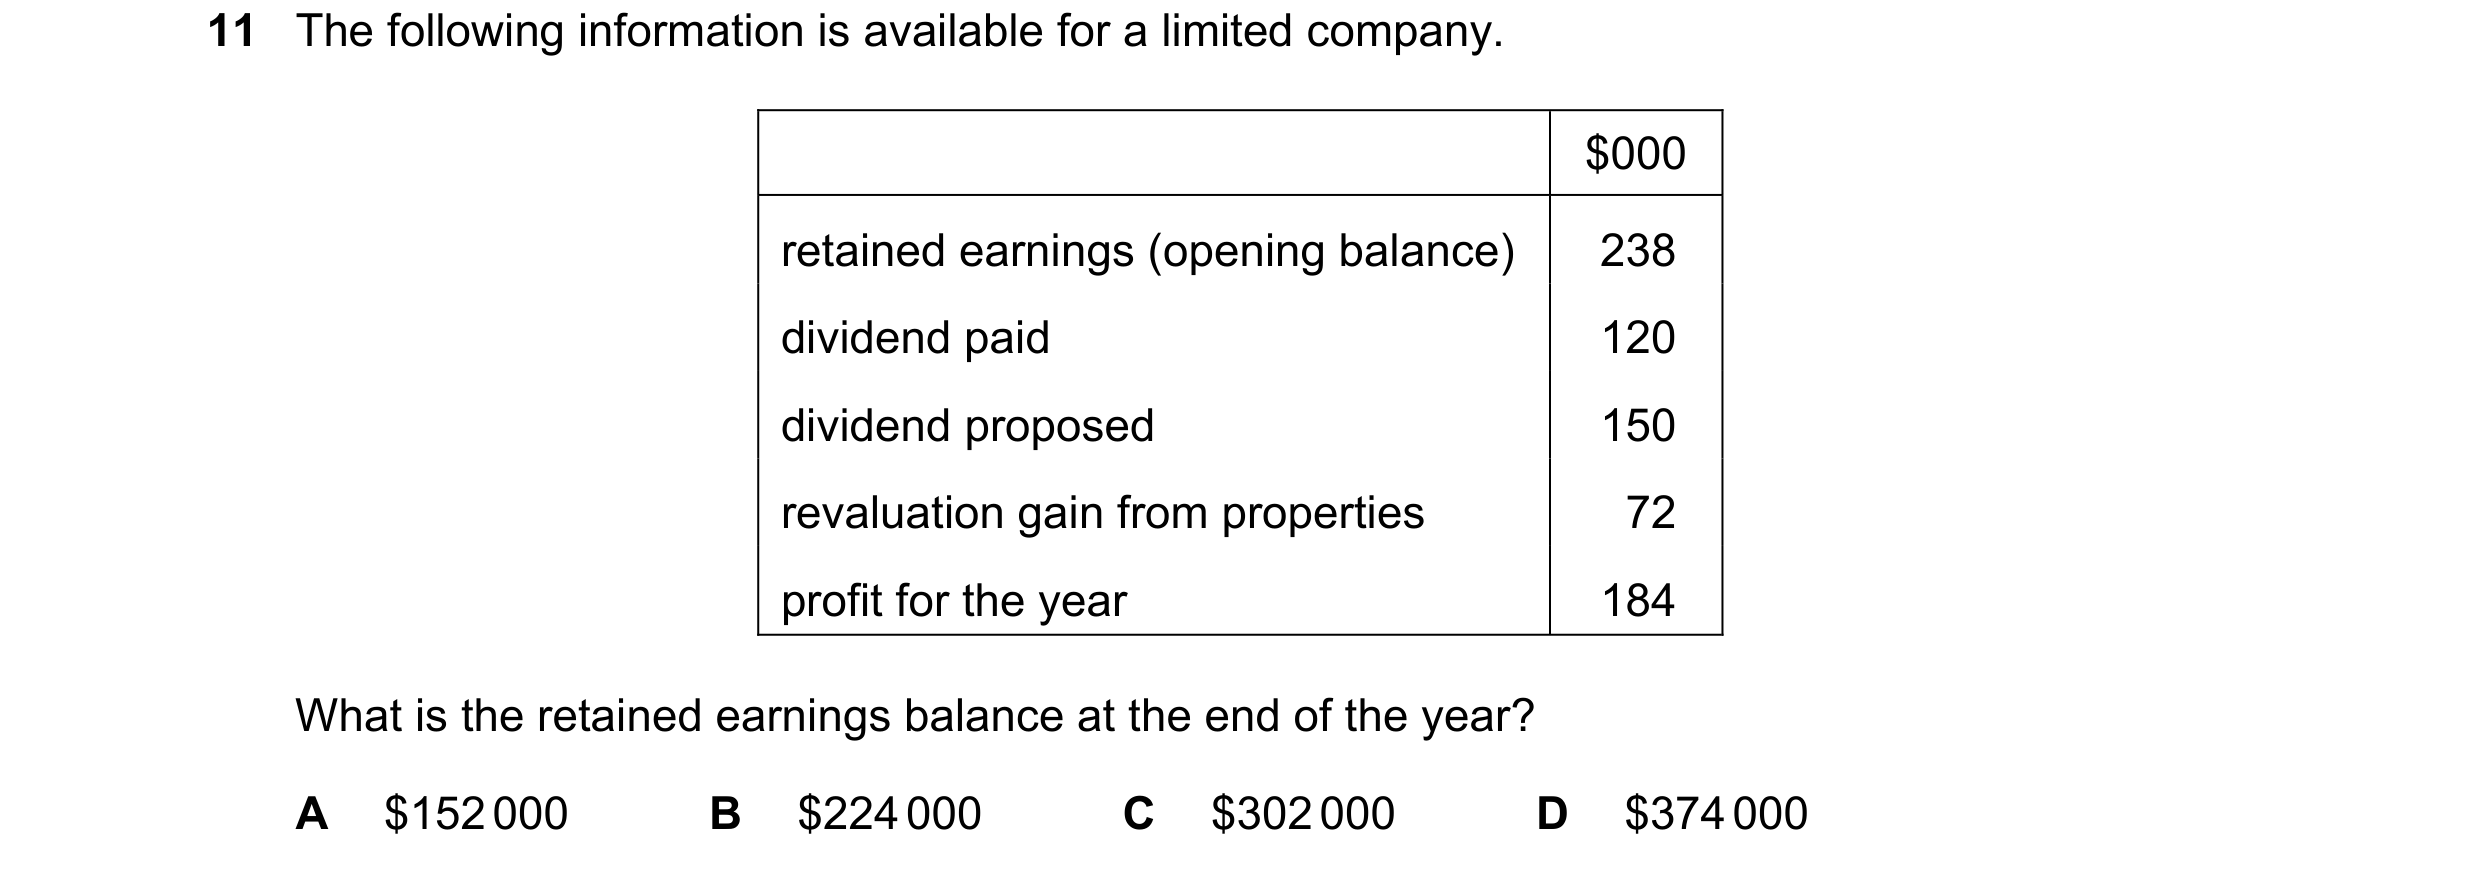
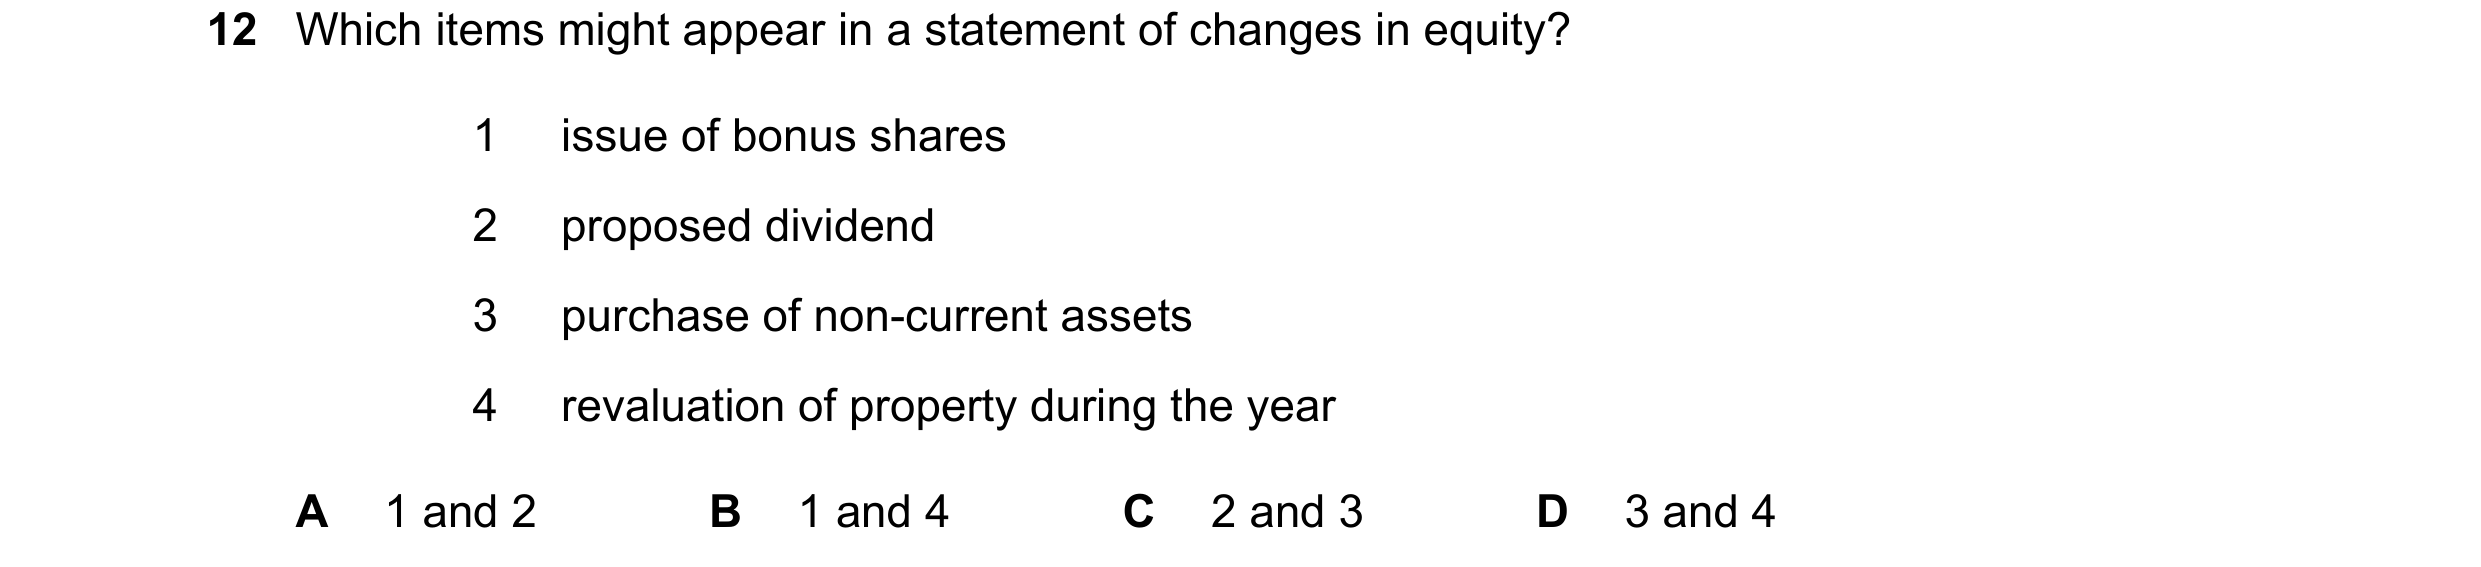 61 / 62
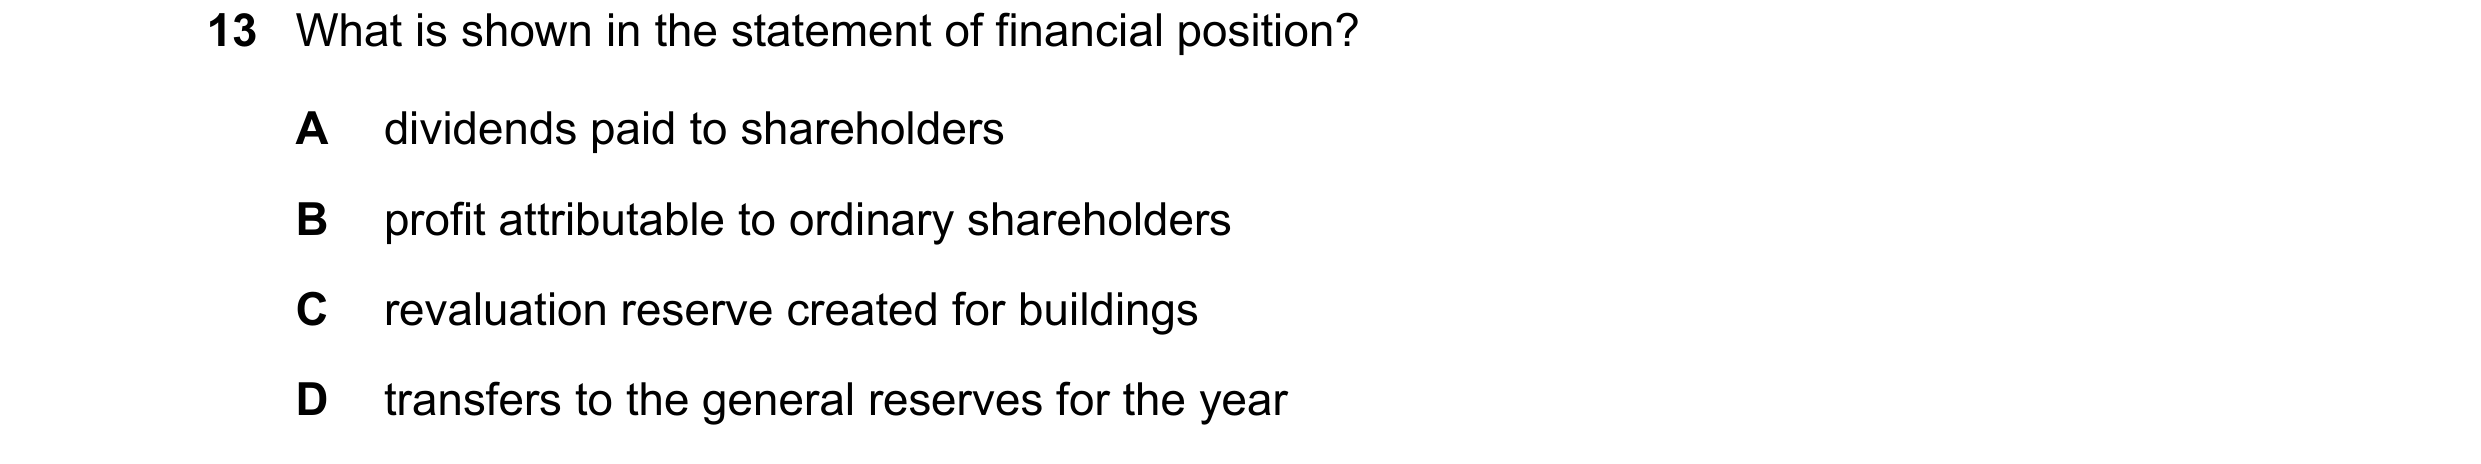
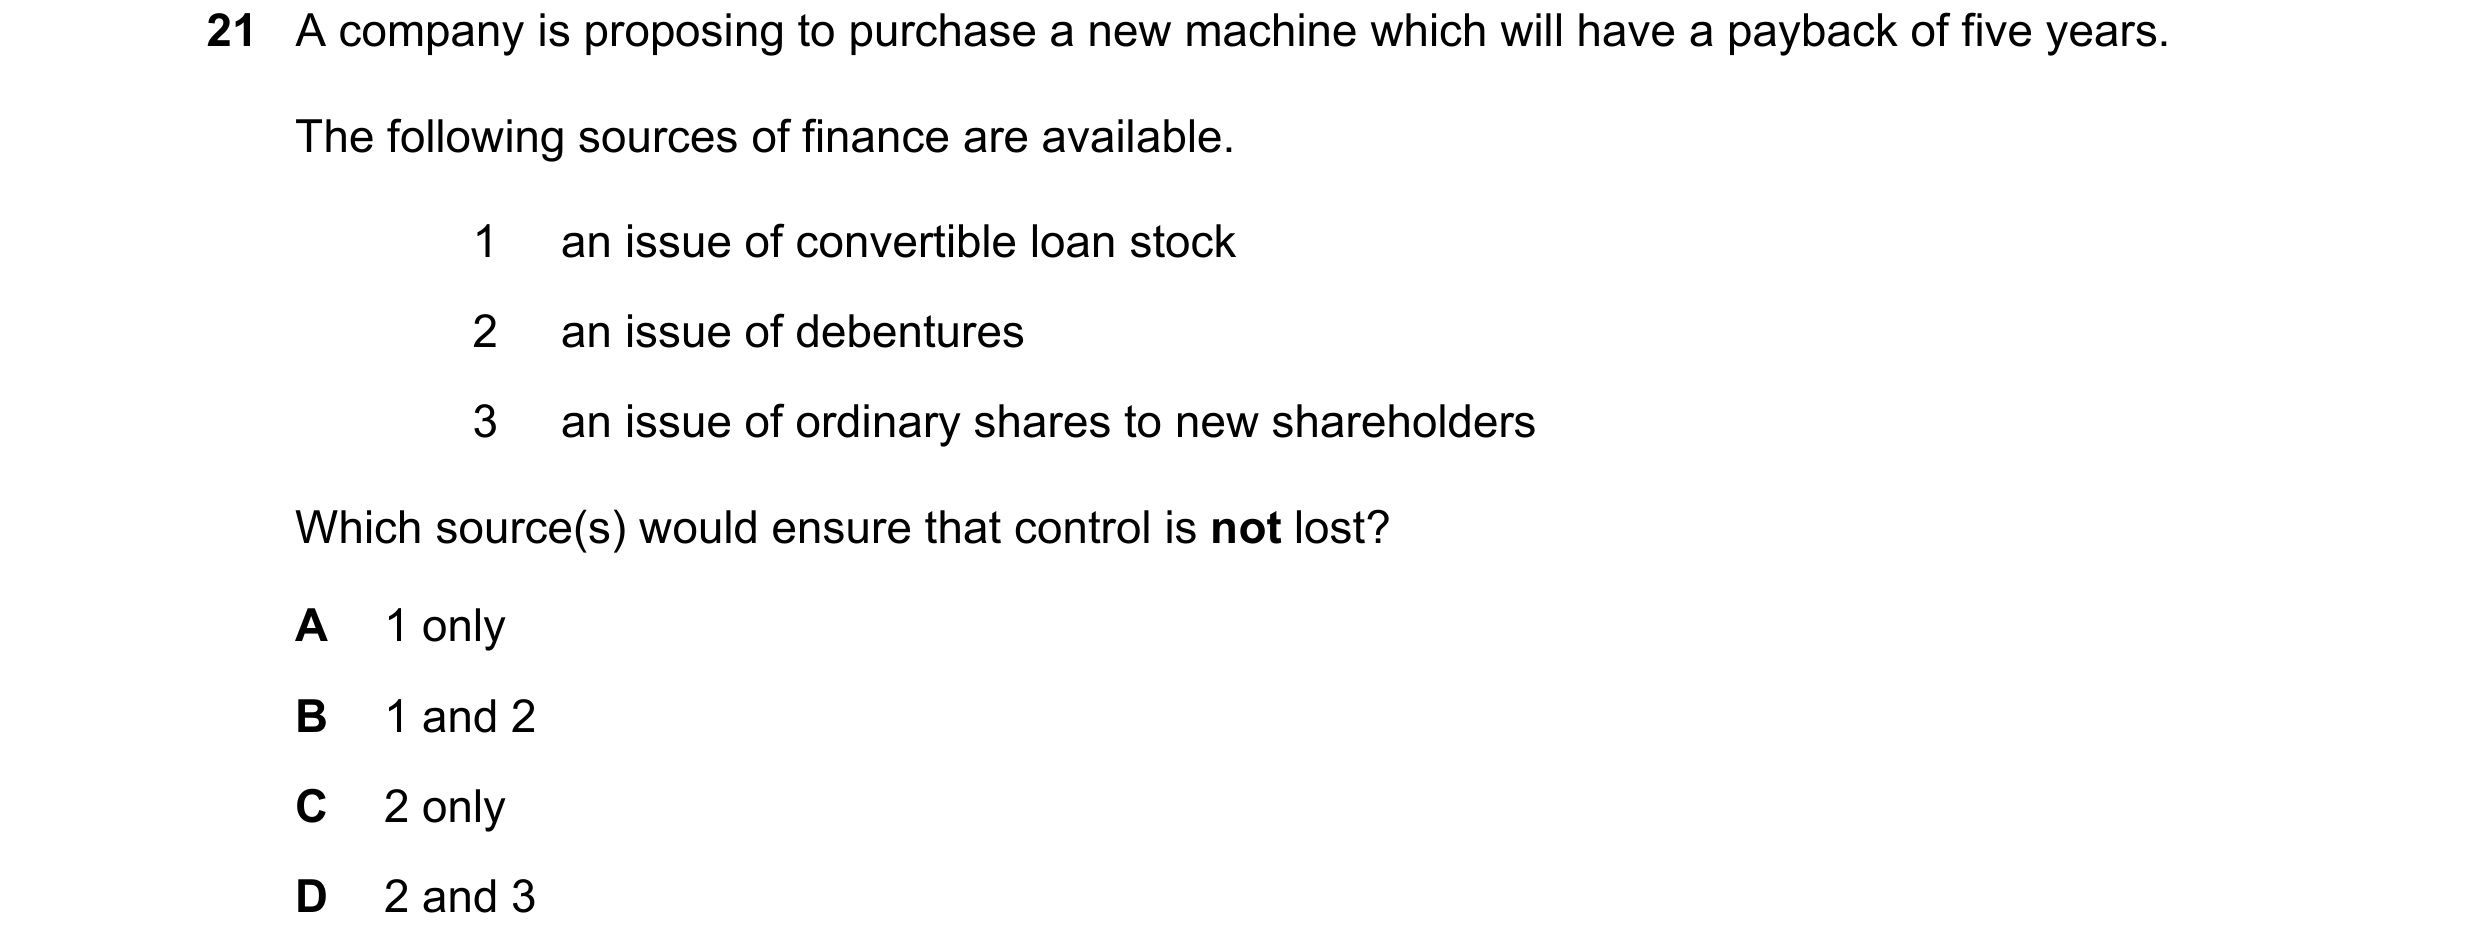 62 / 62