Questions as text
Q1 · A company is evaluating its plans to close a unit within its business 9706/31 Oct/Nov 2009
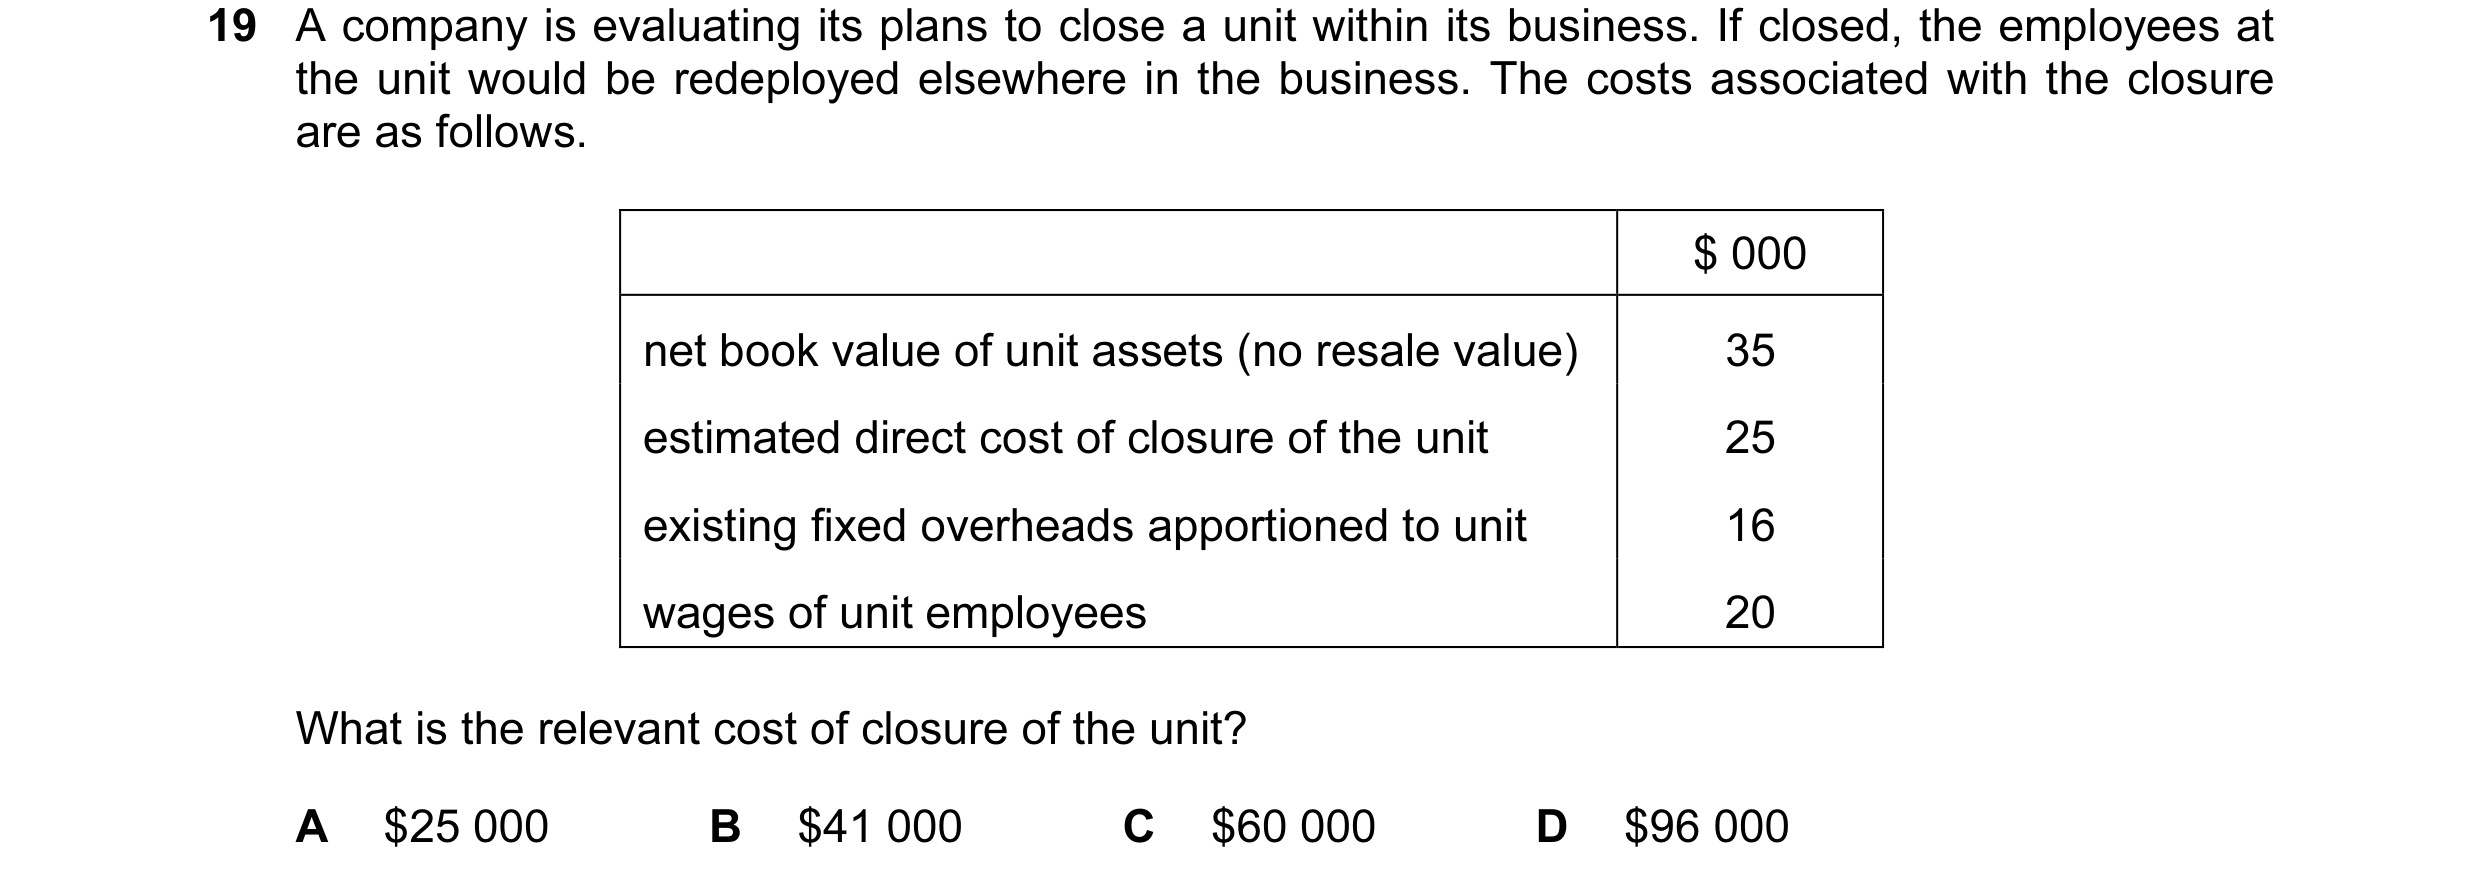
19 A company is evaluating its plans to close a unit within its business. If closed, the employees at the unit would be redeployed elsewhere in the business. The costs associated with the closure are as follows. $ 000 net book value of unit assets (no resale value) 35 estimated direct cost of closure of the unit 25 existing fixed overheads apportioned to unit 16 wages of unit employees 20 What is the relevant cost of closure of the unit? A $25 000 B $41 000 C $60 000 D $96 000
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2009
Q2 · A company is evaluating its plans to close a unit within its business 9706/32 Oct/Nov 2009
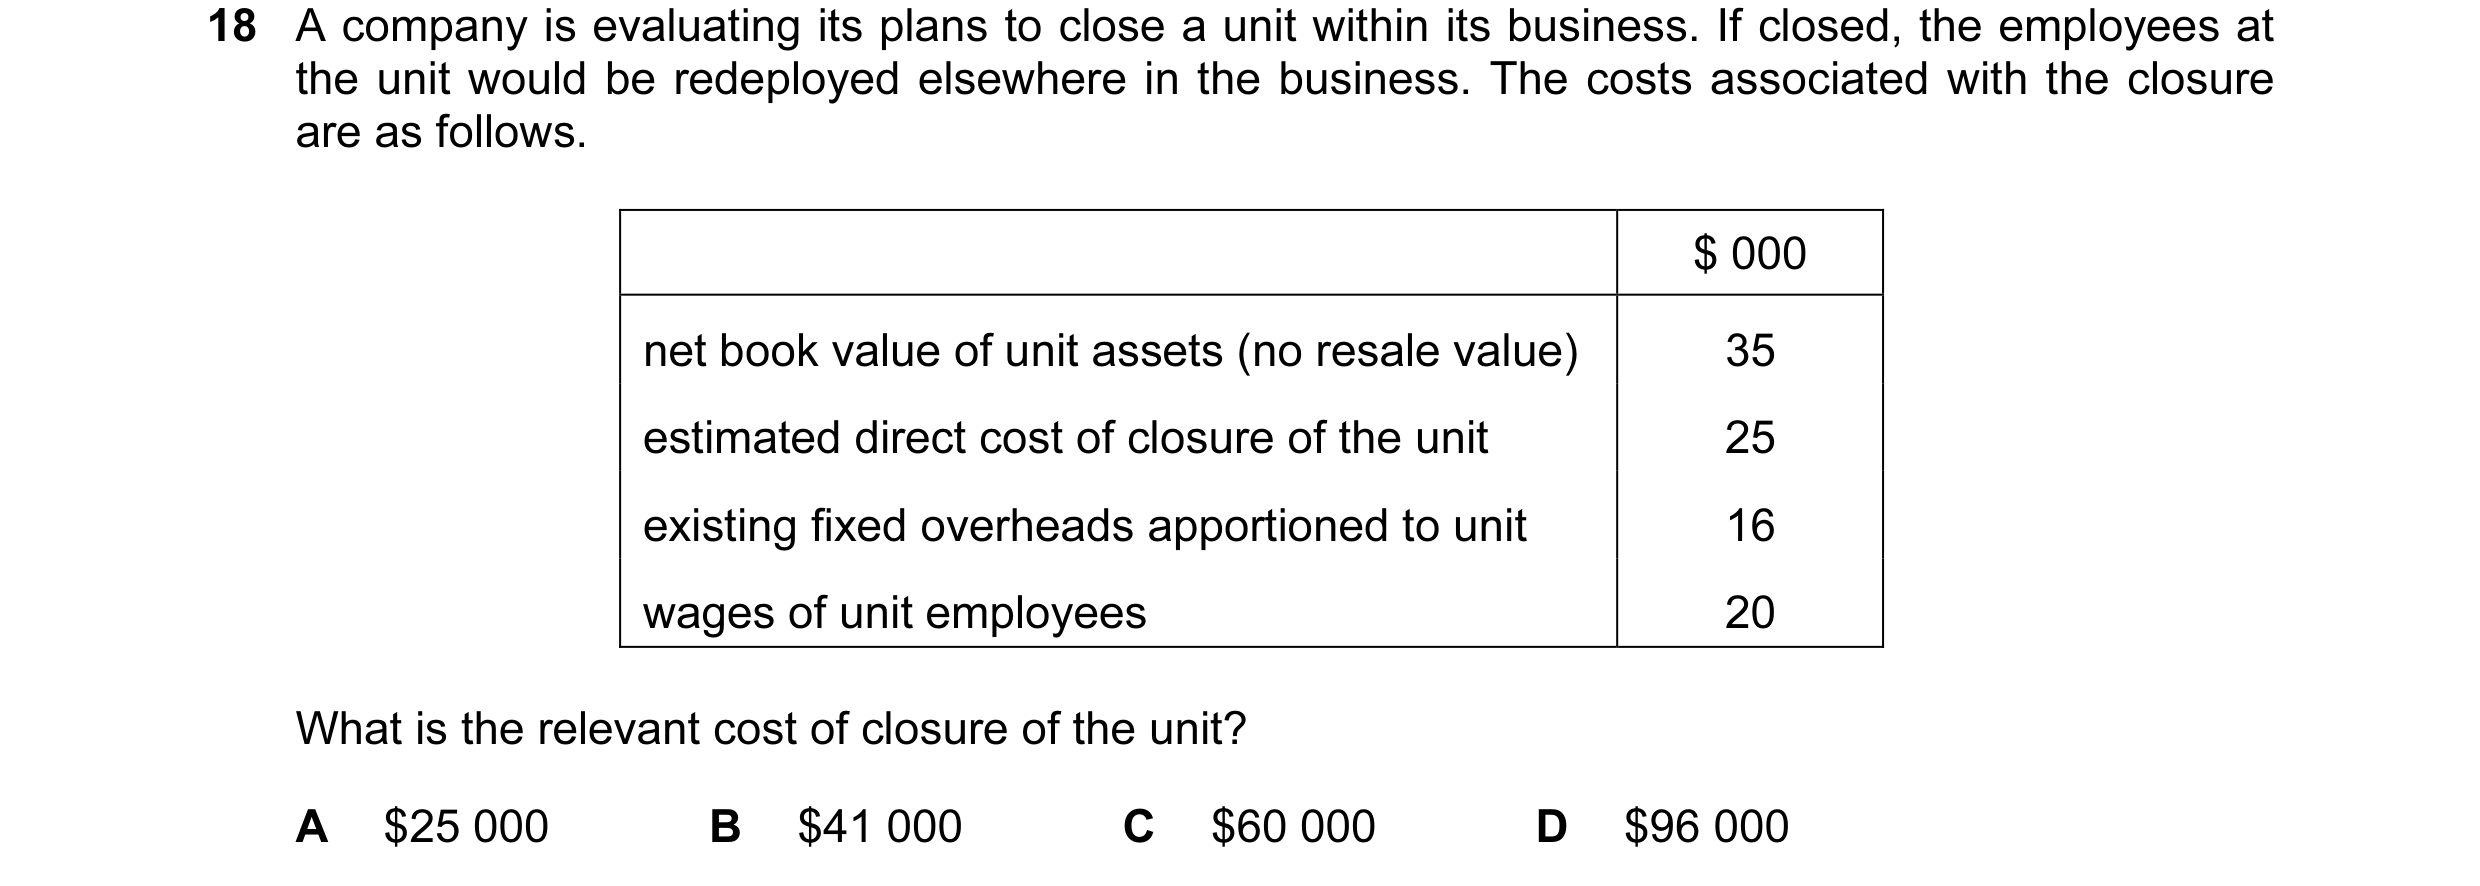
18 A company is evaluating its plans to close a unit within its business. If closed, the employees at the unit would be redeployed elsewhere in the business. The costs associated with the closure are as follows. $ 000 net book value of unit assets (no resale value) 35 estimated direct cost of closure of the unit 25 existing fixed overheads apportioned to unit 16 wages of unit employees 20 What is the relevant cost of closure of the unit? A $25 000 B $41 000 C $60 000 D $96 000
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2009
Q3 · In marginal costing, how can the total contribution from a given activity be calculated? 9706/32 May/June 2010
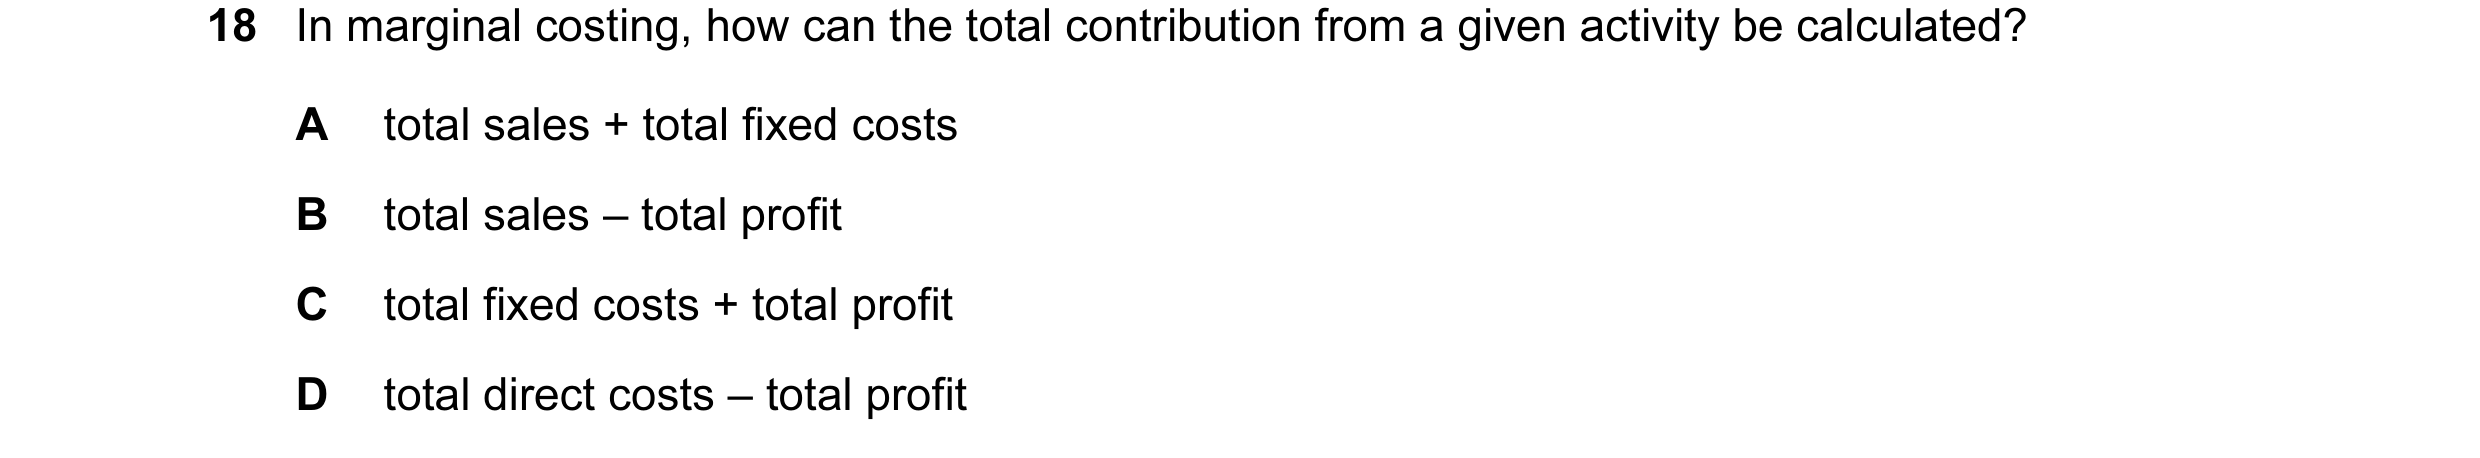
18 In marginal costing, how can the total contribution from a given activity be calculated? A total sales + total fixed costs B total sales – total profit C total fixed costs + total profit D total direct costs – total profit
1 marks
Answer: C
This question in 9706/32 May/June 2010
Q4 · A product is sold for $100 per unit 9706/32 May/June 2010
19 A product is sold for $100 per unit. Fixed costs are $90 000 and variable costs are 60 % of the selling price. What is the break-even sales revenue? A $36 000 B $90 000 C $150 000 D $225 000
1 marks
Answer: D
This question in 9706/32 May/June 2010
Q5 · A company currently uses a fixed budget 9706/32 May/June 2010
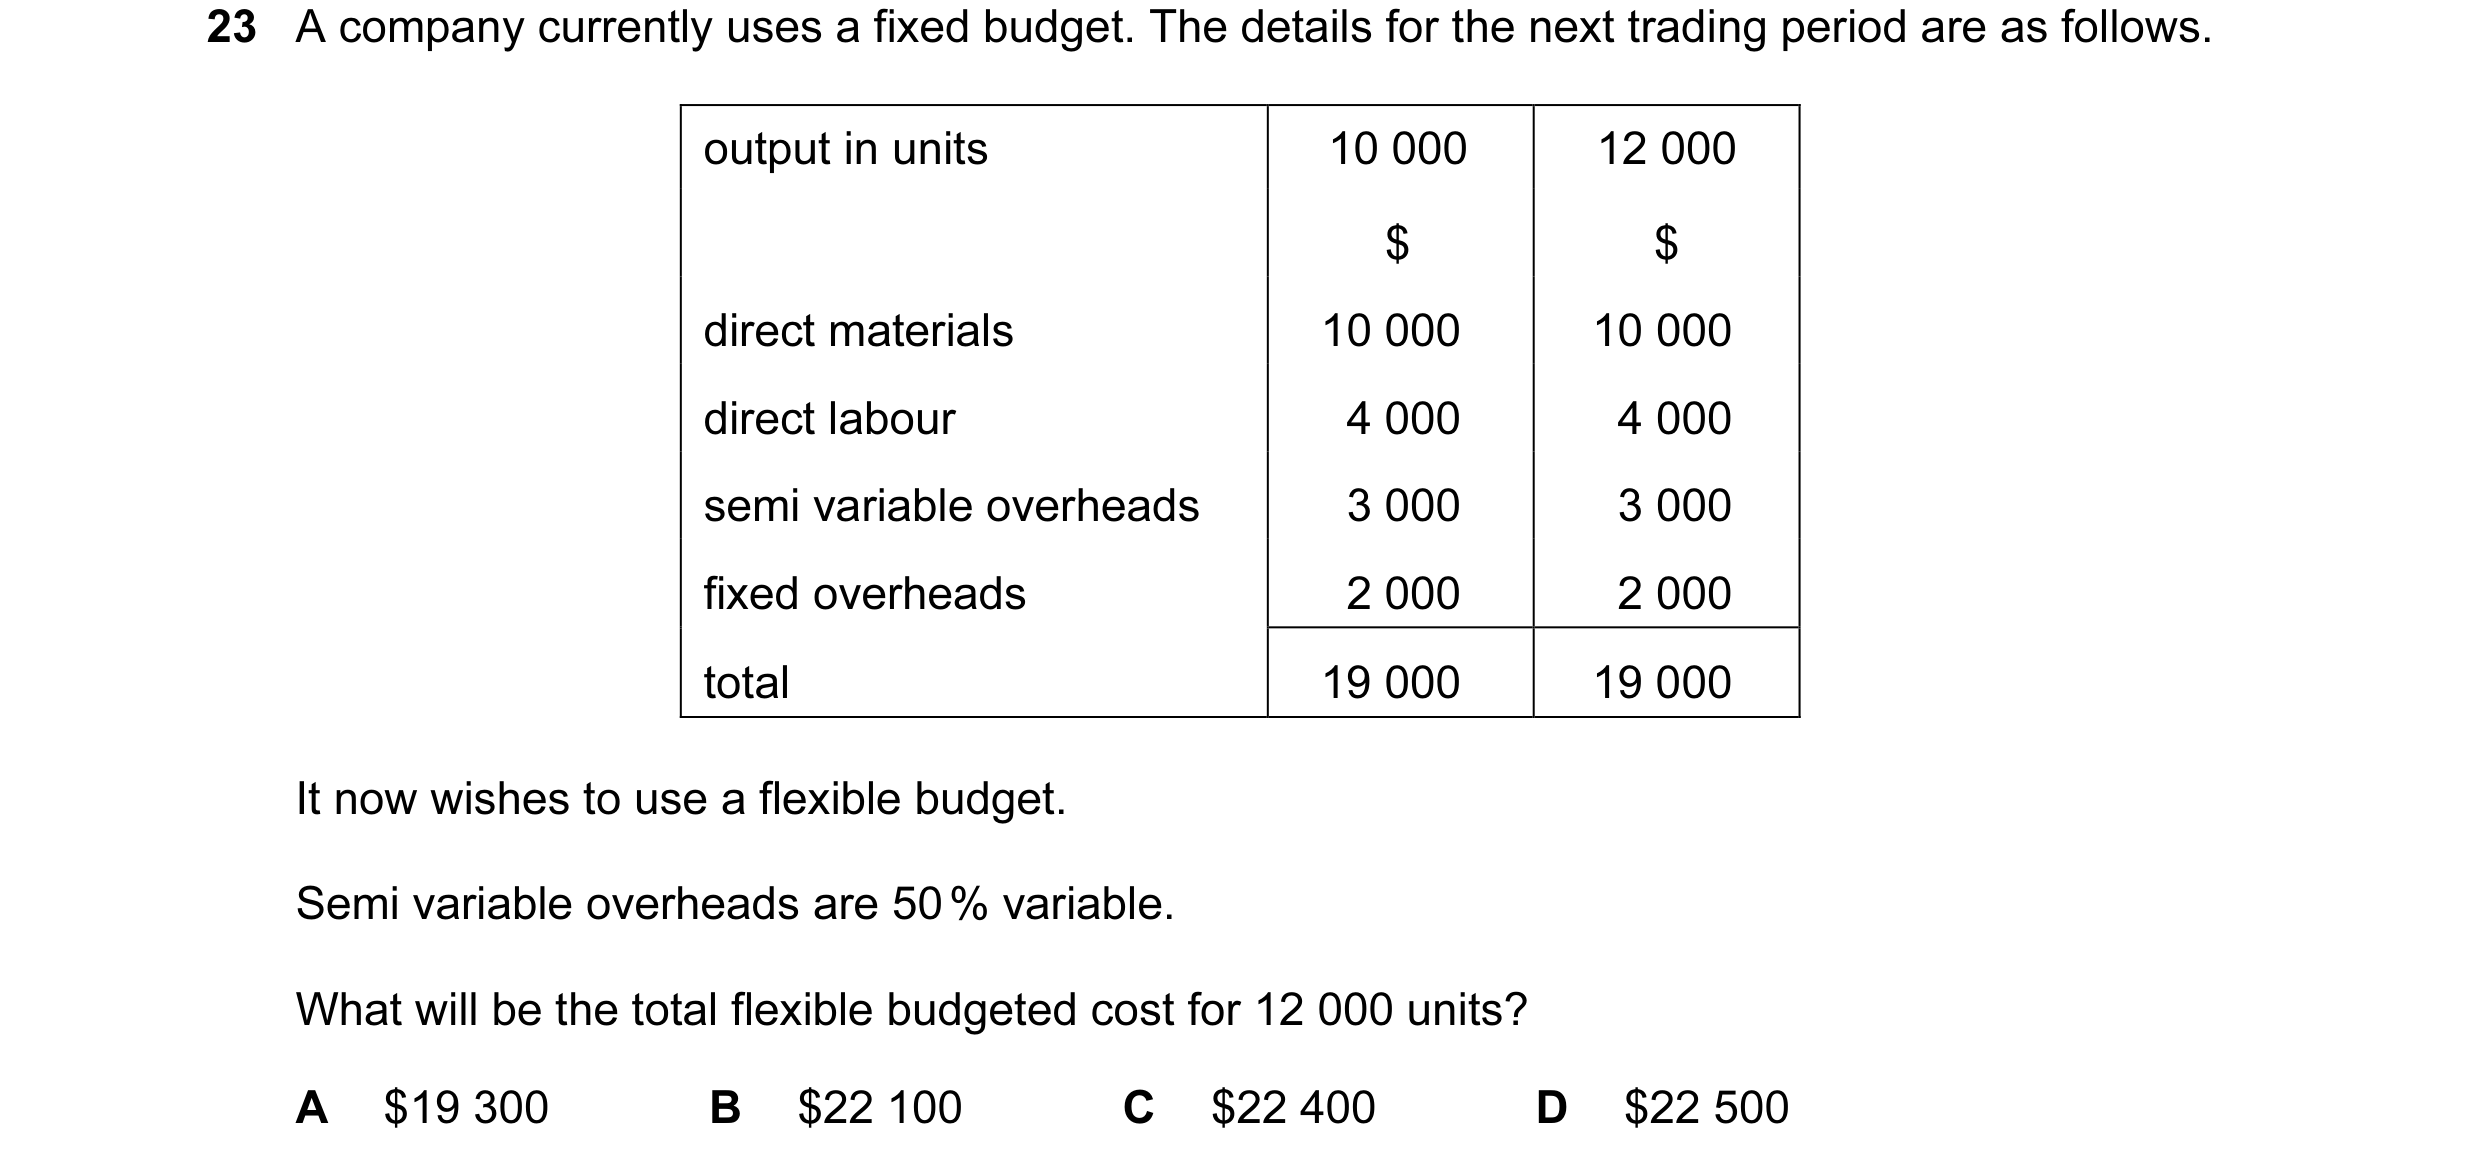
23 A company currently uses a fixed budget. The details for the next trading period are as follows. output in units 10 000 12 000 $ $ direct materials 10 000 10 000 direct labour 4 000 4 000 semi variable overheads 3 000 3 000 fixed overheads 2 000 2 000 total 19 000 19 000 It now wishes to use a flexible budget. Semi variable overheads are 50 % variable. What will be the total flexible budgeted cost for 12 000 units? A $19 300 B $22 100 C $22 400 D $22 500
1 marks
Answer: B
This question in 9706/32 May/June 2010
Q6 · A product is sold for $100 per unit 9706/33 May/June 2010
18 A product is sold for $100 per unit. Fixed costs are $90 000 and variable costs are 60 % of the selling price. What is the break-even sales revenue? A $36 000 B $90 000 C $150 000 D $225 000
1 marks
Answer: D
This question in 9706/33 May/June 2010
Q7 · A company currently uses a fixed budget 9706/33 May/June 2010
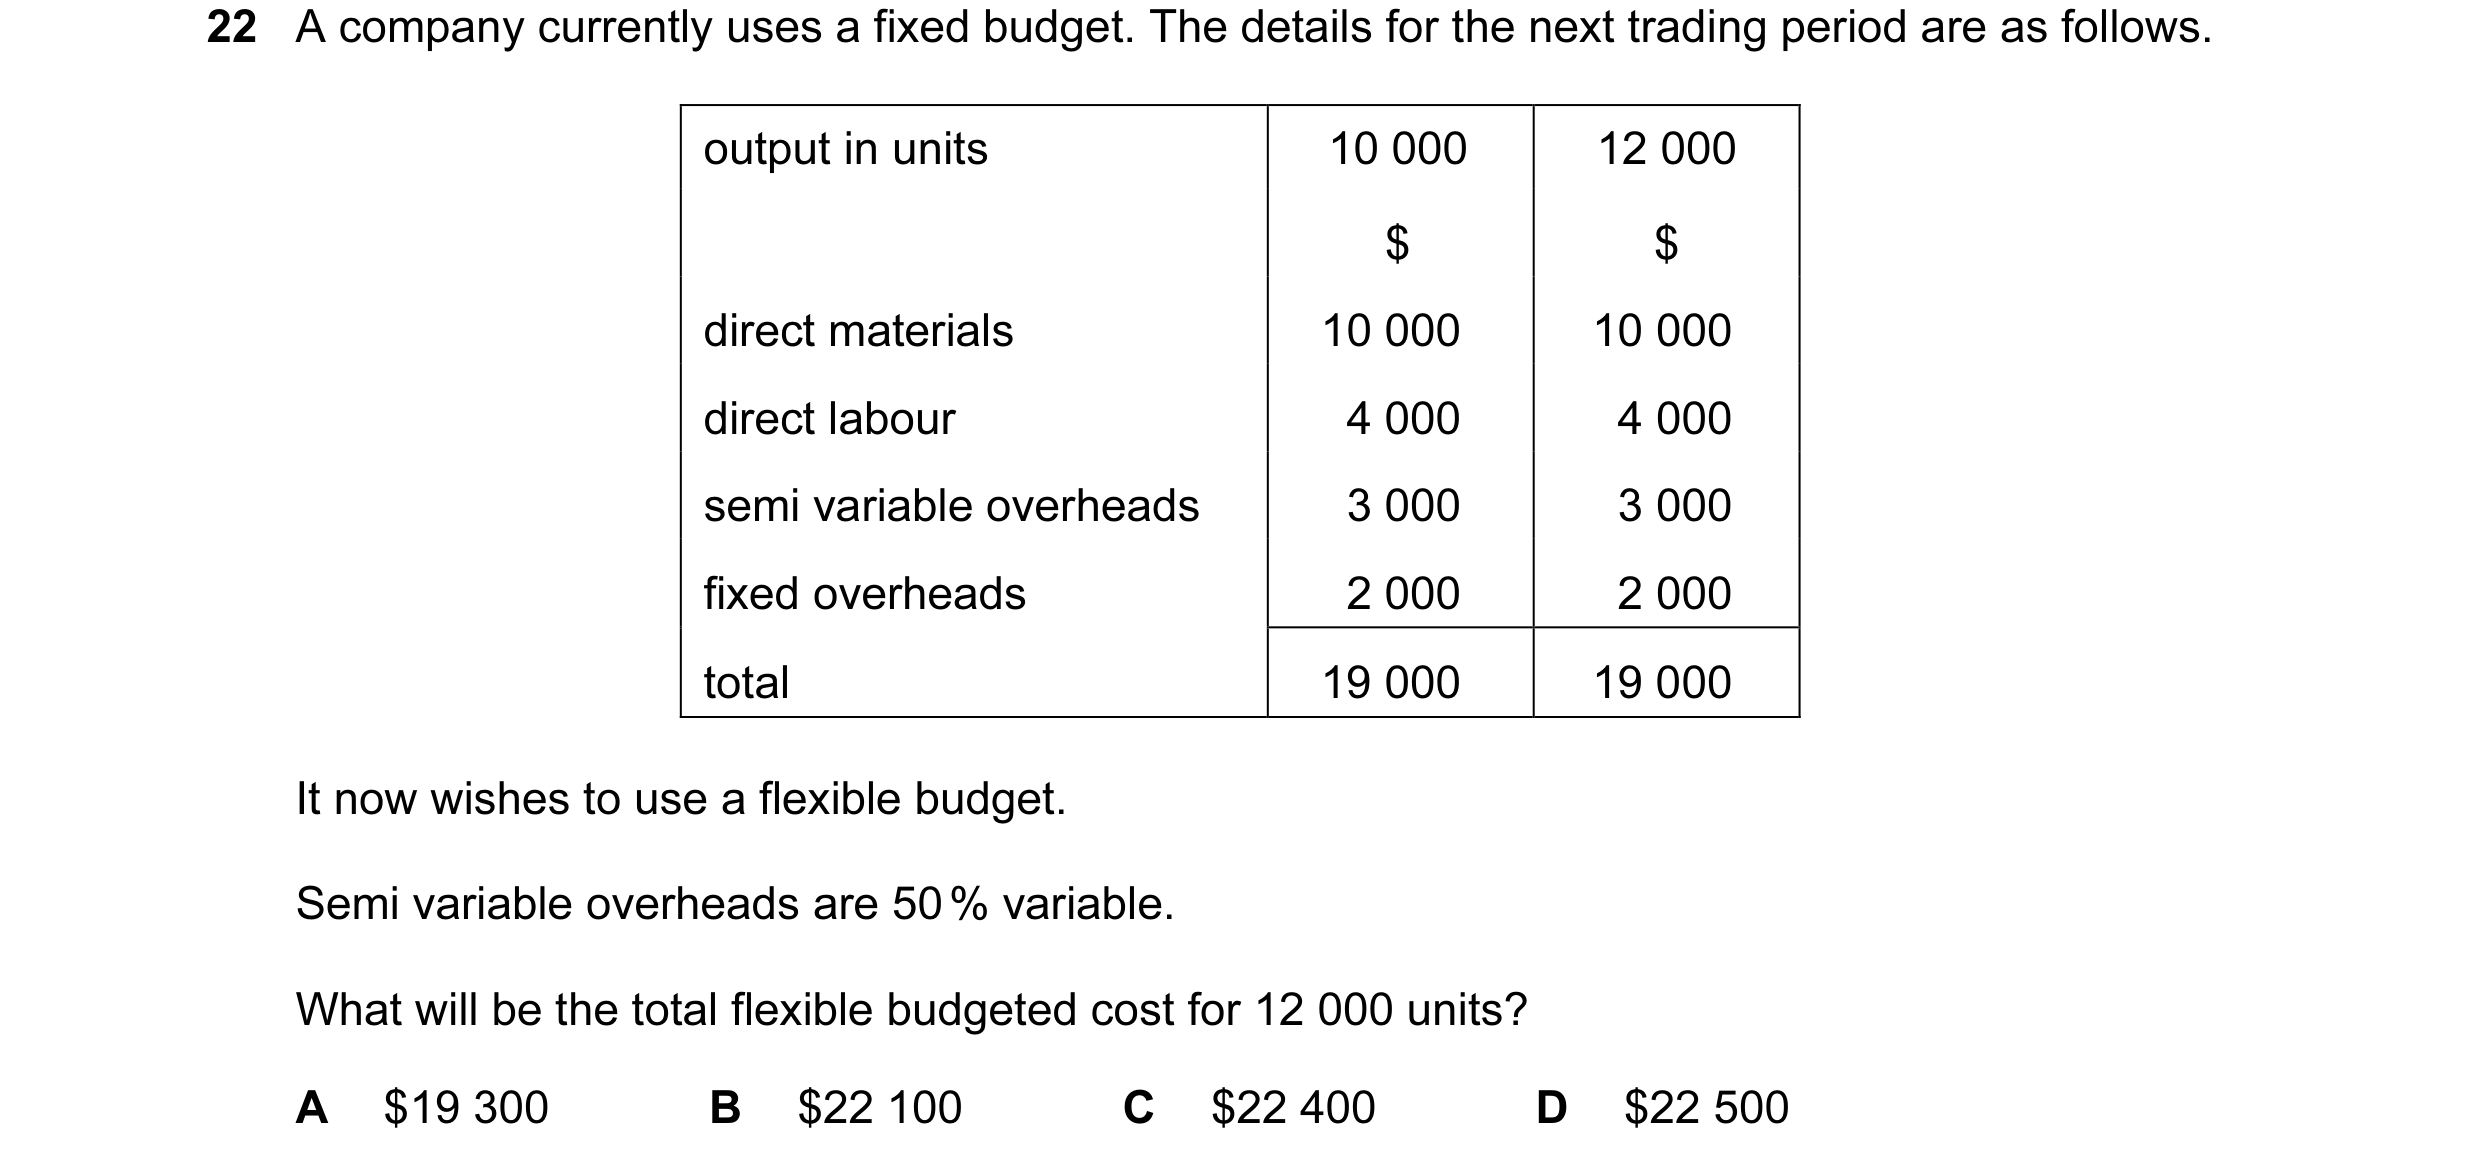
22 A company currently uses a fixed budget. The details for the next trading period are as follows. output in units 10 000 12 000 $ $ direct materials 10 000 10 000 direct labour 4 000 4 000 semi variable overheads 3 000 3 000 fixed overheads 2 000 2 000 total 19 000 19 000 It now wishes to use a flexible budget. Semi variable overheads are 50 % variable. What will be the total flexible budgeted cost for 12 000 units? A $19 300 B $22 100 C $22 400 D $22 500
1 marks
Answer: B
This question in 9706/33 May/June 2010
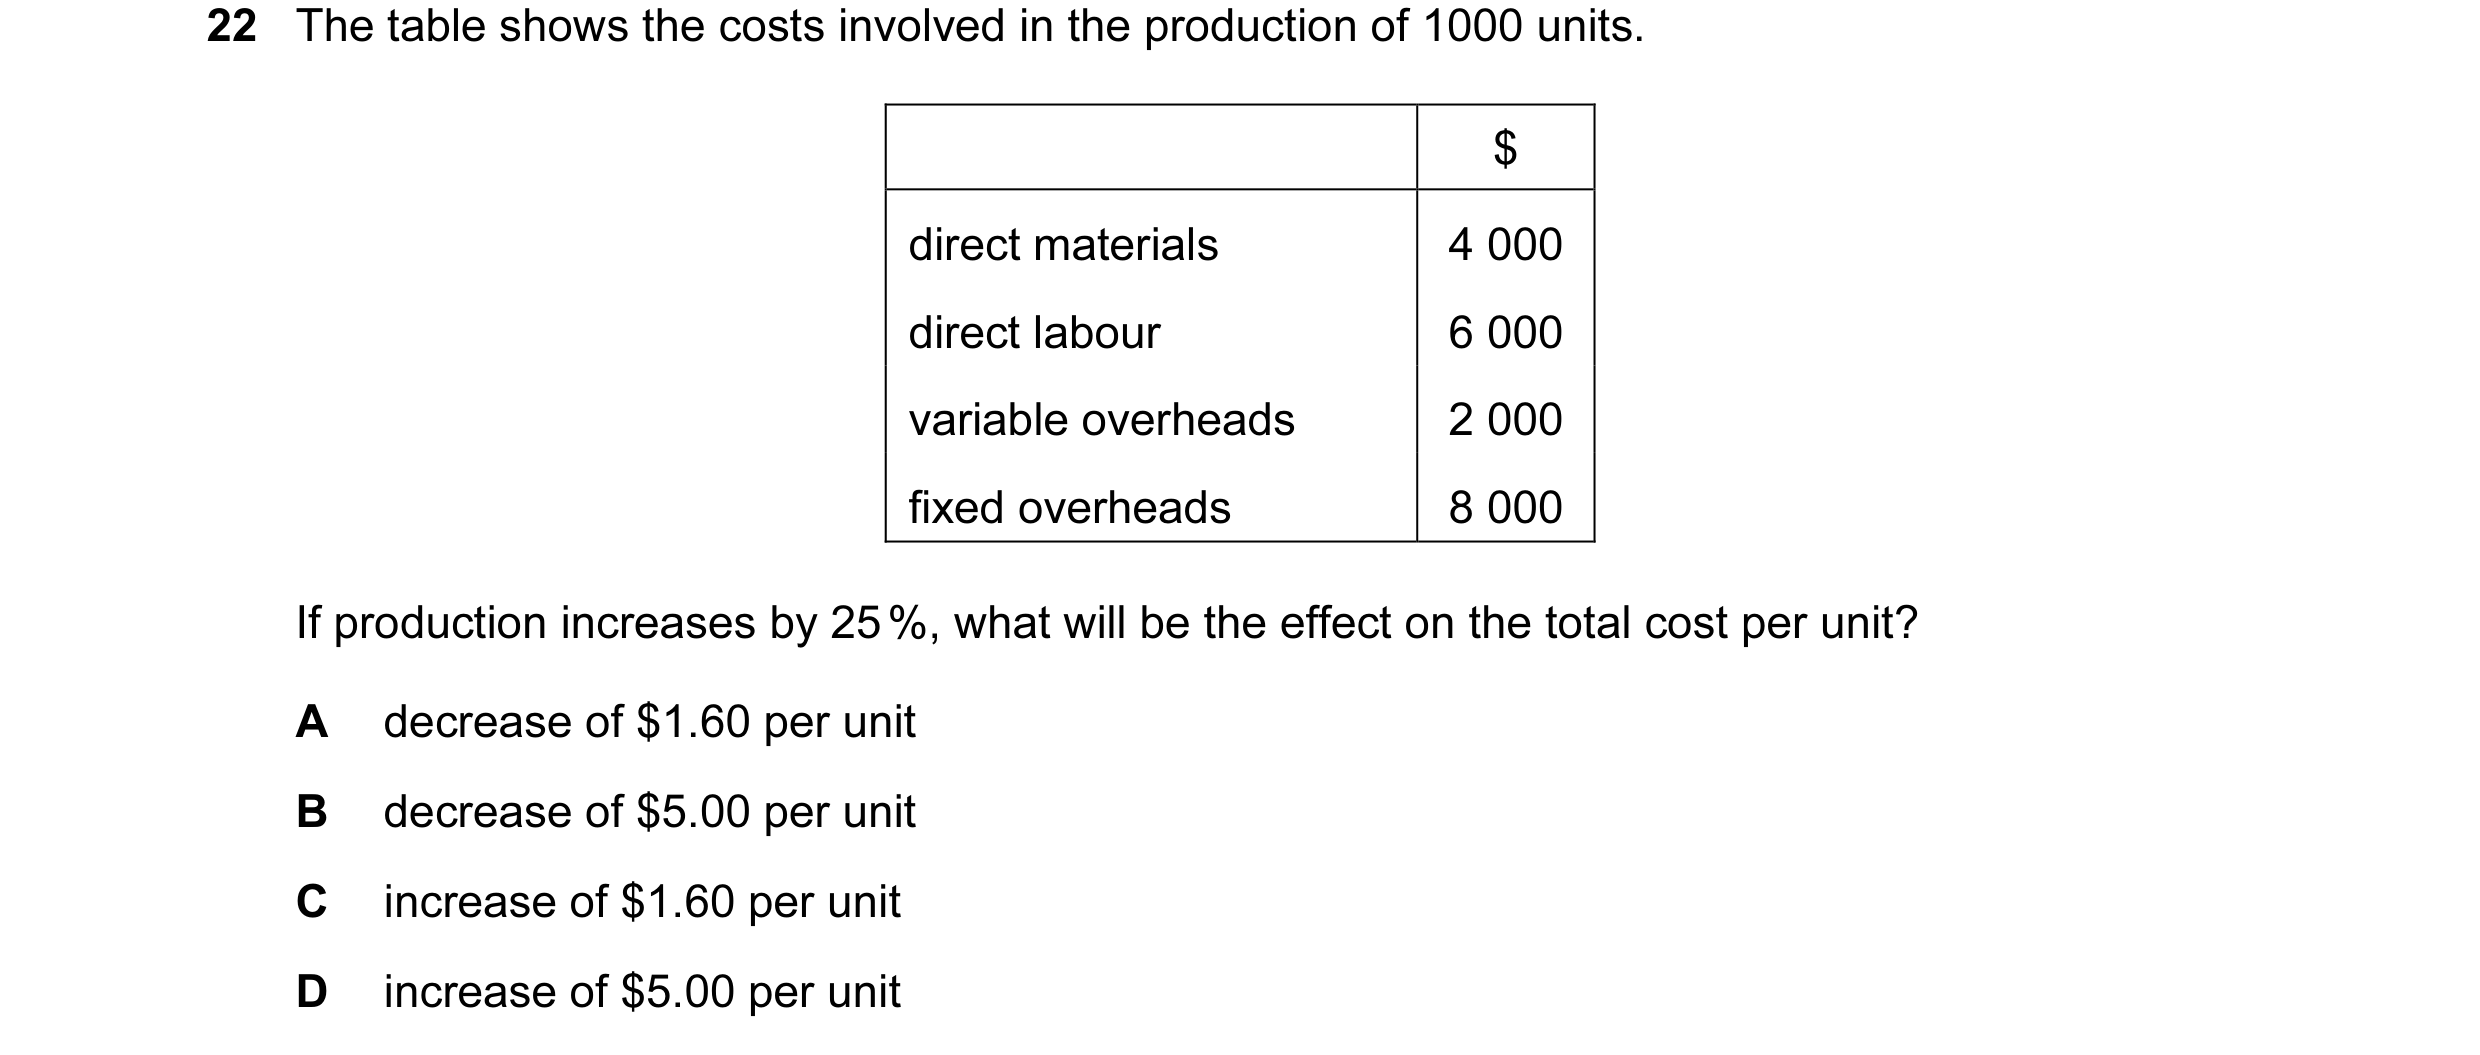
Q8 · The table shows the costs involved in the production of 1000 units 9706/31 Oct/Nov 2010
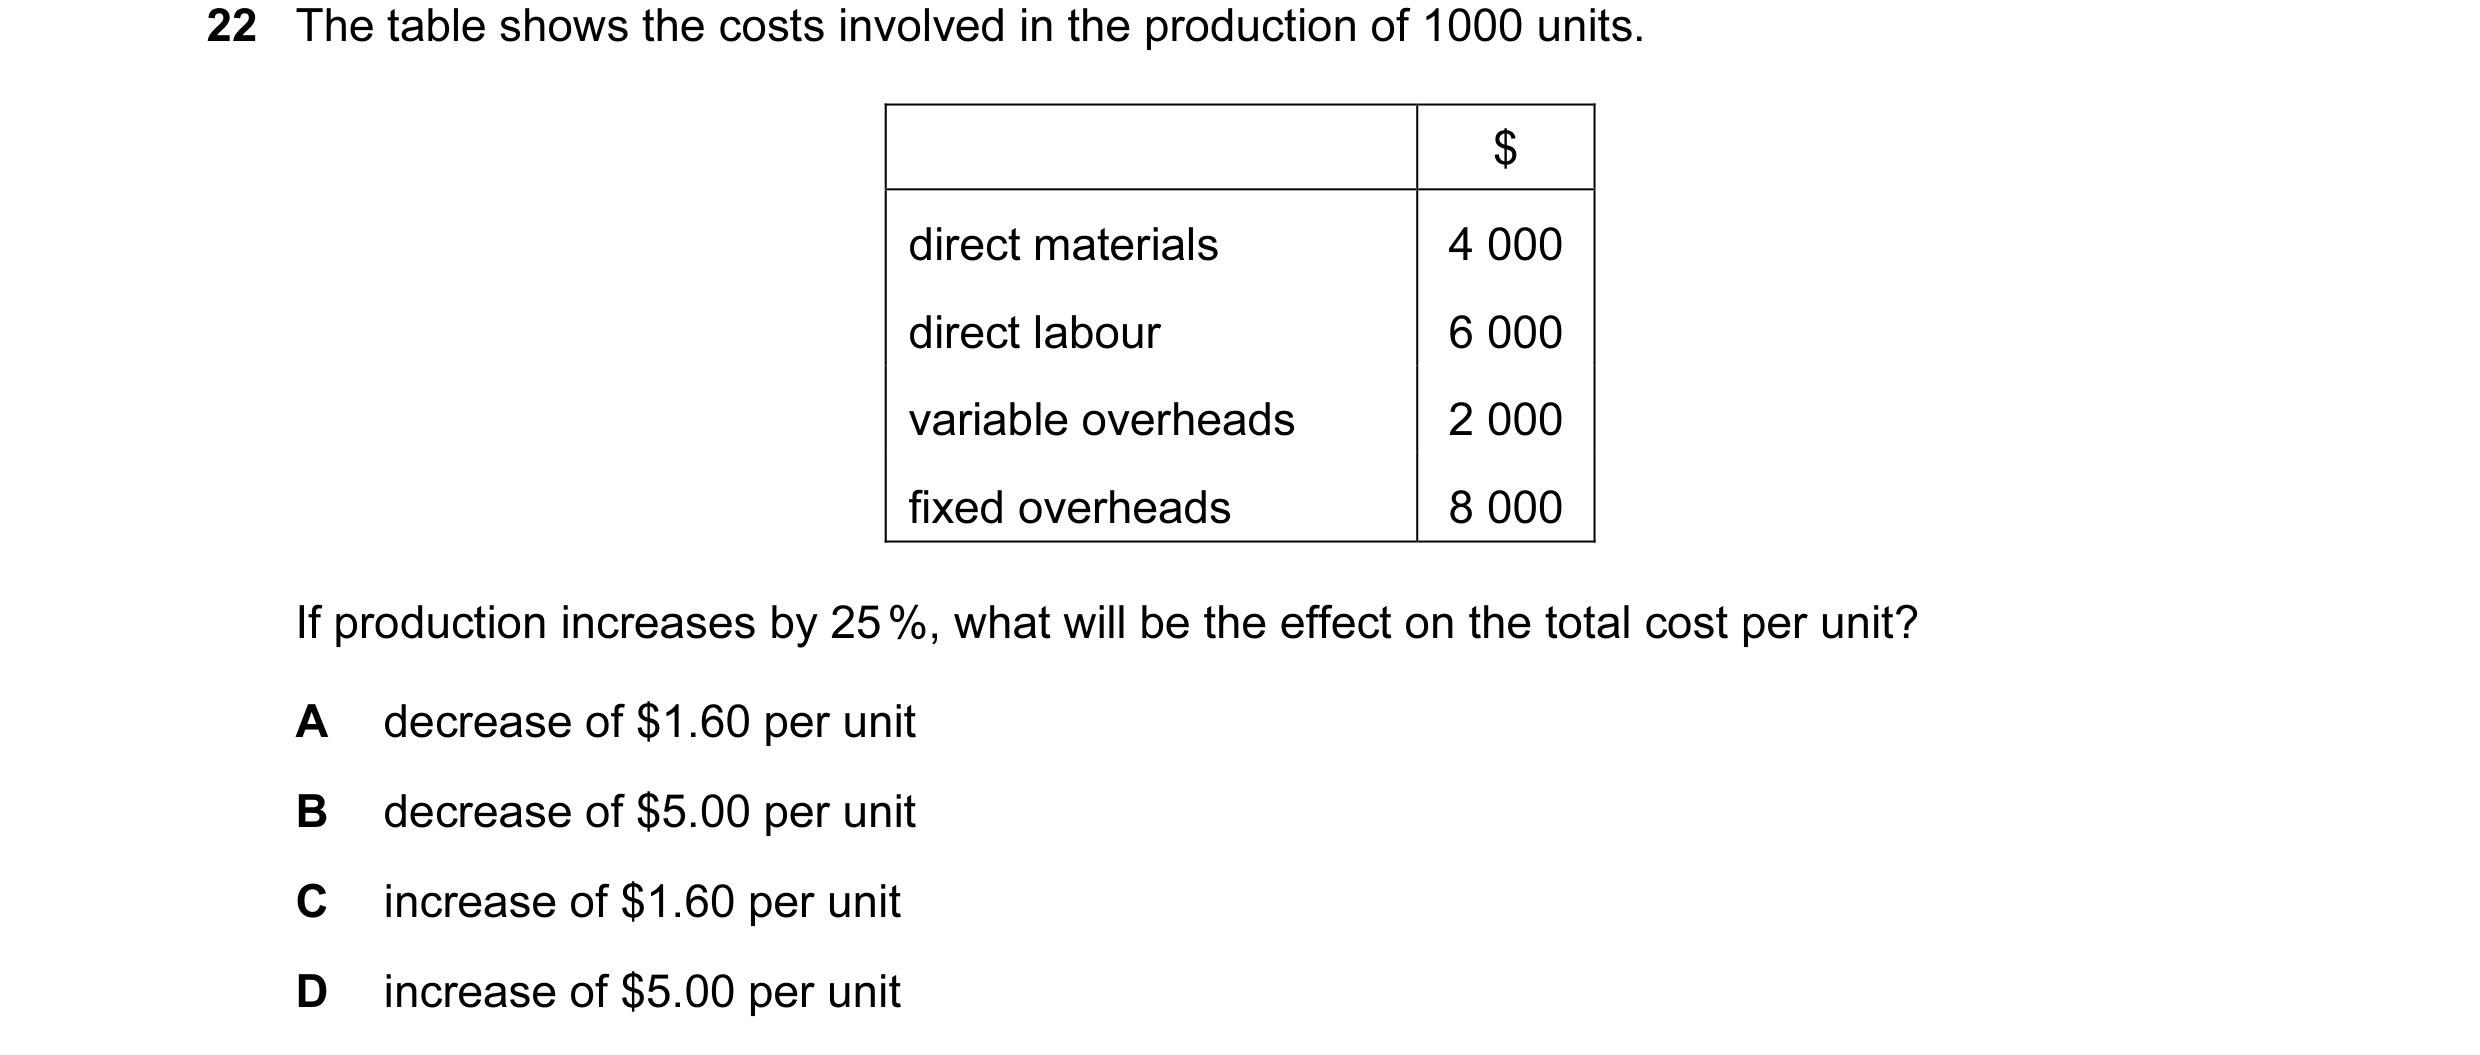
22 The table shows the costs involved in the production of 1000 units. $ direct materials 4 000 direct labour 6 000 variable overheads 2 000 fixed overheads 8 000 If production increases by 25 %, what will be the effect on the total cost per unit? A decrease of $1.60 per unit B decrease of $5.00 per unit C increase of $1.60 per unit D increase of $5.00 per unit
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2010
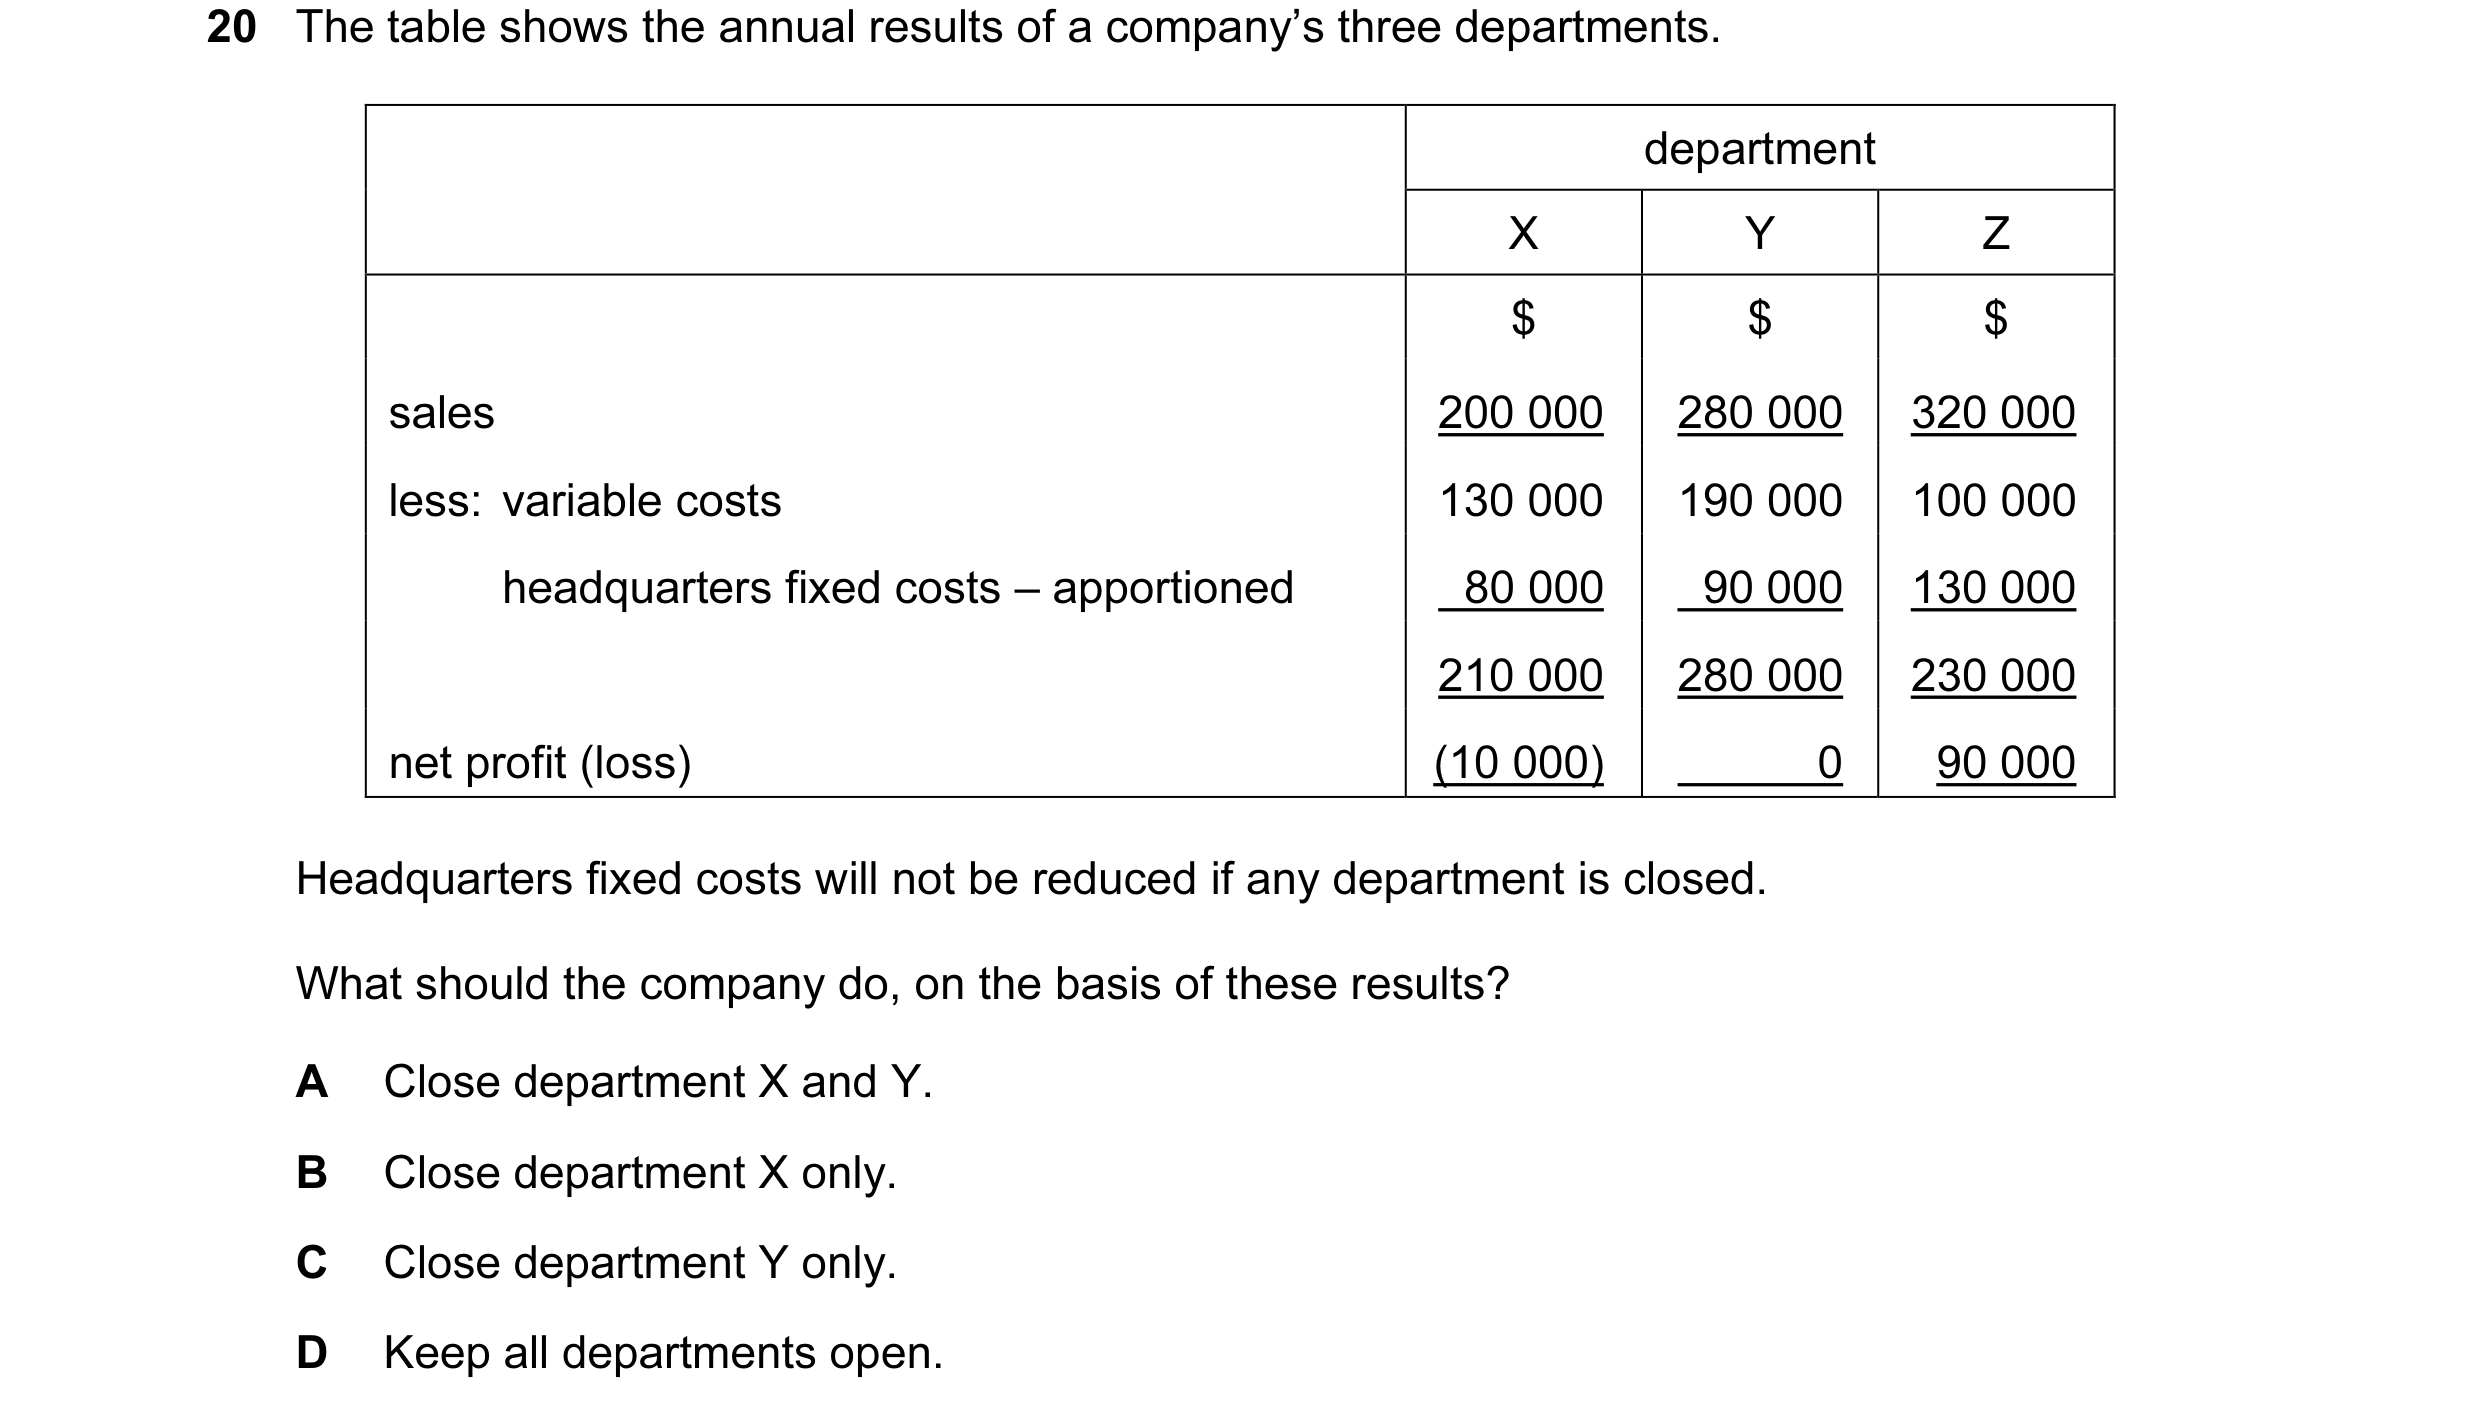
Q9 · The table shows the annual results of a company’s three departments 9706/32 Oct/Nov 2010
20 The table shows the annual results of a company’s three departments. department X Y Z $ $ $ sales 200 000 280 000 320 000 less: variable costs 130 000 190 000 100 000 headquarters fixed costs – apportioned 80 000 90 000 130 000 210 000 280 000 230 000 net profit (loss) (10 000) 0 90 000 Headquarters fixed costs will not be reduced if any department is closed. What should the company do, on the basis of these results? A Close department X and Y. B Close department X only. C Close department Y only. D Keep all departments open.
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2010
Q10 · The table shows the costs involved in the production of 1000 units 9706/32 Oct/Nov 2010
22 The table shows the costs involved in the production of 1000 units. $ direct materials 4 000 direct labour 6 000 variable overheads 2 000 fixed overheads 8 000 If production increases by 25 %, what will be the effect on the total cost per unit? A decrease of $1.60 per unit B decrease of $5.00 per unit C increase of $1.60 per unit D increase of $5.00 per unit
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2010
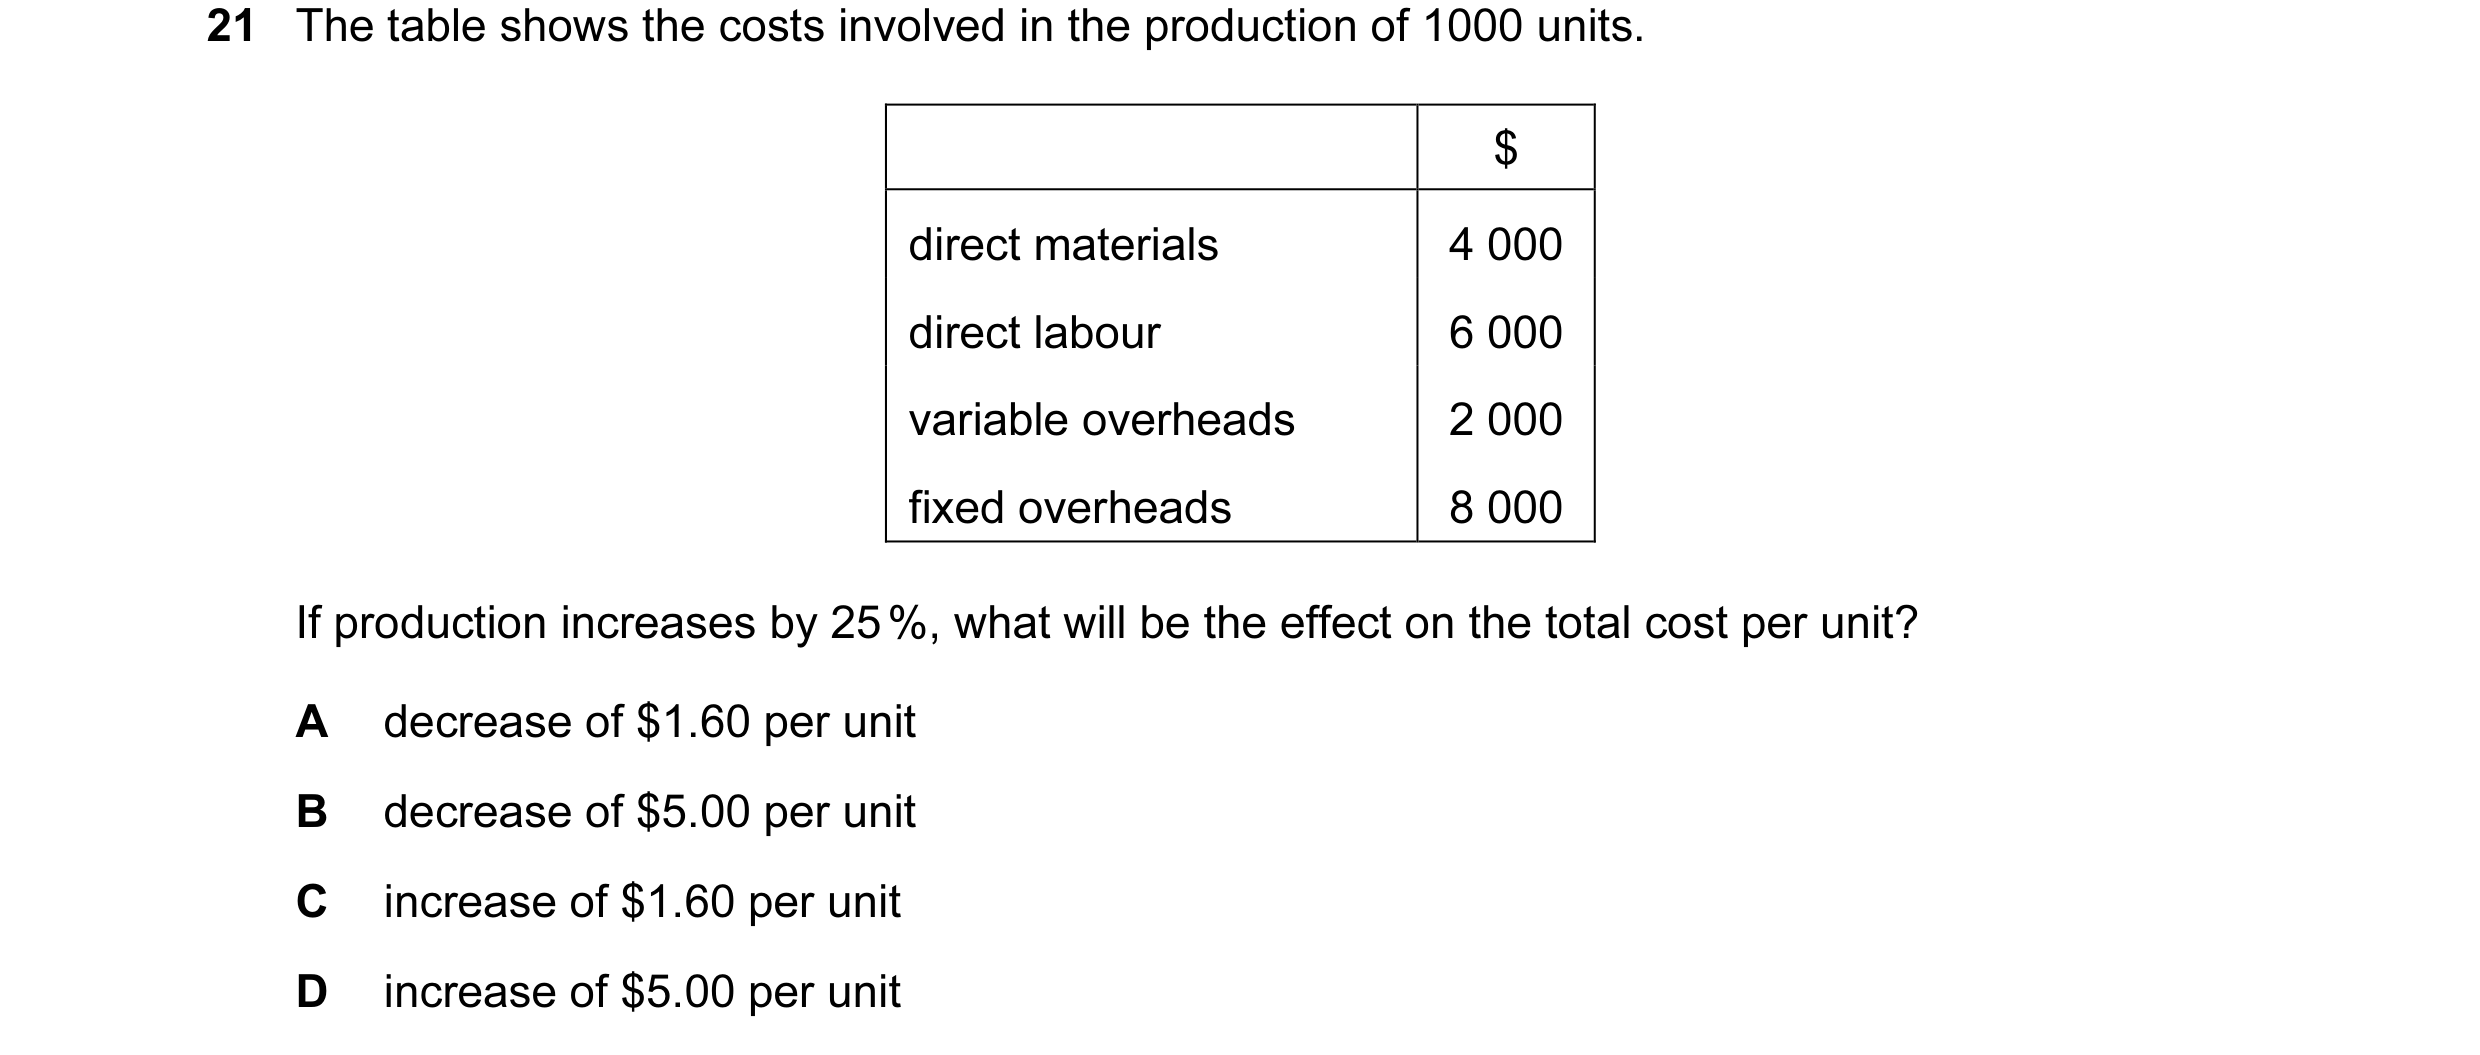
Q11 · The table shows the costs involved in the production of 1000 units 9706/33 Oct/Nov 2010
21 The table shows the costs involved in the production of 1000 units. $ direct materials 4 000 direct labour 6 000 variable overheads 2 000 fixed overheads 8 000 If production increases by 25 %, what will be the effect on the total cost per unit? A decrease of $1.60 per unit B decrease of $5.00 per unit C increase of $1.60 per unit D increase of $5.00 per unit
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2010
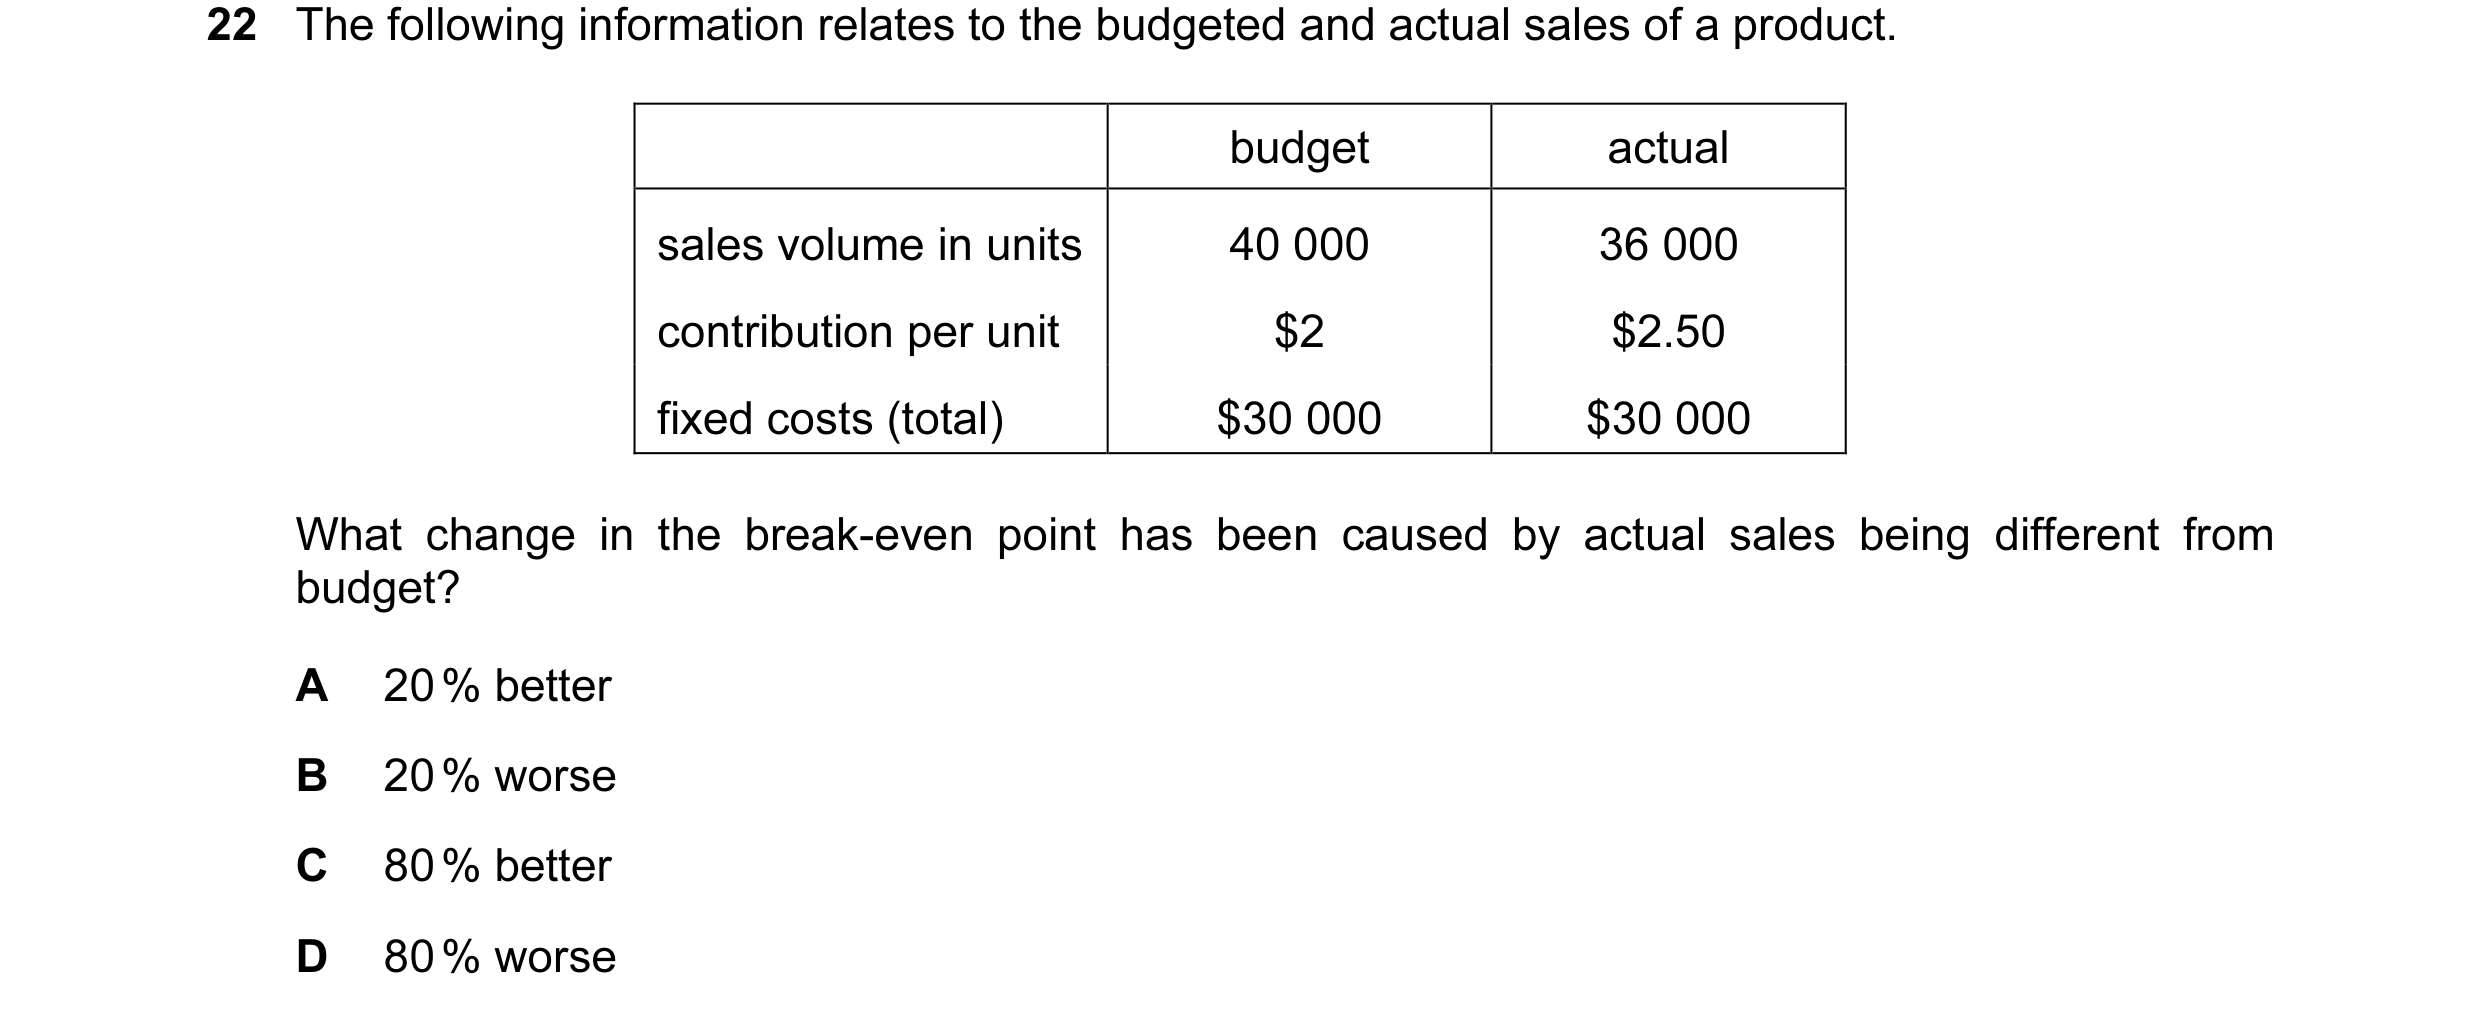
Q12 · The following information relates to the budgeted and actual sales of a product 9706/32 May/June 2011
22 The following information relates to the budgeted and actual sales of a product. budget actual sales volume in units 40 000 36 000 contribution per unit $2 $2.50 fixed costs (total) $30 000 $30 000 What change in the break-even point has been caused by actual sales being different from budget? A 20 % better B 20 % worse C 80 % better D 80 % worse
1 marks
Answer: A
This question in 9706/32 May/June 2011
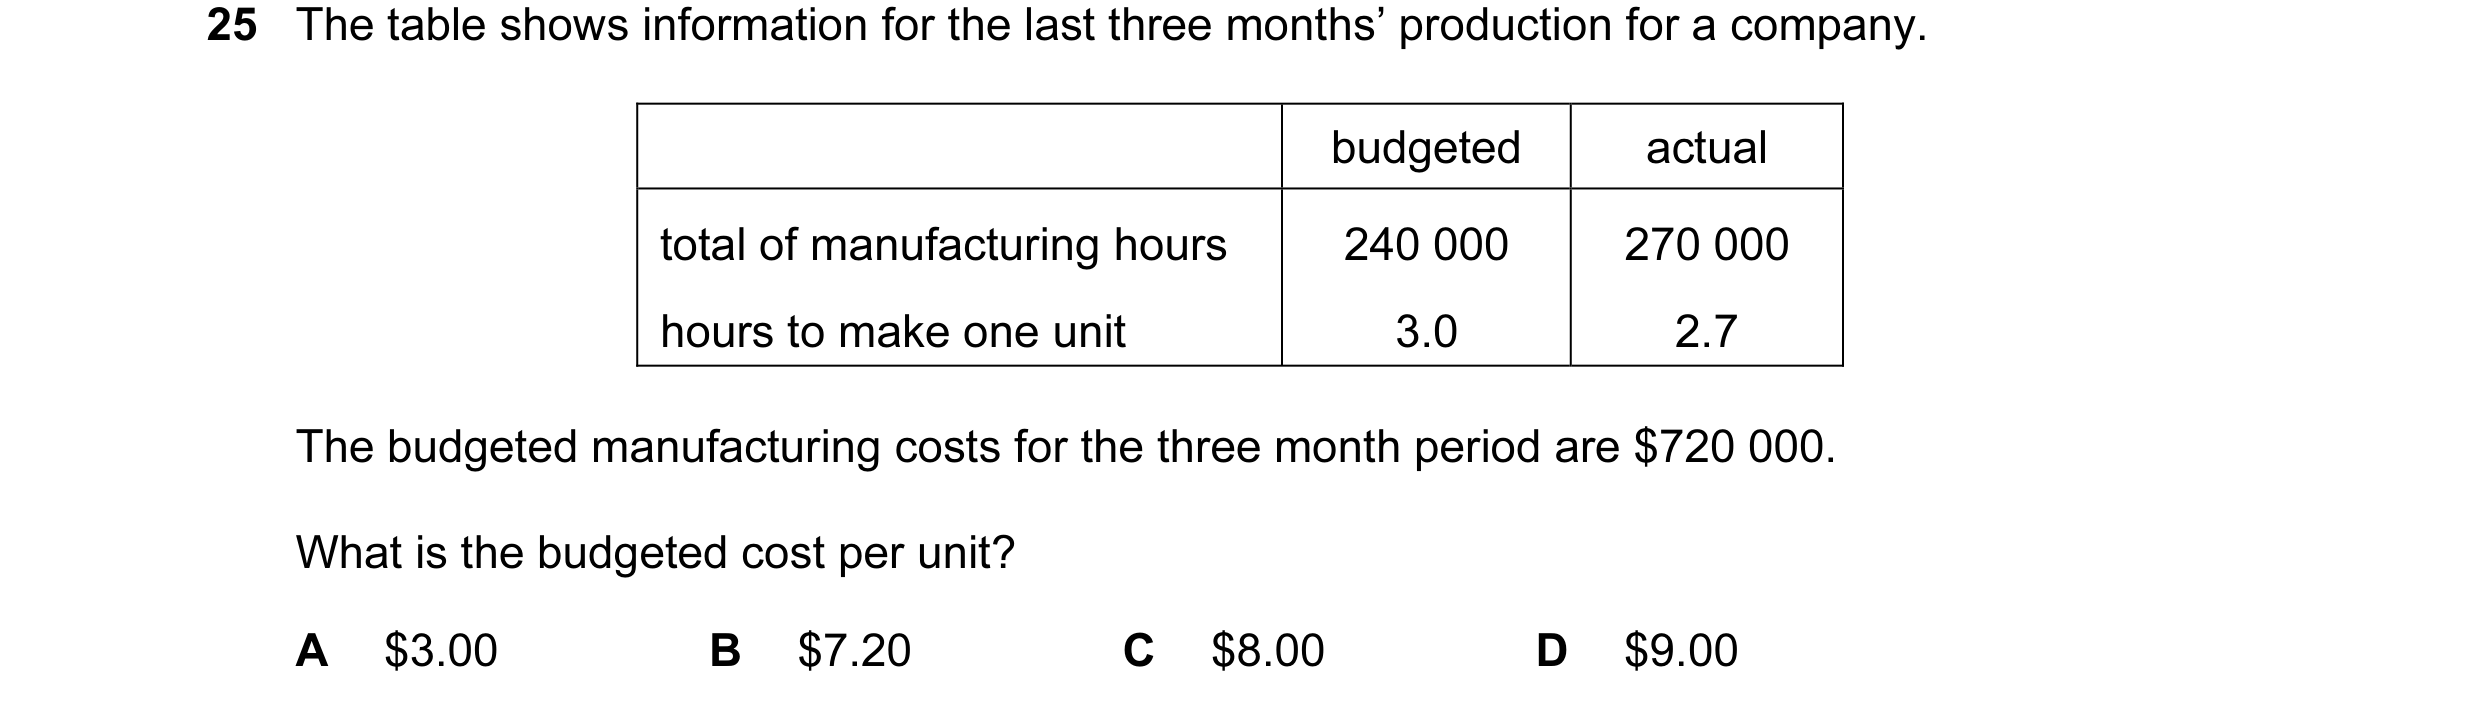
Q13 · The table shows information for the last three months’ production for a company 9706/32 May/June 2011
25 The table shows information for the last three months’ production for a company. budgeted actual total of manufacturing hours 240 000 270 000 hours to make one unit 3.0 2.7 The budgeted manufacturing costs for the three month period are $720 000. What is the budgeted cost per unit? A $3.00 B $7.20 C $8.00 D $9.00
1 marks
Answer: D
This question in 9706/32 May/June 2011
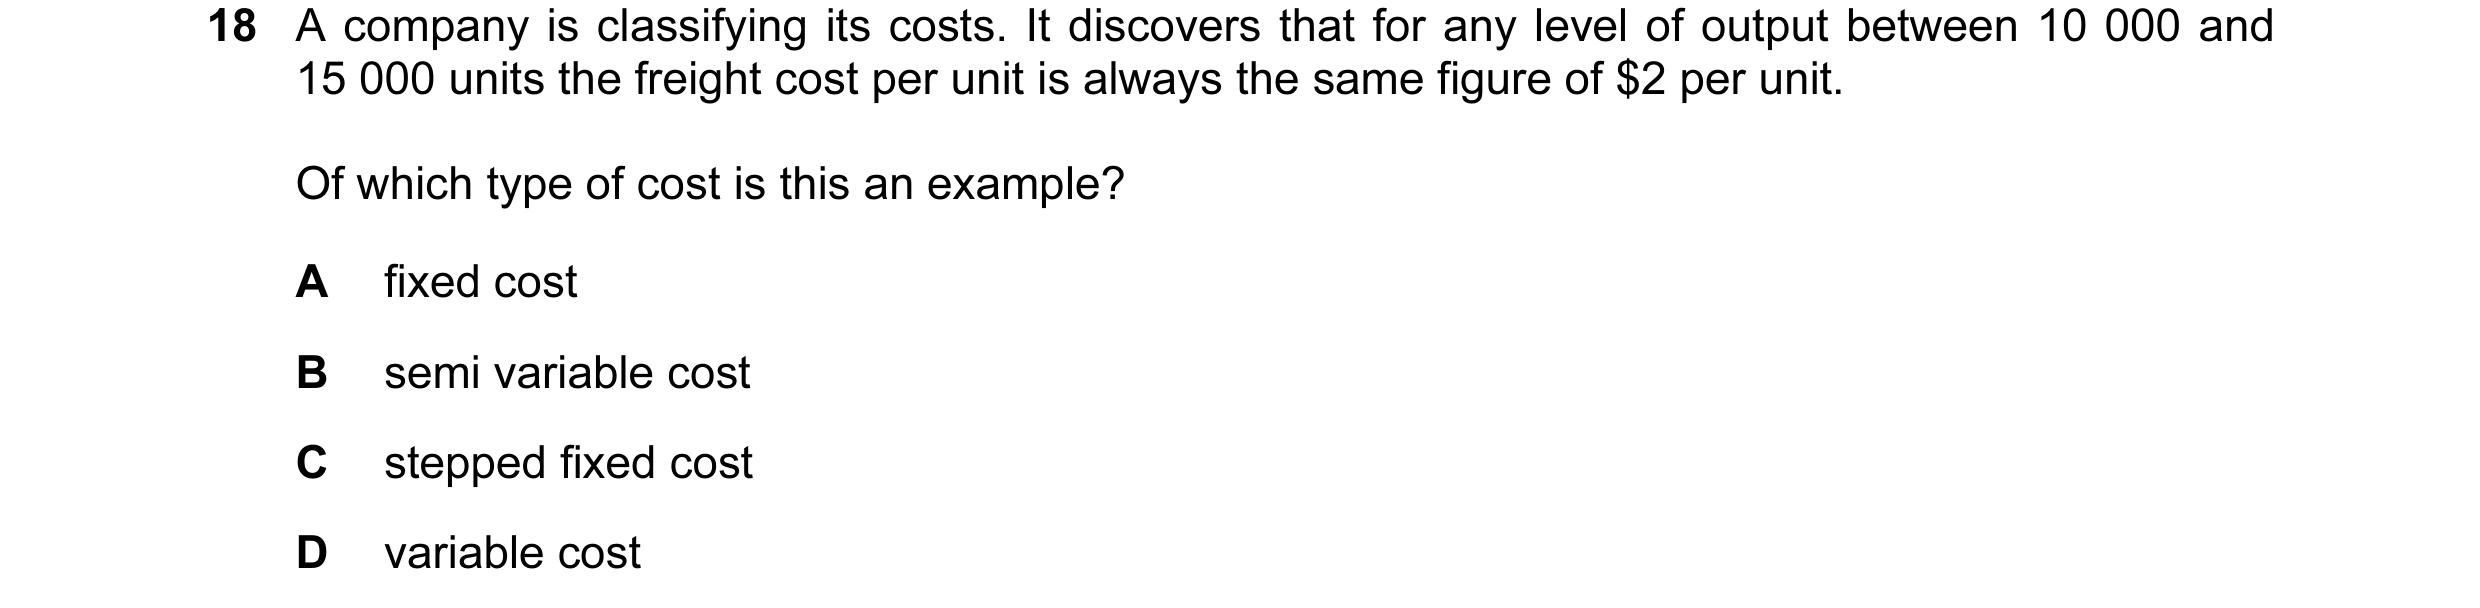
Q14 · A company is classifying its costs 9706/31 Oct/Nov 2011
18 A company is classifying its costs. It discovers that for any level of output between 10 000 and 15 000 units the freight cost per unit is always the same figure of $2 per unit. Of which type of cost is this an example? A fixed cost B semi variable cost C stepped fixed cost D variable cost
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2011
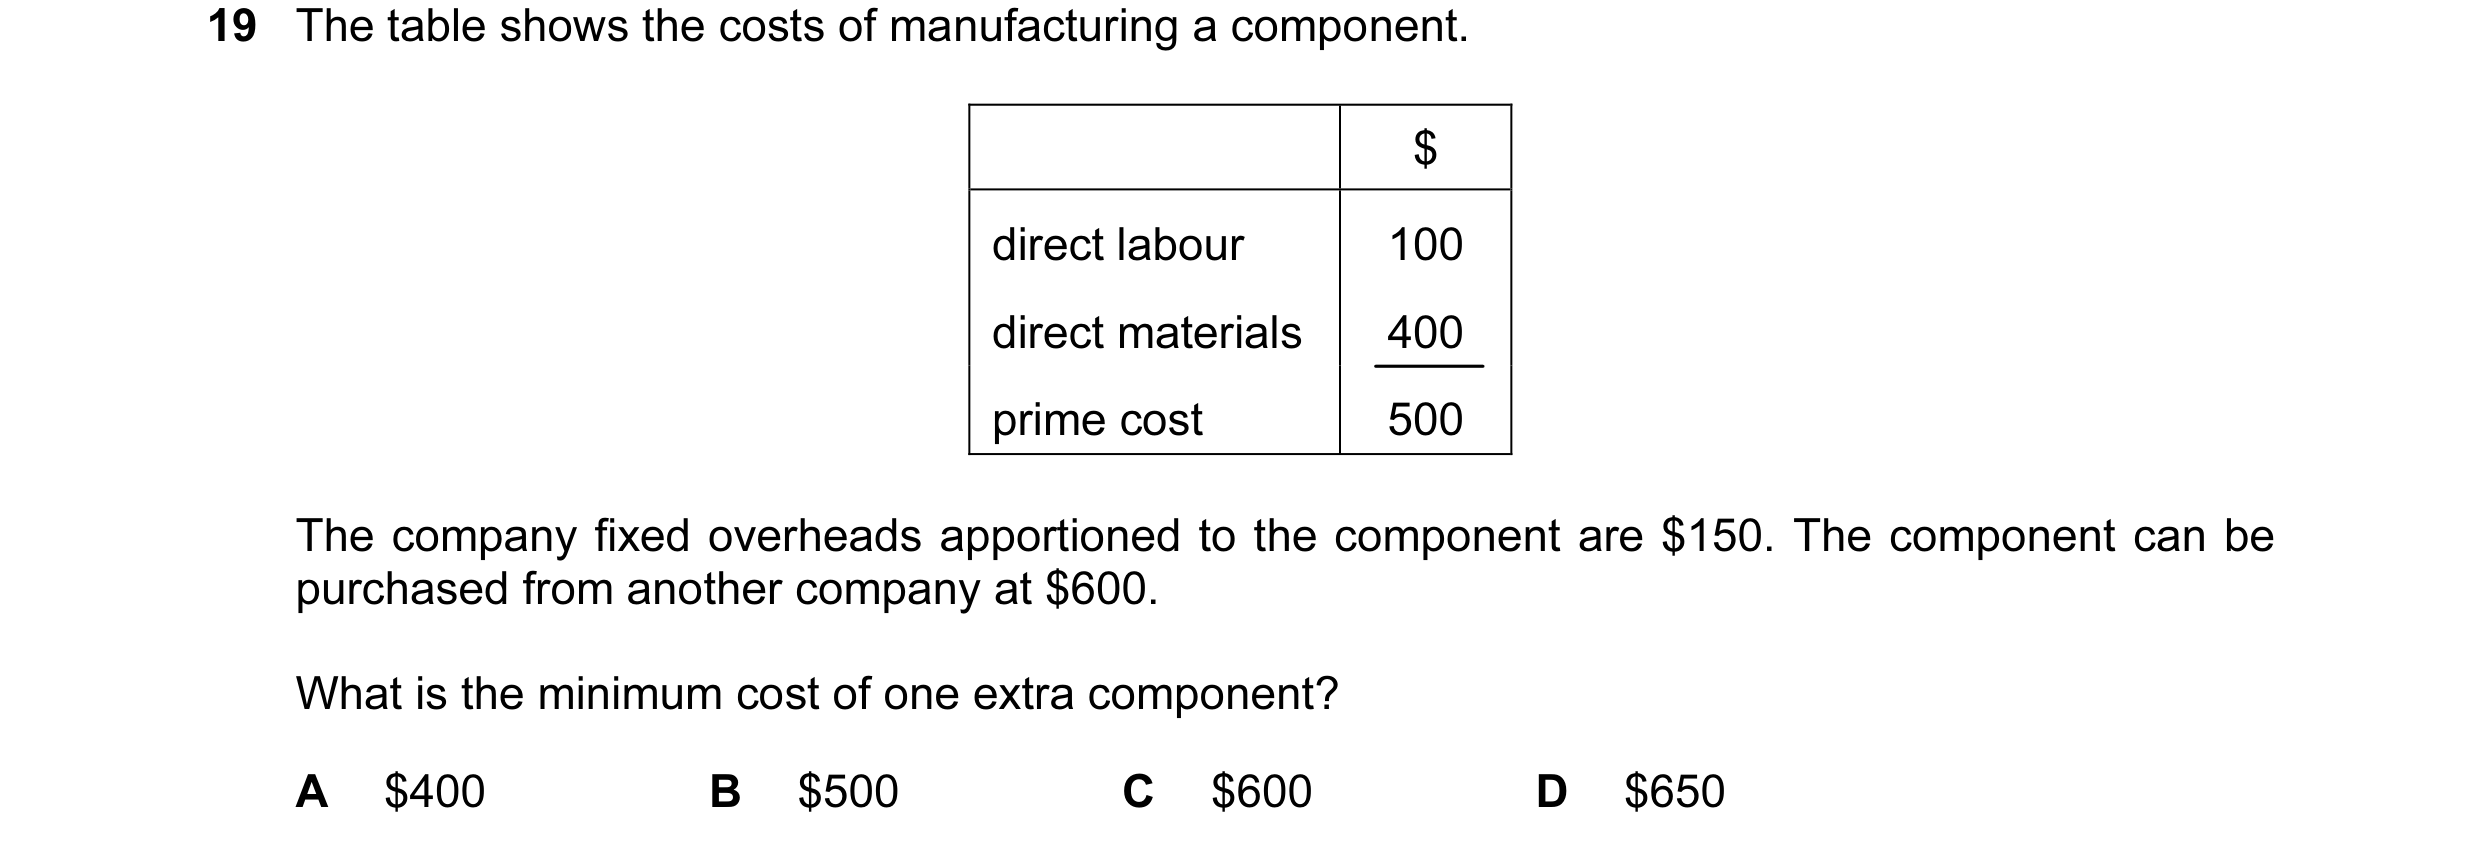
Q15 · The table shows the costs of manufacturing a component 9706/31 Oct/Nov 2011
19 The table shows the costs of manufacturing a component. $ direct labour 100 direct materials 400 prime cost 500 The company fixed overheads apportioned to the component are $150. The component can be purchased from another company at $600. What is the minimum cost of one extra component? A $400 B $500 C $600 D $650
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2011
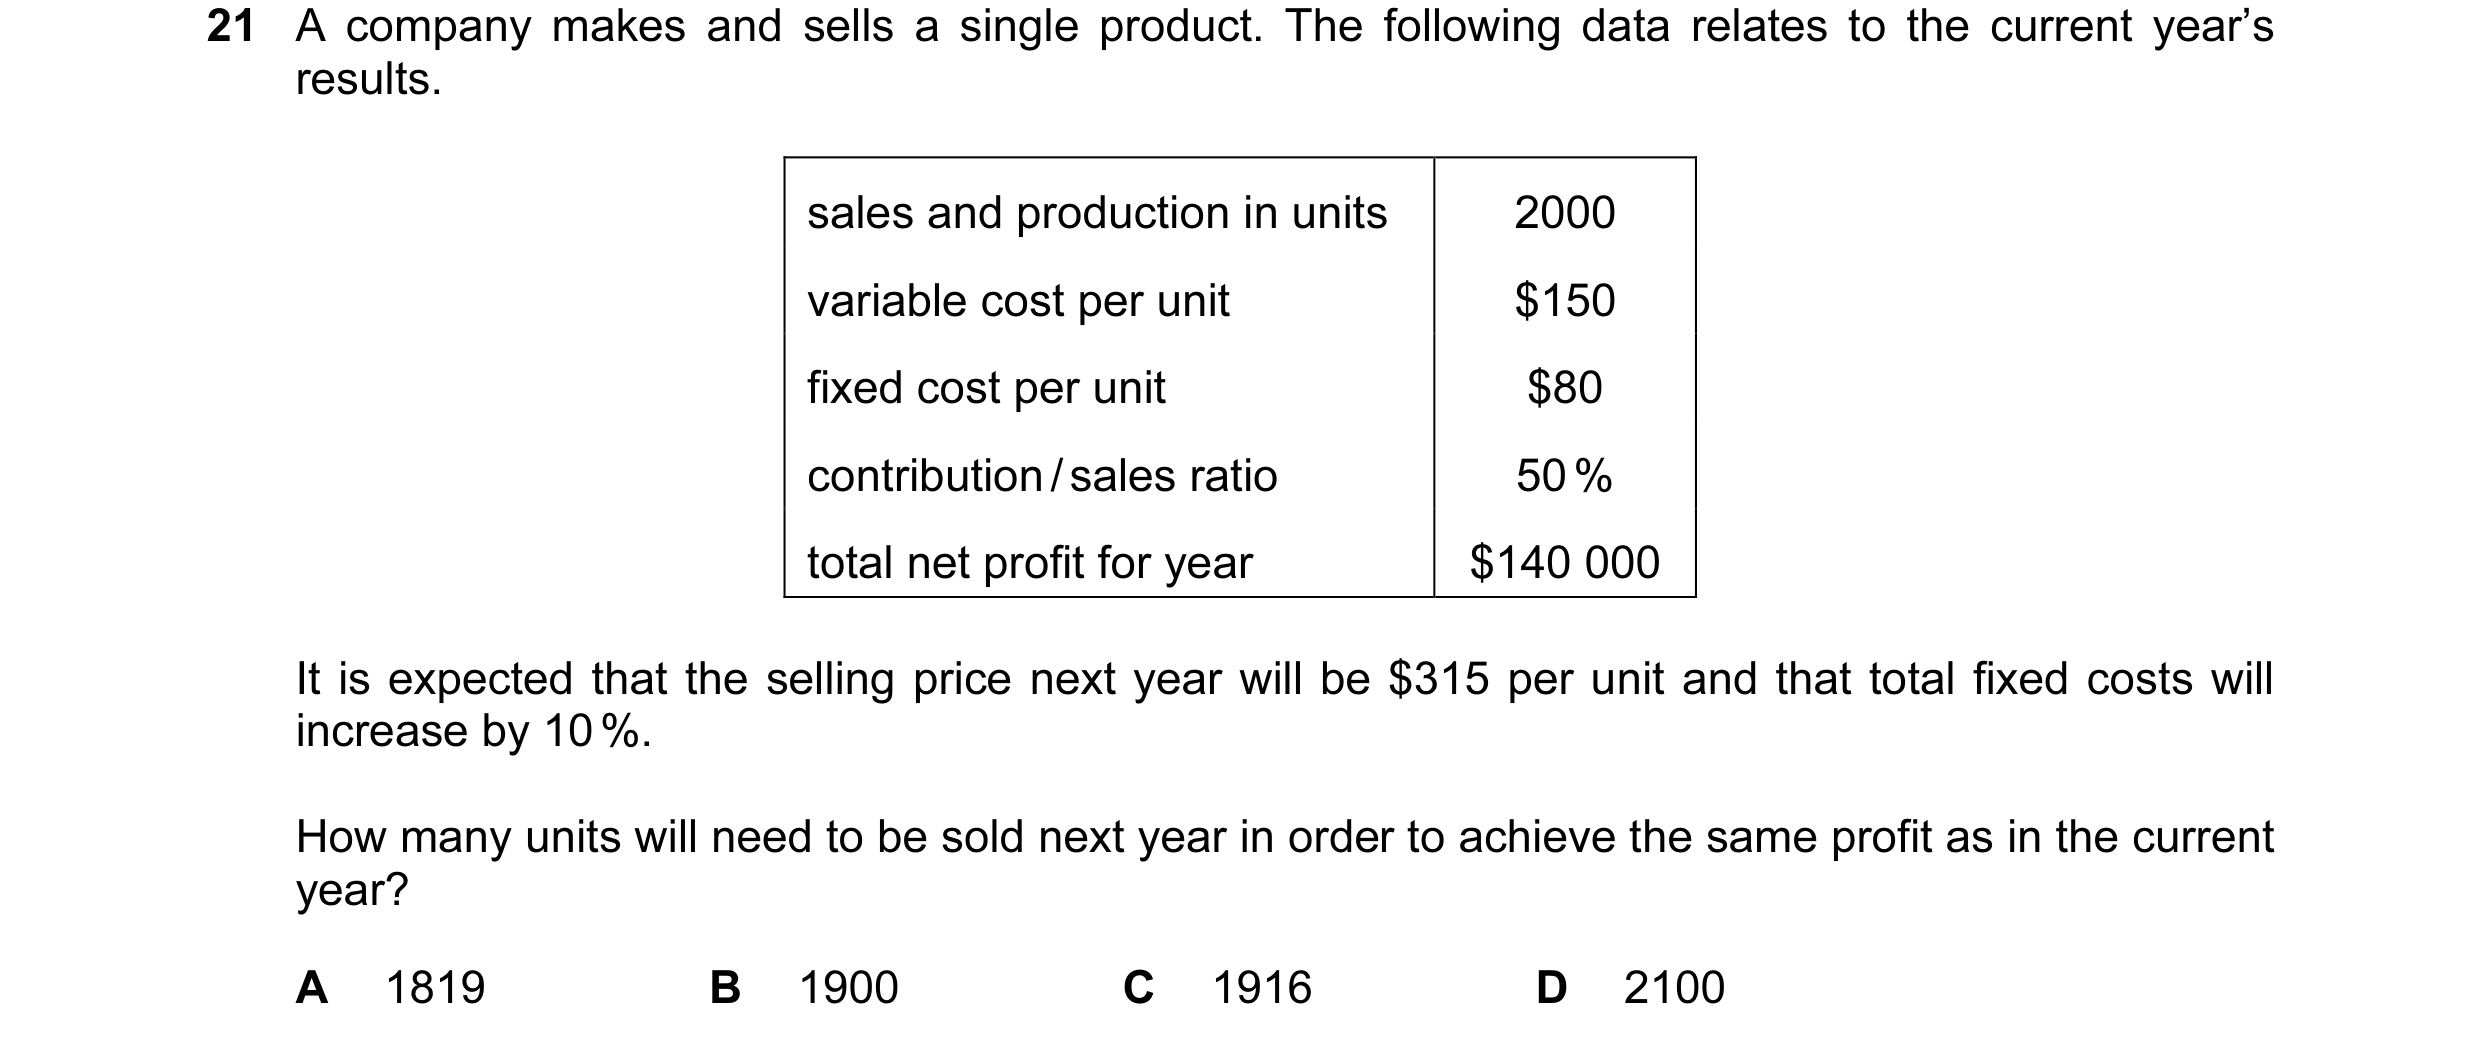
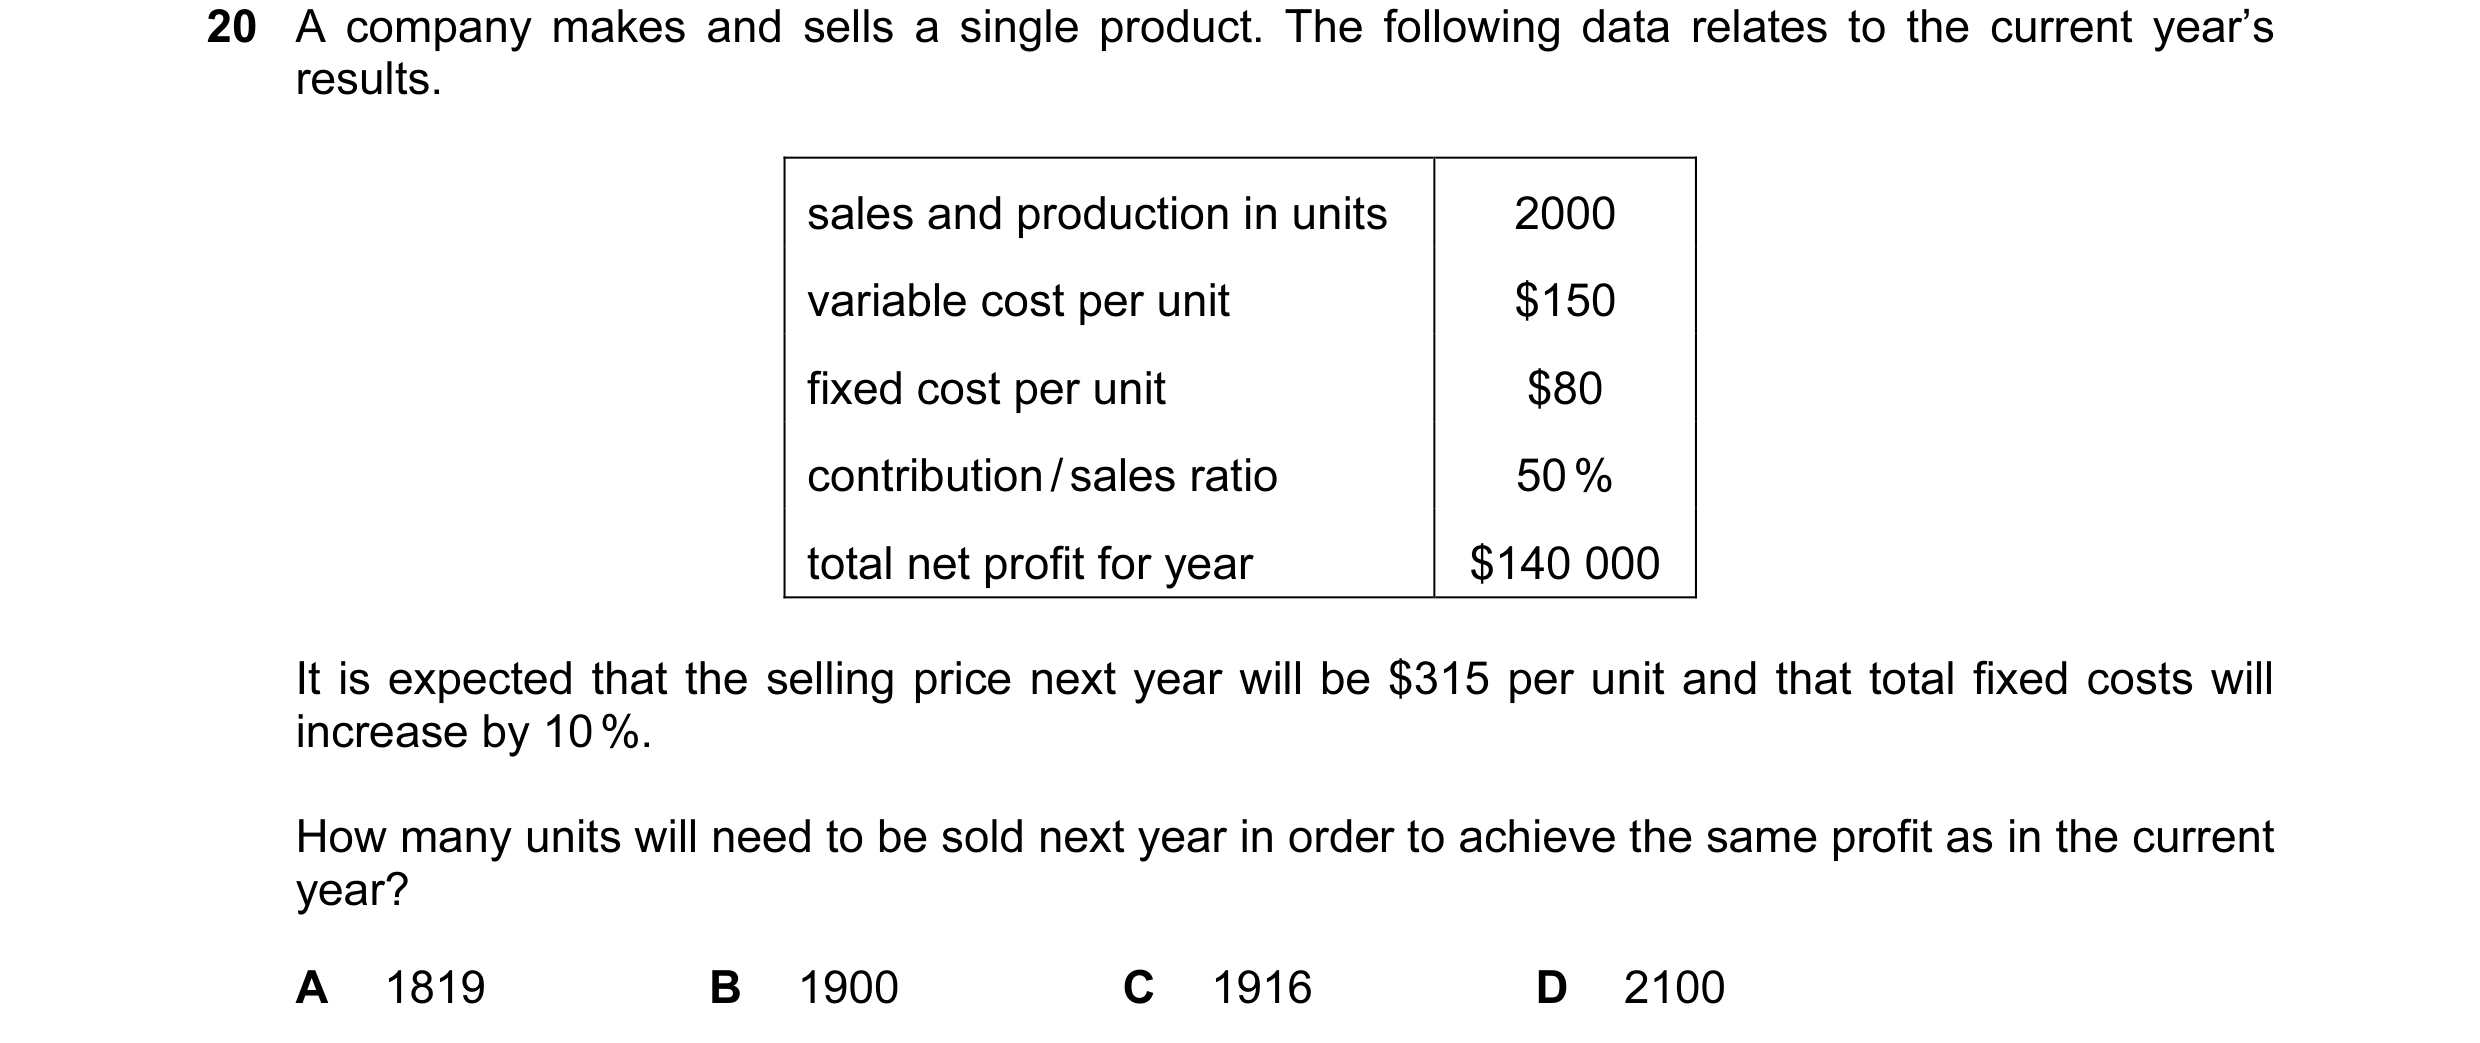
Q16 · A company makes and sells a single product 9706/31 Oct/Nov 2011
21 A company makes and sells a single product. The following data relates to the current year’s results. sales and production in units 2000 variable cost per unit $150 fixed cost per unit $80 contribution / sales ratio 50 % total net profit for year $140 000 It is expected that the selling price next year will be $315 per unit and that total fixed costs will increase by 10 %. How many units will need to be sold next year in order to achieve the same profit as in the current year? A 1819 B 1900 C 1916 D 2100
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2011
Q17 · A particular cost is classified as fixed 9706/32 Oct/Nov 2011
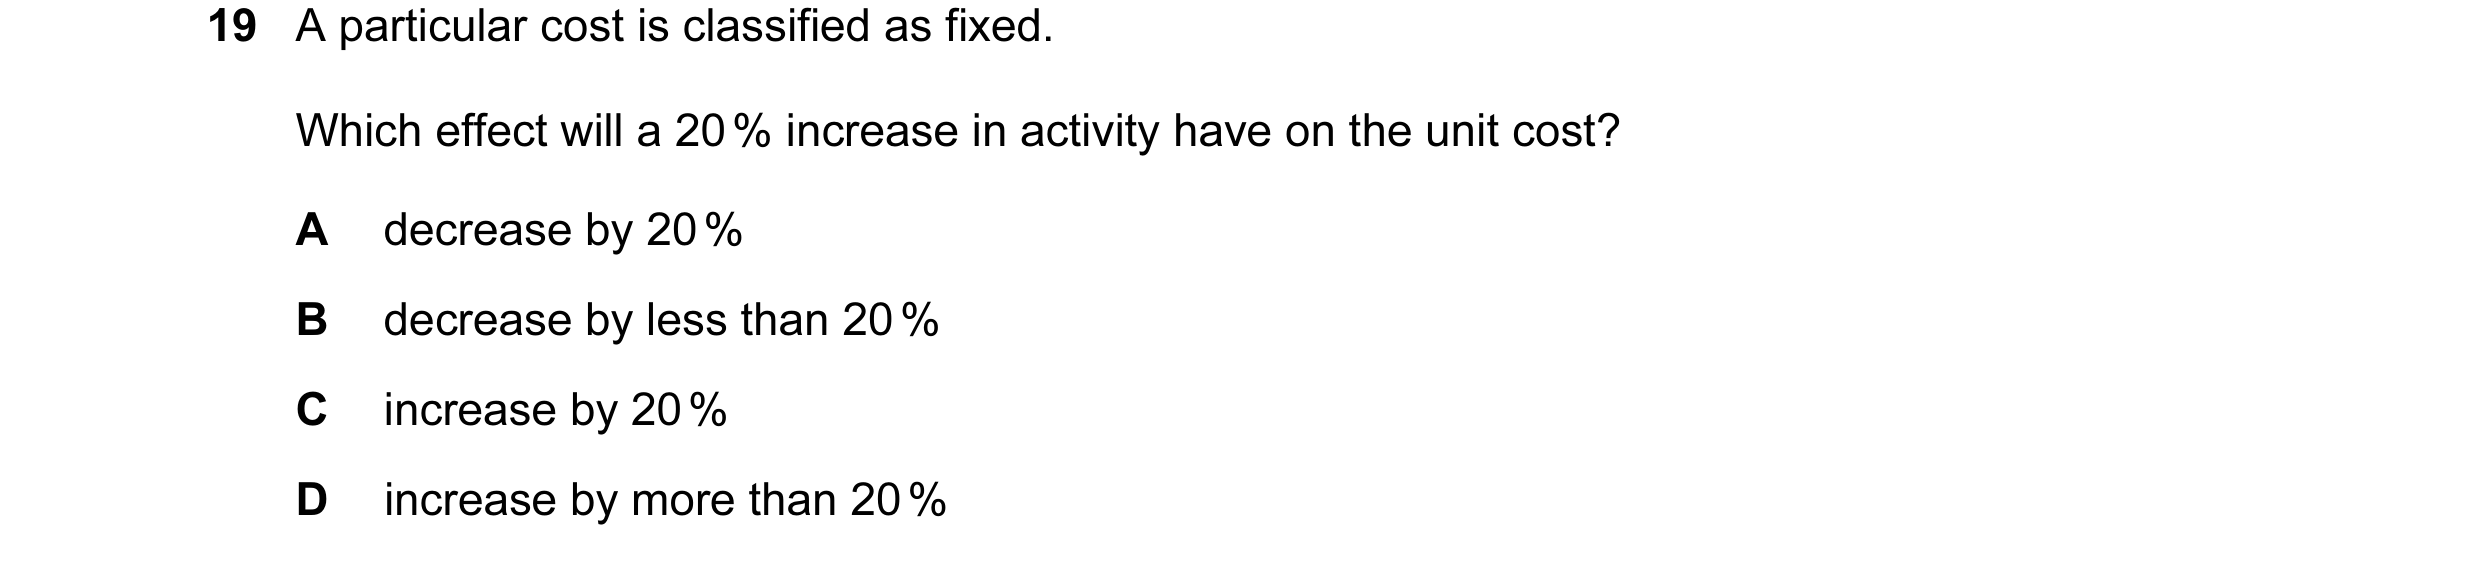
19 A particular cost is classified as fixed. Which effect will a 20 % increase in activity have on the unit cost? A decrease by 20 % B decrease by less than 20 % C increase by 20 % D increase by more than 20 %
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2011
Q18 · The information below shows an annual budget for production of 10 000 units 9706/32 Oct/Nov 2011
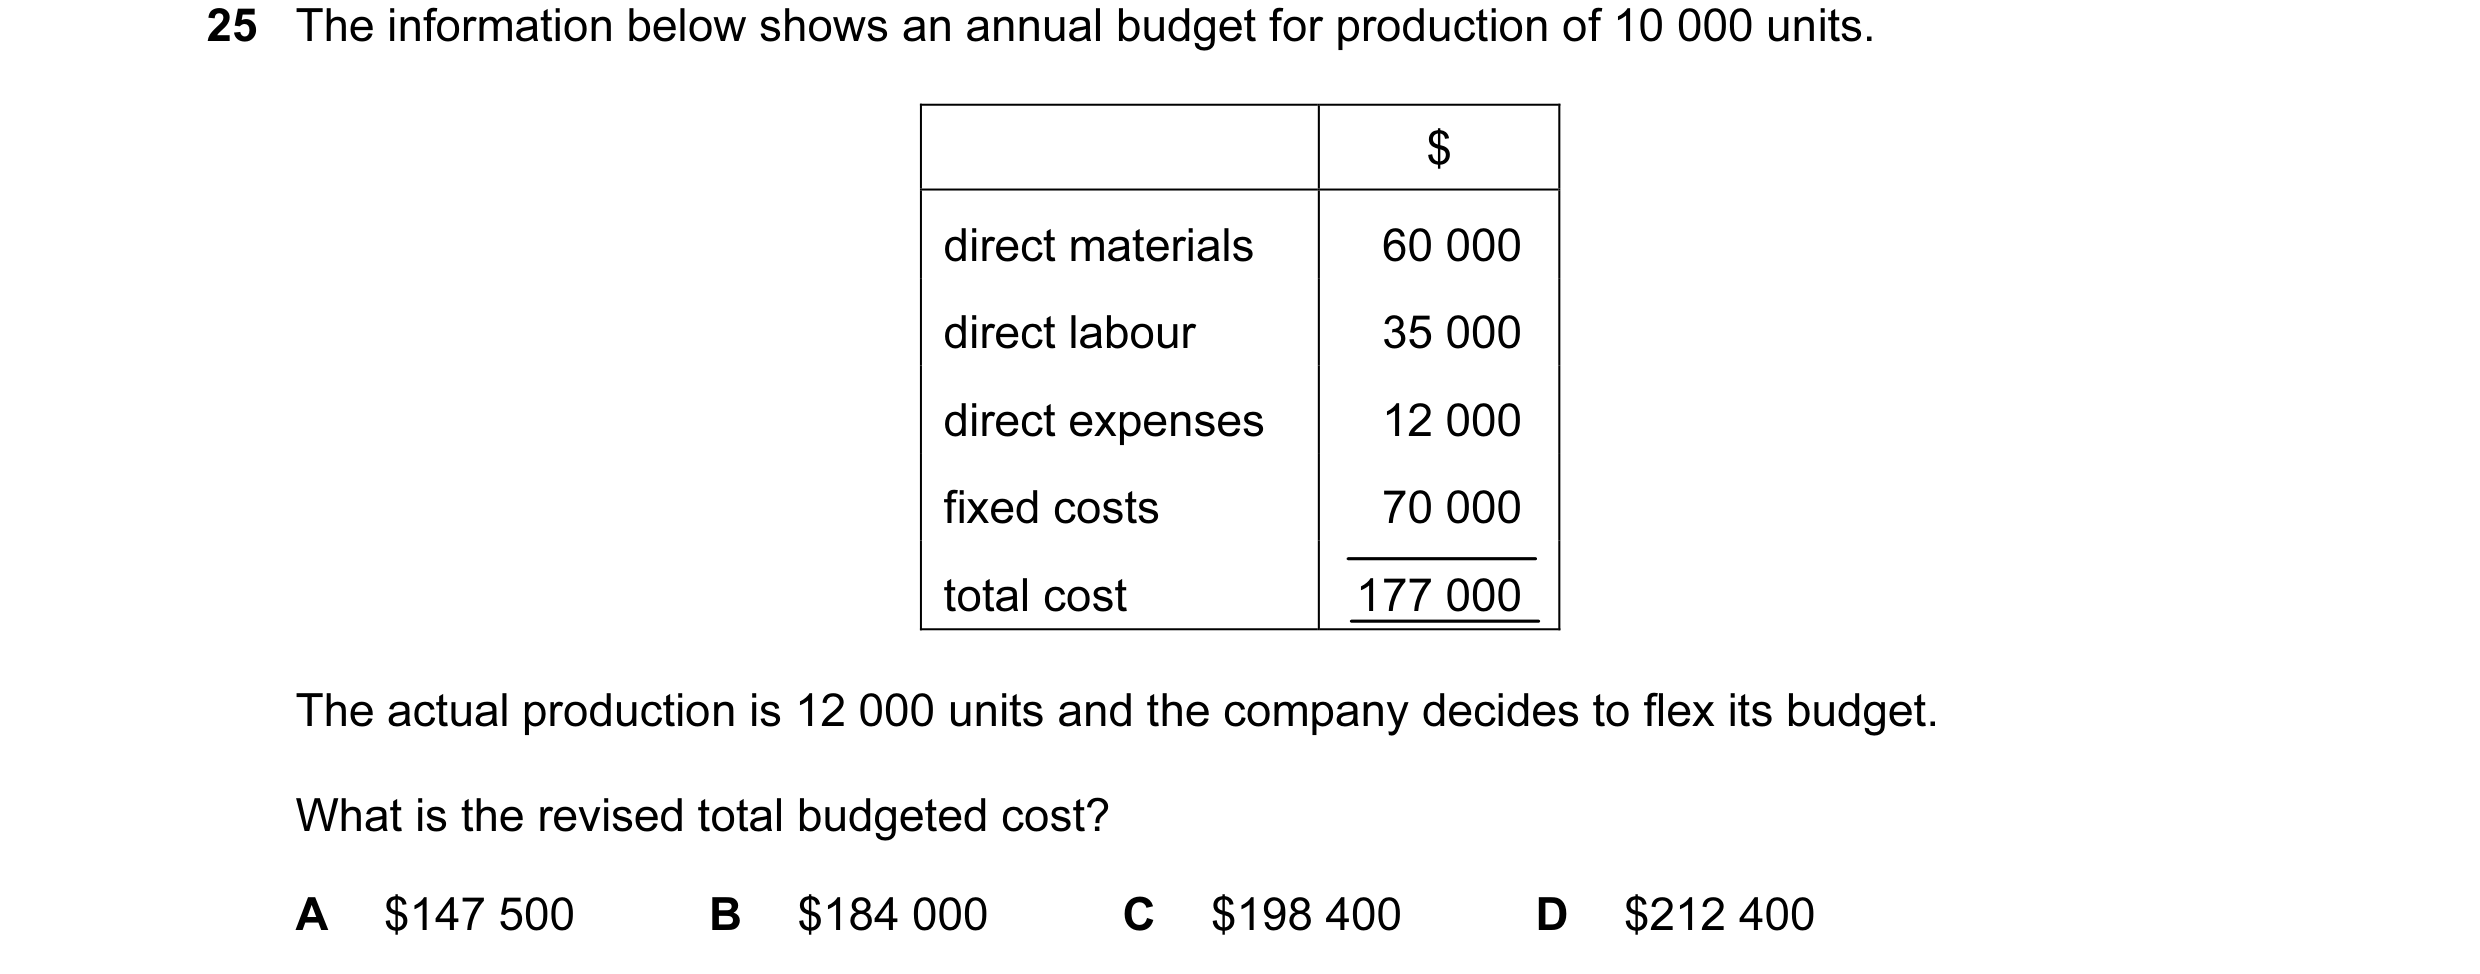
25 The information below shows an annual budget for production of 10 000 units. $ direct materials 60 000 direct labour 35 000 direct expenses 12 000 fixed costs 70 000 total cost 177 000 The actual production is 12 000 units and the company decides to flex its budget. What is the revised total budgeted cost? A $147 500 B $184 000 C $198 400 D $212 400
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2011
Q19 · A company is classifying its costs 9706/33 Oct/Nov 2011
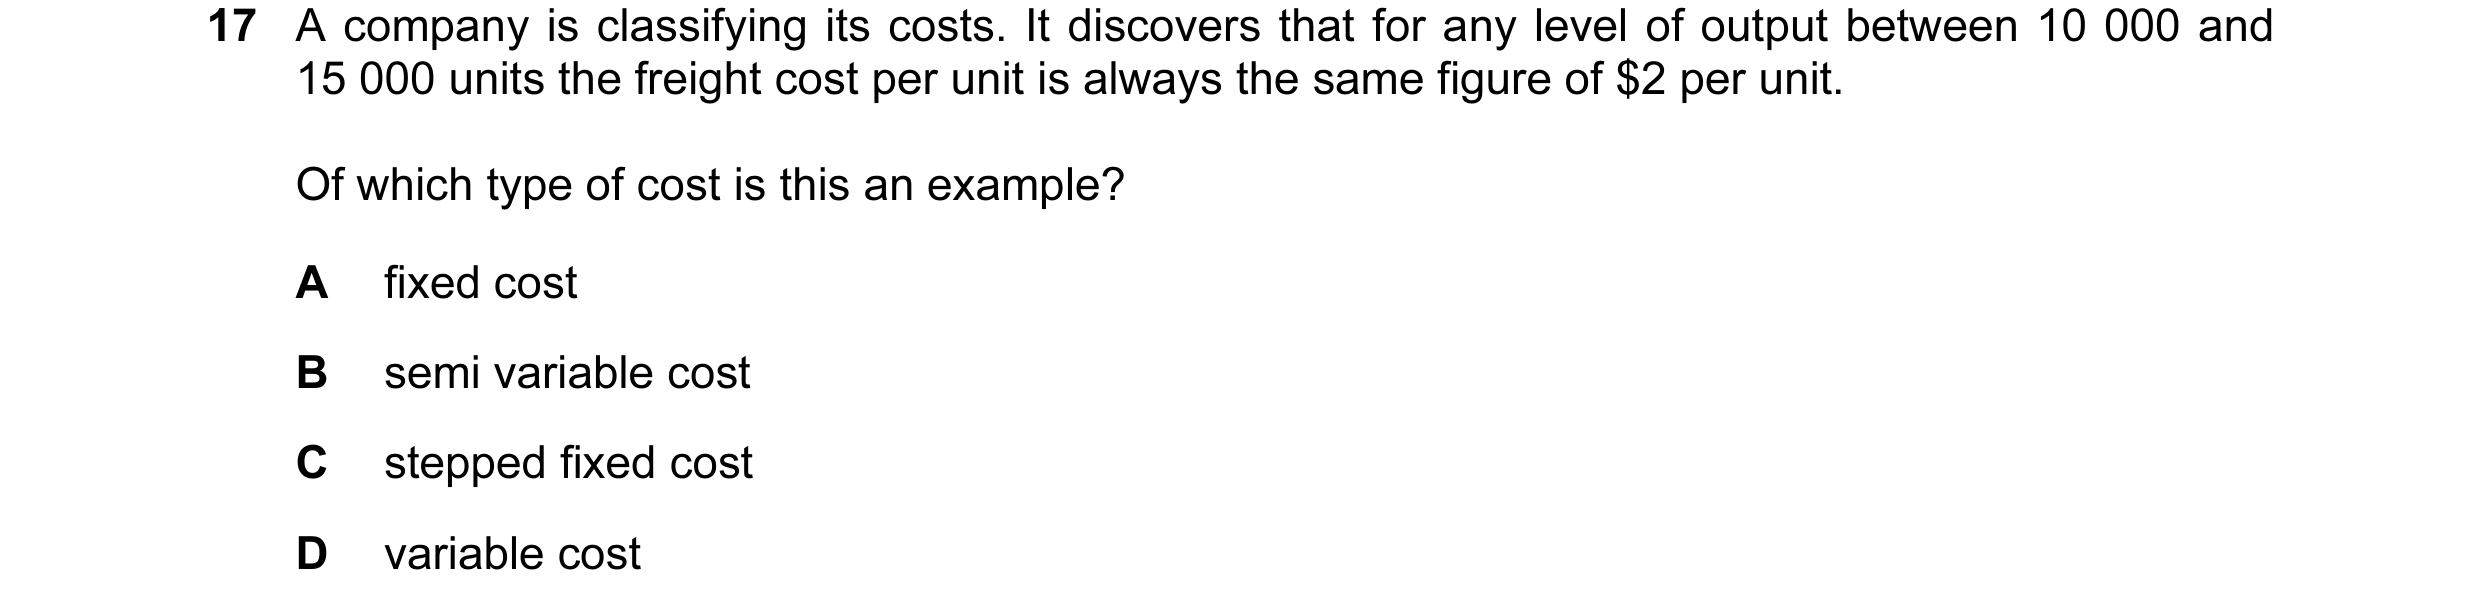
17 A company is classifying its costs. It discovers that for any level of output between 10 000 and 15 000 units the freight cost per unit is always the same figure of $2 per unit. Of which type of cost is this an example? A fixed cost B semi variable cost C stepped fixed cost D variable cost
1 marks
Answer: D
This question in 9706/33 Oct/Nov 2011
Q20 · The table shows the costs of manufacturing a component 9706/33 Oct/Nov 2011
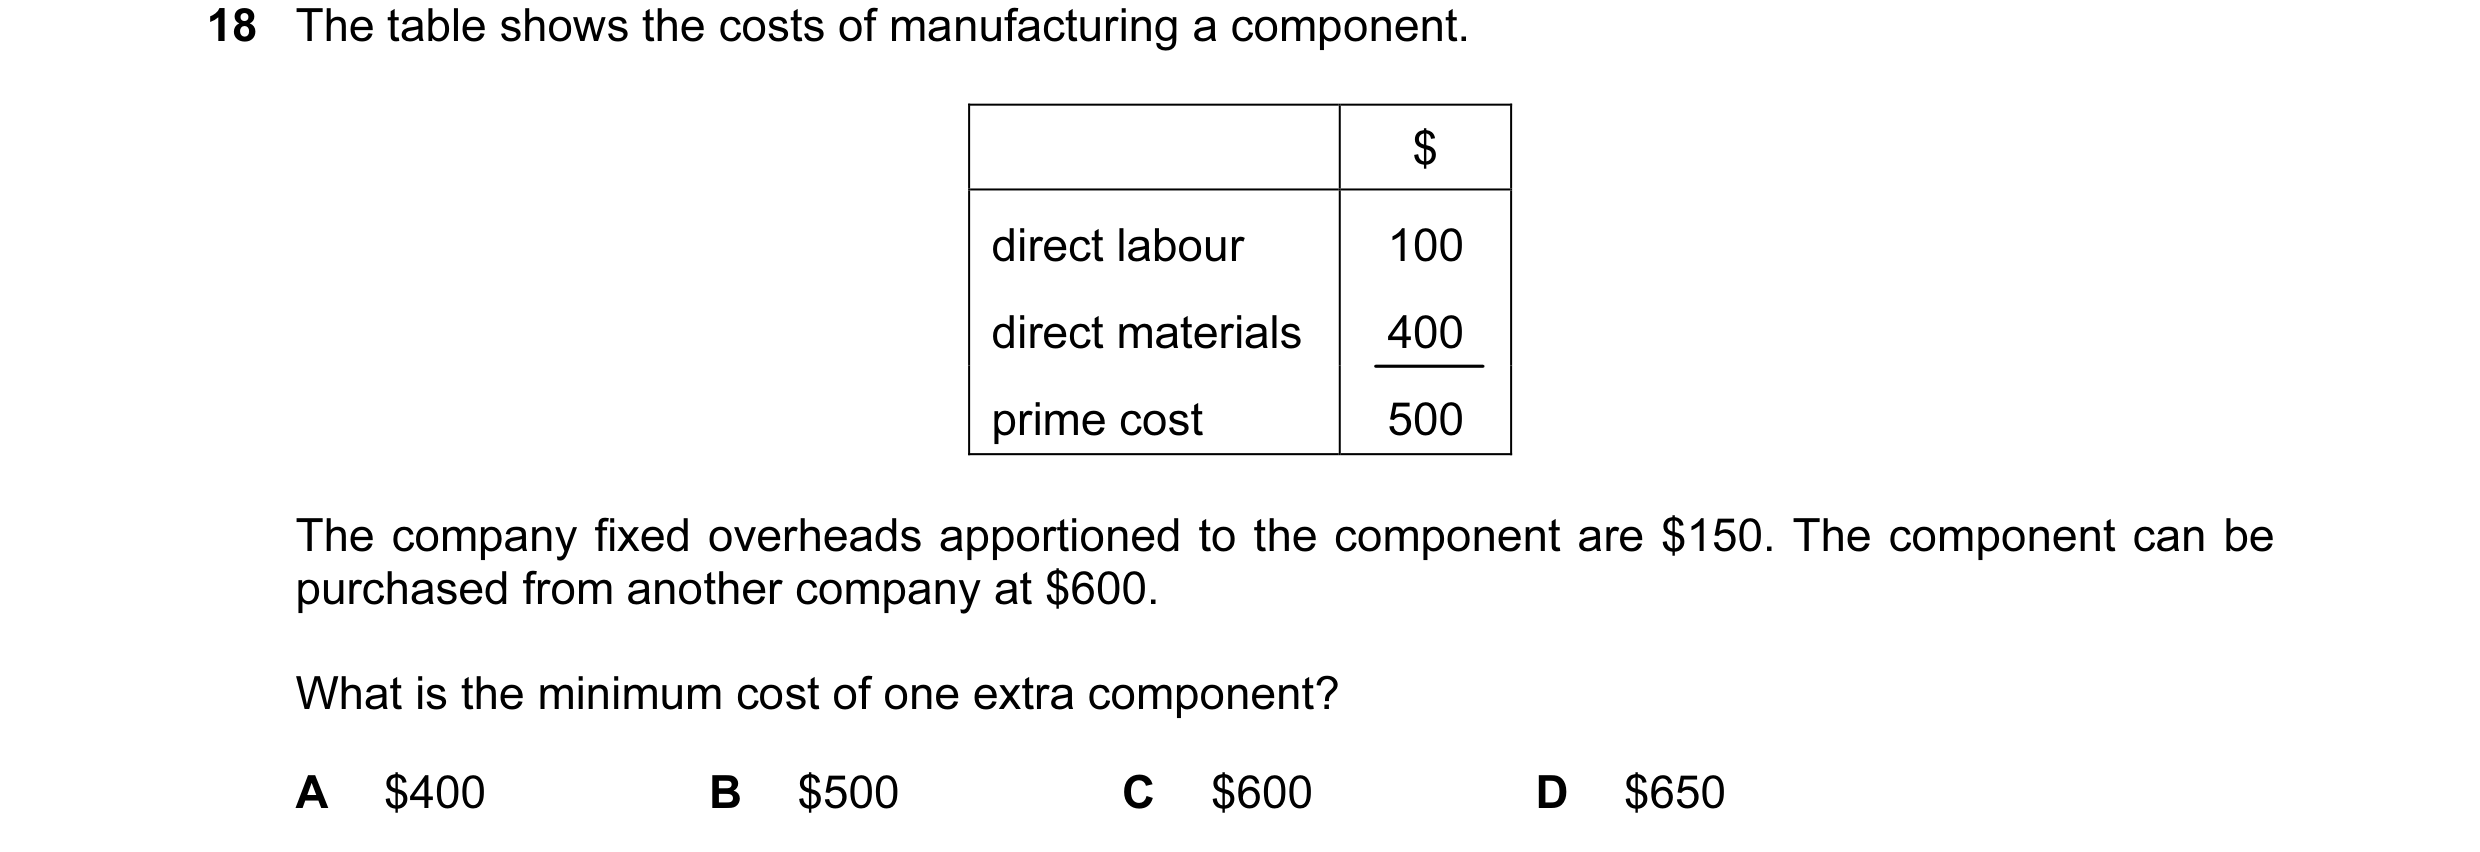
18 The table shows the costs of manufacturing a component. $ direct labour 100 direct materials 400 prime cost 500 The company fixed overheads apportioned to the component are $150. The component can be purchased from another company at $600. What is the minimum cost of one extra component? A $400 B $500 C $600 D $650
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2011
Q21 · A company makes and sells a single product 9706/33 Oct/Nov 2011
20 A company makes and sells a single product. The following data relates to the current year’s results. sales and production in units 2000 variable cost per unit $150 fixed cost per unit $80 contribution / sales ratio 50 % total net profit for year $140 000 It is expected that the selling price next year will be $315 per unit and that total fixed costs will increase by 10 %. How many units will need to be sold next year in order to achieve the same profit as in the current year? A 1819 B 1900 C 1916 D 2100
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2011
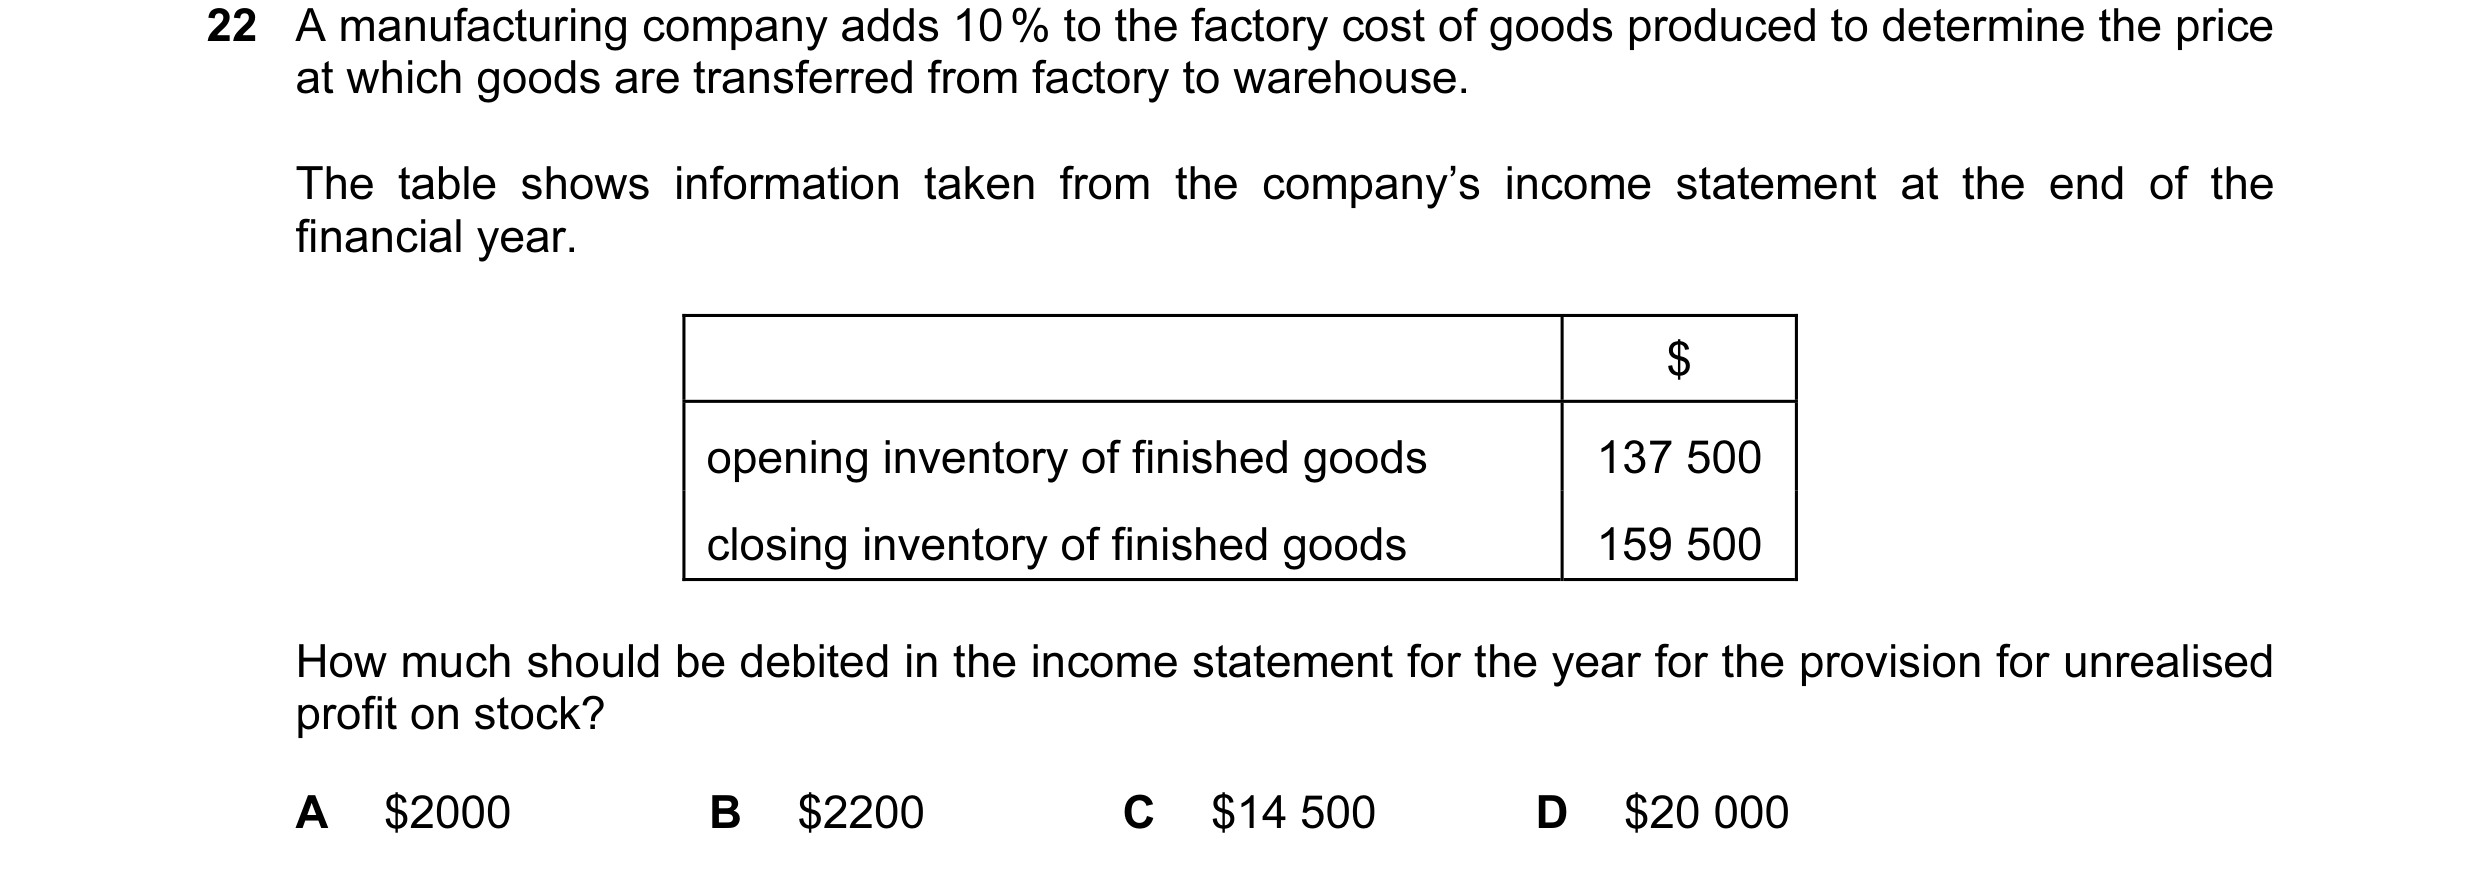
Q22 · A manufacturing company adds 10 % to the factory cost of goods produced to determine the… 9706/31 May/June 2012
22 A manufacturing company adds 10 % to the factory cost of goods produced to determine the price at which goods are transferred from factory to warehouse. The table shows information taken from the company’s income statement at the end of the financial year. $ opening inventory of finished goods 137 500 closing inventory of finished goods 159 500 How much should be debited in the income statement for the year for the provision for unrealised profit on stock? A $2000 B $2200 C $14 500 D $20 000
1 marks
Answer: A
This question in 9706/31 May/June 2012
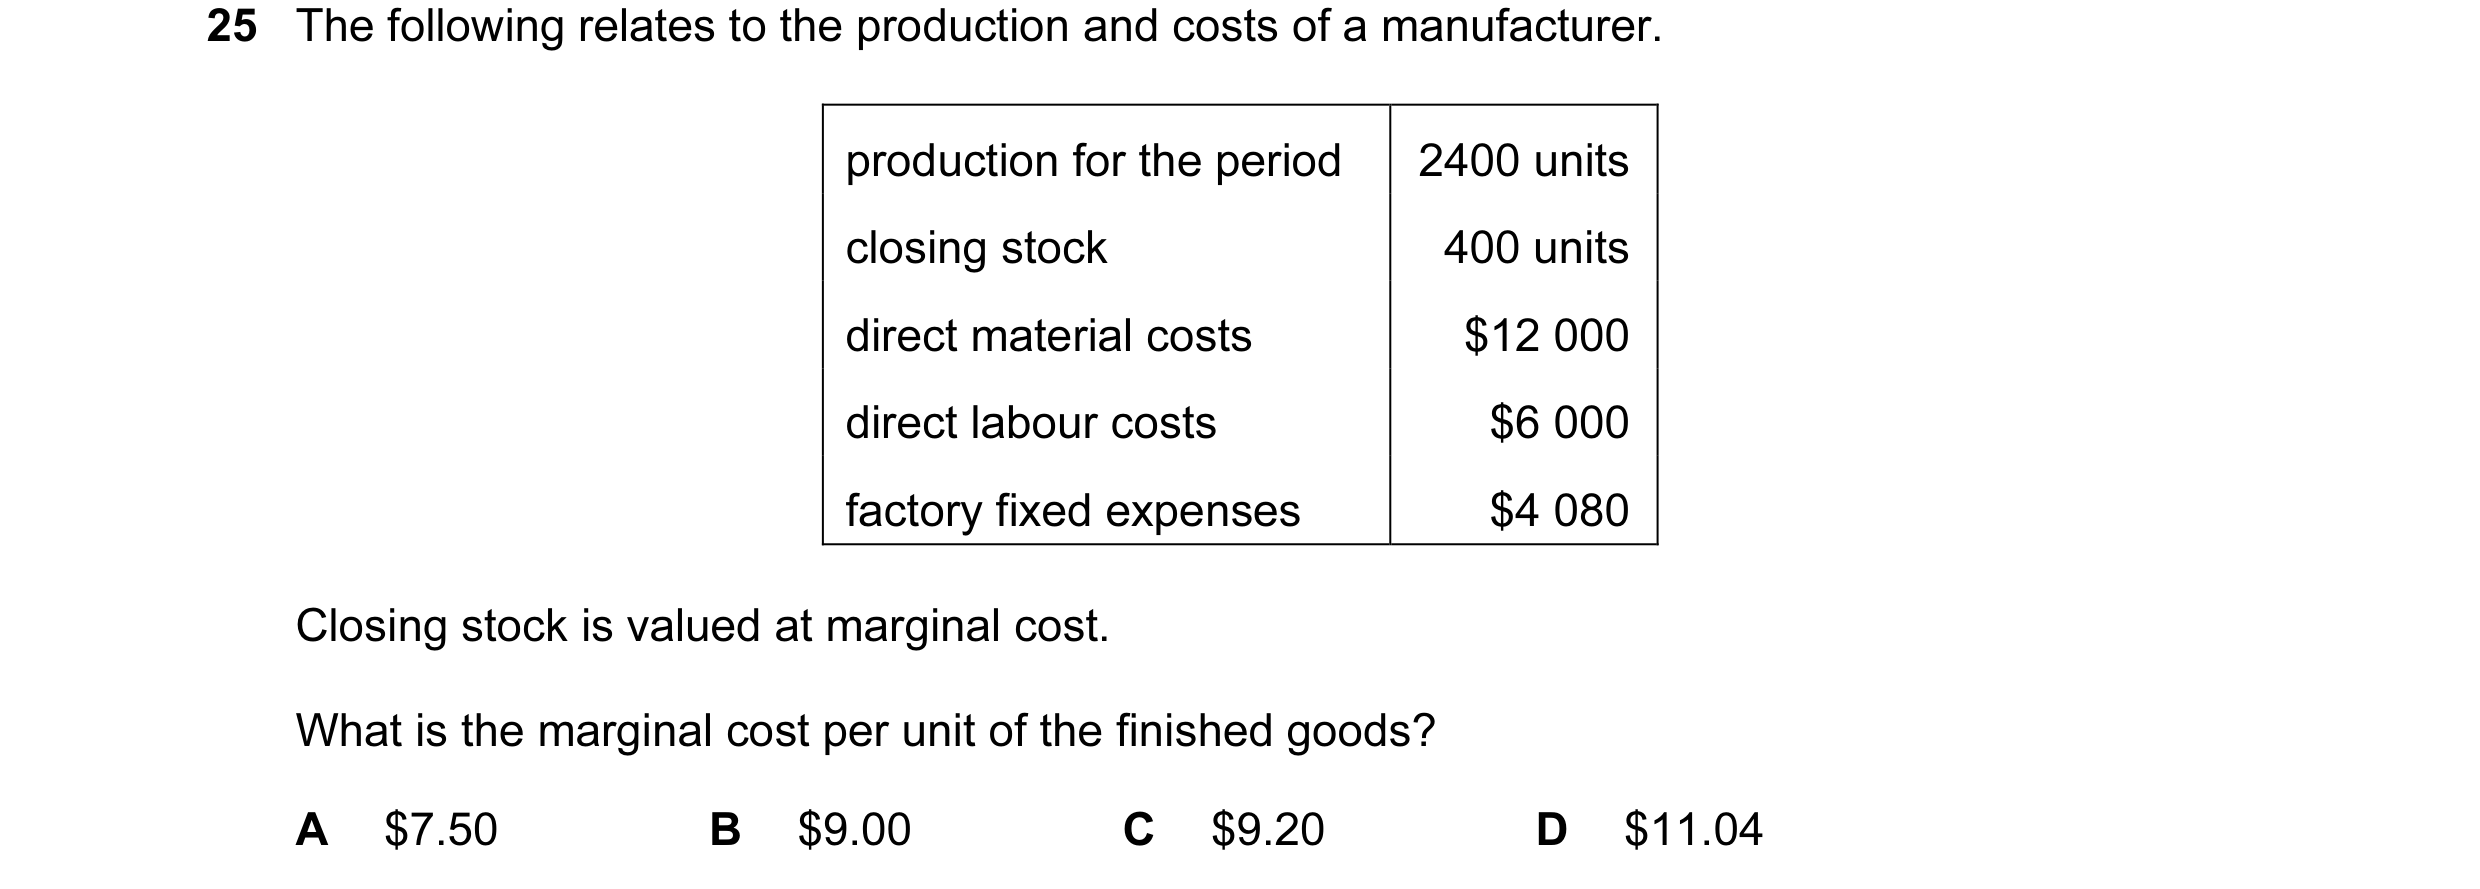
Q23 · The following relates to the production and costs of a manufacturer 9706/31 May/June 2012
25 The following relates to the production and costs of a manufacturer. production for the period 2400 units closing stock 400 units direct material costs $12 000 direct labour costs $6 000 factory fixed expenses $4 080 Closing stock is valued at marginal cost. What is the marginal cost per unit of the finished goods? A $7.50 B $9.00 C $9.20 D $11.04
1 marks
Answer: A
This question in 9706/31 May/June 2012
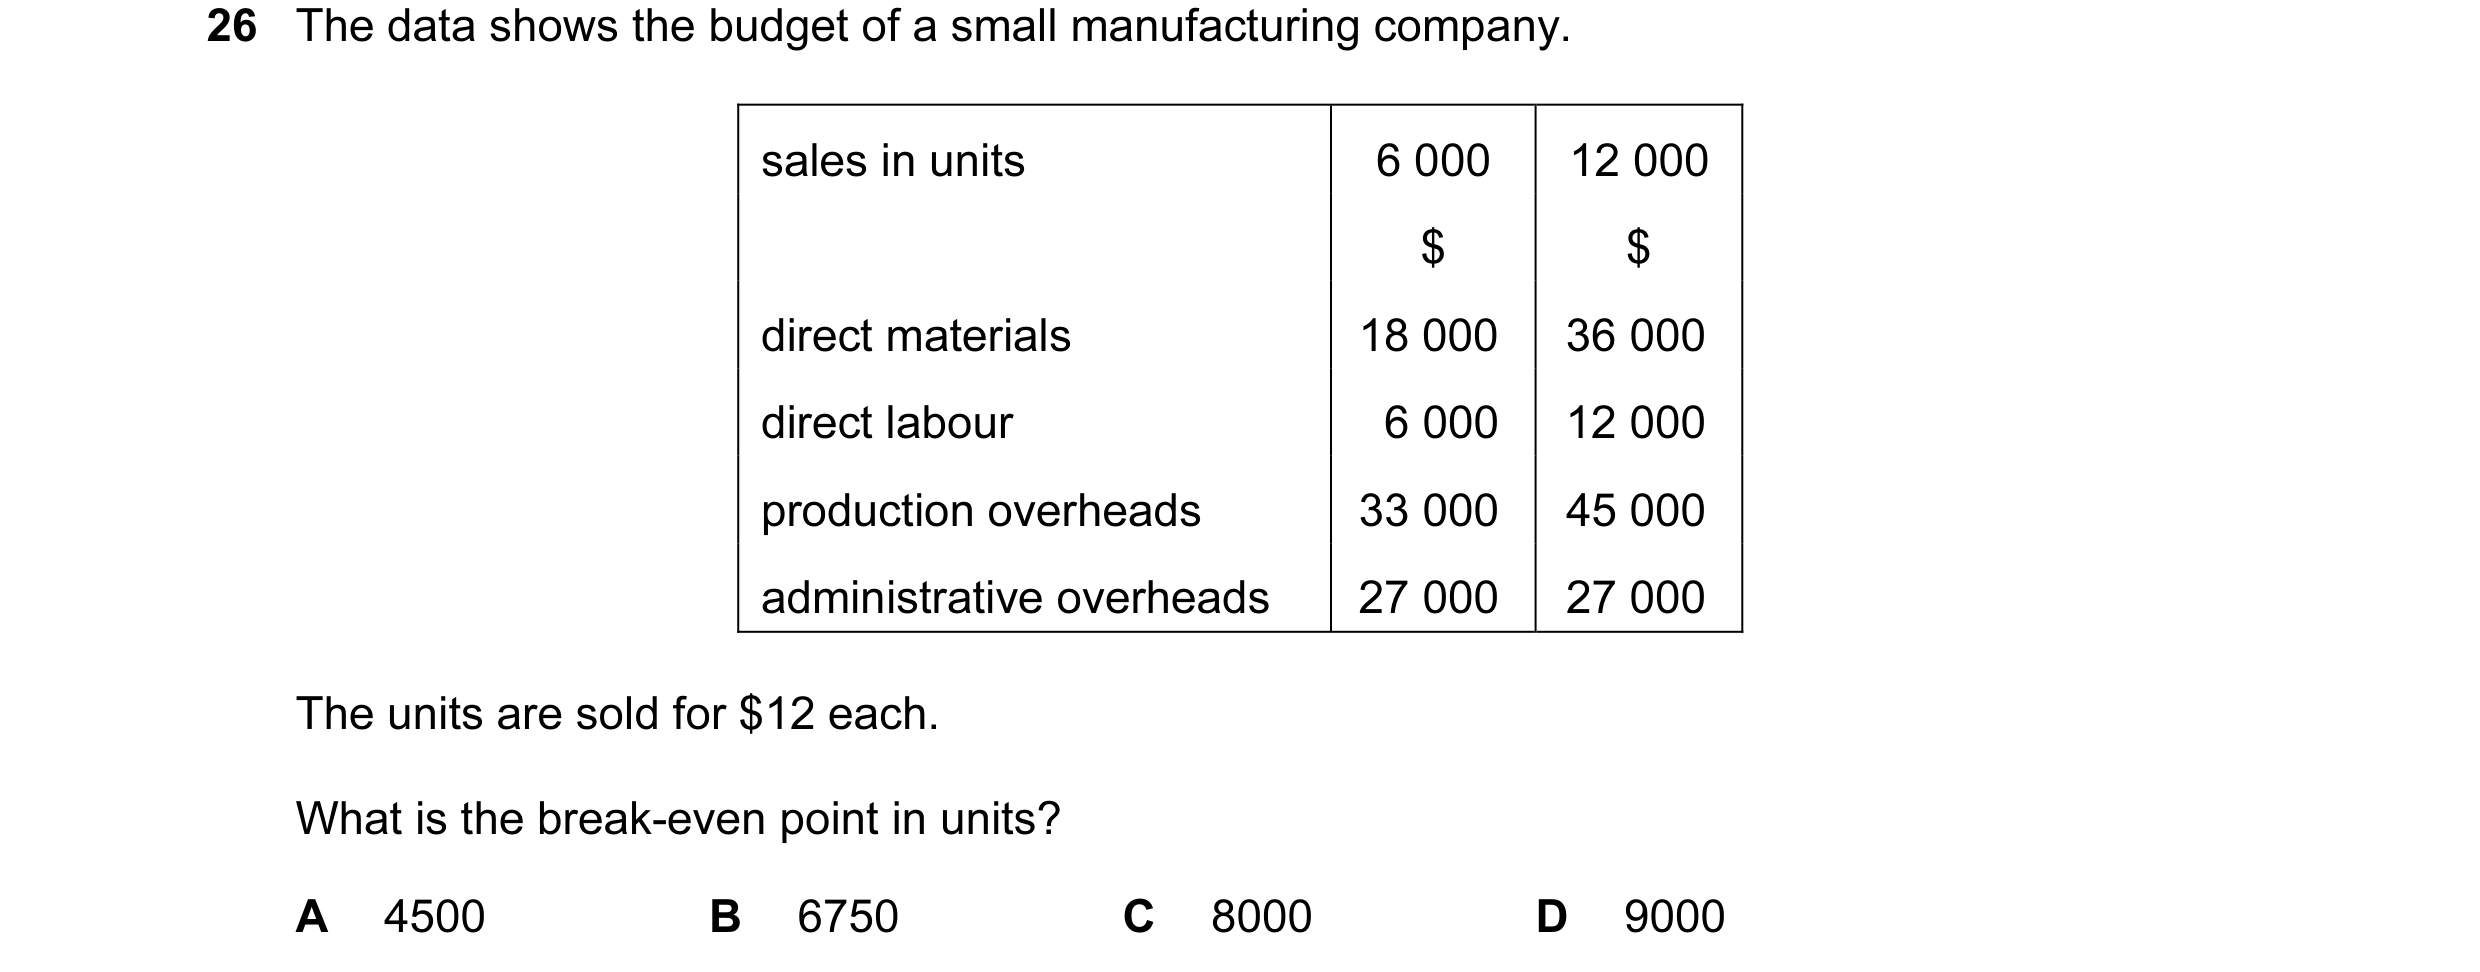
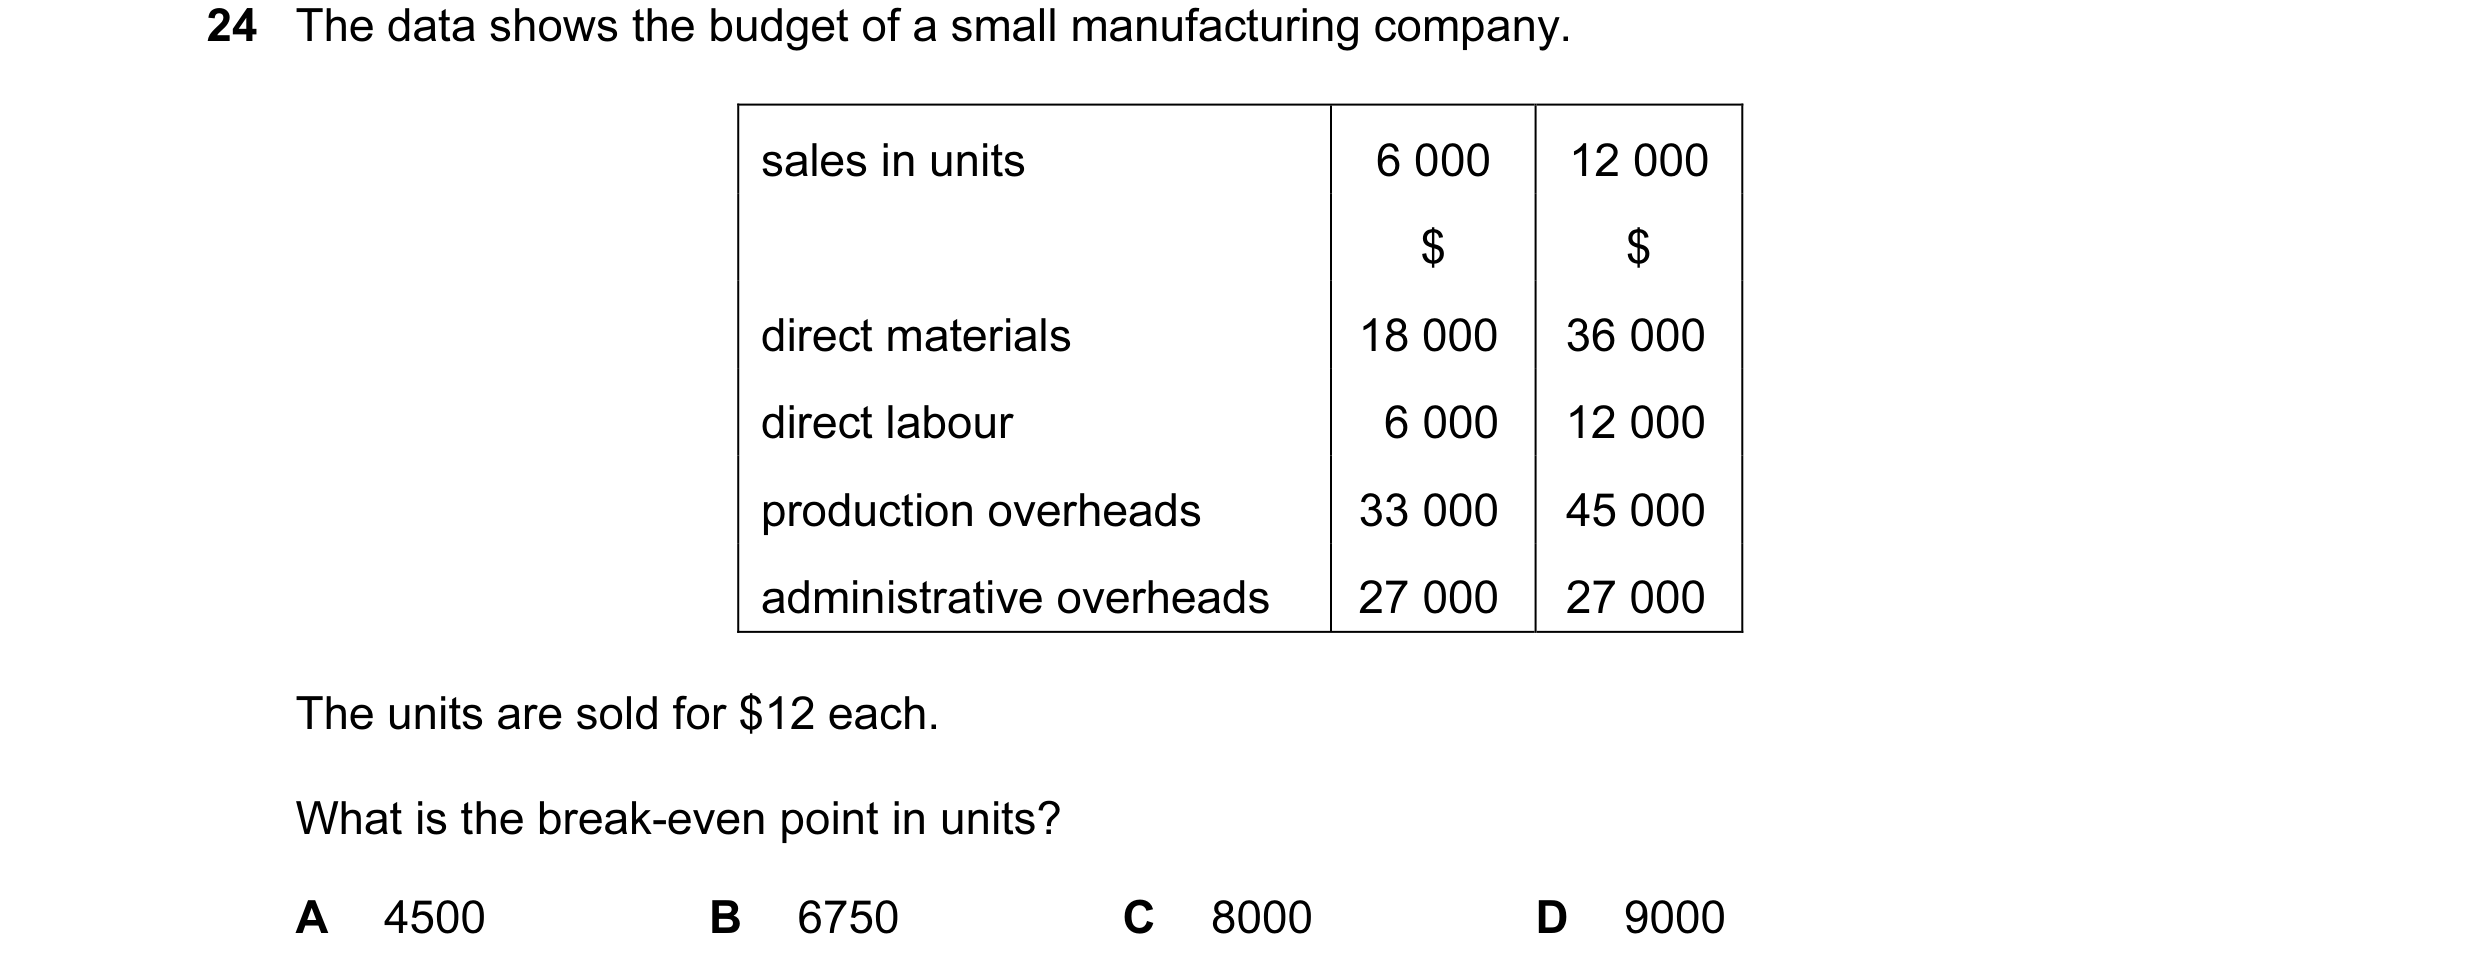
Q24 · The data shows the budget of a small manufacturing company 9706/31 May/June 2012
26 The data shows the budget of a small manufacturing company. sales in units 6 000 12 000 $ $ direct materials 18 000 36 000 direct labour 6 000 12 000 production overheads 33 000 45 000 administrative overheads 27 000 27 000 The units are sold for $12 each. What is the break-even point in units? A 4500 B 6750 C 8000 D 9000
1 marks
Answer: C
This question in 9706/31 May/June 2012
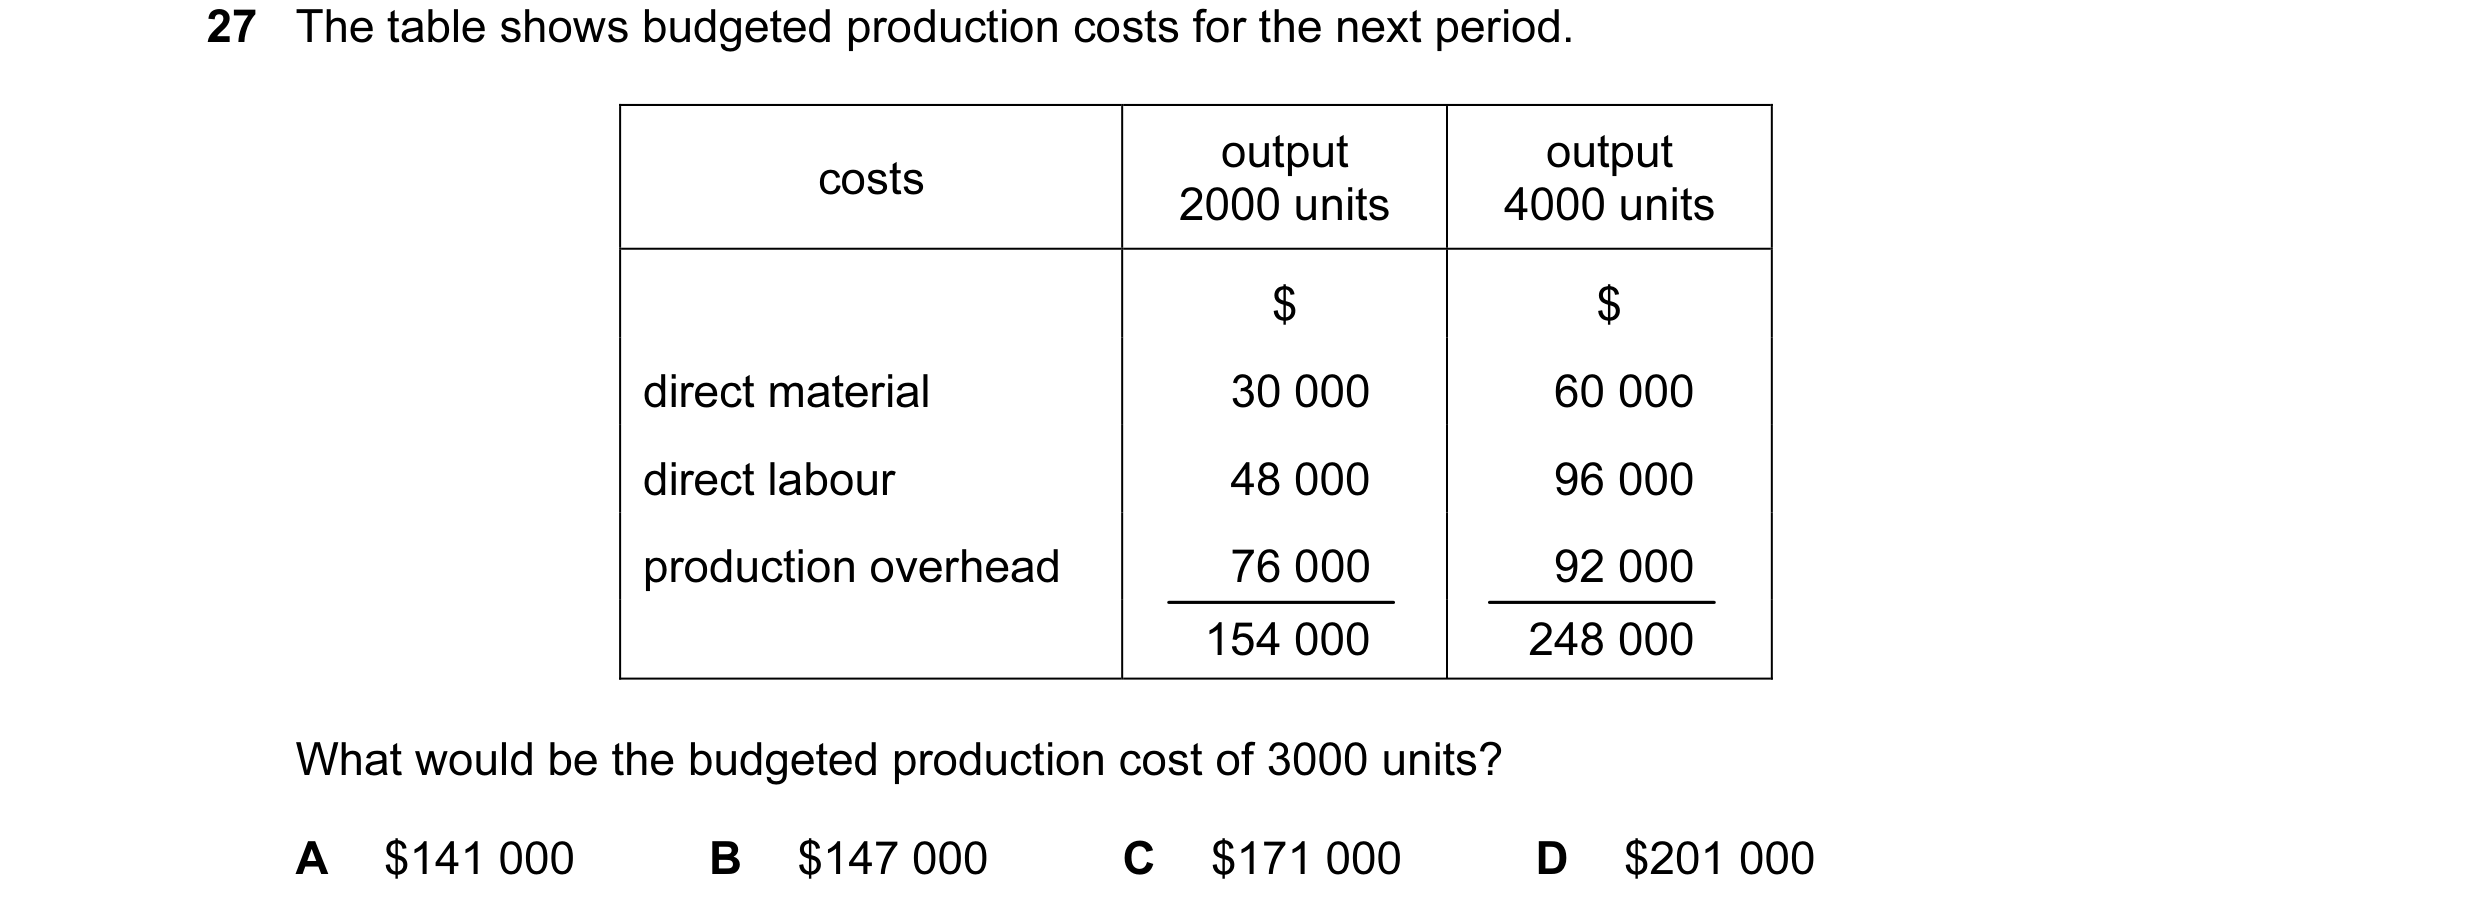
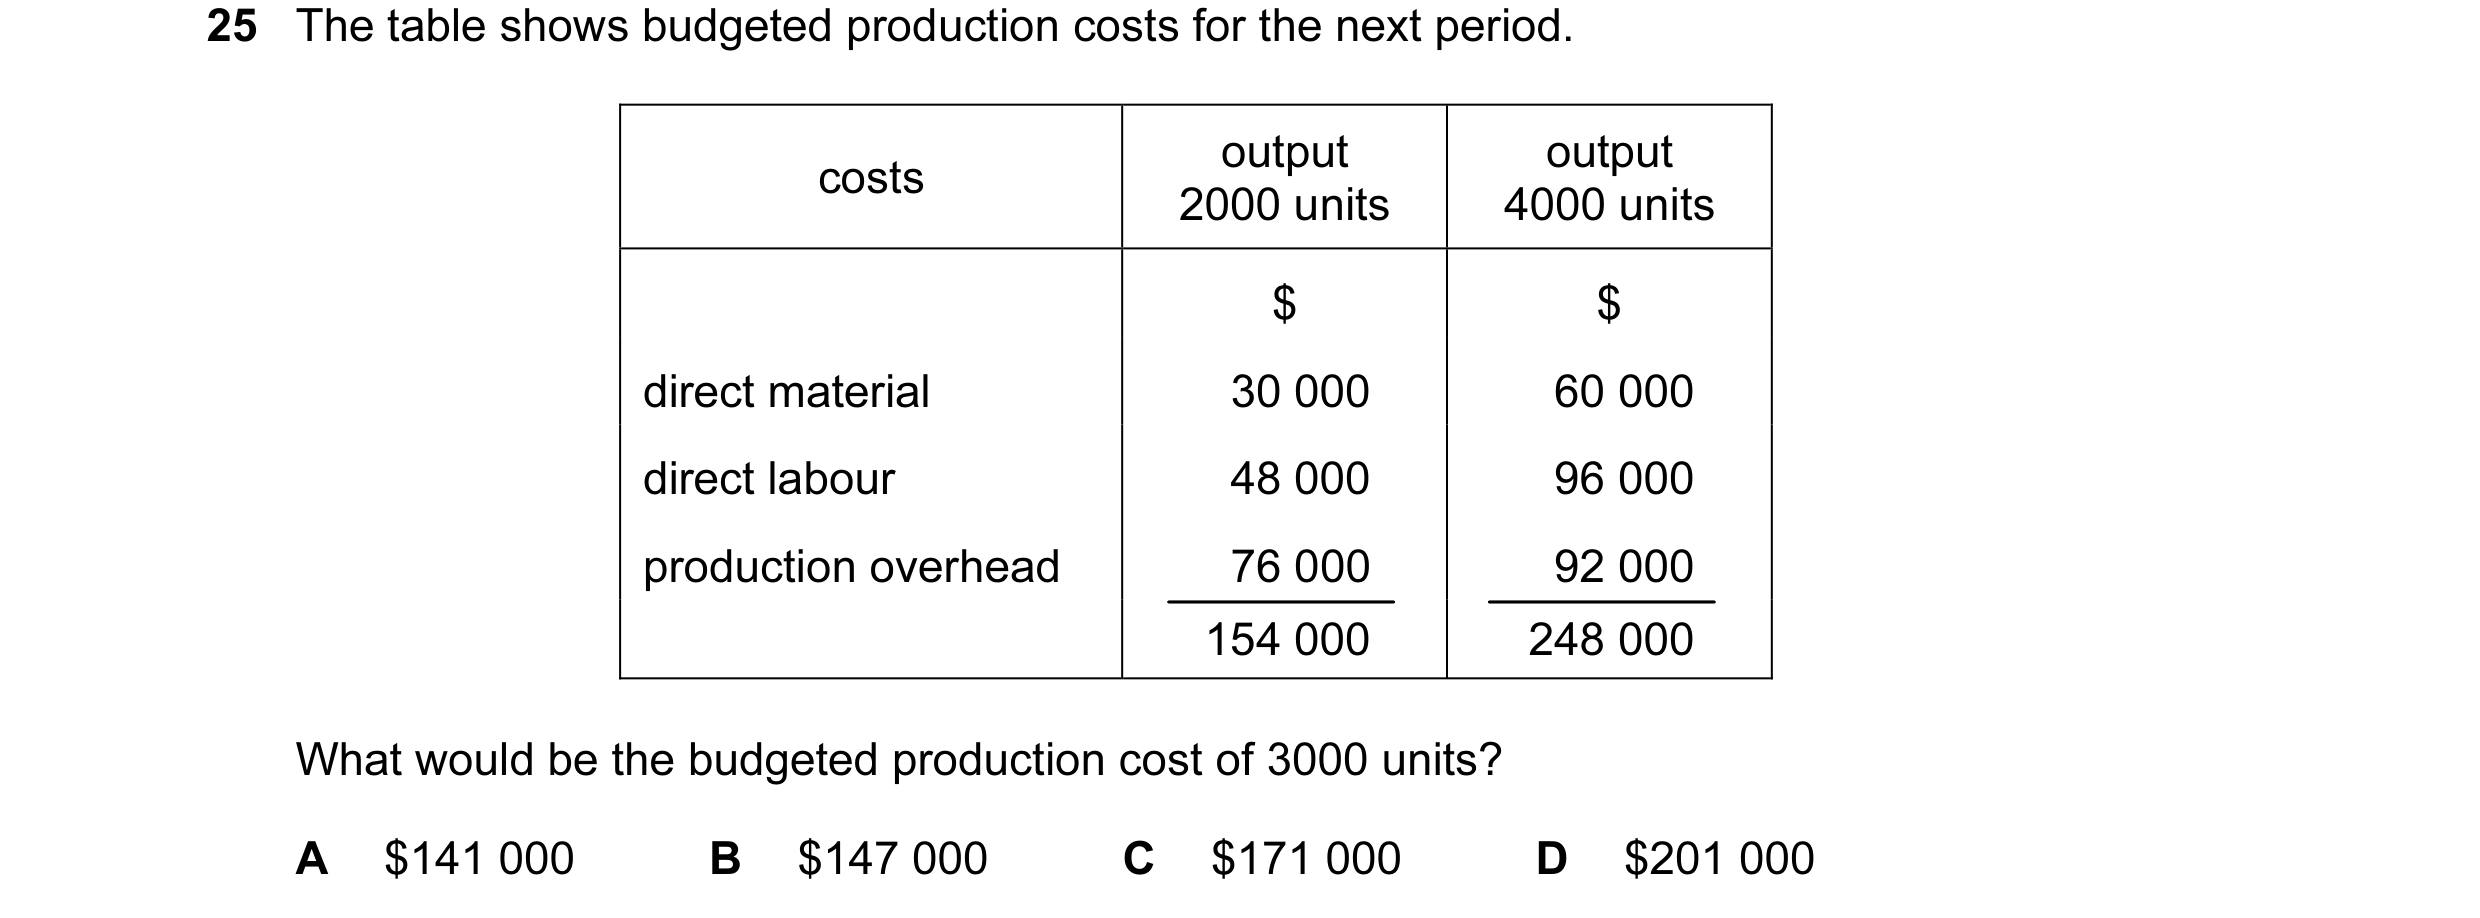
Q25 · The table shows budgeted production costs for the next period 9706/31 May/June 2012
27 The table shows budgeted production costs for the next period. output output costs 2000 units 4000 units $ $ direct material 30 000 60 000 direct labour 48 000 96 000 production overhead 76 000 92 000 154 000 248 000 What would be the budgeted production cost of 3000 units? A $141 000 B $147 000 C $171 000 D $201 000
1 marks
Answer: D
This question in 9706/31 May/June 2012
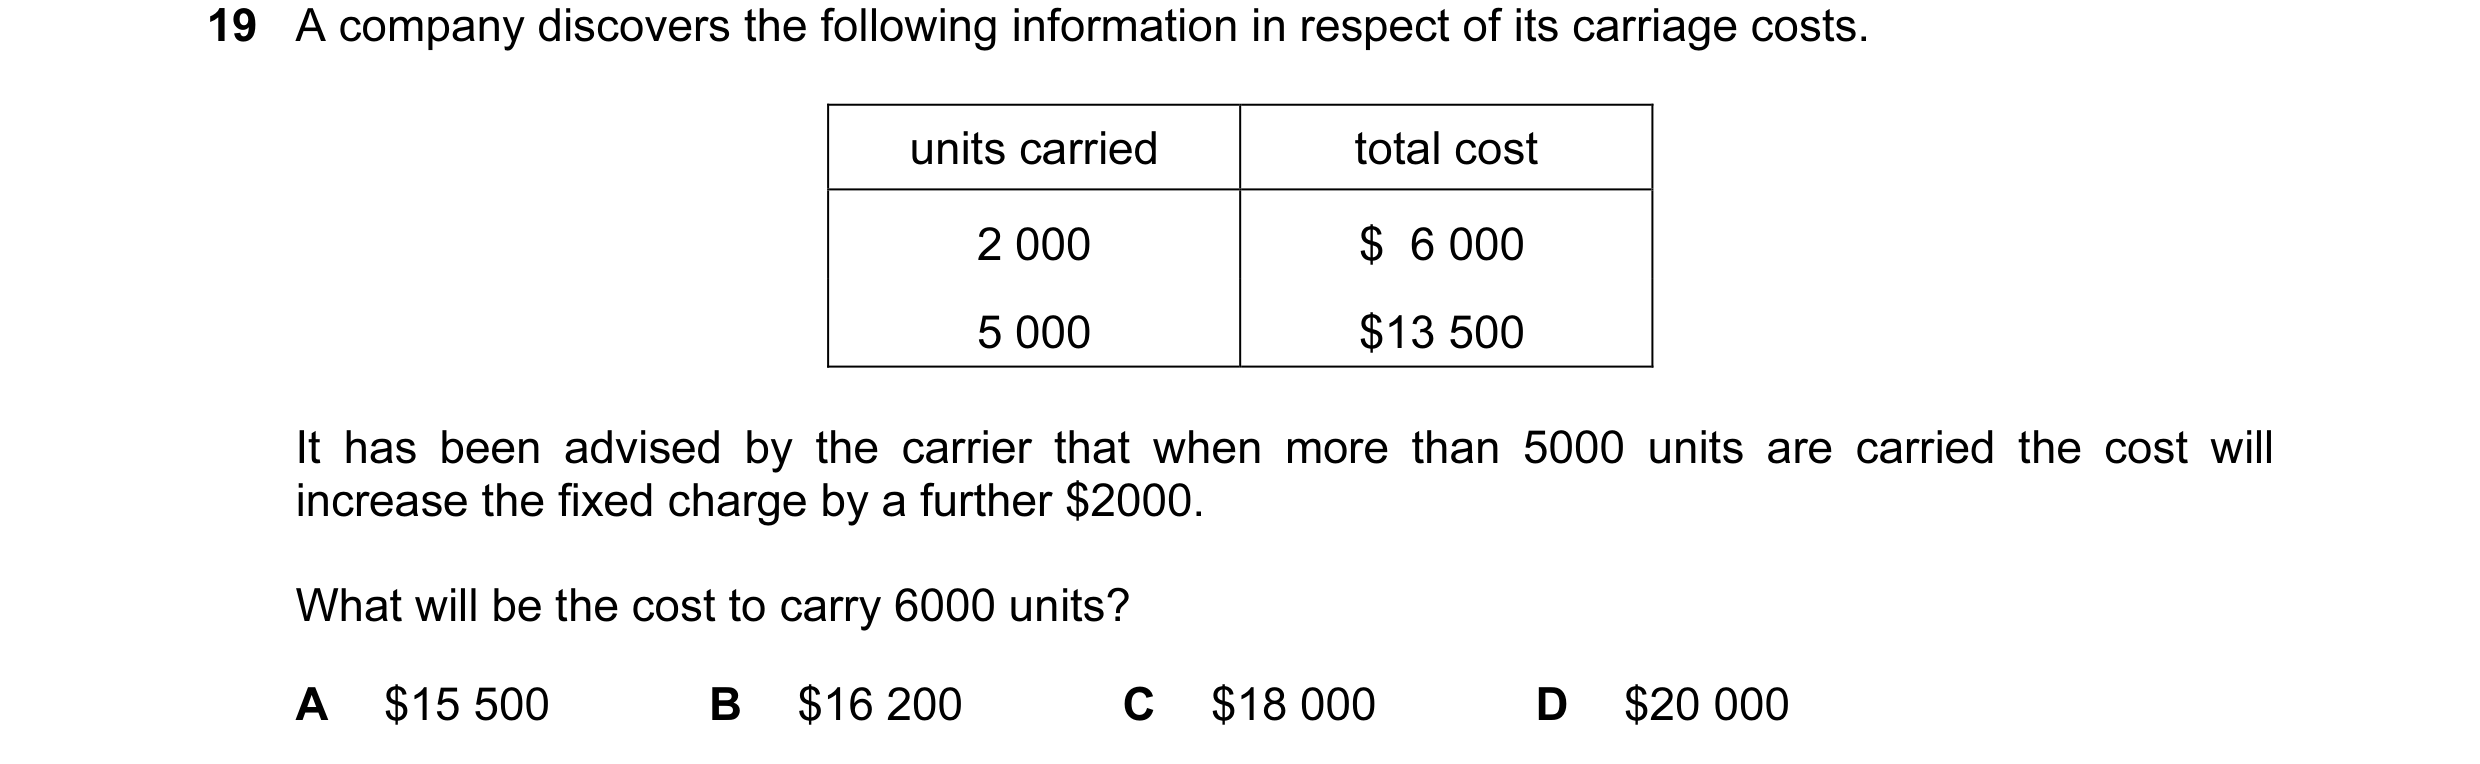
Q26 · A company discovers the following information in respect of its carriage costs 9706/32 May/June 2012
19 A company discovers the following information in respect of its carriage costs. units carried total cost 2 000 $ 6 000 5 000 $13 500 It has been advised by the carrier that when more than 5000 units are carried the cost will increase the fixed charge by a further $2000. What will be the cost to carry 6000 units? A $15 500 B $16 200 C $18 000 D $20 000
1 marks
Answer: C
This question in 9706/32 May/June 2012
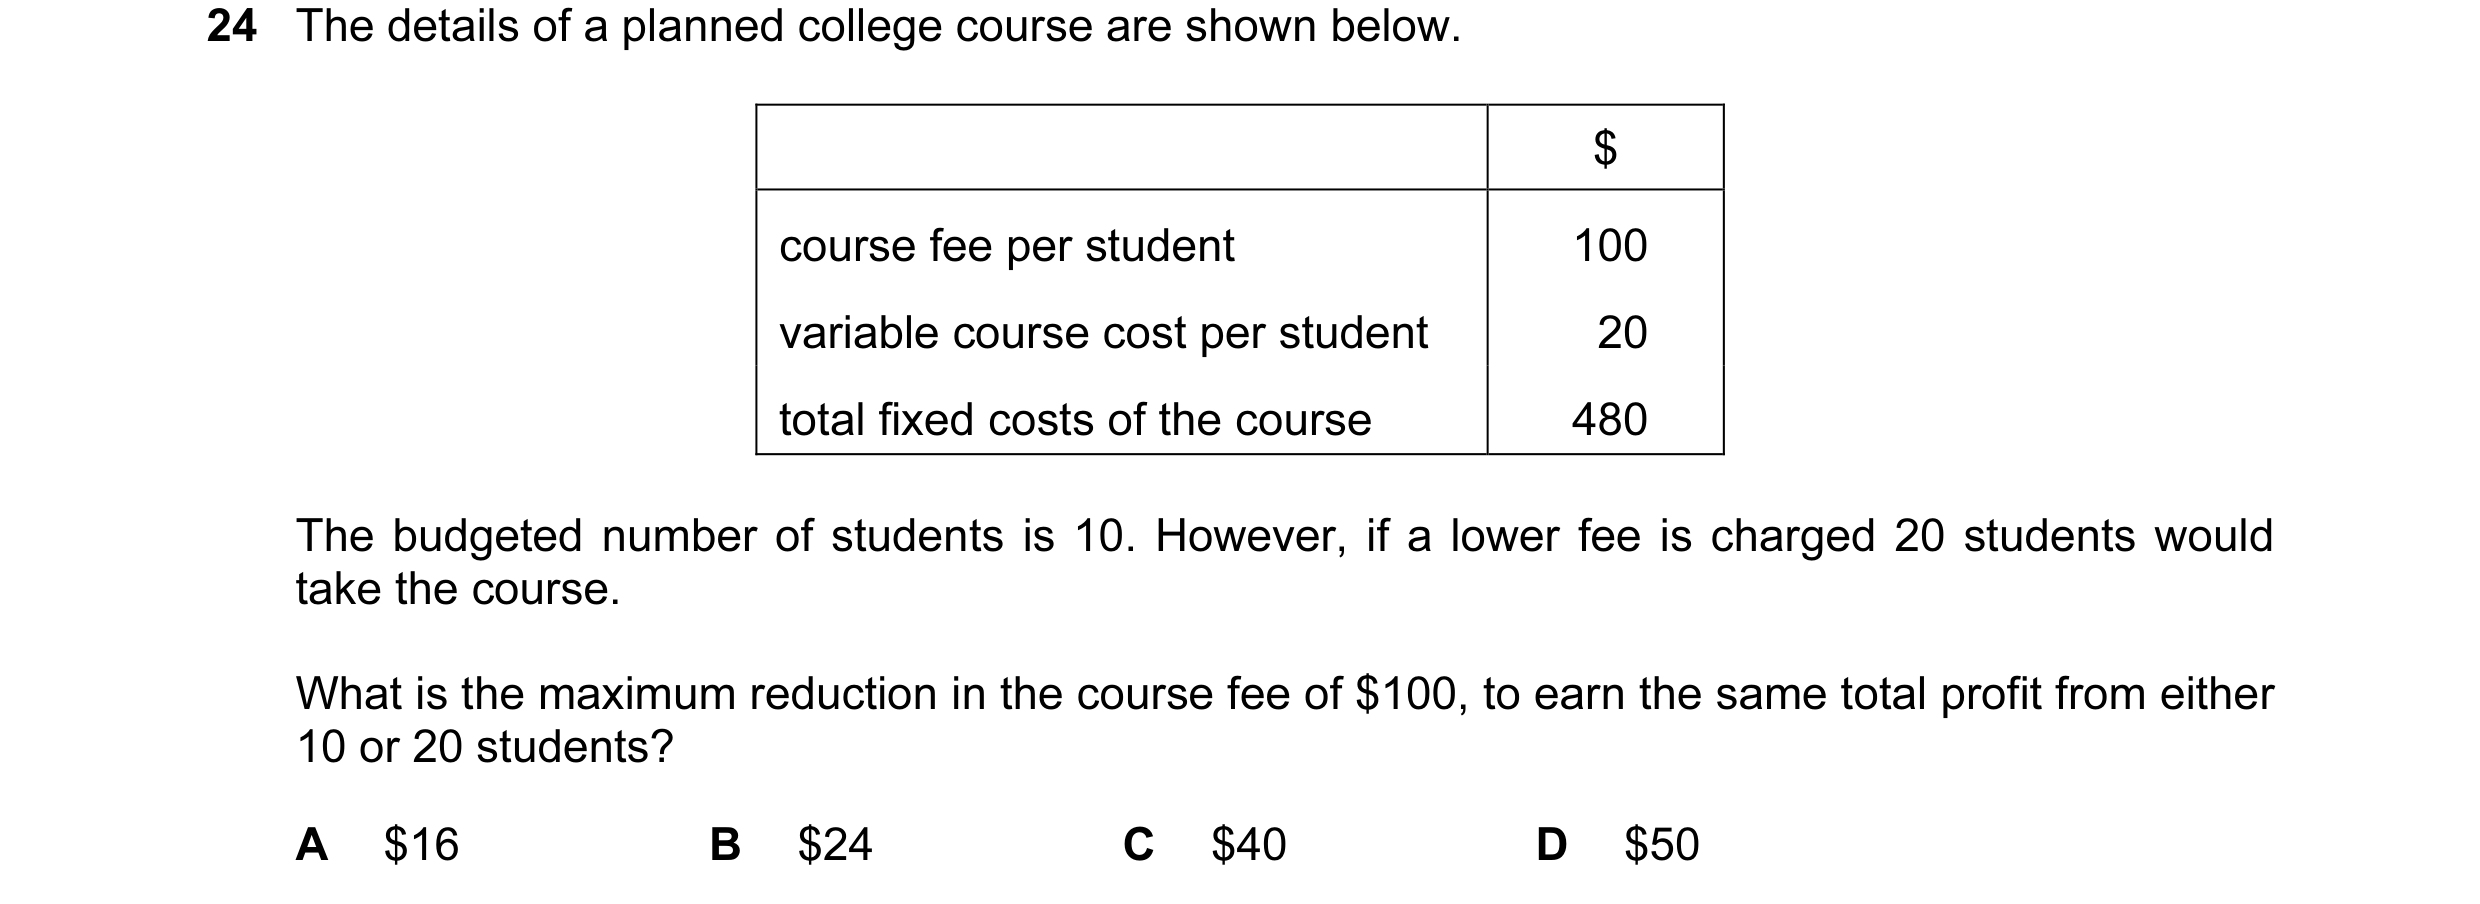
Q27 · The details of a planned college course are shown below 9706/32 May/June 2012
24 The details of a planned college course are shown below. $ course fee per student 100 variable course cost per student 20 total fixed costs of the course 480 The budgeted number of students is 10. However, if a lower fee is charged 20 students would take the course. What is the maximum reduction in the course fee of $100, to earn the same total profit from either 10 or 20 students? A $16 B $24 C $40 D $50
1 marks
Answer: C
This question in 9706/32 May/June 2012
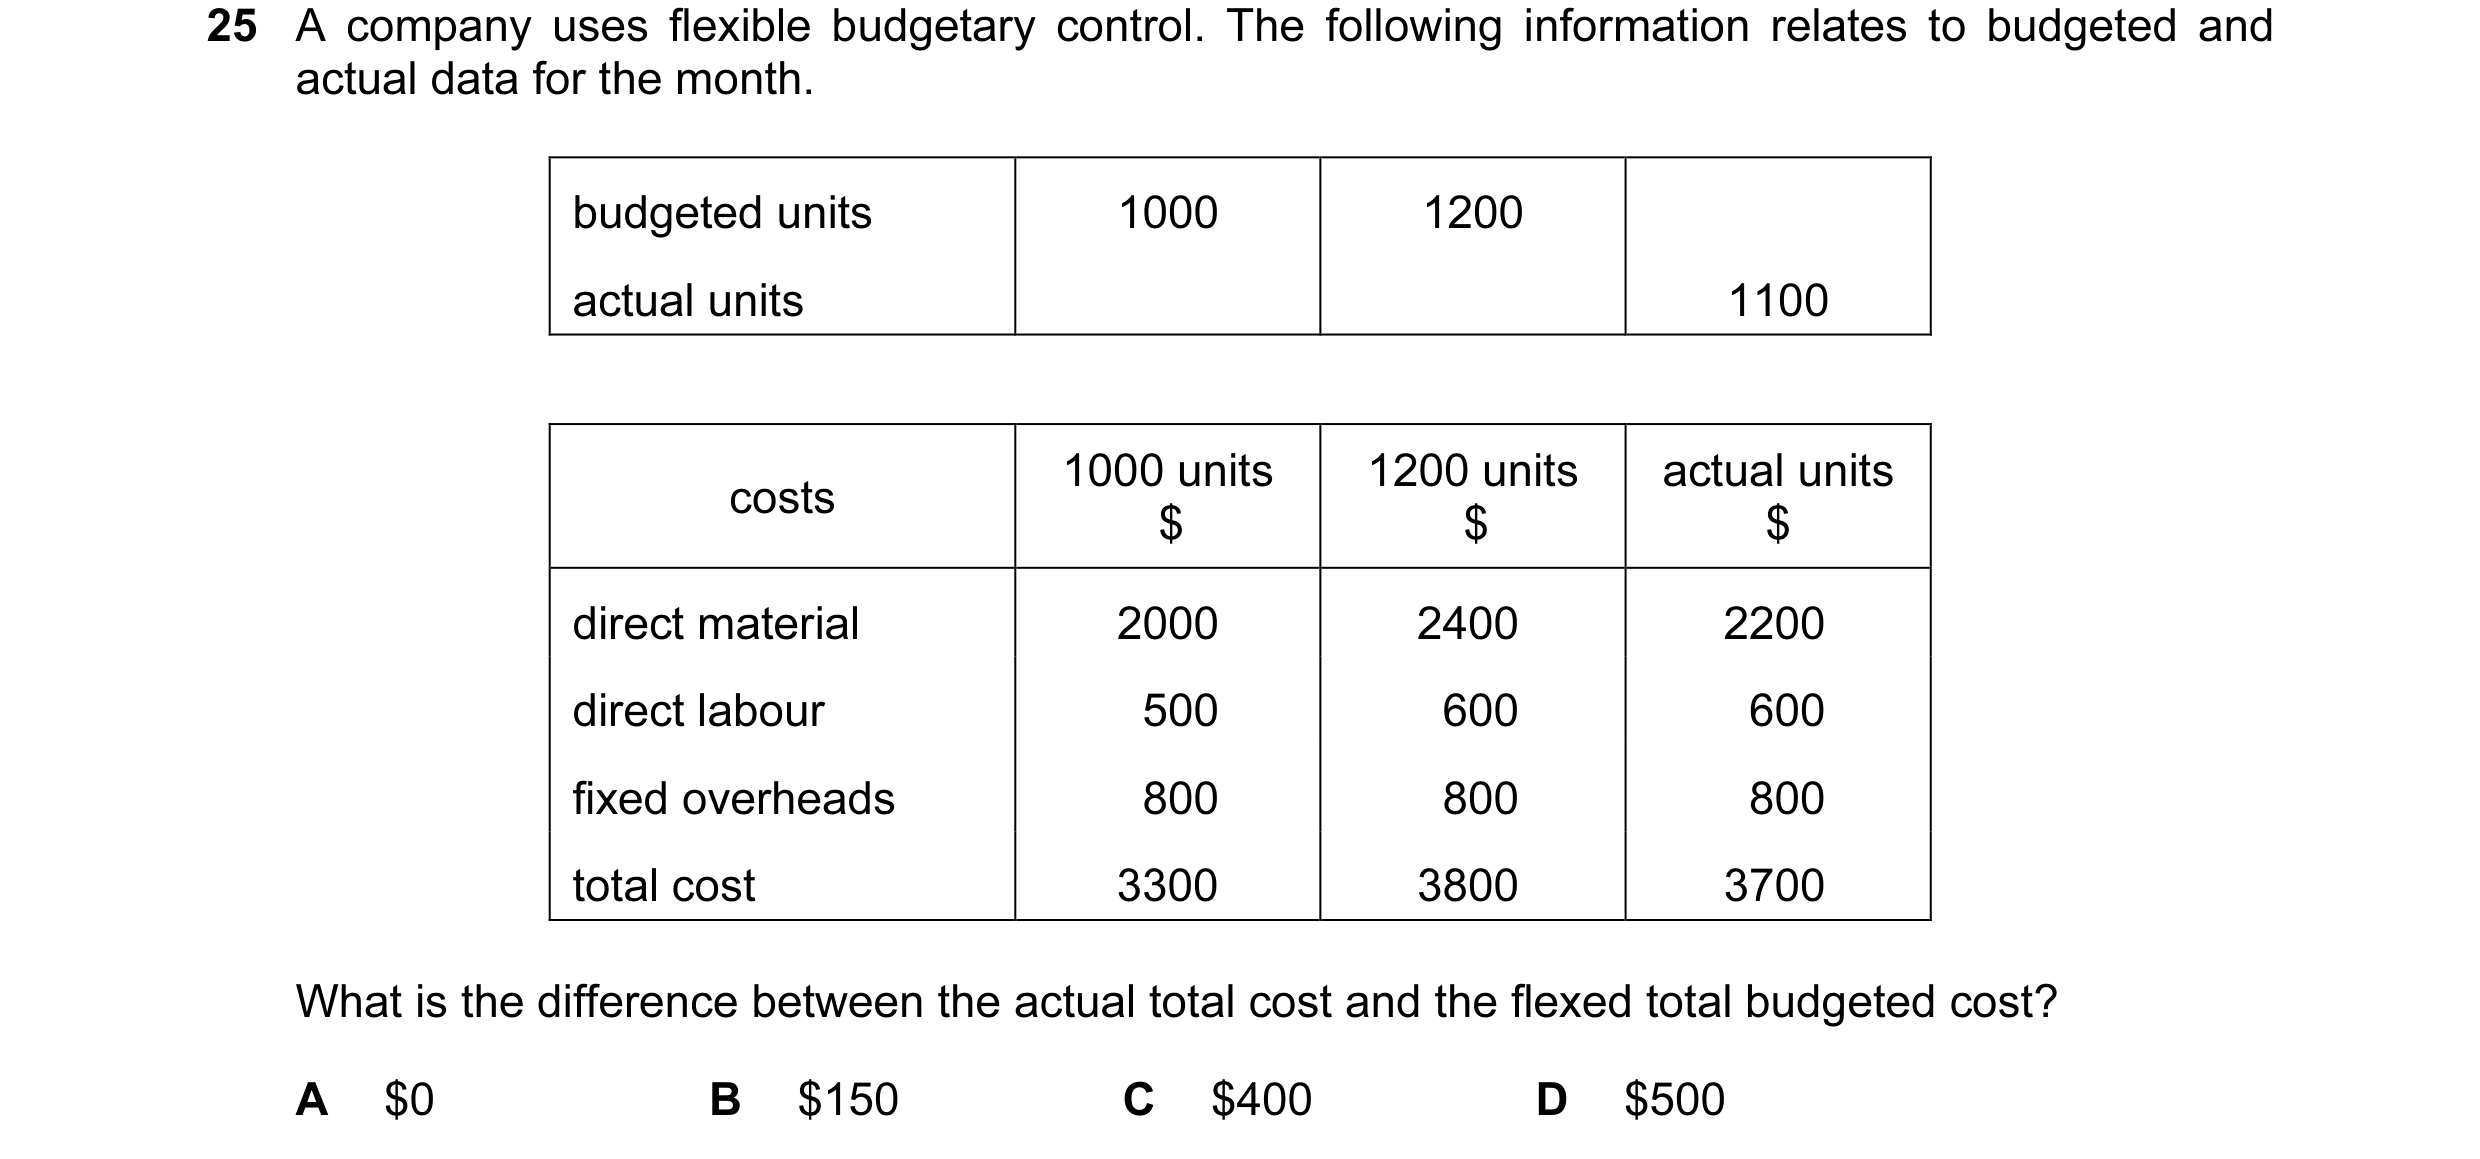
Q28 · A company uses flexible budgetary control 9706/32 May/June 2012
25 A company uses flexible budgetary control. The following information relates to budgeted and actual data for the month. budgeted units 1000 1200 actual units 1100 1000 units 1200 units actual units costs $ $ $ direct material 2000 2400 2200 direct labour 500 600 600 fixed overheads 800 800 800 total cost 3300 3800 3700 What is the difference between the actual total cost and the flexed total budgeted cost? A $0 B $150 C $400 D $500
1 marks
Answer: B
This question in 9706/32 May/June 2012
Q29 · The data shows the budget of a small manufacturing company 9706/33 May/June 2012
24 The data shows the budget of a small manufacturing company. sales in units 6 000 12 000 $ $ direct materials 18 000 36 000 direct labour 6 000 12 000 production overheads 33 000 45 000 administrative overheads 27 000 27 000 The units are sold for $12 each. What is the break-even point in units? A 4500 B 6750 C 8000 D 9000
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q30 · The table shows budgeted production costs for the next period 9706/33 May/June 2012
25 The table shows budgeted production costs for the next period. output output costs 2000 units 4000 units $ $ direct material 30 000 60 000 direct labour 48 000 96 000 production overhead 76 000 92 000 154 000 248 000 What would be the budgeted production cost of 3000 units? A $141 000 B $147 000 C $171 000 D $201 000
1 marks
Answer: D
This question in 9706/33 May/June 2012
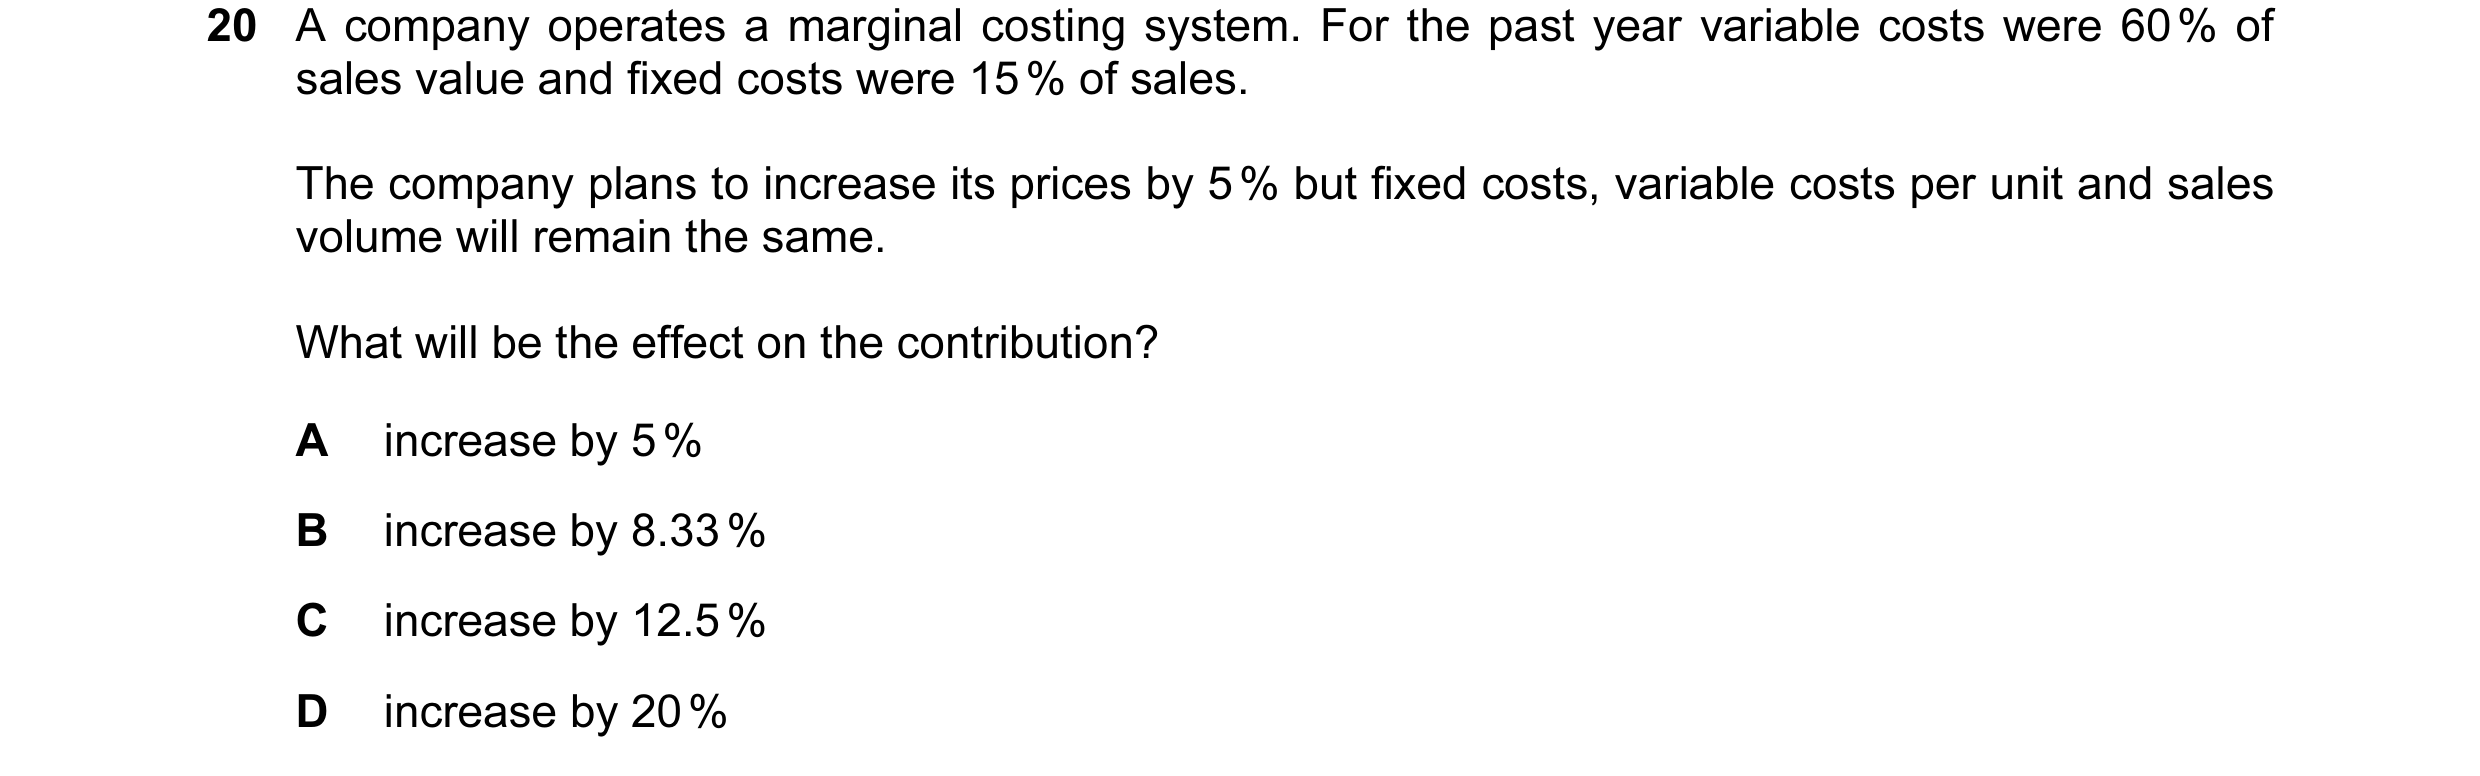
Q31 · A company operates a marginal costing system 9706/31 Oct/Nov 2012
20 A company operates a marginal costing system. For the past year variable costs were 60 % of sales value and fixed costs were 15 % of sales. The company plans to increase its prices by 5 % but fixed costs, variable costs per unit and sales volume will remain the same. What will be the effect on the contribution? A increase by 5 % B increase by 8.33 % C increase by 12.5 % D increase by 20 %
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2012
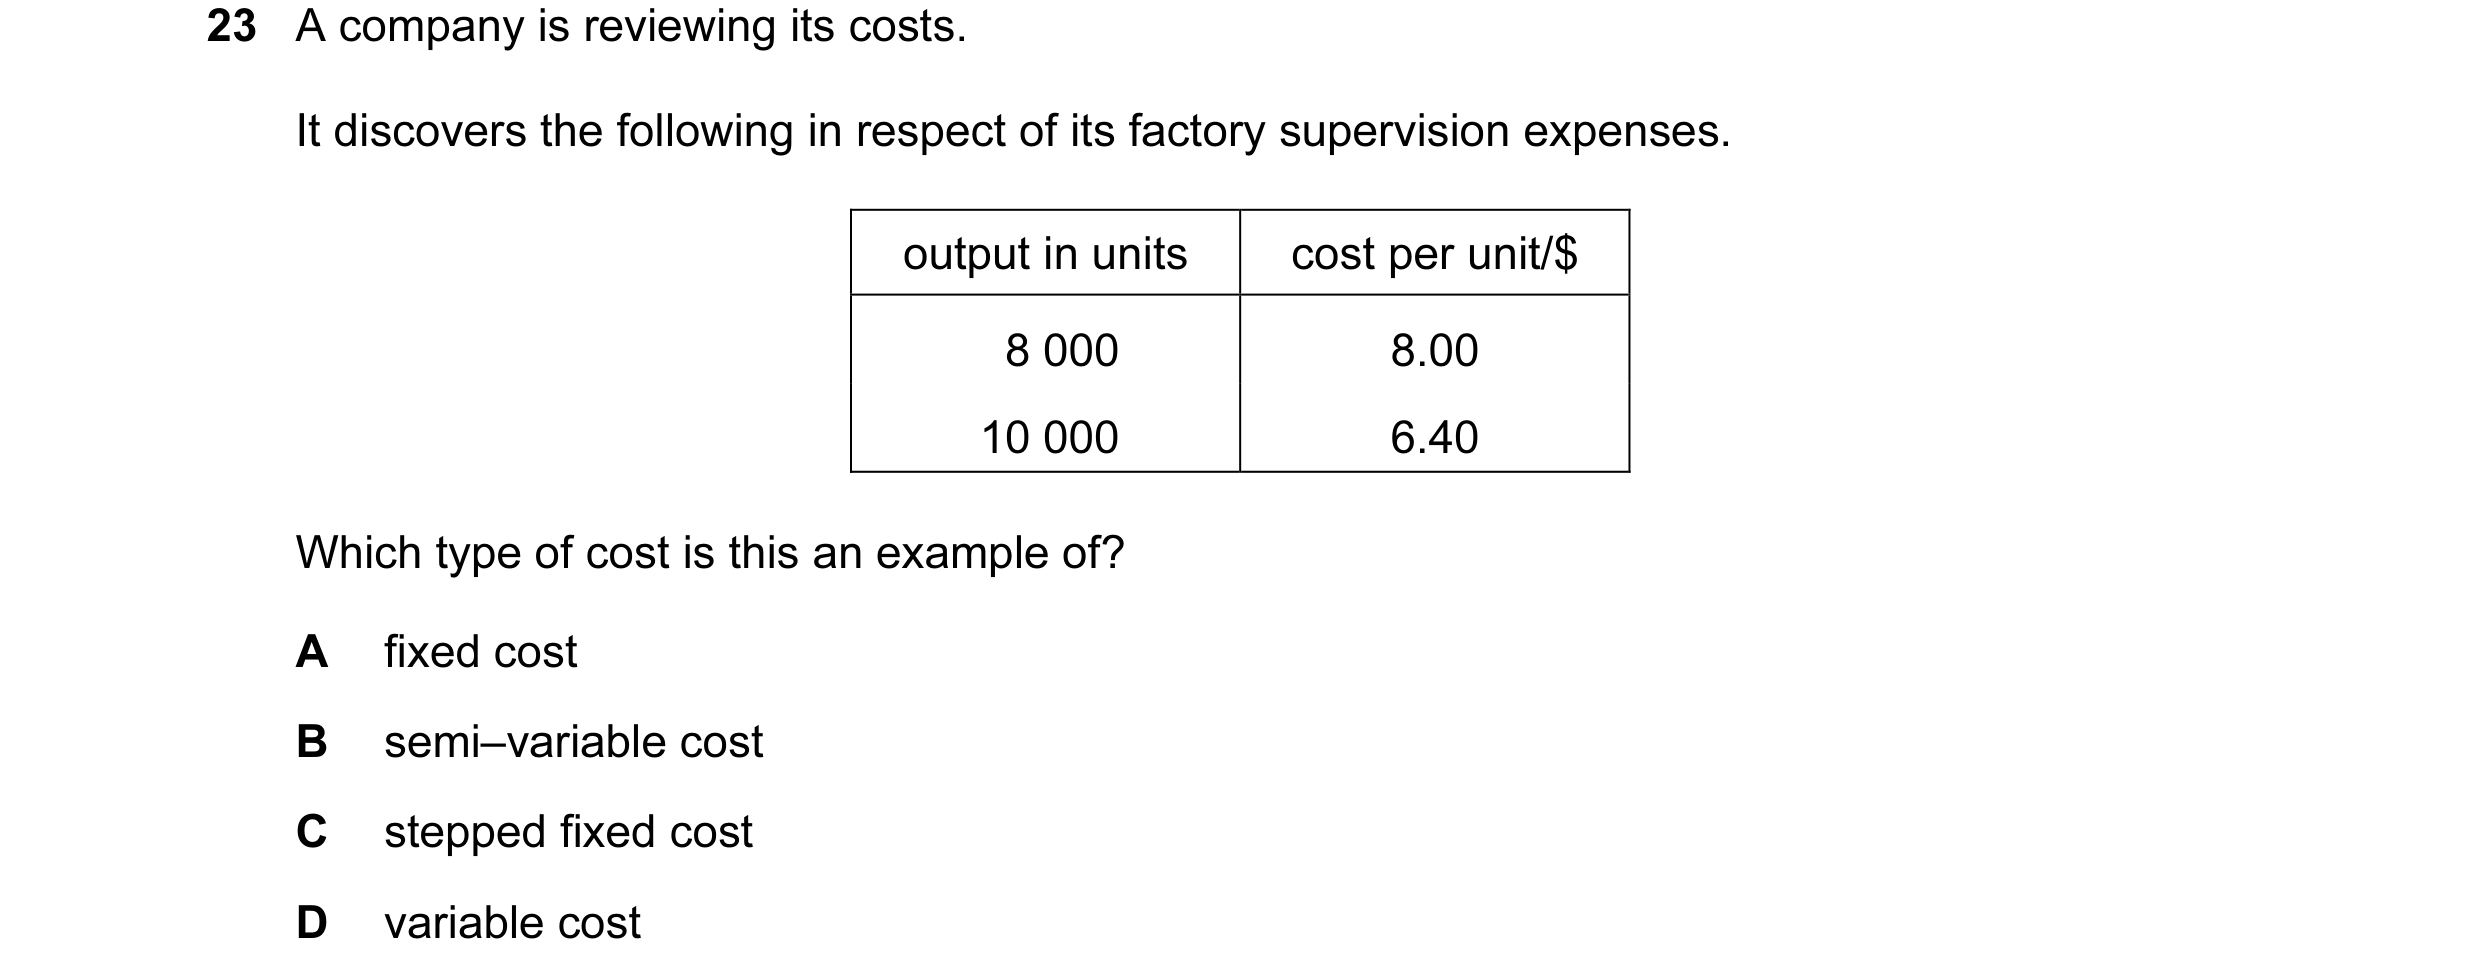
Q32 · A company is reviewing its costs 9706/31 Oct/Nov 2012
23 A company is reviewing its costs. It discovers the following in respect of its factory supervision expenses. output in units cost per unit/$ 8 000 8.00 10 000 6.40 Which type of cost is this an example of? A fixed cost B semi–variable cost C stepped fixed cost D variable cost
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2012
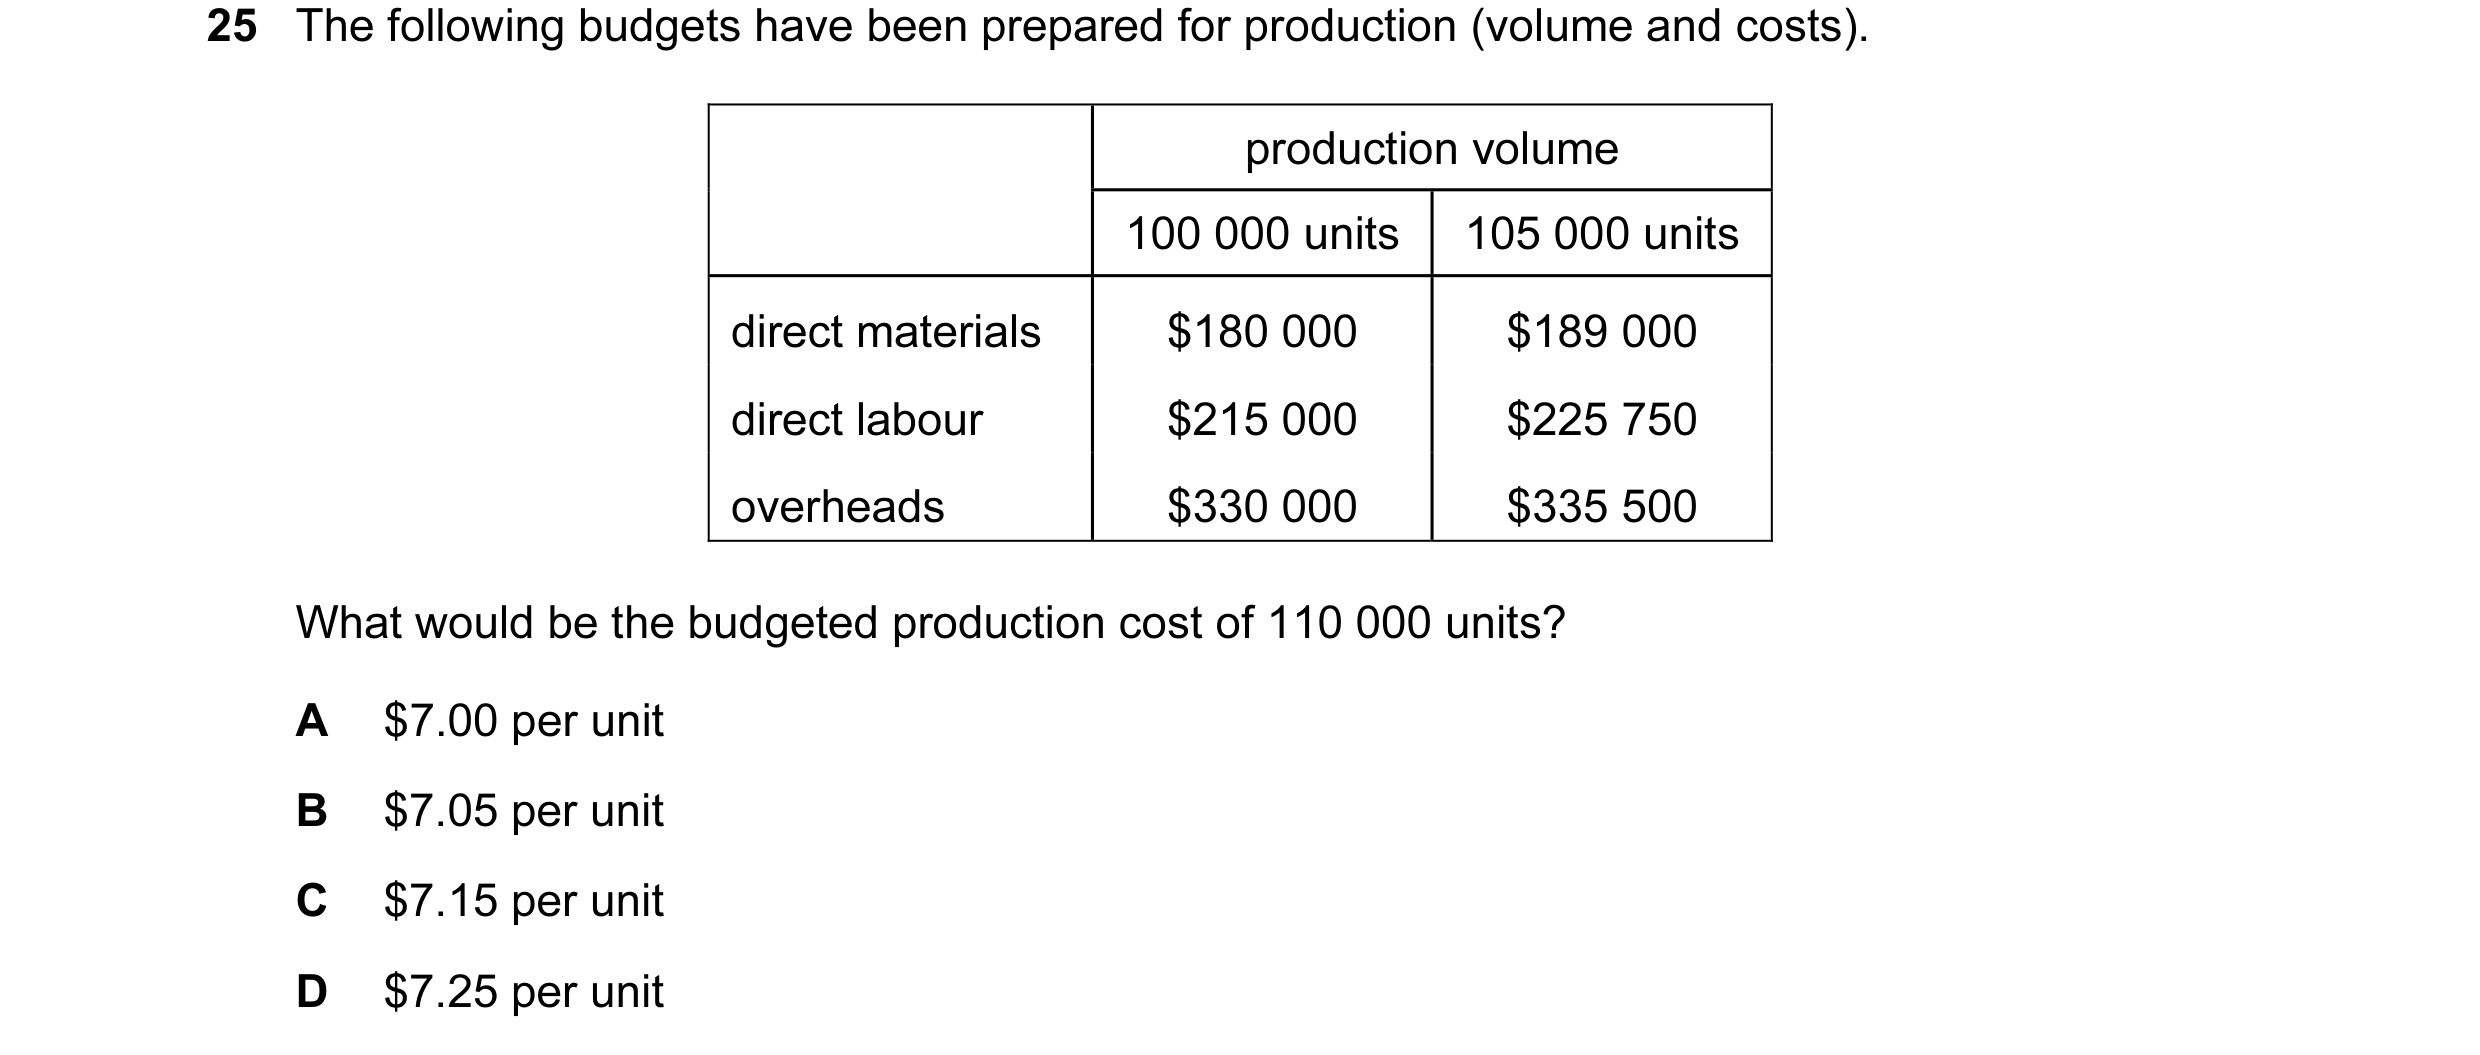
Q33 · The following budgets have been prepared for production (volume and costs) 9706/31 Oct/Nov 2012
25 The following budgets have been prepared for production (volume and costs). production volume 100 000 units 105 000 units direct materials $180 000 $189 000 direct labour $215 000 $225 750 overheads $330 000 $335 500 What would be the budgeted production cost of 110 000 units? A $7.00 per unit B $7.05 per unit C $7.15 per unit D $7.25 per unit
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2012
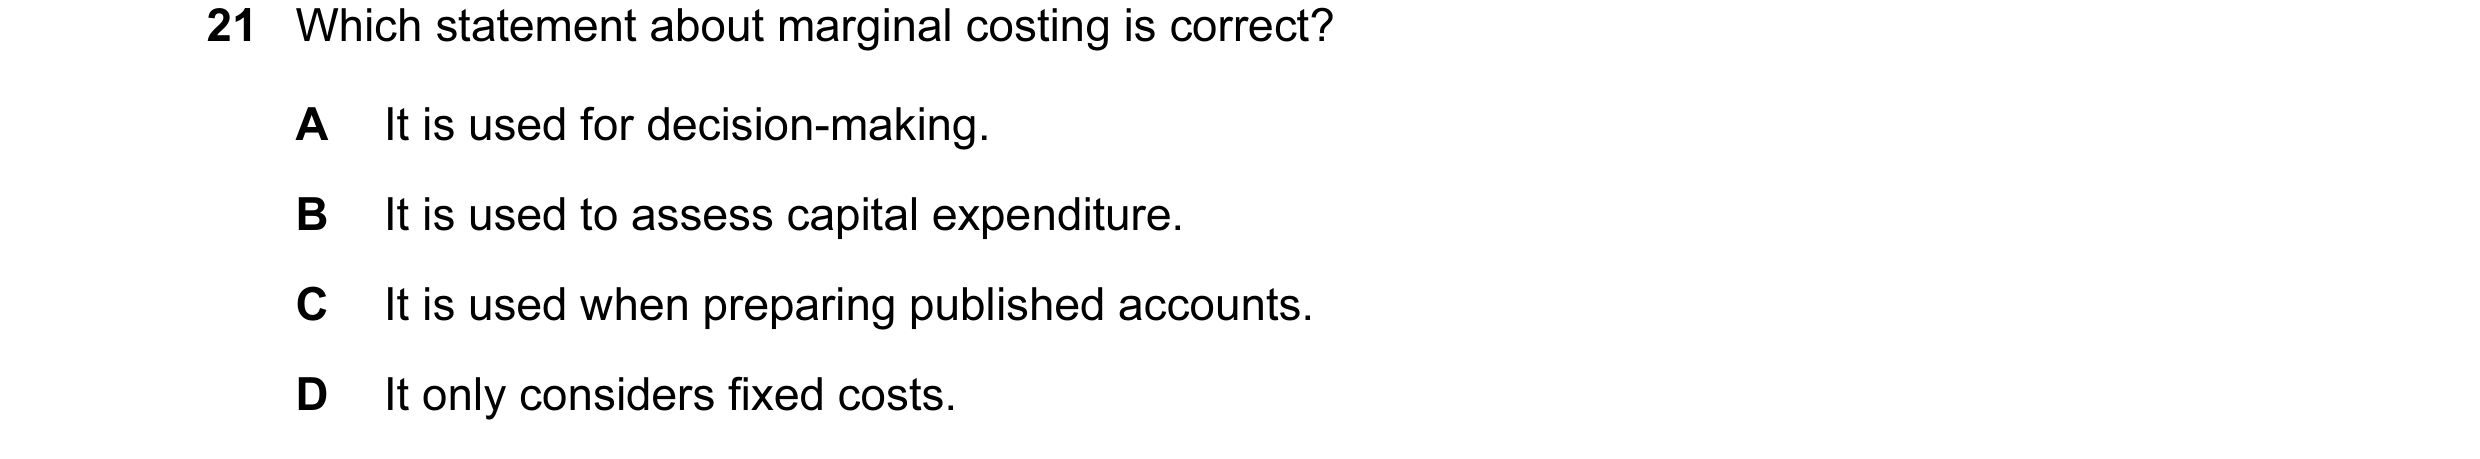
Q34 · Which statement about marginal costing is correct? 9706/32 Oct/Nov 2012
21 Which statement about marginal costing is correct? A It is used for decision-making. B It is used to assess capital expenditure. C It is used when preparing published accounts. D It only considers fixed costs.
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2012
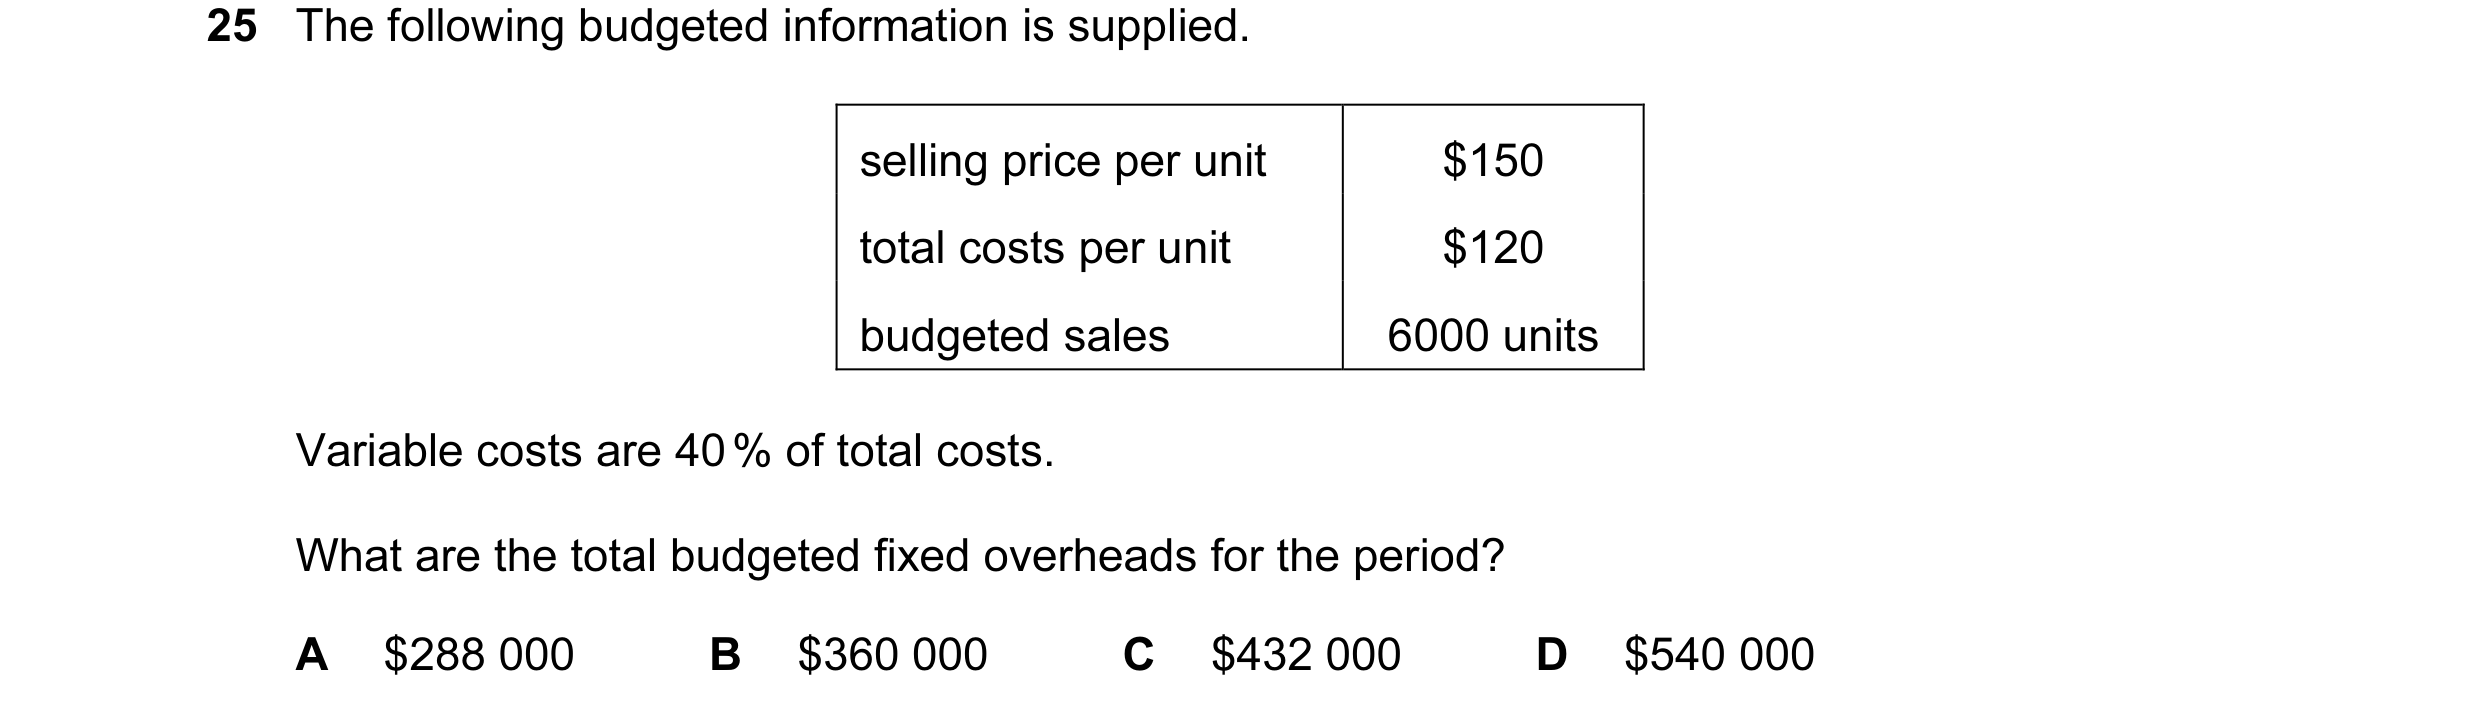
Q35 · The following budgeted information is supplied 9706/32 Oct/Nov 2012
25 The following budgeted information is supplied. selling price per unit $150 total costs per unit $120 budgeted sales 6000 units Variable costs are 40 % of total costs. What are the total budgeted fixed overheads for the period? A $288 000 B $360 000 C $432 000 D $540 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2012
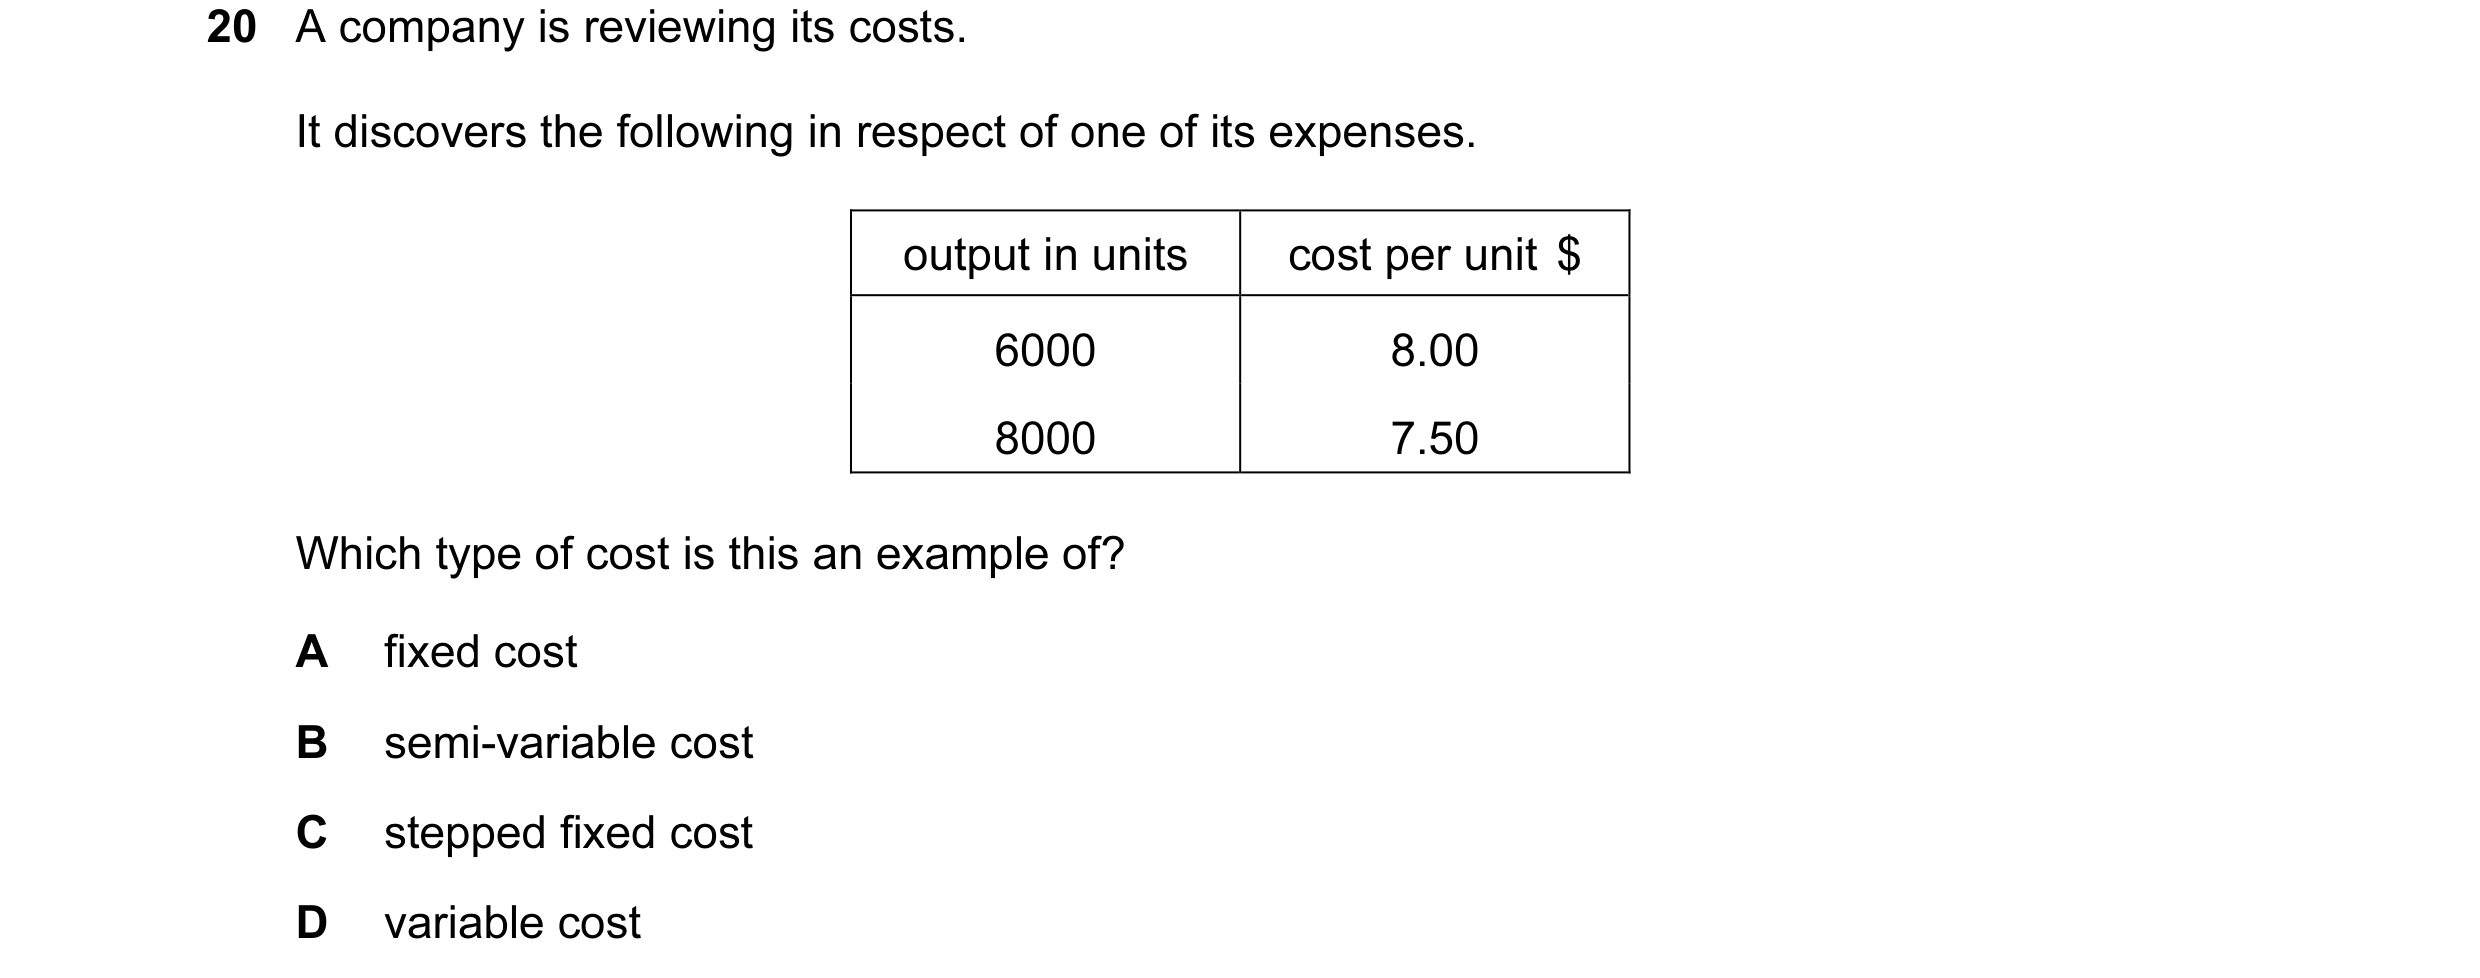
Q36 · A company is reviewing its costs 9706/33 Oct/Nov 2012
20 A company is reviewing its costs. It discovers the following in respect of one of its expenses. output in units cost per unit $ 6000 8.00 8000 7.50 Which type of cost is this an example of? A fixed cost B semi-variable cost C stepped fixed cost D variable cost
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2012
Q37 · A company has creditors valued at $100 000 and they are currently paid in 30 days 9706/33 Oct/Nov 2012
22 A company has creditors valued at $100 000 and they are currently paid in 30 days. It is budgeting to increase this immediately by 40 % and increase the payment period to 60 days. How much will this generate as a one-off cash saving for the business? A $40 000 B $100 000 C $140 000 D $180 000
1 marks
Answer: D
This question in 9706/33 Oct/Nov 2012
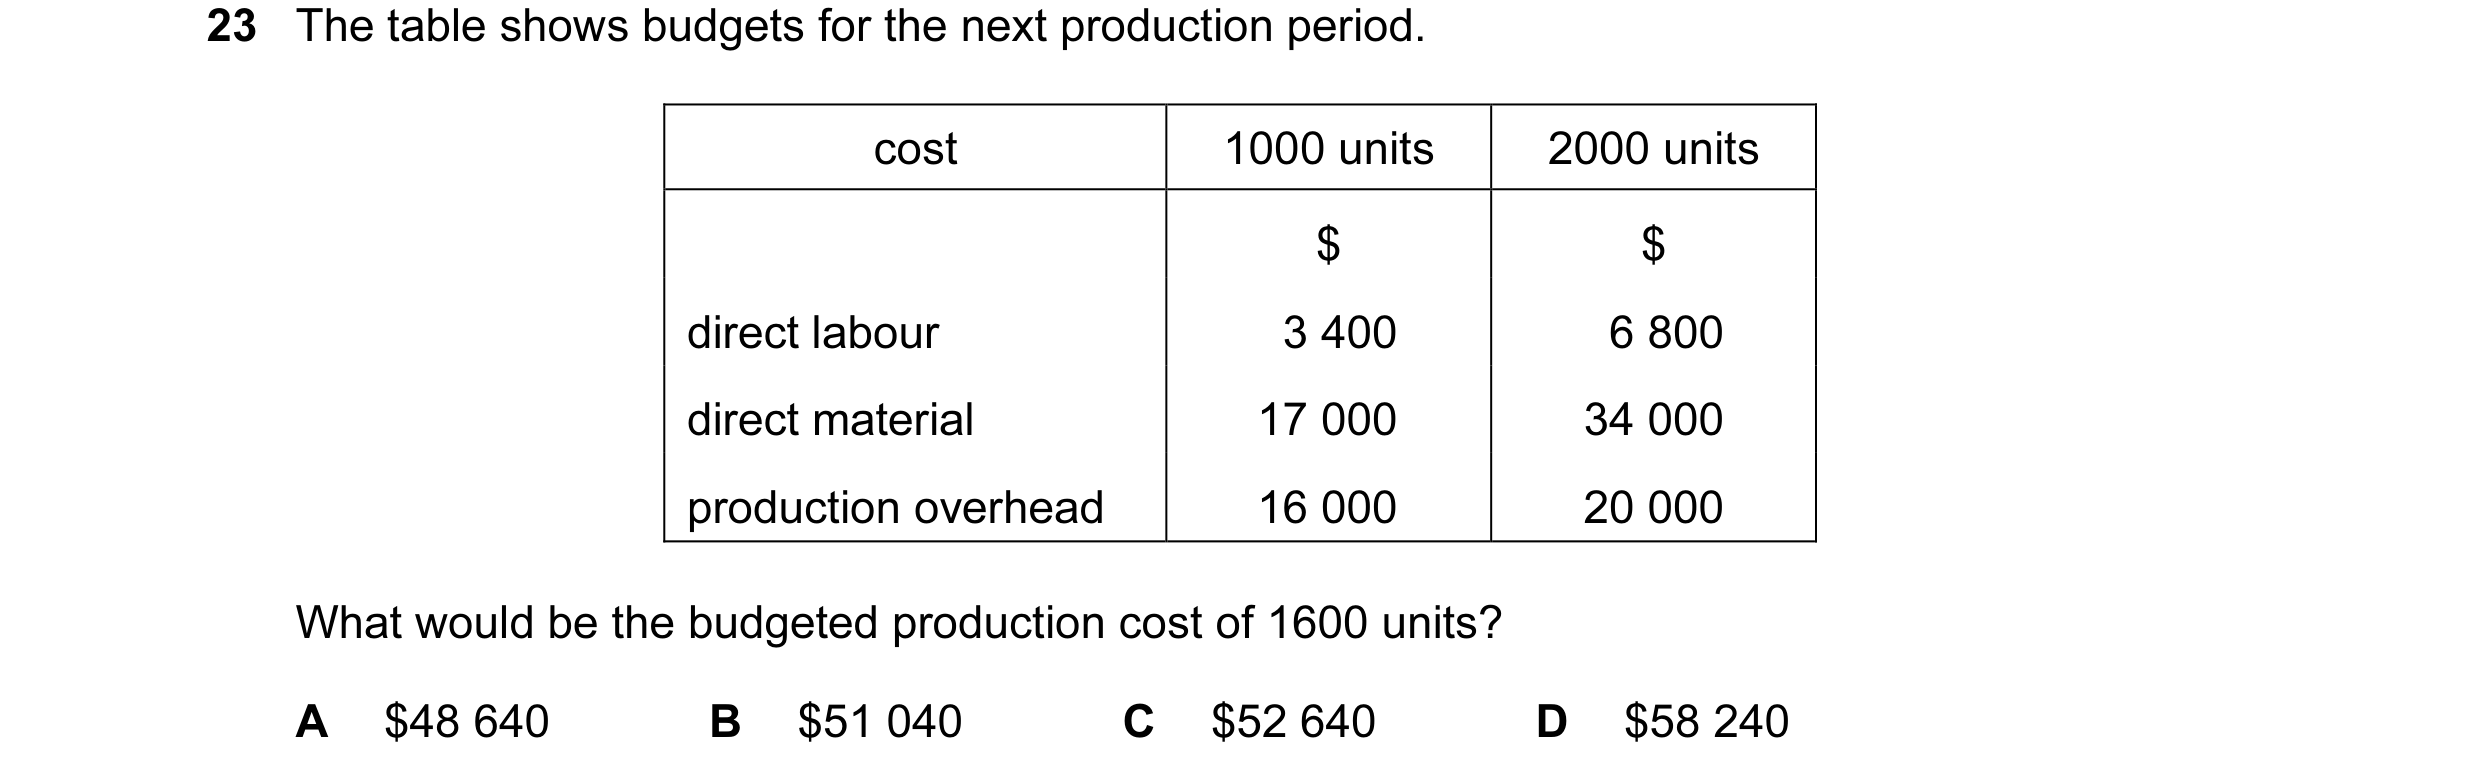
Q38 · The table shows budgets for the next production period 9706/33 Oct/Nov 2012
23 The table shows budgets for the next production period. cost 1000 units 2000 units $ $ direct labour 3 400 6 800 direct material 17 000 34 000 production overhead 16 000 20 000 What would be the budgeted production cost of 1600 units? A $48 640 B $51 040 C $52 640 D $58 240
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2012
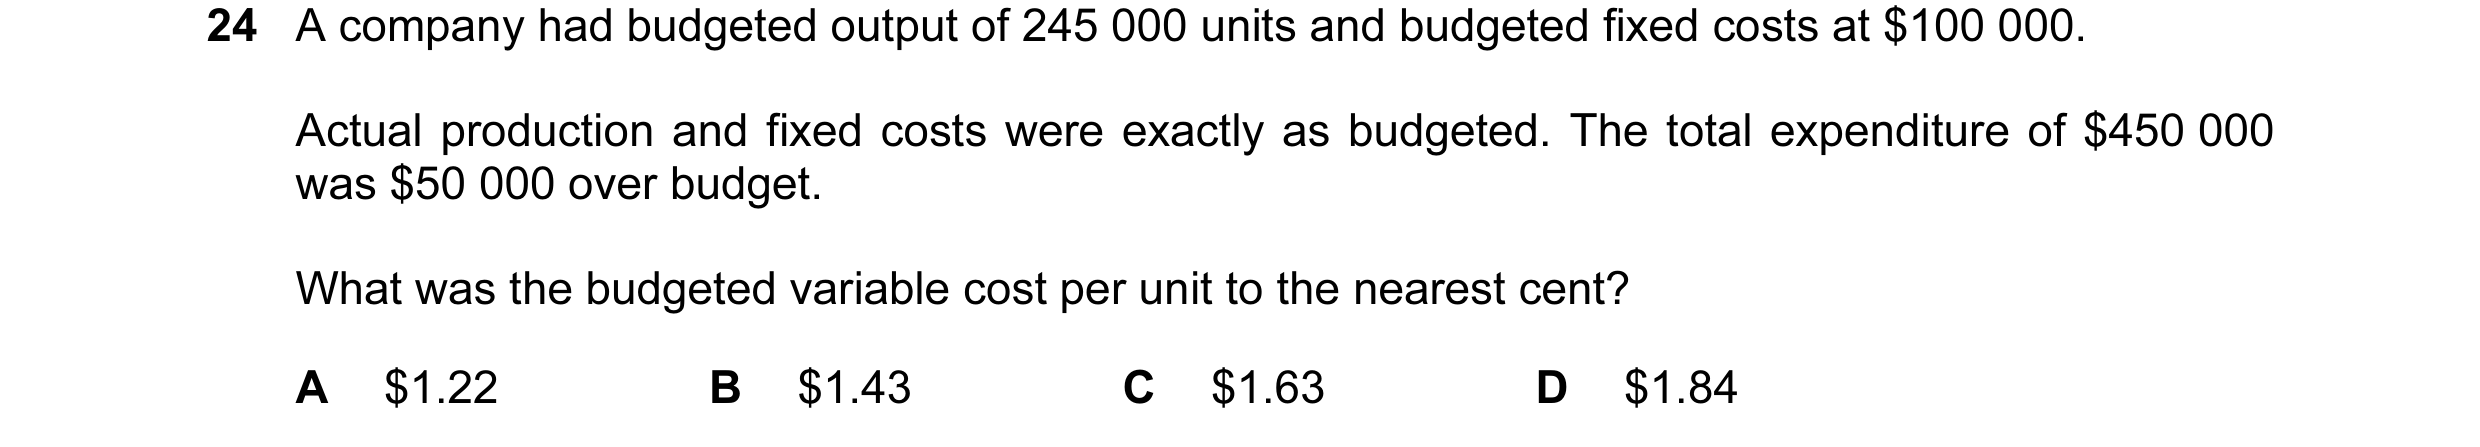
Q39 · A company had budgeted output of 245 000 units and budgeted fixed costs at $100 000 9706/33 Oct/Nov 2012
24 A company had budgeted output of 245 000 units and budgeted fixed costs at $100 000. Actual production and fixed costs were exactly as budgeted. The total expenditure of $450 000 was $50 000 over budget. What was the budgeted variable cost per unit to the nearest cent? A $1.22 B $1.43 C $1.63 D $1.84
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2012
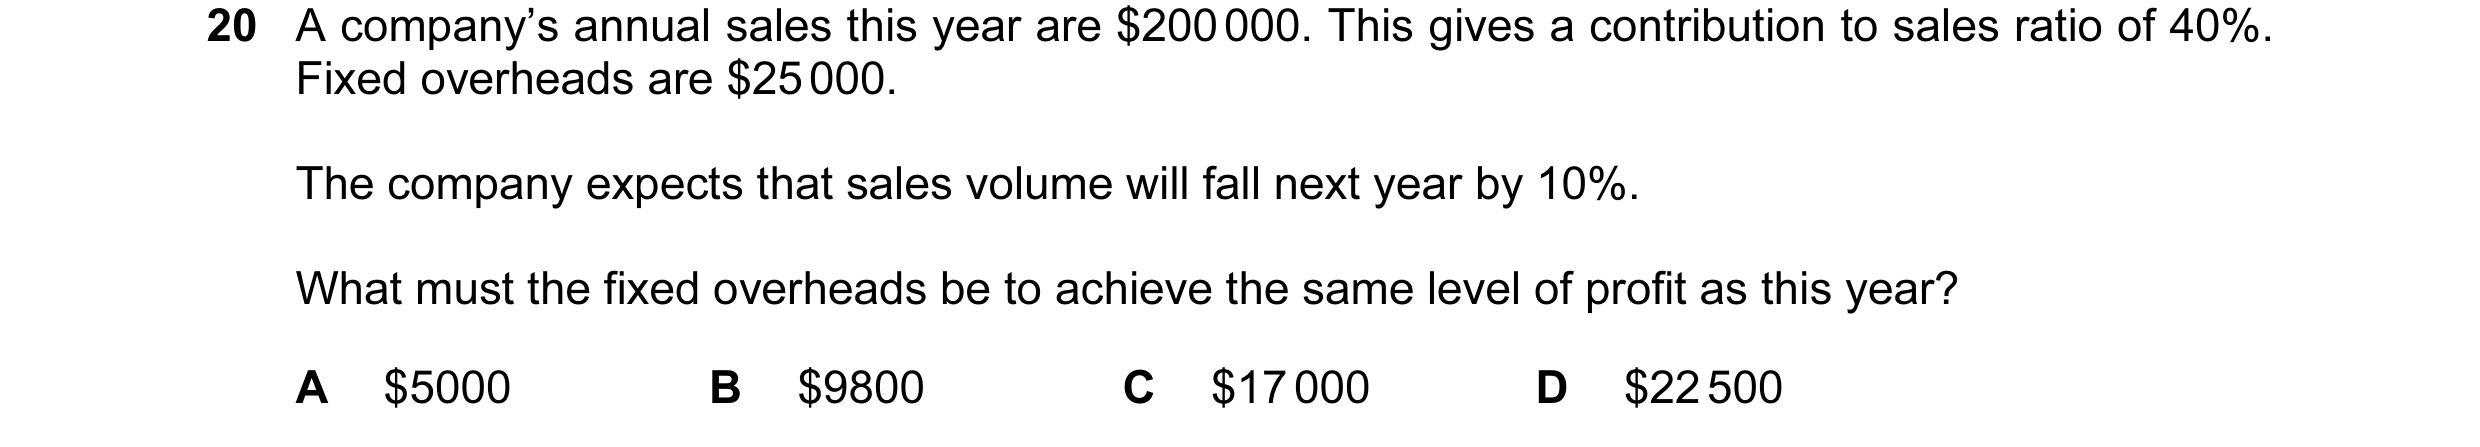
Q40 · A company’s annual sales this year are $200 000 9706/31 May/June 2013
20 A company’s annual sales this year are $200 000. This gives a contribution to sales ratio of 40%. Fixed overheads are $25 000. The company expects that sales volume will fall next year by 10%. What must the fixed overheads be to achieve the same level of profit as this year? A $5000 B $9800 C $17 000 D $22 500
1 marks
Answer: C
This question in 9706/31 May/June 2013
Q41 · A business currently manufactures a single product 9706/32 May/June 2013
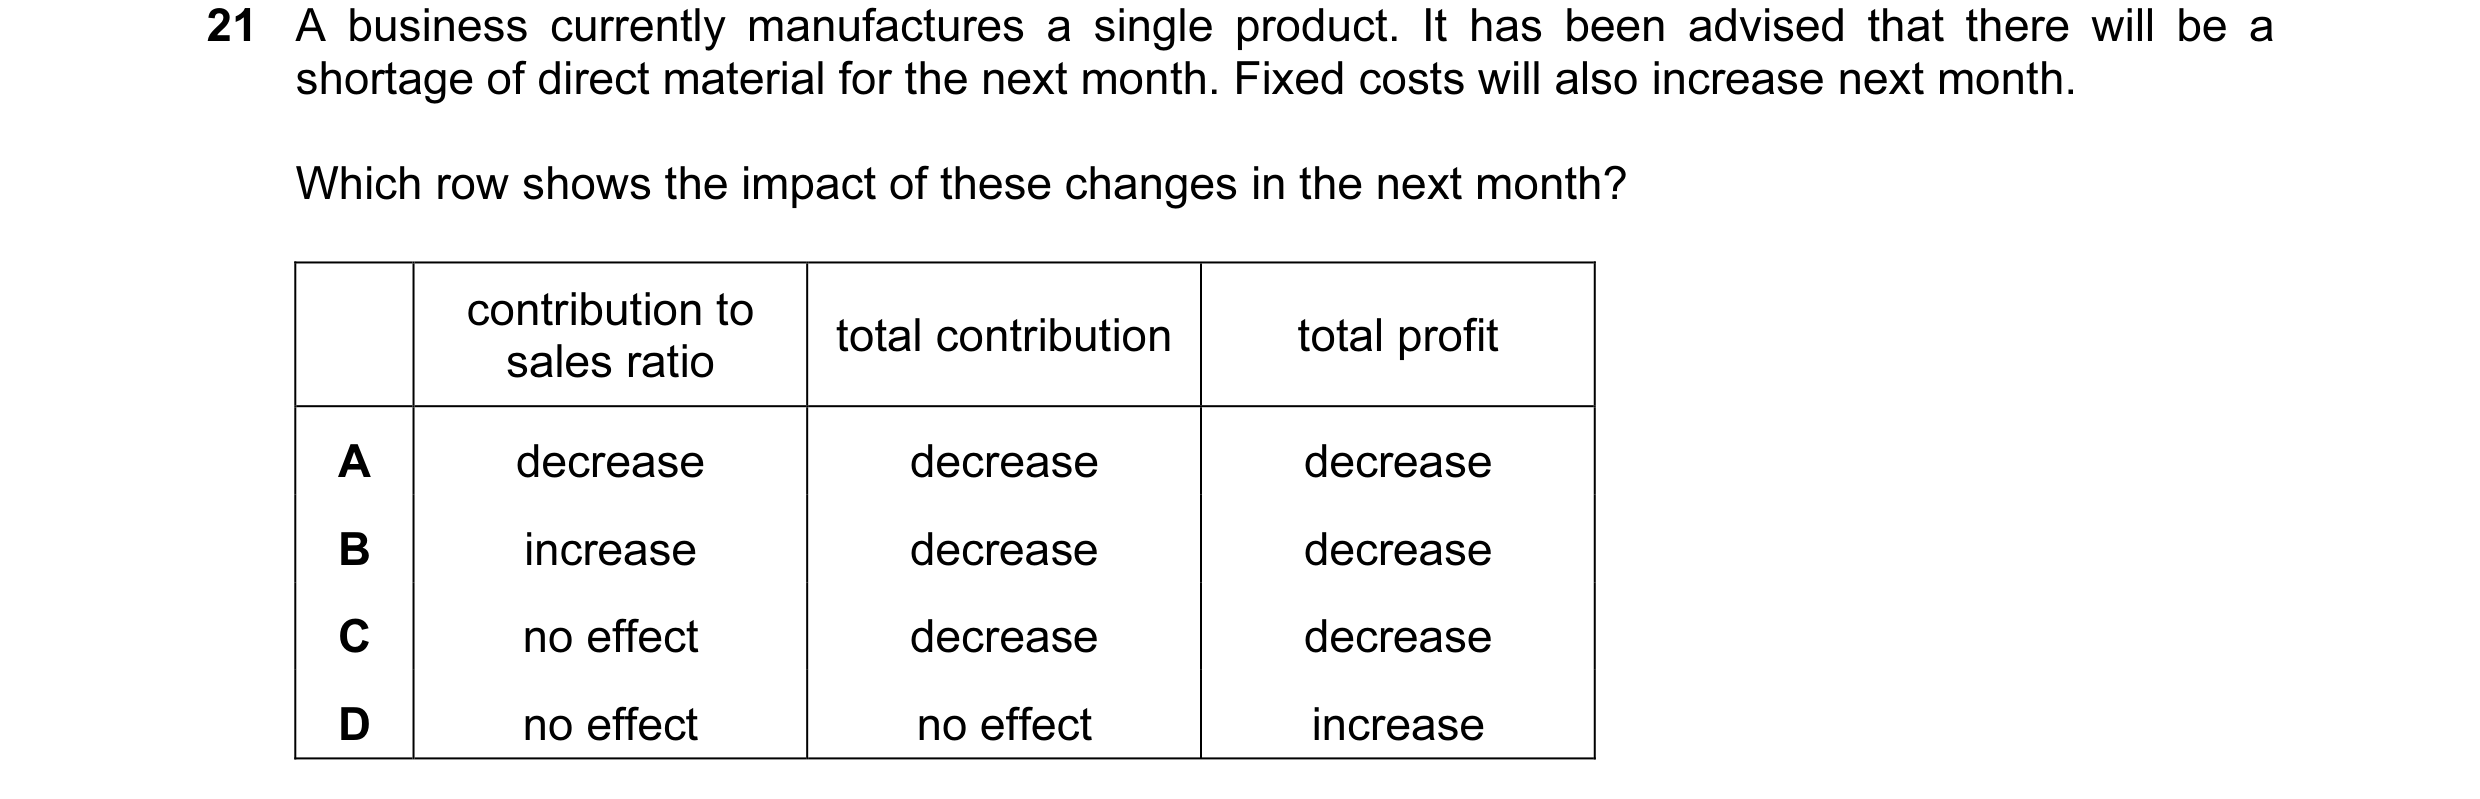
21 A business currently manufactures a single product. It has been advised that there will be a shortage of direct material for the next month. Fixed costs will also increase next month. Which row shows the impact of these changes in the next month? contribution to total contribution total profit sales ratio A decrease decrease decrease B increase decrease decrease C no effect decrease decrease D no effect no effect increase
1 marks
Answer: C
This question in 9706/32 May/June 2013
Q42 · What is shown by the graph? 9706/32 May/June 2013
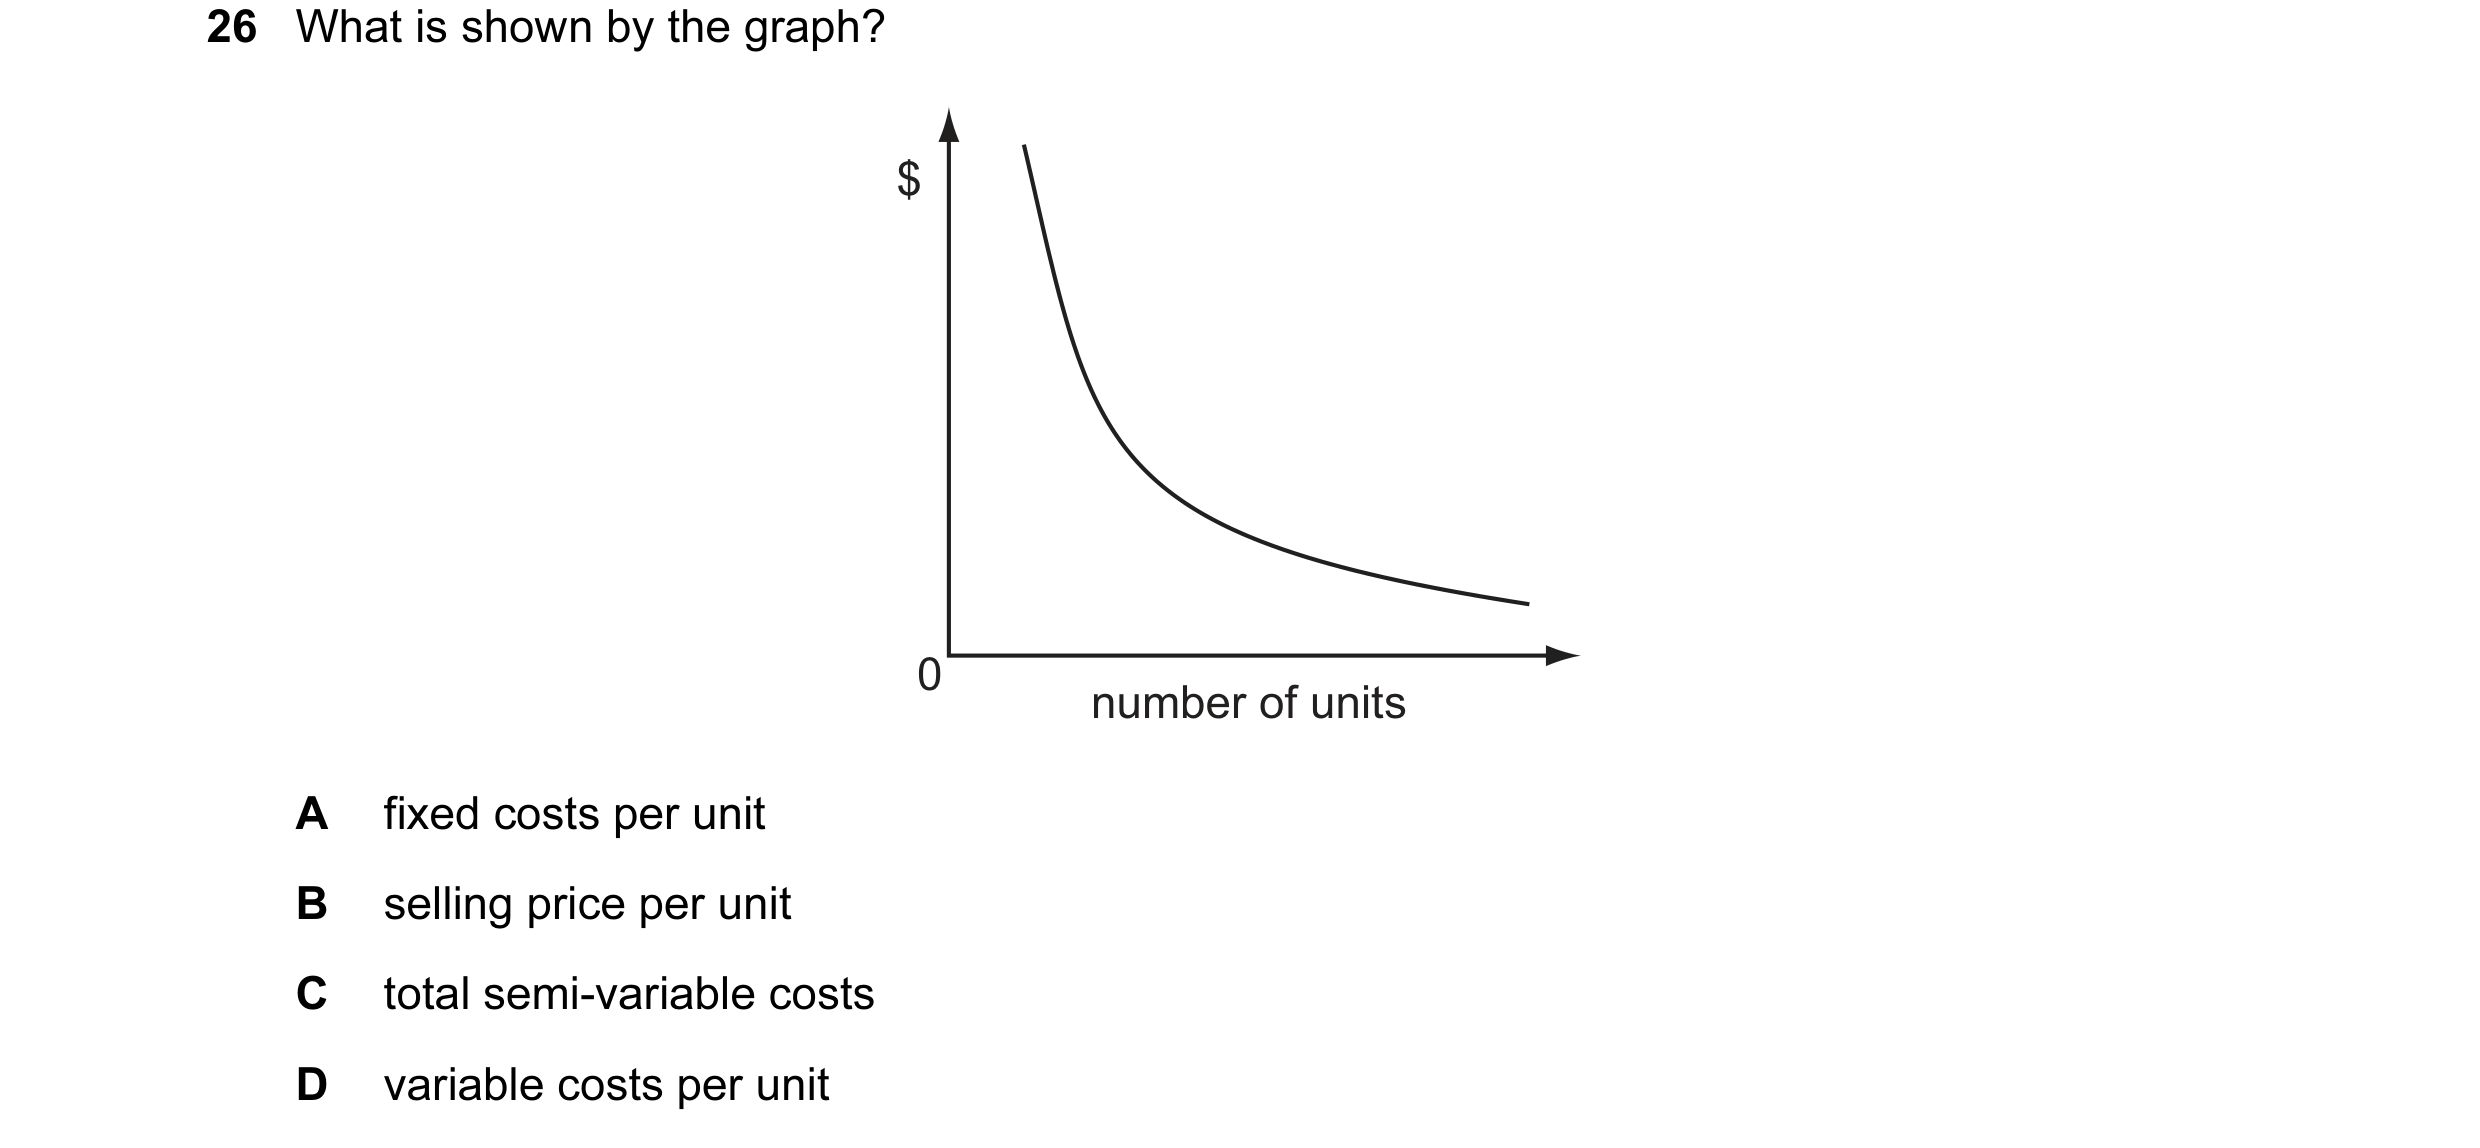
26 What is shown by the graph? $ 0 number of units A fixed costs per unit B selling price per unit C total semi-variable costs D variable costs per unit
1 marks
Answer: A
This question in 9706/32 May/June 2013
Q43 · A company has the following budgeted information 9706/33 May/June 2013
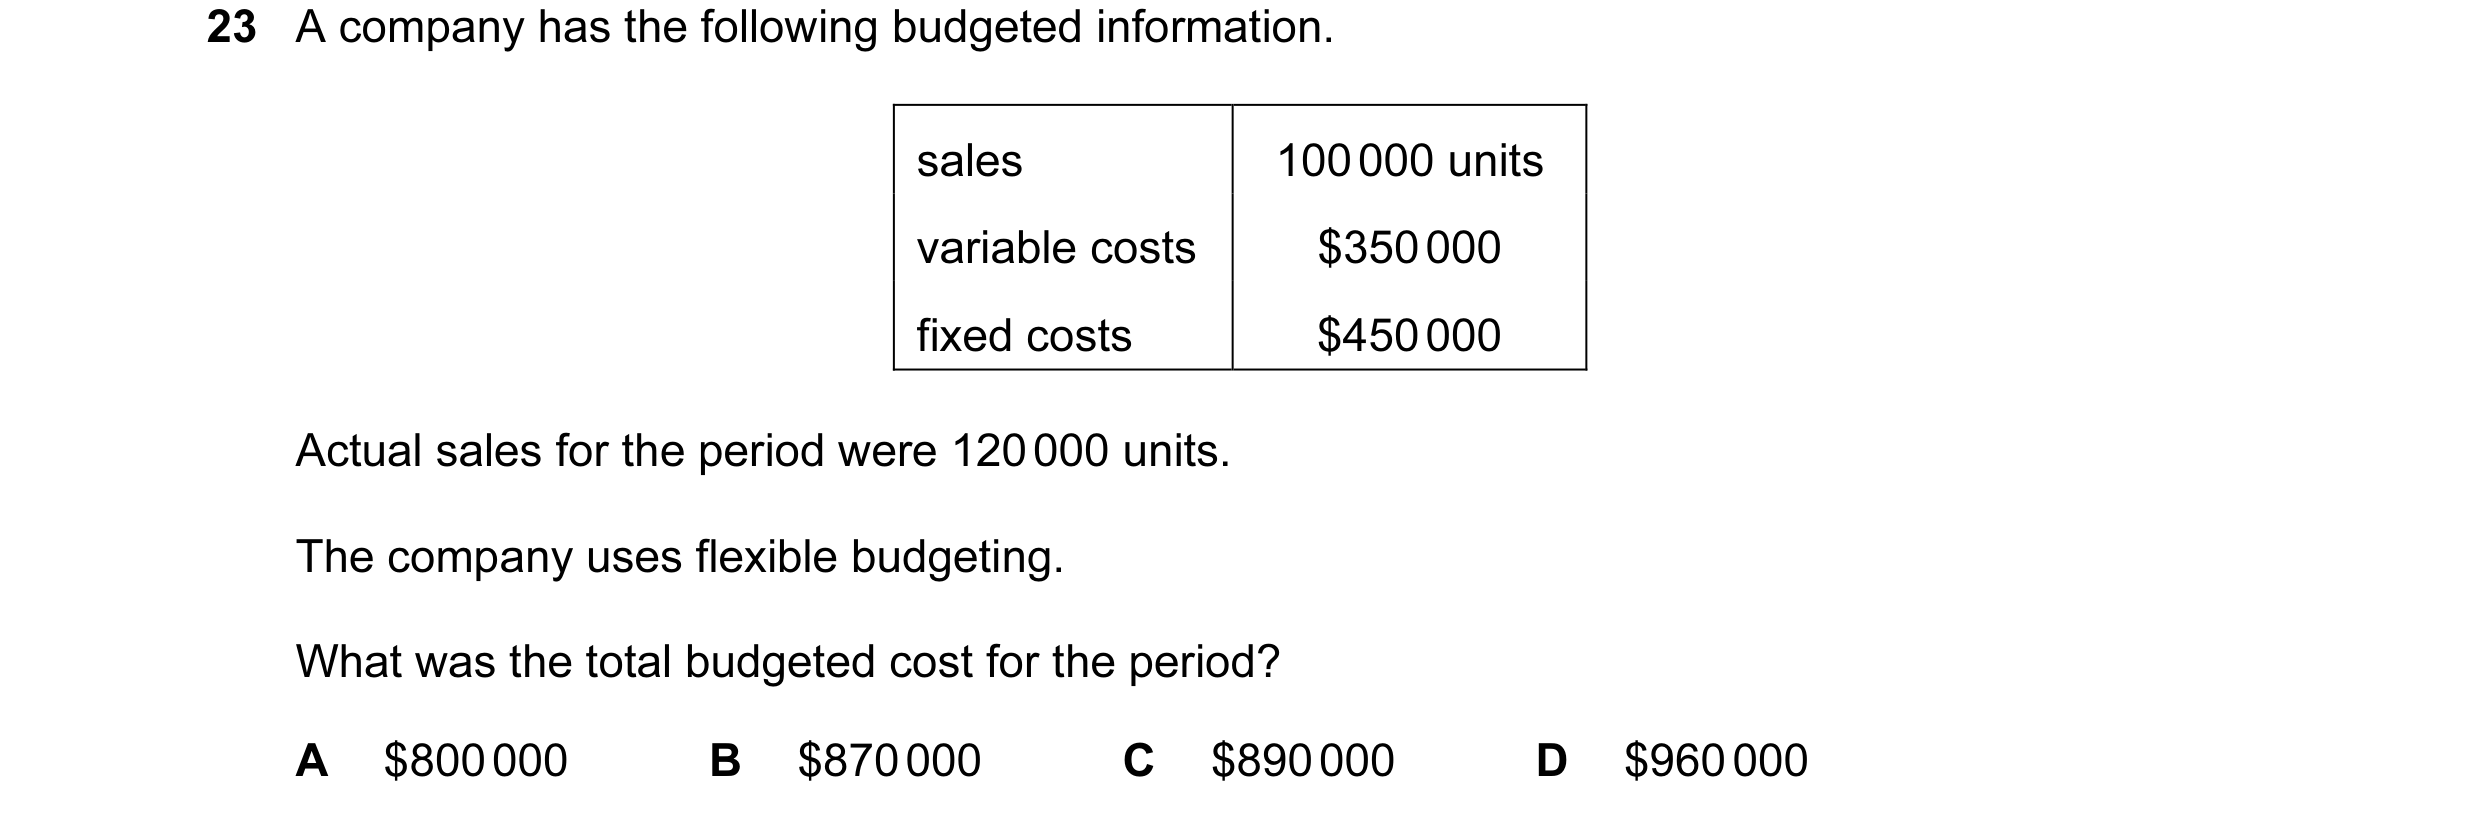
23 A company has the following budgeted information. sales 100 000 units variable costs $350 000 fixed costs $450 000 Actual sales for the period were 120 000 units. The company uses flexible budgeting. What was the total budgeted cost for the period? A $800 000 B $870 000 C $890 000 D $960 000
1 marks
Answer: B
This question in 9706/33 May/June 2013
Q44 · A company values its work in progress and finished goods in the way set out by IAS2 9706/31 Oct/Nov 2013
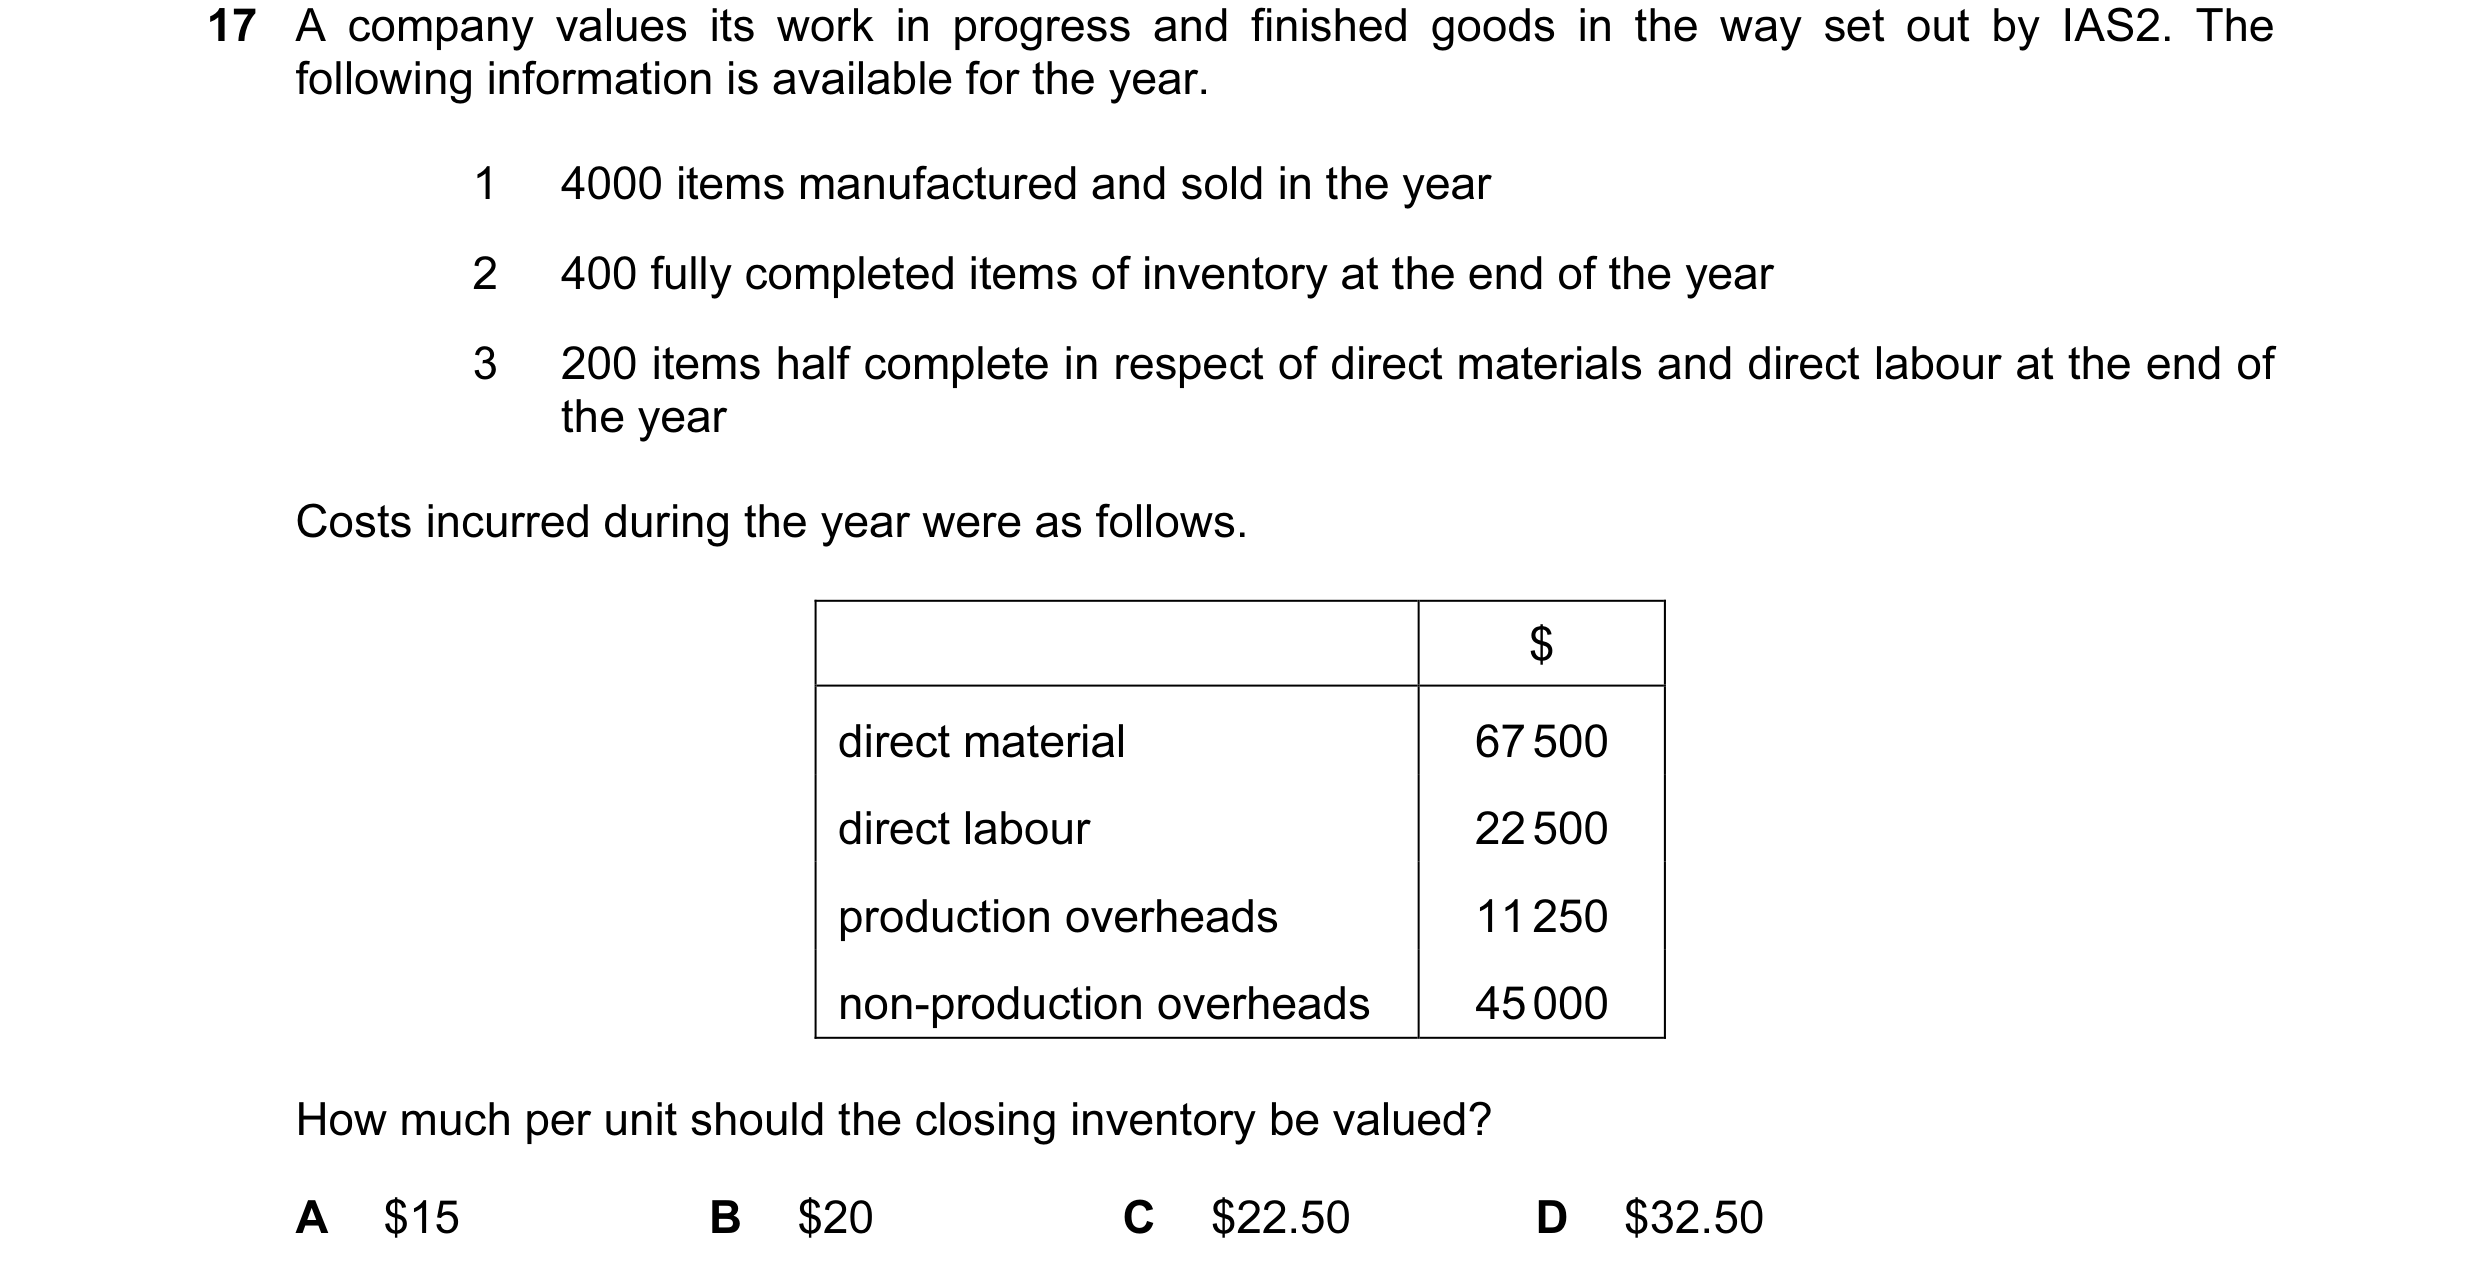
17 A company values its work in progress and finished goods in the way set out by IAS2. The following information is available for the year. 1 4000 items manufactured and sold in the year 2 400 fully completed items of inventory at the end of the year 3 200 items half complete in respect of direct materials and direct labour at the end of the year Costs incurred during the year were as follows. $ direct material 67 500 direct labour 22 500 production overheads 11 250 non-production overheads 45 000 How much per unit should the closing inventory be valued? A $15 B $20 C $22.50 D $32.50
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2013
Q45 · A company has fixed costs of $5000 9706/31 Oct/Nov 2013
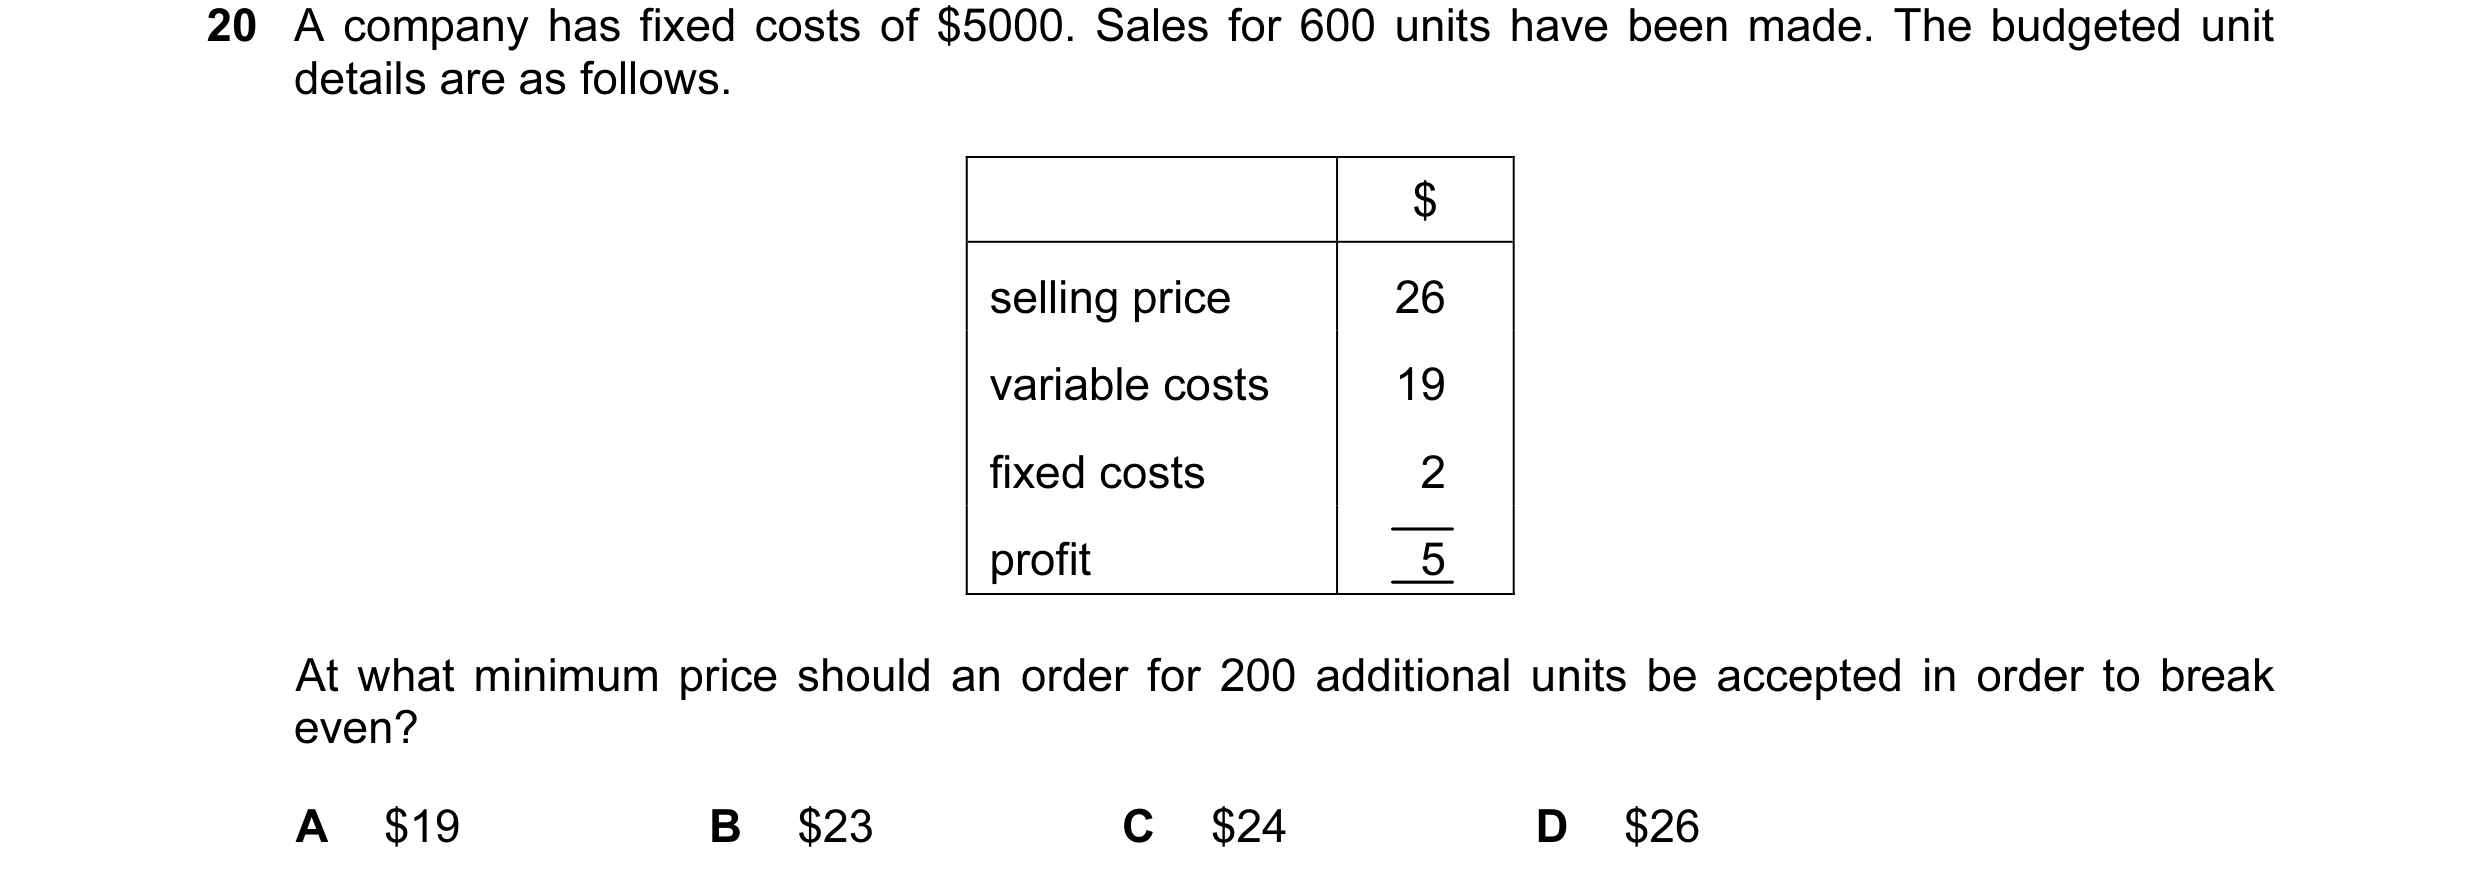
20 A company has fixed costs of $5000. Sales for 600 units have been made. The budgeted unit details are as follows. $ selling price 26 variable costs 19 fixed costs 2 profit 5 At what minimum price should an order for 200 additional units be accepted in order to break even? A $19 B $23 C $24 D $26
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2013
Q46 · A company is considering opening a new division of the business 9706/31 Oct/Nov 2013
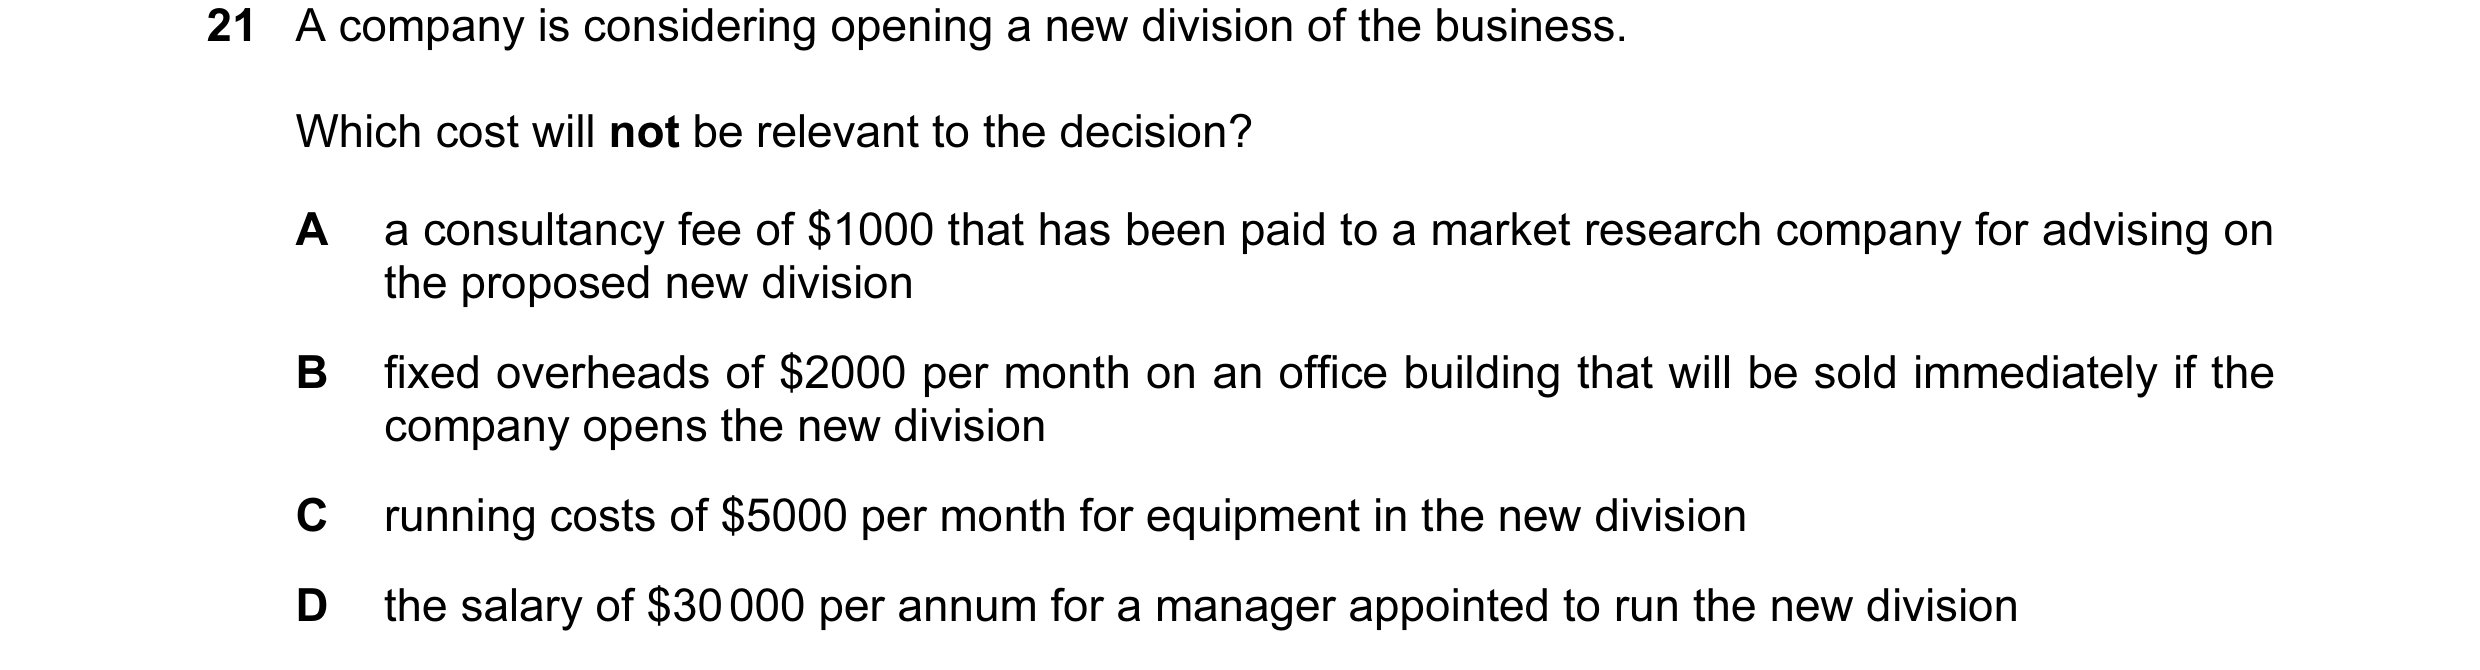
21 A company is considering opening a new division of the business. Which cost will not be relevant to the decision? A a consultancy fee of $1000 that has been paid to a market research company for advising on the proposed new division B fixed overheads of $2000 per month on an office building that will be sold immediately if the company opens the new division C running costs of $5000 per month for equipment in the new division D the salary of $30 000 per annum for a manager appointed to run the new division
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2013
Q47 · A product passes through two processes 9706/31 Oct/Nov 2013
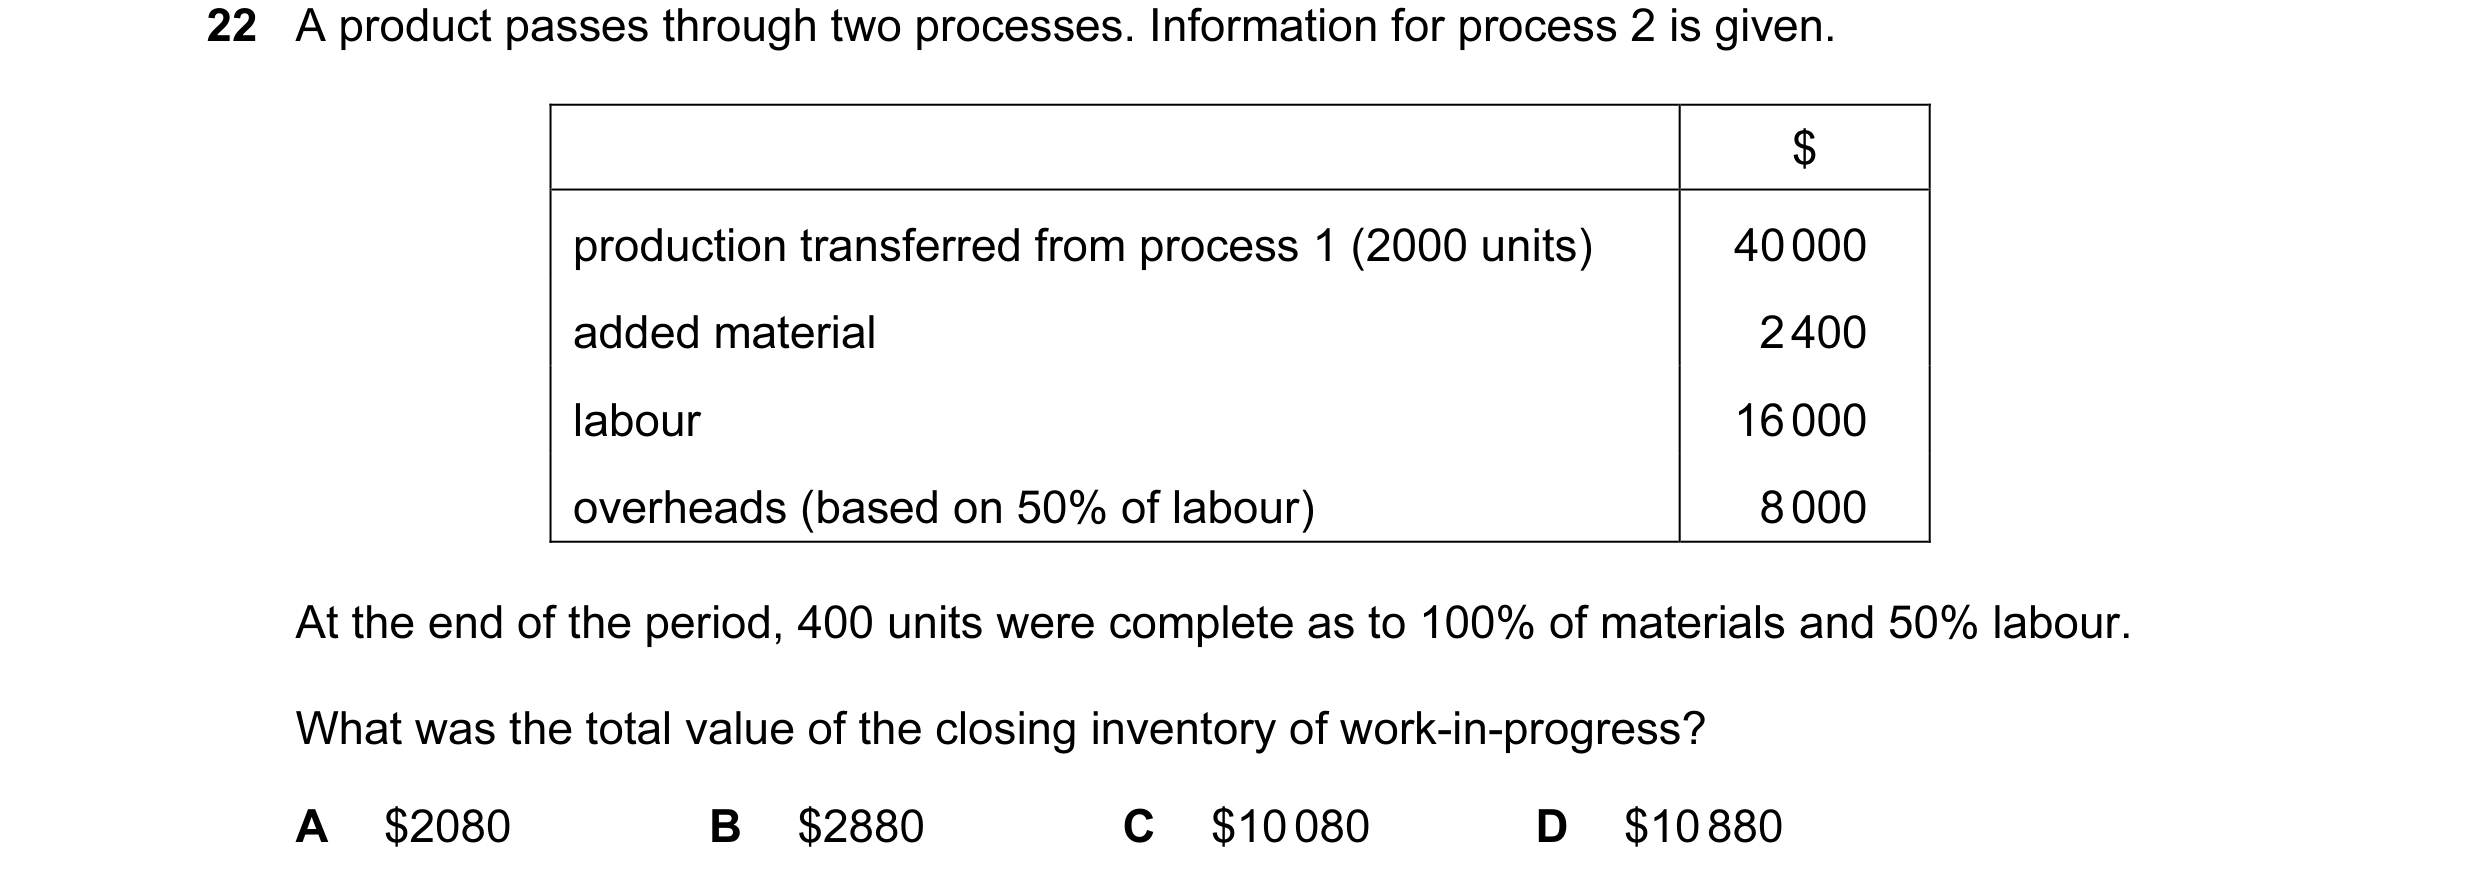
22 A product passes through two processes. Information for process 2 is given. $ production transferred from process 1 (2000 units) 40 000 added material 2 400 labour 16 000 overheads (based on 50% of labour) 8 000 At the end of the period, 400 units were complete as to 100% of materials and 50% labour. What was the total value of the closing inventory of work-in-progress? A $2080 B $2880 C $10 080 D $10 880
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2013
Q48 · The following information relates to the sales and production of a product 9706/32 Oct/Nov 2013
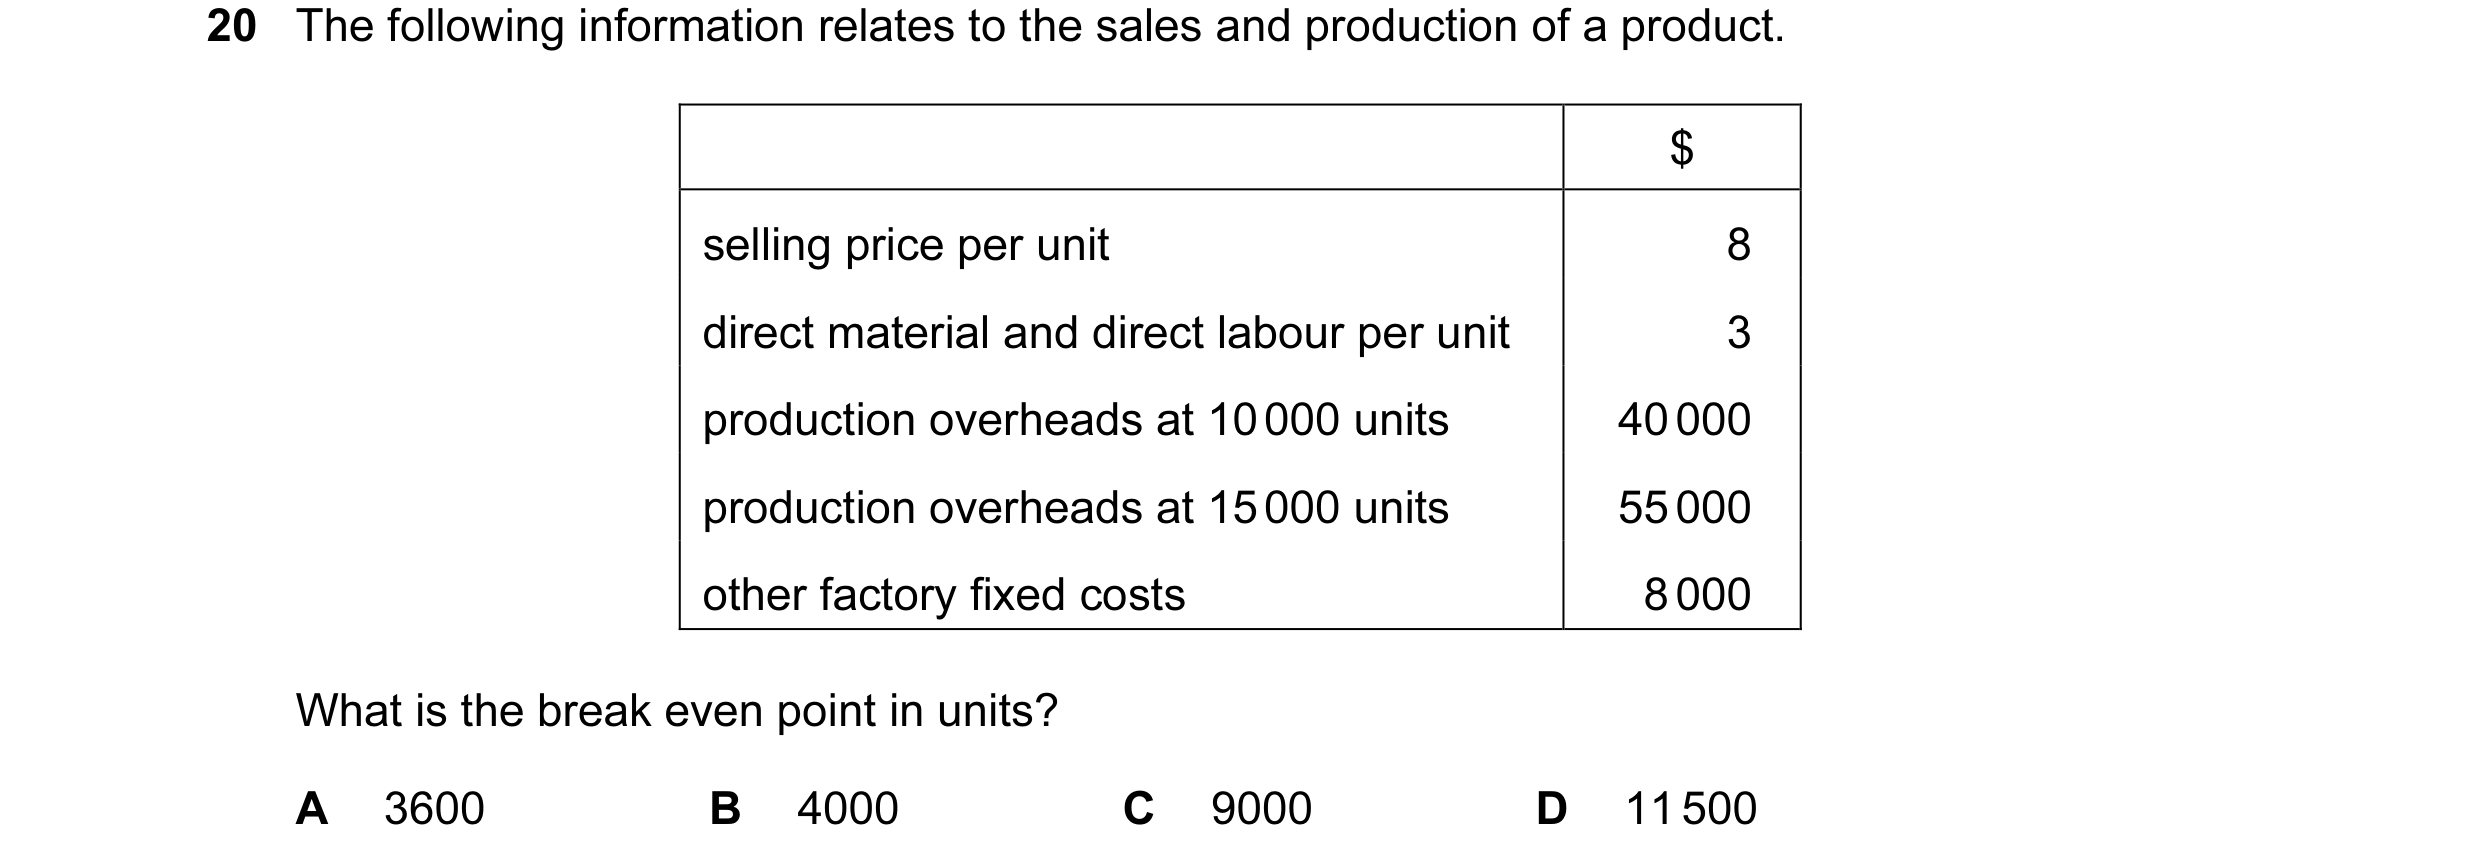
20 The following information relates to the sales and production of a product. $ selling price per unit 8 direct material and direct labour per unit 3 production overheads at 10 000 units 40 000 production overheads at 15 000 units 55 000 other factory fixed costs 8 000 What is the break even point in units? A 3600 B 4000 C 9000 D 11 500
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2013
Q49 · The production of an item in March has a budgeted total cost of $43 200 for 2400 units 9706/32 Oct/Nov 2013
25 The production of an item in March has a budgeted total cost of $43 200 for 2400 units. The fixed costs make up 24% of the total cost and the balance is variable. What is the expected expenditure for March if actual production is 2200 units? A $30 096 B $39 600 C $40 464 D $43 200
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2013
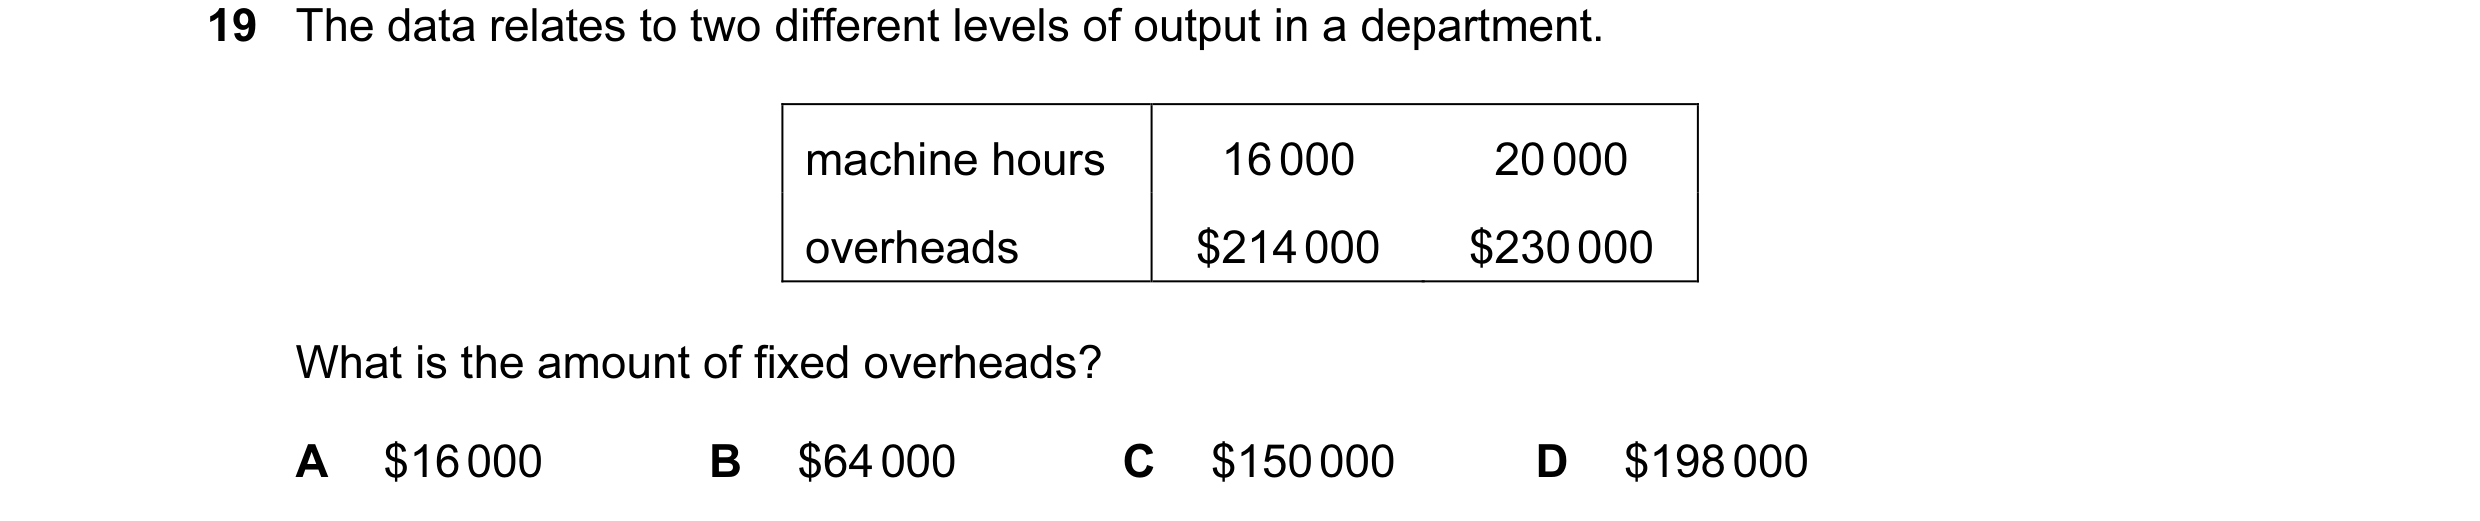
Q50 · The data relates to two different levels of output in a department 9706/33 Oct/Nov 2013
19 The data relates to two different levels of output in a department. machine hours 16 000 20 000 overheads $214 000 $230 000 What is the amount of fixed overheads? A $16 000 B $64 000 C $150 000 D $198 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2013
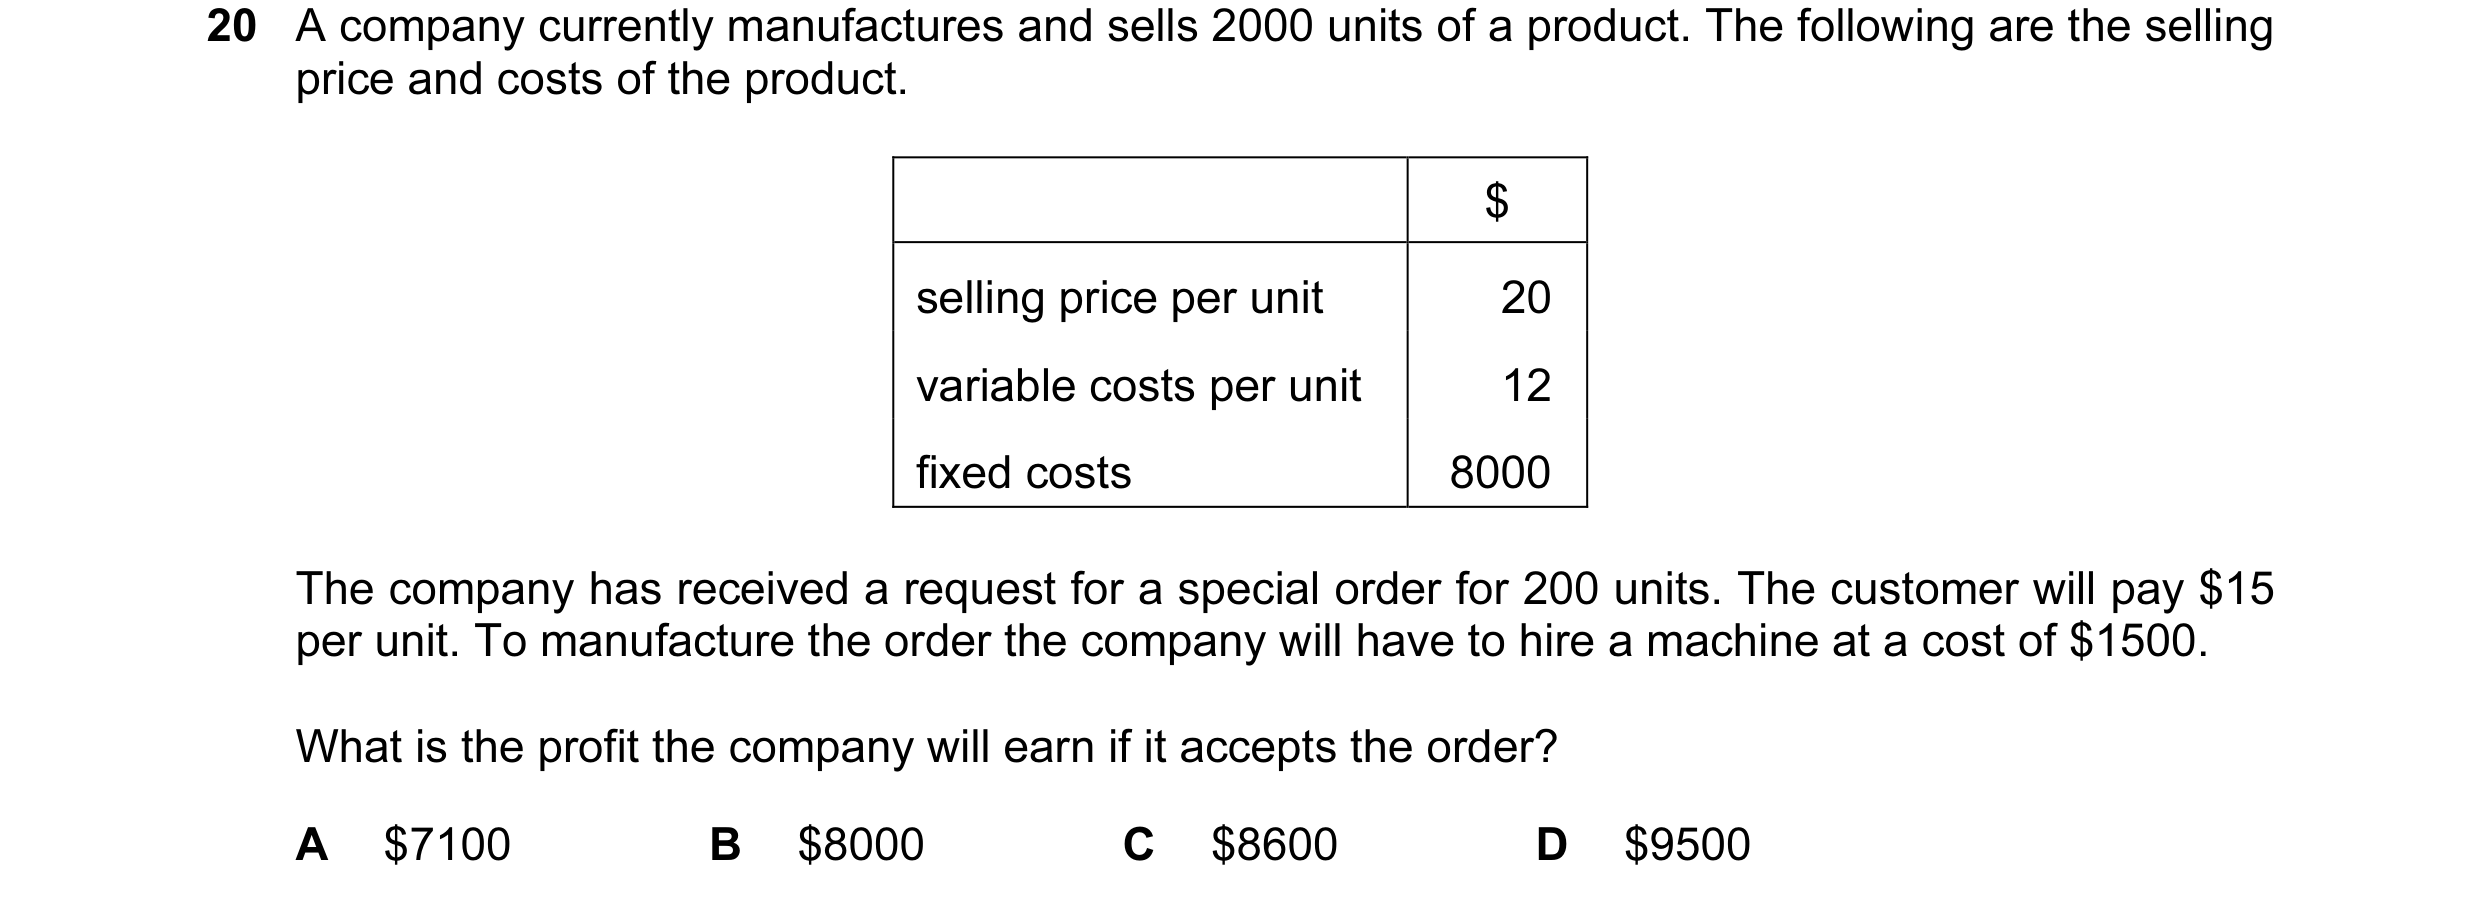
Q51 · A company currently manufactures and sells 2000 units of a product 9706/33 Oct/Nov 2013
20 A company currently manufactures and sells 2000 units of a product. The following are the selling price and costs of the product. $ selling price per unit 20 variable costs per unit 12 fixed costs 8000 The company has received a request for a special order for 200 units. The customer will pay $15 per unit. To manufacture the order the company will have to hire a machine at a cost of $1500. What is the profit the company will earn if it accepts the order? A $7100 B $8000 C $8600 D $9500
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2013
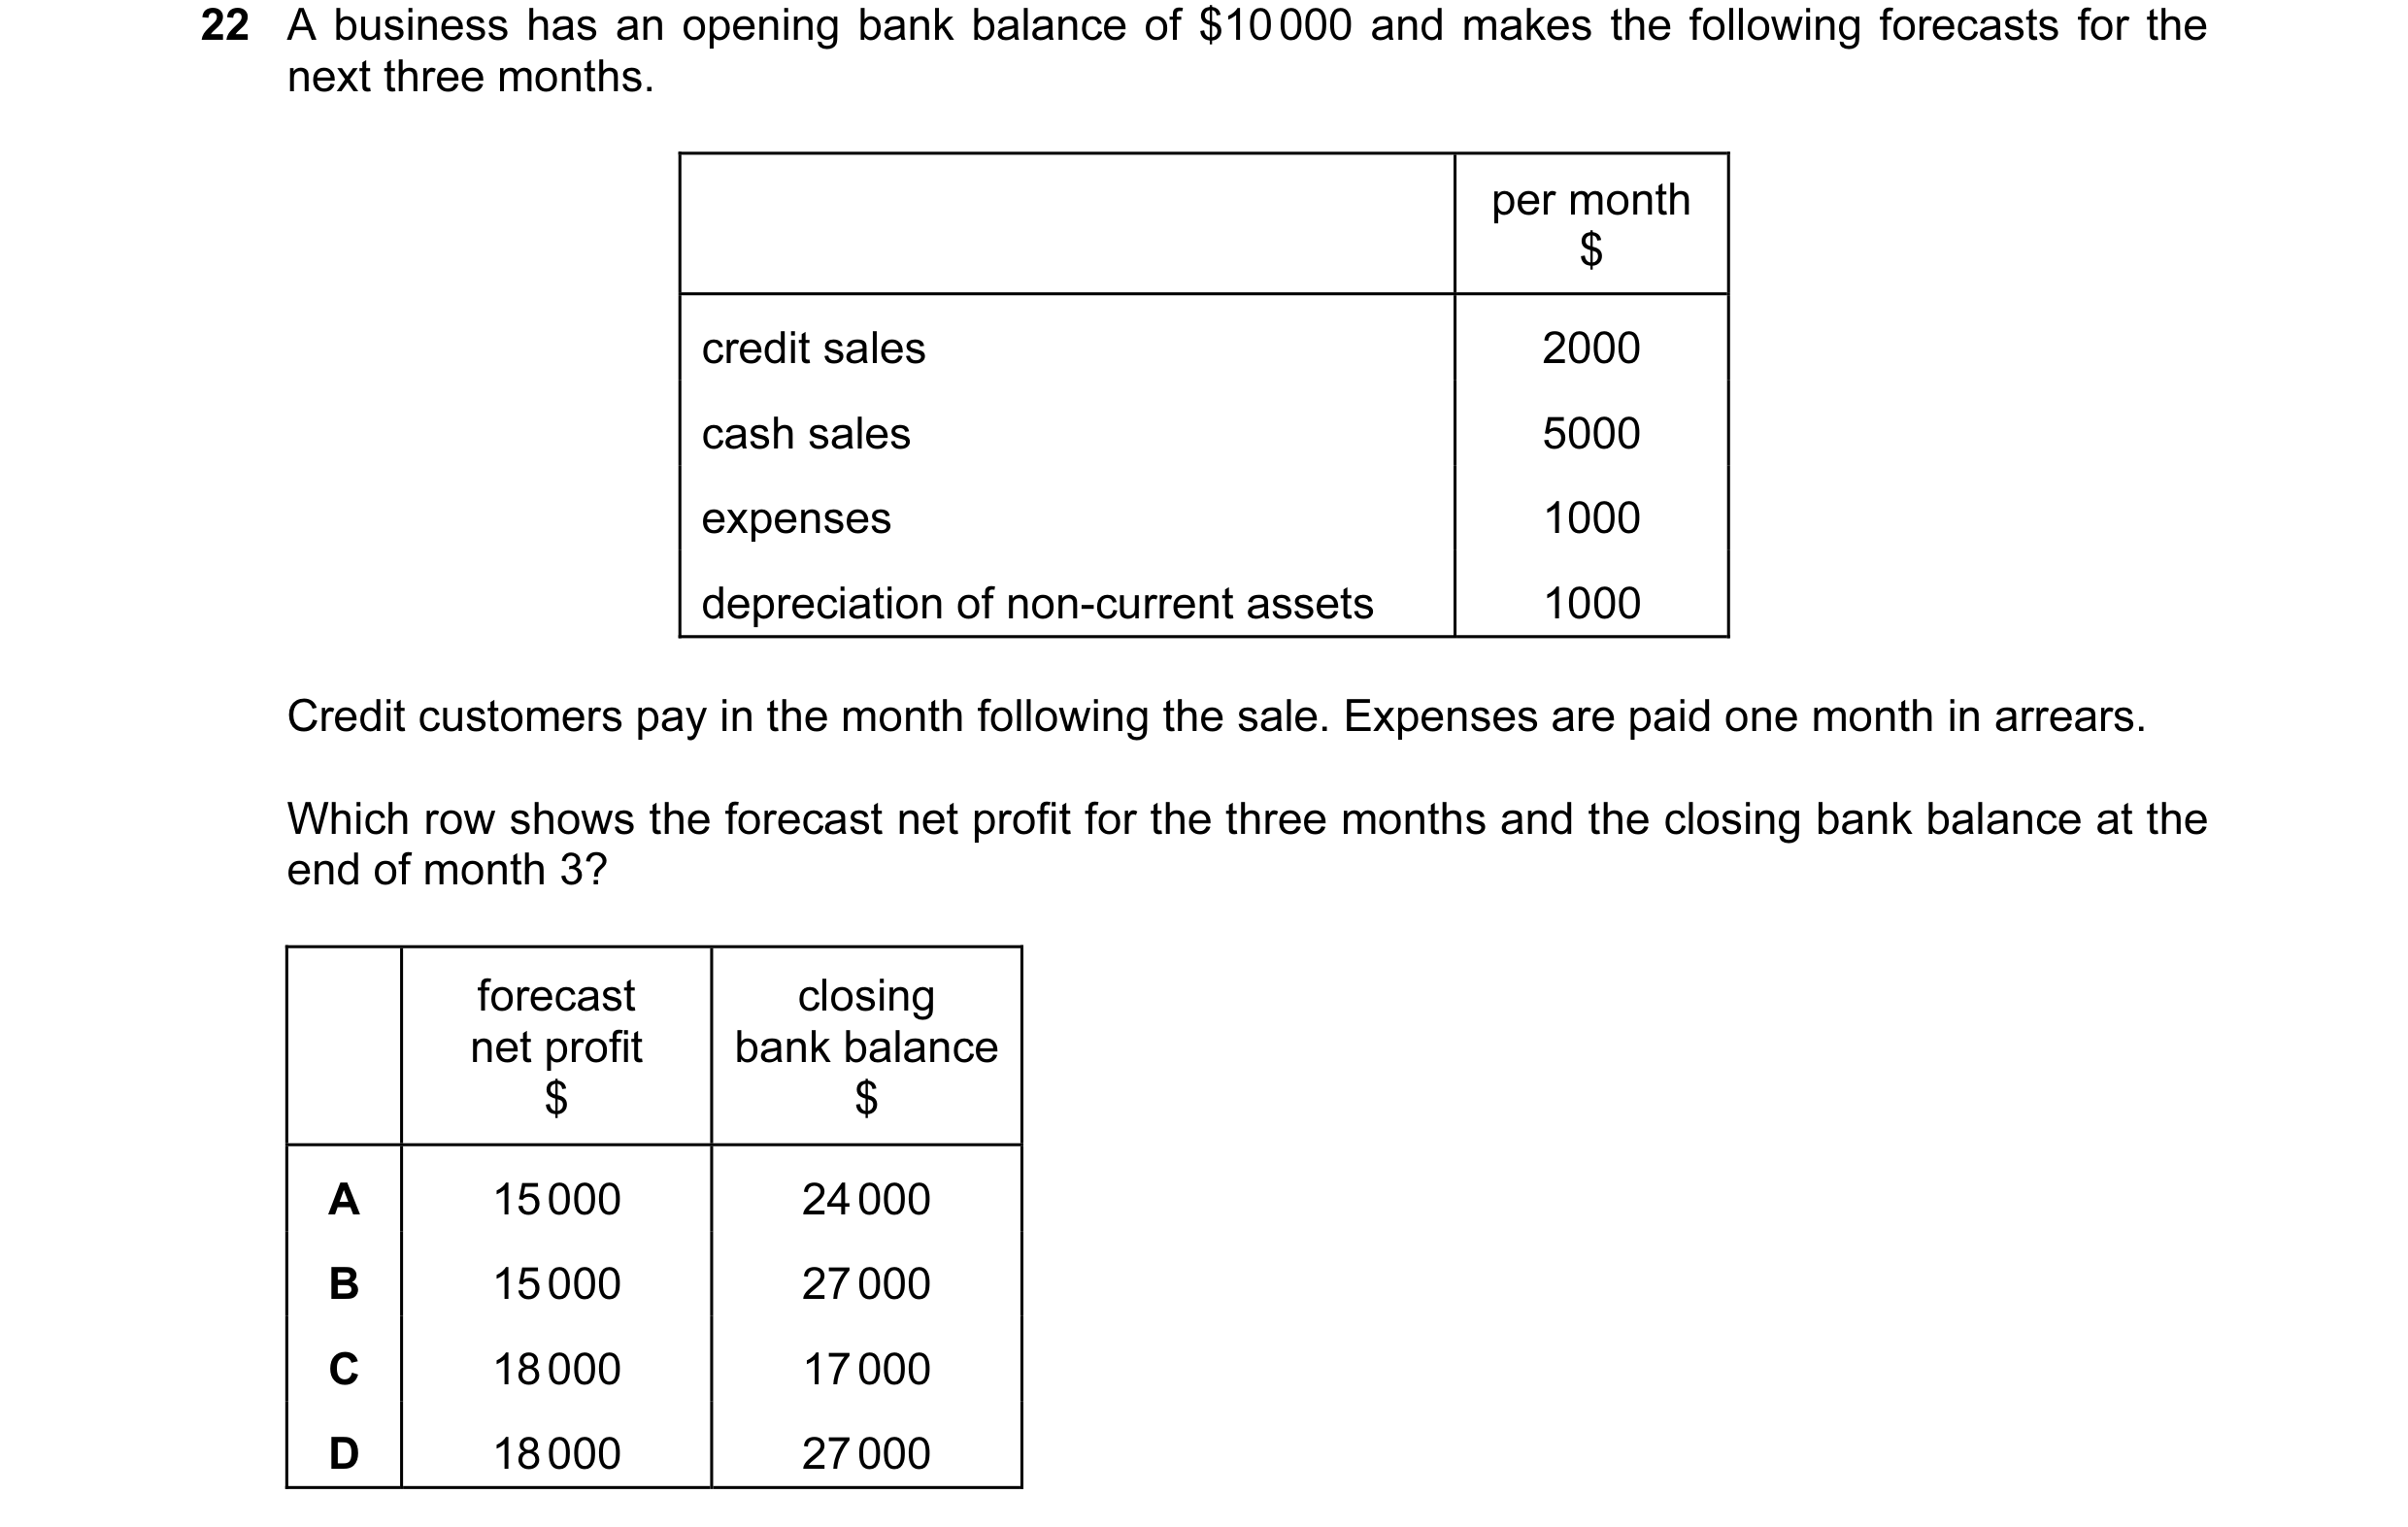
Q52 · A business has an opening bank balance of $10 000 and makes the following forecasts for… 9706/33 Oct/Nov 2013
22 A business has an opening bank balance of $10 000 and makes the following forecasts for the next three months. per month $ credit sales 2000 cash sales 5000 expenses 1000 depreciation of non-current assets 1000 Credit customers pay in the month following the sale. Expenses are paid one month in arrears. Which row shows the forecast net profit for the three months and the closing bank balance at the end of month 3? forecast closing net profit bank balance $ $ A 15 000 24 000 B 15 000 27 000 C 18 000 17 000 D 18 000 27 000
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2013
Q53 · A company currently uses a fixed budget 9706/31 May/June 2014
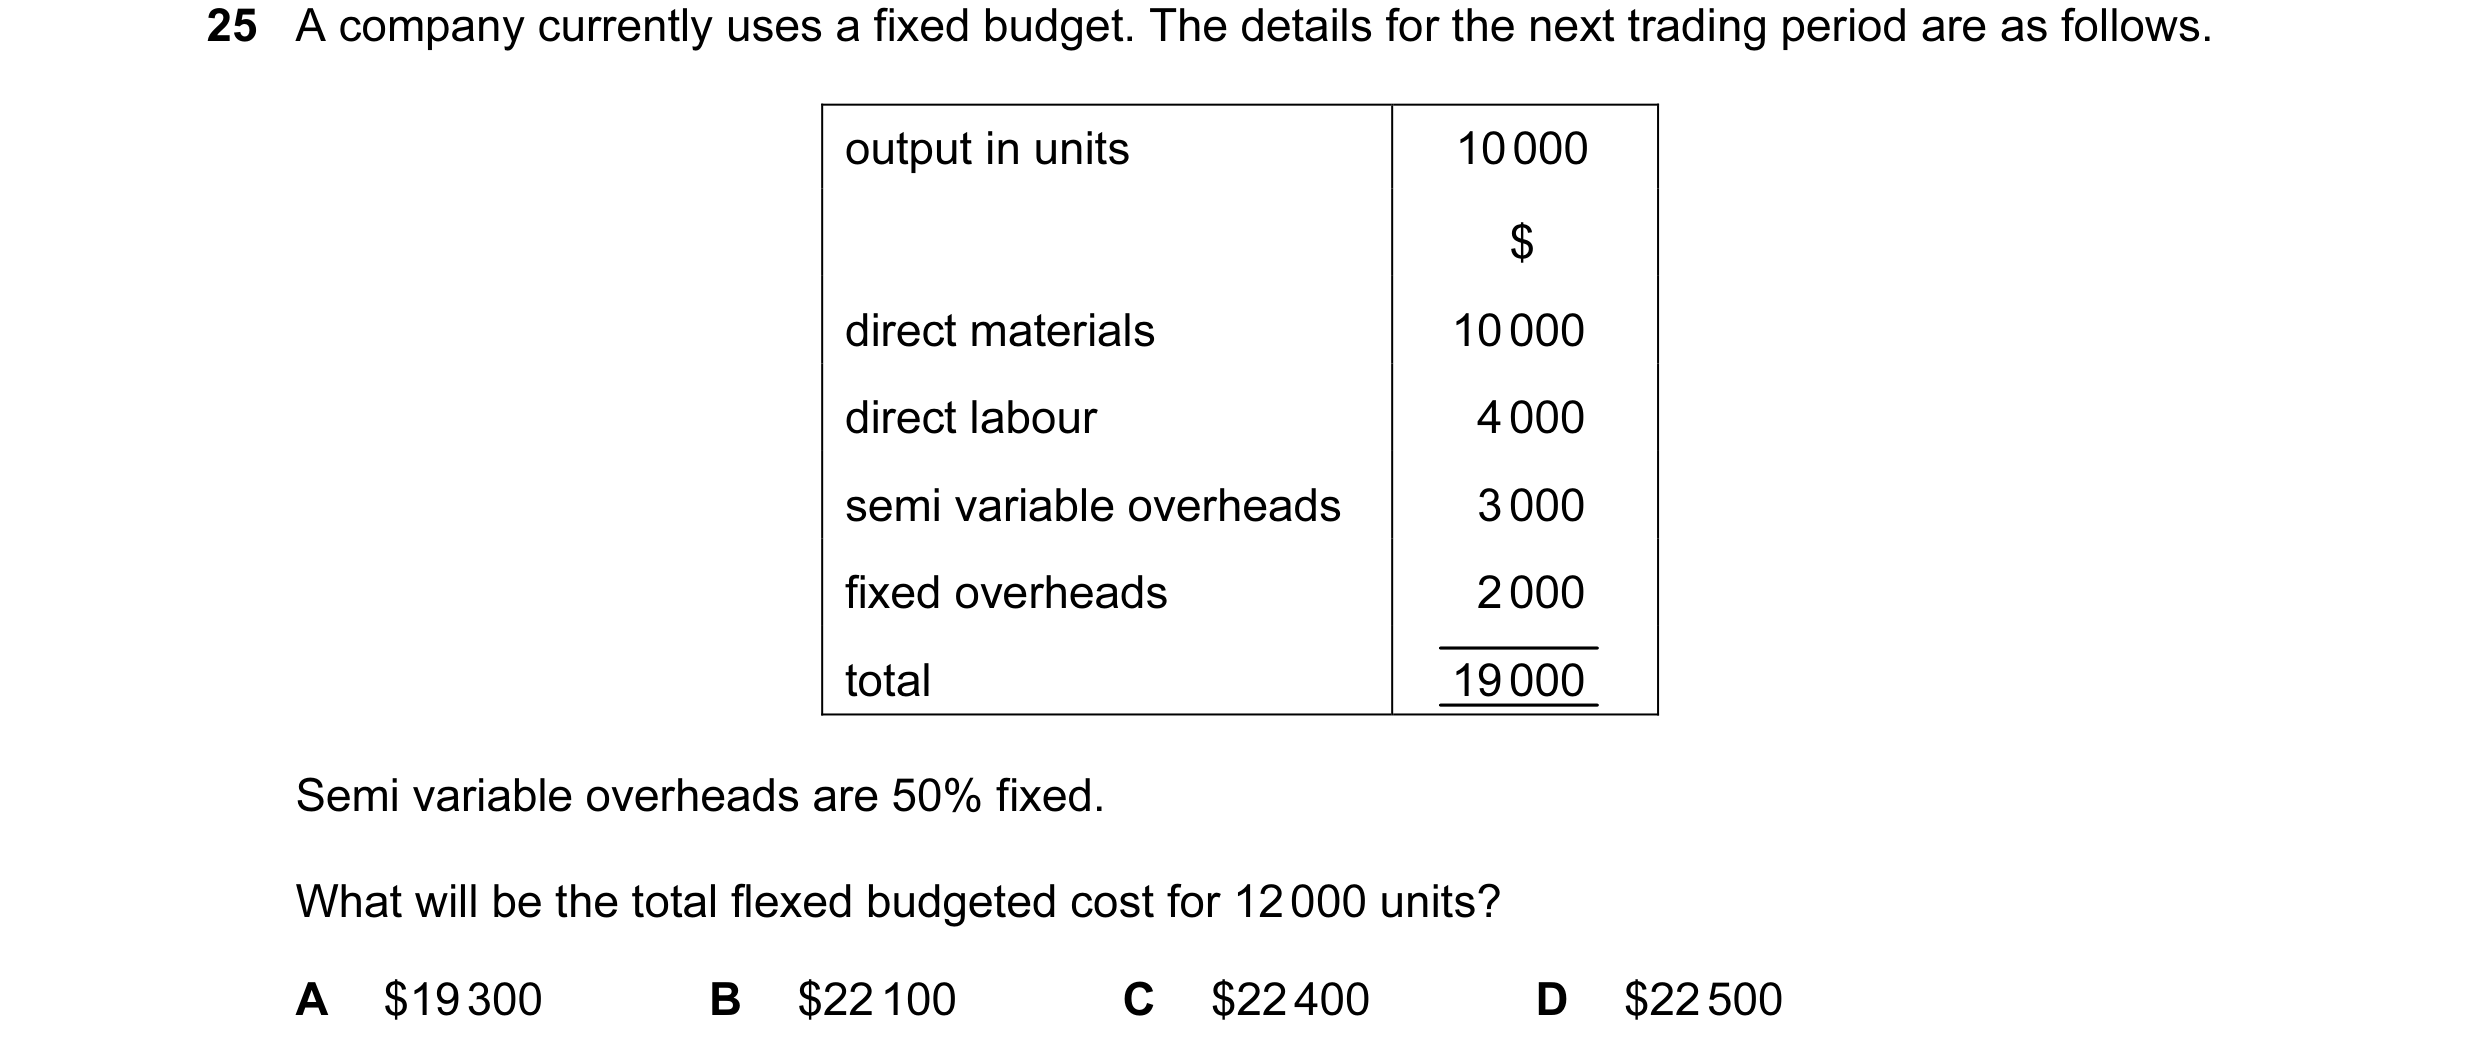
25 A company currently uses a fixed budget. The details for the next trading period are as follows. output in units 10 000 $ direct materials 10 000 direct labour 4 000 semi variable overheads 3 000 fixed overheads 2 000 total 19 000 Semi variable overheads are 50% fixed. What will be the total flexed budgeted cost for 12 000 units? A $19 300 B $22 100 C $22 400 D $22 500
1 marks
Answer: B
This question in 9706/31 May/June 2014
Q54 · A company currently uses a fixed budget 9706/32 May/June 2014
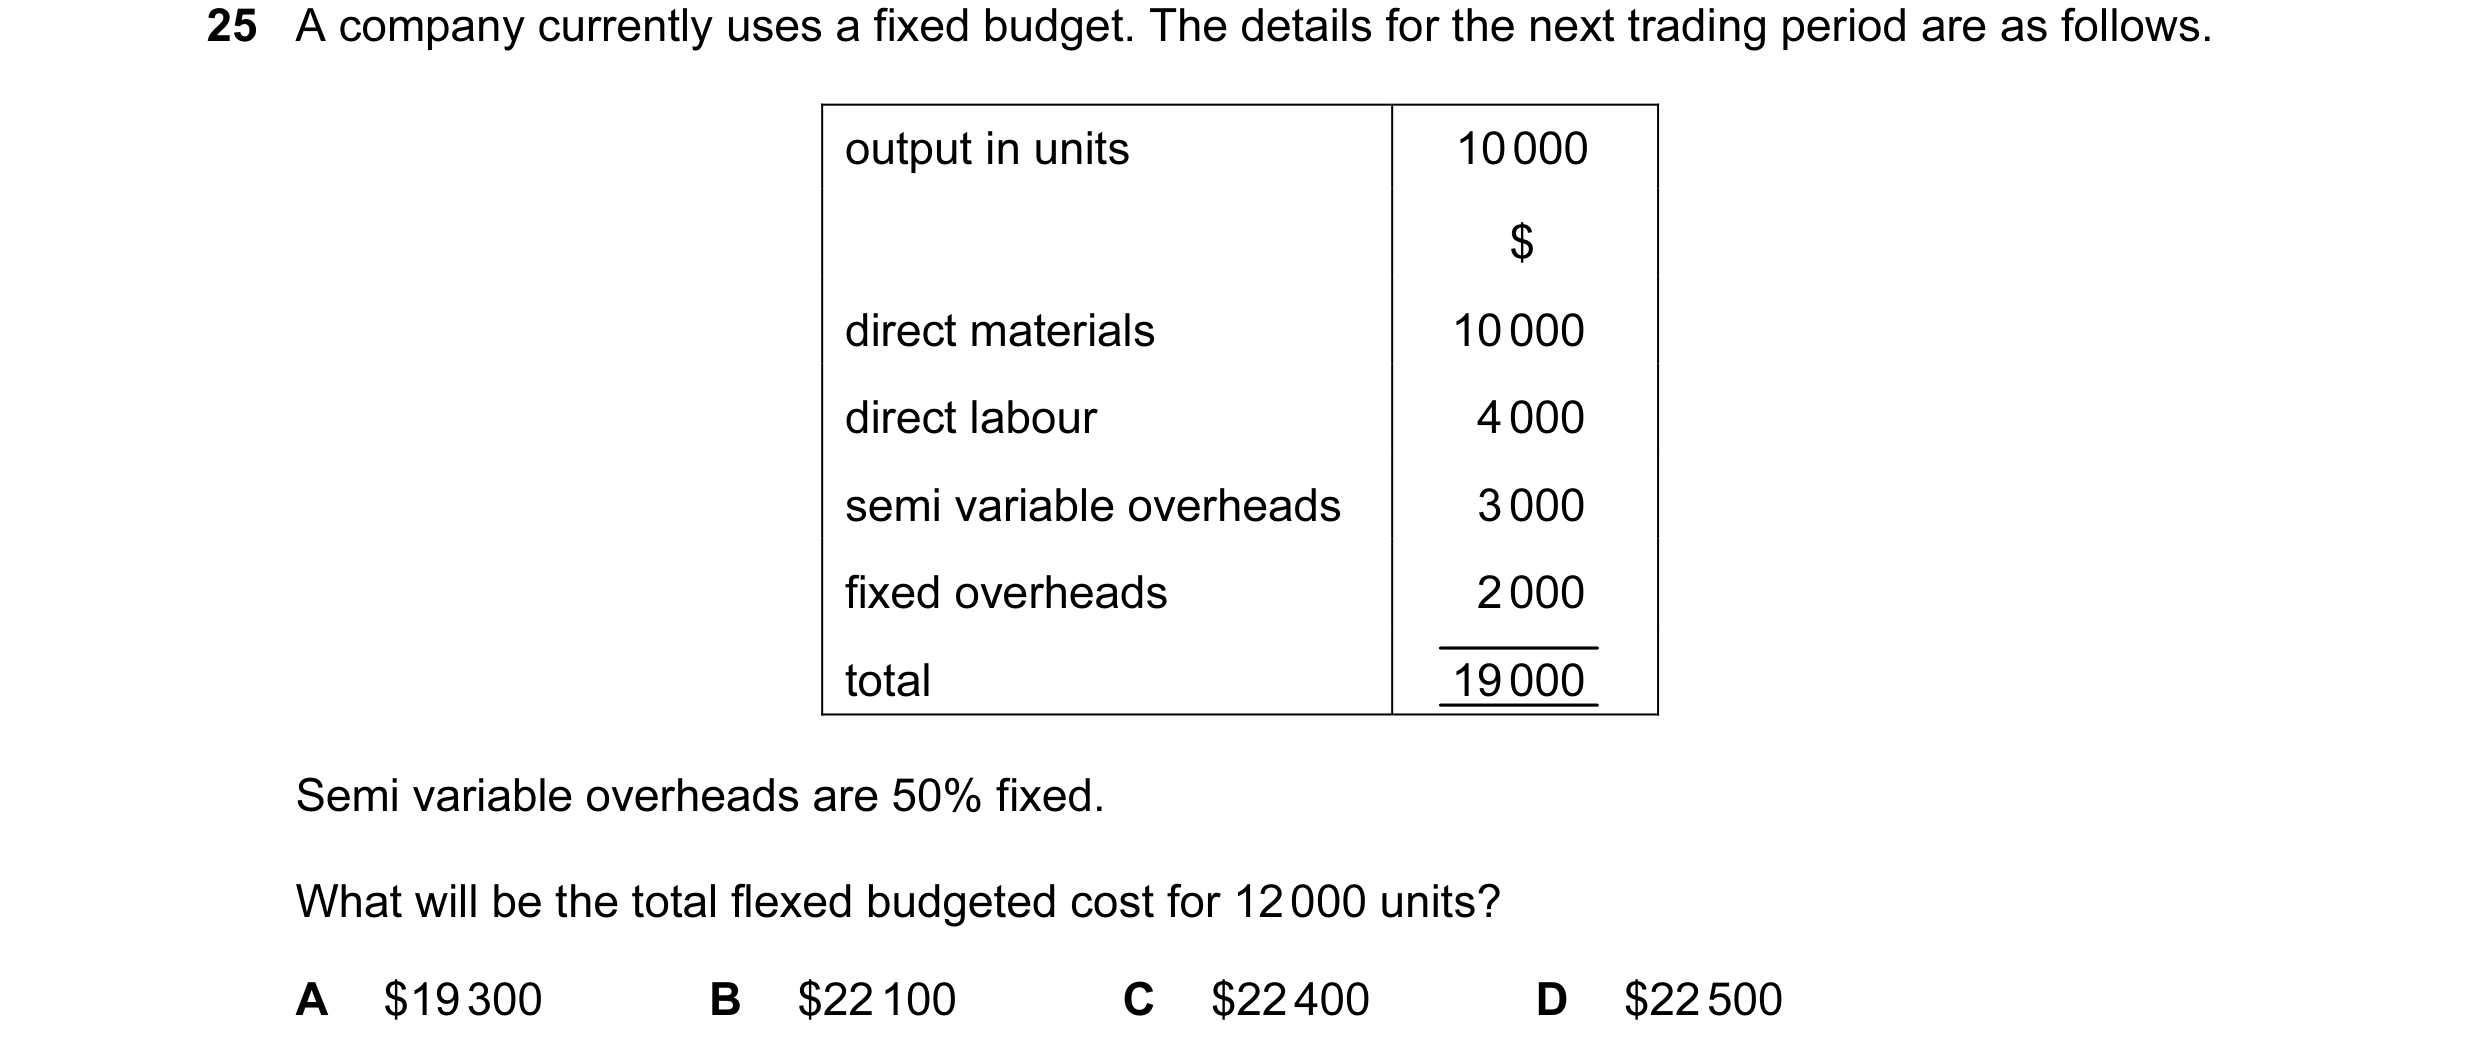
25 A company currently uses a fixed budget. The details for the next trading period are as follows. output in units 10 000 $ direct materials 10 000 direct labour 4 000 semi variable overheads 3 000 fixed overheads 2 000 total 19 000 Semi variable overheads are 50% fixed. What will be the total flexed budgeted cost for 12 000 units? A $19 300 B $22 100 C $22 400 D $22 500
1 marks
Answer: B
This question in 9706/32 May/June 2014
Q55 · A company provides the following information about a product 9706/33 May/June 2014
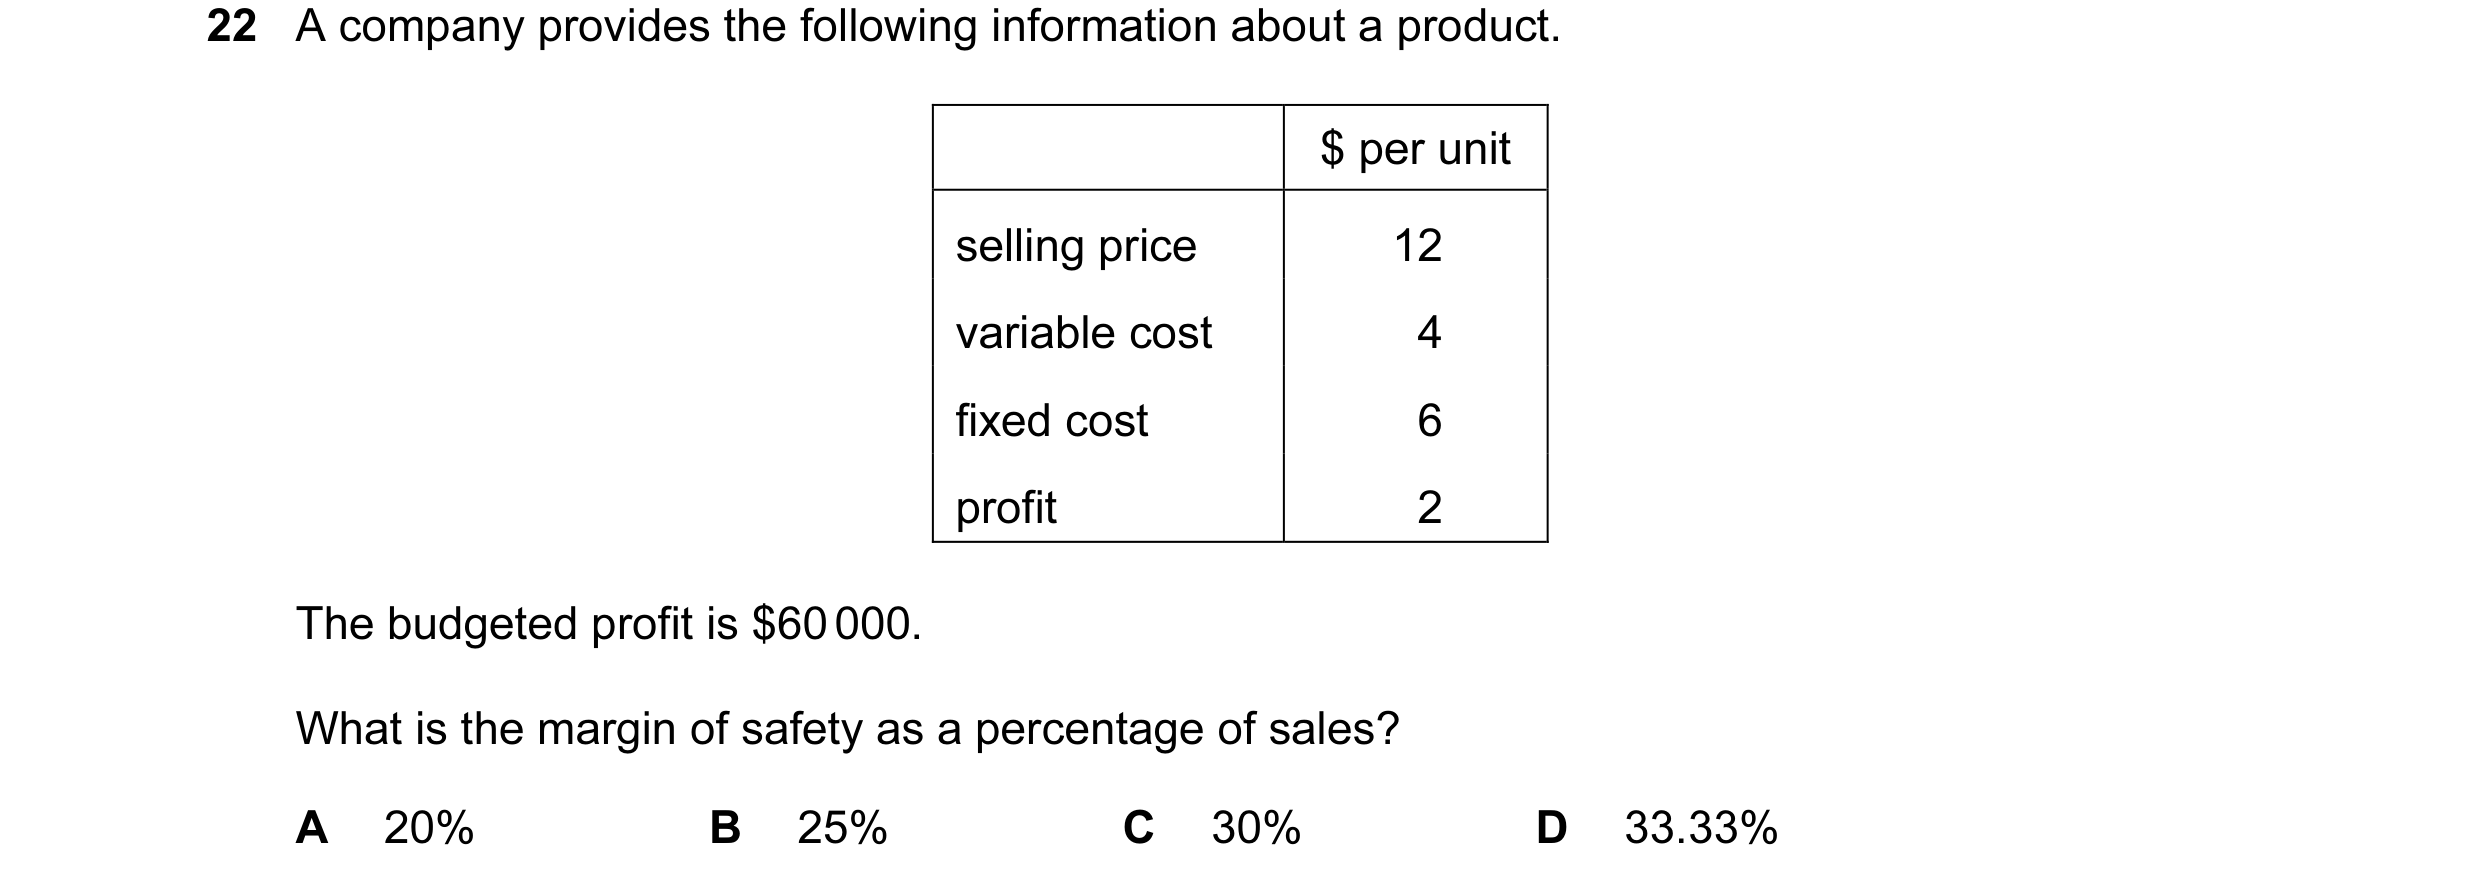
22 A company provides the following information about a product. $ per unit selling price 12 variable cost 4 fixed cost 6 profit 2 The budgeted profit is $60 000. What is the margin of safety as a percentage of sales? A 20% B 25% C 30% D 33.33%
1 marks
Answer: B
This question in 9706/33 May/June 2014
Q56 · The following data relates to a manufacturing company for a month 9706/33 May/June 2014
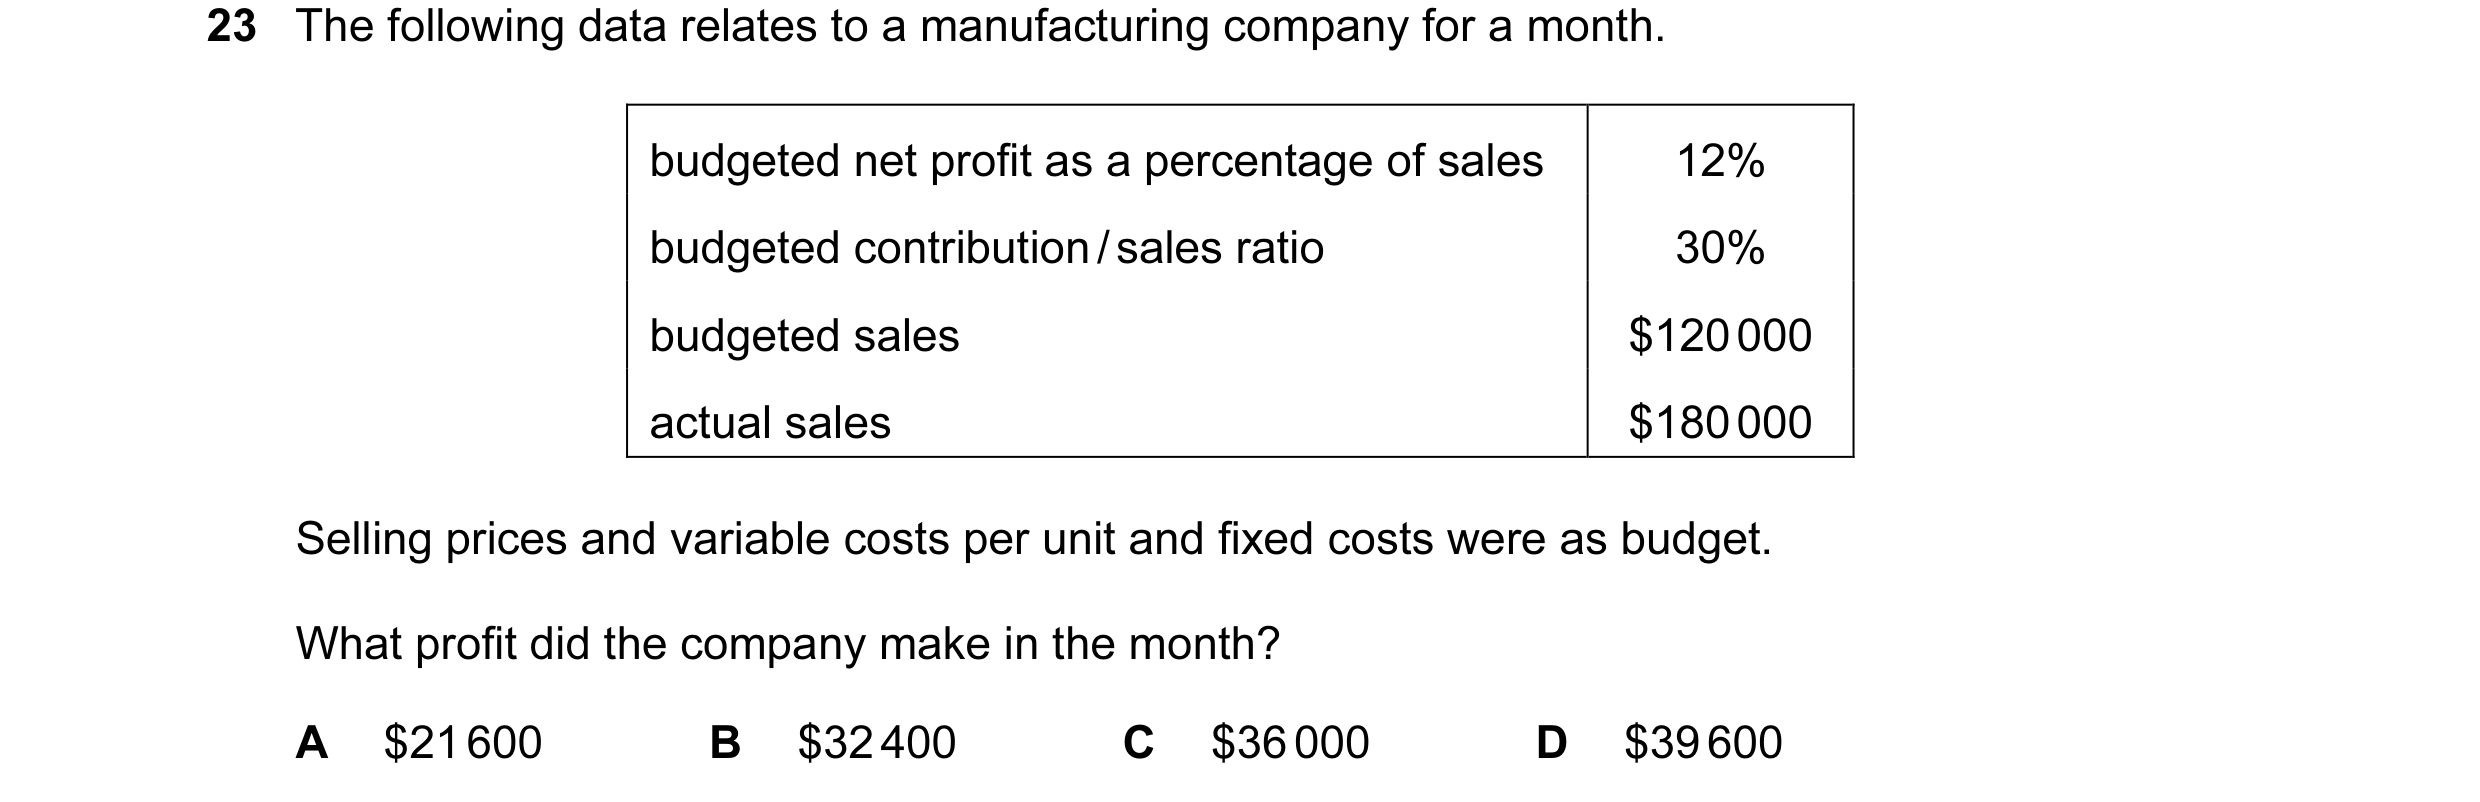
23 The following data relates to a manufacturing company for a month. budgeted net profit as a percentage of sales 12% budgeted contribution / sales ratio 30% budgeted sales $120 000 actual sales $180 000 Selling prices and variable costs per unit and fixed costs were as budget. What profit did the company make in the month? A $21 600 B $32 400 C $36 000 D $39 600
1 marks
Answer: B
This question in 9706/33 May/June 2014
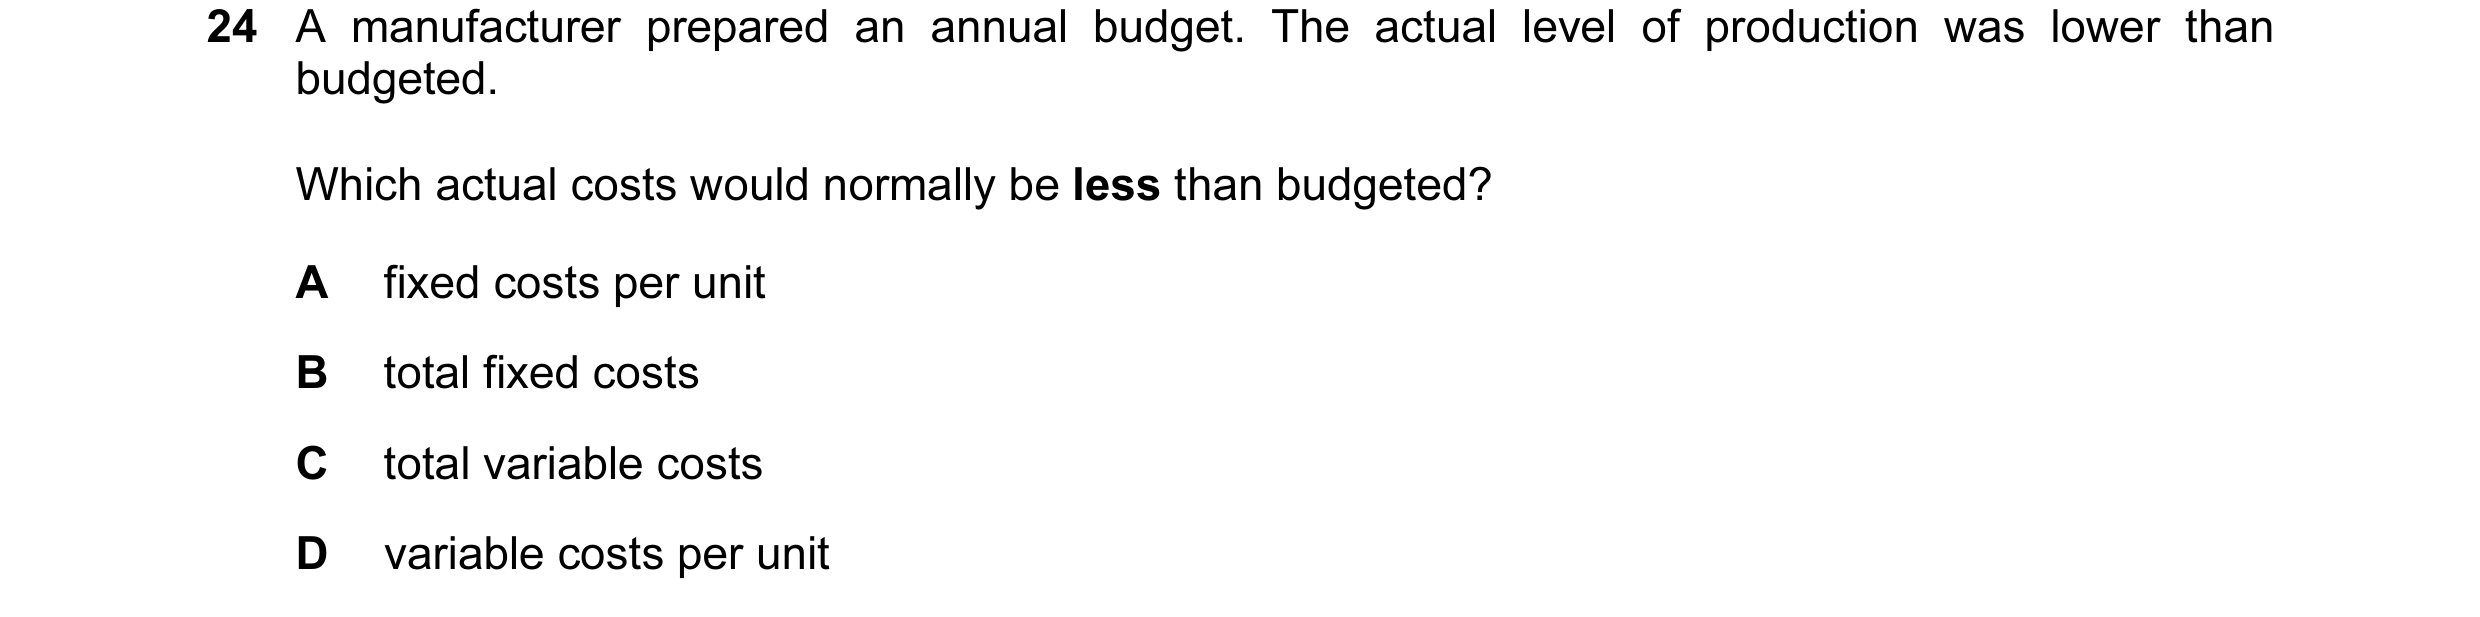
Q57 · A manufacturer prepared an annual budget 9706/33 May/June 2014
24 A manufacturer prepared an annual budget. The actual level of production was lower than budgeted. Which actual costs would normally be less than budgeted? A fixed costs per unit B total fixed costs C total variable costs D variable costs per unit
1 marks
Answer: C
This question in 9706/33 May/June 2014
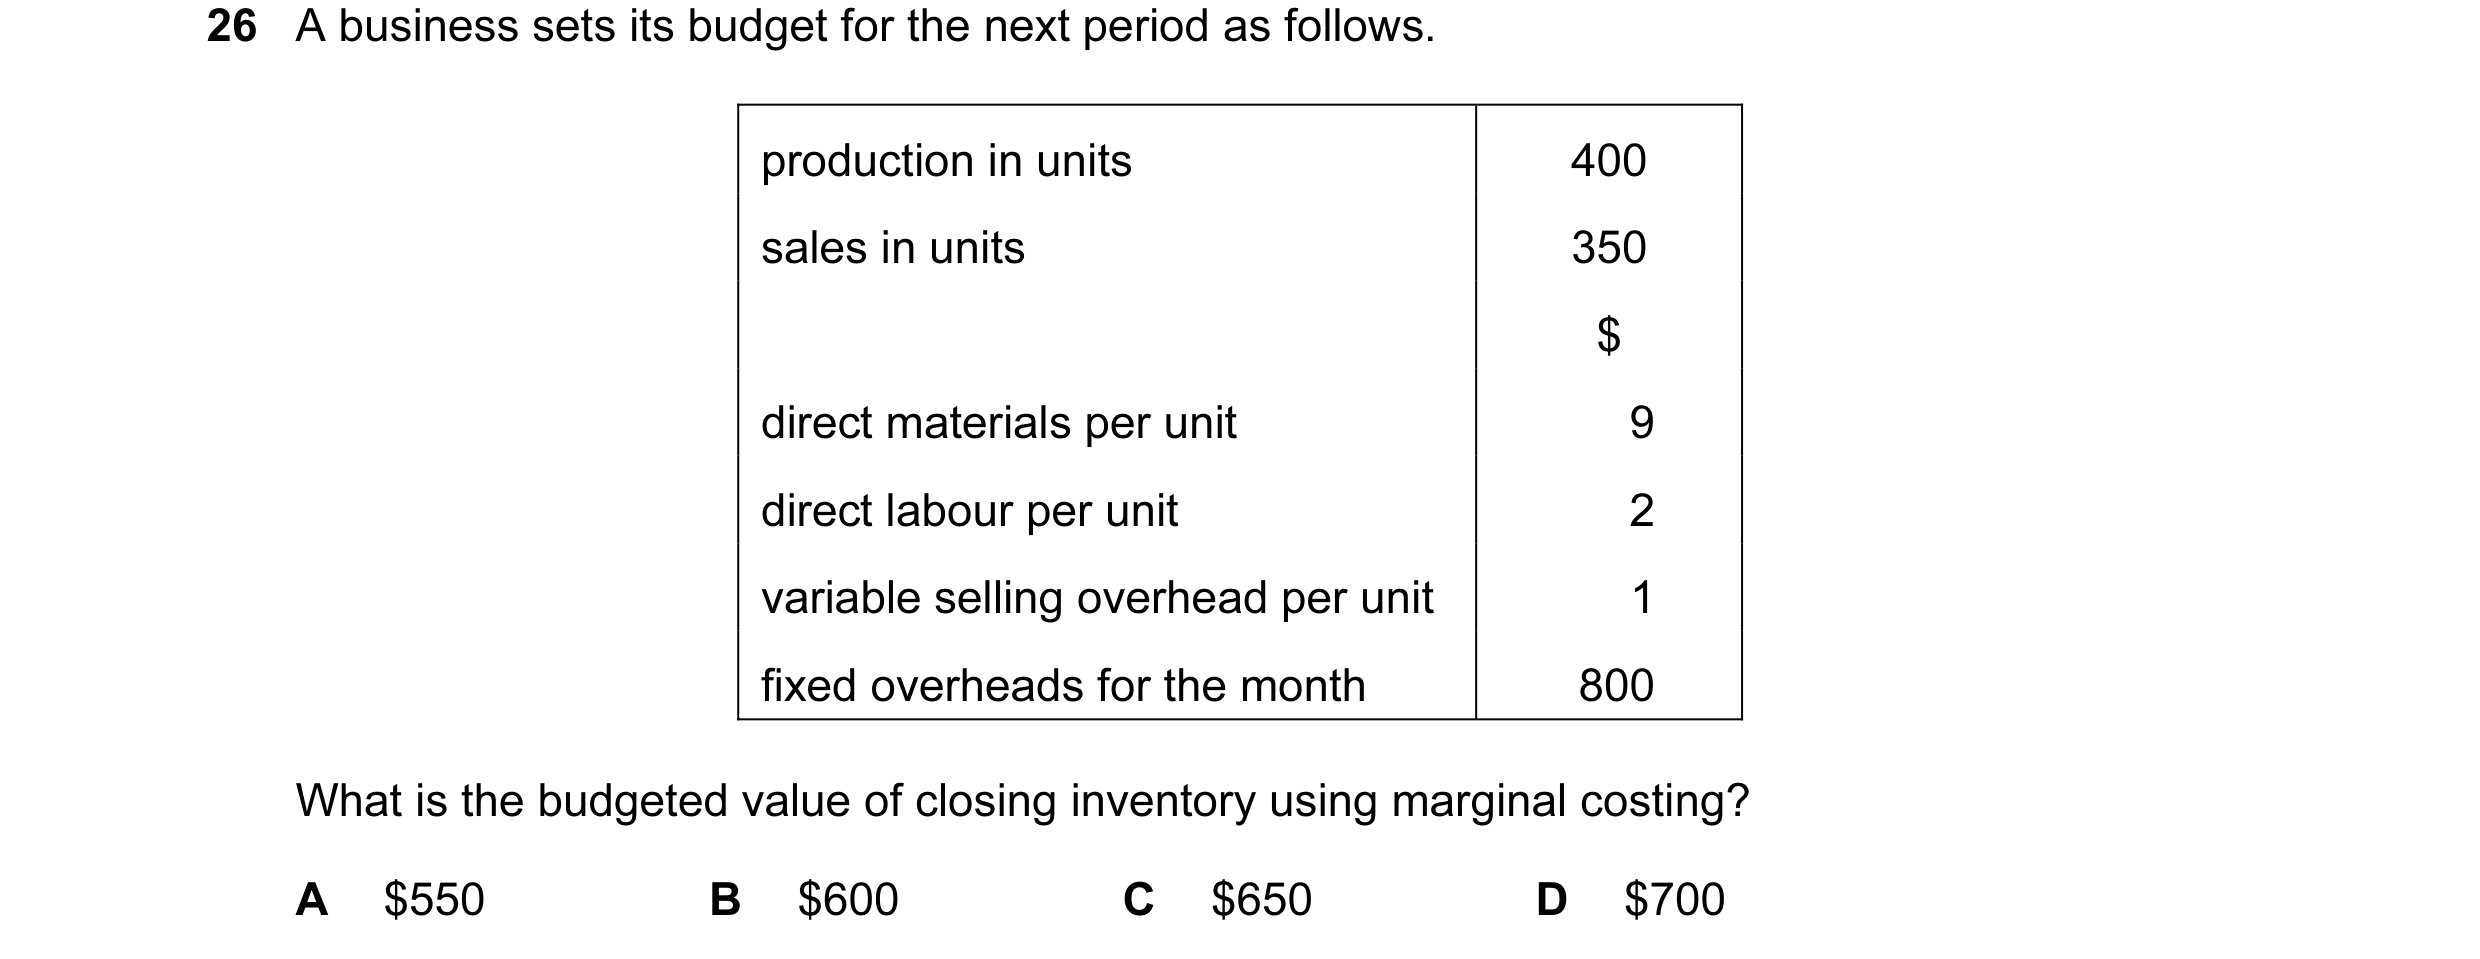
Q58 · A business sets its budget for the next period as follows 9706/33 May/June 2014
26 A business sets its budget for the next period as follows. production in units 400 sales in units 350 $ direct materials per unit 9 direct labour per unit 2 variable selling overhead per unit 1 fixed overheads for the month 800 What is the budgeted value of closing inventory using marginal costing? A $550 B $600 C $650 D $700
1 marks
Answer: A
This question in 9706/33 May/June 2014
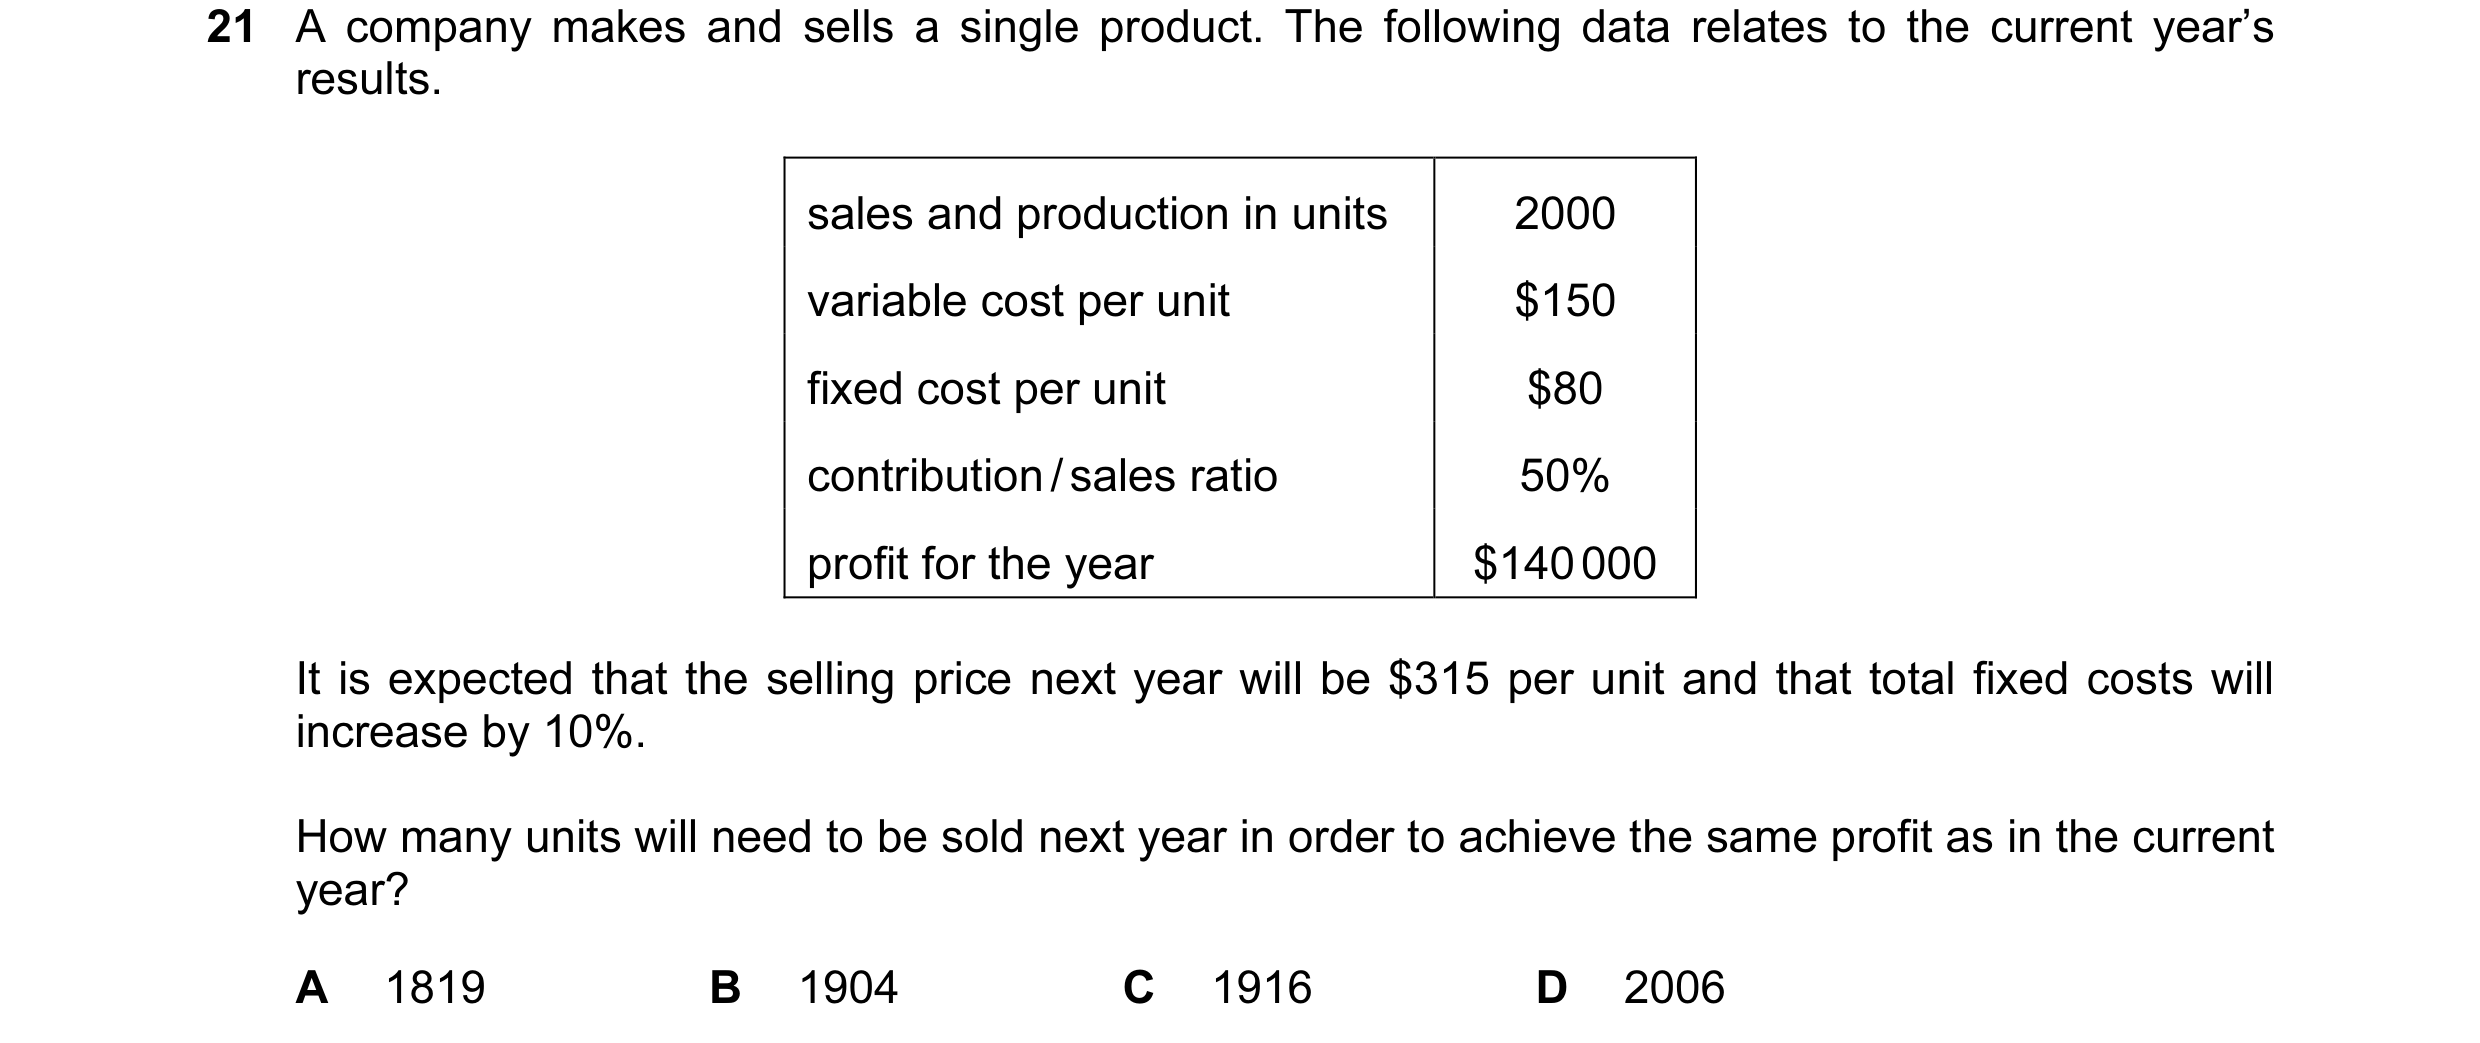
Q59 · A company makes and sells a single product 9706/31 Oct/Nov 2015
21 A company makes and sells a single product. The following data relates to the current year’s results. sales and production in units 2000 variable cost per unit $150 fixed cost per unit $80 contribution / sales ratio 50% profit for the year $140 000 It is expected that the selling price next year will be $315 per unit and that total fixed costs will increase by 10%. How many units will need to be sold next year in order to achieve the same profit as in the current year? A 1819 B 1904 C 1916 D 2006
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2015
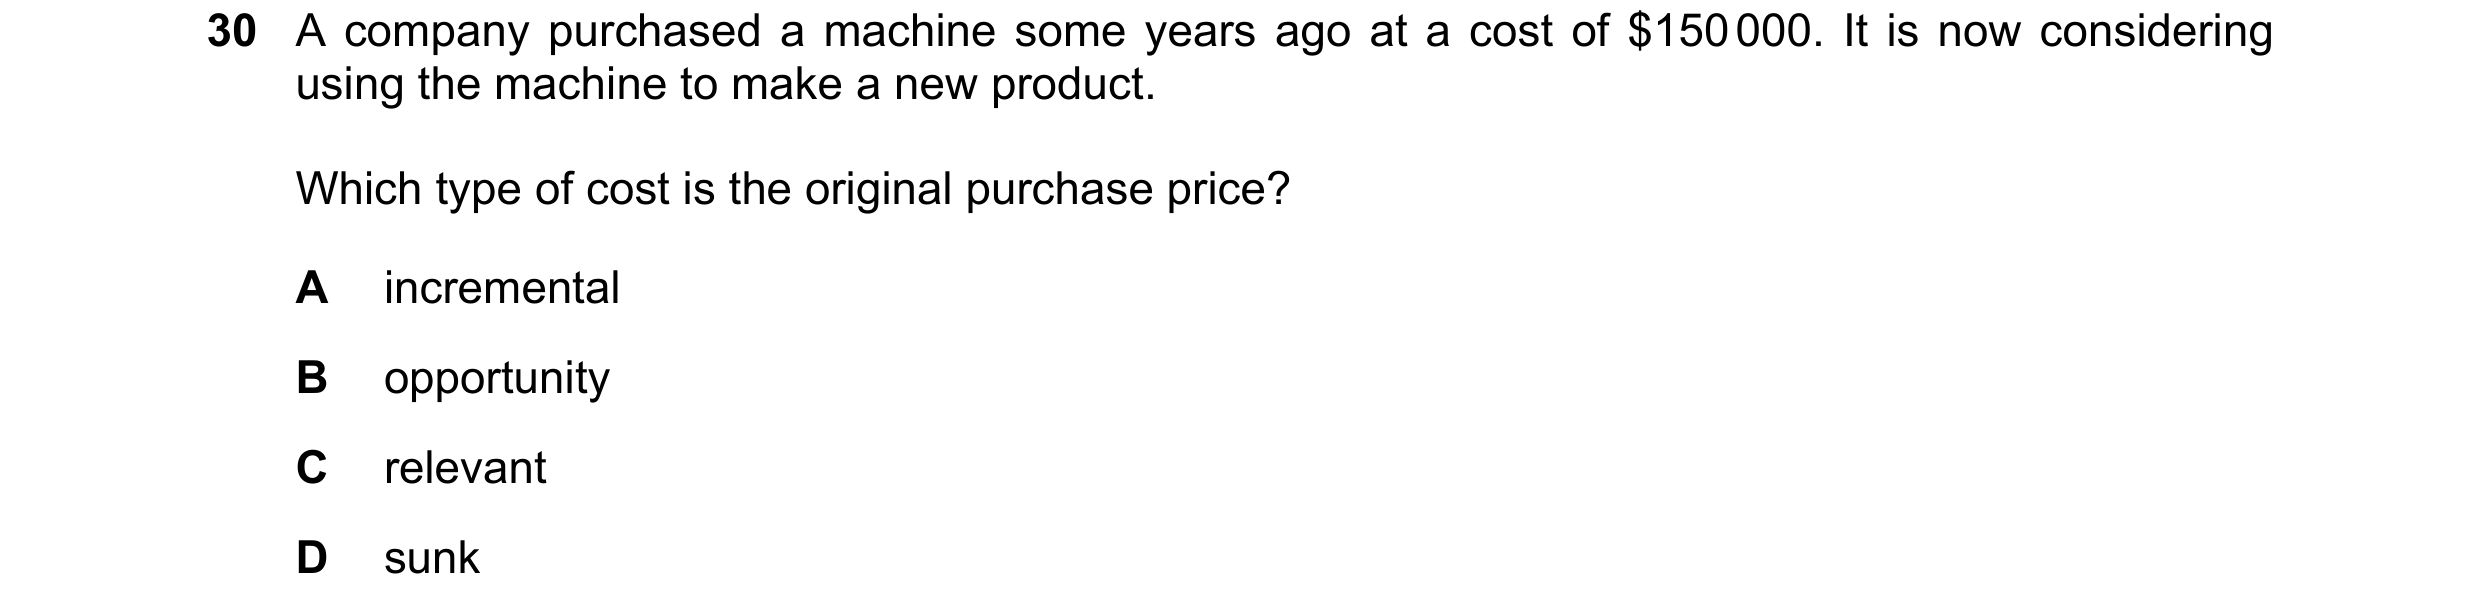
Q60 · A company purchased a machine some years ago at a cost of $150 000 9706/32 Oct/Nov 2015
30 A company purchased a machine some years ago at a cost of $150 000. It is now considering using the machine to make a new product. Which type of cost is the original purchase price? A incremental B opportunity C relevant D sunk
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2015
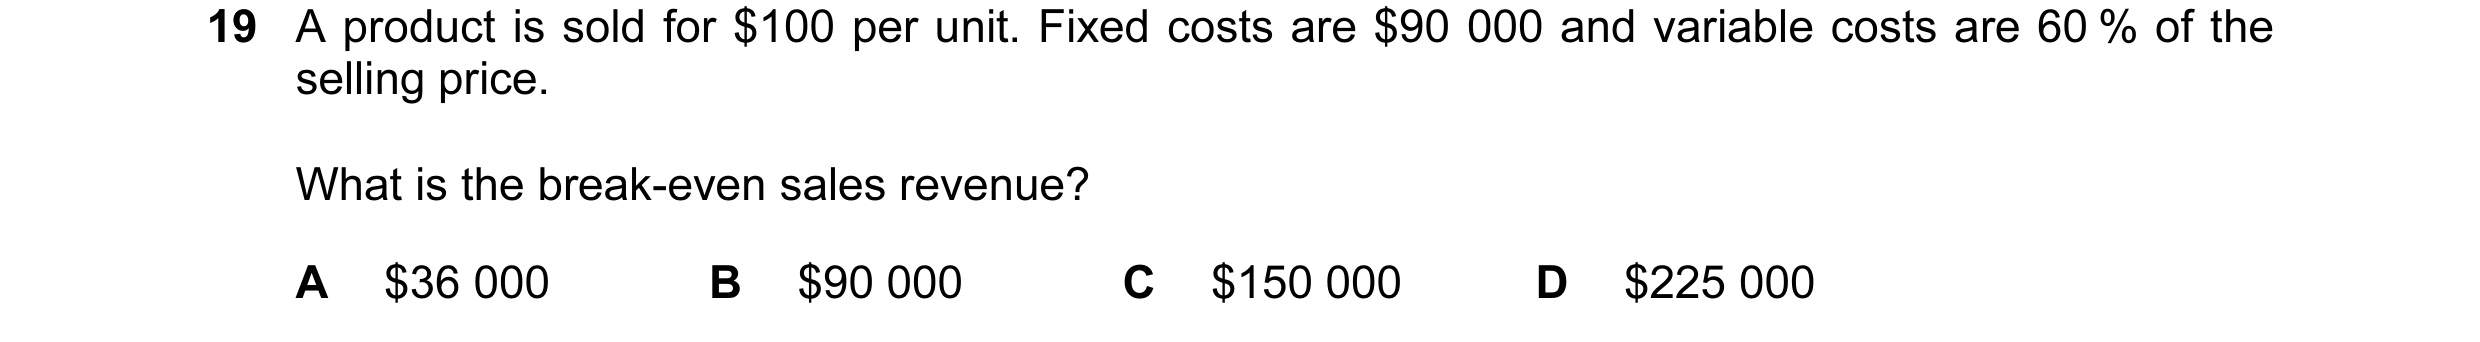 1 / 18
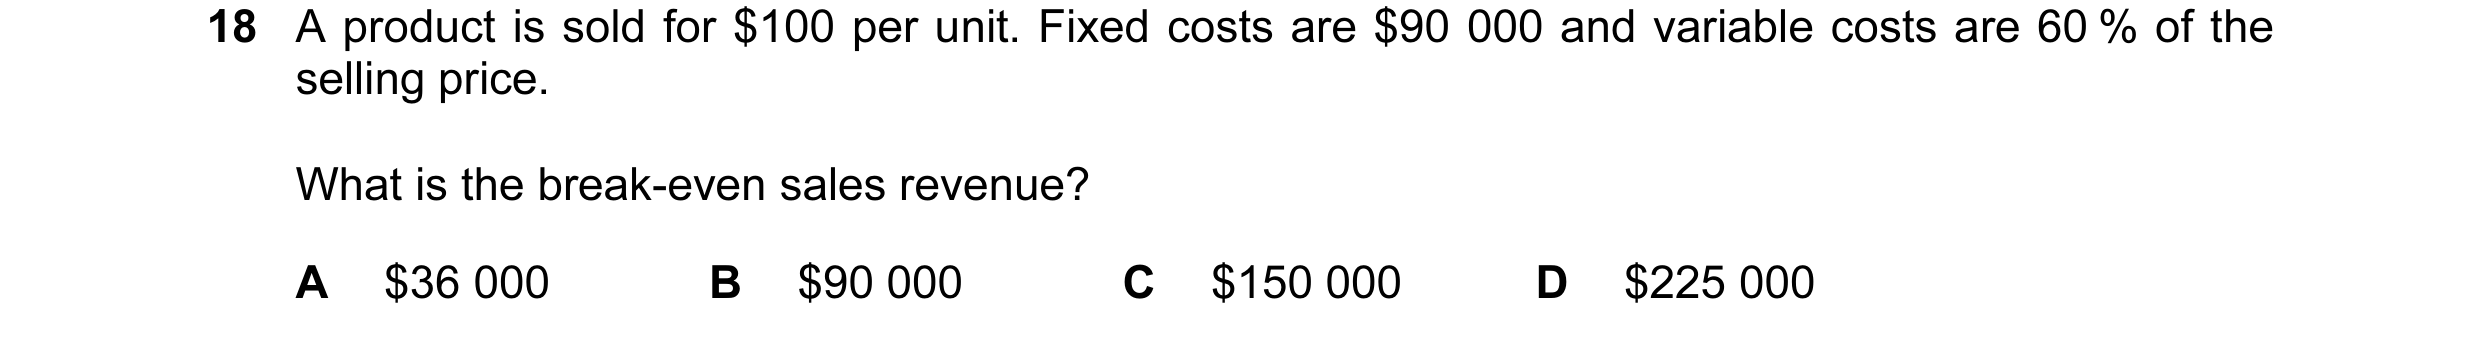
 2 / 18
 3 / 18
 4 / 18
 5 / 18
 6 / 18
 7 / 18
 8 / 18
 9 / 18
 10 / 18
 11 / 18
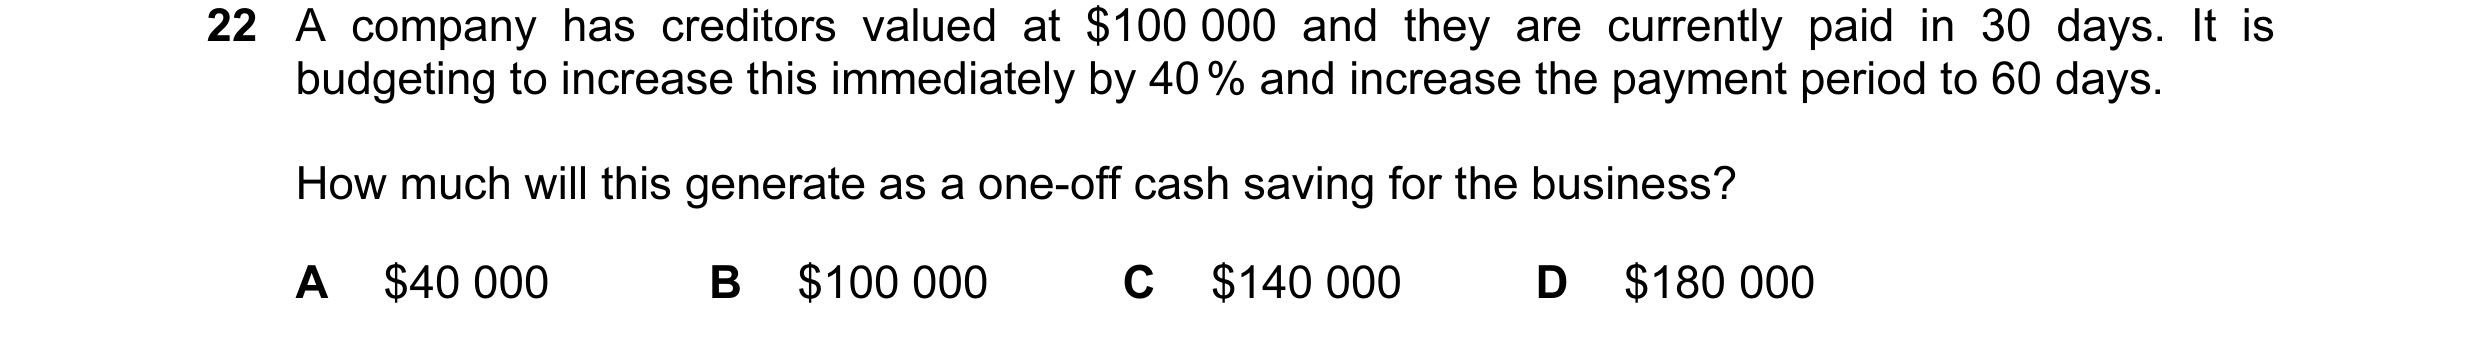
 12 / 18
 13 / 18
 14 / 18
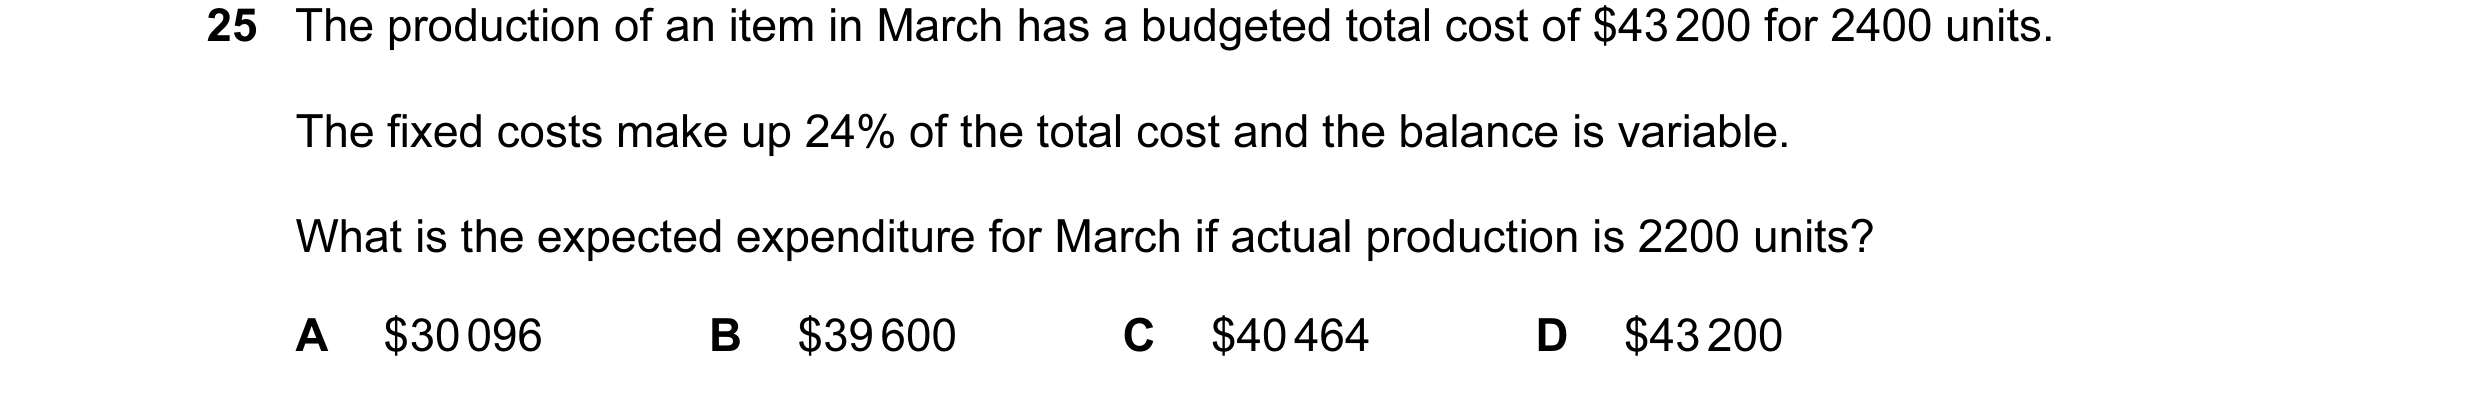
 15 / 18
 16 / 18
 17 / 18
 18 / 18