Cambridge A Level Accounting 9706 — 2013 Oct/Nov Paper 3 · Variant 3
9706/33/O/N/13 · 30 questions · 30 marks · ≈34 min
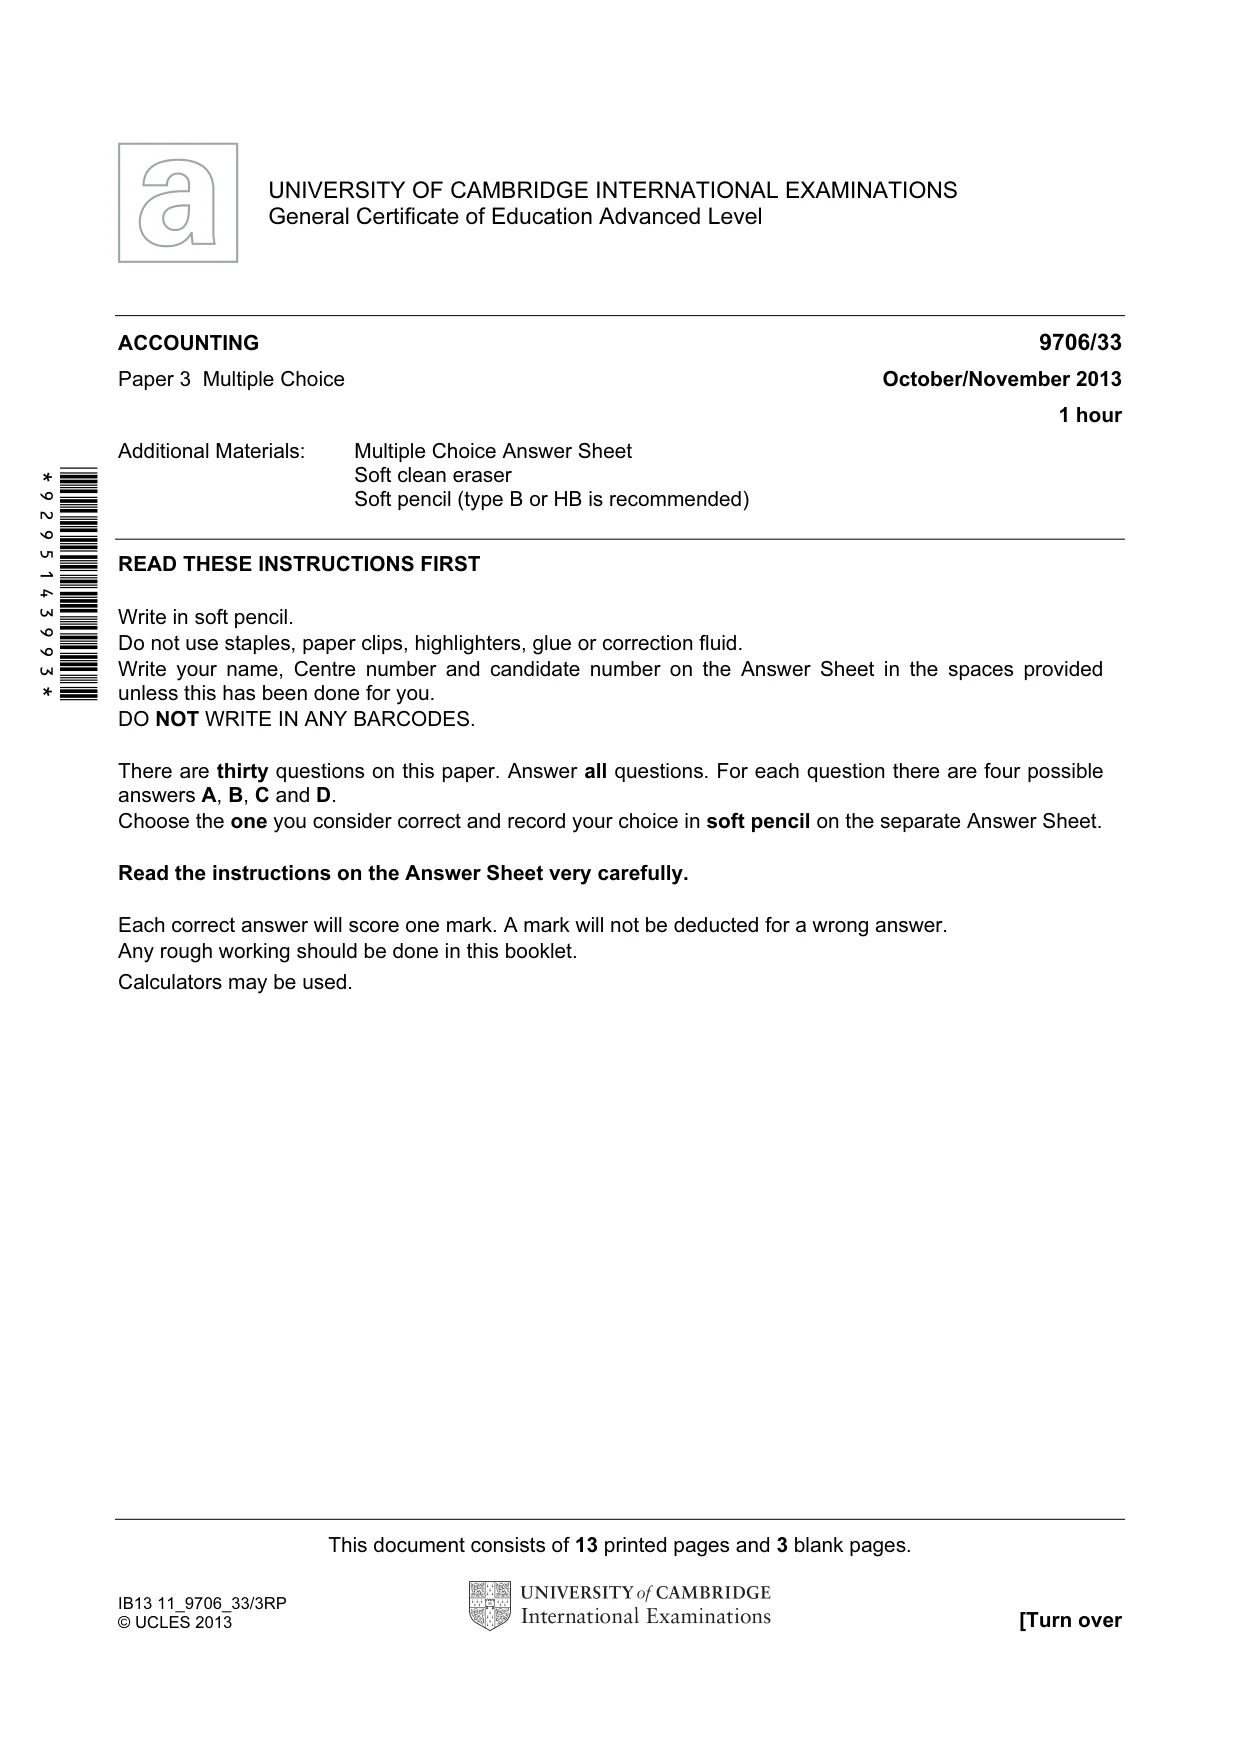
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
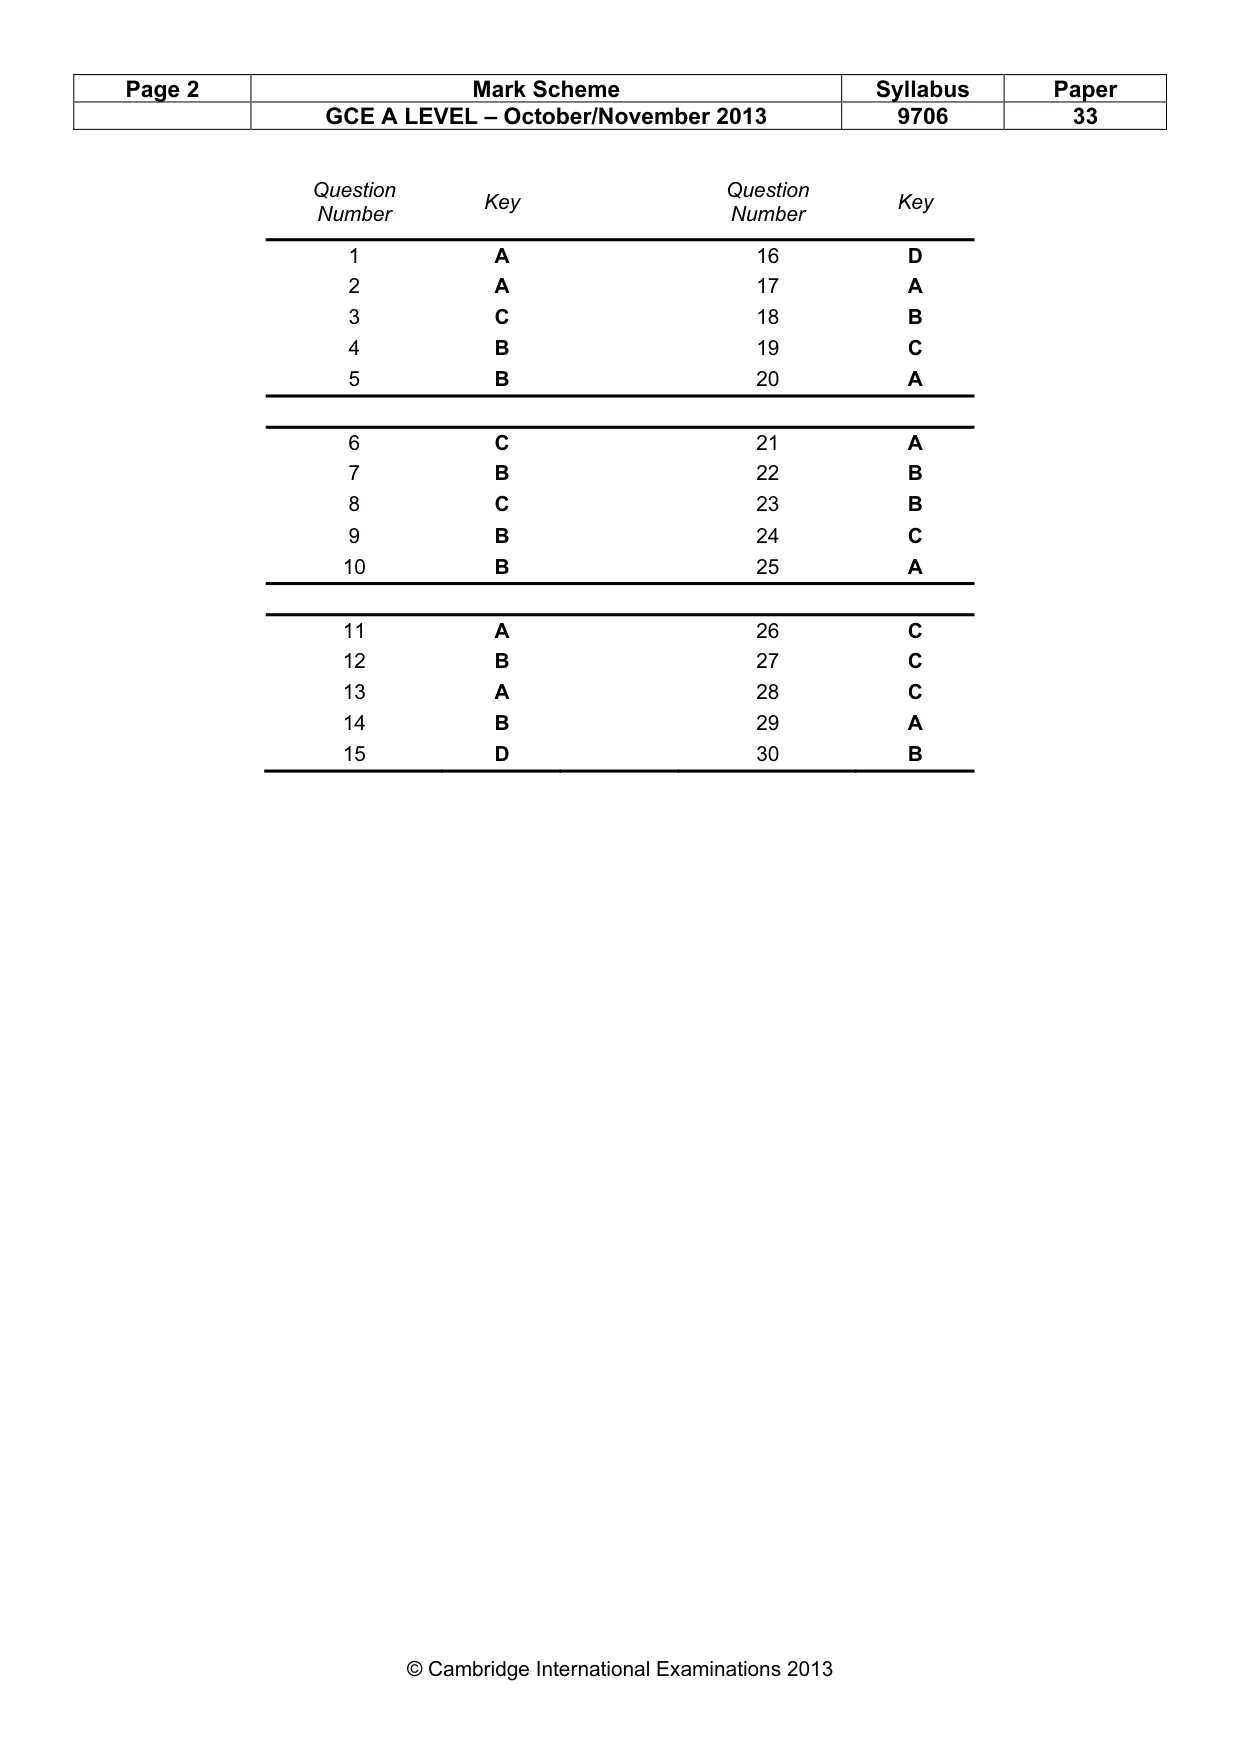
Mark scheme2 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · A trade receivable’s balance of $720 has been set-off against the purchase ledger
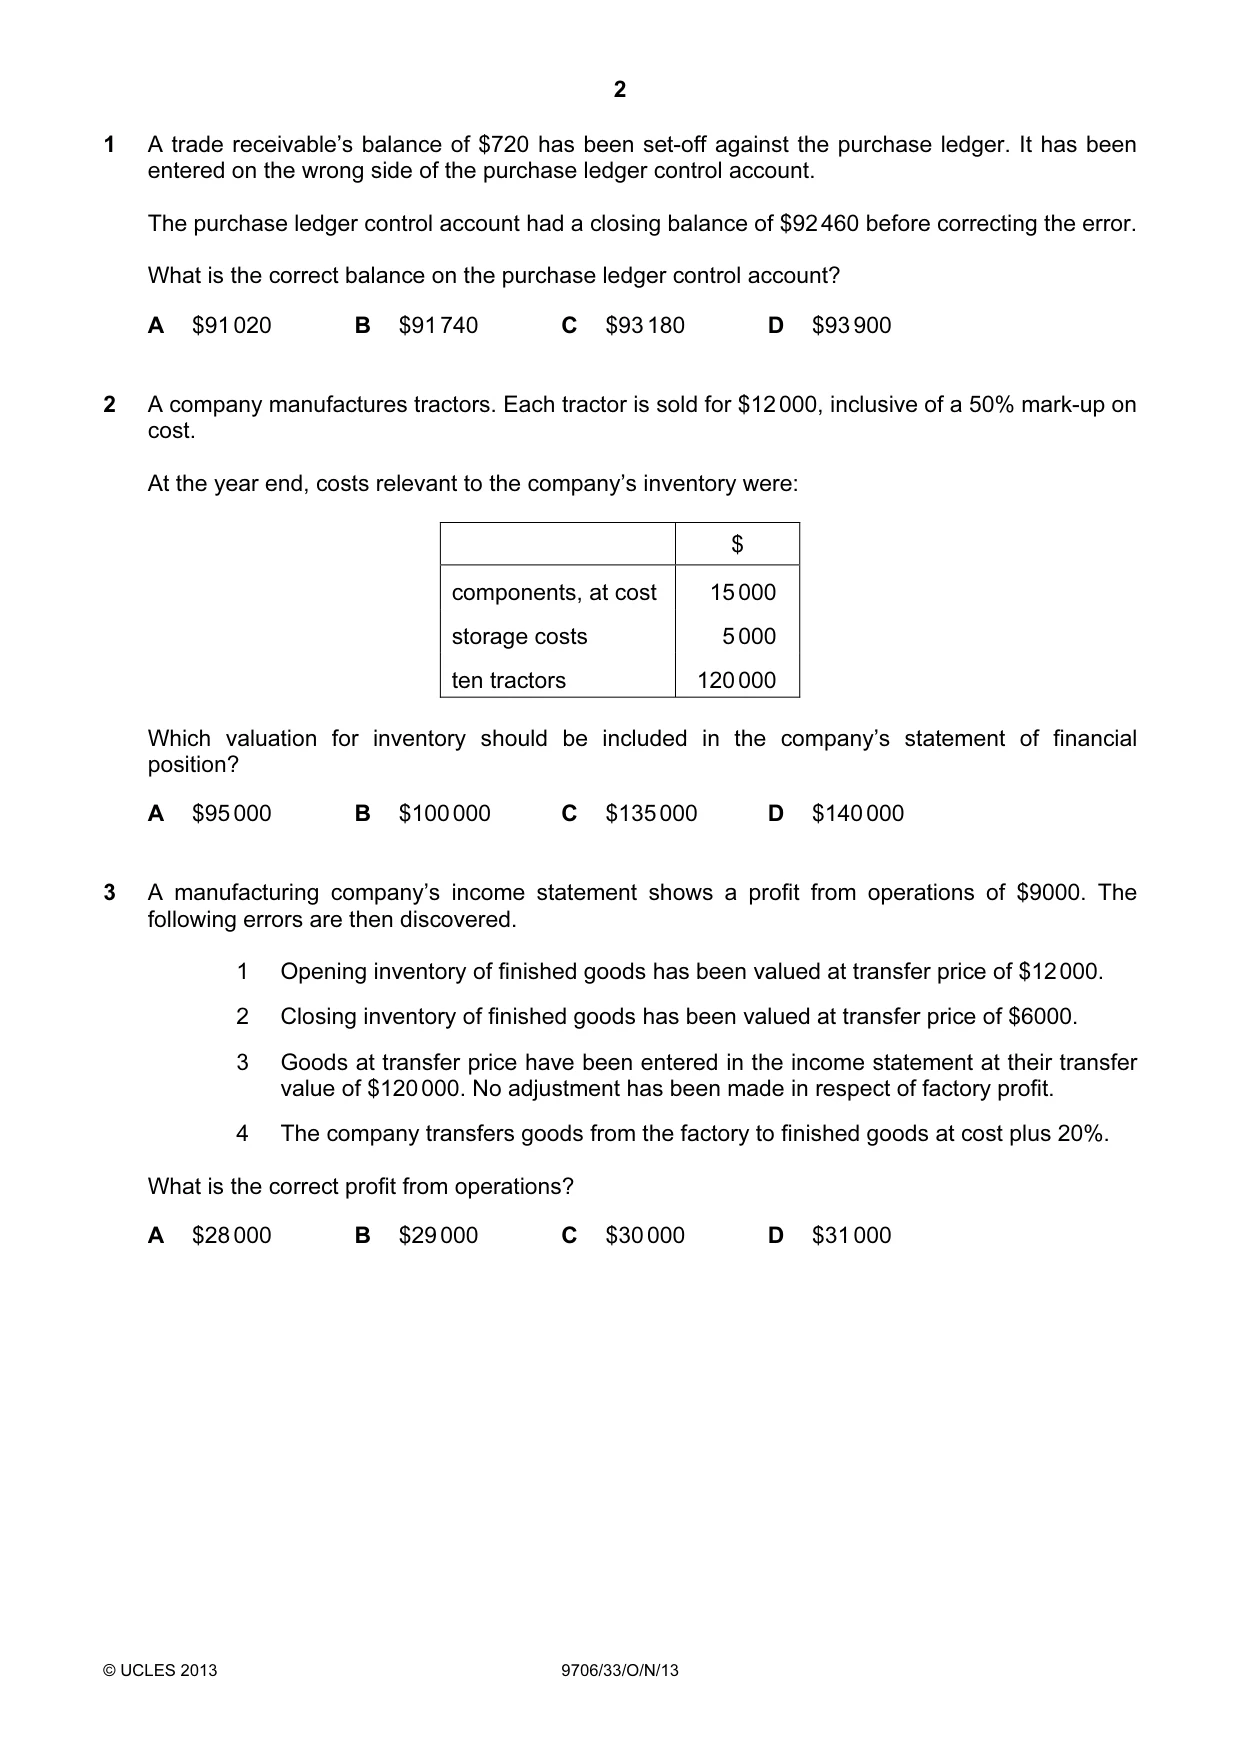
1 A trade receivable’s balance of $720 has been set-off against the purchase ledger. It has been entered on the wrong side of the purchase ledger control account. The purchase ledger control account had a closing balance of $92 460 before correcting the error. What is the correct balance on the purchase ledger control account? A $91 020 B $91 740 C $93 180 D $93 900
Mark scheme: A
Q2 · A company manufactures tractors
2 A company manufactures tractors. Each tractor is sold for $12 000, inclusive of a 50% mark-up on cost. At the year end, costs relevant to the company’s inventory were: $ components, at cost 15 000 storage costs 5 000 ten tractors 120 000 Which valuation for inventory should be included in the company’s statement of financial position? A $95 000 B $100 000 C $135 000 D $140 000
Mark scheme: A
Q3 · A manufacturing company’s income statement shows a profit from operations of $9000
3 A manufacturing company’s income statement shows a profit from operations of $9000. The following errors are then discovered. 1 Opening inventory of finished goods has been valued at transfer price of $12 000. 2 Closing inventory of finished goods has been valued at transfer price of $6000. 3 Goods at transfer price have been entered in the income statement at their transfer value of $120 000. No adjustment has been made in respect of factory profit. 4 The company transfers goods from the factory to finished goods at cost plus 20%. What is the correct profit from operations? A $28 000 B $29 000 C $30 000 D $31 000
Mark scheme: C
Q4 · The financial statements of a public limited company includes the following information
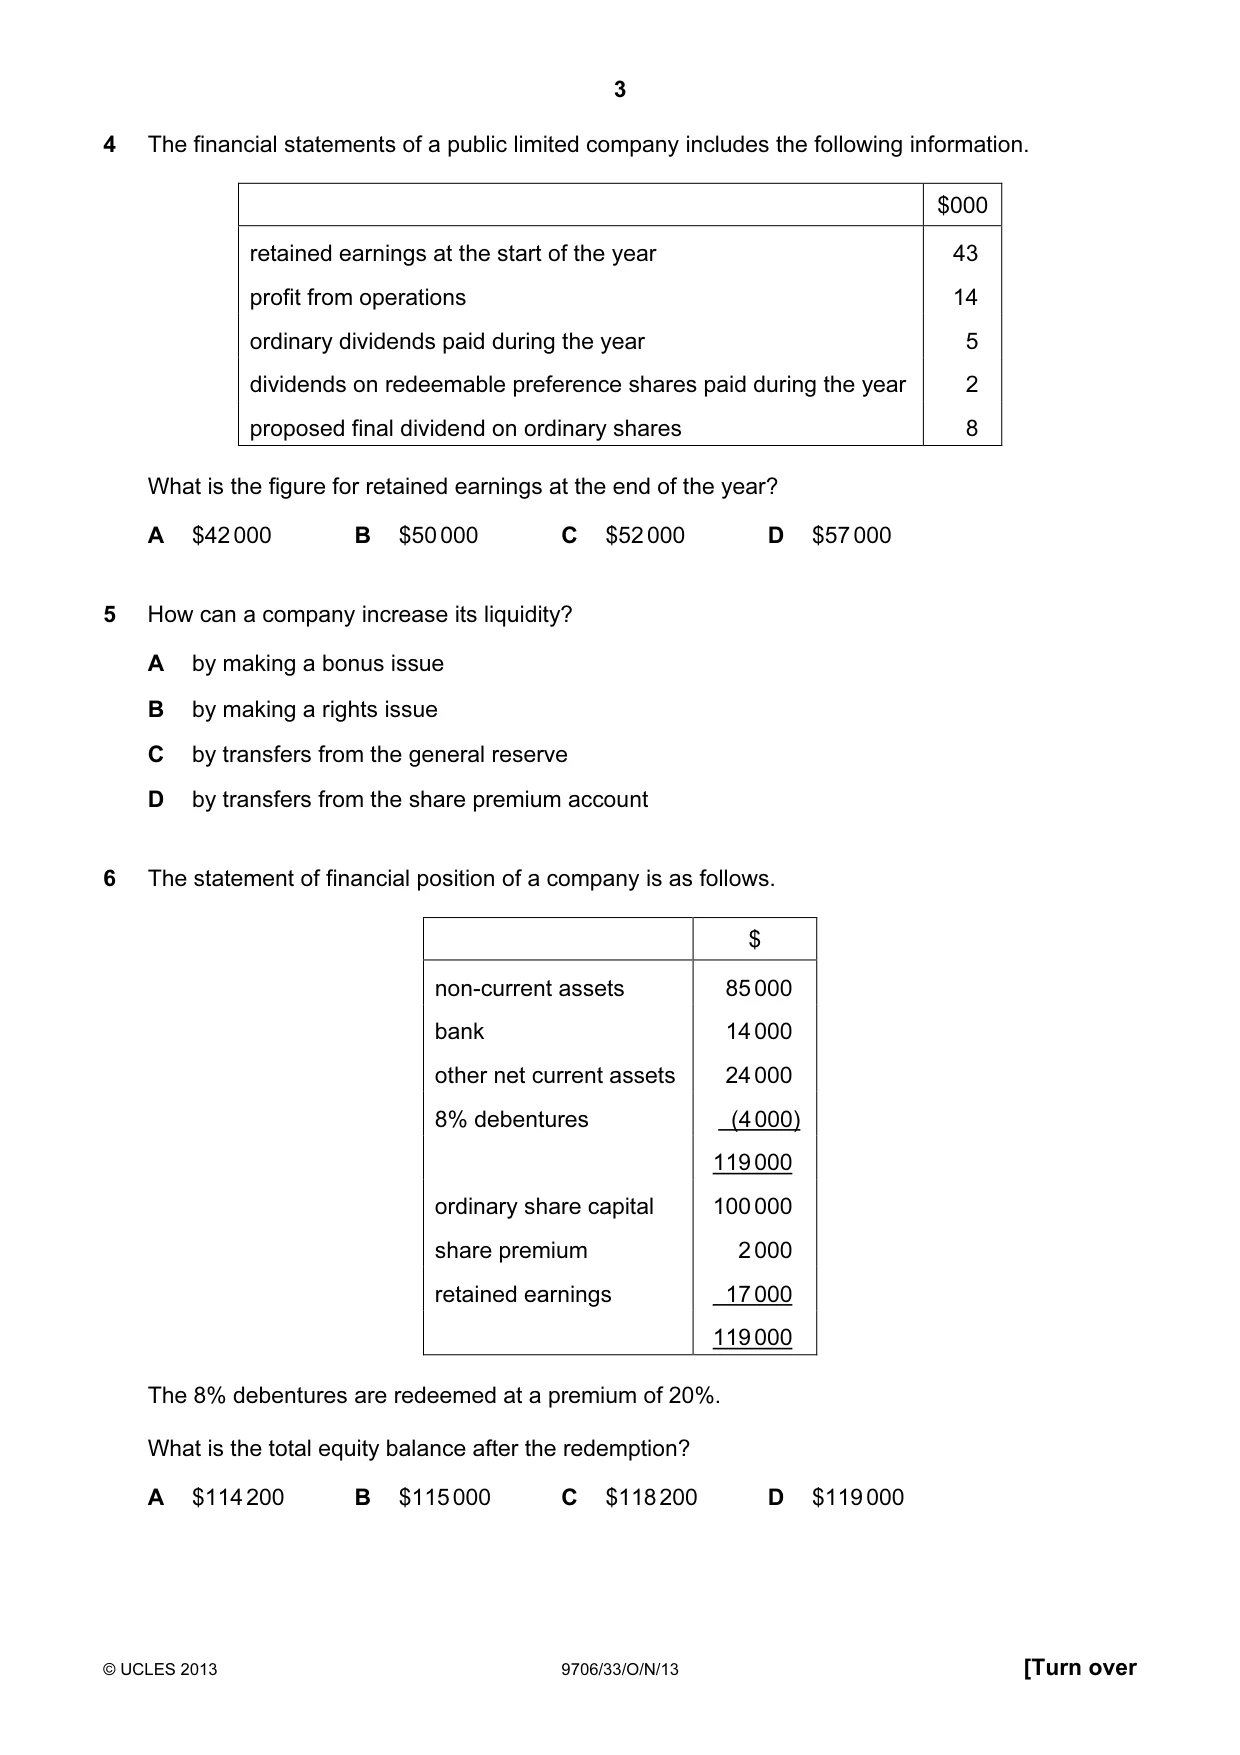
4 The financial statements of a public limited company includes the following information. $000 retained earnings at the start of the year 43 profit from operations 14 ordinary dividends paid during the year 5 dividends on redeemable preference shares paid during the year 2 proposed final dividend on ordinary shares 8 What is the figure for retained earnings at the end of the year? A $42 000 B $50 000 C $52 000 D $57 000
Mark scheme: B
Q5 · How can a company increase its liquidity?
5 How can a company increase its liquidity? A by making a bonus issue B by making a rights issue C by transfers from the general reserve D by transfers from the share premium account
Mark scheme: B
More questions on Analysis and communication of accounting information
Q6 · The statement of financial position of a company is as follows
6 The statement of financial position of a company is as follows. $ non-current assets 85 000 bank 14 000 other net current assets 24 000 8% debentures (4 000) 119 000 ordinary share capital 100 000 share premium 2 000 retained earnings 17 000 119 000 The 8% debentures are redeemed at a premium of 20%. What is the total equity balance after the redemption? A $114 200 B $115 000 C $118 200 D $119 000
Mark scheme: C
Q7 · $100 000 is available for investment
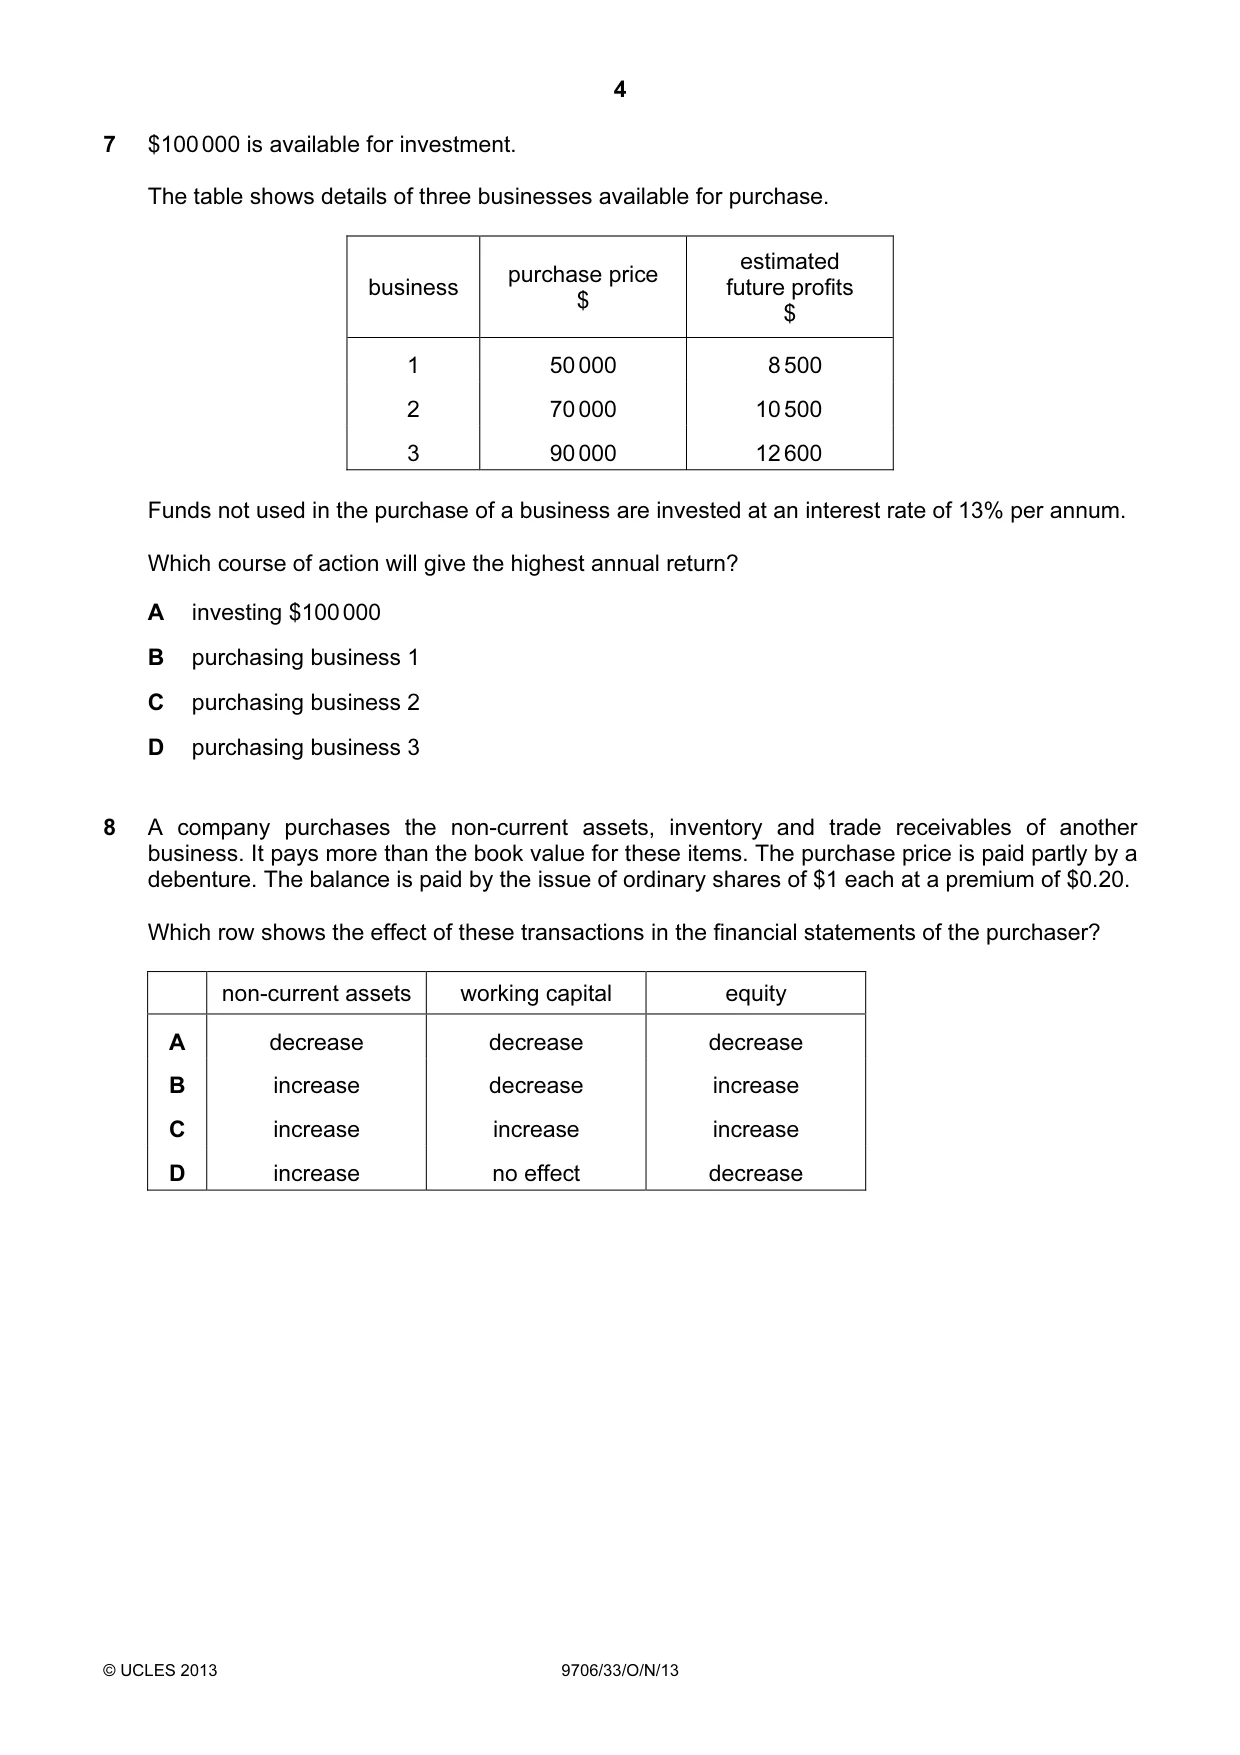
7 $100 000 is available for investment. The table shows details of three businesses available for purchase. estimated purchase price business future profits $ $ 1 50 000 8 500 2 70 000 10 500 3 90 000 12 600 Funds not used in the purchase of a business are invested at an interest rate of 13% per annum. Which course of action will give the highest annual return? A investing $100 000 B purchasing business 1 C purchasing business 2 D purchasing business 3
Mark scheme: B
Q8 · A company purchases the non-current assets, inventory and trade receivables of another…
8 A company purchases the non-current assets, inventory and trade receivables of another business. It pays more than the book value for these items. The purchase price is paid partly by a debenture. The balance is paid by the issue of ordinary shares of $1 each at a premium of $0.20. Which row shows the effect of these transactions in the financial statements of the purchaser? non-current assets working capital equity A decrease decrease decrease B increase decrease increase C increase increase increase D increase no effect decrease
Mark scheme: C
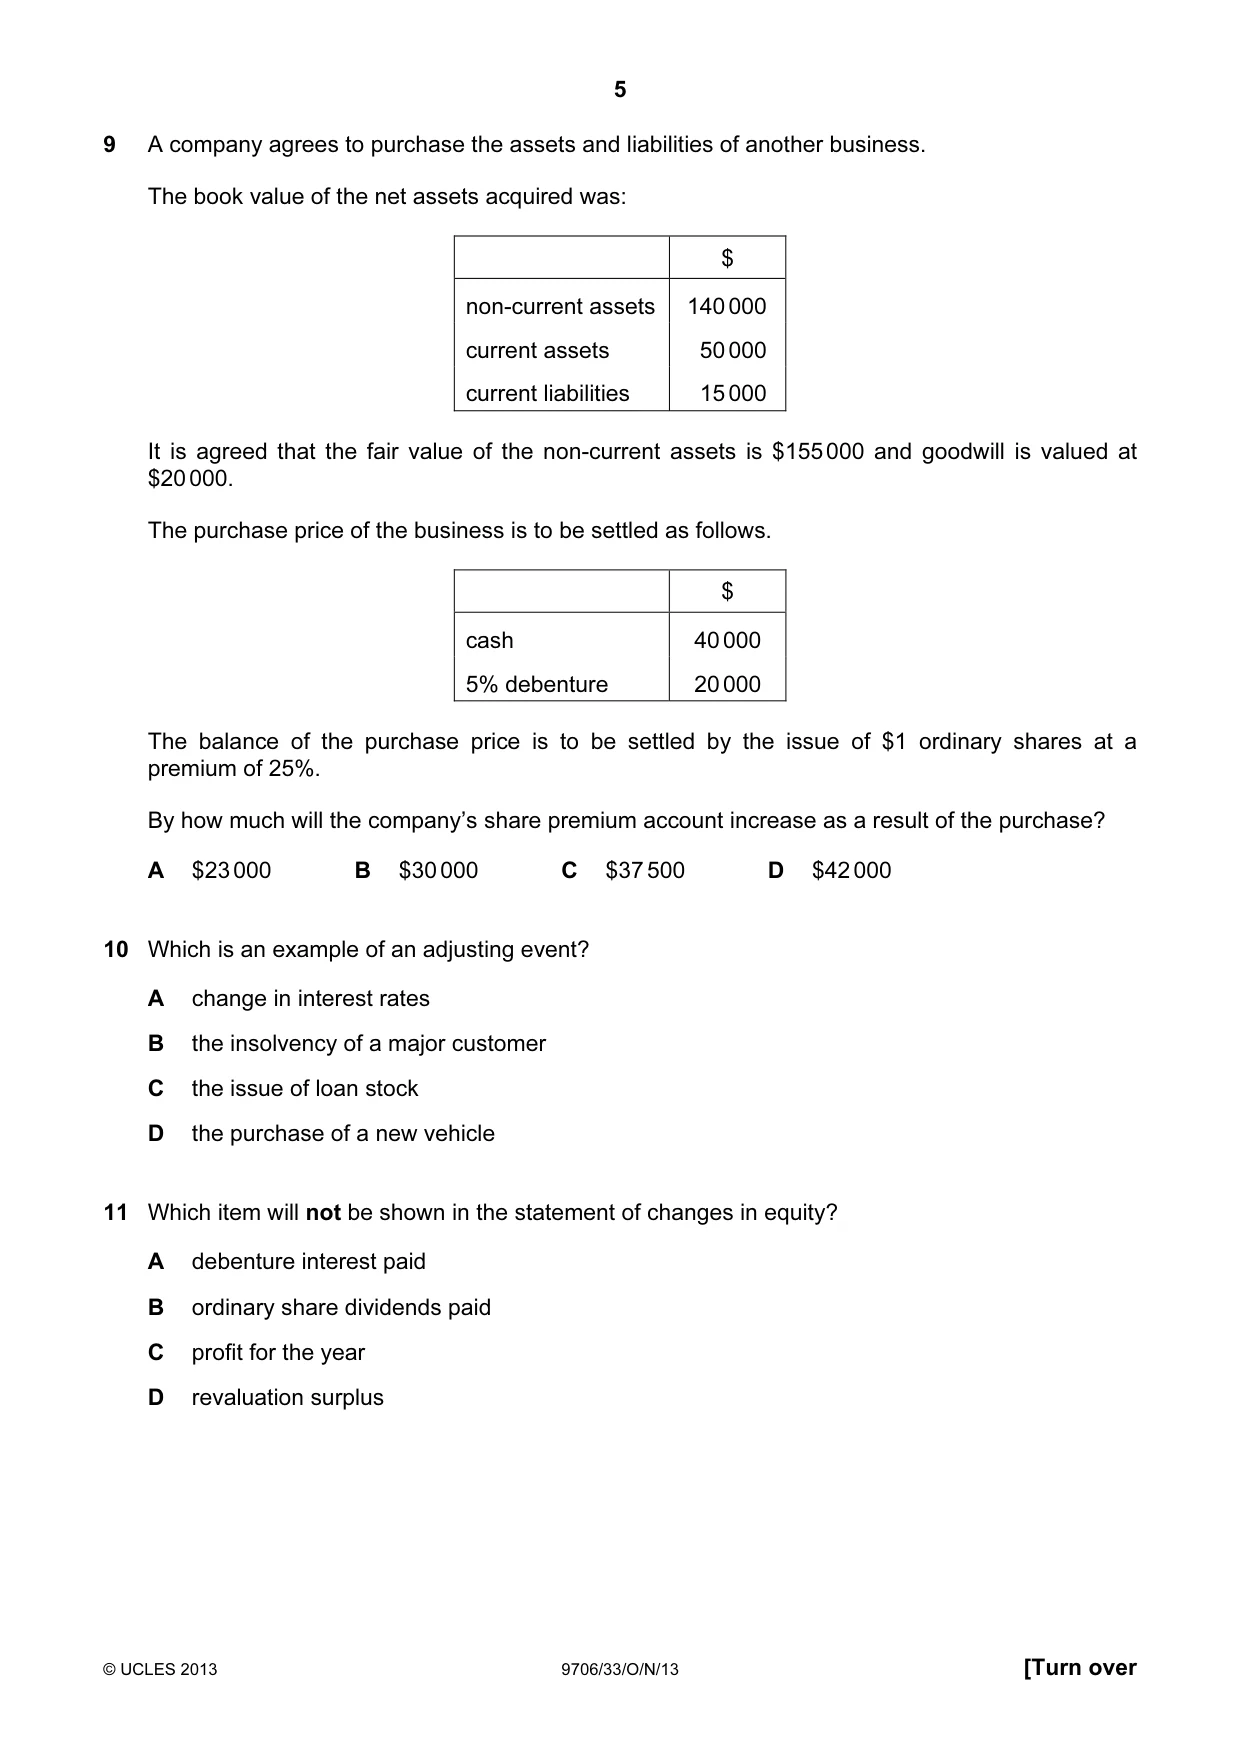
Q9 · A company agrees to purchase the assets and liabilities of another business
9 A company agrees to purchase the assets and liabilities of another business. The book value of the net assets acquired was: $ non-current assets 140 000 current assets 50 000 current liabilities 15 000 It is agreed that the fair value of the non-current assets is $155 000 and goodwill is valued at $20 000. The purchase price of the business is to be settled as follows. $ cash 40 000 5% debenture 20 000 The balance of the purchase price is to be settled by the issue of $1 ordinary shares at a premium of 25%. By how much will the company’s share premium account increase as a result of the purchase? A $23 000 B $30 000 C $37 500 D $42 000
Mark scheme: B
Q10 · Which is an example of an adjusting event?
10 Which is an example of an adjusting event? A change in interest rates B the insolvency of a major customer C the issue of loan stock D the purchase of a new vehicle
Mark scheme: B
Q11 · Which item will not be shown in the statement of changes in equity?
11 Which item will not be shown in the statement of changes in equity? A debenture interest paid B ordinary share dividends paid C profit for the year D revaluation surplus
Mark scheme: A
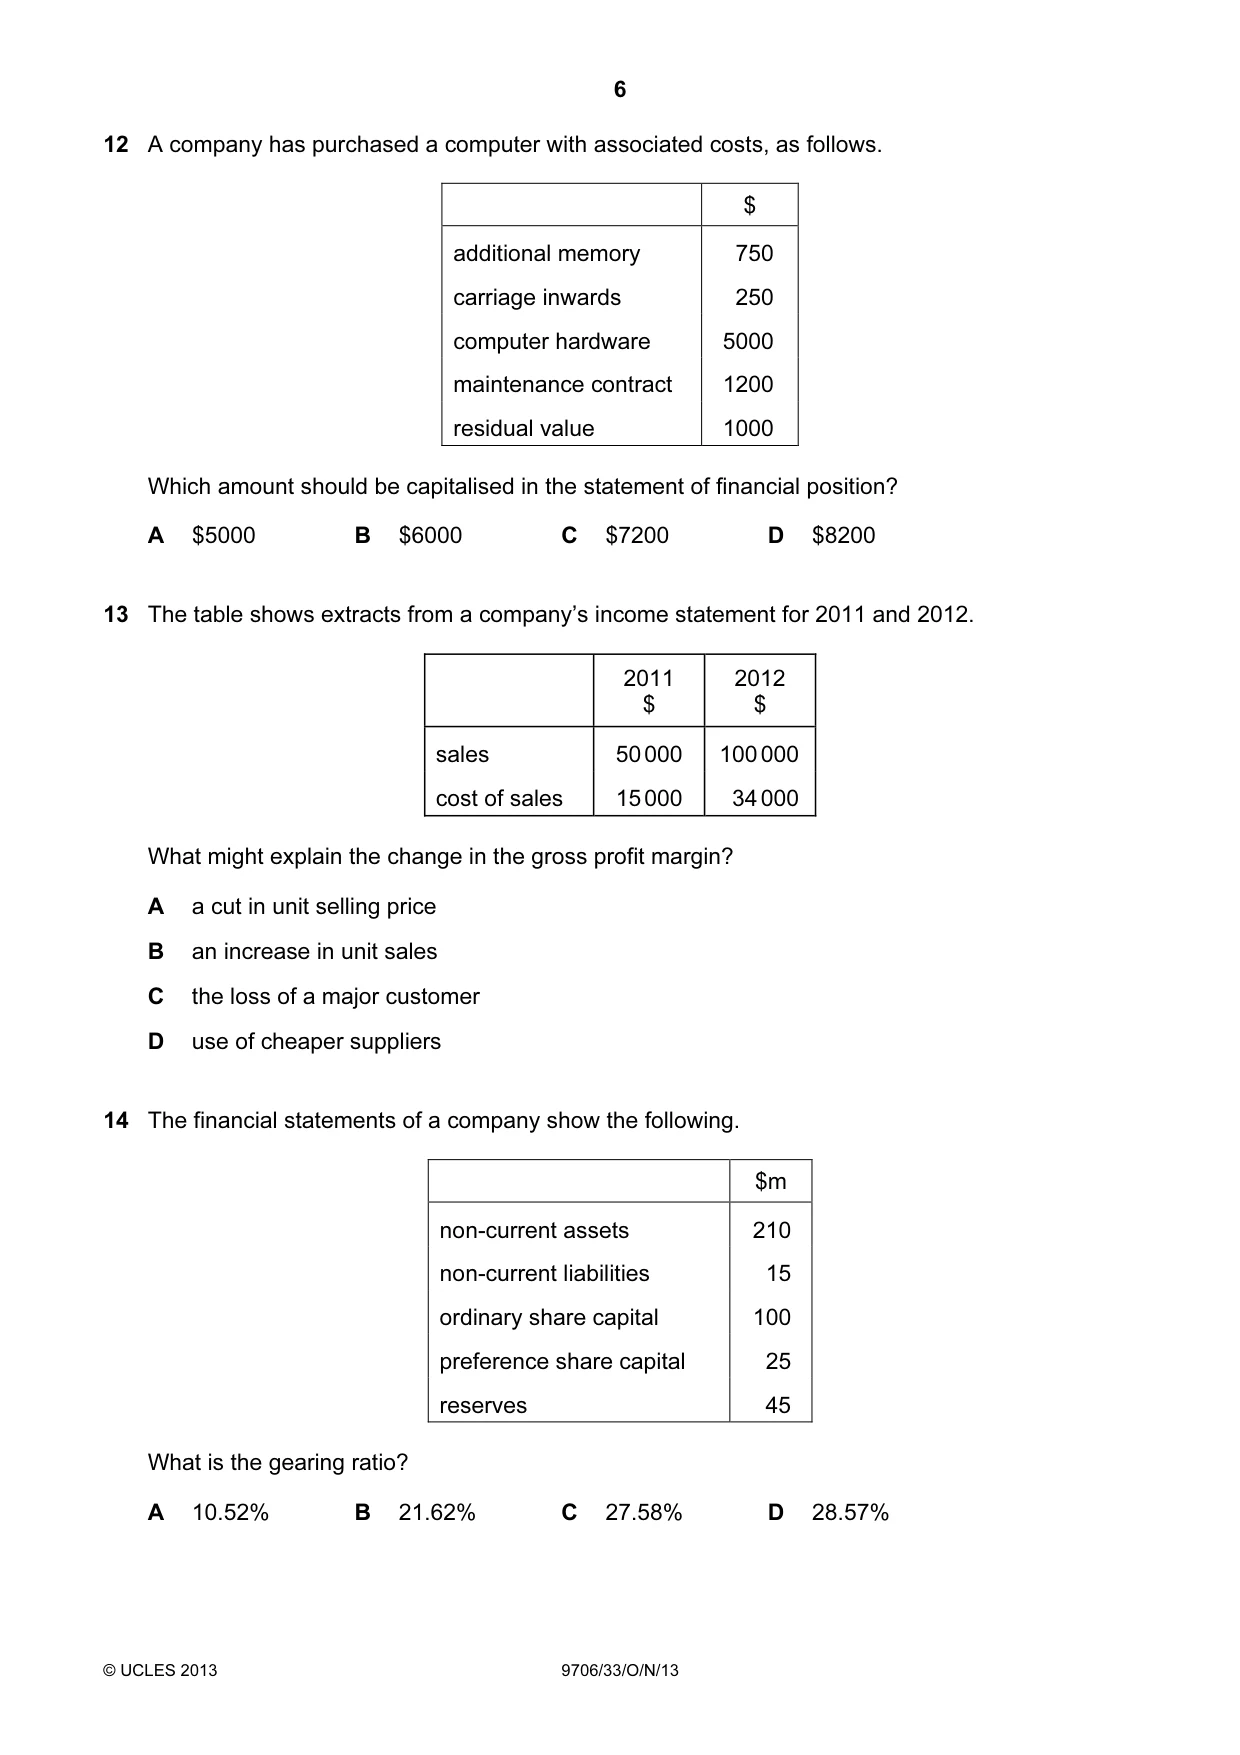
Q12 · A company has purchased a computer with associated costs, as follows
12 A company has purchased a computer with associated costs, as follows. $ additional memory 750 carriage inwards 250 computer hardware 5000 maintenance contract 1200 residual value 1000 Which amount should be capitalised in the statement of financial position? A $5000 B $6000 C $7200 D $8200
Mark scheme: B
Q13 · The table shows extracts from a company’s income statement for 2011 and 2012
13 The table shows extracts from a company’s income statement for 2011 and 2012. 2011 2012 $ $ sales 50 000 100 000 cost of sales 15 000 34 000 What might explain the change in the gross profit margin? A a cut in unit selling price B an increase in unit sales C the loss of a major customer D use of cheaper suppliers
Mark scheme: A
More questions on Analysis and communication of accounting information
Q14 · The financial statements of a company show the following
14 The financial statements of a company show the following. $m non-current assets 210 non-current liabilities 15 ordinary share capital 100 preference share capital 25 reserves 45 What is the gearing ratio? A 10.52% B 21.62% C 27.58% D 28.57%
Mark scheme: B
More questions on Analysis and communication of accounting information
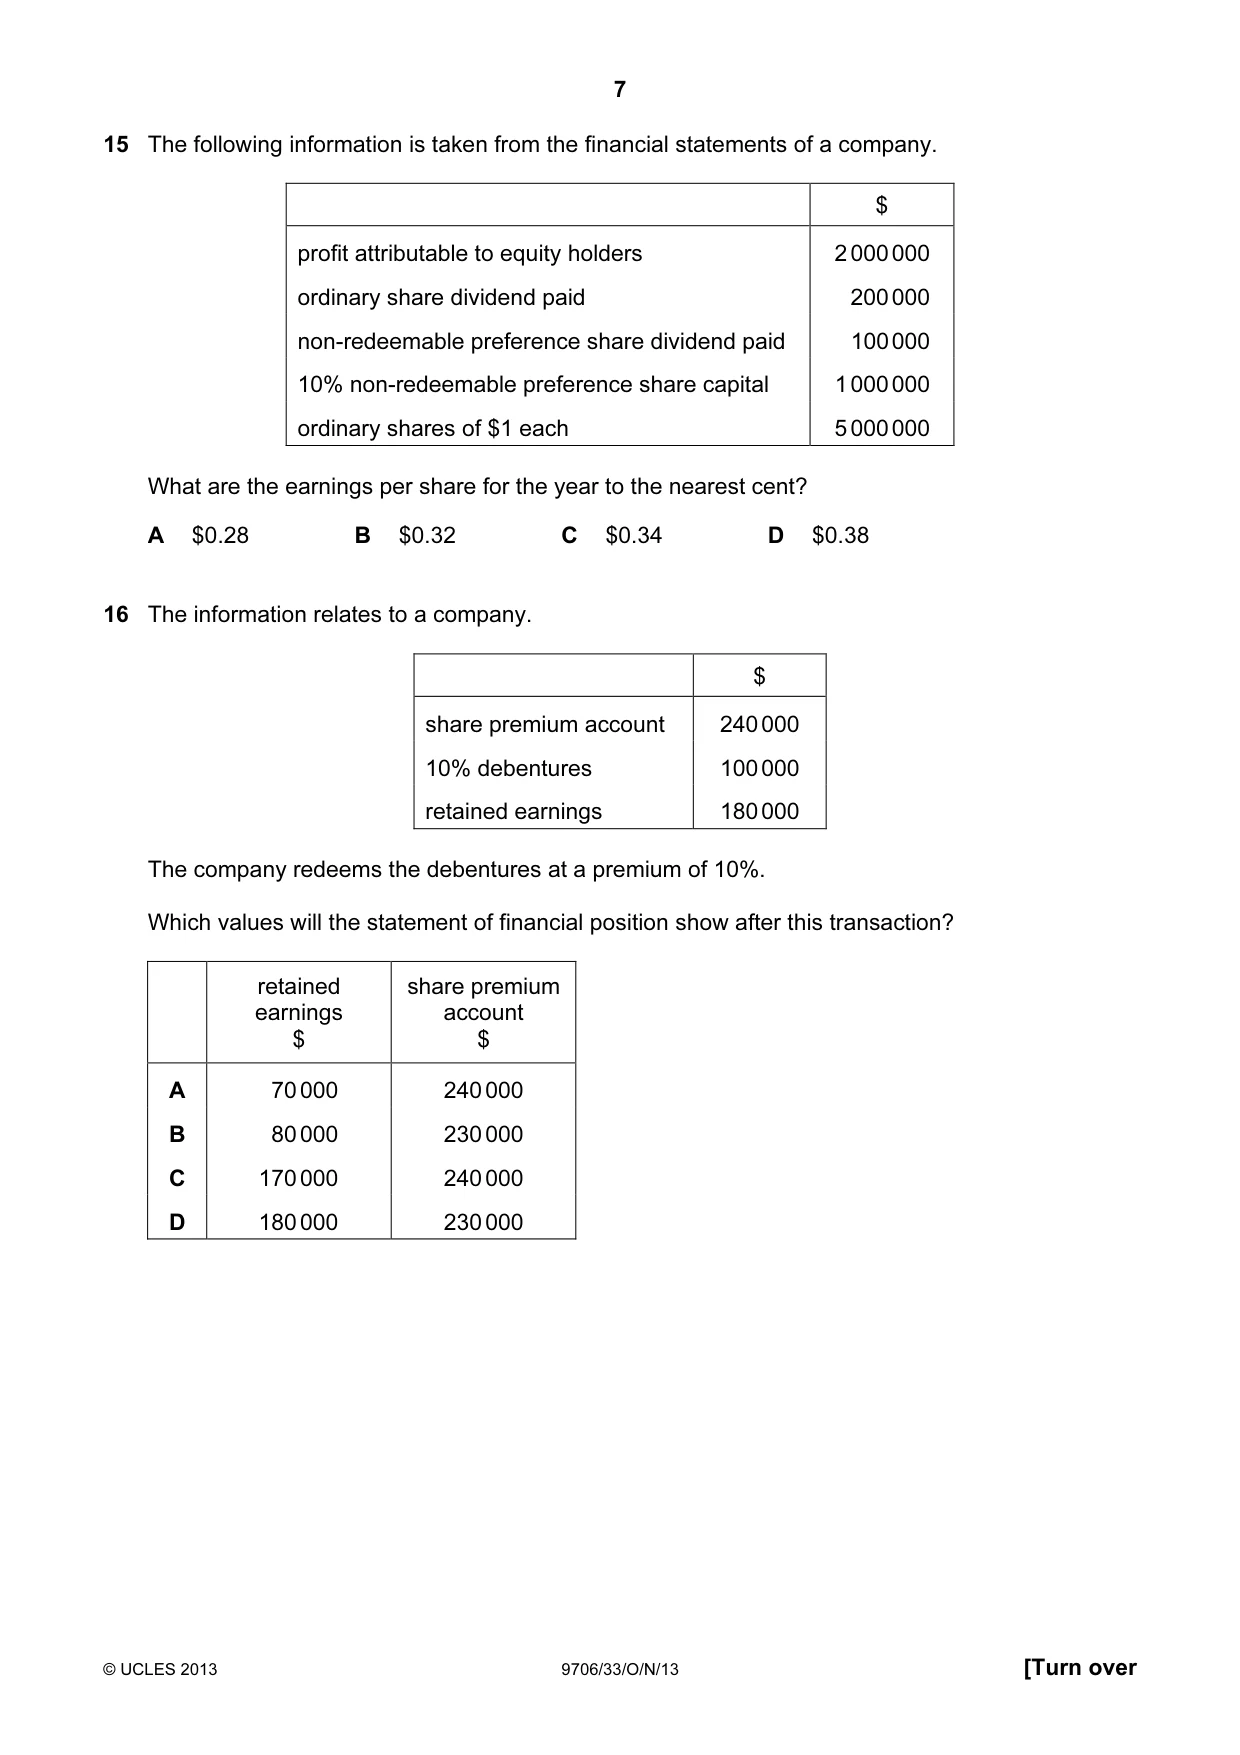
Q15 · The following information is taken from the financial statements of a company
15 The following information is taken from the financial statements of a company. $ profit attributable to equity holders 2 000 000 ordinary share dividend paid 200 000 non-redeemable preference share dividend paid 100 000 10% non-redeemable preference share capital 1 000 000 ordinary shares of $1 each 5 000 000 What are the earnings per share for the year to the nearest cent? A $0.28 B $0.32 C $0.34 D $0.38
Mark scheme: D
More questions on Analysis and communication of accounting information
Q16 · The information relates to a company
16 The information relates to a company. $ share premium account 240 000 10% debentures 100 000 retained earnings 180 000 The company redeems the debentures at a premium of 10%. Which values will the statement of financial position show after this transaction? retained share premium earnings account $ $ A 70 000 240 000 B 80 000 230 000 C 170 000 240 000 D 180 000 230 000
Mark scheme: D
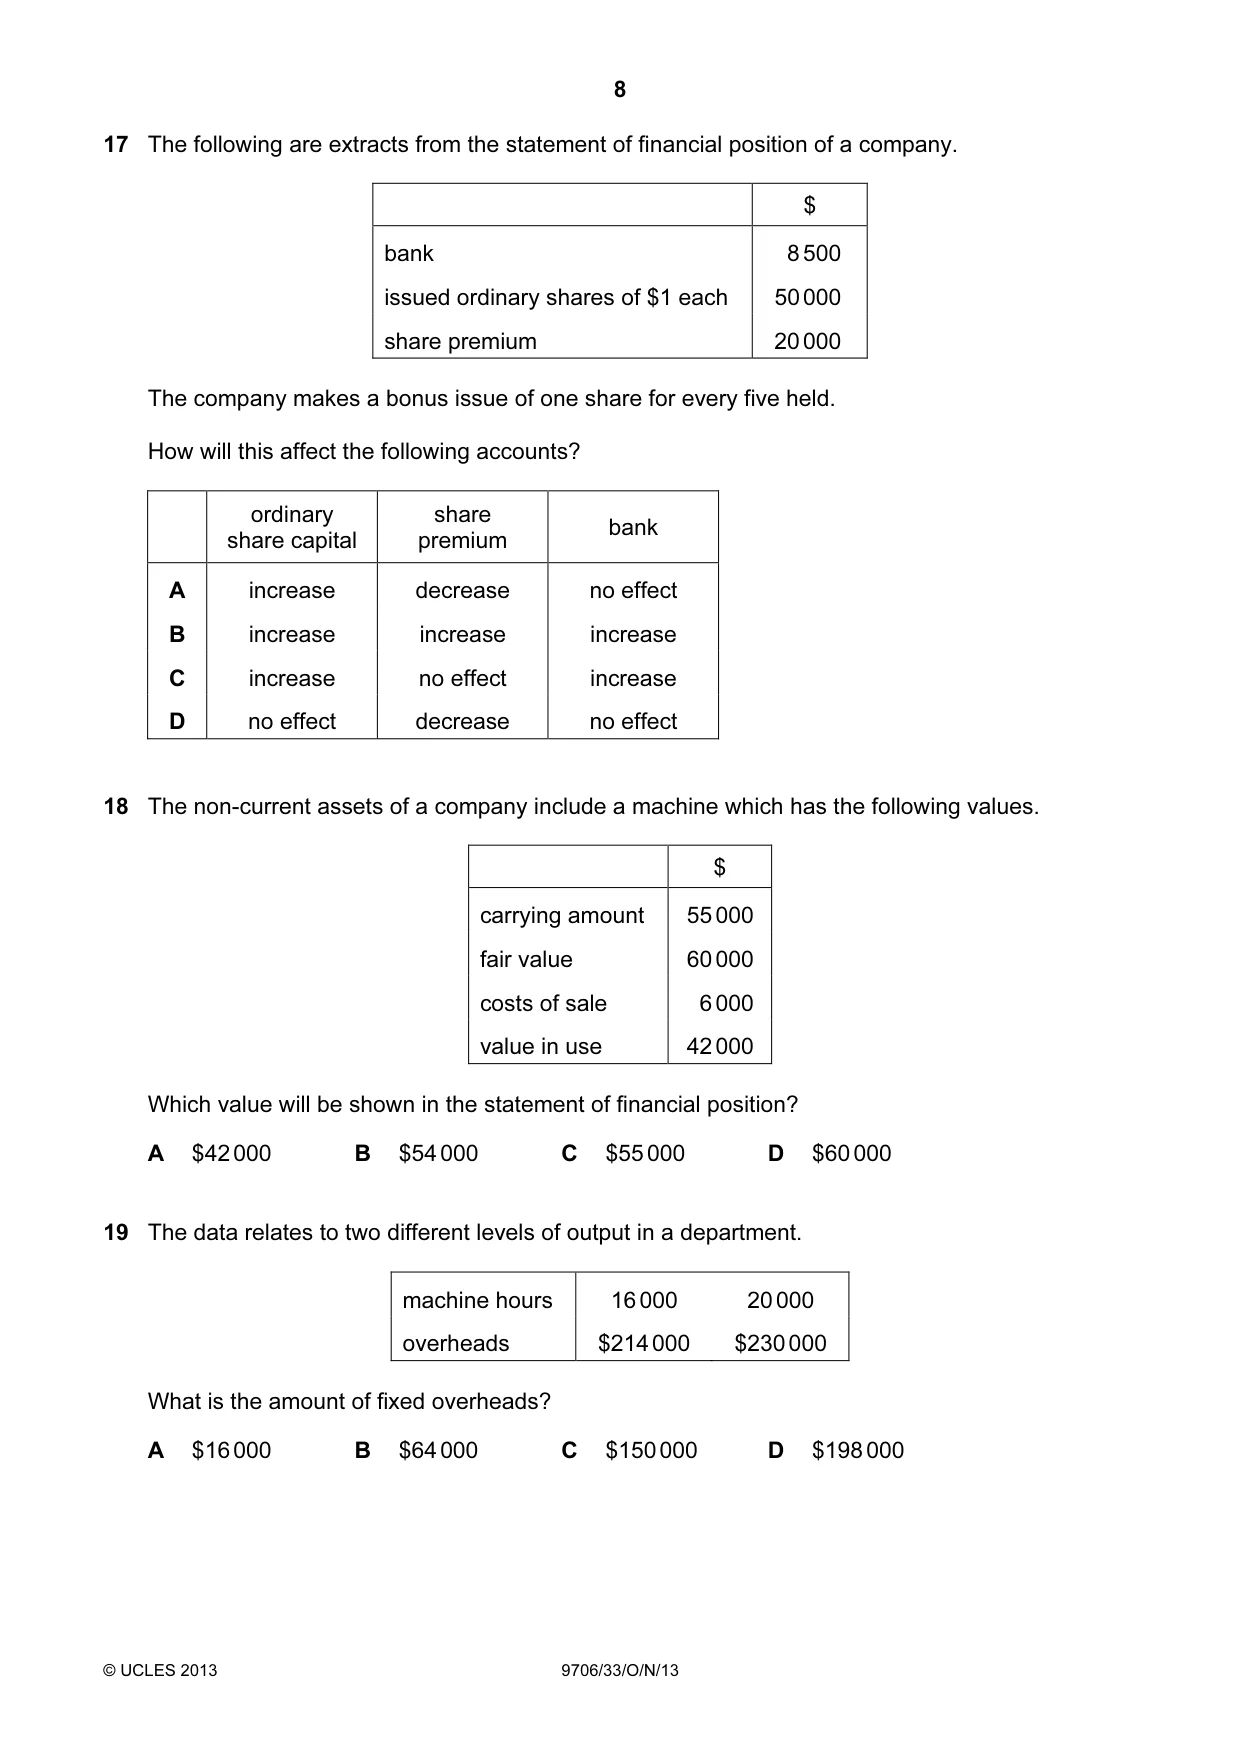
Q17 · The following are extracts from the statement of financial position of a company
17 The following are extracts from the statement of financial position of a company. $ bank 8 500 issued ordinary shares of $1 each 50 000 share premium 20 000 The company makes a bonus issue of one share for every five held. How will this affect the following accounts? ordinary share bank share capital premium A increase decrease no effect B increase increase increase C increase no effect increase D no effect decrease no effect
Mark scheme: A
Q18 · The non-current assets of a company include a machine which has the following values
18 The non-current assets of a company include a machine which has the following values. $ carrying amount 55 000 fair value 60 000 costs of sale 6 000 value in use 42 000 Which value will be shown in the statement of financial position? A $42 000 B $54 000 C $55 000 D $60 000
Mark scheme: B
Q19 · The data relates to two different levels of output in a department
19 The data relates to two different levels of output in a department. machine hours 16 000 20 000 overheads $214 000 $230 000 What is the amount of fixed overheads? A $16 000 B $64 000 C $150 000 D $198 000
Mark scheme: C
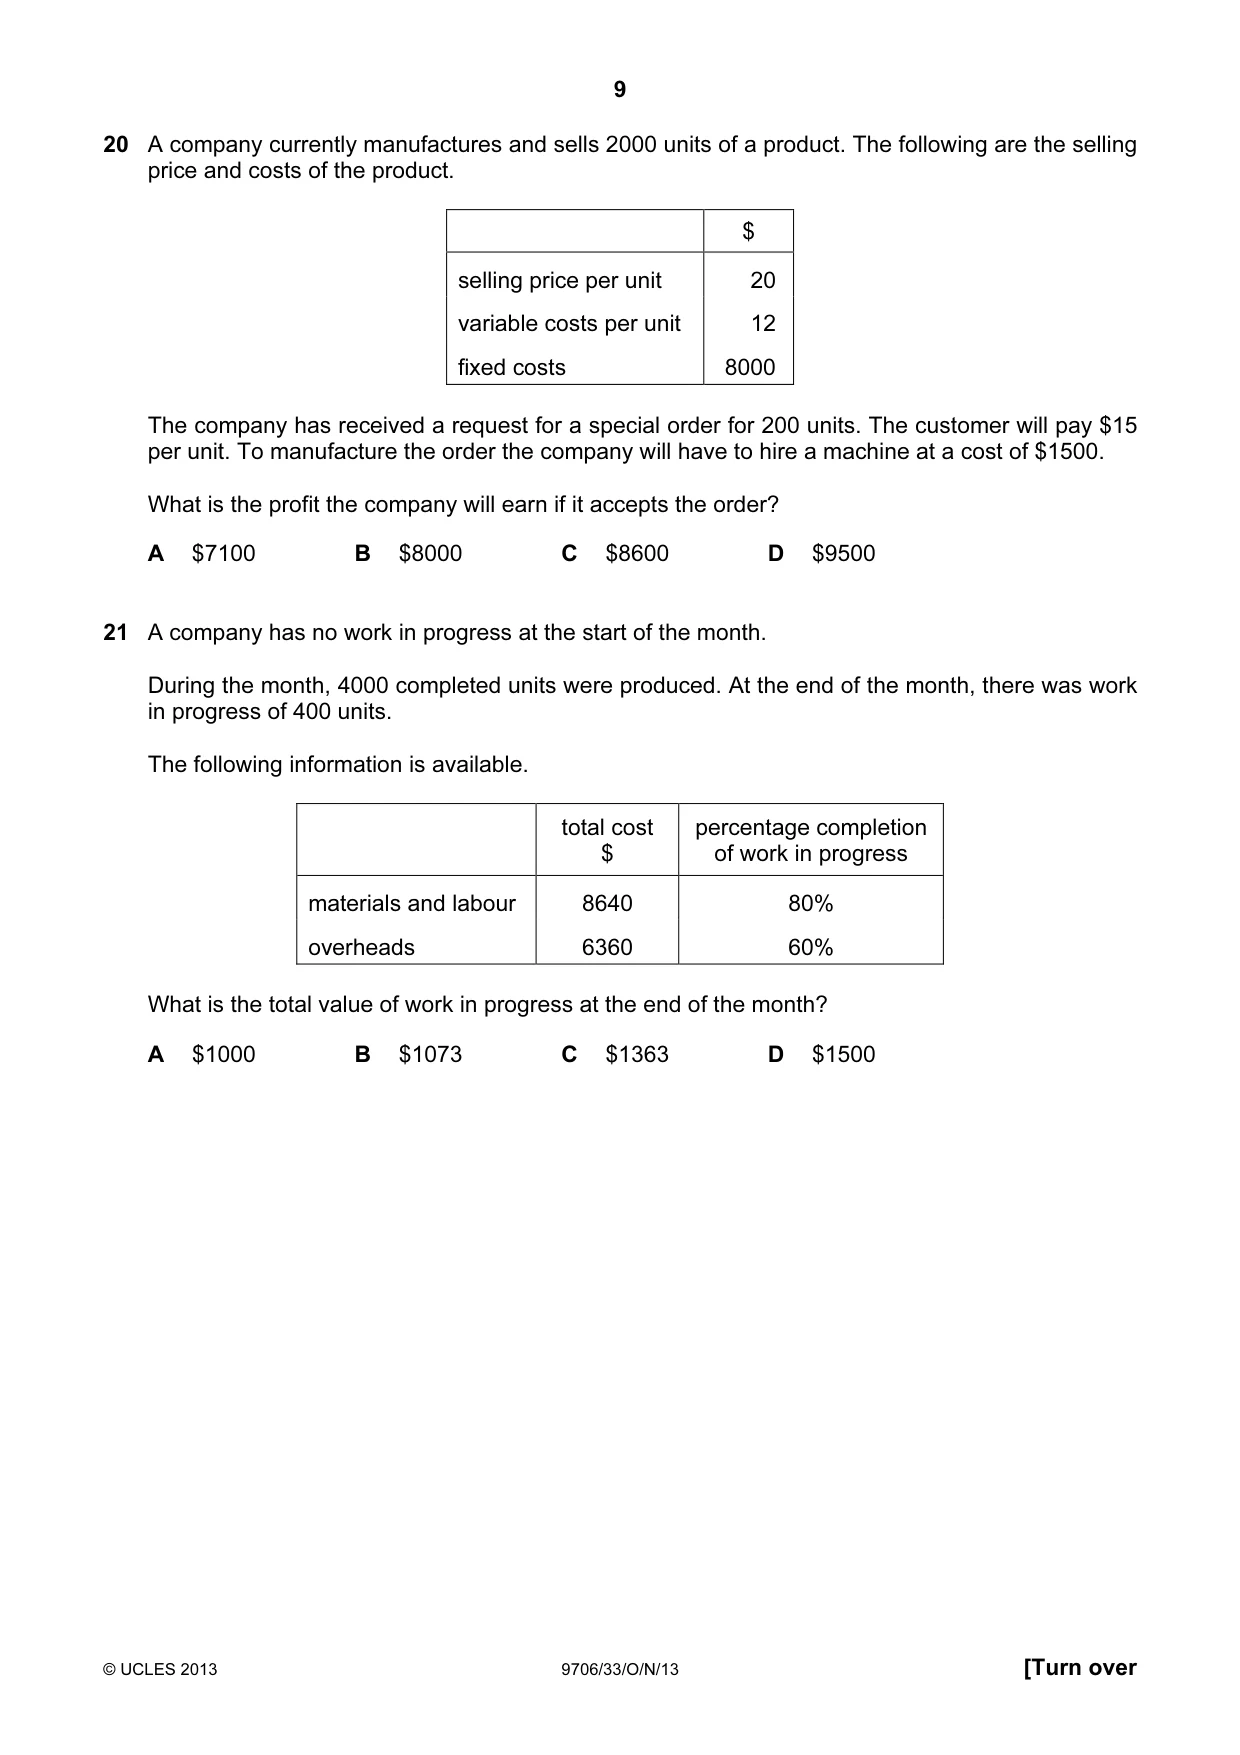
Q20 · A company currently manufactures and sells 2000 units of a product
20 A company currently manufactures and sells 2000 units of a product. The following are the selling price and costs of the product. $ selling price per unit 20 variable costs per unit 12 fixed costs 8000 The company has received a request for a special order for 200 units. The customer will pay $15 per unit. To manufacture the order the company will have to hire a machine at a cost of $1500. What is the profit the company will earn if it accepts the order? A $7100 B $8000 C $8600 D $9500
Mark scheme: A
Q21 · A company has no work in progress at the start of the month
21 A company has no work in progress at the start of the month. During the month, 4000 completed units were produced. At the end of the month, there was work in progress of 400 units. The following information is available. total cost percentage completion $ of work in progress materials and labour 8640 80% overheads 6360 60% What is the total value of work in progress at the end of the month? A $1000 B $1073 C $1363 D $1500
Mark scheme: A
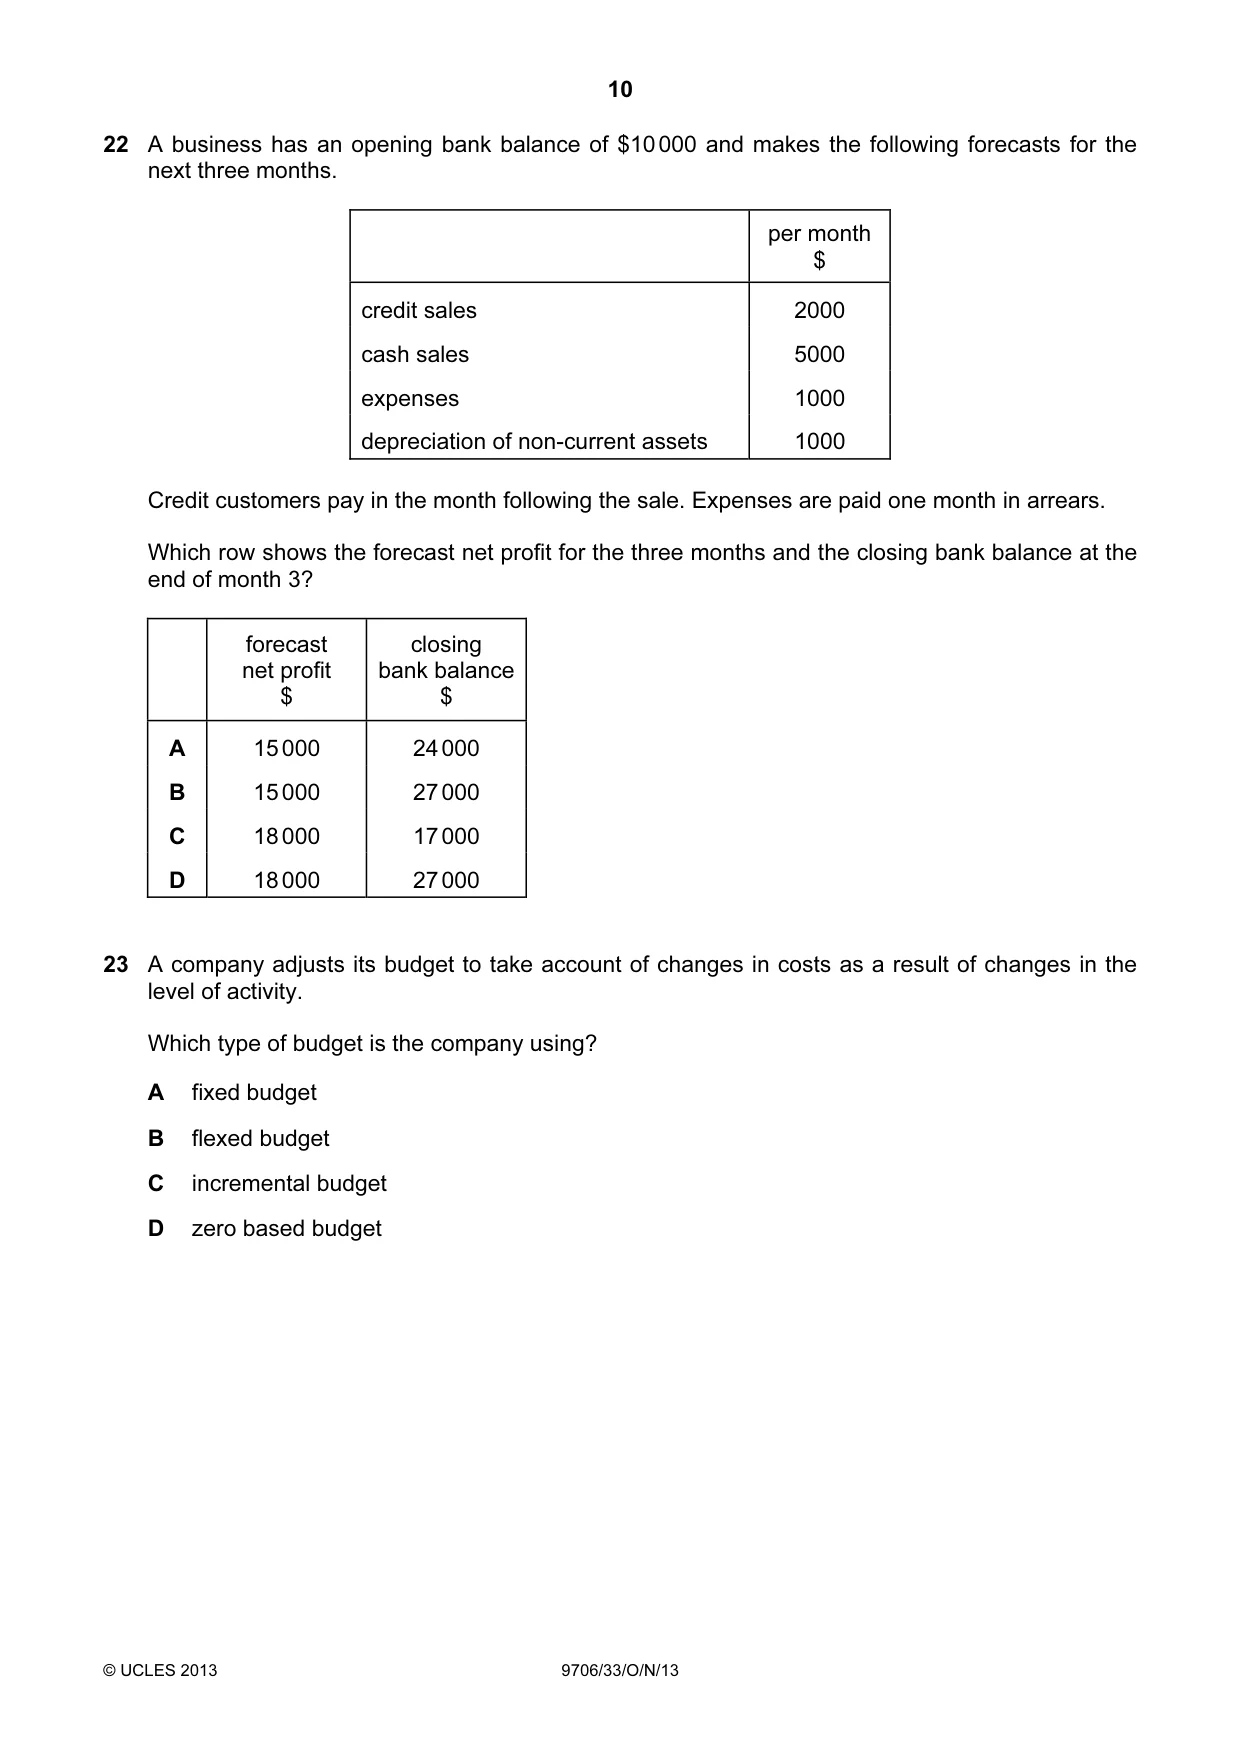
Q22 · A business has an opening bank balance of $10 000 and makes the following forecasts for…
22 A business has an opening bank balance of $10 000 and makes the following forecasts for the next three months. per month $ credit sales 2000 cash sales 5000 expenses 1000 depreciation of non-current assets 1000 Credit customers pay in the month following the sale. Expenses are paid one month in arrears. Which row shows the forecast net profit for the three months and the closing bank balance at the end of month 3? forecast closing net profit bank balance $ $ A 15 000 24 000 B 15 000 27 000 C 18 000 17 000 D 18 000 27 000
Mark scheme: B
Q23 · A company adjusts its budget to take account of changes in costs as a result of changes…
23 A company adjusts its budget to take account of changes in costs as a result of changes in the level of activity. Which type of budget is the company using? A fixed budget B flexed budget C incremental budget D zero based budget
Mark scheme: B
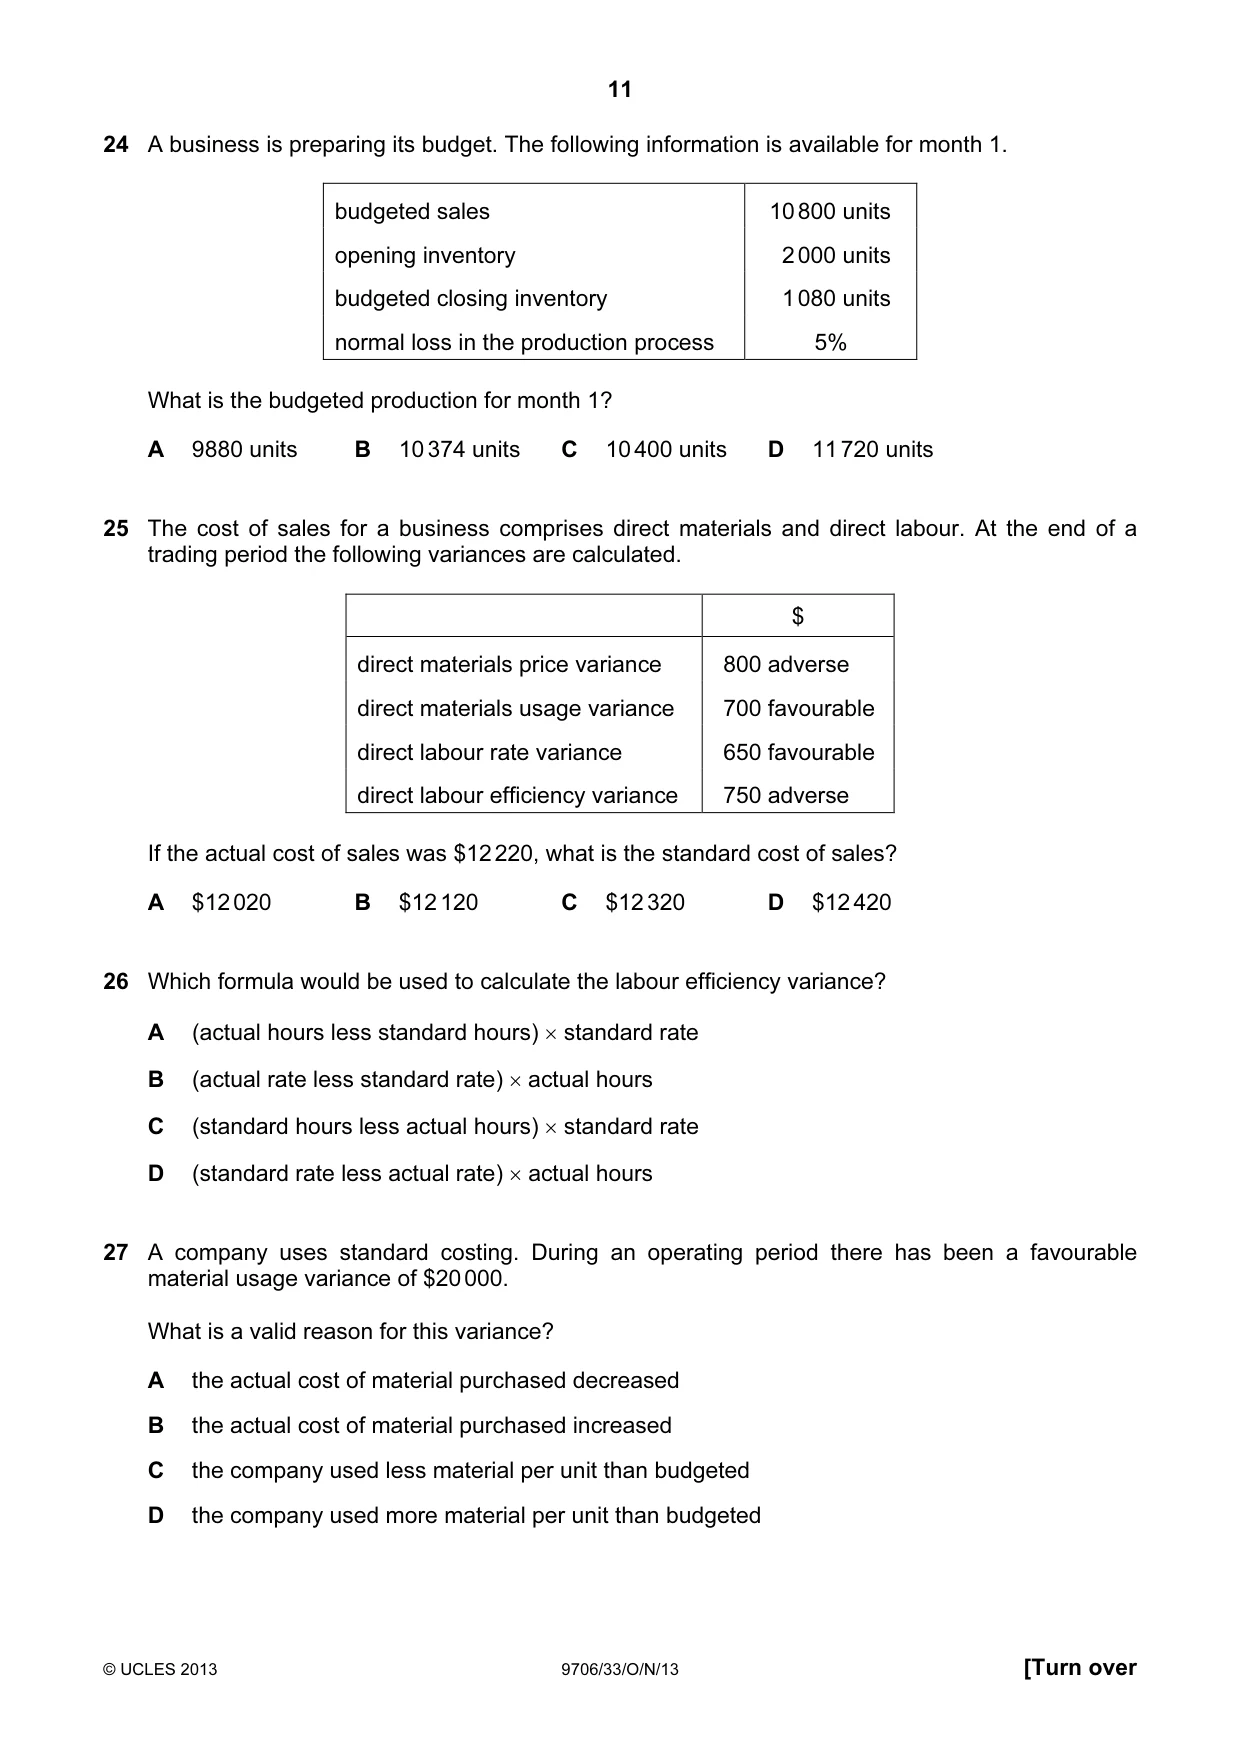
Q24 · A business is preparing its budget
24 A business is preparing its budget. The following information is available for month 1. budgeted sales 10 800 units opening inventory 2 000 units budgeted closing inventory 1 080 units normal loss in the production process 5% What is the budgeted production for month 1? A 9880 units B 10 374 units C 10 400 units D 11 720 units
Mark scheme: C
Q25 · The cost of sales for a business comprises direct materials and direct labour
25 The cost of sales for a business comprises direct materials and direct labour. At the end of a trading period the following variances are calculated. $ direct materials price variance 800 adverse direct materials usage variance 700 favourable direct labour rate variance 650 favourable direct labour efficiency variance 750 adverse If the actual cost of sales was $12 220, what is the standard cost of sales? A $12 020 B $12 120 C $12 320 D $12 420
Mark scheme: A
Q26 · Which formula would be used to calculate the labour efficiency variance?
26 Which formula would be used to calculate the labour efficiency variance? A (actual hours less standard hours) × standard rate B (actual rate less standard rate) × actual hours C (standard hours less actual hours) × standard rate D (standard rate less actual rate) × actual hours
Mark scheme: C
Q27 · A company uses standard costing
27 A company uses standard costing. During an operating period there has been a favourable material usage variance of $20 000. What is a valid reason for this variance? A the actual cost of material purchased decreased B the actual cost of material purchased increased C the company used less material per unit than budgeted D the company used more material per unit than budgeted
Mark scheme: C
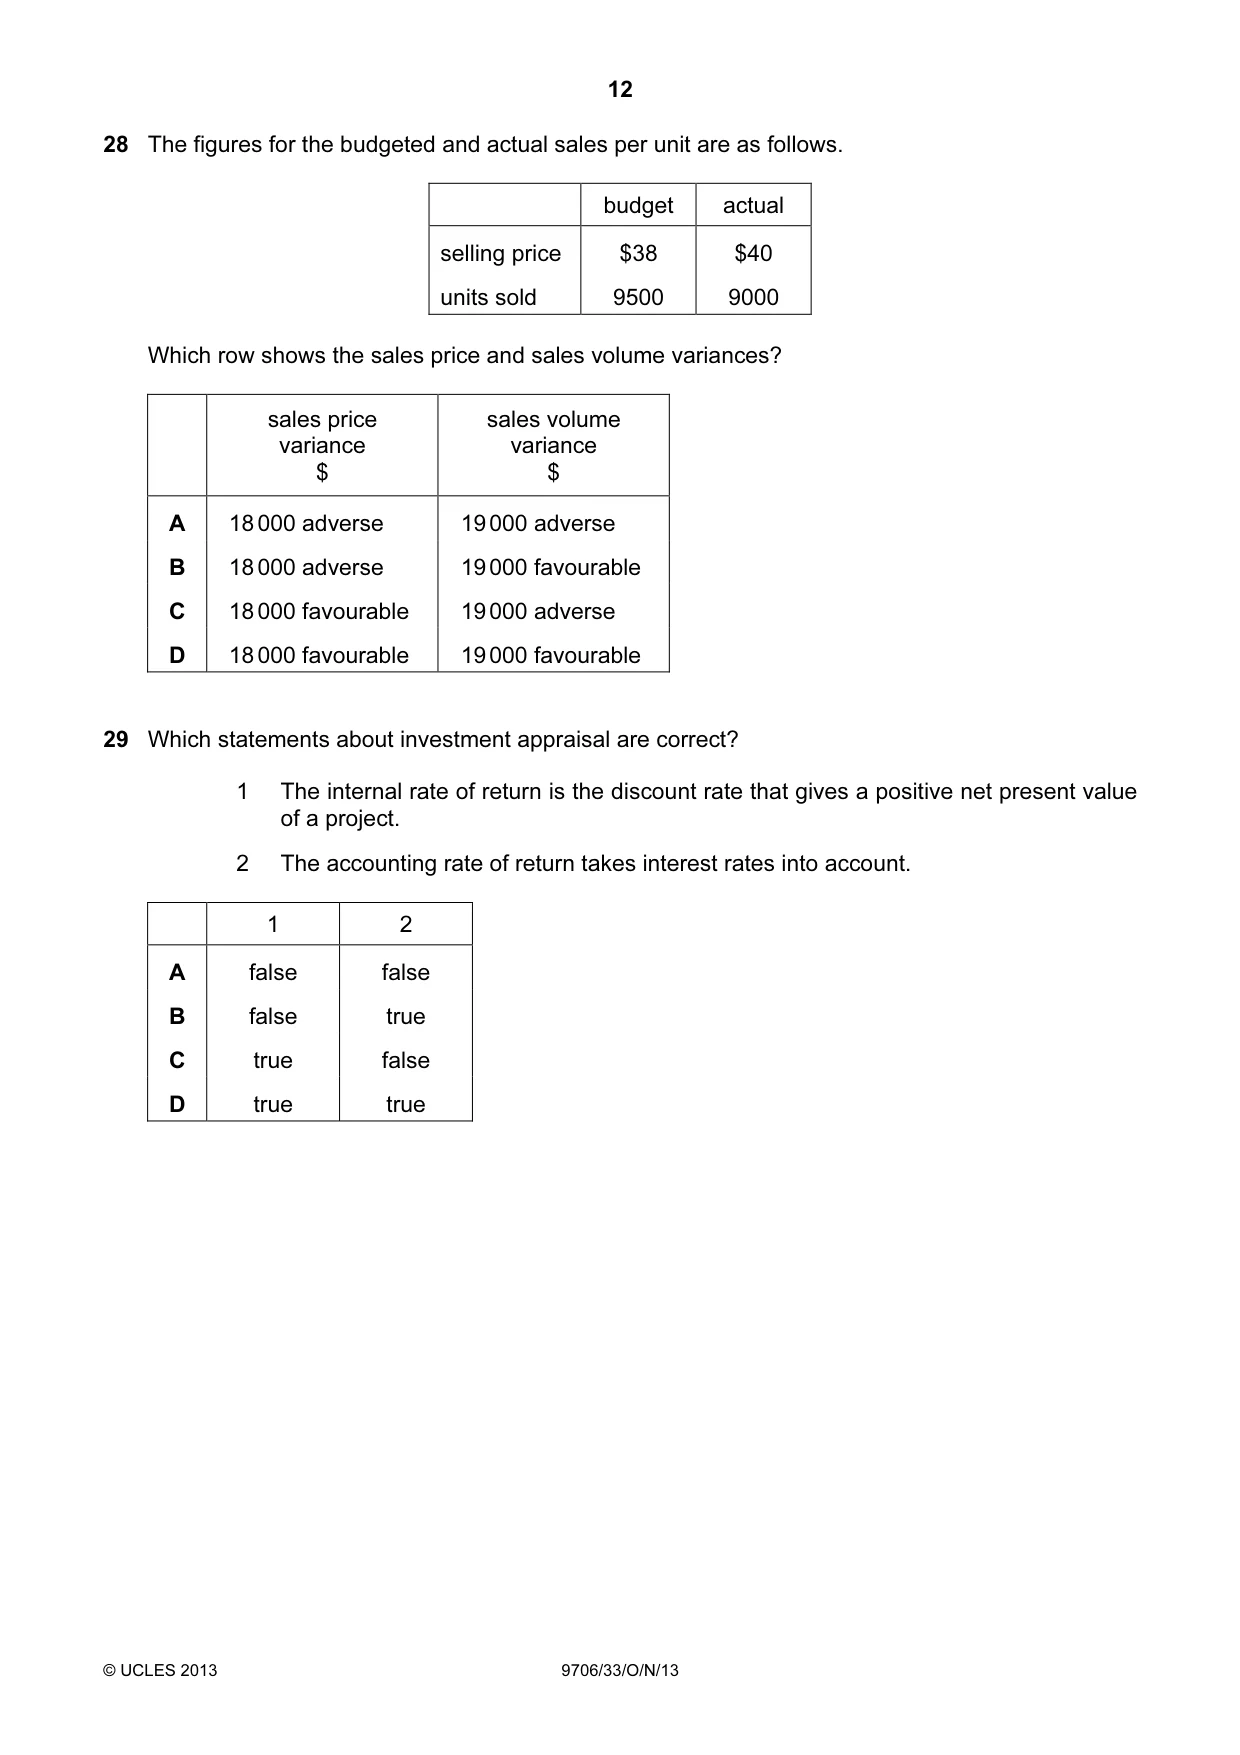
Q28 · The figures for the budgeted and actual sales per unit are as follows
28 The figures for the budgeted and actual sales per unit are as follows. budget actual selling price $38 $40 units sold 9500 9000 Which row shows the sales price and sales volume variances? sales price sales volume variance variance $ $ A 18 000 adverse 19 000 adverse B 18 000 adverse 19 000 favourable C 18 000 favourable 19 000 adverse D 18 000 favourable 19 000 favourable
Mark scheme: C
Q29 · Which statements about investment appraisal are correct?
29 Which statements about investment appraisal are correct? 1 The internal rate of return is the discount rate that gives a positive net present value of a project. 2 The accounting rate of return takes interest rates into account. 1 2 A false false B false true C true false D true true
Mark scheme: A
Q30 · Discounted cash flow has been used to evaluate an investment project over a three year…
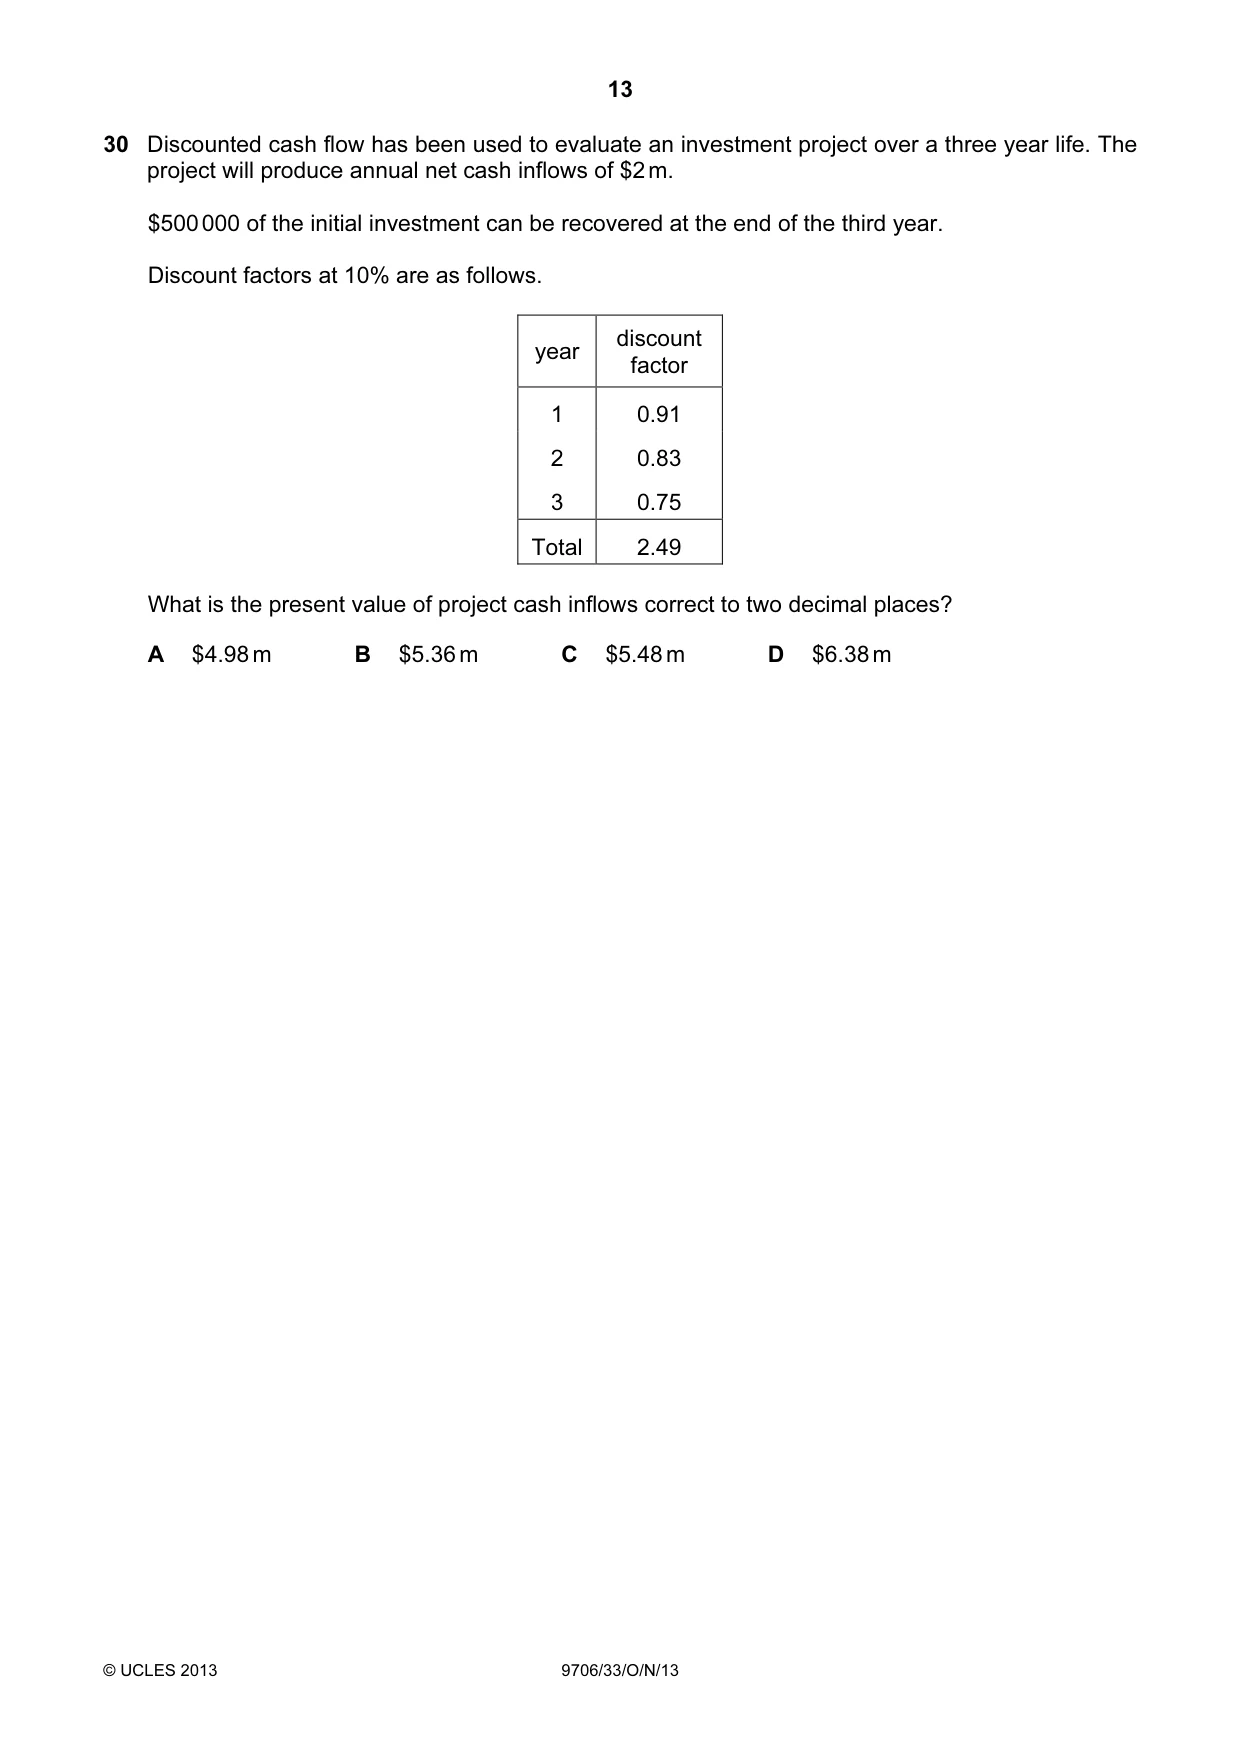
30 Discounted cash flow has been used to evaluate an investment project over a three year life. The project will produce annual net cash inflows of $2 m. $500 000 of the initial investment can be recovered at the end of the third year. Discount factors at 10% are as follows. discount year factor 1 0.91 2 0.83 3 0.75 Total 2.49 What is the present value of project cash inflows correct to two decimal places? A $4.98 m B $5.36 m C $5.48 m D $6.38 m
Mark scheme: B
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
6Standard costing4Analysis and communication of accounting information3Budgeting and budgetary control3Investment appraisal3Business acquisition and merger2Regulatory and ethical considerations2Traditional costing methods2Accounting for non-current assets1Analysis and communication of accounting information1Costs and cost behaviour1Preparation of financial statements1Reconciliation and verification1What you needed in this session
Cambridge’s own grade thresholds for 2013 Oct/Nov, Paper 3 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.