Cambridge A Level Accounting 9706 — 2011 May/June Paper 3 · Variant 2
9706/32/M/J/11 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme2 pages
Answers below. Sit the paper first if you are practising.
Questions as text
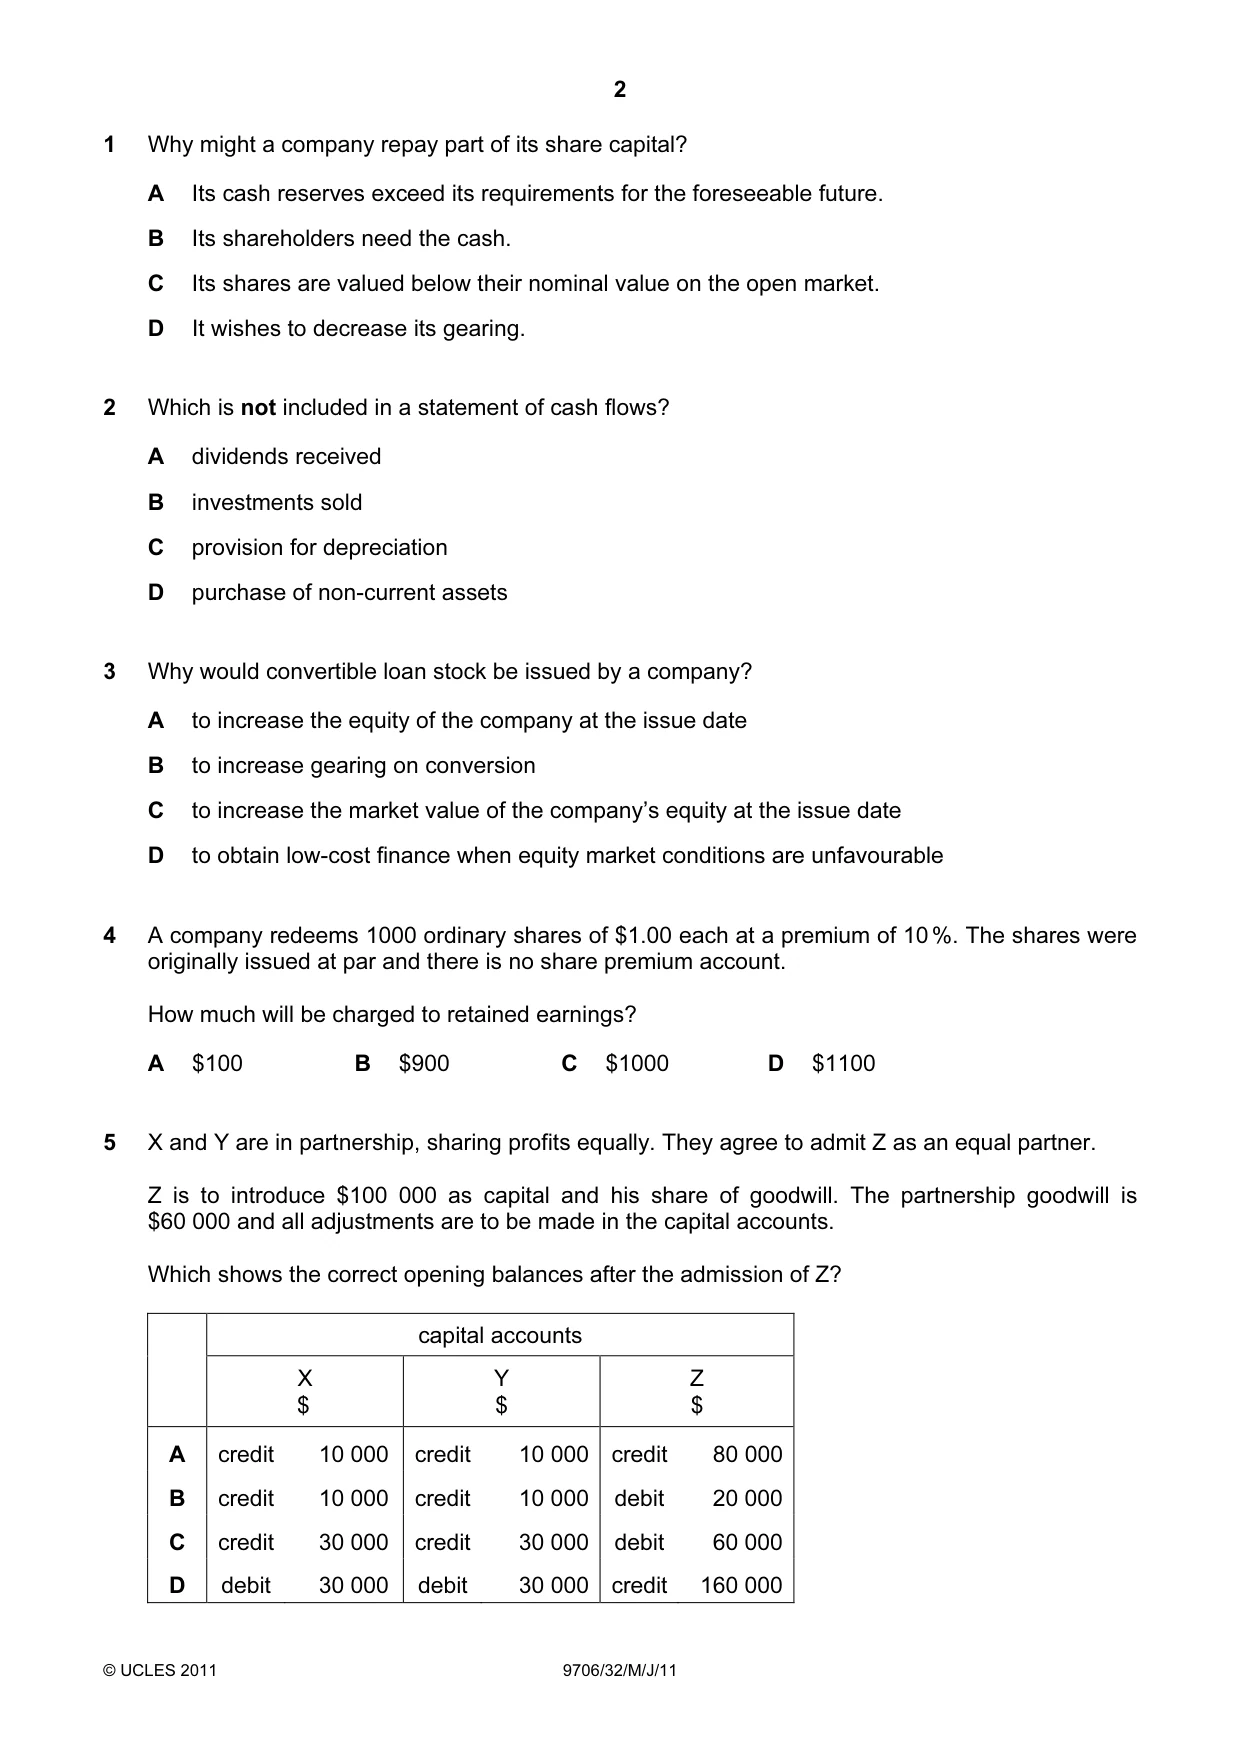
Q1 · Why might a company repay part of its share capital?
1 Why might a company repay part of its share capital? A Its cash reserves exceed its requirements for the foreseeable future. B Its shareholders need the cash. C Its shares are valued below their nominal value on the open market. D It wishes to decrease its gearing.
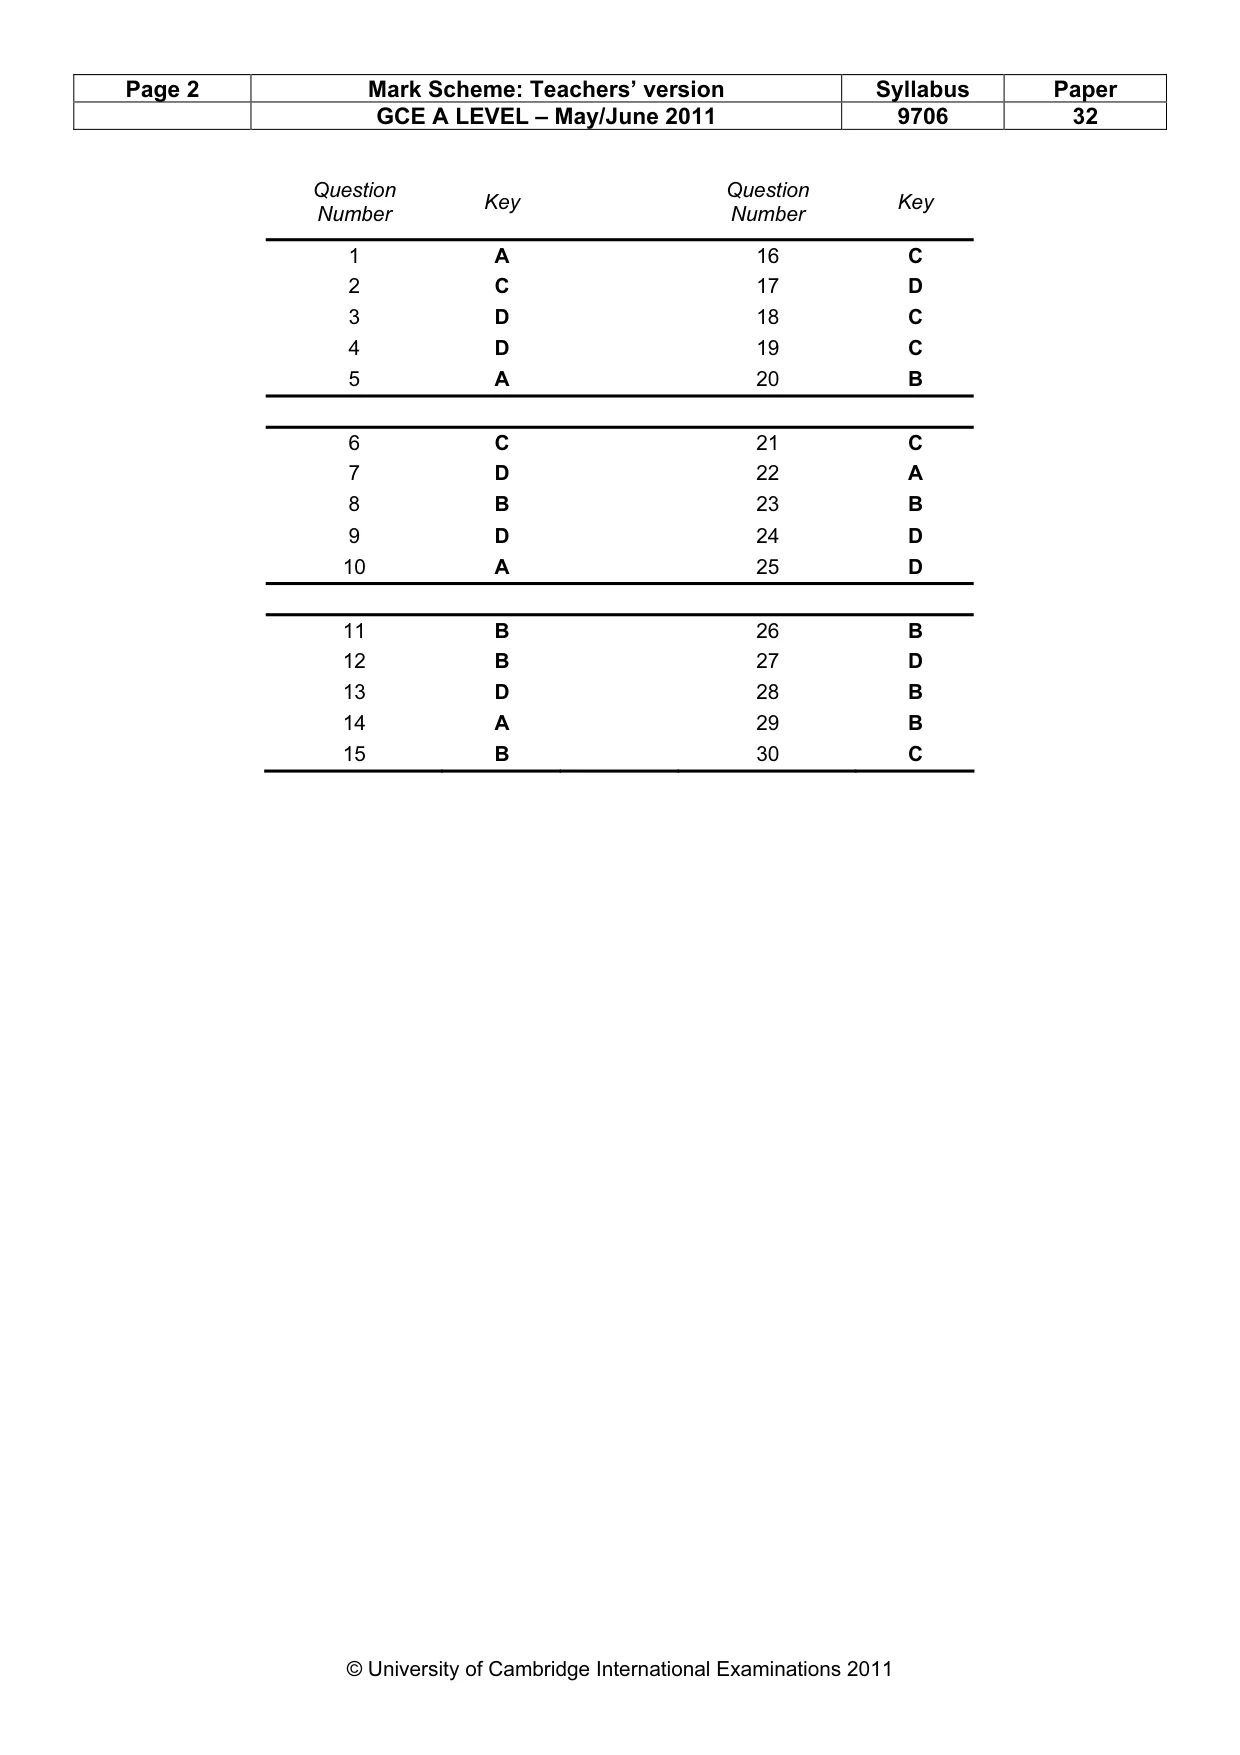
Mark scheme: A
Q2 · Which is not included in a statement of cash flows?
2 Which is not included in a statement of cash flows? A dividends received B investments sold C provision for depreciation D purchase of non-current assets
Mark scheme: C
Q3 · Why would convertible loan stock be issued by a company?
3 Why would convertible loan stock be issued by a company? A to increase the equity of the company at the issue date B to increase gearing on conversion C to increase the market value of the company’s equity at the issue date D to obtain low-cost finance when equity market conditions are unfavourable
Mark scheme: D
Q4 · A company redeems 1000 ordinary shares of $1.00 each at a premium of 10 %
4 A company redeems 1000 ordinary shares of $1.00 each at a premium of 10 %. The shares were originally issued at par and there is no share premium account. How much will be charged to retained earnings? A $100 B $900 C $1000 D $1100
Mark scheme: D
Q5 · X and Y are in partnership, sharing profits equally
5 X and Y are in partnership, sharing profits equally. They agree to admit Z as an equal partner. Z is to introduce $100 000 as capital and his share of goodwill. The partnership goodwill is $60 000 and all adjustments are to be made in the capital accounts. Which shows the correct opening balances after the admission of Z? capital accounts X Y Z $ $ $ A credit 10 000 credit 10 000 credit 80 000 B credit 10 000 credit 10 000 debit 20 000 C credit 30 000 credit 30 000 debit 60 000 D debit 30 000 debit 30 000 credit 160 000
Mark scheme: A
Q6 · Ess is to purchase the business of Tee
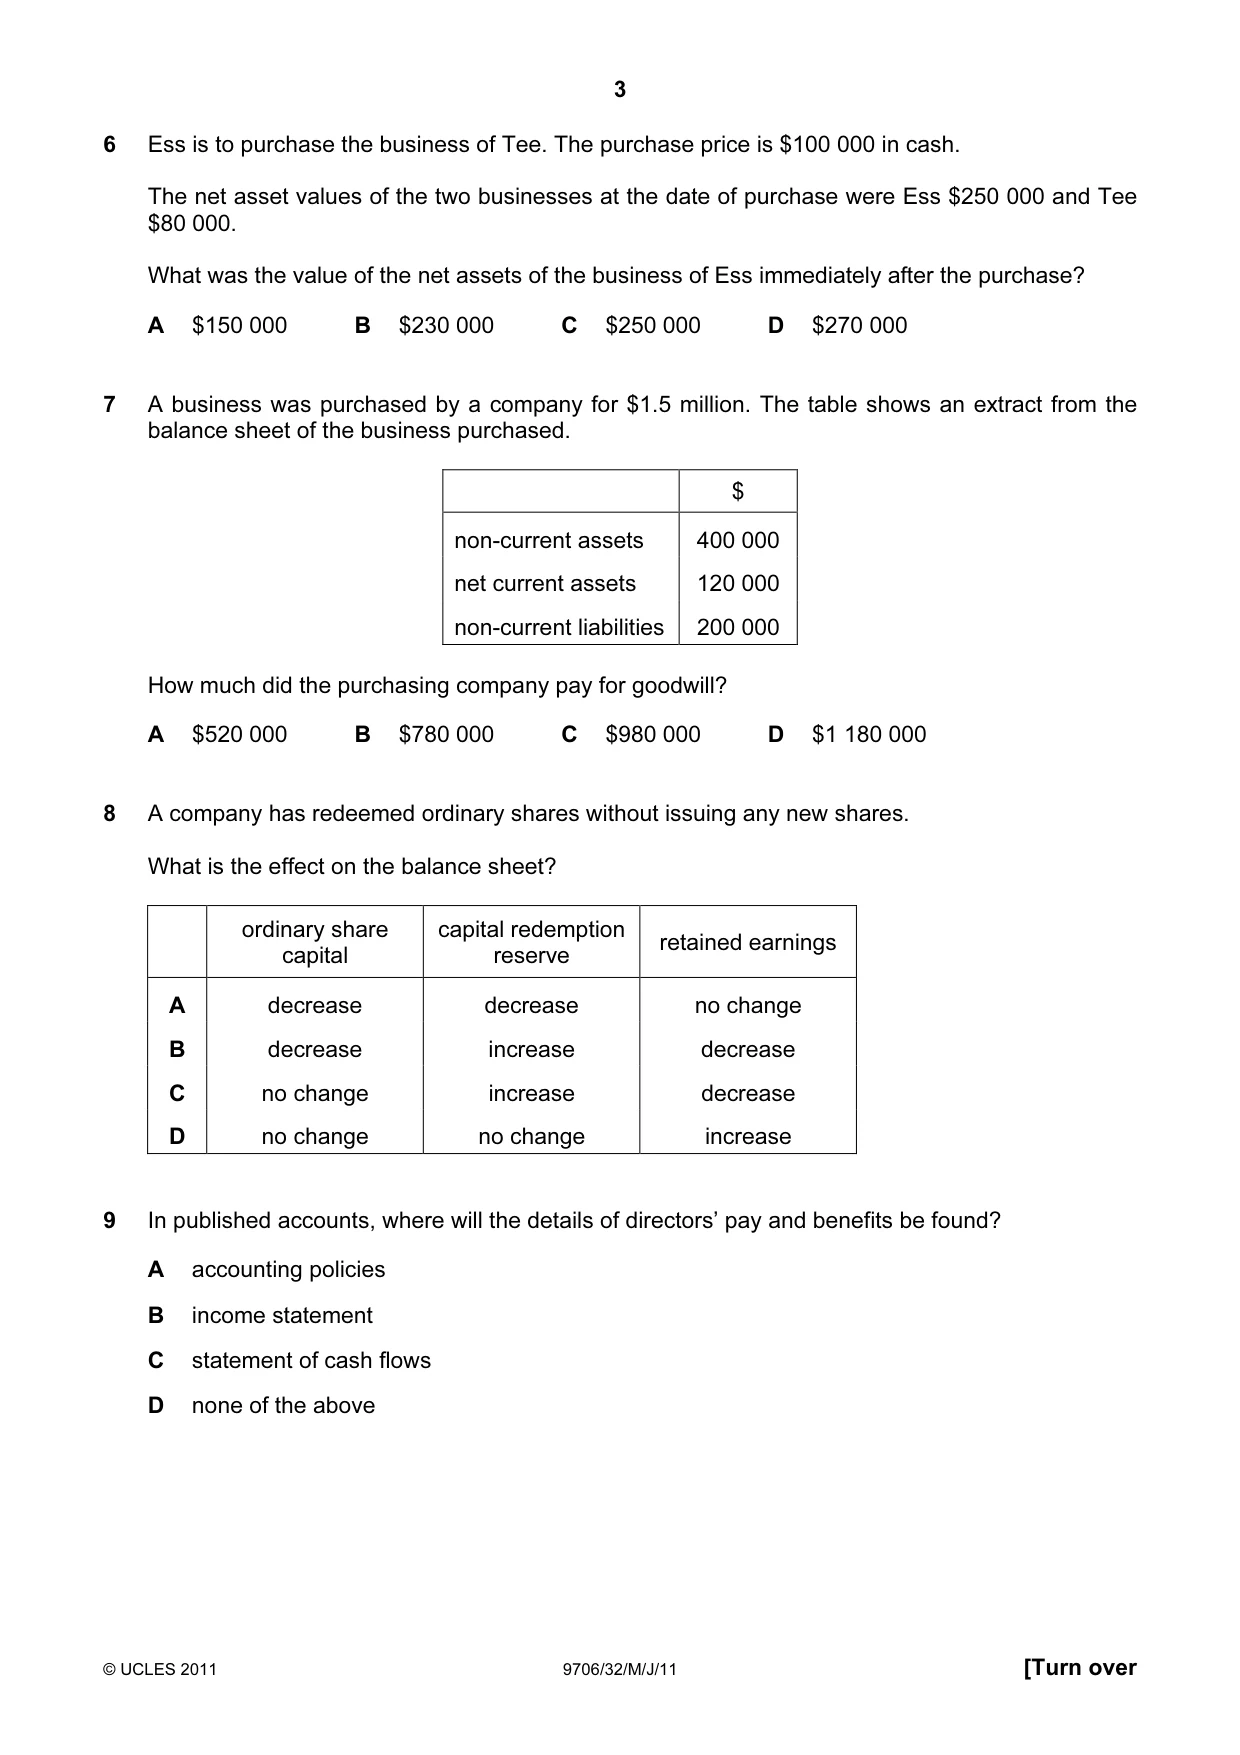
6 Ess is to purchase the business of Tee. The purchase price is $100 000 in cash. The net asset values of the two businesses at the date of purchase were Ess $250 000 and Tee $80 000. What was the value of the net assets of the business of Ess immediately after the purchase? A $150 000 B $230 000 C $250 000 D $270 000
Mark scheme: C
Q7 · A business was purchased by a company for $1.5 million
7 A business was purchased by a company for $1.5 million. The table shows an extract from the balance sheet of the business purchased. $ non-current assets 400 000 net current assets 120 000 non-current liabilities 200 000 How much did the purchasing company pay for goodwill? A $520 000 B $780 000 C $980 000 D $1 180 000
Mark scheme: D
Q8 · A company has redeemed ordinary shares without issuing any new shares
8 A company has redeemed ordinary shares without issuing any new shares. What is the effect on the balance sheet? ordinary share capital redemption retained earnings capital reserve A decrease decrease no change B decrease increase decrease C no change increase decrease D no change no change increase
Mark scheme: B
Q9 · In published accounts, where will the details of directors’ pay and benefits be found?
9 In published accounts, where will the details of directors’ pay and benefits be found? A accounting policies B income statement C statement of cash flows D none of the above
Mark scheme: D
Q10 · The reserves of a company are as follows: $ share premium 60 000 property revaluation…
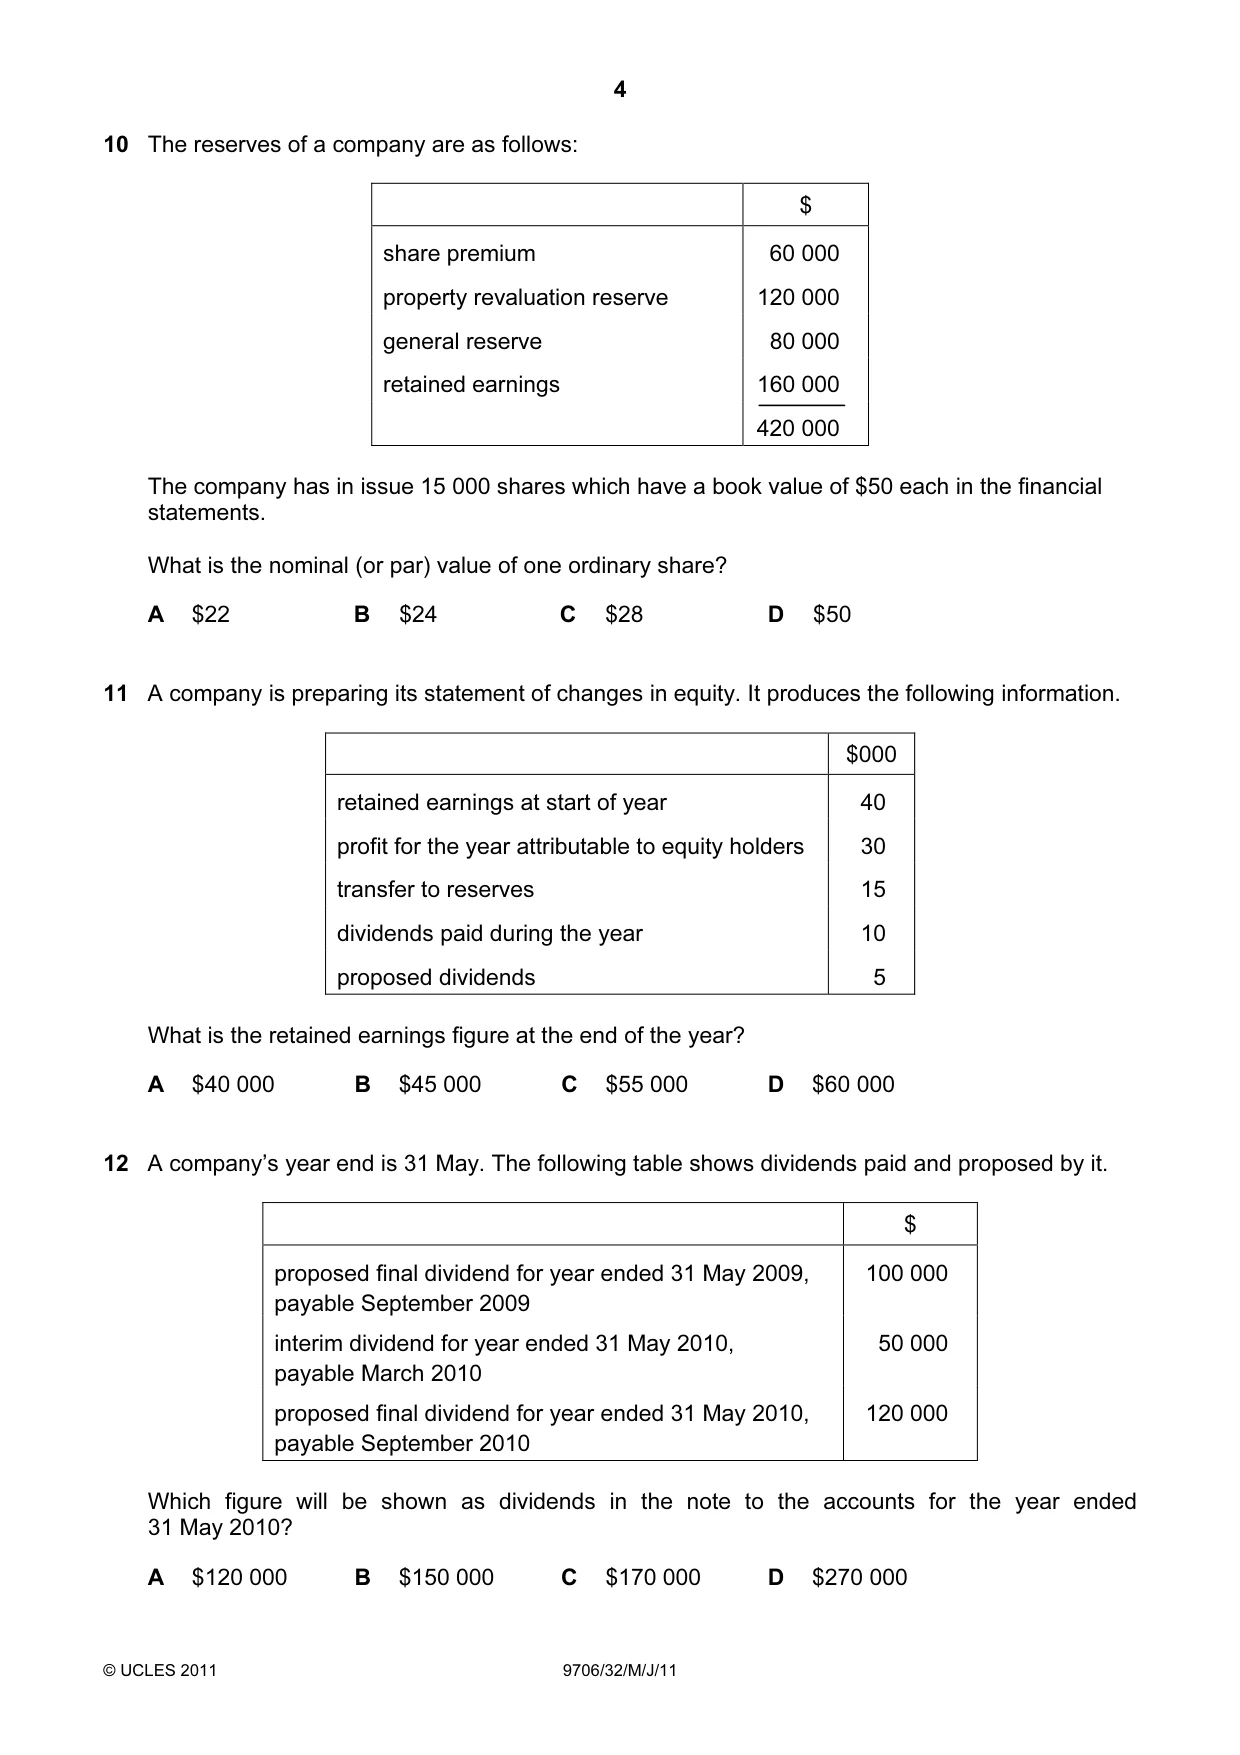
10 The reserves of a company are as follows: $ share premium 60 000 property revaluation reserve 120 000 general reserve 80 000 retained earnings 160 000 420 000 The company has in issue 15 000 shares which have a book value of $50 each in the financial statements. What is the nominal (or par) value of one ordinary share? A $22 B $24 C $28 D $50
Mark scheme: A
Q11 · A company is preparing its statement of changes in equity
11 A company is preparing its statement of changes in equity. It produces the following information. $000 retained earnings at start of year 40 profit for the year attributable to equity holders 30 transfer to reserves 15 dividends paid during the year 10 proposed dividends 5 What is the retained earnings figure at the end of the year? A $40 000 B $45 000 C $55 000 D $60 000
Mark scheme: B
Q12 · A company’s year end is 31 May
12 A company’s year end is 31 May. The following table shows dividends paid and proposed by it. $ proposed final dividend for year ended 31 May 2009, 100 000 payable September 2009 interim dividend for year ended 31 May 2010, 50 000 payable March 2010 proposed final dividend for year ended 31 May 2010, 120 000 payable September 2010 Which figure will be shown as dividends in the note to the accounts for the year ended 31 May 2010? A $120 000 B $150 000 C $170 000 D $270 000
Mark scheme: B
Q13 · The following is an extract from the statement of financial position of Zed Ltd
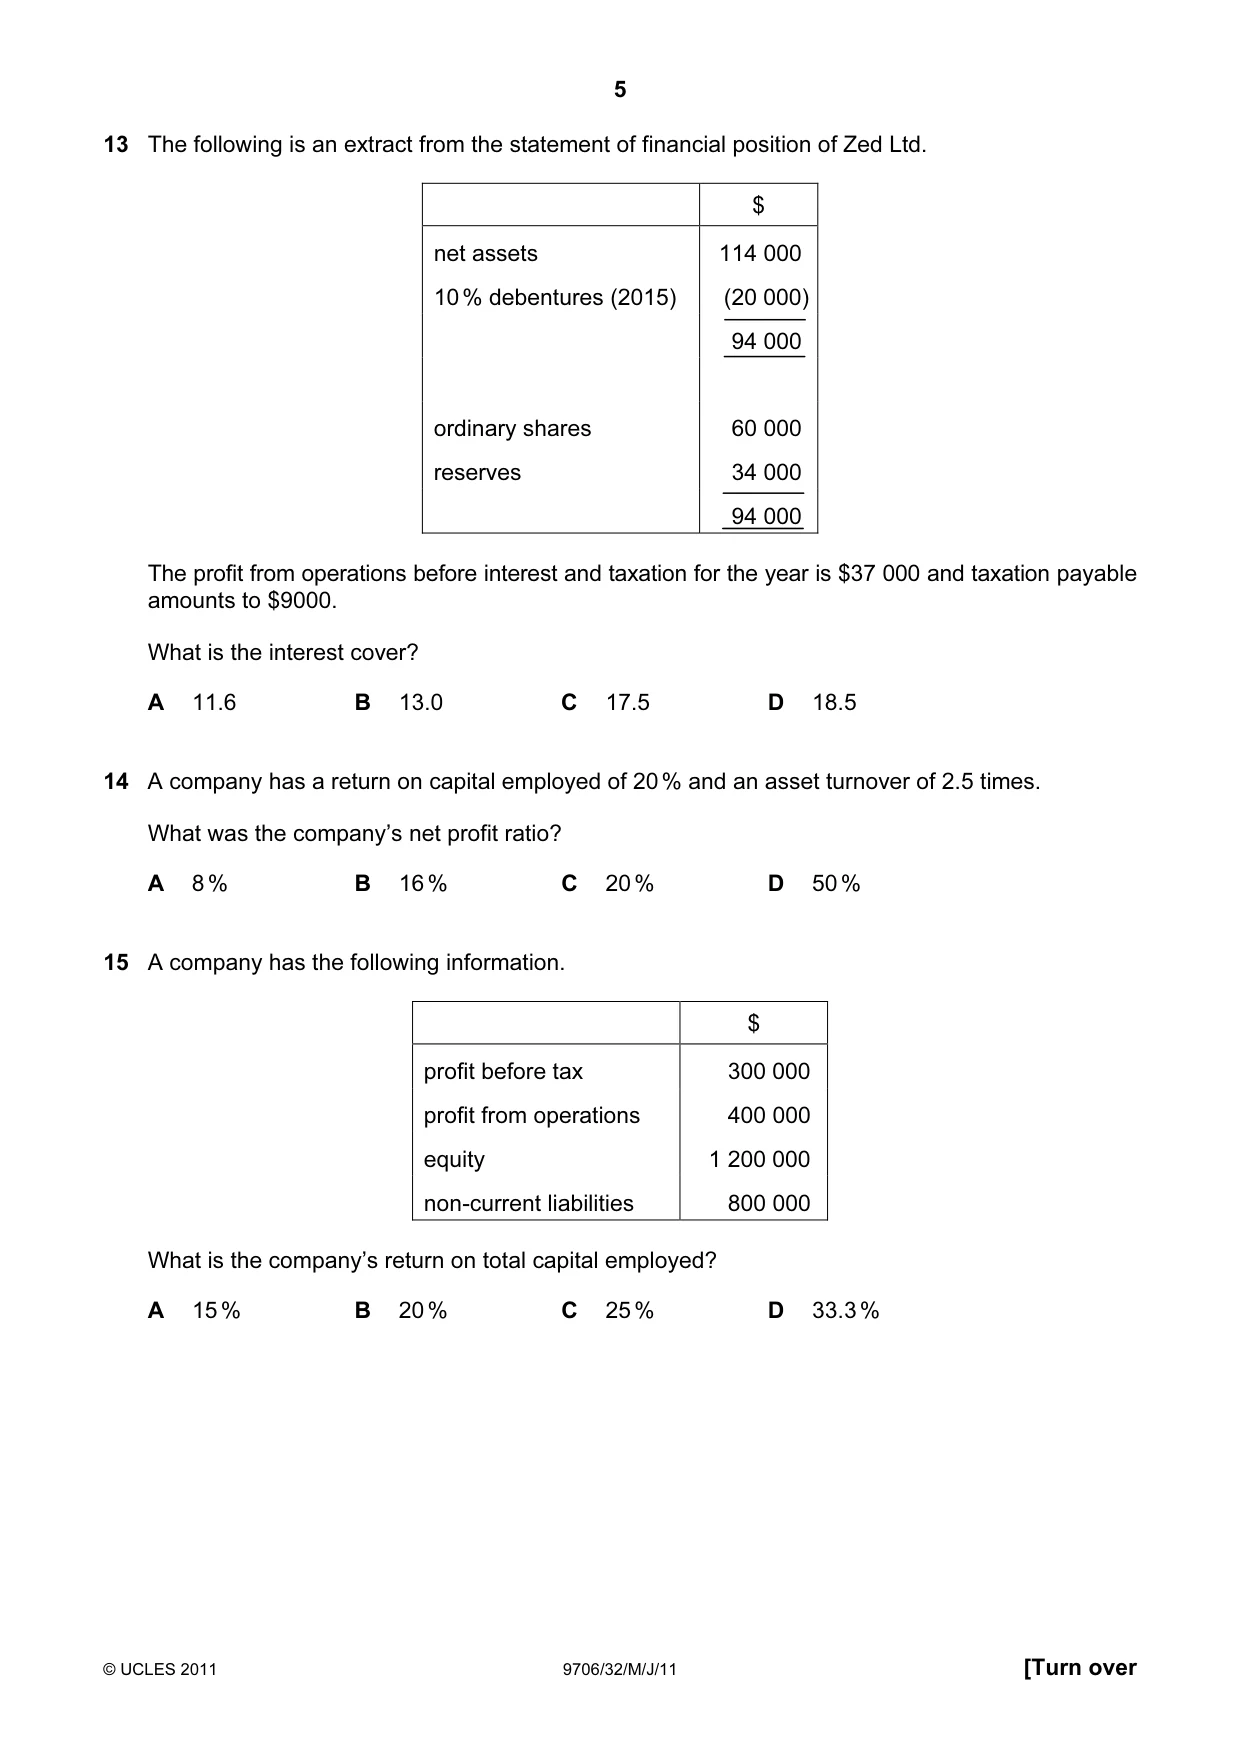
13 The following is an extract from the statement of financial position of Zed Ltd. $ net assets 114 000 10 % debentures (2015) (20 000) 94 000 ordinary shares 60 000 reserves 34 000 94 000 The profit from operations before interest and taxation for the year is $37 000 and taxation payable amounts to $9000. What is the interest cover? A 11.6 B 13.0 C 17.5 D 18.5
Mark scheme: D
More questions on Analysis and communication of accounting information
Q14 · A company has a return on capital employed of 20 % and an asset turnover of 2.5 times
14 A company has a return on capital employed of 20 % and an asset turnover of 2.5 times. What was the company’s net profit ratio? A 8 % B 16 % C 20 % D 50 %
Mark scheme: A
More questions on Analysis and communication of accounting information
Q15 · A company has the following information
15 A company has the following information. $ profit before tax 300 000 profit from operations 400 000 equity 1 200 000 non-current liabilities 800 000 What is the company’s return on total capital employed? A 15 % B 20 % C 25 % D 33.3 %
Mark scheme: B
More questions on Analysis and communication of accounting information
Q16 · The following data is available for the first year of trading for a business to 31…
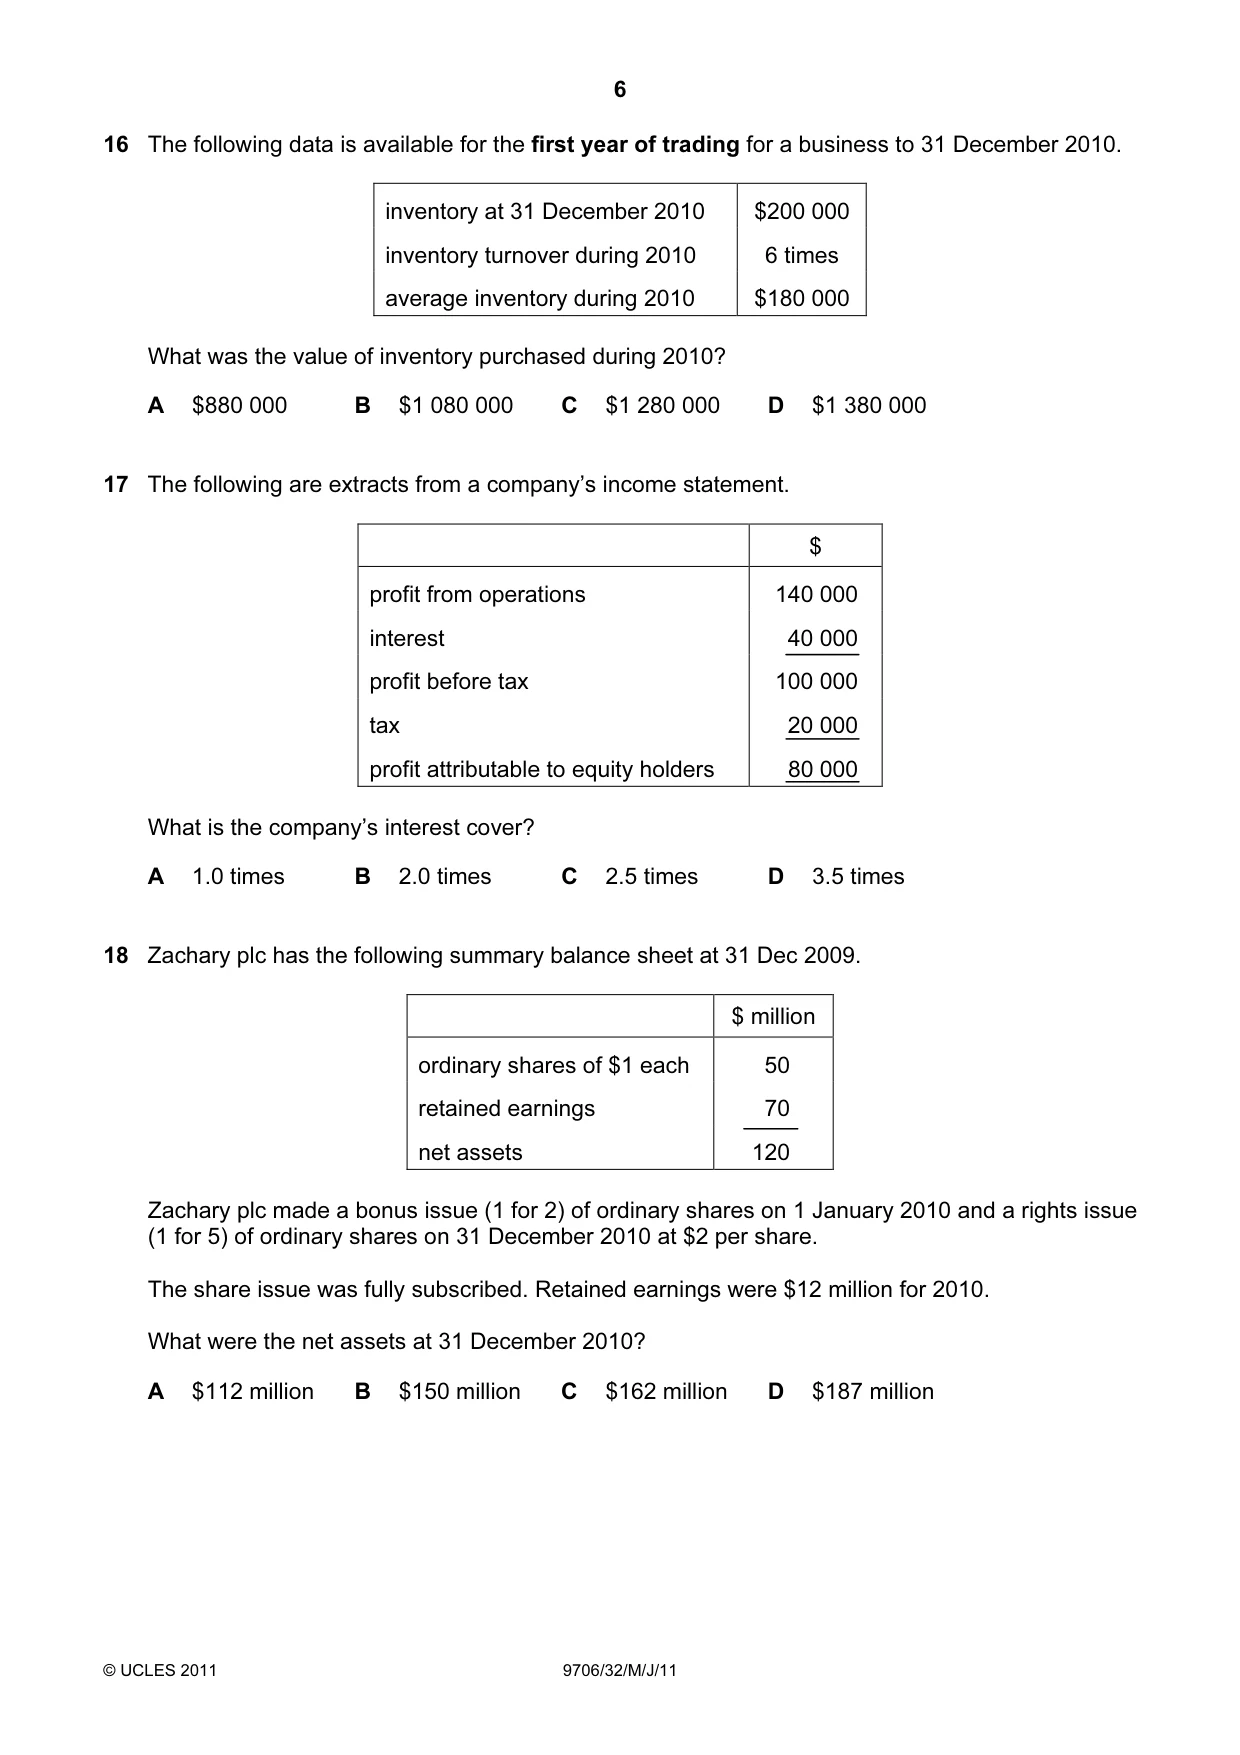
16 The following data is available for the first year of trading for a business to 31 December 2010. inventory at 31 December 2010 $200 000 inventory turnover during 2010 6 times average inventory during 2010 $180 000 What was the value of inventory purchased during 2010? A $880 000 B $1 080 000 C $1 280 000 D $1 380 000
Mark scheme: C
More questions on Analysis and communication of accounting information
Q17 · The following are extracts from a company’s income statement
17 The following are extracts from a company’s income statement. $ profit from operations 140 000 interest 40 000 profit before tax 100 000 tax 20 000 profit attributable to equity holders 80 000 What is the company’s interest cover? A 1.0 times B 2.0 times C 2.5 times D 3.5 times
Mark scheme: D
More questions on Analysis and communication of accounting information
Q18 · Zachary plc has the following summary balance sheet at 31 Dec 2009
18 Zachary plc has the following summary balance sheet at 31 Dec 2009. $ million ordinary shares of $1 each 50 retained earnings 70 net assets 120 Zachary plc made a bonus issue (1 for 2) of ordinary shares on 1 January 2010 and a rights issue (1 for 5) of ordinary shares on 31 December 2010 at $2 per share. The share issue was fully subscribed. Retained earnings were $12 million for 2010. What were the net assets at 31 December 2010? A $112 million B $150 million C $162 million D $187 million
Mark scheme: C
Q19 · A company has the following production budget details for the next period
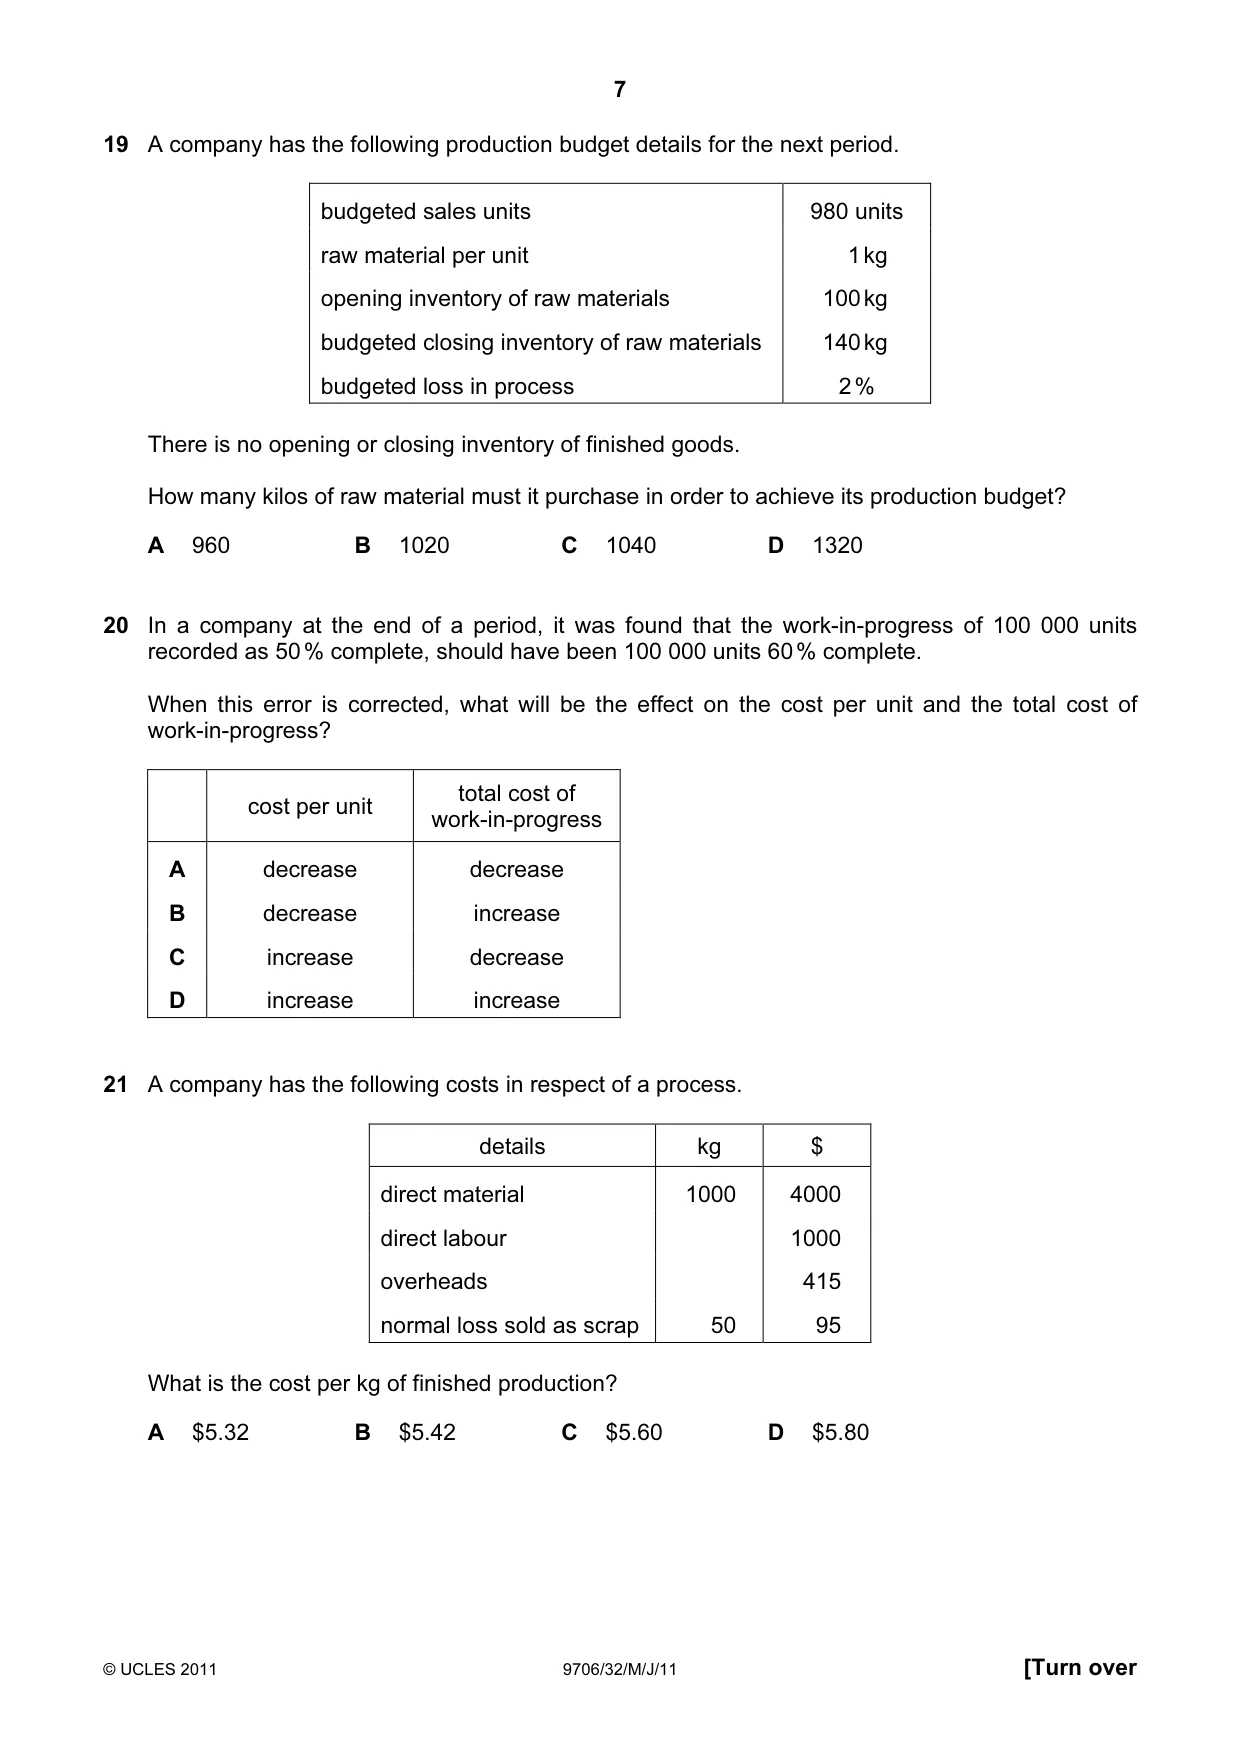
19 A company has the following production budget details for the next period. budgeted sales units 980 units raw material per unit 1 kg opening inventory of raw materials 100 kg budgeted closing inventory of raw materials 140 kg budgeted loss in process 2 % There is no opening or closing inventory of finished goods. How many kilos of raw material must it purchase in order to achieve its production budget? A 960 B 1020 C 1040 D 1320
Mark scheme: C
Q20 · In a company at the end of a period, it was found that the work-in-progress of 100 000…
20 In a company at the end of a period, it was found that the work-in-progress of 100 000 units recorded as 50 % complete, should have been 100 000 units 60 % complete. When this error is corrected, what will be the effect on the cost per unit and the total cost of work-in-progress? total cost of cost per unit work-in-progress A decrease decrease B decrease increase C increase decrease D increase increase
Mark scheme: B
Q21 · A company has the following costs in respect of a process
21 A company has the following costs in respect of a process. details kg $ direct material 1000 4000 direct labour 1000 overheads 415 normal loss sold as scrap 50 95 What is the cost per kg of finished production? A $5.32 B $5.42 C $5.60 D $5.80
Mark scheme: C
Q22 · The following information relates to the budgeted and actual sales of a product
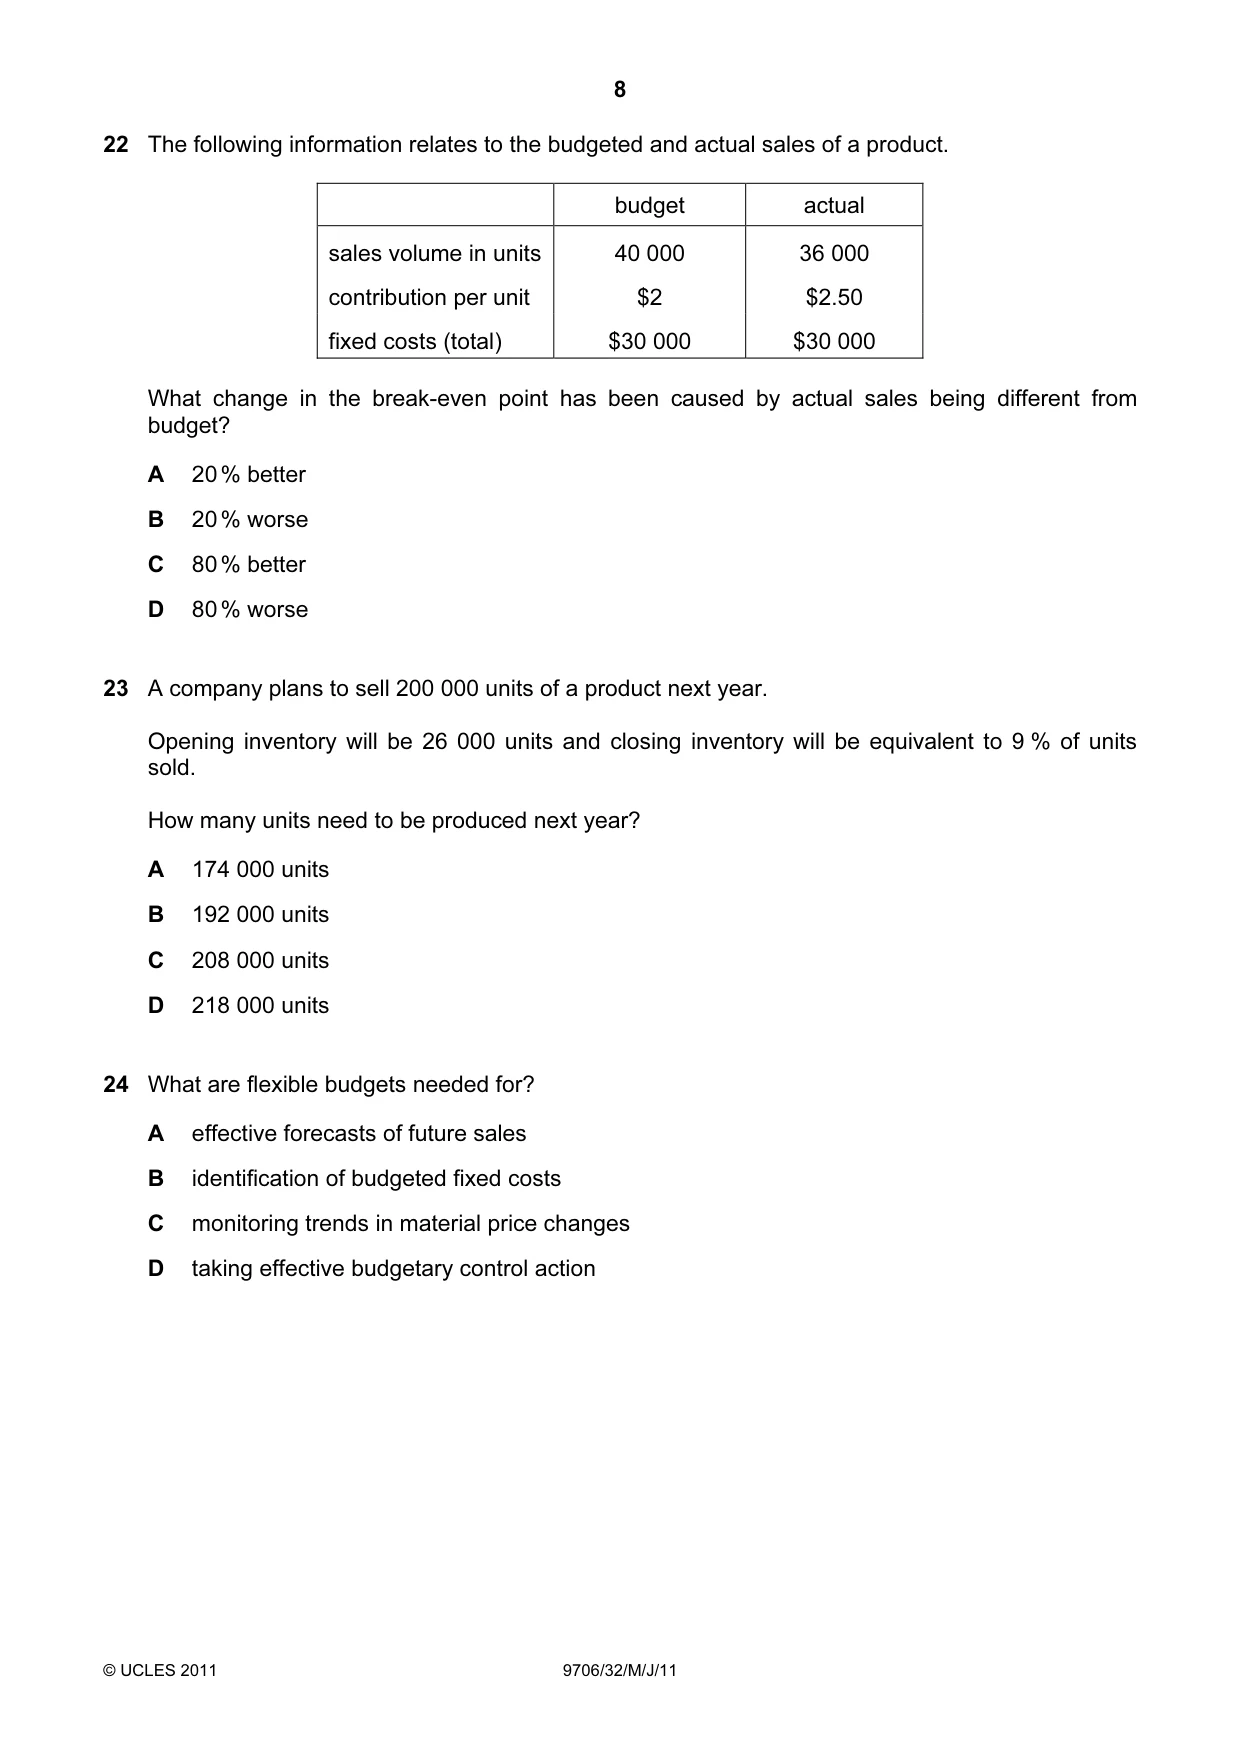
22 The following information relates to the budgeted and actual sales of a product. budget actual sales volume in units 40 000 36 000 contribution per unit $2 $2.50 fixed costs (total) $30 000 $30 000 What change in the break-even point has been caused by actual sales being different from budget? A 20 % better B 20 % worse C 80 % better D 80 % worse
Mark scheme: A
Q23 · A company plans to sell 200 000 units of a product next year
23 A company plans to sell 200 000 units of a product next year. Opening inventory will be 26 000 units and closing inventory will be equivalent to 9 % of units sold. How many units need to be produced next year? A 174 000 units B 192 000 units C 208 000 units D 218 000 units
Mark scheme: B
Q24 · What are flexible budgets needed for?
24 What are flexible budgets needed for? A effective forecasts of future sales B identification of budgeted fixed costs C monitoring trends in material price changes D taking effective budgetary control action
Mark scheme: D
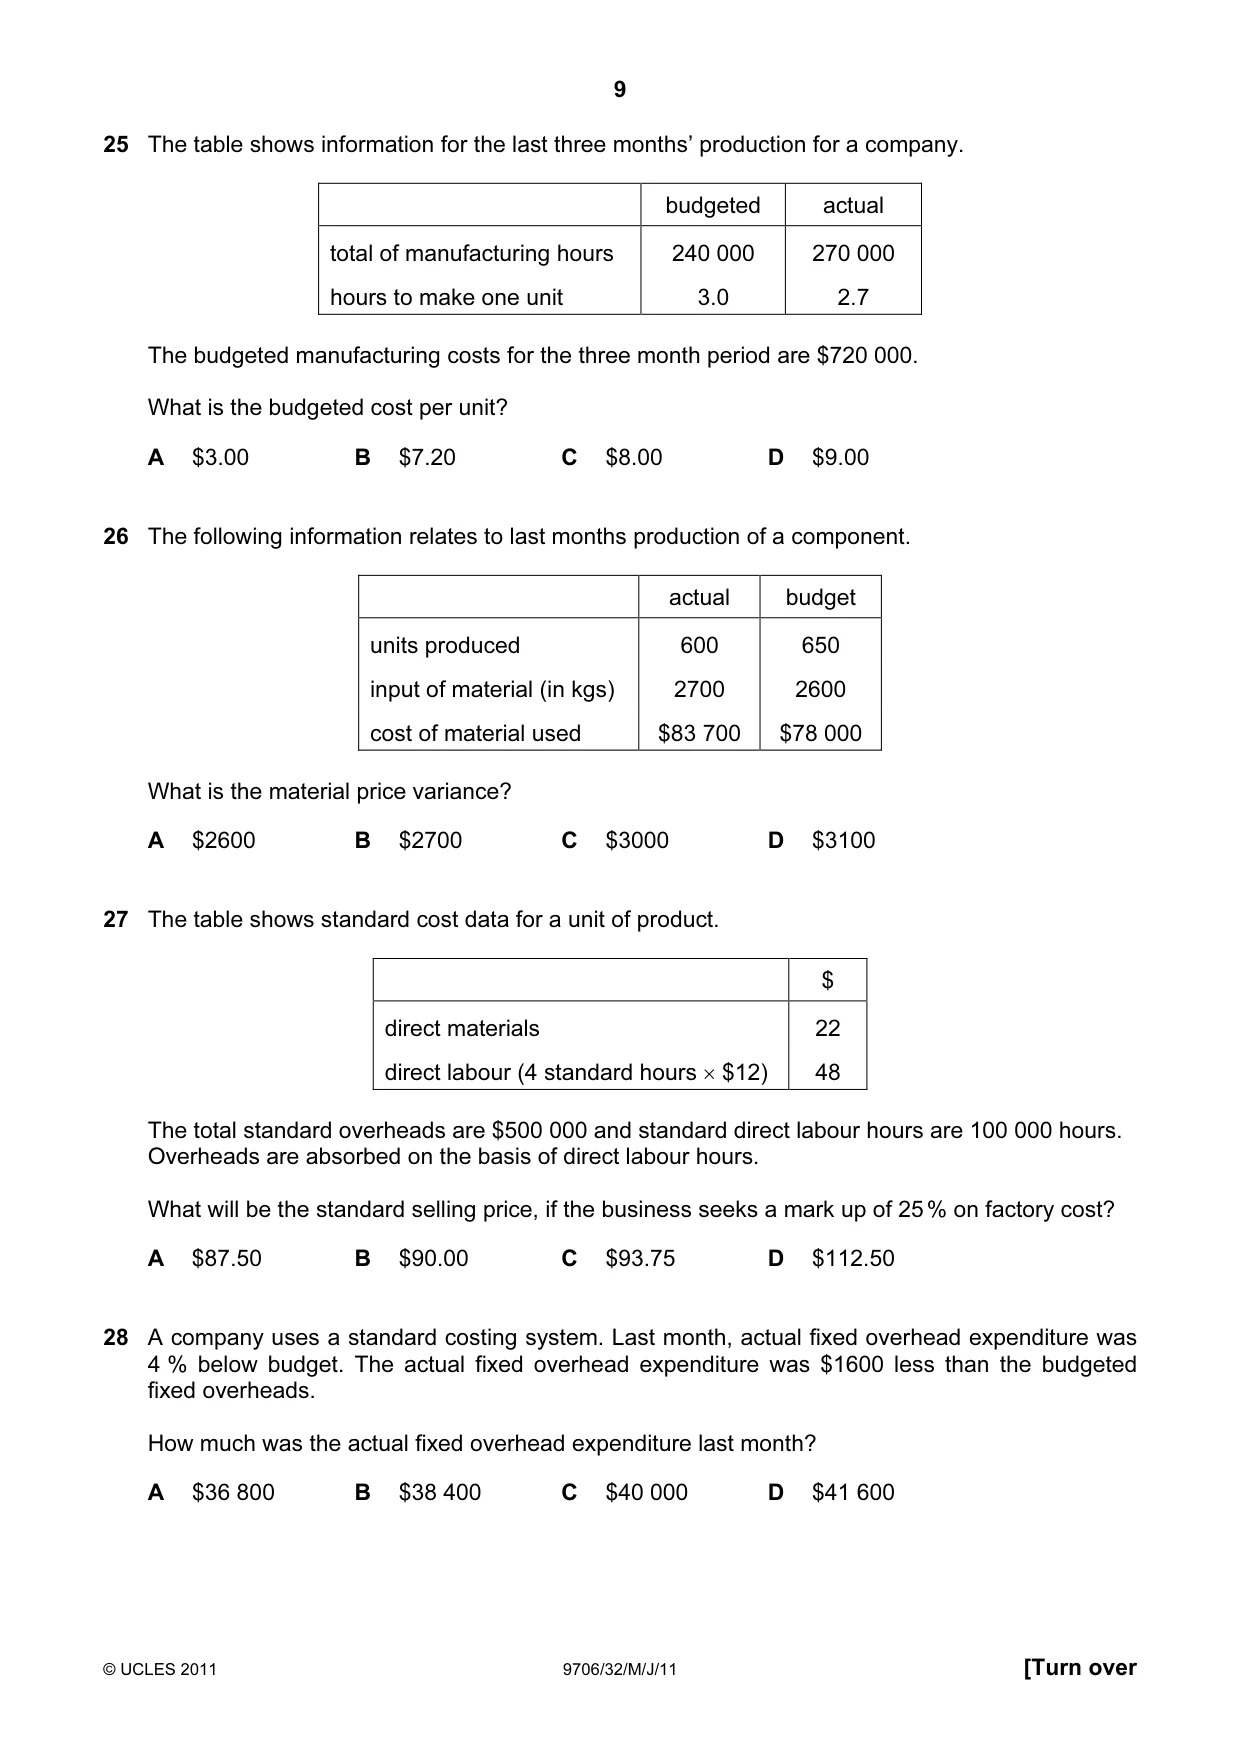
Q25 · The table shows information for the last three months’ production for a company
25 The table shows information for the last three months’ production for a company. budgeted actual total of manufacturing hours 240 000 270 000 hours to make one unit 3.0 2.7 The budgeted manufacturing costs for the three month period are $720 000. What is the budgeted cost per unit? A $3.00 B $7.20 C $8.00 D $9.00
Mark scheme: D
Q26 · The following information relates to last months production of a component
26 The following information relates to last months production of a component. actual budget units produced 600 650 input of material (in kgs) 2700 2600 cost of material used $83 700 $78 000 What is the material price variance? A $2600 B $2700 C $3000 D $3100
Mark scheme: B
Q27 · The table shows standard cost data for a unit of product
27 The table shows standard cost data for a unit of product. $ direct materials 22 direct labour (4 standard hours × $12) 48 The total standard overheads are $500 000 and standard direct labour hours are 100 000 hours. Overheads are absorbed on the basis of direct labour hours. What will be the standard selling price, if the business seeks a mark up of 25 % on factory cost? A $87.50 B $90.00 C $93.75 D $112.50
Mark scheme: D
Q28 · A company uses a standard costing system
28 A company uses a standard costing system. Last month, actual fixed overhead expenditure was 4 % below budget. The actual fixed overhead expenditure was $1600 less than the budgeted fixed overheads. How much was the actual fixed overhead expenditure last month? A $36 800 B $38 400 C $40 000 D $41 600
Mark scheme: B
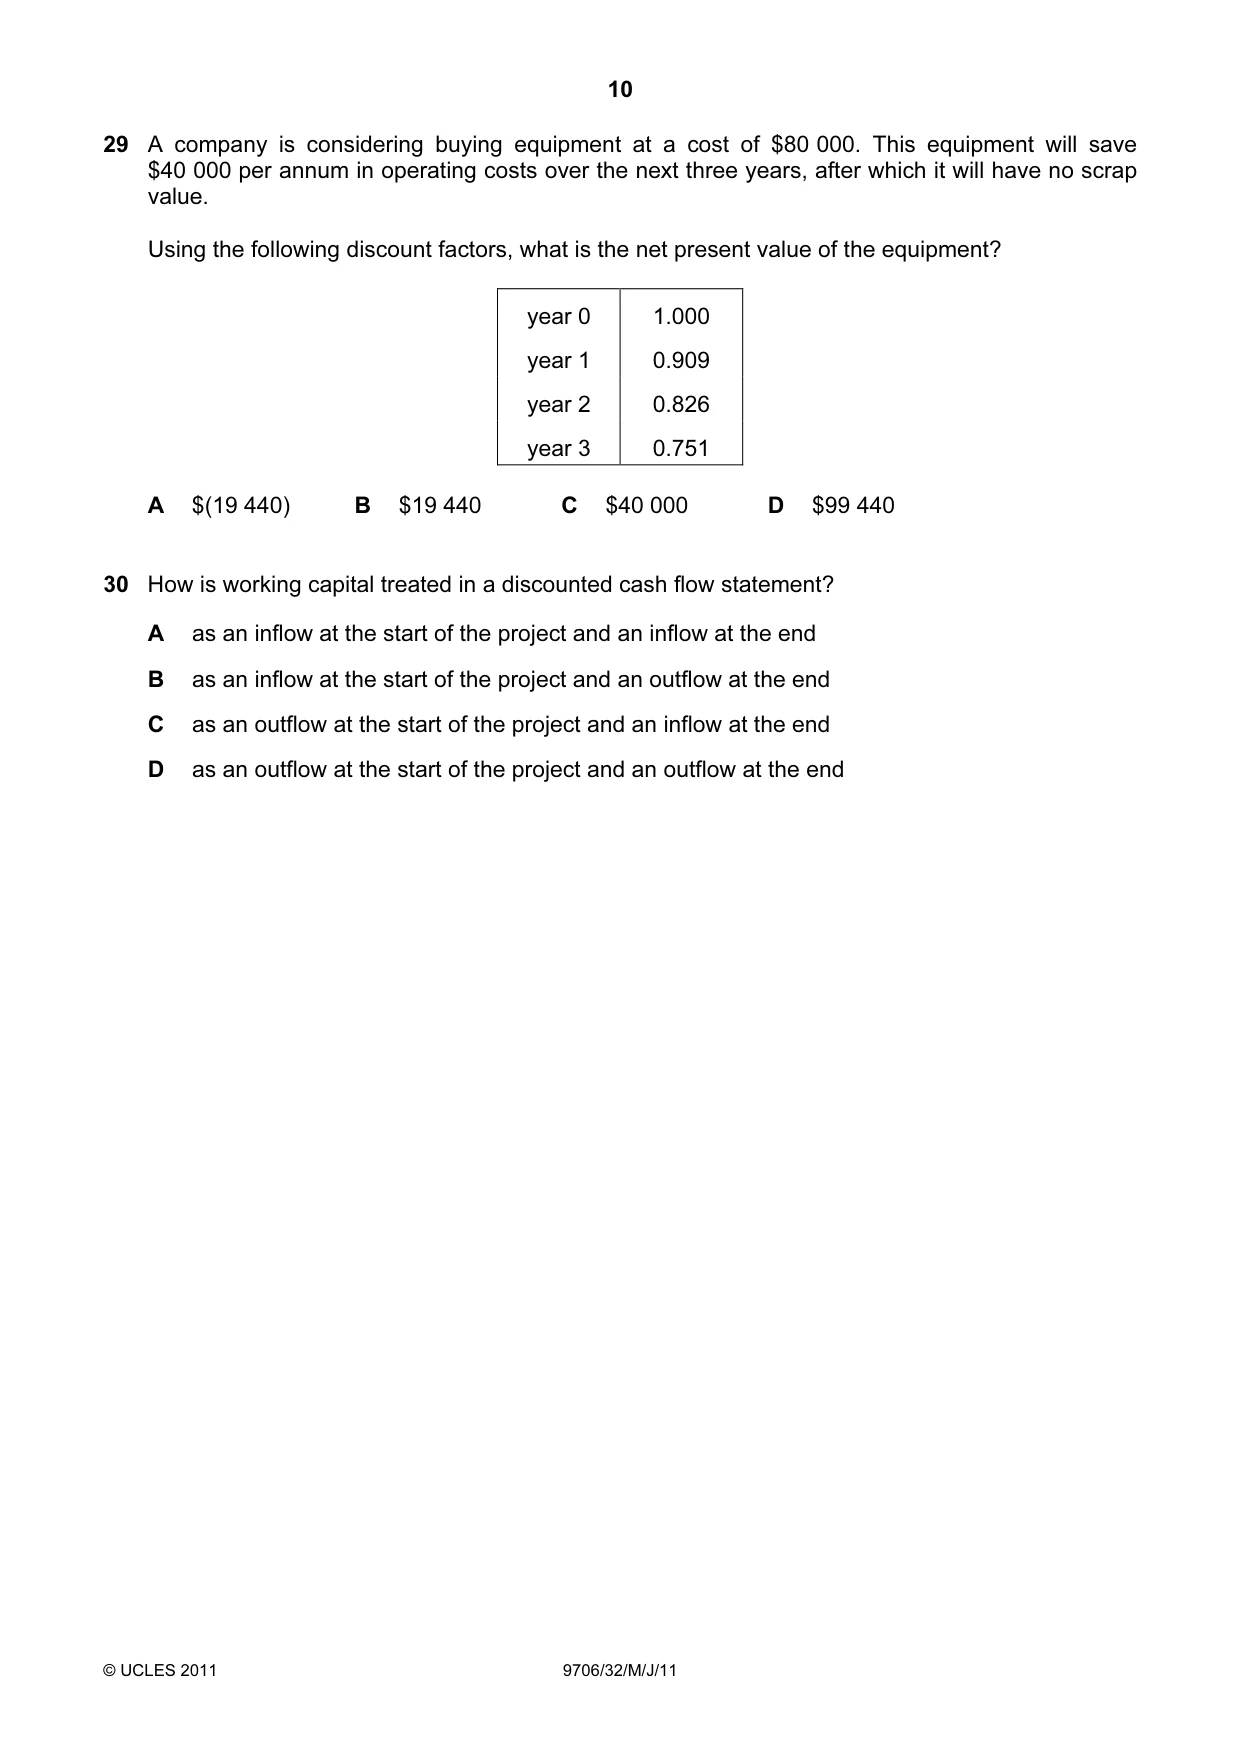
Q29 · A company is considering buying equipment at a cost of $80 000
29 A company is considering buying equipment at a cost of $80 000. This equipment will save $40 000 per annum in operating costs over the next three years, after which it will have no scrap value. Using the following discount factors, what is the net present value of the equipment? year 0 1.000 year 1 0.909 year 2 0.826 year 3 0.751 A $(19 440) B $19 440 C $40 000 D $99 440
Mark scheme: B
Q30 · How is working capital treated in a discounted cash flow statement?
30 How is working capital treated in a discounted cash flow statement? A as an inflow at the start of the project and an inflow at the end B as an inflow at the start of the project and an outflow at the end C as an outflow at the start of the project and an inflow at the end D as an outflow at the start of the project and an outflow at the end
Mark scheme: C
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
8Analysis and communication of accounting information3Budgeting and budgetary control3Traditional costing methods3Analysis and communication of accounting information2Business acquisition and merger2Costs and cost behaviour2Investment appraisal2Standard costing2Preparation of financial statements1Regulatory and ethical considerations1Types of business entity1What you needed in this session
Cambridge’s own grade thresholds for 2011 May/June, Paper 3 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.