Cambridge A Level Accounting 9706 — 2011 Oct/Nov Paper 3 · Variant 3
9706/33/O/N/11 · 30 questions · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme2 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · 600 000 shares are issued at $5.00 per share
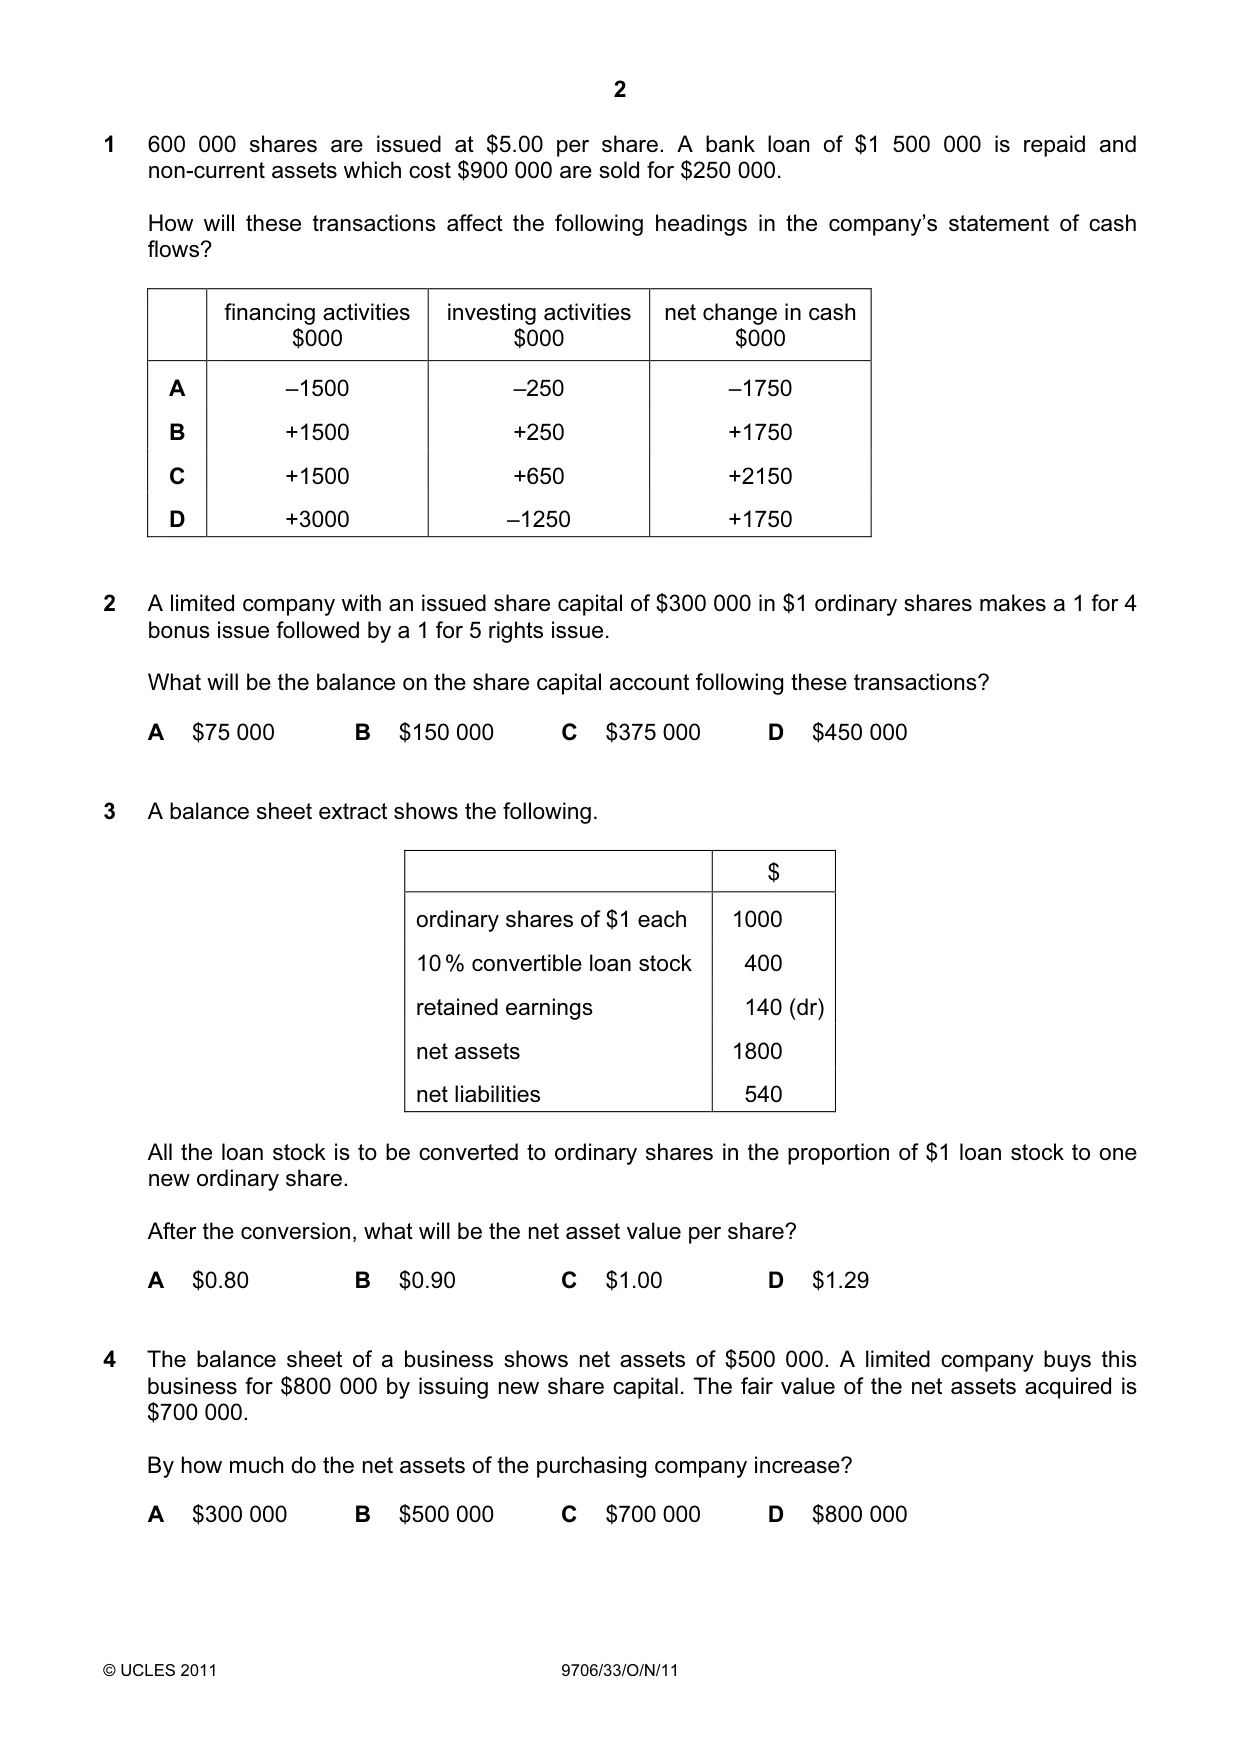
1 600 000 shares are issued at $5.00 per share. A bank loan of $1 500 000 is repaid and non-current assets which cost $900 000 are sold for $250 000. How will these transactions affect the following headings in the company’s statement of cash flows? financing activities investing activities net change in cash $000 $000 $000 A –1500 –250 –1750 B +1500 +250 +1750 C +1500 +650 +2150 D +3000 –1250 +1750
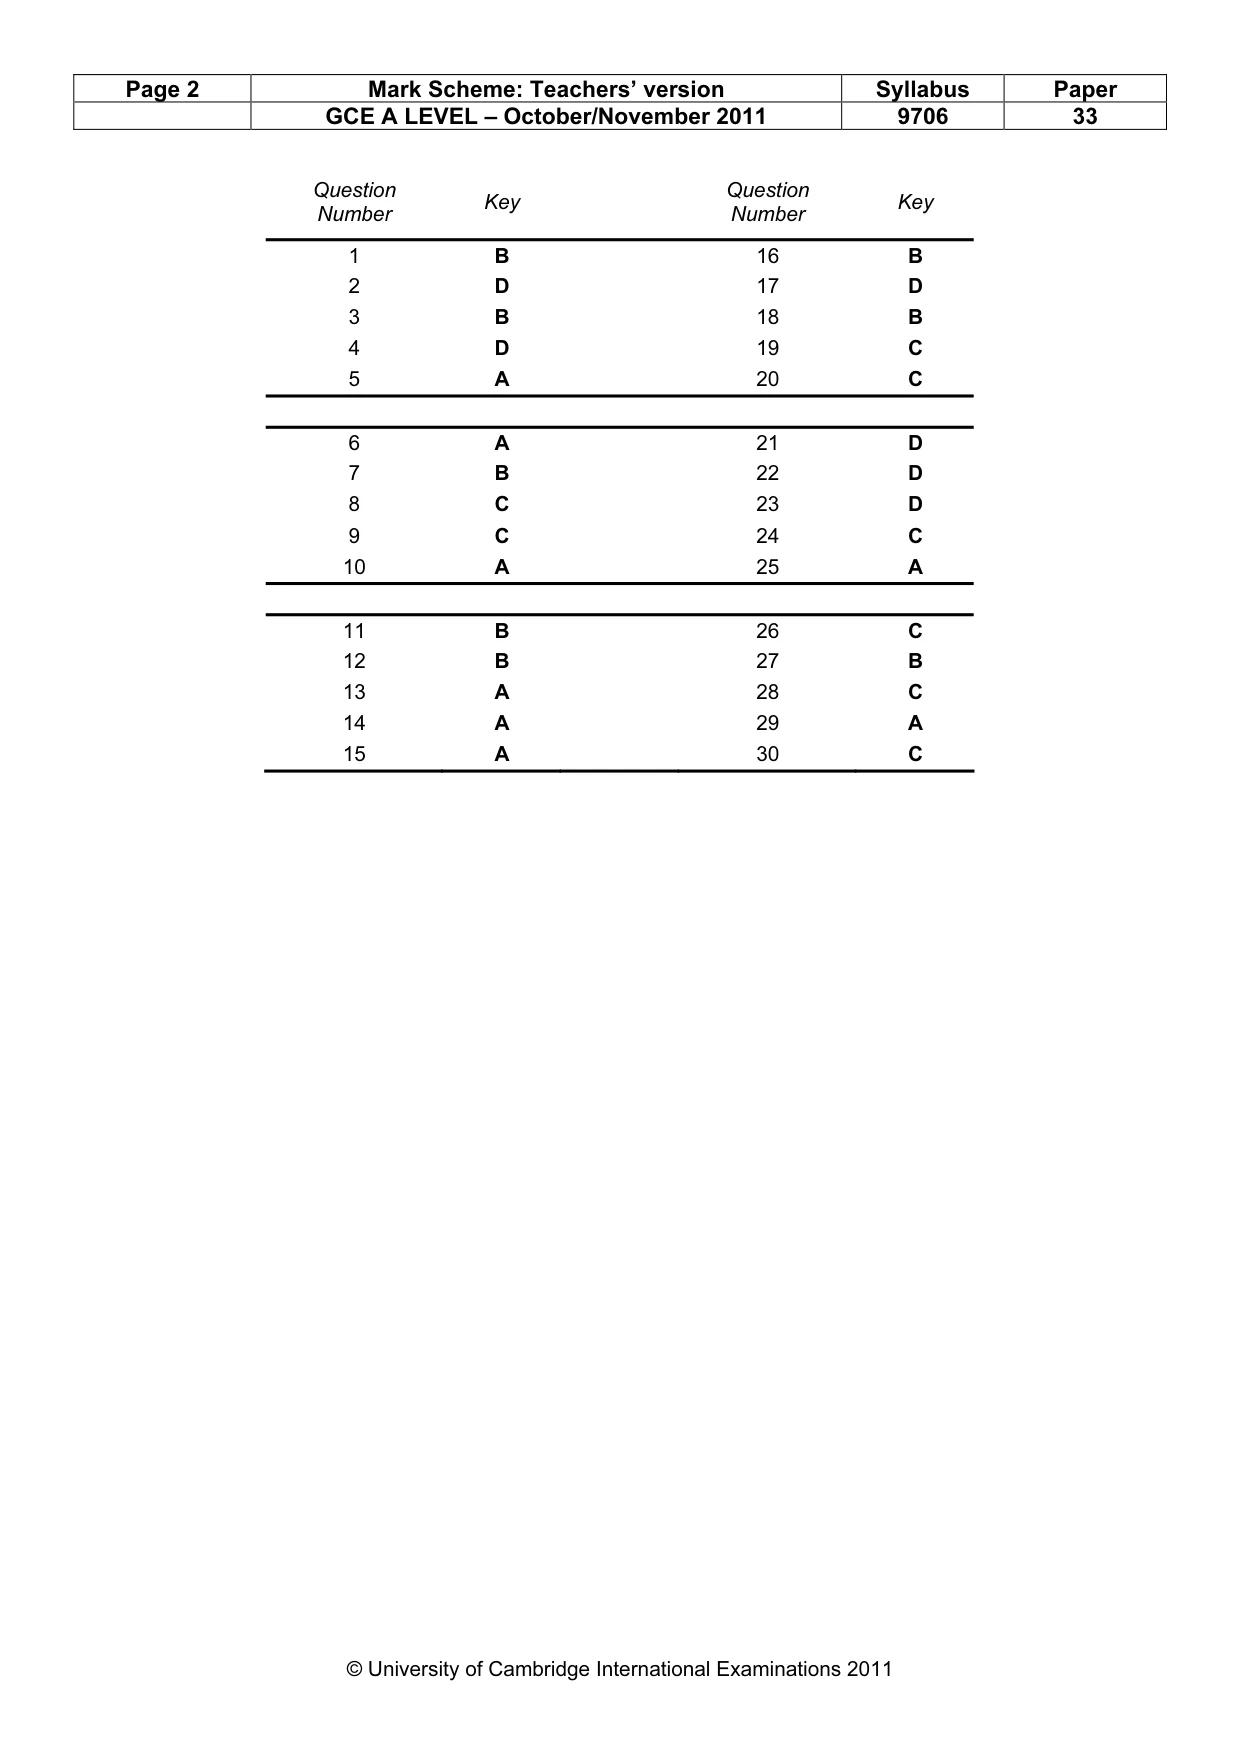
Mark scheme: B
Q2 · A limited company with an issued share capital of $300 000 in $1 ordinary shares makes a…
2 A limited company with an issued share capital of $300 000 in $1 ordinary shares makes a 1 for 4 bonus issue followed by a 1 for 5 rights issue. What will be the balance on the share capital account following these transactions? A $75 000 B $150 000 C $375 000 D $450 000
Mark scheme: D
Q3 · A balance sheet extract shows the following
3 A balance sheet extract shows the following. $ ordinary shares of $1 each 1000 10 % convertible loan stock 400 retained earnings 140 (dr) net assets 1800 net liabilities 540 All the loan stock is to be converted to ordinary shares in the proportion of $1 loan stock to one new ordinary share. After the conversion, what will be the net asset value per share? A $0.80 B $0.90 C $1.00 D $1.29
Mark scheme: B
Q4 · The balance sheet of a business shows net assets of $500 000
4 The balance sheet of a business shows net assets of $500 000. A limited company buys this business for $800 000 by issuing new share capital. The fair value of the net assets acquired is $700 000. By how much do the net assets of the purchasing company increase? A $300 000 B $500 000 C $700 000 D $800 000
Mark scheme: D
Q5 · A partner receives 8 % interest on a partnership loan of $100 000
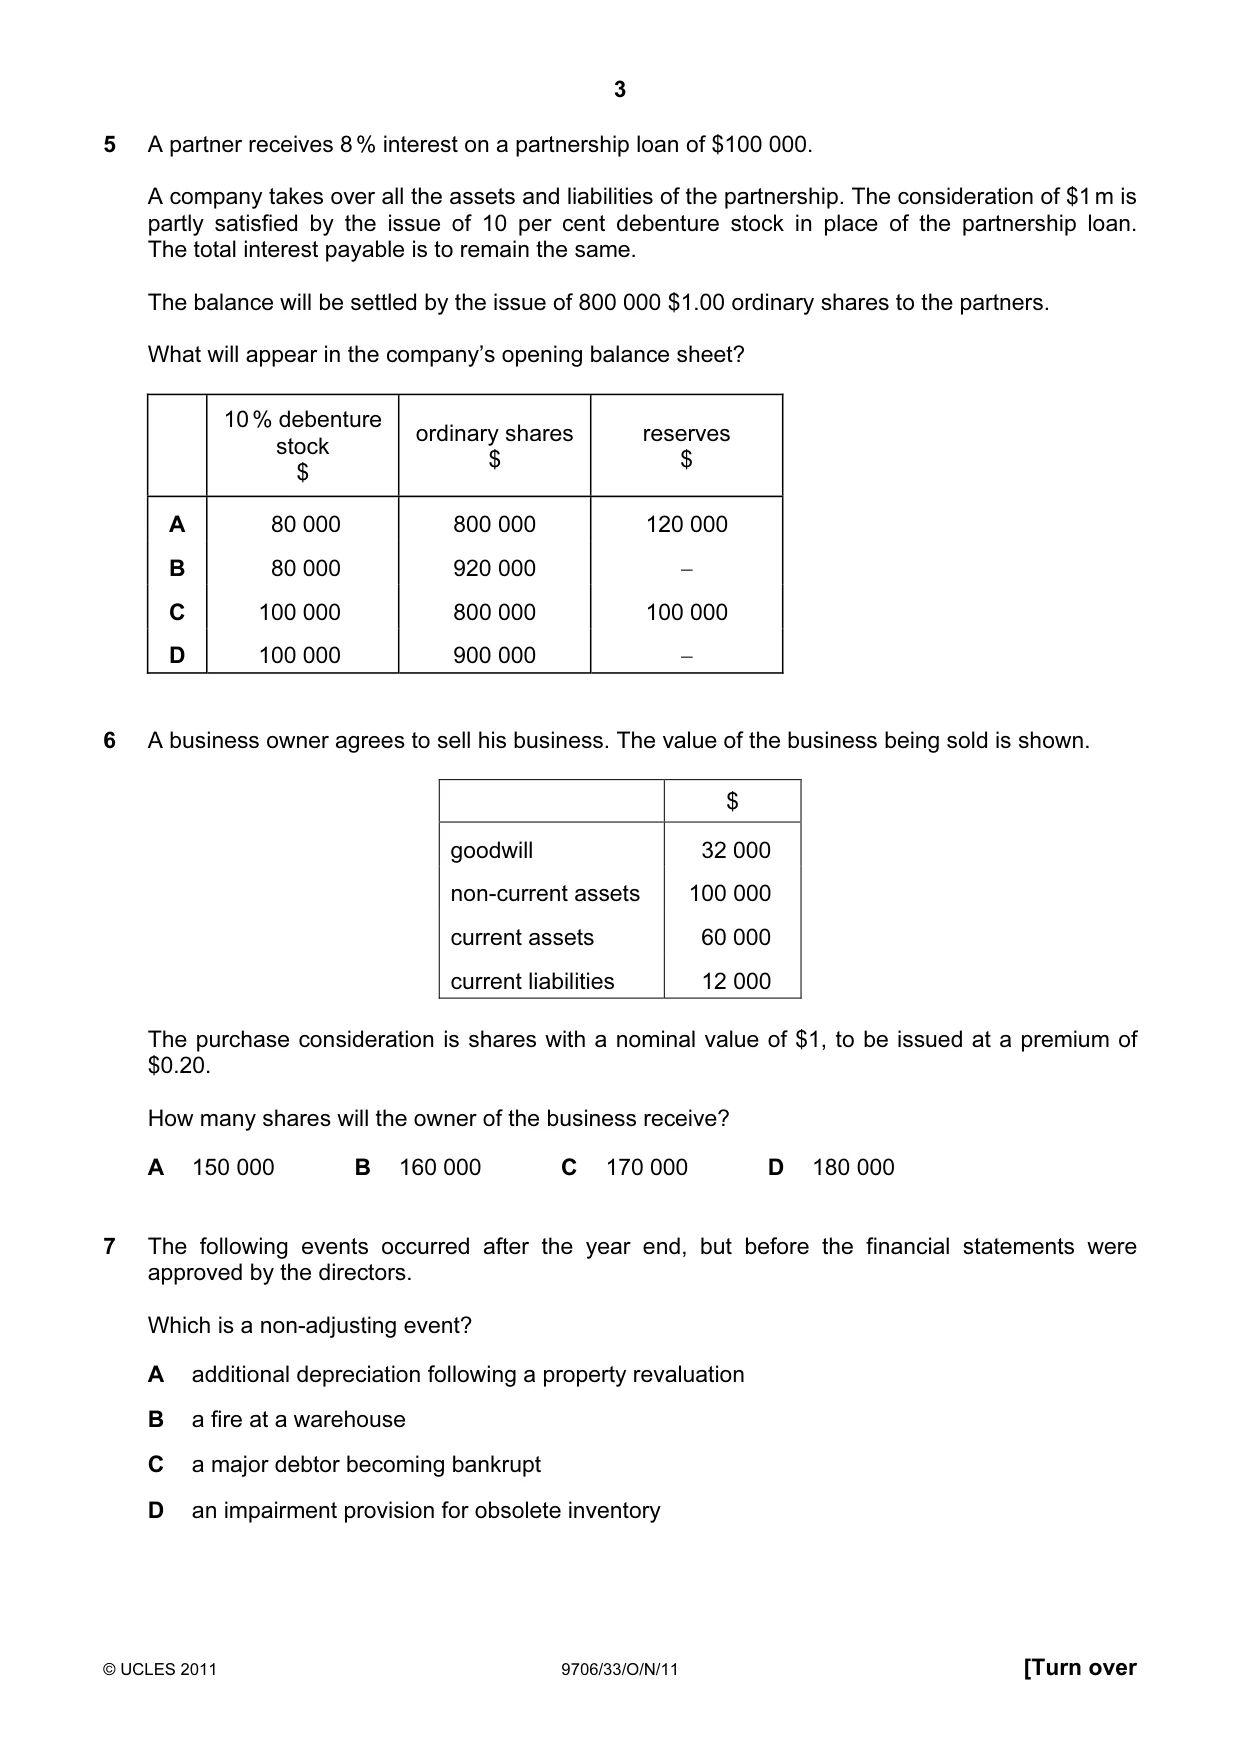
5 A partner receives 8 % interest on a partnership loan of $100 000. A company takes over all the assets and liabilities of the partnership. The consideration of $1 m is partly satisfied by the issue of 10 per cent debenture stock in place of the partnership loan. The total interest payable is to remain the same. The balance will be settled by the issue of 800 000 $1.00 ordinary shares to the partners. What will appear in the company’s opening balance sheet? 10 % debenture ordinary shares reserves stock $ $ $ A 80 000 800 000 120 000 B 80 000 920 000 − C 100 000 800 000 100 000 D 100 000 900 000 −
Mark scheme: A
Q6 · A business owner agrees to sell his business
6 A business owner agrees to sell his business. The value of the business being sold is shown. $ goodwill 32 000 non-current assets 100 000 current assets 60 000 current liabilities 12 000 The purchase consideration is shares with a nominal value of $1, to be issued at a premium of $0.20. How many shares will the owner of the business receive? A 150 000 B 160 000 C 170 000 D 180 000
Mark scheme: A
Q7 · The following events occurred after the year end, but before the financial statements…
7 The following events occurred after the year end, but before the financial statements were approved by the directors. Which is a non-adjusting event? A additional depreciation following a property revaluation B a fire at a warehouse C a major debtor becoming bankrupt D an impairment provision for obsolete inventory
Mark scheme: B
Q8 · A company shows the following balance sheet extract at 31 December
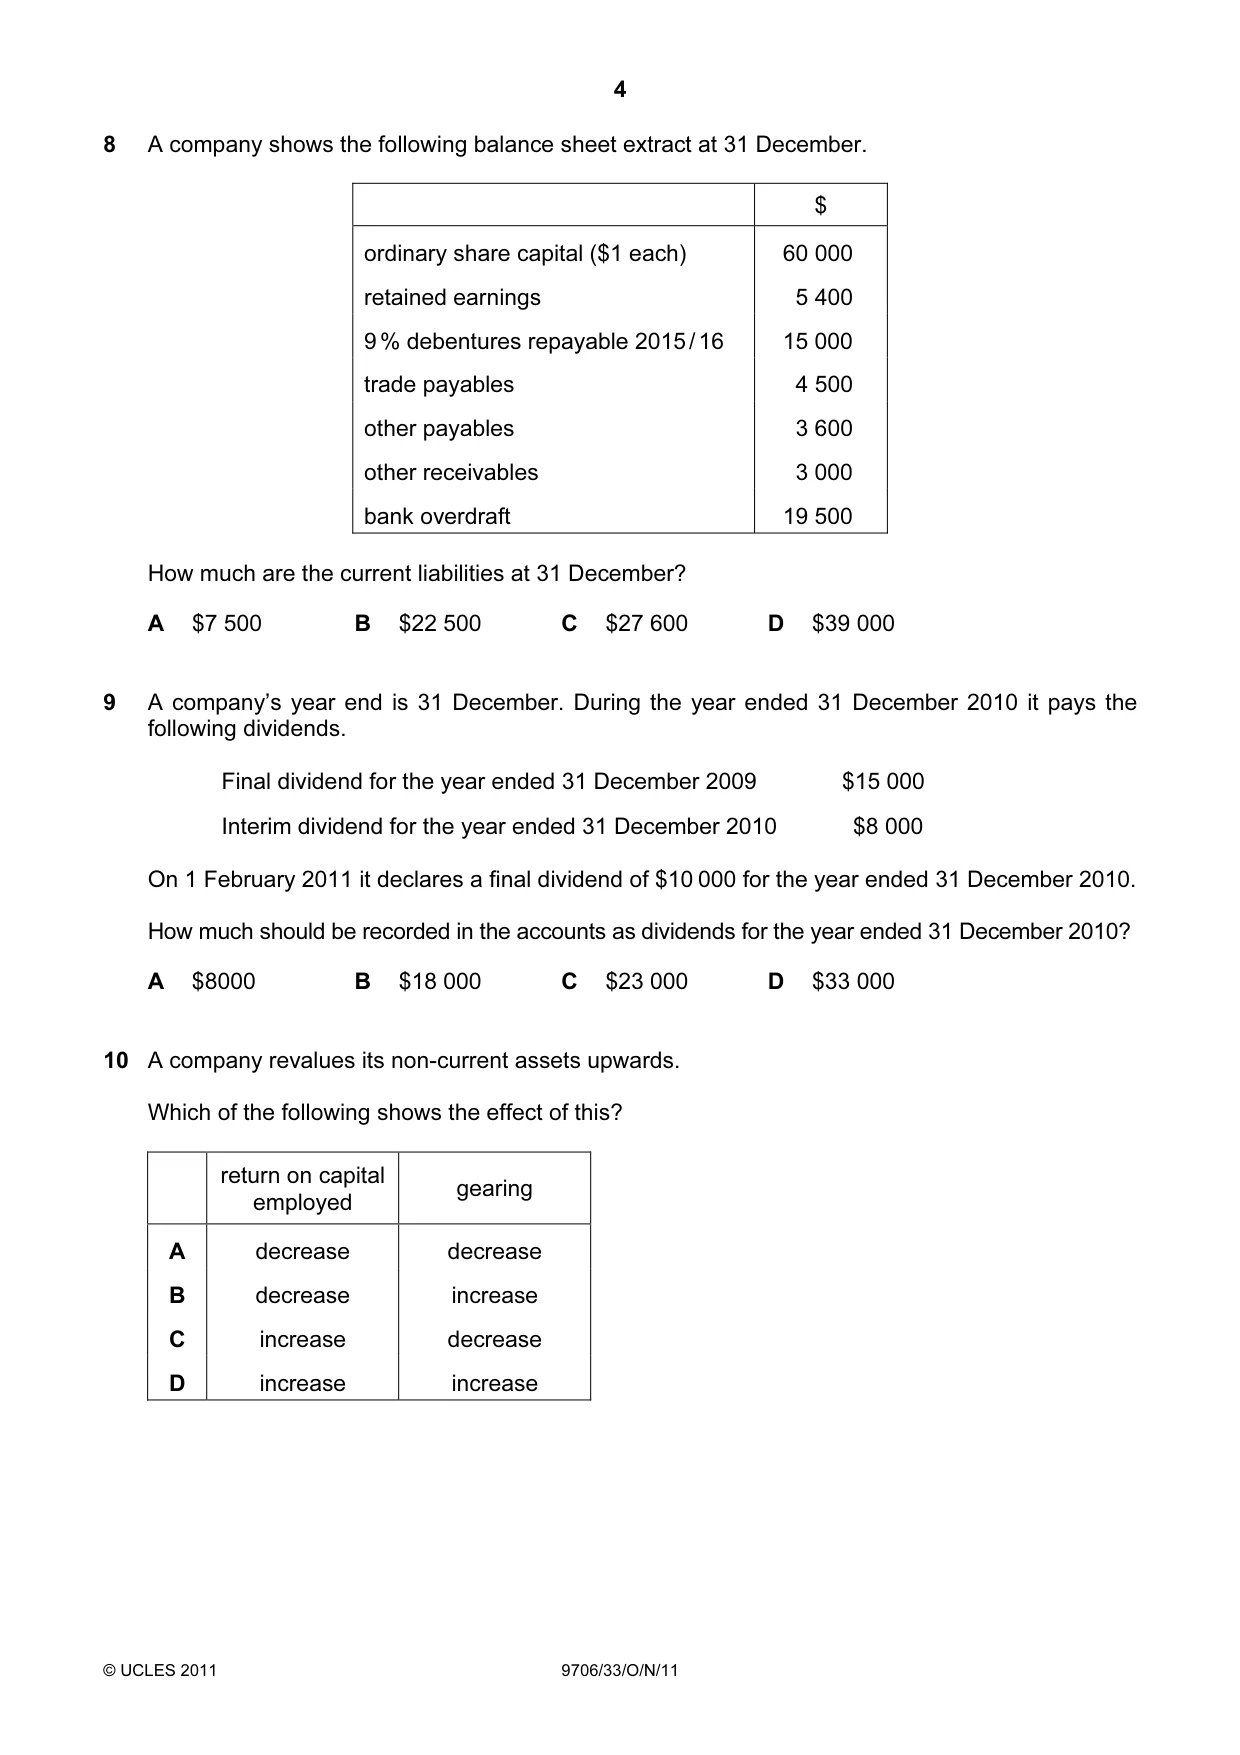
8 A company shows the following balance sheet extract at 31 December. $ ordinary share capital ($1 each) 60 000 retained earnings 5 400 9 % debentures repayable 2015 / 16 15 000 trade payables 4 500 other payables 3 600 other receivables 3 000 bank overdraft 19 500 How much are the current liabilities at 31 December? A $7 500 B $22 500 C $27 600 D $39 000
Mark scheme: C
Q9 · A company’s year end is 31 December
9 A company’s year end is 31 December. During the year ended 31 December 2010 it pays the following dividends. Final dividend for the year ended 31 December 2009 $15 000 Interim dividend for the year ended 31 December 2010 $8 000 On 1 February 2011 it declares a final dividend of $10 000 for the year ended 31 December 2010. How much should be recorded in the accounts as dividends for the year ended 31 December 2010? A $8000 B $18 000 C $23 000 D $33 000
Mark scheme: C
Q10 · A company revalues its non-current assets upwards
10 A company revalues its non-current assets upwards. Which of the following shows the effect of this? return on capital gearing employed A decrease decrease B decrease increase C increase decrease D increase increase
Mark scheme: A
More questions on Analysis and communication of accounting information
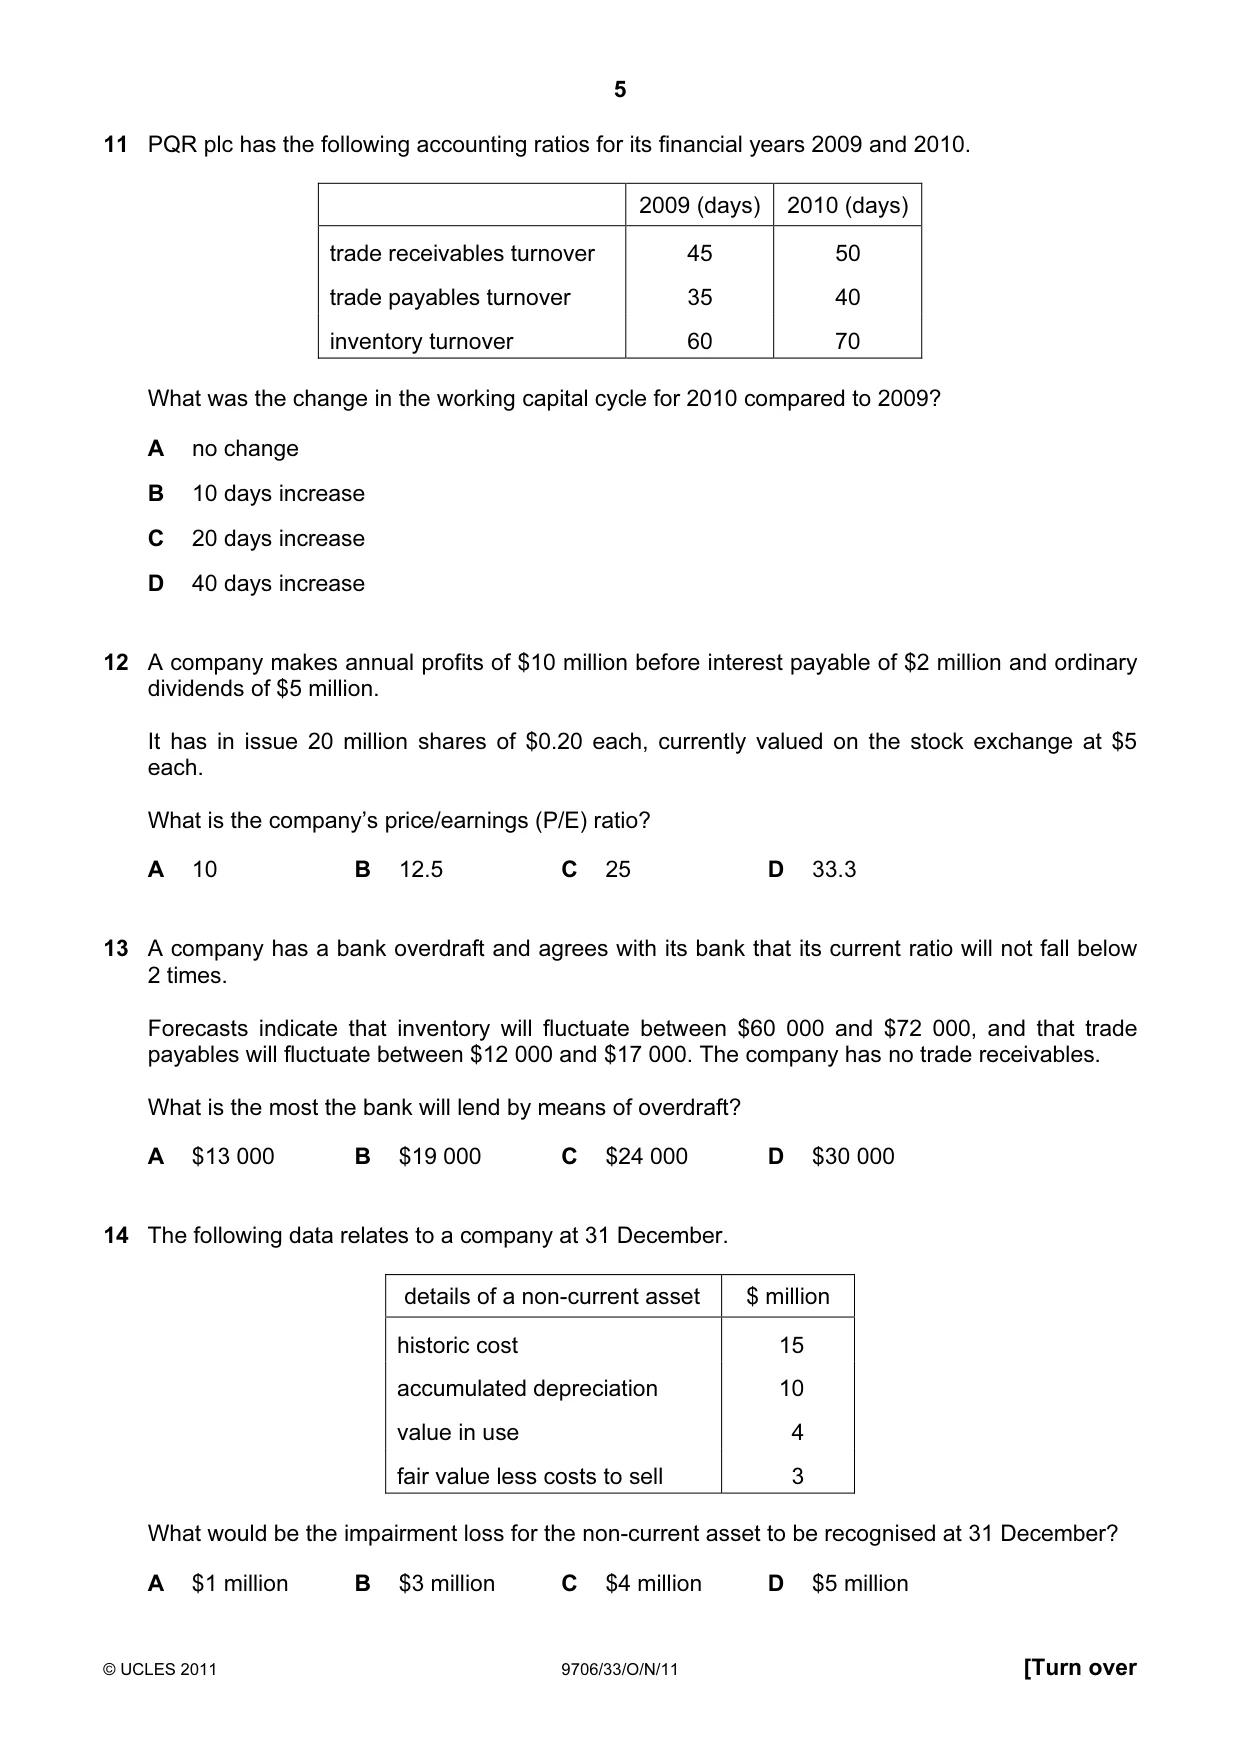
Q11 · PQR plc has the following accounting ratios for its financial years 2009 and 2010
11 PQR plc has the following accounting ratios for its financial years 2009 and 2010. 2009 (days) 2010 (days) trade receivables turnover 45 50 trade payables turnover 35 40 inventory turnover 60 70 What was the change in the working capital cycle for 2010 compared to 2009? A no change B 10 days increase C 20 days increase D 40 days increase
Mark scheme: B
More questions on Analysis and communication of accounting information
Q12 · A company makes annual profits of $10 million before interest payable of $2 million and…
12 A company makes annual profits of $10 million before interest payable of $2 million and ordinary dividends of $5 million. It has in issue 20 million shares of $0.20 each, currently valued on the stock exchange at $5 each. What is the company’s price/earnings (P/E) ratio? A 10 B 12.5 C 25 D 33.3
Mark scheme: B
More questions on Analysis and communication of accounting information
Q13 · A company has a bank overdraft and agrees with its bank that its current ratio will not…
13 A company has a bank overdraft and agrees with its bank that its current ratio will not fall below 2 times. Forecasts indicate that inventory will fluctuate between $60 000 and $72 000, and that trade payables will fluctuate between $12 000 and $17 000. The company has no trade receivables. What is the most the bank will lend by means of overdraft? A $13 000 B $19 000 C $24 000 D $30 000
Mark scheme: A
More questions on Analysis and communication of accounting information
Q14 · The following data relates to a company at 31 December
14 The following data relates to a company at 31 December. details of a non-current asset $ million historic cost 15 accumulated depreciation 10 value in use 4 fair value less costs to sell 3 What would be the impairment loss for the non-current asset to be recognised at 31 December? A $1 million B $3 million C $4 million D $5 million
Mark scheme: A
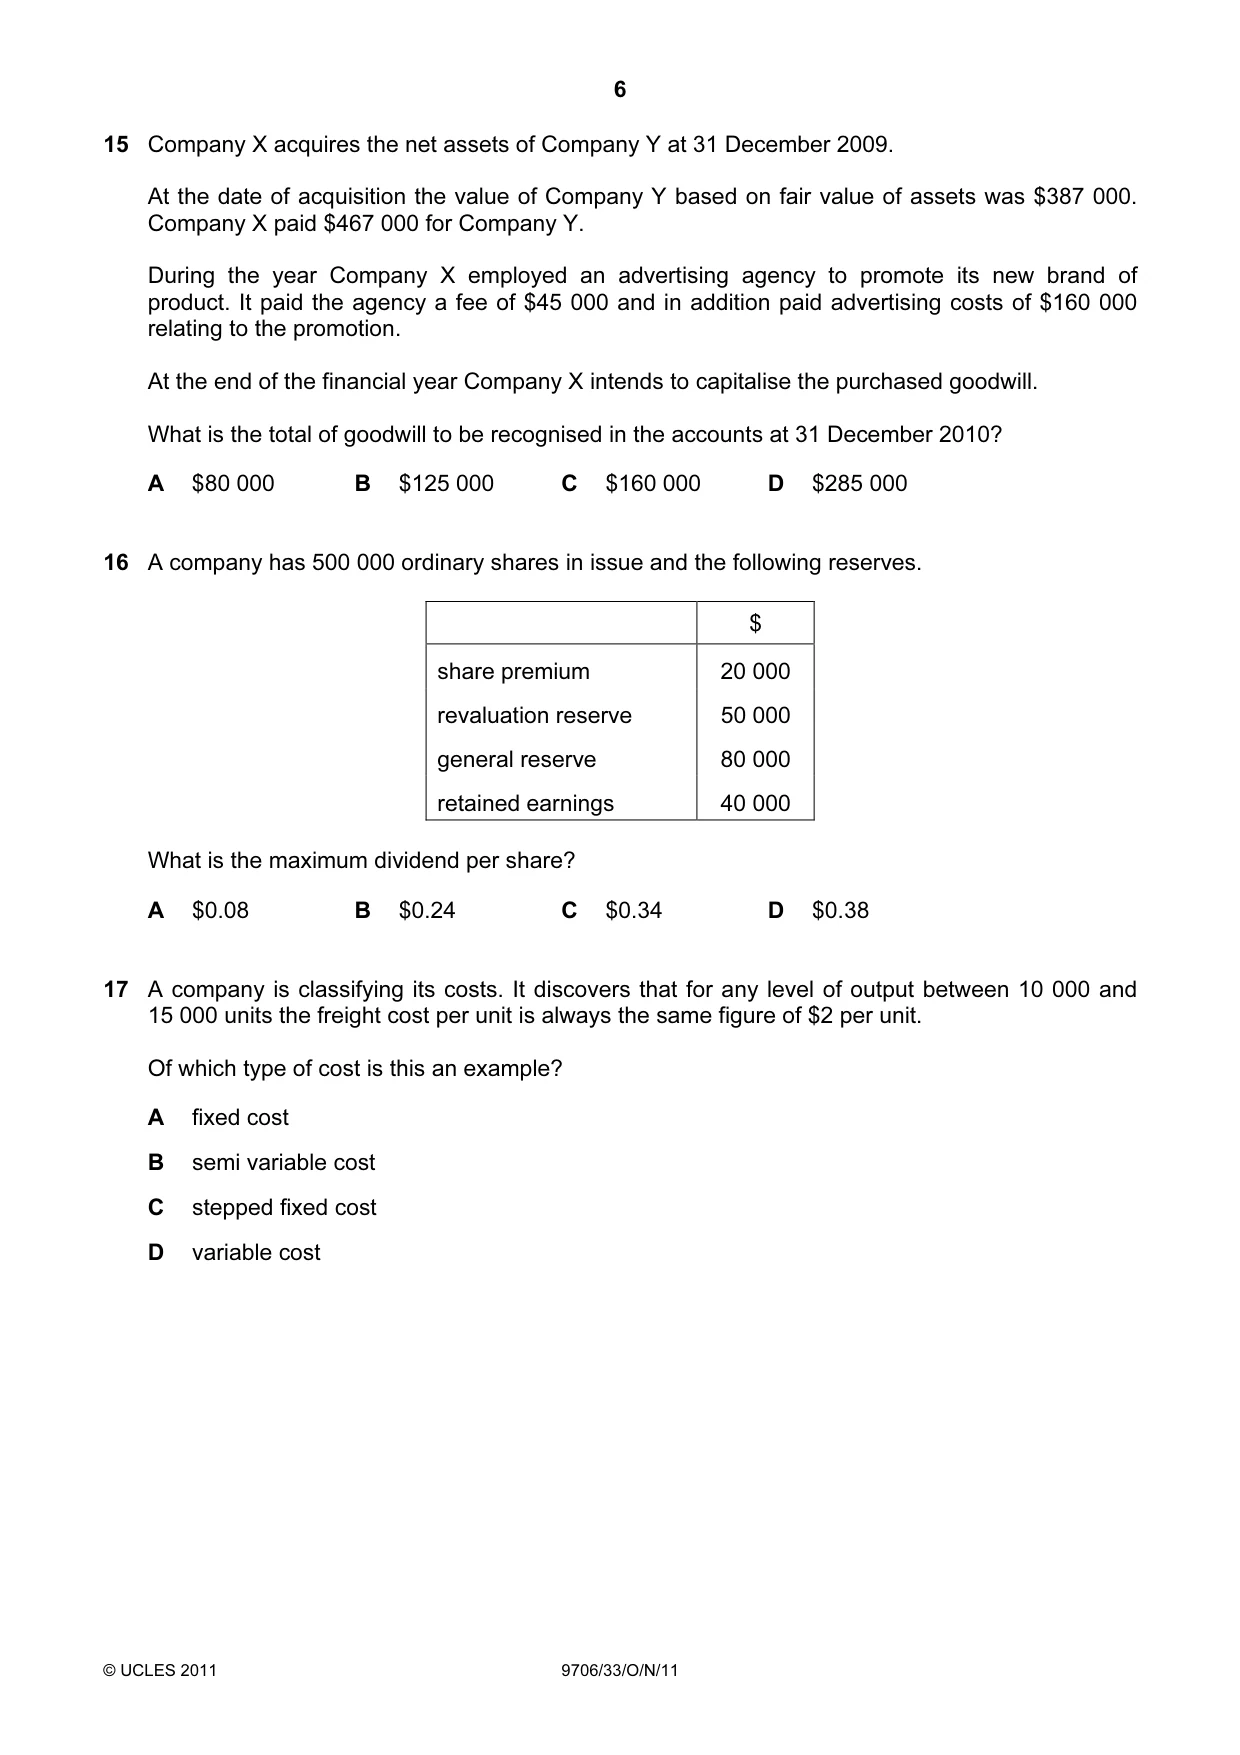
Q15 · Company X acquires the net assets of Company Y at 31 December 2009
15 Company X acquires the net assets of Company Y at 31 December 2009. At the date of acquisition the value of Company Y based on fair value of assets was $387 000. Company X paid $467 000 for Company Y. During the year Company X employed an advertising agency to promote its new brand of product. It paid the agency a fee of $45 000 and in addition paid advertising costs of $160 000 relating to the promotion. At the end of the financial year Company X intends to capitalise the purchased goodwill. What is the total of goodwill to be recognised in the accounts at 31 December 2010? A $80 000 B $125 000 C $160 000 D $285 000
Mark scheme: A
Q16 · A company has 500 000 ordinary shares in issue and the following reserves
16 A company has 500 000 ordinary shares in issue and the following reserves. $ share premium 20 000 revaluation reserve 50 000 general reserve 80 000 retained earnings 40 000 What is the maximum dividend per share? A $0.08 B $0.24 C $0.34 D $0.38
Mark scheme: B
Q17 · A company is classifying its costs
17 A company is classifying its costs. It discovers that for any level of output between 10 000 and 15 000 units the freight cost per unit is always the same figure of $2 per unit. Of which type of cost is this an example? A fixed cost B semi variable cost C stepped fixed cost D variable cost
Mark scheme: D
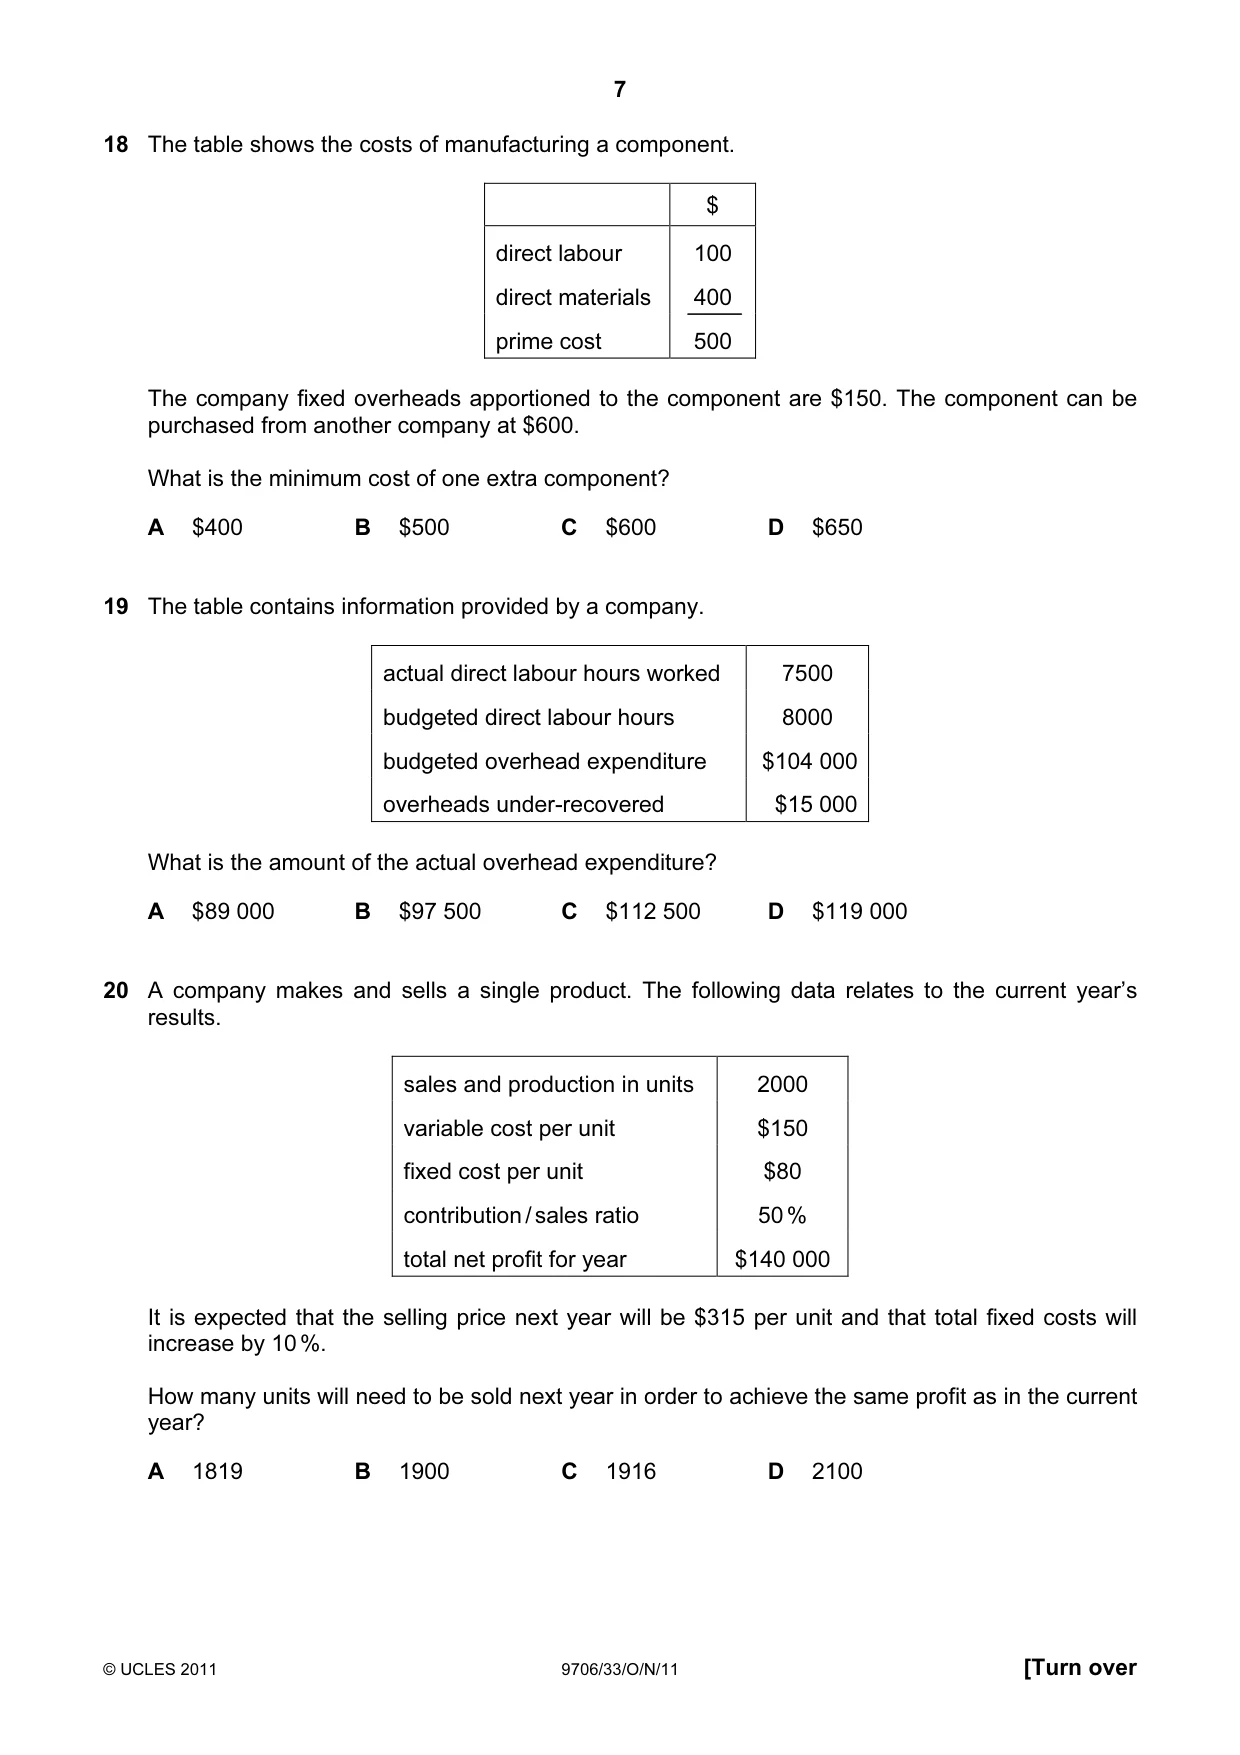
Q18 · The table shows the costs of manufacturing a component
18 The table shows the costs of manufacturing a component. $ direct labour 100 direct materials 400 prime cost 500 The company fixed overheads apportioned to the component are $150. The component can be purchased from another company at $600. What is the minimum cost of one extra component? A $400 B $500 C $600 D $650
Mark scheme: B
Q19 · The table contains information provided by a company
19 The table contains information provided by a company. actual direct labour hours worked 7500 budgeted direct labour hours 8000 budgeted overhead expenditure $104 000 overheads under-recovered $15 000 What is the amount of the actual overhead expenditure? A $89 000 B $97 500 C $112 500 D $119 000
Mark scheme: C
Q20 · A company makes and sells a single product
20 A company makes and sells a single product. The following data relates to the current year’s results. sales and production in units 2000 variable cost per unit $150 fixed cost per unit $80 contribution / sales ratio 50 % total net profit for year $140 000 It is expected that the selling price next year will be $315 per unit and that total fixed costs will increase by 10 %. How many units will need to be sold next year in order to achieve the same profit as in the current year? A 1819 B 1900 C 1916 D 2100
Mark scheme: C
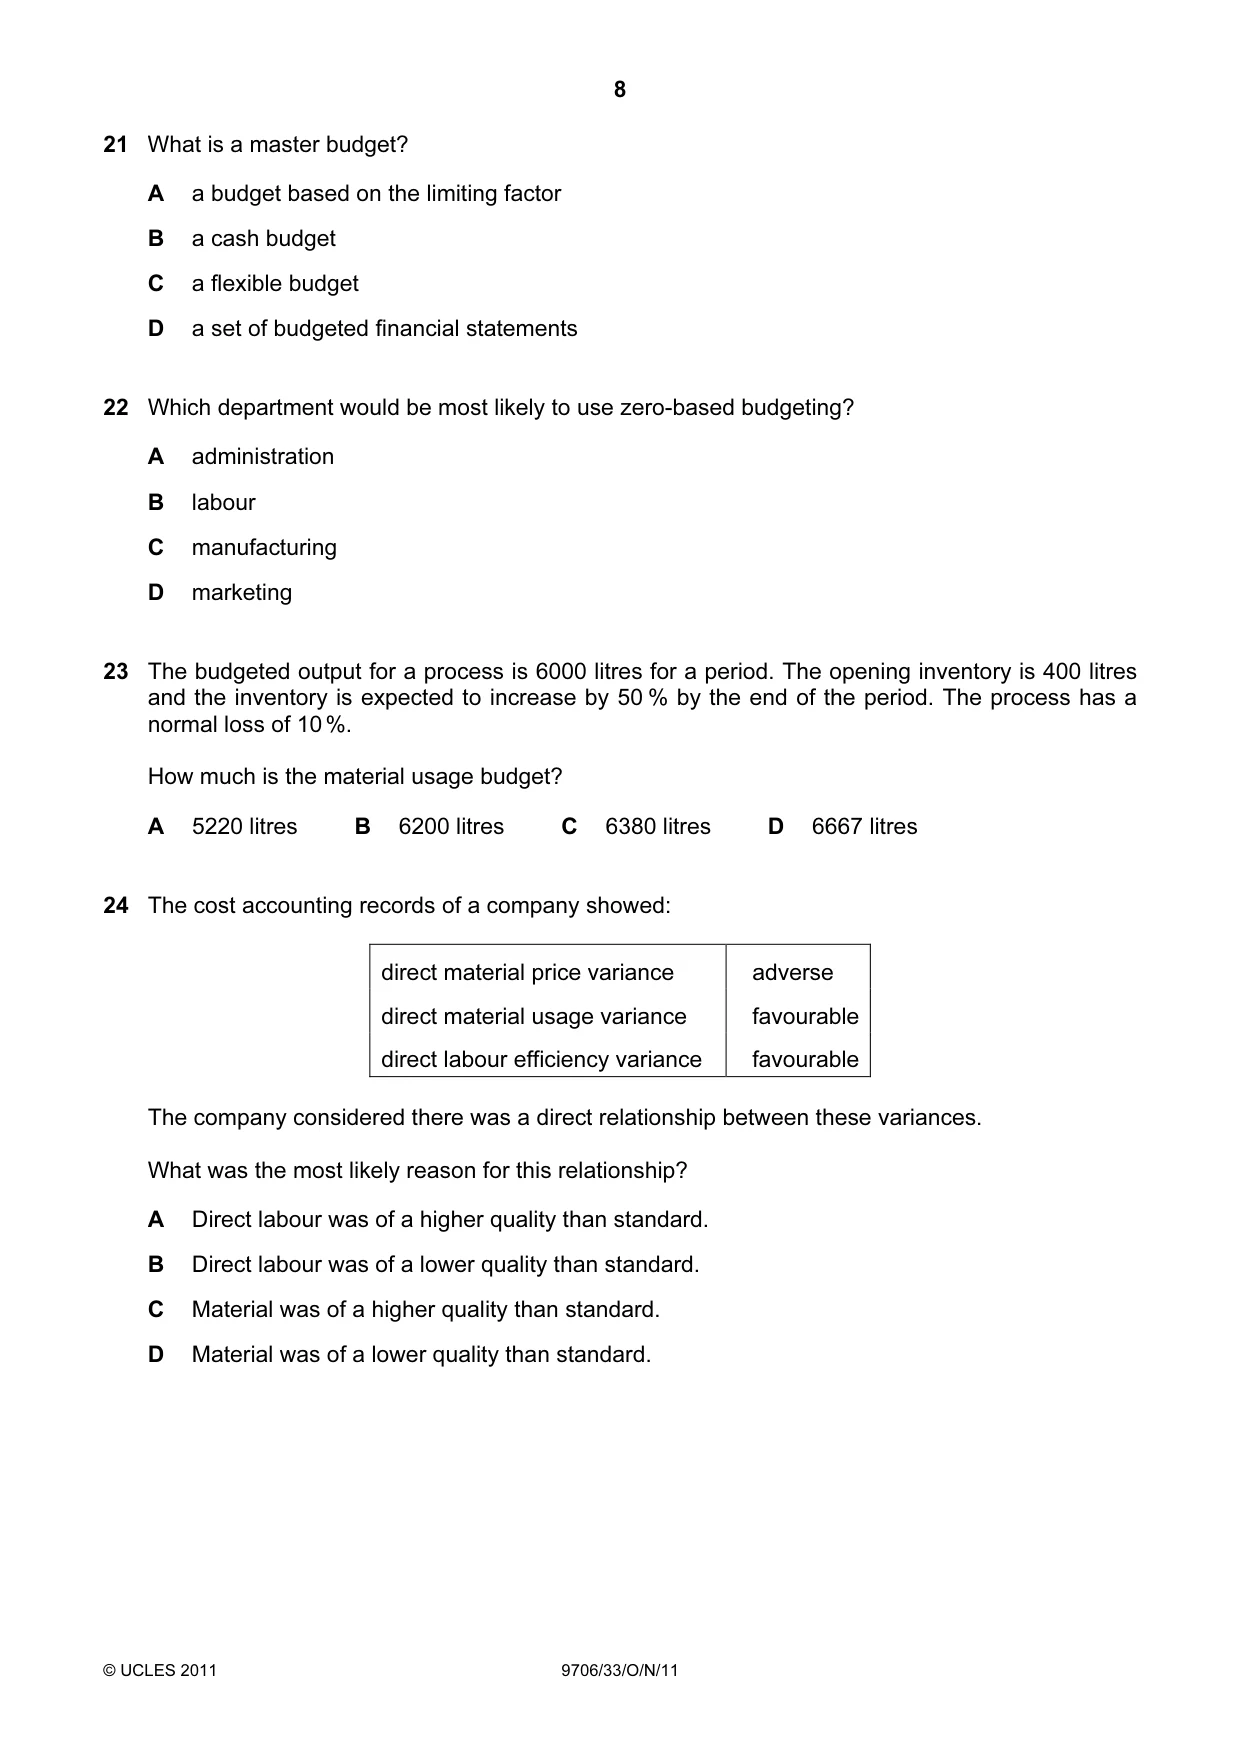
Q21 · What is a master budget?
21 What is a master budget? A a budget based on the limiting factor B a cash budget C a flexible budget D a set of budgeted financial statements
Mark scheme: D
Q22 · Which department would be most likely to use zero-based budgeting?
22 Which department would be most likely to use zero-based budgeting? A administration B labour C manufacturing D marketing
Mark scheme: D
Q23 · The budgeted output for a process is 6000 litres for a period
23 The budgeted output for a process is 6000 litres for a period. The opening inventory is 400 litres and the inventory is expected to increase by 50 % by the end of the period. The process has a normal loss of 10 %. How much is the material usage budget? A 5220 litres B 6200 litres C 6380 litres D 6667 litres
Mark scheme: D
Q24 · The cost accounting records of a company showed: direct material price variance adverse…
24 The cost accounting records of a company showed: direct material price variance adverse direct material usage variance favourable direct labour efficiency variance favourable The company considered there was a direct relationship between these variances. What was the most likely reason for this relationship? A Direct labour was of a higher quality than standard. B Direct labour was of a lower quality than standard. C Material was of a higher quality than standard. D Material was of a lower quality than standard.
Mark scheme: C
Q25 · The budgeted direct labour cost for the production of 1000 units is $104 000 based on an…
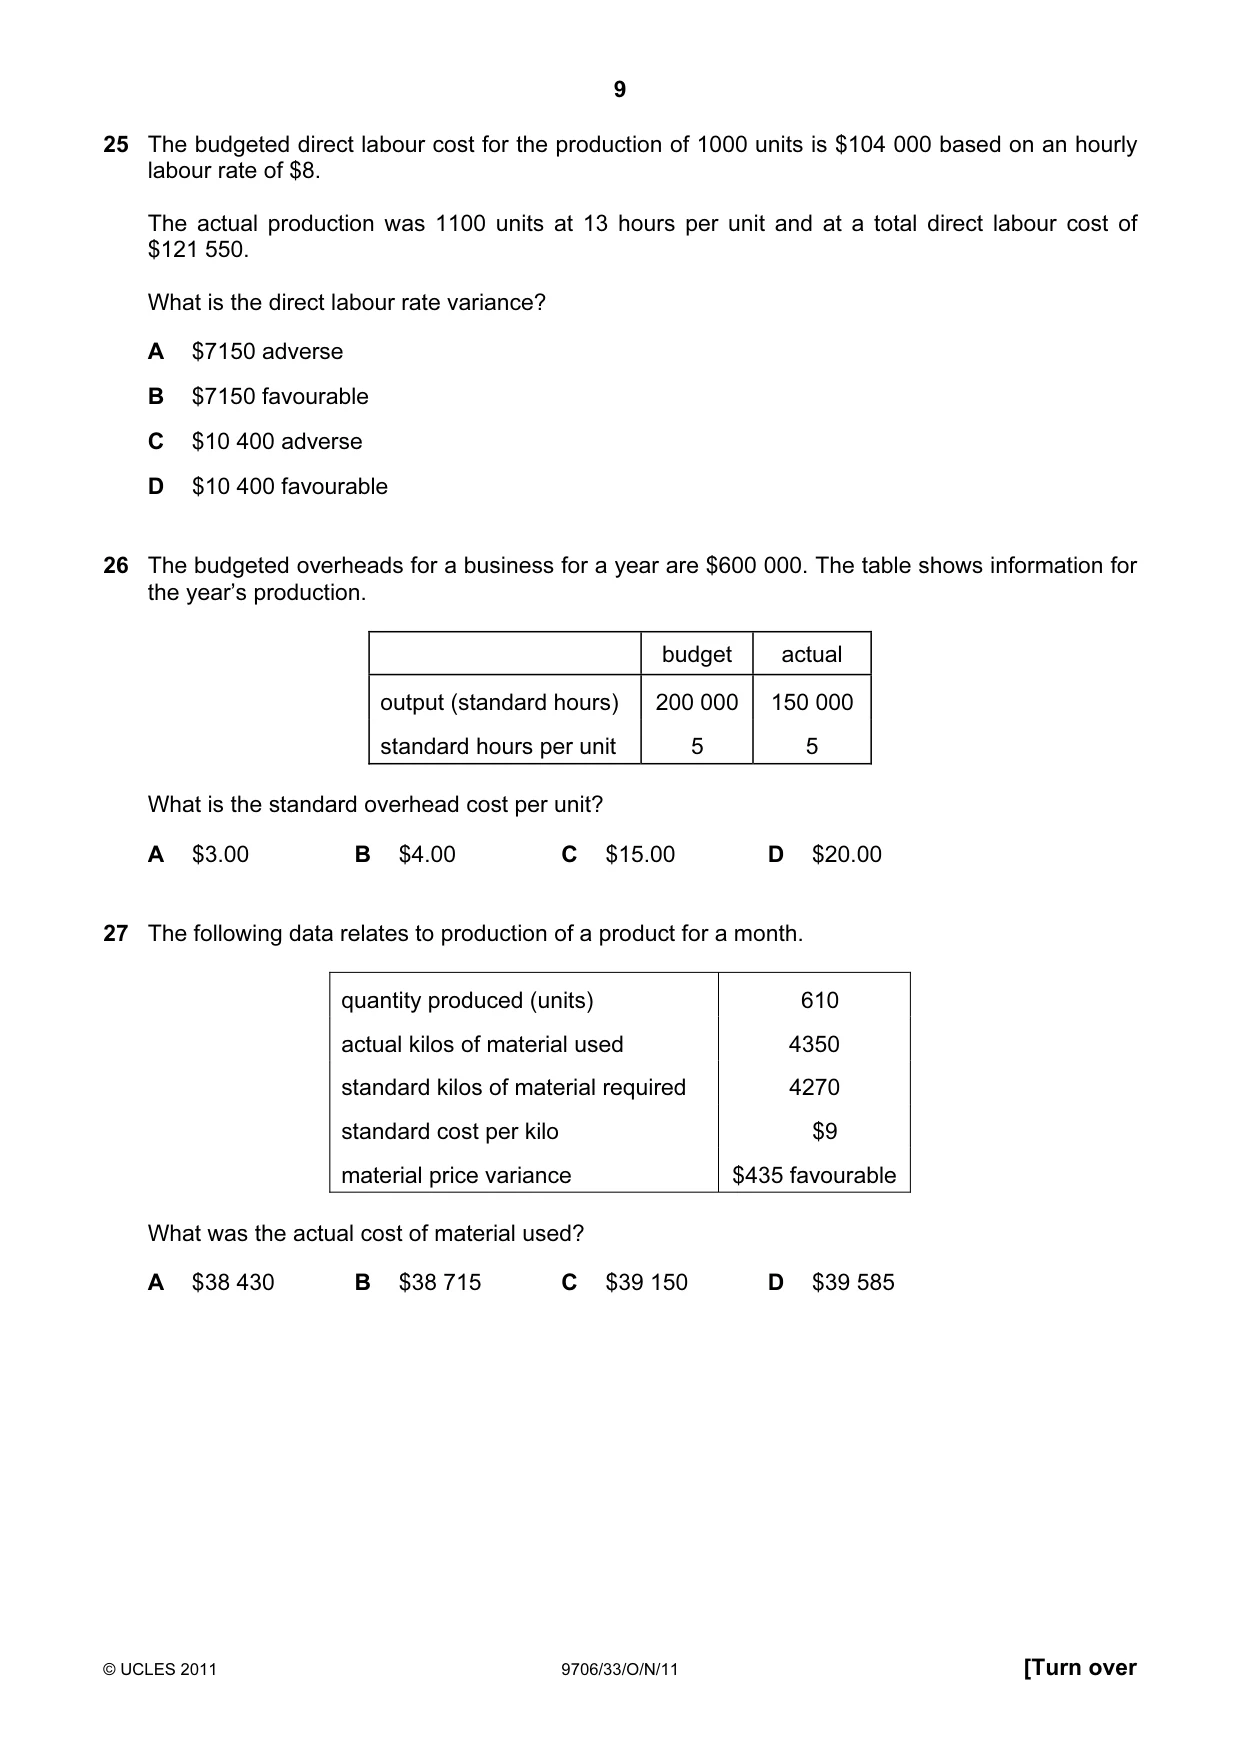
25 The budgeted direct labour cost for the production of 1000 units is $104 000 based on an hourly labour rate of $8. The actual production was 1100 units at 13 hours per unit and at a total direct labour cost of $121 550. What is the direct labour rate variance? A $7150 adverse B $7150 favourable C $10 400 adverse D $10 400 favourable
Mark scheme: A
Q26 · The budgeted overheads for a business for a year are $600 000
26 The budgeted overheads for a business for a year are $600 000. The table shows information for the year’s production. budget actual output (standard hours) 200 000 150 000 standard hours per unit 5 5 What is the standard overhead cost per unit? A $3.00 B $4.00 C $15.00 D $20.00
Mark scheme: C
Q27 · The following data relates to production of a product for a month
27 The following data relates to production of a product for a month. quantity produced (units) 610 actual kilos of material used 4350 standard kilos of material required 4270 standard cost per kilo $9 material price variance $435 favourable What was the actual cost of material used? A $38 430 B $38 715 C $39 150 D $39 585
Mark scheme: B
Q28 · Two projects have the same capital cost
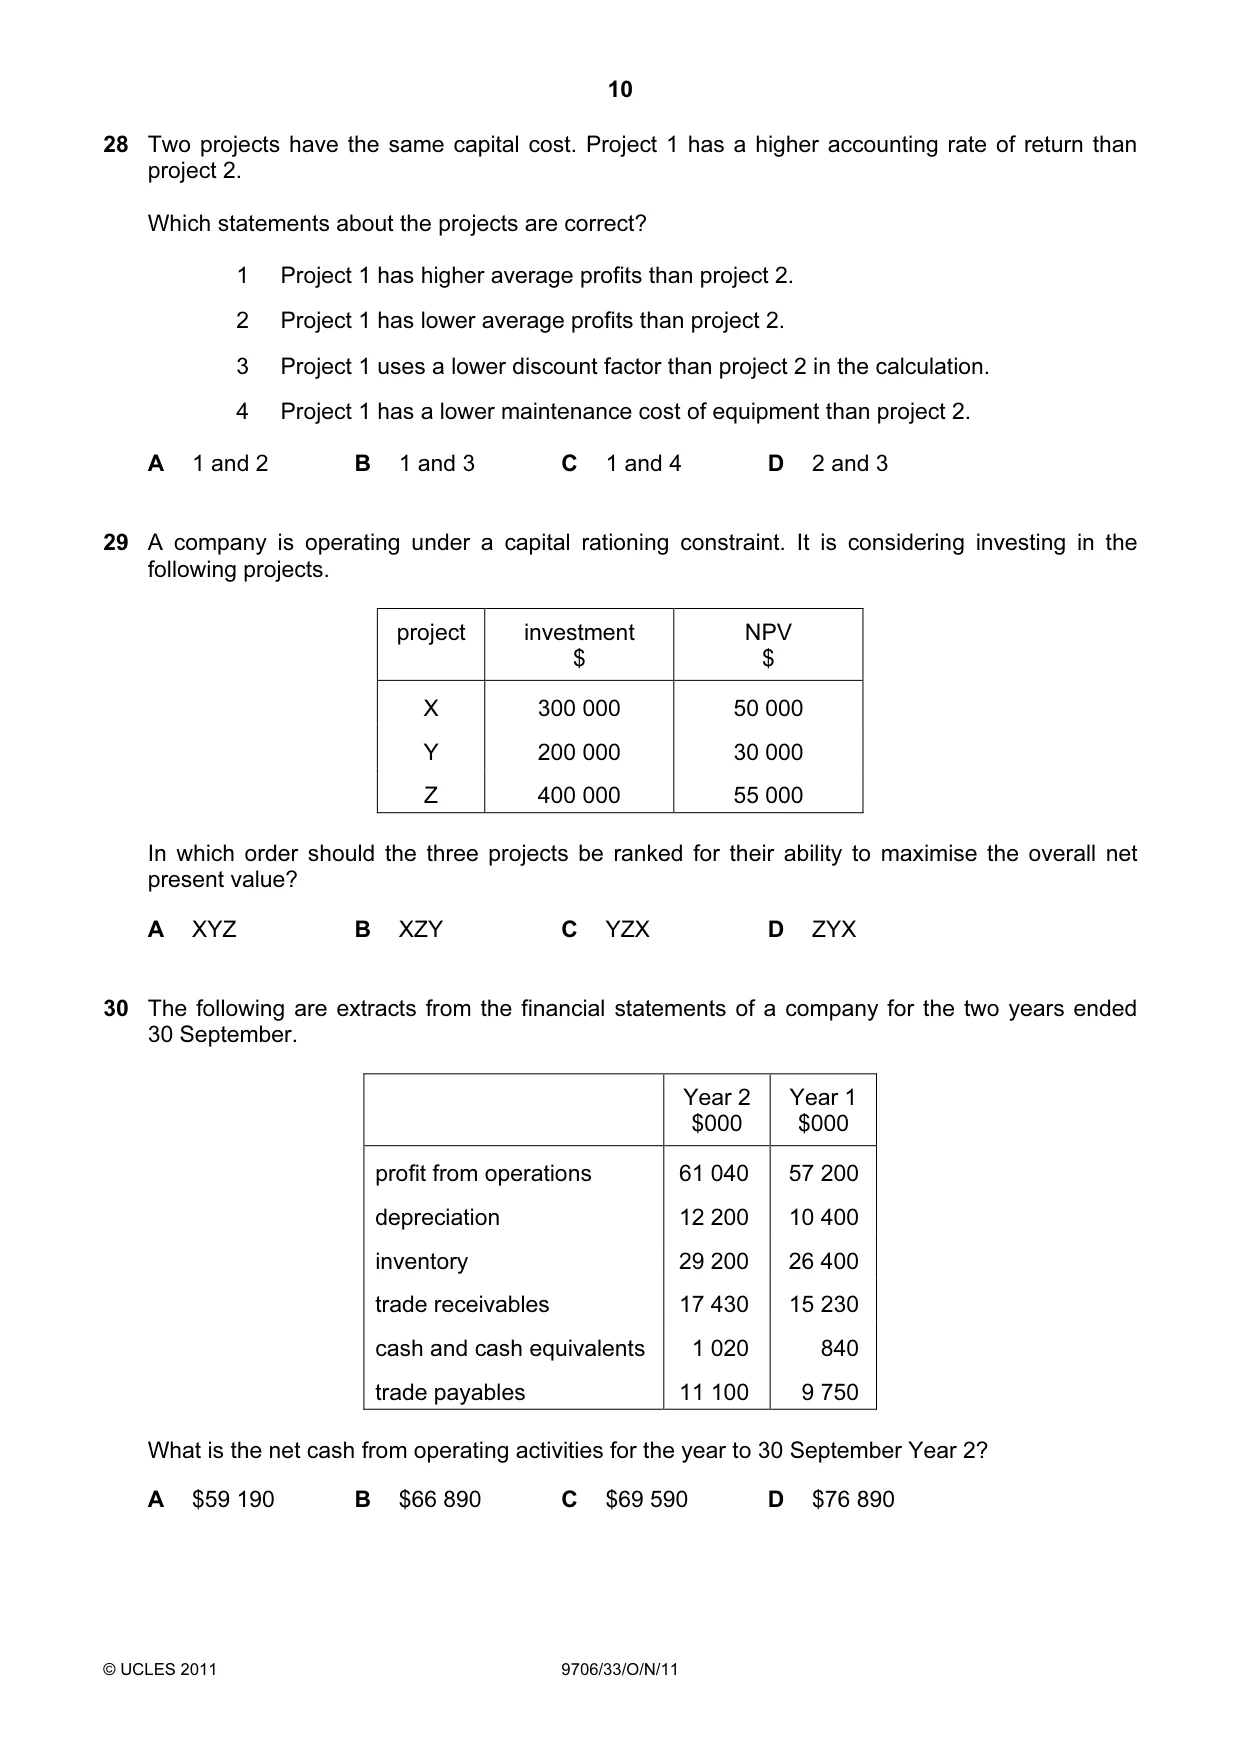
28 Two projects have the same capital cost. Project 1 has a higher accounting rate of return than project 2. Which statements about the projects are correct? 1 Project 1 has higher average profits than project 2. 2 Project 1 has lower average profits than project 2. 3 Project 1 uses a lower discount factor than project 2 in the calculation. 4 Project 1 has a lower maintenance cost of equipment than project 2. A 1 and 2 B 1 and 3 C 1 and 4 D 2 and 3
Mark scheme: C
Q29 · A company is operating under a capital rationing constraint
29 A company is operating under a capital rationing constraint. It is considering investing in the following projects. project investment NPV $ $ X 300 000 50 000 Y 200 000 30 000 Z 400 000 55 000 In which order should the three projects be ranked for their ability to maximise the overall net present value? A XYZ B XZY C YZX D ZYX
Mark scheme: A
Q30 · The following are extracts from the financial statements of a company for the two years…
30 The following are extracts from the financial statements of a company for the two years ended 30 September. Year 2 Year 1 $000 $000 profit from operations 61 040 57 200 depreciation 12 200 10 400 inventory 29 200 26 400 trade receivables 17 430 15 230 cash and cash equivalents 1 020 840 trade payables 11 100 9 750 What is the net cash from operating activities for the year to 30 September Year 2? A $59 190 B $66 890 C $69 590 D $76 890
Mark scheme: C
What was in this paper
The subtopics covered by these 30 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
7Business acquisition and merger4Standard costing4Budgeting and budgetary control3Costs and cost behaviour3Analysis and communication of accounting information2Analysis and communication of accounting information2Investment appraisal2Preparation of financial statements1Regulatory and ethical considerations1Traditional costing methods1What you needed in this session
Cambridge’s own grade thresholds for 2011 Oct/Nov, Paper 3 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.