Questions as text
Q1 · The table shows data for a company 9706/31 Oct/Nov 2009
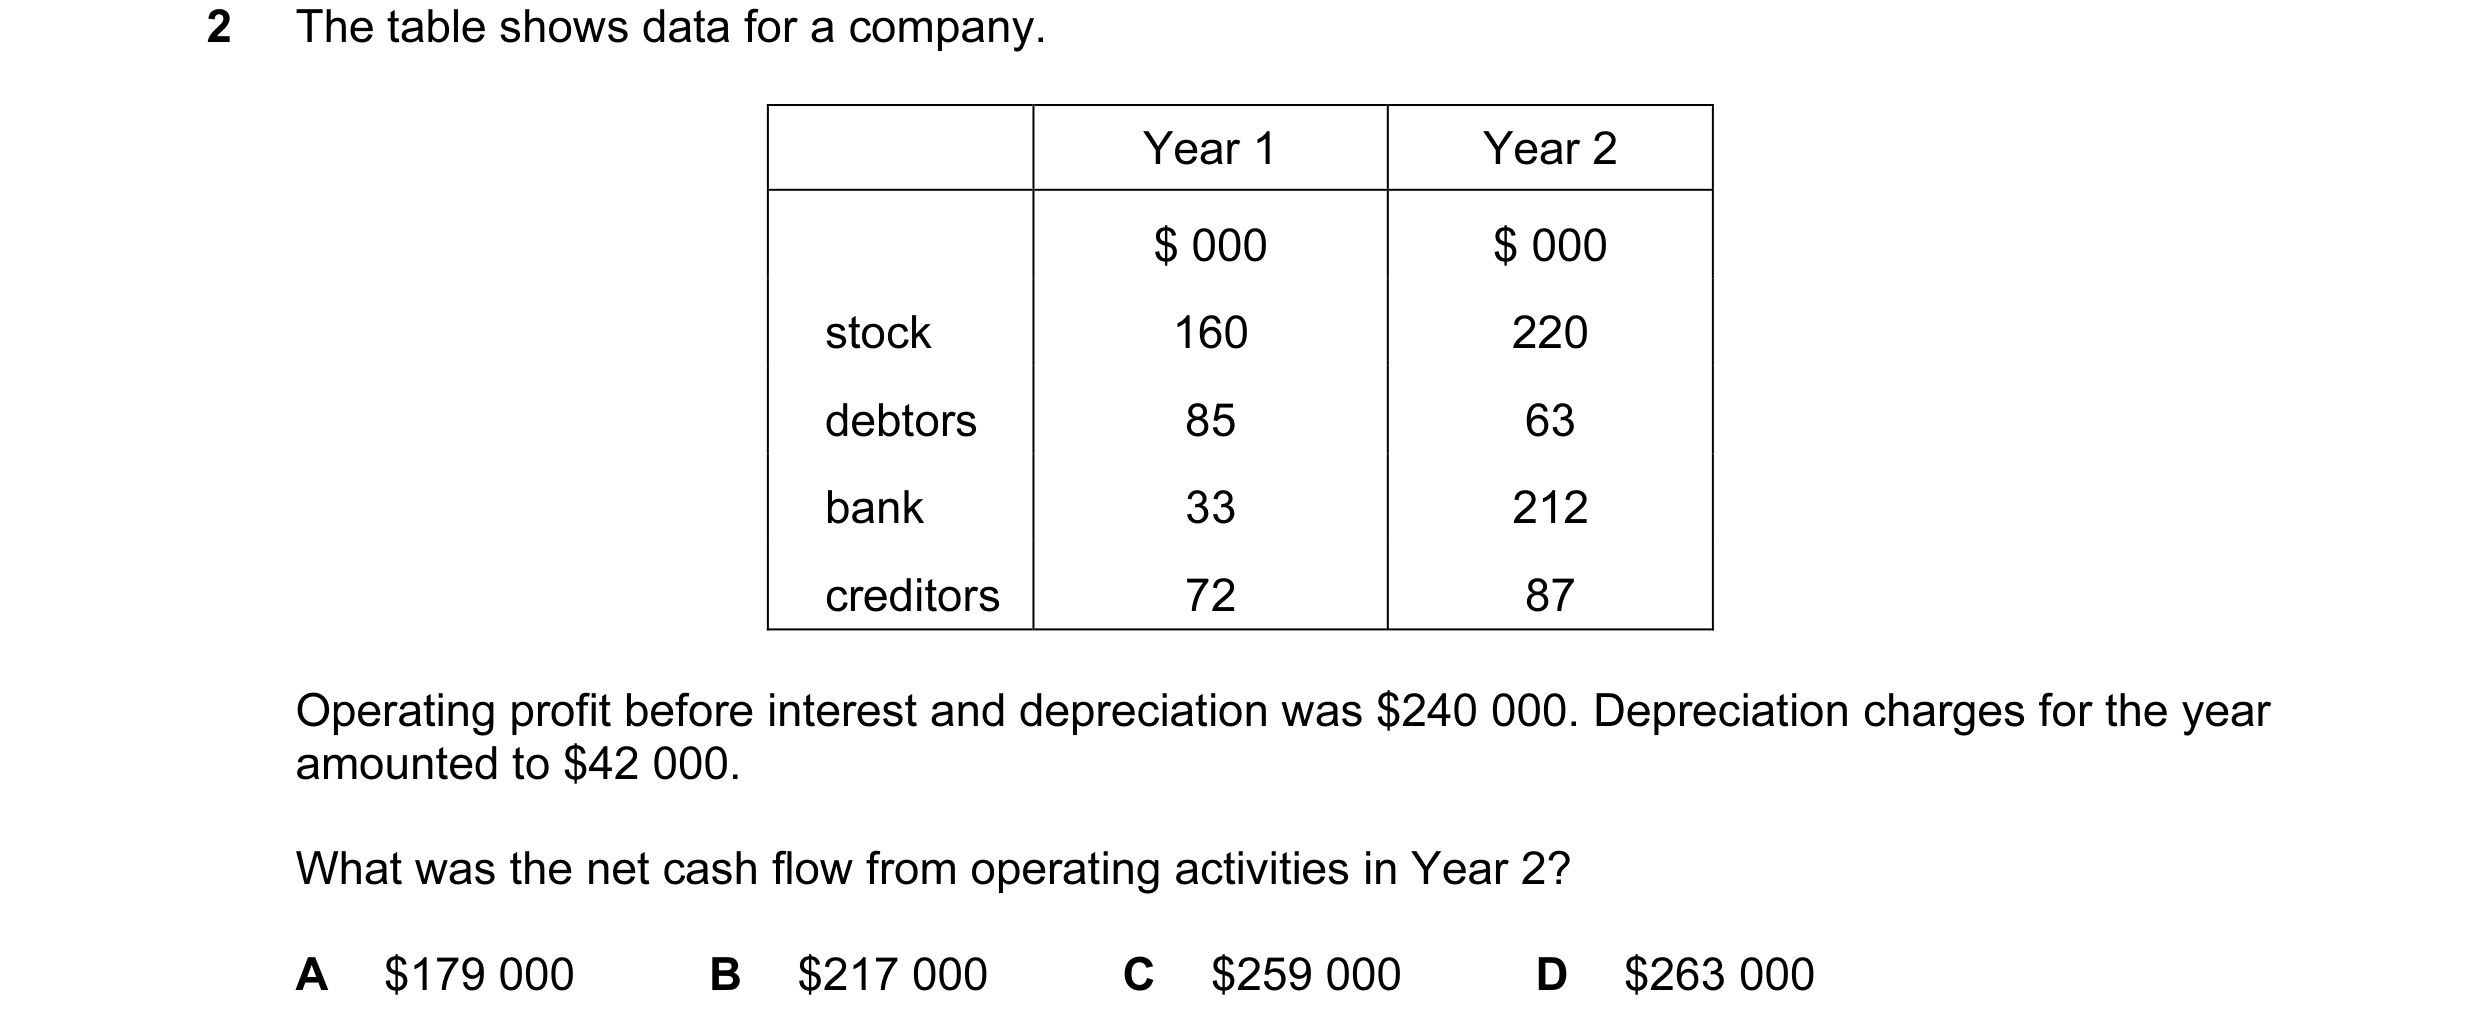
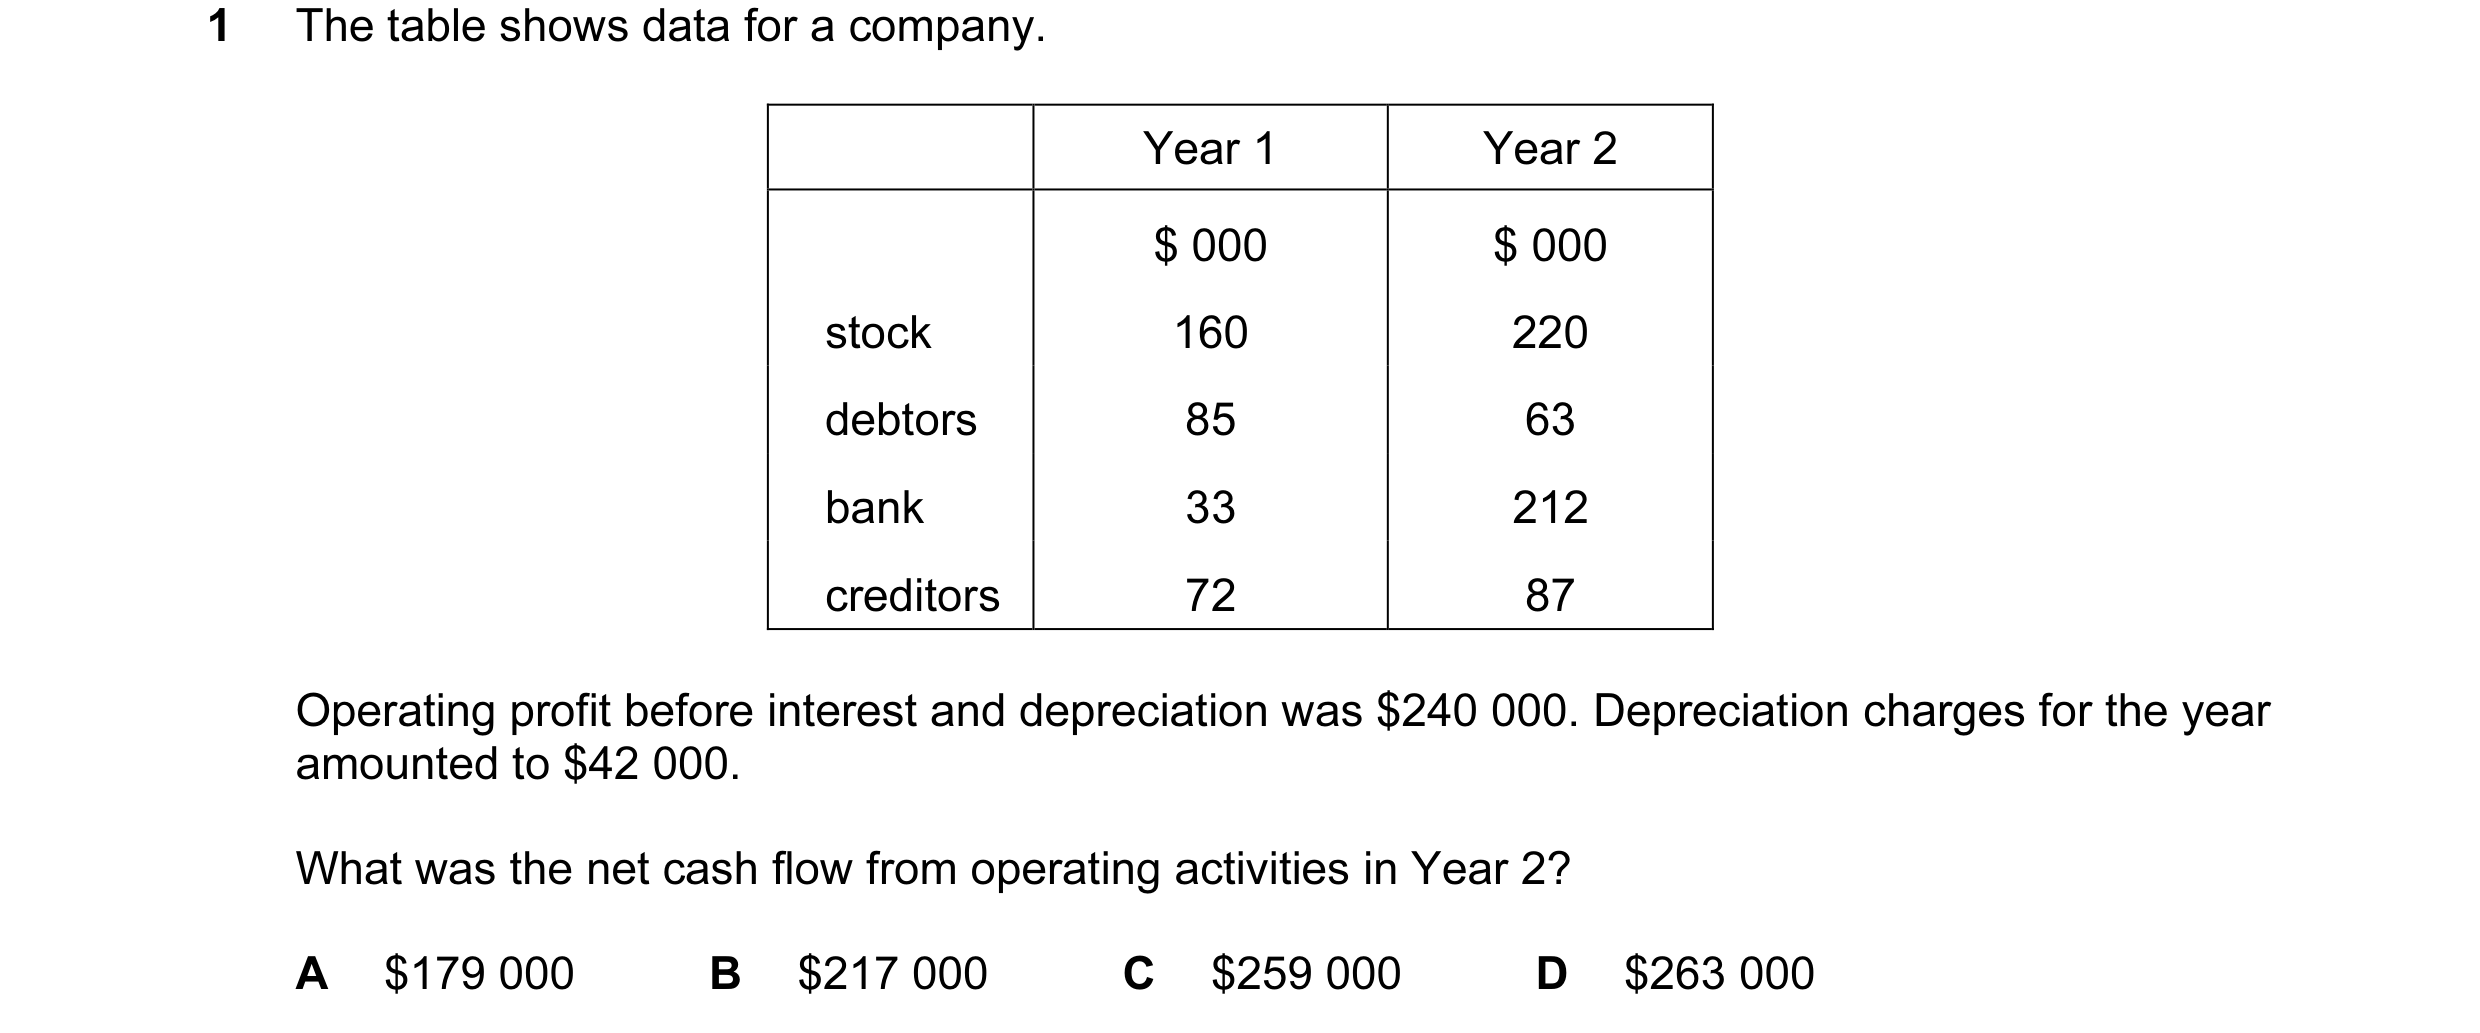
2 The table shows data for a company. Year 1 Year 2 $ 000 $ 000 stock 160 220 debtors 85 63 bank 33 212 creditors 72 87 Operating profit before interest and depreciation was $240 000. Depreciation charges for the year amounted to $42 000. What was the net cash flow from operating activities in Year 2? A $179 000 B $217 000 C $259 000 D $263 000
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2009
Q2 · A company’s financial statements include the following 9706/31 Oct/Nov 2009
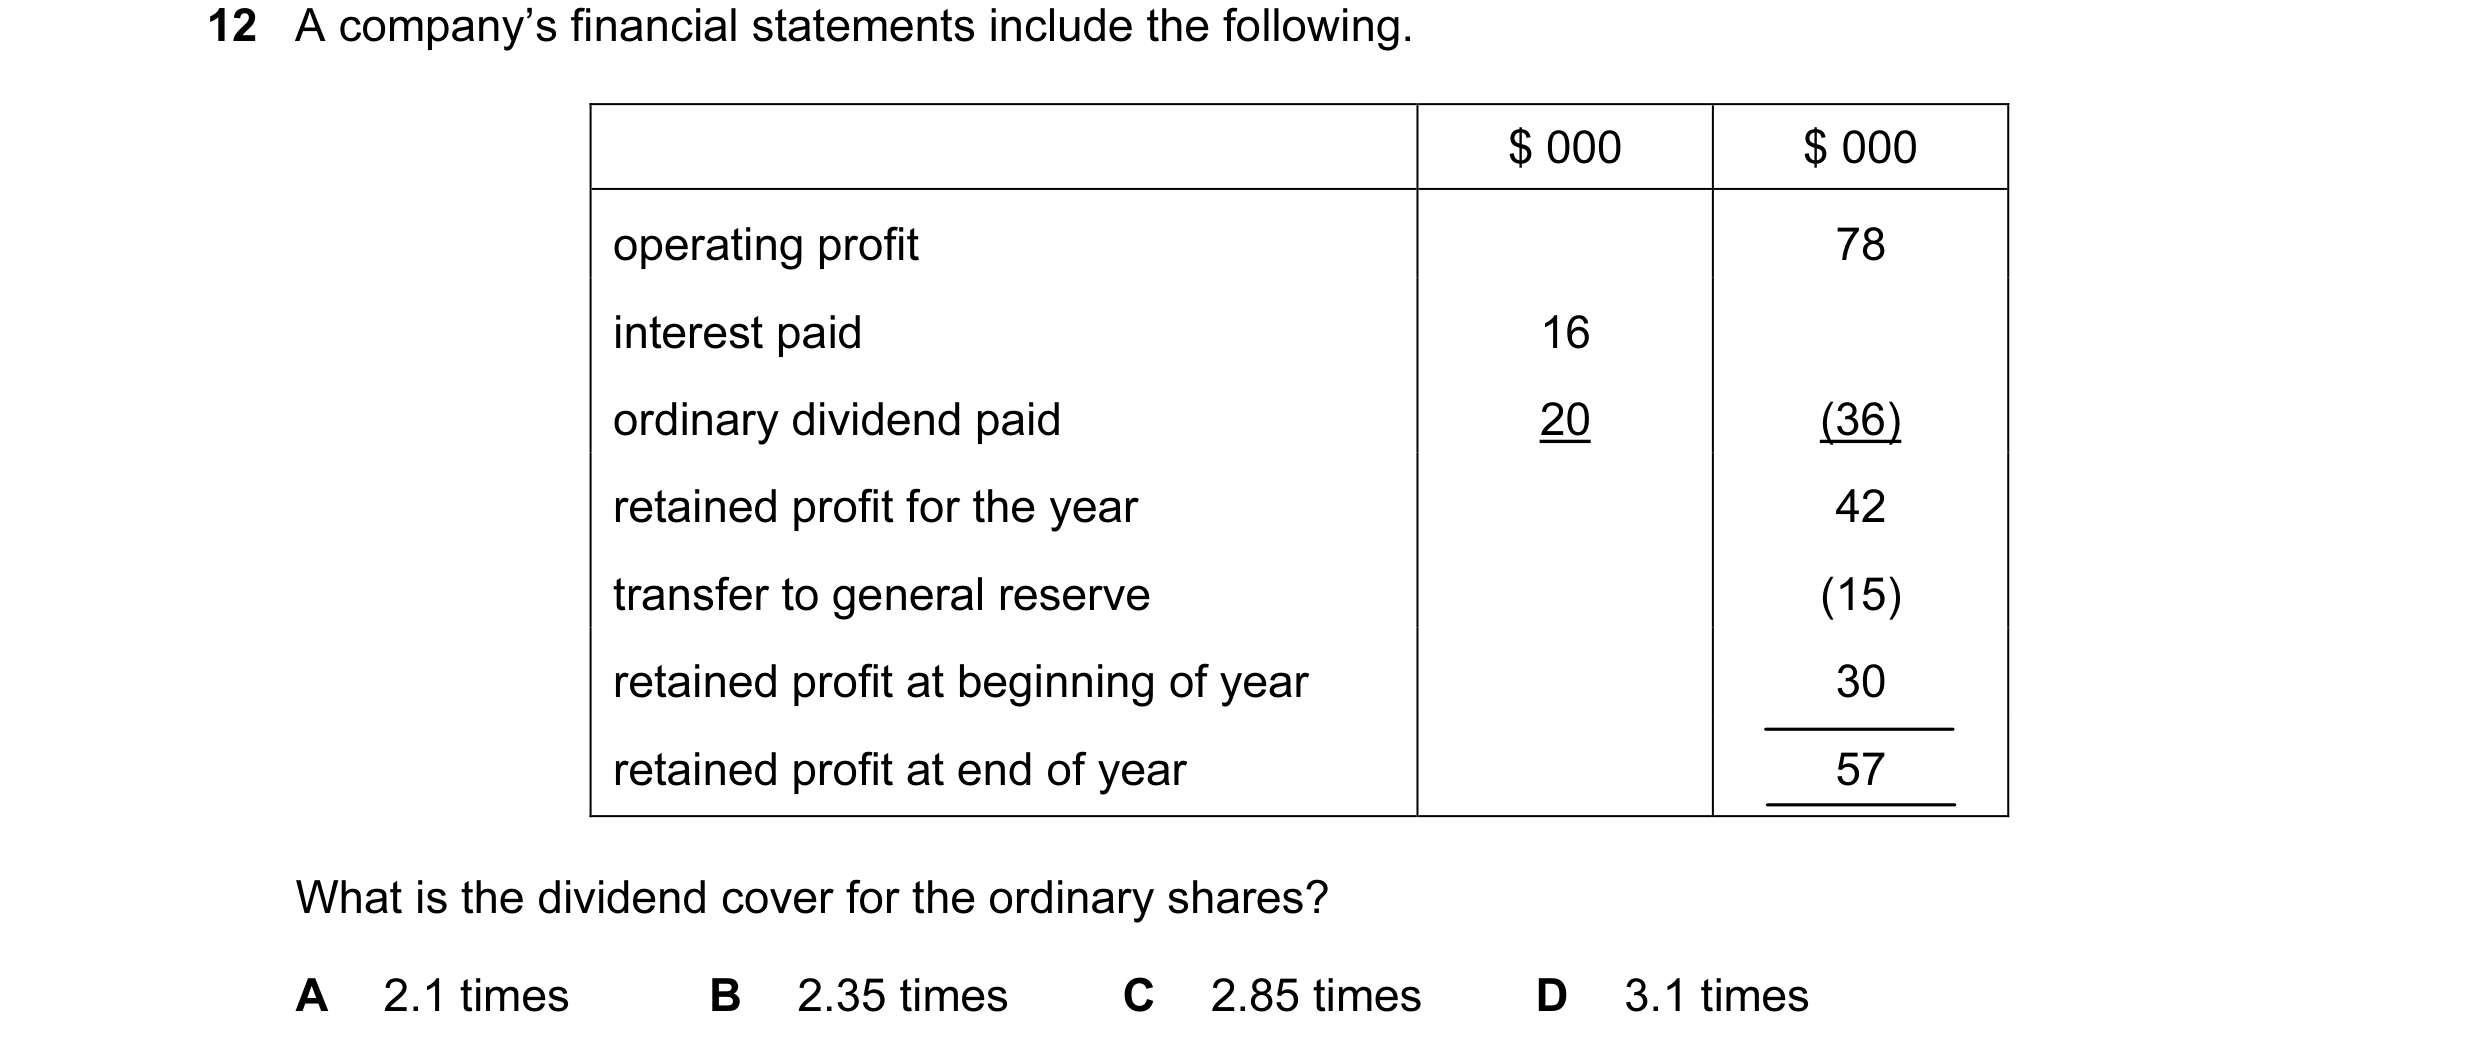
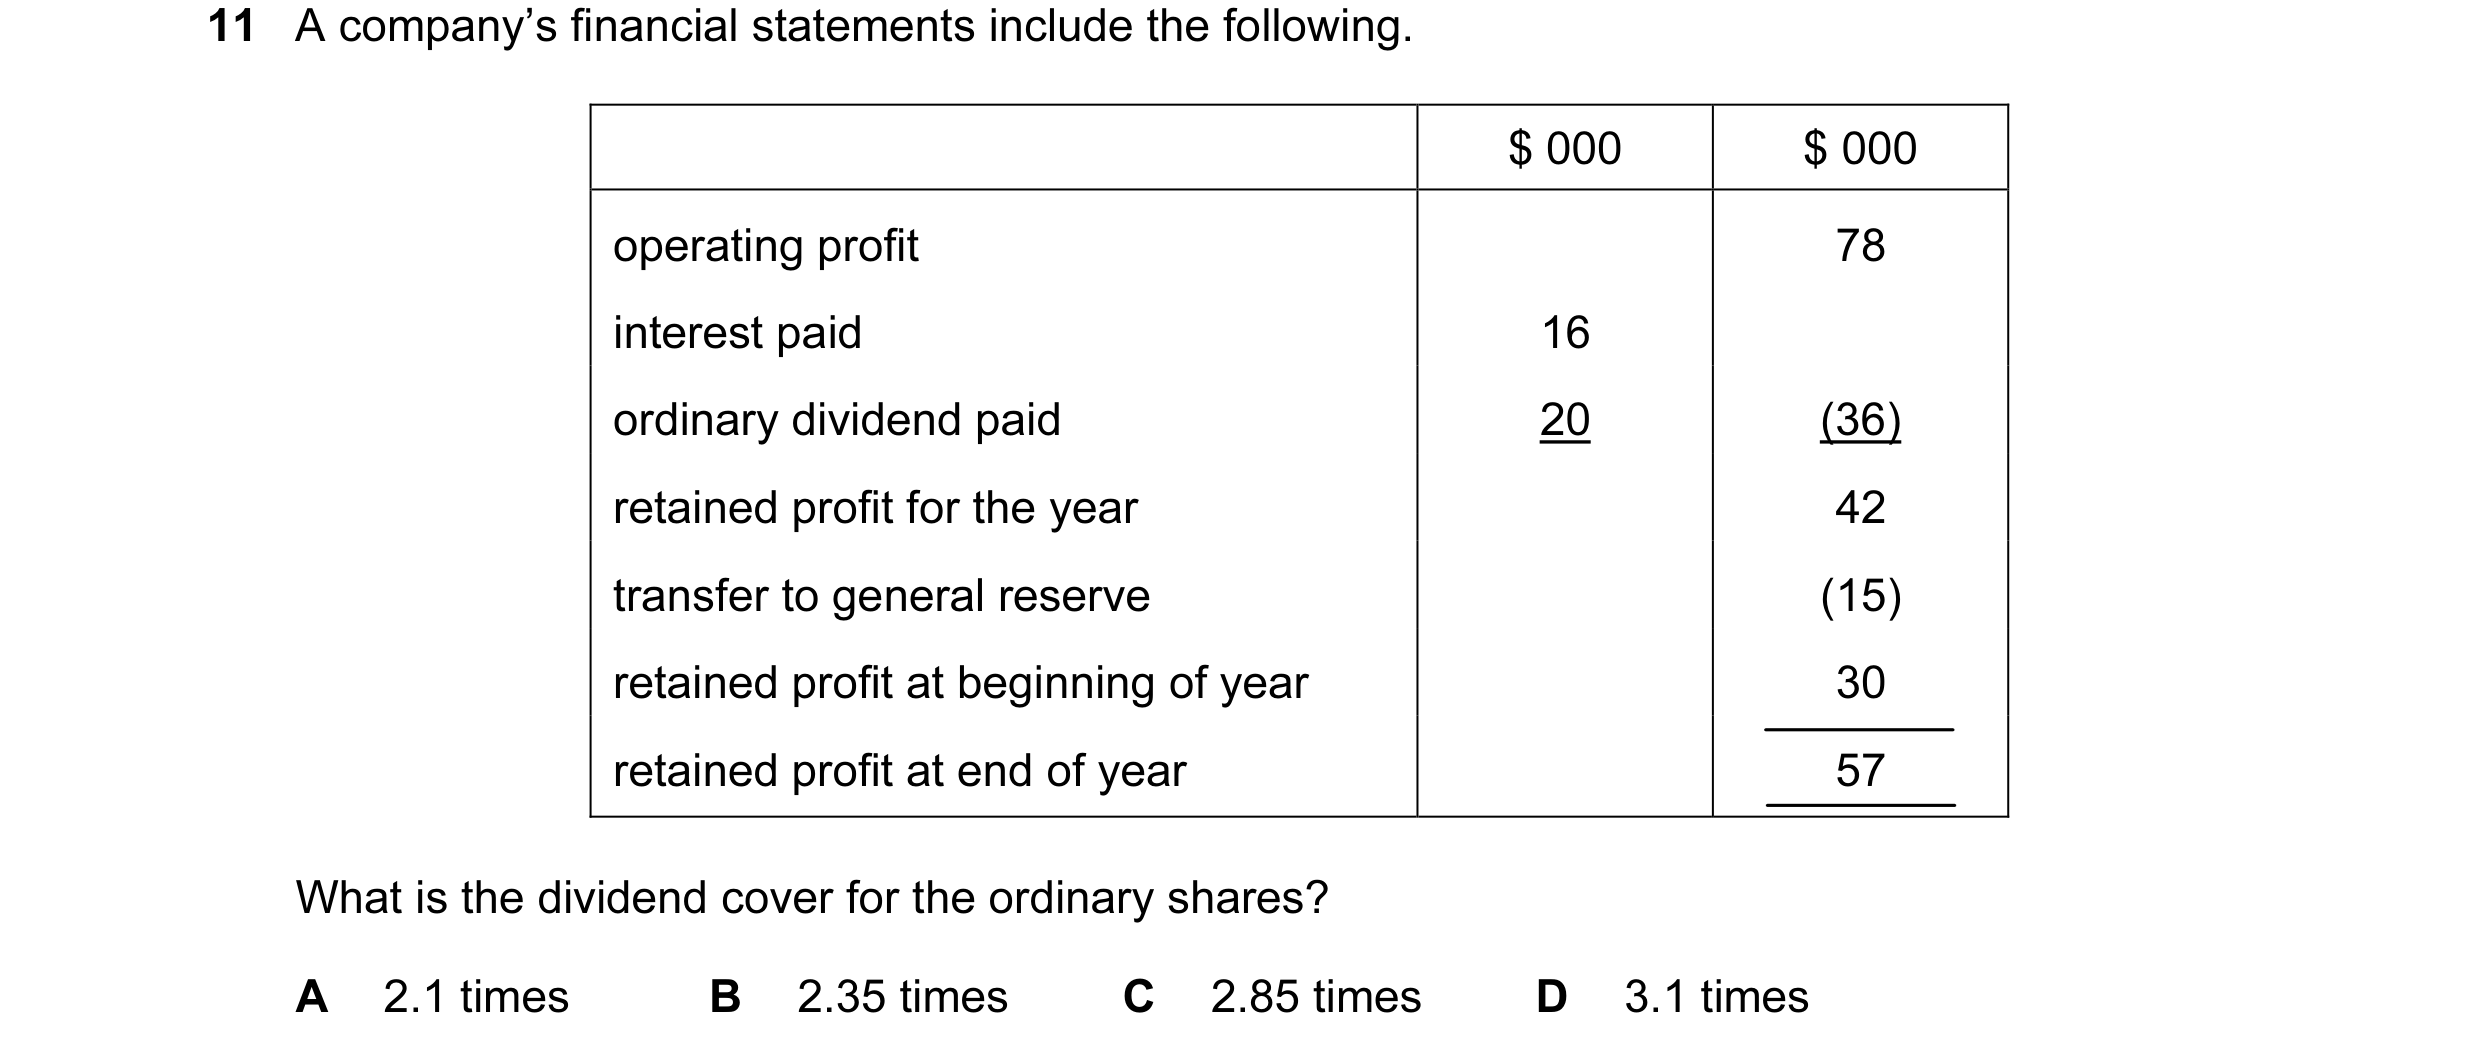
12 A company’s financial statements include the following. $ 000 $ 000 operating profit 78 interest paid 16 ordinary dividend paid 20 (36) retained profit for the year 42 transfer to general reserve (15) retained profit at beginning of year 30 retained profit at end of year 57 What is the dividend cover for the ordinary shares? A 2.1 times B 2.35 times C 2.85 times D 3.1 times
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2009
Q3 · The issued share capital of a company is: 200 000 5 % preference shares of $1.00 each… 9706/31 Oct/Nov 2009
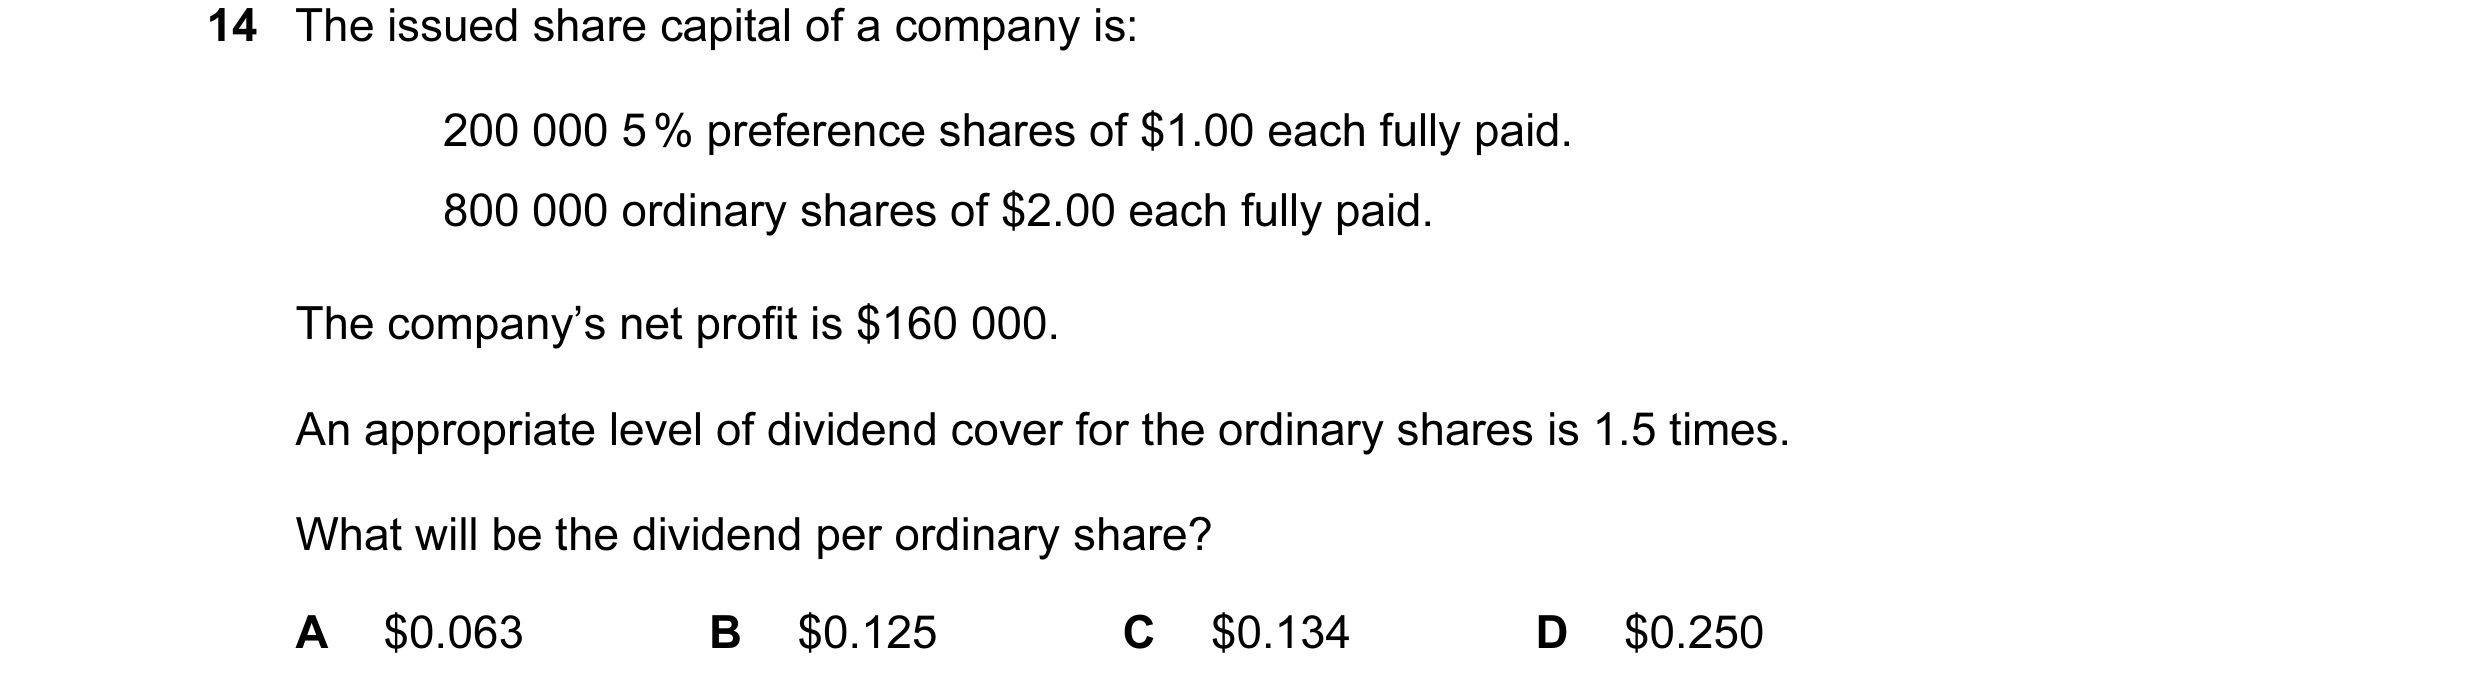
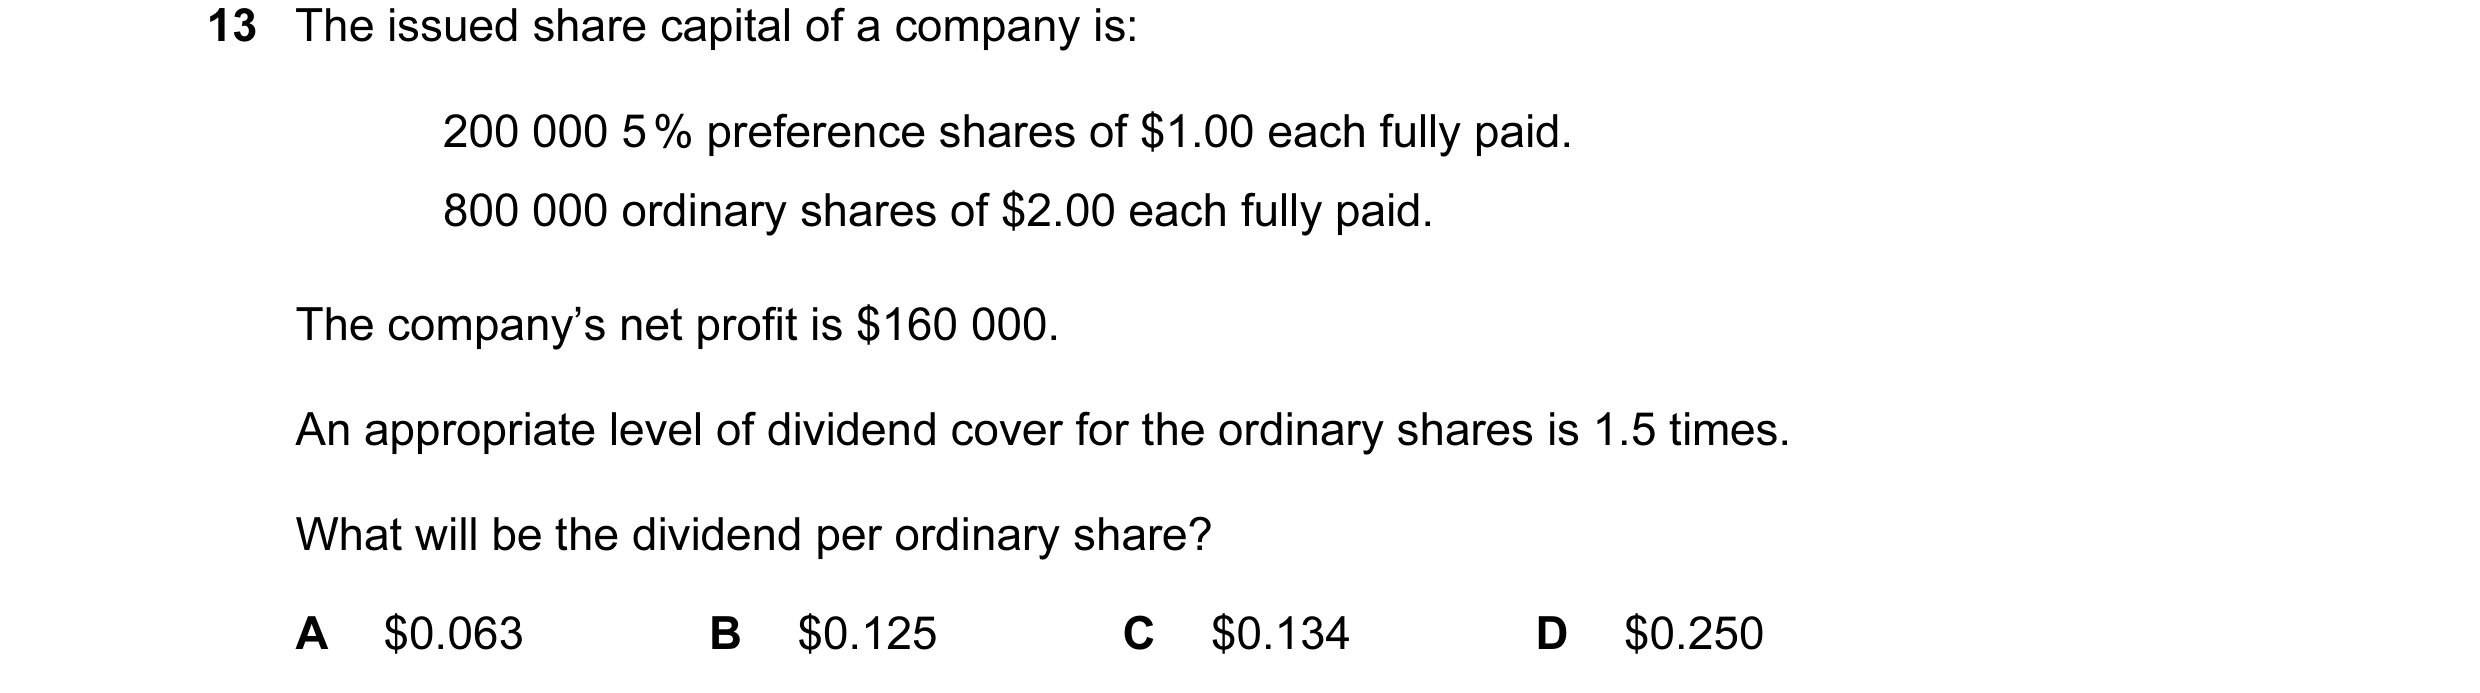
14 The issued share capital of a company is: 200 000 5 % preference shares of $1.00 each fully paid. 800 000 ordinary shares of $2.00 each fully paid. The company’s net profit is $160 000. An appropriate level of dividend cover for the ordinary shares is 1.5 times. What will be the dividend per ordinary share? A $0.063 B $0.125 C $0.134 D $0.250
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2009
Q4 · Which action would reduce a company’s gearing level? 9706/31 Oct/Nov 2009
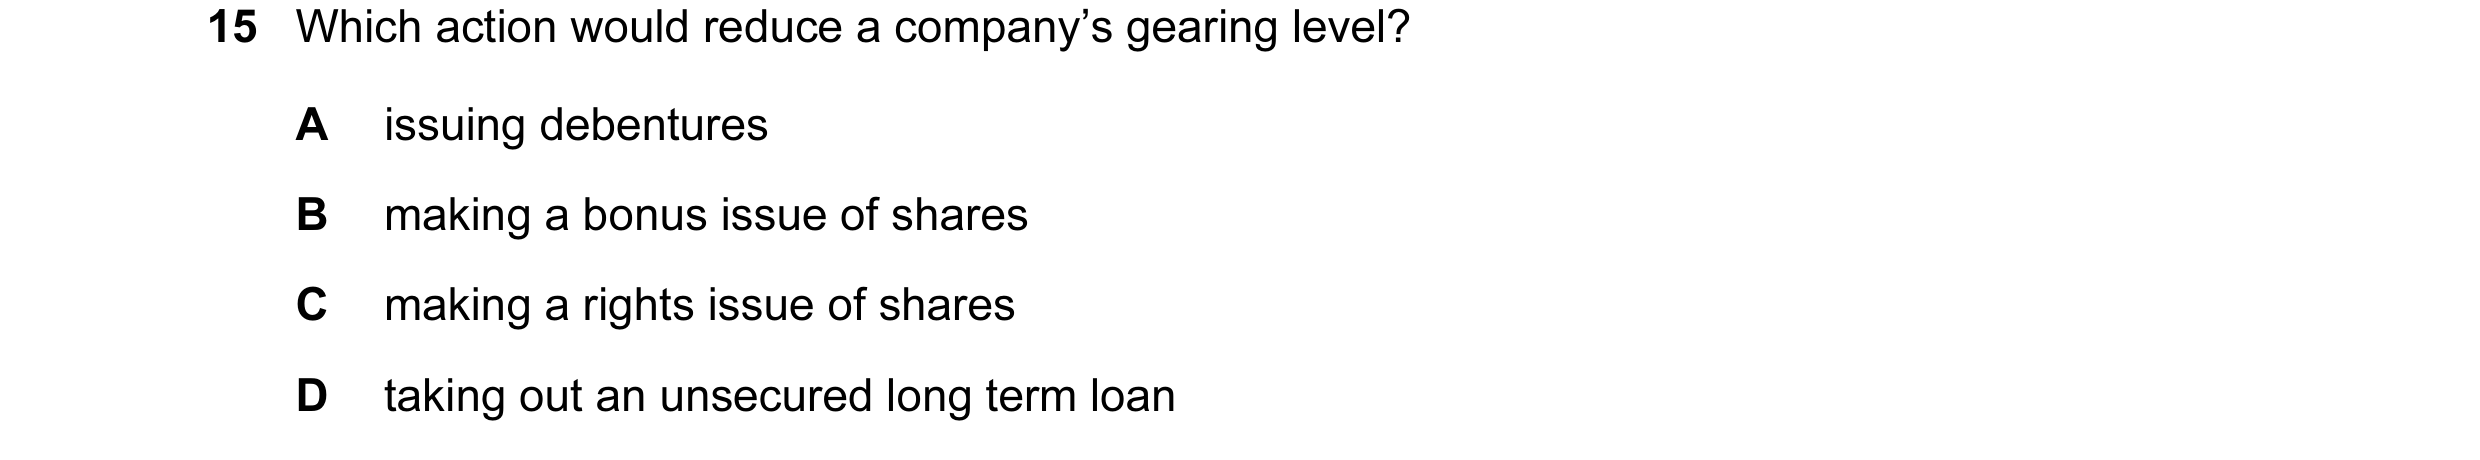
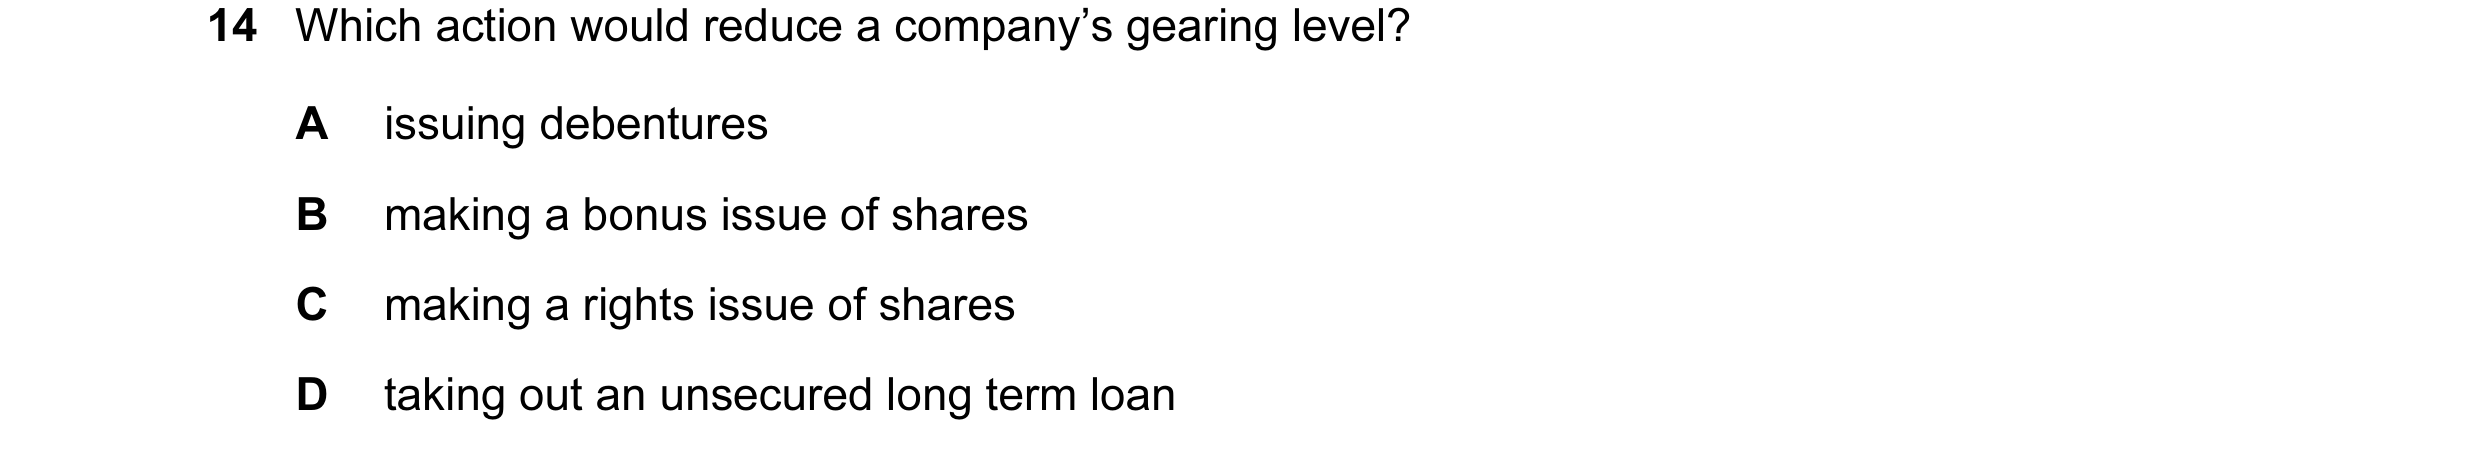
15 Which action would reduce a company’s gearing level? A issuing debentures B making a bonus issue of shares C making a rights issue of shares D taking out an unsecured long term loan
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2009
Q5 · Which characteristics would be present in a highly geared company? 9706/31 Oct/Nov 2009
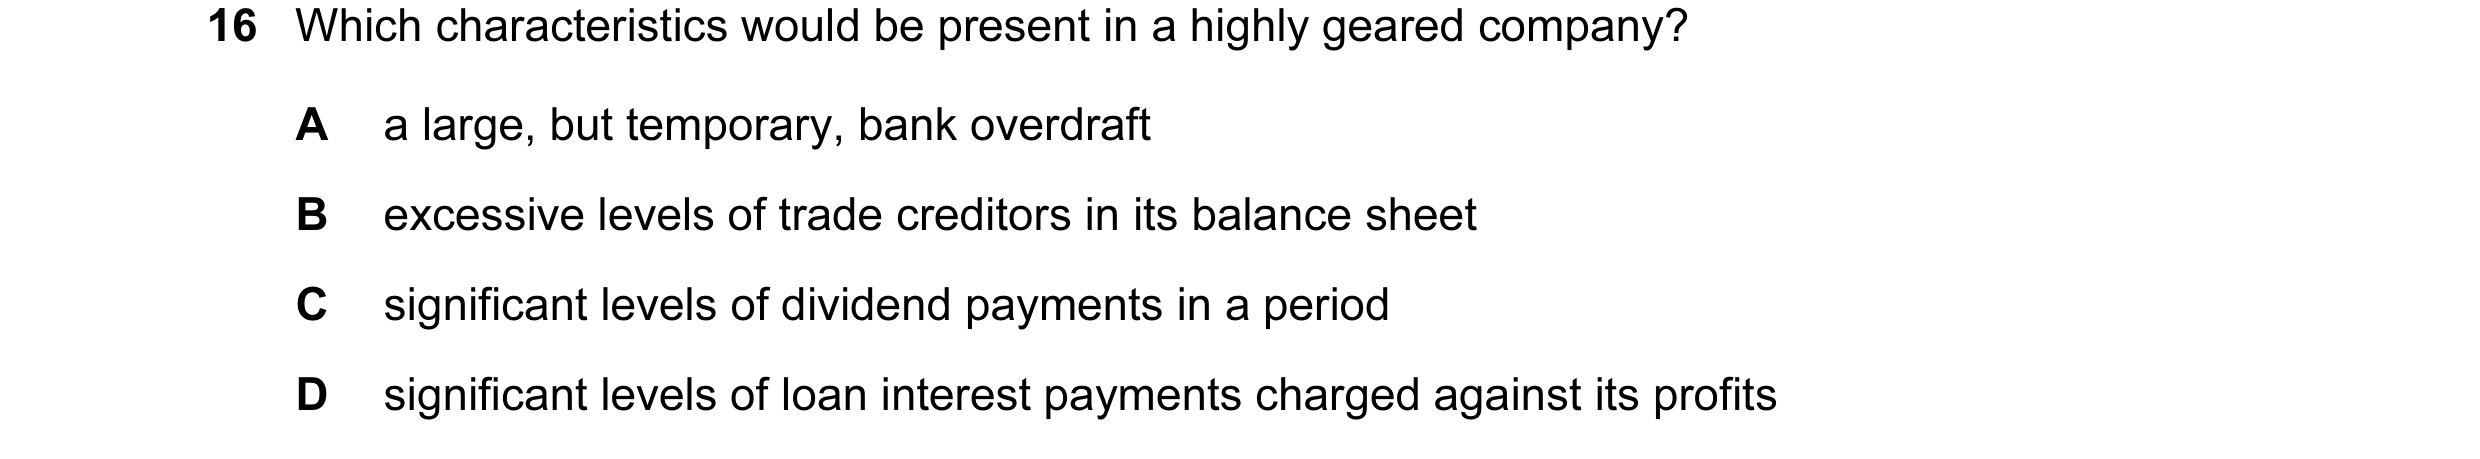
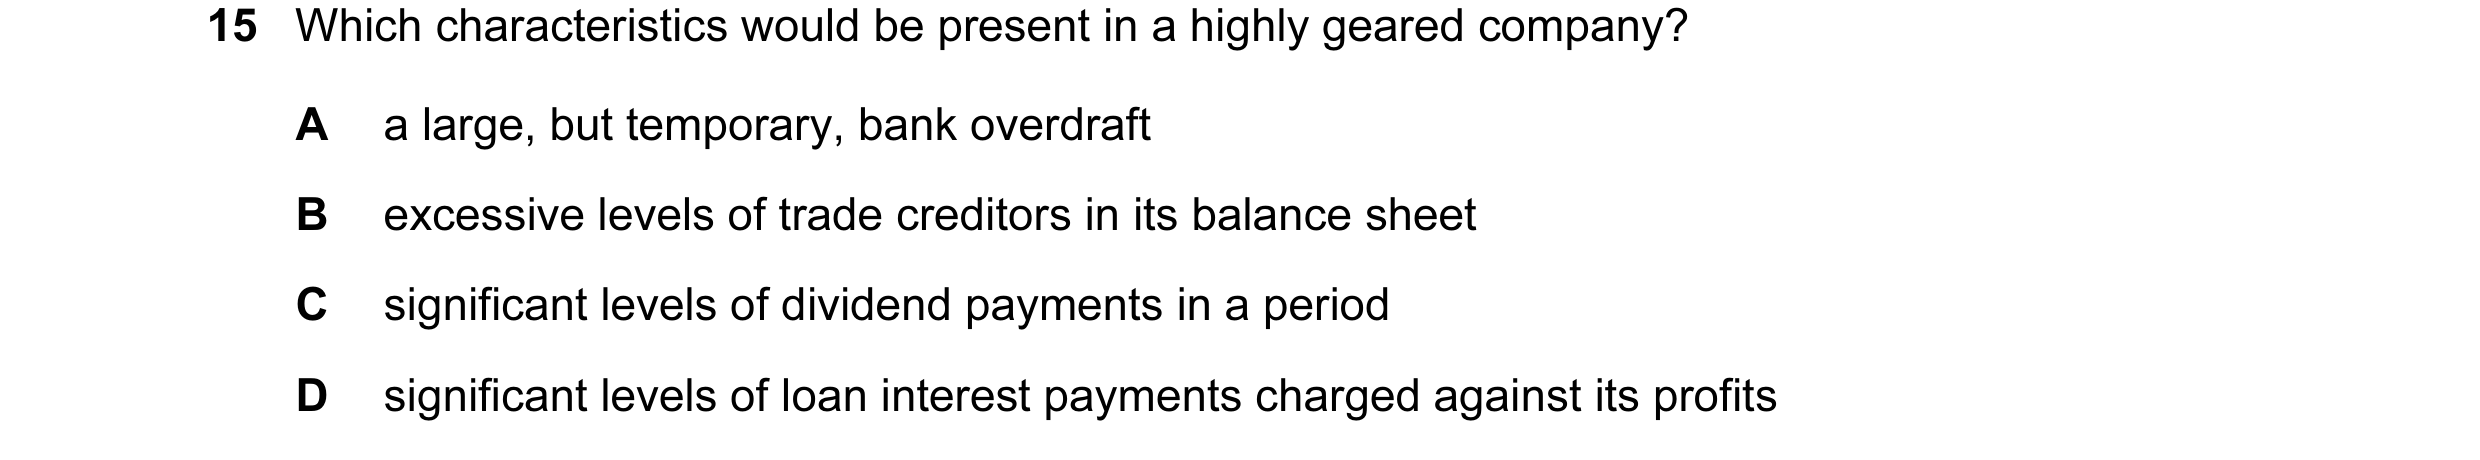
16 Which characteristics would be present in a highly geared company? A a large, but temporary, bank overdraft B excessive levels of trade creditors in its balance sheet C significant levels of dividend payments in a period D significant levels of loan interest payments charged against its profits
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2009
Q6 · The table shows data for a company 9706/32 Oct/Nov 2009
1 The table shows data for a company. Year 1 Year 2 $ 000 $ 000 stock 160 220 debtors 85 63 bank 33 212 creditors 72 87 Operating profit before interest and depreciation was $240 000. Depreciation charges for the year amounted to $42 000. What was the net cash flow from operating activities in Year 2? A $179 000 B $217 000 C $259 000 D $263 000
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2009
Q7 · A company’s financial statements include the following 9706/32 Oct/Nov 2009
11 A company’s financial statements include the following. $ 000 $ 000 operating profit 78 interest paid 16 ordinary dividend paid 20 (36) retained profit for the year 42 transfer to general reserve (15) retained profit at beginning of year 30 retained profit at end of year 57 What is the dividend cover for the ordinary shares? A 2.1 times B 2.35 times C 2.85 times D 3.1 times
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2009
Q8 · The issued share capital of a company is: 200 000 5 % preference shares of $1.00 each… 9706/32 Oct/Nov 2009
13 The issued share capital of a company is: 200 000 5 % preference shares of $1.00 each fully paid. 800 000 ordinary shares of $2.00 each fully paid. The company’s net profit is $160 000. An appropriate level of dividend cover for the ordinary shares is 1.5 times. What will be the dividend per ordinary share? A $0.063 B $0.125 C $0.134 D $0.250
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2009
Q9 · Which action would reduce a company’s gearing level? 9706/32 Oct/Nov 2009
14 Which action would reduce a company’s gearing level? A issuing debentures B making a bonus issue of shares C making a rights issue of shares D taking out an unsecured long term loan
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2009
Q10 · Which characteristics would be present in a highly geared company? 9706/32 Oct/Nov 2009
15 Which characteristics would be present in a highly geared company? A a large, but temporary, bank overdraft B excessive levels of trade creditors in its balance sheet C significant levels of dividend payments in a period D significant levels of loan interest payments charged against its profits
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2009
Q11 · The financial statements of a company for the year to 30 June includes the following 9706/31 May/June 2010
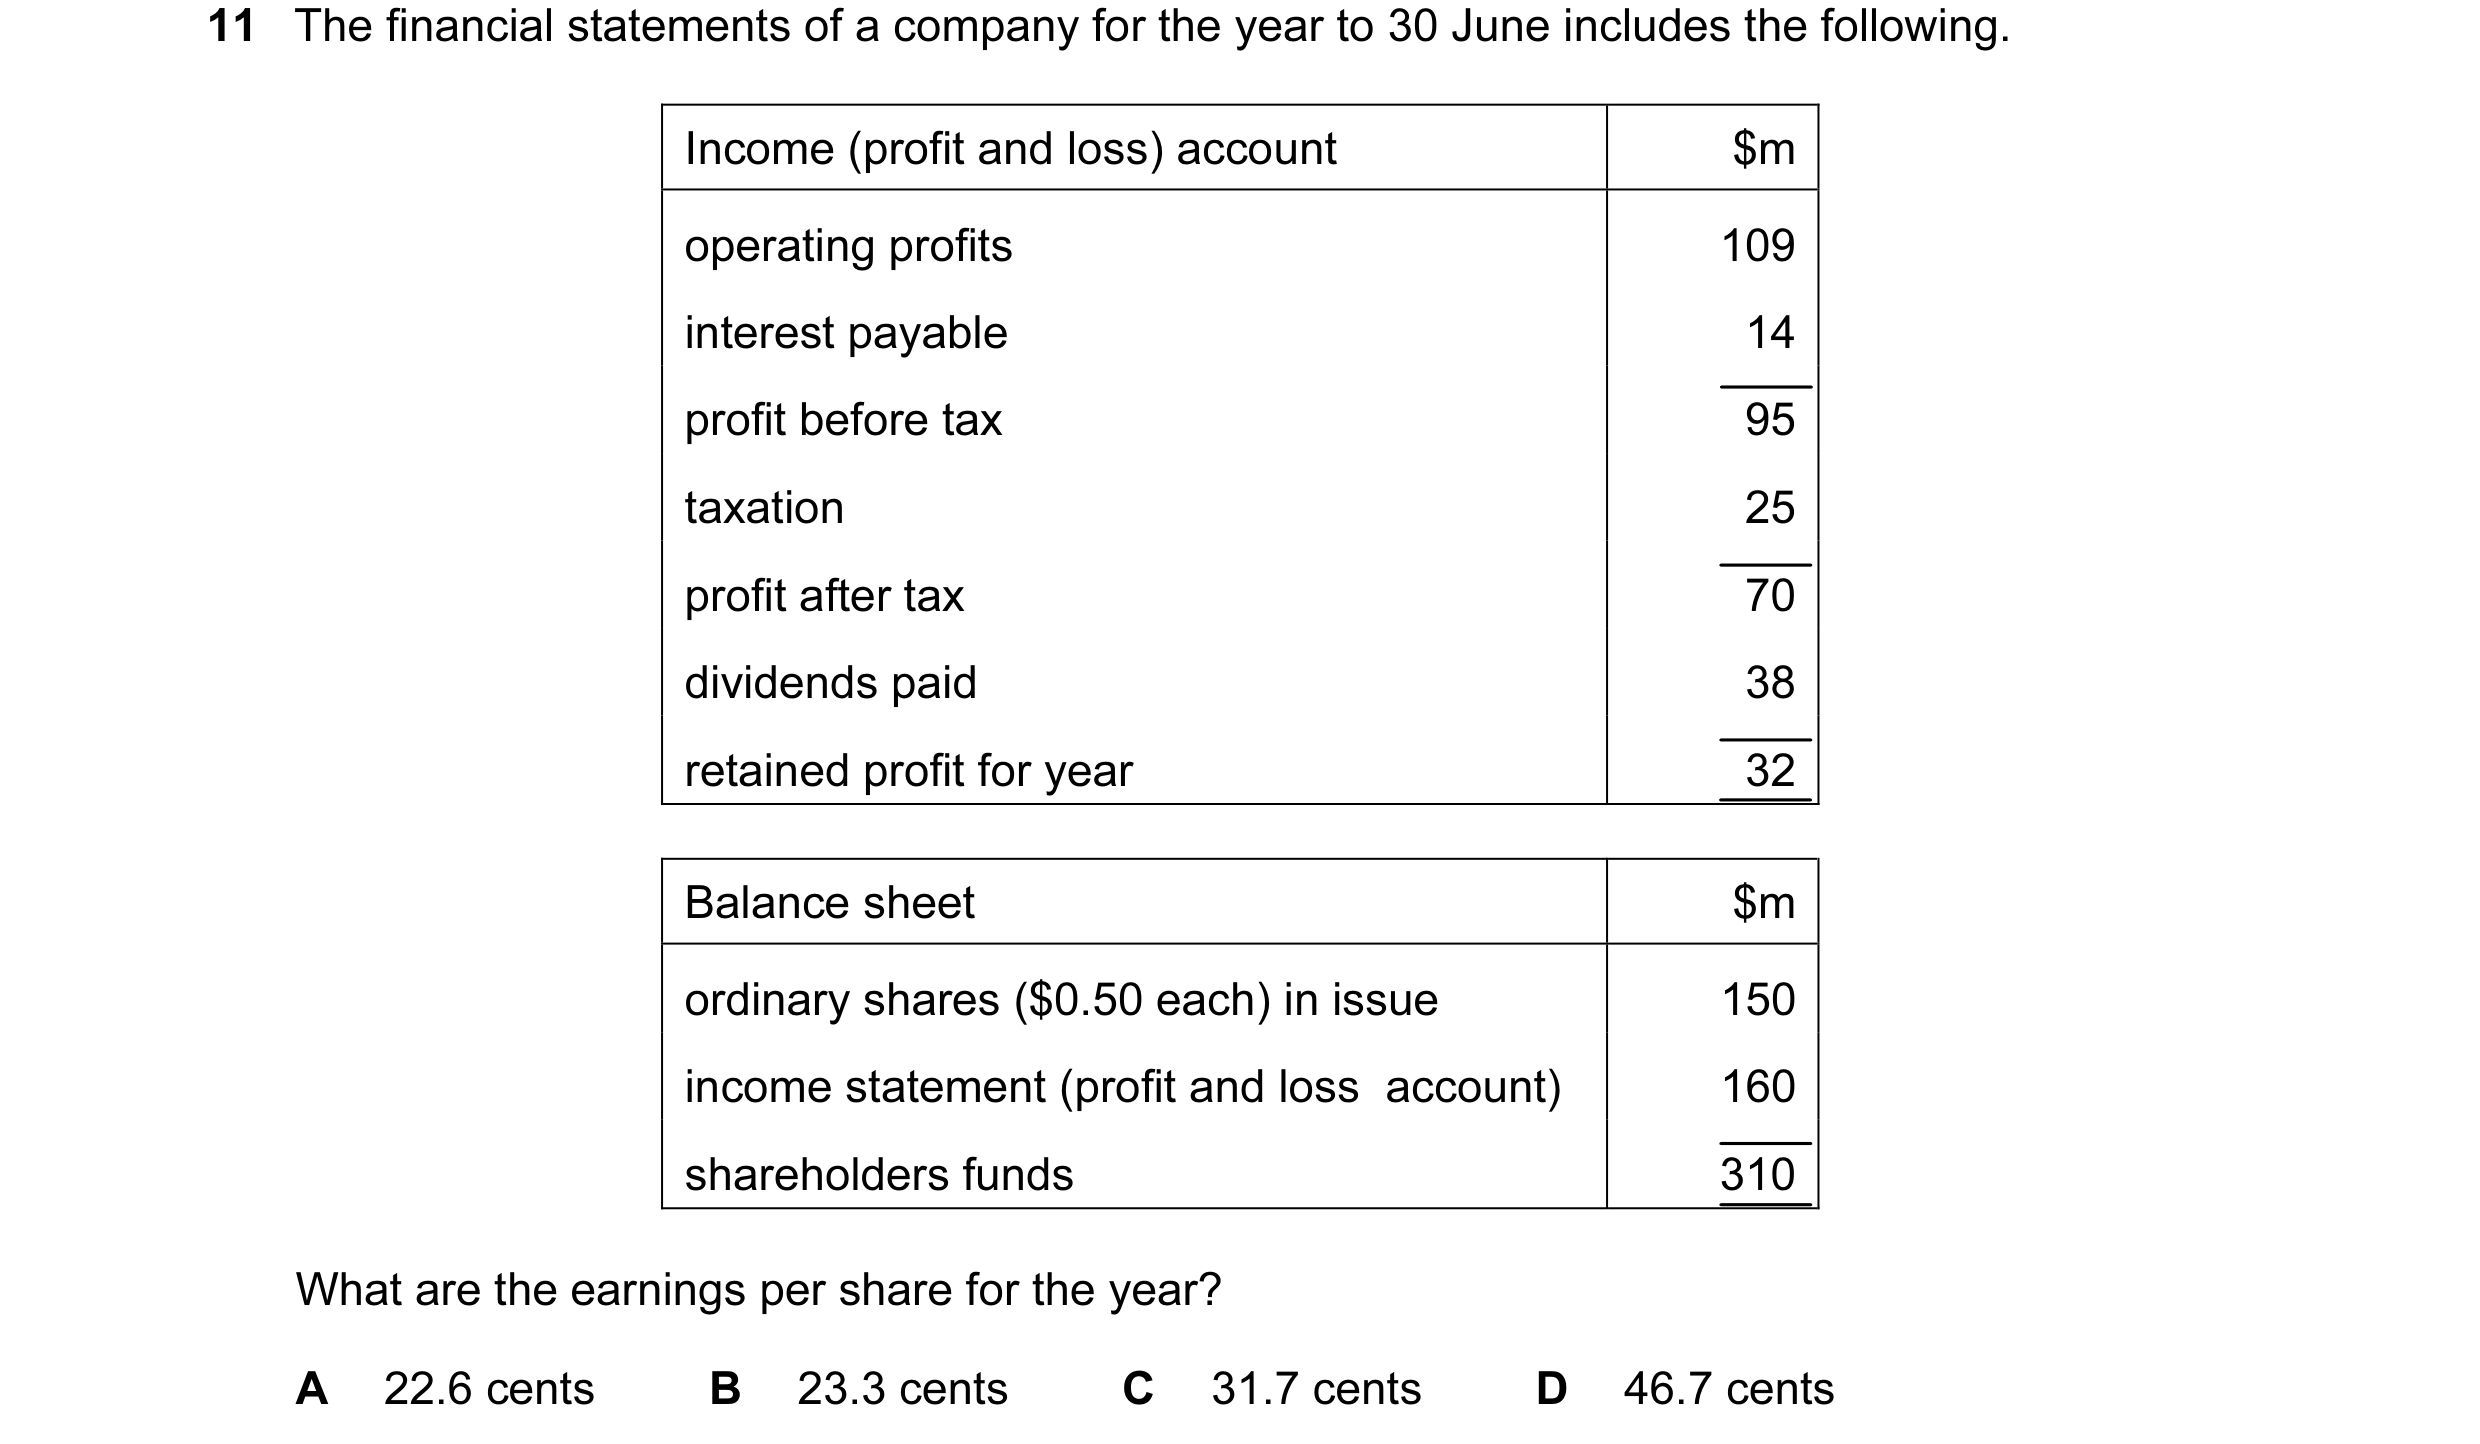
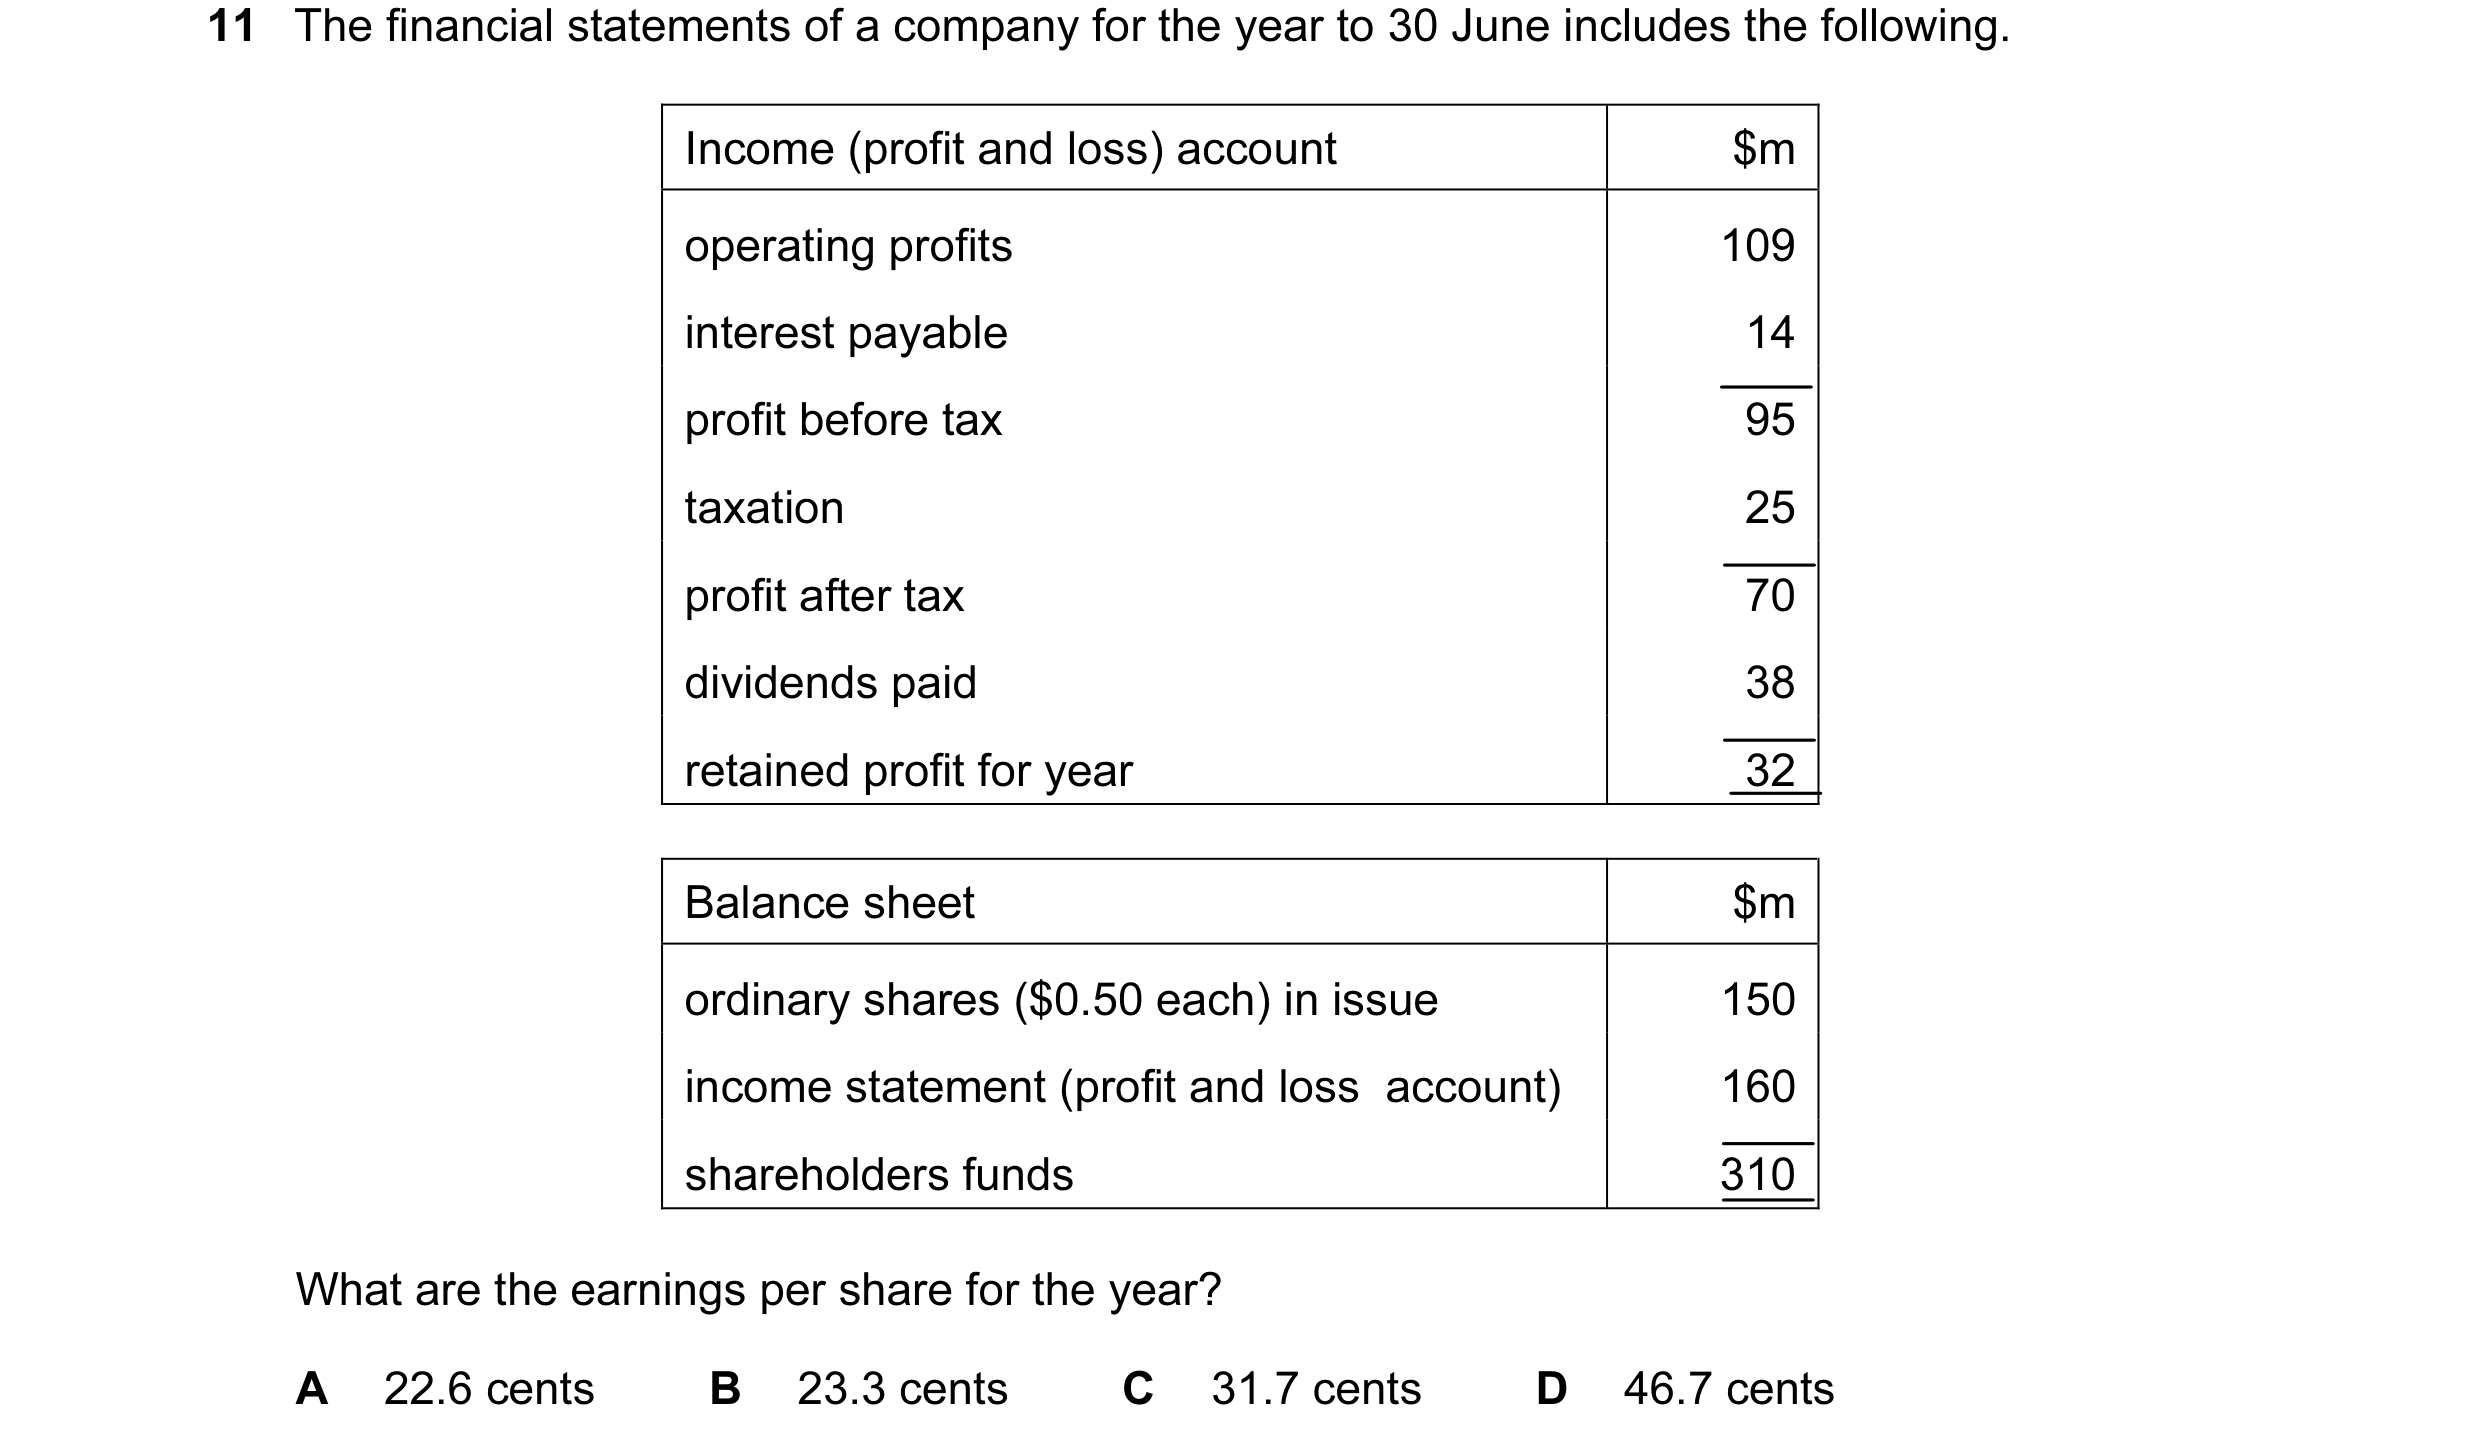
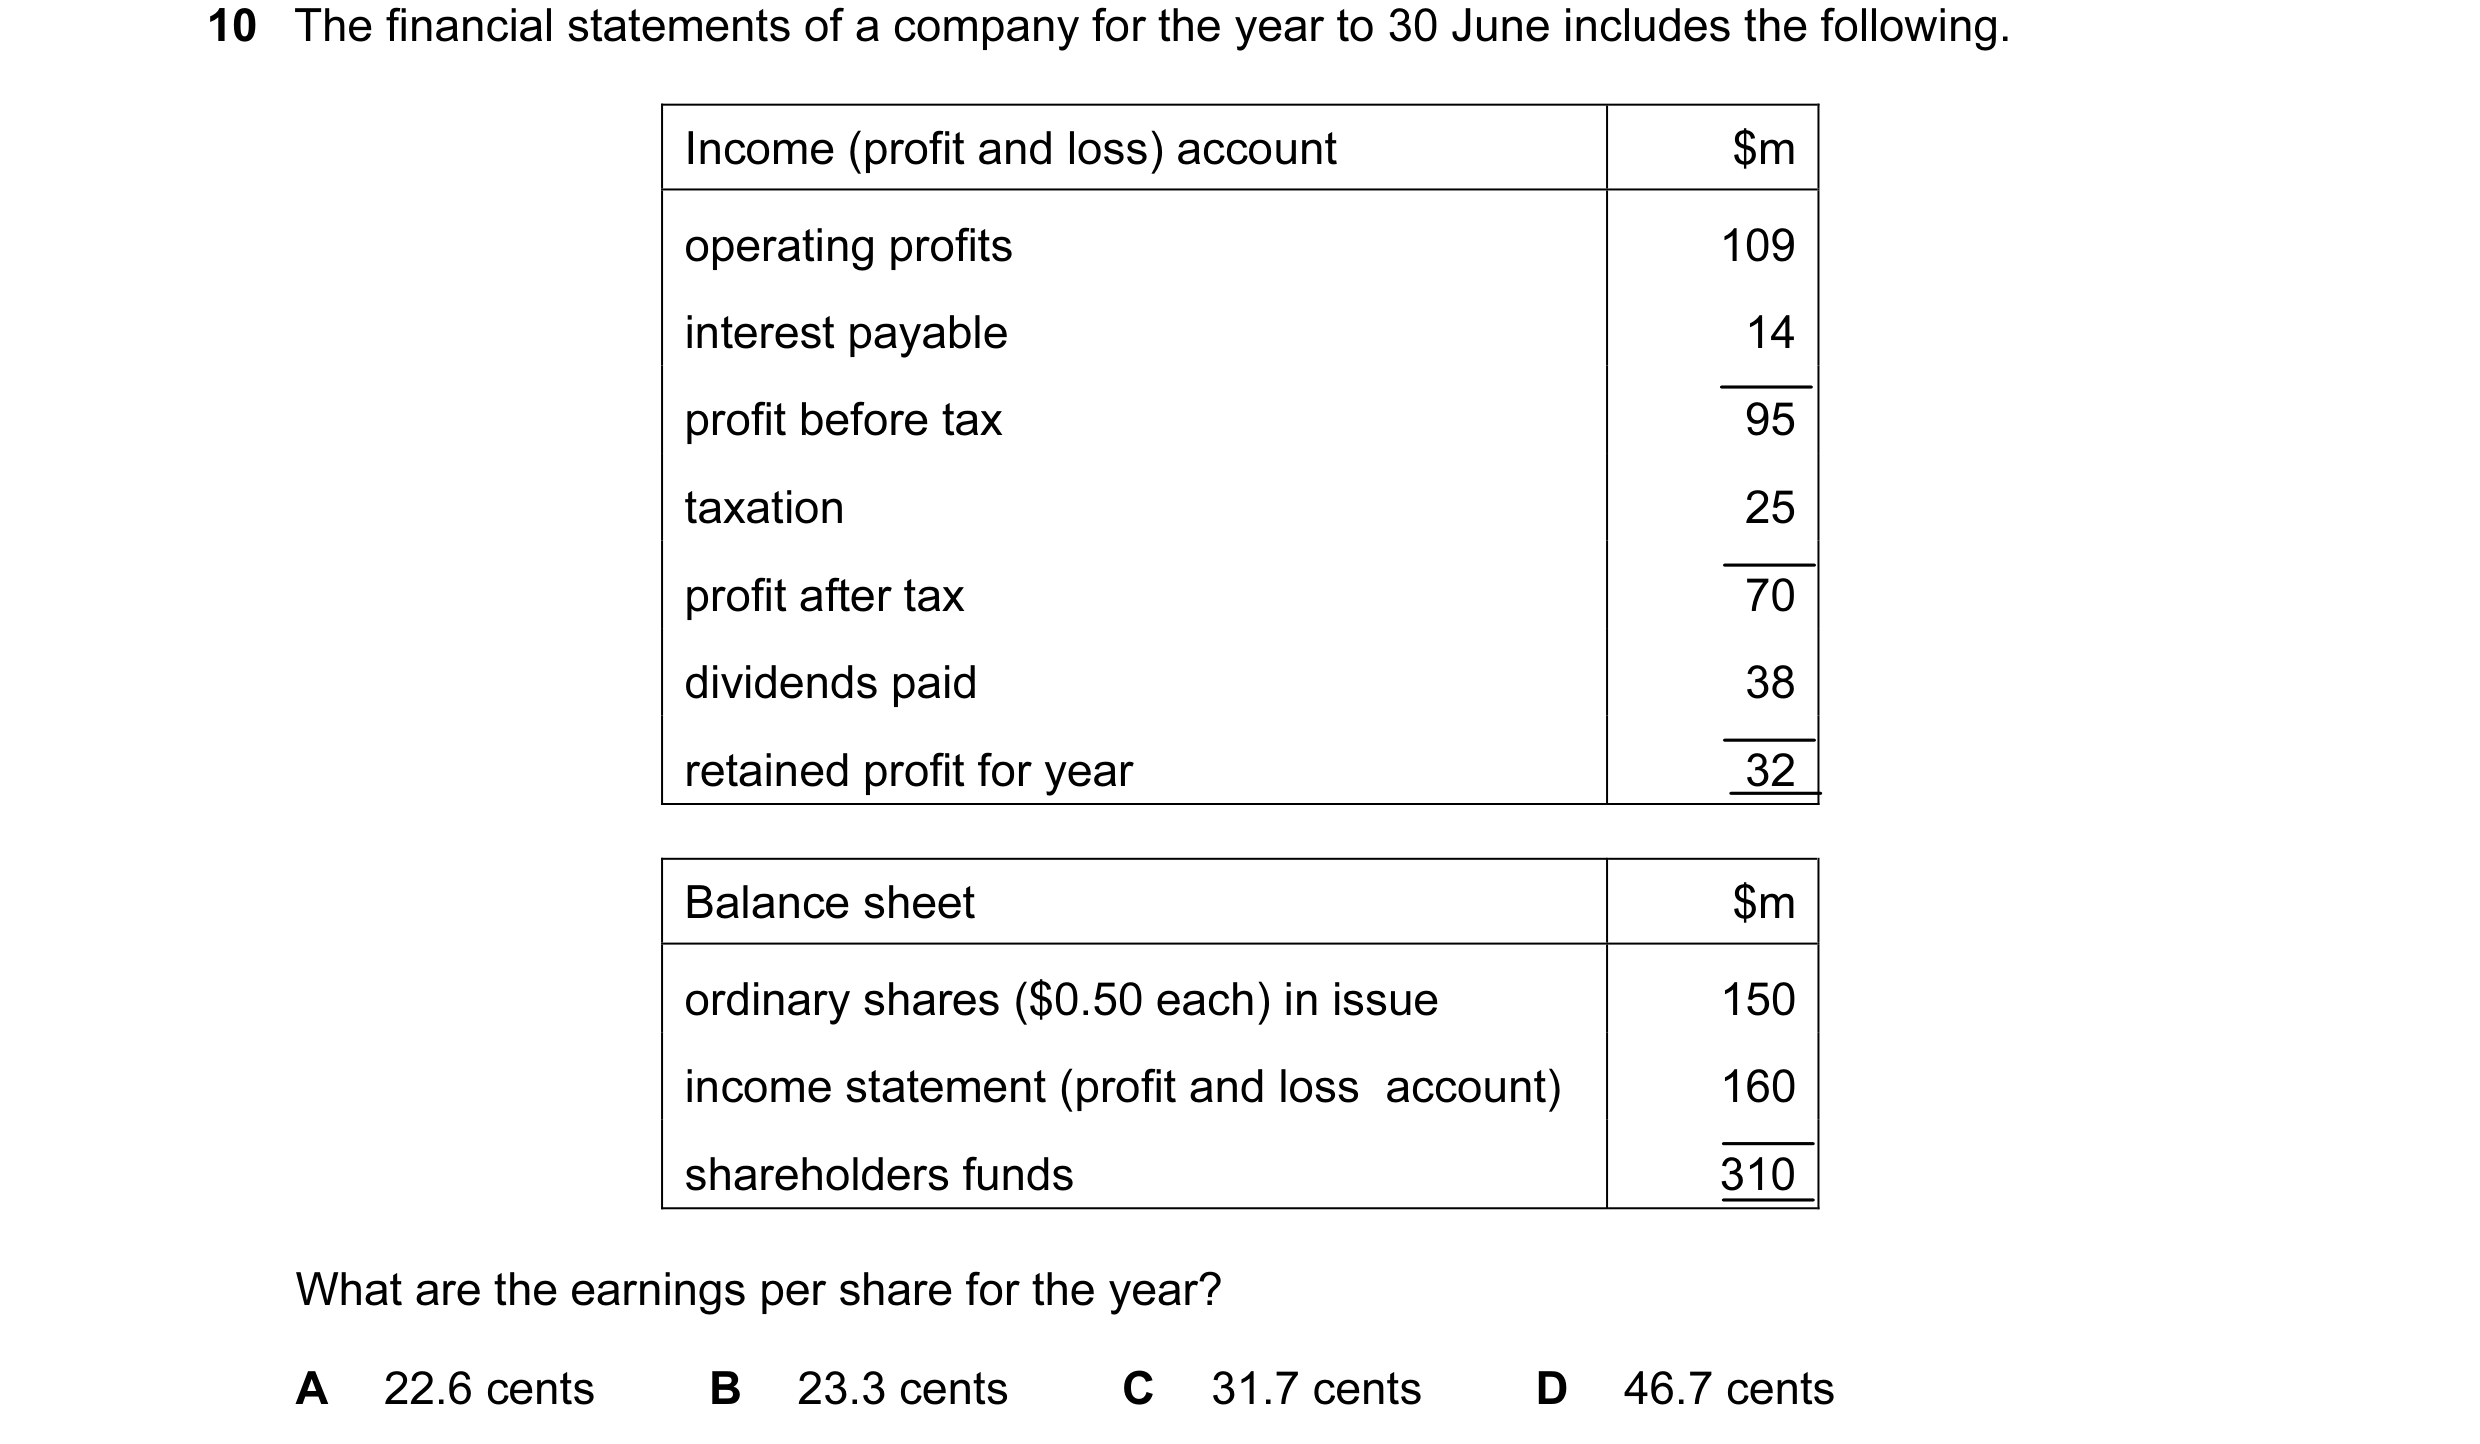
11 The financial statements of a company for the year to 30 June includes the following. Income (profit and loss) account $m operating profits 109 interest payable 14 profit before tax 95 taxation 25 profit after tax 70 dividends paid 38 retained profit for year 32 Balance sheet $m ordinary shares ($0.50 each) in issue 150 income statement (profit and loss account) 160 shareholders funds 310 What are the earnings per share for the year? A 22.6 cents B 23.3 cents C 31.7 cents D 46.7 cents
1 marks
Answer: B
This question in 9706/31 May/June 2010
Q12 · A company has an issued share capital of 50 000 $1 ordinary shares 9706/31 May/June 2010
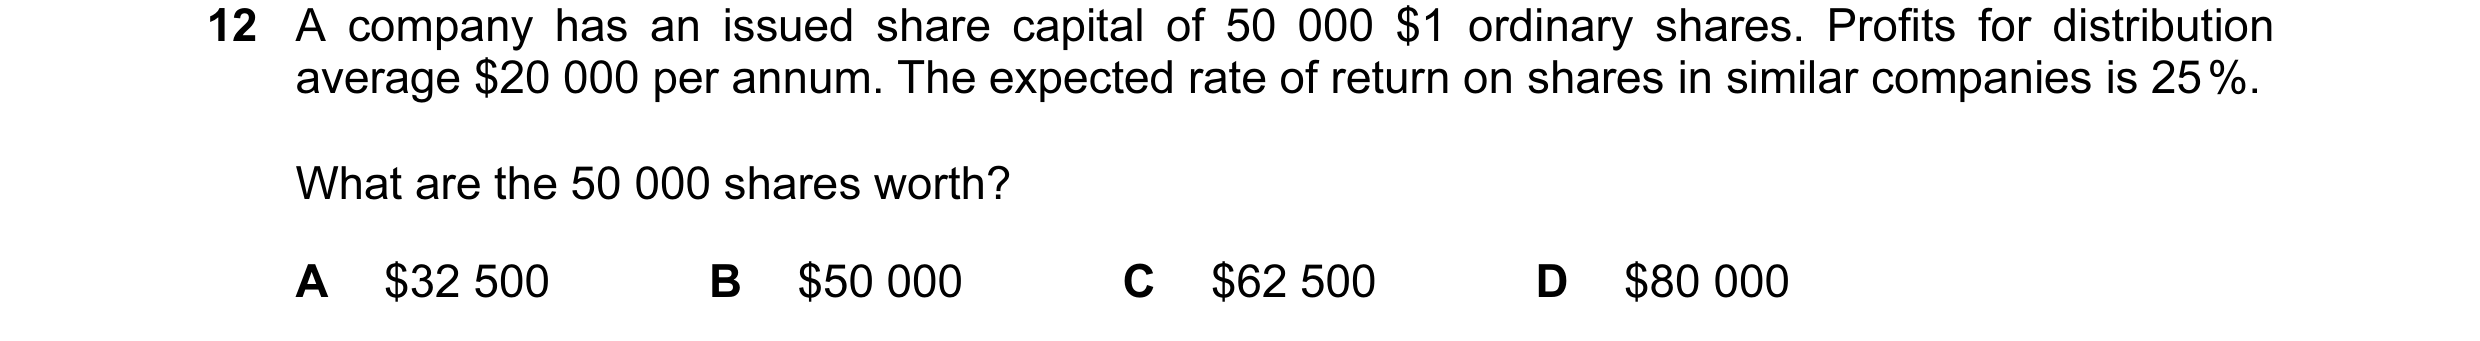
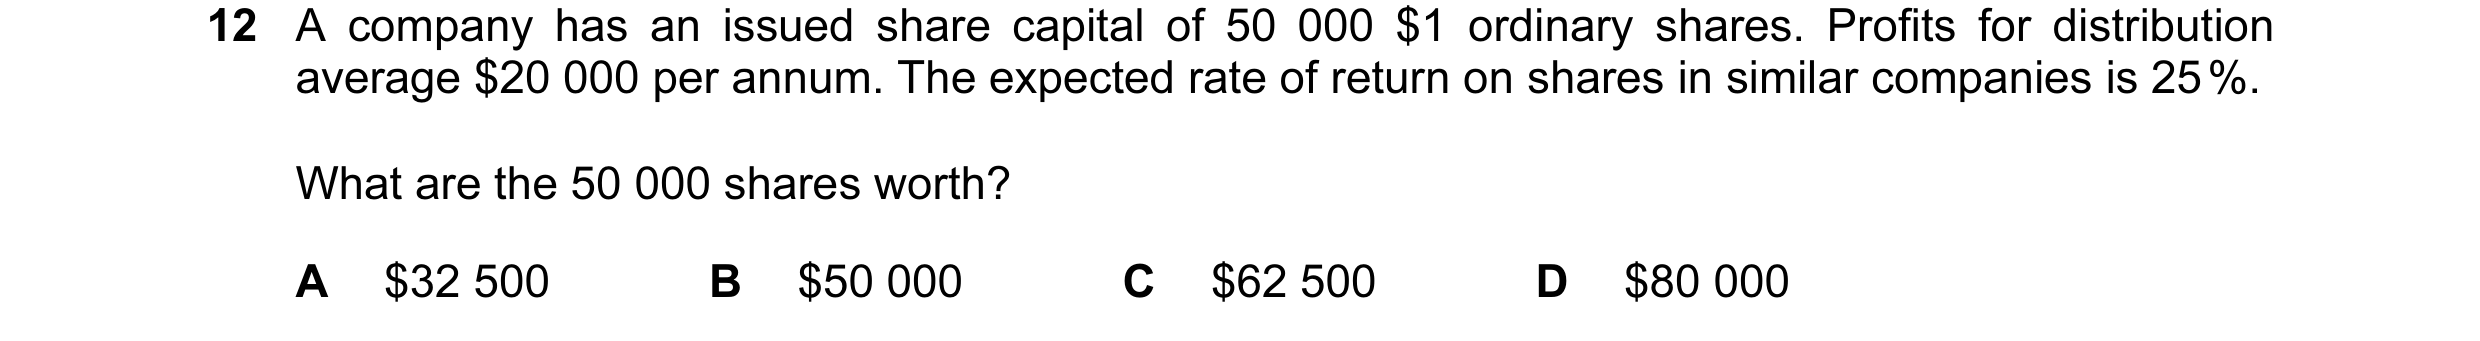
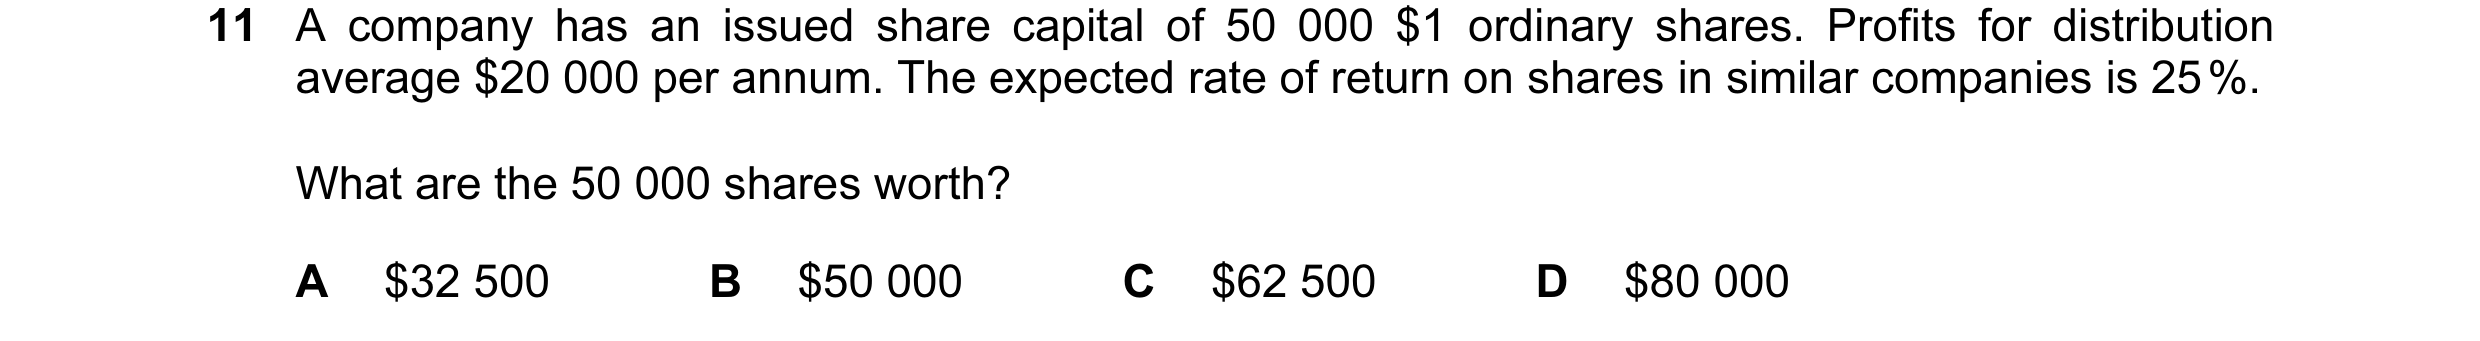
12 A company has an issued share capital of 50 000 $1 ordinary shares. Profits for distribution average $20 000 per annum. The expected rate of return on shares in similar companies is 25 %. What are the 50 000 shares worth? A $32 500 B $50 000 C $62 500 D $80 000
1 marks
Answer: D
This question in 9706/31 May/June 2010
Q13 · The following investment information is available 9706/31 May/June 2010
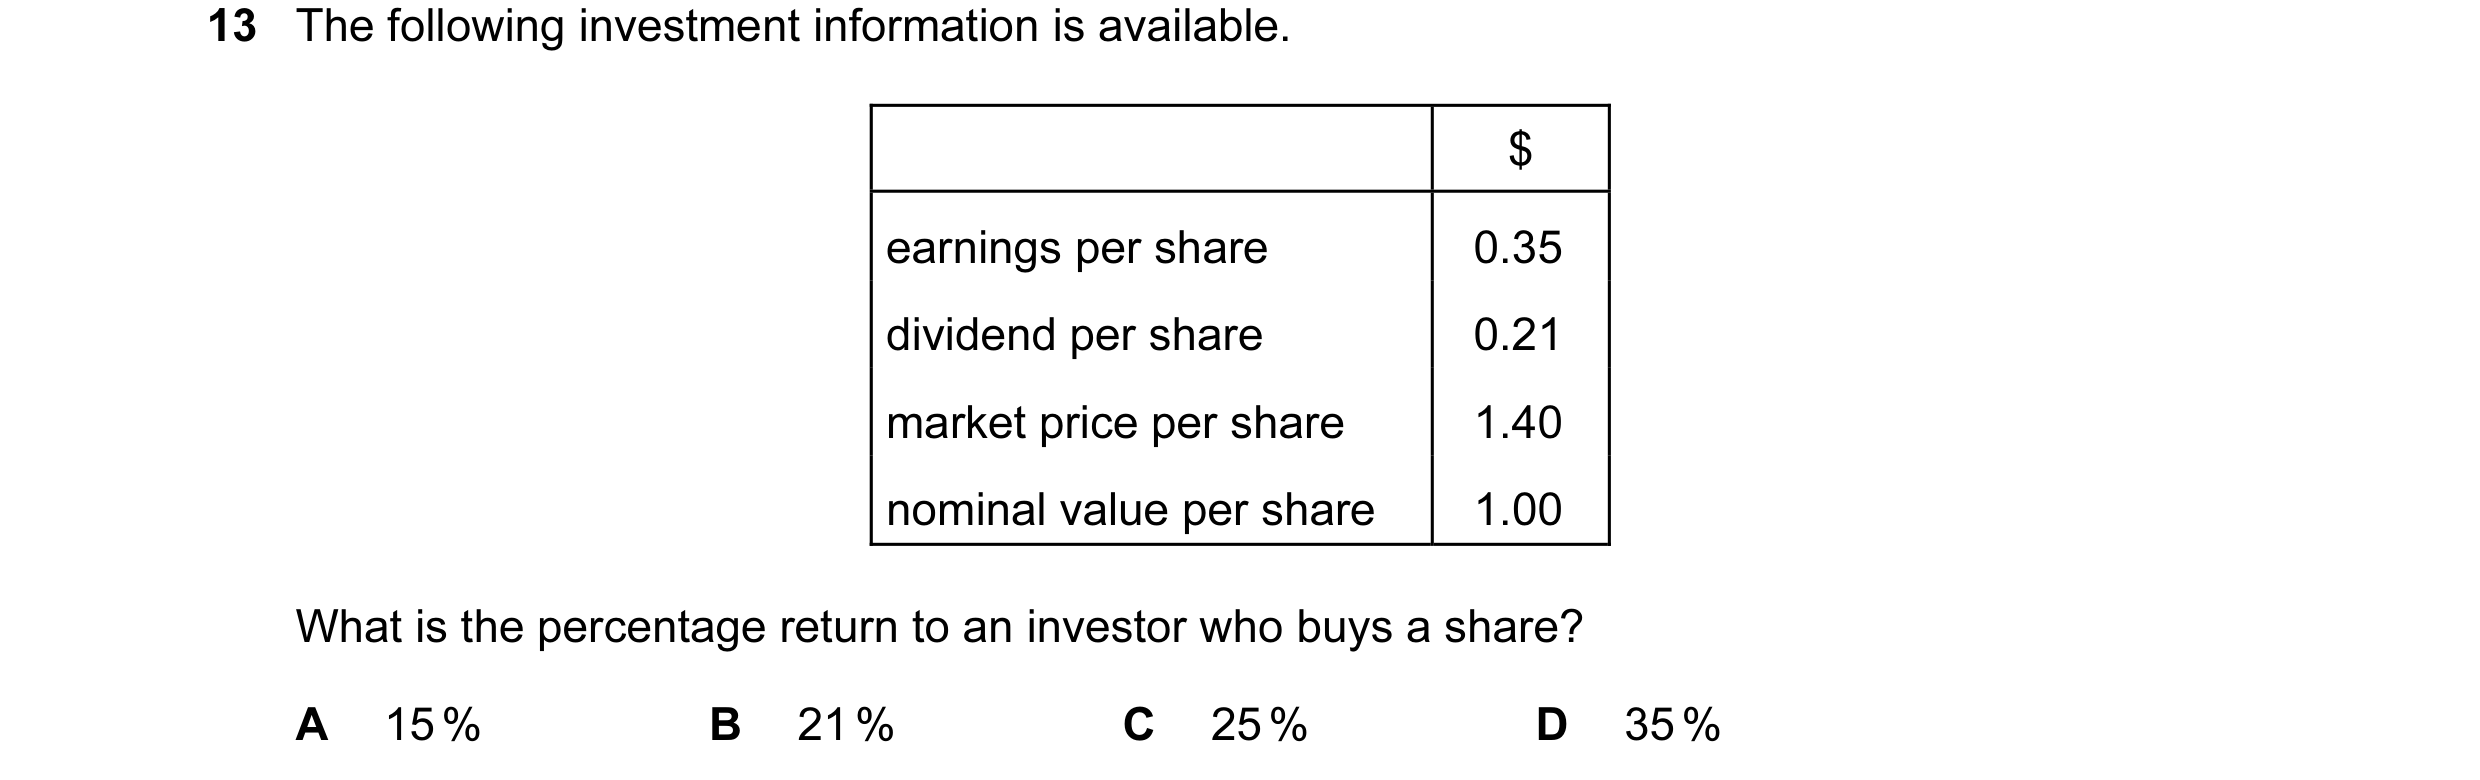
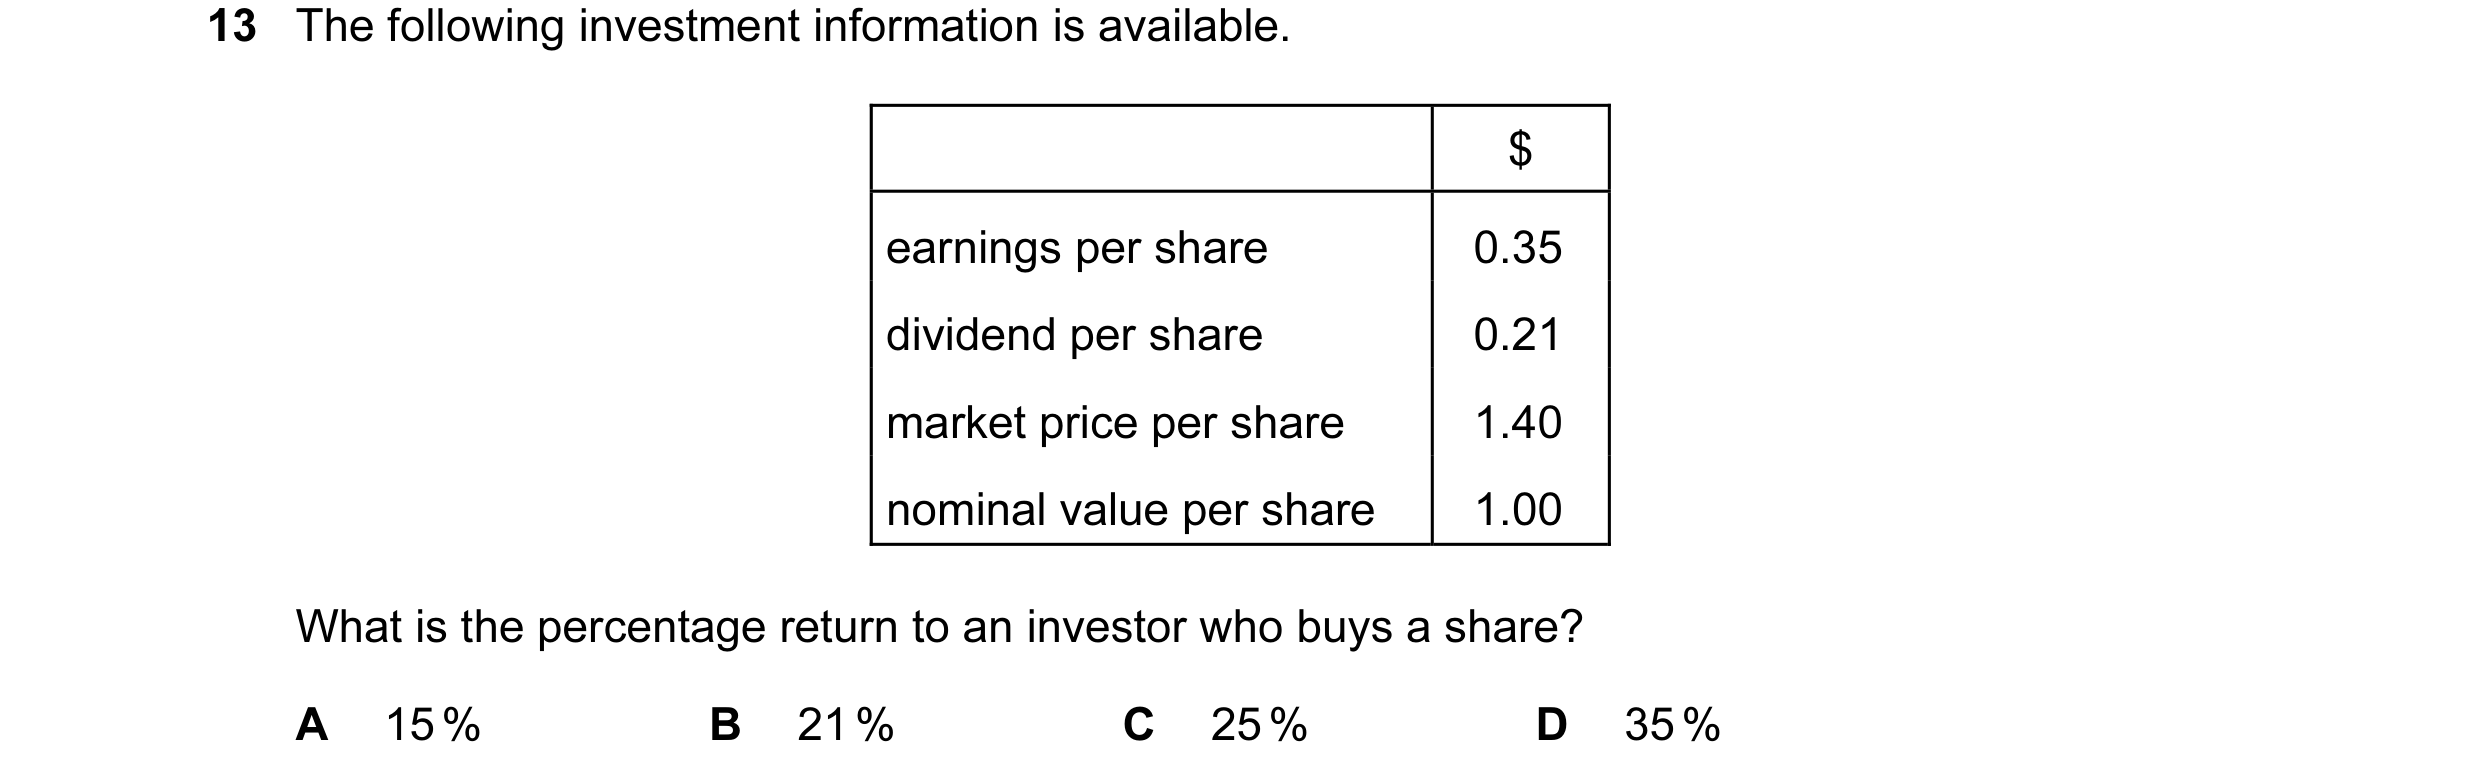
13 The following investment information is available. $ earnings per share 0.35 dividend per share 0.21 market price per share 1.40 nominal value per share 1.00 What is the percentage return to an investor who buys a share? A 15 % B 21 % C 25 % D 35 %
1 marks
Answer: A
This question in 9706/31 May/June 2010
Q14 · Which action will reduce the gearing of a company? 9706/31 May/June 2010
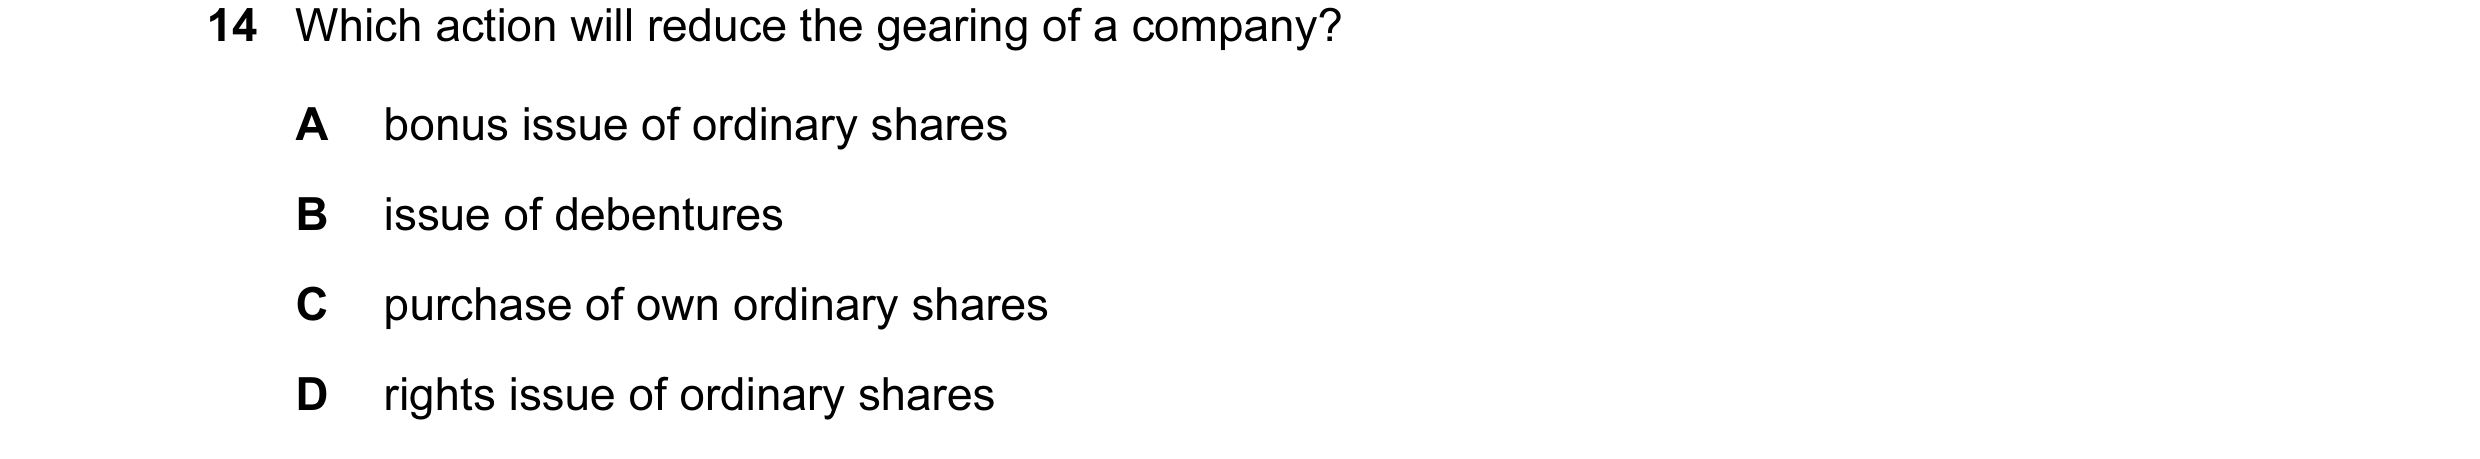
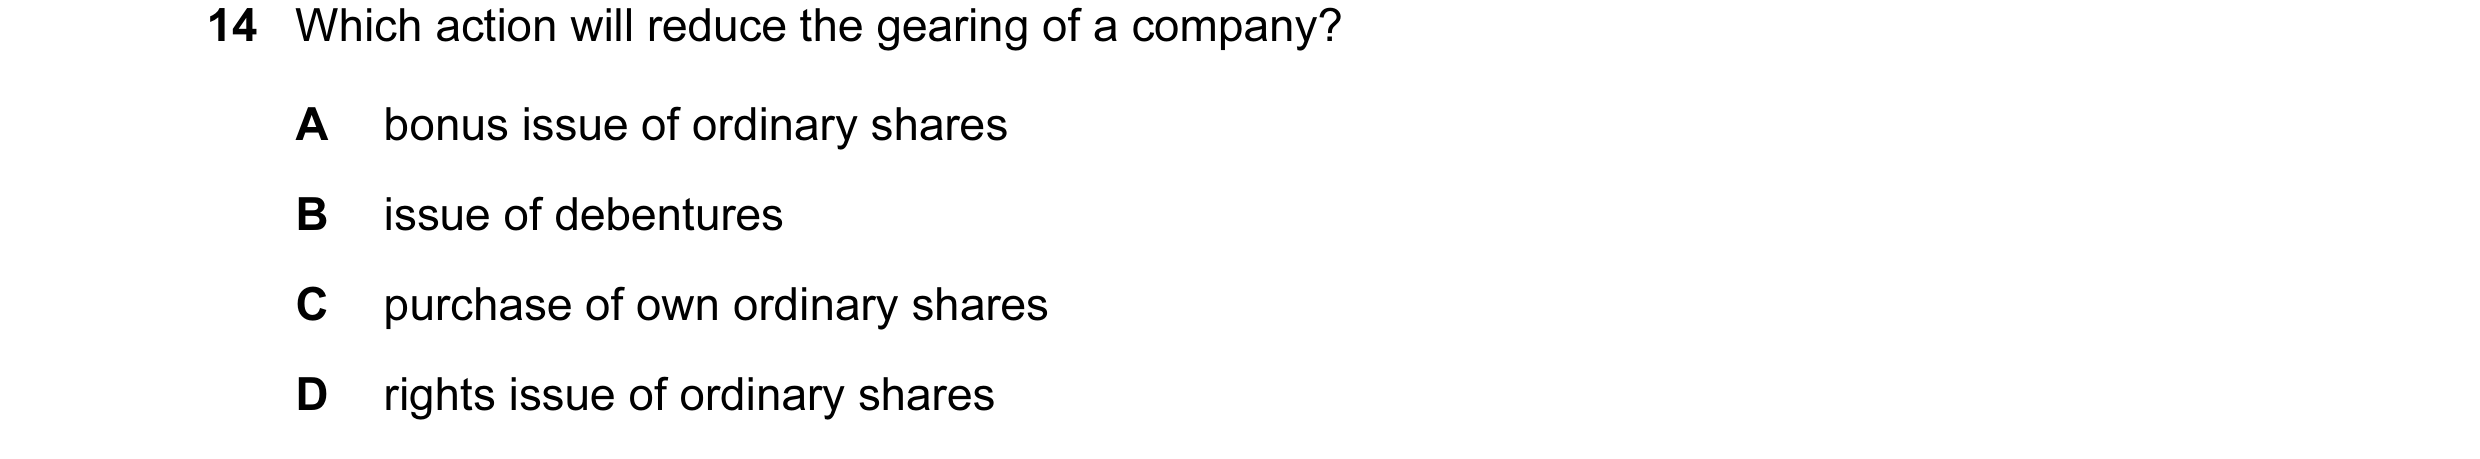
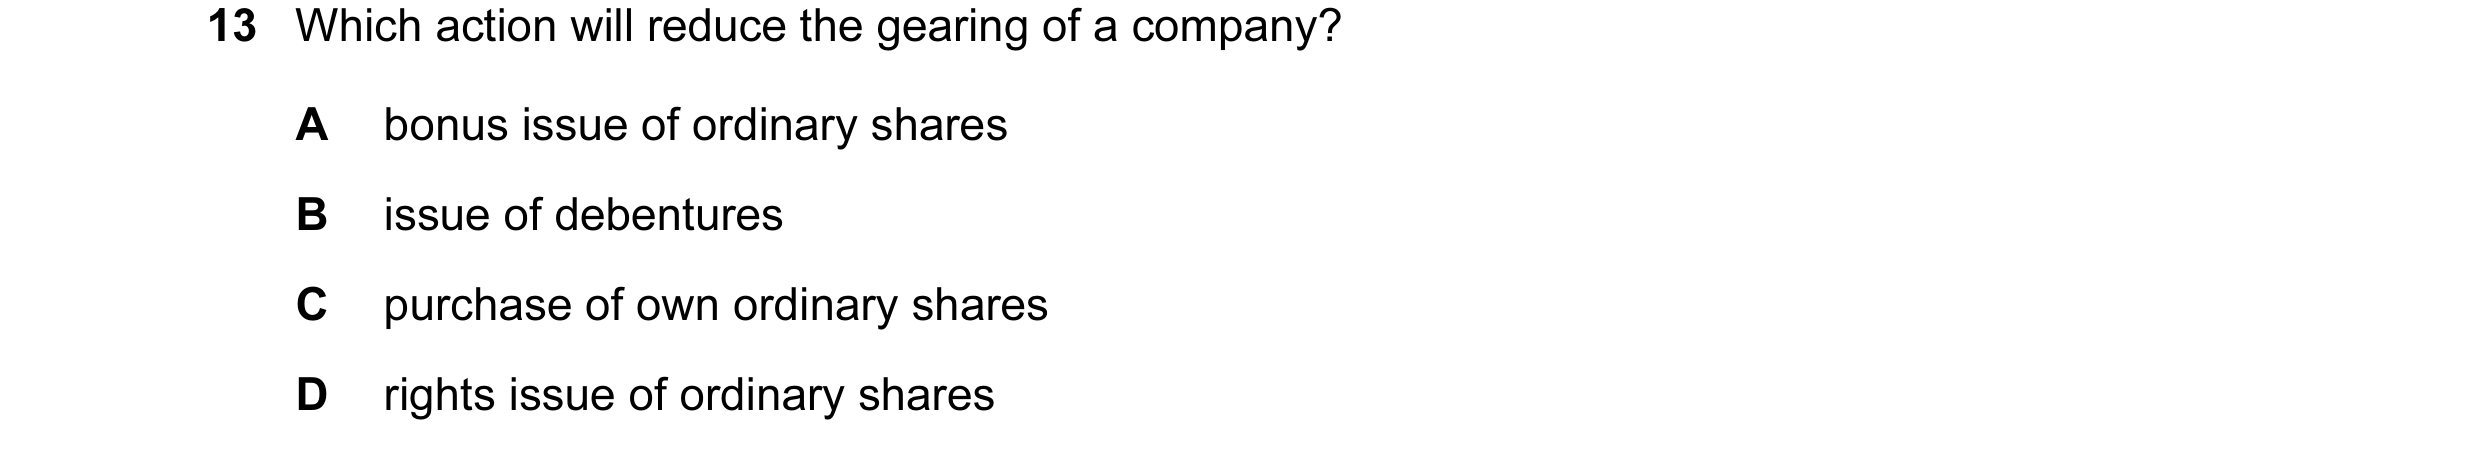
14 Which action will reduce the gearing of a company? A bonus issue of ordinary shares B issue of debentures C purchase of own ordinary shares D rights issue of ordinary shares
1 marks
Answer: D
This question in 9706/31 May/June 2010
Q15 · A company calculated its gearing as loan capital plus bank and other borrowings as a… 9706/31 May/June 2010
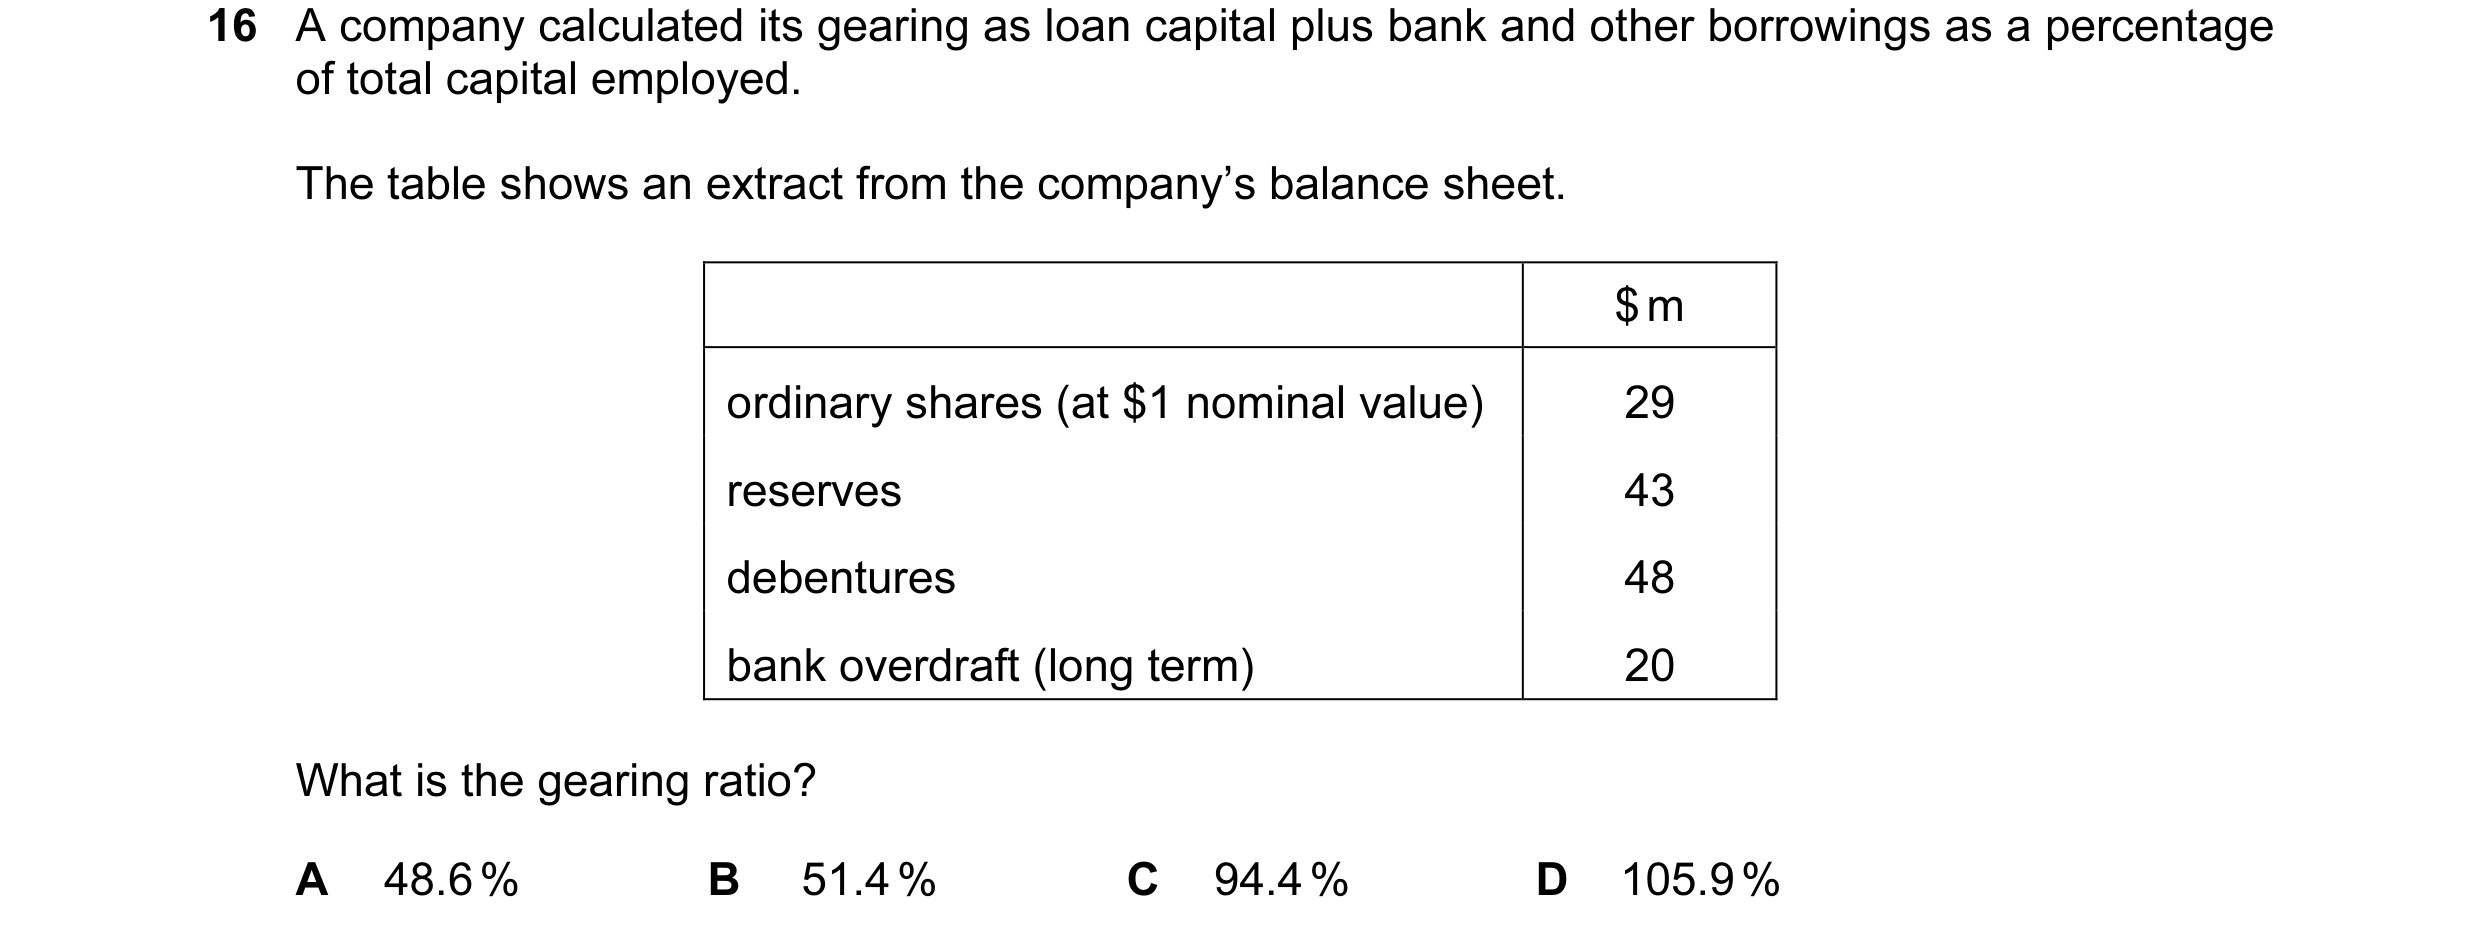
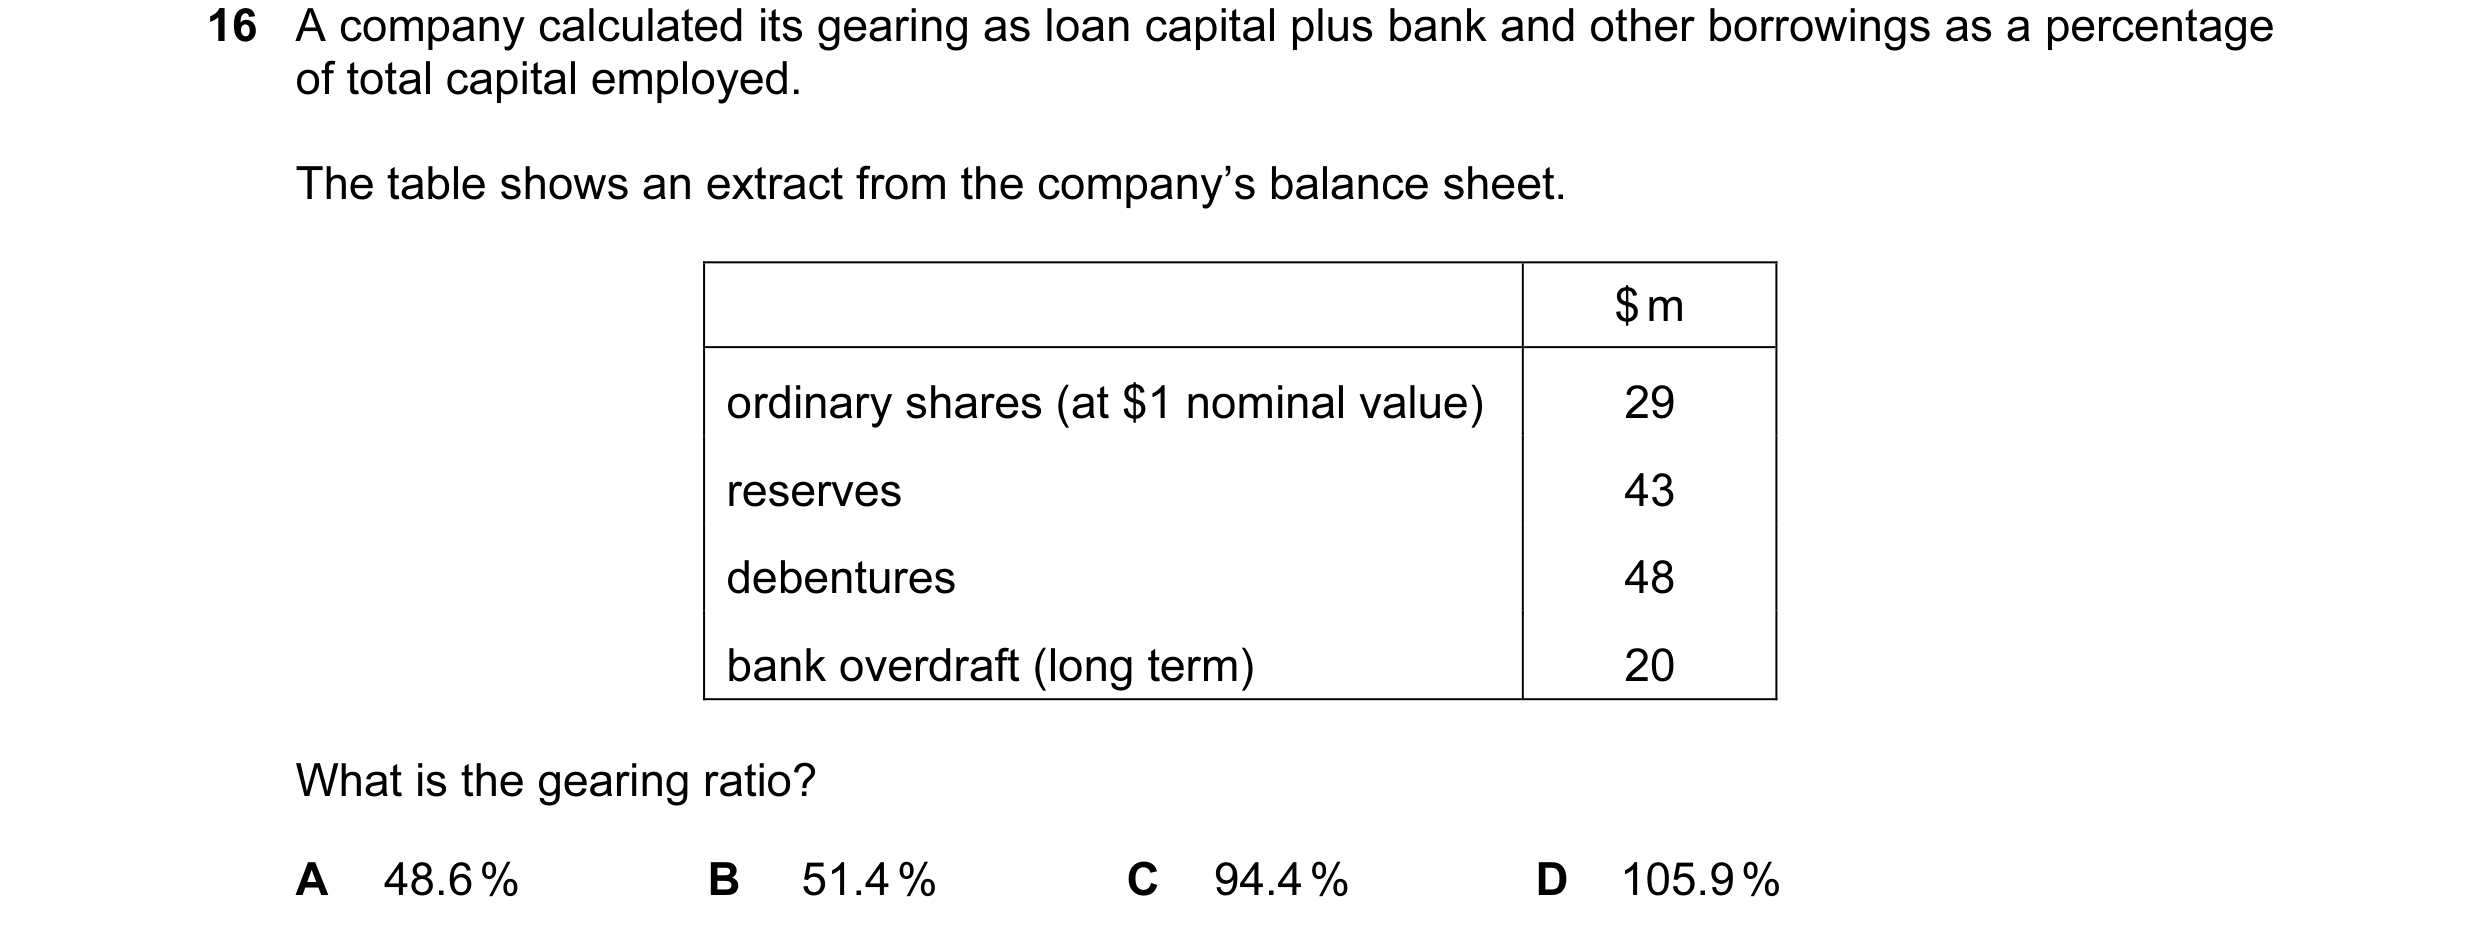
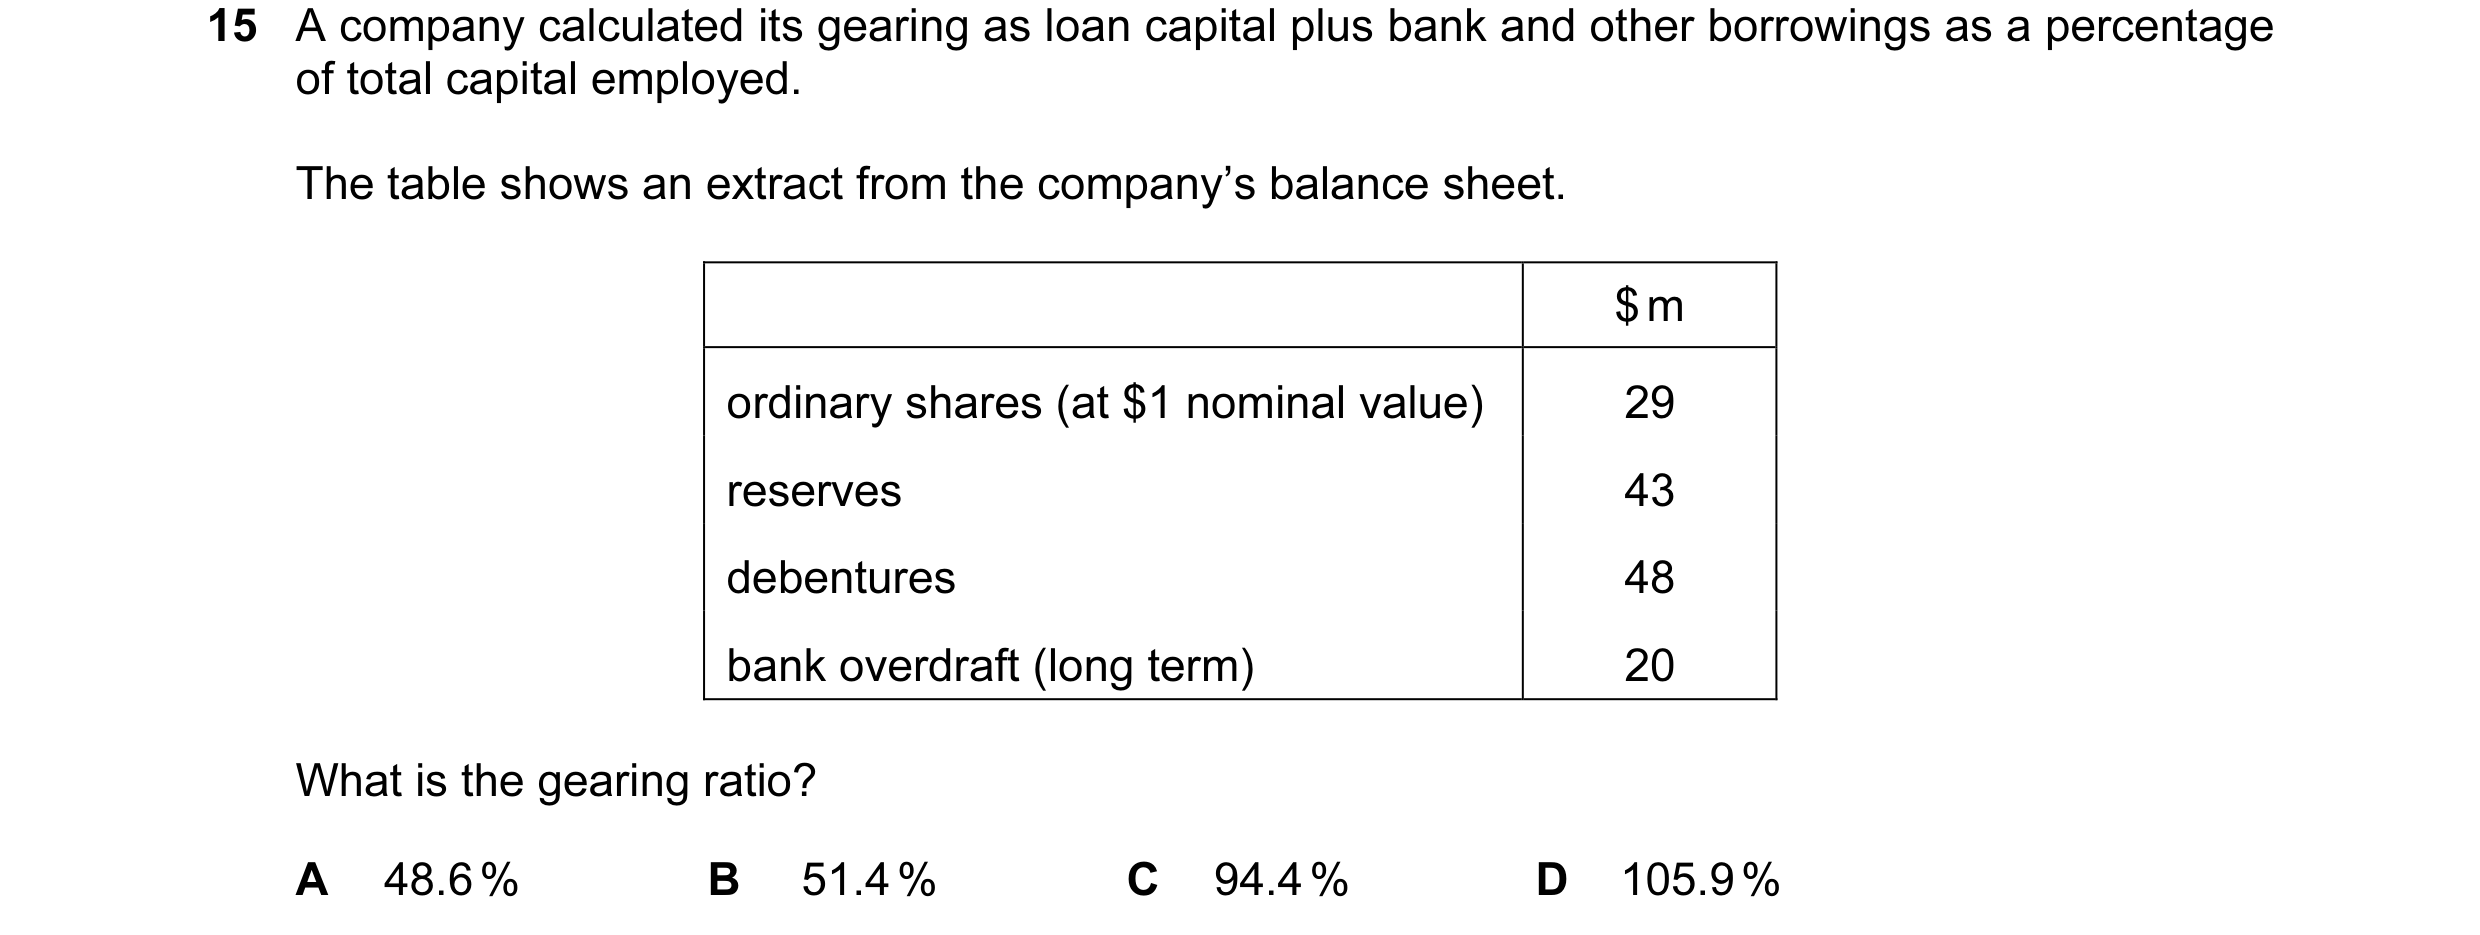
16 A company calculated its gearing as loan capital plus bank and other borrowings as a percentage of total capital employed. The table shows an extract from the company’s balance sheet. $ m ordinary shares (at $1 nominal value) 29 reserves 43 debentures 48 bank overdraft (long term) 20 What is the gearing ratio? A 48.6 % B 51.4 % C 94.4 % D 105.9 %
1 marks
Answer: A
This question in 9706/31 May/June 2010
Q16 · The financial statements of a company for the year to 30 June includes the following 9706/32 May/June 2010
11 The financial statements of a company for the year to 30 June includes the following. Income (profit and loss) account $m operating profits 109 interest payable 14 profit before tax 95 taxation 25 profit after tax 70 dividends paid 38 retained profit for year 32 Balance sheet $m ordinary shares ($0.50 each) in issue 150 income statement (profit and loss account) 160 shareholders funds 310 What are the earnings per share for the year? A 22.6 cents B 23.3 cents C 31.7 cents D 46.7 cents
1 marks
Answer: B
This question in 9706/32 May/June 2010
Q17 · A company has an issued share capital of 50 000 $1 ordinary shares 9706/32 May/June 2010
12 A company has an issued share capital of 50 000 $1 ordinary shares. Profits for distribution average $20 000 per annum. The expected rate of return on shares in similar companies is 25 %. What are the 50 000 shares worth? A $32 500 B $50 000 C $62 500 D $80 000
1 marks
Answer: D
This question in 9706/32 May/June 2010
Q18 · The following investment information is available 9706/32 May/June 2010
13 The following investment information is available. $ earnings per share 0.35 dividend per share 0.21 market price per share 1.40 nominal value per share 1.00 What is the percentage return to an investor who buys a share? A 15 % B 21 % C 25 % D 35 %
1 marks
Answer: A
This question in 9706/32 May/June 2010
Q19 · Which action will reduce the gearing of a company? 9706/32 May/June 2010
14 Which action will reduce the gearing of a company? A bonus issue of ordinary shares B issue of debentures C purchase of own ordinary shares D rights issue of ordinary shares
1 marks
Answer: D
This question in 9706/32 May/June 2010
Q20 · A company calculated its gearing as loan capital plus bank and other borrowings as a… 9706/32 May/June 2010
16 A company calculated its gearing as loan capital plus bank and other borrowings as a percentage of total capital employed. The table shows an extract from the company’s balance sheet. $ m ordinary shares (at $1 nominal value) 29 reserves 43 debentures 48 bank overdraft (long term) 20 What is the gearing ratio? A 48.6 % B 51.4 % C 94.4 % D 105.9 %
1 marks
Answer: A
This question in 9706/32 May/June 2010
Q21 · The financial statements of a company for the year to 30 June includes the following 9706/33 May/June 2010
10 The financial statements of a company for the year to 30 June includes the following. Income (profit and loss) account $m operating profits 109 interest payable 14 profit before tax 95 taxation 25 profit after tax 70 dividends paid 38 retained profit for year 32 Balance sheet $m ordinary shares ($0.50 each) in issue 150 income statement (profit and loss account) 160 shareholders funds 310 What are the earnings per share for the year? A 22.6 cents B 23.3 cents C 31.7 cents D 46.7 cents
1 marks
Answer: B
This question in 9706/33 May/June 2010
Q22 · A company has an issued share capital of 50 000 $1 ordinary shares 9706/33 May/June 2010
11 A company has an issued share capital of 50 000 $1 ordinary shares. Profits for distribution average $20 000 per annum. The expected rate of return on shares in similar companies is 25 %. What are the 50 000 shares worth? A $32 500 B $50 000 C $62 500 D $80 000
1 marks
Answer: D
This question in 9706/33 May/June 2010
Q23 · Which action will reduce the gearing of a company? 9706/33 May/June 2010
13 Which action will reduce the gearing of a company? A bonus issue of ordinary shares B issue of debentures C purchase of own ordinary shares D rights issue of ordinary shares
1 marks
Answer: D
This question in 9706/33 May/June 2010
Q24 · A company calculated its gearing as loan capital plus bank and other borrowings as a… 9706/33 May/June 2010
15 A company calculated its gearing as loan capital plus bank and other borrowings as a percentage of total capital employed. The table shows an extract from the company’s balance sheet. $ m ordinary shares (at $1 nominal value) 29 reserves 43 debentures 48 bank overdraft (long term) 20 What is the gearing ratio? A 48.6 % B 51.4 % C 94.4 % D 105.9 %
1 marks
Answer: A
This question in 9706/33 May/June 2010
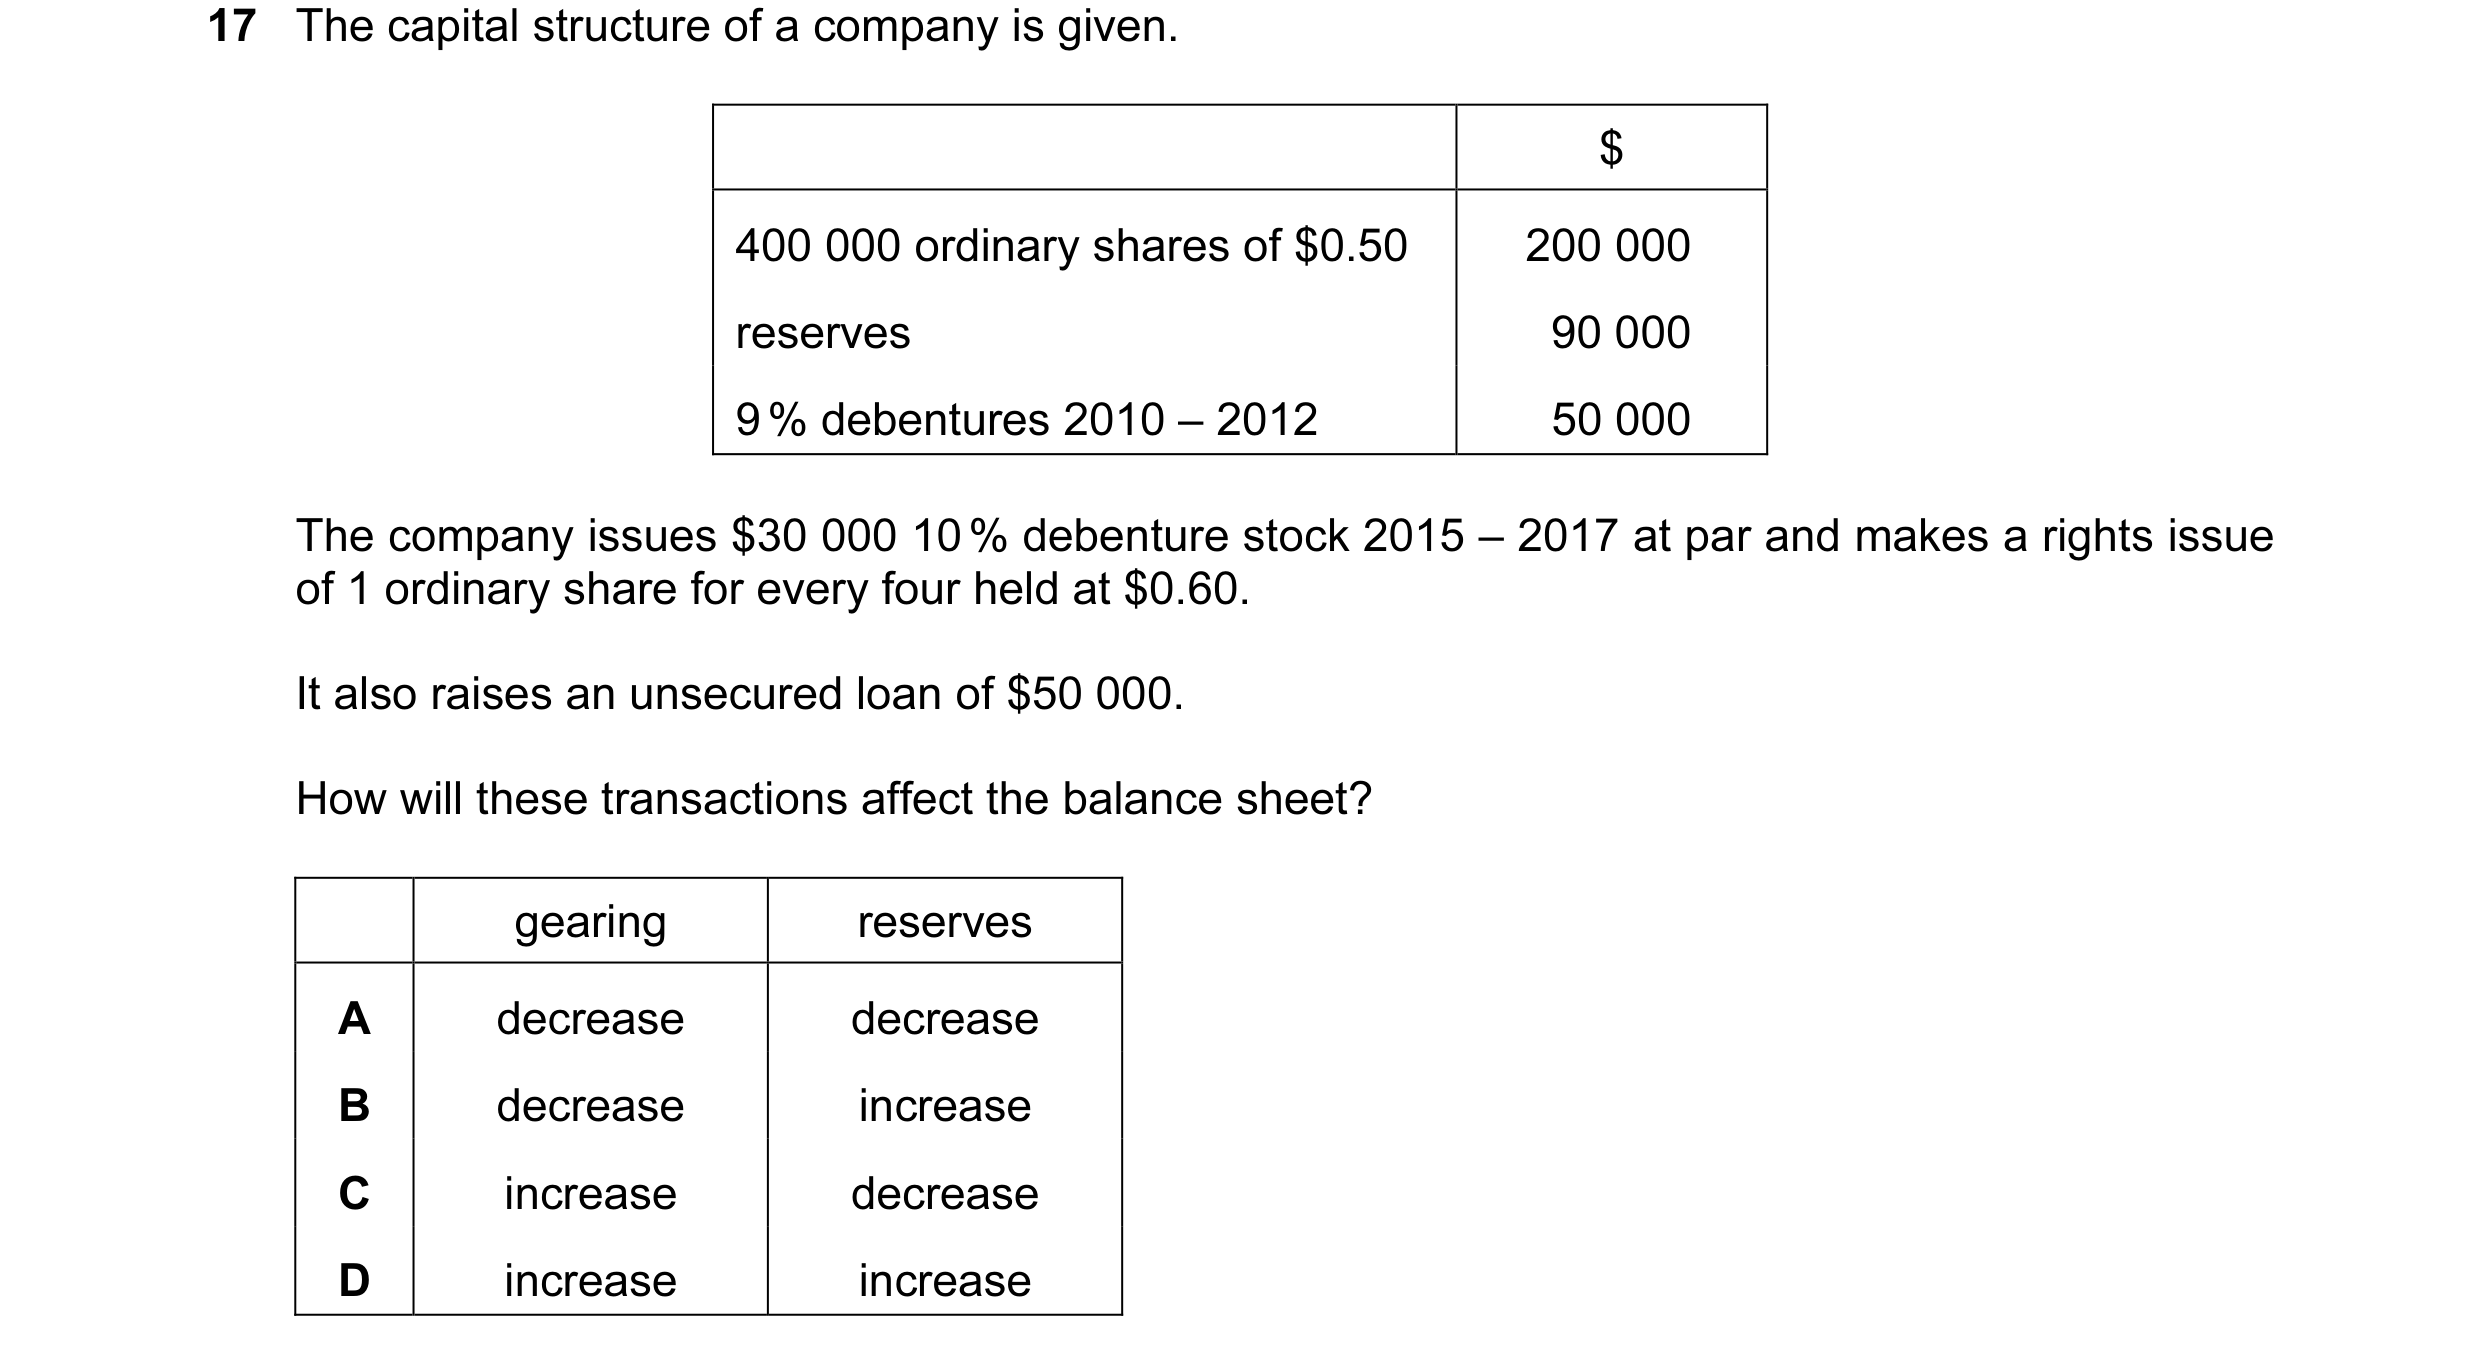
Q25 · The capital structure of a company is given 9706/31 Oct/Nov 2010
17 The capital structure of a company is given. $ 400 000 ordinary shares of $0.50 200 000 reserves 90 000 9 % debentures 2010 – 2012 50 000 The company issues $30 000 10 % debenture stock 2015 – 2017 at par and makes a rights issue of 1 ordinary share for every four held at $0.60. It also raises an unsecured loan of $50 000. How will these transactions affect the balance sheet? gearing reserves A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2010
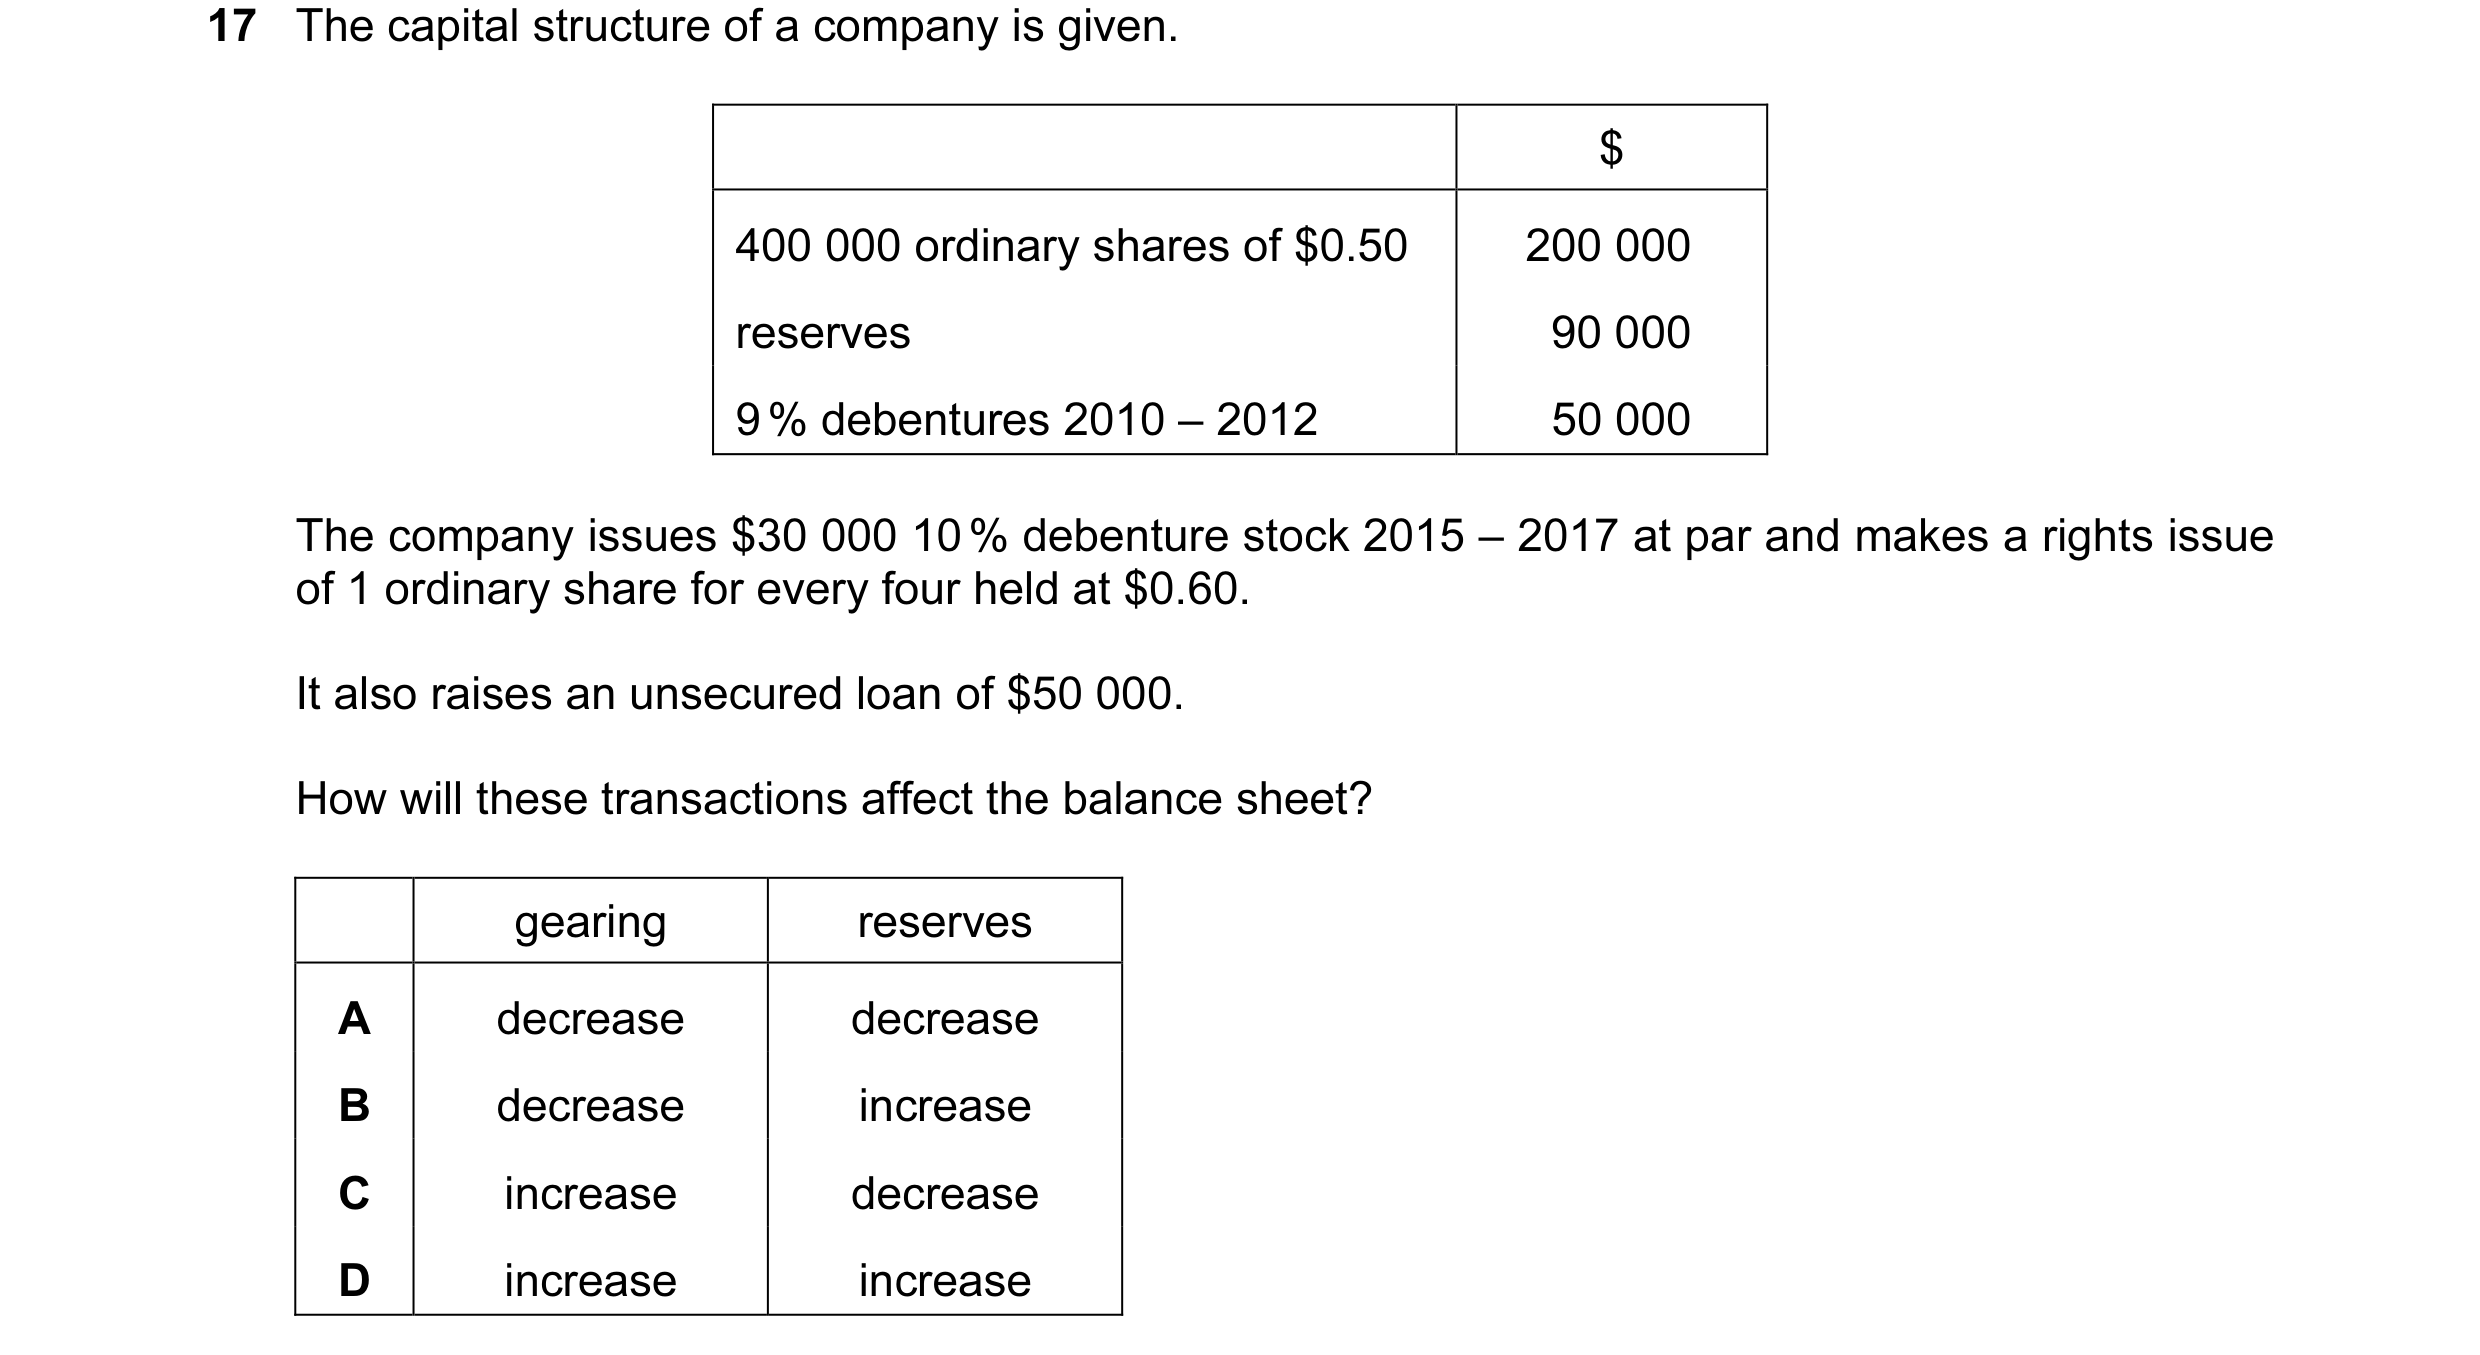
Q26 · The capital structure of a company is given 9706/32 Oct/Nov 2010
17 The capital structure of a company is given. $ 400 000 ordinary shares of $0.50 200 000 reserves 90 000 9 % debentures 2010 – 2012 50 000 The company issues $30 000 10 % debenture stock 2015 – 2017 at par and makes a rights issue of 1 ordinary share for every four held at $0.60. It also raises an unsecured loan of $50 000. How will these transactions affect the balance sheet? gearing reserves A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2010
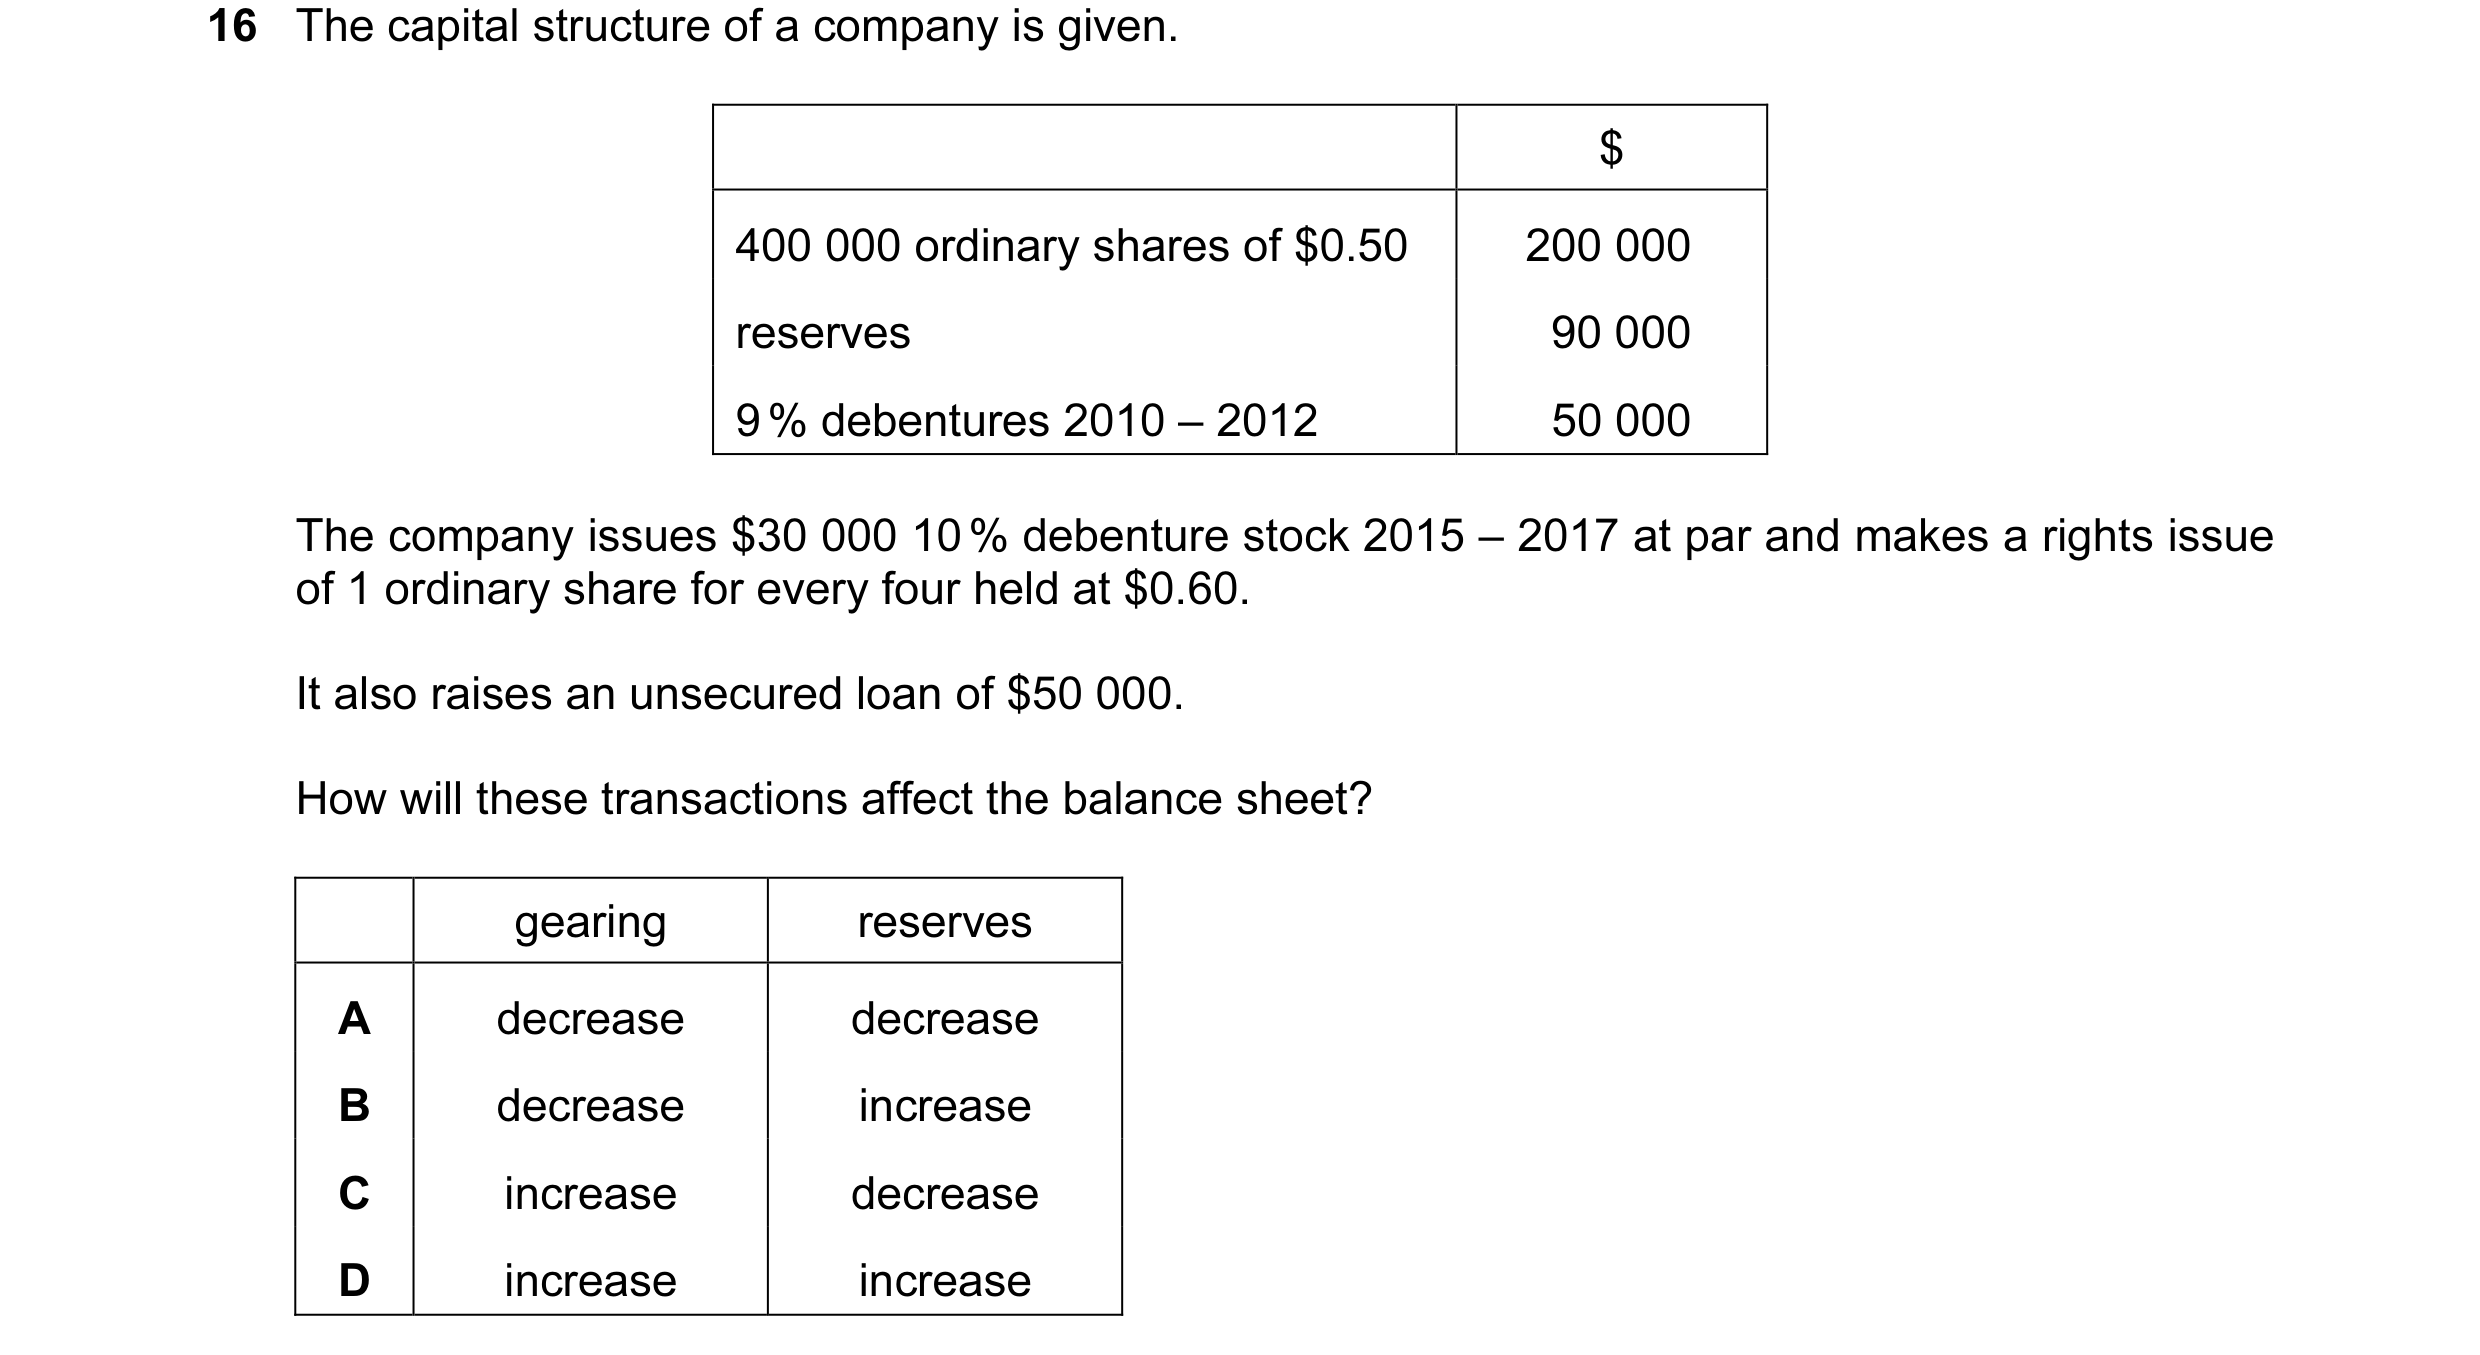
Q27 · The capital structure of a company is given 9706/33 Oct/Nov 2010
16 The capital structure of a company is given. $ 400 000 ordinary shares of $0.50 200 000 reserves 90 000 9 % debentures 2010 – 2012 50 000 The company issues $30 000 10 % debenture stock 2015 – 2017 at par and makes a rights issue of 1 ordinary share for every four held at $0.60. It also raises an unsecured loan of $50 000. How will these transactions affect the balance sheet? gearing reserves A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: D
This question in 9706/33 Oct/Nov 2010
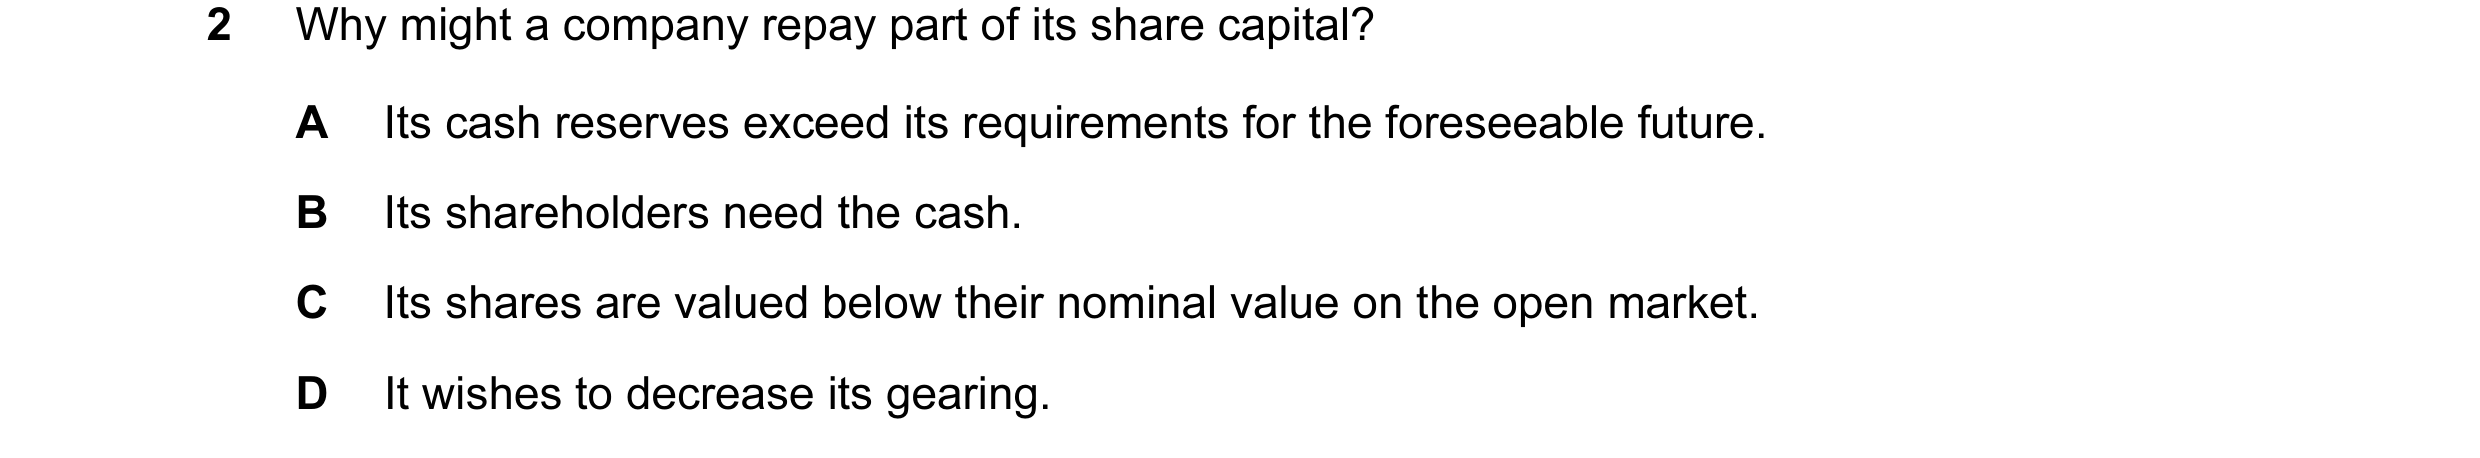
Q28 · Why might a company repay part of its share capital? 9706/31 May/June 2011
2 Why might a company repay part of its share capital? A Its cash reserves exceed its requirements for the foreseeable future. B Its shareholders need the cash. C Its shares are valued below their nominal value on the open market. D It wishes to decrease its gearing.
1 marks
Answer: A
This question in 9706/31 May/June 2011
Q29 · Why would convertible loan stock be issued by a company? 9706/31 May/June 2011
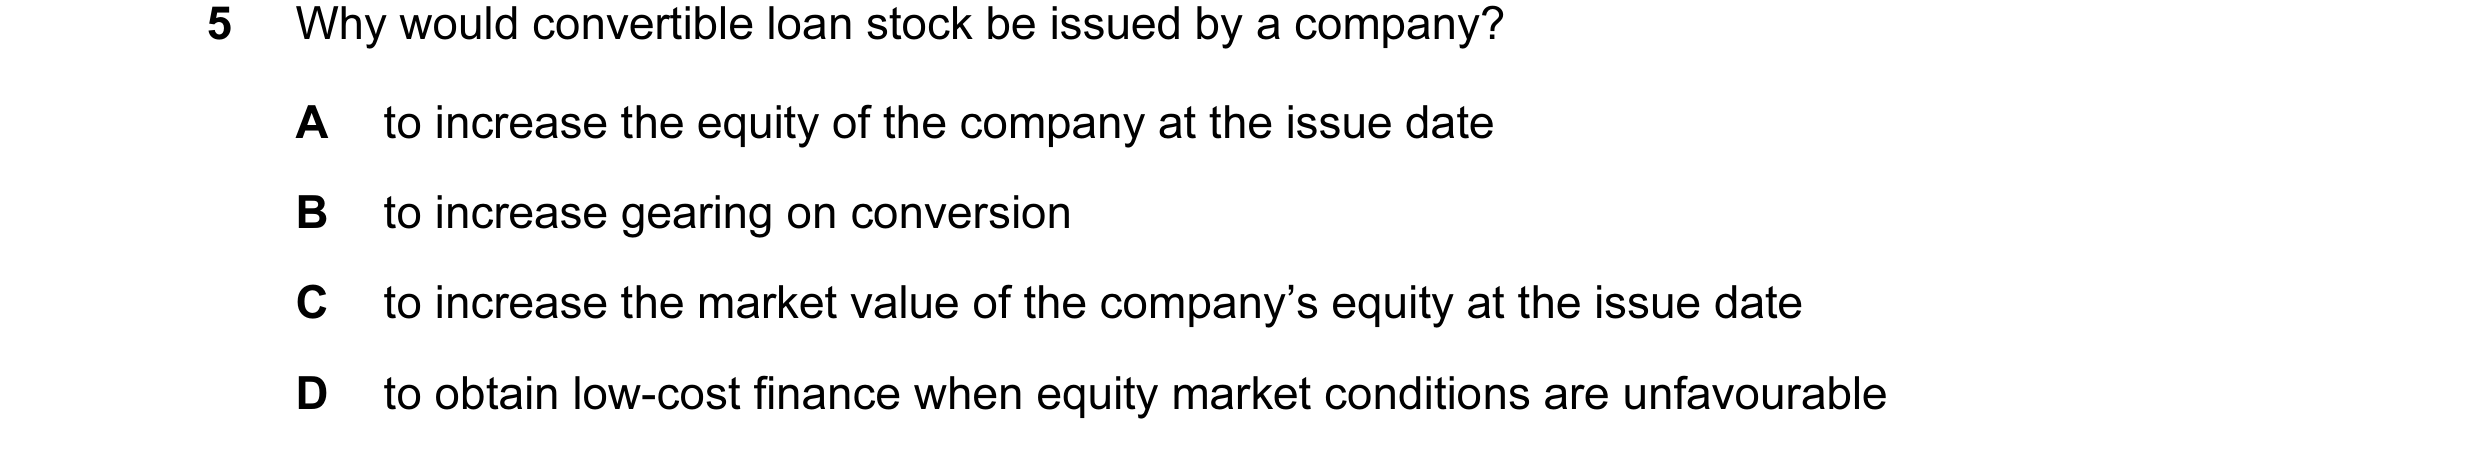
5 Why would convertible loan stock be issued by a company? A to increase the equity of the company at the issue date B to increase gearing on conversion C to increase the market value of the company’s equity at the issue date D to obtain low-cost finance when equity market conditions are unfavourable
1 marks
Answer: D
This question in 9706/31 May/June 2011
Q30 · A company has a return on capital employed of 20 % and an asset turnover of 2.5 times 9706/31 May/June 2011
13 A company has a return on capital employed of 20 % and an asset turnover of 2.5 times. What was the company’s net profit ratio? A 8 % B 16 % C 20 % D 50 %
1 marks
Answer: A
This question in 9706/31 May/June 2011
Q31 · The following is an extract from the statement of financial position of Zed Ltd 9706/31 May/June 2011
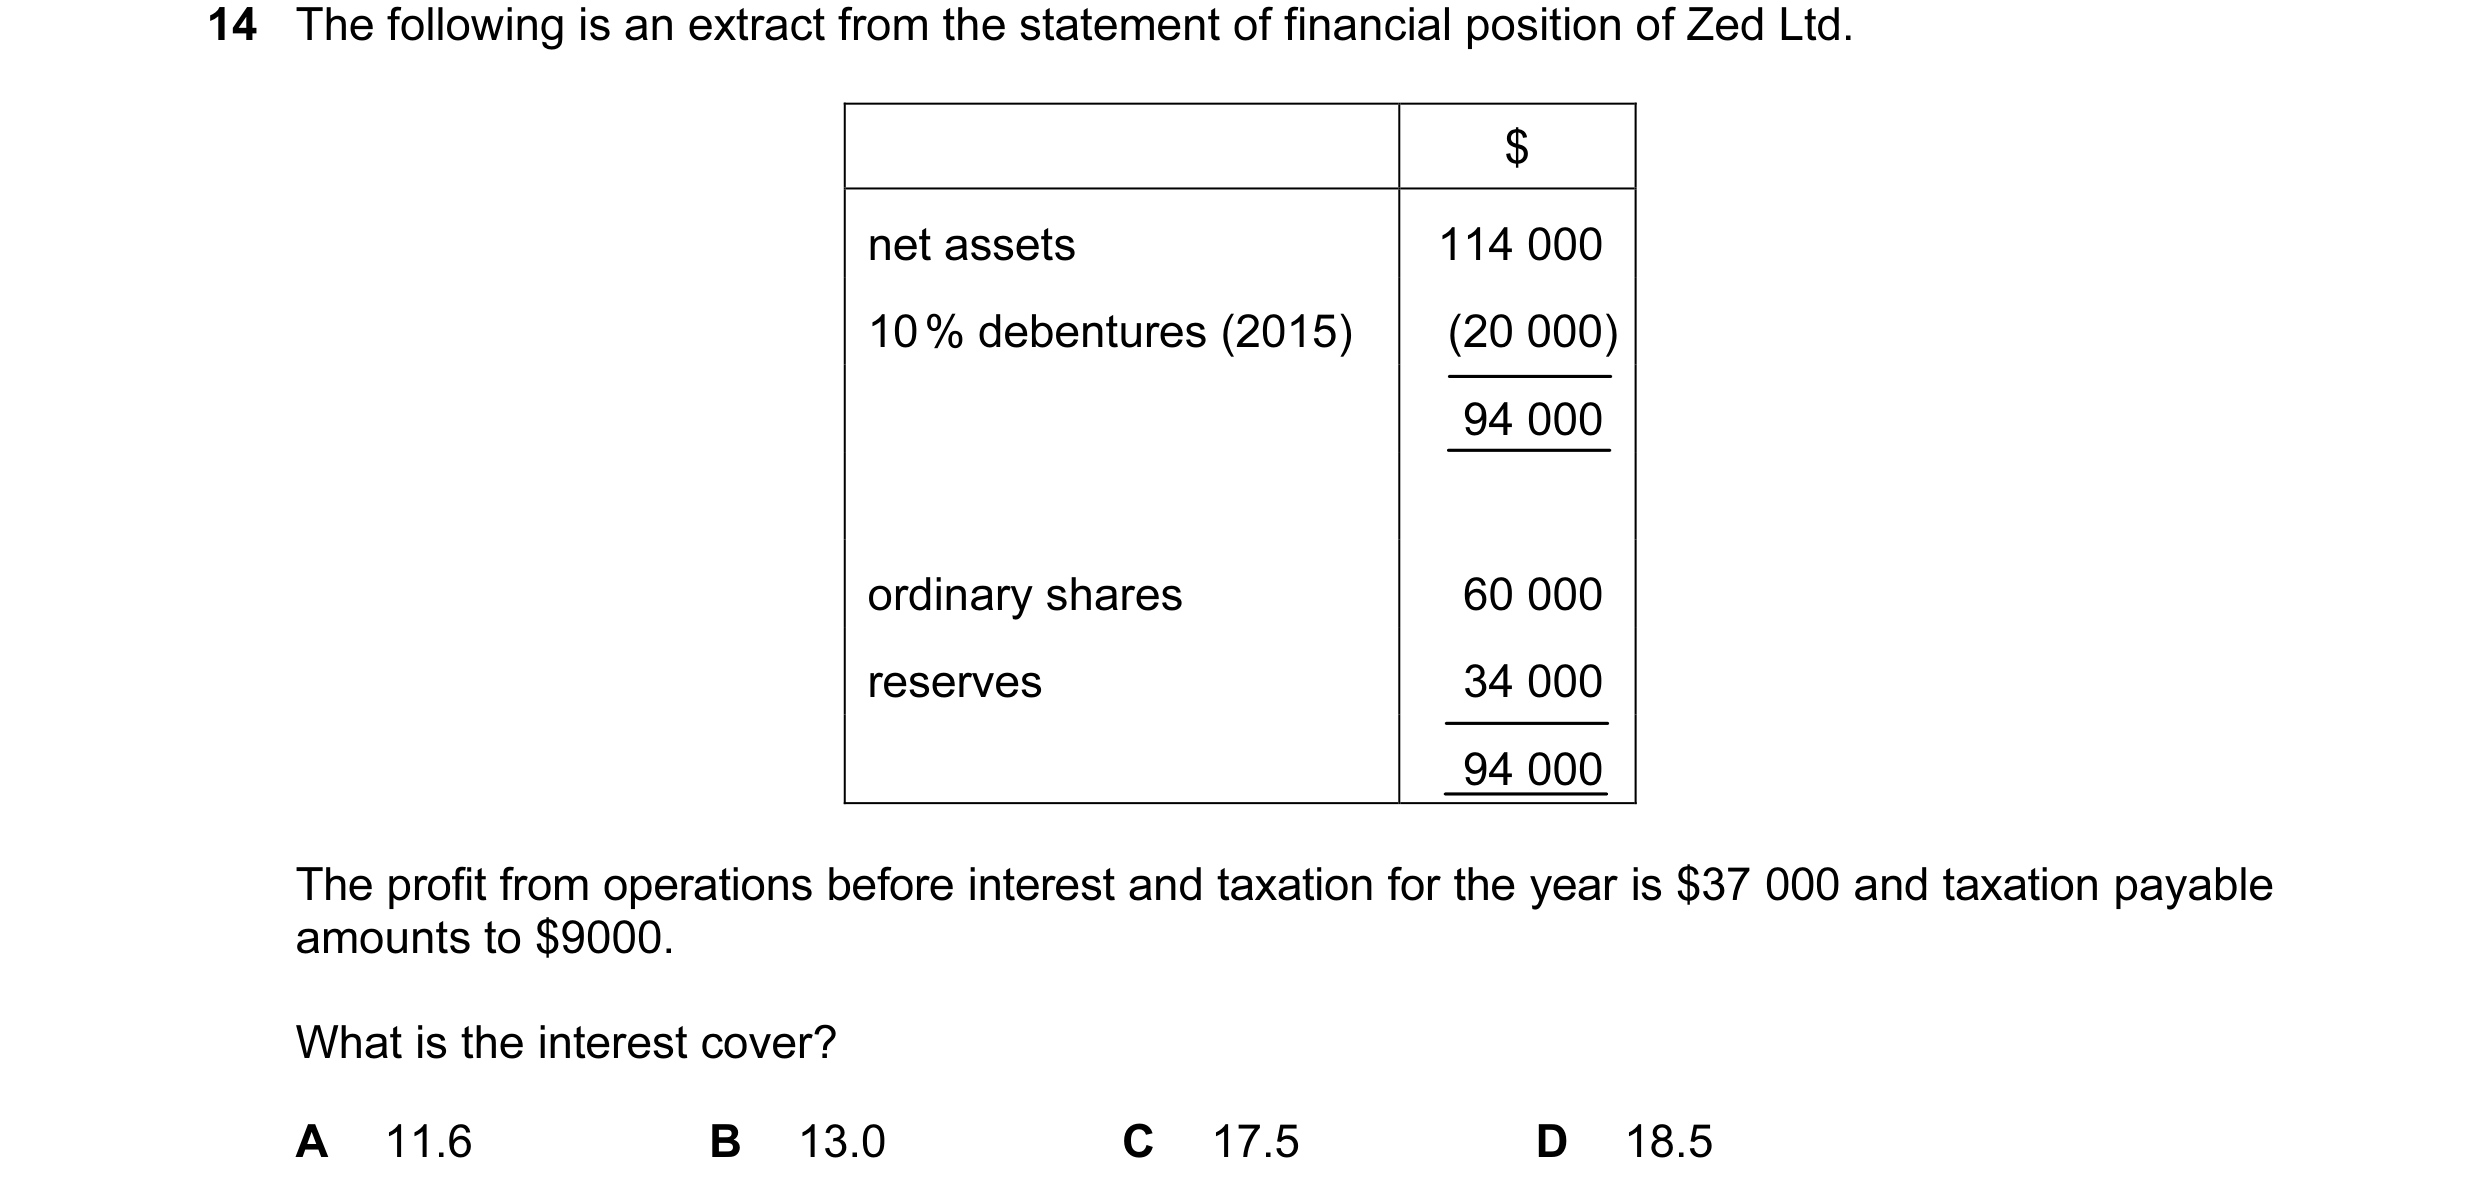
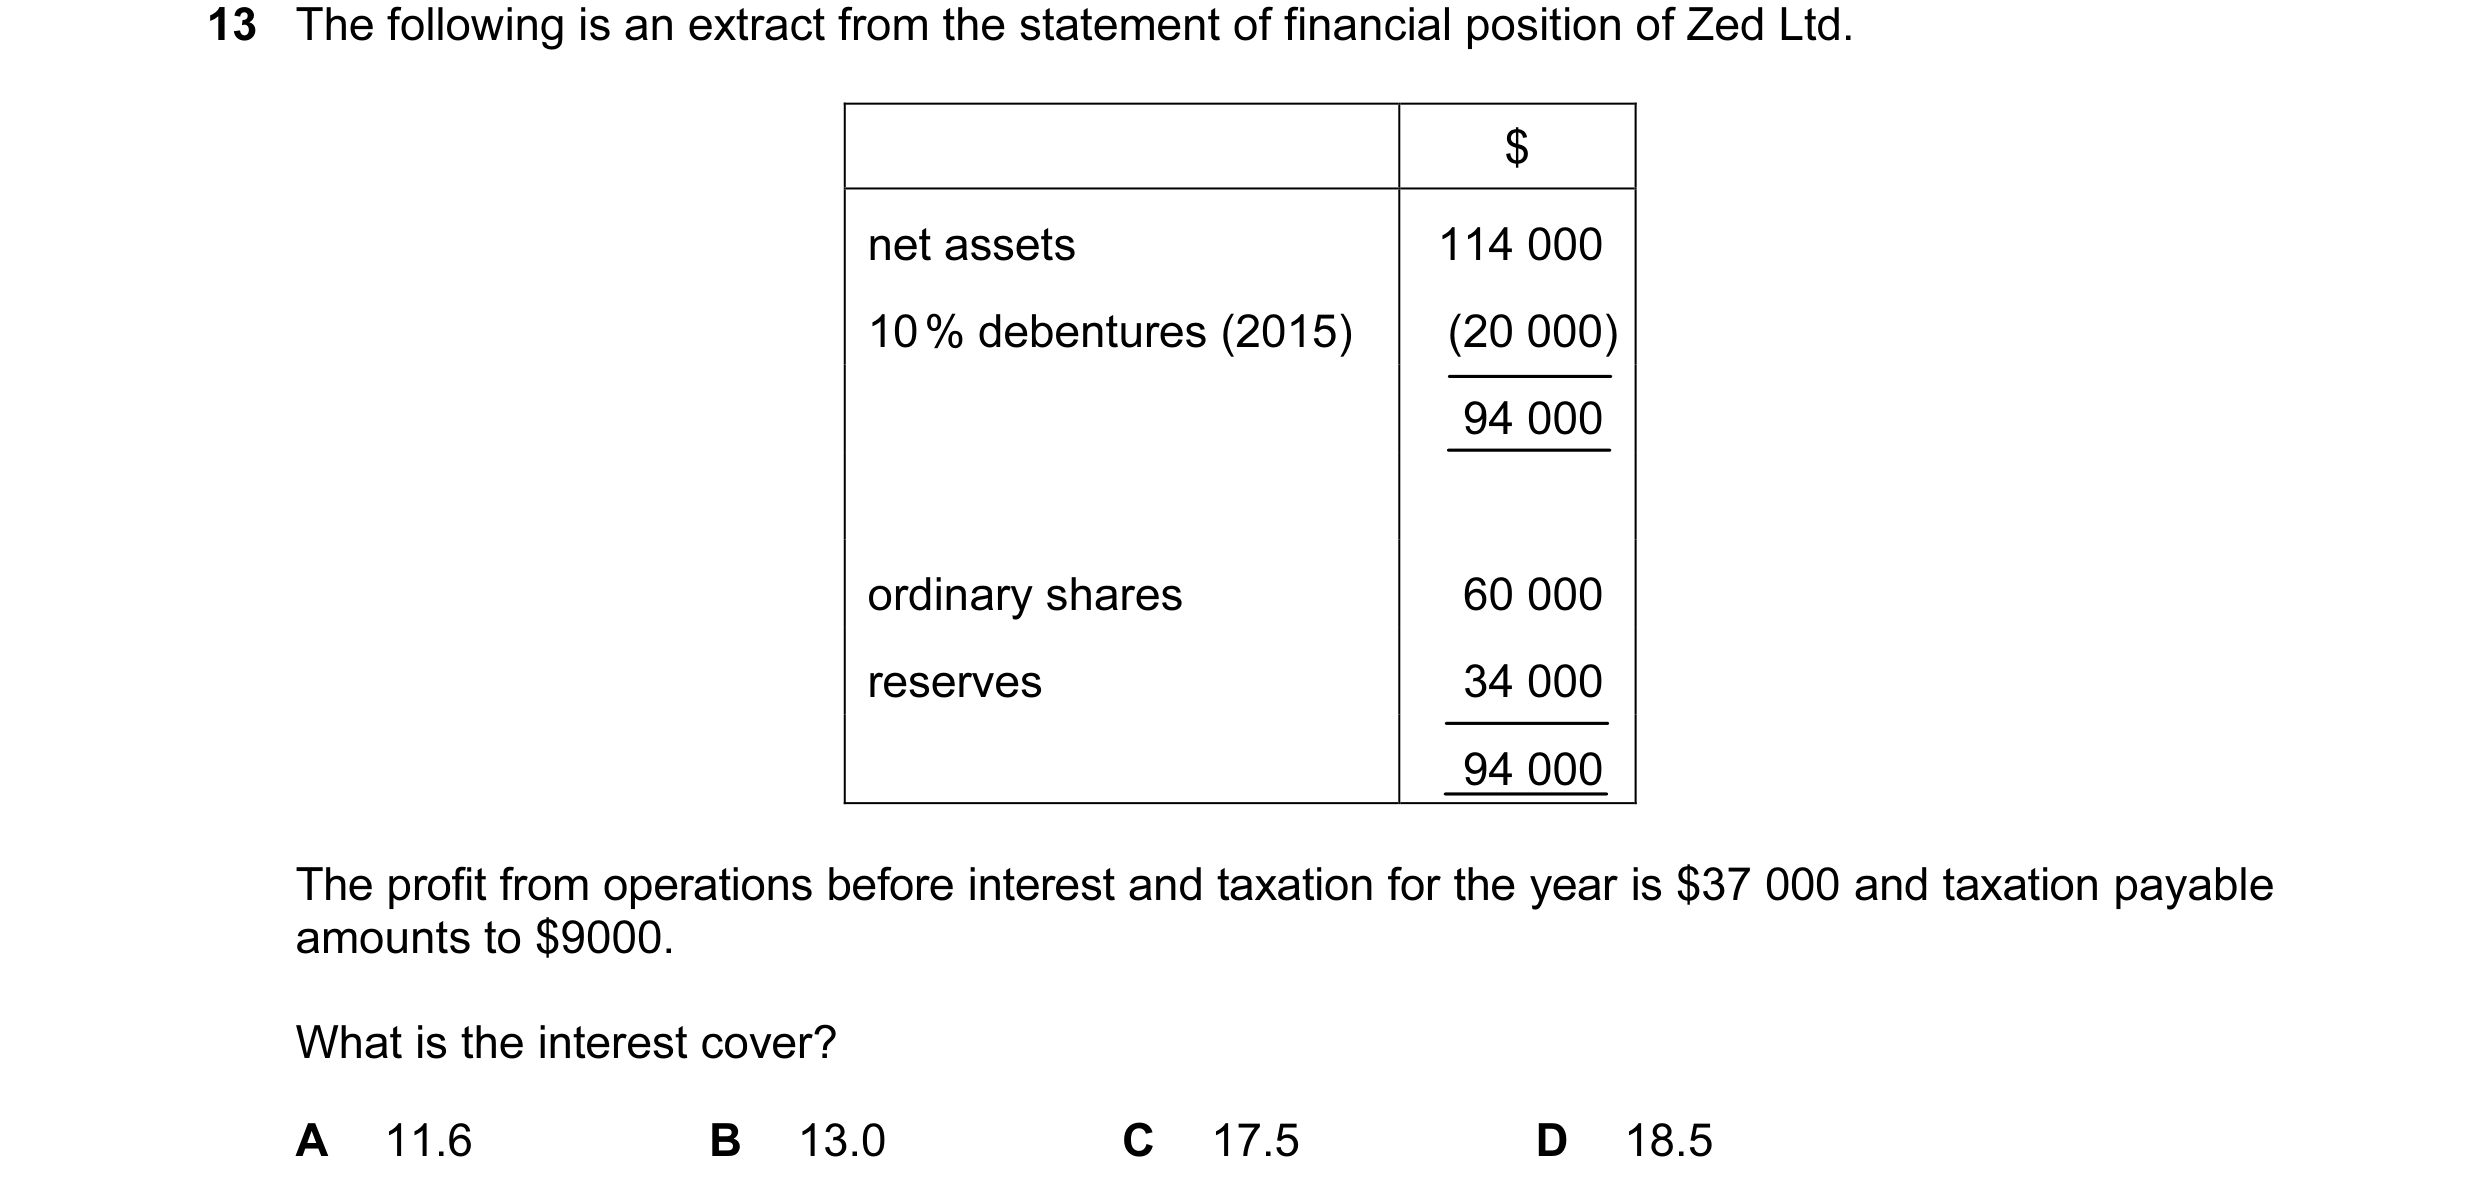
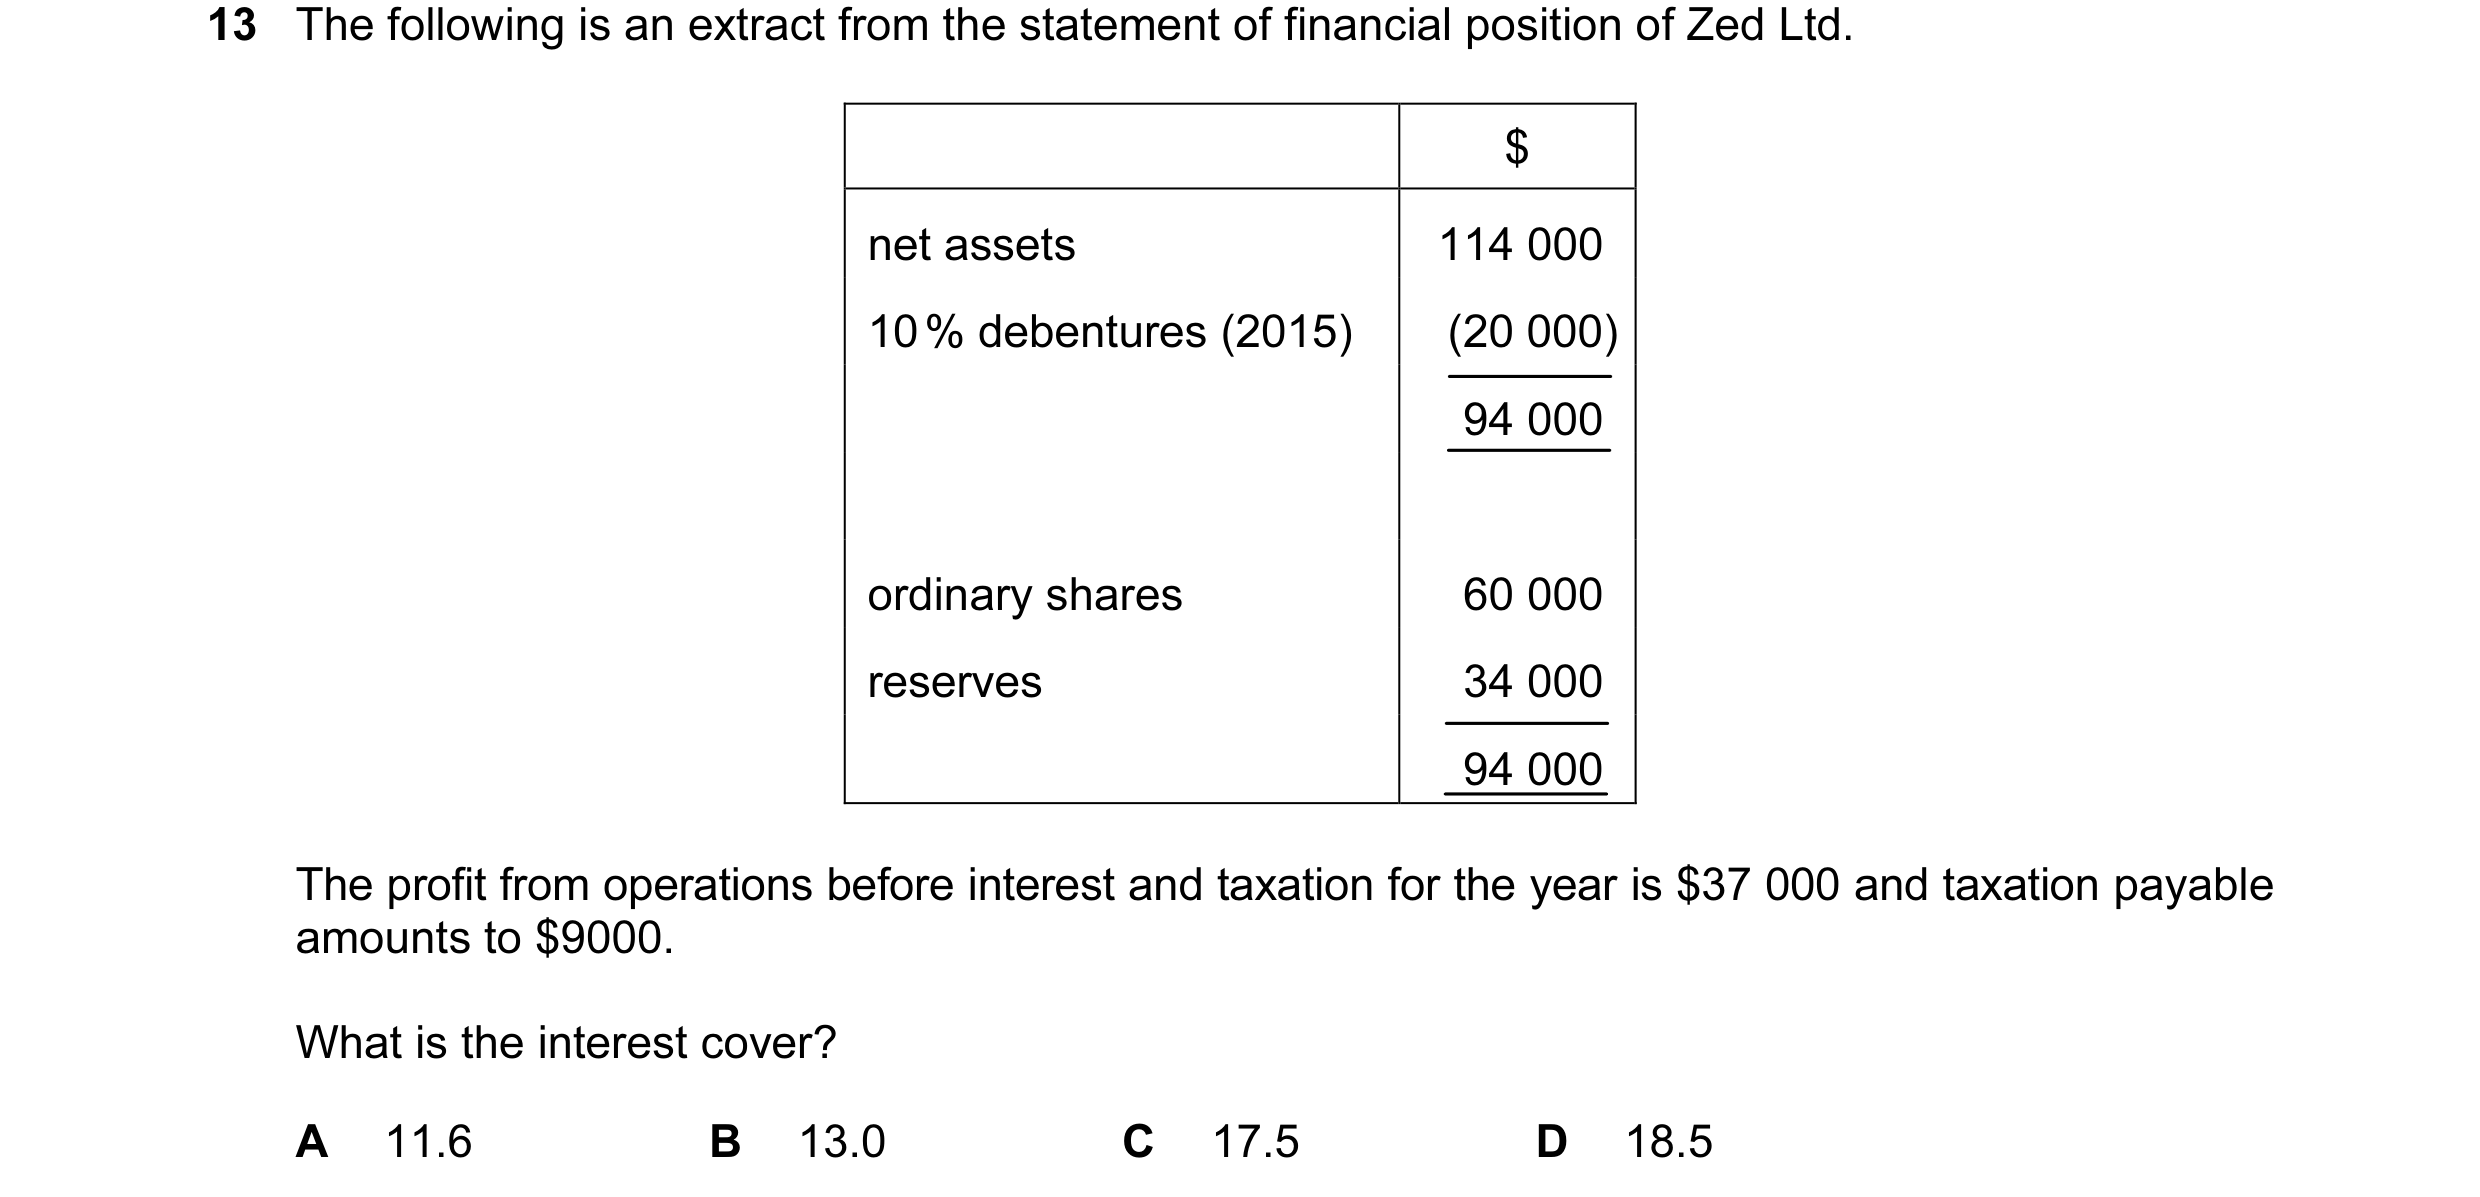
14 The following is an extract from the statement of financial position of Zed Ltd. $ net assets 114 000 10 % debentures (2015) (20 000) 94 000 ordinary shares 60 000 reserves 34 000 94 000 The profit from operations before interest and taxation for the year is $37 000 and taxation payable amounts to $9000. What is the interest cover? A 11.6 B 13.0 C 17.5 D 18.5
1 marks
Answer: D
This question in 9706/31 May/June 2011
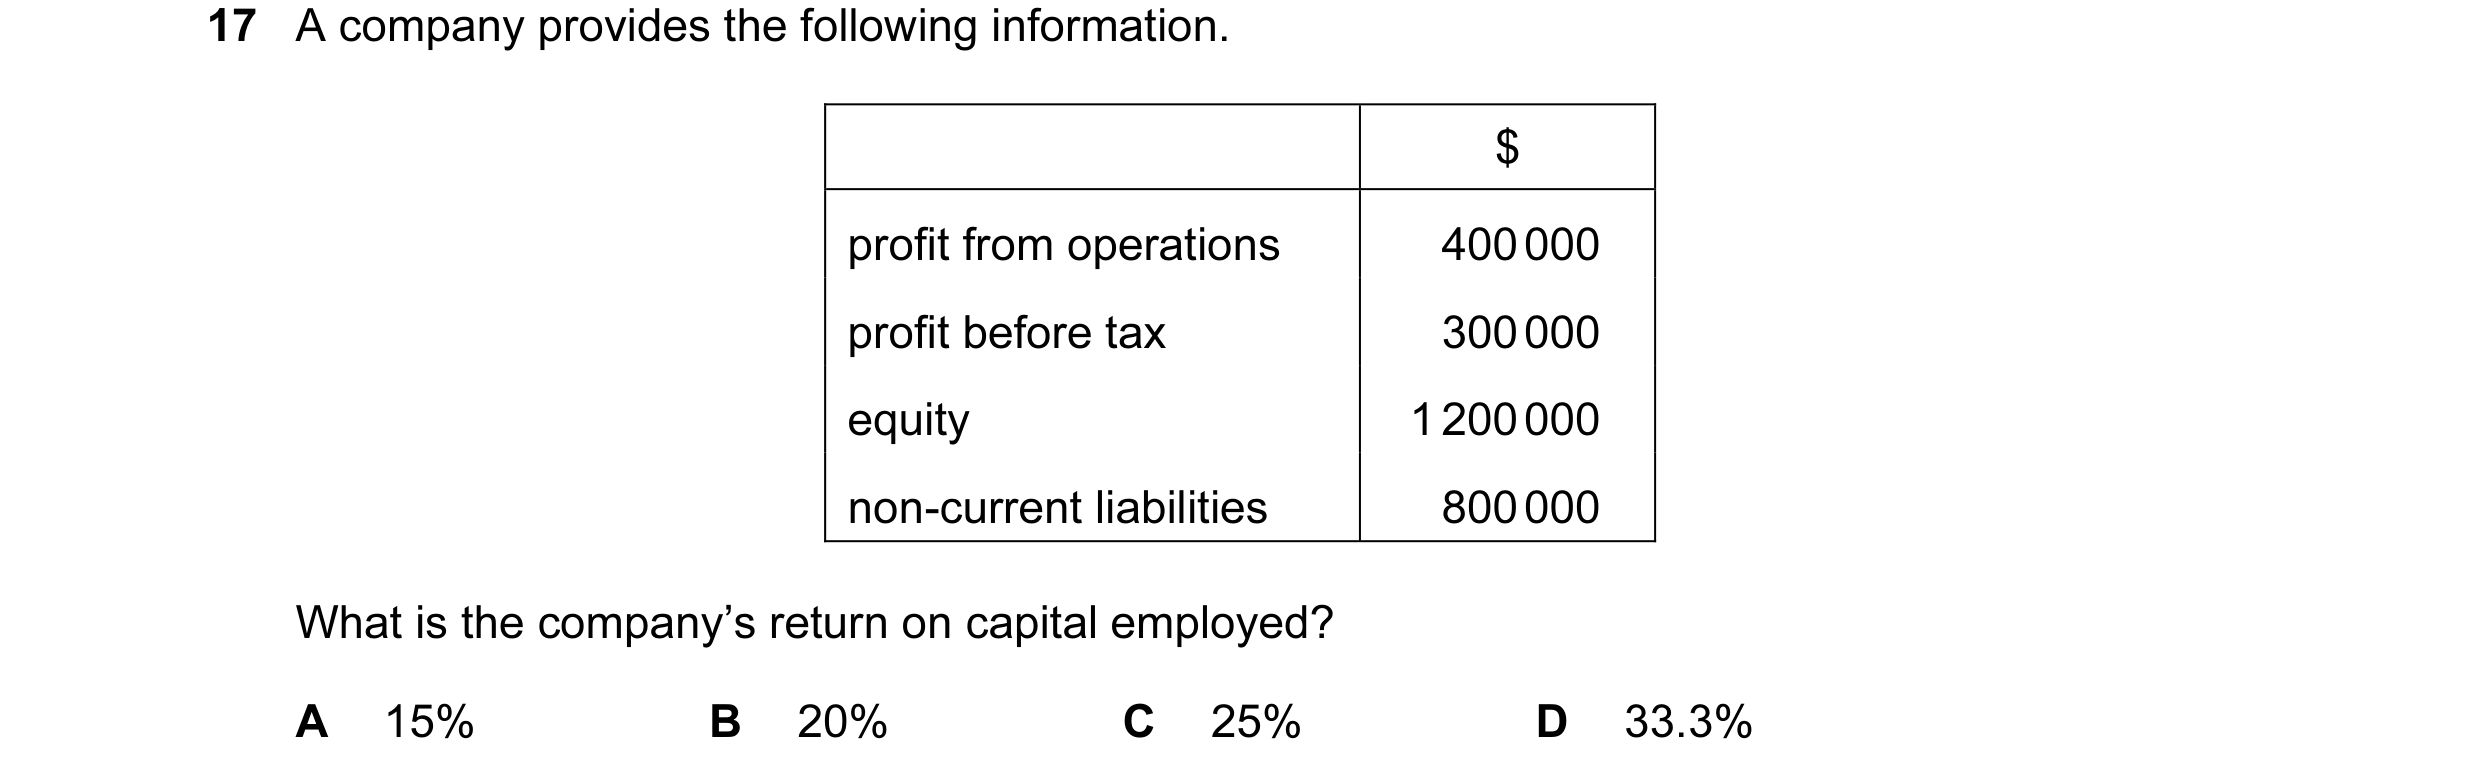
Q32 · A company has the following information 9706/31 May/June 2011
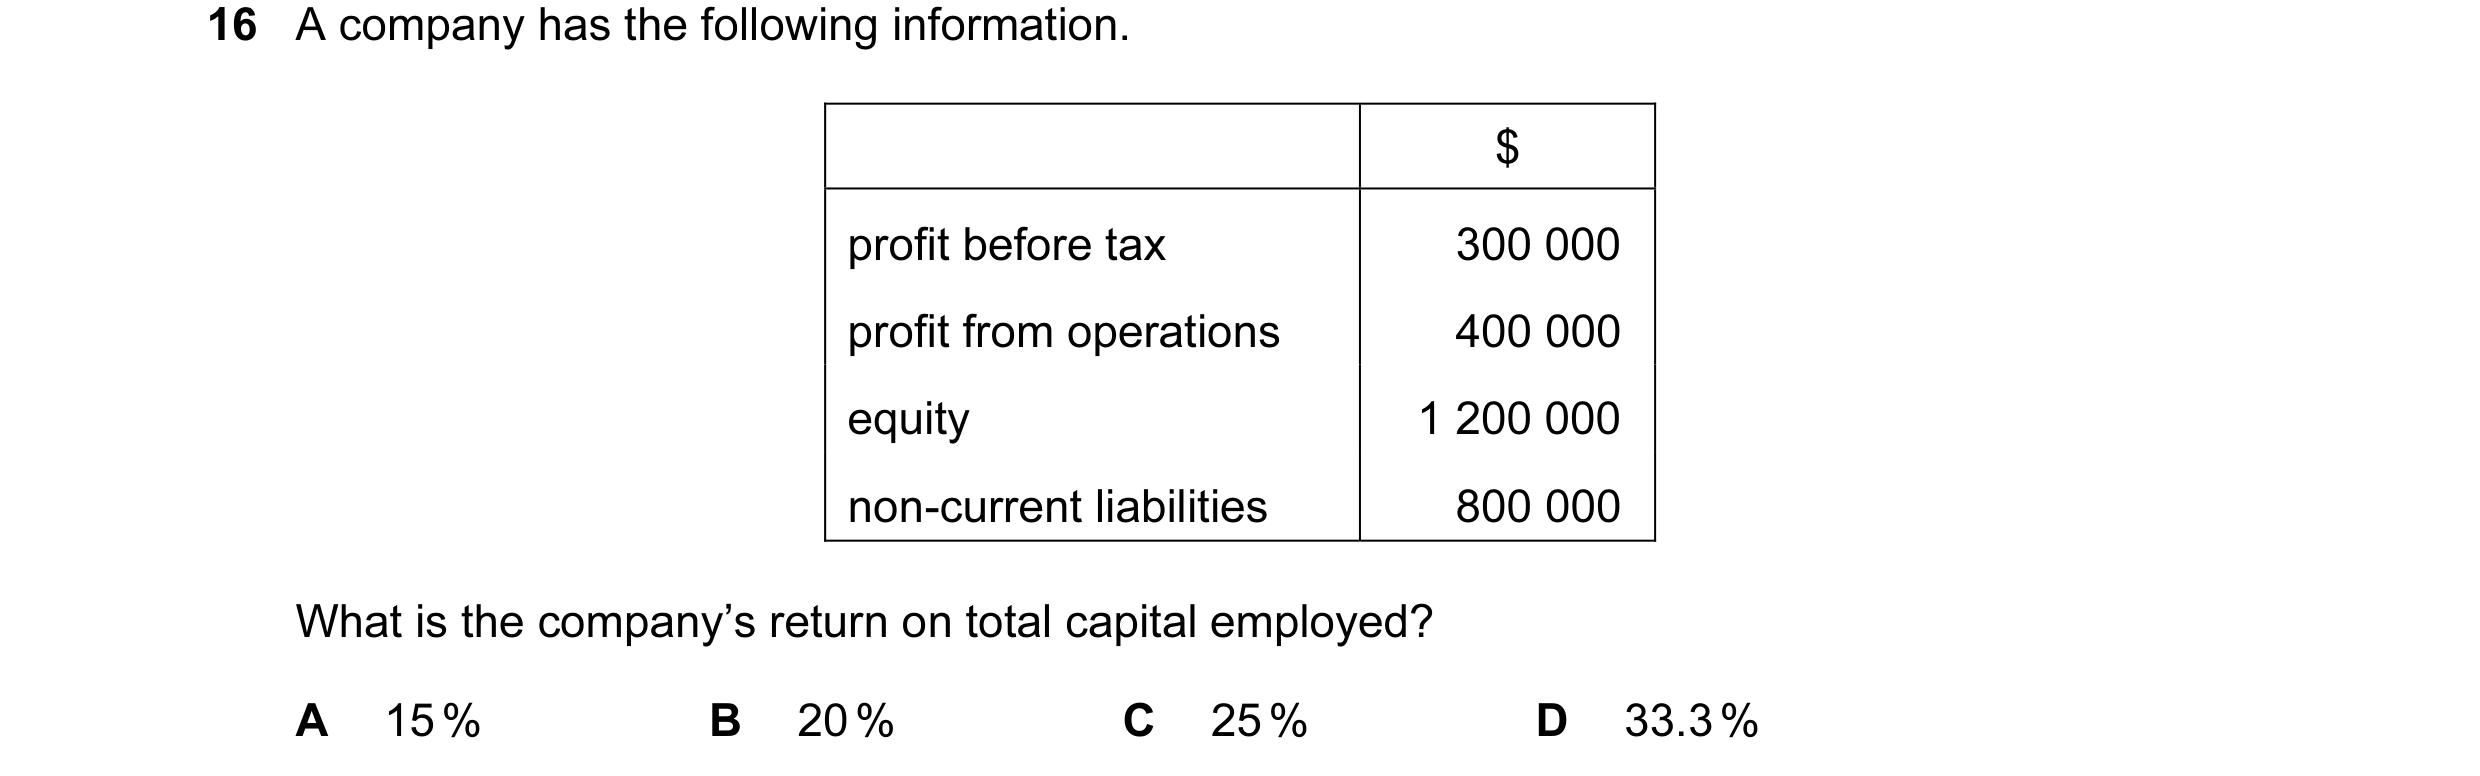
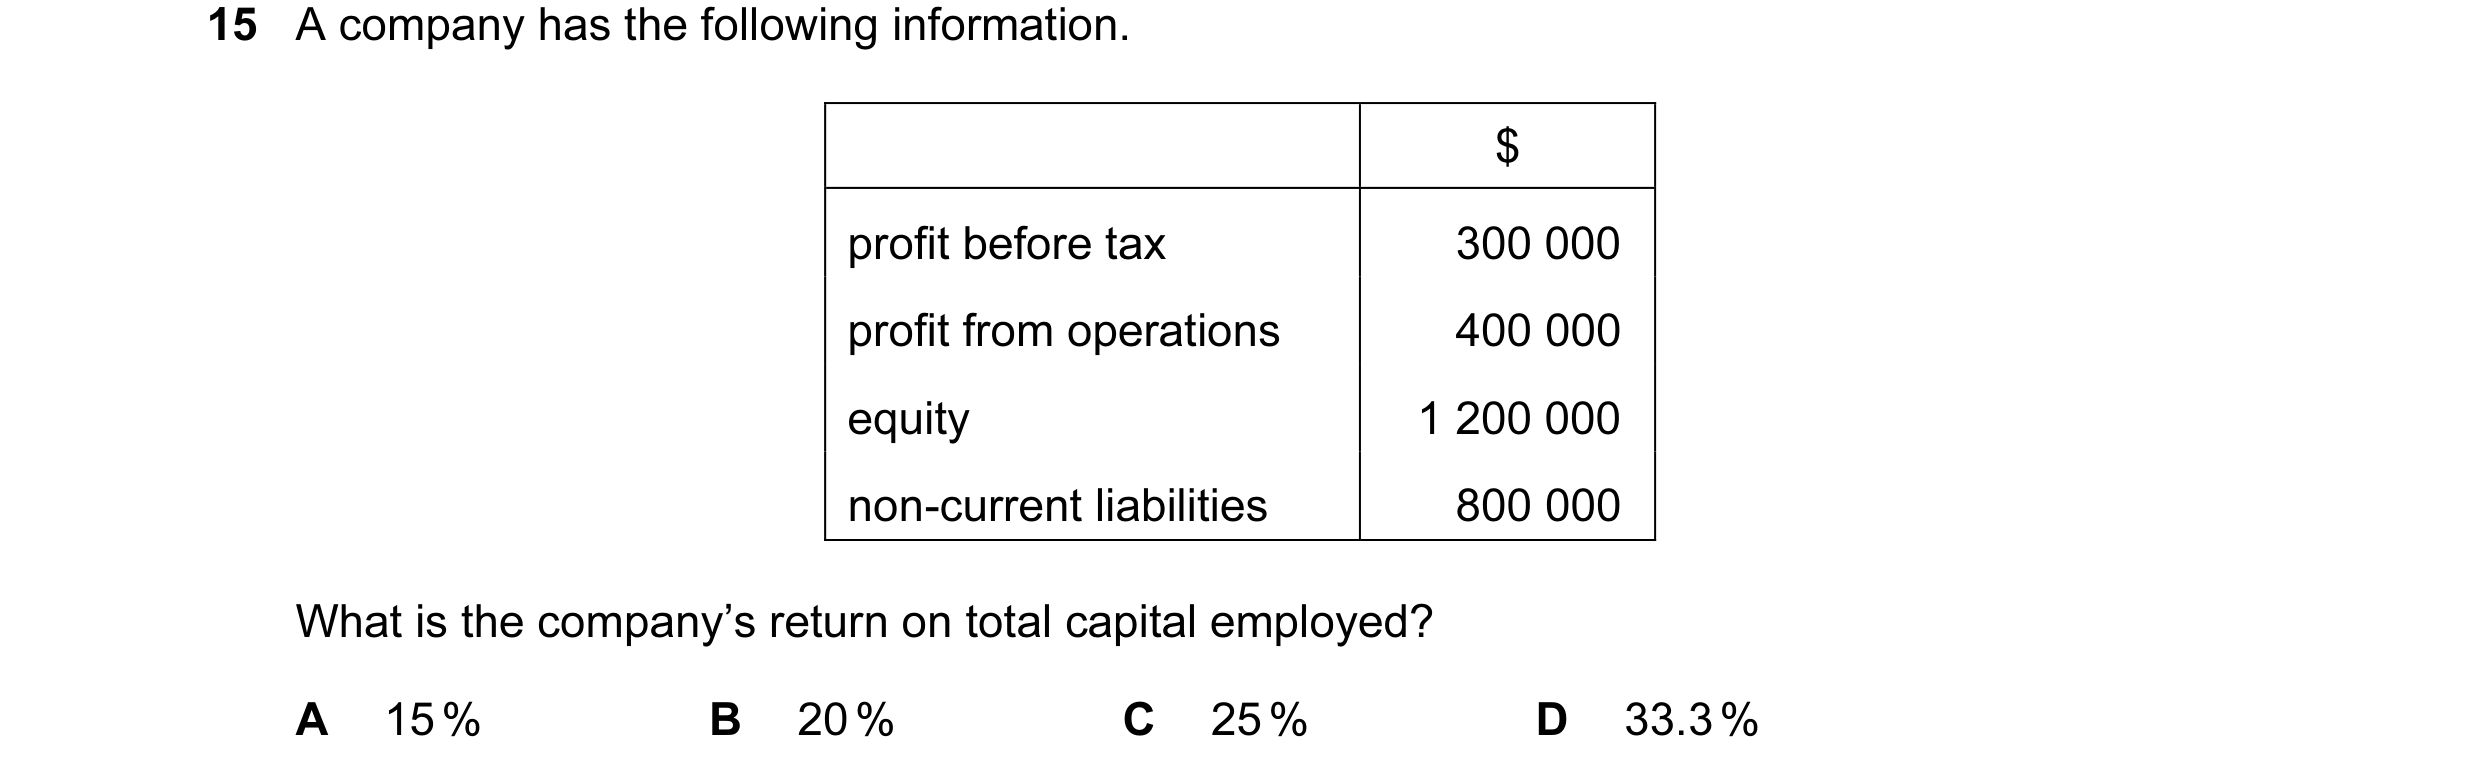
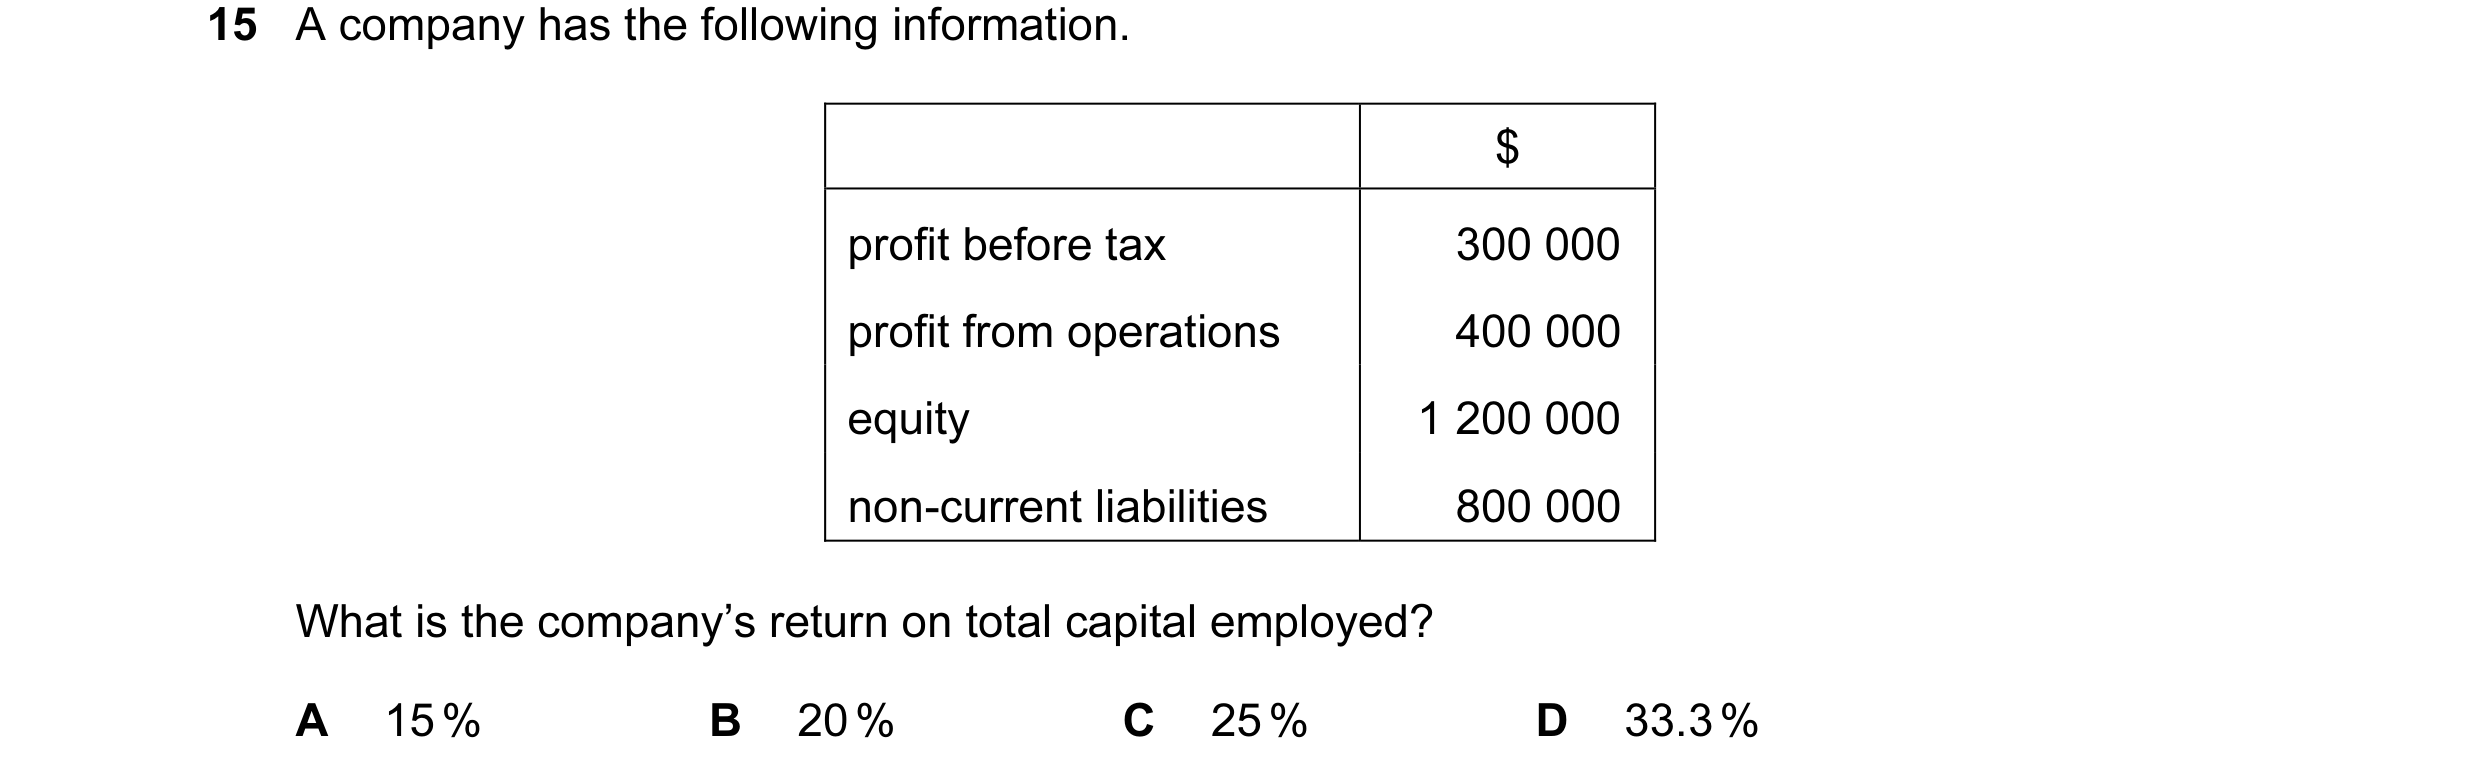
16 A company has the following information. $ profit before tax 300 000 profit from operations 400 000 equity 1 200 000 non-current liabilities 800 000 What is the company’s return on total capital employed? A 15 % B 20 % C 25 % D 33.3 %
1 marks
Answer: B
This question in 9706/31 May/June 2011
Q33 · The following are extracts from a company’s income statement 9706/31 May/June 2011
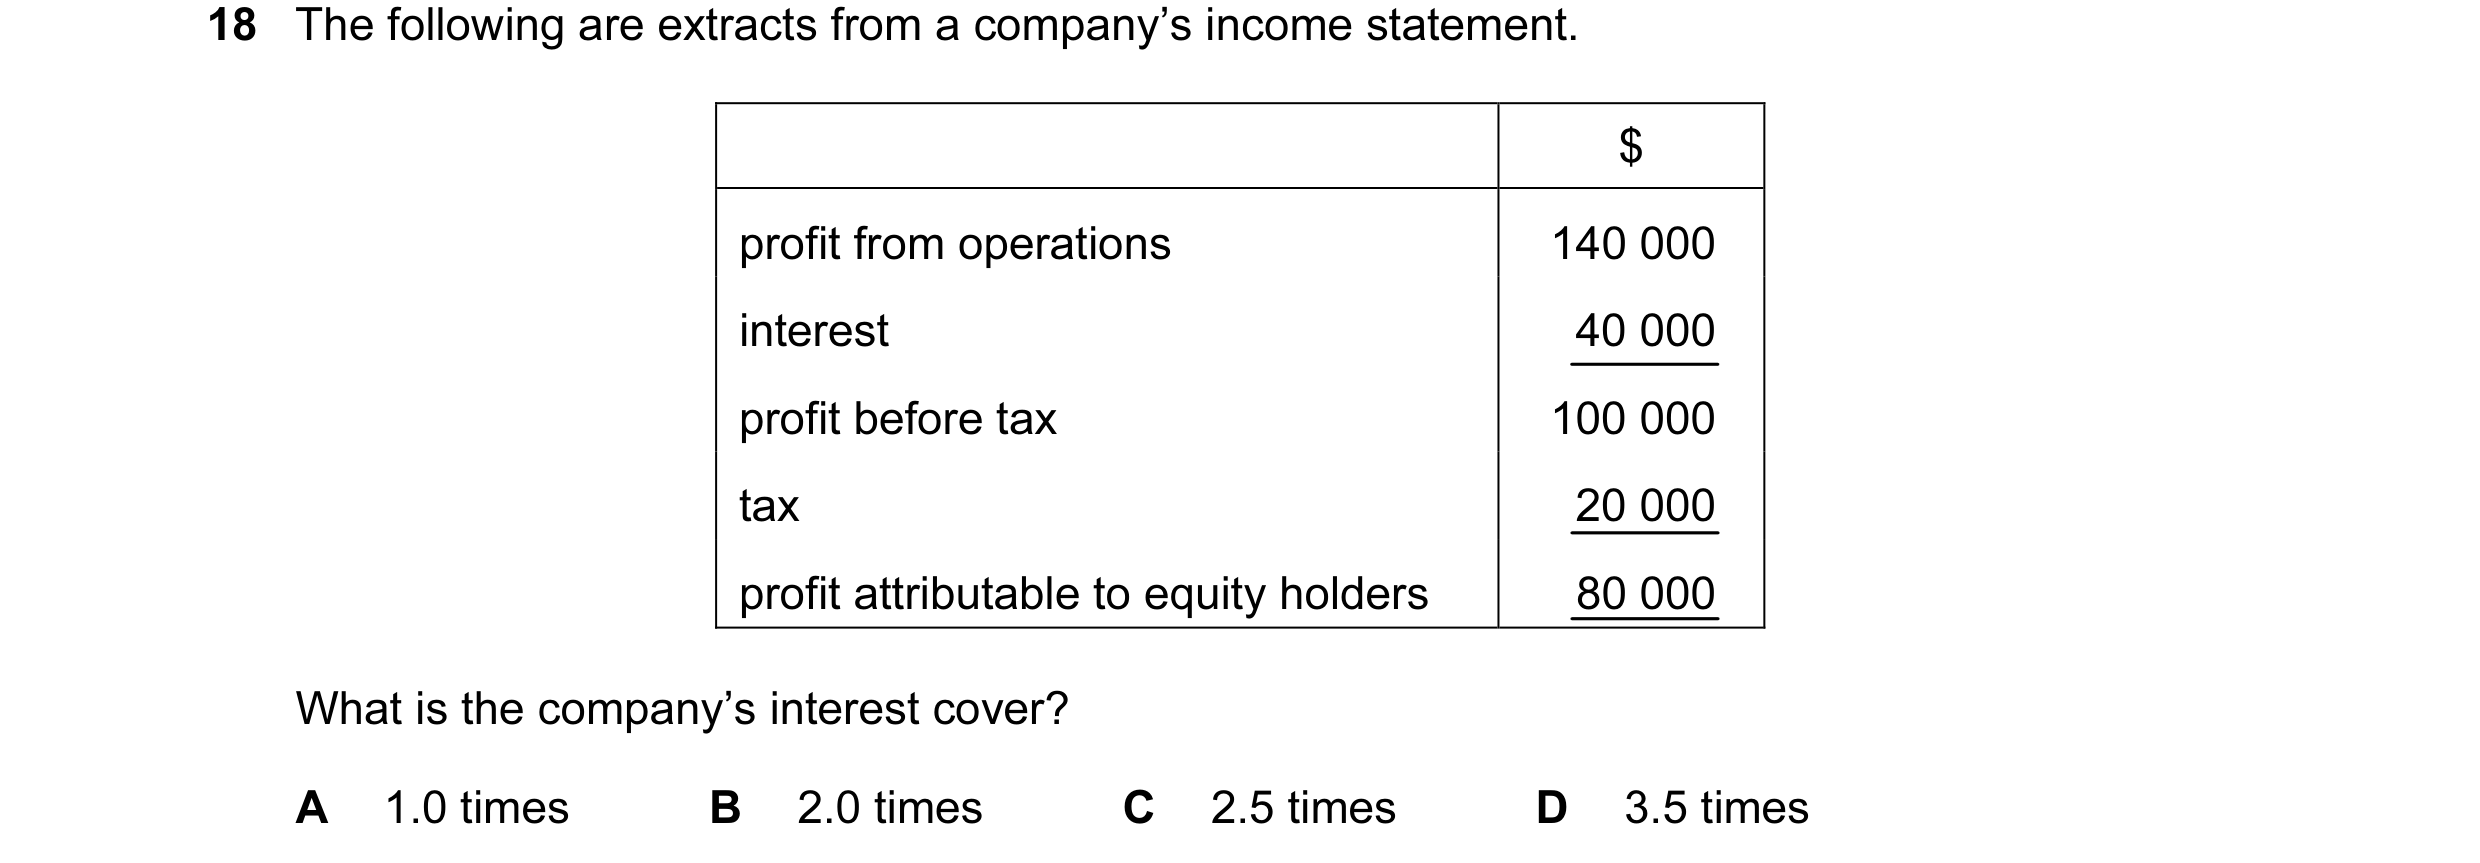
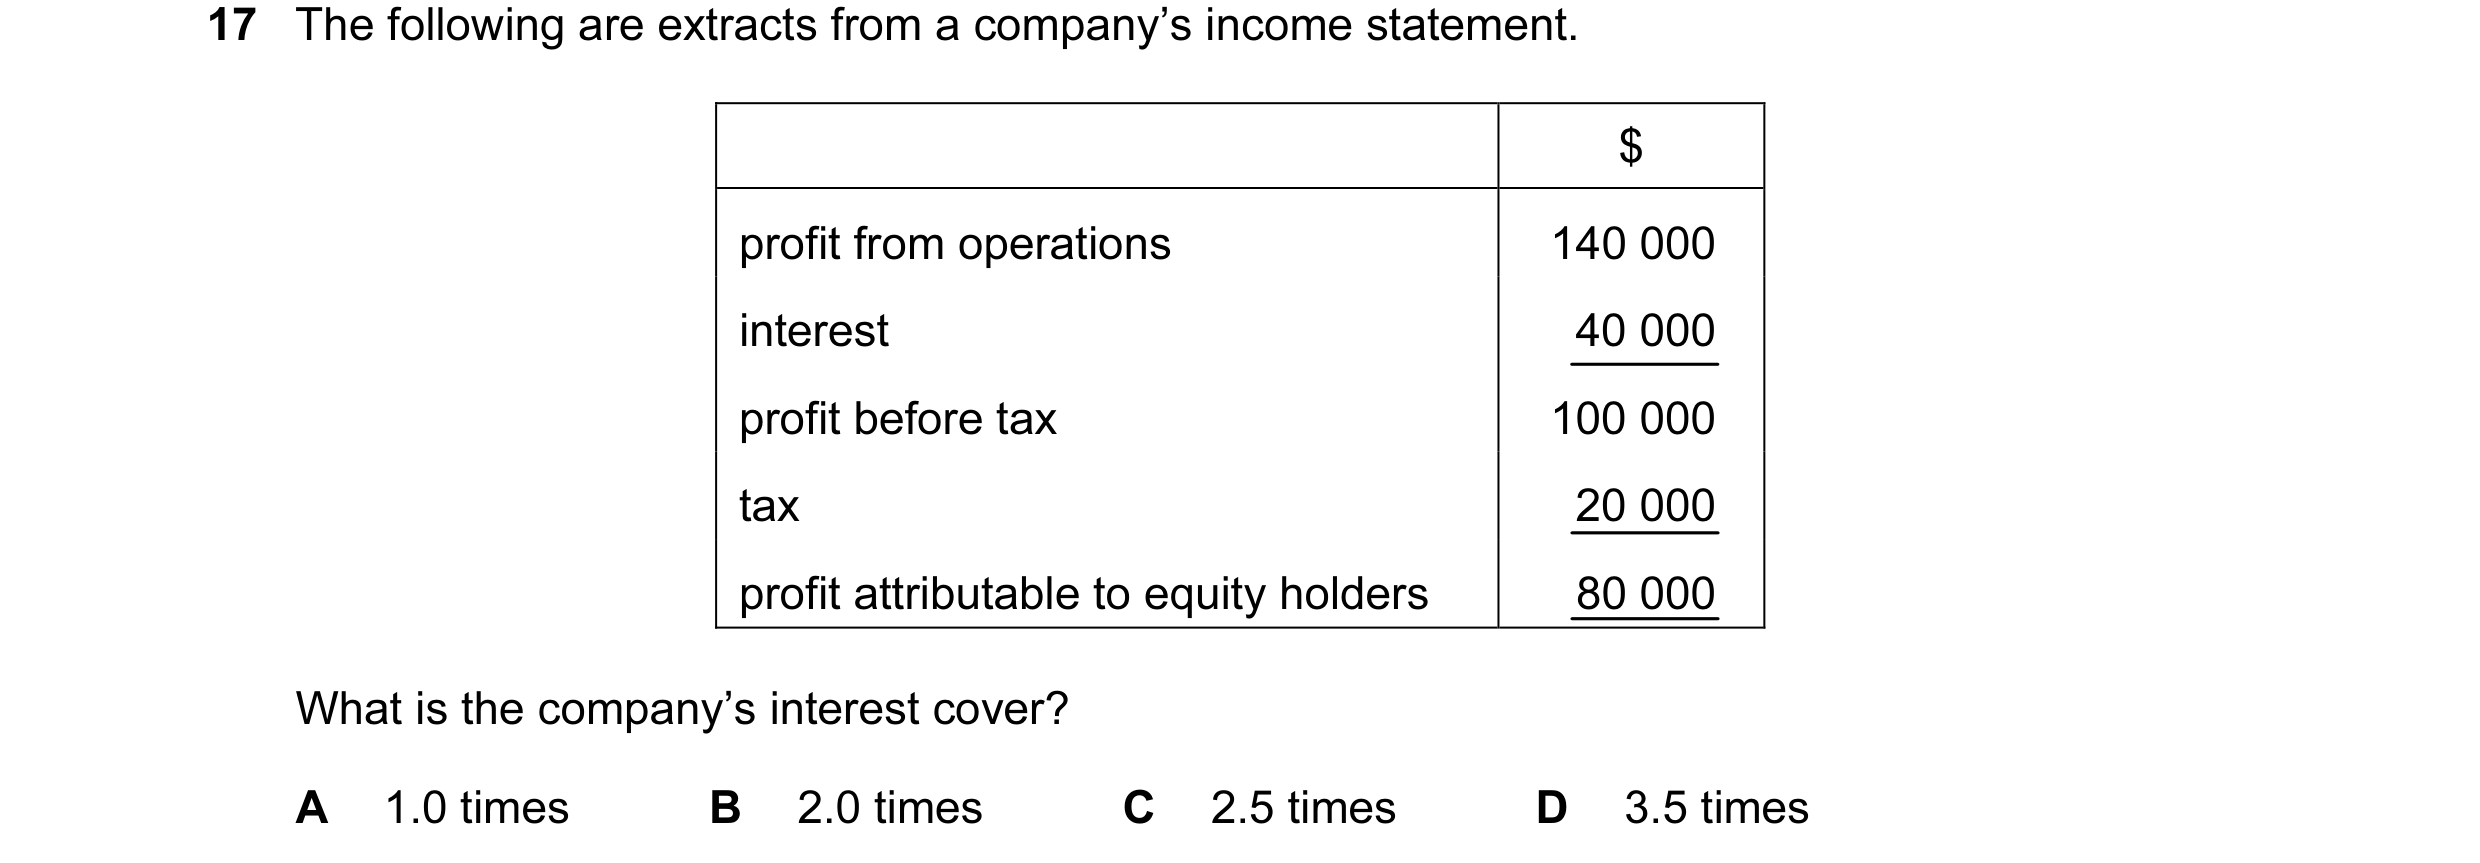
18 The following are extracts from a company’s income statement. $ profit from operations 140 000 interest 40 000 profit before tax 100 000 tax 20 000 profit attributable to equity holders 80 000 What is the company’s interest cover? A 1.0 times B 2.0 times C 2.5 times D 3.5 times
1 marks
Answer: D
This question in 9706/31 May/June 2011
Q34 · The following is an extract from the statement of financial position of Zed Ltd 9706/32 May/June 2011
13 The following is an extract from the statement of financial position of Zed Ltd. $ net assets 114 000 10 % debentures (2015) (20 000) 94 000 ordinary shares 60 000 reserves 34 000 94 000 The profit from operations before interest and taxation for the year is $37 000 and taxation payable amounts to $9000. What is the interest cover? A 11.6 B 13.0 C 17.5 D 18.5
1 marks
Answer: D
This question in 9706/32 May/June 2011
Q35 · A company has the following information 9706/32 May/June 2011
15 A company has the following information. $ profit before tax 300 000 profit from operations 400 000 equity 1 200 000 non-current liabilities 800 000 What is the company’s return on total capital employed? A 15 % B 20 % C 25 % D 33.3 %
1 marks
Answer: B
This question in 9706/32 May/June 2011
Q36 · The following is an extract from the statement of financial position of Zed Ltd 9706/33 May/June 2011
13 The following is an extract from the statement of financial position of Zed Ltd. $ net assets 114 000 10 % debentures (2015) (20 000) 94 000 ordinary shares 60 000 reserves 34 000 94 000 The profit from operations before interest and taxation for the year is $37 000 and taxation payable amounts to $9000. What is the interest cover? A 11.6 B 13.0 C 17.5 D 18.5
1 marks
Answer: D
This question in 9706/33 May/June 2011
Q37 · A company has the following information 9706/33 May/June 2011
15 A company has the following information. $ profit before tax 300 000 profit from operations 400 000 equity 1 200 000 non-current liabilities 800 000 What is the company’s return on total capital employed? A 15 % B 20 % C 25 % D 33.3 %
1 marks
Answer: B
This question in 9706/33 May/June 2011
Q38 · Zachary plc has the following summary balance sheet at 31 Dec 2009 9706/33 May/June 2011
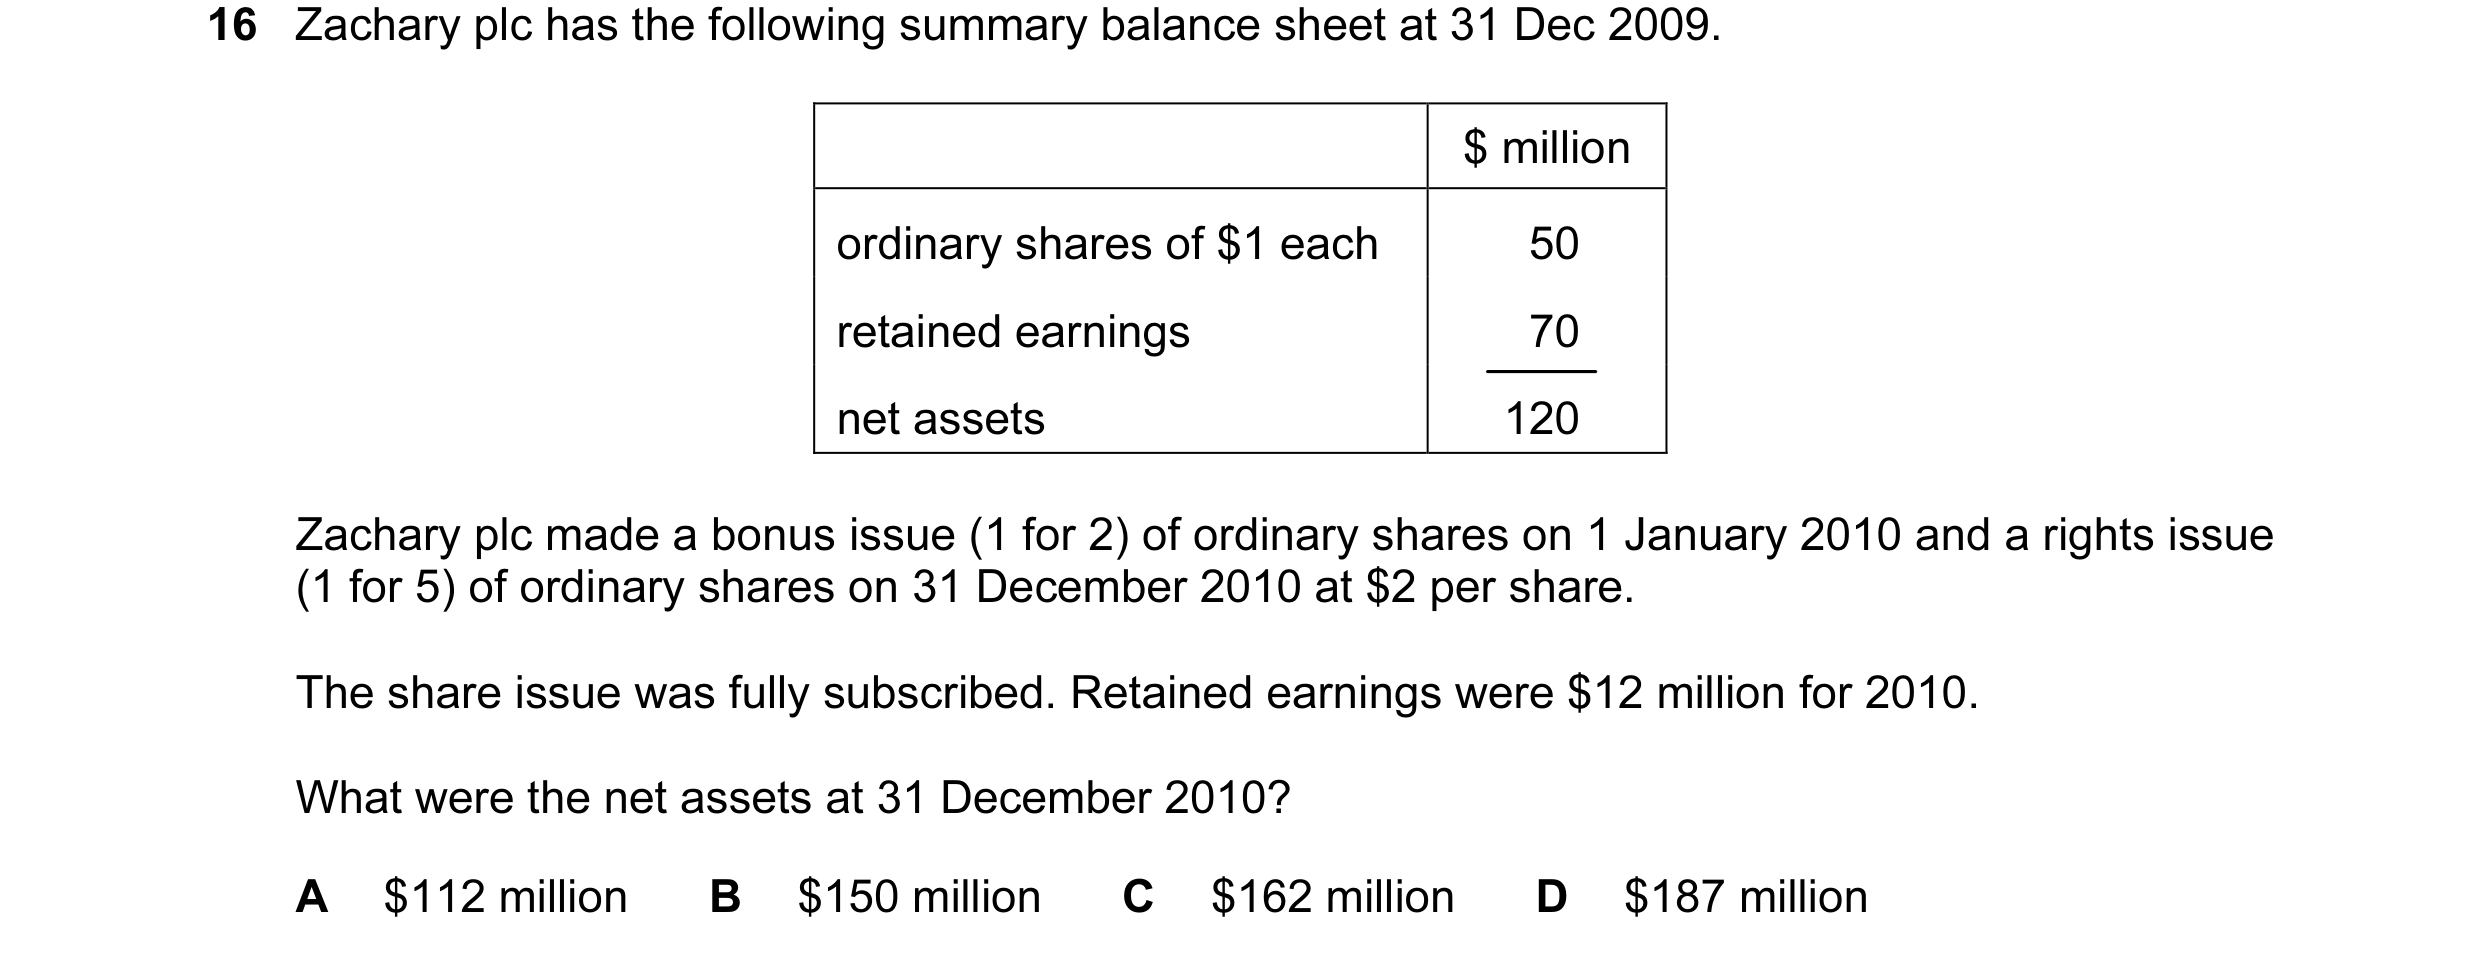
16 Zachary plc has the following summary balance sheet at 31 Dec 2009. $ million ordinary shares of $1 each 50 retained earnings 70 net assets 120 Zachary plc made a bonus issue (1 for 2) of ordinary shares on 1 January 2010 and a rights issue (1 for 5) of ordinary shares on 31 December 2010 at $2 per share. The share issue was fully subscribed. Retained earnings were $12 million for 2010. What were the net assets at 31 December 2010? A $112 million B $150 million C $162 million D $187 million
1 marks
Answer: C
This question in 9706/33 May/June 2011
Q39 · The following are extracts from a company’s income statement 9706/33 May/June 2011
17 The following are extracts from a company’s income statement. $ profit from operations 140 000 interest 40 000 profit before tax 100 000 tax 20 000 profit attributable to equity holders 80 000 What is the company’s interest cover? A 1.0 times B 2.0 times C 2.5 times D 3.5 times
1 marks
Answer: D
This question in 9706/33 May/June 2011
Q40 · A balance sheet extract shows the following 9706/31 Oct/Nov 2011
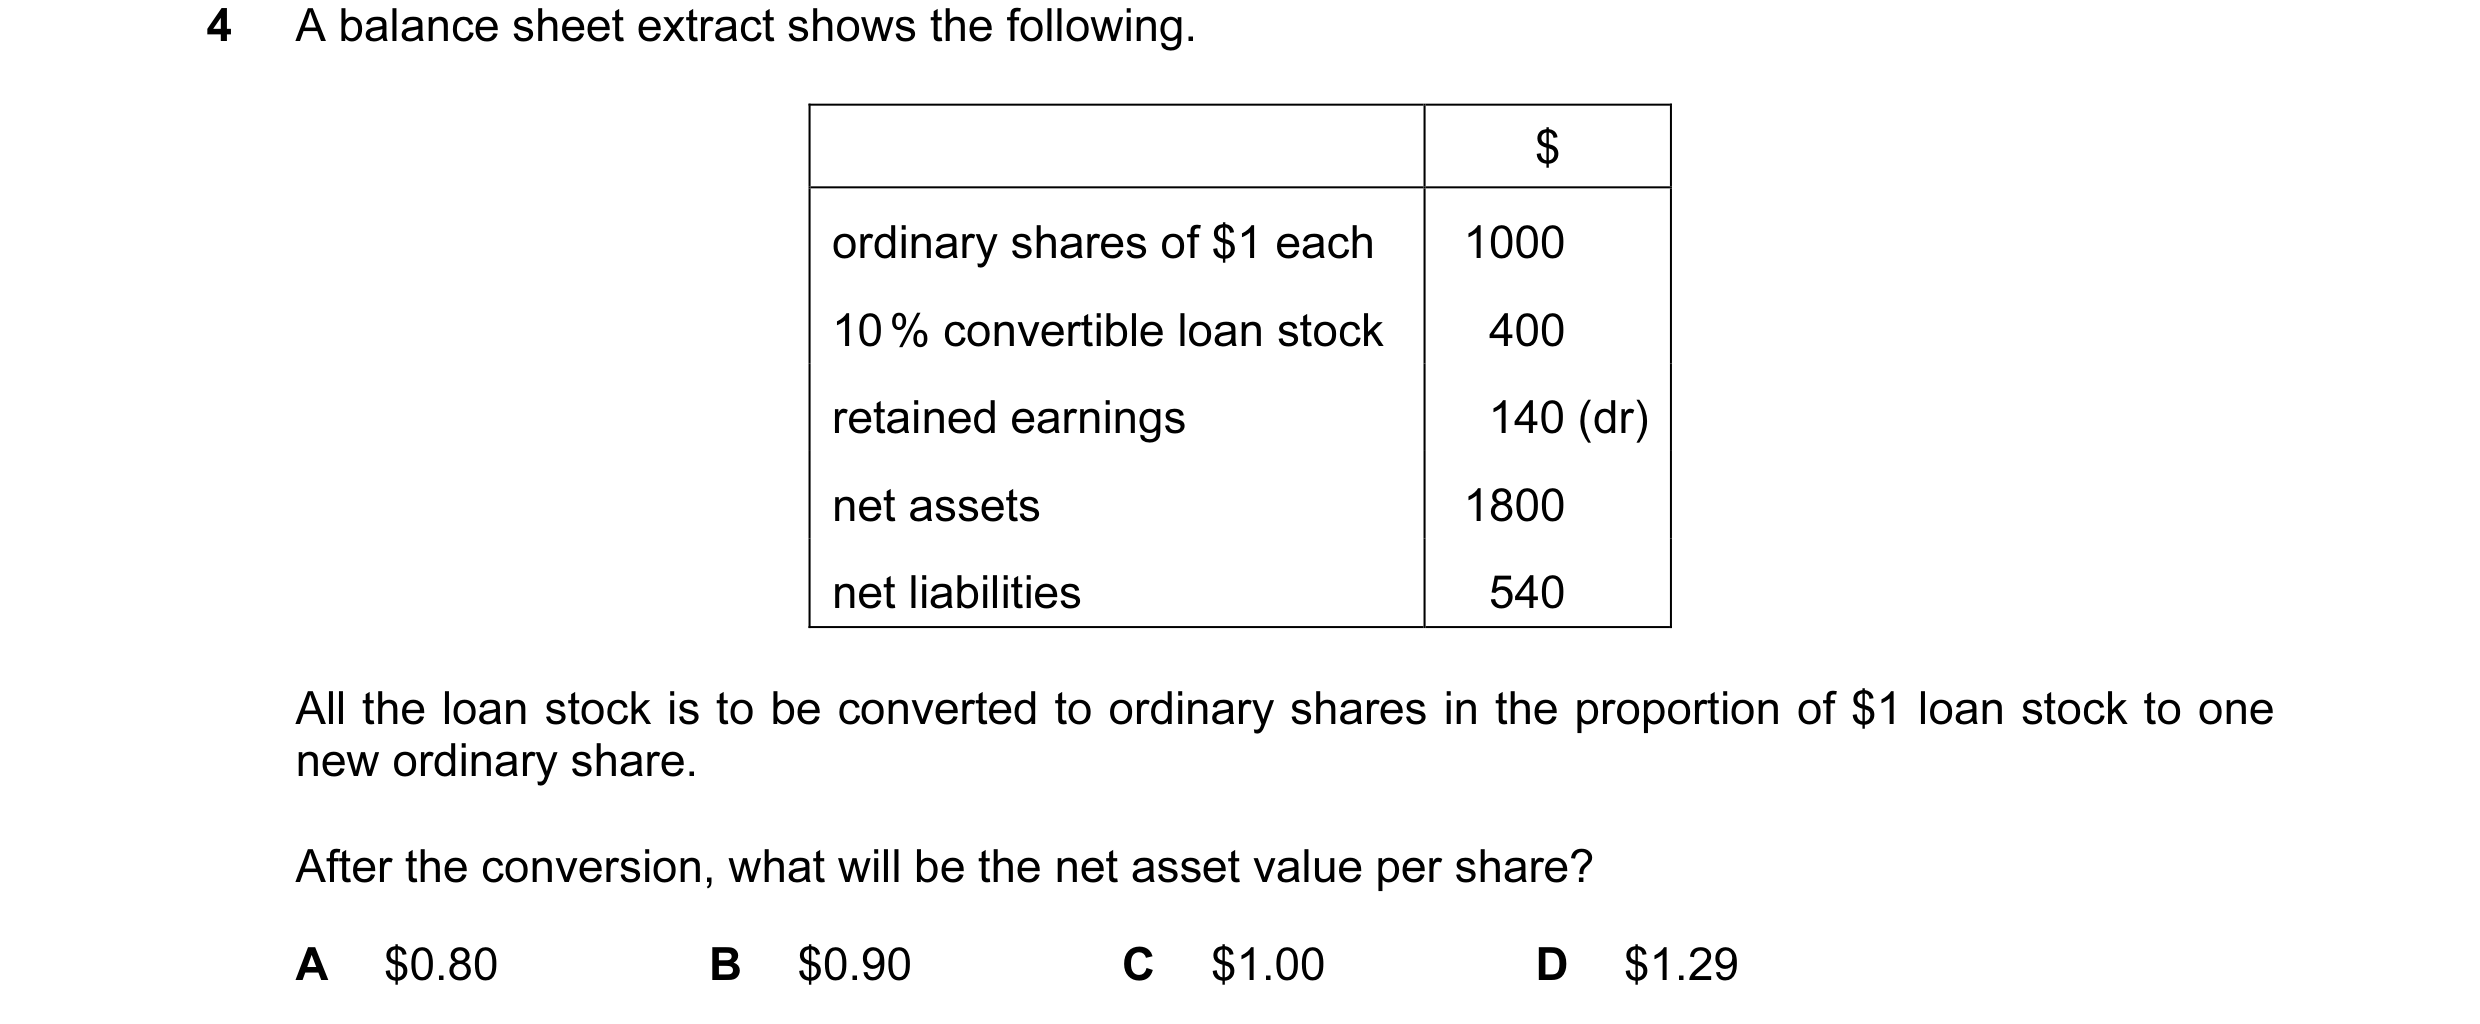
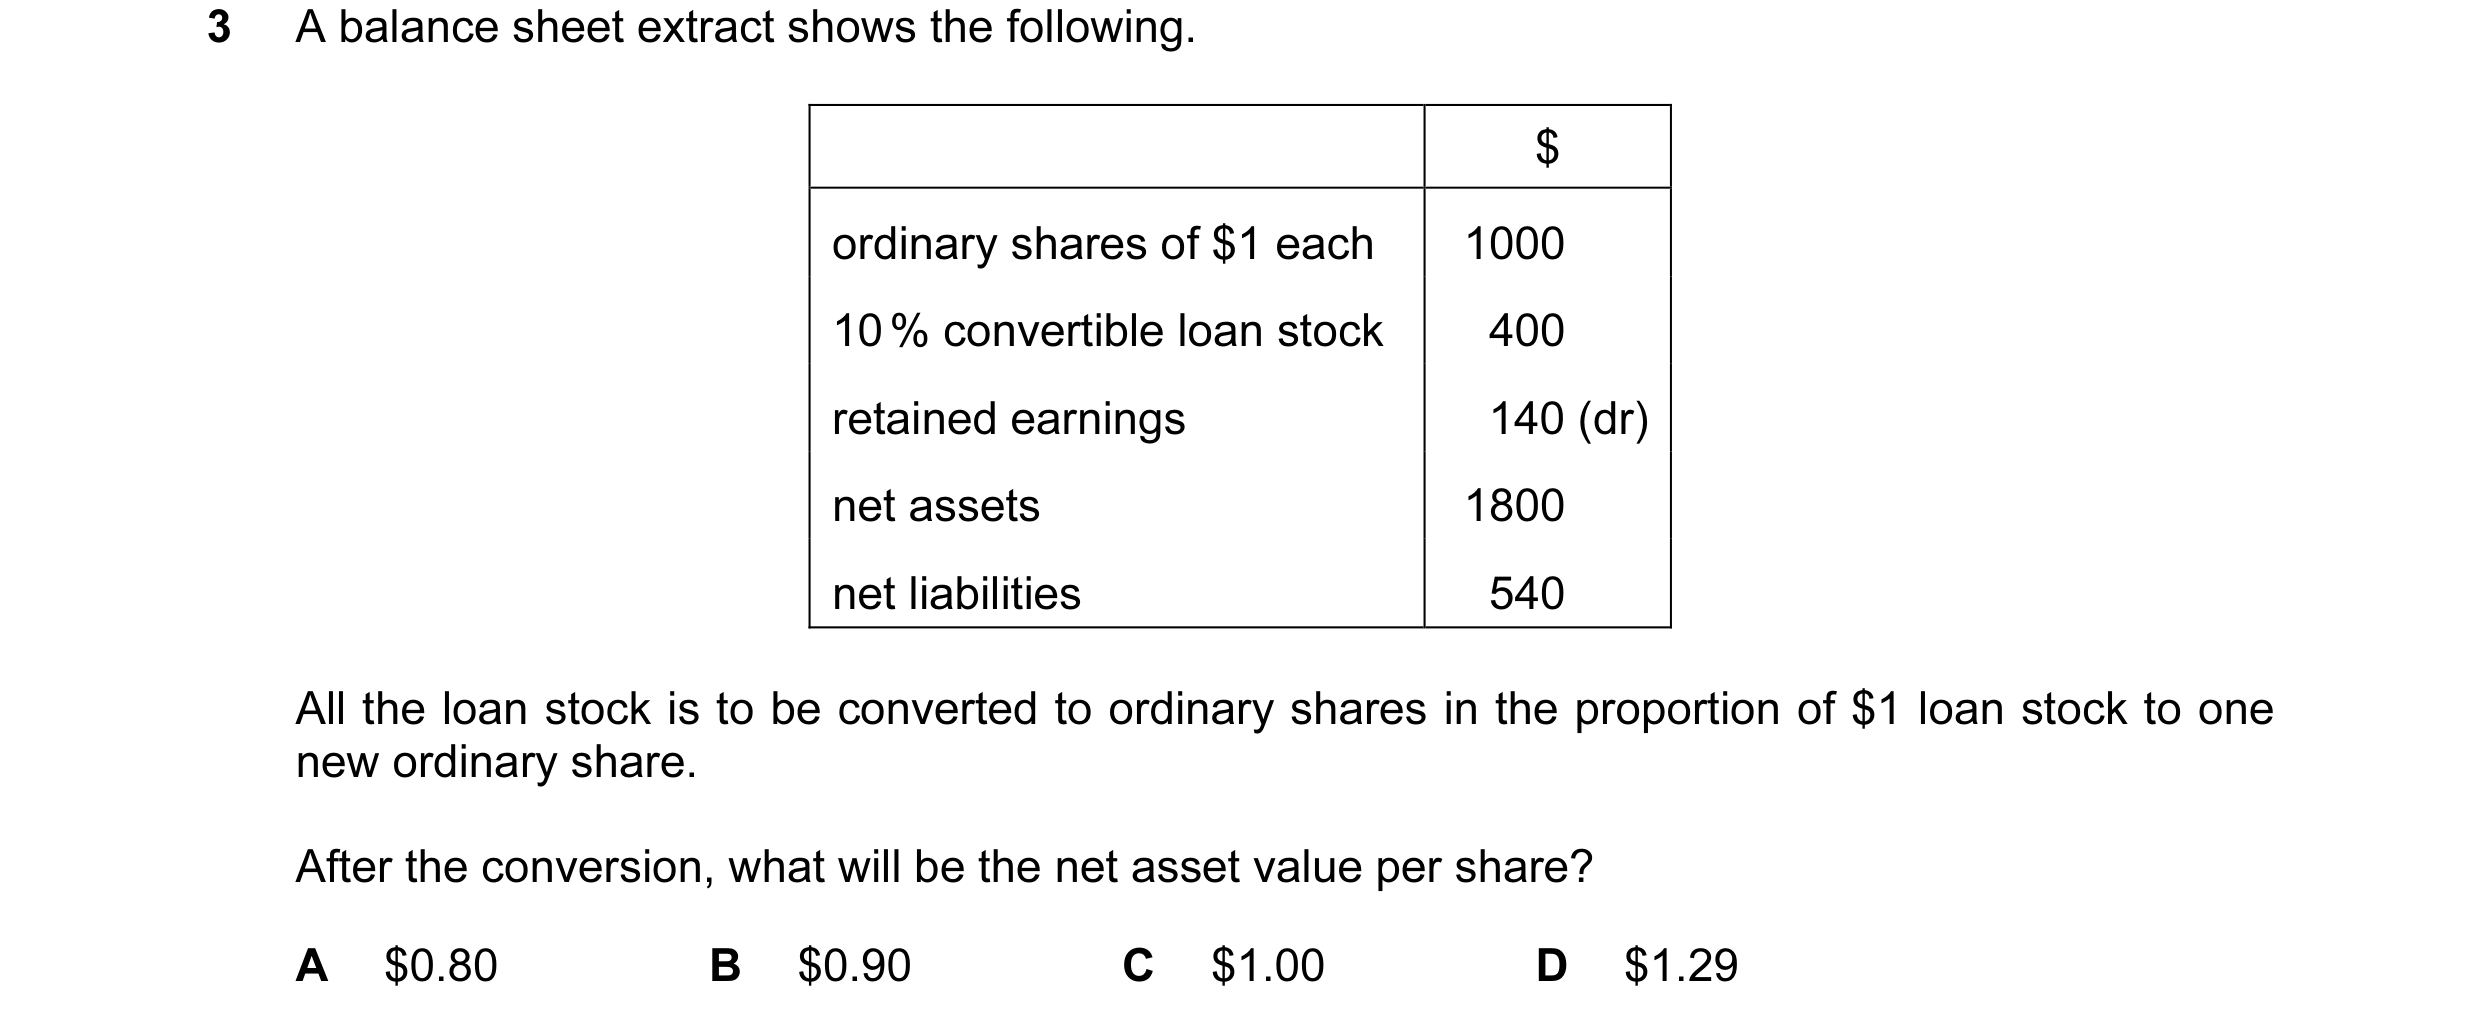
4 A balance sheet extract shows the following. $ ordinary shares of $1 each 1000 10 % convertible loan stock 400 retained earnings 140 (dr) net assets 1800 net liabilities 540 All the loan stock is to be converted to ordinary shares in the proportion of $1 loan stock to one new ordinary share. After the conversion, what will be the net asset value per share? A $0.80 B $0.90 C $1.00 D $1.29
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2011
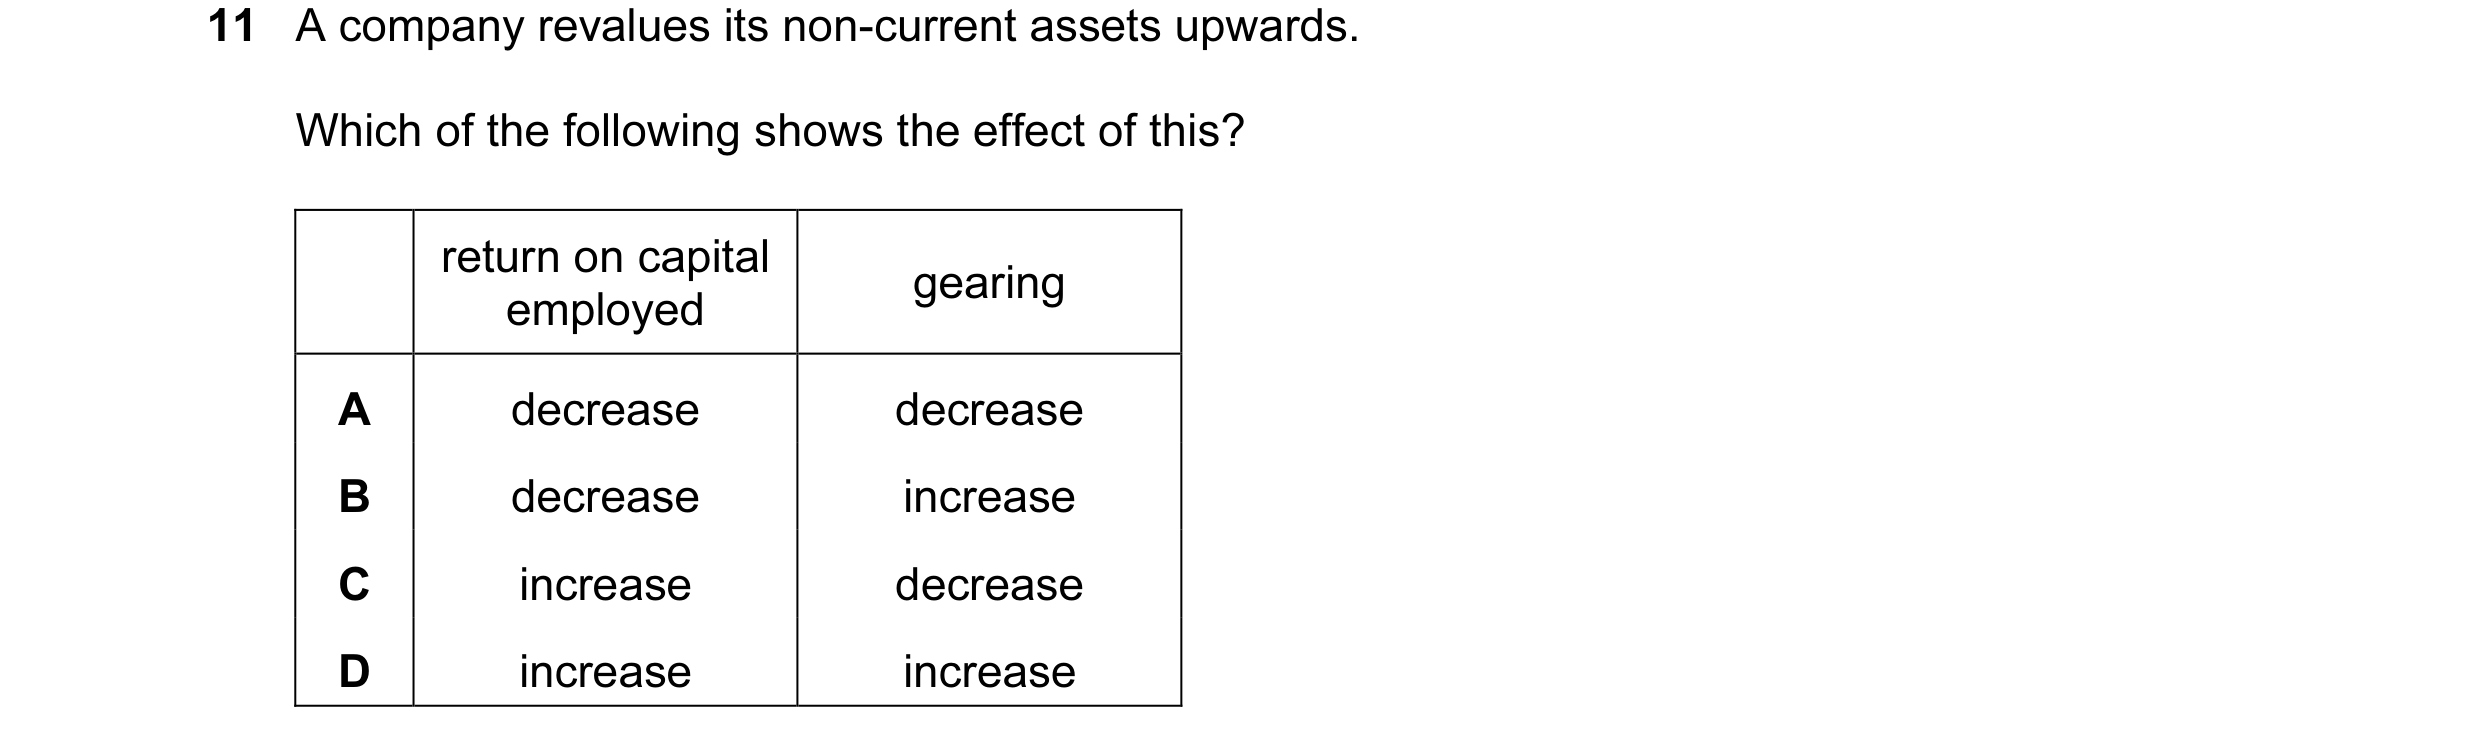
Q41 · A company revalues its non-current assets upwards 9706/31 Oct/Nov 2011
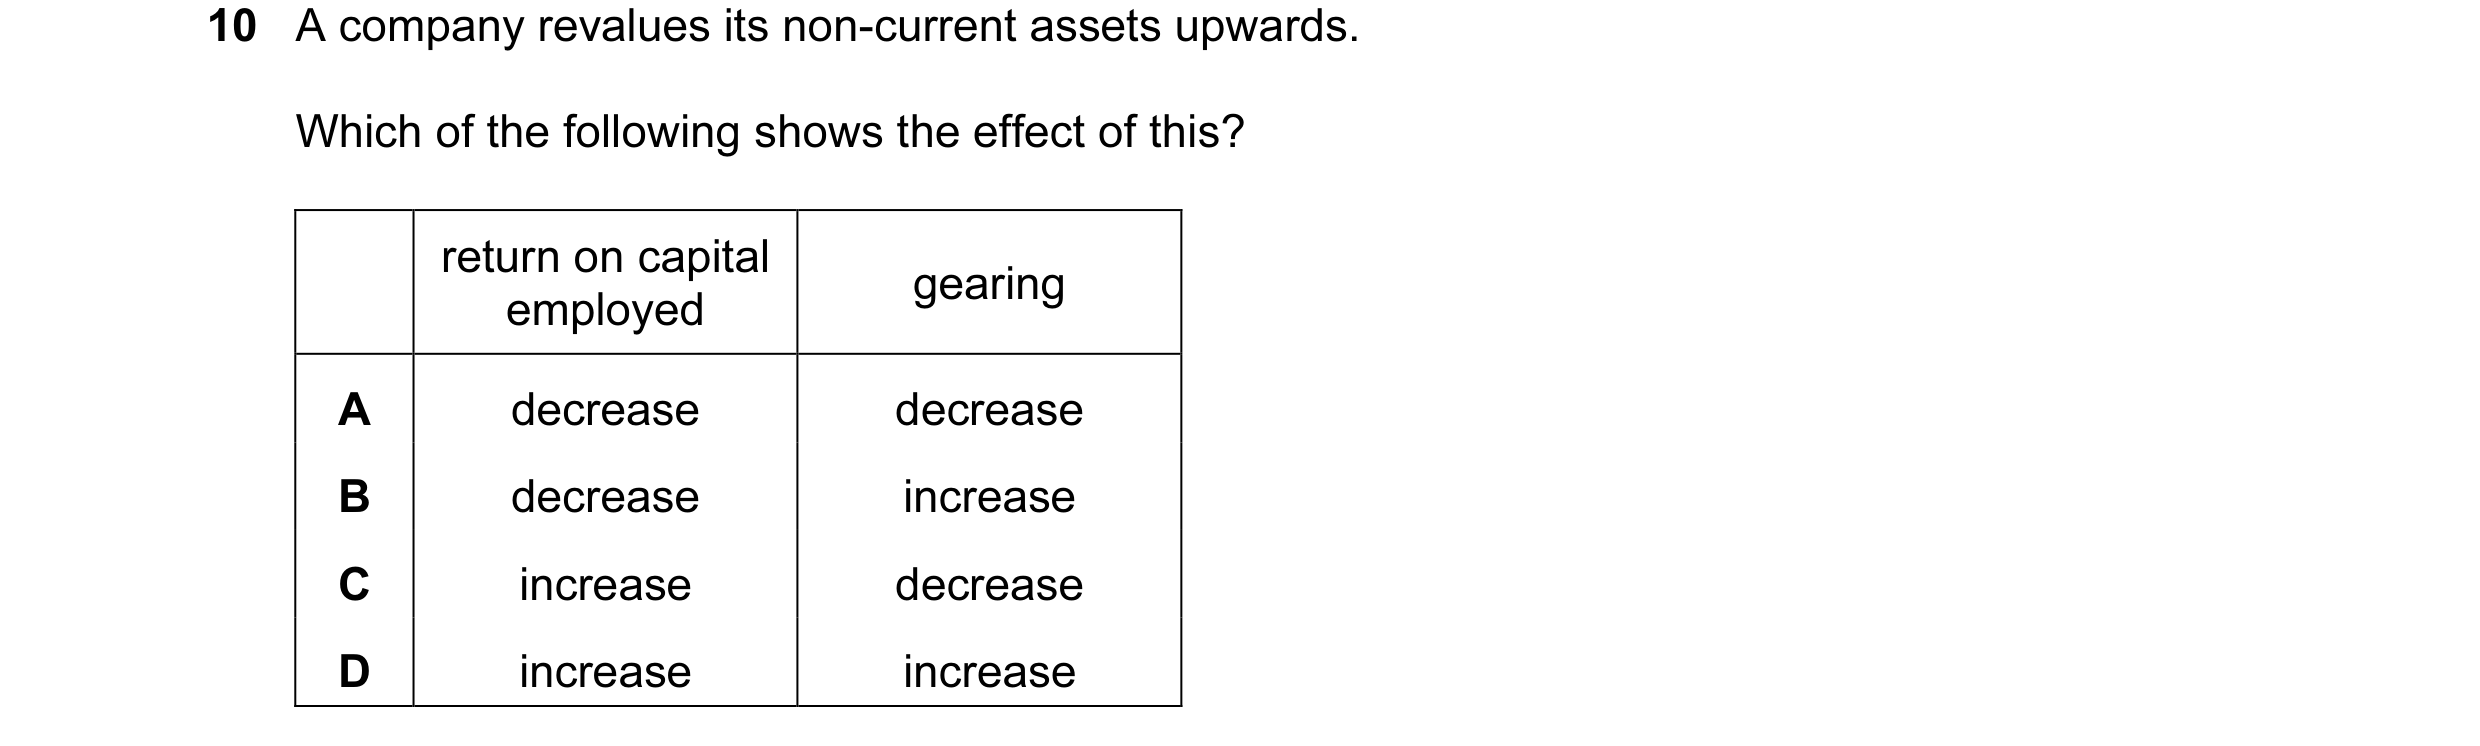
11 A company revalues its non-current assets upwards. Which of the following shows the effect of this? return on capital gearing employed A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2011
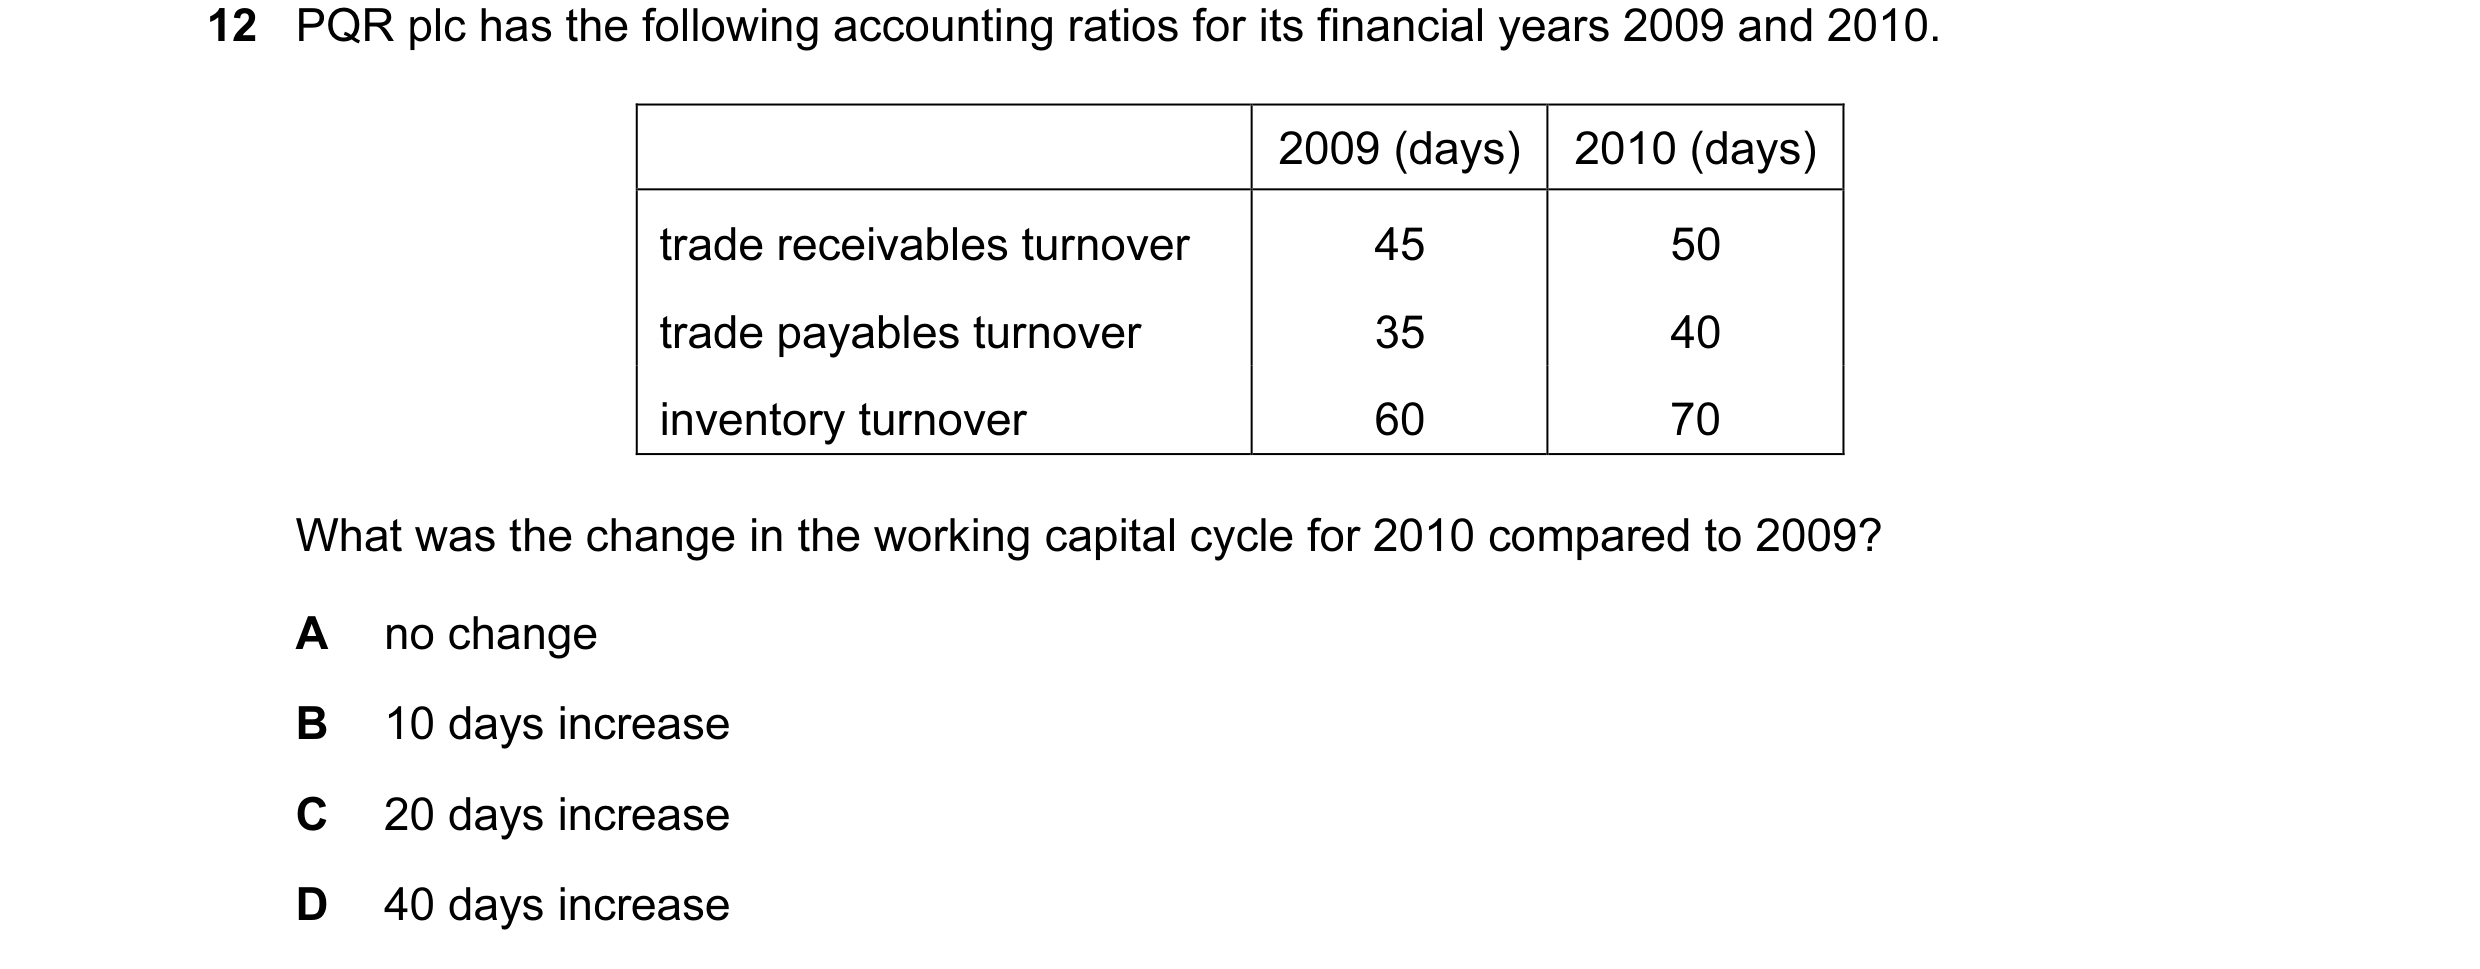
Q42 · PQR plc has the following accounting ratios for its financial years 2009 and 2010 9706/31 Oct/Nov 2011
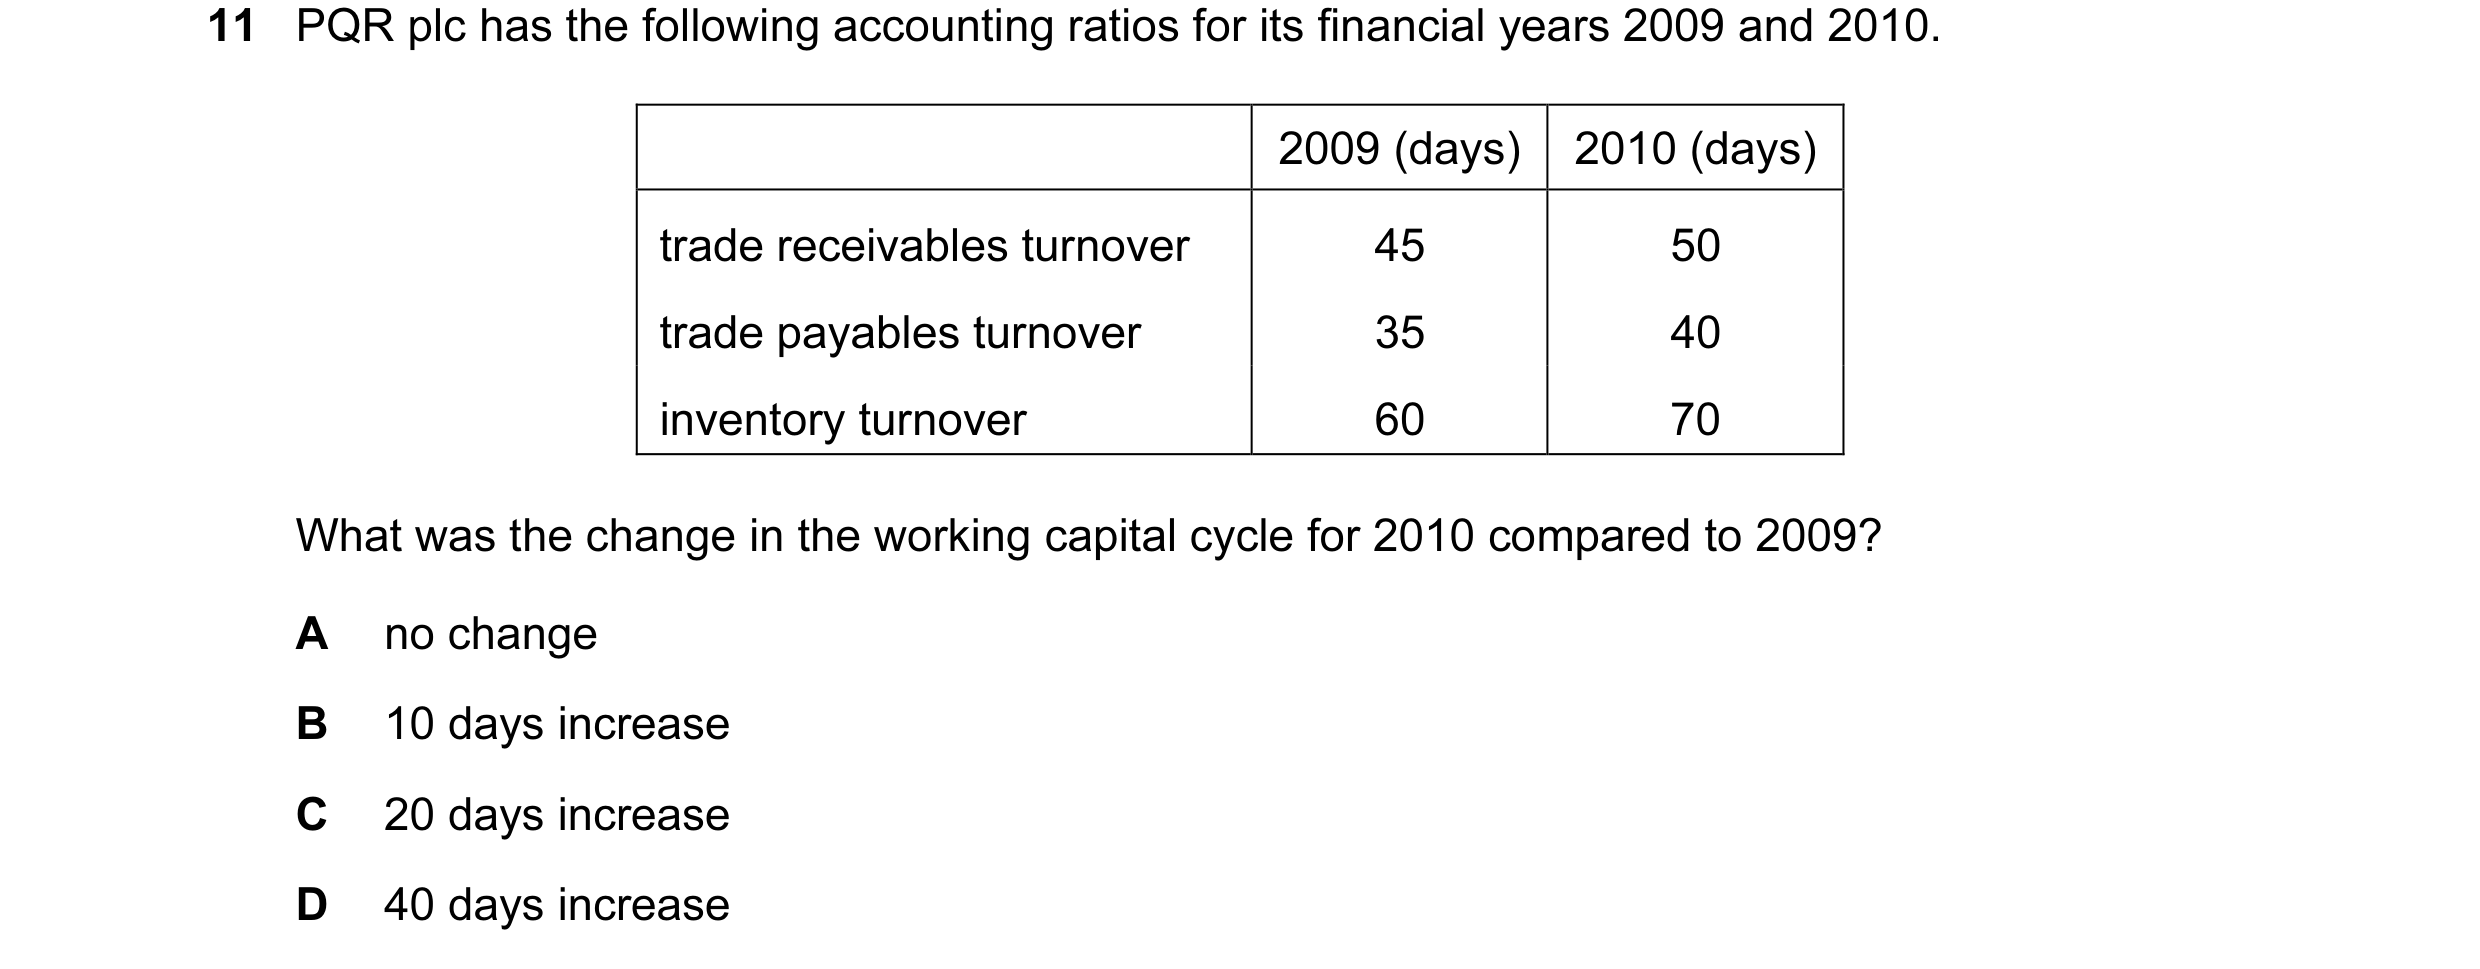
12 PQR plc has the following accounting ratios for its financial years 2009 and 2010. 2009 (days) 2010 (days) trade receivables turnover 45 50 trade payables turnover 35 40 inventory turnover 60 70 What was the change in the working capital cycle for 2010 compared to 2009? A no change B 10 days increase C 20 days increase D 40 days increase
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2011
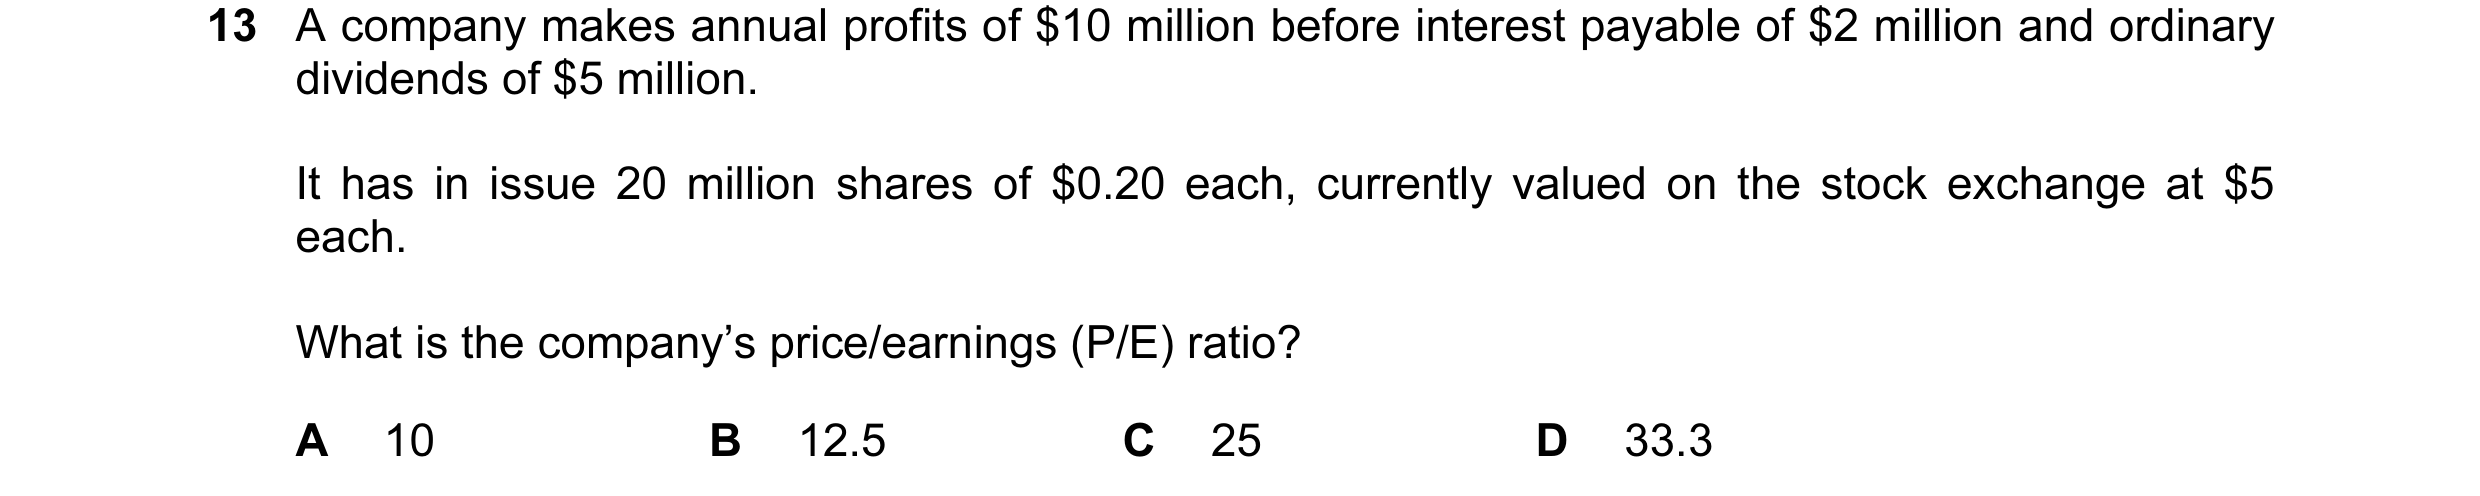
Q43 · A company makes annual profits of $10 million before interest payable of $2 million and… 9706/31 Oct/Nov 2011
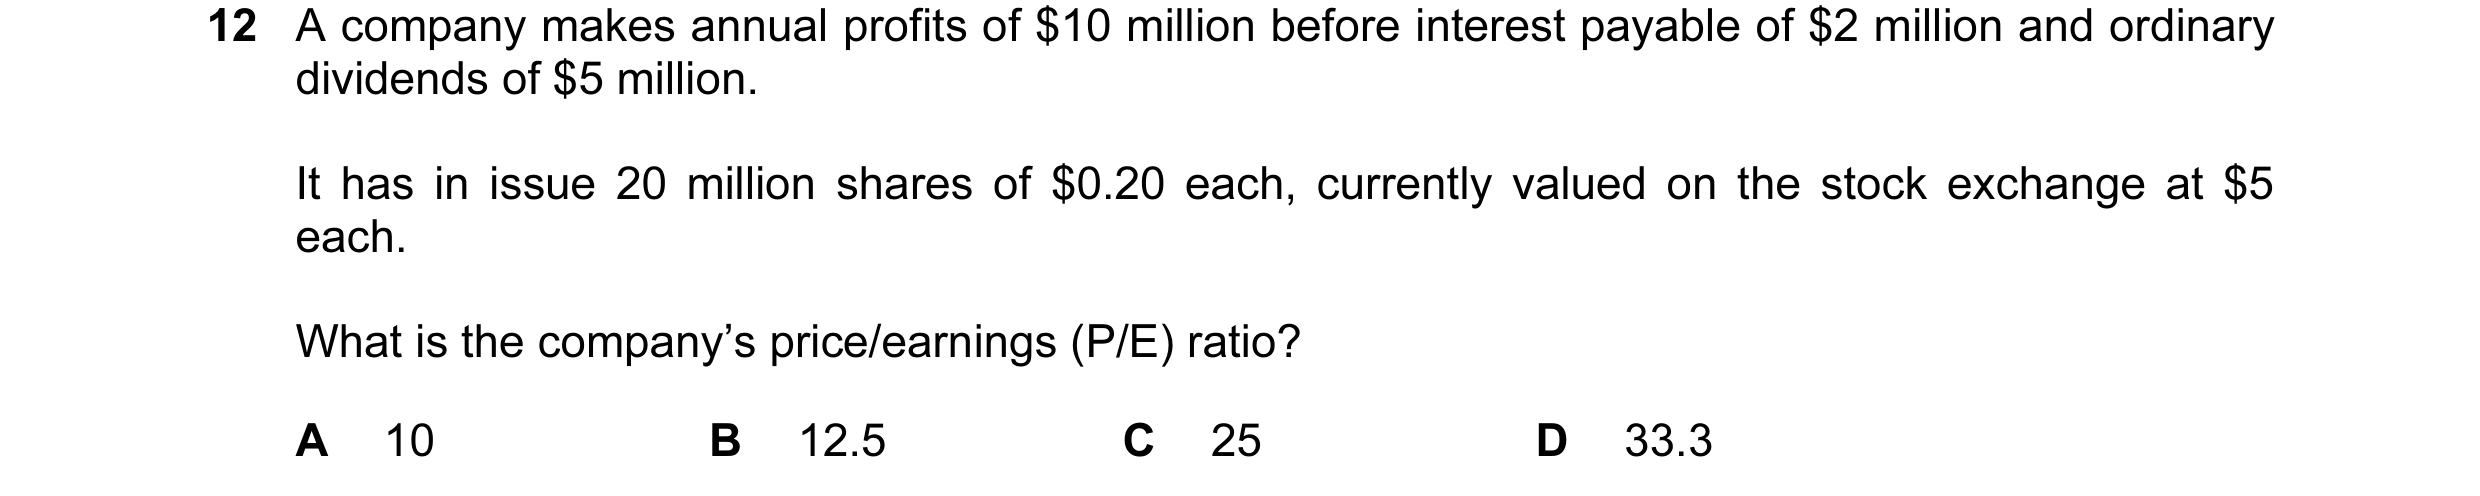
13 A company makes annual profits of $10 million before interest payable of $2 million and ordinary dividends of $5 million. It has in issue 20 million shares of $0.20 each, currently valued on the stock exchange at $5 each. What is the company’s price/earnings (P/E) ratio? A 10 B 12.5 C 25 D 33.3
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2011
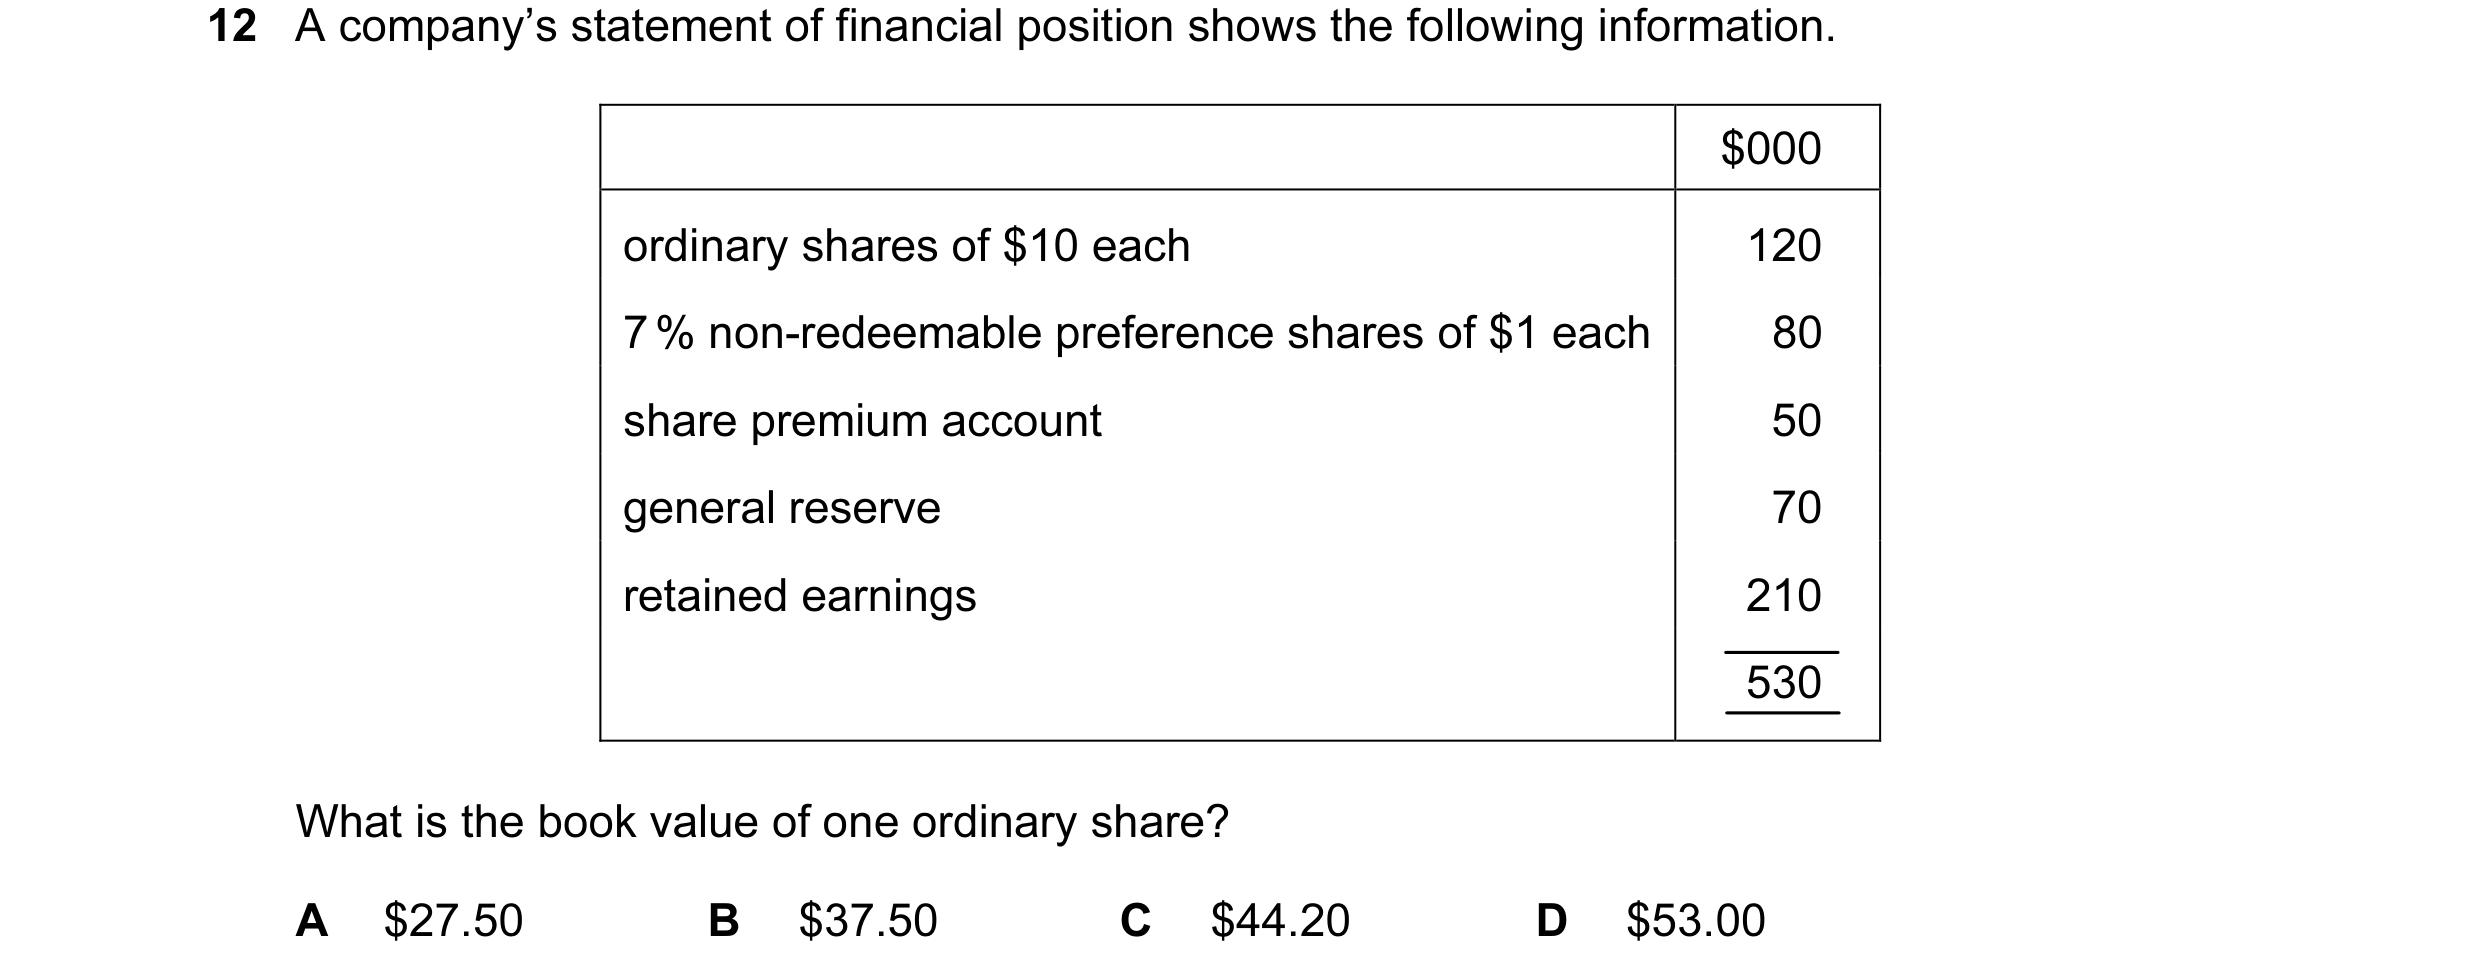
Q44 · A company’s statement of financial position shows the following information 9706/32 Oct/Nov 2011
12 A company’s statement of financial position shows the following information. $000 ordinary shares of $10 each 120 7 % non-redeemable preference shares of $1 each 80 share premium account 50 general reserve 70 retained earnings 210 530 What is the book value of one ordinary share? A $27.50 B $37.50 C $44.20 D $53.00
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2011
Q45 · A company makes annual profits of $50 million, before paying interest of $10 million and… 9706/32 Oct/Nov 2011
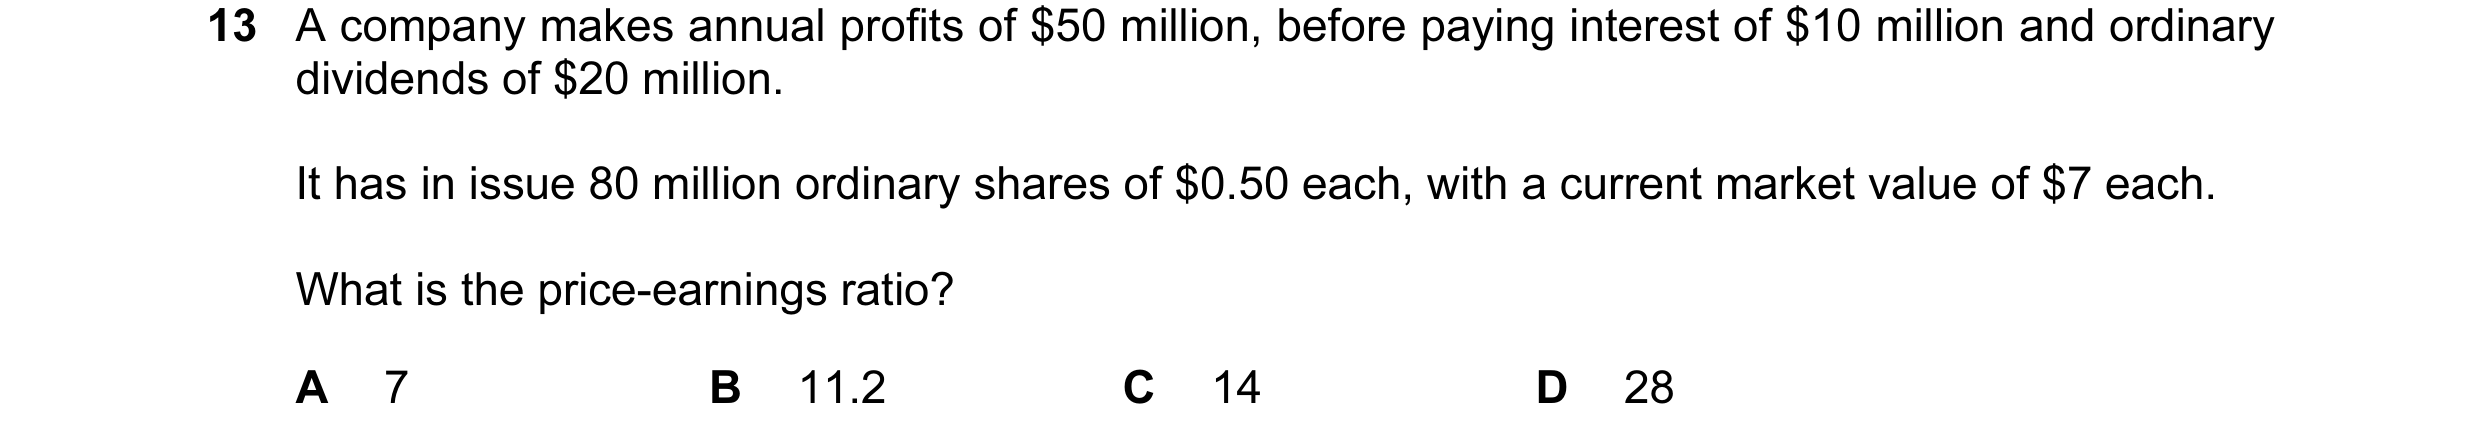
13 A company makes annual profits of $50 million, before paying interest of $10 million and ordinary dividends of $20 million. It has in issue 80 million ordinary shares of $0.50 each, with a current market value of $7 each. What is the price-earnings ratio? A 7 B 11.2 C 14 D 28
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2011
Q46 · The issued share capital of a company is as follows 9706/32 Oct/Nov 2011
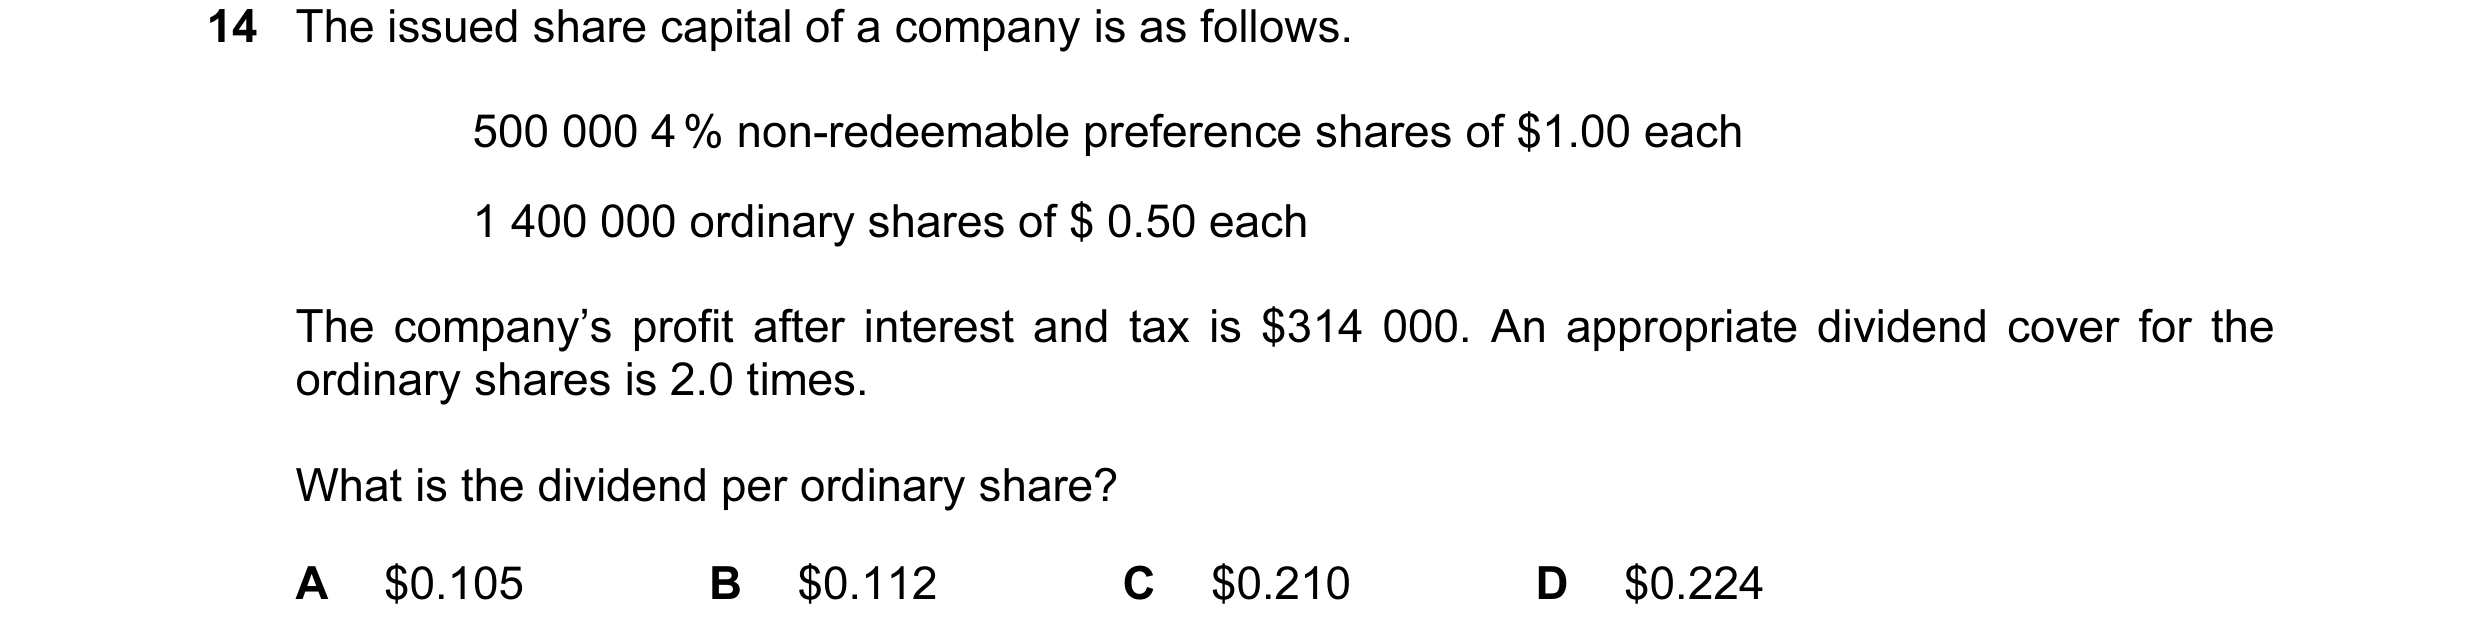
14 The issued share capital of a company is as follows. 500 000 4 % non-redeemable preference shares of $1.00 each 1 400 000 ordinary shares of $ 0.50 each The company’s profit after interest and tax is $314 000. An appropriate dividend cover for the ordinary shares is 2.0 times. What is the dividend per ordinary share? A $0.105 B $0.112 C $0.210 D $0.224
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2011
Q47 · A company revalues its buildings upwards 9706/32 Oct/Nov 2011
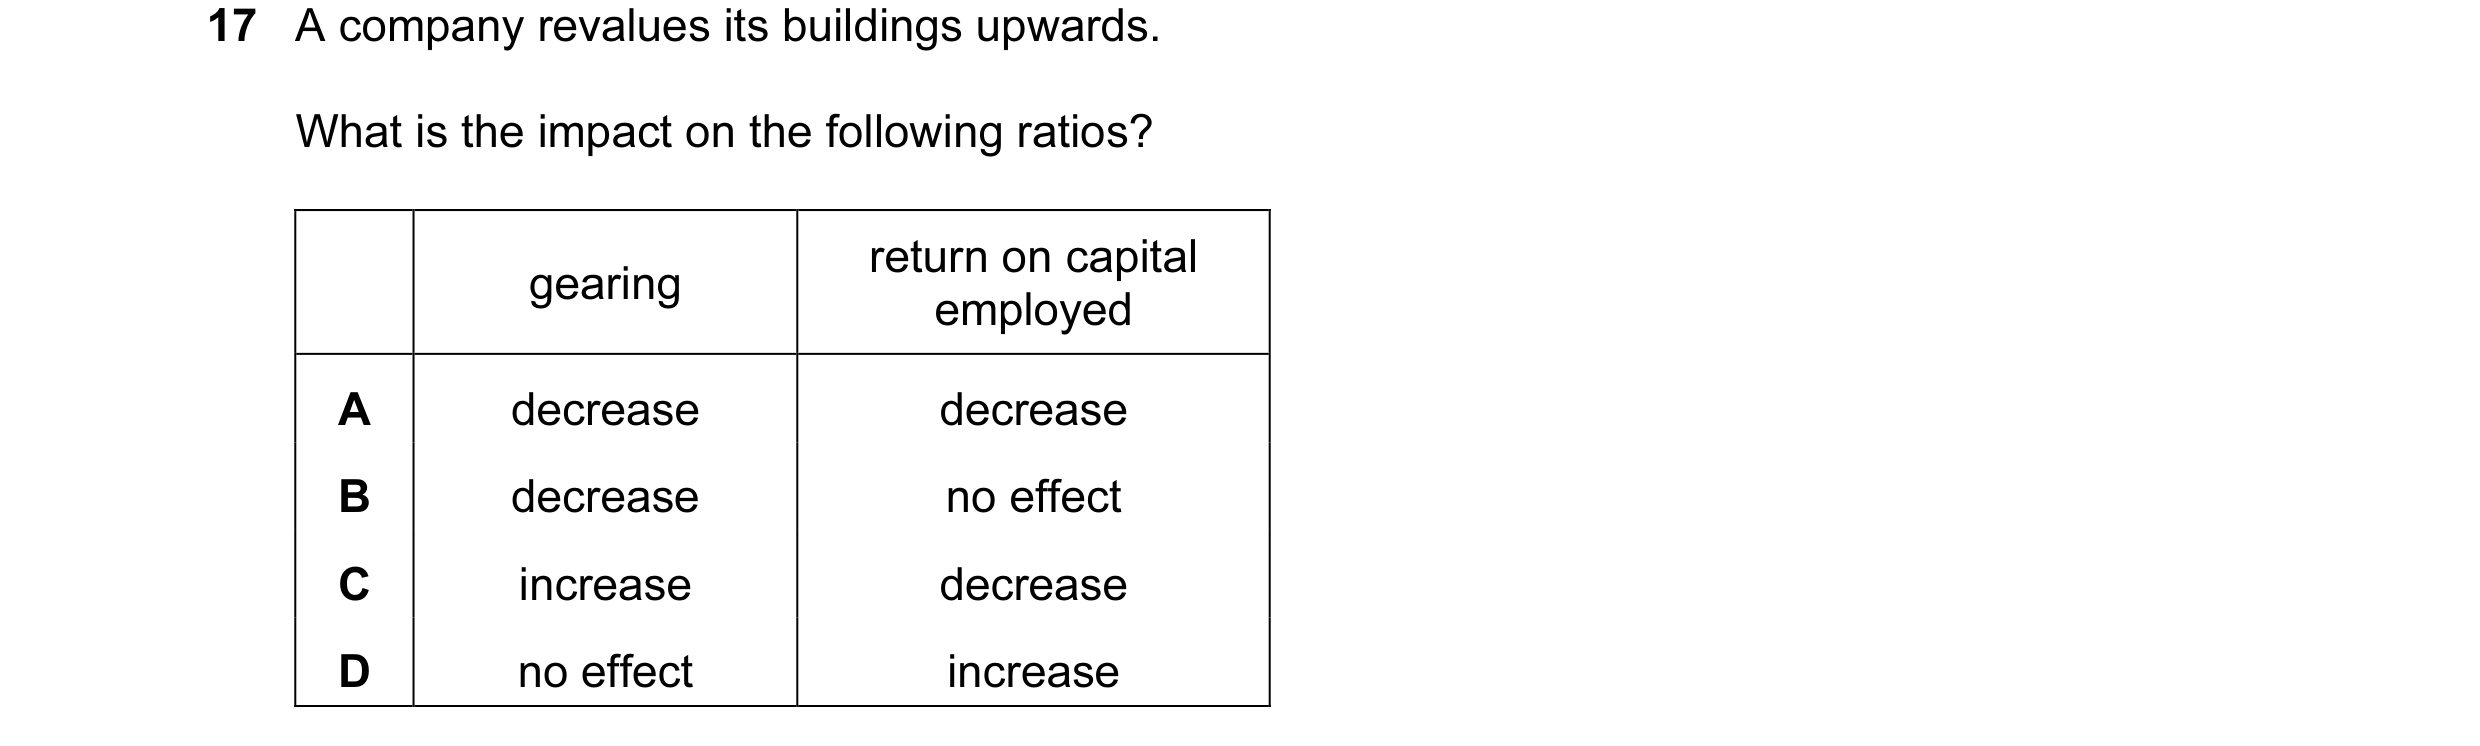
17 A company revalues its buildings upwards. What is the impact on the following ratios? return on capital gearing employed A decrease decrease B decrease no effect C increase decrease D no effect increase
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2011
Q48 · Which effect will a bonus issue of shares have on a company’s gearing ratio and earnings… 9706/32 Oct/Nov 2011
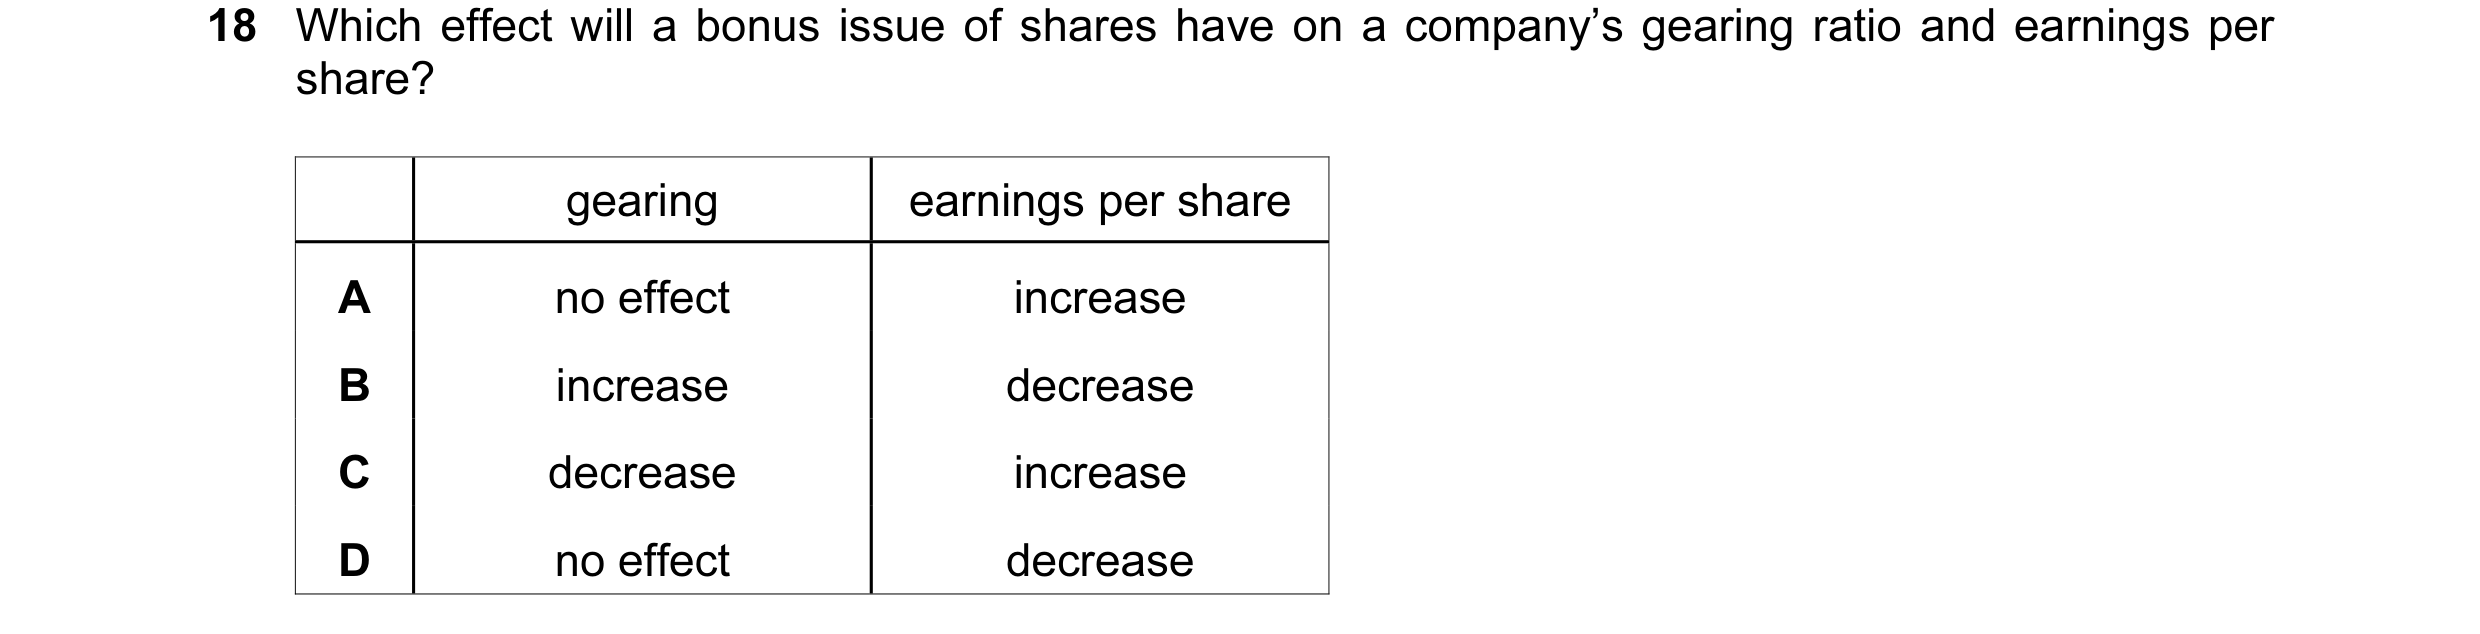
18 Which effect will a bonus issue of shares have on a company’s gearing ratio and earnings per share? gearing earnings per share A no effect increase B increase decrease C decrease increase D no effect decrease
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2011
Q49 · A balance sheet extract shows the following 9706/33 Oct/Nov 2011
3 A balance sheet extract shows the following. $ ordinary shares of $1 each 1000 10 % convertible loan stock 400 retained earnings 140 (dr) net assets 1800 net liabilities 540 All the loan stock is to be converted to ordinary shares in the proportion of $1 loan stock to one new ordinary share. After the conversion, what will be the net asset value per share? A $0.80 B $0.90 C $1.00 D $1.29
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2011
Q50 · A company revalues its non-current assets upwards 9706/33 Oct/Nov 2011
10 A company revalues its non-current assets upwards. Which of the following shows the effect of this? return on capital gearing employed A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2011
Q51 · PQR plc has the following accounting ratios for its financial years 2009 and 2010 9706/33 Oct/Nov 2011
11 PQR plc has the following accounting ratios for its financial years 2009 and 2010. 2009 (days) 2010 (days) trade receivables turnover 45 50 trade payables turnover 35 40 inventory turnover 60 70 What was the change in the working capital cycle for 2010 compared to 2009? A no change B 10 days increase C 20 days increase D 40 days increase
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2011
Q52 · A company makes annual profits of $10 million before interest payable of $2 million and… 9706/33 Oct/Nov 2011
12 A company makes annual profits of $10 million before interest payable of $2 million and ordinary dividends of $5 million. It has in issue 20 million shares of $0.20 each, currently valued on the stock exchange at $5 each. What is the company’s price/earnings (P/E) ratio? A 10 B 12.5 C 25 D 33.3
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2011
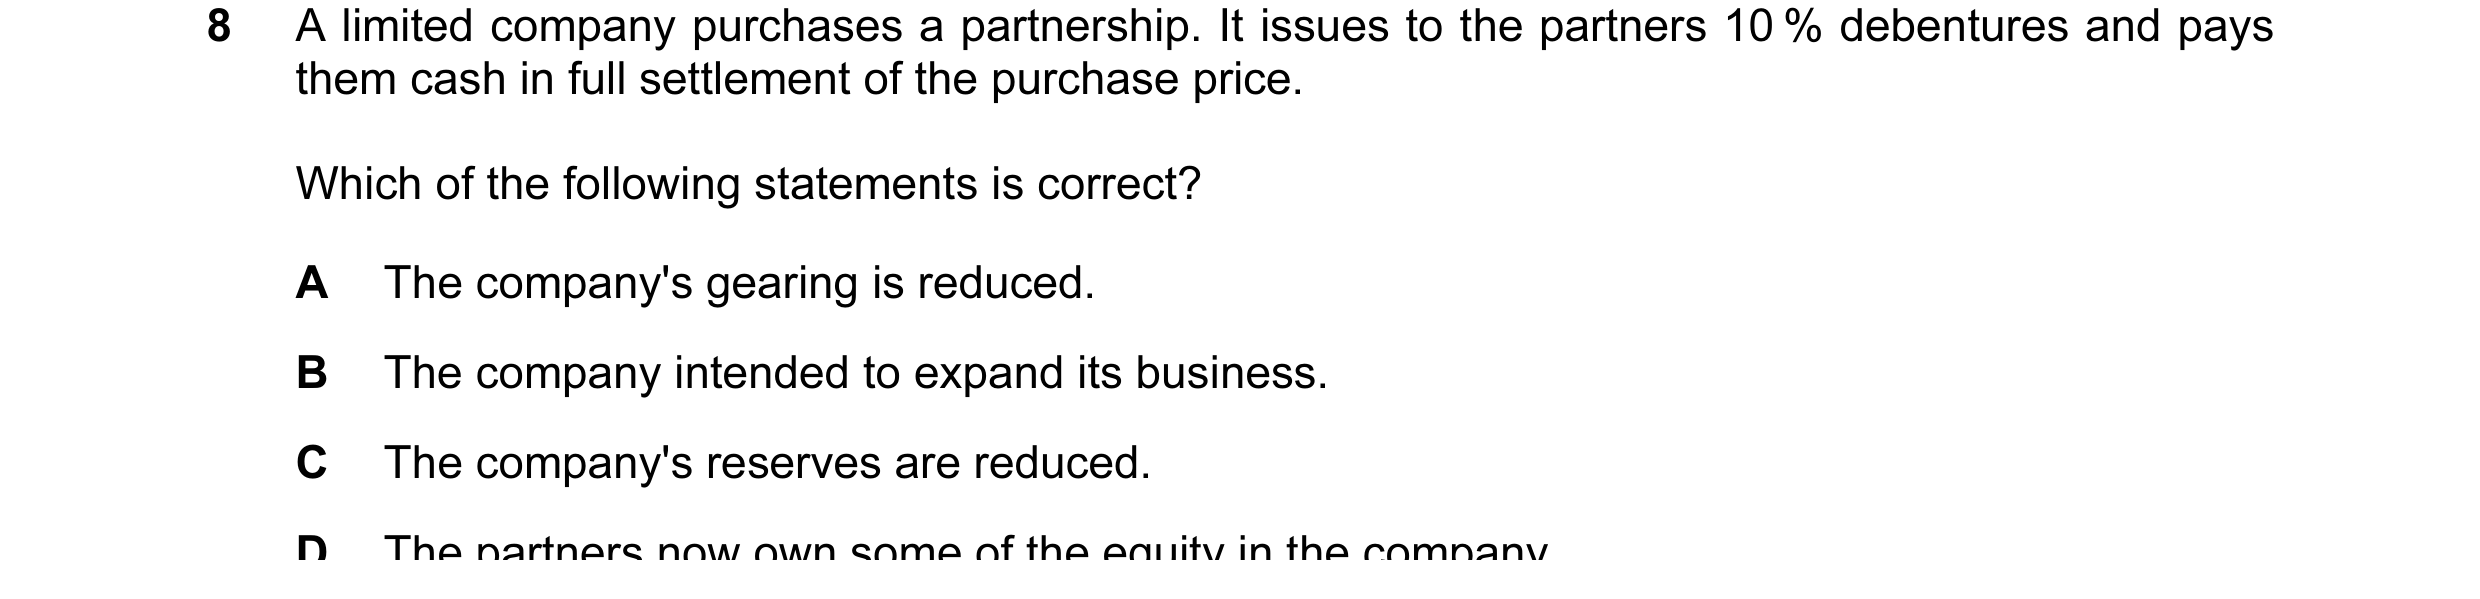
Q53 · A limited company purchases a partnership 9706/31 May/June 2012
8 A limited company purchases a partnership. It issues to the partners 10 % debentures and pays them cash in full settlement of the purchase price. Which of the following statements is correct? A The company's gearing is reduced. B The company intended to expand its business. C The company's reserves are reduced. D The partners now own some of the equity in the company.
1 marks
Answer: B
This question in 9706/31 May/June 2012
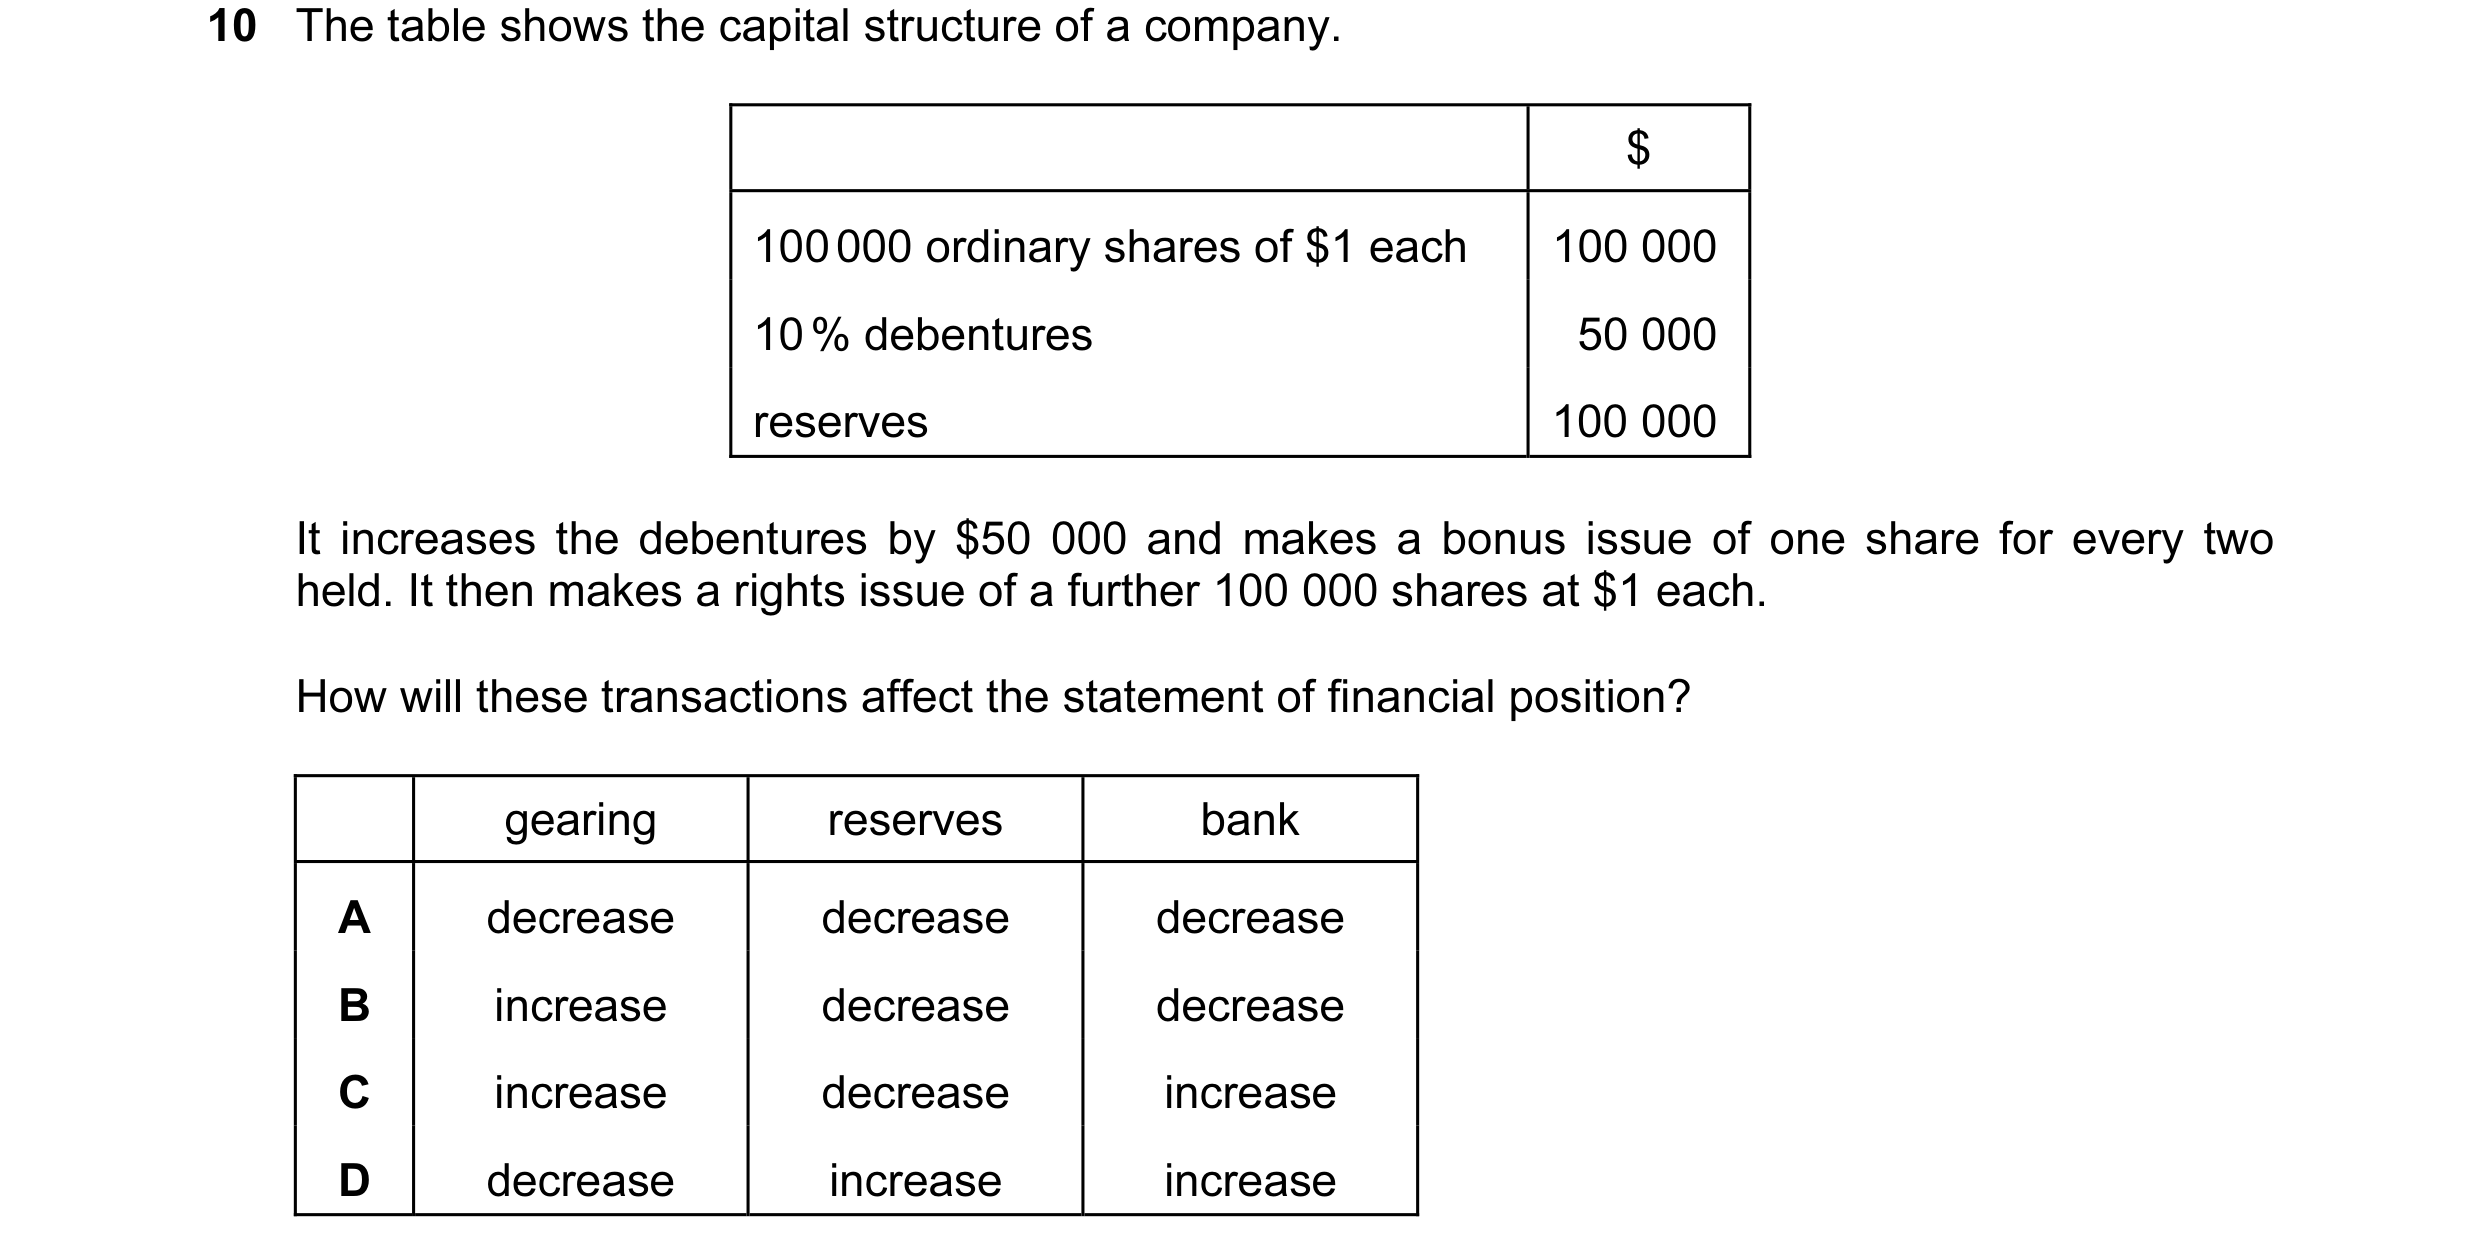
Q54 · The table shows the capital structure of a company 9706/31 May/June 2012
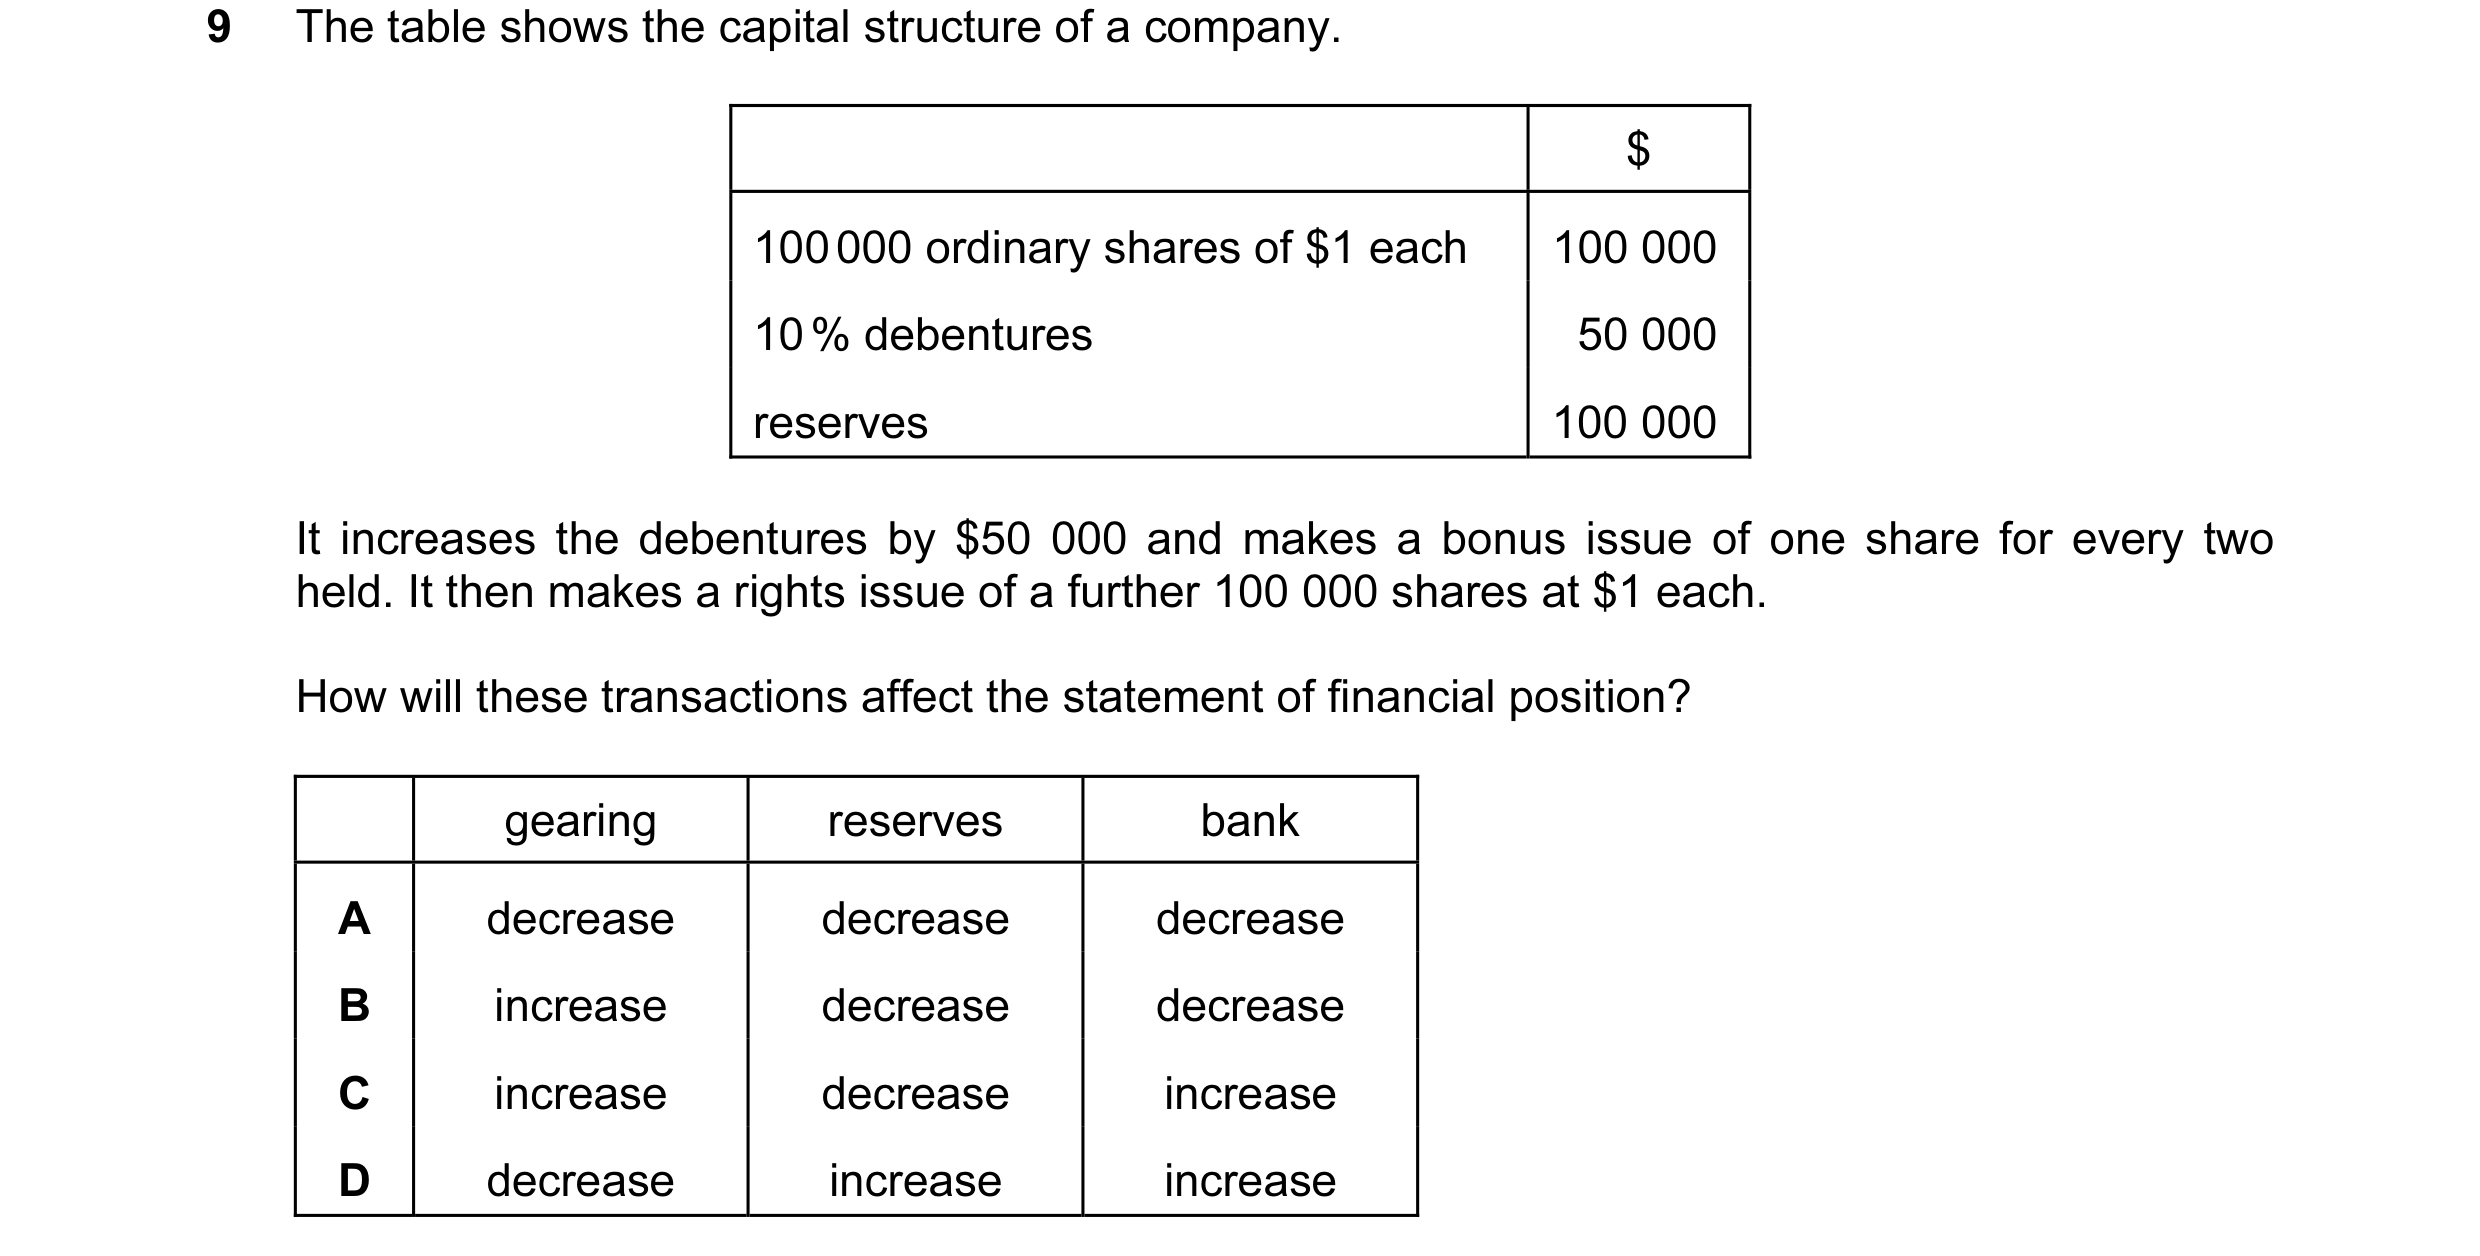
10 The table shows the capital structure of a company. $ 100 000 ordinary shares of $1 each 100 000 10 % debentures 50 000 reserves 100 000 It increases the debentures by $50 000 and makes a bonus issue of one share for every two held. It then makes a rights issue of a further 100 000 shares at $1 each. How will these transactions affect the statement of financial position? gearing reserves bank A decrease decrease decrease B increase decrease decrease C increase decrease increase D decrease increase increase
1 marks
Answer: C
This question in 9706/31 May/June 2012
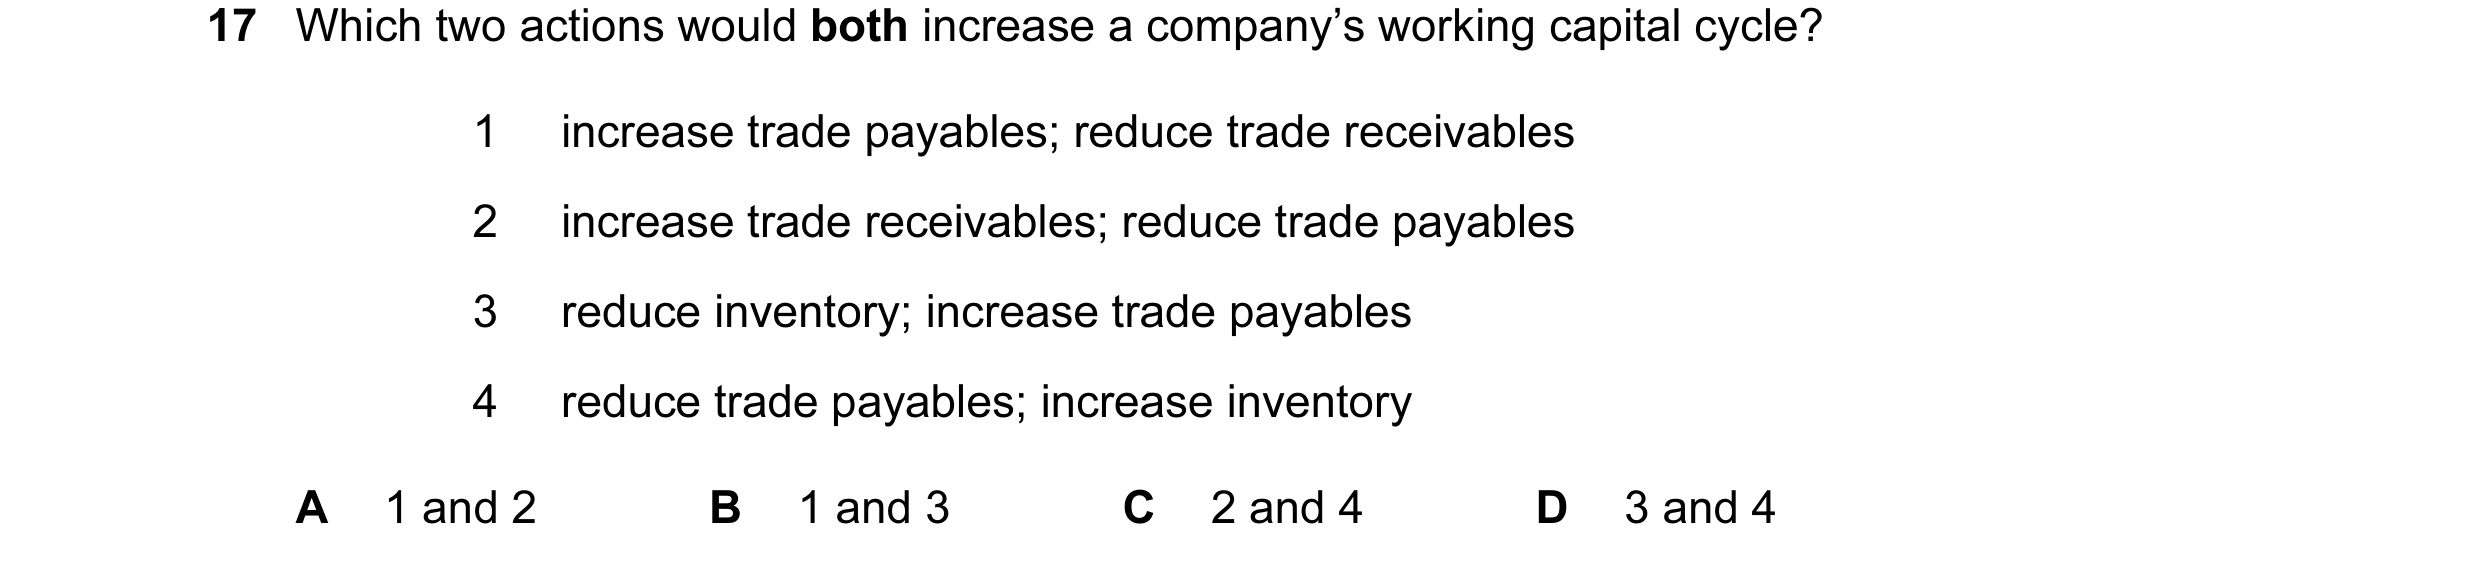
Q55 · Which two actions would both increase a company’s working capital cycle? 9706/31 May/June 2012
17 Which two actions would both increase a company’s working capital cycle? 1 increase trade payables; reduce trade receivables 2 increase trade receivables; reduce trade payables 3 reduce inventory; increase trade payables 4 reduce trade payables; increase inventory A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: C
This question in 9706/31 May/June 2012
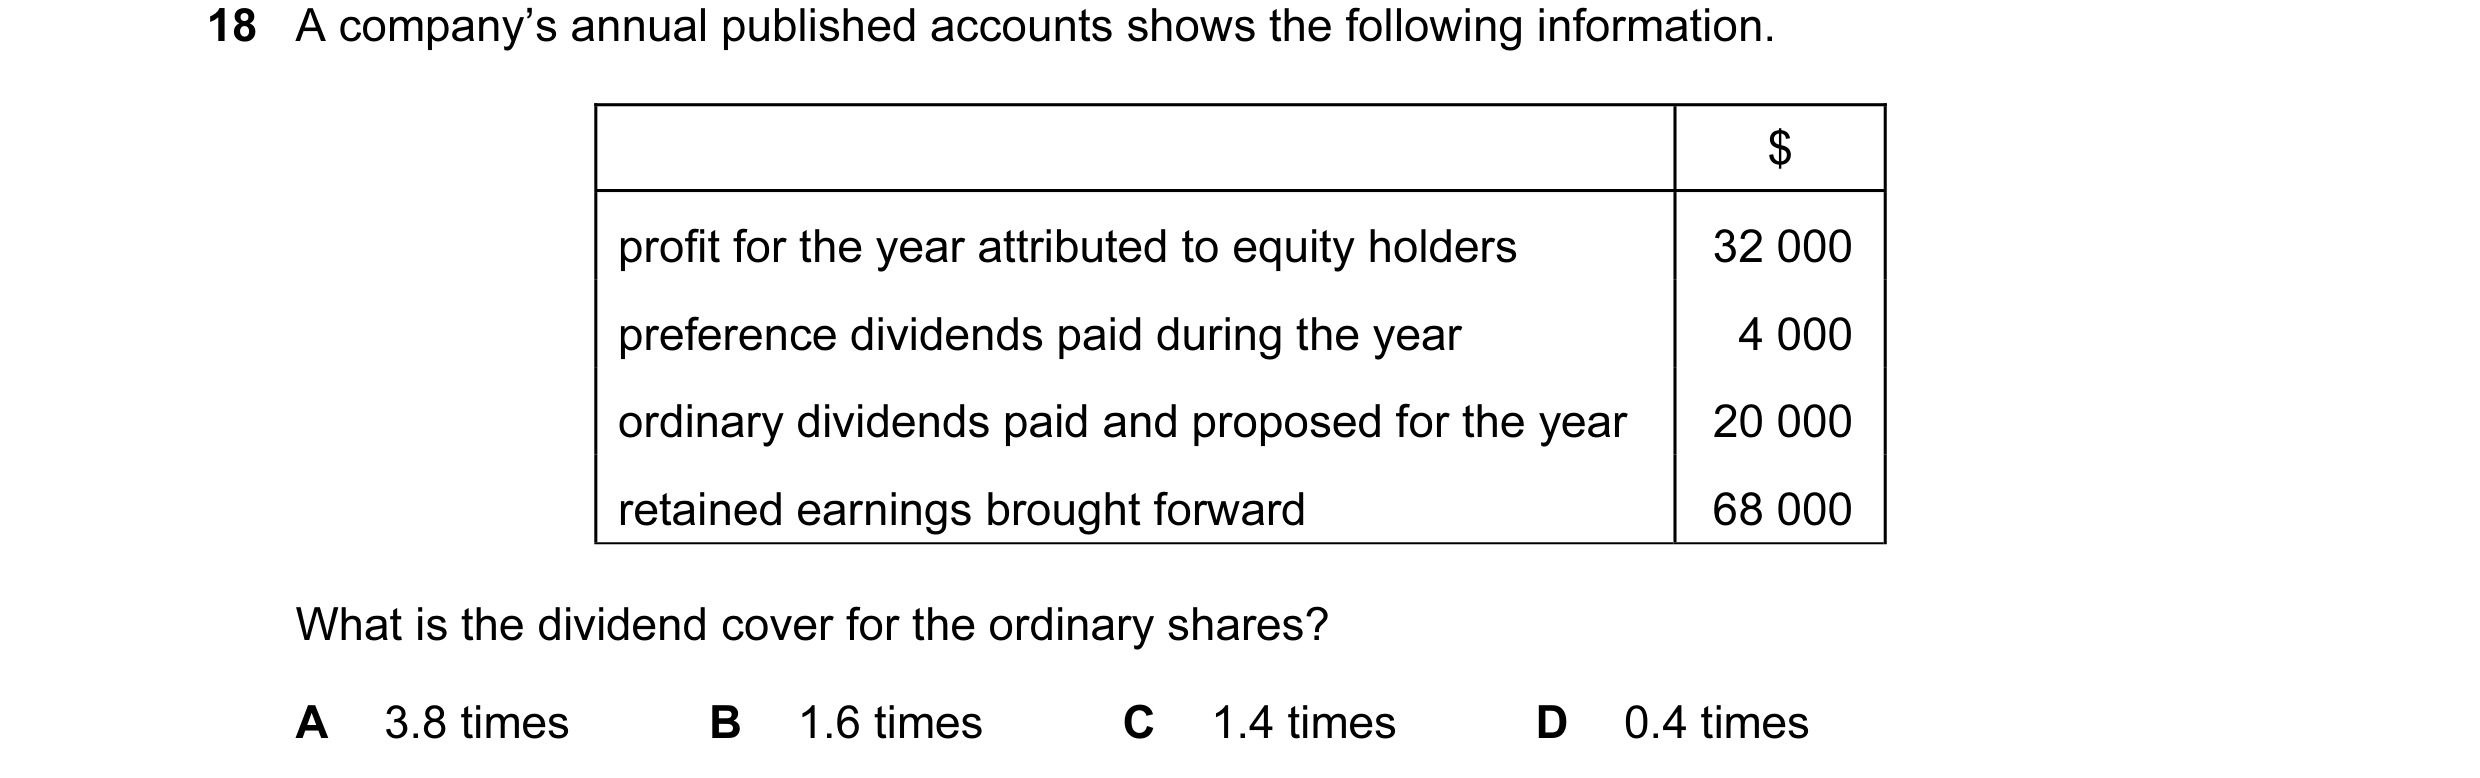
Q56 · A company’s annual published accounts shows the following information 9706/31 May/June 2012
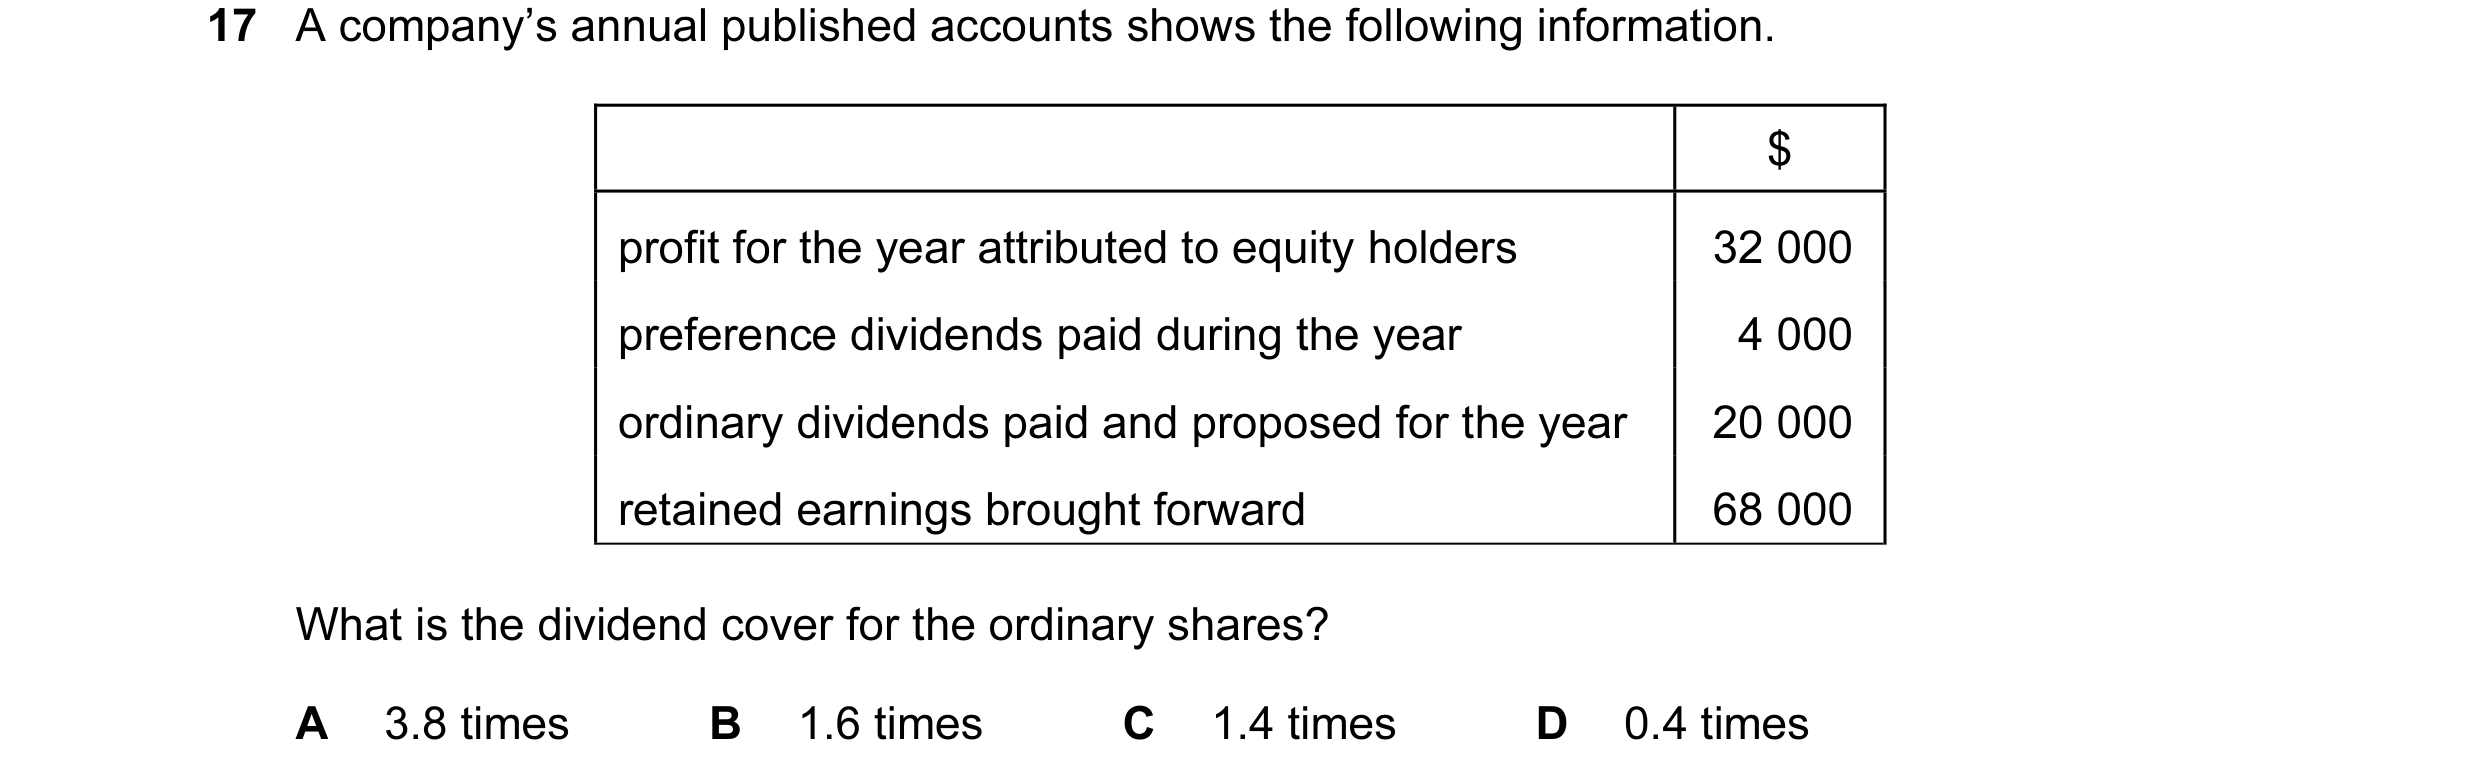
18 A company’s annual published accounts shows the following information. $ profit for the year attributed to equity holders 32 000 preference dividends paid during the year 4 000 ordinary dividends paid and proposed for the year 20 000 retained earnings brought forward 68 000 What is the dividend cover for the ordinary shares? A 3.8 times B 1.6 times C 1.4 times D 0.4 times
1 marks
Answer: B
This question in 9706/31 May/June 2012
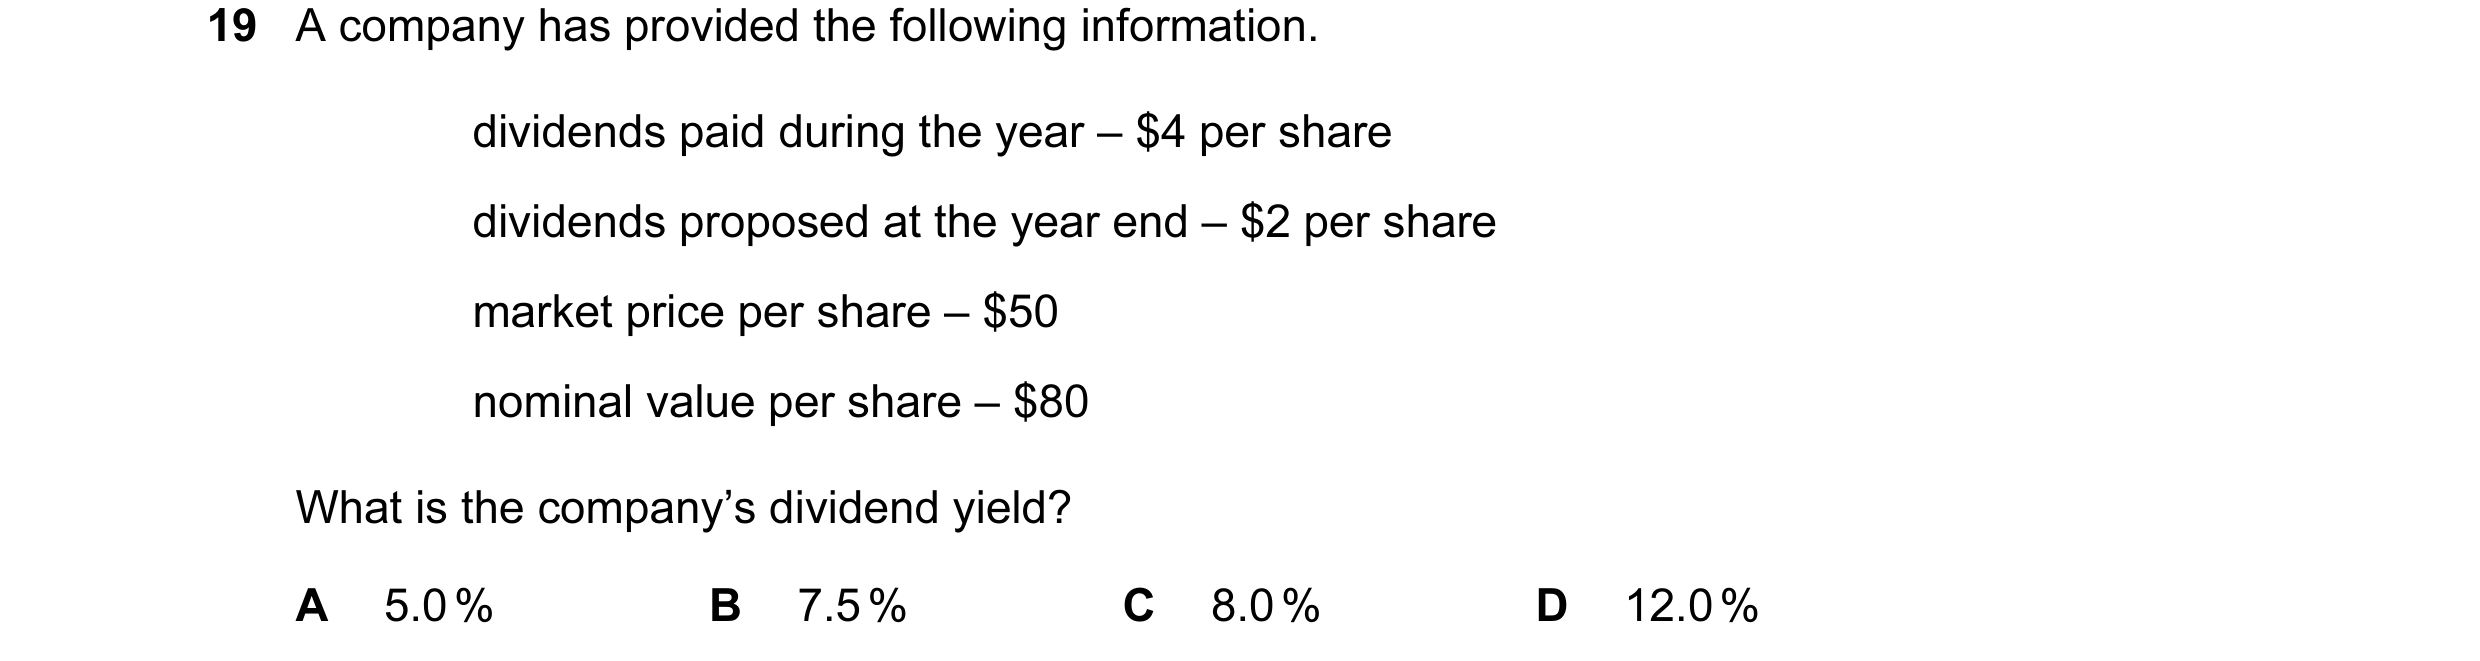
Q57 · A company has provided the following information 9706/31 May/June 2012
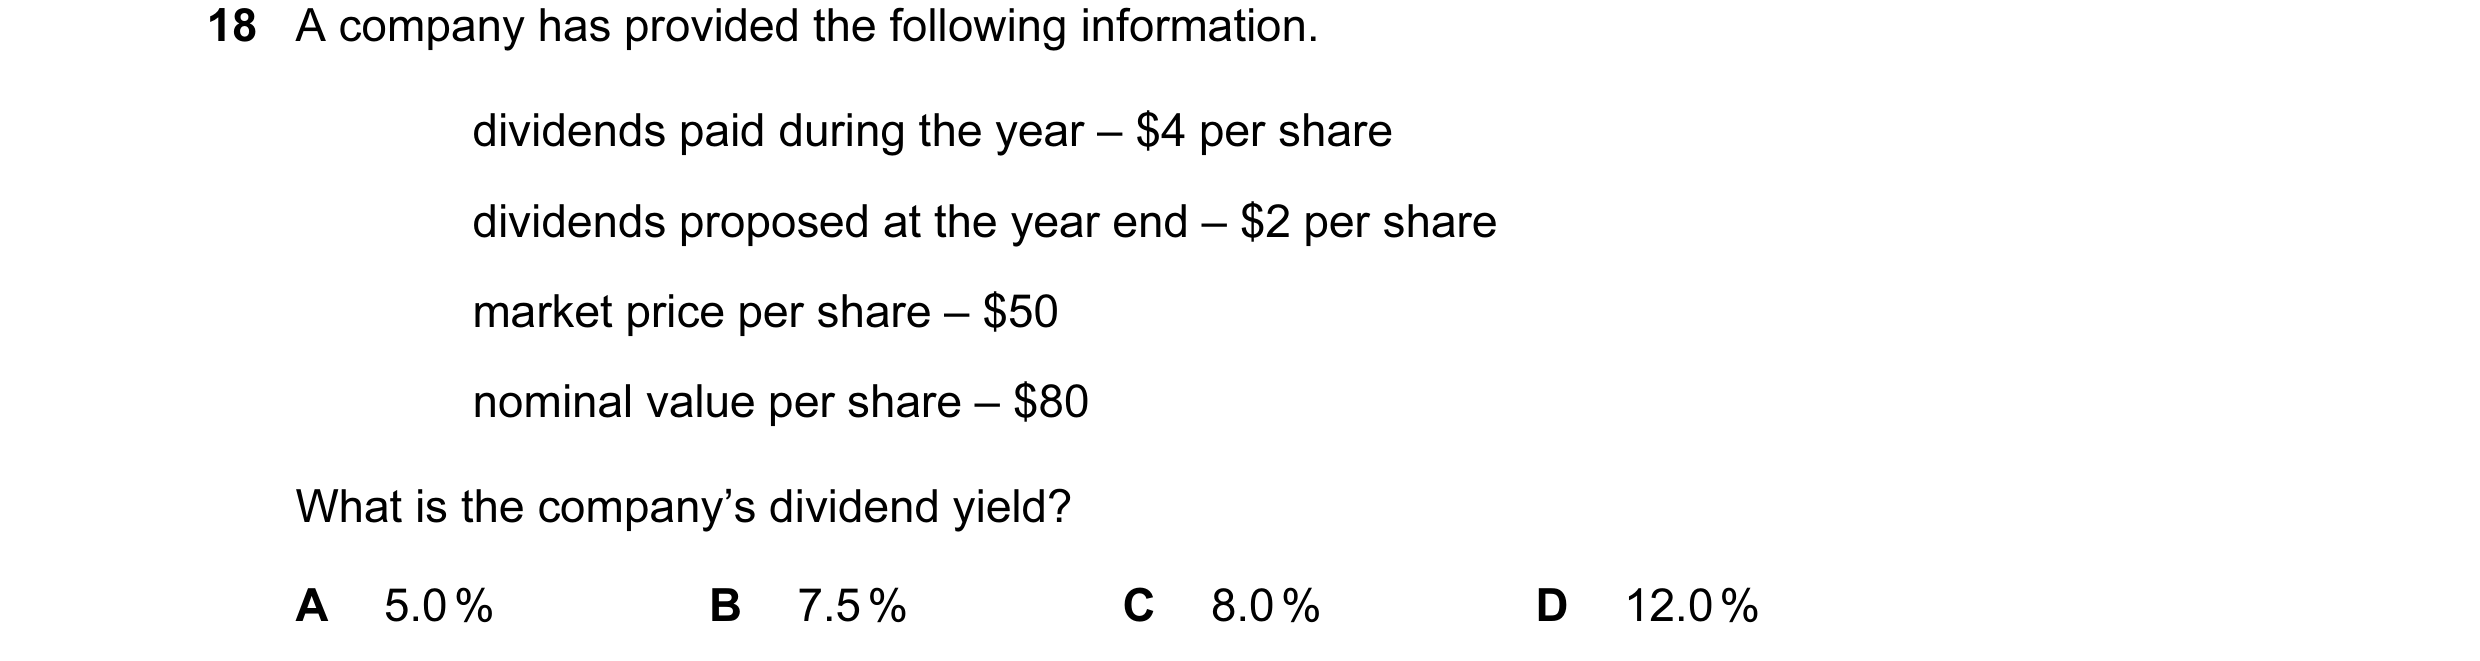
19 A company has provided the following information. dividends paid during the year – $4 per share dividends proposed at the year end – $2 per share market price per share – $50 nominal value per share – $80 What is the company’s dividend yield? A 5.0 % B 7.5 % C 8.0 % D 12.0 %
1 marks
Answer: D
This question in 9706/31 May/June 2012
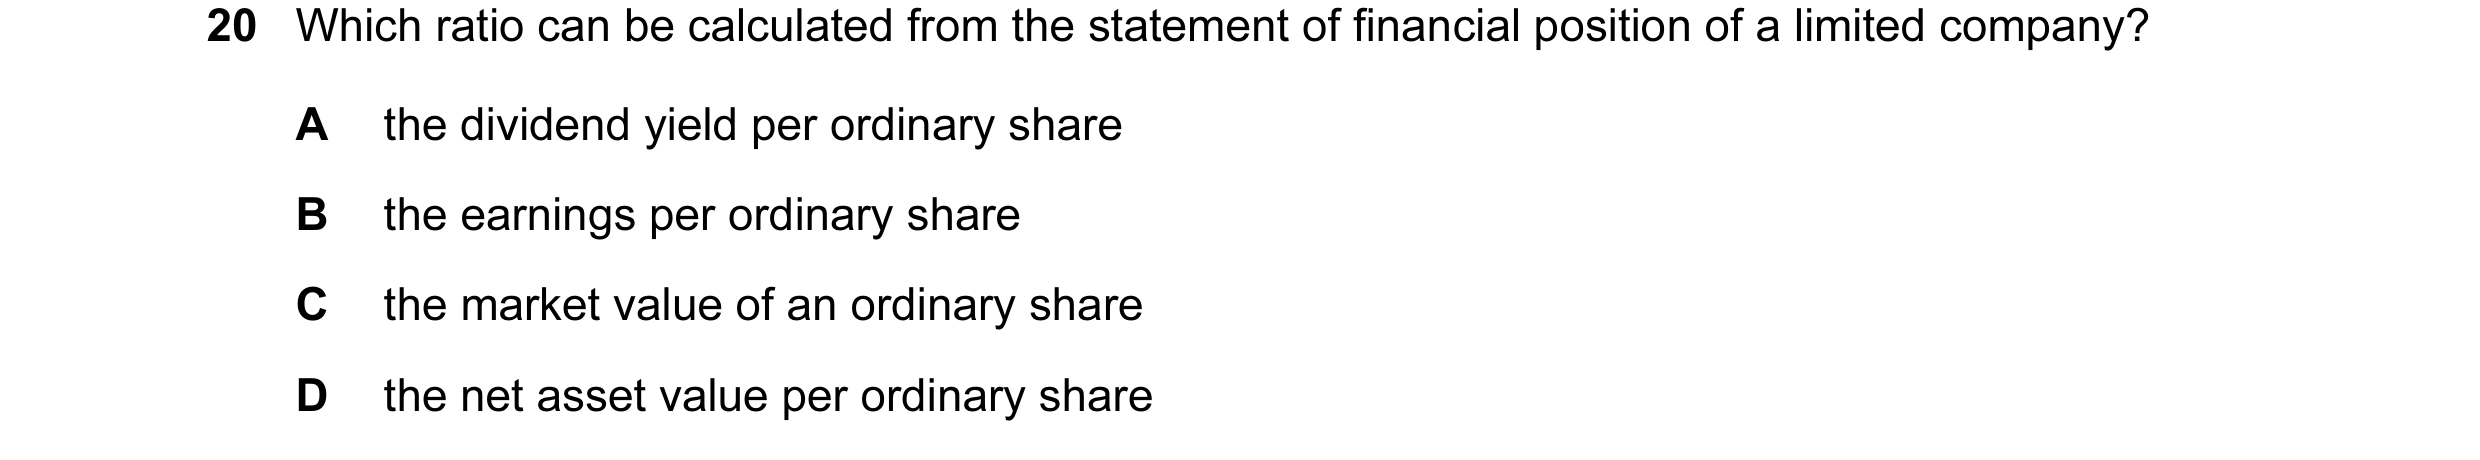
Q58 · Which ratio can be calculated from the statement of financial position of a limited… 9706/31 May/June 2012
20 Which ratio can be calculated from the statement of financial position of a limited company? A the dividend yield per ordinary share B the earnings per ordinary share C the market value of an ordinary share D the net asset value per ordinary share
1 marks
Answer: D
This question in 9706/31 May/June 2012
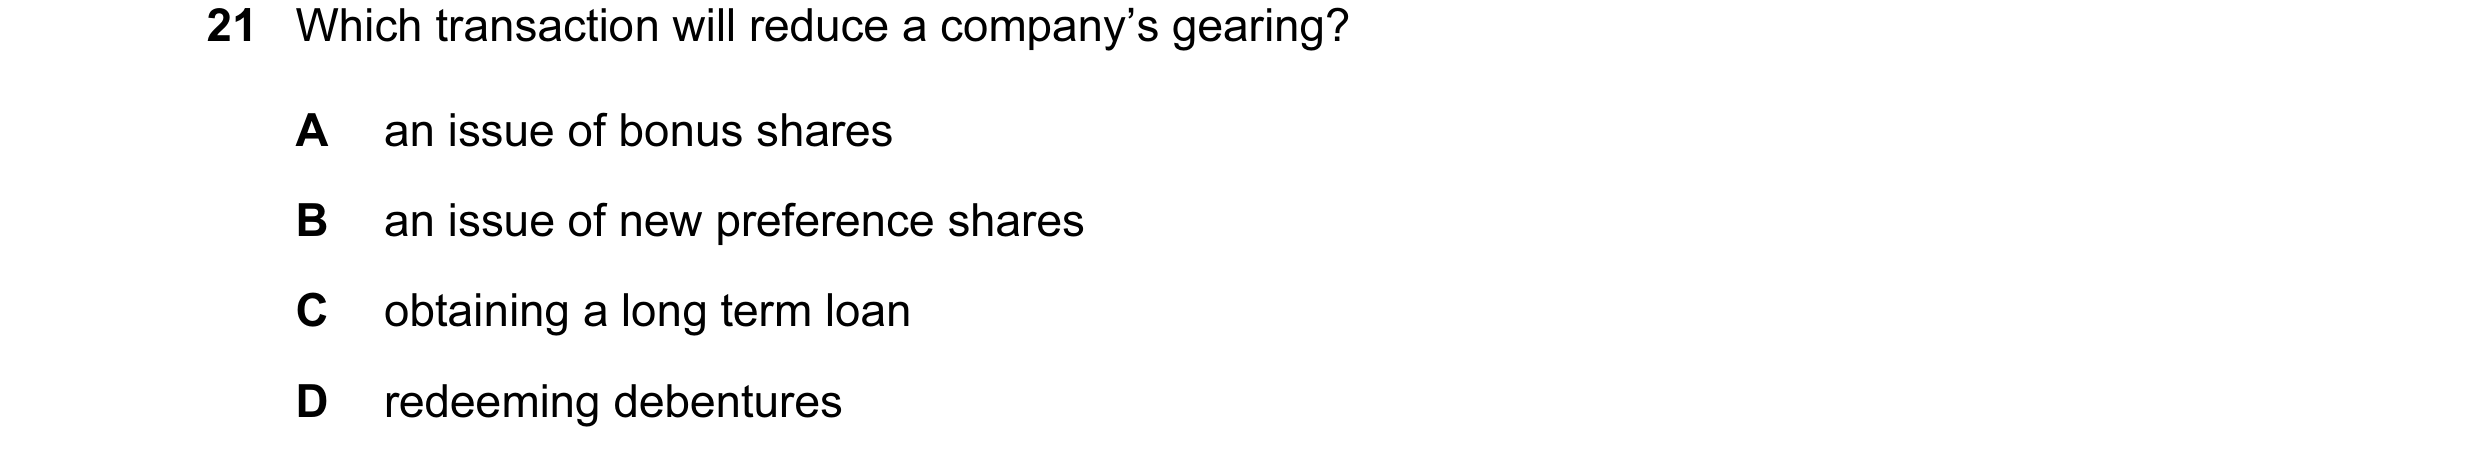
Q59 · Which transaction will reduce a company’s gearing? 9706/31 May/June 2012
21 Which transaction will reduce a company’s gearing? A an issue of bonus shares B an issue of new preference shares C obtaining a long term loan D redeeming debentures
1 marks
Answer: D
This question in 9706/31 May/June 2012
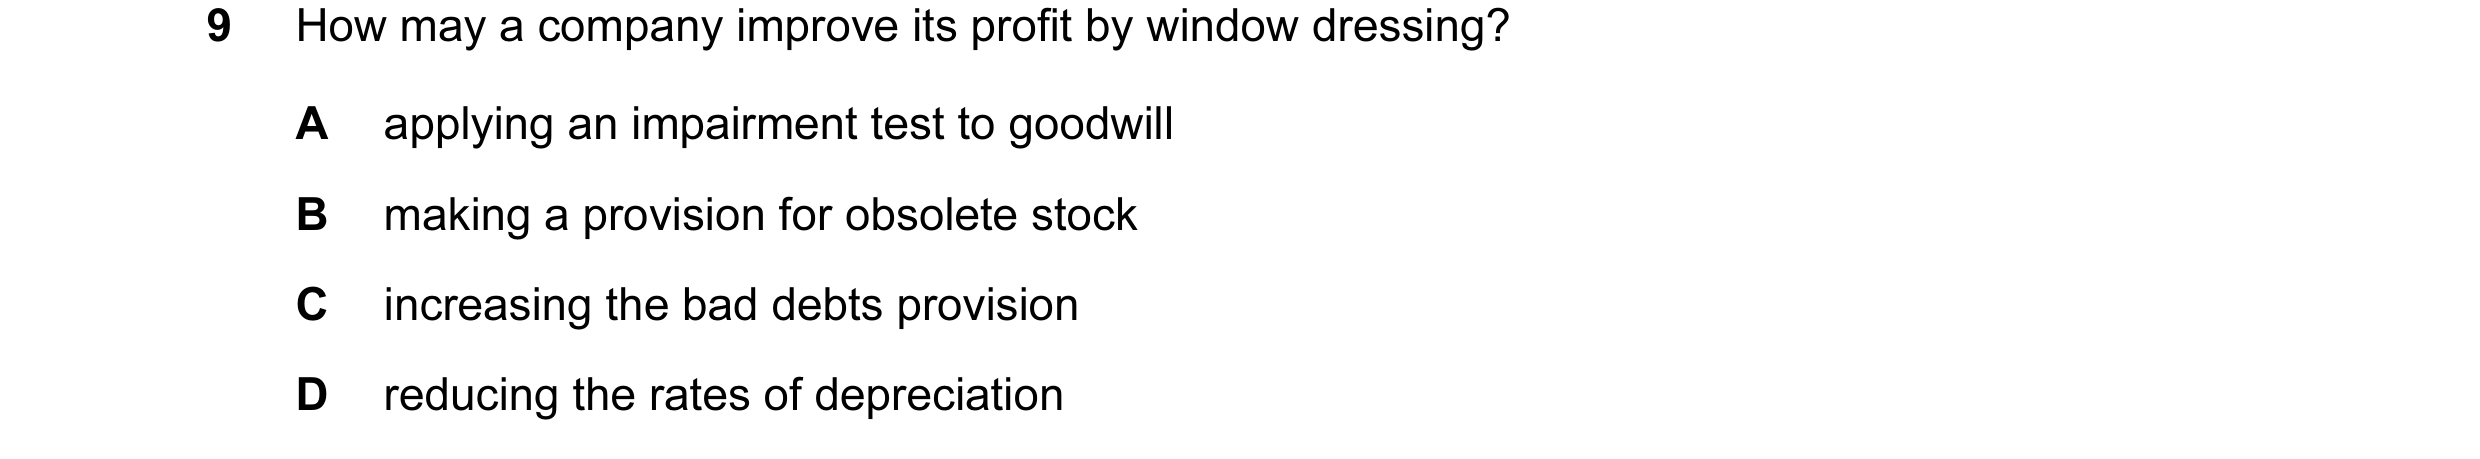
Q60 · How may a company improve its profit by window dressing? 9706/32 May/June 2012
9 How may a company improve its profit by window dressing? A applying an impairment test to goodwill B making a provision for obsolete stock C increasing the bad debts provision D reducing the rates of depreciation
1 marks
Answer: D
This question in 9706/32 May/June 2012
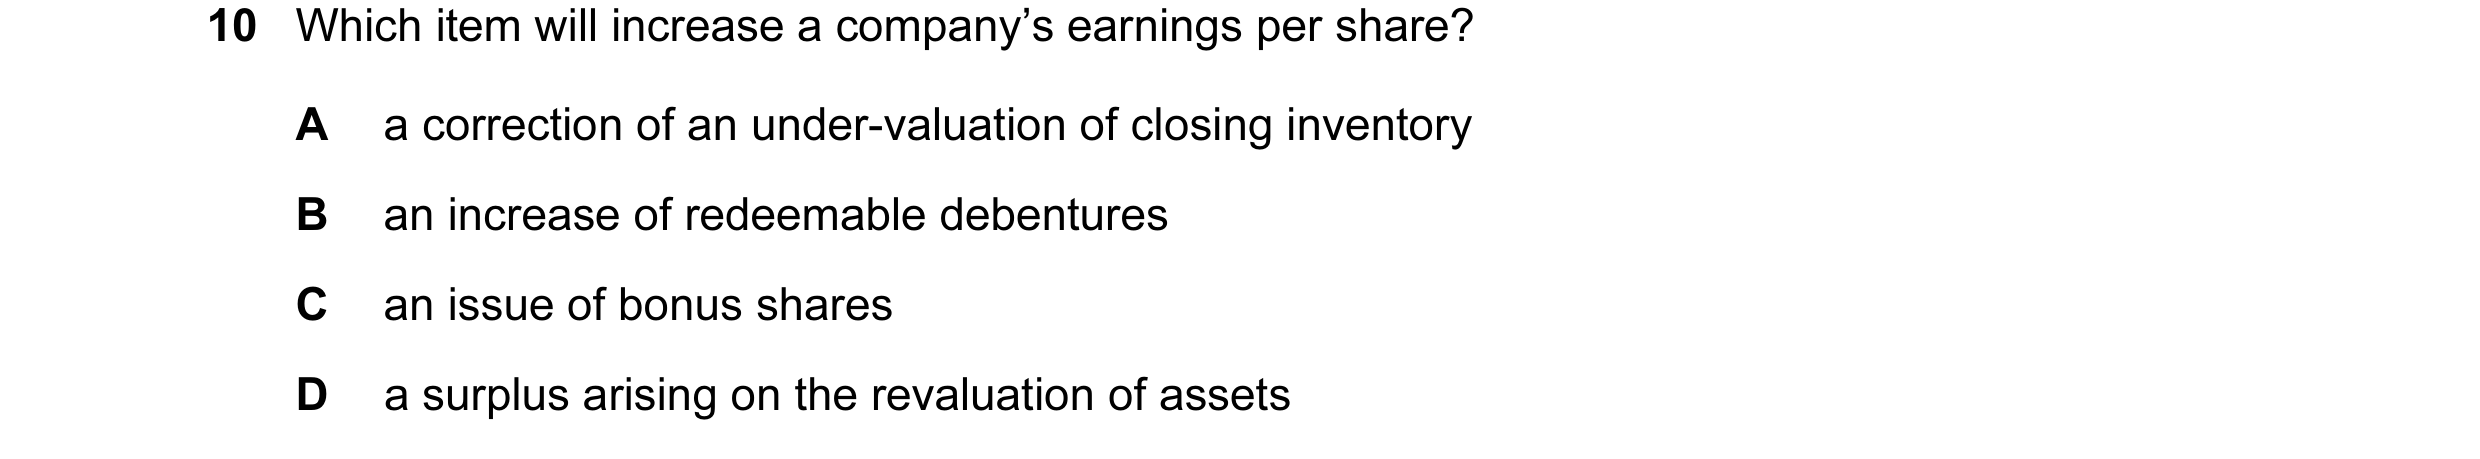
Q61 · Which item will increase a company’s earnings per share? 9706/32 May/June 2012
10 Which item will increase a company’s earnings per share? A a correction of an under-valuation of closing inventory B an increase of redeemable debentures C an issue of bonus shares D a surplus arising on the revaluation of assets
1 marks
Answer: A
This question in 9706/32 May/June 2012
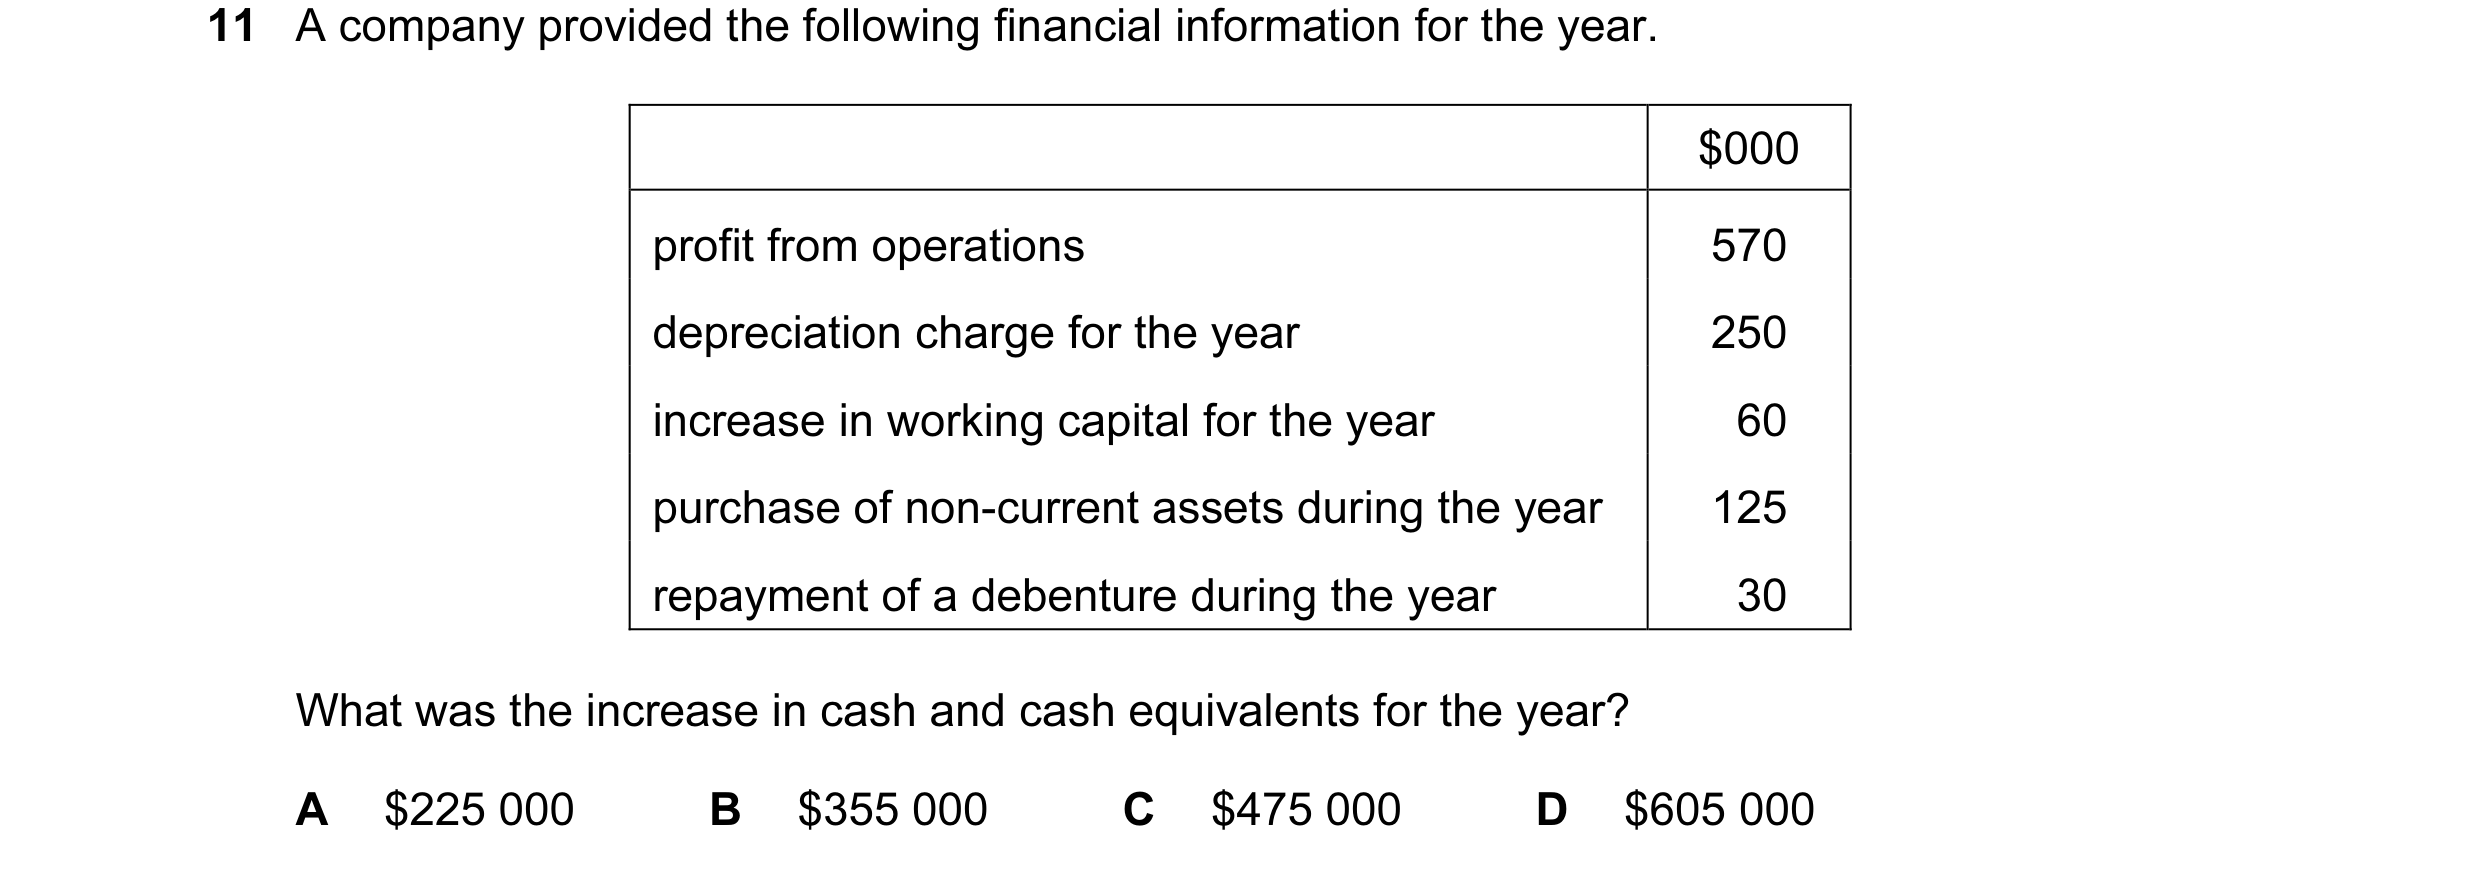
Q62 · A company provided the following financial information for the year 9706/32 May/June 2012
11 A company provided the following financial information for the year. $000 profit from operations 570 depreciation charge for the year 250 increase in working capital for the year 60 purchase of non-current assets during the year 125 repayment of a debenture during the year 30 What was the increase in cash and cash equivalents for the year? A $225 000 B $355 000 C $475 000 D $605 000
1 marks
Answer: D
This question in 9706/32 May/June 2012
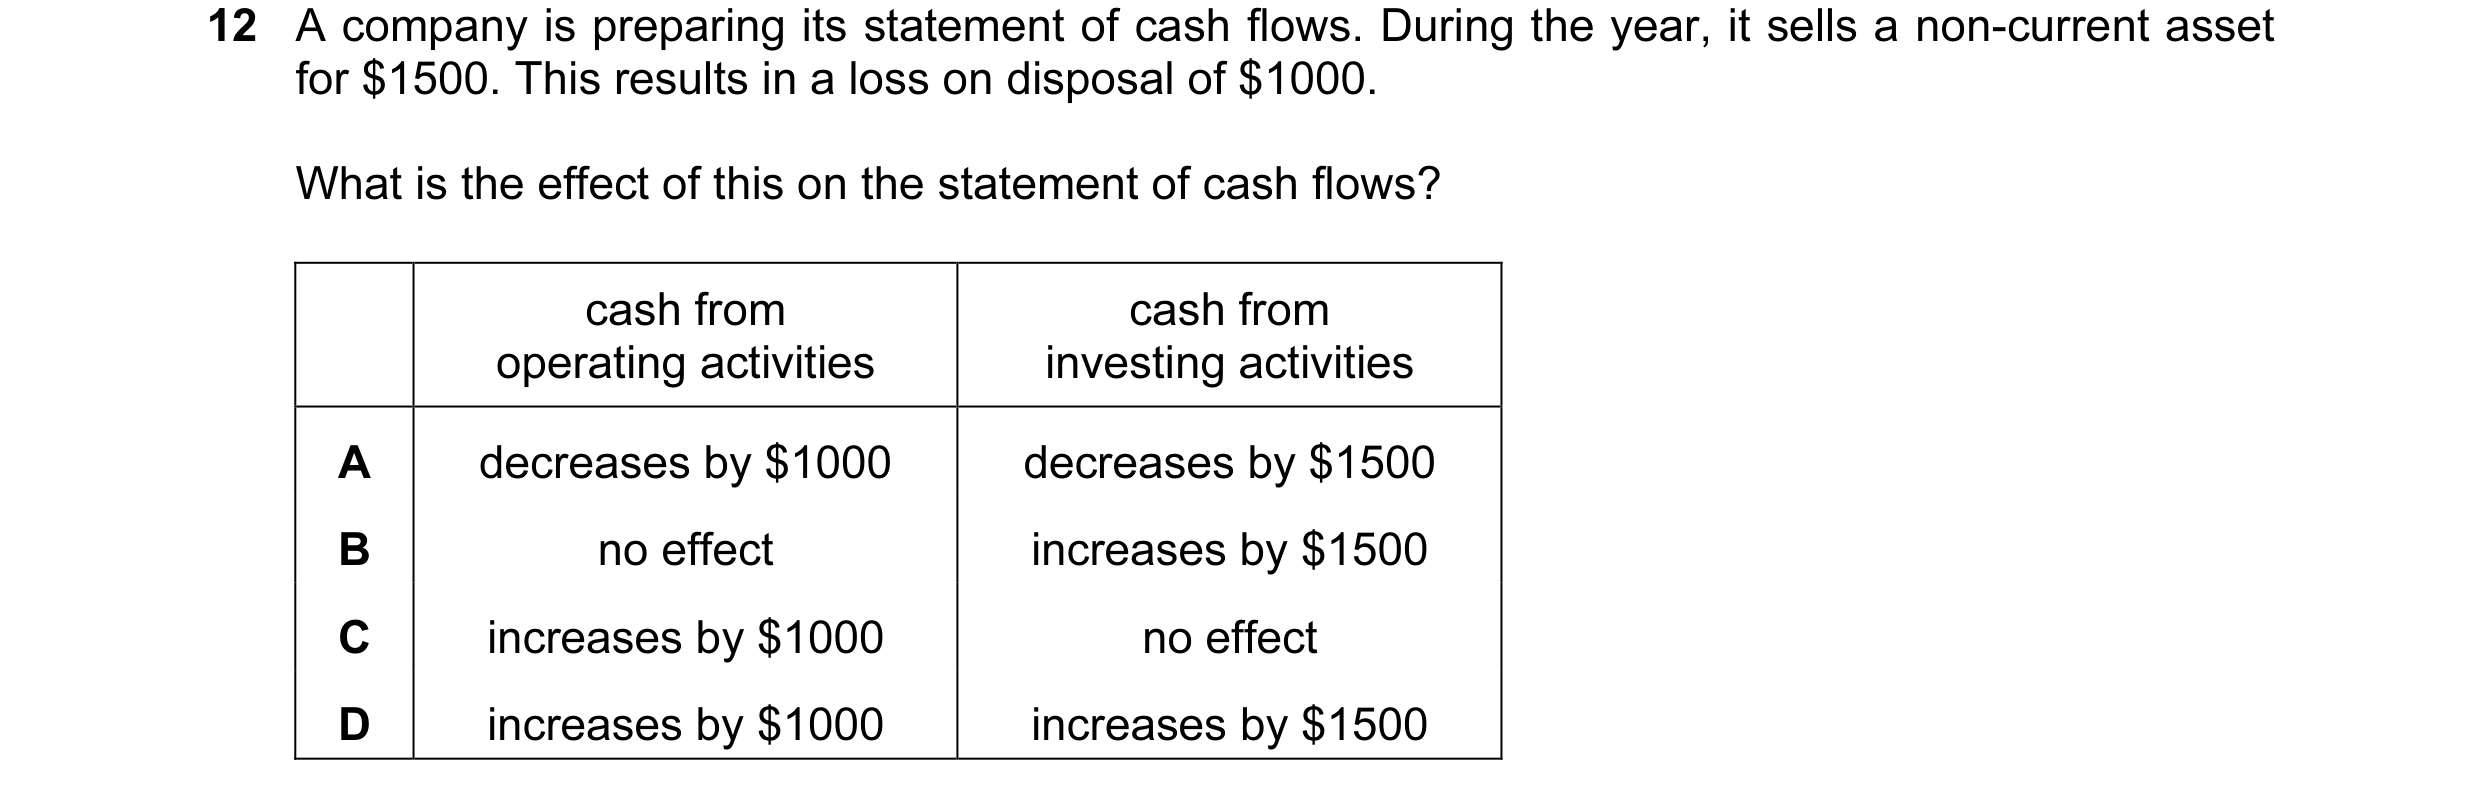
Q63 · A company is preparing its statement of cash flows 9706/32 May/June 2012
12 A company is preparing its statement of cash flows. During the year, it sells a non-current asset for $1500. This results in a loss on disposal of $1000. What is the effect of this on the statement of cash flows? cash from cash from operating activities investing activities A decreases by $1000 decreases by $1500 B no effect increases by $1500 C increases by $1000 no effect D increases by $1000 increases by $1500
1 marks
Answer: D
This question in 9706/32 May/June 2012
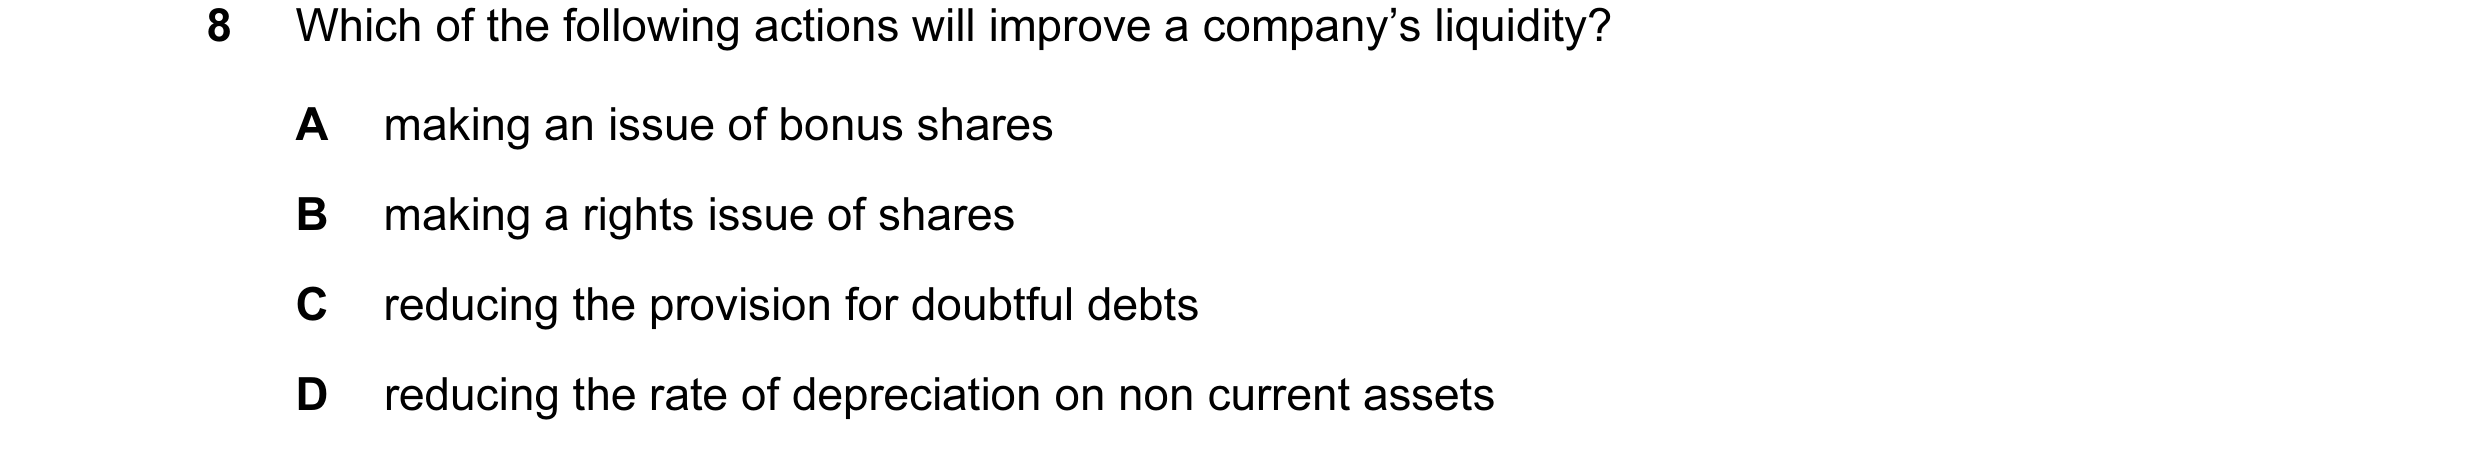
Q64 · Which of the following actions will improve a company’s liquidity? 9706/33 May/June 2012
8 Which of the following actions will improve a company’s liquidity? A making an issue of bonus shares B making a rights issue of shares C reducing the provision for doubtful debts D reducing the rate of depreciation on non current assets
1 marks
Answer: B
This question in 9706/33 May/June 2012
Q65 · The table shows the capital structure of a company 9706/33 May/June 2012
9 The table shows the capital structure of a company. $ 100 000 ordinary shares of $1 each 100 000 10 % debentures 50 000 reserves 100 000 It increases the debentures by $50 000 and makes a bonus issue of one share for every two held. It then makes a rights issue of a further 100 000 shares at $1 each. How will these transactions affect the statement of financial position? gearing reserves bank A decrease decrease decrease B increase decrease decrease C increase decrease increase D decrease increase increase
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q66 · The following information relates to the shares of a limited company 9706/33 May/June 2012
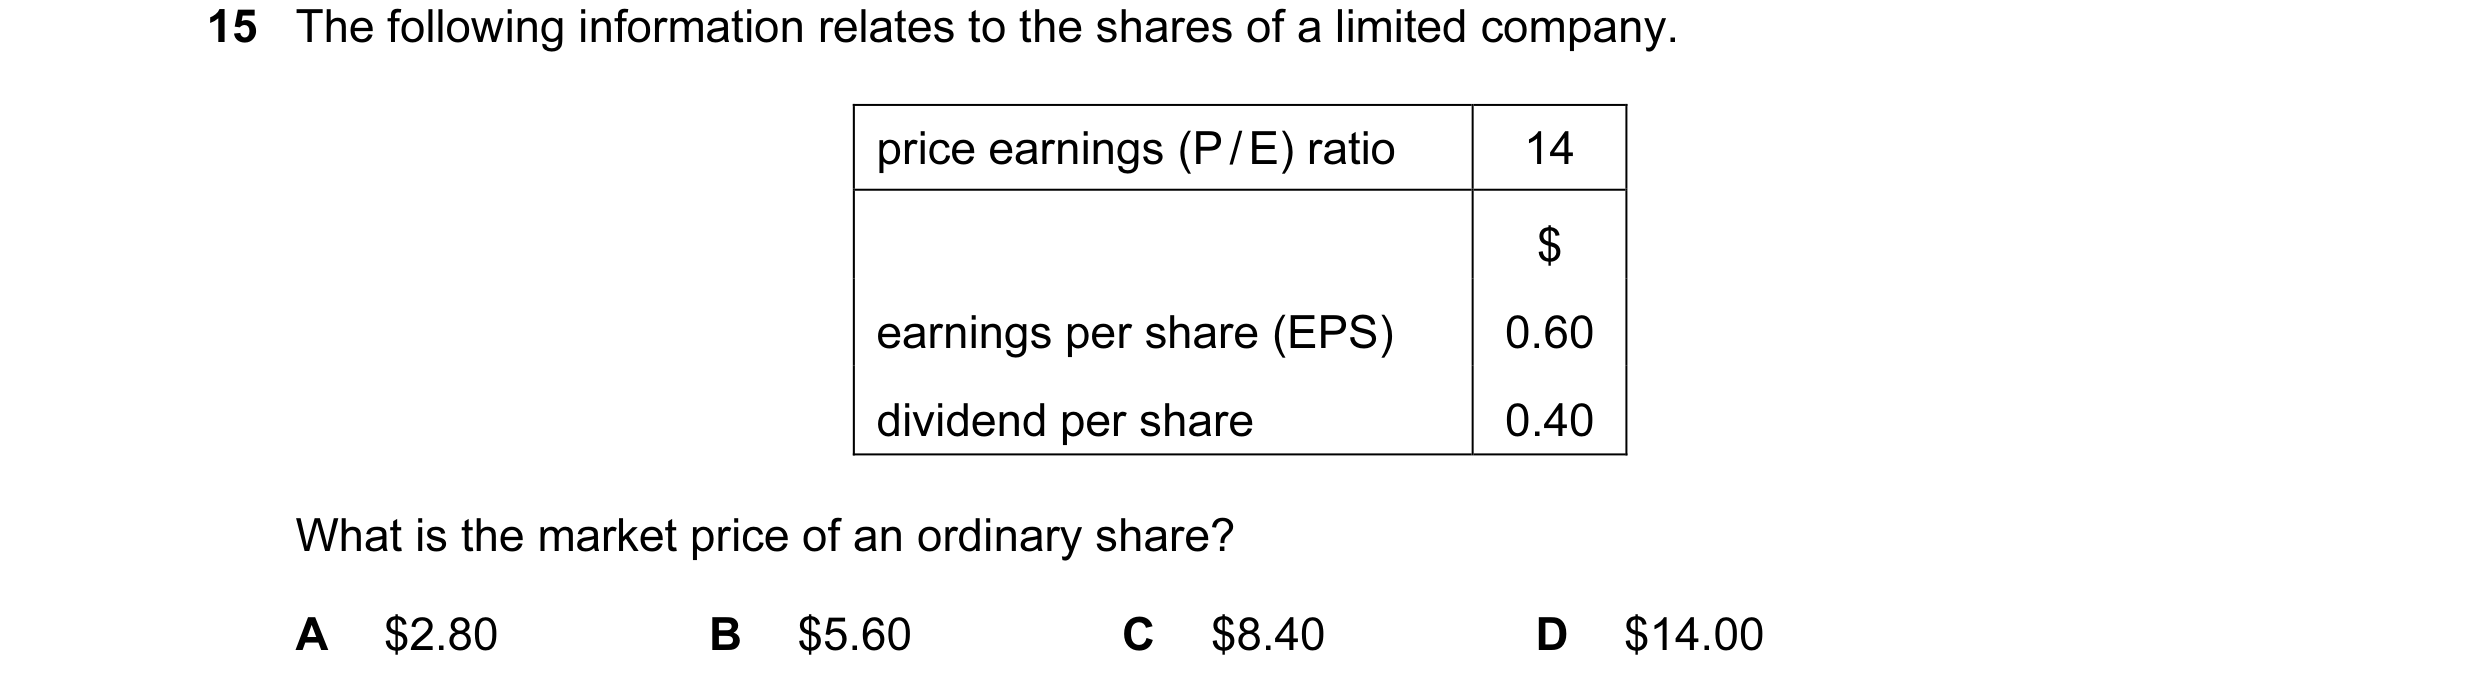
15 The following information relates to the shares of a limited company. price earnings (P / E) ratio 14 $ earnings per share (EPS) 0.60 dividend per share 0.40 What is the market price of an ordinary share? A $2.80 B $5.60 C $8.40 D $14.00
1 marks
Answer: C
This question in 9706/33 May/June 2012
Q67 · A company’s annual published accounts shows the following information 9706/33 May/June 2012
17 A company’s annual published accounts shows the following information. $ profit for the year attributed to equity holders 32 000 preference dividends paid during the year 4 000 ordinary dividends paid and proposed for the year 20 000 retained earnings brought forward 68 000 What is the dividend cover for the ordinary shares? A 3.8 times B 1.6 times C 1.4 times D 0.4 times
1 marks
Answer: B
This question in 9706/33 May/June 2012
Q68 · A company has provided the following information 9706/33 May/June 2012
18 A company has provided the following information. dividends paid during the year – $4 per share dividends proposed at the year end – $2 per share market price per share – $50 nominal value per share – $80 What is the company’s dividend yield? A 5.0 % B 7.5 % C 8.0 % D 12.0 %
1 marks
Answer: D
This question in 9706/33 May/June 2012
Q69 · Which ratio can be calculated from the statement of financial position of a limited… 9706/33 May/June 2012
19 Which ratio can be calculated from the statement of financial position of a limited company? A the dividend yield per ordinary share B the earnings per ordinary share C the market value of an ordinary share D the net asset value per ordinary share
1 marks
Answer: D
This question in 9706/33 May/June 2012
Q70 · Which transaction will reduce a company’s gearing? 9706/33 May/June 2012
20 Which transaction will reduce a company’s gearing? A an issue of bonus shares B an issue of new preference shares C obtaining a long term loan D redeeming debentures
1 marks
Answer: D
This question in 9706/33 May/June 2012
Q71 · Why would an investor use a price/earnings (P/E) ratio for a public limited company? 9706/31 Oct/Nov 2012
17 Why would an investor use a price/earnings (P/E) ratio for a public limited company? A to assess the level of borrowing in a company B to assess the liquidity of the company C to calculate earnings per share for the company D to compare its performance against other similar companies
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2012
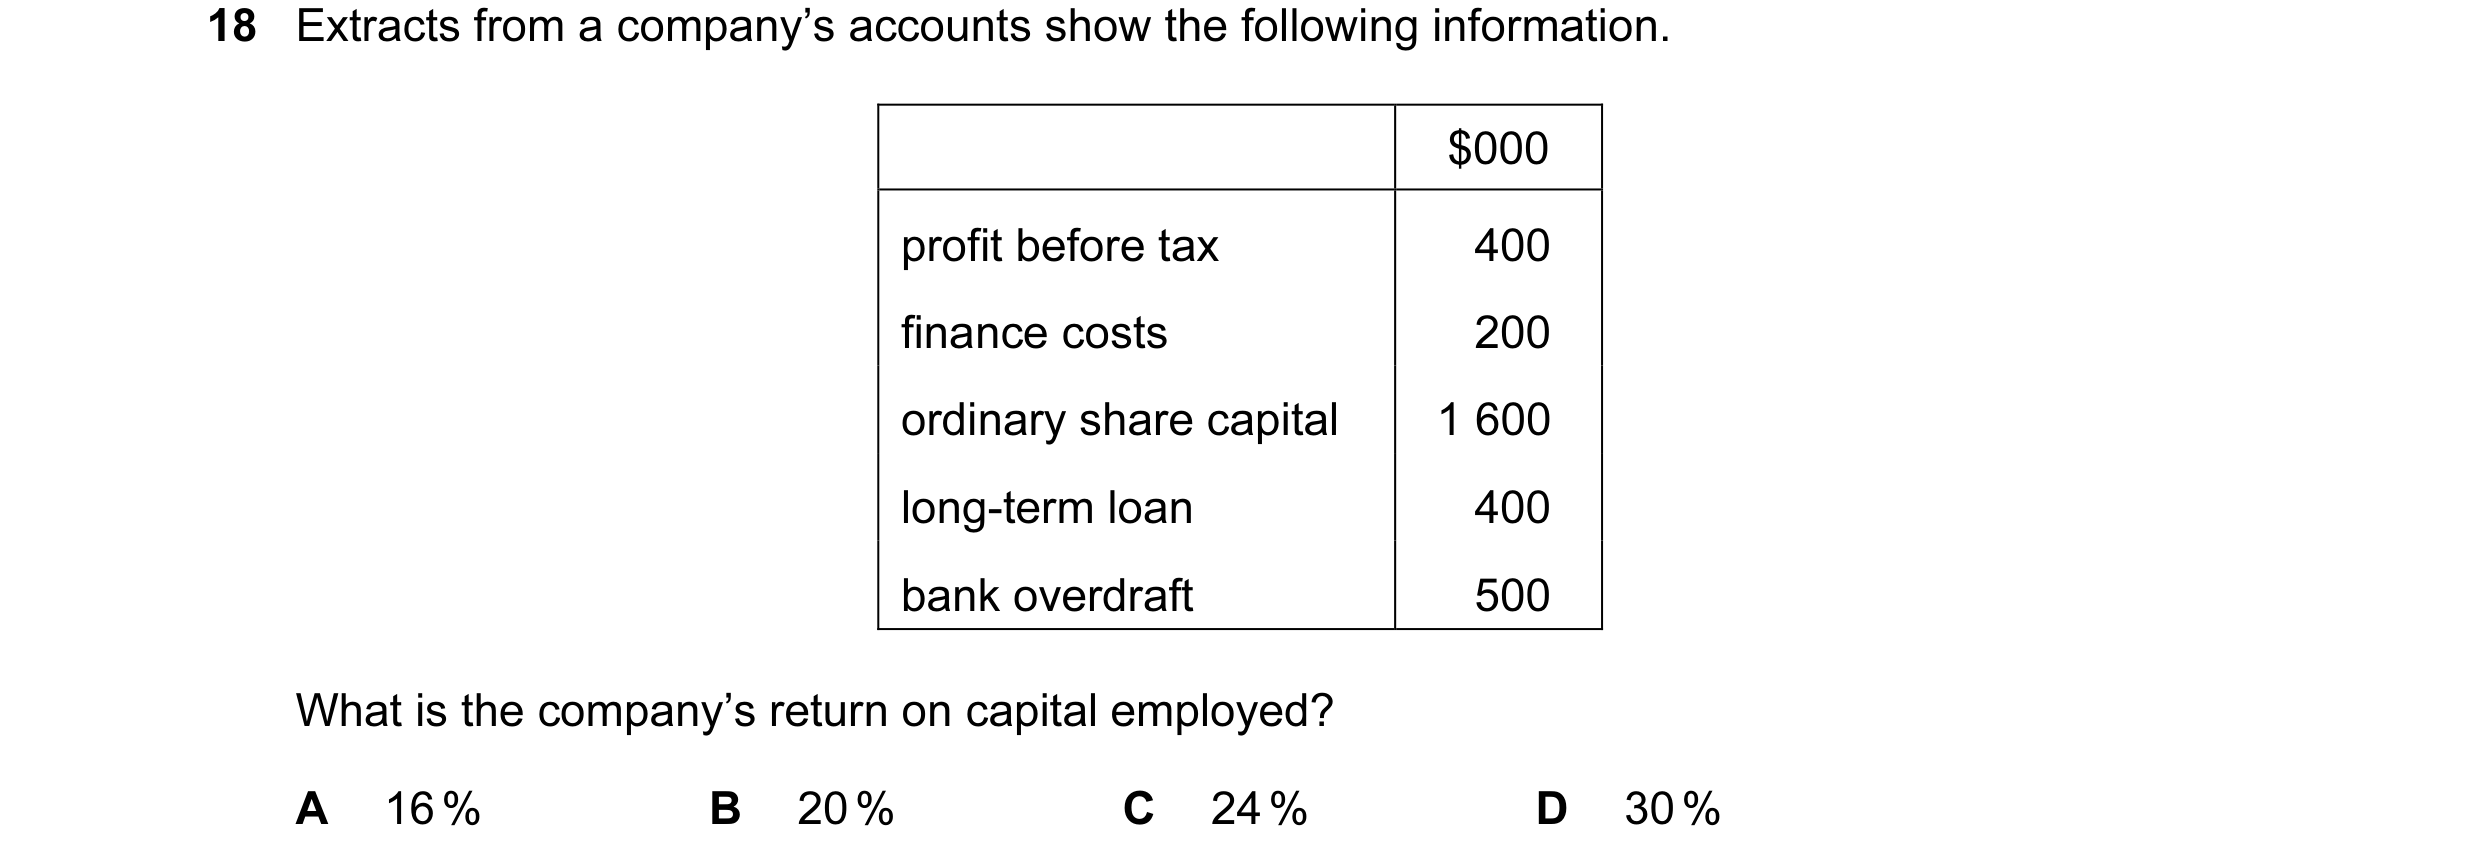
Q72 · Extracts from a company’s accounts show the following information 9706/31 Oct/Nov 2012
18 Extracts from a company’s accounts show the following information. $000 profit before tax 400 finance costs 200 ordinary share capital 1 600 long-term loan 400 bank overdraft 500 What is the company’s return on capital employed? A 16 % B 20 % C 24 % D 30 %
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2012
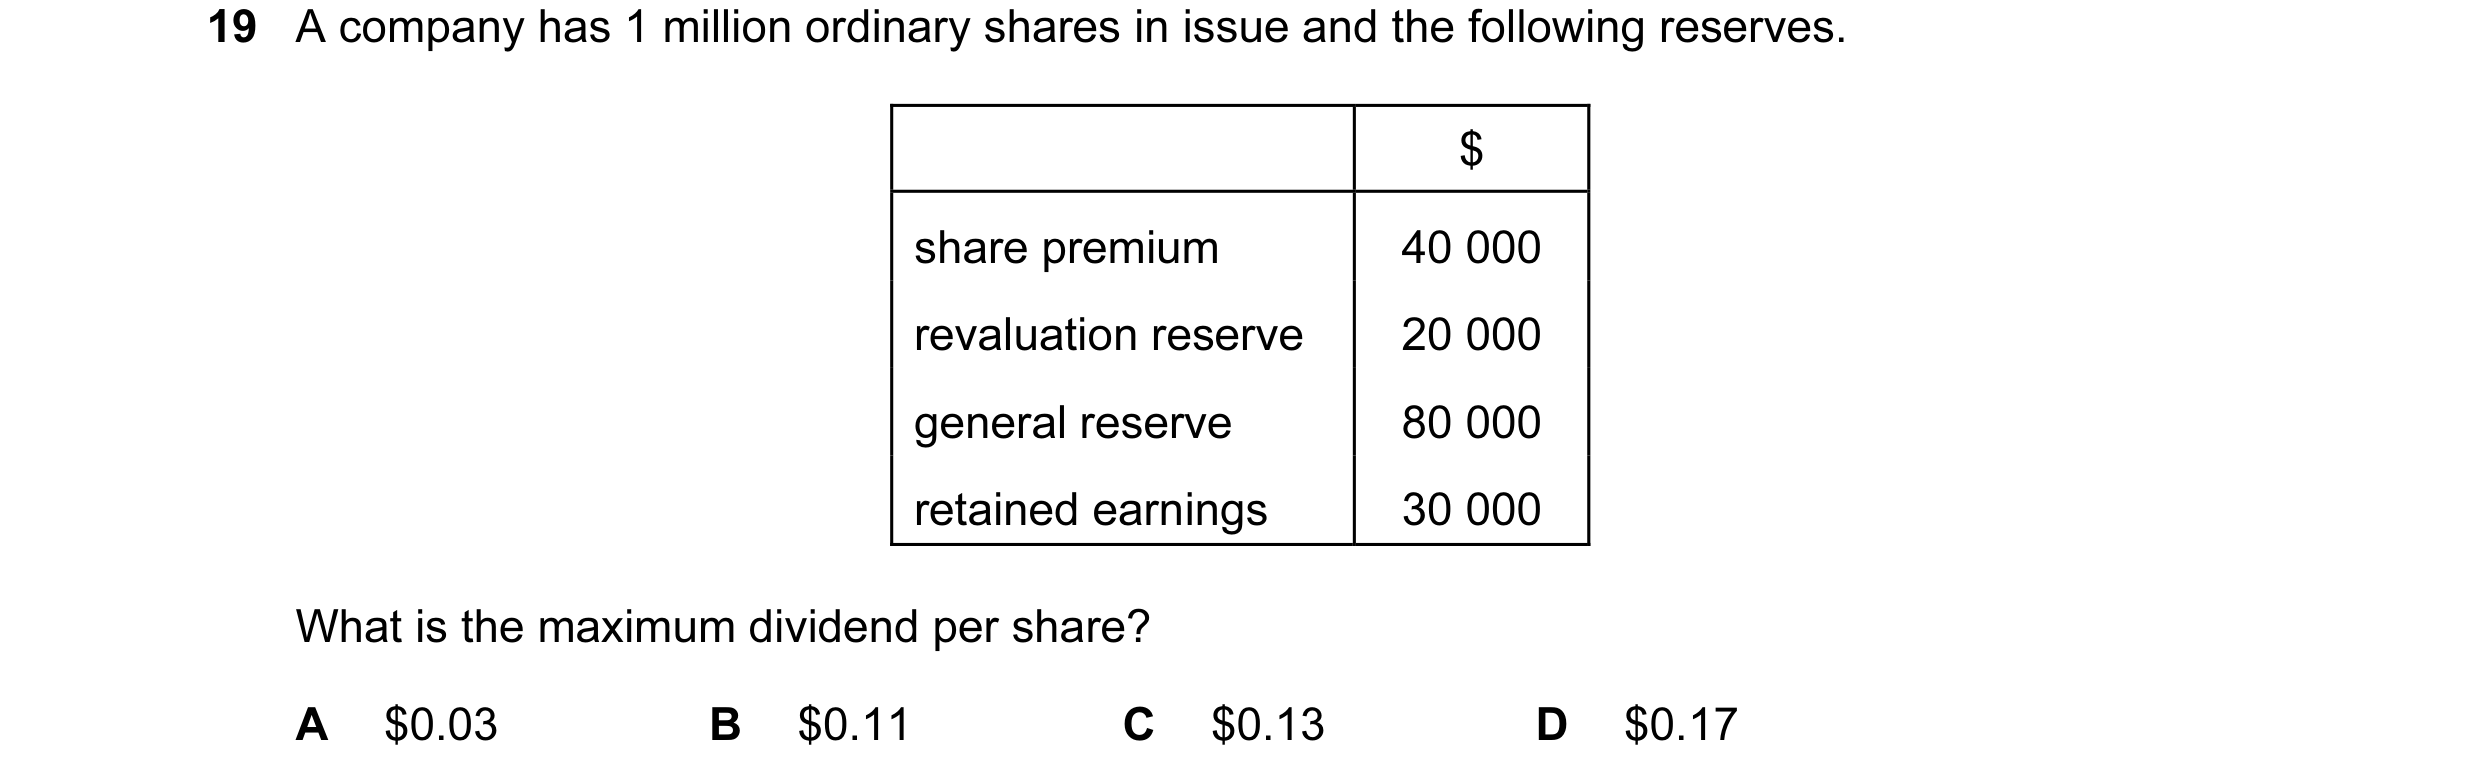
Q73 · A company has 1 million ordinary shares in issue and the following reserves 9706/31 Oct/Nov 2012
19 A company has 1 million ordinary shares in issue and the following reserves. $ share premium 40 000 revaluation reserve 20 000 general reserve 80 000 retained earnings 30 000 What is the maximum dividend per share? A $0.03 B $0.11 C $0.13 D $0.17
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2012
Q74 · A company has a share price that gives a dividend yield of 4 % 9706/32 Oct/Nov 2012
16 A company has a share price that gives a dividend yield of 4 %. Earnings per share are $0.32 and half the earnings are paid out as dividends. What is the share price? A $2.00 B $4.00 C $6.00 D $8.00
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2012
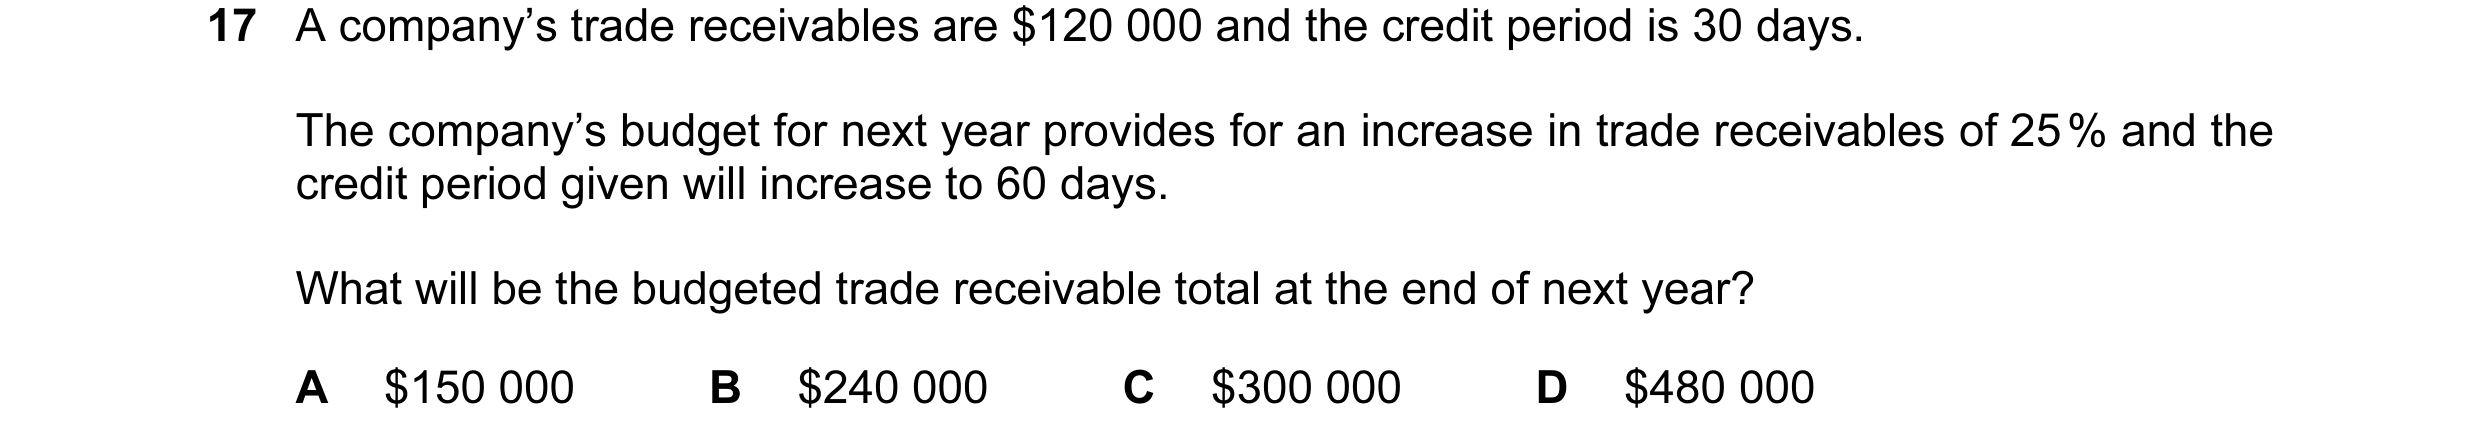
Q75 · A company’s trade receivables are $120 000 and the credit period is 30 days 9706/32 Oct/Nov 2012
17 A company’s trade receivables are $120 000 and the credit period is 30 days. The company’s budget for next year provides for an increase in trade receivables of 25 % and the credit period given will increase to 60 days. What will be the budgeted trade receivable total at the end of next year? A $150 000 B $240 000 C $300 000 D $480 000
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2012
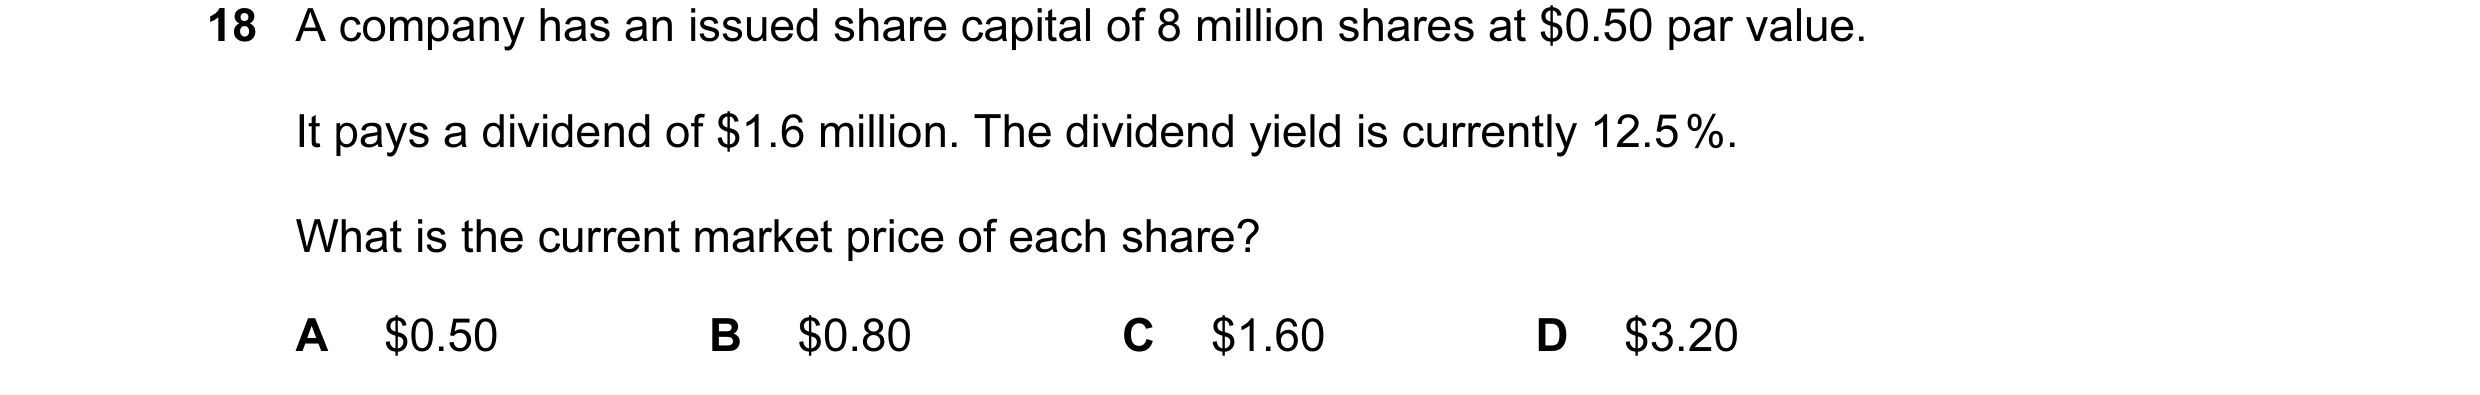
Q76 · A company has an issued share capital of 8 million shares at $0.50 par value 9706/32 Oct/Nov 2012
18 A company has an issued share capital of 8 million shares at $0.50 par value. It pays a dividend of $1.6 million. The dividend yield is currently 12.5 %. What is the current market price of each share? A $0.50 B $0.80 C $1.60 D $3.20
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2012
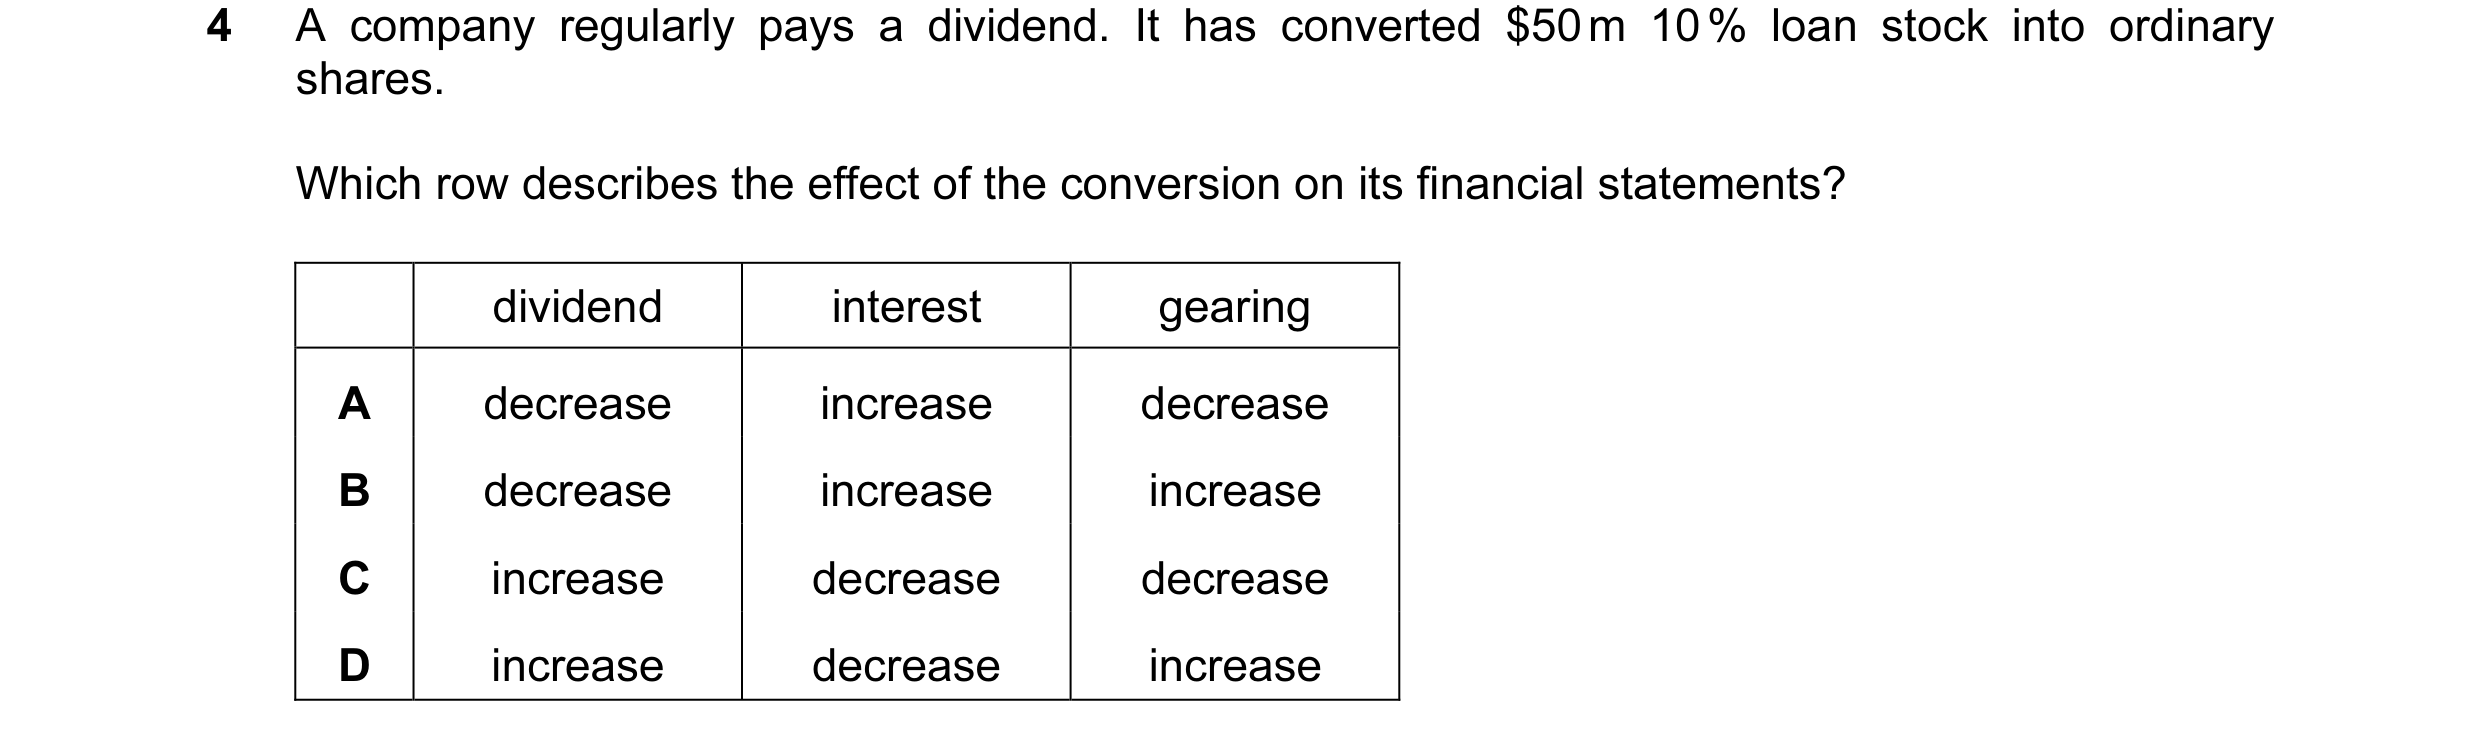
Q77 · A company regularly pays a dividend 9706/33 Oct/Nov 2012
4 A company regularly pays a dividend. It has converted $50 m 10 % loan stock into ordinary shares. Which row describes the effect of the conversion on its financial statements? dividend interest gearing A decrease increase decrease B decrease increase increase C increase decrease decrease D increase decrease increase
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
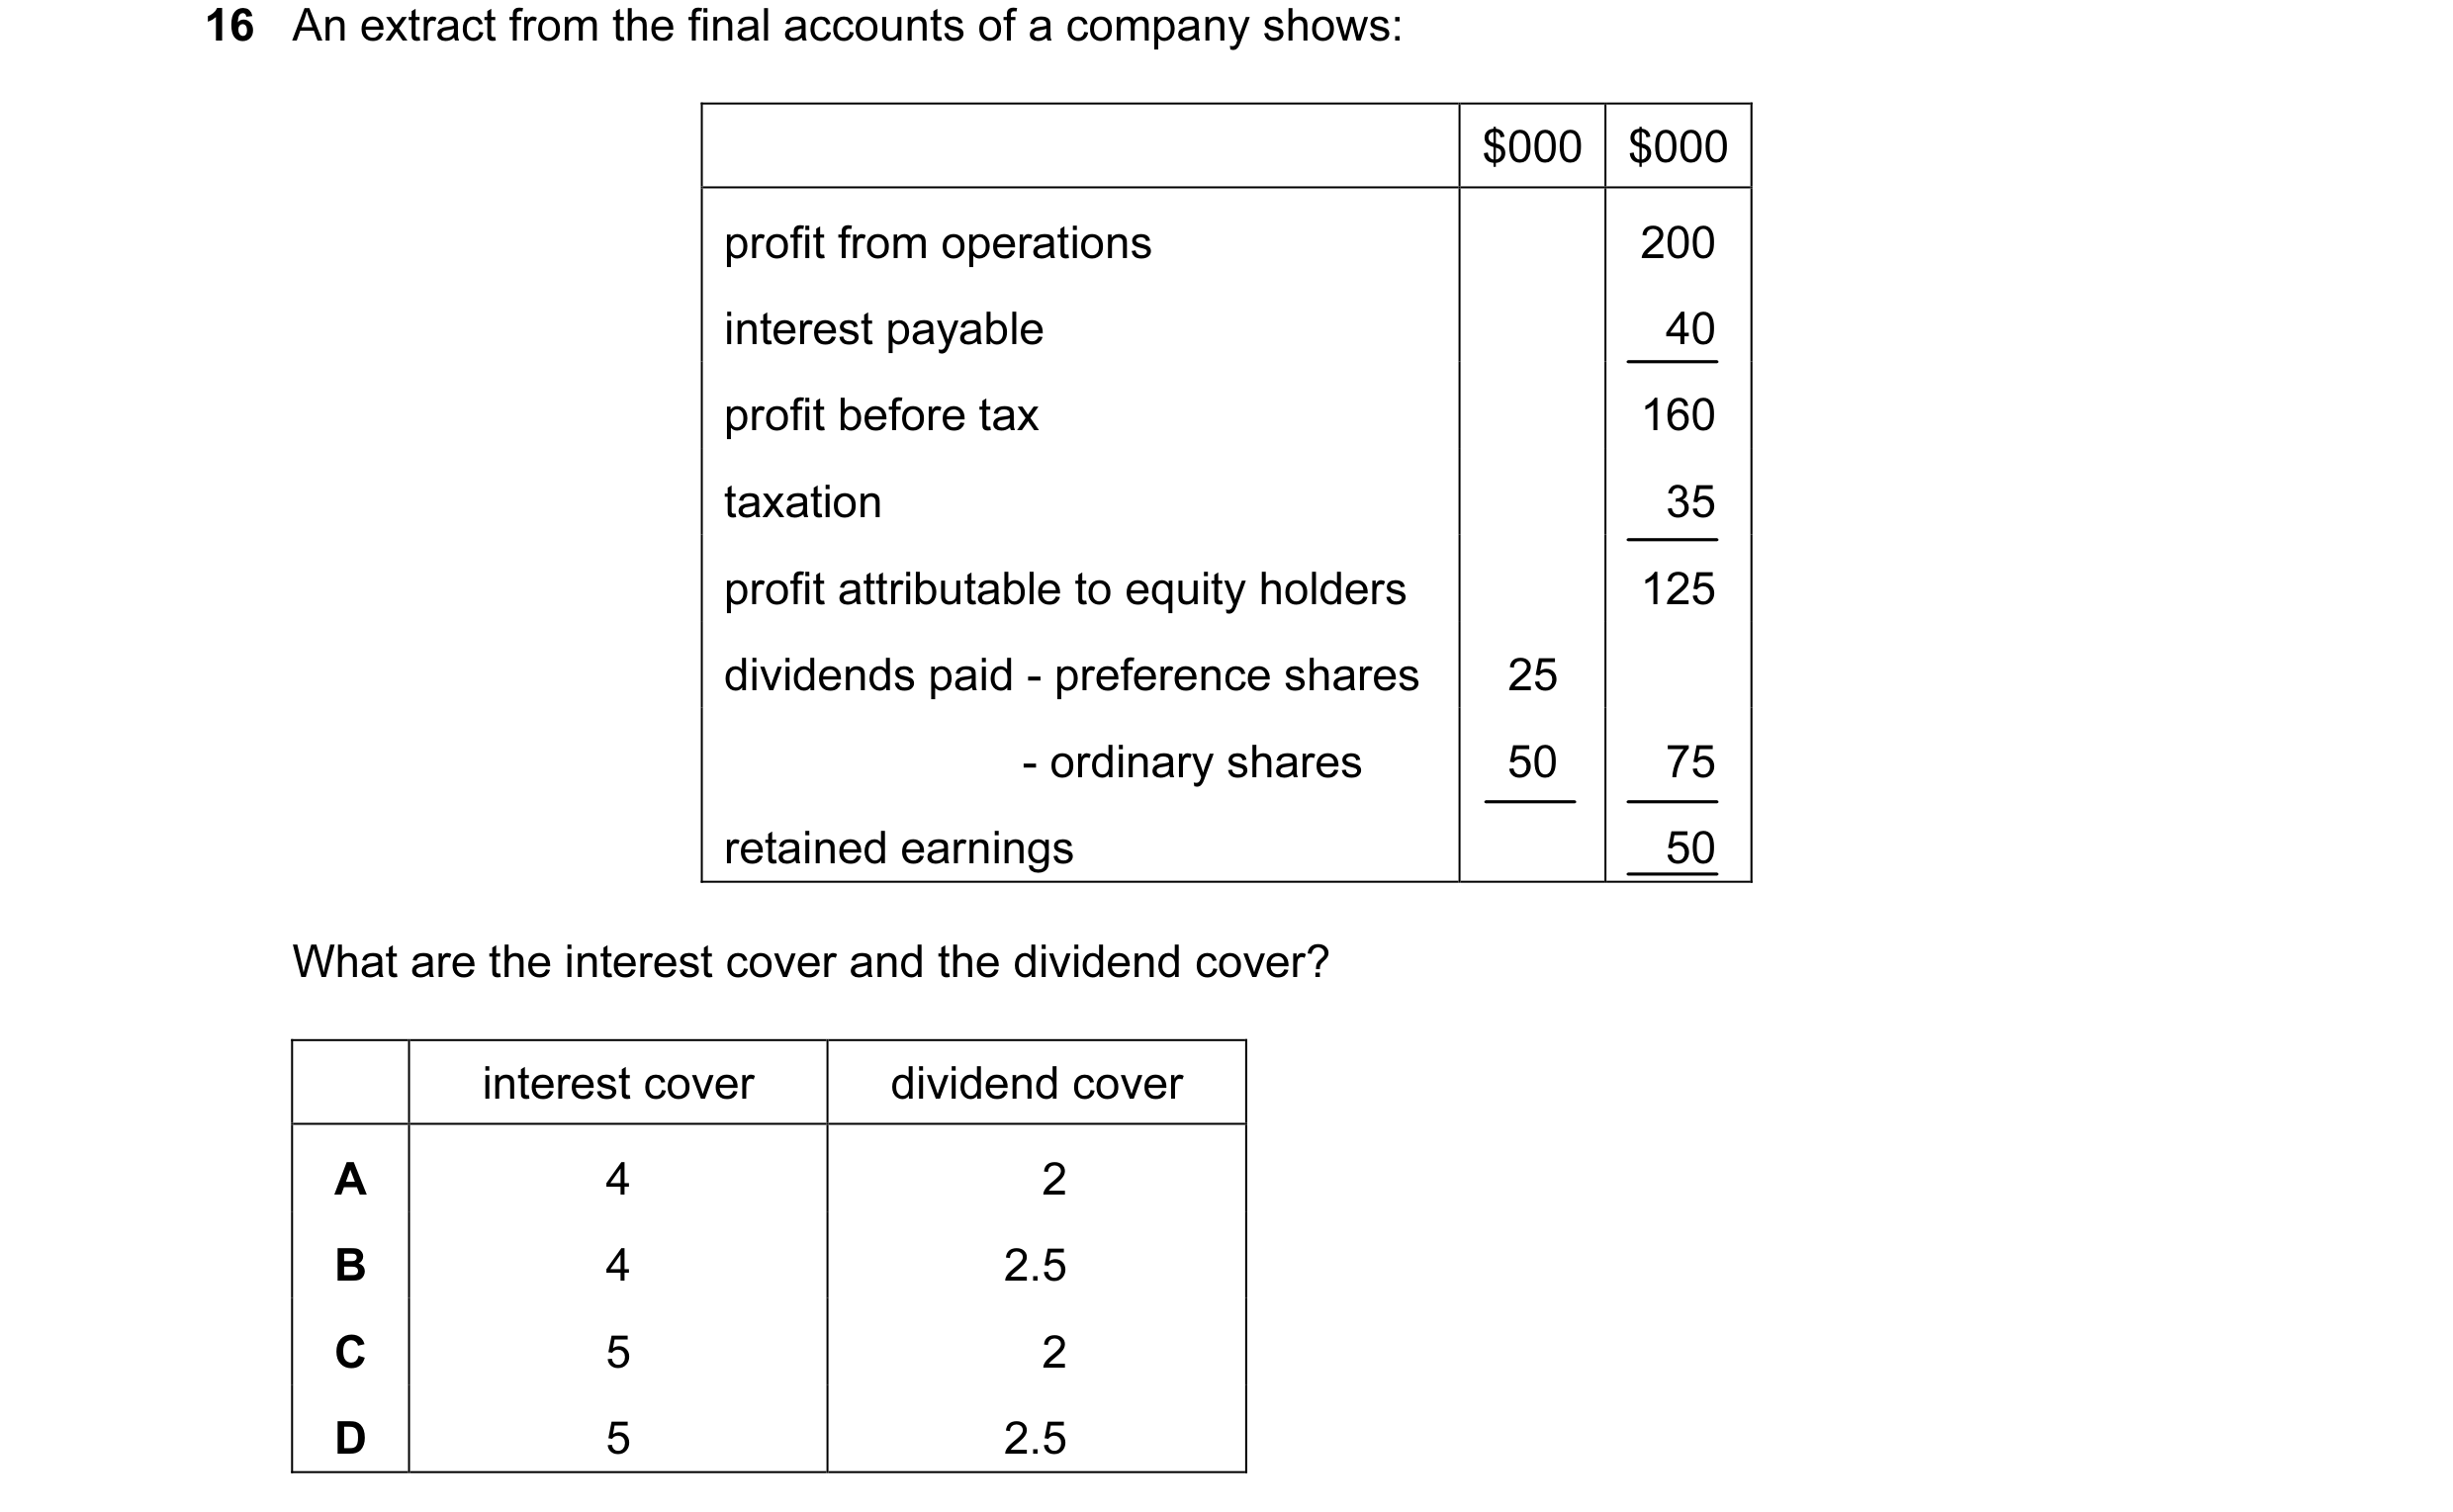
Q78 · An extract from the final accounts of a company shows: $000 $000 profit from operations… 9706/33 Oct/Nov 2012
16 An extract from the final accounts of a company shows: $000 $000 profit from operations 200 interest payable 40 profit before tax 160 taxation 35 profit attributable to equity holders 125 dividends paid - preference shares 25 - ordinary shares 50 75 retained earnings 50 What are the interest cover and the dividend cover? interest cover dividend cover A 4 2 B 4 2.5 C 5 2 D 5 2.5
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
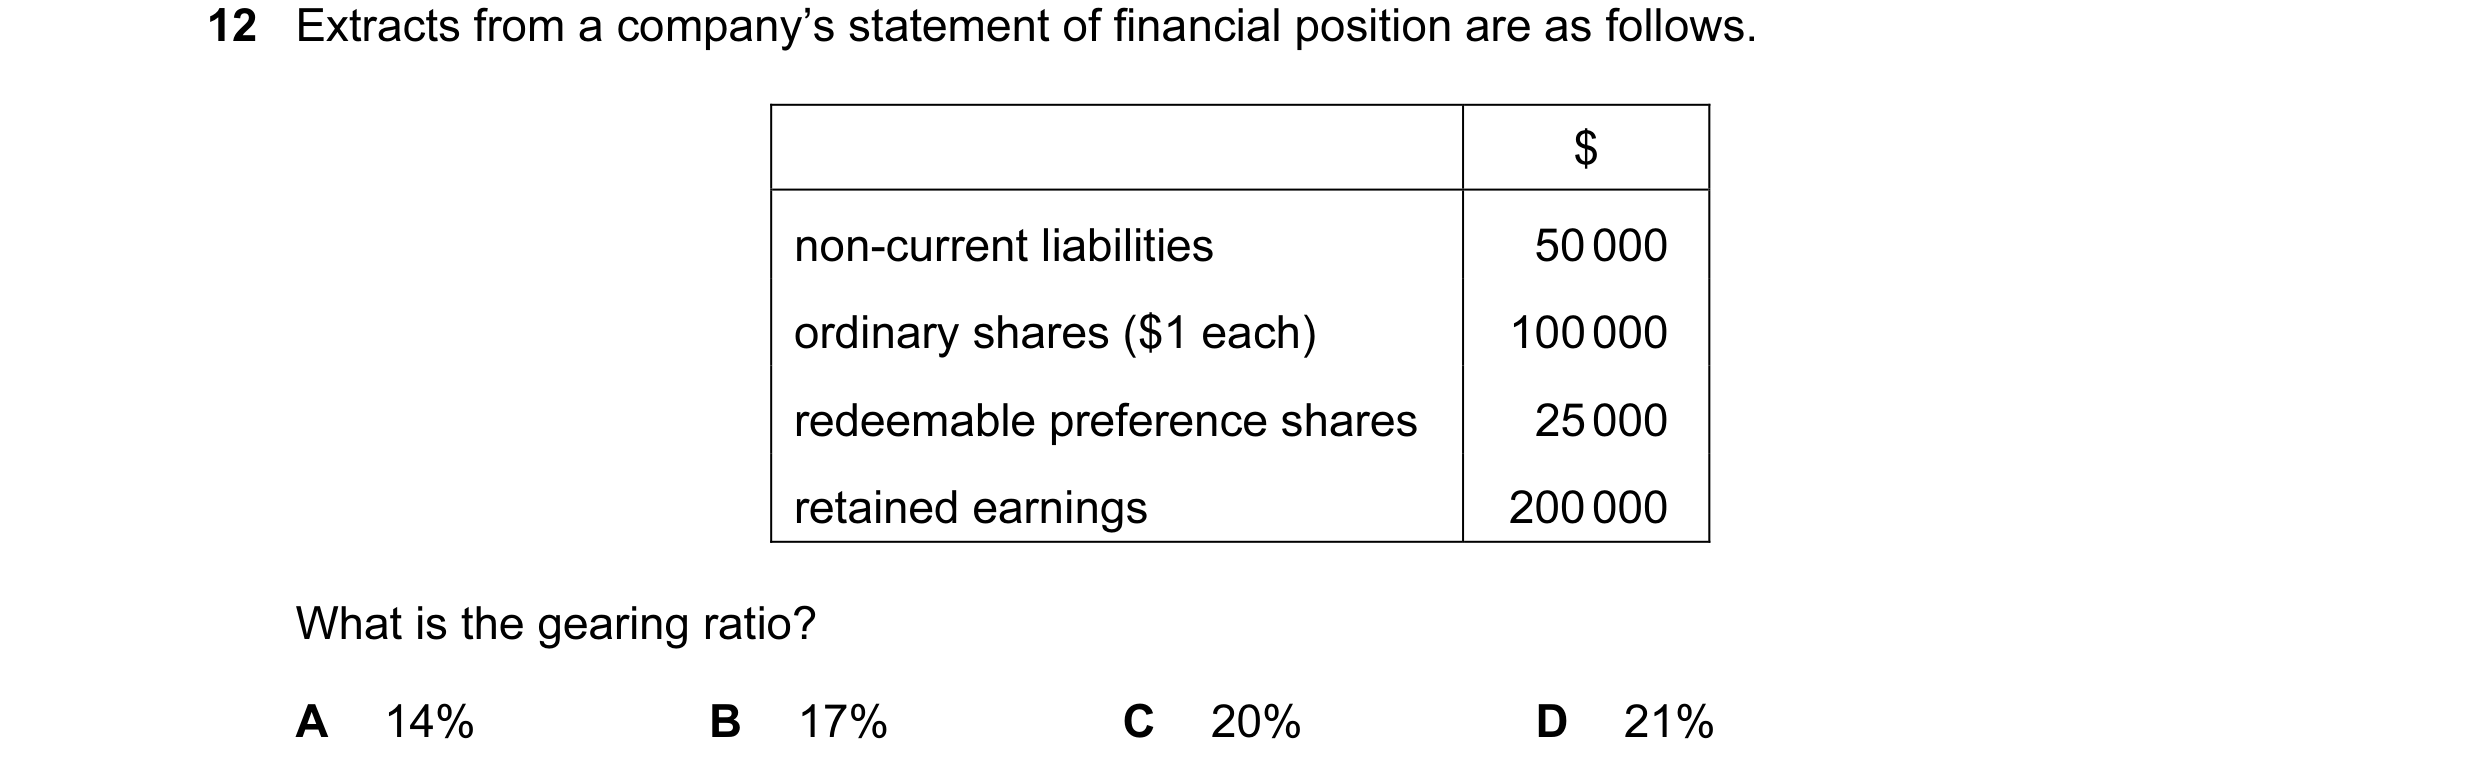
Q79 · Extracts from a company’s statement of financial position are as follows 9706/31 May/June 2013
12 Extracts from a company’s statement of financial position are as follows. $ non-current liabilities 50 000 ordinary shares ($1 each) 100 000 redeemable preference shares 25 000 retained earnings 200 000 What is the gearing ratio? A 14% B 17% C 20% D 21%
1 marks
Answer: C
This question in 9706/31 May/June 2013
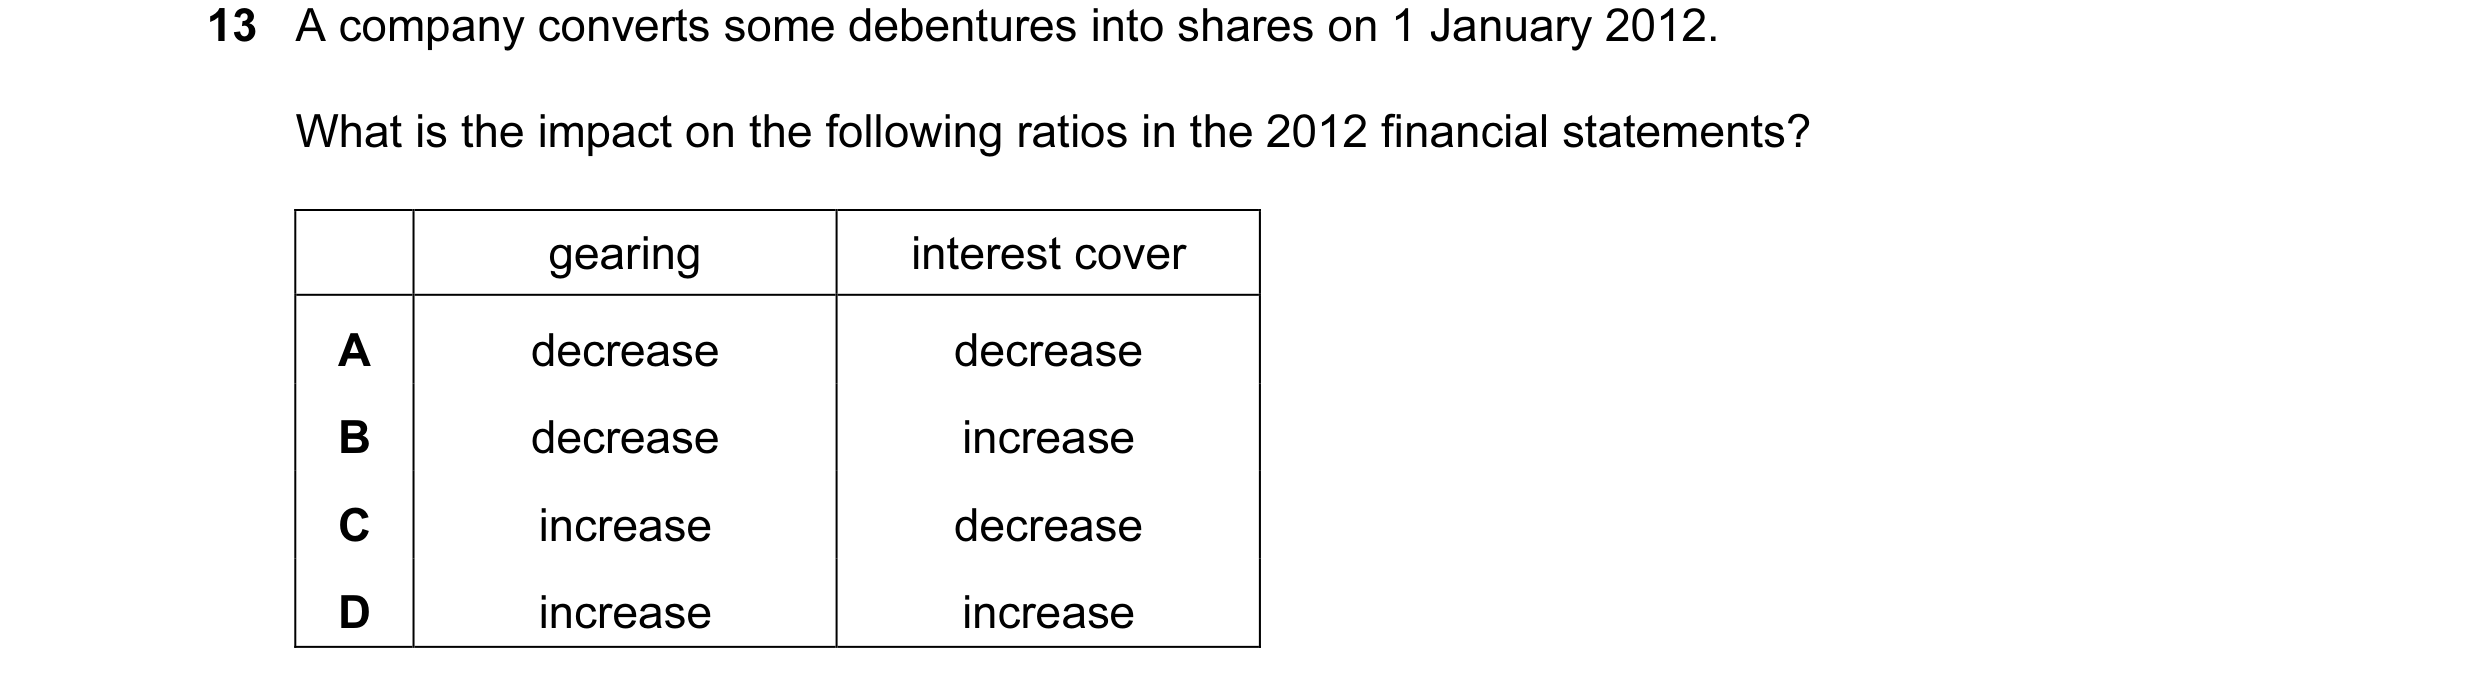
Q80 · A company converts some debentures into shares on 1 January 2012 9706/31 May/June 2013
13 A company converts some debentures into shares on 1 January 2012. What is the impact on the following ratios in the 2012 financial statements? gearing interest cover A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: B
This question in 9706/31 May/June 2013
Q81 · A company has a Price Earnings ratio of 15 9706/31 May/June 2013
15 A company has a Price Earnings ratio of 15. This is 20% less than the average for this type of business. Its earnings per share are $0.20. What is the company’s share price? A $0.60 B $2.40 C $3.00 D $3.60
1 marks
Answer: C
This question in 9706/31 May/June 2013
Q82 · The financial statements of limited companies must disclose changes in the methods of… 9706/32 May/June 2013
9 The financial statements of limited companies must disclose changes in the methods of providing for depreciation of non-current assets. Why is this important to the users of corporate reports? A It allows the market value of assets to be shown. B It enables comparison with previous years. C It helps to assess company liquidity. D It helps to assess future dividends.
1 marks
Answer: B
This question in 9706/32 May/June 2013
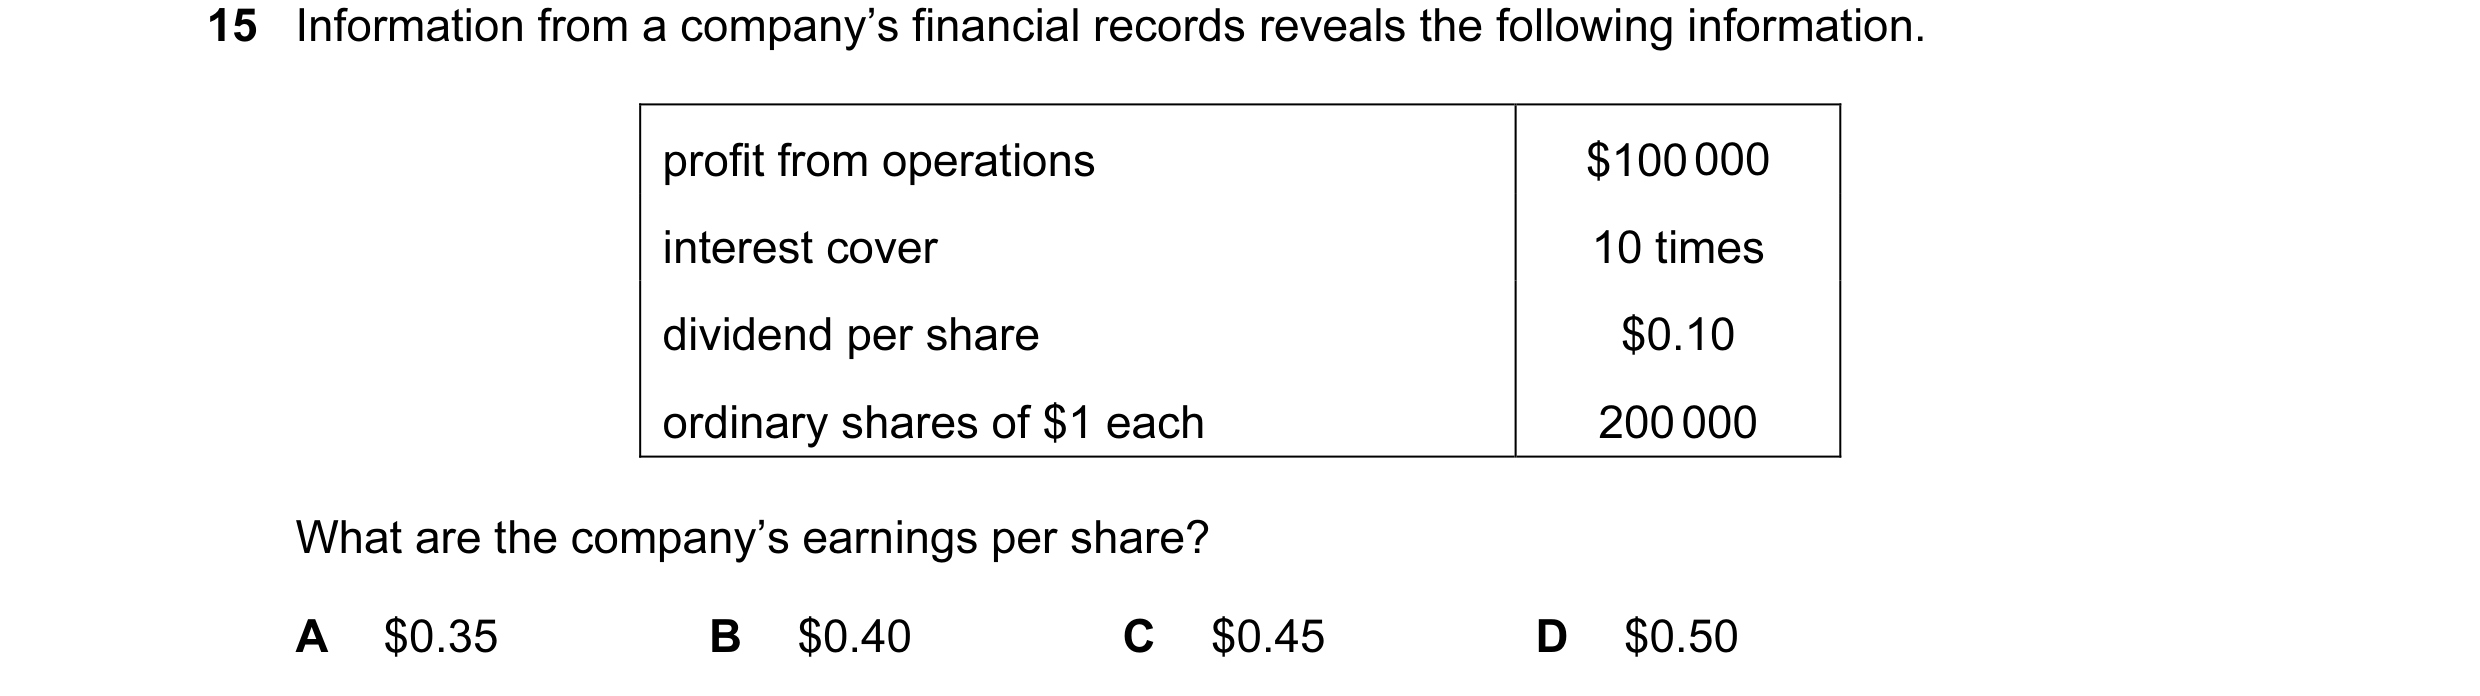
Q83 · Information from a company’s financial records reveals the following information 9706/32 May/June 2013
15 Information from a company’s financial records reveals the following information. profit from operations $100 000 interest cover 10 times dividend per share $0.10 ordinary shares of $1 each 200 000 What are the company’s earnings per share? A $0.35 B $0.40 C $0.45 D $0.50
1 marks
Answer: C
This question in 9706/32 May/June 2013
Q84 · Which expense is not deducted before arriving at operating profit? 9706/33 May/June 2013
12 Which expense is not deducted before arriving at operating profit? A auditor’s fee B debenture interest C directors’ remuneration D distribution costs
1 marks
Answer: B
This question in 9706/33 May/June 2013
Q85 · The working capital cycle of a business was 100 days in 2012 and 130 days in 2013 9706/33 May/June 2013
13 The working capital cycle of a business was 100 days in 2012 and 130 days in 2013. Which statement explains the change? A Cash and cash equivalents have increased during 2013. B Inventory increased during 2013. C The company increased the period taken to pay its suppliers in 2013. D Trade receivables decreased during 2013.
1 marks
Answer: B
This question in 9706/33 May/June 2013
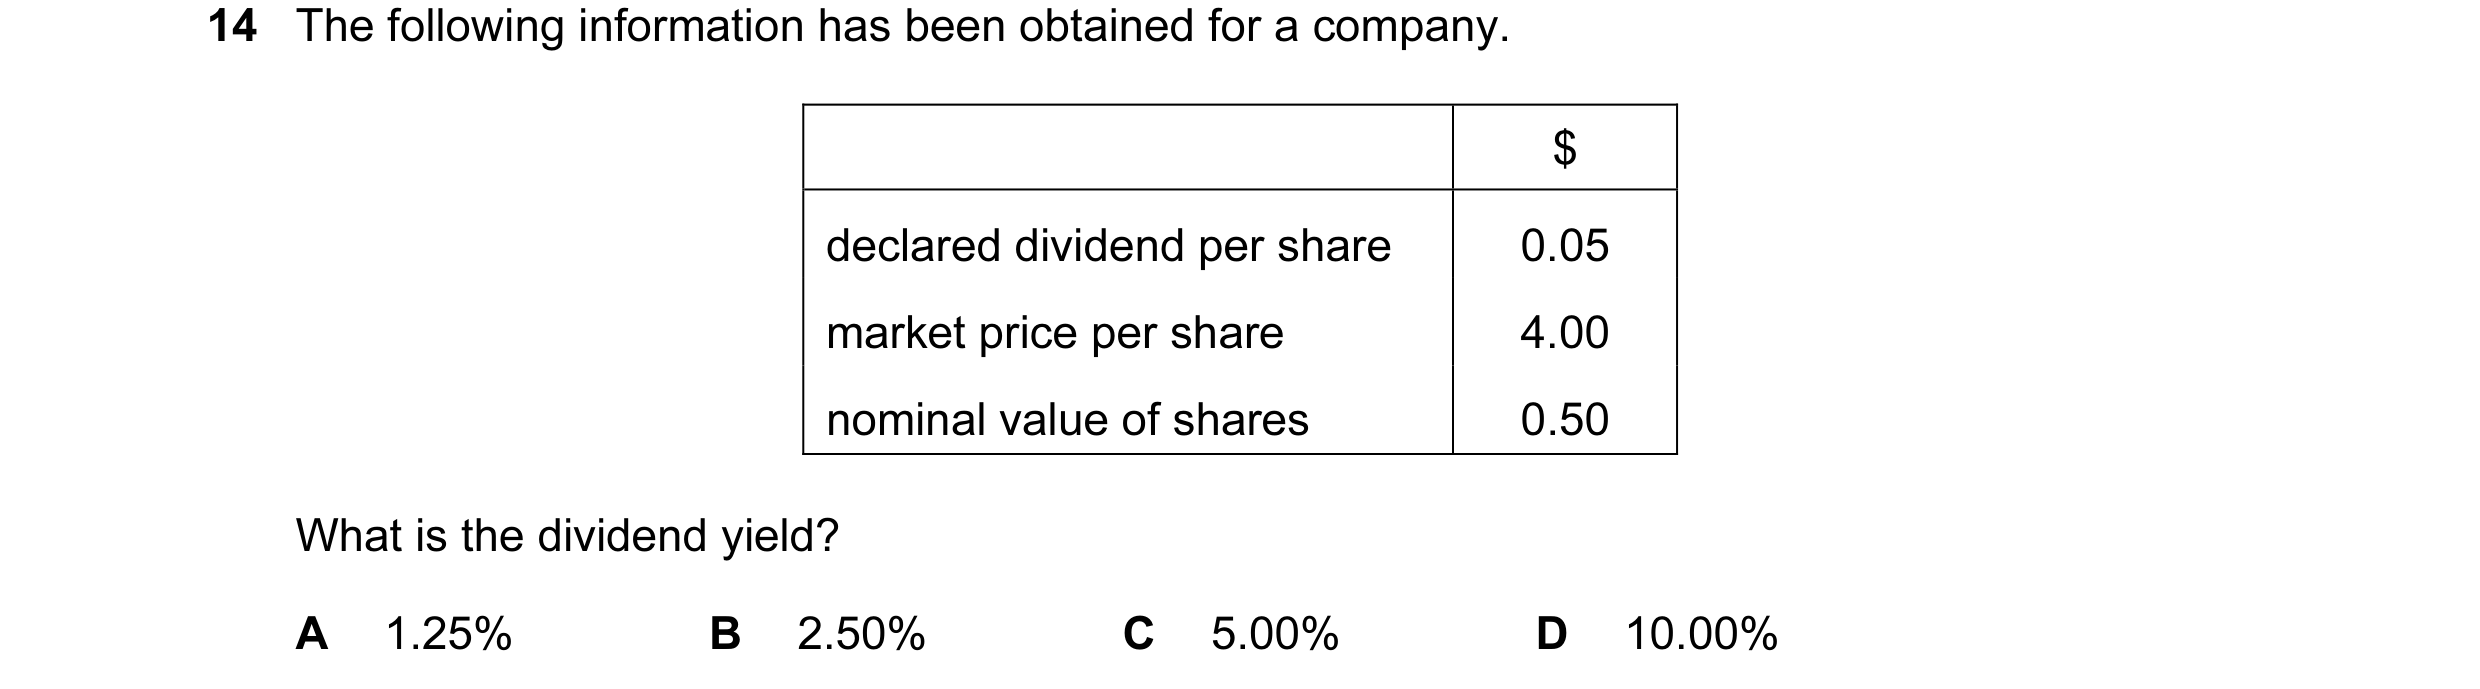
Q86 · The following information has been obtained for a company 9706/33 May/June 2013
14 The following information has been obtained for a company. $ declared dividend per share 0.05 market price per share 4.00 nominal value of shares 0.50 What is the dividend yield? A 1.25% B 2.50% C 5.00% D 10.00%
1 marks
Answer: A
This question in 9706/33 May/June 2013
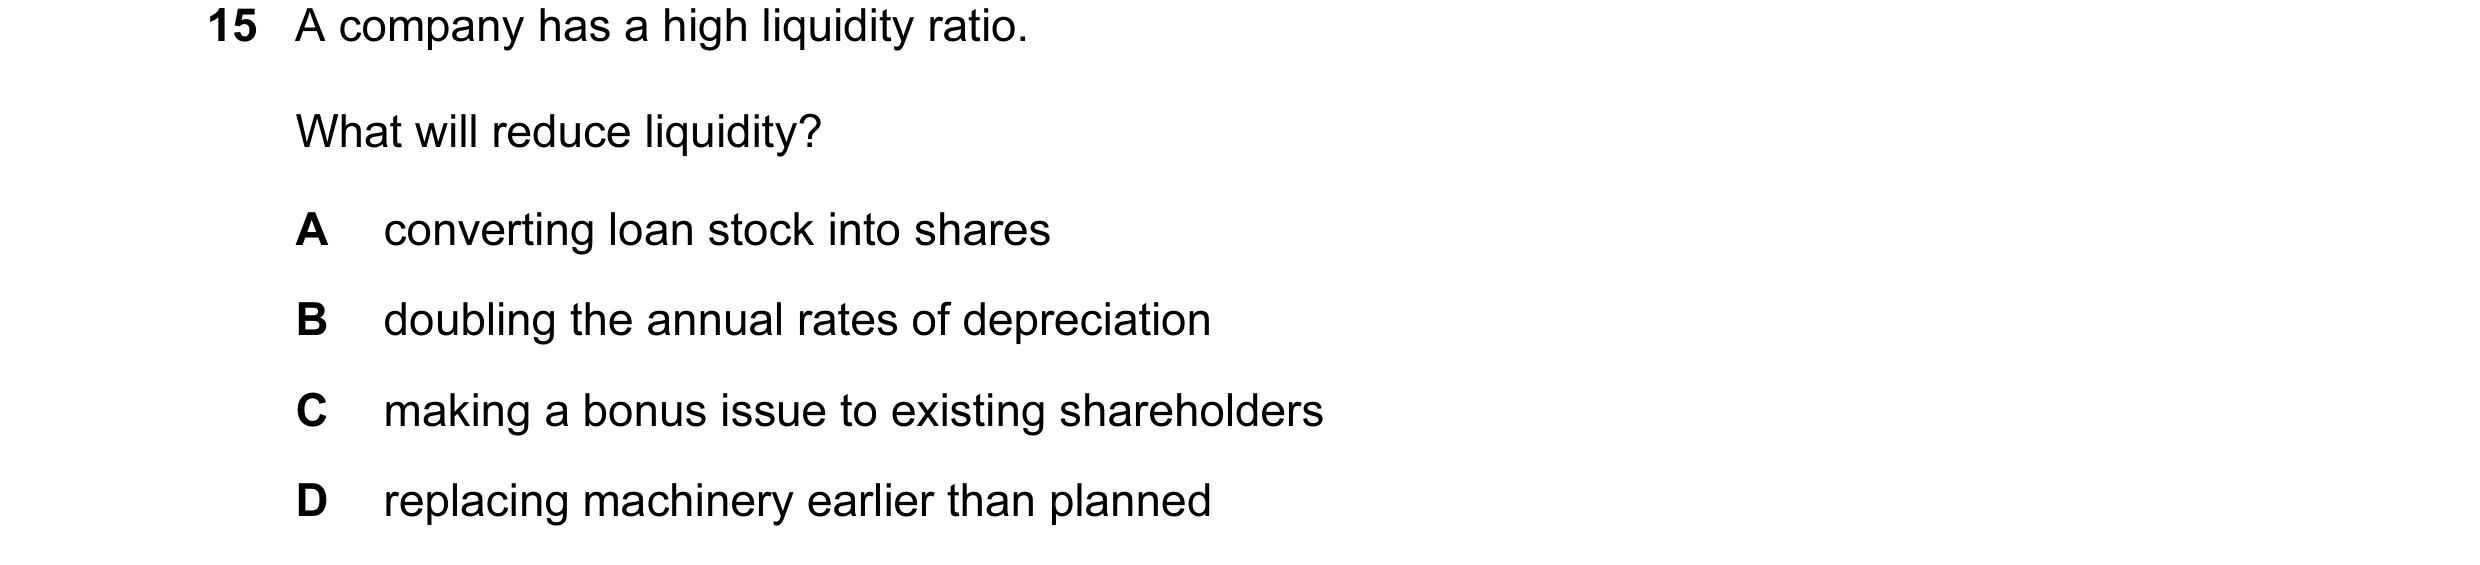
Q87 · A company has a high liquidity ratio 9706/33 May/June 2013
15 A company has a high liquidity ratio. What will reduce liquidity? A converting loan stock into shares B doubling the annual rates of depreciation C making a bonus issue to existing shareholders D replacing machinery earlier than planned
1 marks
Answer: D
This question in 9706/33 May/June 2013
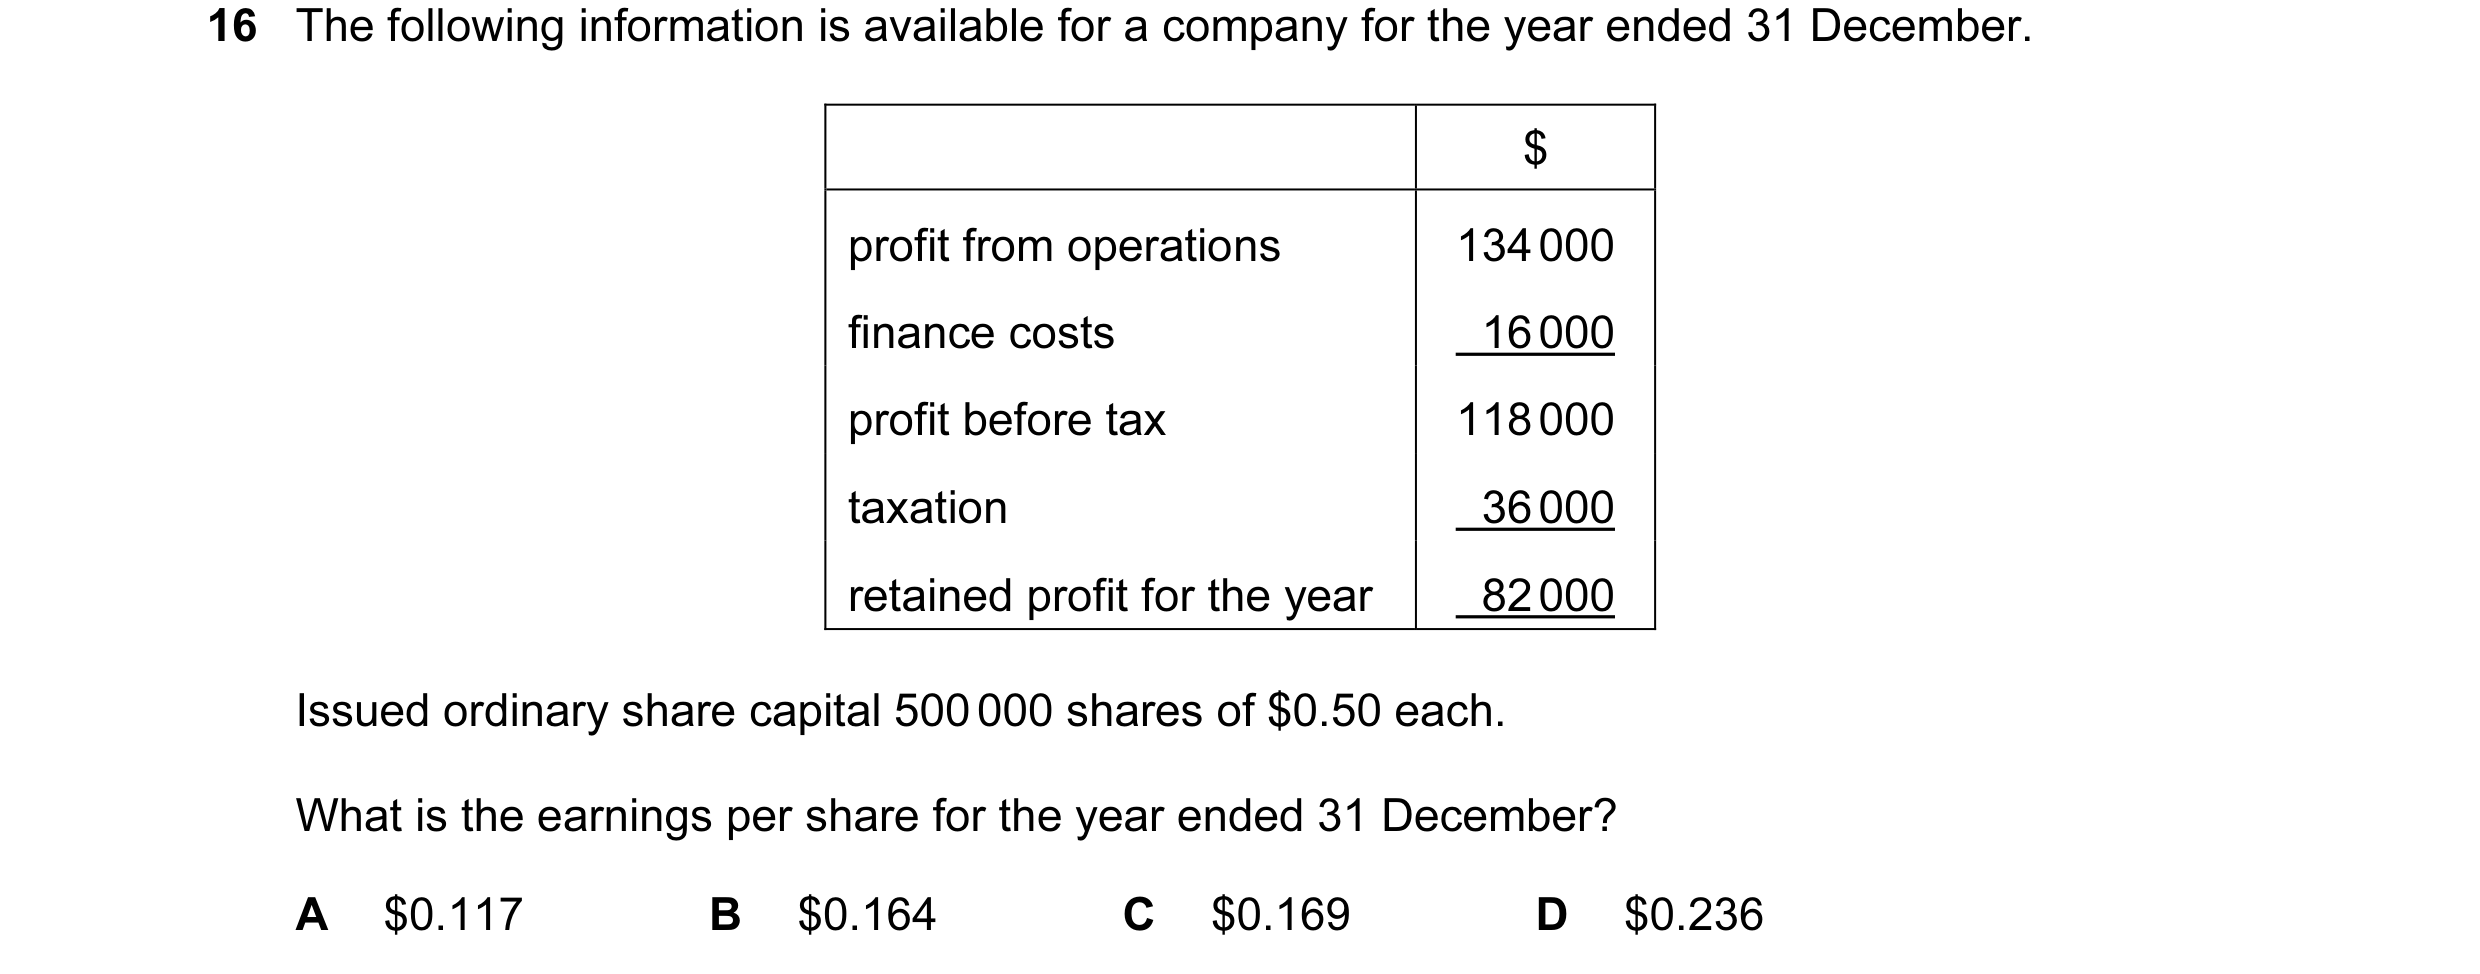
Q88 · The following information is available for a company for the year ended 31 December 9706/33 May/June 2013
16 The following information is available for a company for the year ended 31 December. $ profit from operations 134 000 finance costs 16 000 profit before tax 118 000 taxation 36 000 retained profit for the year 82 000 Issued ordinary share capital 500 000 shares of $0.50 each. What is the earnings per share for the year ended 31 December? A $0.117 B $0.164 C $0.169 D $0.236
1 marks
Answer: B
This question in 9706/33 May/June 2013
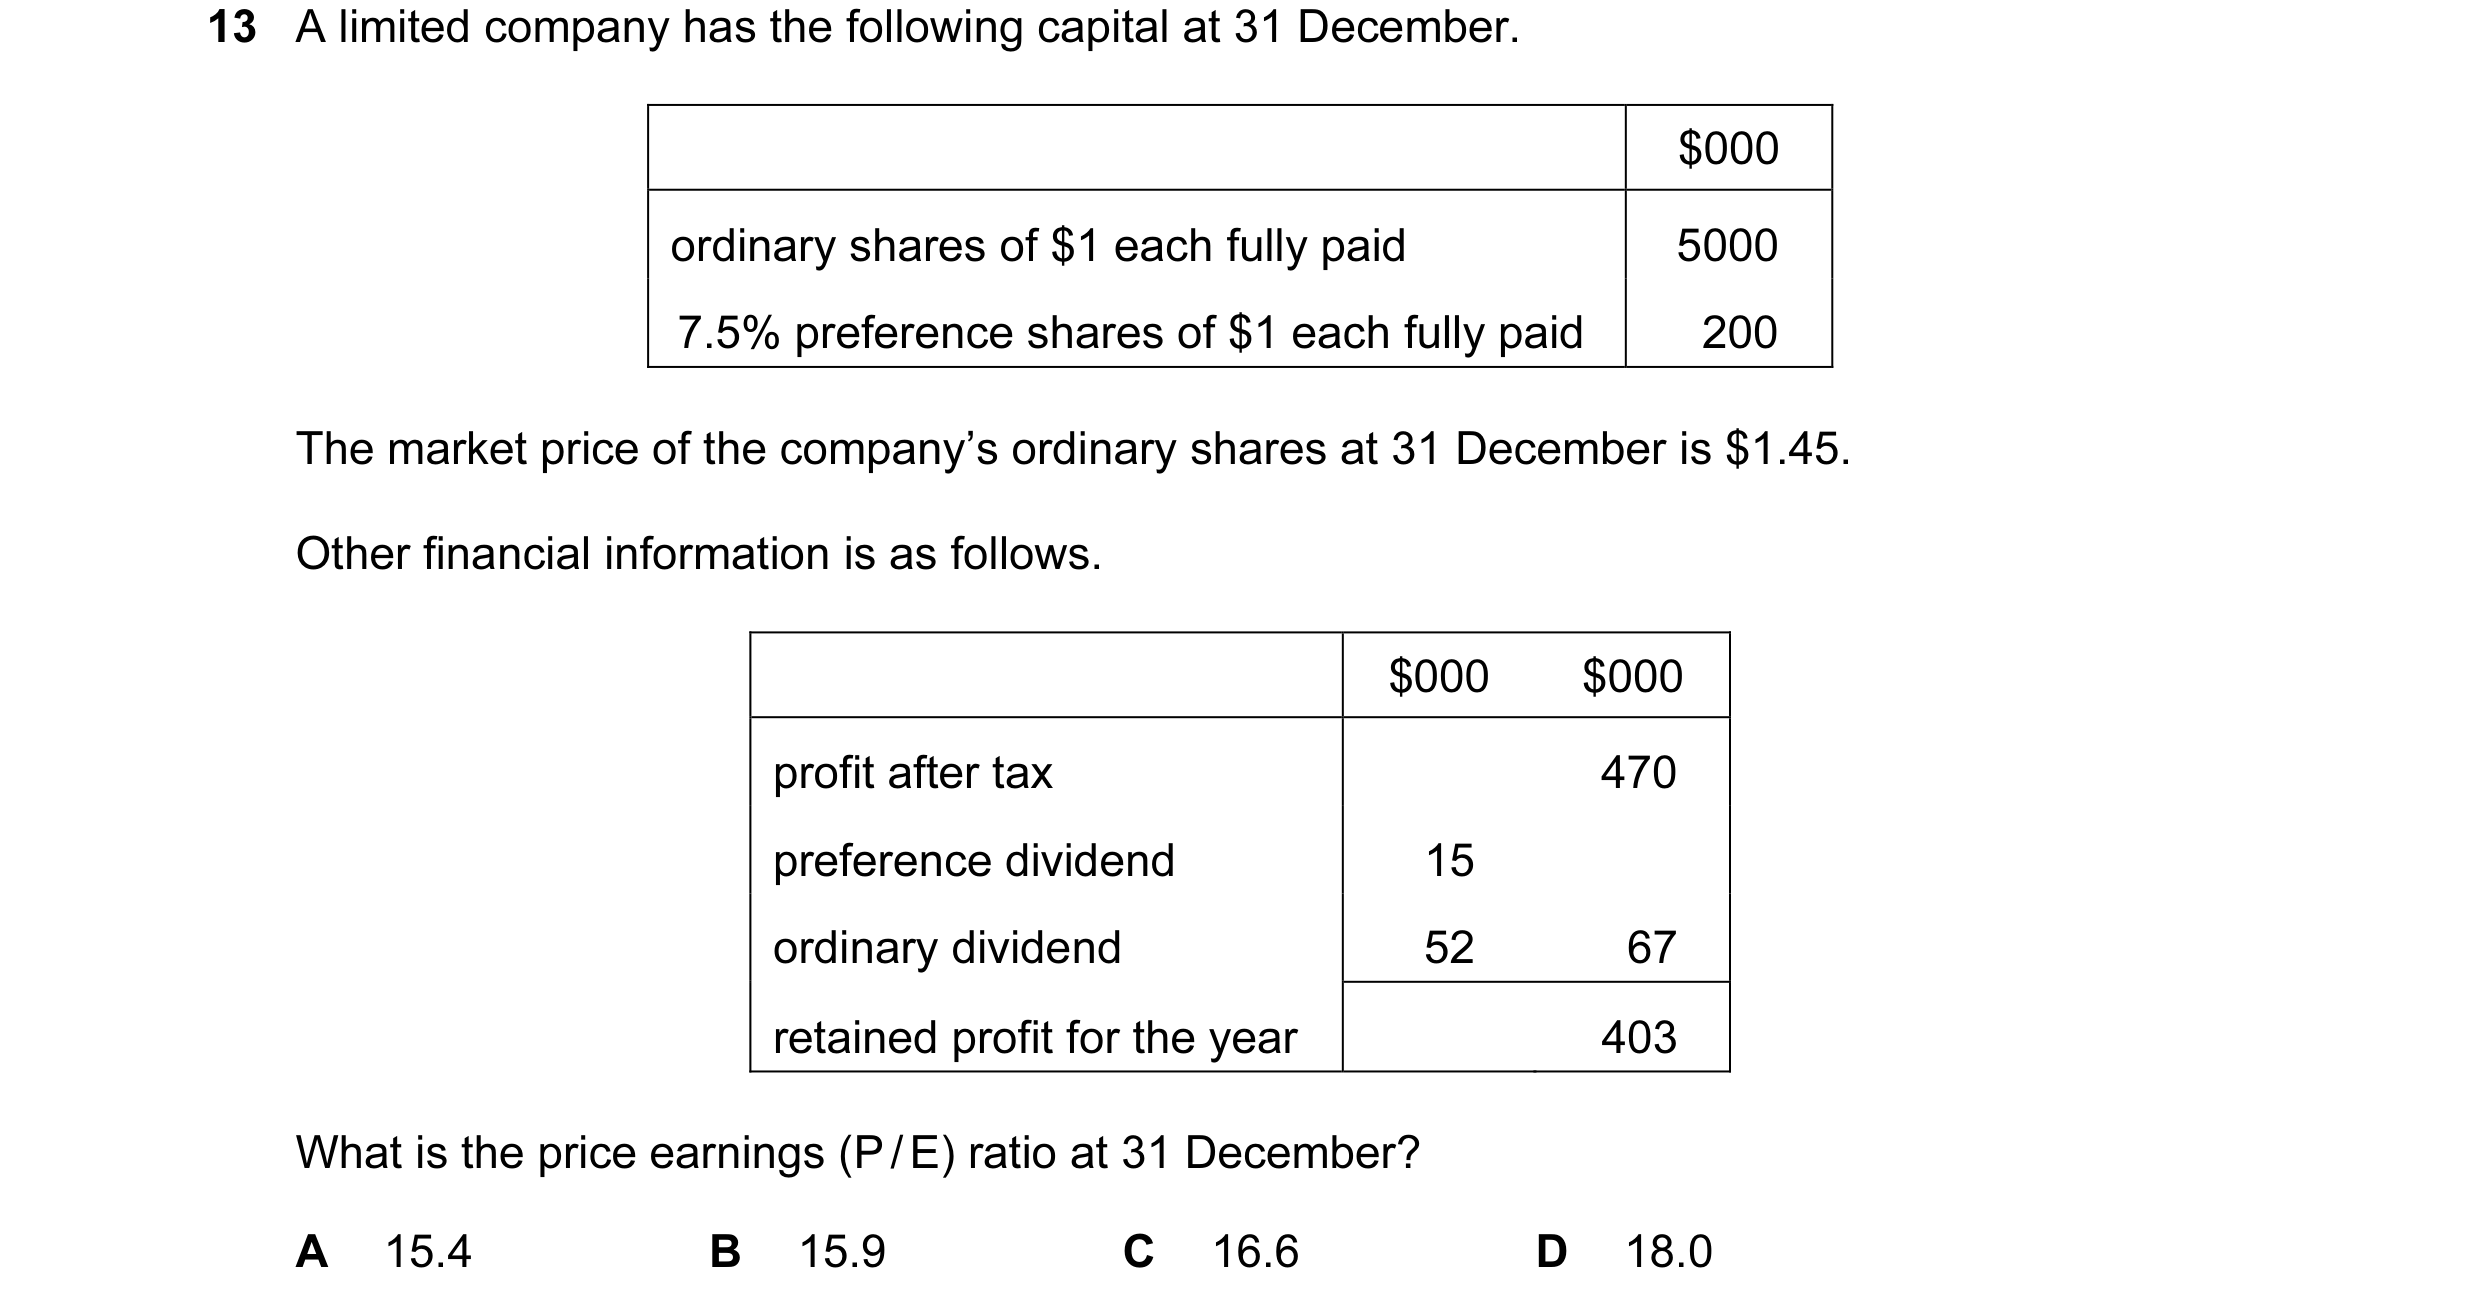
Q89 · A limited company has the following capital at 31 December 9706/31 Oct/Nov 2013
13 A limited company has the following capital at 31 December. $000 ordinary shares of $1 each fully paid 5000 7.5% preference shares of $1 each fully paid 200 The market price of the company’s ordinary shares at 31 December is $1.45. Other financial information is as follows. $000 $000 profit after tax 470 preference dividend 15 ordinary dividend 52 67 retained profit for the year 403 What is the price earnings (P / E) ratio at 31 December? A 15.4 B 15.9 C 16.6 D 18.0
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2013
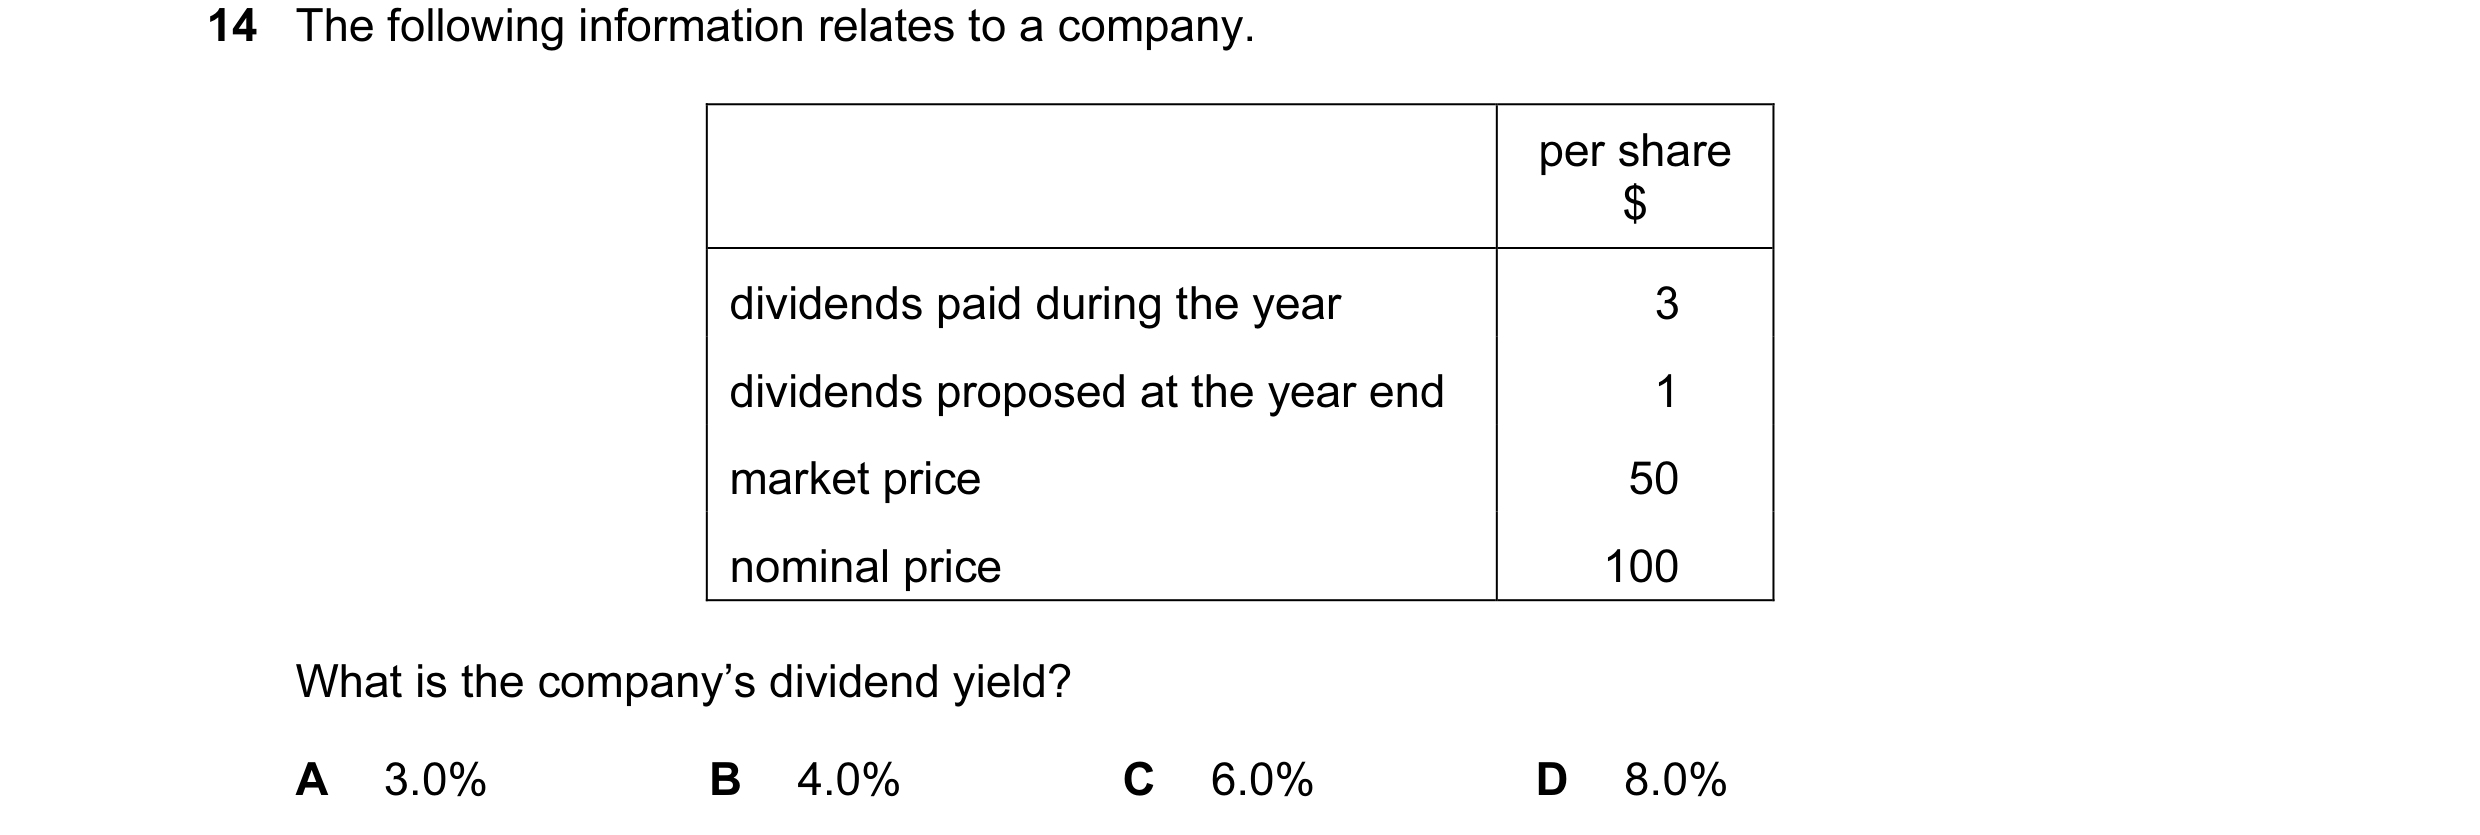
Q90 · The following information relates to a company 9706/31 Oct/Nov 2013
14 The following information relates to a company. per share $ dividends paid during the year 3 dividends proposed at the year end 1 market price 50 nominal price 100 What is the company’s dividend yield? A 3.0% B 4.0% C 6.0% D 8.0%
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2013
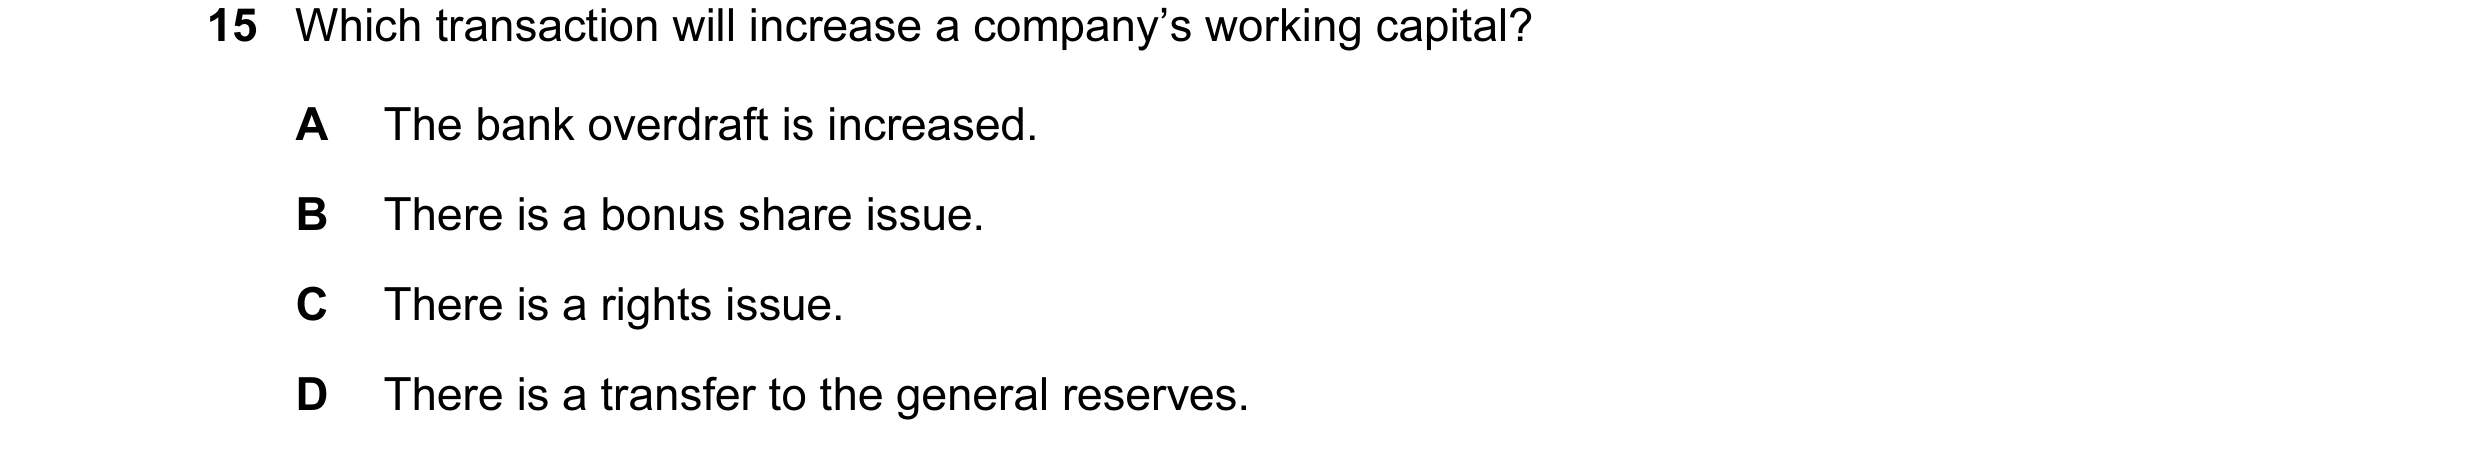
Q91 · Which transaction will increase a company’s working capital? 9706/31 Oct/Nov 2013
15 Which transaction will increase a company’s working capital? A The bank overdraft is increased. B There is a bonus share issue. C There is a rights issue. D There is a transfer to the general reserves.
1 marks
Answer: C
This question in 9706/31 Oct/Nov 2013
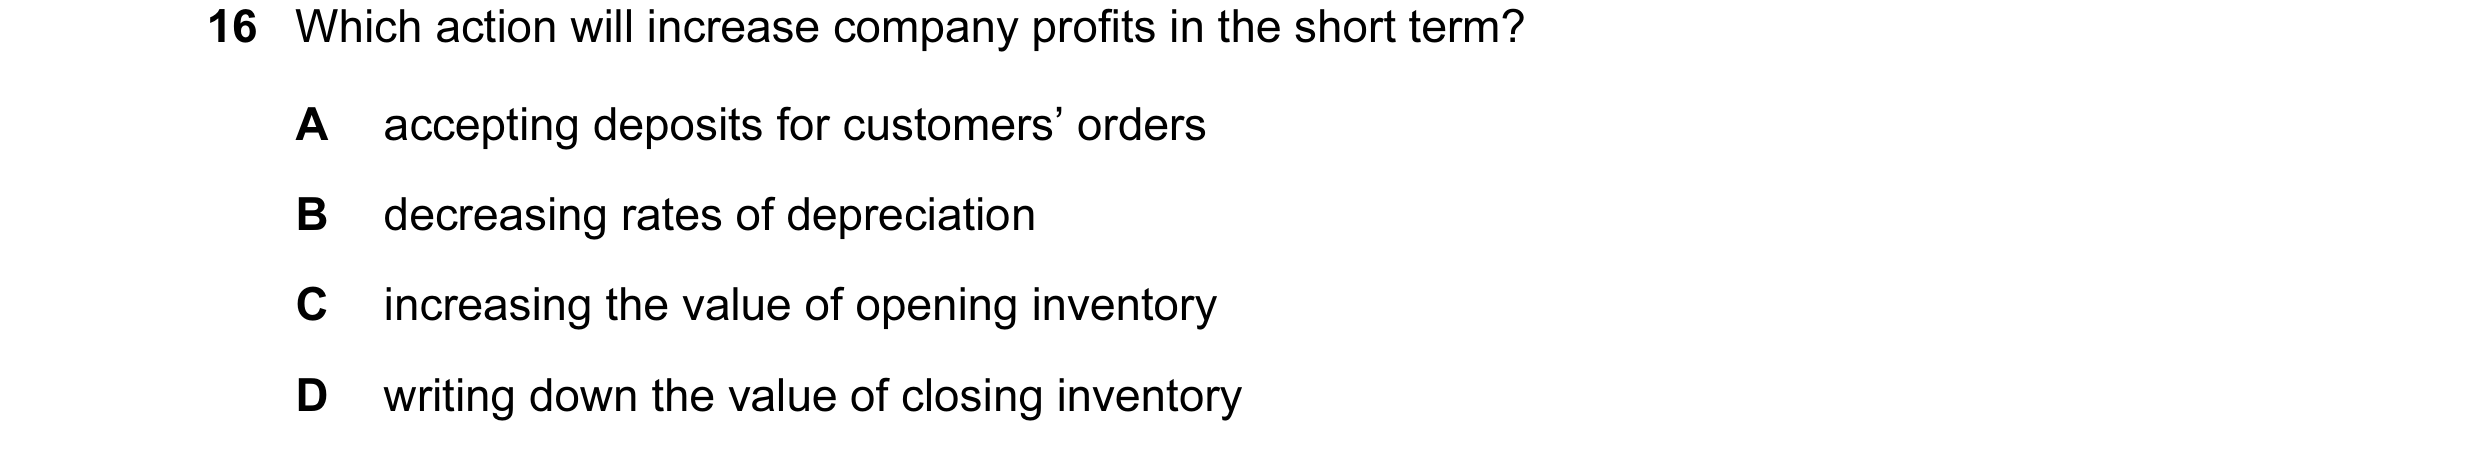
Q92 · Which action will increase company profits in the short term? 9706/31 Oct/Nov 2013
16 Which action will increase company profits in the short term? A accepting deposits for customers’ orders B decreasing rates of depreciation C increasing the value of opening inventory D writing down the value of closing inventory
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2013
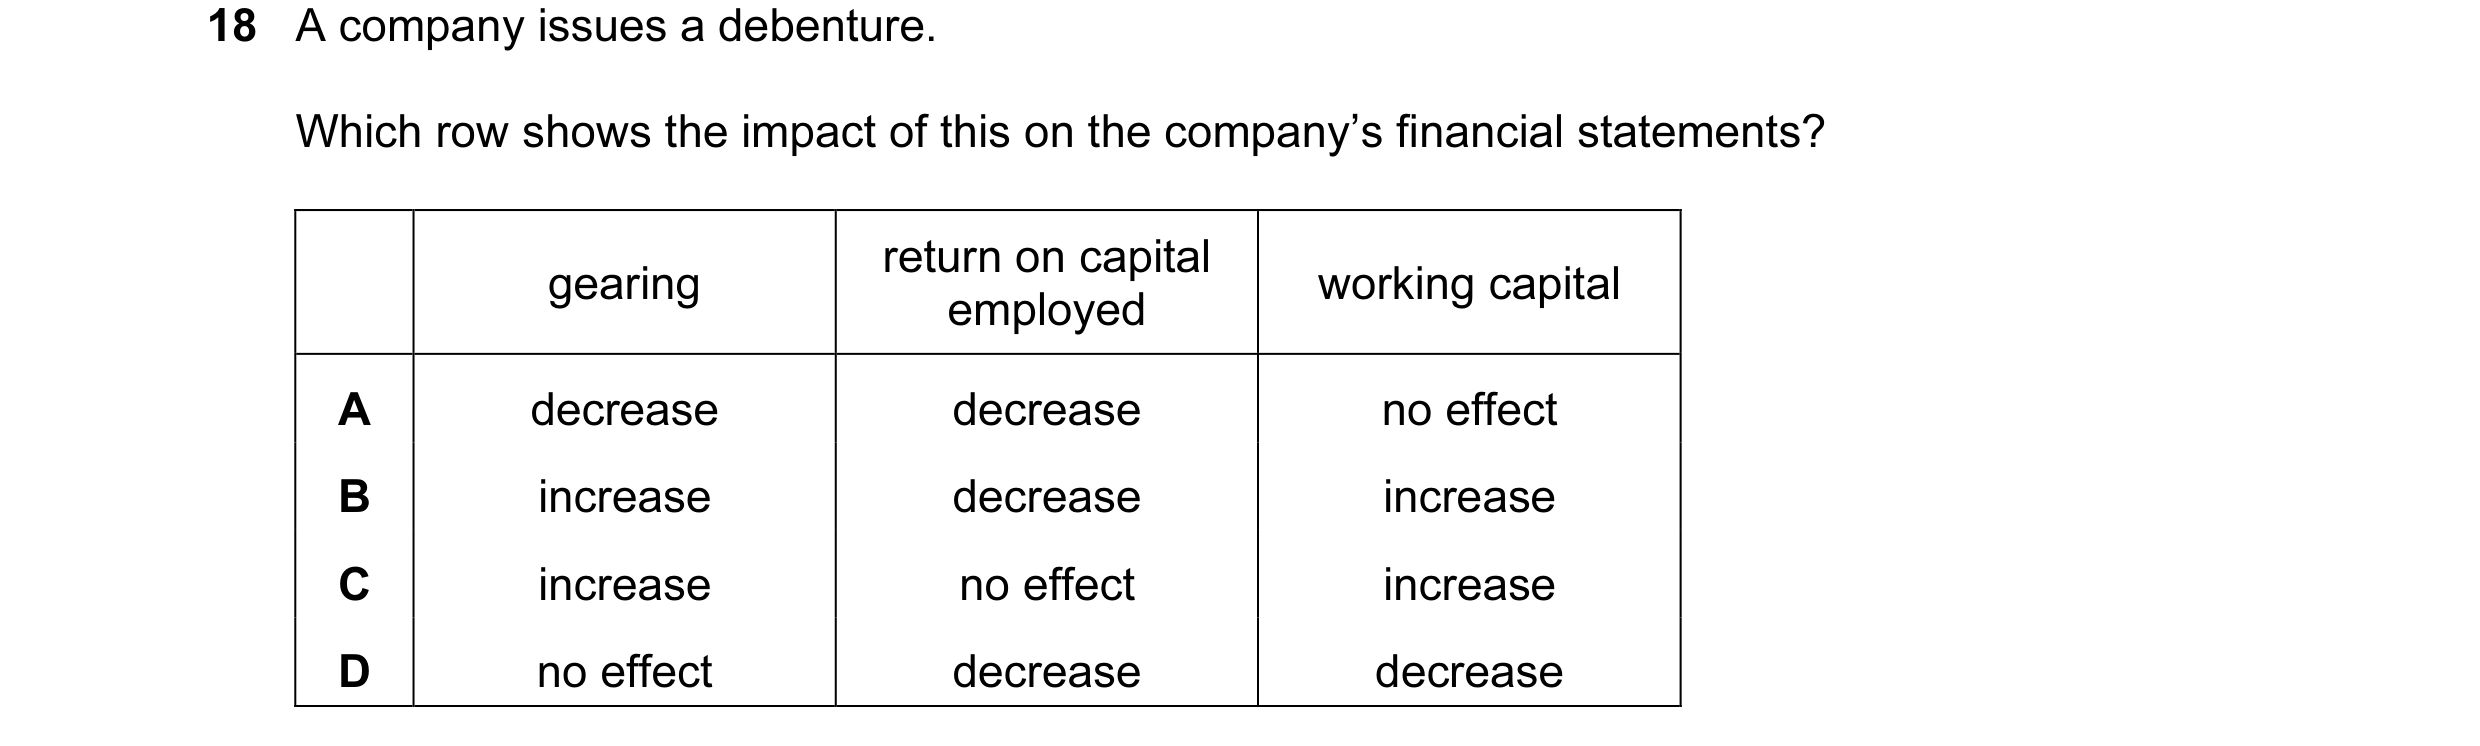
Q93 · A company issues a debenture 9706/31 Oct/Nov 2013
18 A company issues a debenture. Which row shows the impact of this on the company’s financial statements? return on capital gearing working capital employed A decrease decrease no effect B increase decrease increase C increase no effect increase D no effect decrease decrease
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2013
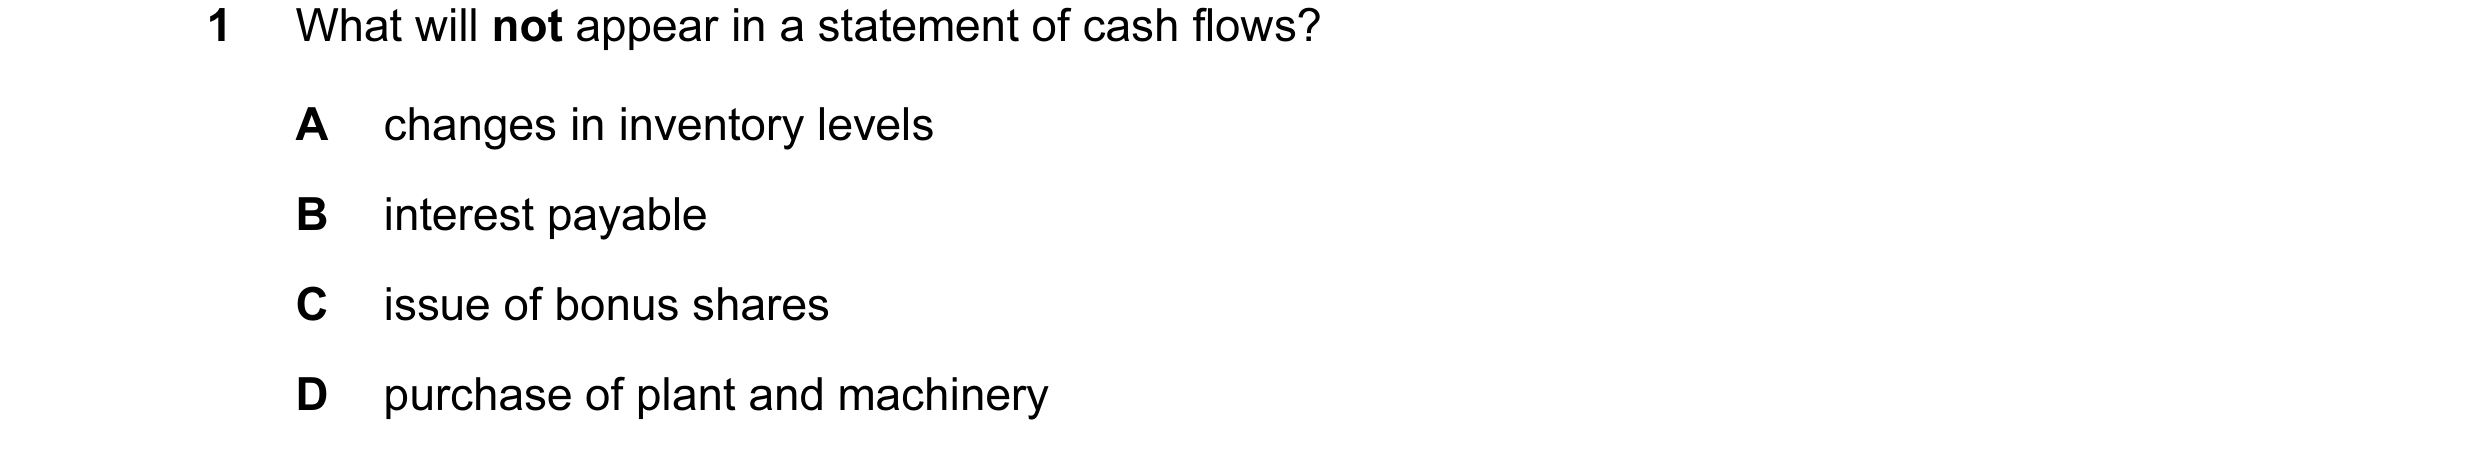
Q94 · What will not appear in a statement of cash flows? 9706/32 Oct/Nov 2013
1 What will not appear in a statement of cash flows? A changes in inventory levels B interest payable C issue of bonus shares D purchase of plant and machinery
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2013
Q95 · An ordinary share in a company has a nominal value of $0.50 9706/32 Oct/Nov 2013
11 An ordinary share in a company has a nominal value of $0.50. The latest financial statements show earnings per share of $0.10 and a price-earnings ratio of 15. What is the market value of an ordinary share? A $0.50 B $1.50 C $2.00 D $2.50
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2013
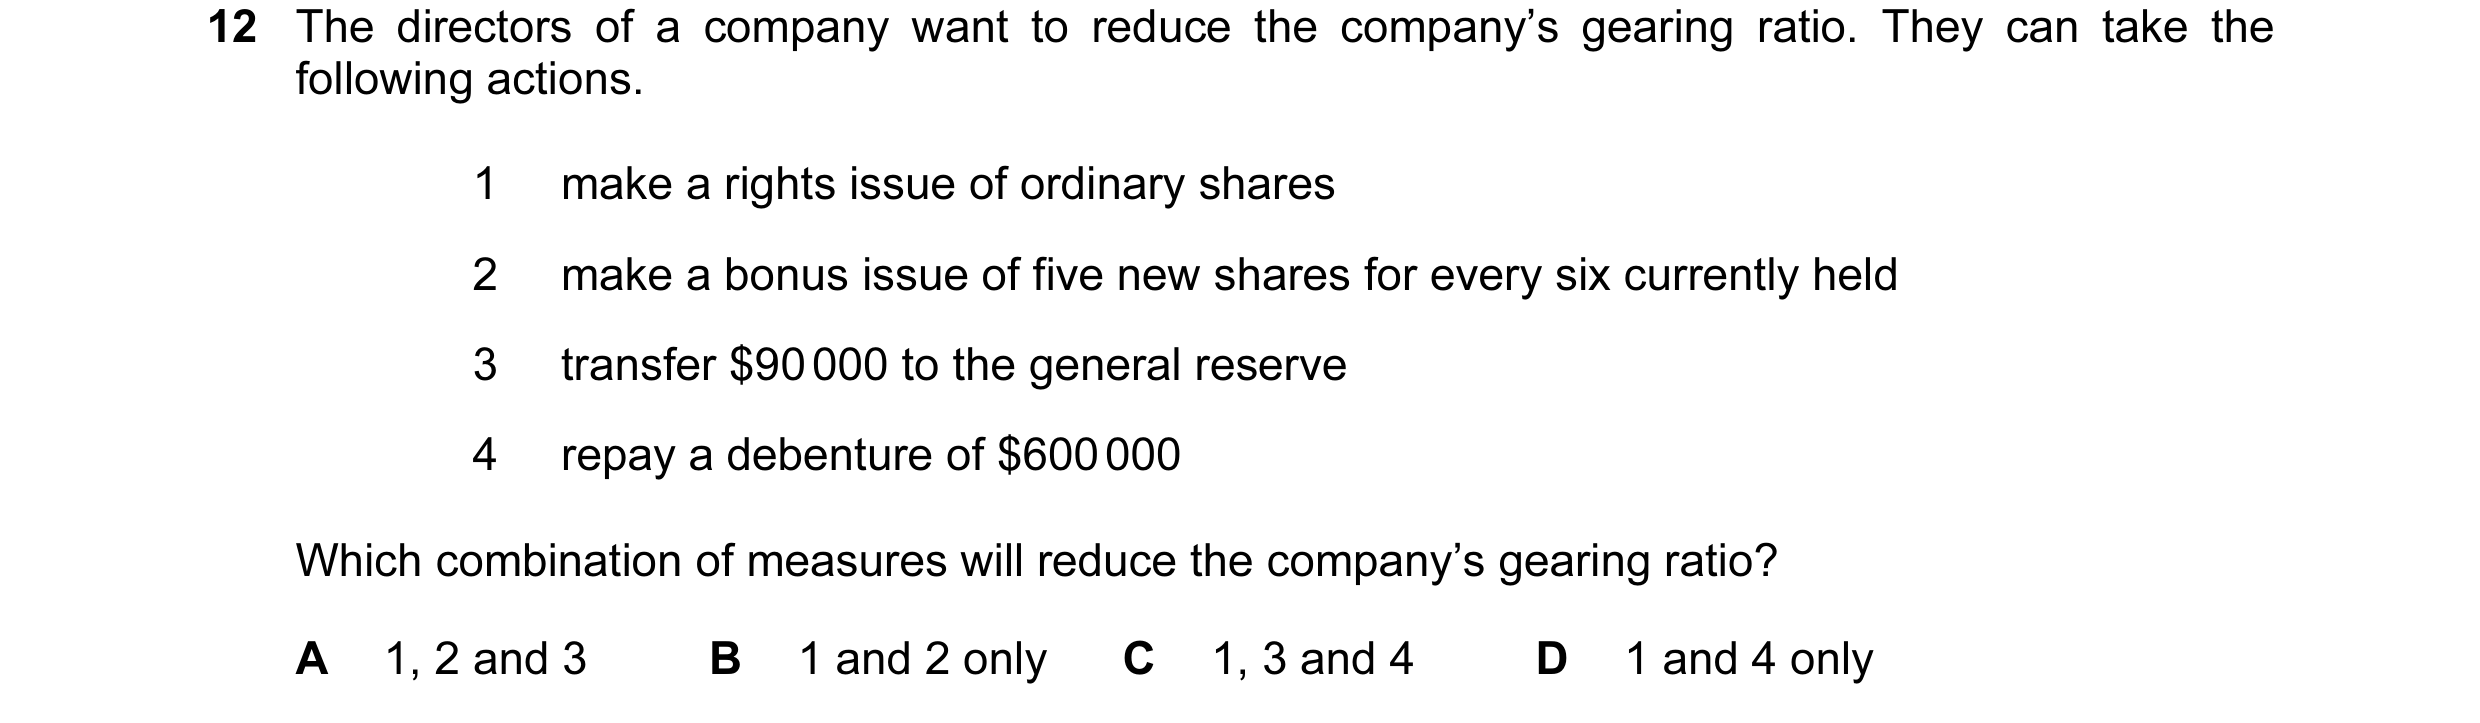
Q96 · The directors of a company want to reduce the company’s gearing ratio 9706/32 Oct/Nov 2013
12 The directors of a company want to reduce the company’s gearing ratio. They can take the following actions. 1 make a rights issue of ordinary shares 2 make a bonus issue of five new shares for every six currently held 3 transfer $90 000 to the general reserve 4 repay a debenture of $600 000 Which combination of measures will reduce the company’s gearing ratio? A 1, 2 and 3 B 1 and 2 only C 1, 3 and 4 D 1 and 4 only
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2013
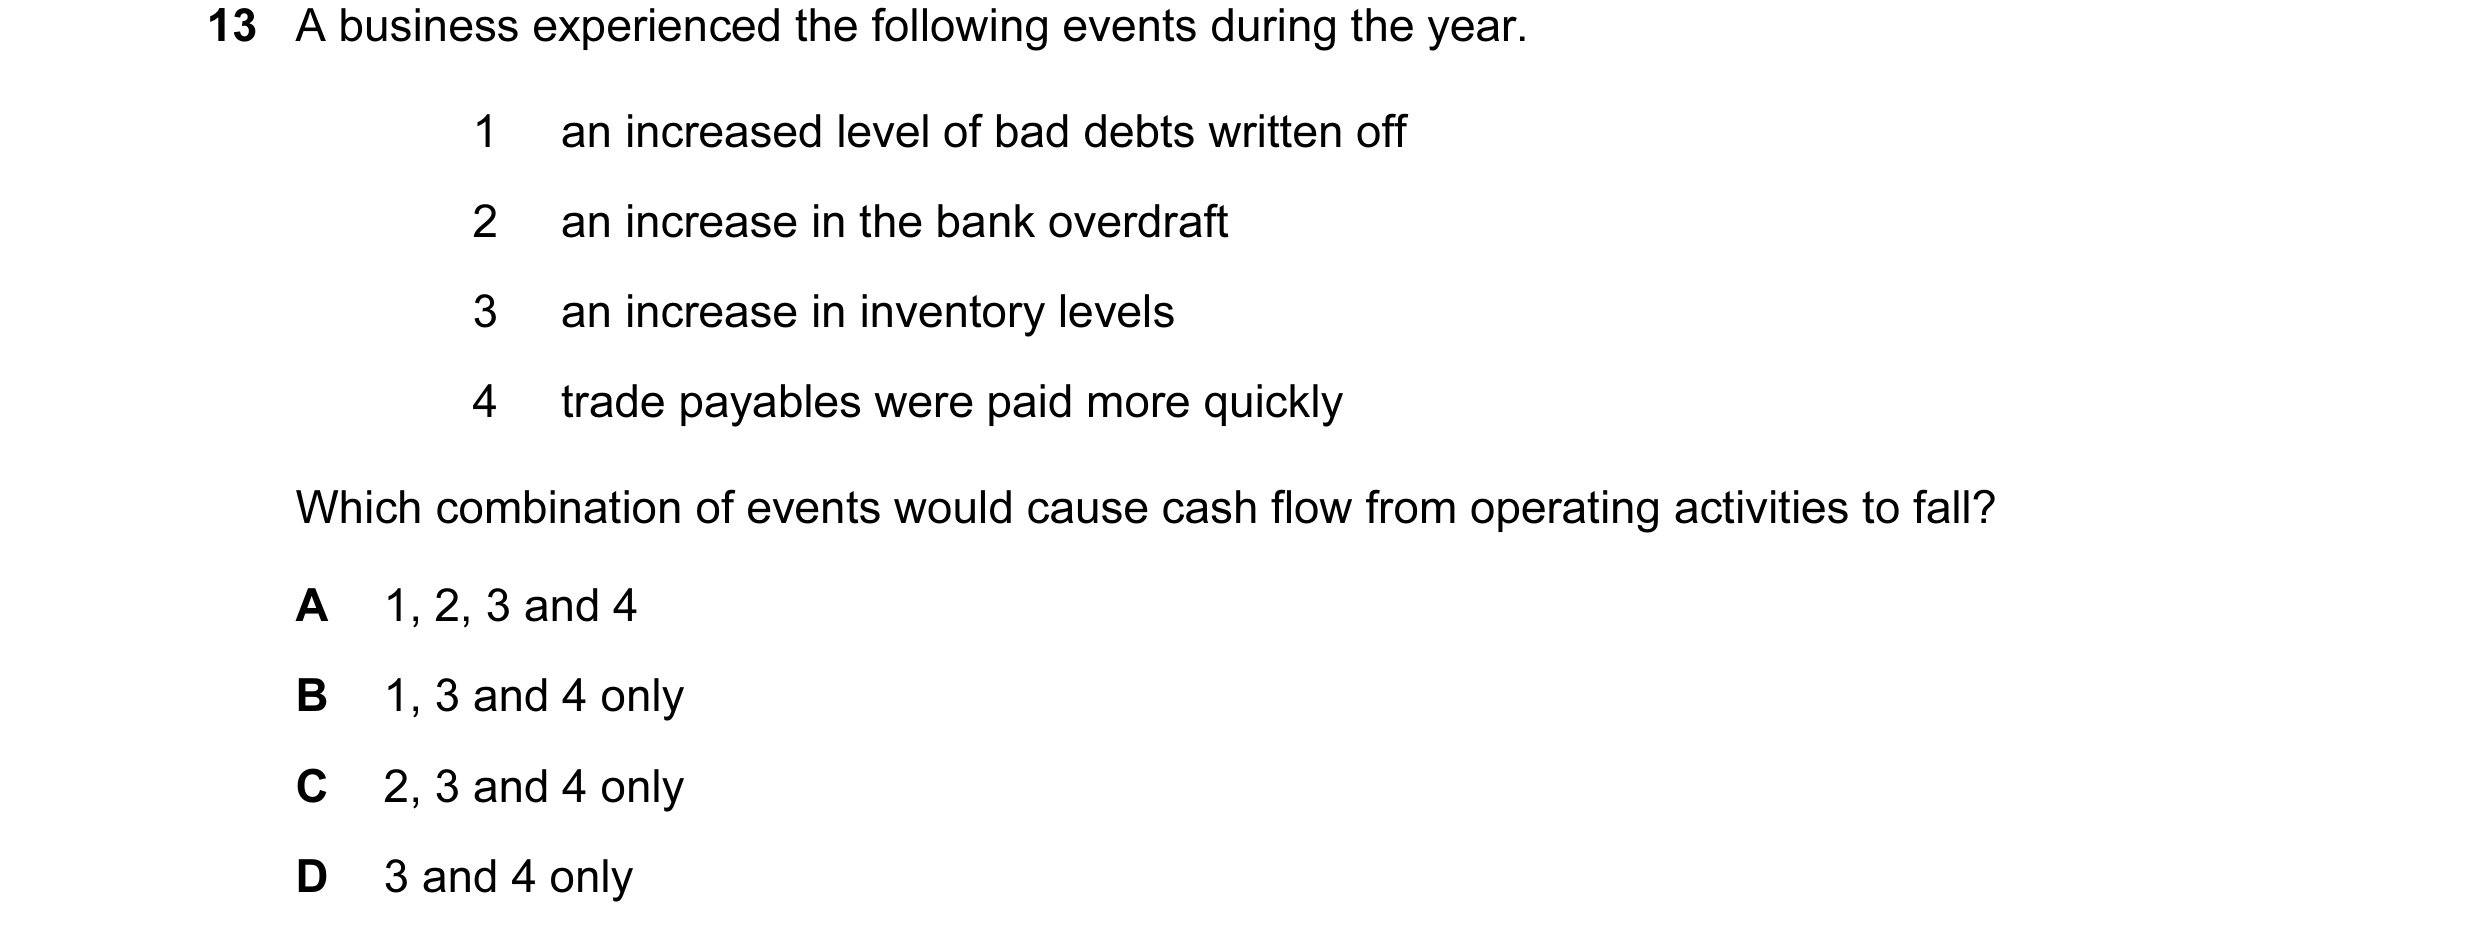
Q97 · A business experienced the following events during the year 9706/32 Oct/Nov 2013
13 A business experienced the following events during the year. 1 an increased level of bad debts written off 2 an increase in the bank overdraft 3 an increase in inventory levels 4 trade payables were paid more quickly Which combination of events would cause cash flow from operating activities to fall? A 1, 2, 3 and 4 B 1, 3 and 4 only C 2, 3 and 4 only D 3 and 4 only
1 marks
Answer: D
This question in 9706/32 Oct/Nov 2013
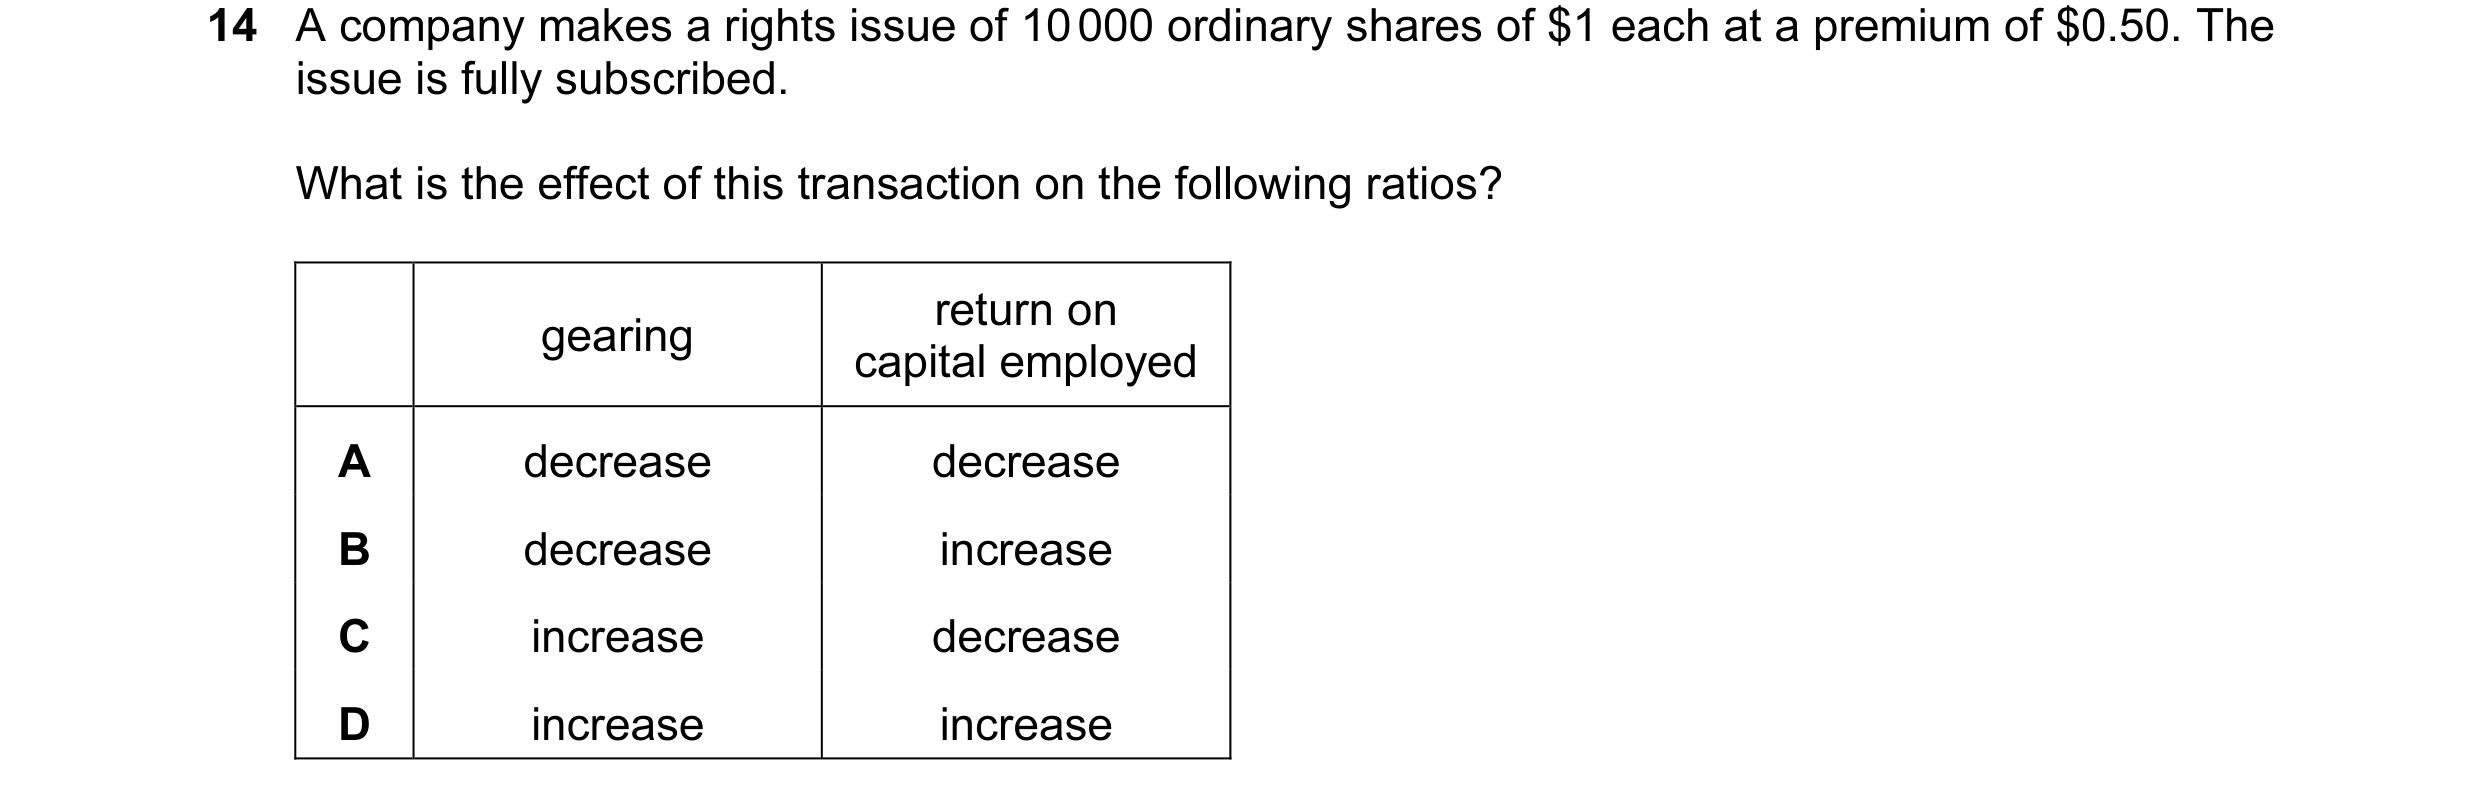
Q98 · A company makes a rights issue of 10 000 ordinary shares of $1 each at a premium of $0.50 9706/32 Oct/Nov 2013
14 A company makes a rights issue of 10 000 ordinary shares of $1 each at a premium of $0.50. The issue is fully subscribed. What is the effect of this transaction on the following ratios? return on gearing capital employed A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2013
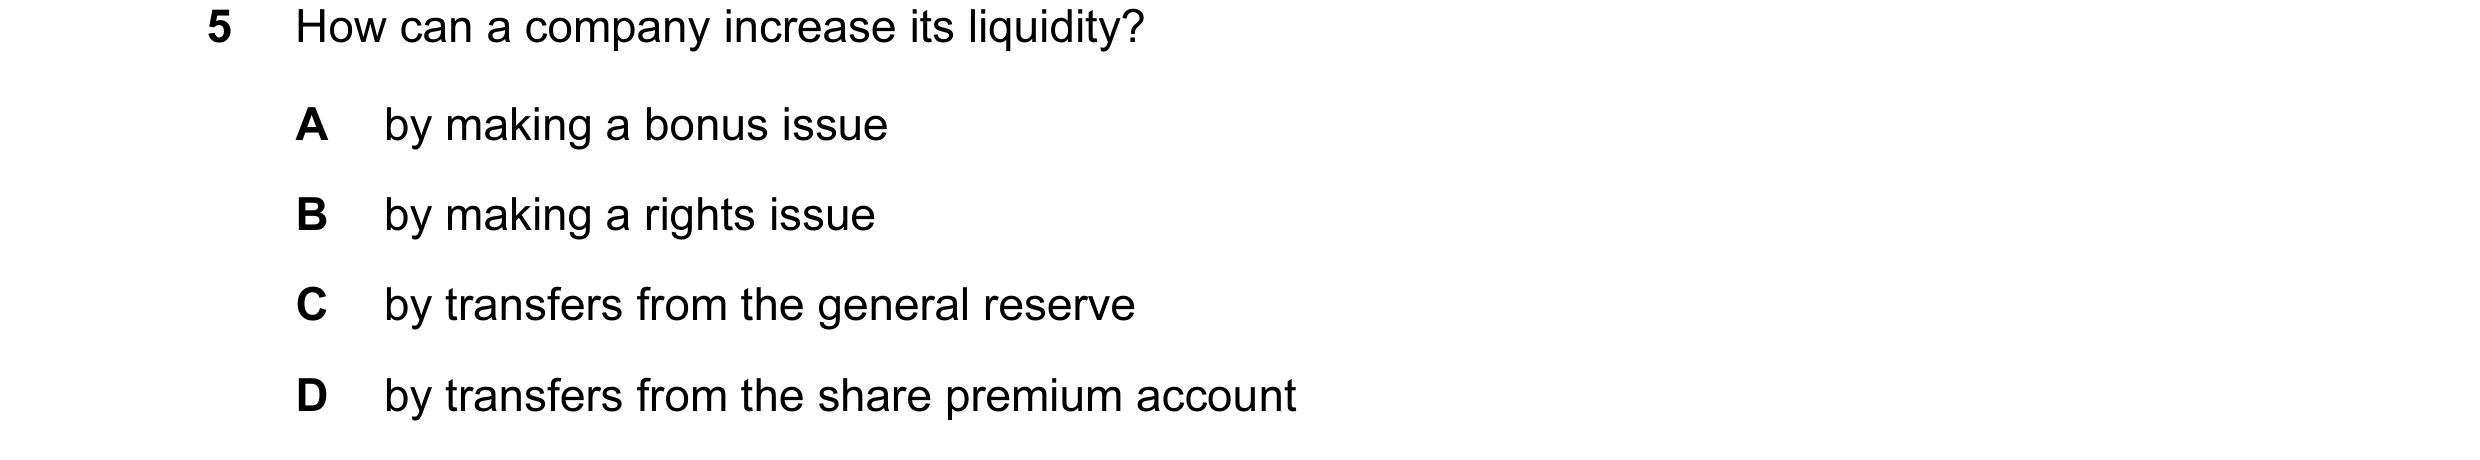
Q99 · How can a company increase its liquidity? 9706/33 Oct/Nov 2013
5 How can a company increase its liquidity? A by making a bonus issue B by making a rights issue C by transfers from the general reserve D by transfers from the share premium account
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2013
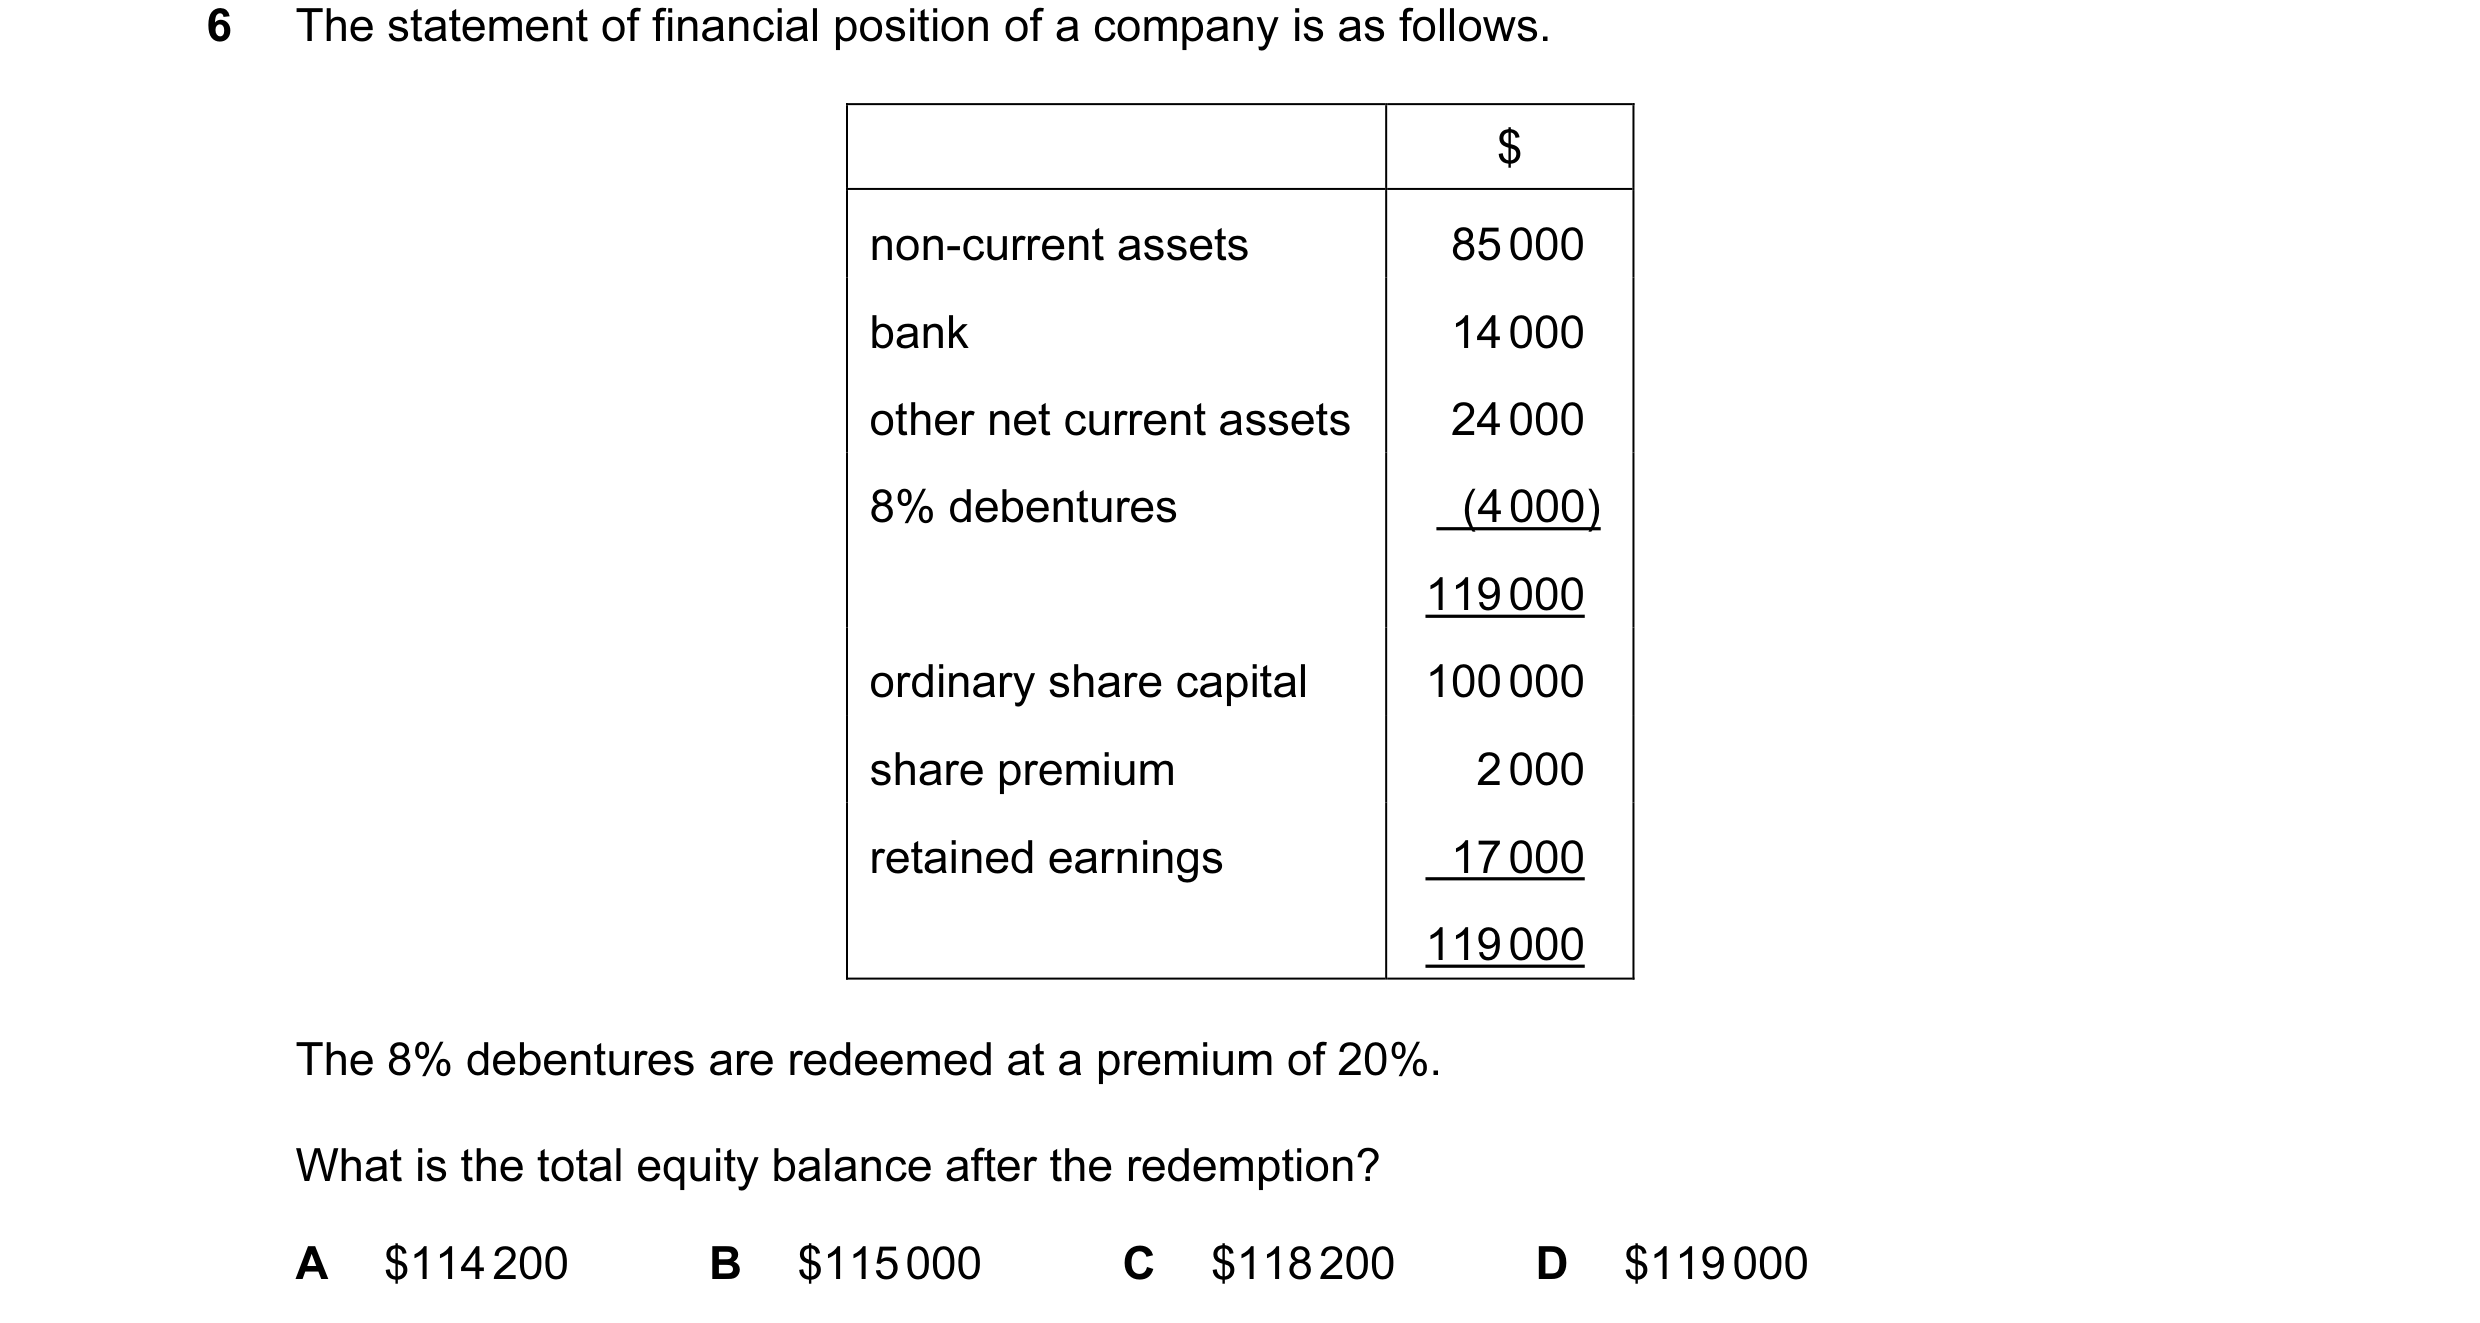
Q100 · The statement of financial position of a company is as follows 9706/33 Oct/Nov 2013
6 The statement of financial position of a company is as follows. $ non-current assets 85 000 bank 14 000 other net current assets 24 000 8% debentures (4 000) 119 000 ordinary share capital 100 000 share premium 2 000 retained earnings 17 000 119 000 The 8% debentures are redeemed at a premium of 20%. What is the total equity balance after the redemption? A $114 200 B $115 000 C $118 200 D $119 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2013
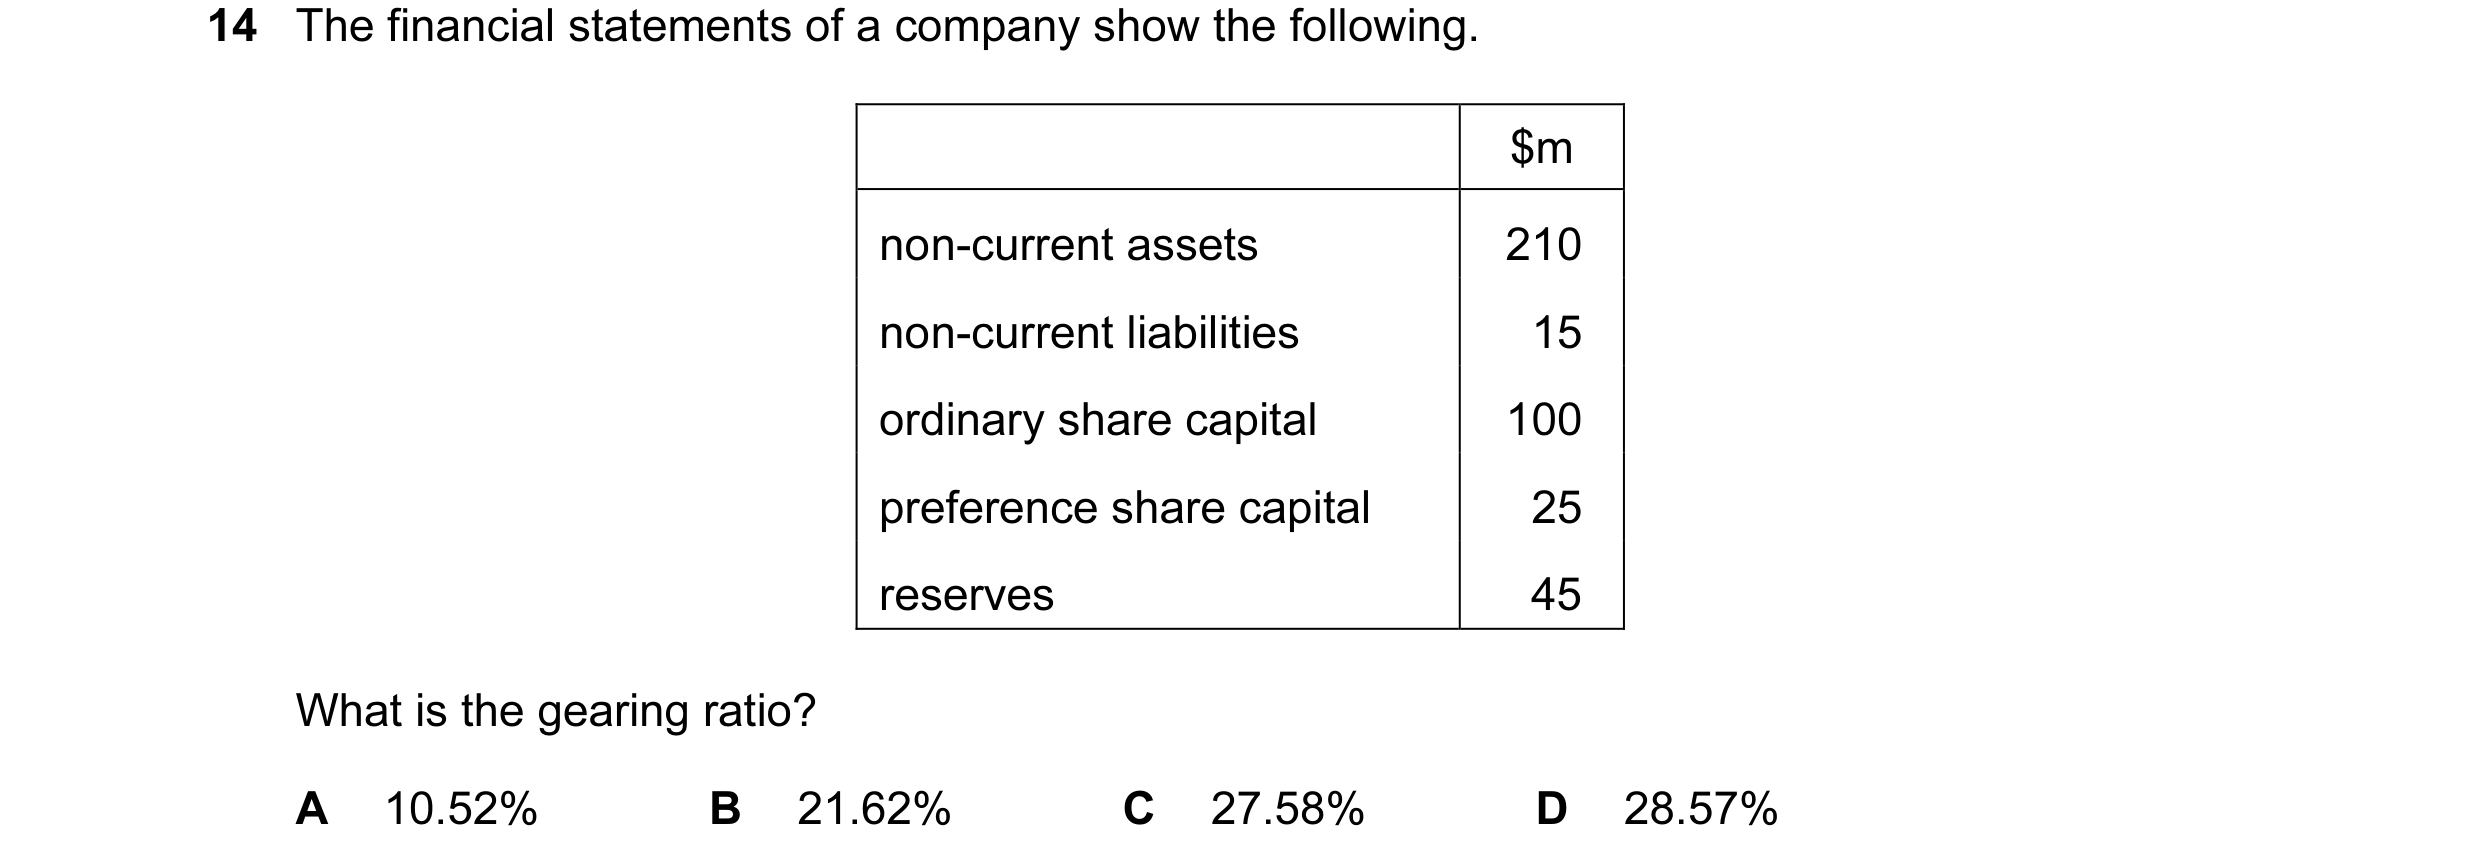
Q101 · The financial statements of a company show the following 9706/33 Oct/Nov 2013
14 The financial statements of a company show the following. $m non-current assets 210 non-current liabilities 15 ordinary share capital 100 preference share capital 25 reserves 45 What is the gearing ratio? A 10.52% B 21.62% C 27.58% D 28.57%
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2013
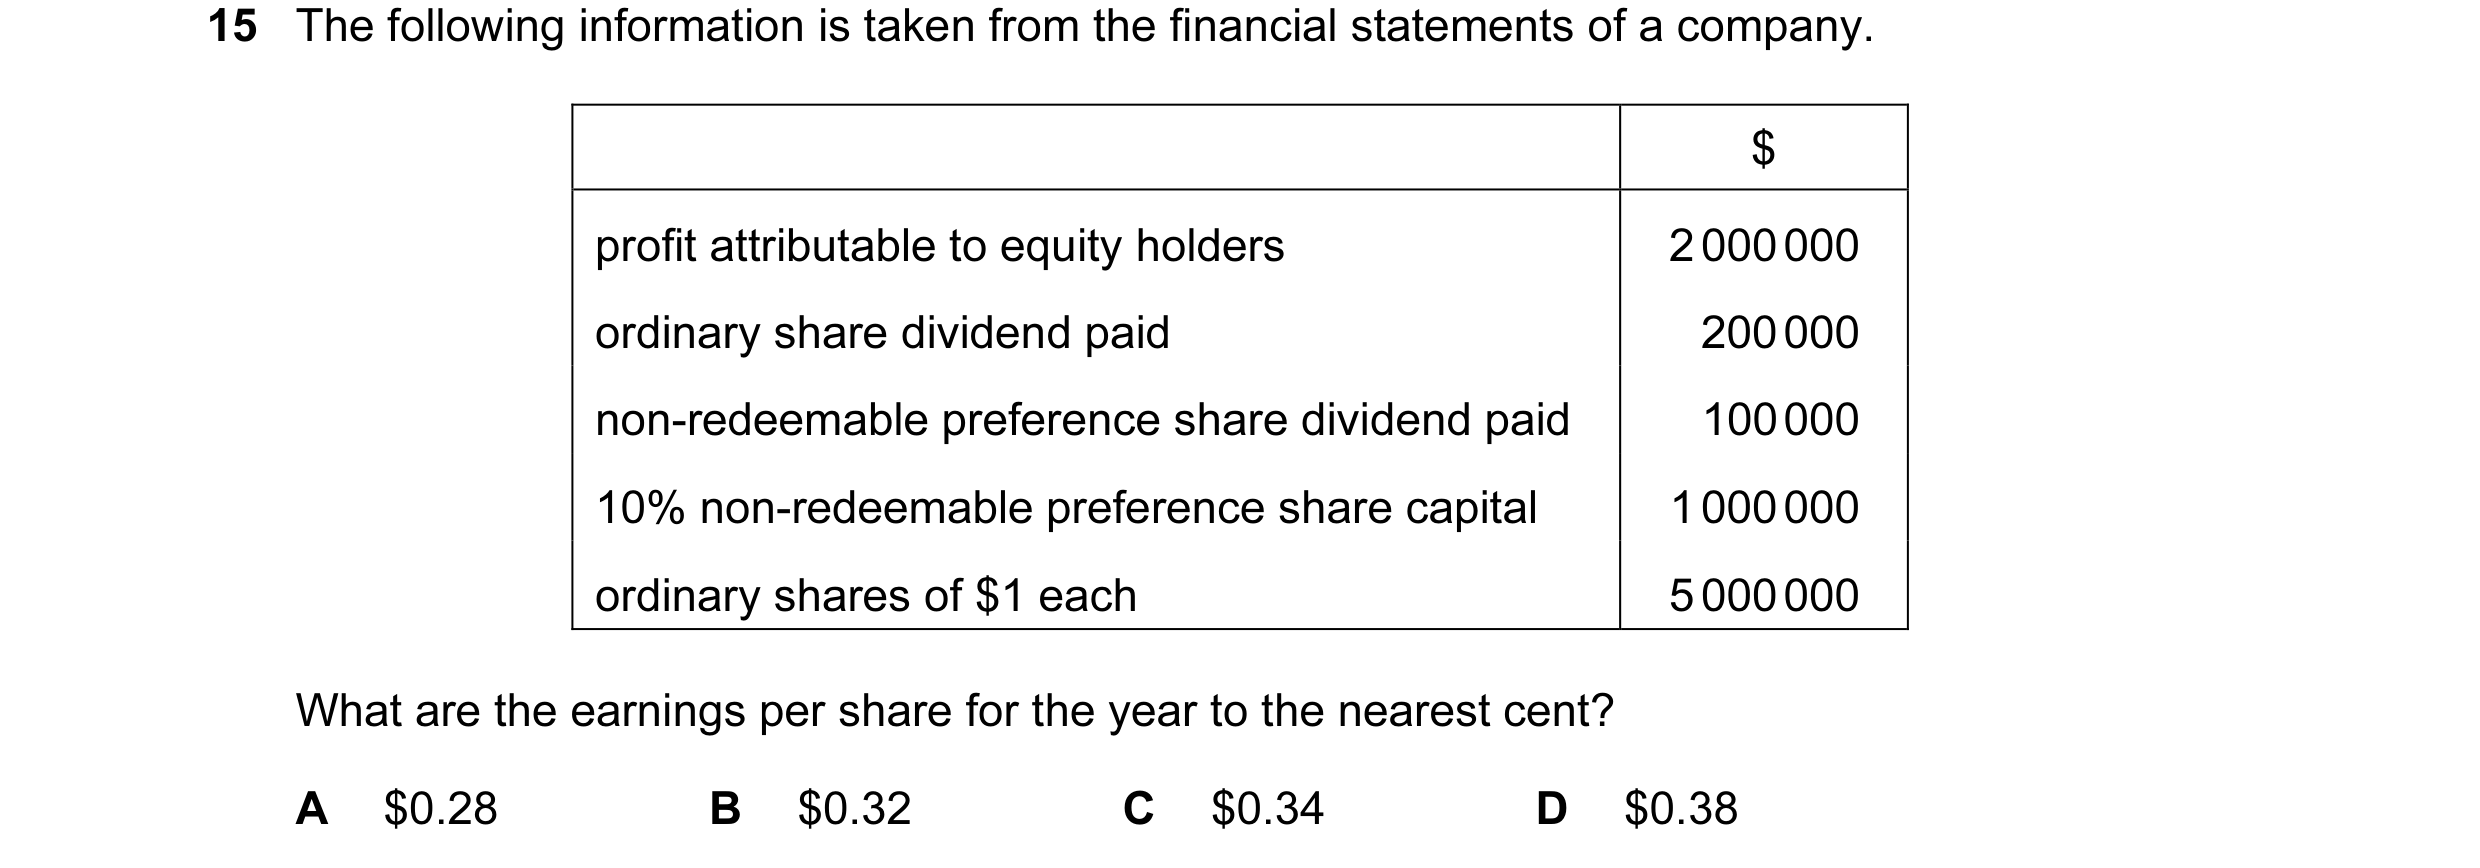
Q102 · The following information is taken from the financial statements of a company 9706/33 Oct/Nov 2013
15 The following information is taken from the financial statements of a company. $ profit attributable to equity holders 2 000 000 ordinary share dividend paid 200 000 non-redeemable preference share dividend paid 100 000 10% non-redeemable preference share capital 1 000 000 ordinary shares of $1 each 5 000 000 What are the earnings per share for the year to the nearest cent? A $0.28 B $0.32 C $0.34 D $0.38
1 marks
Answer: D
This question in 9706/33 Oct/Nov 2013
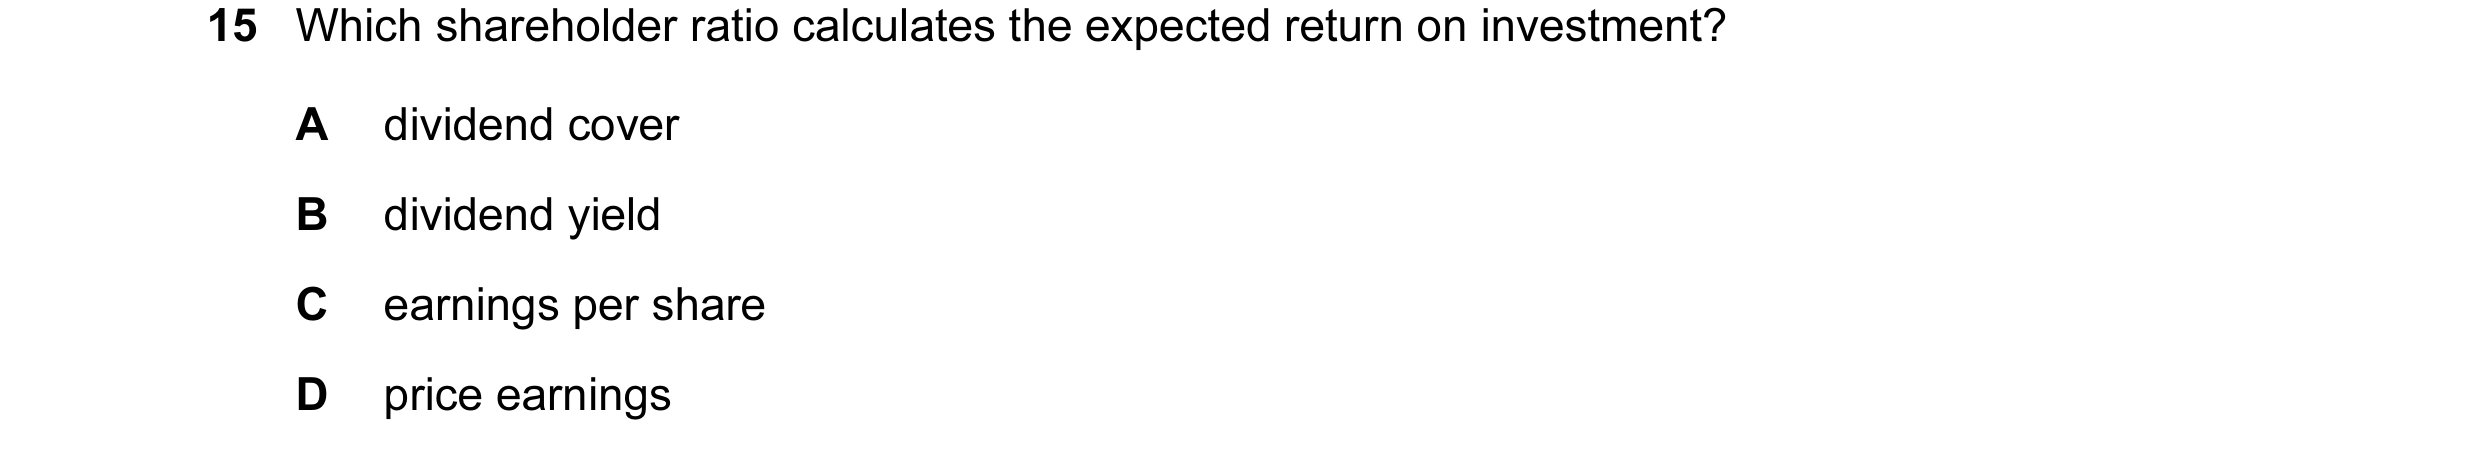
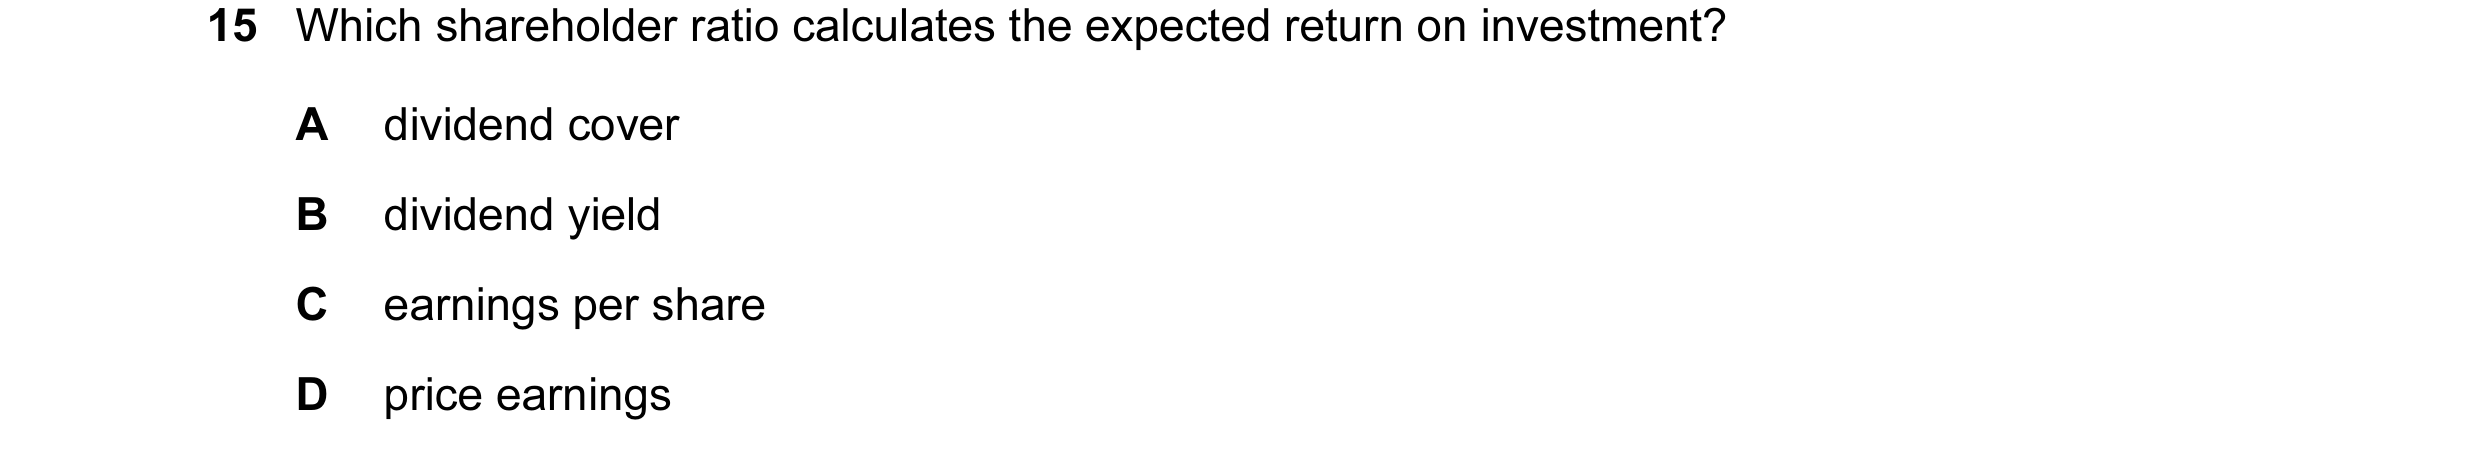
Q103 · Which shareholder ratio calculates the expected return on investment? 9706/31 May/June 2014
15 Which shareholder ratio calculates the expected return on investment? A dividend cover B dividend yield C earnings per share D price earnings
1 marks
Answer: B
This question in 9706/31 May/June 2014
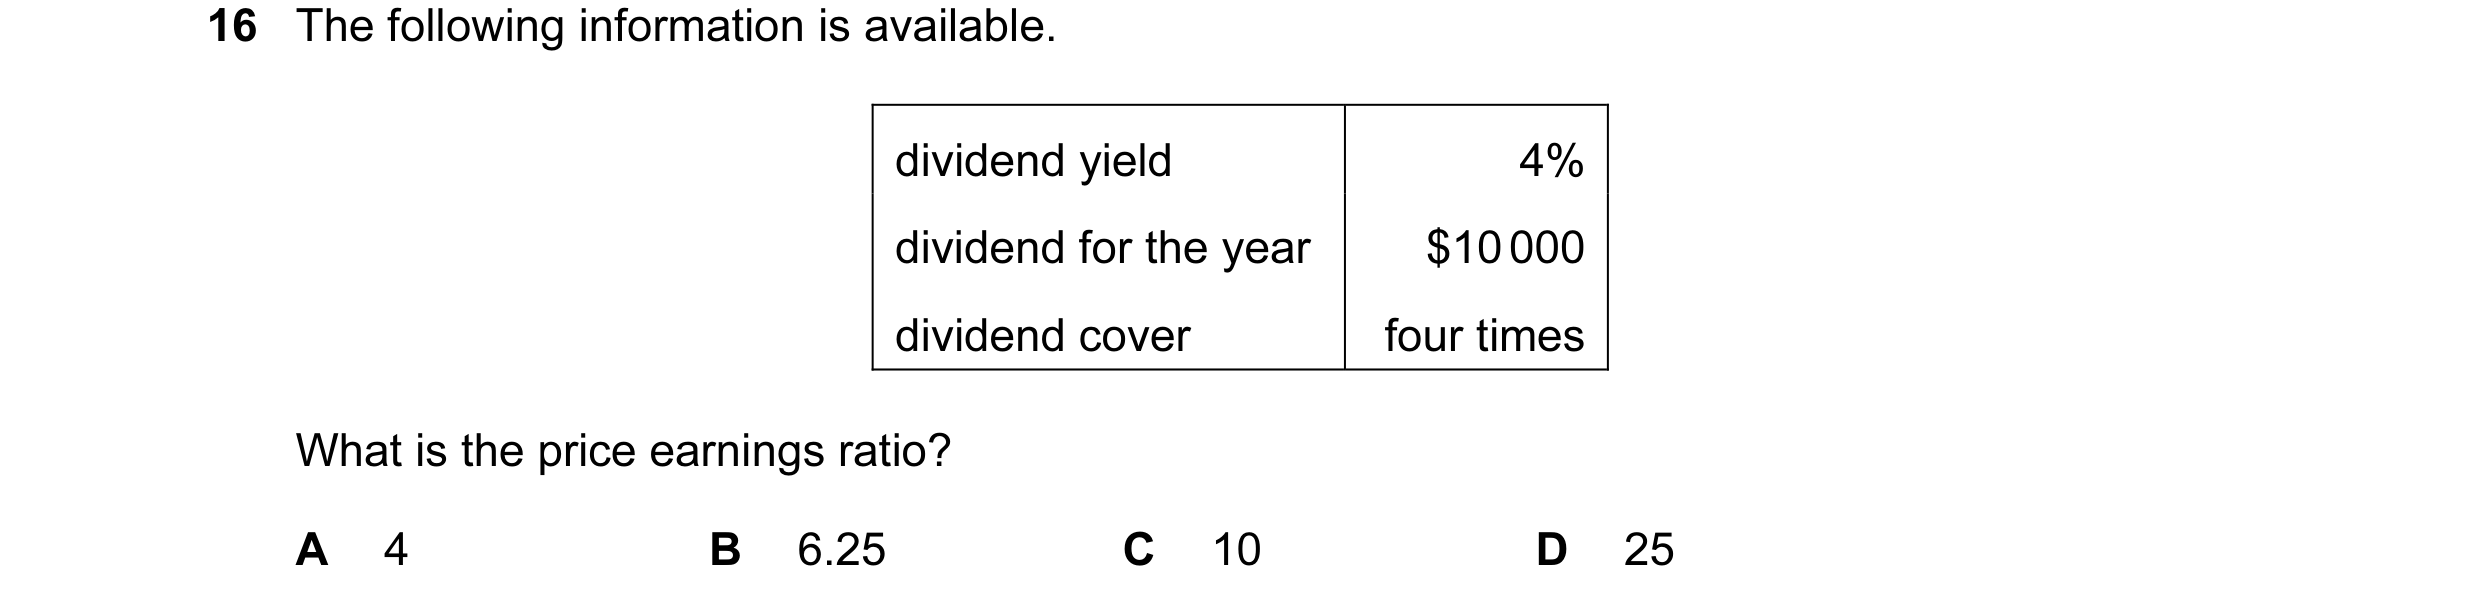
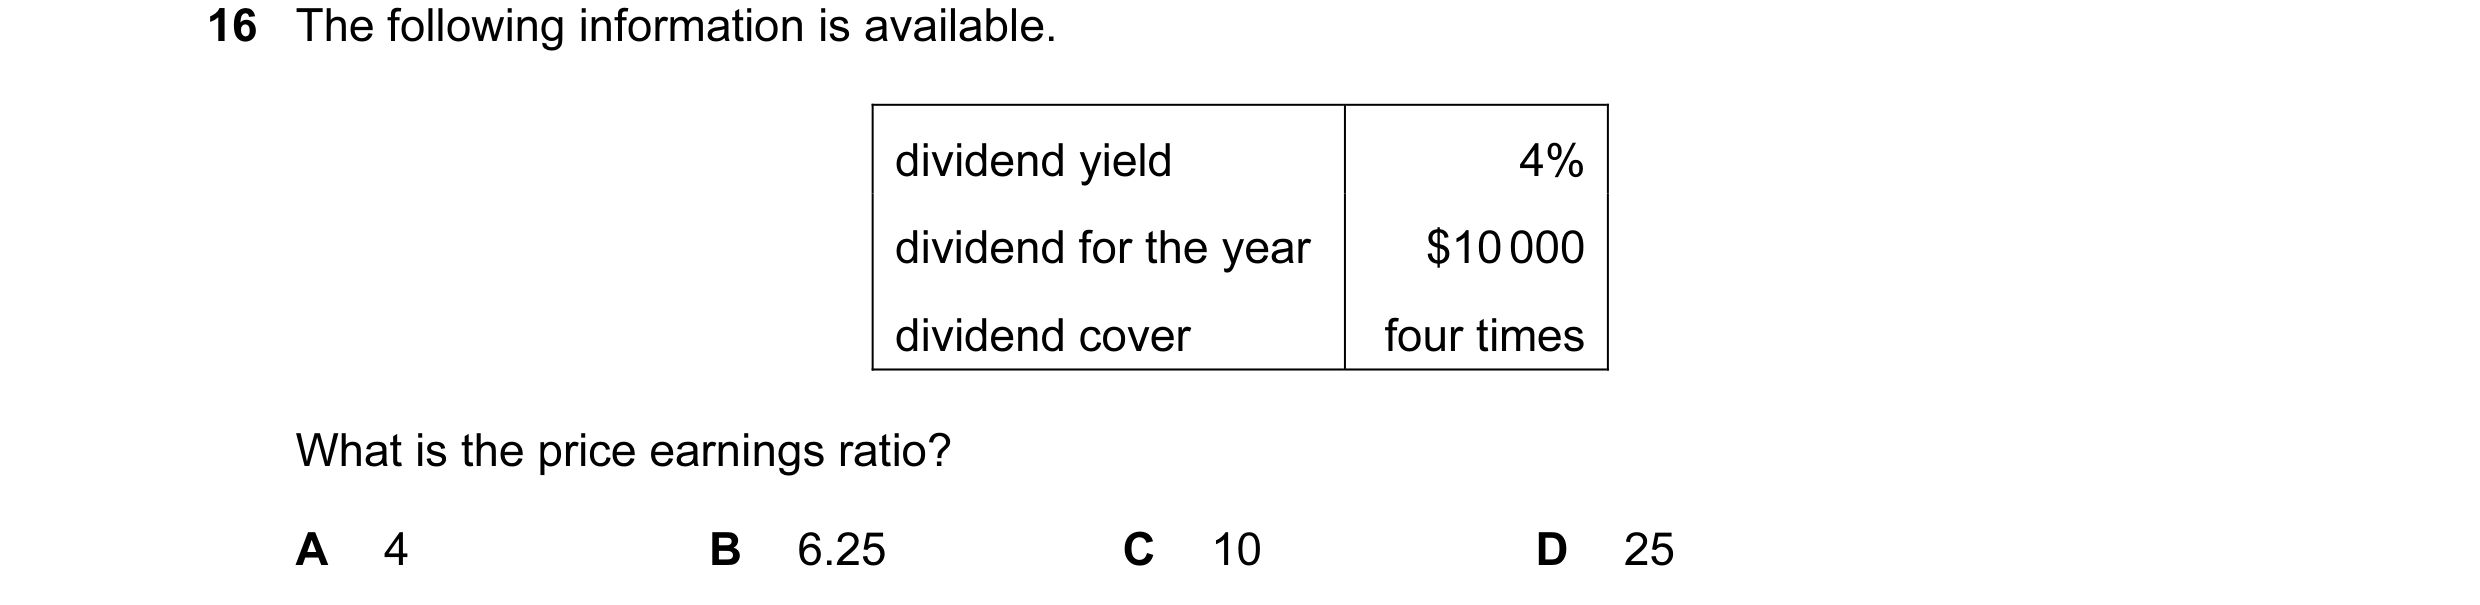
Q104 · The following information is available 9706/31 May/June 2014
16 The following information is available. dividend yield 4% dividend for the year $10 000 dividend cover four times What is the price earnings ratio? A 4 B 6.25 C 10 D 25
1 marks
Answer: B
This question in 9706/31 May/June 2014
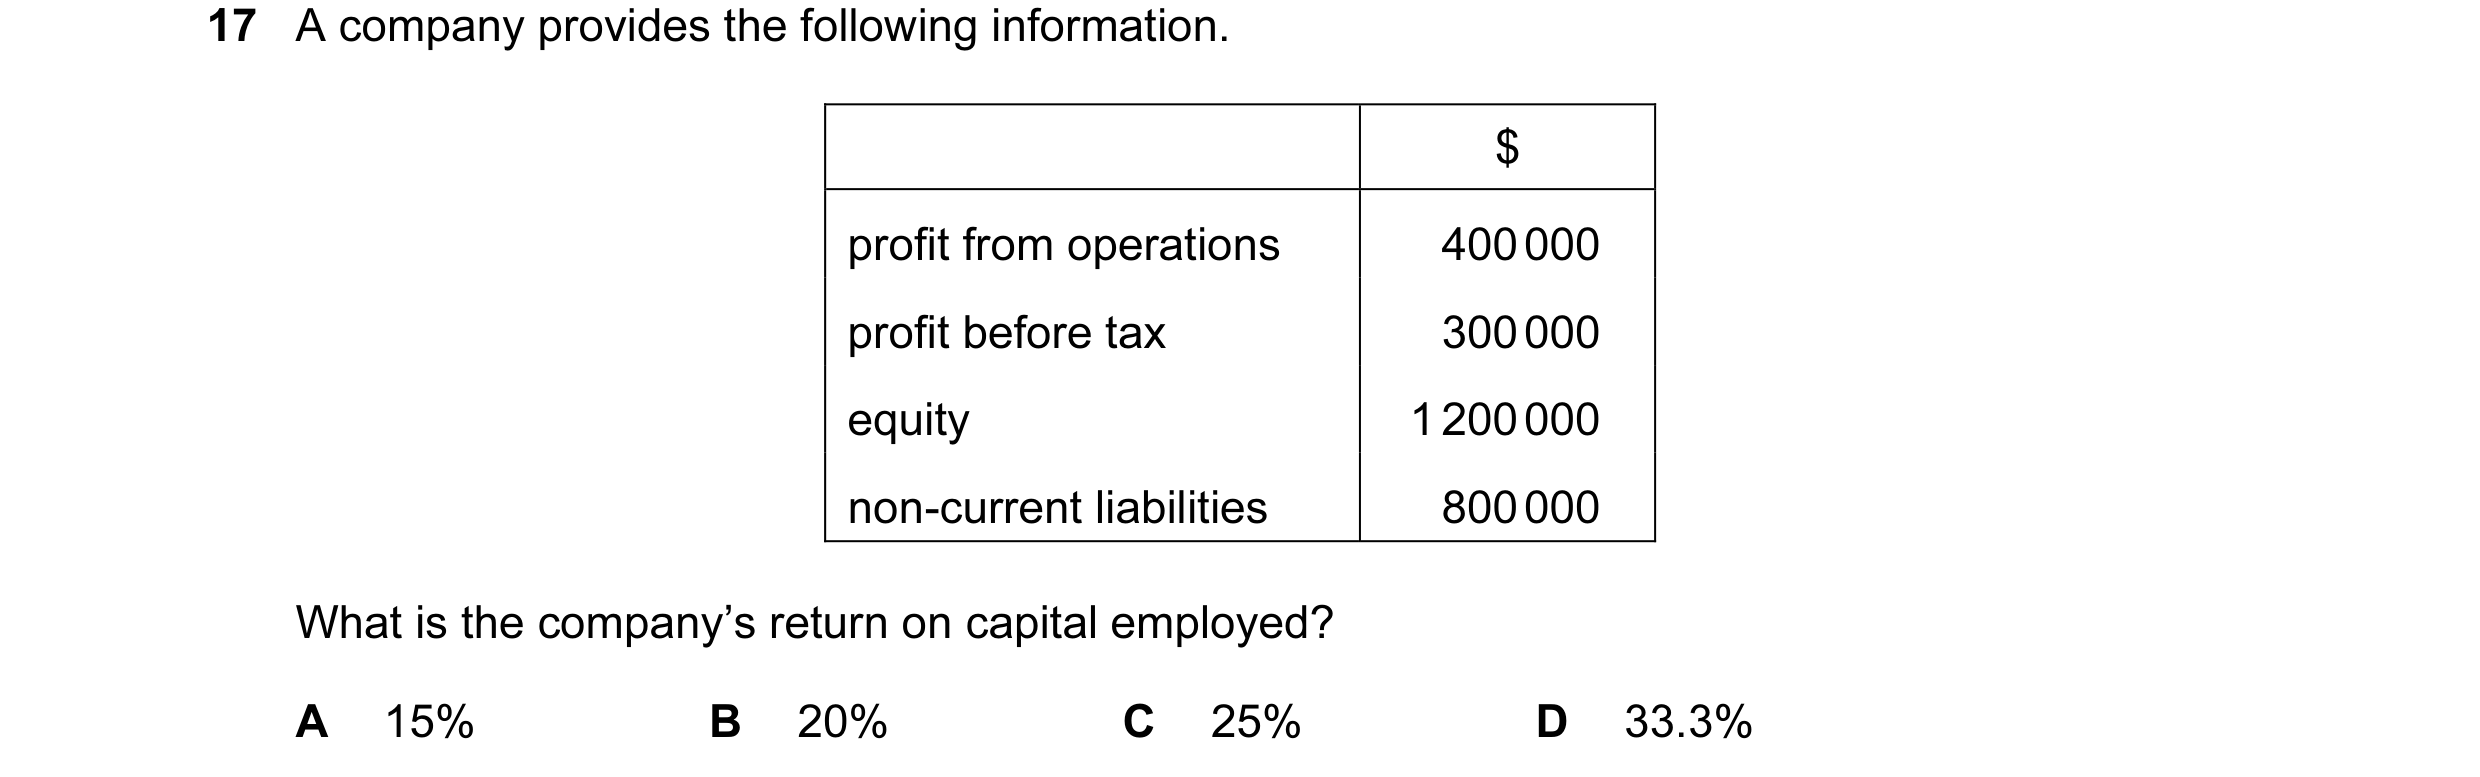
Q105 · A company provides the following information 9706/31 May/June 2014
17 A company provides the following information. $ profit from operations 400 000 profit before tax 300 000 equity 1 200 000 non-current liabilities 800 000 What is the company’s return on capital employed? A 15% B 20% C 25% D 33.3%
1 marks
Answer: B
This question in 9706/31 May/June 2014
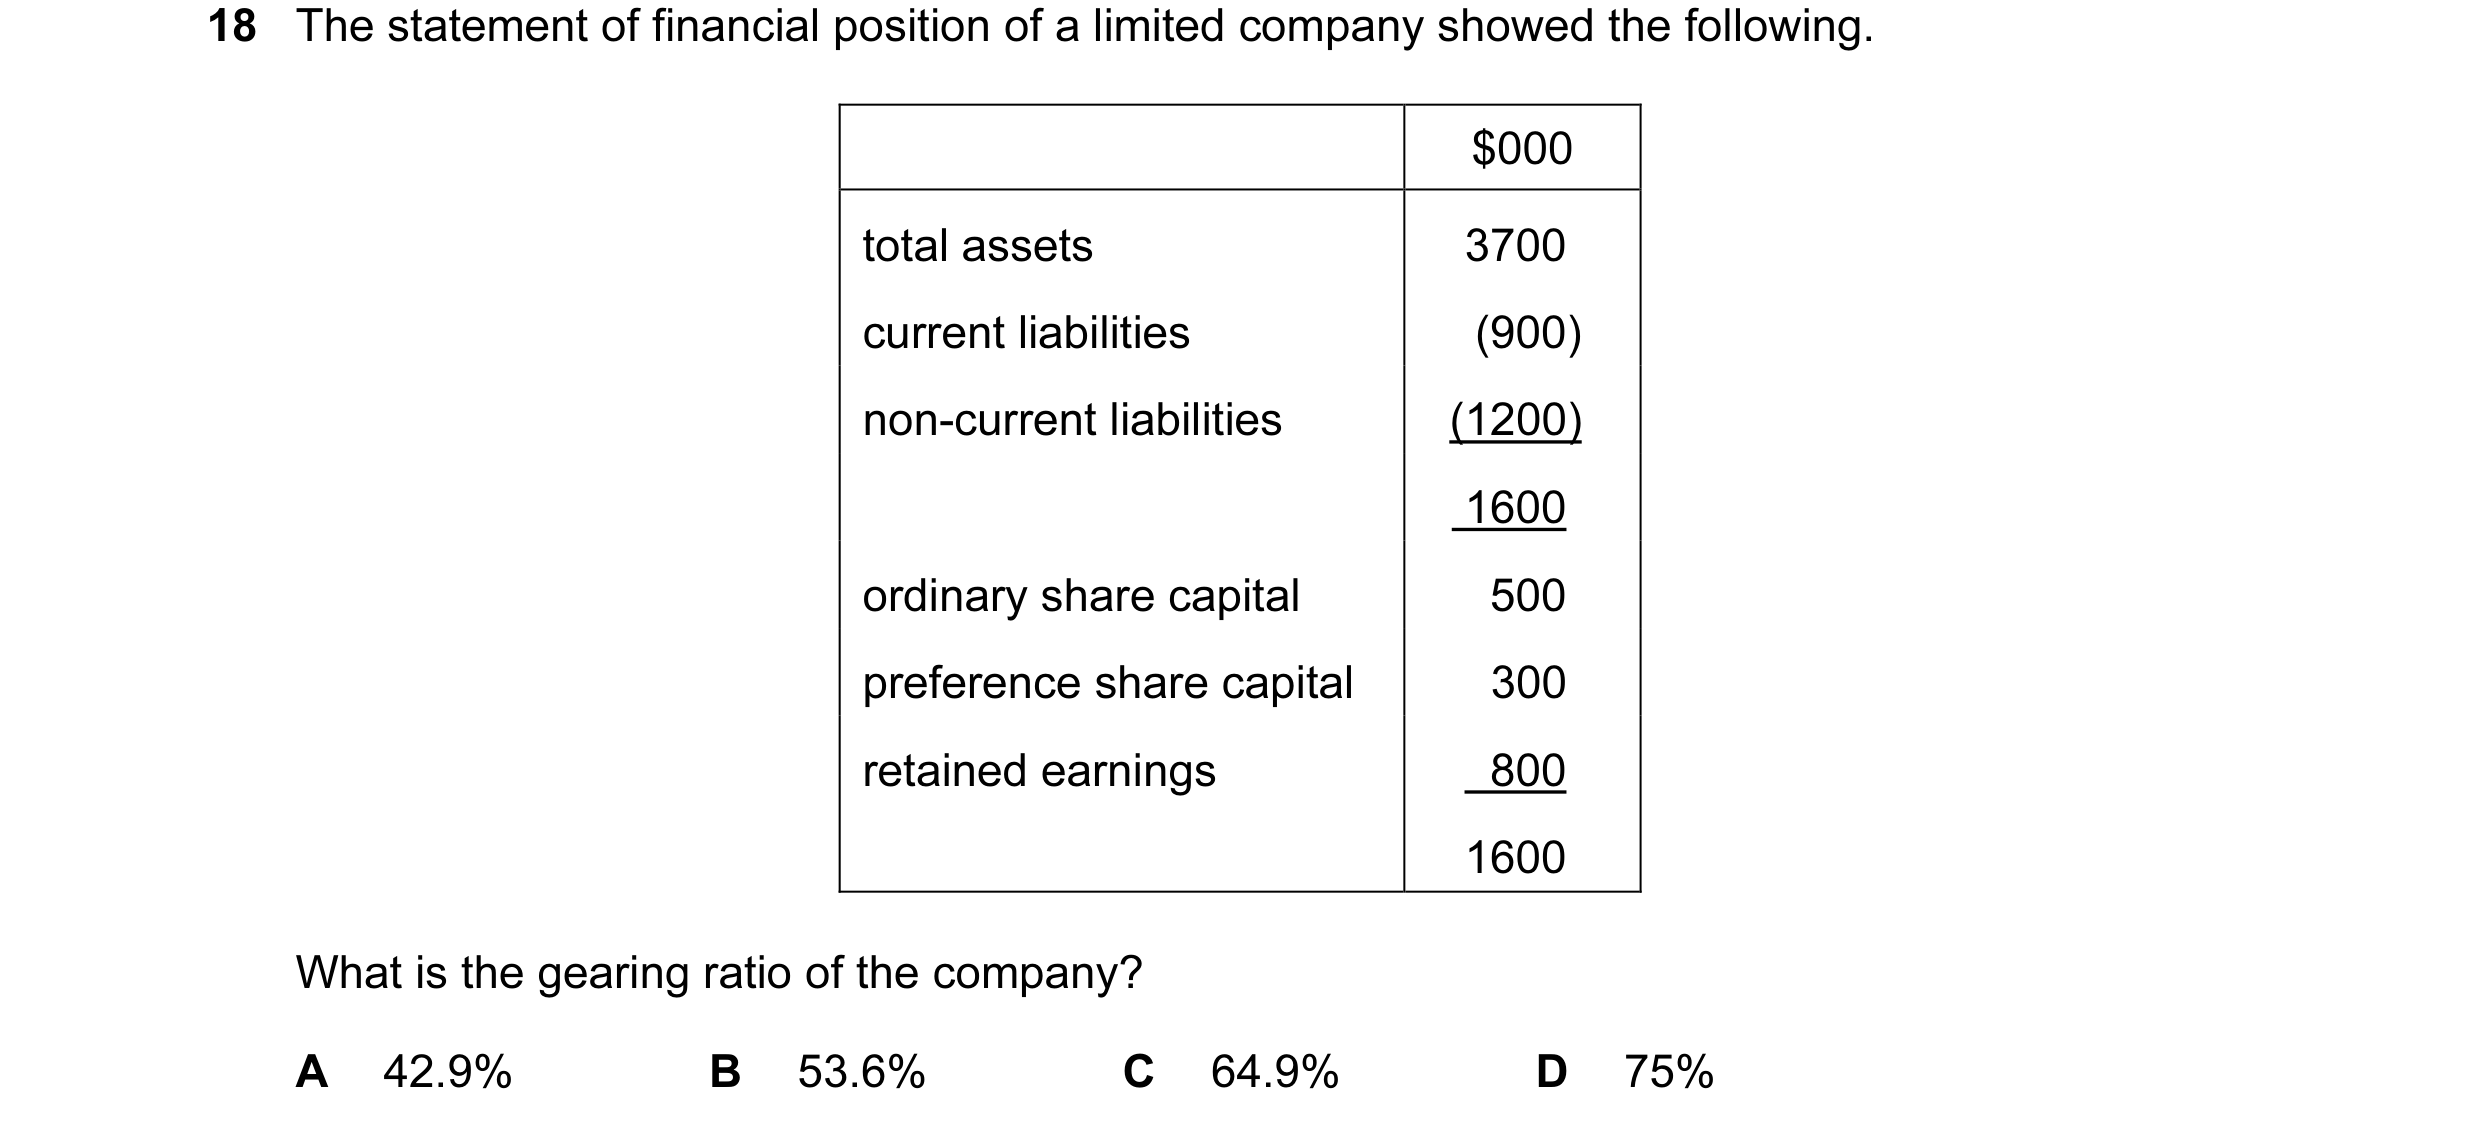
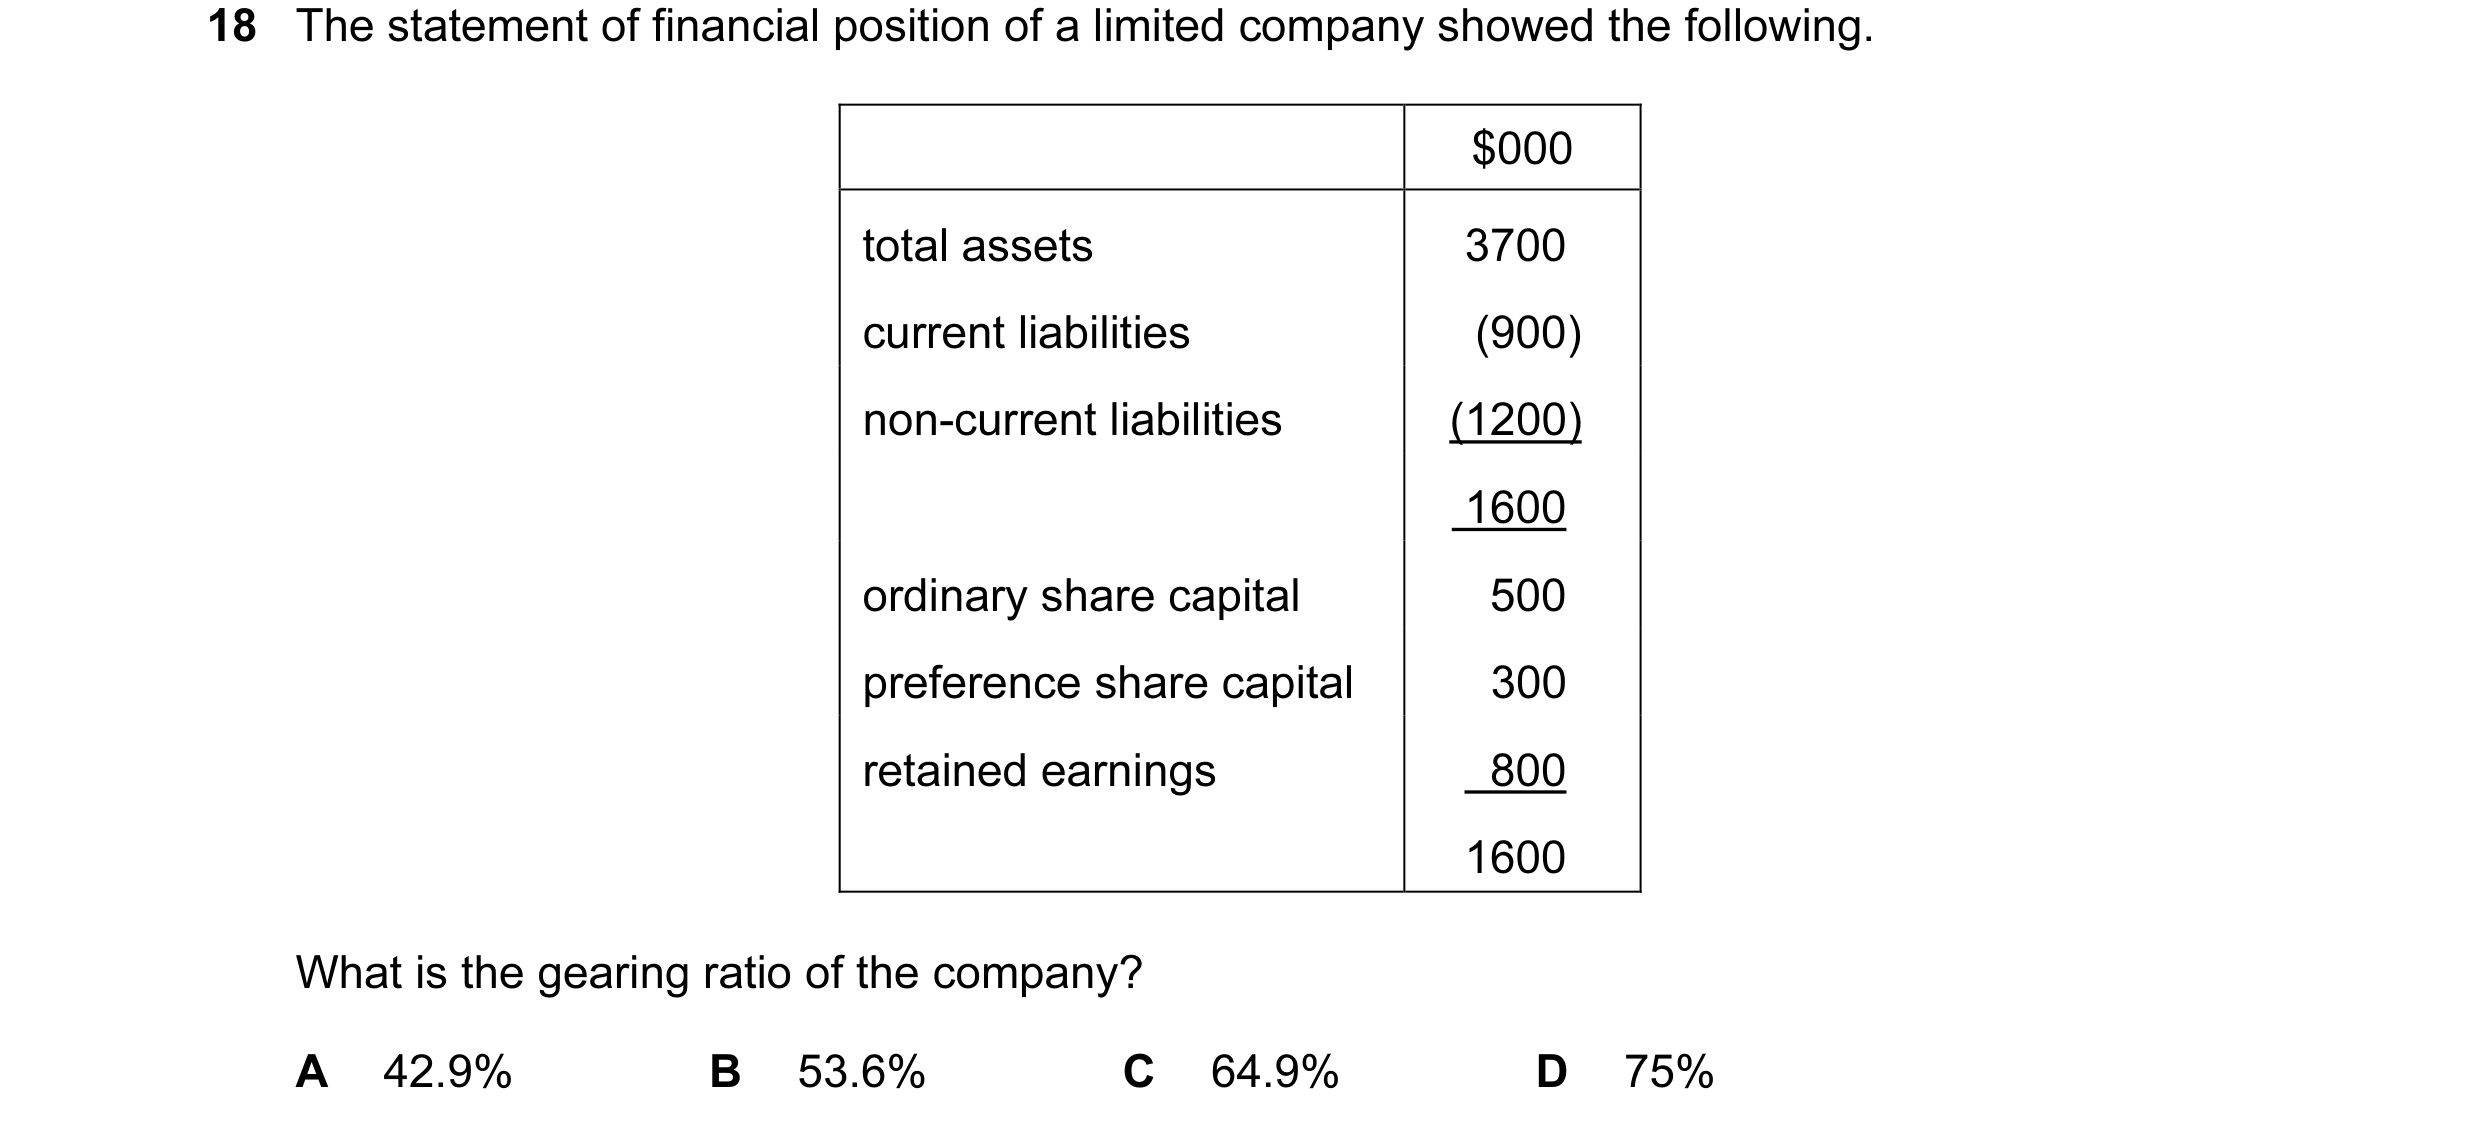
Q106 · The statement of financial position of a limited company showed the following 9706/31 May/June 2014
18 The statement of financial position of a limited company showed the following. $000 total assets 3700 current liabilities (900) non-current liabilities (1200) 1600 ordinary share capital 500 preference share capital 300 retained earnings 800 1600 What is the gearing ratio of the company? A 42.9% B 53.6% C 64.9% D 75%
1 marks
Answer: B
This question in 9706/31 May/June 2014
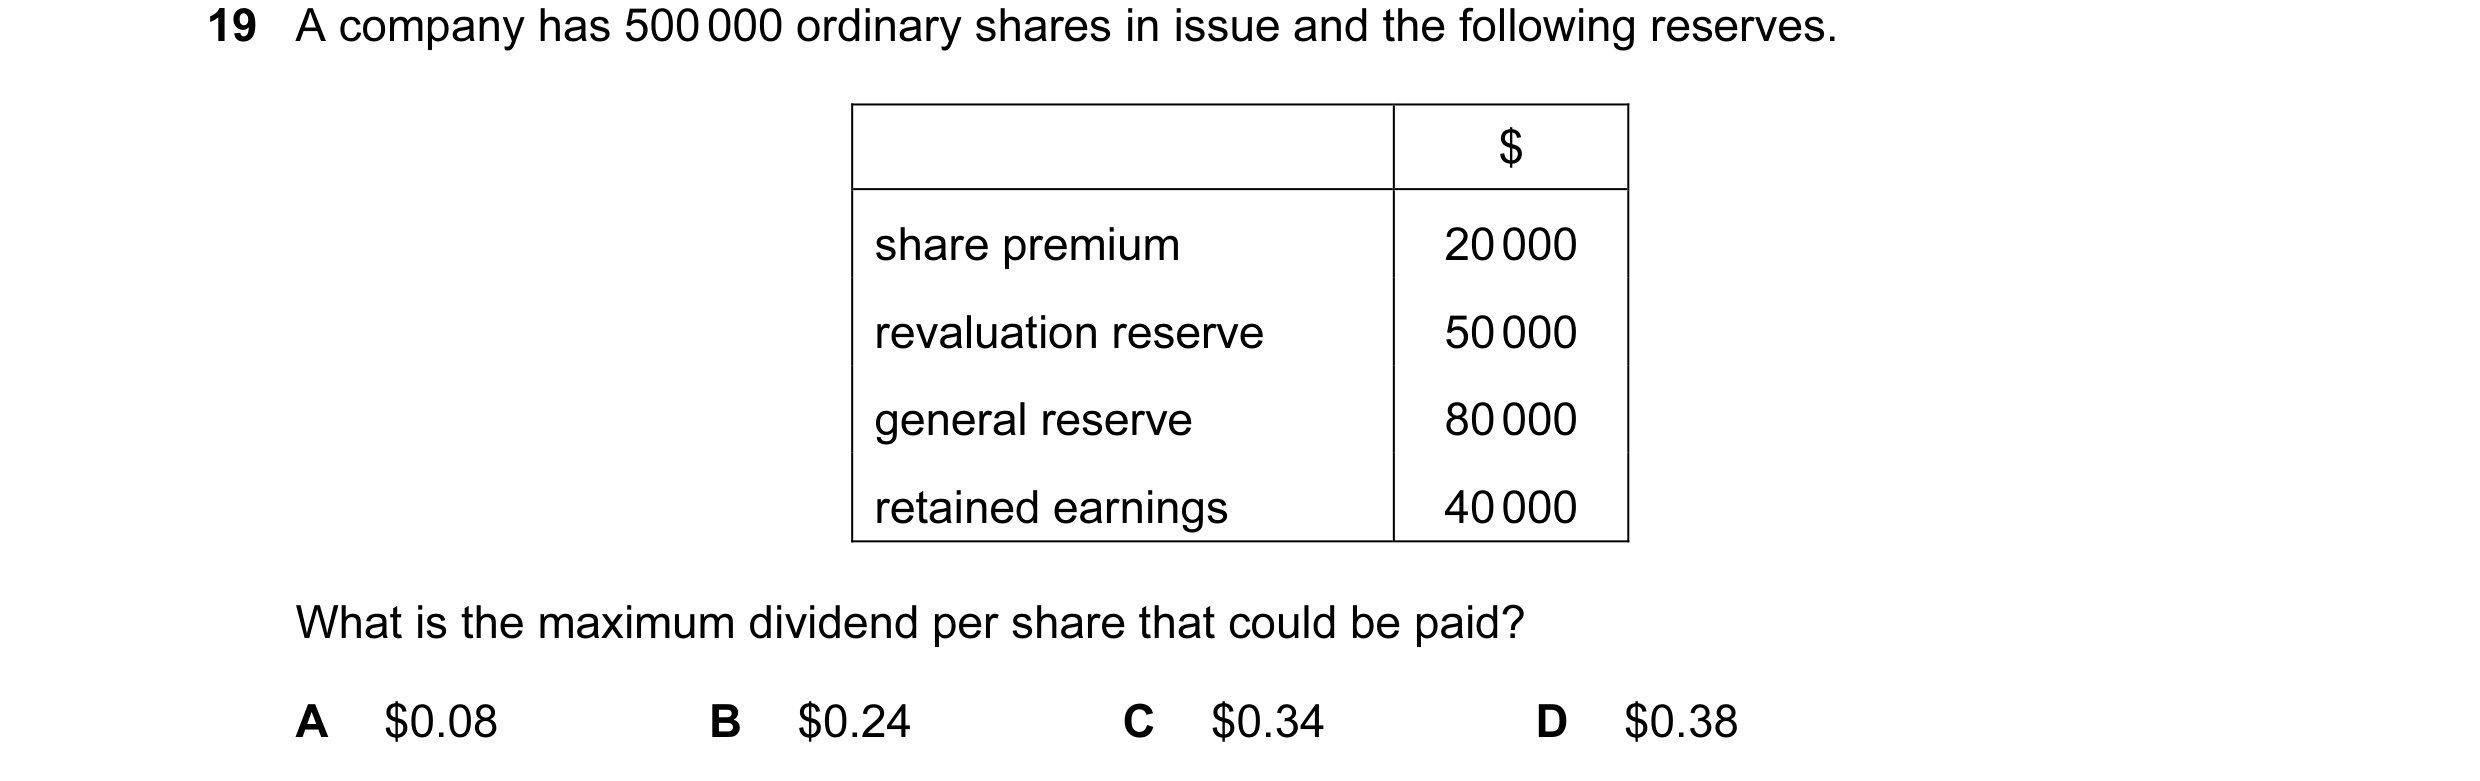
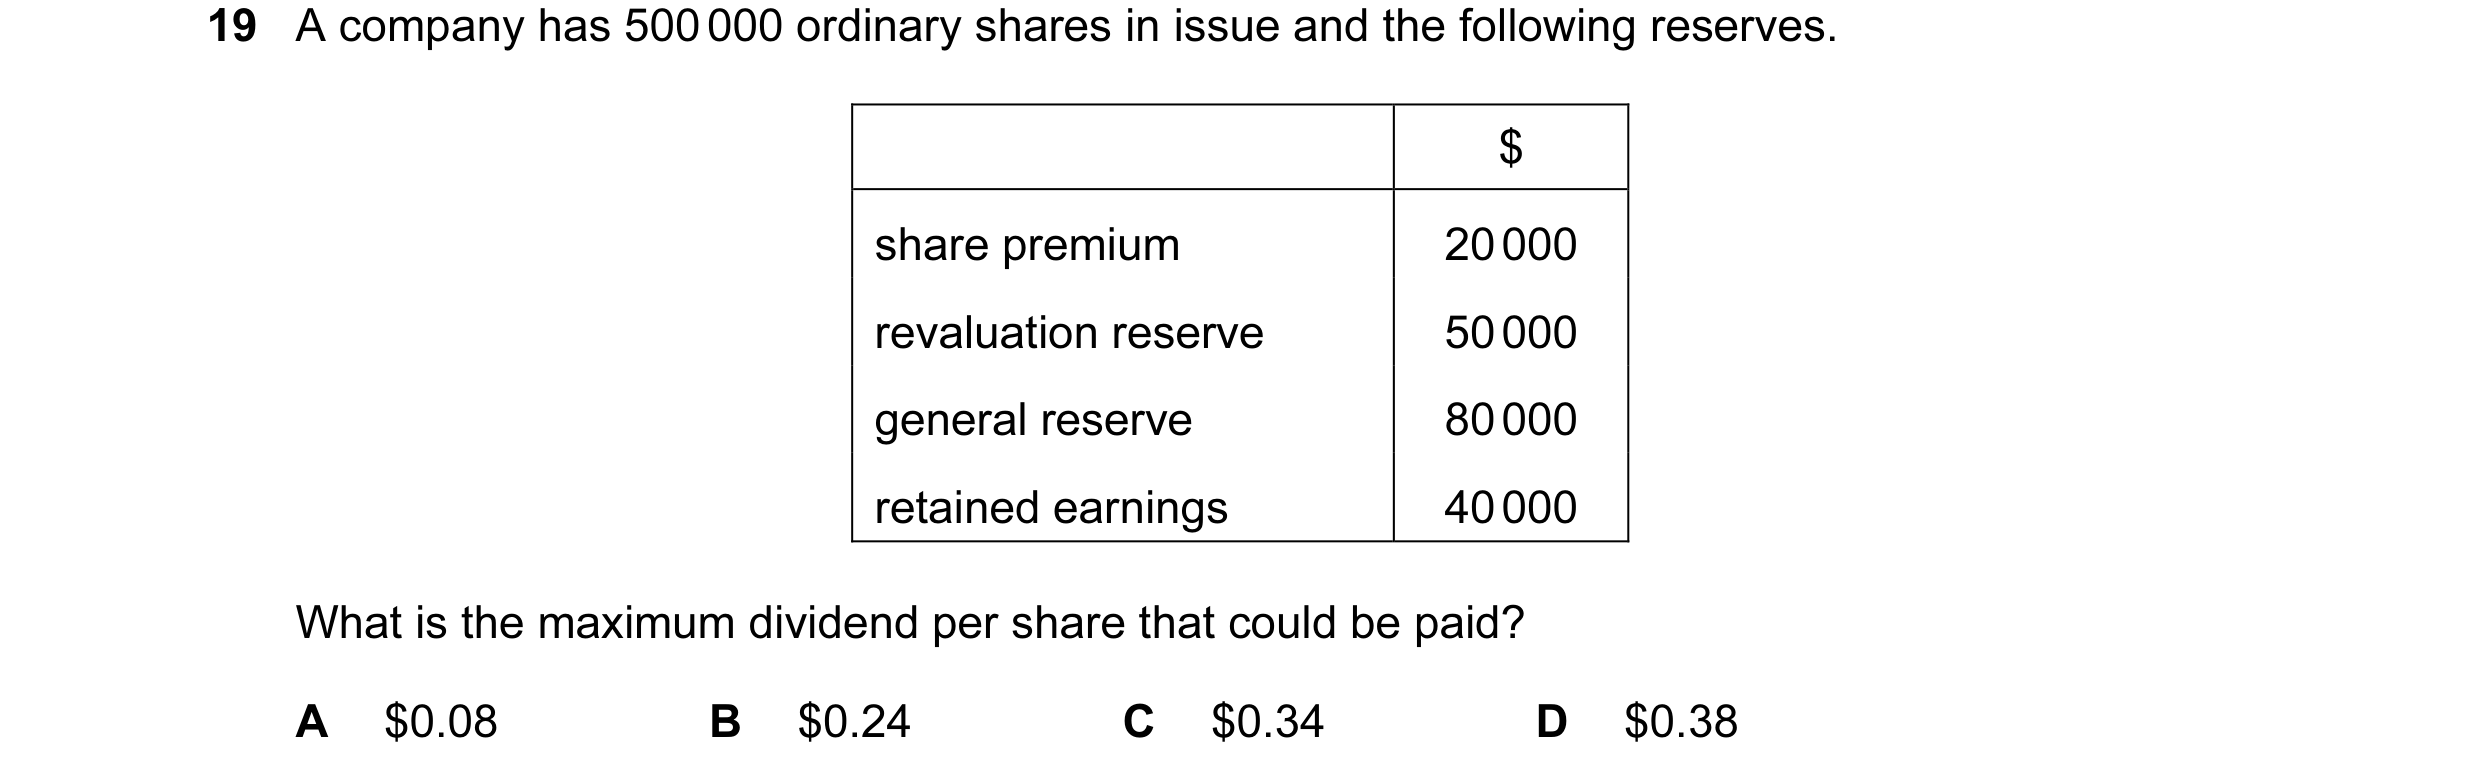
Q107 · A company has 500 000 ordinary shares in issue and the following reserves 9706/31 May/June 2014
19 A company has 500 000 ordinary shares in issue and the following reserves. $ share premium 20 000 revaluation reserve 50 000 general reserve 80 000 retained earnings 40 000 What is the maximum dividend per share that could be paid? A $0.08 B $0.24 C $0.34 D $0.38
1 marks
Answer: B
This question in 9706/31 May/June 2014
Q108 · Which shareholder ratio calculates the expected return on investment? 9706/32 May/June 2014
15 Which shareholder ratio calculates the expected return on investment? A dividend cover B dividend yield C earnings per share D price earnings
1 marks
Answer: B
This question in 9706/32 May/June 2014
Q109 · The following information is available 9706/32 May/June 2014
16 The following information is available. dividend yield 4% dividend for the year $10 000 dividend cover four times What is the price earnings ratio? A 4 B 6.25 C 10 D 25
1 marks
Answer: B
This question in 9706/32 May/June 2014
Q110 · A company provides the following information 9706/32 May/June 2014
17 A company provides the following information. $ profit from operations 400 000 profit before tax 300 000 equity 1 200 000 non-current liabilities 800 000 What is the company’s return on capital employed? A 15% B 20% C 25% D 33.3%
1 marks
Answer: B
This question in 9706/32 May/June 2014
Q111 · The statement of financial position of a limited company showed the following 9706/32 May/June 2014
18 The statement of financial position of a limited company showed the following. $000 total assets 3700 current liabilities (900) non-current liabilities (1200) 1600 ordinary share capital 500 preference share capital 300 retained earnings 800 1600 What is the gearing ratio of the company? A 42.9% B 53.6% C 64.9% D 75%
1 marks
Answer: B
This question in 9706/32 May/June 2014
Q112 · A company has 500 000 ordinary shares in issue and the following reserves 9706/32 May/June 2014
19 A company has 500 000 ordinary shares in issue and the following reserves. $ share premium 20 000 revaluation reserve 50 000 general reserve 80 000 retained earnings 40 000 What is the maximum dividend per share that could be paid? A $0.08 B $0.24 C $0.34 D $0.38
1 marks
Answer: B
This question in 9706/32 May/June 2014
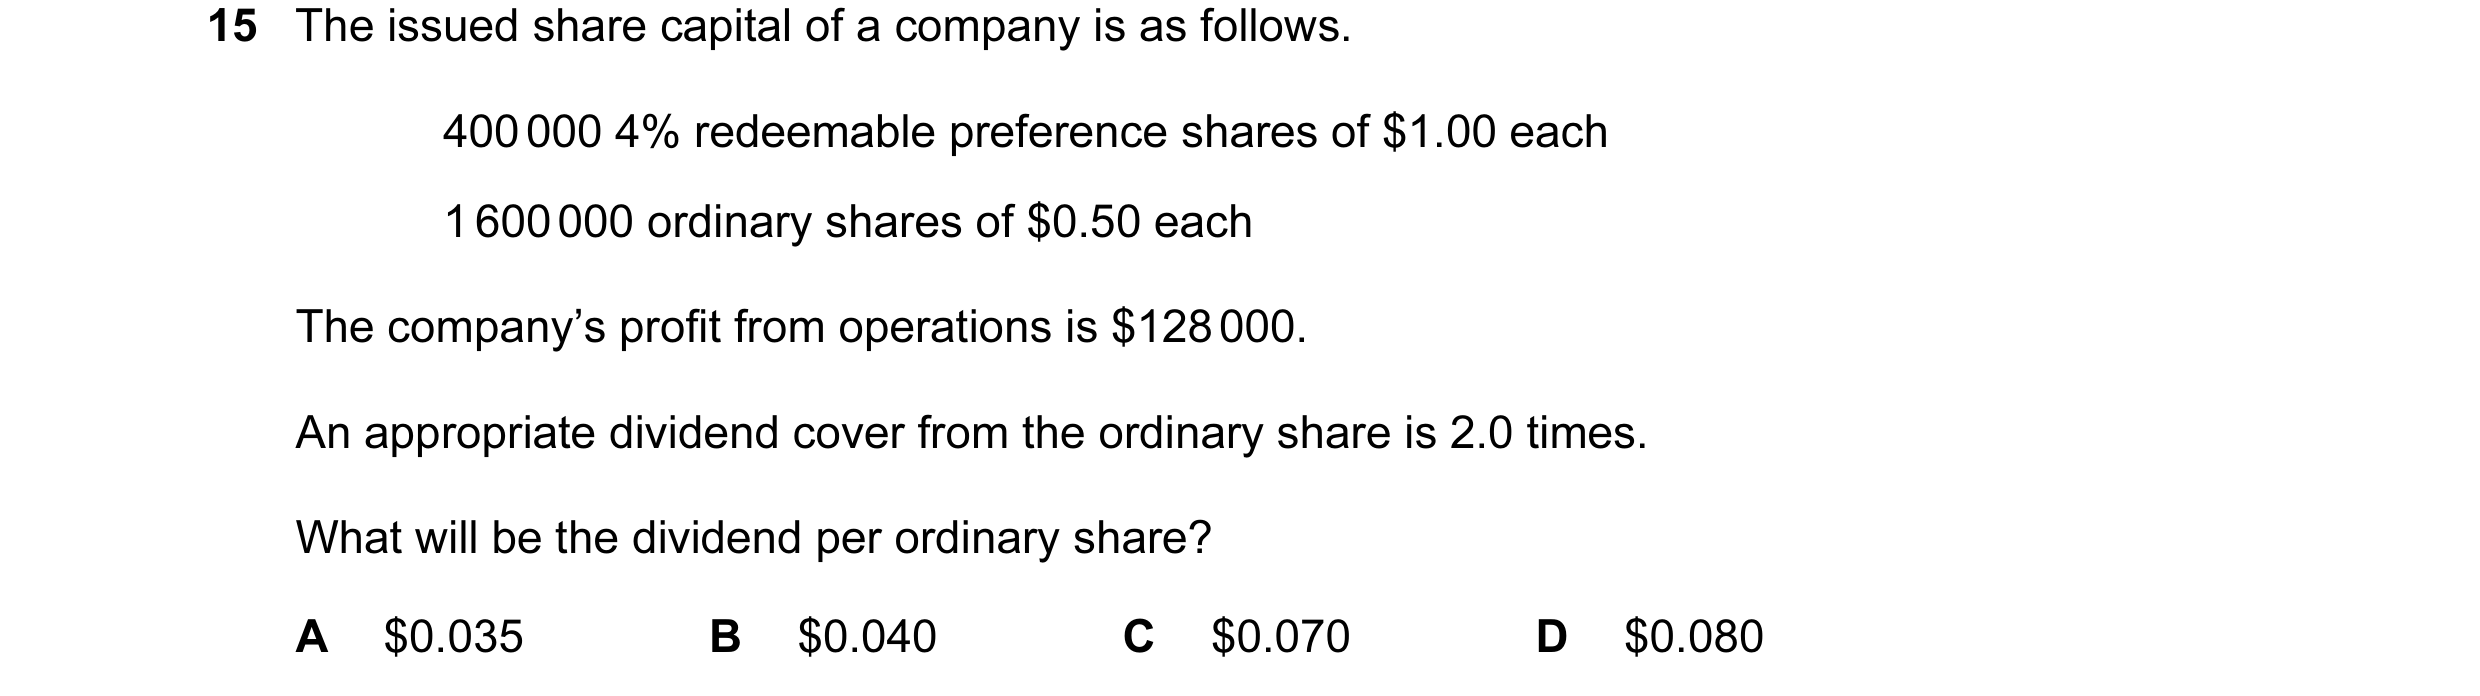
Q113 · The issued share capital of a company is as follows 9706/33 May/June 2014
15 The issued share capital of a company is as follows. 400 000 4% redeemable preference shares of $1.00 each 1 600 000 ordinary shares of $0.50 each The company’s profit from operations is $128 000. An appropriate dividend cover from the ordinary share is 2.0 times. What will be the dividend per ordinary share? A $0.035 B $0.040 C $0.070 D $0.080
1 marks
Answer: A
This question in 9706/33 May/June 2014
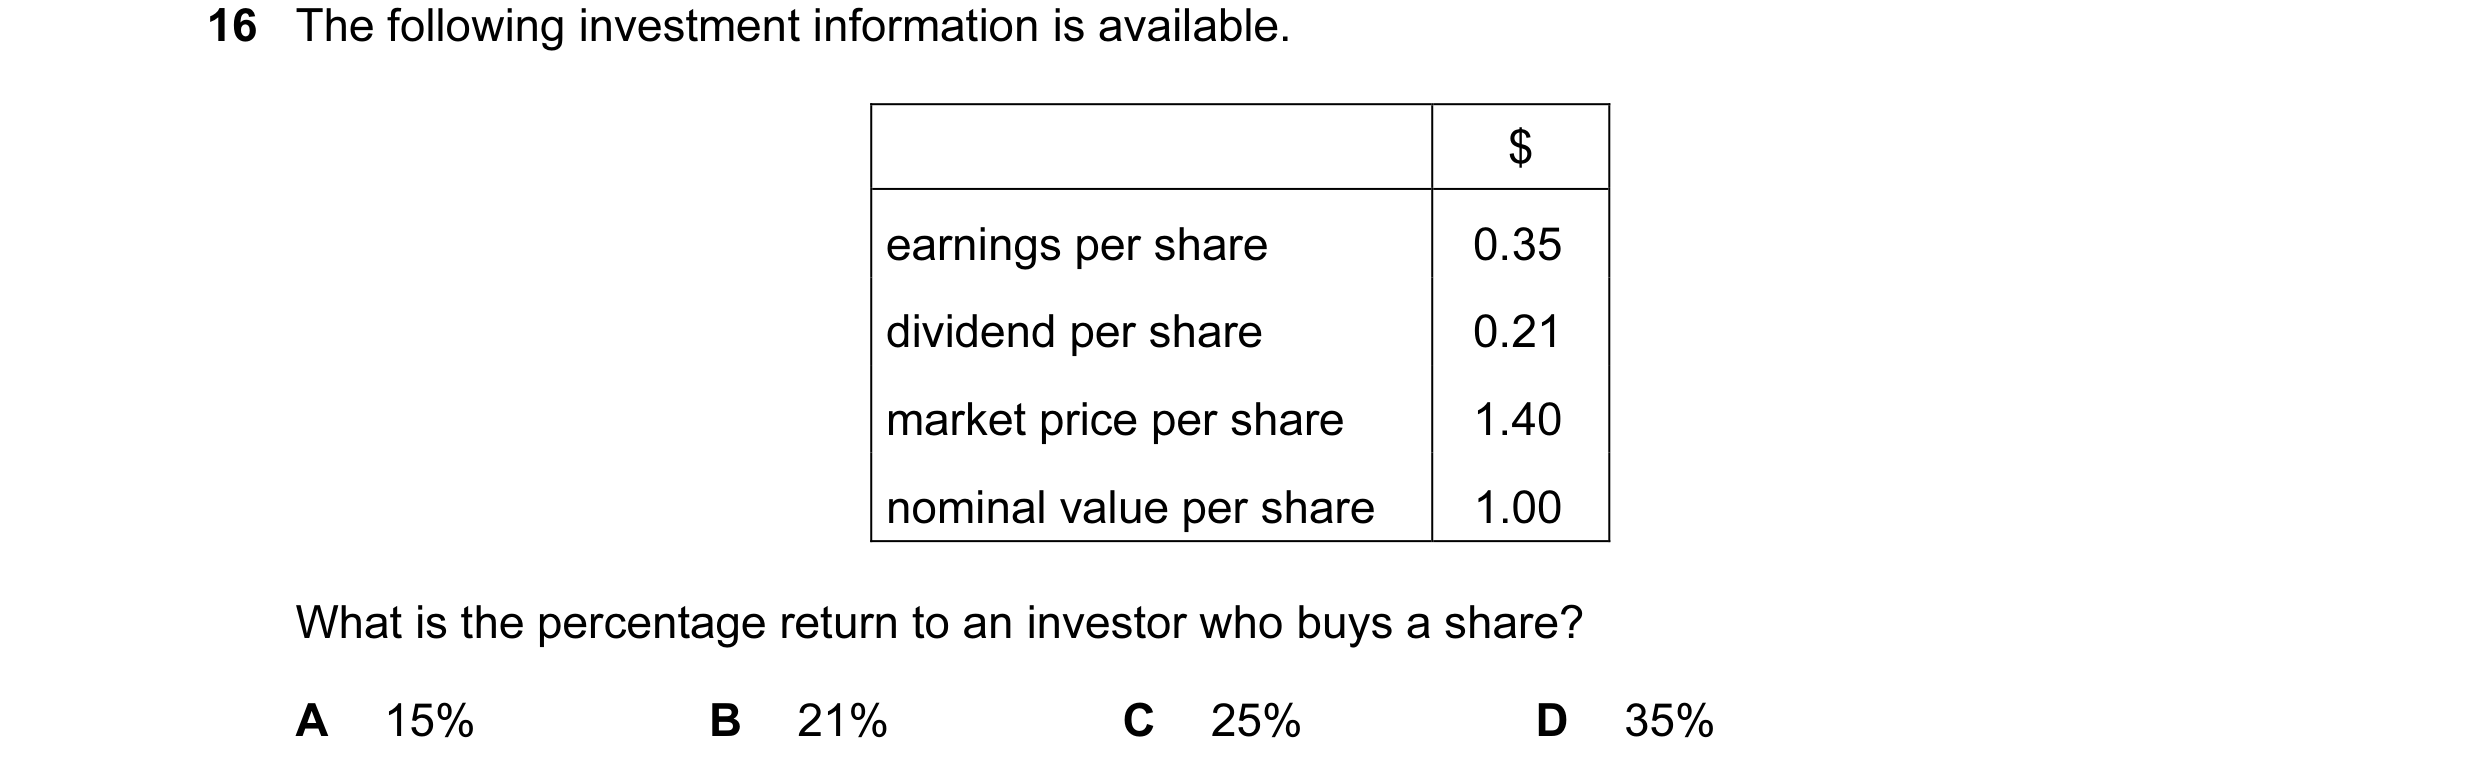
Q114 · The following investment information is available 9706/33 May/June 2014
16 The following investment information is available. $ earnings per share 0.35 dividend per share 0.21 market price per share 1.40 nominal value per share 1.00 What is the percentage return to an investor who buys a share? A 15% B 21% C 25% D 35%
1 marks
Answer: A
This question in 9706/33 May/June 2014
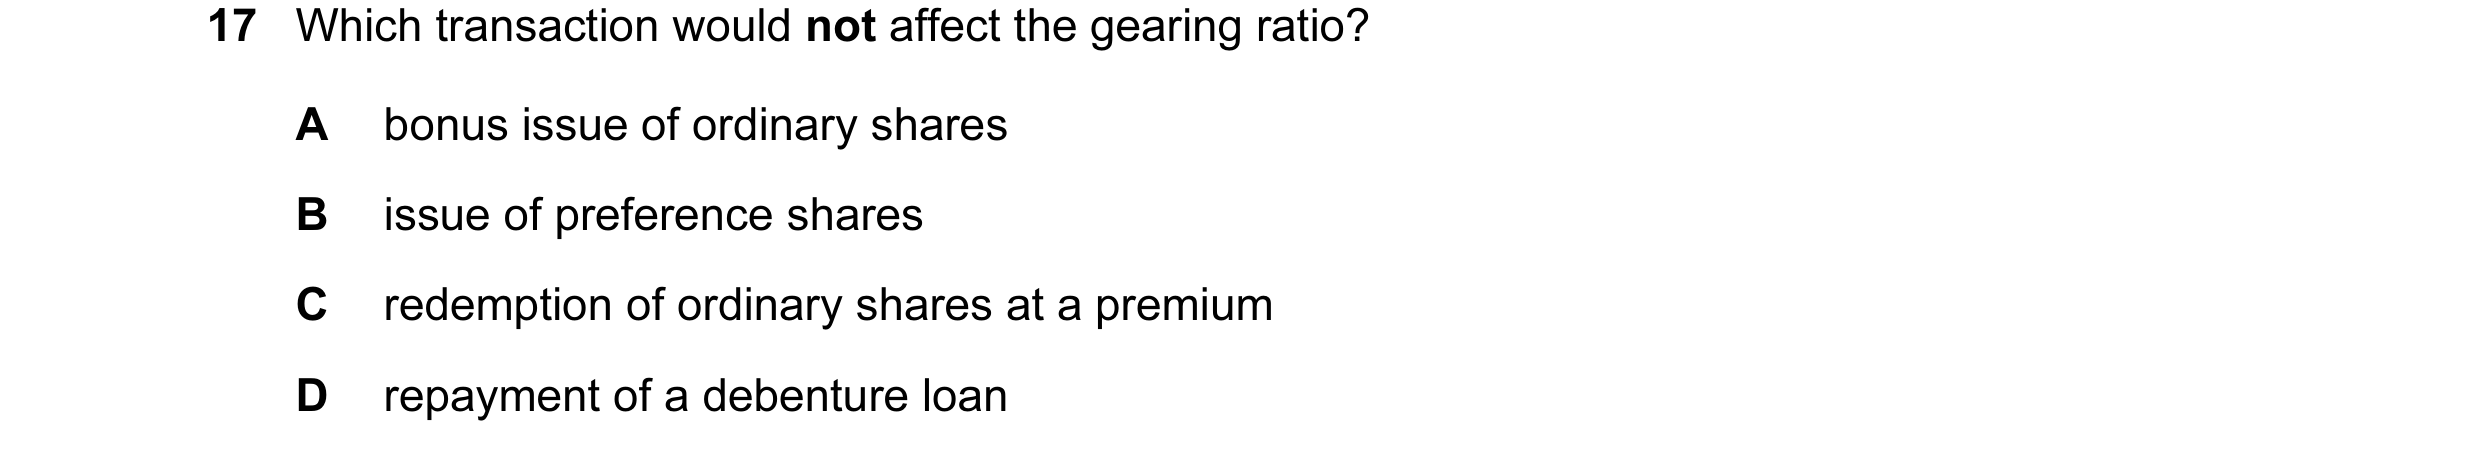
Q115 · Which transaction would not affect the gearing ratio? 9706/33 May/June 2014
17 Which transaction would not affect the gearing ratio? A bonus issue of ordinary shares B issue of preference shares C redemption of ordinary shares at a premium D repayment of a debenture loan
1 marks
Answer: A
This question in 9706/33 May/June 2014
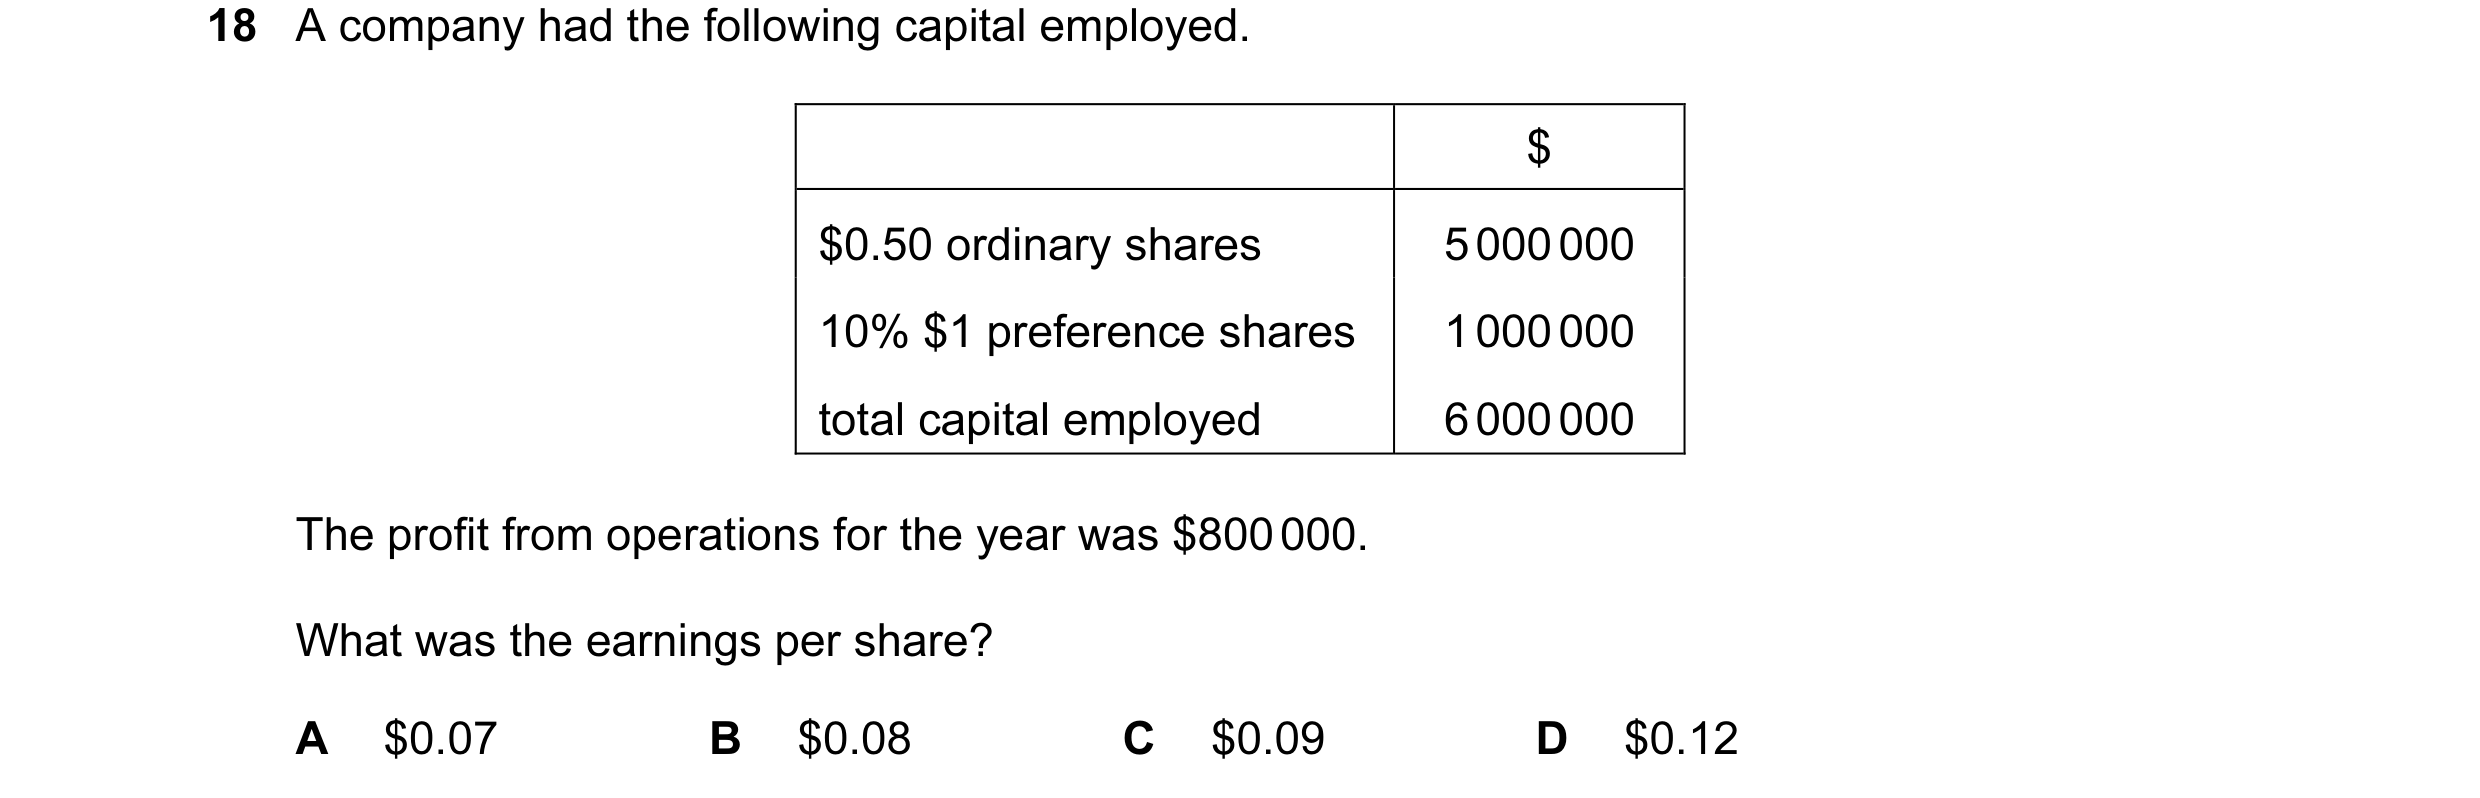
Q116 · A company had the following capital employed 9706/33 May/June 2014
18 A company had the following capital employed. $ $0.50 ordinary shares 5 000 000 10% $1 preference shares 1 000 000 total capital employed 6 000 000 The profit from operations for the year was $800 000. What was the earnings per share? A $0.07 B $0.08 C $0.09 D $0.12
1 marks
Answer: A
This question in 9706/33 May/June 2014
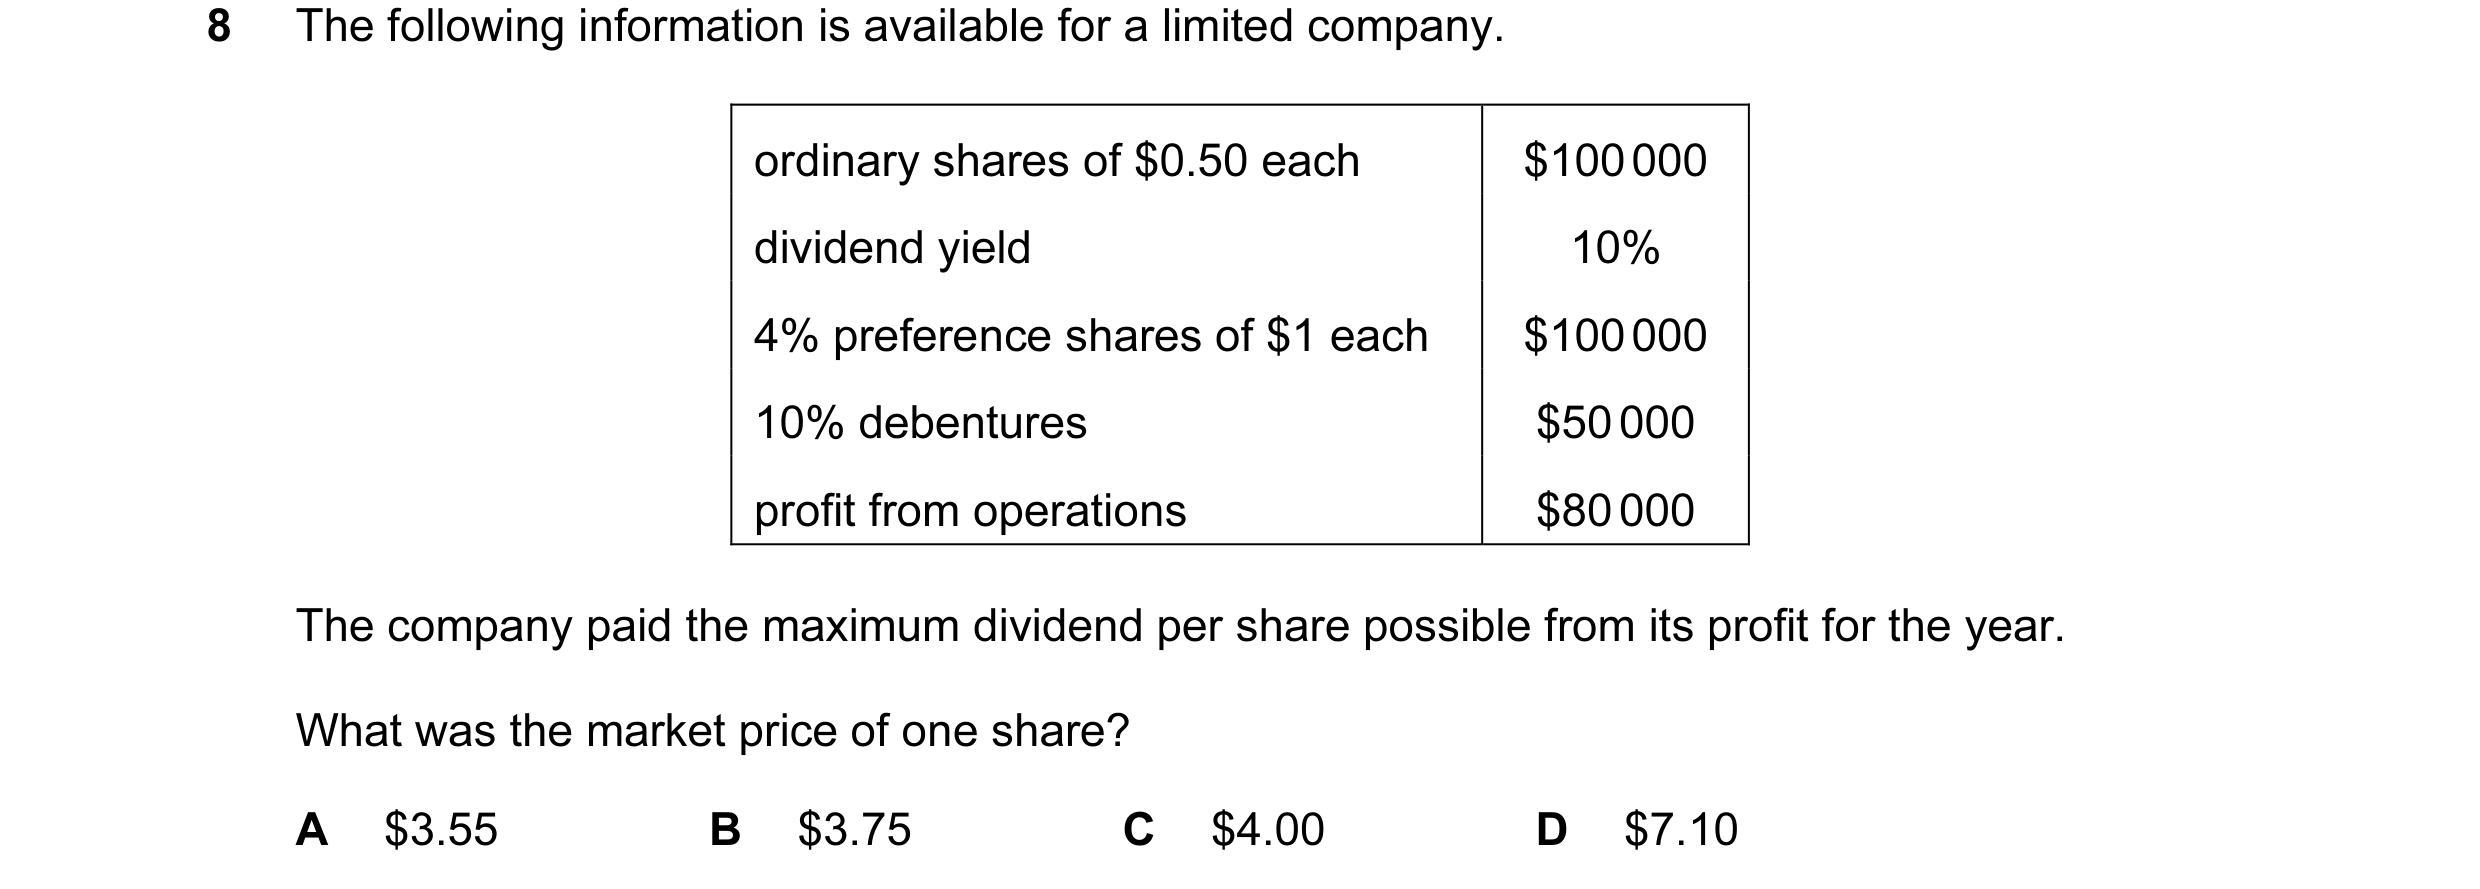
Q117 · The following information is available for a limited company 9706/31 Oct/Nov 2015
8 The following information is available for a limited company. ordinary shares of $0.50 each $100 000 dividend yield 10% 4% preference shares of $1 each $100 000 10% debentures $50 000 profit from operations $80 000 The company paid the maximum dividend per share possible from its profit for the year. What was the market price of one share? A $3.55 B $3.75 C $4.00 D $7.10
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2015
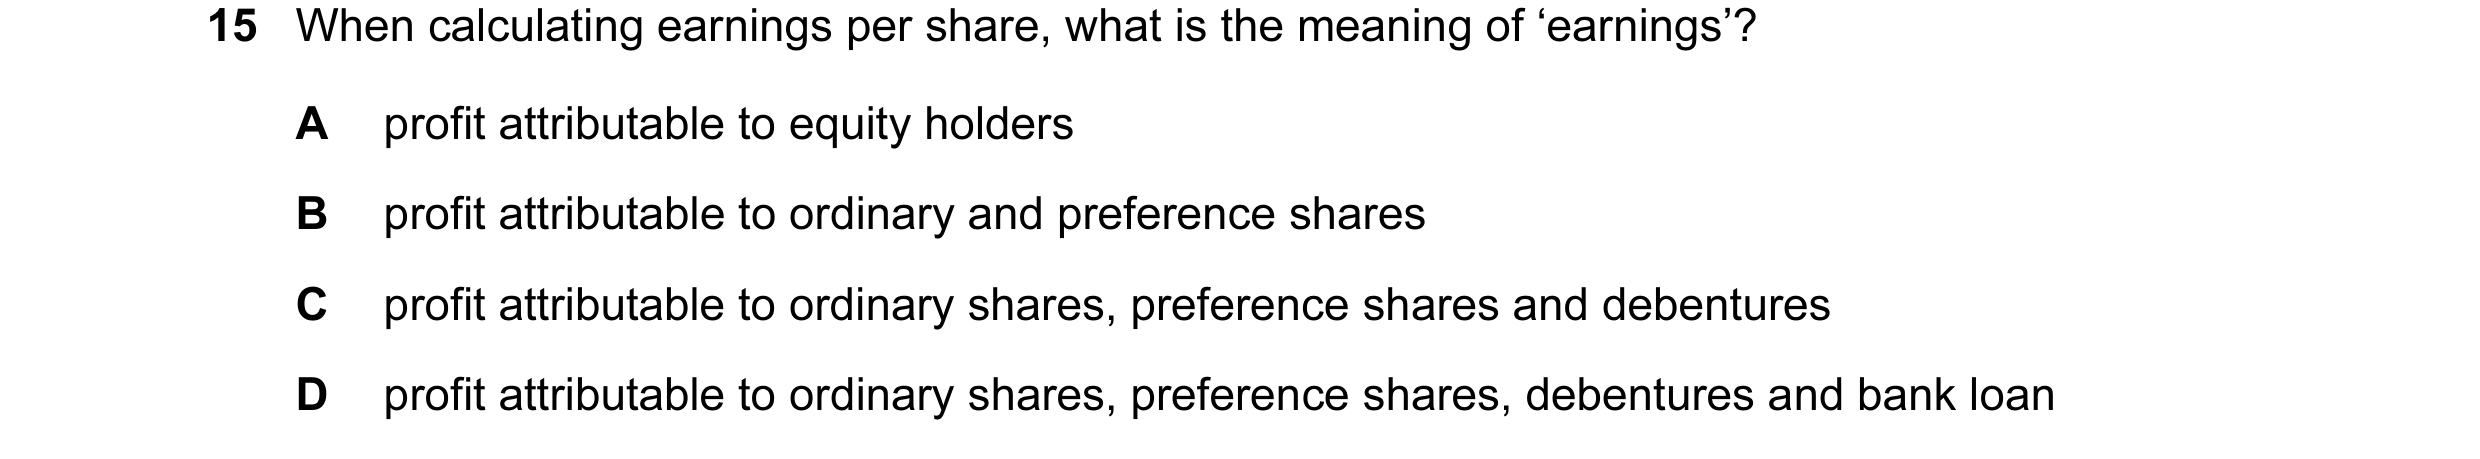
Q118 · When calculating earnings per share, what is the meaning of ‘earnings’? 9706/31 Oct/Nov 2015
15 When calculating earnings per share, what is the meaning of ‘earnings’? A profit attributable to equity holders B profit attributable to ordinary and preference shares C profit attributable to ordinary shares, preference shares and debentures D profit attributable to ordinary shares, preference shares, debentures and bank loan
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2015
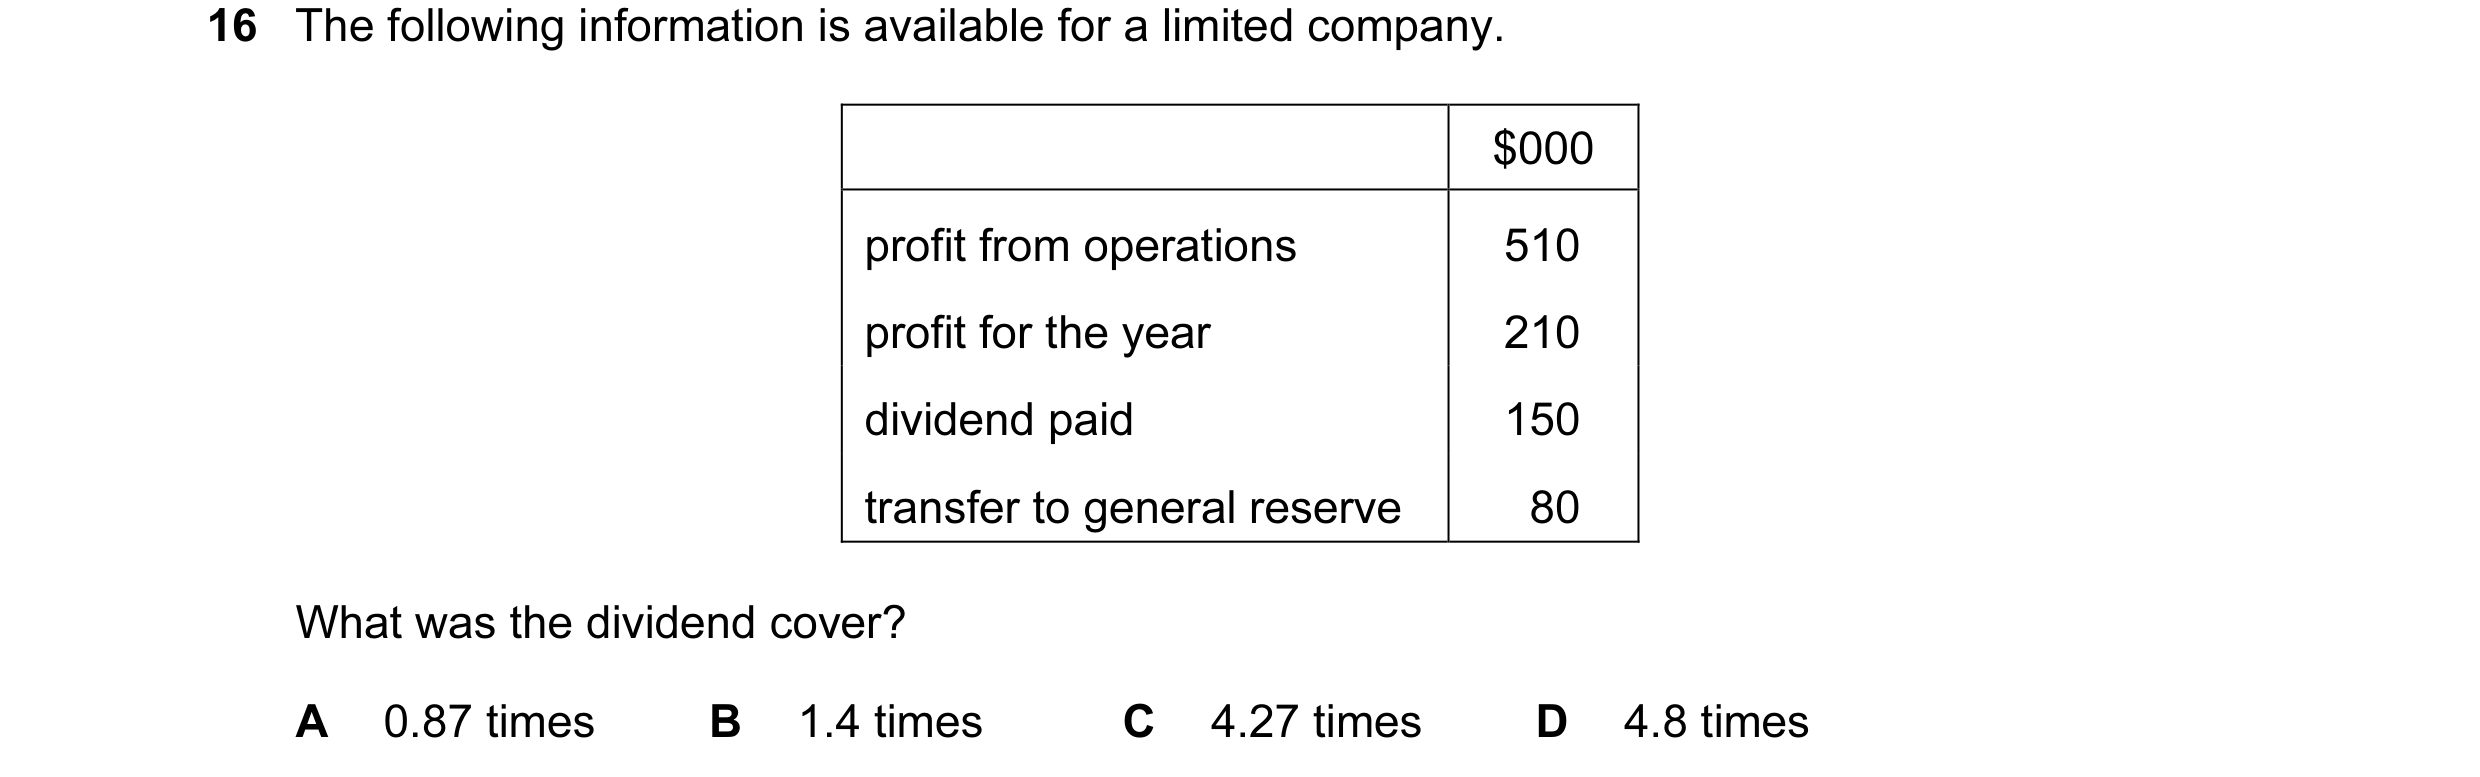
Q119 · The following information is available for a limited company 9706/31 Oct/Nov 2015
16 The following information is available for a limited company. $000 profit from operations 510 profit for the year 210 dividend paid 150 transfer to general reserve 80 What was the dividend cover? A 0.87 times B 1.4 times C 4.27 times D 4.8 times
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2015
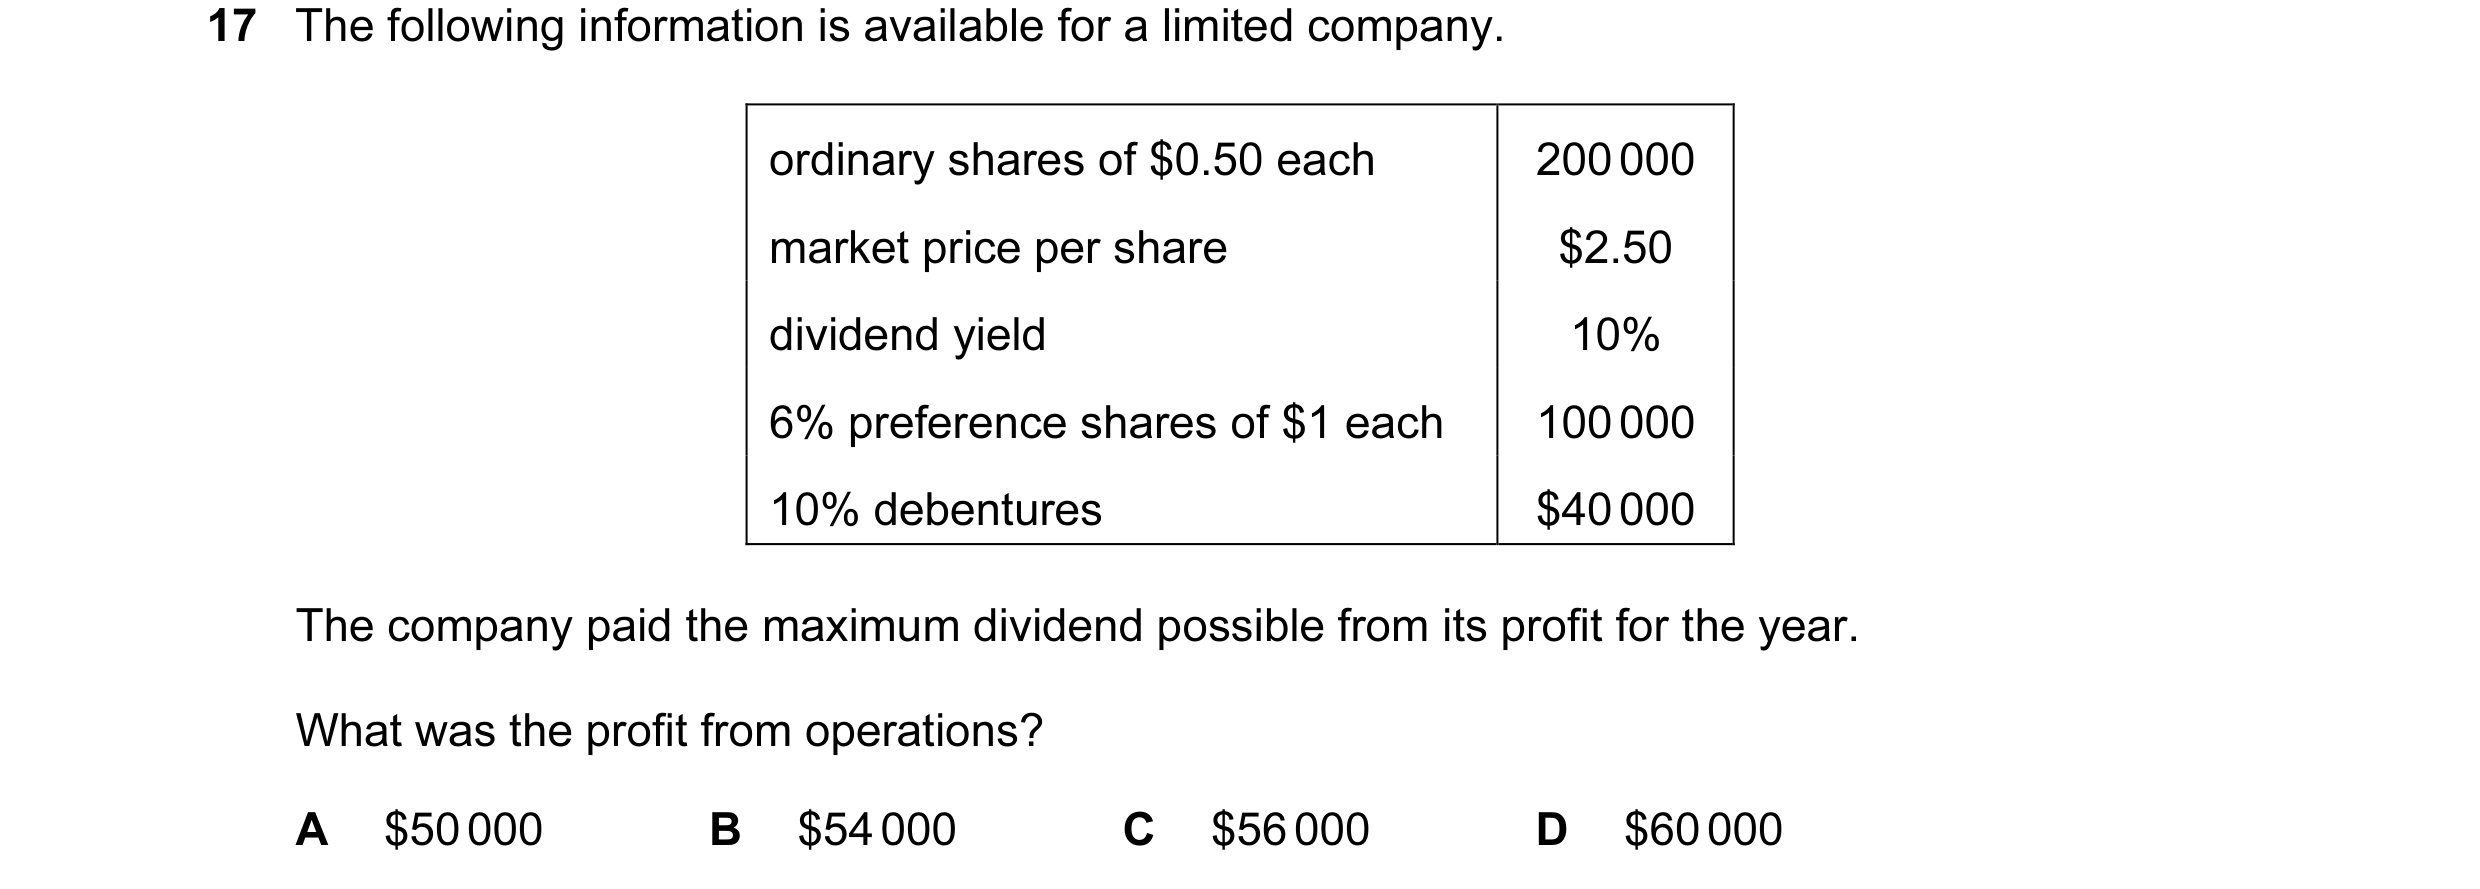
Q120 · The following information is available for a limited company 9706/31 Oct/Nov 2015
17 The following information is available for a limited company. ordinary shares of $0.50 each 200 000 market price per share $2.50 dividend yield 10% 6% preference shares of $1 each 100 000 10% debentures $40 000 The company paid the maximum dividend possible from its profit for the year. What was the profit from operations? A $50 000 B $54 000 C $56 000 D $60 000
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2015
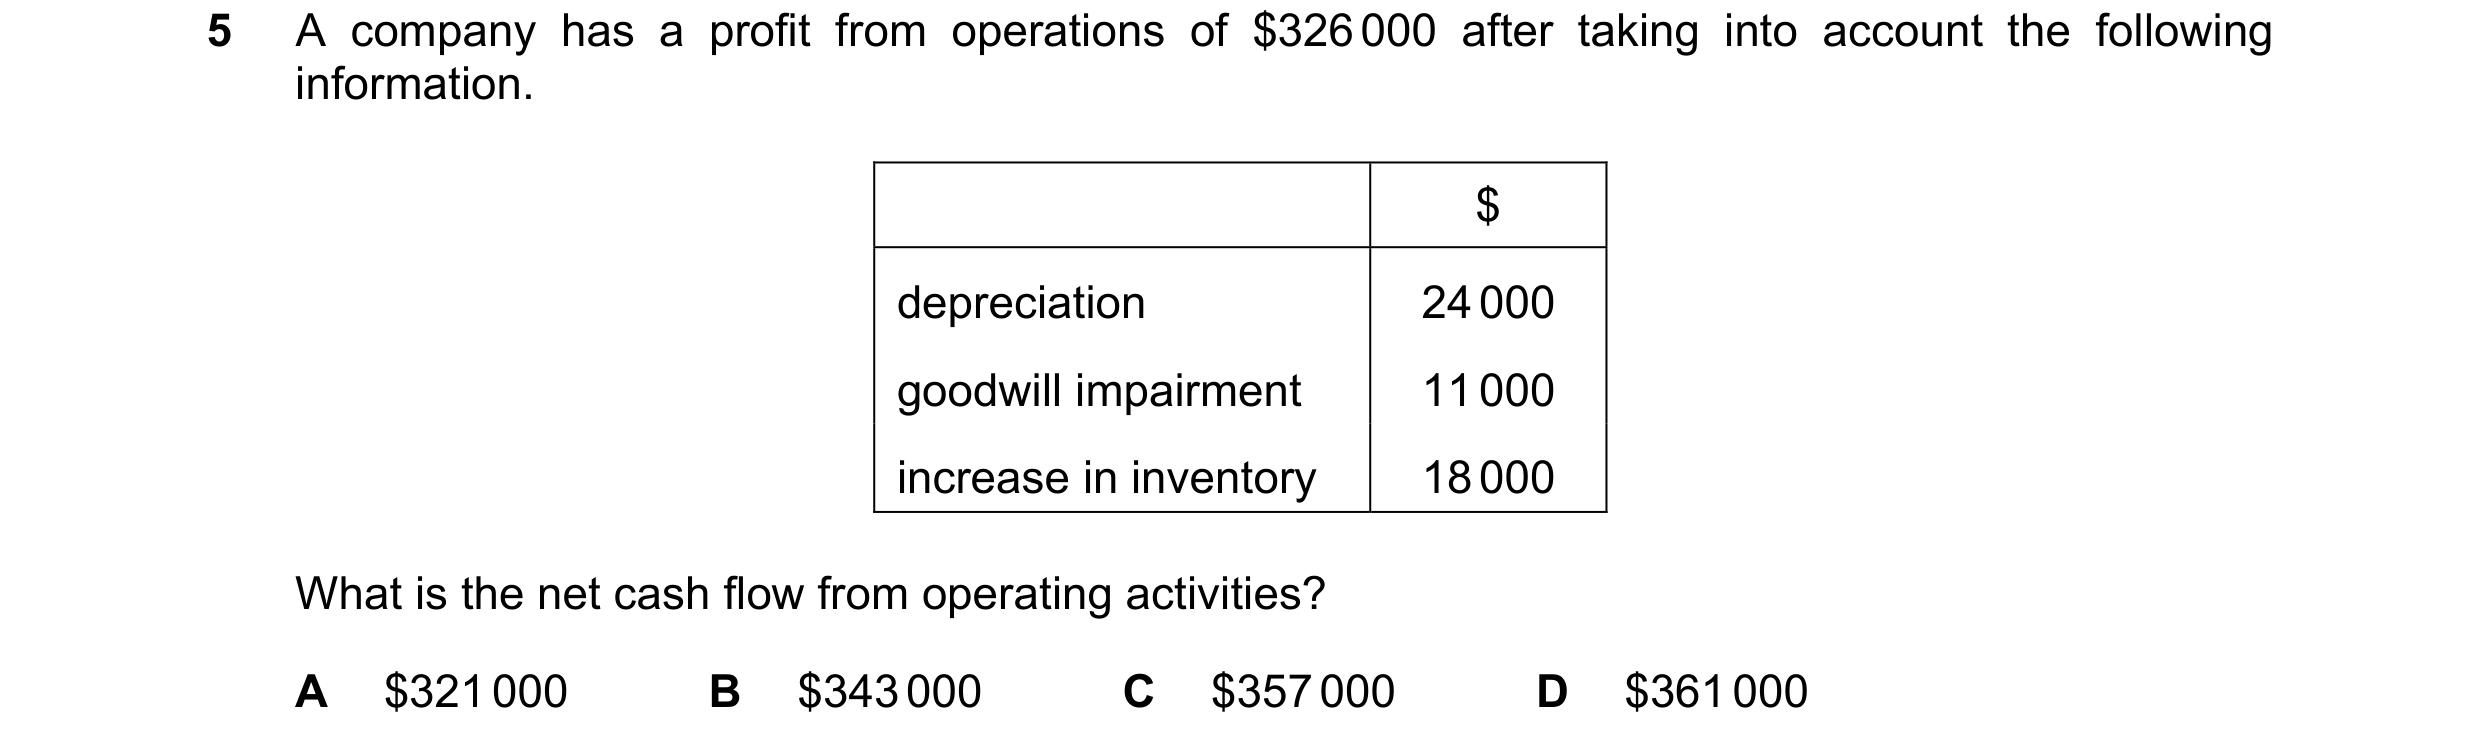
Q121 · A company has a profit from operations of $326 000 after taking into account the… 9706/32 Oct/Nov 2015
5 A company has a profit from operations of $326 000 after taking into account the following information. $ depreciation 24 000 goodwill impairment 11 000 increase in inventory 18 000 What is the net cash flow from operating activities? A $321 000 B $343 000 C $357 000 D $361 000
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2015
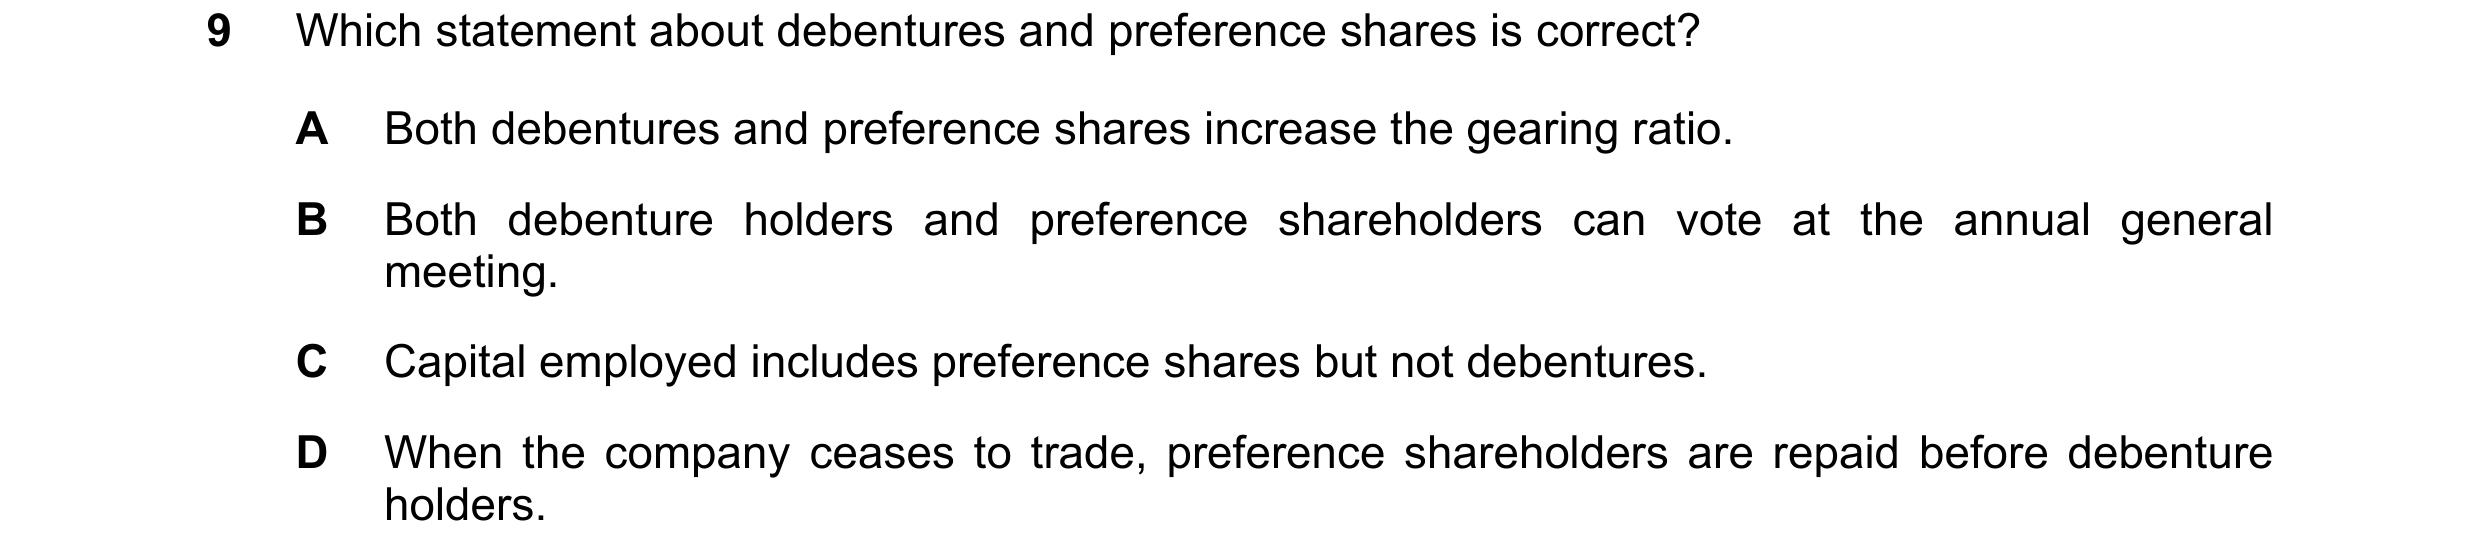
Q122 · Which statement about debentures and preference shares is correct? 9706/32 Oct/Nov 2015
9 Which statement about debentures and preference shares is correct? A Both debentures and preference shares increase the gearing ratio. B Both debenture holders and preference shareholders can vote at the annual general meeting. C Capital employed includes preference shares but not debentures. D When the company ceases to trade, preference shareholders are repaid before debenture holders.
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2015
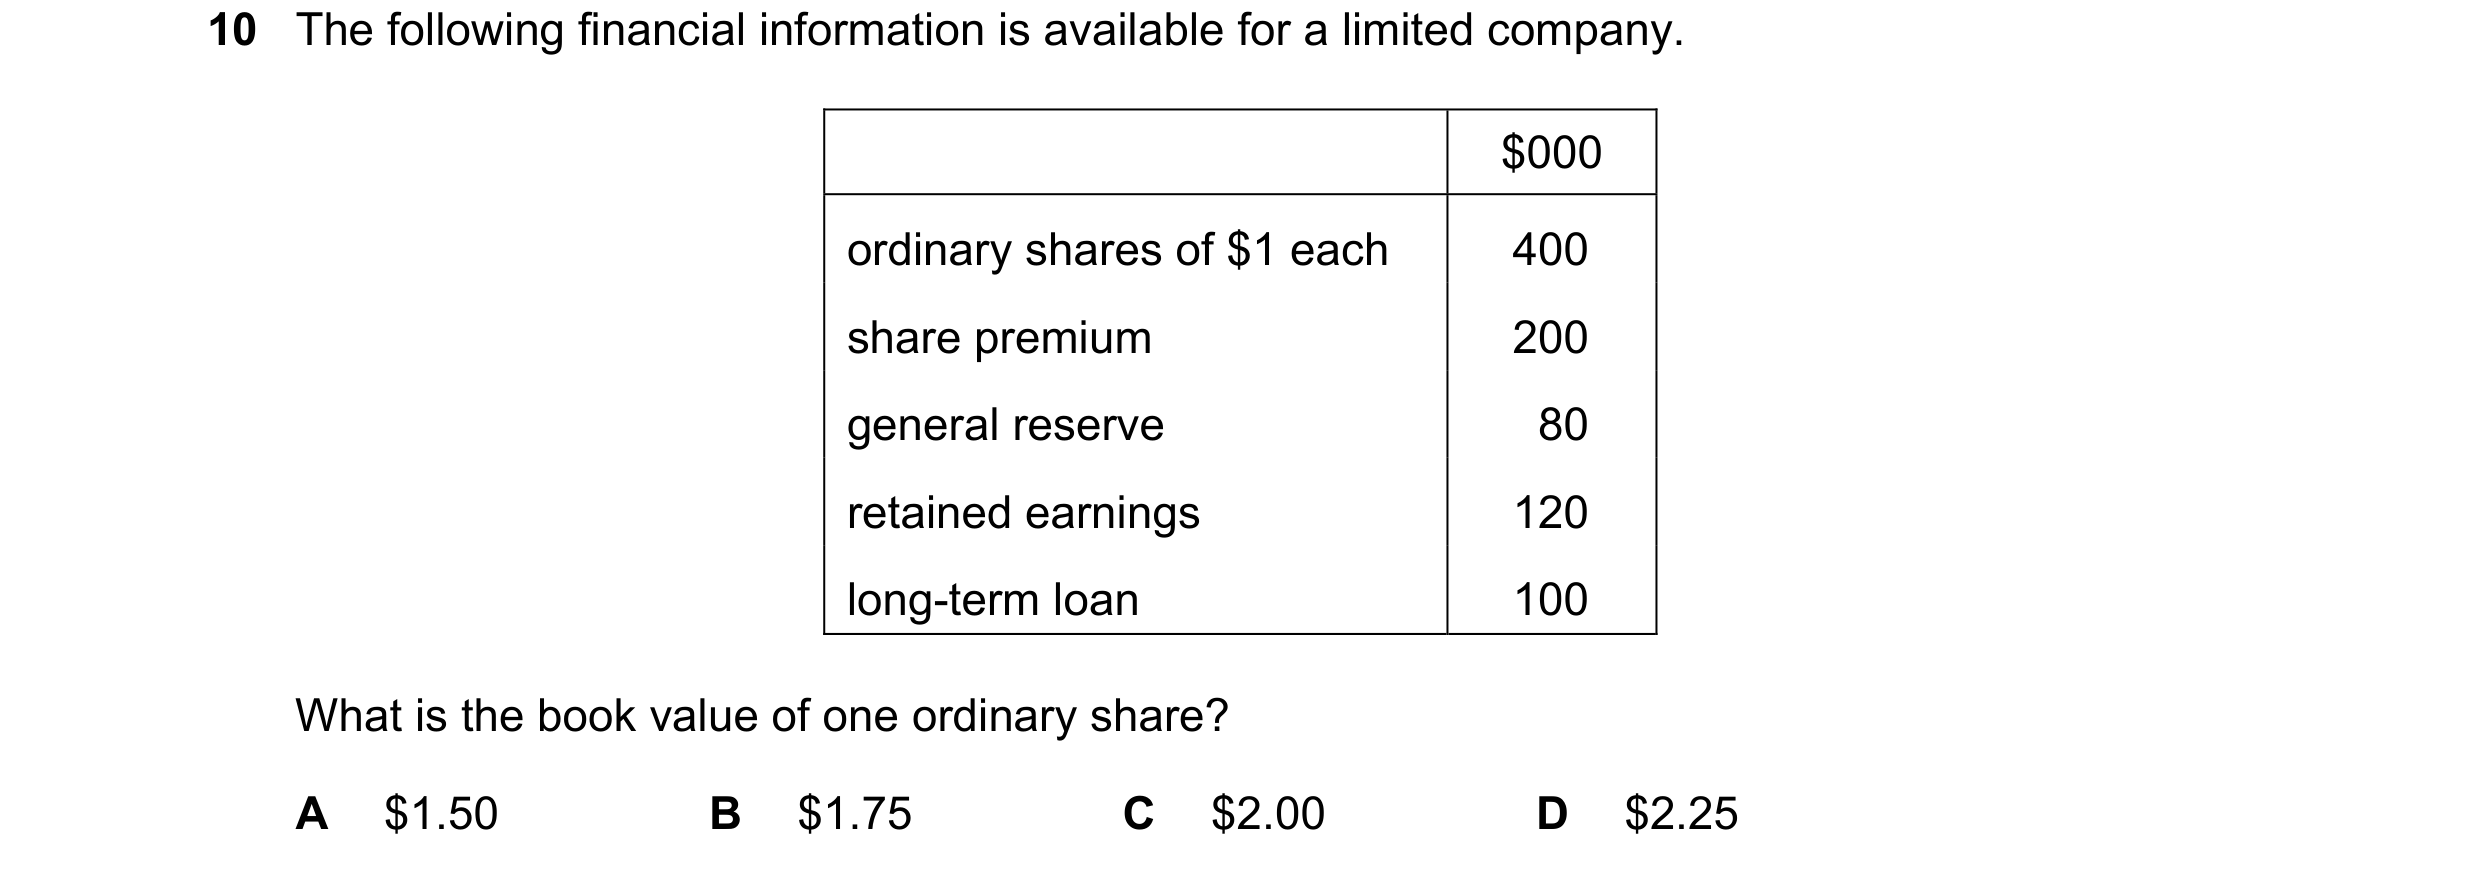
Q123 · The following financial information is available for a limited company 9706/32 Oct/Nov 2015
10 The following financial information is available for a limited company. $000 ordinary shares of $1 each 400 share premium 200 general reserve 80 retained earnings 120 long-term loan 100 What is the book value of one ordinary share? A $1.50 B $1.75 C $2.00 D $2.25
1 marks
Answer: C
This question in 9706/32 Oct/Nov 2015
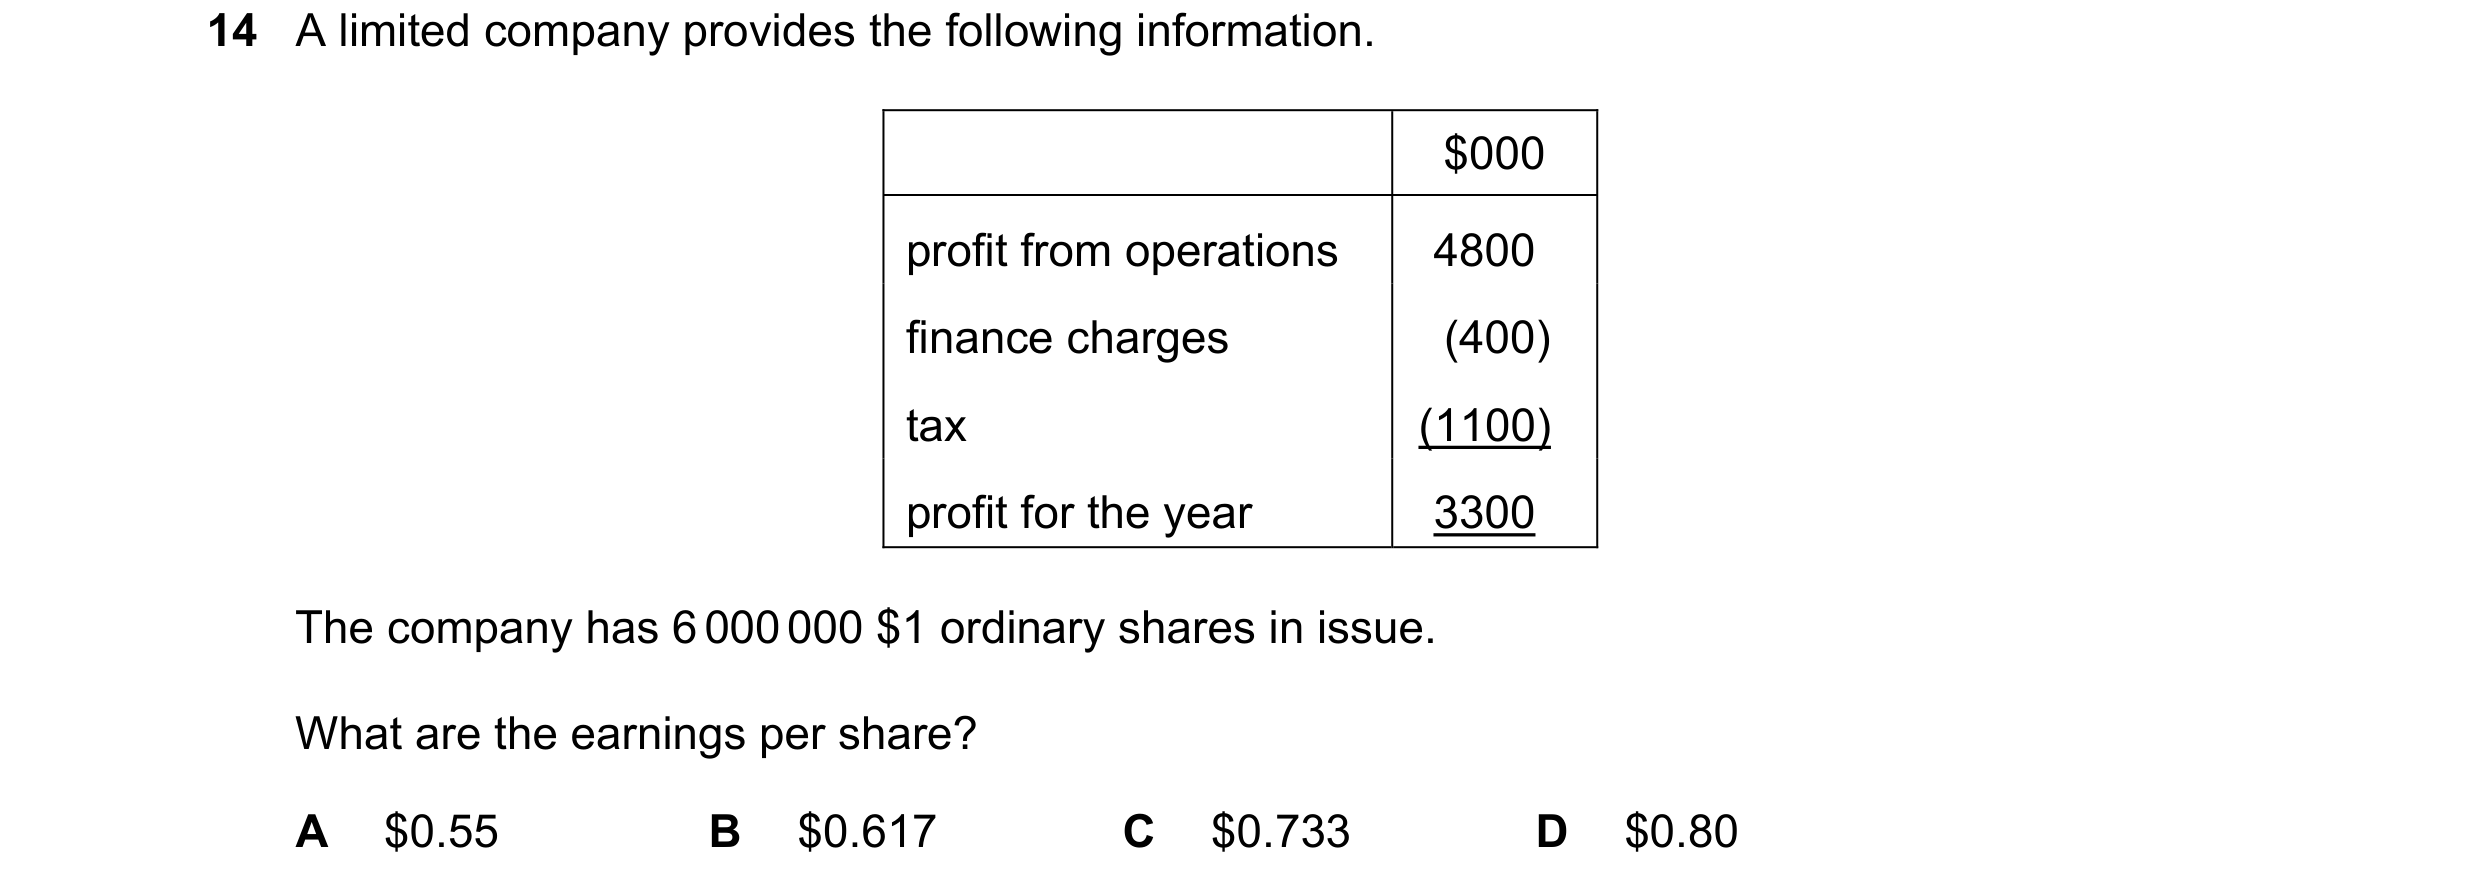
Q124 · A limited company provides the following information 9706/32 Oct/Nov 2015
14 A limited company provides the following information. $000 profit from operations 4800 finance charges (400) tax (1100) profit for the year 3300 The company has 6 000 000 $1 ordinary shares in issue. What are the earnings per share? A $0.55 B $0.617 C $0.733 D $0.80
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2015
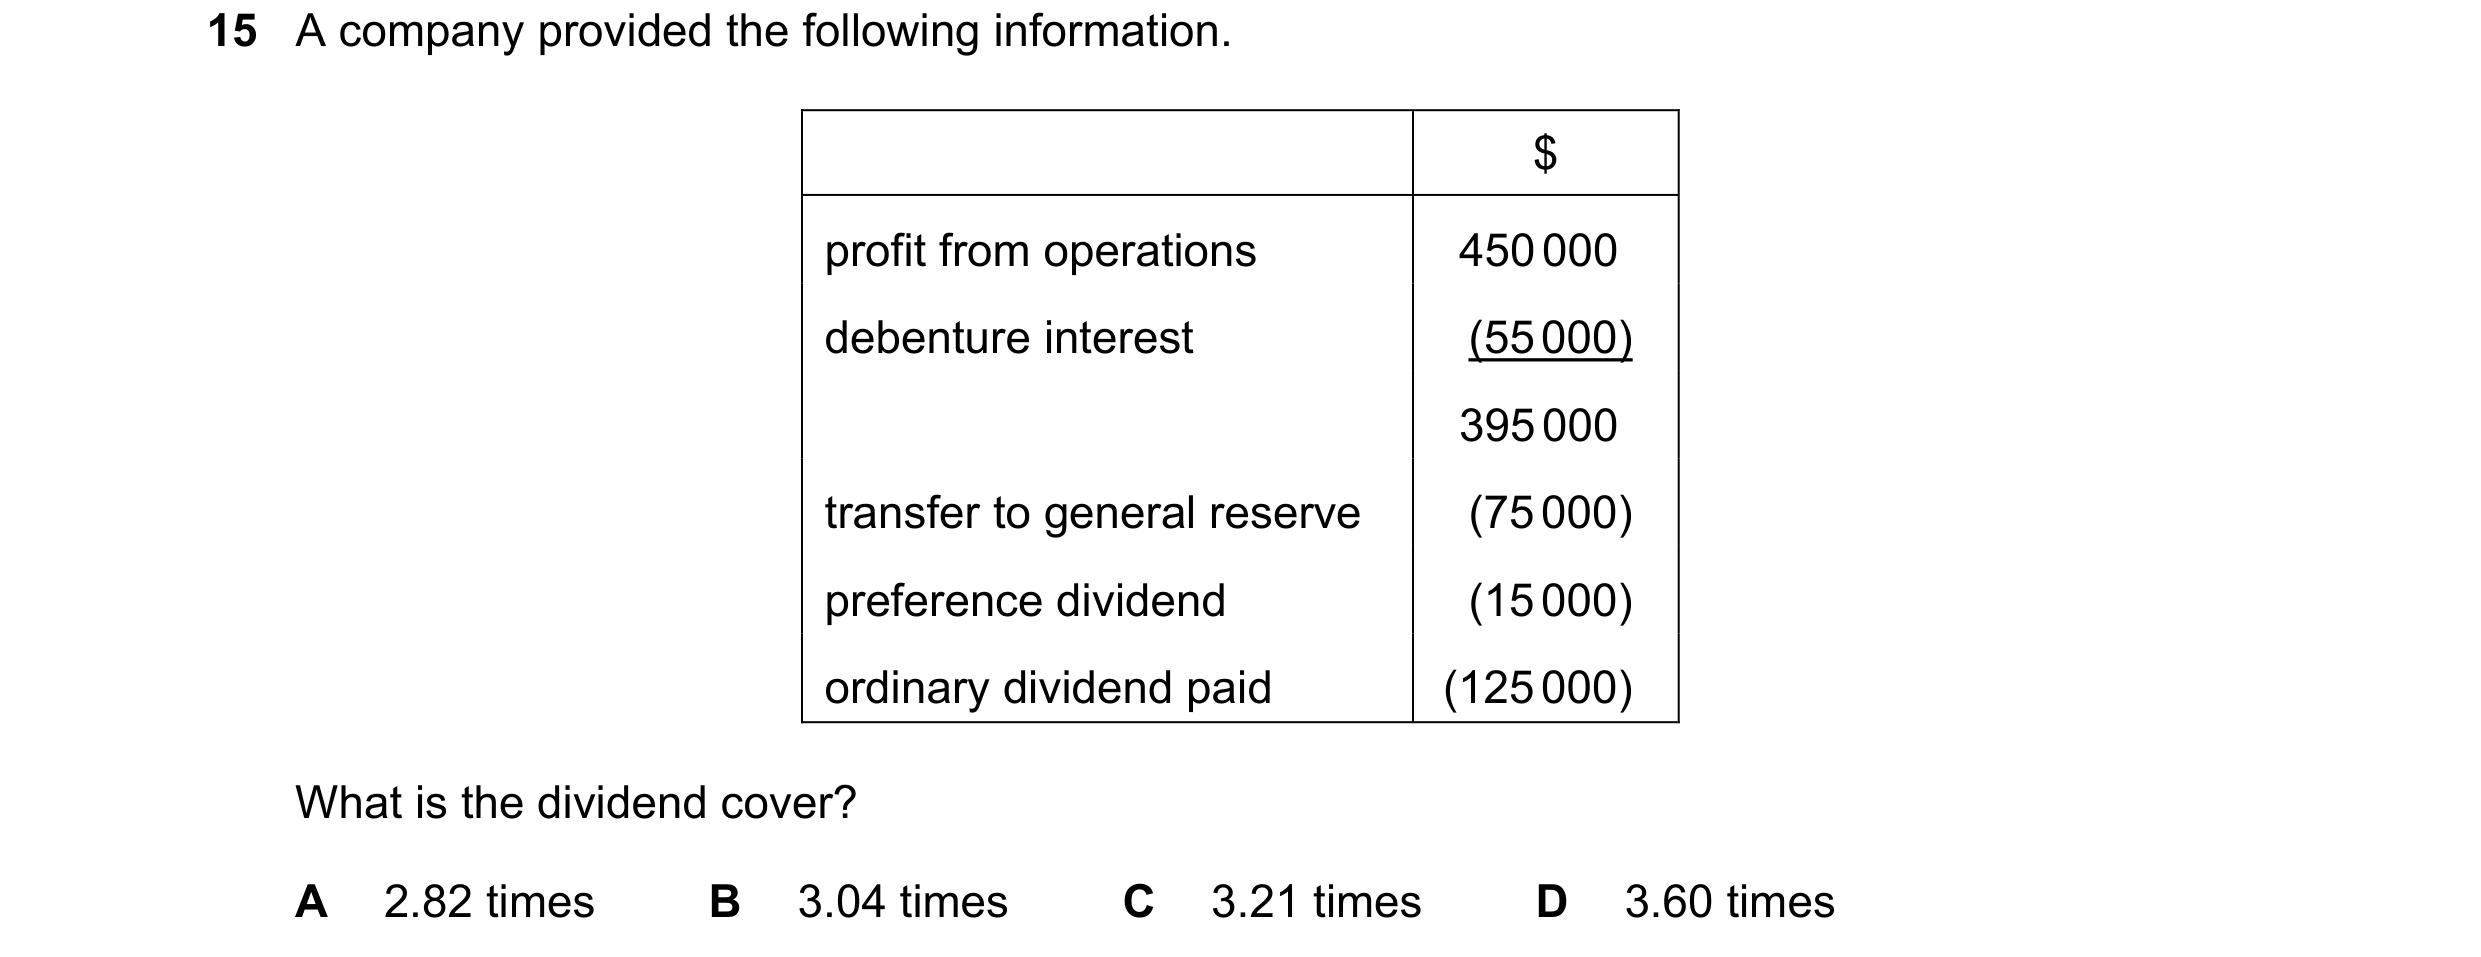
Q125 · A company provided the following information 9706/32 Oct/Nov 2015
15 A company provided the following information. $ profit from operations 450 000 debenture interest (55 000) 395 000 transfer to general reserve (75 000) preference dividend (15 000) ordinary dividend paid (125 000) What is the dividend cover? A 2.82 times B 3.04 times C 3.21 times D 3.60 times
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2015
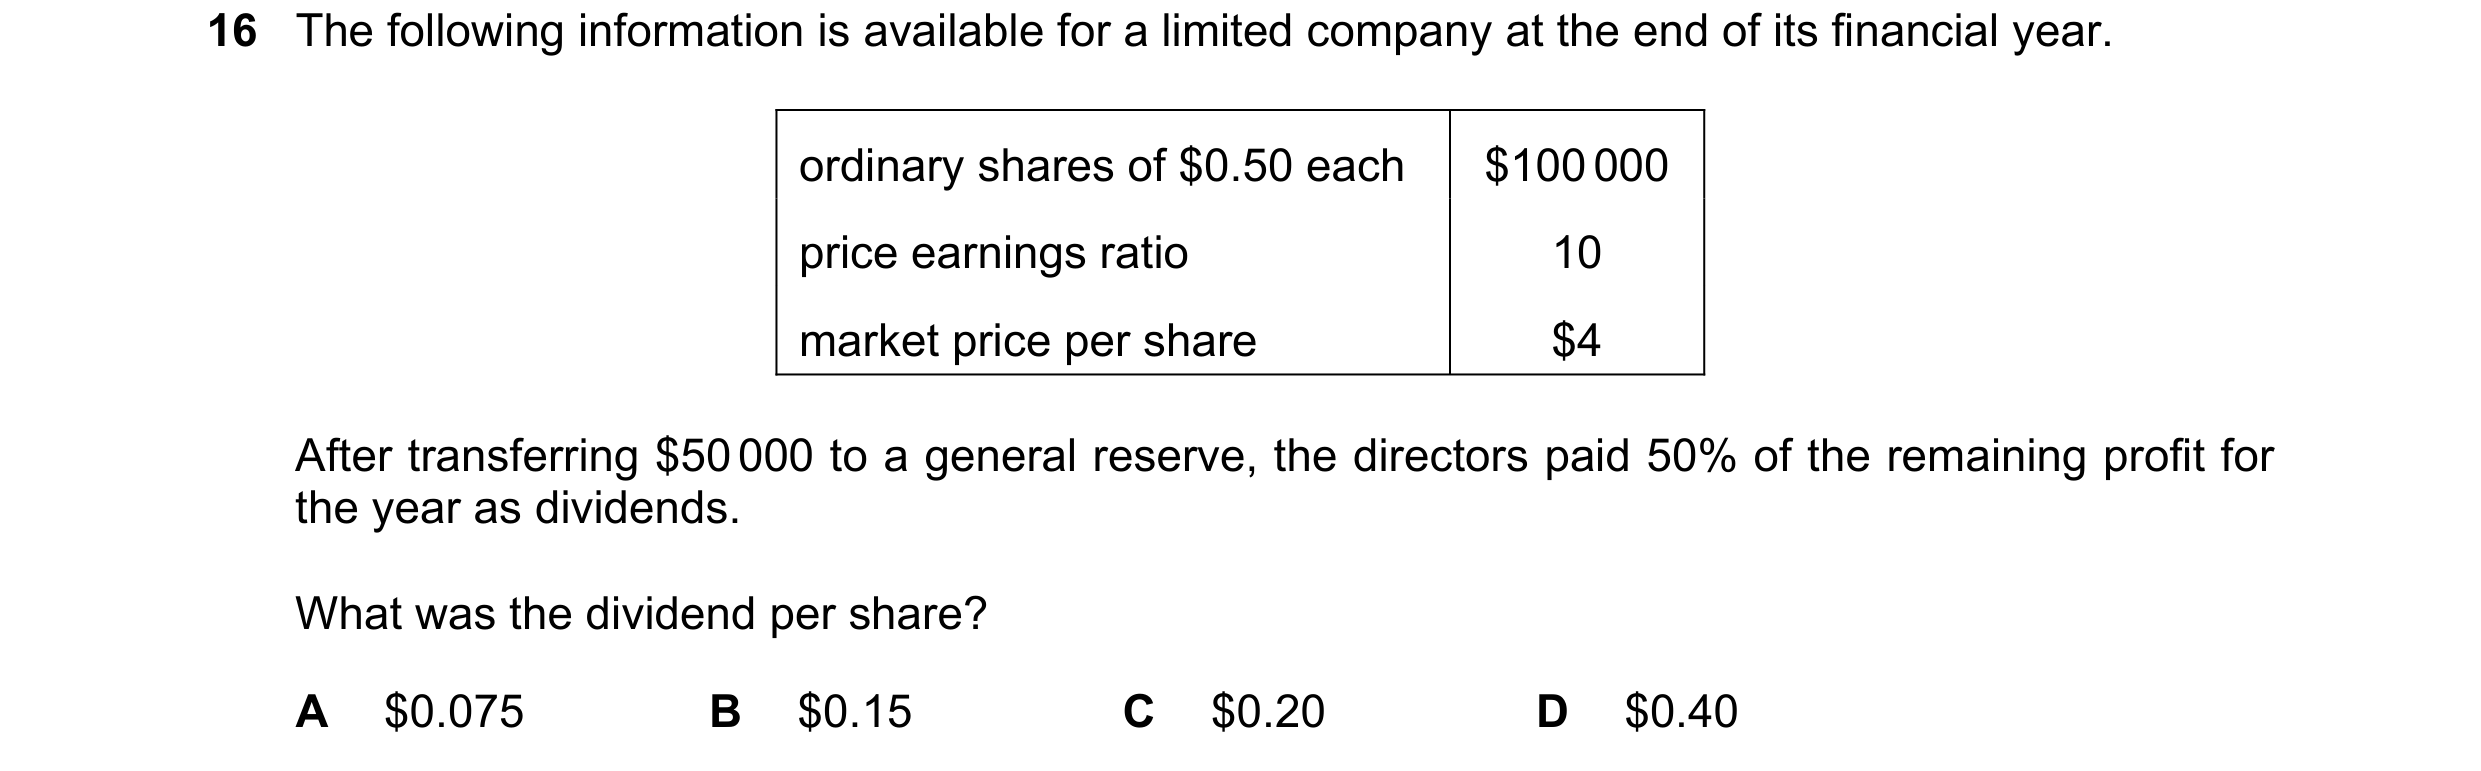
Q126 · The following information is available for a limited company at the end of its financial… 9706/32 Oct/Nov 2015
16 The following information is available for a limited company at the end of its financial year. ordinary shares of $0.50 each $100 000 price earnings ratio 10 market price per share $4 After transferring $50 000 to a general reserve, the directors paid 50% of the remaining profit for the year as dividends. What was the dividend per share? A $0.075 B $0.15 C $0.20 D $0.40
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2015
 1 / 33
 2 / 33
 3 / 33
 4 / 33
 5 / 33
 6 / 33
 7 / 33
 8 / 33
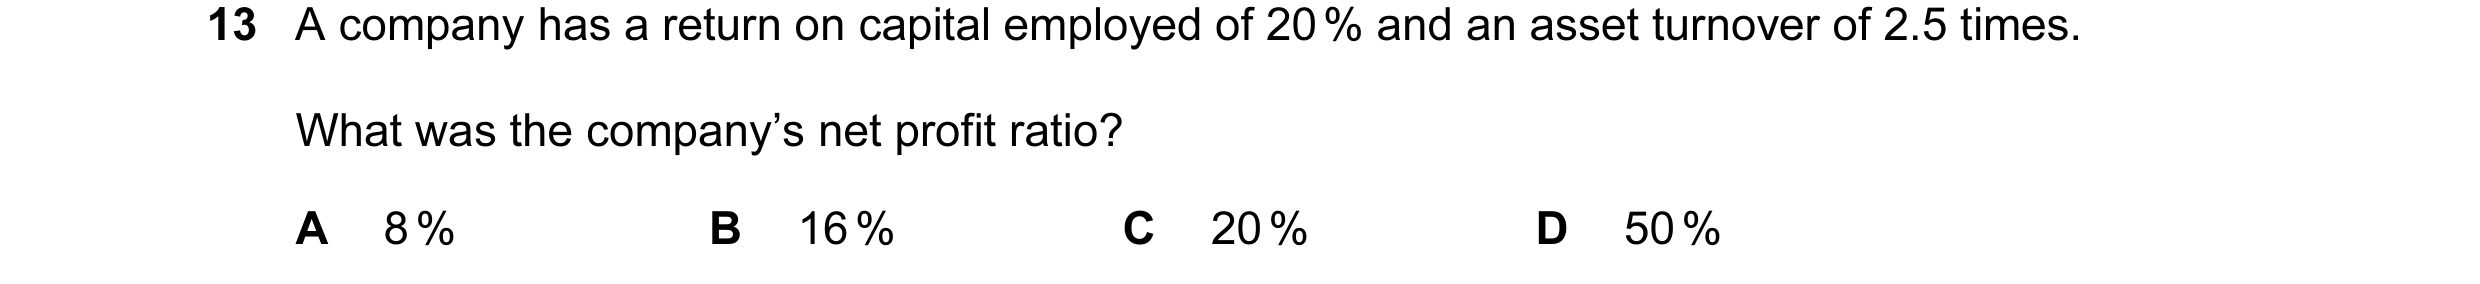
 9 / 33
 10 / 33
 11 / 33
 12 / 33
 13 / 33
 14 / 33
 15 / 33
 16 / 33
 17 / 33
 18 / 33
 19 / 33
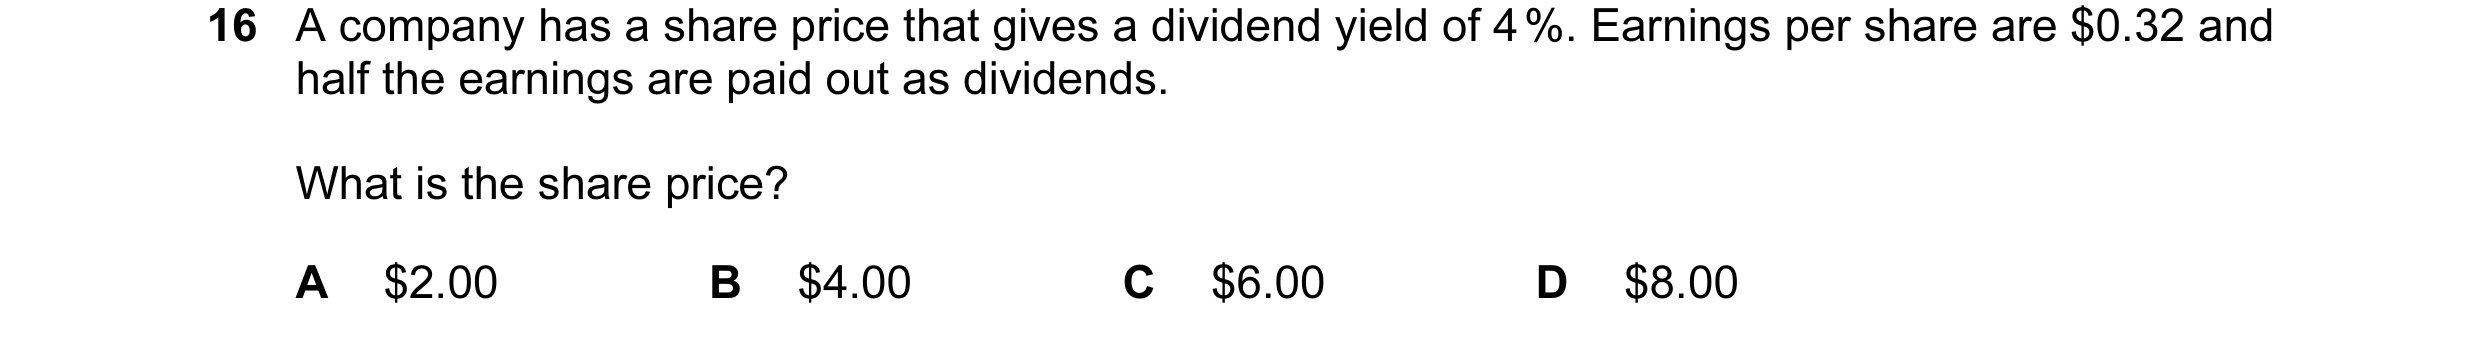
 20 / 33
 21 / 33
 22 / 33
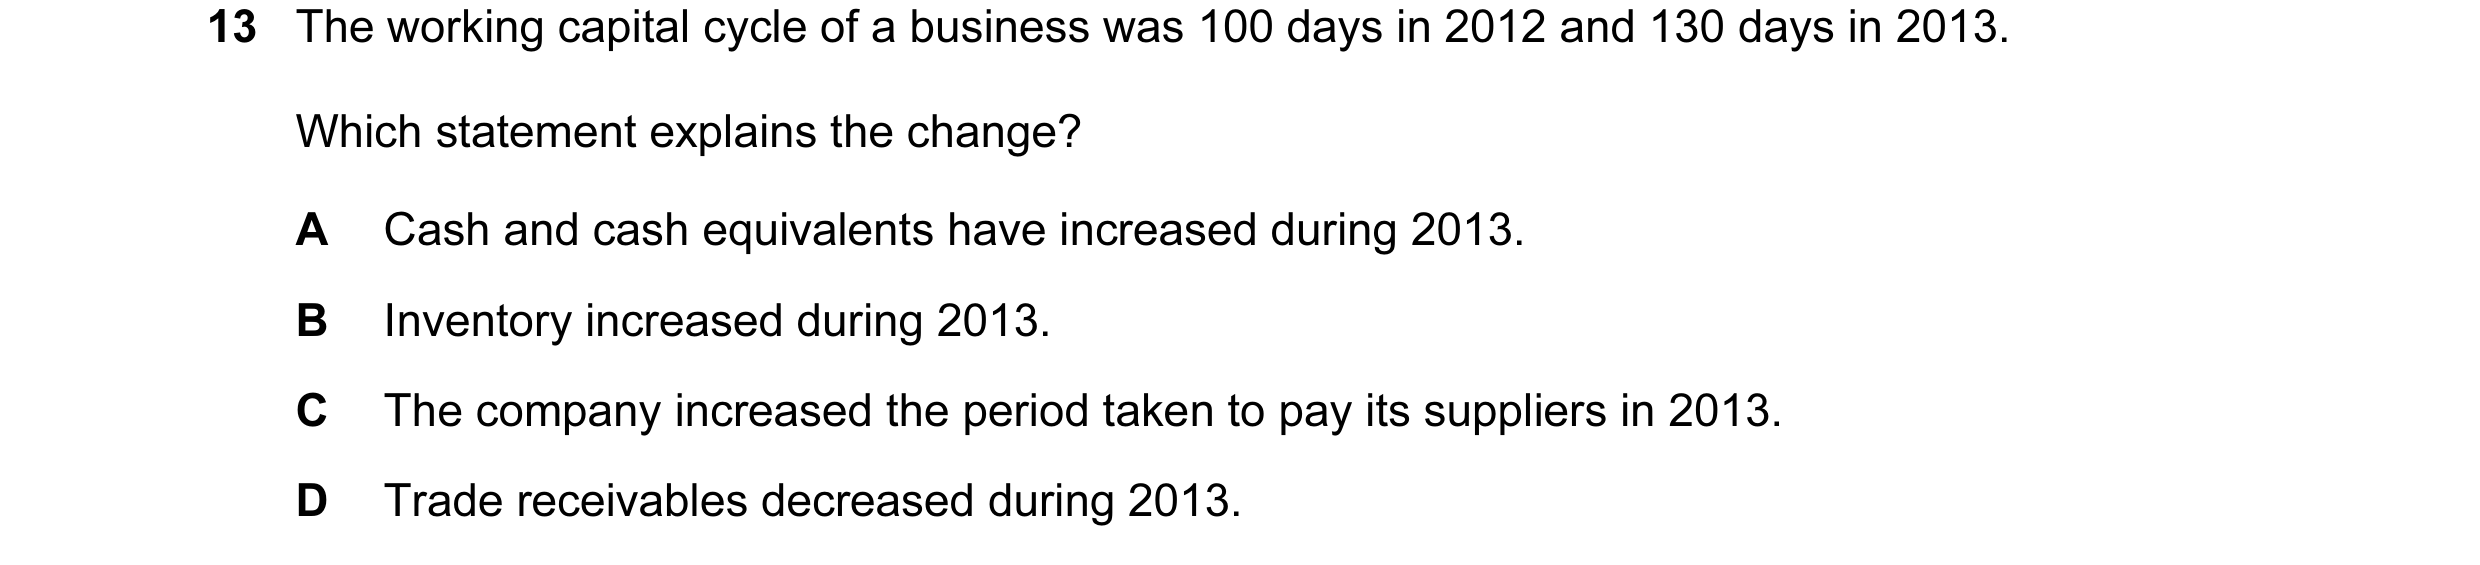
 23 / 33
 24 / 33
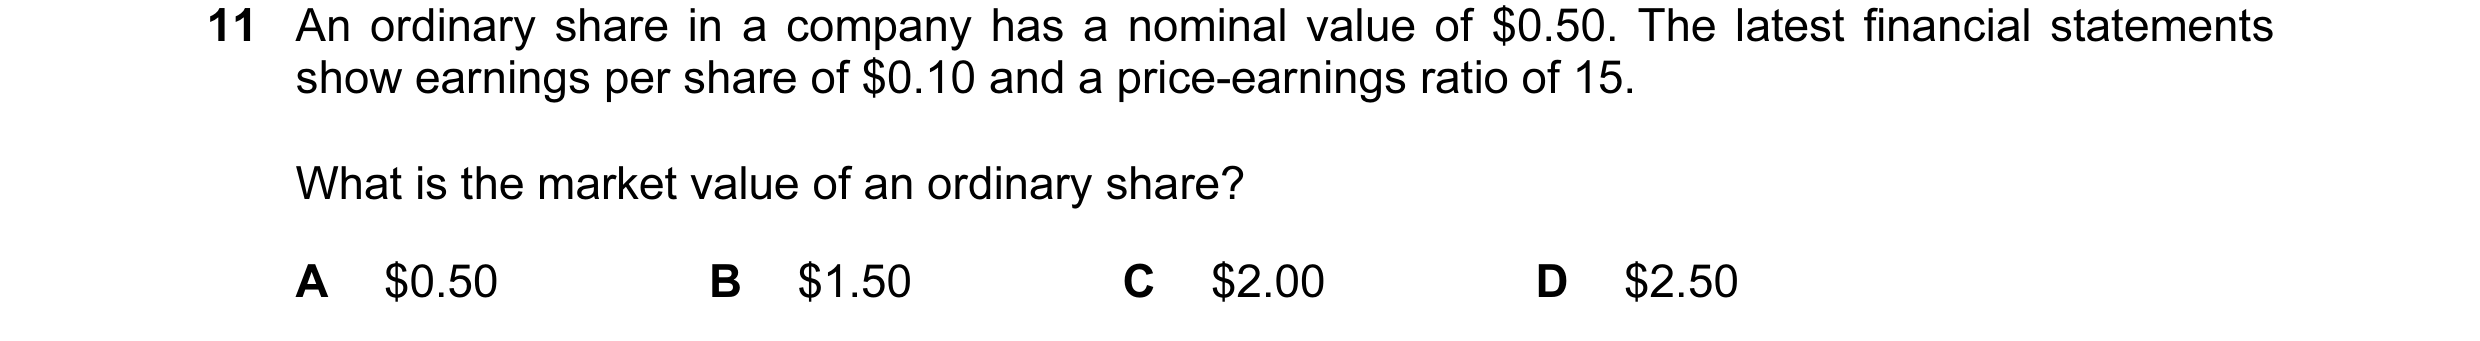
 25 / 33
 26 / 33
 27 / 33
 28 / 33
 29 / 33
 30 / 33
 31 / 33
 32 / 33
 33 / 33