Questions as text
Q1 · Read Source A in the insert 9706/42 Feb/March 2023
1 Read Source A in the insert. (a) Prepare the cash budget for each of the four months from January 2024 to April 2024. … … … … … … … … … … … … … … … … … … … … … … … … … … [7] Additional information One of the directors has made the suggestion that from 1 January 2024 the company should make half of its purchases in cash from some of the suppliers so as to receive a discount of 5%. The credit purchases would continue to be paid for in the month after purchase or as soon as funds allowed. The overdraft limit and the company policy on its overdraft would remain unchanged. (b) Prepare a revised cash budget for each of the four months from January 2024 to April 2024 on the basis of this director’s suggestion. … … … … … … … … … … … … … … … … … … … … … … … [11] (c) Advise the directors whether or not they should accept the suggestion to make half of the purchases in cash. Justify your answer. … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: Question Answer Marks 1(a) Prepare the cash budget for each of the four months from January 2024 to April 2024. 7 Cash budget for January to April 2024 January February March April $ $ $ $ Receipts Sales 56 000 59 500 61 200 59 200 Payments Trade payables 27 100 (1) 28 600 (1) 30 200 (1) 33 300(1) Operating expenses 24 200 25 100 26 100 25 900 } Loan repayment 8 000 0 0 0 }(1) rows Capital expenditure 0 4 800 7 600 0 } Total payments 59 300 58 500 63 900 59 200 Net (3 300) 1 000 (2 700) 0 receipts/(payments) Balance b/f 3 000 (1) (300) 700 (2 000) Balance c/f (300) 700 (2 000) (2 000) (1)OF 1(b) Prepare a revised cash budget for each of the four months from January 2024 to April 2024 on the basis of this 11 director’s suggestion. Cash budget for January to April 2024 January February March April $ $ $ $ Receipts Sales 56 000 59 500 61 200 59 200 Payments Cash purchases 13 585 (1) 14 725 (1) 15 675 (1) 16 150 (1) (W1) Trade payables 15 215 (1) 14 875 (1) 11 825 (1) 17 150 (1) Operating expenses 24 200 25 100 26 100 25 900 } Loan repayment 8 000 0 0 0 }(1) rows Capital expenditure 0 4 800 7 600 0 } Total payments 61 000 59 500 61 200 59 200 Net (5 000) 0 0 0 receipts/(payments) Balance b/f 3 000 (1) (2 000) (2 000) (2 000) Balance c/f (2 000) (2 000) (2 000) (2 000) (1)OF 1(b) W1 January 28 600 0.5 0.95 = 13 585 February 31 000 0.5 0.95 = 14 725 March 33 000 0.5 0.95 = 15 675 April 34 000 0.5 0.95 = 16 150 1(c) Advise the directors whether or not they should accept the suggestion to make half of the purchases in cash. 7 Justify your answer. The discount would increase profits (1). Relationships with the suppliers of the cash purchases could improve (1). The business would be operating at the maximum overdraft (1) which could produce financial constraints should other demands occur (1) and this would increase interest payable (1) and decrease profits (1). The bank overdraft limit might need to be renegotiated (1). Relationships with suppliers of credit purchases would be likely to deteriorate (1) as they would be waiting for longer for their money (1). Interest may become payable on overdue accounts (1). If additional funds could be made available in January or if other expenditure could be delayed, some or all of the opening trade payables could be paid off, and the increase in payment period could be avoided (1). The problems arising from the introduction of the new approach would be largely short term and the advantages of it could become more apparent in the longer term (1). Accept other valid responses. Max 6 marks for comments 1 mark for decision supported with comment
This question in 9706/42 Feb/March 2023
Q2 · Read Source B in the insert 9706/41 May/June 2023
2 Read Source B in the insert. (a) Prepare the production budget (in units) for each of the months from January to April. … … … … … … … … … … … … … … [7] (b) Explain how the budgeted revenue for the four months from January to April should be calculated. … … … … [2] Additional information At present, storage space is limited, such that the maximum number of units which can be held in inventory is 3200. (c) Advise the directors of the company whether or not they should invest in a new, larger storage facility. Justify your answer. … … … … … … … … … … … … … … [7] Additional information Each unit requires two kilos of direct material. The production manager expects that this material will cost $6 per kilo in January and $7 per kilo thereafter. No inventory of direct material is kept. Half of the purchases are paid for in the month of purchase. The remainder are paid for in the following month. (d) Prepare the trade payables budget for each of the months of February and March. Include the balance of trade payables at the beginning and the end of each month. Assume that production is still as in your answer to part (a). … … … … … … … … … … … … … … [7] Additional information The directors are considering asking the company’s suppliers to introduce a cash discount of 4% on payments made in the month of purchase. (e) Explain how this change would affect the budgeted statement of profit or loss. … … … … [2]
25 marks
Mark scheme: 2(a) Prepare the production budget (in units) for each of the months from January to April. January February March April Opening inventory 1 500 (1) 2 100} 3 200} 400} (1) Production 6 600 9 500 10 000 (1) 10 000 (1) 8 100 11 600 13 200 10 400 Sales (6 000) (8 400) (12 800) (10 400) (1) Closing inventory 2 100 (1) 3 200 400 0 (1) Question Answer Marks 2(b) Explain how the budgeted revenue for the four months from January to April should be calculated. The number of sales units which equals the demand times the selling price (1) but the production constraint must be taken into account for the sales arising in April (1) Max 2 Accept other valid responses. 2 2(c) Advise the directors whether or not they should invest in a new, larger storage facility. Justify your answer. Max 6 marks for comments 1 mark for decision supported by a comment. This would enable the business to build up their inventory prior to times of expected high demand (1) which should reduce the possibility of losing sales because of a lack of goods (1). If the business had been able to hold more units of inventory at the end of February then sales would not have been lost in April (1). This would also require a change to the policy of holding only 25% of the following month’s sales (1). The business would have space to keep an inventory of direct materials as well as finished goods (1) reducing the risk inherent in relying so heavily on the ability of the supplier to keep up with demand (1). The cost of the new facility could exceed the profit foregone on the lost sales (1). There would be an impact on cash flow (1) and storage costs would also increase (1). The more inventory is held, the greater the chances of some or all being damaged, stolen, or becoming obsolete or out of fashion (1). It might be better to concentrate on increasing the maximum number of units which can be produced in a month (1) but if demand falls then it will have resulted in unnecessary costs (1). 7 Question Answer Marks 2(d) Prepare the trade payables budget for each of the months of February and March. Include the balance of trade payables at the beginning and the end of each month. Assume that production is still as in your answer to part (a). February $ March $ Opening trade payables 39 600 W1 (2)OF 66 500 (1)OF Purchases 133 000 140 000 (1)OF both 172 600 206 500 Bank – previous month (39 600) (66 500) (1)OF both Bank –current month (66 500) (70 000) (1)OF both Closing trade payables 66 500 70 000 (1)OF both W1 (6 600 6 2) (1)OF) 50% = $39 600 (1)OF 7 2(e) Explain how this change would affect the budgeted statement of profit or loss. The budgeted statement of profit or loss would then include an entry for discount received. (1) This would increase budgeted profit by 2% of purchases (1) OR Budgeted cost of sales/gross profit would be unchanged (1). 2
This question in 9706/41 May/June 2023
Q3 · Read Source B in the insert 9706/43 May/June 2023
2 Read Source B in the insert. (a) Prepare the production budget (in units) for each of the months from January to April. … … … … … … … … … … … … … … [7] (b) Explain how the budgeted revenue for the four months from January to April should be calculated. … … … … [2] Additional information At present, storage space is limited, such that the maximum number of units which can be held in inventory is 3200. (c) Advise the directors of the company whether or not they should invest in a new, larger storage facility. Justify your answer. … … … … … … … … … … … … … … [7] Additional information Each unit requires two kilos of direct material. The production manager expects that this material will cost $6 per kilo in January and $7 per kilo thereafter. No inventory of direct material is kept. Half of the purchases are paid for in the month of purchase. The remainder are paid for in the following month. (d) Prepare the trade payables budget for each of the months of February and March. Include the balance of trade payables at the beginning and the end of each month. Assume that production is still as in your answer to part (a). … … … … … … … … … … … … … … [7] Additional information The directors are considering asking the company’s suppliers to introduce a cash discount of 4% on payments made in the month of purchase. (e) Explain how this change would affect the budgeted statement of profit or loss. … … … … [2]
25 marks
Mark scheme: 2(a) Prepare the production budget (in units) for each of the months from January to April. January February March April Opening inventory 1 500 (1) 2 100} 3 200} 400} (1) Production 6 600 9 500 10 000 (1) 10 000 (1) 8 100 11 600 13 200 10 400 Sales (6 000) (8 400) (12 800) (10 400) (1) Closing inventory 2 100 (1) 3 200 400 0 (1) Question Answer Marks 2(b) Explain how the budgeted revenue for the four months from January to April should be calculated. The number of sales units which equals the demand times the selling price (1) but the production constraint must be taken into account for the sales arising in April (1) Max 2 Accept other valid responses. 2 2(c) Advise the directors whether or not they should invest in a new, larger storage facility. Justify your answer. Max 6 marks for comments 1 mark for decision supported by a comment. This would enable the business to build up their inventory prior to times of expected high demand (1) which should reduce the possibility of losing sales because of a lack of goods (1). If the business had been able to hold more units of inventory at the end of February then sales would not have been lost in April (1). This would also require a change to the policy of holding only 25% of the following month’s sales (1). The business would have space to keep an inventory of direct materials as well as finished goods (1) reducing the risk inherent in relying so heavily on the ability of the supplier to keep up with demand (1). The cost of the new facility could exceed the profit foregone on the lost sales (1). There would be an impact on cash flow (1) and storage costs would also increase (1). The more inventory is held, the greater the chances of some or all being damaged, stolen, or becoming obsolete or out of fashion (1). It might be better to concentrate on increasing the maximum number of units which can be produced in a month (1) but if demand falls then it will have resulted in unnecessary costs (1). 7 Question Answer Marks 2(d) Prepare the trade payables budget for each of the months of February and March. Include the balance of trade payables at the beginning and the end of each month. Assume that production is still as in your answer to part (a). February $ March $ Opening trade payables 39 600 W1 (2)OF 66 500 (1)OF Purchases 133 000 140 000 (1)OF both 172 600 206 500 Bank – previous month (39 600) (66 500) (1)OF both Bank –current month (66 500) (70 000) (1)OF both Closing trade payables 66 500 70 000 (1)OF both W1 (6 600 6 2) (1)OF) 50% = $39 600 (1)OF 7 2(e) Explain how this change would affect the budgeted statement of profit or loss. The budgeted statement of profit or loss would then include an entry for discount received. (1) This would increase budgeted profit by 2% of purchases (1) OR Budgeted cost of sales/gross profit would be unchanged (1). 2
This question in 9706/43 May/June 2023
Q4 · Read Source A in the insert 9706/41 Oct/Nov 2023
1 Read Source A in the insert. (a) State two purposes of preparing a cash budget. 1 … … 2 … … [2] (b) Prepare the cash budget for each of the months November, December and January. … … … … … … … … … … … … … … … … … … … … … … … … … … … … Workings: [12] (c) Prepare the budgeted statement of profit or loss for the three-month budgeted period ending 31 January. Start your answer with the gross profit. … … … … … … … … … … … … … Workings: [4] Additional information To improve the future cash position the directors have two options. Option 1 Offer a cash discount of 2.5% to credit customers if they pay one month after sales. It is estimated that 80% of the credit customers will take the cash discount. Option 2 Pay the suppliers two months after the purchases. (d) Advise the directors which option, if either, they should choose. Justify your answer. … … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: Question Answer Marks 1(a) State two purposes of preparing a cash budget. 2 To identify any cash deficit so that funding, i.e. bank loan can be arranged in advance.(1) To identify any cash surplus so that cash can be fully utilized, i.e. investment (1) Max 2 Accept other valid responses. 1(b) Prepare the cash budget for each of the months November, December and January. 12 November December January $ $ $ Cash sales W1 39 000 45 000 37 500 (1) row Two months credit after irrecoverable debt W2 317 520 (1) 370 440 (1) 343 980 (1) 356 520 415 440 381480 Suppliers W3 267 920 271 860 275 800 (6) Operating expenses W4 129 450 129 450 129 450 (1) row 397 370 401 310 405 250 Surplus/deficit for the month (40 850) 14 130 (23 770) Opening cash balance 95 000 54 150 68 280 Closing cash balance 54 150 68 280 44 510 (1)OF row 1(b) W1 $390 000 10% = $39 000; $450 000 10% = $45 000; $375 000 10% = $37 500 W2 $360 000 90% 98% = $317 520 $420 000 90% 98% = $370 440 $390 000 90% 98% = $343 980 W3 Oct Nov Dec Jan $ $ $ $ Sales 420 000 390 000 450 000 375 000 Cost of sales (2/3 of sales) 280 000 260 000 300 000 250 000 (1) row Closing inventory (40% of next month's cost of 104 000 120 000 100 000 sales) Opening inventory (112 000) (104 000) (120 000) (1)both Purchases for the month 272 000 276 000 280 000 (1) row Payment to suppliers with 1.5% cash discount 267 920 271 860 275 800 (1) (1) (1) $272 000 98.5% = $267 920 $276 000 98.5% = $271 860 $280 000 98.5% = $275 800 W4 Monthly depreciation [$124 000 15%] ÷ 12 = $1 550 $131 000 –$1 550 = $129 450 1(c) Prepare the budgeted statement of profit or loss for the three-month budgeted period. Start your answer with the 4 gross profit. $ Gross profit W1 405 000 (1) Discount received W2 12 420 (1) 417 420 Operating expenses 393 000 Irrecoverable debt W3 21 060 (1) 414 060 Budgeted profit 3 360 (1)OF W1 Sales for three months ($390 000 + $450 000 + $375 000) = $1 215 000 1 Gross profit $1 215 000 = $405 000 3 W2 ($272 000 + $276 000 + $280 000) 1.5% = $12 420 W3 ($360 000 + $420 000 + $390 000) 90% 2% = $21 060 1(d) Advise the directors which option, if either, they should choose. Justify your answer. 7 Option 1 (Max 3) Credit customers may not take the cash discount (1) Will cause cash inflow to be higher in the first month but lower thereafter (1) Cash will be received quicker (1) Irrecoverable debts will be reduced (1) Discount allowed will increase expenses / reduce profit (1) Discount allowed may or may not be compensated by the reduction of irrecoverable debts (1) Option 2 (Max 3) Discount received will be lost (1) Profit will be reduced (1) Cash saving will be reduced (1) A change of payment period from one month to two months may hamper the credibility with the suppliers (1) The cash outflow will be lower in the first month and higher thereafter (1) Cash will be held for a further month (1) Accept other valid responses. (1) mark for decision supported by a comment (option 1, option 2 or neither)
This question in 9706/41 Oct/Nov 2023
Q5 · Read Source B in the insert 9706/42 Oct/Nov 2023
2 Read Source B in the insert. (a) State three advantages of budgeting. 1 … … 2 … … 3 … … [3] (b) Prepare the following budgets for each of the months of May and June: (i) trade receivables, showing the opening and closing balances for May and June … … … … … … … … … … … … Workings: [7] (ii) production (in units) … … … … … … … … … … … … [4] (iii) purchases (in dollars). … … … … … … … … … … … … [4] Additional information During the budget committee meeting, the sales manager requested $100 000 for a sales promotion for the existing product. The production manager requested the same amount for research and development for a new product. The accountant reported that due to a financial constraint only one of the requests could be allowed. (c) Advise the budget committee which request should be allowed. Justify your answer. … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: 2(a) State three advantages of budgeting. 3 Coordinate plans of different departments (1) Planning / controlling costs (1) Motivates employees to achieve common goal (1) Forward looking / decision making, e.g. remedial actions taken for any shortage of resources / limiting factors (1) Responsibility accounting (1) Communication (1) Max 3 Accept other valid responses 2(b)(i) Prepare the following budgets for each of the months of May and June: 7 trade receivables, showing the opening and closing balances for May and June Trade receivables budget May June $ $ Balance b/d (100% of last month +60% of previous month) 510 000 } 561 000 } (1) row Credit sales of current month 363 000 } 399 300 } (1) row Bank receipts (40% of last month <5% discount> + 60% of previous month) (305 400) (1) (335 940) (1) Discount allowed (6600) (1) (7260) (1) Balance c/d 561 000 } 617 100 } (1) OF row Workings: March April May June Sales (units) 20 000 22 000 24 200 26 620 Sales (in dollars) $400 000 $440 000 $484 000 $532 400 Credit sales 75% $300 000 $330 000 $363 000 $399 300 2(b)(ii) production (in units). 4 Production budget (in units) May June Closing inventory (25% of sales next month) 6655 6655 (1) row Add: Sales 24 200 26 620 (1) row Less: Opening inventory (25% of sales current month) 6050 6655 (1) row Units to be produced 24 805 26 620 (1) row Workings: March April May June July Sales (units) 20 000 22 000 24 200 26 620 26 620 2(b)(iii) purchases (in dollars). 4 Purchases budget (in dollars) May June $ $ Closing inventory (50% of production required next month) 79 860 79 860 (1) row Add: Used for production of current month 148 830 159 720 (1) OF row Less: Opening inventory (50% of production required current month) 74 415 79 860 (1) OF row Purchases (in dollars) 154 275 159 720 (1) OF row Alternative answer Purchases budget (in kilos) May June Closing inventory (50% of production required next month) 53 240 53 240 (1) row Add: Used for production of current month 99 220 106 480 (1) OF row Less: Opening inventory (50% of production required current month) 49 610 53 240 (1) OF row Purchases (in kilos) 102 850 106 480 Purchases (in dollars) $1.50 per kilo $154 275 $159 720 (1) OF row Alternative answer Purchases budget (in units) May June Closing inventory (50% of production required next month) 13 310 13 310 (1) row Add: Used for production of current month 24 805 26 620 (1) OF row Less: Opening inventory (50% of production required current month) 12 402.5 13 310 (1) OF row Purchases (in units) 25 712.5 26 620 Purchases (in dollars) $6 per unit $154 275 $159 720 (1) OF row 2(b)(iii) Workings: May June July Units to be produced 24 805 26 620 26 620 4 kilos per unit 99 220 106 480 106 480 @$1.50 per kilo $148 830 $159 720 $159 720 2(c) Advise the budget committee which request should be allowed. Justify your answer. 7 Sales promotion for existing product (max 3) can boost sales / demand / market share and increase revenue / profit (1) can promote the reputation/goodwill of the company associated with the product (1) product life cycle may be at the declining stage (1) should not aim at short-term profit/revenue at the expense of the long-term development of product (1) Research and development for new product (max 3) should aim for new products to keep abreast with the customers’ changing tastes (1) new products ensure the competitiveness of the business in the future (1) the success of any new product is uncertain (1) the financial benefits from a new product may not be realised for a period of time (1) (1) mark for decision supported by a comment. Accept other valid responses.
This question in 9706/42 Oct/Nov 2023
Q6 · Read Source A in the insert 9706/43 Oct/Nov 2023
1 Read Source A in the insert. (a) Prepare the flexible budget statement for the month of April. … … … … … … … … [3] (b) Calculate the following variances: (i) sales price … … … … [2] (ii) sales volume (as a measure of change in profit) … … … … [2] (iii) fixed overhead expenditure … … … … [2] (iv) fixed overhead volume. … … … … [2] (c) Prepare a statement to reconcile the flexible budgeted profit as calculated in (a) with the actual profit. Your statement should start with the flexible budgeted profit. … … … … … … … … … … … … … … [7] Additional information An analysis of direct material variance shows that both the material price and material usage have an adverse variance. The directors of T Limited are considering changing the existing supplier. They have two potential suppliers to consider. Local supplier A Overseas supplier B Usage per unit after wastage 2.8 kilos 2.5 kilos Purchase price per kilo quoted by supplier $13.75 $15.40 (d) Advise the directors which supplier they should choose. Justify your answer and support it with relevant calculations. … … … … … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: Question Answer Marks 1(a) Prepare the flexible budget statement for the month of April. 3 $ Sales revenue ($184 000/2 000) 2180 200 560 } Direct materials ($84 000/2 000) 2180 91 560 } Direct labour ($60 000/2 000) 2180 65 400 } (1) Fixed overhead ($18 000/2 000) 2180 19 620 (1) Total cost 176 580 Budgeted profit 23 980 (1) OF 1(b)(i) Calculate the following variances: 2 sales price Sales price variance $184 000/2000 = $92 (2180 $92) – $196 200= $4360 (1) A (1) 1(b)(ii) Calculate the following variances: 2 sales volume (as a measure of change in profit) Sales volume variance $22 000/2000 =$11 (2180 – $2000) $11=$1980 (1) F (1) 1(b)(iii) Calculate the following variances: 2 fixed overhead expenditure Fixed overhead expenditure $18 400 – $18 000 = $400 (1) A (1) 1(b)(iv) Calculate the following variances: 2 fixed overhead volume Fixed overhead volume $19 620 OF – $18 000 = $1620 (1) F (1) 1(c) Prepare a statement to reconcile the flexible budgeted profit as calculated in (a) with the actual profit. Your 7 statement should start with the flexible budgeted profit. $ Flexible budgeted profit 23 980 (1)OF Sales price variance (4 360) A} Direct materials variance ($113 796 – $91 560) (22 236) A (2) Direct labour variance ($65 400 – 55 590) 9 810 F (2) Fixed overhead expenditure (400) A} Fixed overhead volume 1 620 F} (1)OF Actual profit 8 414 (1) 1(d) Advise the directors which supplier they should choose. Justify your answer and support it with relevant 7 calculations. Calculations The unit cost for both suppliers is the same – (2.8 $13.75) = (2.5 $15.40) = $38.50 (1) The unit cost $38.5 by either supplier is lower than the budgeted cost of $42 ($84 000/2 000) and actual cost of $52.20 ($113 796/2 180) (1) Max 2 Comments The quality of materials from supplier B is better than from A (1) because of less wastage (1) Direct material of poor quality may affect the efficiency of workers as well as the quality of final product (1) The unit purchase price of supplier A is lower than B (1) Additional costs may be incurred for supplier B, i.e. import duty, freight charge and insurance (1) As delivery takes time, prompt delivery from supplier B may not be possible (1) for an urgent order (1) Max 4 Decision supported by a comment (1) Accept other valid responses.
This question in 9706/43 Oct/Nov 2023
Q7 · Read Source B in the insert 9706/42 Feb/March 2024
2 Read Source B in the insert. (a) Prepare, for January 2024, in a columnar format, the fixed budget and the flexible budget statement. Your answer should include the fixed budget profit or loss for the month and the flexible budget profit or loss for the month. … … … … … … … … … … [5] Additional information Actual results for January 2024 included the following: $ Direct material 82 460 using 3.1 kilos per unit Direct labour 182 700 paid at $5.80 per hour (b) Calculate the following variances: (i) direct material price … … … … [2] (ii) direct material usage … … … … [2] (iii) direct labour rate … … … … [2] (iv) direct labour efficiency. … … … … [2] Additional information The actual fixed overheads for the month amounted to $78 000. The fixed overhead expenditure variance was $2000 favourable, and the fixed overhead volume variance was $10 000 adverse. (c) Explain why the fixed overhead volume variance was adverse. Your answer should consider the sub-variances of the fixed overhead volume variance, but calculation of these is not required. … … … … … … … … … … [5] Additional information The company has been preparing sales, production, purchases and labour budgets for several years. It has now been suggested that the company should also prepare budgets for trade receivables and trade payables. (d) Advise the directors whether or not the company should start to prepare budgets for trade receivables and trade payables. Justify your answer. … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: 2(a) Prepare, for January 2024 in a columnar format, the fixed budget and the 5 flexible budget statement. Fixed Flexible budget budget $ $ Sales revenue 544 000 476 000 (1) row Direct material (96 000) (84 000) (1) row Direct labour W1 (192 000) (168 000) (1) row Fixed overheads (80 000) (70 000) (1) row Profit 176 000 154 000 (1)OF row W1: 32000 hours x $6 = $192 000 28000 hours x $6 = $168 000 2(b)(i) Calculate the following variances: 2 Direct material price 21 700 (4 – 3.80) = 4340 (1) F (1) 2(b)(ii) Direct material usage 2 4 (21 700 – 21 000) = 2800 (1) A (1) 2(b)(iii) Direct labour rate 2 31 500 (6 – 5.80) = 6300 (1) F (1) 2(b)(iv) Direct labour efficiency 2 6 (31 500 – 28 000) = 21 000 (1) A (1) 2(c) Explain why the fixed overhead volume variance was adverse. Your 5 answer should consider the sub-variances of the fixed overhead volume variance but calculation of these is not required. The fixed overhead volume variance was adverse because actual production was less than budgeted production (1). The fixed overhead capacity variance (1) was adverse because actual hours worked were less than the hours from the fixed budget as 31500 hours is less than 32000 hours (1). The fixed overhead efficiency variance (1) was adverse because actual hours worked were greater than the hours from the flexible budget statement as 31500 hours is more than 28 000 hours (1). Accept other valid responses 2(d) Advise the directors whether or not the company should start to prepare 7 budgets for both trade receivables and trade payables. Justify your answer For (max 3) Predicts cash inflows and cash outflows. (1) Enables a cash budget to be prepared. (1) Assists in the production of master budget / budgeted statement of financial position. (1) Could give a benchmark for monitoring the performance of credit control. (1) Cash is often more important than profit. (1) Against (max 3) The company may make all sales and purchases on a cash basis. (1) More time consuming/increased administrative costs. (1) The budget won’t make the trade receivables pay up/won’t stop irrecoverable debts. (1) Doesn’t ensure there is enough cash to pay the trade payables. (1) Decision supported by a comment (1) Accept other valid responses
This question in 9706/42 Feb/March 2024
Q8 · Read Source B in the insert 9706/41 May/June 2024
2 Read Source B in the insert. (a) Calculate: (i) the actual unit selling price … … … … [2] (ii) the unit selling price which would have given the same actual total contribution in April 2024 as the standard total contribution for the month … … … … … … [3] (iii) the actual total quantity of direct materials used (in kilos) … … … … … … [3] (iv) the actual price paid per kilo of direct material … … … … [2] (v) the actual hours used by direct labour per unit. … … … … … … [3] (b) Name the budget which P Limited would have prepared if actual sales units had been more or less than the budgeted 11 000 units. … [1] (c) Suggest four reasons why the company uses standard costs. 1 … … 2 … … 3 … … 4 … … [4] Additional information P Limited has always prepared all its budgets manually. The directors are now considering the use of spreadsheets in preparing the budgets. (d) Advise the directors whether or not they should use spreadsheets in the preparation of the company’s budgets. Justify your answer. … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: 2(a)(i) Calculate the actual unit selling price. 2 55 000/11 000 = 5 (1) 210 – 5 = $205 (1) 2(a)(ii) Calculate the unit selling price which would have given the same actual 3 total contribution in April 2024 as the standard total contribution for the month (57 750 – 4290 – 8360) (1)/11 000 = 4.10 (1) 210 + 4.10 = $214.10 (1) OF OR (55 000 + 57 750 – 4290 – 8360) (1)/11 000 = 9.10 (1) 205 + 9.10 = $214.10 (1) OF 2(a)(iii) Calculate the actual total quantity of direct materials used (in kilos) 3 8360/7.60 = 1100 (1) (11 000 4) (1) – 1100 = 42 900 kilos (1) OF 2(a)(iv) Calculate the actual price paid per kilo of direct material 2 4290/42 900 = 0.10 (1) OF 7.60 – 0.10 = $7.50 (1) OF 2(a)(v) Calculate the actual hours used by direct labour per unit. 3 57 750/(10.50 11000) (1) = 0.5 (1) OF 3 + 0.5 = 3.5 hours (1) OF 2(b) Name the budget which P Limited would have prepared if actual sales 1 units had been more or less than the standard 11000 units. flexible budget statement (1) 2(c) Suggest four reasons why the company uses standard costs. 4 To help cost control/cost reduction (1) To provide a benchmark against which actual results can be compared (1) To help with decision making (1) To motivate staff (1) To use in estimating future requirements for materials or labour (1) To simplify the setting of selling prices (1) To simplify the valuation of inventory (1) To co-ordinate the different functions in the business whilst setting the standards (1) Accept other valid responses. Max 4 2(d) Advise the directors whether or not they should use spreadsheets in the 7 preparation of the company’s budgets. Justify your answer. For (max 3) Arithmetical errors should be avoided. (1) Speed of calculation will be improved. (1) There is automatic recalculation if one variable is changed. (1) Enables ‘what if’ questions to be asked. (1) Security can be enhanced with passwords. (1) Information can be easily sent from one office/department to another. (1) Multiple user applications may be available. (1) ‘Sort’ or ‘select’ functions may be useful. (1) Against (max 3) Some staff may not be familiar with the software. (1) The budgets will still only be as good as the estimates made. (1) Security of data may be compromised. (1) Errors in data entry can be made. (1) Incorrect formulae can be used. (1) Accept other valid responses. Decision supported by a comment (1)
This question in 9706/41 May/June 2024
Q9 · Read Source A in the insert 9706/42 May/June 2024
1 Read Source A in the insert. (a) Prepare the production budget (in units) for each of the months April, May, June and July 2025. … … … … … … … … … [4] Additional information The budgeted cost structure of each unit is as follows: $ Direct 25 These are purchased on credit in the month of production. materials • One fifth (20%) is paid for in the month following purchase after a 5% discount. • Another fifth (20%) is paid for in the month following purchase but without any discount. • The remainder (60%) is paid for in the second month after purchase. Direct labour 30 This is all paid in the month of production. Other costs 40 These are all paid in the month after production, with the exception of a $4 per unit charge for depreciation. (b) Prepare an extract from the cash budget for each of the months June and July 2025 to show the payments related to production. … … … … … … … … … … … … … … Workings: [7] Additional information The company usually makes all its sales on a cash basis for a selling price of $150 per unit. It expects to operate with a bank overdraft throughout 2025. The company has received an order from a prospective new customer who is based overseas. This order is for 900 units to be supplied in June 2025. The customer is prepared to pay $156 per unit, paying in six equal monthly instalments starting in August 2025. (c) Calculate the change in the expected bank overdraft at the end of each of the months June, July and August 2025 if the order was accepted. Assume that all the extra production would take place in the month in which the units are supplied. … … … … … … … … … … … … … … … … … … … … … … [7] (d) Advise the directors whether or not the company should accept the order. Justify your answer. … … … … … … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: 1(a) Prepare the production budget (in units) for each of the months April, May, June and July 2025. April May June July Sales 1 000 1 200 1 500 1 300 (1) row Closing inventory 240 300 260 220 (1) row Opening inventory (200) (1) (240) (300) (260) Production 1 040 1 260 1 460 1 260 (1)OF row Alternative answer April May June July Opening inventory 200 (1) 240 300 260 Production 1 040 1 260 1 460 1 260 (1)OF row Sales (1 000) (1 200) (1 500) (1 300) (1) row Closing inventory 240 300 260 220 (1) row 4 Question Answer Marks 1(b) Prepare an extract from the cash budget for each of the months June and July 2025 to show the payments related to production. Payments June $ July $ Trade payables – month after purchase W1 12 285 (1)OF 14 235 (1)OF Trade payables – two months after purchase W2 15 600 (1)OF 18 900 (1)OF Direct labour W3 43 800 37 800 (1)OF both Other costs W4 45 360 (1)OF 52 560 (1)OF Total production payments 117 045 123 495 7 W1 based on units for May = 0.39 1 260 25 = 12 285 based on units for June = 0.39 1 460 25 = 14 235 OR W1 based on units for May = (0.2 1 260 25) + (0.2 1 260 25 0.95) = 12 285 based on units for June = (0.2 1 460 25) +(0.2 1 460 25 0.95) = 14 235 OR W1 based on units for May = 9.75 1 260 = 12 285 based on units for June = 9.75 1 460 = 14 235 W2 based on units for April = 0.6 1 040 25 = 15 600 based on units for May = 0.6 1 260 25 = 18 900 W3 1 460 30 = 43 800 and 1 260 30 = 37 800 W4 based on units for May = 1260 (40 – 4) = 45 360 based on units for June = 1460 (40 – 4) = 52 560 Question Answer Marks 1(c) Calculate the change in the expected bank overdraft at the end of each of the months June, July and August 2025 if the order was accepted. Assume that all the extra production would take place in the month in which the units are supplied. $ June – direct labour 900 30 27 000 Increase in overdraft at end June 27 000 (1) July – direct materials 900 25 0.39 8 775 (1) – other costs 900 36 32 400 (1) Increase in overdraft at end July 68 175 (1)OF August – direct materials 900 25 0.6 13 500 (1) receipt from customer 900 156 1/6 (23 400) (1) Increase in overdraft at end August 58 275 (1)OF 7 Question Answer Marks 1(d) Advise the directors whether or not the company should accept the order. Justify your answer. For (max 3) It would be more profitable than the usual sales. (1) It might make use of spare capacity. (1) It would increase market share / enter overseas market. (1) There might be repeat orders. (1) If other costs are largely fixed, they would reduce per unit as they are spread over more units, further increasing profit. (1) Against (max 3) Regular customers may also request credit. (1) There might not be enough capacity in the factory. (1) Existing machinery may become exhausted / new machinery may be required. (1) Additional labour and materials may not be available. (1) Workers may be overworked / overtime may be required. (1) Finance will be needed – the overdraft limit may need to be renegotiated. (1) Increased overdraft interest (1) will reduce profit. Credit checks will be needed on the new customer. (1) The company may have to adopt credit control / collection procedures. (1) The longer the credit period the greater the risk of not being paid. (1) More administration/delivery costs may be incurred for an overseas customer. (1) Accept other valid responses. Decision supported with a comment (1) 7
This question in 9706/42 May/June 2024
Q10 · Read Source B in the insert 9706/43 May/June 2024
2 Read Source B in the insert. (a) Calculate: (i) the actual unit selling price … … … … [2] (ii) the unit selling price which would have given the same actual total contribution in April 2024 as the standard total contribution for the month … … … … … … [3] (iii) the actual total quantity of direct materials used (in kilos) … … … … … … [3] (iv) the actual price paid per kilo of direct material … … … … [2] (v) the actual hours used by direct labour per unit. … … … … … … [3] (b) Name the budget which P Limited would have prepared if actual sales units had been more or less than the budgeted 11 000 units. … [1] (c) Suggest four reasons why the company uses standard costs. 1 … … 2 … … 3 … … 4 … … [4] Additional information P Limited has always prepared all its budgets manually. The directors are now considering the use of spreadsheets in preparing the budgets. (d) Advise the directors whether or not they should use spreadsheets in the preparation of the company’s budgets. Justify your answer. … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: 2(a)(i) Calculate the actual unit selling price. 2 55 000/11 000 = 5 (1) 210 – 5 = $205 (1) 2(a)(ii) Calculate the unit selling price which would have given the same actual 3 total contribution in April 2024 as the standard total contribution for the month (57 750 – 4290 – 8360) (1)/11 000 = 4.10 (1) 210 + 4.10 = $214.10 (1) OF OR (55 000 + 57 750 – 4290 – 8360) (1)/11 000 = 9.10 (1) 205 + 9.10 = $214.10 (1) OF 2(a)(iii) Calculate the actual total quantity of direct materials used (in kilos) 3 8360/7.60 = 1100 (1) (11 000 4) (1) – 1100 = 42 900 kilos (1) OF 2(a)(iv) Calculate the actual price paid per kilo of direct material 2 4290/42 900 = 0.10 (1) OF 7.60 – 0.10 = $7.50 (1) OF 2(a)(v) Calculate the actual hours used by direct labour per unit. 3 57 750/(10.50 11000) (1) = 0.5 (1) OF 3 + 0.5 = 3.5 hours (1) OF 2(b) Name the budget which P Limited would have prepared if actual sales 1 units had been more or less than the standard 11000 units. flexible budget statement (1) 2(c) Suggest four reasons why the company uses standard costs. 4 To help cost control/cost reduction (1) To provide a benchmark against which actual results can be compared (1) To help with decision making (1) To motivate staff (1) To use in estimating future requirements for materials or labour (1) To simplify the setting of selling prices (1) To simplify the valuation of inventory (1) To co-ordinate the different functions in the business whilst setting the standards (1) Accept other valid responses. Max 4 2(d) Advise the directors whether or not they should use spreadsheets in the 7 preparation of the company’s budgets. Justify your answer. For (max 3) Arithmetical errors should be avoided. (1) Speed of calculation will be improved. (1) There is automatic recalculation if one variable is changed. (1) Enables ‘what if’ questions to be asked. (1) Security can be enhanced with passwords. (1) Information can be easily sent from one office/department to another. (1) Multiple user applications may be available. (1) ‘Sort’ or ‘select’ functions may be useful. (1) Against (max 3) Some staff may not be familiar with the software. (1) The budgets will still only be as good as the estimates made. (1) Security of data may be compromised. (1) Errors in data entry can be made. (1) Incorrect formulae can be used. (1) Accept other valid responses. Decision supported by a comment (1)
This question in 9706/43 May/June 2024
Q11 · Read Source A in the insert 9706/41 Oct/Nov 2024
1 Read Source A in the insert. (a) Explain two advantages of preparing a budget. 1 … … … … 2 … … … … [4] (b) Prepare the following budgets for T Limited for the months of April, May and June. (i) production budget (in units) April May June [4] (ii) purchases budget (in kilos and dollars) April May June [6] Additional information All goods are sold on a credit basis for $200 each. The credit period is 2 months. However, if the customers settle their accounts in the following month after sale, they will be allowed a discount of 3%. It is expected that 40% of the customers will take the discount. (c) Prepare a trade receivables budget for the month of June, showing the opening and closing balances. … … … … … … … … … … [4] Additional information The sales for December 2025 are expected to be high. The directors have been informed that the maximum supply of direct materials for the months of November and December will be reduced. The directors have two options. Option 1 Reduce the production. Option 2 Buy the shortage from a new supplier at the cost of $15 per kilo. (d) Advise the directors which option they should choose. Justify your answer. … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: Question Answer Marks 1(a) Explain two advantages of preparing a budget. 4 It sets a target for the departmental managers to achieve. (1) Every manager is responsible for the target set for each of them and they will strive to achieve the target. (1) This will motivate the employees. (1) They have the sense of direction, and they know what is expected from them. (1) It is good for planning. (1) It facilitates the planning for resources and finance. (1) Max 2 advantages, 2 marks each Accept other valid responses. 1(b)(i) Prepare the following budgets for T Limited for the months of April, May and June. 4 production budget (in units) April May June Closing inventory (25% of next month's sales) 305 275 300 (1) row Sales 1 280 1 220 1 100 (1) row Opening inventory (25% of current month's sales) (320) (305) (275) (1) row Production (in units) 1 265 1 190 1 125 (1)OF row 1(b)(ii) Prepare the following budgets for the months of April, May and June. 6 purchases budget (in kilos and dollars) April May June 450}(1)O Closing inventory (10% of next month's production need) 476} F 474 W1 (1) Production required (4 kilos per unit produced in current month) 5 060 4 760 4 500 (1)OF row Opening inventory (10% of current month's production need) (506) (476) (450) (1) OF row Total direct materials purchased (in kilos) 5 030 4 734 4 524 (1)OF row Total purchases ($10 per kilo) $50 300 $47 340 $45 240 (1)OF row W1 July’s production 1 200 + (25% x1 140) -(25% 1 200) =1 185 units, 1 185 4 10%= 474 1(c) Prepare a trade receivables budget for the month of June, showing the opening and closing balances. 4 $ Balance b/d (1 280 $200 60%) + (1 220x$200) 397 600 (1) Sales for the month (1 100 $200) 220 000 Discount allowed (1 220 $200 3% 40%) (2 928) (1) Receipts (1 280 $200 60%) + (1 220 $200 97% 40%) (248 272) (1) Balance c/d (1 220x$200x60%) + (1 100 $200) 366 400 (1) OF 1(d) Advise the directors which option they should choose. Justify your answer. 7 Option 1 Reduced production cannot satisfy the customers and may lose the loyal customers (1) The reputation of the company may be jeopardised (1) Reduced production may leave some capacity idle (1) The shortage in supply is only temporary (1) Option 2 A new supplier may not be reliable (1) The quality of direct materials may not be guaranteed (1) The increased cost may be acceptable if a gross profit is achieved / there may be a fall in profit (1) T Limited may change the inventory policy to increase inventory in advance (1) Max 6 for comments Decision supported with a comment (1) Accept other valid responses.
This question in 9706/41 Oct/Nov 2024
Q12 · Read Source A in the insert 9706/42 Oct/Nov 2024
1 Read Source A in the insert. (a) Explain two reasons why a business may conduct variance analysis. 1 … … … … 2 … … … … [4] (b) State how to calculate a fixed overhead capacity variance. … … … … [2] (c) Prepare the flexible budget statement for the month of August. … … … … … … … … … … [5] (d) Prepare a statement reconciling the flexible budget profit in (c) with the actual profit. … … … … … … … … … [3] Additional information The actual labour hour rate in August was $15.50. (e) Explain the likely reasons for the favourable direct labour variance of $1980 with reference to the analysis of its two sub-variances. … … … … … … … … … … … … [4] Additional information The directors are aware of an upward trend in the direct material price. To keep the current profit level, they have two options. Option 1 Modify the existing product so that it requires less direct material. Option 2 Reduce the advertising cost by one-third. (f) Advise the directors which option they should choose. Justify your answer. … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: Question Answer Marks 1(a) Explain two reasons why a business may conduct variance analysis. 4 Comparing the actual result and the budget (1) so that actions can be taken for remedy or improvement (1) Measuring the performance of the managers (1) to determine bonus eligibility (1) Max 2 reasons, 2 marks each Accept other valid responses. 1(b) State how to calculate a fixed overhead capacity variance. 2 The difference between the total direct labour hours under fixed budget and the total actual labour hours (1) times the standard overhead absorption rate (1) Or (Standard hours for budgeted production – actual hours) (1) x Standard fixed overhead rate per hour (1) 1(c) Prepare the flexible budget statement for the month of August. 5 $ Sales ($239 400 – $5 400) 234 000 (1) Direct materials ($44 640 – $1 440)/(1 800 $24) 43 200 (1) Direct labour ($106 020 + $1 980)/(1 800 60) 108 000 (1) Fixed overhead ($84 000 – $12 000)/(1800 40) 72 000 (1) Profit 10 800 (1)OF 1(d) Prepare a statement reconciling the flexible budget profit in (c) with the actual profit. 3 $ Flexible budget profit 10 800 (1) OF Variances Sales price 5 400 F } Total direct material 1 440 A }(1) Total direct labour 1 980 F } Total fixed overhead 12 000 A }(1) Actual profit 4 740 1(e) Explain the likely reasons for the favourable direct labour variance of $1 980 with reference to the analysis of its 4 two sub-variances. The labour rate variance is $3 420 A. (1) The higher wage may be due to more skilled labour or trained labour. (1) The labour efficiency variance is $5 400 F. (1) The decreased hours worked may be due to the use of higher quality materials. (1) Accept other valid responses. 1(f) Advise the directors which option they should choose. Justify your answer. 7 Option 1 Max (3) The modified product may be perceived to be poor quality / adverse effect on brand image (1). Loyal customers may not like the modified product / may cause demand to fall (1). This can save direct material cost to maintain or increase the current profit level (1). A modified product may be perceived as a new product and appeal to new customers (1). Option 2 Max (3) Advertising helps retain existing customers (1). Advertising increases the awareness of the product / less advertising may lead to the loss of customers (1). Reducing advertising cost may maintain or increase profit (1). Reducing advertising cost can avoid the company increasing the selling price. (1). Decision supported with a comment (1) Accept other valid responses.
This question in 9706/42 Oct/Nov 2024
Q13 · Read Source B in the insert 9706/42 Oct/Nov 2024
2 Read Source B in the insert. (a) Calculate: (i) the net present value (NPV) … … … … … … … … … … [4] (ii) the internal rate of return (IRR) … … … … … … … … … … [5] (iii) the accounting rate of return (ARR). … … … … [3] Additional information The directors adopt the NPV method for this investment appraisal and are about to make the decision to buy the machine. The sales manager, however, thinks that the annual estimated sales revenue may be only $380 000. All other information will remain the same. (b) Discuss whether the directors should be concerned about the uncertainty over the estimated sales revenue. Support your answer with calculations. … … … … … … … … … … … … … … [6] Additional information The directors are preparing the cash budget for Year 4. They have two options available for an amount of $80 000. Option 1 Continue to manufacture Product A for two more years by launching a promotional campaign. (Despite the machine being fully depreciated, it can continue to be used for two more years.) Option 2 Start designing a new product, Product B, to be launched in Year 5. (c) Advise the directors which option they should choose. Justify your answer. … … … … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: 2(a)(i) Calculate: 4 the net present value (NPV) Net cashflow 12% PV $ $ Year 0 (240 000) 1 (240 000) (1) Year 1 W1 87 000 (1) 0.893 77 691 } Year 2 87 000 0.797 69 339 } Year 3 87 000 0.712 61 944 } Year 4 87 000 0.636 55 332 } (1) NPV 24 306 (1)OF OR $87 000 (1) 3.038 (1) – $240 000 (1) = $24 306 (1)OF W1 $27 000 + ($240 000/4) = $87 000 2(a)(ii) Calculate: 5 the internal rate of return (IRR) NPV at the discount rate of 18% $87 000 x 2.69 (1) - $240 000= ($5 970) (1)OF 12% + $24 306/ ($24 306+$5 970) (1)OF x (18%-12%) (1) = 16.82% (1)OF Alternatively $ $ 0 (240 000) 1.00 (240 000) 1 87 000 0.847} 73 689 2 87 000 0.718} 62 466 3 87 000 0.609} 52 983 4 87 000 0.516}(1) 44 892 NPV (5 970) (1)OF 12% + $24 306/($24 306 + $5 970) (1)OF (18% – 12%) (1) = 16.82% (1)OF 2(a)(iii) Calculate: 3 the accounting rate of return (ARR) ARR = (27 000 (1) / 120 000 (1)) 100 = 22.5% (1)OF 2(b) Discuss whether the directors should be concerned about the uncertainty over the estimated sales revenue. 6 Support your answer with calculations. Net cashflow 12% PV $ $ Year 0 (240 000) 1 (240 000) (1) Year 1 67 000 OF 0.893} 59 831 Year 2 67 000 0.797} 53 399 Year 3 67 000 0.712} 47 704 Year 4 67 000 0.636} (1) 42 612 NPV (36 454) (1)OF OR $67 000 (1)OF 3.038 (1) – $240 000 =$(36 454) (1) OF Comments NPV / investment appraisal always depends on estimates (1) The NPV reduces / is negative (1) The directors should be concerned about the uncertainty / would change their decision (1) Max 3 for calculations Max 3 for comments Accept other valid responses. 2(c) Advise the directors which option they should choose. Justify your answer. 7 Option 1 max (3) No need to spend money to design new product in Year 5 and 6 (1). No need to buy new machine for 2 years (1). No need to train workers for 2 years (1). Should plan beyond these extra 2 years (1). The annual profit will increase from year 4 due to there being no depreciation (1). The annual profit may decrease due to increased repairs and maintenance cost (1). It is uncertain whether the sales level can be maintained (1). Option 2 max (3) Should plan for replacing a declining product by a new product in order to sustain profitability (1). New product can appeal to existing customers / diversification as well as new customers (1). More time and cost may be needed for designing a new product (1). A new machine for Product B may be required (1). Workers need training for new machine (1). The commercial success of Product B is uncertain (1). Decision supported with a comment (1) Accept other valid responses
This question in 9706/42 Oct/Nov 2024
Q14 · Read Source A in the insert 9706/43 Oct/Nov 2024
1 Read Source A in the insert. (a) Define the term ‘master budget’. … … … … [2] (b) Prepare the cash budget for each of the months of January, February and March 2025. … … … … … … … … … … … … … … … … … … … … … Workings: [14] Additional information Mo wishes to have a cash balance of $80 000 at 31 March 2025. (c) Calculate the total amount of capital that Mo has to invest on 1 January 2025. … … … … [2] Additional information Mo is optimistic about his business. He estimates that the sales will increase by 20% every month in the first year. He also plans to form a limited company in 2026 and is considering preparing a master budget every year. (d) Advise Mo whether or not he should prepare a master budget every year. Justify your answer. … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: Question Answer Marks 1(a) Define the term ‘master budget’. 2 A master budget is a comprehensive financial plan (1). (1) further development mark is to give identifying at least three components of the master budgets, including: • operating budget (sales budget, purchases budget, trade receivables budget and trade payables budget; • financial budget (cash budget, budgeted statement of profit or loss and budgeted statement of financial position) Accept other valid responses. 1(b) Prepare the cash budget for each of the months of January, February and March 2025. 14 January February March $ $ $ Receipts from cash sales 30 000 } 36 000 }(1) Receipts from credit customers W1 35 280 (1) 30 000 71 280 Expenditure Equipment 15 000 }* }*(1 Salaries 16 000 ) 20 000 (1) 25 000 (1) Cash payment to a supplier 10 000 (1) 12 000 (1) 14 400 (1) Payment to other suppliers W2 90 000 (1) 108 000 (1) Other operating expenses W3 24 325 (1) 34 750 }** 34 750 }**(1) Sales commission 6 000 (1) 65 325 156 750 188 150 Net deficit for the month (65 325) (126 750) (116 870) (1)OF row W1: 2500 $60 80% 30% 98% = 35280 W2: January February March April $ $ $ $ Sales revenue 150 000 180 000 216 000 Cost of sales 100 000 120 000 144 000 Purchases 100 000 120 000 144 000 Payment to credit suppliers 90% 90 000 108 000 W3: Depreciation ($15 000 20%) / 12=$250 ($35 000 – $250) = $34 750 $34 750 70% = $24 325 1(c) Calculate the total amount of capital that Mo has to invest on 1 January 2025. 2 ($65 325 + $126 750 + $116 870) (1)OF + $80 000 = $388 945(1)OF 1(d) Advise Mo whether or not he should prepare a master budget every year. Justify your answer. 7 For (max 3) A master budget can serve the functions of planning (1), controlling and monitoring etc (1). A master budget would aid his plans to form a limited company (1). If the business grows and the operations become more complex, the master budget will encourage responsibility accounting (1). If his business is growing, budgeting can encourage a more efficient allocation of resources (1). Budget can motivate employees (1) Against (max 3) He needs to hire a specialist, such as a management accountant to prepare the master budget (1). He needs to have a good information/accounting system which takes time and is costly (1). His business is still at its infant stage. Cost may exceed benefits in preparing a master budget every year (1). In January 2025, he has limited resource of manpower to prepare a master budget (1). Budget may also demotivate employees (1). Decision supported with a comment (1) Accept other valid responses.
This question in 9706/43 Oct/Nov 2024
Q15 · Read Source B in the insert 9706/42 Feb/March 2025
2 Read Source B in the insert. (a) State how a budget may be: (i) a motivating influence for staff … … [1] (ii) a demotivating influence for staff. … … [1] (b) Calculate the percentage of credit customers who pay in the month following sale. … … [1] Additional information The directors believe that too much cash is tied up in trade receivables and wish to see the credit customers pay sooner. They would like to see the effect of offering customers a 10% cash discount on sales made after 1 January 2026 if payment is received in the month after sale. They think that 80% of customers will then pay in the month after sale and receive the discount, with the remainder paying in the month after that. (c) Prepare a revised trade receivables budget for February and March based on the directors’ assumptions about the discount. … … … … … … … … … … [6] (d) Prepare a revised budgeted statement of financial position at 31 March 2026 based on the directors’ assumptions about the discount. … … … … … … … … … … … … … … … … … … … … … … … [4] (e) State three reasons why the company might find it useful to prepare its budgets using spreadsheets rather than manually. 1 … … … 2 … … … 3 … … … [3] Additional information When actual results become available, they are reviewed with the aid of variance analysis. (f) State two advantages of using variance analysis. 1 … … … 2 … … … [2]
18 marks
Mark scheme: 2(a)(i) State how a budget may be: 1 a motivating influence for staff If staff are involved in the setting of the budgets they may be motivated (1). Accept other valid responses 2(a)(ii) State how a budget may be: 1 a demotivating influence for staff. If the budgets are imposed on staff they may be demotivated (1). Accept other valid responses 2(b) Calculate the percentage of credit customers who pay in the month 1 following sale. 20% (1) 2(c) Prepare a revised trade receivables budget for February and March 6 based on the directors’ assumptions about the discount. February March $ $ Balance b/f 172 400 * 120 400 Sales 100 000 92 000 272 400 212 400 Receipts – one month after sale 73 440 (1) 72 000 (1) Discount 8 160 (1) 8 000 (1) Receipts – two months after 70 400 *(1) 20 400 sale Balance c/f 120 400 112 000 (1)OF *(1) for both items unaffected as pre-change 2(d) Prepare a revised budgeted statement of financial position at 31 March 4 2026 based on the directors’ assumptions about the discount. $ Non-current assets 426 000 Current assets Inventory 91 000 Trade receivables 112 000 (1)OF Bank (-22180+43840) 21 660 (1)OF Total assets 650 660 Equity Share capital 500 000 Retained earnings (77320 – 16160) 61 160 (1)OF Current liabilities Trade payables 89 500 Total equity and liabilities 650 660 (1) if both totals agree 2(e) State three reasons why the company might find it useful to prepare its 3 budgets using spreadsheets rather than manually. Arithmetical errors should be avoided. (1) Speed of calculation will be improved. (1) There is automatic recalculation if one variable is changed. (1) Security can be enhanced with passwords. (1) Multiple user applications may be available. (1) ‘Sort’ or ‘select’ functions may be useful. (1) Enhanced presentation. (1) Max 3 Accept other valid responses 2(f) State two advantages of using variance analysis. 2 Measures the deviation from budgeted costs and revenues (1) Identify reasons / causes of deviations (1) Leads to improvements in future plans / take remedial action (1) Max 2 Accept other valid responses 2(g) Advise the directors whether or not they should make one of the 7 supervisors redundant. Justify your answer. The fixed overhead expenditure variance would have been $10 000 favourable (1) and so the problem may not lie with the amount spent (1) so much as with actual output being less than budgeted (1). Redundancy costs might be incurred (1) and labour efficiency might be affected adversely (1) which may lead to defective production (1) which may lead to customers not being satisfied (1). When the next budget is set the budgeted fixed overheads will fall (1). The change would save money / improve profitability (1) but the remaining supervisor may be demotivated (1). Max 6 Decision supported with a comment (1) Accept other valid responses
This question in 9706/42 Feb/March 2025
Q16 · Read Source B in the insert 9706/41 May/June 2025
2 Read Source B in the insert. (a) Calculate the number of units expected to be in inventory at 31 May. … … [1] (b) Calculate the total amount shown in the cash budget in March for expenditure, other than payments to suppliers. … … … … … … … … … … … … … … … … … … Workings: [7] Additional information Terri is concerned about the expected bank overdrafts shown in the cash budget. She is considering two options. Option 1 Terri could have a special promotion for the month of April only. She could reduce the selling price to $45 per unit for all sales, with the expectation that this would increase sales by an extra 140 units. Option 2 Terri could take advantage of a special offer from her suppliers. She could increase her purchases in April by 300 units and be able to buy all her units in that month for $25 each. (c) Calculate the effect that option 1 would have on Terri’s overdraft, assuming that there is no change to purchases, at the end of: (i) April … … … … … [2] (ii) May. … … … … … … [3] (d) Calculate the effect that option 2 would have on Terri’s overdraft, assuming there is no change to sales, at the end of: (i) April … … … … [2] (ii) May. … … … … … … … … [3]
18 marks
Mark scheme: 2(a) Calculate the number of units expected to be in inventory at 31 May. 1 200 – 4310 + 4280 = 170 units (1) 2(b) Calculate the total amount shown in the cash budget for expenditure, other than payments to suppliers, in March. 7 $ $ Cash sales: March 22 750 (1) Credit sales: February 21 250 (1) 44 000 Less: Cash purchases: March 2 720 (1) Credit purchases: February 10 773 (1) Credit purchases: January 11 205 (1) (24 698) Add: Increase in overdraft (6198-6000) 198 (1) Other expenditure 19 500 (1)OF 2(b) OR Cash budget for March March $ Receipts Cash sales March 22 750 (1) Credit sales February 21 250 (1) 44 000 Payments Cash purchases March 2 720 (1) Credit purchases February 10 773 (1) Credit purchases January 11 205 (1) Other expenditure 19 500 (1)OF Total payments 44 198 Net receipts/(payments) (198) Balance b/f (6 000) } Balance c/f (6 198) } (1) 2(b) Workings: cash sales March 910 50 0.5 credit sales February 850 50 0.5 cash purchases March 850 32 0.1 credit purchases February 840 30 0.9 0.5 0.95 credit purchases January 830 30 0.9 0.5 2(c)(i) Calculate the effect that option 1 would have on Terri’s overdraft, assuming that there is no change to purchases, 2 at the end of: April Increase in cash sales (22 950 – 22 880) = $70 (1) decrease in overdraft (1) 2(c)(ii) Calculate the effect that option 1 would have on Terri’s overdraft, assuming that there is no change to purchases, 3 at the end of: May $ Increase in receipts from credit customers 70 (1) Increase in cash sales from previous month 70 OF Decrease in overdraft (1) 140 (1)OF 2(d)(i) Calculate the effect that option 2 would have on Terri’s overdraft, assuming there is no change to sales, at the end 2 of: April Increase in cash purchases (3 000 – 2 880) = $120 (1) increase in overdraft (1) 2(d)(ii) Calculate the effect that option 2 would have on Terri’s overdraft, assuming there is no change to sales, at the end 3 of: May $ Increase in payments to credit suppliers 513 (1) (12 825 – 12 312) Increase in cash purchases from previous month 120 OF Increase in overdraft (1) 633 (1)OF 2(e) Advise Terri whether she should proceed with option 1 or option 2 or both. Justify your answer. 7 Option 1 alone (Max 2) This does improve the bank overdraft (1) but by such a small amount it may be of little use (1). It reduces the inventory level significantly (1). This increases the risk of a stock out (1). It may bring about a cash saving in terms of storage/insurance if Terri continues to keep less inventory (1). The sales would still generate a positive contribution (1). The cut in selling price could increase demand (1). It might be difficult to achieve the expected level of sales in May (1). Option 2 alone (Max 2) This actually increases the bank overdraft (1). The amount of the increase would be still higher in June when the final payment for April’s purchases is made (1). May meet excessive demands during busy periods (1). The contribution per unit, once the units are sold, will be higher (1). However Terri will hold a much higher level of inventory (1) which may be useful if unit purchase prices continue to rise (1) although storage/ insurance costs could increase (1). Both (Max 2) The net effect still increases the bank overdraft (1). However it softens the effect on the level of inventory (1). The gross profit per unit on the units sold in April ($20) is the same as if neither option was taken (1) but will be higher when the surplus is sold in May (1). Decision supported with a comment (1) Accept other valid responses
This question in 9706/41 May/June 2025
Q17 · Read Source B in the insert 9706/43 May/June 2025
2 Read Source B in the insert. (a) Calculate the number of units expected to be in inventory at 31 May. … … [1] (b) Calculate the total amount shown in the cash budget in March for expenditure, other than payments to suppliers. … … … … … … … … … … … … … … … … … … Workings: [7] Additional information Terri is concerned about the expected bank overdrafts shown in the cash budget. She is considering two options. Option 1 Terri could have a special promotion for the month of April only. She could reduce the selling price to $45 per unit for all sales, with the expectation that this would increase sales by an extra 140 units. Option 2 Terri could take advantage of a special offer from her suppliers. She could increase her purchases in April by 300 units and be able to buy all her units in that month for $25 each. (c) Calculate the effect that option 1 would have on Terri’s overdraft, assuming that there is no change to purchases, at the end of: (i) April … … … … … [2] (ii) May. … … … … … … [3] (d) Calculate the effect that option 2 would have on Terri’s overdraft, assuming there is no change to sales, at the end of: (i) April … … … … [2] (ii) May. … … … … … … … … [3]
18 marks
Mark scheme: 2(a) Calculate the number of units expected to be in inventory at 31 May. 1 200 – 4310 + 4280 = 170 units (1) 2(b) Calculate the total amount shown in the cash budget for expenditure, other than payments to suppliers, in March. 7 $ $ Cash sales: March 22 750 (1) Credit sales: February 21 250 (1) 44 000 Less: Cash purchases: March 2 720 (1) Credit purchases: February 10 773 (1) Credit purchases: January 11 205 (1) (24 698) Add: Increase in overdraft (6198-6000) 198 (1) Other expenditure 19 500 (1)OF 2(b) OR Cash budget for March March $ Receipts Cash sales March 22 750 (1) Credit sales February 21 250 (1) 44 000 Payments Cash purchases March 2 720 (1) Credit purchases February 10 773 (1) Credit purchases January 11 205 (1) Other expenditure 19 500 (1)OF Total payments 44 198 Net receipts/(payments) (198) Balance b/f (6 000) } Balance c/f (6 198) } (1) 2(b) Workings: cash sales March 910 50 0.5 credit sales February 850 50 0.5 cash purchases March 850 32 0.1 credit purchases February 840 30 0.9 0.5 0.95 credit purchases January 830 30 0.9 0.5 2(c)(i) Calculate the effect that option 1 would have on Terri’s overdraft, assuming that there is no change to purchases, 2 at the end of: April Increase in cash sales (22 950 – 22 880) = $70 (1) decrease in overdraft (1) 2(c)(ii) Calculate the effect that option 1 would have on Terri’s overdraft, assuming that there is no change to purchases, 3 at the end of: May $ Increase in receipts from credit customers 70 (1) Increase in cash sales from previous month 70 OF Decrease in overdraft (1) 140 (1)OF 2(d)(i) Calculate the effect that option 2 would have on Terri’s overdraft, assuming there is no change to sales, at the end 2 of: April Increase in cash purchases (3 000 – 2 880) = $120 (1) increase in overdraft (1) 2(d)(ii) Calculate the effect that option 2 would have on Terri’s overdraft, assuming there is no change to sales, at the end 3 of: May $ Increase in payments to credit suppliers 513 (1) (12 825 – 12 312) Increase in cash purchases from previous month 120 OF Increase in overdraft (1) 633 (1)OF 2(e) Advise Terri whether she should proceed with option 1 or option 2 or both. Justify your answer. 7 Option 1 alone (Max 2) This does improve the bank overdraft (1) but by such a small amount it may be of little use (1). It reduces the inventory level significantly (1). This increases the risk of a stock out (1). It may bring about a cash saving in terms of storage/insurance if Terri continues to keep less inventory (1). The sales would still generate a positive contribution (1). The cut in selling price could increase demand (1). It might be difficult to achieve the expected level of sales in May (1). Option 2 alone (Max 2) This actually increases the bank overdraft (1). The amount of the increase would be still higher in June when the final payment for April’s purchases is made (1). May meet excessive demands during busy periods (1). The contribution per unit, once the units are sold, will be higher (1). However Terri will hold a much higher level of inventory (1) which may be useful if unit purchase prices continue to rise (1) although storage/ insurance costs could increase (1). Both (Max 2) The net effect still increases the bank overdraft (1). However it softens the effect on the level of inventory (1). The gross profit per unit on the units sold in April ($20) is the same as if neither option was taken (1) but will be higher when the surplus is sold in May (1). Decision supported with a comment (1) Accept other valid responses
This question in 9706/43 May/June 2025
Q18 · Read Source A in the insert 9706/42 Oct/Nov 2025
1 Read Source A in the insert. (a) State two benefits of preparing a: (i) cash budget 1 … … 2 … … [2] (ii) production budget. 1 … … 2 … … [2] (b) Prepare the production budget (in units) for each of the months of April, May and June. April May June … … … … … … … … [4] (c) Calculate the payments to suppliers for each of the months of April, May and June. … … … … … … … … … … … … … … [4] (d) Prepare the cash budget for each of the months of April, May and June. April May June … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [6] Additional information The directors think that they will have some surplus cash at the end of June 2026 which could be used for other purposes. They have two options: Option 1: use the surplus cash to incur expenditure on developing a new product Option 2: place the surplus cash in a fixed deposit account at an estimated interest of 2% per annum. (e) Advise the directors which option they should choose. Justify your answer. … … … … … … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: Question Answer Marks 1(a)(i) State two benefits of preparing a: 2 cash budget Ensuring that the payments are made to avoid a shortage of cash / liquidity problems. (1) Ensuring arrangements are made for the investment of surplus funds. (1) Max 2 Accept other valid responses. 1(a)(ii) State two benefits of preparing a: 2 production budget Ensuring right amount of inventory to meet the customers’ demand. (1) Ensuring resources are available to meet the production target. (1) Max 2 Accept other valid responses. 1(b) 4 Prepare the production budget (in units) for each of the months of April, May and June. April May June Sales of next month (units) 3 100 3 000 2 800 (1) row Opening inventory (units) (160) (155) (150) (1) row Closing inventory (units) 155 150 140 (1) row Production (units) 3 095 2 995 2 790 (1)OF row 1(c) Calculate the payments to suppliers for each of the months of April, May and June. 4 March April May June $ $ $ $ Units produced 3 235 W1 3 095 2 995 Direct material required per unit (kilos) 3 3 3 Total direct material required (kilos) 9 705 9 285 8 985 Decrease in base inventory (200) (1) Total direct material purchased (kilos) 9 705 9 285 8 785 Direct material cost per kilo $8 $8 $8 Purchases payable next month 77 640 74 280 70 280 Payment to suppliers 77 640 (1) 74 280 (1)OF 70 280 (1)OF W1 3200 + 160 – 125 = 3 235 units 1(d) Prepare the cash budget for each of the months of April, May and June. 6 April May June $ $ $ Receipts February sales 156 000 March sales 48 500 150 000 April sales 62 080 192 000 May sales 63 147 204 500 (1) 212 080 (1) 255 147 (1) Payments Suppliers 77 640 74 280 70 280 OF Direct wages and variable overheads 61 900 59 900 55 800 (1)OF row Fixed overheads 52 000 55640 55640 (1) row Promotion cost 20 000 211 540 189 820 181 720 Net cash increase/(decrease) (7 040) 22 260 73 427 Opening balance 38 000 30 960 53 220 Closing balance 30 960 53 220 126 647 (1)OF row 1(e) Advise the directors which option they should choose. Justify your answer. 7 Option 1 (Max 3) Existing product may be coming to the end of its product life cycle. (1) Developing a new product is important for the future of the business. (1) Further costs may be incurred on development / promotion of new product. (1) Research and development may fail / it is risky. (1) Option 2 (Max 3) It has less risk (1) Interest income increases the profit or cash / return from the interest income is too low (1) Cash can be used for other investments to generate a higher return (1) Cash is not available for long-term investment / emergency use in the business (1) Decision supported with a comment (1) Accept other valid responses.
This question in 9706/42 Oct/Nov 2025
Q19 · Read Source B in the insert 9706/42 Oct/Nov 2025
2 Read Source B in the insert. (a) Prepare the fixed budget for August showing the budgeted profit. … … … … … … … … … [3] Additional information In August, 7500 units were produced and sold. The actual result was as follows: $ Sales (7500 units) 607 500 Direct material (33 750 kilos) 168 750 Direct labour (24 000 hours) 372 000 Fixed overhead 66 000 Profit 750 C Limited prepared a flexible budget statement and the following statement reconciling the flexible budget profit with actual profit. $ Flexible budget profit 64 500 Sales price variance 7 500 Adverse Direct material variance 18 750 Adverse Direct labour variance 34 500 Adverse Fixed overhead variance 3 000 Adverse Actual profit 750 (b) Explain why a business prepares a flexible budget statement. … … … … [2] (c) Calculate the following variances: (i) fixed overhead expenditure … … … … … [2] (ii) fixed overhead volume. … … … … … [3] Additional information The directors are concerned about the adverse variances of both the total direct material cost and the total direct labour cost. (d) Explain the likely causes for the adverse variances of: (i) the total direct material cost … … … … … … … … [4] (ii) the total direct labour cost. … … … … … … … … [4]
18 marks
Mark scheme: 2(a) Prepare the fixed budget for August showing the budgeted profit. 3 Fixed budget $ Sales (8 000 units) 656 000 } Direct material 160 000 } Direct labour 360 000 }(1) Fixed overhead 67 200 (1) Profit 68 800 (1)OF 2(b) Explain why a business prepares a flexible budget statement. 2 Flexible budget allows a business to prepare a budget based on the actual level of activity. (1) It facilitates variance analysis / a comparison between the actual result and the flexed budget. (1) Accept other valid responses. 2(c)(i) Calculate the following variances: 2 Fixed overhead expenditure $67 200 – $66 000 = $1 200 (1) F (1) 2(c)(ii) Calculate the following variances: 3 Fixed overhead volume (24 000 – (7 500 3)) $2.8 (1)= $4 200 (1) A (1) 2(d)(i) Explain the likely causes for the adverse variances of: 4 the total direct material cost There is no material price variance (1) This is because the actual price paid was the same as the standard price. (1) The material usage variance is $18 750 A. (1) This may be due to low quality of direct material / increased wastage / inefficient use by labour (1) Accept other valid responses. 2(d)(ii) Explain the likely causes for the adverse variances of: 4 the total direct labour cost. The labour rate variance is $12 000 A. (1) This may be due to inflation causing the increase in hourly rate. (1) The labour efficiency variance is $22 500 A. (1) This may be due to inefficient labour force / low quality of direct material / lack of training / low motivation. (1) Accept other valid responses. 2(e) Advise the directors whether or not they should switch to the overseas supplier. Justify your answer. 7 For (Max 3) The quality should be better (1) There is likely to be less wastage (1) Returns of direct materials can be reduced (1) Better quality of direct material may lead to a better final product (1) The customer can be charged a premium price for a better quality product (1) Against (Max 3) Changing the supplier may not solve the problem of labour inefficiency (1) Transportation cost/ import duties / fluctuating exchange rate may erode profit (1) Delivery from overseas of direct material takes time (1) It takes time to build up a good relationship with a new supplier (1) Not sure whether the new supplier is reliable (1) Decision supported with a comment (1) Accept other valid responses.
This question in 9706/42 Oct/Nov 2025
Q20 · Read Source A in the insert 9706/43 Oct/Nov 2025
1 Read Source A in the insert. (a) Prepare the flexible budget statement for March showing the budgeted profit. … … … … … … … [3] (b) Calculate the following variances: (i) material price … … … … [2] (ii) material usage … … … … [2] (iii) labour rate … … … … [2] (iv) labour efficiency. … … … … [2] Additional information The fixed overhead variance is analysed as follows: $ Fixed overhead expenditure 1 000 adverse Fixed overhead volume 20 000 favourable (c) Explain the occurrence of the fixed overhead volume variance. … … … … [2] (d) Prepare a statement reconciling the flexible budget profit with the actual profit. … … … … … … … … … … [5] Additional information One of the directors is of the opinion that the standard data is artificial resulting in a significant difference from the actual results. She suggests that W Limited should stop using the standard costing system. (e) Advise the directors whether or not W Limited should stop using the standard costing system. Justify your answer. … … … … … … … … … … … … … … [7] [Total: 25]
25 marks
Mark scheme: Question Answer Marks 1(a) Prepare the flexible budget statement for March showing the budgeted profit. 3 $ Sales revenue 800 000 } Direct materials 150 000 } (1) Direct labour 480 000 } Fixed overhead 100 000 } (1) Budgeted profit 70 000 (1) OF 1(b)(i) Calculate the following variances: 2 Material price variance $5 31 500 – $149 625 = $7 875 (1) F (1) 1(b)(ii) Calculate the following variances: 2 Material usage variance (10 000 3 kilos – 31 500 kilos) $5 = $7 500 (1) A (1) 1(b)(iii) Calculate the following variances: 2 Labour rate variance $12 40 500 – $510 300 = $24 300 (1) A (1) 1(b)(iv) Calculate the following variances: 2 Labour efficiency variance (10 000 4 hours – 40 500 hours) $12 = $6 000 (1) A (1) 1(c) Explain the occurrence of the fixed overhead volume variance. 2 If actual production volume (10 000 units) is greater than the budgeted production volume (8 000 units), then the overhead is over-absorbed. (1). Fixed overhead volume variance results from the difference between the budgeted fixed overhead and the standard fixed overhead absorbed to production costs. (1). It measures the utilisation of fixed capacity cost, and the favourable variance suggest that fixed cost resources are used efficiently. (1) Max 2 Accept other valid responses. 1(d) Prepare a statement reconciling the flexible budget profit with the actual profit. 5 Favourable Adverse $ $ $ Flexible budget profit 70 000 Selling price variance $795 000 – (10 000 $80) 5 000 (2) * Material price variance 7 875 } Material usage variance 7 500 } (1)OF Labour rate variance 24 300 } Labour efficiency variance 6 000 } (1)OF Fixed overhead expenditure variance 1 000 Fixed overhead volume variance 20 000 27 875 43 800 (15 925) Actual profit 54 075 (1) *1 mark for figure and 1 mark for direction 1(e) Advise the directors whether or not W Limited should stop using the standard costing system. Justify your 7 answer. Continuing (Max 3) Standard cost is used as a benchmark against which to evaluate the actual costs. (1) Variances are investigated (1) and corrective action will be taken for improving operations. (1) It provides useful information for planning and decision making, e.g. quoting the selling price. (1) Managers are more cost conscious to seek improved methods to finish the task. (1) Stopping (Max 3) Standards may be artificial if they are not reviewed and updated regularly. (1) If the standards are not realistic, staff will be demotivated. (1) It is costly / time consuming to set up standards in the first place. (1) Managers may be blamed for those uncontrollable factors. (1) Decision supported with a comment (1) Accept other valid responses.
This question in 9706/43 Oct/Nov 2025
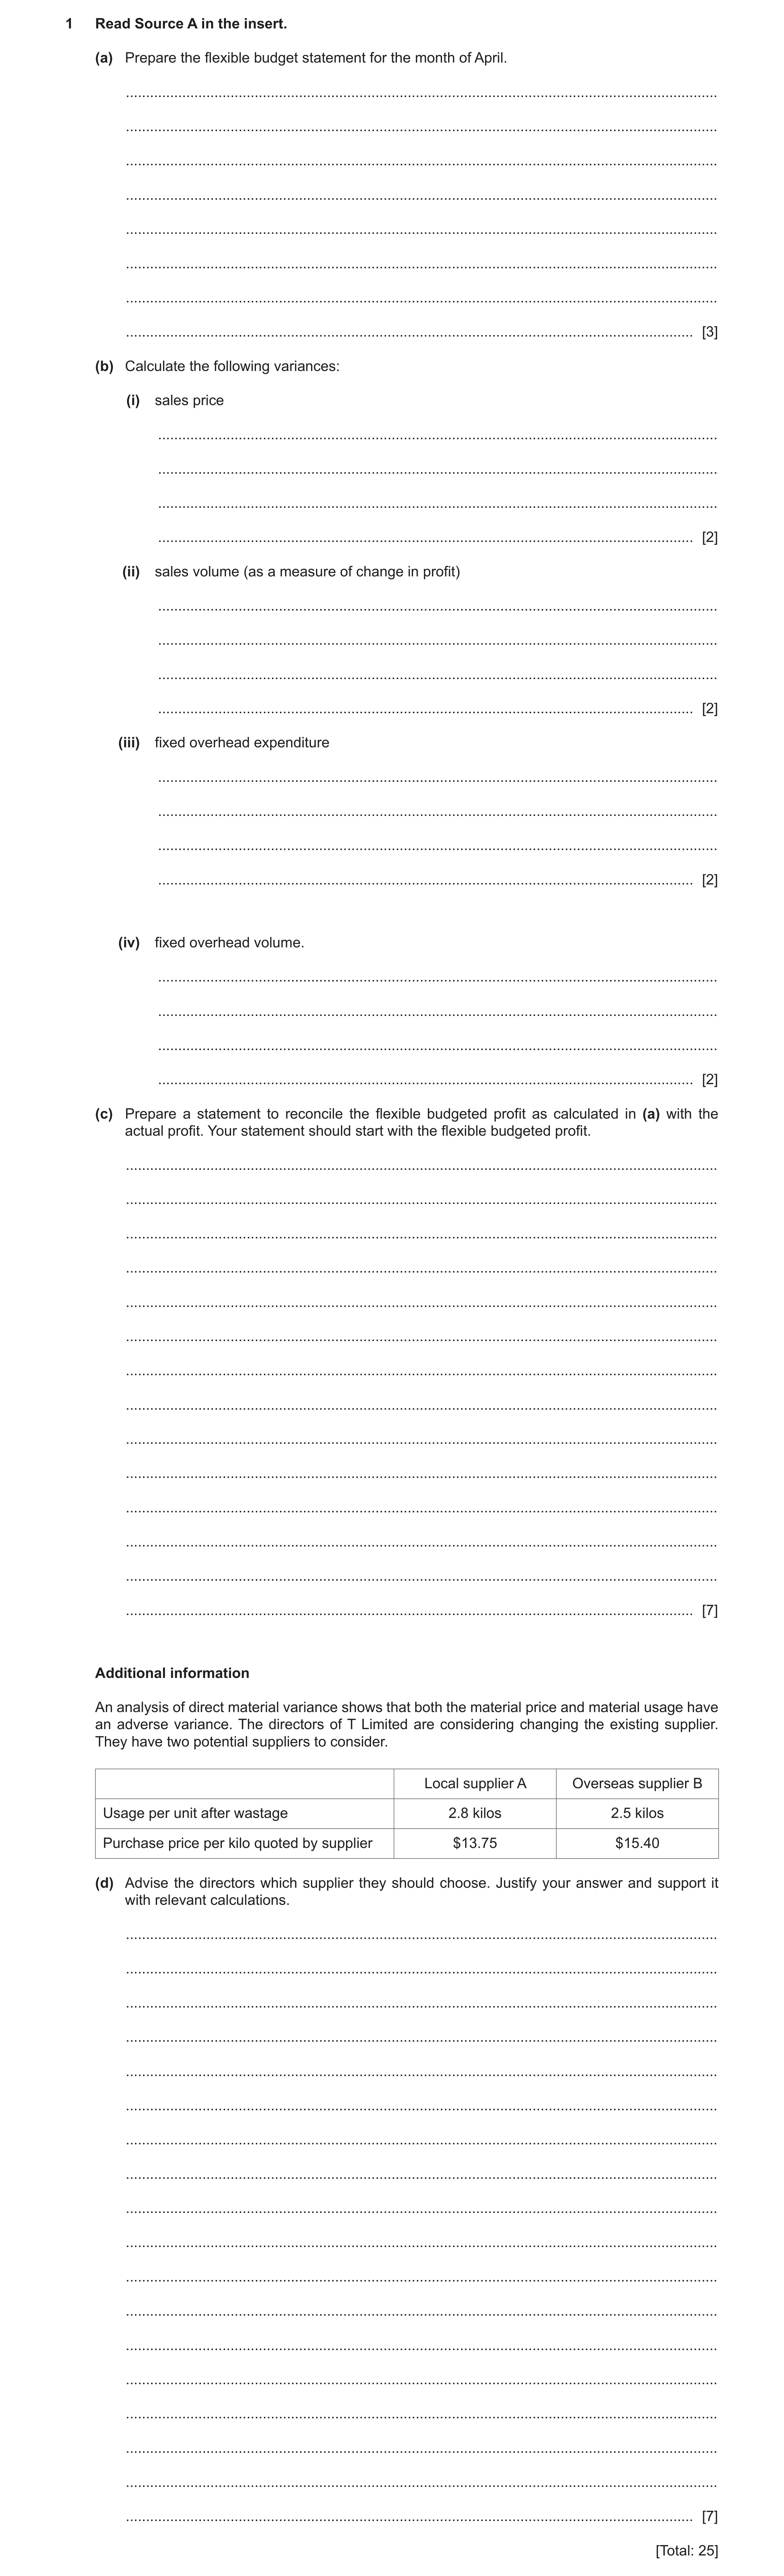
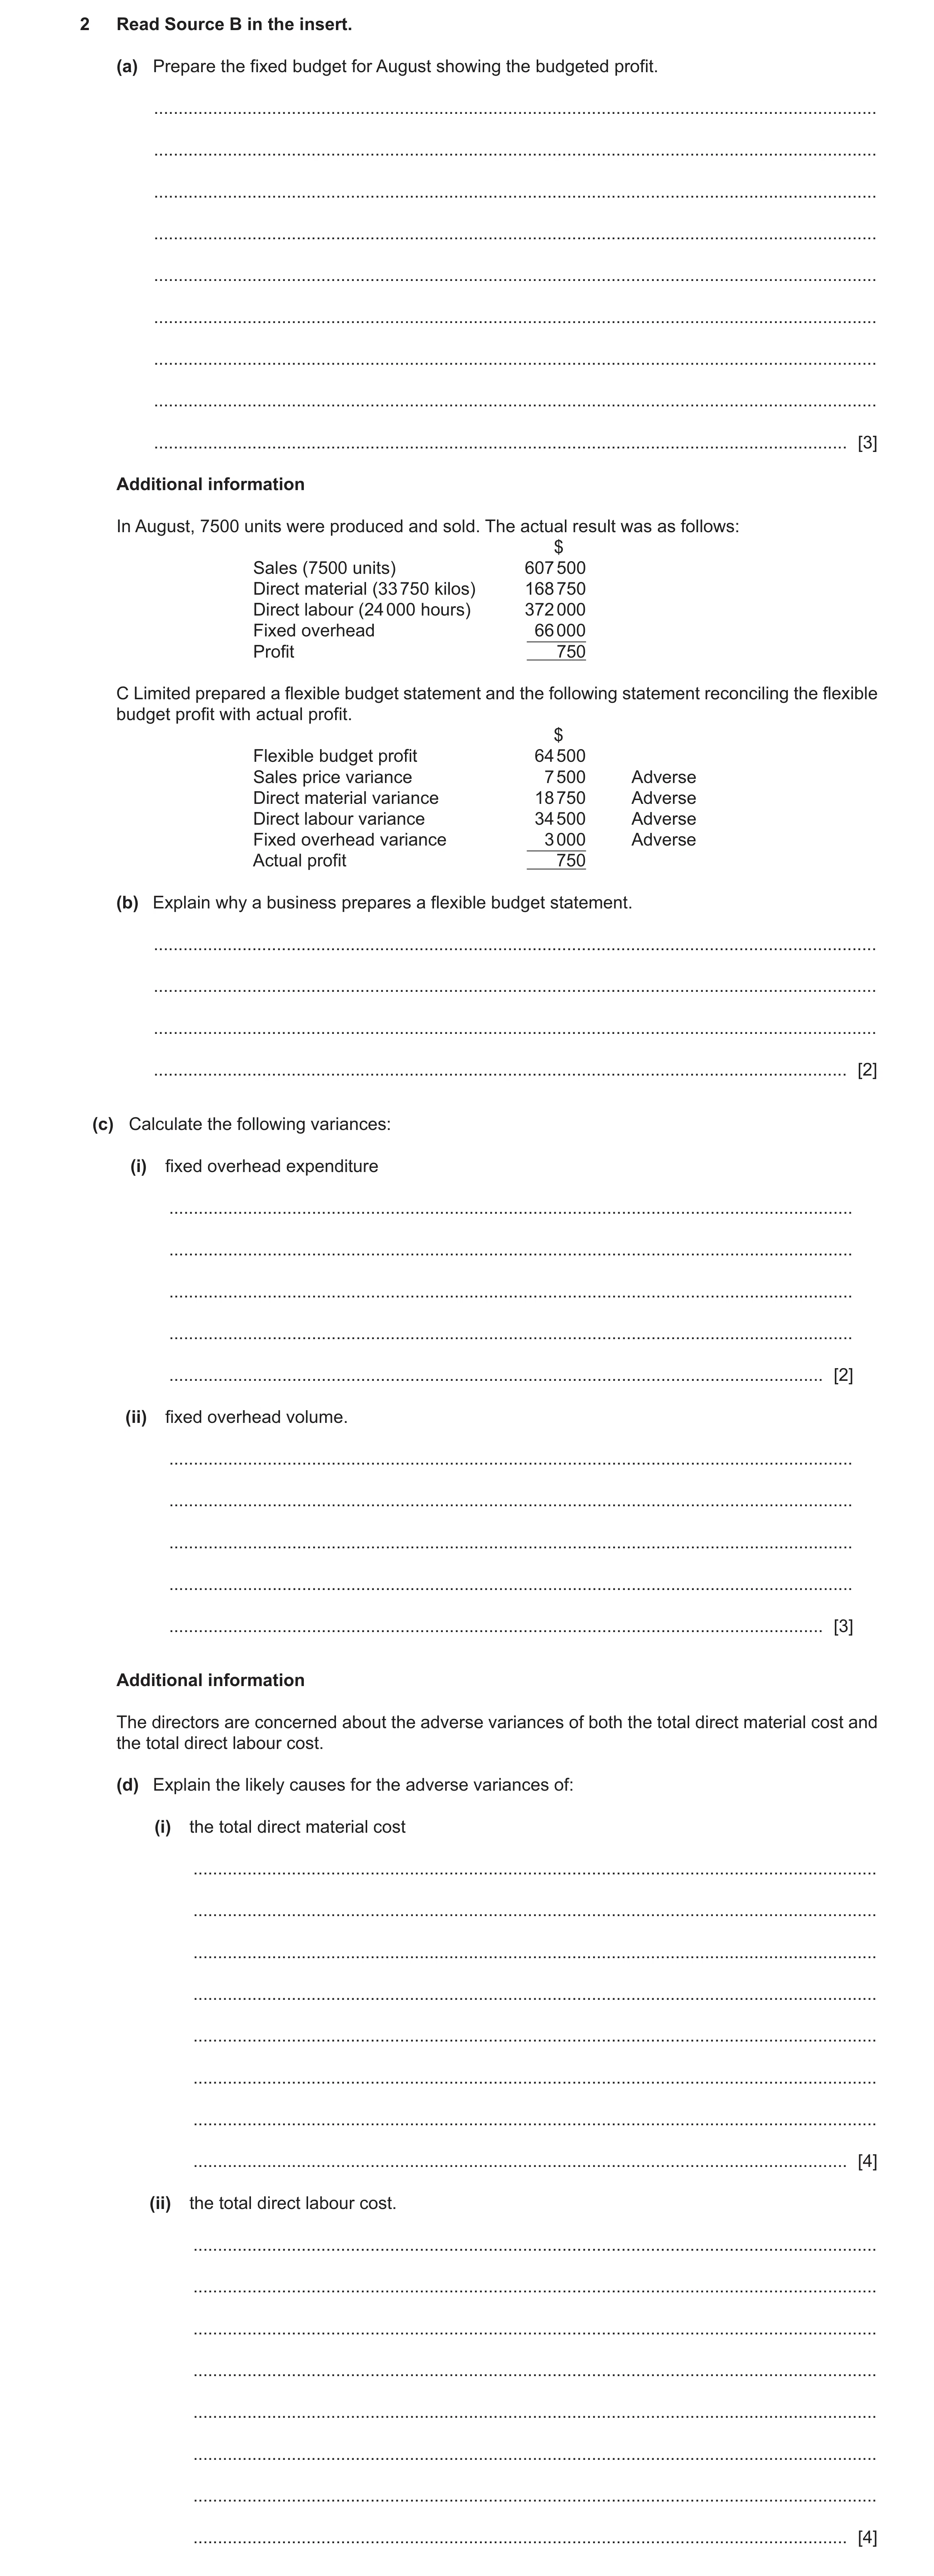
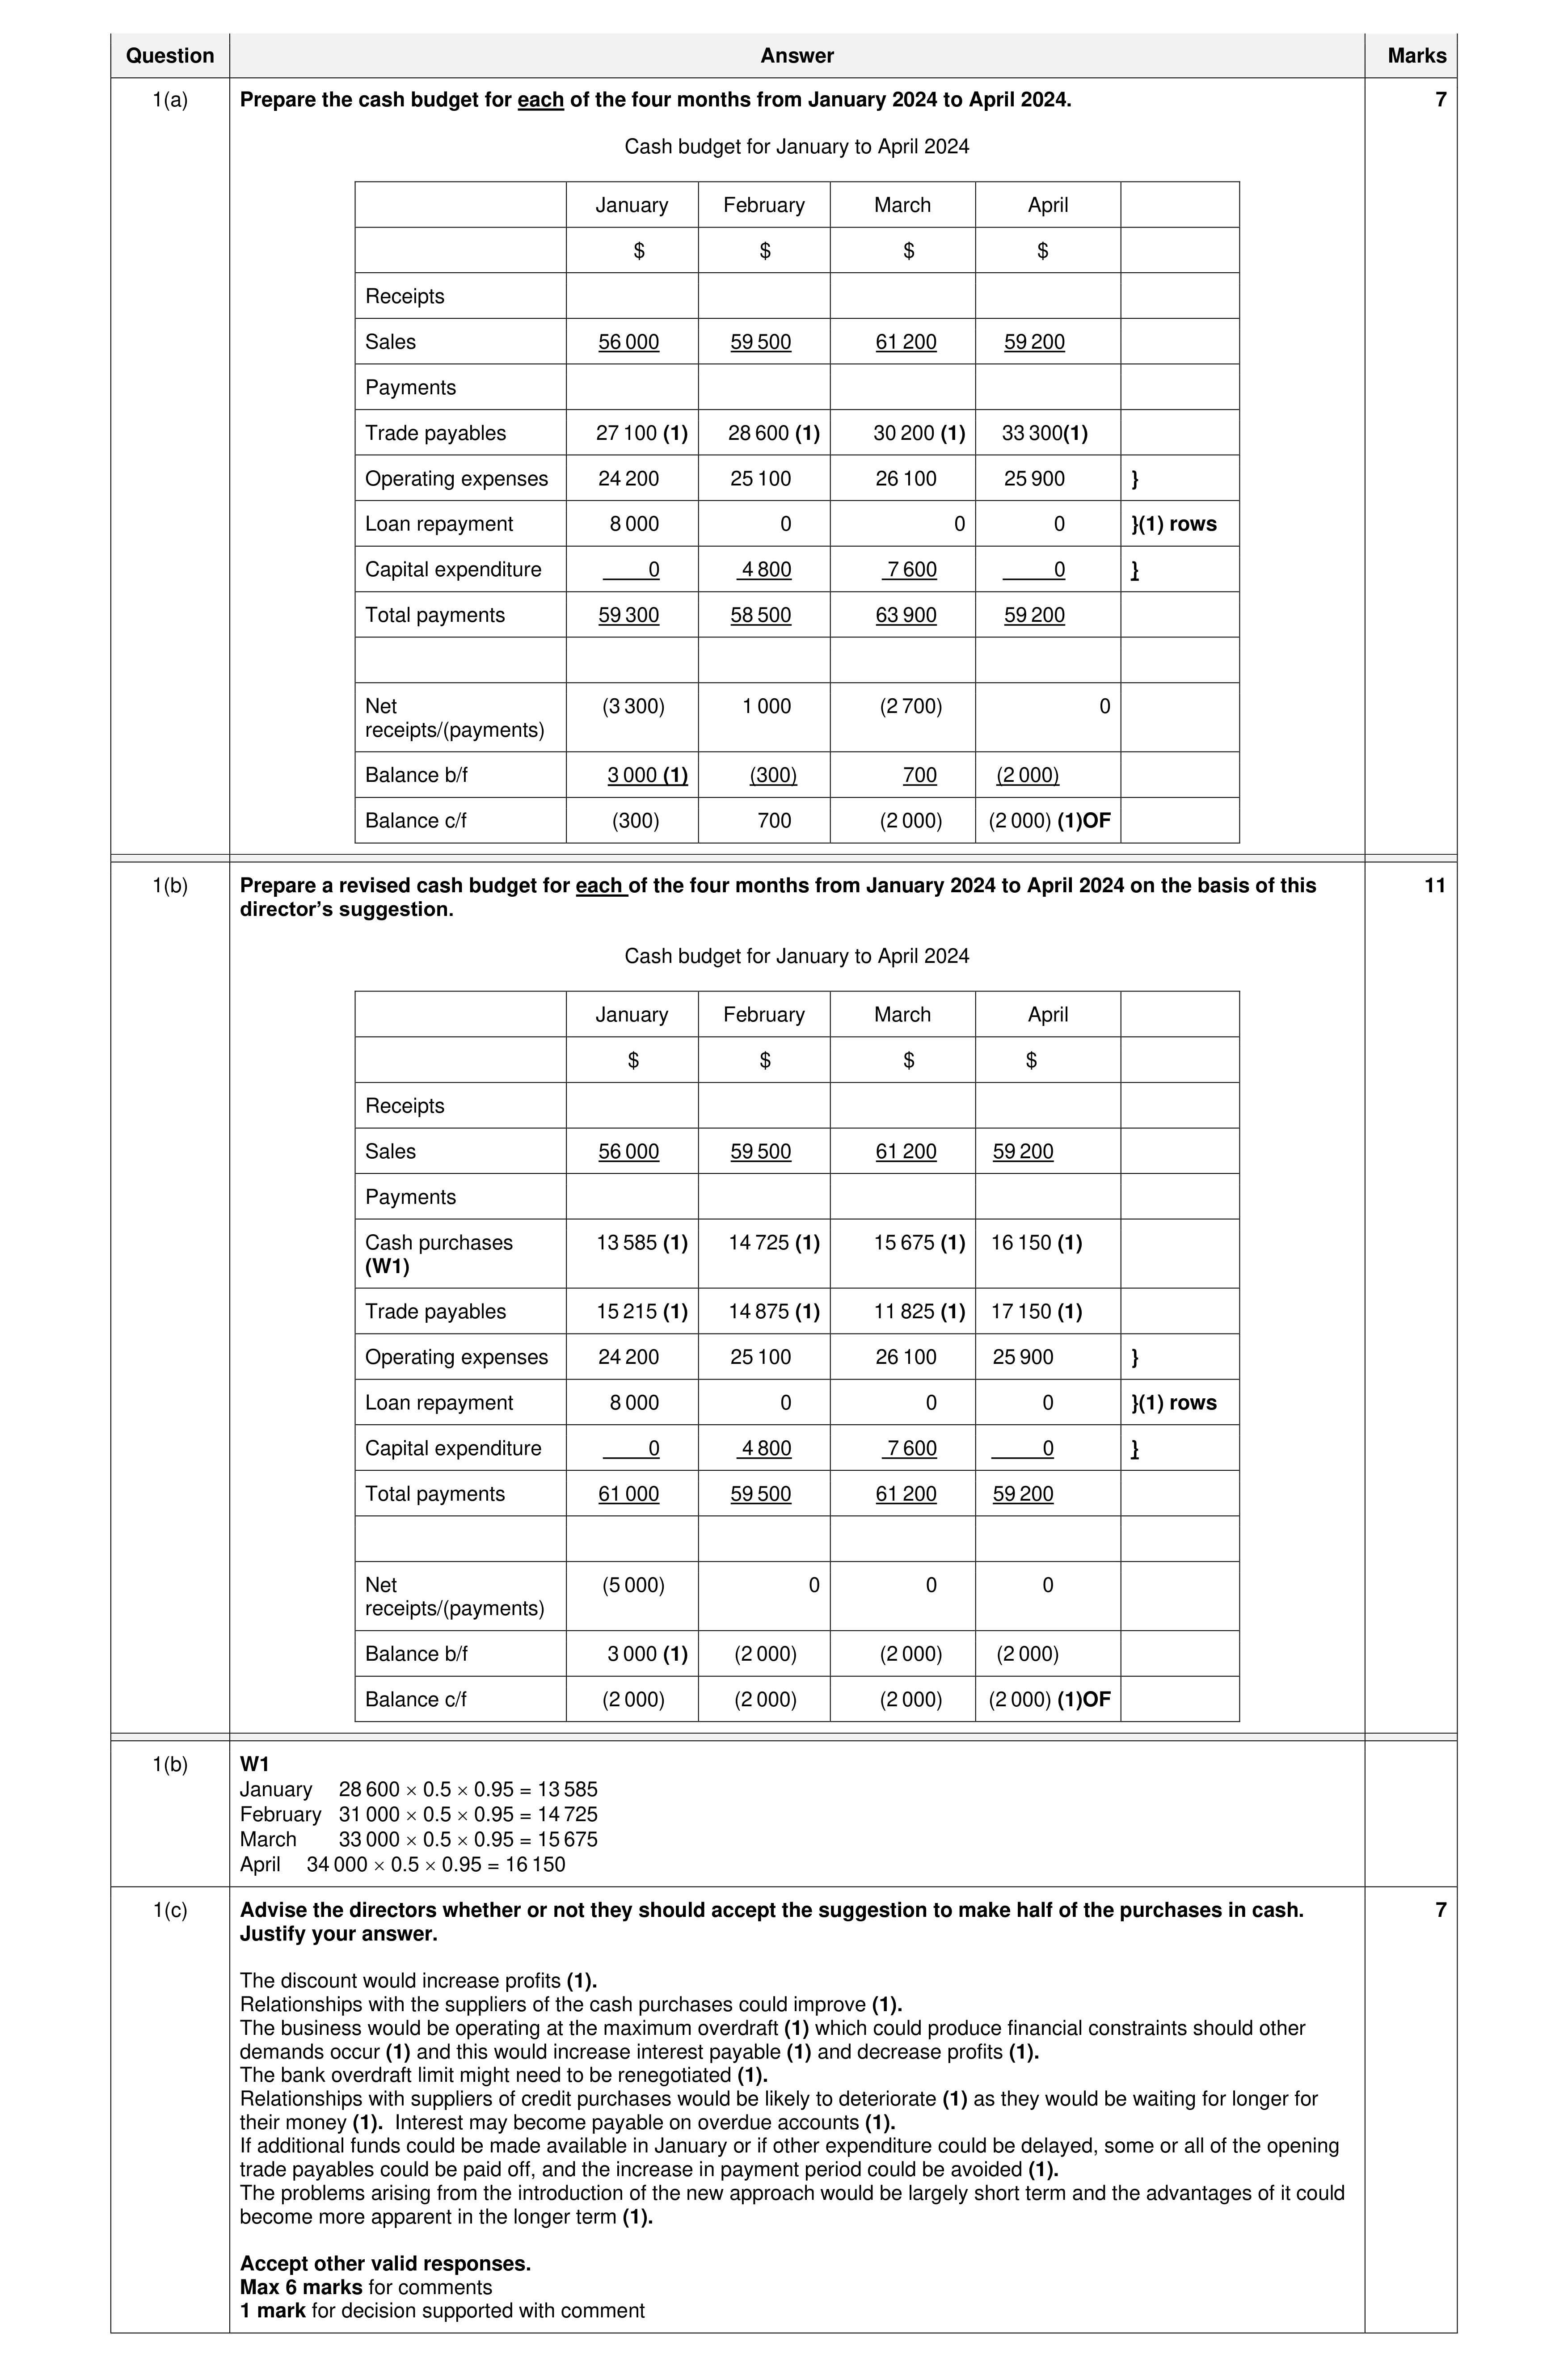 25
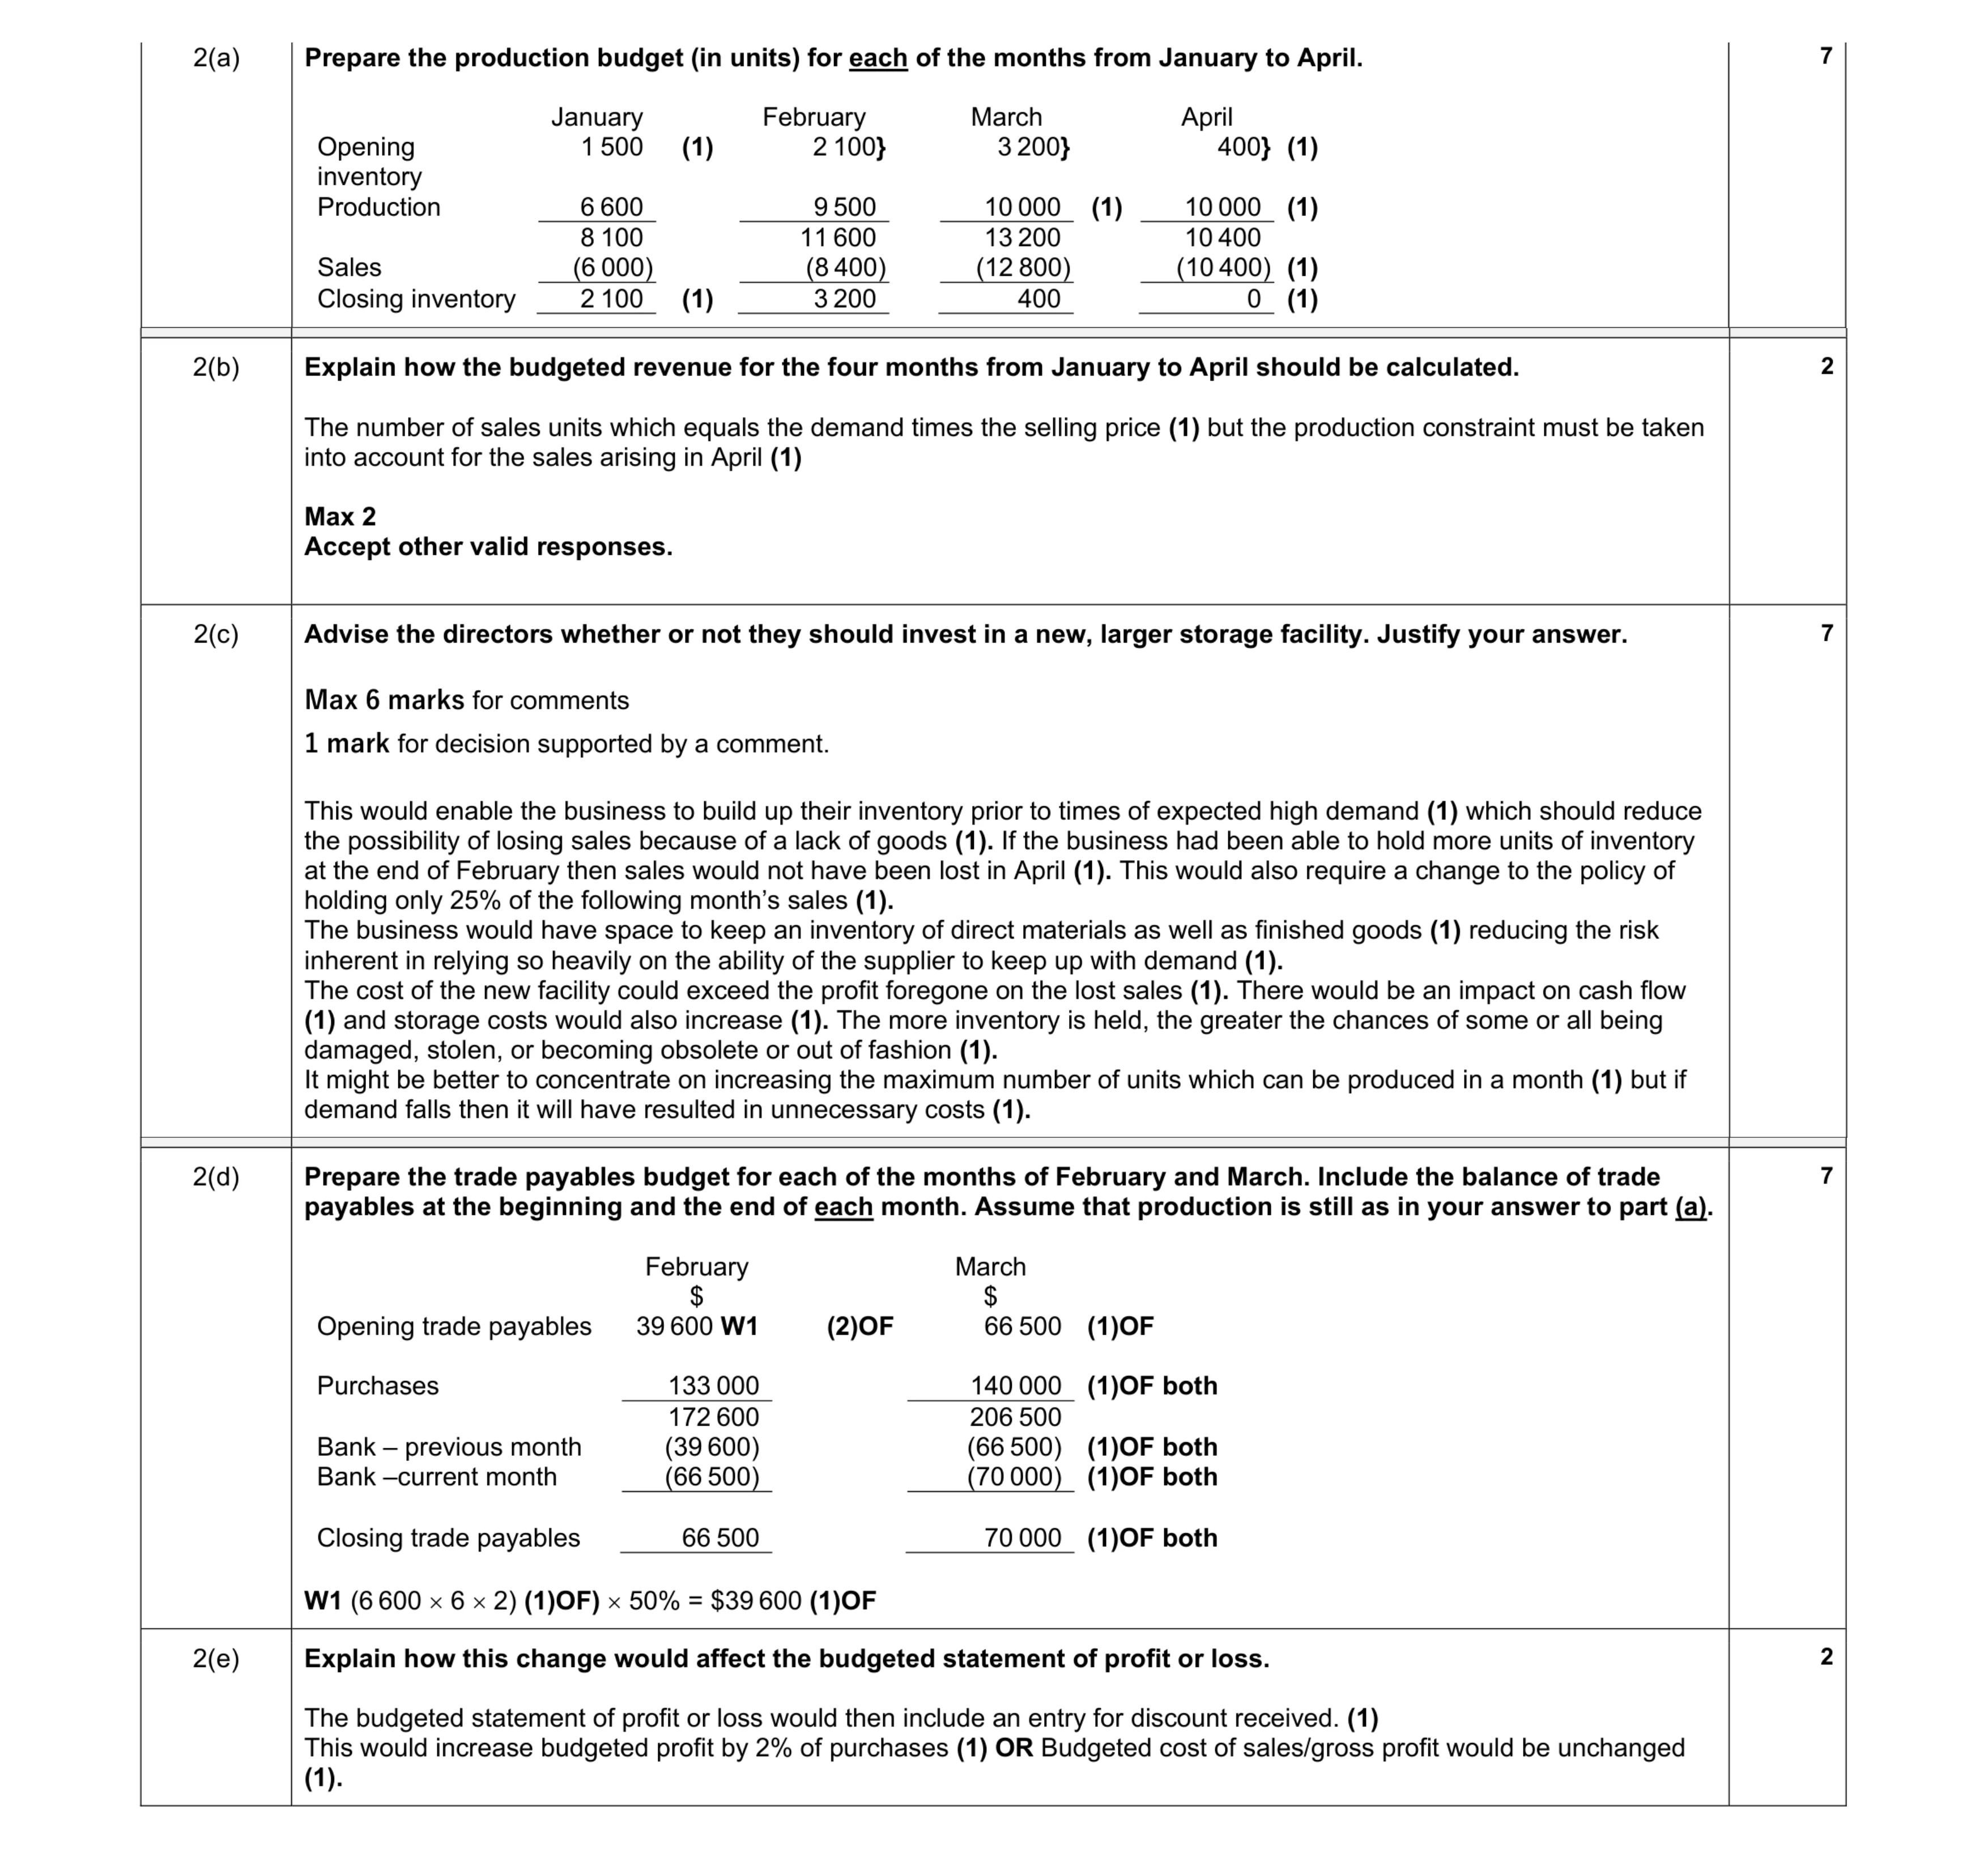 25
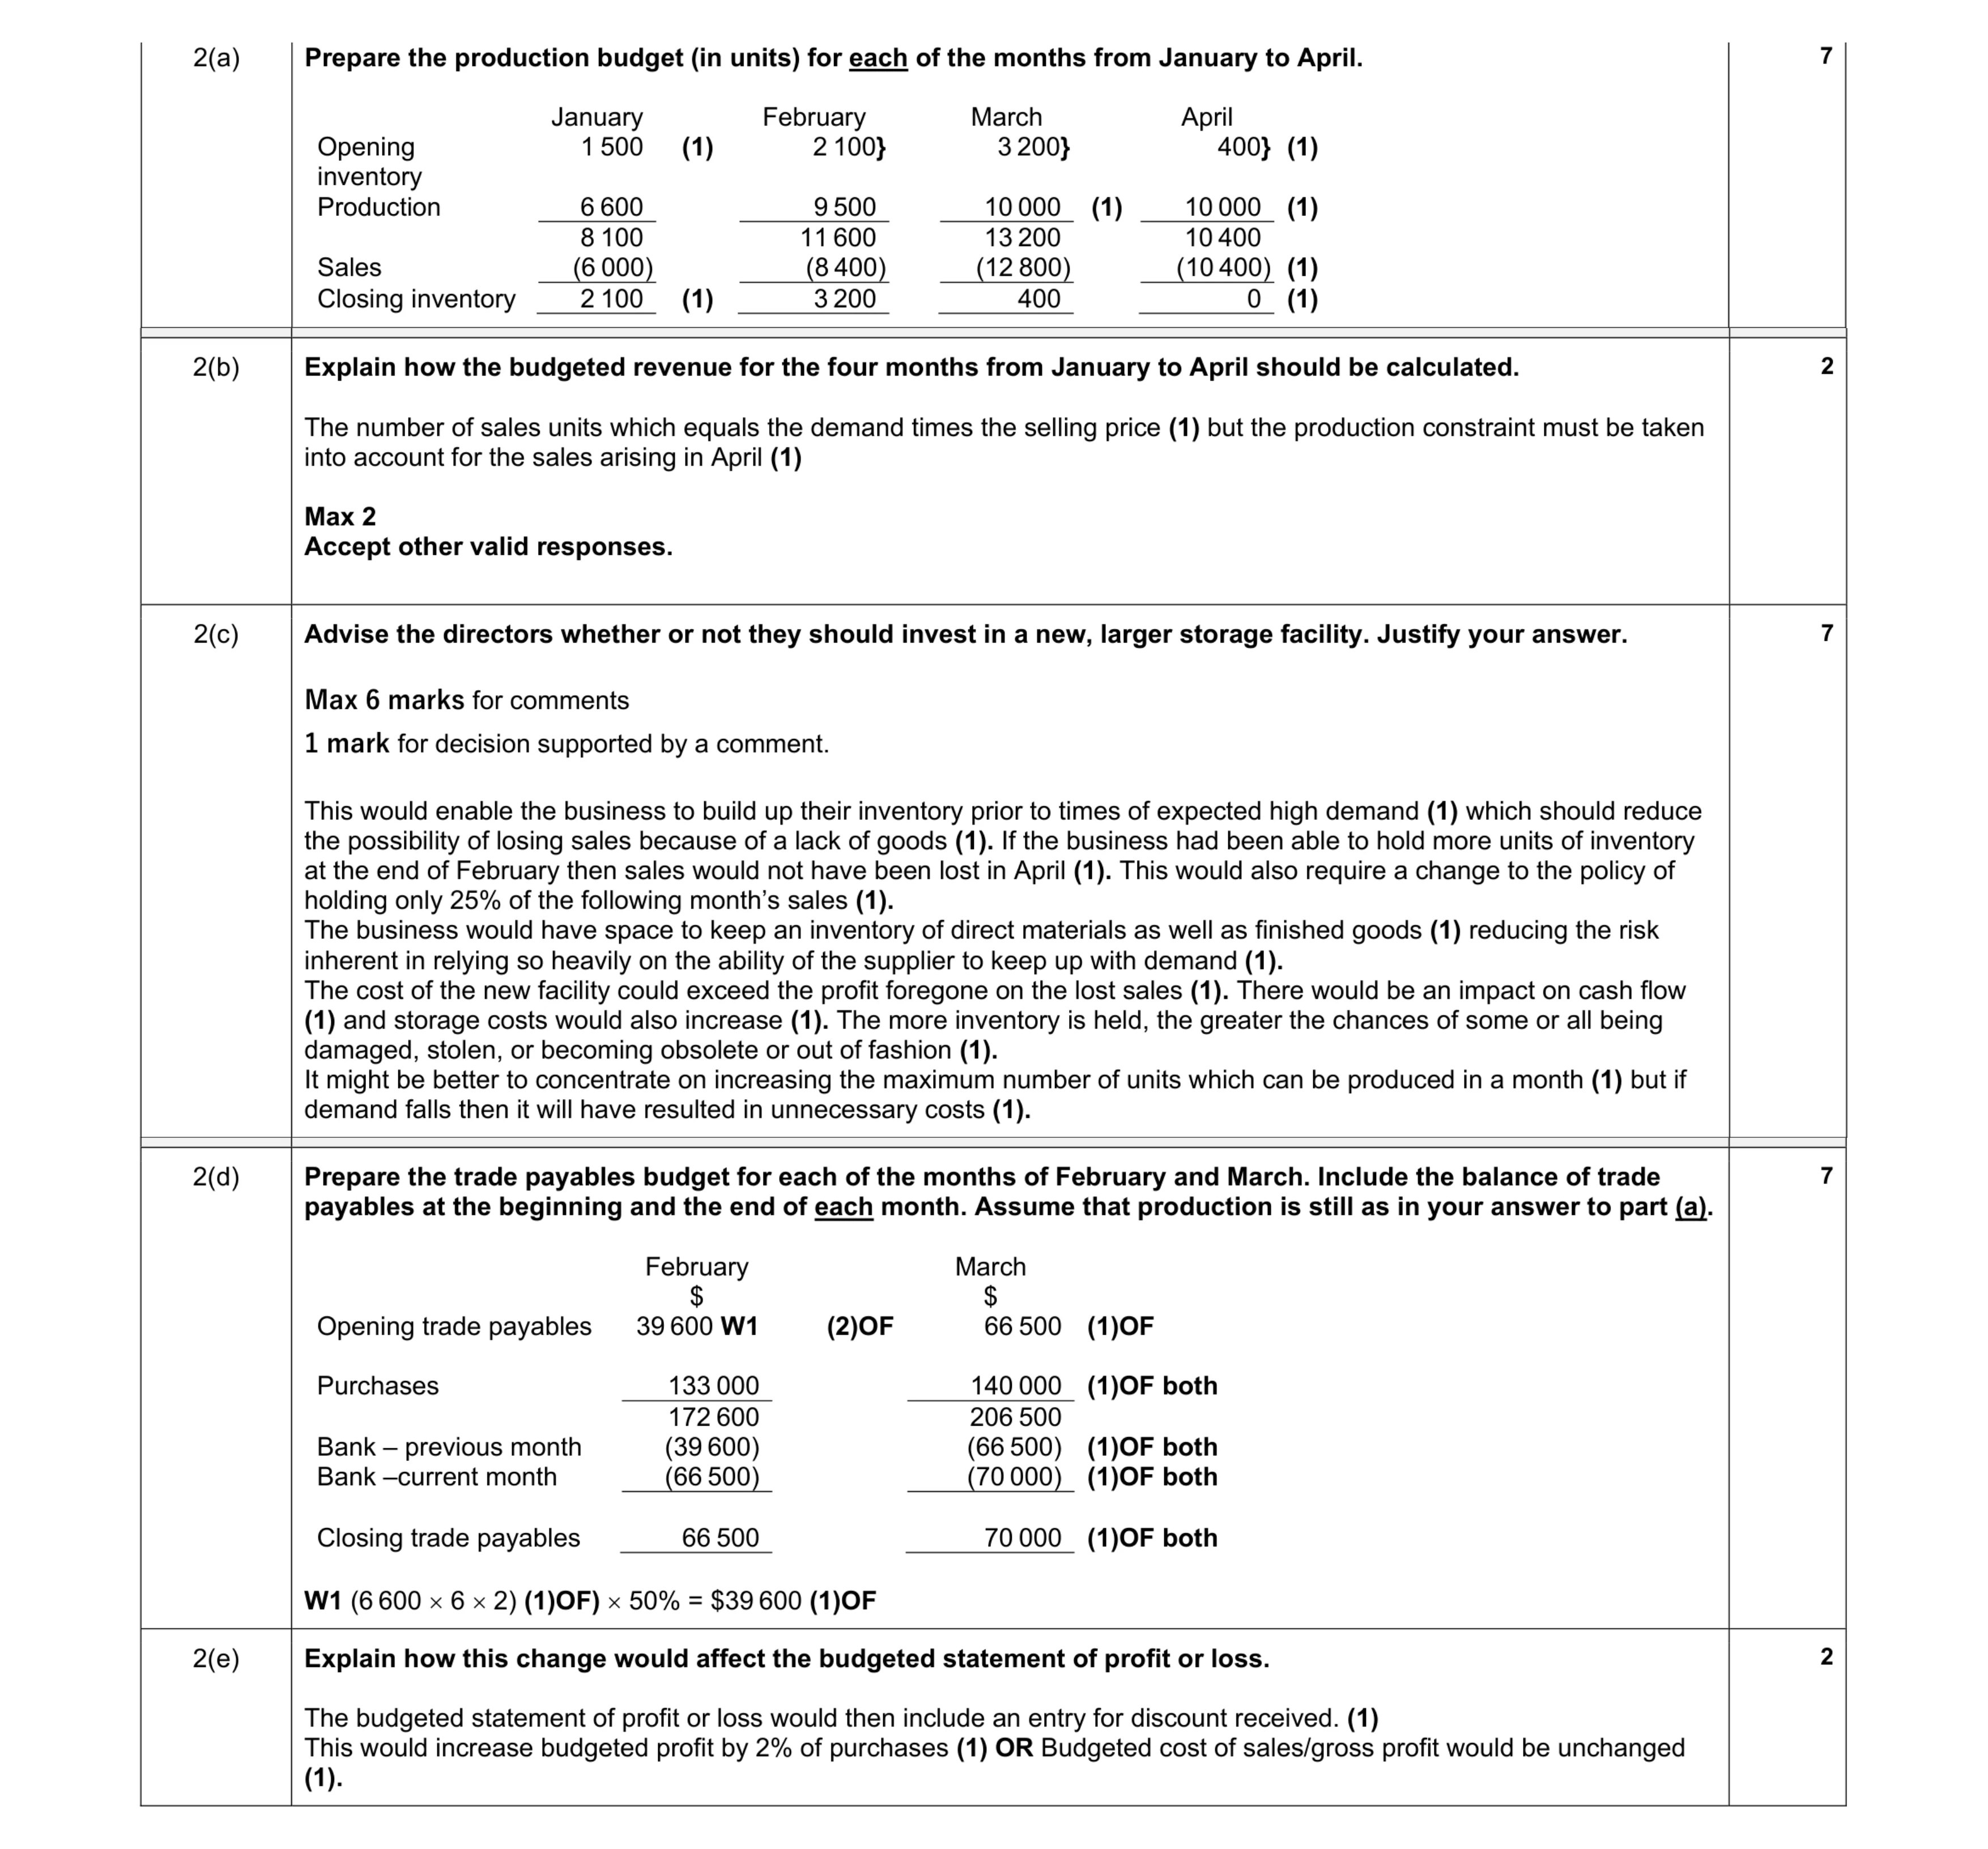 25
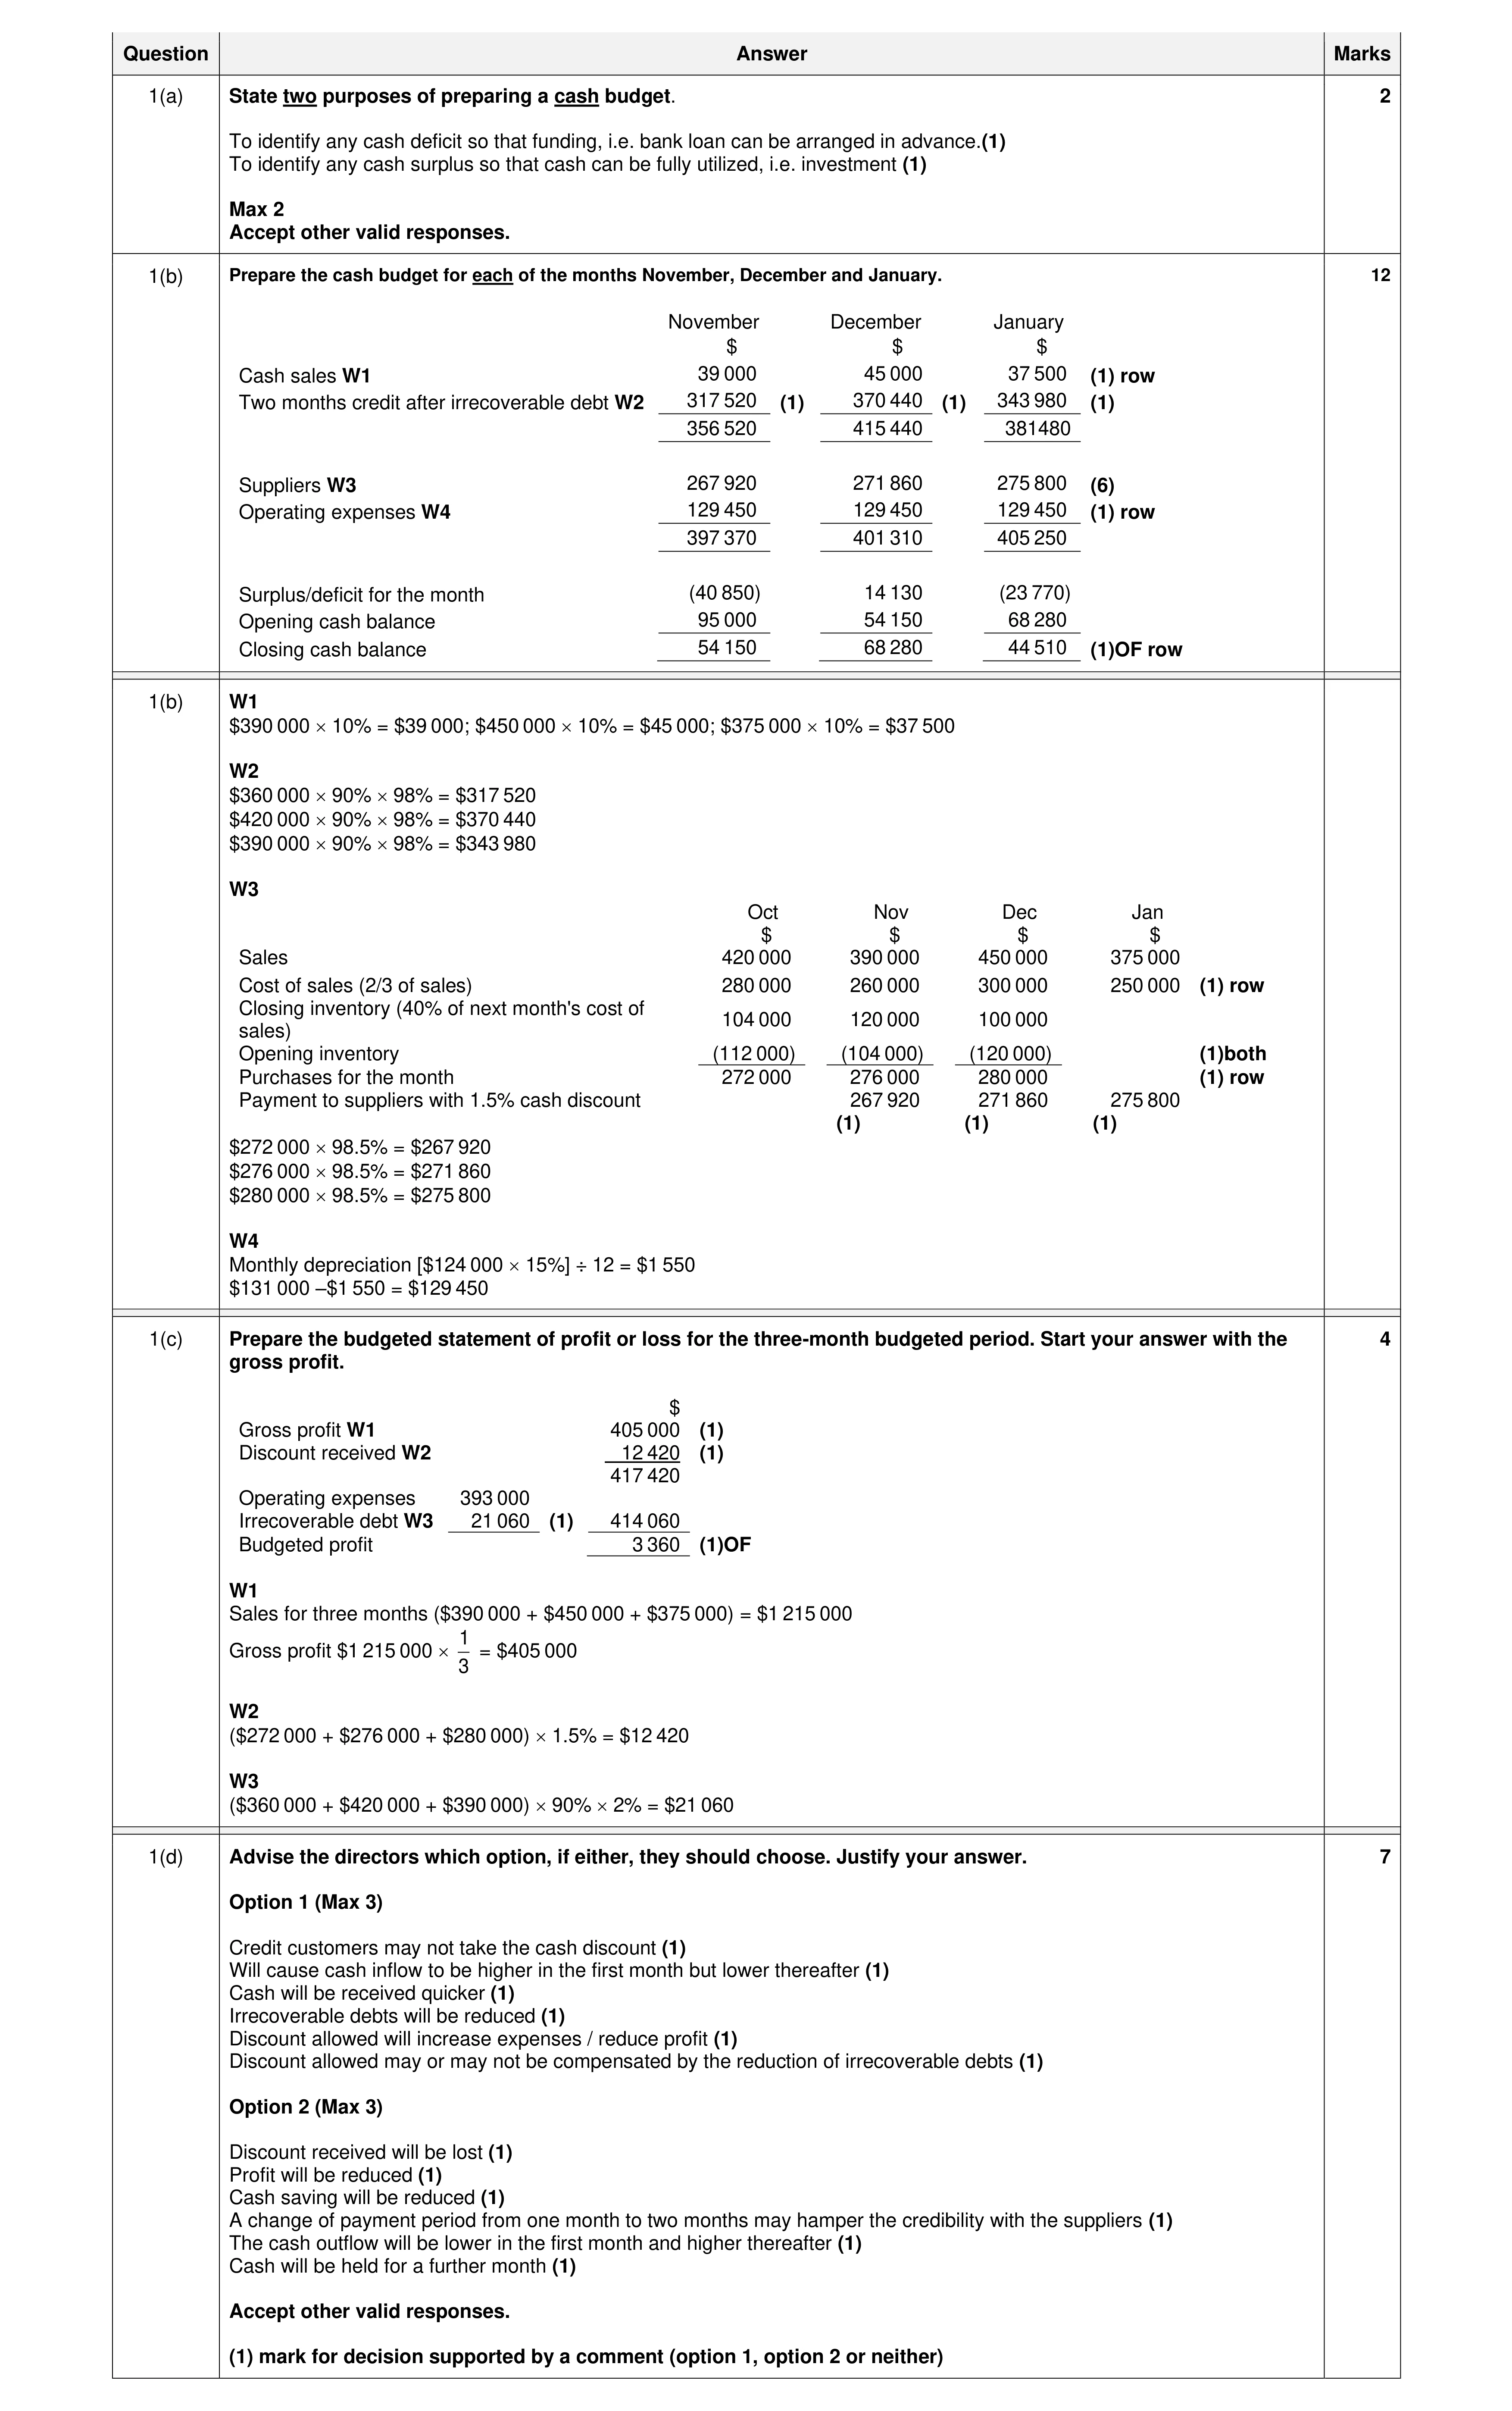 25
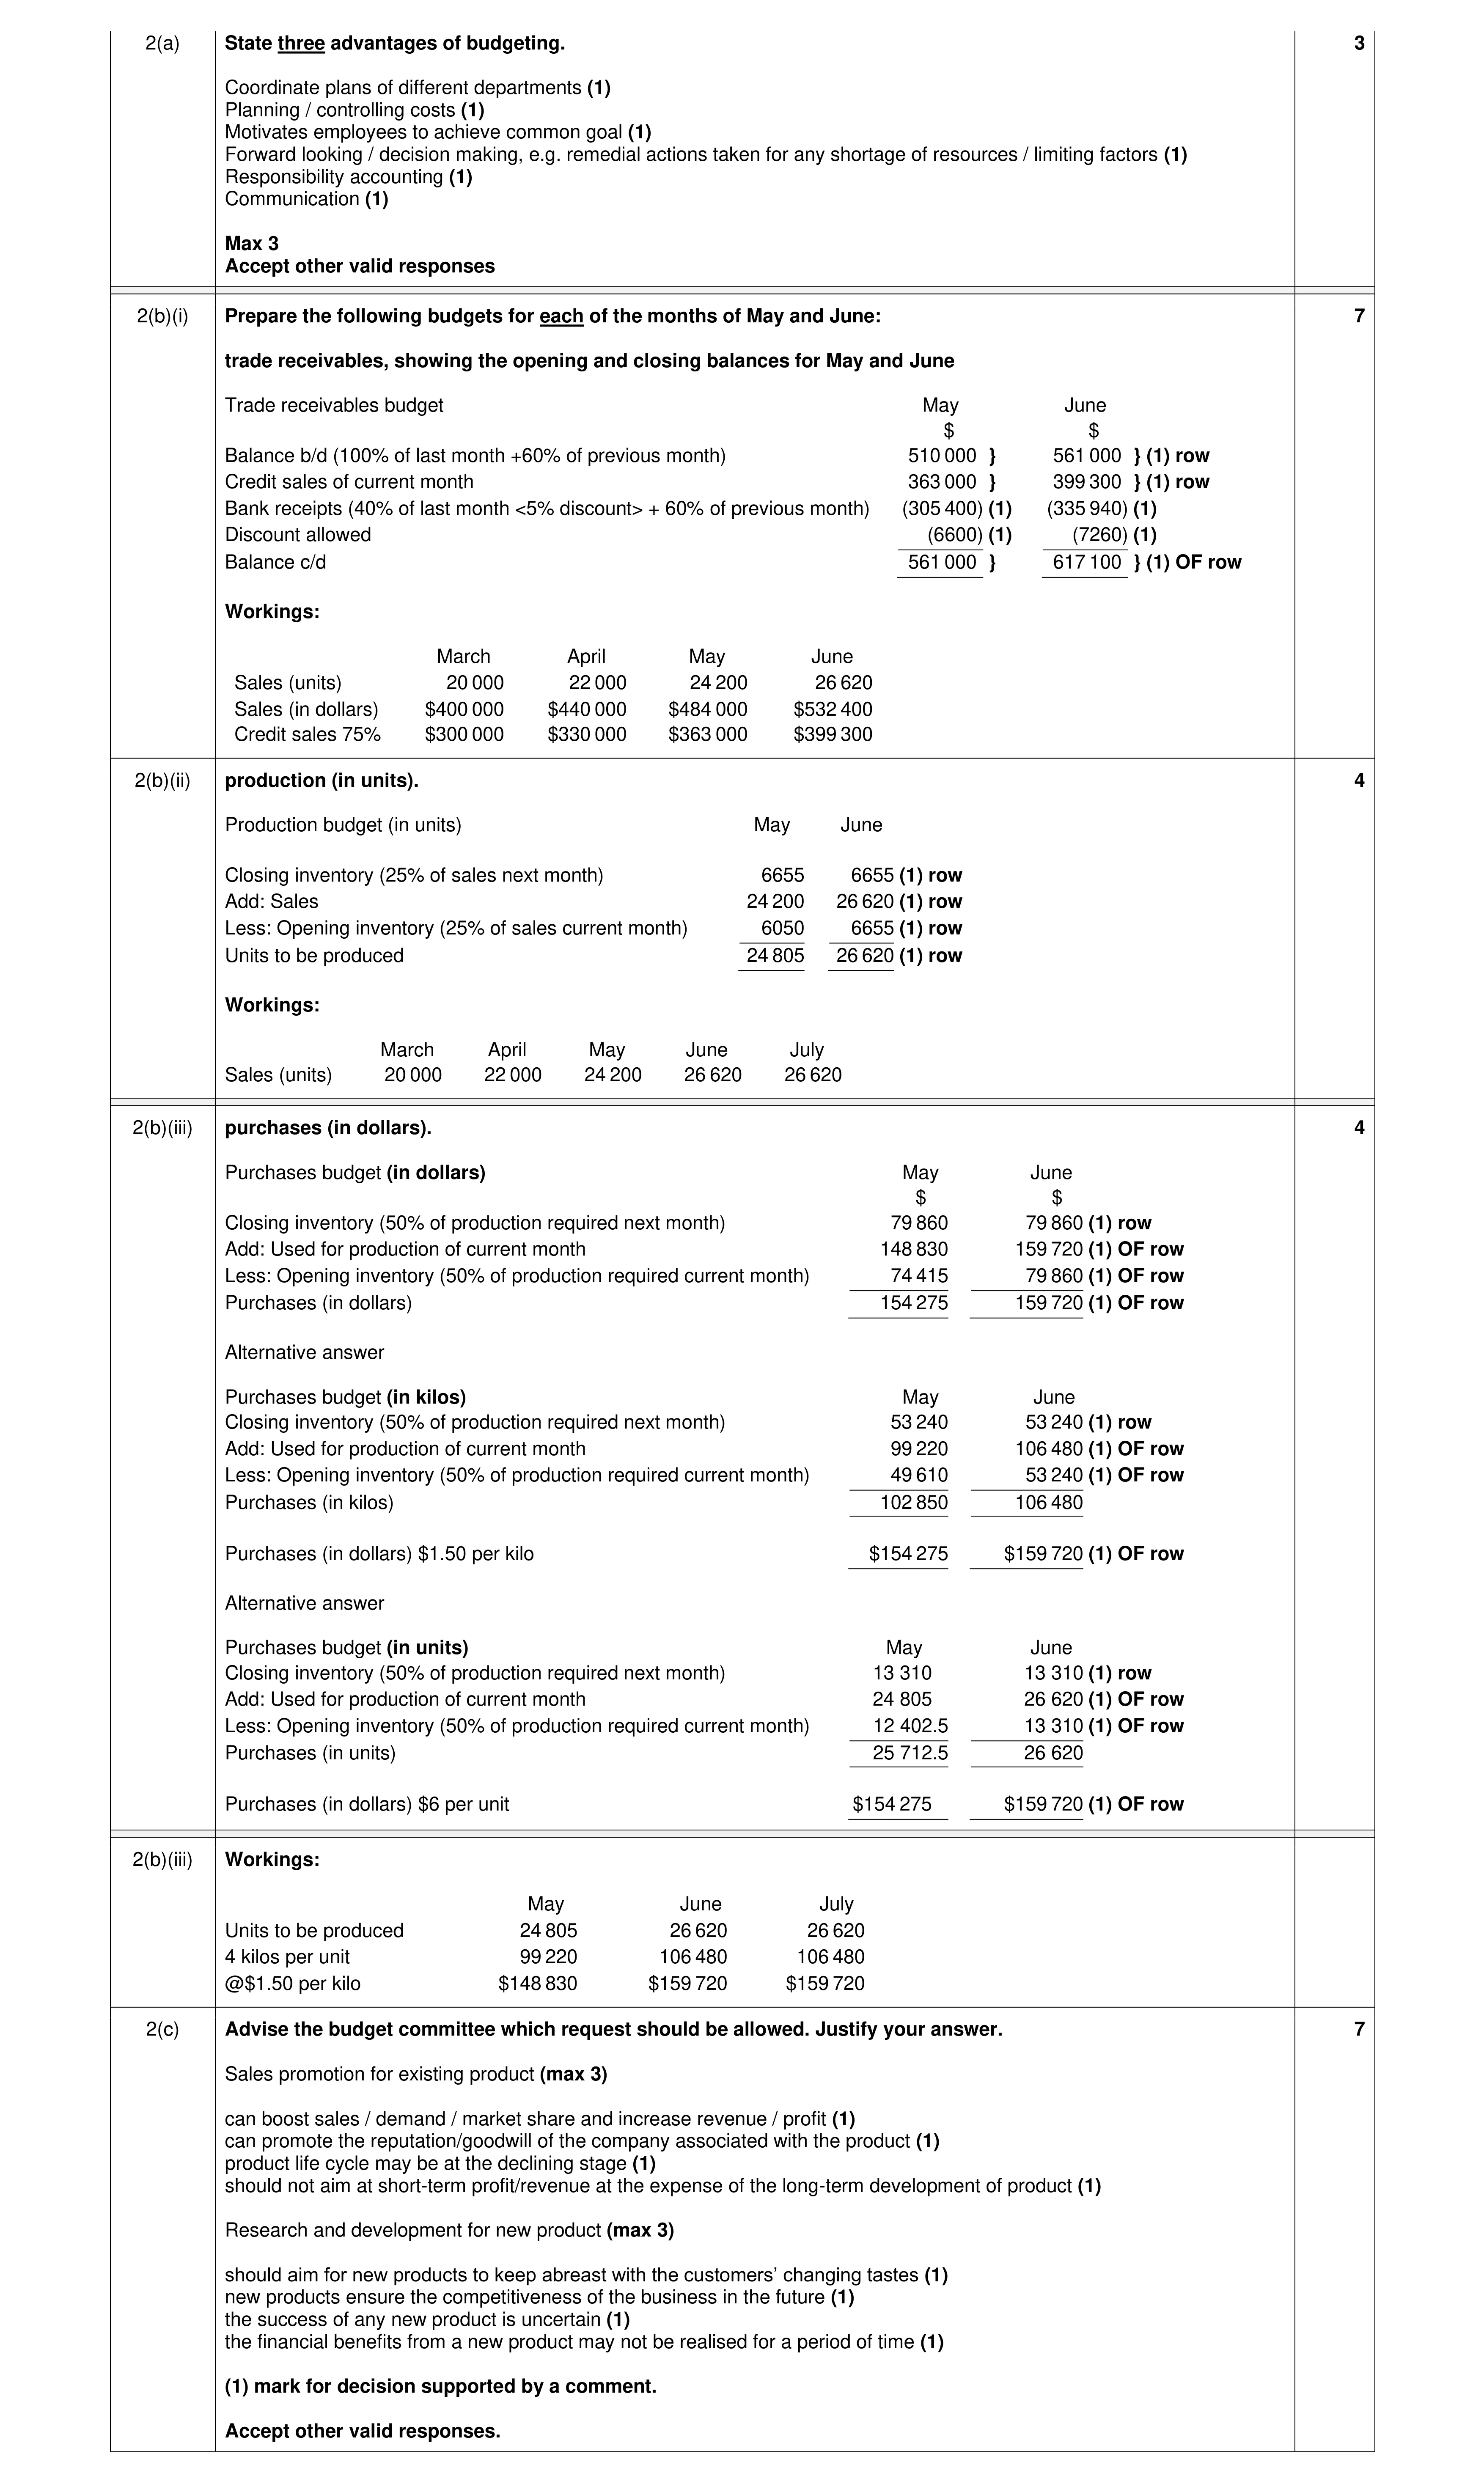 25
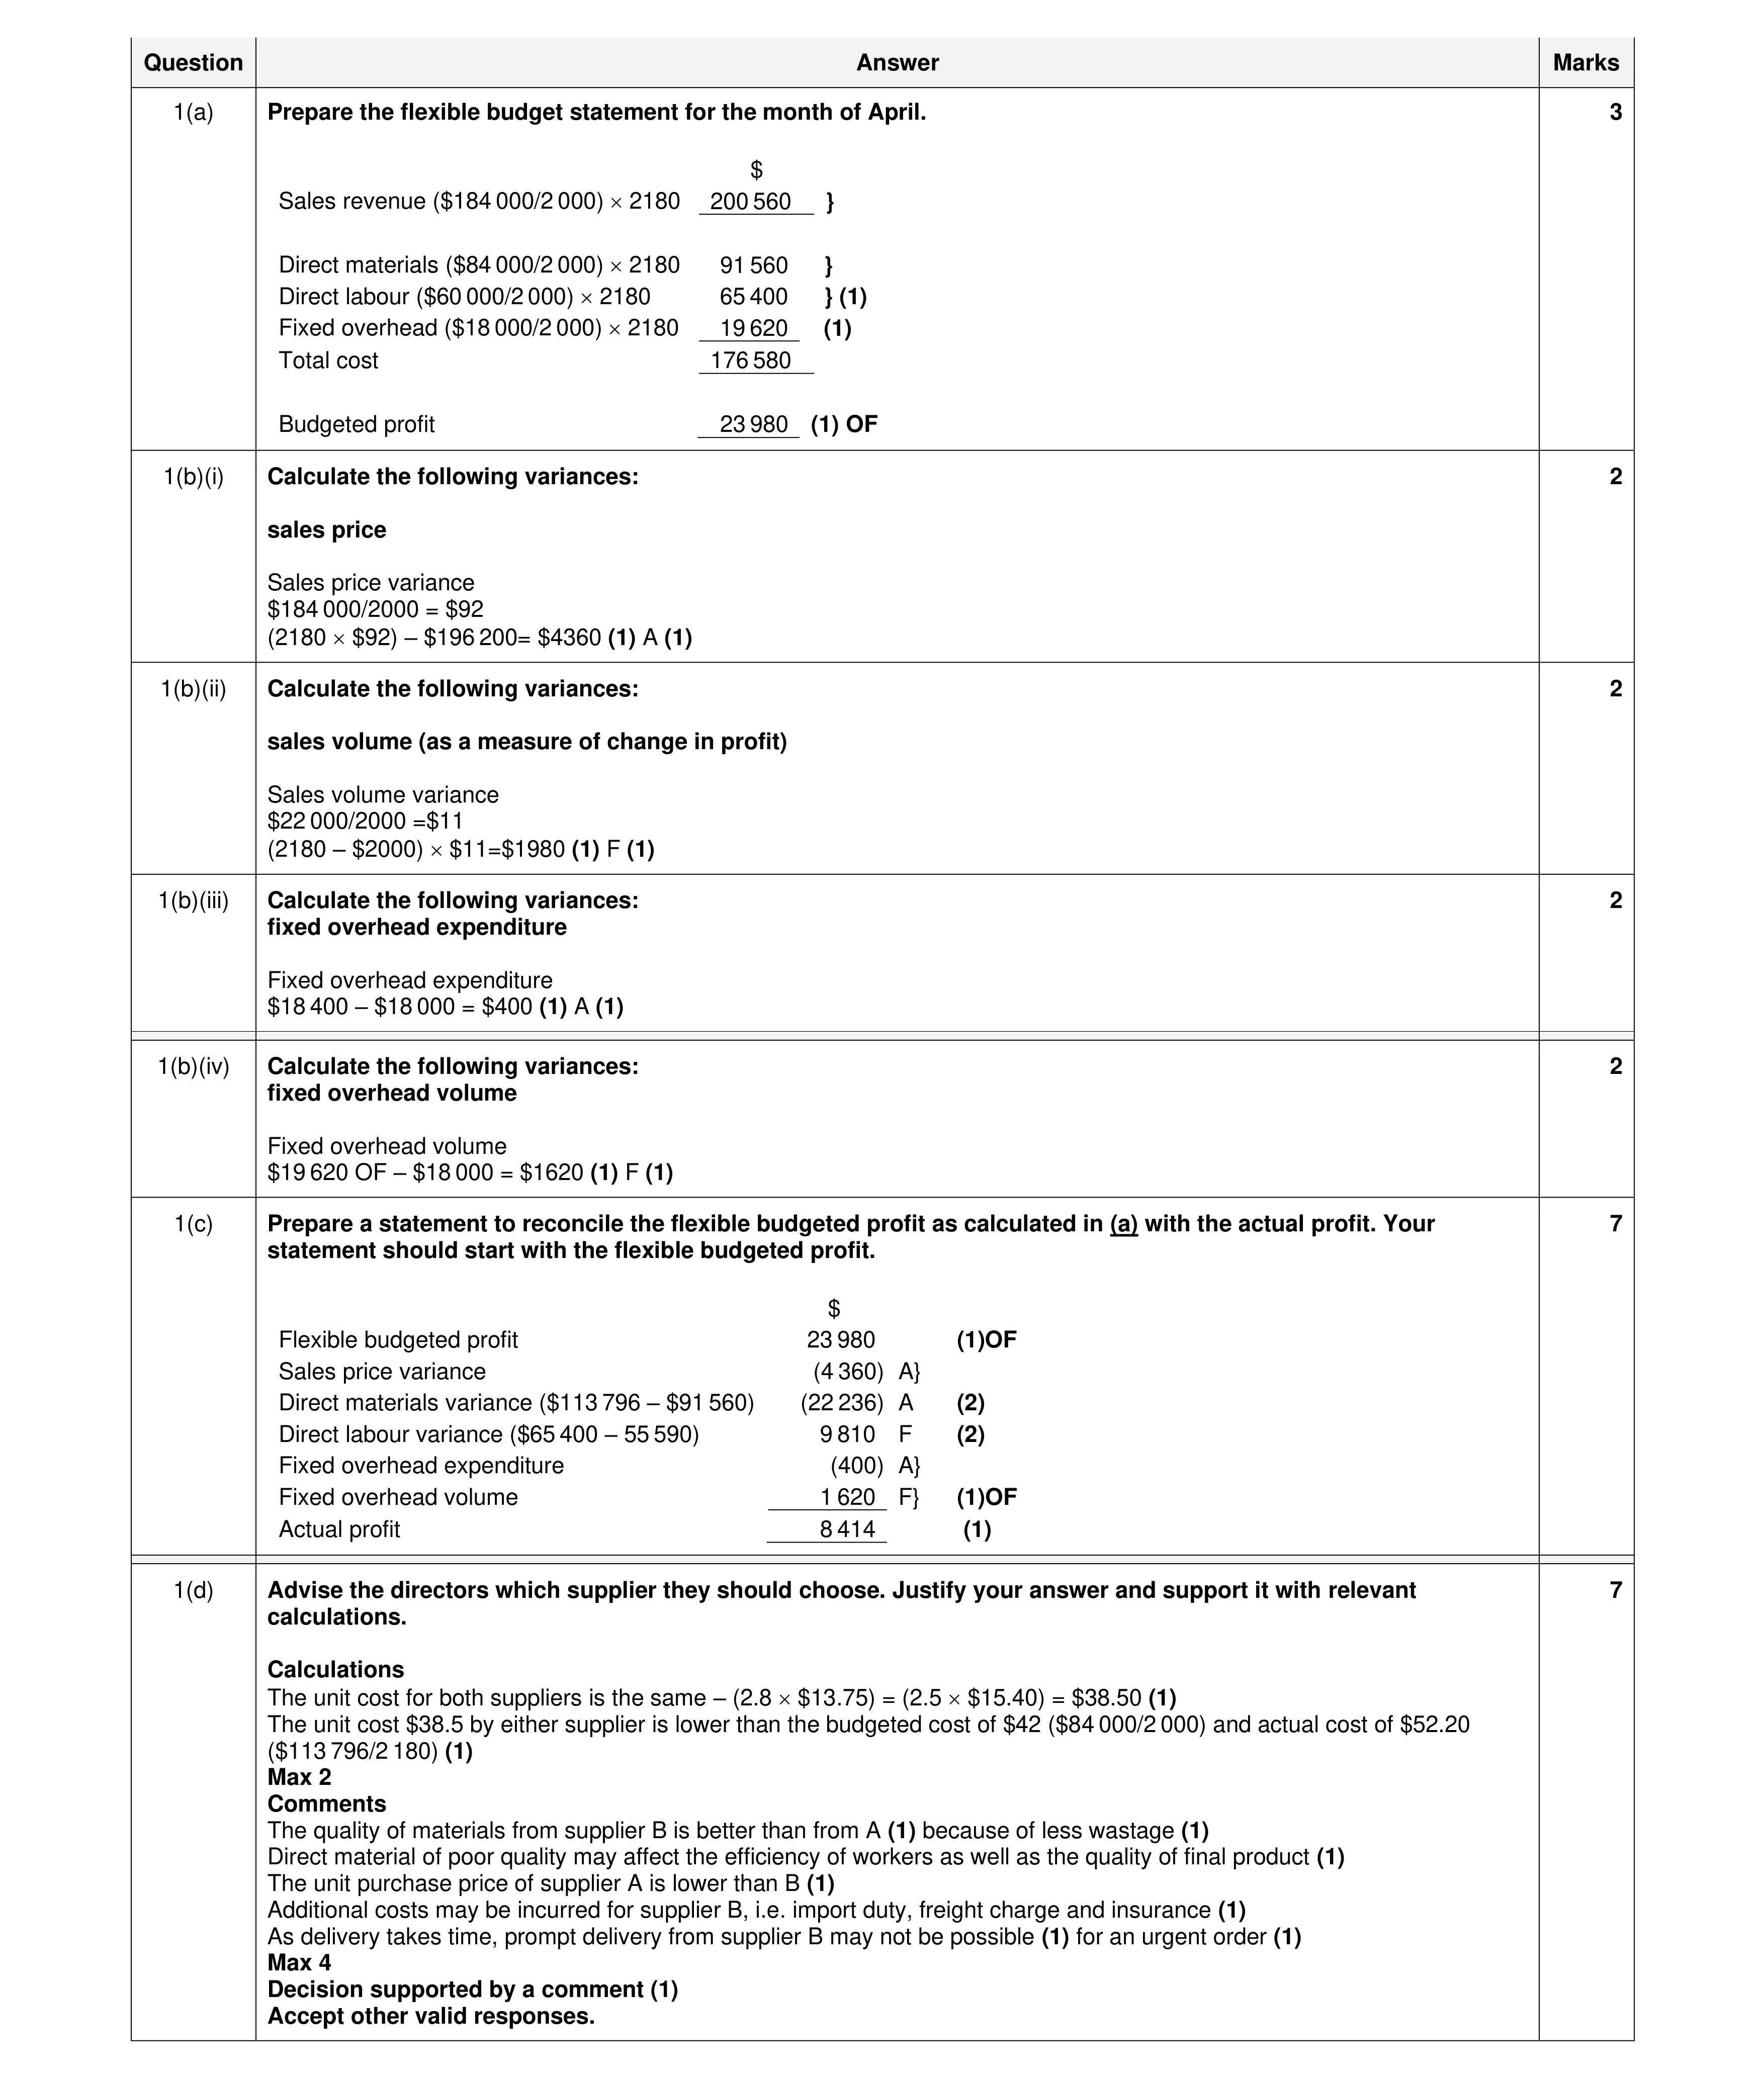 25
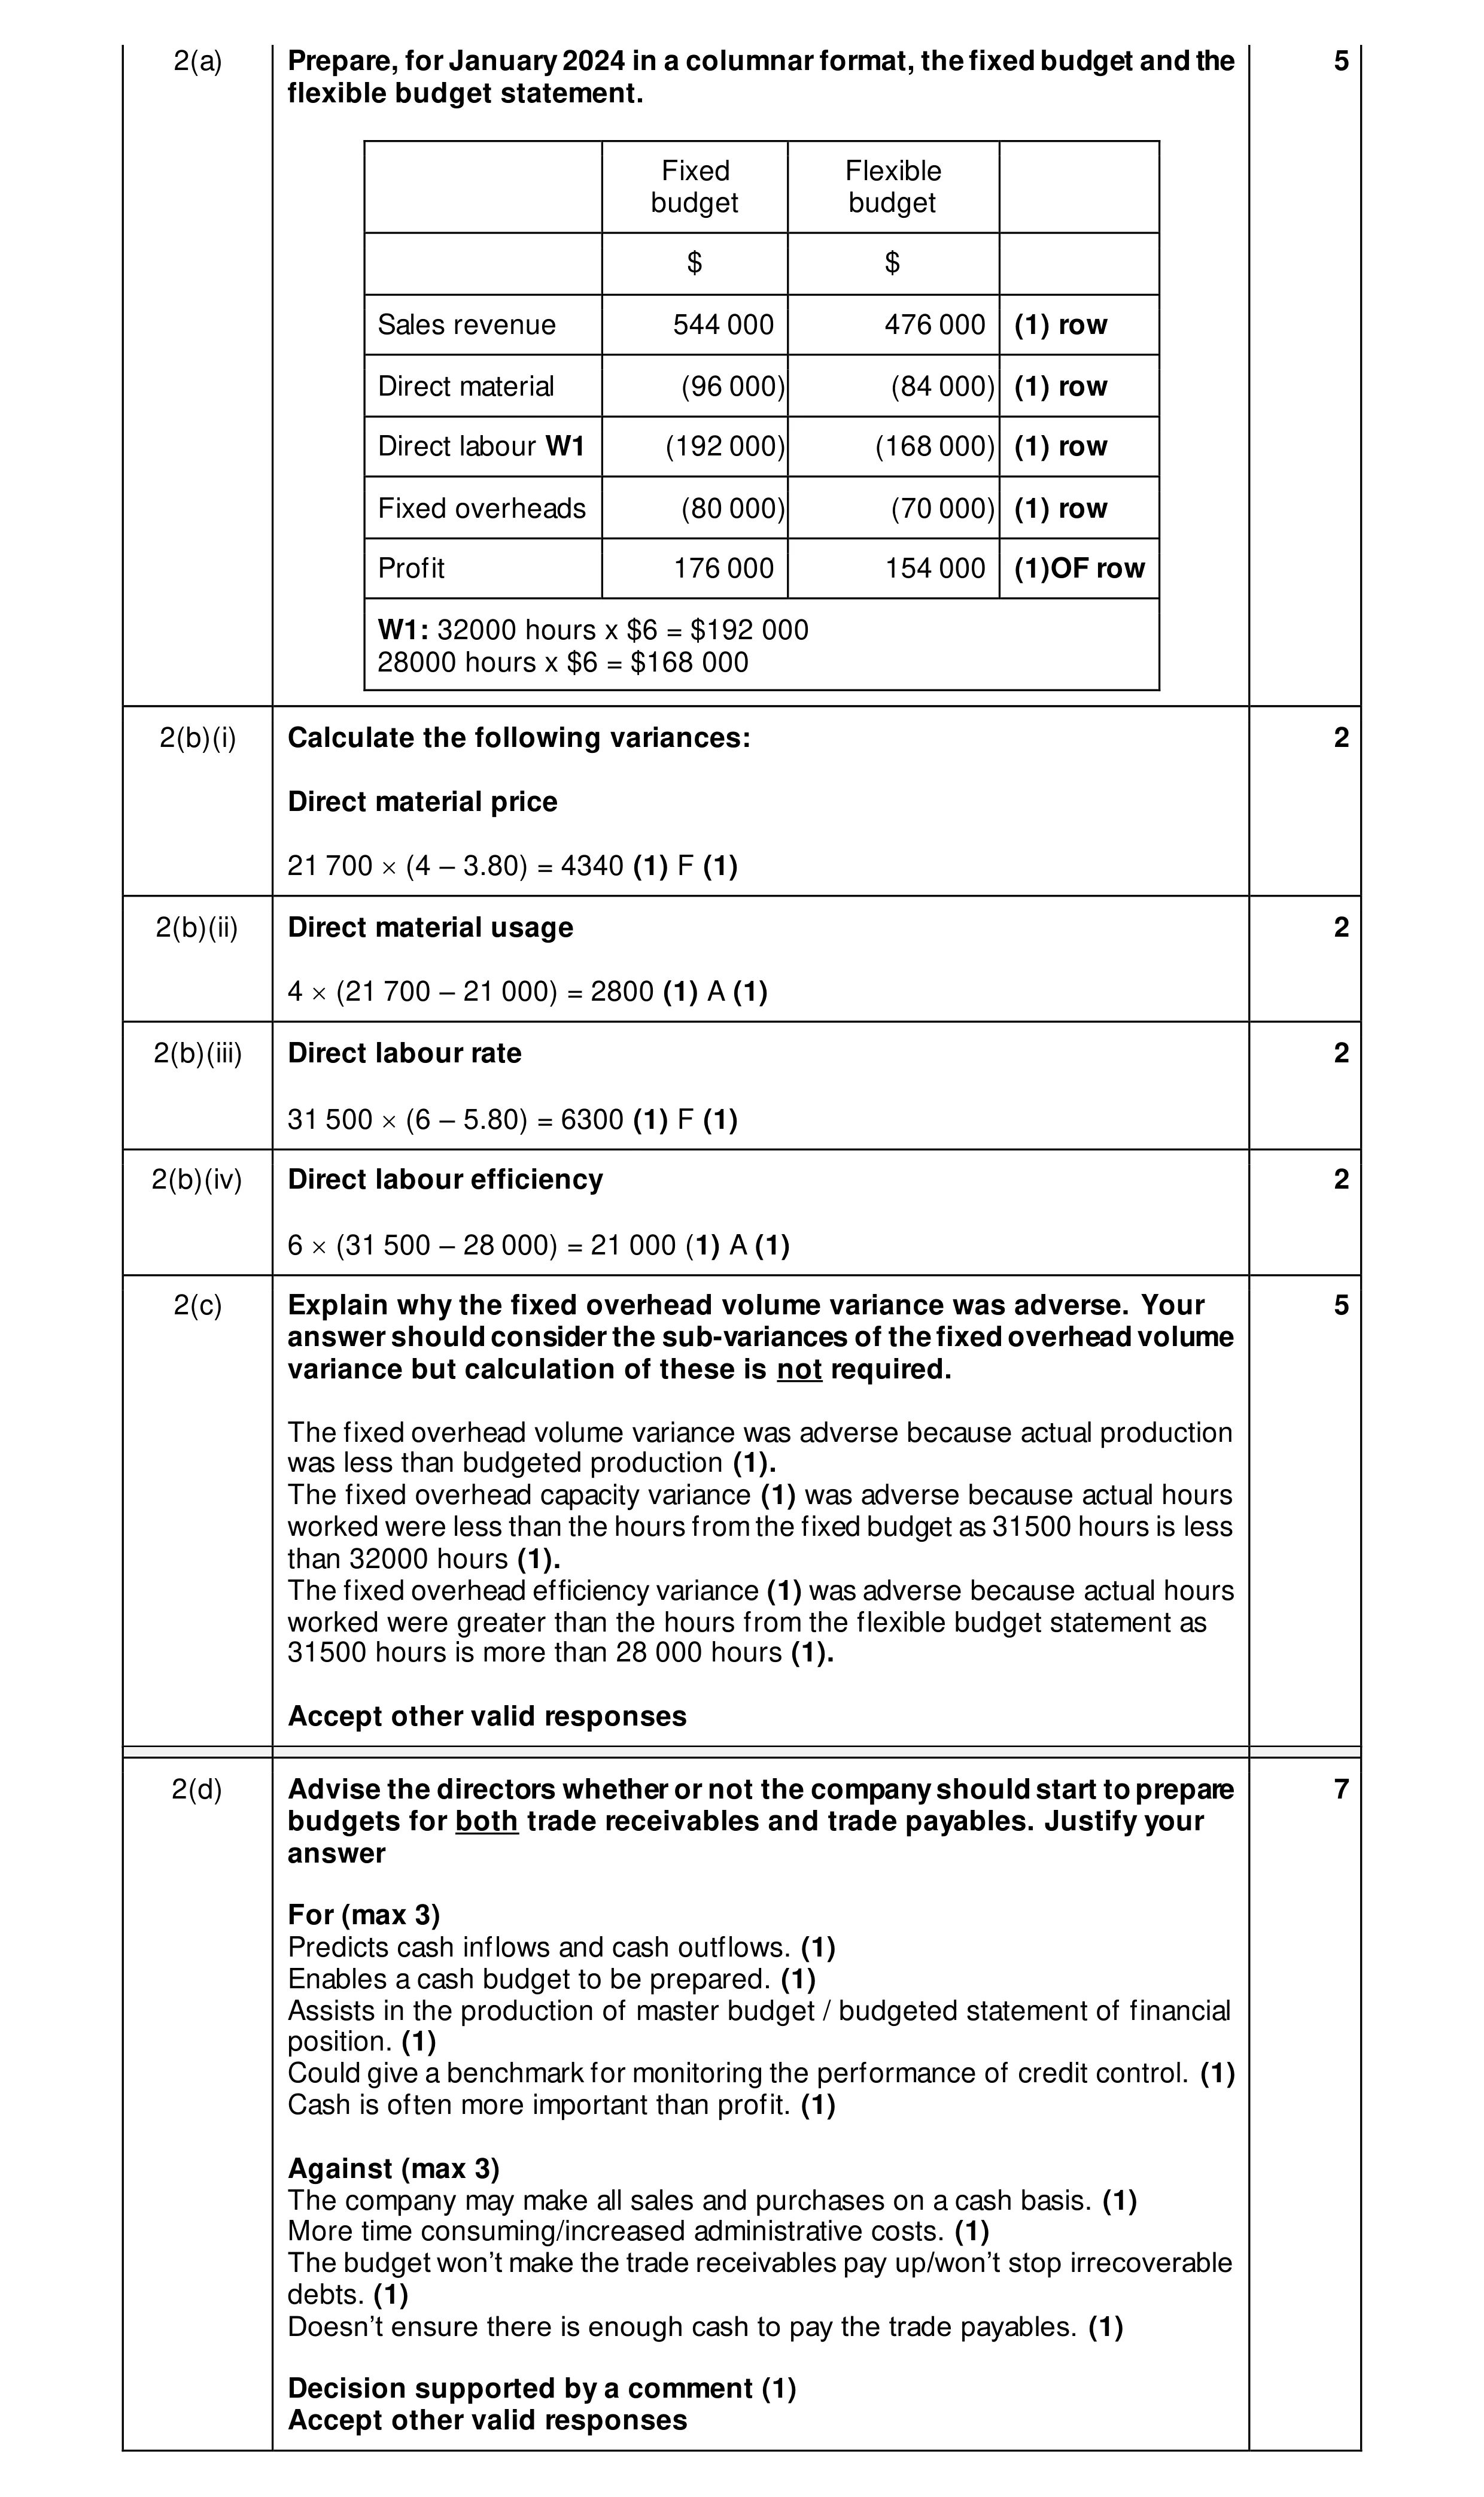 25
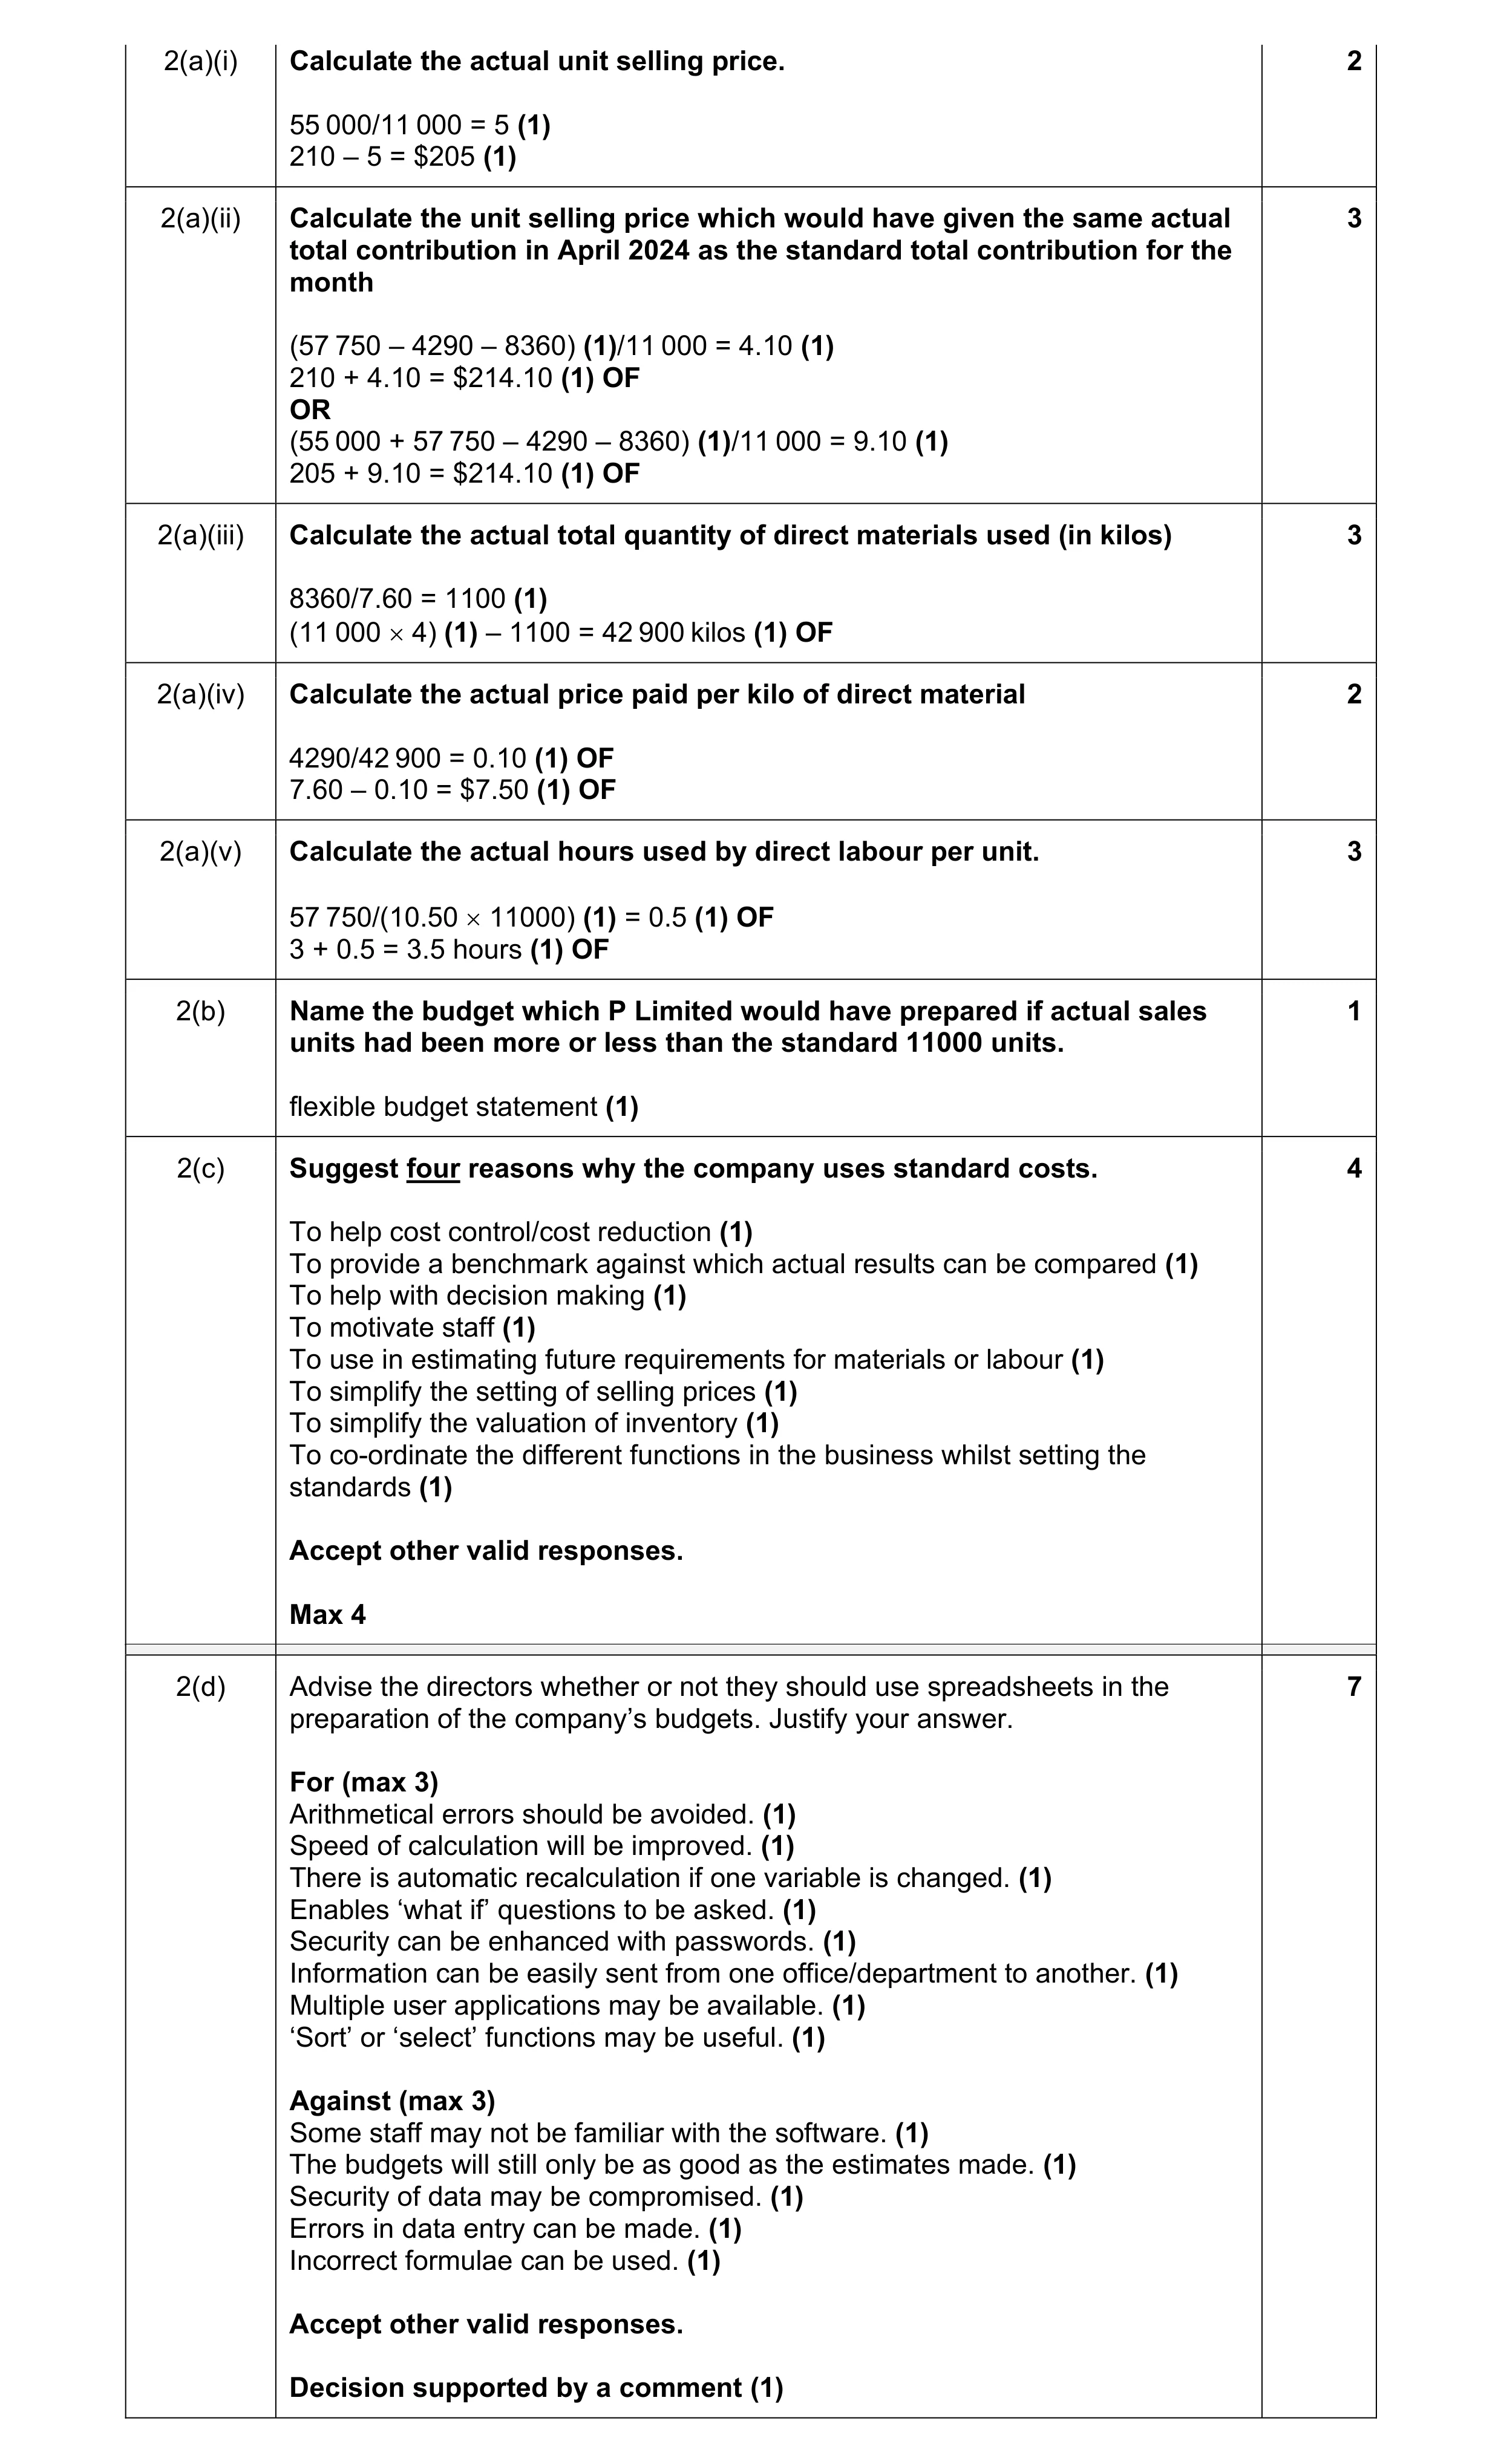 25
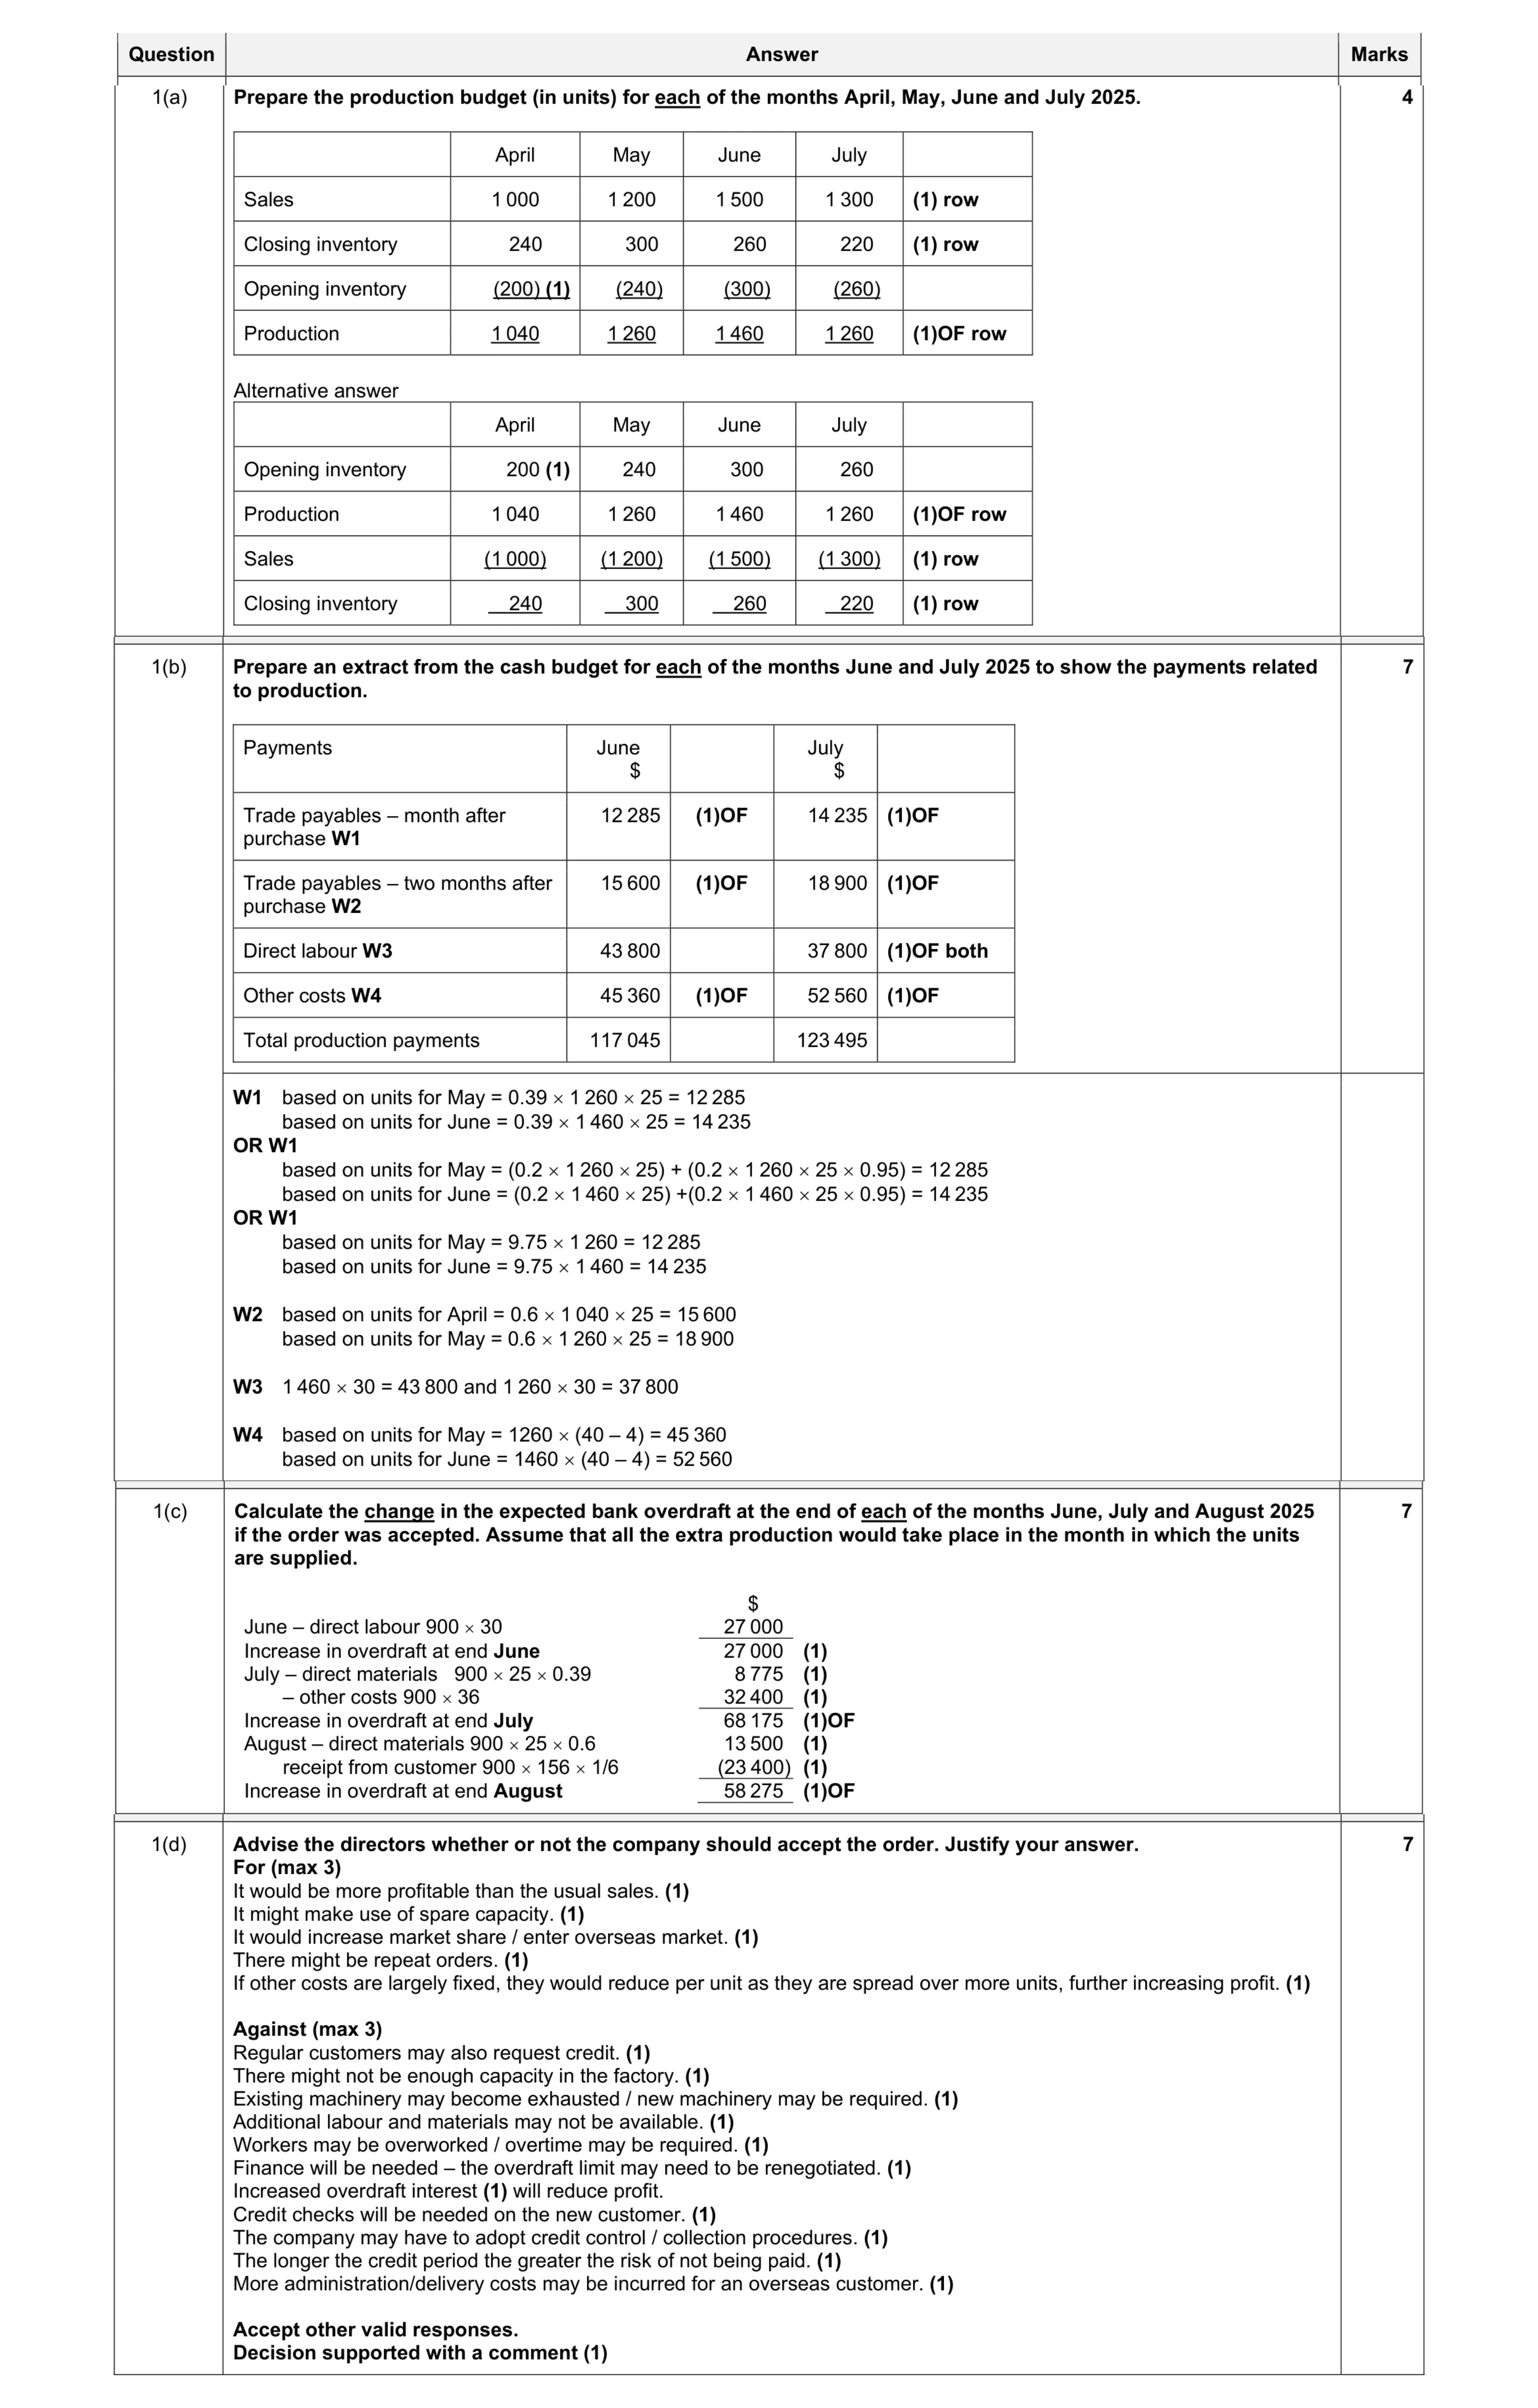 25
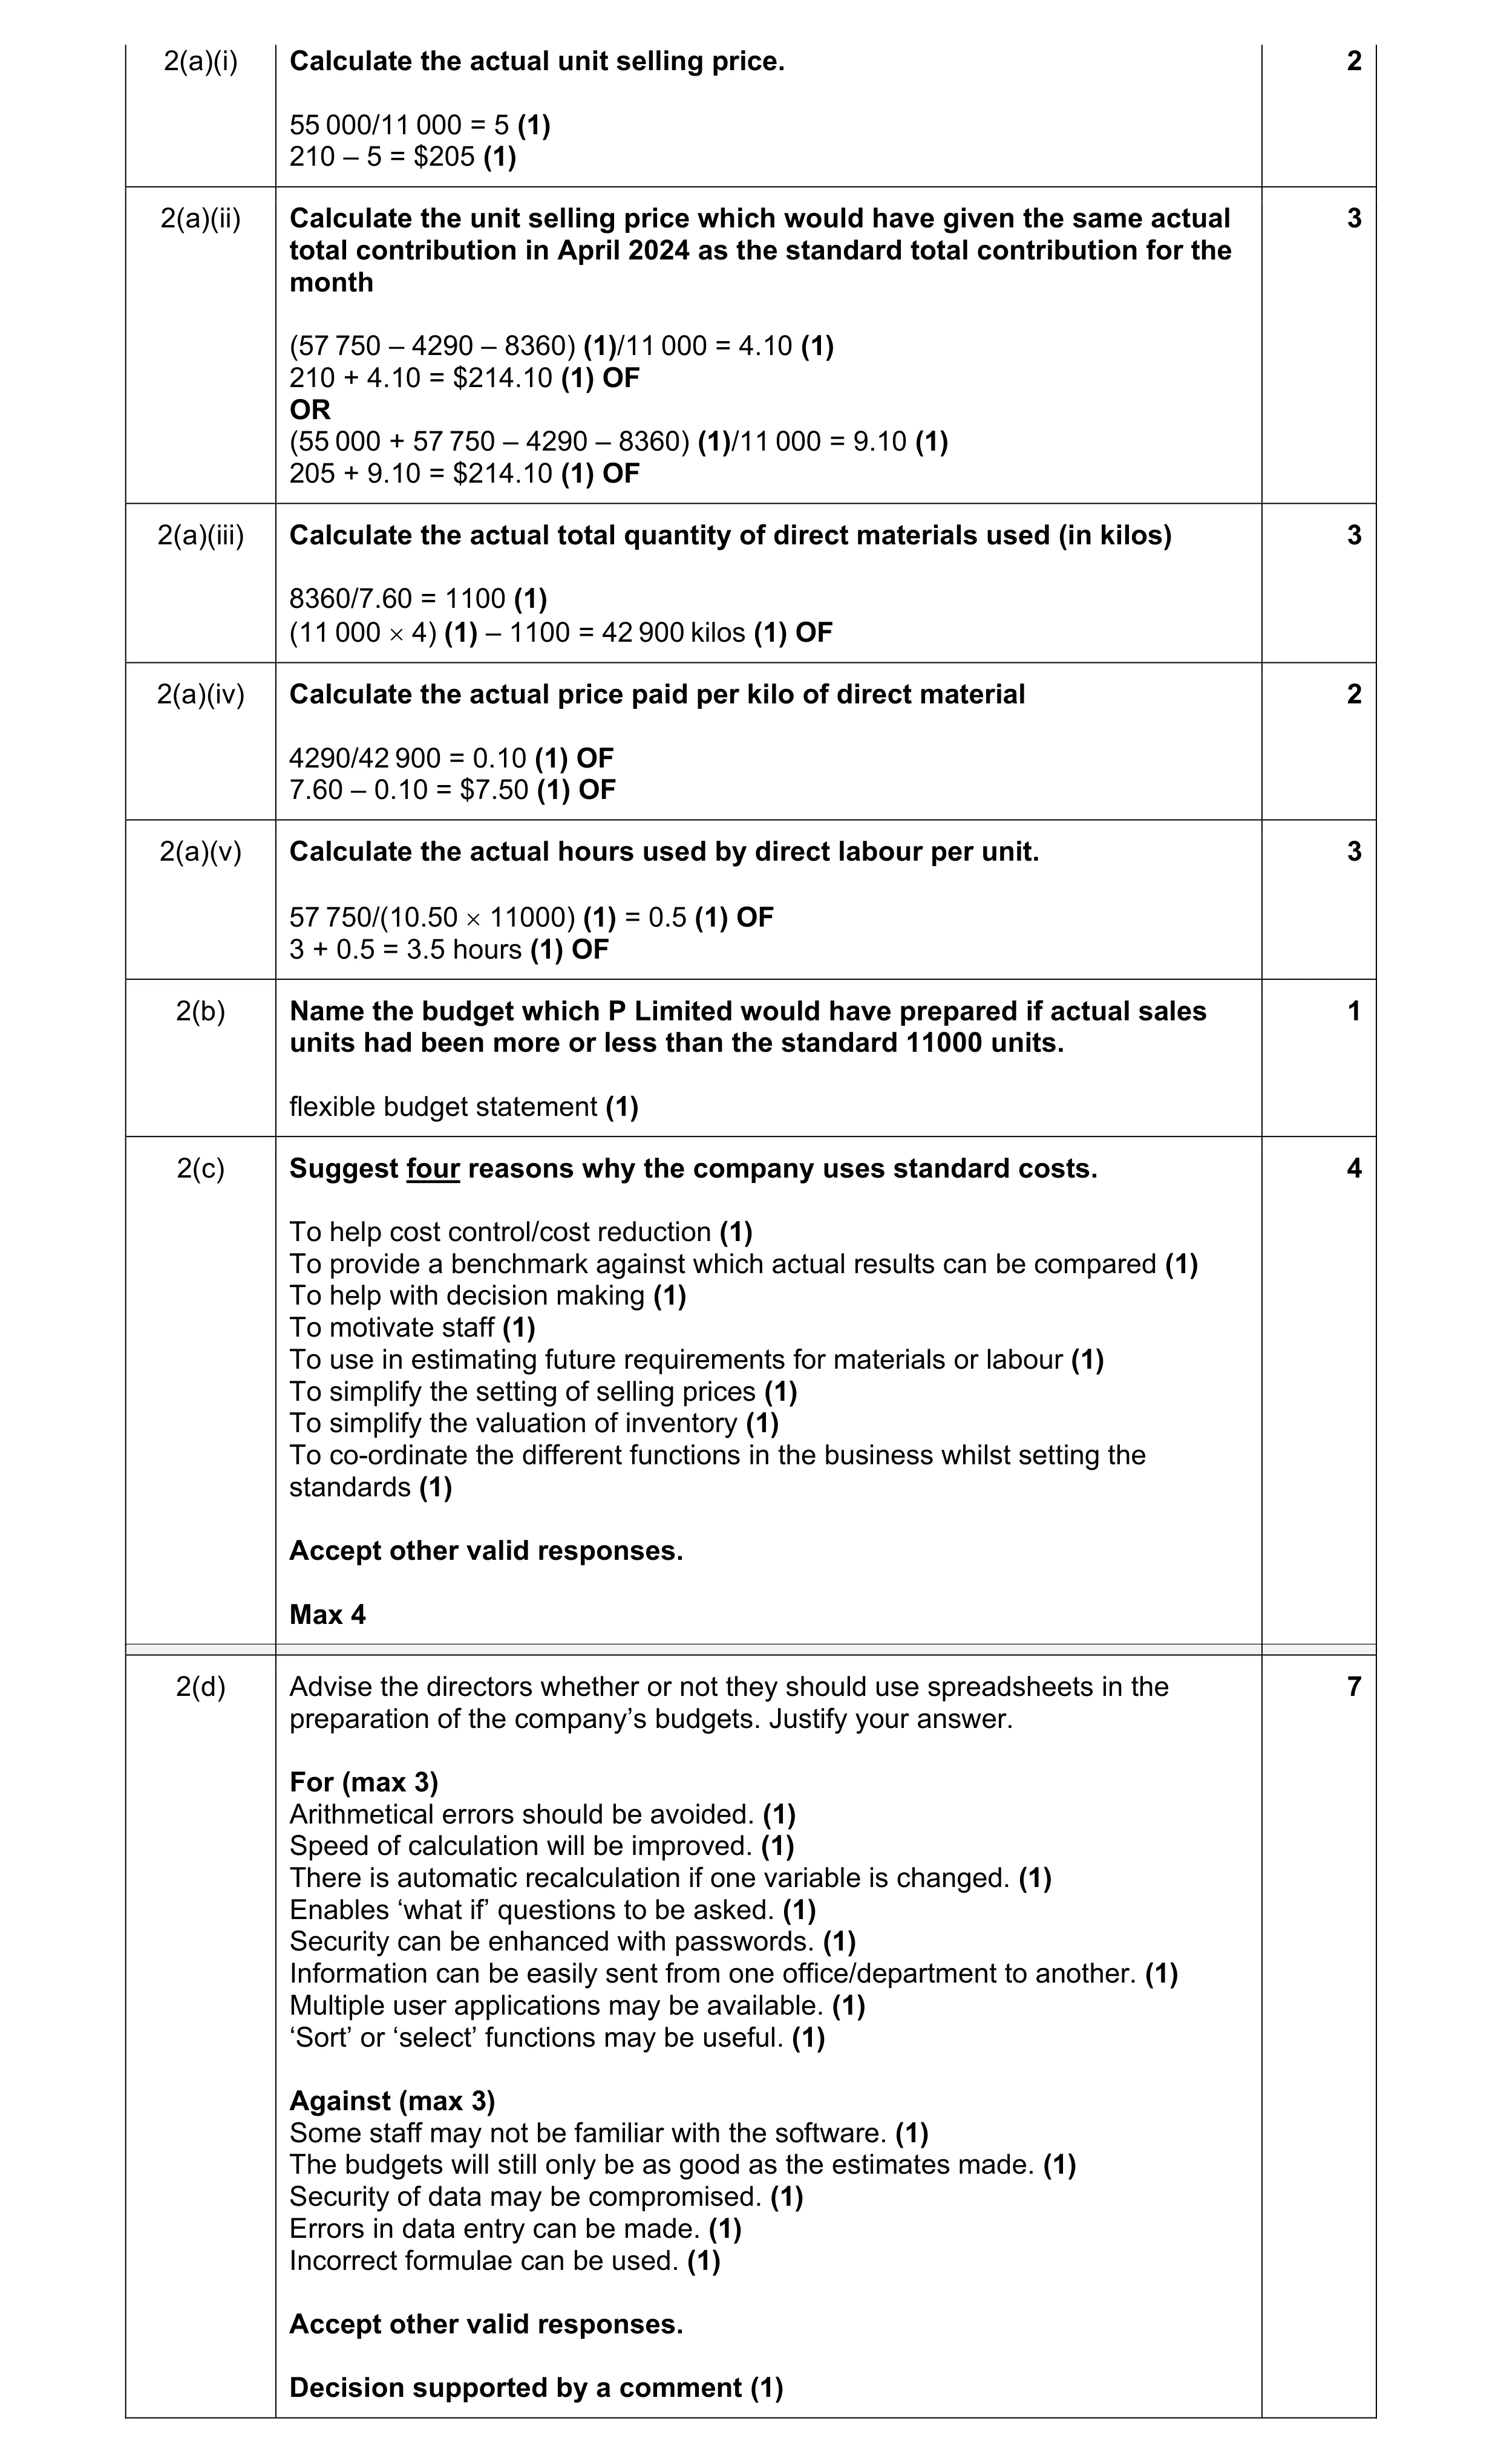 25
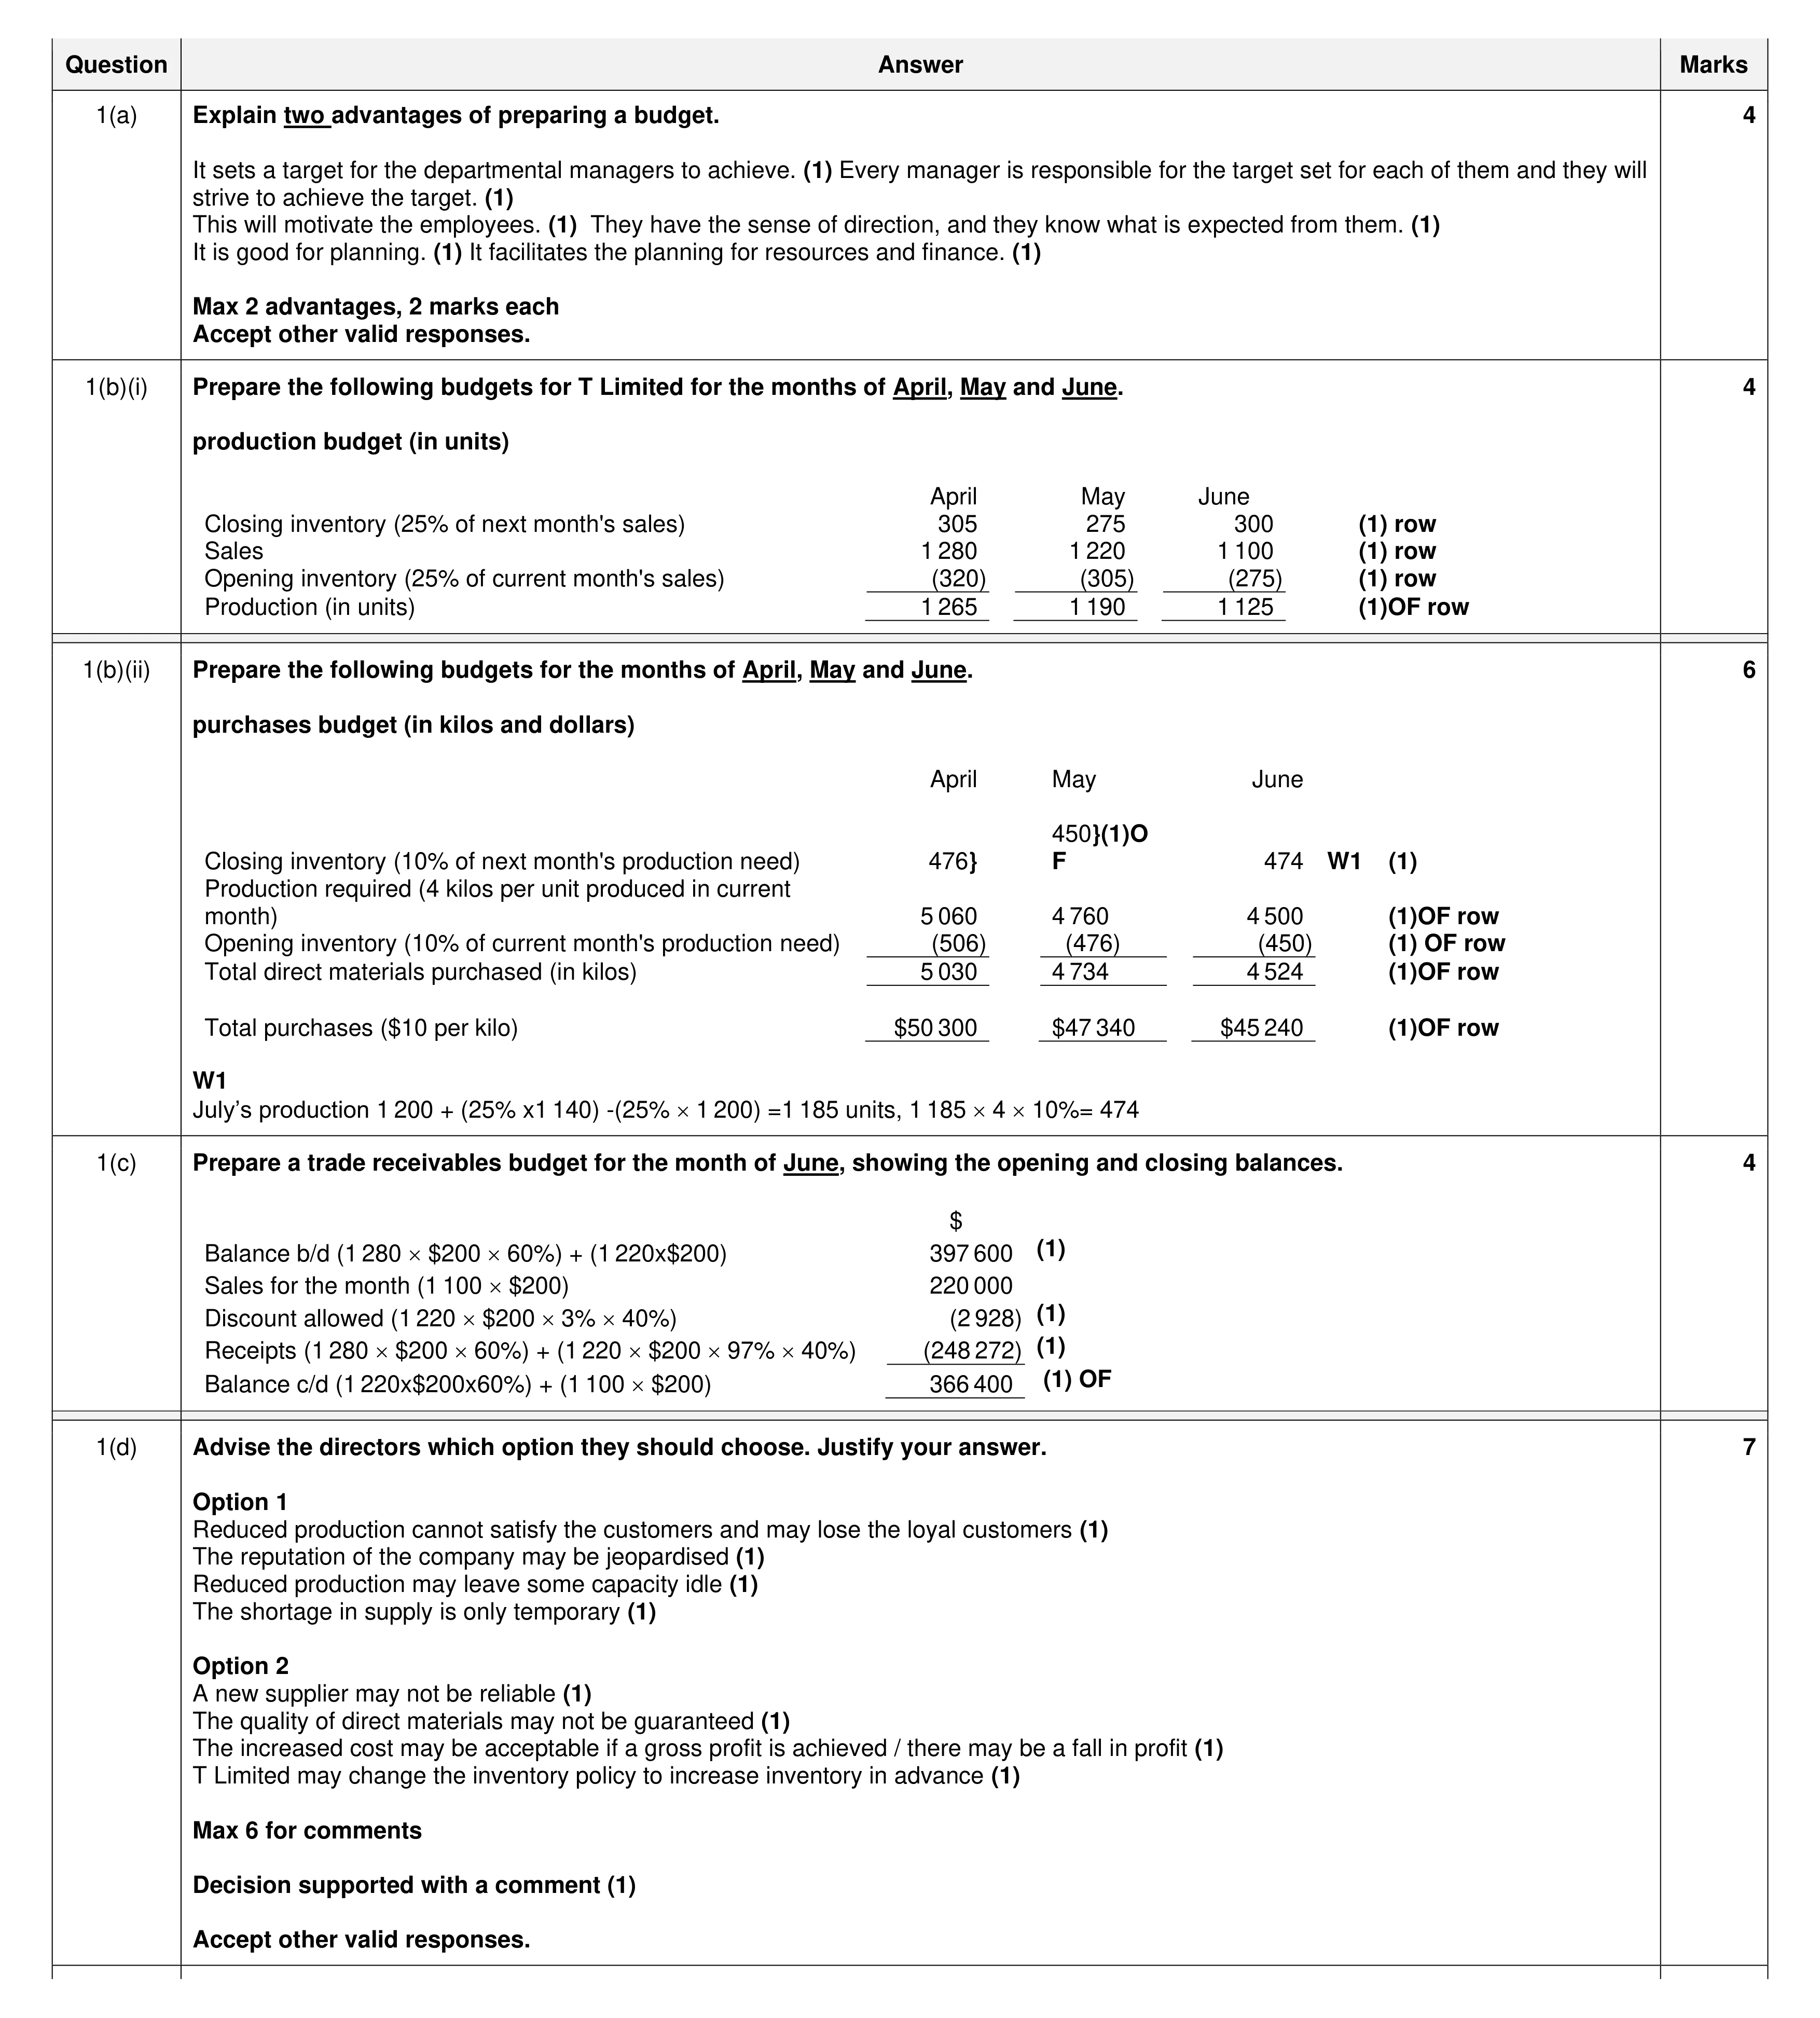 25
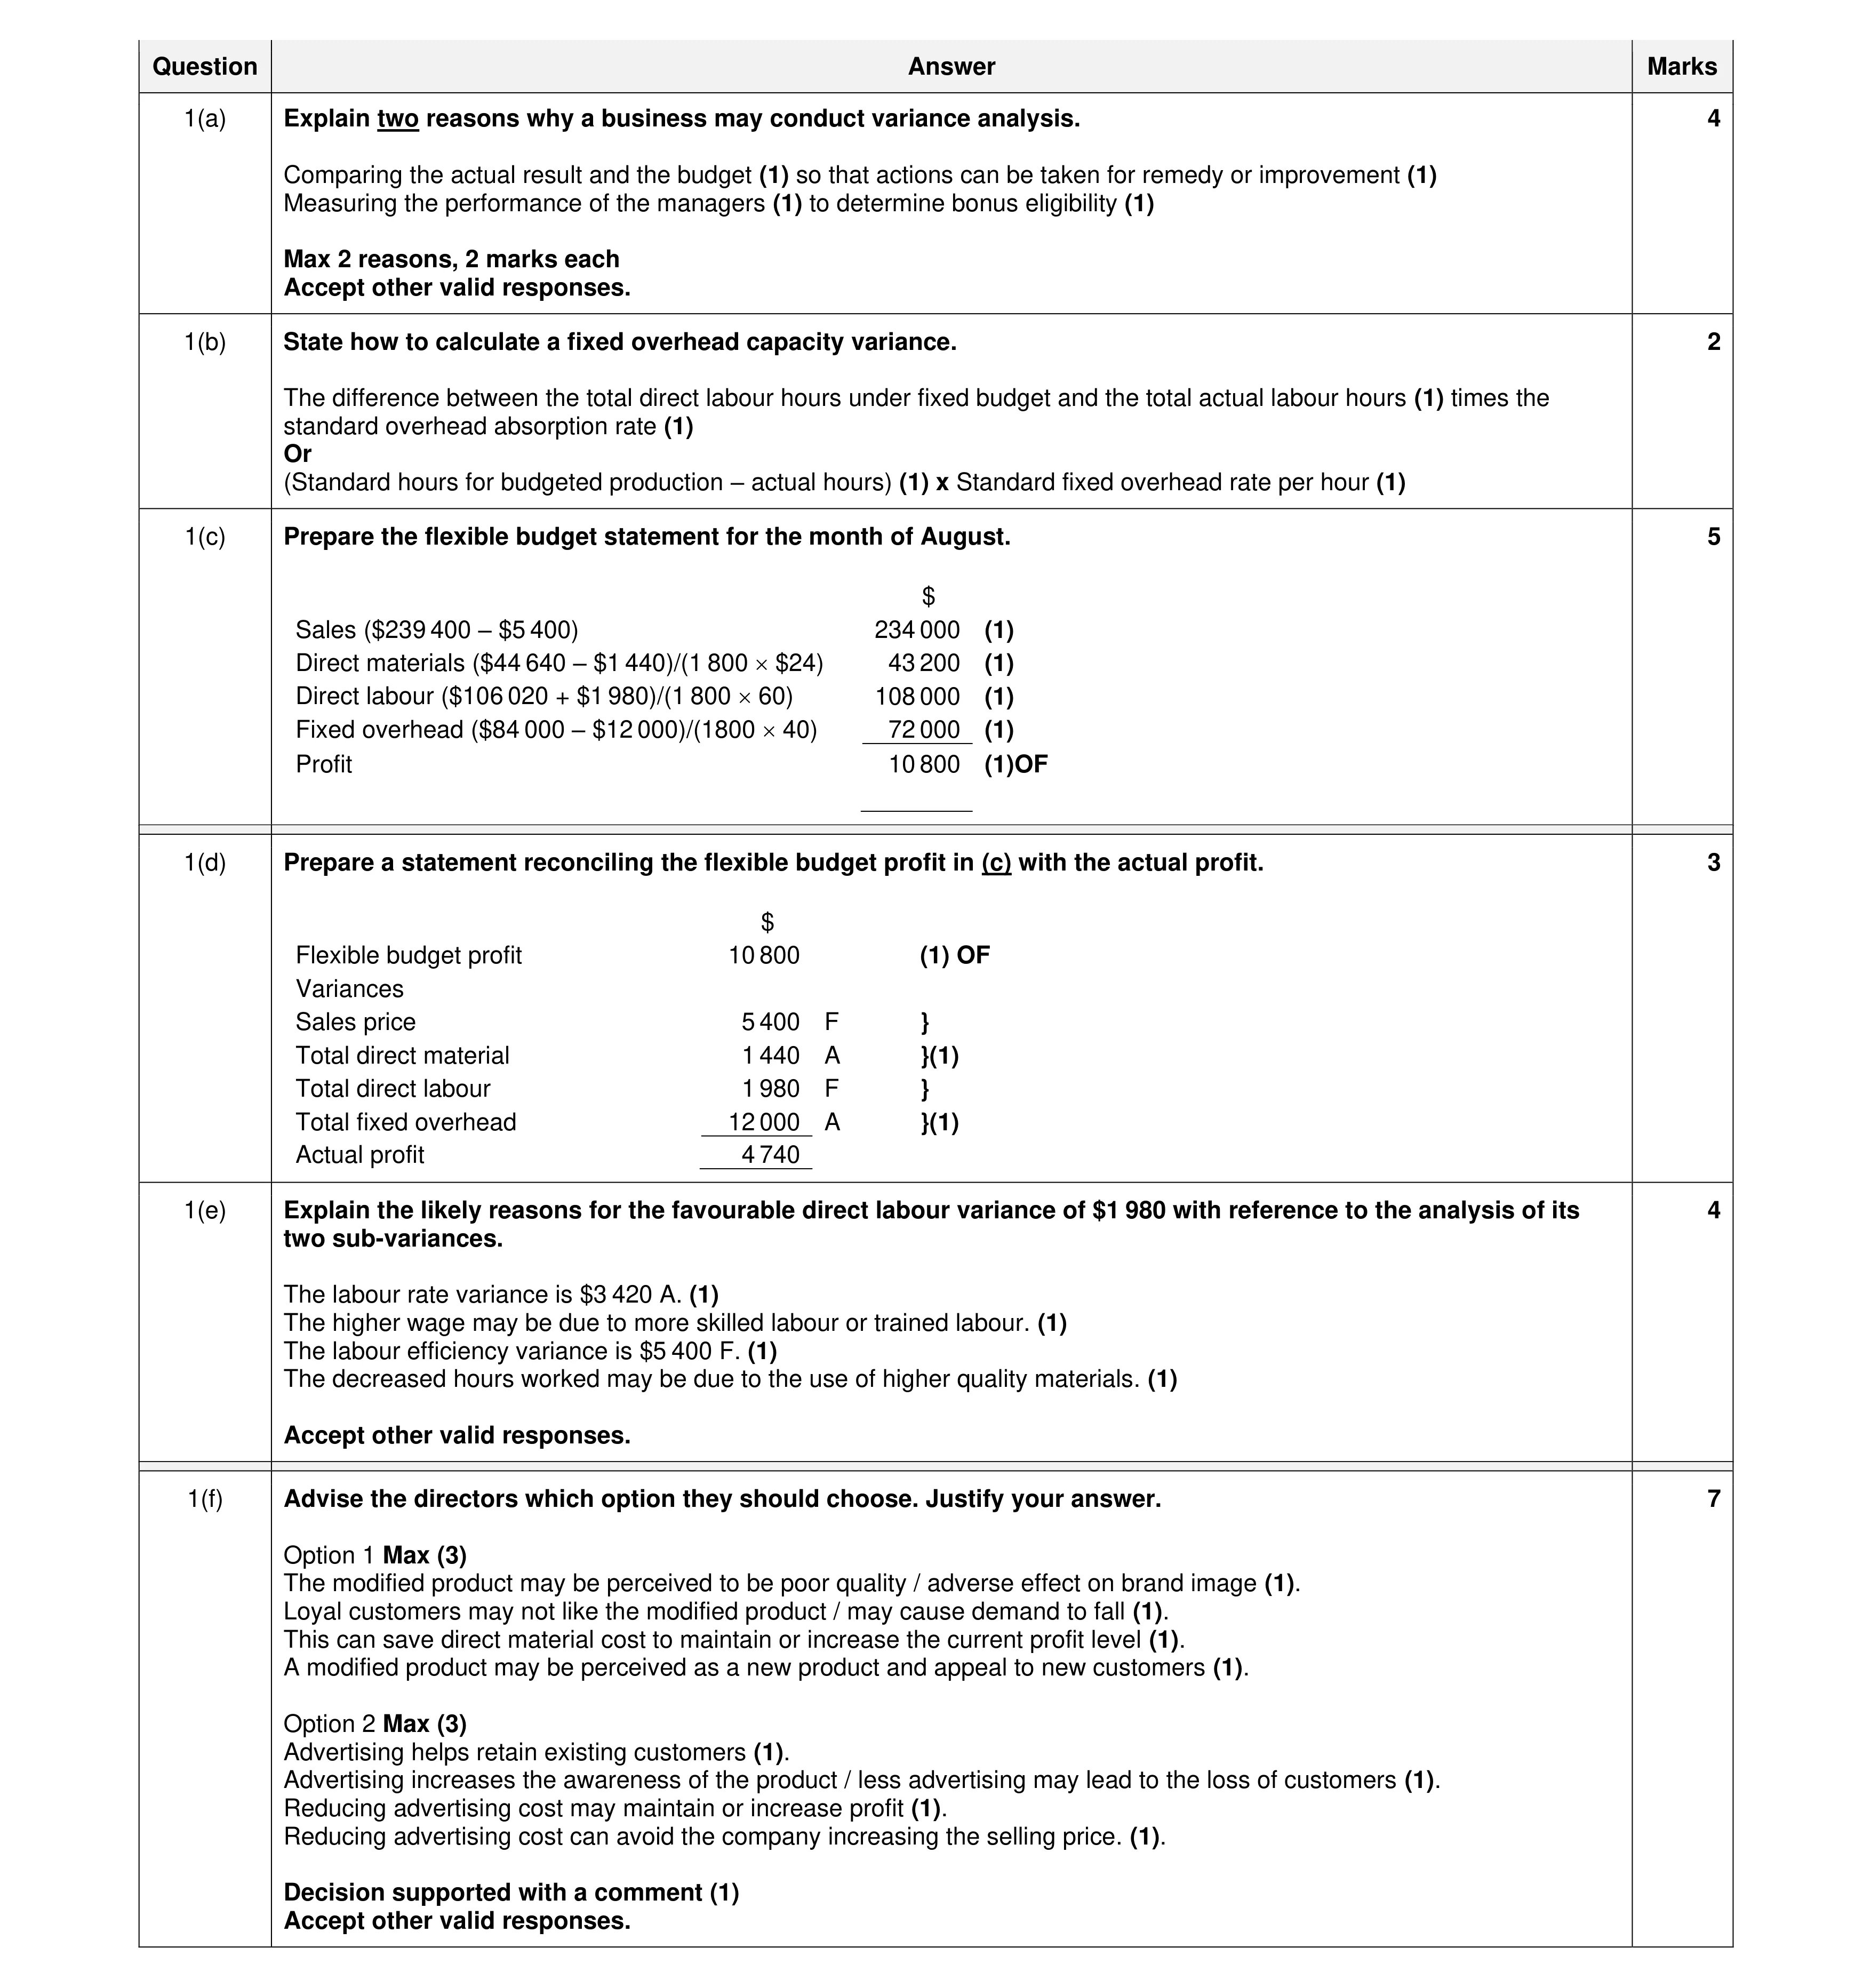 25
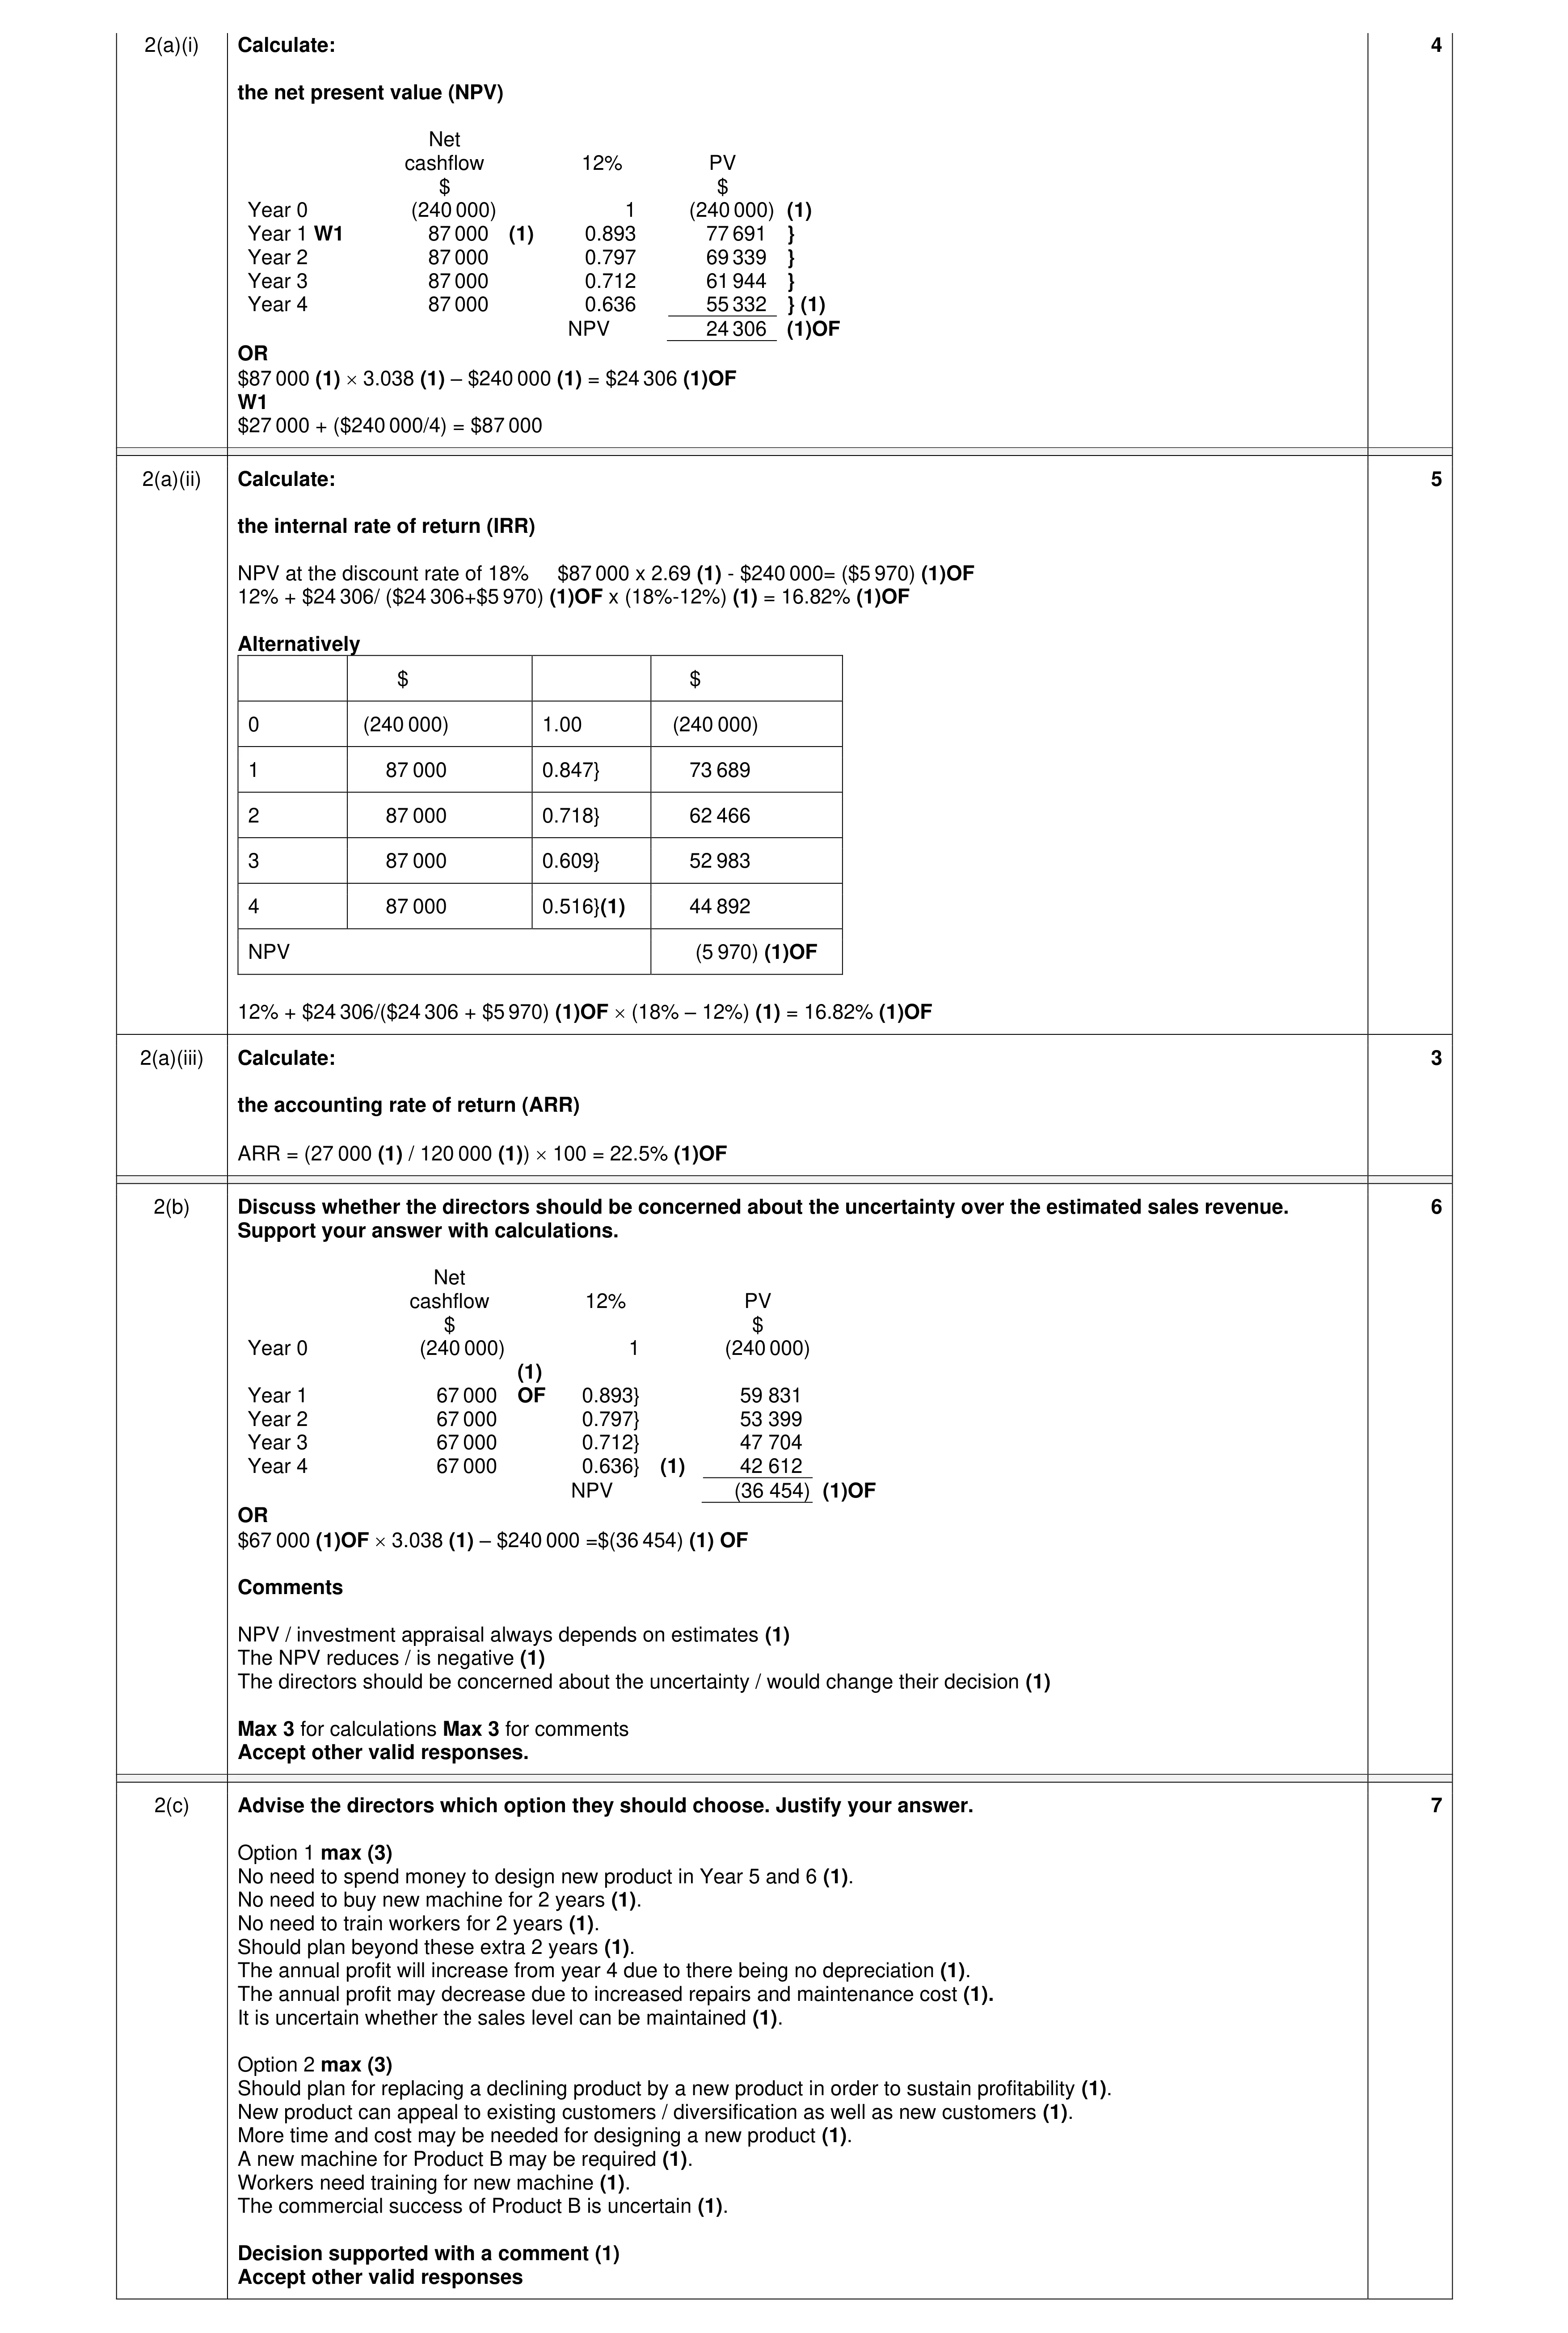 25
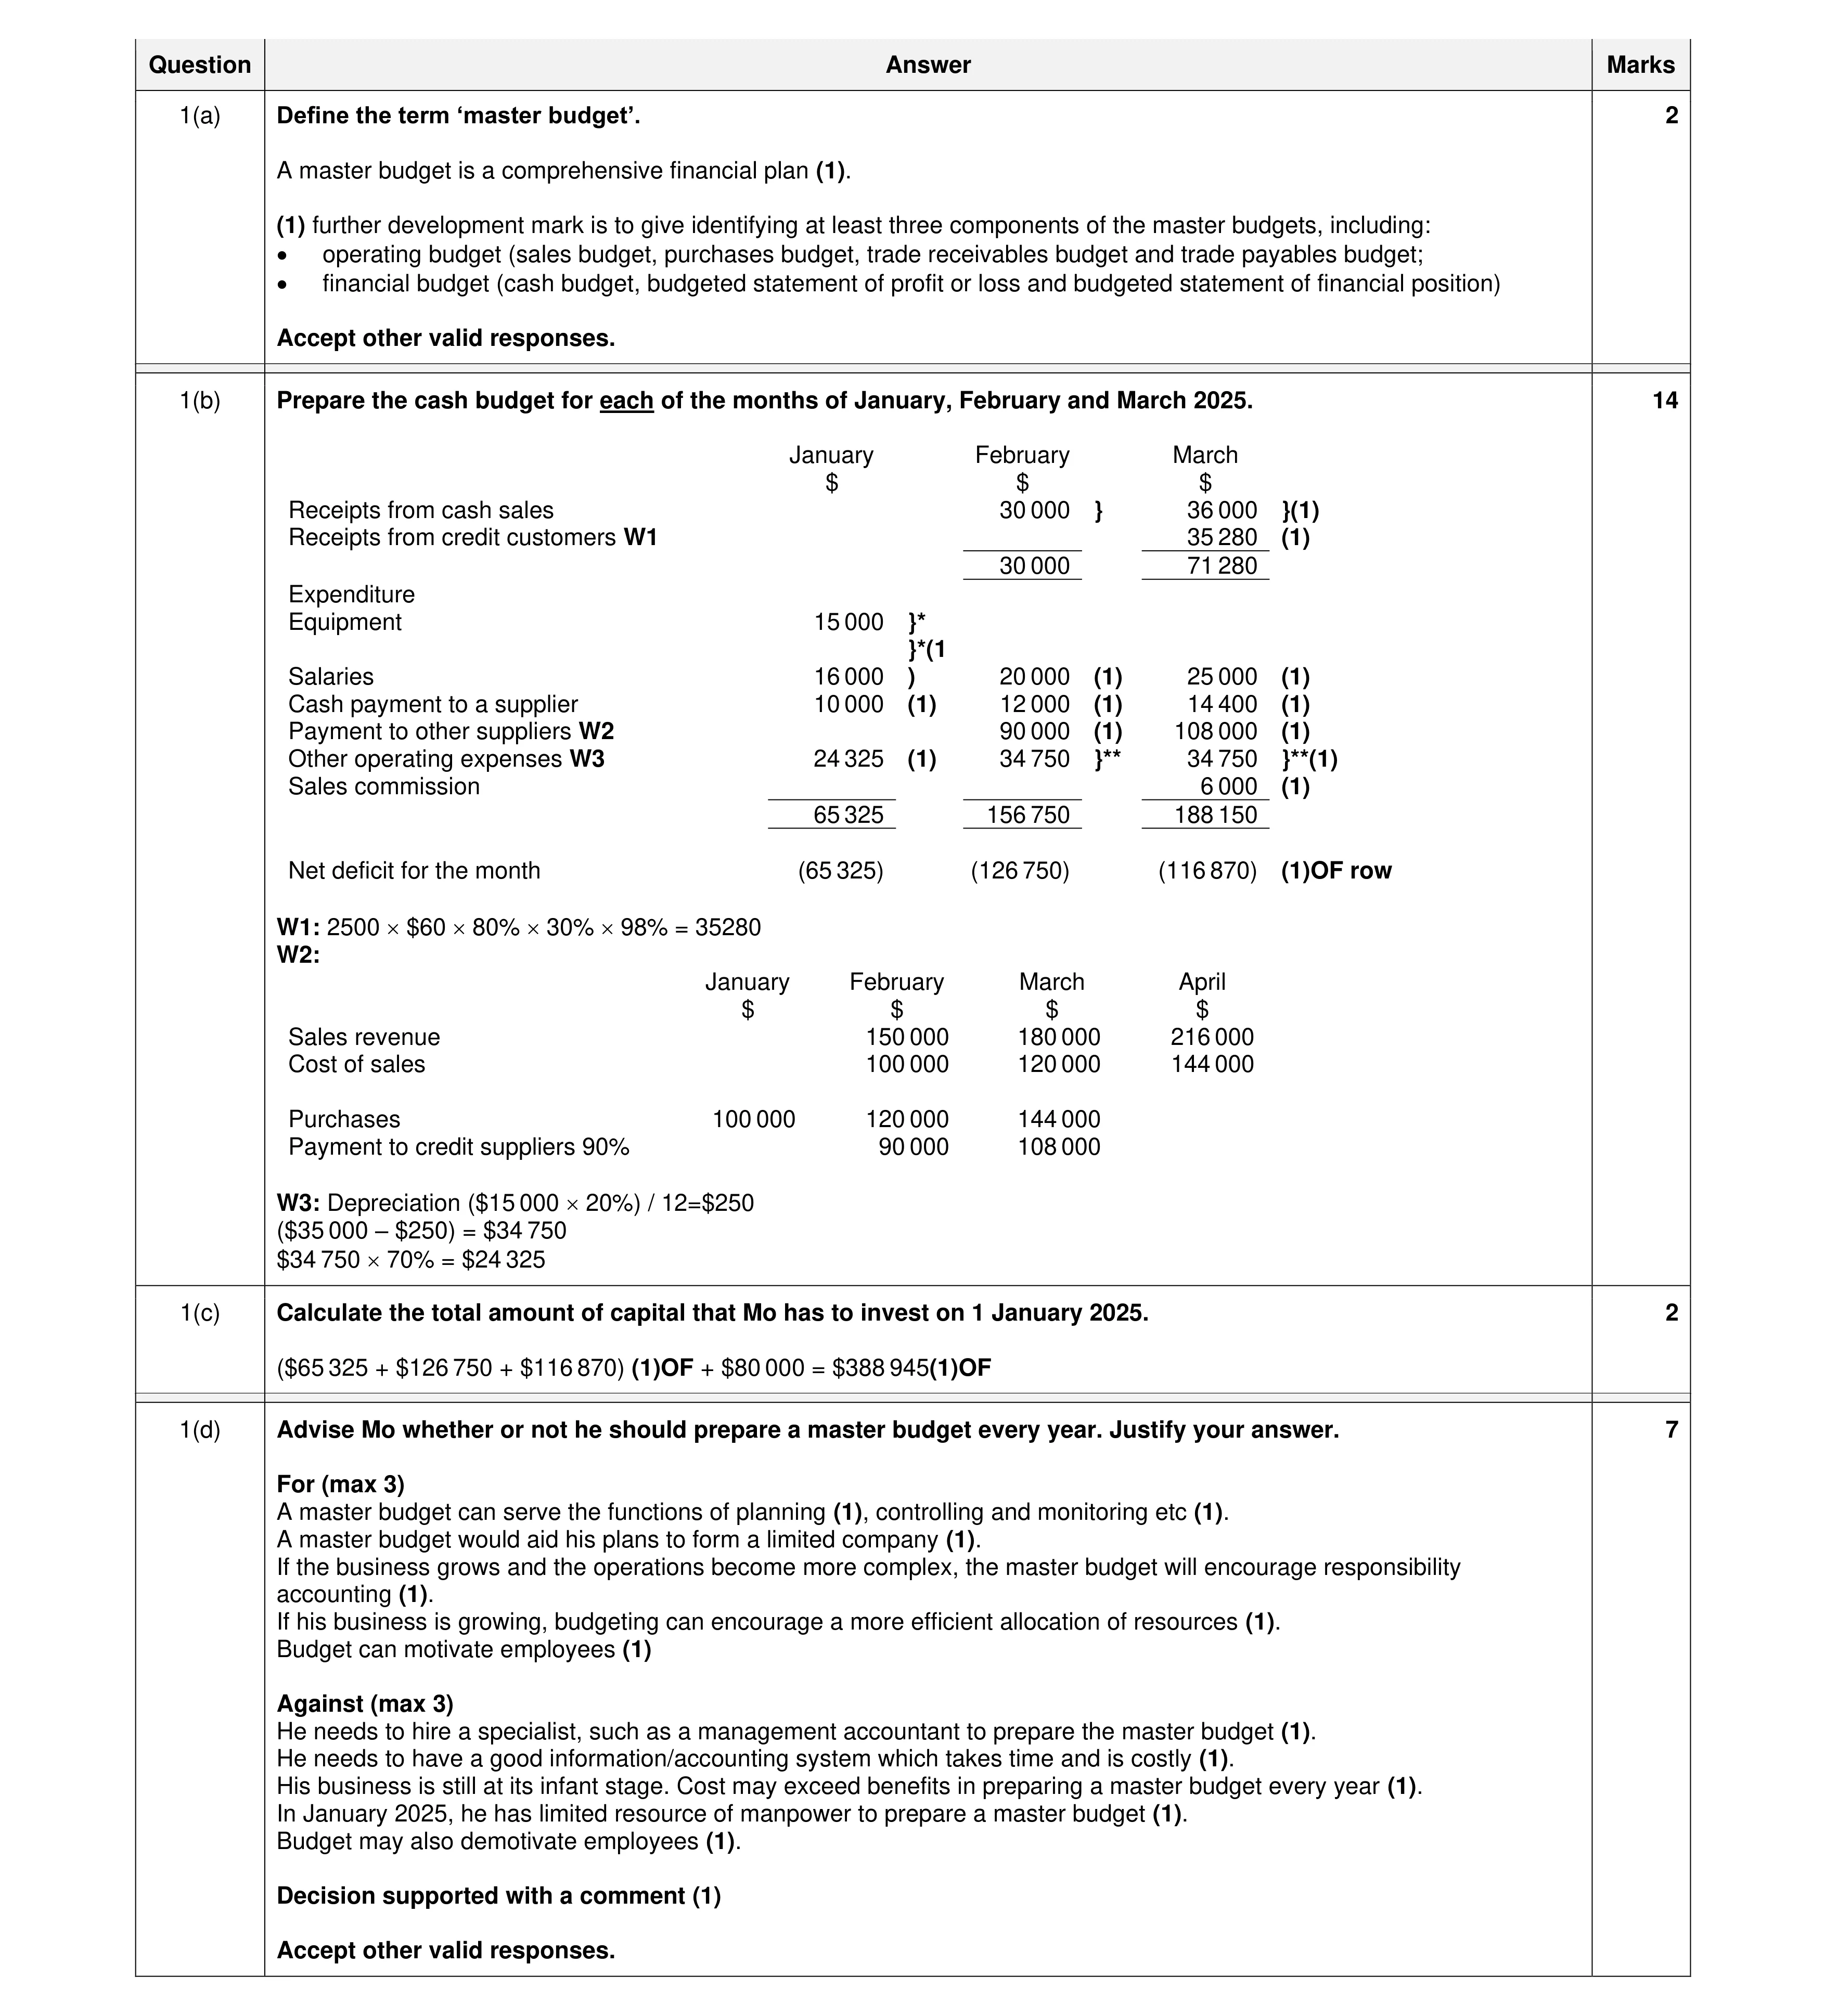 25
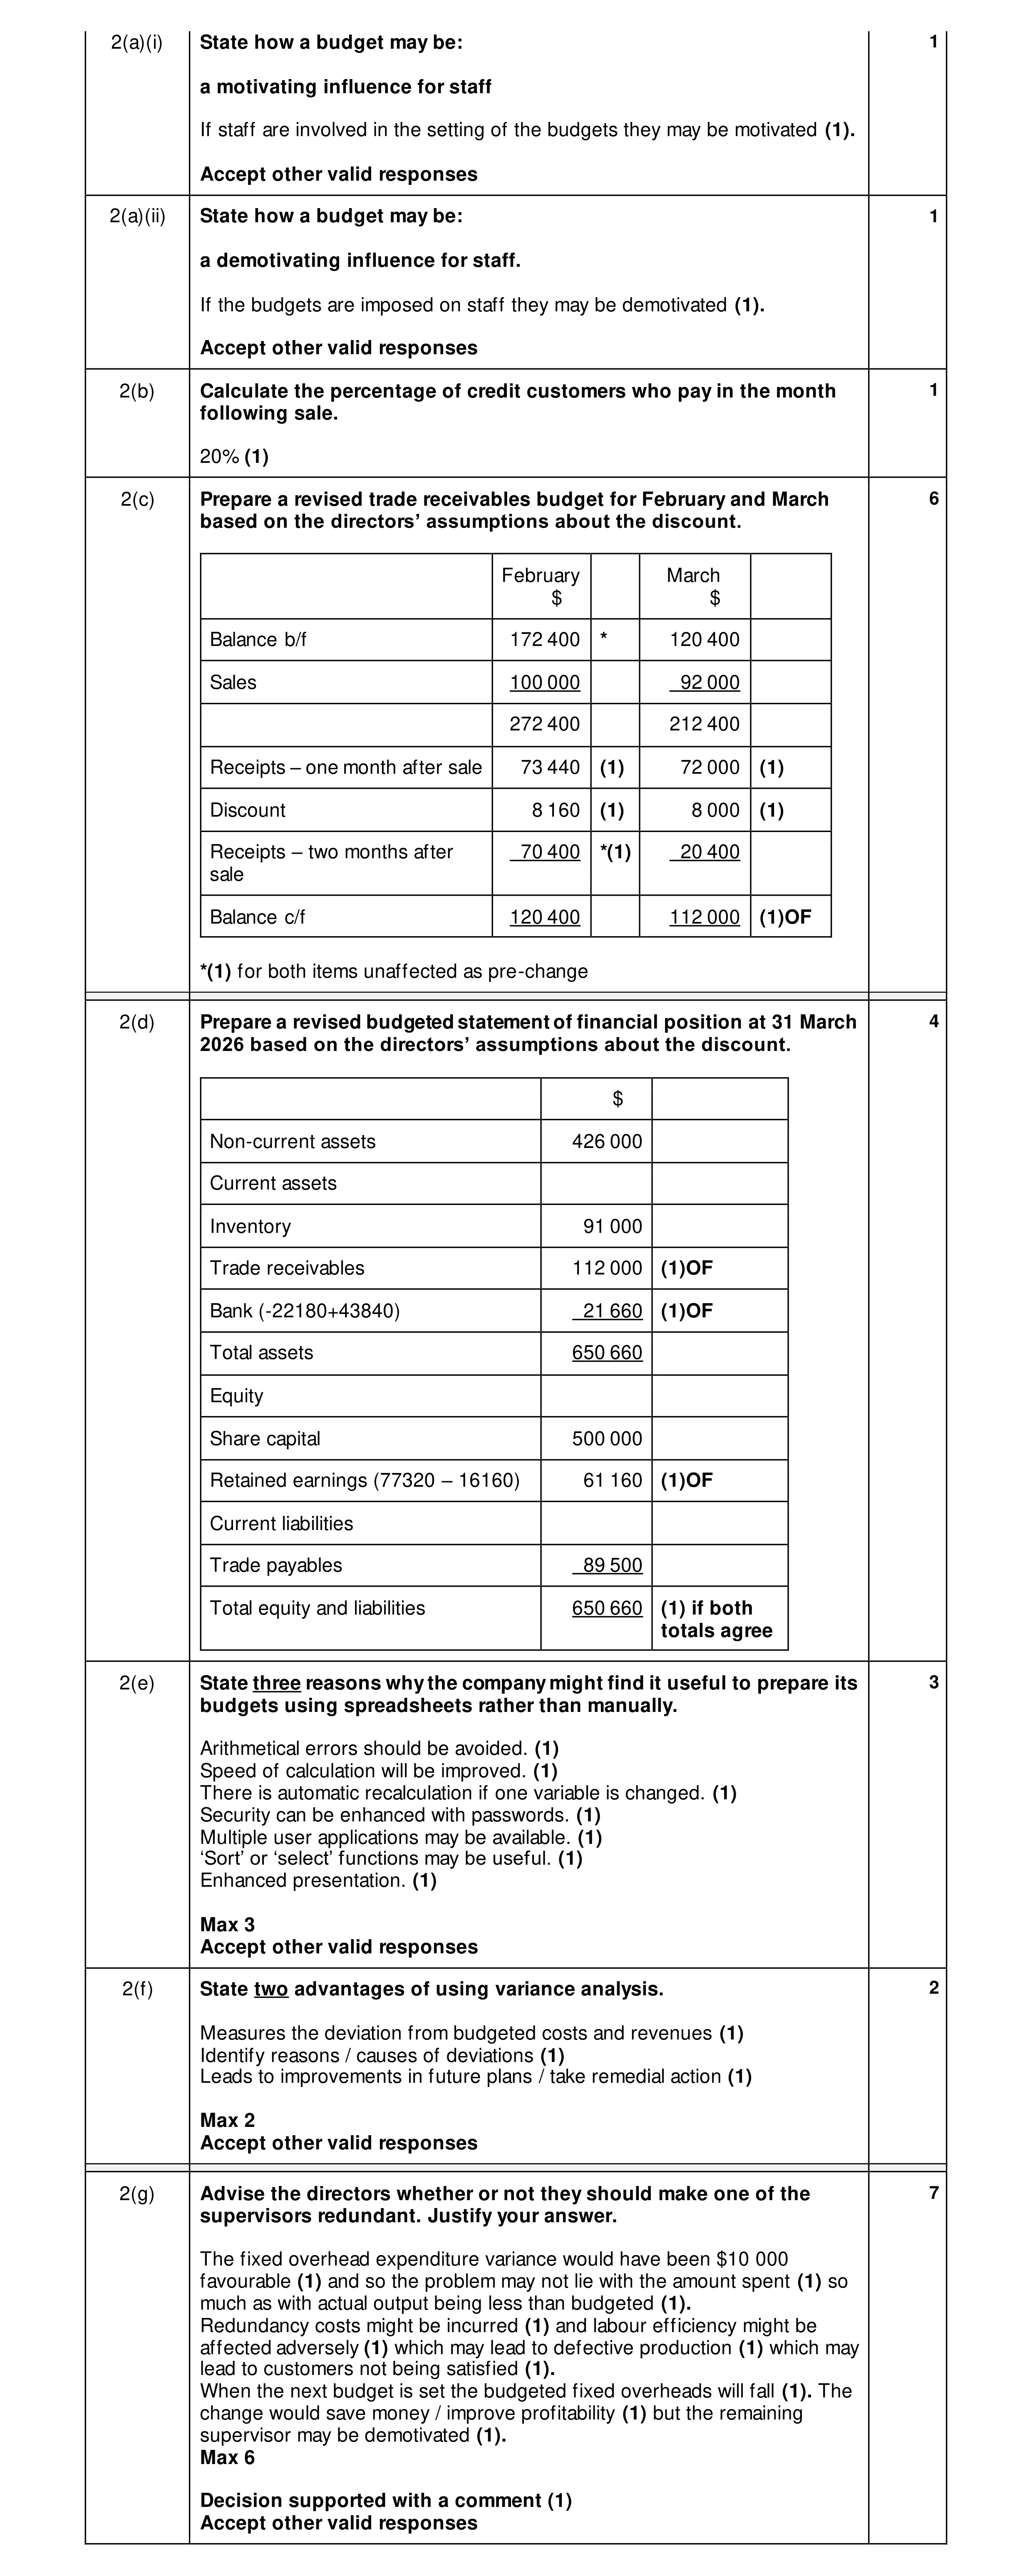 18
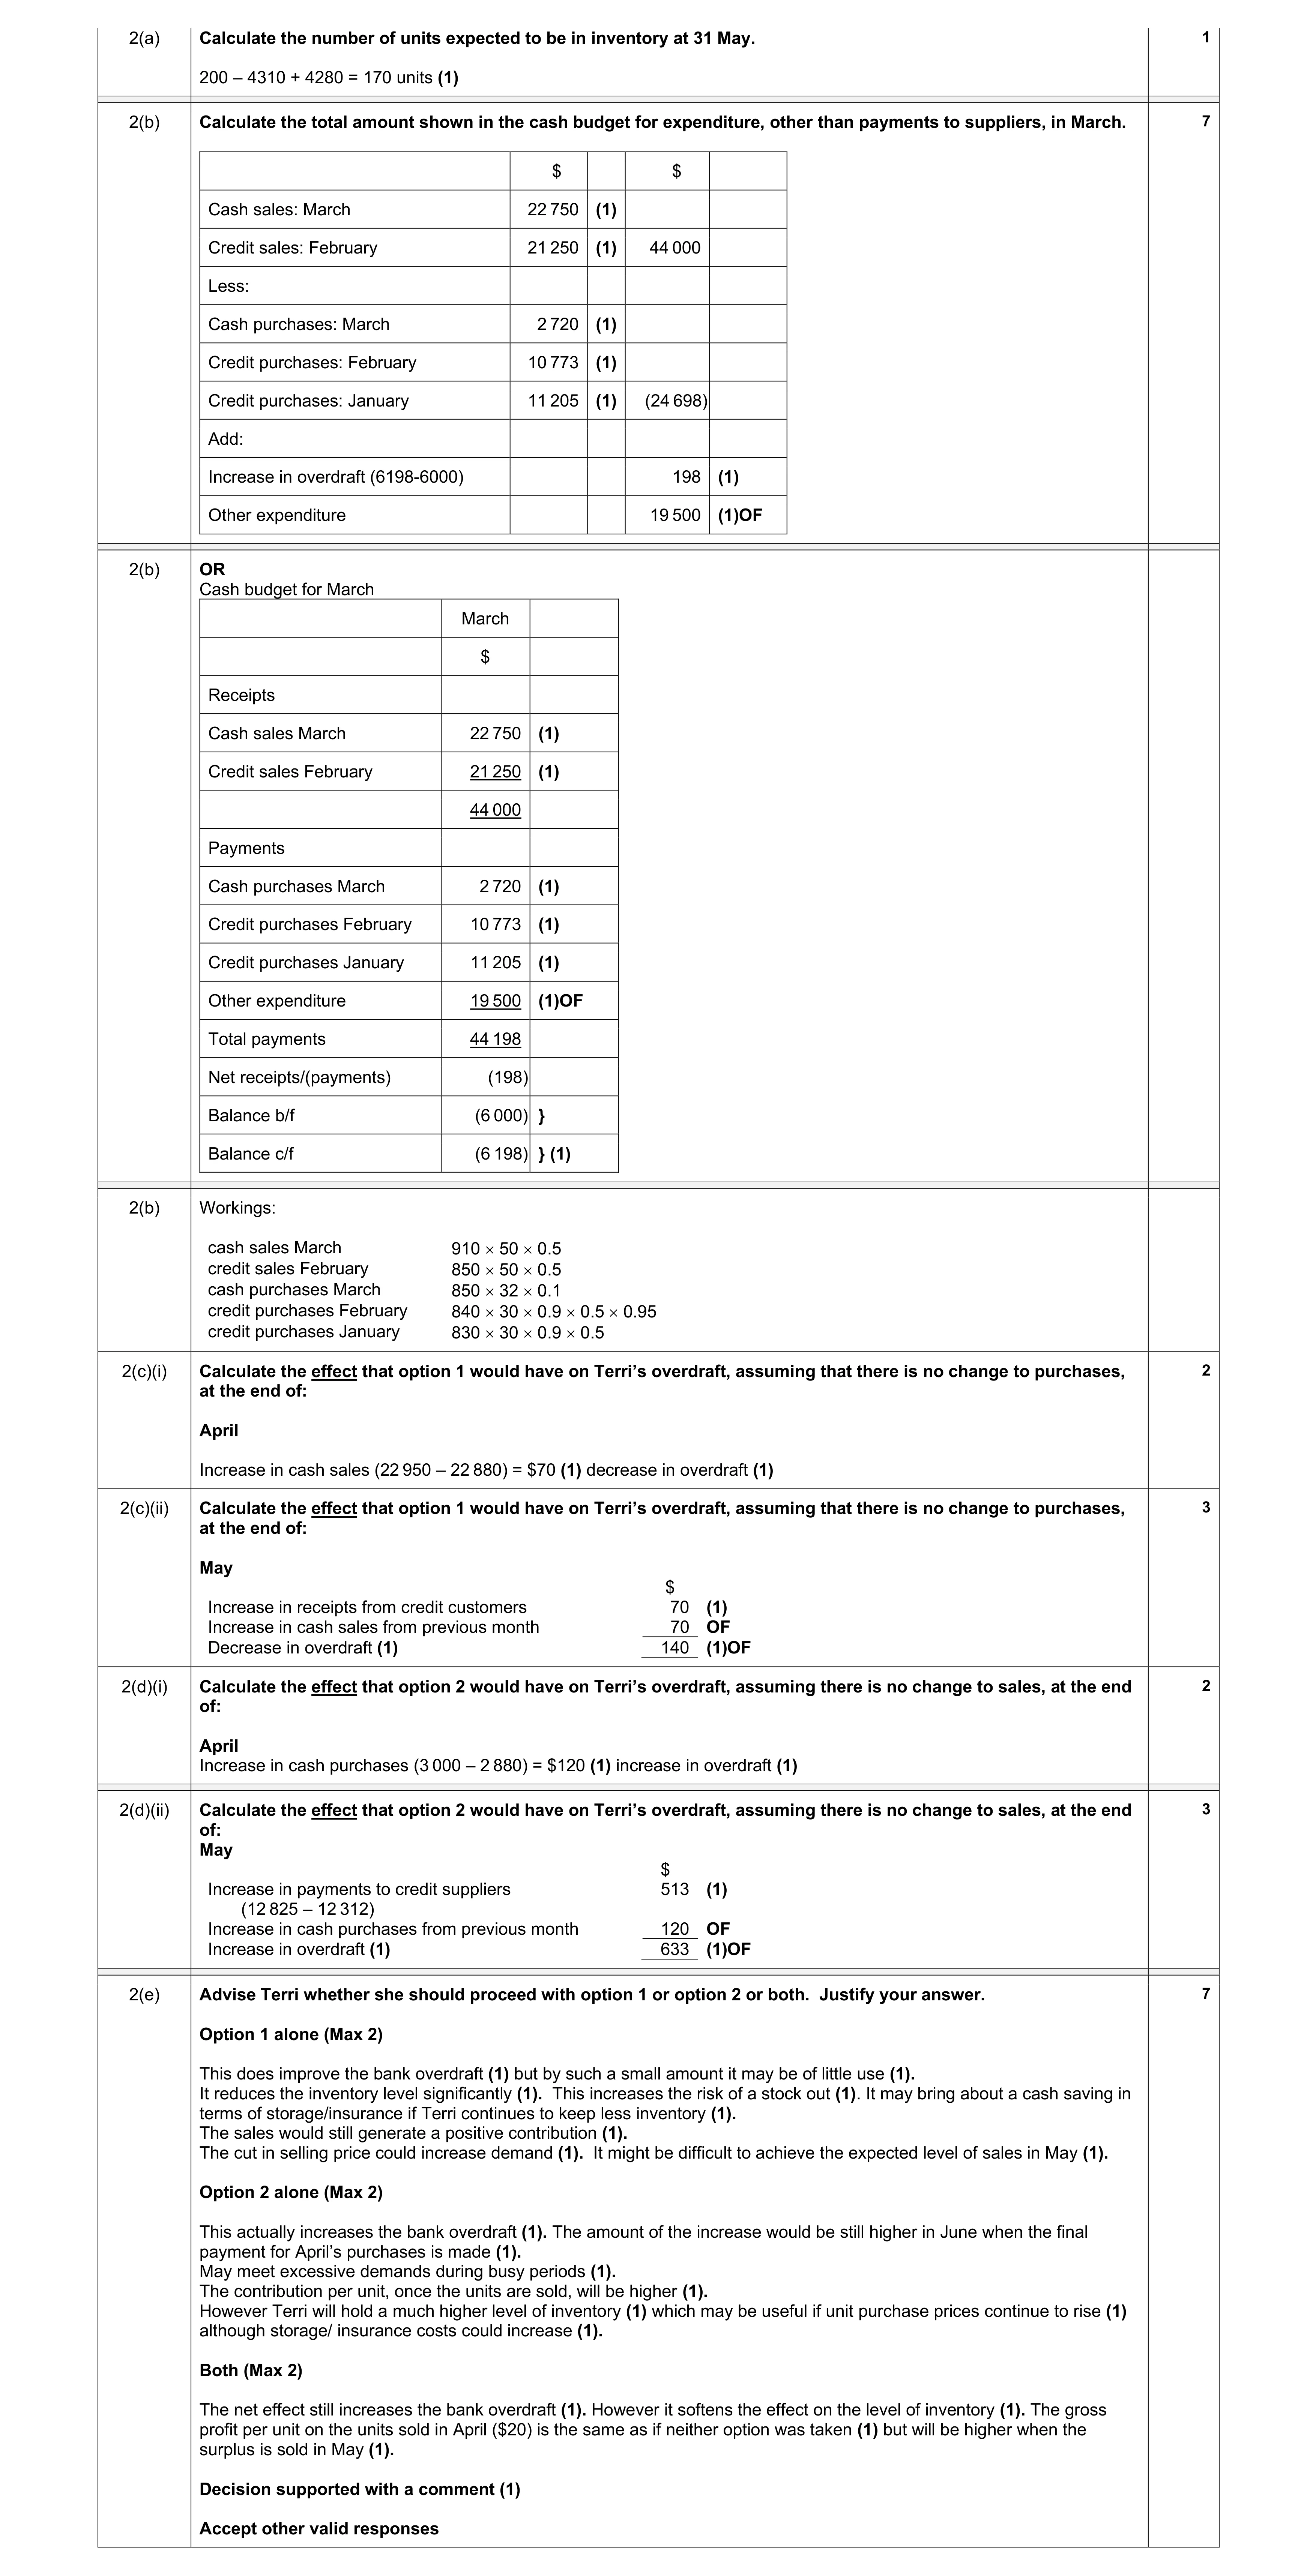 18
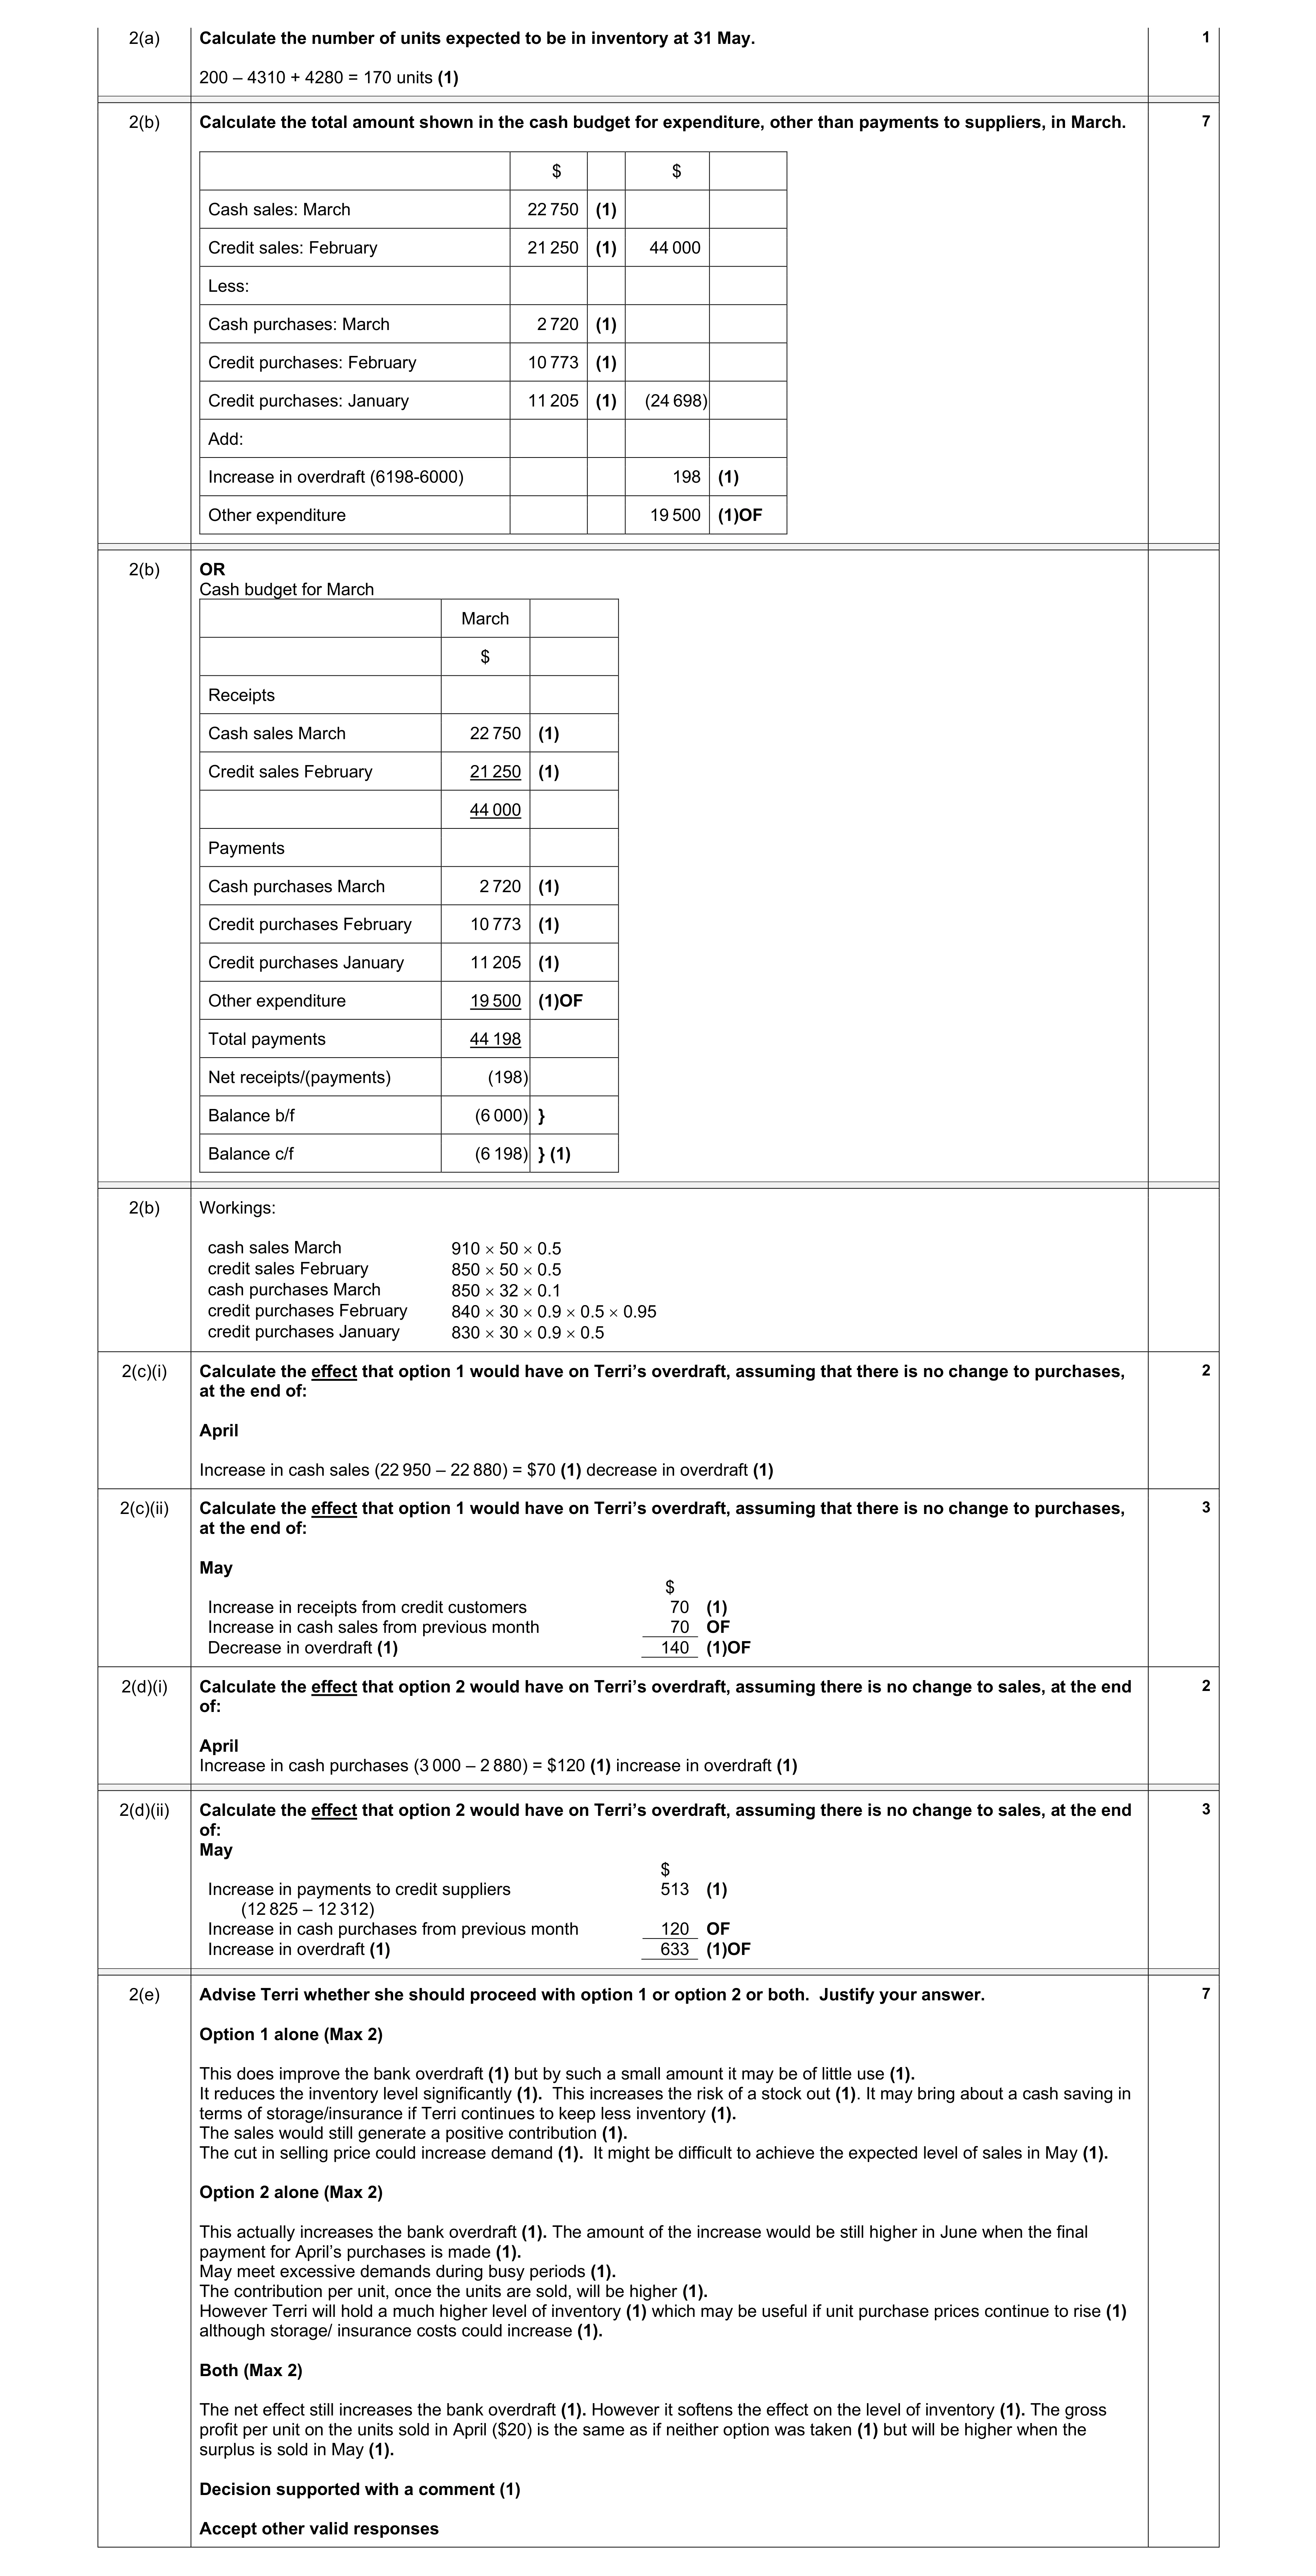 18
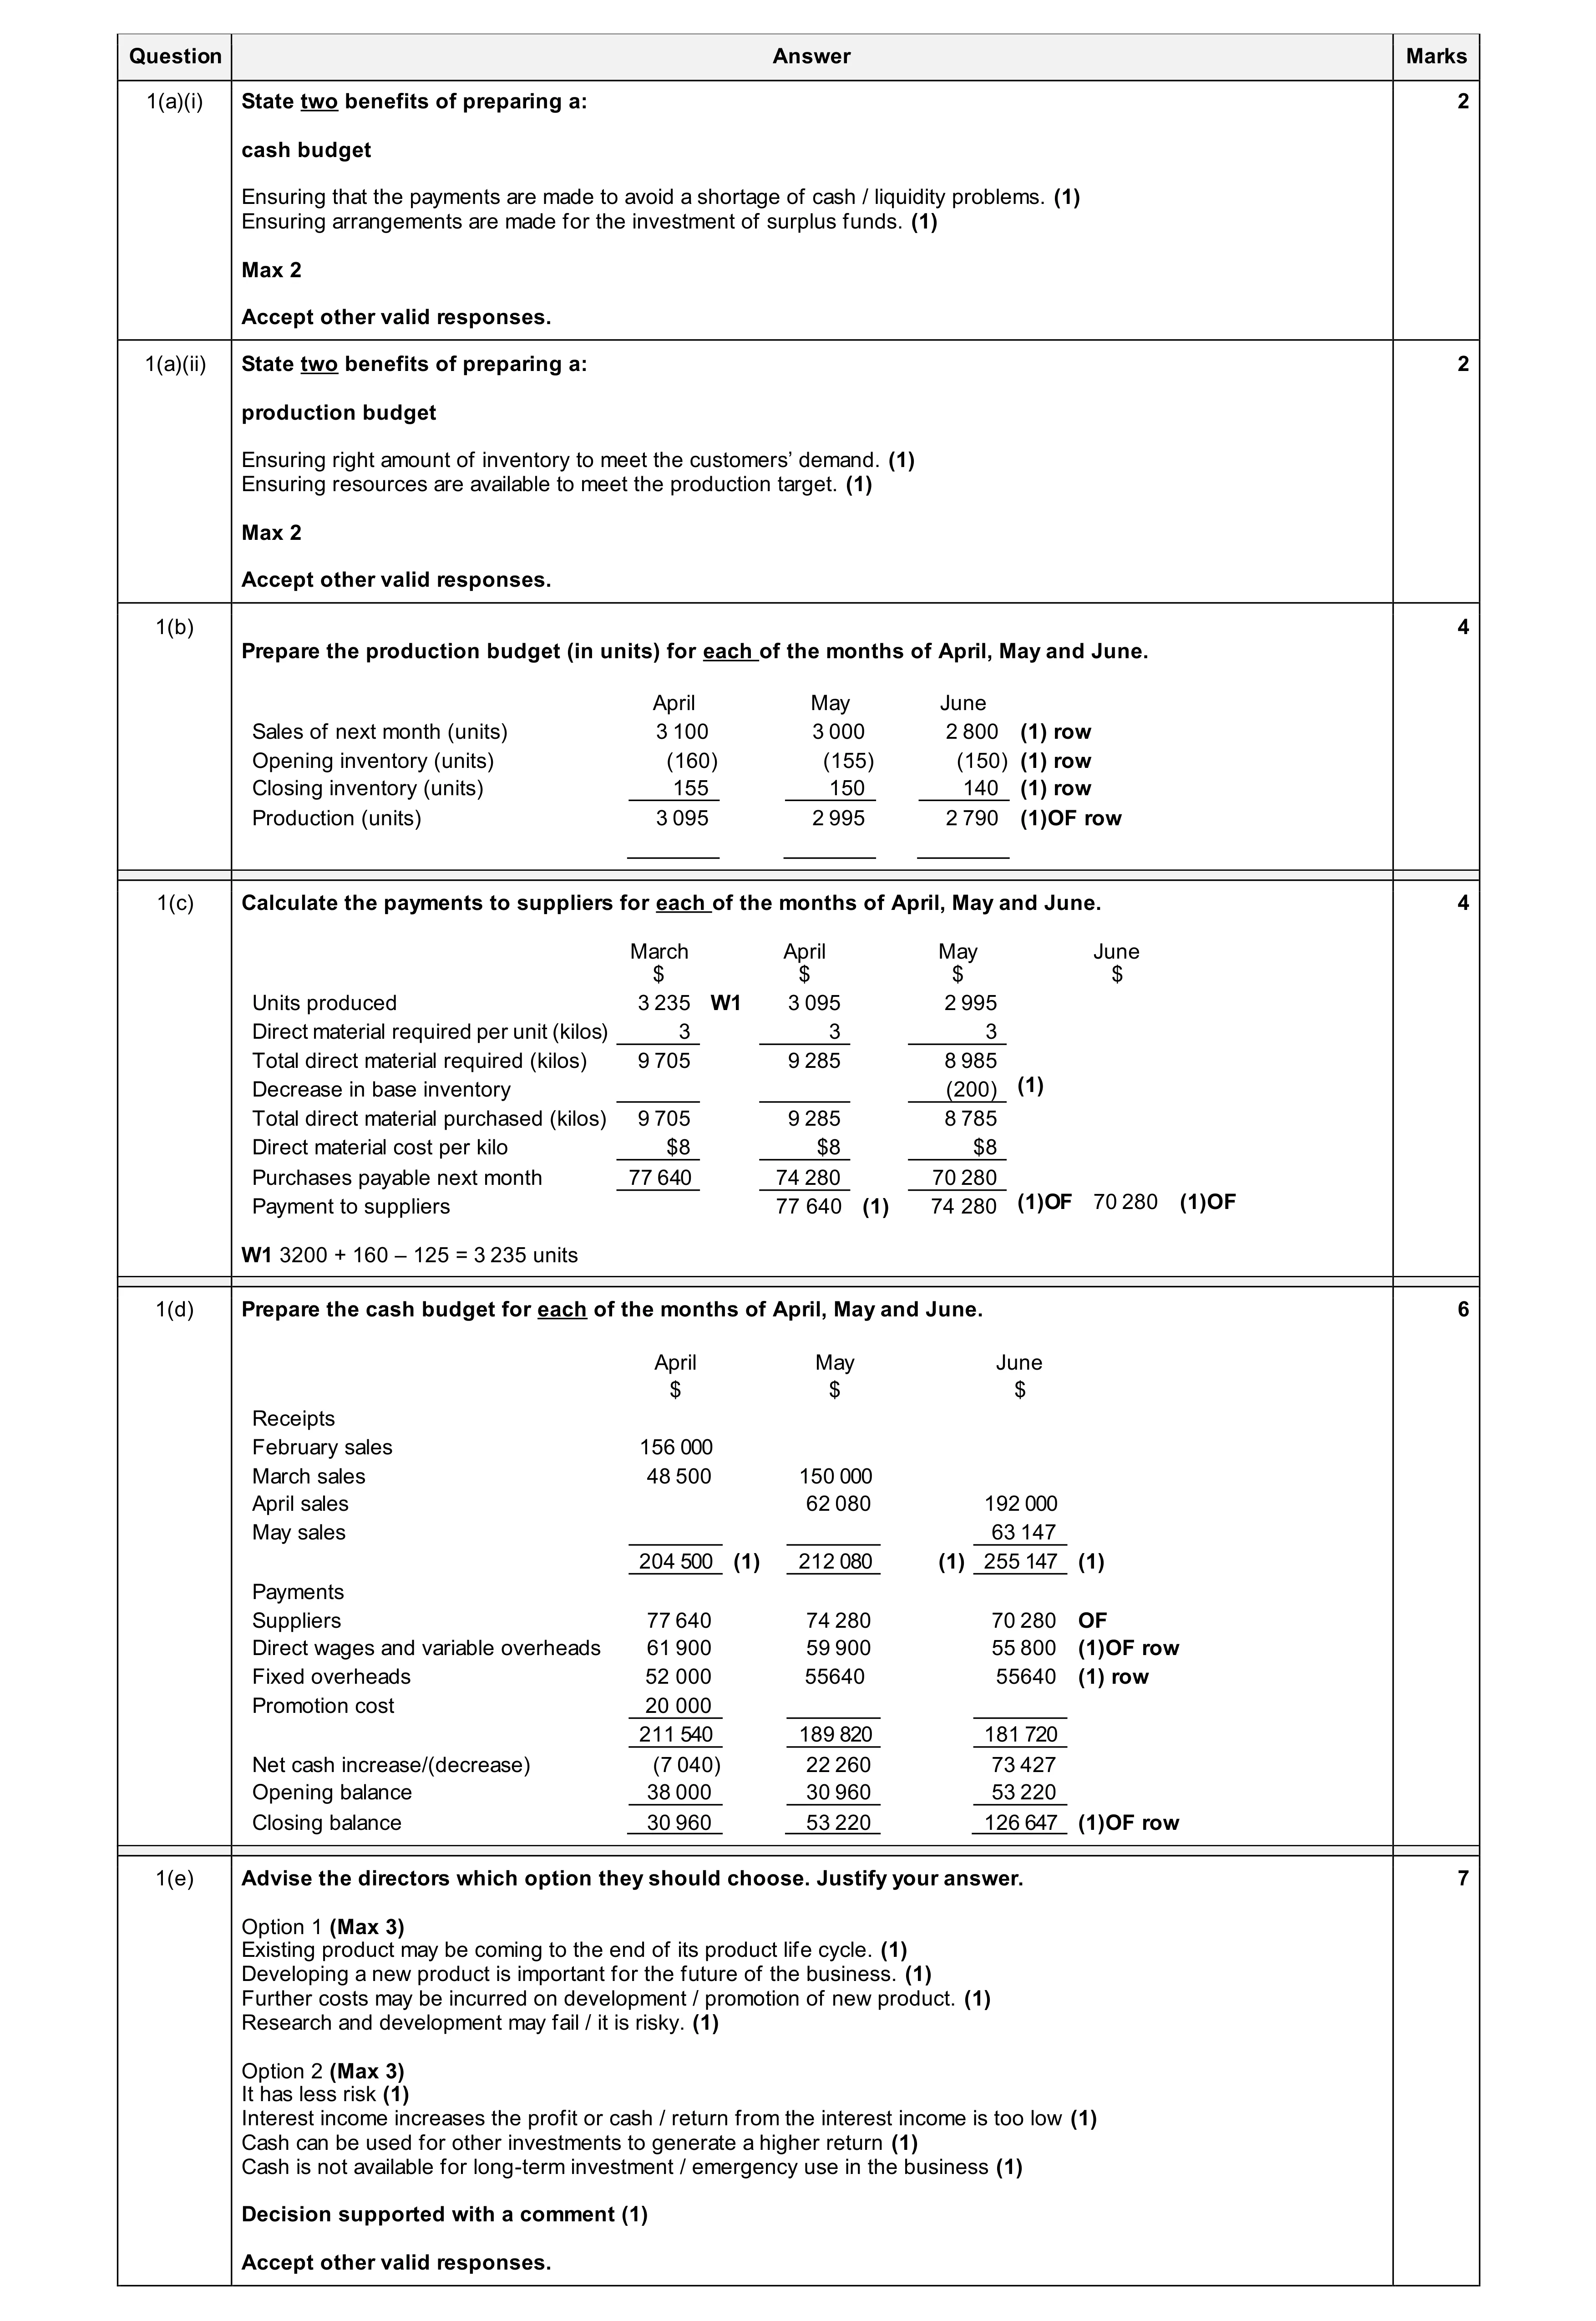 25
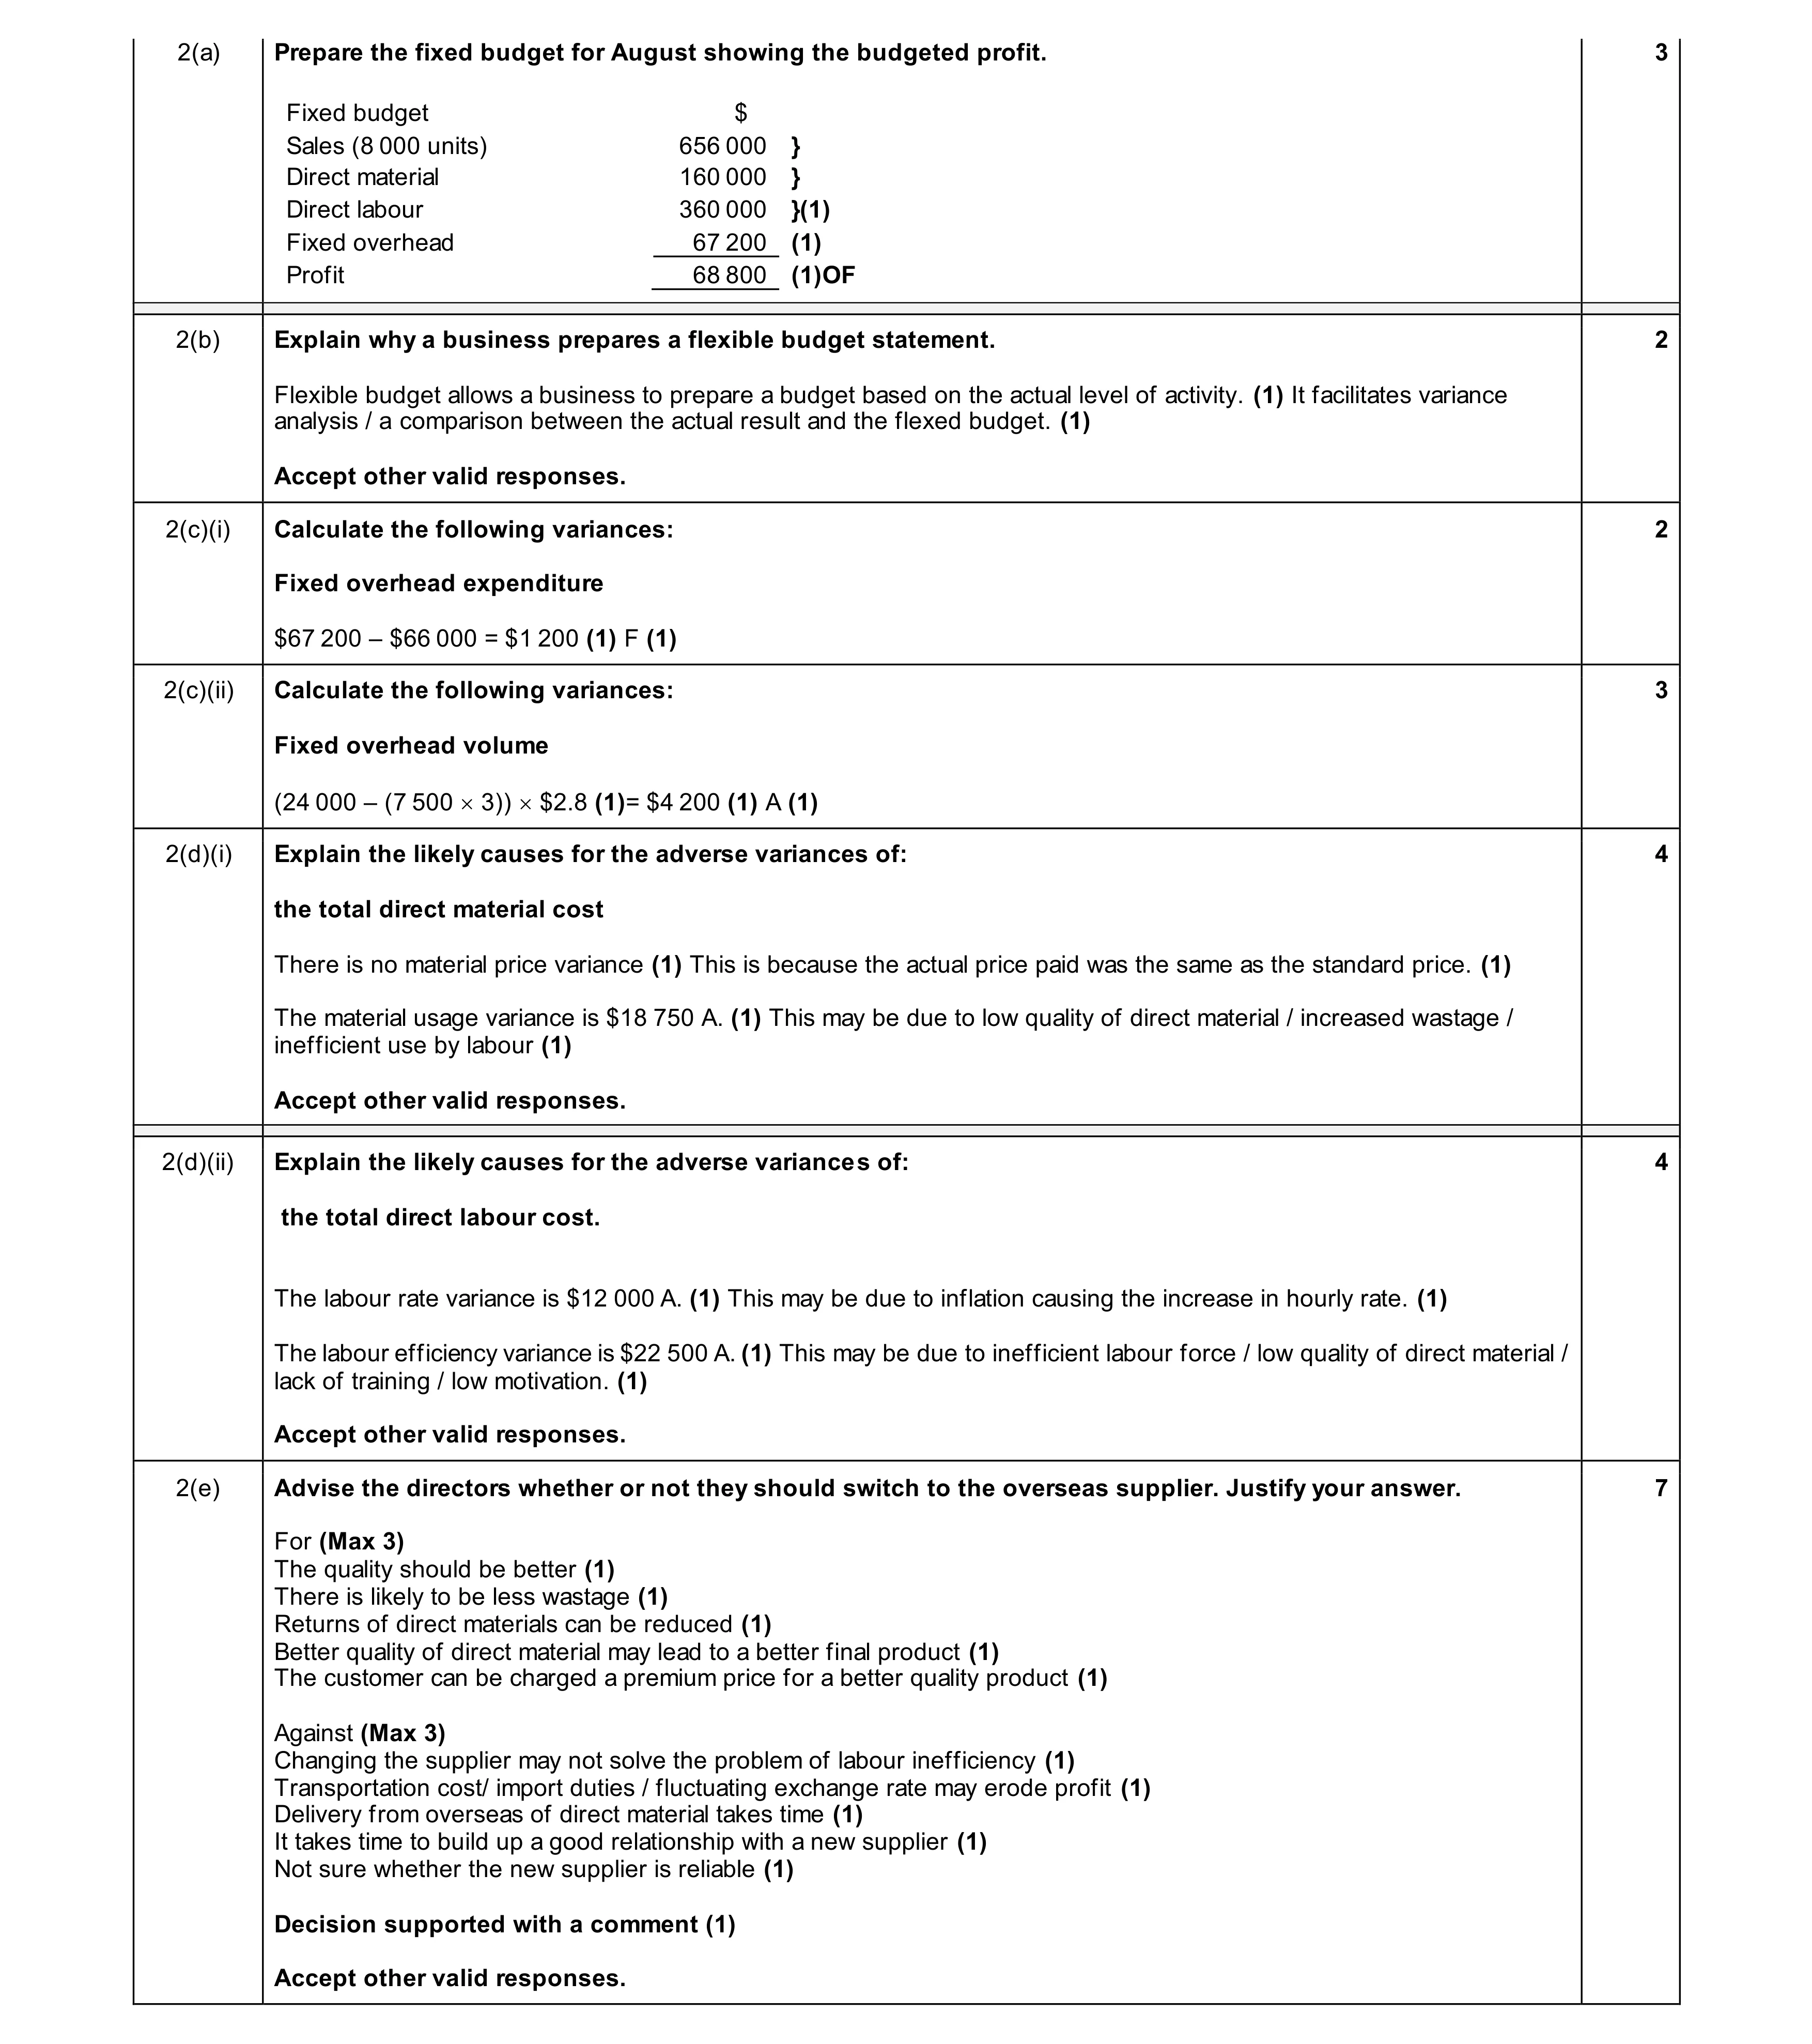 18
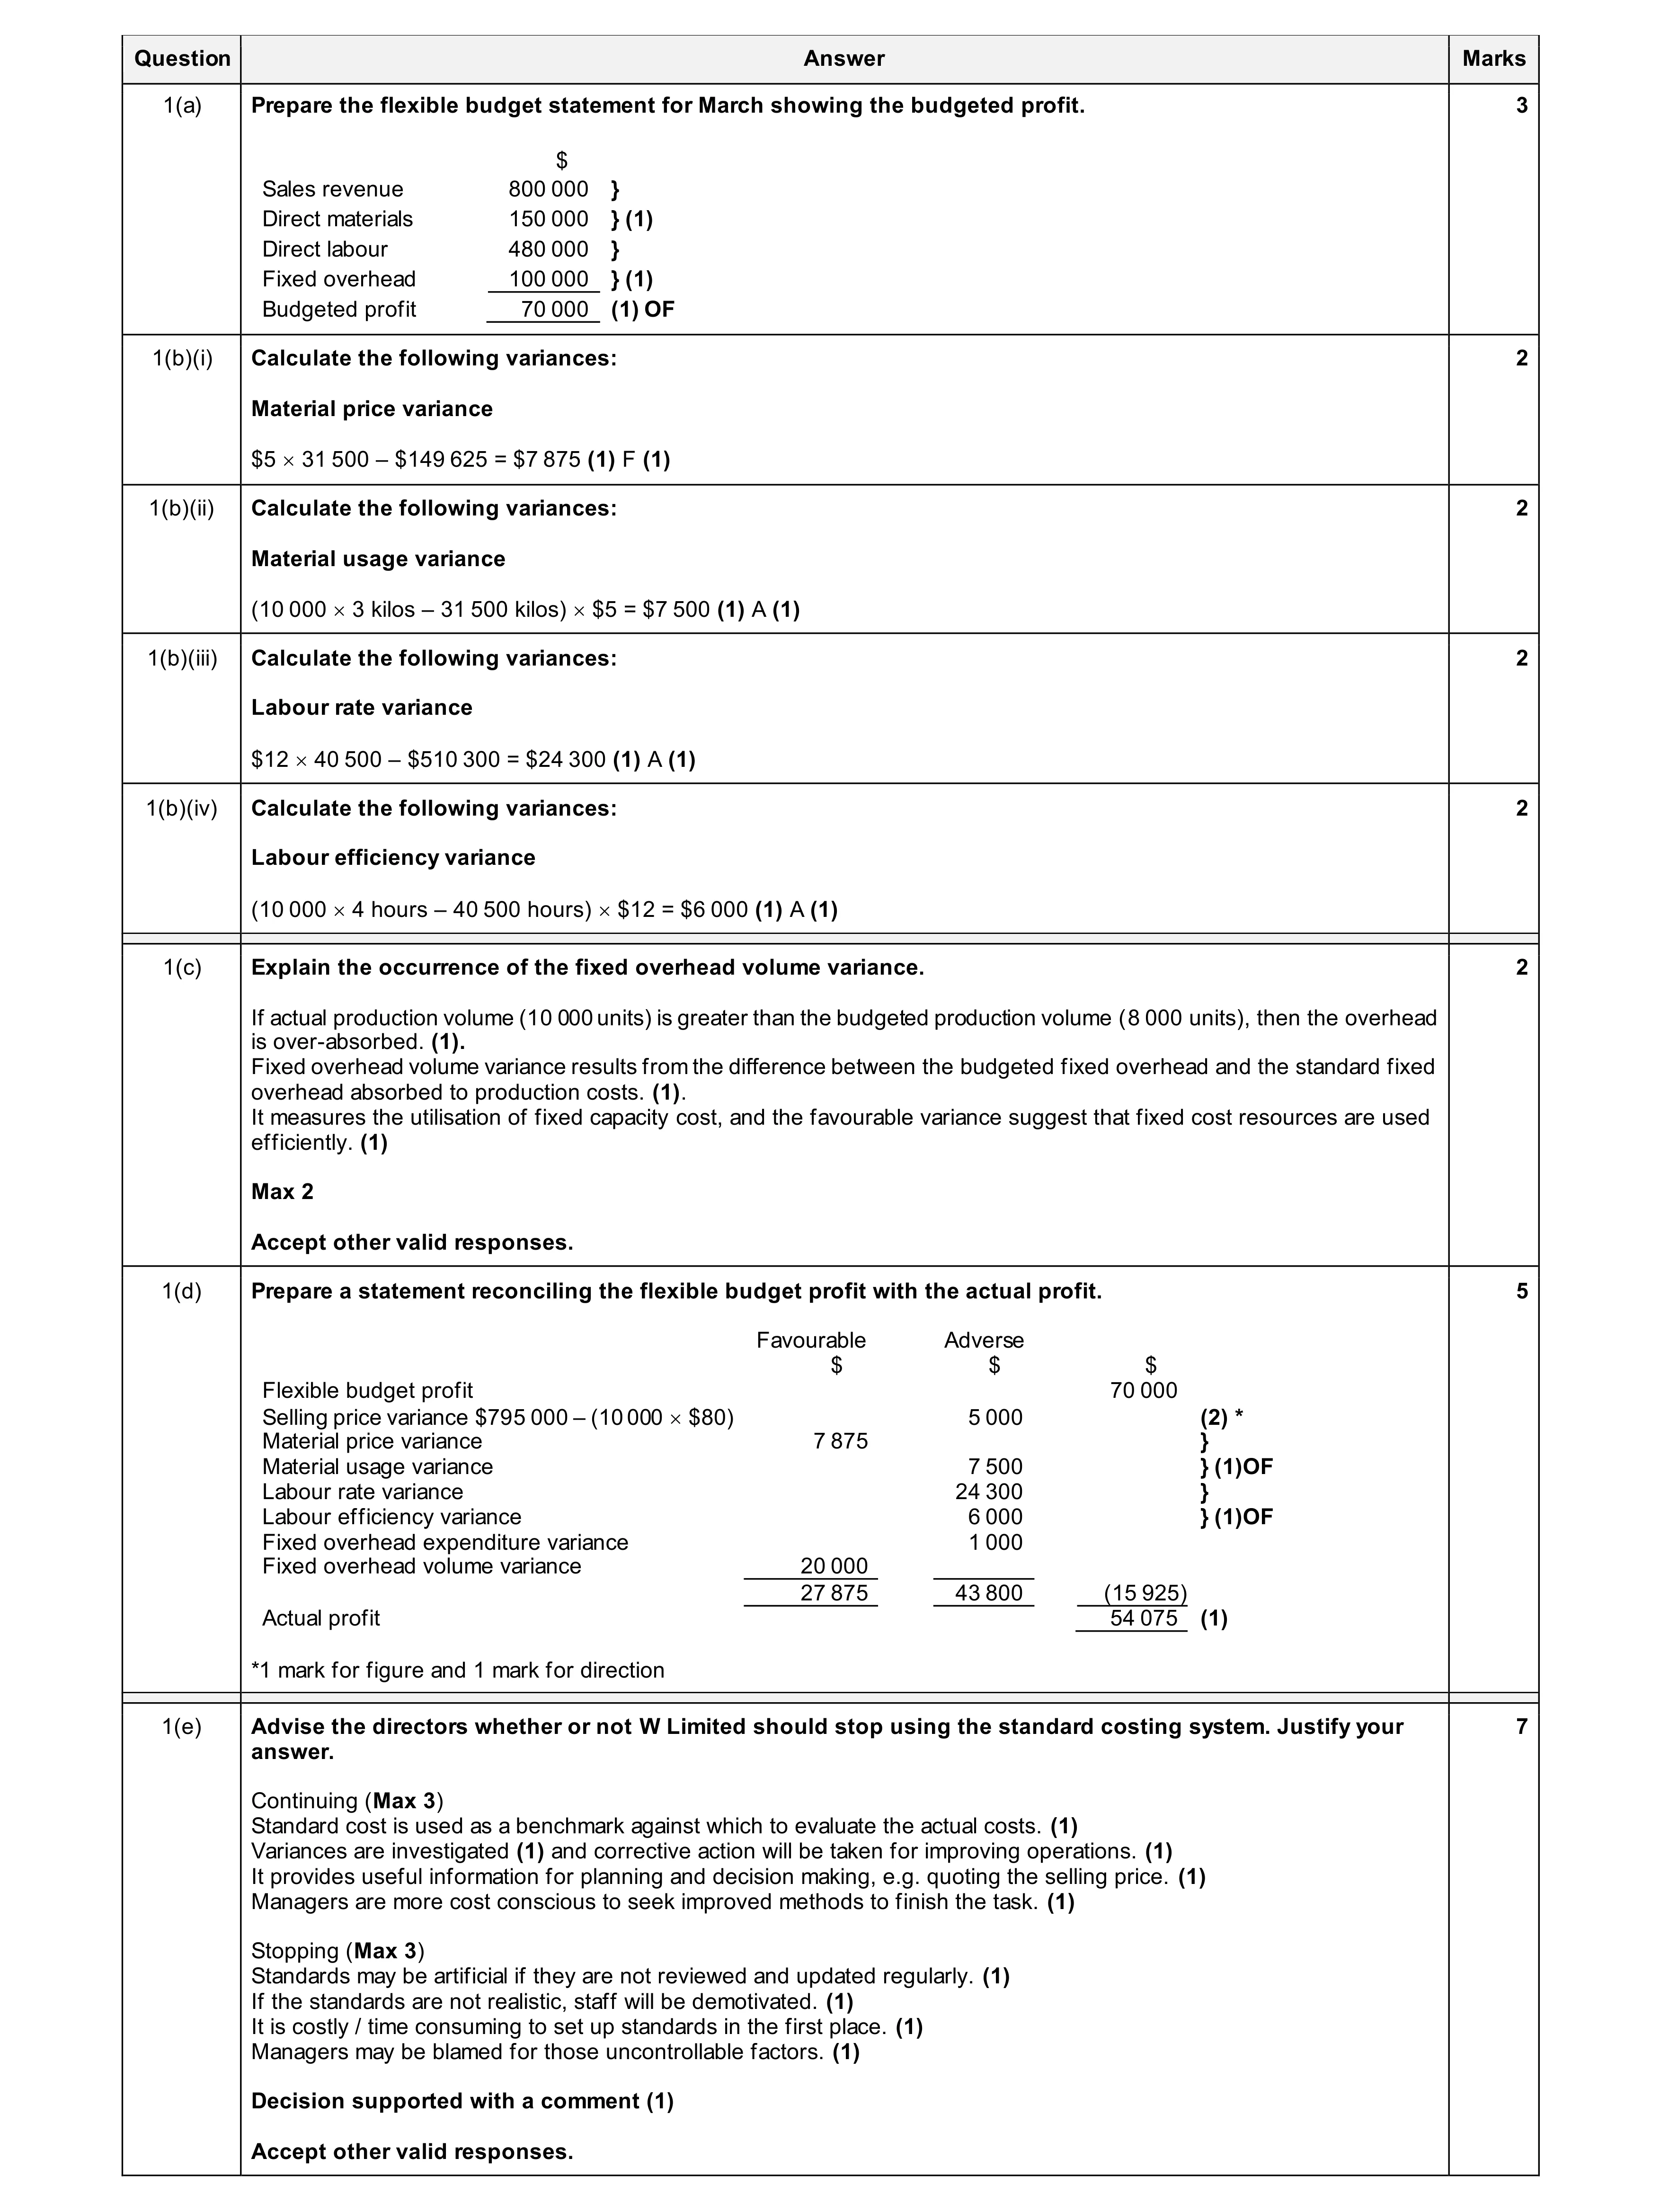 25