Cambridge A Level Accounting 9706 — 2023 Oct/Nov Paper 4 · Variant 2
9706/42/O/N/23 · 2 questions · 50 marks · ≈56 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper8 pages
Mark scheme13 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Read Source A in the insert
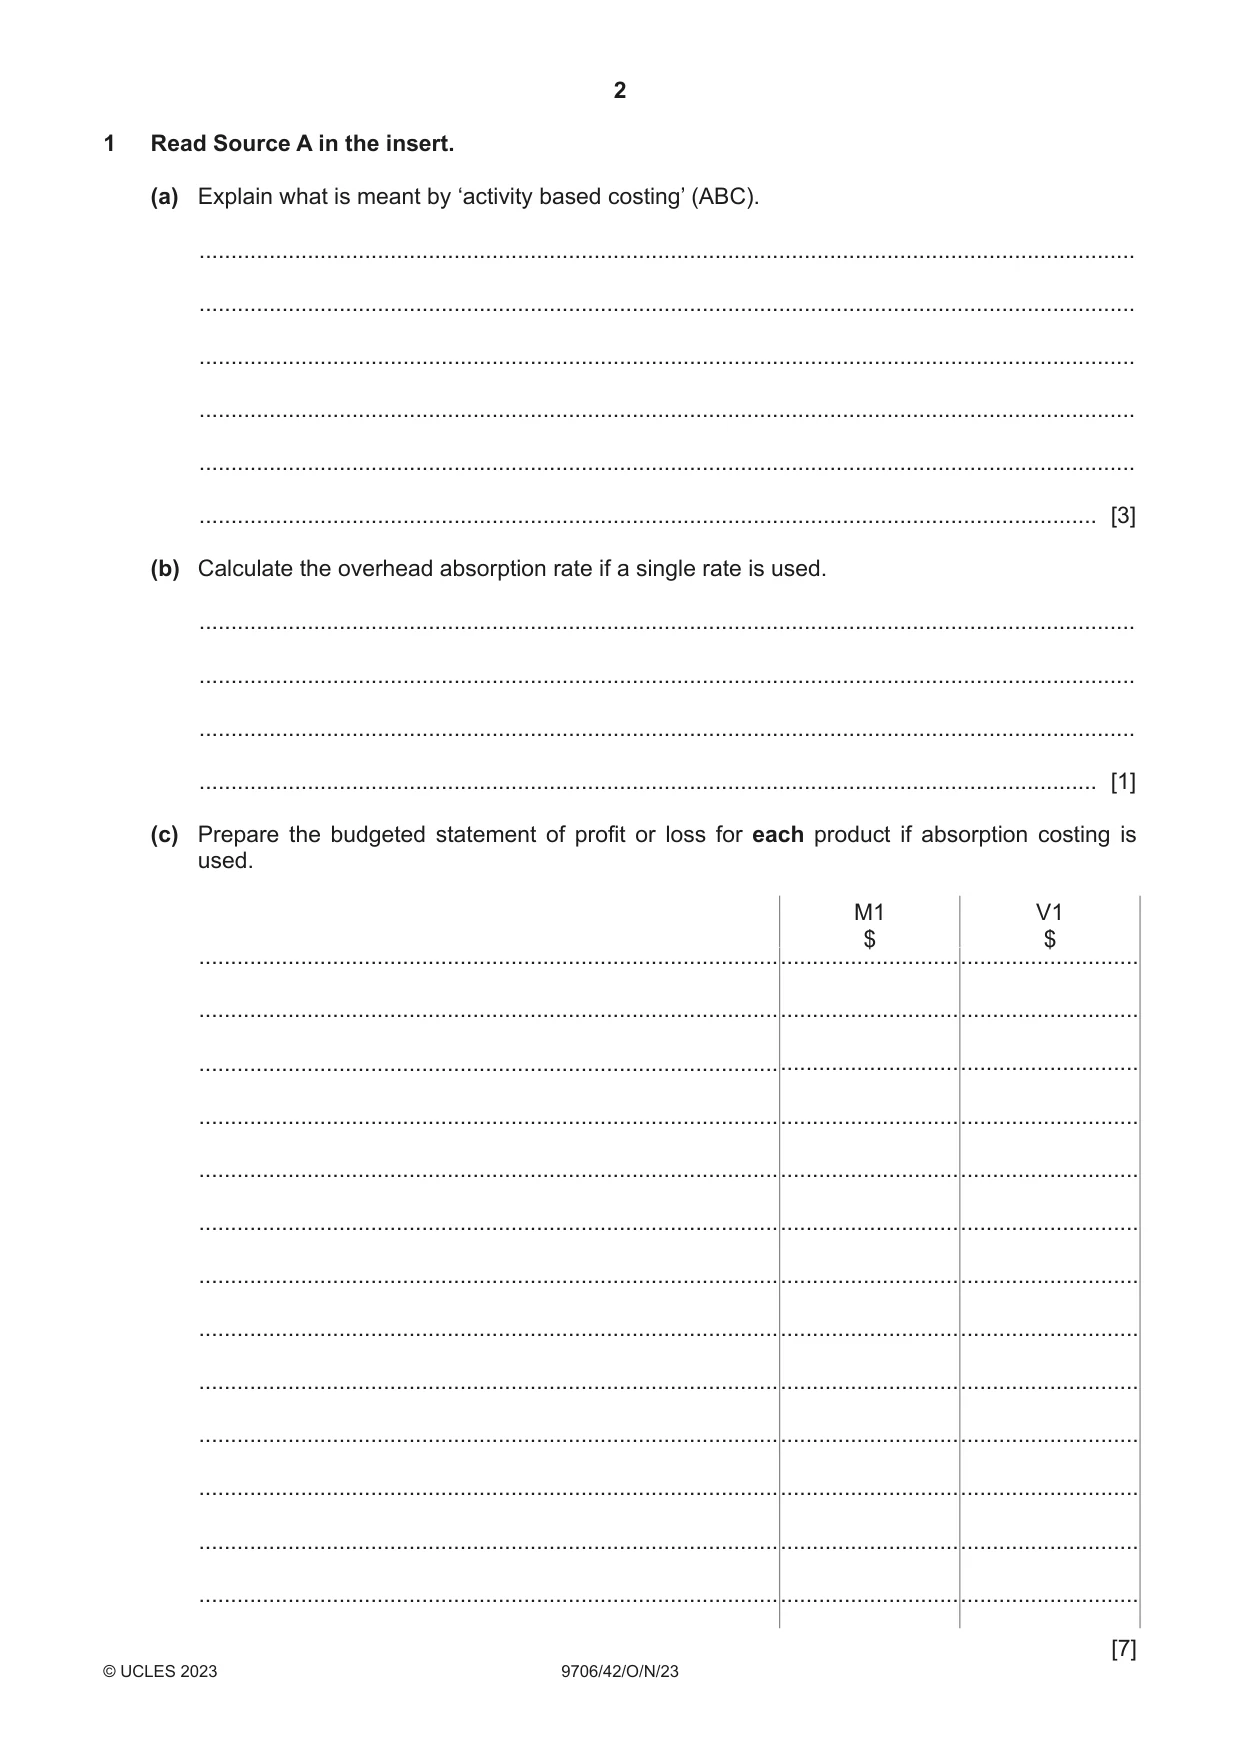
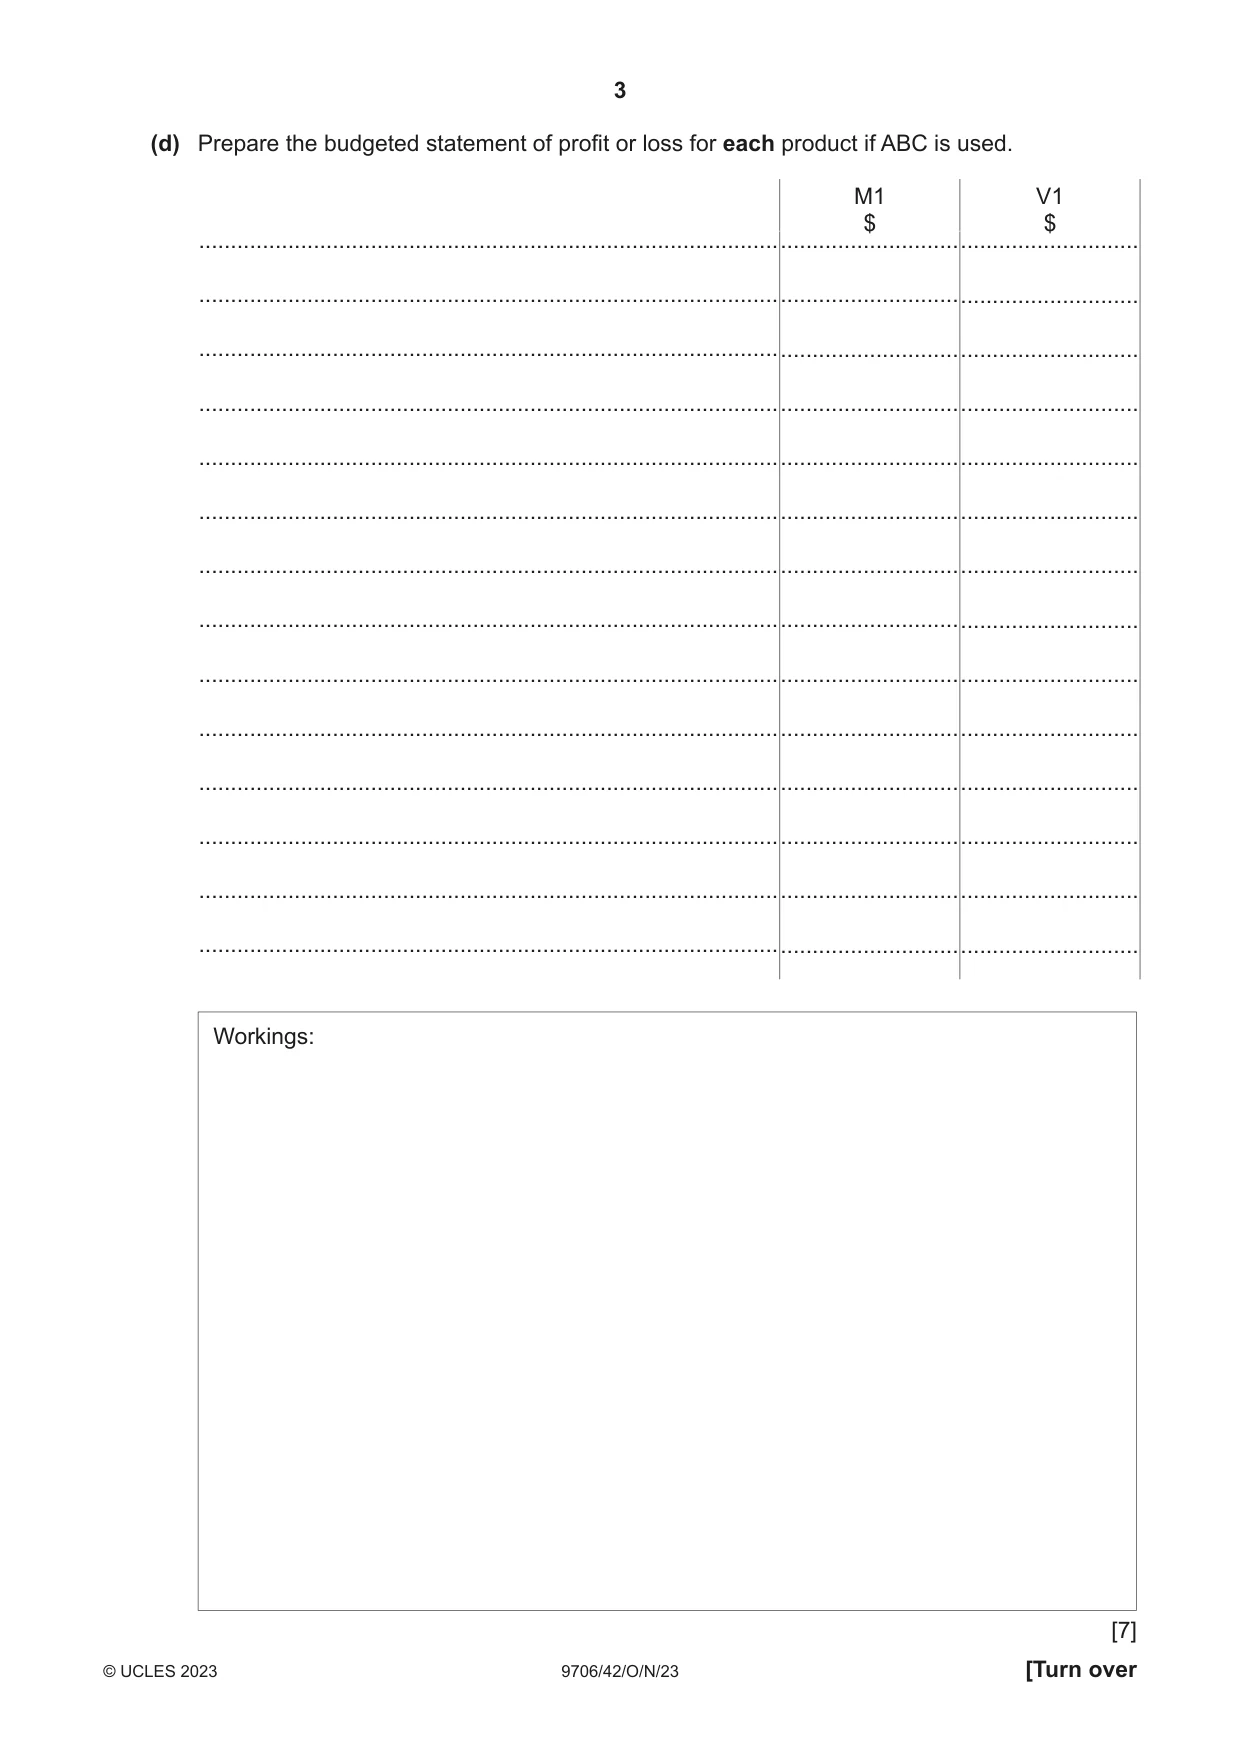
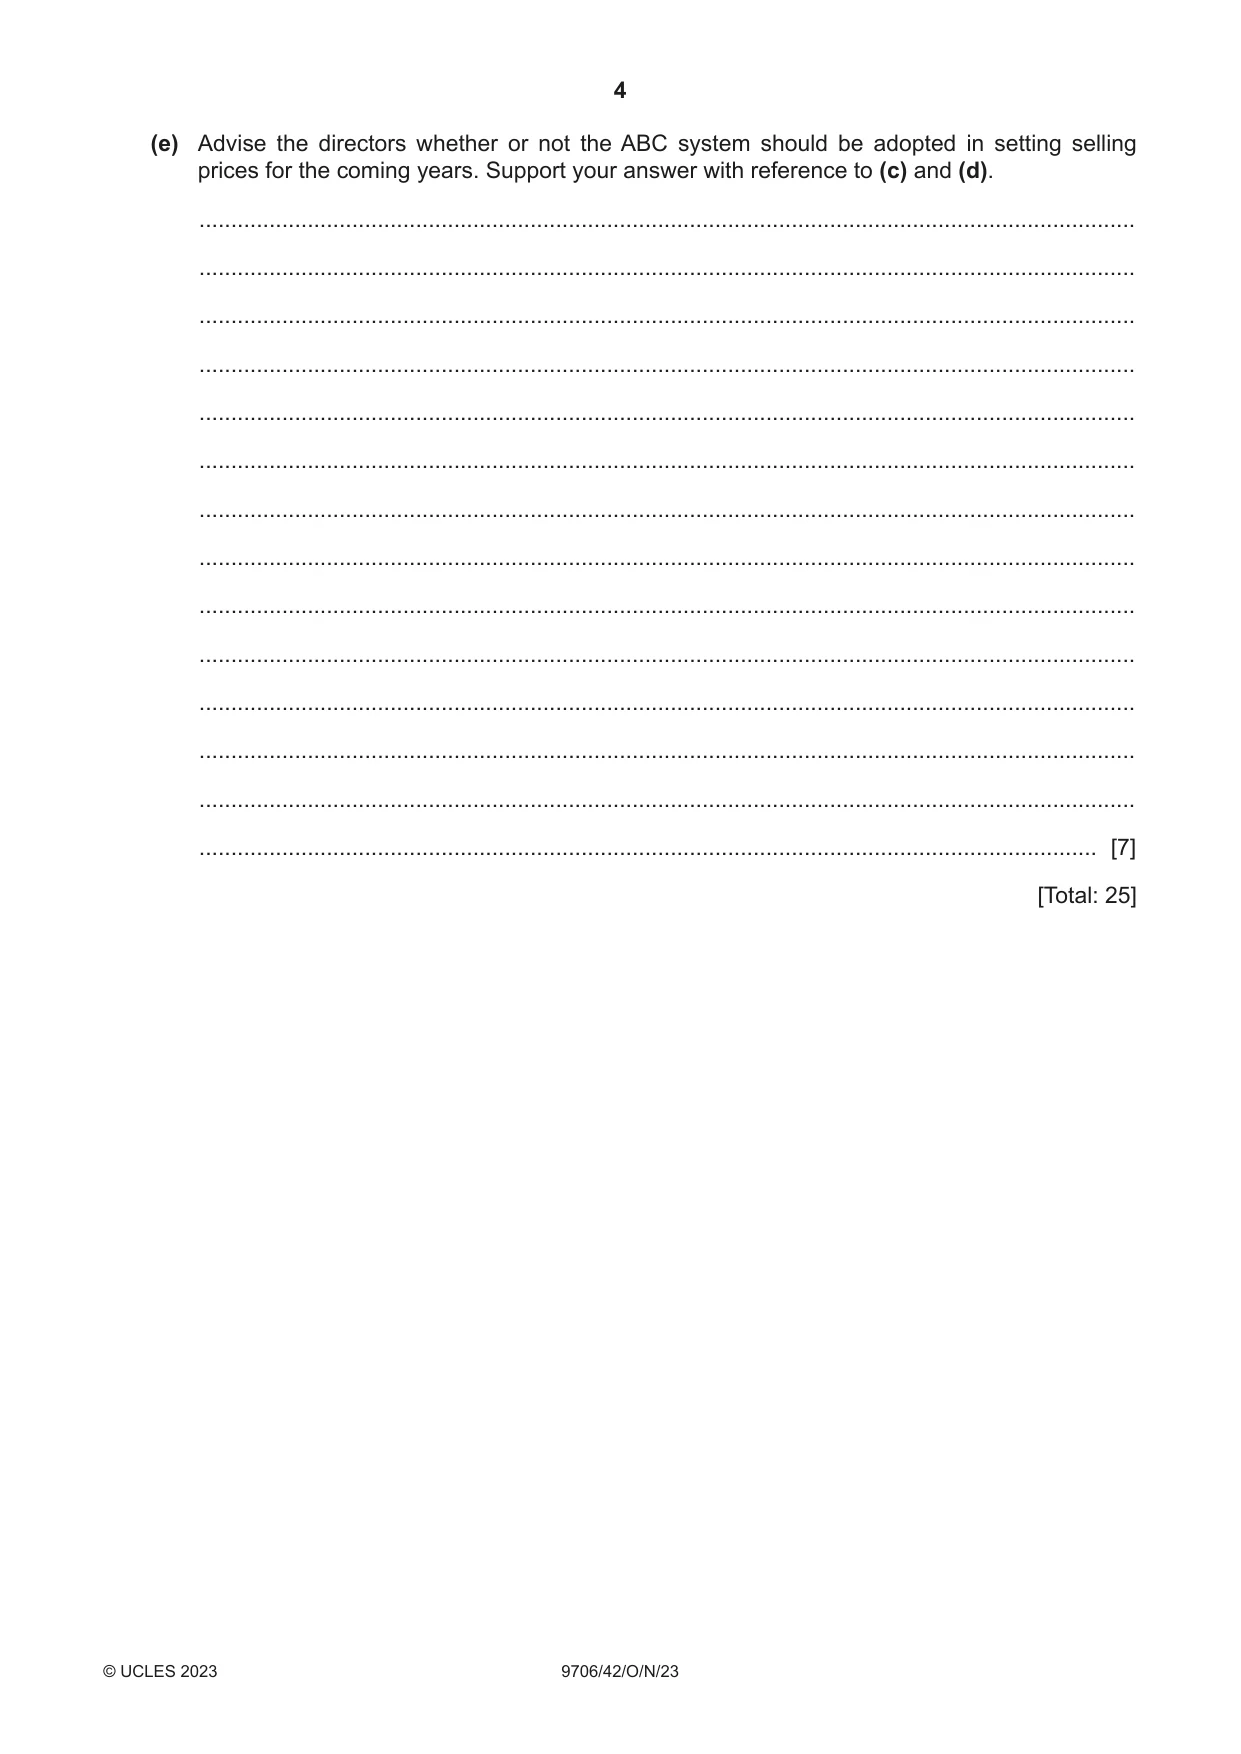
1 Read Source A in the insert. (a) Explain what is meant by ‘activity based costing’ (ABC). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (b) Calculate the overhead absorption rate if a single rate is used. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [1] (c) Prepare the budgeted statement of profit or loss for each product if absorption costing is used. M1 V1 $ $ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ [7] (d) Prepare the budgeted statement of profit or loss for each product if ABC is used. M1 V1 $ $ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ ........................................................................................... ............................ ............................ Workings: [7] (e) Advise the directors whether or not the ABC system should be adopted in setting selling prices for the coming years. Support your answer with reference to (c) and (d). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 25]
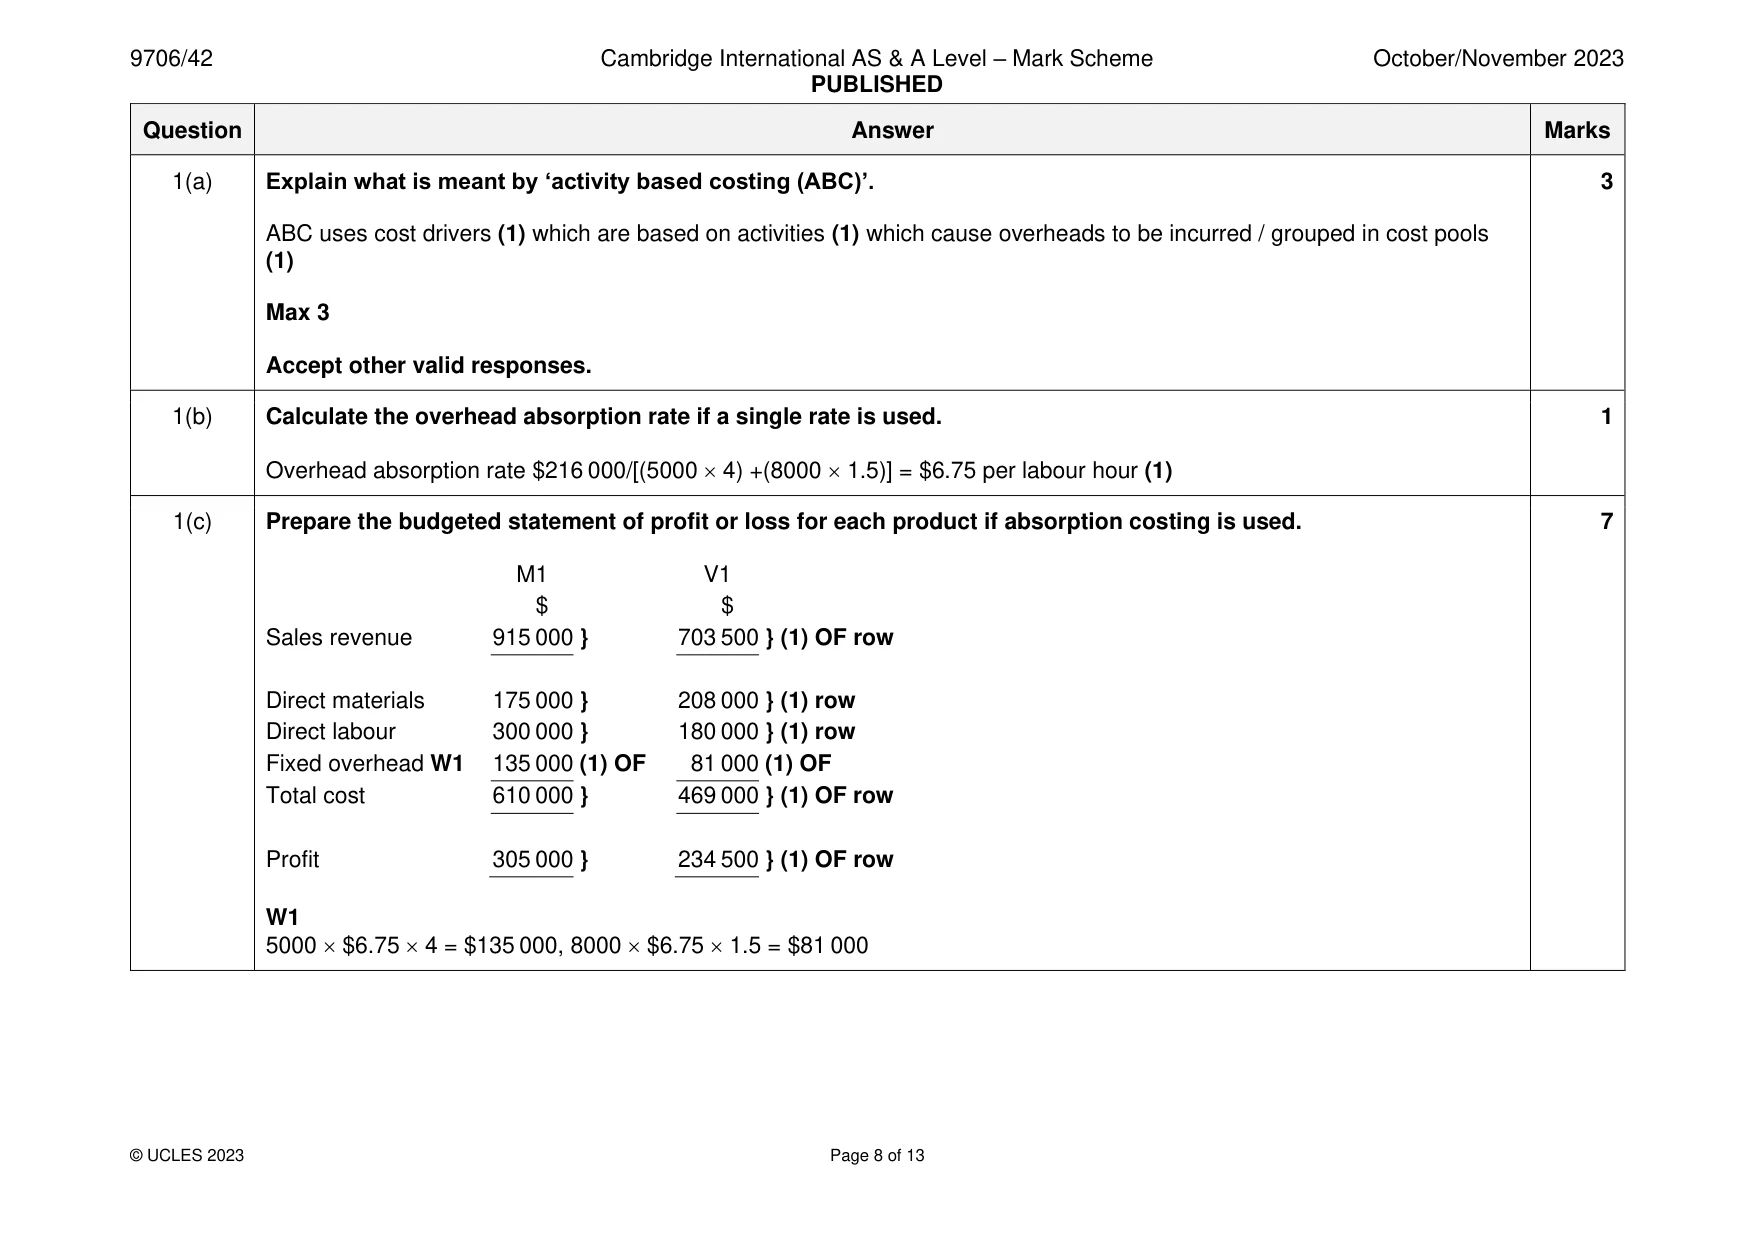
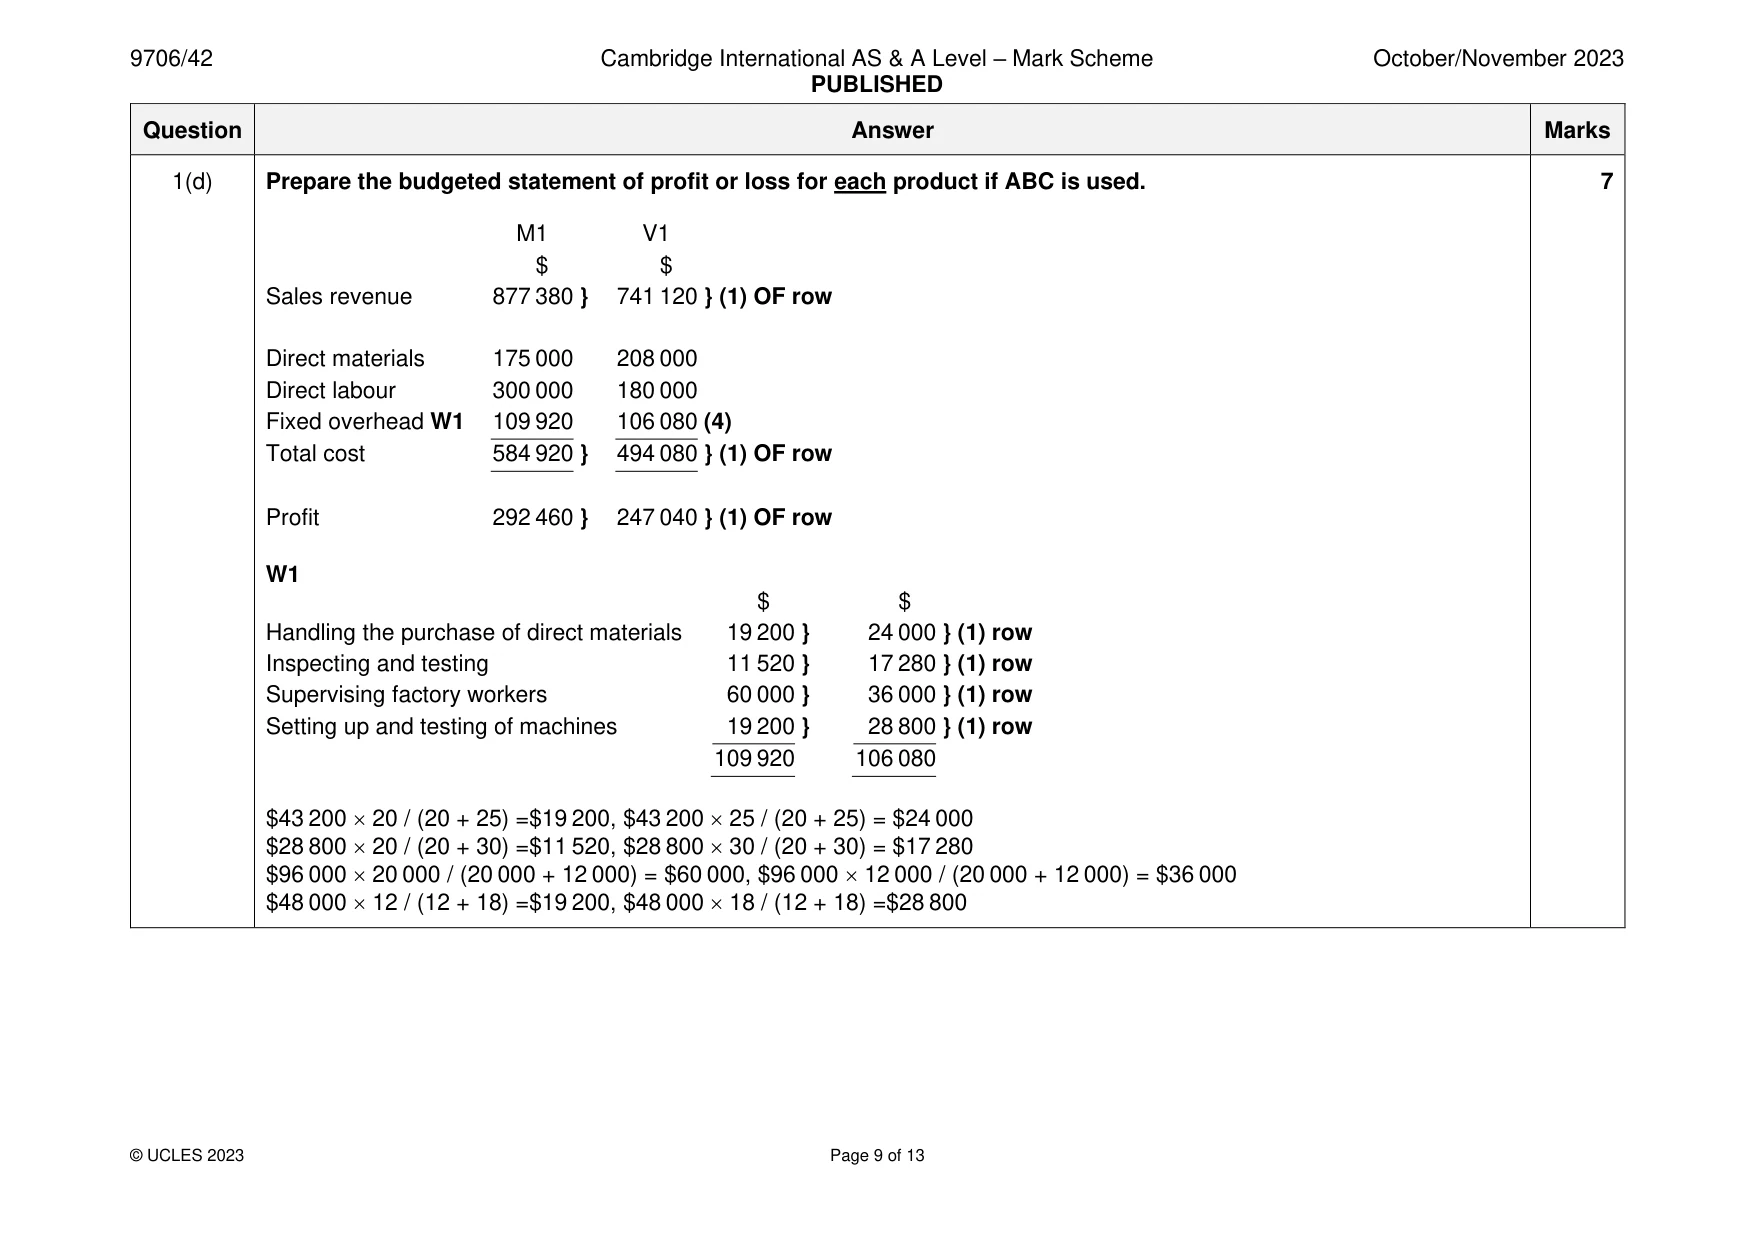
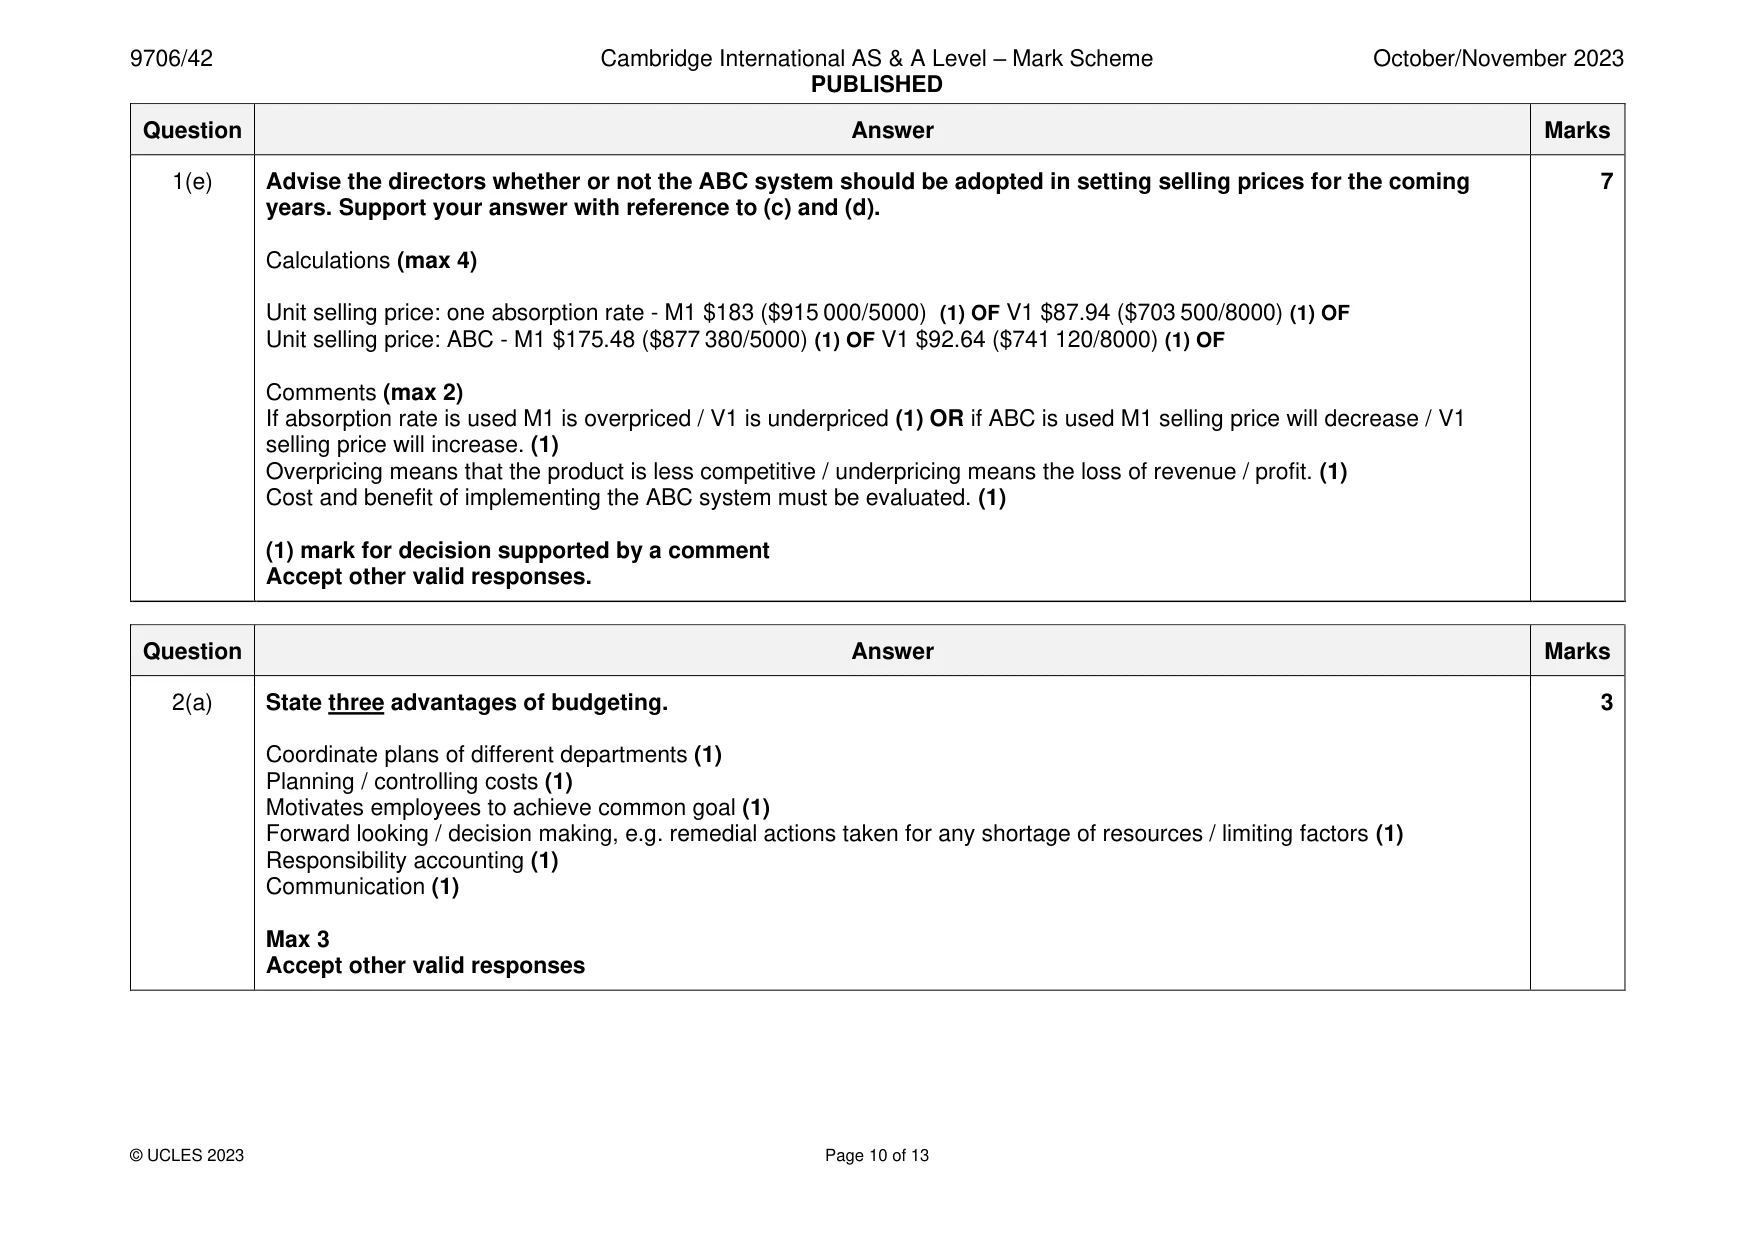
Mark scheme: Question Answer Marks 1(a) Explain what is meant by ‘activity based costing (ABC)’. 3 ABC uses cost drivers (1) which are based on activities (1) which cause overheads to be incurred / grouped in cost pools (1) Max 3 Accept other valid responses. 1(b) Calculate the overhead absorption rate if a single rate is used. 1 Overhead absorption rate $216 000/[(5000 4) +(8000 1.5)] = $6.75 per labour hour (1) 1(c) Prepare the budgeted statement of profit or loss for each product if absorption costing is used. 7 M1 V1 $ $ Sales revenue 915 000 } 703 500 } (1) OF row Direct materials 175 000 } 208 000 } (1) row Direct labour 300 000 } 180 000 } (1) row Fixed overhead W1 135 000 (1) OF 81 000 (1) OF Total cost 610 000 } 469 000 } (1) OF row Profit 305 000 } 234 500 } (1) OF row W1 5000 $6.75 4 = $135 000, 8000 $6.75 1.5 = $81 000 1(d) Prepare the budgeted statement of profit or loss for each product if ABC is used. 7 M1 V1 $ $ Sales revenue 877 380 } 741 120 } (1) OF row Direct materials 175 000 208 000 Direct labour 300 000 180 000 Fixed overhead W1 109 920 106 080 (4) Total cost 584 920 } 494 080 } (1) OF row Profit 292 460 } 247 040 } (1) OF row W1 $ $ Handling the purchase of direct materials 19 200 } 24 000 } (1) row Inspecting and testing 11 520 } 17 280 } (1) row Supervising factory workers 60 000 } 36 000 } (1) row Setting up and testing of machines 19 200 } 28 800 } (1) row 109 920 106 080 $43 200 20 / (20 + 25) =$19 200, $43 200 25 / (20 + 25) = $24 000 $28 800 20 / (20 + 30) =$11 520, $28 800 30 / (20 + 30) = $17 280 $96 000 20 000 / (20 000 + 12 000) = $60 000, $96 000 12 000 / (20 000 + 12 000) = $36 000 $48 000 12 / (12 + 18) =$19 200, $48 000 18 / (12 + 18) =$28 800 1(e) Advise the directors whether or not the ABC system should be adopted in setting selling prices for the coming 7 years. Support your answer with reference to (c) and (d). Calculations (max 4) Unit selling price: one absorption rate - M1 $183 ($915 000/5000) (1) OF V1 $87.94 ($703 500/8000) (1) OF Unit selling price: ABC - M1 $175.48 ($877 380/5000) (1) OF V1 $92.64 ($741 120/8000) (1) OF Comments (max 2) If absorption rate is used M1 is overpriced / V1 is underpriced (1) OR if ABC is used M1 selling price will decrease / V1 selling price will increase. (1) Overpricing means that the product is less competitive / underpricing means the loss of revenue / profit. (1) Cost and benefit of implementing the ABC system must be evaluated. (1) (1) mark for decision supported by a comment Accept other valid responses.
Q2 · Read Source B in the insert
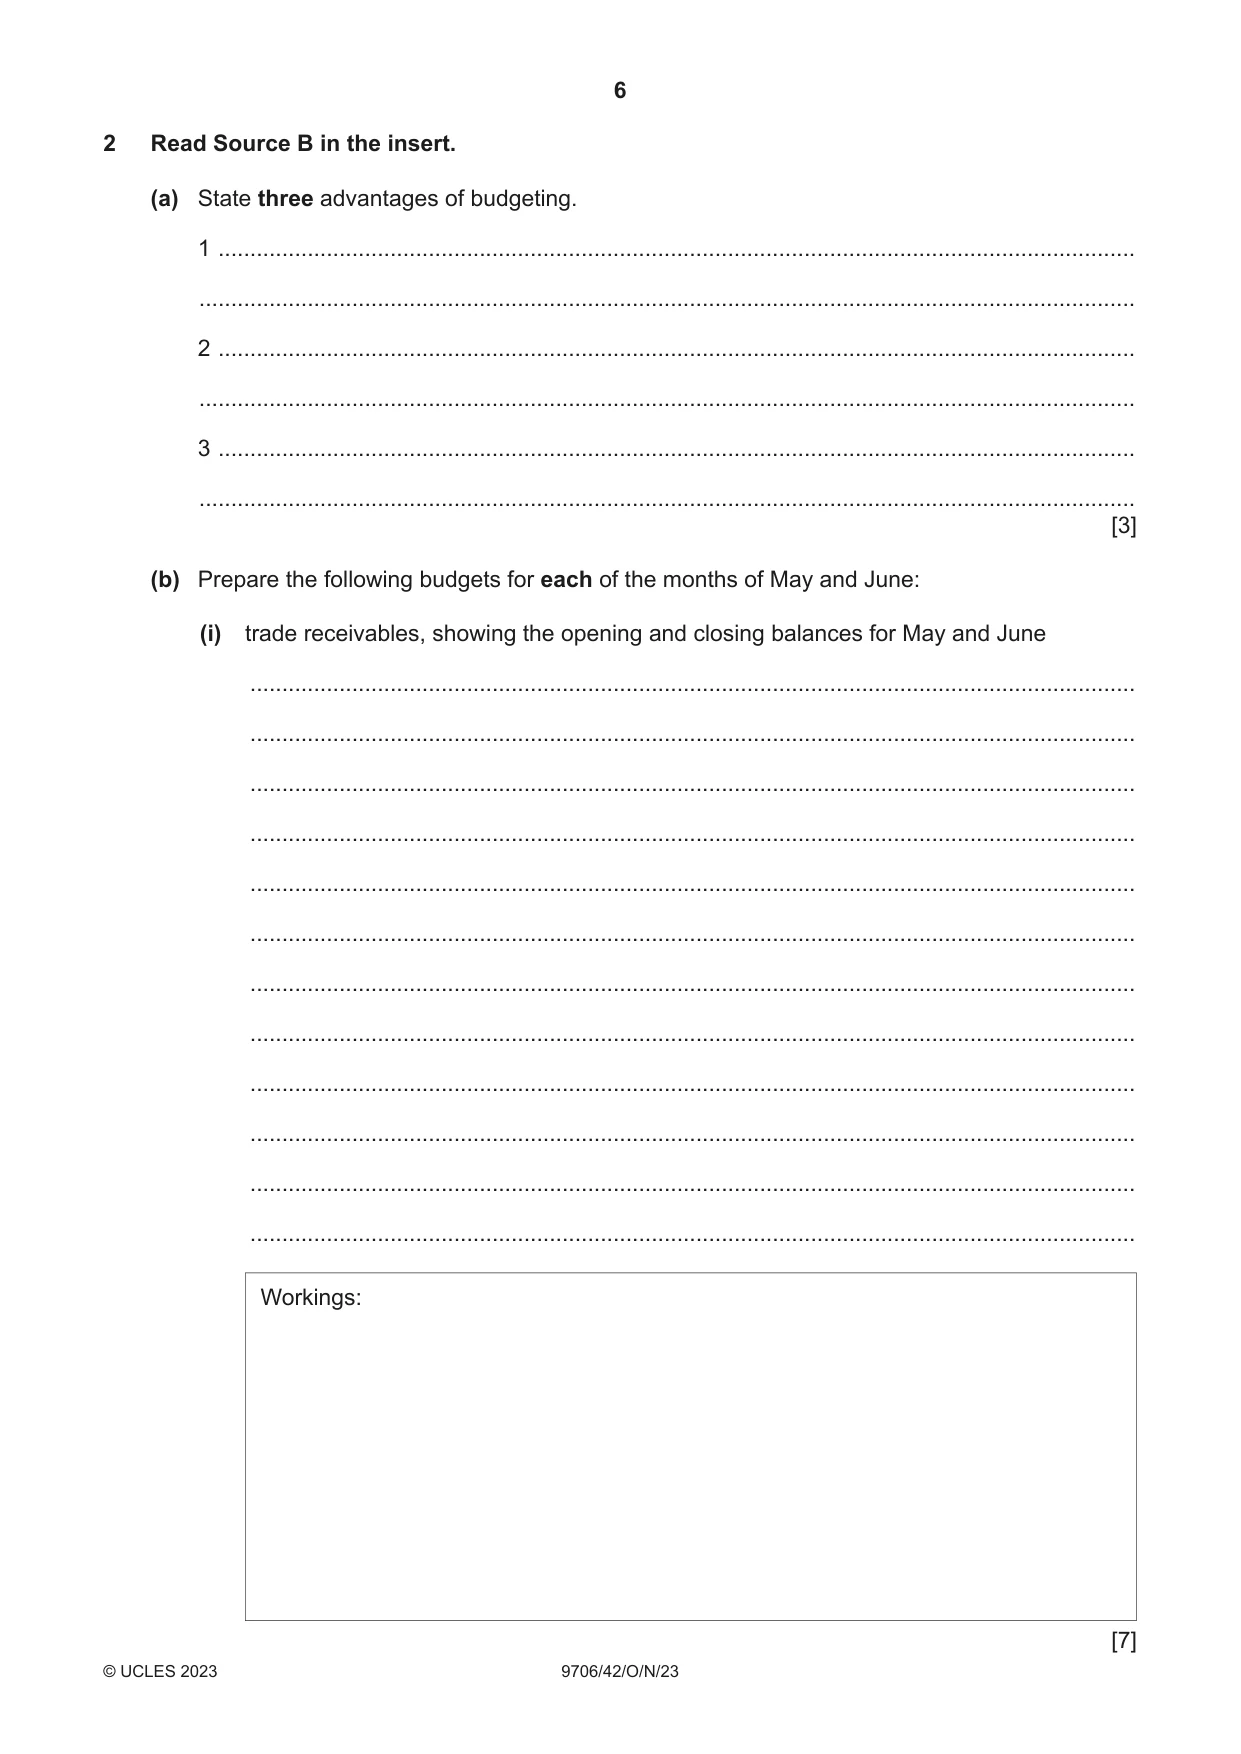
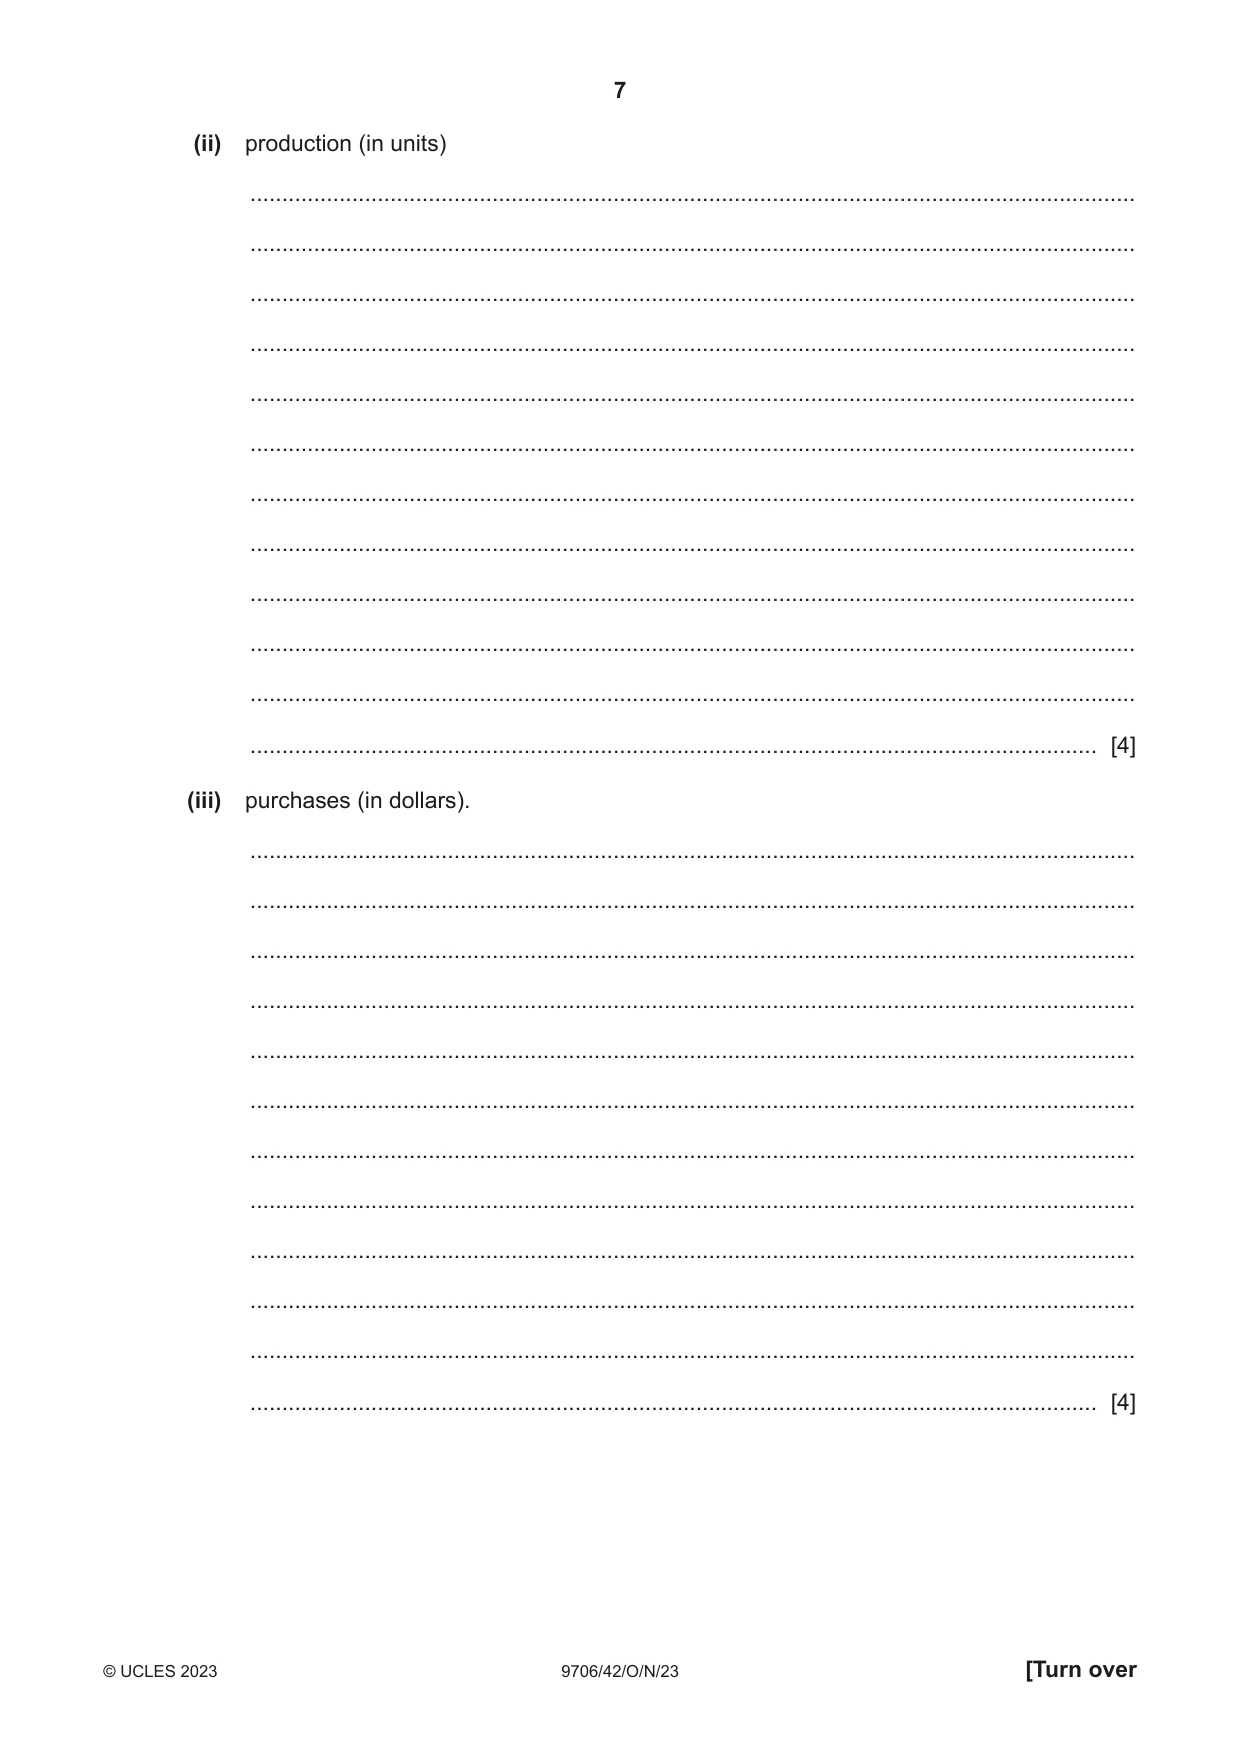
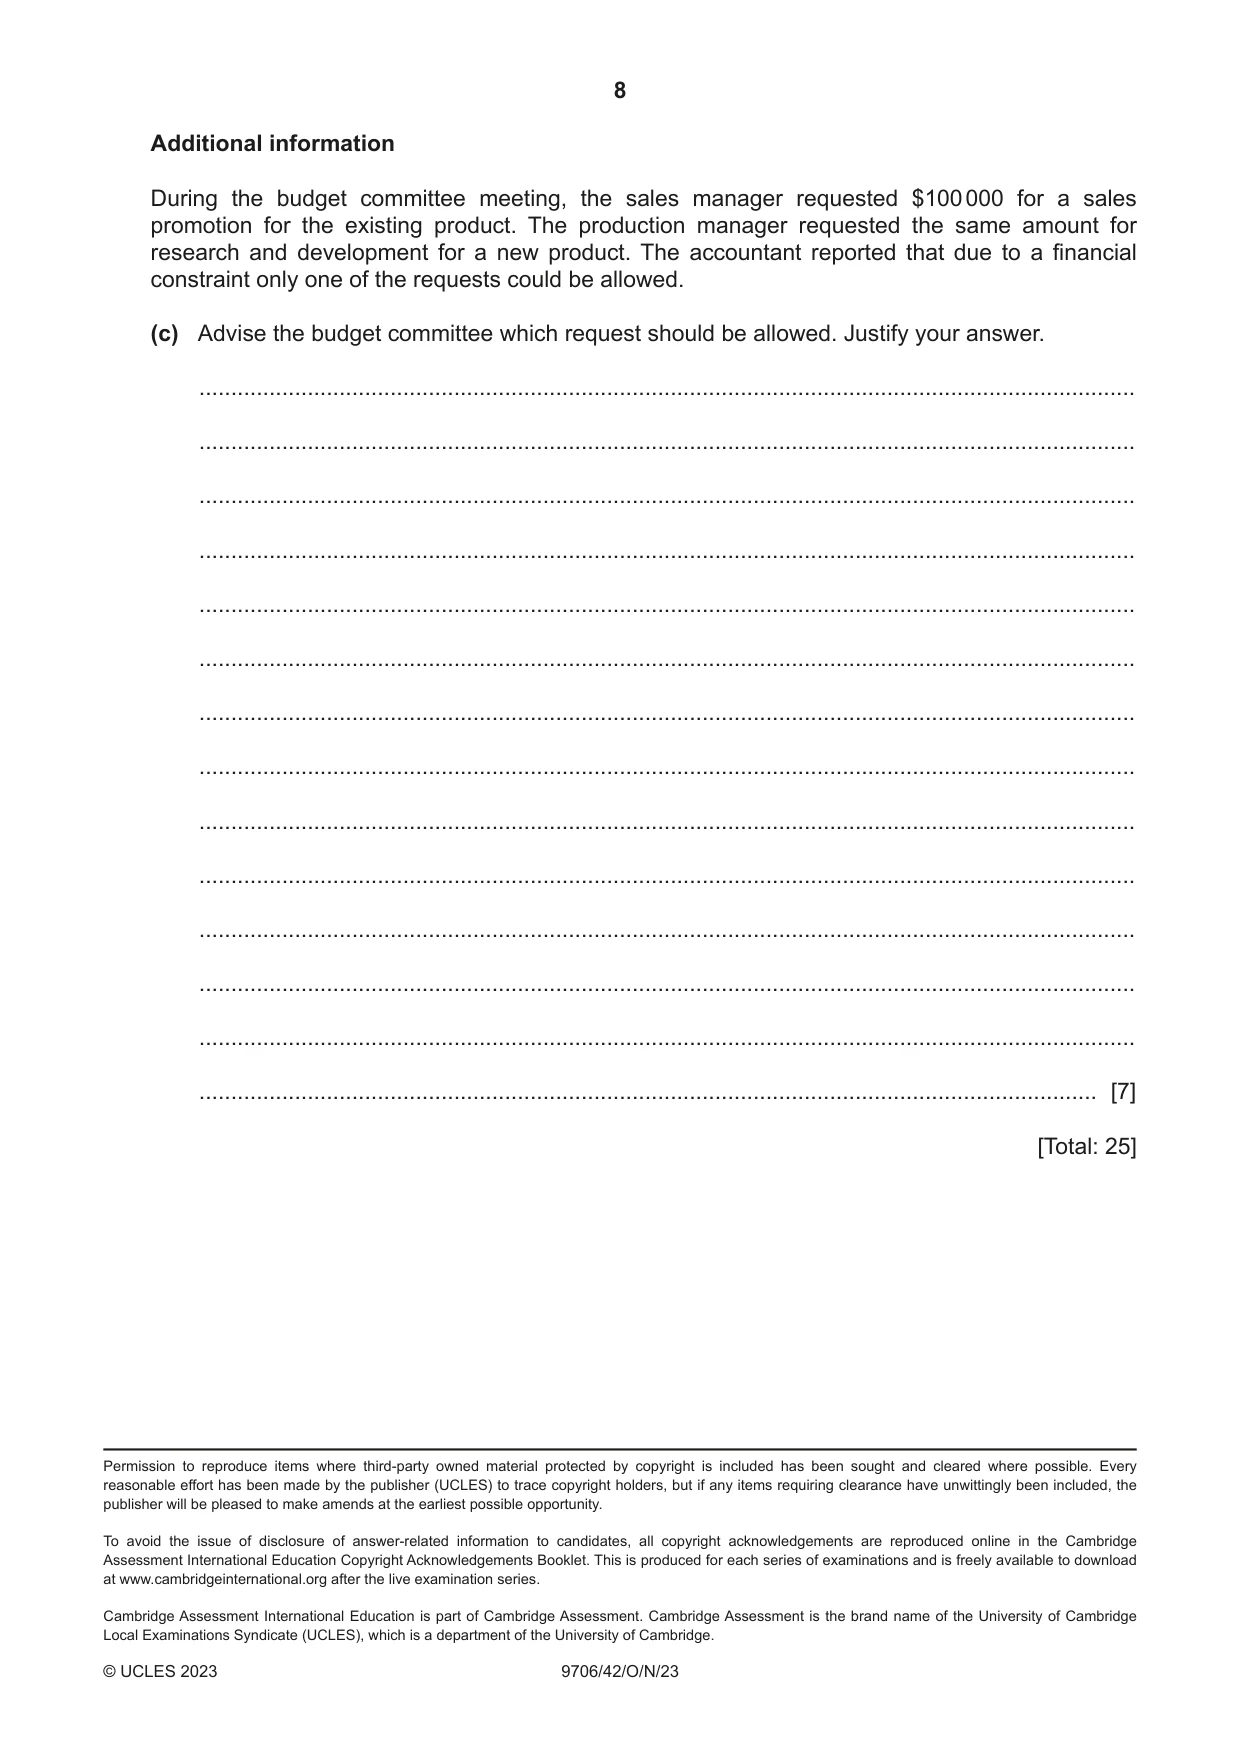
2 Read Source B in the insert. (a) State three advantages of budgeting. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... [3] (b) Prepare the following budgets for each of the months of May and June: (i) trade receivables, showing the opening and closing balances for May and June ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... Workings: [7] (ii) production (in units) ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [4] (iii) purchases (in dollars). ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [4] Additional information During the budget committee meeting, the sales manager requested $100 000 for a sales promotion for the existing product. The production manager requested the same amount for research and development for a new product. The accountant reported that due to a financial constraint only one of the requests could be allowed. (c) Advise the budget committee which request should be allowed. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 25]
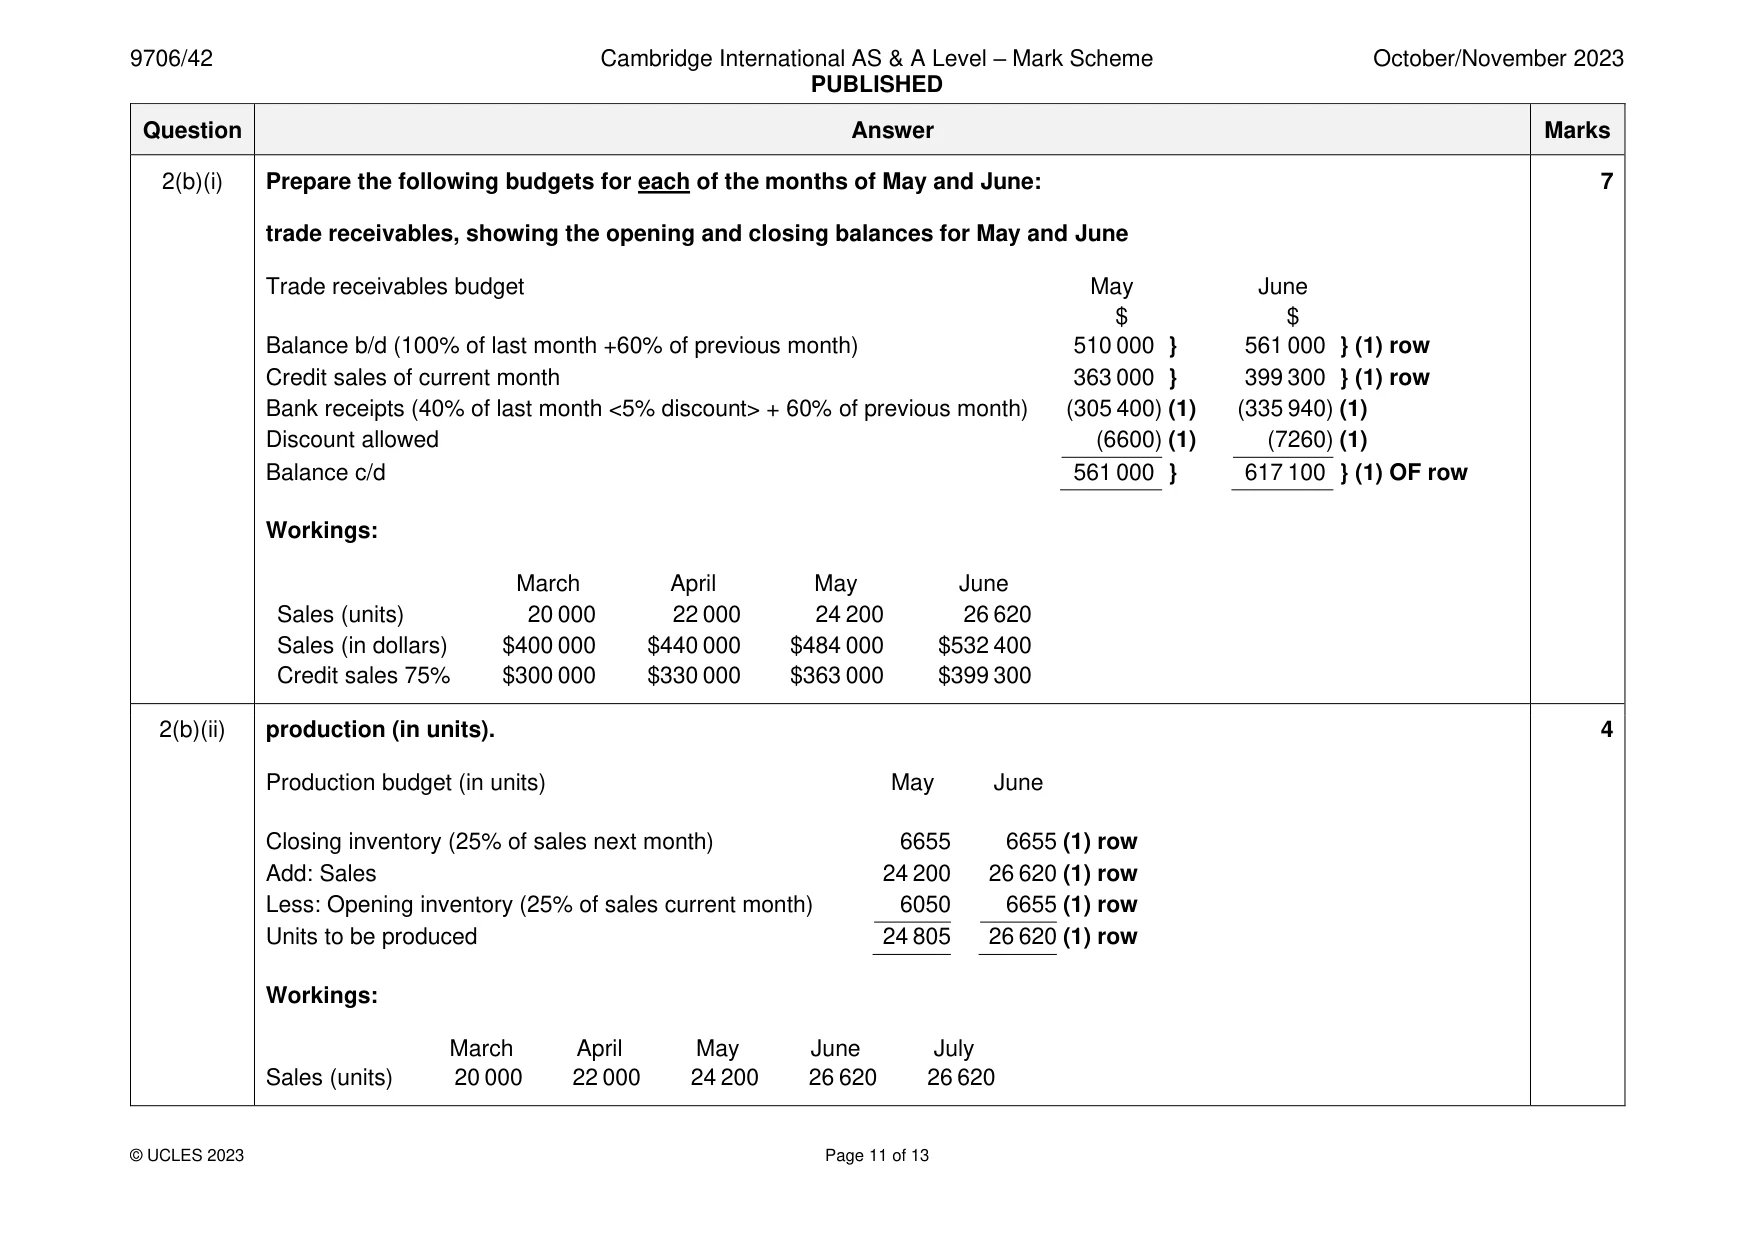
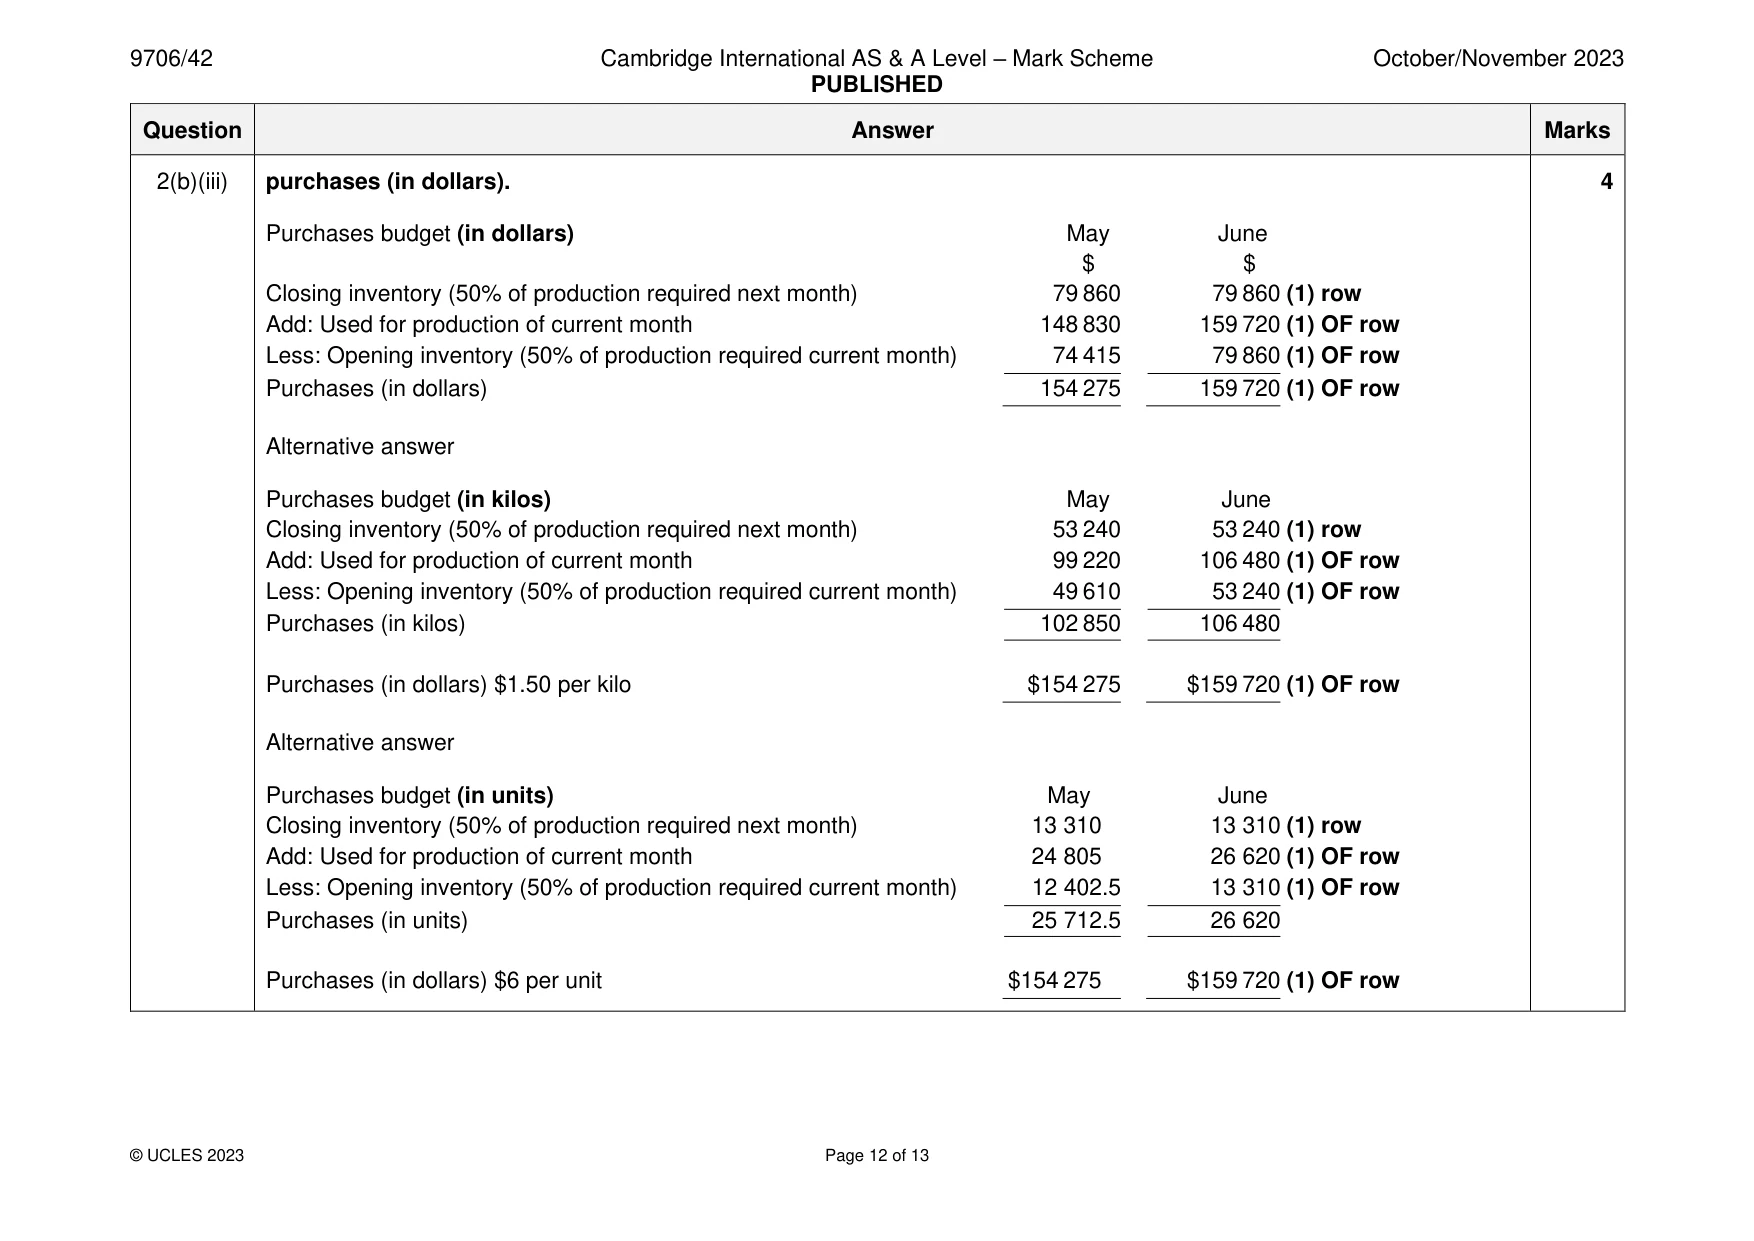
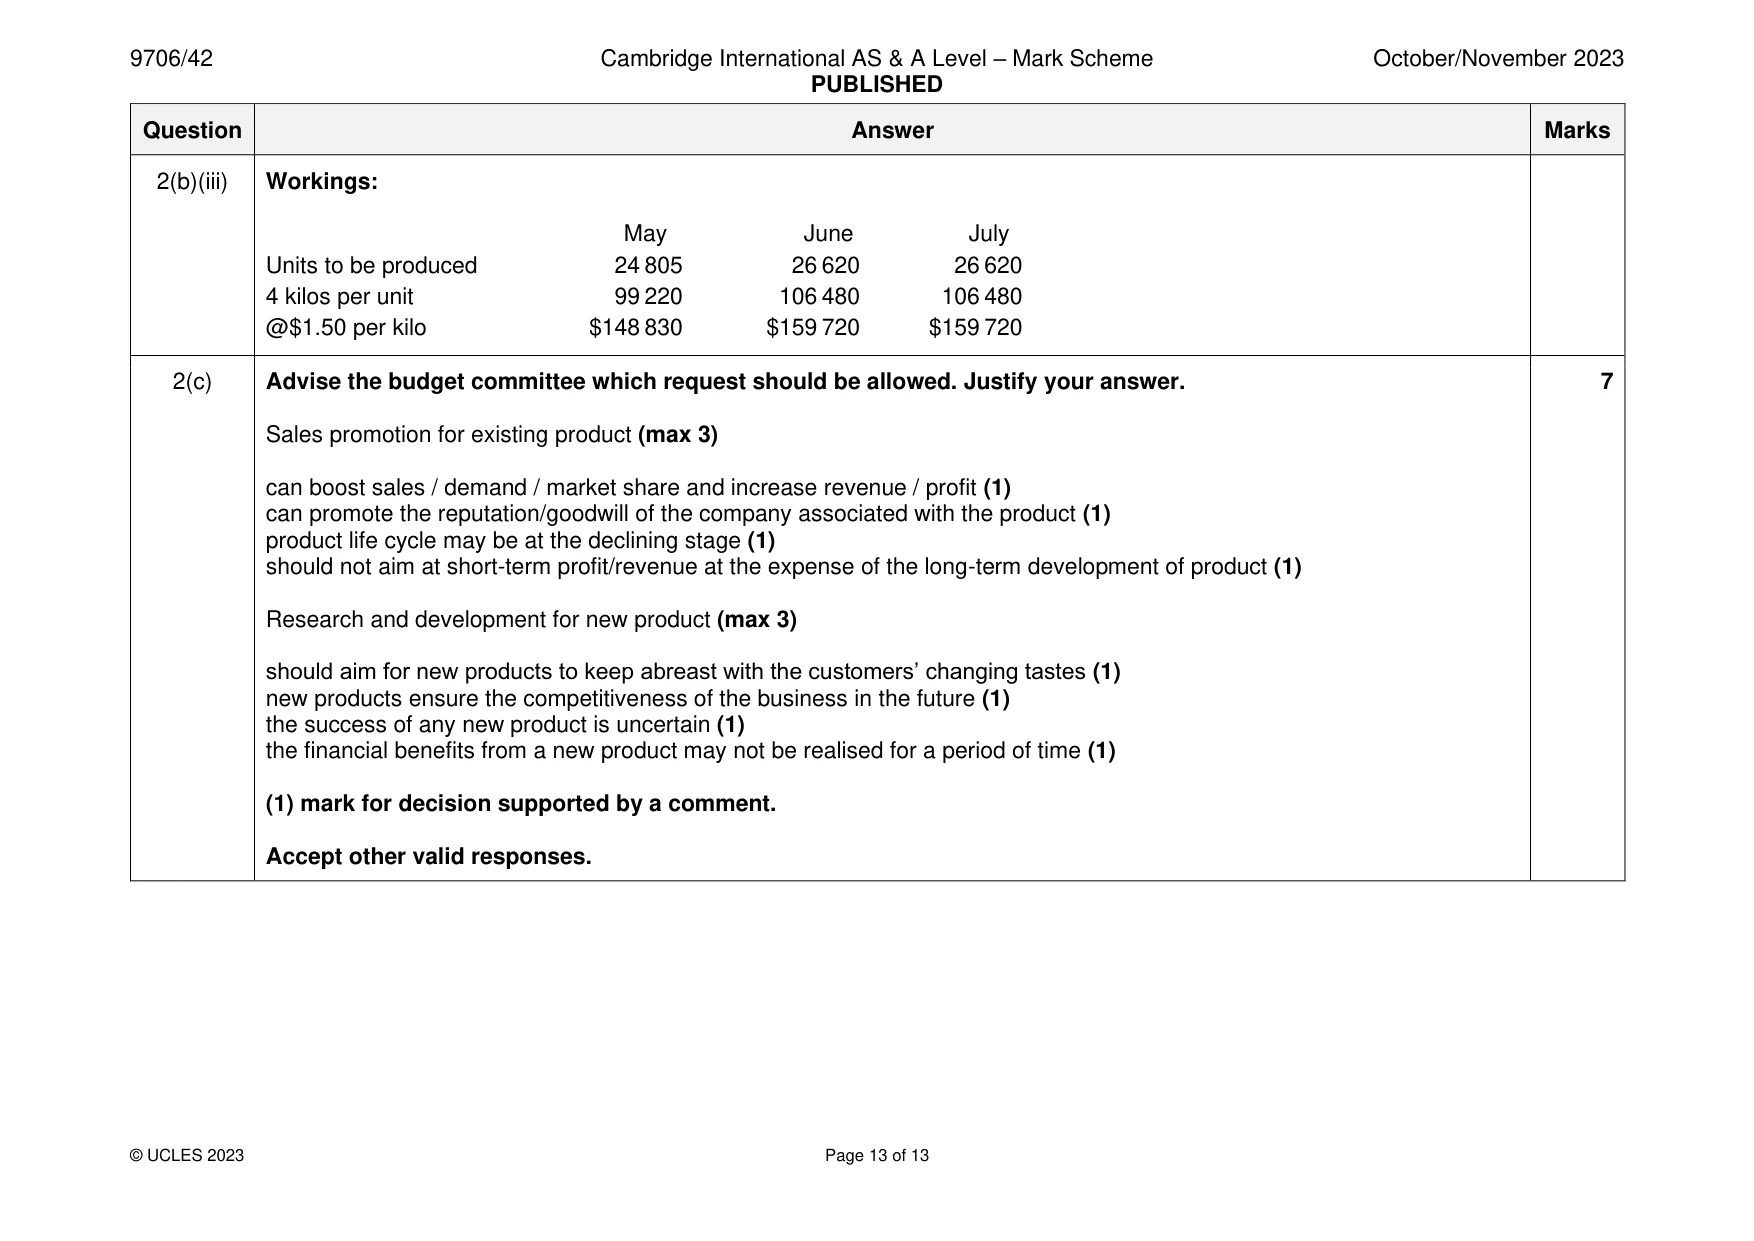
Mark scheme: 2(a) State three advantages of budgeting. 3 Coordinate plans of different departments (1) Planning / controlling costs (1) Motivates employees to achieve common goal (1) Forward looking / decision making, e.g. remedial actions taken for any shortage of resources / limiting factors (1) Responsibility accounting (1) Communication (1) Max 3 Accept other valid responses 2(b)(i) Prepare the following budgets for each of the months of May and June: 7 trade receivables, showing the opening and closing balances for May and June Trade receivables budget May June $ $ Balance b/d (100% of last month +60% of previous month) 510 000 } 561 000 } (1) row Credit sales of current month 363 000 } 399 300 } (1) row Bank receipts (40% of last month <5% discount> + 60% of previous month) (305 400) (1) (335 940) (1) Discount allowed (6600) (1) (7260) (1) Balance c/d 561 000 } 617 100 } (1) OF row Workings: March April May June Sales (units) 20 000 22 000 24 200 26 620 Sales (in dollars) $400 000 $440 000 $484 000 $532 400 Credit sales 75% $300 000 $330 000 $363 000 $399 300 2(b)(ii) production (in units). 4 Production budget (in units) May June Closing inventory (25% of sales next month) 6655 6655 (1) row Add: Sales 24 200 26 620 (1) row Less: Opening inventory (25% of sales current month) 6050 6655 (1) row Units to be produced 24 805 26 620 (1) row Workings: March April May June July Sales (units) 20 000 22 000 24 200 26 620 26 620 2(b)(iii) purchases (in dollars). 4 Purchases budget (in dollars) May June $ $ Closing inventory (50% of production required next month) 79 860 79 860 (1) row Add: Used for production of current month 148 830 159 720 (1) OF row Less: Opening inventory (50% of production required current month) 74 415 79 860 (1) OF row Purchases (in dollars) 154 275 159 720 (1) OF row Alternative answer Purchases budget (in kilos) May June Closing inventory (50% of production required next month) 53 240 53 240 (1) row Add: Used for production of current month 99 220 106 480 (1) OF row Less: Opening inventory (50% of production required current month) 49 610 53 240 (1) OF row Purchases (in kilos) 102 850 106 480 Purchases (in dollars) $1.50 per kilo $154 275 $159 720 (1) OF row Alternative answer Purchases budget (in units) May June Closing inventory (50% of production required next month) 13 310 13 310 (1) row Add: Used for production of current month 24 805 26 620 (1) OF row Less: Opening inventory (50% of production required current month) 12 402.5 13 310 (1) OF row Purchases (in units) 25 712.5 26 620 Purchases (in dollars) $6 per unit $154 275 $159 720 (1) OF row 2(b)(iii) Workings: May June July Units to be produced 24 805 26 620 26 620 4 kilos per unit 99 220 106 480 106 480 @$1.50 per kilo $148 830 $159 720 $159 720 2(c) Advise the budget committee which request should be allowed. Justify your answer. 7 Sales promotion for existing product (max 3) can boost sales / demand / market share and increase revenue / profit (1) can promote the reputation/goodwill of the company associated with the product (1) product life cycle may be at the declining stage (1) should not aim at short-term profit/revenue at the expense of the long-term development of product (1) Research and development for new product (max 3) should aim for new products to keep abreast with the customers’ changing tastes (1) new products ensure the competitiveness of the business in the future (1) the success of any new product is uncertain (1) the financial benefits from a new product may not be realised for a period of time (1) (1) mark for decision supported by a comment. Accept other valid responses.
What was in this paper
The subtopics covered by these 2 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 Oct/Nov, Paper 4 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.