Cambridge A Level Accounting 9706 — 2023 Feb/March Paper 4 · Variant 2
9706/42/F/M/23 · 2 questions · 50 marks · ≈56 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper8 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Read Source A in the insert
1 Read Source A in the insert. (a) Prepare the cash budget for each of the four months from January 2024 to April 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] Additional information One of the directors has made the suggestion that from 1 January 2024 the company should make half of its purchases in cash from some of the suppliers so as to receive a discount of 5%. The credit purchases would continue to be paid for in the month after purchase or as soon as funds allowed. The overdraft limit and the company policy on its overdraft would remain unchanged. (b) Prepare a revised cash budget for each of the four months from January 2024 to April 2024 on the basis of this director’s suggestion. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ........................................................................................................................................... [11] (c) Advise the directors whether or not they should accept the suggestion to make half of the purchases in cash. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 25]
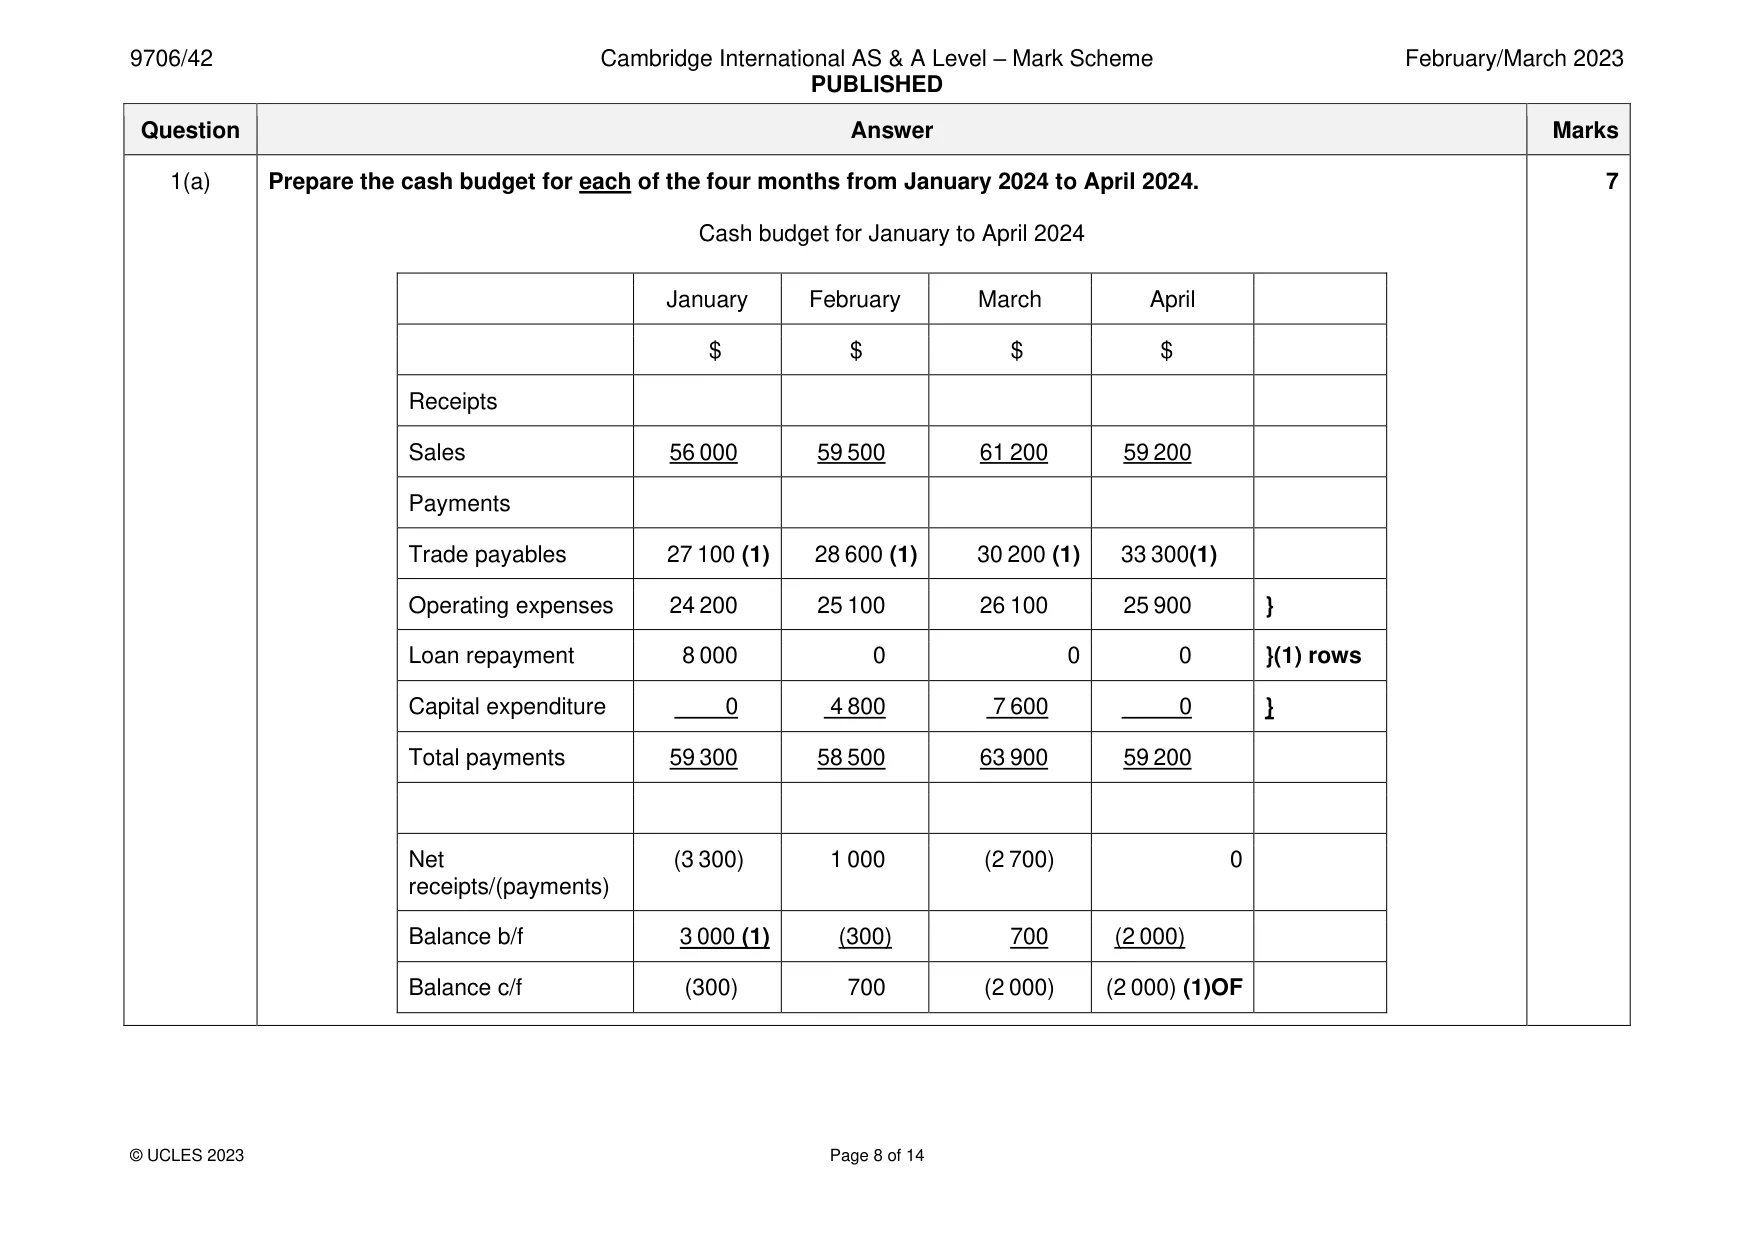
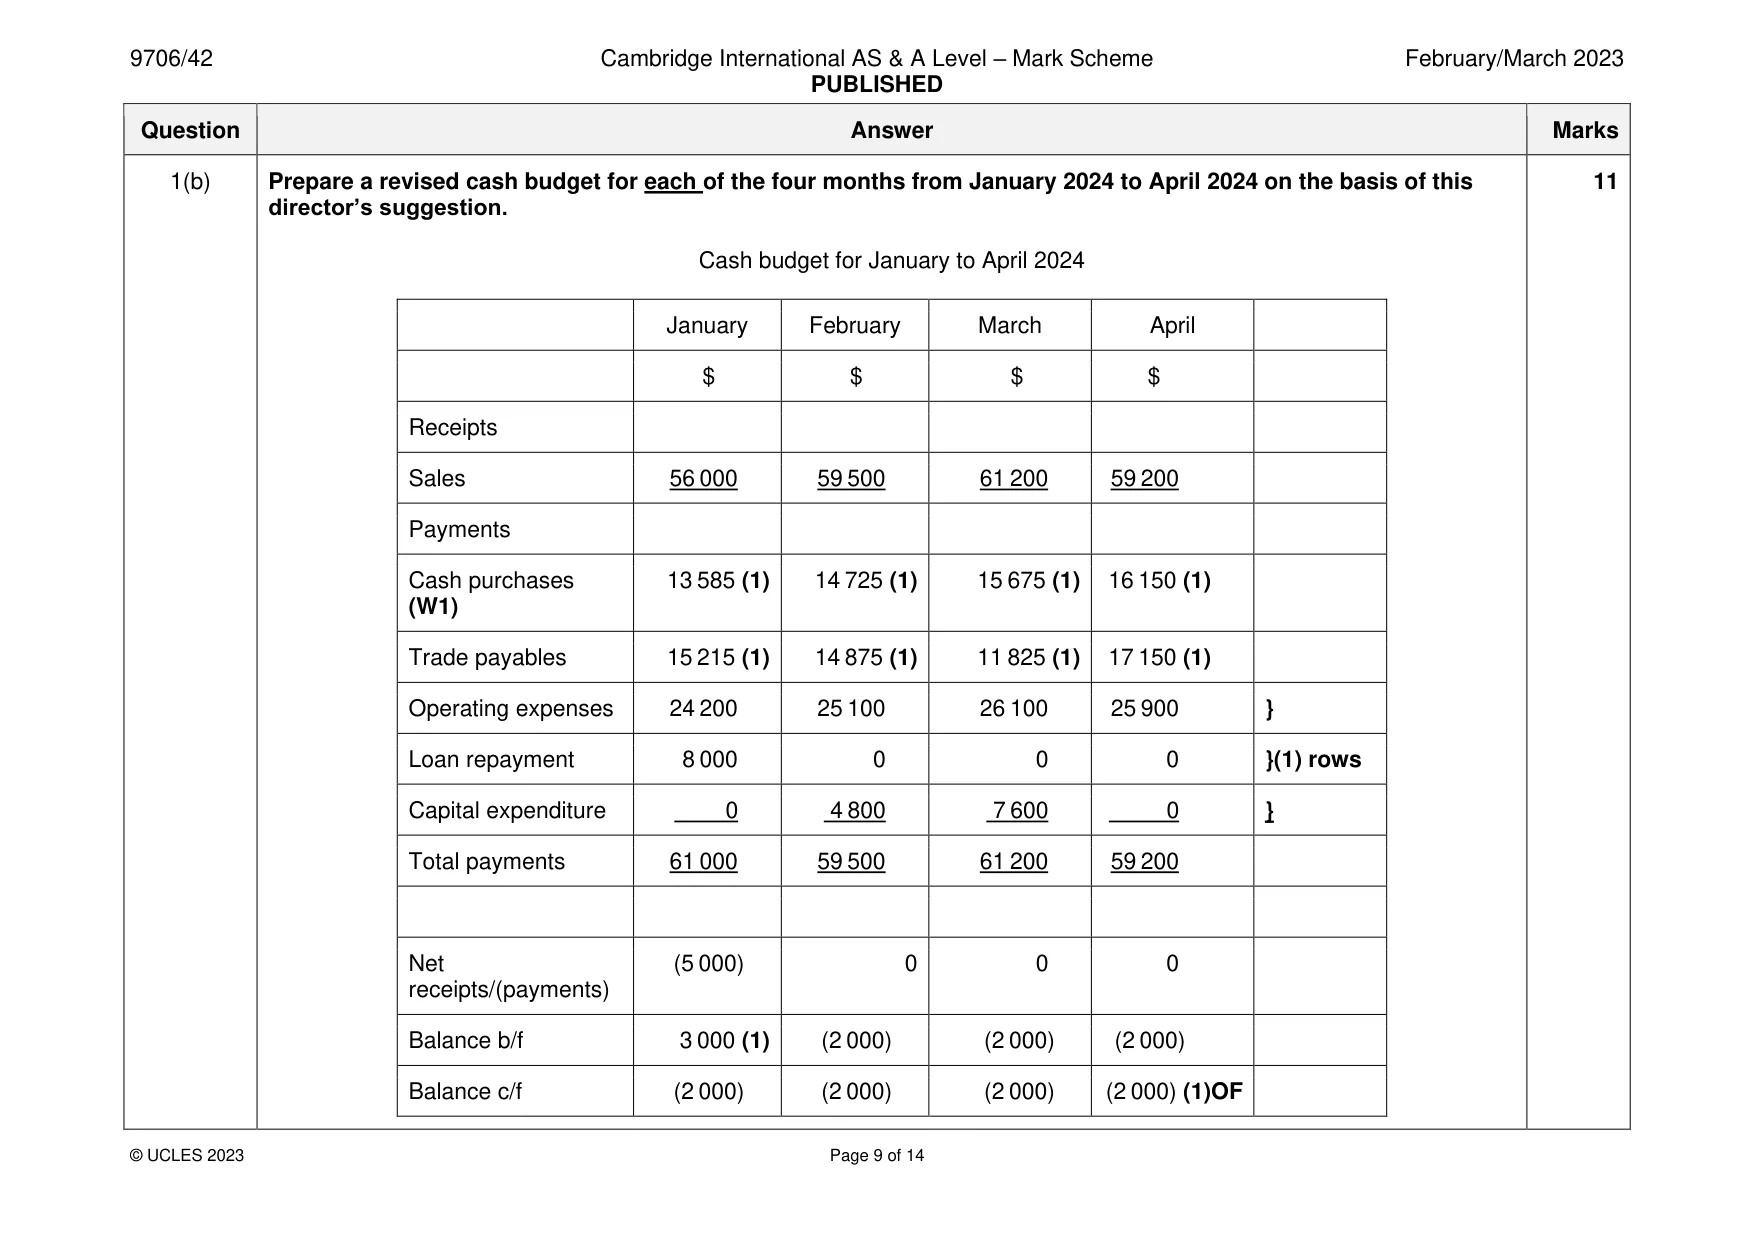
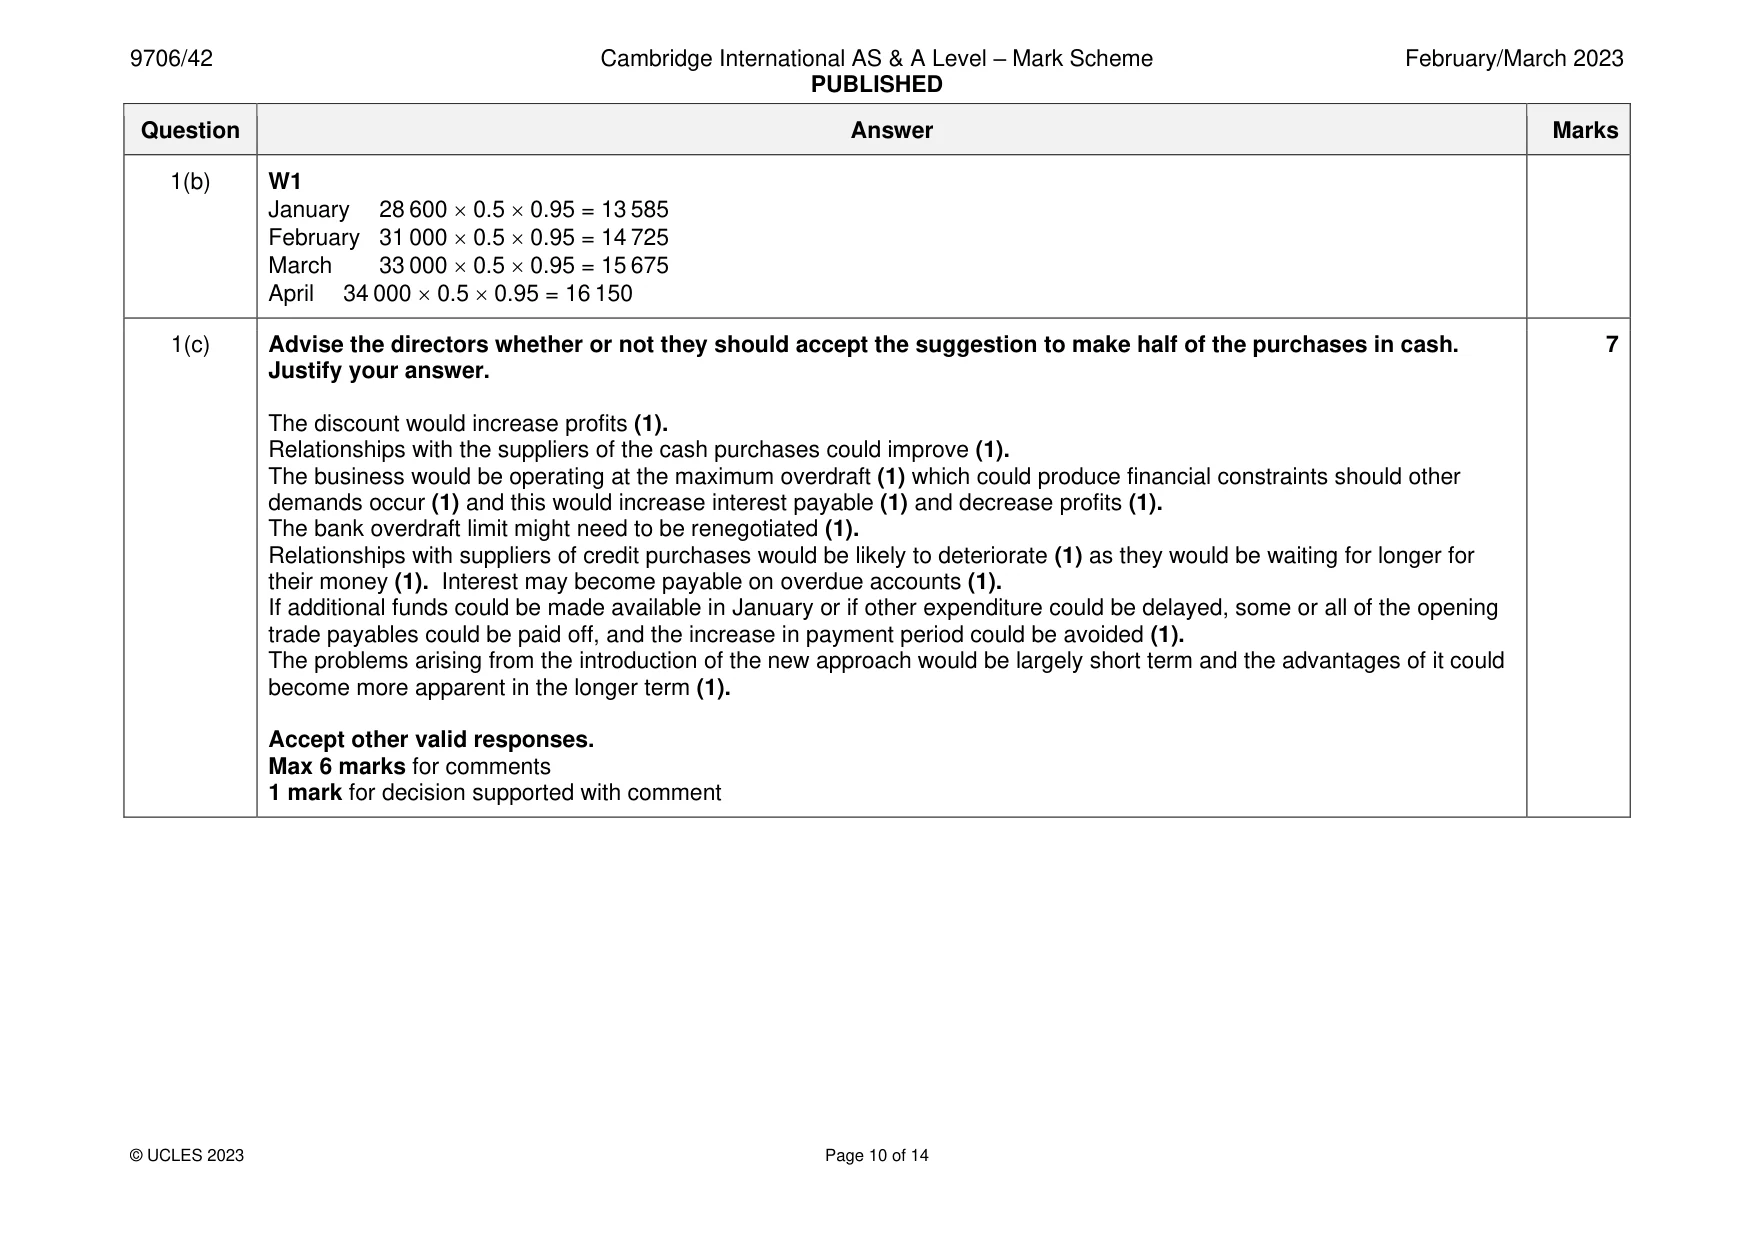
Mark scheme: Question Answer Marks 1(a) Prepare the cash budget for each of the four months from January 2024 to April 2024. 7 Cash budget for January to April 2024 January February March April $ $ $ $ Receipts Sales 56 000 59 500 61 200 59 200 Payments Trade payables 27 100 (1) 28 600 (1) 30 200 (1) 33 300(1) Operating expenses 24 200 25 100 26 100 25 900 } Loan repayment 8 000 0 0 0 }(1) rows Capital expenditure 0 4 800 7 600 0 } Total payments 59 300 58 500 63 900 59 200 Net (3 300) 1 000 (2 700) 0 receipts/(payments) Balance b/f 3 000 (1) (300) 700 (2 000) Balance c/f (300) 700 (2 000) (2 000) (1)OF 1(b) Prepare a revised cash budget for each of the four months from January 2024 to April 2024 on the basis of this 11 director’s suggestion. Cash budget for January to April 2024 January February March April $ $ $ $ Receipts Sales 56 000 59 500 61 200 59 200 Payments Cash purchases 13 585 (1) 14 725 (1) 15 675 (1) 16 150 (1) (W1) Trade payables 15 215 (1) 14 875 (1) 11 825 (1) 17 150 (1) Operating expenses 24 200 25 100 26 100 25 900 } Loan repayment 8 000 0 0 0 }(1) rows Capital expenditure 0 4 800 7 600 0 } Total payments 61 000 59 500 61 200 59 200 Net (5 000) 0 0 0 receipts/(payments) Balance b/f 3 000 (1) (2 000) (2 000) (2 000) Balance c/f (2 000) (2 000) (2 000) (2 000) (1)OF 1(b) W1 January 28 600 0.5 0.95 = 13 585 February 31 000 0.5 0.95 = 14 725 March 33 000 0.5 0.95 = 15 675 April 34 000 0.5 0.95 = 16 150 1(c) Advise the directors whether or not they should accept the suggestion to make half of the purchases in cash. 7 Justify your answer. The discount would increase profits (1). Relationships with the suppliers of the cash purchases could improve (1). The business would be operating at the maximum overdraft (1) which could produce financial constraints should other demands occur (1) and this would increase interest payable (1) and decrease profits (1). The bank overdraft limit might need to be renegotiated (1). Relationships with suppliers of credit purchases would be likely to deteriorate (1) as they would be waiting for longer for their money (1). Interest may become payable on overdue accounts (1). If additional funds could be made available in January or if other expenditure could be delayed, some or all of the opening trade payables could be paid off, and the increase in payment period could be avoided (1). The problems arising from the introduction of the new approach would be largely short term and the advantages of it could become more apparent in the longer term (1). Accept other valid responses. Max 6 marks for comments 1 mark for decision supported with comment
Q2 · Read Source B in the insert
2 Read Source B in the insert. (a) State what is meant by the term ‘cost driver’. ................................................................................................................................................... ............................................................................................................................................. [1] (b) Calculate the total profit or loss made from the production of each product for a year. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: [11] Additional information Simran was concerned about the high volume of units being returned. She believed that the workers were not paying enough attention when assembling the products. She considered installing a system of surveillance cameras in the factory so that the workers could be monitored. She believed that this would totally eliminate the returns. Simran would rent the camera system for a fixed period of three years. The costs of renting and monitoring the cameras would amount to $18 000 per annum. Simran decided that this would be added to the cost of the quality inspections. The increased total would then be allocated on the same basis as before. (c) Calculate the revised total profit or loss made from the production of each product for a year if the surveillance cameras were introduced and all the returns were eliminated. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) Advise Simran whether or not she should install the system of surveillance cameras. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [6] (e) Comment on the suitability of the cost driver to account for the cost of the surveillance cameras. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 25]
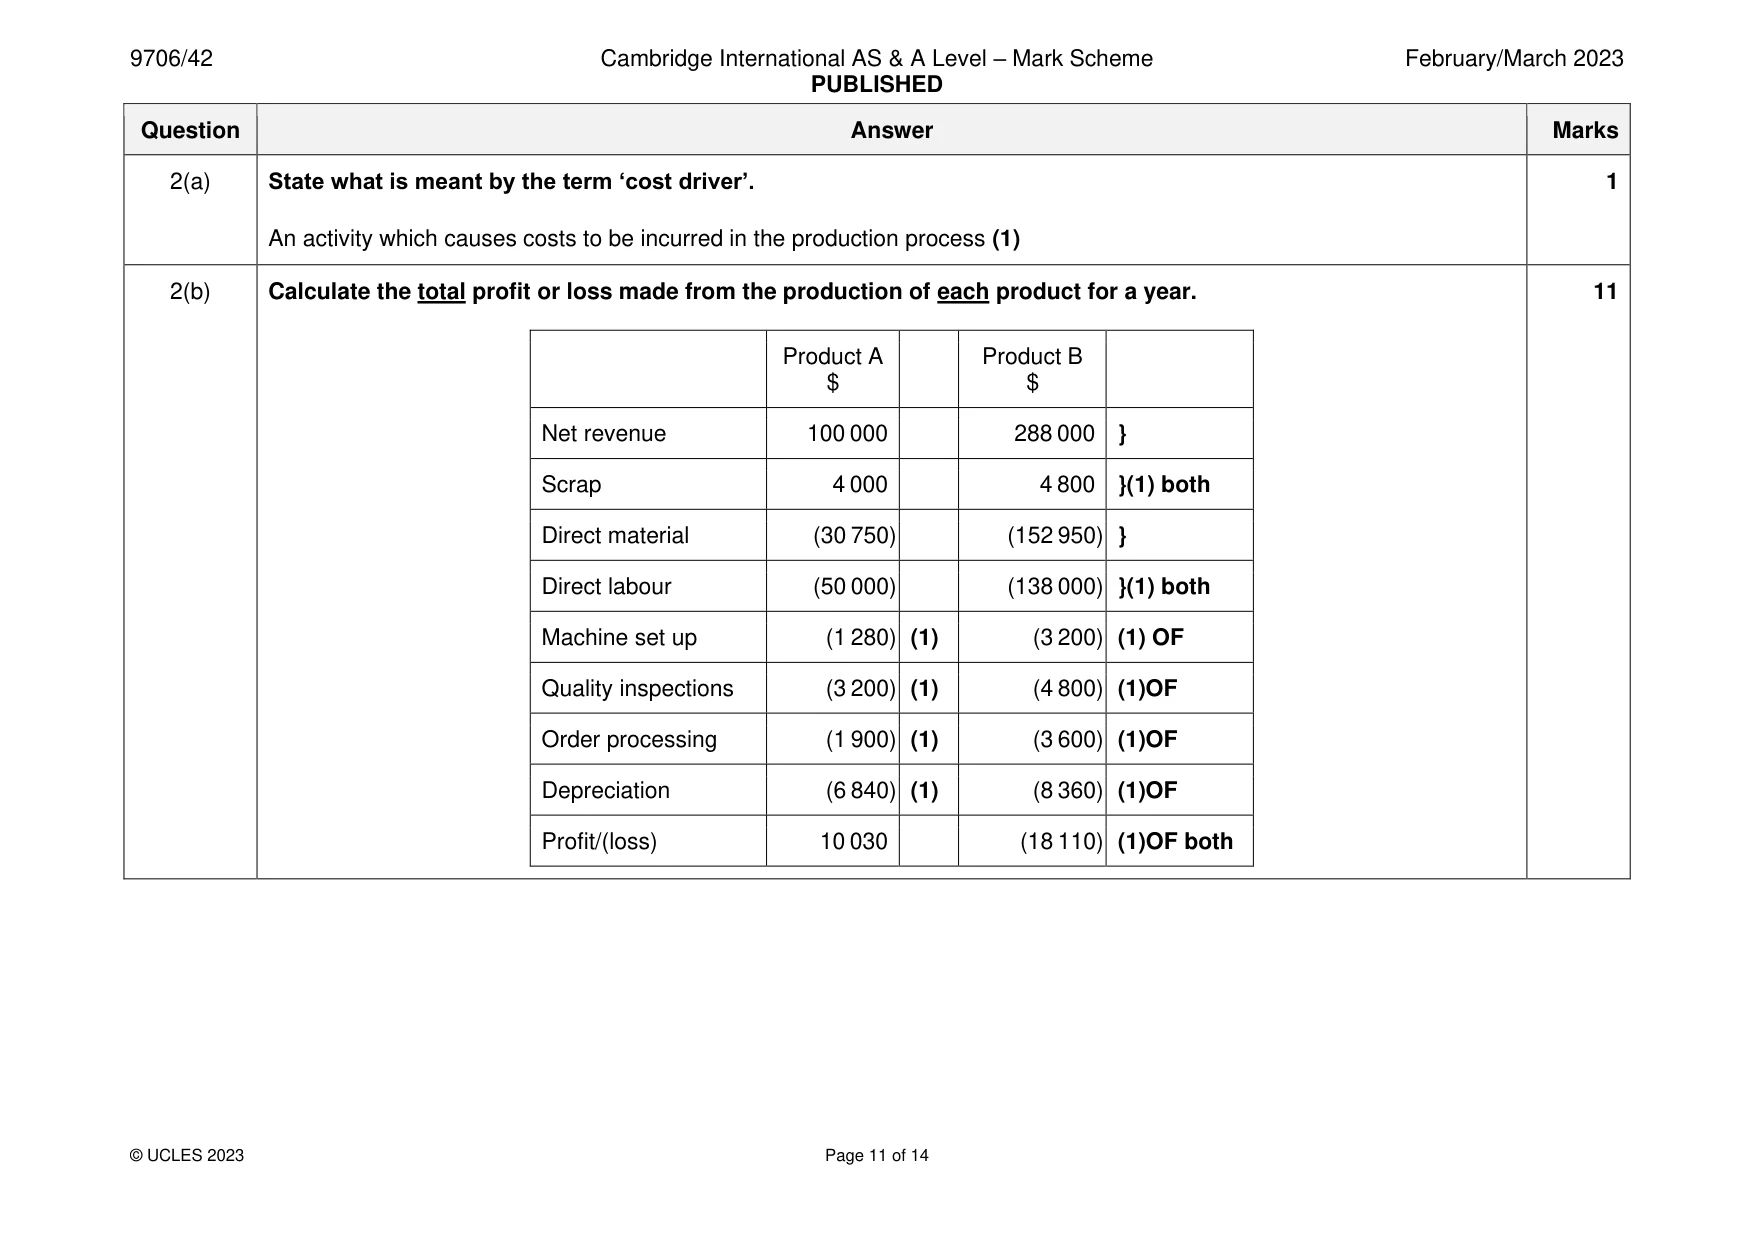
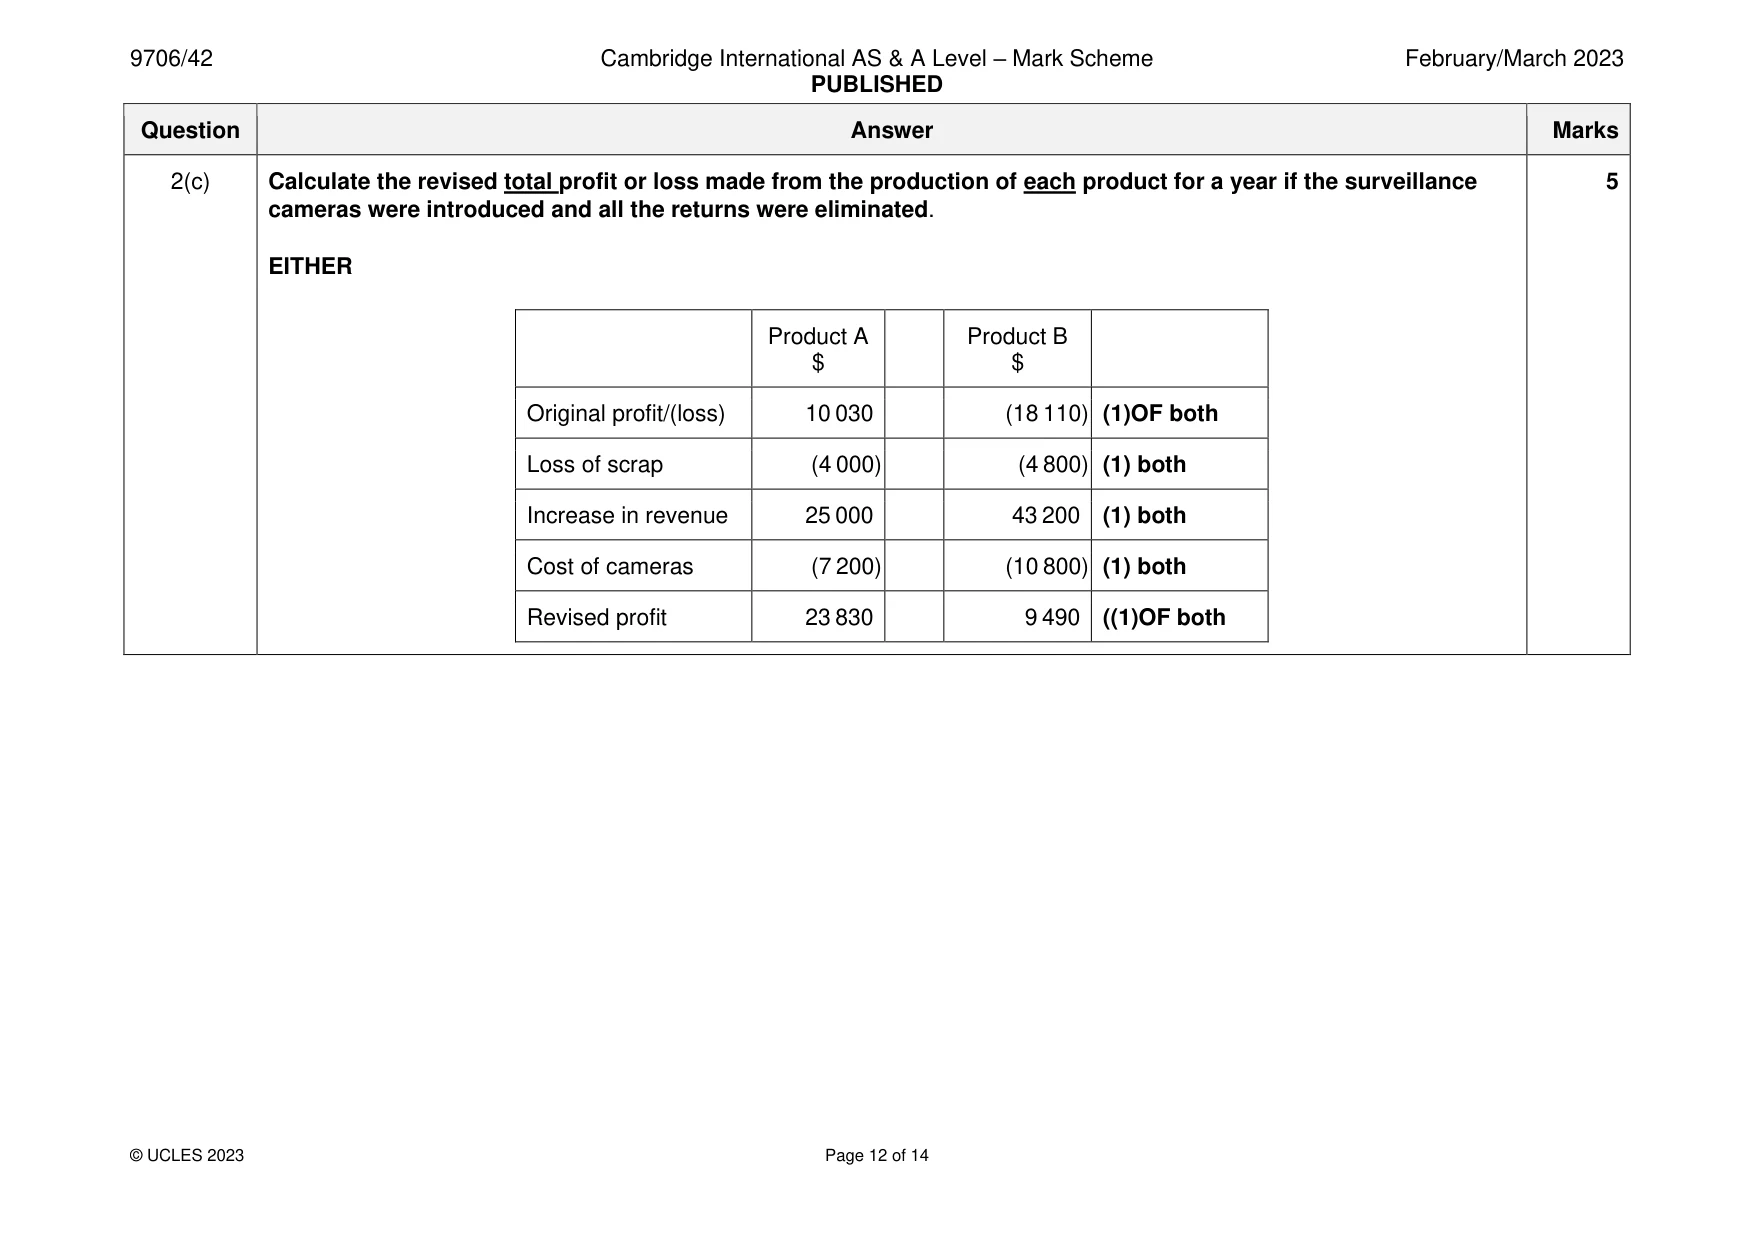
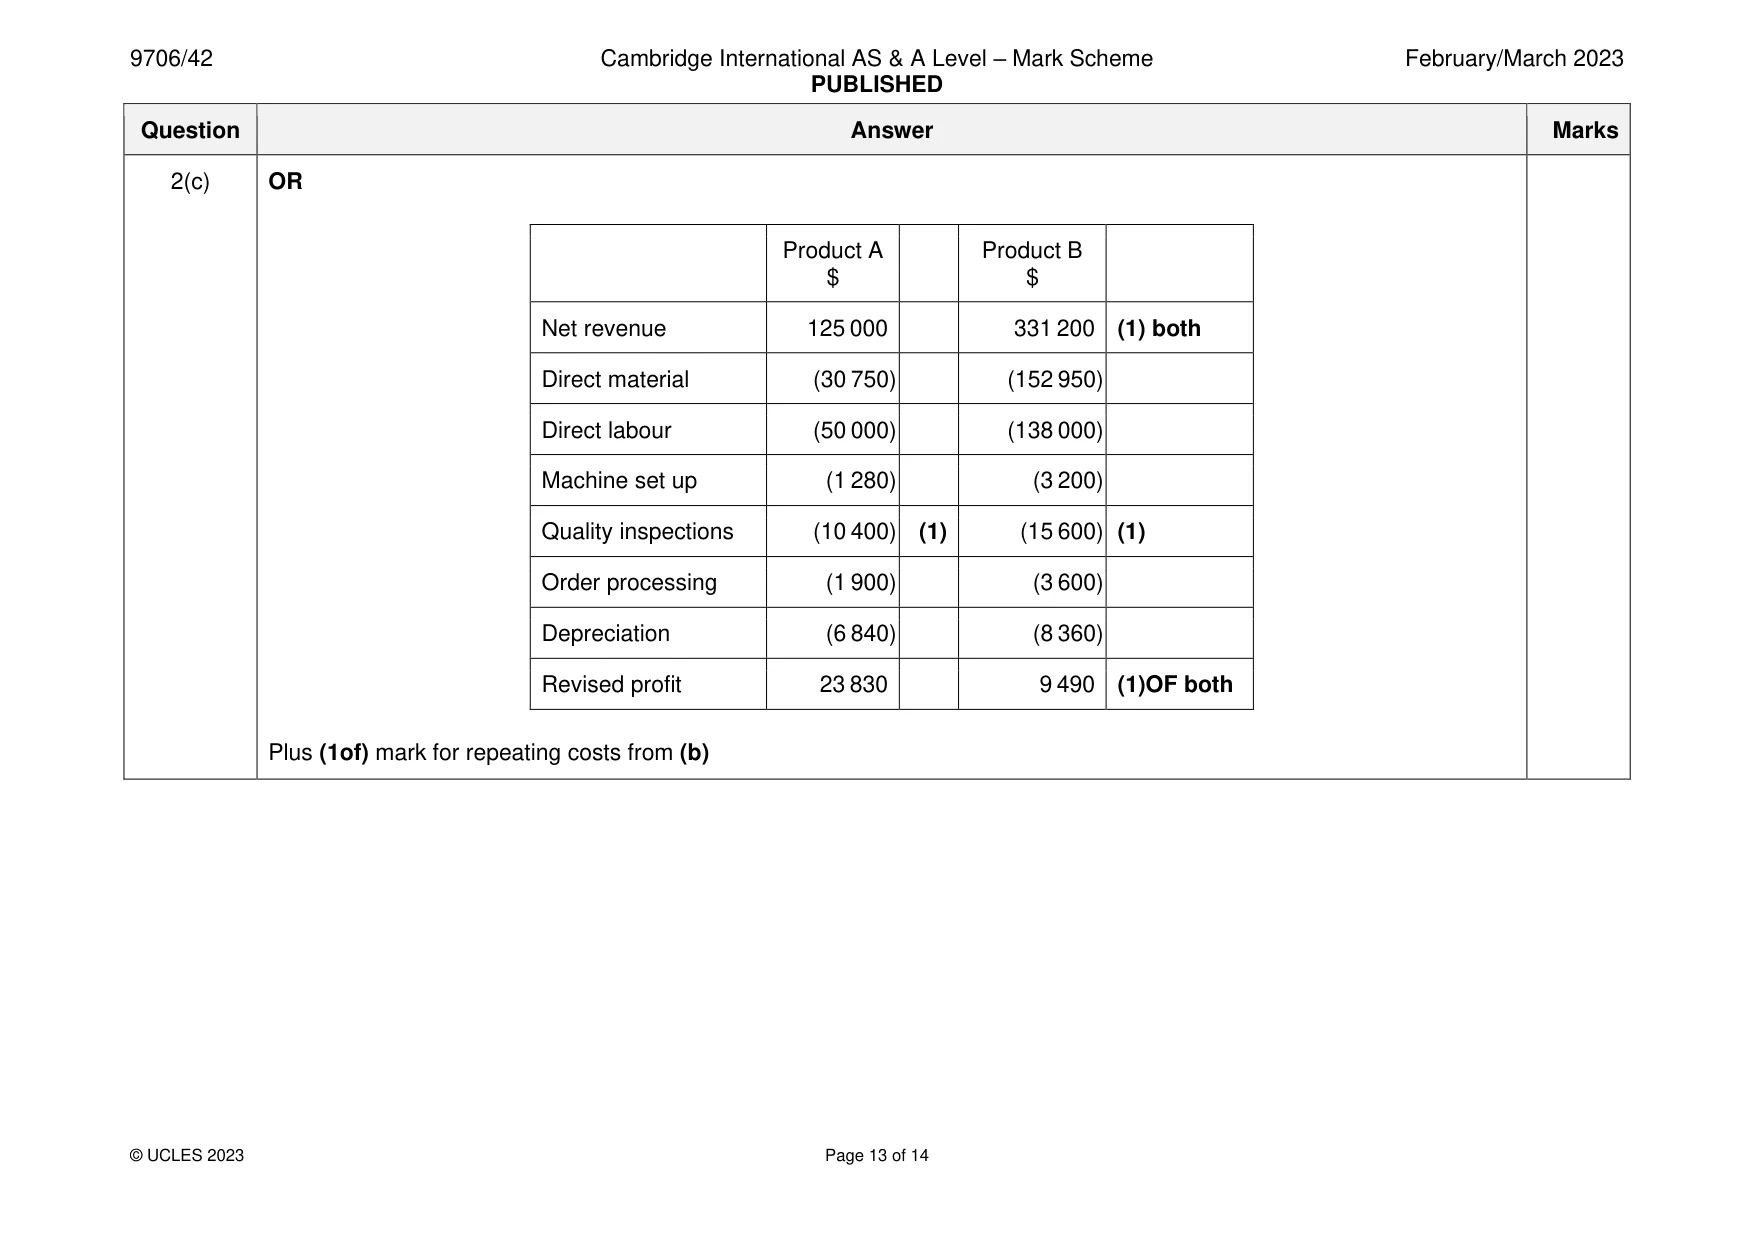
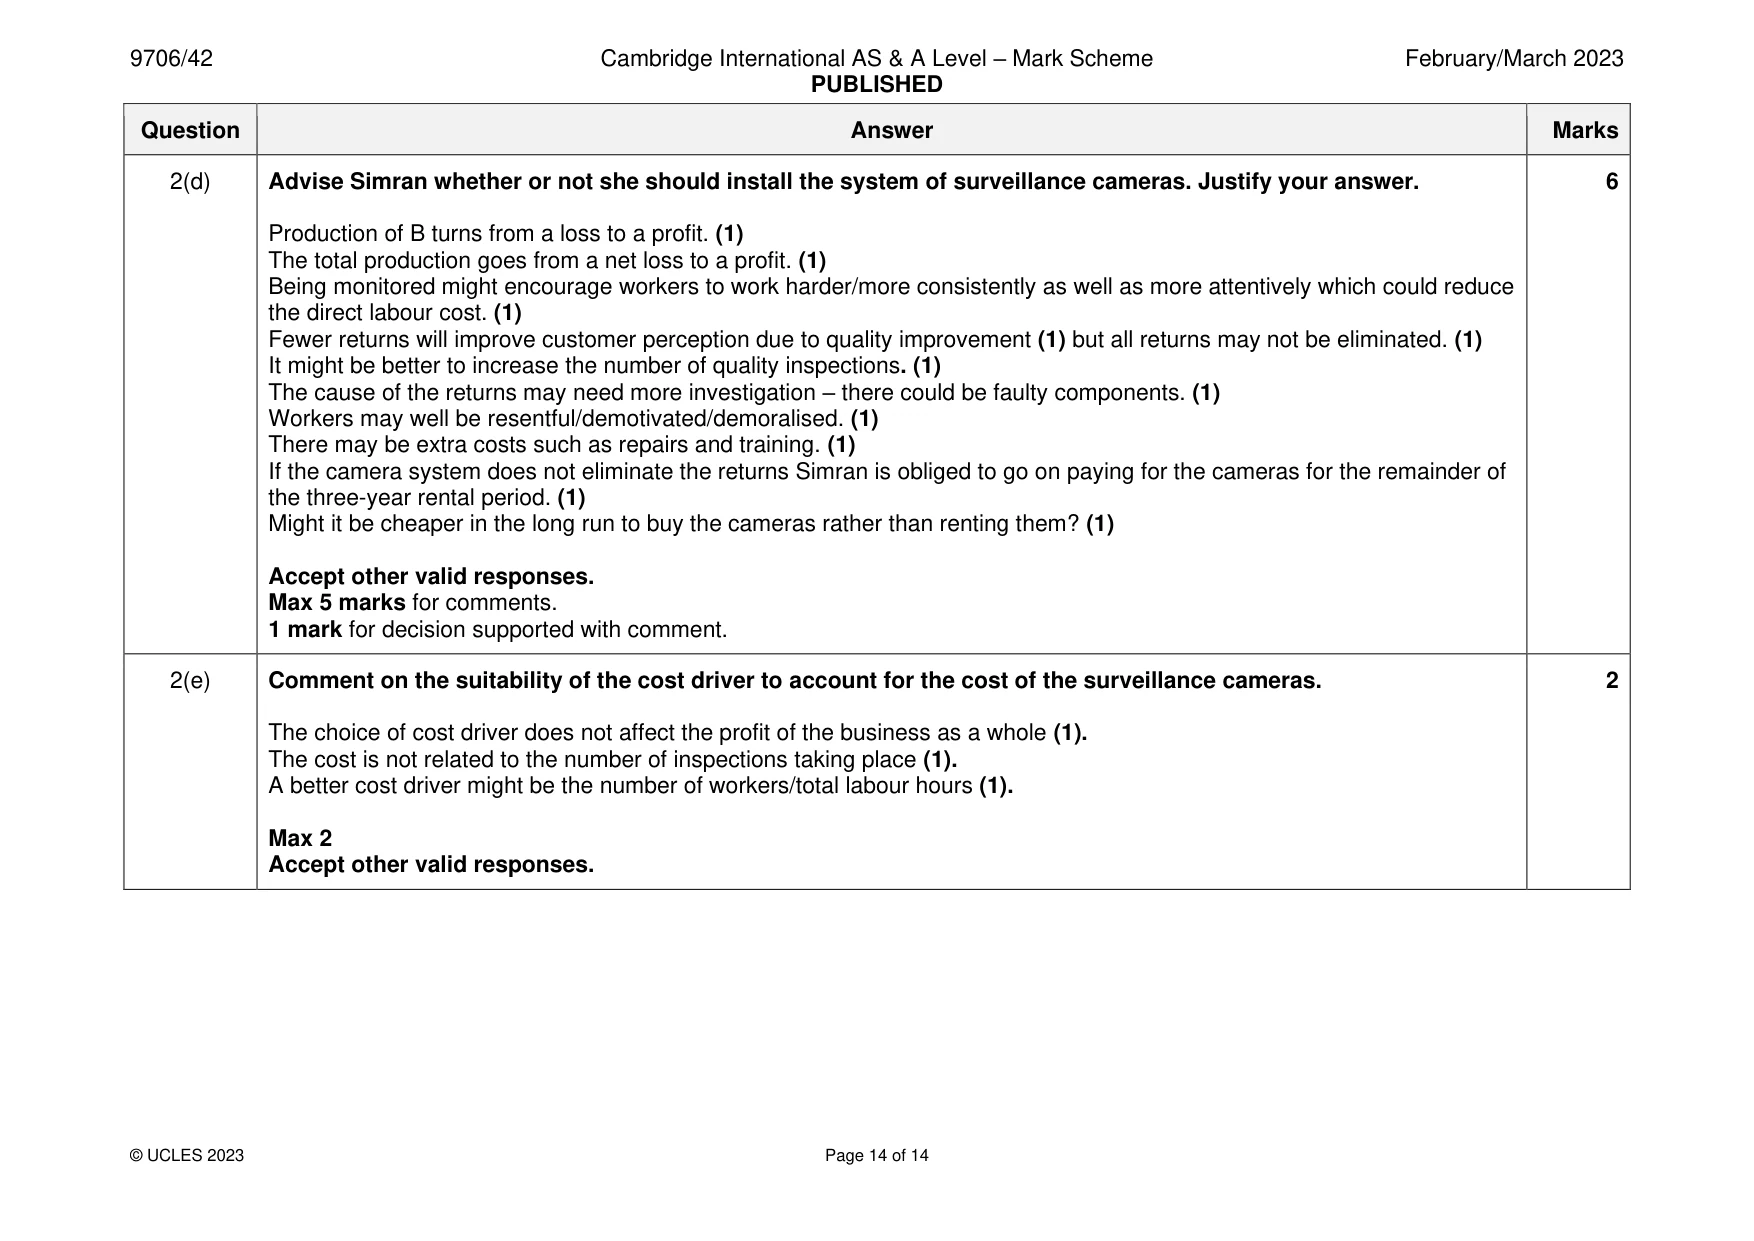
Mark scheme: 2(a) State what is meant by the term ‘cost driver’. 1 An activity which causes costs to be incurred in the production process (1) 2(b) Calculate the total profit or loss made from the production of each product for a year. 11 Product A Product B $ $ Net revenue 100 000 288 000 } Scrap 4 000 4 800 }(1) both Direct material (30 750) (152 950) } Direct labour (50 000) (138 000) }(1) both Machine set up (1 280) (1) (3 200) (1) OF Quality inspections (3 200) (1) (4 800) (1)OF Order processing (1 900) (1) (3 600) (1)OF Depreciation (6 840) (1) (8 360) (1)OF Profit/(loss) 10 030 (18 110) (1)OF both 2(c) Calculate the revised total profit or loss made from the production of each product for a year if the surveillance 5 cameras were introduced and all the returns were eliminated. EITHER Product A Product B $ $ Original profit/(loss) 10 030 (18 110) (1)OF both Loss of scrap (4 000) (4 800) (1) both Increase in revenue 25 000 43 200 (1) both Cost of cameras (7 200) (10 800) (1) both Revised profit 23 830 9 490 ((1)OF both 2(c) OR Product A Product B $ $ Net revenue 125 000 331 200 (1) both Direct material (30 750) (152 950) Direct labour (50 000) (138 000) Machine set up (1 280) (3 200) Quality inspections (10 400) (1) (15 600) (1) Order processing (1 900) (3 600) Depreciation (6 840) (8 360) Revised profit 23 830 9 490 (1)OF both Plus (1of) mark for repeating costs from (b) 2(d) Advise Simran whether or not she should install the system of surveillance cameras. Justify your answer. 6 Production of B turns from a loss to a profit. (1) The total production goes from a net loss to a profit. (1) Being monitored might encourage workers to work harder/more consistently as well as more attentively which could reduce the direct labour cost. (1) Fewer returns will improve customer perception due to quality improvement (1) but all returns may not be eliminated. (1) It might be better to increase the number of quality inspections. (1) The cause of the returns may need more investigation – there could be faulty components. (1) Workers may well be resentful/demotivated/demoralised. (1) There may be extra costs such as repairs and training. (1) If the camera system does not eliminate the returns Simran is obliged to go on paying for the cameras for the remainder of the three-year rental period. (1) Might it be cheaper in the long run to buy the cameras rather than renting them? (1) Accept other valid responses. Max 5 marks for comments. 1 mark for decision supported with comment. 2(e) Comment on the suitability of the cost driver to account for the cost of the surveillance cameras. 2 The choice of cost driver does not affect the profit of the business as a whole (1). The cost is not related to the number of inspections taking place (1). A better cost driver might be the number of workers/total labour hours (1). Max 2 Accept other valid responses.
What was in this paper
The subtopics covered by these 2 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 Feb/March, Paper 4 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.