Questions as text
Q1 · Mui owns a household appliance store 0452/12 Feb/March 2020
4 Mui owns a household appliance store. He took home a washing machine for his personal use. Mui recorded this transaction as follows. account debited account credited drawings sales Did Mui make the correct entries to record this transaction? debit entry credit entry A no no B no yes C yes no D yes yes
1 marks
Answer: C
This question in 0452/12 Feb/March 2020
Q2 · The totals of a trial balance agreed but it was found that the purchase of office… 0452/12 Feb/March 2020
8 The totals of a trial balance agreed but it was found that the purchase of office equipment had been debited to office expenses account. Which type of error has been made? A commission B compensating C original entry D principle
1 marks
Answer: D
This question in 0452/12 Feb/March 2020
Q3 · Equipment costing $20 000 was purchased on 1 January 2019 0452/12 Feb/March 2020
13 Equipment costing $20 000 was purchased on 1 January 2019. It has a useful working life of 5 years and a residual value of $3000. Depreciation using the straight-line method was included in the income statement for the year ended 31 December 2019. It was then found that the reducing balance method at 30% per annum should have been used. What was the effect on the profit for the year ended 31 December 2019 of this error? A $2000 overstated B $2000 understated C $2600 overstated D $2600 understated
1 marks
Answer: C
This question in 0452/12 Feb/March 2020
Q4 · The income statement of a business showed a loss for the year of $16 000 0452/11 May/June 2020
11 The income statement of a business showed a loss for the year of $16 000. On checking the books the following errors were discovered. 1 No adjustment had been made for insurance prepaid, $480. 2 No entry had been made for bank charges, $620. What was the correct loss for the year? A $14 900 B $15 860 C $16 140 D $17 100
1 marks
Answer: C
This question in 0452/11 May/June 2020
Q5 · A non-current asset was depreciated at the end of the first year of ownership using the… 0452/11 May/June 2020
15 A non-current asset was depreciated at the end of the first year of ownership using the straight-line method based on the following information. cost $20 000 working life 4 years residual value $4000 It was then found that the reducing balance method at 30% per annum should have been used. What was the effect on the profit for the year of correcting this error? A decrease by $2000 B increase by $2000 C decrease by $6000 D increase by $6000
1 marks
Answer: A
This question in 0452/11 May/June 2020
Q6 · The owner of a business took goods for his own use but forgot to make an entry in the… 0452/11 May/June 2020
22 The owner of a business took goods for his own use but forgot to make an entry in the accounts. What was the effect of this error? profit for the year capital employed A overstated no effect B overstated understated C understated no effect D understated overstated
1 marks
Answer: C
This question in 0452/11 May/June 2020
Q7 · Sita discovers that $1000 received from the sale of fixtures had been entered in the… 0452/12 May/June 2020
10 Sita discovers that $1000 received from the sale of fixtures had been entered in the sales account. Which journal entry corrected this error? debit credit $ $ bank 1000 A disposal of fixtures 1000 bank 1000 B fixtures 1000 sales 1000 C disposal of fixtures 1000 sales 1000 D fixtures 1000
1 marks
Answer: C
This question in 0452/12 May/June 2020
Q8 · The totals of a trial balance did not agree and $200 was debited to a suspense account 0452/12 May/June 2020
11 The totals of a trial balance did not agree and $200 was debited to a suspense account. On checking the books it was found that two errors had been made. 1 A sales invoice for $700 had been recorded in the sales journal as $770. 2 The sales journal had been totalled incorrectly. What was the error made in totalling the sales journal? A overcast by $130 B overcast by $200 C undercast by $130 D undercast by $200
1 marks
Answer: B
This question in 0452/12 May/June 2020
Q9 · The income statement of a business showed a loss for the year of $16 000 0452/12 May/June 2020
12 The income statement of a business showed a loss for the year of $16 000. On checking the books the following errors were discovered. 1 No adjustment had been made for insurance prepaid, $480. 2 No entry had been made for bank charges, $620. What was the correct loss for the year? A $14 900 B $15 860 C $16 140 D $17 100
1 marks
Answer: C
This question in 0452/12 May/June 2020
Q10 · The owner of a business took goods for his own use but forgot to make an entry in the… 0452/12 May/June 2020
21 The owner of a business took goods for his own use but forgot to make an entry in the accounts. What was the effect of this error? profit for the year capital employed A overstated no effect B overstated understated C understated no effect D understated overstated
1 marks
Answer: C
This question in 0452/12 May/June 2020
Q11 · Sita discovers that $1000 received from the sale of fixtures had been entered in the… 0452/13 May/June 2020
10 Sita discovers that $1000 received from the sale of fixtures had been entered in the sales account. Which journal entry corrected this error? debit credit $ $ bank 1000 A disposal of fixtures 1000 bank 1000 B fixtures 1000 sales 1000 C disposal of fixtures 1000 sales 1000 D fixtures 1000
1 marks
Answer: C
This question in 0452/13 May/June 2020
Q12 · The totals of a trial balance did not agree and $200 was debited to a suspense account 0452/13 May/June 2020
11 The totals of a trial balance did not agree and $200 was debited to a suspense account. On checking the books it was found that two errors had been made. 1 A sales invoice for $700 had been recorded in the sales journal as $770. 2 The sales journal had been totalled incorrectly. What was the error made in totalling the sales journal? A overcast by $130 B overcast by $200 C undercast by $130 D undercast by $200
1 marks
Answer: B
This question in 0452/13 May/June 2020
Q13 · The income statement of a business showed a loss for the year of $16 000 0452/13 May/June 2020
12 The income statement of a business showed a loss for the year of $16 000. On checking the books the following errors were discovered. 1 No adjustment had been made for insurance prepaid, $480. 2 No entry had been made for bank charges, $620. What was the correct loss for the year? A $14 900 B $15 860 C $16 140 D $17 100
1 marks
Answer: C
This question in 0452/13 May/June 2020
Q14 · A non-current asset was depreciated at the end of the first year of ownership using the… 0452/13 May/June 2020
16 A non-current asset was depreciated at the end of the first year of ownership using the straight-line method based on the following information. cost $20 000 working life 4 years residual value $4000 It was then found that the reducing balance method at 30% per annum should have been used. What was the effect on the profit for the year of correcting this error? A decrease by $2000 B increase by $2000 C decrease by $6000 D increase by $6000
1 marks
Answer: A
This question in 0452/13 May/June 2020
Q15 · The owner of a business took goods for his own use but forgot to make an entry in the… 0452/13 May/June 2020
21 The owner of a business took goods for his own use but forgot to make an entry in the accounts. What was the effect of this error? profit for the year capital employed A overstated no effect B overstated understated C understated no effect D understated overstated
1 marks
Answer: C
This question in 0452/13 May/June 2020
Q16 · A computer system purchased from Ace Computers for $1430 had been incorrectly recorded as… 0452/11 Oct/Nov 2020
8 A computer system purchased from Ace Computers for $1430 had been incorrectly recorded as $1340 and was entered in the stationery account instead of the office equipment account. Which journal entry corrects this error? debit credit $ $ A Ace computers 90 stationery 1340 office equipment 1340 B Ace computers 90 stationery 1340 office equipment 1430 C office equipment 1340 Ace computers 90 stationery 1340 D office equipment 1430 Ace computers 90 stationery 1340
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2020
Q17 · Kate calculated her draft profit for the year at $28 400 0452/11 Oct/Nov 2020
9 Kate calculated her draft profit for the year at $28 400. She later discovered the following errors. 1 Rent prepaid by Kate was understated by $1000. 2 Closing inventory was understated by $1500. What was the correct profit for the year? A $25 900 B $27 900 C $28 900 D $30 900
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2020
Q18 · A trader debited the cost of repairing office equipment to the office equipment account 0452/11 Oct/Nov 2020
11 A trader debited the cost of repairing office equipment to the office equipment account. How did this error affect the financial statements? profit for non-current the year assets A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 0452/11 Oct/Nov 2020
Q19 · Rashid provided the following information at 31 December 0452/11 Oct/Nov 2020
13 Rashid provided the following information at 31 December. $ machinery at cost 52 000 provision for depreciation of machinery 23 000 Depreciation for the year is calculated at 20% on cost. After the statement of financial position was prepared it was found that the machinery repairs costing $2000 had been debited to the machinery account. What is the correct balance on the provision for the depreciation of machinery account? A $21 000 B $22 600 C $23 400 D $25 000
1 marks
Answer: B
This question in 0452/11 Oct/Nov 2020
Q20 · A transaction was posted to the wrong account of the same class 0452/12 Oct/Nov 2020
9 A transaction was posted to the wrong account of the same class. Which type of error was made? A commission B original entry C principle D reversal
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2020
Q21 · Motor vehicle expenses, $50, were incorrectly debited to the motor vehicles account 0452/12 Oct/Nov 2020
10 Motor vehicle expenses, $50, were incorrectly debited to the motor vehicles account. Which journal entry corrects this error? debit credit $ $ A motor vehicle expenses 50 motor vehicles 50 B motor vehicles 50 motor vehicle expenses 50 C motor vehicles expenses 50 motor vehicles 50 suspense 100 D suspense 100 motor vehicles expenses 50 motor vehicles 50
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2020
Q22 · Kate calculated her draft profit for the year at $28 400 0452/12 Oct/Nov 2020
11 Kate calculated her draft profit for the year at $28 400. She later discovered the following errors. 1 Rent prepaid by Kate was understated by $1000. 2 Closing inventory was understated by $1500. What was the correct profit for the year? A $25 900 B $27 900 C $28 900 D $30 900
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2020
Q23 · A trader debited the cost of repairing office equipment to the office equipment account 0452/12 Oct/Nov 2020
15 A trader debited the cost of repairing office equipment to the office equipment account. How did this error affect the financial statements? profit for non-current the year assets A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2020
Q24 · Rashid provided the following information at 31 December 0452/12 Oct/Nov 2020
16 Rashid provided the following information at 31 December. $ machinery at cost 52 000 provision for depreciation of machinery 23 000 Depreciation for the year is calculated at 20% on cost. After the statement of financial position was prepared it was found that the machinery repairs costing $2000 had been debited to the machinery account. What is the correct balance on the provision for the depreciation of machinery account? A $21 000 B $22 600 C $23 400 D $25 000
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2020
Q25 · Ziningi prepared a trial balance 0452/13 Oct/Nov 2020
6 Ziningi prepared a trial balance. The total of the debit column was $225 750 and the total of the credit column was $225 250. What could explain the difference? A Bank overdraft, $250, was recorded as a debit balance. B Inventory, $500, was included as a debit balance. C Purchases returns, $250, were included as a credit balance. D Sales returns, $250, were included as a debit balance.
1 marks
Answer: A
This question in 0452/13 Oct/Nov 2020
Q26 · Rent received from a tenant was debited to the rent receivable account and credited to… 0452/13 Oct/Nov 2020
7 Rent received from a tenant was debited to the rent receivable account and credited to the cash book. Which type of error has been made? A commission B compensating C complete reversal D principle
1 marks
Answer: C
This question in 0452/13 Oct/Nov 2020
Q27 · A computer system purchased from Ace Computers for $1430 had been incorrectly recorded as… 0452/13 Oct/Nov 2020
8 A computer system purchased from Ace Computers for $1430 had been incorrectly recorded as $1340 and was entered in the stationery account instead of the office equipment account. Which journal entry corrects this error? debit credit $ $ A Ace computers 90 stationery 1340 office equipment 1340 B Ace computers 90 stationery 1340 office equipment 1430 C office equipment 1340 Ace computers 90 stationery 1340 D office equipment 1430 Ace computers 90 stationery 1340
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2020
Q28 · Kate calculated her draft profit for the year at $28 400 0452/13 Oct/Nov 2020
9 Kate calculated her draft profit for the year at $28 400. She later discovered the following errors. 1 Rent prepaid by Kate was understated by $1000. 2 Closing inventory was understated by $1500. What was the correct profit for the year? A $25 900 B $27 900 C $28 900 D $30 900
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2020
Q29 · A trader debited the cost of repairing office equipment to the office equipment account 0452/13 Oct/Nov 2020
11 A trader debited the cost of repairing office equipment to the office equipment account. How did this error affect the financial statements? profit for non-current the year assets A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 0452/13 Oct/Nov 2020
Q30 · Rashid provided the following information at 31 December 0452/13 Oct/Nov 2020
13 Rashid provided the following information at 31 December. $ machinery at cost 52 000 provision for depreciation of machinery 23 000 Depreciation for the year is calculated at 20% on cost. After the statement of financial position was prepared it was found that the machinery repairs costing $2000 had been debited to the machinery account. What is the correct balance on the provision for the depreciation of machinery account? A $21 000 B $22 600 C $23 400 D $25 000
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2020
Q31 · Which transaction is recorded in the general journal? 0452/12 Feb/March 2021
8 Which transaction is recorded in the general journal? A correction of an error in recording sales returns B drawings in cash by the owner C purchase of a motor vehicle by cheque D purchase of goods on credit
1 marks
Answer: A
This question in 0452/12 Feb/March 2021
Q32 · The totals of a trial balance failed to agree 0452/12 Feb/March 2021
10 The totals of a trial balance failed to agree. The total of the credit column was $10 000. Two errors were later found. The sales journal had been overcast by $100. Goods sold to Sarah on credit for $200 had been incorrectly debited to Zara. What was the total of the debit column of the trial balance? A $9700 B $9900 C $10 100 D $10 300
1 marks
Answer: B
This question in 0452/12 Feb/March 2021
Q33 · Motor vehicle repairs, $2000, were debited to the motor vehicles account 0452/12 Feb/March 2021
13 Motor vehicle repairs, $2000, were debited to the motor vehicles account. Motor vehicles are depreciated at 20% per annum on the balance of the account at the year end. What was the effect of the error? effect on motor vehicles effect on in statement of financial profit for the year position $ $ A overstated 1600 overstated 1600 B overstated 2000 overstated 2000 C understated 1600 understated 1600 D understated 2000 understated 2000
1 marks
Answer: A
This question in 0452/12 Feb/March 2021
Q34 · Which items would be recorded in the general journal of a bakery? 0452/11 May/June 2021
6 Which items would be recorded in the general journal of a bakery? 1 correction of an error of principle relating to an oven repair 2 purchase of a delivery vehicle on credit 3 purchase of flour on credit 4 return by a customer of a faulty batch of bread A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: A
This question in 0452/11 May/June 2021
Q35 · Which error is an error of original entry? 0452/12 May/June 2021
10 Which error is an error of original entry? A sale of surplus office equipment on credit to Janet for $230 entered as $320 in both the disposal account and Janet’s account B sale of surplus office equipment on credit to Janet for $230 entered in the office equipment account and Jason’s account C sale of surplus office equipment on credit to Janet for $230 entered in the sales account and Janet’s account D sale of surplus office equipment on credit to Janet for $230 not entered in any accounts
1 marks
Answer: A
This question in 0452/12 May/June 2021
Q36 · A cheque, $85, received from Shakeel, was credited to the account of Shamz 0452/12 May/June 2021
11 A cheque, $85, received from Shakeel, was credited to the account of Shamz. Which journal entry corrects this error? debit credit $ $ A bank 85 Shakeel 85 B Shakeel 85 Shamz 85 C Shamz 85 bank 85 D Shamz 85 Shakeel 85
1 marks
Answer: D
This question in 0452/12 May/June 2021
Q37 · Nia sold equipment with a net book value of $200 0452/12 May/June 2021
16 Nia sold equipment with a net book value of $200. The proceeds of the sale, $250, were credited to the sales account and debited in the cash book. What was the effect of this error on Nia’s gross profit and profit for the year? gross profit $ profit for the year $ A overstated 50 overstated 50 B overstated 200 understated 250 C overstated 250 overstated 200 D understated 250 understated 200
1 marks
Answer: C
This question in 0452/12 May/June 2021
Q38 · Which error is an error of original entry? 0452/13 May/June 2021
10 Which error is an error of original entry? A sale of surplus office equipment on credit to Janet for $230 entered as $320 in both the disposal account and Janet’s account B sale of surplus office equipment on credit to Janet for $230 entered in the office equipment account and Jason’s account C sale of surplus office equipment on credit to Janet for $230 entered in the sales account and Janet’s account D sale of surplus office equipment on credit to Janet for $230 not entered in any accounts
1 marks
Answer: A
This question in 0452/13 May/June 2021
Q39 · A cheque, $85, received from Shakeel, was credited to the account of Shamz 0452/13 May/June 2021
11 A cheque, $85, received from Shakeel, was credited to the account of Shamz. Which journal entry corrects this error? debit credit $ $ A bank 85 Shakeel 85 B Shakeel 85 Shamz 85 C Shamz 85 bank 85 D Shamz 85 Shakeel 85
1 marks
Answer: D
This question in 0452/13 May/June 2021
Q40 · Nia sold equipment with a net book value of $200 0452/13 May/June 2021
16 Nia sold equipment with a net book value of $200. The proceeds of the sale, $250, were credited to the sales account and debited in the cash book. What was the effect of this error on Nia’s gross profit and profit for the year? gross profit $ profit for the year $ A overstated 50 overstated 50 B overstated 200 understated 250 C overstated 250 overstated 200 D understated 250 understated 200
1 marks
Answer: C
This question in 0452/13 May/June 2021
Q41 · At the end of each year, PT Limited transfers 20% of the profit for the year to the… 0452/11 Oct/Nov 2021
10 At the end of each year, PT Limited transfers 20% of the profit for the year to the general reserve. Draft financial statements were prepared for the year ended 30 September 2021. It was then discovered that the inventory at 30 September 2021 had been overstated by $1500. Which effects did the correction of this error have on retained earnings and general reserve at 30 September 2021? retained earnings $ general reserve $ A decrease 300 increase 300 B decrease 1200 decrease 300 C increase 300 increase 1200 D increase 1500 no effect
1 marks
Answer: B
This question in 0452/11 Oct/Nov 2021
Q42 · The following errors were found after a statement of financial position had been prepared 0452/11 Oct/Nov 2021
16 The following errors were found after a statement of financial position had been prepared. 1 A loan repayable in two year’s time had been included as a current liability. 2 A provision for doubtful debts should have been created. What is the effect of correcting these errors? current current non-current owner’s assets liabilities liabilities equity A decrease decrease increase decrease B decrease increase decrease increase C increase decrease decrease increase D increase increase decrease decrease
1 marks
Answer: A
This question in 0452/11 Oct/Nov 2021
Q43 · A sales invoice for $800 was incorrectly recorded in the sales journal as $1800 0452/12 Oct/Nov 2021
10 A sales invoice for $800 was incorrectly recorded in the sales journal as $1800. How did this error affect the trial balance? A The trial balance balanced but both totals were overstated by $1000. B The trial balance balanced but both totals were understated by $1000. C The trial balance did not balance because the credits were overstated by $1000. D The trial balance did not balance because the debits were understated by $1000.
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2021
Q44 · After preparing draft financial statements at the end of her first year of trading, Lucy… 0452/12 Oct/Nov 2021
16 After preparing draft financial statements at the end of her first year of trading, Lucy discovered two errors. 1 Damaged inventory had been valued at cost price, $340. It was expected to sell for $180. 2 100 items which had been expected to sell for $12 each had been valued at their cost price of $7 each. Carriage inwards of $1 for each item had not been included in the cost. What was the effect of these errors on the gross profit? A overstated $60 B overstated $240 C understated $60 D understated $240
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2021
Q45 · At the end of each year, PT Limited transfers 20% of the profit for the year to the… 0452/13 Oct/Nov 2021
10 At the end of each year, PT Limited transfers 20% of the profit for the year to the general reserve. Draft financial statements were prepared for the year ended 30 September 2021. It was then discovered that the inventory at 30 September 2021 had been overstated by $1500. Which effects did the correction of this error have on retained earnings and general reserve at 30 September 2021? retained earnings $ general reserve $ A decrease 300 increase 300 B decrease 1200 decrease 300 C increase 300 increase 1200 D increase 1500 no effect
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2021
Q46 · The following errors were found after a statement of financial position had been prepared 0452/13 Oct/Nov 2021
16 The following errors were found after a statement of financial position had been prepared. 1 A loan repayable in two year’s time had been included as a current liability. 2 A provision for doubtful debts should have been created. What is the effect of correcting these errors? current current non-current owner’s assets liabilities liabilities equity A decrease decrease increase decrease B decrease increase decrease increase C increase decrease decrease increase D increase increase decrease decrease
1 marks
Answer: A
This question in 0452/13 Oct/Nov 2021
Q47 · The total of the debit column of a trial balance was more than the total of the credit… 0452/12 Feb/March 2022
8 The total of the debit column of a trial balance was more than the total of the credit column. One account balance had been entered in the wrong column. Which one was it? A cash B discount received C drawings D irrecoverable debts
1 marks
Answer: B
This question in 0452/12 Feb/March 2022
Q48 · Davi prepared the following journal entry to correct an error 0452/12 Feb/March 2022
9 Davi prepared the following journal entry to correct an error. debit credit $ $ Samir 40 Samuel 40 Which error was being corrected? A Cash paid to Samir had been credited to Samuel. B Cash received from Samuel had been debited to Samir. C Goods bought from Samir had been credited to Samuel. D Goods sold to Samir had been debited to Samuel.
1 marks
Answer: D
This question in 0452/12 Feb/March 2022
Q49 · A suspense account was opened with a credit balance of $840 0452/12 Feb/March 2022
10 A suspense account was opened with a credit balance of $840. Which error caused this? A A cheque for $420 received from a customer was debited to his account. B Discounts allowed, $420, was debited twice in the discounts allowed account. C Goods costing $420, taken by the owner of the business for own use, were credited to his drawings account. D Rent received, $420, was credited twice in the rent receivable account.
1 marks
Answer: A
This question in 0452/12 Feb/March 2022
Q50 · What is an example of a compensating error? 0452/11 May/June 2022
9 What is an example of a compensating error? A A payment for office equipment repairs was debited to the office equipment account. B A purchase of goods from C Jones was credited to the account of C Johns. C The sale of goods, $65, to A Aziz was entered in the books as $56. D The wages account was undercast by $100 and the rent account was overcast by $100.
1 marks
Answer: D
This question in 0452/11 May/June 2022
Q51 · After the preparation of Abdul’s draft financial statements, two errors were discovered 0452/11 May/June 2022
10 After the preparation of Abdul’s draft financial statements, two errors were discovered. The purchase of a machine by bank transfer, $5000, was omitted from the accounts. The purchase of a motor vehicle, $15 000, was entered in the motor vehicle repair account. What effect will correcting these errors have on the non-current assets and the working capital? non-current assets working capital $ $ A increase 15 000 decrease 5000 B increase 15 000 no effect C increase 20 000 decrease 5000 D increase 20 000 no effect
1 marks
Answer: C
This question in 0452/11 May/June 2022
Q52 · On 1 January, Zac entered the cost of repairing equipment, $420, in the equipment account 0452/11 May/June 2022
15 On 1 January, Zac entered the cost of repairing equipment, $420, in the equipment account. On 31 December, depreciation of 20% per annum, using the straight-line method, was charged on the balance of the equipment account. What was the overall effect on the book value of the equipment on 31 December? A $84 understated B $336 overstated C $420 overstated D $504 understated
1 marks
Answer: B
This question in 0452/11 May/June 2022
Q53 · What is an example of a compensating error? 0452/12 May/June 2022
7 What is an example of a compensating error? A A payment for office equipment repairs was debited to the office equipment account. B A purchase of goods from C Jones was credited to the account of C Johns. C The sale of goods, $65, to A Aziz was entered in the books as $56. D The wages account was undercast by $100 and the rent account was overcast by $100.
1 marks
Answer: D
This question in 0452/12 May/June 2022
Q54 · After the preparation of Abdul’s draft financial statements, two errors were discovered 0452/12 May/June 2022
8 After the preparation of Abdul’s draft financial statements, two errors were discovered. The purchase of a machine by bank transfer, $5000, was omitted from the accounts. The purchase of a motor vehicle, $15 000, was entered in the motor vehicle repair account. What effect will correcting these errors have on the non-current assets and the working capital? non-current assets working capital $ $ A increase 15 000 decrease 5000 B increase 15 000 no effect C increase 20 000 decrease 5000 D increase 20 000 no effect
1 marks
Answer: C
This question in 0452/12 May/June 2022
Q55 · Maria’s draft income statement for the year ended 31 March 2022 showed a profit for the… 0452/12 May/June 2022
11 Maria’s draft income statement for the year ended 31 March 2022 showed a profit for the year of $38 750. On 31 December 2021, Maria received a 5% bank loan of $4800 which was incorrectly treated as a revenue receipt. In error, a whole year’s interest on the bank loan was included in the draft income statement for the year ended 31 March 2022. What was the correct profit for the year ended 31 March 2022? A $33 770 B $34 130 C $43 370 D $43 730
1 marks
Answer: B
This question in 0452/12 May/June 2022
Q56 · What is an example of a compensating error? 0452/13 May/June 2022
7 What is an example of a compensating error? A A payment for office equipment repairs was debited to the office equipment account. B A purchase of goods from C Jones was credited to the account of C Johns. C The sale of goods, $65, to A Aziz was entered in the books as $56. D The wages account was undercast by $100 and the rent account was overcast by $100.
1 marks
Answer: D
This question in 0452/13 May/June 2022
Q57 · After the preparation of Abdul’s draft financial statements, two errors were discovered 0452/13 May/June 2022
8 After the preparation of Abdul’s draft financial statements, two errors were discovered. The purchase of a machine by bank transfer, $5000, was omitted from the accounts. The purchase of a motor vehicle, $15 000, was entered in the motor vehicle repair account. What effect will correcting these errors have on the non-current assets and the working capital? non-current assets working capital $ $ A increase 15 000 decrease 5000 B increase 15 000 no effect C increase 20 000 decrease 5000 D increase 20 000 no effect
1 marks
Answer: C
This question in 0452/13 May/June 2022
Q58 · Maria’s draft income statement for the year ended 31 March 2022 showed a profit for the… 0452/13 May/June 2022
11 Maria’s draft income statement for the year ended 31 March 2022 showed a profit for the year of $38 750. On 31 December 2021, Maria received a 5% bank loan of $4800 which was incorrectly treated as a revenue receipt. In error, a whole year’s interest on the bank loan was included in the draft income statement for the year ended 31 March 2022. What was the correct profit for the year ended 31 March 2022? A $33 770 B $34 130 C $43 370 D $43 730
1 marks
Answer: B
This question in 0452/13 May/June 2022
Q59 · After the financial statements for the year ended 30 April 2022 had been prepared, a… 0452/13 May/June 2022
16 After the financial statements for the year ended 30 April 2022 had been prepared, a trader discovered that the closing inventory had been over-valued. What will be the effect of this error? profit for the year capital on profit for the year ended 30 April 2022 30 April 2022 ending 30 April 2023 A overstated overstated understated B overstated understated no effect C understated no effect no effect D understated understated overstated
1 marks
Answer: A
This question in 0452/13 May/June 2022
Q60 · Which errors would be revealed by the preparation of a trial balance? 0452/11 Oct/Nov 2022
9 Which errors would be revealed by the preparation of a trial balance? 1 credit purchases, $240, entered as $420 in both the purchases account and the trade payable’s account 2 credit sales entered as $96 in the sales account and $69 in the trade receivable’s account 3 purchase of a motor vehicle, $15 000, entered in the motor vehicle repairs account 4 wages paid, $1050, debited in both the wages account and the bank account A 1 and 2 B 1 and 3 C 2 and 4 only D 2, 3 and 4
1 marks
Answer: C
This question in 0452/11 Oct/Nov 2022
Q61 · Saddique’s trial balance failed to balance 0452/11 Oct/Nov 2022
10 Saddique’s trial balance failed to balance. The debit column totalled $12 250 and the credit column totalled $12 200. The following errors were discovered. No entry had been made for cash sales, $150. The total of the discount received account, $50, had been omitted from the trial balance. What were the totals of the trial balance after the errors had been corrected? A $12 250 B $12 300 C $12 350 D $12 400
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2022
Q62 · Jacob purchased a motor vehicle for business use on credit from Waheed for $20 000 0452/11 Oct/Nov 2022
11 Jacob purchased a motor vehicle for business use on credit from Waheed for $20 000. This was not recorded in Jacob’s books. Which journal entry would correct this error in Jacob’s books? debit credit $ $ A Jacob 20 000 motor vehicles 20 000 B motor vehicles 20 000 Jacob 20 000 C motor vehicles 20 000 Waheed 20 000 D Waheed 20 000 motor vehicles 20 000
1 marks
Answer: C
This question in 0452/11 Oct/Nov 2022
Q63 · After the preparation of her income statement, Emma discovered the following errors 0452/11 Oct/Nov 2022
12 After the preparation of her income statement, Emma discovered the following errors. A debt, $1500, should have been written off as irrecoverable. No adjustment had been made for rent prepaid by Emma of $2800. The draft profit for the year was $35 000. What was the corrected profit for the year? A $30 700 B $33 700 C $36 300 D $39 300
1 marks
Answer: C
This question in 0452/11 Oct/Nov 2022
Q64 · Saddique’s trial balance failed to balance 0452/12 Oct/Nov 2022
9 Saddique’s trial balance failed to balance. The debit column totalled $12 250 and the credit column totalled $12 200. The following errors were discovered. No entry had been made for cash sales, $150. The total of the discount received account, $50, had been omitted from the trial balance. What were the totals of the trial balance after the errors had been corrected? A $12 250 B $12 300 C $12 350 D $12 400
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2022
Q65 · $68 paid by credit transfer for insurance was entered in the accounting records as $86 0452/12 Oct/Nov 2022
10 $68 paid by credit transfer for insurance was entered in the accounting records as $86. Which double entry will correct this error? account debited $ account credited $ A bank 18 insurance 18 B bank 68 insurance 68 C insurance 18 bank 18 D insurance 68 bank 68
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2022
Q66 · After the preparation of her income statement, Emma discovered the following errors 0452/12 Oct/Nov 2022
11 After the preparation of her income statement, Emma discovered the following errors. A debt, $1500, should have been written off as irrecoverable. No adjustment had been made for rent prepaid by Emma of $2800. The draft profit for the year was $35 000. What was the corrected profit for the year? A $30 700 B $33 700 C $36 300 D $39 300
1 marks
Answer: C
This question in 0452/12 Oct/Nov 2022
Q67 · Which errors would be revealed by the preparation of a trial balance? 0452/13 Oct/Nov 2022
9 Which errors would be revealed by the preparation of a trial balance? 1 credit purchases, $240, entered as $420 in both the purchases account and the trade payable’s account 2 credit sales entered as $96 in the sales account and $69 in the trade receivable’s account 3 purchase of a motor vehicle, $15 000, entered in the motor vehicle repairs account 4 wages paid, $1050, debited in both the wages account and the bank account A 1 and 2 B 1 and 3 C 2 and 4 only D 2, 3 and 4
1 marks
Answer: C
This question in 0452/13 Oct/Nov 2022
Q68 · Saddique’s trial balance failed to balance 0452/13 Oct/Nov 2022
10 Saddique’s trial balance failed to balance. The debit column totalled $12 250 and the credit column totalled $12 200. The following errors were discovered. No entry had been made for cash sales, $150. The total of the discount received account, $50, had been omitted from the trial balance. What were the totals of the trial balance after the errors had been corrected? A $12 250 B $12 300 C $12 350 D $12 400
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2022
Q69 · Jacob purchased a motor vehicle for business use on credit from Waheed for $20 000 0452/13 Oct/Nov 2022
11 Jacob purchased a motor vehicle for business use on credit from Waheed for $20 000. This was not recorded in Jacob’s books. Which journal entry would correct this error in Jacob’s books? debit credit $ $ A Jacob 20 000 motor vehicles 20 000 B motor vehicles 20 000 Jacob 20 000 C motor vehicles 20 000 Waheed 20 000 D Waheed 20 000 motor vehicles 20 000
1 marks
Answer: C
This question in 0452/13 Oct/Nov 2022
Q70 · After the preparation of her income statement, Emma discovered the following errors 0452/13 Oct/Nov 2022
12 After the preparation of her income statement, Emma discovered the following errors. A debt, $1500, should have been written off as irrecoverable. No adjustment had been made for rent prepaid by Emma of $2800. The draft profit for the year was $35 000. What was the corrected profit for the year? A $30 700 B $33 700 C $36 300 D $39 300
1 marks
Answer: C
This question in 0452/13 Oct/Nov 2022
Q71 · The following errors were found after a trial balance had been completed 0452/12 Feb/March 2023
8 The following errors were found after a trial balance had been completed. The total of the sales account was overstated by $25. The total of the wages account was overstated by $25. Which statement is correct about the trial balance that had been completed? A The total of the debit column was $25 more than that of the credit column. B The total of the credit column was $50 more than that of the debit column. C The total of the debit column was $50 more than that of the credit column. D The total of the debit column and the total of the credit column were equal.
1 marks
Answer: D
This question in 0452/12 Feb/March 2023
Q72 · Mona paid $32 000 for a new motor vehicle 0452/12 Feb/March 2023
10 Mona paid $32 000 for a new motor vehicle. This included $100 for fuel and $250 for road tax. She debited the purchases account and credited the bank account with $32 000. Which journal entry corrects this error? debit credit $ $ A motor vehicle 32 000 purchases 32 000 B purchases 32 000 motor vehicles 32 000 C motor vehicles 31 650 motor vehicle expenses 350 purchases 32 000 D purchases 32 000 motor vehicles 31 650 motor vehicle expenses 350
1 marks
Answer: C
This question in 0452/12 Feb/March 2023
Q73 · Shazia’s trial balance failed to agree and the difference was placed in a suspense account 0452/12 Feb/March 2023
11 Shazia’s trial balance failed to agree and the difference was placed in a suspense account. Shazia discovered the following errors. 1 A cheque received, $280, had been credited to the bank account. 2 A cheque to Nunu, $50, had not been entered in Nunu’s account. What was the balance on the suspense account before the errors were corrected? A $230 debit B $330 credit C $510 credit D $610 debit
1 marks
Answer: D
This question in 0452/12 Feb/March 2023
Q74 · After completing the trial balance, it was found that an amount of $4000 for motor… 0452/11 May/June 2023
9 After completing the trial balance, it was found that an amount of $4000 for motor vehicle repairs had been entered in the motor vehicle account. Which type of error is this? A commission B compensating C omission D principle
1 marks
Answer: D
This question in 0452/11 May/June 2023
Q75 · At the end of his financial year, Zane opened a suspense account 0452/11 May/June 2023
10 At the end of his financial year, Zane opened a suspense account. Why was it necessary to open this account? A the suspense account had been omitted from the ledger B the trial balance totals did not agree C to correct an error of commission D to make sure no errors were made in the ledger
1 marks
Answer: B
This question in 0452/11 May/June 2023
Q76 · Jack has opened a suspense account 0452/11 May/June 2023
11 Jack has opened a suspense account. He has found that rent paid of $250 has been correctly entered in the rent account but credited to the bank account as $520. Which entries will correct this error? debit $ credit $ A bank account 270 suspense account 270 B bank account 520 suspense account 520 C suspense account 270 bank account 270 D suspense account 520 bank account 520
1 marks
Answer: A
This question in 0452/11 May/June 2023
Q77 · Rashid provided the following balances at 31 December 0452/11 May/June 2023
17 Rashid provided the following balances at 31 December. $ machinery at cost 52 000 provision for depreciation of machinery 23 000 Depreciation for the year was calculated at 20% on cost and is included in the balance for the provision. After the balances had been extracted, it was found that machinery repairs costing $2000 had been debited in error to the machinery account. What is the correct balance on the provision for the depreciation of machinery account? A $21 000 B $22 600 C $23 400 D $25 000
1 marks
Answer: B
This question in 0452/11 May/June 2023
Q78 · Which error causes the gross profit to be overstated? 0452/11 May/June 2023
20 Which error causes the gross profit to be overstated? A closing inventory under-valued B opening inventory omitted from the income statement C purchases recorded before deduction of trade discount D sales invoices omitted from the sales journal
1 marks
Answer: B
This question in 0452/11 May/June 2023
Q79 · P Limited maintains a provision for doubtful debts account 0452/11 May/June 2023
27 P Limited maintains a provision for doubtful debts account. On 1 April 2022, this account had a balance of $6200. The provision should have been increased to $7400 on 31 March 2023, but this adjustment was not made. What was the effect of this error on the retained earnings in the statement of financial position on 31 March 2023? A overstated $1200 B overstated $7400 C understated $1200 D understated $7400
1 marks
Answer: A
This question in 0452/11 May/June 2023
Q80 · Tahir prepared a trial balance 0452/12 May/June 2023
7 Tahir prepared a trial balance. He entered both the balance on the discount allowed account, $900, and the bank overdraft, $750, in the wrong column. Which total of the trial balance was higher and what was the amount of the difference between the debit total and the credit total? amount of total that difference was higher $ A credit column 300 B credit column 1650 C debit column 150 D debit column 3300
1 marks
Answer: A
This question in 0452/12 May/June 2023
Q81 · Goods sold on credit to J Sharp were debited in error to the account of T Sharpe 0452/12 May/June 2023
8 Goods sold on credit to J Sharp were debited in error to the account of T Sharpe. Which type of error has been made? A commission B complete reversal C original entry D principle
1 marks
Answer: A
This question in 0452/12 May/June 2023
Q82 · Khalid made entries in a suspense account to correct two errors found in his ledger… 0452/12 May/June 2023
9 Khalid made entries in a suspense account to correct two errors found in his ledger accounts. Once the errors were corrected, the suspense account was closed. error 1 $700 sales had been omitted from the sales account. error 2 The purchases journal had been overcast by $550. Which entry was made in the suspense account to balance the trial balance? A credit $150 B credit $1250 C debit $150 D debit $1250
1 marks
Answer: B
This question in 0452/12 May/June 2023
Q83 · A trader debited the cost of repairing office equipment to the office equipment account 0452/12 May/June 2023
15 A trader debited the cost of repairing office equipment to the office equipment account. How did this error affect the financial statements? profit for non-current the year assets A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 0452/12 May/June 2023
Q84 · Goods sold on credit to J Sharp were debited in error to the account of T Sharpe 0452/13 May/June 2023
8 Goods sold on credit to J Sharp were debited in error to the account of T Sharpe. Which type of error has been made? A commission B complete reversal C original entry D principle
1 marks
Answer: A
This question in 0452/13 May/June 2023
Q85 · Khalid made entries in a suspense account to correct two errors found in his ledger… 0452/13 May/June 2023
9 Khalid made entries in a suspense account to correct two errors found in his ledger accounts. Once the errors were corrected, the suspense account was closed. error 1 $700 sales had been omitted from the sales account. error 2 The purchases journal had been overcast by $550. Which entry was made in the suspense account to balance the trial balance? A credit $150 B credit $1250 C debit $150 D debit $1250
1 marks
Answer: B
This question in 0452/13 May/June 2023
Q86 · Maya depreciates her motor vehicle at 25% per annum using the straight-line method 0452/13 May/June 2023
10 Maya depreciates her motor vehicle at 25% per annum using the straight-line method. The motor vehicle cost $15 000. The depreciation for the current financial year was incorrectly calculated at 15% per annum. How will correcting the error affect the profit for the year? A decrease $1500 B decrease $2250 C increase $1500 D increase $2250
1 marks
Answer: A
This question in 0452/13 May/June 2023
Q87 · A trader debited the cost of repairing office equipment to the office equipment account 0452/13 May/June 2023
15 A trader debited the cost of repairing office equipment to the office equipment account. How did this error affect the financial statements? profit for non-current the year assets A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 0452/13 May/June 2023
Q88 · The following entry was made in a journal to record the correction of an error 0452/11 Oct/Nov 2023
9 The following entry was made in a journal to record the correction of an error. debit credit $ $ Wasim 320 bank 320 Which error has been corrected? A A cheque, $160, was credited to Wasim’s account but no debit entry was made. B A cheque, $160, was debited to the bank account but no credit entry was made. C A cheque paid to Wasim, $160, was credited to his account and debited to the bank. D A cheque received from Wasim, $160, was credited to his account and debited to the bank.
1 marks
Answer: C
This question in 0452/11 Oct/Nov 2023
Q89 · Which statement correctly describes a suspense account? 0452/11 Oct/Nov 2023
10 Which statement correctly describes a suspense account? A It is an account opened to check for errors in a trial balance. B It is a permanent account used to correct the statement of financial position. C It is a temporary account used to correct errors of complete reversal. D It is an account that is opened when the totals of a trial balance disagree.
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2023
Q90 · A trader prepared a draft income statement which showed a profit for the year of $36 000 0452/11 Oct/Nov 2023
11 A trader prepared a draft income statement which showed a profit for the year of $36 000. A check of the books revealed the following information. 1 Drawings made by the owner of $900 had been debited to the wages account. 2 The provision for doubtful debts was increased by $20 at the year-end. The income statement was charged with the total provision of $260. 3 The total of the discount allowed column in the cash book, $140, for one month had not been debited to the discount allowed account. What was the correct profit for the year? A $34 720 B $36 520 C $37 000 D $37 280
1 marks
Answer: C
This question in 0452/11 Oct/Nov 2023
Q91 · Jane wished to make a contra entry between a sales ledger account and a purchases ledger… 0452/11 Oct/Nov 2023
14 Jane wished to make a contra entry between a sales ledger account and a purchases ledger account. The credit entry was made correctly but the debit entry was entered in the sales returns account in error. What was the effect of this error? A Total purchases ledger balances were overstated. B Total purchases ledger balances were understated. C Total sales ledger balances were overstated. D Total sales ledger balances were understated.
1 marks
Answer: A
This question in 0452/11 Oct/Nov 2023
Q92 · Sales returns were incorrectly recorded as purchases returns in an income statement 0452/11 Oct/Nov 2023
16 Sales returns were incorrectly recorded as purchases returns in an income statement. What was the effect of this error? A Capital employed was understated. B Cost of sales was overstated. C Gross profit was understated. D Profit for the year was overstated.
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2023
Q93 · A cheque received from Joe was credited to Joanna’s account 0452/12 Oct/Nov 2023
8 A cheque received from Joe was credited to Joanna’s account. Which type of error was made? A commission B compensating C original entry D principle
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2023
Q94 · A trader’s journal shows the following entry 0452/12 Oct/Nov 2023
9 A trader’s journal shows the following entry. debit credit details $ $ John 300 Jane 300 correction of error Both John and Jane are credit customers of the trader. Which error is the journal entry correcting? A Goods bought from Jane were wrongly credited to John. B Goods bought from John were wrongly credited to Jane. C Goods sold to Jane were wrongly debited to John. D Goods sold to John were wrongly debited to Jane.
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2023
Q95 · A trial balance does not balance and a suspense account is opened 0452/12 Oct/Nov 2023
10 A trial balance does not balance and a suspense account is opened. It is found that a sale of $250 was credited in the sales account as $2500. Which entry will correct this error? account to account to $ $ be debited be credited A sales 250 suspense 250 B sales 2250 suspense 2250 C suspense 2250 sales 2250 D suspense 2500 sales 2500
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2023
Q96 · A cheque received from D Pawson, a trade receivable, was correctly debited to the bank… 0452/12 Oct/Nov 2023
11 A cheque received from D Pawson, a trade receivable, was correctly debited to the bank account but was credited to the account of P Dawson, a trade payable. What was the effect of correcting this error? trade trade receivables payables A decrease decrease B decrease increase C increase decrease D increase increase
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2023
Q97 · Plant and machinery, $2000, was incorrectly posted to the credit side of the purchases… 0452/12 Oct/Nov 2023
15 Plant and machinery, $2000, was incorrectly posted to the credit side of the purchases account. The draft profit for the year was $63 000. Ignore depreciation. What was the revised profit for the year after the correction of the error? A $59 000 B $61 000 C $65 000 D $67 000
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2023
Q98 · Ariadne prepares her financial statements to 31 December each year 0452/12 Oct/Nov 2023
19 Ariadne prepares her financial statements to 31 December each year. She valued all her inventory at cost on 31 December 2021, even though some inventory with a cost of $500 had a net realisable value of $350. What was the effect of this error? A Gross profit for the year 2021 was overstated. B Total assets at 31 December 2021 were understated. C Profit for the year 2022 was overstated. D Capital at 31 December 2022 was understated.
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2023
Q99 · The following entry was made in a journal to record the correction of an error 0452/13 Oct/Nov 2023
9 The following entry was made in a journal to record the correction of an error. debit credit $ $ Wasim 320 bank 320 Which error has been corrected? A A cheque, $160, was credited to Wasim’s account but no debit entry was made. B A cheque, $160, was debited to the bank account but no credit entry was made. C A cheque paid to Wasim, $160, was credited to his account and debited to the bank. D A cheque received from Wasim, $160, was credited to his account and debited to the bank.
1 marks
Answer: C
This question in 0452/13 Oct/Nov 2023
Q100 · Which statement correctly describes a suspense account? 0452/13 Oct/Nov 2023
10 Which statement correctly describes a suspense account? A It is an account opened to check for errors in a trial balance. B It is a permanent account used to correct the statement of financial position. C It is a temporary account used to correct errors of complete reversal. D It is an account that is opened when the totals of a trial balance disagree.
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2023
Q101 · A trader prepared a draft income statement which showed a profit for the year of $36 000 0452/13 Oct/Nov 2023
11 A trader prepared a draft income statement which showed a profit for the year of $36 000. A check of the books revealed the following information. 1 Drawings made by the owner of $900 had been debited to the wages account. 2 The provision for doubtful debts was increased by $20 at the year-end. The income statement was charged with the total provision of $260. 3 The total of the discount allowed column in the cash book, $140, for one month had not been debited to the discount allowed account. What was the correct profit for the year? A $34 720 B $36 520 C $37 000 D $37 280
1 marks
Answer: C
This question in 0452/13 Oct/Nov 2023
Q102 · Jane wished to make a contra entry between a sales ledger account and a purchases ledger… 0452/13 Oct/Nov 2023
14 Jane wished to make a contra entry between a sales ledger account and a purchases ledger account. The credit entry was made correctly but the debit entry was entered in the sales returns account in error. What was the effect of this error? A Total purchases ledger balances were overstated. B Total purchases ledger balances were understated. C Total sales ledger balances were overstated. D Total sales ledger balances were understated.
1 marks
Answer: A
This question in 0452/13 Oct/Nov 2023
Q103 · Sales returns were incorrectly recorded as purchases returns in an income statement 0452/13 Oct/Nov 2023
16 Sales returns were incorrectly recorded as purchases returns in an income statement. What was the effect of this error? A Capital employed was understated. B Cost of sales was overstated. C Gross profit was understated. D Profit for the year was overstated.
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2023
Q104 · A trader introduced additional capital of $4000 0452/12 Feb/March 2024
8 A trader introduced additional capital of $4000. This was debited to the capital account and credited to the bank account in error. What is the effect on the statement of financial position of correcting this error? capital bank $ $ A decreases by 4000 decreases by 4000 B decreases by 8000 decreases by 8000 C increases by 4000 increases by 4000 D increases by 8000 increases by 8000
1 marks
Answer: D
This question in 0452/12 Feb/March 2024
Q105 · The totals of a trial balance did not agree, and a suspense account was opened 0452/12 Feb/March 2024
9 The totals of a trial balance did not agree, and a suspense account was opened. It was later found that purchases returns, $560, had been debited to the sales returns account. Which journal entry was required to correct this error? debit credit $ $ A purchases returns 560 sales returns 560 B purchases returns 560 suspense 560 C purchases returns 1120 sales returns 560 suspense 560 D suspense 1120 purchases returns 560 sales returns 560
1 marks
Answer: D
This question in 0452/12 Feb/March 2024
Q106 · After the preparation of his financial statements, a trader discovered the following… 0452/12 Feb/March 2024
15 After the preparation of his financial statements, a trader discovered the following errors. 1 A revenue receipt of $1000 had been recorded as a capital receipt. 2 Capital expenditure of $800 had been recorded as revenue expenditure. 3 A capital receipt of $900 had been recorded as a revenue receipt. What was the overall effect of these errors on the profit for the year? A overstated by $700 B overstated by $900 C understated by $700 D understated by $900
1 marks
Answer: D
This question in 0452/12 Feb/March 2024
Q107 · Vikram made two errors when preparing his draft financial statements 0452/12 Feb/March 2024
19 Vikram made two errors when preparing his draft financial statements. These caused his gross profit to be overstated by $600 and his profit for the year to be understated by $250. Which two errors had he made? closing inventory depreciation charge A $600 overstated $350 overstated B $600 overstated $850 overstated C $600 understated $350 understated D $600 understated $850 understated
1 marks
Answer: B
This question in 0452/12 Feb/March 2024
Q108 · The owner of a business took goods for his own use but forgot to make an entry in the… 0452/12 Feb/March 2024
23 The owner of a business took goods for his own use but forgot to make an entry in the accounts. What was the effect of this error? profit for the year capital A overstated no effect B overstated understated C understated no effect D understated overstated
1 marks
Answer: C
This question in 0452/12 Feb/March 2024
Q109 · Trevor prepared his financial statements for the year ended 31 December 2020 0452/11 May/June 2024
8 Trevor prepared his financial statements for the year ended 31 December 2020. He then discovered that he had omitted to record a cash payment, $240, for insurance for the 12 months ending 30 November 2021. What was the effect of this error on his statement of financial position? cash other receivables capital A $240 overstated $20 understated $220 overstated B $240 overstated $220 understated $20 overstated C $240 understated $20 overstated $220 understated D $240 understated $220 overstated $20 understated
1 marks
Answer: B
This question in 0452/11 May/June 2024
Q110 · A payment of $68 for insurance has been entered in the insurance account as $86 0452/11 May/June 2024
9 A payment of $68 for insurance has been entered in the insurance account as $86. Which double entry will correct this? debit credit A insurance $18 suspense $18 B insurance $36 suspense $36 C suspense $18 insurance $18 D suspense $36 insurance $36
1 marks
Answer: C
This question in 0452/11 May/June 2024
Q111 · At the end of the financial year Cindy valued her inventory at cost 0452/11 May/June 2024
19 At the end of the financial year Cindy valued her inventory at cost. This valuation incorrectly included damaged goods costing $300. Cindy estimated these goods could be sold for $100. What is the effect of correcting the inventory valuation? gross profit profit for the year current assets A decreases by $200 decreases by $200 decreases by $200 B decreases by $300 decreases by $300 decreases by $300 C increases by $100 increases by $100 increases by $100 D increases by $200 increases by $200 increases by $200
1 marks
Answer: A
This question in 0452/11 May/June 2024
Q112 · A book-keeper made two errors which cancelled each other out 0452/12 May/June 2024
7 A book-keeper made two errors which cancelled each other out. Which type of error did he make? A compensating B complete reversal C original entry D principle
1 marks
Answer: A
This question in 0452/12 May/June 2024
Q113 · The totals of a trial balance did not agree and $200 was debited to a suspense account 0452/12 May/June 2024
8 The totals of a trial balance did not agree and $200 was debited to a suspense account. The book-keeper then checked the books and found the following two errors. 1. A sales invoice for $700 had been recorded in the sales journal as $770. 2. The sales journal had been totalled incorrectly. What error was made when the sales journal was totalled? A overcast by $130 B overcast by $200 C undercast by $130 D undercast by $200
1 marks
Answer: B
This question in 0452/12 May/June 2024
Q114 · A trader took some goods from the business for his own use 0452/12 May/June 2024
9 A trader took some goods from the business for his own use. He credited the purchases account with the cost price of the goods, $200, and credited the sales account with the selling price, $300. Which entries did he make to correct the error? debit $ credit $ A drawings 200 suspense 300 income statement 100 B drawings 200 suspense 500 sales 300 C suspense 300 drawings 200 income statement 100 D suspense 500 drawings 200 sales 300
1 marks
Answer: B
This question in 0452/12 May/June 2024
Q115 · The cost of repairs to machinery was debited to the machinery account 0452/12 May/June 2024
14 The cost of repairs to machinery was debited to the machinery account. What was the effect of this error? non-current assets profit for the year A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 0452/12 May/June 2024
Q116 · A book-keeper made two errors which cancelled each other out 0452/13 May/June 2024
7 A book-keeper made two errors which cancelled each other out. Which type of error did he make? A compensating B complete reversal C original entry D principle
1 marks
Answer: A
This question in 0452/13 May/June 2024
Q117 · The totals of a trial balance did not agree and $200 was debited to a suspense account 0452/13 May/June 2024
8 The totals of a trial balance did not agree and $200 was debited to a suspense account. The book-keeper then checked the books and found the following two errors. 1. A sales invoice for $700 had been recorded in the sales journal as $770. 2. The sales journal had been totalled incorrectly. What error was made when the sales journal was totalled? A overcast by $130 B overcast by $200 C undercast by $130 D undercast by $200
1 marks
Answer: B
This question in 0452/13 May/June 2024
Q118 · A trader took some goods from the business for his own use 0452/13 May/June 2024
9 A trader took some goods from the business for his own use. He credited the purchases account with the cost price of the goods, $200, and credited the sales account with the selling price, $300. Which entries did he make to correct the error? debit $ credit $ A drawings 200 suspense 300 income statement 100 B drawings 200 suspense 500 sales 300 C suspense 300 drawings 200 income statement 100 D suspense 500 drawings 200 sales 300
1 marks
Answer: B
This question in 0452/13 May/June 2024
Q119 · The cost of repairs to machinery was debited to the machinery account 0452/13 May/June 2024
14 The cost of repairs to machinery was debited to the machinery account. What was the effect of this error? non-current assets profit for the year A overstated overstated B overstated understated C understated overstated D understated understated
1 marks
Answer: A
This question in 0452/13 May/June 2024
Q120 · The totals of a trial balance agreed but it was found that the purchase of office… 0452/11 Oct/Nov 2024
8 The totals of a trial balance agreed but it was found that the purchase of office equipment had been debited to office expenses account. Which type of error has been made? A commission B compensating C original entry D principle
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2024
Q121 · Mandy’s trial balance failed to agree 0452/11 Oct/Nov 2024
9 Mandy’s trial balance failed to agree. The difference of $620 was placed in a suspense account. The suspense account’s balance was shown on the debit side of the trial balance. Which error had caused the difference? A Discounts allowed of $310 had been credited to the discount received account. B Discounts received of $310 had been credited to the discount allowed account. C The value of closing inventory had been overstated by $620. D The value of closing inventory had been understated by $620.
1 marks
Answer: A
This question in 0452/11 Oct/Nov 2024
Q122 · Jane took cash drawings from the business 0452/11 Oct/Nov 2024
10 Jane took cash drawings from the business. The amount was debited to the purchases account and credited to cash. How did this error affect the profit for the year and the current assets in the financial statements? profit for the year current assets A decrease no effect B increase no effect C no effect decrease D no effect increase
1 marks
Answer: A
This question in 0452/11 Oct/Nov 2024
Q123 · On 1 January 2023 Kate paid $400 for a two-year maintenance contract on her machinery… 0452/11 Oct/Nov 2024
16 On 1 January 2023 Kate paid $400 for a two-year maintenance contract on her machinery starting on that date. In error this amount was debited to the machinery account. Kate depreciates her machinery at the rate of 20% per annum. What effect did the error have on Kate’s profit for the year ended 31 December 2023? A overstated by $80 B overstated by $120 C understated by $80 D understated by $120
1 marks
Answer: B
This question in 0452/11 Oct/Nov 2024
Q124 · A trader had prepared her year-end financial statements 0452/12 Oct/Nov 2024
8 A trader had prepared her year-end financial statements. She later discovered that an adjustment to reduce the provision for doubtful debts by $100 had not been made. How did this error affect the trader’s statement of financial position? current assets capital $ $ A overstated 100 overstated 100 B overstated 100 understated 100 C understated 100 overstated 100 D understated 100 understated 100
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2024
Q125 · A trader’s draft income statement showed a profit for the year of $24500 0452/12 Oct/Nov 2024
9 A trader’s draft income statement showed a profit for the year of $24500. The following errors were later discovered. 1 No adjustment had been made for accrued income of $8000. 2 Carriage inwards of $250 had been recorded as carriage outwards. 3 An increase in provision for doubtful debts of $120 had been treated as an addition to the gross profit for the year. What was the corrected profit for the year? A $32010 B $32260 C $32380 D $32740
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2024
Q126 · Hamid owns a grocery store 0452/12 Oct/Nov 2024
14 Hamid owns a grocery store. He bought a motor vehicle, $2000, and fuel, $50. Both of these amounts were incorrectly debited to the purchases account. What was the effect of this error on the income statement for the year? gross profit motor vehicle expenses $ $ A overstated 2000 overstated 2050 B overstated 2050 overstated 50 C understated 2000 understated 2050 D understated 2050 understated 50
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2024
Q127 · The totals of a trial balance agreed but it was found that the purchase of office… 0452/13 Oct/Nov 2024
8 The totals of a trial balance agreed but it was found that the purchase of office equipment had been debited to office expenses account. Which type of error has been made? A commission B compensating C original entry D principle
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2024
Q128 · Mandy’s trial balance failed to agree 0452/13 Oct/Nov 2024
9 Mandy’s trial balance failed to agree. The difference of $620 was placed in a suspense account. The suspense account’s balance was shown on the debit side of the trial balance. Which error had caused the difference? A Discounts allowed of $310 had been credited to the discount received account. B Discounts received of $310 had been credited to the discount allowed account. C The value of closing inventory had been overstated by $620. D The value of closing inventory had been understated by $620.
1 marks
Answer: A
This question in 0452/13 Oct/Nov 2024
Q129 · Jane took cash drawings from the business 0452/13 Oct/Nov 2024
10 Jane took cash drawings from the business. The amount was debited to the purchases account and credited to cash. How did this error affect the profit for the year and the current assets in the financial statements? profit for the year current assets A decrease no effect B increase no effect C no effect decrease D no effect increase
1 marks
Answer: A
This question in 0452/13 Oct/Nov 2024
Q130 · On 1 January 2023 Kate paid $400 for a two-year maintenance contract on her machinery… 0452/13 Oct/Nov 2024
16 On 1 January 2023 Kate paid $400 for a two-year maintenance contract on her machinery starting on that date. In error this amount was debited to the machinery account. Kate depreciates her machinery at the rate of 20% per annum. What effect did the error have on Kate’s profit for the year ended 31 December 2023? A overstated by $80 B overstated by $120 C understated by $80 D understated by $120
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2024
Q131 · Arnaud’s draft profit for the year was $17000 0452/12 Feb/March 2025
10 Arnaud’s draft profit for the year was $17000. His actual correct profit was $17400. Which error had been made? A A purchases invoice for $2600 had been recorded in the purchases journal as $2200. B A sales invoice for $2600 had been recorded in the sales journal as $2200. C Discount allowed of $400 had been posted to the credit side of the discount allowed account. D Discount received of $400 had been posted to the debit side of the discount received account.
1 marks
Answer: B
This question in 0452/12 Feb/March 2025
Q132 · Paul calculated his profit for the year to be $40000 0452/12 Feb/March 2025
11 Paul calculated his profit for the year to be $40000. Paul then discovered the following errors. • The expenses included rates prepaid, $1000, for the following year. • $600 owed for electricity had been omitted. • Sales returns of $10000 had not been recorded. What was the correct profit for the year? A $28400 B $30400 C $49600 D $51600
1 marks
Answer: B
This question in 0452/12 Feb/March 2025
Q133 · The totals of Simon’s trial balance did not agree, and he opened a suspense account 0452/12 Feb/March 2025
12 The totals of Simon’s trial balance did not agree, and he opened a suspense account. He then found that when he had restored the imprest with $70, he had recorded it correctly in the petty cash book but had recorded it on the wrong side of the main cash book. This was the only error. What was the opening entry in the suspense account? A $70 on the credit side B $70 on the debit side C $140 on the credit side D $140 on the debit side
1 marks
Answer: C
This question in 0452/12 Feb/March 2025
Q134 · After preparing his financial statements, Jonty discovered two errors had been made in… 0452/12 Feb/March 2025
15 After preparing his financial statements, Jonty discovered two errors had been made in his accounting records. error 1 Vehicle repair costs of $1500 had been debited to the vehicles account. error 2 Legal fees of $2100, relating to the purchase of new premises, had been included in expenses. Ignoring depreciation, what was the effect of these errors on Jonty’s profit for the year? A $600 overstated B $600 understated C $3600 overstated D $3600 understated
1 marks
Answer: B
This question in 0452/12 Feb/March 2025
Q135 · The totals of a trial balance did not agree, and a suspense account was opened 0452/11 May/June 2025
8 The totals of a trial balance did not agree, and a suspense account was opened. It was later found that the total of the discount allowed column in the cash book of $100 had been credited to the discount allowed account. Which journal entry corrects this error? debit credit $ $ A discount allowed 100 suspense 100 B discount allowed 200 suspense 200 C suspense 100 discount allowed 100 D suspense 200 discount allowed 200
1 marks
Answer: B
This question in 0452/11 May/June 2025
Q136 · After calculating his profit for the year, Yui discovered the following errors 0452/11 May/June 2025
9 After calculating his profit for the year, Yui discovered the following errors. 1 A purchase of a new motor vehicle for $3200 was debited to motor expenses. 2 The purchases account was overcast by $500. What was the effect on the profit for the year after correcting these errors (ignore depreciation)? A It decreased by $2700. B It decreased by $3700. C It increased by $2700. D It increased by $3700.
1 marks
Answer: D
This question in 0452/11 May/June 2025
Q137 · Jerry received a cheque of $450 from Fatima 0452/11 May/June 2025
10 Jerry received a cheque of $450 from Fatima. He entered the receipt of the cheque correctly in his cash book. The posting to Fatima’s account was reversed in error. Which journal entry corrects this error? account debited account credited A bank $450 Fatima $450 B bank $900 suspense $900 C suspense $450 bank $450 D suspense $900 Fatima $900
1 marks
Answer: D
This question in 0452/11 May/June 2025
Q138 · What is the effect of incorrectly treating expenses as capital expenditure? 0452/11 May/June 2025
14 What is the effect of incorrectly treating expenses as capital expenditure? income statement profit for the year expenses total A overstated overstated B overstated understated C understated understated D understated overstated
1 marks
Answer: B
This question in 0452/11 May/June 2025
Q139 · Ziningi prepared a trial balance 0452/12 May/June 2025
7 Ziningi prepared a trial balance. The total of the debit column was $225750, and the total of the credit column was $225250. What could explain the difference? A The bank overdraft of $250 was included as a debit balance. B Discount allowed of $500 was included as a debit balance. C Purchases returns for $250 were included as a credit balance. D Sales returns of $500 were included as a debit balance.
1 marks
Answer: A
This question in 0452/12 May/June 2025
Q140 · Michael opened a suspense account when he prepared draft financial statements 0452/12 May/June 2025
8 Michael opened a suspense account when he prepared draft financial statements. He then discovered that purchases of $68 had been credited to the purchases account as $86. Which entry was made in the suspense account when this error was corrected? A $18 credit B $18 debit C $154 credit D $154 debit
1 marks
Answer: C
This question in 0452/12 May/June 2025
Q141 · Sameer calculated that his profit for the year was $6300 0452/12 May/June 2025
9 Sameer calculated that his profit for the year was $6300. He then found two errors. 1 A cheque for $3250, received from a credit customer, had only been recorded in the cash book. 2 The total of the discount allowed column in the cash book, $300, had been credited to the discount received account. What was Sameer’s corrected profit for the year? A $2450 B $2750 C $5700 D $6000
1 marks
Answer: C
This question in 0452/12 May/June 2025
Q142 · Miguel’s cash book showed a debit bank balance of $4220 0452/12 May/June 2025
10 Miguel’s cash book showed a debit bank balance of $4220. He later discovered the following errors. 1 A cheque for $200, issued for the purchase of office equipment, had been recorded in error in the office expenses account. 2 Bank charges of $30 had been recorded in the cash book as $70. What was the effect of these errors on his statement of financial position? non-current assets (cost) current assets A overstated by $200 no effect B understated by $200 no effect C understated by $200 overstated by $30 D understated by $200 understated by $40
1 marks
Answer: D
This question in 0452/12 May/June 2025
Q143 · The totals of a trial balance did not agree, and a suspense account was opened 0452/13 May/June 2025
8 The totals of a trial balance did not agree, and a suspense account was opened. It was later found that the total of the discount allowed column in the cash book of $100 had been credited to the discount allowed account. Which journal entry corrects this error? debit credit $ $ A discount allowed 100 suspense 100 B discount allowed 200 suspense 200 C suspense 100 discount allowed 100 D suspense 200 discount allowed 200
1 marks
Answer: B
This question in 0452/13 May/June 2025
Q144 · After calculating his profit for the year, Yui discovered the following errors 0452/13 May/June 2025
9 After calculating his profit for the year, Yui discovered the following errors. 1 A purchase of a new motor vehicle for $3200 was debited to motor expenses. 2 The purchases account was overcast by $500. What was the effect on the profit for the year after correcting these errors (ignore depreciation)? A It decreased by $2700. B It decreased by $3700. C It increased by $2700. D It increased by $3700.
1 marks
Answer: D
This question in 0452/13 May/June 2025
Q145 · Jerry received a cheque of $450 from Fatima 0452/13 May/June 2025
10 Jerry received a cheque of $450 from Fatima. He entered the receipt of the cheque correctly in his cash book. The posting to Fatima’s account was reversed in error. Which journal entry corrects this error? account debited account credited A bank $450 Fatima $450 B bank $900 suspense $900 C suspense $450 bank $450 D suspense $900 Fatima $900
1 marks
Answer: D
This question in 0452/13 May/June 2025
Q146 · Ahmed’s trial balance totals did not agree 0452/12 Oct/Nov 2025
9 Ahmed’s trial balance totals did not agree. He entered the difference in a suspense account. The following errors were later discovered. 1 A payment of $200 for a vehicle repair had been debited to the motor vehicles account. 2 Drawings of $150, correctly recorded in the cash book, had not been posted to the drawings account. 3 The sales journal had been undercast by $900. What was the original balance on Ahmed’s suspense account? A $550 B $750 C $950 D $1050 Susanne is a trader. She received a cheque from Zahir, a credit customer, for $300. This cheque
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2025
Q147 · Was incorrectly debited to Zahir’s account and credited to the bank account 0452/12 Oct/Nov 2025
10 was incorrectly debited to Zahir’s account and credited to the bank account. Which journal entry corrects this error? debit credit $ $ A bank 300 Zahir 300 B bank 600 Zahir 600 C Zahir 300 bank 300 D Zahir 600 bank 600 A trial balance does not agree, and a suspense account is opened.
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2025
Q148 · Which statement is not correct? 0452/12 Oct/Nov 2025
11 Which statement is not correct? A Errors of commission and errors of original entry are entered in the suspense account. B The trial balance difference is entered in the suspense account. C The suspense account remains open until all the errors preventing the agreement of the trial balance have been corrected. D When all of the errors found have been corrected, there will be no balance carried down in the suspense account.
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2025
Q149 · The totals of a trial balance do not agree because the debit total is more than the… 0452/13 Oct/Nov 2025
8 The totals of a trial balance do not agree because the debit total is more than the credit total. Which error would have to be corrected to balance the trial balance? A expenses paid in cash omitted from the accounting records B goods sold on credit to Smith debited to the account of Small C repairs to equipment debited to the equipment account D total of the sales returns account overcast
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2025
Q150 · A trial balance did not agree, and a suspense account was opened 0452/13 Oct/Nov 2025
9 A trial balance did not agree, and a suspense account was opened. After the following errors had been corrected the suspense account balanced and was closed. 1 The total of the discount allowed column in the cash book for November of $250 had been credited to the discount received account. 2 Cash sales of $50 had been correctly entered in the cash book, but had not been posted to the sales account. What was the difference which was originally entered in the suspense account? A $200 credit B $200 debit C $450 credit D $450 debit
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2025
Q151 · Kate’s draft profit for the year was $9800 0452/13 Oct/Nov 2025
10 Kate’s draft profit for the year was $9800. She then discovered the following errors. 1 Sales for $120 had been recorded as commission income. 2 A computer repair for $95 had been recorded as computer equipment. What is Kate’s revised profit for the year after correcting the errors (ignore depreciation)? A $9585 B $9705 C $9825 D $9895
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2025
Q152 · An owner bought machinery for her business costing $5000 0452/13 Oct/Nov 2025
15 An owner bought machinery for her business costing $5000. This was entered as revenue expenditure in the accounting records. She also invested $2000 of additional capital into the business and entered this as a revenue receipt in the accounting records. What was the net effect of these errors on her profit for the year (ignore depreciation)? A $3000 overstated B $3000 understated C $7000 overstated D $7000 understated
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2025
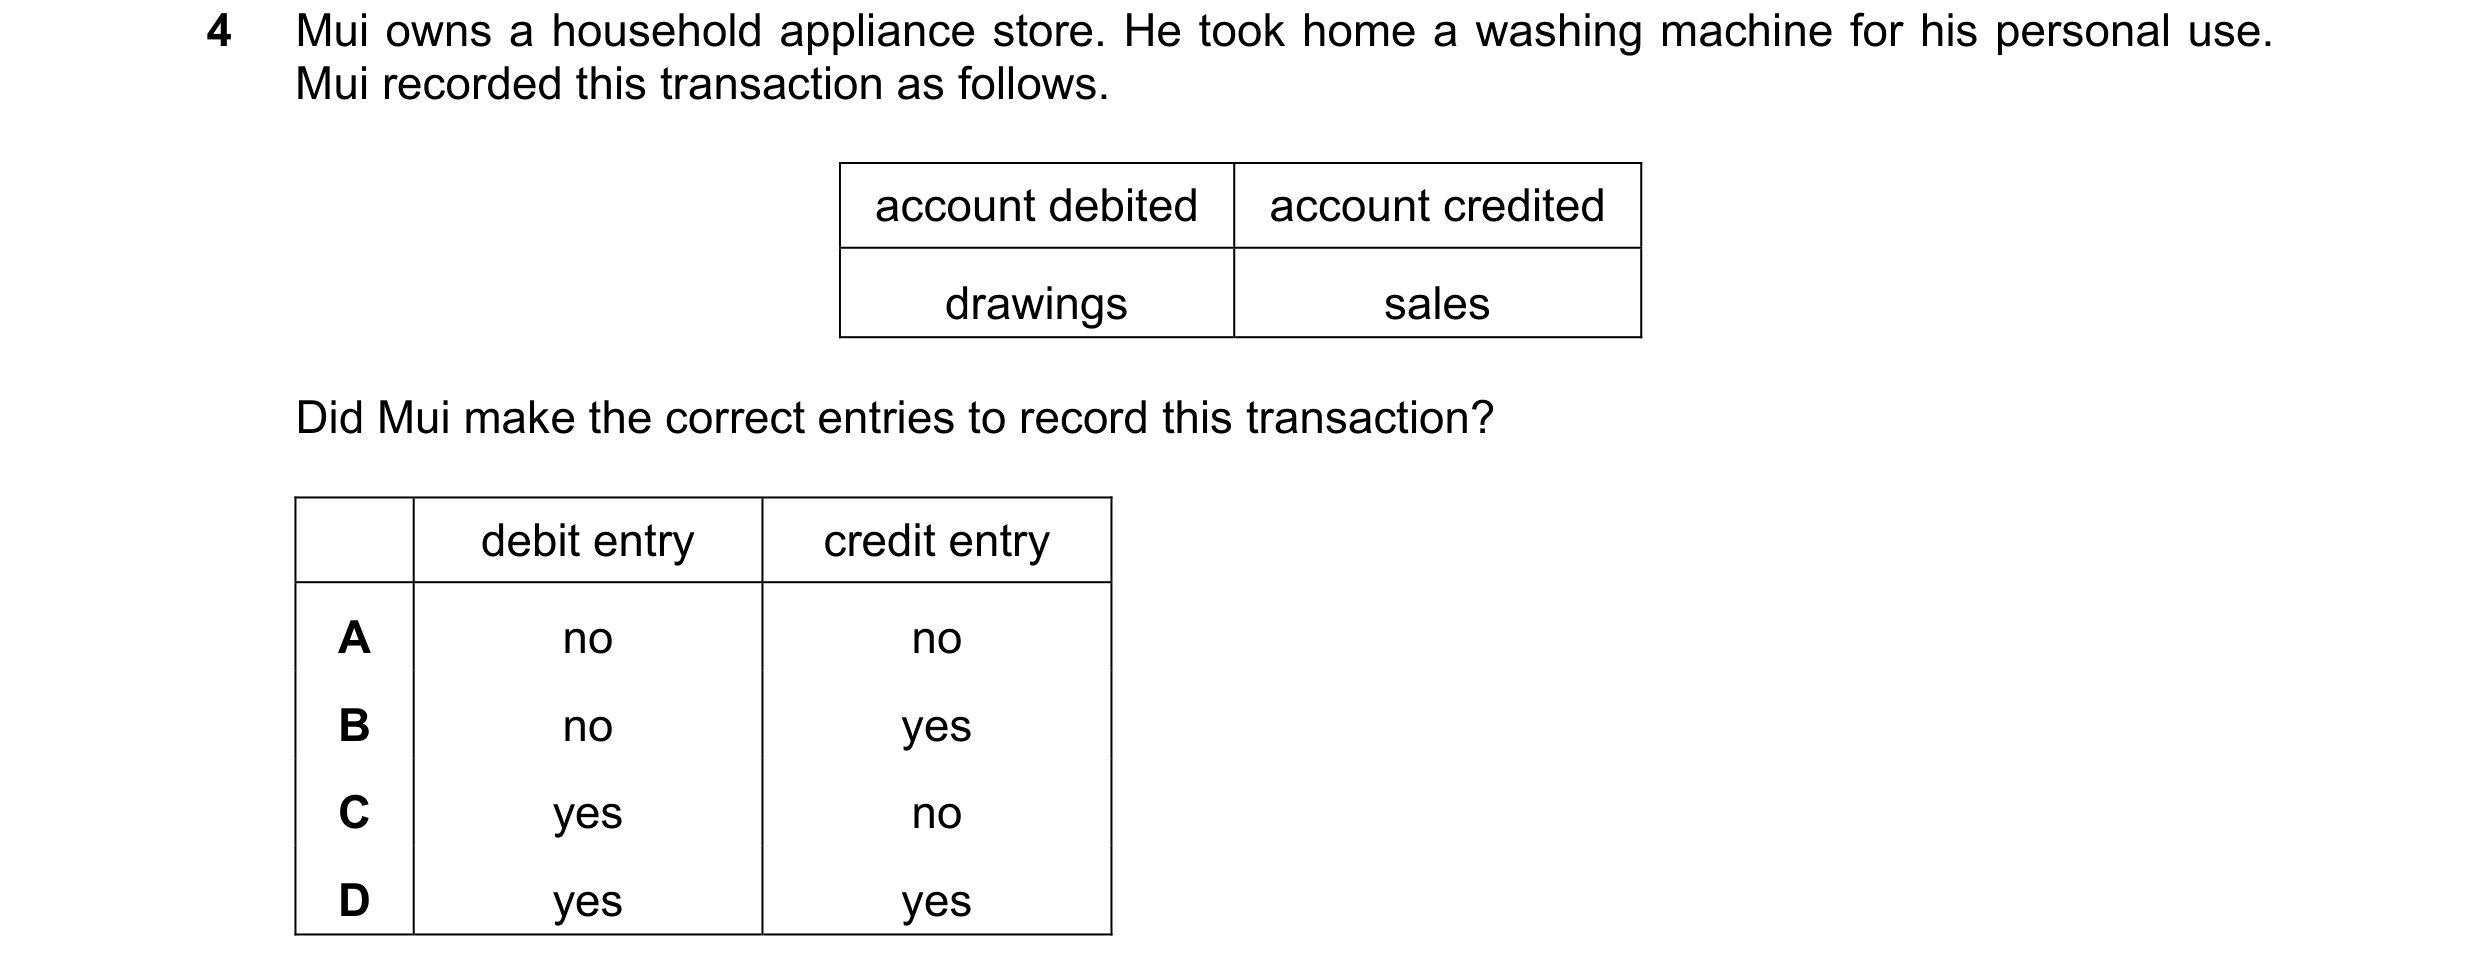
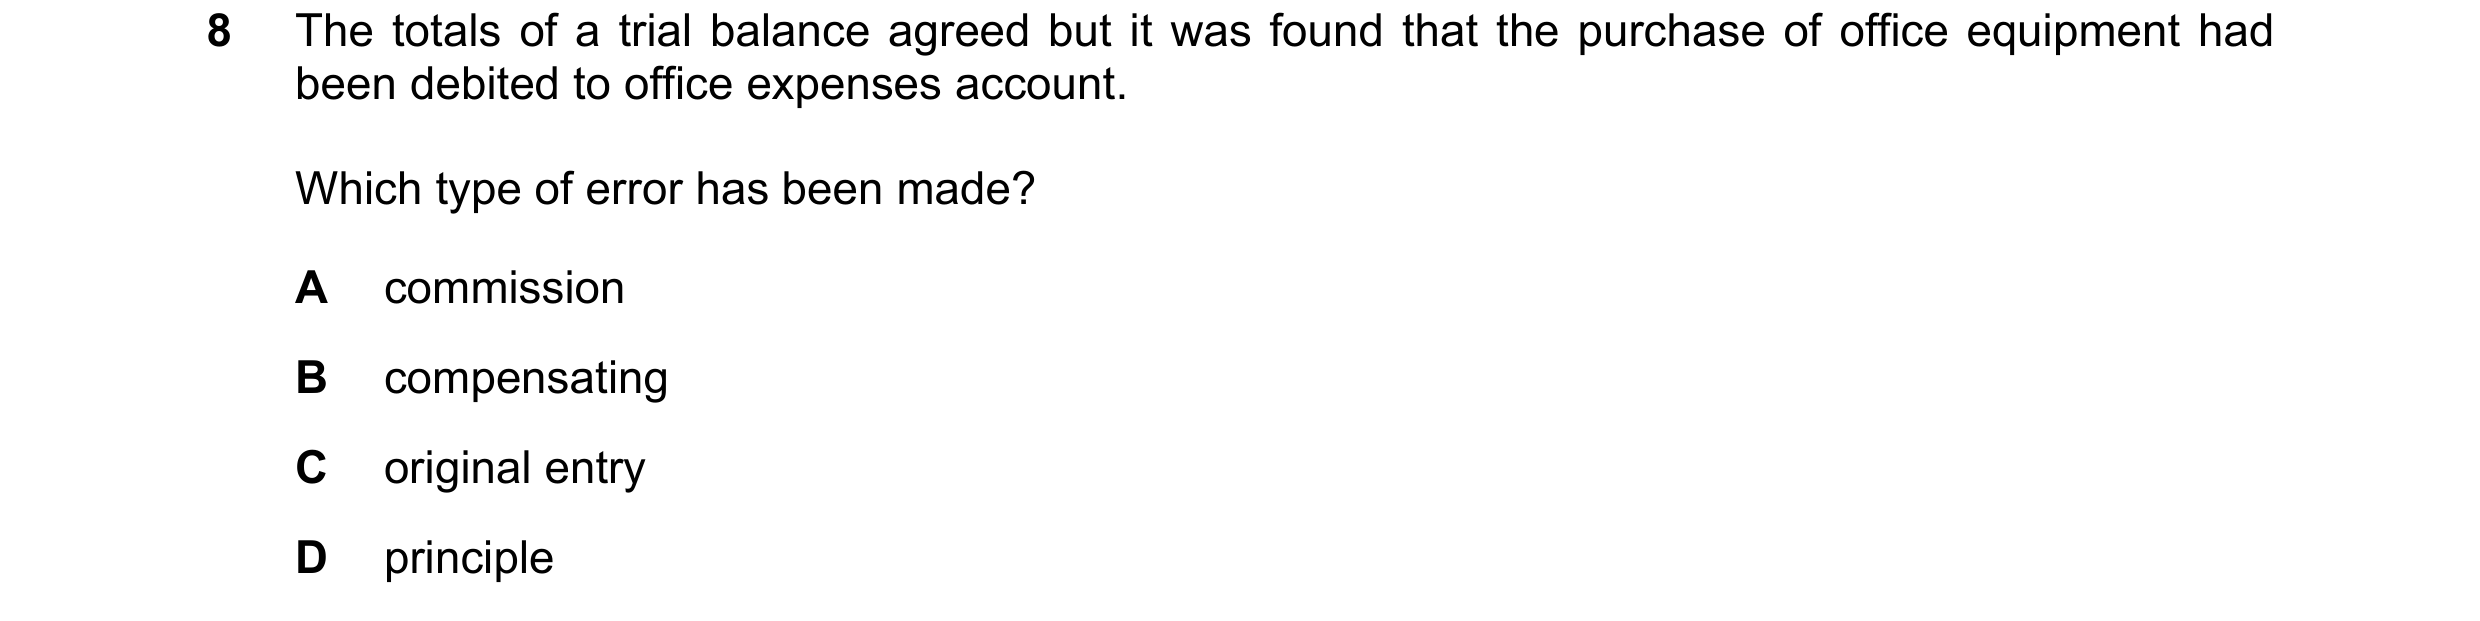
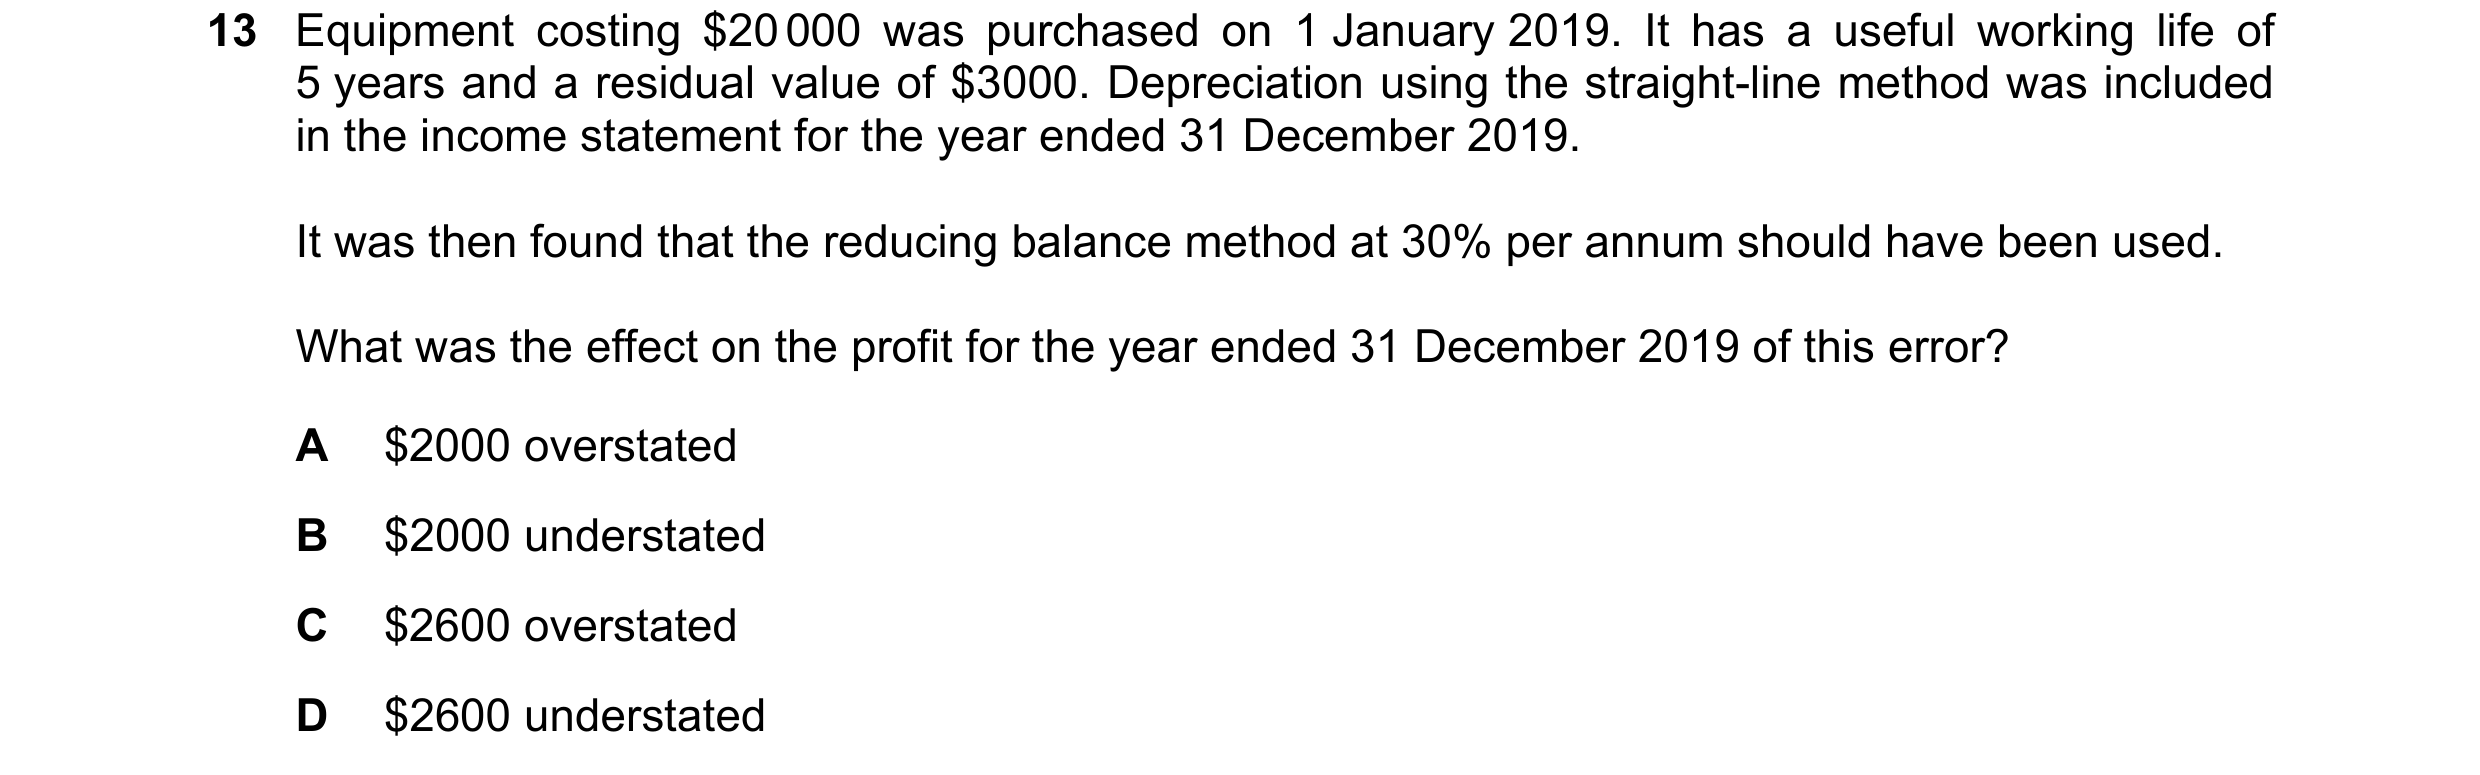
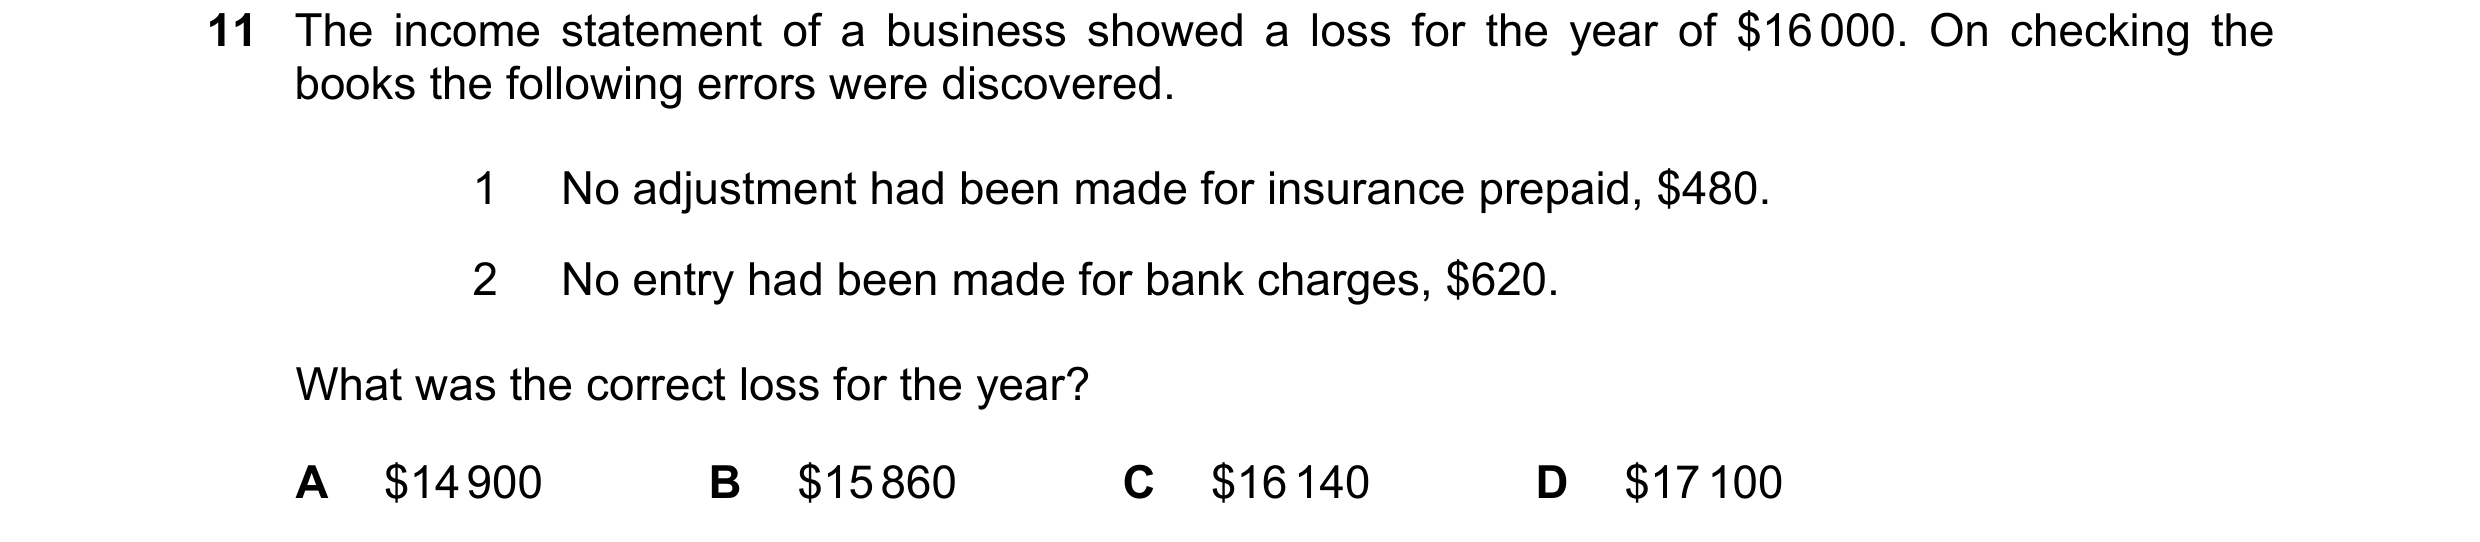 1 / 41
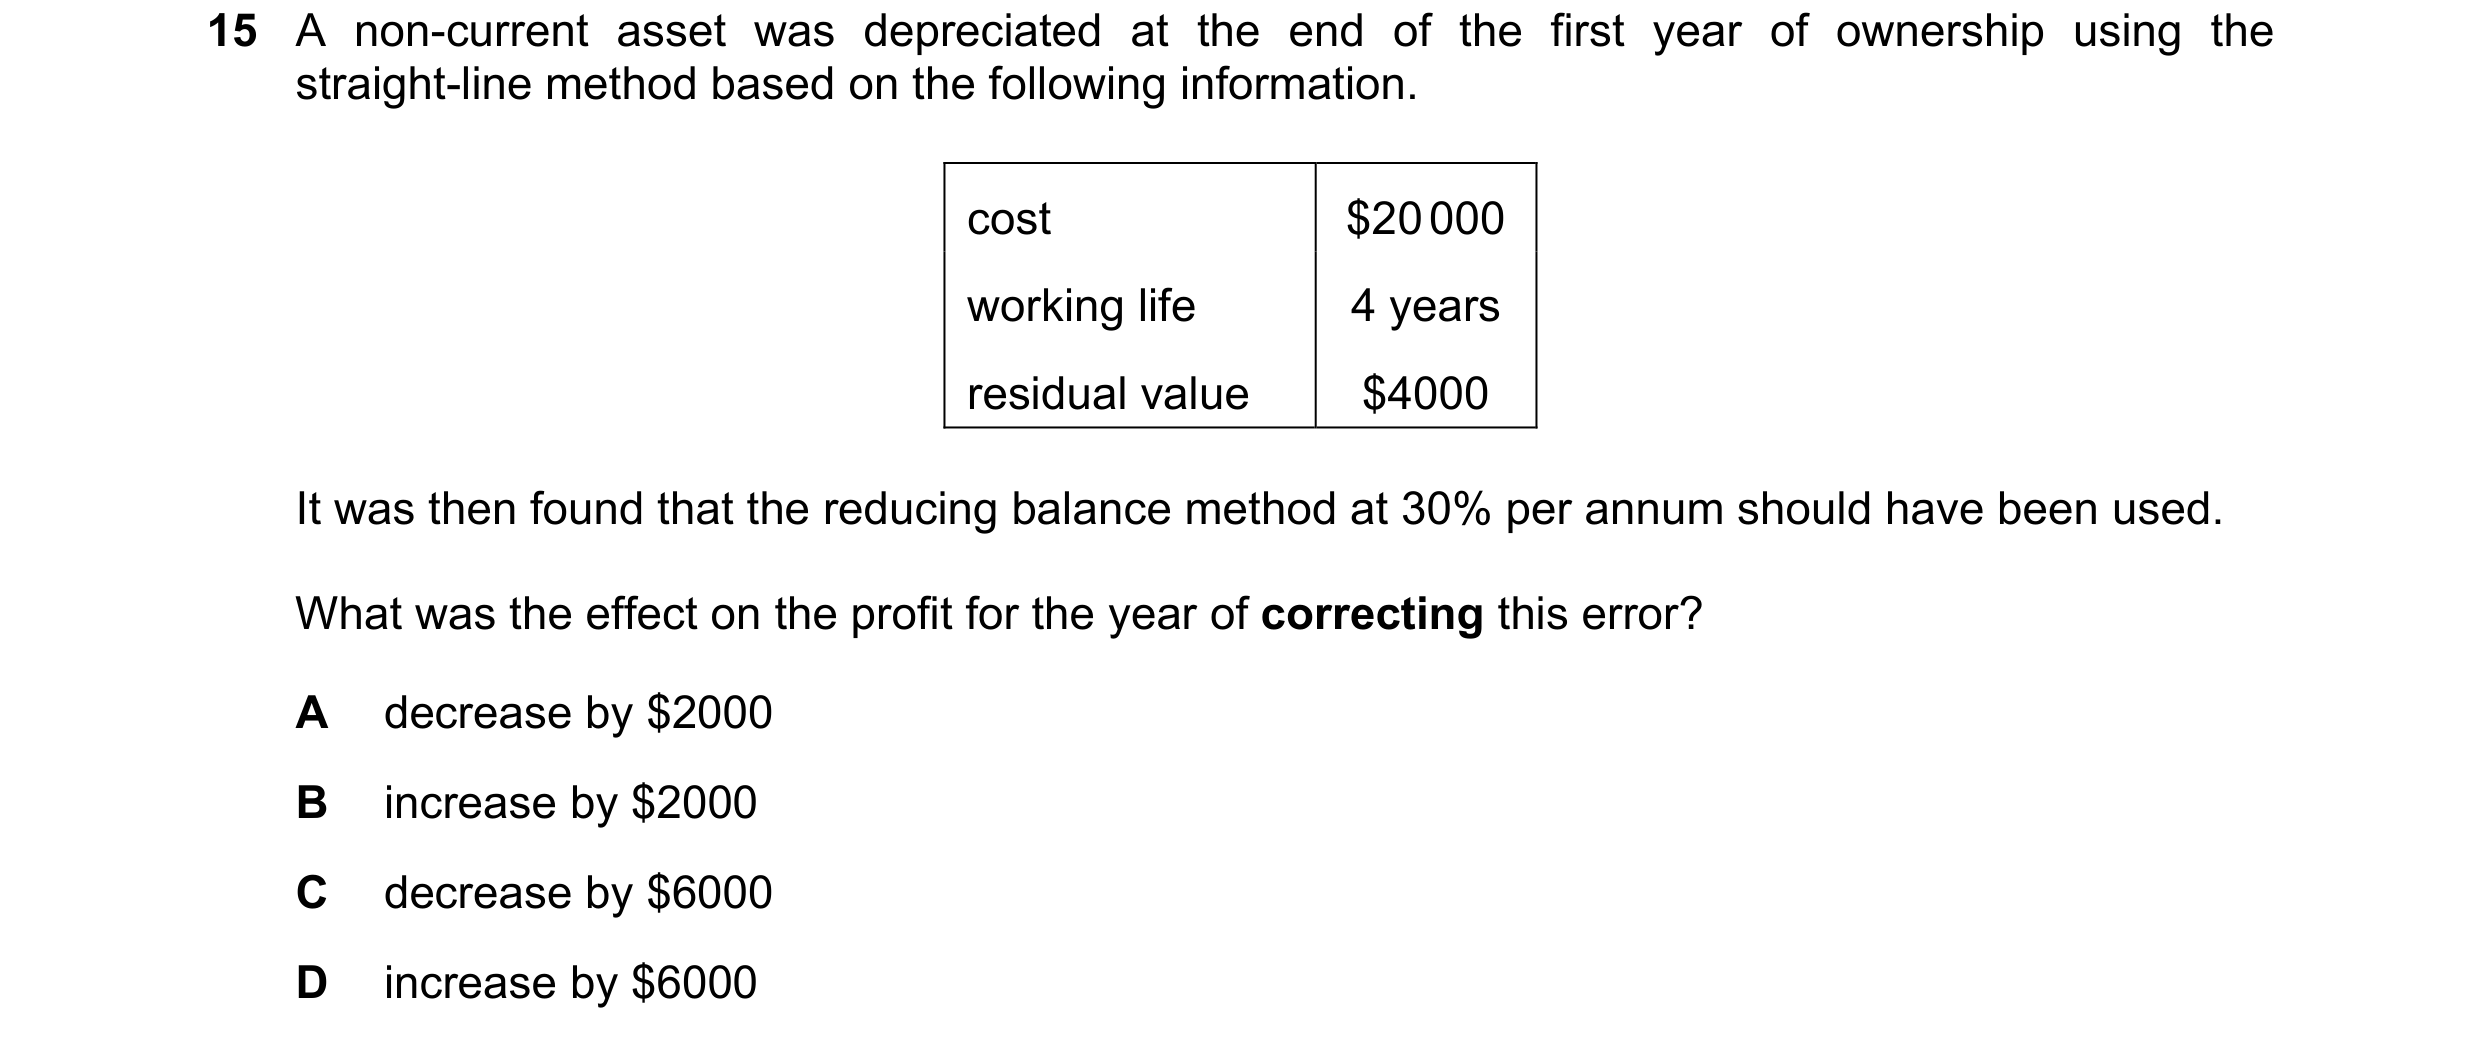
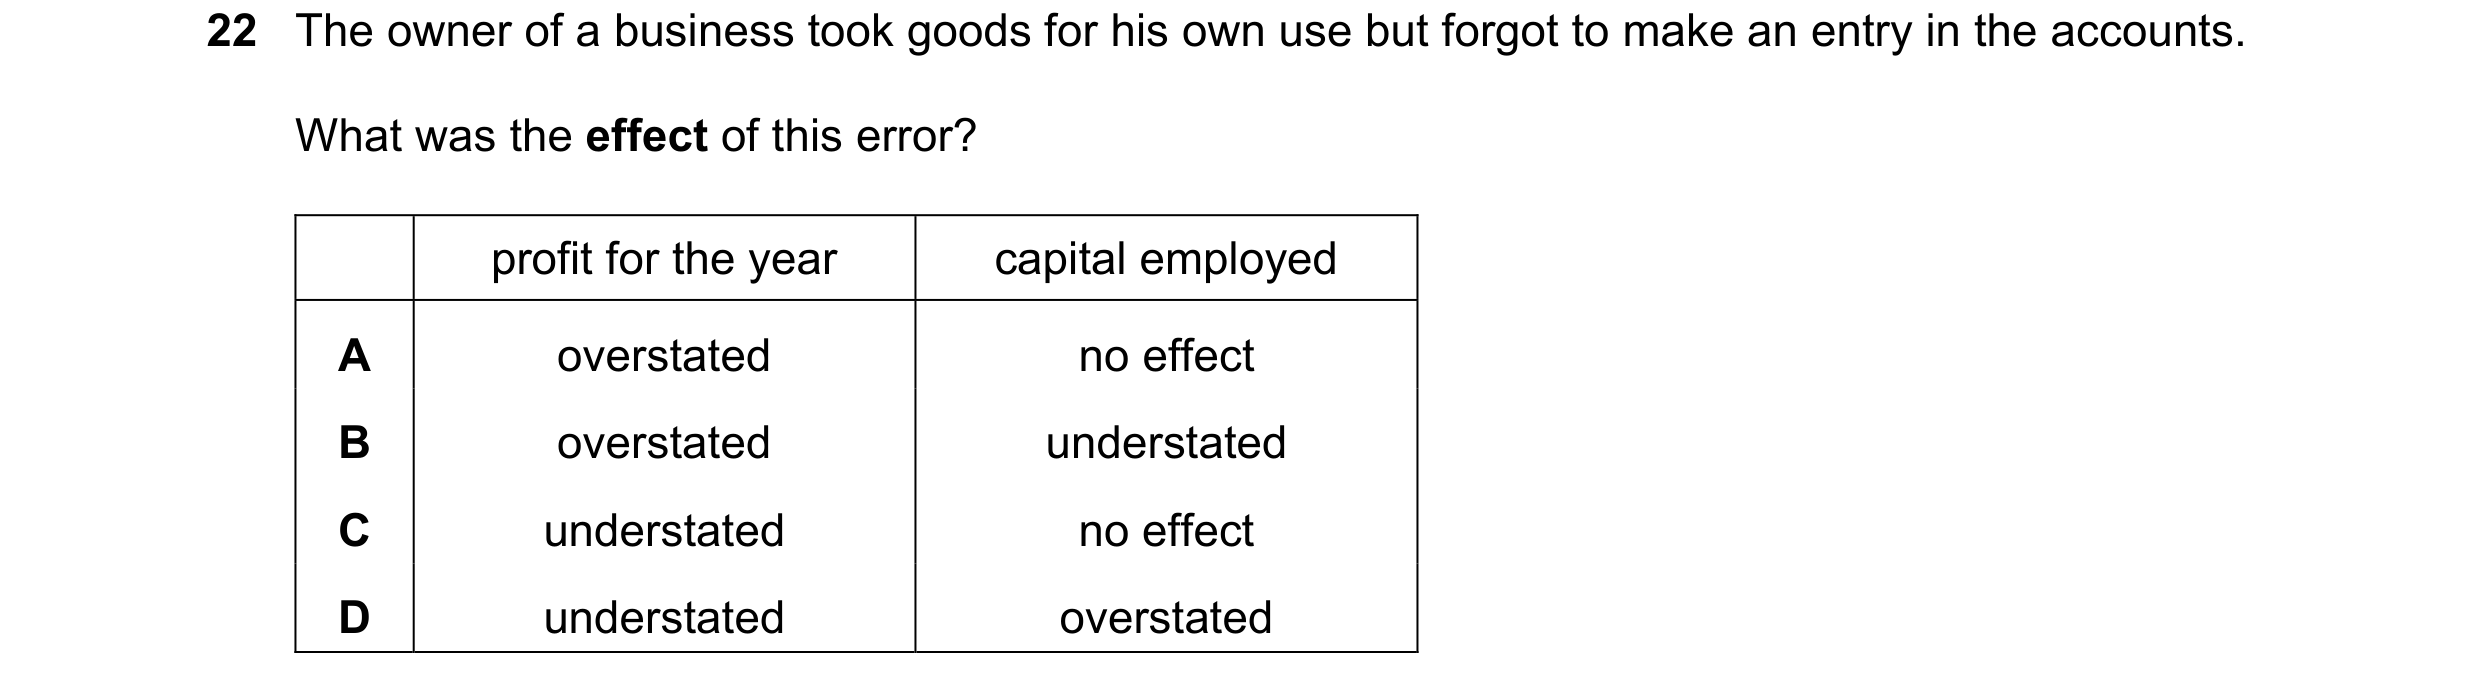
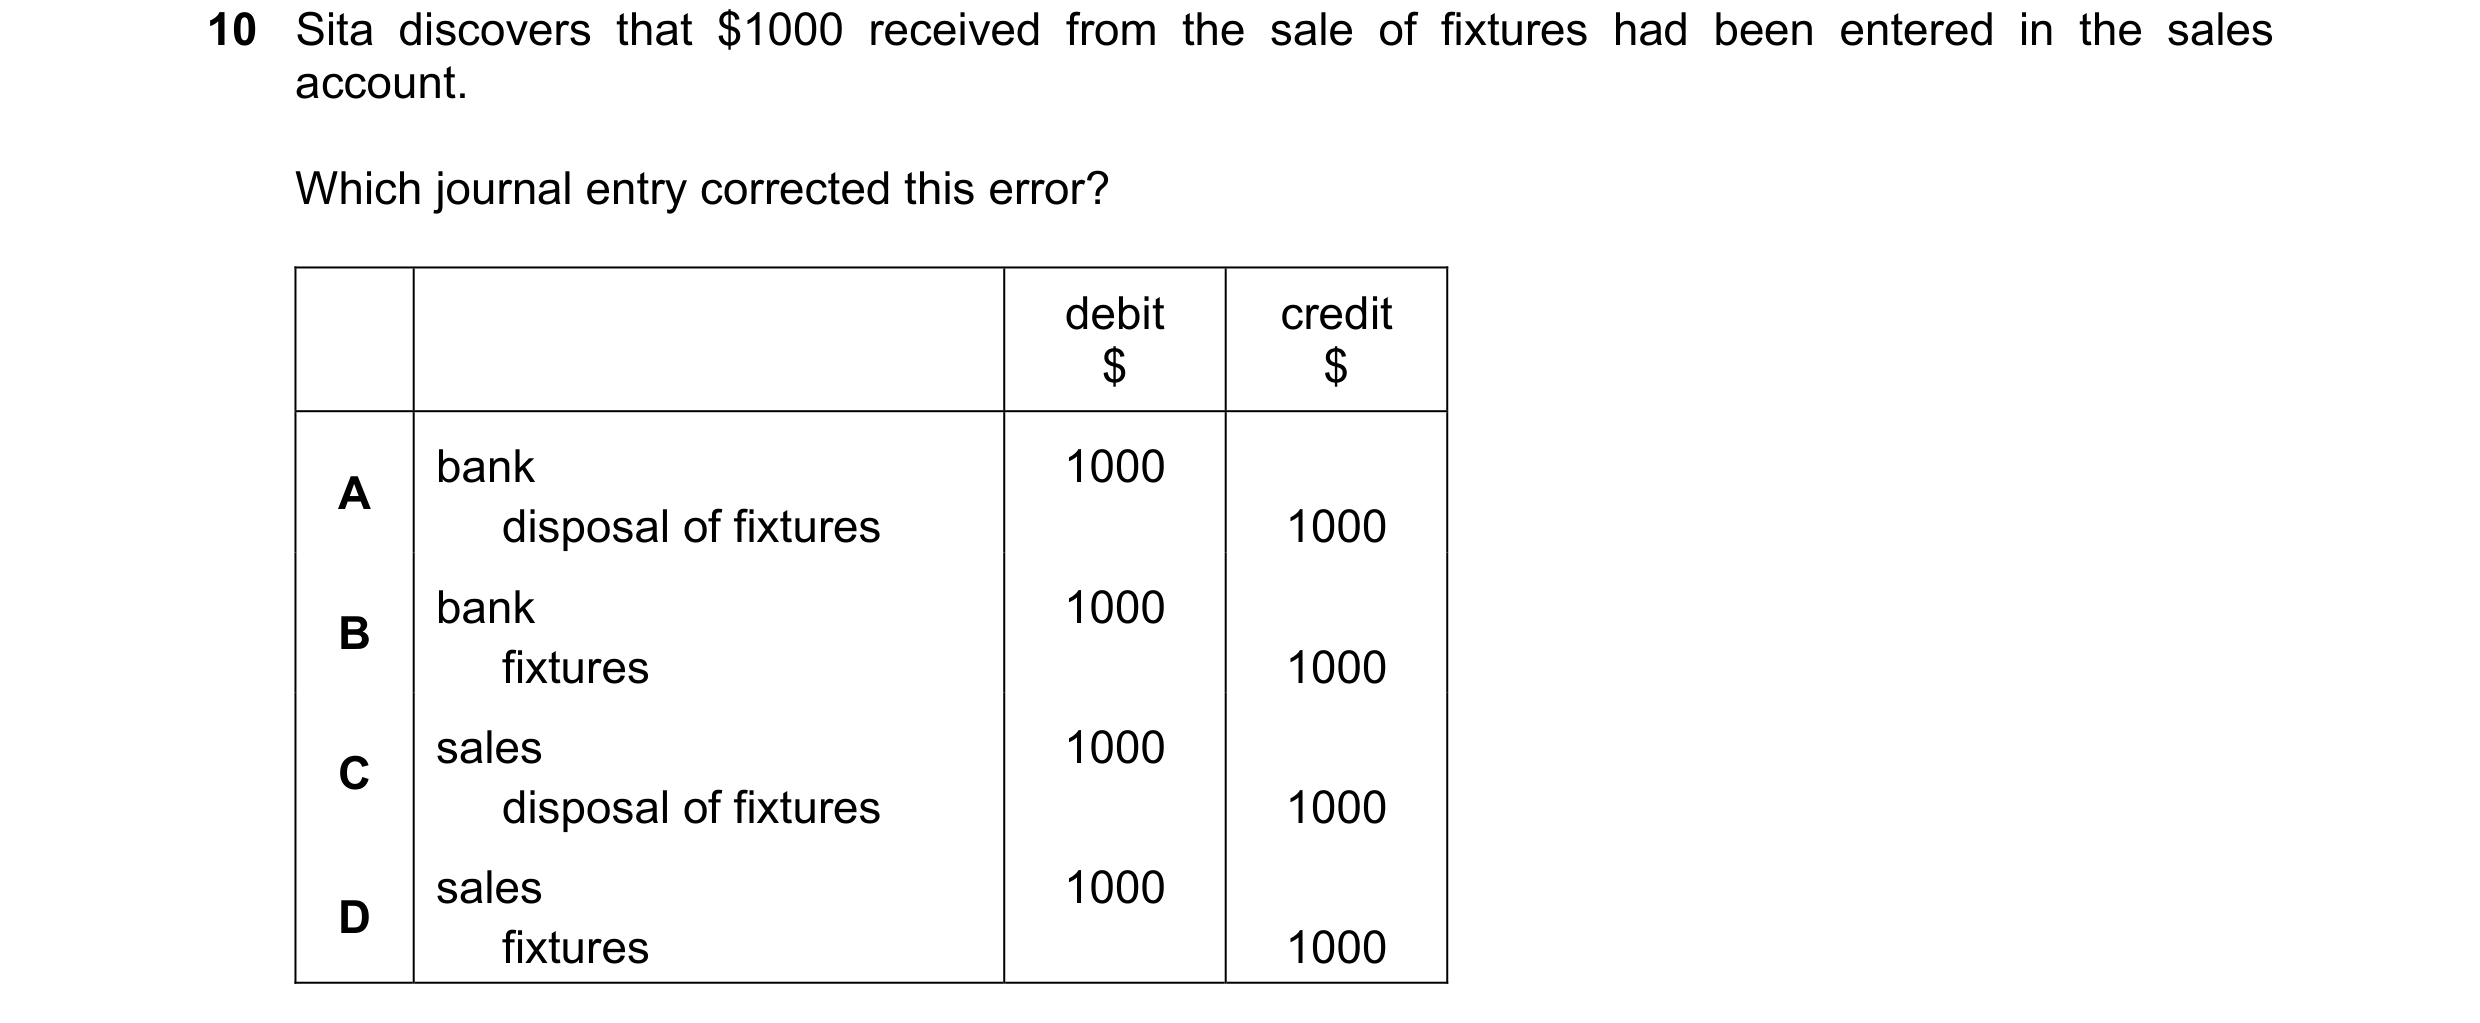 2 / 41
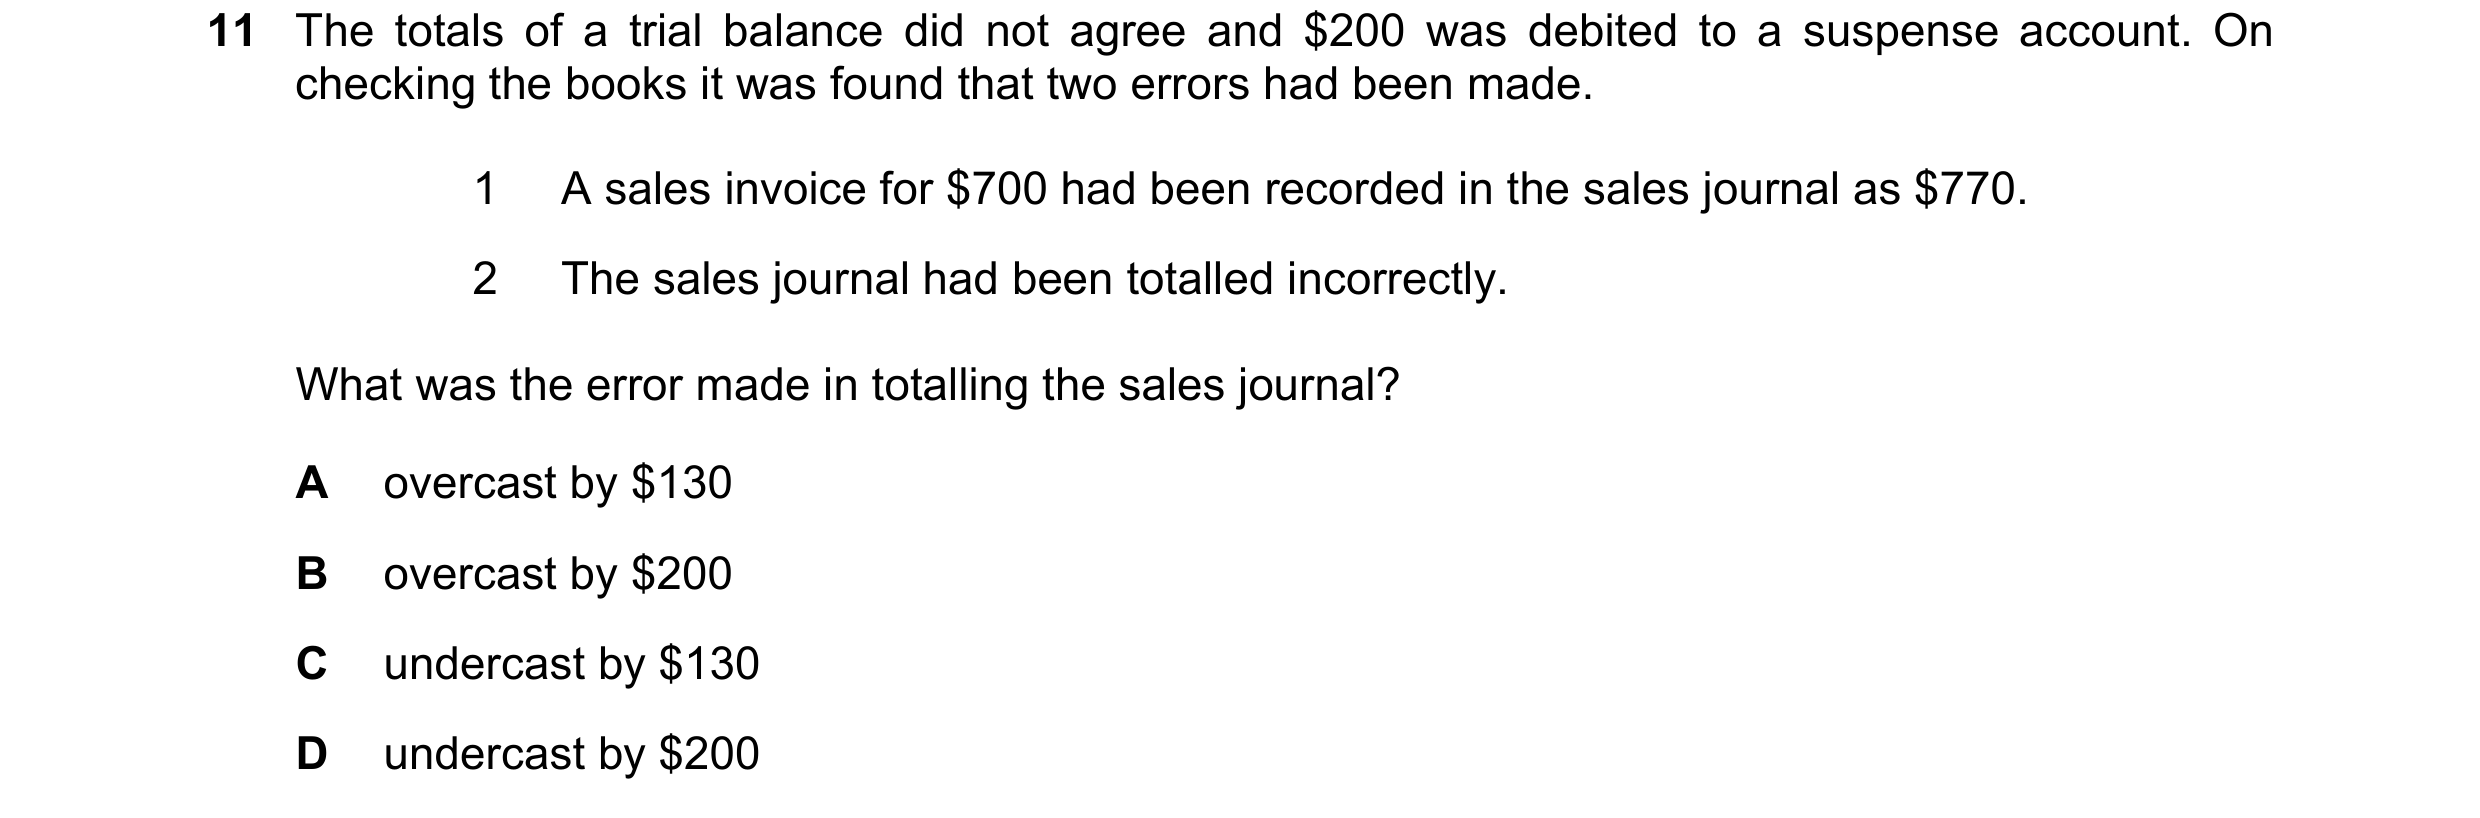
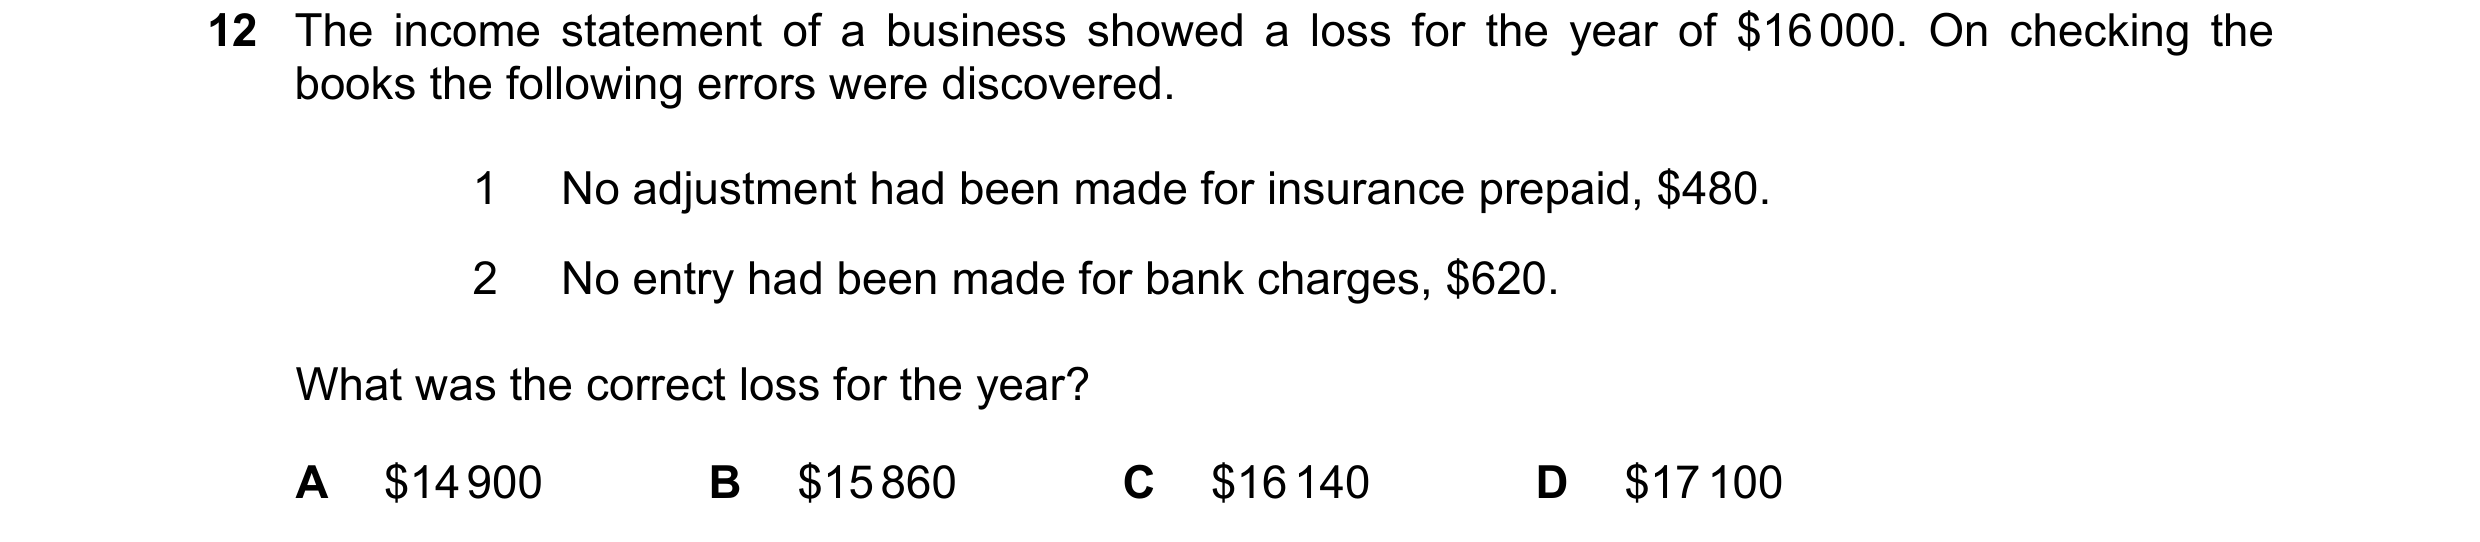
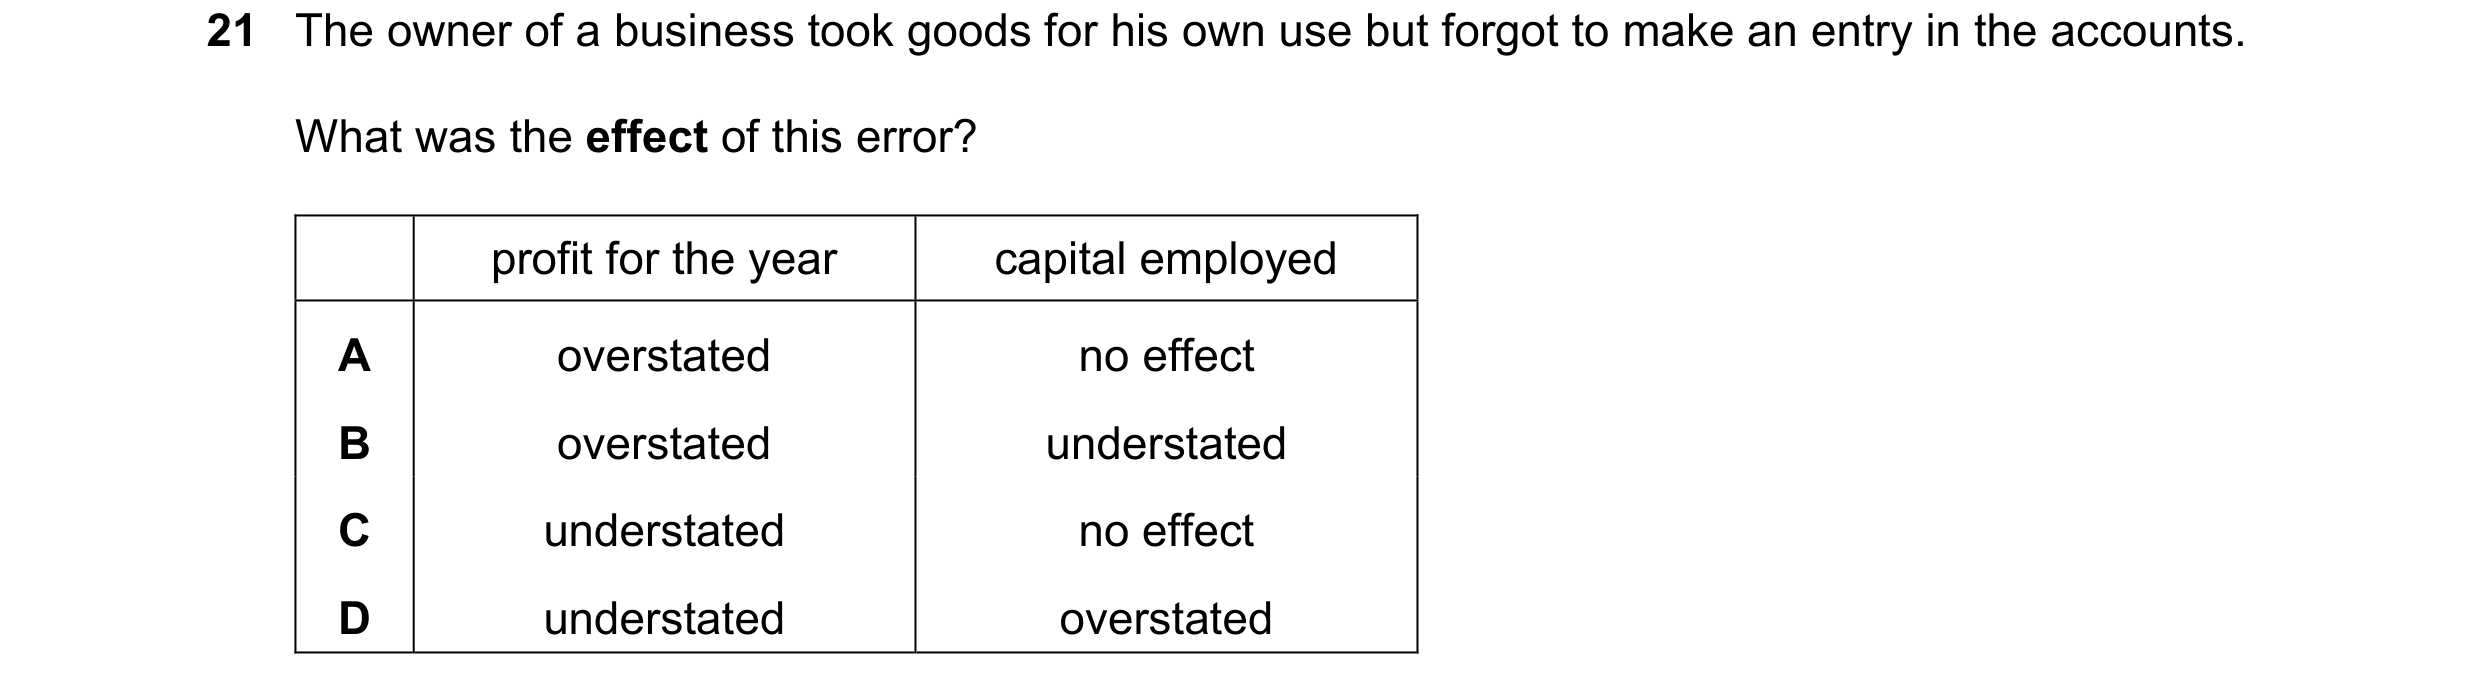
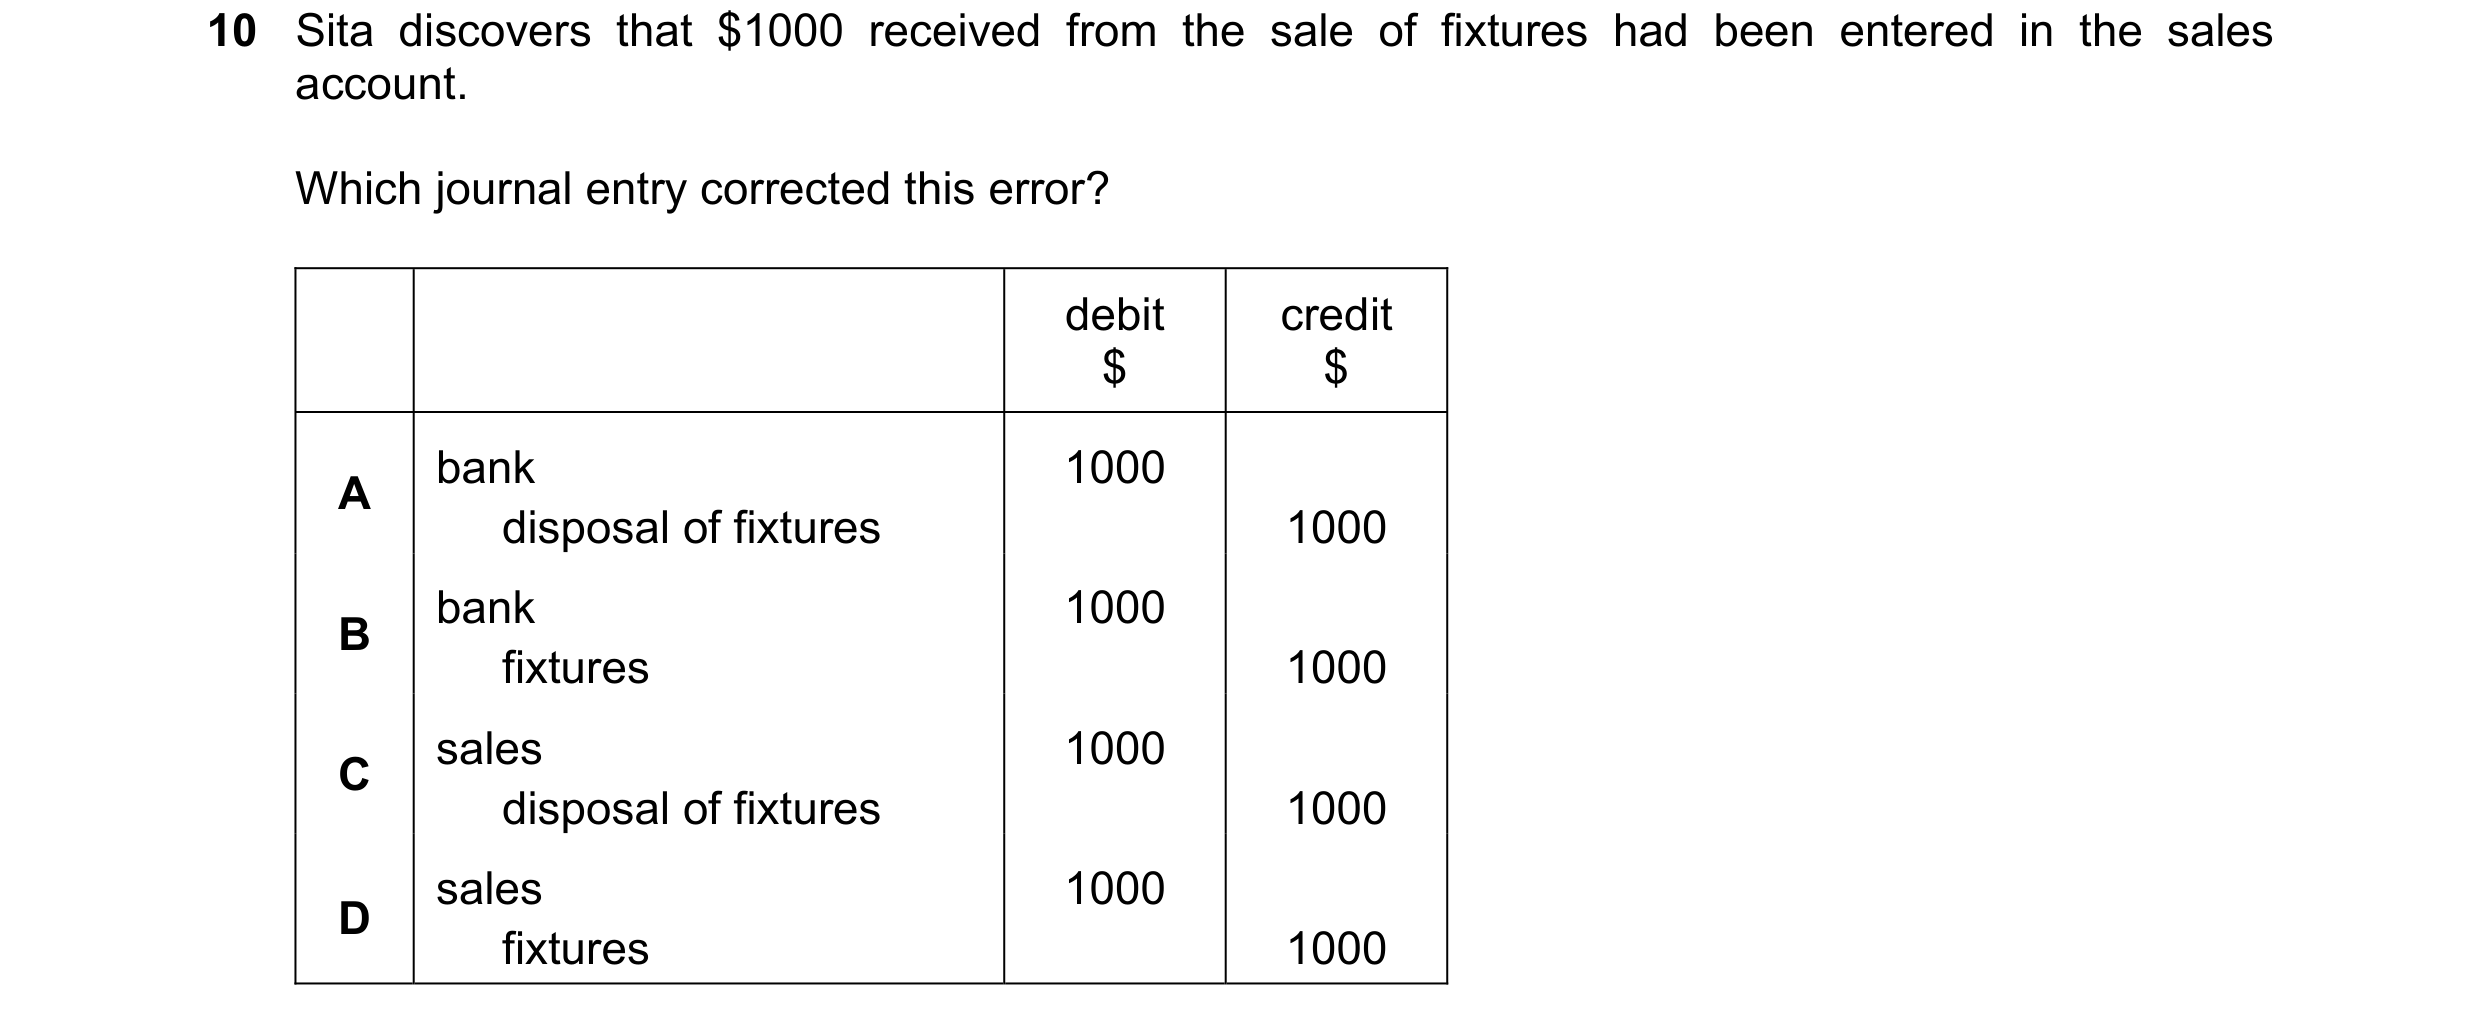 3 / 41
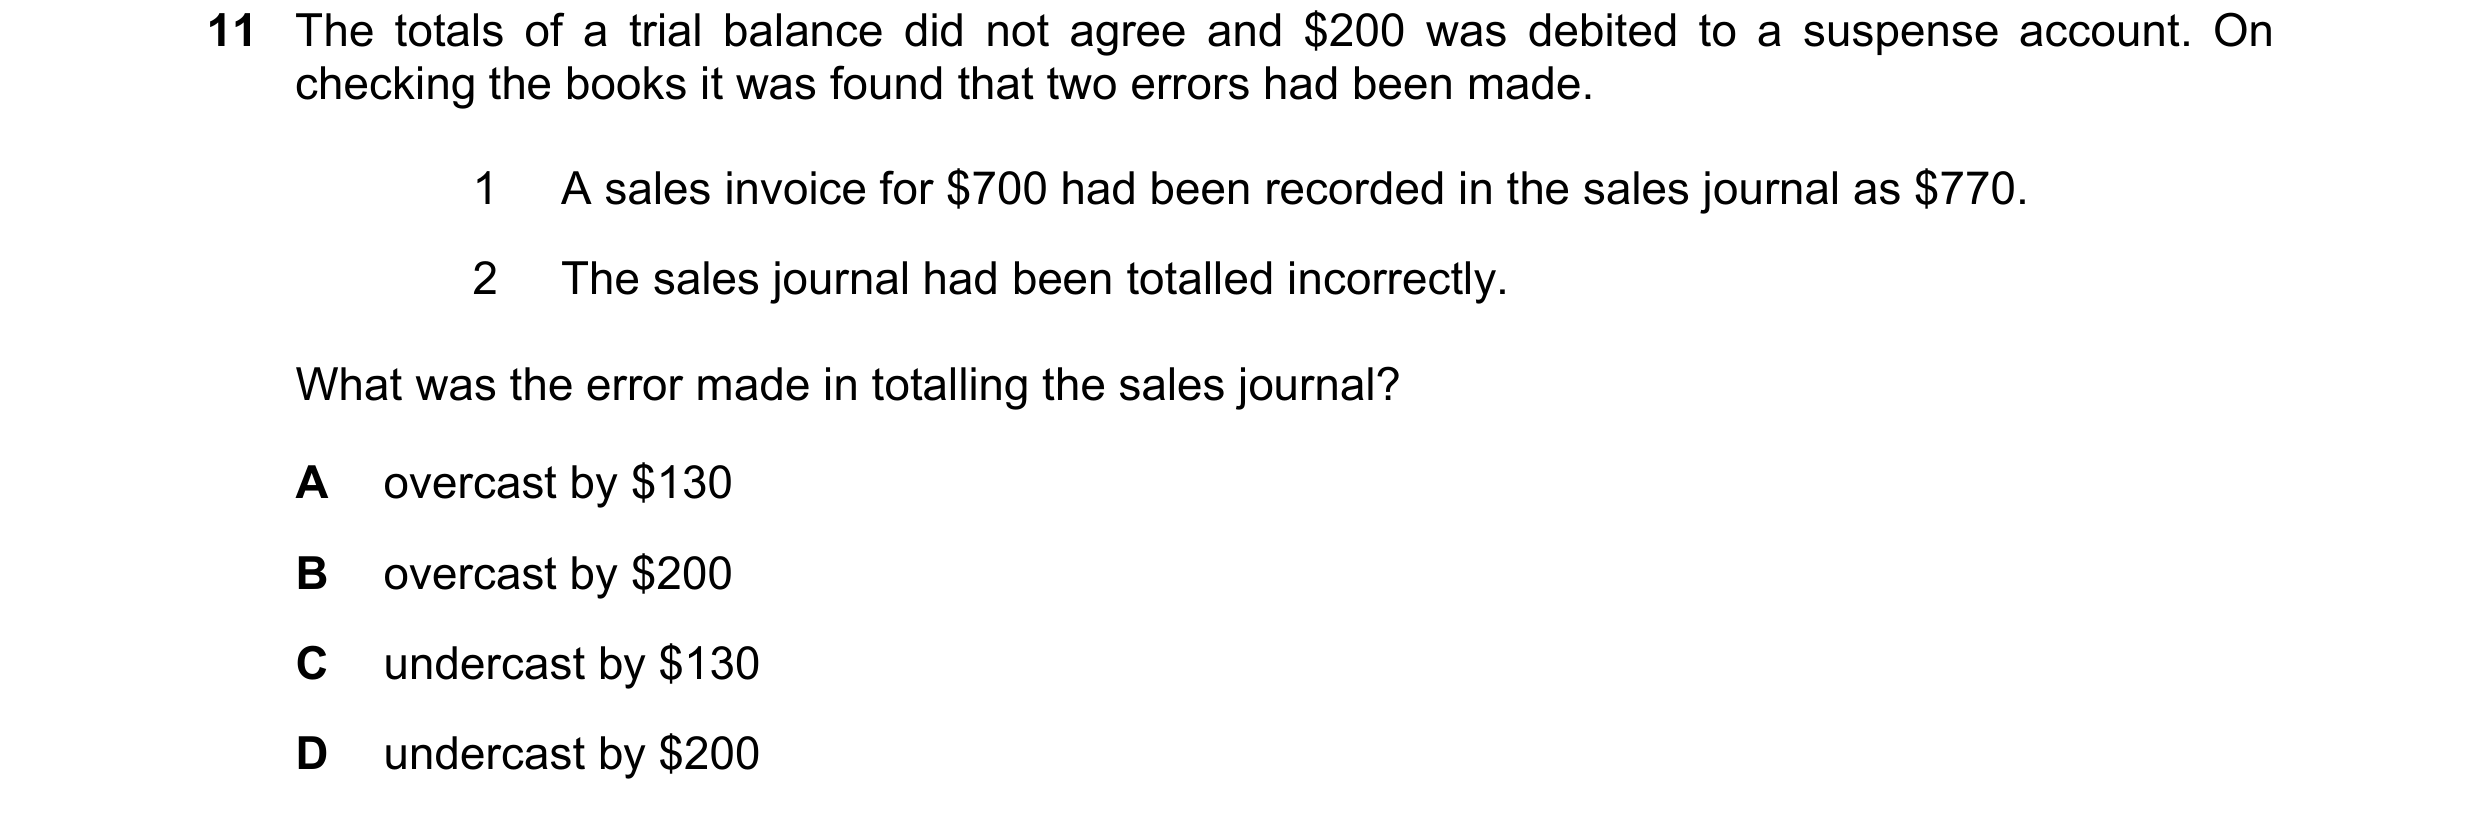
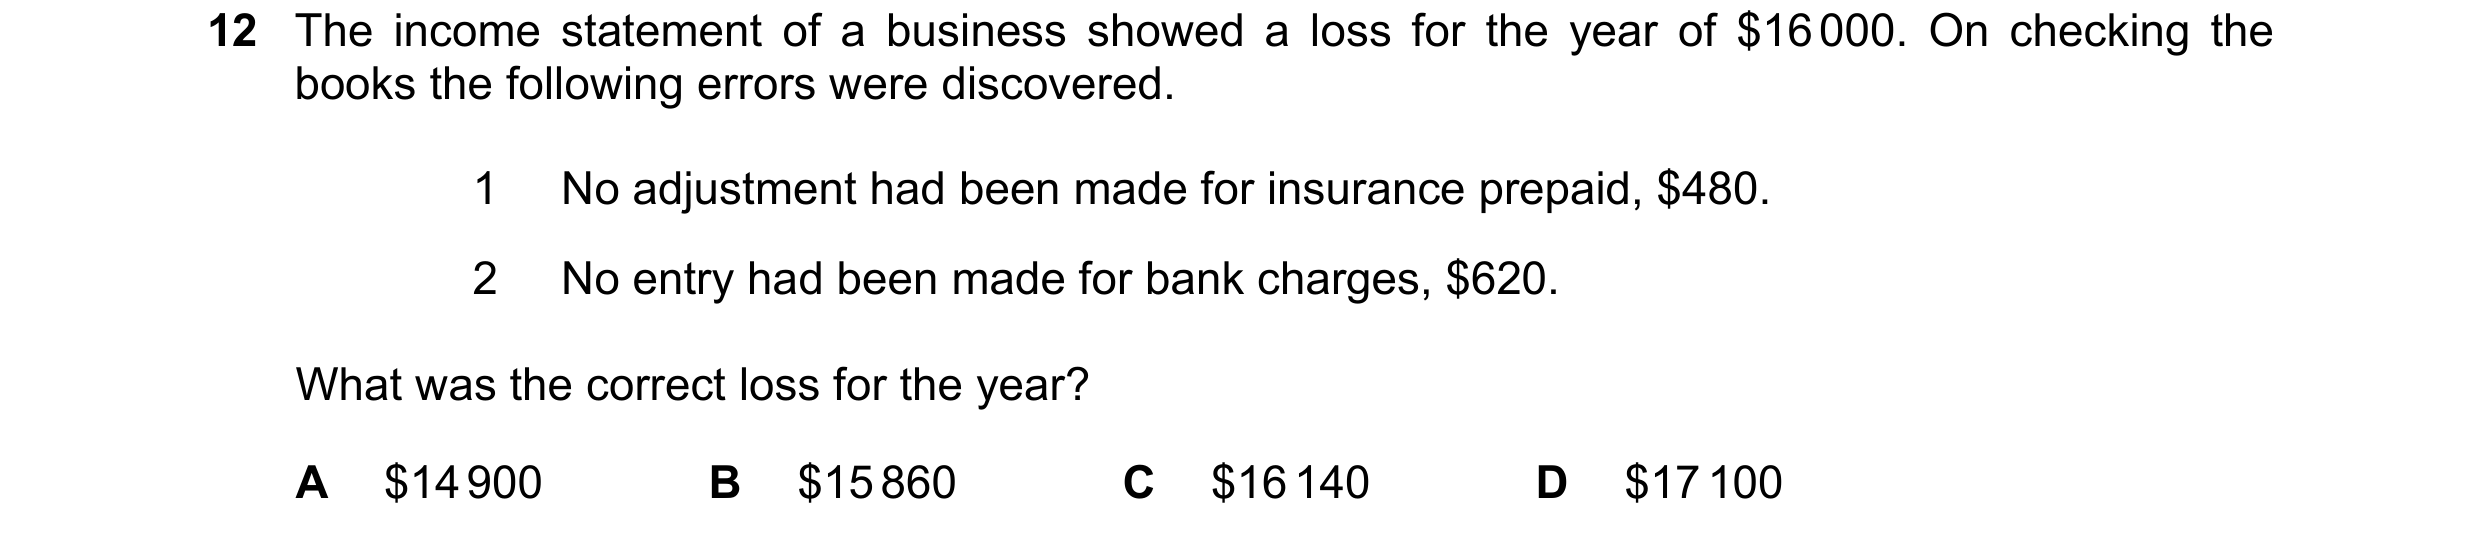
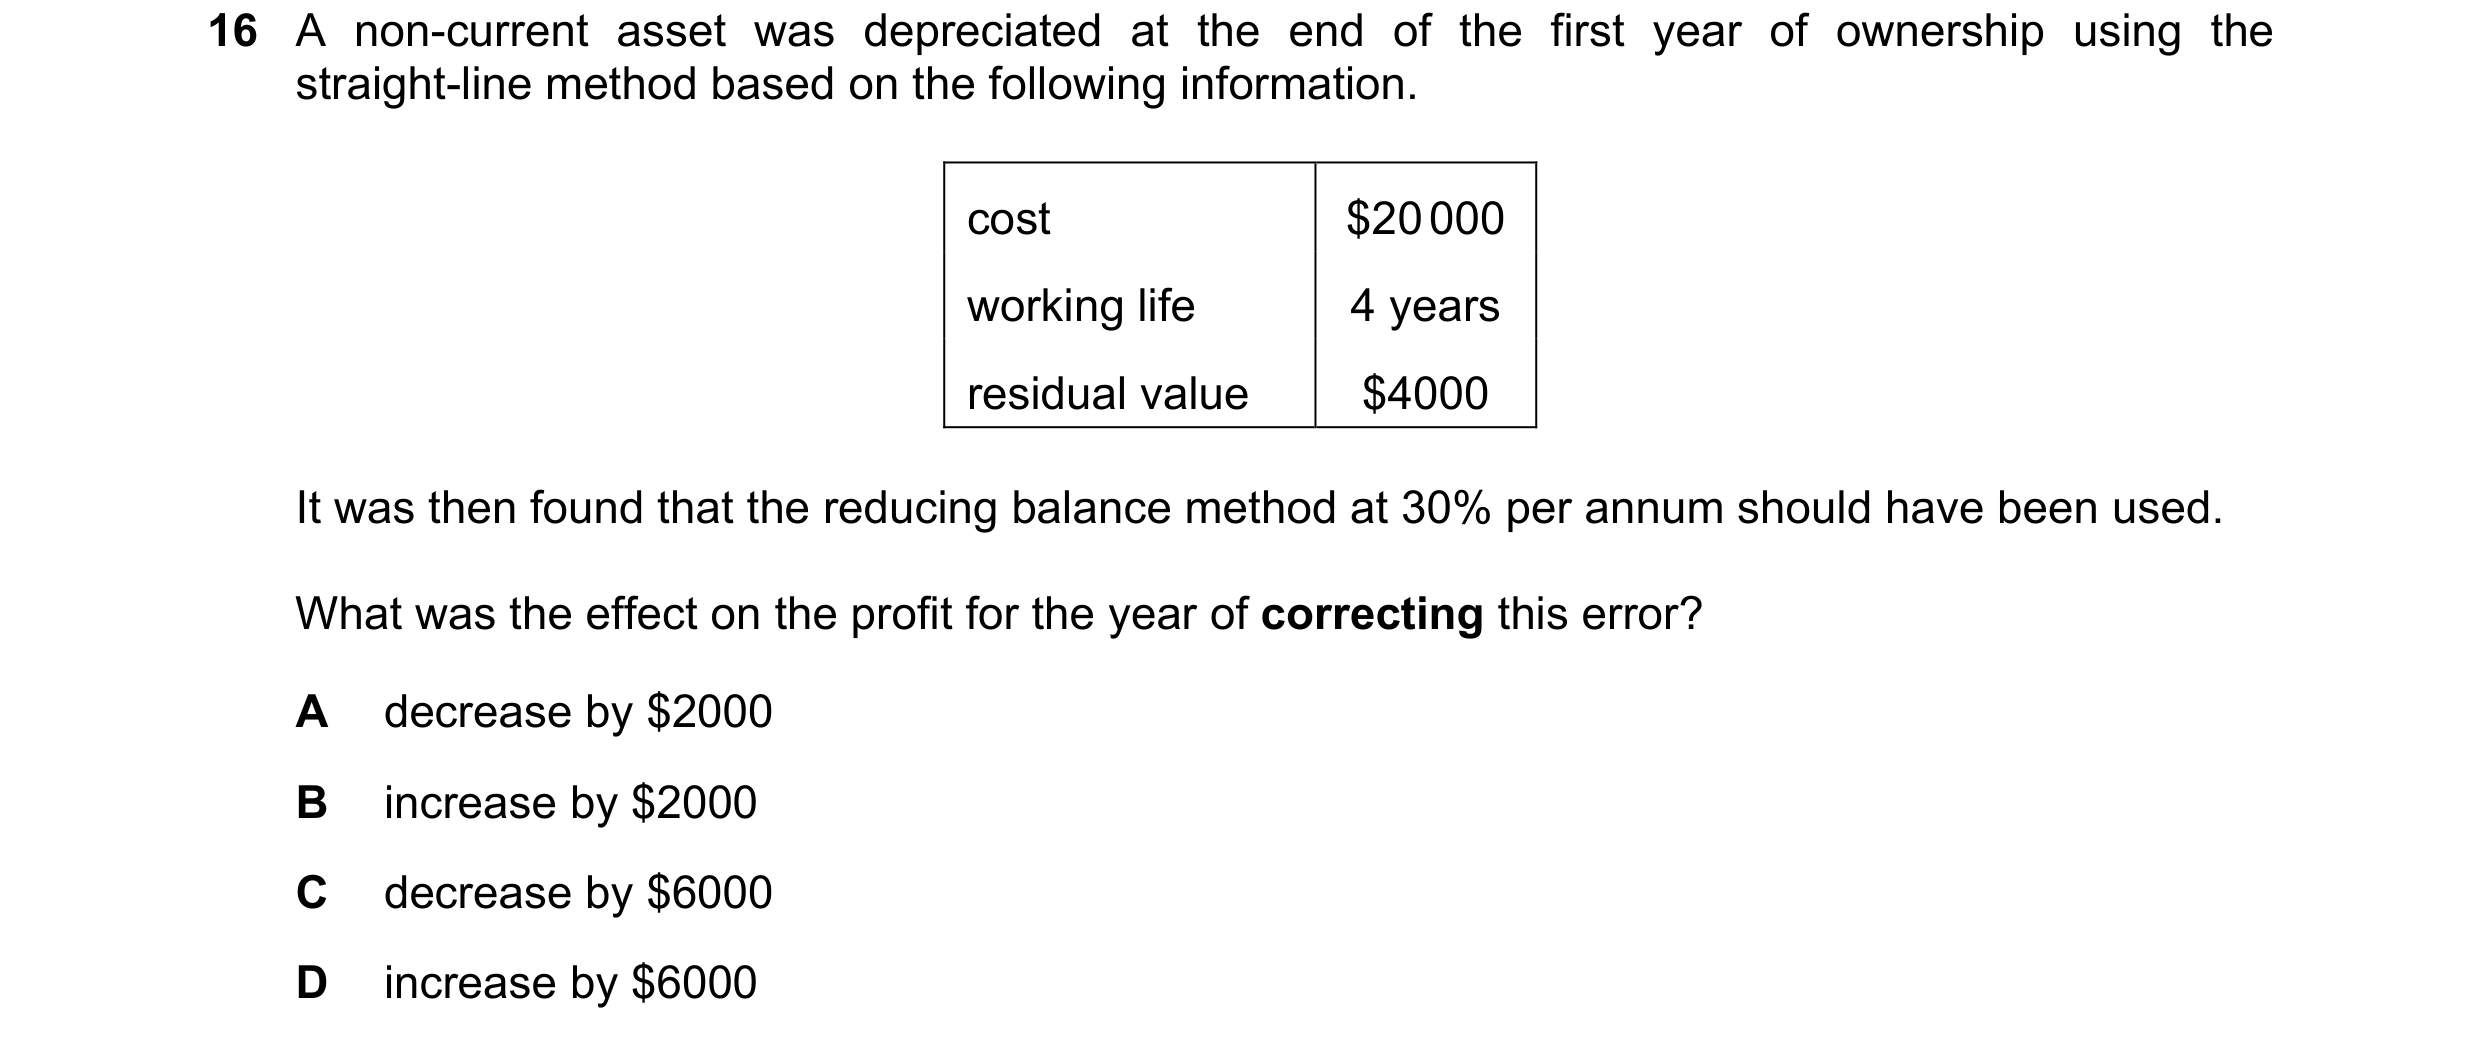
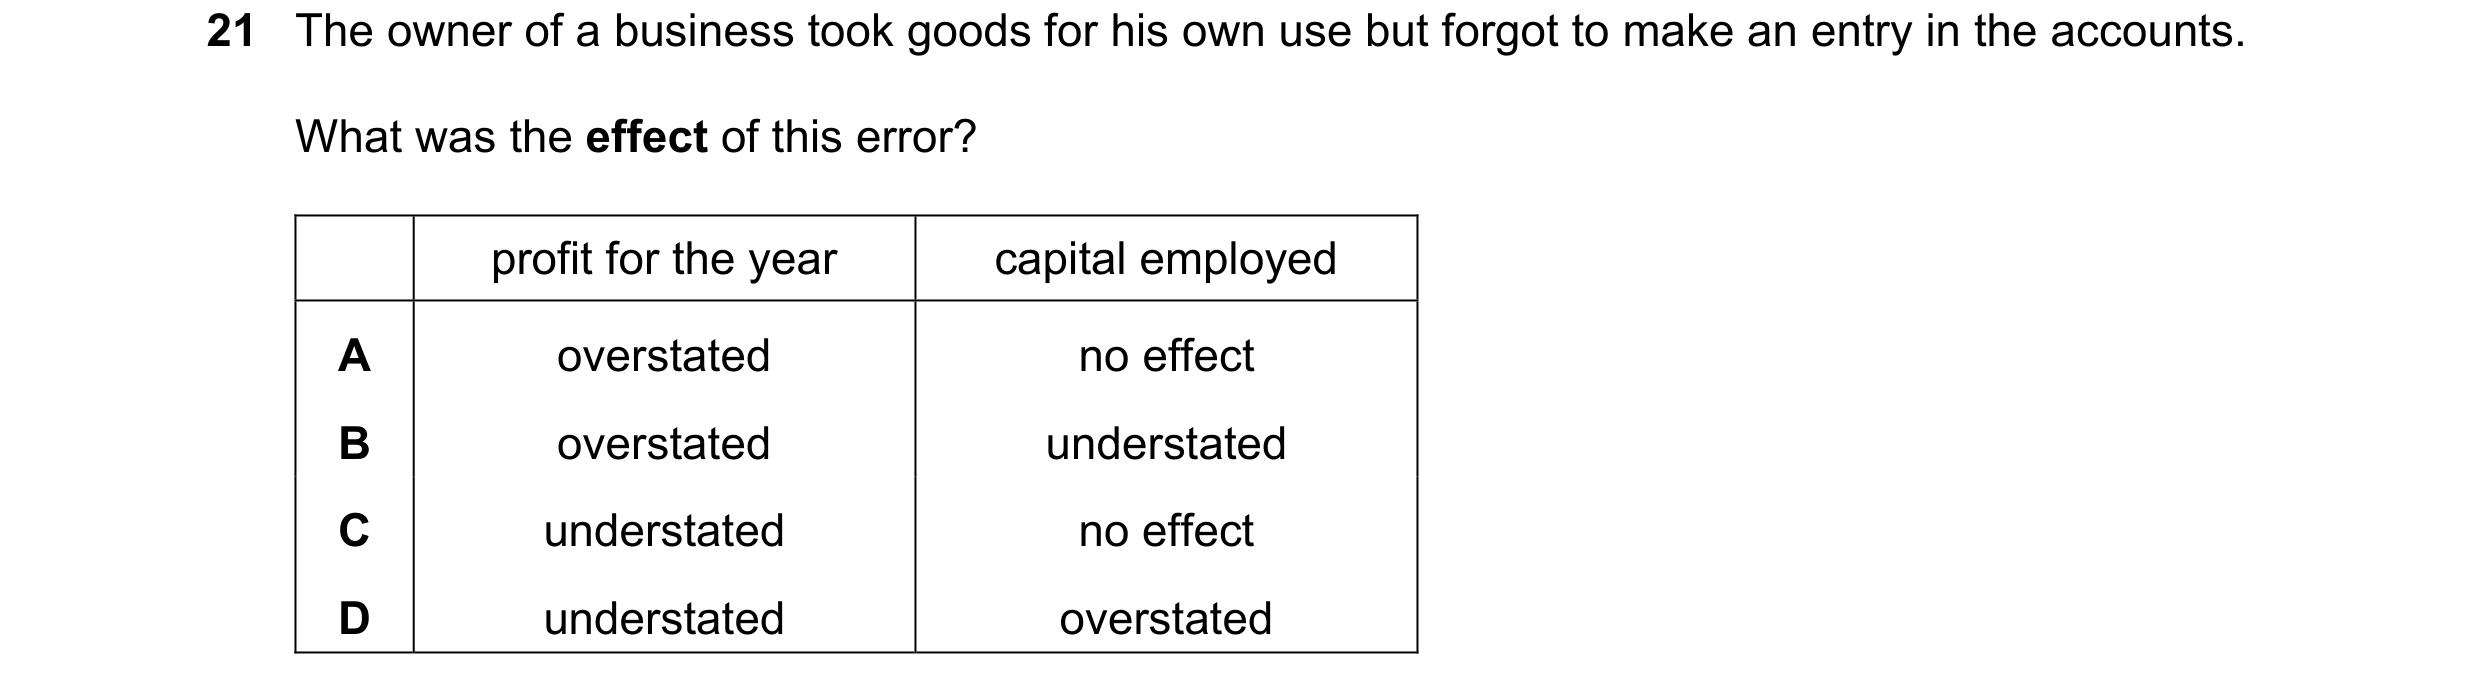 4 / 41
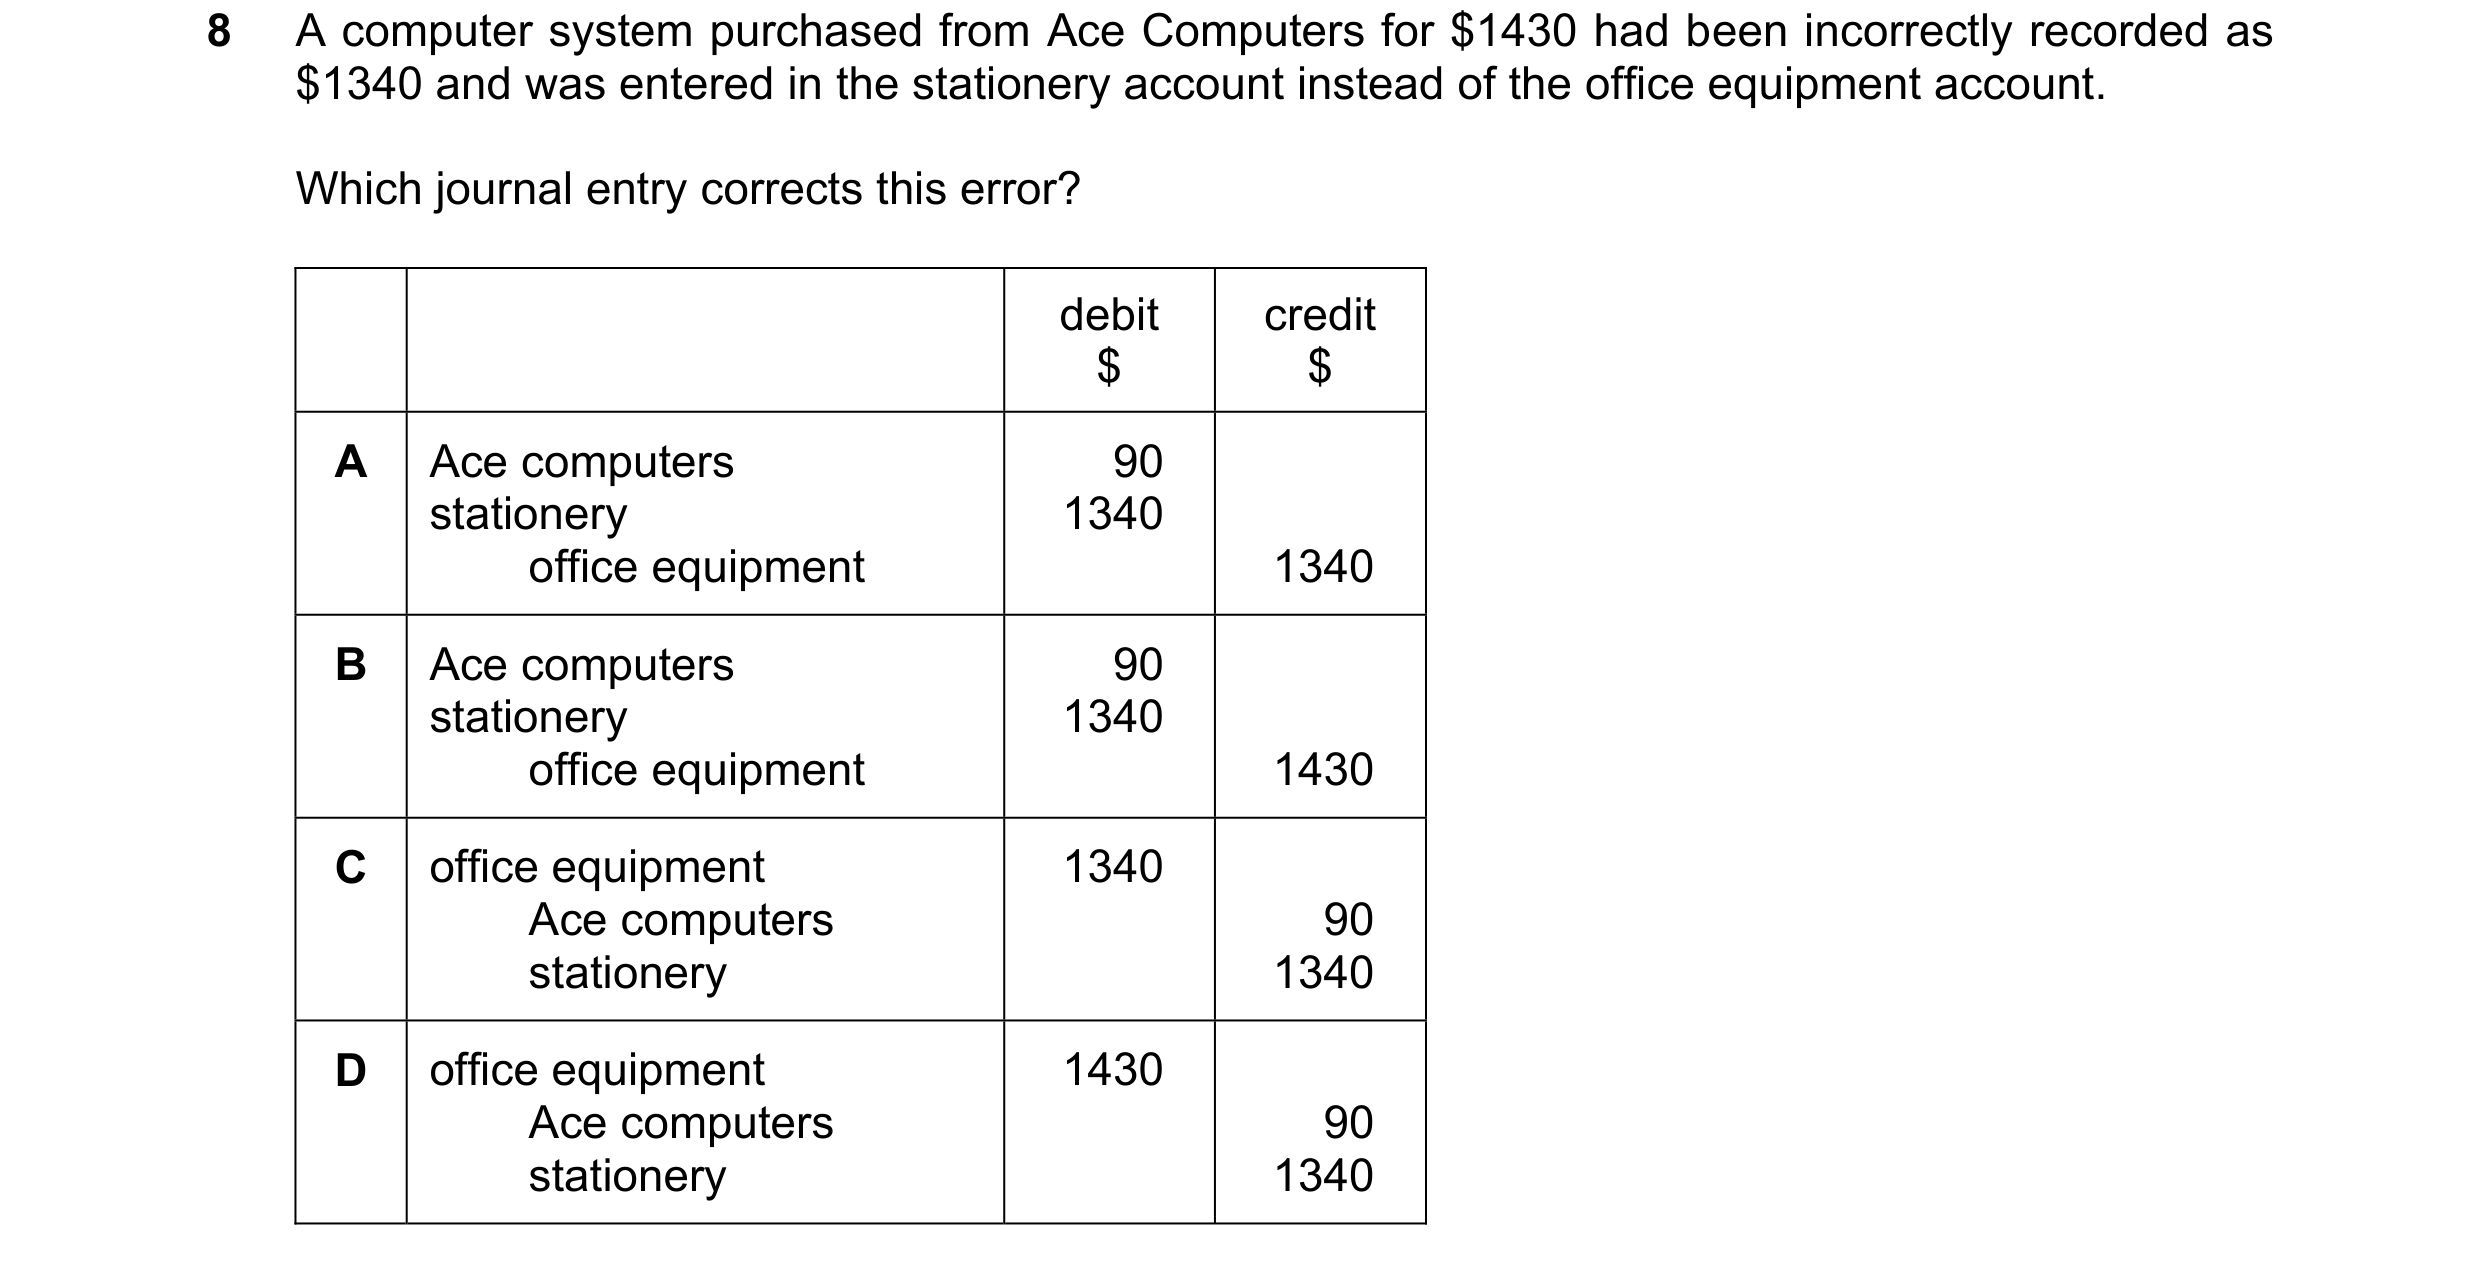
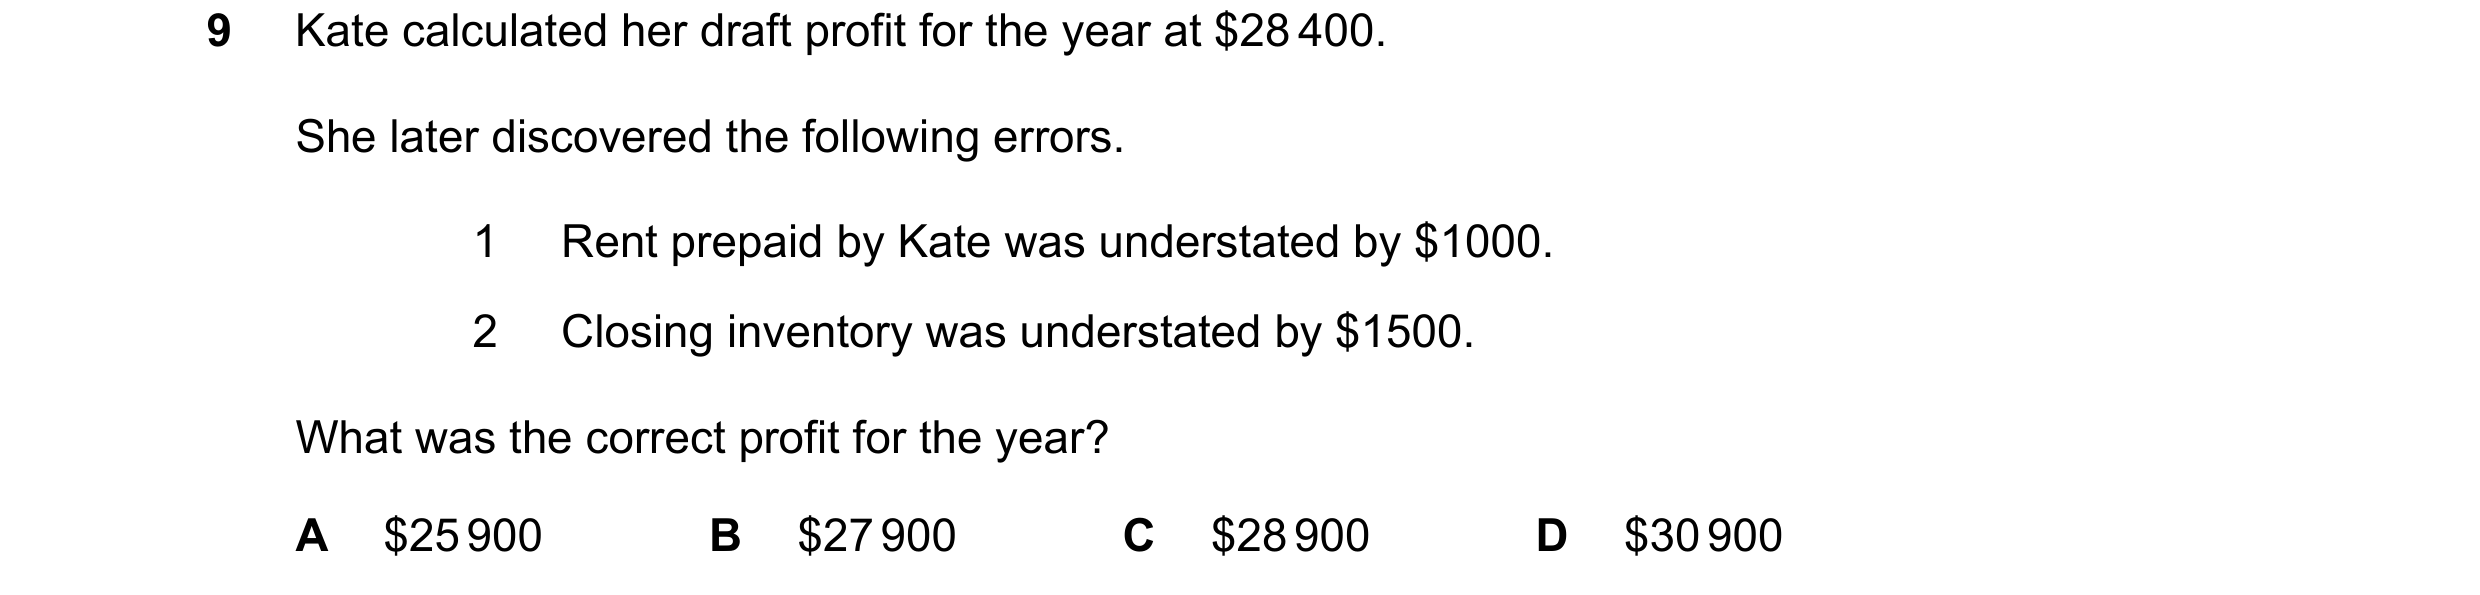
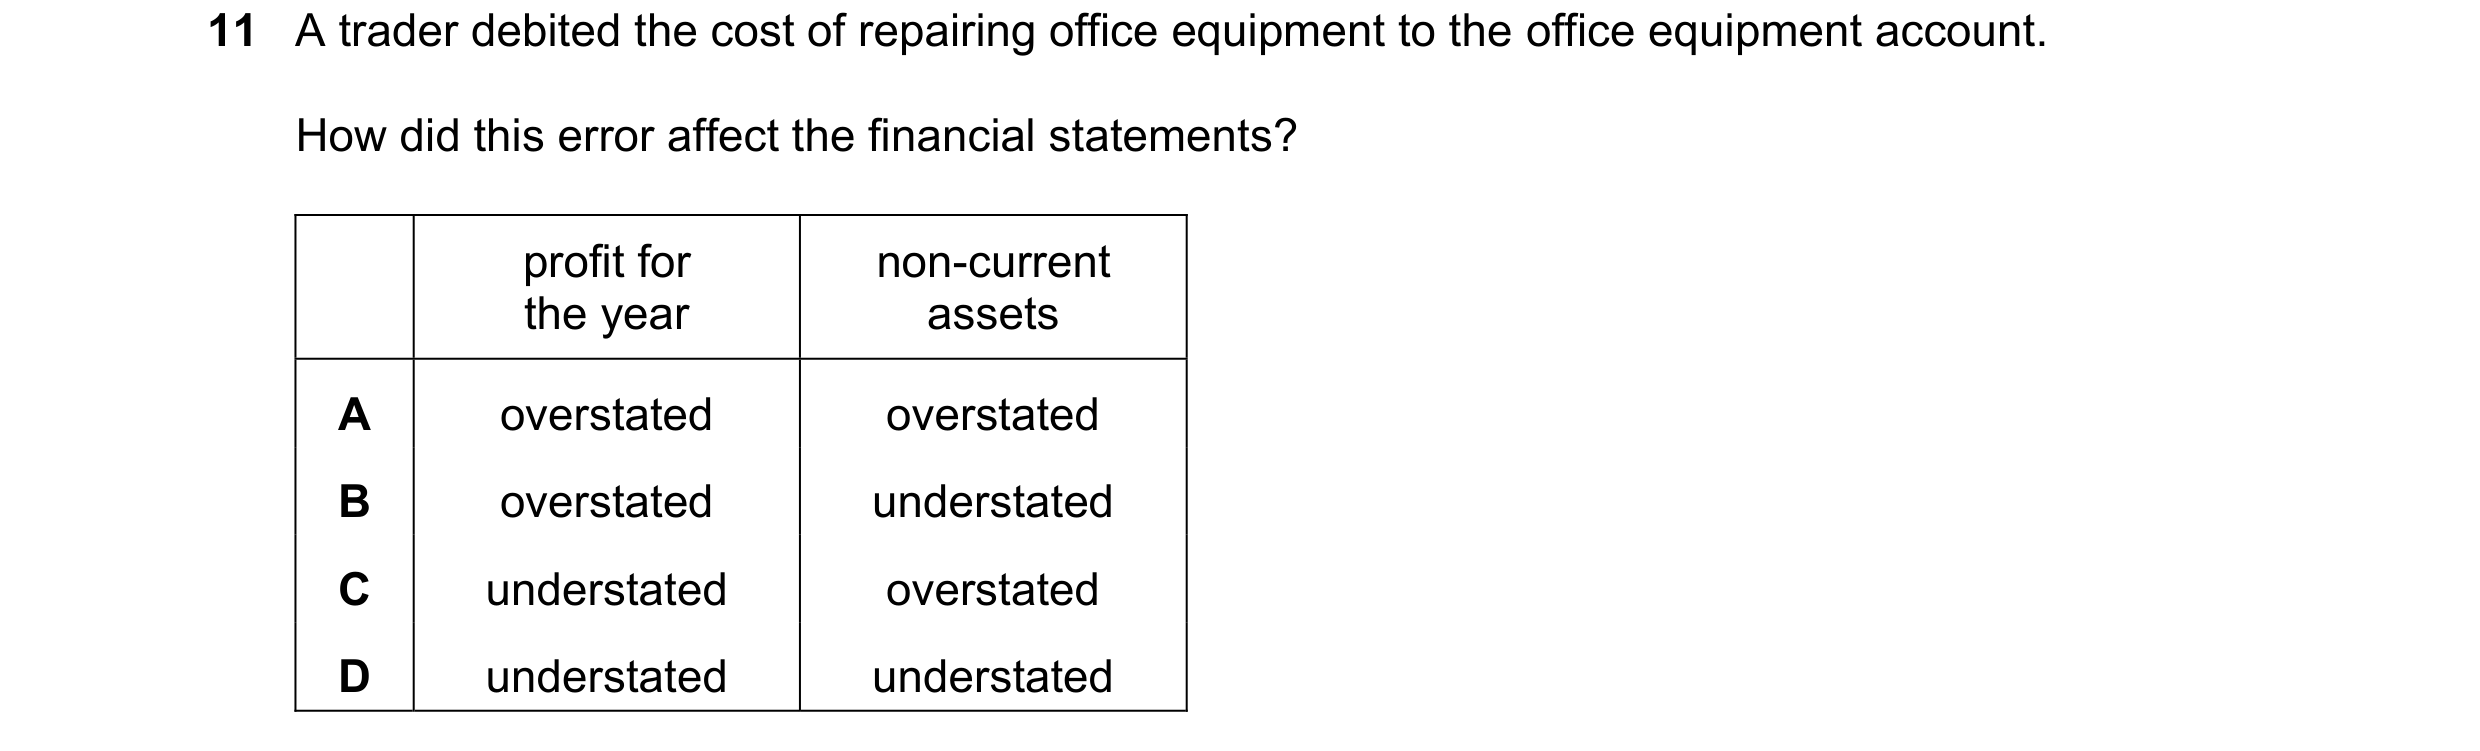 5 / 41
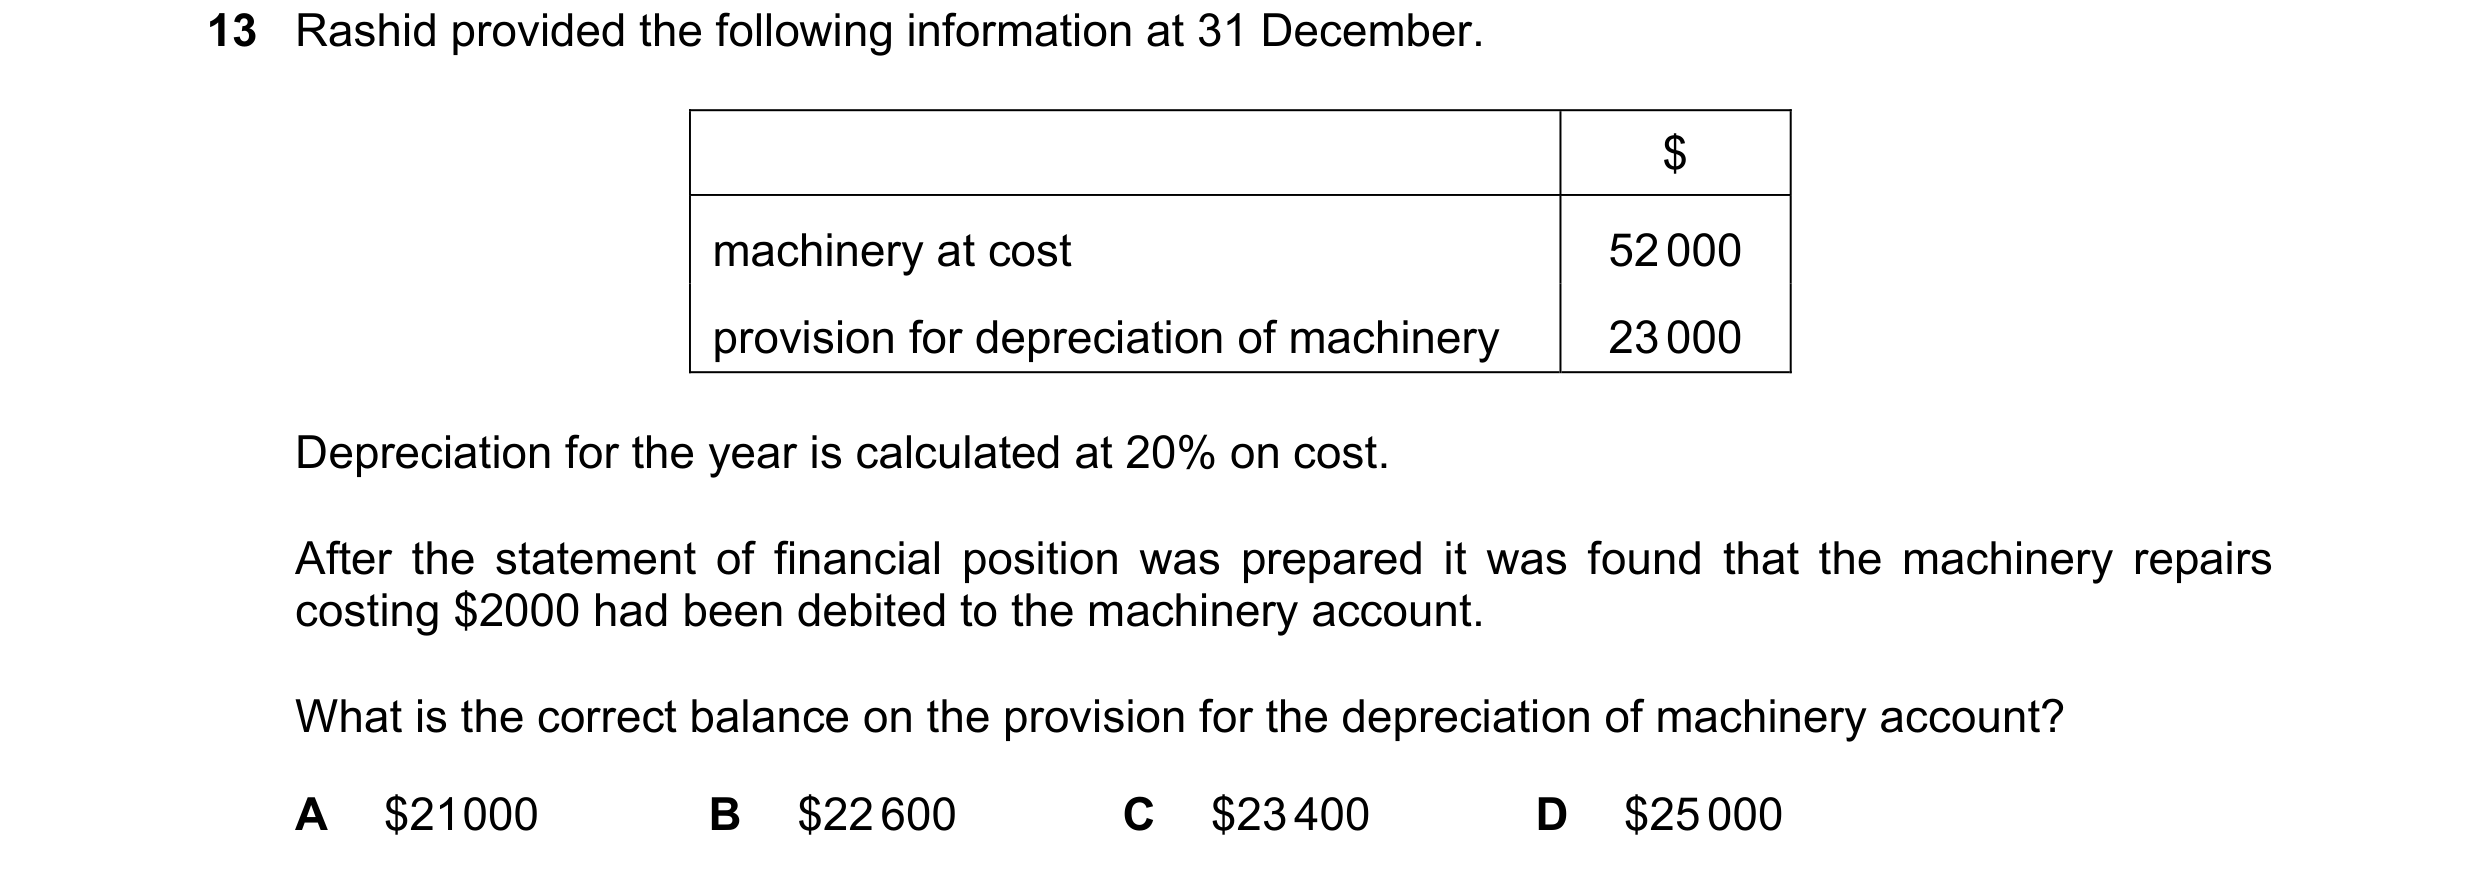
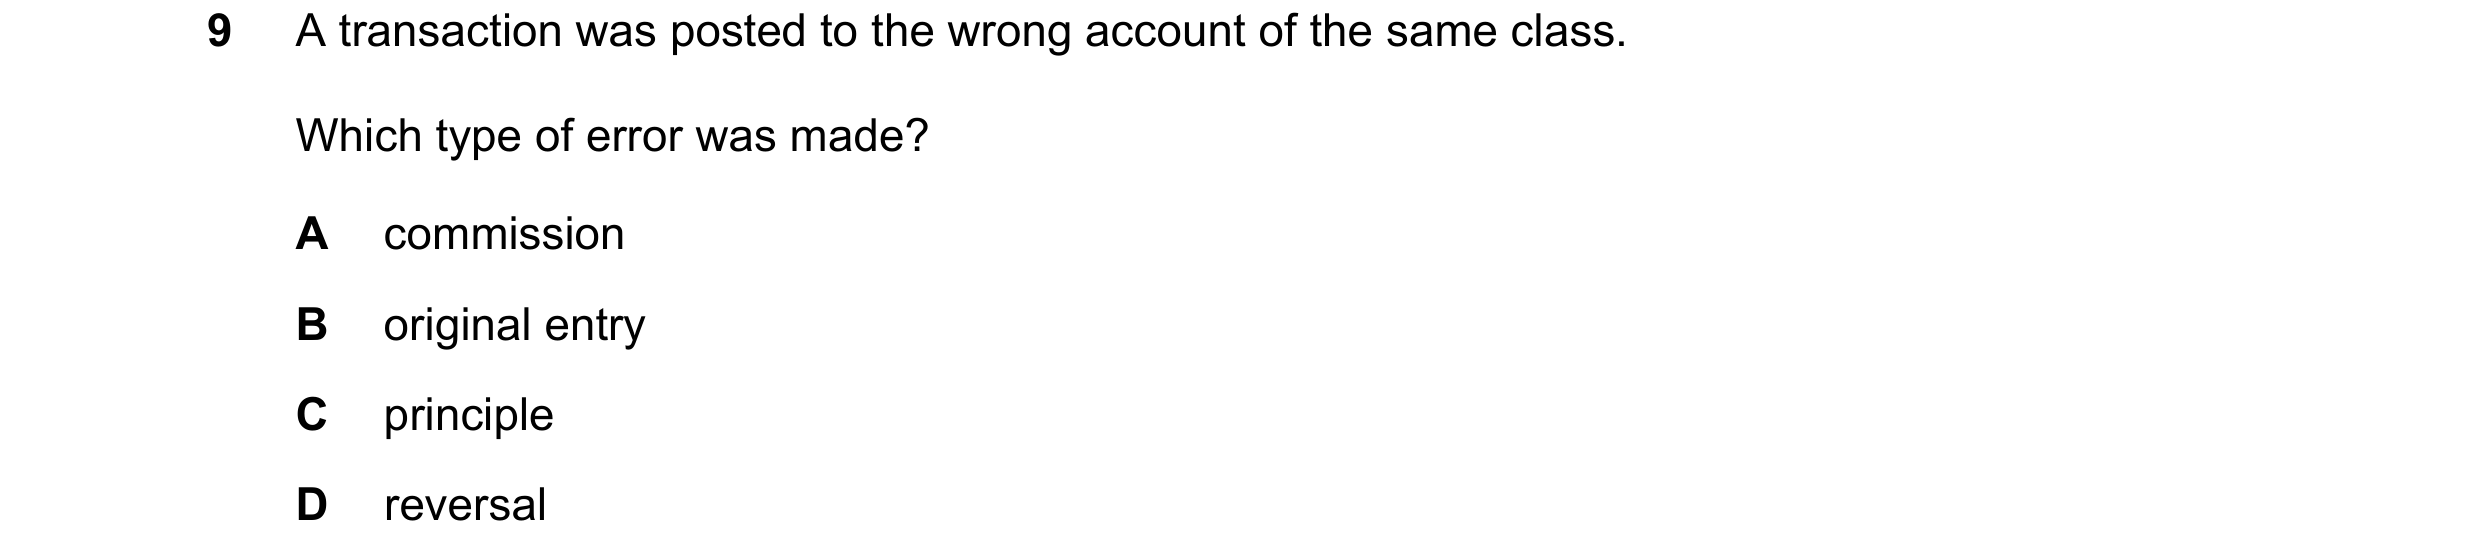
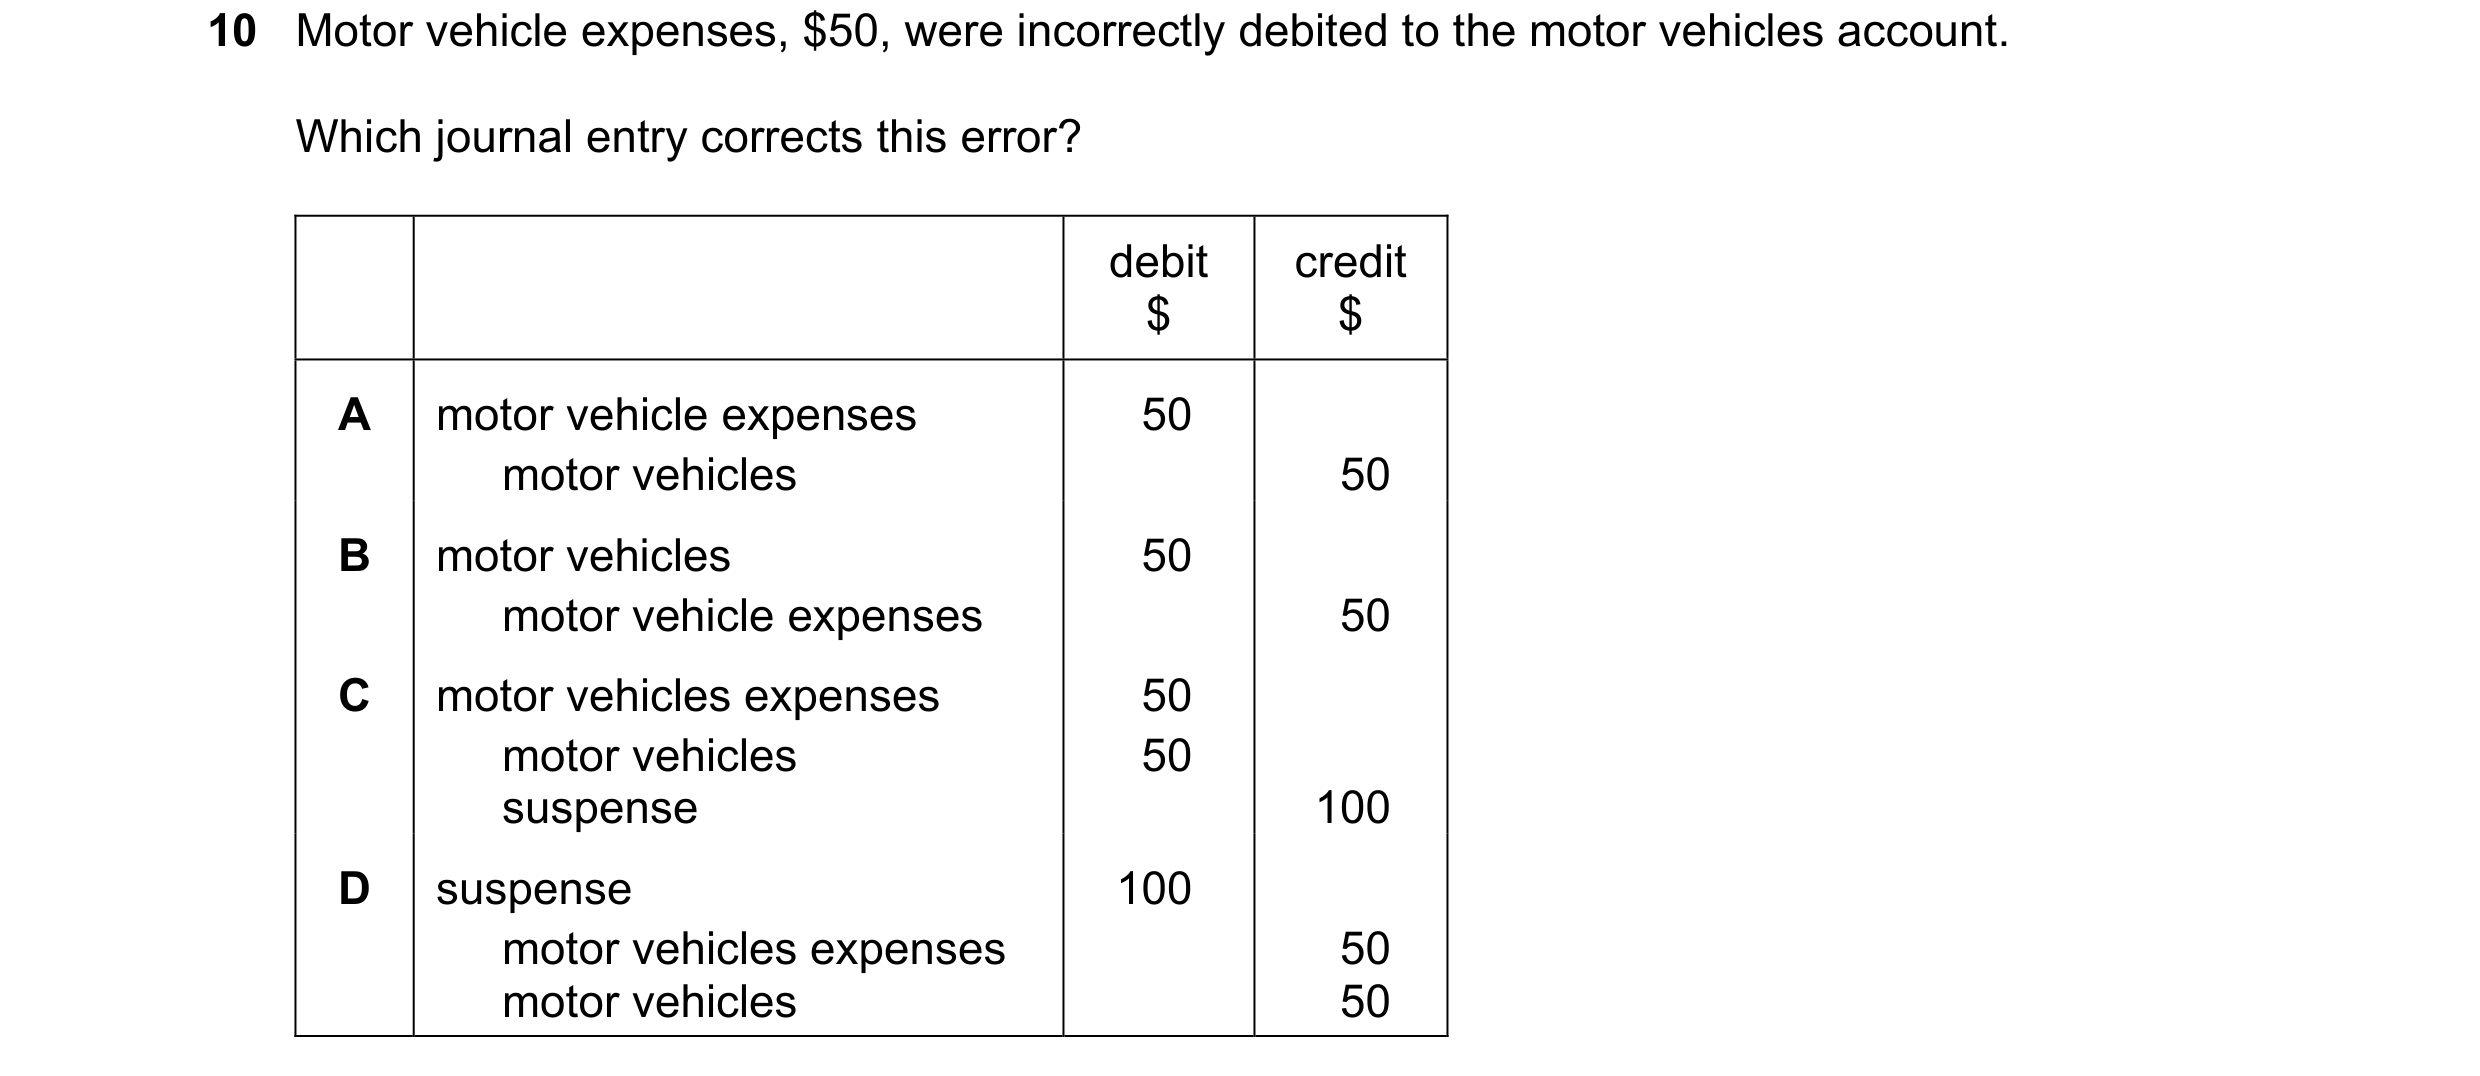
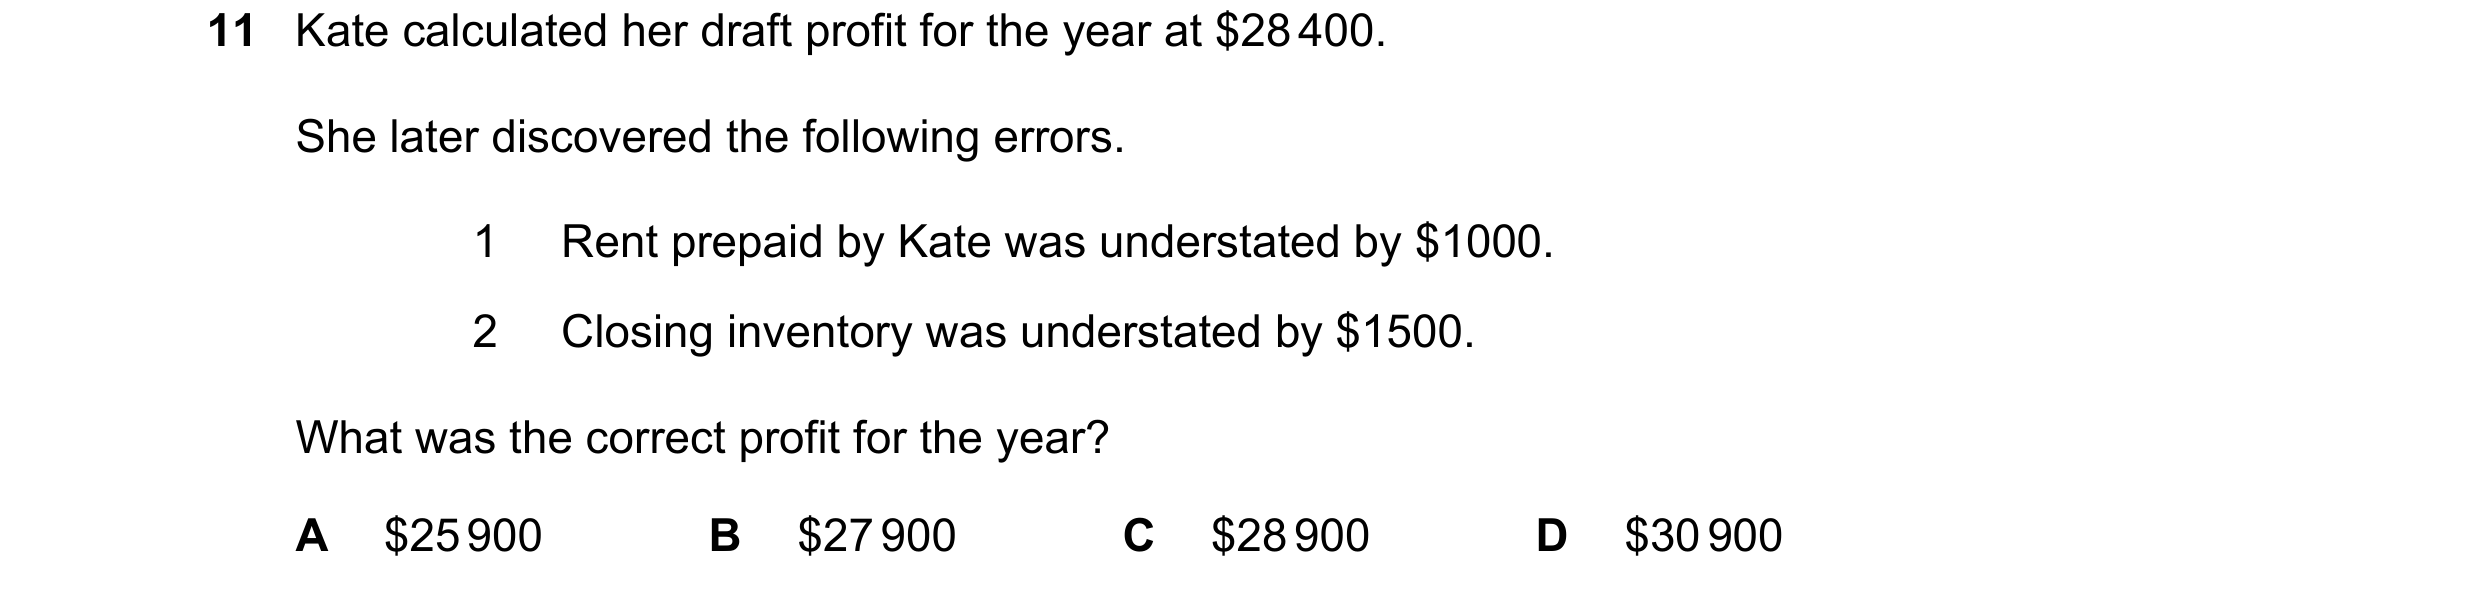 6 / 41
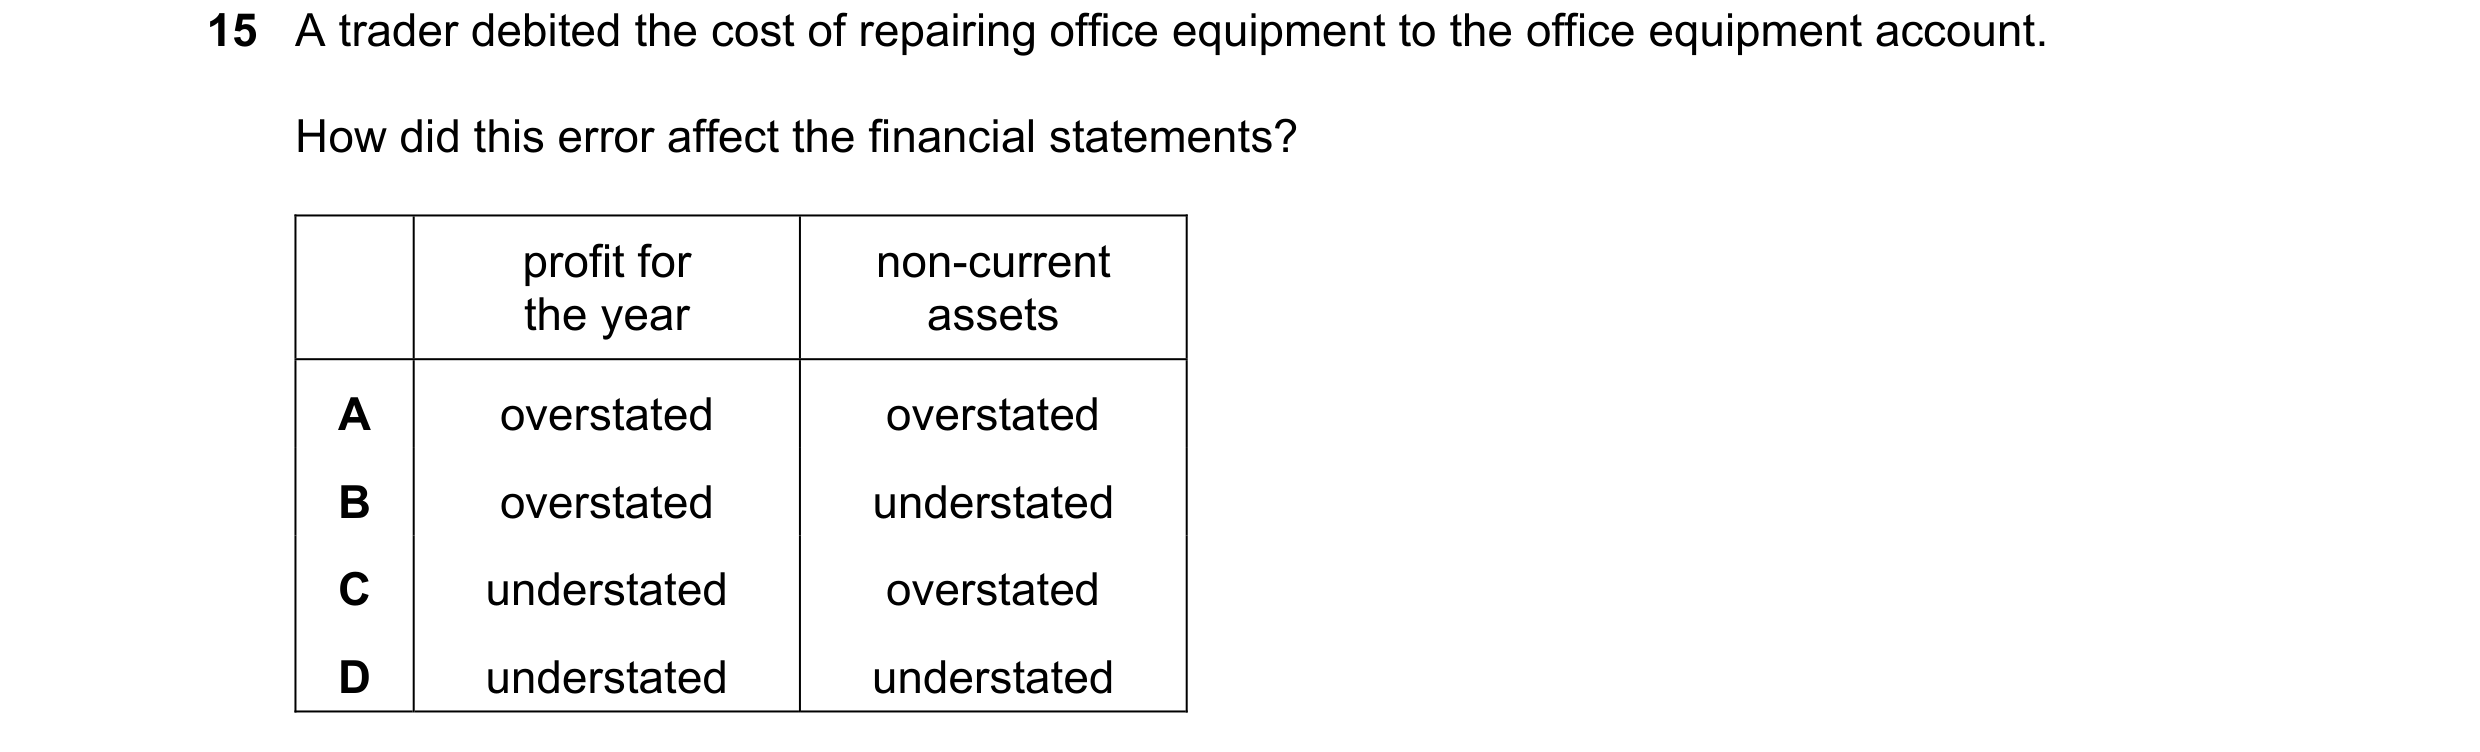
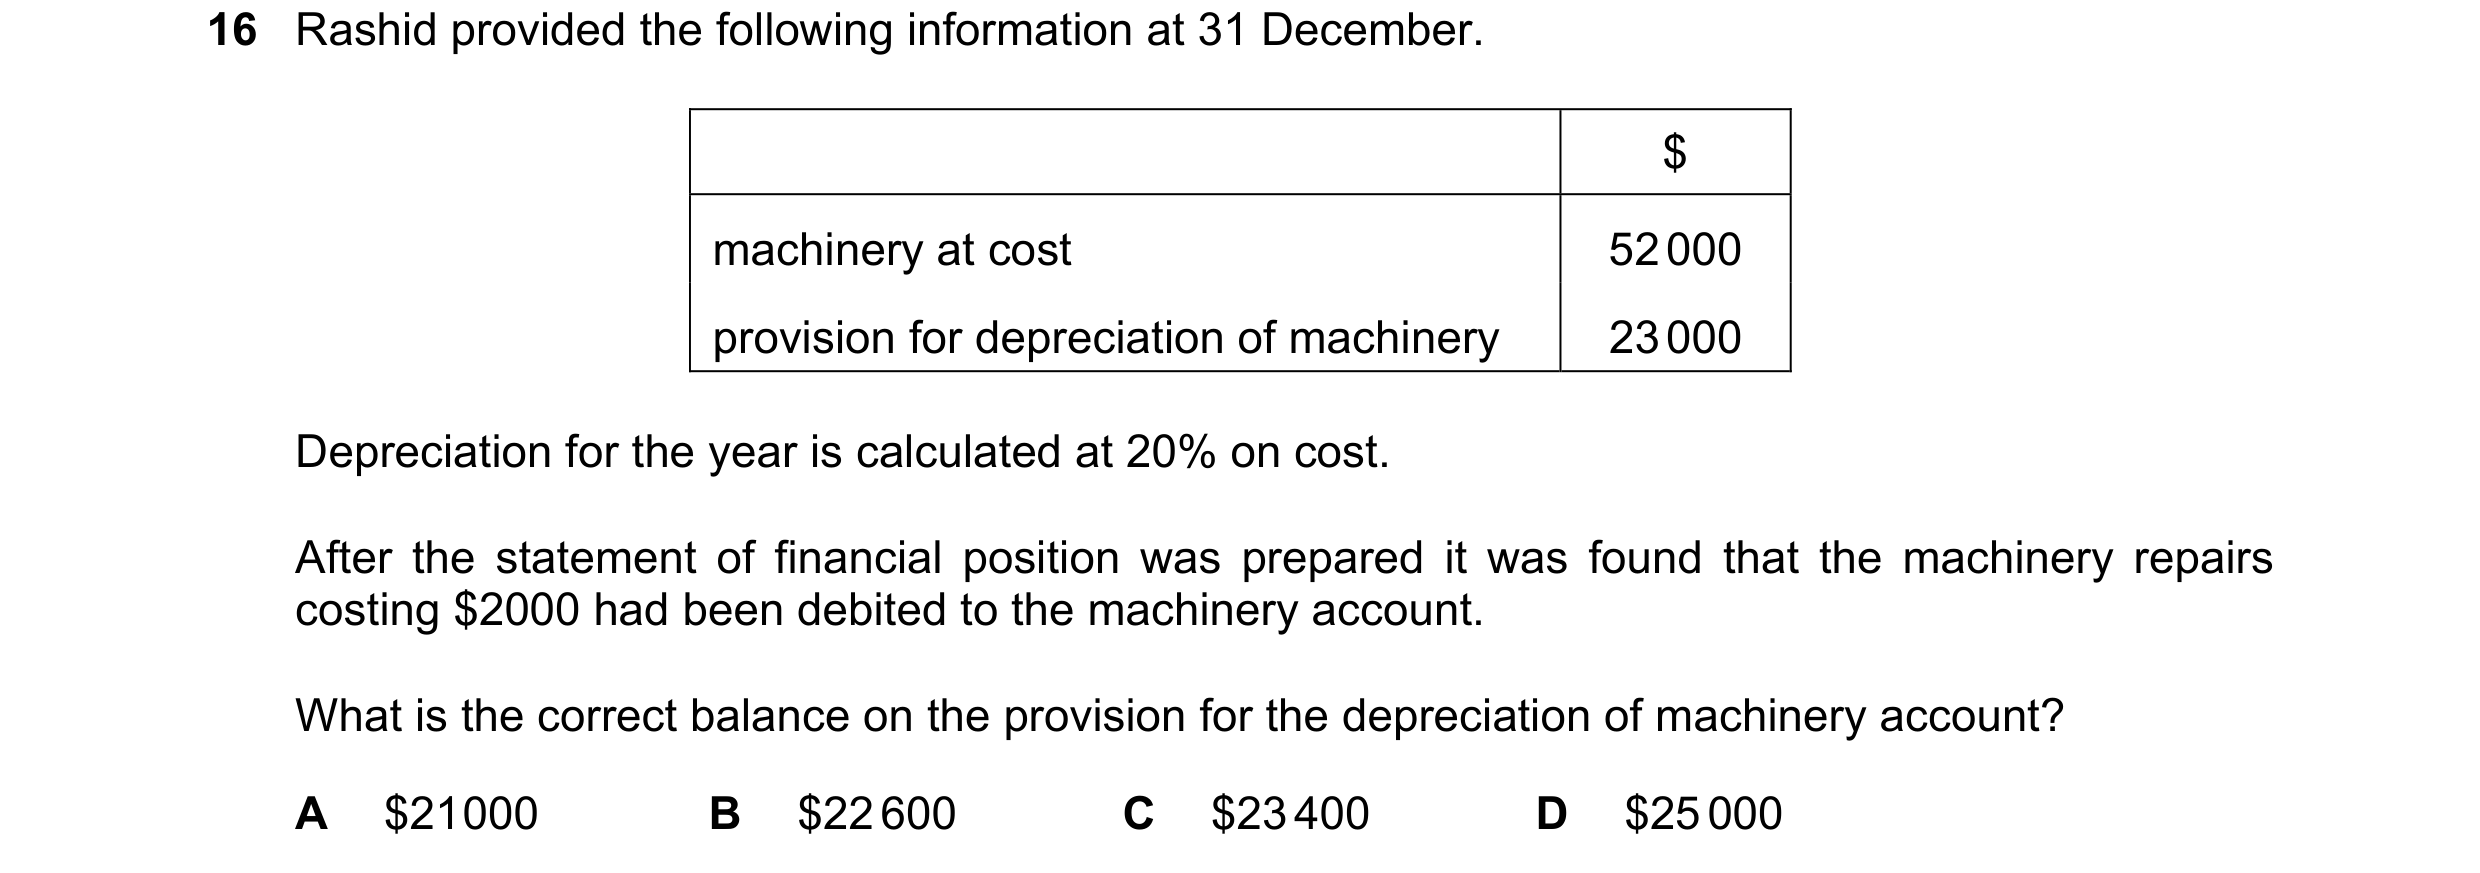
 7 / 41
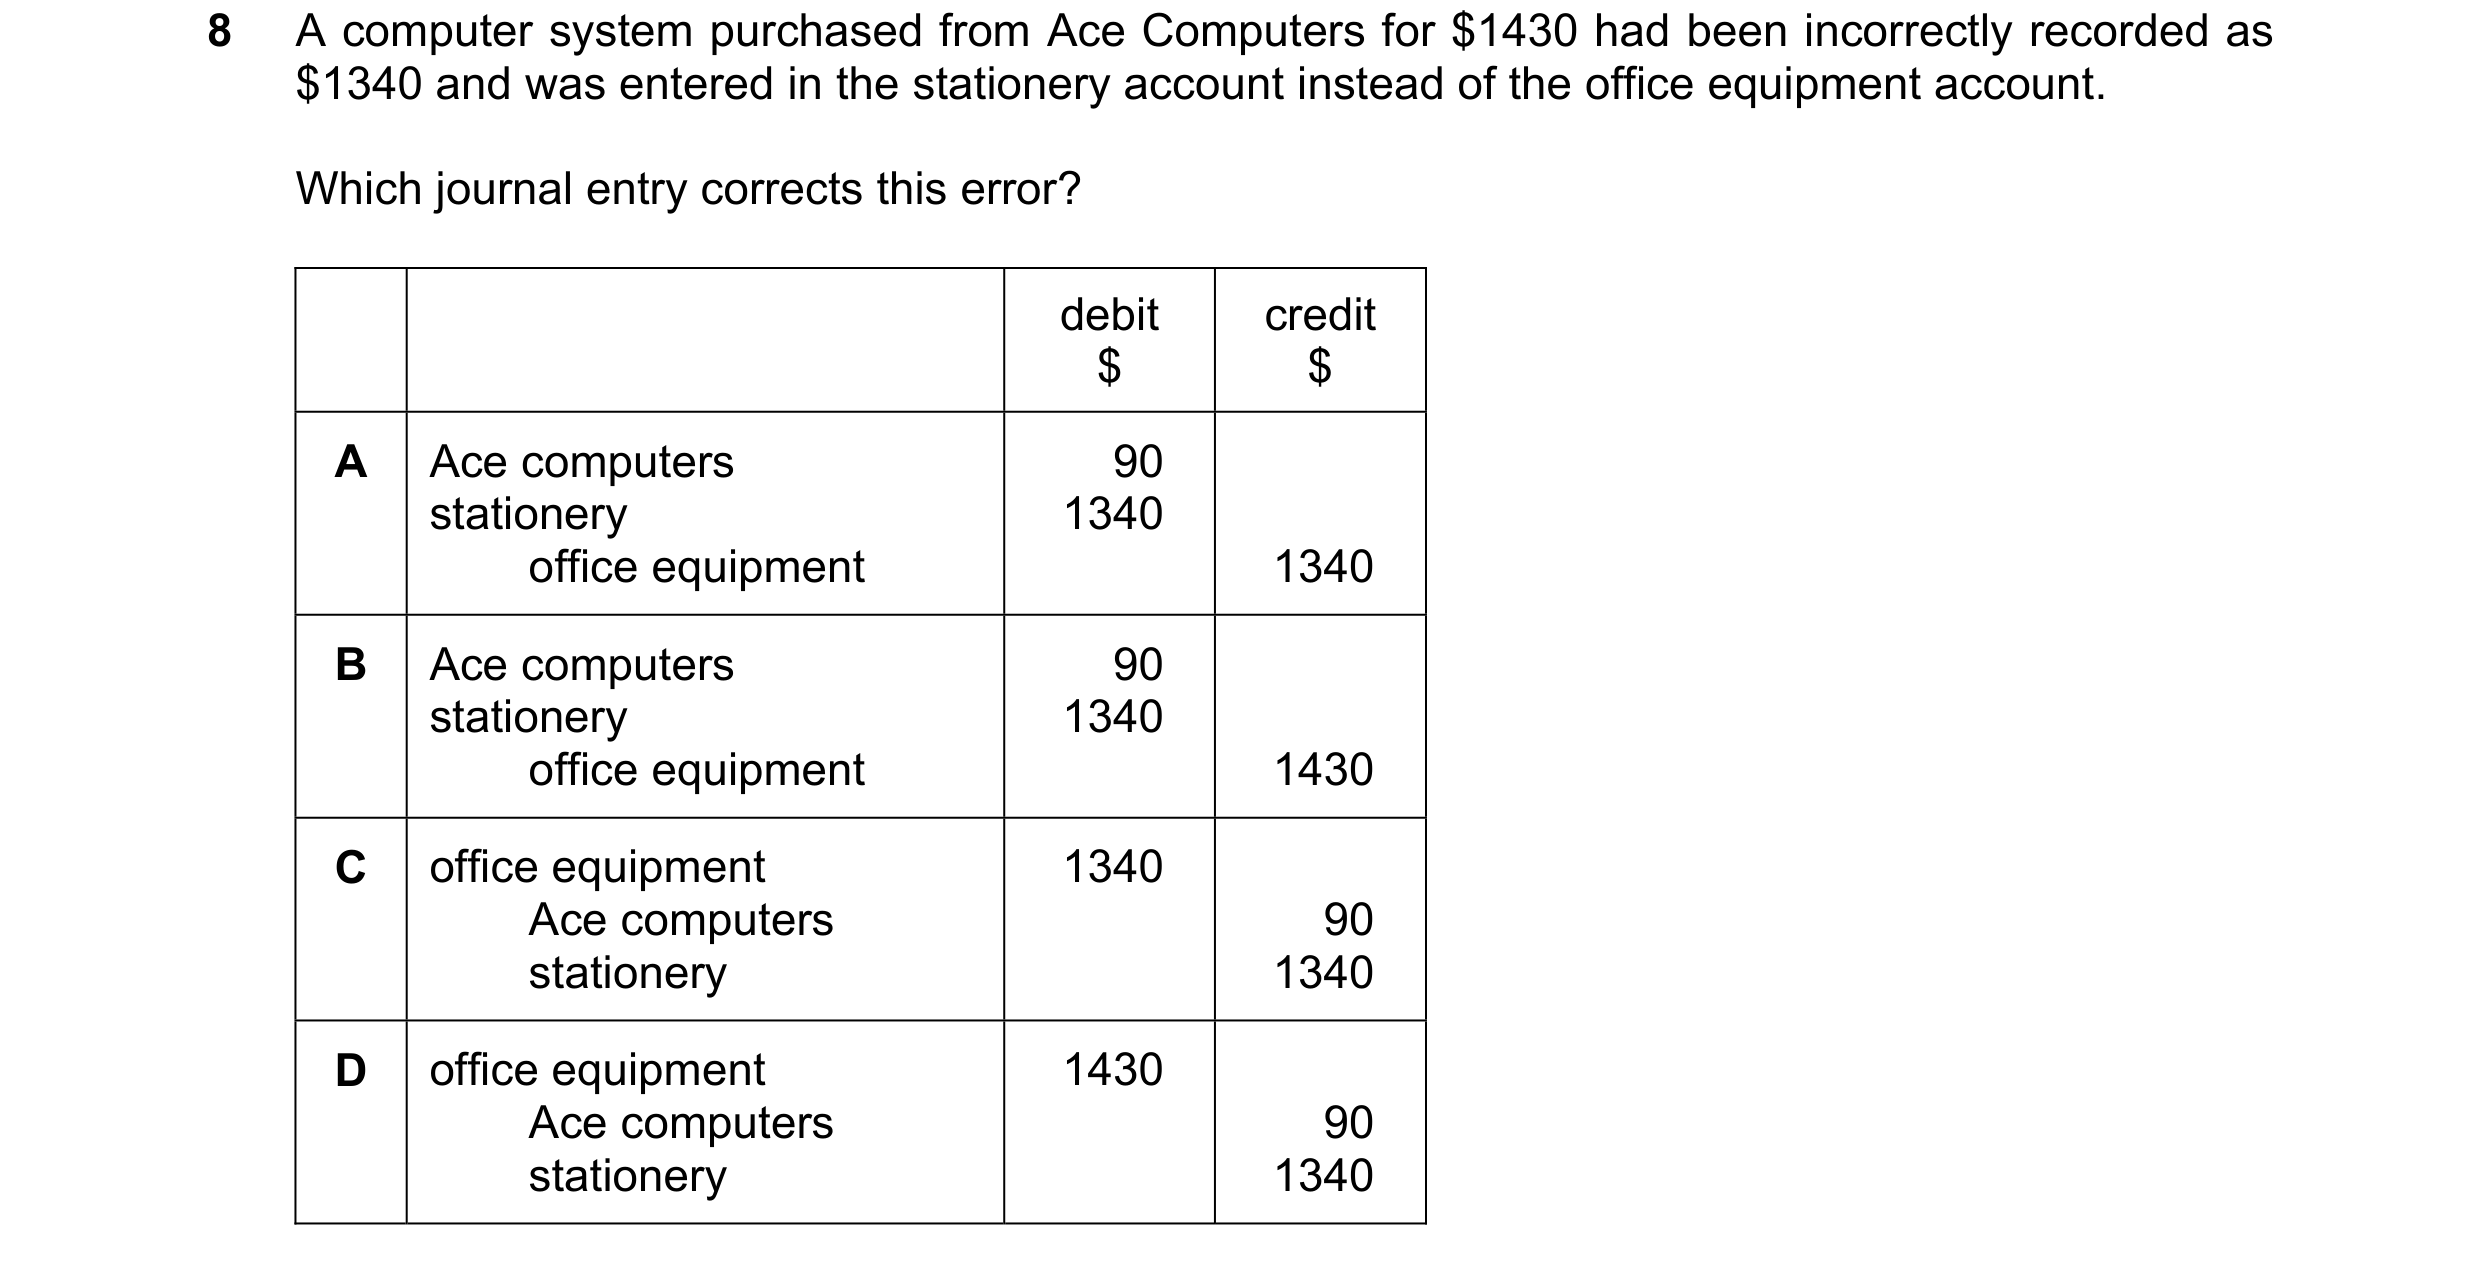
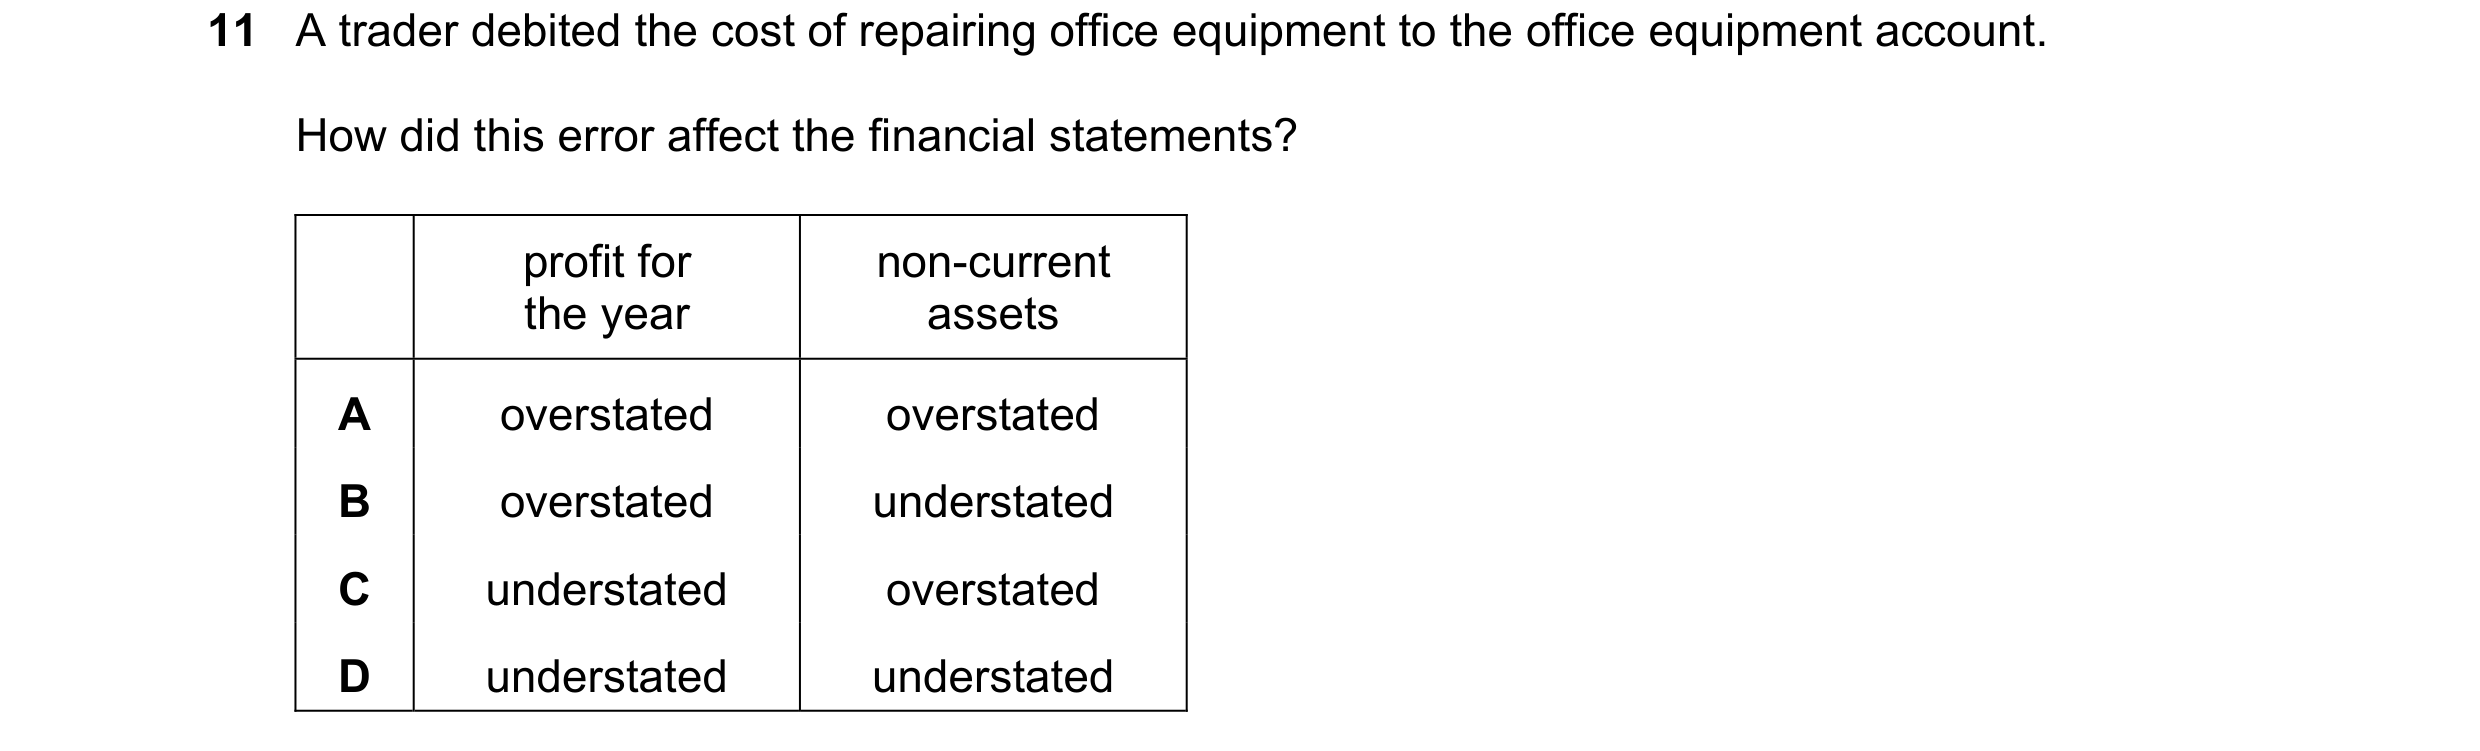 8 / 41
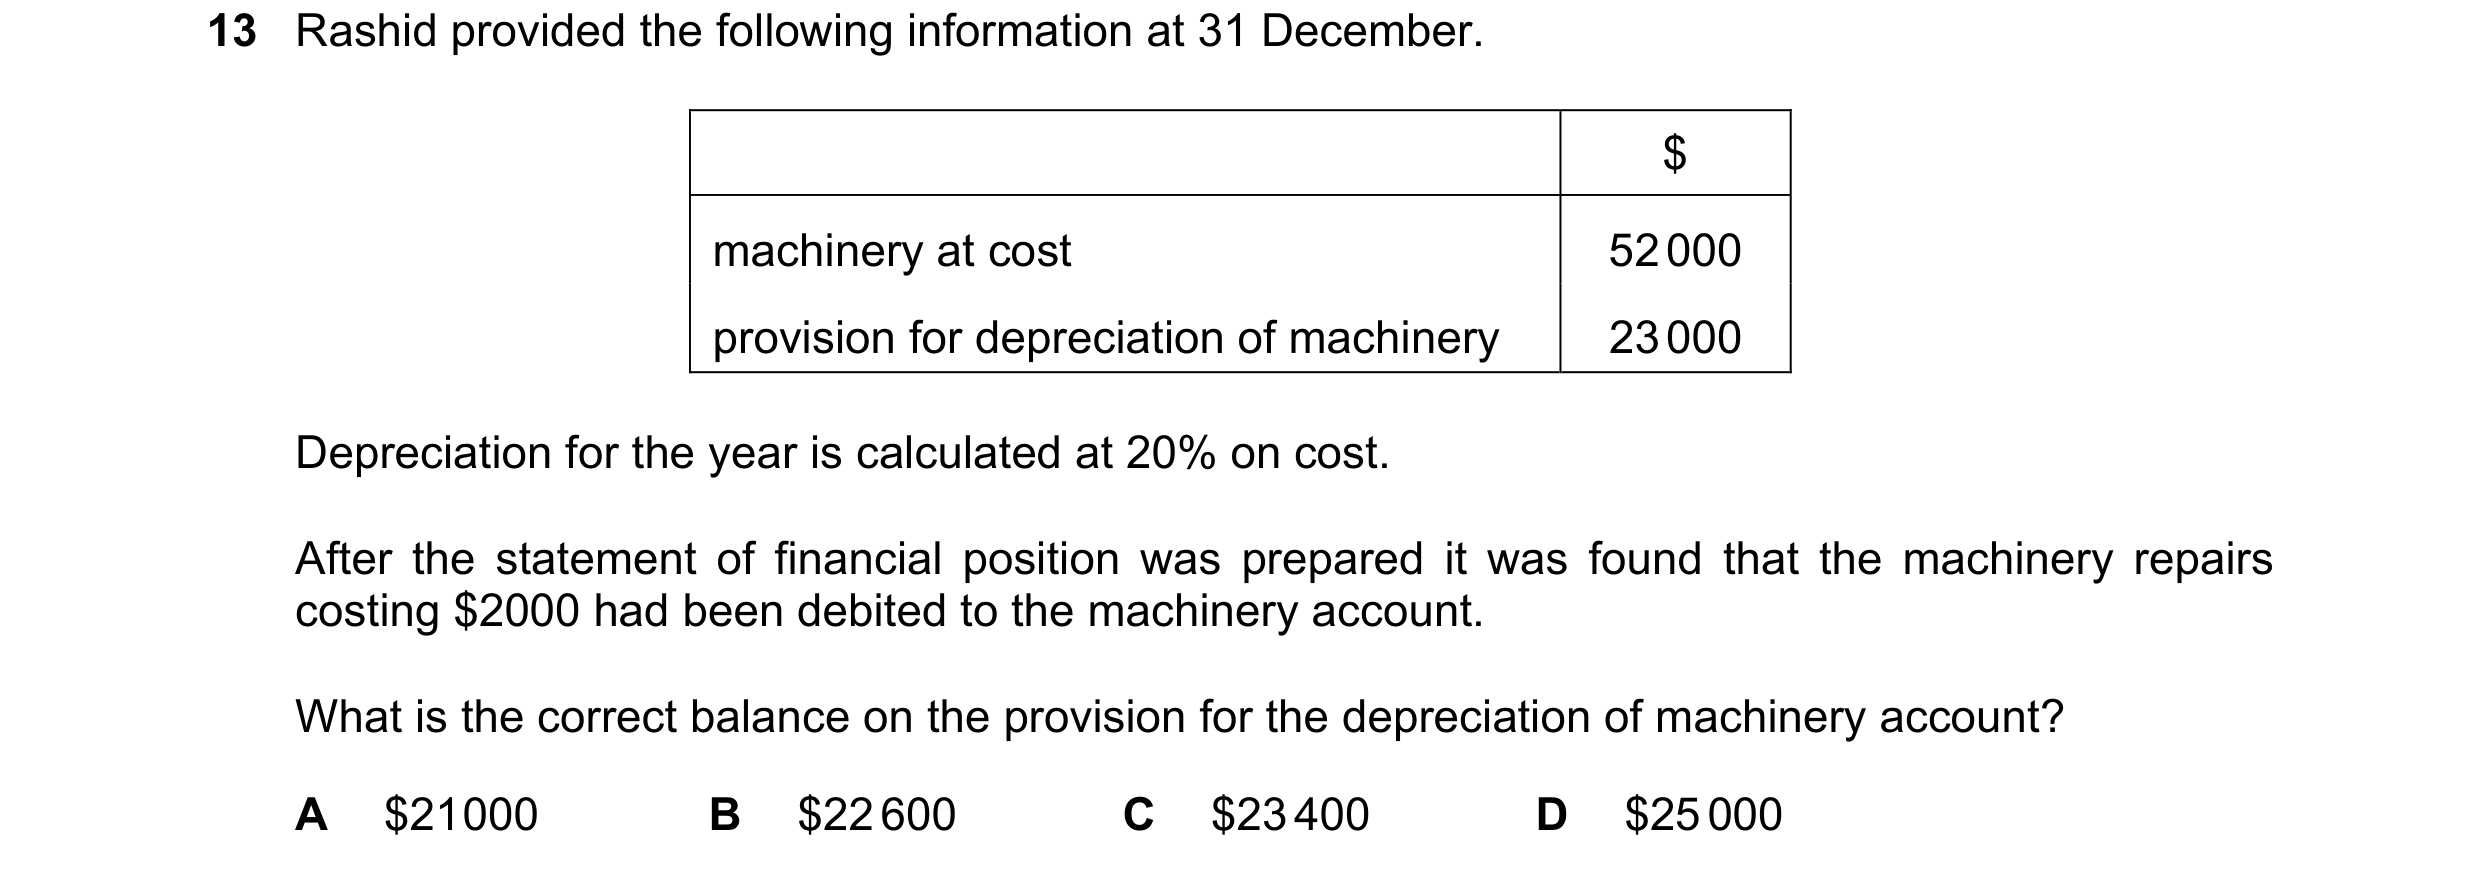
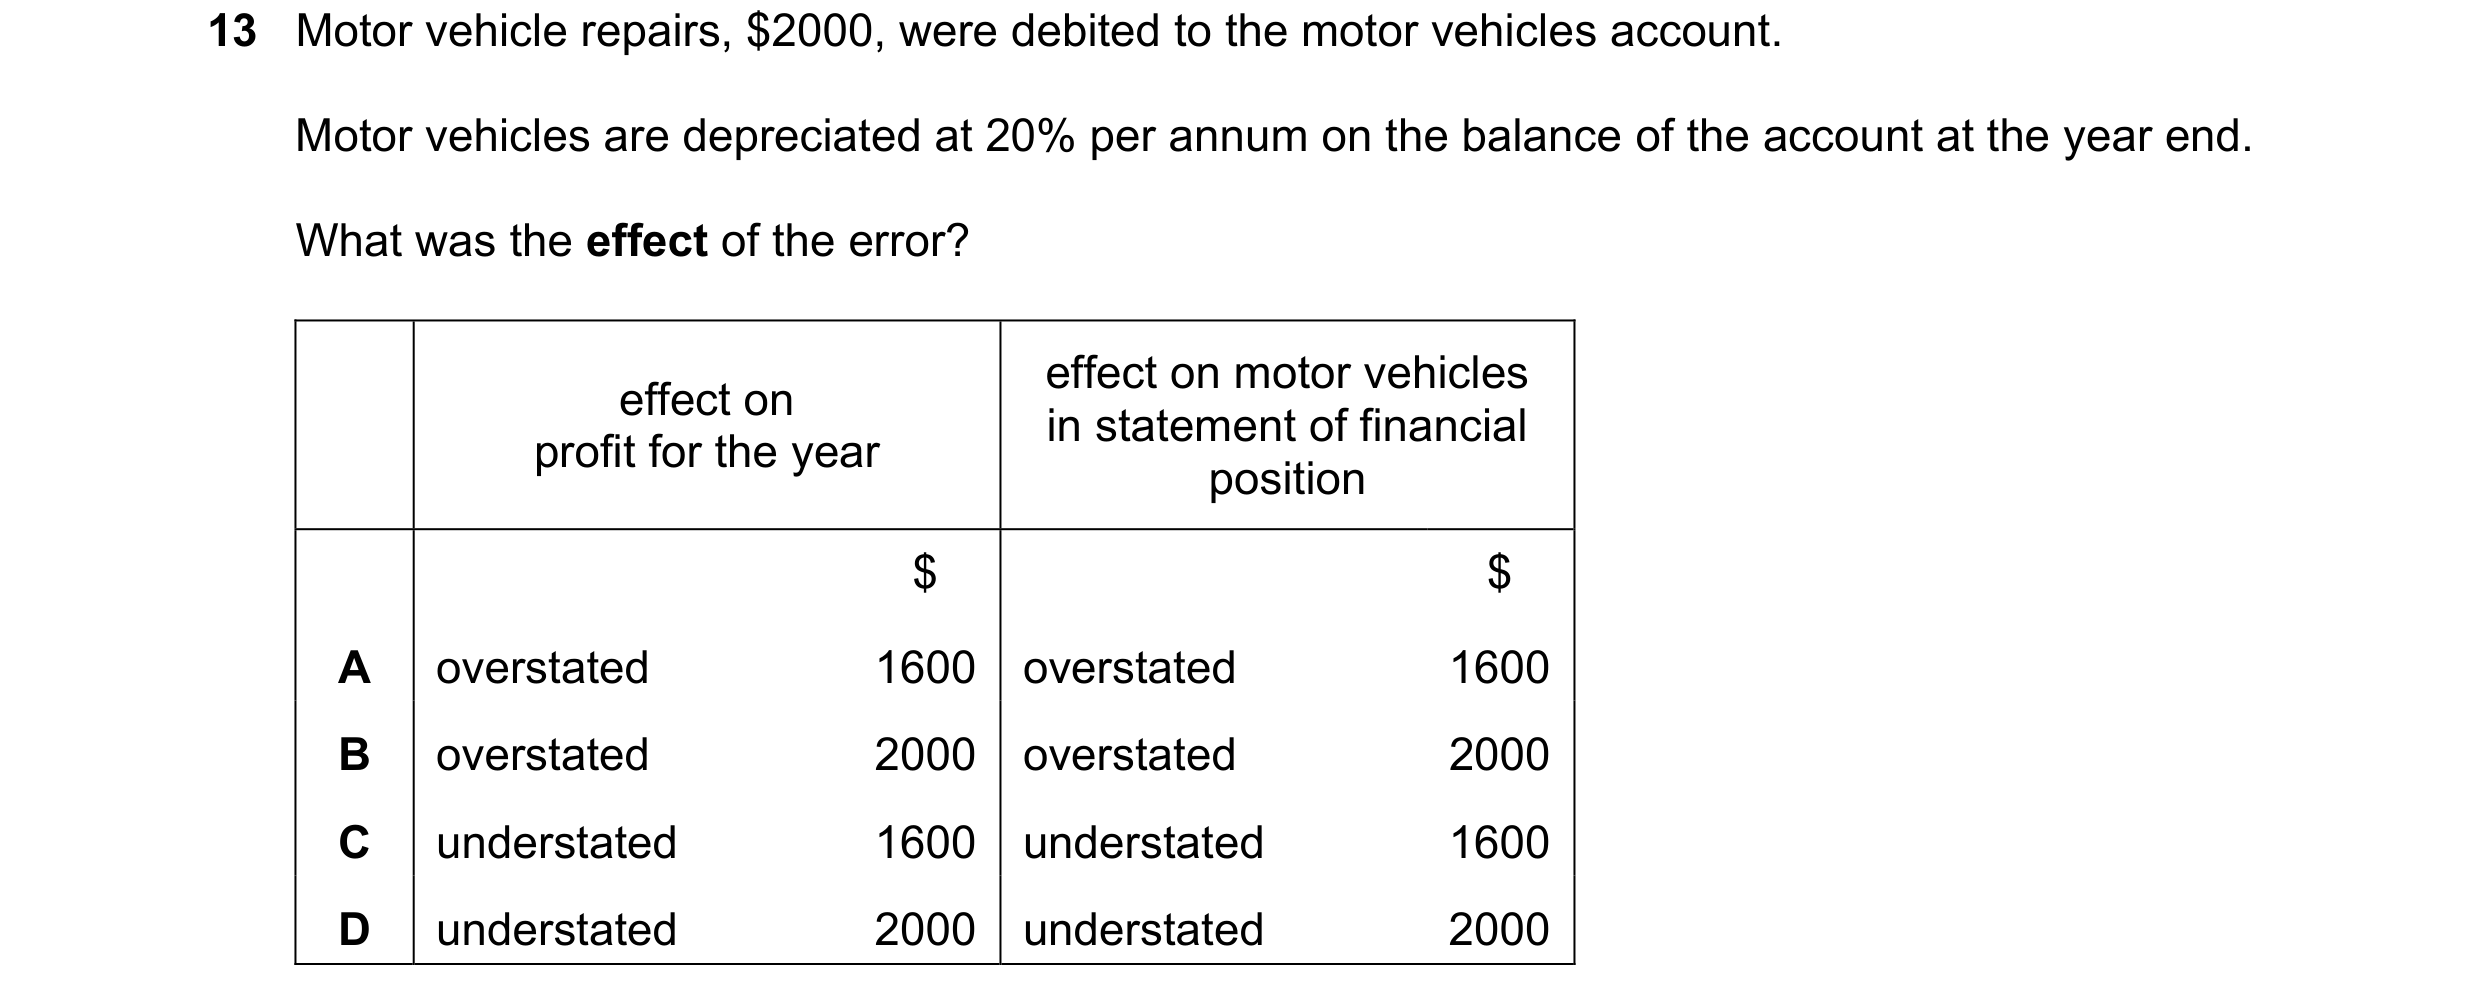 9 / 41
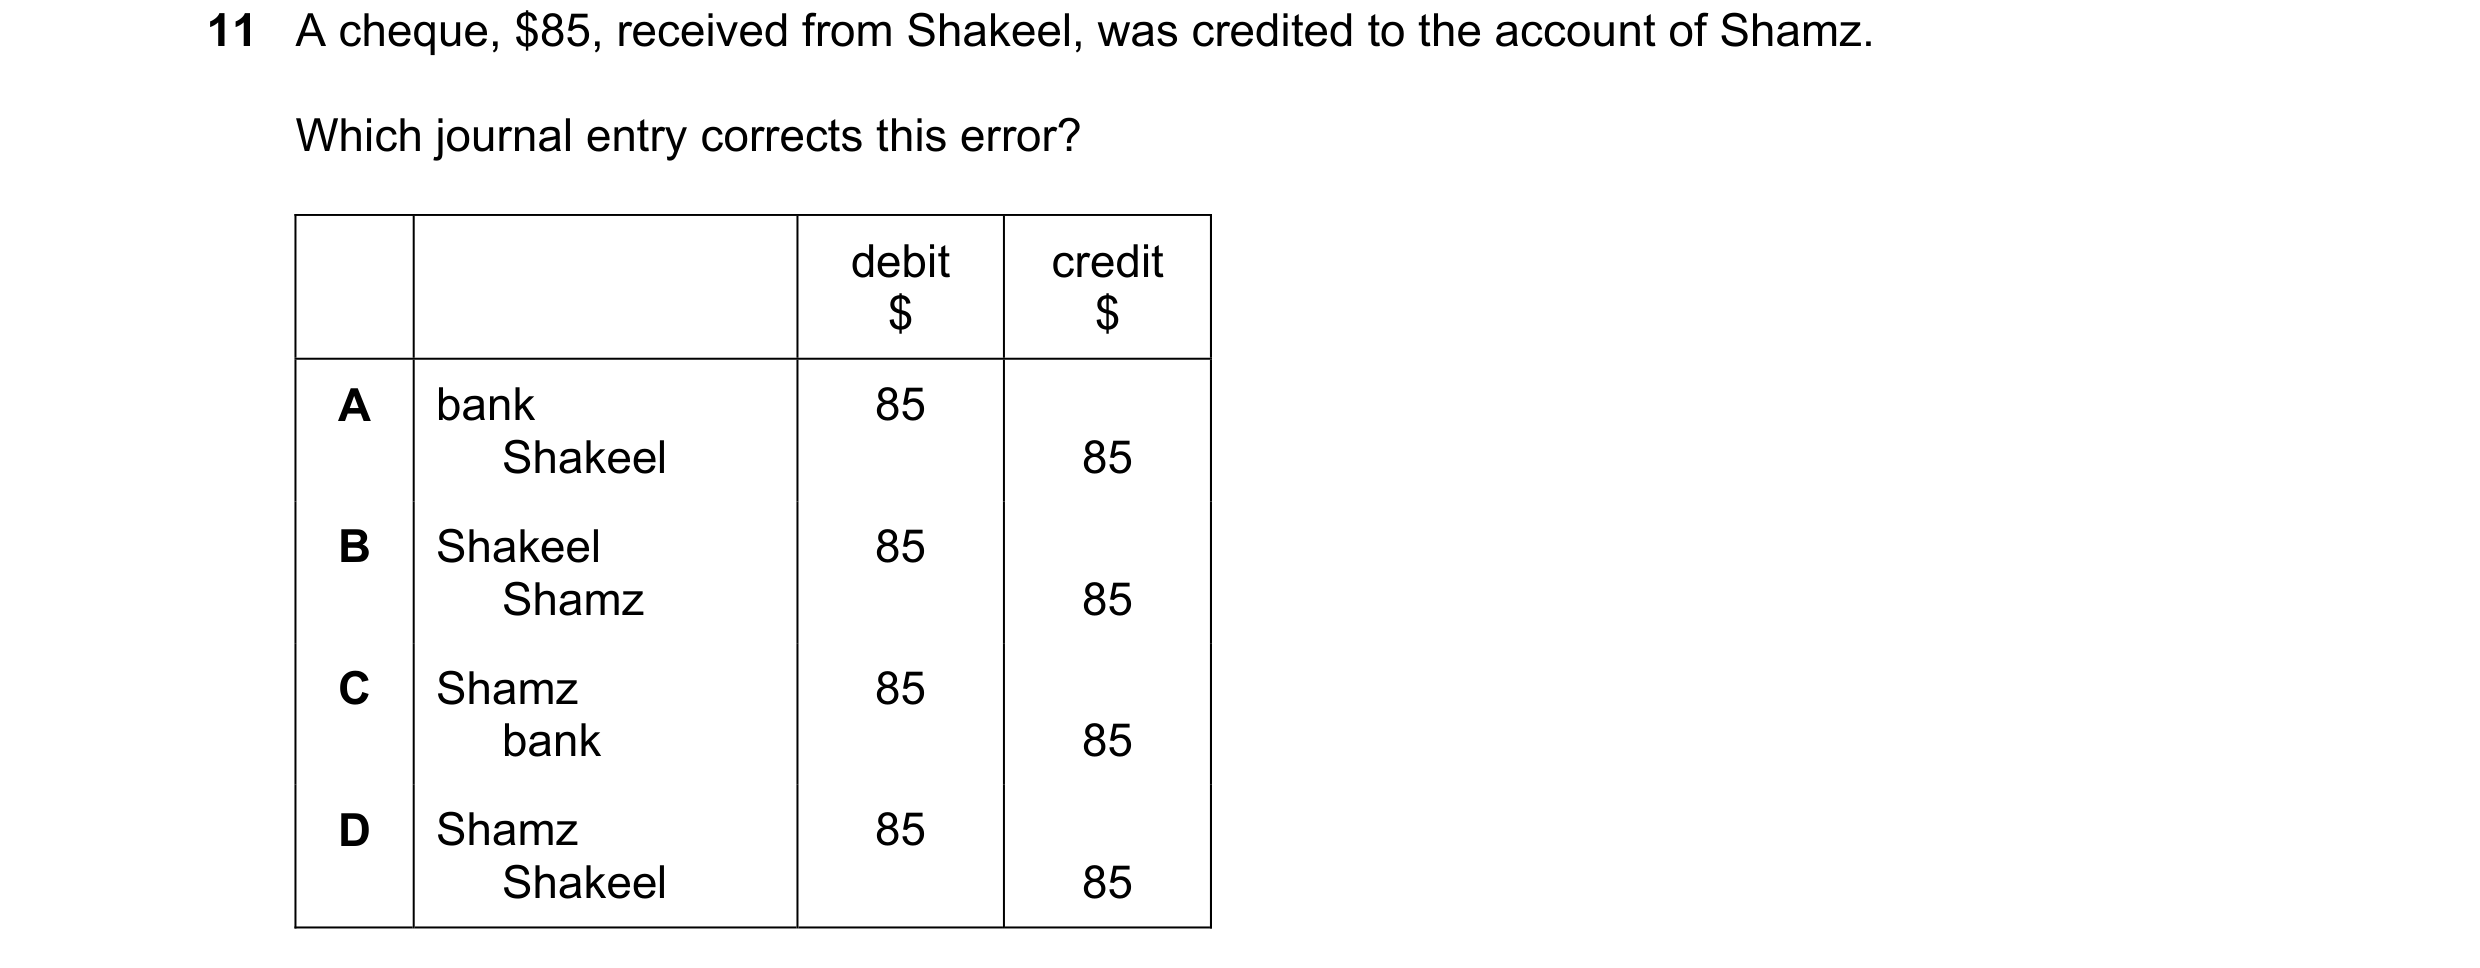
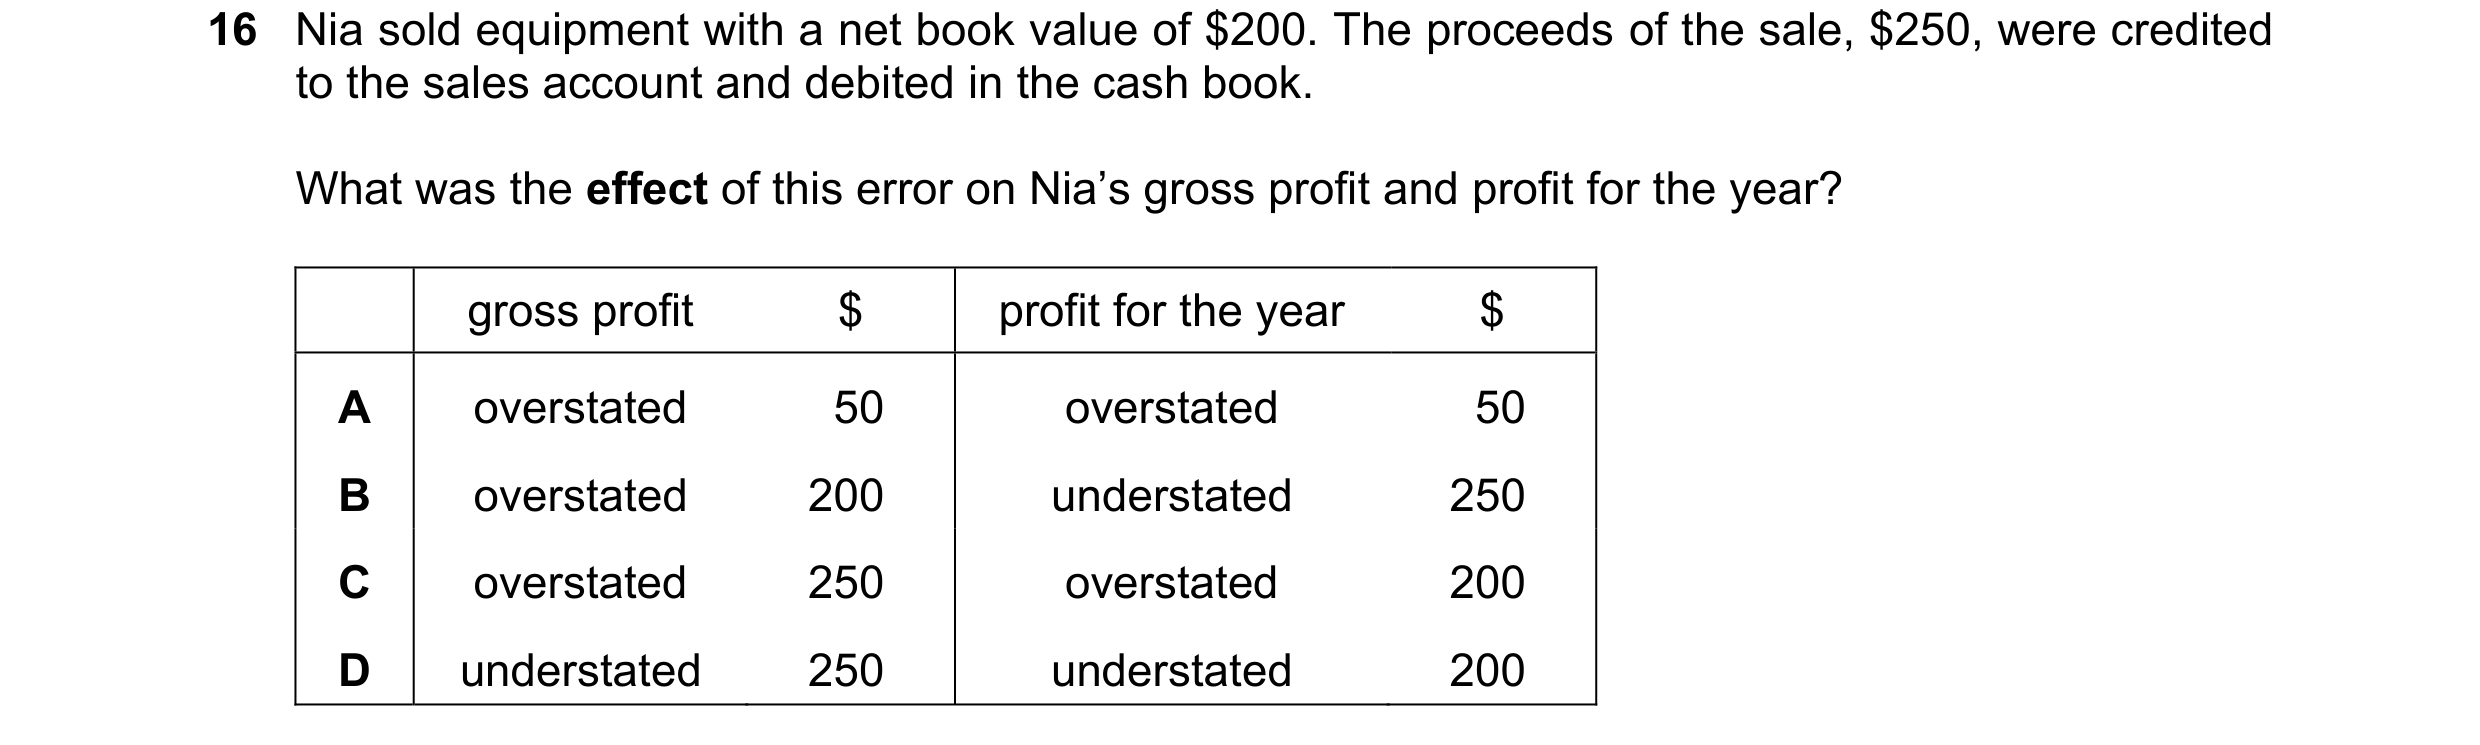 10 / 41
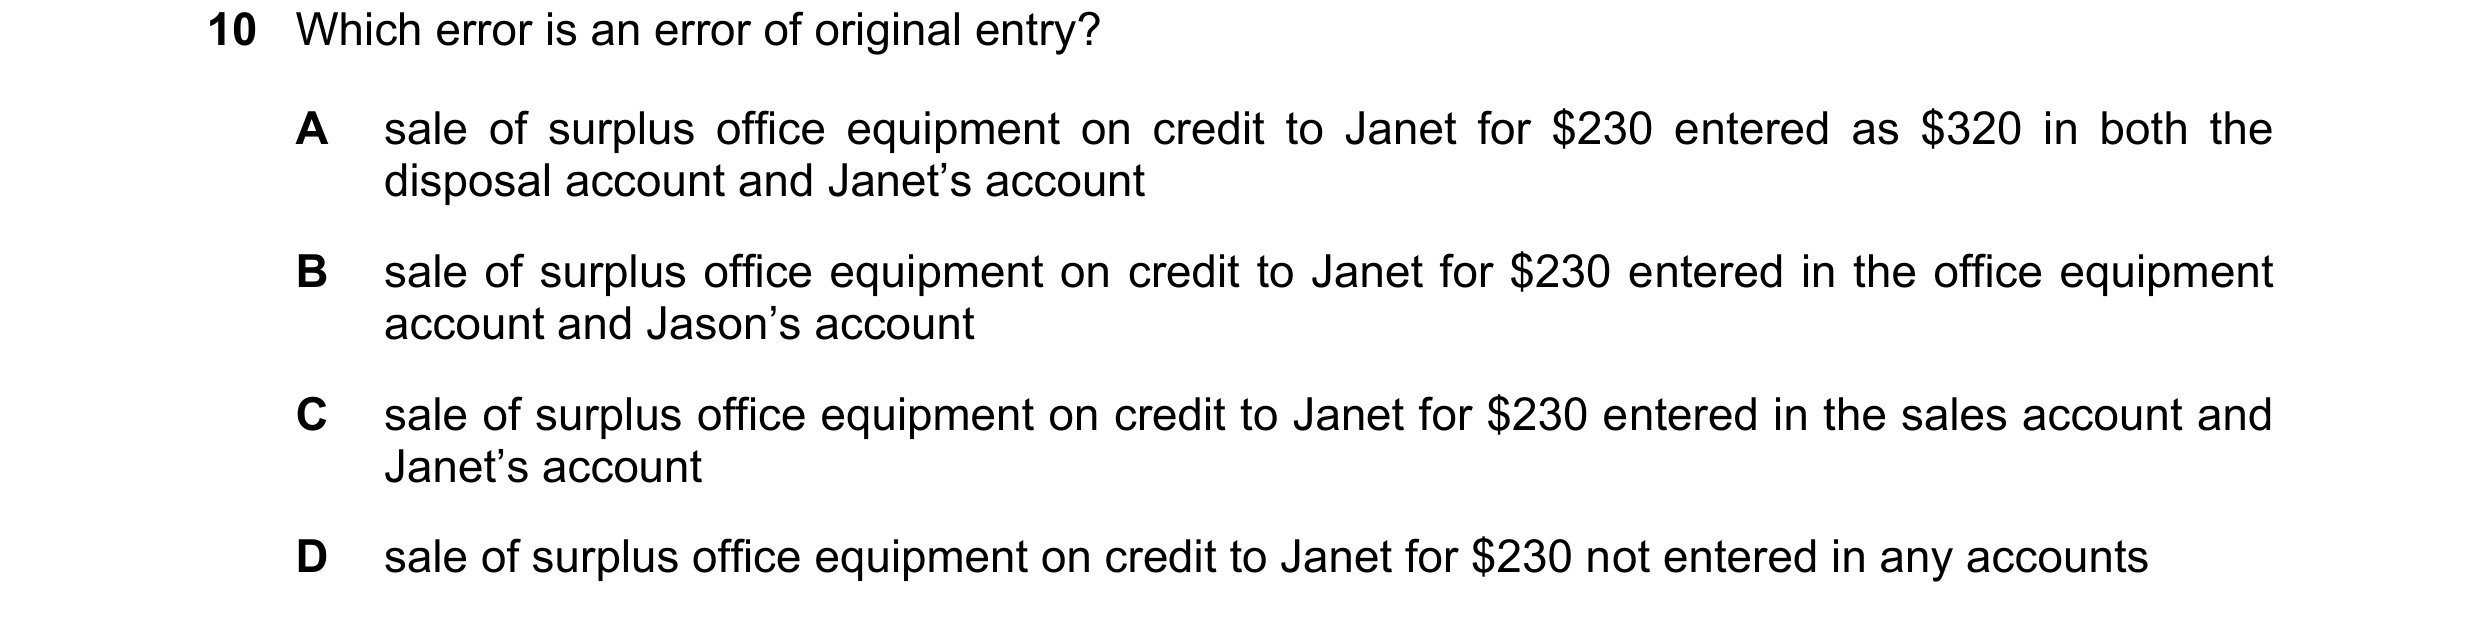
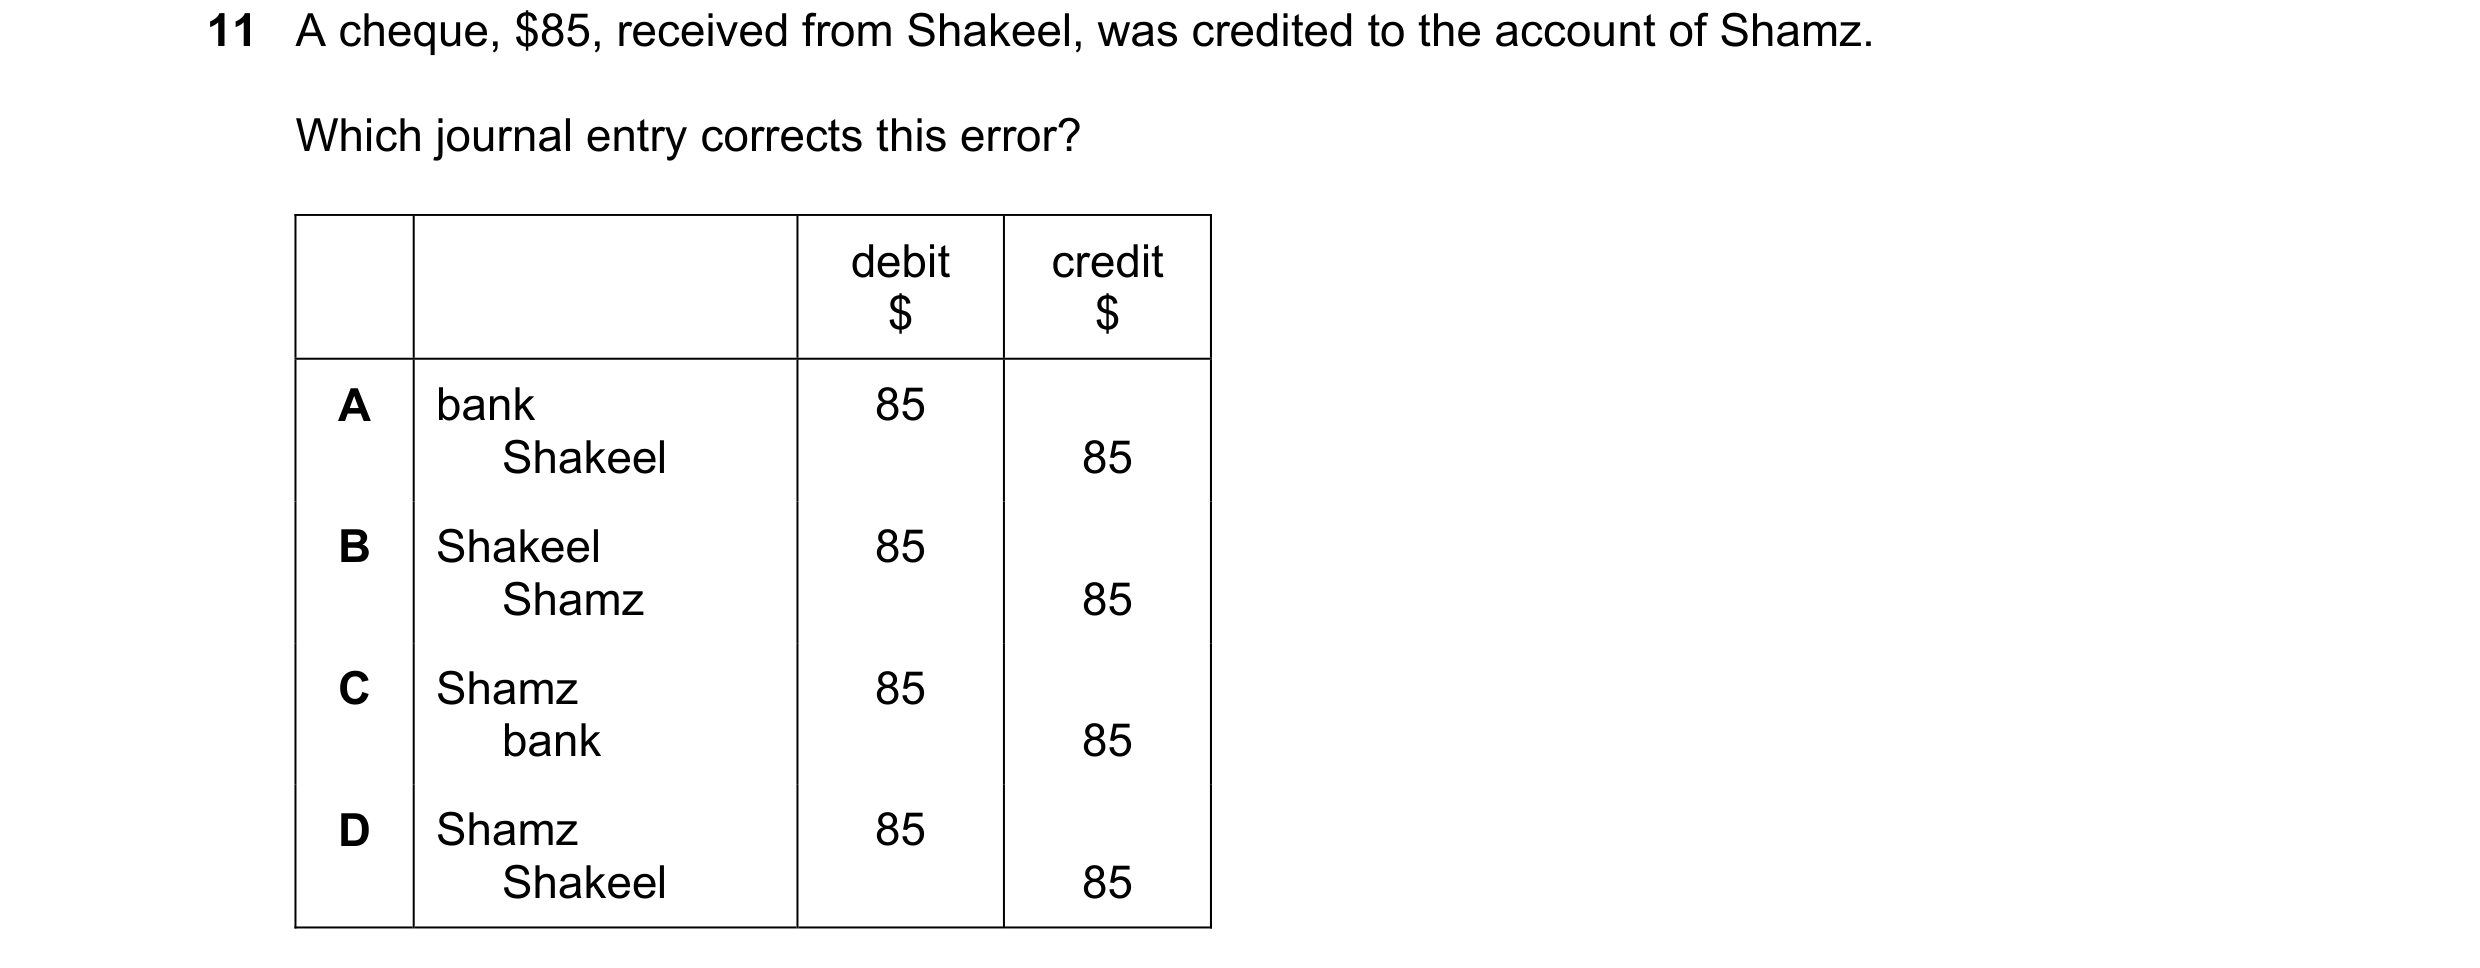
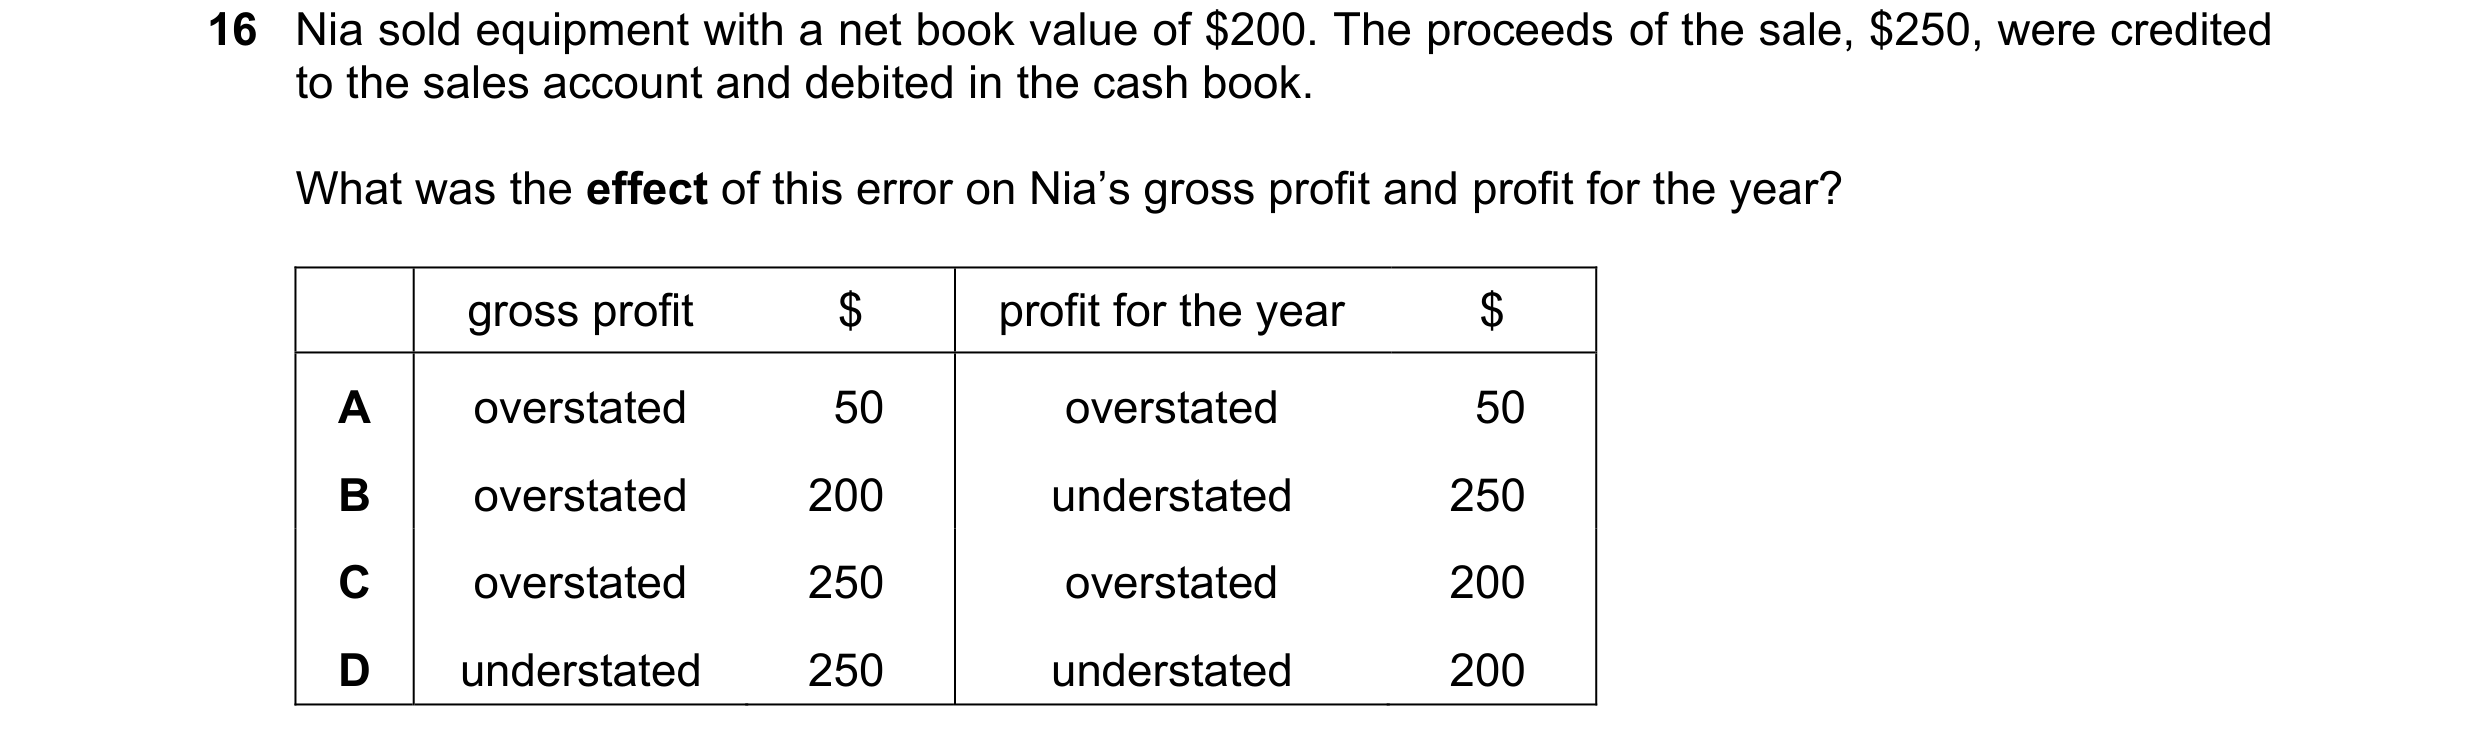
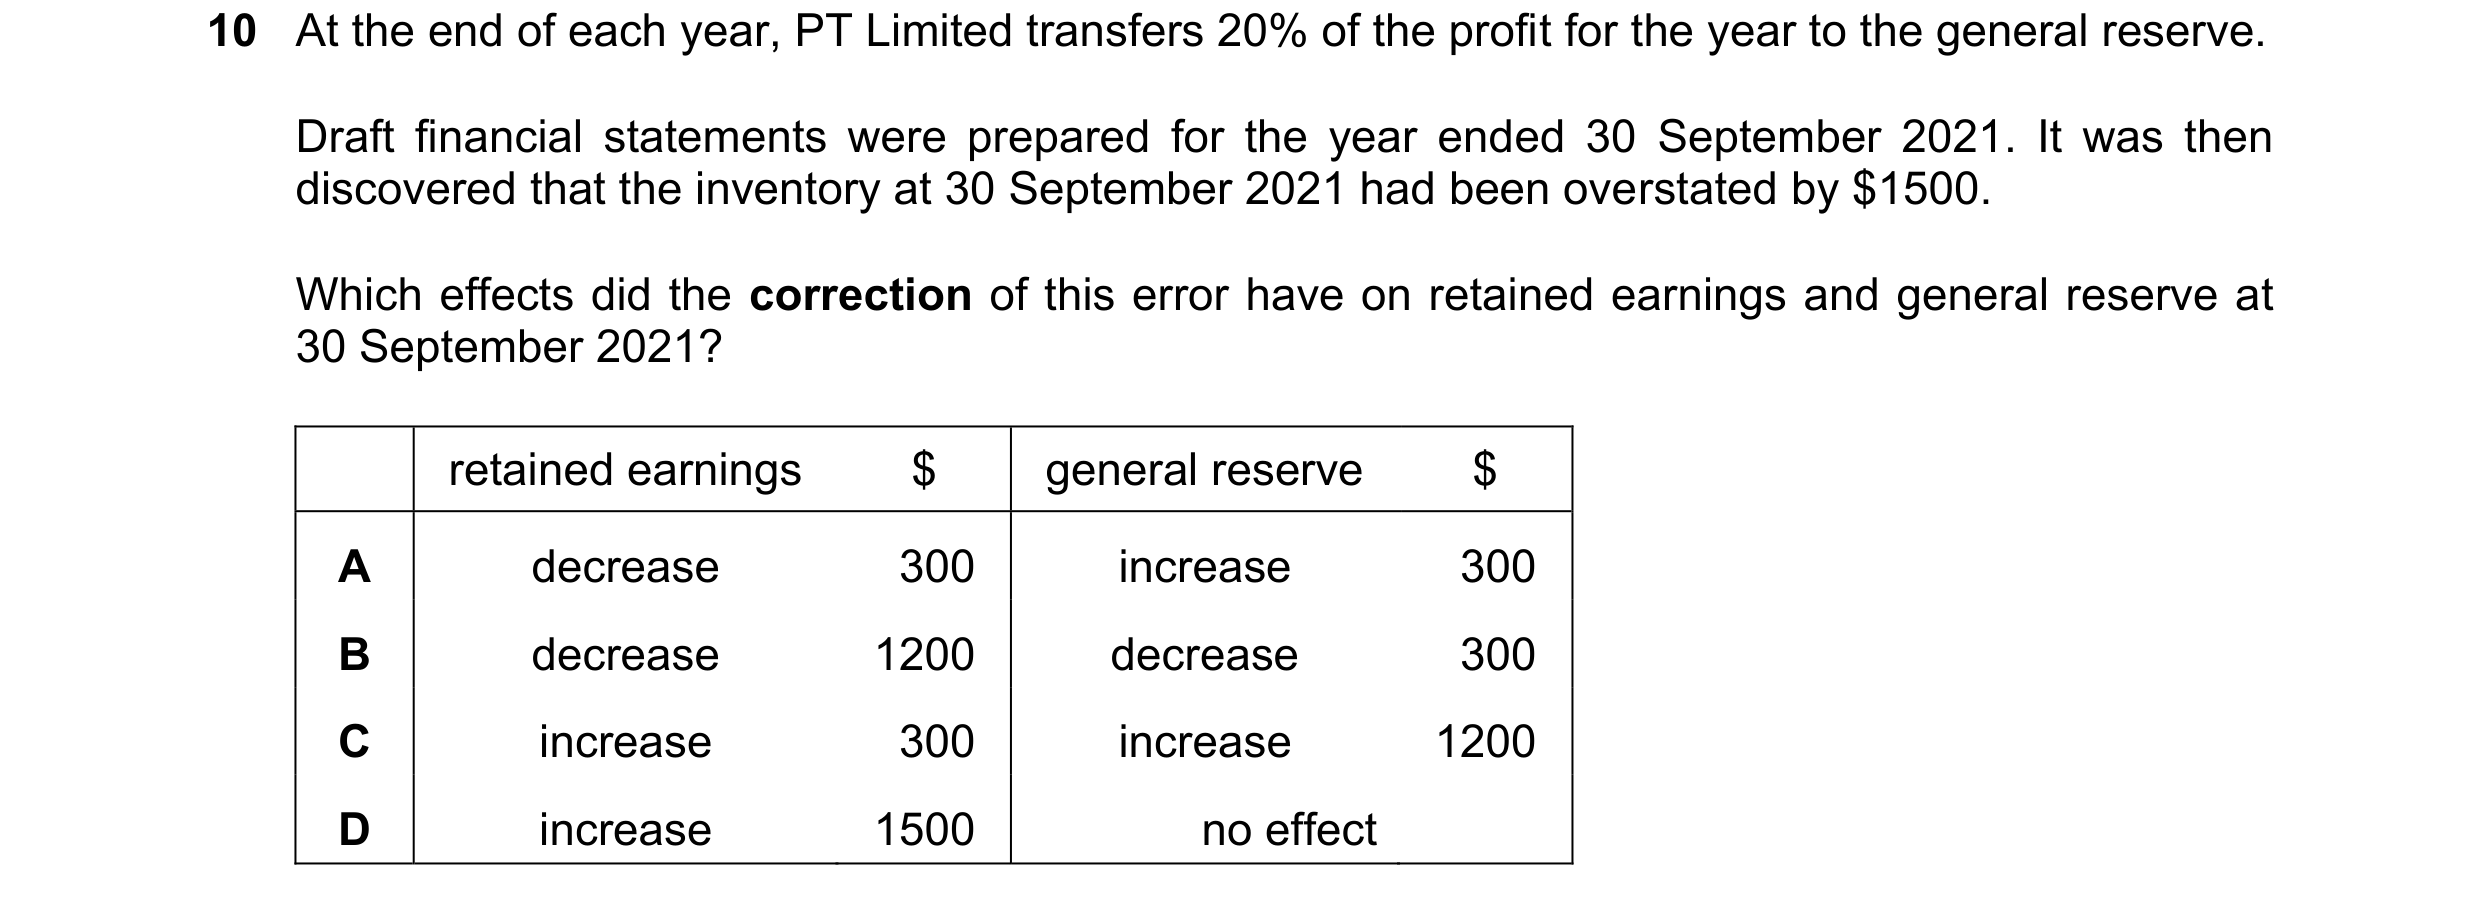 11 / 41
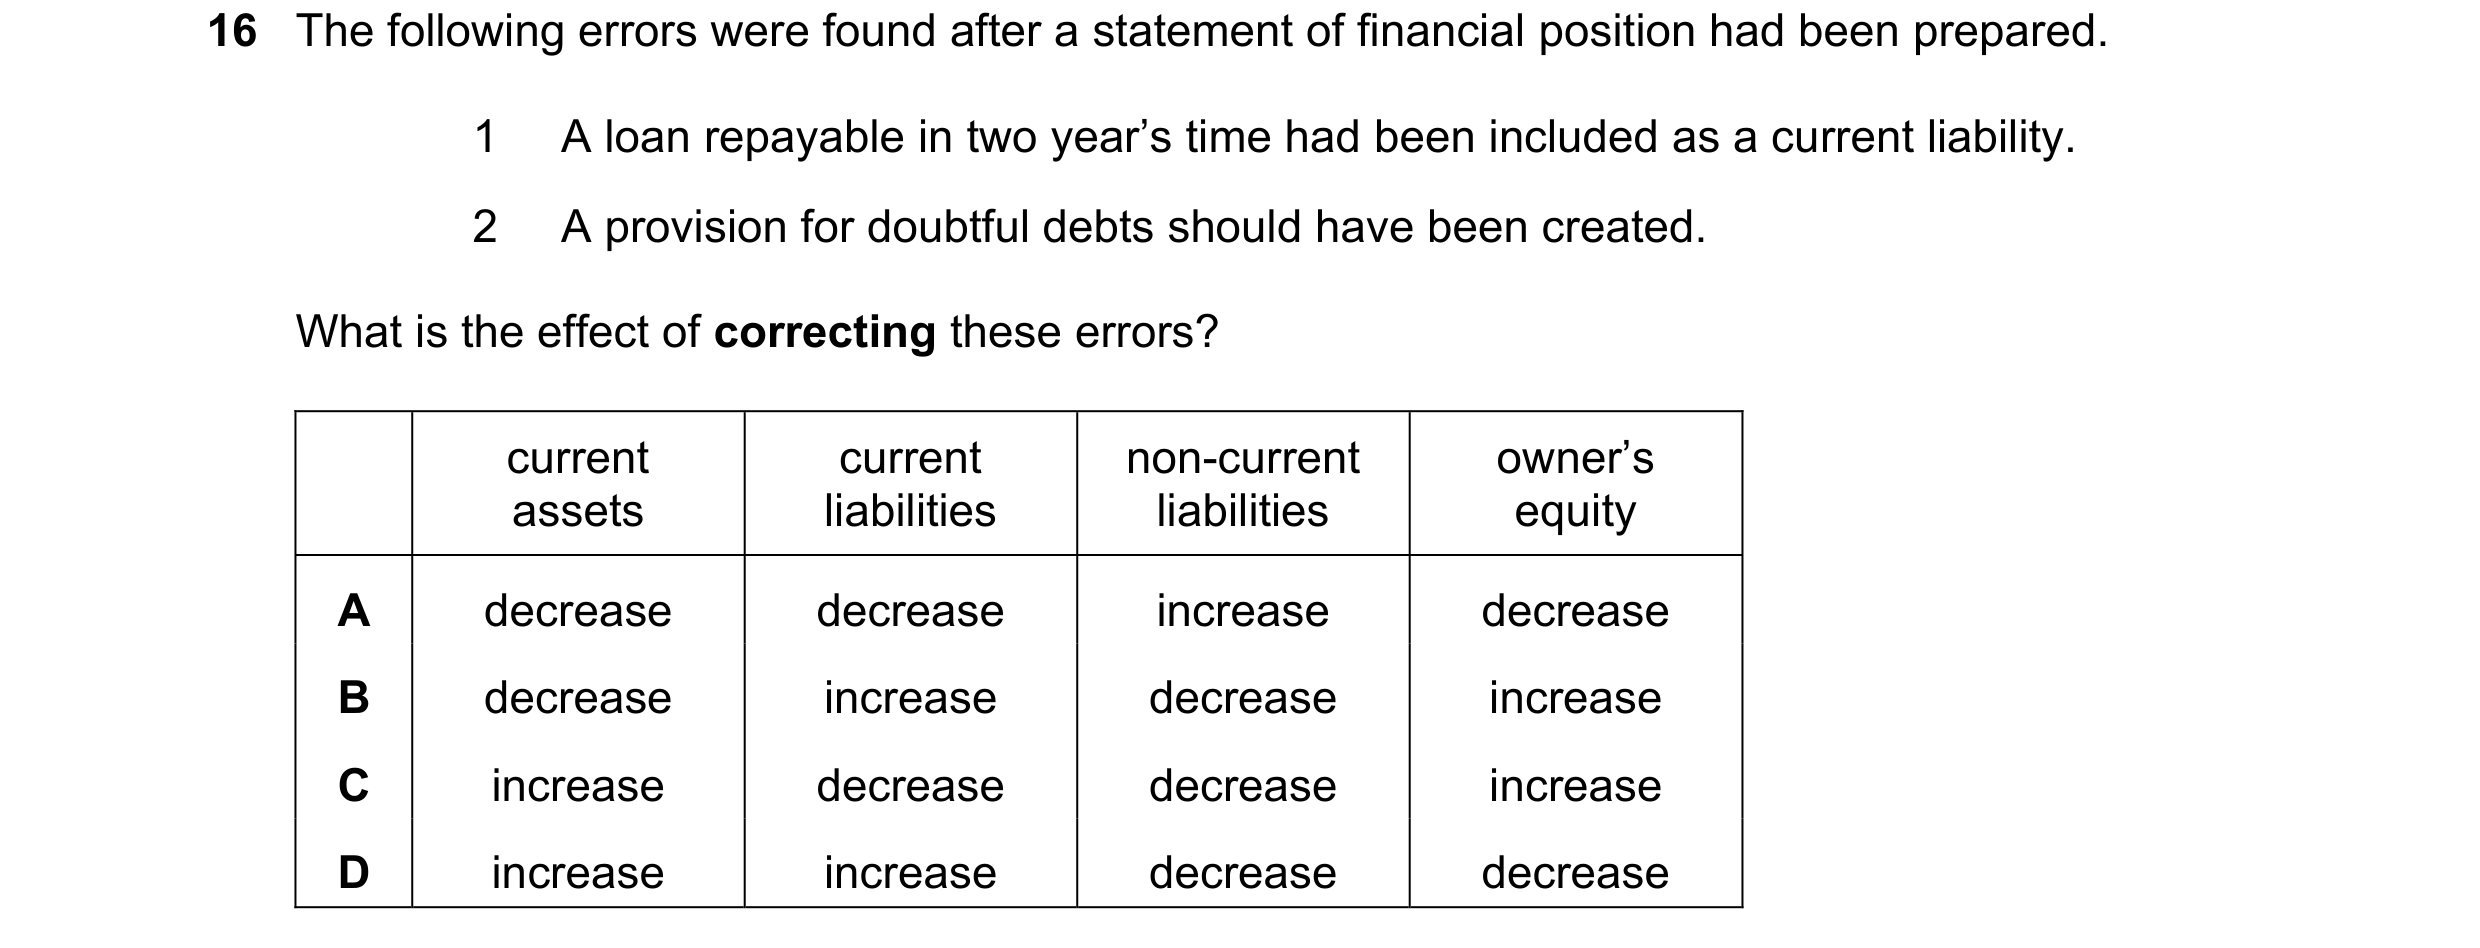
 12 / 41
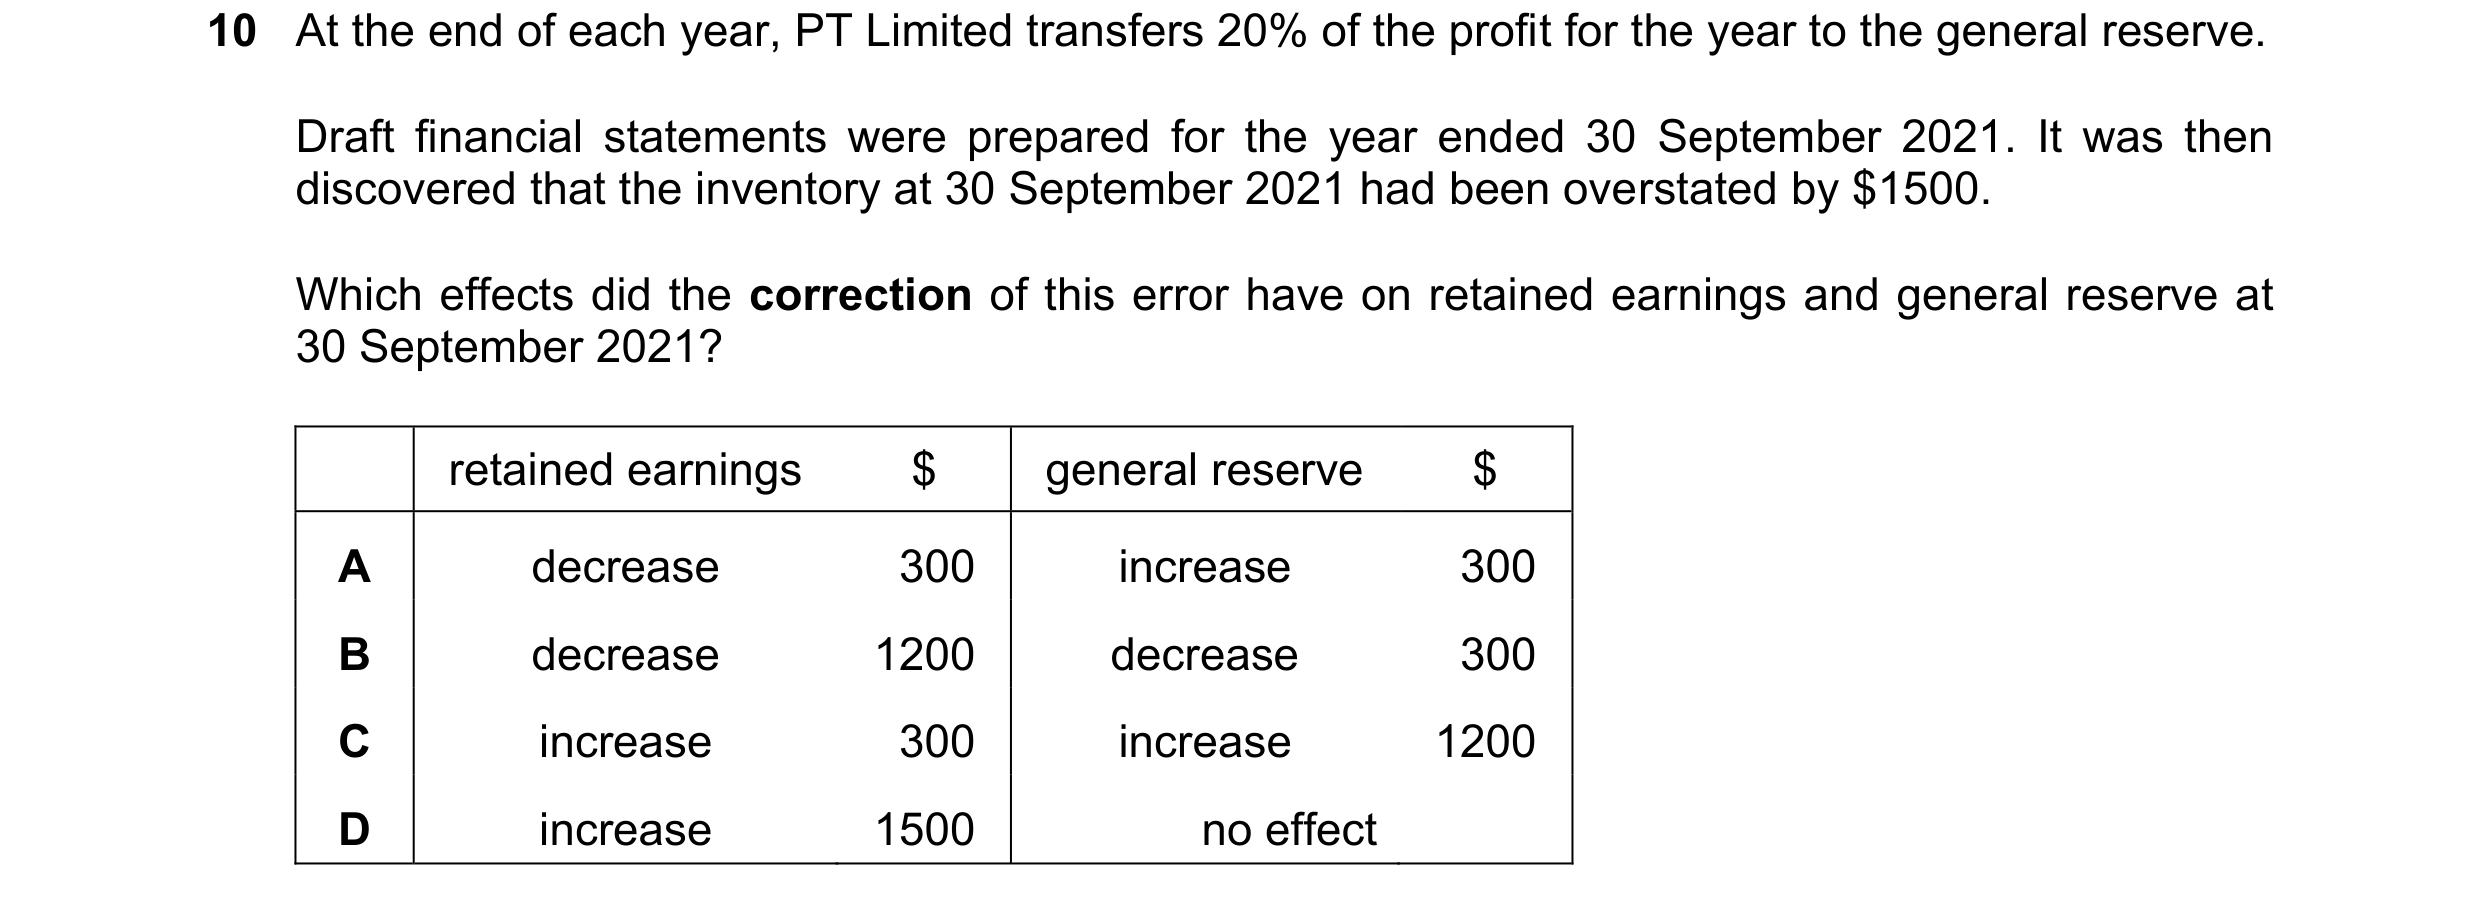
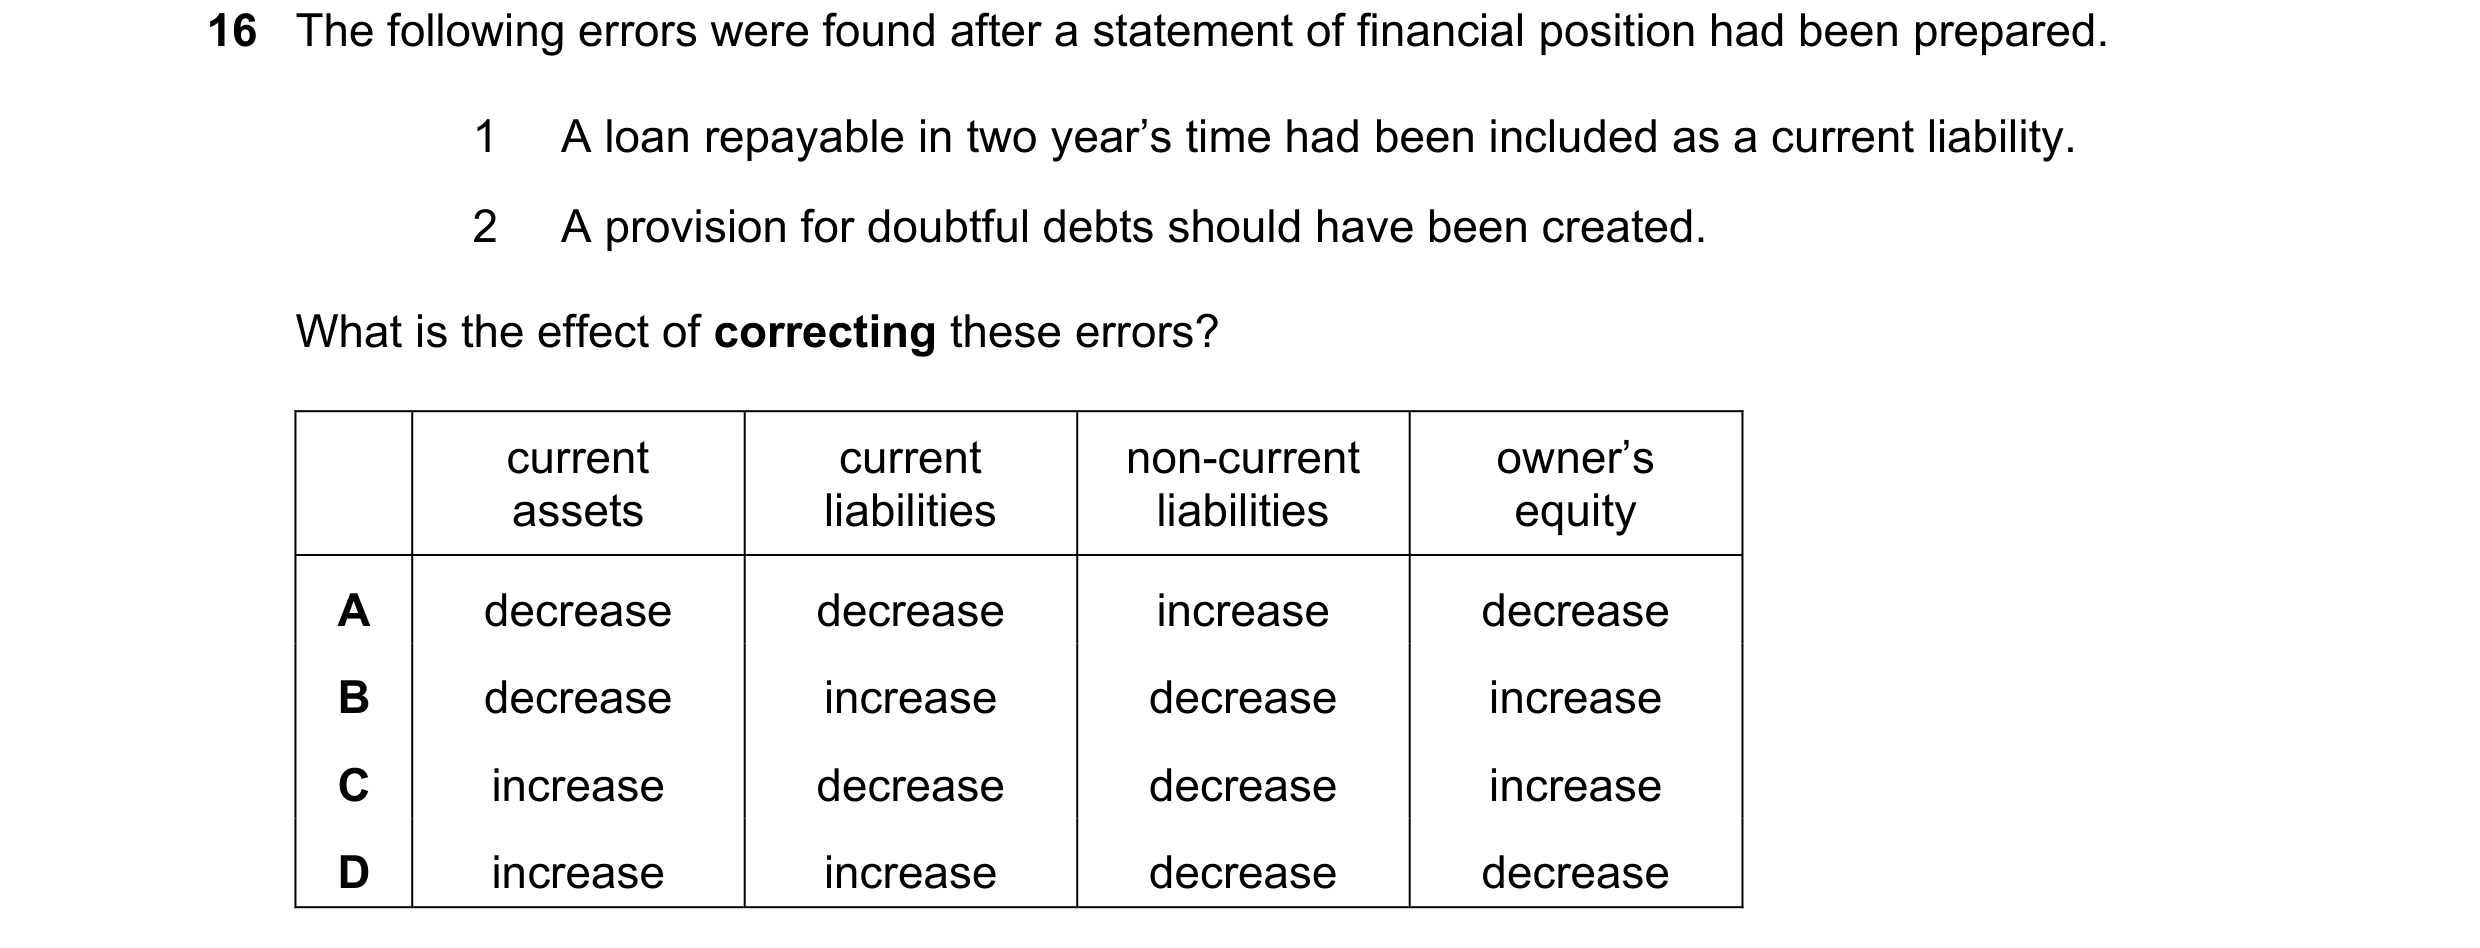
 13 / 41
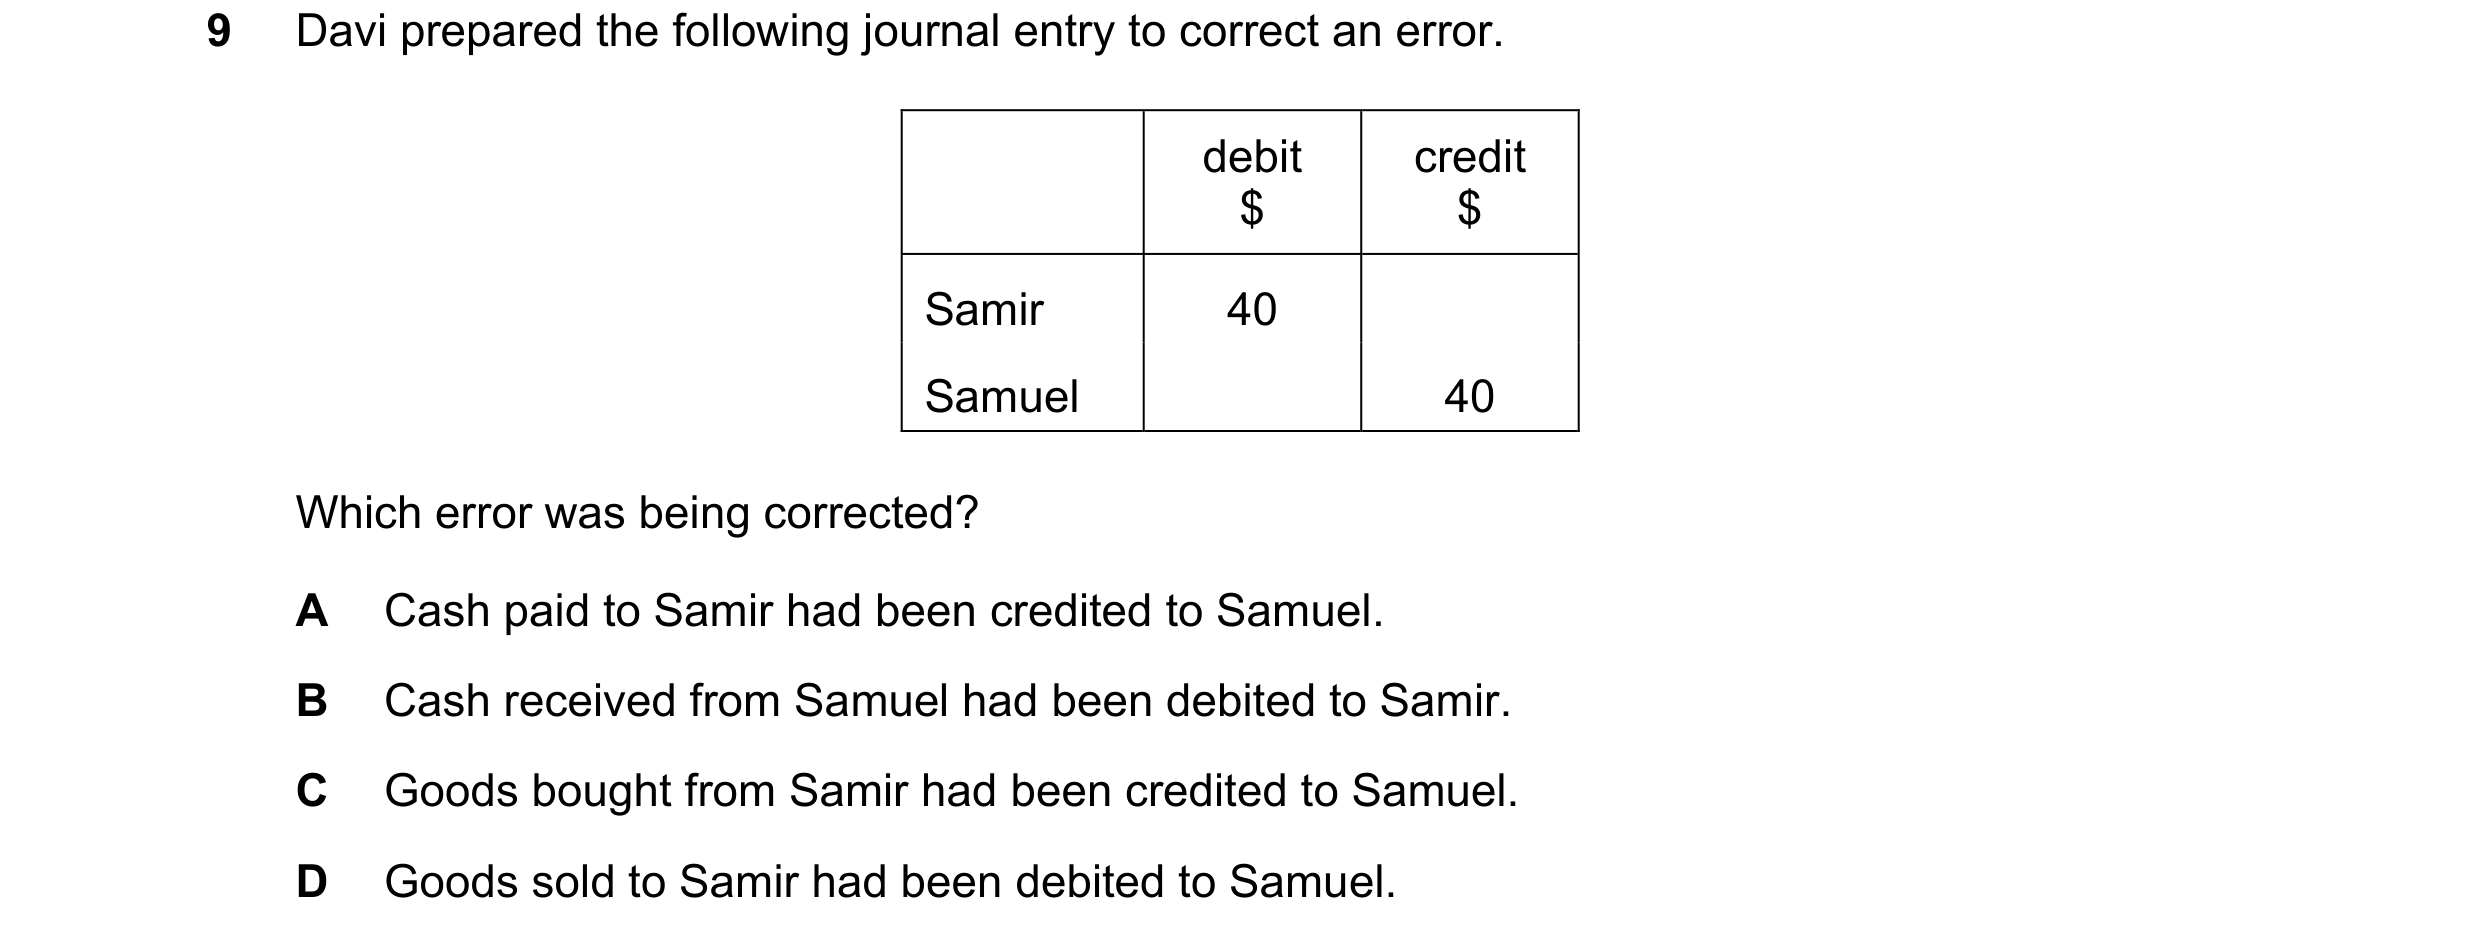
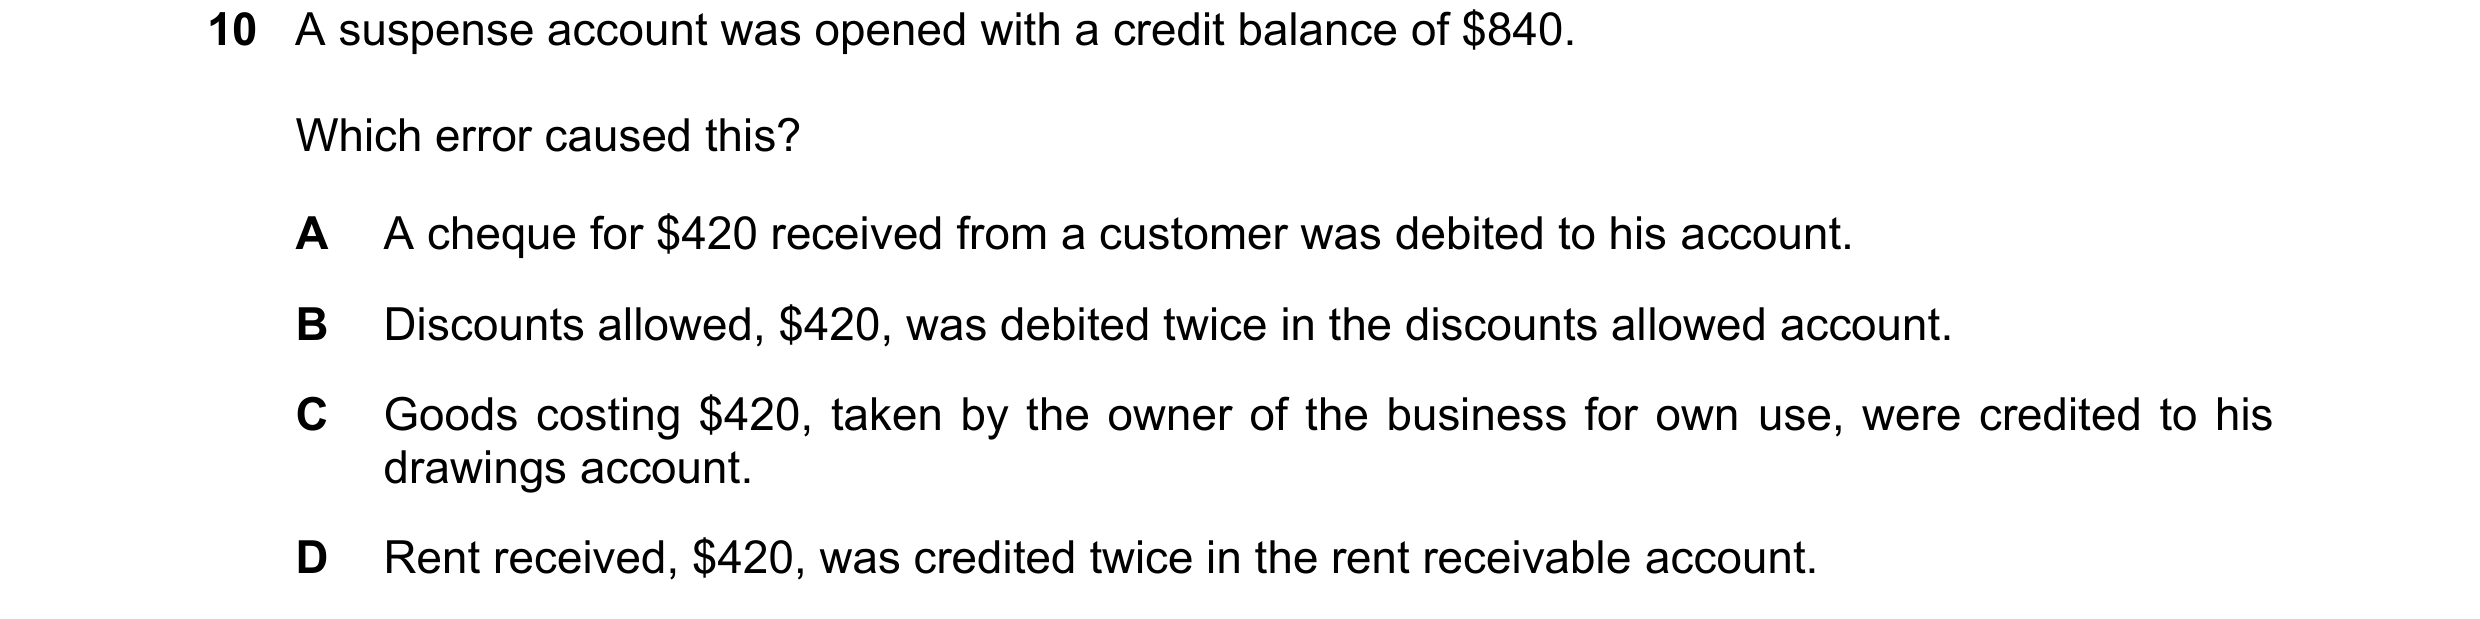
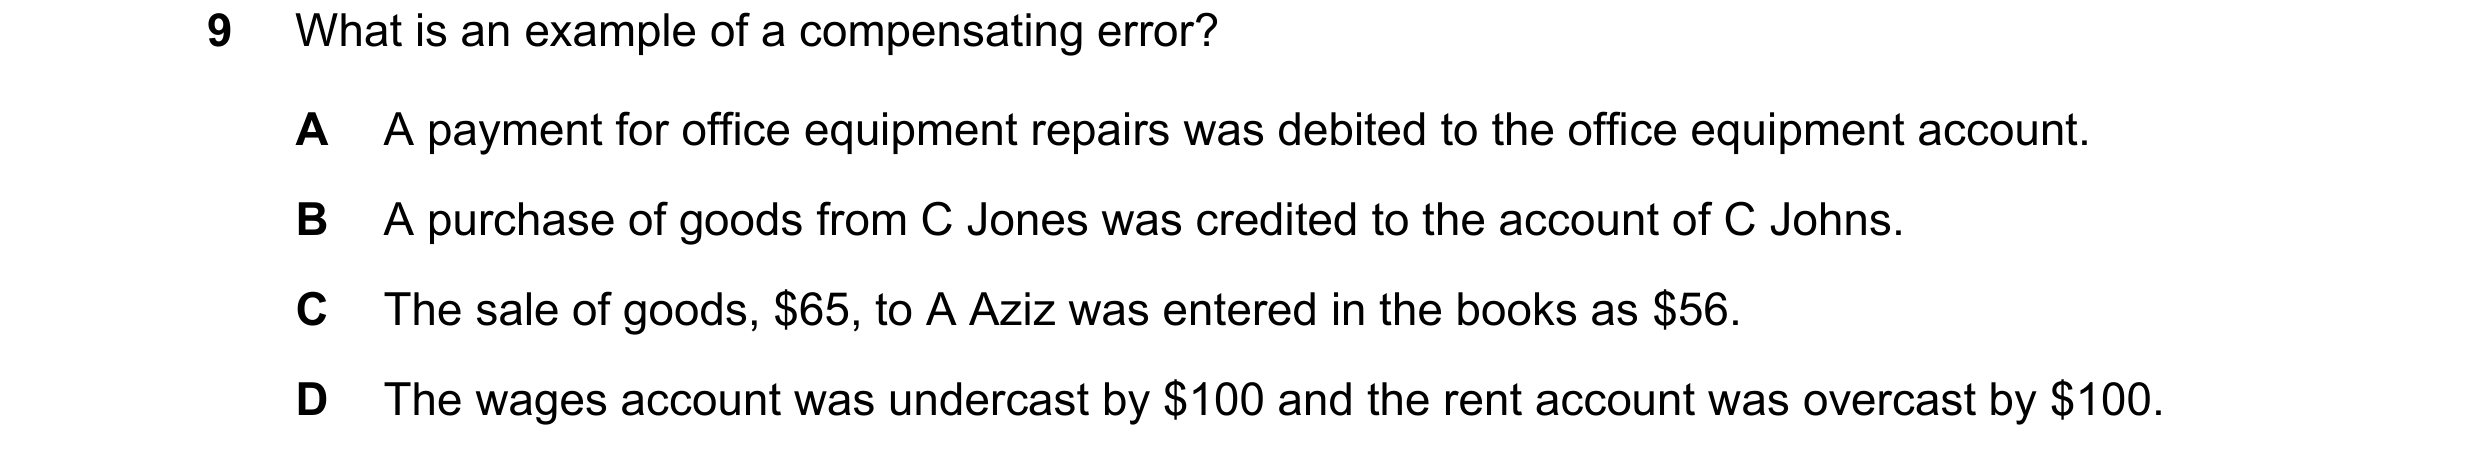
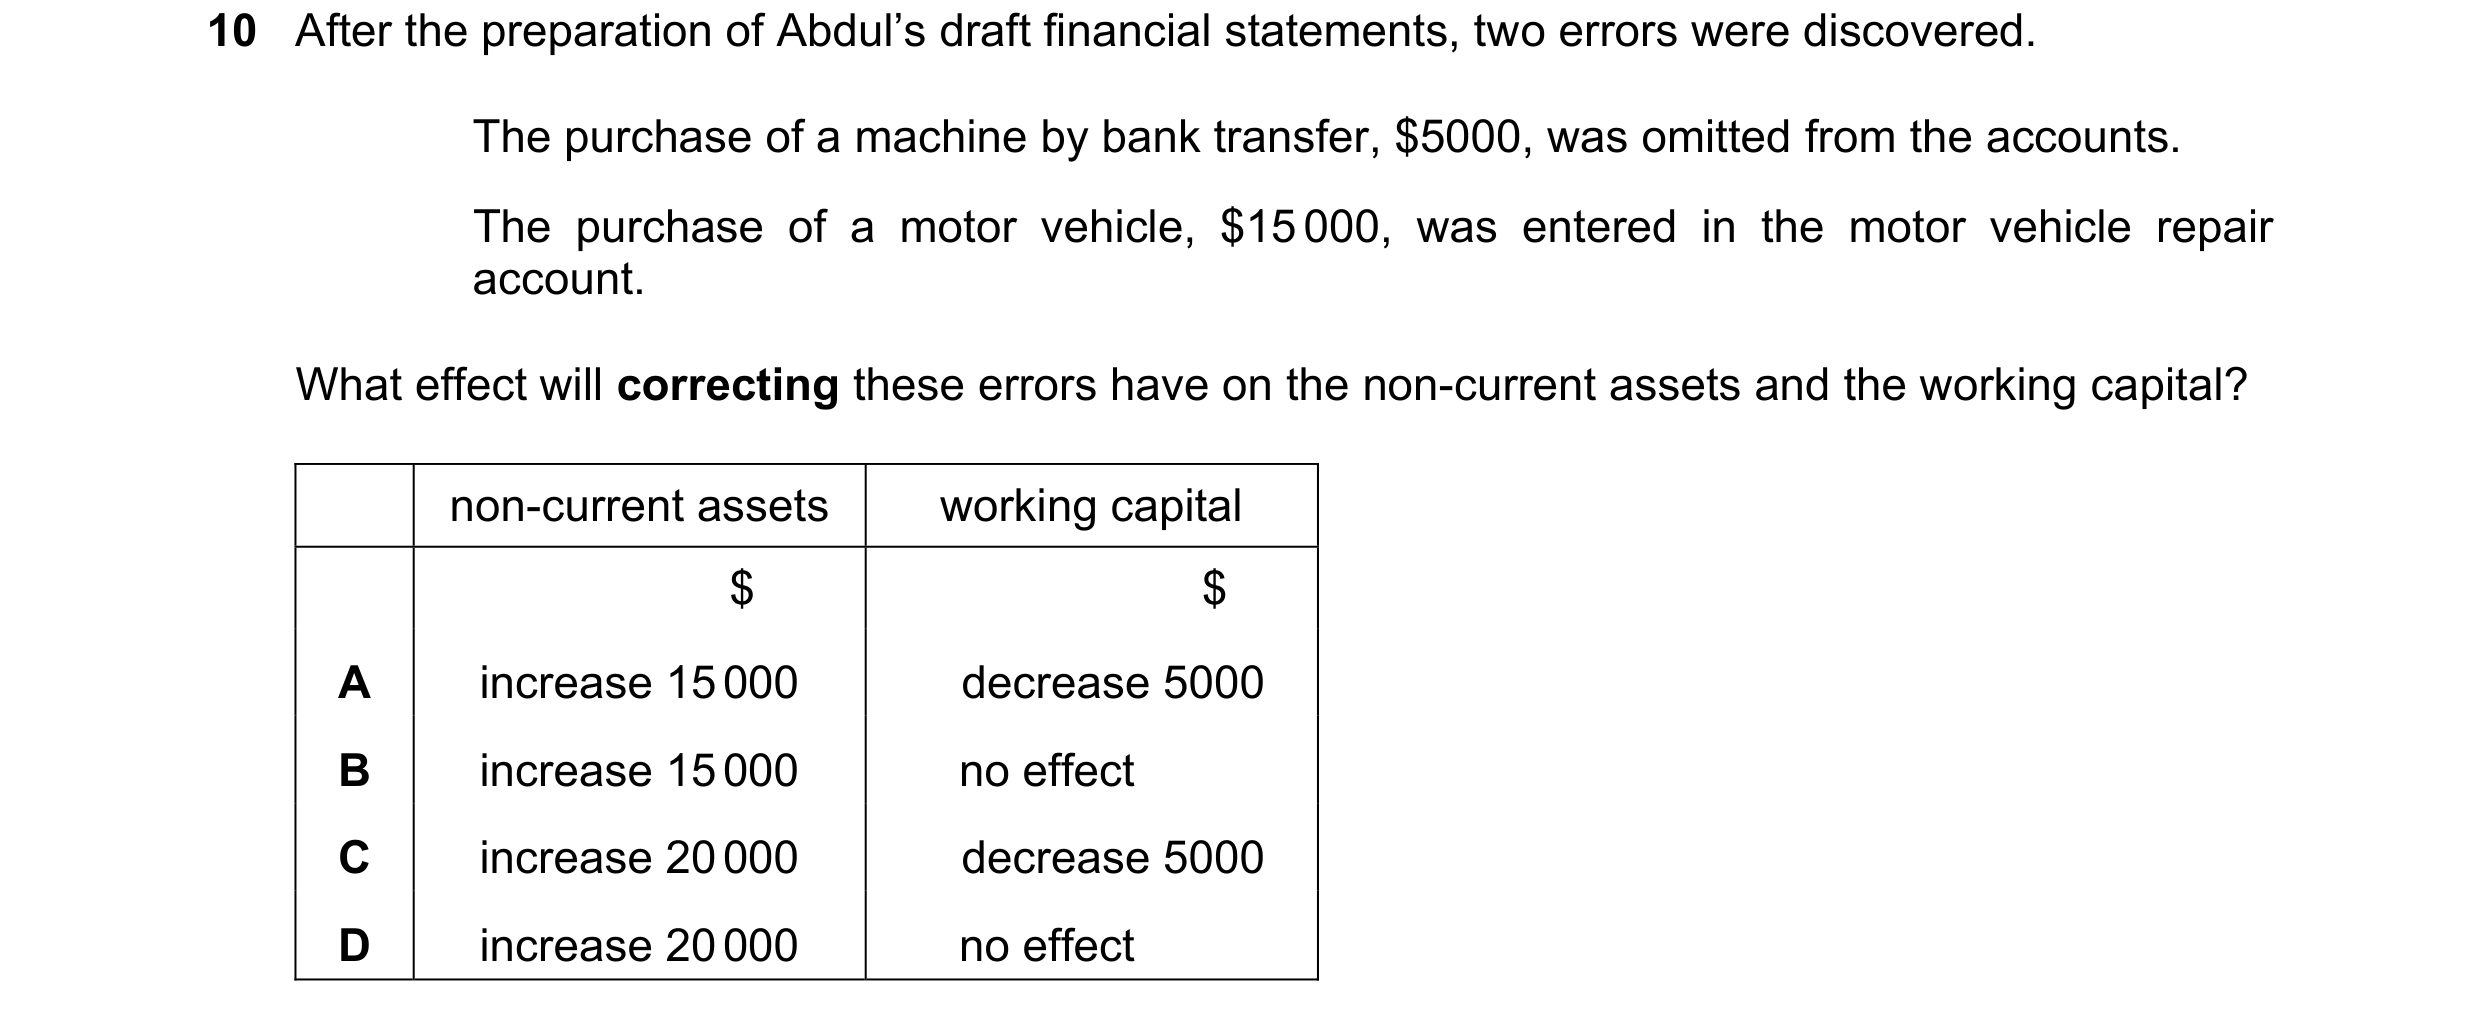 14 / 41
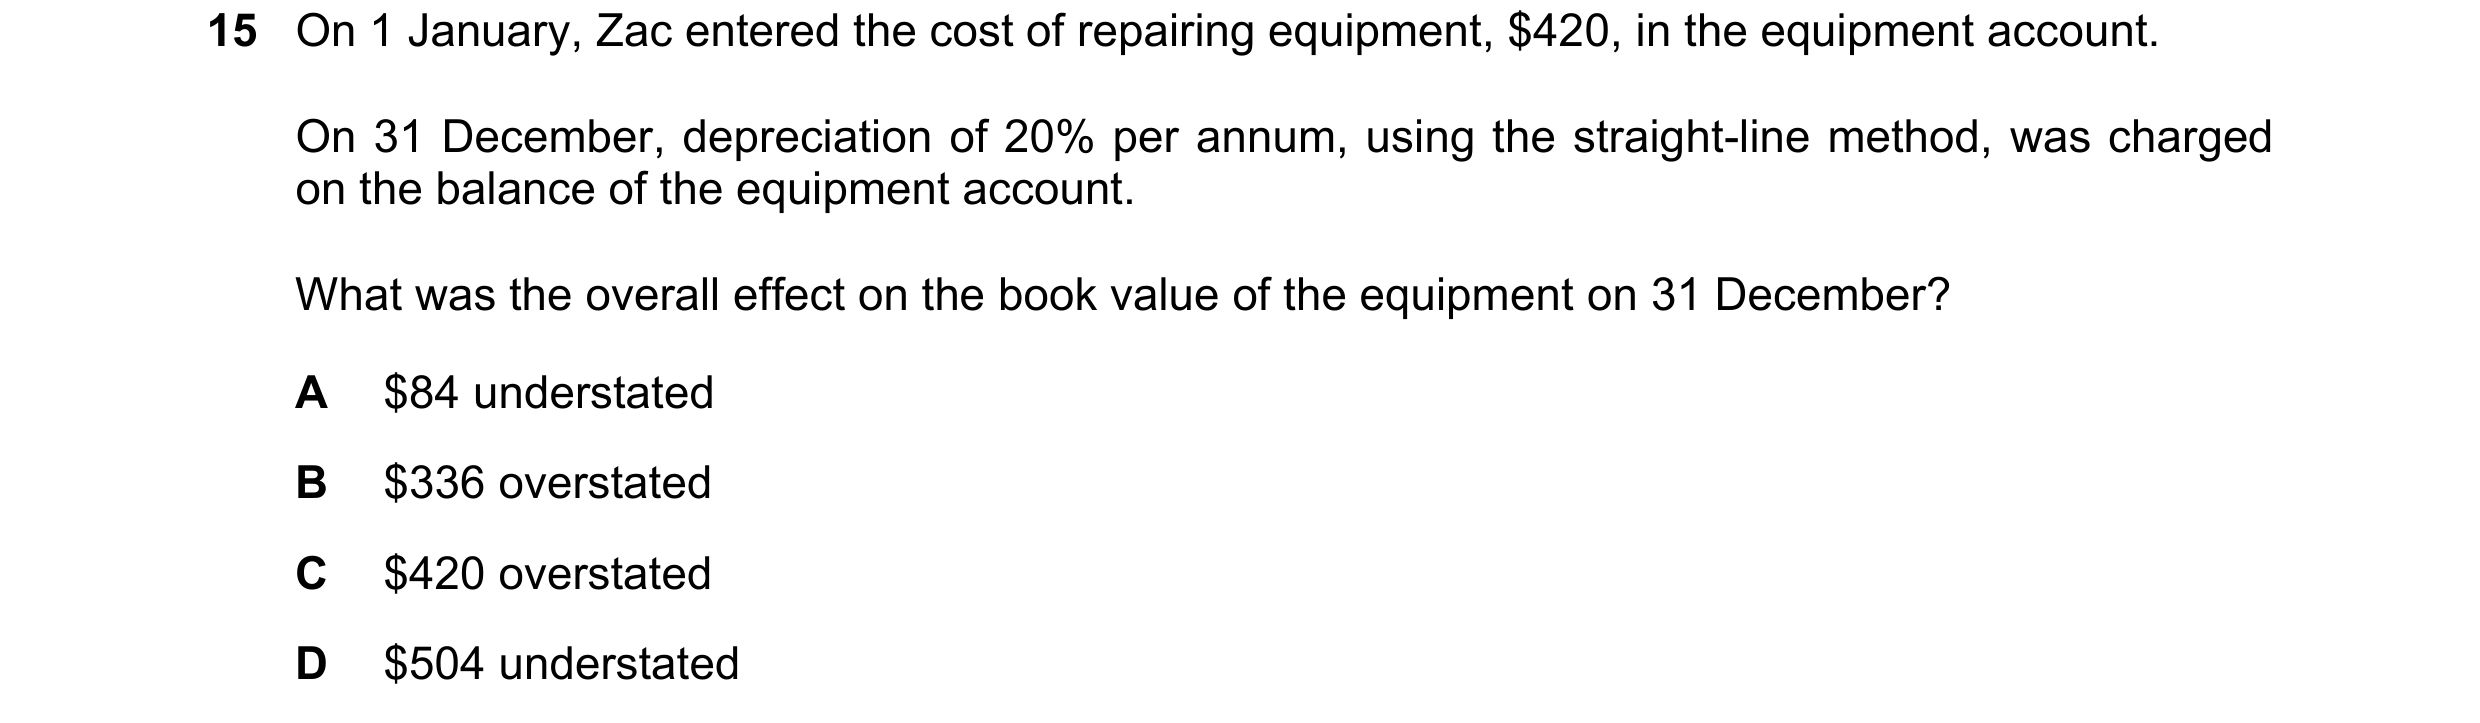
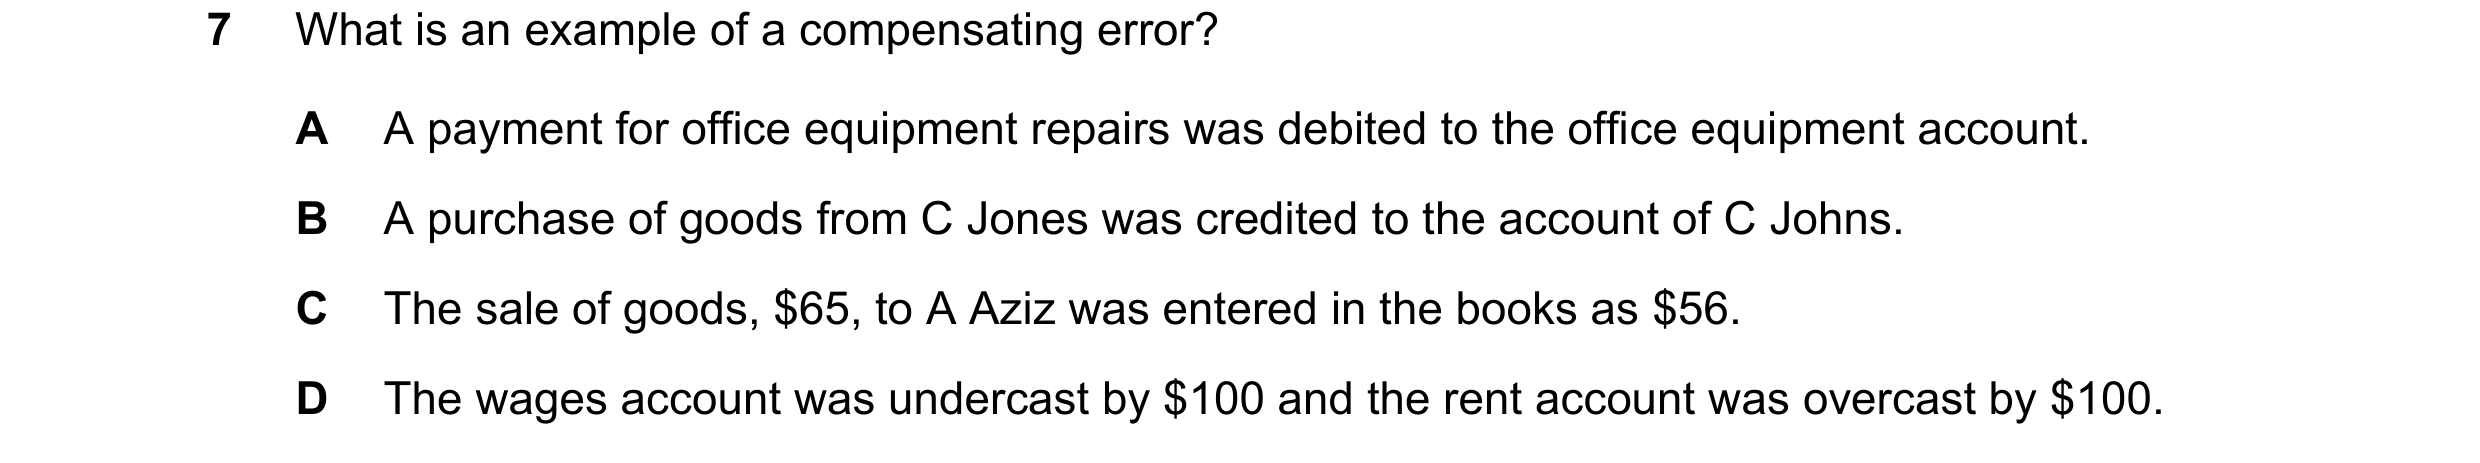
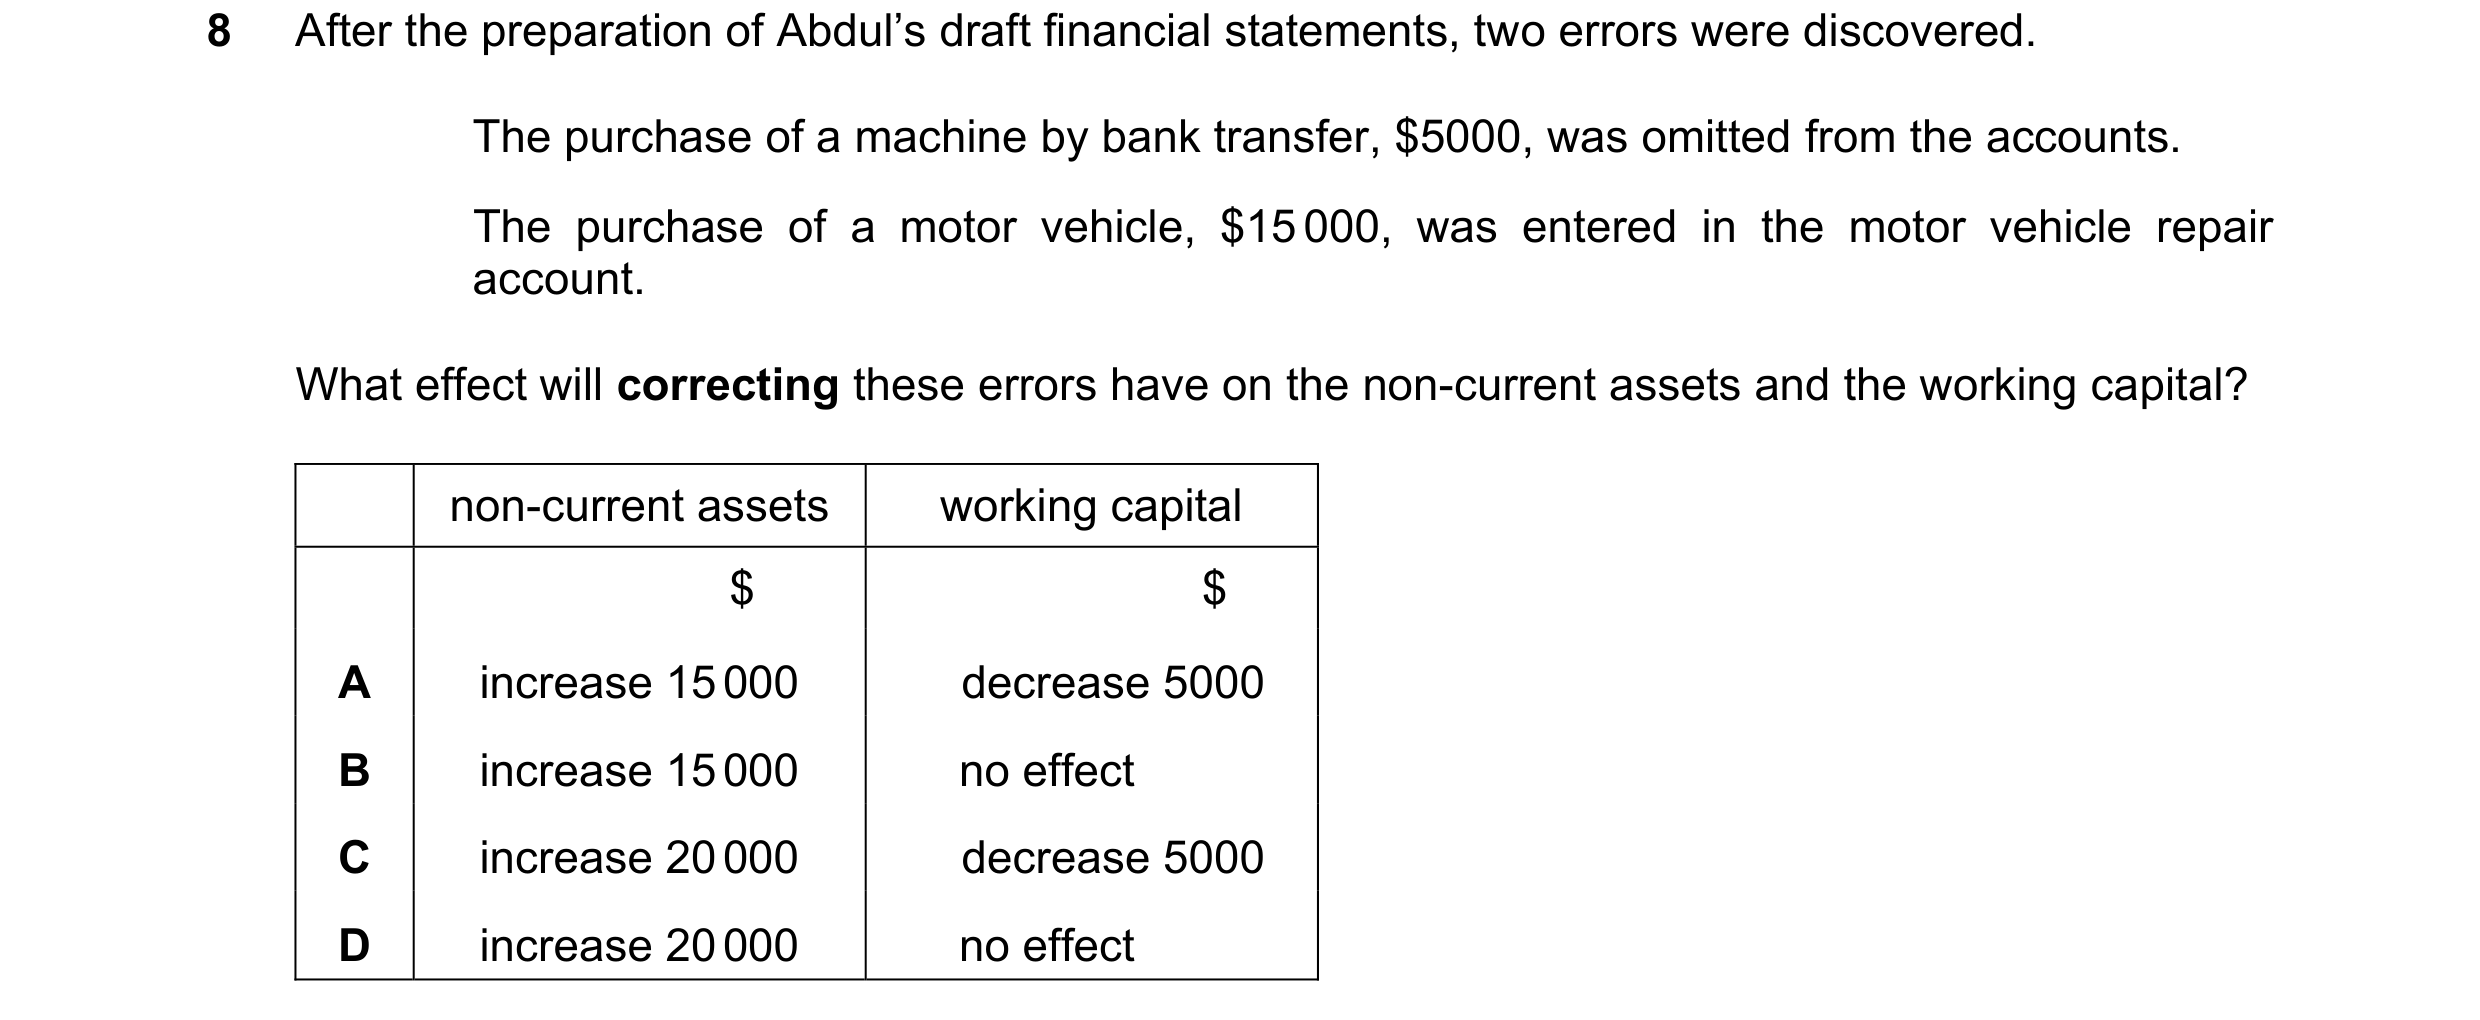
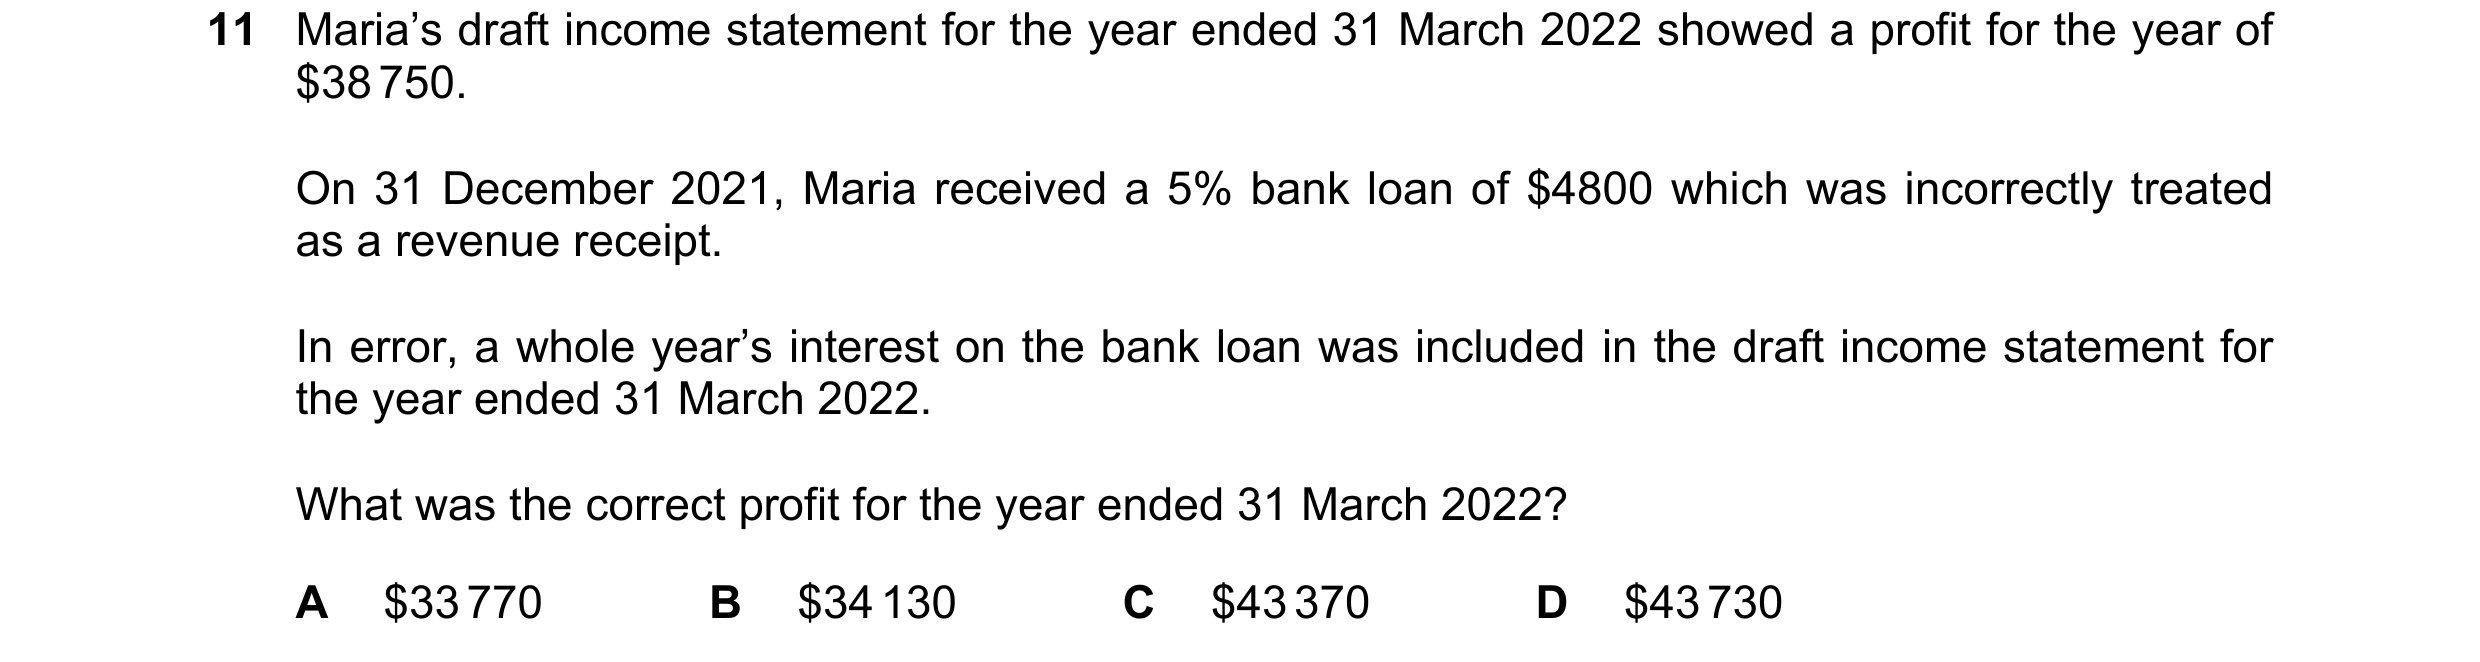 15 / 41
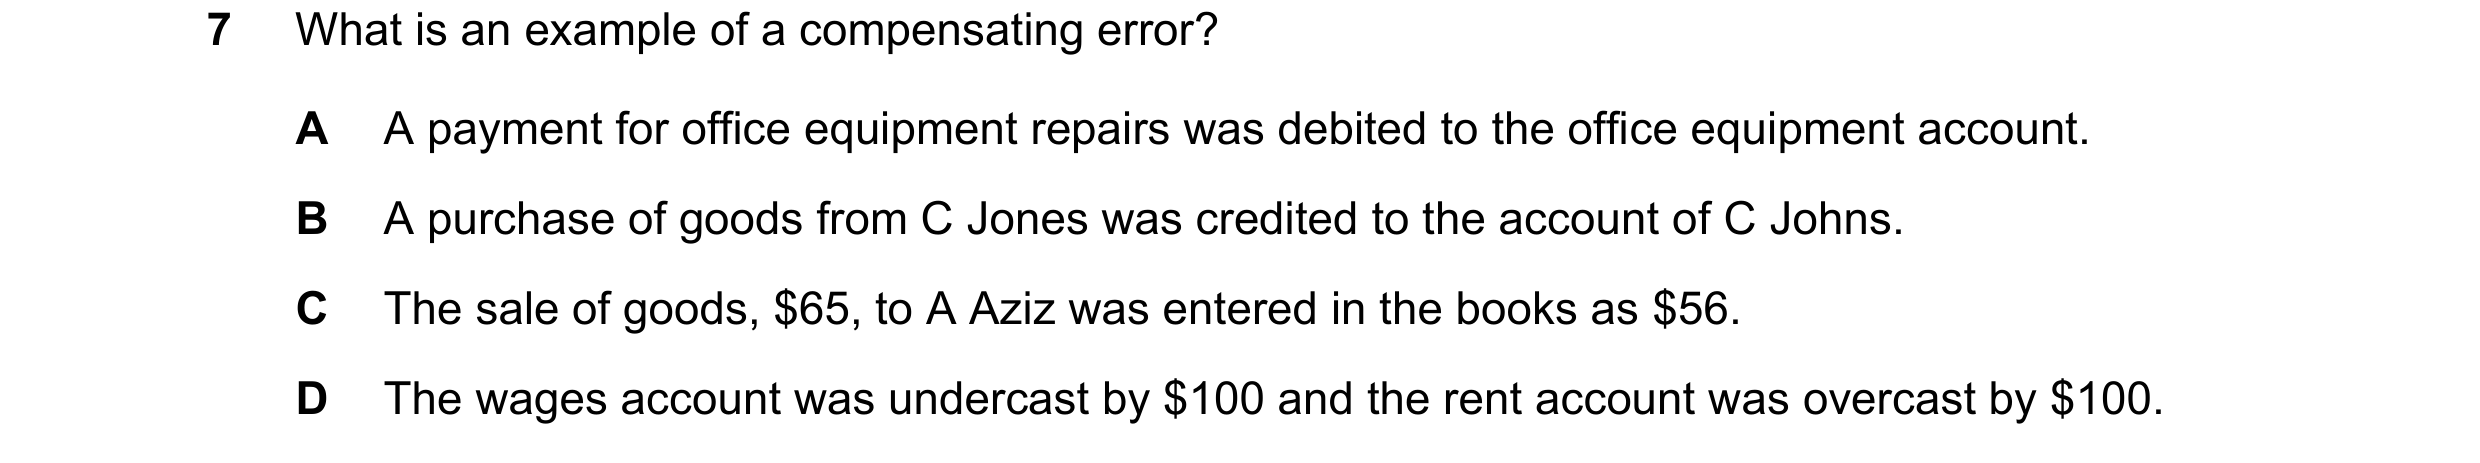
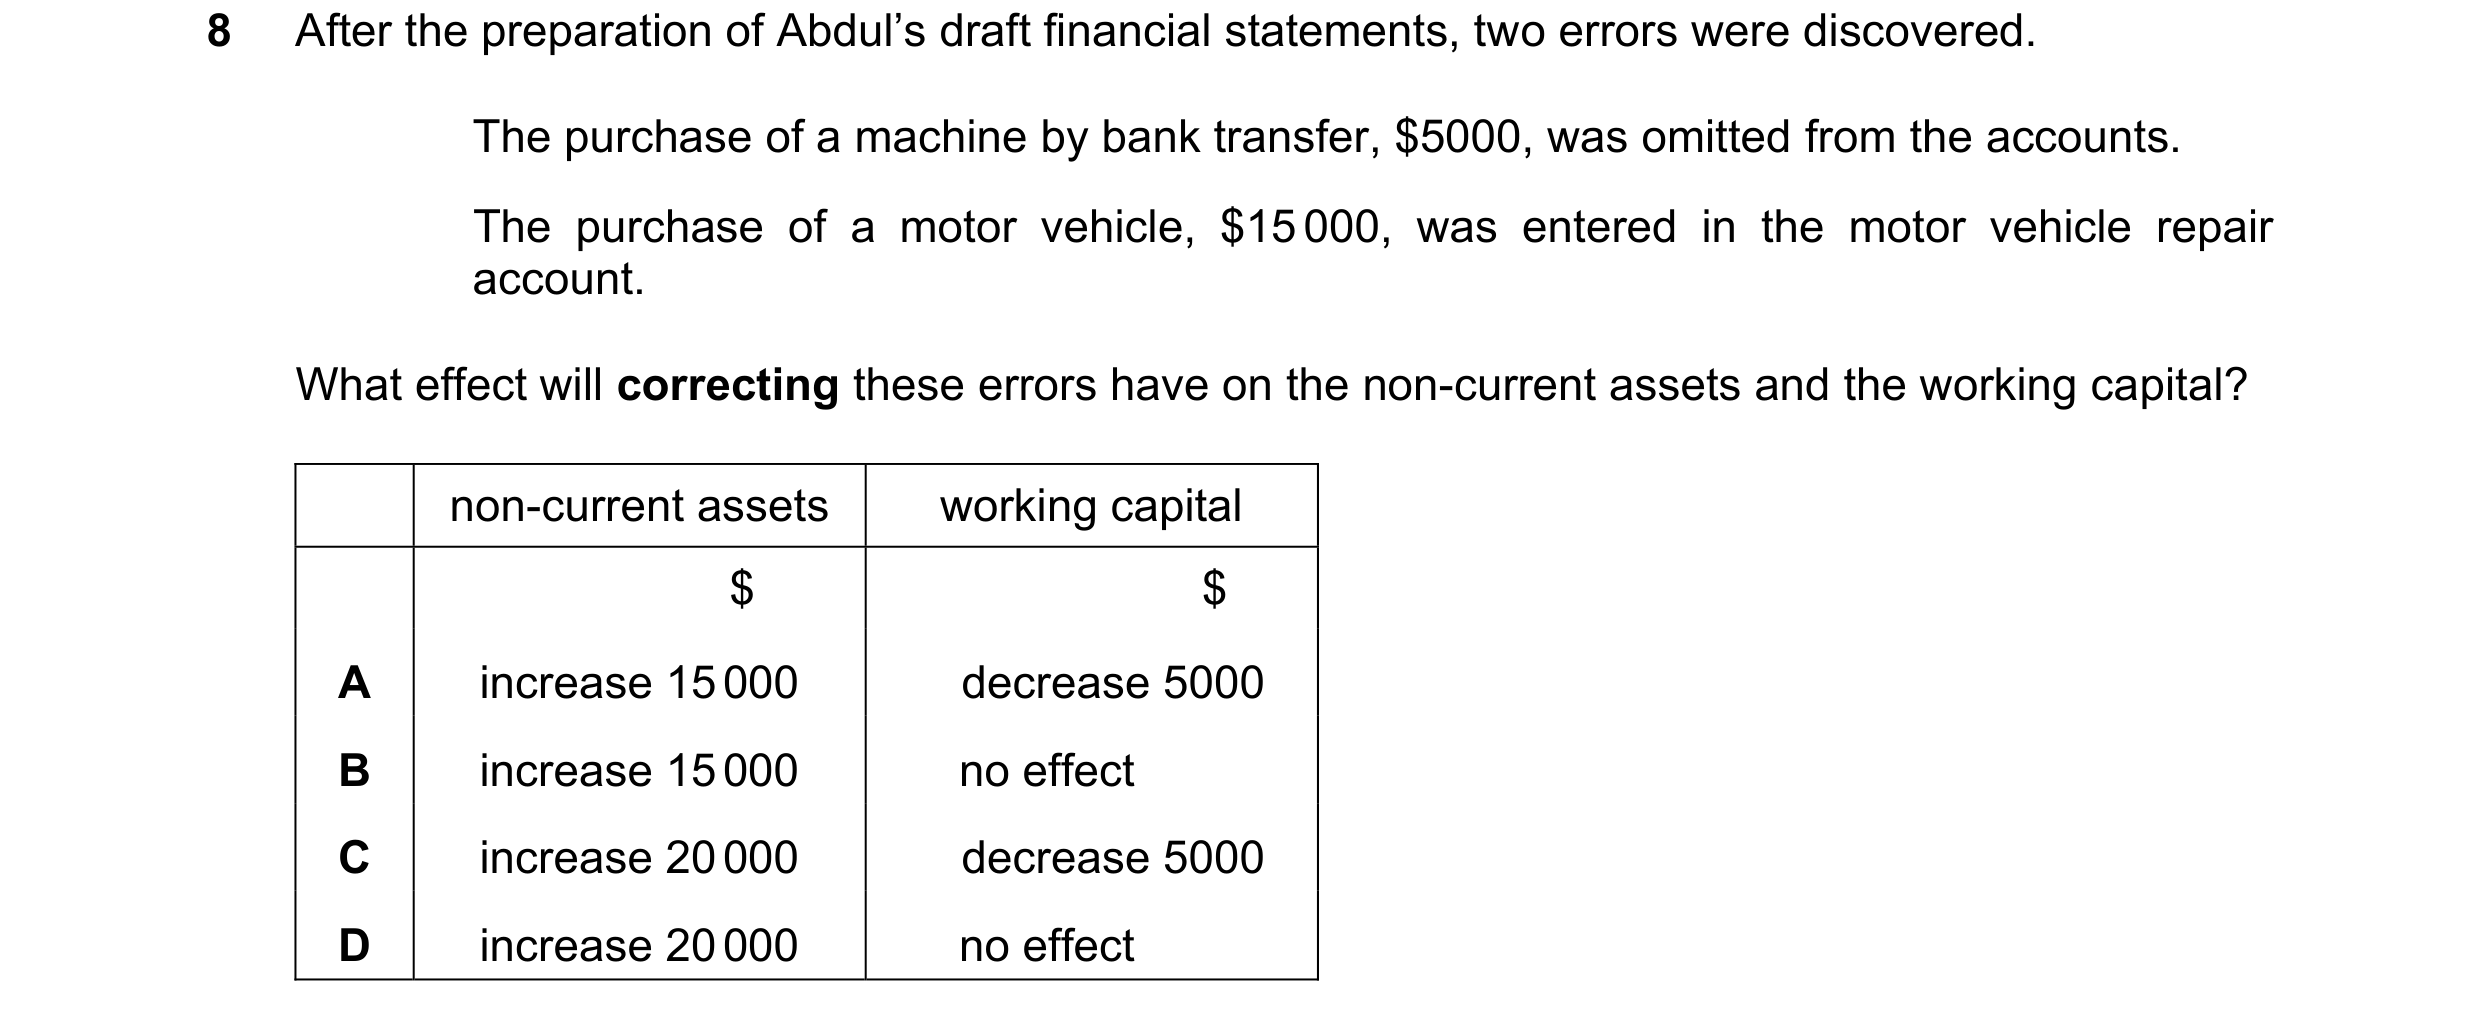
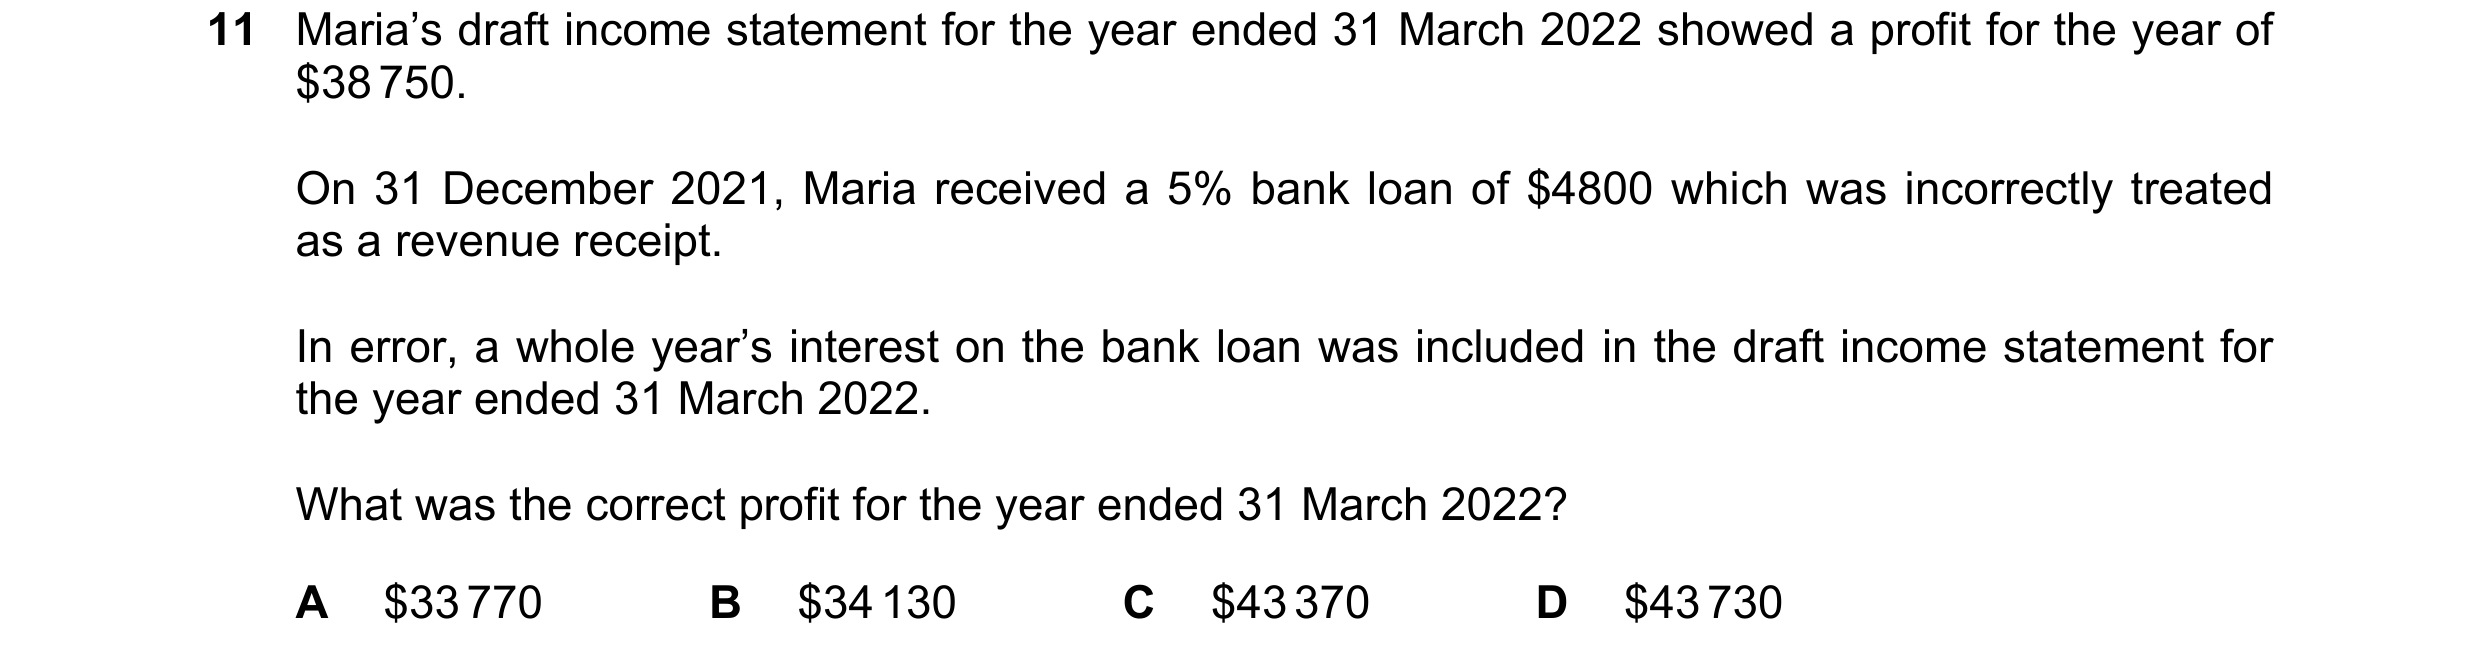
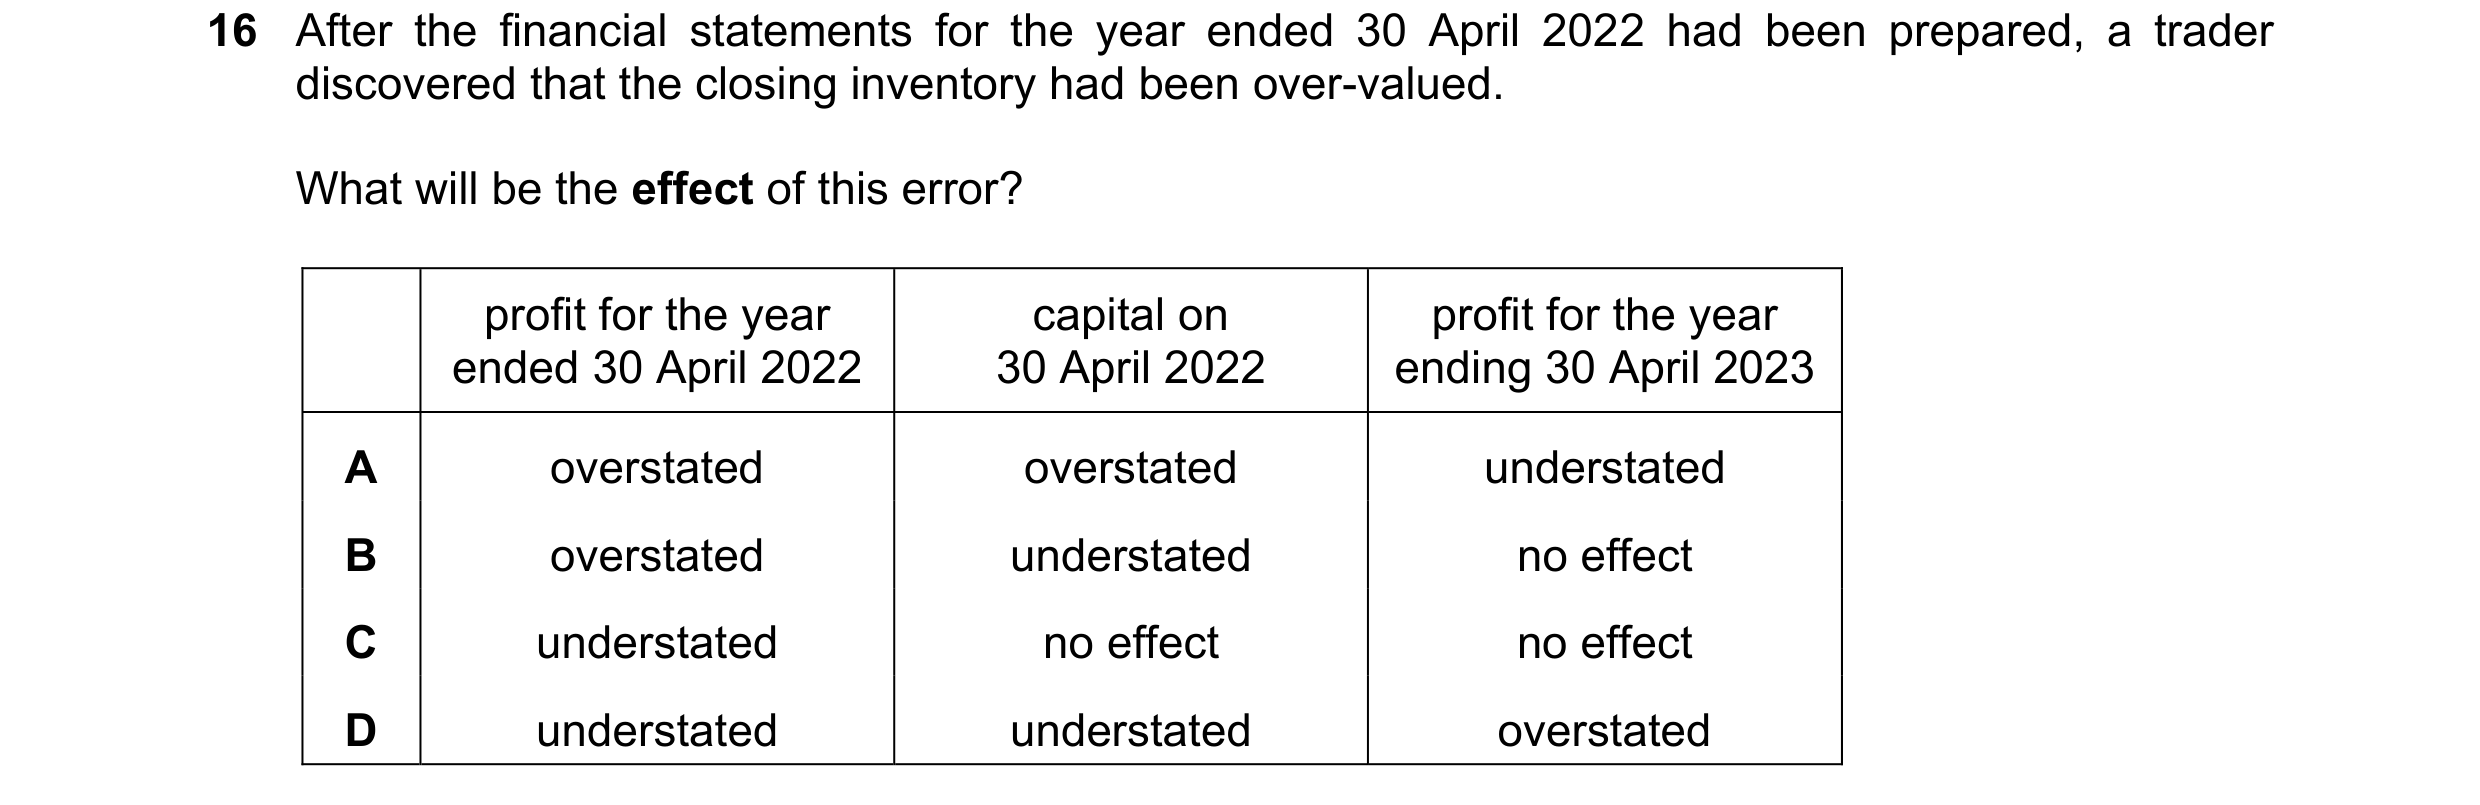 16 / 41
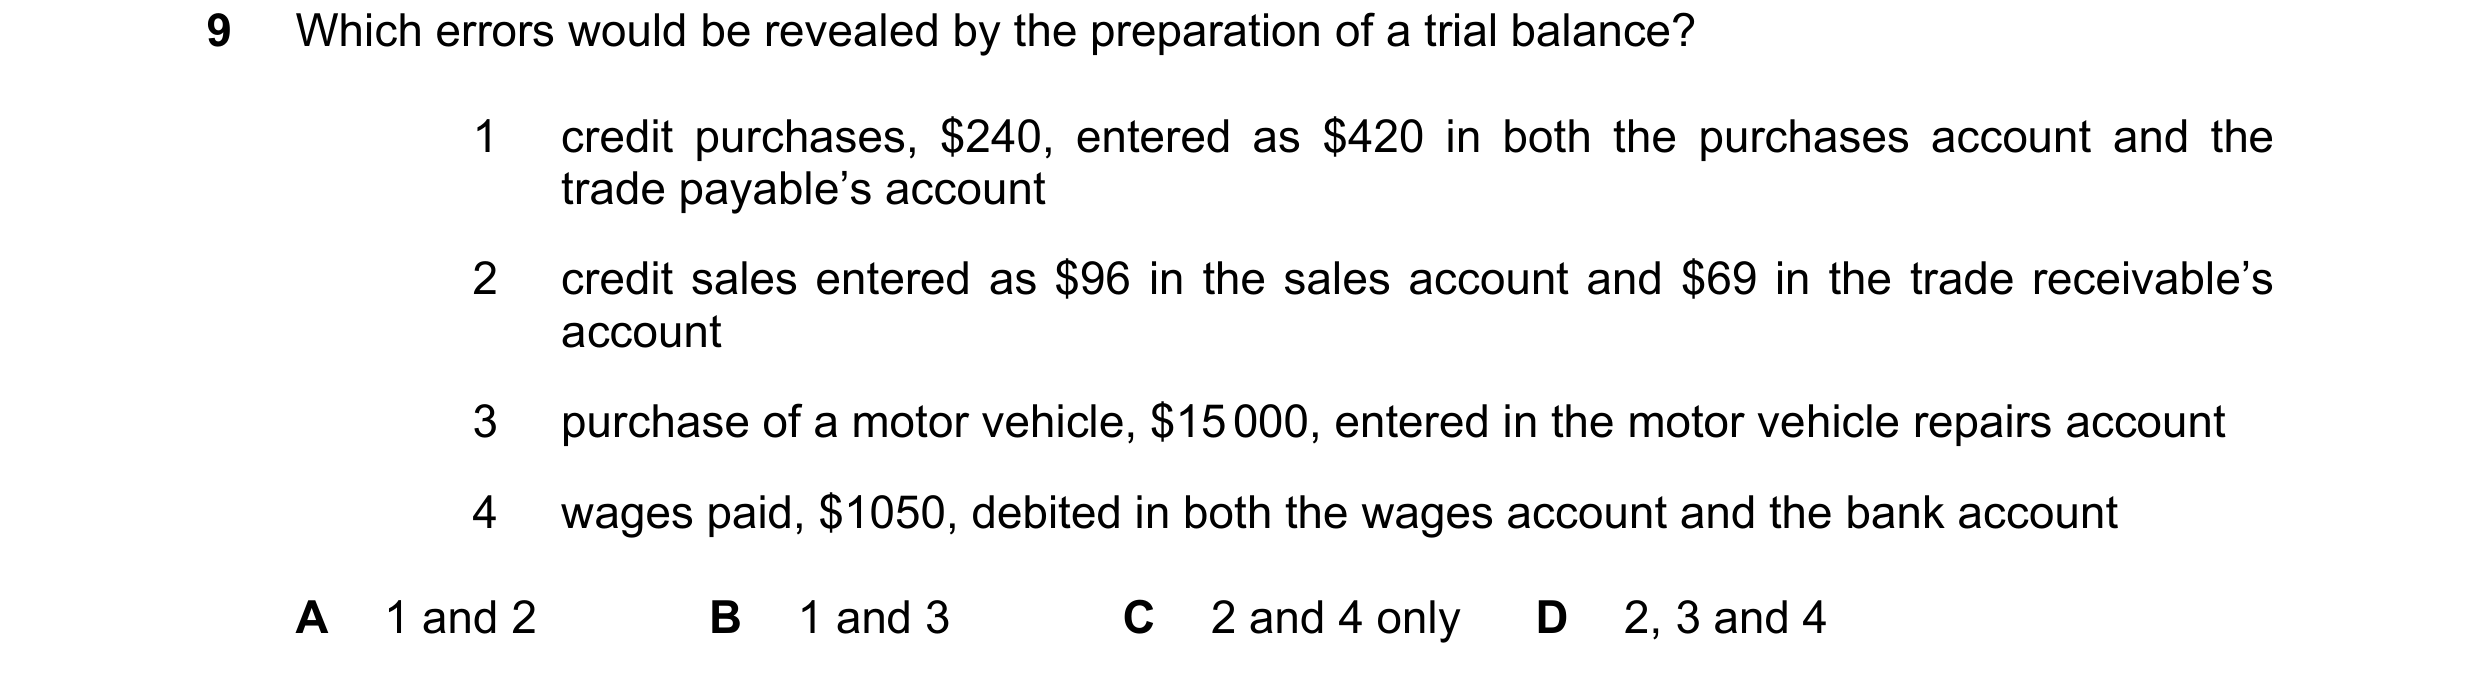
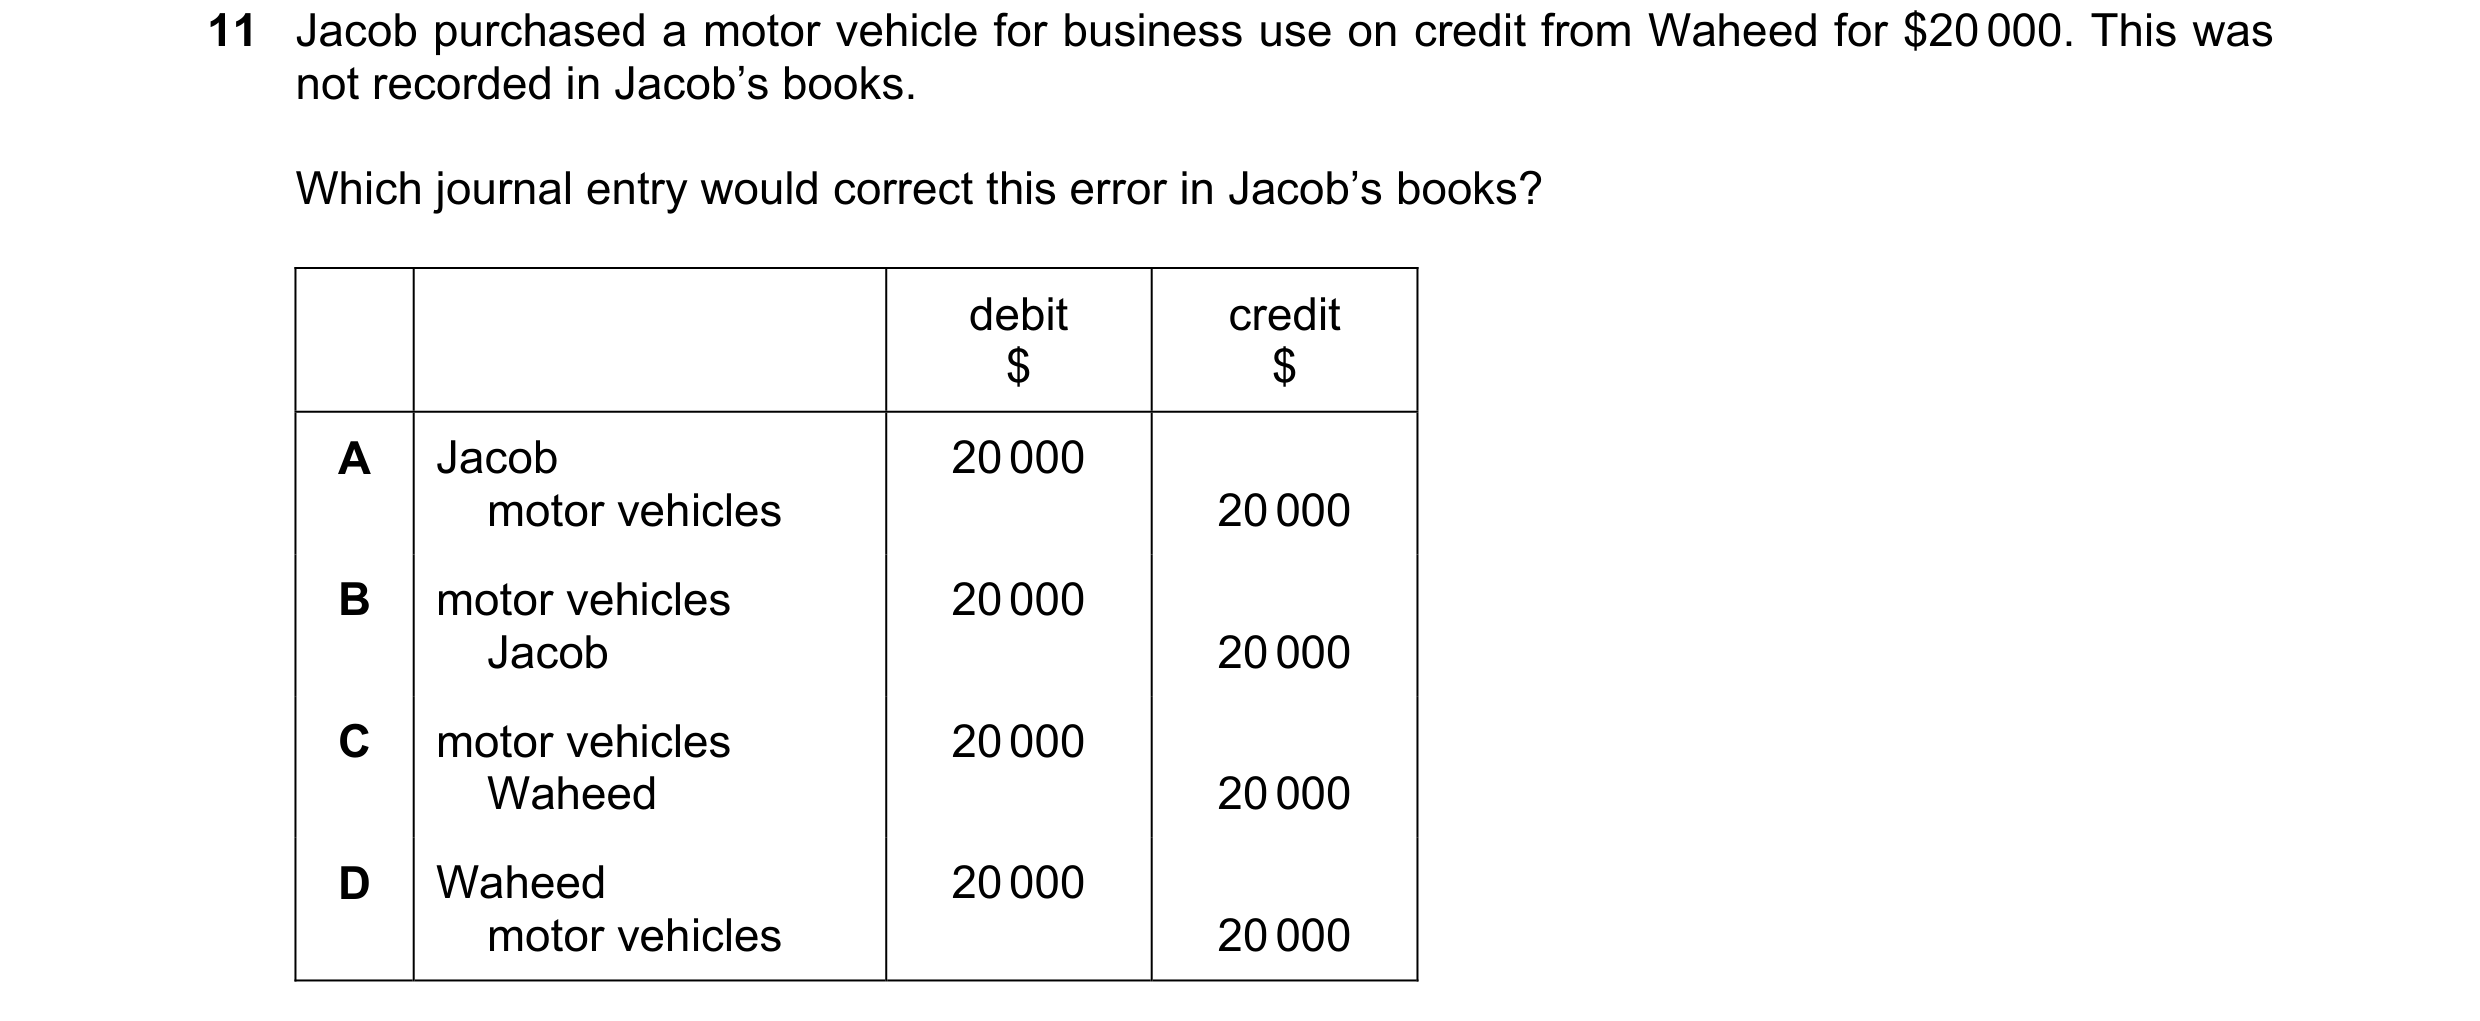
 17 / 41
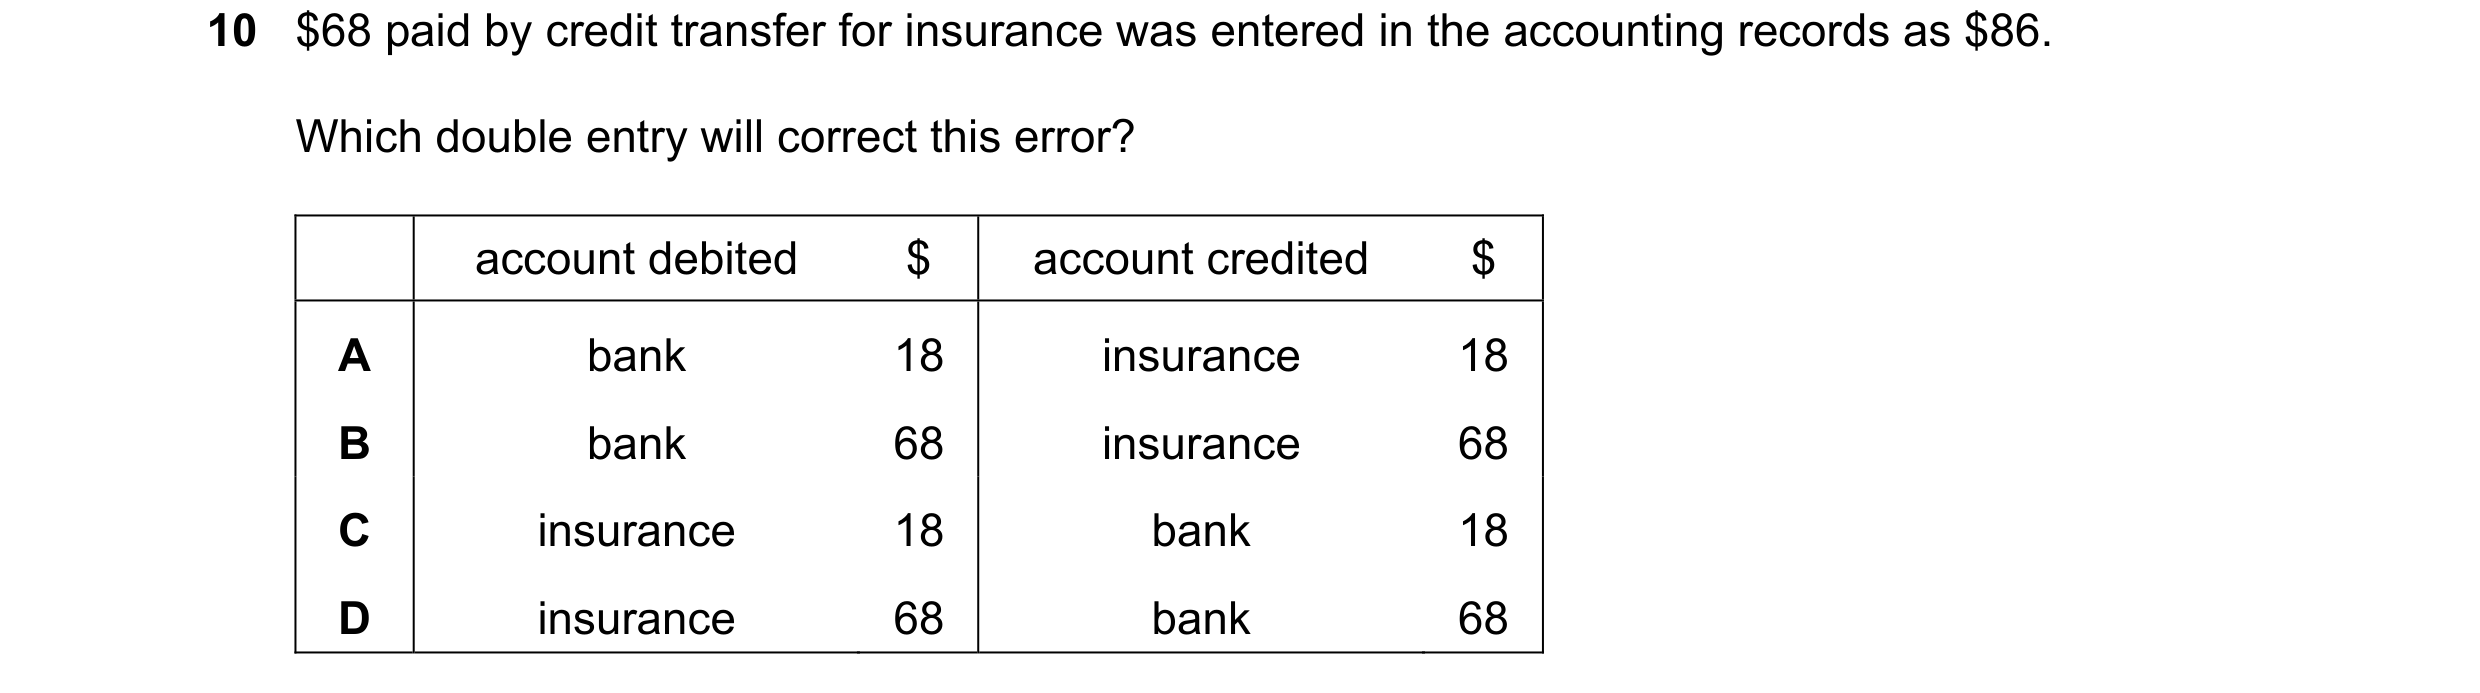
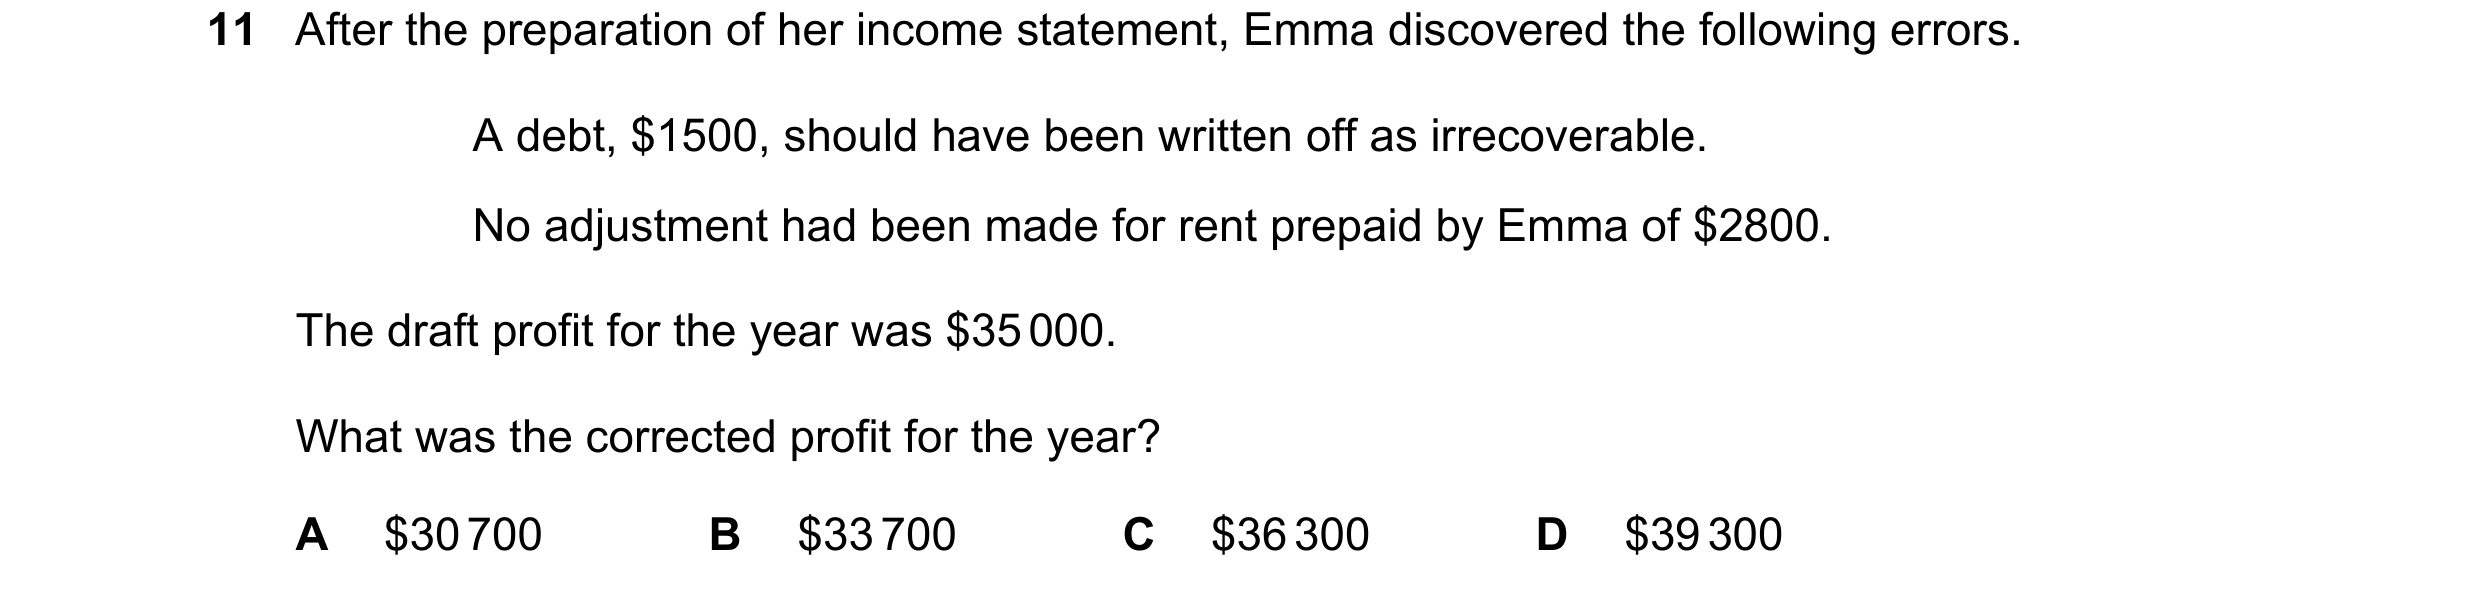
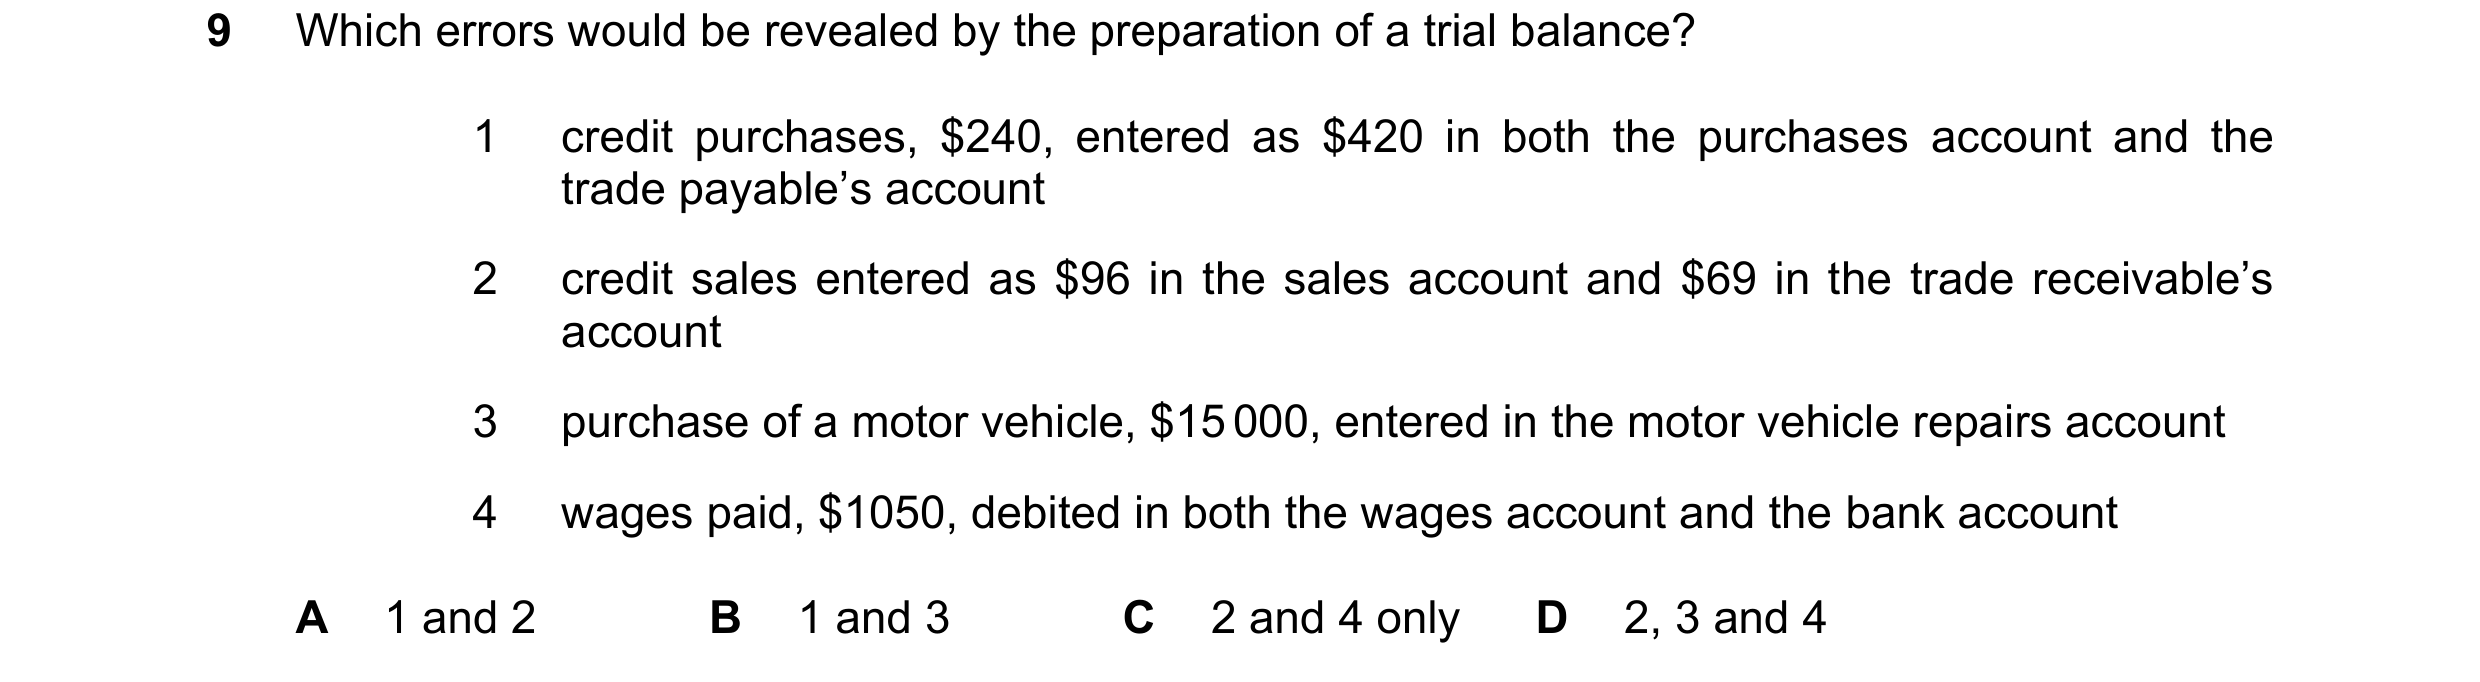
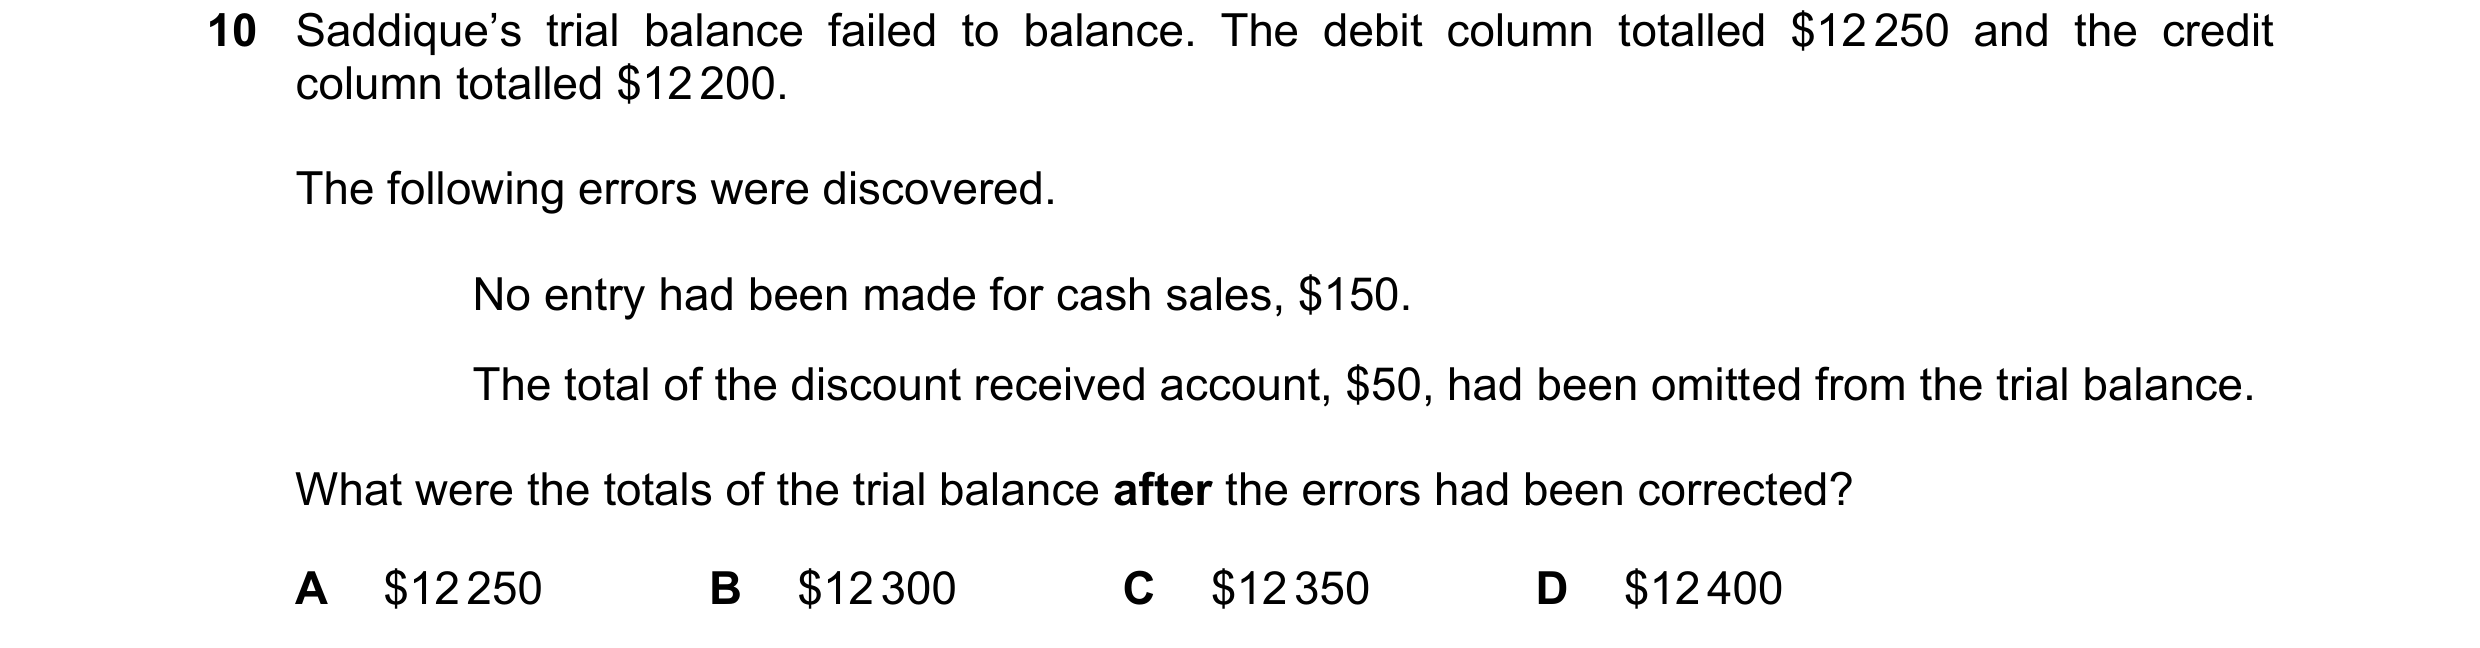 18 / 41
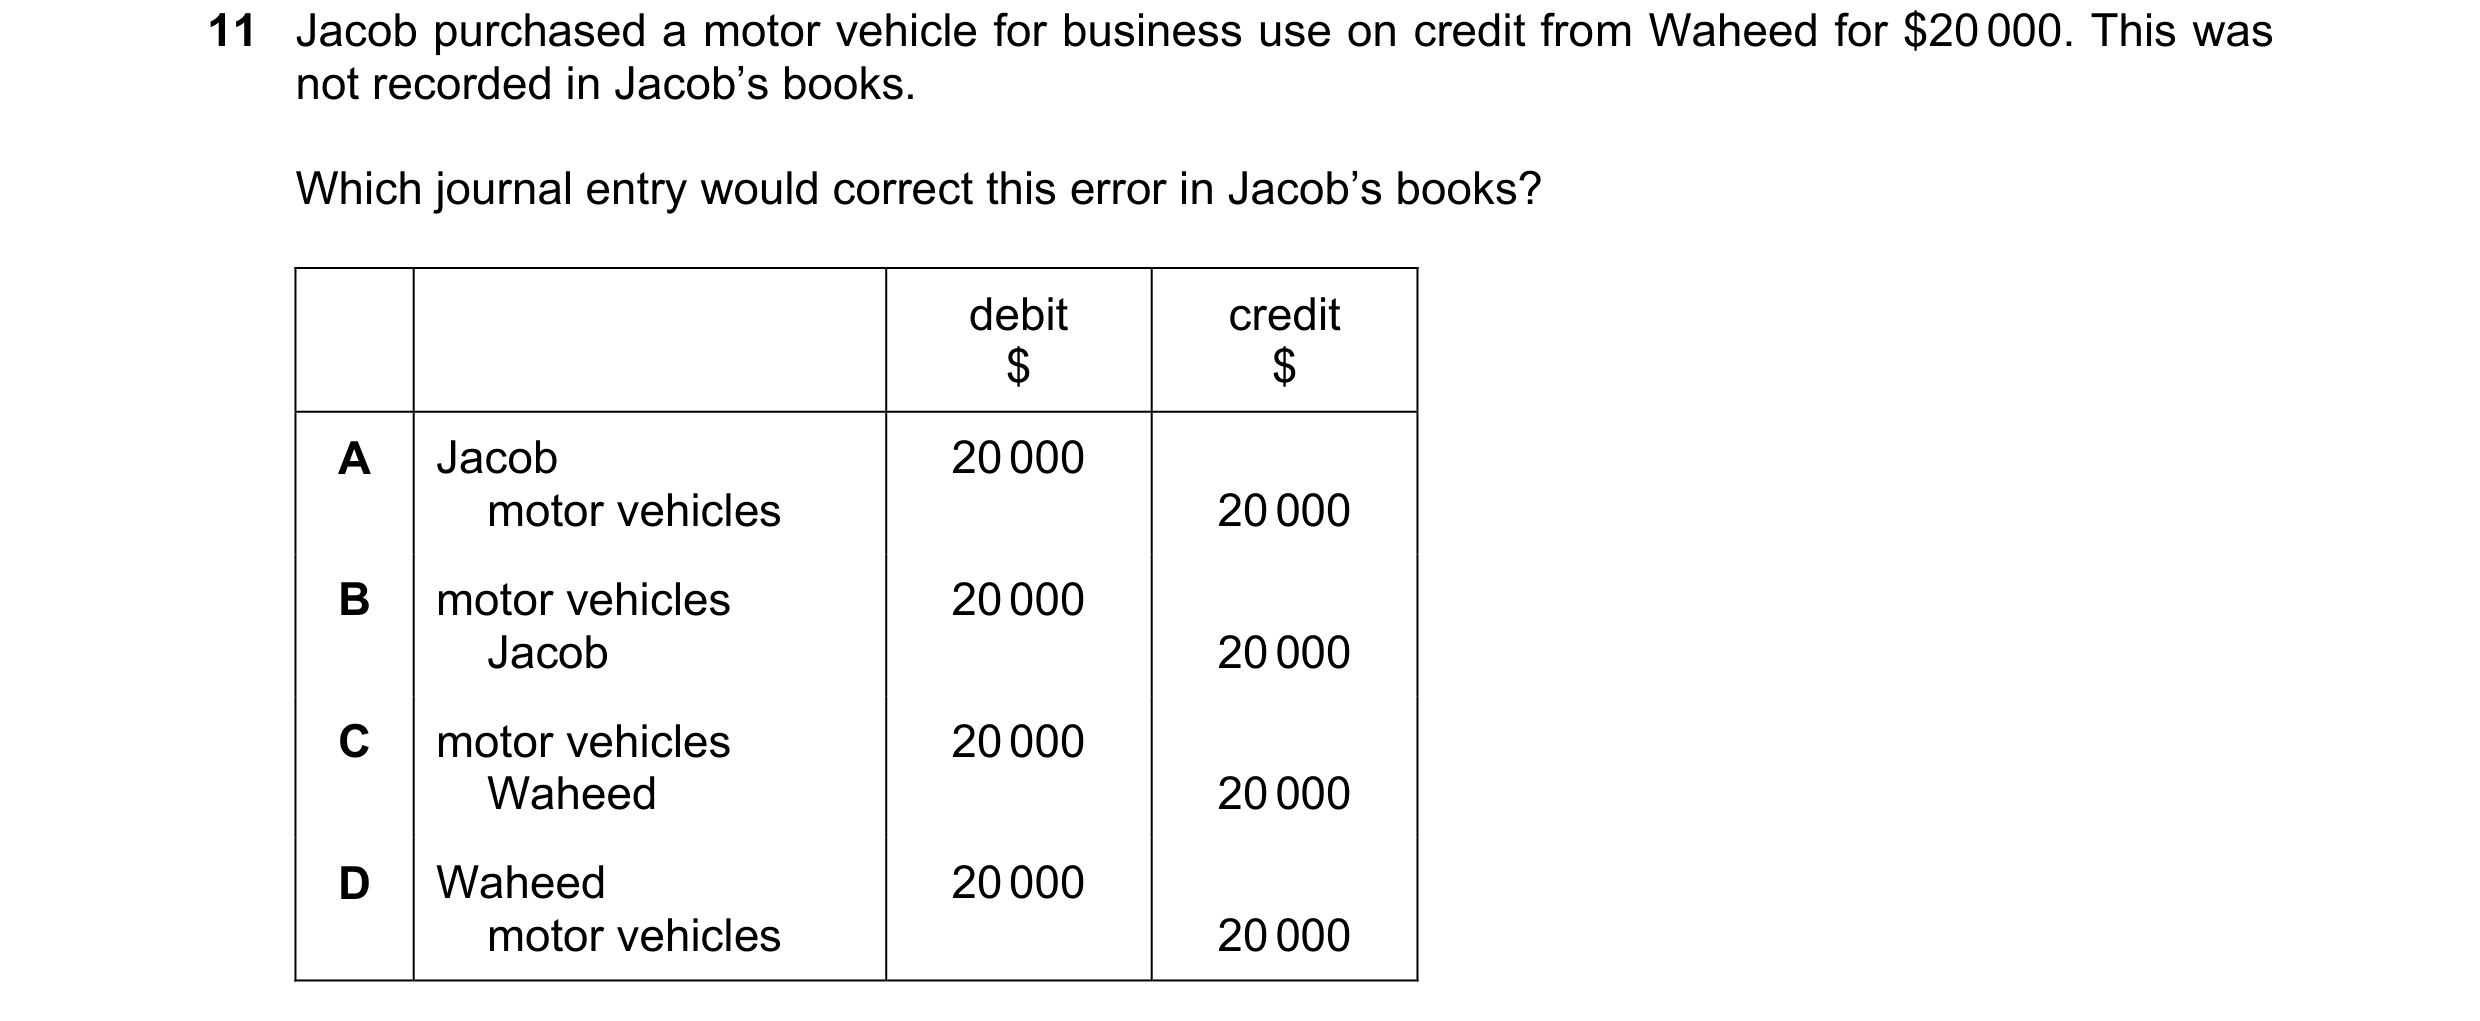
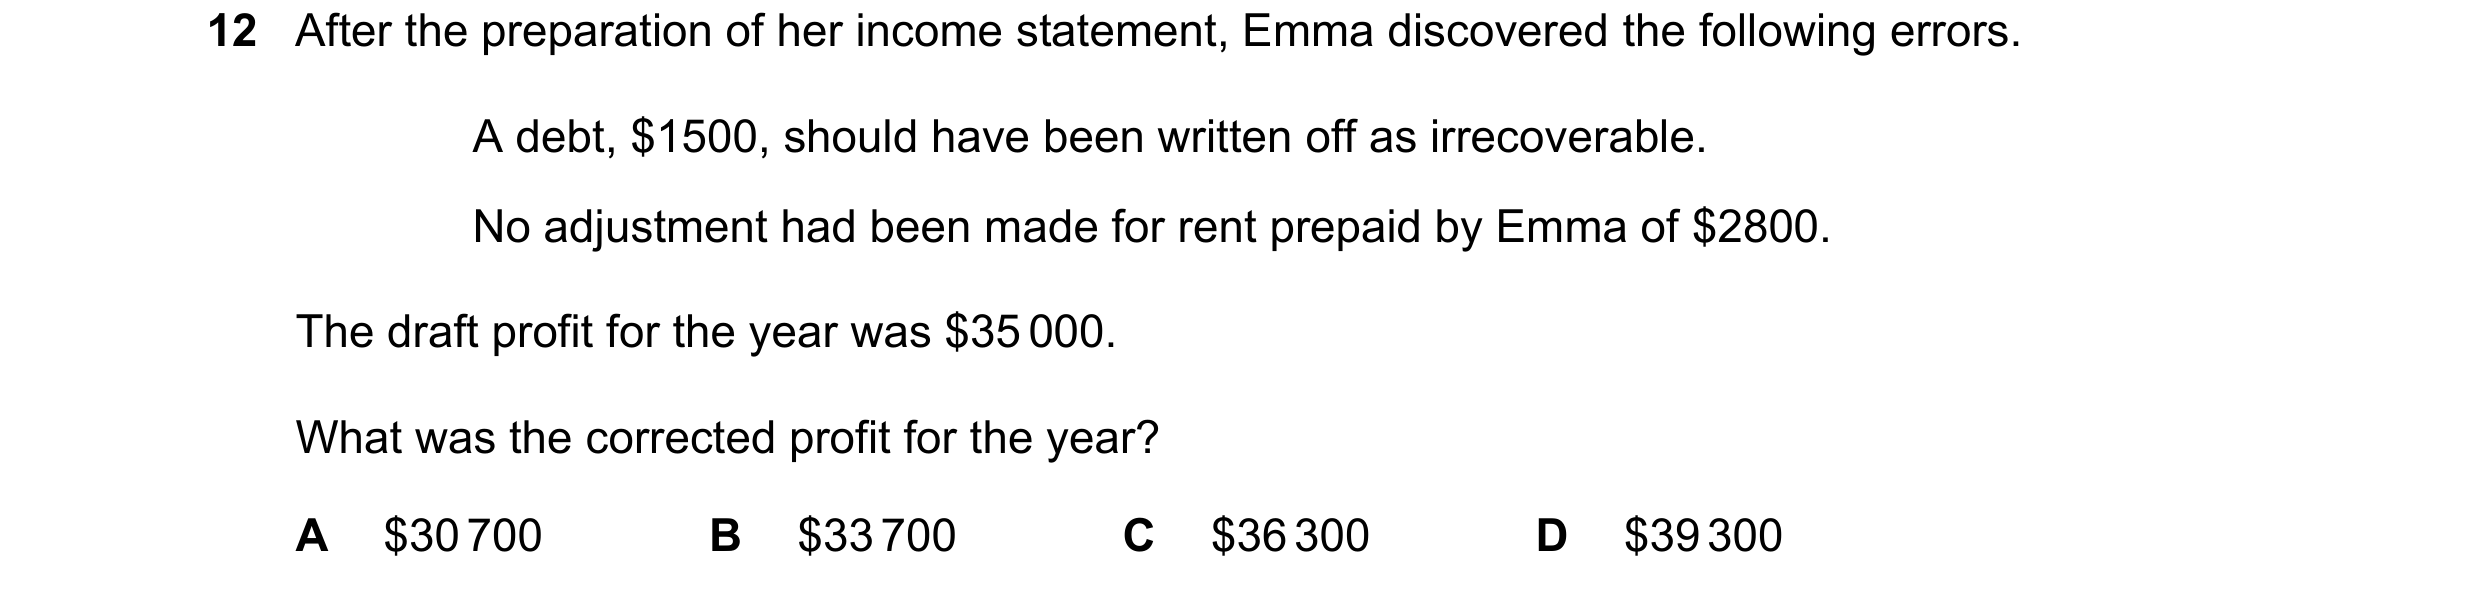
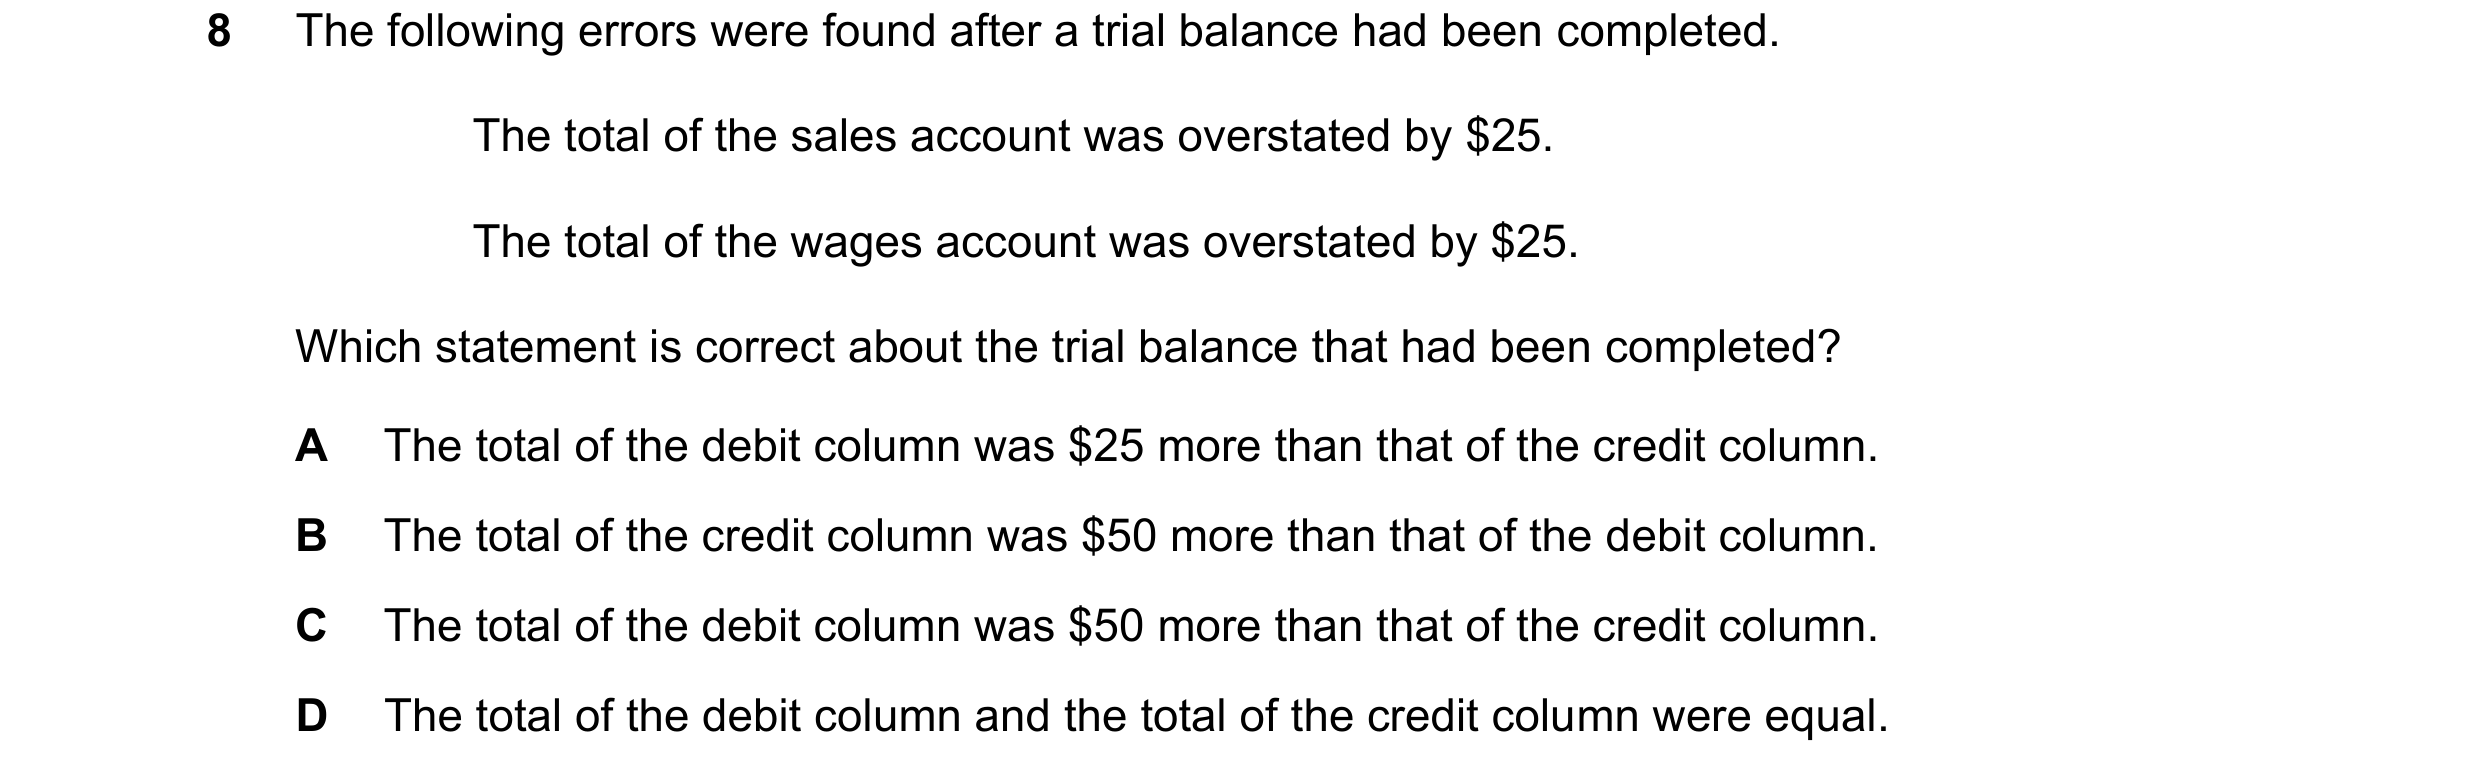 19 / 41
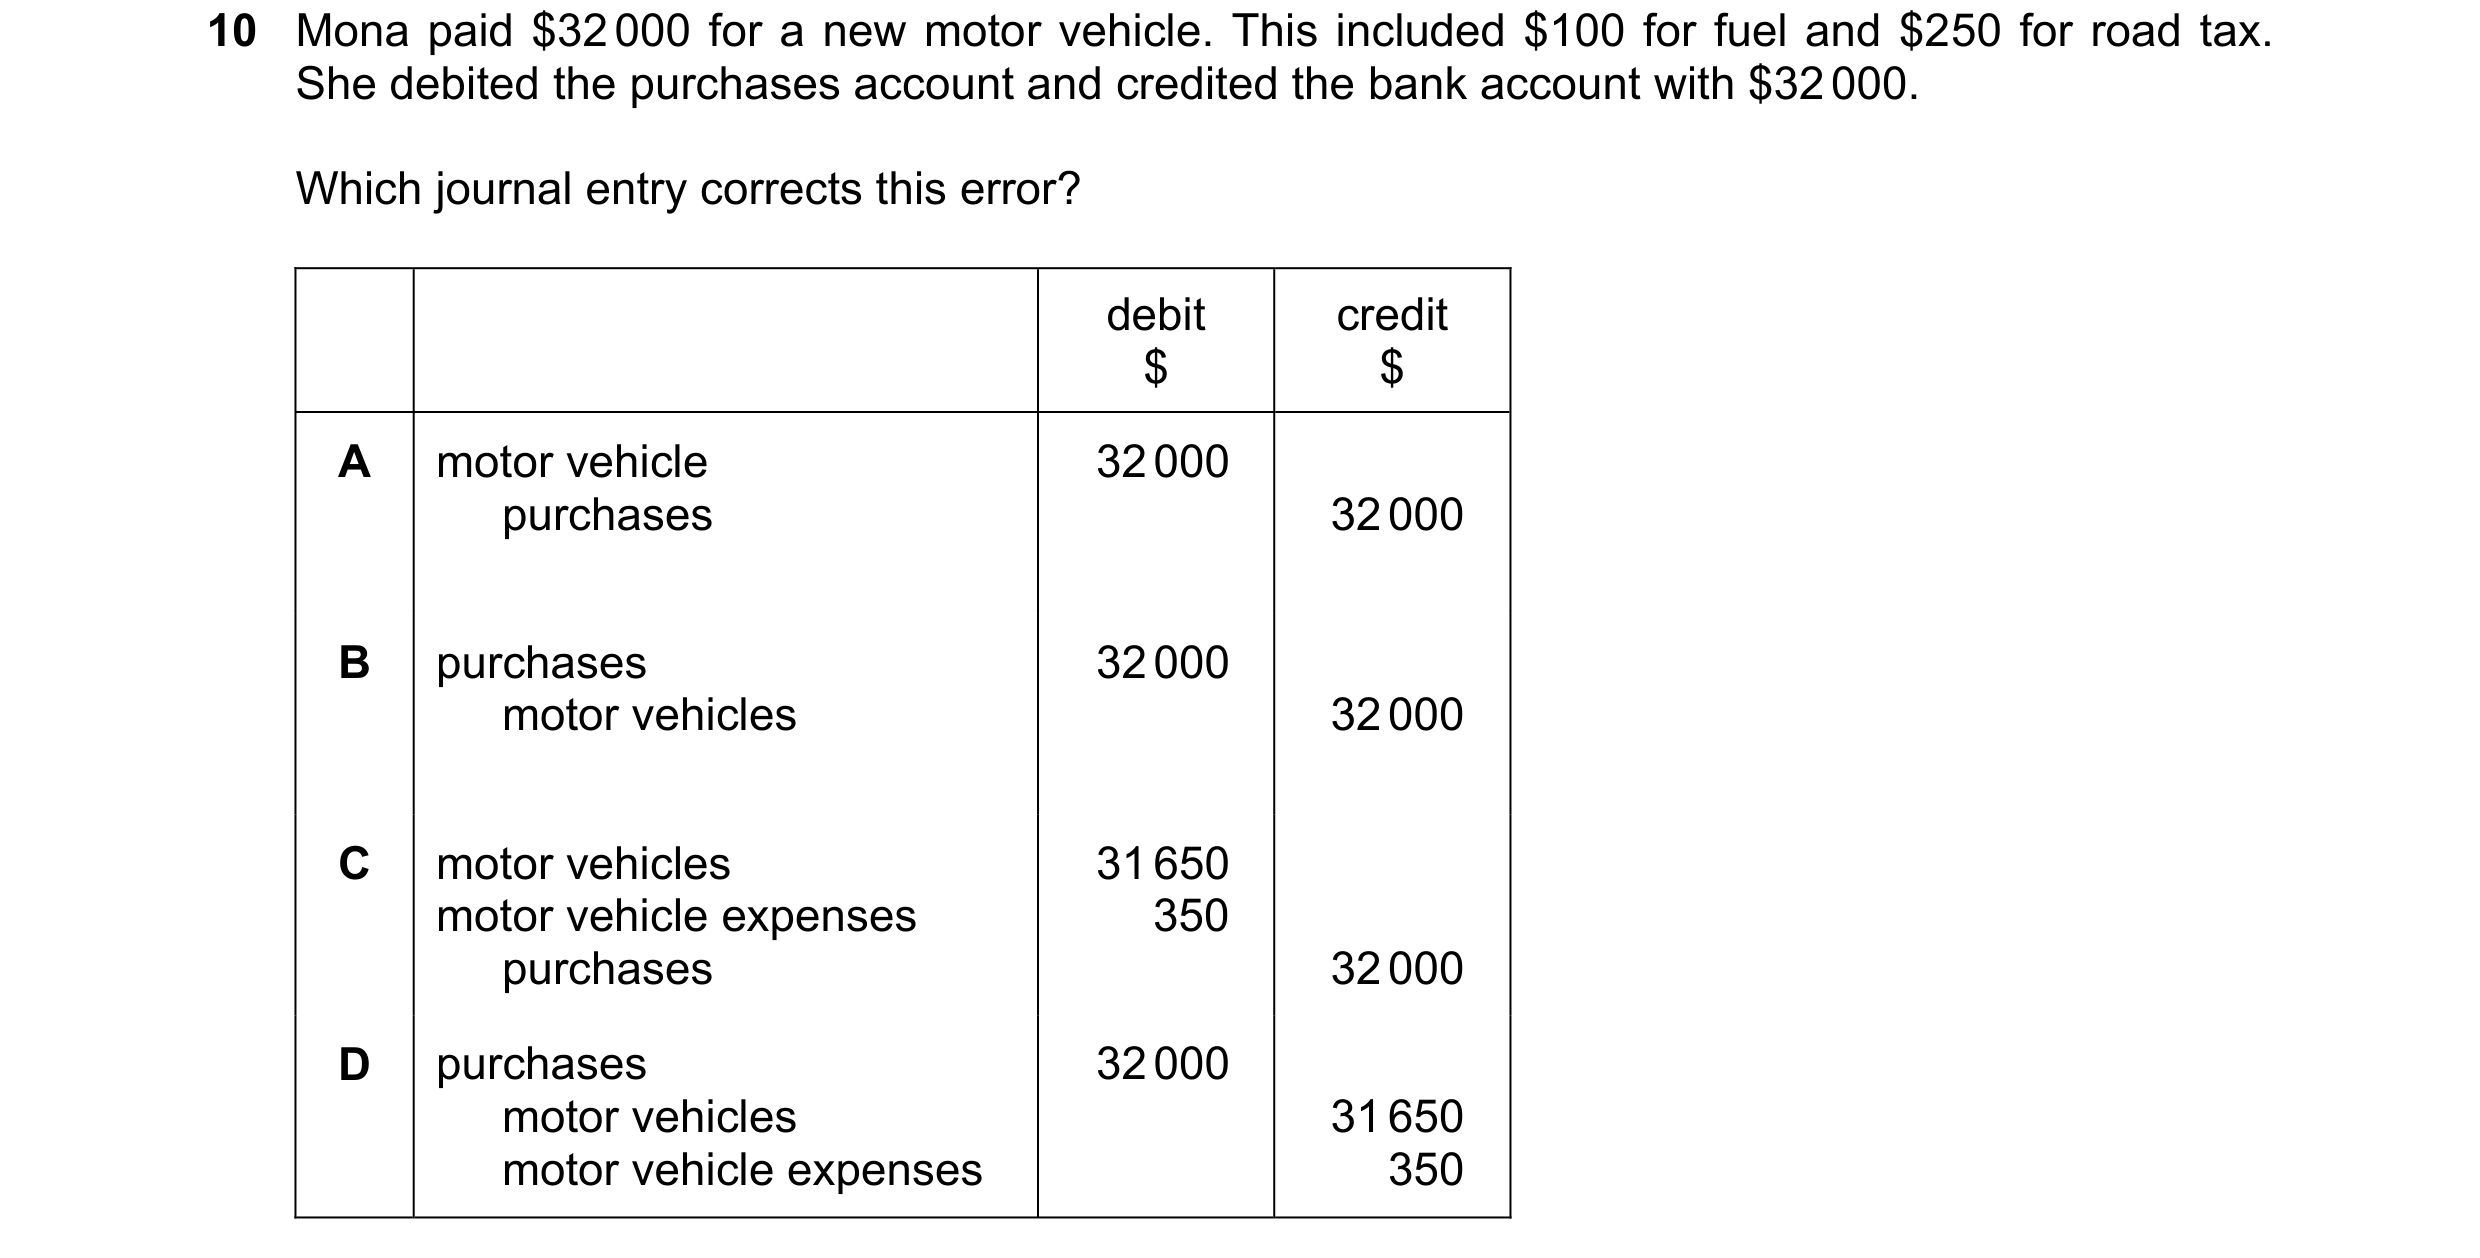
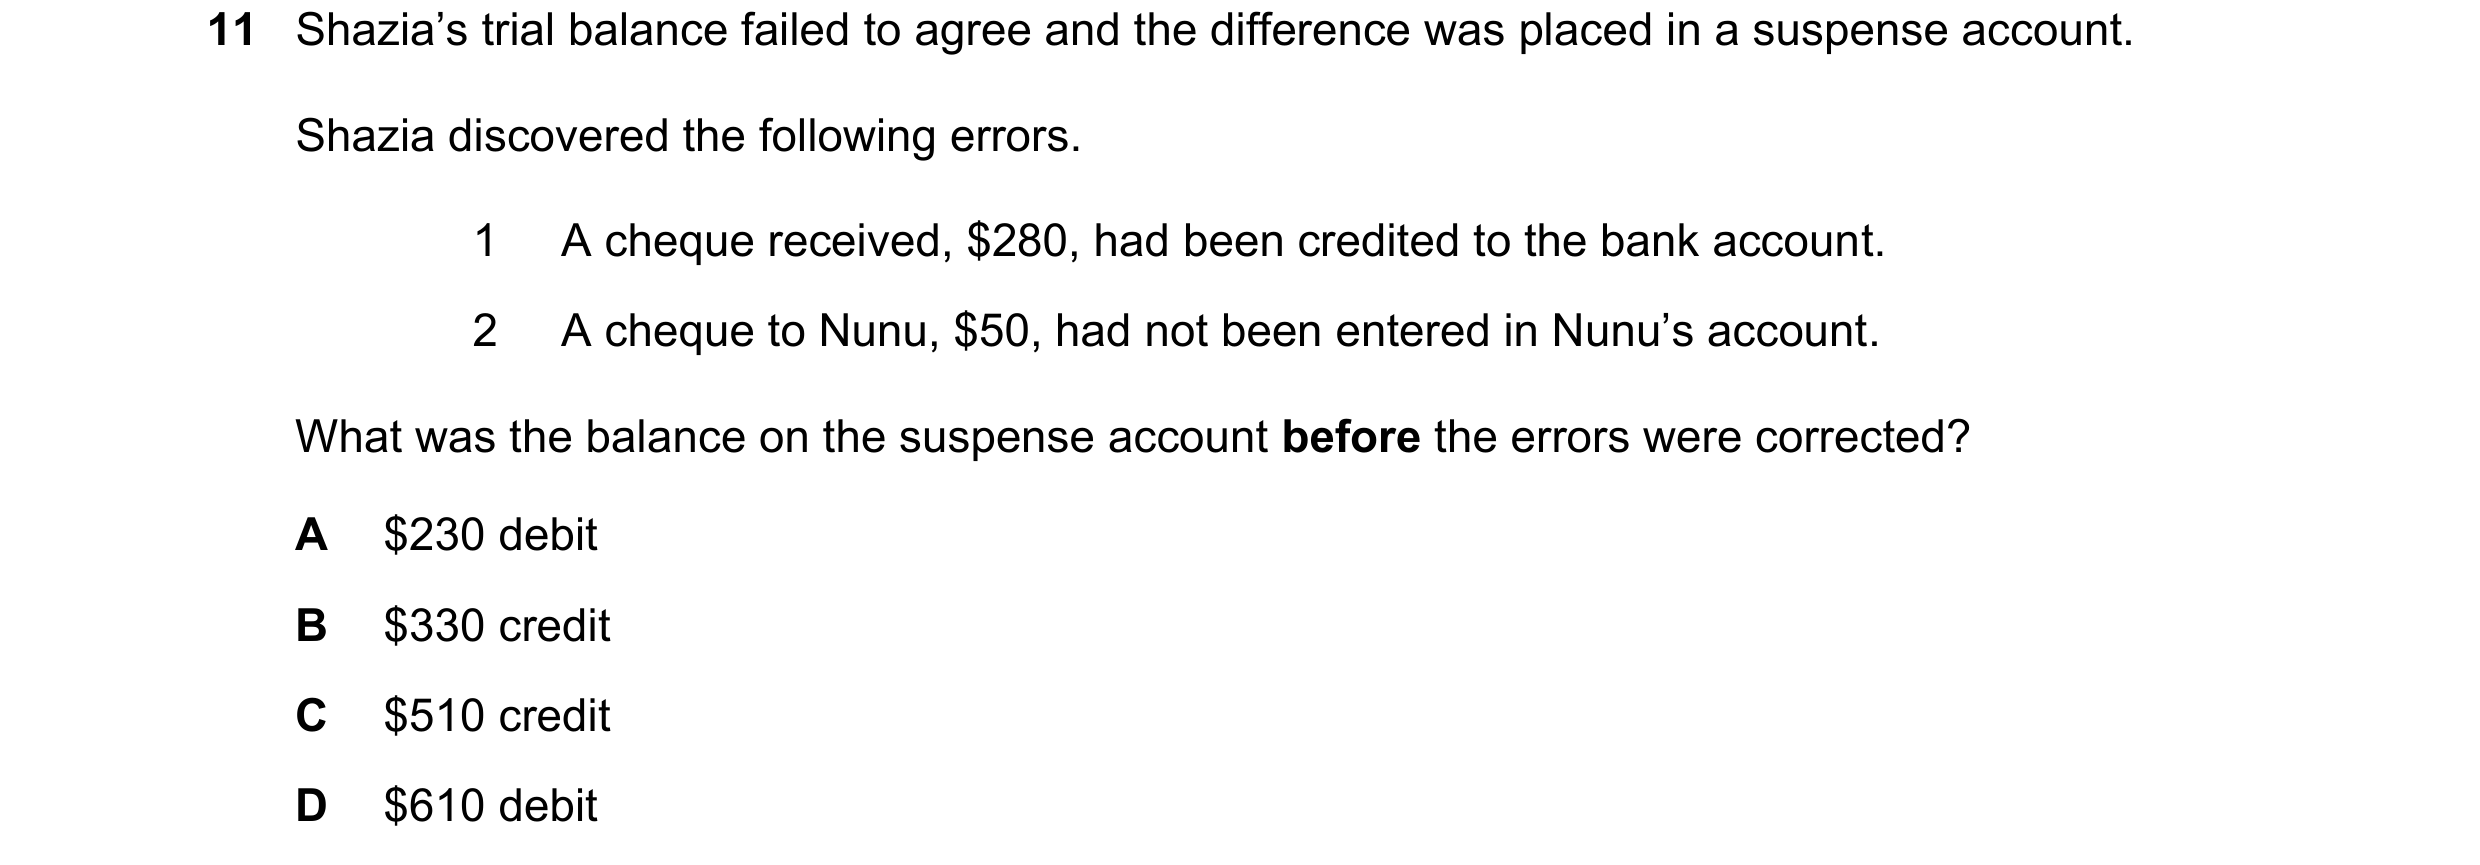
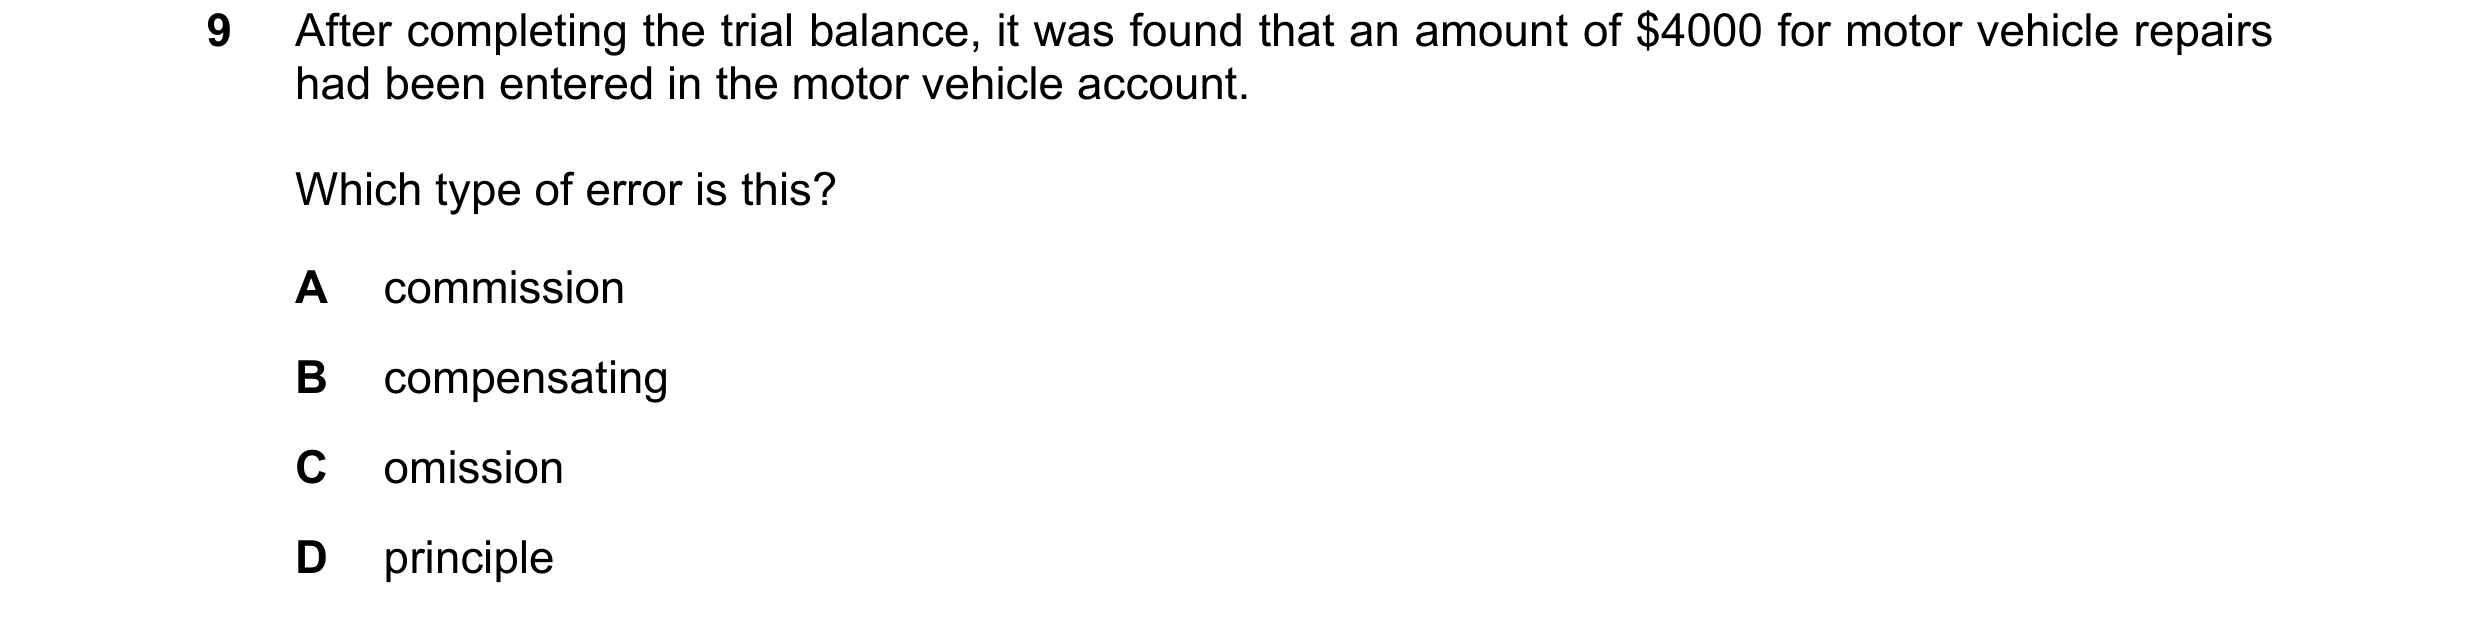
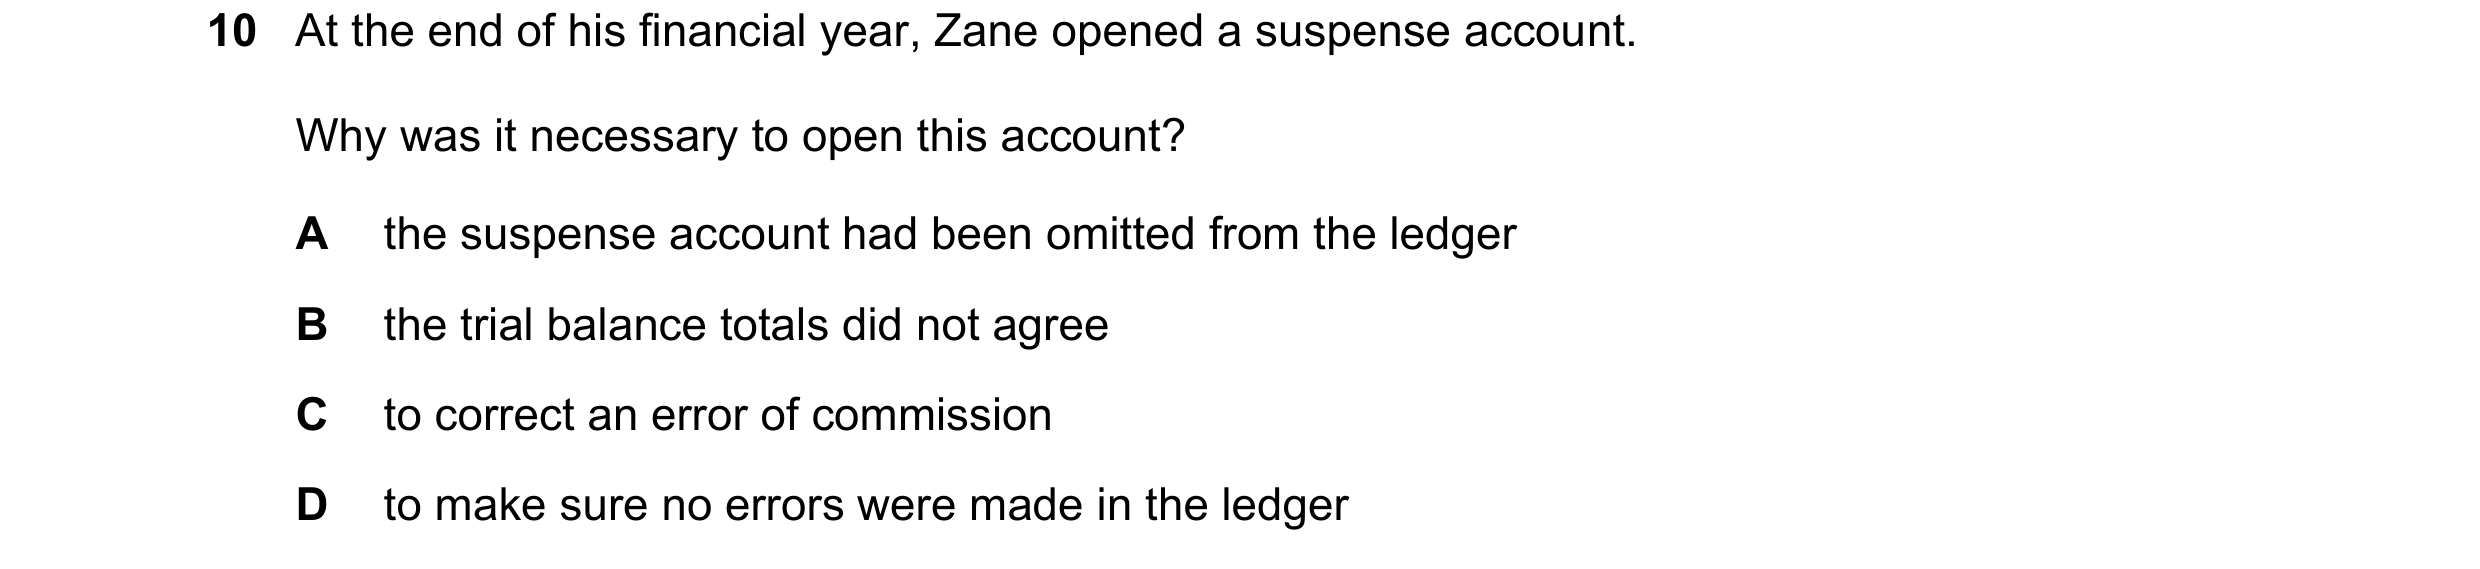 20 / 41
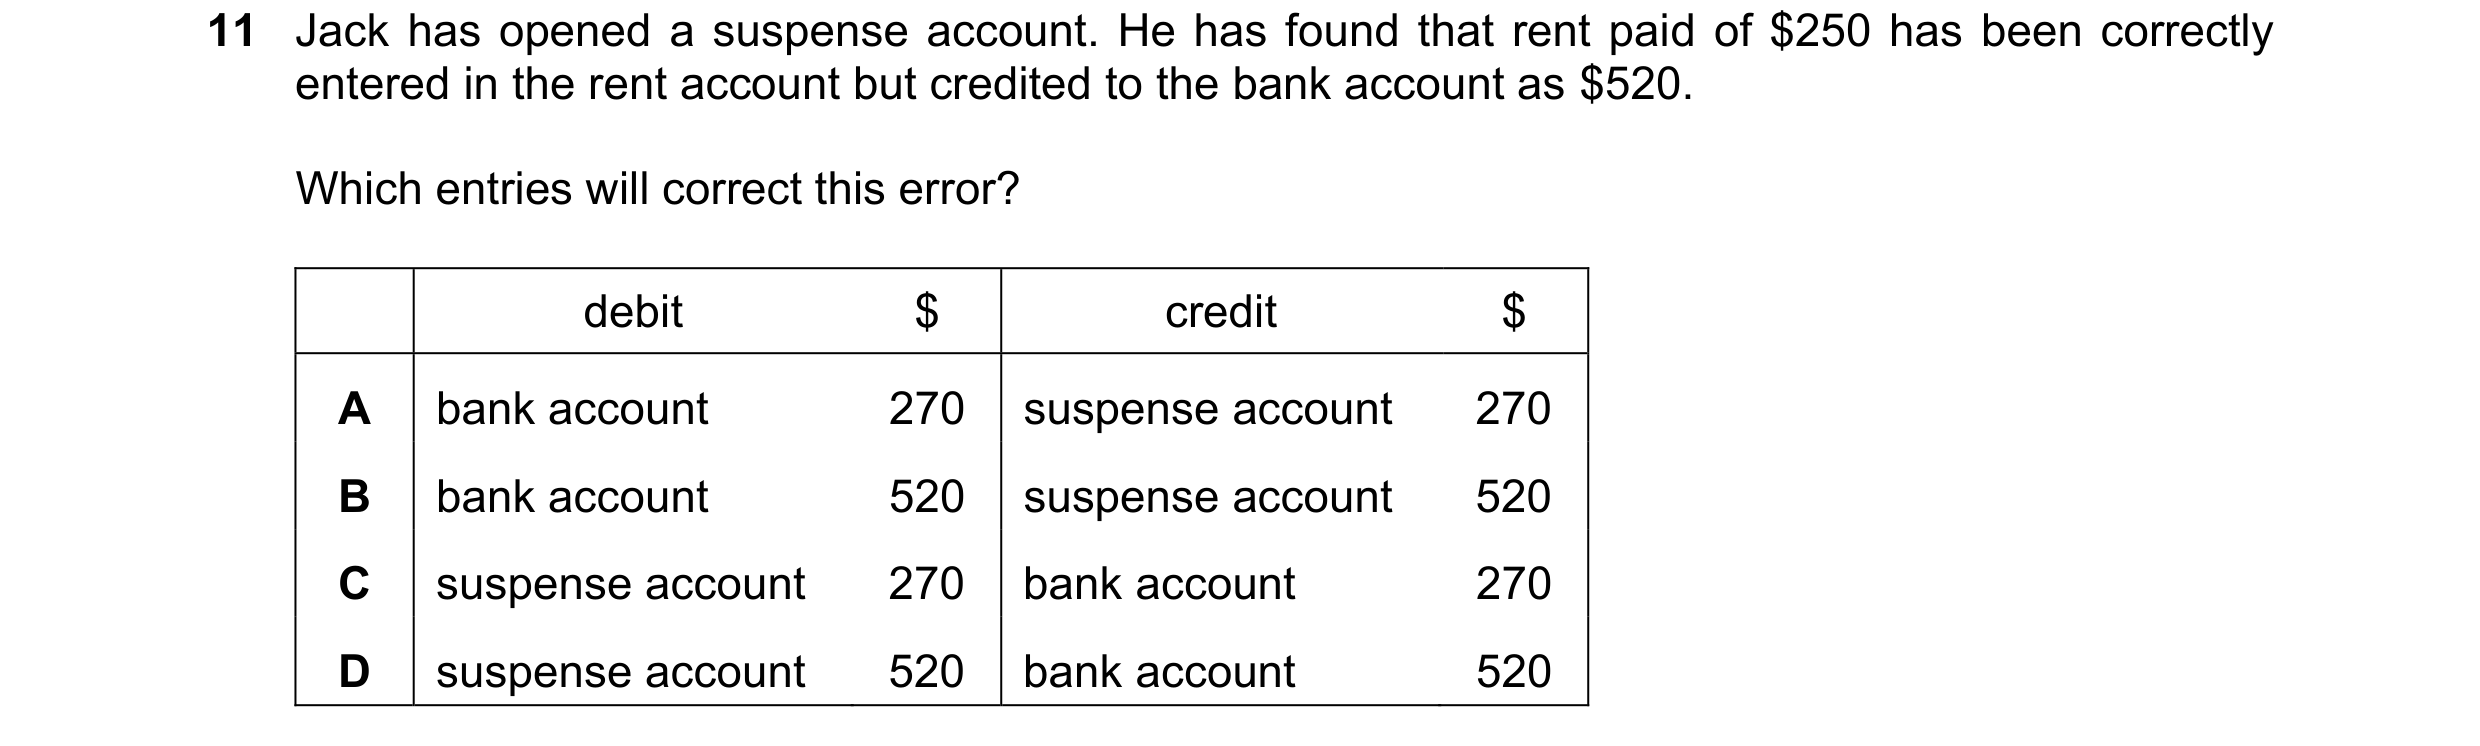
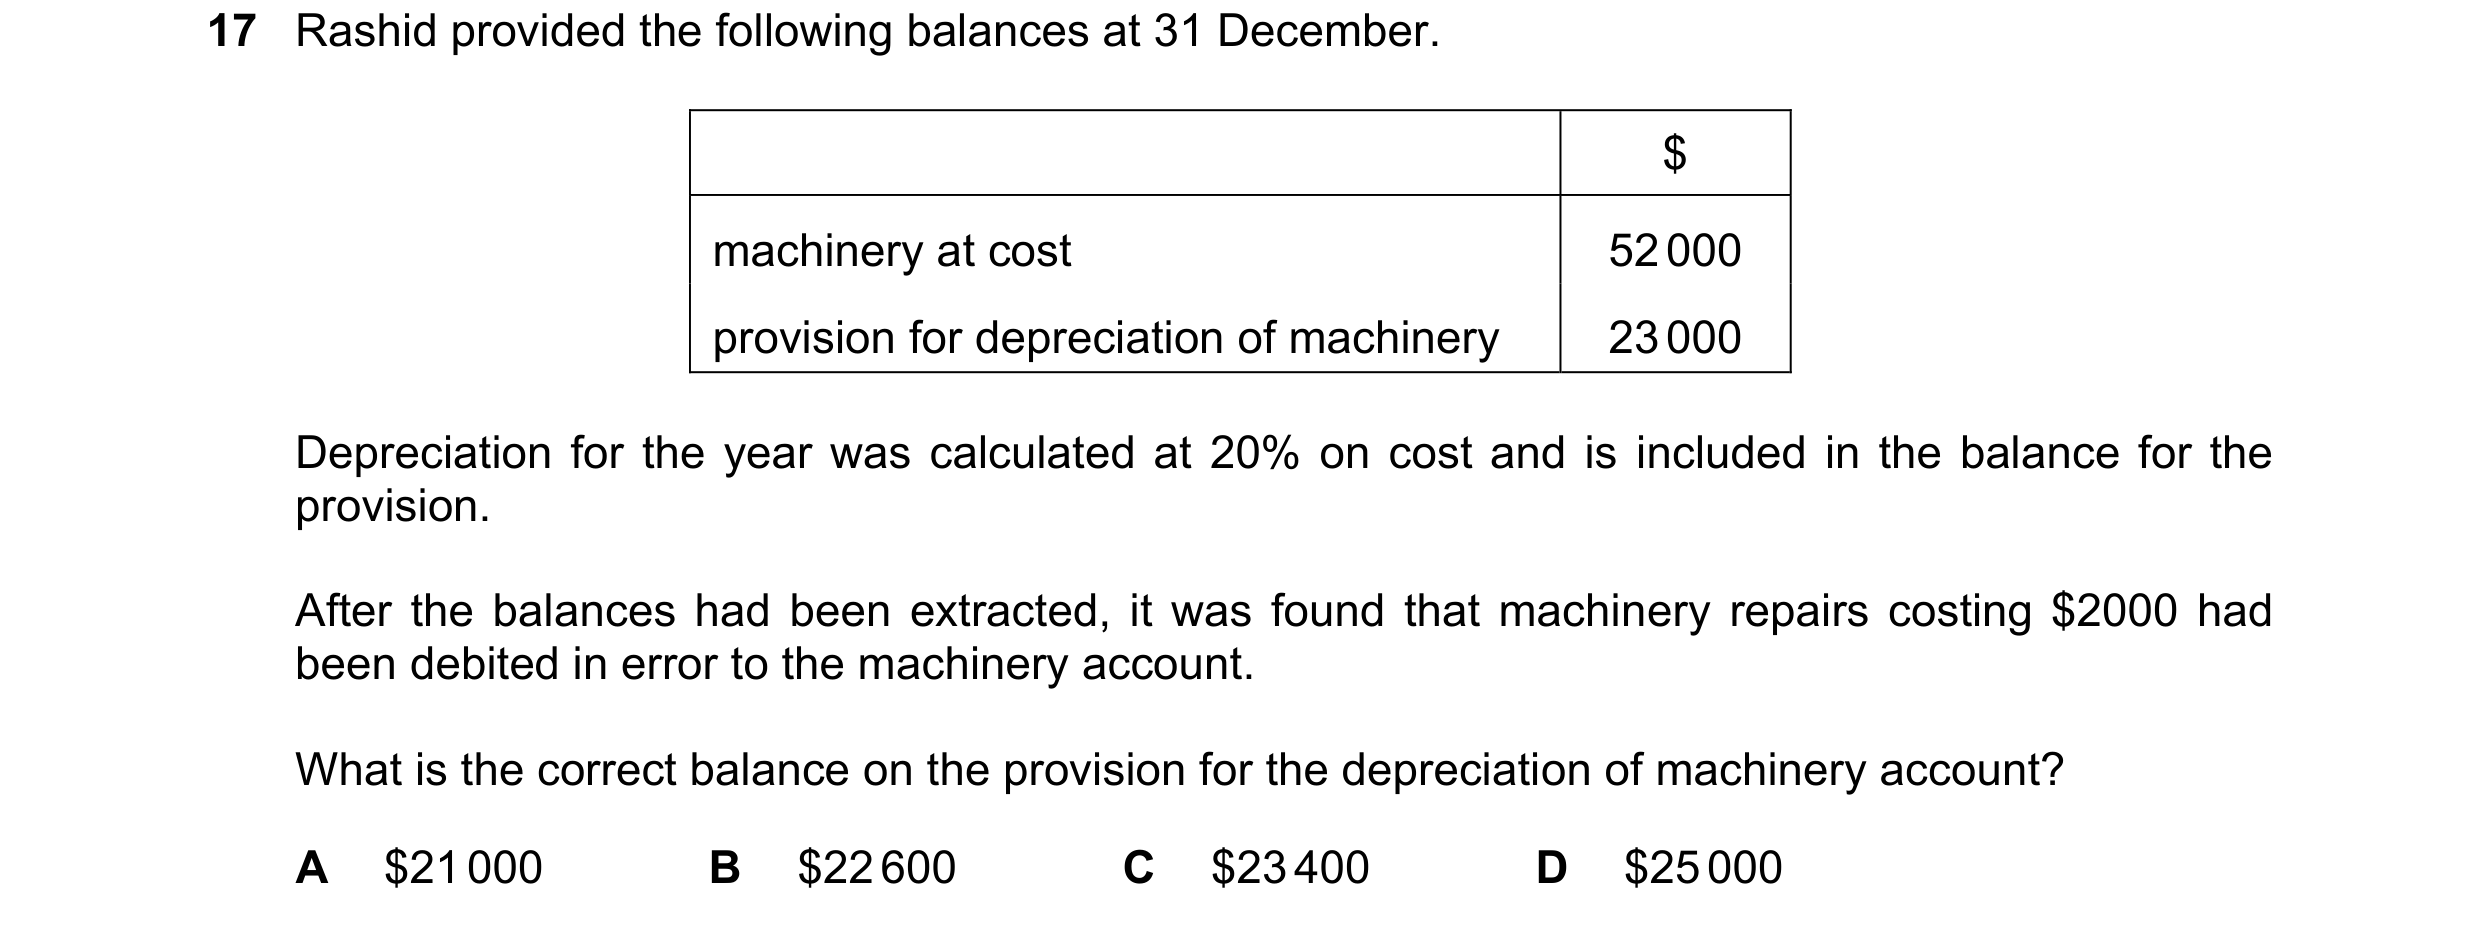
 21 / 41
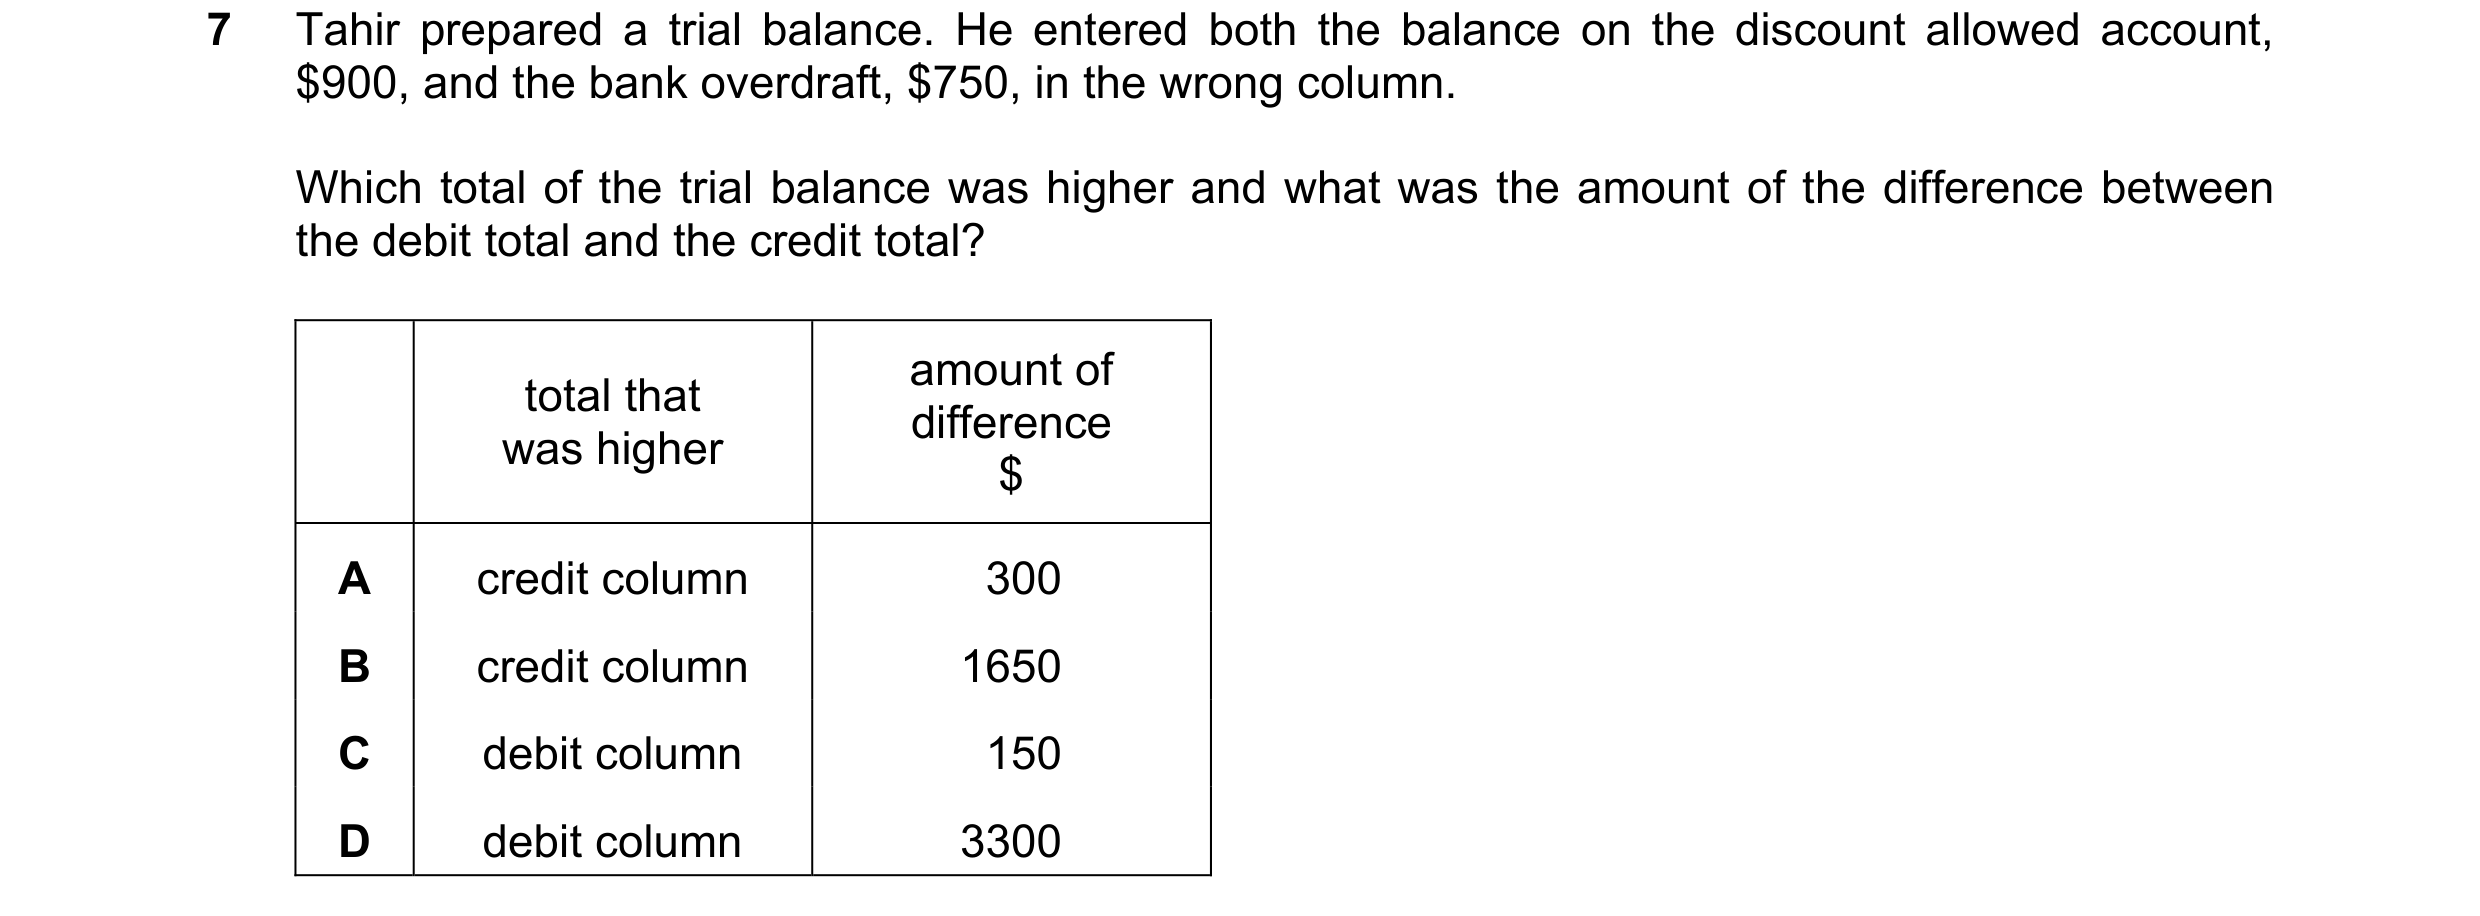
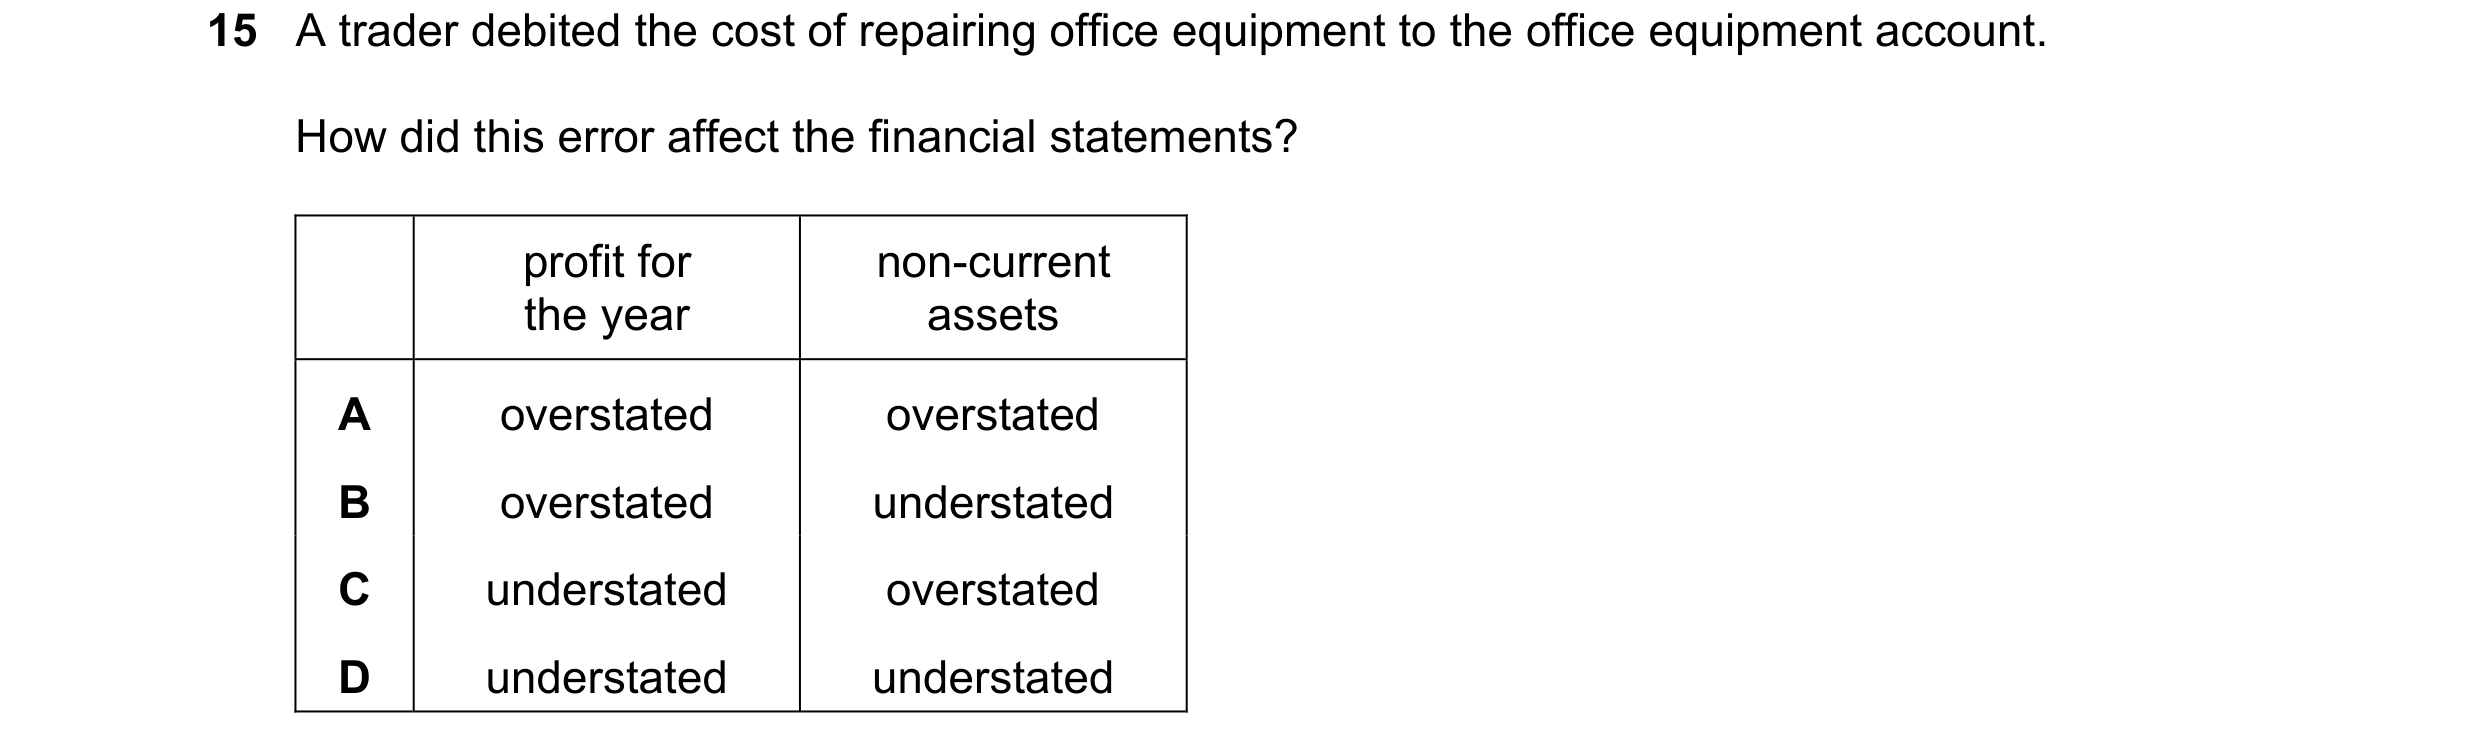 22 / 41
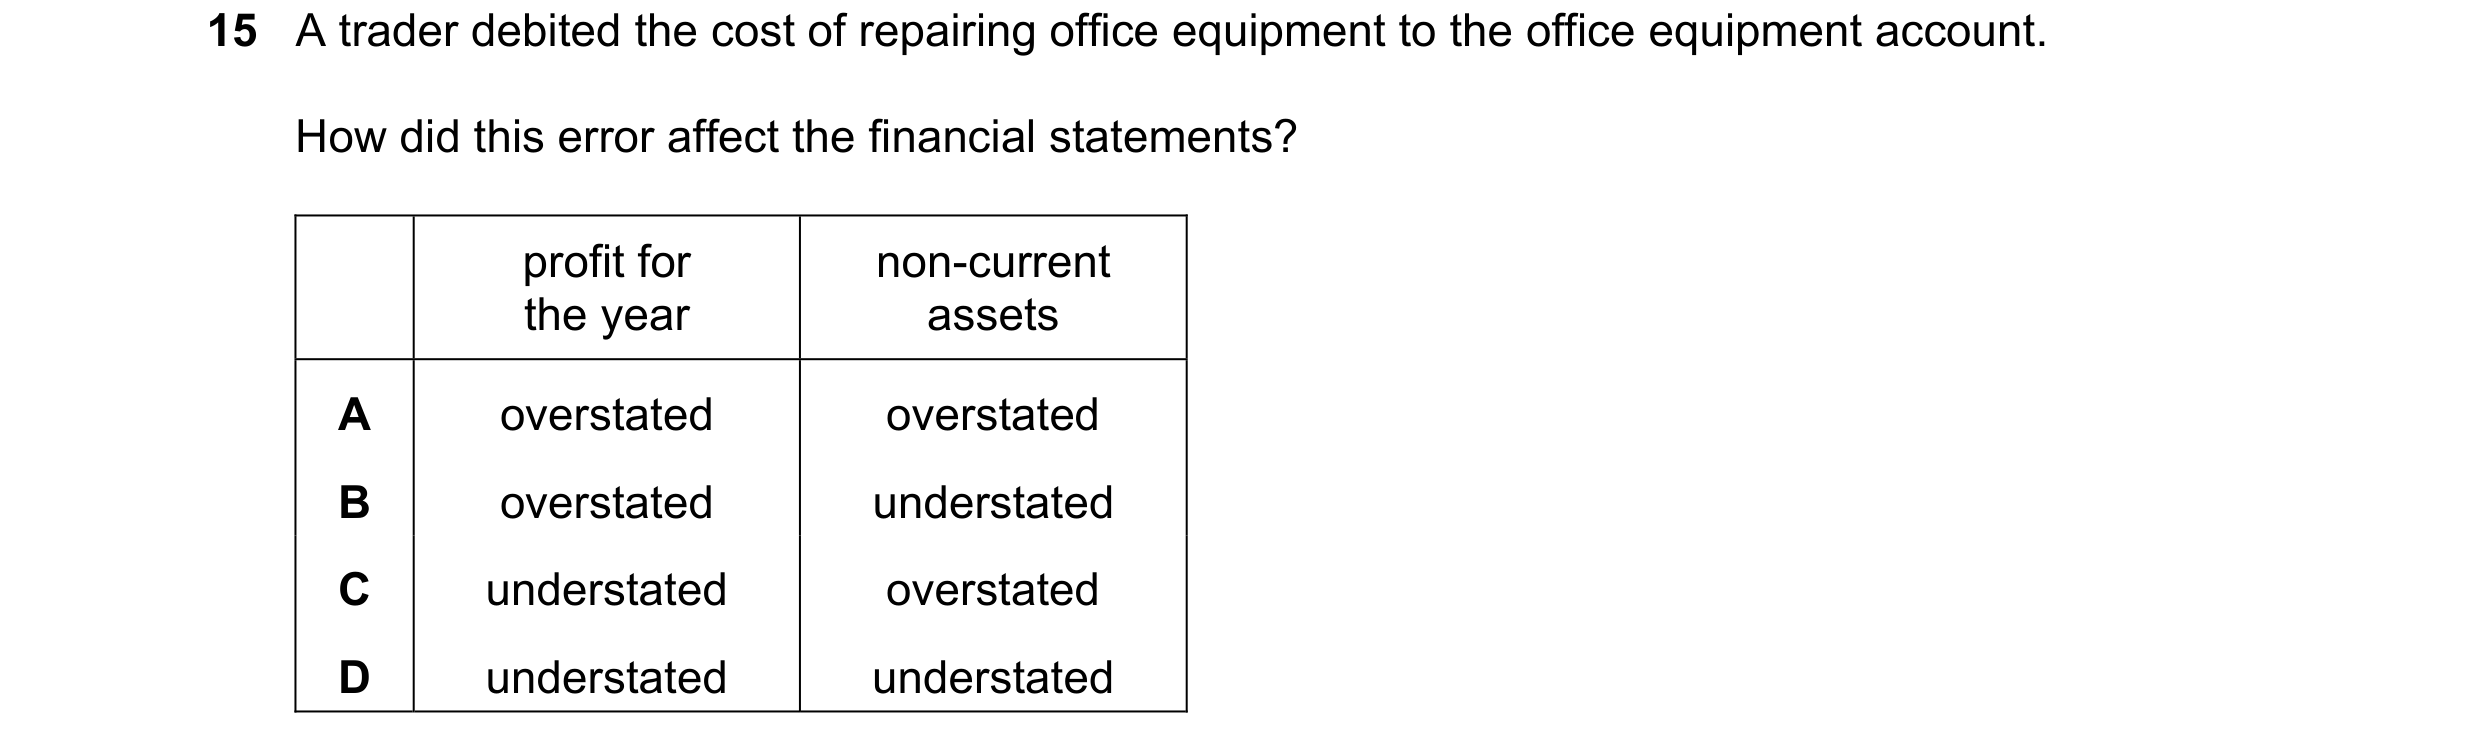 23 / 41
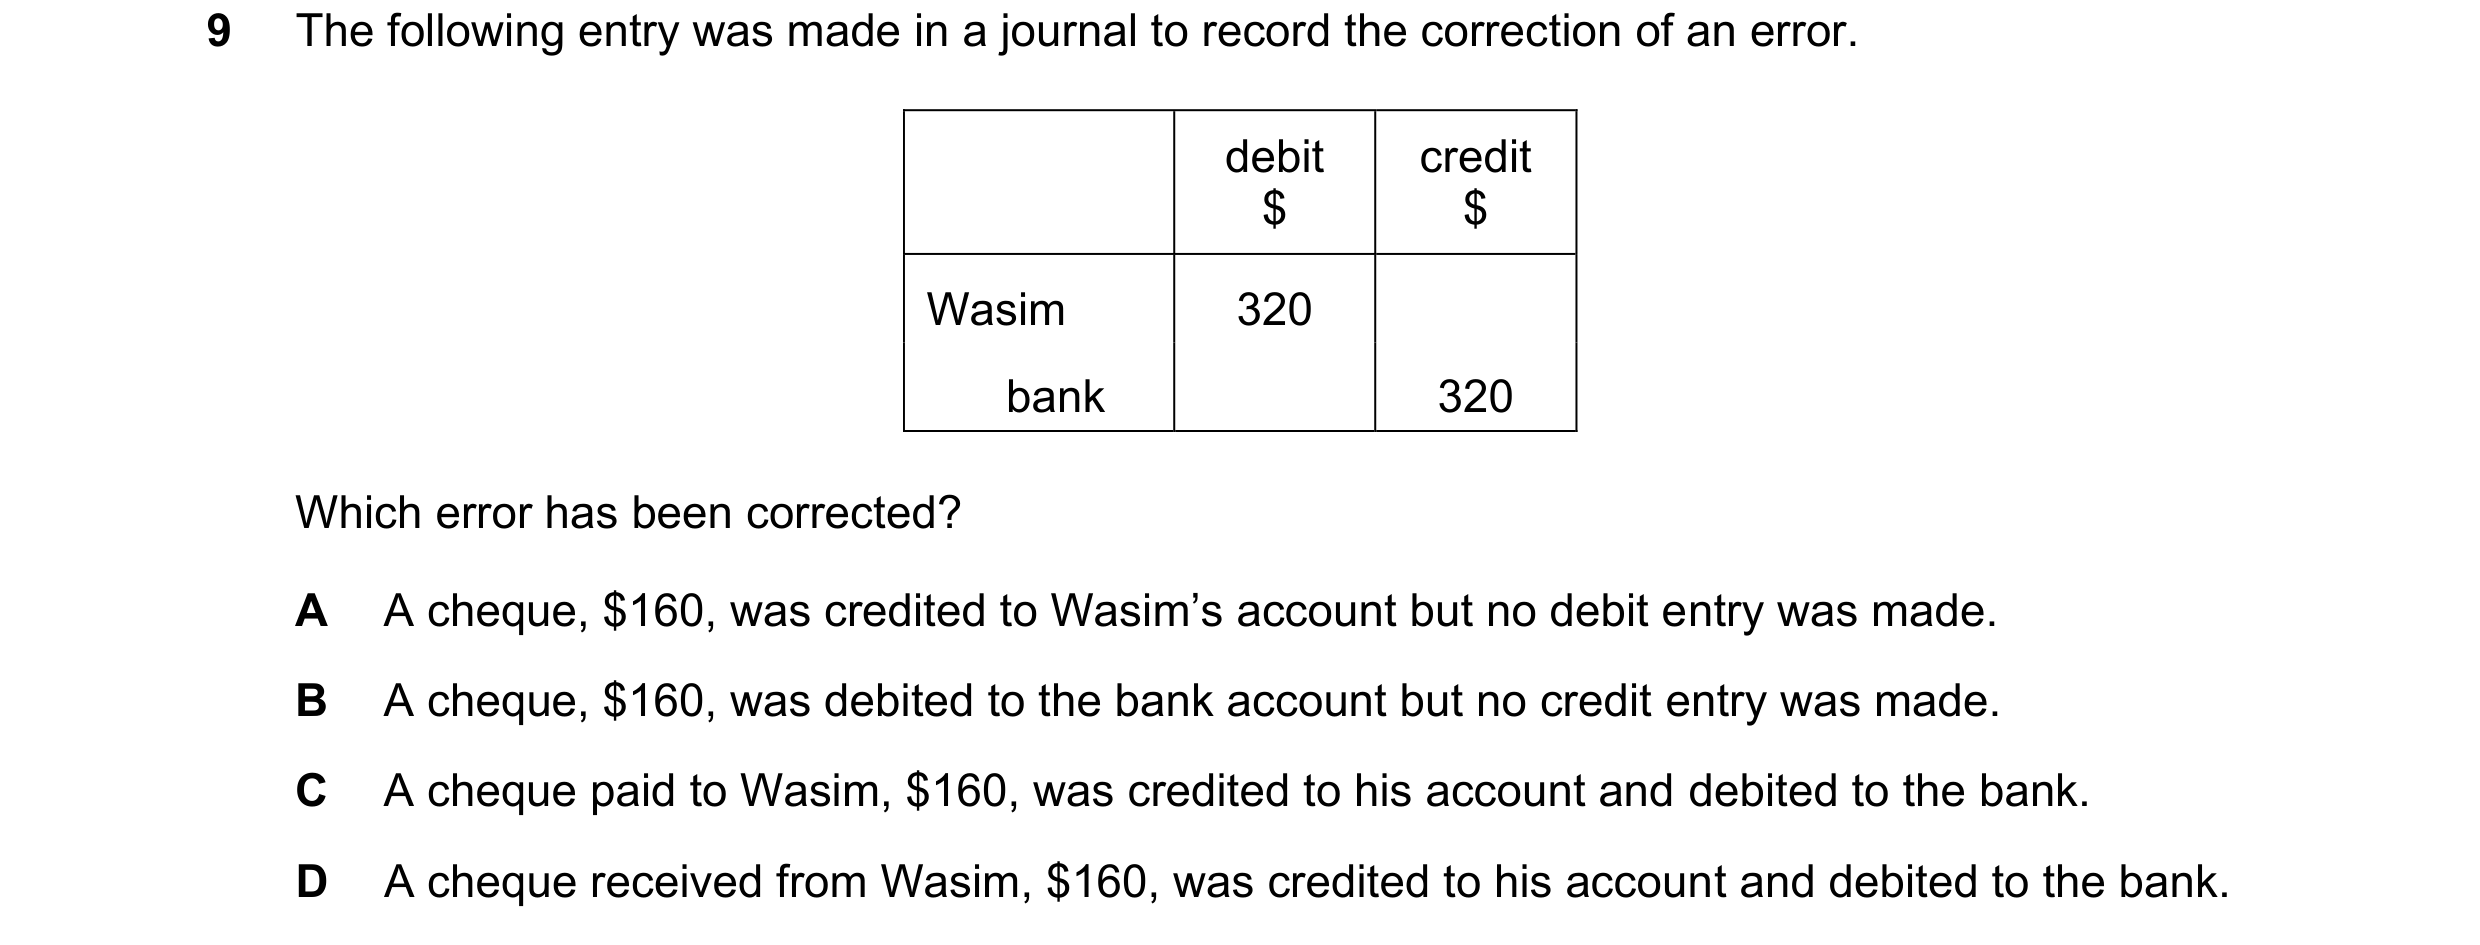
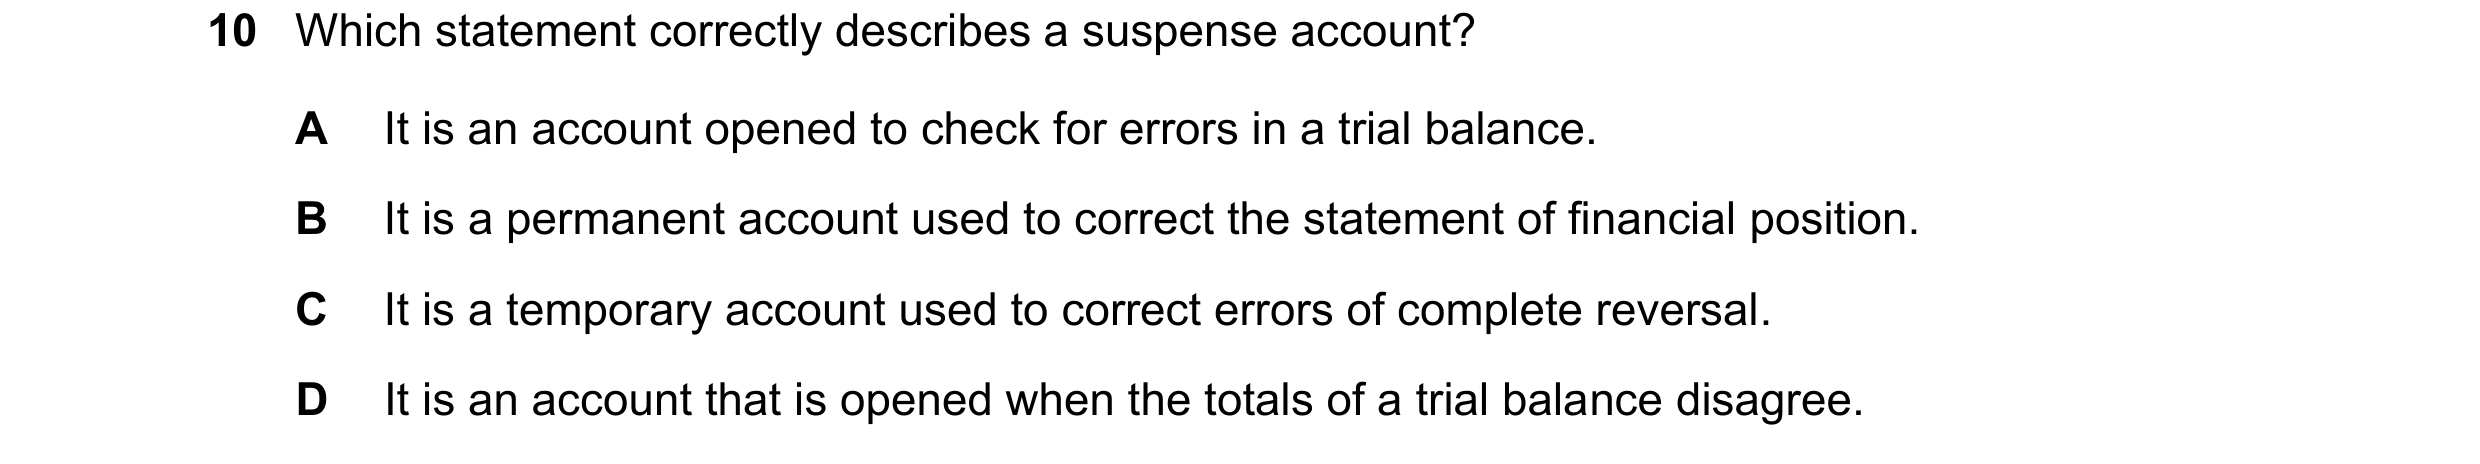
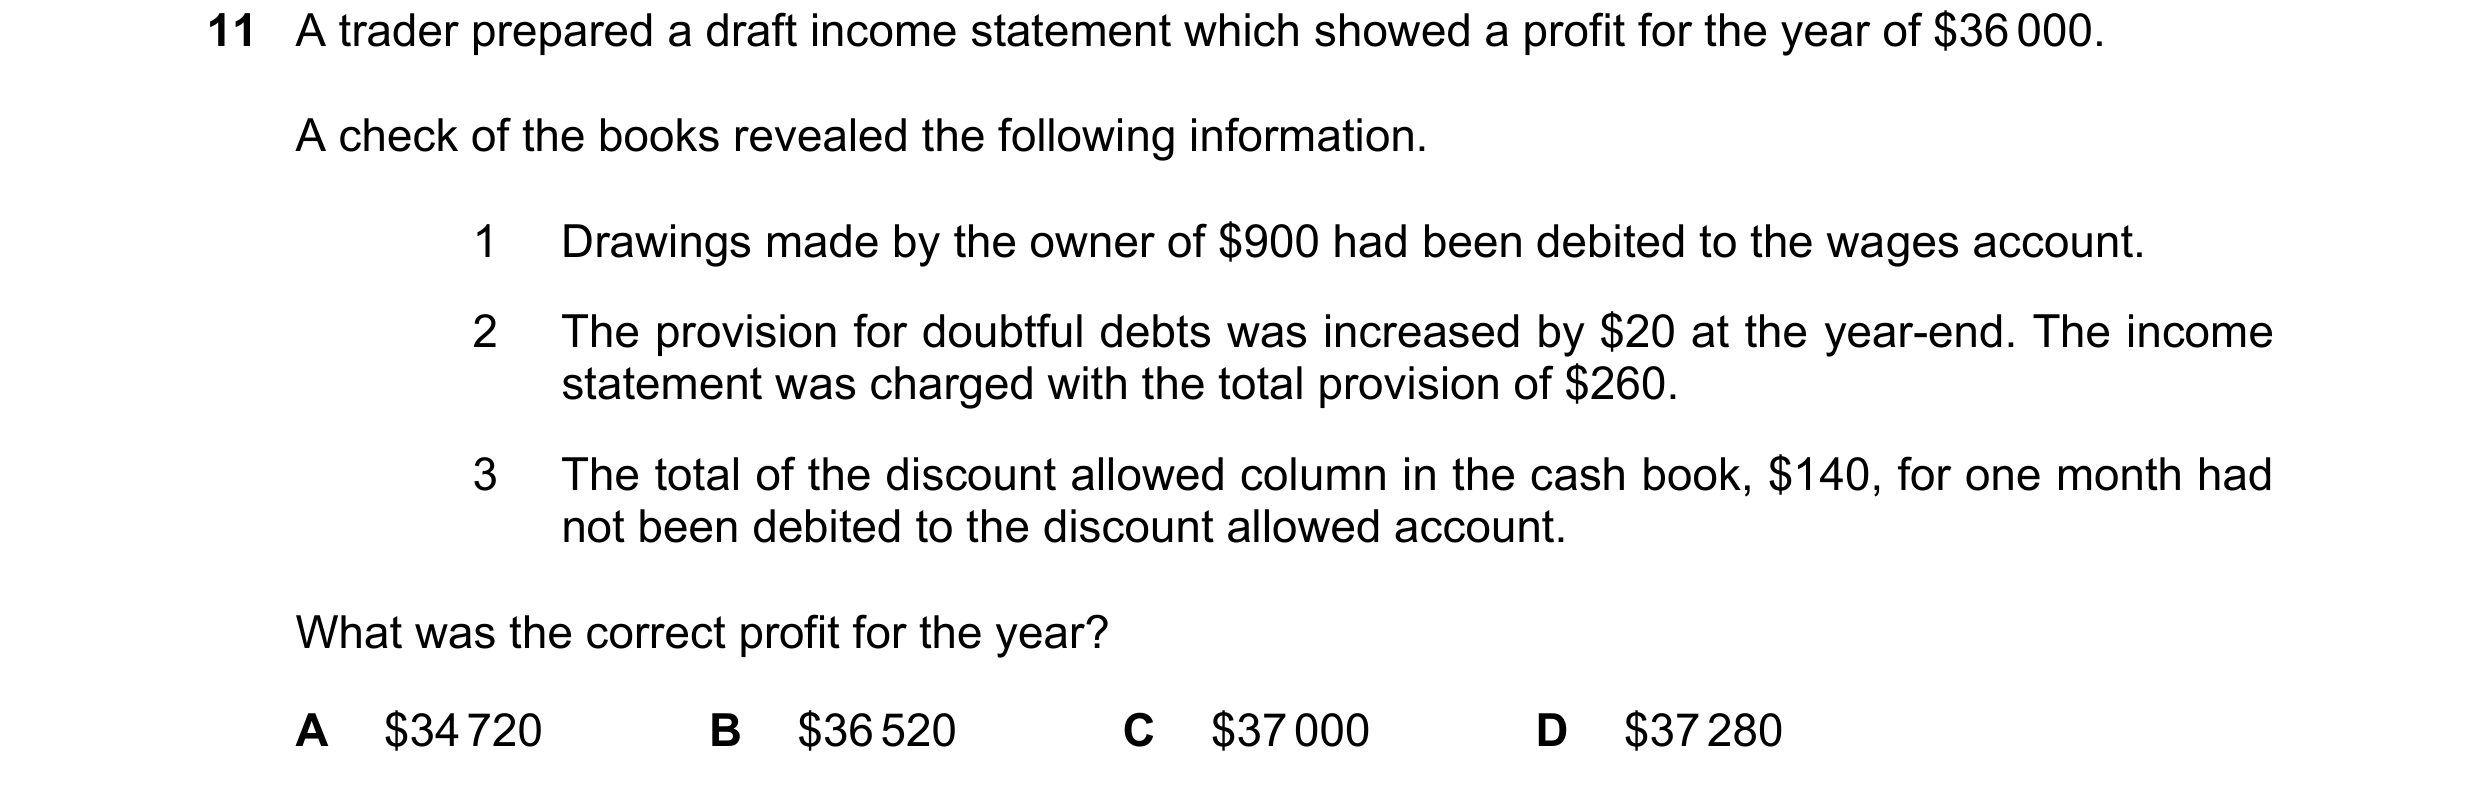
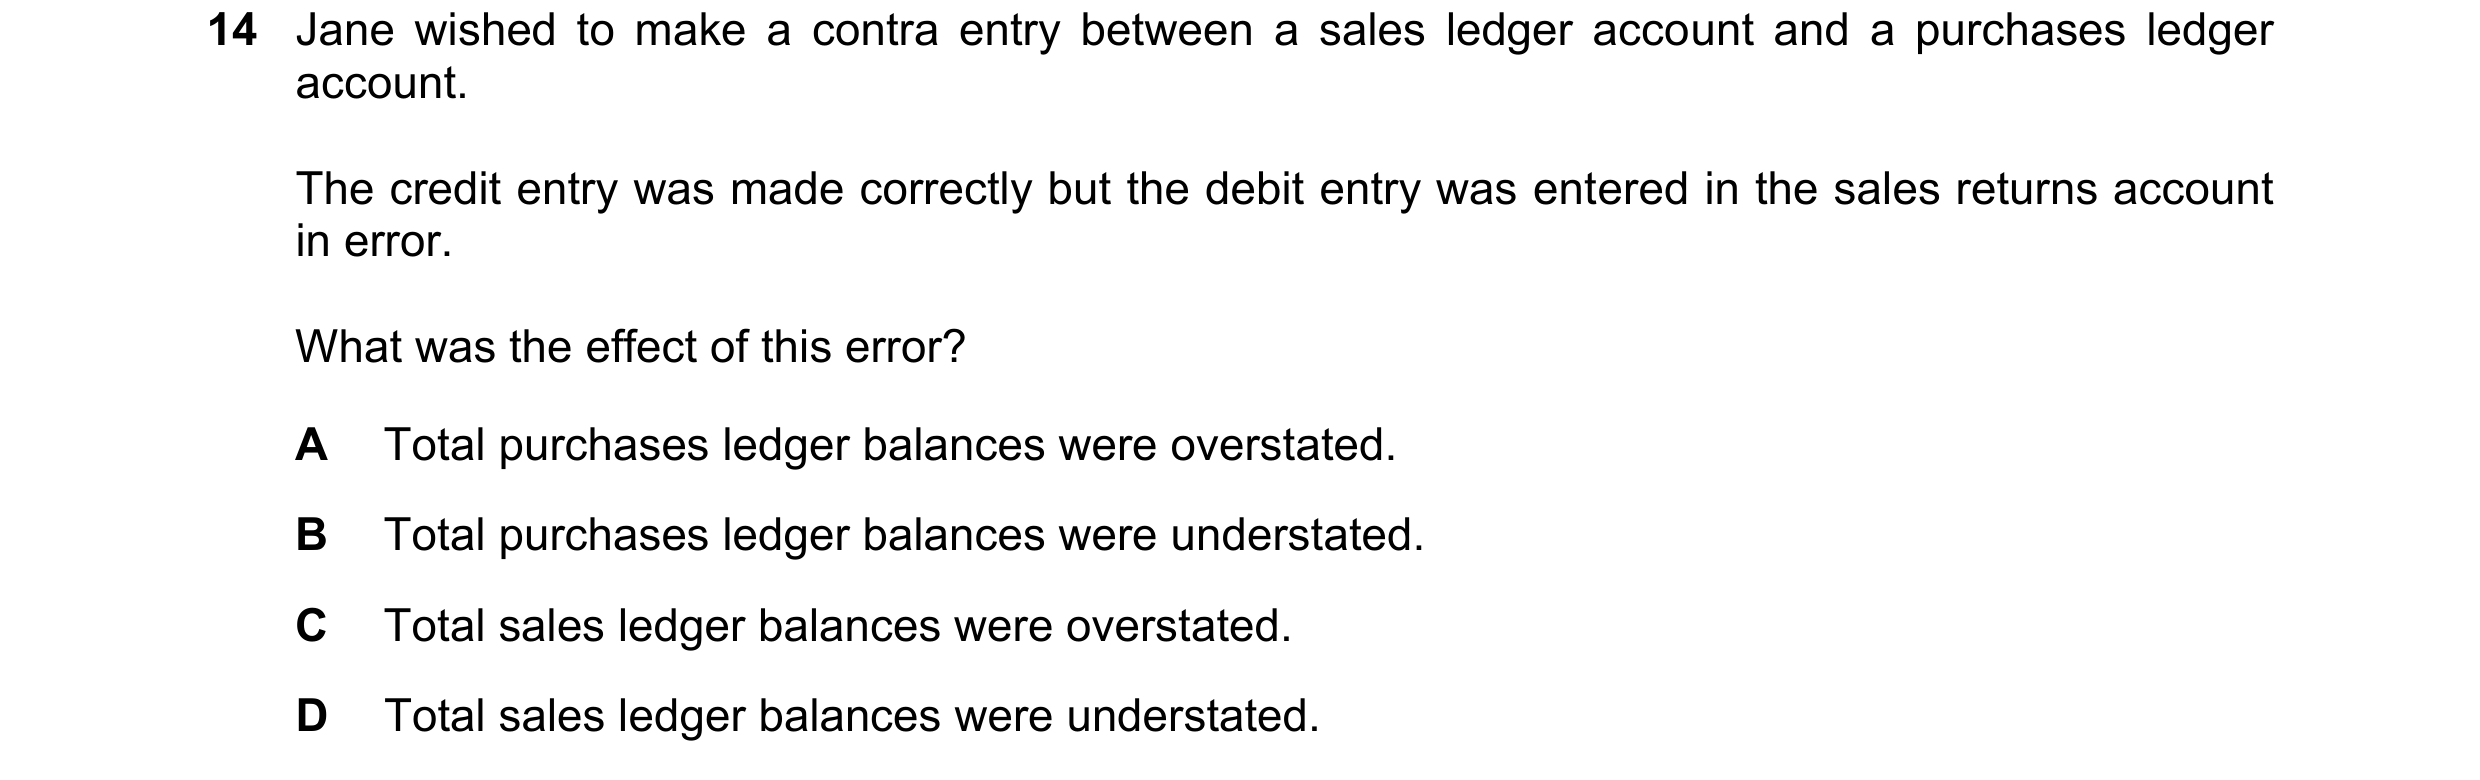 24 / 41
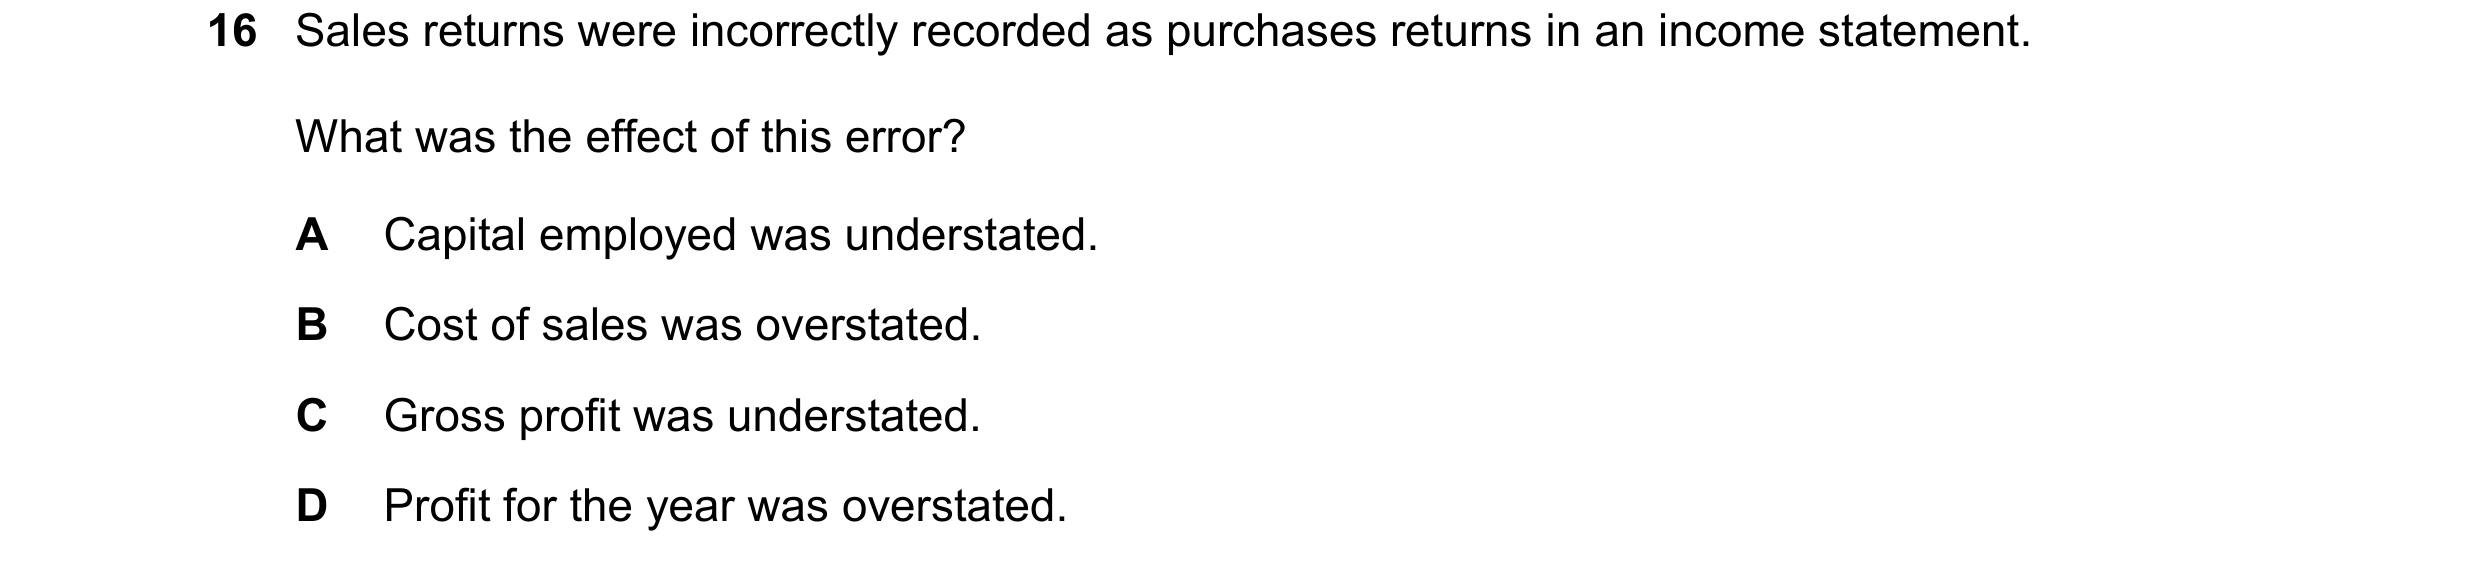
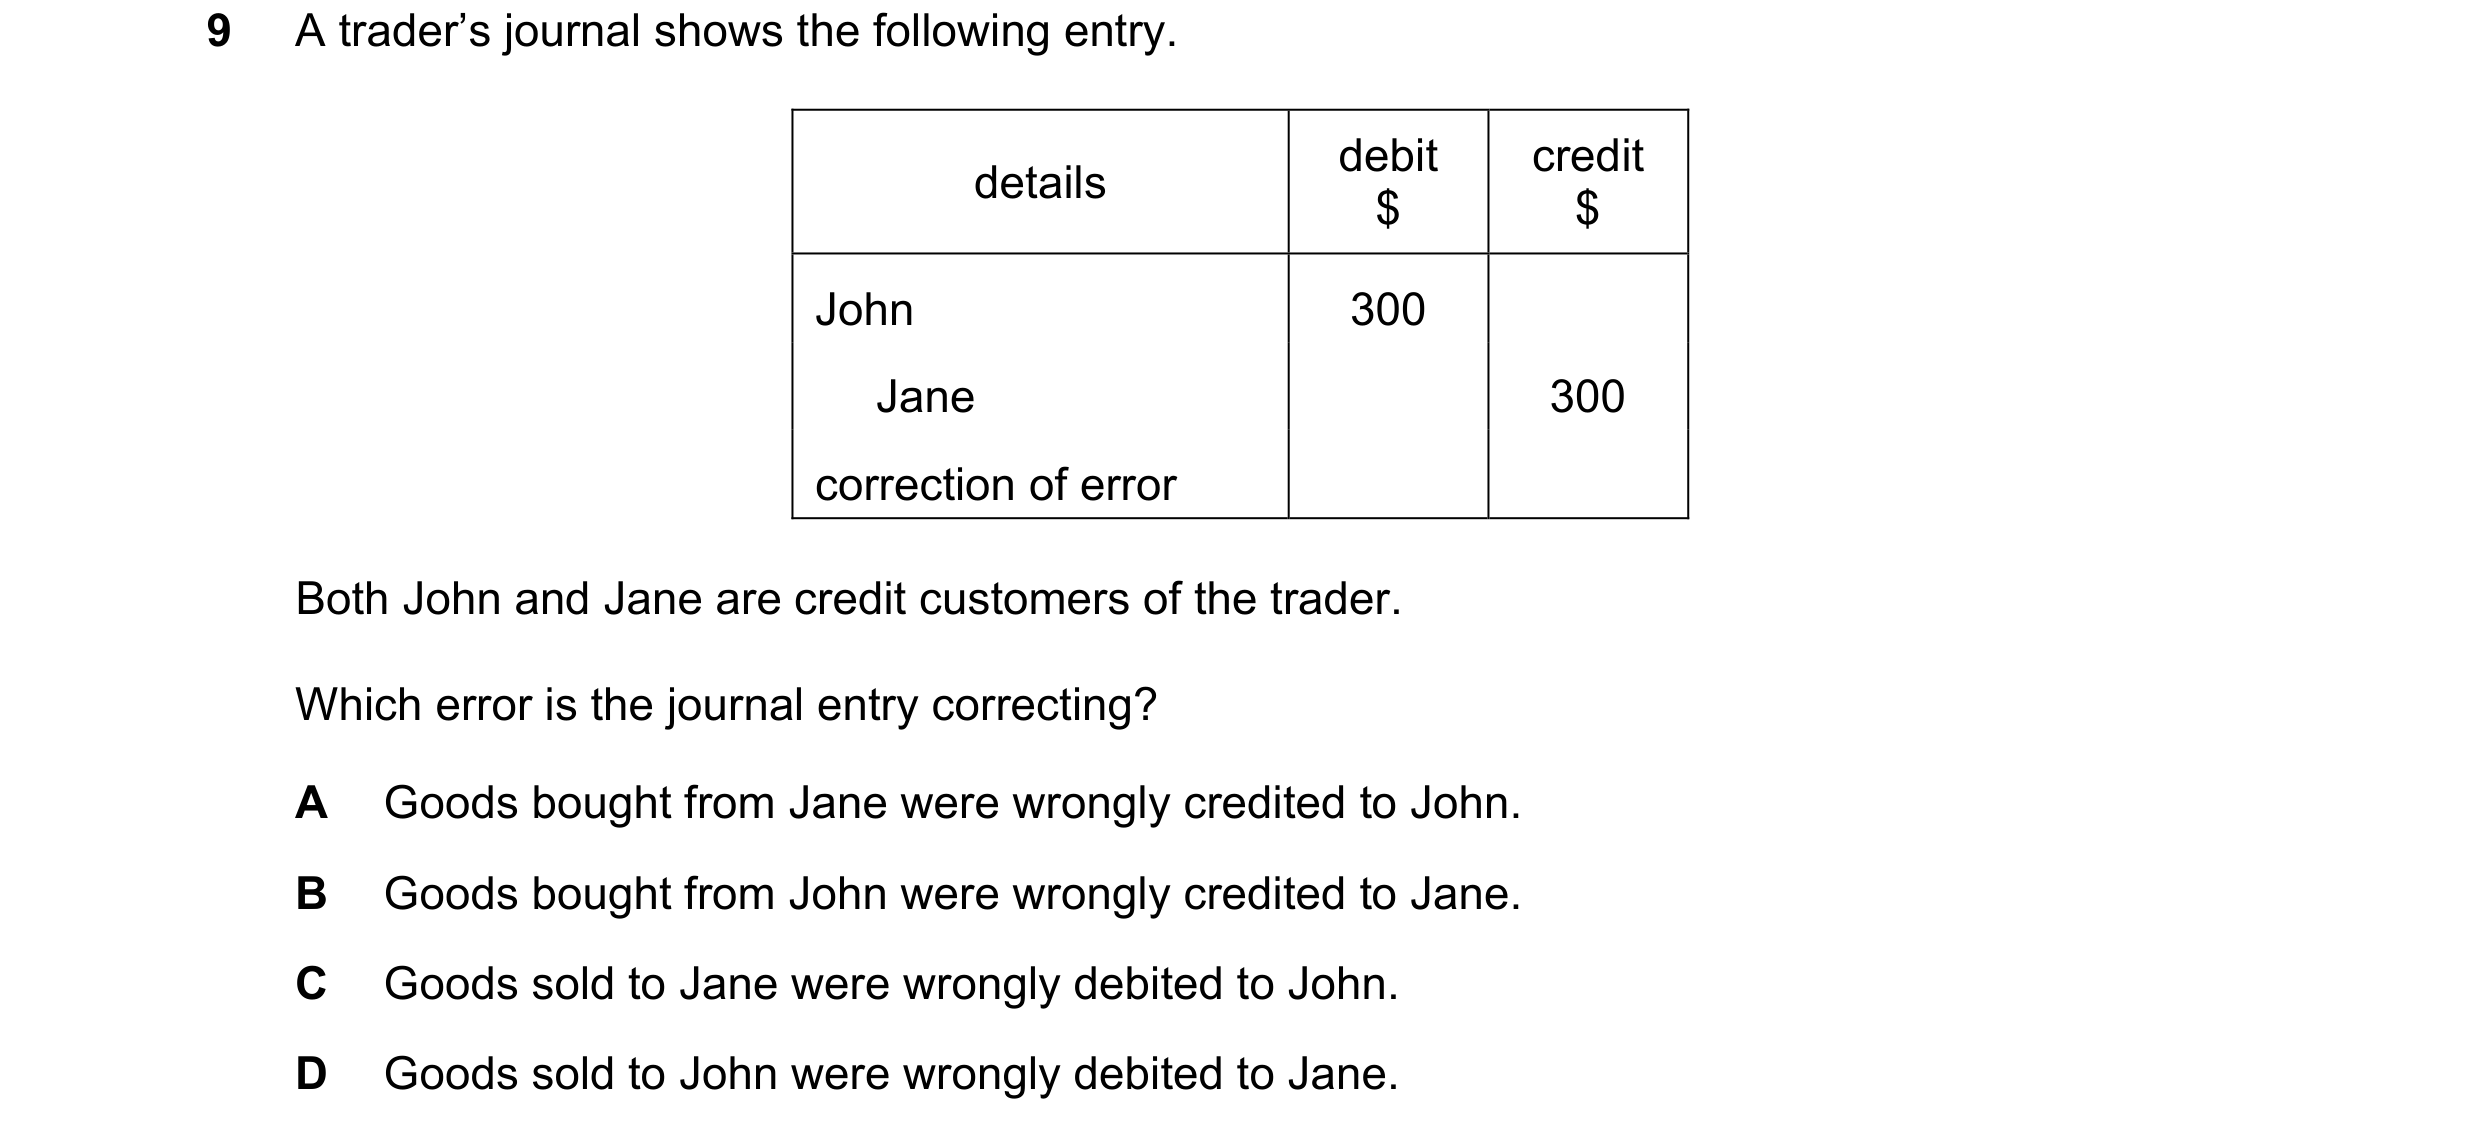
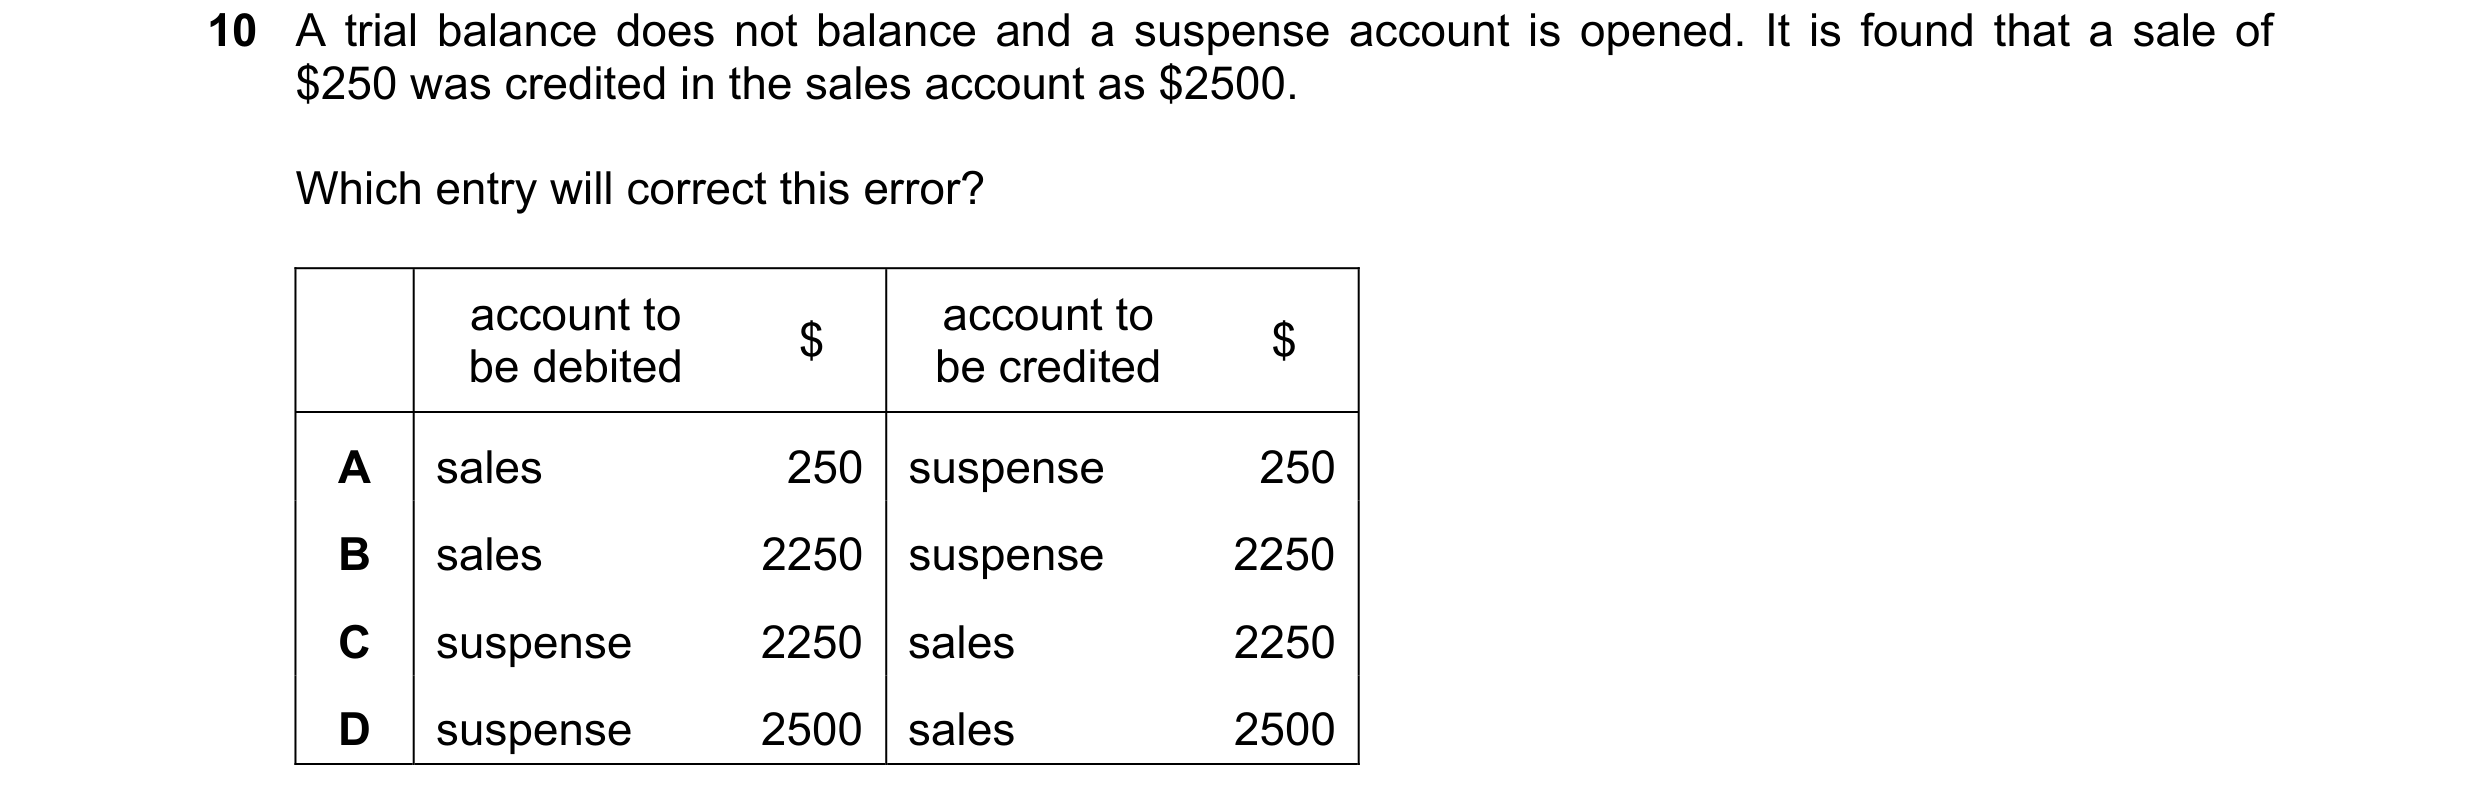 25 / 41
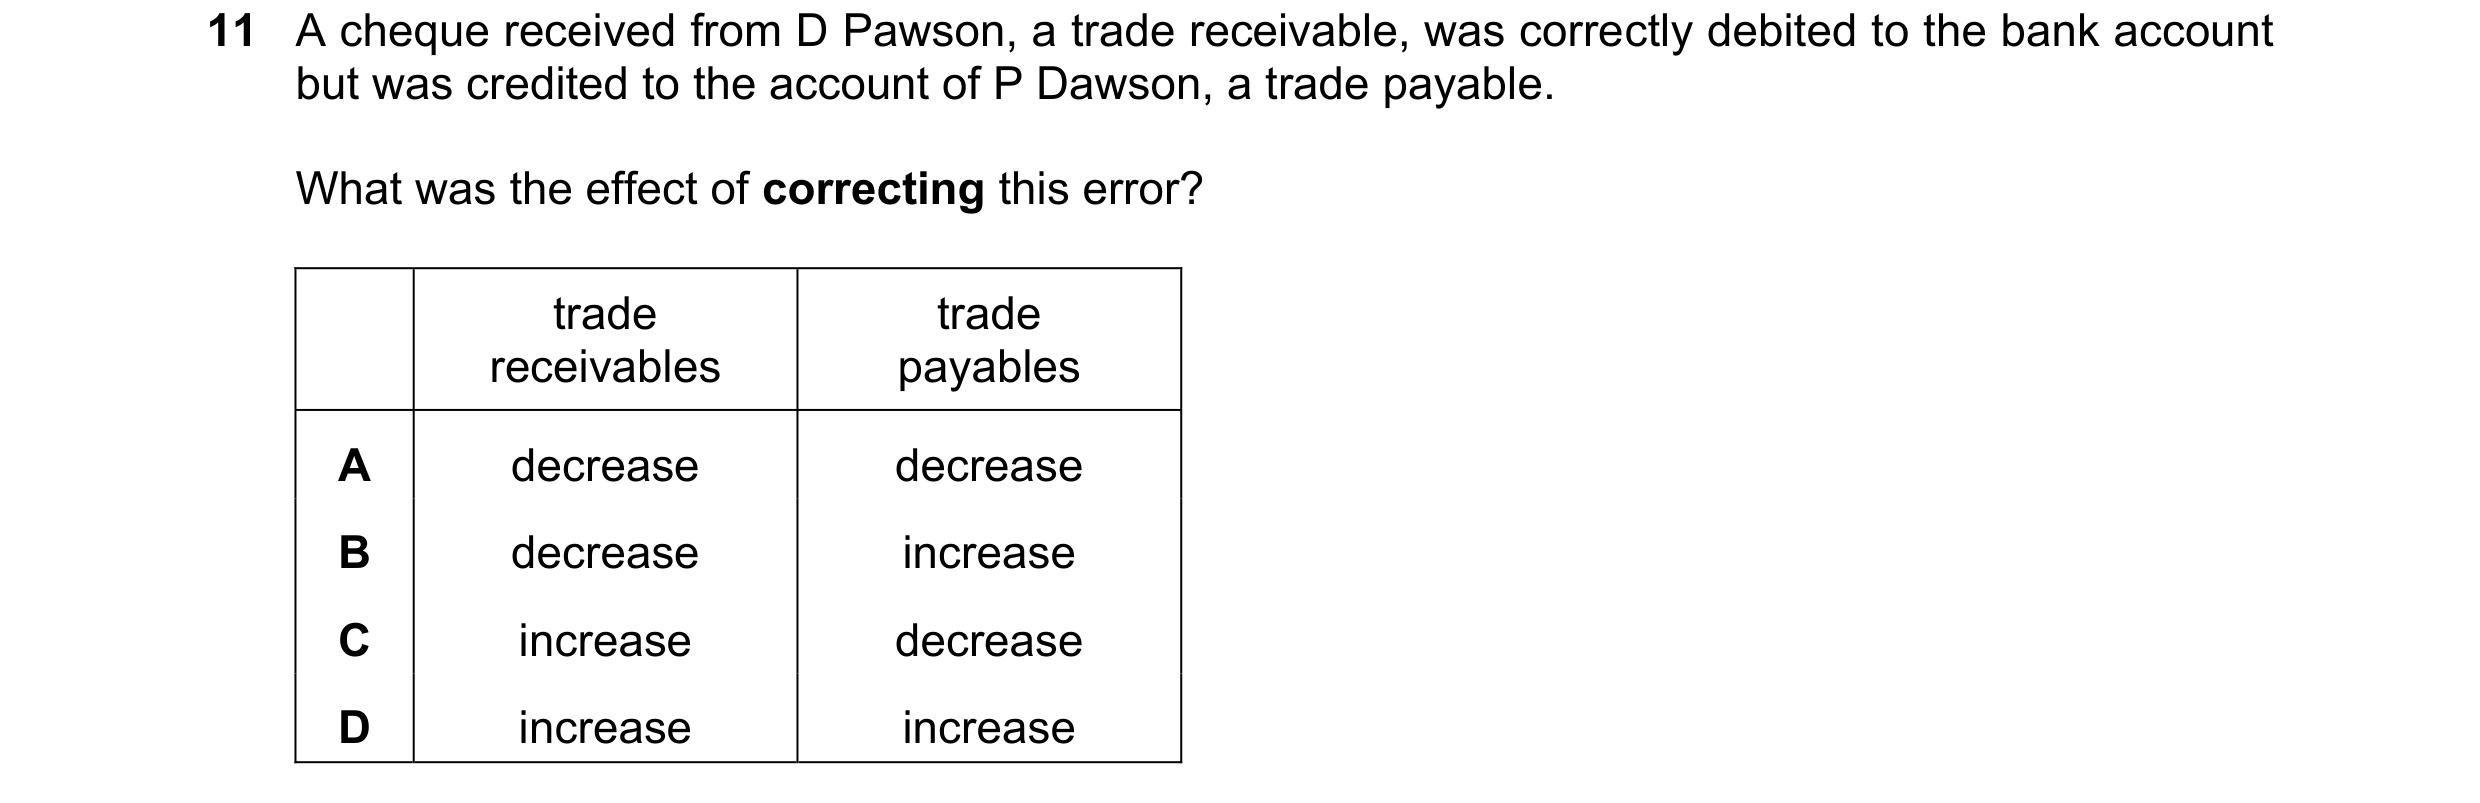
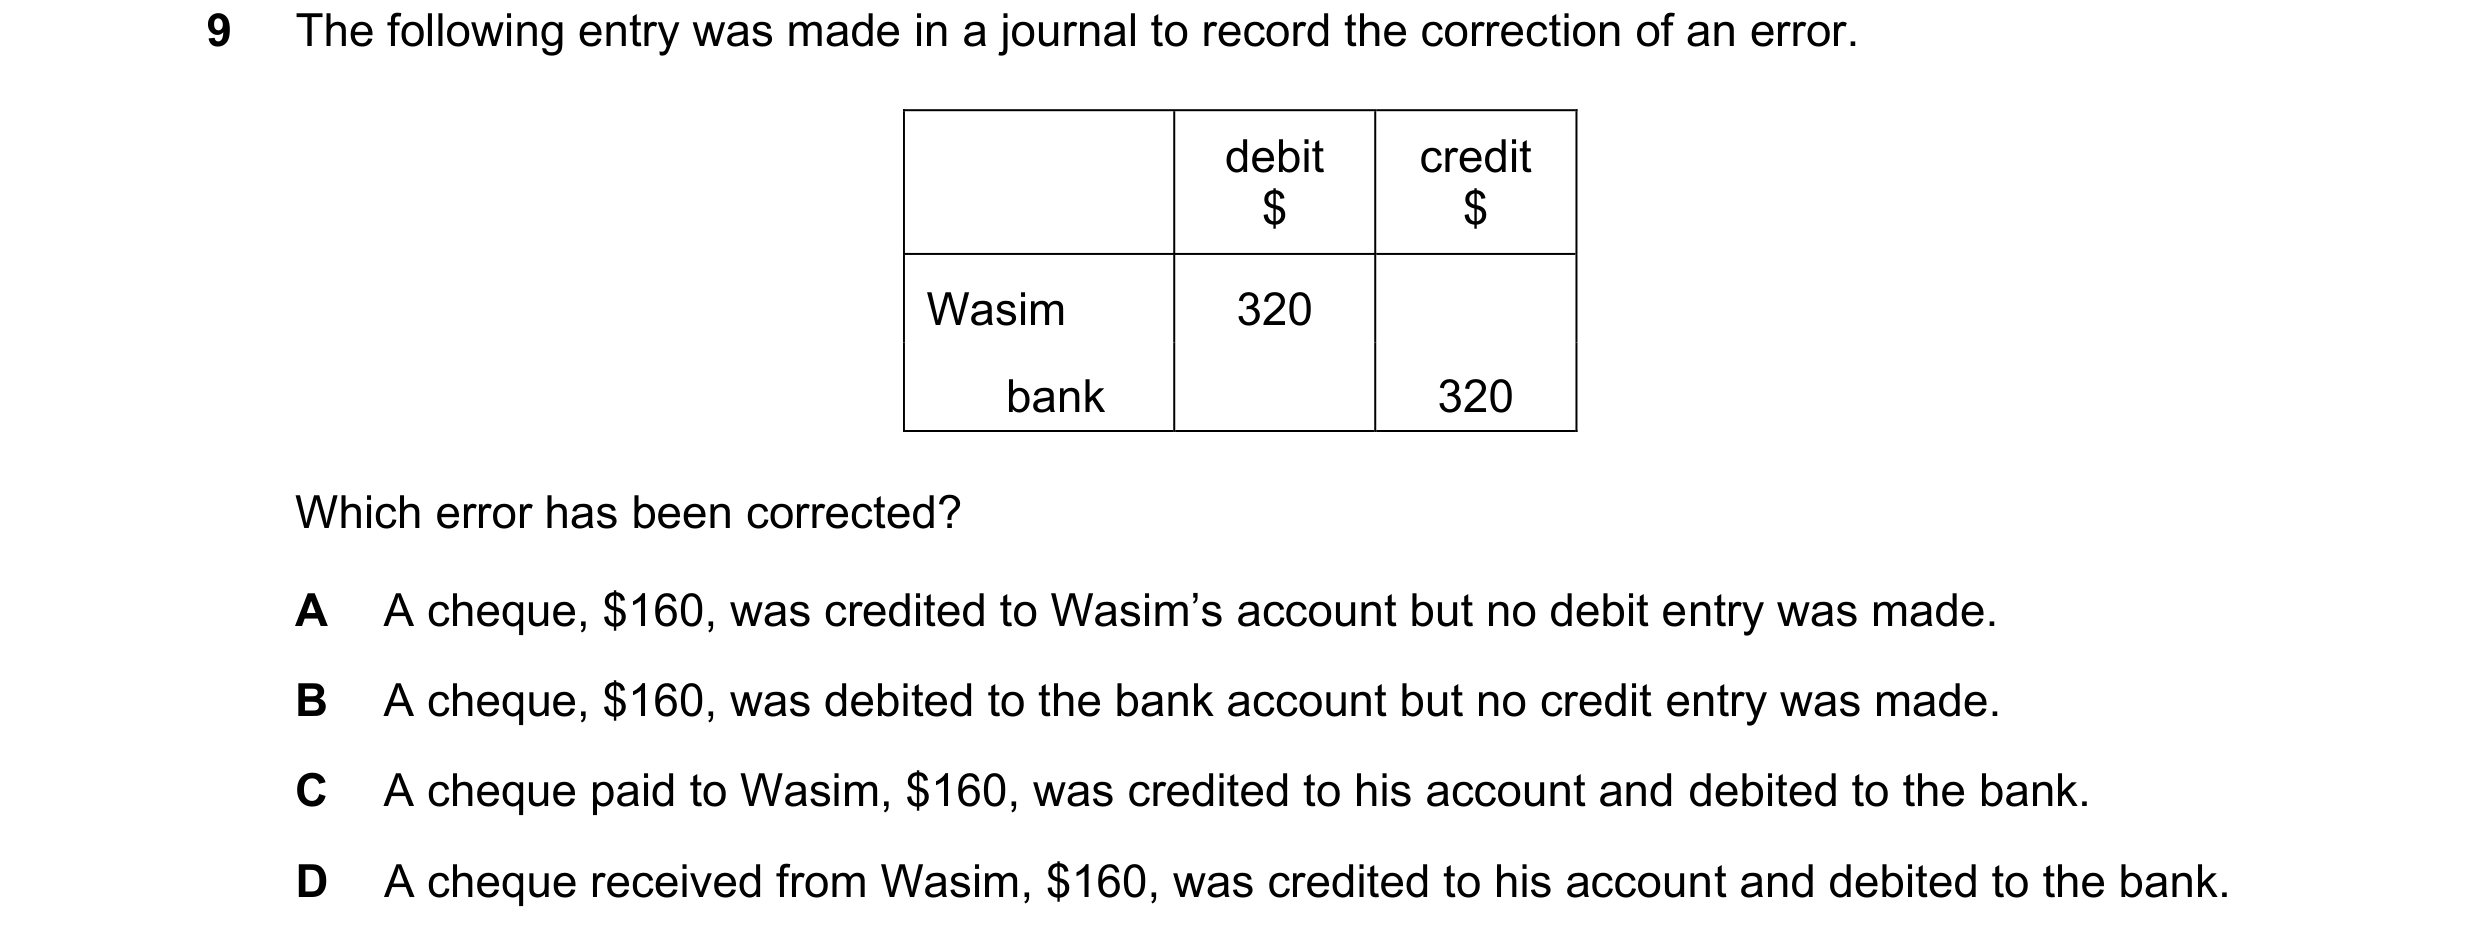 26 / 41
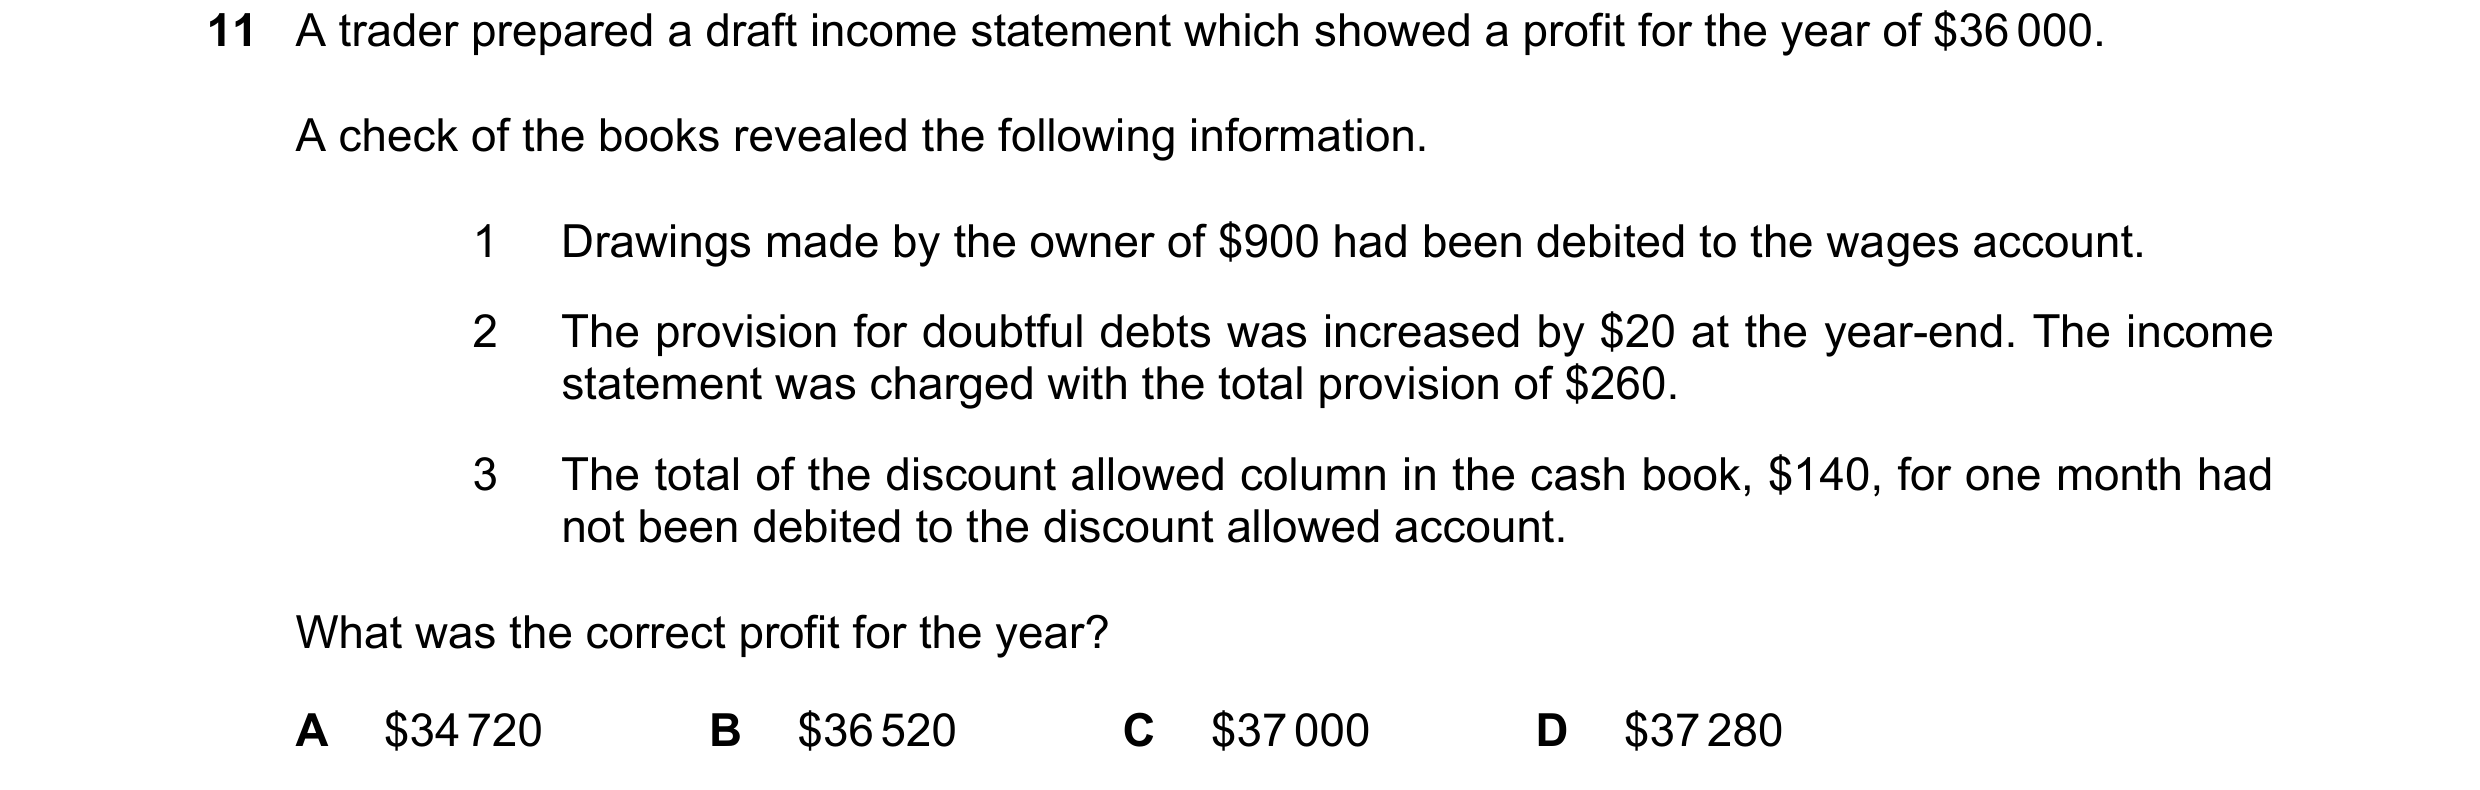
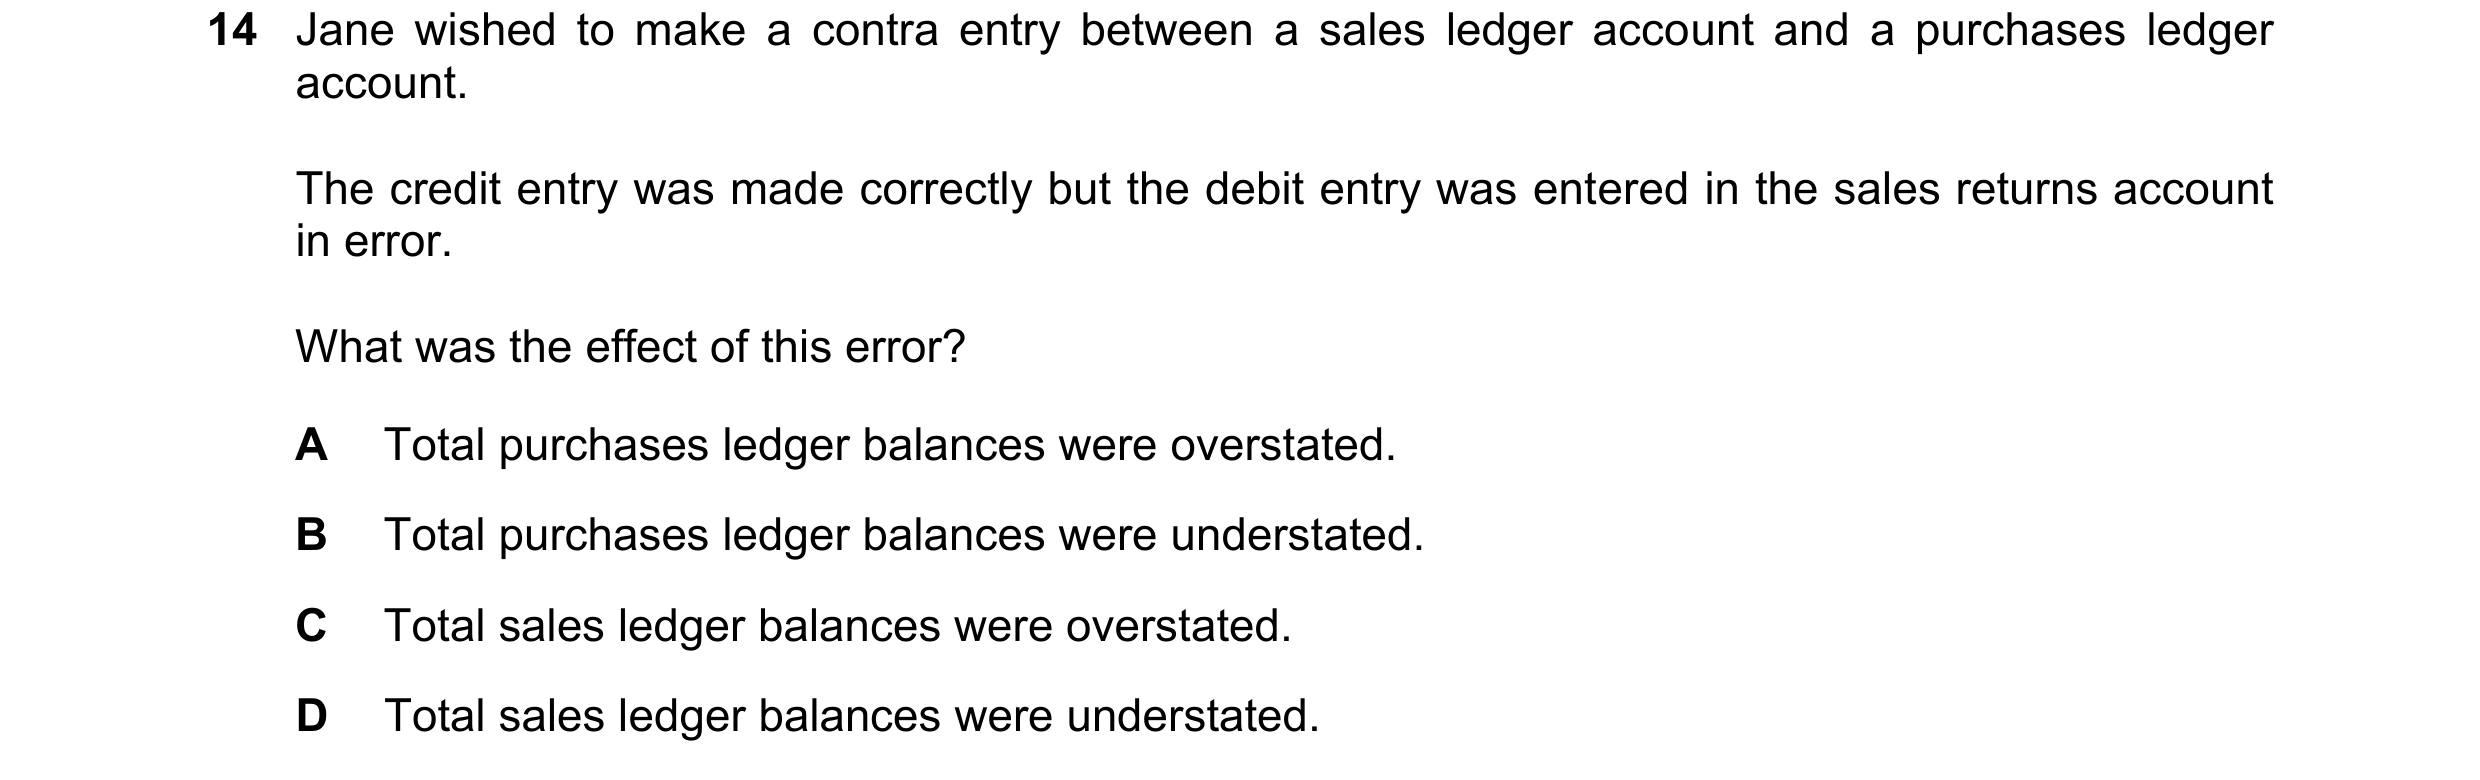
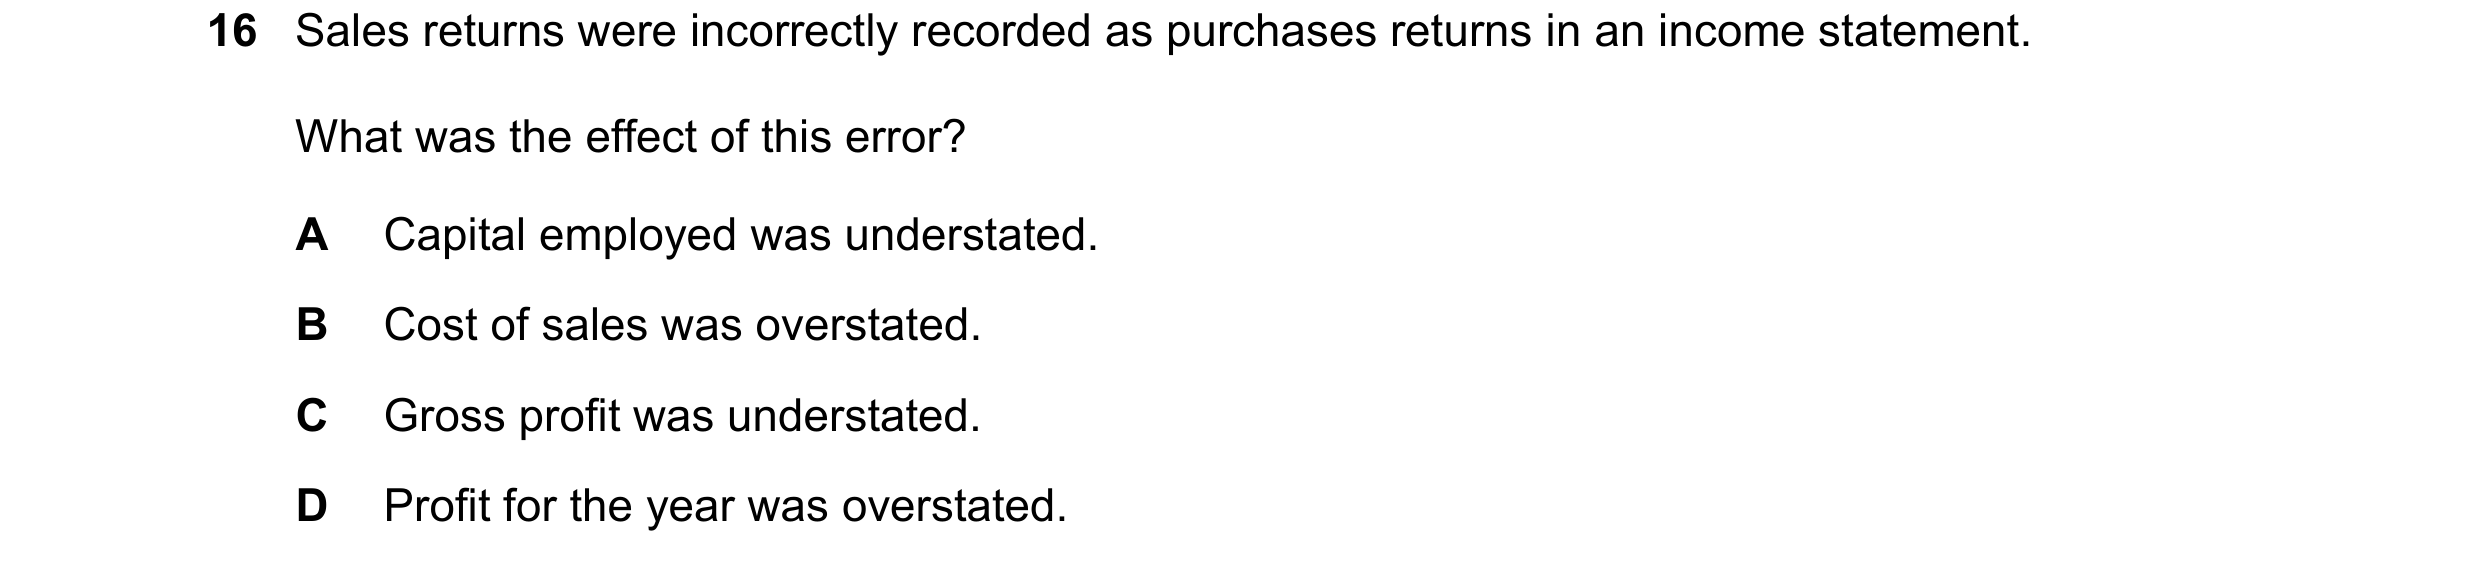 27 / 41
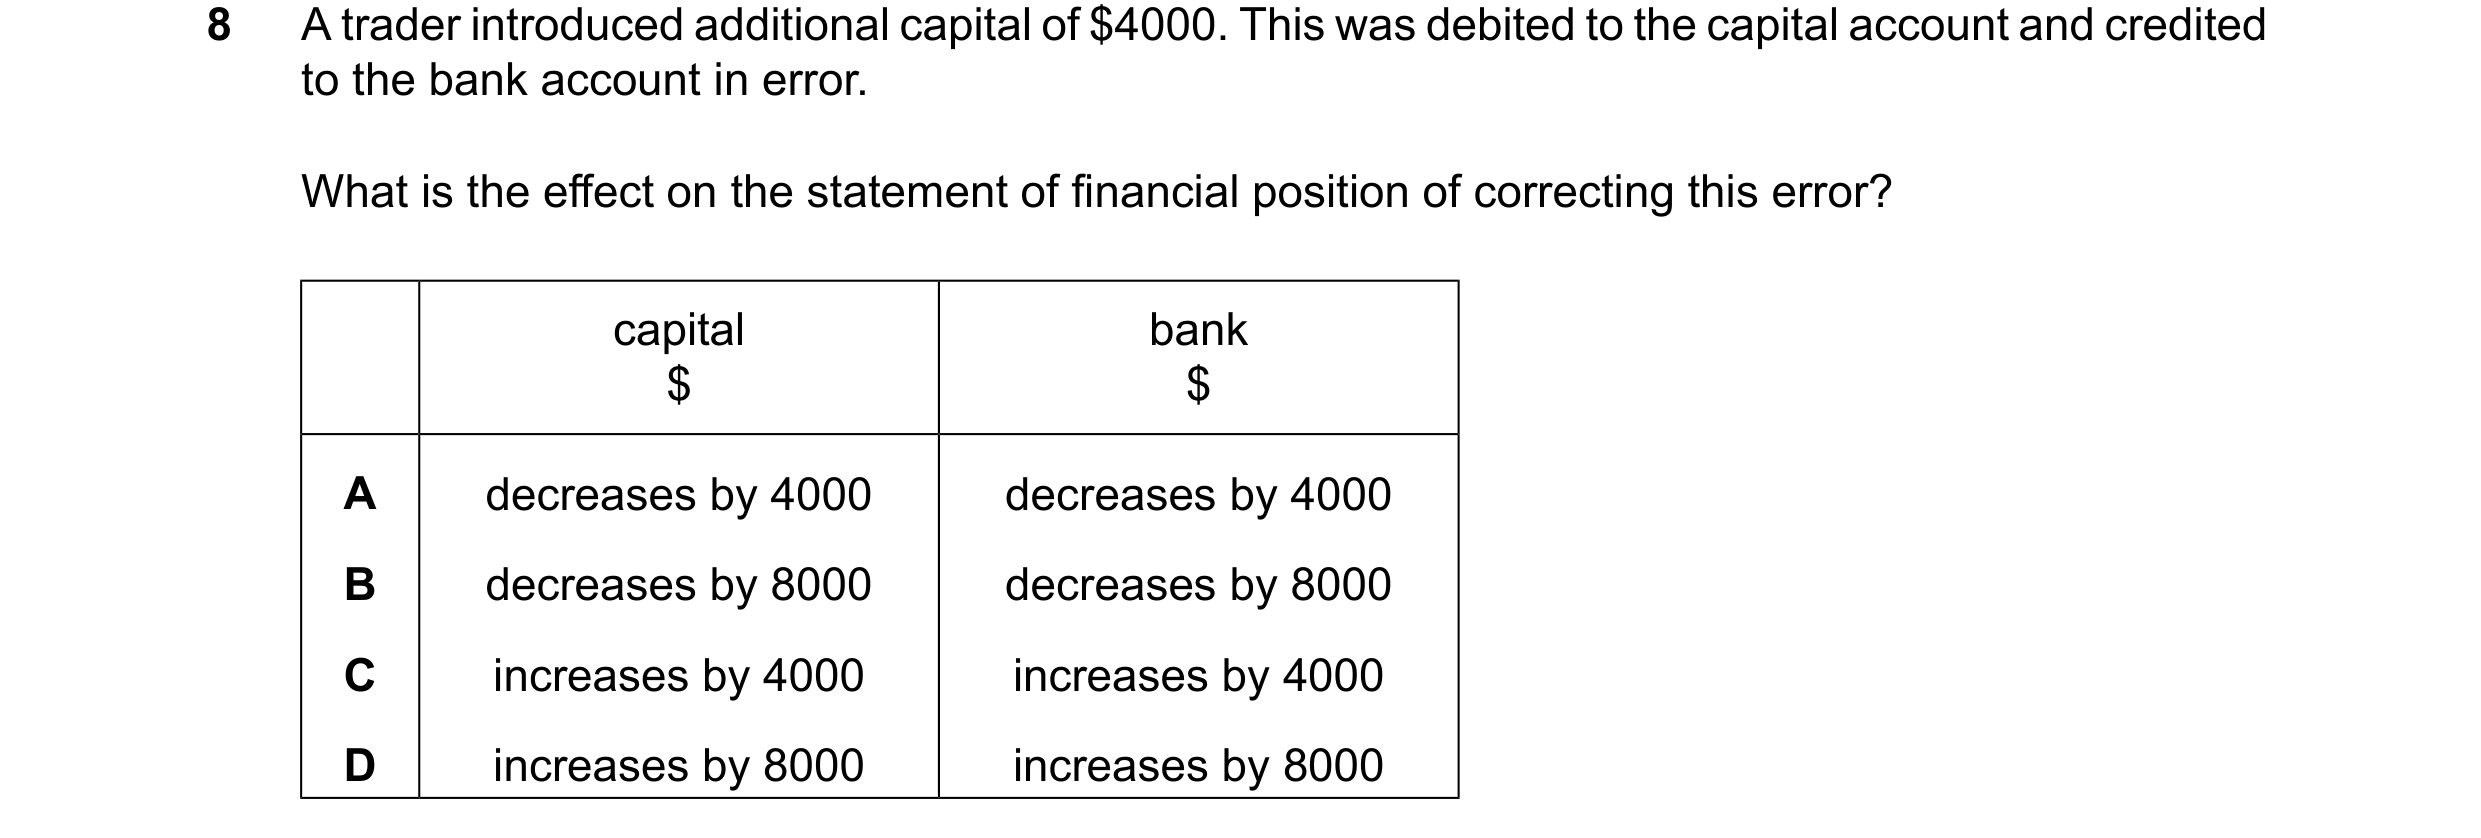
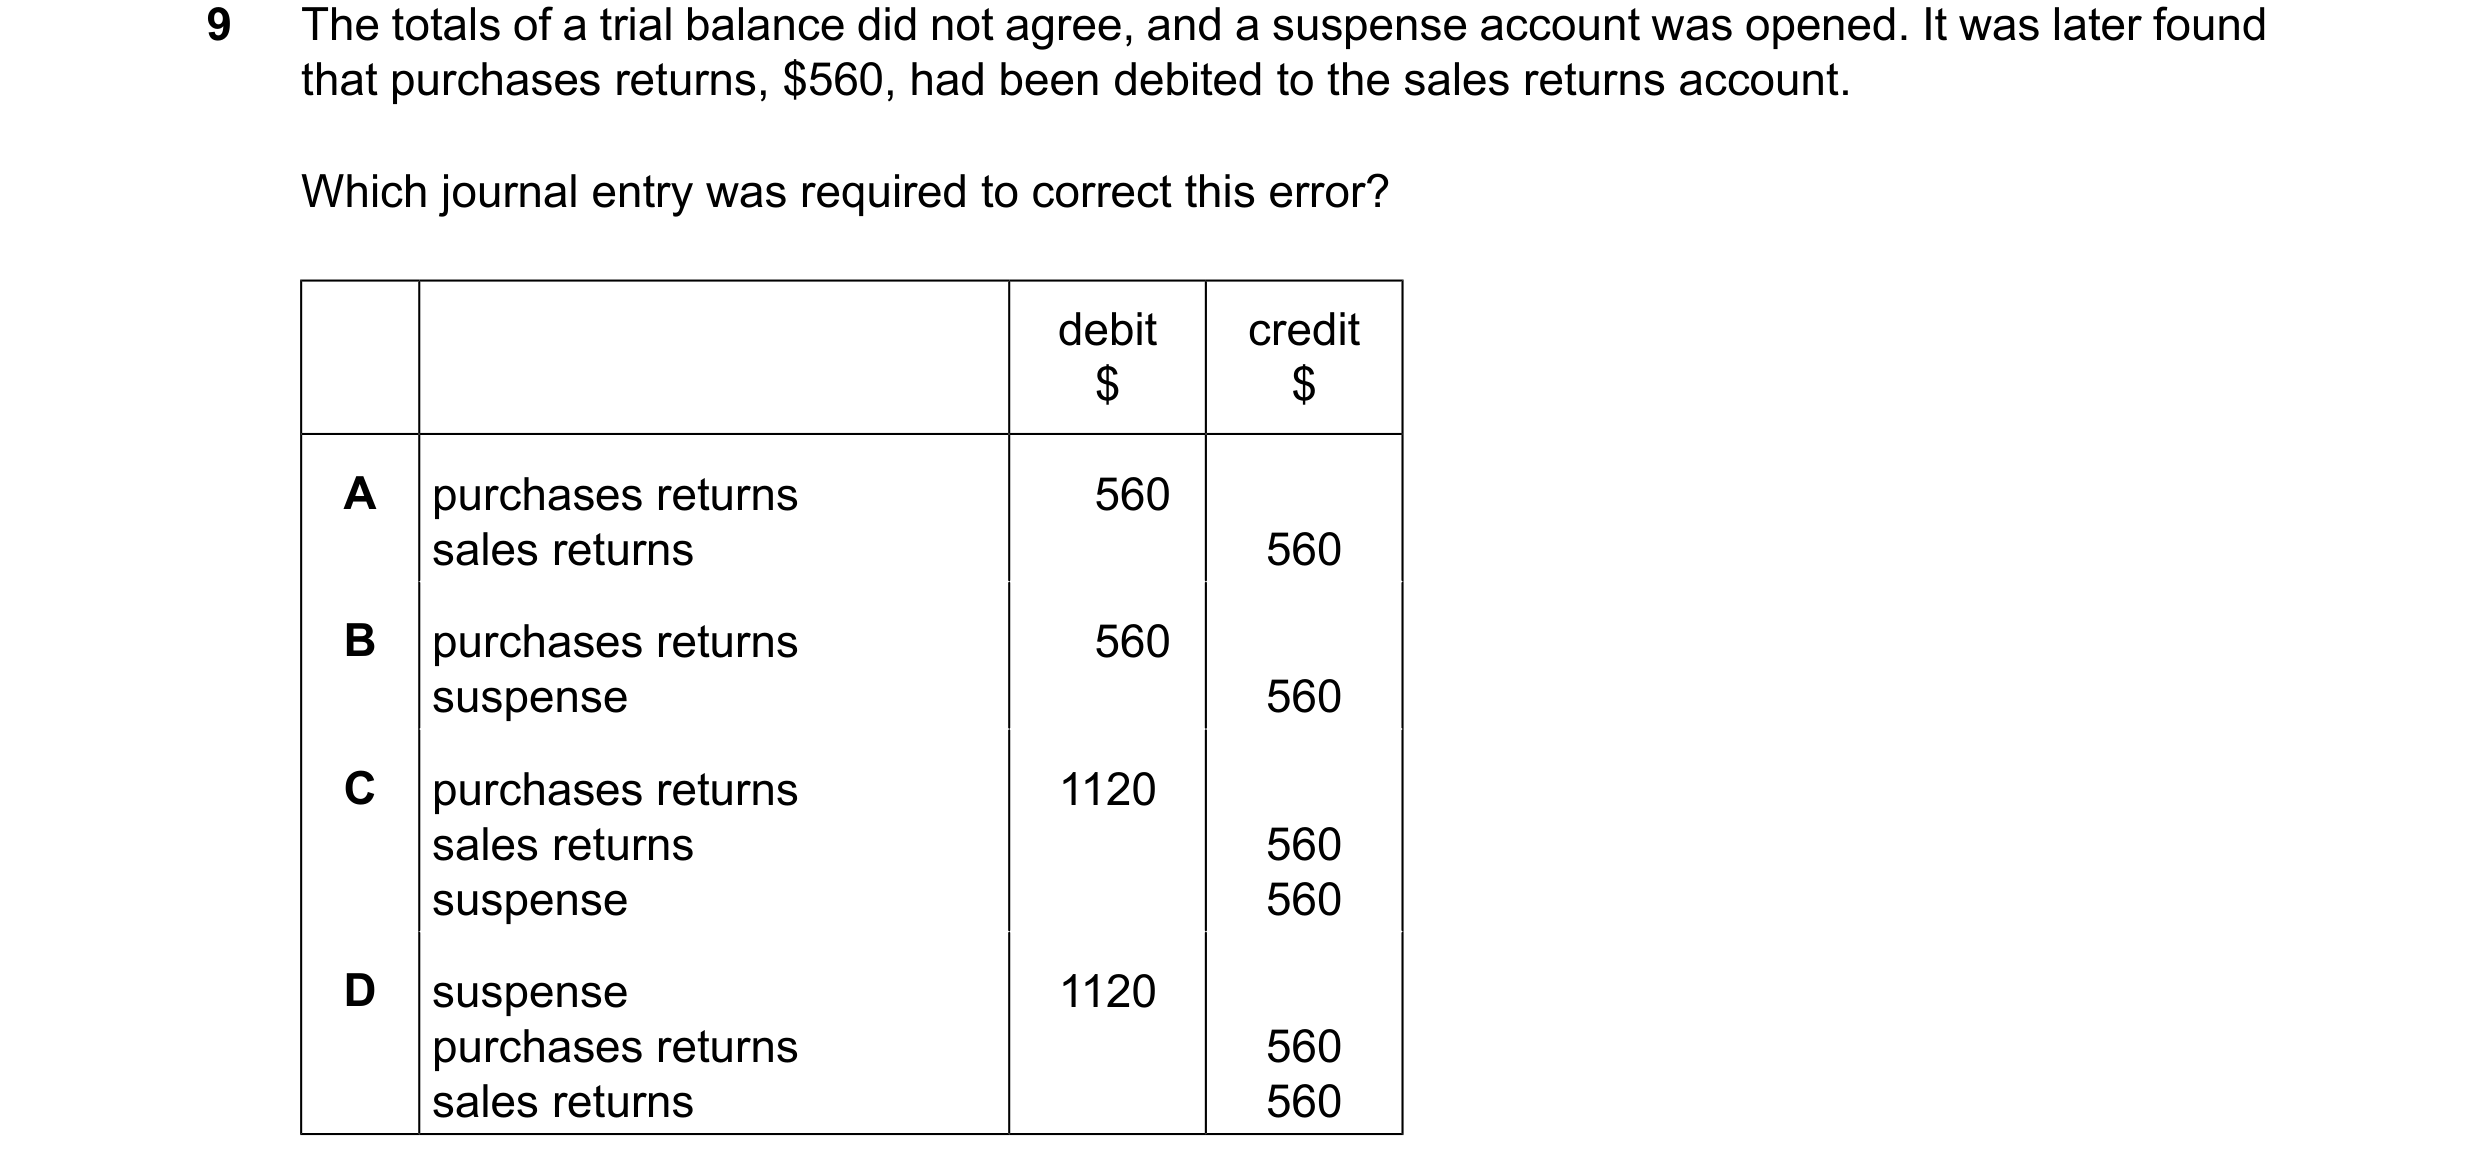
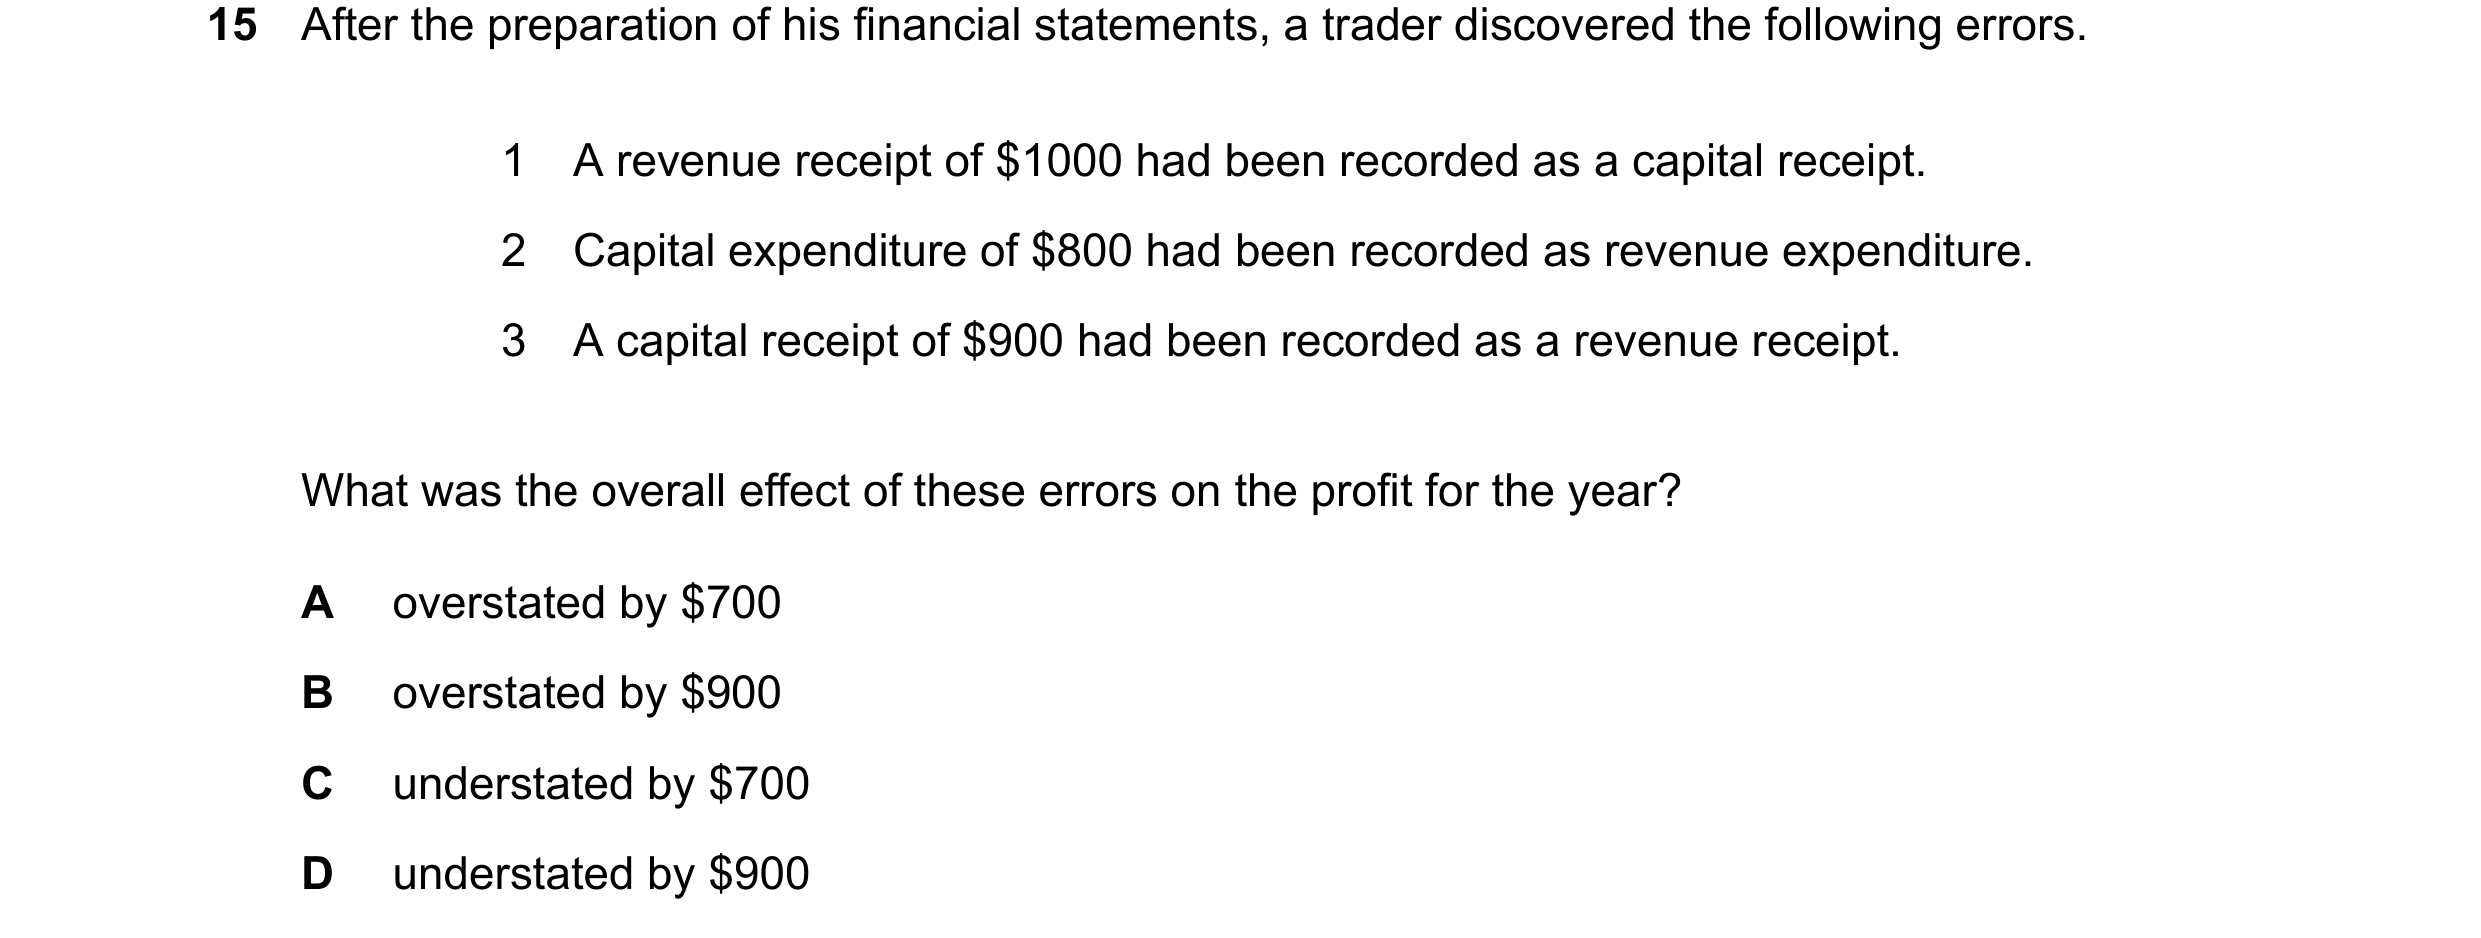 28 / 41
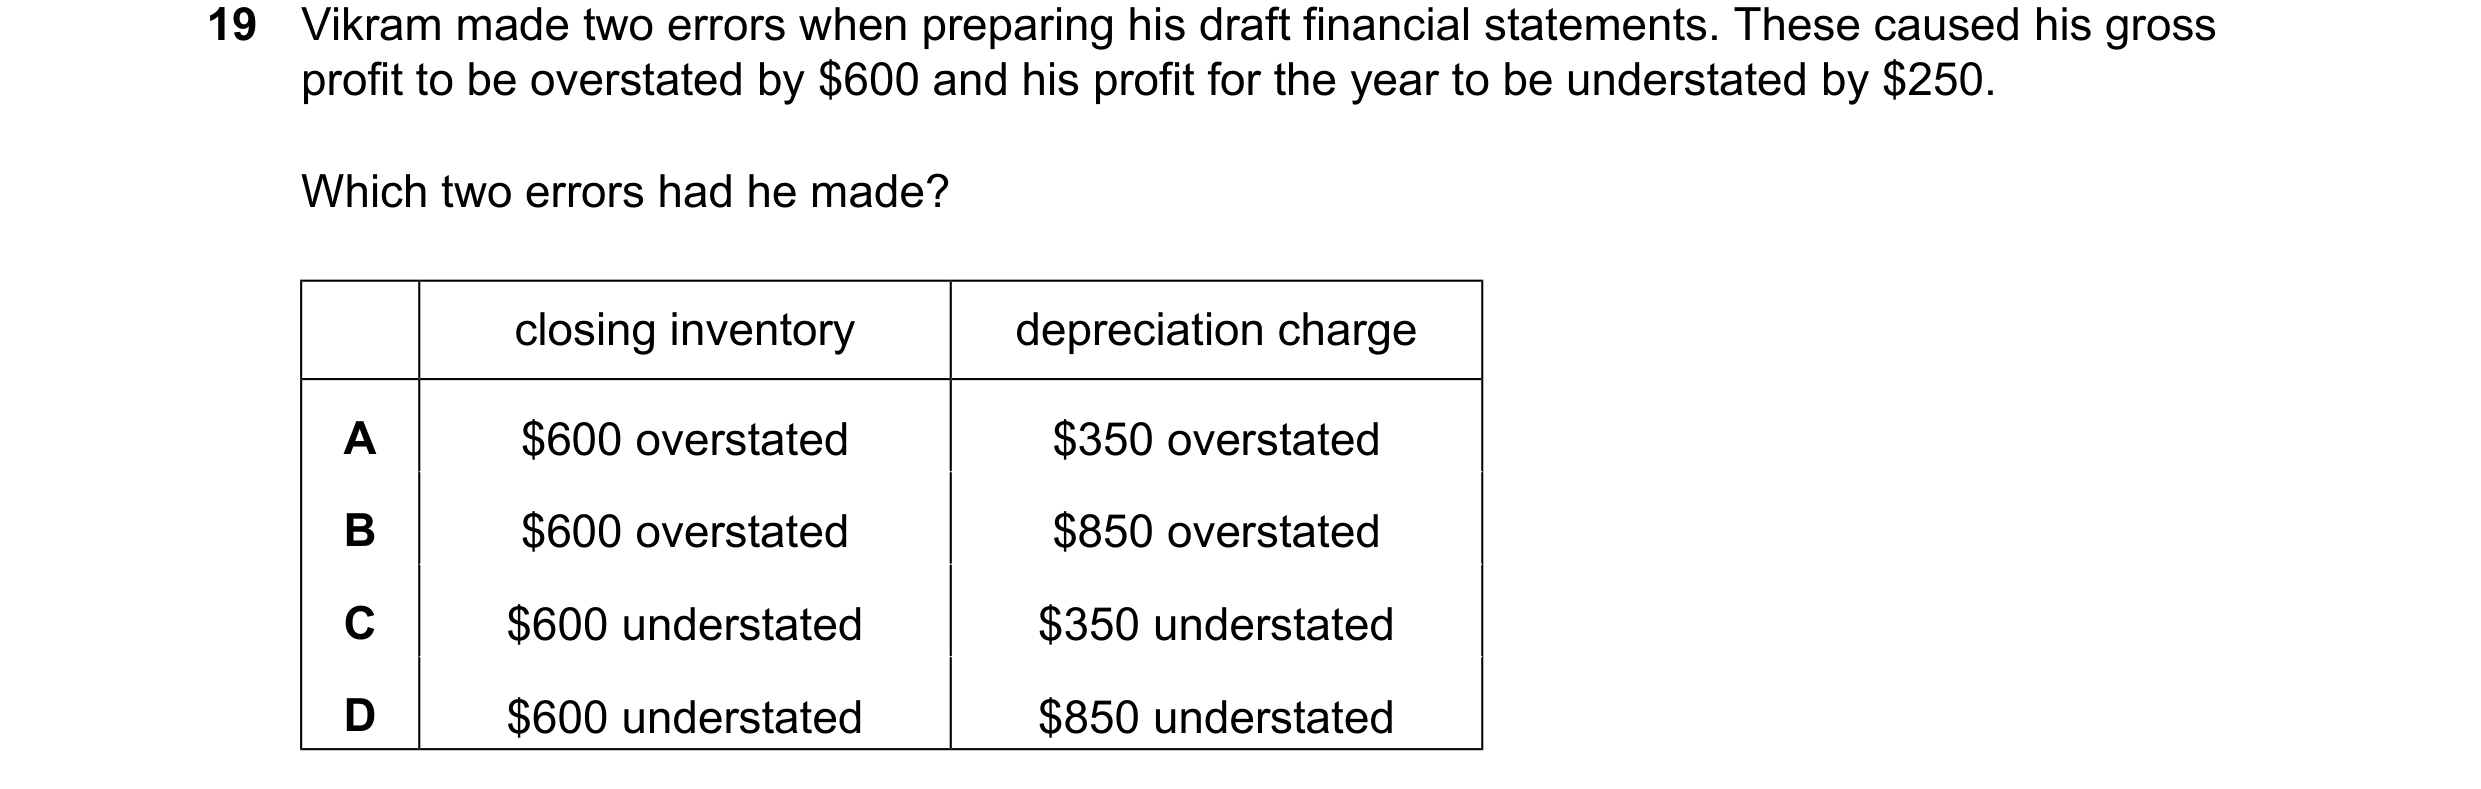
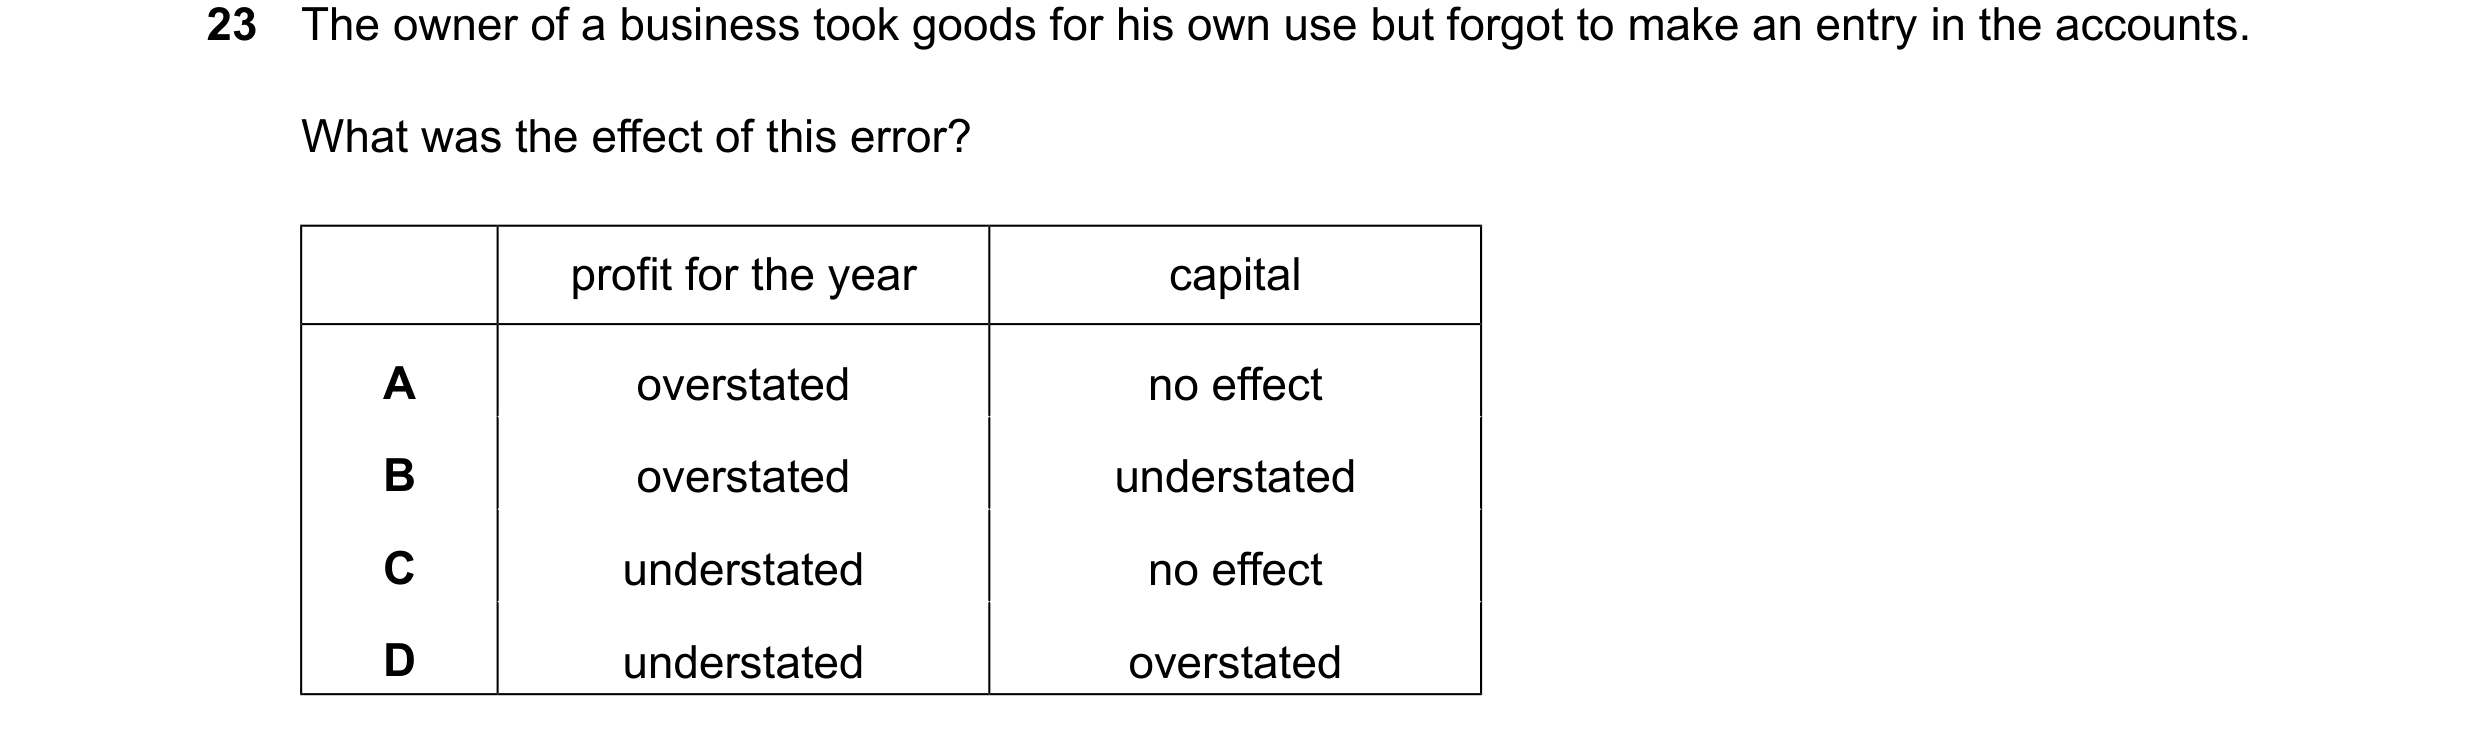
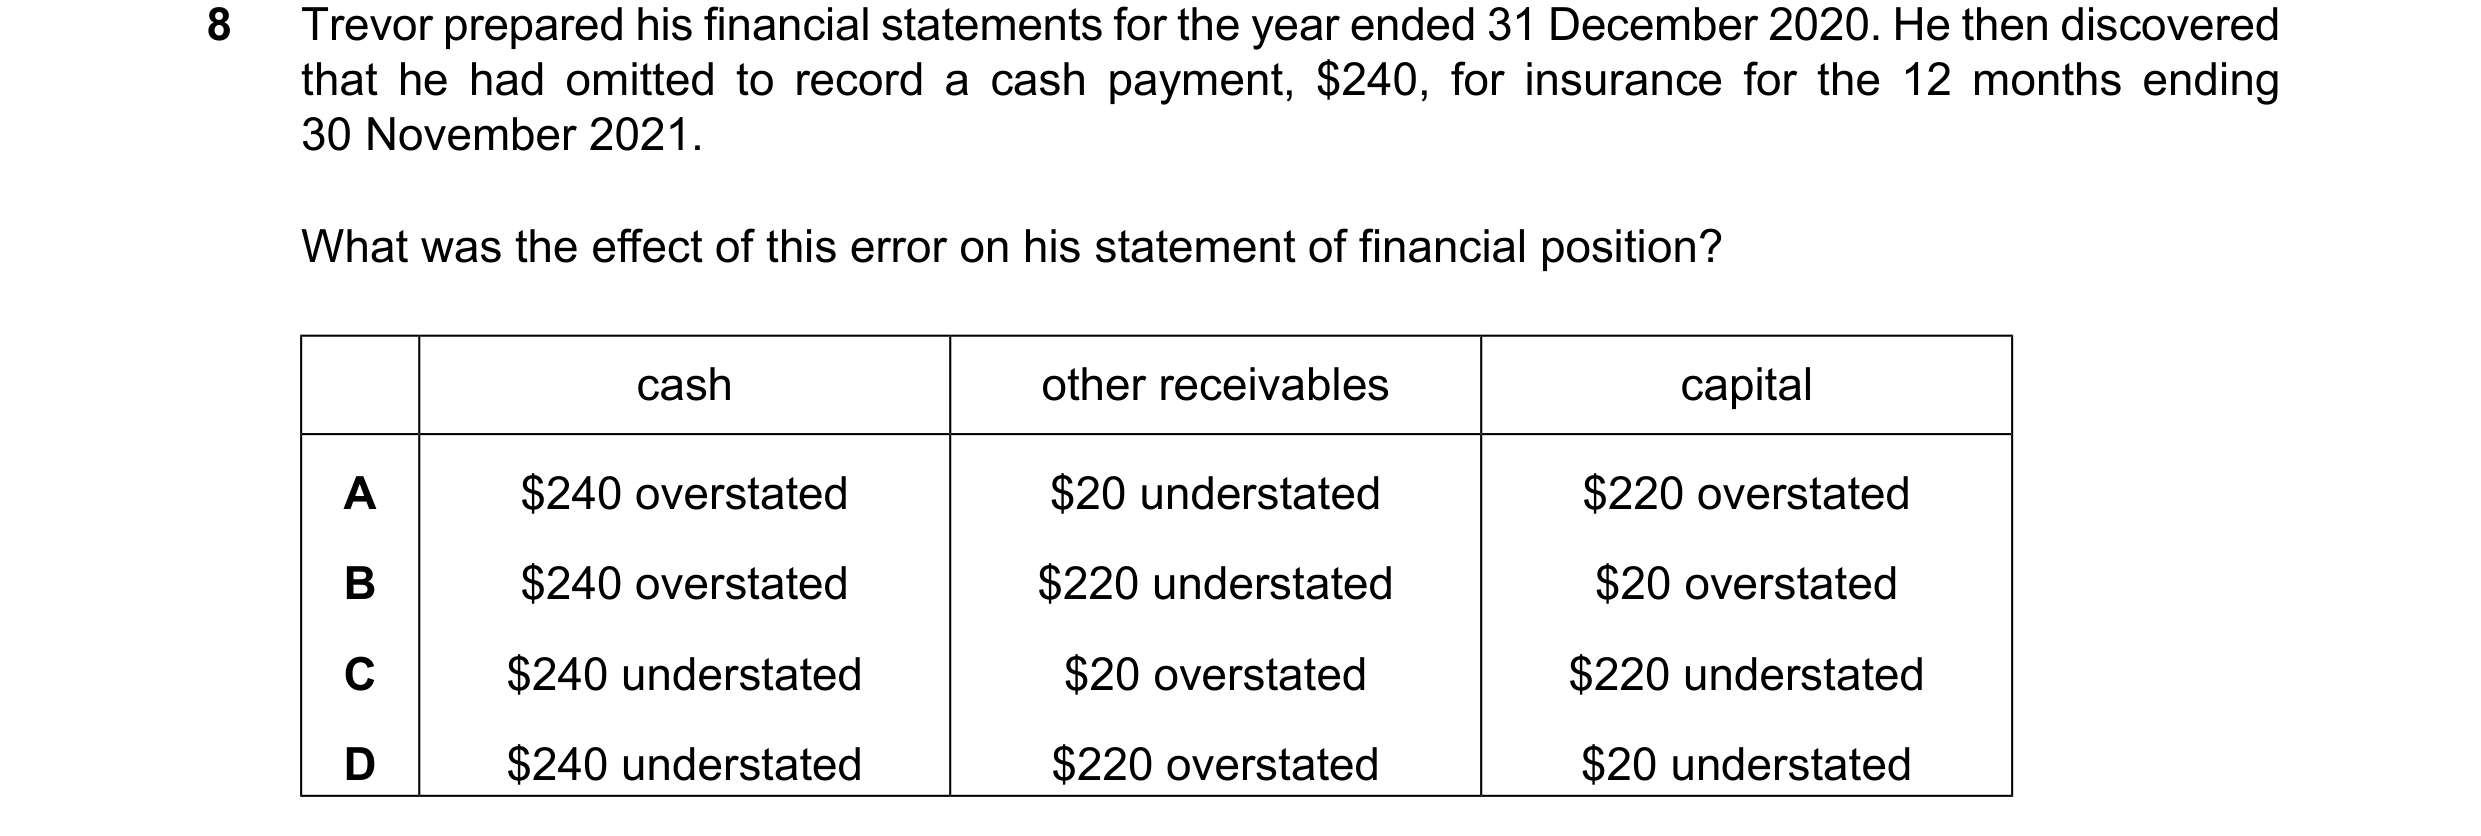
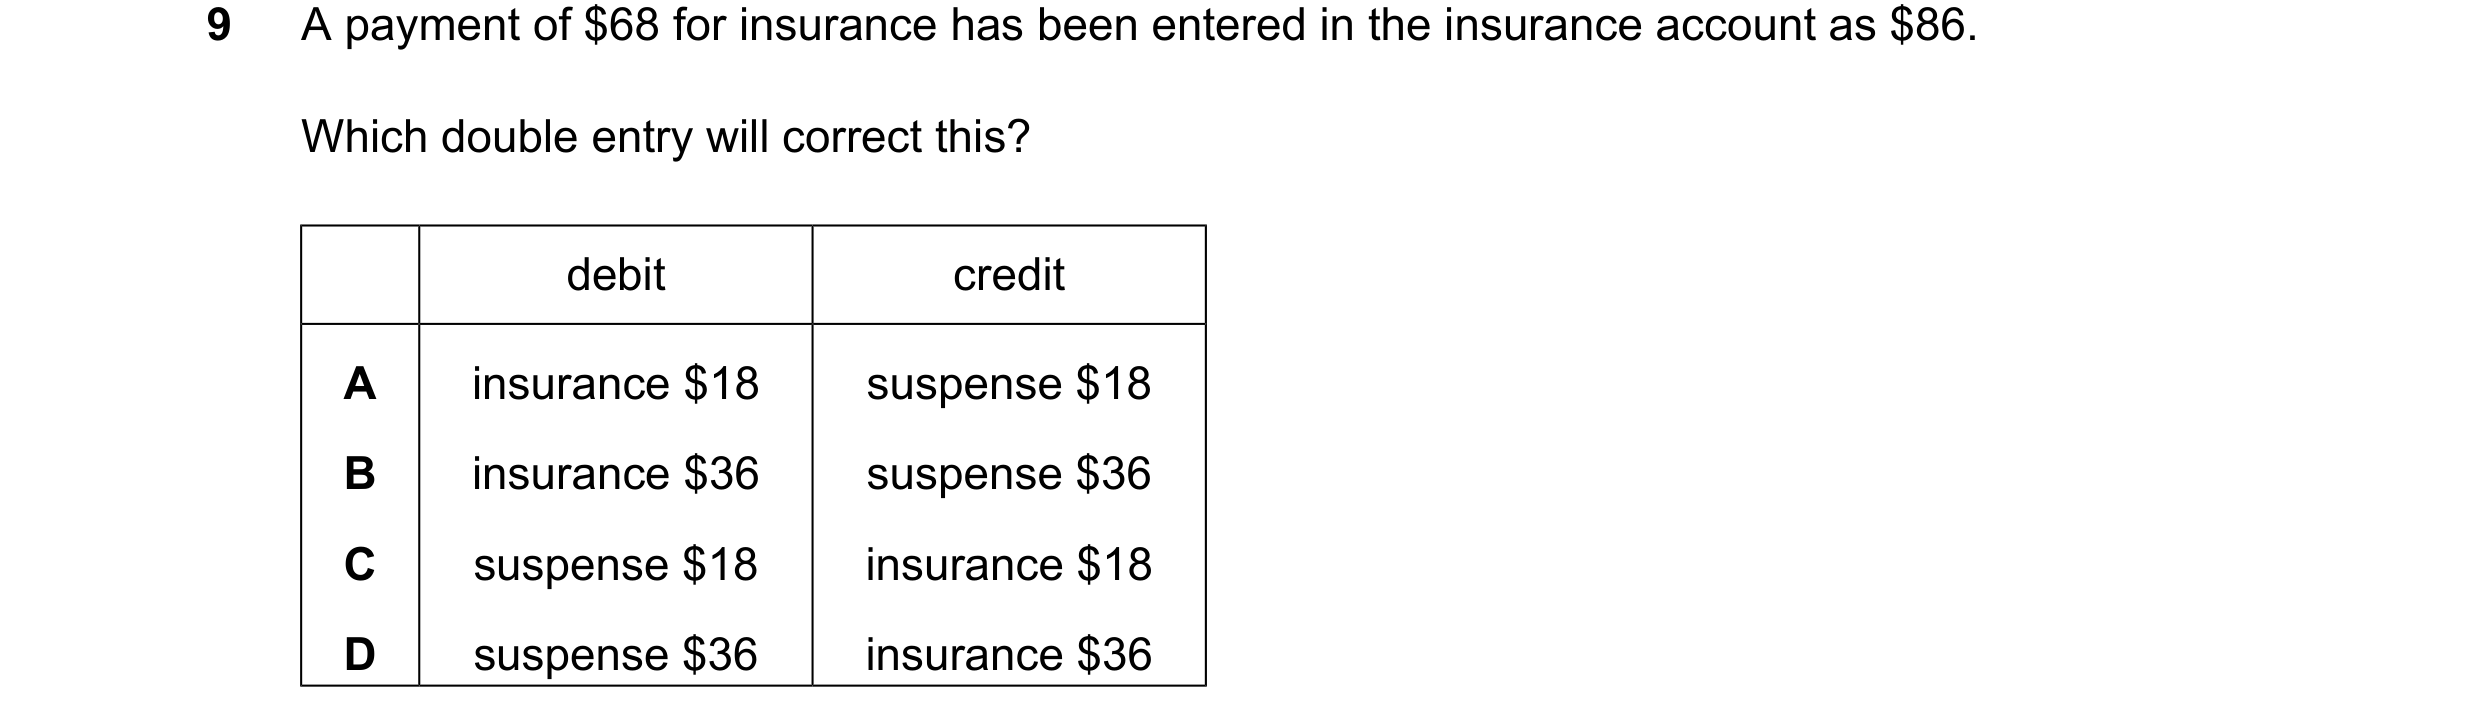 29 / 41
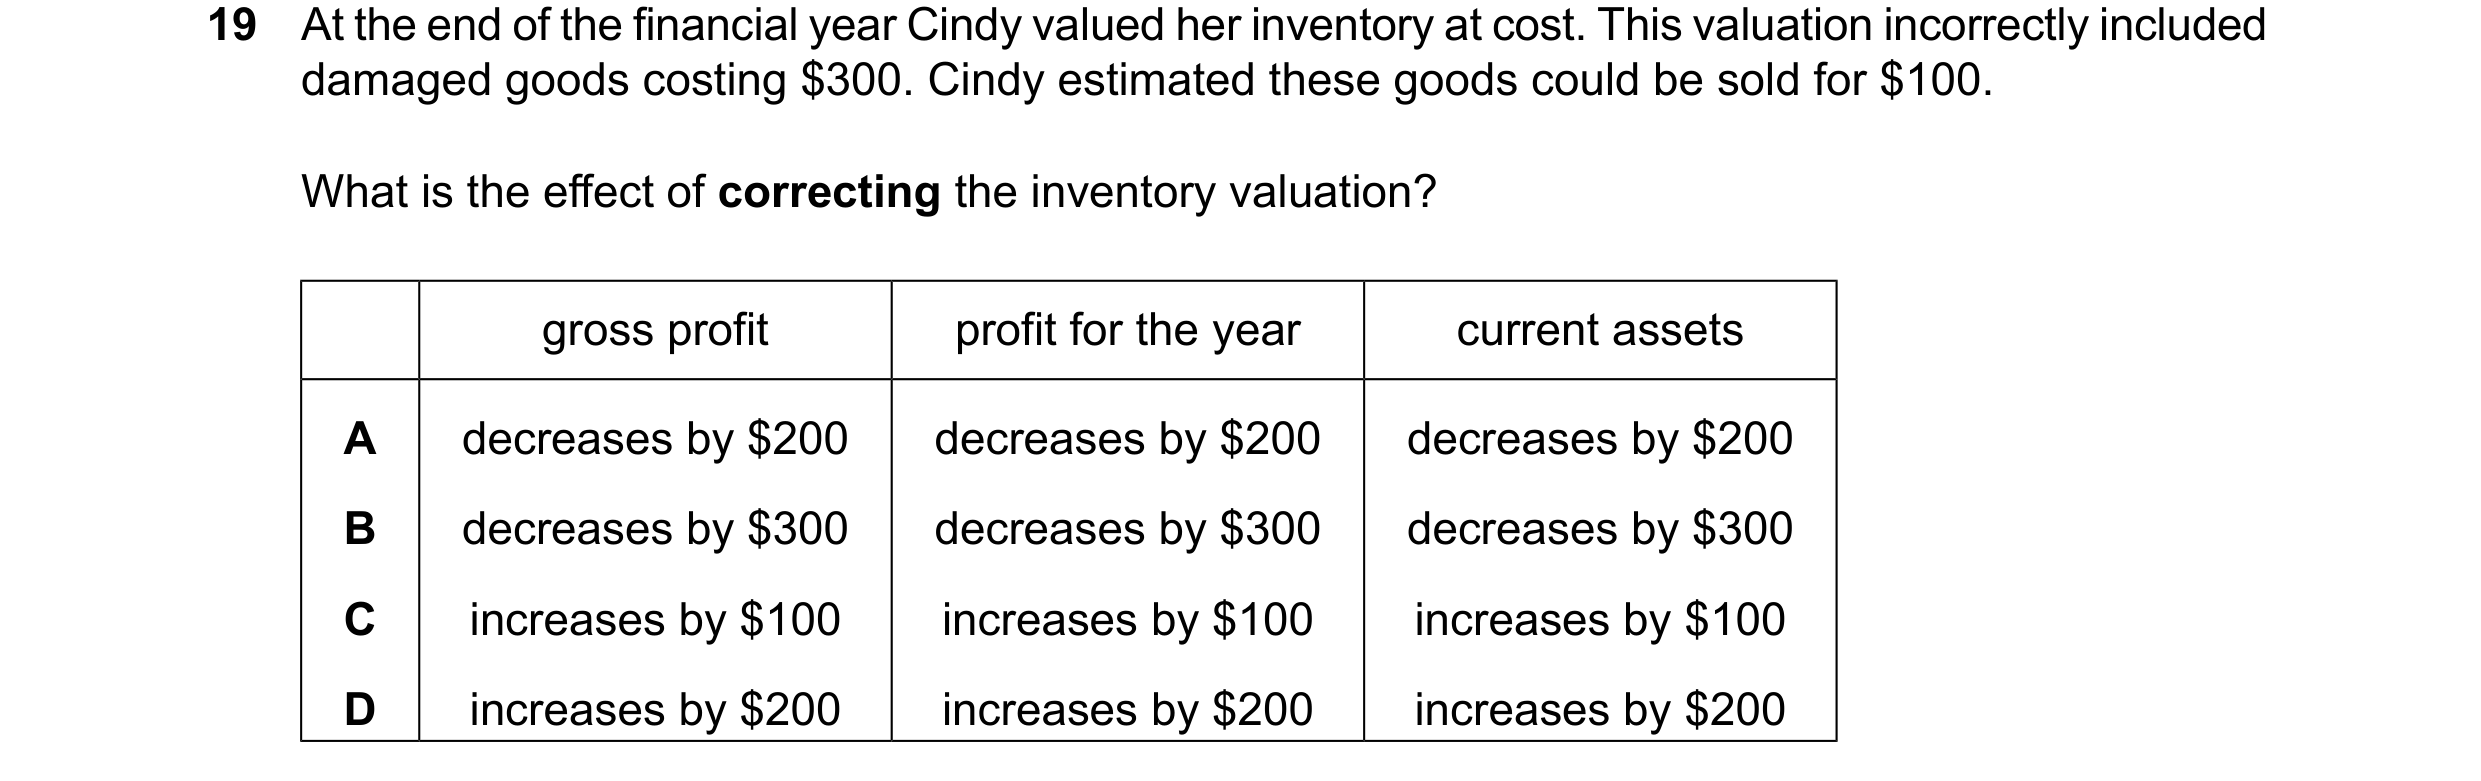
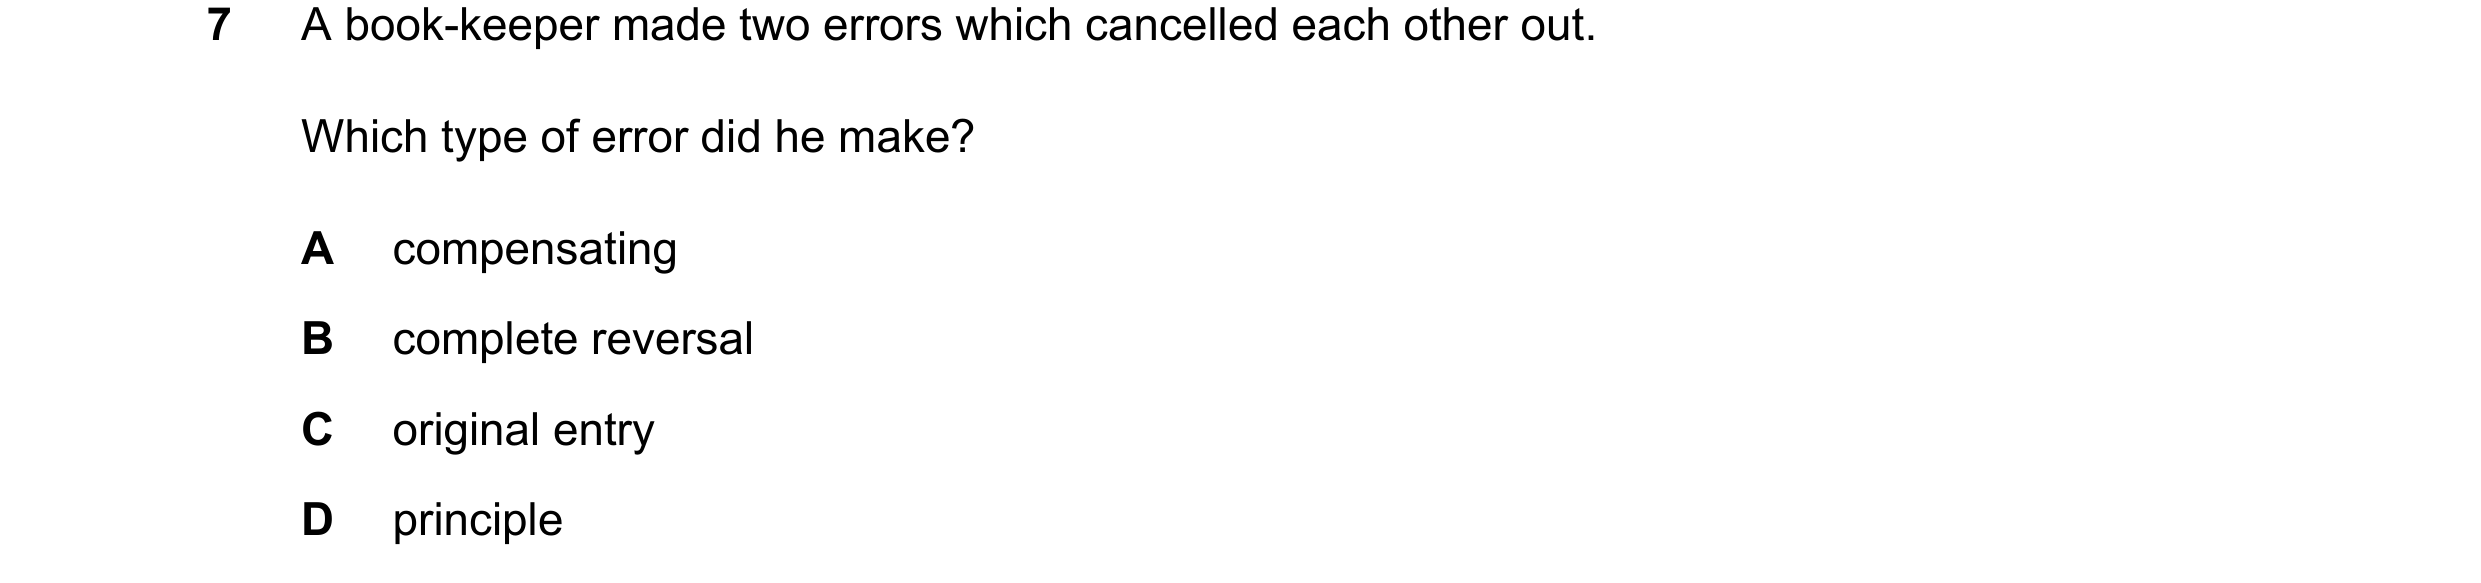
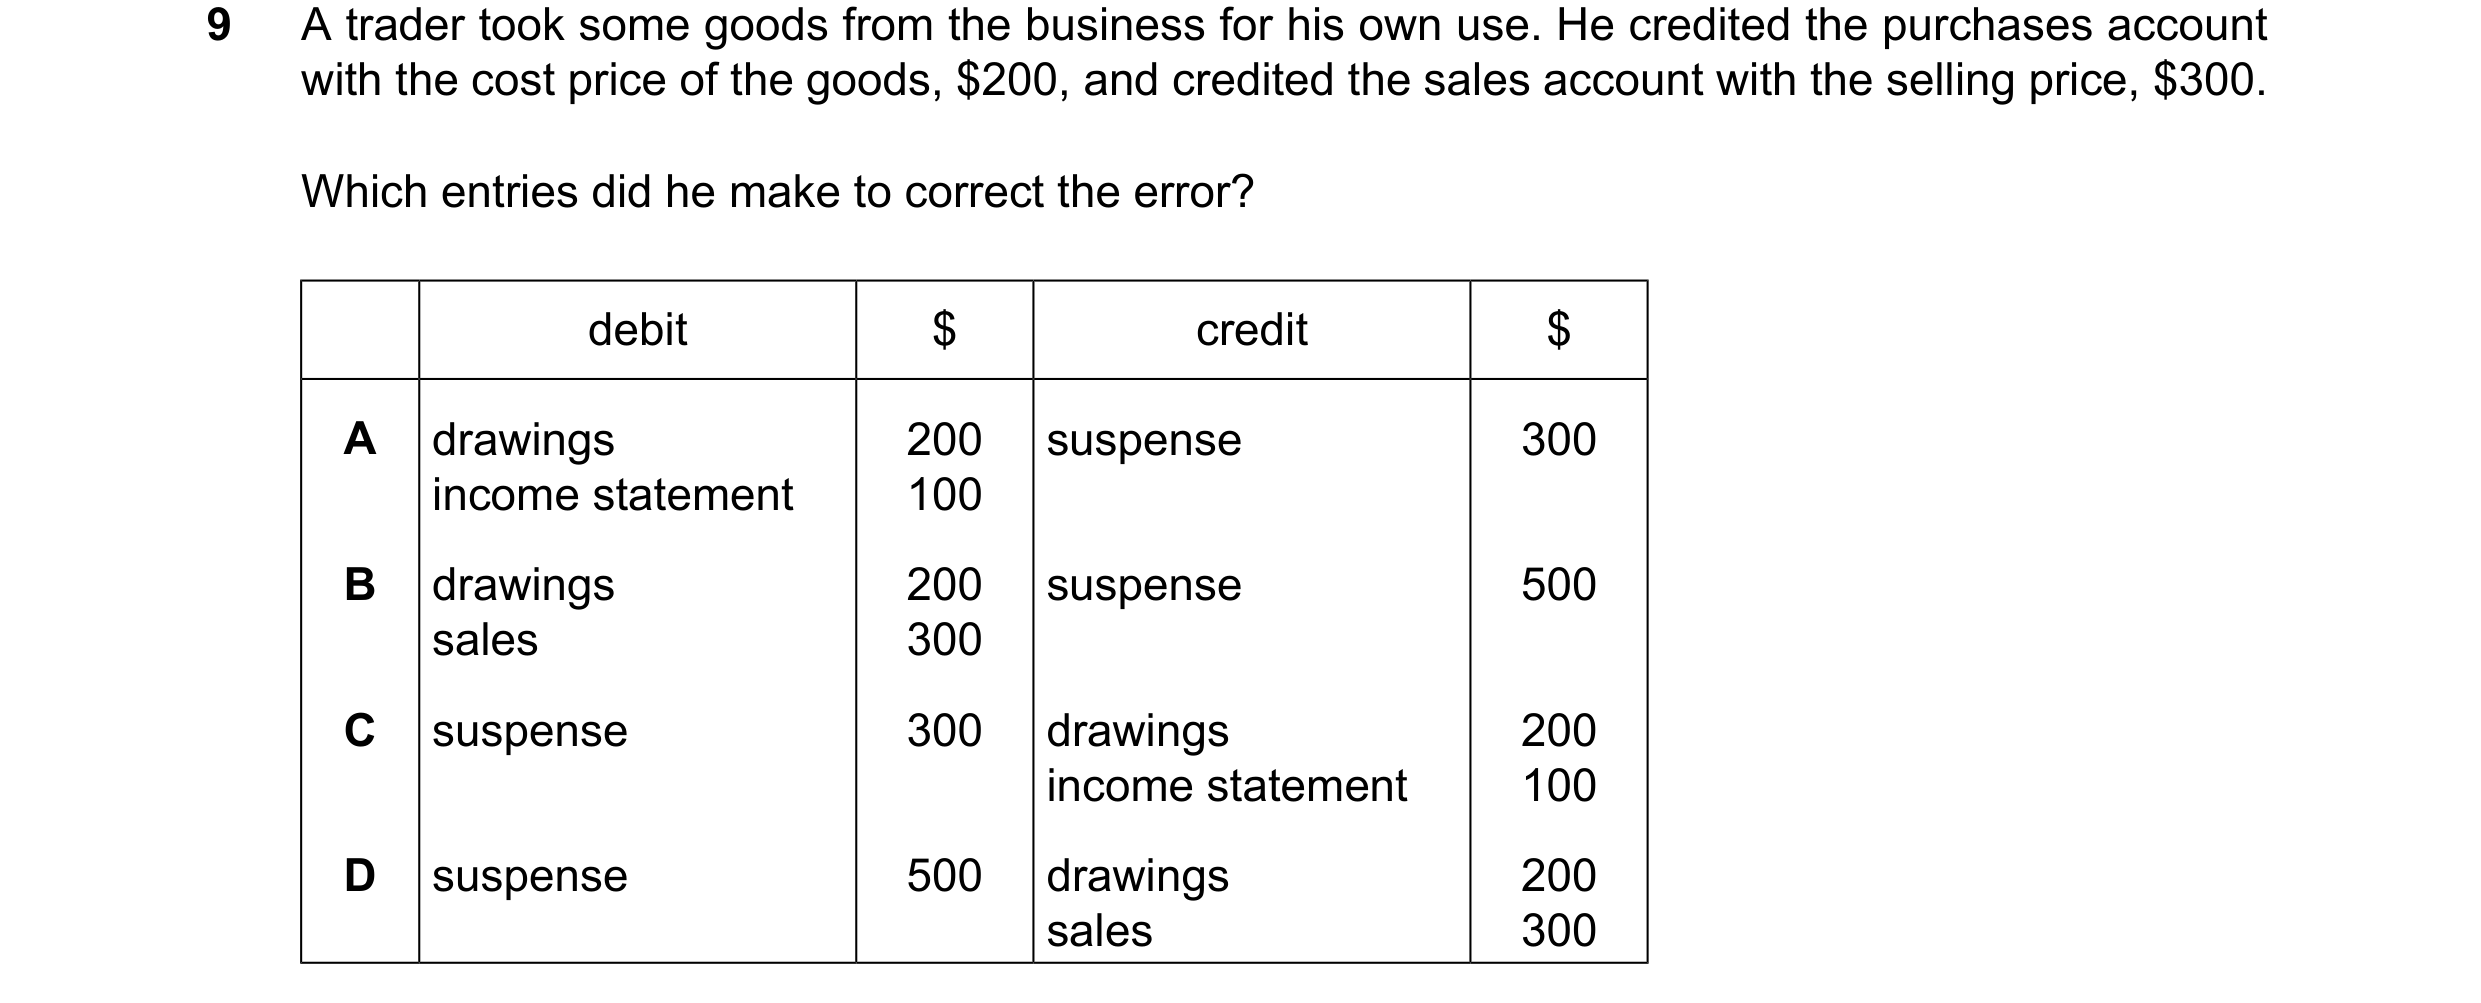 30 / 41
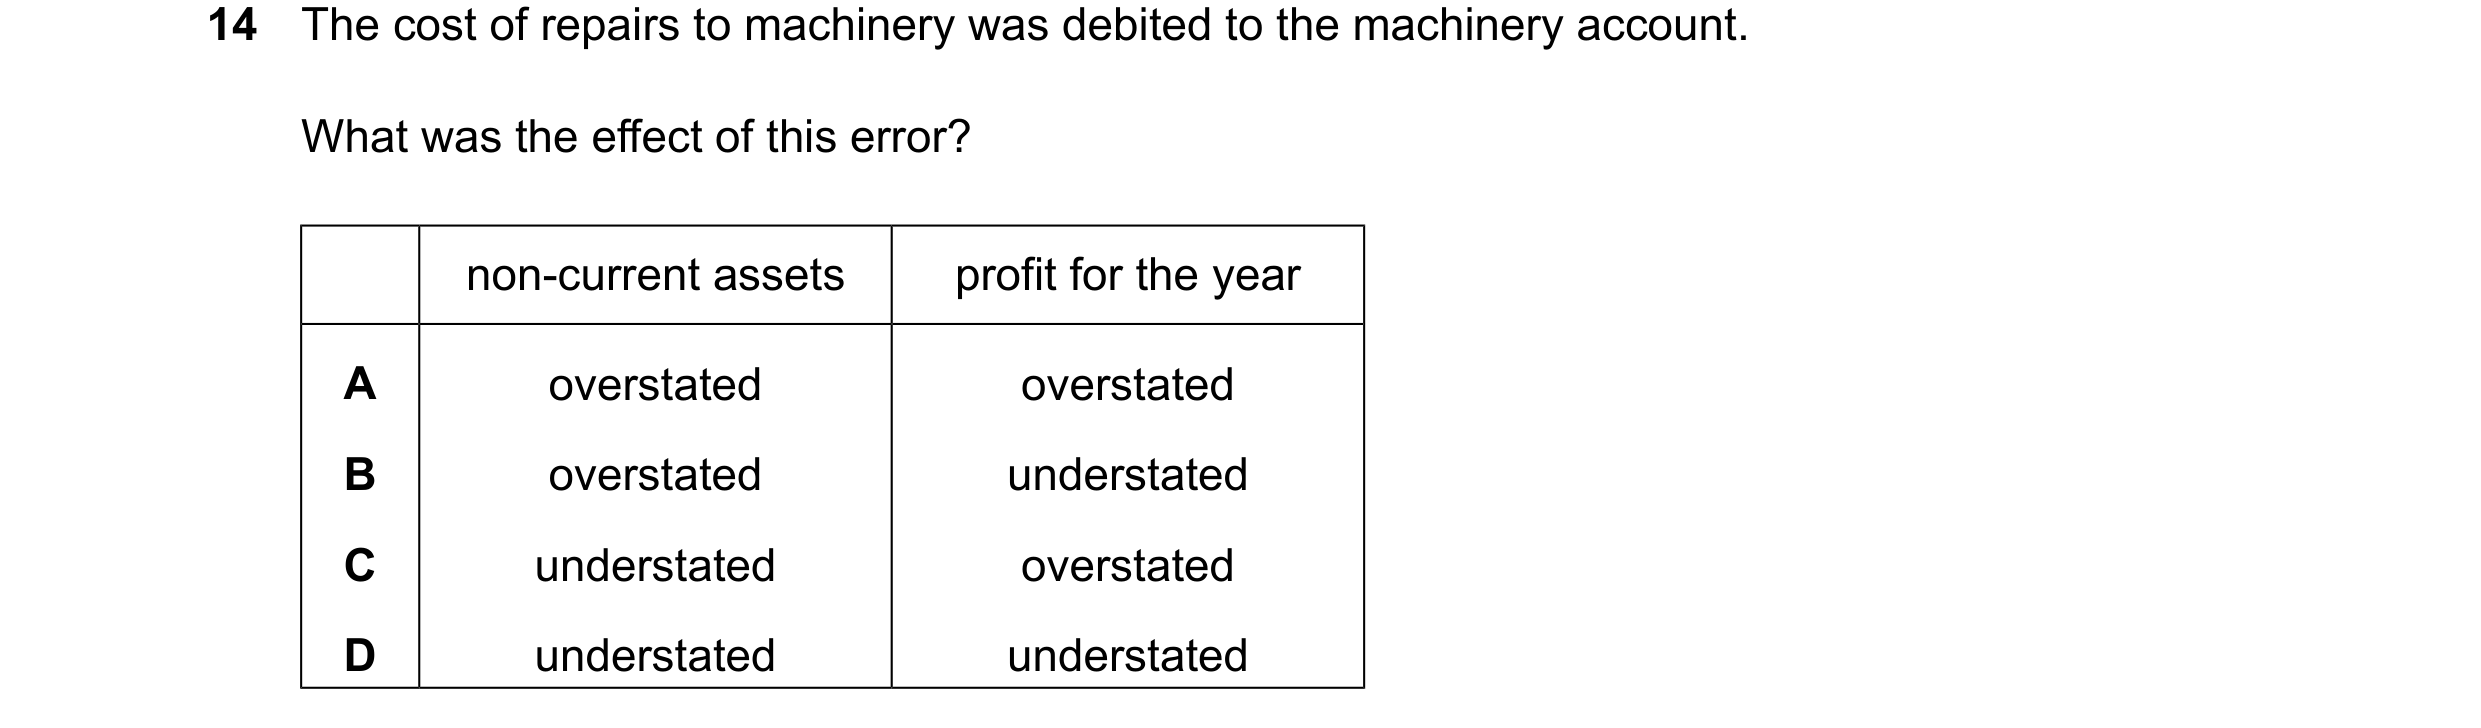
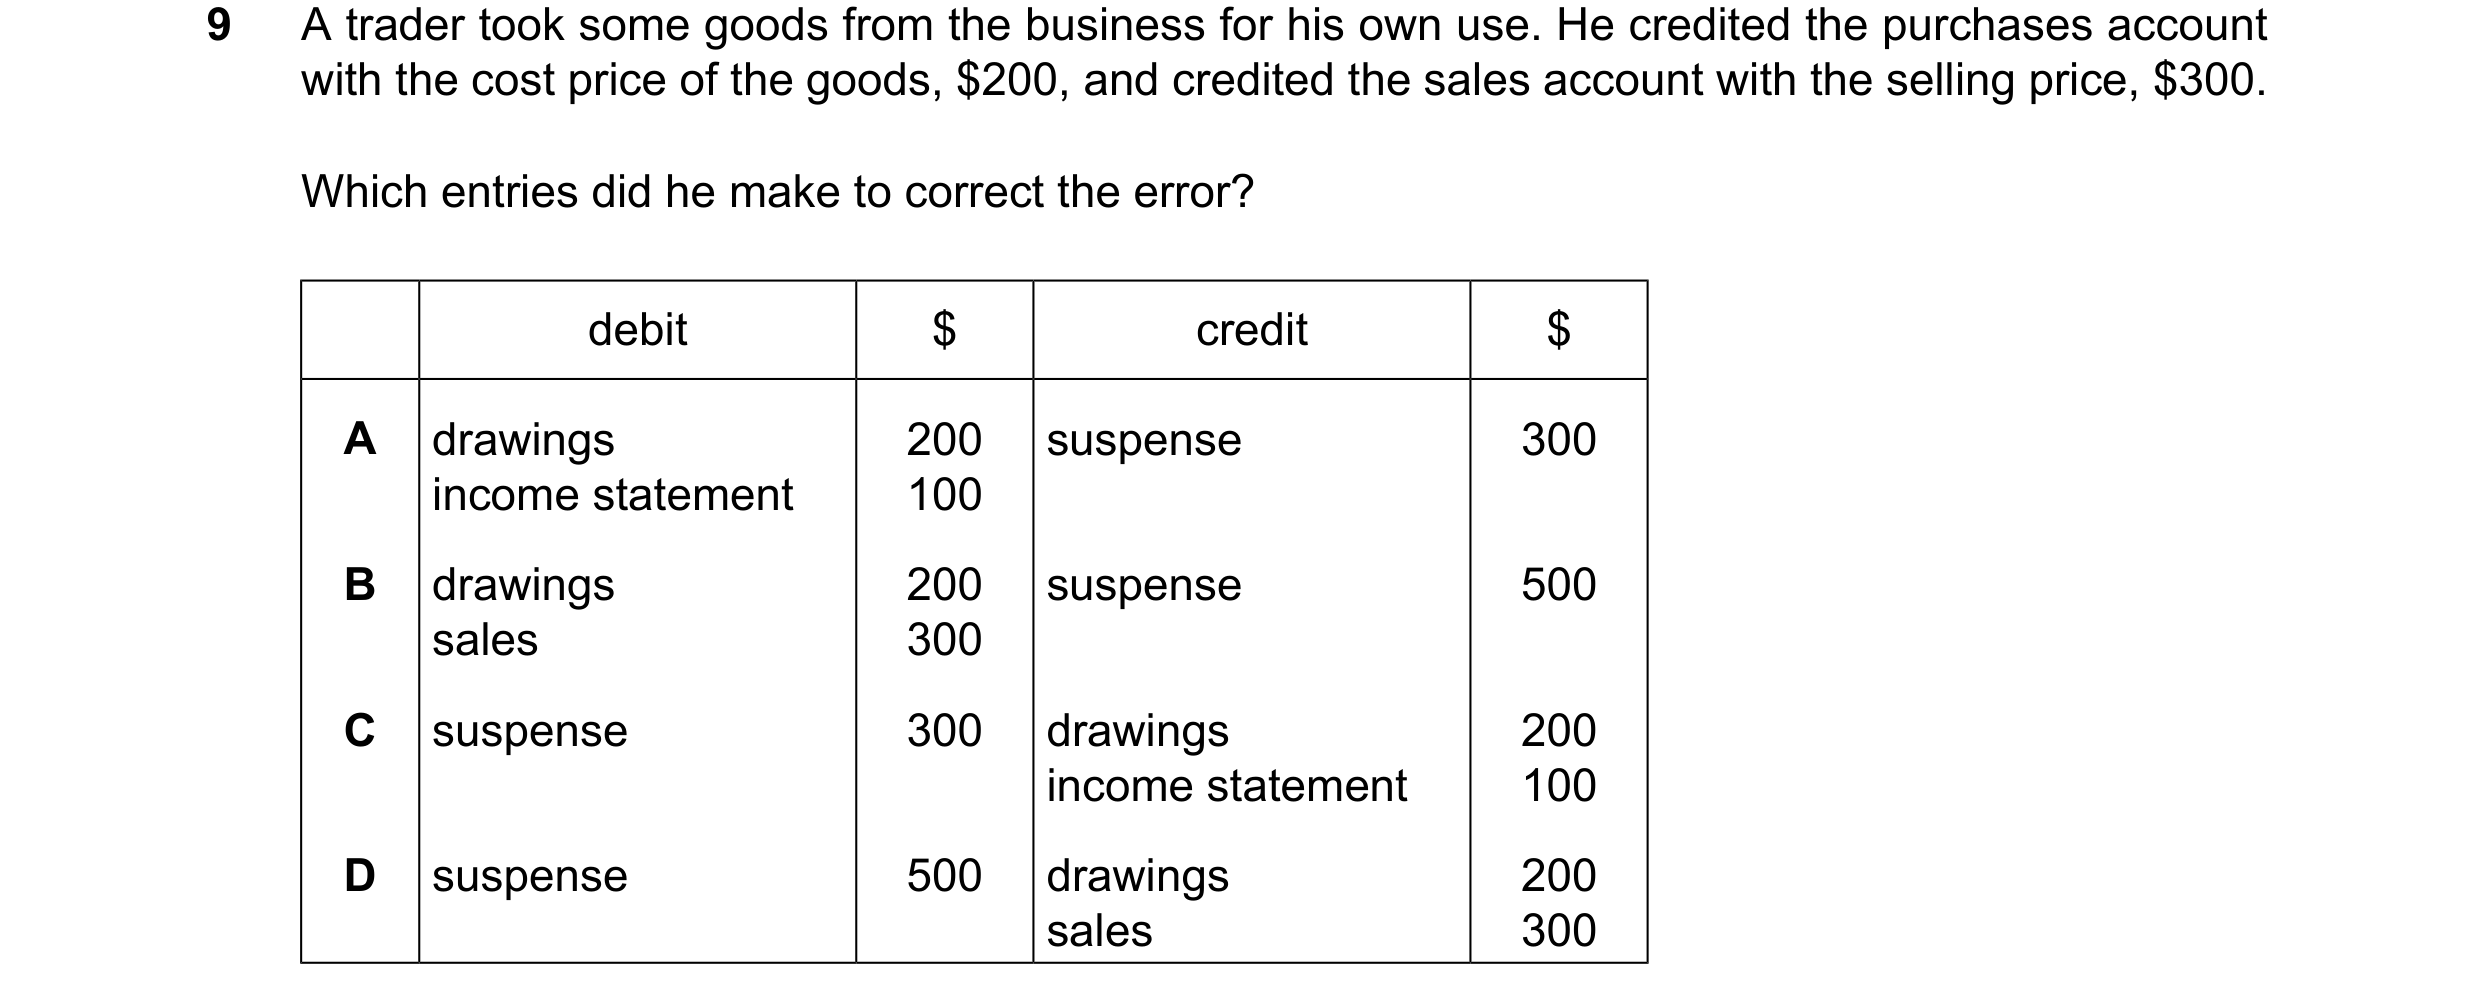 31 / 41
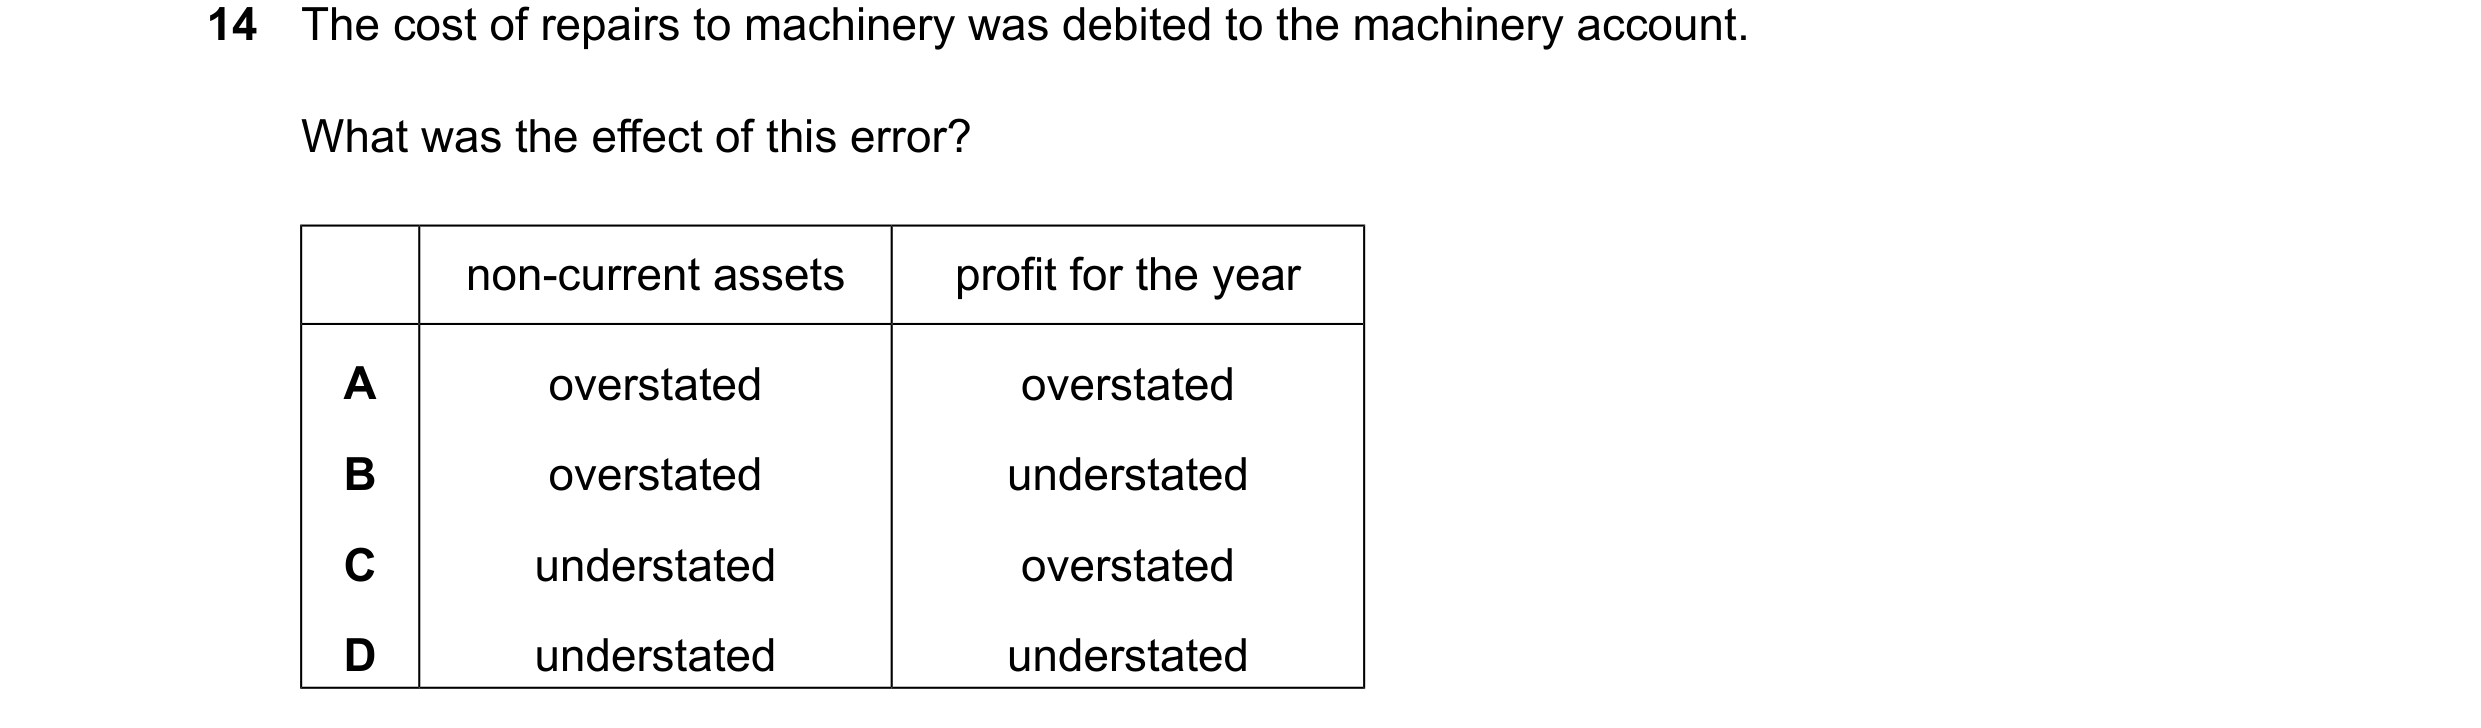
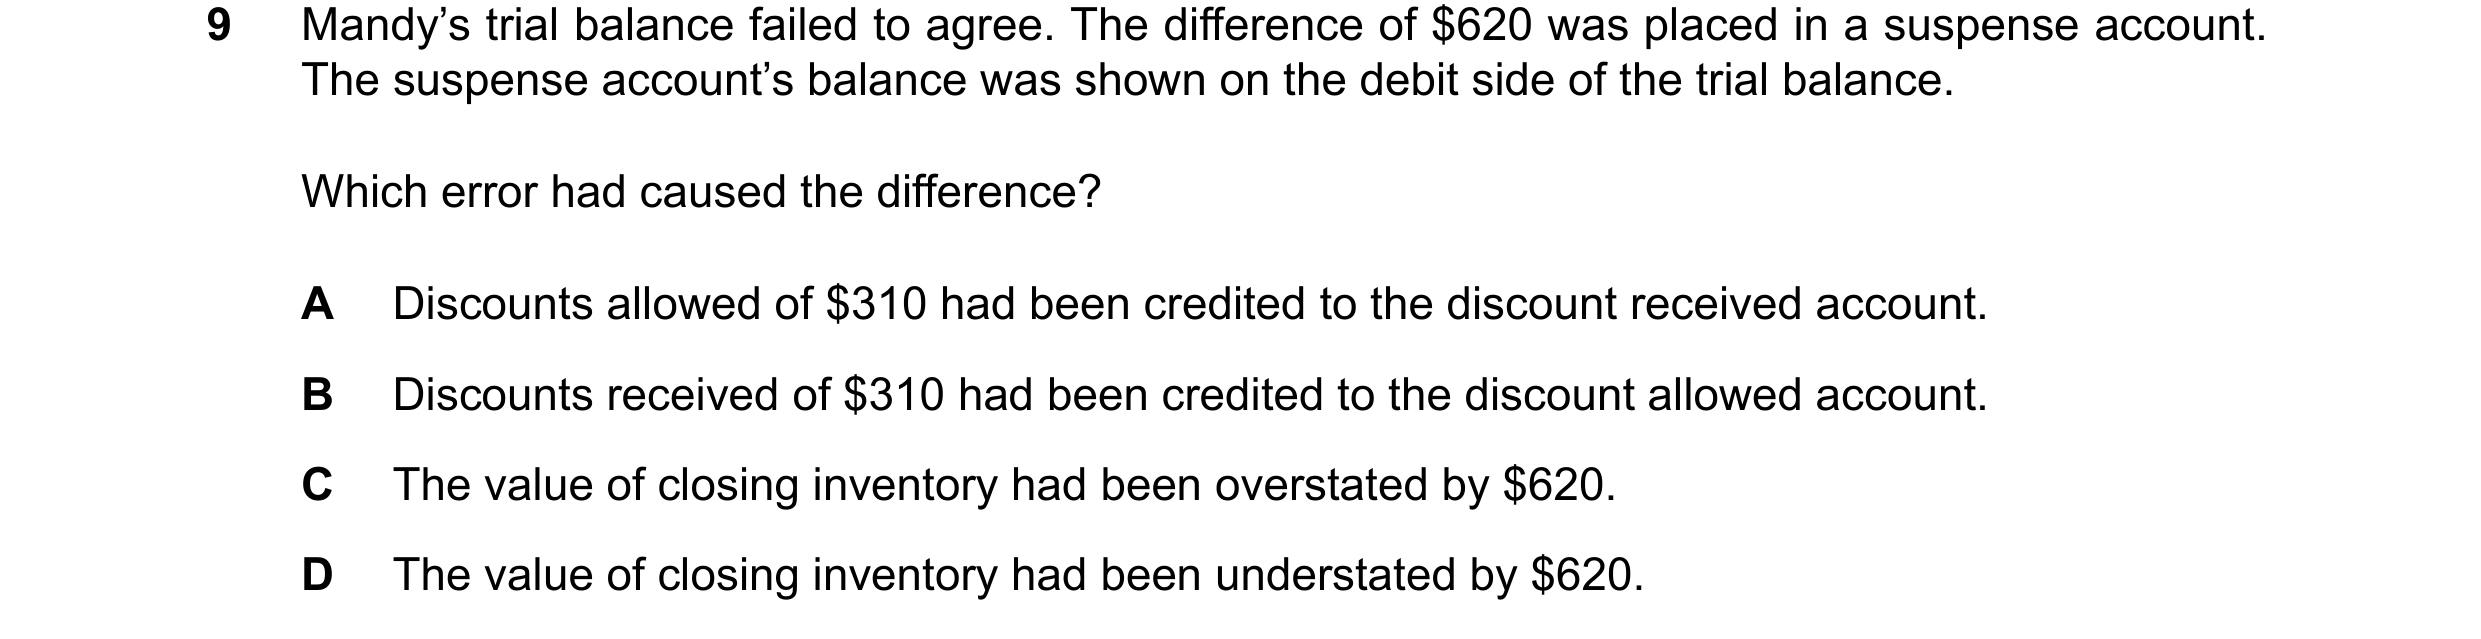
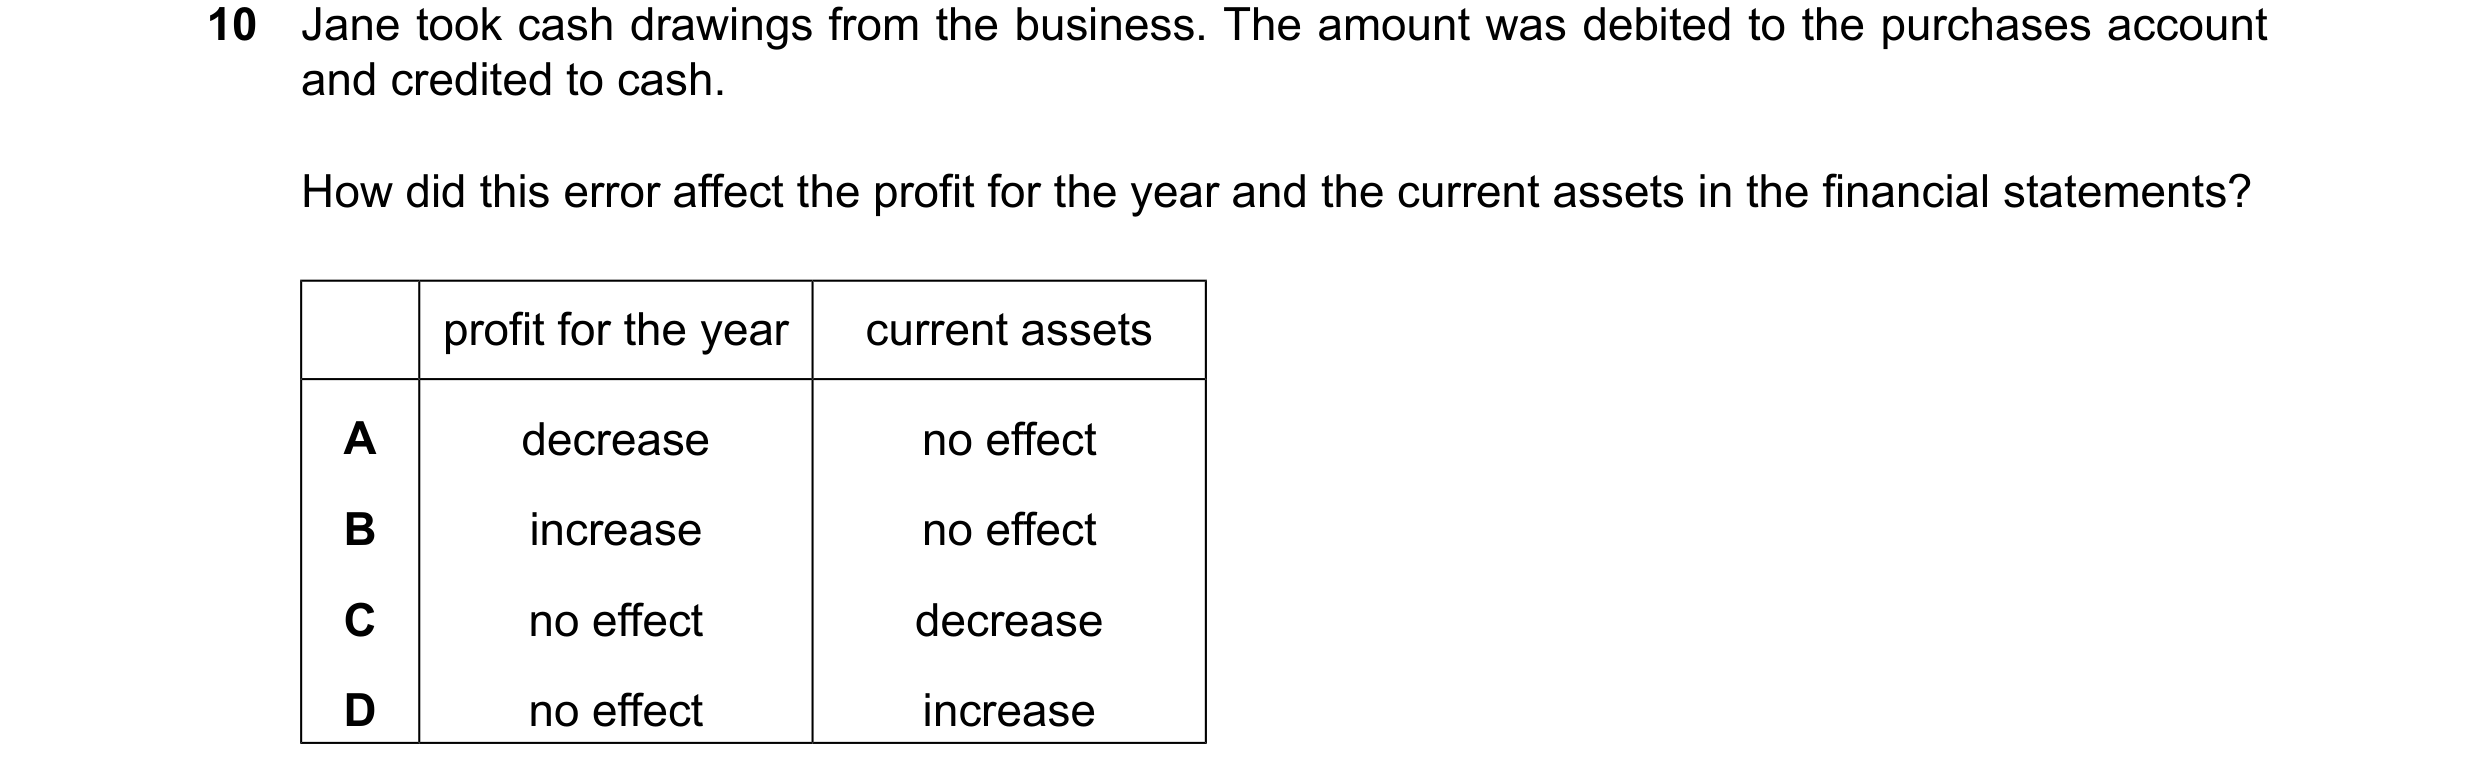 32 / 41
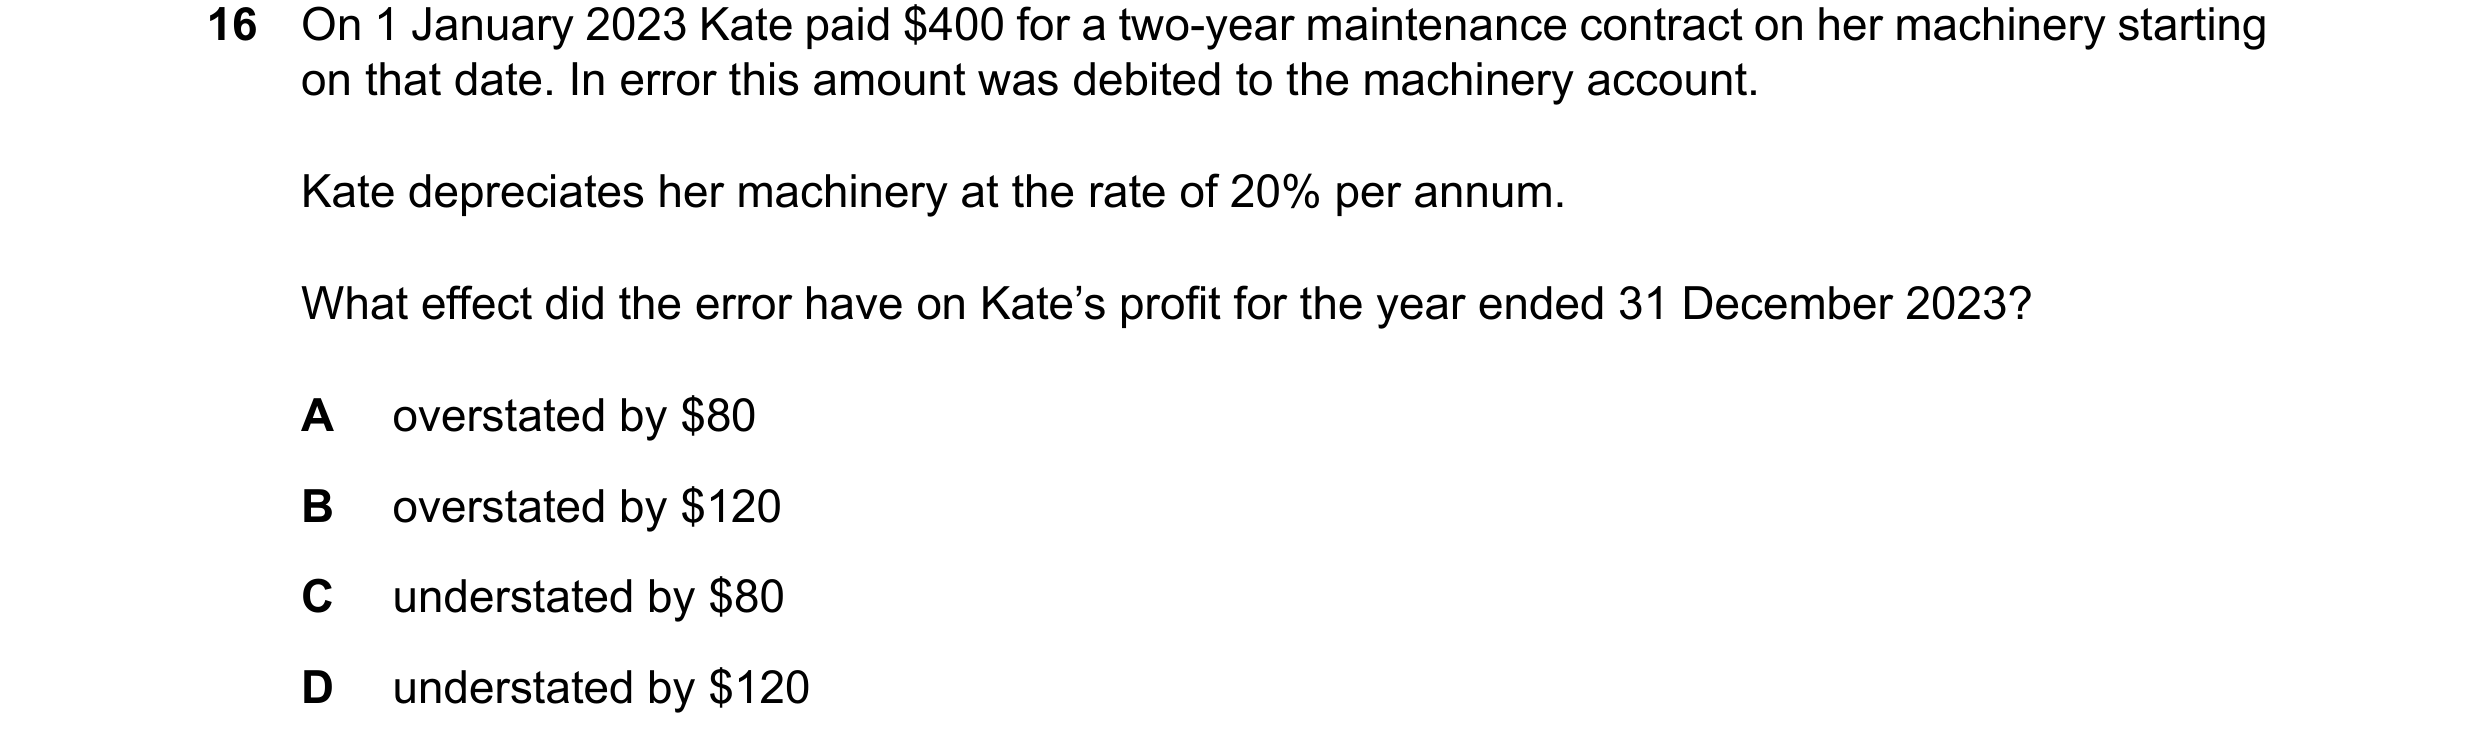
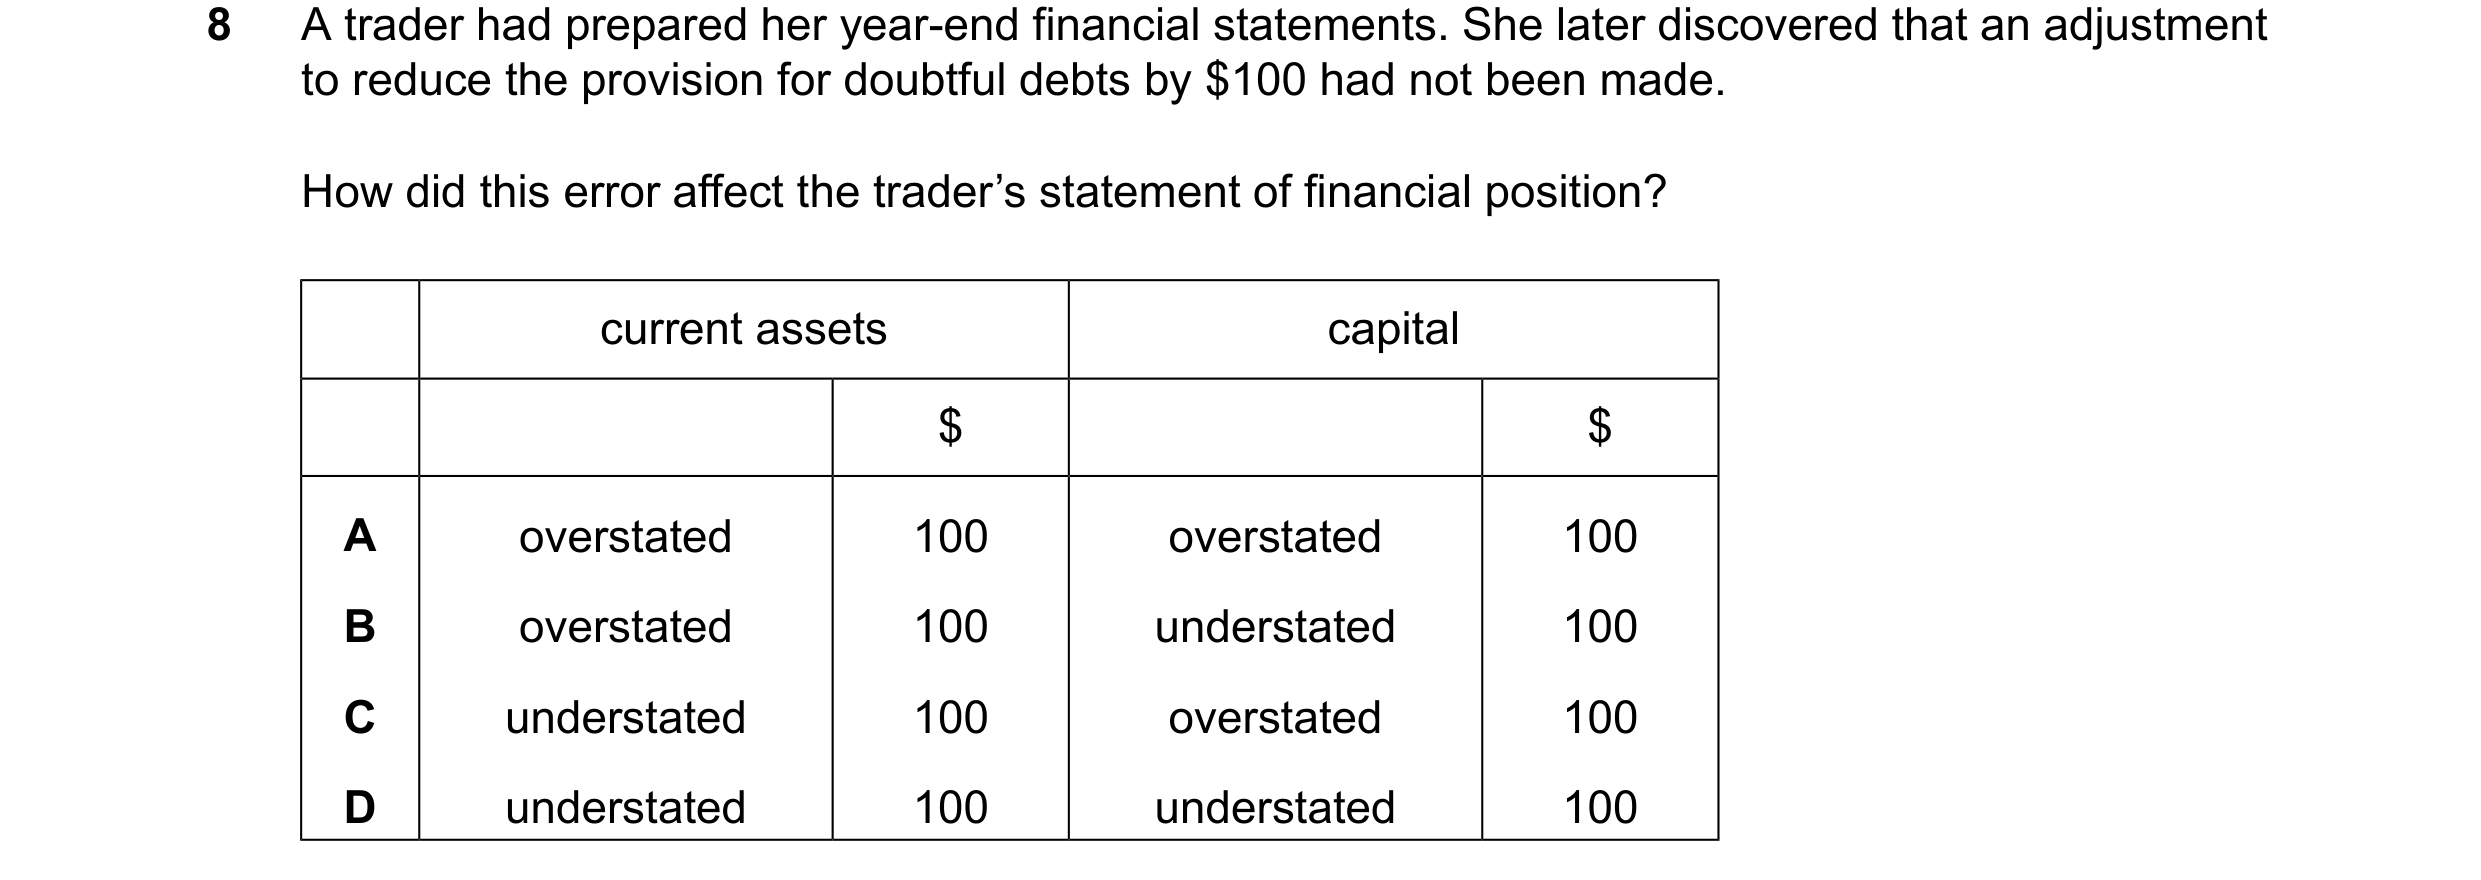
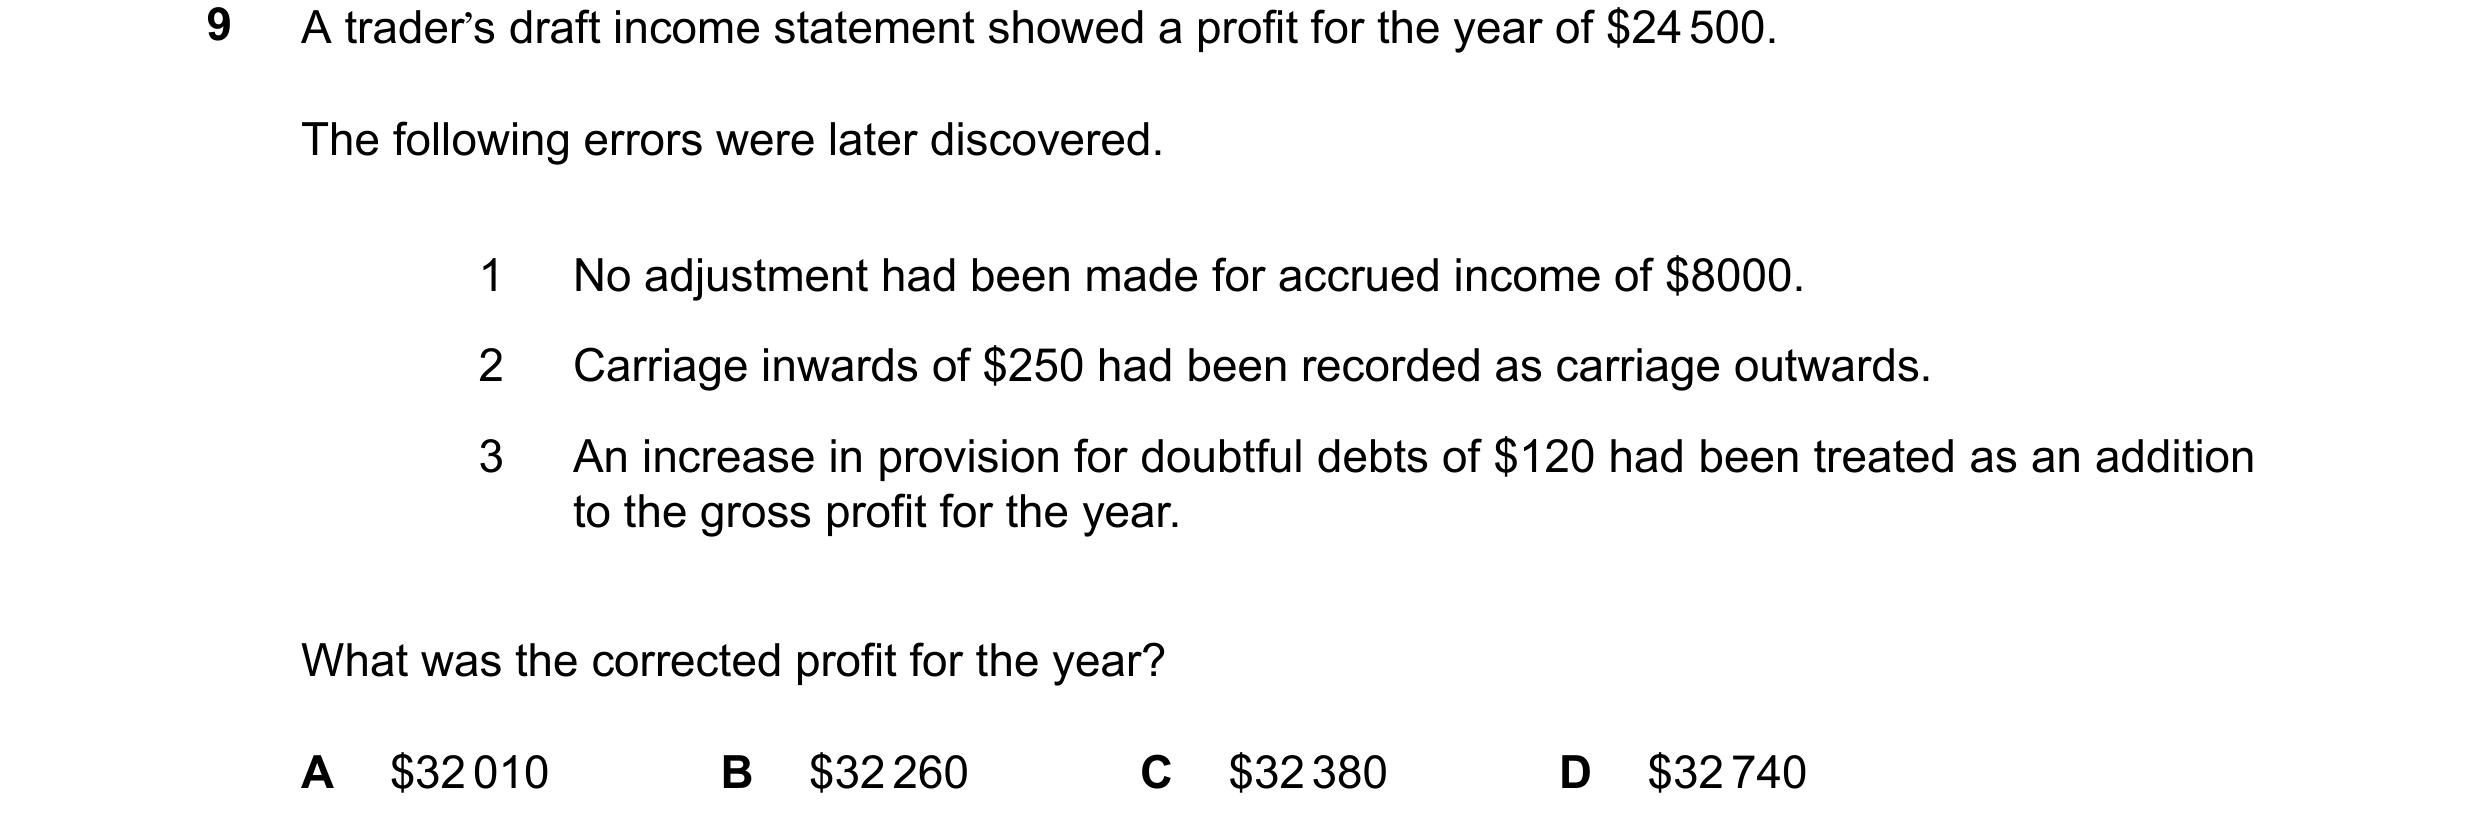
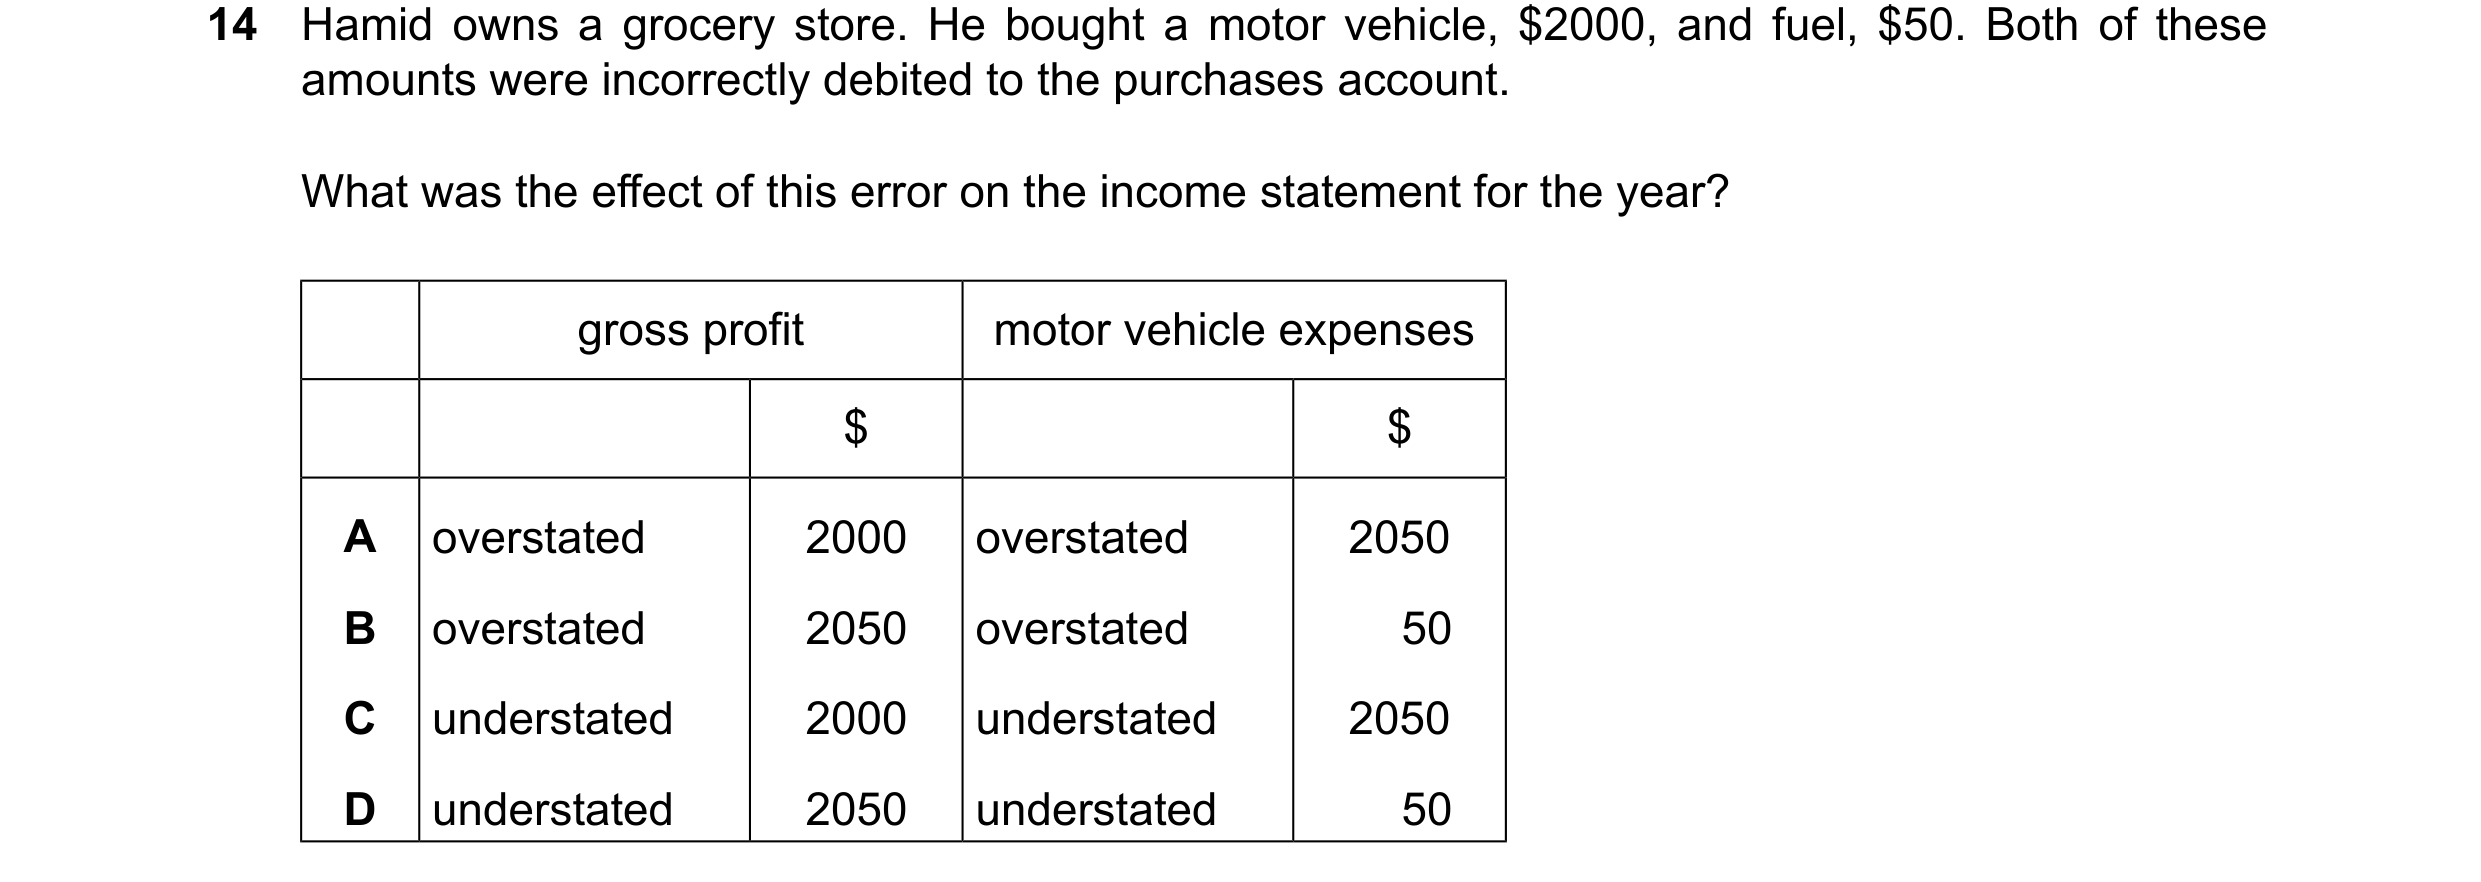 33 / 41
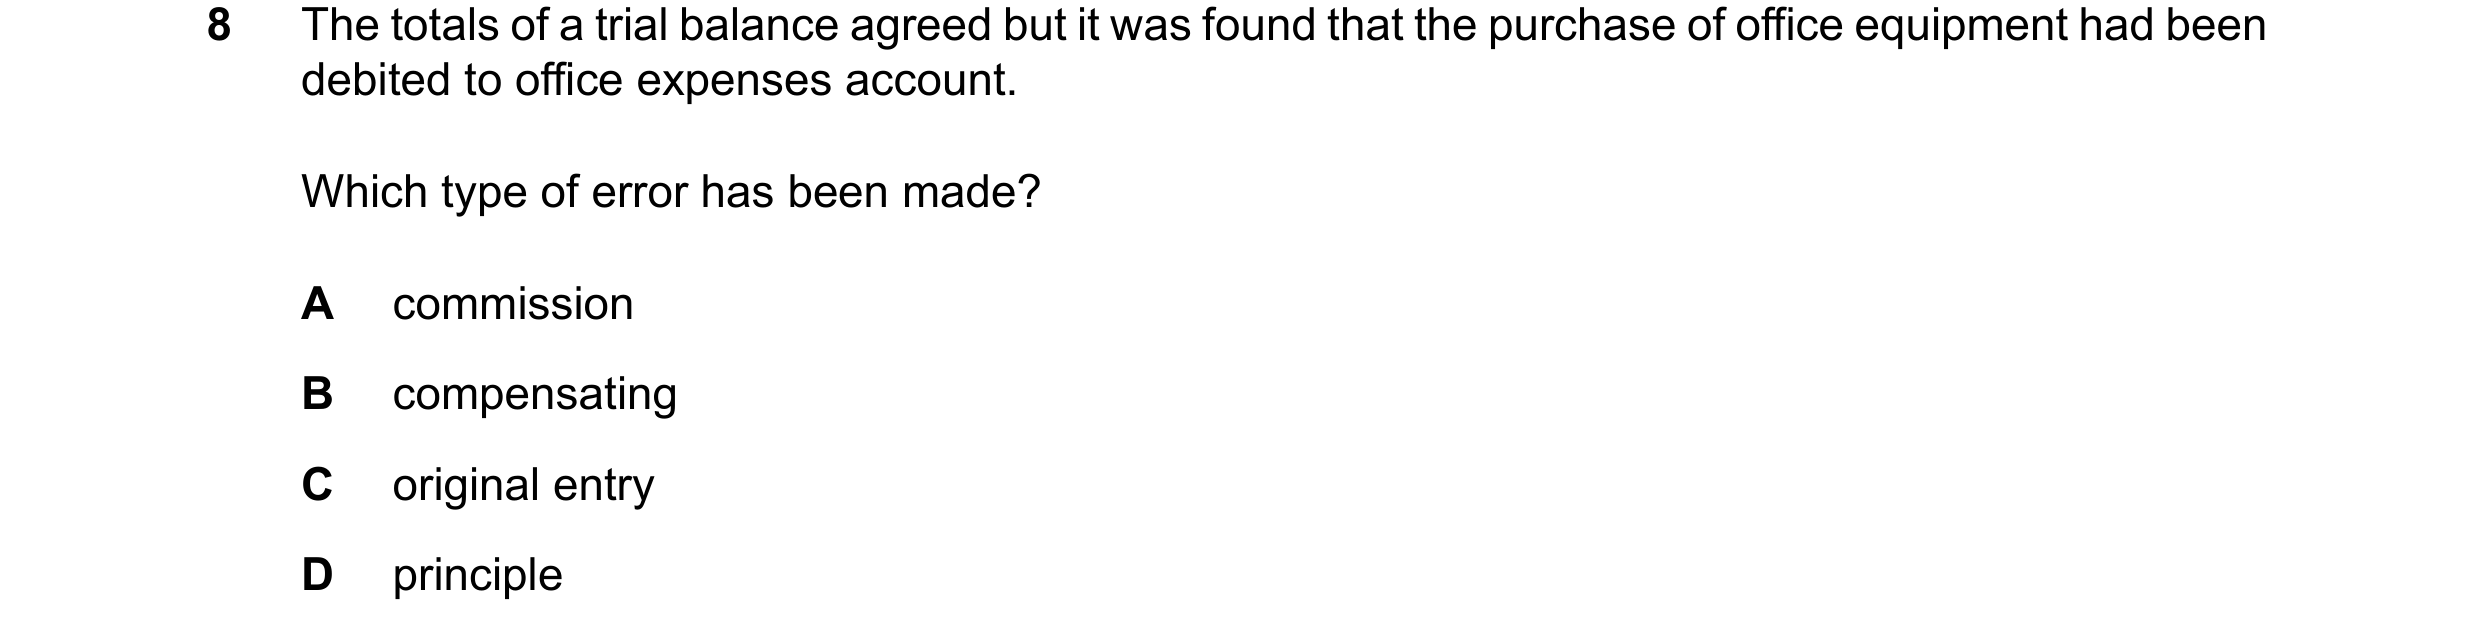
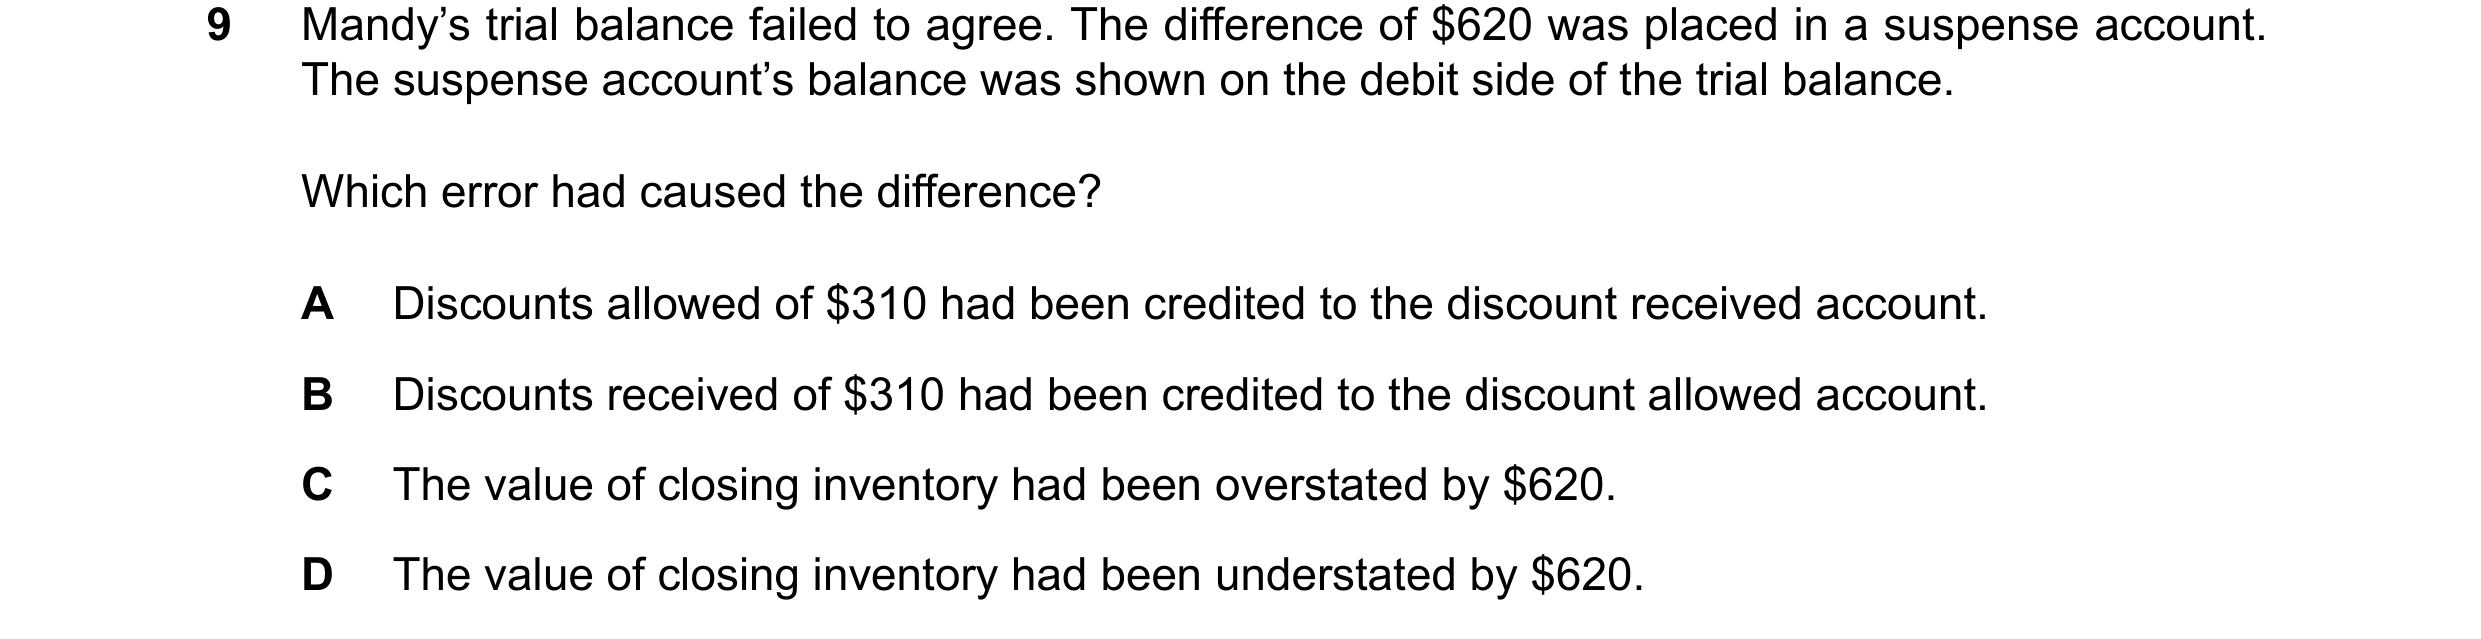
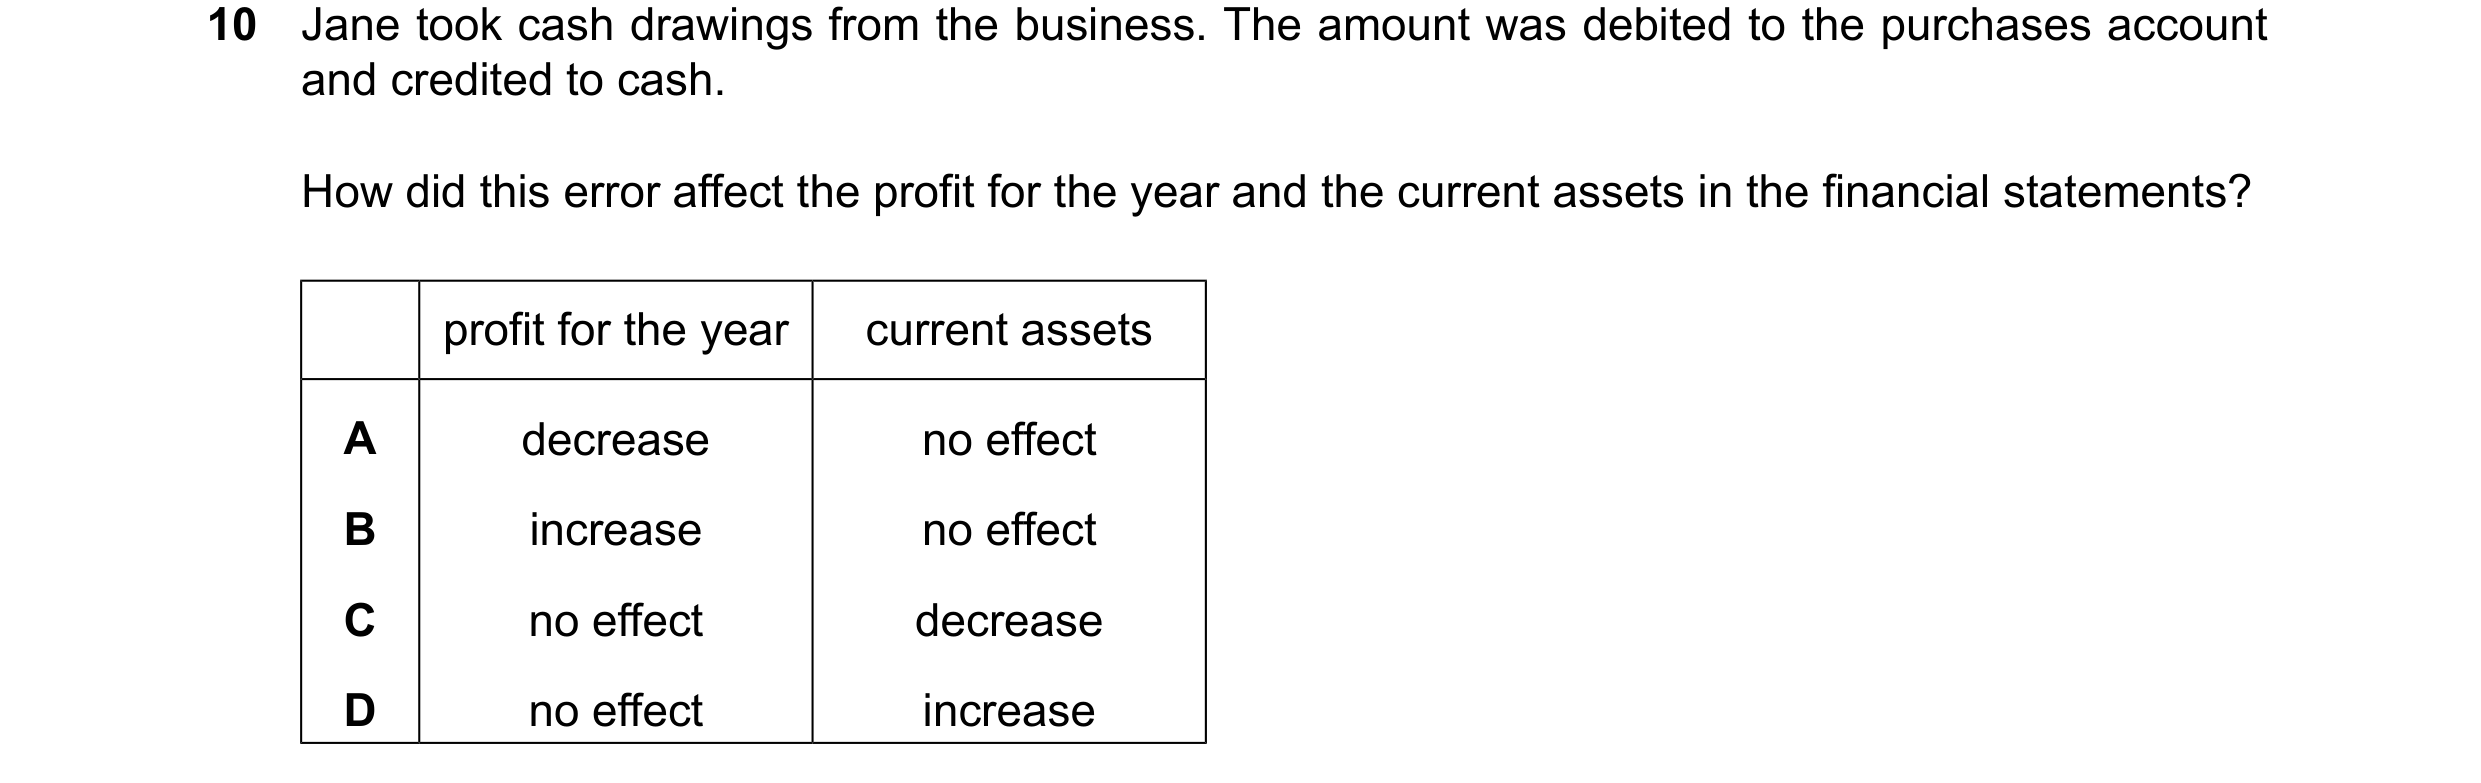
 34 / 41
 35 / 41
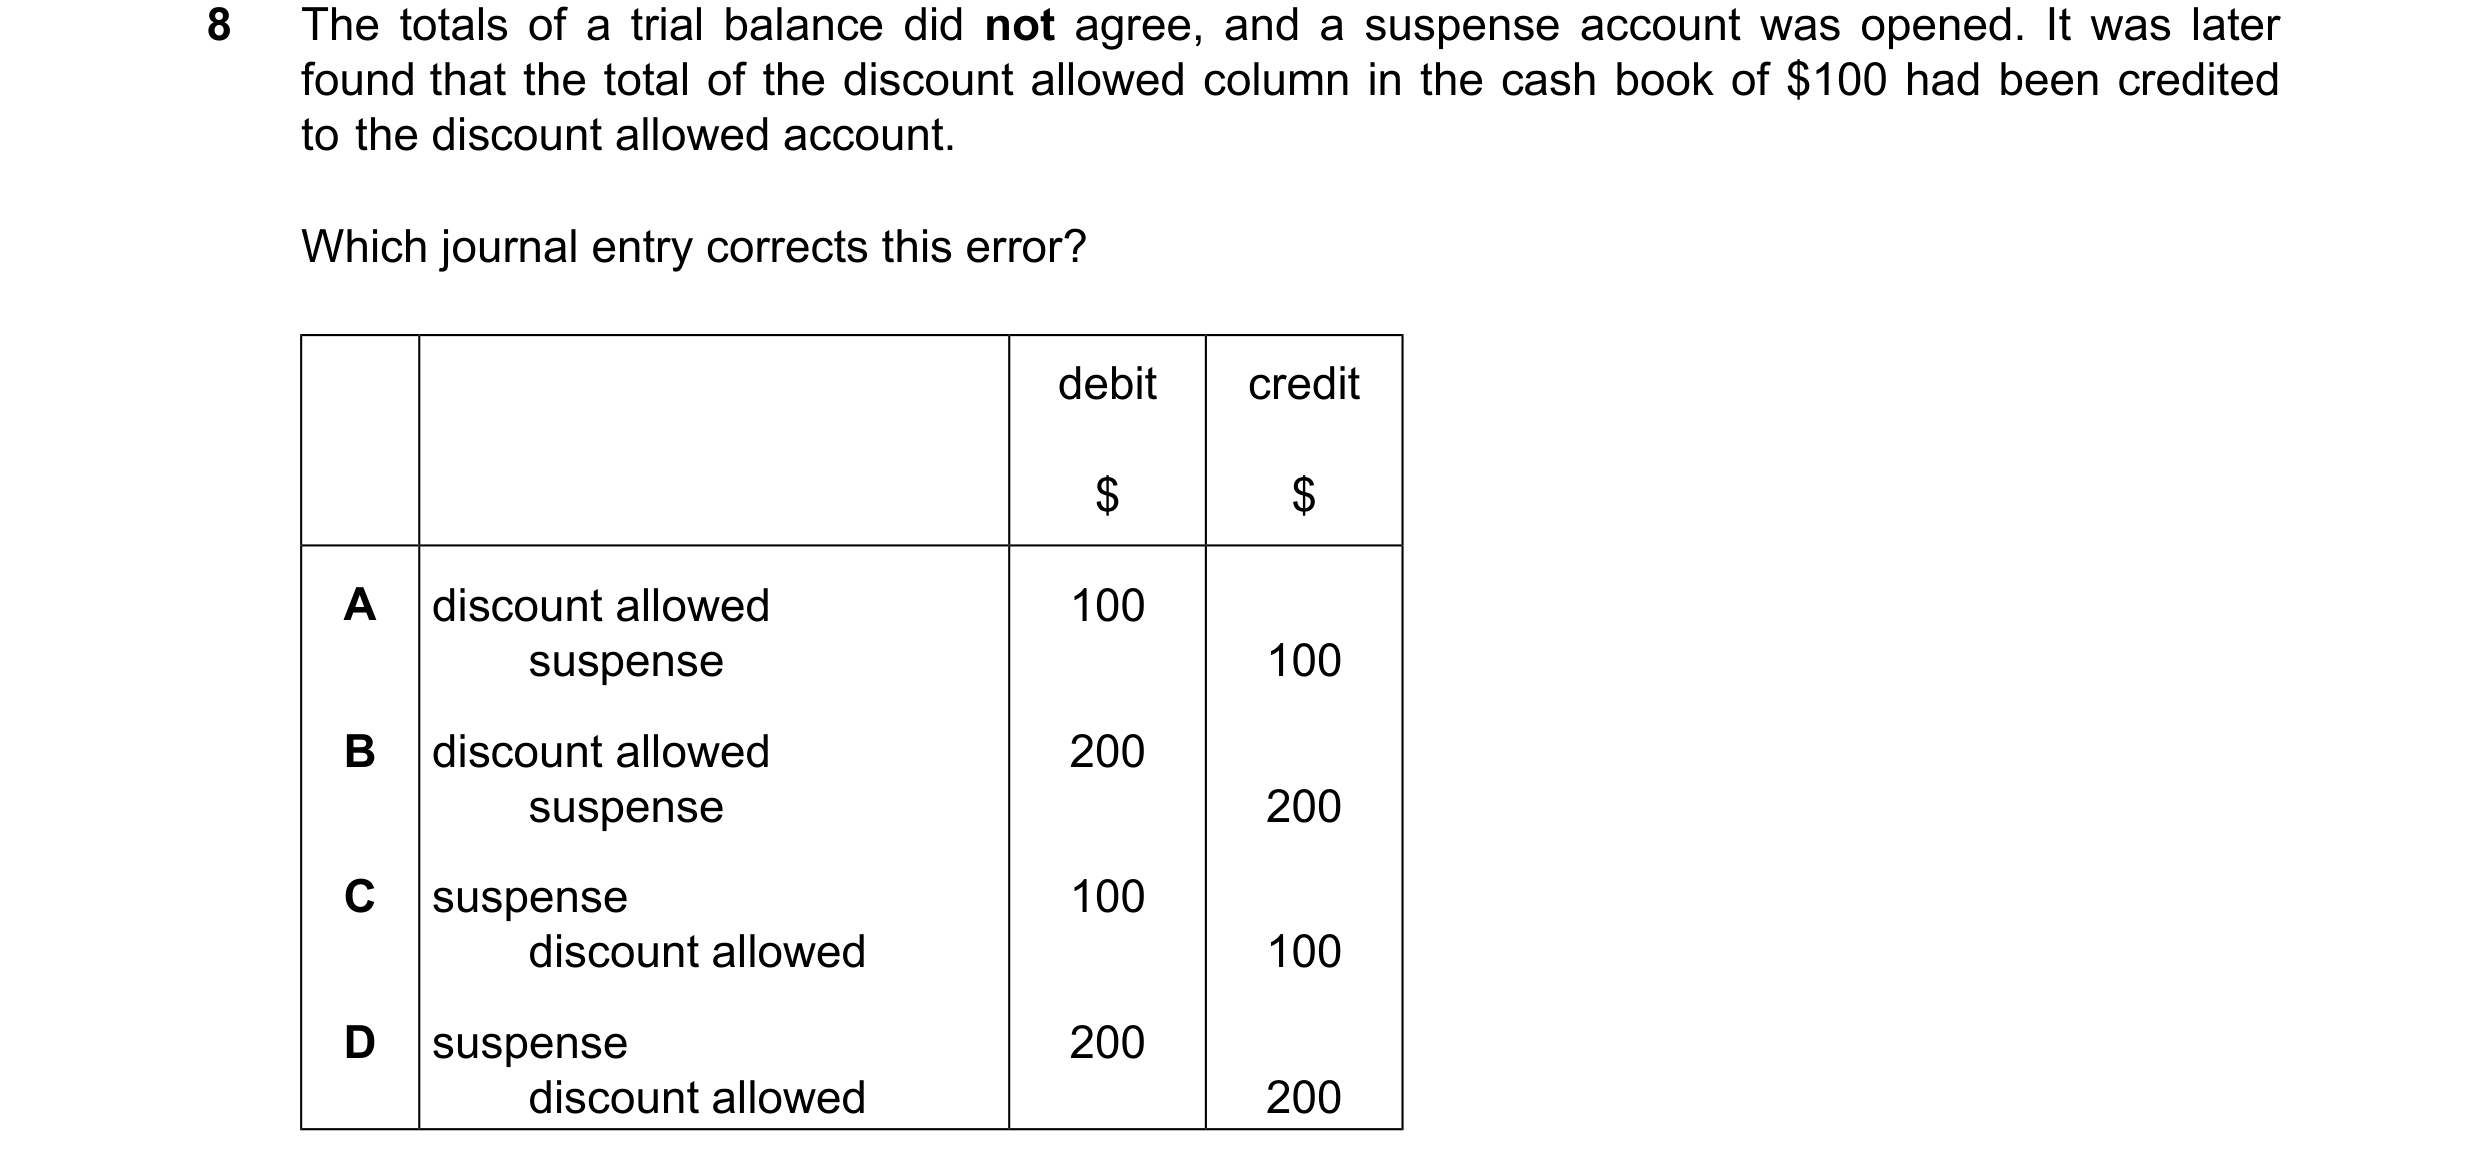
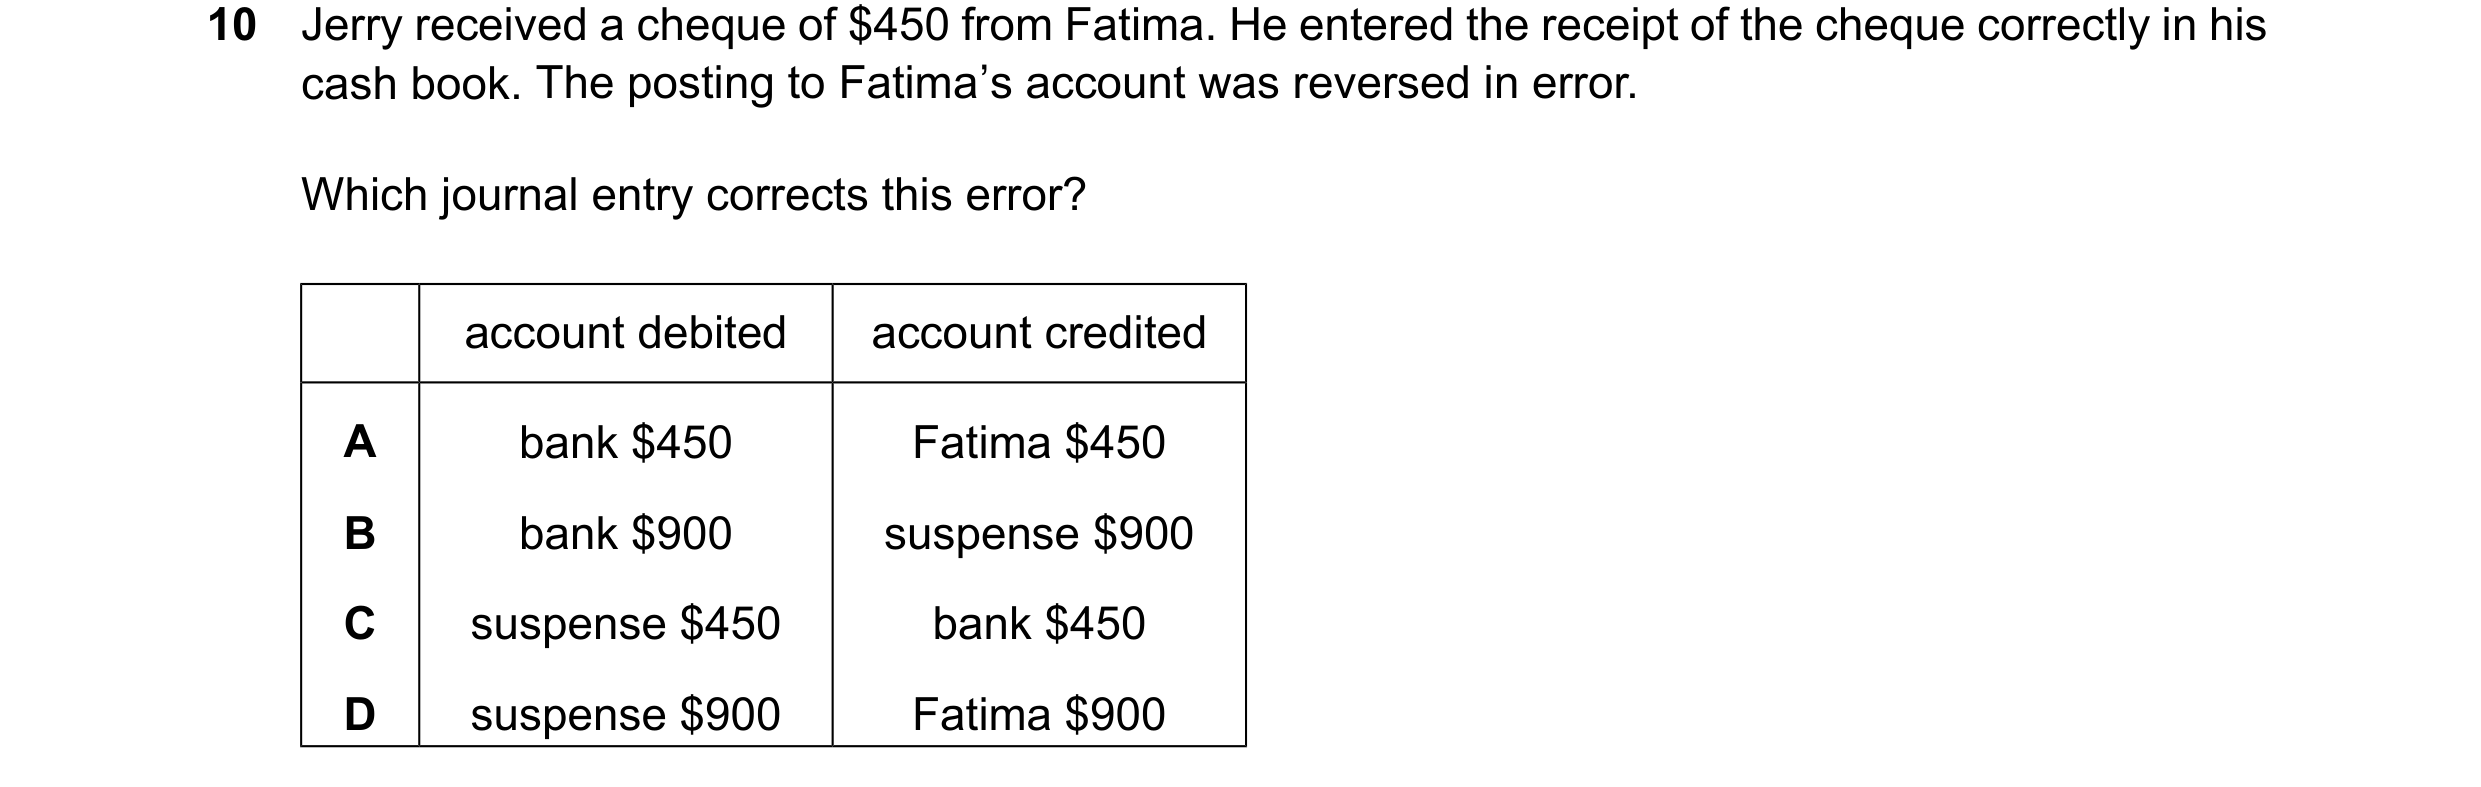 36 / 41
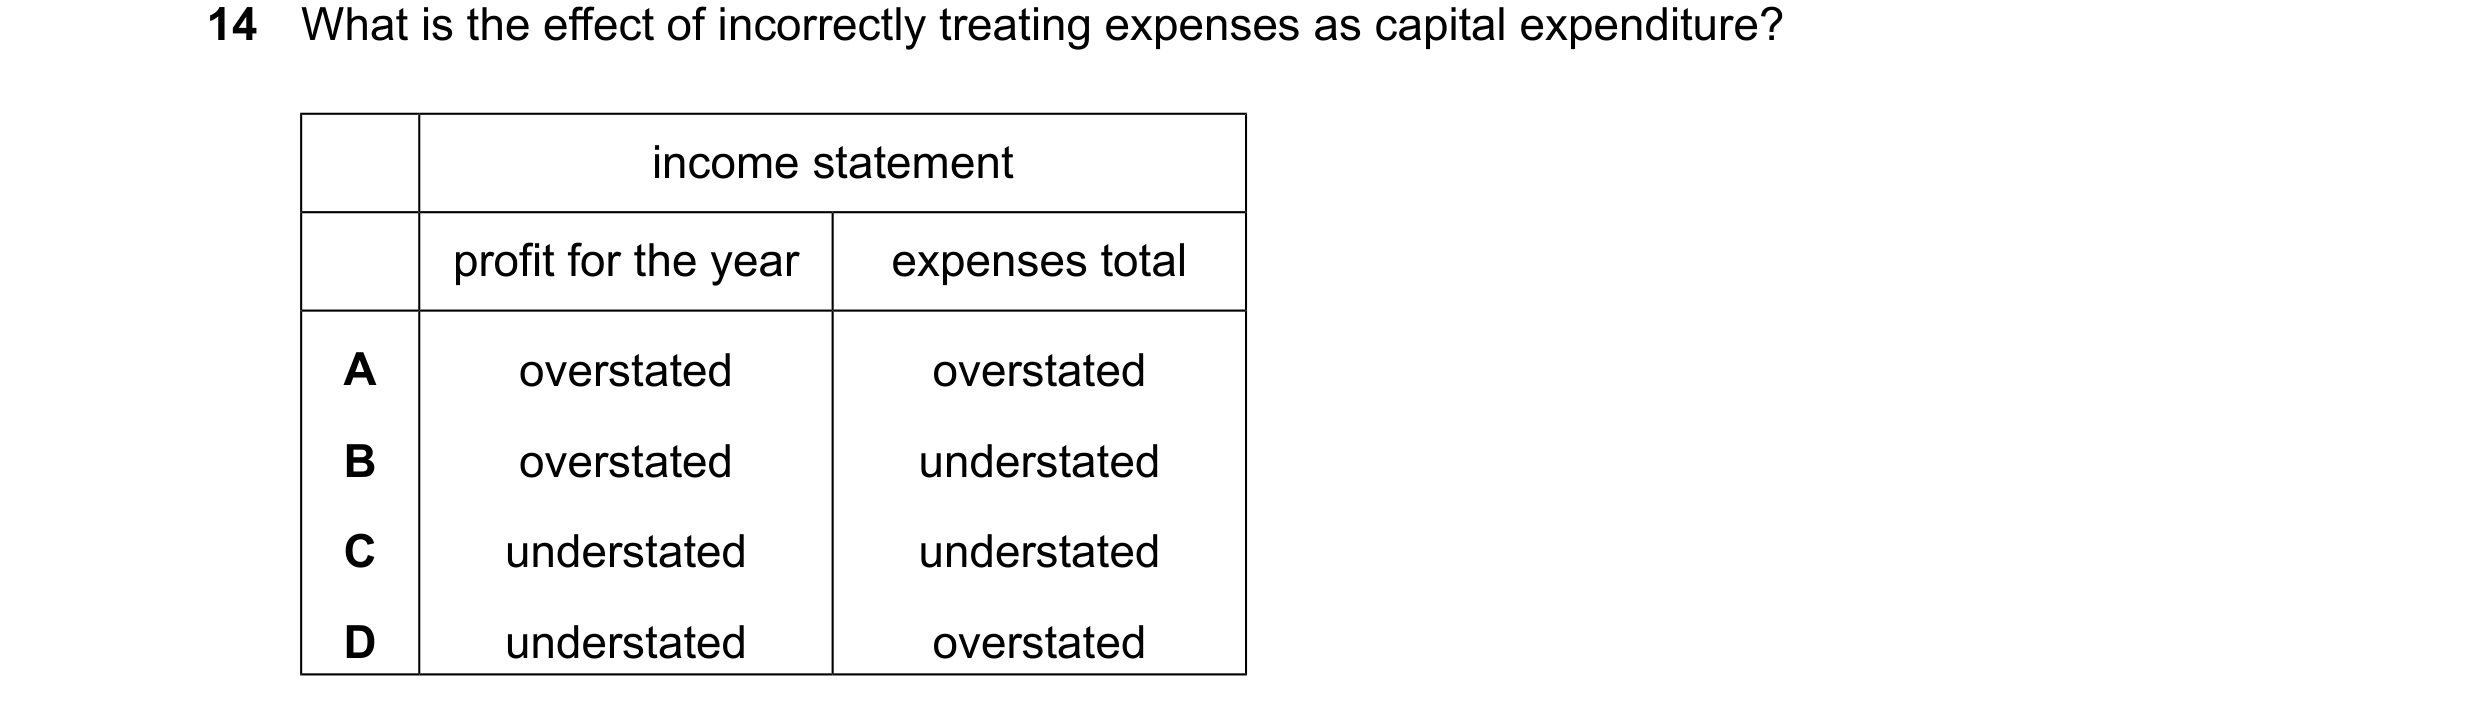
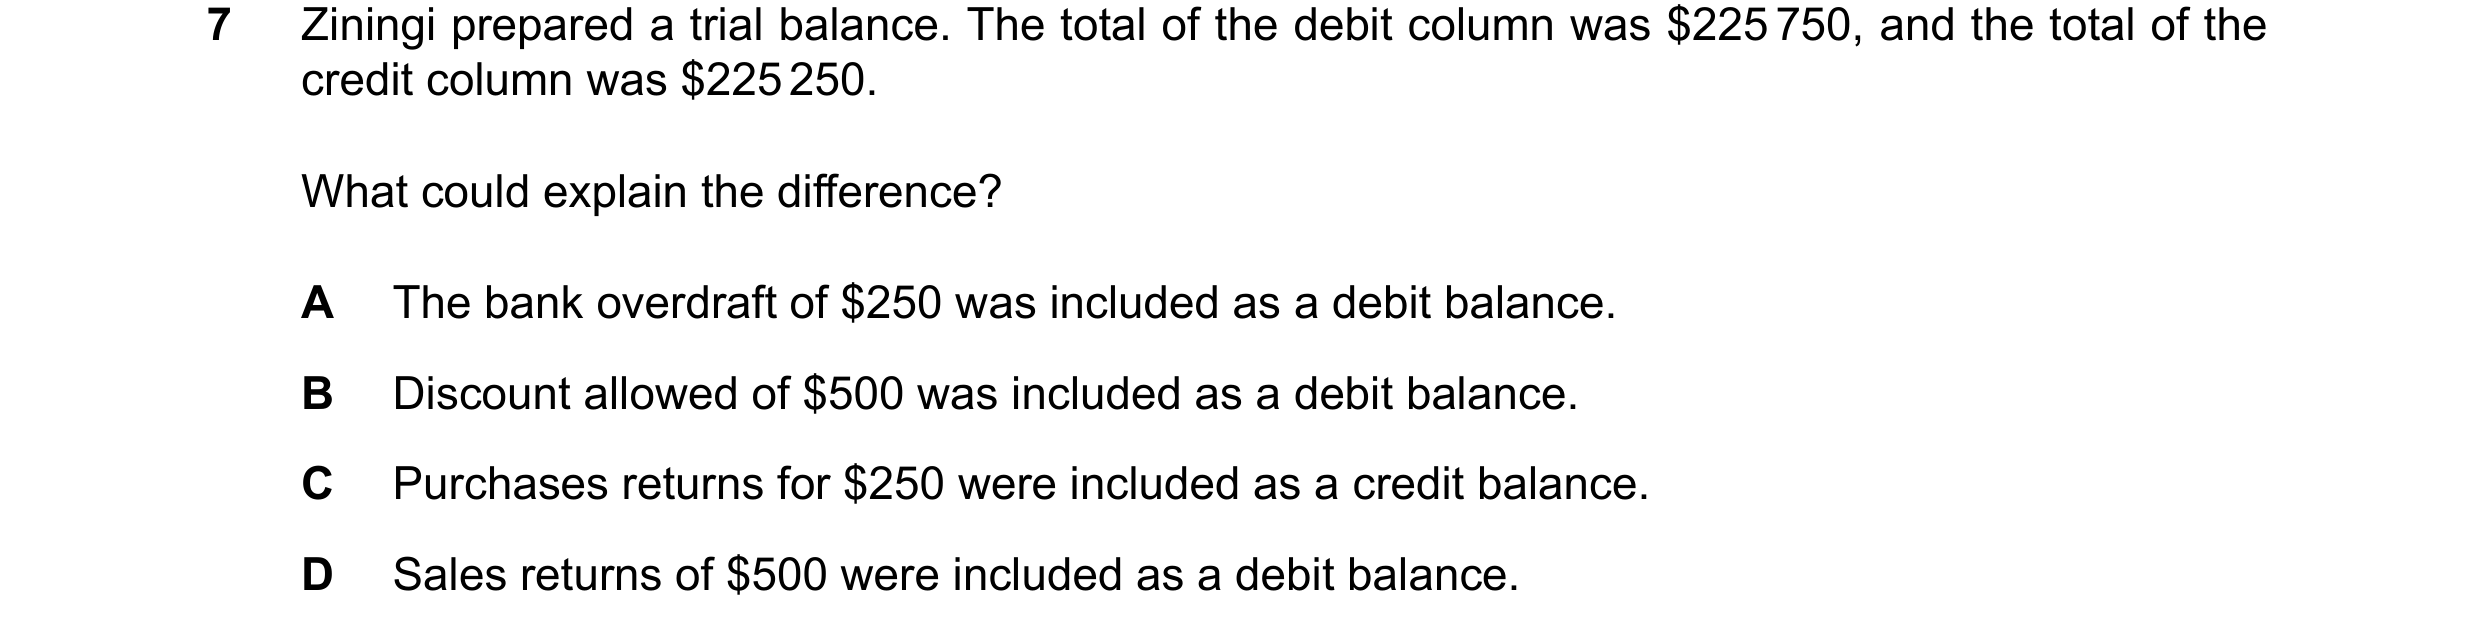
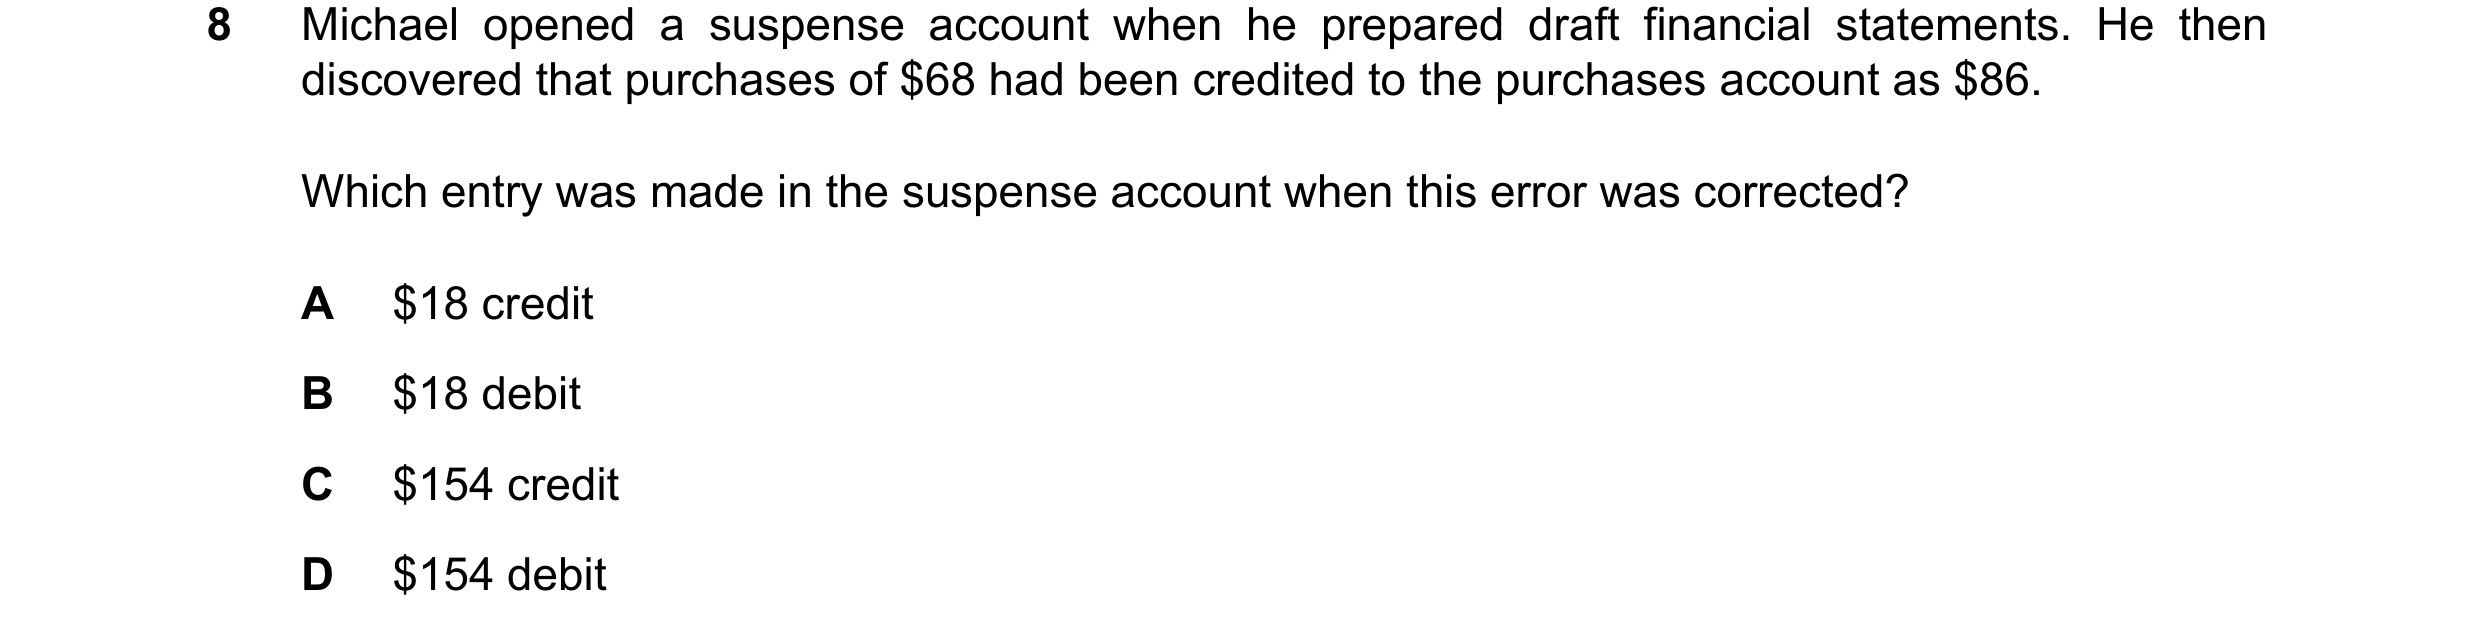
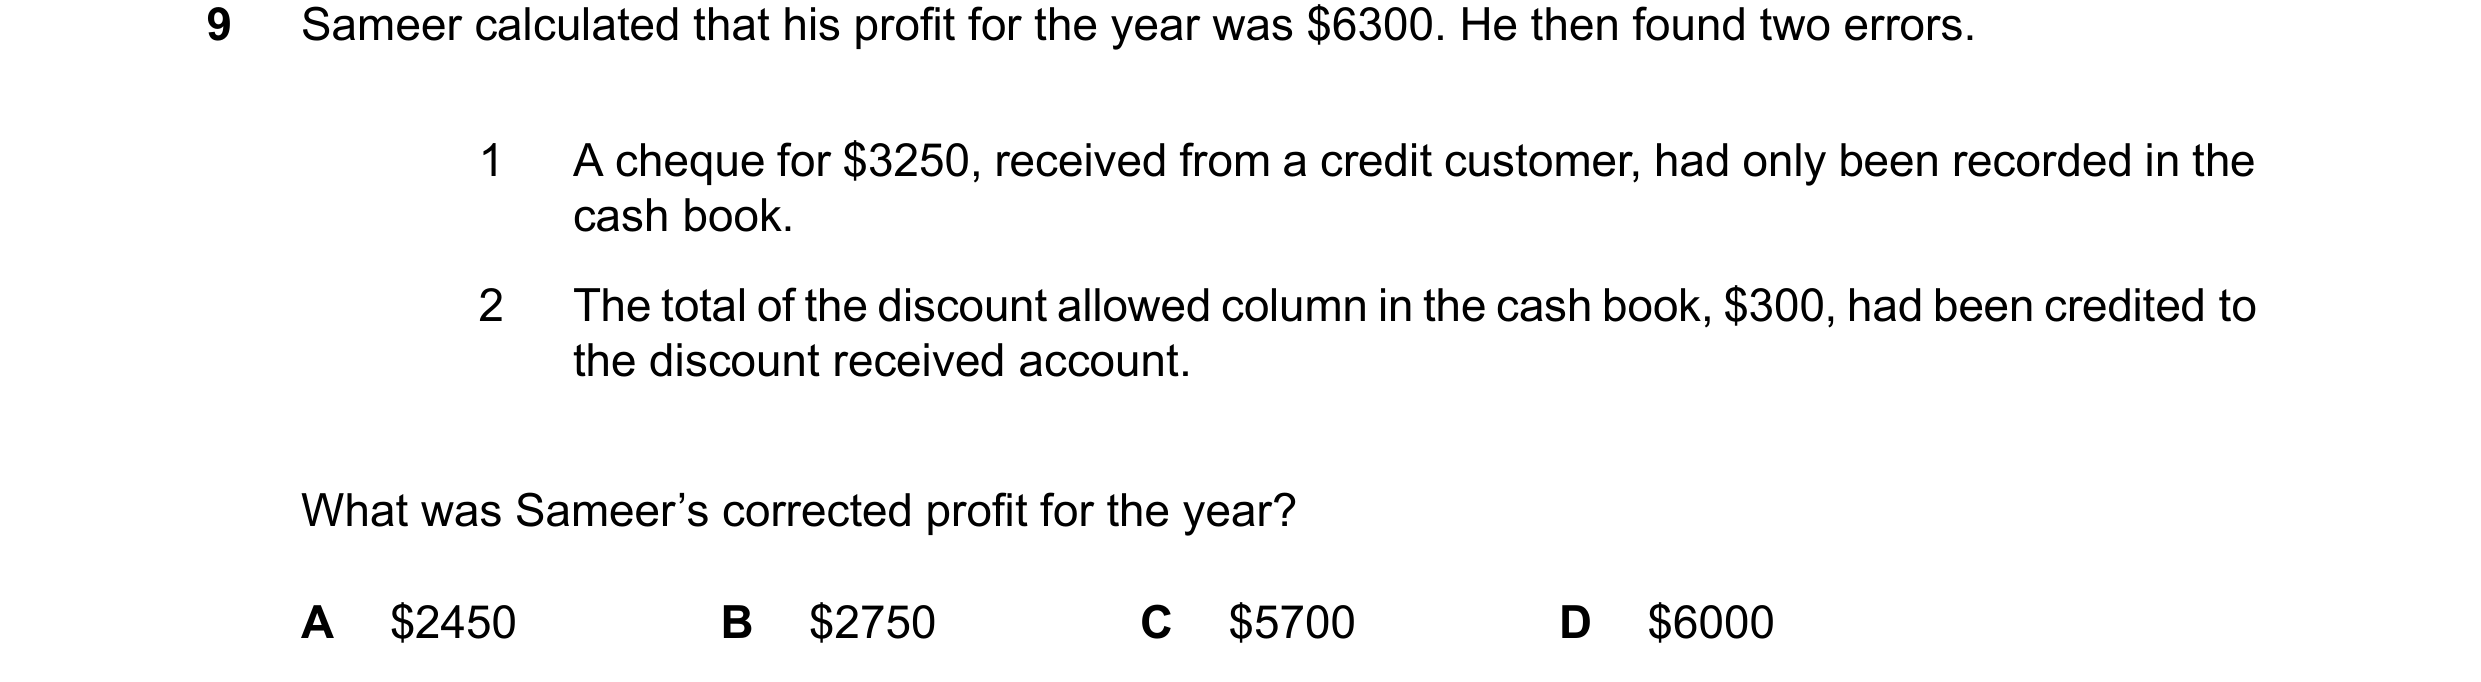 37 / 41
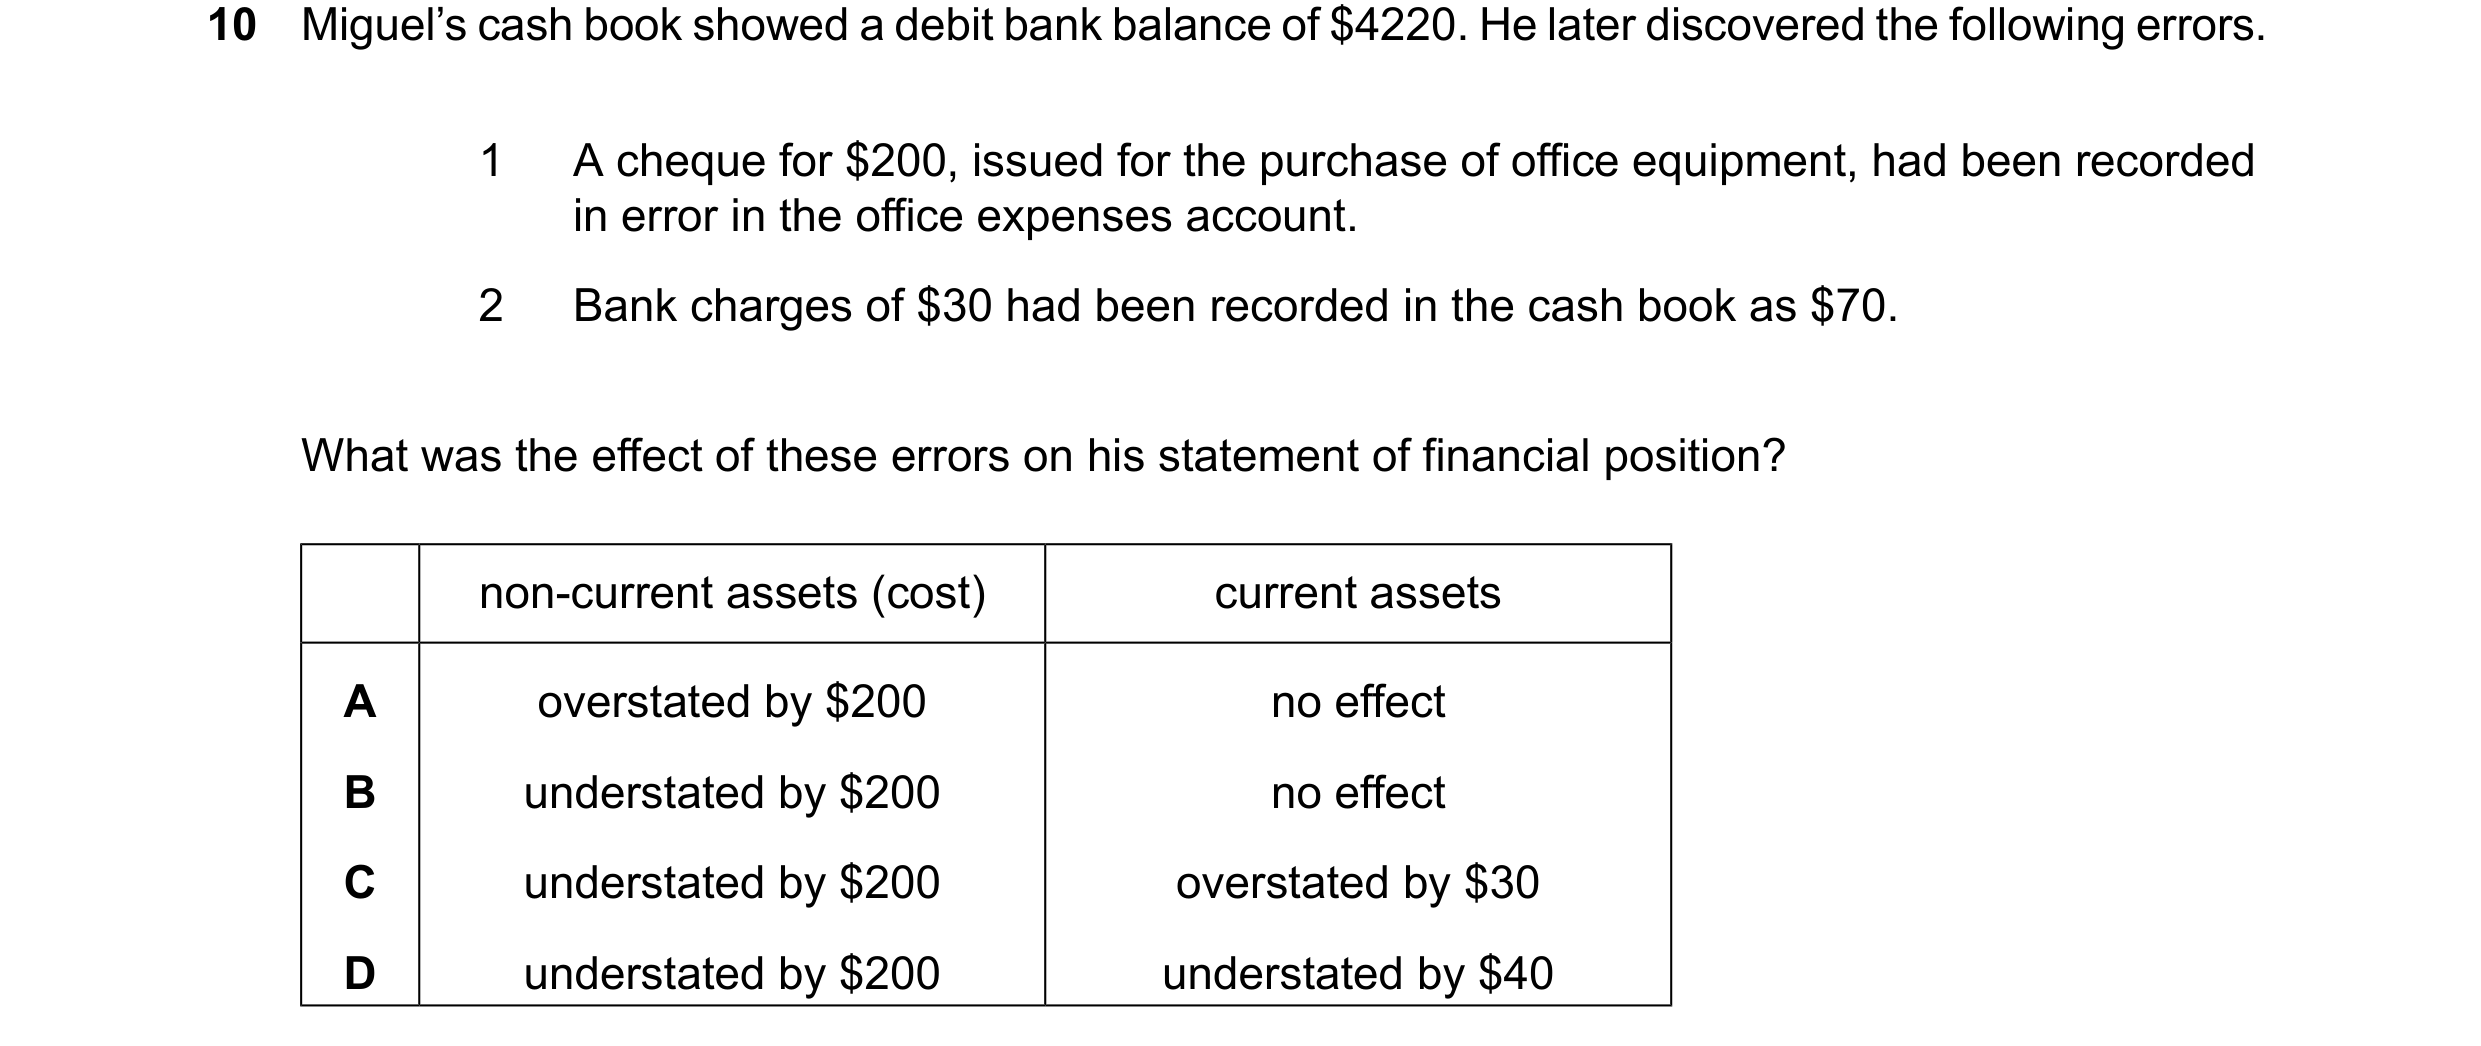
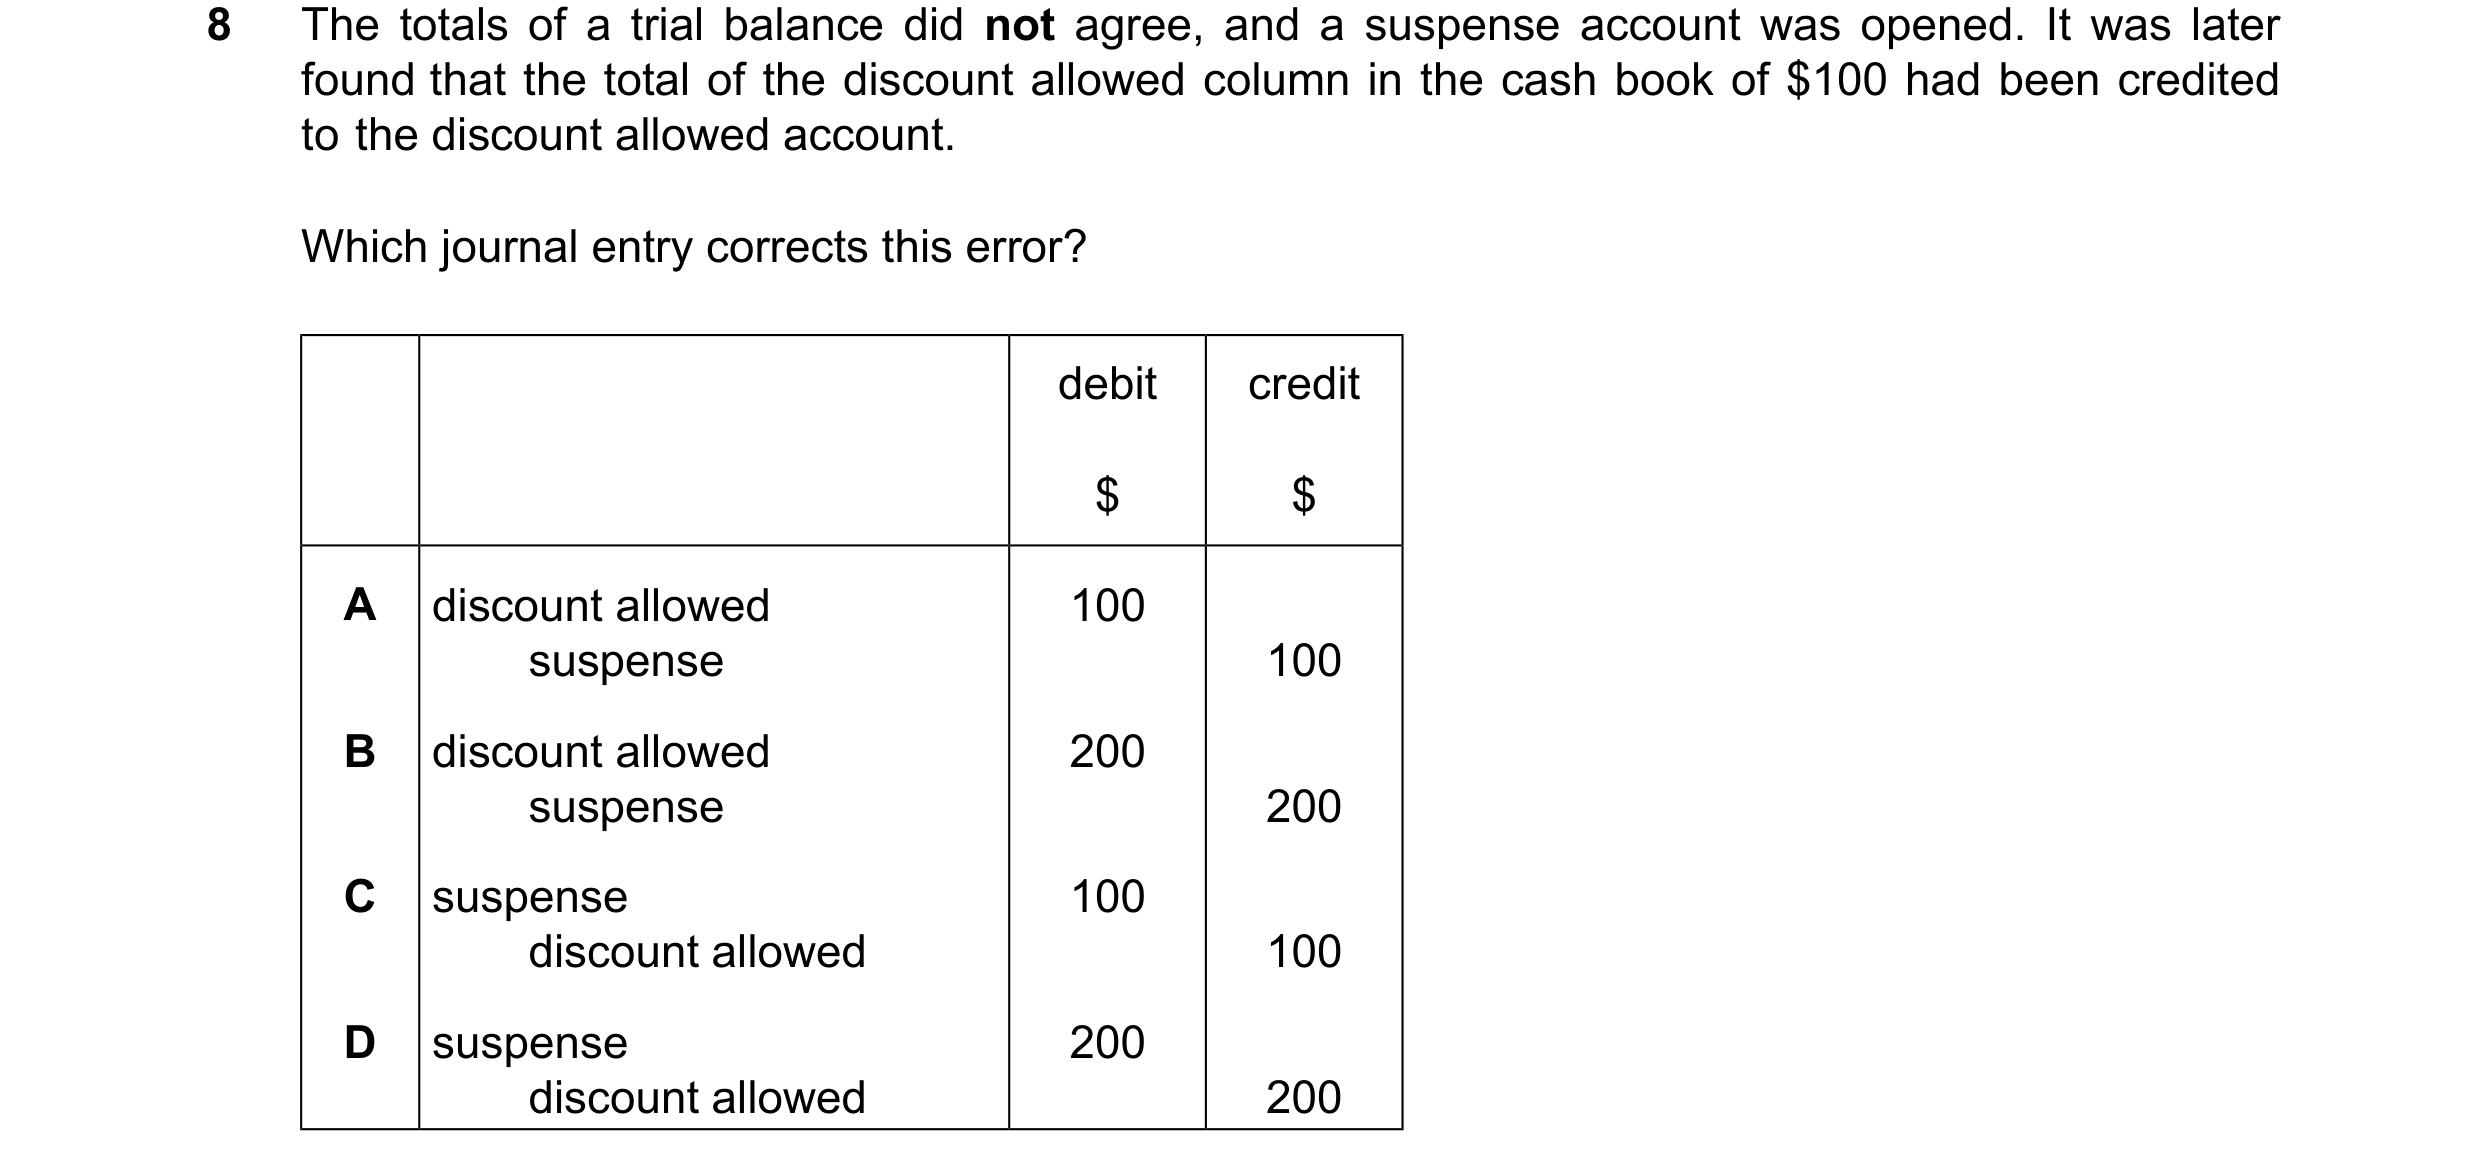
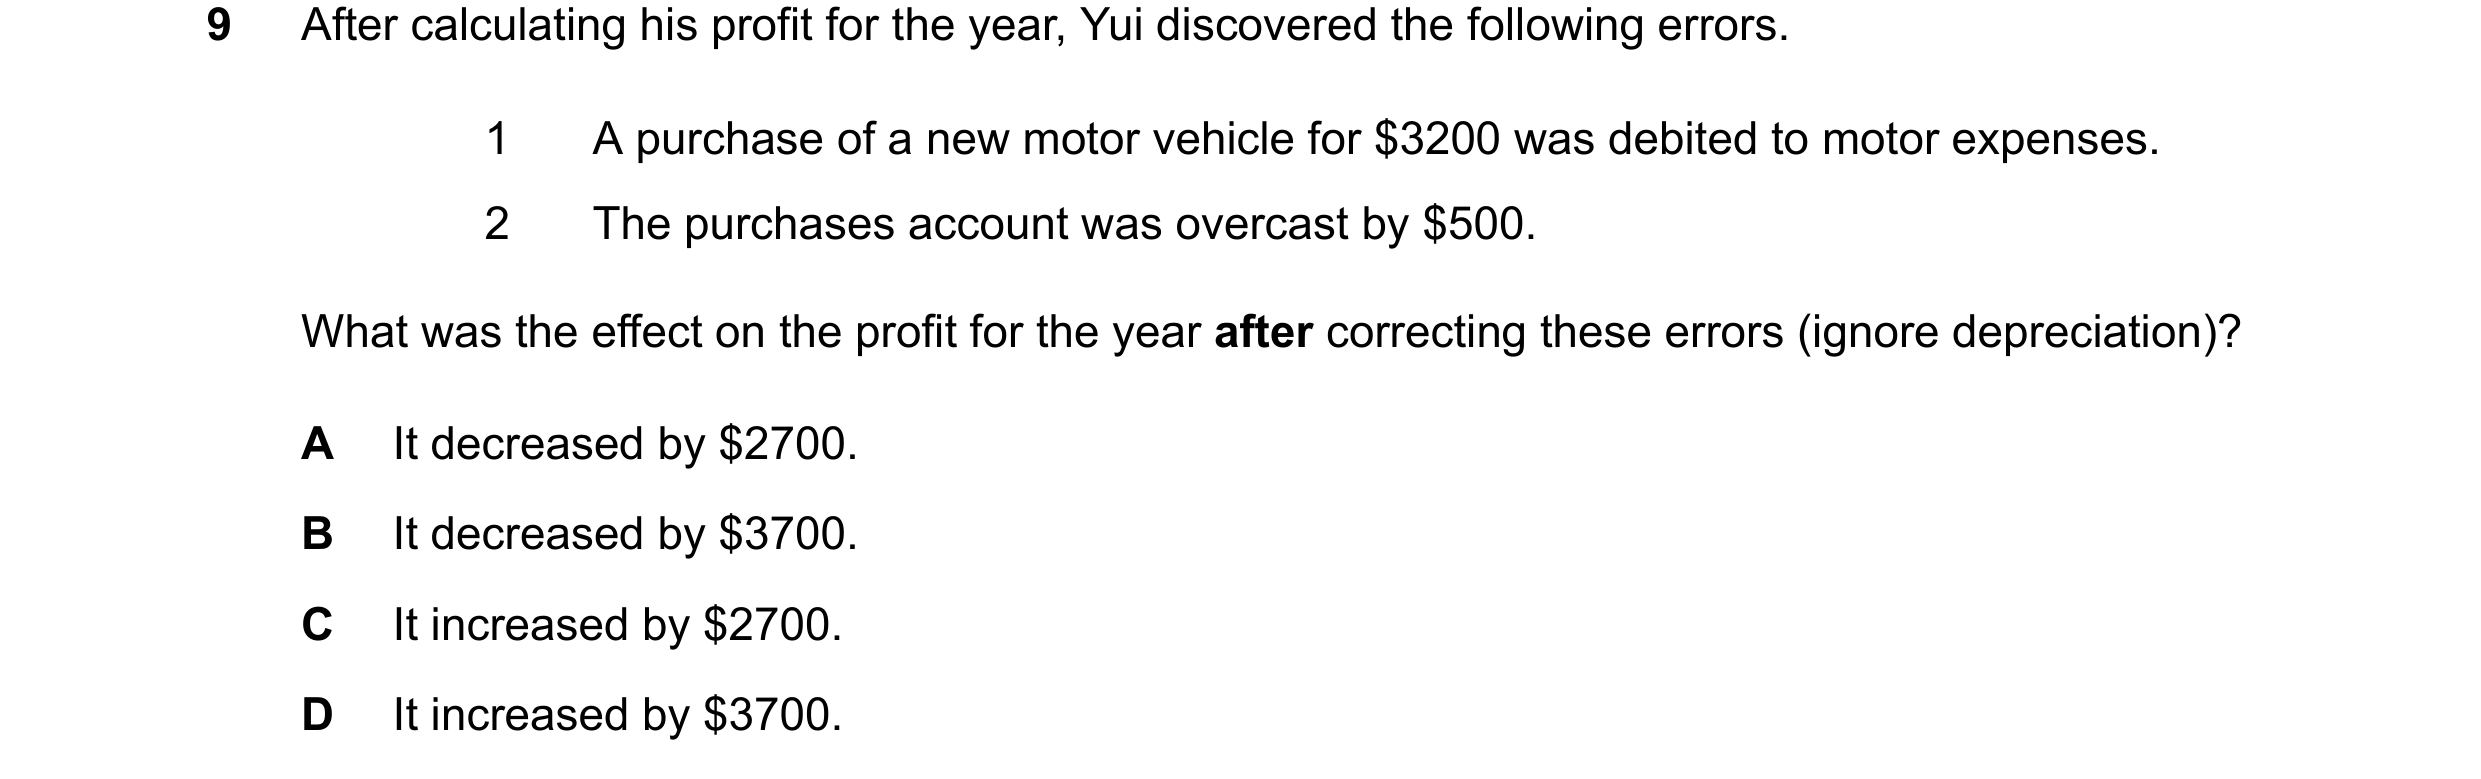 38 / 41
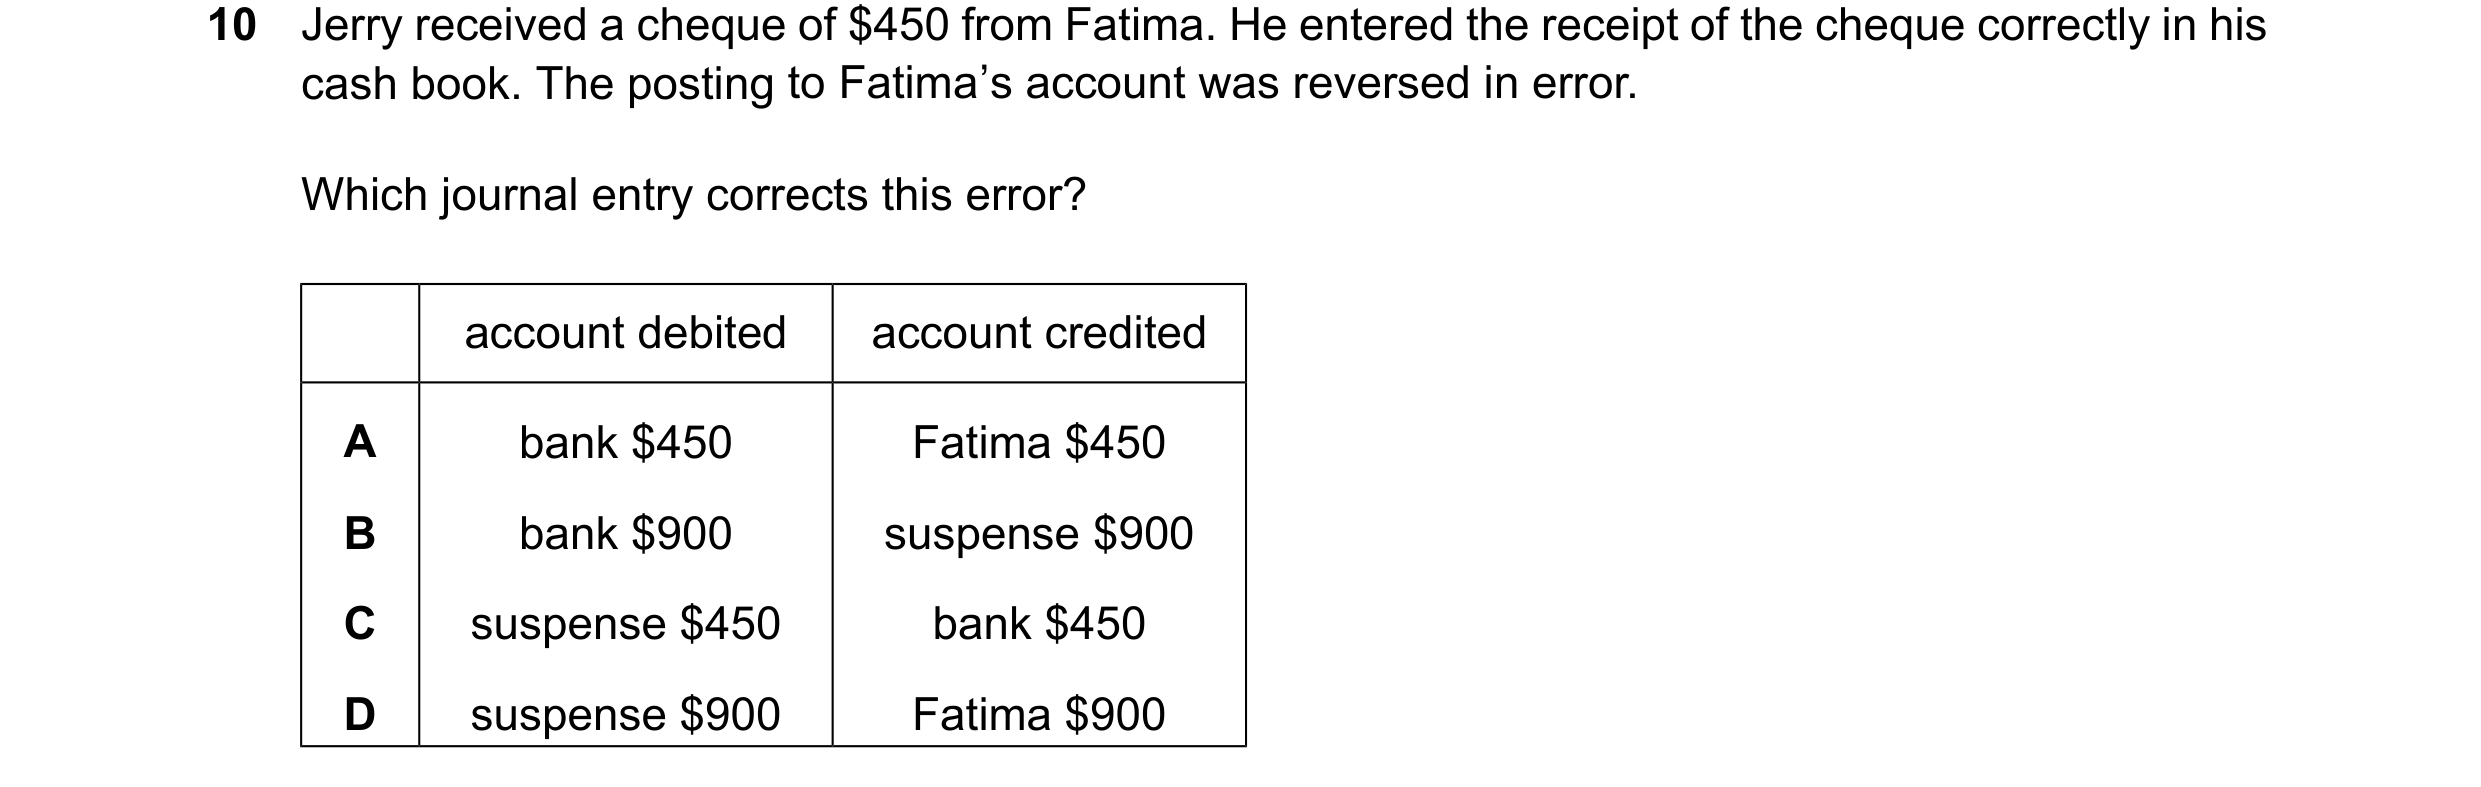
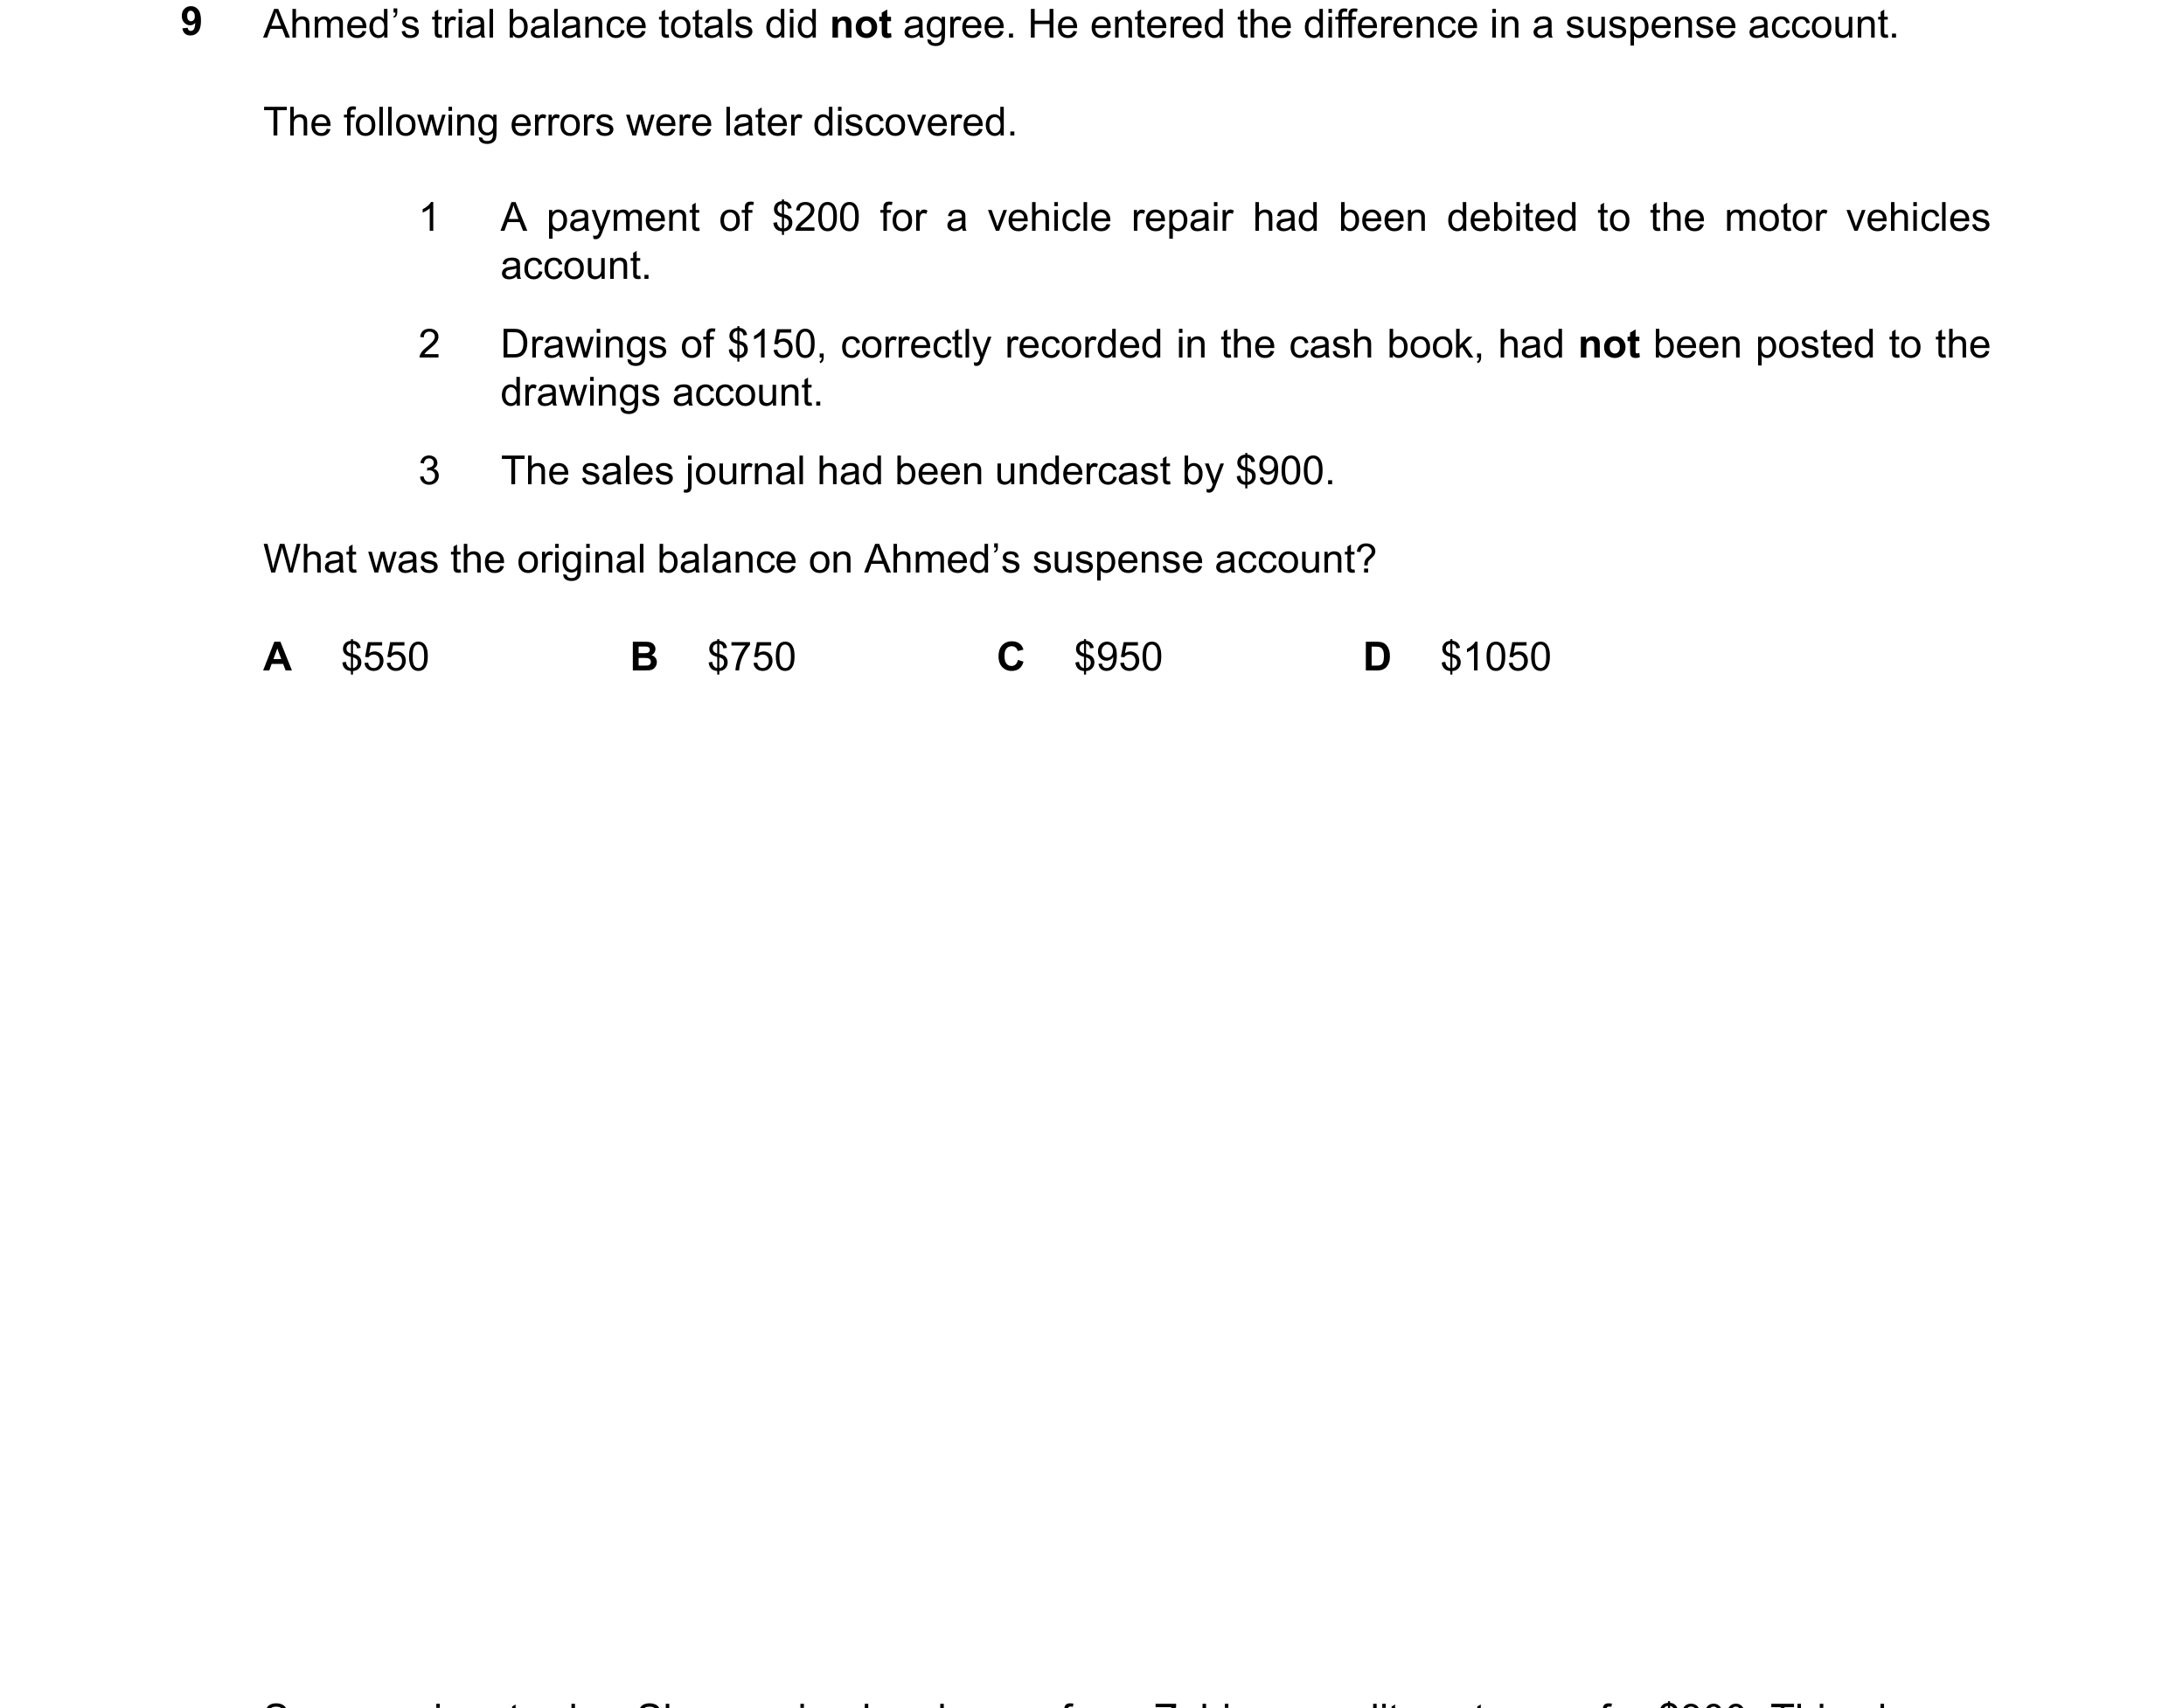 39 / 41
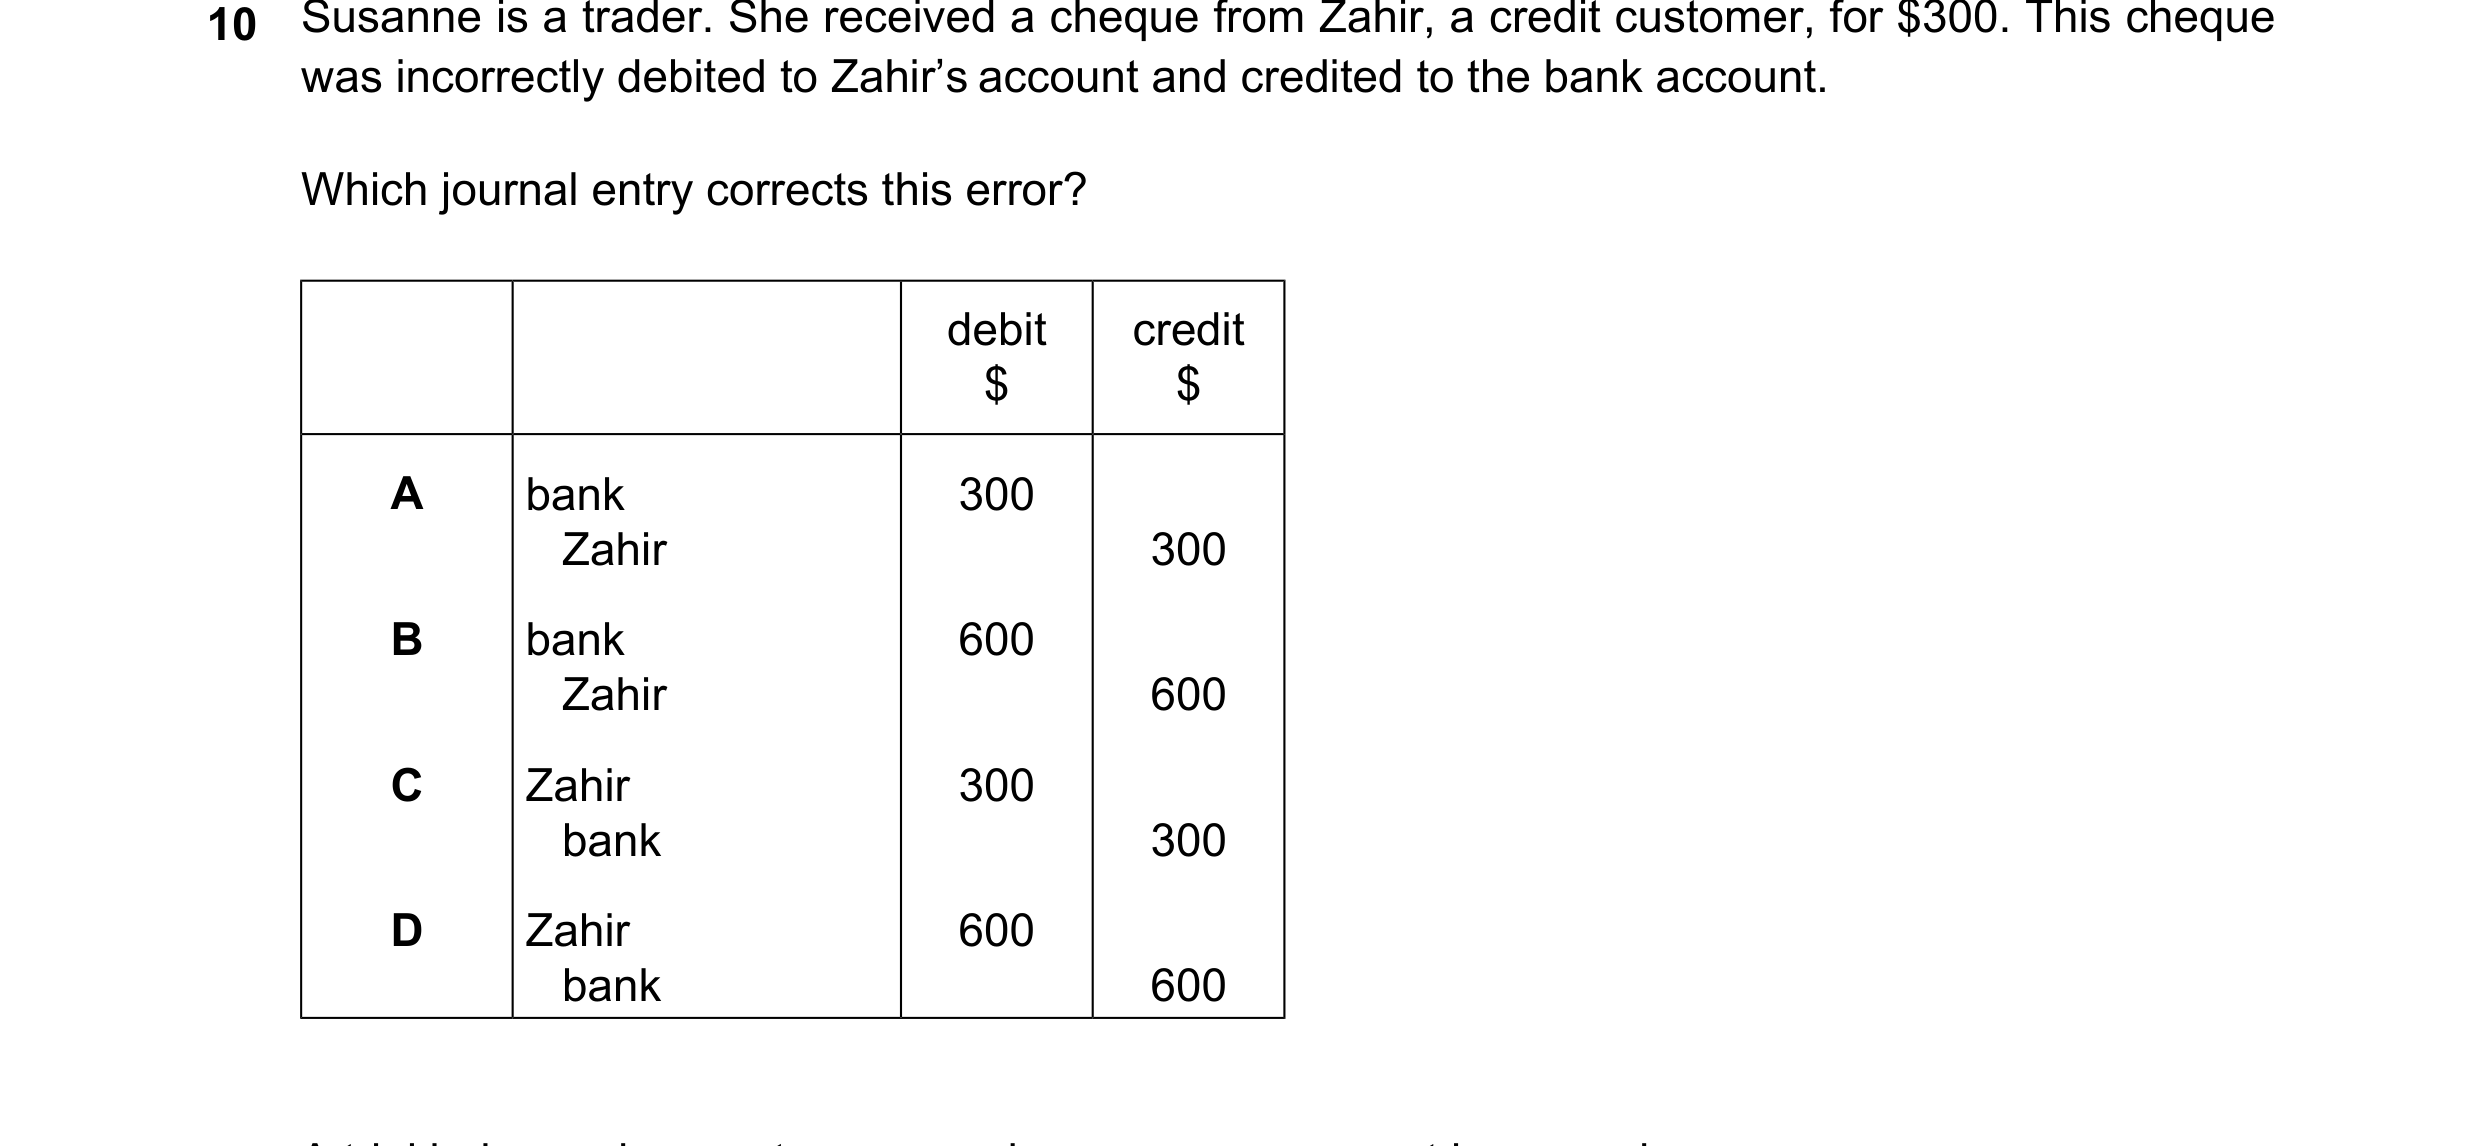
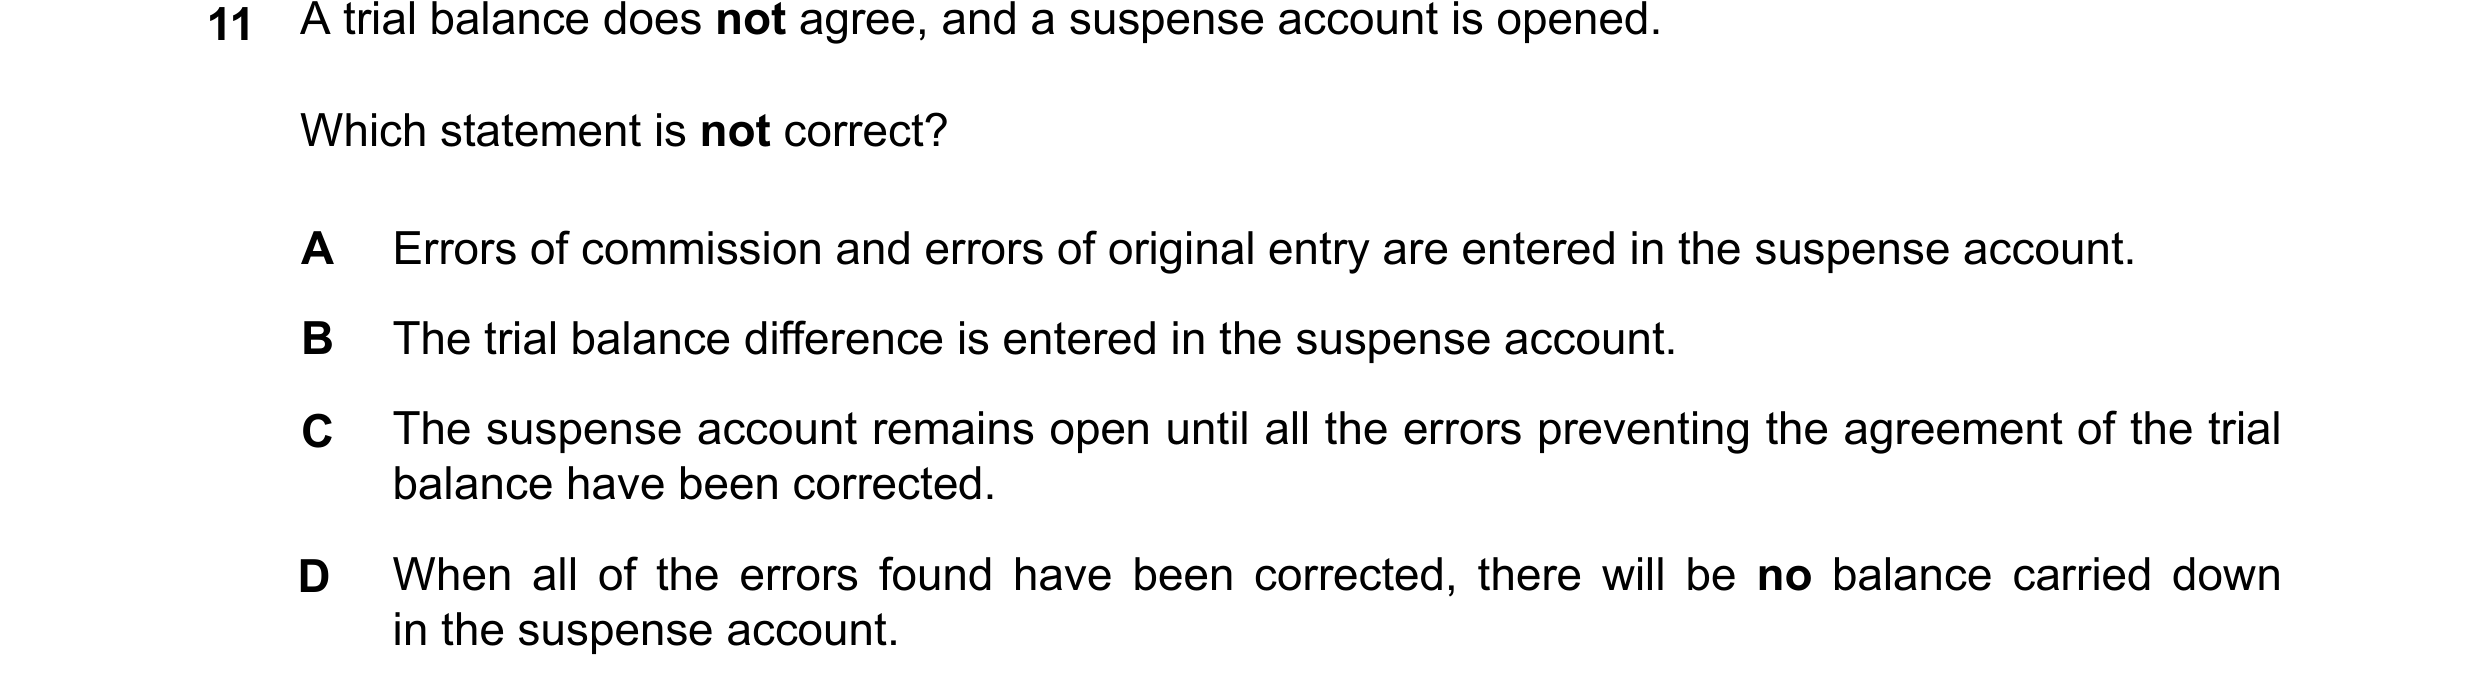
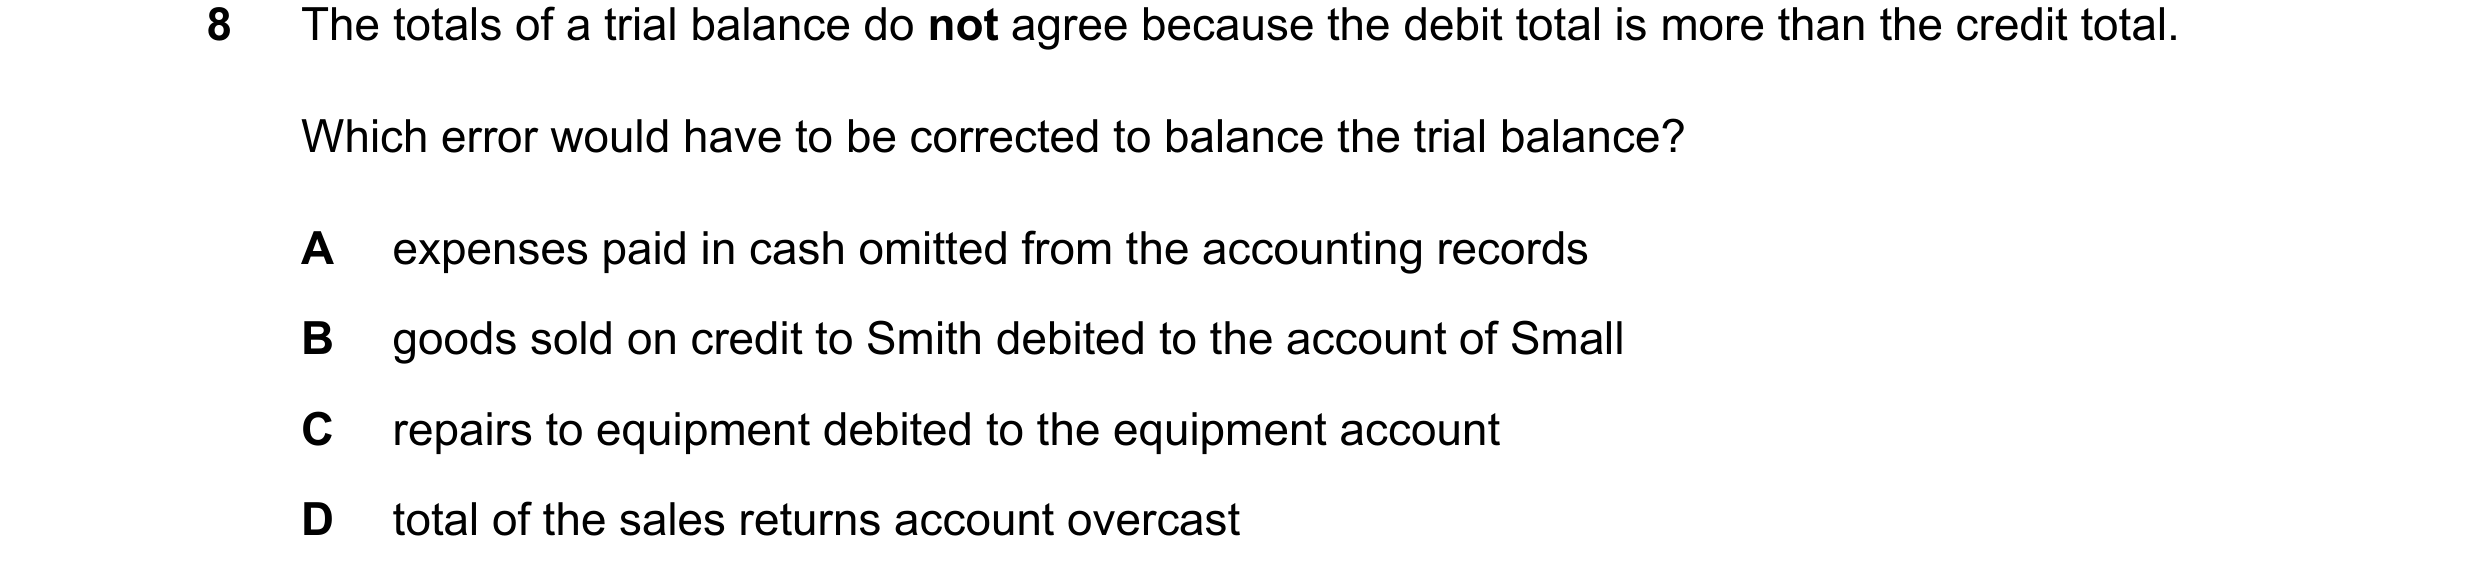 40 / 41
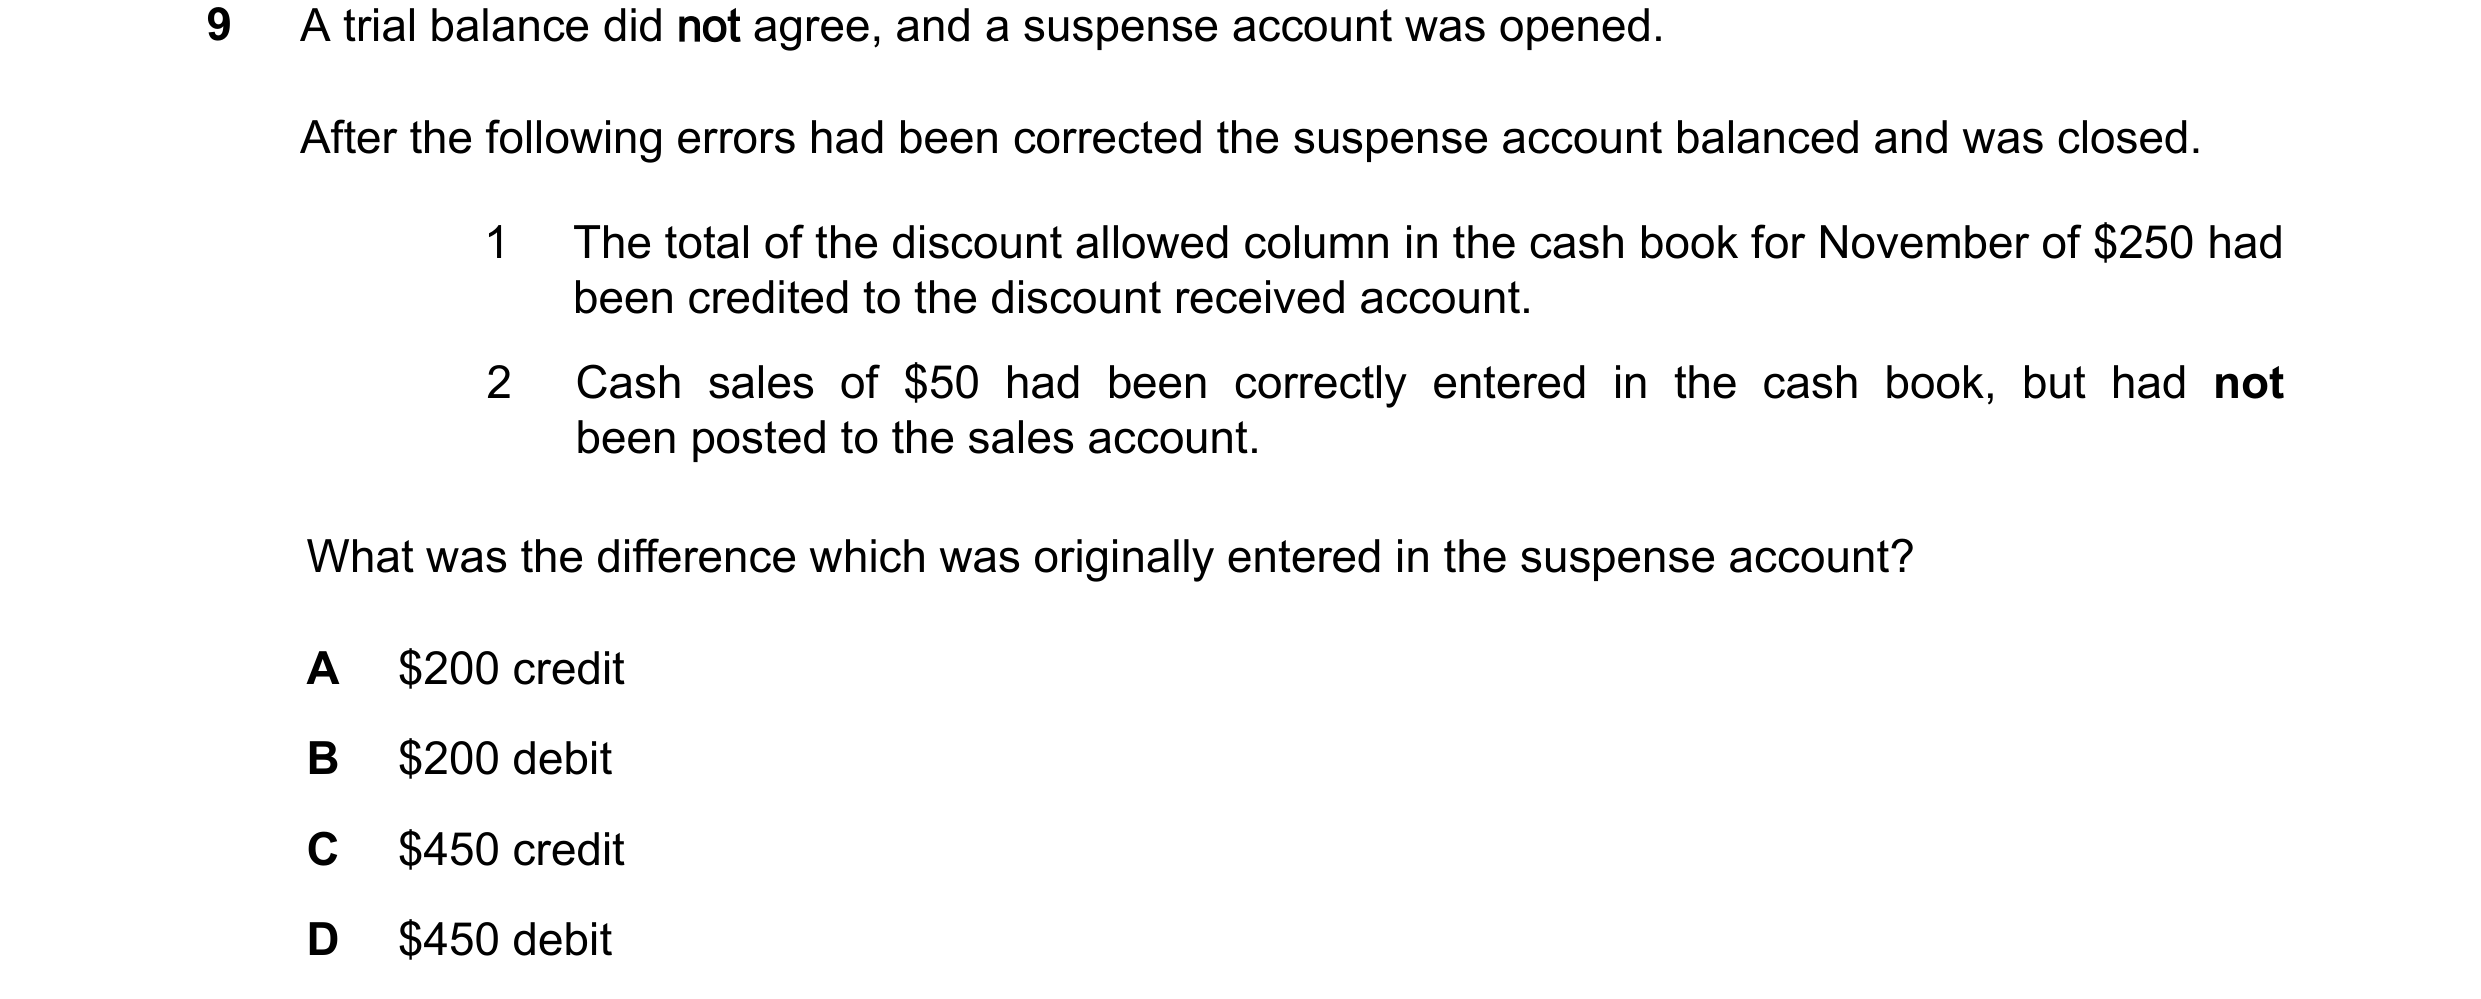
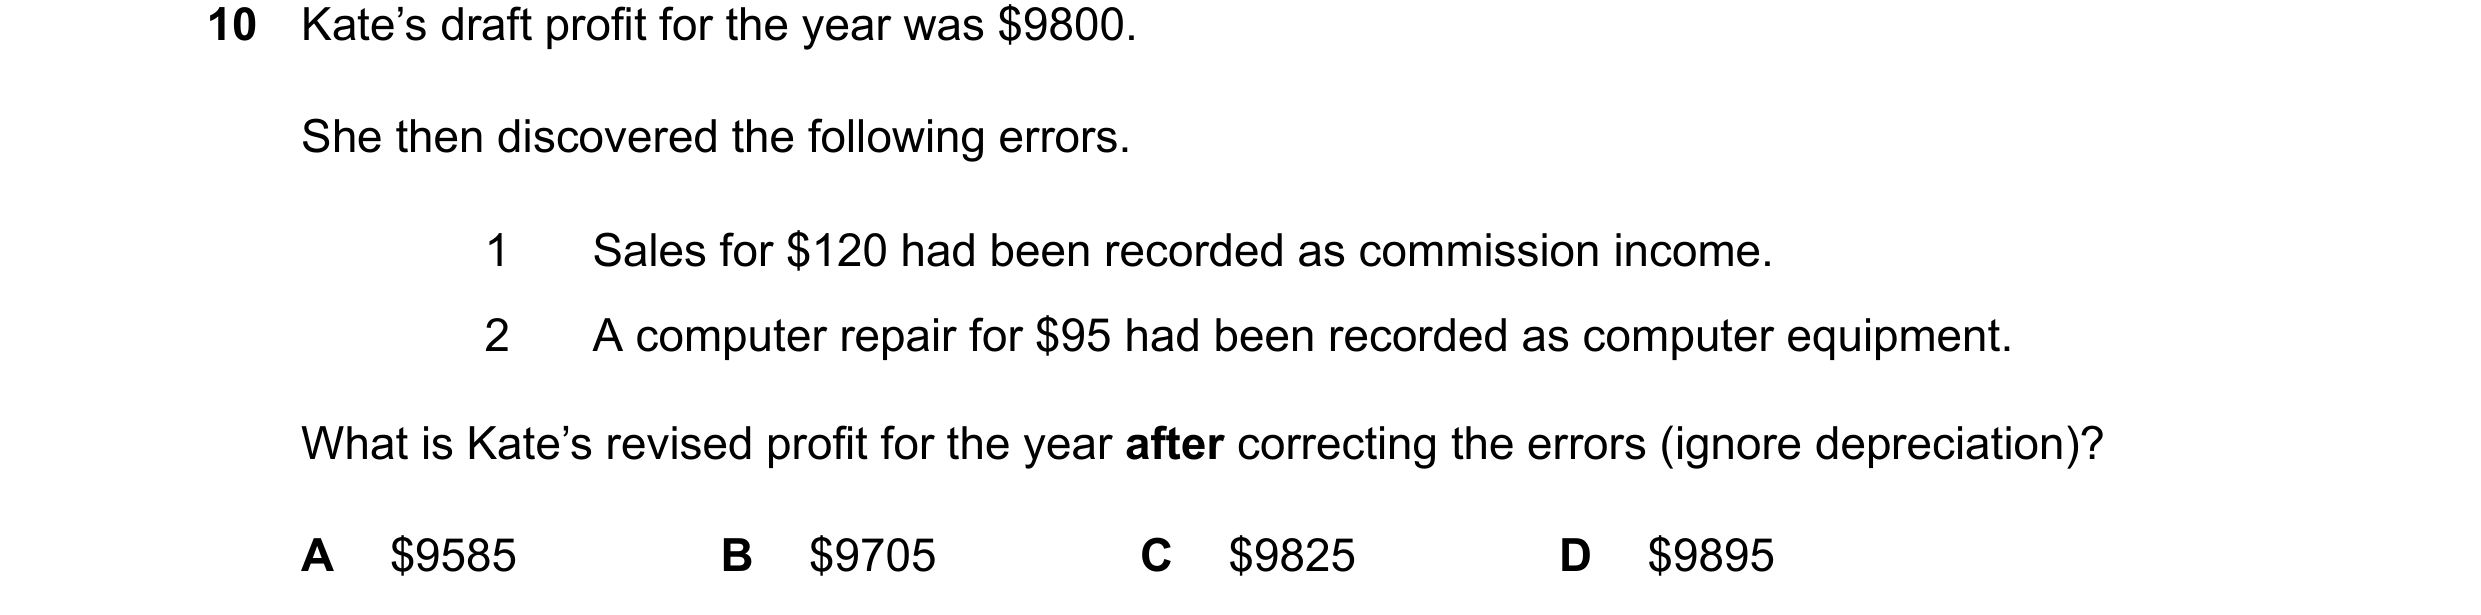
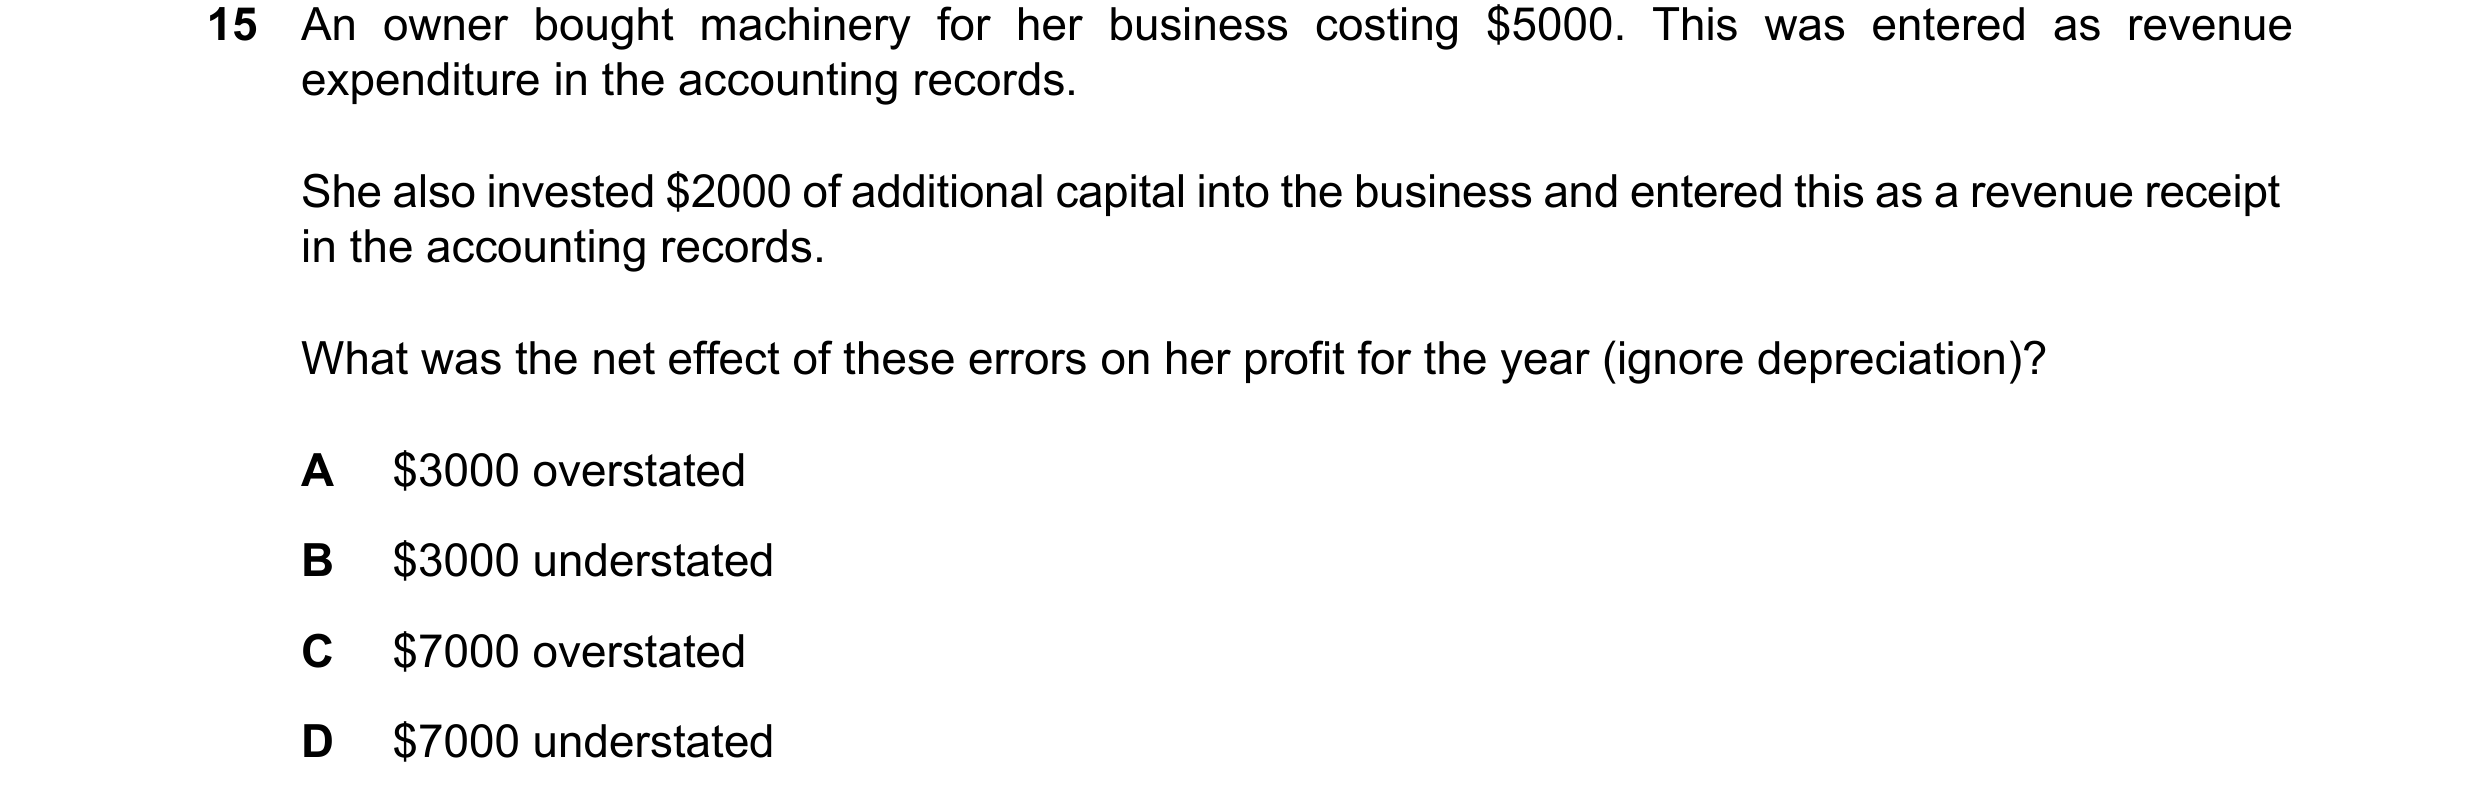 41 / 41