Cambridge IGCSE Accounting 0452 — 2024 Oct/Nov Paper 1 · Variant 3
0452/13/O/N/24 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · What is the purpose of measuring business profit and loss?
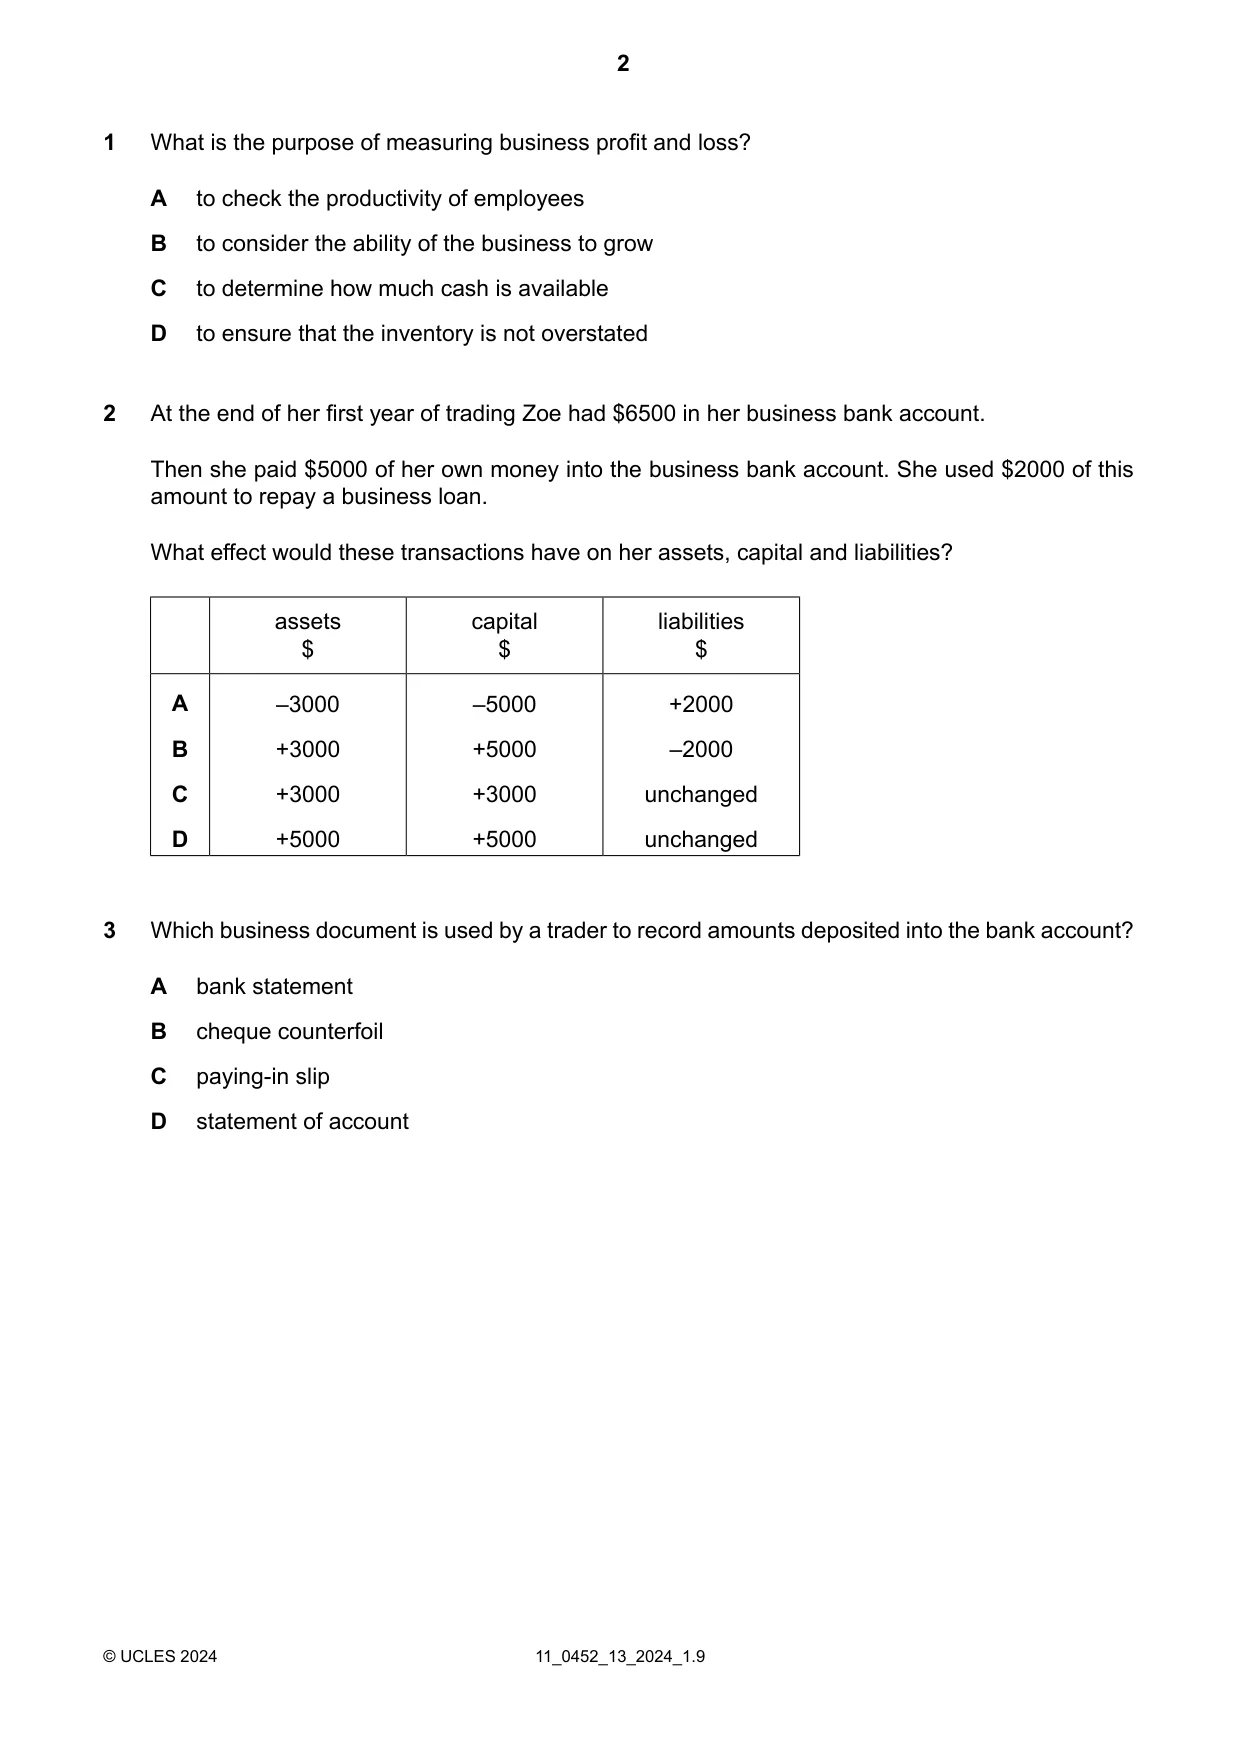
1 What is the purpose of measuring business profit and loss? A to check the productivity of employees B to consider the ability of the business to grow C to determine how much cash is available D to ensure that the inventory is not overstated
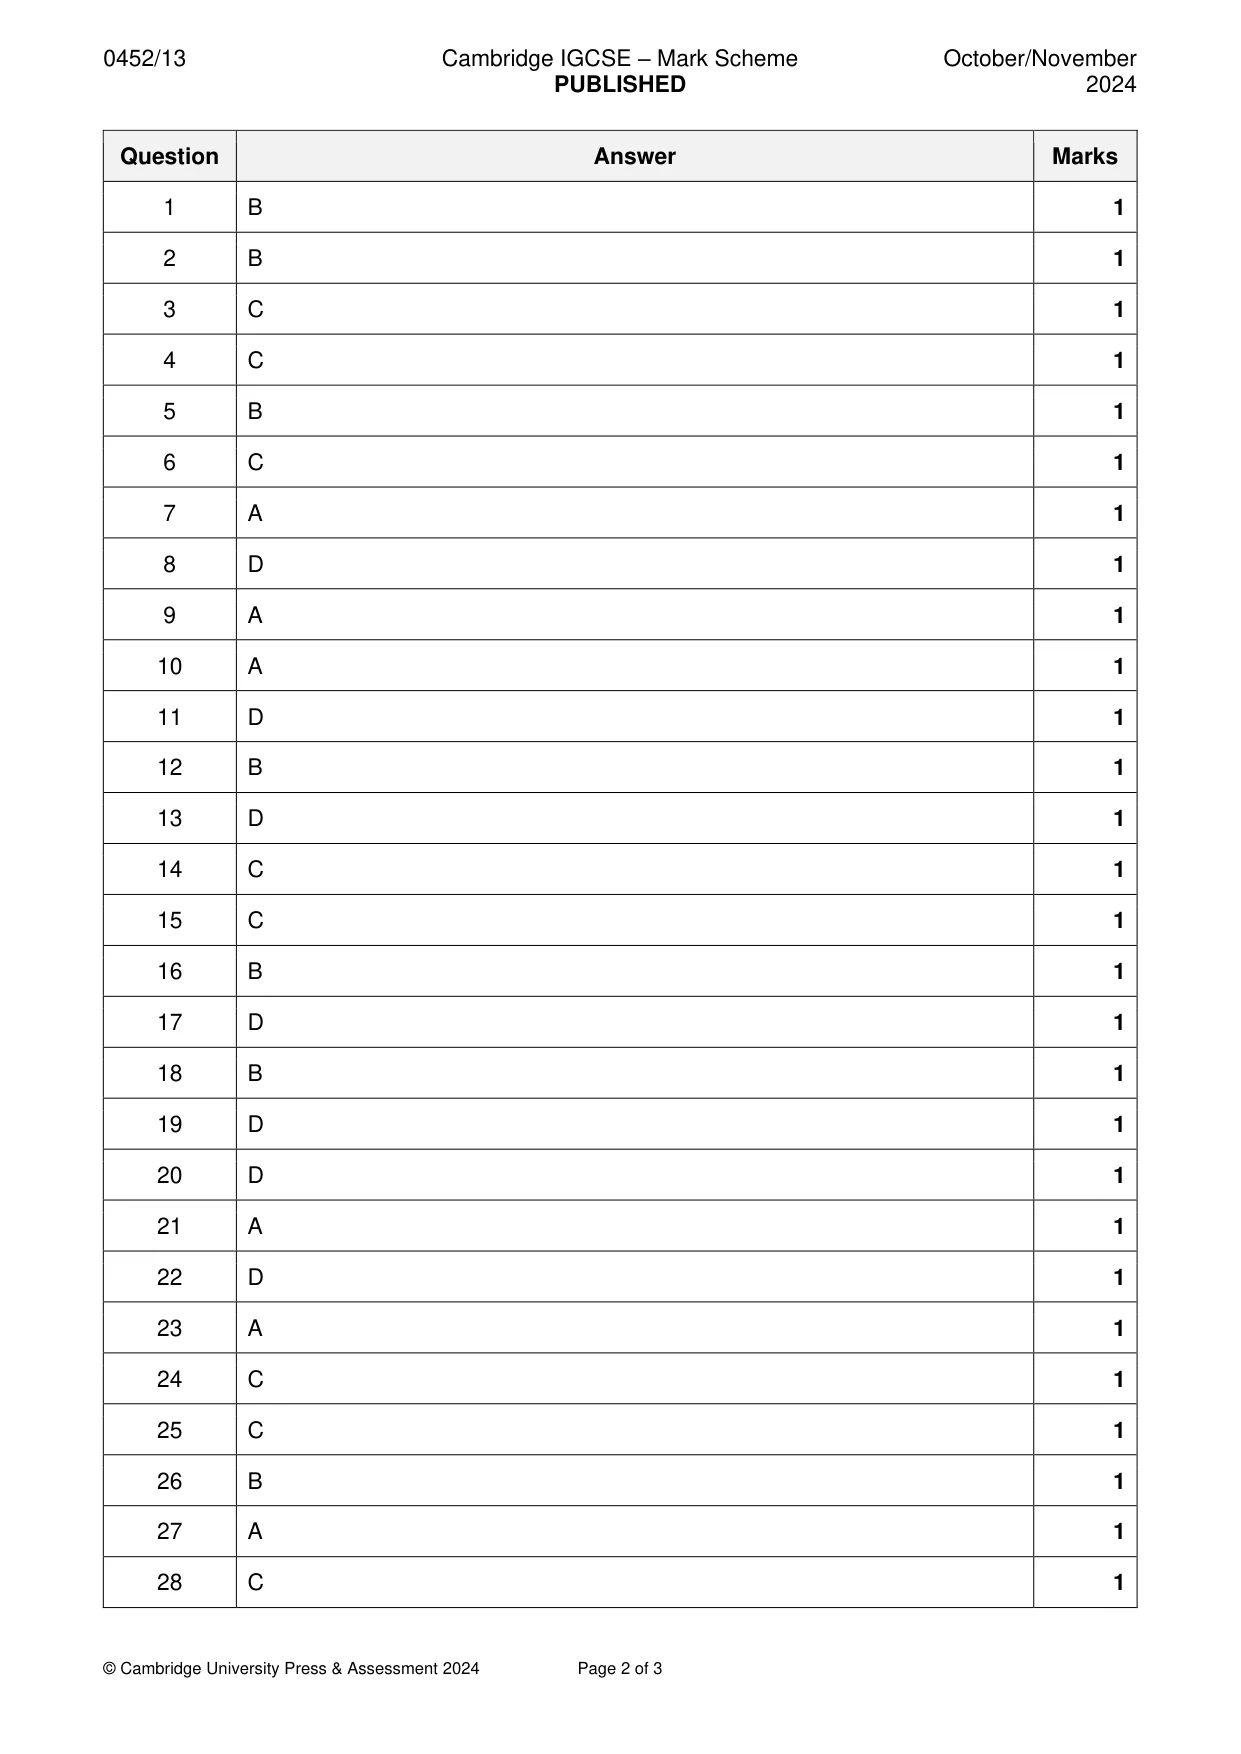
Mark scheme: B
Q2 · At the end of her first year of trading Zoe had $6500 in her business bank account
2 At the end of her first year of trading Zoe had $6500 in her business bank account. Then she paid $5000 of her own money into the business bank account. She used $2000 of this amount to repay a business loan. What effect would these transactions have on her assets, capital and liabilities? assets capital liabilities $ $ $ A –3000 –5000 +2000 B +3000 +5000 –2000 C +3000 +3000 unchanged D +5000 +5000 unchanged
Mark scheme: B
Q3 · Which business document is used by a trader to record amounts deposited into the bank…
3 Which business document is used by a trader to record amounts deposited into the bank account? A bank statement B cheque counterfoil C paying-in slip D statement of account
Mark scheme: C
Q4 · A trader kept a petty cash book using the imprest system
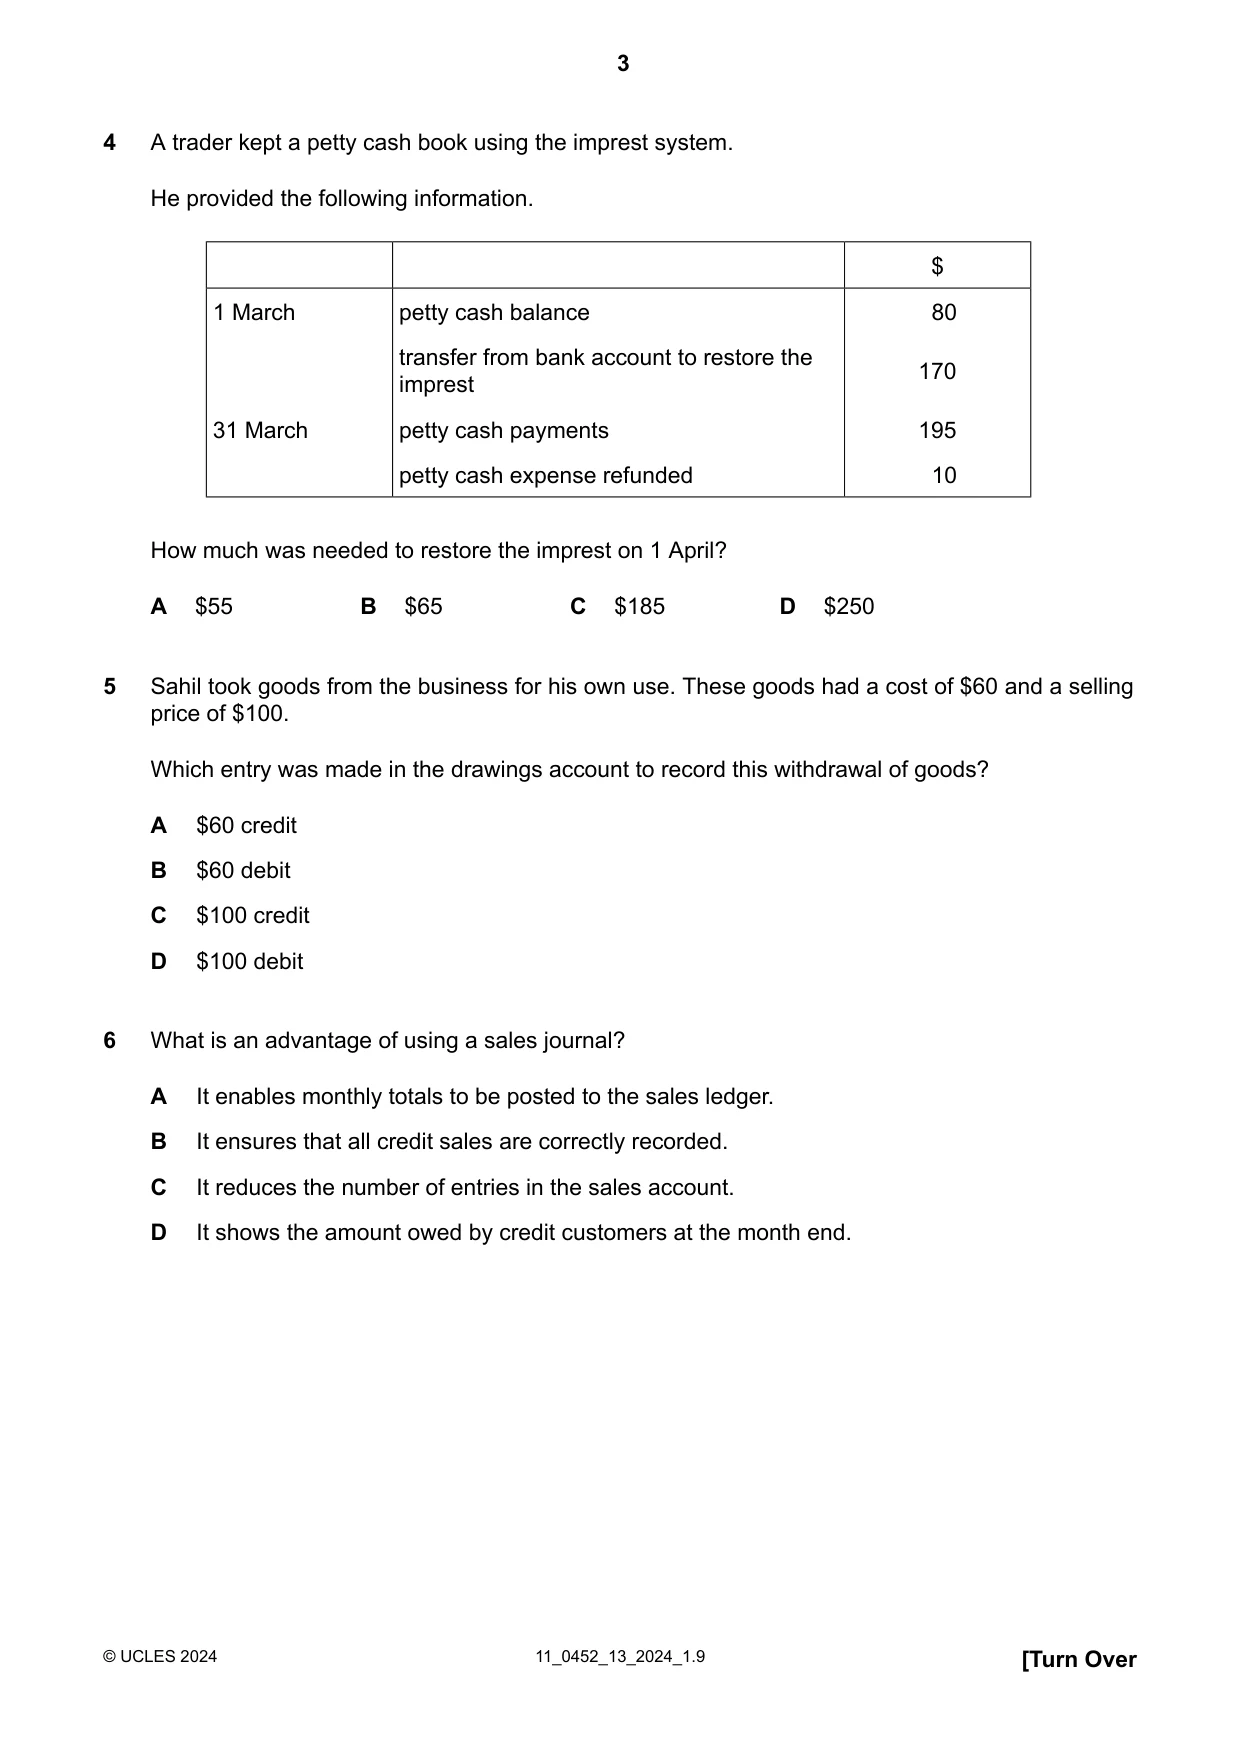
4 A trader kept a petty cash book using the imprest system. He provided the following information. $ 1 March petty cash balance 80 transfer from bank account to restore the 170 imprest 31 March petty cash payments 195 petty cash expense refunded 10 How much was needed to restore the imprest on 1 April? A $55 B $65 C $185 D $250
Mark scheme: C
Q5 · Sahil took goods from the business for his own use
5 Sahil took goods from the business for his own use. These goods had a cost of $60 and a selling price of $100. Which entry was made in the drawings account to record this withdrawal of goods? A $60 credit B $60 debit C $100 credit D $100 debit
Mark scheme: B
Q6 · What is an advantage of using a sales journal?
6 What is an advantage of using a sales journal? A It enables monthly totals to be posted to the sales ledger. B It ensures that all credit sales are correctly recorded. C It reduces the number of entries in the sales account. D It shows the amount owed by credit customers at the month end.
Mark scheme: C
Q7 · The following account appeared in the ledger of Eli
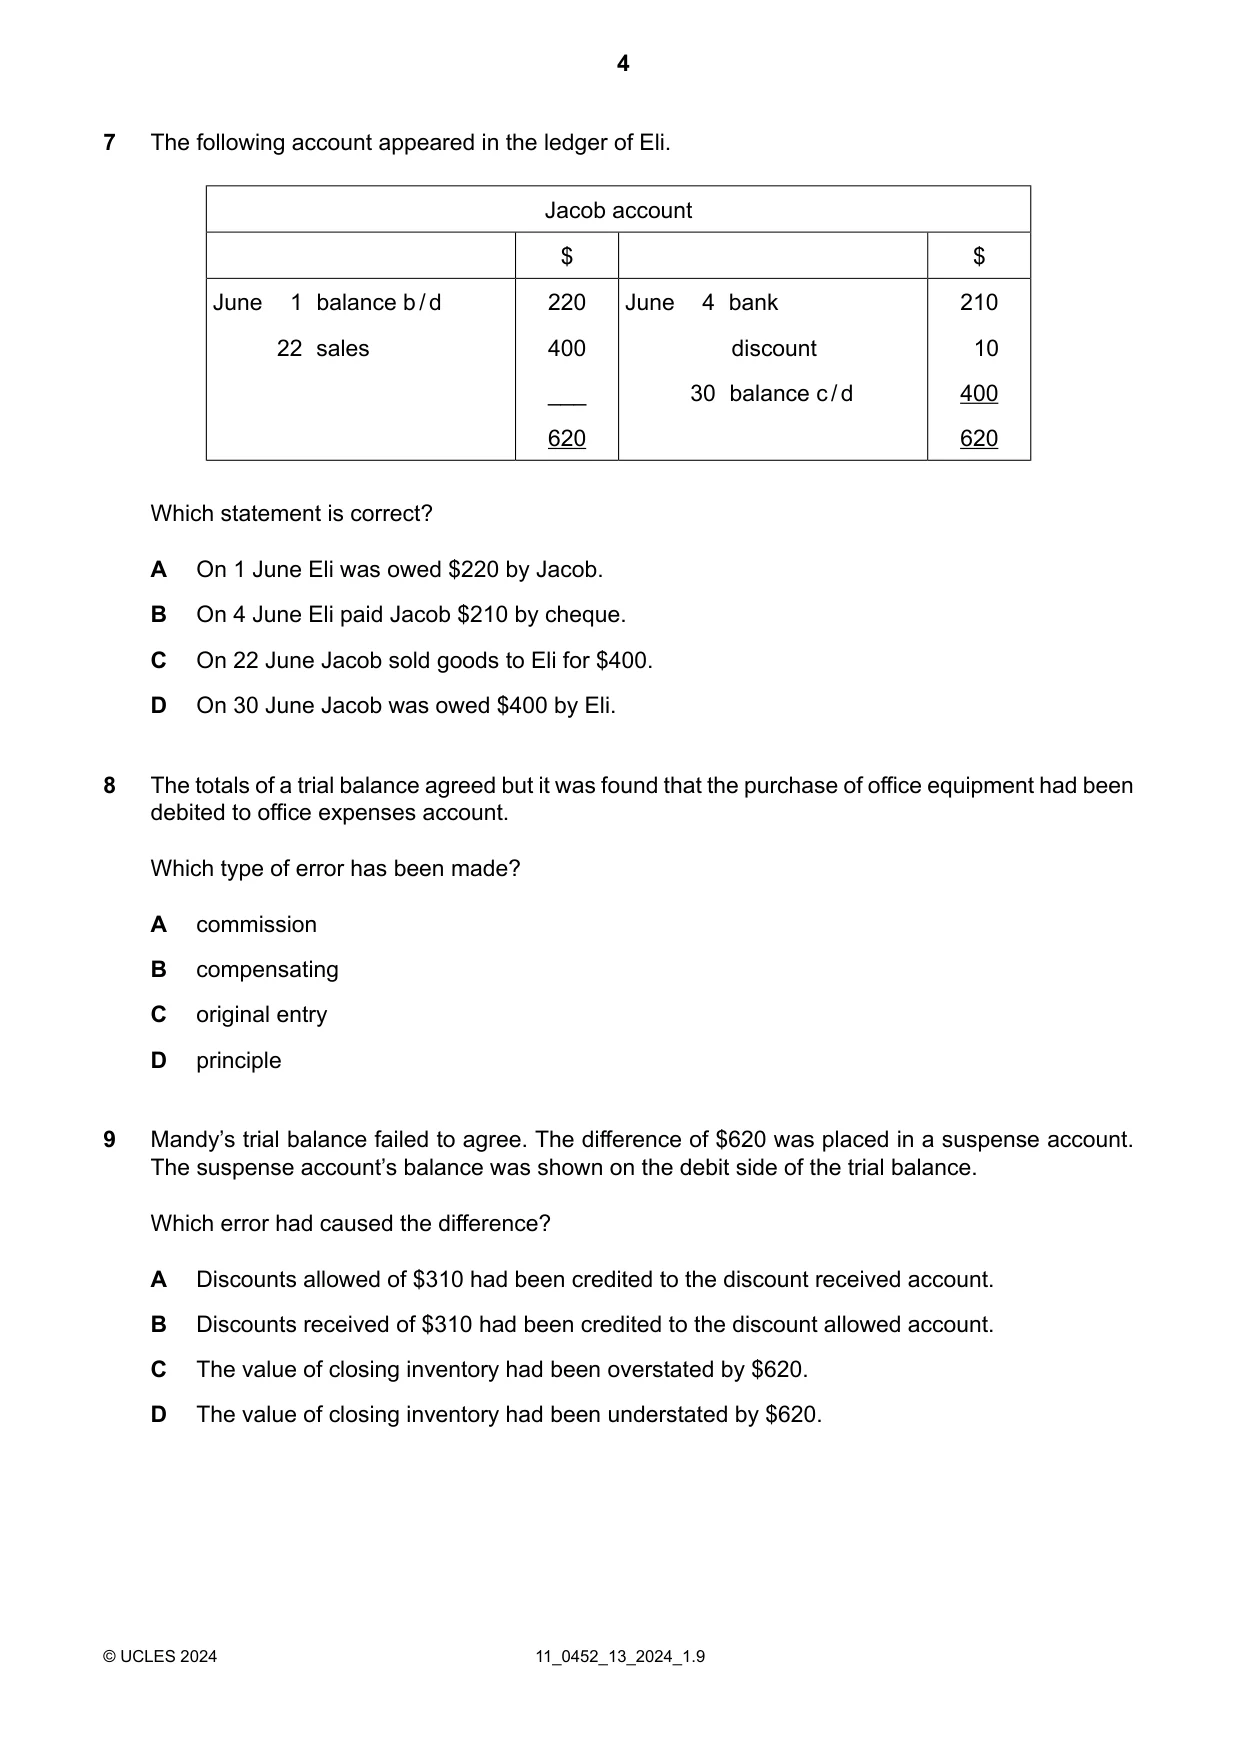
7 The following account appeared in the ledger of Eli. Jacob account $ $ June 1 balance b/d 220 June 4 bank 210 22 sales 400 discount 10 ___ 30 balance c/d 400 620 620 Which statement is correct? A On 1 June Eli was owed $220 by Jacob. B On 4 June Eli paid Jacob $210 by cheque. C On 22 June Jacob sold goods to Eli for $400. D On 30 June Jacob was owed $400 by Eli.
Mark scheme: A
Q8 · The totals of a trial balance agreed but it was found that the purchase of office…
8 The totals of a trial balance agreed but it was found that the purchase of office equipment had been debited to office expenses account. Which type of error has been made? A commission B compensating C original entry D principle
Mark scheme: D
Q9 · Mandy’s trial balance failed to agree
9 Mandy’s trial balance failed to agree. The difference of $620 was placed in a suspense account. The suspense account’s balance was shown on the debit side of the trial balance. Which error had caused the difference? A Discounts allowed of $310 had been credited to the discount received account. B Discounts received of $310 had been credited to the discount allowed account. C The value of closing inventory had been overstated by $620. D The value of closing inventory had been understated by $620.
Mark scheme: A
Q10 · Jane took cash drawings from the business
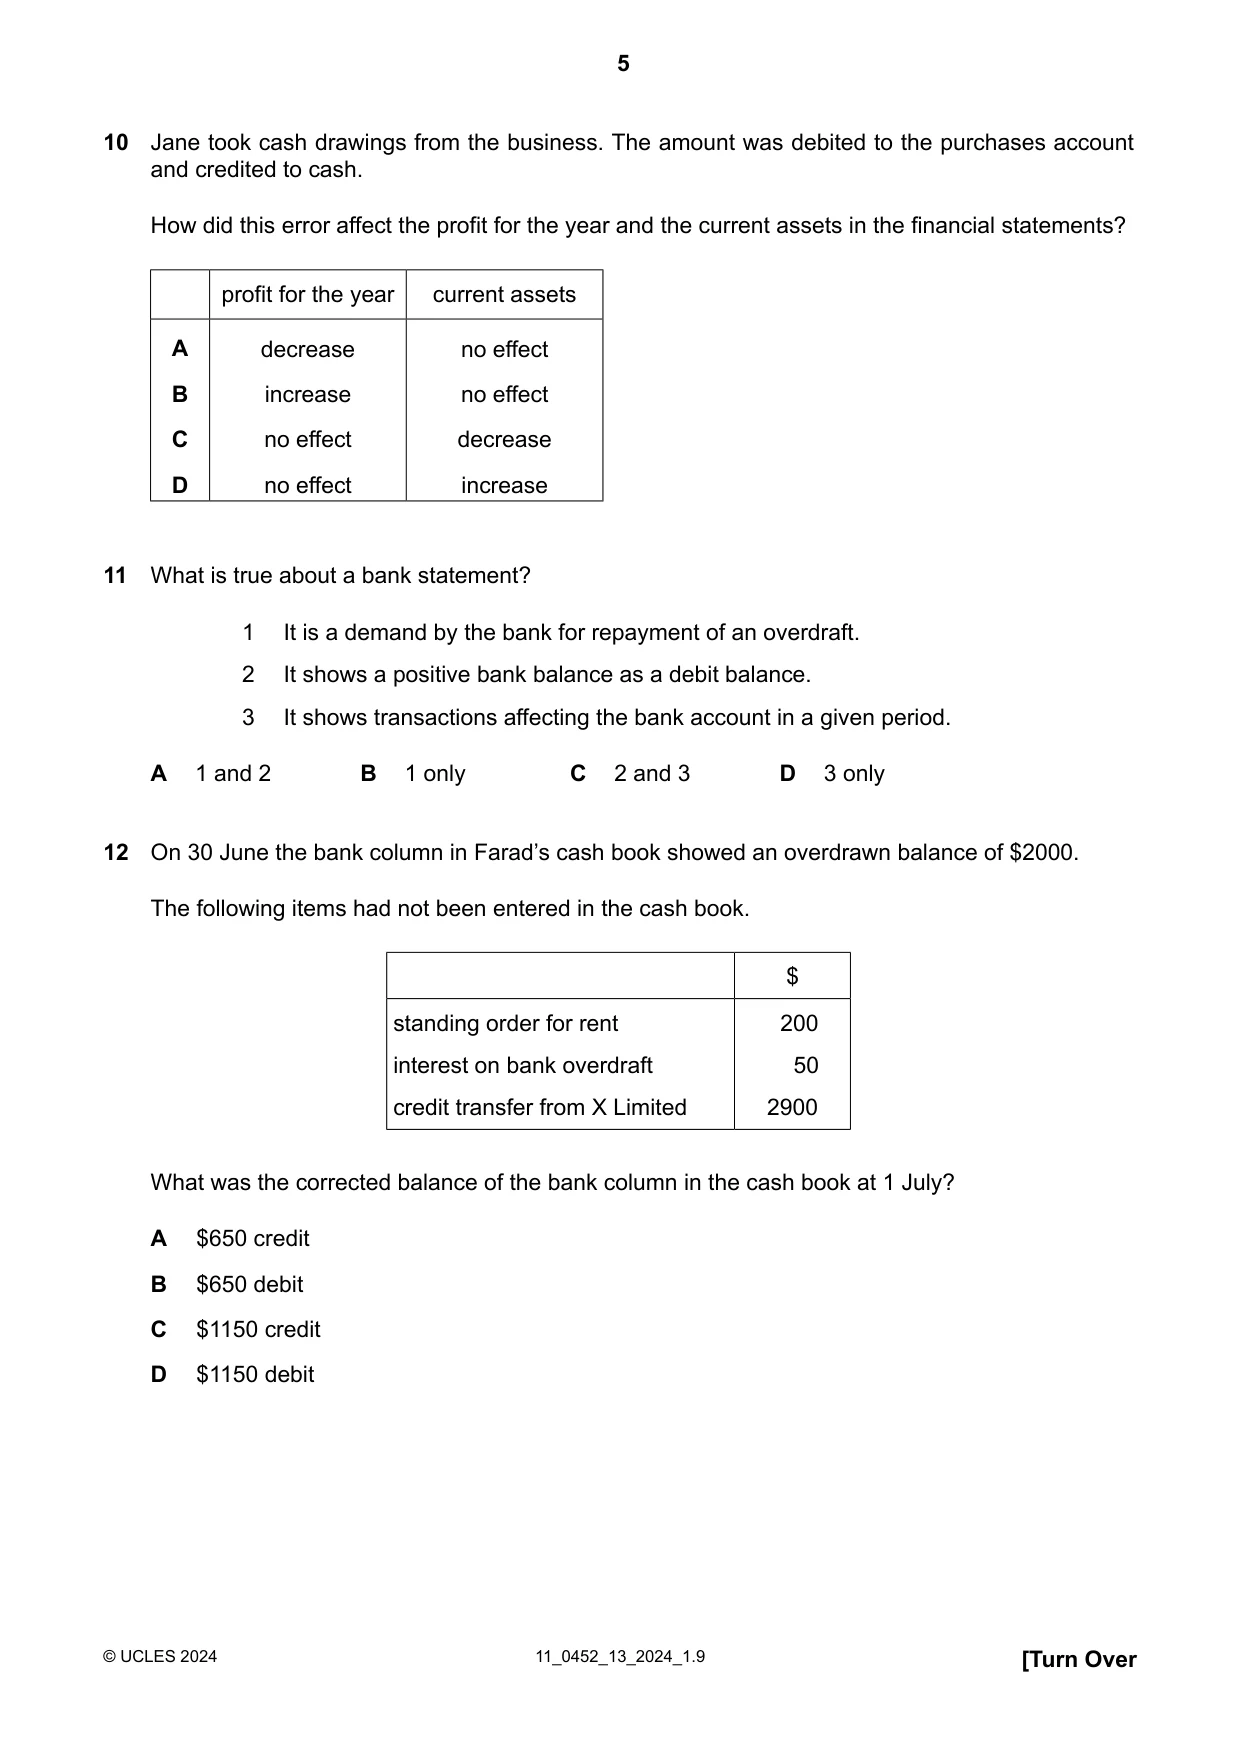
10 Jane took cash drawings from the business. The amount was debited to the purchases account and credited to cash. How did this error affect the profit for the year and the current assets in the financial statements? profit for the year current assets A decrease no effect B increase no effect C no effect decrease D no effect increase
Mark scheme: A
Q11 · What is true about a bank statement?
11 What is true about a bank statement? 1 It is a demand by the bank for repayment of an overdraft. 2 It shows a positive bank balance as a debit balance. 3 It shows transactions affecting the bank account in a given period. A 1 and 2 B 1 only C 2 and 3 D 3 only
Mark scheme: D
Q12 · On 30 June the bank column in Farad’s cash book showed an overdrawn balance of $2000
12 On 30 June the bank column in Farad’s cash book showed an overdrawn balance of $2000. The following items had not been entered in the cash book. $ standing order for rent 200 interest on bank overdraft 50 credit transfer from X Limited 2900 What was the corrected balance of the bank column in the cash book at 1 July? A $650 credit B $650 debit C $1150 credit D $1150 debit
Mark scheme: B
Q13 · What is an advantage of maintaining a purchases ledger control account?
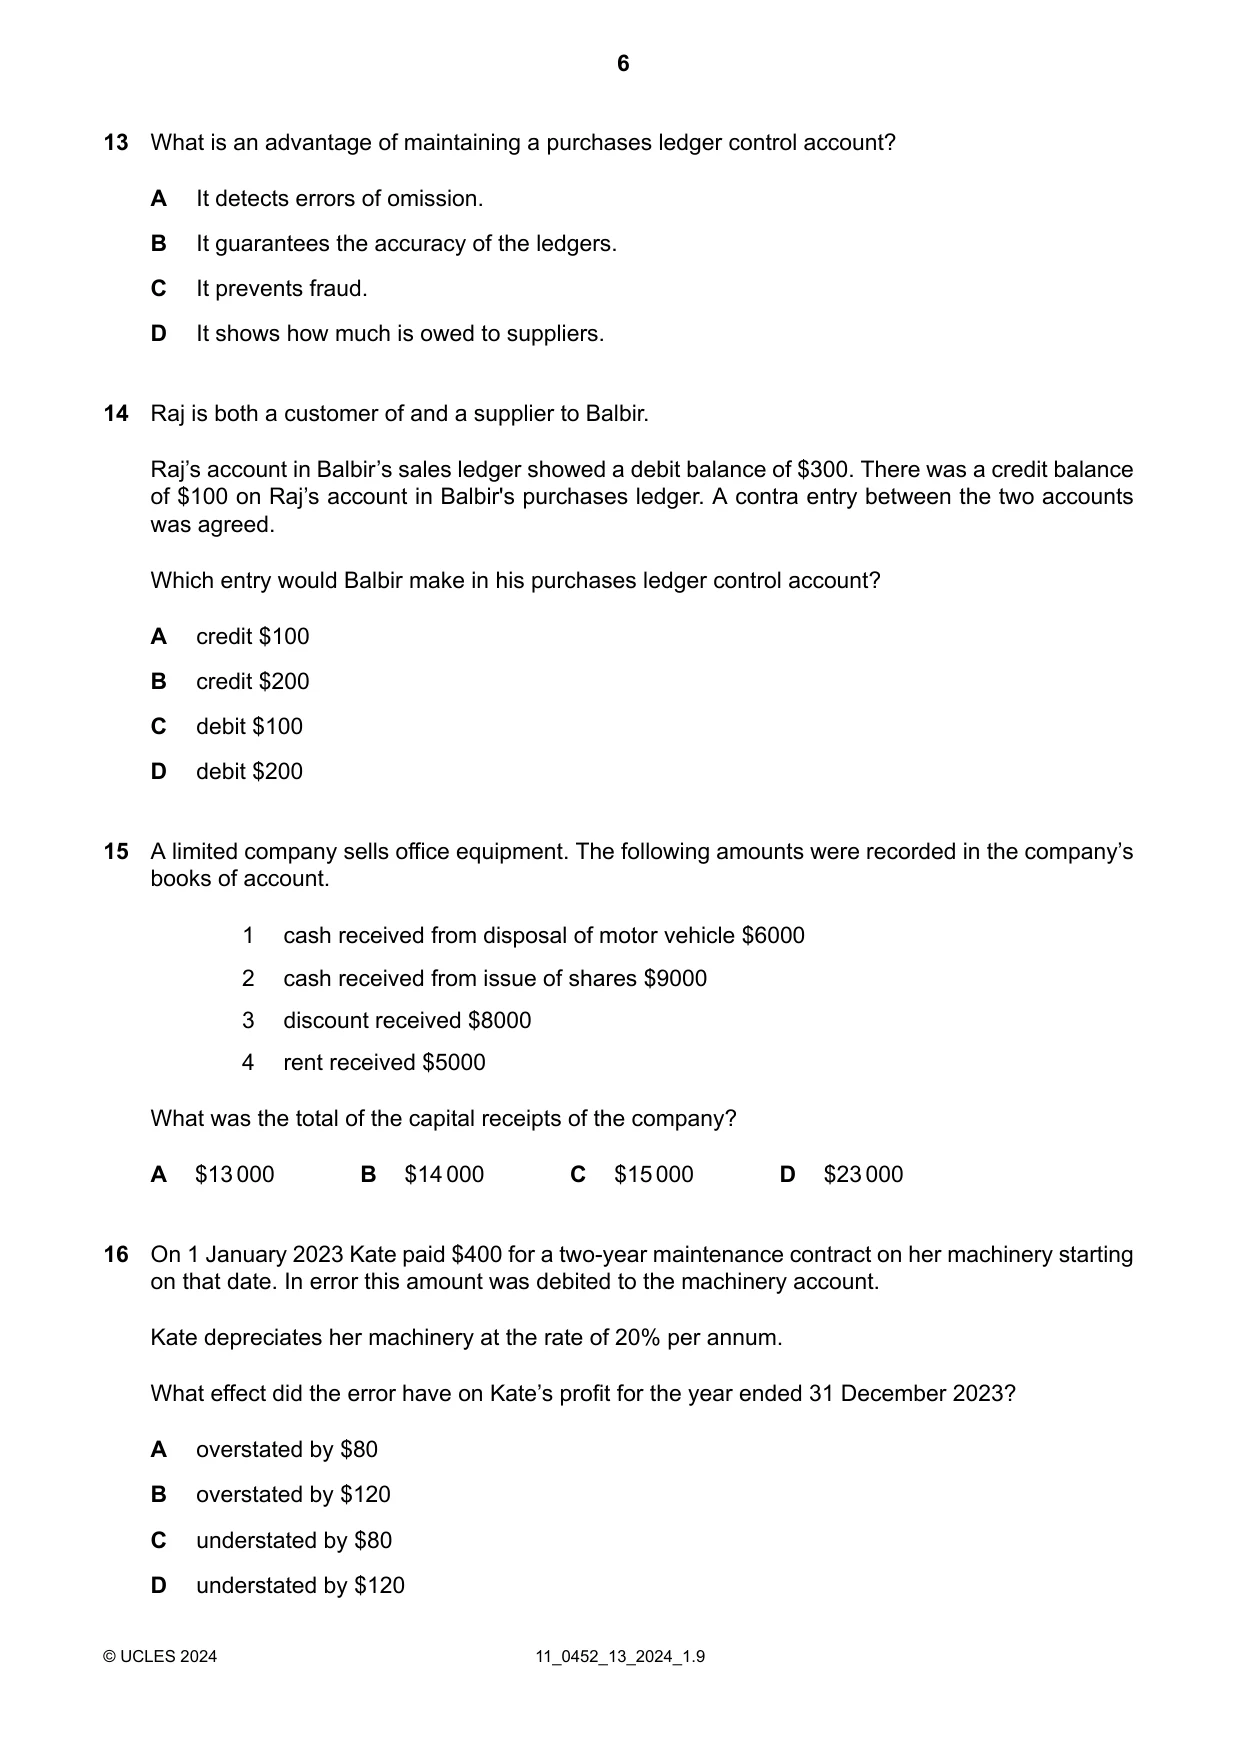
13 What is an advantage of maintaining a purchases ledger control account? A It detects errors of omission. B It guarantees the accuracy of the ledgers. C It prevents fraud. D It shows how much is owed to suppliers.
Mark scheme: D
Q14 · Raj is both a customer of and a supplier to Balbir
14 Raj is both a customer of and a supplier to Balbir. Raj’s account in Balbir’s sales ledger showed a debit balance of $300. There was a credit balance of $100 on Raj’s account in Balbir's purchases ledger. A contra entry between the two accounts was agreed. Which entry would Balbir make in his purchases ledger control account? A credit $100 B credit $200 C debit $100 D debit $200
Mark scheme: C
Q15 · A limited company sells office equipment
15 A limited company sells office equipment. The following amounts were recorded in the company’s books of account. 1 cash received from disposal of motor vehicle $6000 2 cash received from issue of shares $9000 3 discount received $8000 4 rent received $5000 What was the total of the capital receipts of the company? A $13000 B $14000 C $15000 D $23000
Mark scheme: C
More questions on Capital and revenue expenditure and receipts
Q16 · On 1 January 2023 Kate paid $400 for a two-year maintenance contract on her machinery…
16 On 1 January 2023 Kate paid $400 for a two-year maintenance contract on her machinery starting on that date. In error this amount was debited to the machinery account. Kate depreciates her machinery at the rate of 20% per annum. What effect did the error have on Kate’s profit for the year ended 31 December 2023? A overstated by $80 B overstated by $120 C understated by $80 D understated by $120
Mark scheme: B
Q17 · Why should a business depreciate its non-current assets?
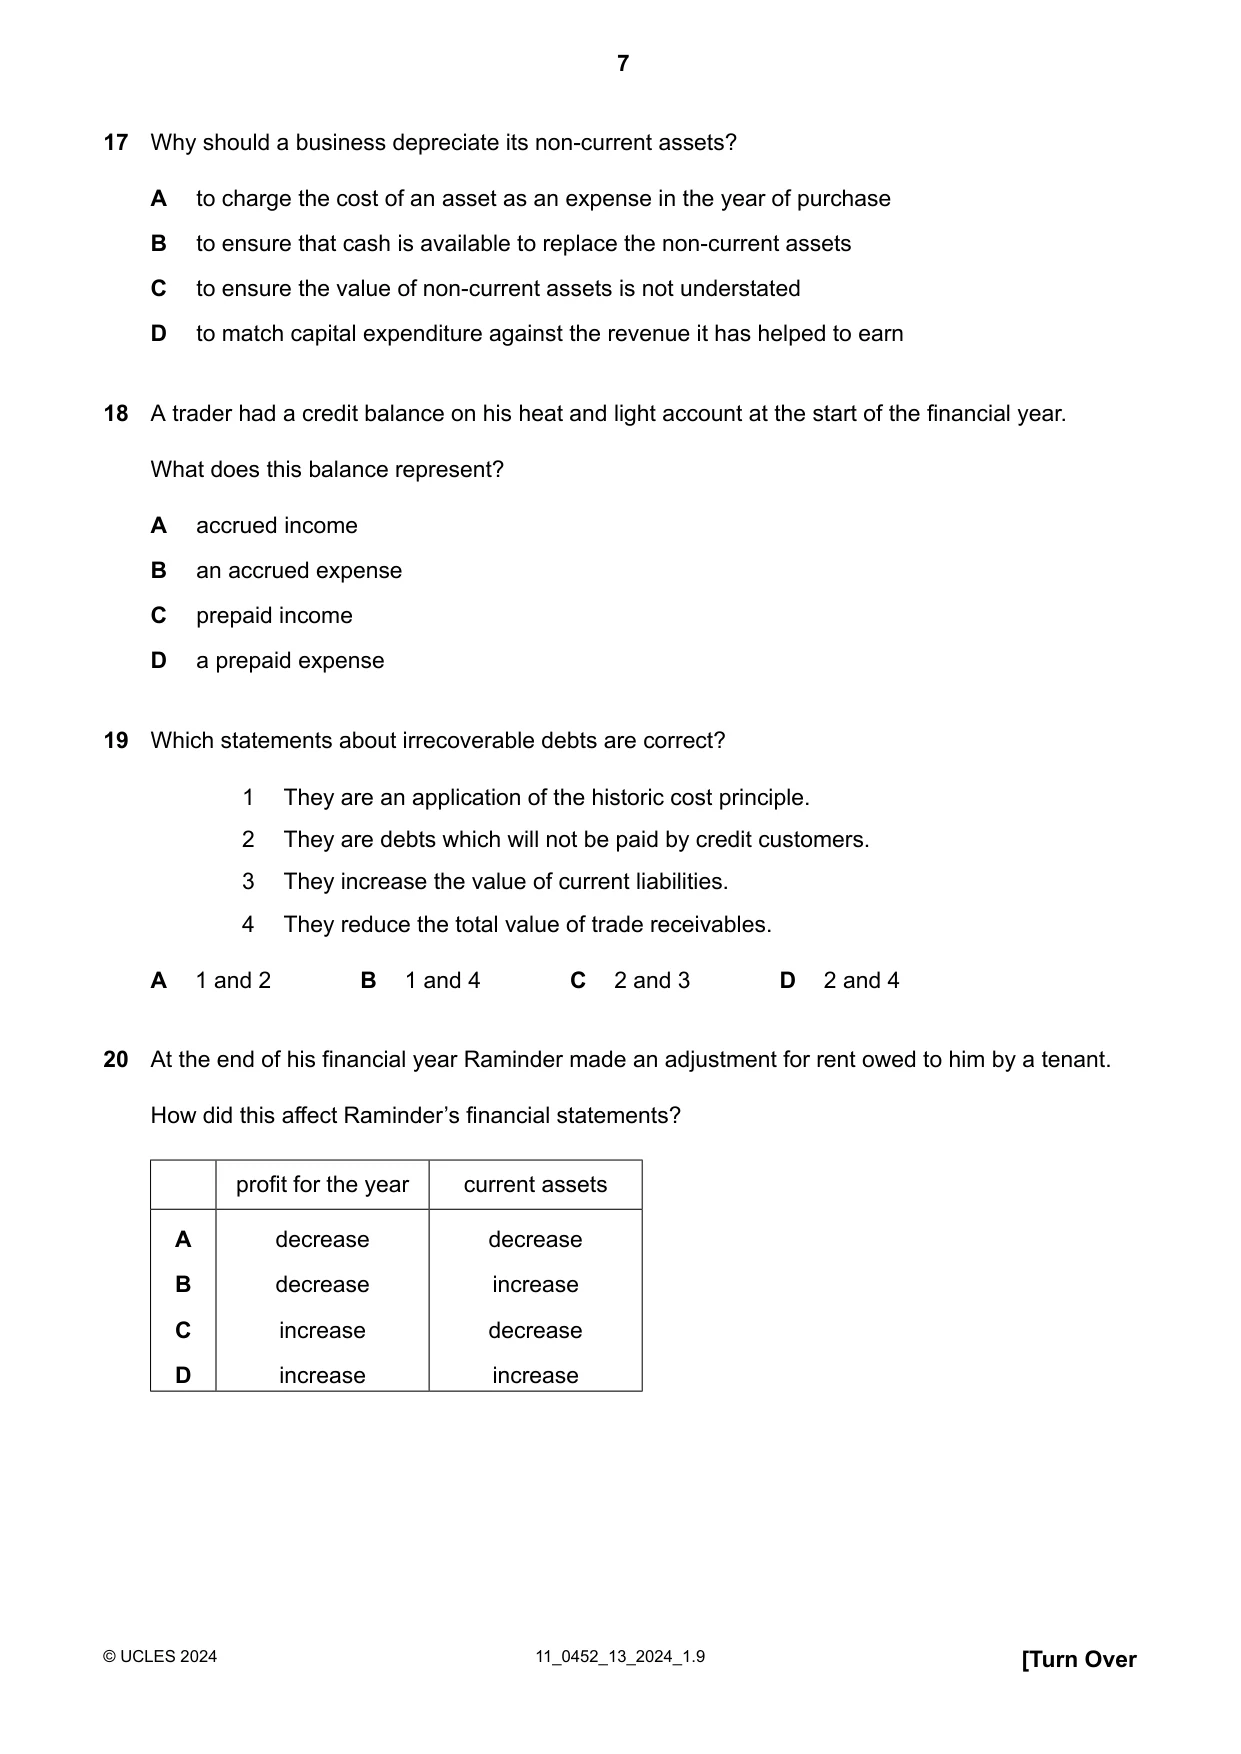
17 Why should a business depreciate its non-current assets? A to charge the cost of an asset as an expense in the year of purchase B to ensure that cash is available to replace the non-current assets C to ensure the value of non-current assets is not understated D to match capital expenditure against the revenue it has helped to earn
Mark scheme: D
More questions on Accounting for depreciation and disposal of non-current assets
Q18 · A trader had a credit balance on his heat and light account at the start of the financial…
18 A trader had a credit balance on his heat and light account at the start of the financial year. What does this balance represent? A accrued income B an accrued expense C prepaid income D a prepaid expense
Mark scheme: B
Q19 · Which statements about irrecoverable debts are correct?
19 Which statements about irrecoverable debts are correct? 1 They are an application of the historic cost principle. 2 They are debts which will not be paid by credit customers. 3 They increase the value of current liabilities. 4 They reduce the total value of trade receivables. A 1 and 2 B 1 and 4 C 2 and 3 D 2 and 4
Mark scheme: D
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q20 · At the end of his financial year Raminder made an adjustment for rent owed to him by a…
20 At the end of his financial year Raminder made an adjustment for rent owed to him by a tenant. How did this affect Raminder’s financial statements? profit for the year current assets A decrease decrease B decrease increase C increase decrease D increase increase
Mark scheme: D
Q21 · What is a disadvantage of operating as a sole trader?
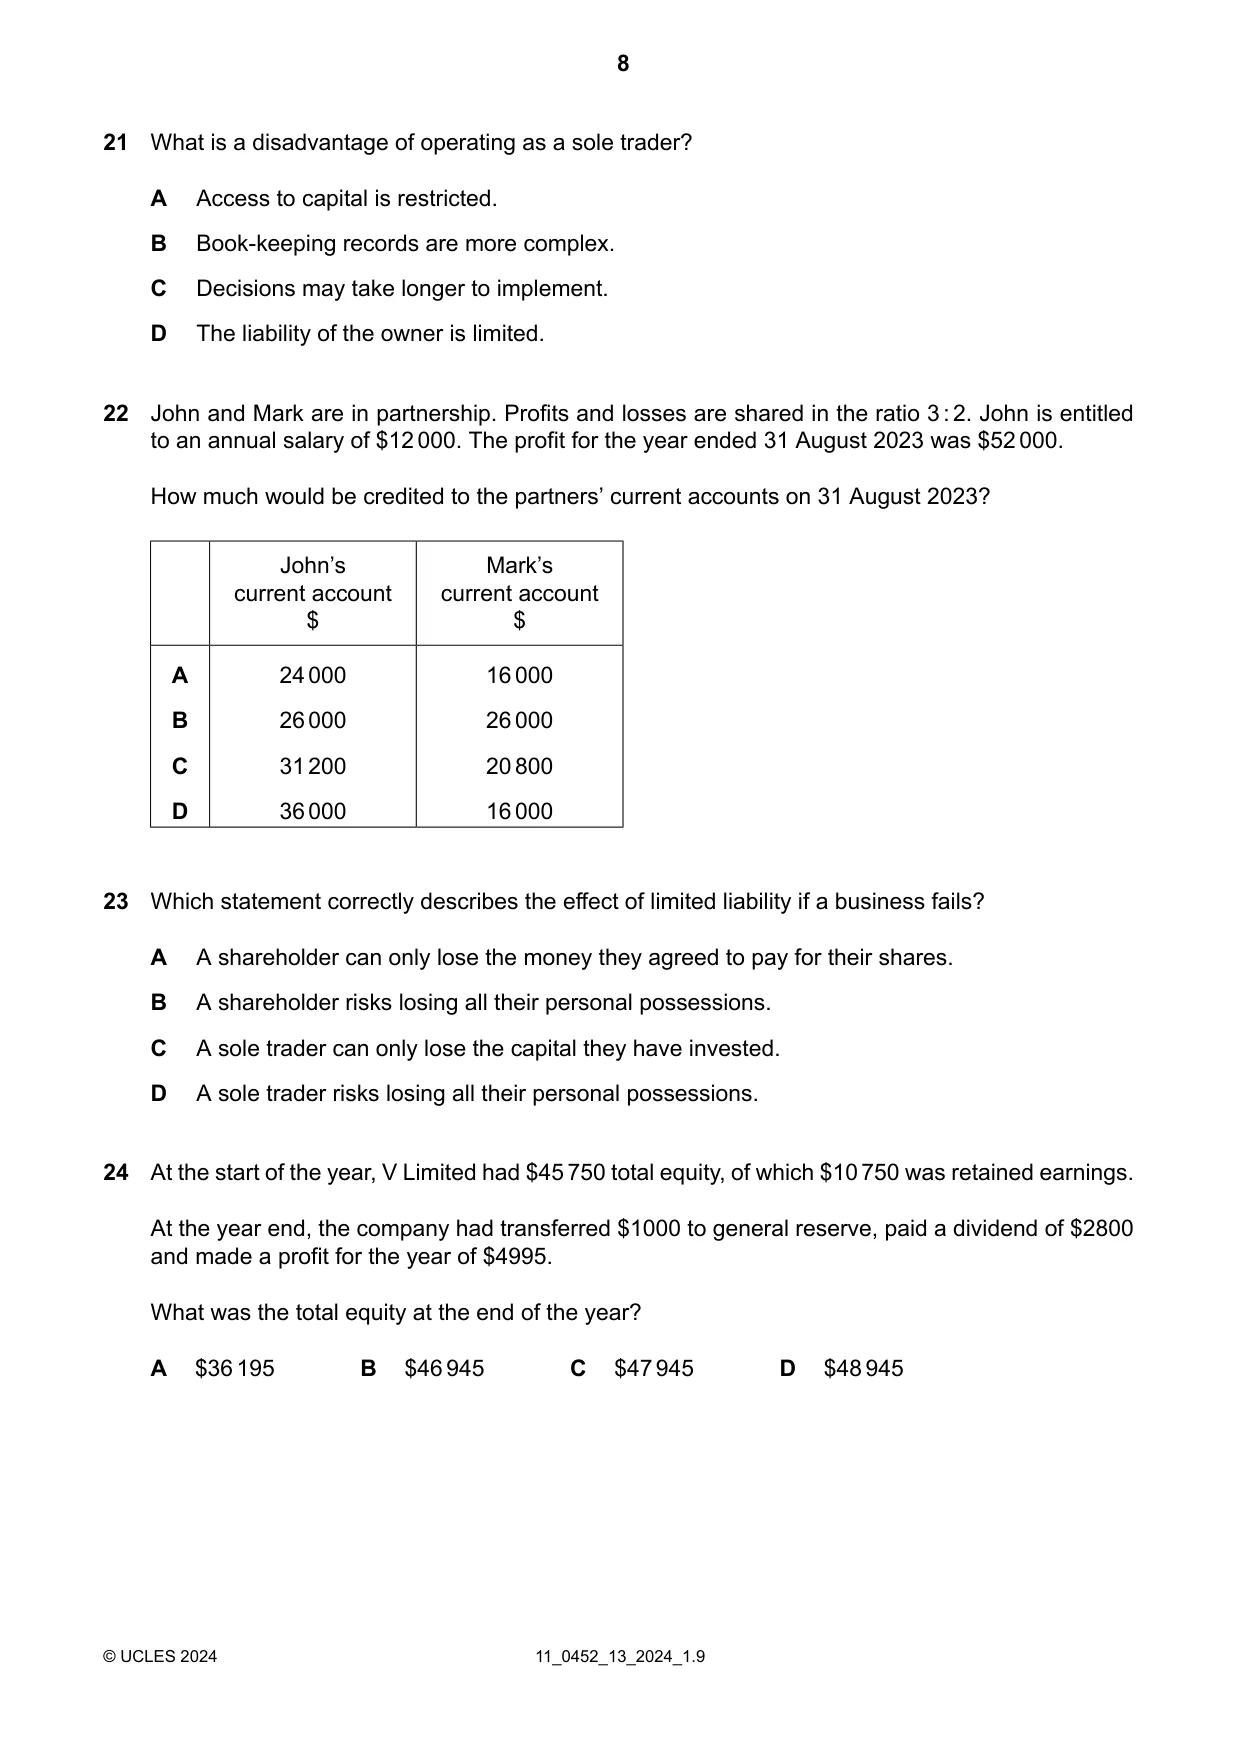
21 What is a disadvantage of operating as a sole trader? A Access to capital is restricted. B Book-keeping records are more complex. C Decisions may take longer to implement. D The liability of the owner is limited.
Mark scheme: A
Q22 · John and Mark are in partnership
22 John and Mark are in partnership. Profits and losses are shared in the ratio 3:2. John is entitled to an annual salary of $12000. The profit for the year ended 31 August 2023 was $52000. How much would be credited to the partners’ current accounts on 31 August 2023? John’s Mark’s current account current account $ $ A 24000 16000 B 26000 26000 C 31200 20800 D 36000 16000
Mark scheme: D
Q23 · Which statement correctly describes the effect of limited liability if a business fails?
23 Which statement correctly describes the effect of limited liability if a business fails? A A shareholder can only lose the money they agreed to pay for their shares. B A shareholder risks losing all their personal possessions. C A sole trader can only lose the capital they have invested. D A sole trader risks losing all their personal possessions.
Mark scheme: A
Q24 · At the start of the year, V Limited had $45750 total equity, of which $10750 was retained…
24 At the start of the year, V Limited had $45750 total equity, of which $10750 was retained earnings. At the year end, the company had transferred $1000 to general reserve, paid a dividend of $2800 and made a profit for the year of $4995. What was the total equity at the end of the year? A $36195 B $46945 C $47945 D $48945
Mark scheme: C
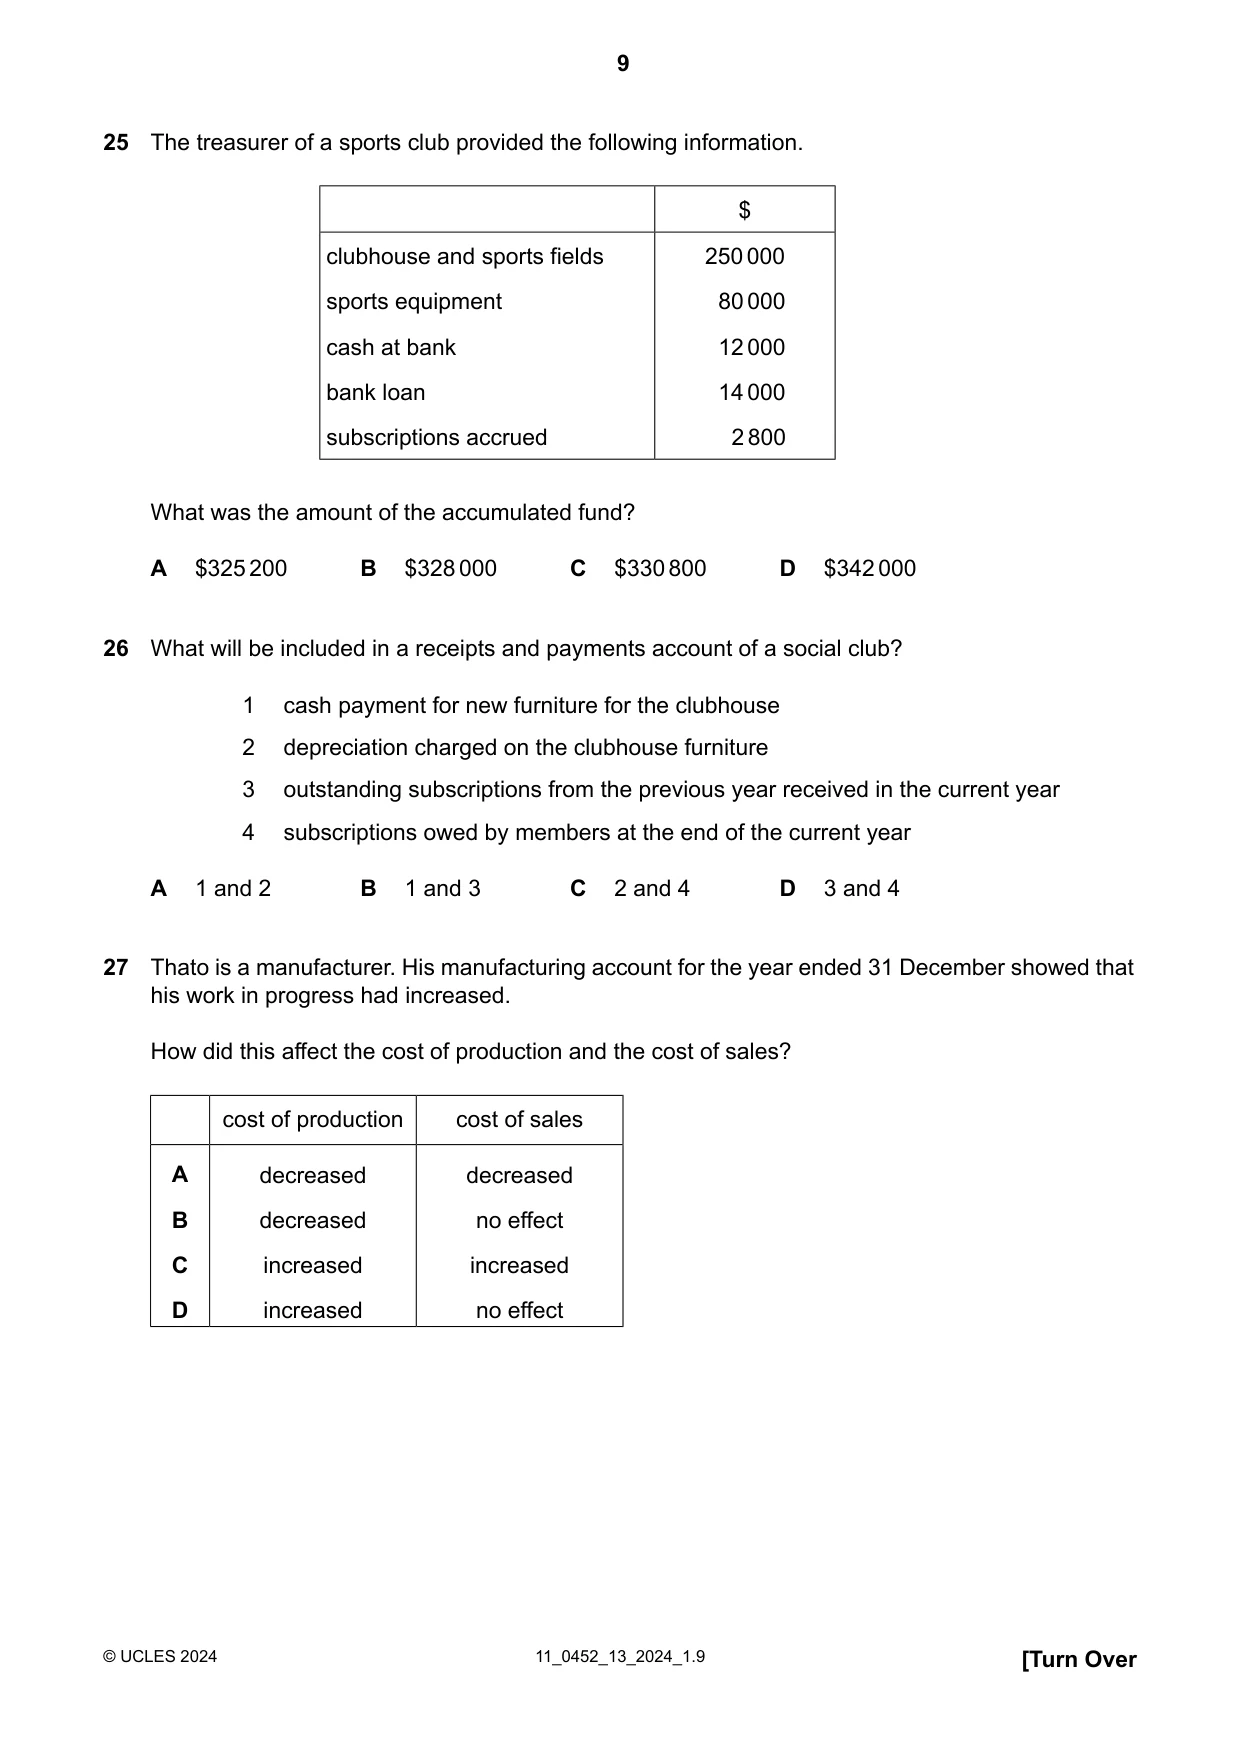
Q25 · The treasurer of a sports club provided the following information
25 The treasurer of a sports club provided the following information. $ clubhouse and sports fields 250000 sports equipment 80000 cash at bank 12000 bank loan 14000 subscriptions accrued 2800 What was the amount of the accumulated fund? A $325200 B $328000 C $330800 D $342000
Mark scheme: C
Q26 · What will be included in a receipts and payments account of a social club?
26 What will be included in a receipts and payments account of a social club? 1 cash payment for new furniture for the clubhouse 2 depreciation charged on the clubhouse furniture 3 outstanding subscriptions from the previous year received in the current year 4 subscriptions owed by members at the end of the current year A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
Mark scheme: B
Q27 · Thato is a manufacturer
27 Thato is a manufacturer. His manufacturing account for the year ended 31 December showed that his work in progress had increased. How did this affect the cost of production and the cost of sales? cost of production cost of sales A decreased decreased B decreased no effect C increased increased D increased no effect
Mark scheme: A
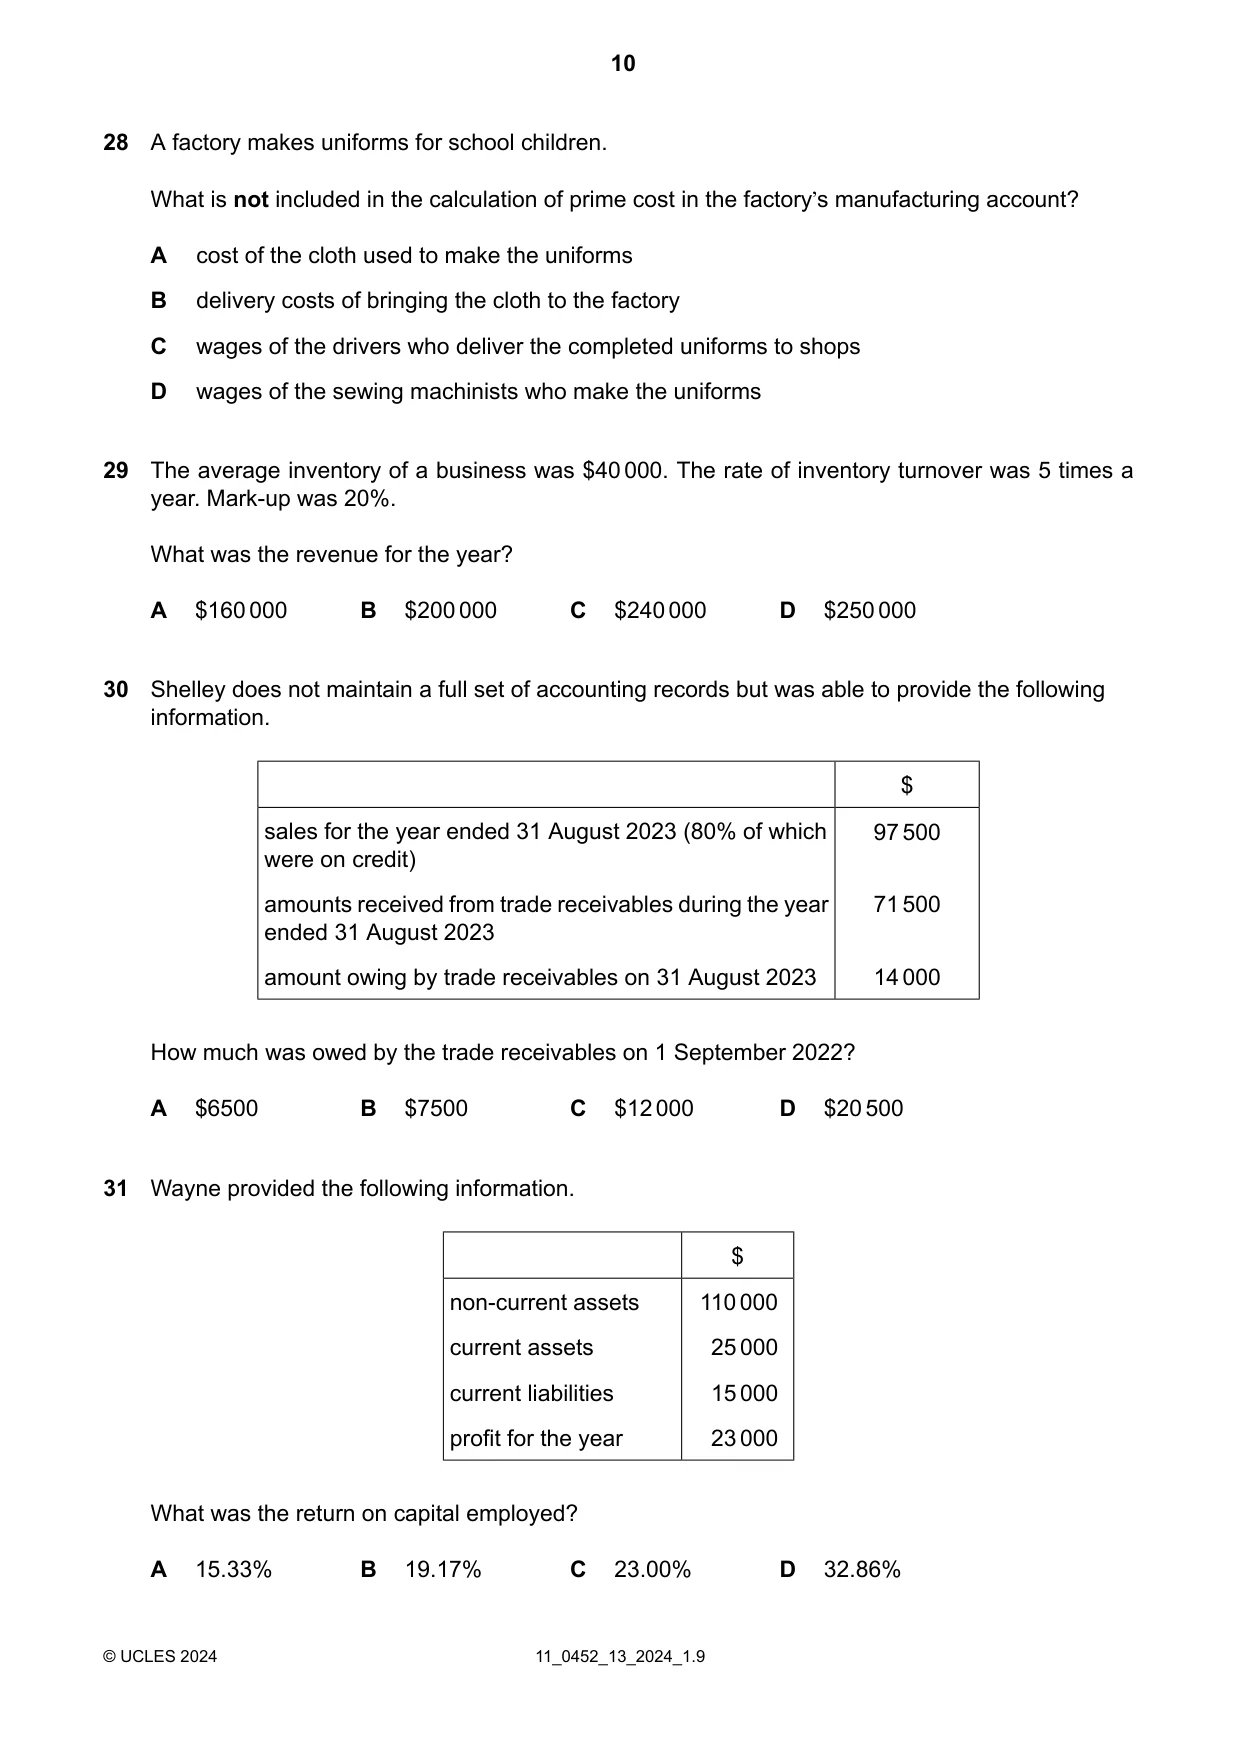
Q28 · A factory makes uniforms for school children
28 A factory makes uniforms for school children. What is not included in the calculation of prime cost in the factory’s manufacturing account? A cost of the cloth used to make the uniforms B delivery costs of bringing the cloth to the factory C wages of the drivers who deliver the completed uniforms to shops D wages of the sewing machinists who make the uniforms
Mark scheme: C
Q29 · The average inventory of a business was $40000
29 The average inventory of a business was $40000. The rate of inventory turnover was 5 times a year. Mark-up was 20%. What was the revenue for the year? A $160000 B $200000 C $240000 D $250000
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
Q30 · Shelley does not maintain a full set of accounting records but was able to provide the…
30 Shelley does not maintain a full set of accounting records but was able to provide the following information. $ sales for the year ended 31 August 2023 (80% of which 97500 were on credit) amounts received from trade receivables during the year 71500 ended 31 August 2023 amount owing by trade receivables on 31 August 2023 14000 How much was owed by the trade receivables on 1 September 2022? A $6500 B $7500 C $12000 D $20500
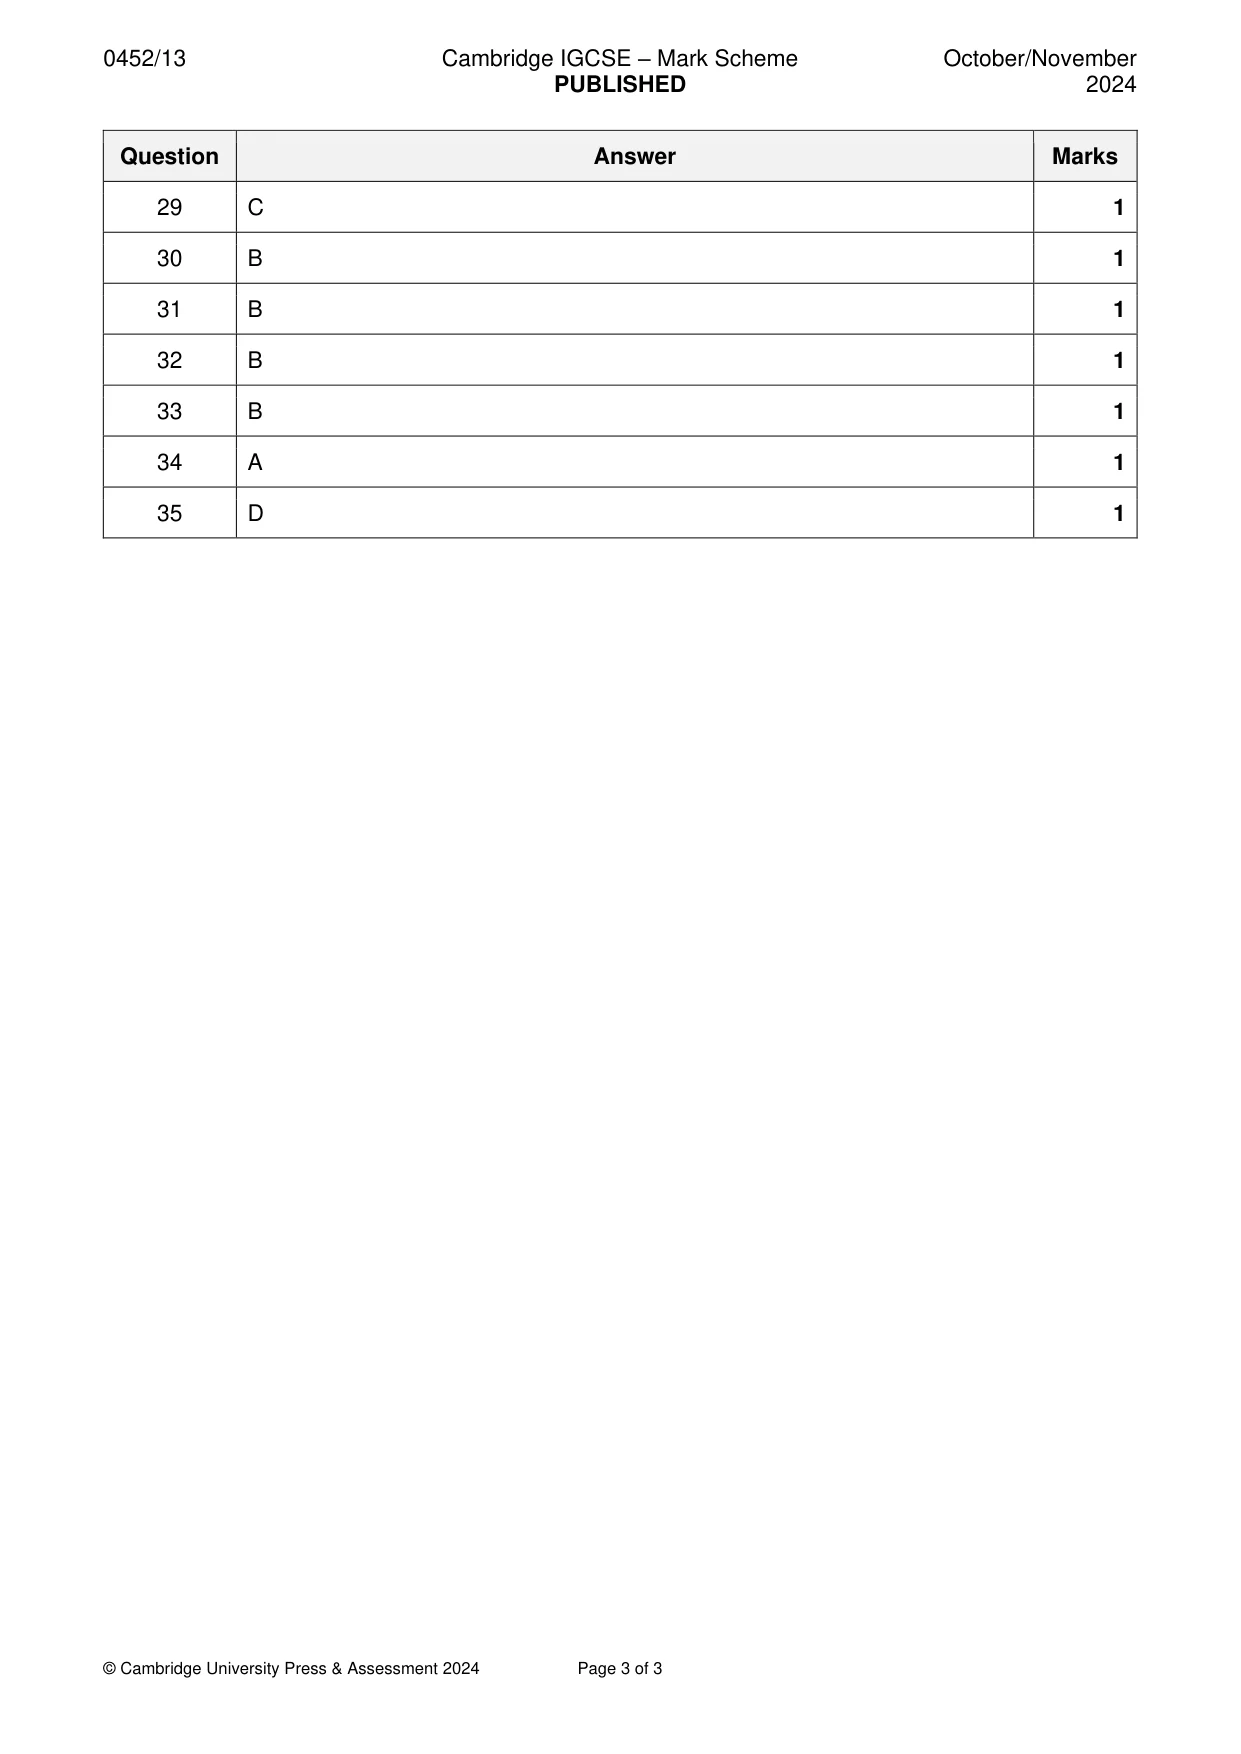
Mark scheme: B
Q31 · Wayne provided the following information
31 Wayne provided the following information. $ non-current assets 110000 current assets 25000 current liabilities 15000 profit for the year 23000 What was the return on capital employed? A 15.33% B 19.17% C 23.00% D 32.86%
Mark scheme: B
More questions on Calculation and understanding of accounting ratios
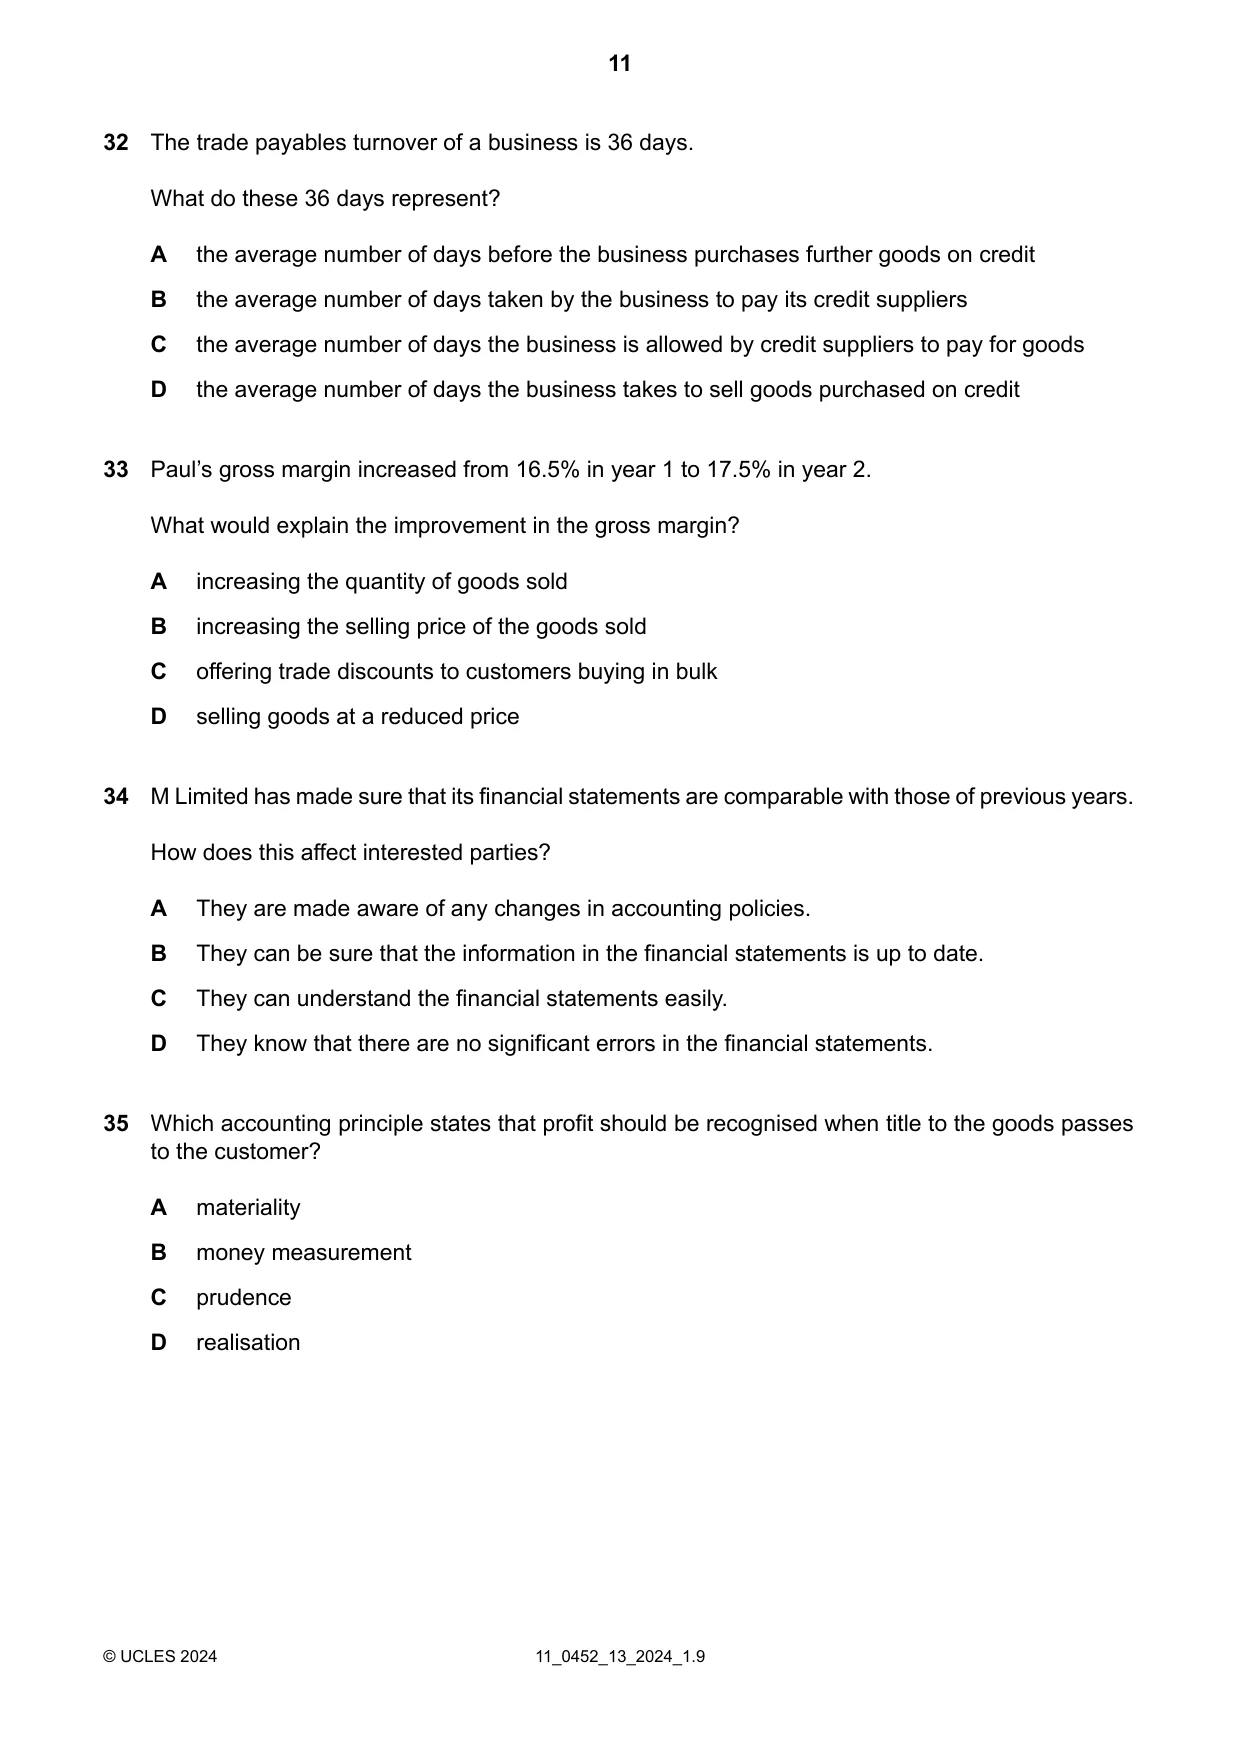
Q32 · The trade payables turnover of a business is 36 days
32 The trade payables turnover of a business is 36 days. What do these 36 days represent? A the average number of days before the business purchases further goods on credit B the average number of days taken by the business to pay its credit suppliers C the average number of days the business is allowed by credit suppliers to pay for goods D the average number of days the business takes to sell goods purchased on credit
Mark scheme: B
Q33 · Paul’s gross margin increased from 16.5% in year 1 to 17.5% in year 2
33 Paul’s gross margin increased from 16.5% in year 1 to 17.5% in year 2. What would explain the improvement in the gross margin? A increasing the quantity of goods sold B increasing the selling price of the goods sold C offering trade discounts to customers buying in bulk D selling goods at a reduced price
Mark scheme: B
Q34 · M Limited has made sure that its financial statements are comparable with those of…
34 M Limited has made sure that its financial statements are comparable with those of previous years. How does this affect interested parties? A They are made aware of any changes in accounting policies. B They can be sure that the information in the financial statements is up to date. C They can understand the financial statements easily. D They know that there are no significant errors in the financial statements.
Mark scheme: A
Q35 · Which accounting principle states that profit should be recognised when title to the…
35 Which accounting principle states that profit should be recognised when title to the goods passes to the customer? A materiality B money measurement C prudence D realisation
Mark scheme: D
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
4Accounting concepts2Bank reconciliation2Books of prime entry2Calculation and understanding of accounting ratios2Clubs and societies2Control accounts2Interpretation of accounting ratios2Limited companies2Manufacturing accounts2Other payables and other receivables2The double entry system of book-keeping2Accounting for depreciation and disposal of non-current assets1Business documents1Capital and revenue expenditure and receipts1Incomplete records1Irrecoverable debts and allowance for irrecoverable debts1Partnerships1Sole traders1The accounting equation1The purpose of accounting1What you needed in this session
Cambridge’s own grade thresholds for 2024 Oct/Nov, Paper 1 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.