Cambridge IGCSE Accounting 0452 — 2021 Oct/Nov Paper 1 · Variant 3
0452/13/O/N/21 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
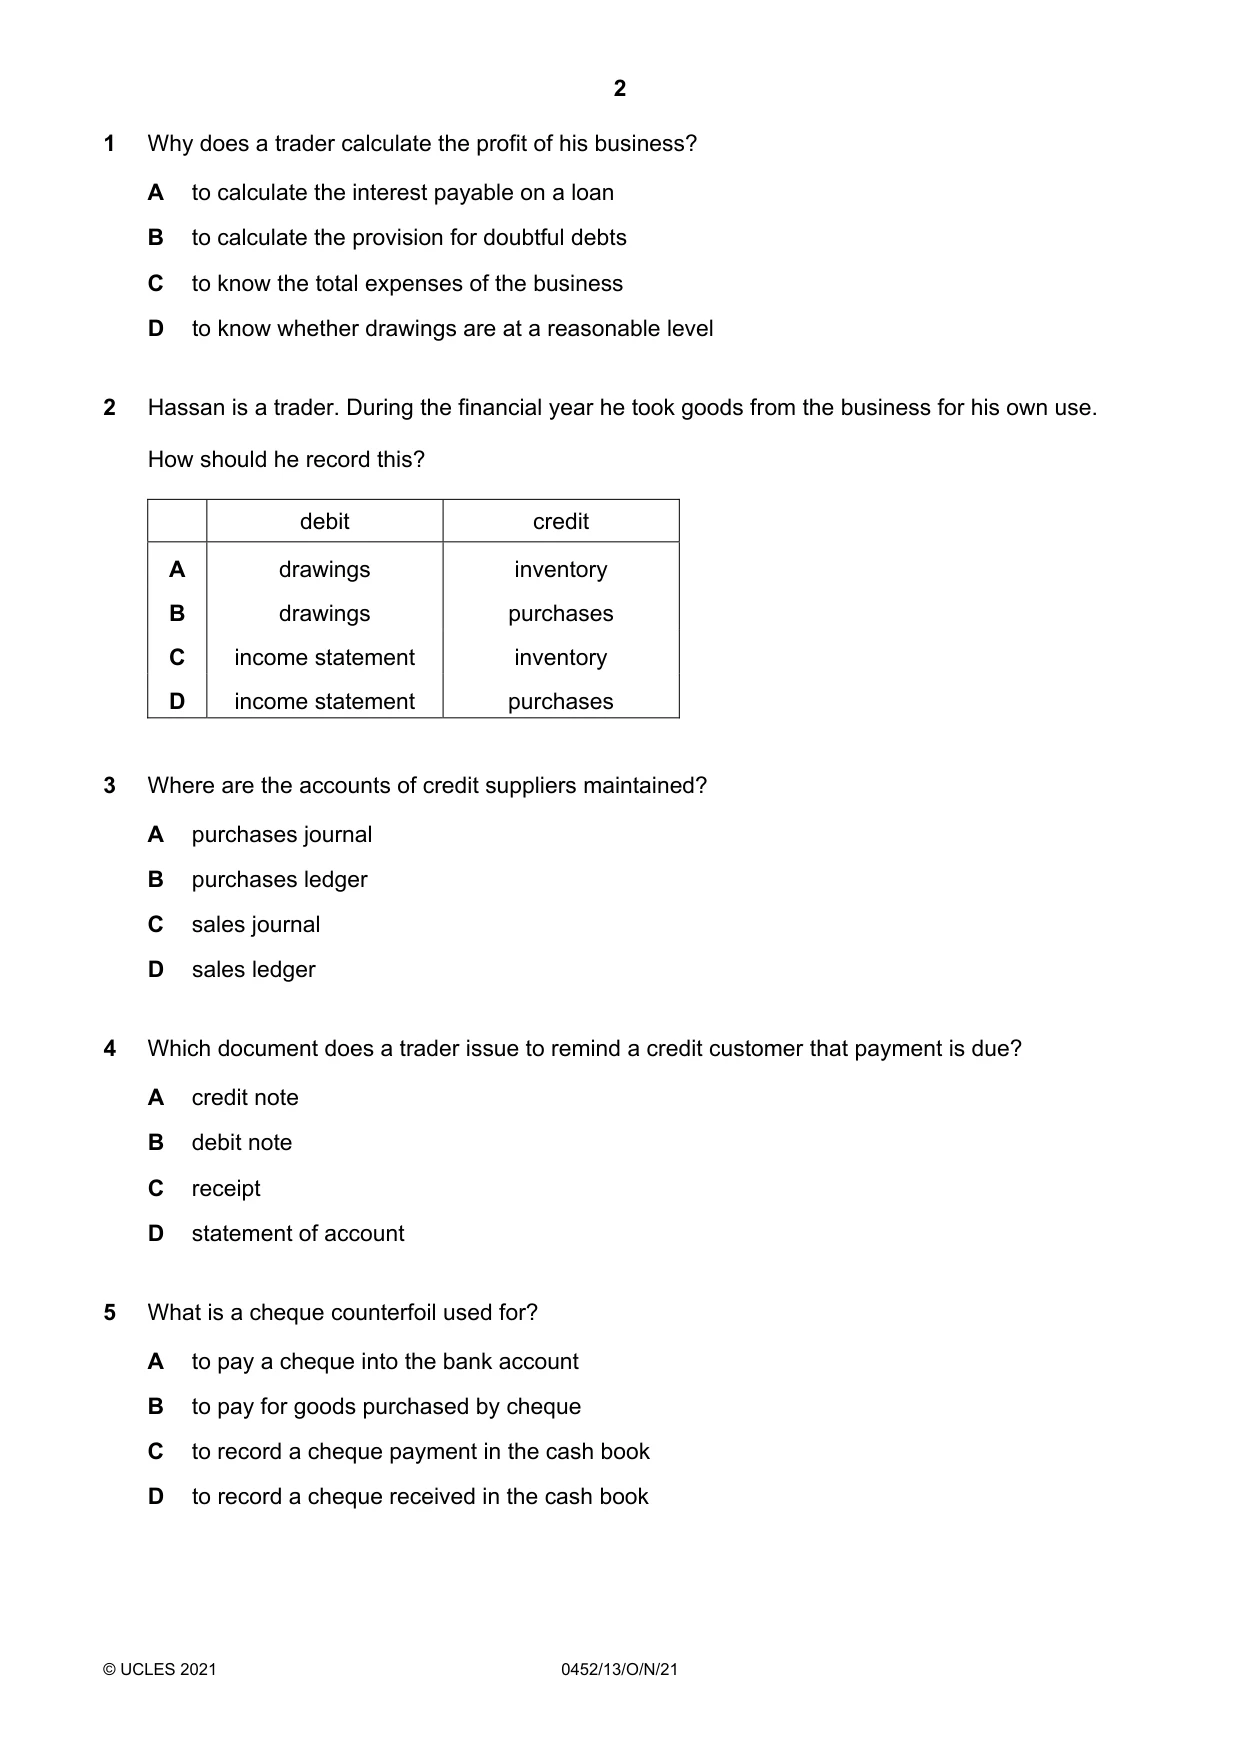
Q1 · Why does a trader calculate the profit of his business?
1 Why does a trader calculate the profit of his business? A to calculate the interest payable on a loan B to calculate the provision for doubtful debts C to know the total expenses of the business D to know whether drawings are at a reasonable level
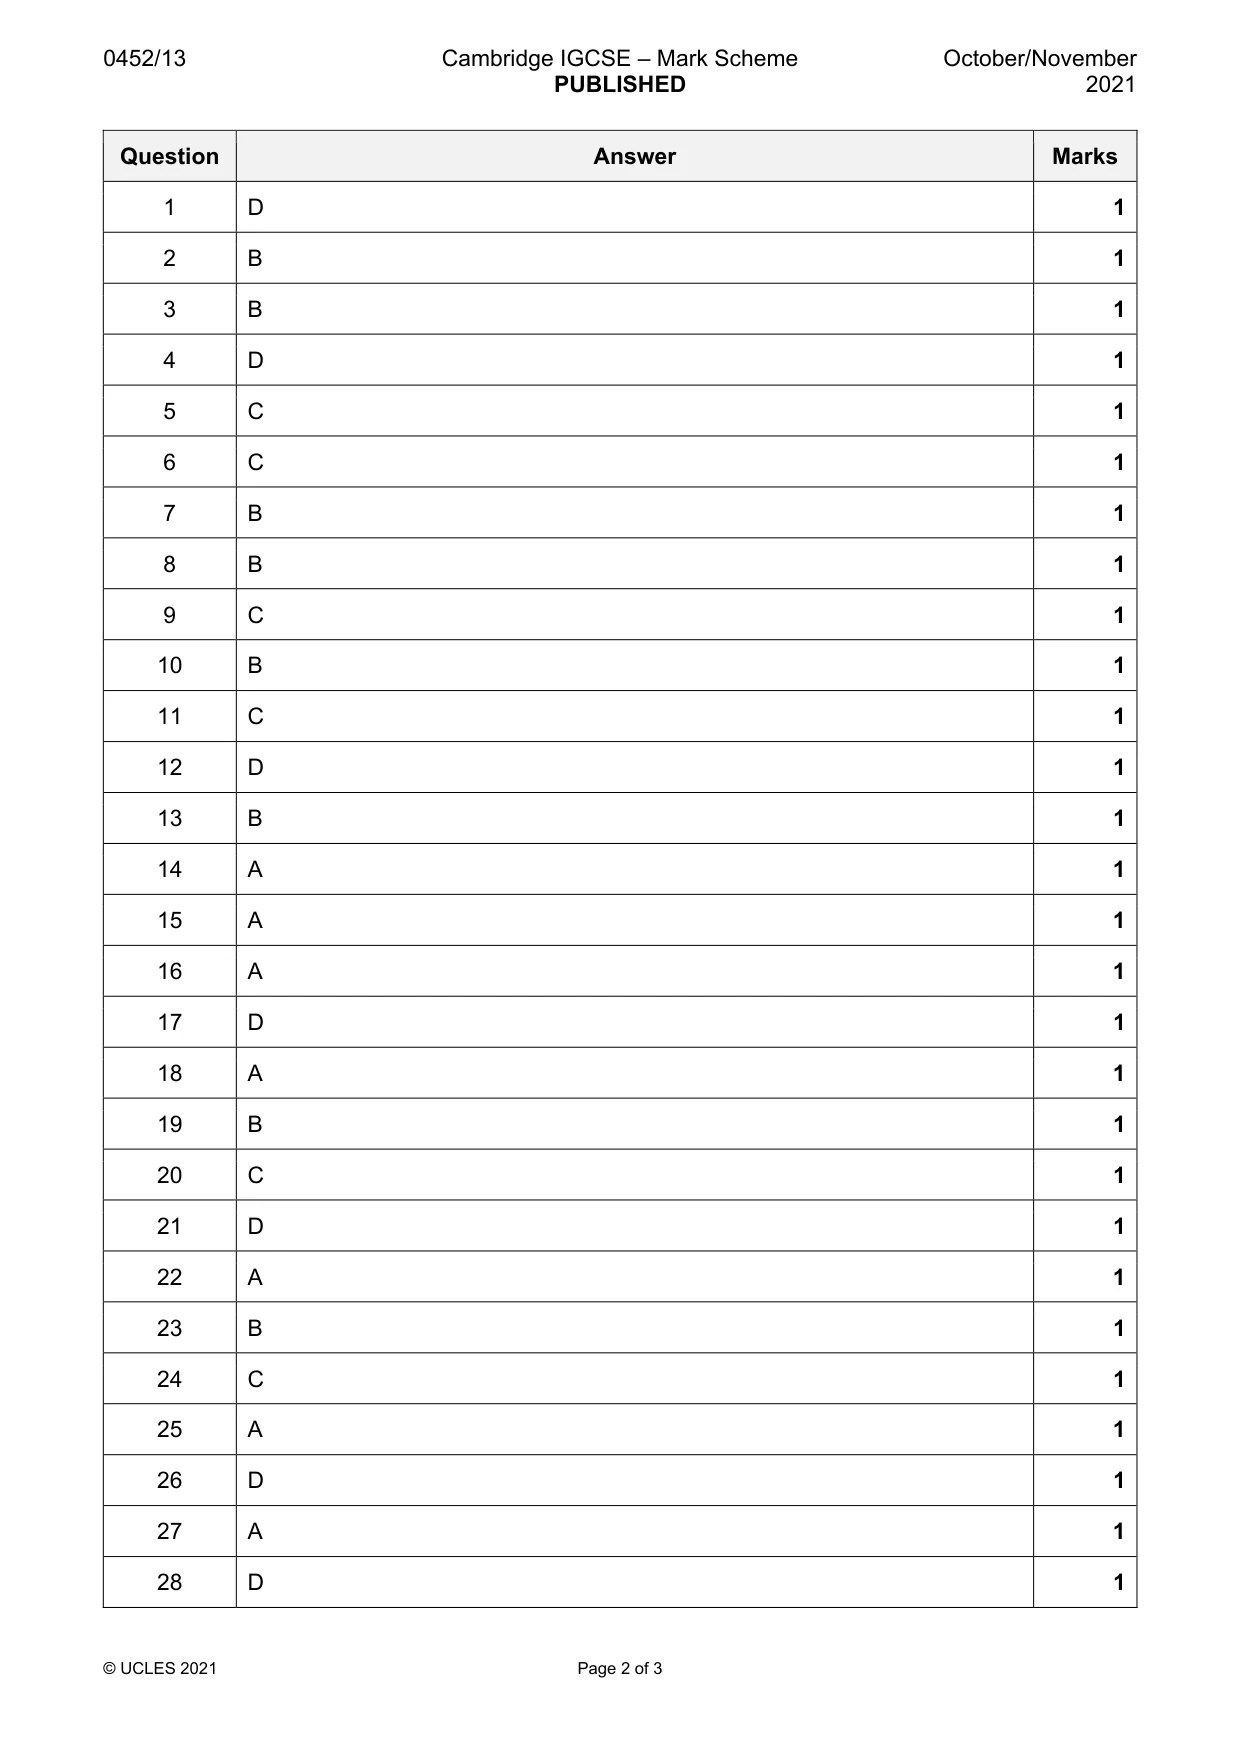
Mark scheme: D
Q2 · Hassan is a trader
2 Hassan is a trader. During the financial year he took goods from the business for his own use. How should he record this? debit credit A drawings inventory B drawings purchases C income statement inventory D income statement purchases
Mark scheme: B
Q3 · Where are the accounts of credit suppliers maintained?
3 Where are the accounts of credit suppliers maintained? A purchases journal B purchases ledger C sales journal D sales ledger
Mark scheme: B
Q4 · Which document does a trader issue to remind a credit customer that payment is due?
4 Which document does a trader issue to remind a credit customer that payment is due? A credit note B debit note C receipt D statement of account
Mark scheme: D
Q5 · What is a cheque counterfoil used for?
5 What is a cheque counterfoil used for? A to pay a cheque into the bank account B to pay for goods purchased by cheque C to record a cheque payment in the cash book D to record a cheque received in the cash book
Mark scheme: C
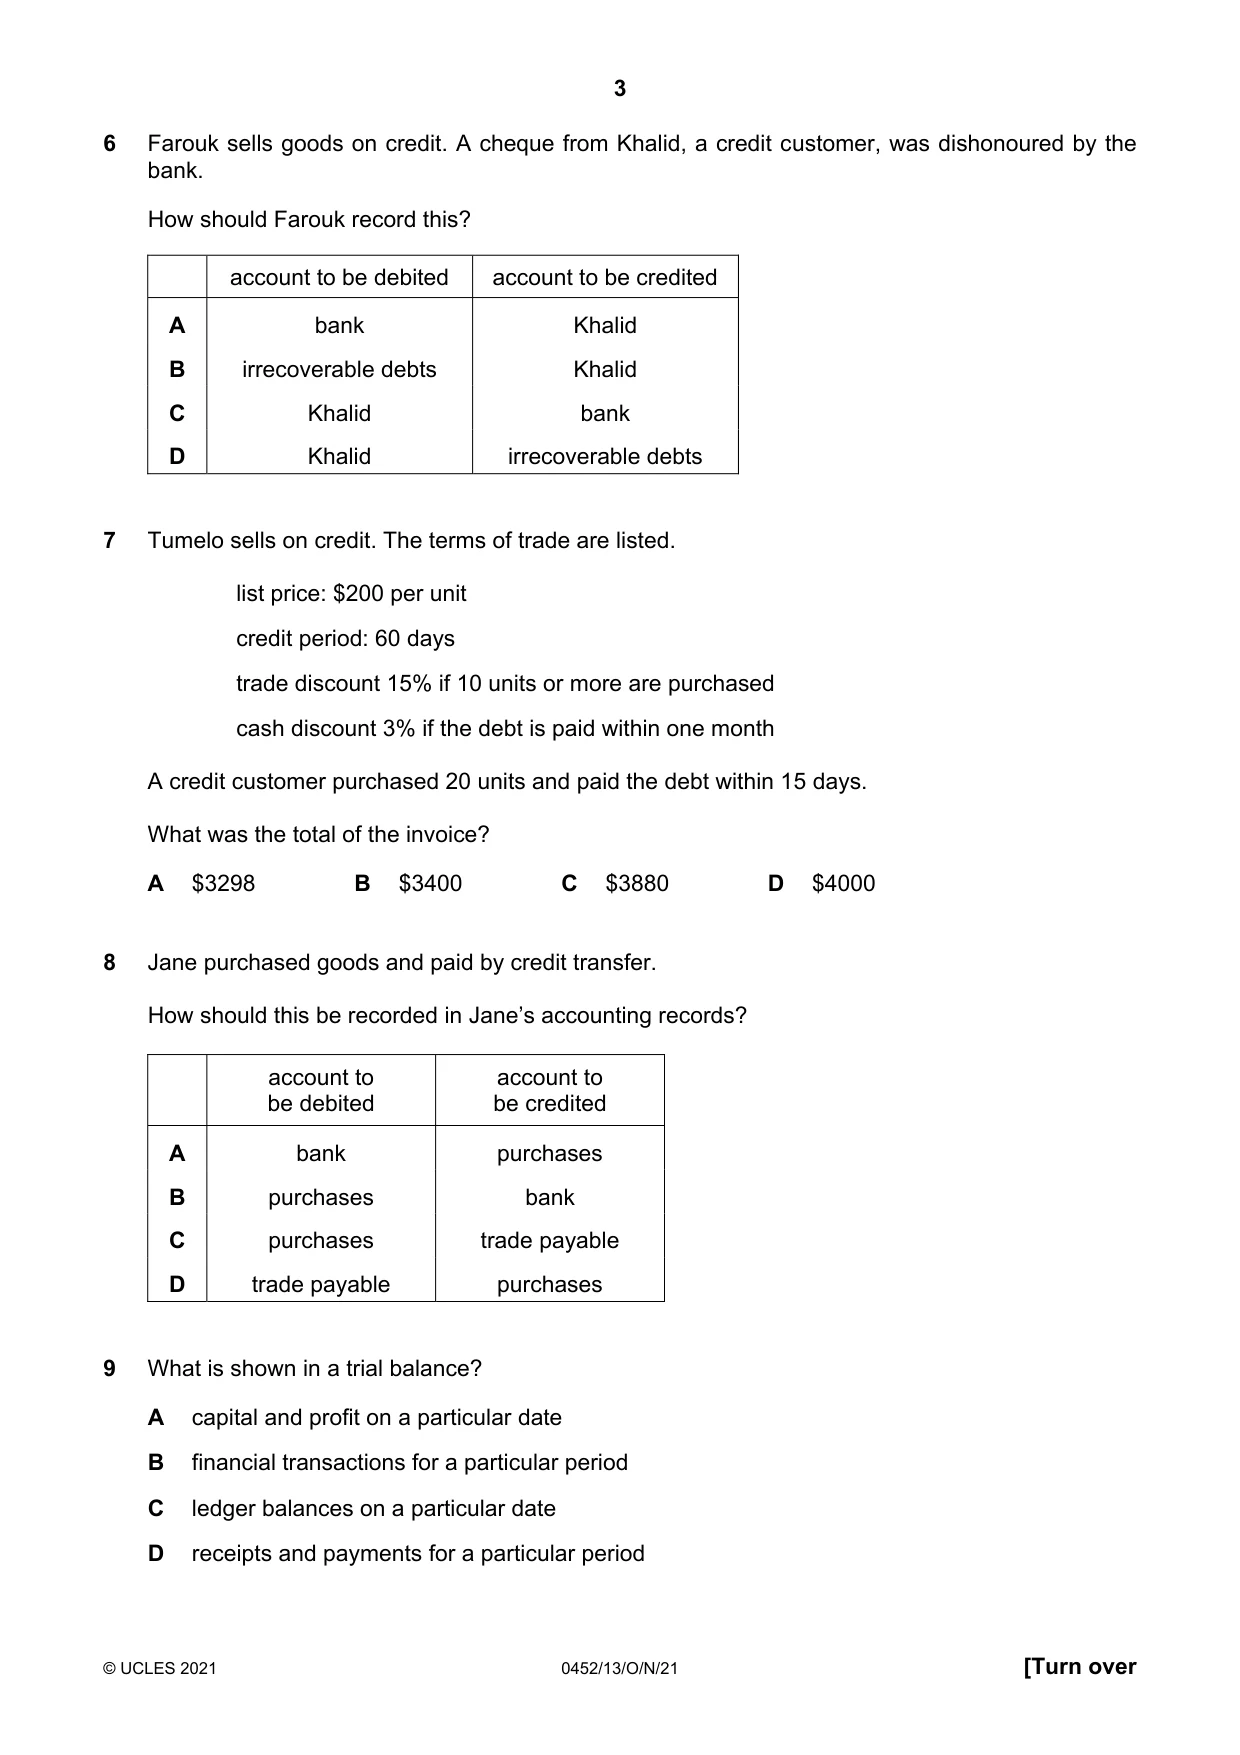
Q6 · Farouk sells goods on credit
6 Farouk sells goods on credit. A cheque from Khalid, a credit customer, was dishonoured by the bank. How should Farouk record this? account to be debited account to be credited A bank Khalid B irrecoverable debts Khalid C Khalid bank D Khalid irrecoverable debts
Mark scheme: C
Q7 · Tumelo sells on credit
7 Tumelo sells on credit. The terms of trade are listed. list price: $200 per unit credit period: 60 days trade discount 15% if 10 units or more are purchased cash discount 3% if the debt is paid within one month A credit customer purchased 20 units and paid the debt within 15 days. What was the total of the invoice? A $3298 B $3400 C $3880 D $4000
Mark scheme: B
Q8 · Jane purchased goods and paid by credit transfer
8 Jane purchased goods and paid by credit transfer. How should this be recorded in Jane’s accounting records? account to account to be debited be credited A bank purchases B purchases bank C purchases trade payable D trade payable purchases
Mark scheme: B
Q9 · What is shown in a trial balance?
9 What is shown in a trial balance? A capital and profit on a particular date B financial transactions for a particular period C ledger balances on a particular date D receipts and payments for a particular period
Mark scheme: C
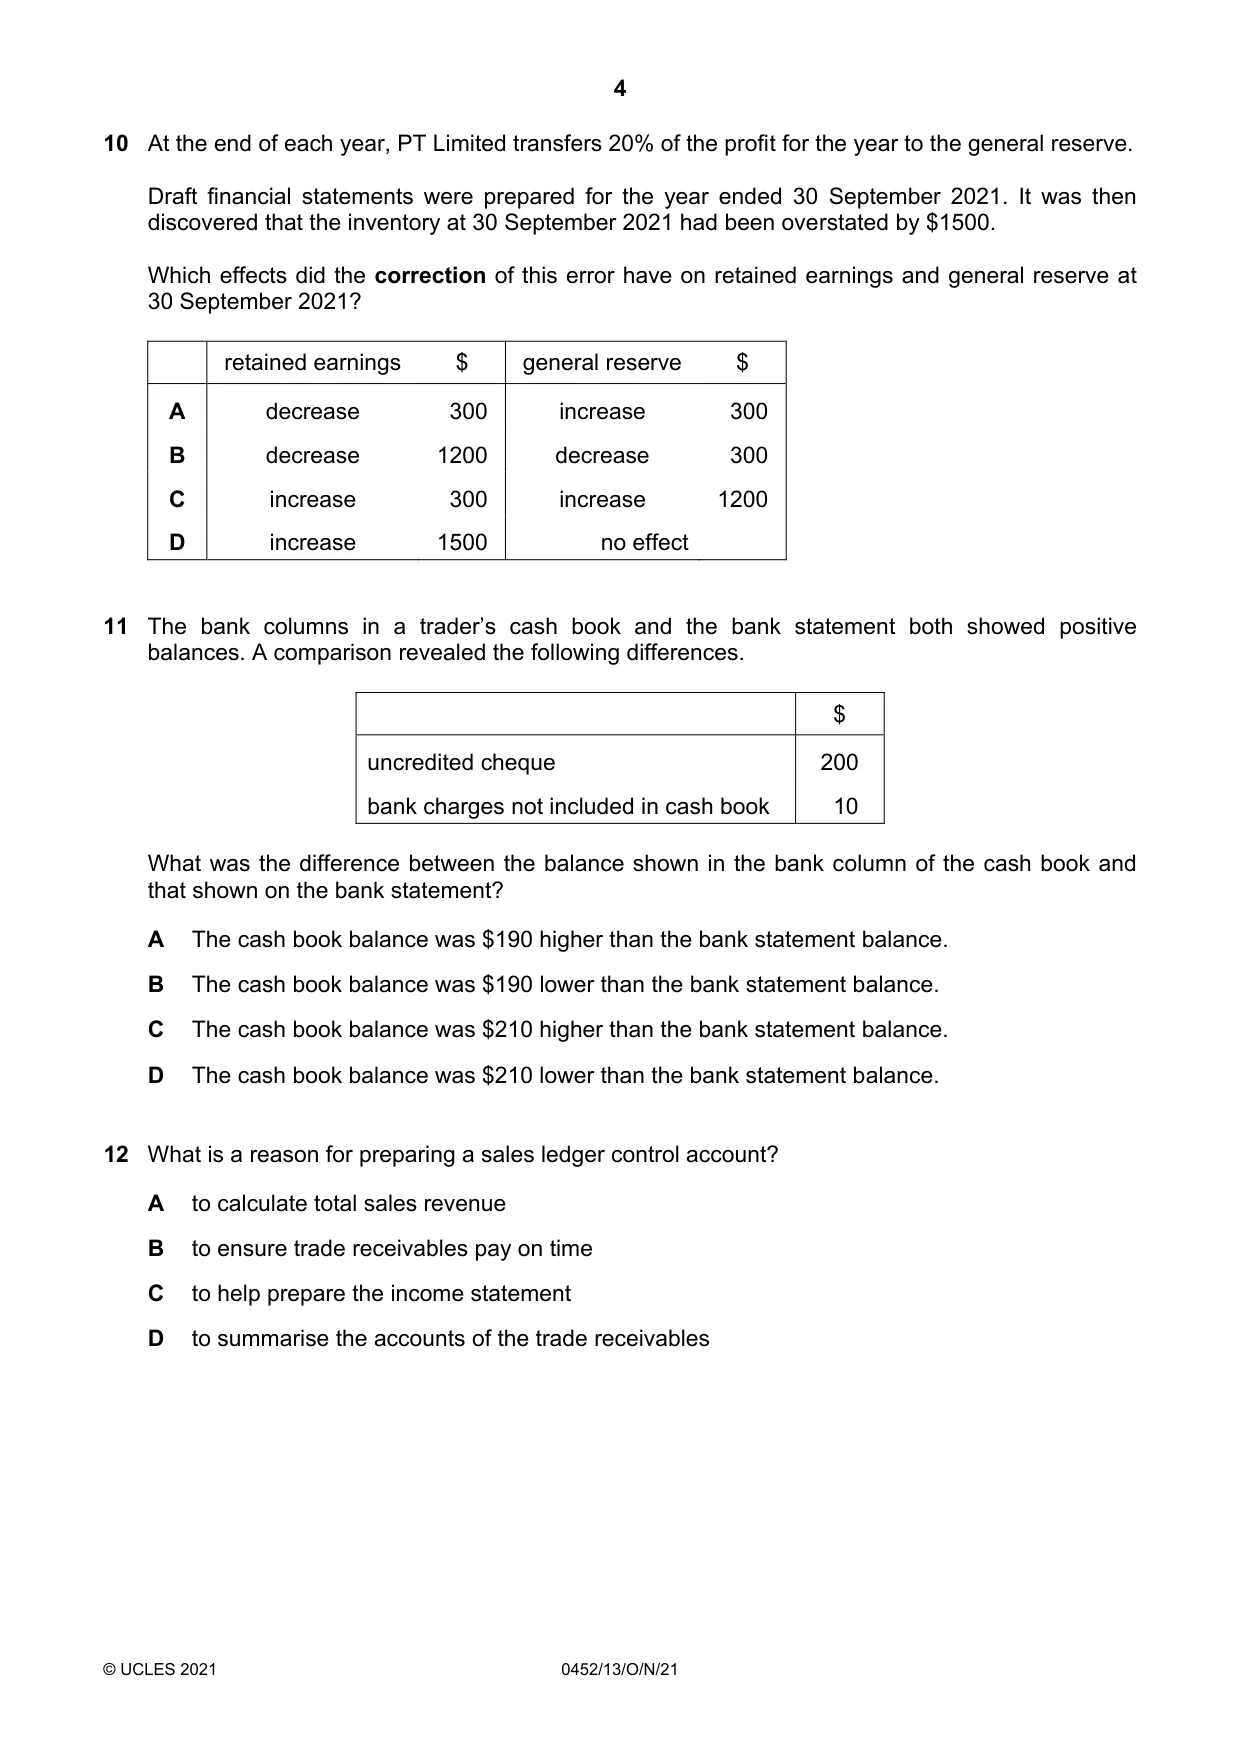
Q10 · At the end of each year, PT Limited transfers 20% of the profit for the year to the…
10 At the end of each year, PT Limited transfers 20% of the profit for the year to the general reserve. Draft financial statements were prepared for the year ended 30 September 2021. It was then discovered that the inventory at 30 September 2021 had been overstated by $1500. Which effects did the correction of this error have on retained earnings and general reserve at 30 September 2021? retained earnings $ general reserve $ A decrease 300 increase 300 B decrease 1200 decrease 300 C increase 300 increase 1200 D increase 1500 no effect
Mark scheme: B
Q11 · The bank columns in a trader’s cash book and the bank statement both showed positive…
11 The bank columns in a trader’s cash book and the bank statement both showed positive balances. A comparison revealed the following differences. $ uncredited cheque 200 bank charges not included in cash book 10 What was the difference between the balance shown in the bank column of the cash book and that shown on the bank statement? A The cash book balance was $190 higher than the bank statement balance. B The cash book balance was $190 lower than the bank statement balance. C The cash book balance was $210 higher than the bank statement balance. D The cash book balance was $210 lower than the bank statement balance.
Mark scheme: C
Q12 · What is a reason for preparing a sales ledger control account?
12 What is a reason for preparing a sales ledger control account? A to calculate total sales revenue B to ensure trade receivables pay on time C to help prepare the income statement D to summarise the accounts of the trade receivables
Mark scheme: D
Q13 · Two companies each purchased a motor vehicle for $10 000 at the beginning of year 1
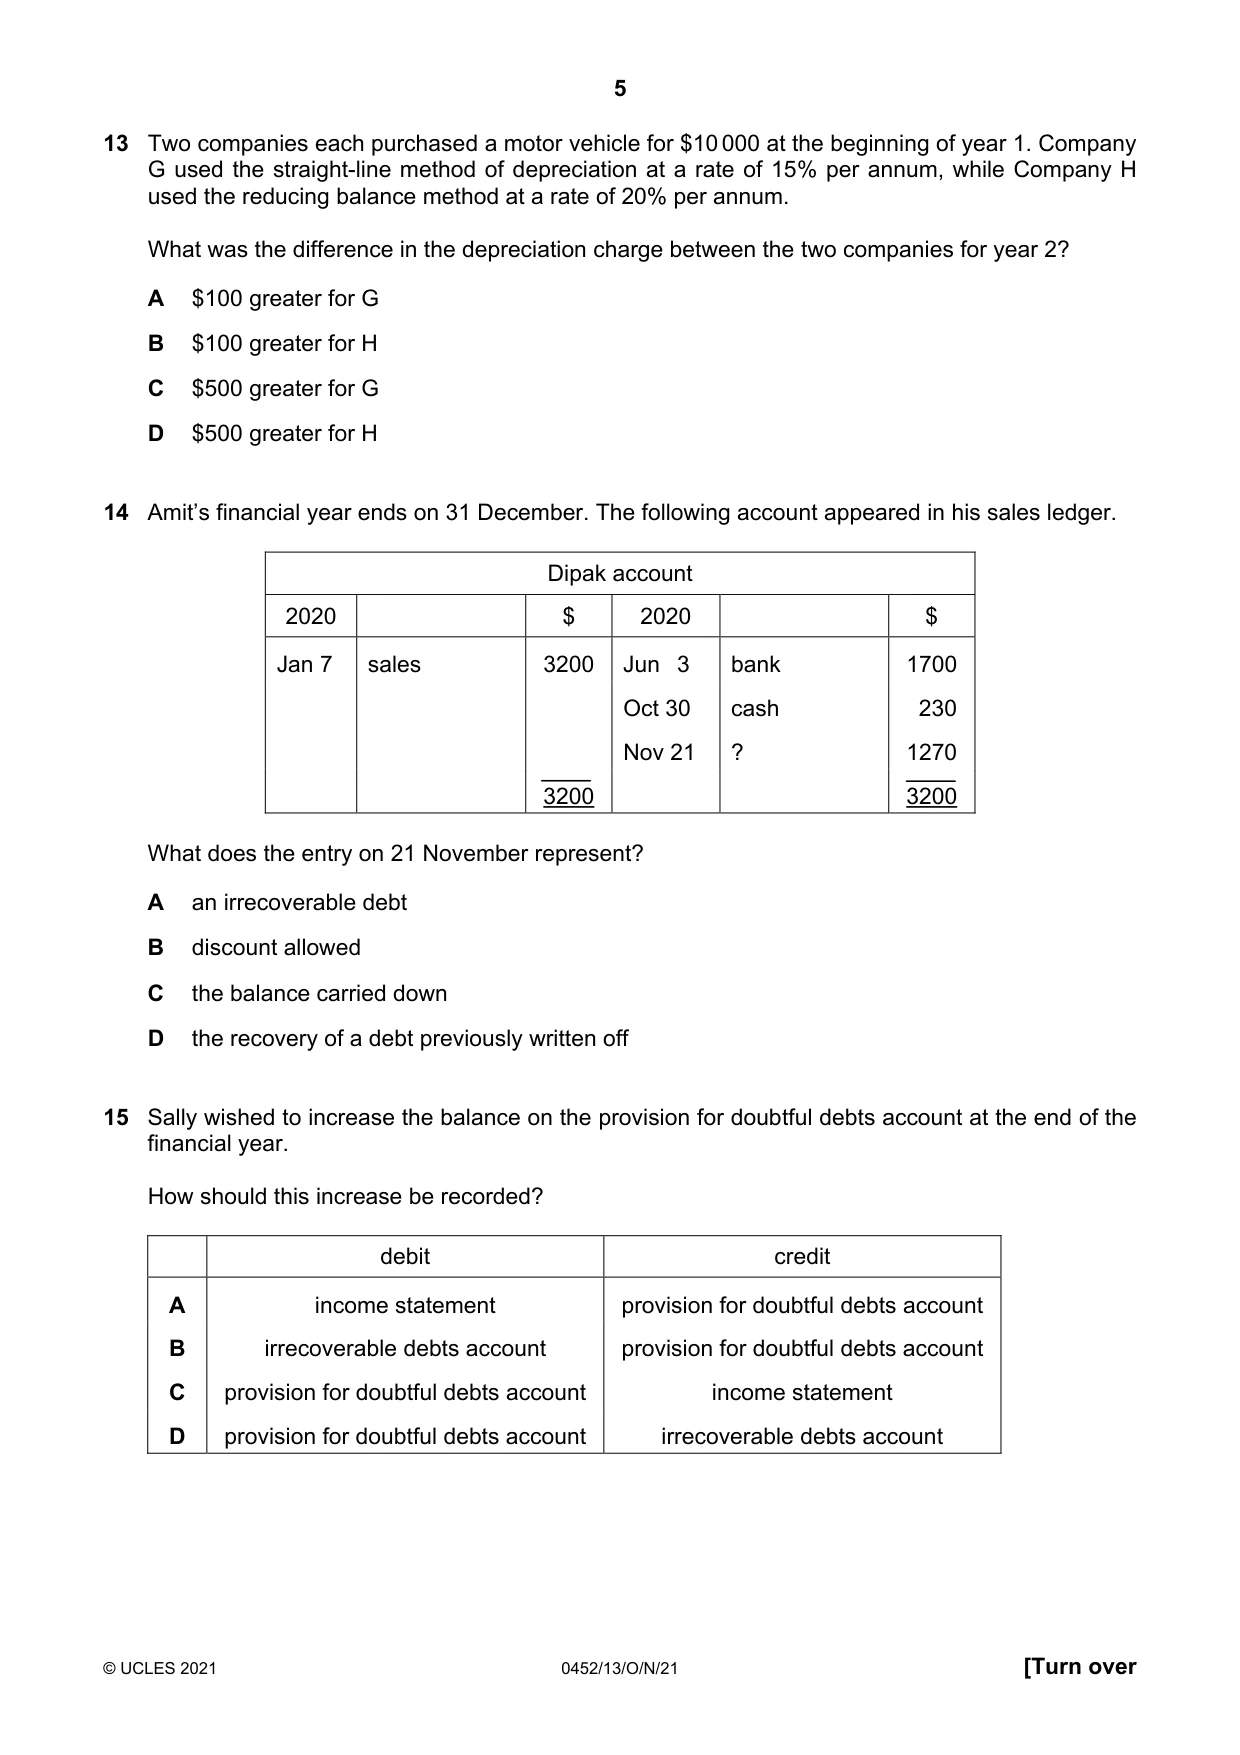
13 Two companies each purchased a motor vehicle for $10 000 at the beginning of year 1. Company G used the straight-line method of depreciation at a rate of 15% per annum, while Company H used the reducing balance method at a rate of 20% per annum. What was the difference in the depreciation charge between the two companies for year 2? A $100 greater for G B $100 greater for H C $500 greater for G D $500 greater for H
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q14 · Amit’s financial year ends on 31 December
14 Amit’s financial year ends on 31 December. The following account appeared in his sales ledger. Dipak account 2020 $ 2020 $ Jan 7 sales 3200 Jun 3 bank 1700 Oct 30 cash 230 Nov 21 ? 1270 3200 3200 What does the entry on 21 November represent? A an irrecoverable debt B discount allowed C the balance carried down D the recovery of a debt previously written off
Mark scheme: A
Q15 · Sally wished to increase the balance on the provision for doubtful debts account at the…
15 Sally wished to increase the balance on the provision for doubtful debts account at the end of the financial year. How should this increase be recorded? debit credit A income statement provision for doubtful debts account B irrecoverable debts account provision for doubtful debts account C provision for doubtful debts account income statement D provision for doubtful debts account irrecoverable debts account
Mark scheme: A
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q16 · The following errors were found after a statement of financial position had been prepared
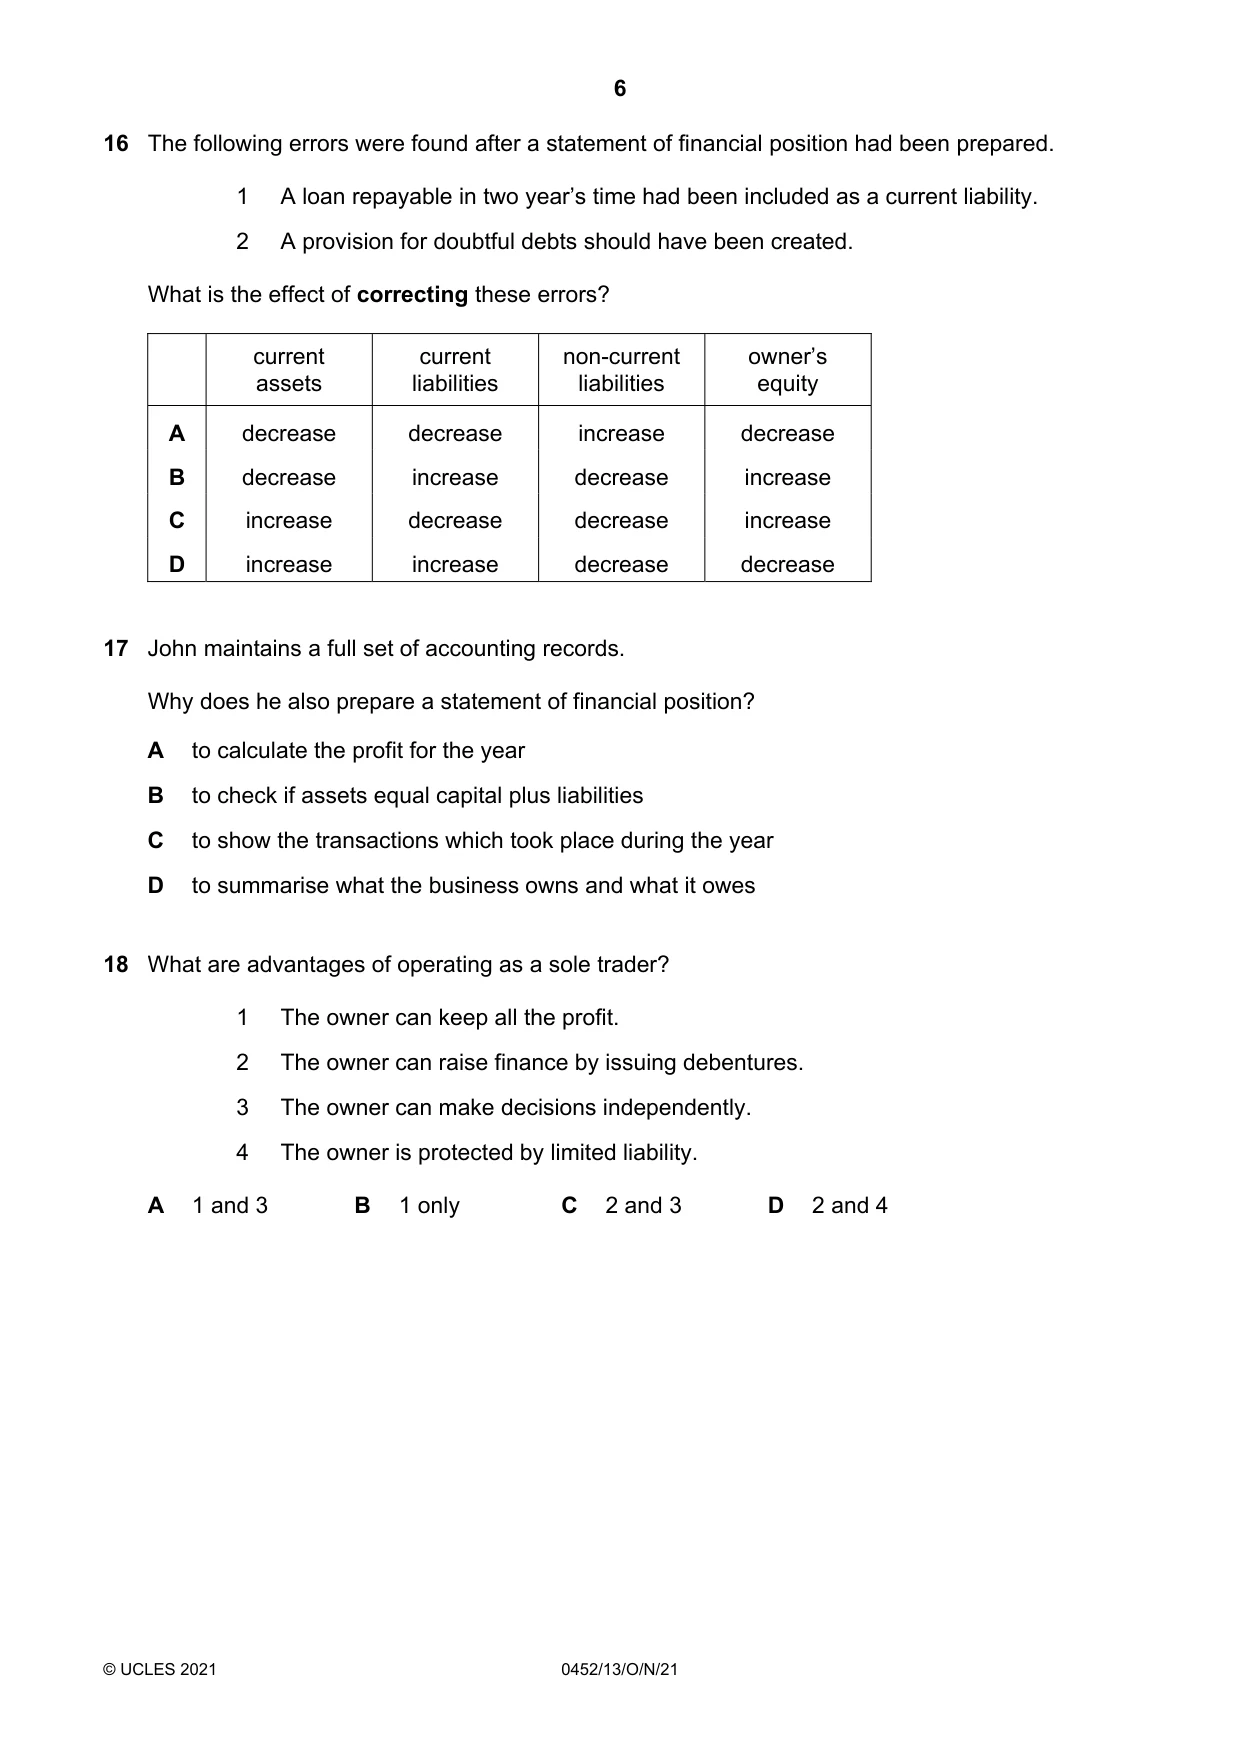
16 The following errors were found after a statement of financial position had been prepared. 1 A loan repayable in two year’s time had been included as a current liability. 2 A provision for doubtful debts should have been created. What is the effect of correcting these errors? current current non-current owner’s assets liabilities liabilities equity A decrease decrease increase decrease B decrease increase decrease increase C increase decrease decrease increase D increase increase decrease decrease
Mark scheme: A
Q17 · John maintains a full set of accounting records
17 John maintains a full set of accounting records. Why does he also prepare a statement of financial position? A to calculate the profit for the year B to check if assets equal capital plus liabilities C to show the transactions which took place during the year D to summarise what the business owns and what it owes
Mark scheme: D
Q18 · What are advantages of operating as a sole trader?
18 What are advantages of operating as a sole trader? 1 The owner can keep all the profit. 2 The owner can raise finance by issuing debentures. 3 The owner can make decisions independently. 4 The owner is protected by limited liability. A 1 and 3 B 1 only C 2 and 3 D 2 and 4
Mark scheme: A
Q19 · Anwar is a sole trader making annual profits of $24 000
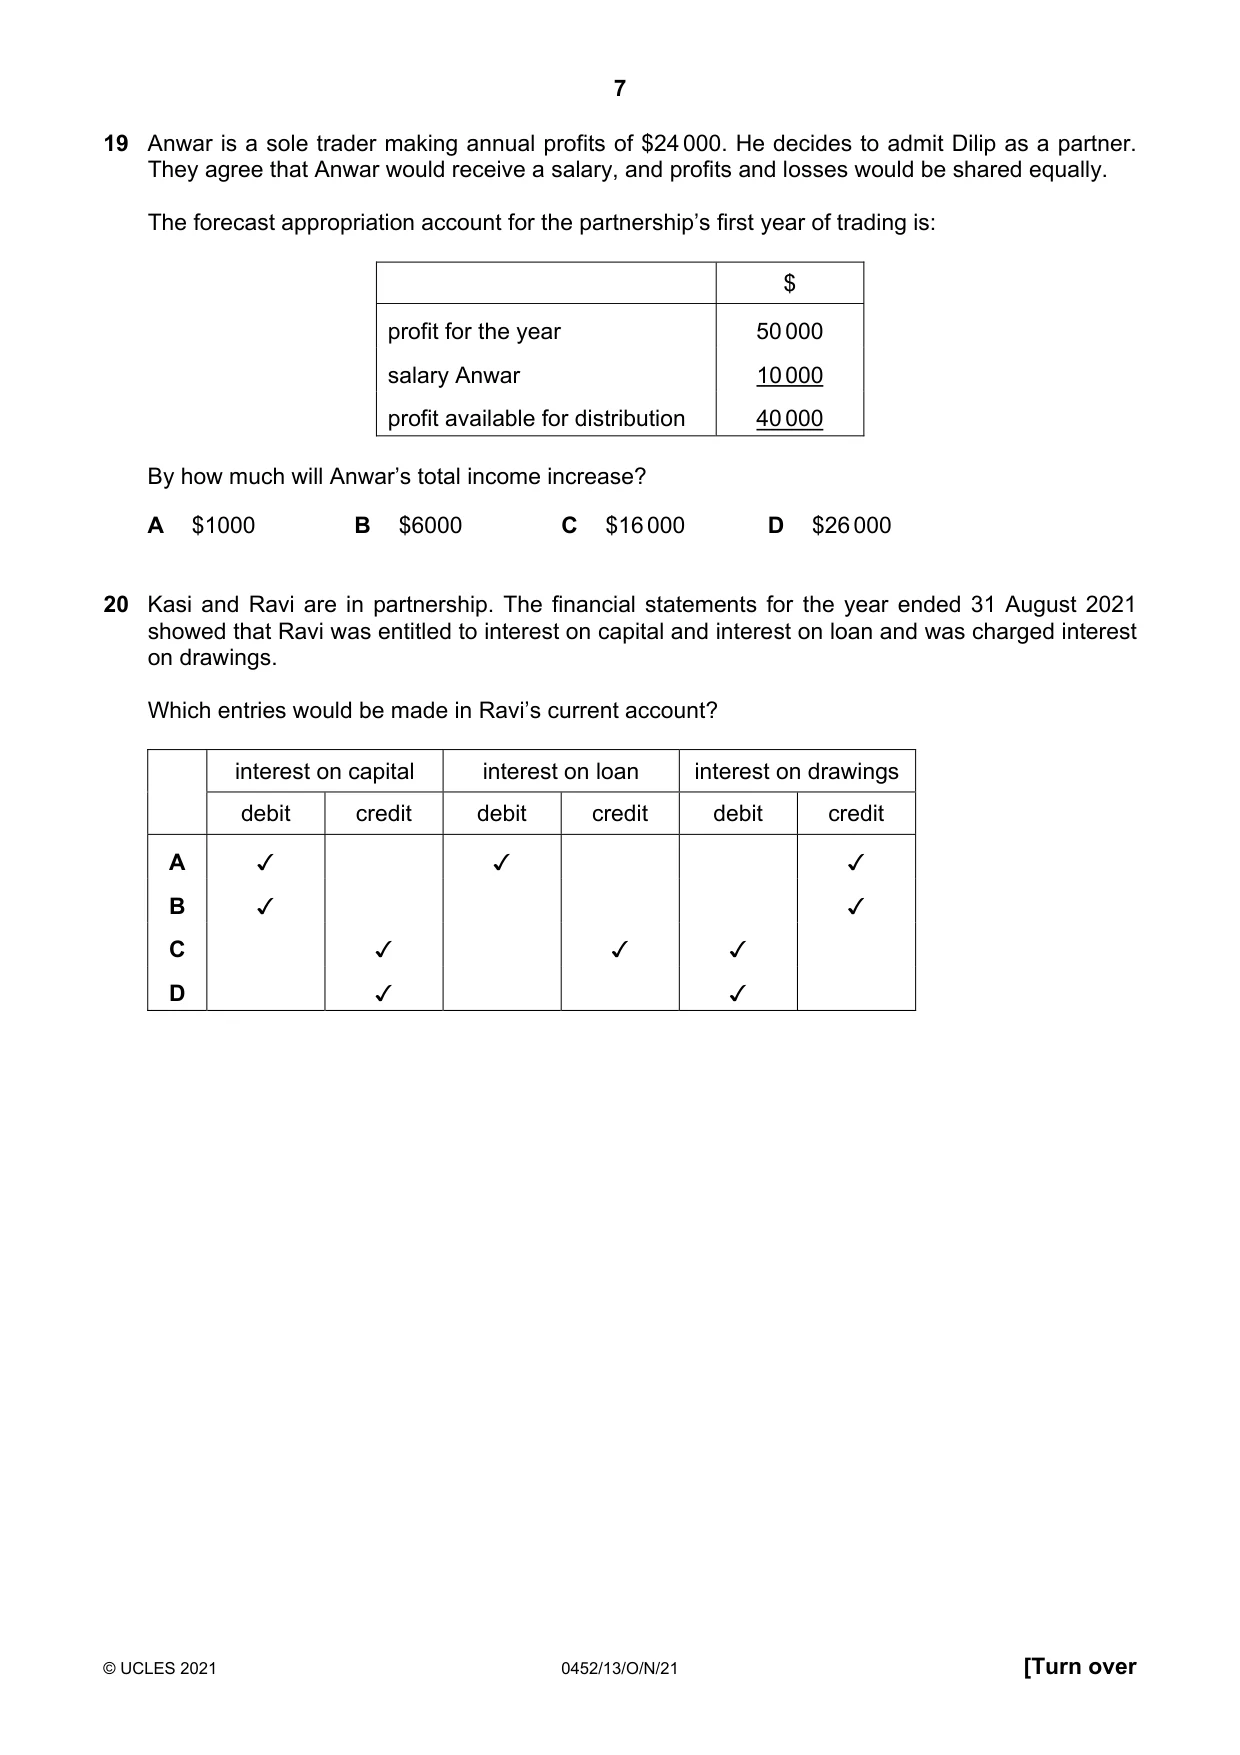
19 Anwar is a sole trader making annual profits of $24 000. He decides to admit Dilip as a partner. They agree that Anwar would receive a salary, and profits and losses would be shared equally. The forecast appropriation account for the partnership’s first year of trading is: $ profit for the year 50 000 salary Anwar 10 000 profit available for distribution 40 000 By how much will Anwar’s total income increase? A $1000 B $6000 C $16 000 D $26 000
Mark scheme: B
Q20 · Kasi and Ravi are in partnership
20 Kasi and Ravi are in partnership. The financial statements for the year ended 31 August 2021 showed that Ravi was entitled to interest on capital and interest on loan and was charged interest on drawings. Which entries would be made in Ravi’s current account? interest on capital interest on loan interest on drawings debit credit debit credit debit credit A v v v B v v Cc v v v D v v
Mark scheme: C
Q21 · BCD Limited provided the following information
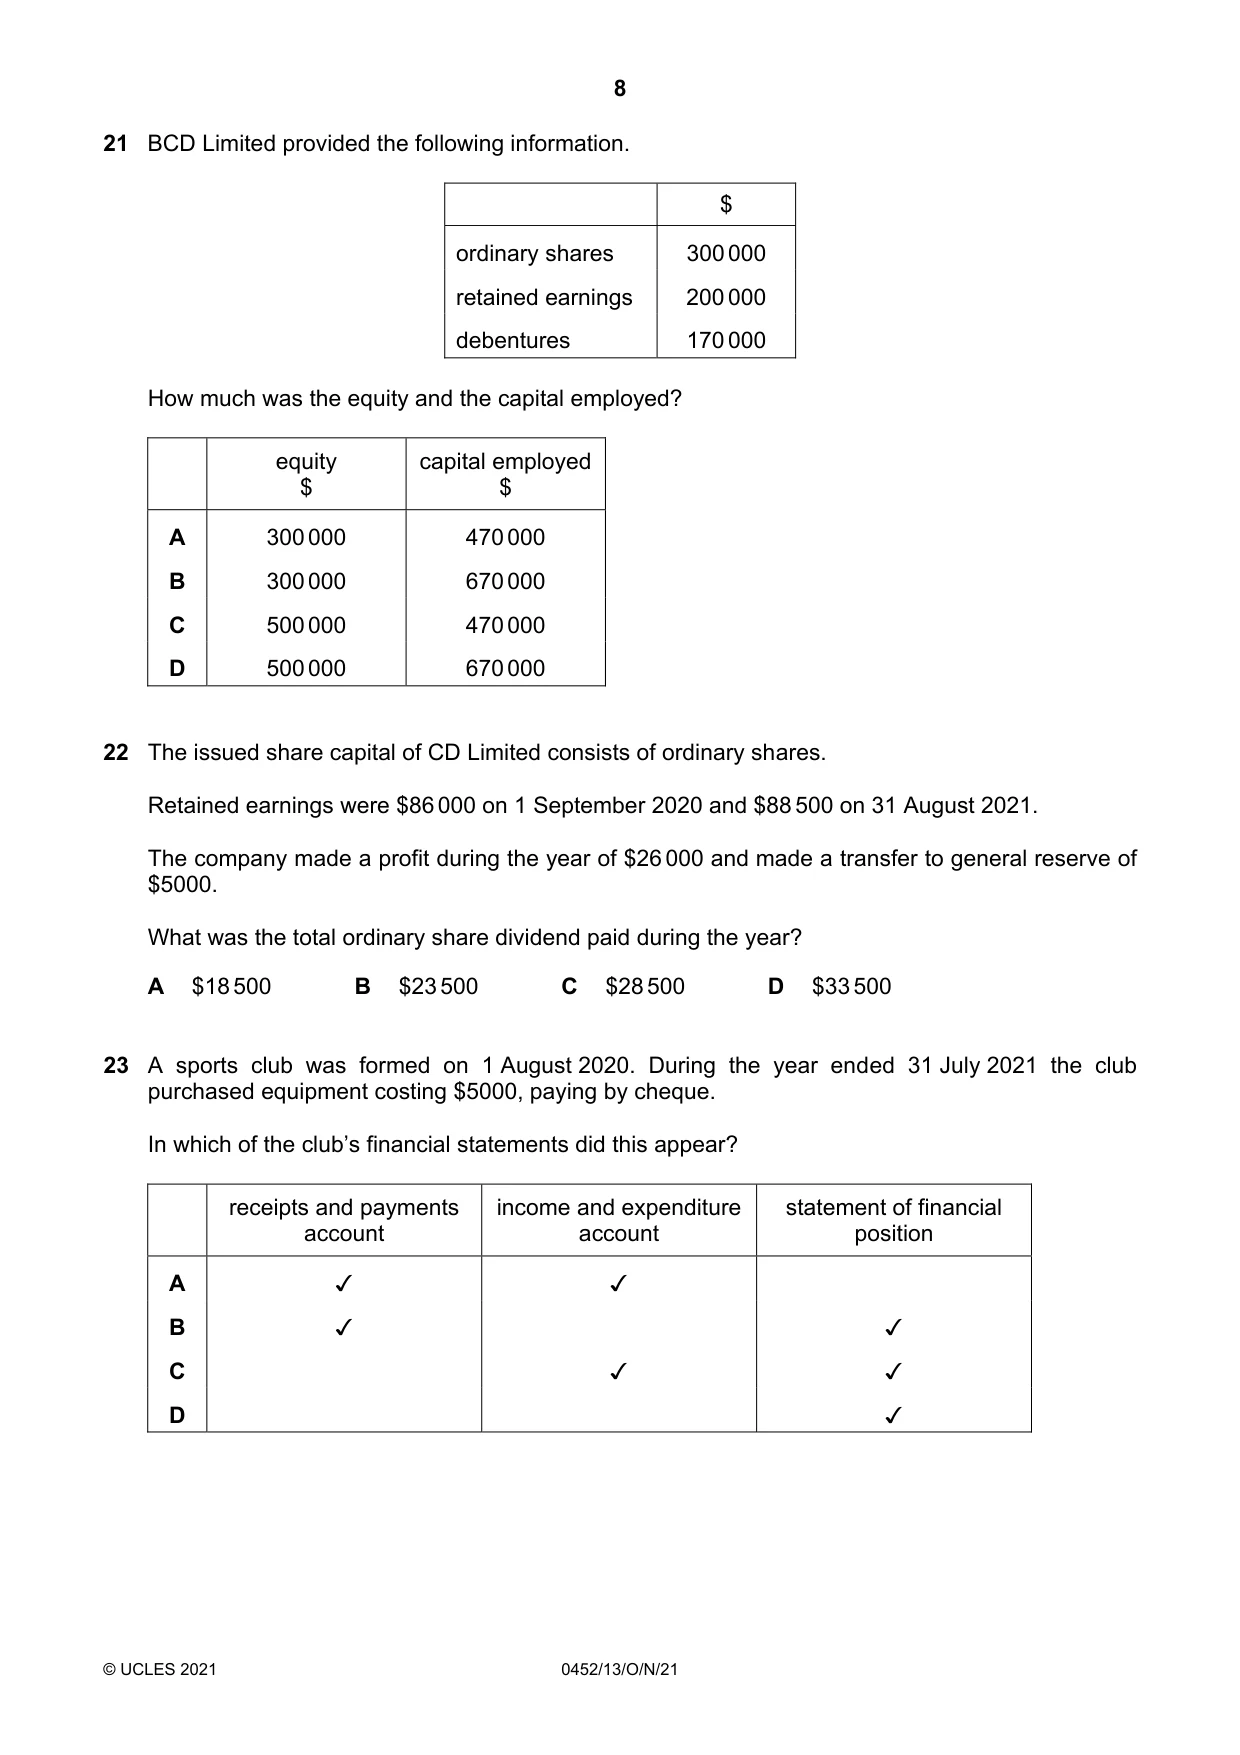
21 BCD Limited provided the following information. $ ordinary shares 300 000 retained earnings 200 000 debentures 170 000 How much was the equity and the capital employed? equity capital employed $ $ A 300 000 470 000 B 300 000 670 000 C 500 000 470 000 D 500 000 670 000
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
Q22 · The issued share capital of CD Limited consists of ordinary shares
22 The issued share capital of CD Limited consists of ordinary shares. Retained earnings were $86 000 on 1 September 2020 and $88 500 on 31 August 2021. The company made a profit during the year of $26 000 and made a transfer to general reserve of $5000. What was the total ordinary share dividend paid during the year? A $18 500 B $23 500 C $28 500 D $33 500
Mark scheme: A
Q23 · A sports club was formed on 1 August 2020
23 A sports club was formed on 1 August 2020. During the year ended 31 July 2021 the club purchased equipment costing $5000, paying by cheque. In which of the club’s financial statements did this appear? receipts and payments | income and expenditure statement of financial account account position A Jv J B Jv J Cc J J D Jv
Mark scheme: B
Q24 · What is not part of the prime cost of a manufacturing business?
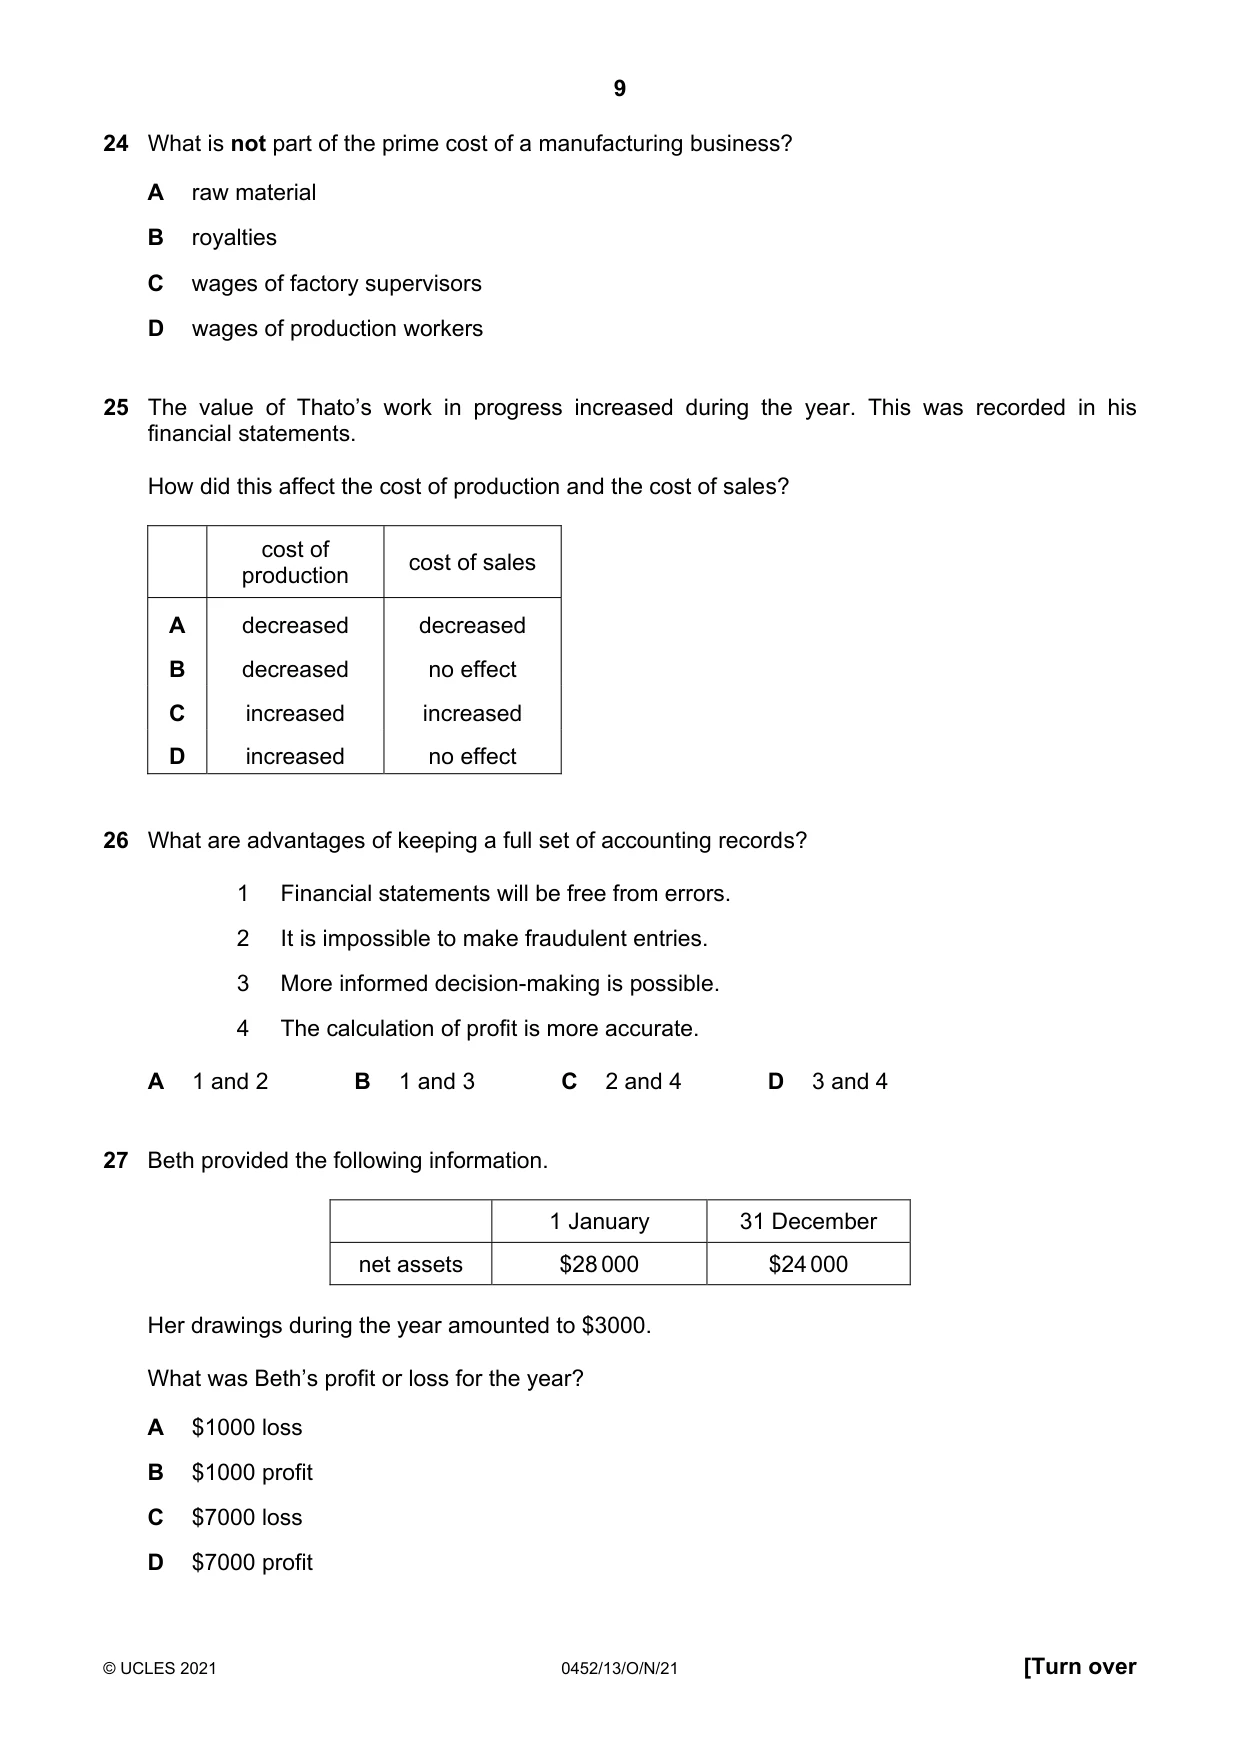
24 What is not part of the prime cost of a manufacturing business? A raw material B royalties C wages of factory supervisors D wages of production workers
Mark scheme: C
Q25 · The value of Thato’s work in progress increased during the year
25 The value of Thato’s work in progress increased during the year. This was recorded in his financial statements. How did this affect the cost of production and the cost of sales? cost of cost of sales production A decreased decreased B decreased no effect C increased increased D increased no effect
Mark scheme: A
Q26 · What are advantages of keeping a full set of accounting records?
26 What are advantages of keeping a full set of accounting records? 1 Financial statements will be free from errors. 2 It is impossible to make fraudulent entries. 3 More informed decision-making is possible. 4 The calculation of profit is more accurate. A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
Mark scheme: D
Q27 · Beth provided the following information
27 Beth provided the following information. 1 January 31 December net assets $28 000 $24 000 Her drawings during the year amounted to $3000. What was Beth’s profit or loss for the year? A $1000 loss B $1000 profit C $7000 loss D $7000 profit
Mark scheme: A
Q28 · Roshan’s sales for his first year of trading were $55 000
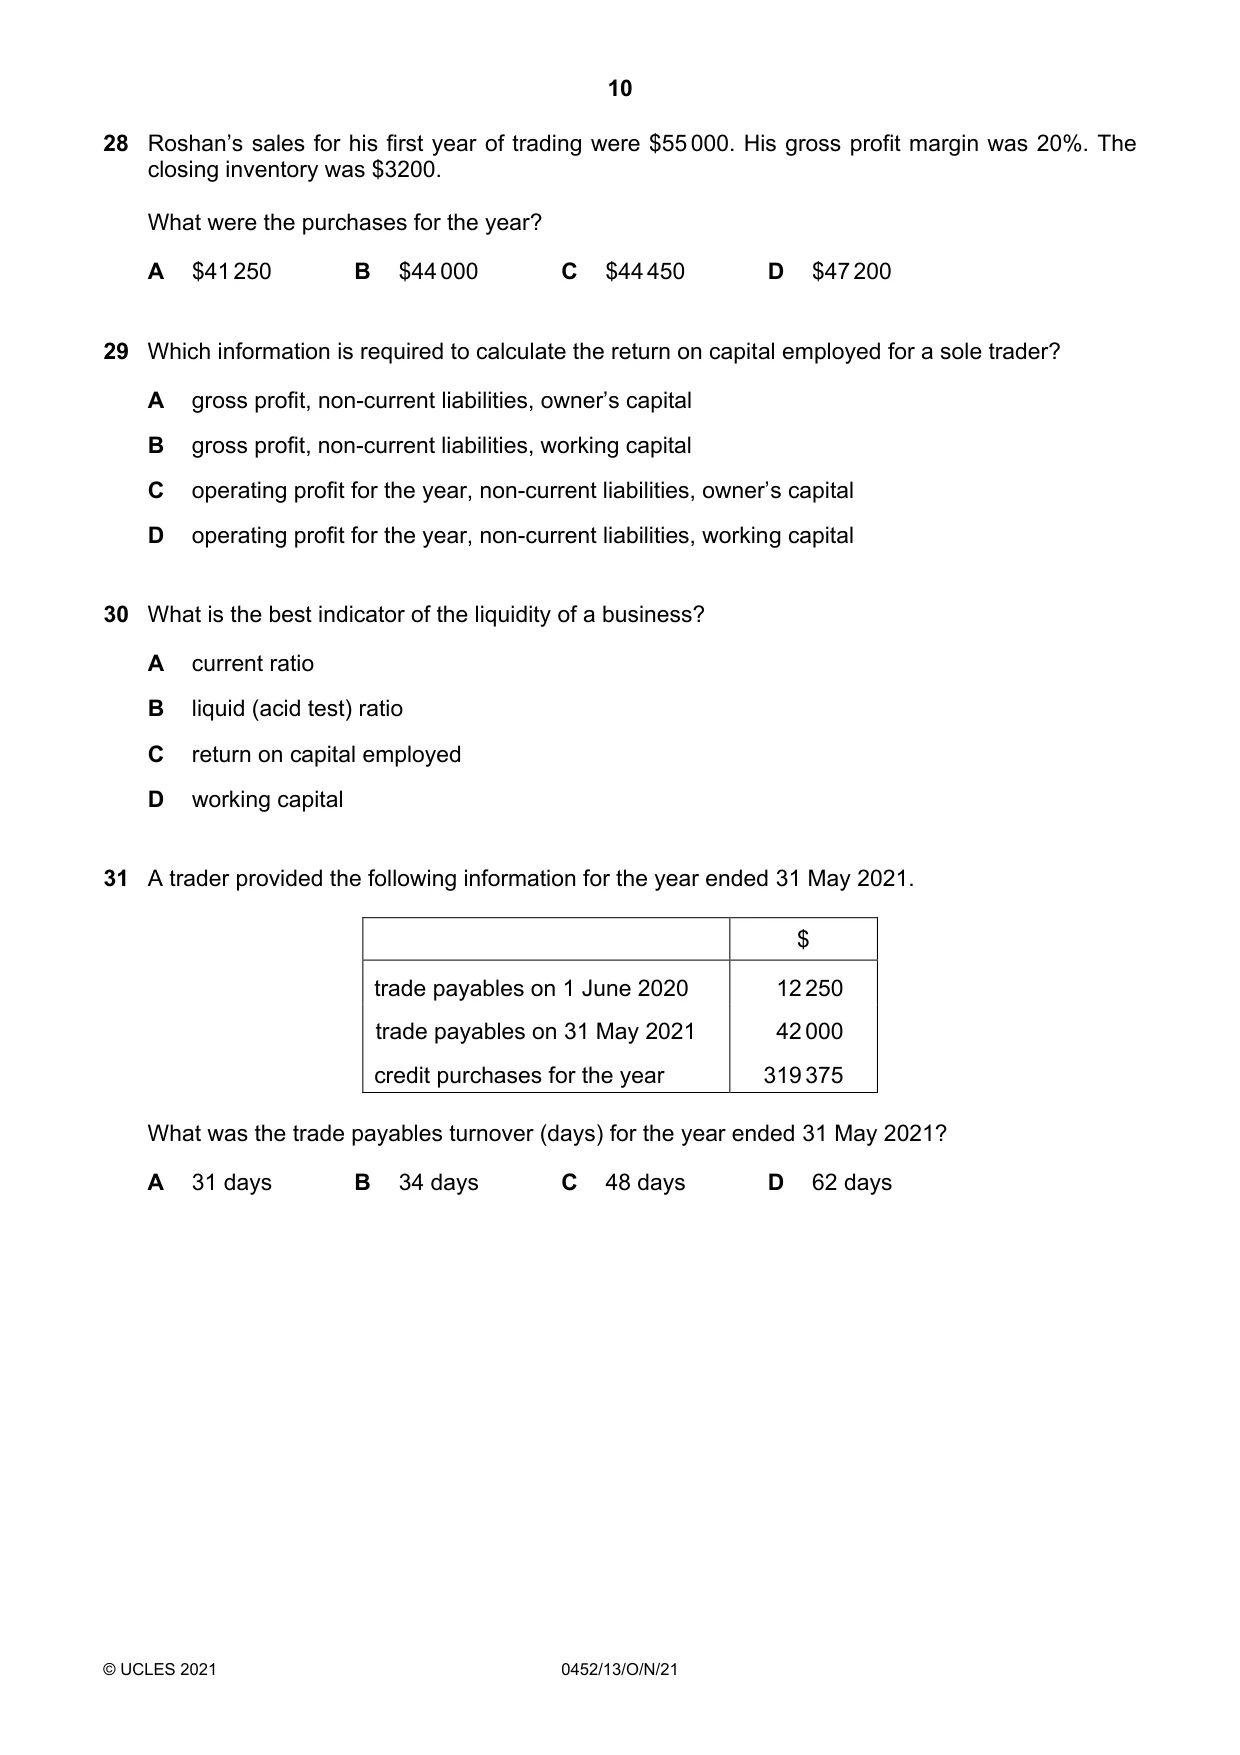
28 Roshan’s sales for his first year of trading were $55 000. His gross profit margin was 20%. The closing inventory was $3200. What were the purchases for the year? A $41 250 B $44 000 C $44 450 D $47 200
Mark scheme: D
Q29 · Which information is required to calculate the return on capital employed for a sole…
29 Which information is required to calculate the return on capital employed for a sole trader? A gross profit, non-current liabilities, owner’s capital B gross profit, non-current liabilities, working capital C operating profit for the year, non-current liabilities, owner’s capital D operating profit for the year, non-current liabilities, working capital
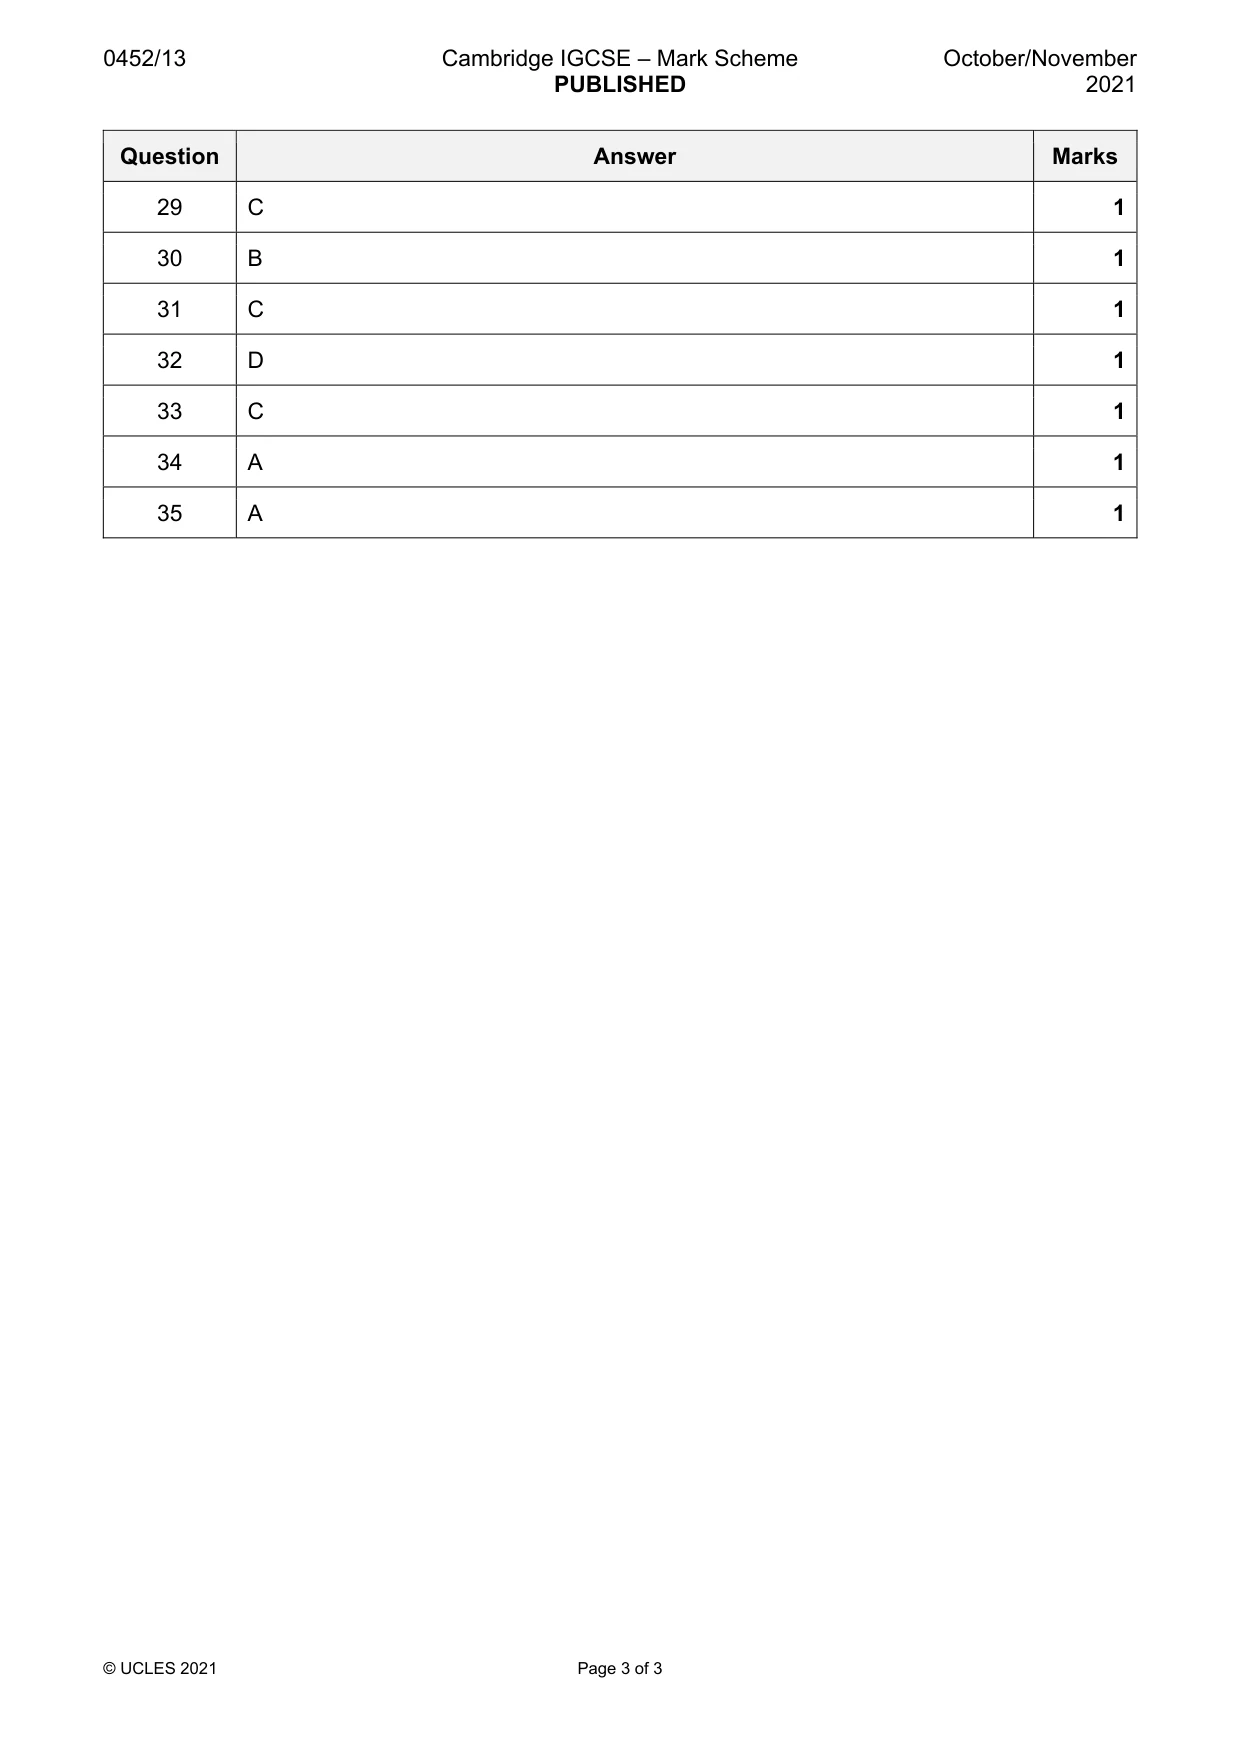
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
Q30 · What is the best indicator of the liquidity of a business?
30 What is the best indicator of the liquidity of a business? A current ratio B liquid (acid test) ratio C return on capital employed D working capital
Mark scheme: B
More questions on Calculation and understanding of accounting ratios
Q31 · A trader provided the following information for the year ended 31 May 2021
31 A trader provided the following information for the year ended 31 May 2021. $ trade payables on 1 June 2020 12 250 trade payables on 31 May 2021 42 000 credit purchases for the year 319 375 What was the trade payables turnover (days) for the year ended 31 May 2021? A 31 days B 34 days C 48 days D 62 days
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
Q32 · A business provided the following information about its gross margin
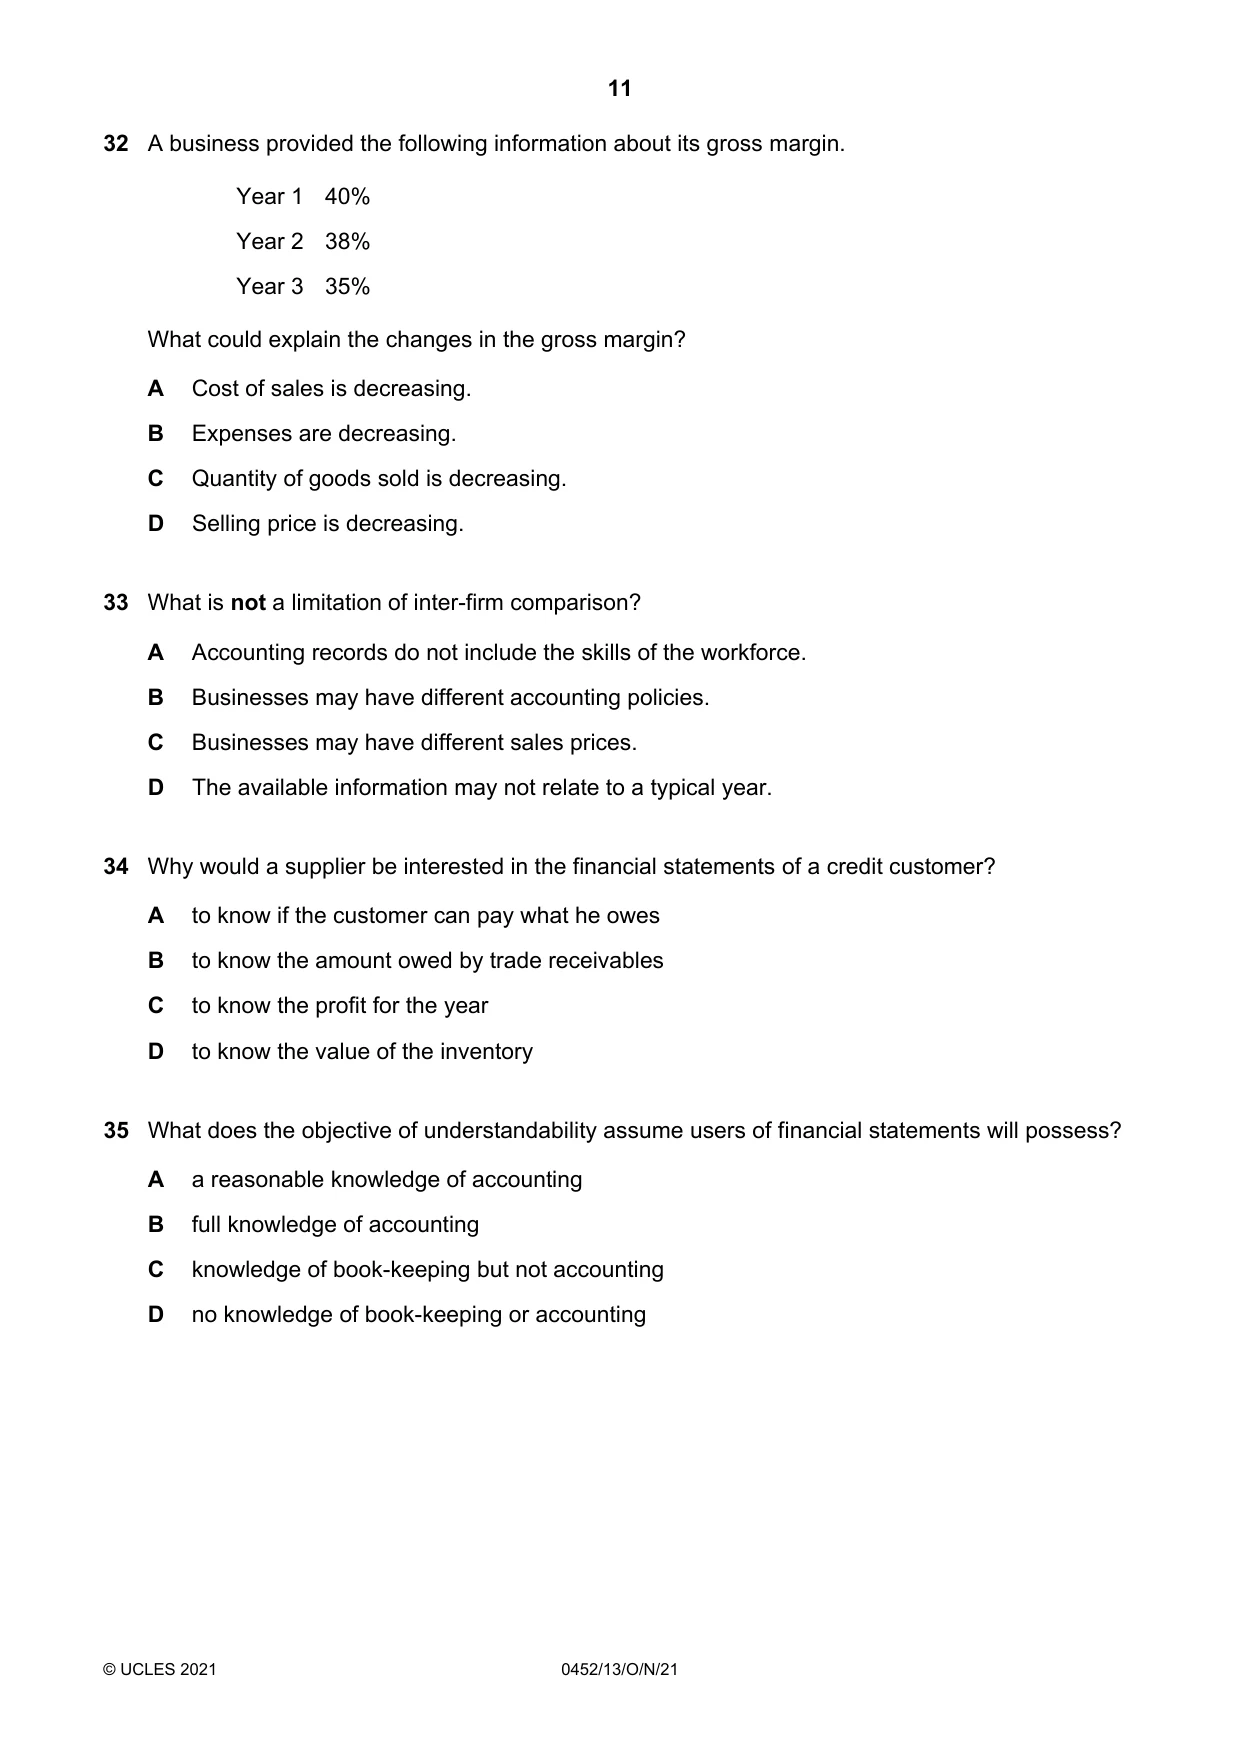
32 A business provided the following information about its gross margin. Year 1 40% Year 2 38% Year 3 35% What could explain the changes in the gross margin? A Cost of sales is decreasing. B Expenses are decreasing. C Quantity of goods sold is decreasing. D Selling price is decreasing.
Mark scheme: D
Q33 · What is not a limitation of inter-firm comparison?
33 What is not a limitation of inter-firm comparison? A Accounting records do not include the skills of the workforce. B Businesses may have different accounting policies. C Businesses may have different sales prices. D The available information may not relate to a typical year.
Mark scheme: C
Q34 · Why would a supplier be interested in the financial statements of a credit customer?
34 Why would a supplier be interested in the financial statements of a credit customer? A to know if the customer can pay what he owes B to know the amount owed by trade receivables C to know the profit for the year D to know the value of the inventory
Mark scheme: A
Q35 · What does the objective of understandability assume users of financial statements will…
35 What does the objective of understandability assume users of financial statements will possess? A a reasonable knowledge of accounting B full knowledge of accounting C knowledge of book-keeping but not accounting D no knowledge of book-keeping or accounting
Mark scheme: A
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
4Business documents3The double entry system of book-keeping3Control accounts2Corrections of errors2Incomplete records2Manufacturing accounts2Partnerships2The purpose of accounting2Accounting concepts1Accounting for depreciation and disposal of non-current assets1Bank reconciliation1Books of prime entry1Clubs and societies1Inter-business comparison1Interested parties1Interpretation of accounting ratios1Irrecoverable debts and allowance for irrecoverable debts1Limited companies1Sole traders1The trial balance1Valuation of inventory1What you needed in this session
Cambridge’s own grade thresholds for 2021 Oct/Nov, Paper 1 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.