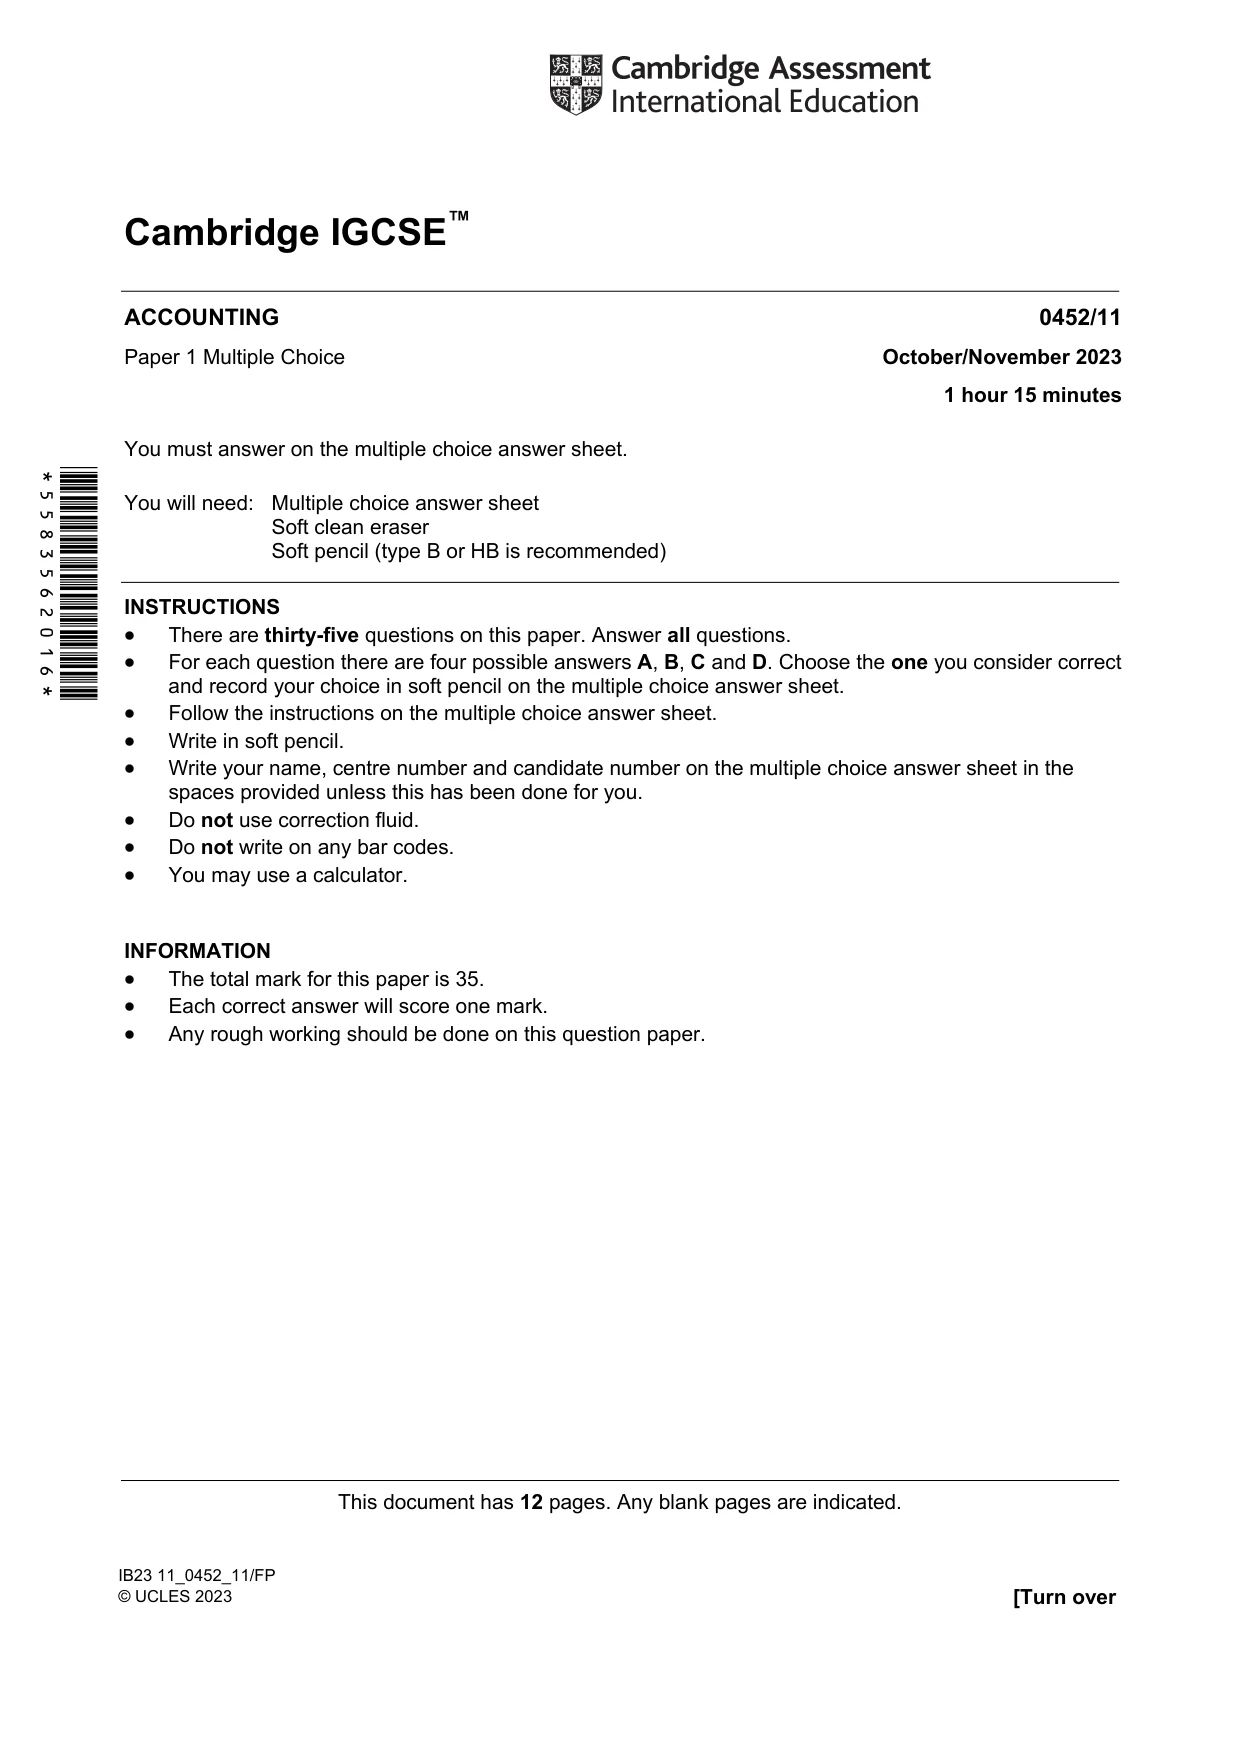
Cambridge IGCSE Accounting 0452 — 2023 Oct/Nov Paper 1 · Variant 1
0452/11/O/N/23 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
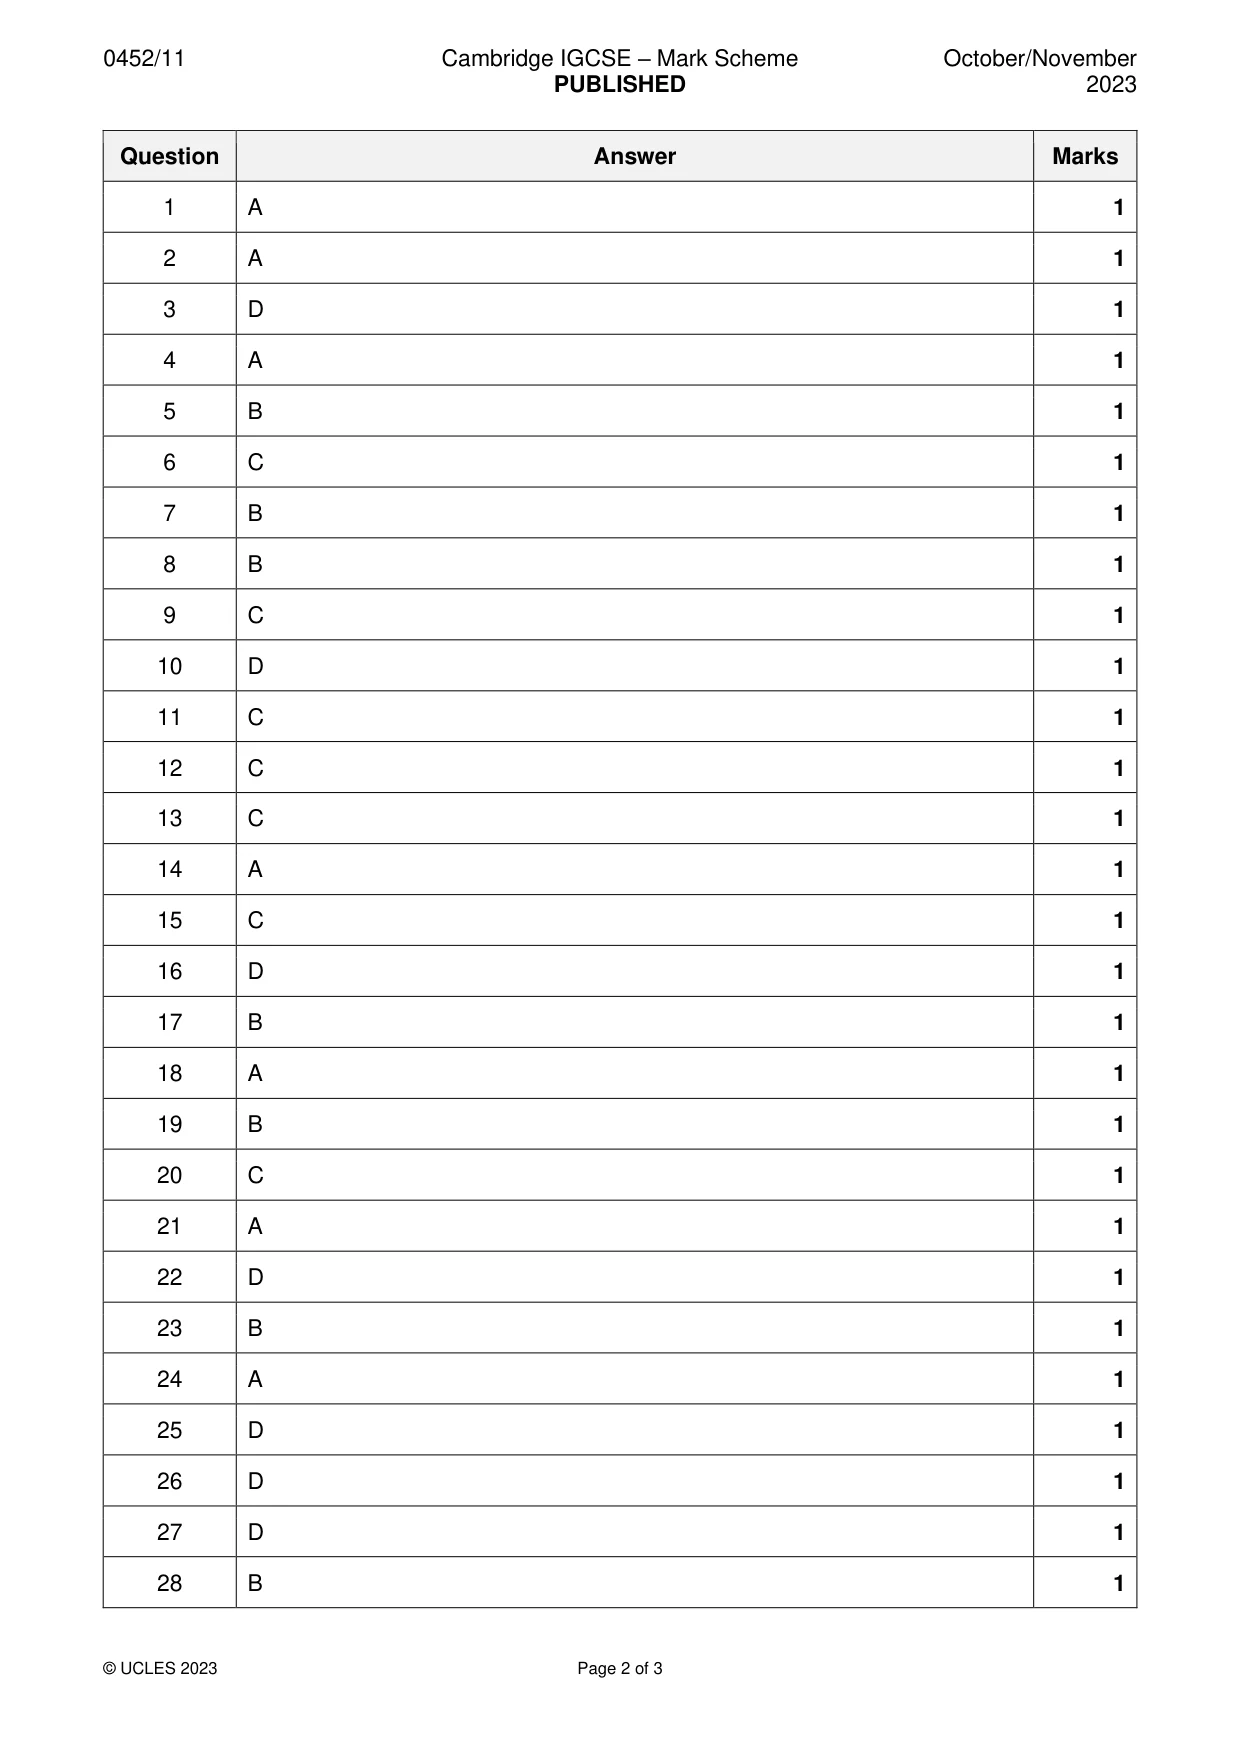
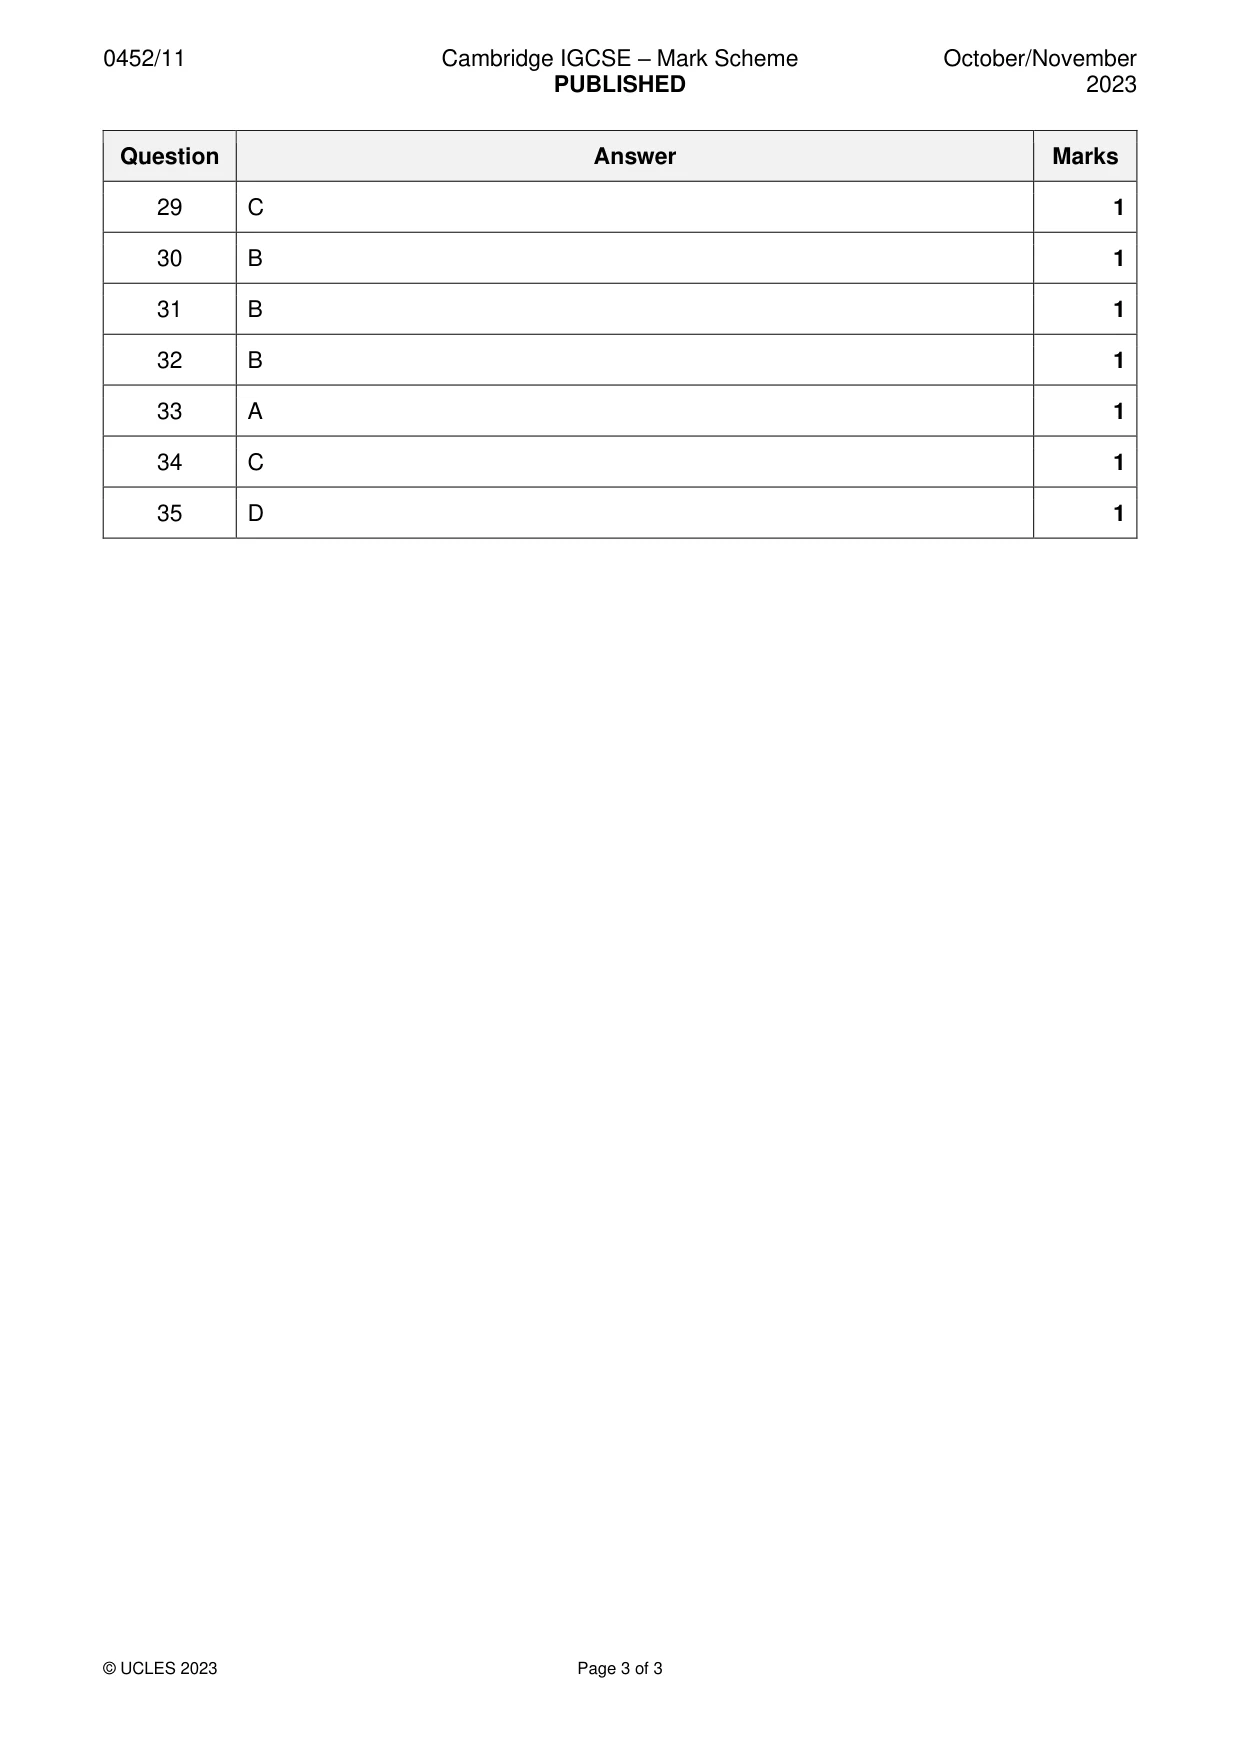
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Which action does not reduce the owner’s capital?
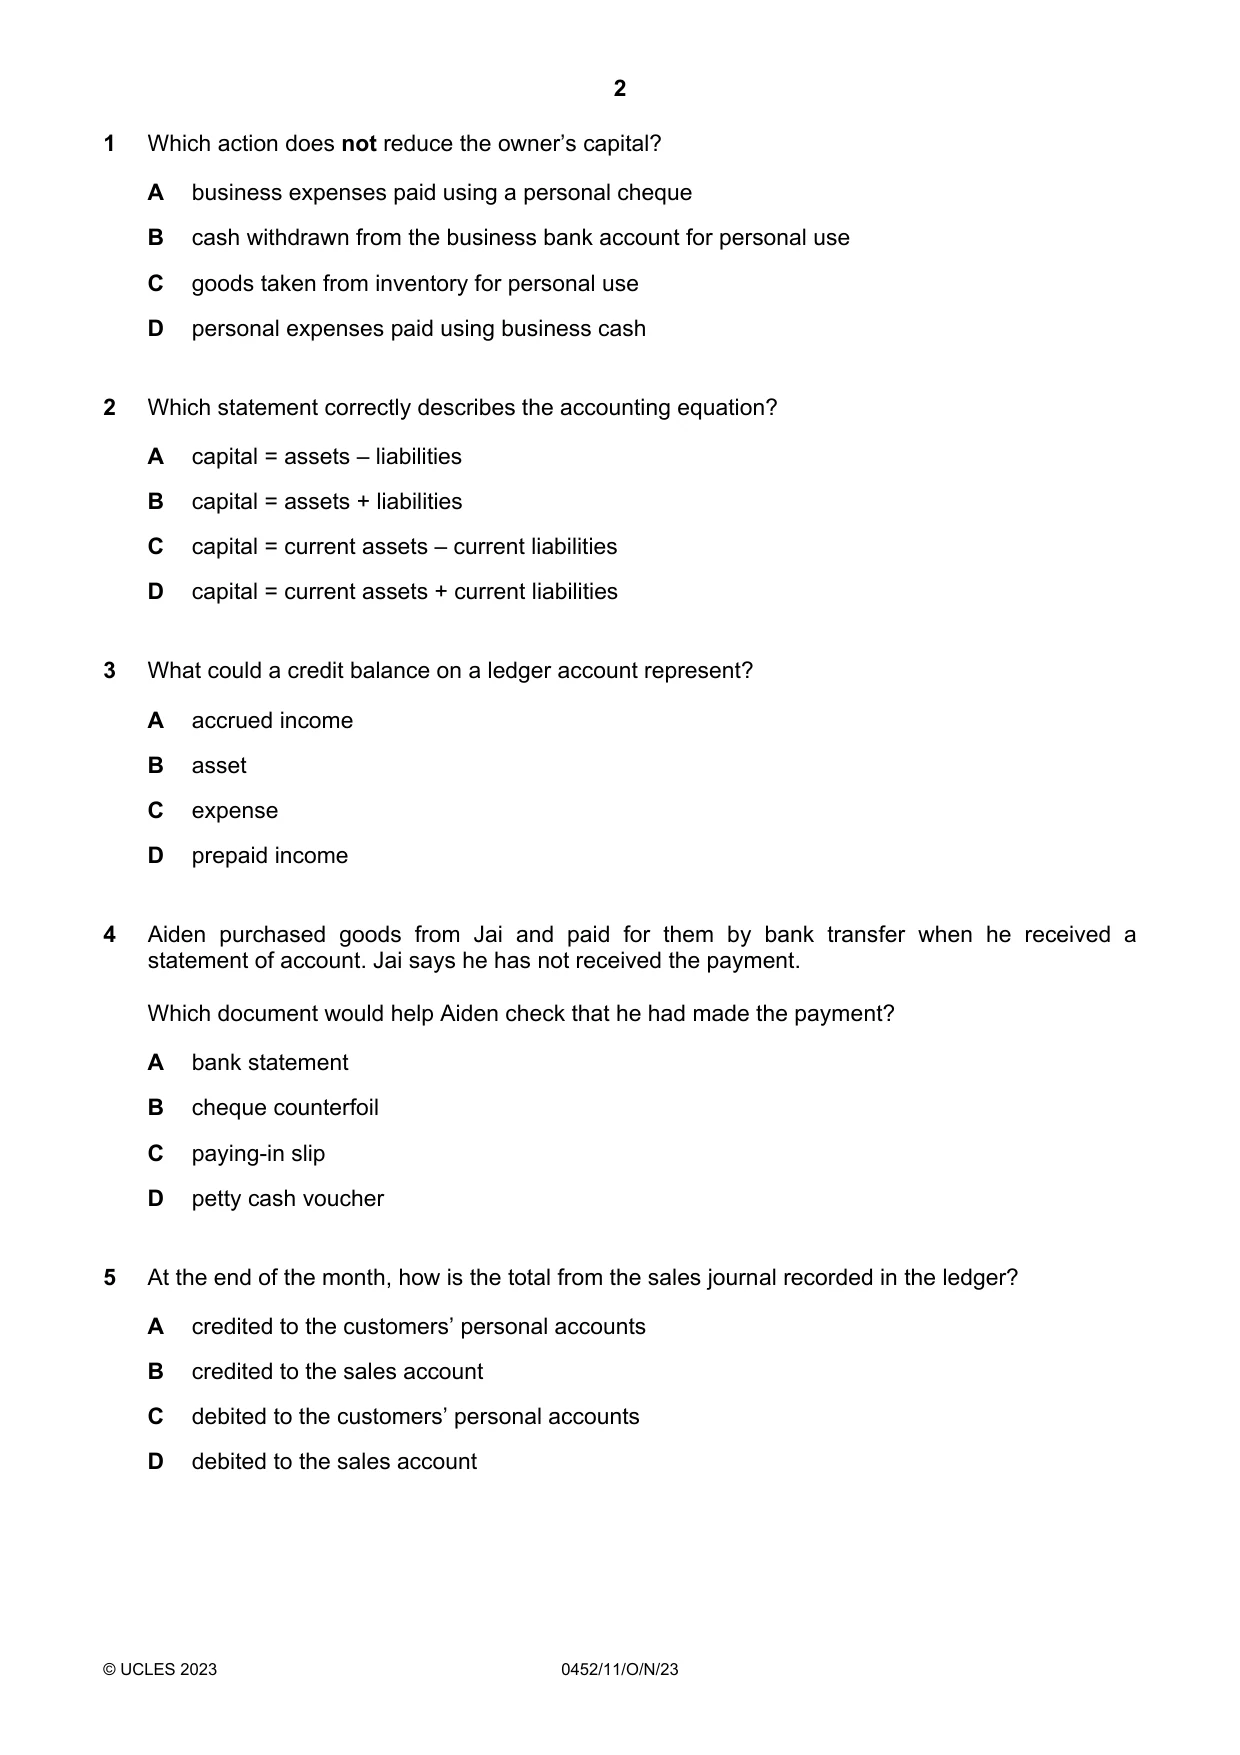
1 Which action does not reduce the owner’s capital? A business expenses paid using a personal cheque B cash withdrawn from the business bank account for personal use C goods taken from inventory for personal use D personal expenses paid using business cash
Mark scheme: A
Q2 · Which statement correctly describes the accounting equation?
2 Which statement correctly describes the accounting equation? A capital = assets – liabilities B capital = assets + liabilities C capital = current assets – current liabilities D capital = current assets + current liabilities
Mark scheme: A
Q3 · What could a credit balance on a ledger account represent?
3 What could a credit balance on a ledger account represent? A accrued income B asset C expense D prepaid income
Mark scheme: D
Q4 · Aiden purchased goods from Jai and paid for them by bank transfer when he received a…
4 Aiden purchased goods from Jai and paid for them by bank transfer when he received a statement of account. Jai says he has not received the payment. Which document would help Aiden check that he had made the payment? A bank statement B cheque counterfoil C paying-in slip D petty cash voucher
Mark scheme: A
Q5 · At the end of the month, how is the total from the sales journal recorded in the ledger?
5 At the end of the month, how is the total from the sales journal recorded in the ledger? A credited to the customers’ personal accounts B credited to the sales account C debited to the customers’ personal accounts D debited to the sales account
Mark scheme: B
Q6 · A customer paid $15 600 to a supplier after receiving a 2 2 1 % cash discount and a trade…
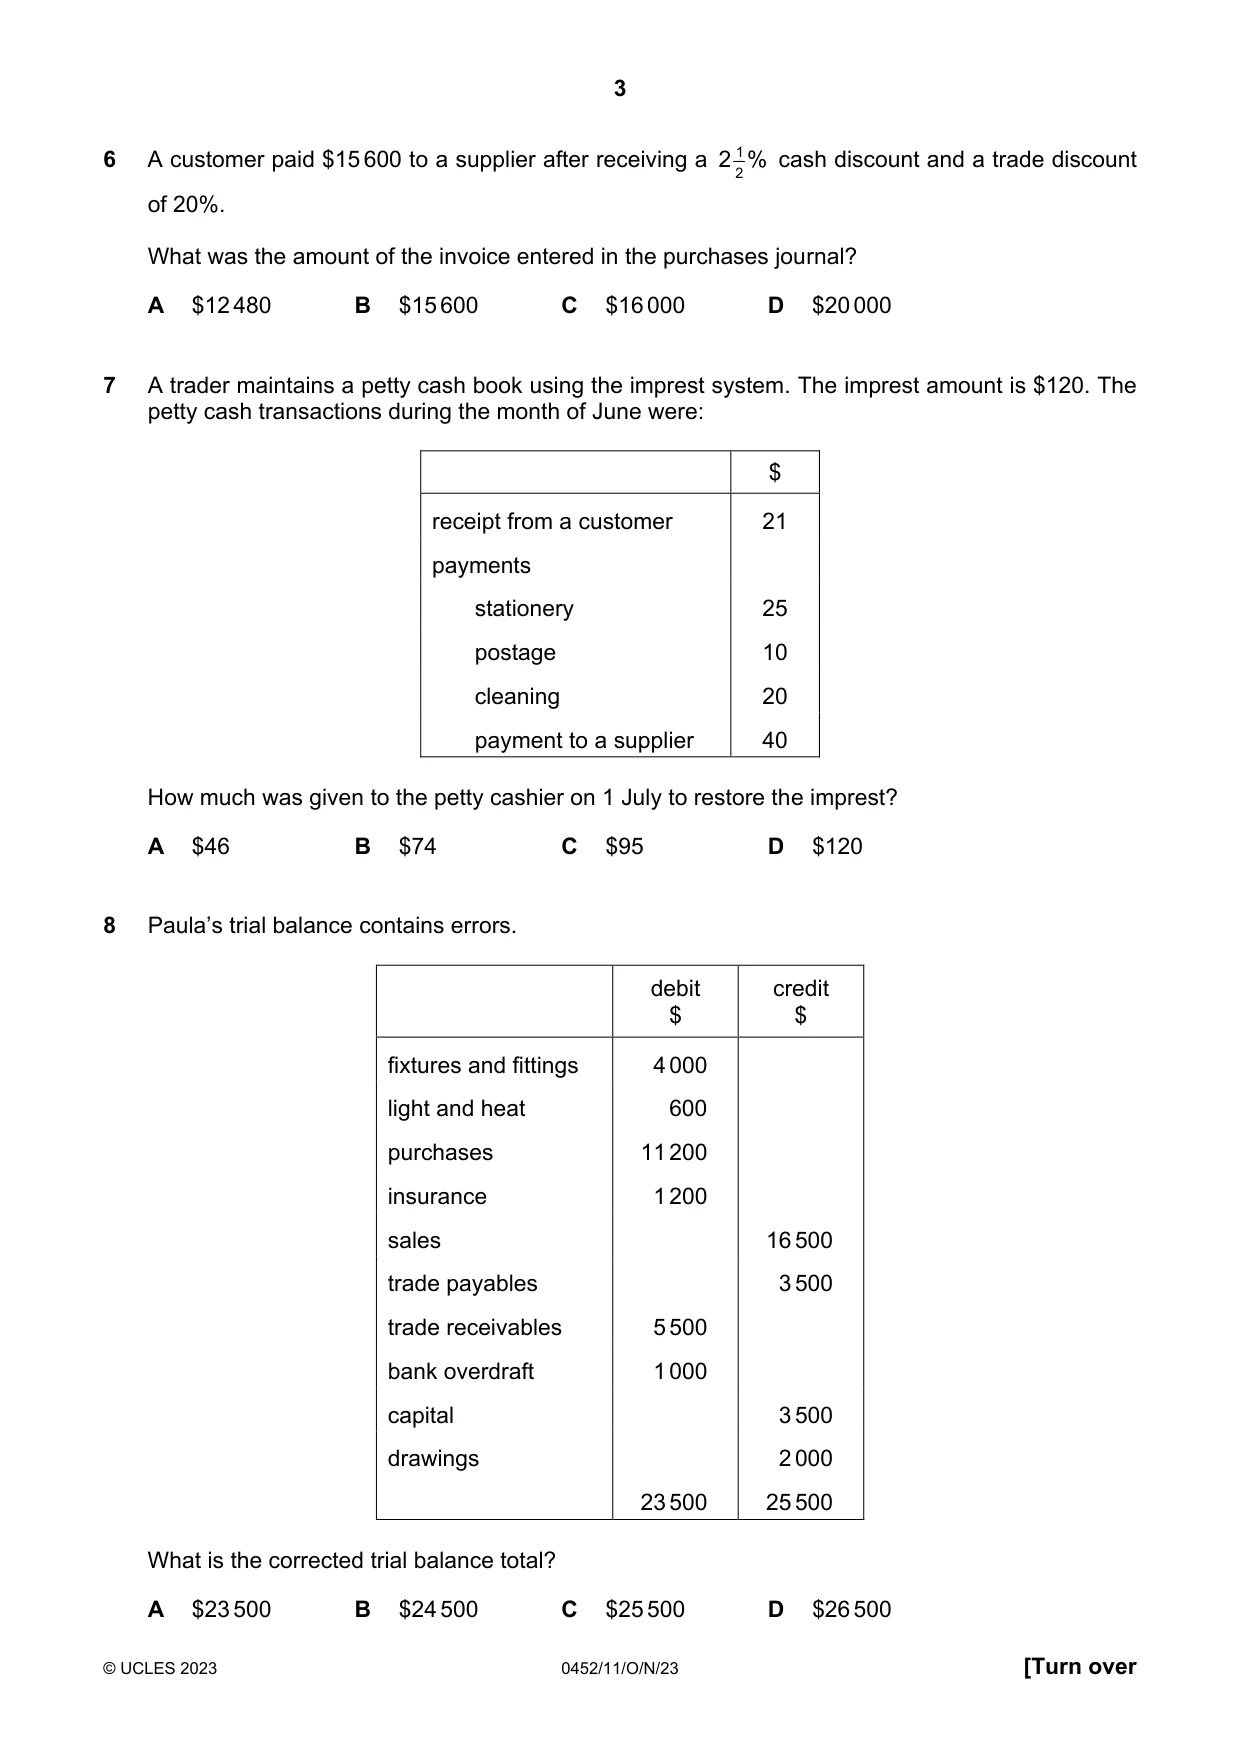
6 A customer paid $15 600 to a supplier after receiving a 2 2 1 % cash discount and a trade discount of 20%. What was the amount of the invoice entered in the purchases journal? A $12 480 B $15 600 C $16 000 D $20 000
Mark scheme: C
Q7 · A trader maintains a petty cash book using the imprest system
7 A trader maintains a petty cash book using the imprest system. The imprest amount is $120. The petty cash transactions during the month of June were: $ receipt from a customer 21 payments stationery 25 postage 10 cleaning 20 payment to a supplier 40 How much was given to the petty cashier on 1 July to restore the imprest? A $46 B $74 C $95 D $120
Mark scheme: B
Q8 · Paula’s trial balance contains errors
8 Paula’s trial balance contains errors. debit credit $ $ fixtures and fittings 4 000 light and heat 600 purchases 11 200 insurance 1 200 sales 16 500 trade payables 3 500 trade receivables 5 500 bank overdraft 1 000 capital 3 500 drawings 2 000 23 500 25 500 What is the corrected trial balance total? A $23 500 B $24 500 C $25 500 D $26 500
Mark scheme: B
Q9 · The following entry was made in a journal to record the correction of an error
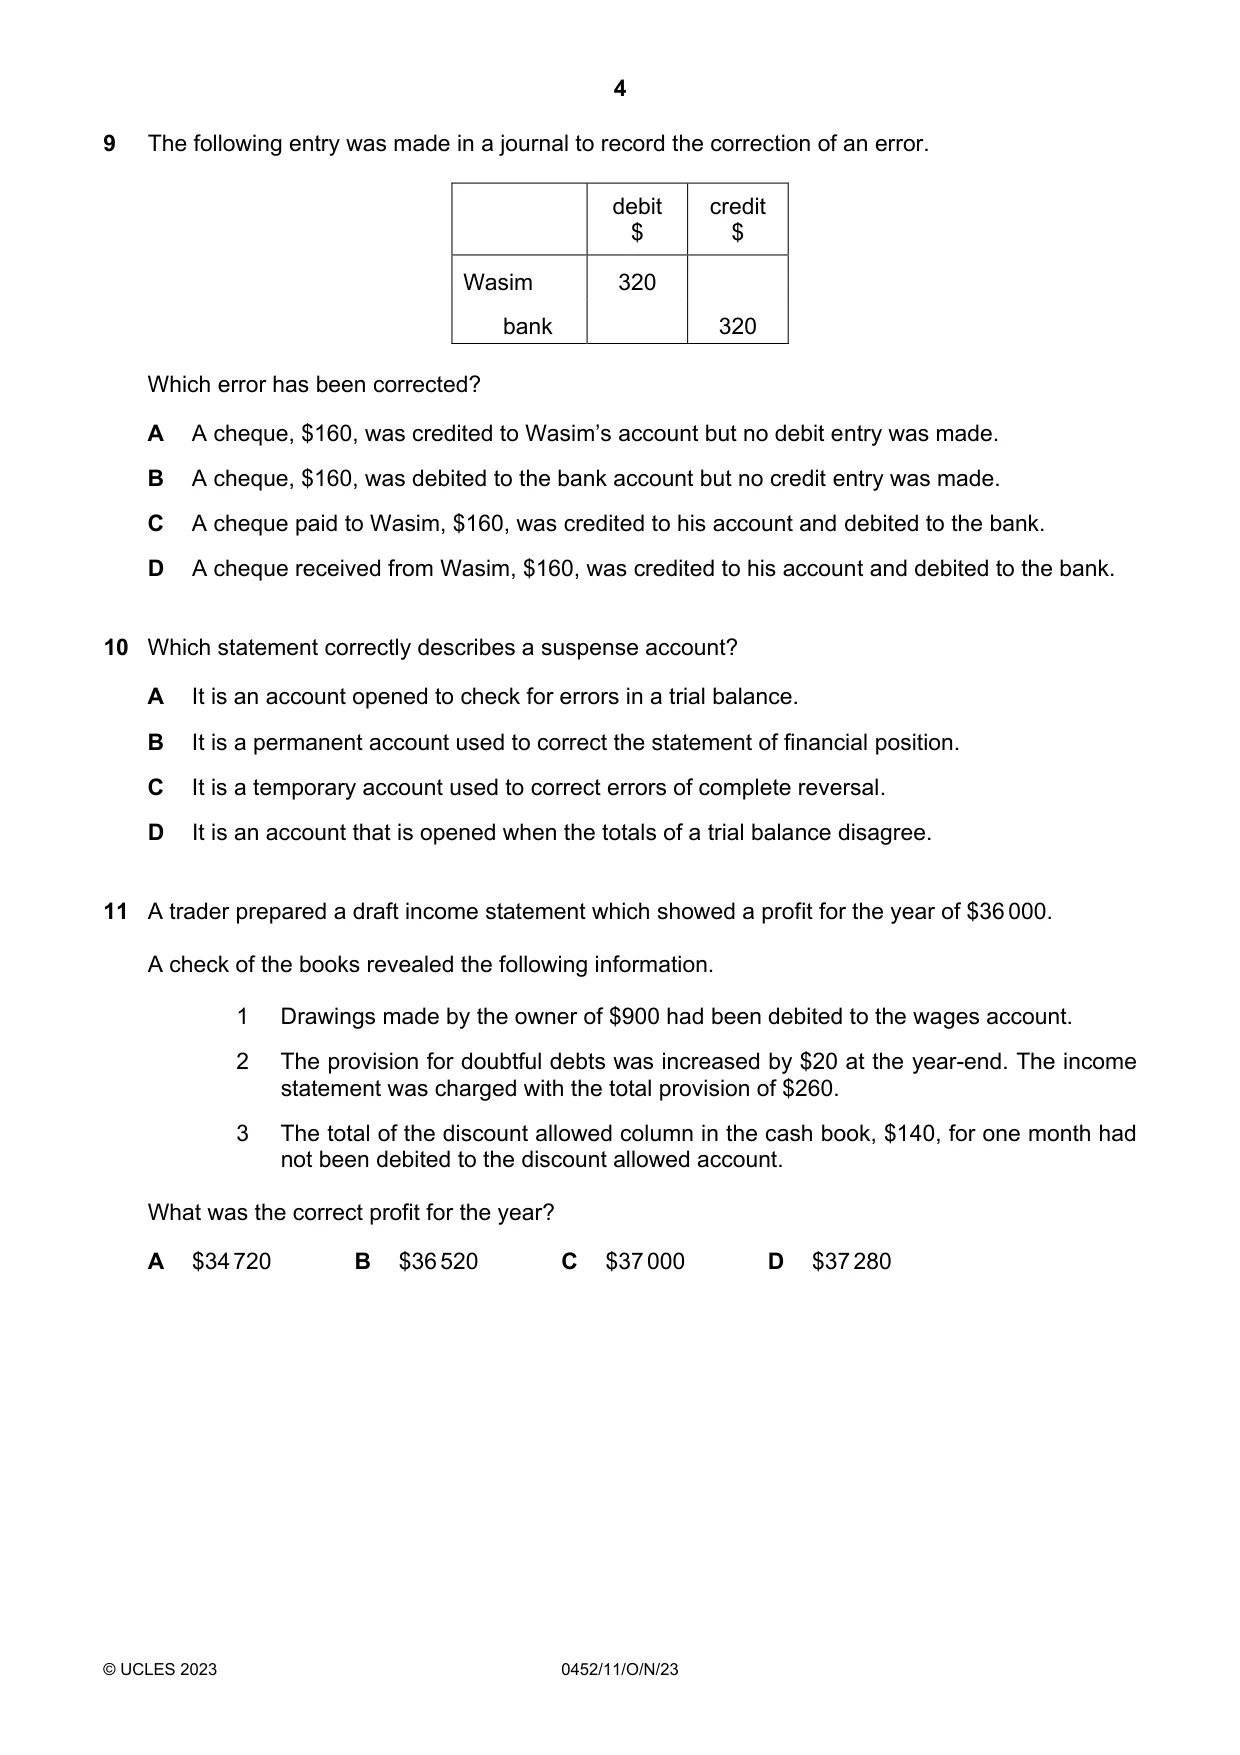
9 The following entry was made in a journal to record the correction of an error. debit credit $ $ Wasim 320 bank 320 Which error has been corrected? A A cheque, $160, was credited to Wasim’s account but no debit entry was made. B A cheque, $160, was debited to the bank account but no credit entry was made. C A cheque paid to Wasim, $160, was credited to his account and debited to the bank. D A cheque received from Wasim, $160, was credited to his account and debited to the bank.
Mark scheme: C
Q10 · Which statement correctly describes a suspense account?
10 Which statement correctly describes a suspense account? A It is an account opened to check for errors in a trial balance. B It is a permanent account used to correct the statement of financial position. C It is a temporary account used to correct errors of complete reversal. D It is an account that is opened when the totals of a trial balance disagree.
Mark scheme: D
Q11 · A trader prepared a draft income statement which showed a profit for the year of $36 000
11 A trader prepared a draft income statement which showed a profit for the year of $36 000. A check of the books revealed the following information. 1 Drawings made by the owner of $900 had been debited to the wages account. 2 The provision for doubtful debts was increased by $20 at the year-end. The income statement was charged with the total provision of $260. 3 The total of the discount allowed column in the cash book, $140, for one month had not been debited to the discount allowed account. What was the correct profit for the year? A $34 720 B $36 520 C $37 000 D $37 280
Mark scheme: C
Q12 · Alicia’s cash book showed a debit balance of $100 on her bank account
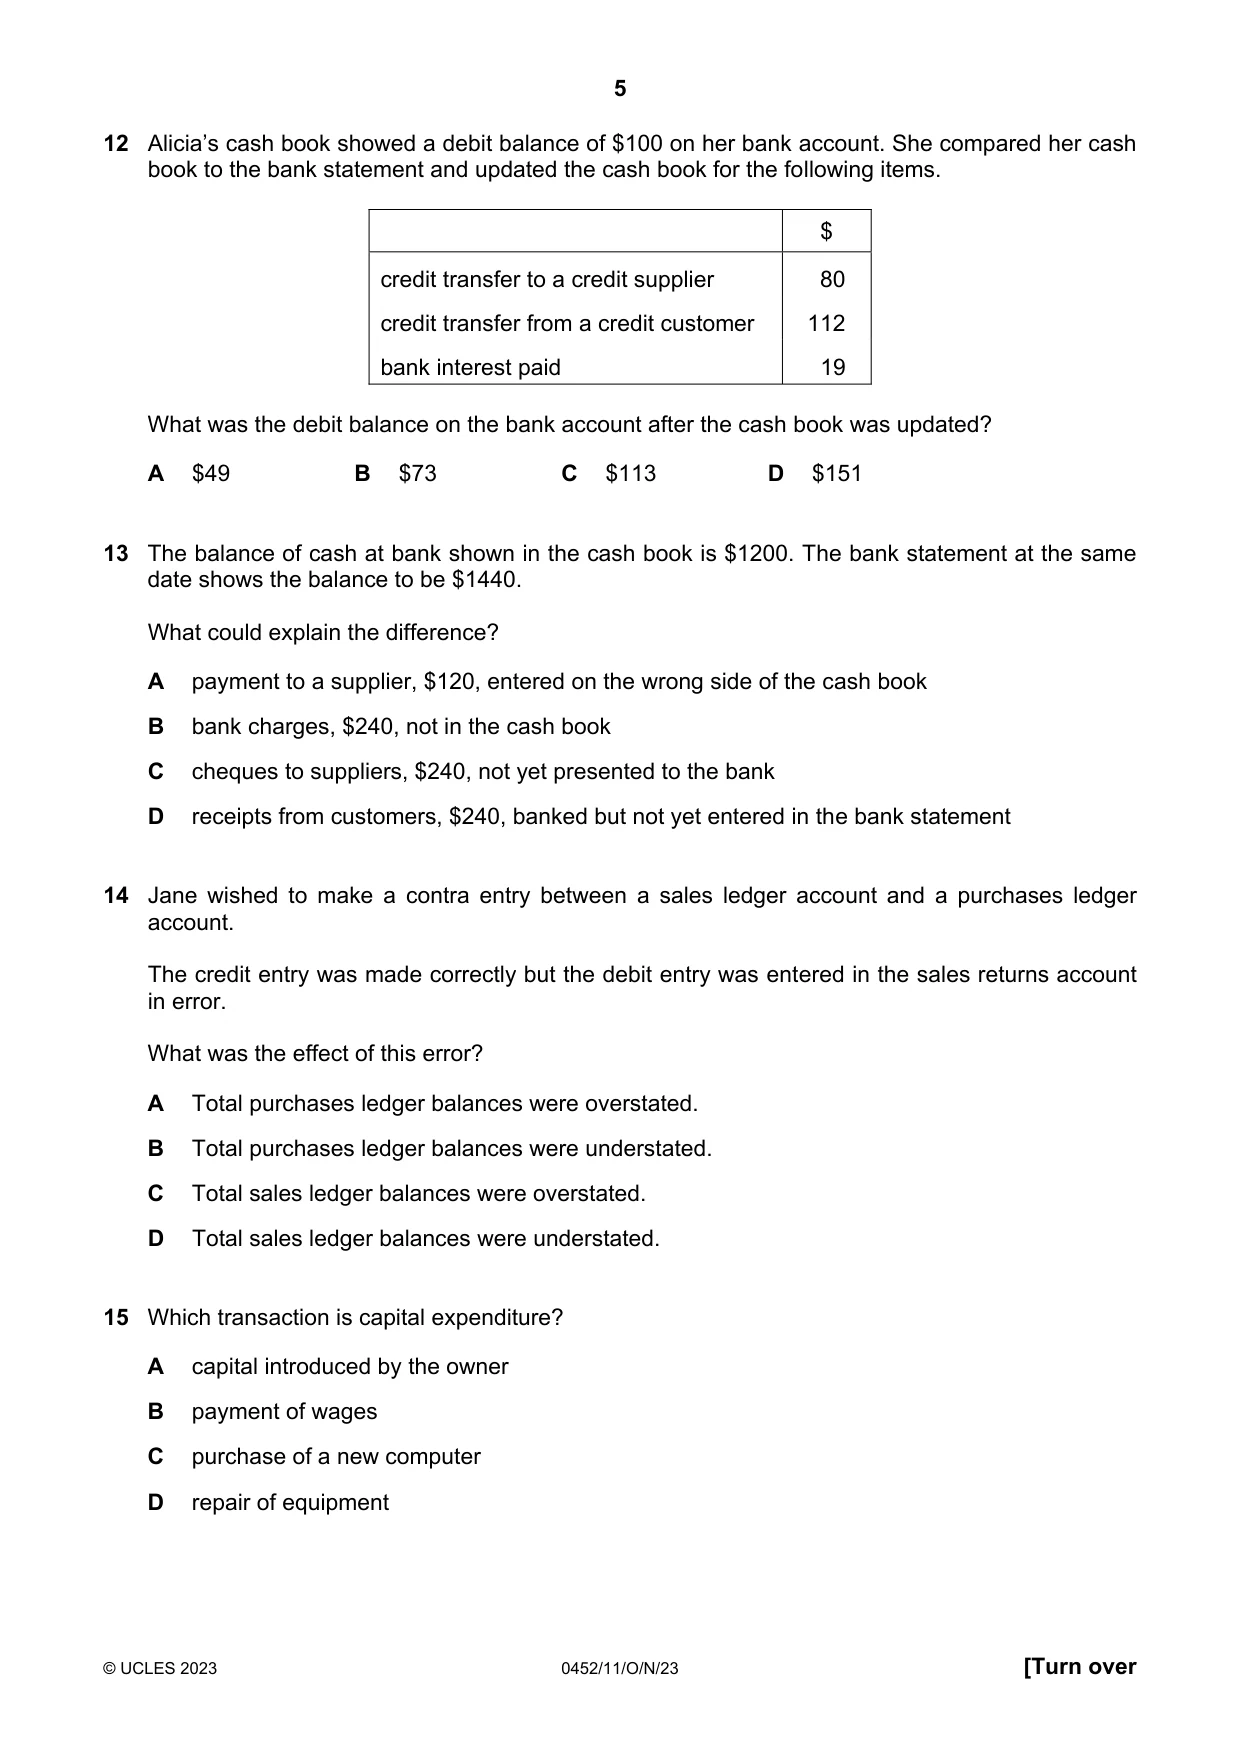
12 Alicia’s cash book showed a debit balance of $100 on her bank account. She compared her cash book to the bank statement and updated the cash book for the following items. $ credit transfer to a credit supplier 80 credit transfer from a credit customer 112 bank interest paid 19 What was the debit balance on the bank account after the cash book was updated? A $49 B $73 C $113 D $151
Mark scheme: C
Q13 · The balance of cash at bank shown in the cash book is $1200
13 The balance of cash at bank shown in the cash book is $1200. The bank statement at the same date shows the balance to be $1440. What could explain the difference? A payment to a supplier, $120, entered on the wrong side of the cash book B bank charges, $240, not in the cash book C cheques to suppliers, $240, not yet presented to the bank D receipts from customers, $240, banked but not yet entered in the bank statement
Mark scheme: C
Q14 · Jane wished to make a contra entry between a sales ledger account and a purchases ledger…
14 Jane wished to make a contra entry between a sales ledger account and a purchases ledger account. The credit entry was made correctly but the debit entry was entered in the sales returns account in error. What was the effect of this error? A Total purchases ledger balances were overstated. B Total purchases ledger balances were understated. C Total sales ledger balances were overstated. D Total sales ledger balances were understated.
Mark scheme: A
Q15 · Which transaction is capital expenditure?
15 Which transaction is capital expenditure? A capital introduced by the owner B payment of wages C purchase of a new computer D repair of equipment
Mark scheme: C
More questions on Capital and revenue expenditure and receipts
Q16 · Sales returns were incorrectly recorded as purchases returns in an income statement
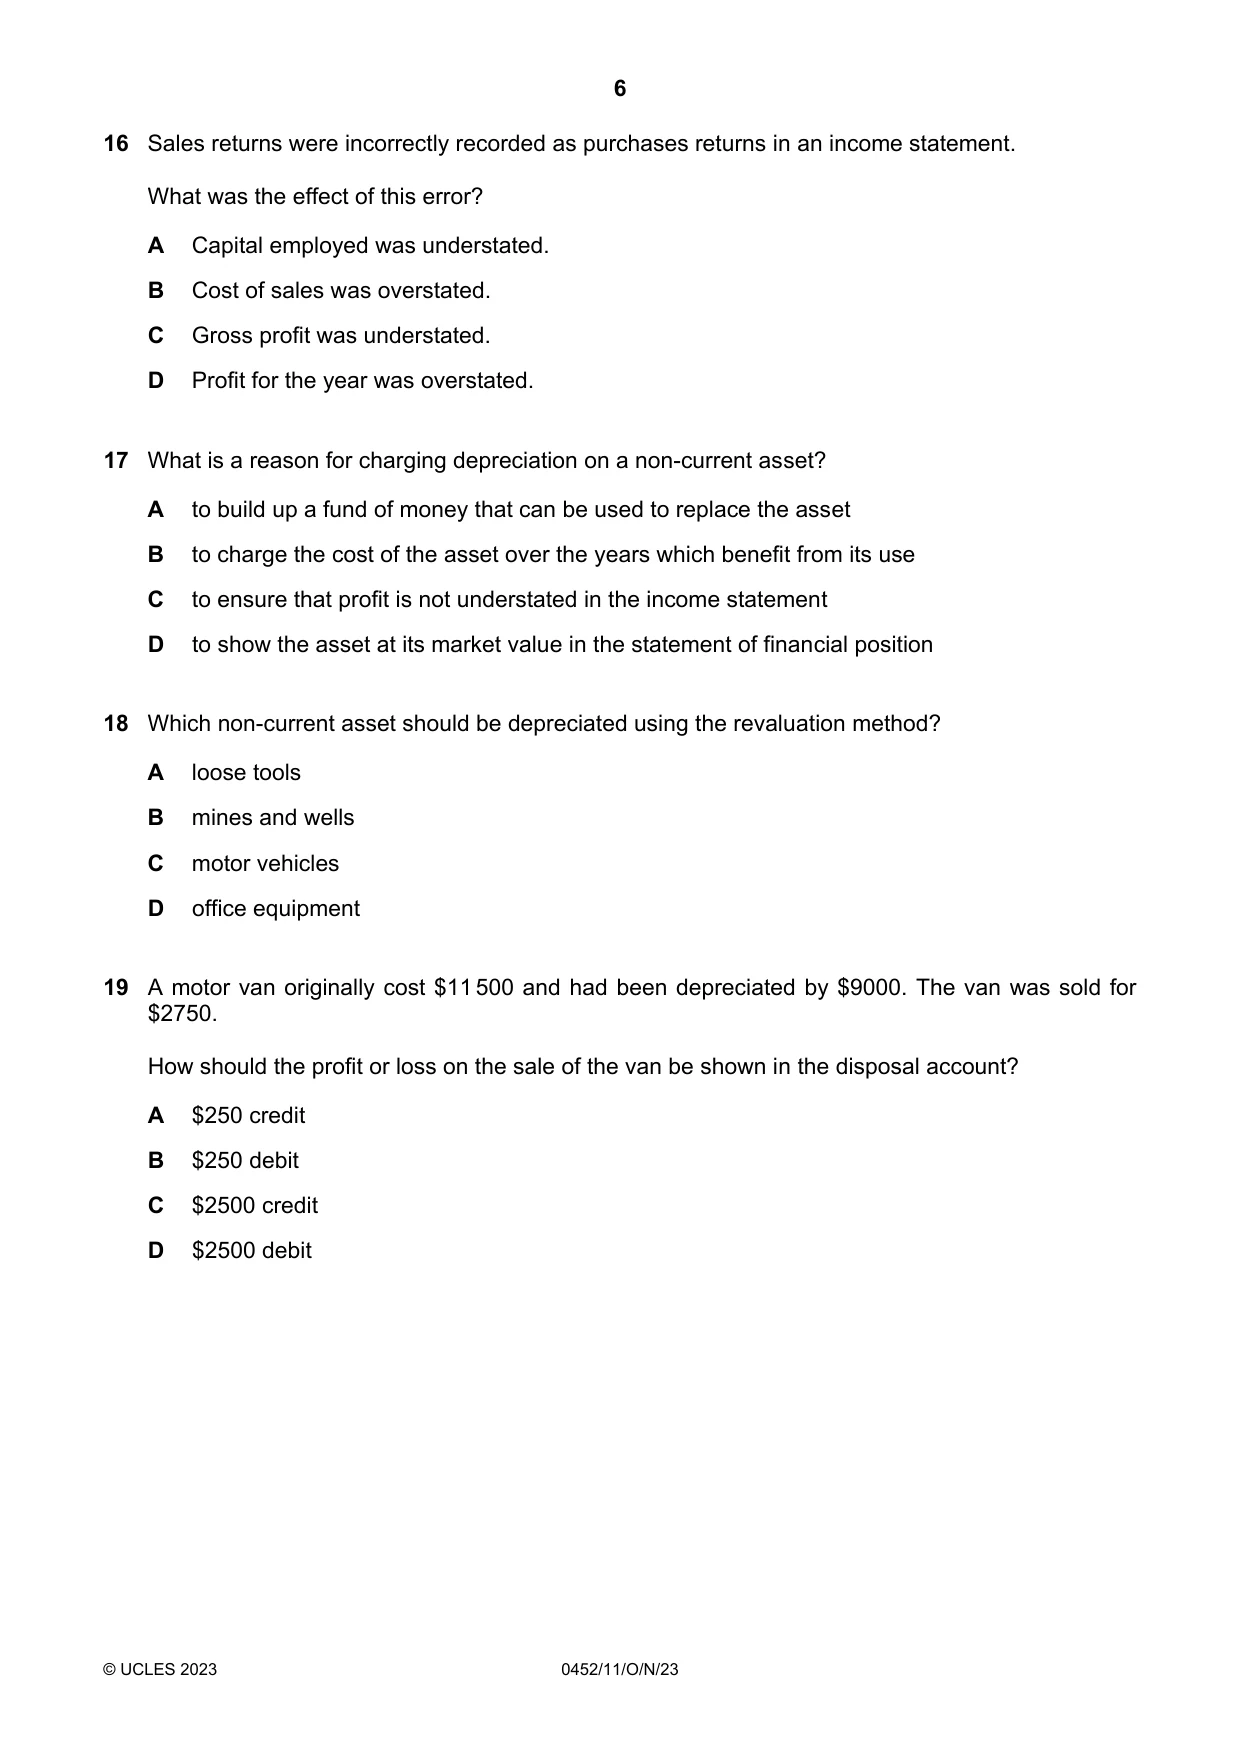
16 Sales returns were incorrectly recorded as purchases returns in an income statement. What was the effect of this error? A Capital employed was understated. B Cost of sales was overstated. C Gross profit was understated. D Profit for the year was overstated.
Mark scheme: D
Q17 · What is a reason for charging depreciation on a non-current asset?
17 What is a reason for charging depreciation on a non-current asset? A to build up a fund of money that can be used to replace the asset B to charge the cost of the asset over the years which benefit from its use C to ensure that profit is not understated in the income statement D to show the asset at its market value in the statement of financial position
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q18 · Which non-current asset should be depreciated using the revaluation method?
18 Which non-current asset should be depreciated using the revaluation method? A loose tools B mines and wells C motor vehicles D office equipment
Mark scheme: A
More questions on Accounting for depreciation and disposal of non-current assets
Q19 · A motor van originally cost $11 500 and had been depreciated by $9000
19 A motor van originally cost $11 500 and had been depreciated by $9000. The van was sold for $2750. How should the profit or loss on the sale of the van be shown in the disposal account? A $250 credit B $250 debit C $2500 credit D $2500 debit
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q20 · Joseph sells goods on credit and maintains a provision for doubtful debts
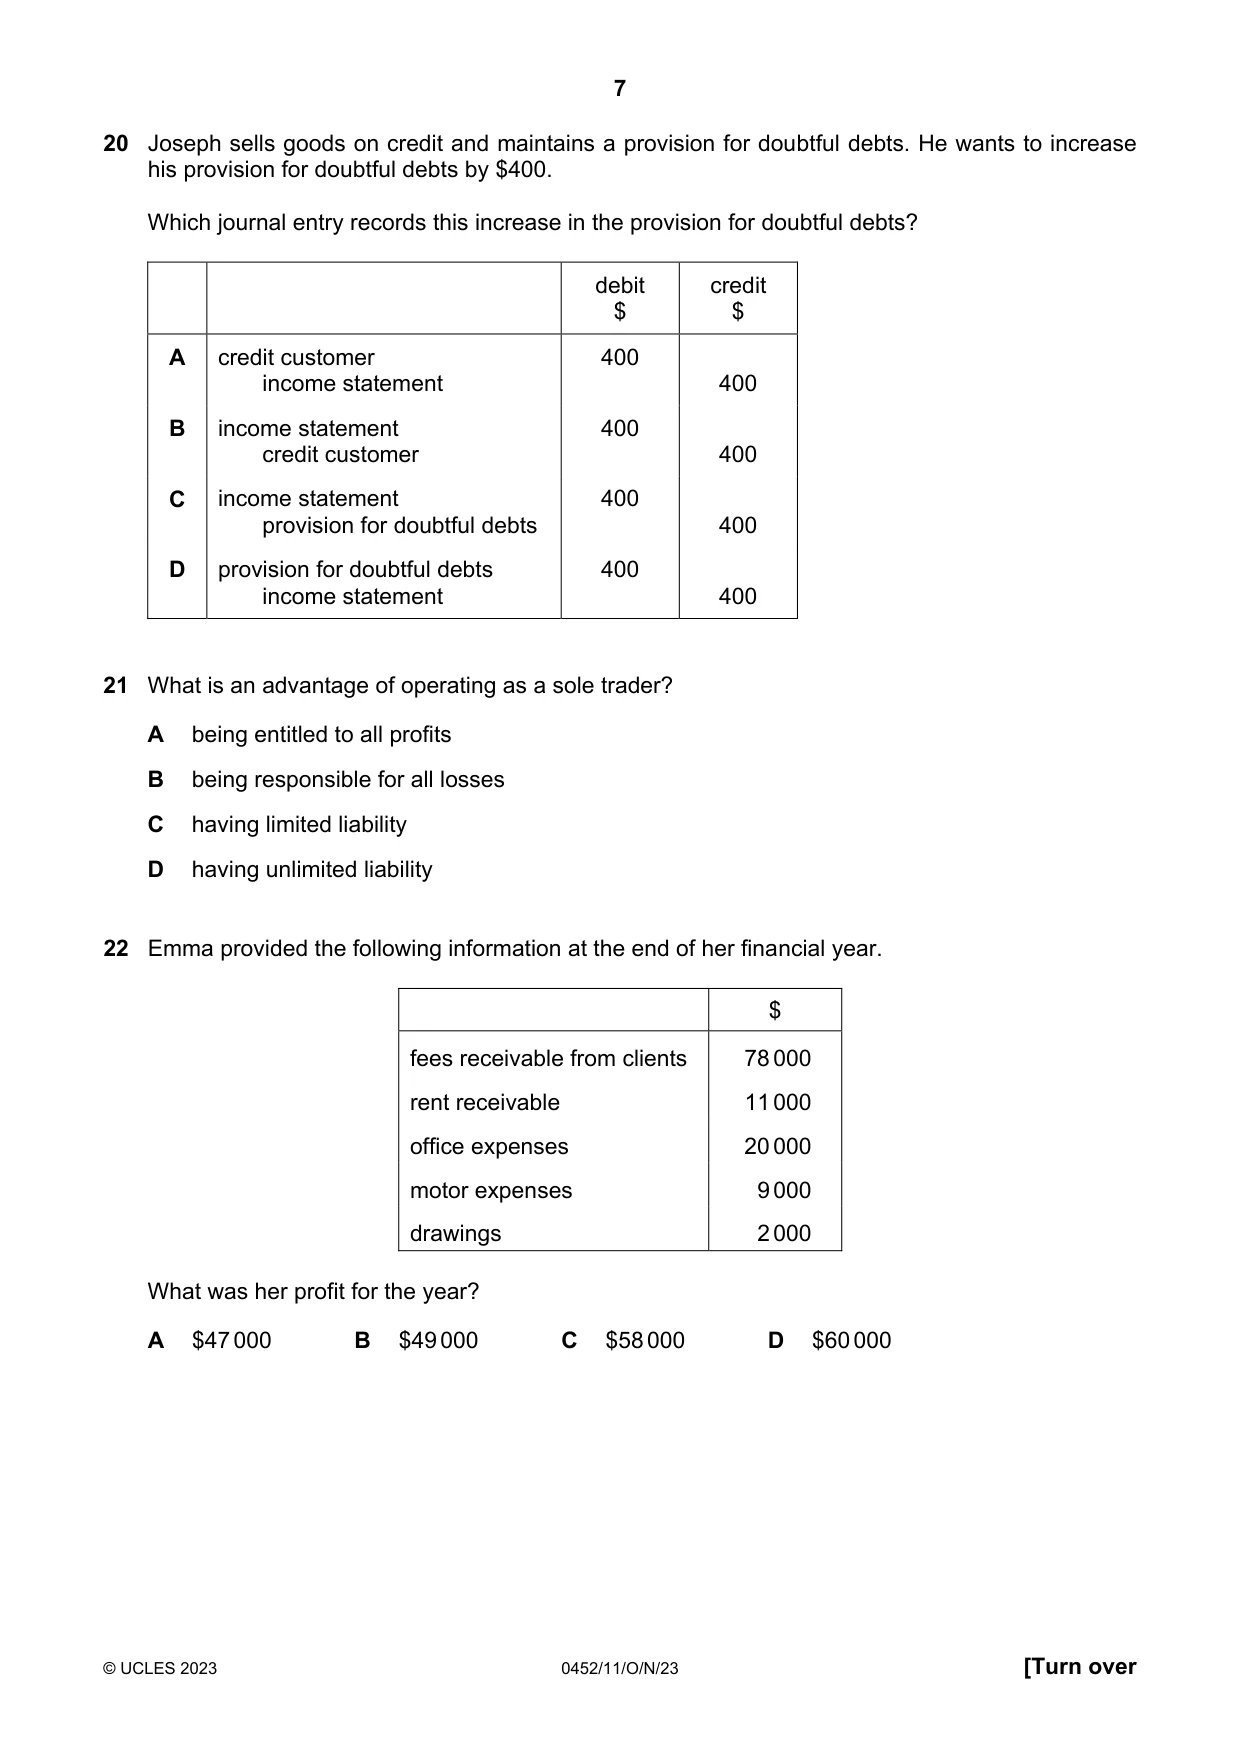
20 Joseph sells goods on credit and maintains a provision for doubtful debts. He wants to increase his provision for doubtful debts by $400. Which journal entry records this increase in the provision for doubtful debts? debit credit $ $ A credit customer 400 income statement 400 B income statement 400 credit customer 400 C income statement 400 provision for doubtful debts 400 D provision for doubtful debts 400 income statement 400
Mark scheme: C
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q21 · What is an advantage of operating as a sole trader?
21 What is an advantage of operating as a sole trader? A being entitled to all profits B being responsible for all losses C having limited liability D having unlimited liability
Mark scheme: A
Q22 · Emma provided the following information at the end of her financial year
22 Emma provided the following information at the end of her financial year. $ fees receivable from clients 78 000 rent receivable 11 000 office expenses 20 000 motor expenses 9 000 drawings 2 000 What was her profit for the year? A $47 000 B $49 000 C $58 000 D $60 000
Mark scheme: D
Q23 · A trader provided the following data
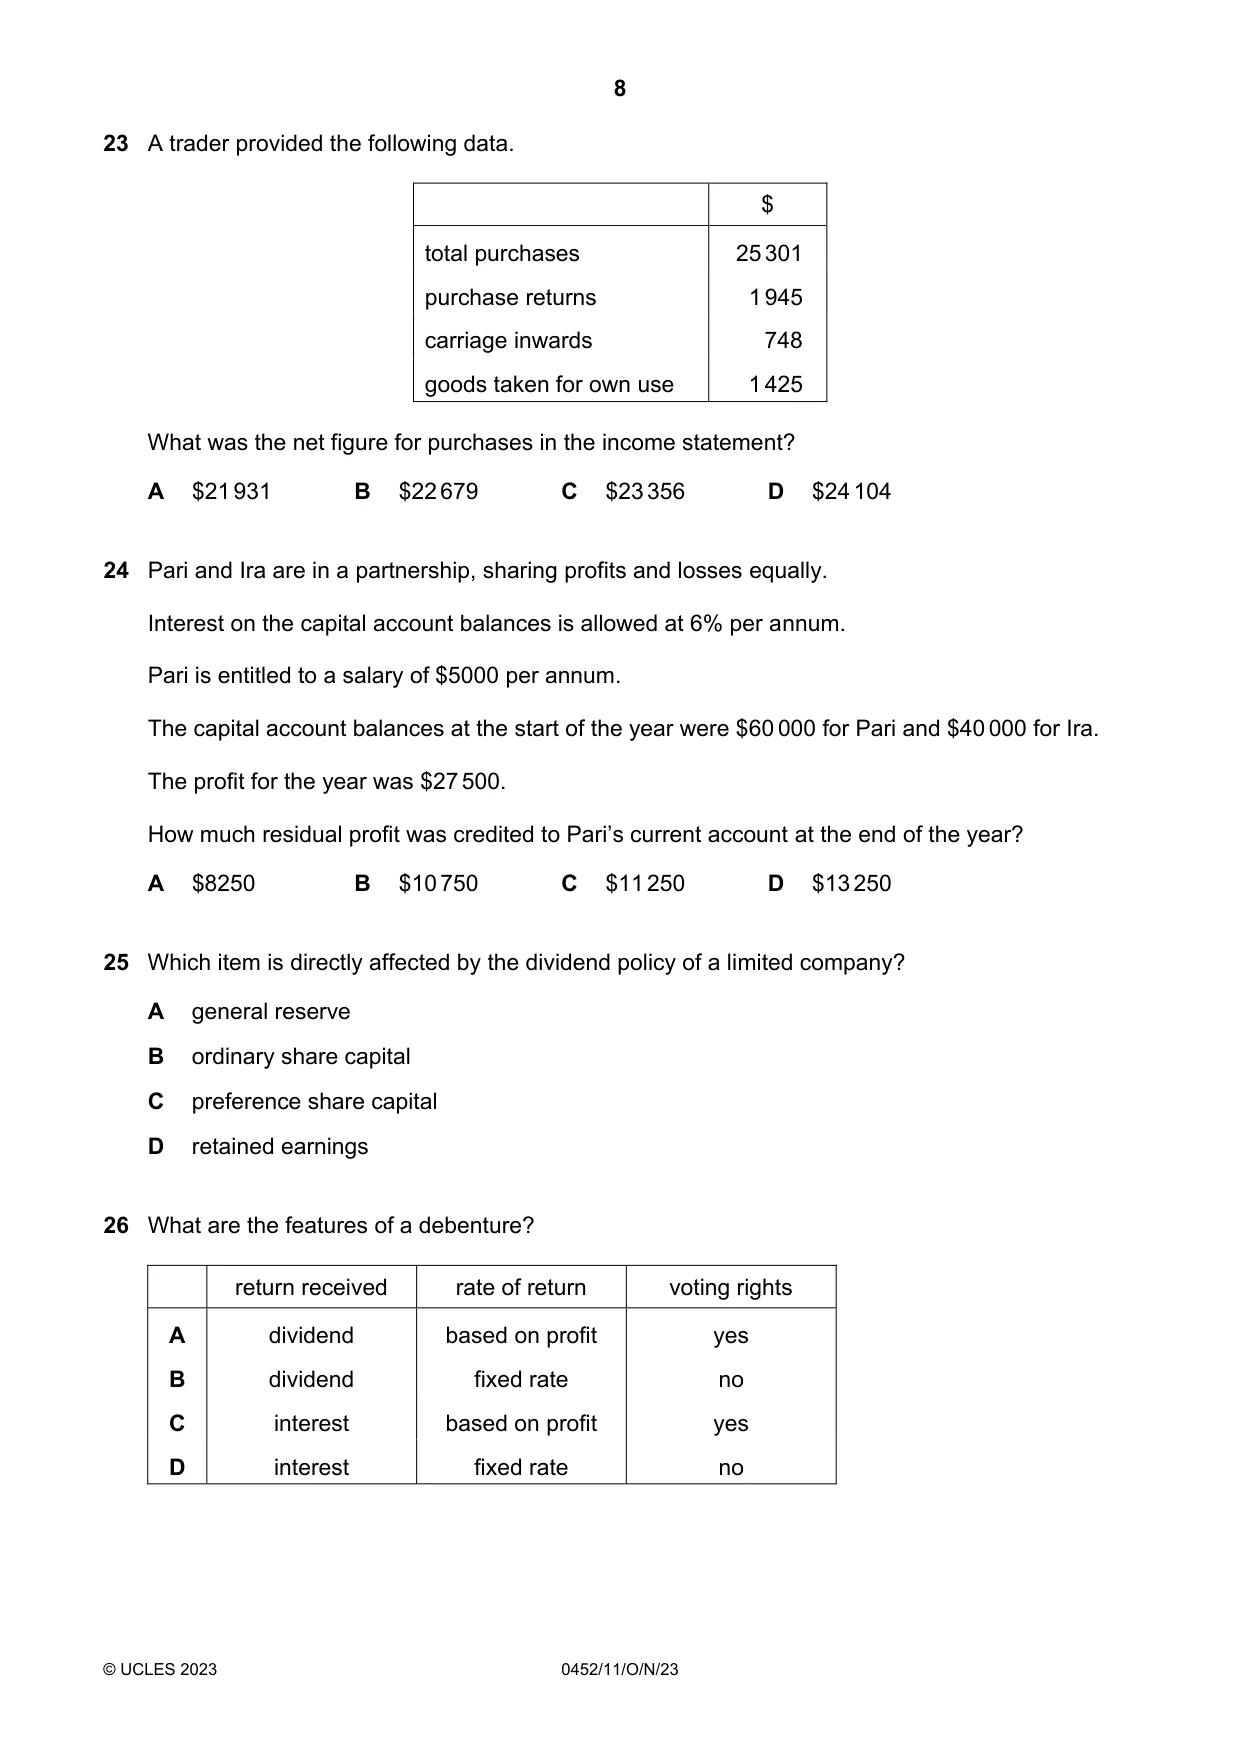
23 A trader provided the following data. $ total purchases 25 301 purchase returns 1 945 carriage inwards 748 goods taken for own use 1 425 What was the net figure for purchases in the income statement? A $21 931 B $22 679 C $23 356 D $24 104
Mark scheme: B
Q24 · Pari and Ira are in a partnership, sharing profits and losses equally
24 Pari and Ira are in a partnership, sharing profits and losses equally. Interest on the capital account balances is allowed at 6% per annum. Pari is entitled to a salary of $5000 per annum. The capital account balances at the start of the year were $60 000 for Pari and $40 000 for Ira. The profit for the year was $27 500. How much residual profit was credited to Pari’s current account at the end of the year? A $8250 B $10 750 C $11 250 D $13 250
Mark scheme: A
Q25 · Which item is directly affected by the dividend policy of a limited company?
25 Which item is directly affected by the dividend policy of a limited company? A general reserve B ordinary share capital C preference share capital D retained earnings
Mark scheme: D
Q26 · What are the features of a debenture?
26 What are the features of a debenture? return received rate of return voting rights A dividend based on profit yes B dividend fixed rate no C interest based on profit yes D interest fixed rate no
Mark scheme: D
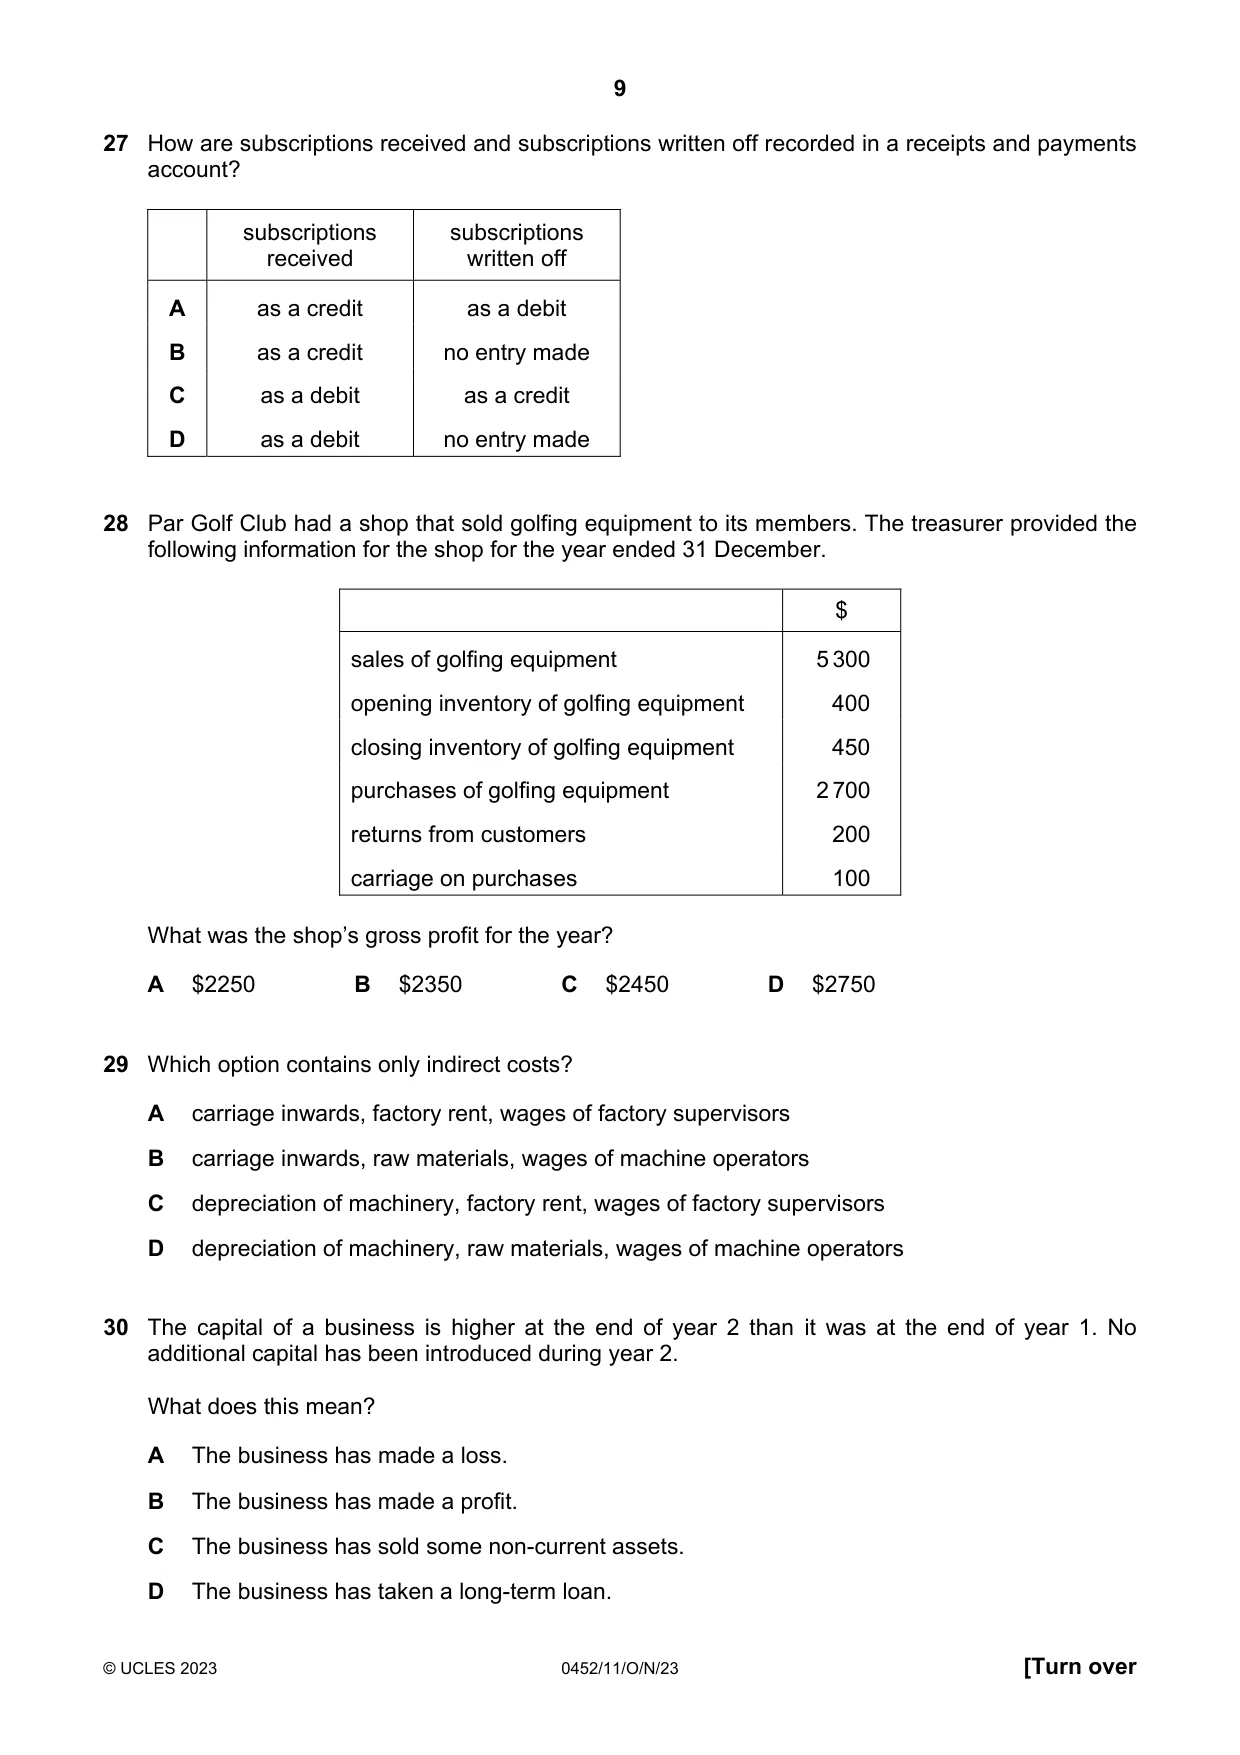
Q27 · How are subscriptions received and subscriptions written off recorded in a receipts and…
27 How are subscriptions received and subscriptions written off recorded in a receipts and payments account? subscriptions subscriptions received written off A as a credit as a debit B as a credit no entry made C as a debit as a credit D as a debit no entry made
Mark scheme: D
Q28 · Par Golf Club had a shop that sold golfing equipment to its members
28 Par Golf Club had a shop that sold golfing equipment to its members. The treasurer provided the following information for the shop for the year ended 31 December. $ sales of golfing equipment 5 300 opening inventory of golfing equipment 400 closing inventory of golfing equipment 450 purchases of golfing equipment 2 700 returns from customers 200 carriage on purchases 100 What was the shop’s gross profit for the year? A $2250 B $2350 C $2450 D $2750
Mark scheme: B
Q29 · Which option contains only indirect costs?
29 Which option contains only indirect costs? A carriage inwards, factory rent, wages of factory supervisors B carriage inwards, raw materials, wages of machine operators C depreciation of machinery, factory rent, wages of factory supervisors D depreciation of machinery, raw materials, wages of machine operators
Mark scheme: C
Q30 · The capital of a business is higher at the end of year 2 than it was at the end of year 1
30 The capital of a business is higher at the end of year 2 than it was at the end of year 1. No additional capital has been introduced during year 2. What does this mean? A The business has made a loss. B The business has made a profit. C The business has sold some non-current assets. D The business has taken a long-term loan.
Mark scheme: B
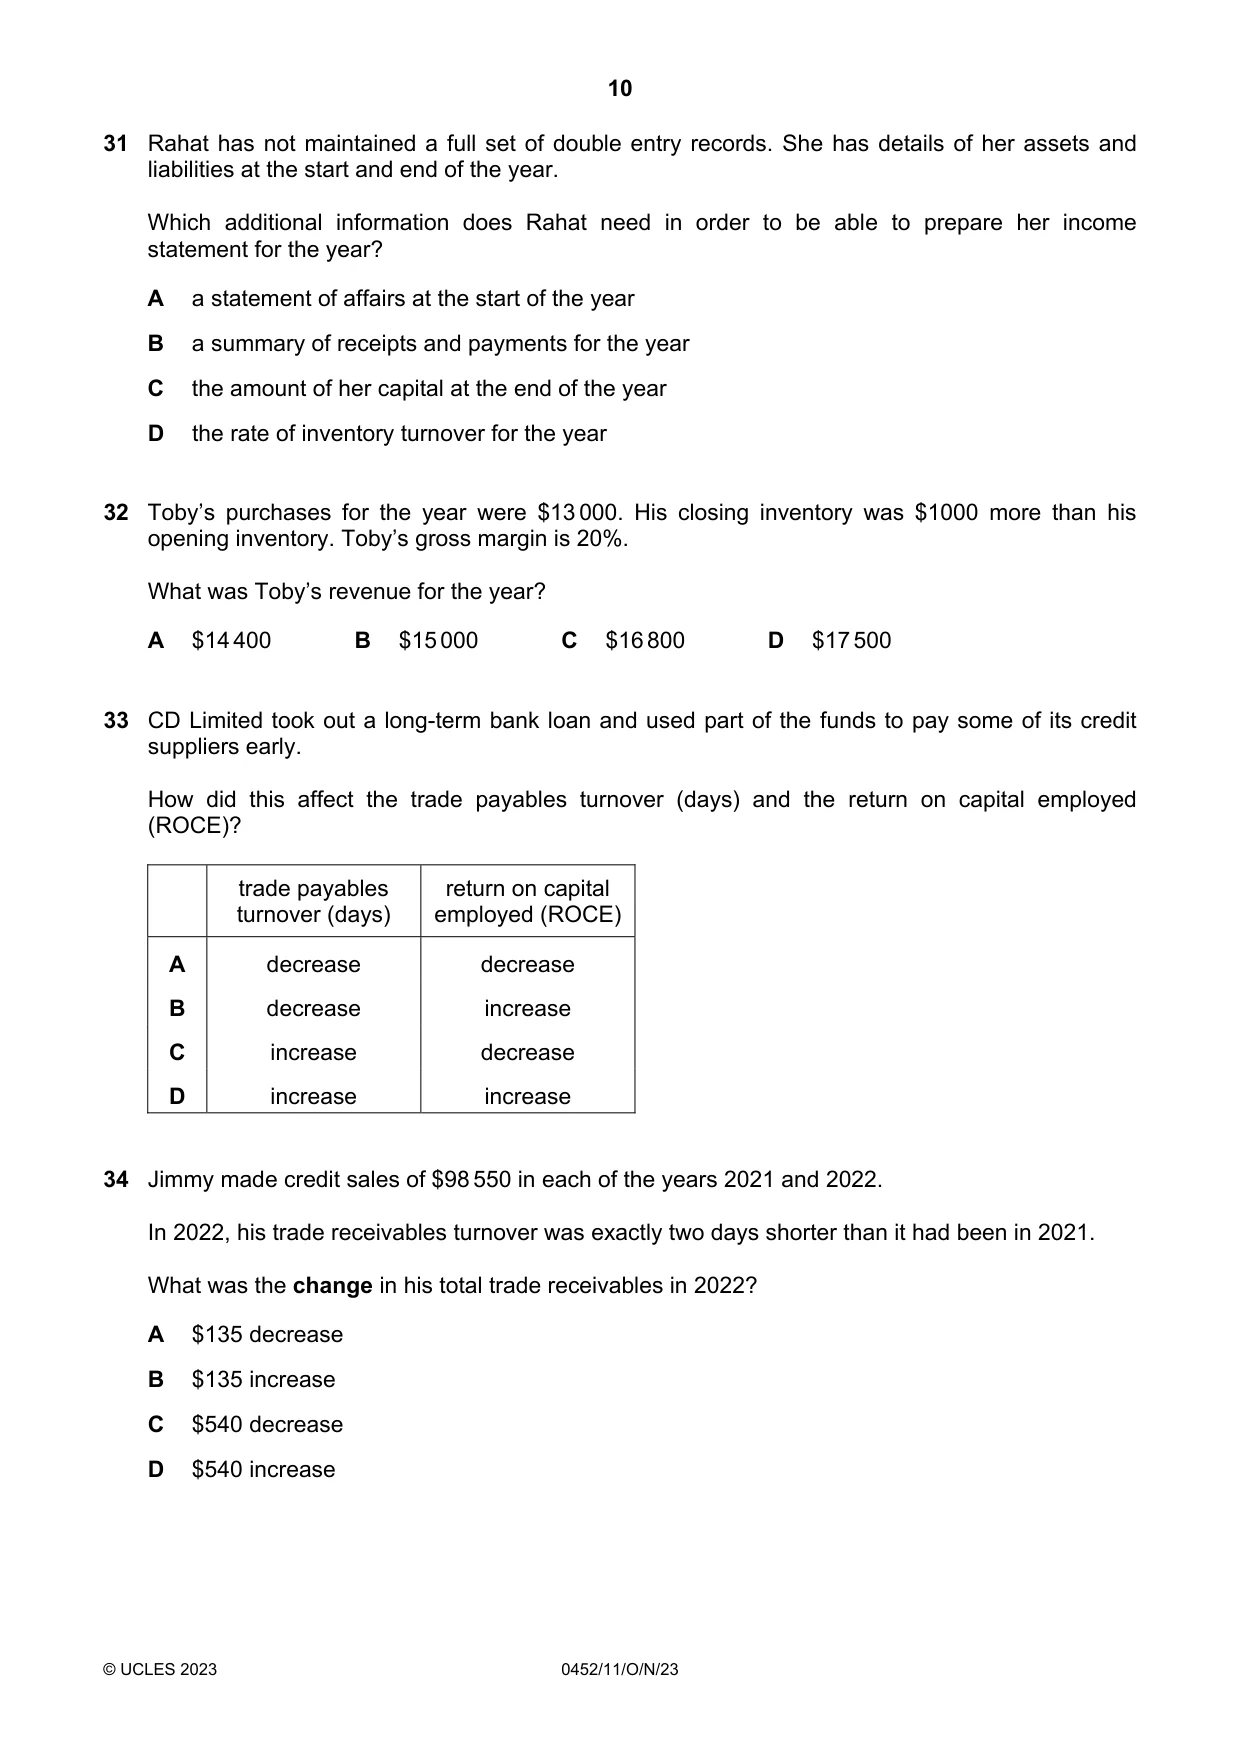
Q31 · Rahat has not maintained a full set of double entry records
31 Rahat has not maintained a full set of double entry records. She has details of her assets and liabilities at the start and end of the year. Which additional information does Rahat need in order to be able to prepare her income statement for the year? A a statement of affairs at the start of the year B a summary of receipts and payments for the year C the amount of her capital at the end of the year D the rate of inventory turnover for the year
Mark scheme: B
Q32 · Toby’s purchases for the year were $13 000
32 Toby’s purchases for the year were $13 000. His closing inventory was $1000 more than his opening inventory. Toby’s gross margin is 20%. What was Toby’s revenue for the year? A $14 400 B $15 000 C $16 800 D $17 500
Mark scheme: B
More questions on Calculation and understanding of accounting ratios
Q33 · CD Limited took out a long-term bank loan and used part of the funds to pay some of its…
33 CD Limited took out a long-term bank loan and used part of the funds to pay some of its credit suppliers early. How did this affect the trade payables turnover (days) and the return on capital employed (ROCE)? trade payables return on capital turnover (days) employed (ROCE) A decrease decrease B decrease increase C increase decrease D increase increase
Mark scheme: A
Q34 · Jimmy made credit sales of $98 550 in each of the years 2021 and 2022
34 Jimmy made credit sales of $98 550 in each of the years 2021 and 2022. In 2022, his trade receivables turnover was exactly two days shorter than it had been in 2021. What was the change in his total trade receivables in 2022? A $135 decrease B $135 increase C $540 decrease D $540 increase
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
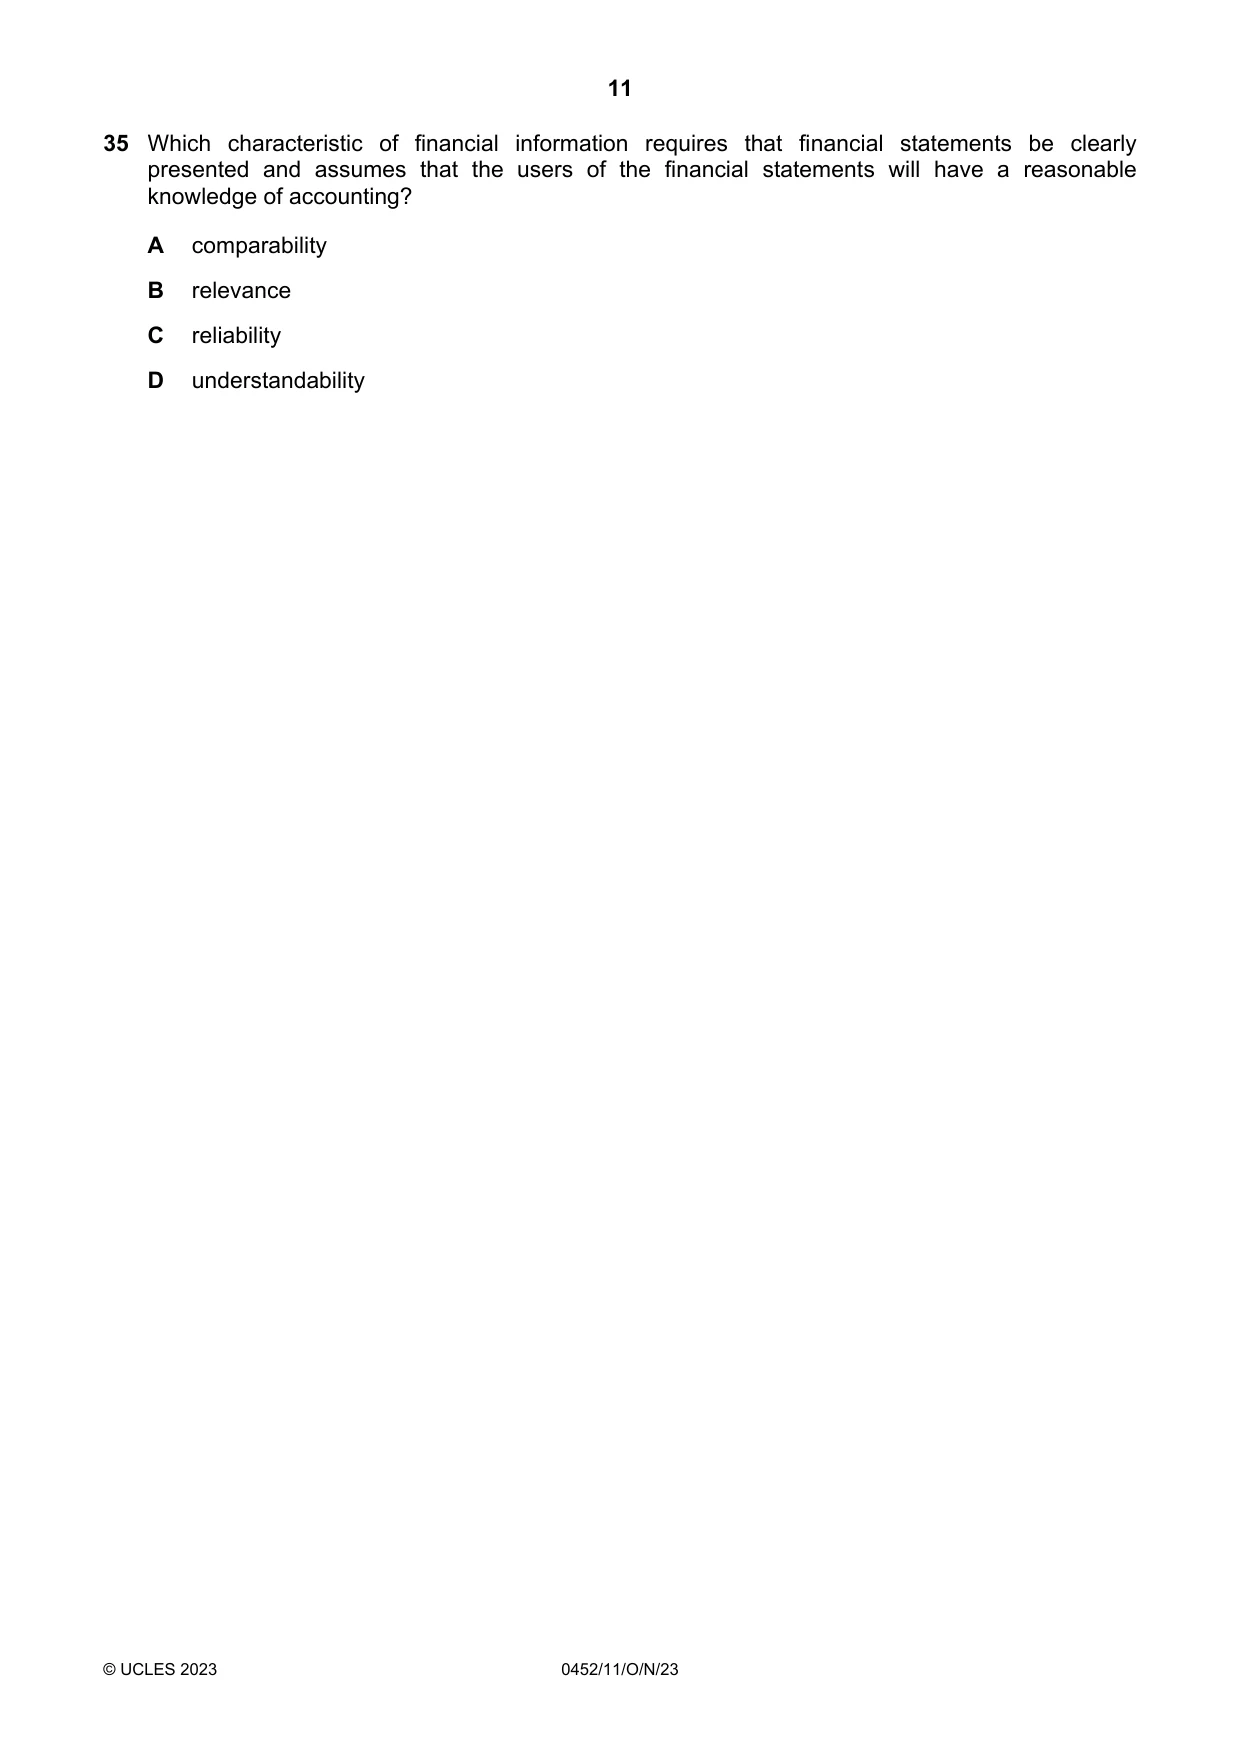
Q35 · Which characteristic of financial information requires that financial statements be…
35 Which characteristic of financial information requires that financial statements be clearly presented and assumes that the users of the financial statements will have a reasonable knowledge of accounting? A comparability B relevance C reliability D understandability
Mark scheme: D
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
5Books of prime entry4Accounting for depreciation and disposal of non-current assets3The accounting equation3Bank reconciliation2Calculation and understanding of accounting ratios2Clubs and societies2Limited companies2Sole traders2Accounting concepts1Business documents1Capital and revenue expenditure and receipts1Incomplete records1Interpretation of accounting ratios1Irrecoverable debts and allowance for irrecoverable debts1Manufacturing accounts1Partnerships1The double entry system of book-keeping1The trial balance1What you needed in this session
Cambridge’s own grade thresholds for 2023 Oct/Nov, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.