Cambridge IGCSE Accounting 0452 — 2020 Oct/Nov Paper 1 · Variant 1
0452/11/O/N/20 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme3 pages
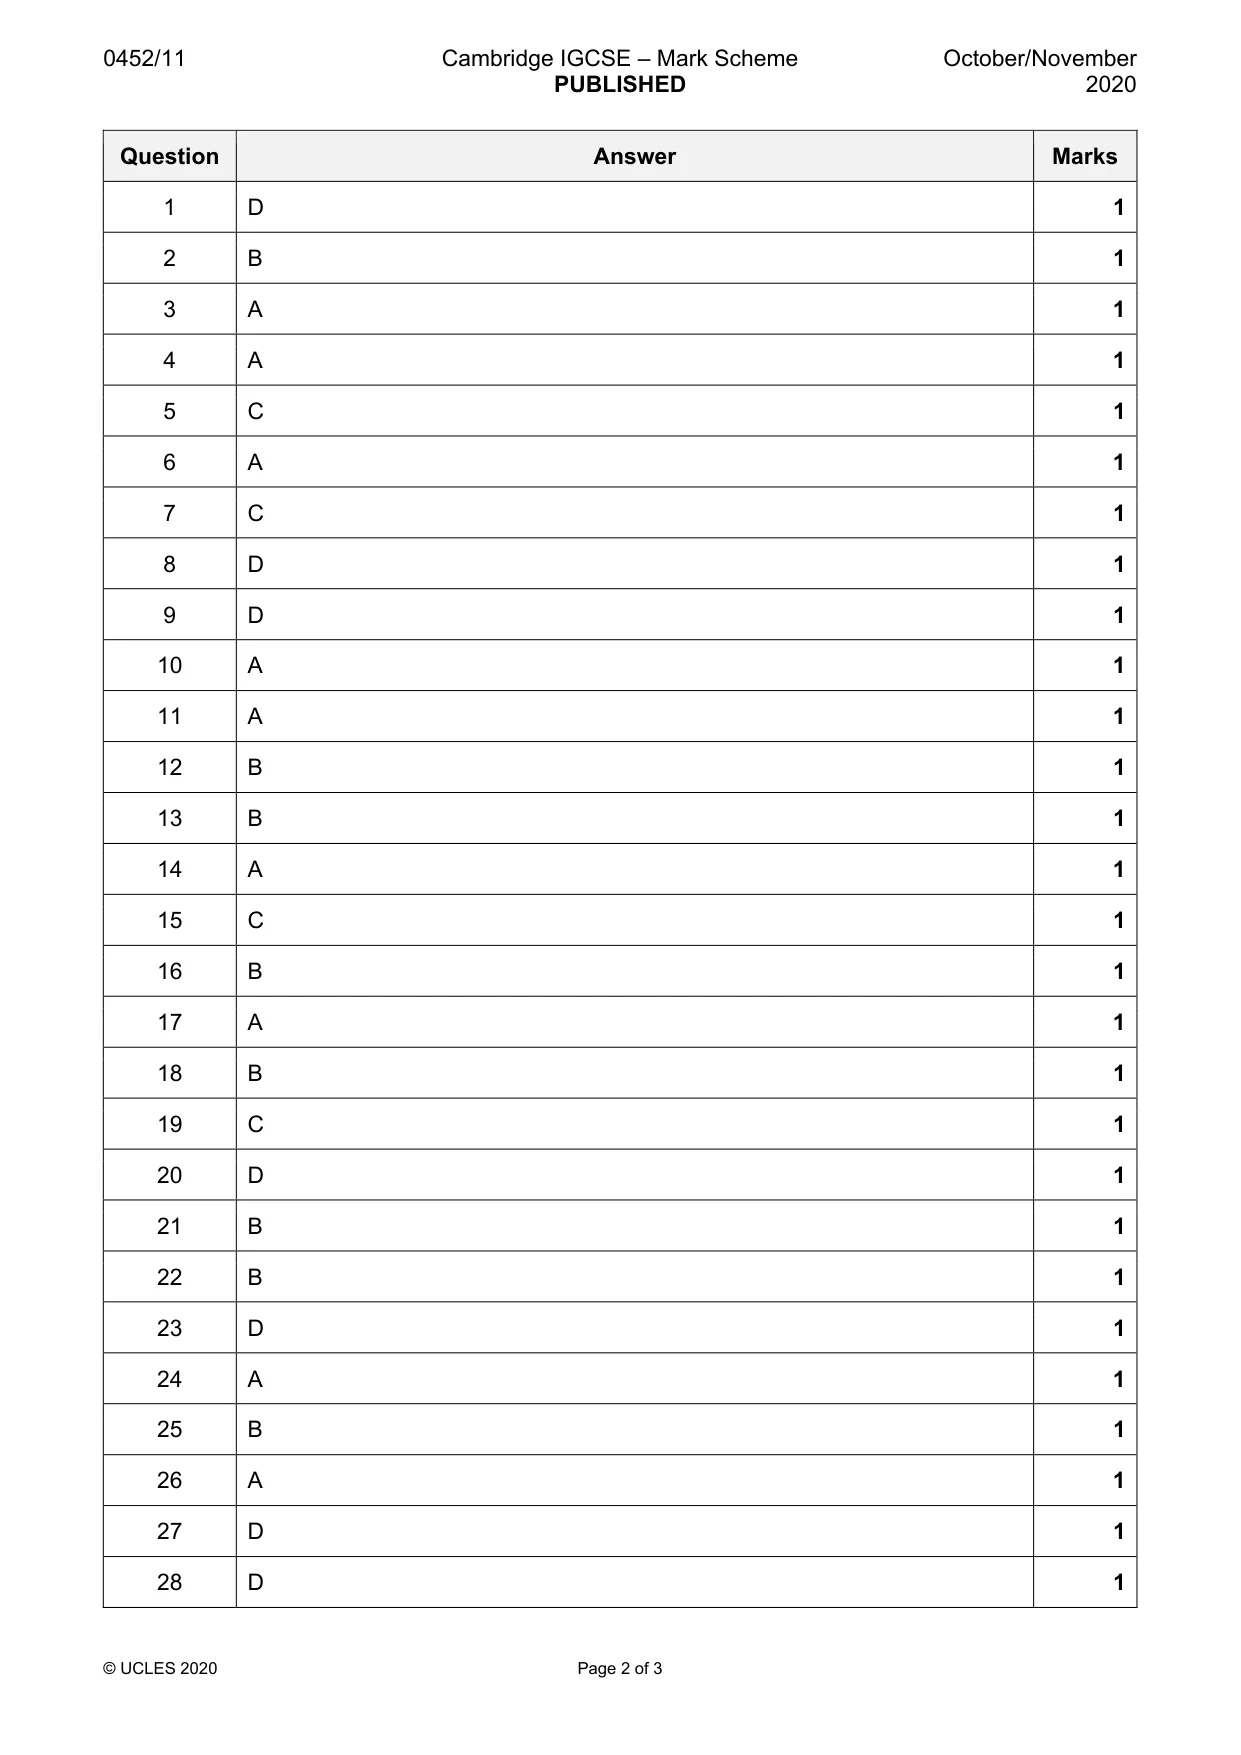
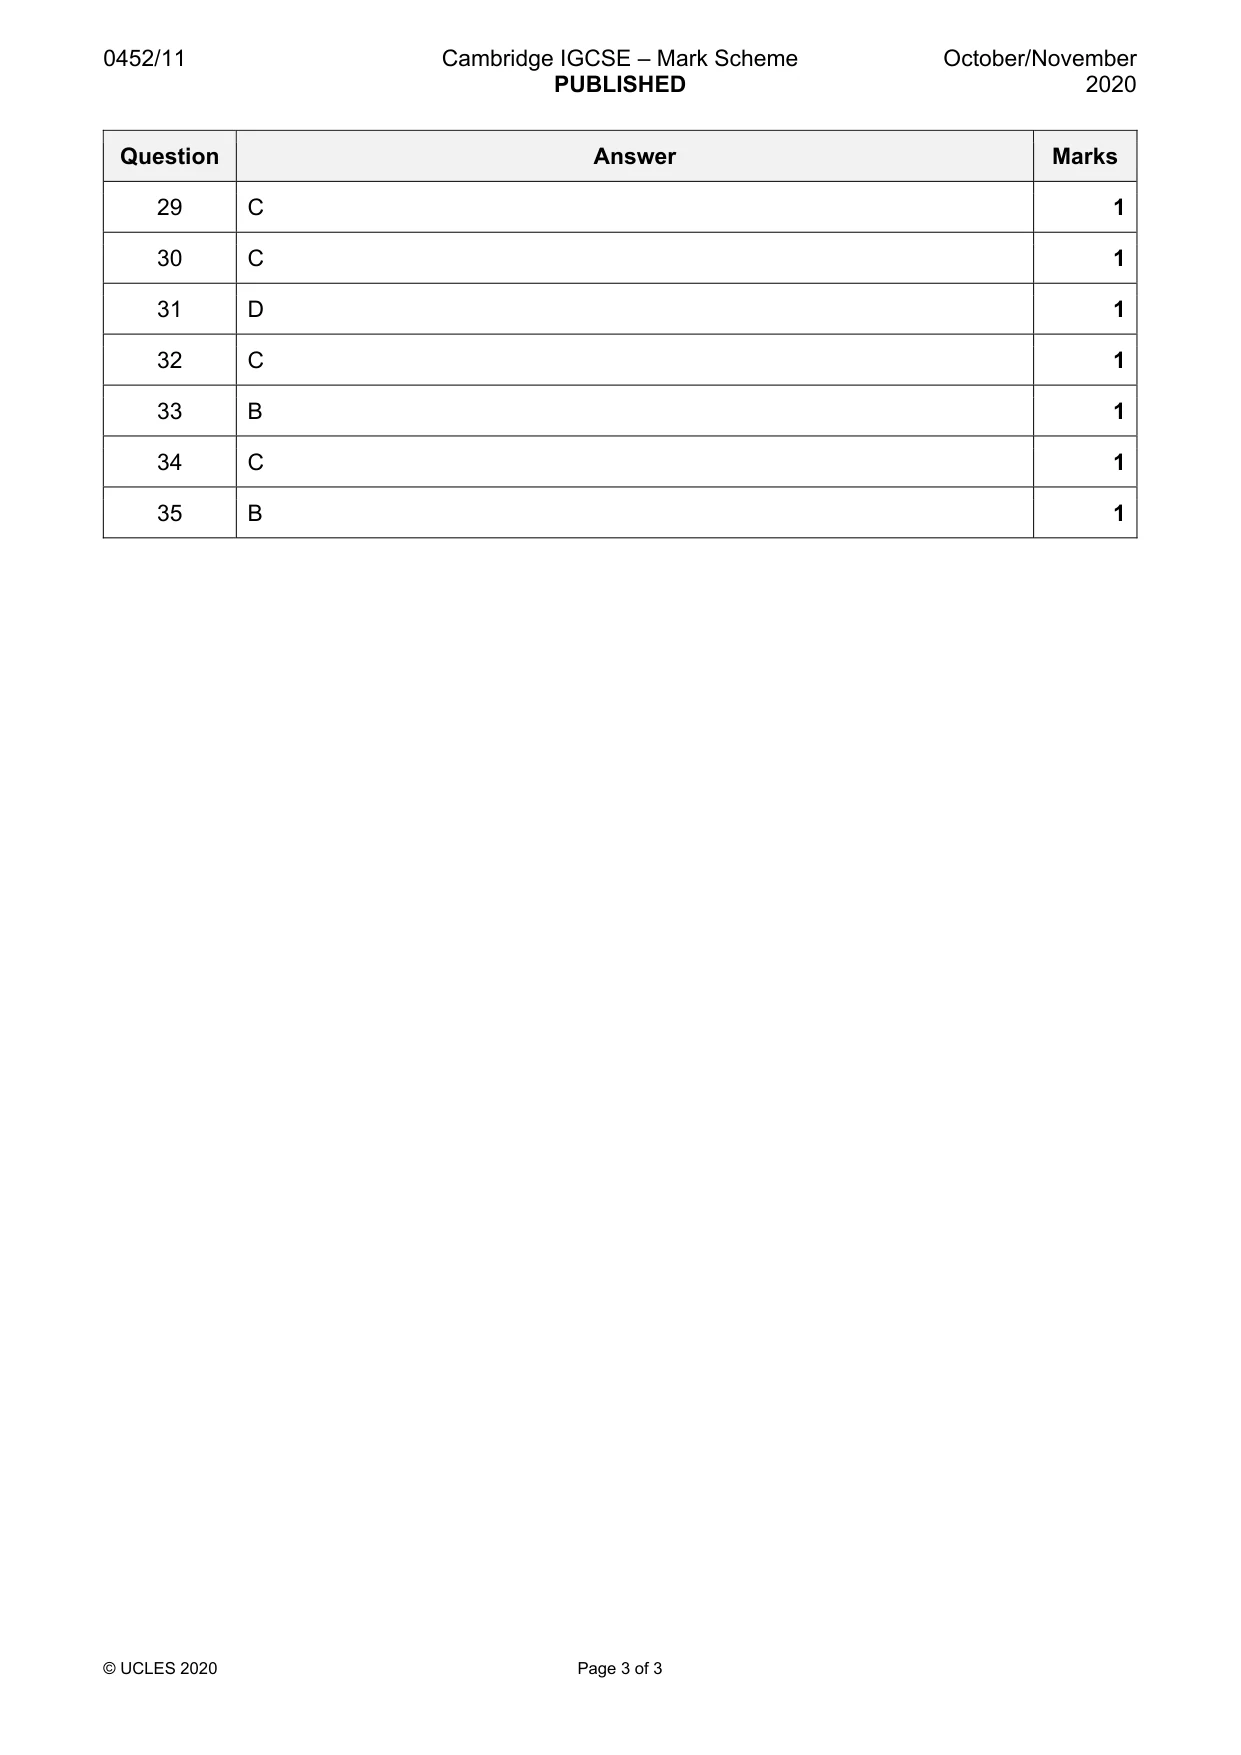
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · A trader prepares financial statements each year
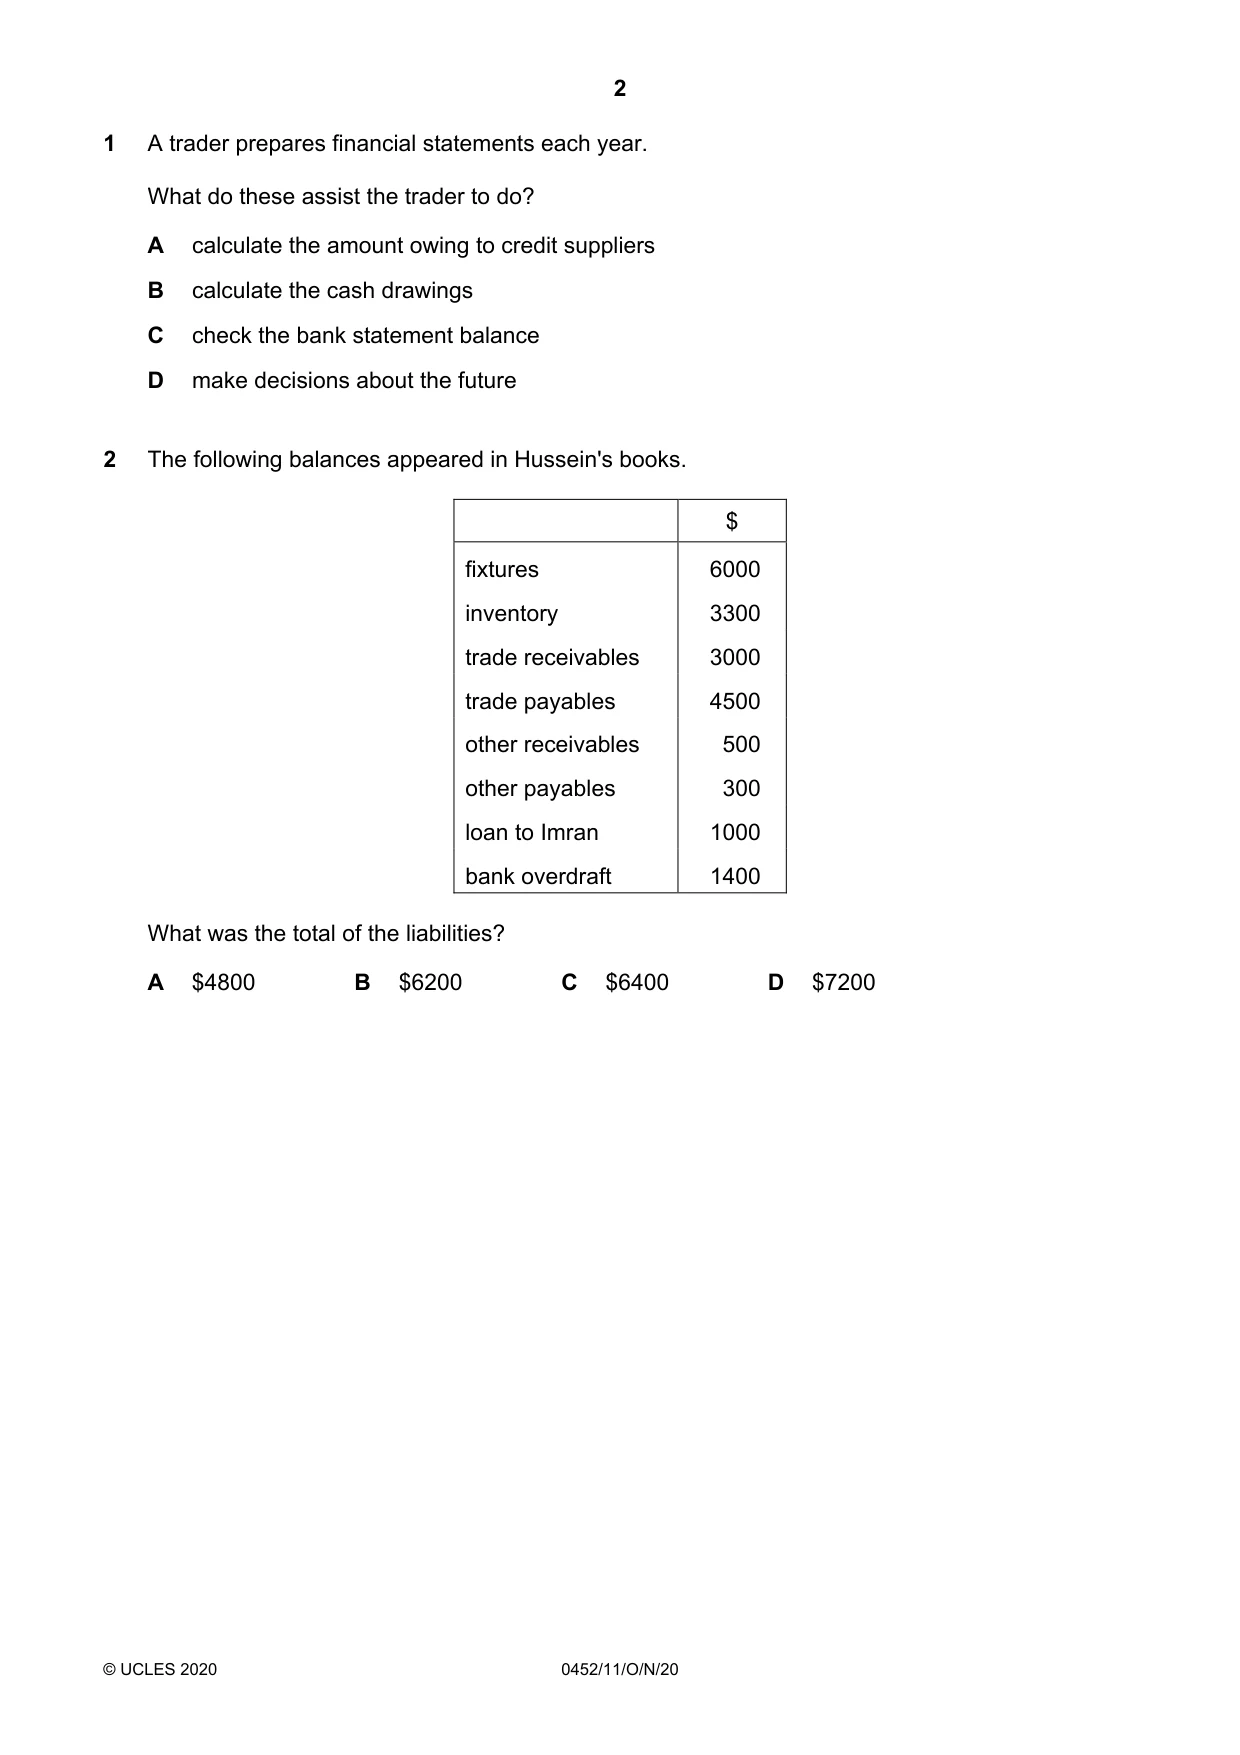
1 A trader prepares financial statements each year. What do these assist the trader to do? A calculate the amount owing to credit suppliers B calculate the cash drawings C check the bank statement balance D make decisions about the future
Mark scheme: D
Q2 · The following balances appeared in Hussein's books
2 The following balances appeared in Hussein's books. $ fixtures 6000 inventory 3300 trade receivables 3000 trade payables 4500 other receivables 500 other payables 300 loan to Imran 1000 bank overdraft 1400 What was the total of the liabilities? A $4800 B $6200 C $6400 D $7200
Mark scheme: B
Q3 · The following account appeared in the books of Mary
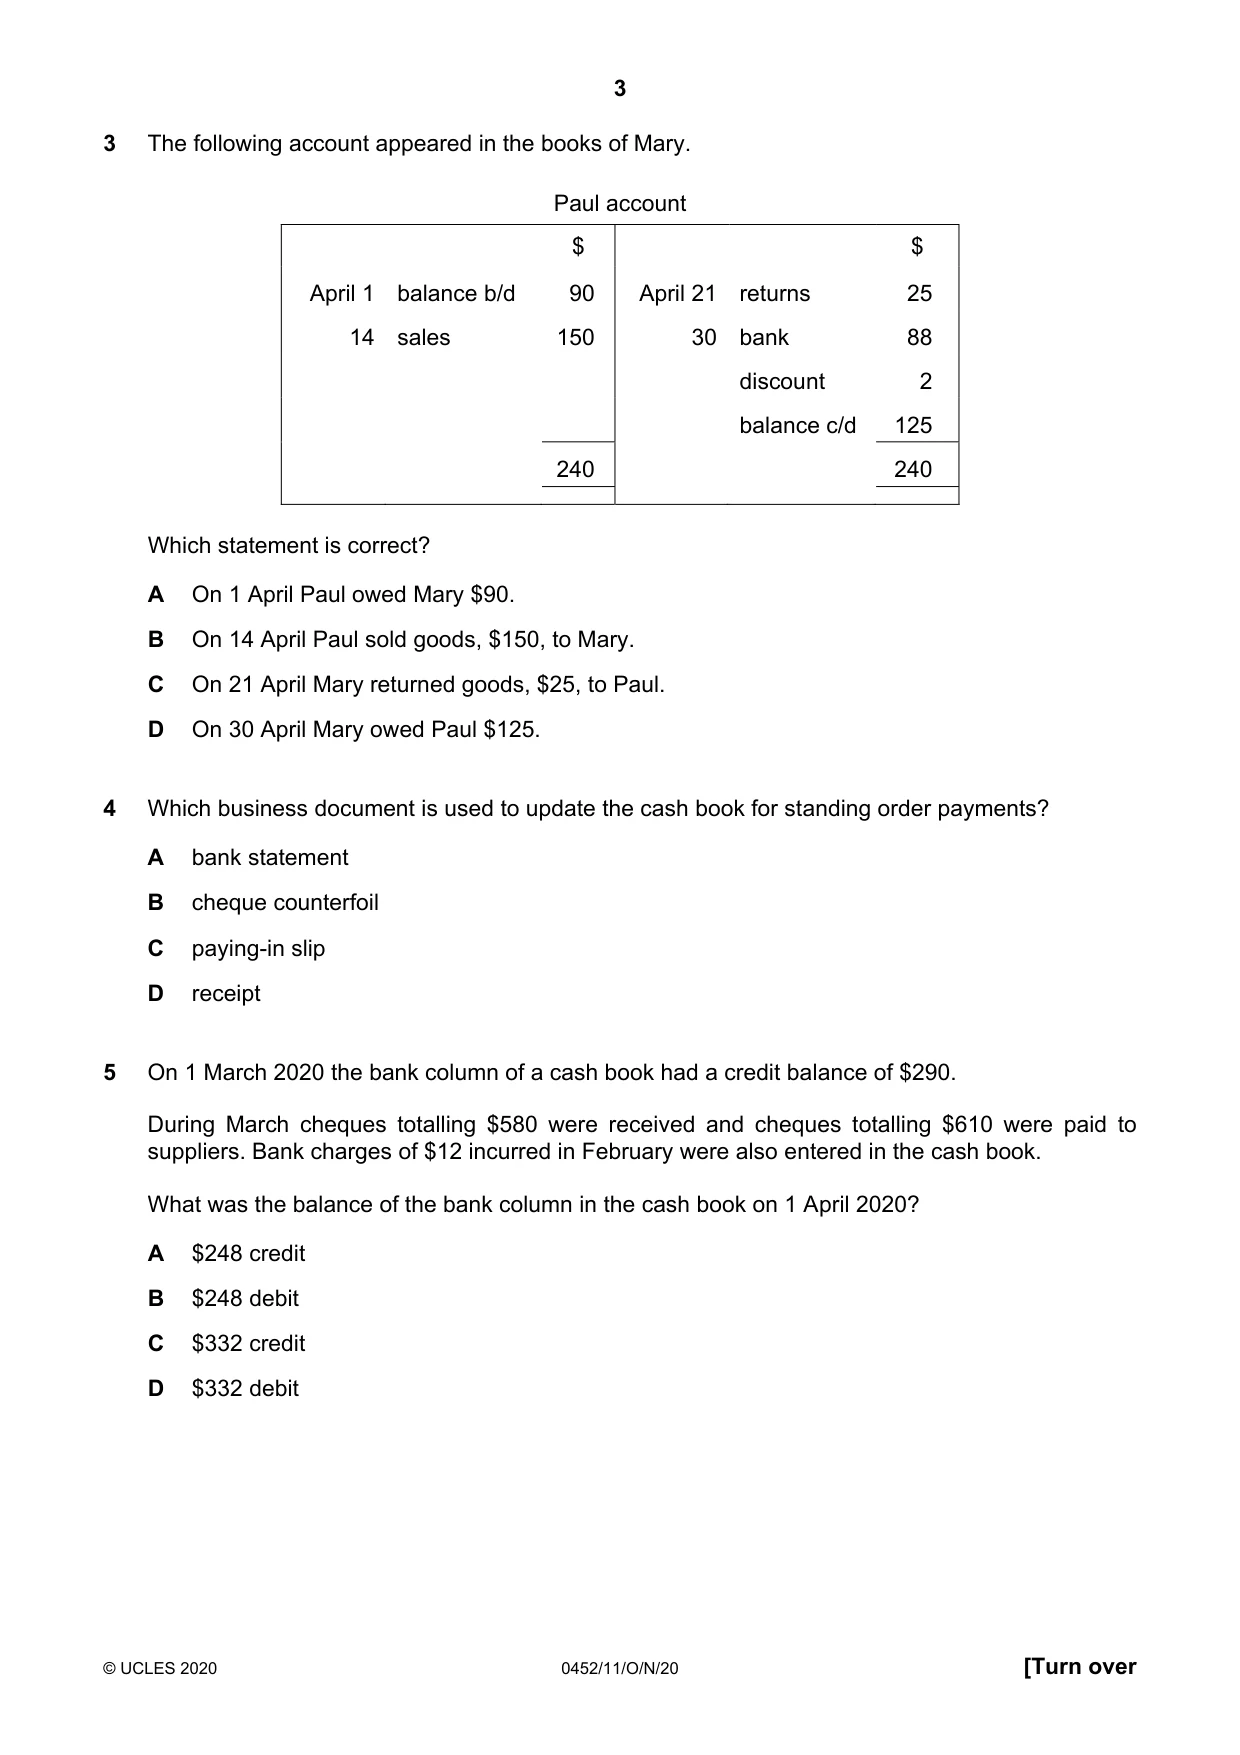
3 The following account appeared in the books of Mary. Paul account $ $ April 1 balance b/d 90 April 21 returns 25 14 sales 150 30 bank 88 discount 2 balance c/d 125 240 240 Which statement is correct? A On 1 April Paul owed Mary $90. B On 14 April Paul sold goods, $150, to Mary. C On 21 April Mary returned goods, $25, to Paul. D On 30 April Mary owed Paul $125.
Mark scheme: A
Q4 · Which business document is used to update the cash book for standing order payments?
4 Which business document is used to update the cash book for standing order payments? A bank statement B cheque counterfoil C paying-in slip D receipt
Mark scheme: A
Q5 · On 1 March 2020 the bank column of a cash book had a credit balance of $290
5 On 1 March 2020 the bank column of a cash book had a credit balance of $290. During March cheques totalling $580 were received and cheques totalling $610 were paid to suppliers. Bank charges of $12 incurred in February were also entered in the cash book. What was the balance of the bank column in the cash book on 1 April 2020? A $248 credit B $248 debit C $332 credit D $332 debit
Mark scheme: C
Q6 · Ziningi prepared a trial balance
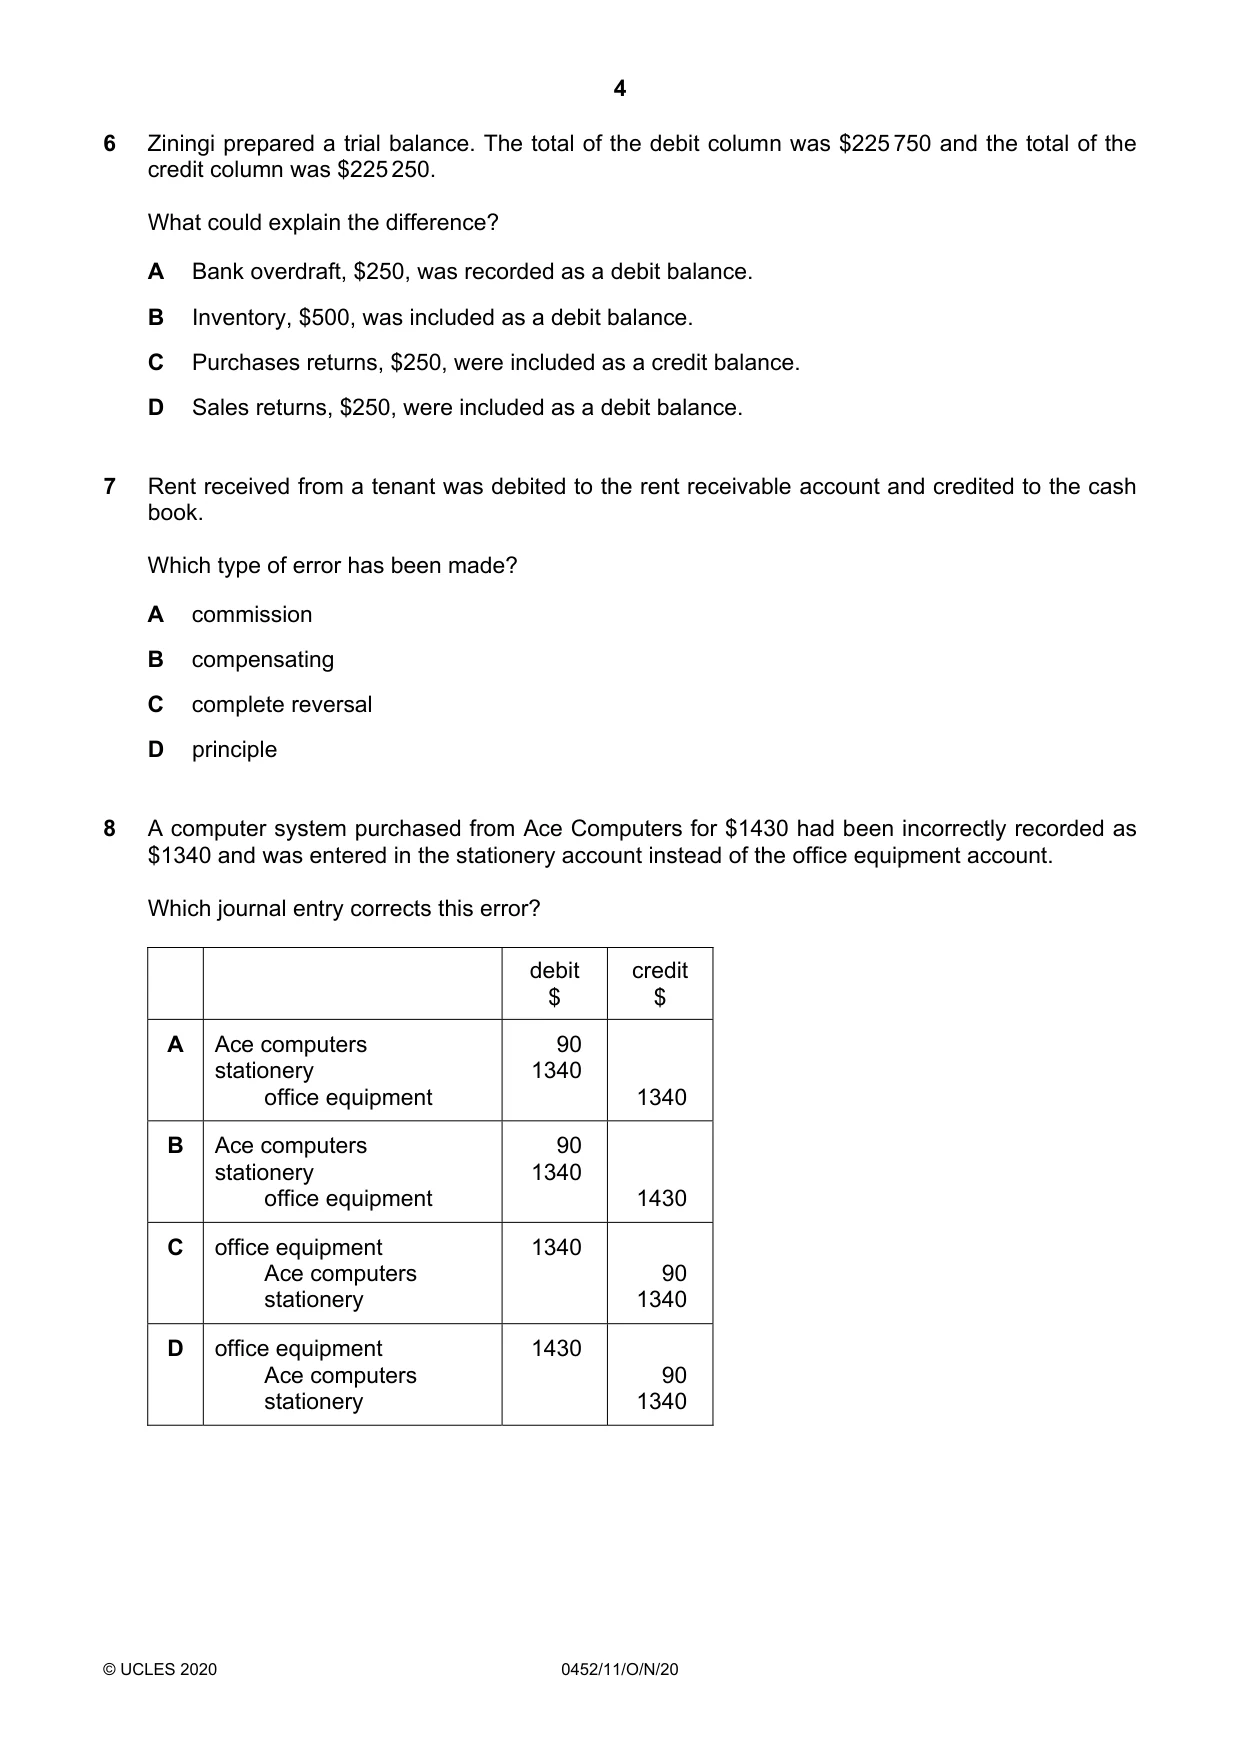
6 Ziningi prepared a trial balance. The total of the debit column was $225 750 and the total of the credit column was $225 250. What could explain the difference? A Bank overdraft, $250, was recorded as a debit balance. B Inventory, $500, was included as a debit balance. C Purchases returns, $250, were included as a credit balance. D Sales returns, $250, were included as a debit balance.
Mark scheme: A
Q7 · Rent received from a tenant was debited to the rent receivable account and credited to…
7 Rent received from a tenant was debited to the rent receivable account and credited to the cash book. Which type of error has been made? A commission B compensating C complete reversal D principle
Mark scheme: C
Q8 · A computer system purchased from Ace Computers for $1430 had been incorrectly recorded as…
8 A computer system purchased from Ace Computers for $1430 had been incorrectly recorded as $1340 and was entered in the stationery account instead of the office equipment account. Which journal entry corrects this error? debit credit $ $ A Ace computers 90 stationery 1340 office equipment 1340 B Ace computers 90 stationery 1340 office equipment 1430 C office equipment 1340 Ace computers 90 stationery 1340 D office equipment 1430 Ace computers 90 stationery 1340
Mark scheme: D
Q9 · Kate calculated her draft profit for the year at $28 400
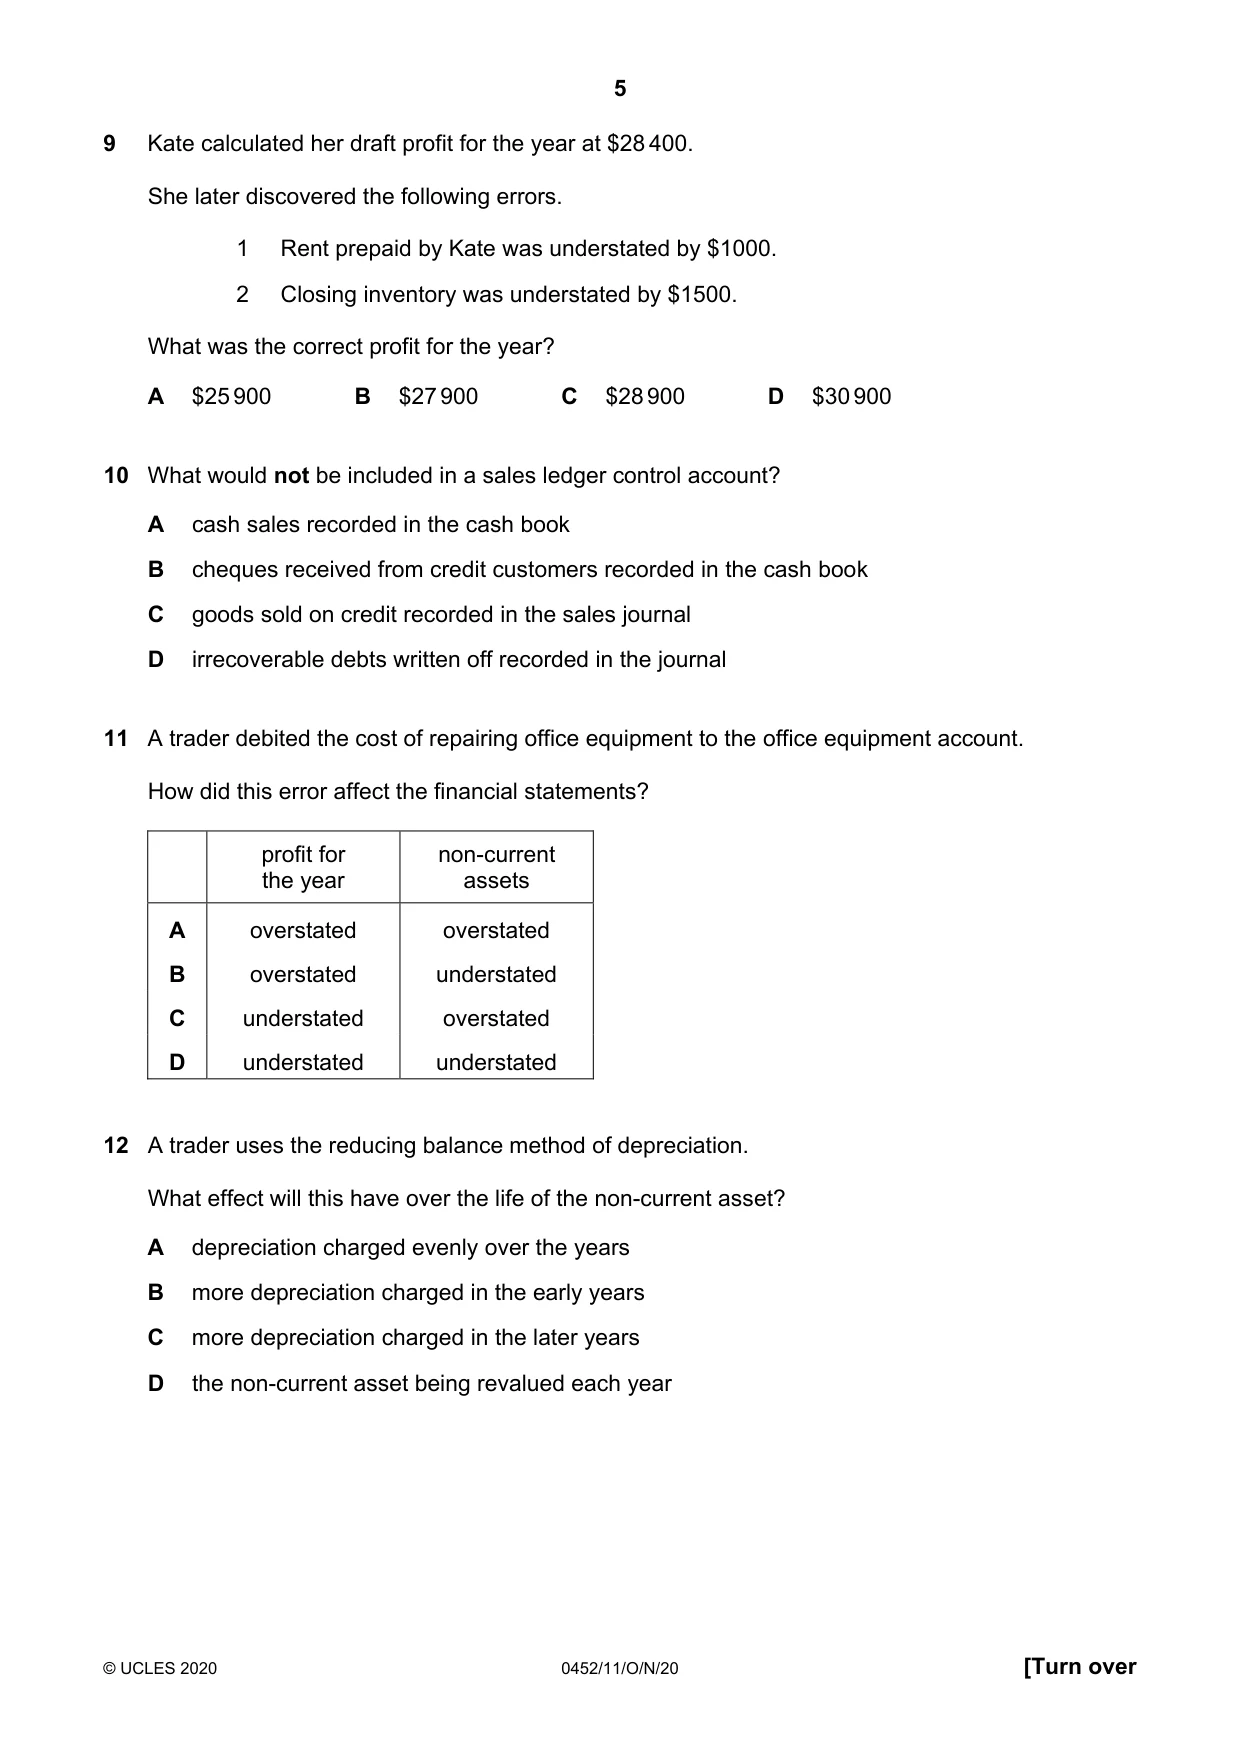
9 Kate calculated her draft profit for the year at $28 400. She later discovered the following errors. 1 Rent prepaid by Kate was understated by $1000. 2 Closing inventory was understated by $1500. What was the correct profit for the year? A $25 900 B $27 900 C $28 900 D $30 900
Mark scheme: D
Q10 · What would not be included in a sales ledger control account?
10 What would not be included in a sales ledger control account? A cash sales recorded in the cash book B cheques received from credit customers recorded in the cash book C goods sold on credit recorded in the sales journal D irrecoverable debts written off recorded in the journal
Mark scheme: A
Q11 · A trader debited the cost of repairing office equipment to the office equipment account
11 A trader debited the cost of repairing office equipment to the office equipment account. How did this error affect the financial statements? profit for non-current the year assets A overstated overstated B overstated understated C understated overstated D understated understated
Mark scheme: A
Q12 · A trader uses the reducing balance method of depreciation
12 A trader uses the reducing balance method of depreciation. What effect will this have over the life of the non-current asset? A depreciation charged evenly over the years B more depreciation charged in the early years C more depreciation charged in the later years D the non-current asset being revalued each year
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q13 · Rashid provided the following information at 31 December
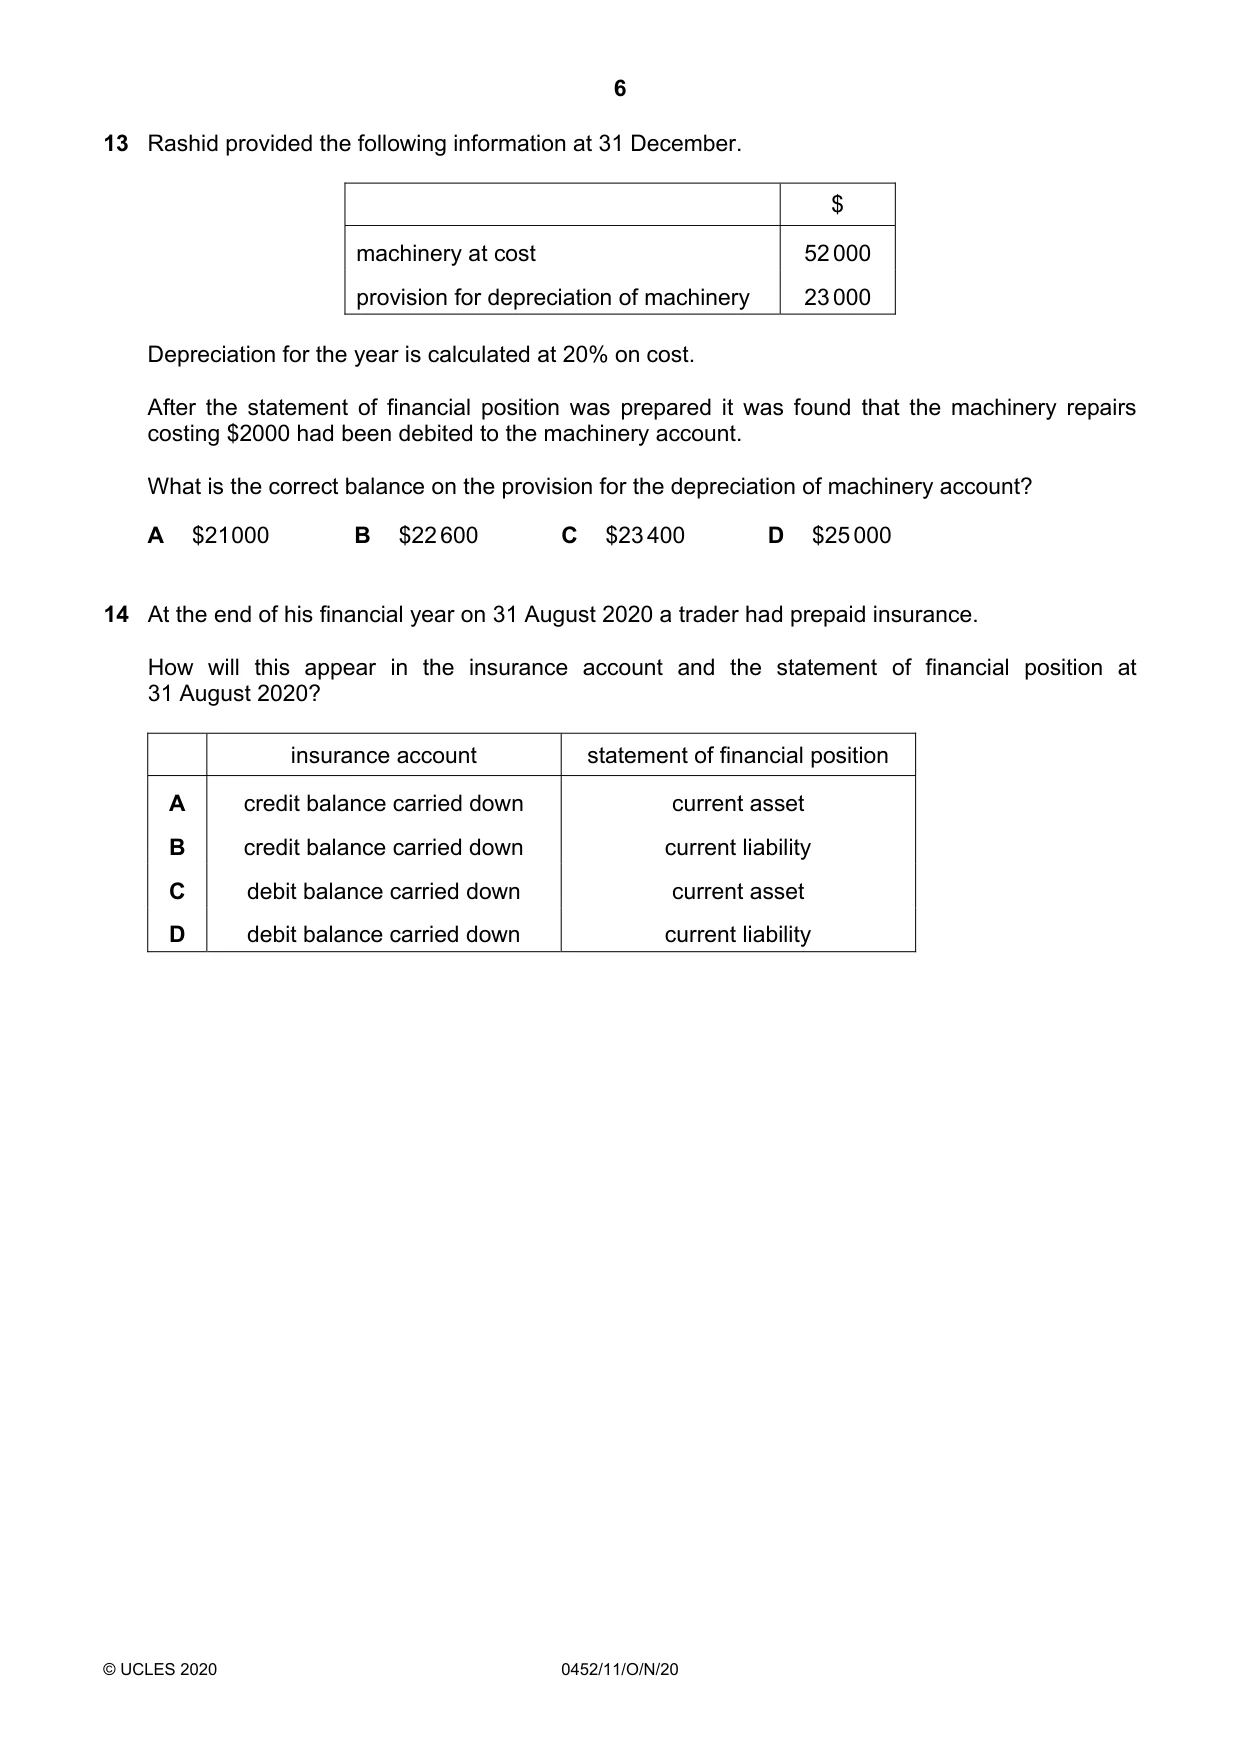
13 Rashid provided the following information at 31 December. $ machinery at cost 52 000 provision for depreciation of machinery 23 000 Depreciation for the year is calculated at 20% on cost. After the statement of financial position was prepared it was found that the machinery repairs costing $2000 had been debited to the machinery account. What is the correct balance on the provision for the depreciation of machinery account? A $21 000 B $22 600 C $23 400 D $25 000
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q14 · At the end of his financial year on 31 August 2020 a trader had prepaid insurance
14 At the end of his financial year on 31 August 2020 a trader had prepaid insurance. How will this appear in the insurance account and the statement of financial position at 31 August 2020? insurance account statement of financial position A credit balance carried down current asset B credit balance carried down current liability C debit balance carried down current asset D debit balance carried down current liability
Mark scheme: A
Q15 · Hayley’s financial year ends on 30 September 2020
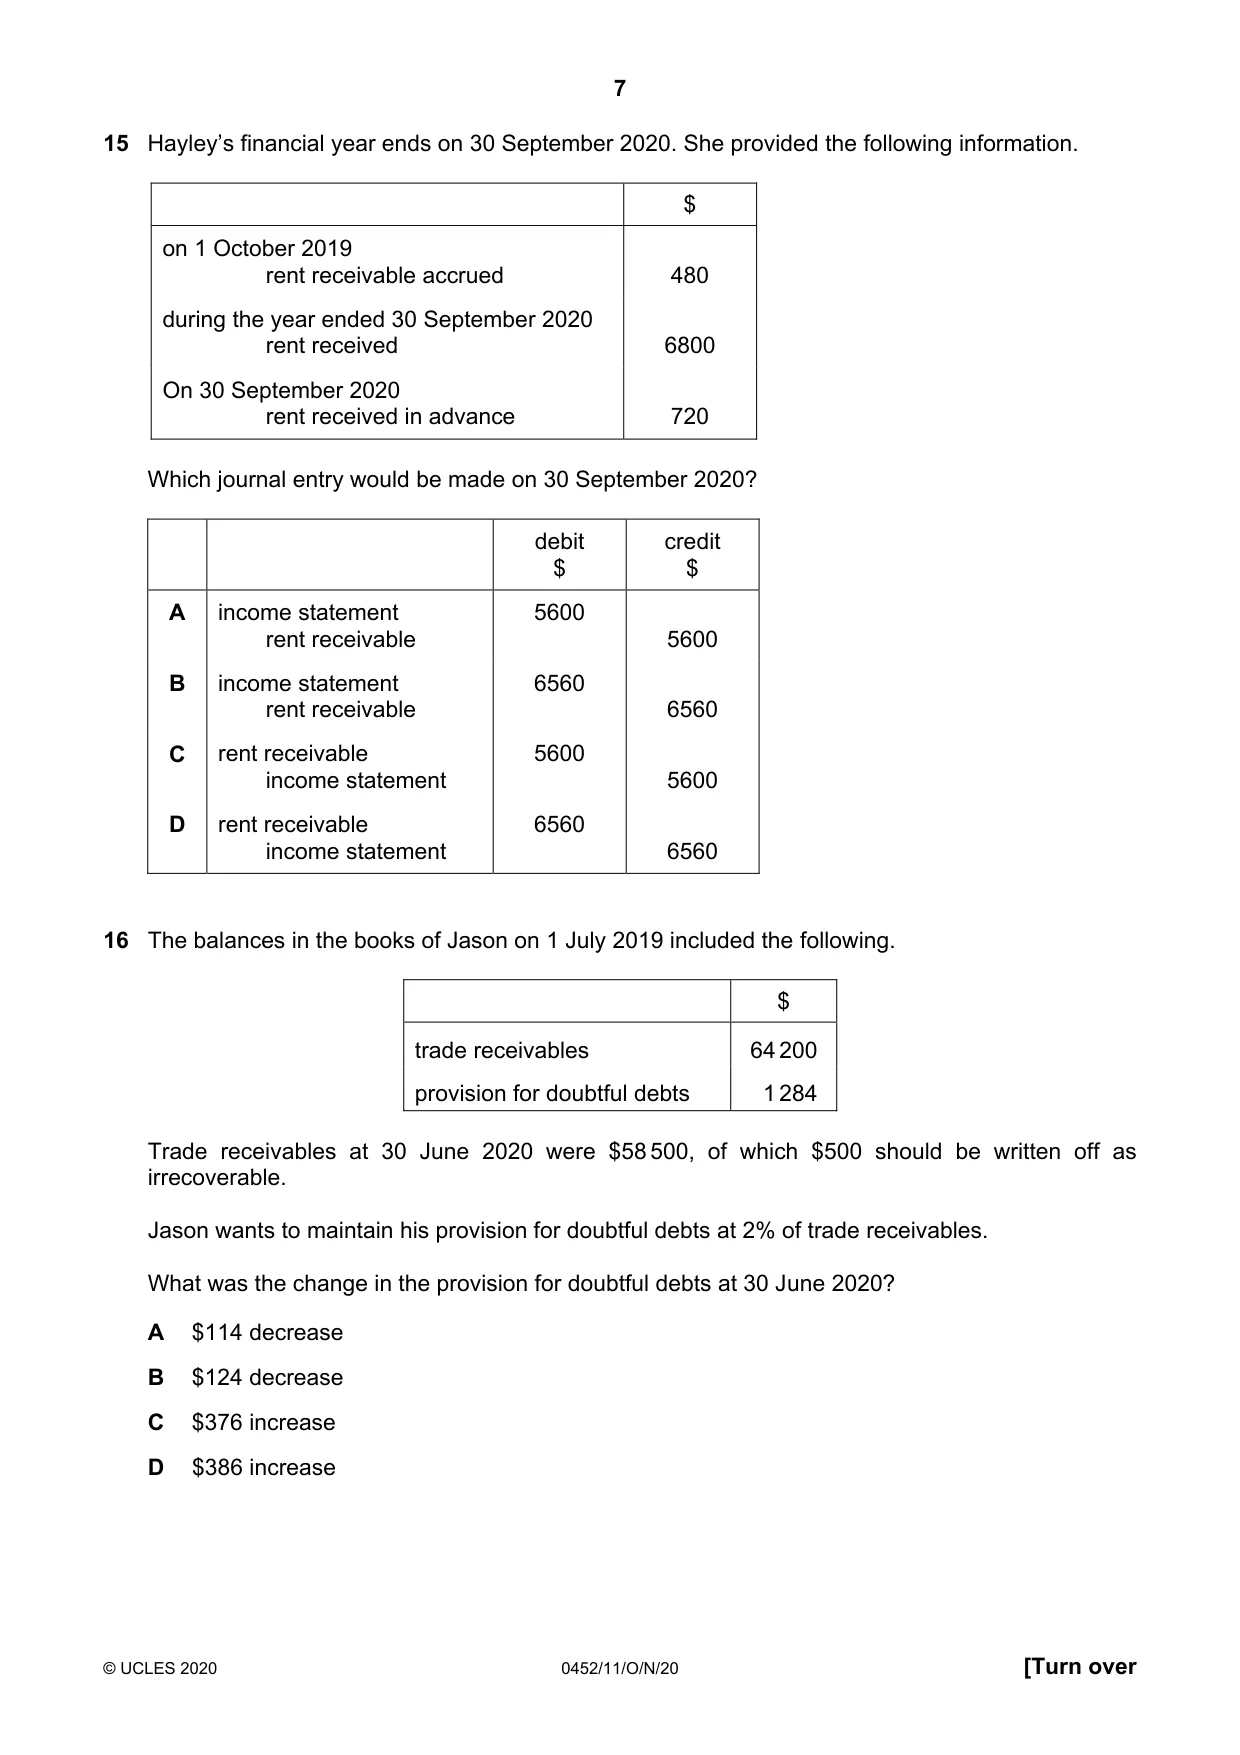
15 Hayley’s financial year ends on 30 September 2020. She provided the following information. $ on 1 October 2019 rent receivable accrued 480 during the year ended 30 September 2020 rent received 6800 On 30 September 2020 rent received in advance 720 Which journal entry would be made on 30 September 2020? debit credit $ $ A income statement 5600 rent receivable 5600 B income statement 6560 rent receivable 6560 C rent receivable 5600 income statement 5600 D rent receivable 6560 income statement 6560
Mark scheme: C
Q16 · The balances in the books of Jason on 1 July 2019 included the following
16 The balances in the books of Jason on 1 July 2019 included the following. $ trade receivables 64 200 provision for doubtful debts 1 284 Trade receivables at 30 June 2020 were $58 500, of which $500 should be written off as irrecoverable. Jason wants to maintain his provision for doubtful debts at 2% of trade receivables. What was the change in the provision for doubtful debts at 30 June 2020? A $114 decrease B $124 decrease C $376 increase D $386 increase
Mark scheme: B
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q17 · Nirmal sells two products, product G and product H
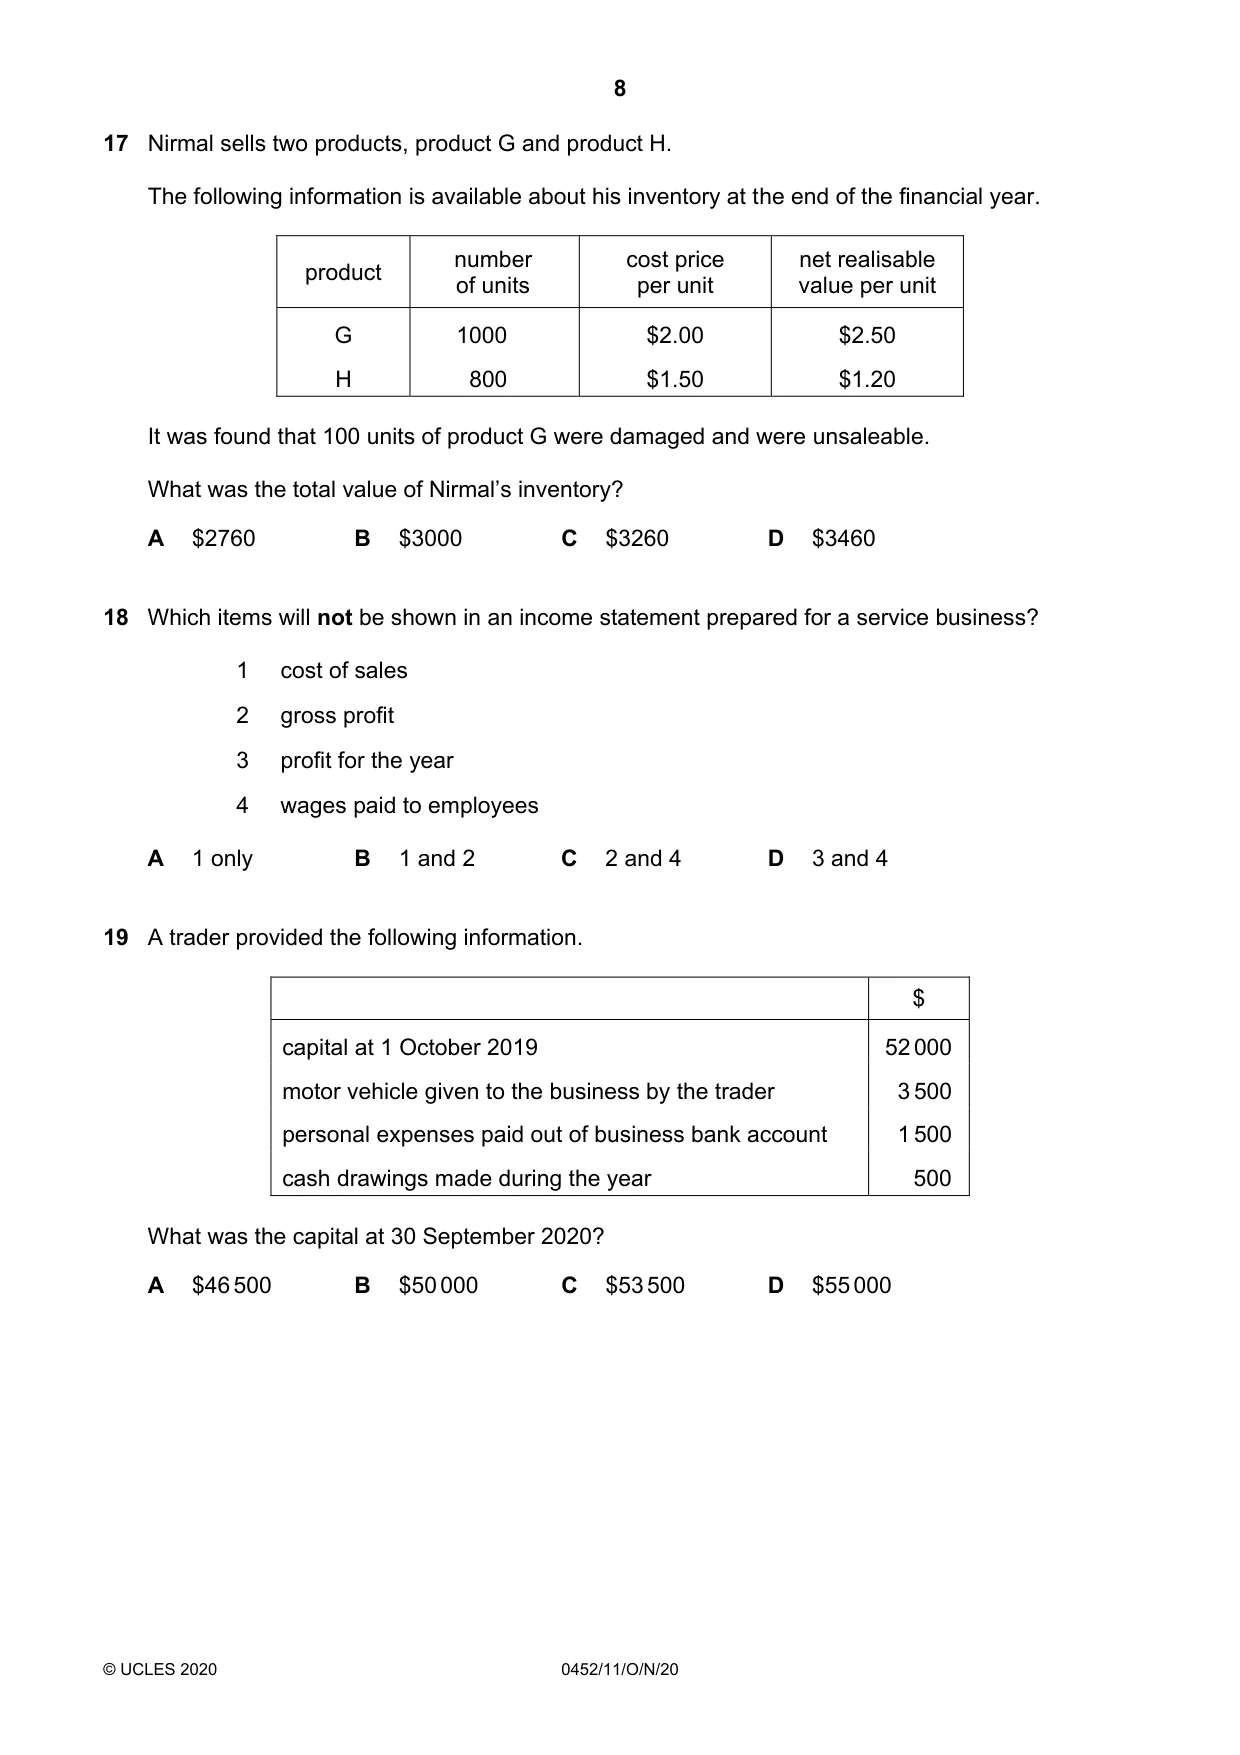
17 Nirmal sells two products, product G and product H. The following information is available about his inventory at the end of the financial year. number cost price net realisable product of units per unit value per unit G 1000 $2.00 $2.50 H 800 $1.50 $1.20 It was found that 100 units of product G were damaged and were unsaleable. What was the total value of Nirmal’s inventory? A $2760 B $3000 C $3260 D $3460
Mark scheme: A
Q18 · Which items will not be shown in an income statement prepared for a service business?
18 Which items will not be shown in an income statement prepared for a service business? 1 cost of sales 2 gross profit 3 profit for the year 4 wages paid to employees A 1 only B 1 and 2 C 2 and 4 D 3 and 4
Mark scheme: B
Q19 · A trader provided the following information
19 A trader provided the following information. $ capital at 1 October 2019 52 000 motor vehicle given to the business by the trader 3 500 personal expenses paid out of business bank account 1 500 cash drawings made during the year 500 What was the capital at 30 September 2020? A $46 500 B $50 000 C $53 500 D $55 000
Mark scheme: C
Q20 · John and Mark are in partnership
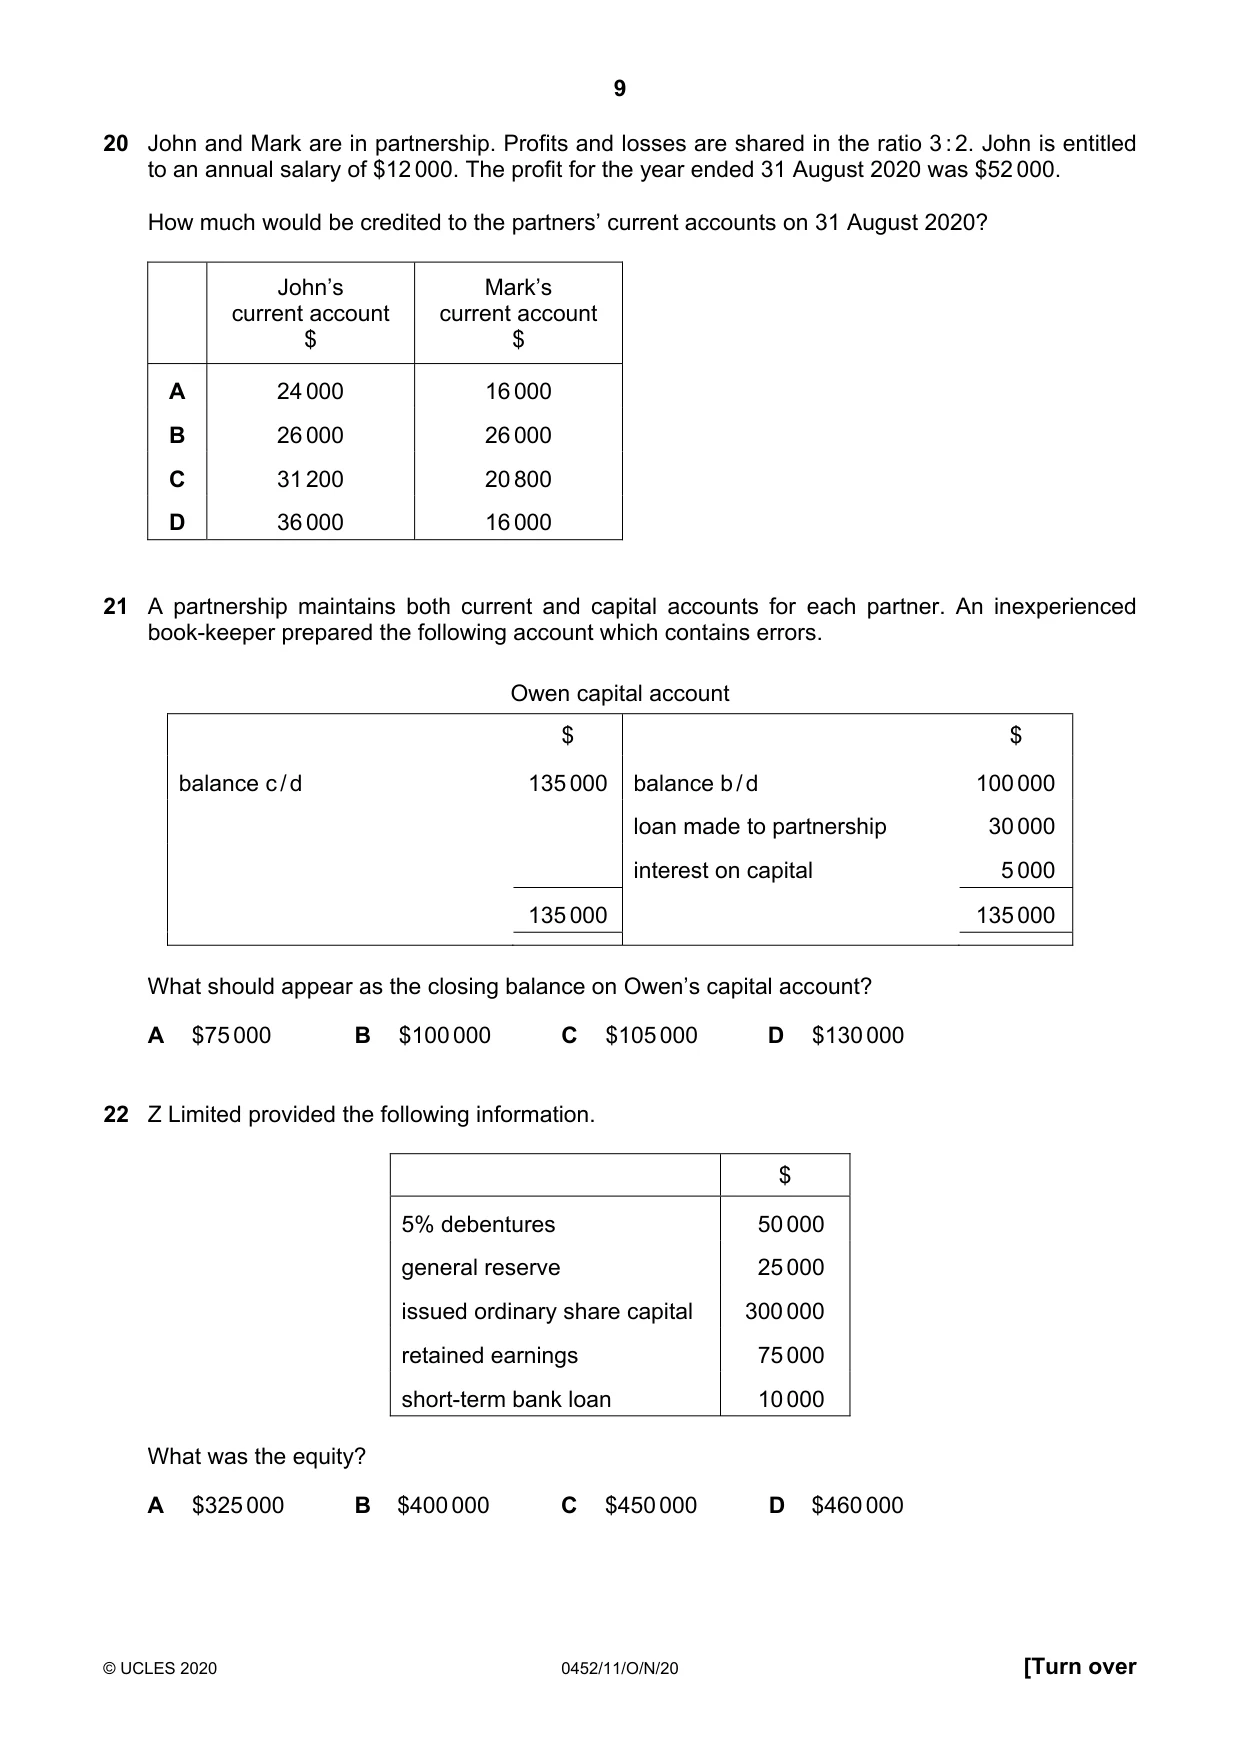
20 John and Mark are in partnership. Profits and losses are shared in the ratio 3 : 2. John is entitled to an annual salary of $12 000. The profit for the year ended 31 August 2020 was $52 000. How much would be credited to the partners’ current accounts on 31 August 2020? John’s Mark’s current account current account $ $ A 24 000 16 000 B 26 000 26 000 C 31 200 20 800 D 36 000 16 000
Mark scheme: D
Q21 · A partnership maintains both current and capital accounts for each partner
21 A partnership maintains both current and capital accounts for each partner. An inexperienced book-keeper prepared the following account which contains errors. Owen capital account $ $ balance c / d 135 000 balance b / d 100 000 loan made to partnership 30 000 interest on capital 5 000 135 000 135 000 What should appear as the closing balance on Owen’s capital account? A $75 000 B $100 000 C $105 000 D $130 000
Mark scheme: B
Q22 · Z Limited provided the following information
22 Z Limited provided the following information. $ 5% debentures 50 000 general reserve 25 000 issued ordinary share capital 300 000 retained earnings 75 000 short-term bank loan 10 000 What was the equity? A $325 000 B $400 000 C $450 000 D $460 000
Mark scheme: B
Q23 · Which statement about preference shares is not correct?
23 Which statement about preference shares is not correct? A Preference shareholders do not have voting rights. B Preference shareholders receive a fixed dividend. C Preference shareholders have a prior claim before ordinary shareholders in the event of liquidation. D Preference shareholders receive their dividend after the ordinary shareholders have been paid.
Mark scheme: D
Q24 · A sports club was formed on 1 September 2019
24 A sports club was formed on 1 September 2019. What may appear in the receipts and payments account for the year ended 31 August 2020? A closing bank balance B closing inventory of club shop C depreciation of sports equipment D subscriptions in arrears
Mark scheme: A
Q25 · A manufacturing company provided the following information
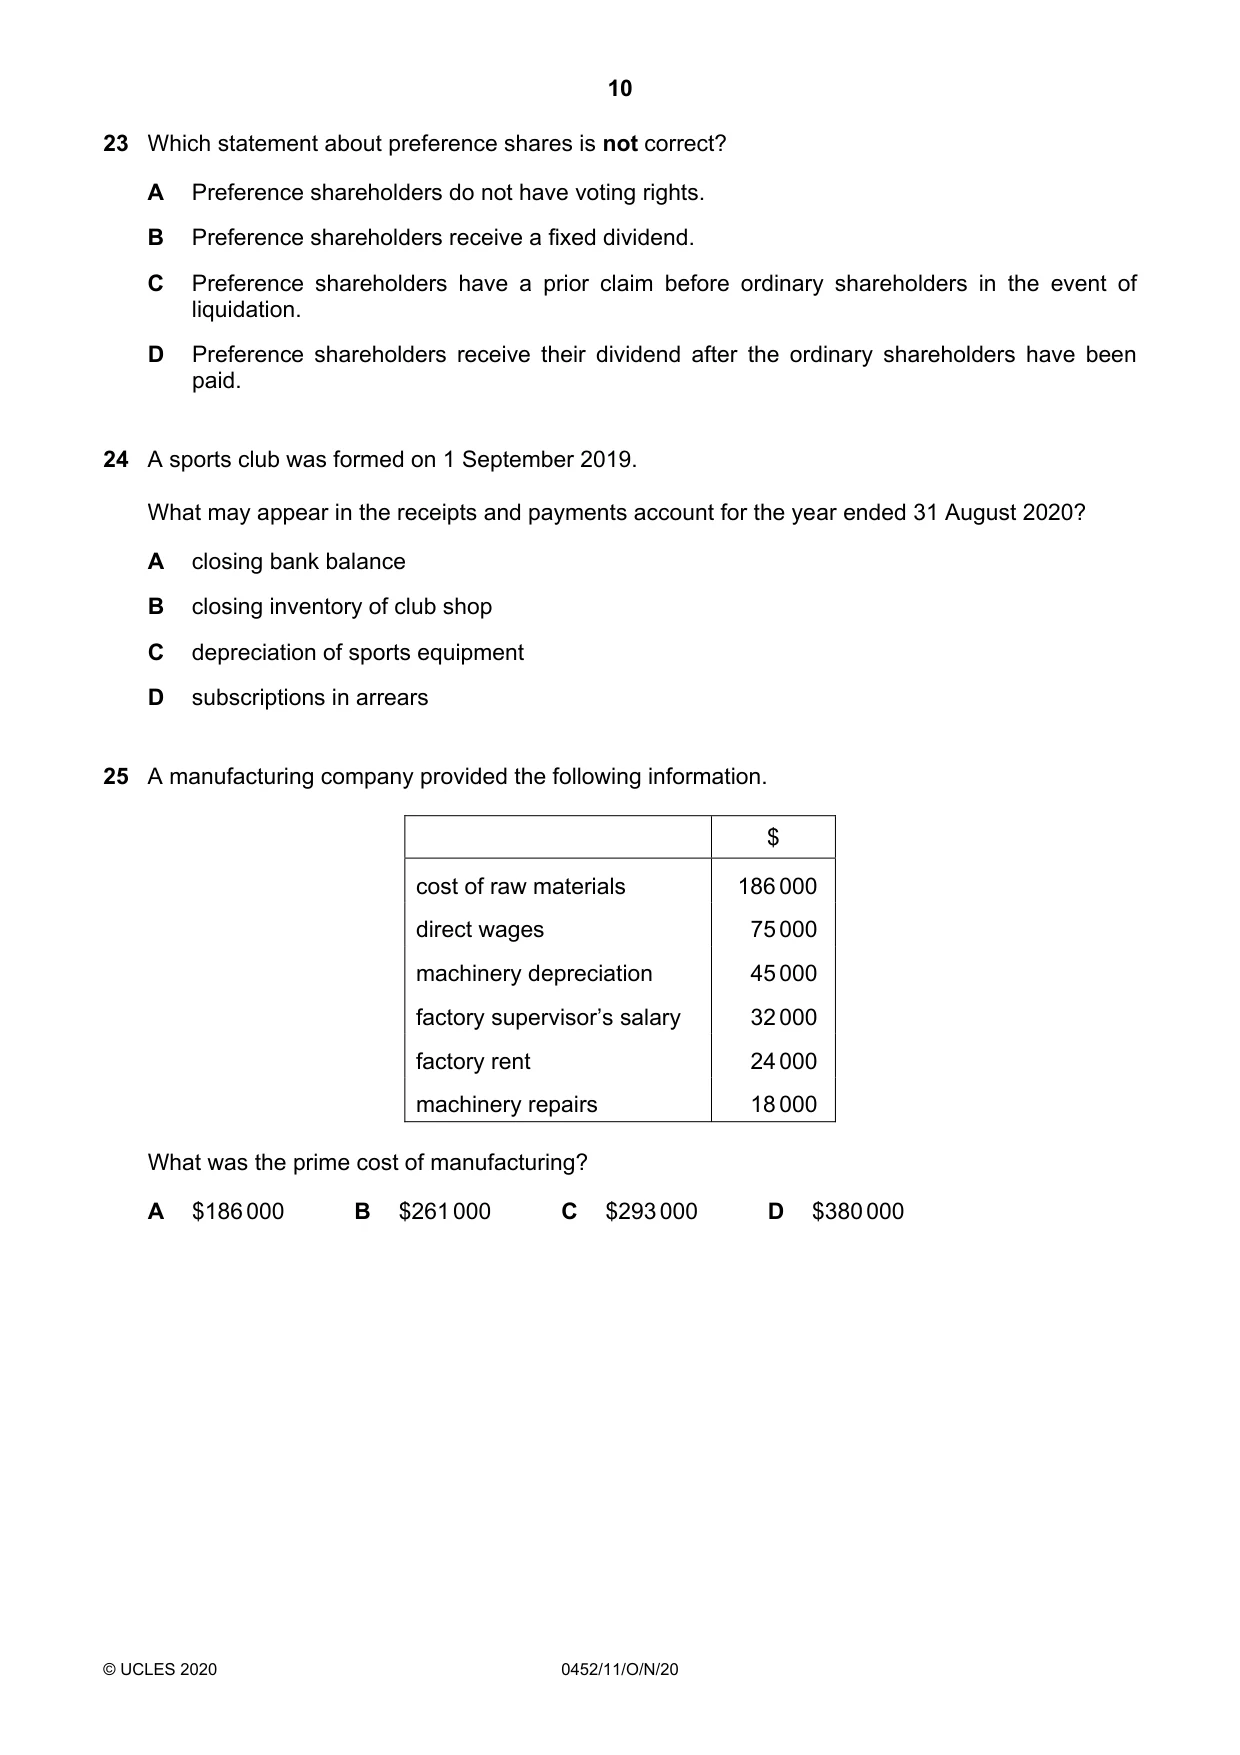
25 A manufacturing company provided the following information. $ cost of raw materials 186 000 direct wages 75 000 machinery depreciation 45 000 factory supervisor’s salary 32 000 factory rent 24 000 machinery repairs 18 000 What was the prime cost of manufacturing? A $186 000 B $261 000 C $293 000 D $380 000
Mark scheme: B
Q26 · A manufacturer’s work in progress at the start of the year was valued at $850
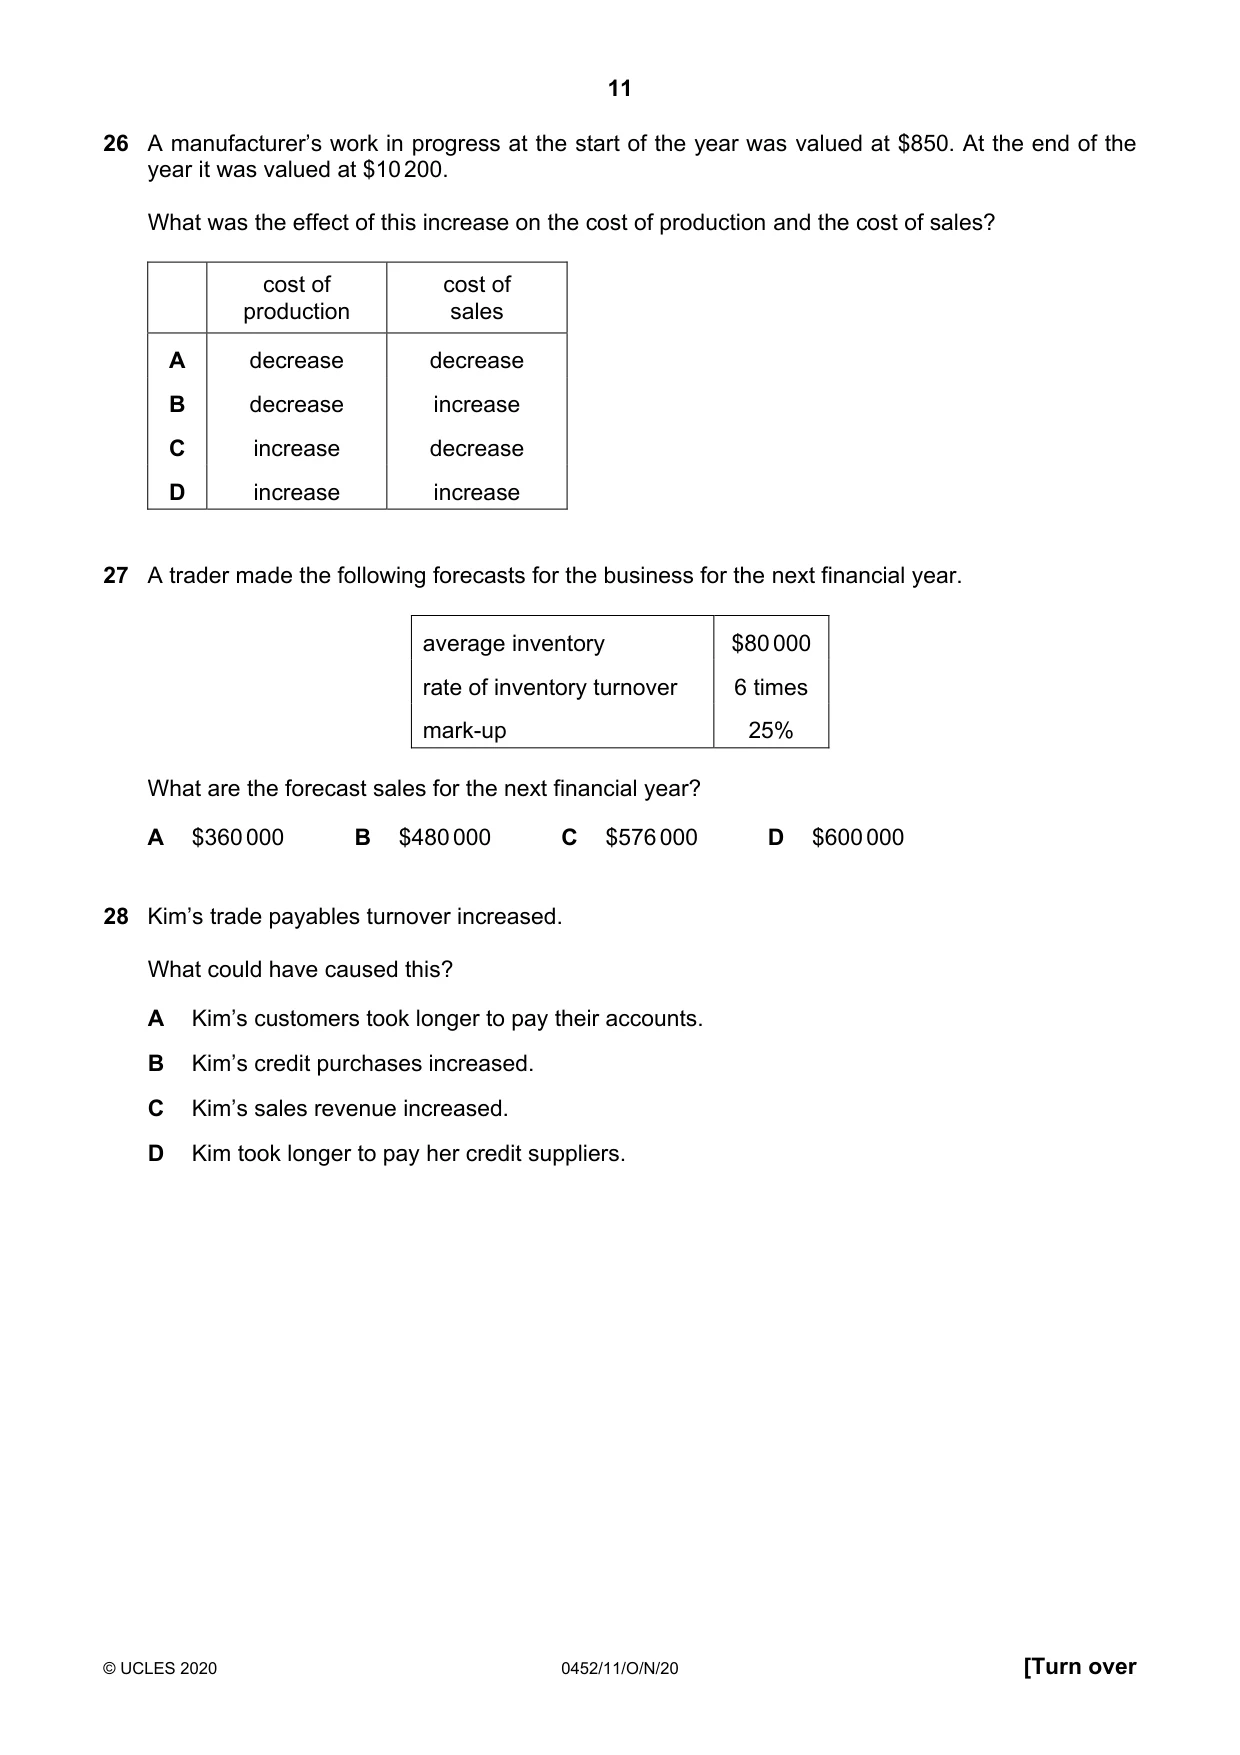
26 A manufacturer’s work in progress at the start of the year was valued at $850. At the end of the year it was valued at $10 200. What was the effect of this increase on the cost of production and the cost of sales? cost of cost of production sales A decrease decrease B decrease increase C increase decrease D increase increase
Mark scheme: A
Q27 · A trader made the following forecasts for the business for the next financial year
27 A trader made the following forecasts for the business for the next financial year. average inventory $80 000 rate of inventory turnover 6 times mark-up 25% What are the forecast sales for the next financial year? A $360 000 B $480 000 C $576 000 D $600 000
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
Q28 · Kim’s trade payables turnover increased
28 Kim’s trade payables turnover increased. What could have caused this? A Kim’s customers took longer to pay their accounts. B Kim’s credit purchases increased. C Kim’s sales revenue increased. D Kim took longer to pay her credit suppliers.
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
Q29 · A company provided the following information about its rate of inventory turnover
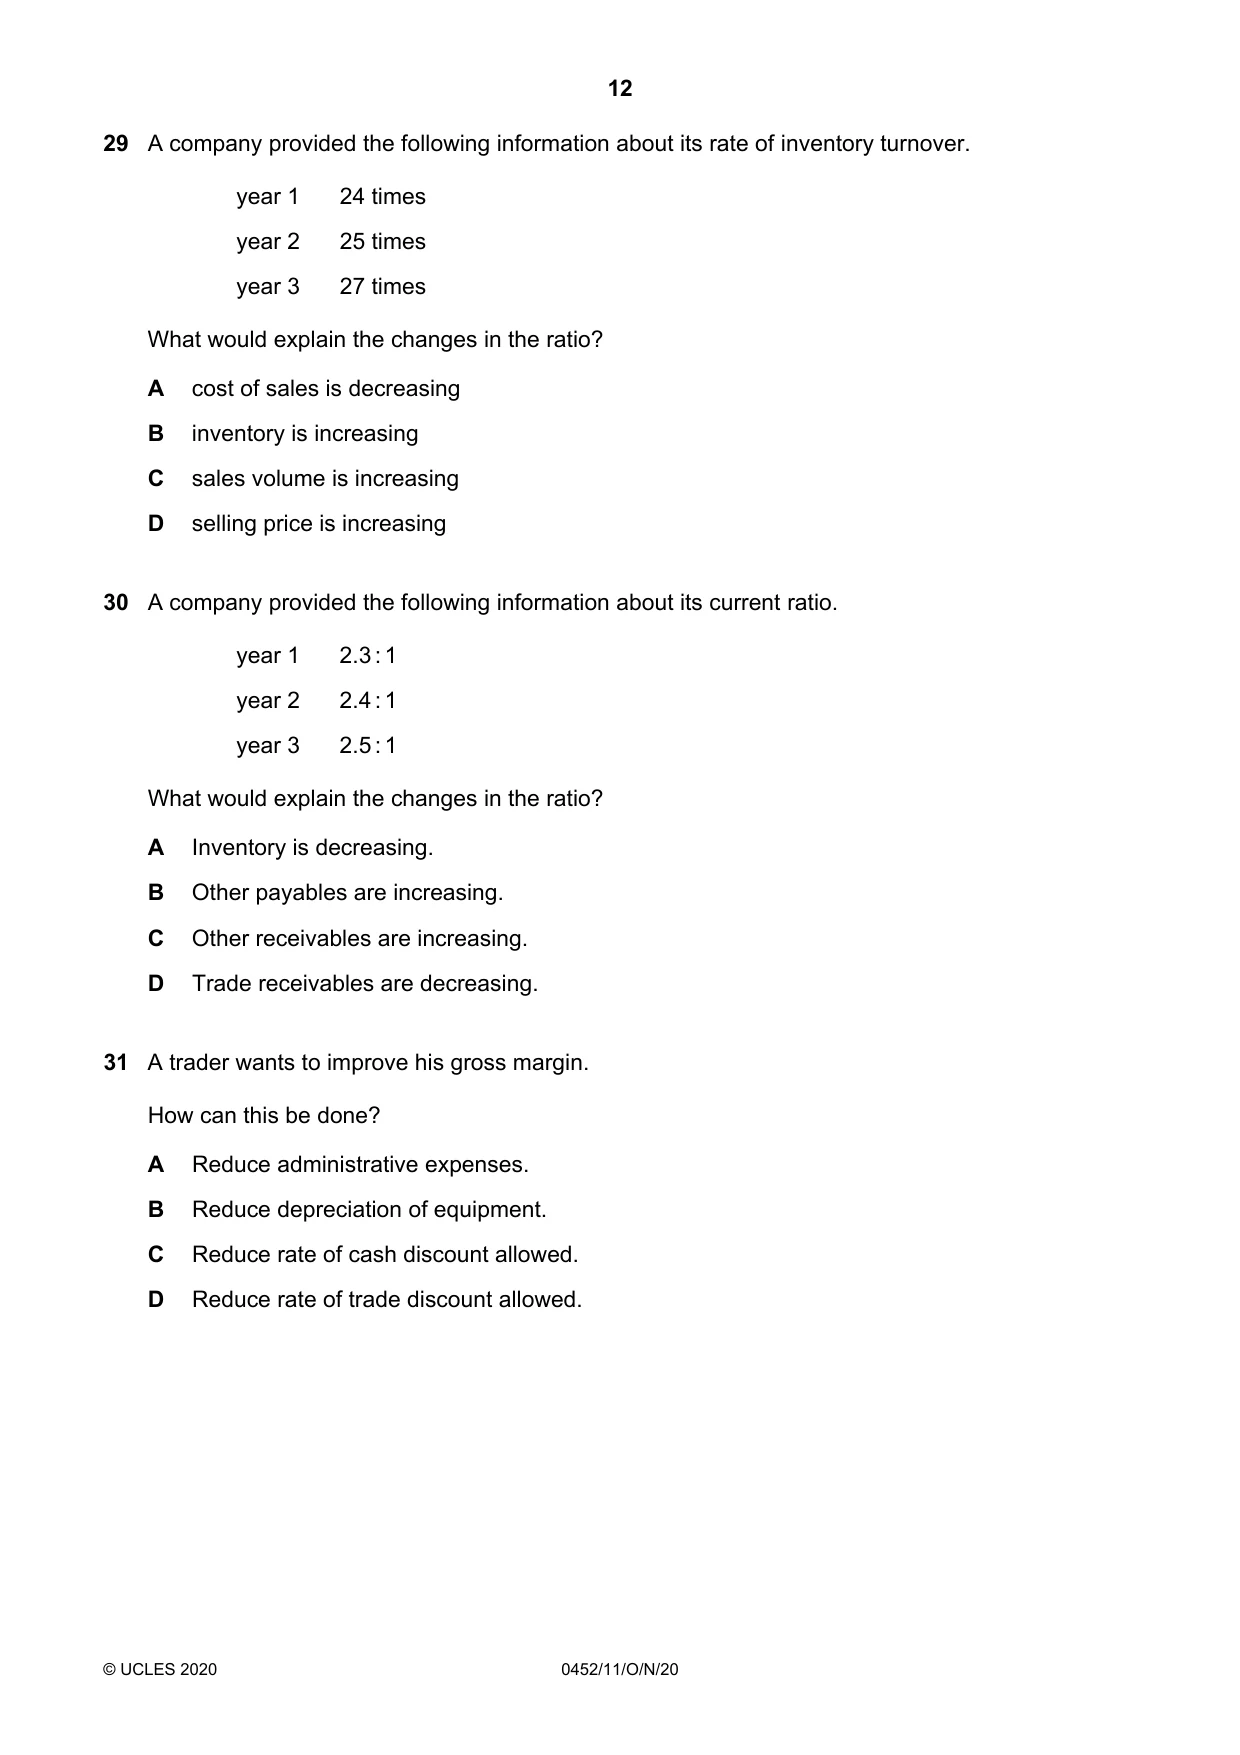
29 A company provided the following information about its rate of inventory turnover. year 1 24 times year 2 25 times year 3 27 times What would explain the changes in the ratio? A cost of sales is decreasing B inventory is increasing C sales volume is increasing D selling price is increasing
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
Q30 · A company provided the following information about its current ratio
30 A company provided the following information about its current ratio. year 1 2.3 : 1 year 2 2.4 : 1 year 3 2.5 : 1 What would explain the changes in the ratio? A Inventory is decreasing. B Other payables are increasing. C Other receivables are increasing. D Trade receivables are decreasing.
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
Q31 · A trader wants to improve his gross margin
31 A trader wants to improve his gross margin. How can this be done? A Reduce administrative expenses. B Reduce depreciation of equipment. C Reduce rate of cash discount allowed. D Reduce rate of trade discount allowed.
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
Q32 · Zak has depreciated his machinery at the rate of 20% per annum using the straight-line…
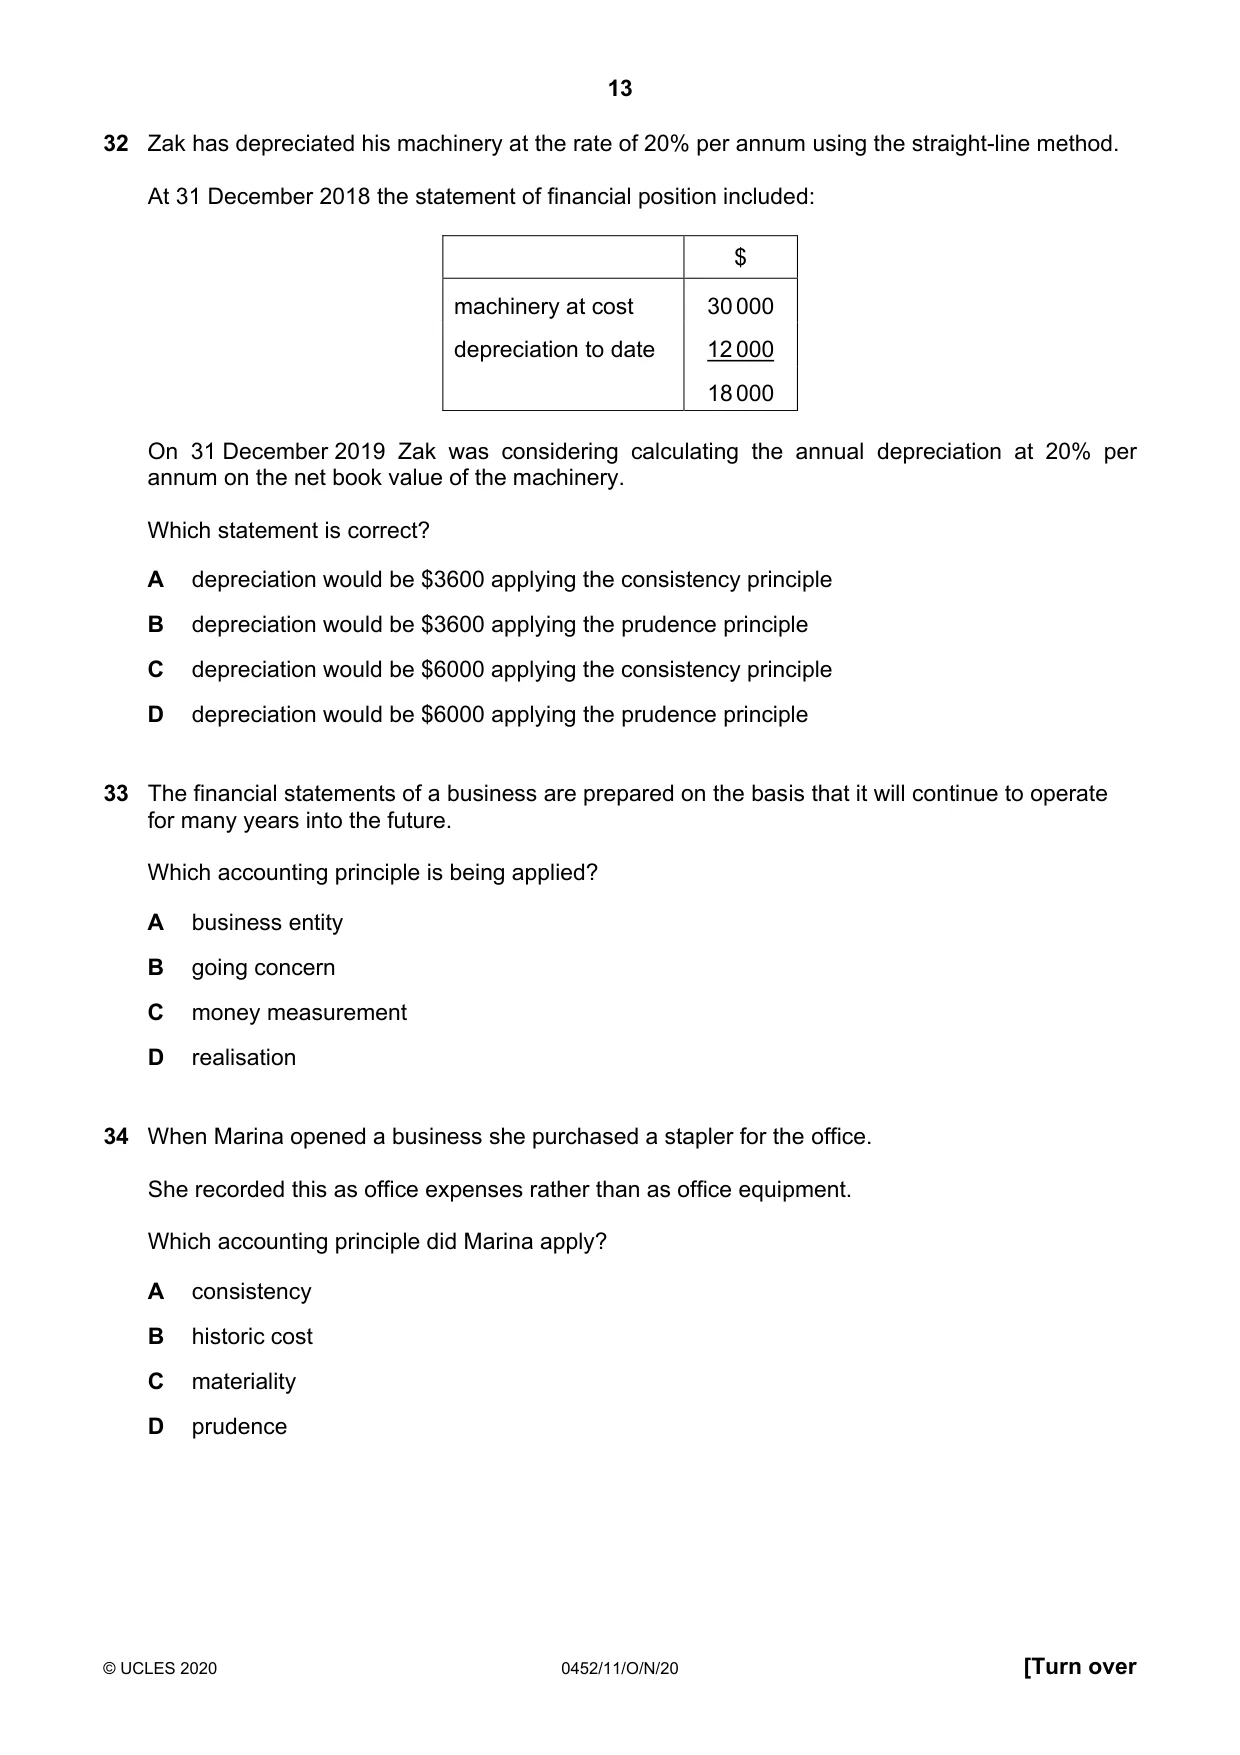
32 Zak has depreciated his machinery at the rate of 20% per annum using the straight-line method. At 31 December 2018 the statement of financial position included: $ machinery at cost 30 000 depreciation to date 12 000 18 000 On 31 December 2019 Zak was considering calculating the annual depreciation at 20% per annum on the net book value of the machinery. Which statement is correct? A depreciation would be $3600 applying the consistency principle B depreciation would be $3600 applying the prudence principle C depreciation would be $6000 applying the consistency principle D depreciation would be $6000 applying the prudence principle
Mark scheme: C
Q33 · The financial statements of a business are prepared on the basis that it will continue to…
33 The financial statements of a business are prepared on the basis that it will continue to operate for many years into the future. Which accounting principle is being applied? A business entity B going concern C money measurement D realisation
Mark scheme: B
Q34 · When Marina opened a business she purchased a stapler for the office
34 When Marina opened a business she purchased a stapler for the office. She recorded this as office expenses rather than as office equipment. Which accounting principle did Marina apply? A consistency B historic cost C materiality D prudence
Mark scheme: C
Q35 · What is not an aim of international accounting standards?
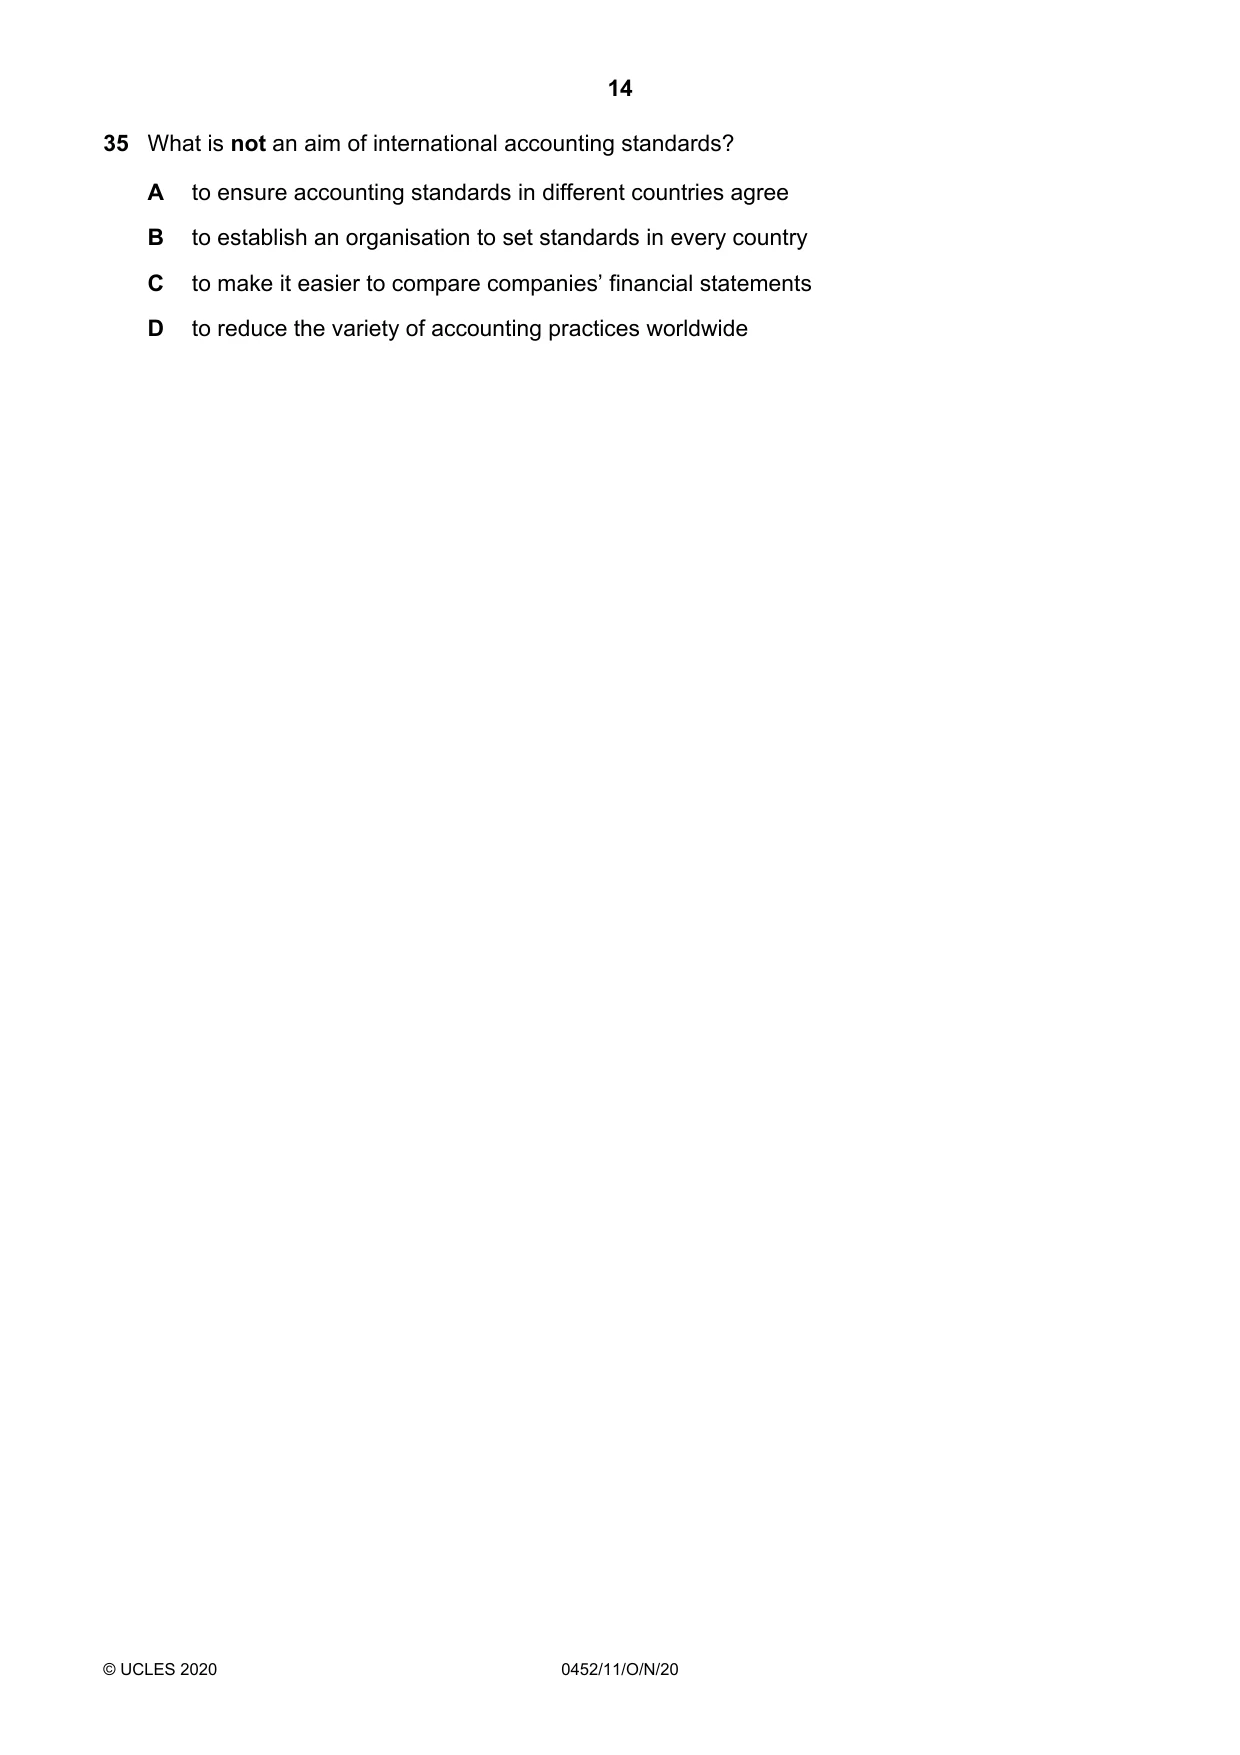
35 What is not an aim of international accounting standards? A to ensure accounting standards in different countries agree B to establish an organisation to set standards in every country C to make it easier to compare companies’ financial statements D to reduce the variety of accounting practices worldwide
Mark scheme: B
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
5Accounting concepts4Corrections of errors3Accounting for depreciation and disposal of non-current assets2Limited companies2Manufacturing accounts2Other payables and other receivables2Partnerships2Sole traders2Bank reconciliation1Business documents1Clubs and societies1Control accounts1Irrecoverable debts and allowance for irrecoverable debts1The accounting equation1The double entry system of book-keeping1The purpose of accounting1The trial balance1Valuation of inventory1What you needed in this session
Cambridge’s own grade thresholds for 2020 Oct/Nov, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.