Cambridge IGCSE Accounting 0452 — 2020 May/June Paper 1 · Variant 3
0452/13/M/J/20 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
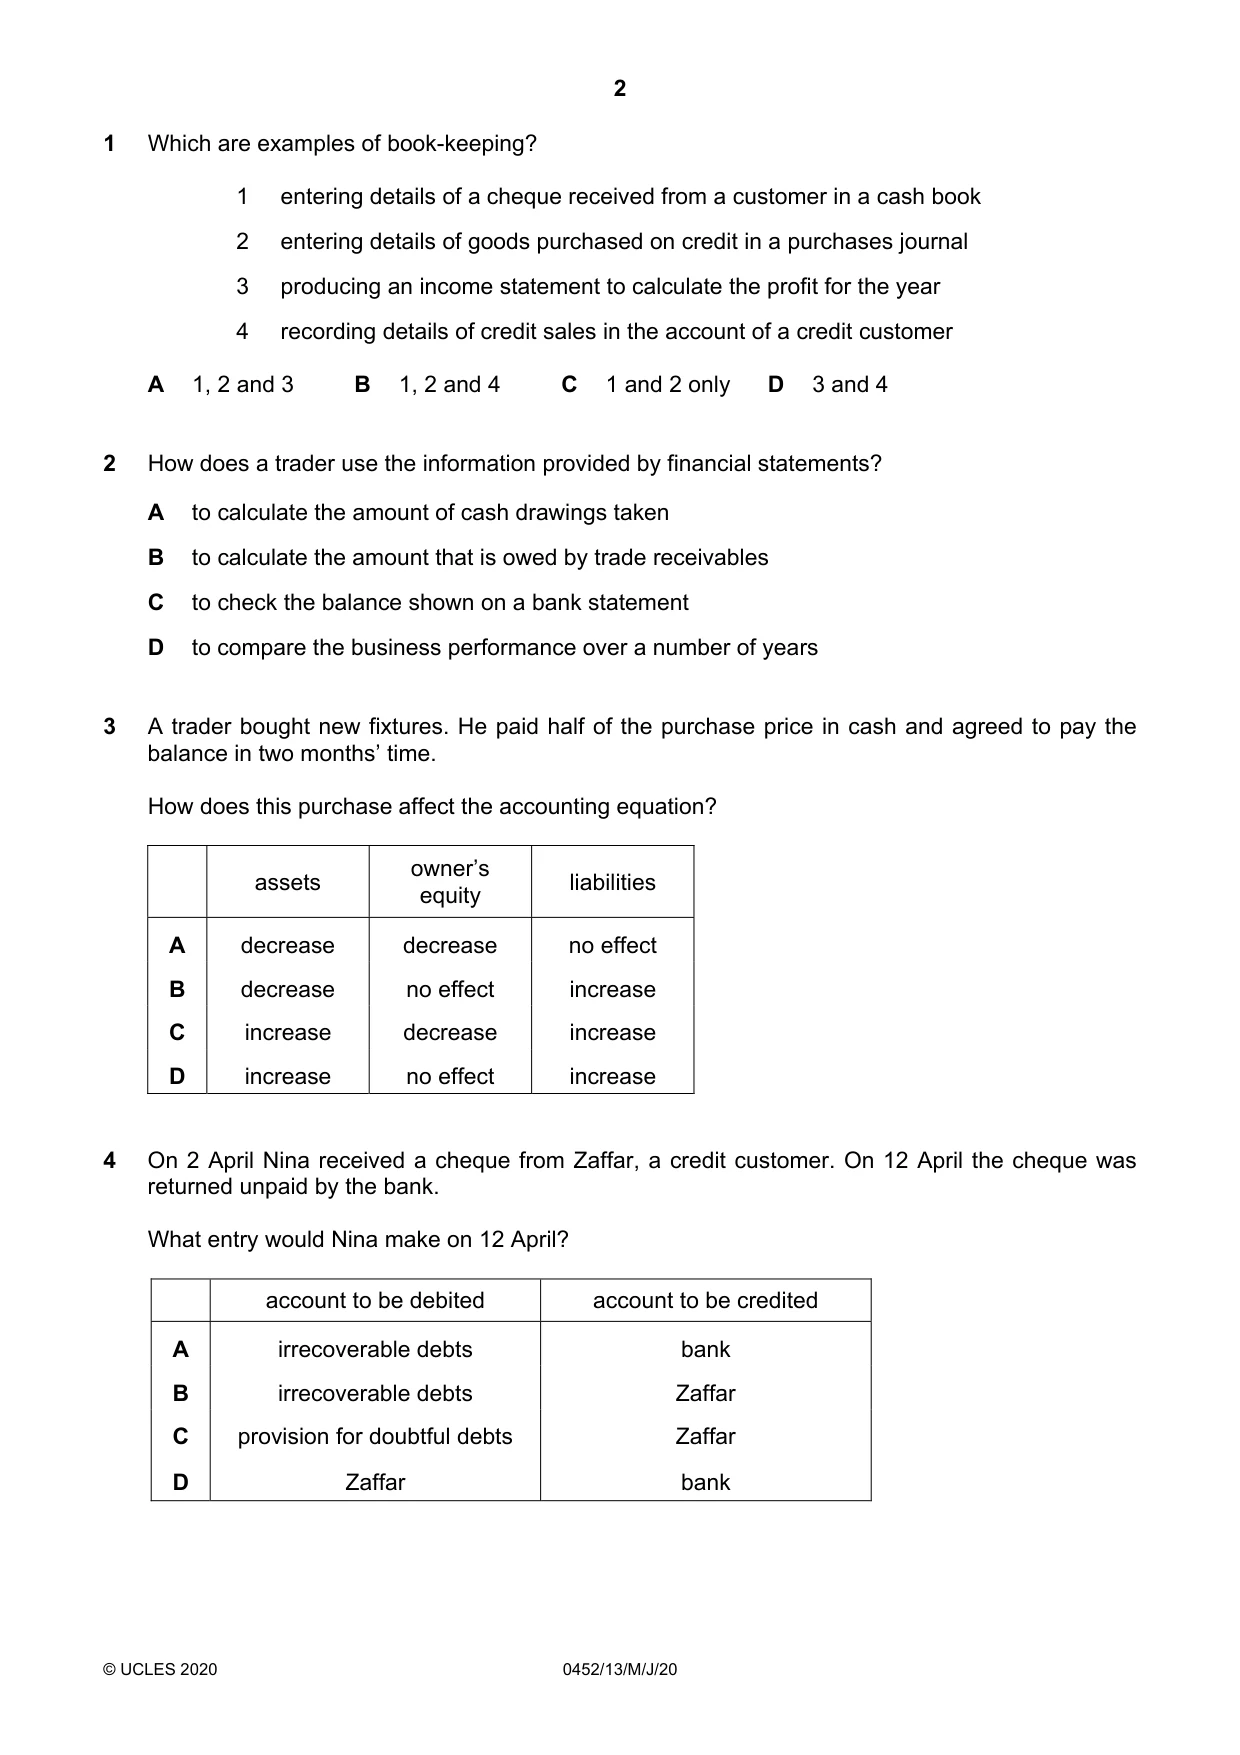
Q1 · Which are examples of book-keeping?
1 Which are examples of book-keeping? 1 entering details of a cheque received from a customer in a cash book 2 entering details of goods purchased on credit in a purchases journal 3 producing an income statement to calculate the profit for the year 4 recording details of credit sales in the account of a credit customer A 1, 2 and 3 B 1, 2 and 4 C 1 and 2 only D 3 and 4
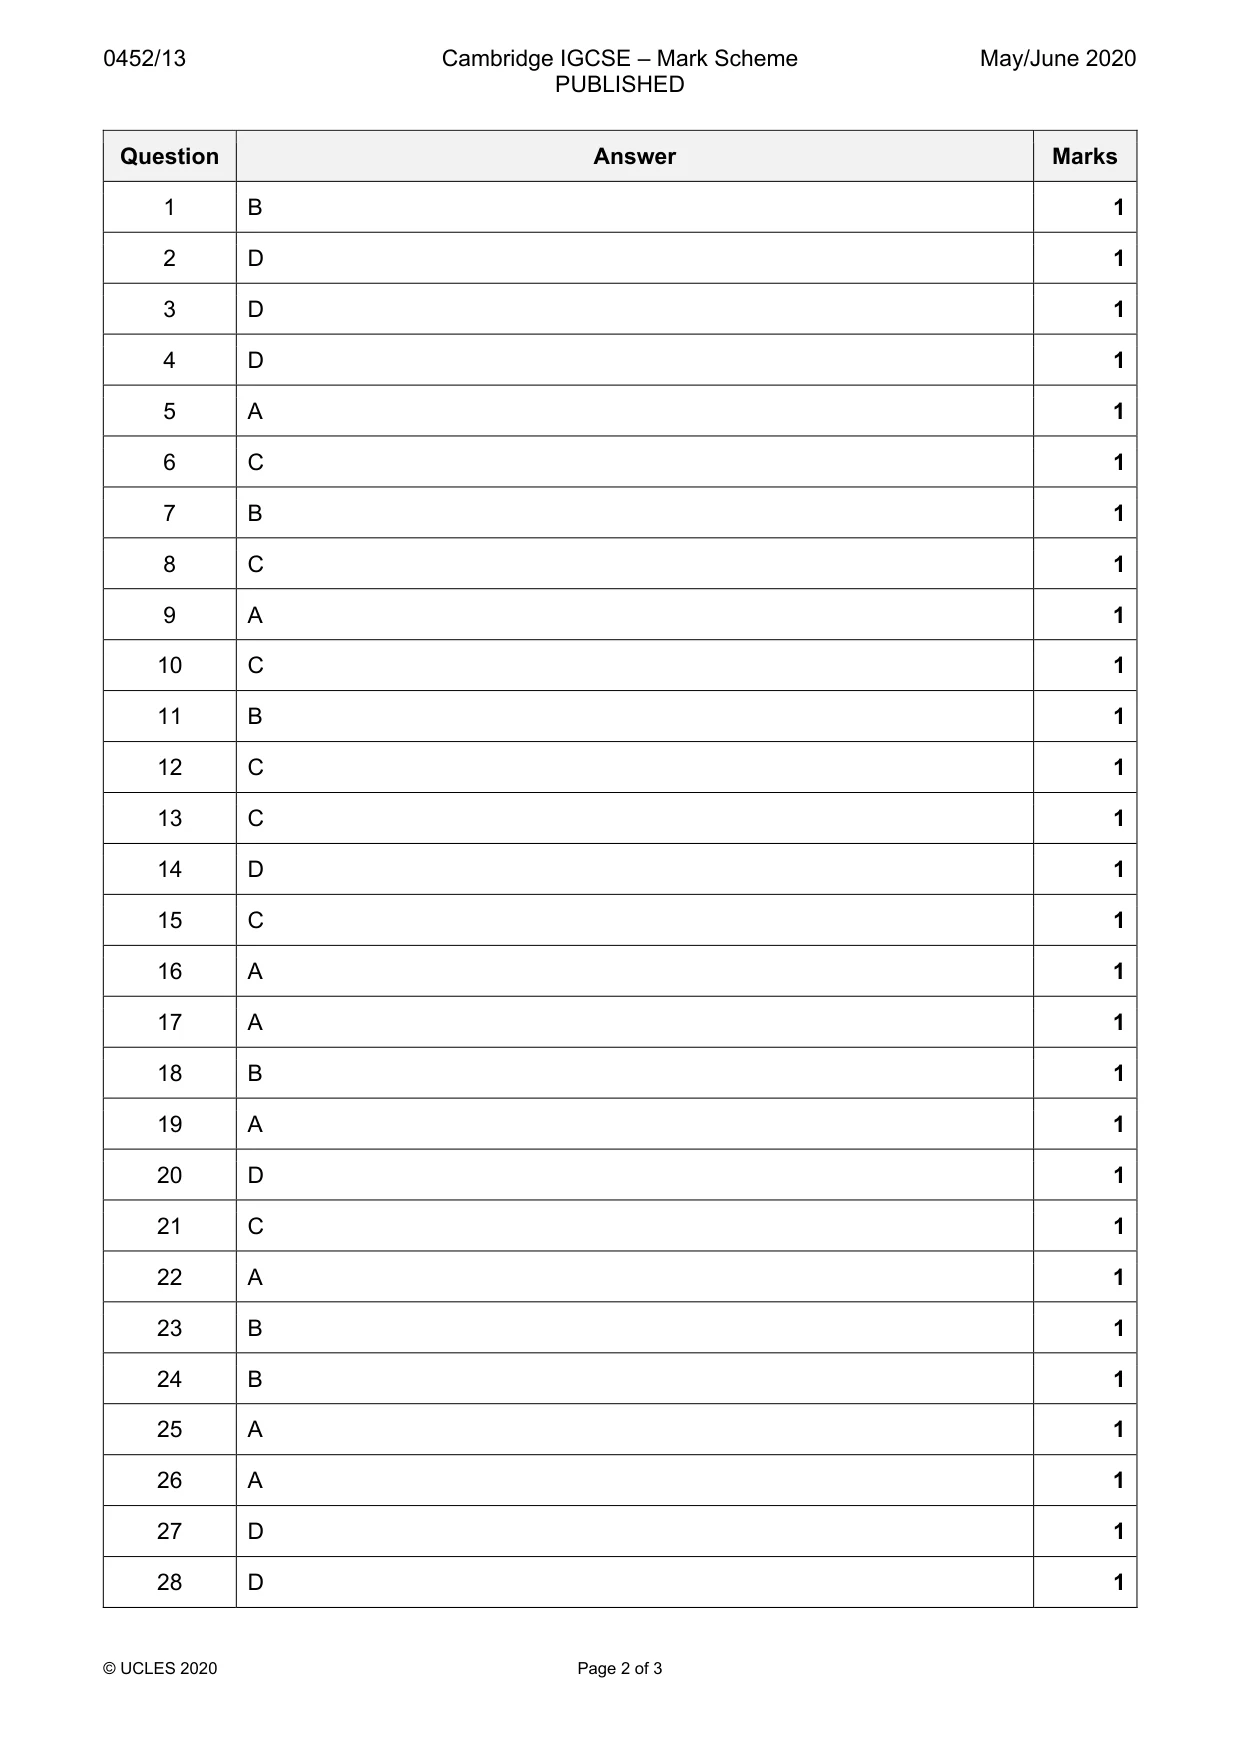
Mark scheme: B
Q2 · How does a trader use the information provided by financial statements?
2 How does a trader use the information provided by financial statements? A to calculate the amount of cash drawings taken B to calculate the amount that is owed by trade receivables C to check the balance shown on a bank statement D to compare the business performance over a number of years
Mark scheme: D
Q3 · A trader bought new fixtures
3 A trader bought new fixtures. He paid half of the purchase price in cash and agreed to pay the balance in two months’ time. How does this purchase affect the accounting equation? owner’s assets liabilities equity A decrease decrease no effect B decrease no effect increase C increase decrease increase D increase no effect increase
Mark scheme: D
Q4 · On 2 April Nina received a cheque from Zaffar, a credit customer
4 On 2 April Nina received a cheque from Zaffar, a credit customer. On 12 April the cheque was returned unpaid by the bank. What entry would Nina make on 12 April? account to be debited account to be credited A irrecoverable debts bank B irrecoverable debts Zaffar C provision for doubtful debts Zaffar D Zaffar bank
Mark scheme: D
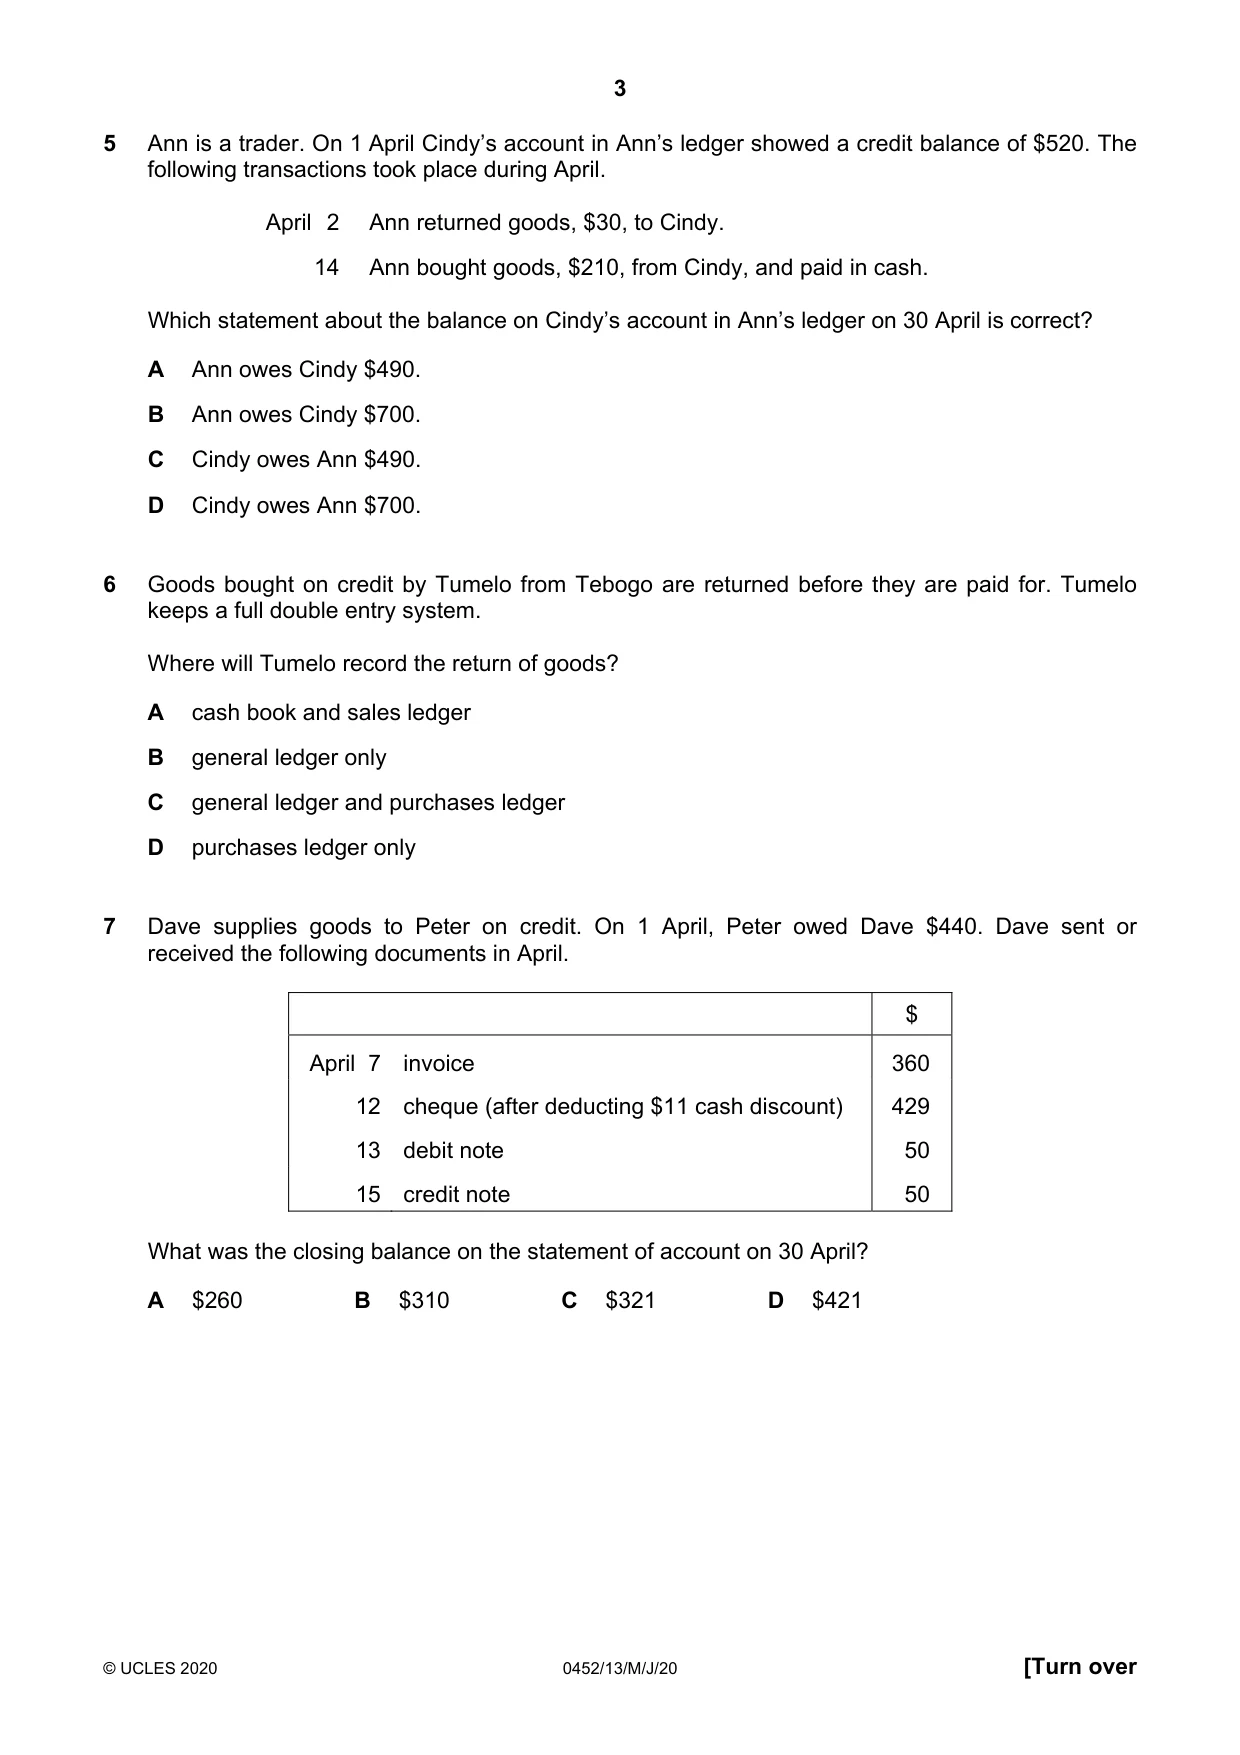
Q5 · Ann is a trader
5 Ann is a trader. On 1 April Cindy’s account in Ann’s ledger showed a credit balance of $520. The following transactions took place during April. April 2 Ann returned goods, $30, to Cindy. 14 Ann bought goods, $210, from Cindy, and paid in cash. Which statement about the balance on Cindy’s account in Ann’s ledger on 30 April is correct? A Ann owes Cindy $490. B Ann owes Cindy $700. C Cindy owes Ann $490. D Cindy owes Ann $700.
Mark scheme: A
Q6 · Goods bought on credit by Tumelo from Tebogo are returned before they are paid for
6 Goods bought on credit by Tumelo from Tebogo are returned before they are paid for. Tumelo keeps a full double entry system. Where will Tumelo record the return of goods? A cash book and sales ledger B general ledger only C general ledger and purchases ledger D purchases ledger only
Mark scheme: C
Q7 · Dave supplies goods to Peter on credit
7 Dave supplies goods to Peter on credit. On 1 April, Peter owed Dave $440. Dave sent or received the following documents in April. $ April 7 invoice 360 12 cheque (after deducting $11 cash discount) 429 13 debit note 50 15 credit note 50 What was the closing balance on the statement of account on 30 April? A $260 B $310 C $321 D $421
Mark scheme: B
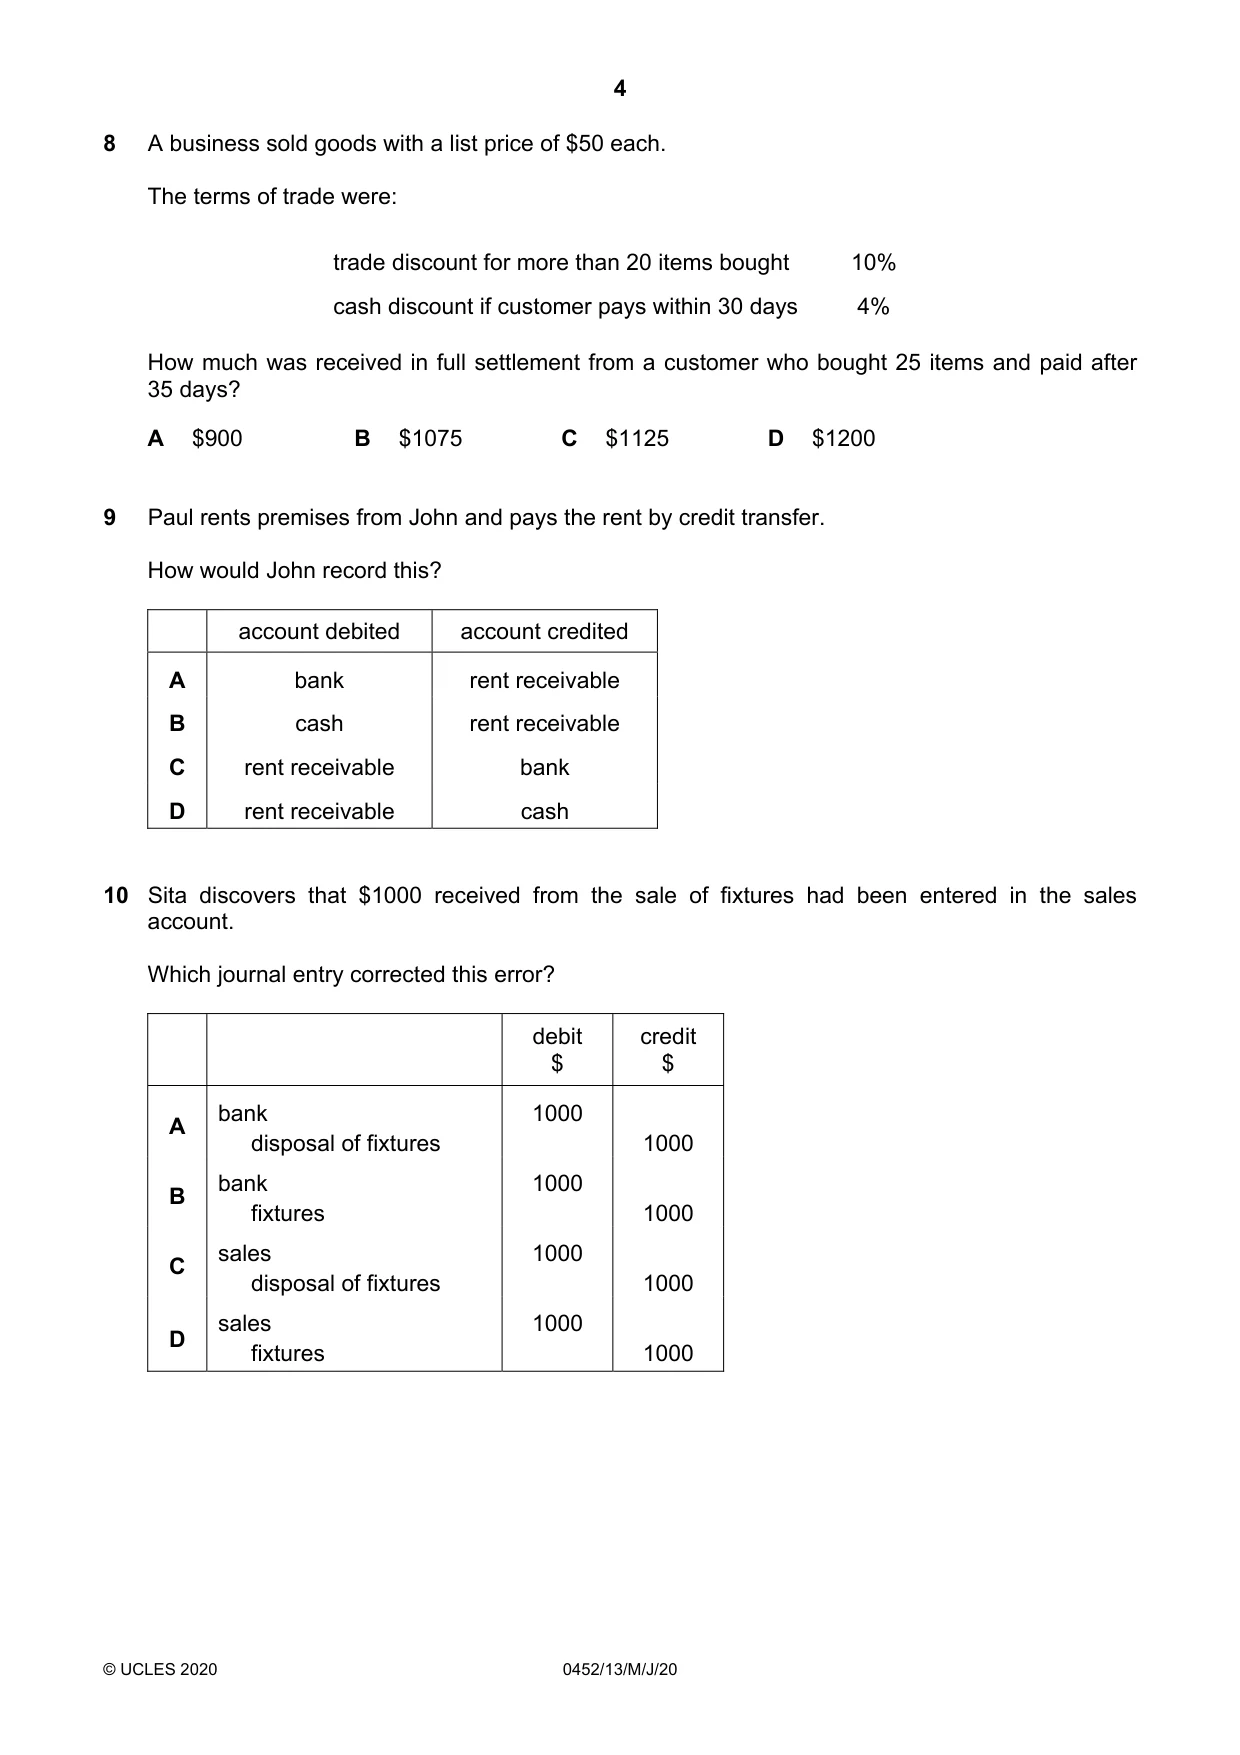
Q8 · A business sold goods with a list price of $50 each
8 A business sold goods with a list price of $50 each. The terms of trade were: trade discount for more than 20 items bought 10% cash discount if customer pays within 30 days 4% How much was received in full settlement from a customer who bought 25 items and paid after 35 days? A $900 B $1075 C $1125 D $1200
Mark scheme: C
Q9 · Paul rents premises from John and pays the rent by credit transfer
9 Paul rents premises from John and pays the rent by credit transfer. How would John record this? account debited account credited A bank rent receivable B cash rent receivable C rent receivable bank D rent receivable cash
Mark scheme: A
Q10 · Sita discovers that $1000 received from the sale of fixtures had been entered in the…
10 Sita discovers that $1000 received from the sale of fixtures had been entered in the sales account. Which journal entry corrected this error? debit credit $ $ bank 1000 A disposal of fixtures 1000 bank 1000 B fixtures 1000 sales 1000 C disposal of fixtures 1000 sales 1000 D fixtures 1000
Mark scheme: C
Q11 · The totals of a trial balance did not agree and $200 was debited to a suspense account
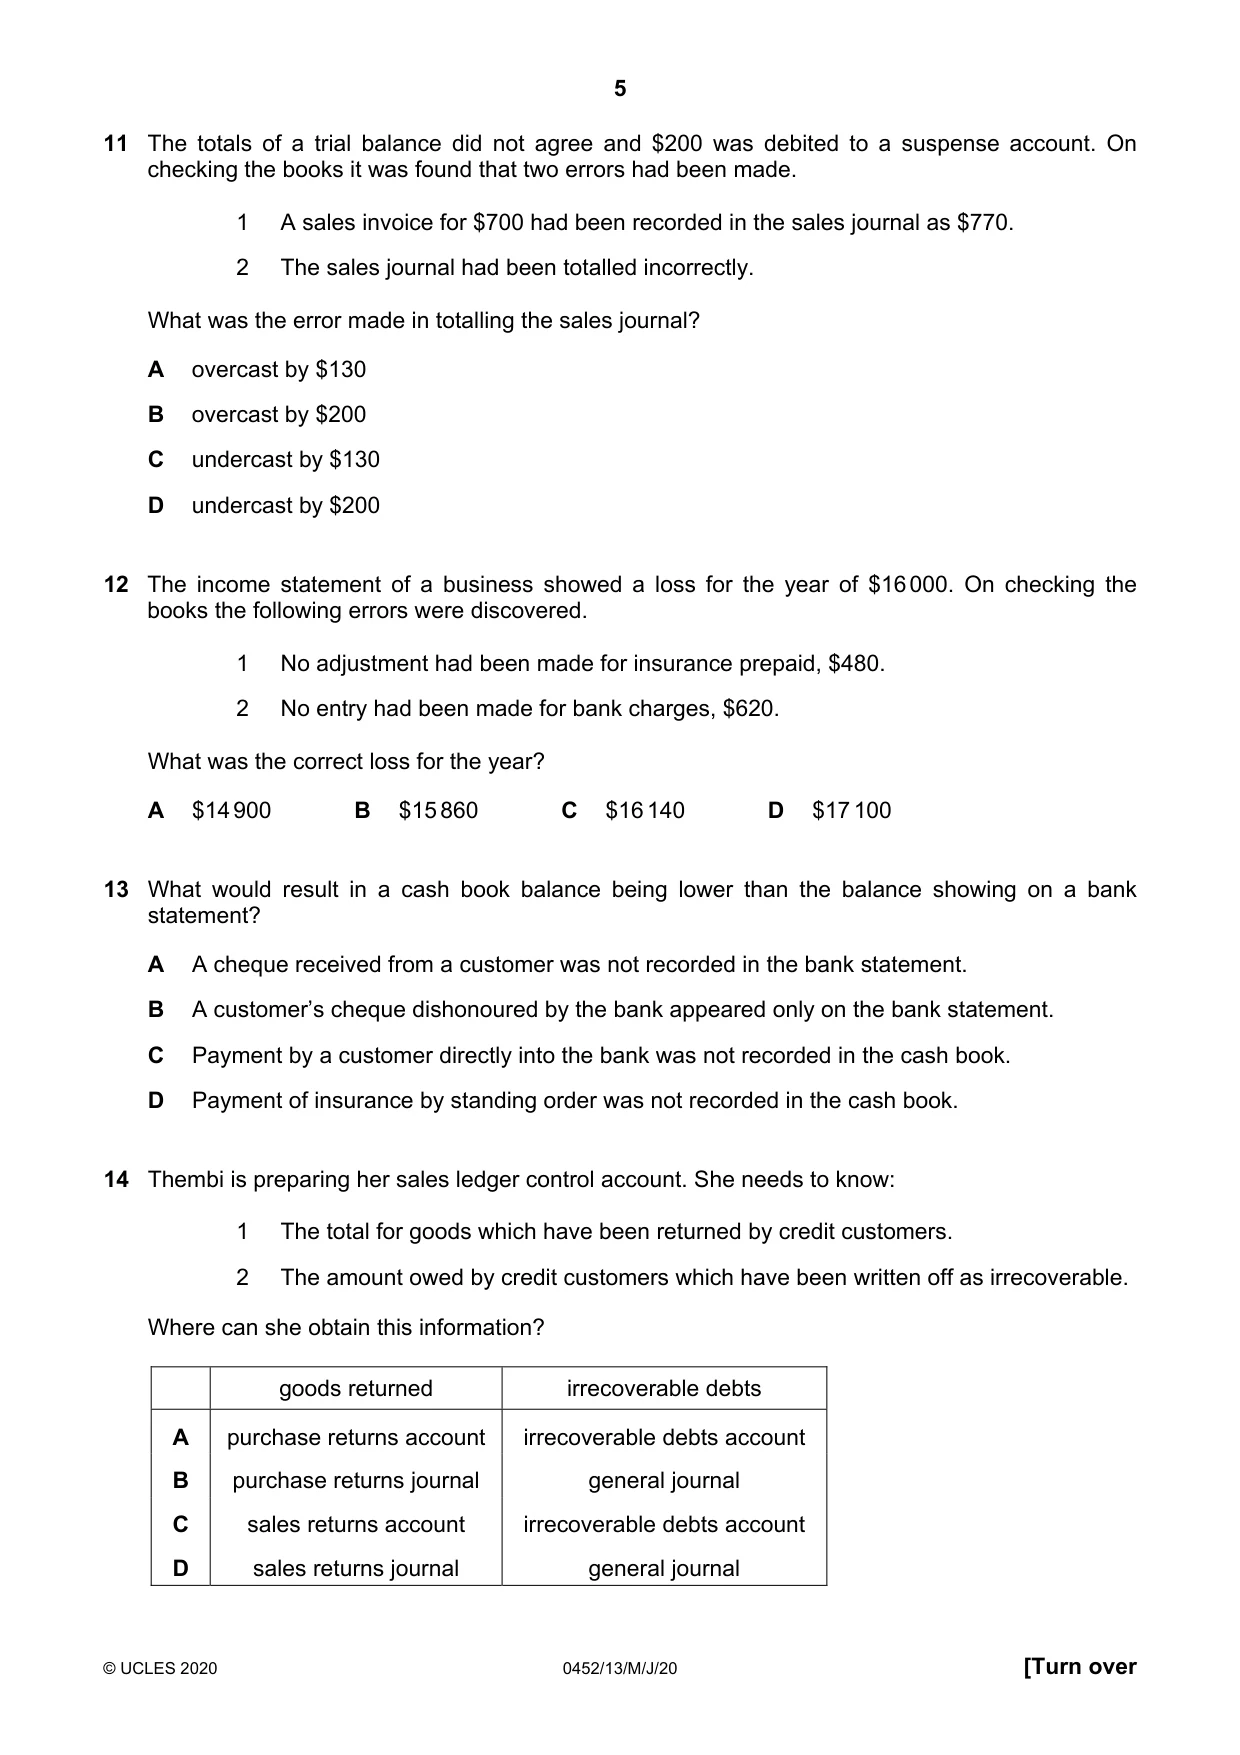
11 The totals of a trial balance did not agree and $200 was debited to a suspense account. On checking the books it was found that two errors had been made. 1 A sales invoice for $700 had been recorded in the sales journal as $770. 2 The sales journal had been totalled incorrectly. What was the error made in totalling the sales journal? A overcast by $130 B overcast by $200 C undercast by $130 D undercast by $200
Mark scheme: B
Q12 · The income statement of a business showed a loss for the year of $16 000
12 The income statement of a business showed a loss for the year of $16 000. On checking the books the following errors were discovered. 1 No adjustment had been made for insurance prepaid, $480. 2 No entry had been made for bank charges, $620. What was the correct loss for the year? A $14 900 B $15 860 C $16 140 D $17 100
Mark scheme: C
Q13 · What would result in a cash book balance being lower than the balance showing on a bank…
13 What would result in a cash book balance being lower than the balance showing on a bank statement? A A cheque received from a customer was not recorded in the bank statement. B A customer’s cheque dishonoured by the bank appeared only on the bank statement. C Payment by a customer directly into the bank was not recorded in the cash book. D Payment of insurance by standing order was not recorded in the cash book.
Mark scheme: C
Q14 · Thembi is preparing her sales ledger control account
14 Thembi is preparing her sales ledger control account. She needs to know: 1 The total for goods which have been returned by credit customers. 2 The amount owed by credit customers which have been written off as irrecoverable. Where can she obtain this information? goods returned irrecoverable debts A purchase returns account irrecoverable debts account B purchase returns journal general journal C sales returns account irrecoverable debts account D sales returns journal general journal
Mark scheme: D
Q15 · The following payments were made when a new machine was purchased
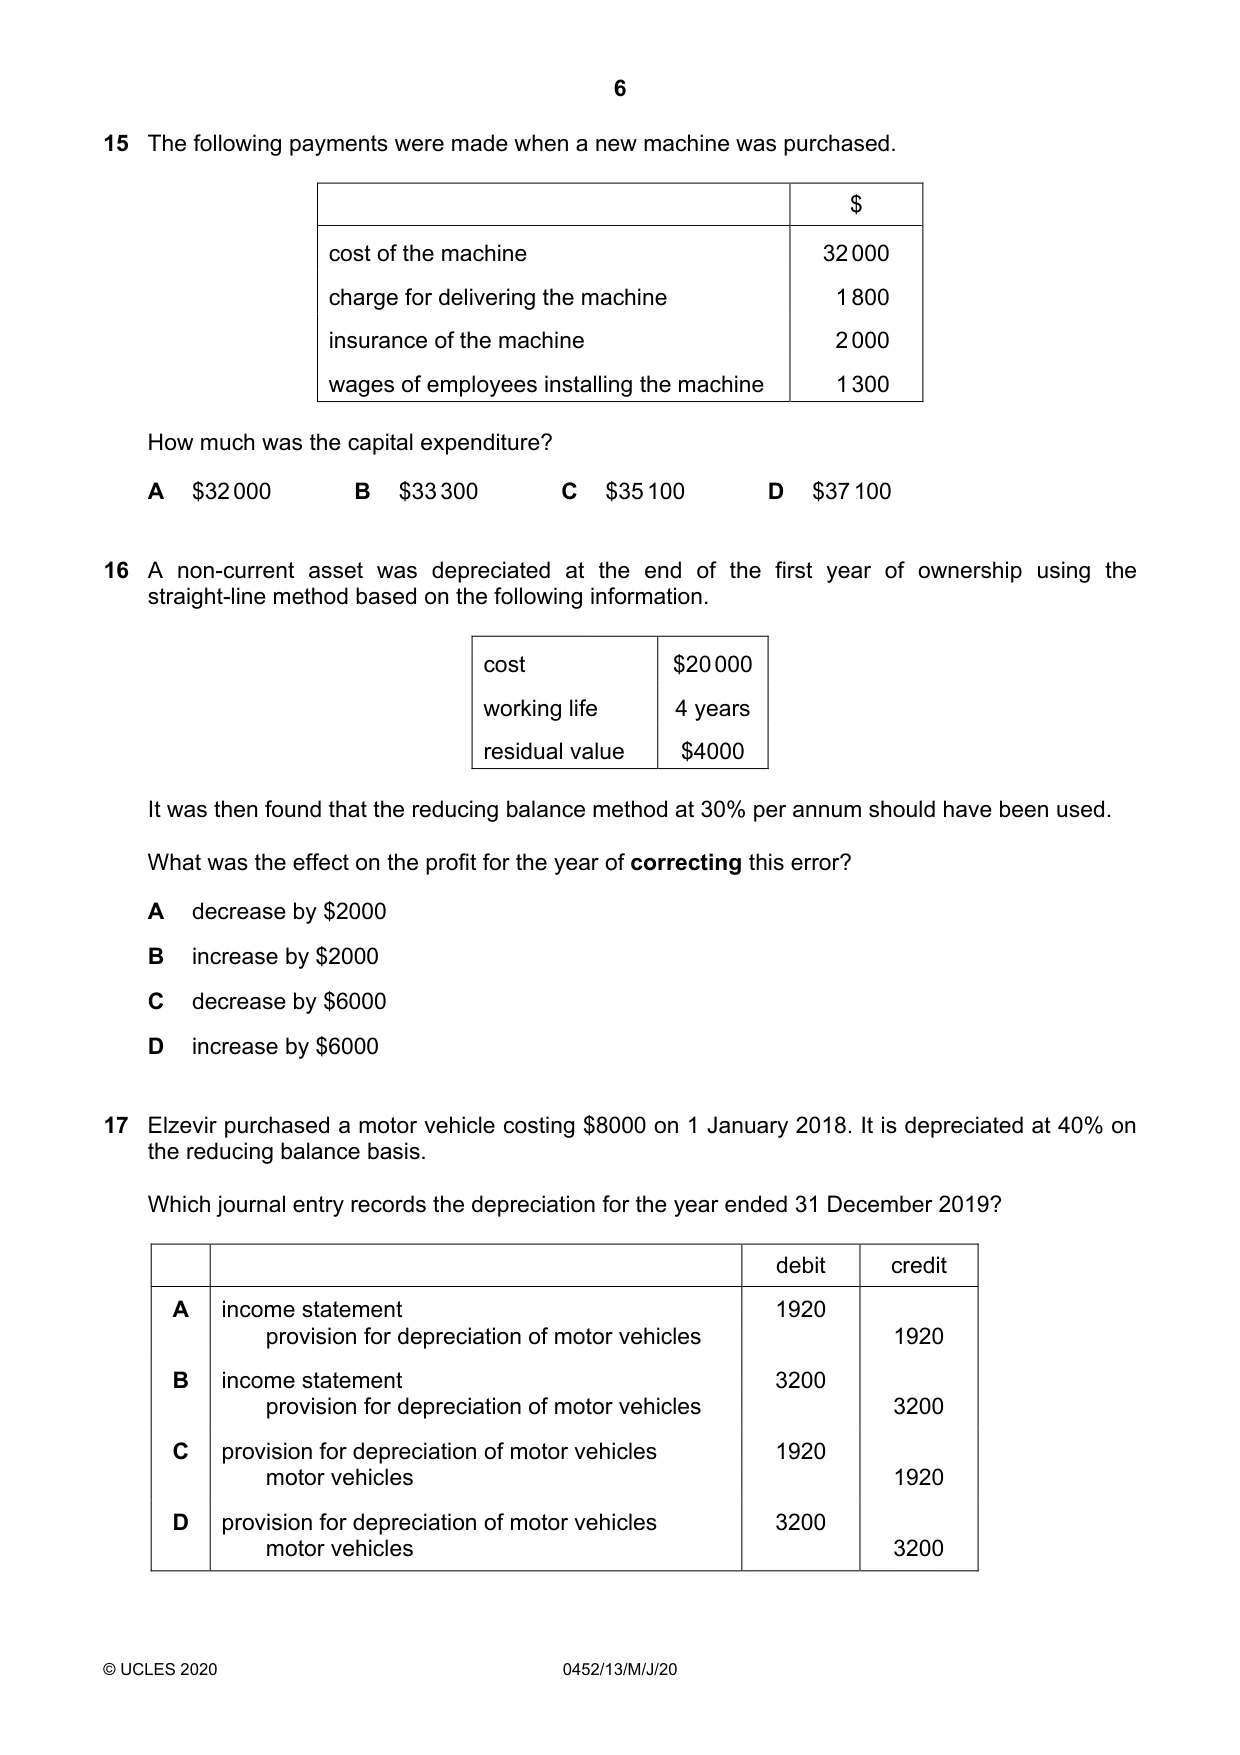
15 The following payments were made when a new machine was purchased. $ cost of the machine 32 000 charge for delivering the machine 1 800 insurance of the machine 2 000 wages of employees installing the machine 1 300 How much was the capital expenditure? A $32 000 B $33 300 C $35 100 D $37 100
Mark scheme: C
More questions on Capital and revenue expenditure and receipts
Q16 · A non-current asset was depreciated at the end of the first year of ownership using the…
16 A non-current asset was depreciated at the end of the first year of ownership using the straight-line method based on the following information. cost $20 000 working life 4 years residual value $4000 It was then found that the reducing balance method at 30% per annum should have been used. What was the effect on the profit for the year of correcting this error? A decrease by $2000 B increase by $2000 C decrease by $6000 D increase by $6000
Mark scheme: A
More questions on Accounting for depreciation and disposal of non-current assets
Q17 · Elzevir purchased a motor vehicle costing $8000 on 1 January 2018
17 Elzevir purchased a motor vehicle costing $8000 on 1 January 2018. It is depreciated at 40% on the reducing balance basis. Which journal entry records the depreciation for the year ended 31 December 2019? debit credit A income statement 1920 provision for depreciation of motor vehicles 1920 B income statement 3200 provision for depreciation of motor vehicles 3200 C provision for depreciation of motor vehicles 1920 motor vehicles 1920 D provision for depreciation of motor vehicles 3200 motor vehicles 3200
Mark scheme: A
More questions on Accounting for depreciation and disposal of non-current assets
Q18 · Alice’s financial year ends on 31 December
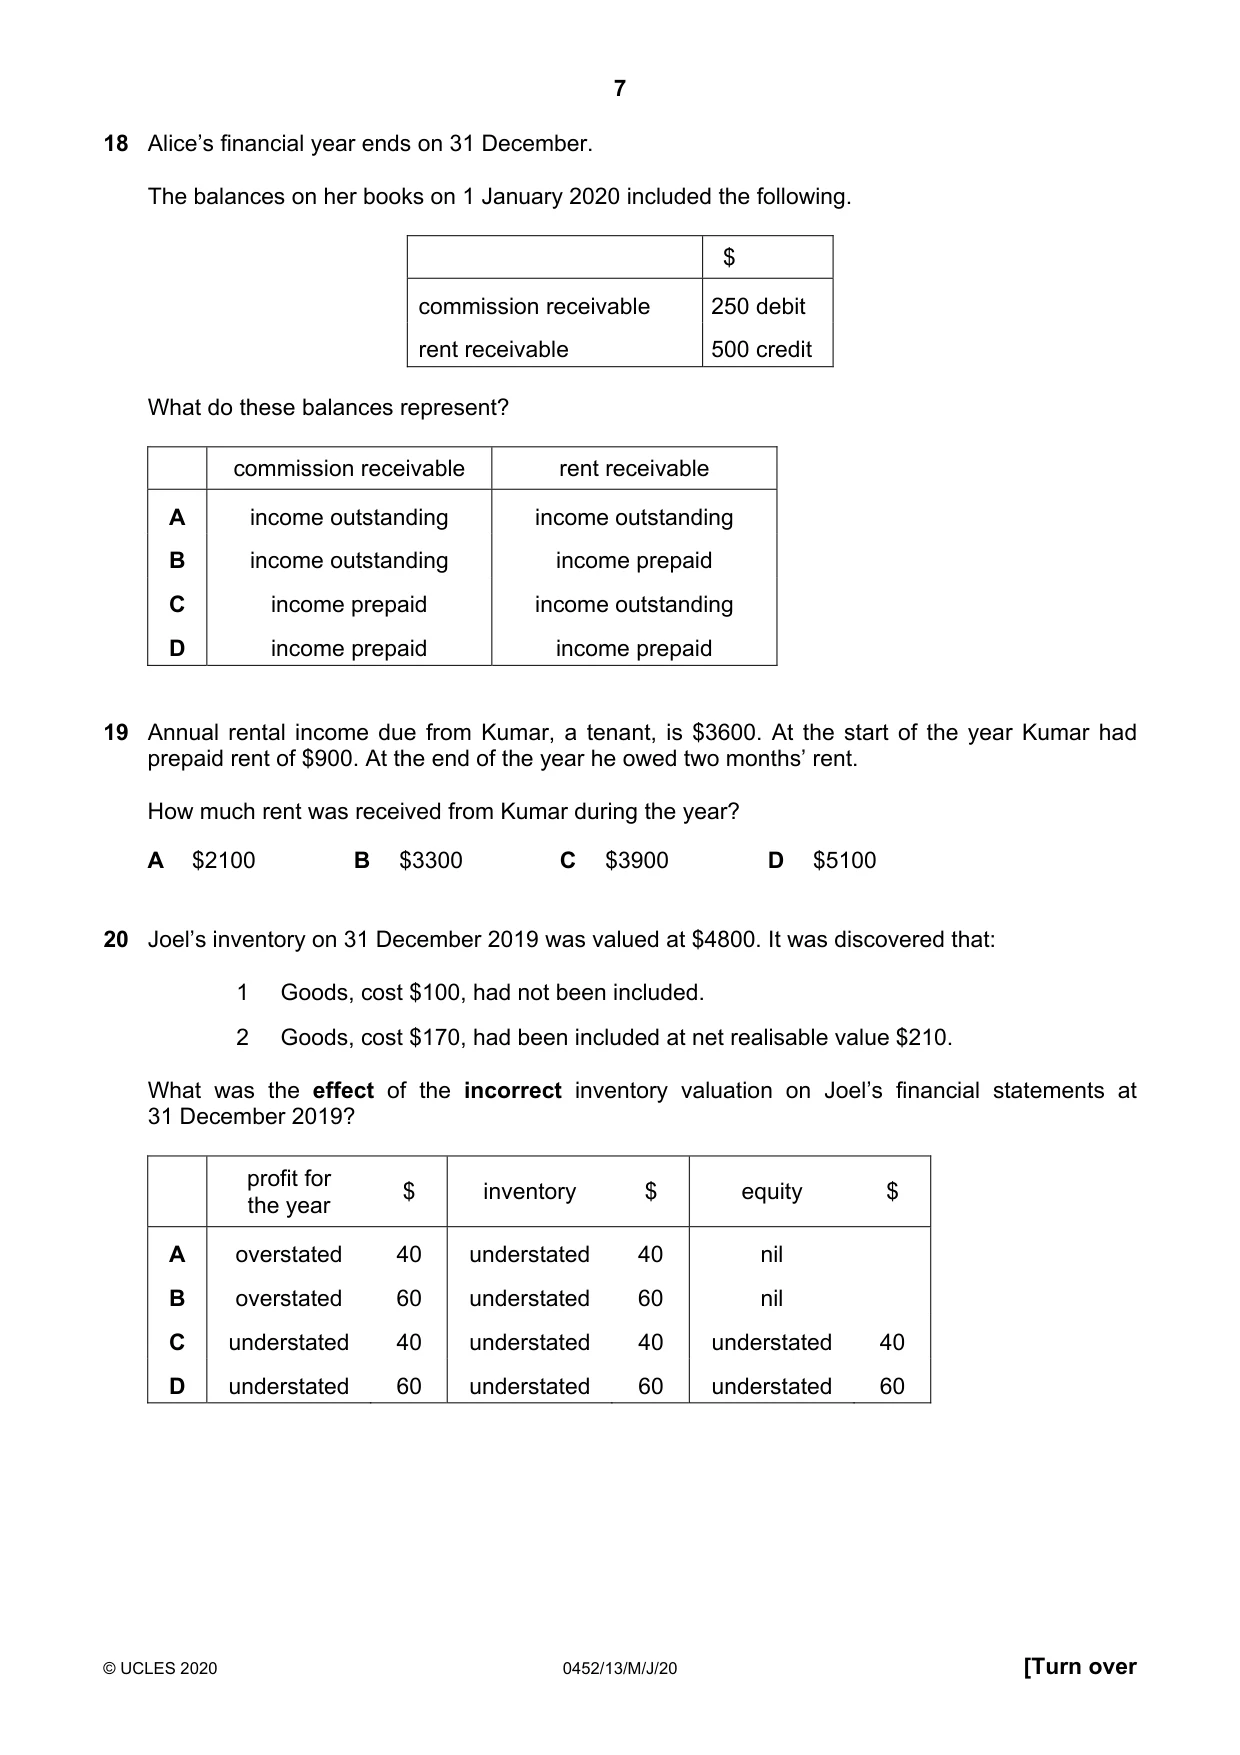
18 Alice’s financial year ends on 31 December. The balances on her books on 1 January 2020 included the following. $ commission receivable 250 debit rent receivable 500 credit What do these balances represent? commission receivable rent receivable A income outstanding income outstanding B income outstanding income prepaid C income prepaid income outstanding D income prepaid income prepaid
Mark scheme: B
Q19 · Annual rental income due from Kumar, a tenant, is $3600
19 Annual rental income due from Kumar, a tenant, is $3600. At the start of the year Kumar had prepaid rent of $900. At the end of the year he owed two months’ rent. How much rent was received from Kumar during the year? A $2100 B $3300 C $3900 D $5100
Mark scheme: A
Q20 · Joel’s inventory on 31 December 2019 was valued at $4800
20 Joel’s inventory on 31 December 2019 was valued at $4800. It was discovered that: 1 Goods, cost $100, had not been included. 2 Goods, cost $170, had been included at net realisable value $210. What was the effect of the incorrect inventory valuation on Joel’s financial statements at 31 December 2019? profit for $ inventory $ equity $ the year A overstated 40 understated 40 nil B overstated 60 understated 60 nil C understated 40 understated 40 understated 40 D understated 60 understated 60 understated 60
Mark scheme: D
Q21 · The owner of a business took goods for his own use but forgot to make an entry in the…
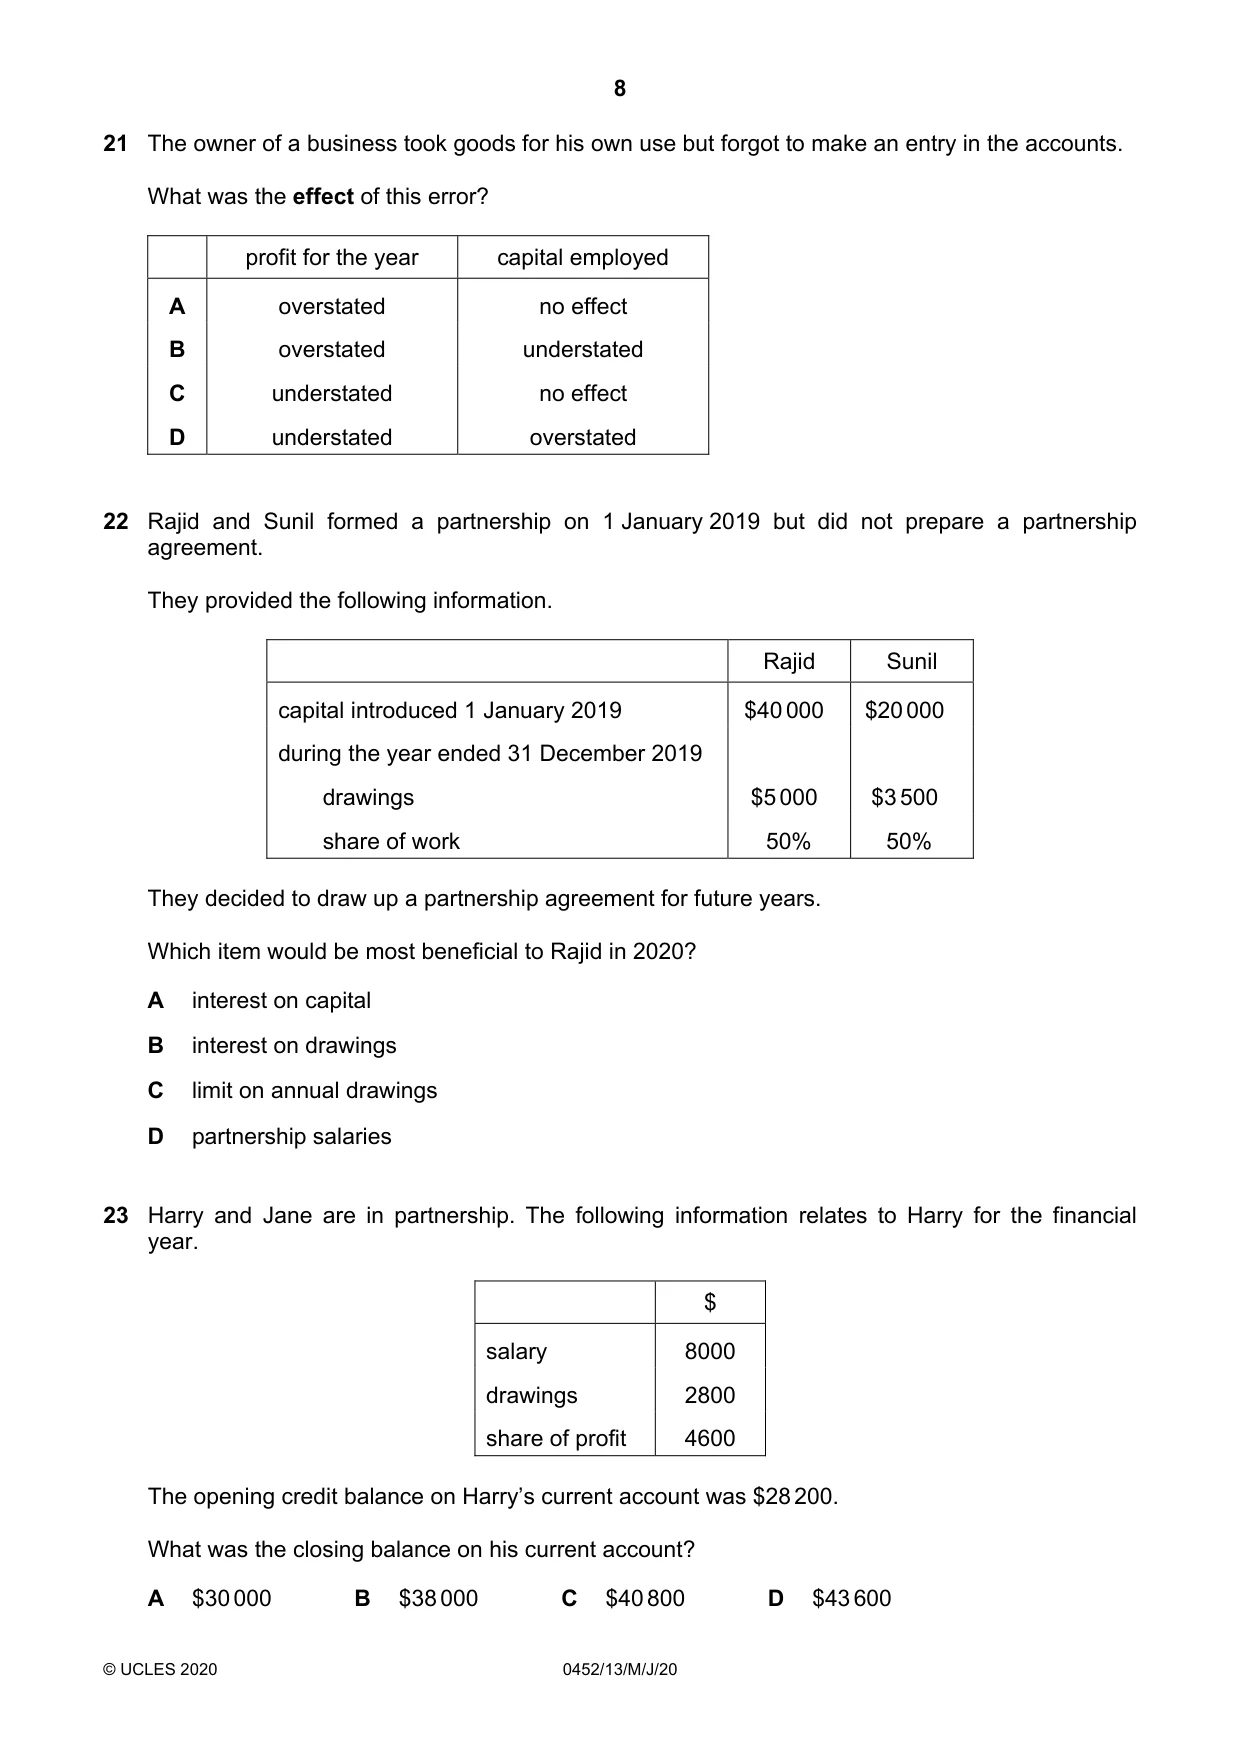
21 The owner of a business took goods for his own use but forgot to make an entry in the accounts. What was the effect of this error? profit for the year capital employed A overstated no effect B overstated understated C understated no effect D understated overstated
Mark scheme: C
Q22 · Rajid and Sunil formed a partnership on 1 January 2019 but did not prepare a partnership…
22 Rajid and Sunil formed a partnership on 1 January 2019 but did not prepare a partnership agreement. They provided the following information. Rajid Sunil capital introduced 1 January 2019 $40 000 $20 000 during the year ended 31 December 2019 drawings $5 000 $3 500 share of work 50% 50% They decided to draw up a partnership agreement for future years. Which item would be most beneficial to Rajid in 2020? A interest on capital B interest on drawings C limit on annual drawings D partnership salaries
Mark scheme: A
Q23 · Harry and Jane are in partnership
23 Harry and Jane are in partnership. The following information relates to Harry for the financial year. $ salary 8000 drawings 2800 share of profit 4600 The opening credit balance on Harry’s current account was $28 200. What was the closing balance on his current account? A $30 000 B $38 000 C $40 800 D $43 600
Mark scheme: B
Q24 · The statement of financial position of X Limited at 31 December 2018 included the…
24 The statement of financial position of X Limited at 31 December 2018 included the following: $ ordinary share capital 40 000 general reserve 8 000 retained earnings 65 000 8% debentures (repayable 2025) 30 000 Profit for the year ended 31 December 2019 was $42 000 and dividends paid totalled $10 000. What was the total equity on 31 December 2019? A $137 000 B $145 000 C $155 000 D $175 000
Mark scheme: B
Q25 · Which is a feature of debentures?
25 Which is a feature of debentures? A are a long-term liability of a company B carry a fixed rate of dividend C carry voting rights D on liquidation are paid back after shareholders
Mark scheme: A
Q26 · Which cost is part of the prime cost for a manufacturing business?
26 Which cost is part of the prime cost for a manufacturing business? A carriage inwards B carriage outwards C factory rent D factory supervisor’s salary
Mark scheme: A
Q27 · A manufacturing business provided the following information
27 A manufacturing business provided the following information. $ prime cost 236 000 factory overheads 42 000 opening work in progress 8 000 closing work in progress 6 000 What was the factory cost of production? A $234 000 B $238 000 C $276 000 D $280 000
Mark scheme: D
Q28 · A trader provided the following information
28 A trader provided the following information. $ trade receivables at start of the year 5 000 trade receivables at end of the year 8 500 cash received from trade receivables 34 700 irrecoverable debts written off 200 discount allowed 185 What was the amount of the credit sales? A $38 200 B $38 385 C $38 400 D $38 585
Mark scheme: D
Q29 · Gordon provided the following information for the year
29 Gordon provided the following information for the year. revenue $90 000 opening inventory $8 000 closing inventory $2 000 mark up 50% Gordon took goods, $7000, for his own use. What were the purchases? A $43 000 B $47 000 C $54 000 D $61 000
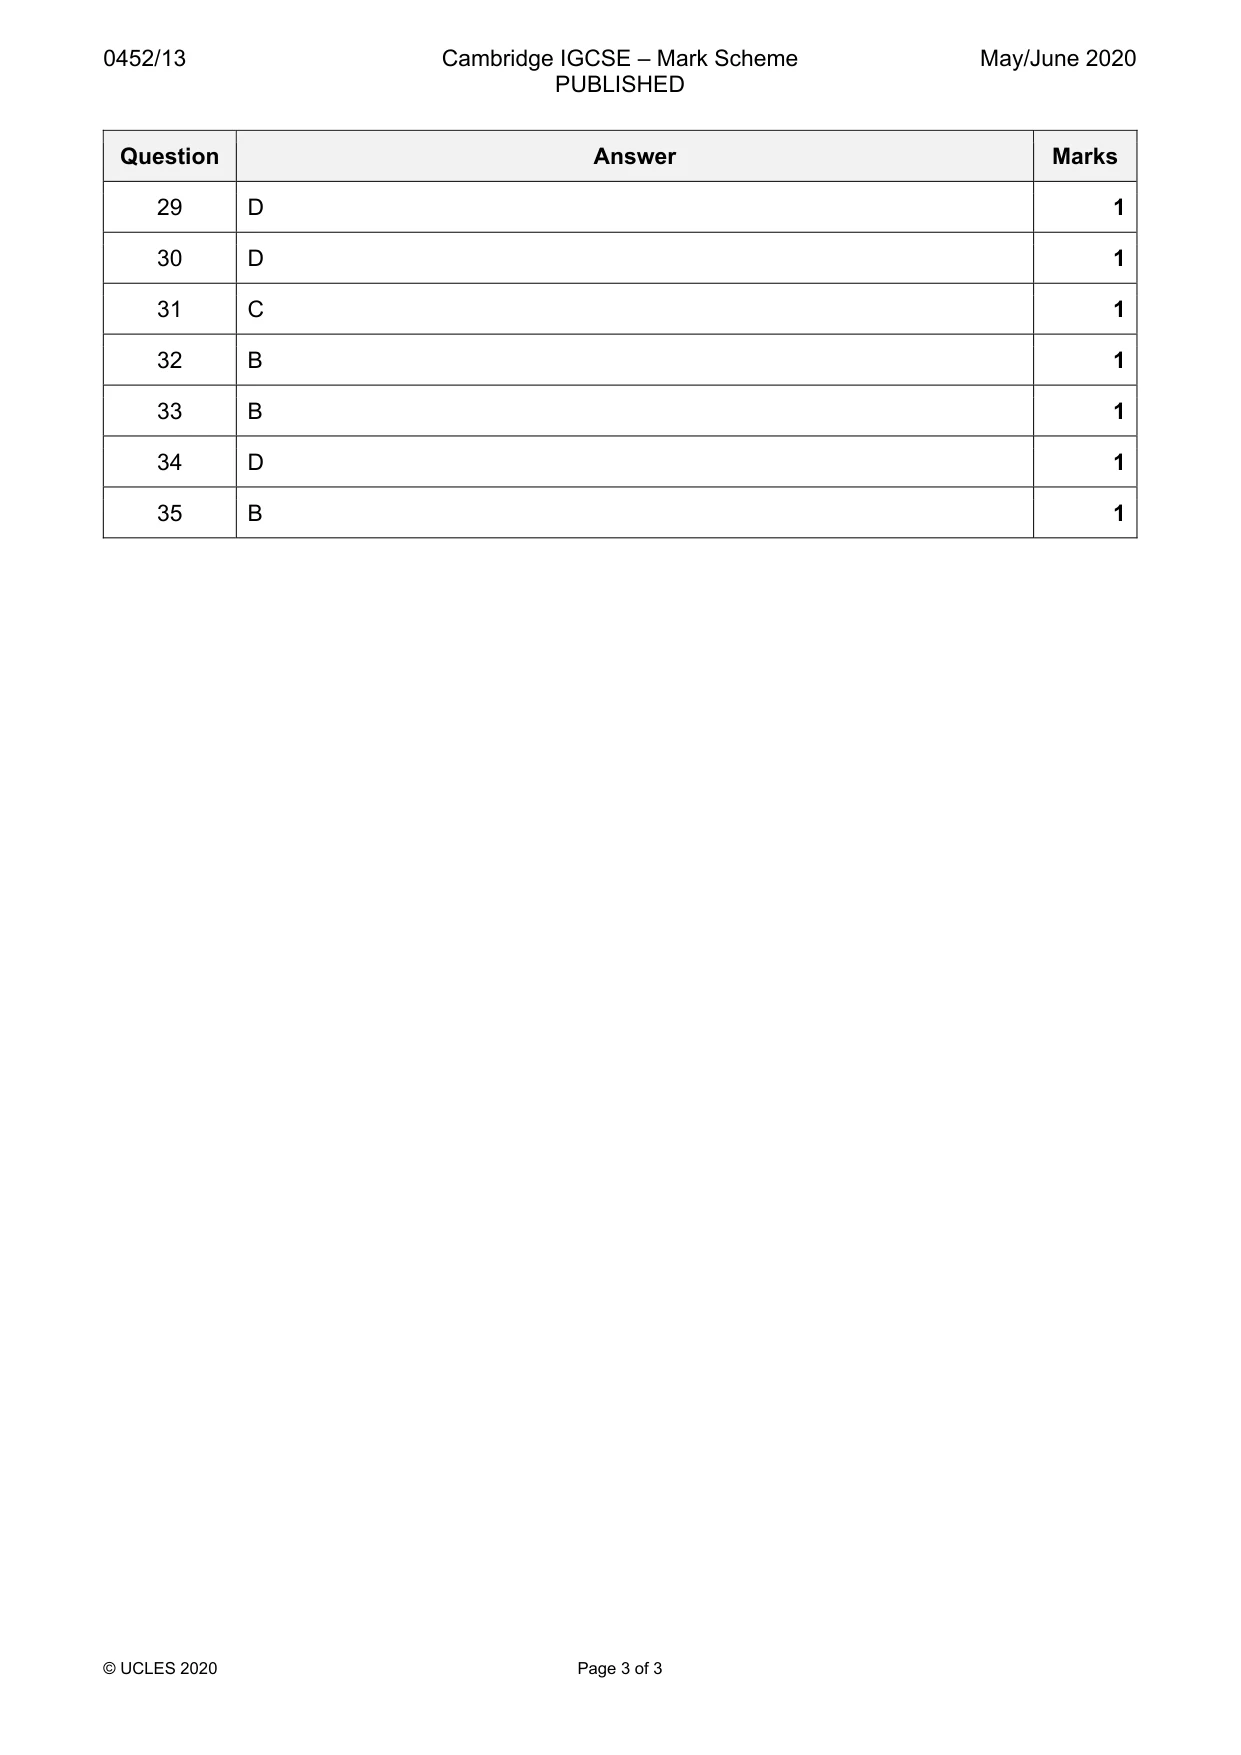
Mark scheme: D
Q30 · Sabelo’s liquid (acid test) ratio was higher on 1 January 2019 than it was on 31 December…
30 Sabelo’s liquid (acid test) ratio was higher on 1 January 2019 than it was on 31 December 2019. What could have caused this? A bank overdraft decreased B inventory decreased C other payables decreased D trade receivables decreased
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
Q31 · The following ratios have been calculated for a trader
31 The following ratios have been calculated for a trader. year 1 year 2 profit margin 15% 20% return on capital employed (ROCE) 9% 6% What explains these changes? A Drawings have increased by more than profit for the year. B Gross profit has increased but profit for the year has decreased. C Profit for the year has increased and capital has been introduced. D Profit for the year has increased and a long-term loan has been repaid.
Mark scheme: C
Q32 · Which external parties would be interested in the accounting ratios of a business?
32 Which external parties would be interested in the accounting ratios of a business? A government B investors C managers D tax authorities
Mark scheme: B
Q33 · At the end of the financial year, a company did not account for the unused stationary…
33 At the end of the financial year, a company did not account for the unused stationary valued at $50. Which accounting principle did the company apply? A matching B materiality C money measurement D prudence
Mark scheme: B
Q34 · A trader wrote off the balance on a credit customer’s account as irrecoverable
34 A trader wrote off the balance on a credit customer’s account as irrecoverable. Which accounting principle was applied? A business entity B consistency C money measurement D prudence
Mark scheme: D
Q35 · A limited company applied the accounting objective of comparability in preparing its…
35 A limited company applied the accounting objective of comparability in preparing its financial statements. What is the effect of this on the interested parties? A They can be sure that information in the financial statements is up to date. B They can identify similarities with the financial statements of other businesses. C They can understand the financial statements easily. D They can use the financial statements in decision-making.
Mark scheme: B
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
4The double entry system of book-keeping3Accounting concepts2Accounting for depreciation and disposal of non-current assets2Business documents2Control accounts2Interpretation of accounting ratios2Limited companies2Manufacturing accounts2Other payables and other receivables2Partnerships2The purpose of accounting2Valuation of inventory2Bank reconciliation1Books of prime entry1Calculation and understanding of accounting ratios1Capital and revenue expenditure and receipts1Interested parties1The accounting equation1