Cambridge IGCSE Accounting 0452 — 2022 May/June Paper 1 · Variant 1
0452/11/M/J/22 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
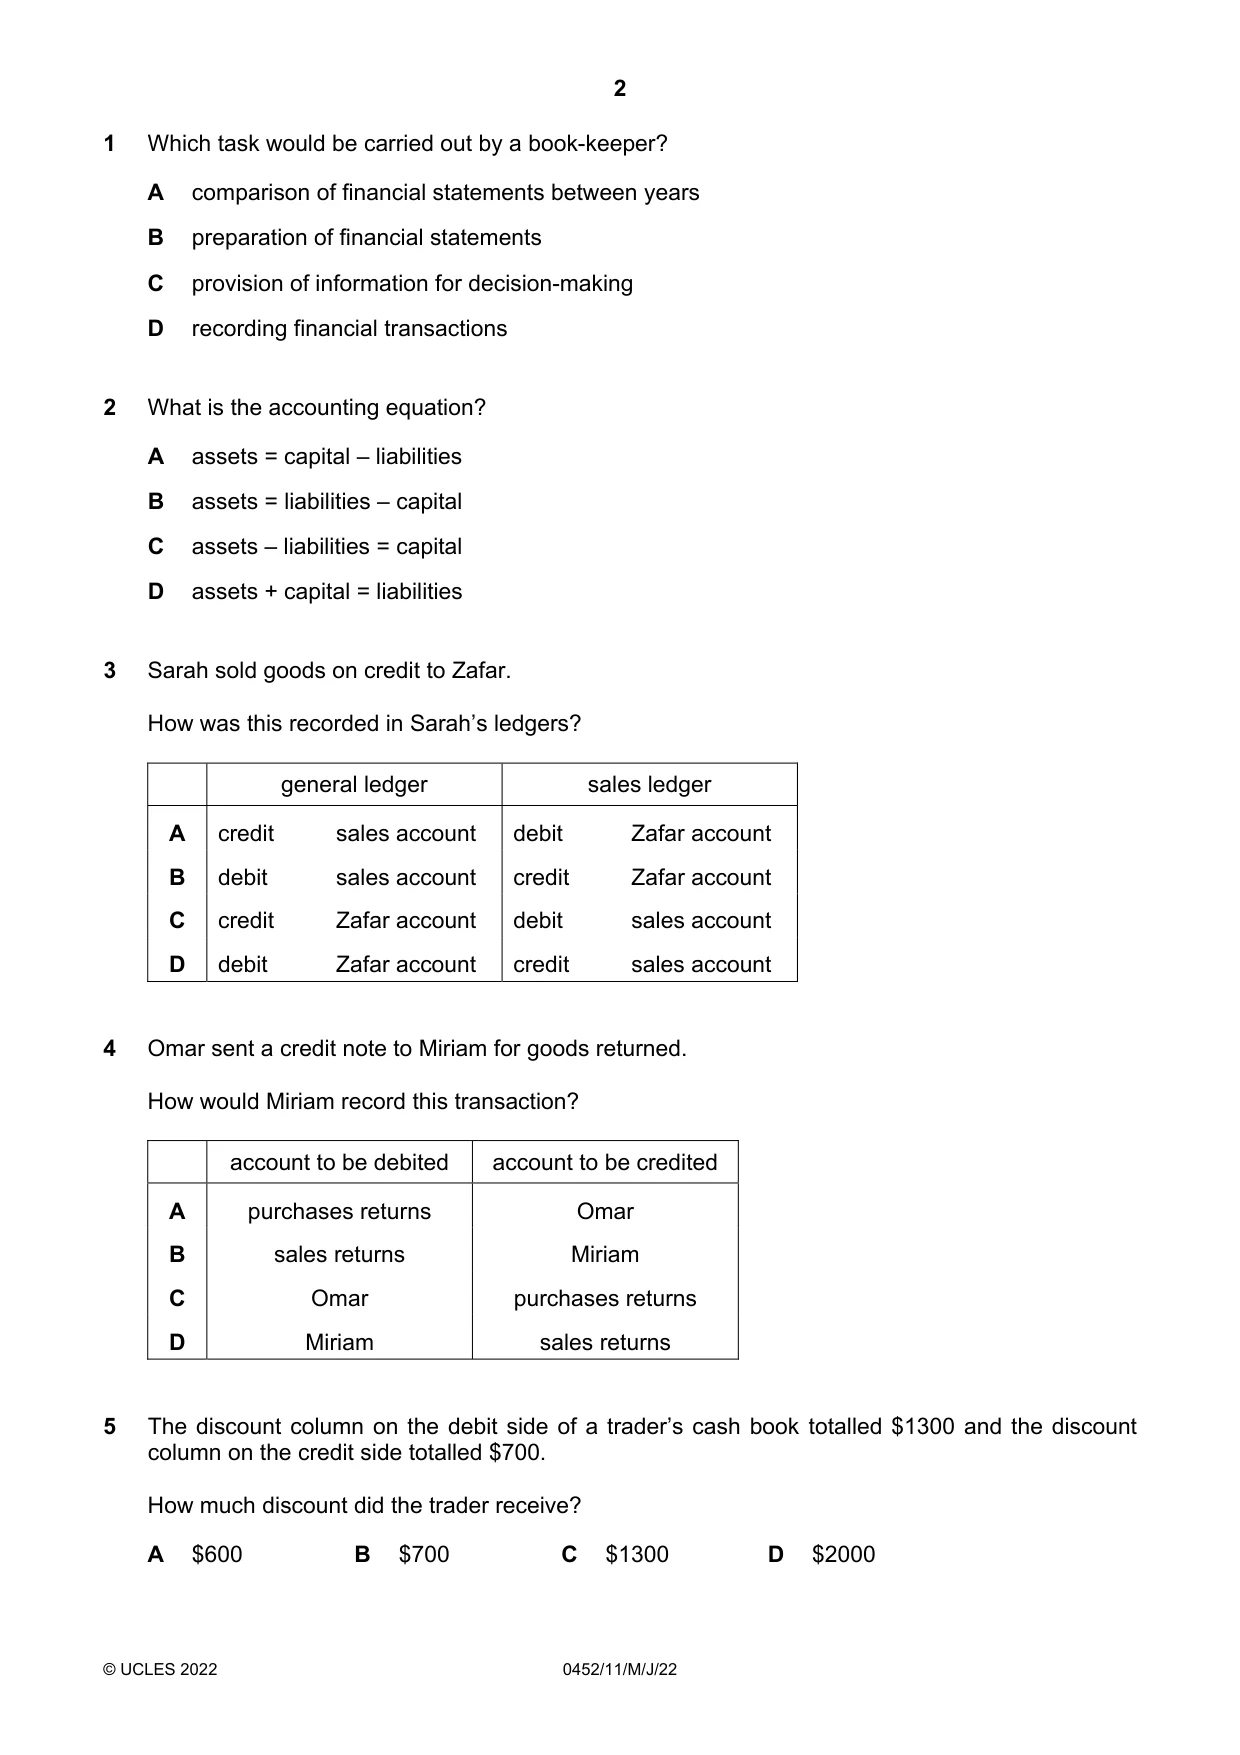
Q1 · Which task would be carried out by a book-keeper?
1 Which task would be carried out by a book-keeper? A comparison of financial statements between years B preparation of financial statements C provision of information for decision-making D recording financial transactions
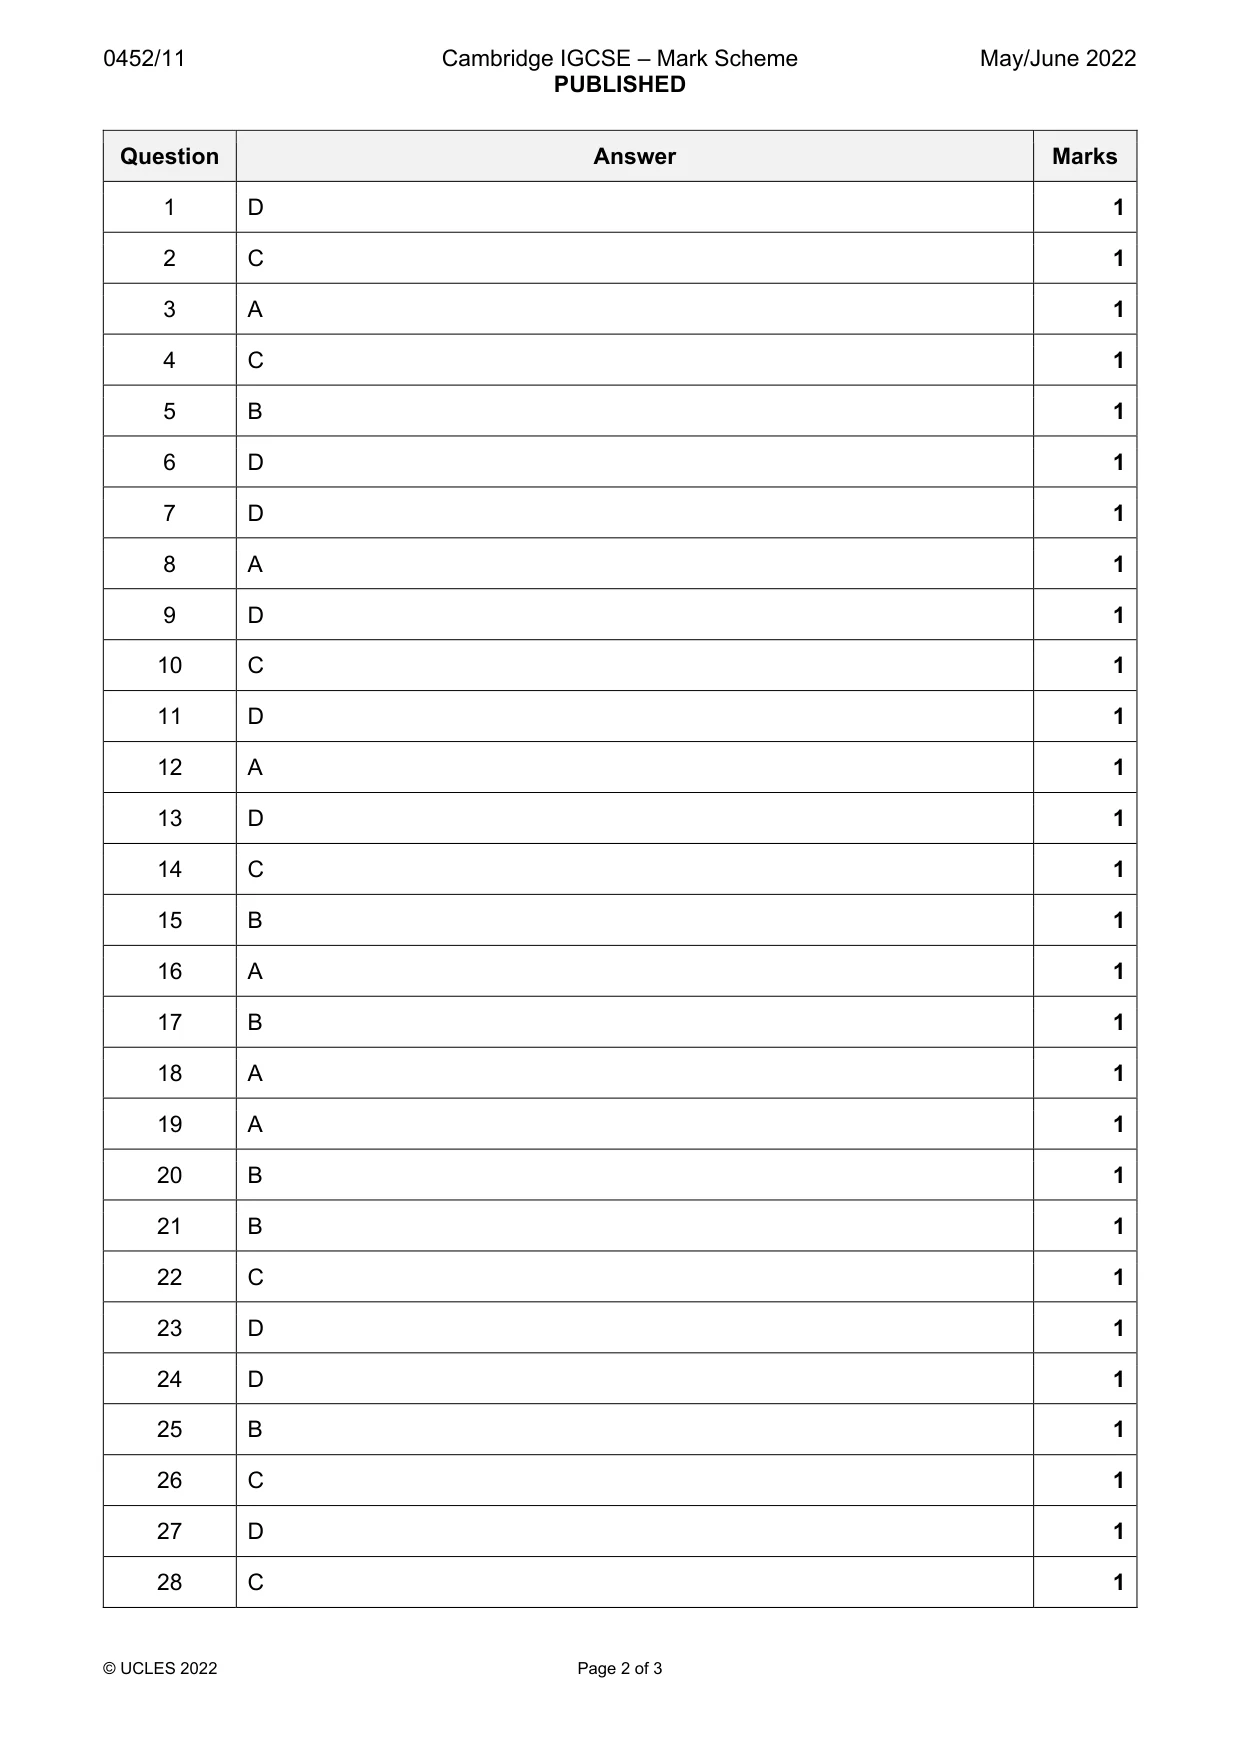
Mark scheme: D
Q2 · What is the accounting equation?
2 What is the accounting equation? A assets = capital – liabilities B assets = liabilities – capital C assets – liabilities = capital D assets + capital = liabilities
Mark scheme: C
Q3 · Sarah sold goods on credit to Zafar
3 Sarah sold goods on credit to Zafar. How was this recorded in Sarah’s ledgers? general ledger sales ledger A credit sales account debit Zafar account B debit sales account credit Zafar account C credit Zafar account debit sales account D debit Zafar account credit sales account
Mark scheme: A
Q4 · Omar sent a credit note to Miriam for goods returned
4 Omar sent a credit note to Miriam for goods returned. How would Miriam record this transaction? account to be debited account to be credited A purchases returns Omar B sales returns Miriam C Omar purchases returns D Miriam sales returns
Mark scheme: C
Q5 · The discount column on the debit side of a trader’s cash book totalled $1300 and the…
5 The discount column on the debit side of a trader’s cash book totalled $1300 and the discount column on the credit side totalled $700. How much discount did the trader receive? A $600 B $700 C $1300 D $2000
Mark scheme: B
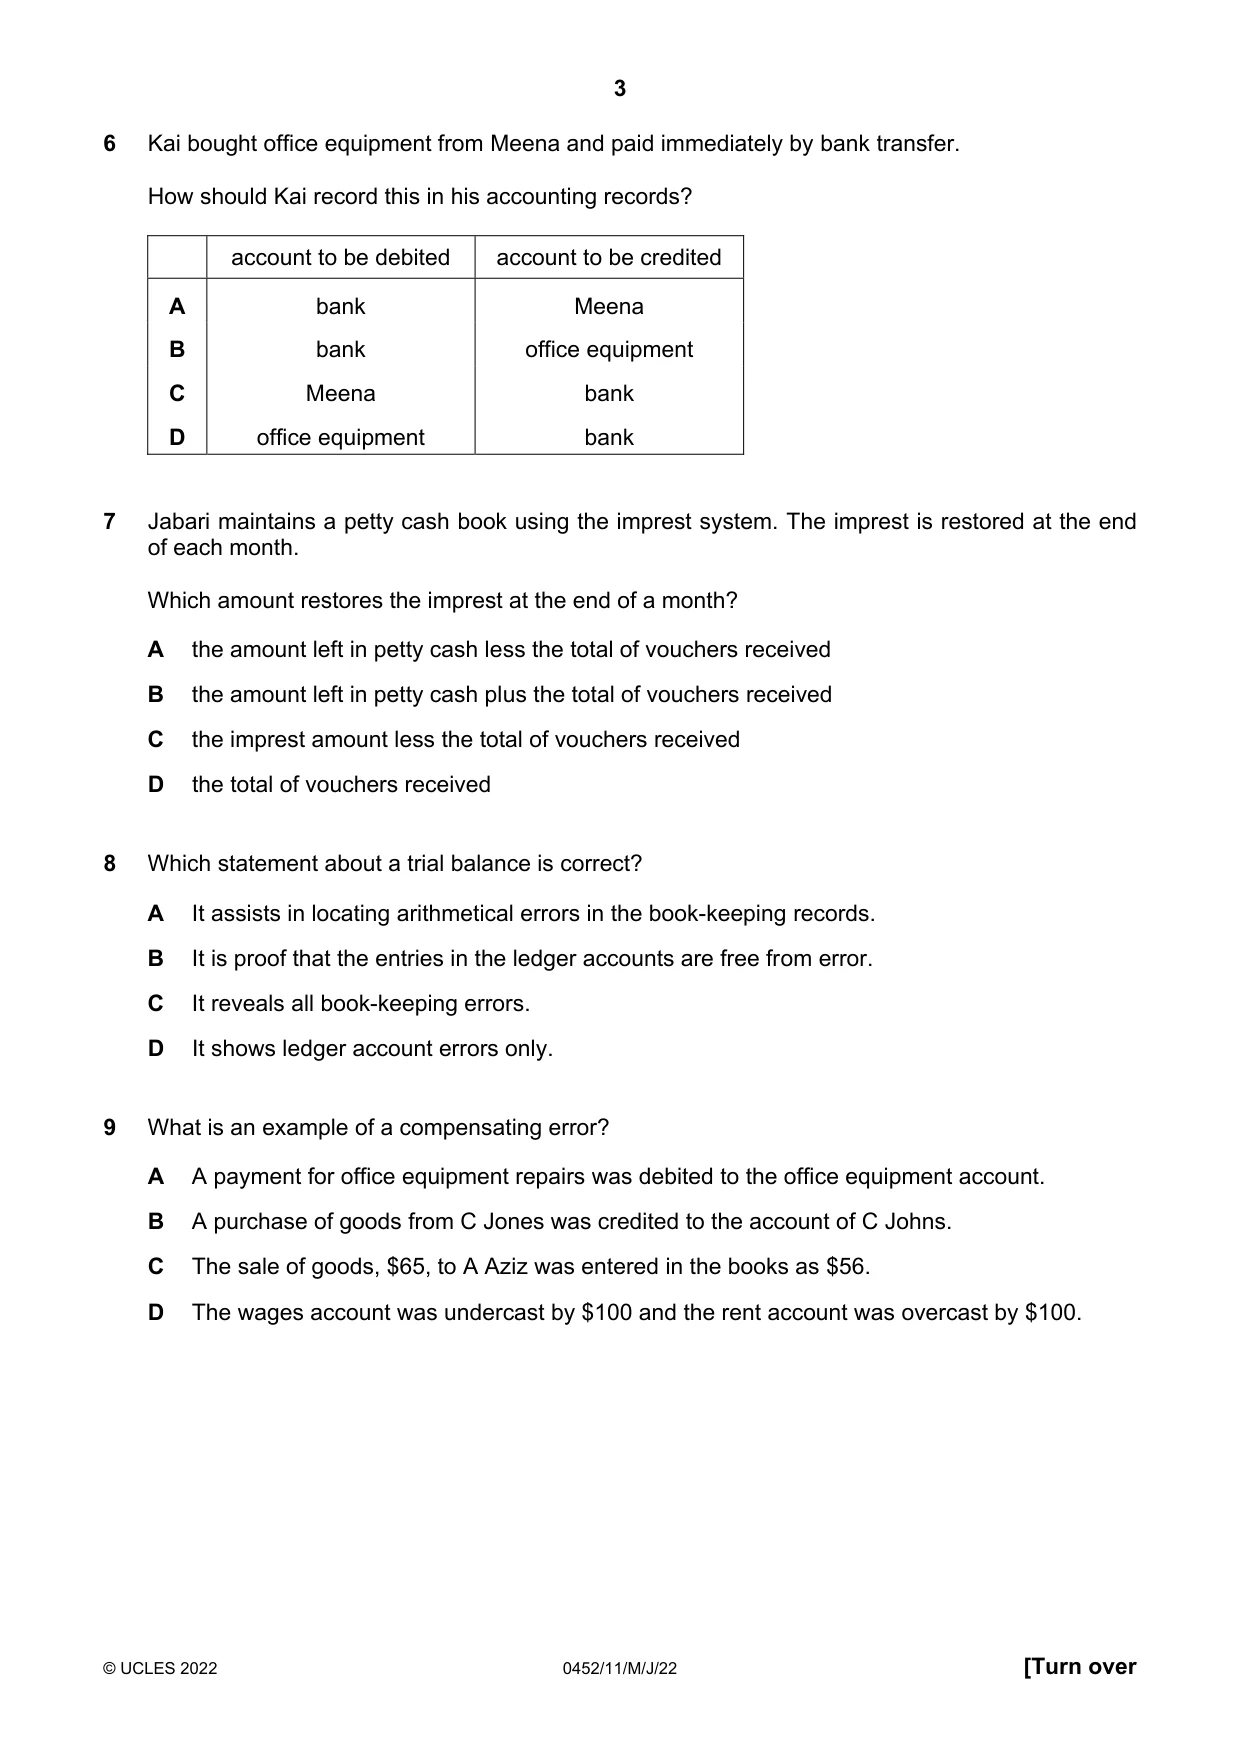
Q6 · Kai bought office equipment from Meena and paid immediately by bank transfer
6 Kai bought office equipment from Meena and paid immediately by bank transfer. How should Kai record this in his accounting records? account to be debited account to be credited A bank Meena B bank office equipment C Meena bank D office equipment bank
Mark scheme: D
Q7 · Jabari maintains a petty cash book using the imprest system
7 Jabari maintains a petty cash book using the imprest system. The imprest is restored at the end of each month. Which amount restores the imprest at the end of a month? A the amount left in petty cash less the total of vouchers received B the amount left in petty cash plus the total of vouchers received C the imprest amount less the total of vouchers received D the total of vouchers received
Mark scheme: D
Q8 · Which statement about a trial balance is correct?
8 Which statement about a trial balance is correct? A It assists in locating arithmetical errors in the book-keeping records. B It is proof that the entries in the ledger accounts are free from error. C It reveals all book-keeping errors. D It shows ledger account errors only.
Mark scheme: A
Q9 · What is an example of a compensating error?
9 What is an example of a compensating error? A A payment for office equipment repairs was debited to the office equipment account. B A purchase of goods from C Jones was credited to the account of C Johns. C The sale of goods, $65, to A Aziz was entered in the books as $56. D The wages account was undercast by $100 and the rent account was overcast by $100.
Mark scheme: D
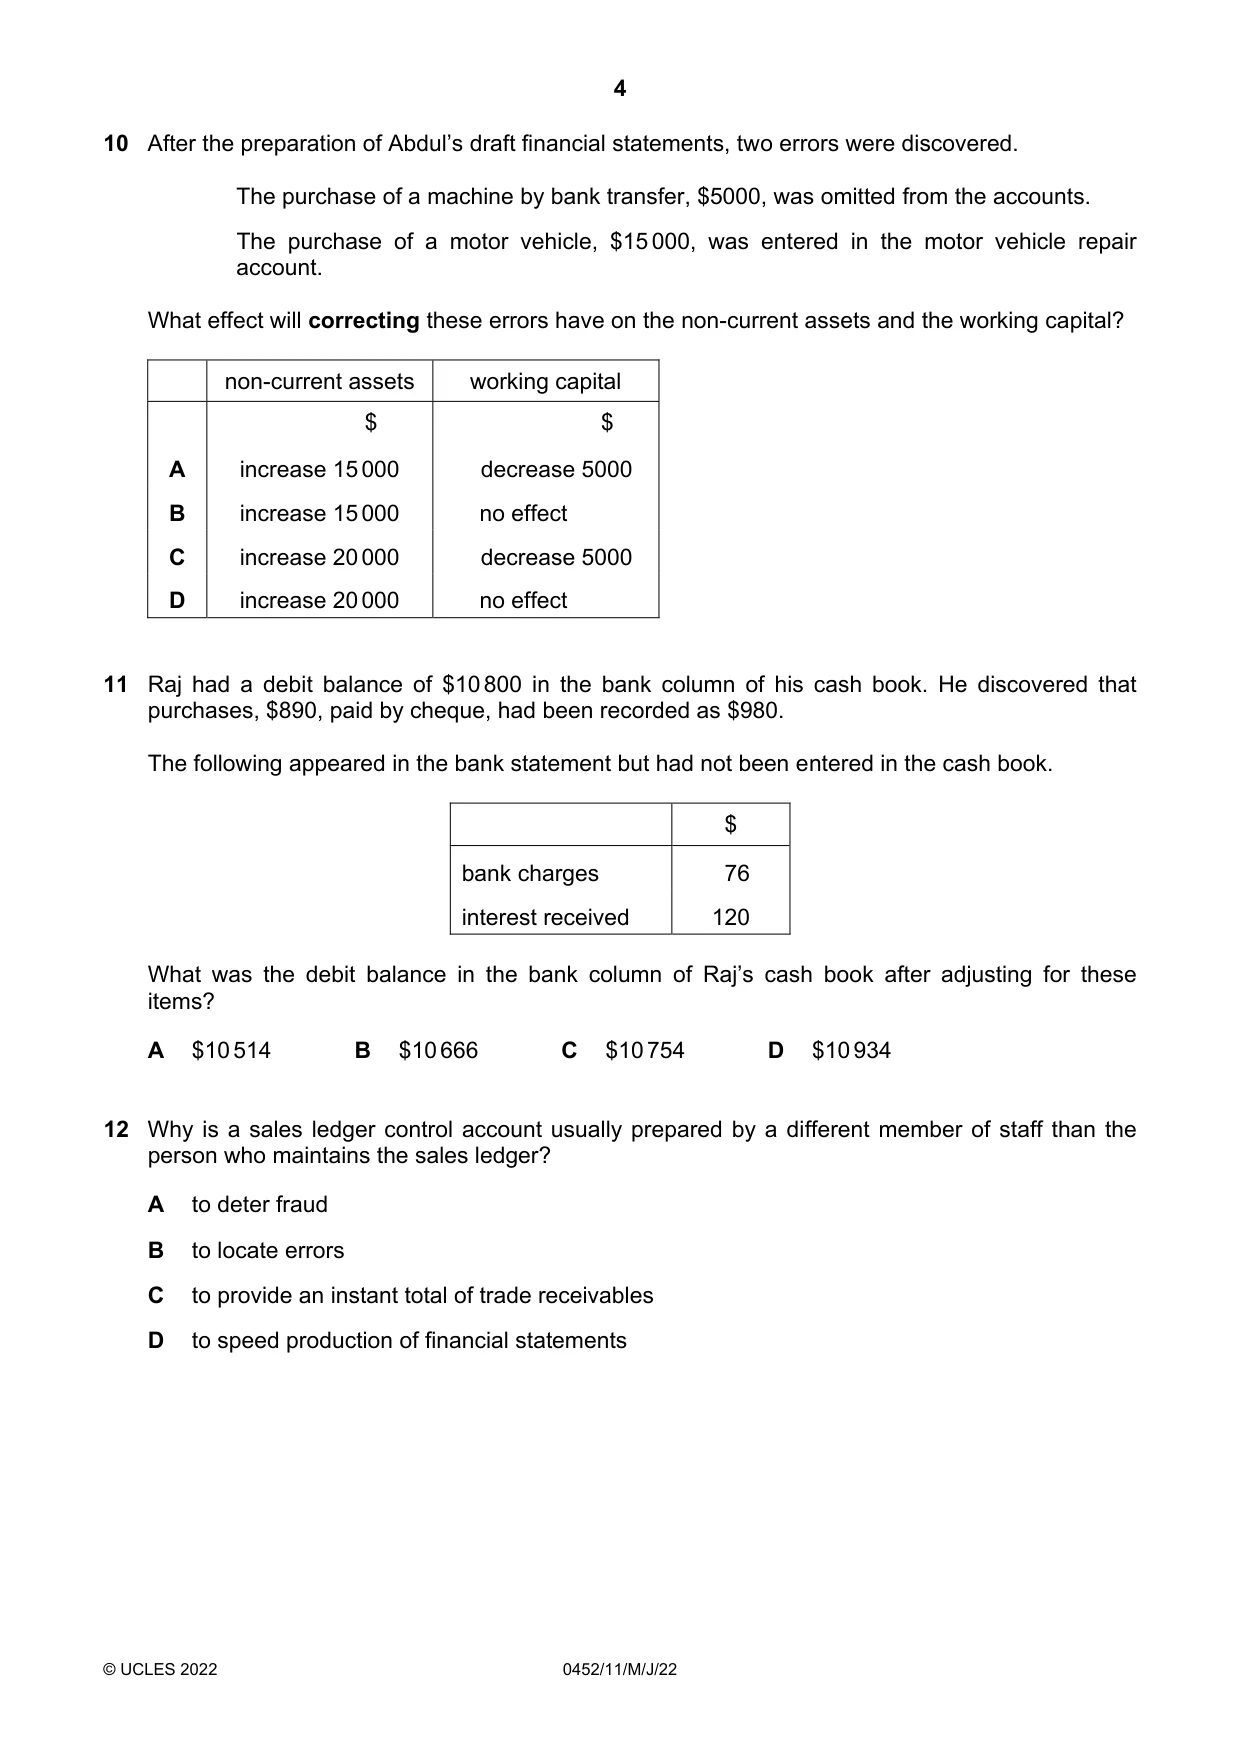
Q10 · After the preparation of Abdul’s draft financial statements, two errors were discovered
10 After the preparation of Abdul’s draft financial statements, two errors were discovered. The purchase of a machine by bank transfer, $5000, was omitted from the accounts. The purchase of a motor vehicle, $15 000, was entered in the motor vehicle repair account. What effect will correcting these errors have on the non-current assets and the working capital? non-current assets working capital $ $ A increase 15 000 decrease 5000 B increase 15 000 no effect C increase 20 000 decrease 5000 D increase 20 000 no effect
Mark scheme: C
More questions on Capital and revenue expenditure and receipts
Q11 · Raj had a debit balance of $10 800 in the bank column of his cash book
11 Raj had a debit balance of $10 800 in the bank column of his cash book. He discovered that purchases, $890, paid by cheque, had been recorded as $980. The following appeared in the bank statement but had not been entered in the cash book. $ bank charges 76 interest received 120 What was the debit balance in the bank column of Raj’s cash book after adjusting for these items? A $10 514 B $10 666 C $10 754 D $10 934
Mark scheme: D
Q12 · Why is a sales ledger control account usually prepared by a different member of staff…
12 Why is a sales ledger control account usually prepared by a different member of staff than the person who maintains the sales ledger? A to deter fraud B to locate errors C to provide an instant total of trade receivables D to speed production of financial statements
Mark scheme: A
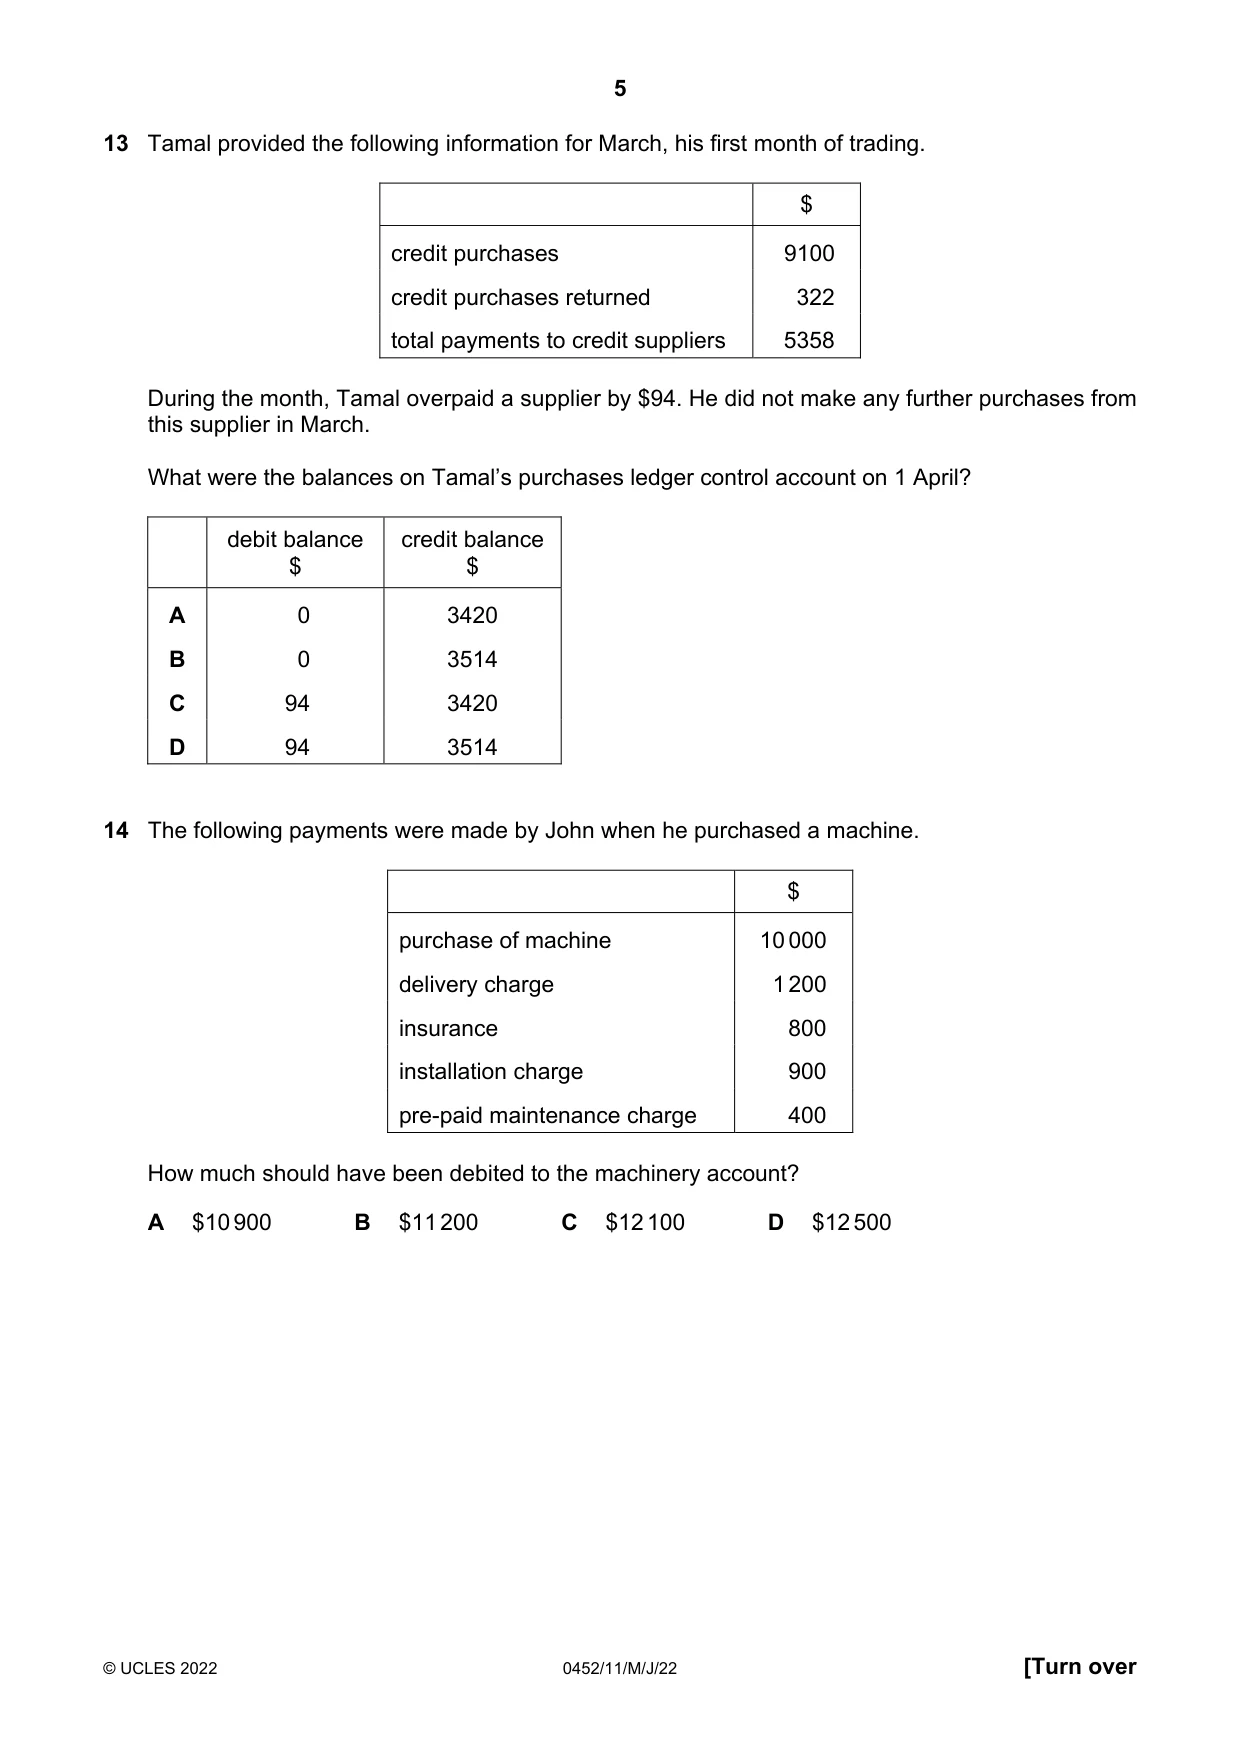
Q13 · Tamal provided the following information for March, his first month of trading
13 Tamal provided the following information for March, his first month of trading. $ credit purchases 9100 credit purchases returned 322 total payments to credit suppliers 5358 During the month, Tamal overpaid a supplier by $94. He did not make any further purchases from this supplier in March. What were the balances on Tamal’s purchases ledger control account on 1 April? debit balance credit balance $ $ A 0 3420 B 0 3514 C 94 3420 D 94 3514
Mark scheme: D
Q14 · The following payments were made by John when he purchased a machine
14 The following payments were made by John when he purchased a machine. $ purchase of machine 10 000 delivery charge 1 200 insurance 800 installation charge 900 pre-paid maintenance charge 400 How much should have been debited to the machinery account? A $10 900 B $11 200 C $12 100 D $12 500
Mark scheme: C
More questions on Capital and revenue expenditure and receipts
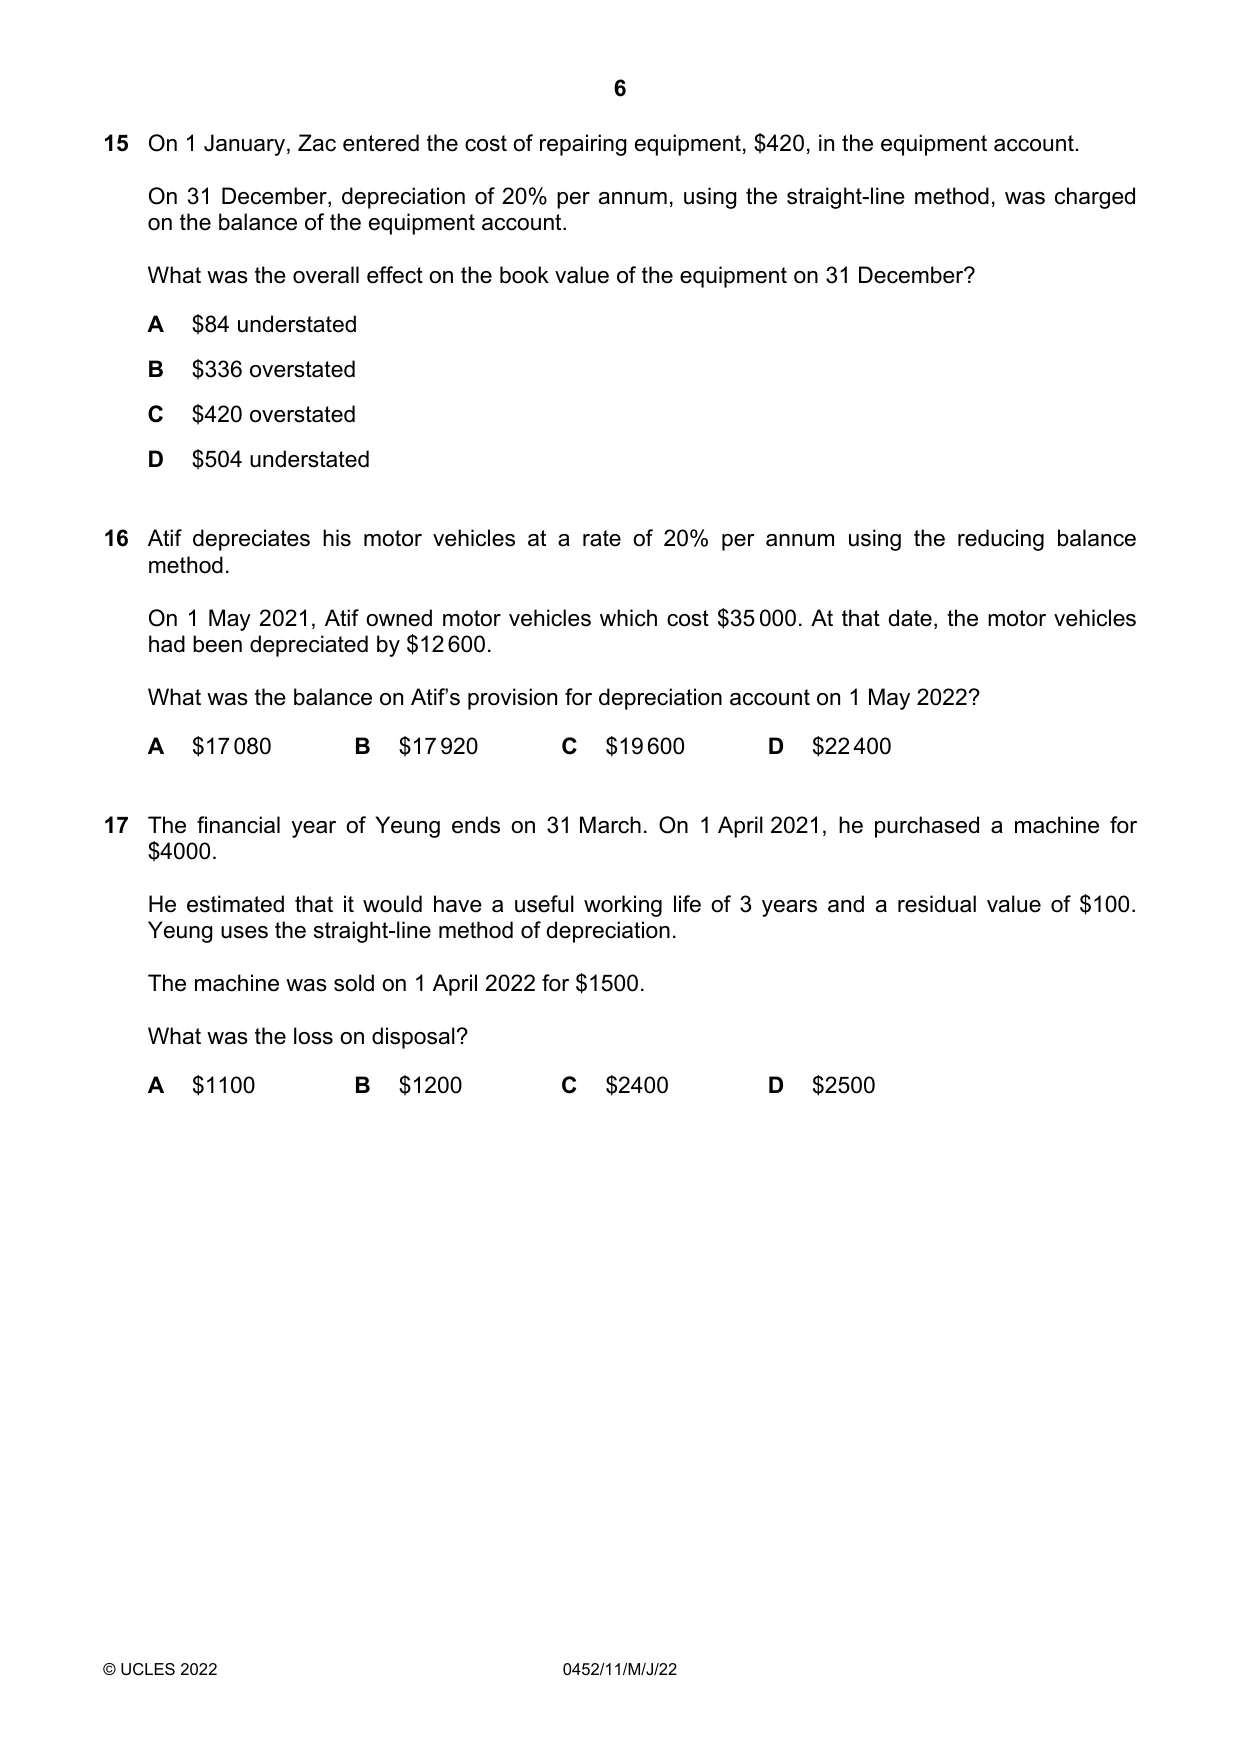
Q15 · On 1 January, Zac entered the cost of repairing equipment, $420, in the equipment account
15 On 1 January, Zac entered the cost of repairing equipment, $420, in the equipment account. On 31 December, depreciation of 20% per annum, using the straight-line method, was charged on the balance of the equipment account. What was the overall effect on the book value of the equipment on 31 December? A $84 understated B $336 overstated C $420 overstated D $504 understated
Mark scheme: B
Q16 · Atif depreciates his motor vehicles at a rate of 20% per annum using the reducing balance…
16 Atif depreciates his motor vehicles at a rate of 20% per annum using the reducing balance method. On 1 May 2021, Atif owned motor vehicles which cost $35 000. At that date, the motor vehicles had been depreciated by $12 600. What was the balance on Atif’s provision for depreciation account on 1 May 2022? A $17 080 B $17 920 C $19 600 D $22 400
Mark scheme: A
More questions on Accounting for depreciation and disposal of non-current assets
Q17 · The financial year of Yeung ends on 31 March
17 The financial year of Yeung ends on 31 March. On 1 April 2021, he purchased a machine for $4000. He estimated that it would have a useful working life of 3 years and a residual value of $100. Yeung uses the straight-line method of depreciation. The machine was sold on 1 April 2022 for $1500. What was the loss on disposal? A $1100 B $1200 C $2400 D $2500
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
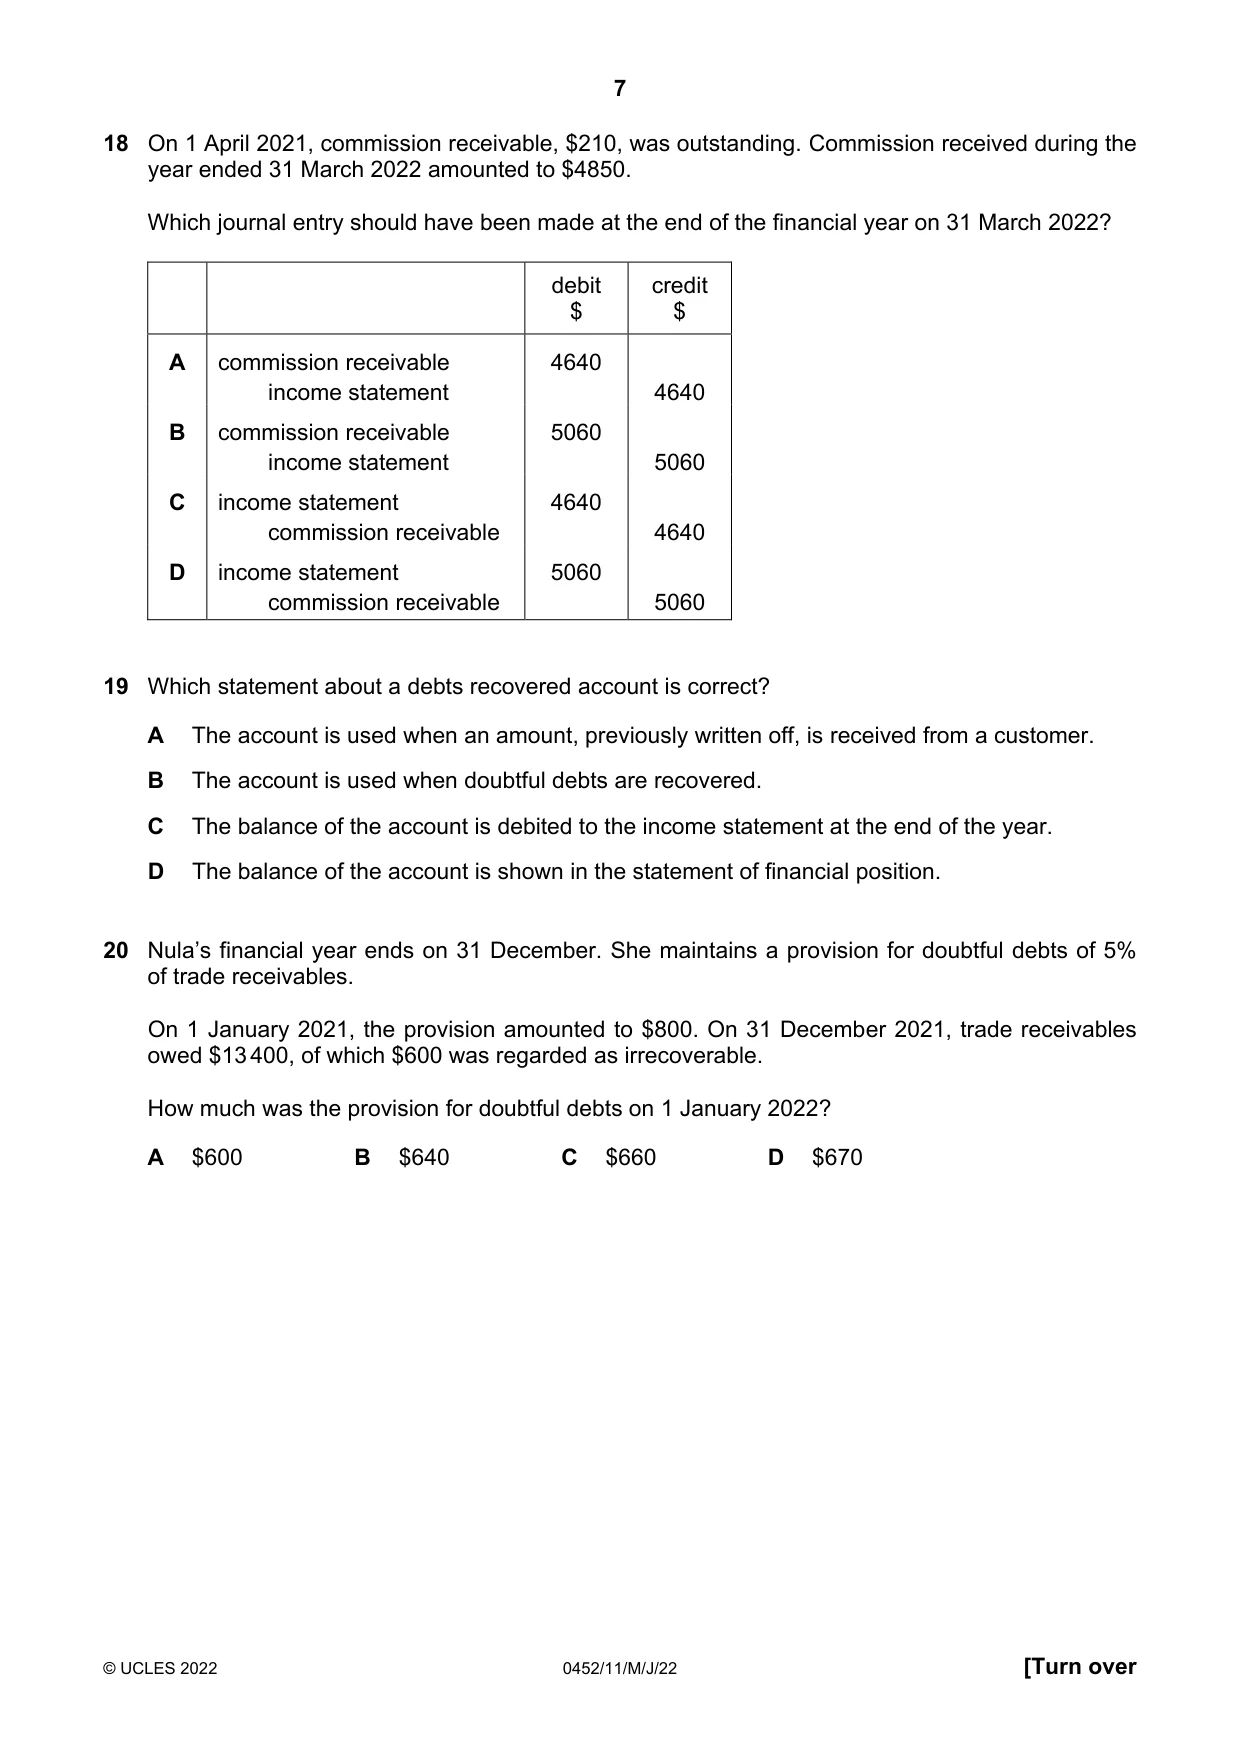
Q18 · On 1 April 2021, commission receivable, $210, was outstanding
18 On 1 April 2021, commission receivable, $210, was outstanding. Commission received during the year ended 31 March 2022 amounted to $4850. Which journal entry should have been made at the end of the financial year on 31 March 2022? debit credit $ $ A commission receivable 4640 income statement 4640 B commission receivable 5060 income statement 5060 C income statement 4640 commission receivable 4640 D income statement 5060 commission receivable 5060
Mark scheme: A
Q19 · Which statement about a debts recovered account is correct?
19 Which statement about a debts recovered account is correct? A The account is used when an amount, previously written off, is received from a customer. B The account is used when doubtful debts are recovered. C The balance of the account is debited to the income statement at the end of the year. D The balance of the account is shown in the statement of financial position.
Mark scheme: A
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q20 · Nula’s financial year ends on 31 December
20 Nula’s financial year ends on 31 December. She maintains a provision for doubtful debts of 5% of trade receivables. On 1 January 2021, the provision amounted to $800. On 31 December 2021, trade receivables owed $13 400, of which $600 was regarded as irrecoverable. How much was the provision for doubtful debts on 1 January 2022? A $600 B $640 C $660 D $670
Mark scheme: B
More questions on Irrecoverable debts and allowance for irrecoverable debts
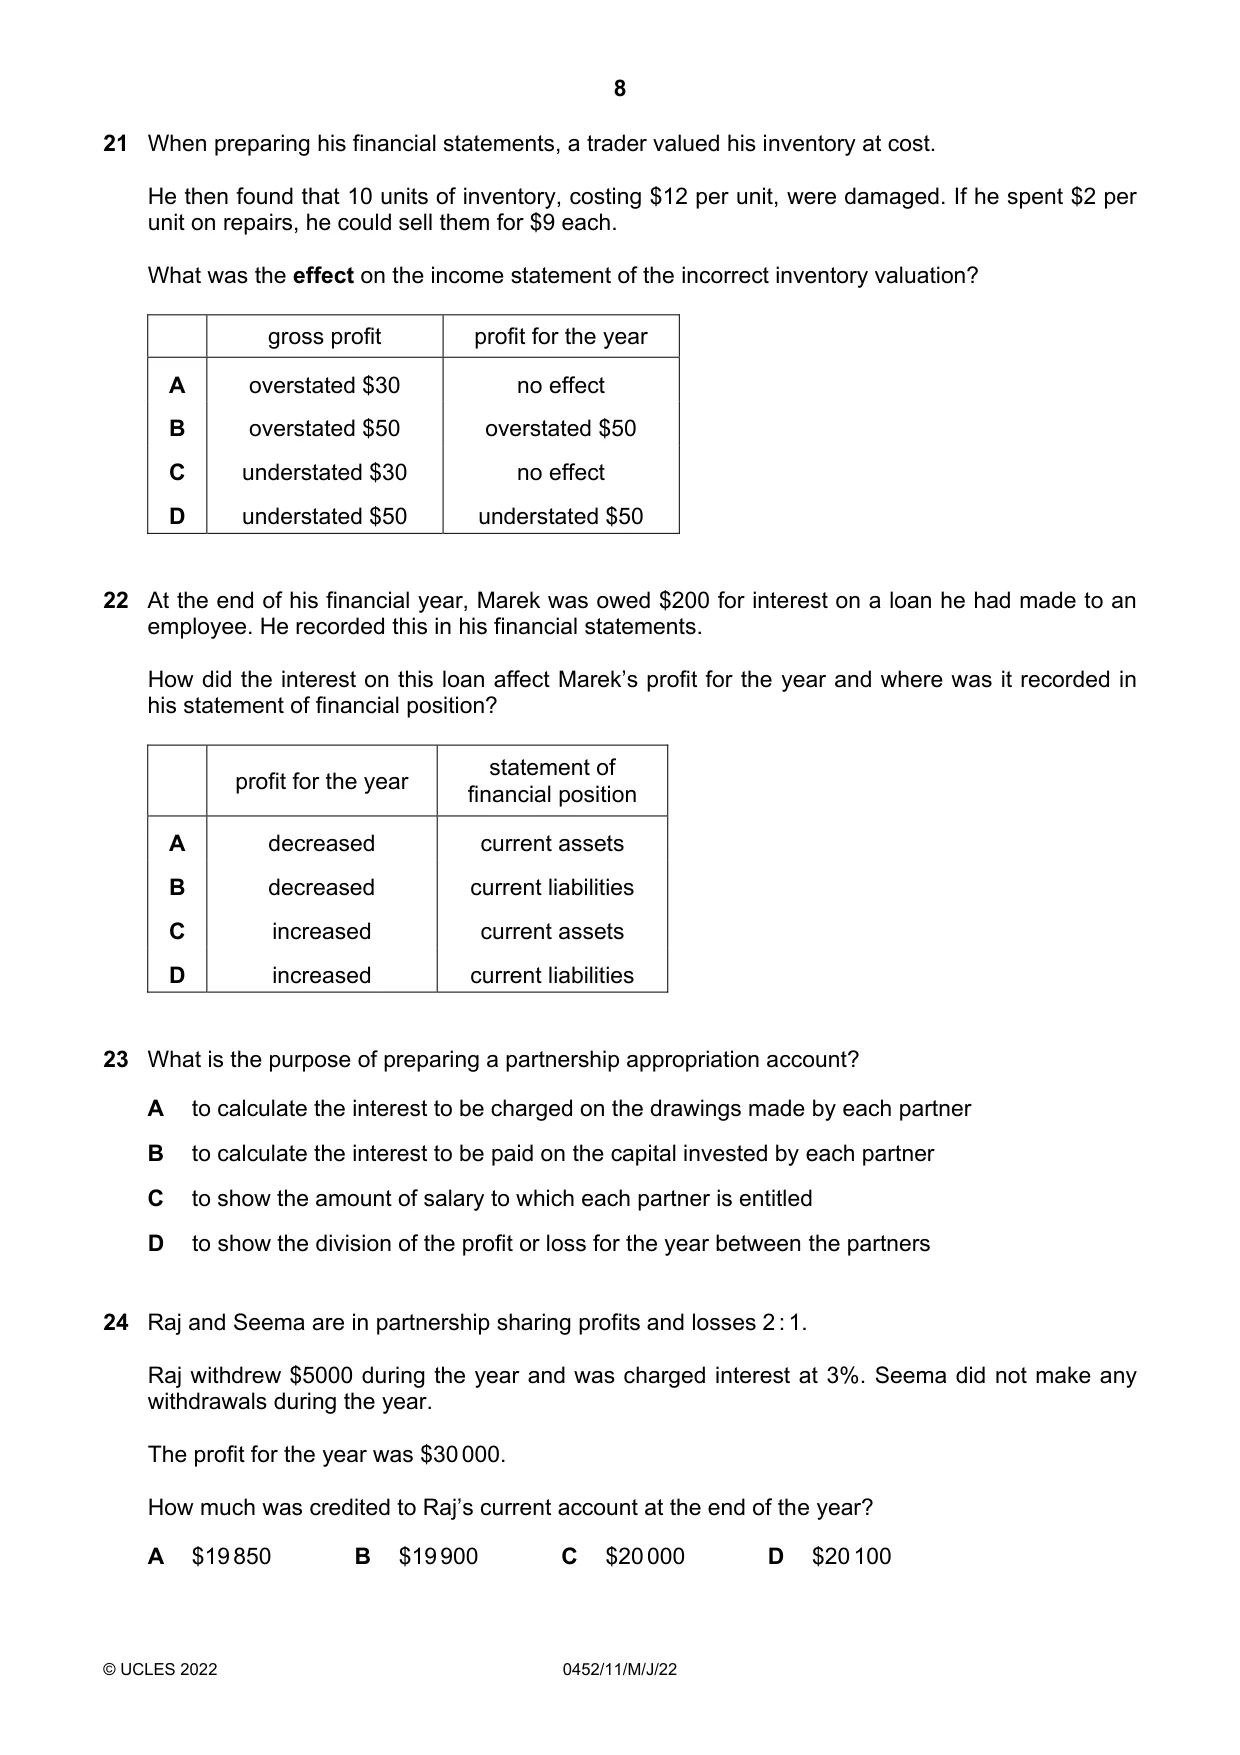
Q21 · When preparing his financial statements, a trader valued his inventory at cost
21 When preparing his financial statements, a trader valued his inventory at cost. He then found that 10 units of inventory, costing $12 per unit, were damaged. If he spent $2 per unit on repairs, he could sell them for $9 each. What was the effect on the income statement of the incorrect inventory valuation? gross profit profit for the year A overstated $30 no effect B overstated $50 overstated $50 C understated $30 no effect D understated $50 understated $50
Mark scheme: B
Q22 · At the end of his financial year, Marek was owed $200 for interest on a loan he had made…
22 At the end of his financial year, Marek was owed $200 for interest on a loan he had made to an employee. He recorded this in his financial statements. How did the interest on this loan affect Marek’s profit for the year and where was it recorded in his statement of financial position? statement of profit for the year financial position A decreased current assets B decreased current liabilities C increased current assets D increased current liabilities
Mark scheme: C
Q23 · What is the purpose of preparing a partnership appropriation account?
23 What is the purpose of preparing a partnership appropriation account? A to calculate the interest to be charged on the drawings made by each partner B to calculate the interest to be paid on the capital invested by each partner C to show the amount of salary to which each partner is entitled D to show the division of the profit or loss for the year between the partners
Mark scheme: D
Q24 · Raj and Seema are in partnership sharing profits and losses 2 : 1
24 Raj and Seema are in partnership sharing profits and losses 2 : 1. Raj withdrew $5000 during the year and was charged interest at 3%. Seema did not make any withdrawals during the year. The profit for the year was $30 000. How much was credited to Raj’s current account at the end of the year? A $19 850 B $19 900 C $20 000 D $20 100
Mark scheme: D
Q25 · A limited company raised funds from an issue of debentures
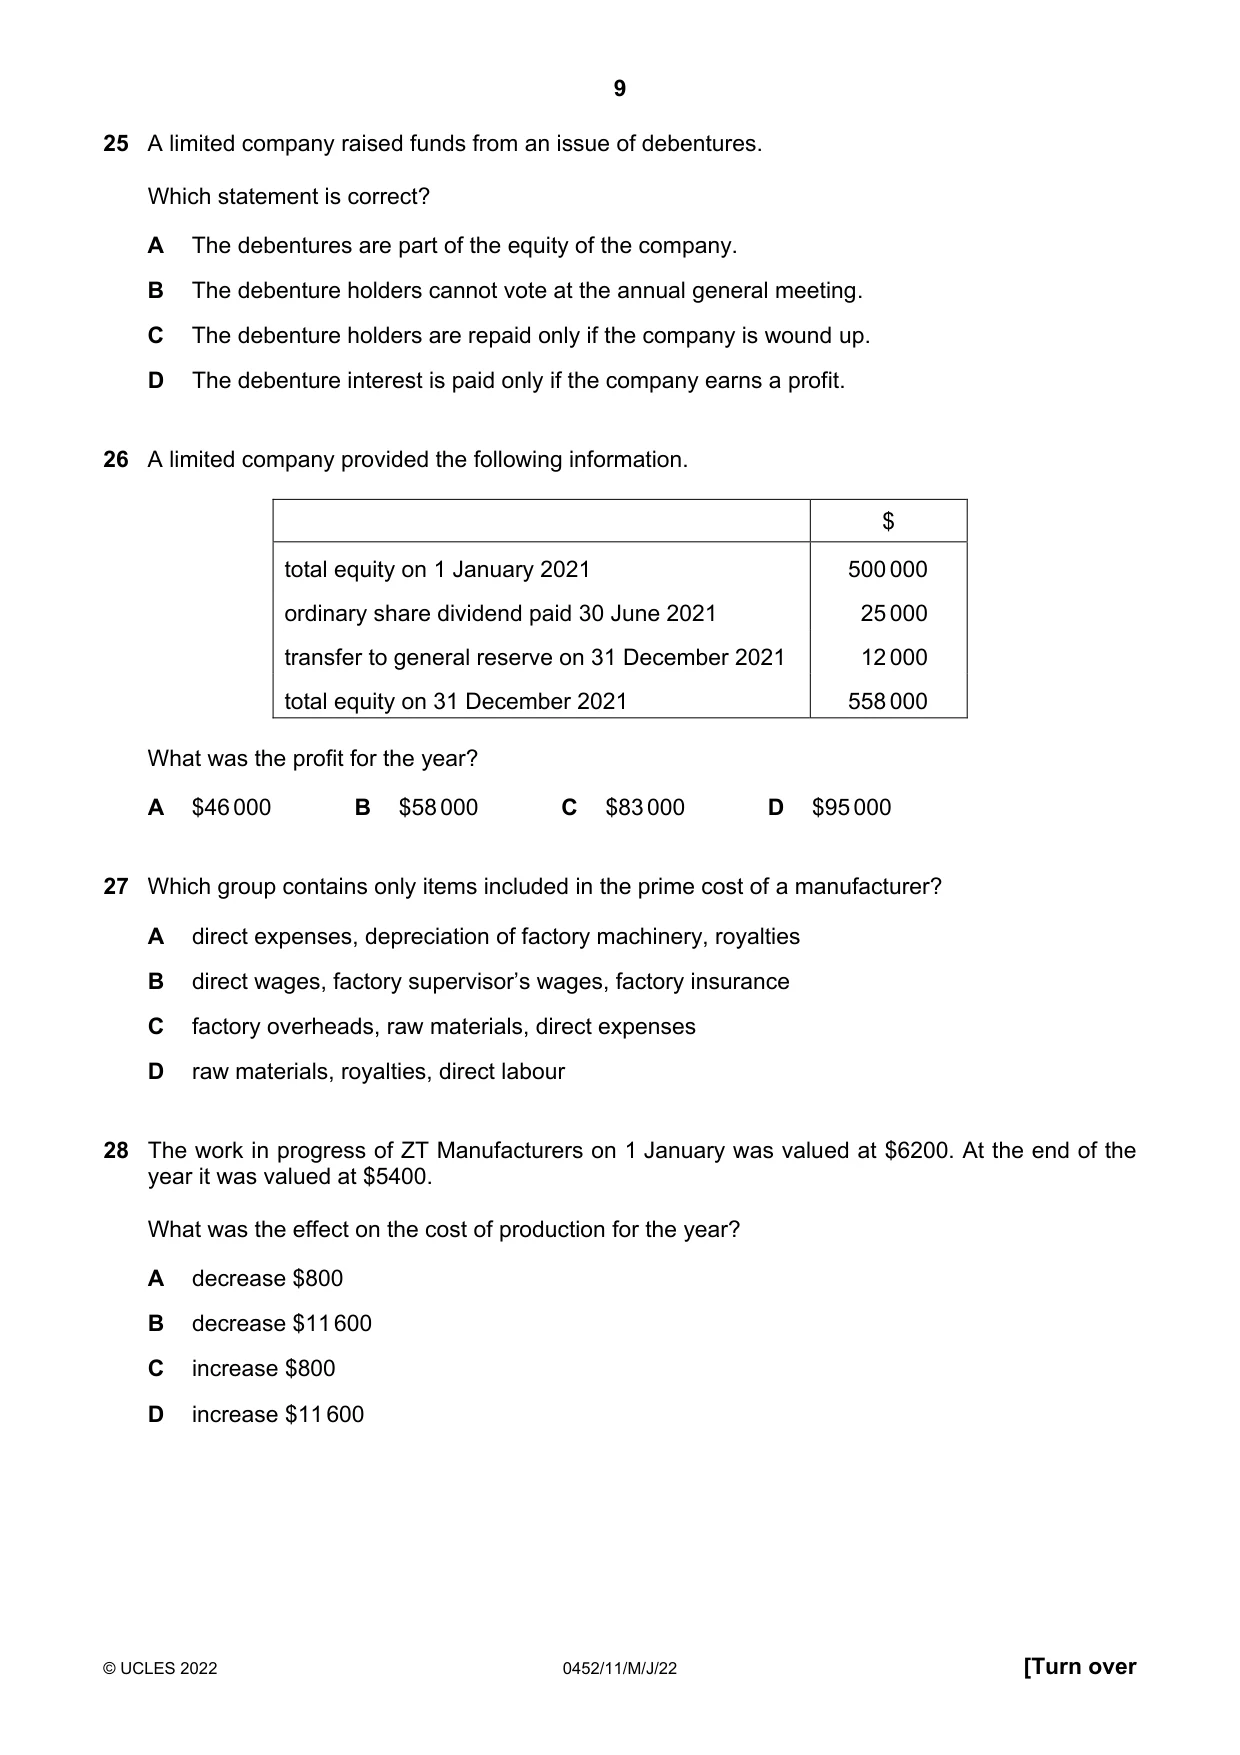
25 A limited company raised funds from an issue of debentures. Which statement is correct? A The debentures are part of the equity of the company. B The debenture holders cannot vote at the annual general meeting. C The debenture holders are repaid only if the company is wound up. D The debenture interest is paid only if the company earns a profit.
Mark scheme: B
Q26 · A limited company provided the following information
26 A limited company provided the following information. $ total equity on 1 January 2021 500 000 ordinary share dividend paid 30 June 2021 25 000 transfer to general reserve on 31 December 2021 12 000 total equity on 31 December 2021 558 000 What was the profit for the year? A $46 000 B $58 000 C $83 000 D $95 000
Mark scheme: C
Q27 · Which group contains only items included in the prime cost of a manufacturer?
27 Which group contains only items included in the prime cost of a manufacturer? A direct expenses, depreciation of factory machinery, royalties B direct wages, factory supervisor’s wages, factory insurance C factory overheads, raw materials, direct expenses D raw materials, royalties, direct labour
Mark scheme: D
Q28 · The work in progress of ZT Manufacturers on 1 January was valued at $6200
28 The work in progress of ZT Manufacturers on 1 January was valued at $6200. At the end of the year it was valued at $5400. What was the effect on the cost of production for the year? A decrease $800 B decrease $11 600 C increase $800 D increase $11 600
Mark scheme: C
Q29 · A trader does not keep full accounting records but was able to provide the following…
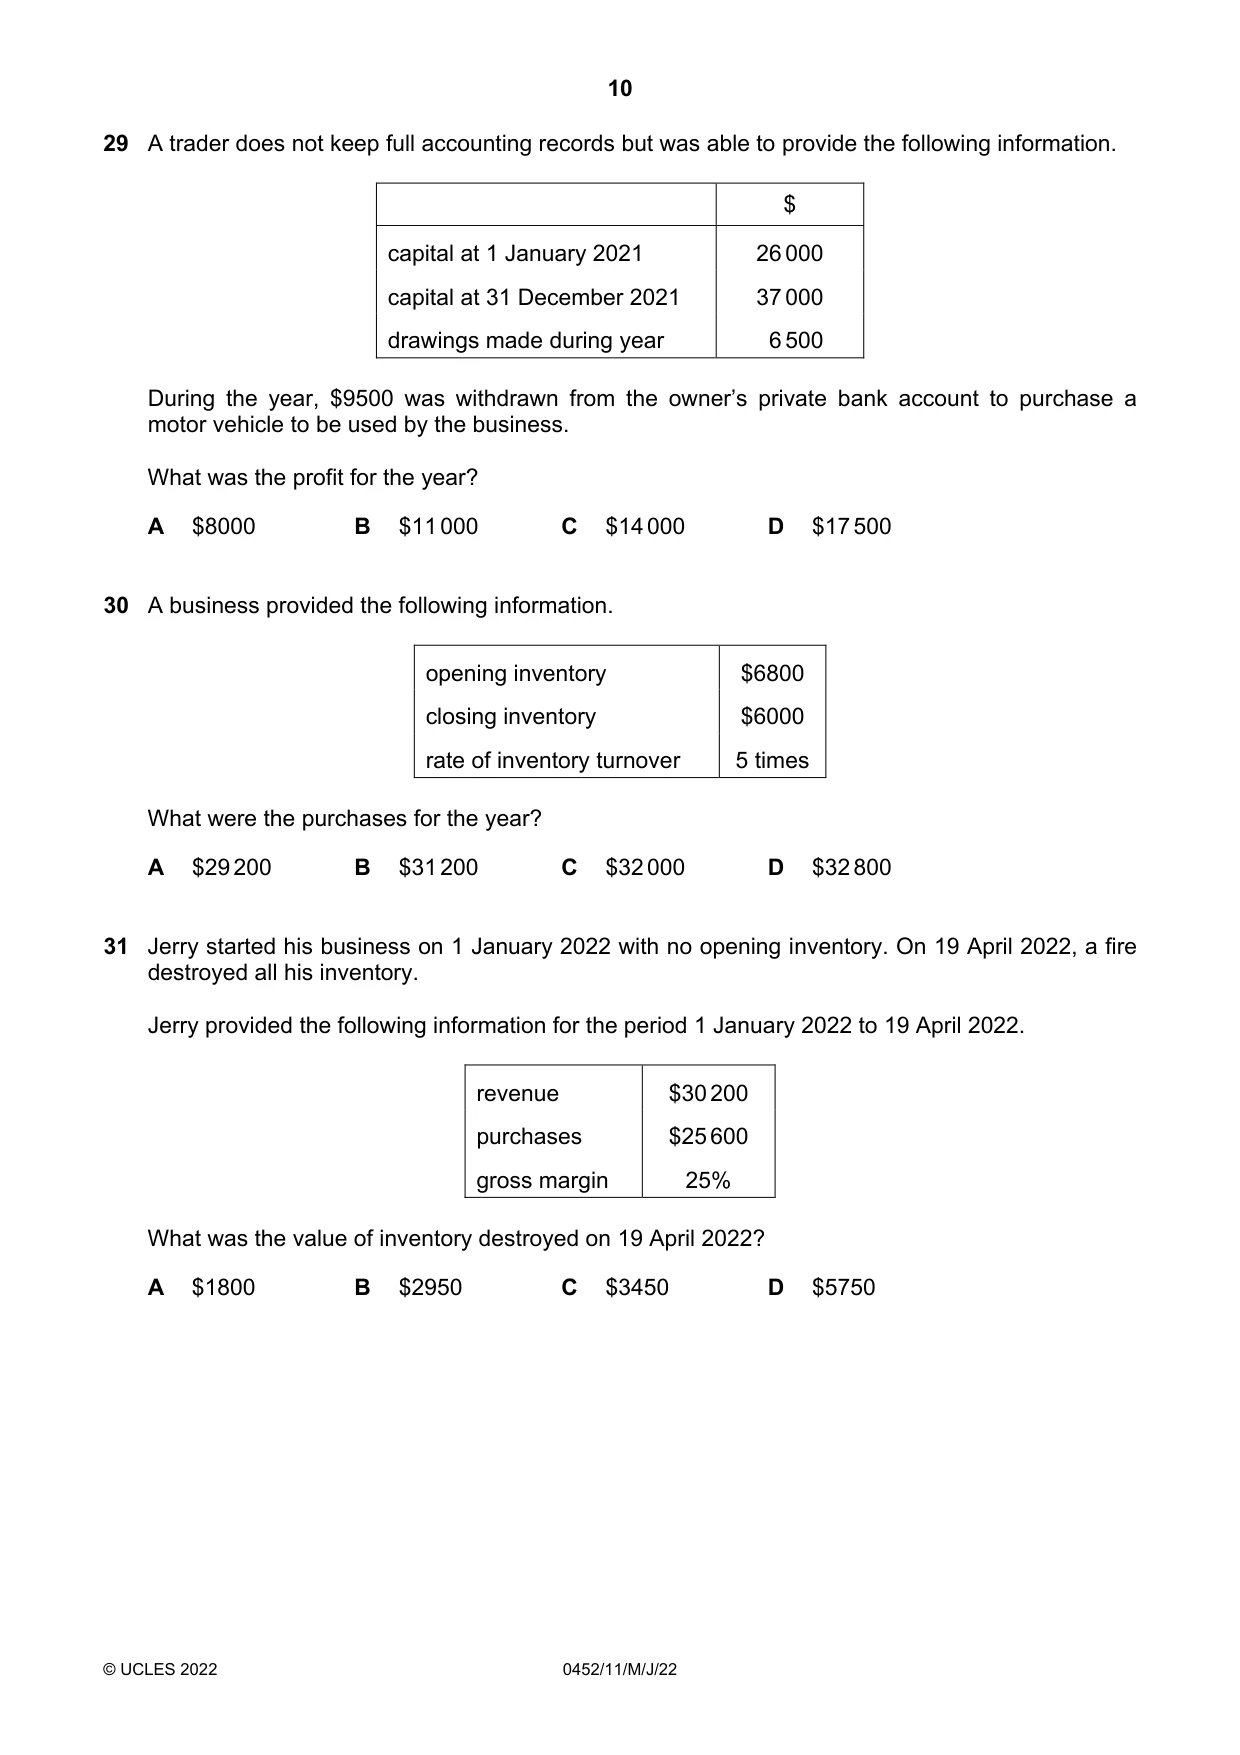
29 A trader does not keep full accounting records but was able to provide the following information. $ capital at 1 January 2021 26 000 capital at 31 December 2021 37 000 drawings made during year 6 500 During the year, $9500 was withdrawn from the owner’s private bank account to purchase a motor vehicle to be used by the business. What was the profit for the year? A $8000 B $11 000 C $14 000 D $17 500
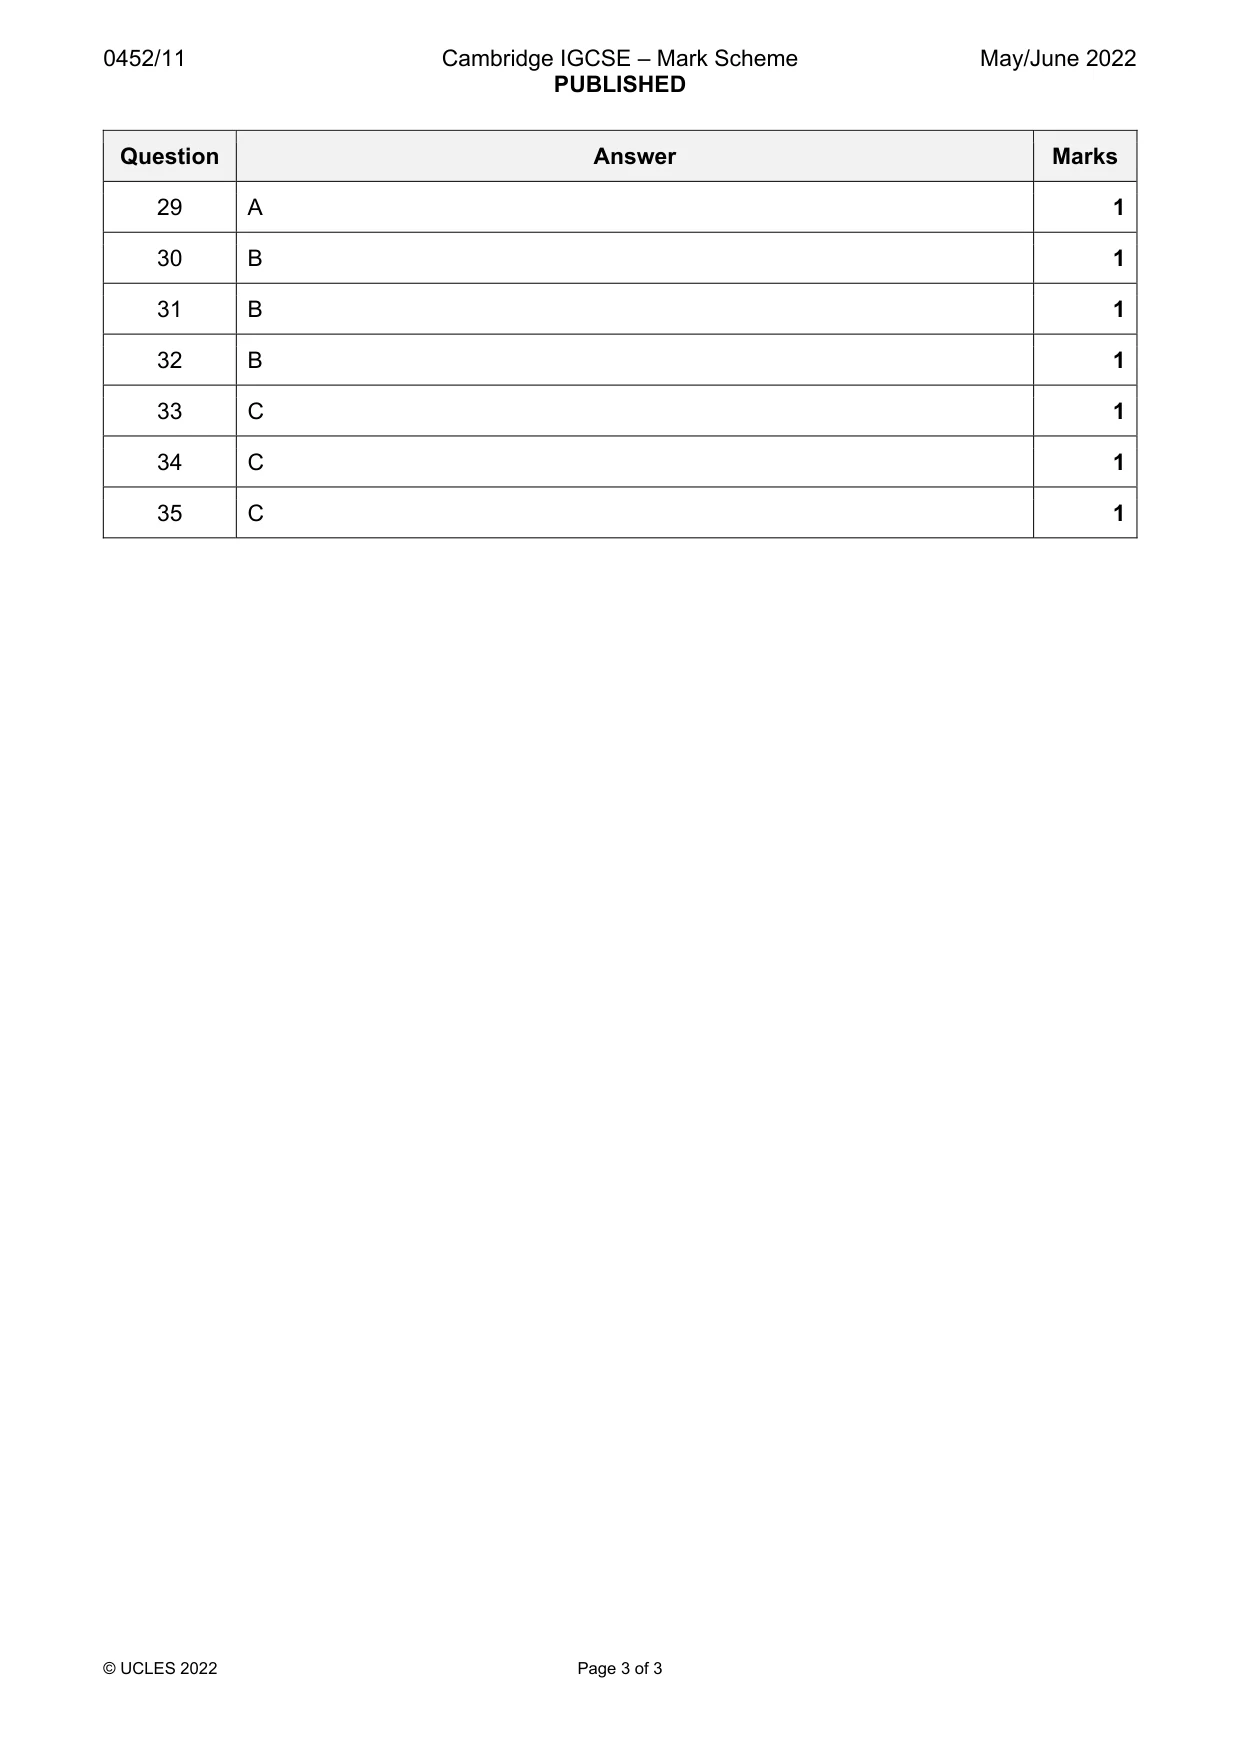
Mark scheme: A
Q30 · A business provided the following information
30 A business provided the following information. opening inventory $6800 closing inventory $6000 rate of inventory turnover 5 times What were the purchases for the year? A $29 200 B $31 200 C $32 000 D $32 800
Mark scheme: B
More questions on Calculation and understanding of accounting ratios
Q31 · Jerry started his business on 1 January 2022 with no opening inventory
31 Jerry started his business on 1 January 2022 with no opening inventory. On 19 April 2022, a fire destroyed all his inventory. Jerry provided the following information for the period 1 January 2022 to 19 April 2022. revenue $30 200 purchases $25 600 gross margin 25% What was the value of inventory destroyed on 19 April 2022? A $1800 B $2950 C $3450 D $5750
Mark scheme: B
Q32 · A trader provided the following information
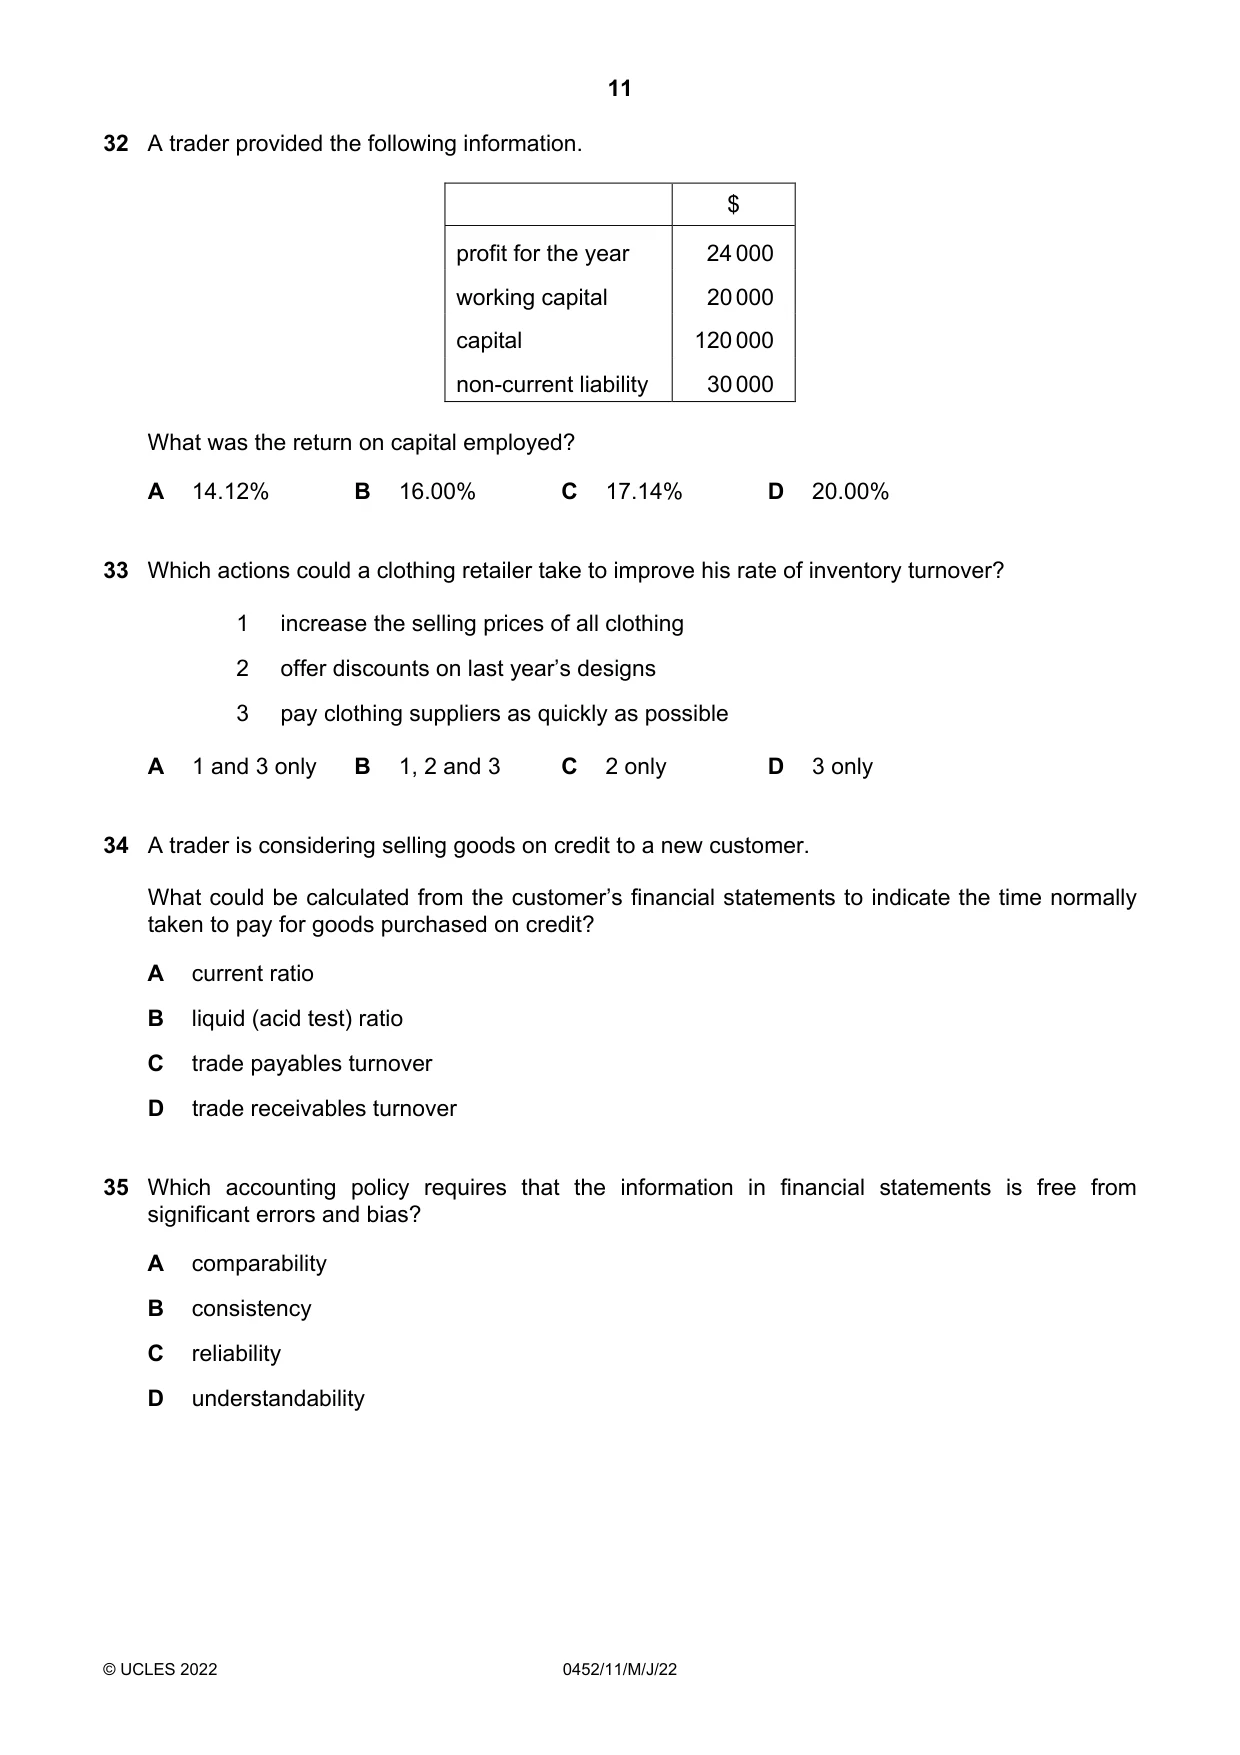
32 A trader provided the following information. $ profit for the year 24 000 working capital 20 000 capital 120 000 non-current liability 30 000 What was the return on capital employed? A 14.12% B 16.00% C 17.14% D 20.00%
Mark scheme: B
More questions on Calculation and understanding of accounting ratios
Q33 · Which actions could a clothing retailer take to improve his rate of inventory turnover?
33 Which actions could a clothing retailer take to improve his rate of inventory turnover? 1 increase the selling prices of all clothing 2 offer discounts on last year’s designs 3 pay clothing suppliers as quickly as possible A 1 and 3 only B 1, 2 and 3 C 2 only D 3 only
Mark scheme: C
Q34 · A trader is considering selling goods on credit to a new customer
34 A trader is considering selling goods on credit to a new customer. What could be calculated from the customer’s financial statements to indicate the time normally taken to pay for goods purchased on credit? A current ratio B liquid (acid test) ratio C trade payables turnover D trade receivables turnover
Mark scheme: C
Q35 · Which accounting policy requires that the information in financial statements is free…
35 Which accounting policy requires that the information in financial statements is free from significant errors and bias? A comparability B consistency C reliability D understandability
Mark scheme: C
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
3Accounting for depreciation and disposal of non-current assets2Books of prime entry2Calculation and understanding of accounting ratios2Capital and revenue expenditure and receipts2Control accounts2Corrections of errors2Interpretation of accounting ratios2Irrecoverable debts and allowance for irrecoverable debts2Limited companies2Manufacturing accounts2Other payables and other receivables2Partnerships2Valuation of inventory2Accounting concepts1Bank reconciliation1Incomplete records1The accounting equation1The purpose of accounting1The trial balance1What you needed in this session
Cambridge’s own grade thresholds for 2022 May/June, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.