Cambridge IGCSE Accounting 0452 — 2023 May/June Paper 1 · Variant 1
0452/11/M/J/23 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Why does the accountant of a business analyse its financial statements?
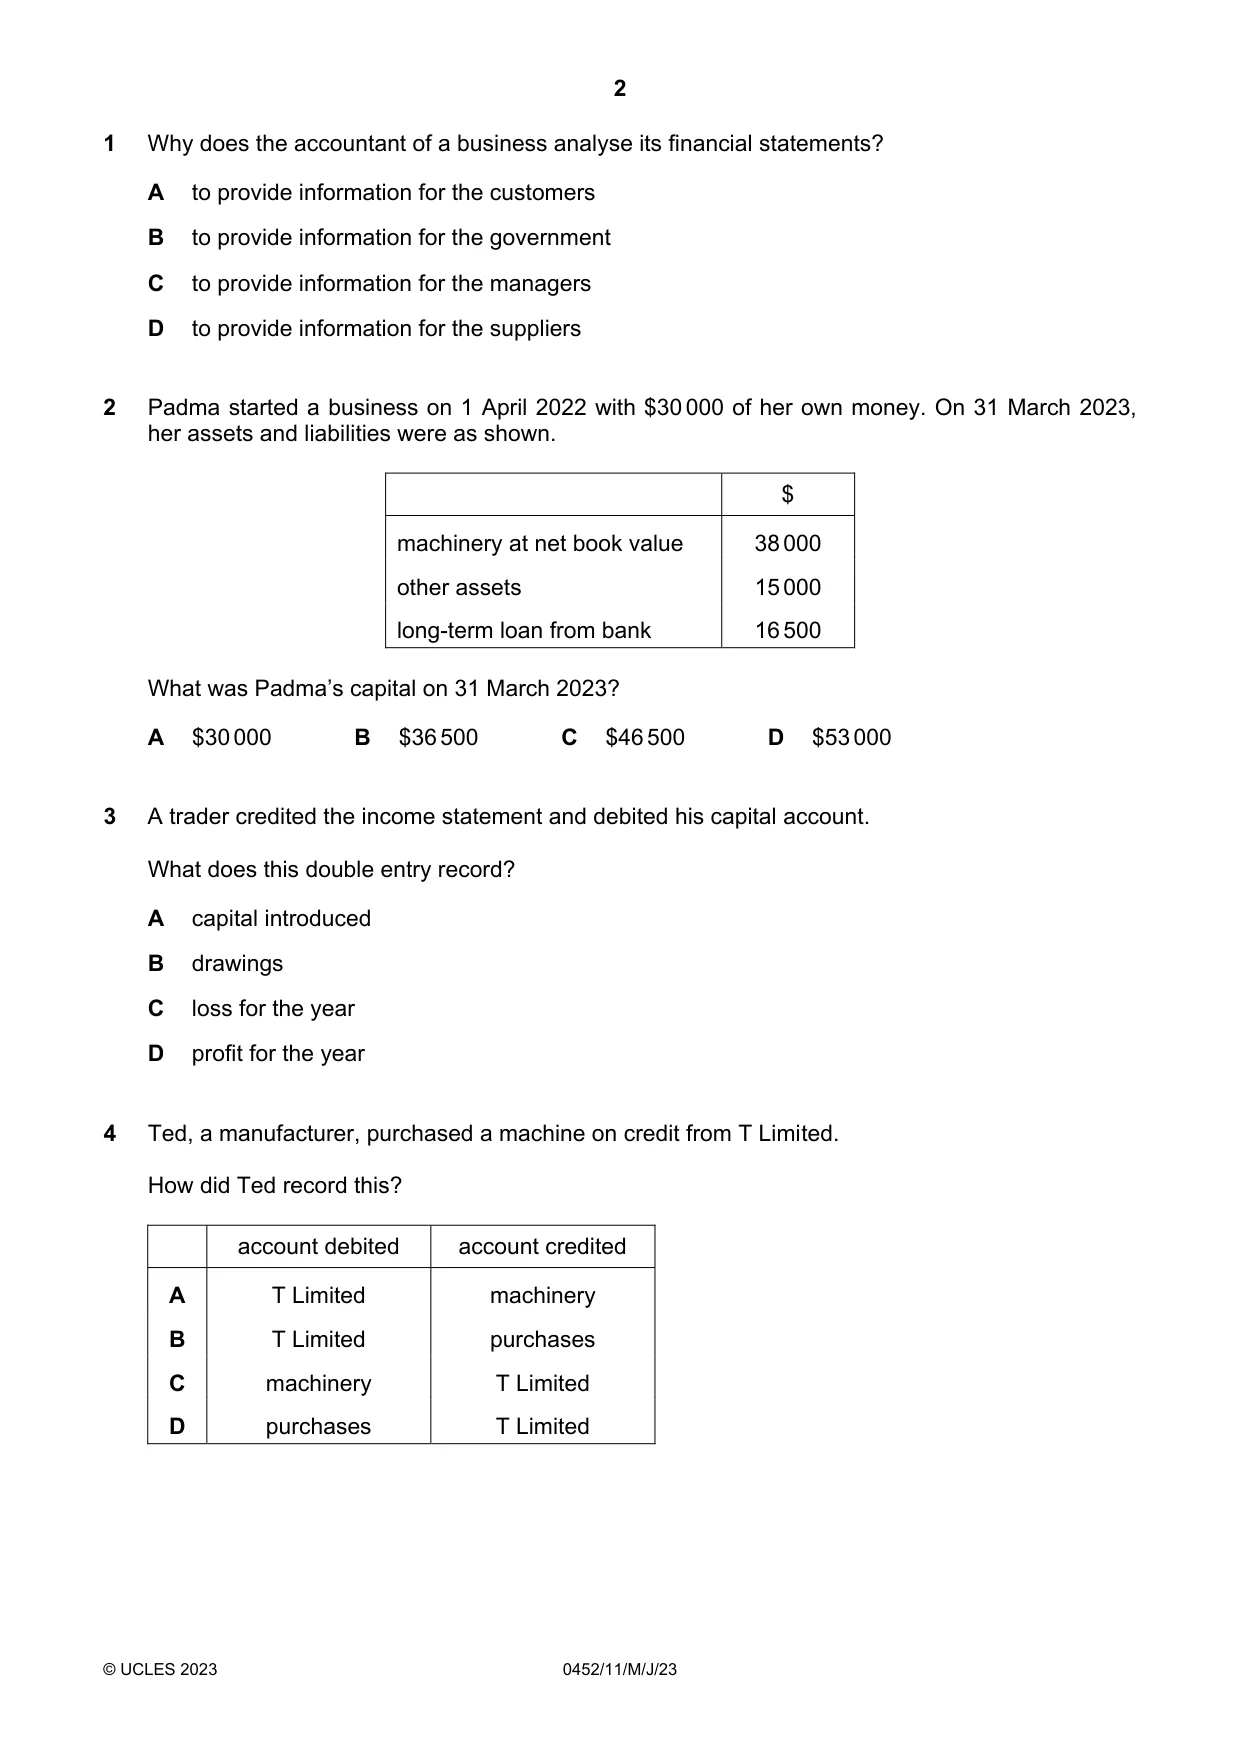
1 Why does the accountant of a business analyse its financial statements? A to provide information for the customers B to provide information for the government C to provide information for the managers D to provide information for the suppliers
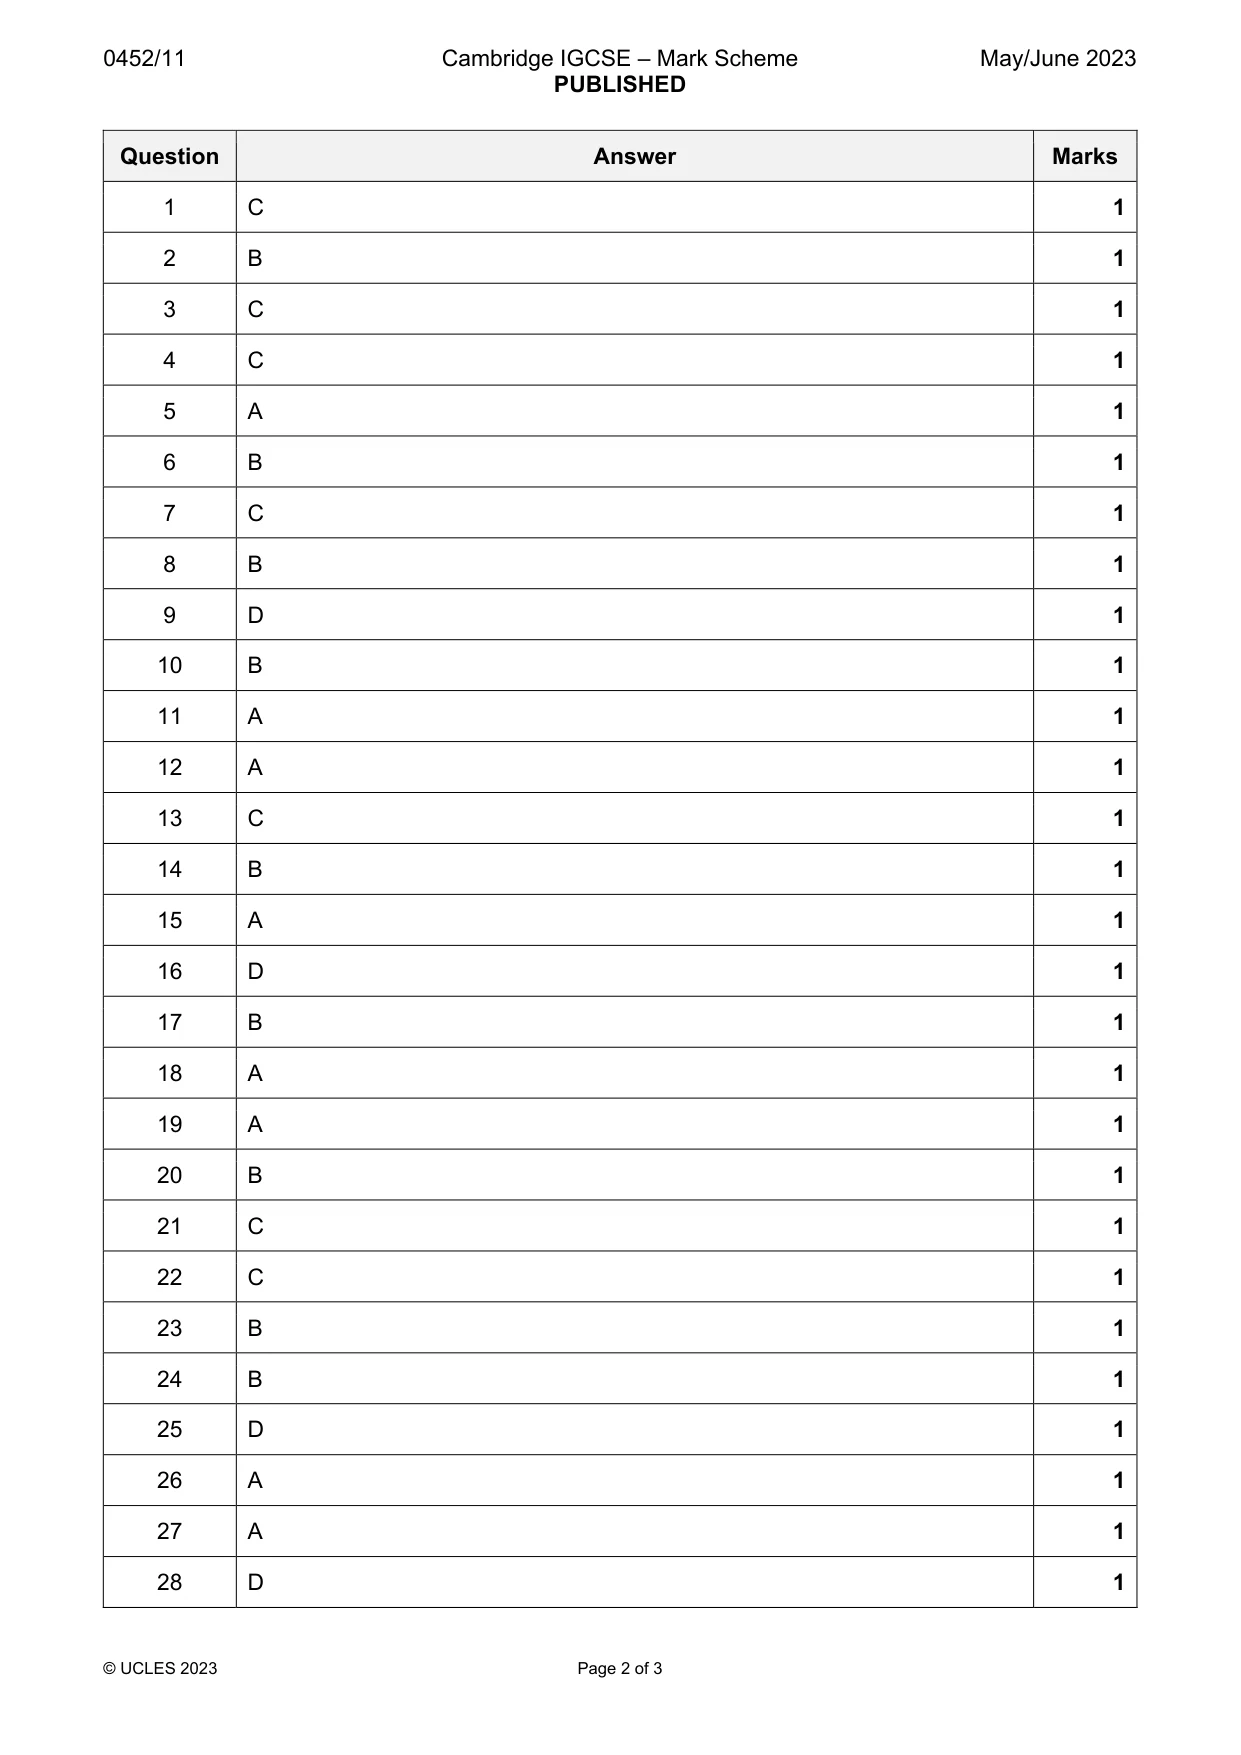
Mark scheme: C
Q2 · Padma started a business on 1 April 2022 with $30 000 of her own money
2 Padma started a business on 1 April 2022 with $30 000 of her own money. On 31 March 2023, her assets and liabilities were as shown. $ machinery at net book value 38 000 other assets 15 000 long-term loan from bank 16 500 What was Padma’s capital on 31 March 2023? A $30 000 B $36 500 C $46 500 D $53 000
Mark scheme: B
Q3 · A trader credited the income statement and debited his capital account
3 A trader credited the income statement and debited his capital account. What does this double entry record? A capital introduced B drawings C loss for the year D profit for the year
Mark scheme: C
Q4 · Ted, a manufacturer, purchased a machine on credit from T Limited
4 Ted, a manufacturer, purchased a machine on credit from T Limited. How did Ted record this? account debited account credited A T Limited machinery B T Limited purchases C machinery T Limited D purchases T Limited
Mark scheme: C
Q5 · The following account appeared in the books of Abdul
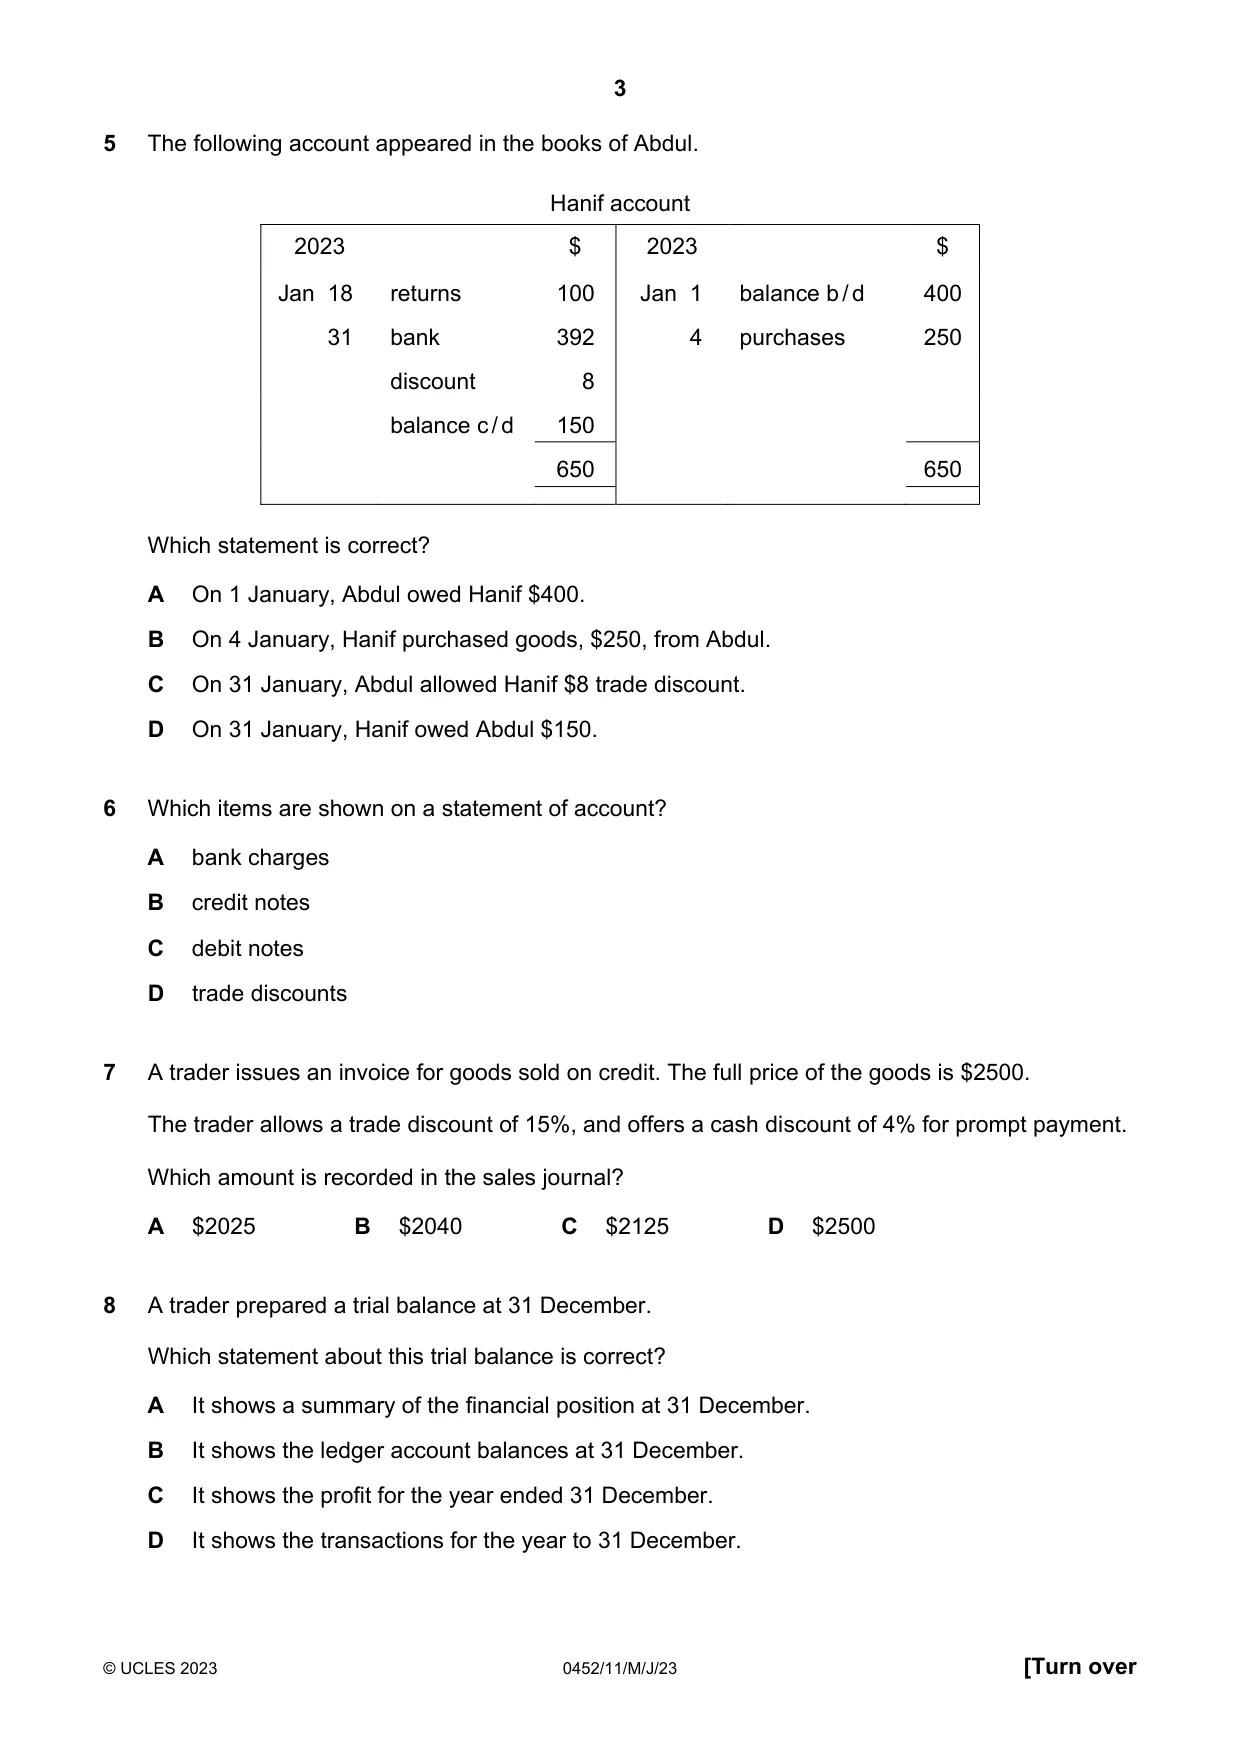
5 The following account appeared in the books of Abdul. Hanif account 2023 $ 2023 $ Jan 18 returns 100 Jan 1 balance b / d 400 31 bank 392 4 purchases 250 discount 8 balance c / d 150 650 650 Which statement is correct? A On 1 January, Abdul owed Hanif $400. B On 4 January, Hanif purchased goods, $250, from Abdul. C On 31 January, Abdul allowed Hanif $8 trade discount. D On 31 January, Hanif owed Abdul $150.
Mark scheme: A
Q6 · Which items are shown on a statement of account?
6 Which items are shown on a statement of account? A bank charges B credit notes C debit notes D trade discounts
Mark scheme: B
Q7 · A trader issues an invoice for goods sold on credit
7 A trader issues an invoice for goods sold on credit. The full price of the goods is $2500. The trader allows a trade discount of 15%, and offers a cash discount of 4% for prompt payment. Which amount is recorded in the sales journal? A $2025 B $2040 C $2125 D $2500
Mark scheme: C
Q8 · A trader prepared a trial balance at 31 December
8 A trader prepared a trial balance at 31 December. Which statement about this trial balance is correct? A It shows a summary of the financial position at 31 December. B It shows the ledger account balances at 31 December. C It shows the profit for the year ended 31 December. D It shows the transactions for the year to 31 December.
Mark scheme: B
Q9 · After completing the trial balance, it was found that an amount of $4000 for motor…
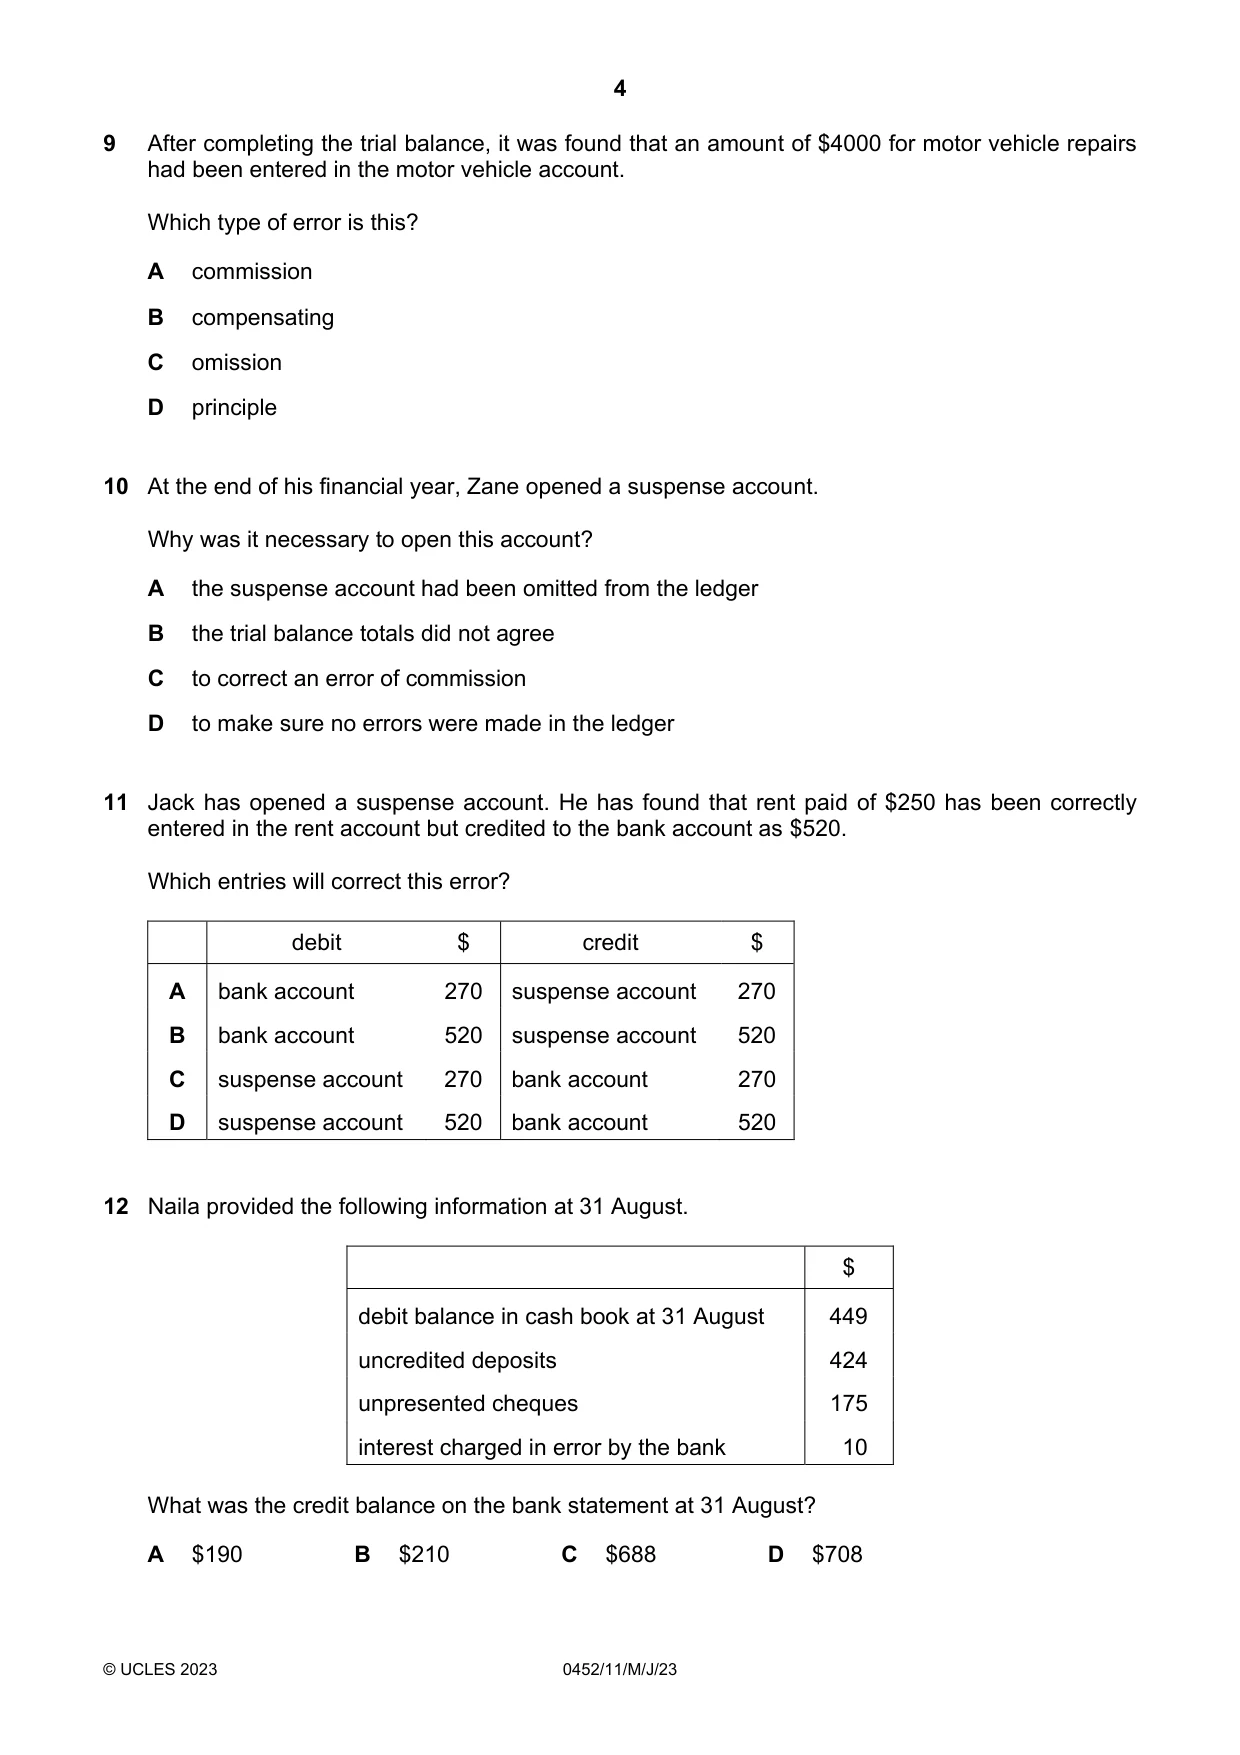
9 After completing the trial balance, it was found that an amount of $4000 for motor vehicle repairs had been entered in the motor vehicle account. Which type of error is this? A commission B compensating C omission D principle
Mark scheme: D
Q10 · At the end of his financial year, Zane opened a suspense account
10 At the end of his financial year, Zane opened a suspense account. Why was it necessary to open this account? A the suspense account had been omitted from the ledger B the trial balance totals did not agree C to correct an error of commission D to make sure no errors were made in the ledger
Mark scheme: B
Q11 · Jack has opened a suspense account
11 Jack has opened a suspense account. He has found that rent paid of $250 has been correctly entered in the rent account but credited to the bank account as $520. Which entries will correct this error? debit $ credit $ A bank account 270 suspense account 270 B bank account 520 suspense account 520 C suspense account 270 bank account 270 D suspense account 520 bank account 520
Mark scheme: A
Q12 · Naila provided the following information at 31 August
12 Naila provided the following information at 31 August. $ debit balance in cash book at 31 August 449 uncredited deposits 424 unpresented cheques 175 interest charged in error by the bank 10 What was the credit balance on the bank statement at 31 August? A $190 B $210 C $688 D $708
Mark scheme: A
Q13 · Which statement about a sales ledger control account is not correct?
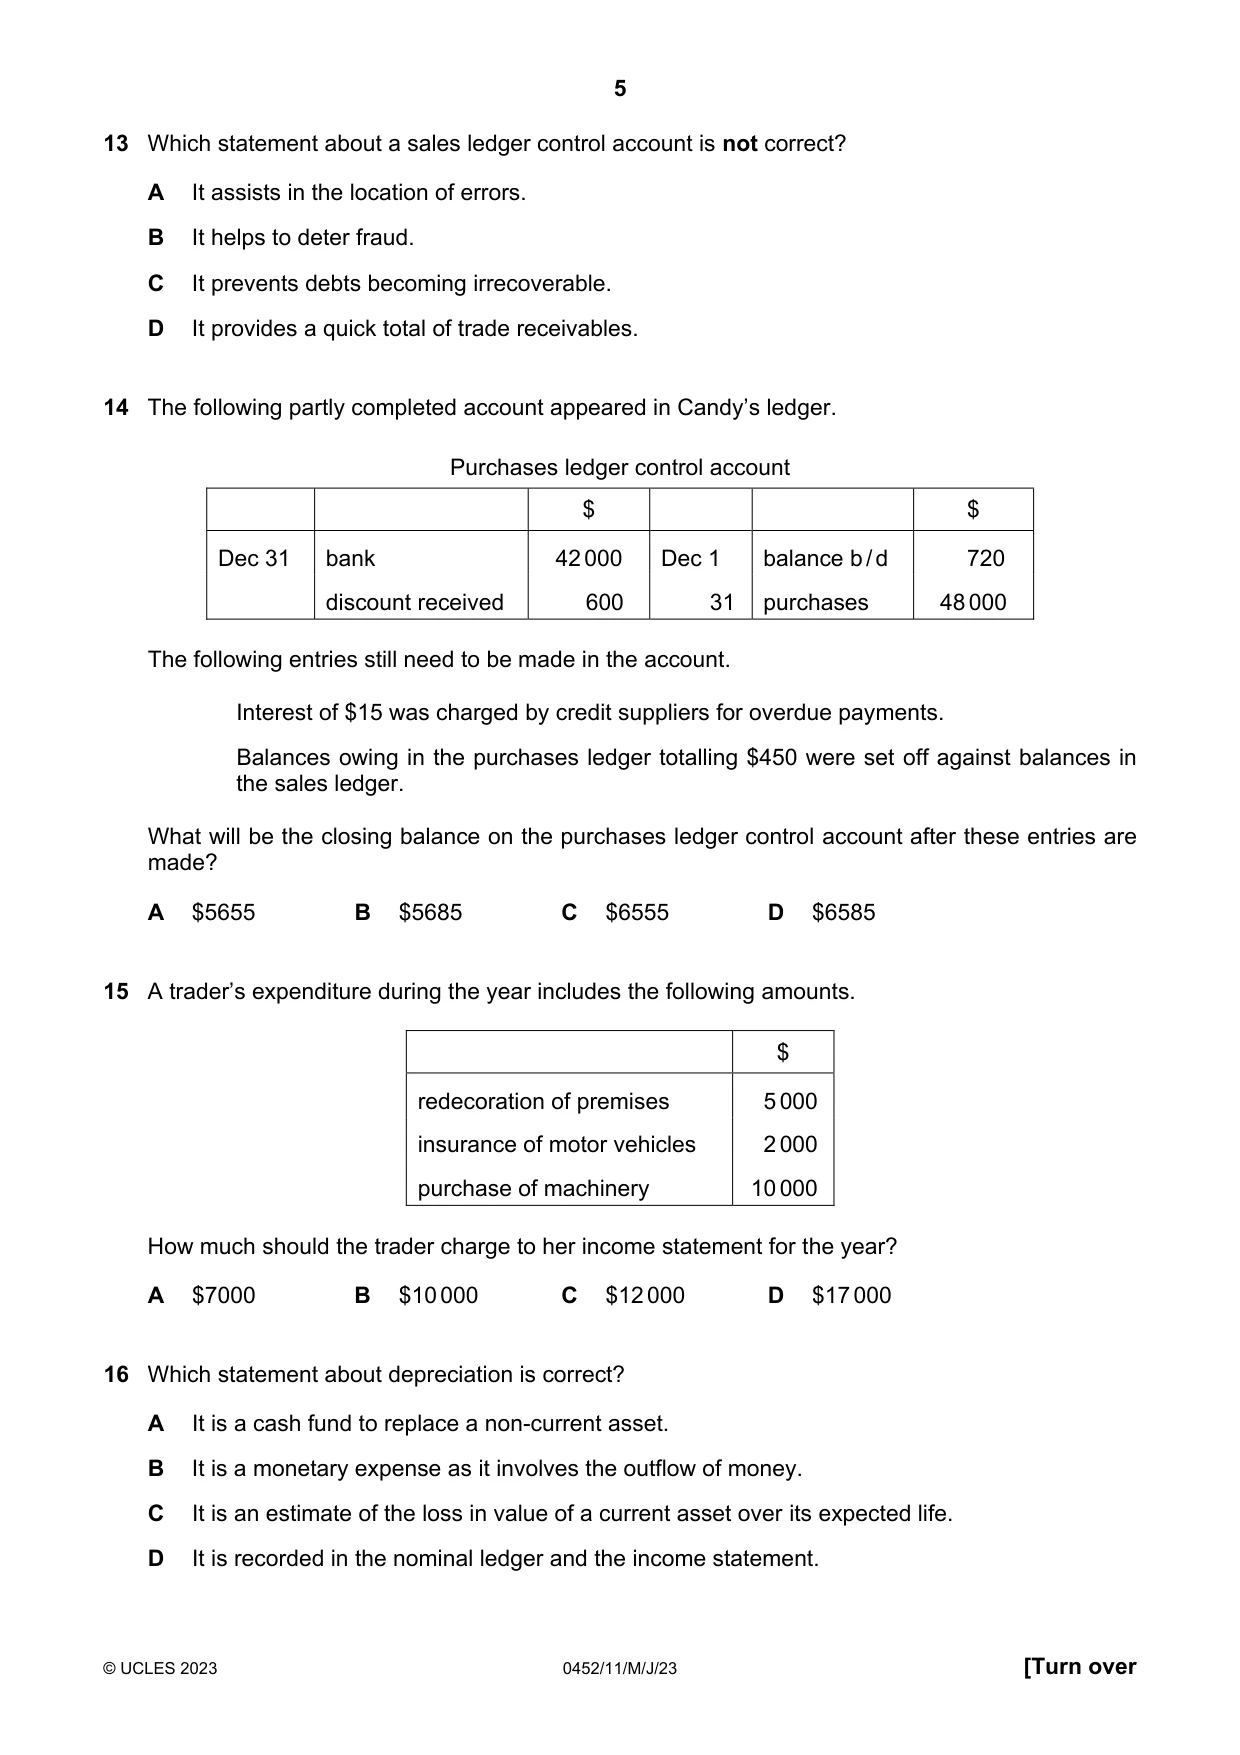
13 Which statement about a sales ledger control account is not correct? A It assists in the location of errors. B It helps to deter fraud. C It prevents debts becoming irrecoverable. D It provides a quick total of trade receivables.
Mark scheme: C
Q14 · The following partly completed account appeared in Candy’s ledger
14 The following partly completed account appeared in Candy’s ledger. Purchases ledger control account $ $ Dec 31 bank 42 000 Dec 1 balance b / d 720 discount received 600 31 purchases 48 000 The following entries still need to be made in the account. Interest of $15 was charged by credit suppliers for overdue payments. Balances owing in the purchases ledger totalling $450 were set off against balances in the sales ledger. What will be the closing balance on the purchases ledger control account after these entries are made? A $5655 B $5685 C $6555 D $6585
Mark scheme: B
Q15 · A trader’s expenditure during the year includes the following amounts
15 A trader’s expenditure during the year includes the following amounts. $ redecoration of premises 5 000 insurance of motor vehicles 2 000 purchase of machinery 10 000 How much should the trader charge to her income statement for the year? A $7000 B $10 000 C $12 000 D $17 000
Mark scheme: A
More questions on Capital and revenue expenditure and receipts
Q16 · Which statement about depreciation is correct?
16 Which statement about depreciation is correct? A It is a cash fund to replace a non-current asset. B It is a monetary expense as it involves the outflow of money. C It is an estimate of the loss in value of a current asset over its expected life. D It is recorded in the nominal ledger and the income statement.
Mark scheme: D
More questions on Accounting for depreciation and disposal of non-current assets
Q17 · Rashid provided the following balances at 31 December
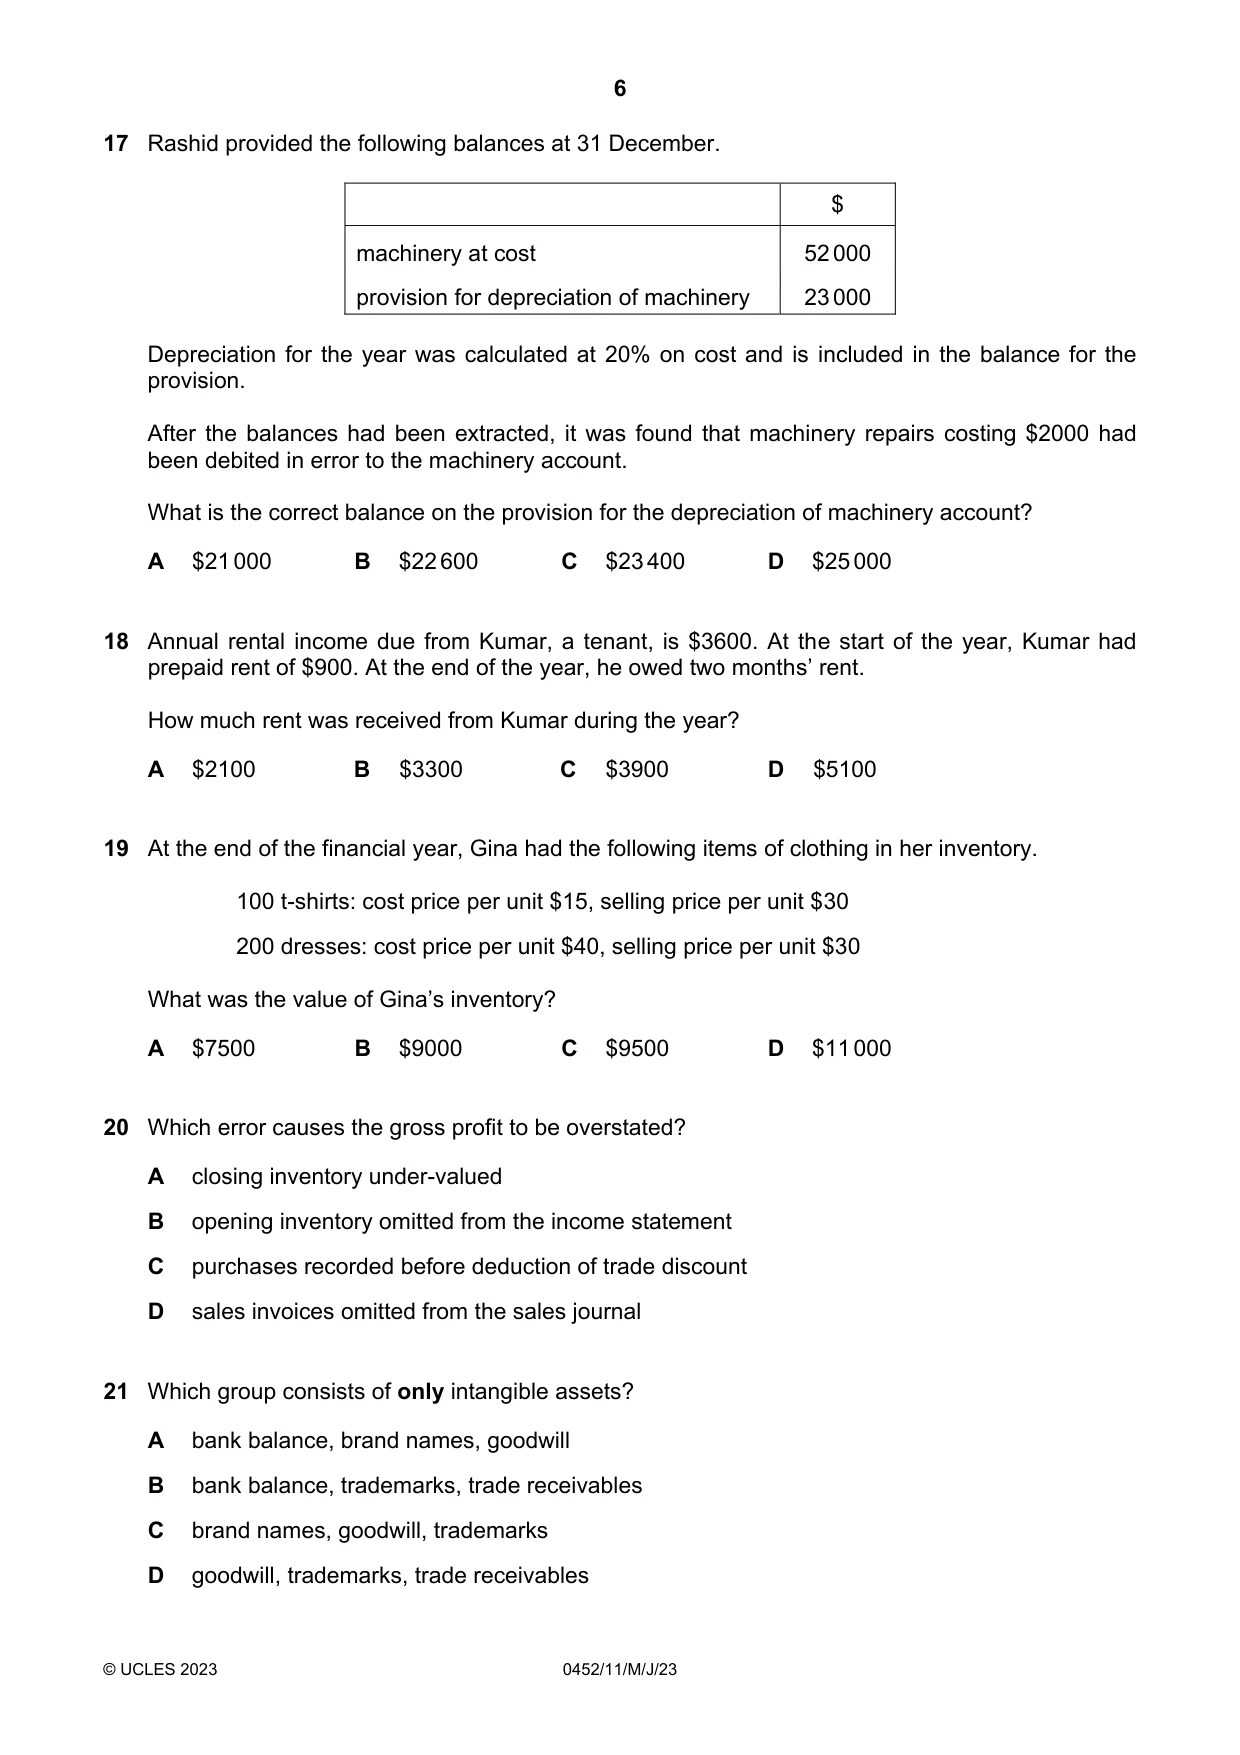
17 Rashid provided the following balances at 31 December. $ machinery at cost 52 000 provision for depreciation of machinery 23 000 Depreciation for the year was calculated at 20% on cost and is included in the balance for the provision. After the balances had been extracted, it was found that machinery repairs costing $2000 had been debited in error to the machinery account. What is the correct balance on the provision for the depreciation of machinery account? A $21 000 B $22 600 C $23 400 D $25 000
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q18 · Annual rental income due from Kumar, a tenant, is $3600
18 Annual rental income due from Kumar, a tenant, is $3600. At the start of the year, Kumar had prepaid rent of $900. At the end of the year, he owed two months’ rent. How much rent was received from Kumar during the year? A $2100 B $3300 C $3900 D $5100
Mark scheme: A
Q19 · At the end of the financial year, Gina had the following items of clothing in her…
19 At the end of the financial year, Gina had the following items of clothing in her inventory. 100 t-shirts: cost price per unit $15, selling price per unit $30 200 dresses: cost price per unit $40, selling price per unit $30 What was the value of Gina’s inventory? A $7500 B $9000 C $9500 D $11 000
Mark scheme: A
Q20 · Which error causes the gross profit to be overstated?
20 Which error causes the gross profit to be overstated? A closing inventory under-valued B opening inventory omitted from the income statement C purchases recorded before deduction of trade discount D sales invoices omitted from the sales journal
Mark scheme: B
Q21 · Which group consists of only intangible assets?
21 Which group consists of only intangible assets? A bank balance, brand names, goodwill B bank balance, trademarks, trade receivables C brand names, goodwill, trademarks D goodwill, trademarks, trade receivables
Mark scheme: C
More questions on Capital and revenue expenditure and receipts
Q22 · At the end of the financial year, Karim decided to increase his provision for doubtful…
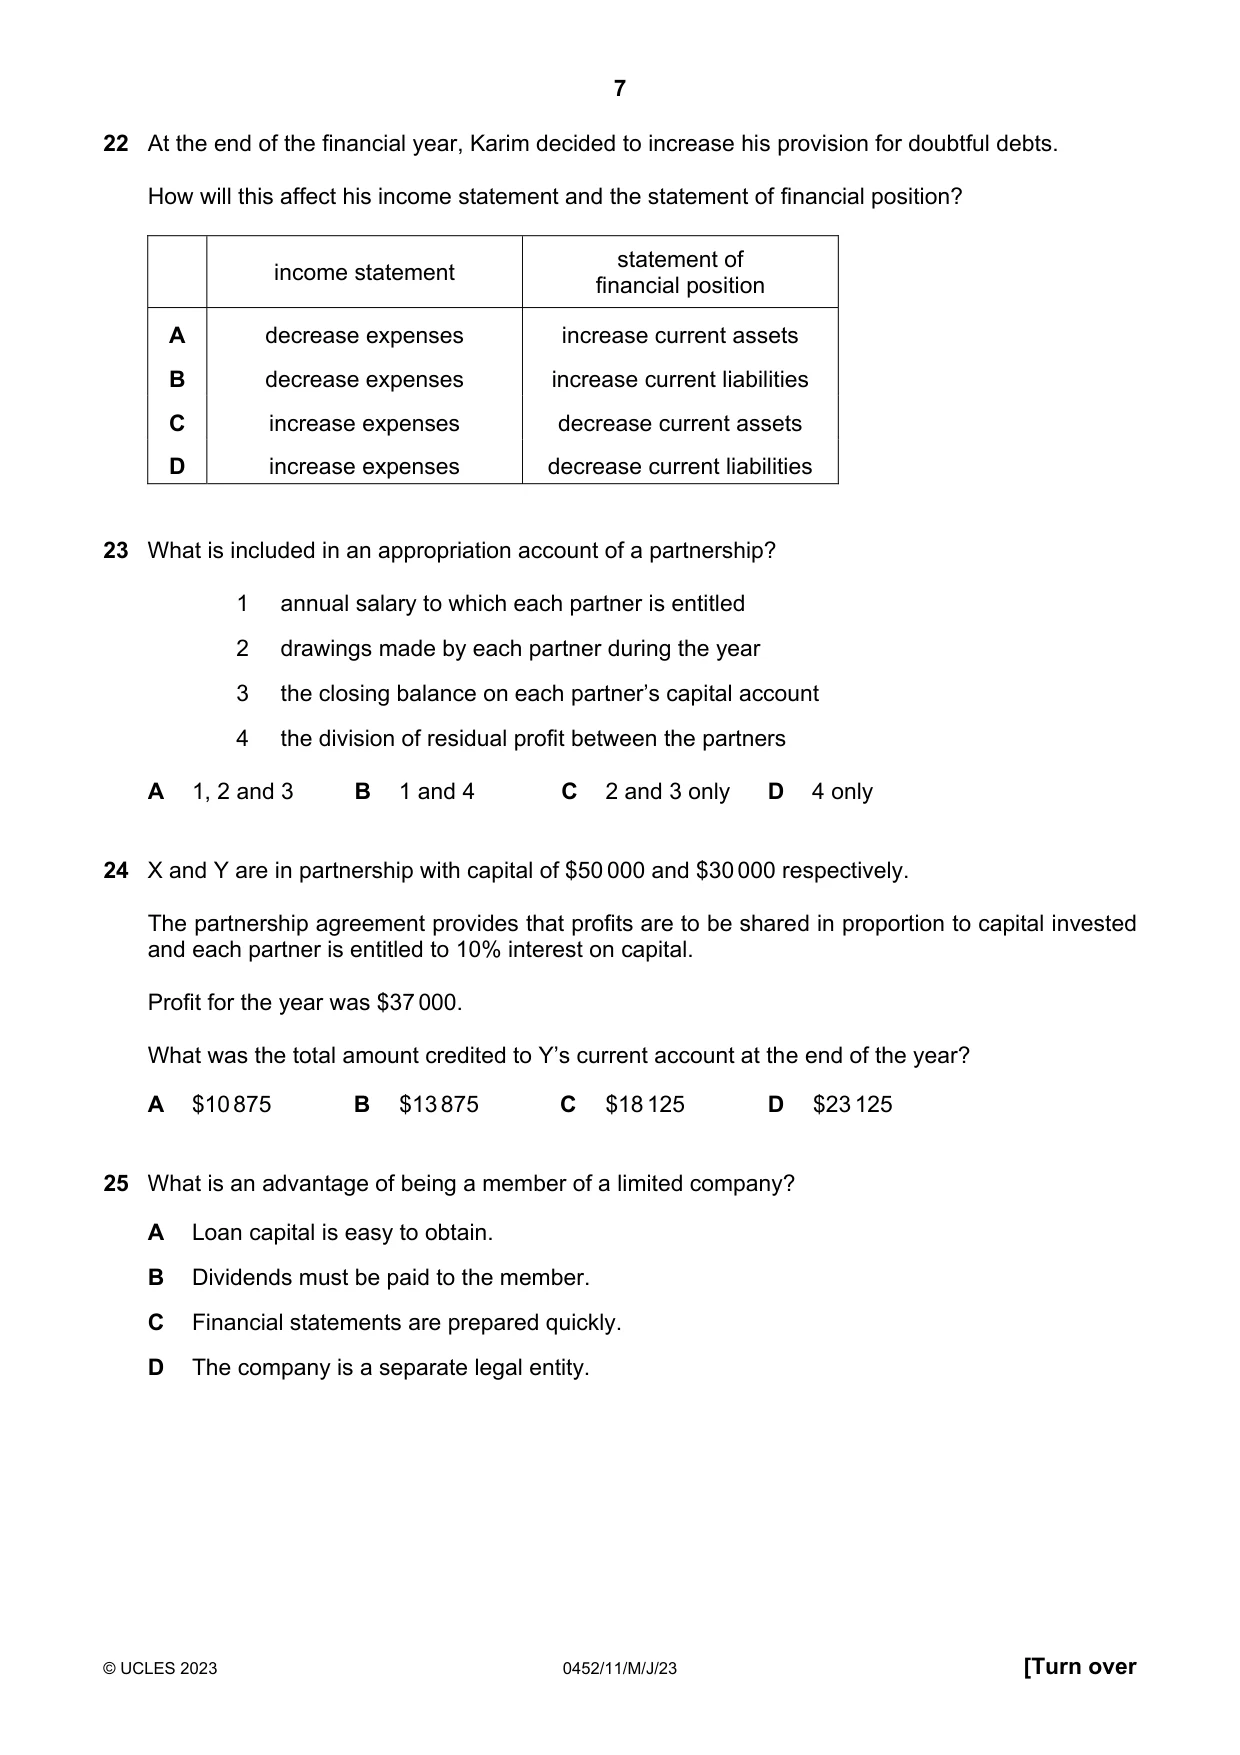
22 At the end of the financial year, Karim decided to increase his provision for doubtful debts. How will this affect his income statement and the statement of financial position? statement of income statement financial position A decrease expenses increase current assets B decrease expenses increase current liabilities C increase expenses decrease current assets D increase expenses decrease current liabilities
Mark scheme: C
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q23 · What is included in an appropriation account of a partnership?
23 What is included in an appropriation account of a partnership? 1 annual salary to which each partner is entitled 2 drawings made by each partner during the year 3 the closing balance on each partner’s capital account 4 the division of residual profit between the partners A 1, 2 and 3 B 1 and 4 C 2 and 3 only D 4 only
Mark scheme: B
Q24 · X and Y are in partnership with capital of $50 000 and $30 000 respectively
24 X and Y are in partnership with capital of $50 000 and $30 000 respectively. The partnership agreement provides that profits are to be shared in proportion to capital invested and each partner is entitled to 10% interest on capital. Profit for the year was $37 000. What was the total amount credited to Y’s current account at the end of the year? A $10 875 B $13 875 C $18 125 D $23 125
Mark scheme: B
Q25 · What is an advantage of being a member of a limited company?
25 What is an advantage of being a member of a limited company? A Loan capital is easy to obtain. B Dividends must be paid to the member. C Financial statements are prepared quickly. D The company is a separate legal entity.
Mark scheme: D
Q26 · A limited company provided the following information
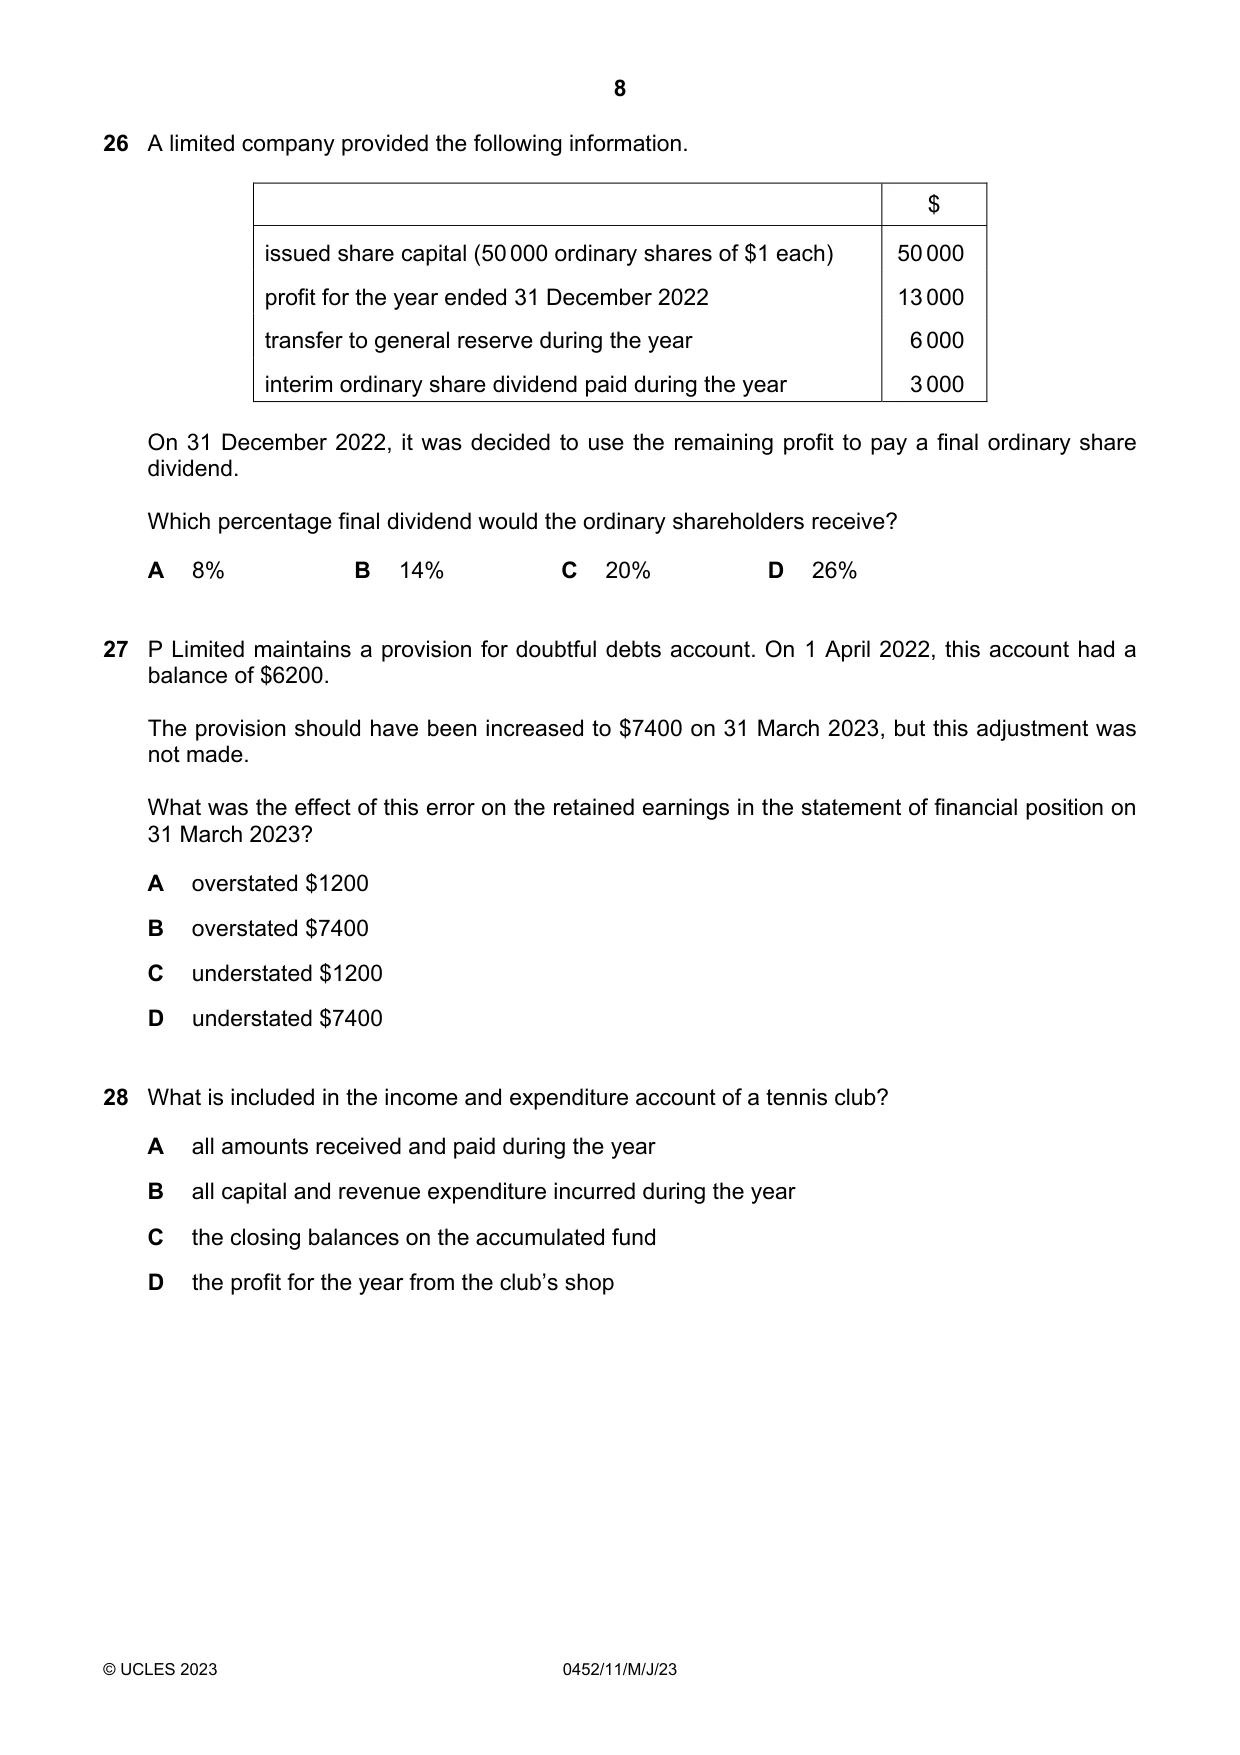
26 A limited company provided the following information. $ issued share capital (50 000 ordinary shares of $1 each) 50 000 profit for the year ended 31 December 2022 13 000 transfer to general reserve during the year 6 000 interim ordinary share dividend paid during the year 3 000 On 31 December 2022, it was decided to use the remaining profit to pay a final ordinary share dividend. Which percentage final dividend would the ordinary shareholders receive? A 8% B 14% C 20% D 26%
Mark scheme: A
Q27 · P Limited maintains a provision for doubtful debts account
27 P Limited maintains a provision for doubtful debts account. On 1 April 2022, this account had a balance of $6200. The provision should have been increased to $7400 on 31 March 2023, but this adjustment was not made. What was the effect of this error on the retained earnings in the statement of financial position on 31 March 2023? A overstated $1200 B overstated $7400 C understated $1200 D understated $7400
Mark scheme: A
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q28 · What is included in the income and expenditure account of a tennis club?
28 What is included in the income and expenditure account of a tennis club? A all amounts received and paid during the year B all capital and revenue expenditure incurred during the year C the closing balances on the accumulated fund D the profit for the year from the club’s shop
Mark scheme: D
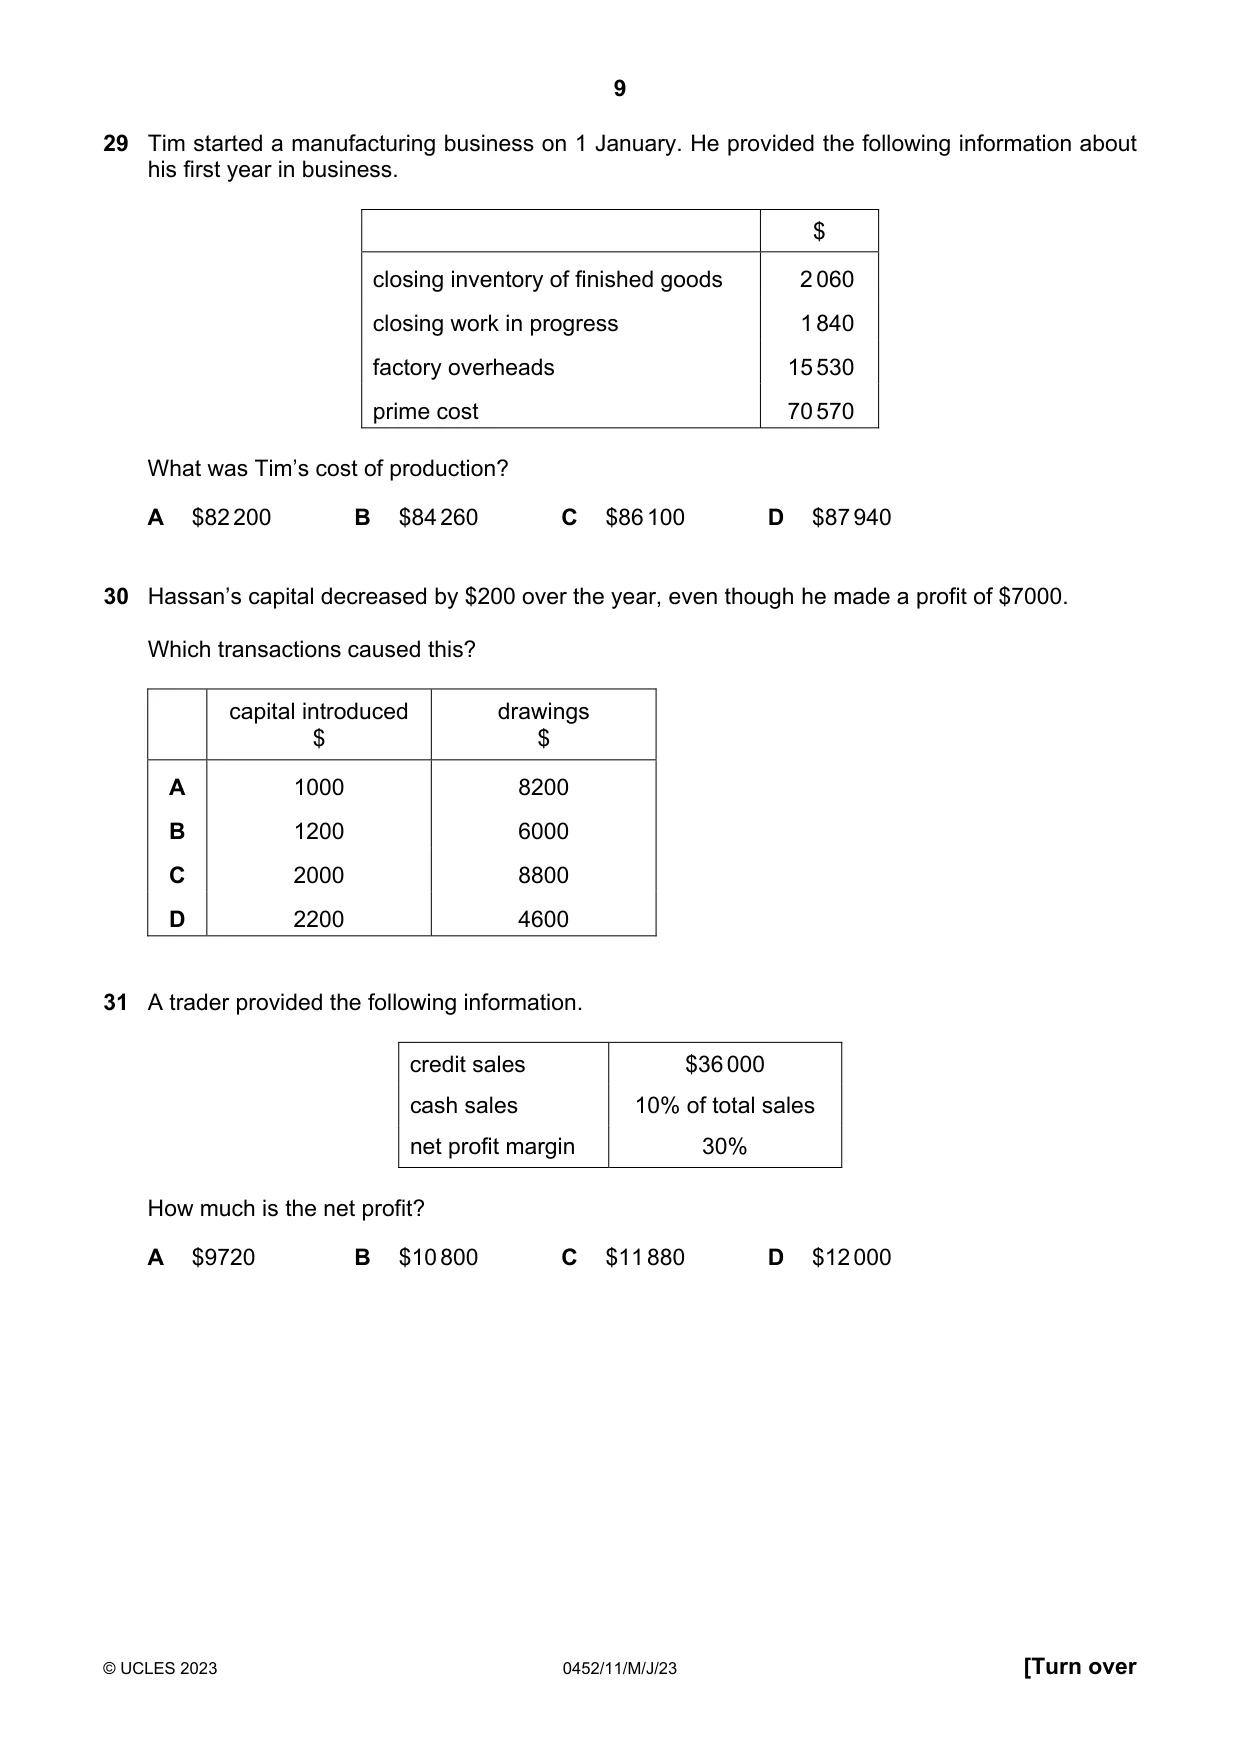
Q29 · Tim started a manufacturing business on 1 January
29 Tim started a manufacturing business on 1 January. He provided the following information about his first year in business. $ closing inventory of finished goods 2 060 closing work in progress 1 840 factory overheads 15 530 prime cost 70 570 What was Tim’s cost of production? A $82 200 B $84 260 C $86 100 D $87 940
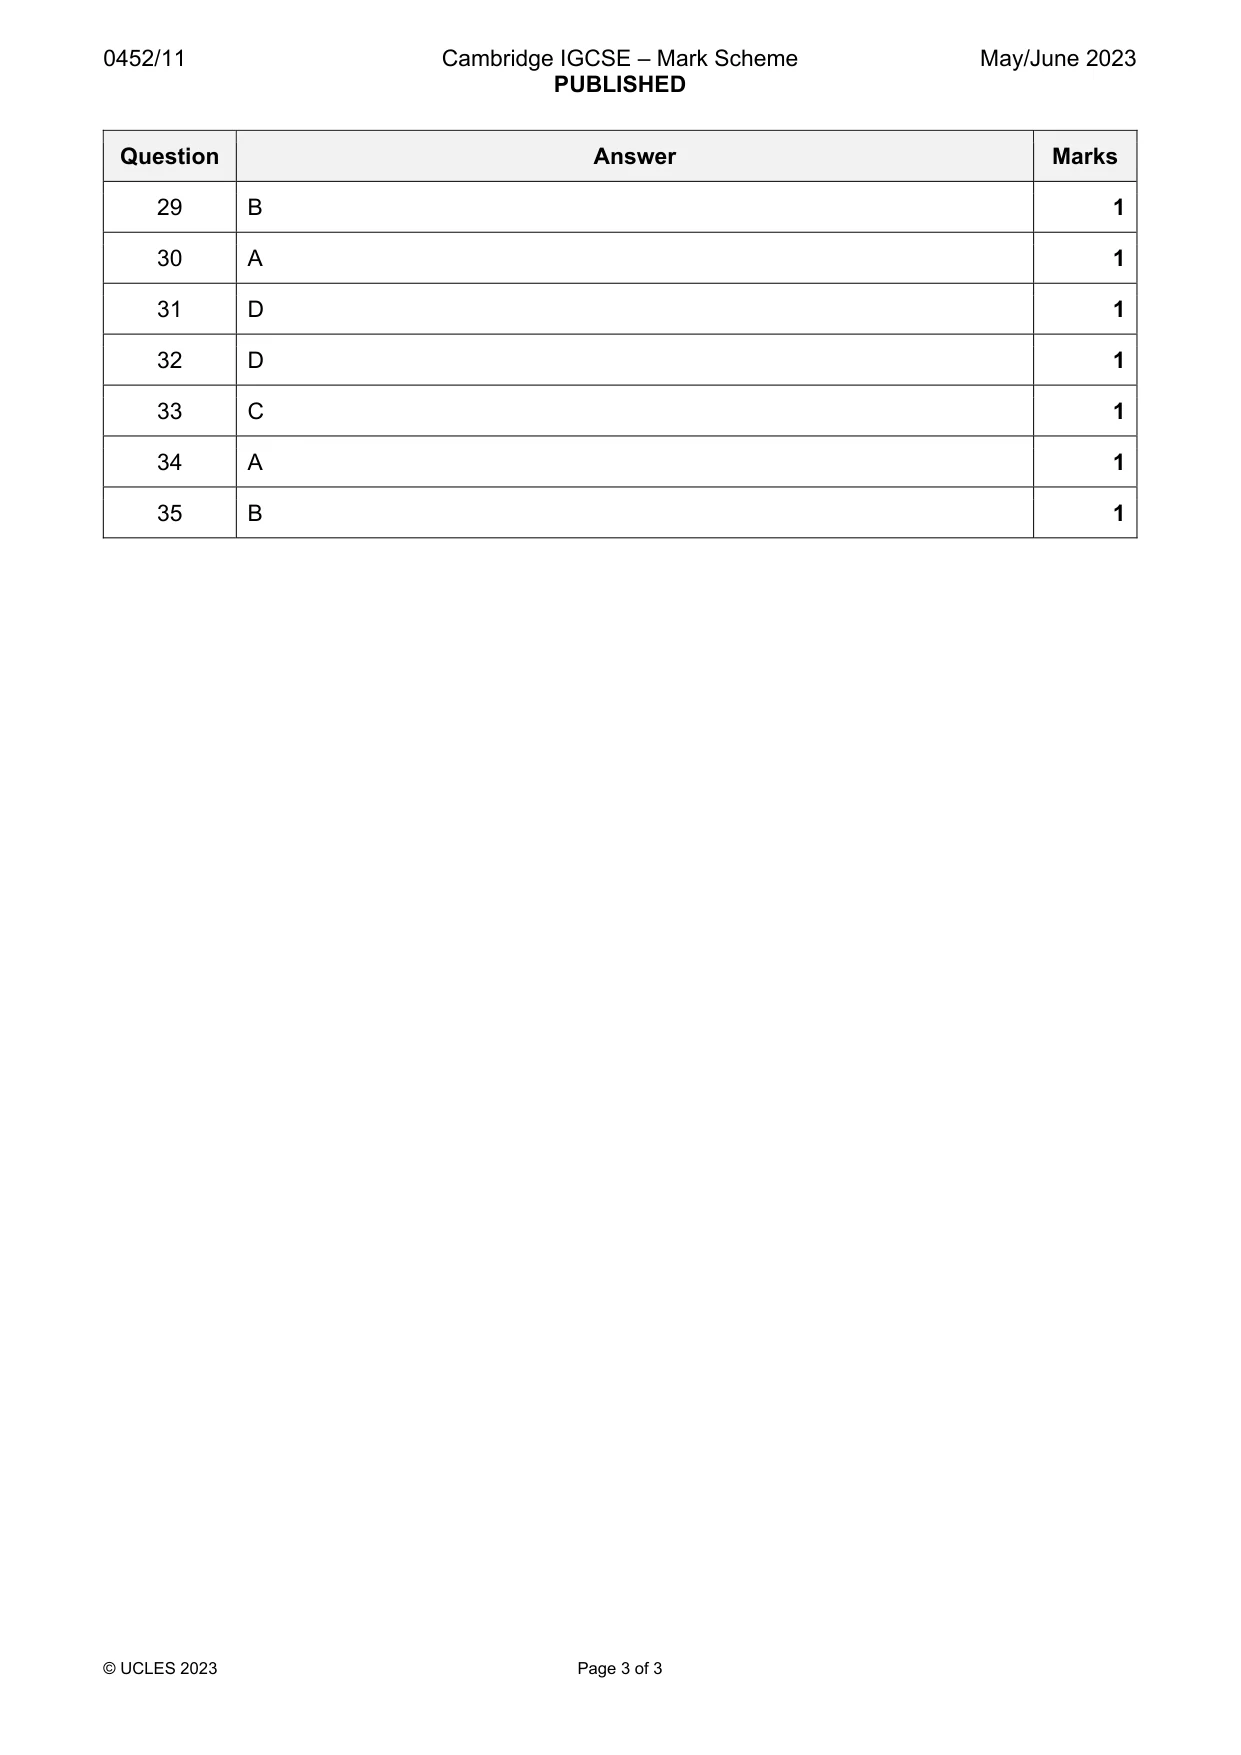
Mark scheme: B
Q30 · Hassan’s capital decreased by $200 over the year, even though he made a profit of $7000
30 Hassan’s capital decreased by $200 over the year, even though he made a profit of $7000. Which transactions caused this? capital introduced drawings $ $ A 1000 8200 B 1200 6000 C 2000 8800 D 2200 4600
Mark scheme: A
Q31 · A trader provided the following information
31 A trader provided the following information. credit sales $36 000 cash sales 10% of total sales net profit margin 30% How much is the net profit? A $9720 B $10 800 C $11 880 D $12 000
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
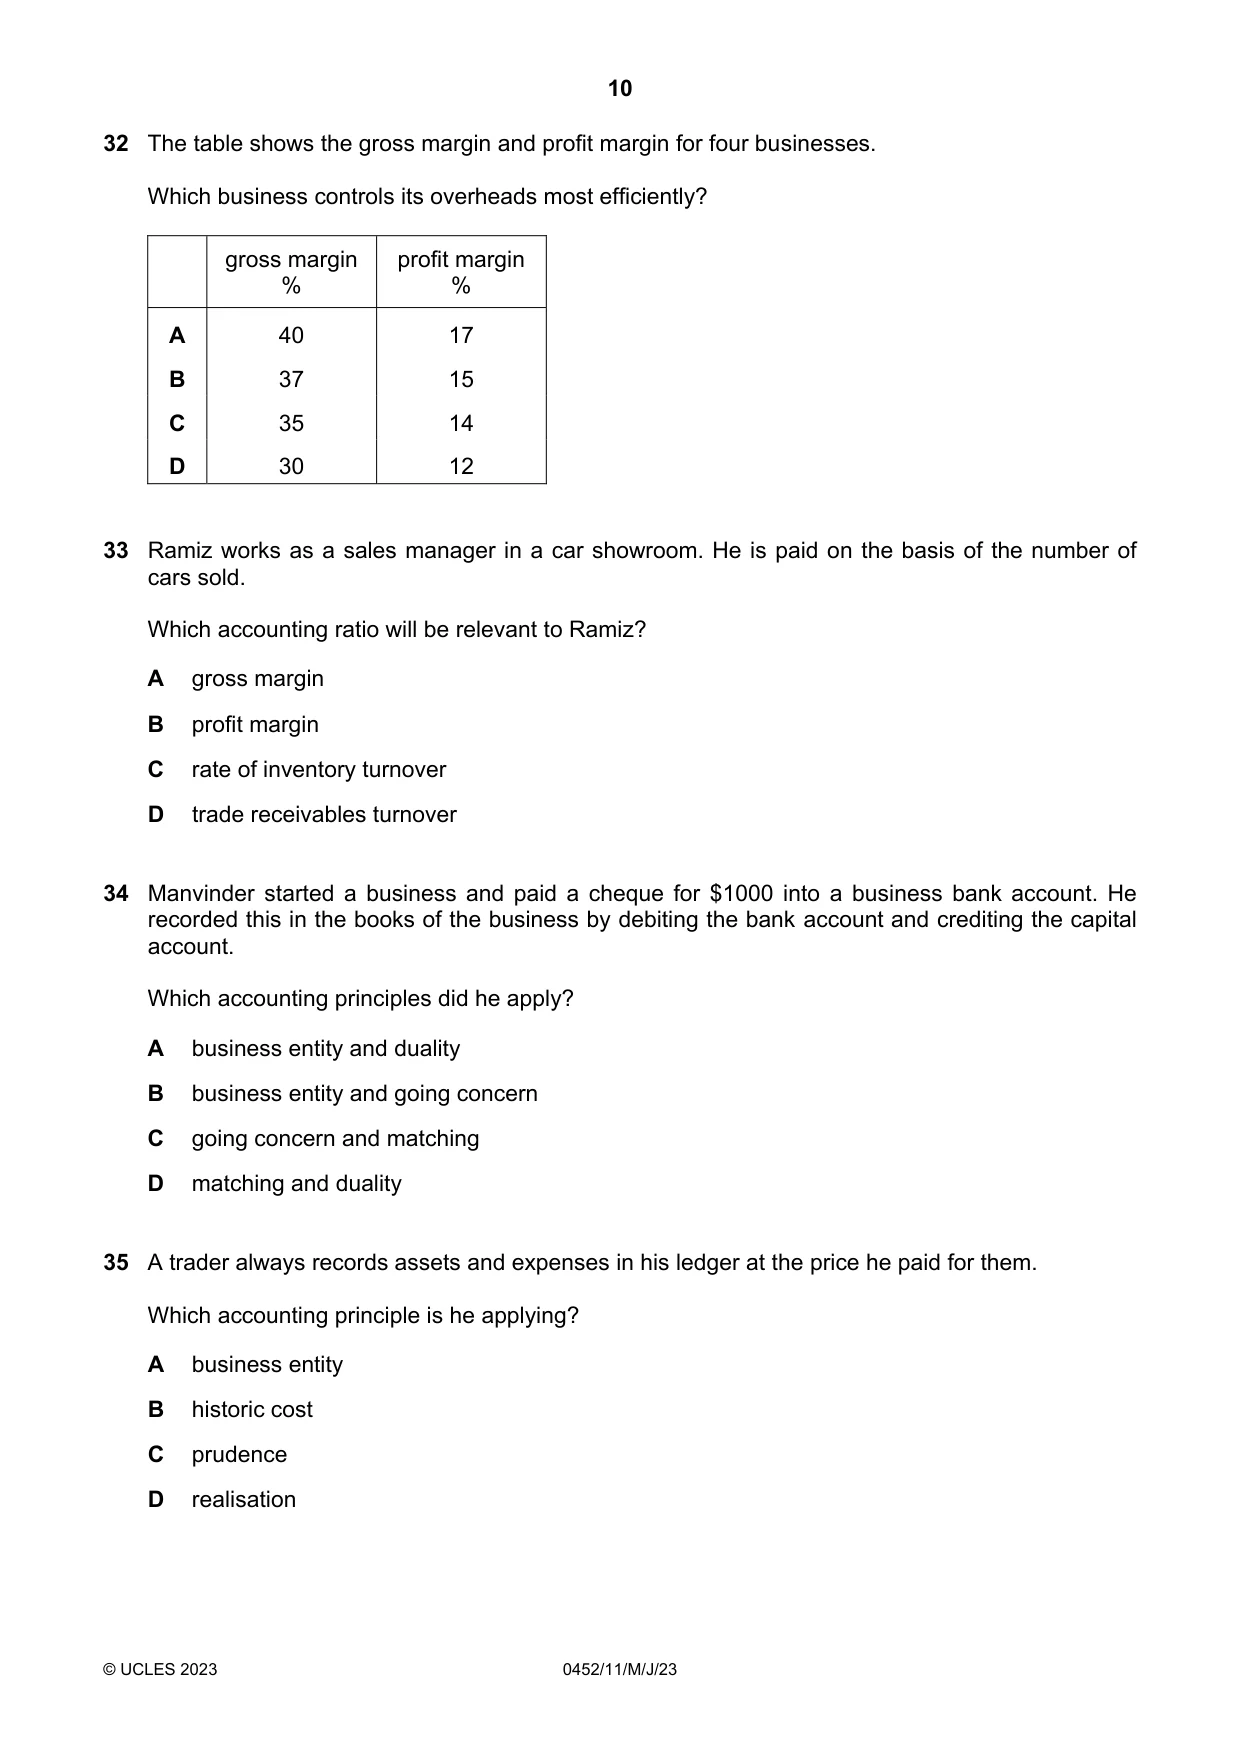
Q32 · The table shows the gross margin and profit margin for four businesses
32 The table shows the gross margin and profit margin for four businesses. Which business controls its overheads most efficiently? gross margin profit margin % % A 40 17 B 37 15 C 35 14 D 30 12
Mark scheme: D
Q33 · Ramiz works as a sales manager in a car showroom
33 Ramiz works as a sales manager in a car showroom. He is paid on the basis of the number of cars sold. Which accounting ratio will be relevant to Ramiz? A gross margin B profit margin C rate of inventory turnover D trade receivables turnover
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
Q34 · Manvinder started a business and paid a cheque for $1000 into a business bank account
34 Manvinder started a business and paid a cheque for $1000 into a business bank account. He recorded this in the books of the business by debiting the bank account and crediting the capital account. Which accounting principles did he apply? A business entity and duality B business entity and going concern C going concern and matching D matching and duality
Mark scheme: A
Q35 · A trader always records assets and expenses in his ledger at the price he paid for them
35 A trader always records assets and expenses in his ledger at the price he paid for them. Which accounting principle is he applying? A business entity B historic cost C prudence D realisation
Mark scheme: B
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
3The double entry system of book-keeping3Accounting concepts2Accounting for depreciation and disposal of non-current assets2Calculation and understanding of accounting ratios2Capital and revenue expenditure and receipts2Control accounts2Irrecoverable debts and allowance for irrecoverable debts2Limited companies2Partnerships2The accounting equation2The trial balance2Bank reconciliation1Books of prime entry1Business documents1Clubs and societies1Interpretation of accounting ratios1Manufacturing accounts1Other payables and other receivables1The purpose of accounting1Valuation of inventory1What you needed in this session
Cambridge’s own grade thresholds for 2023 May/June, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.