Cambridge IGCSE Accounting 0452 — 2023 Feb/March Paper 1 · Variant 2
0452/12/F/M/23 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · What is the purpose of accounting?
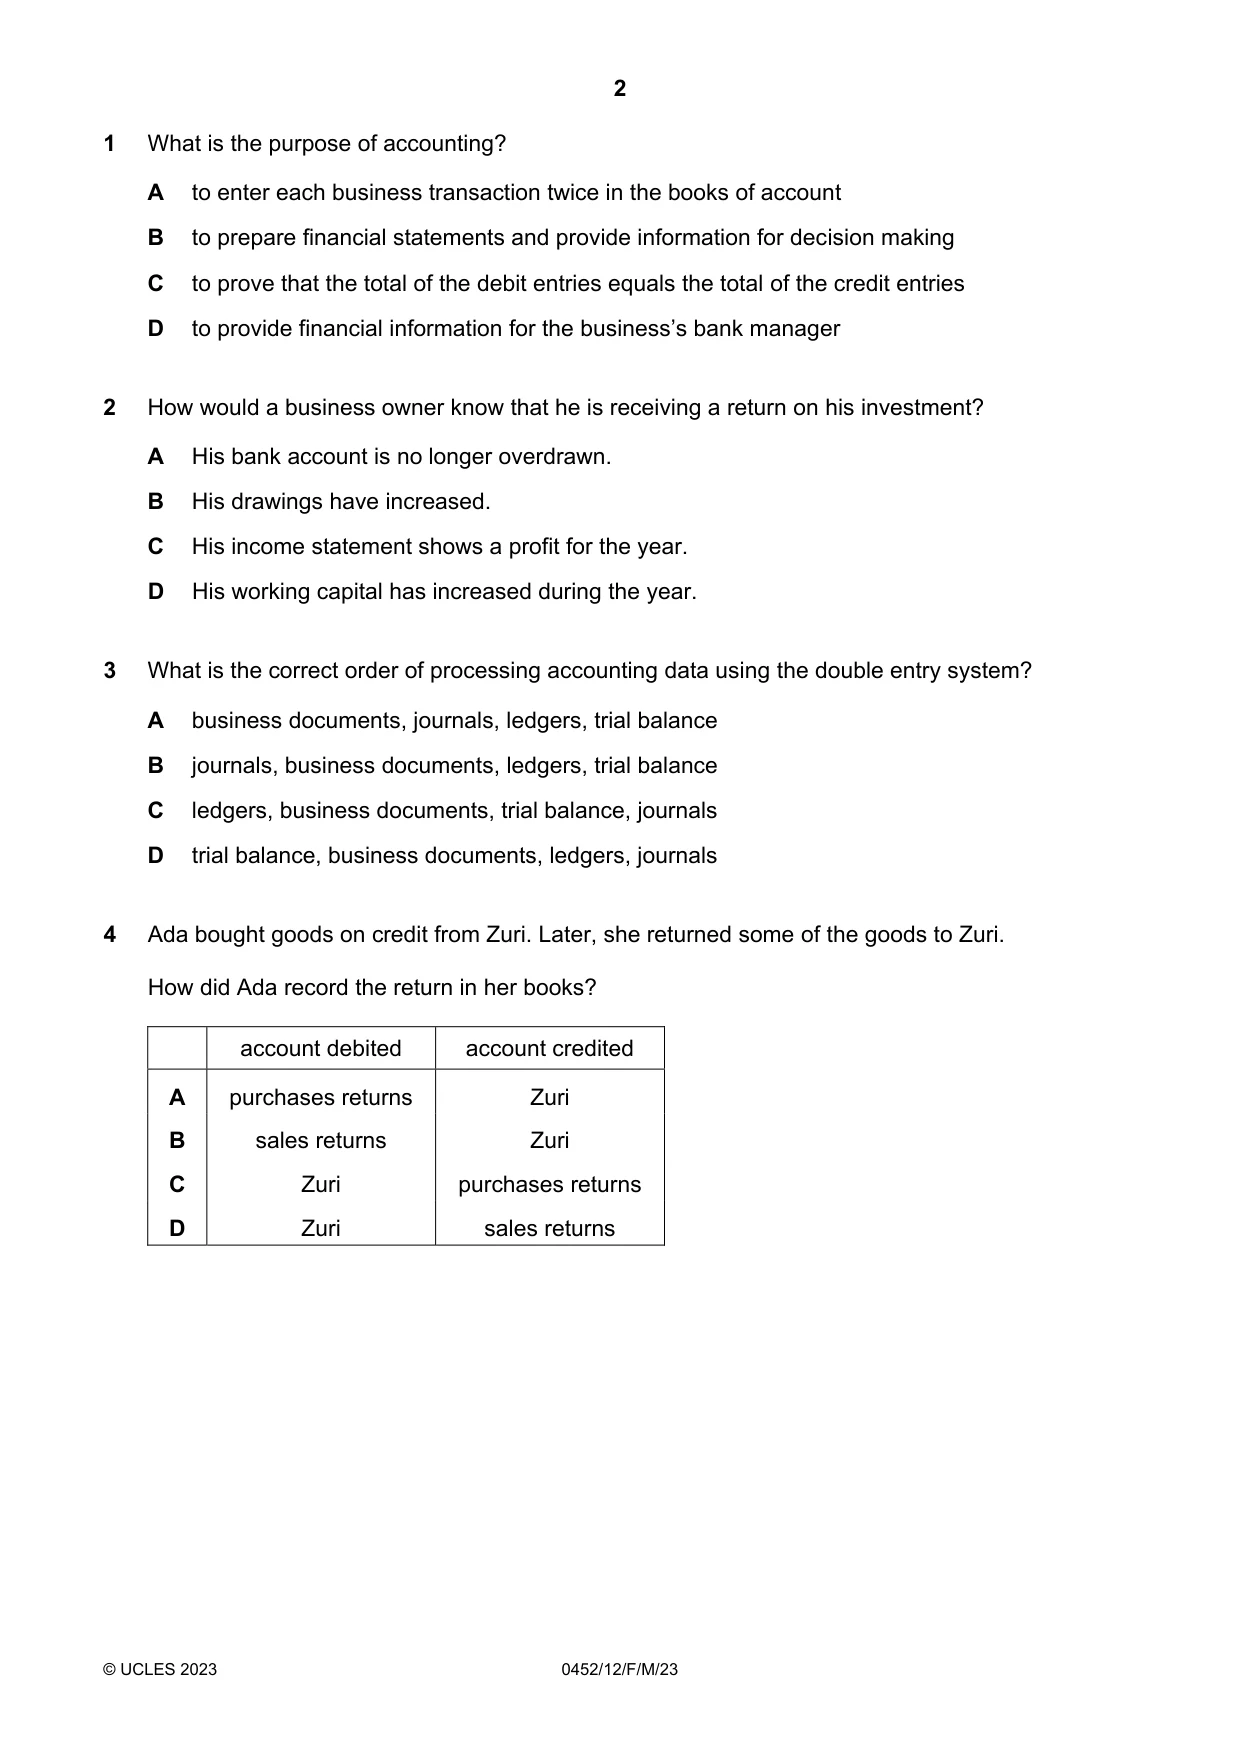
1 What is the purpose of accounting? A to enter each business transaction twice in the books of account B to prepare financial statements and provide information for decision making C to prove that the total of the debit entries equals the total of the credit entries D to provide financial information for the business’s bank manager
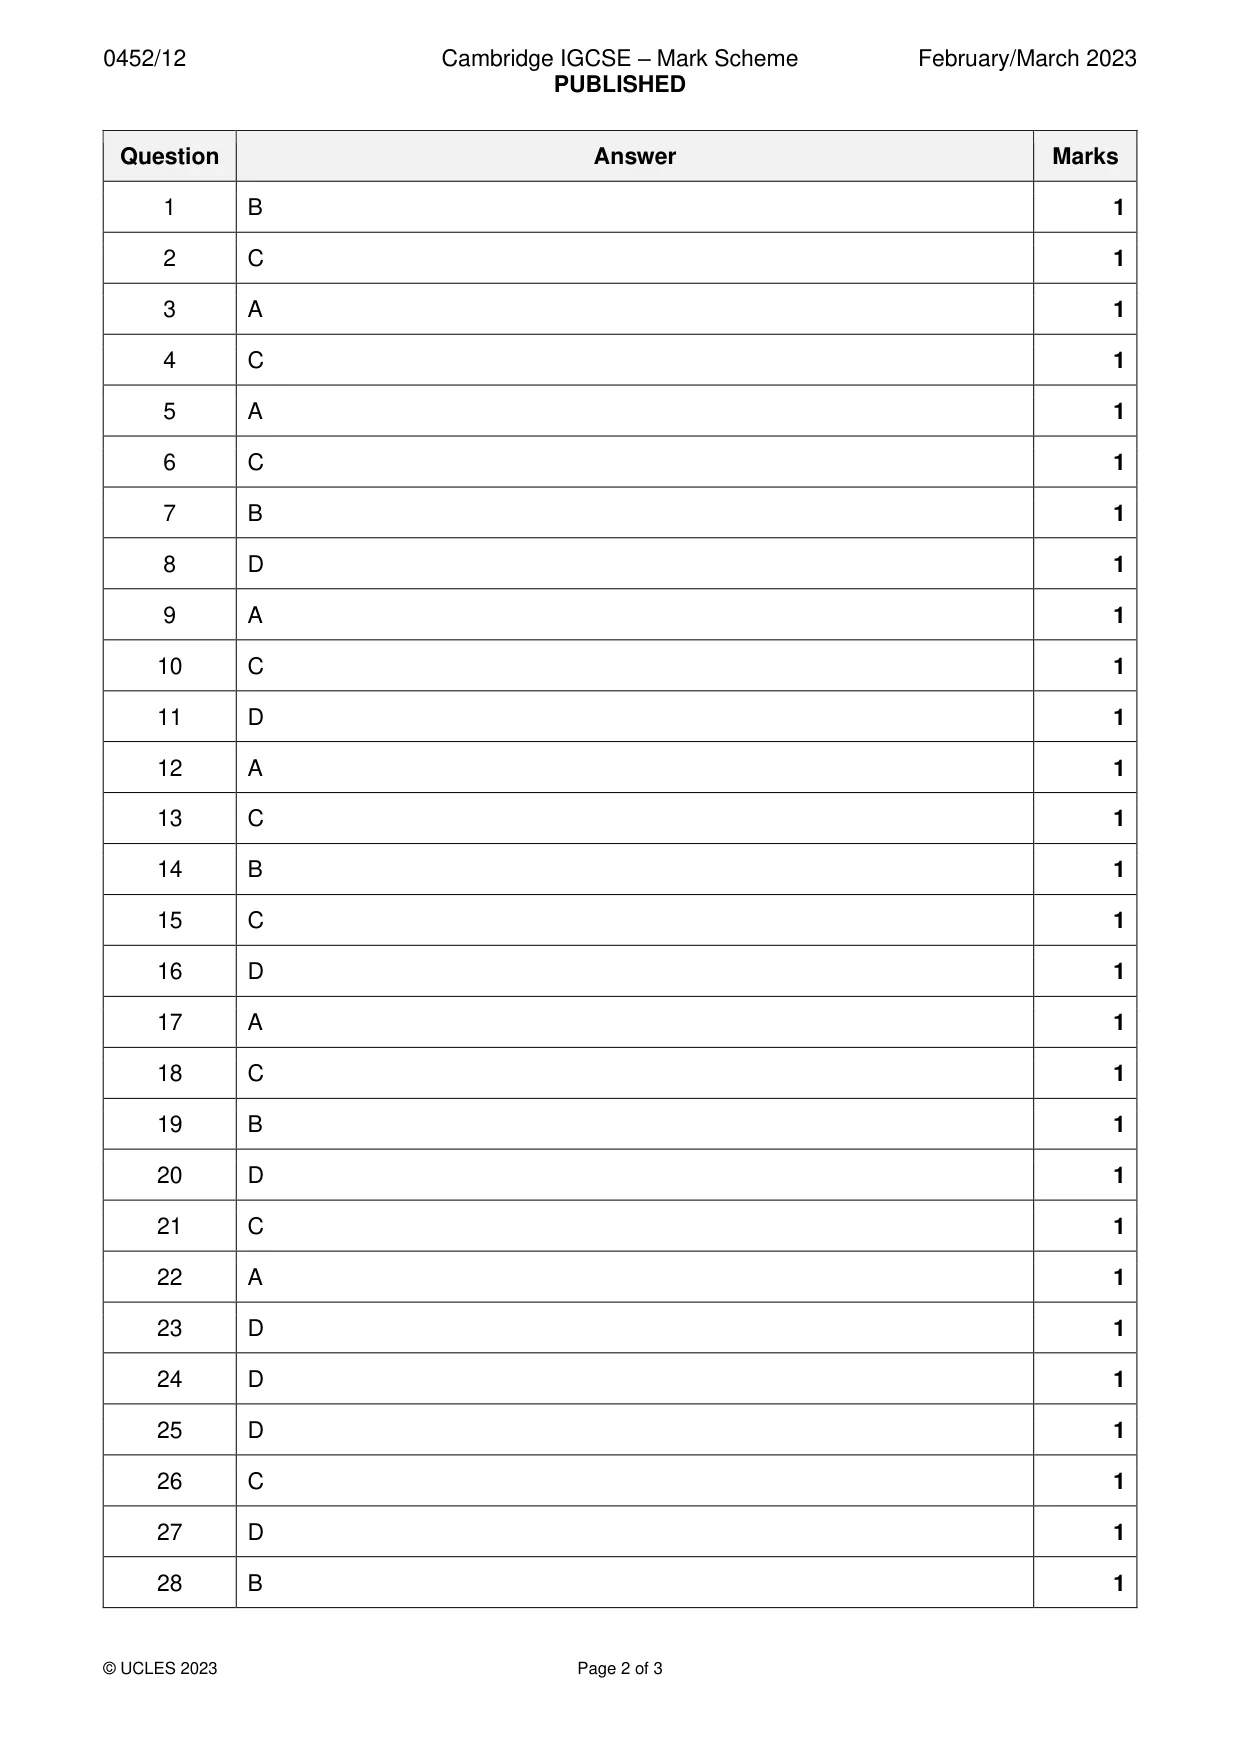
Mark scheme: B
Q2 · How would a business owner know that he is receiving a return on his investment?
2 How would a business owner know that he is receiving a return on his investment? A His bank account is no longer overdrawn. B His drawings have increased. C His income statement shows a profit for the year. D His working capital has increased during the year.
Mark scheme: C
Q3 · What is the correct order of processing accounting data using the double entry system?
3 What is the correct order of processing accounting data using the double entry system? A business documents, journals, ledgers, trial balance B journals, business documents, ledgers, trial balance C ledgers, business documents, trial balance, journals D trial balance, business documents, ledgers, journals
Mark scheme: A
Q4 · Ada bought goods on credit from Zuri
4 Ada bought goods on credit from Zuri. Later, she returned some of the goods to Zuri. How did Ada record the return in her books? account debited account credited A purchases returns Zuri B sales returns Zuri C Zuri purchases returns D Zuri sales returns
Mark scheme: C
Q5 · Samir owns a shop
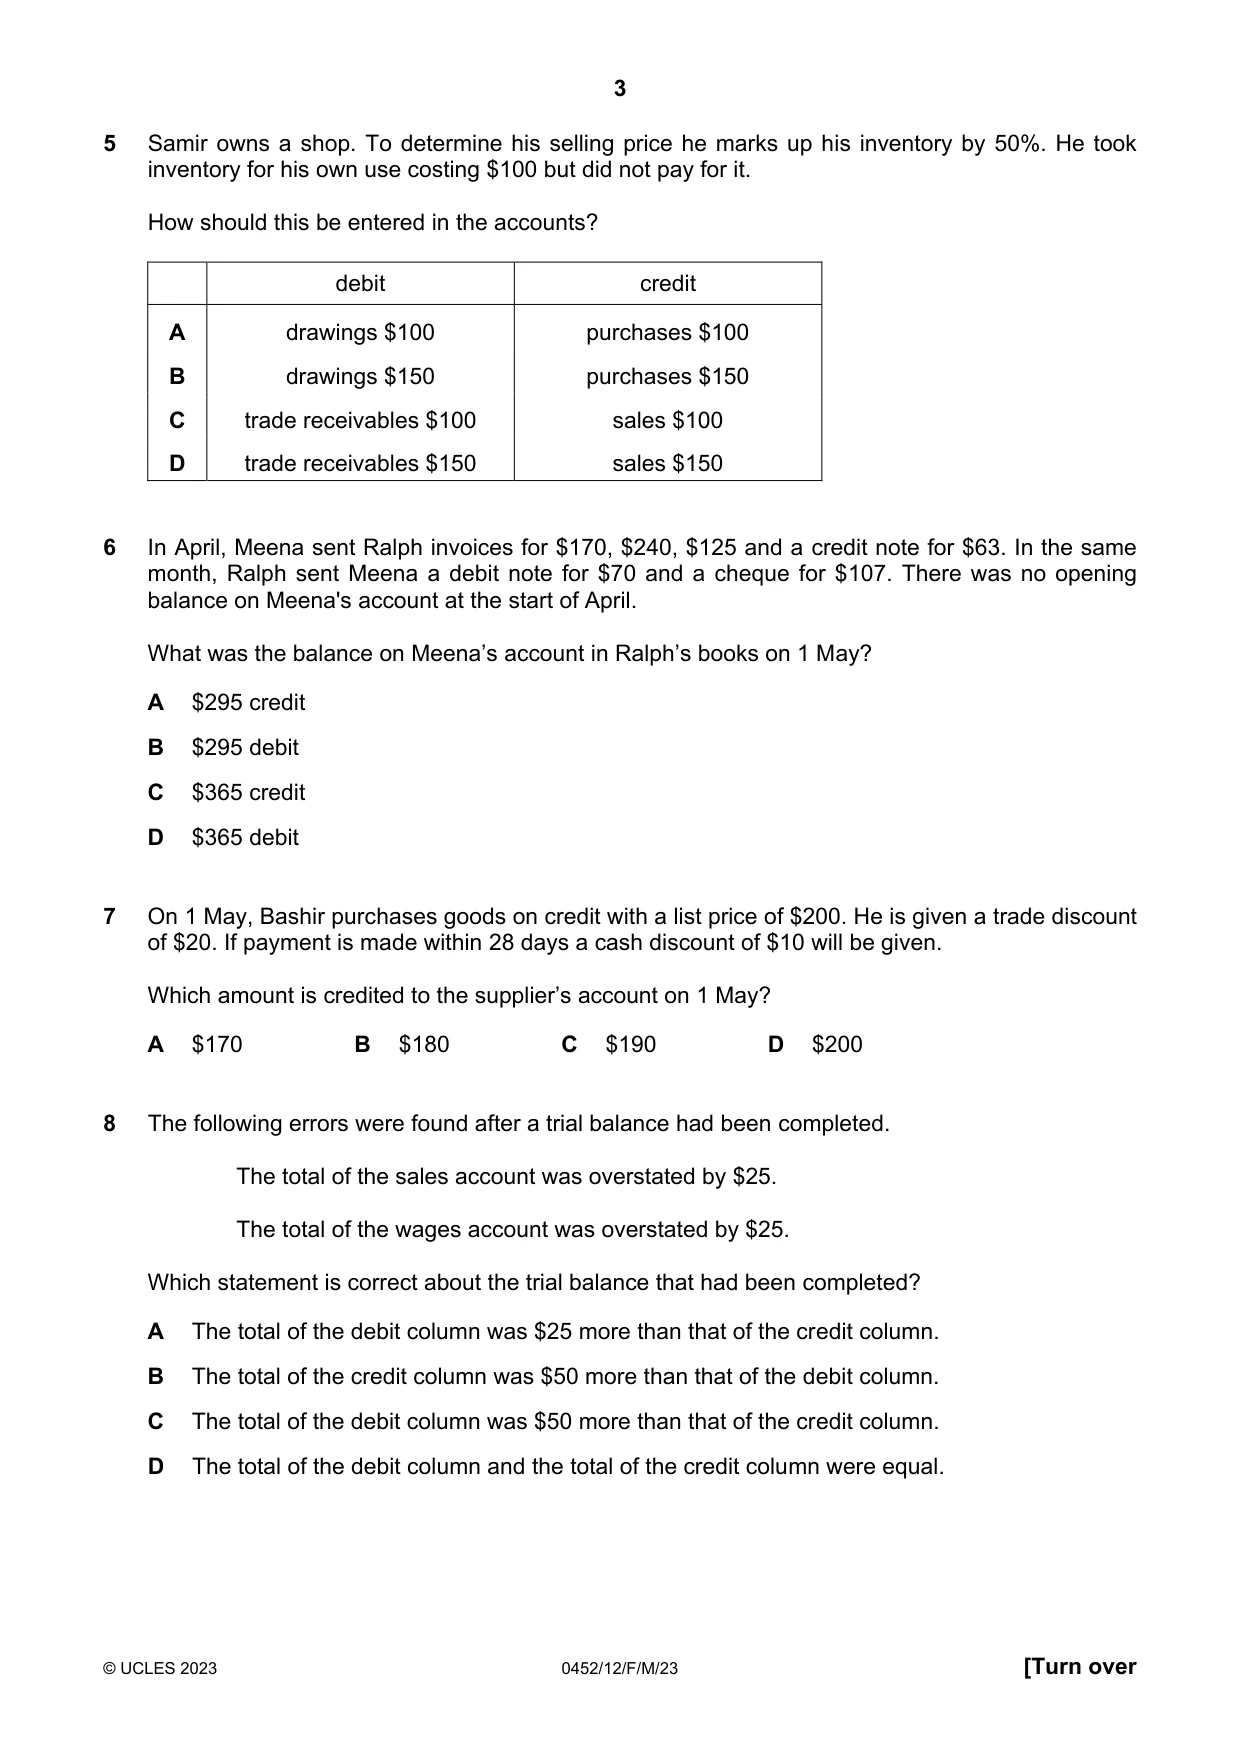
5 Samir owns a shop. To determine his selling price he marks up his inventory by 50%. He took inventory for his own use costing $100 but did not pay for it. How should this be entered in the accounts? debit credit A drawings $100 purchases $100 B drawings $150 purchases $150 C trade receivables $100 sales $100 D trade receivables $150 sales $150
Mark scheme: A
Q6 · In April, Meena sent Ralph invoices for $170, $240, $125 and a credit note for $63
6 In April, Meena sent Ralph invoices for $170, $240, $125 and a credit note for $63. In the same month, Ralph sent Meena a debit note for $70 and a cheque for $107. There was no opening balance on Meena's account at the start of April. What was the balance on Meena’s account in Ralph’s books on 1 May? A $295 credit B $295 debit C $365 credit D $365 debit
Mark scheme: C
Q7 · On 1 May, Bashir purchases goods on credit with a list price of $200
7 On 1 May, Bashir purchases goods on credit with a list price of $200. He is given a trade discount of $20. If payment is made within 28 days a cash discount of $10 will be given. Which amount is credited to the supplier’s account on 1 May? A $170 B $180 C $190 D $200
Mark scheme: B
Q8 · The following errors were found after a trial balance had been completed
8 The following errors were found after a trial balance had been completed. The total of the sales account was overstated by $25. The total of the wages account was overstated by $25. Which statement is correct about the trial balance that had been completed? A The total of the debit column was $25 more than that of the credit column. B The total of the credit column was $50 more than that of the debit column. C The total of the debit column was $50 more than that of the credit column. D The total of the debit column and the total of the credit column were equal.
Mark scheme: D
Q9 · The following trial balance failed to balance
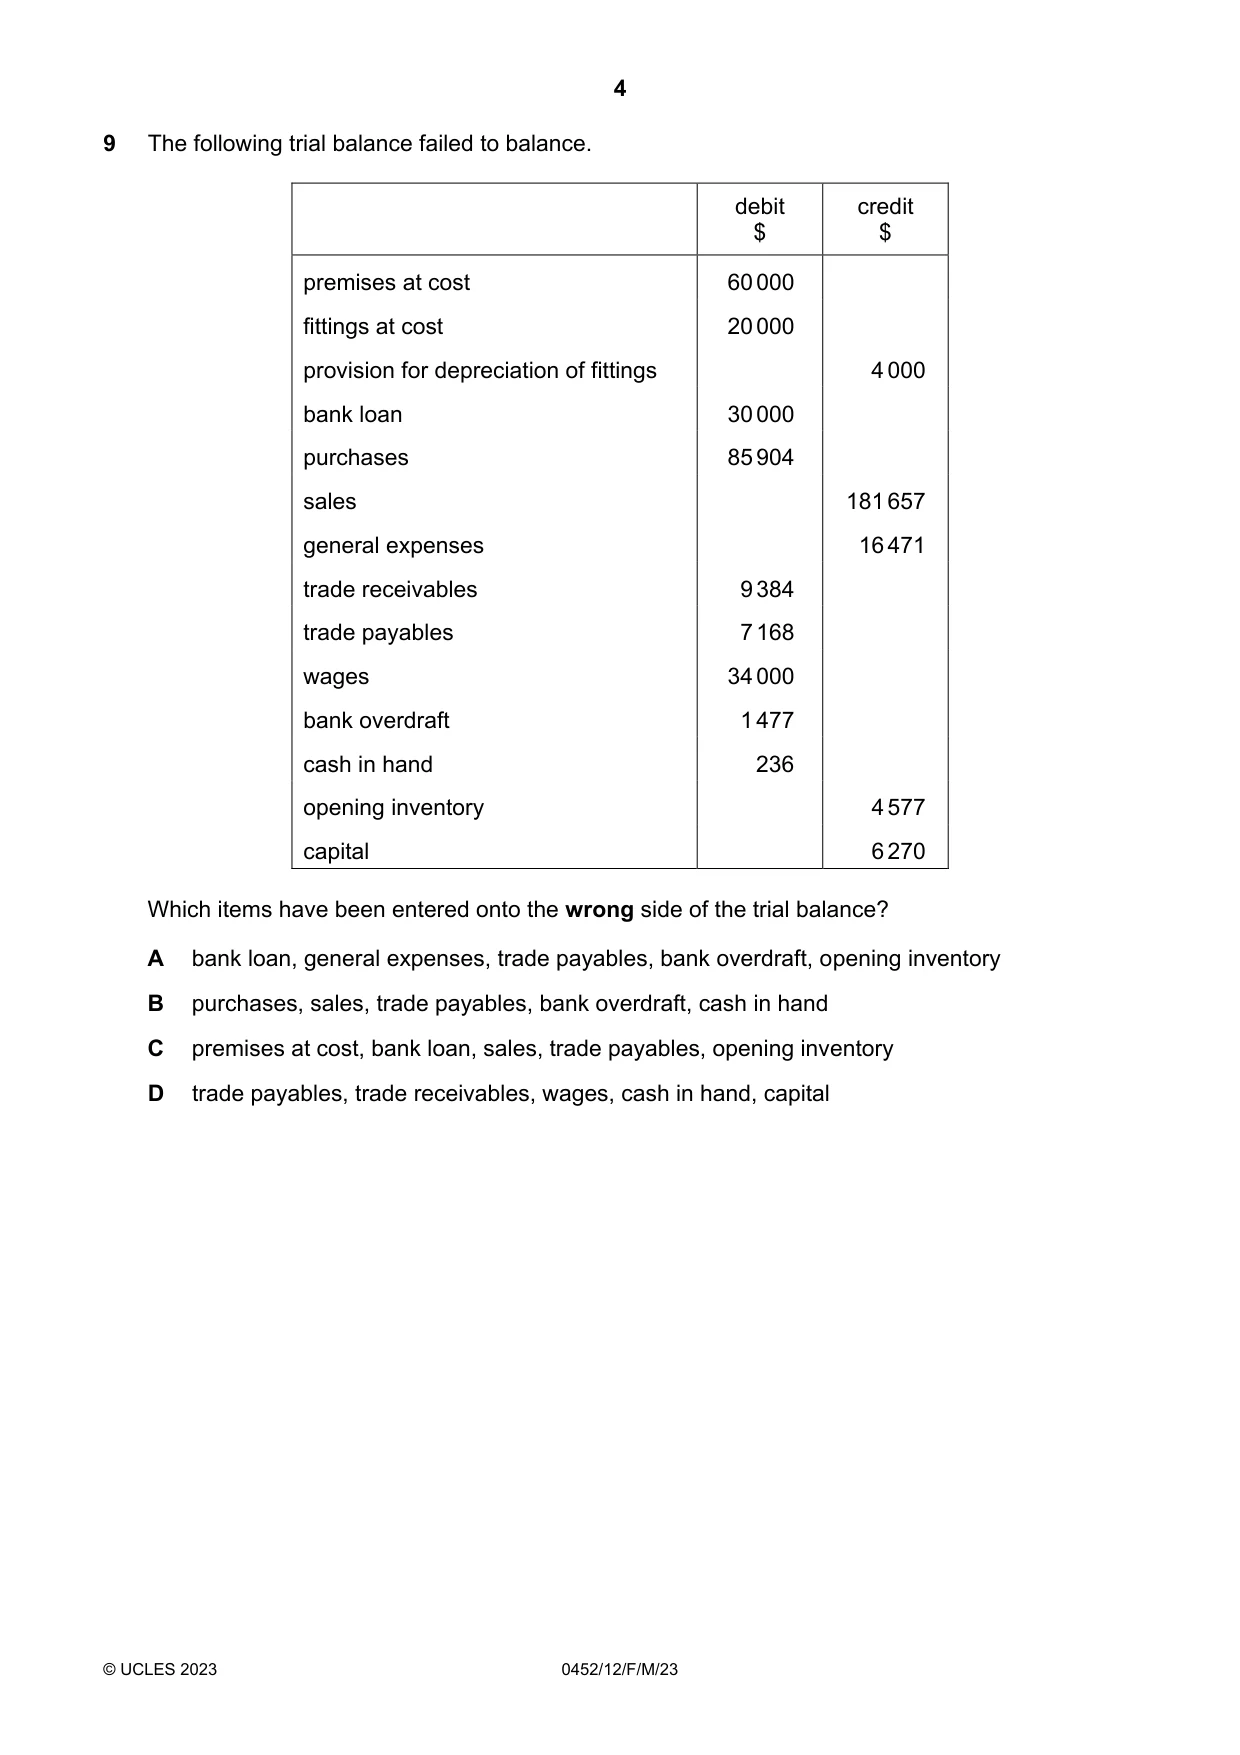
9 The following trial balance failed to balance. debit credit $ $ premises at cost 60 000 fittings at cost 20 000 provision for depreciation of fittings 4 000 bank loan 30 000 purchases 85 904 sales 181 657 general expenses 16 471 trade receivables 9 384 trade payables 7 168 wages 34 000 bank overdraft 1 477 cash in hand 236 opening inventory 4 577 capital 6 270 Which items have been entered onto the wrong side of the trial balance? A bank loan, general expenses, trade payables, bank overdraft, opening inventory B purchases, sales, trade payables, bank overdraft, cash in hand C premises at cost, bank loan, sales, trade payables, opening inventory D trade payables, trade receivables, wages, cash in hand, capital
Mark scheme: A
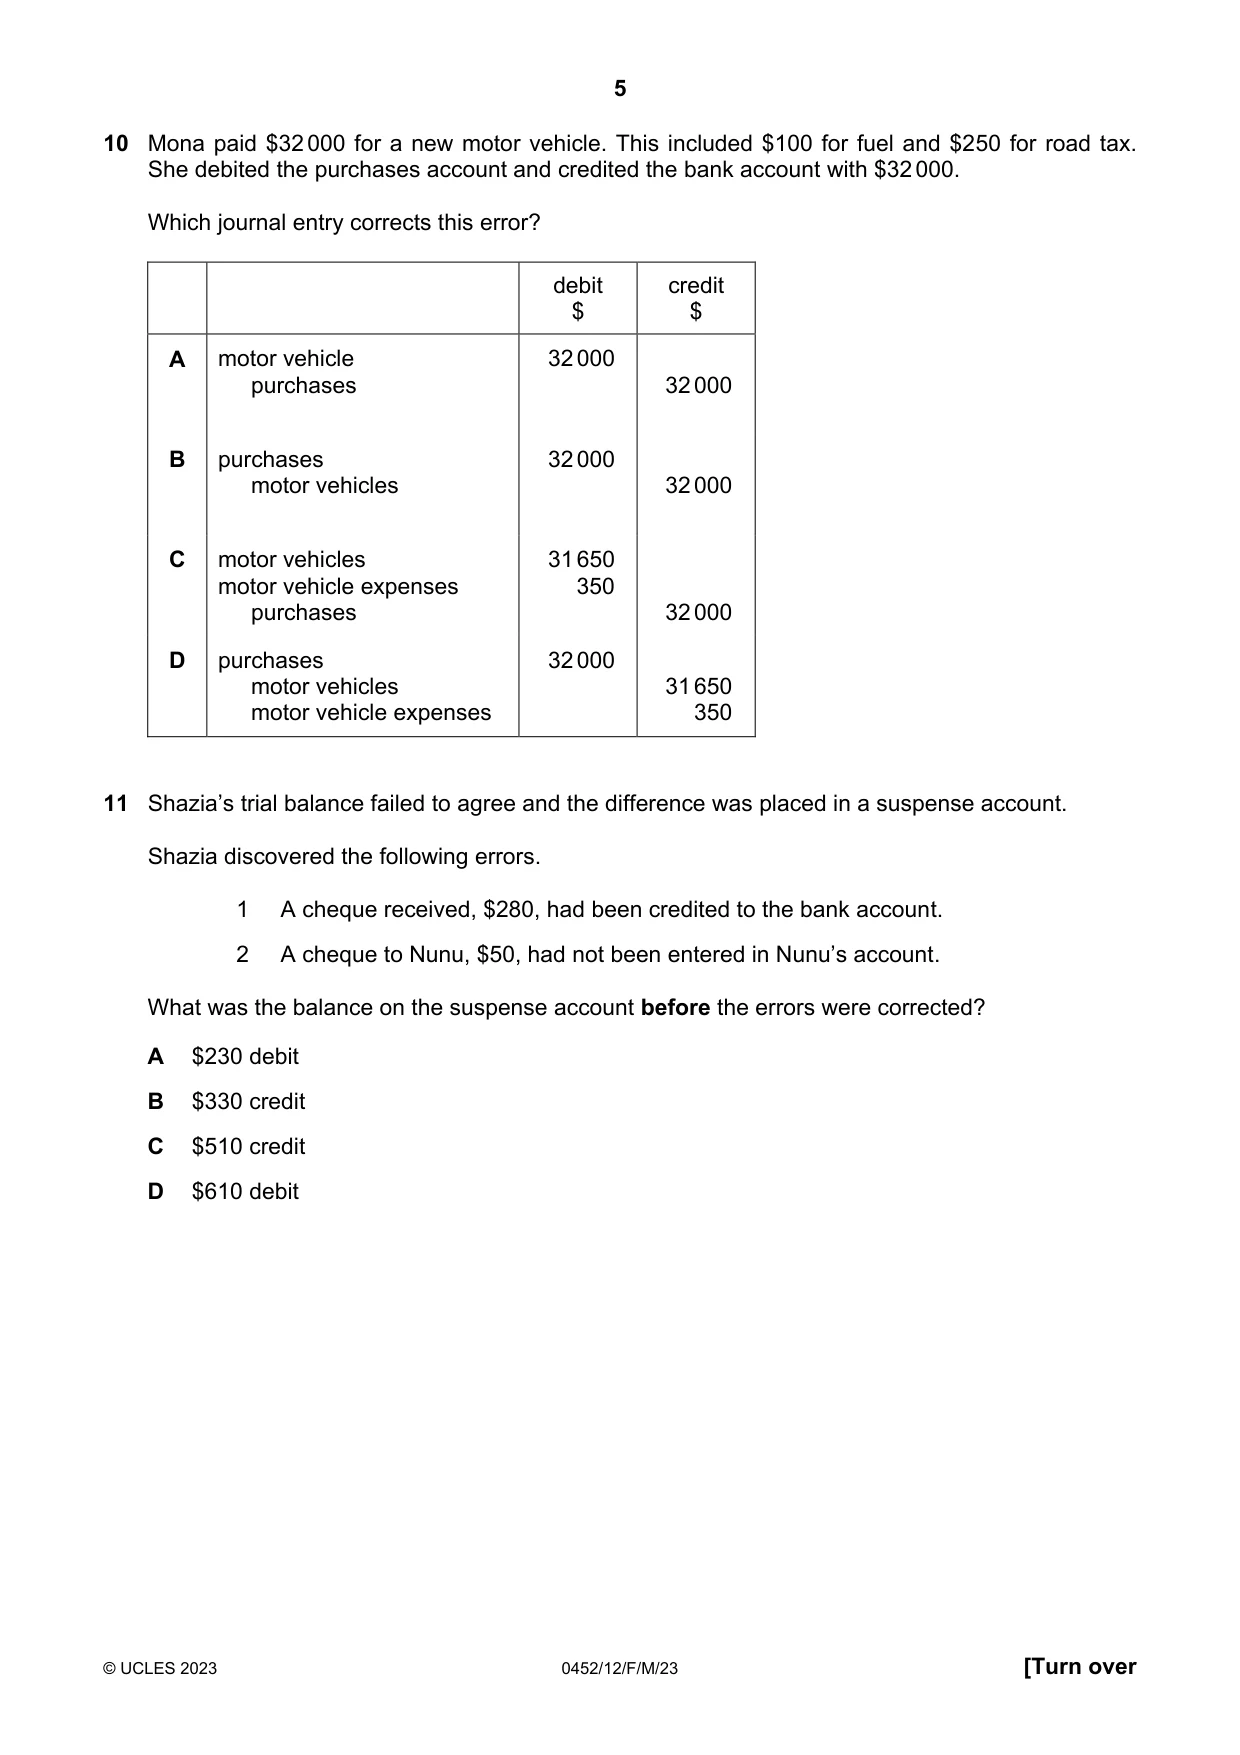
Q10 · Mona paid $32 000 for a new motor vehicle
10 Mona paid $32 000 for a new motor vehicle. This included $100 for fuel and $250 for road tax. She debited the purchases account and credited the bank account with $32 000. Which journal entry corrects this error? debit credit $ $ A motor vehicle 32 000 purchases 32 000 B purchases 32 000 motor vehicles 32 000 C motor vehicles 31 650 motor vehicle expenses 350 purchases 32 000 D purchases 32 000 motor vehicles 31 650 motor vehicle expenses 350
Mark scheme: C
Q11 · Shazia’s trial balance failed to agree and the difference was placed in a suspense account
11 Shazia’s trial balance failed to agree and the difference was placed in a suspense account. Shazia discovered the following errors. 1 A cheque received, $280, had been credited to the bank account. 2 A cheque to Nunu, $50, had not been entered in Nunu’s account. What was the balance on the suspense account before the errors were corrected? A $230 debit B $330 credit C $510 credit D $610 debit
Mark scheme: D
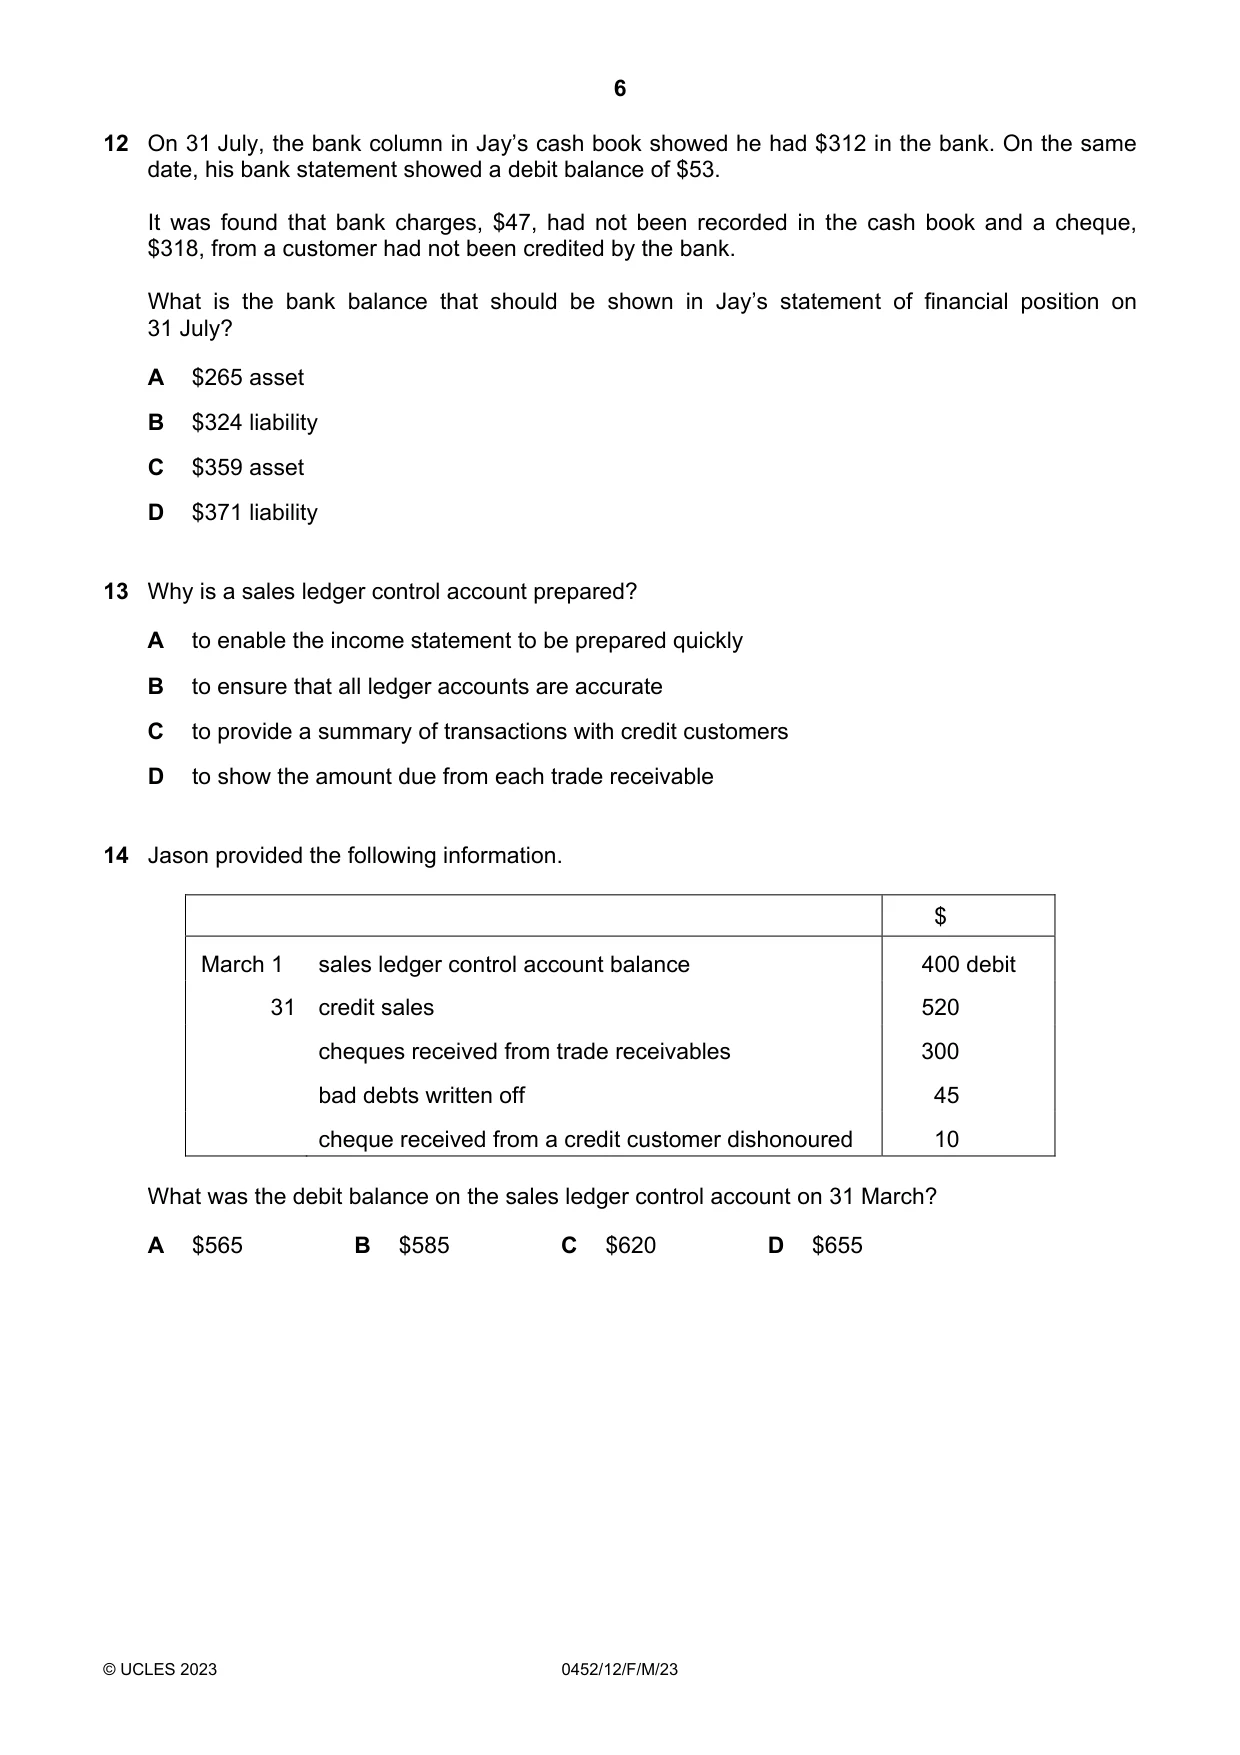
Q12 · On 31 July, the bank column in Jay’s cash book showed he had $312 in the bank
12 On 31 July, the bank column in Jay’s cash book showed he had $312 in the bank. On the same date, his bank statement showed a debit balance of $53. It was found that bank charges, $47, had not been recorded in the cash book and a cheque, $318, from a customer had not been credited by the bank. What is the bank balance that should be shown in Jay’s statement of financial position on 31 July? A $265 asset B $324 liability C $359 asset D $371 liability
Mark scheme: A
Q13 · Why is a sales ledger control account prepared?
13 Why is a sales ledger control account prepared? A to enable the income statement to be prepared quickly B to ensure that all ledger accounts are accurate C to provide a summary of transactions with credit customers D to show the amount due from each trade receivable
Mark scheme: C
Q14 · Jason provided the following information
14 Jason provided the following information. $ March 1 sales ledger control account balance 400 debit 31 credit sales 520 cheques received from trade receivables 300 bad debts written off 45 cheque received from a credit customer dishonoured 10 What was the debit balance on the sales ledger control account on 31 March? A $565 B $585 C $620 D $655
Mark scheme: B
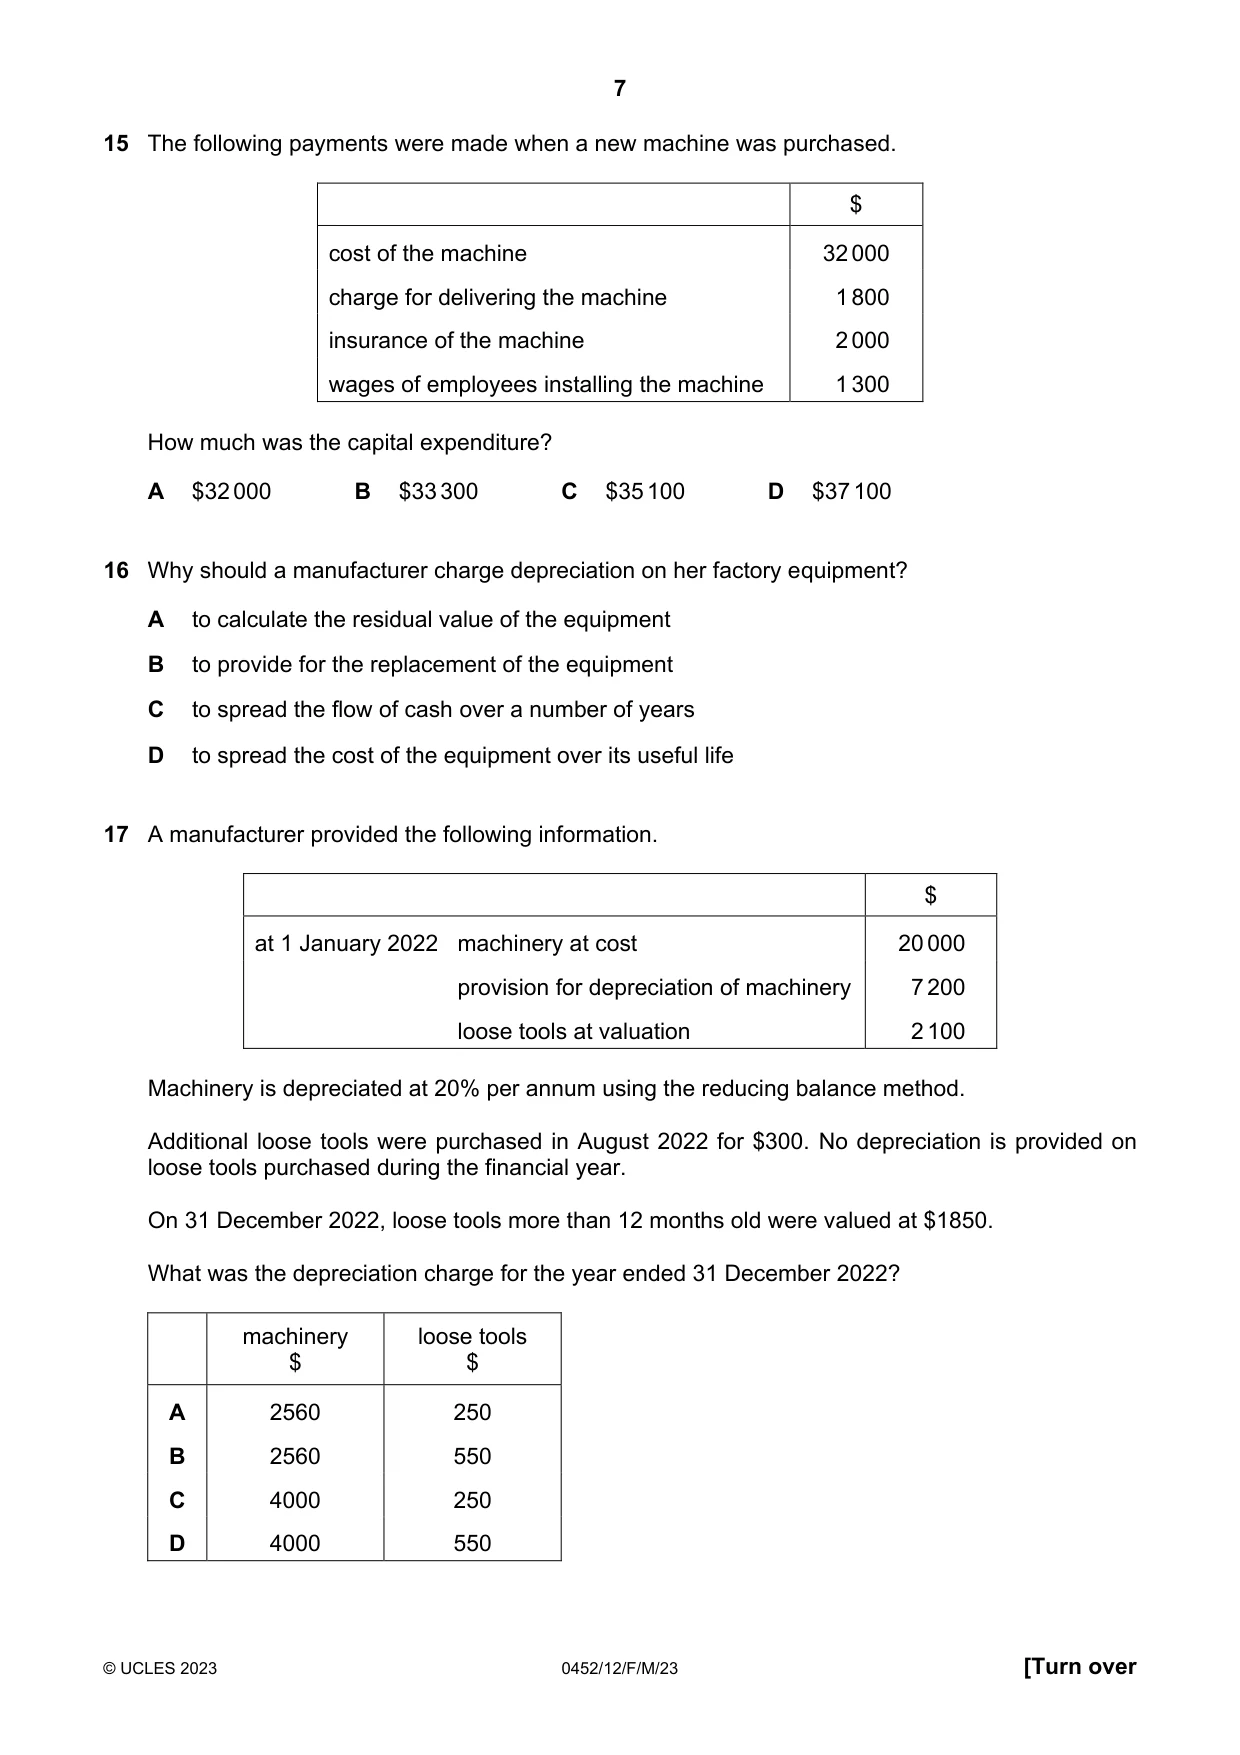
Q15 · The following payments were made when a new machine was purchased
15 The following payments were made when a new machine was purchased. $ cost of the machine 32 000 charge for delivering the machine 1 800 insurance of the machine 2 000 wages of employees installing the machine 1 300 How much was the capital expenditure? A $32 000 B $33 300 C $35 100 D $37 100
Mark scheme: C
More questions on Capital and revenue expenditure and receipts
Q16 · Why should a manufacturer charge depreciation on her factory equipment?
16 Why should a manufacturer charge depreciation on her factory equipment? A to calculate the residual value of the equipment B to provide for the replacement of the equipment C to spread the flow of cash over a number of years D to spread the cost of the equipment over its useful life
Mark scheme: D
More questions on Accounting for depreciation and disposal of non-current assets
Q17 · A manufacturer provided the following information
17 A manufacturer provided the following information. $ at 1 January 2022 machinery at cost 20 000 provision for depreciation of machinery 7 200 loose tools at valuation 2 100 Machinery is depreciated at 20% per annum using the reducing balance method. Additional loose tools were purchased in August 2022 for $300. No depreciation is provided on loose tools purchased during the financial year. On 31 December 2022, loose tools more than 12 months old were valued at $1850. What was the depreciation charge for the year ended 31 December 2022? machinery loose tools $ $ A 2560 250 B 2560 550 C 4000 250 D 4000 550
Mark scheme: A
More questions on Accounting for depreciation and disposal of non-current assets
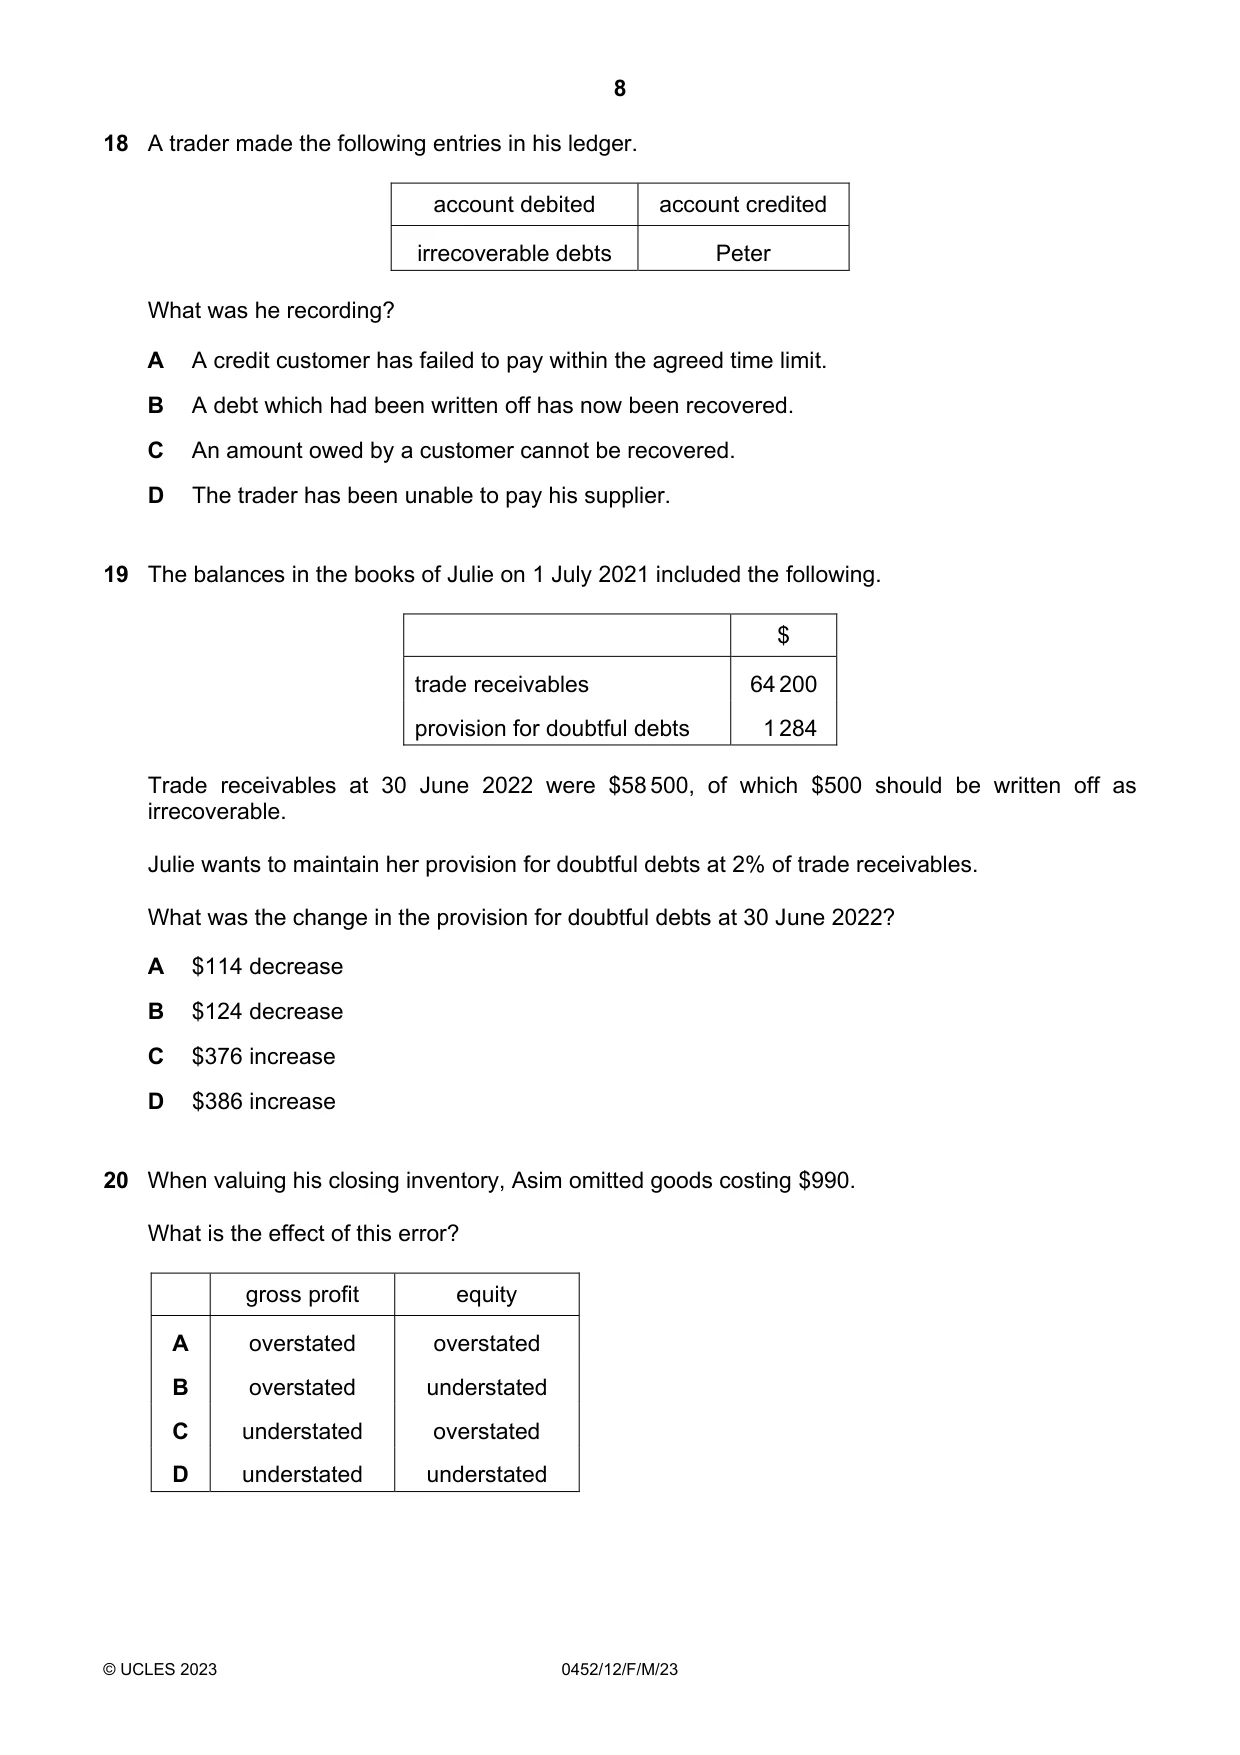
Q18 · A trader made the following entries in his ledger
18 A trader made the following entries in his ledger. account debited account credited irrecoverable debts Peter What was he recording? A A credit customer has failed to pay within the agreed time limit. B A debt which had been written off has now been recovered. C An amount owed by a customer cannot be recovered. D The trader has been unable to pay his supplier.
Mark scheme: C
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q19 · The balances in the books of Julie on 1 July 2021 included the following
19 The balances in the books of Julie on 1 July 2021 included the following. $ trade receivables 64 200 provision for doubtful debts 1 284 Trade receivables at 30 June 2022 were $58 500, of which $500 should be written off as irrecoverable. Julie wants to maintain her provision for doubtful debts at 2% of trade receivables. What was the change in the provision for doubtful debts at 30 June 2022? A $114 decrease B $124 decrease C $376 increase D $386 increase
Mark scheme: B
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q20 · When valuing his closing inventory, Asim omitted goods costing $990
20 When valuing his closing inventory, Asim omitted goods costing $990. What is the effect of this error? gross profit equity A overstated overstated B overstated understated C understated overstated D understated understated
Mark scheme: D
Q21 · The owner of a restaurant is concerned about high operating costs
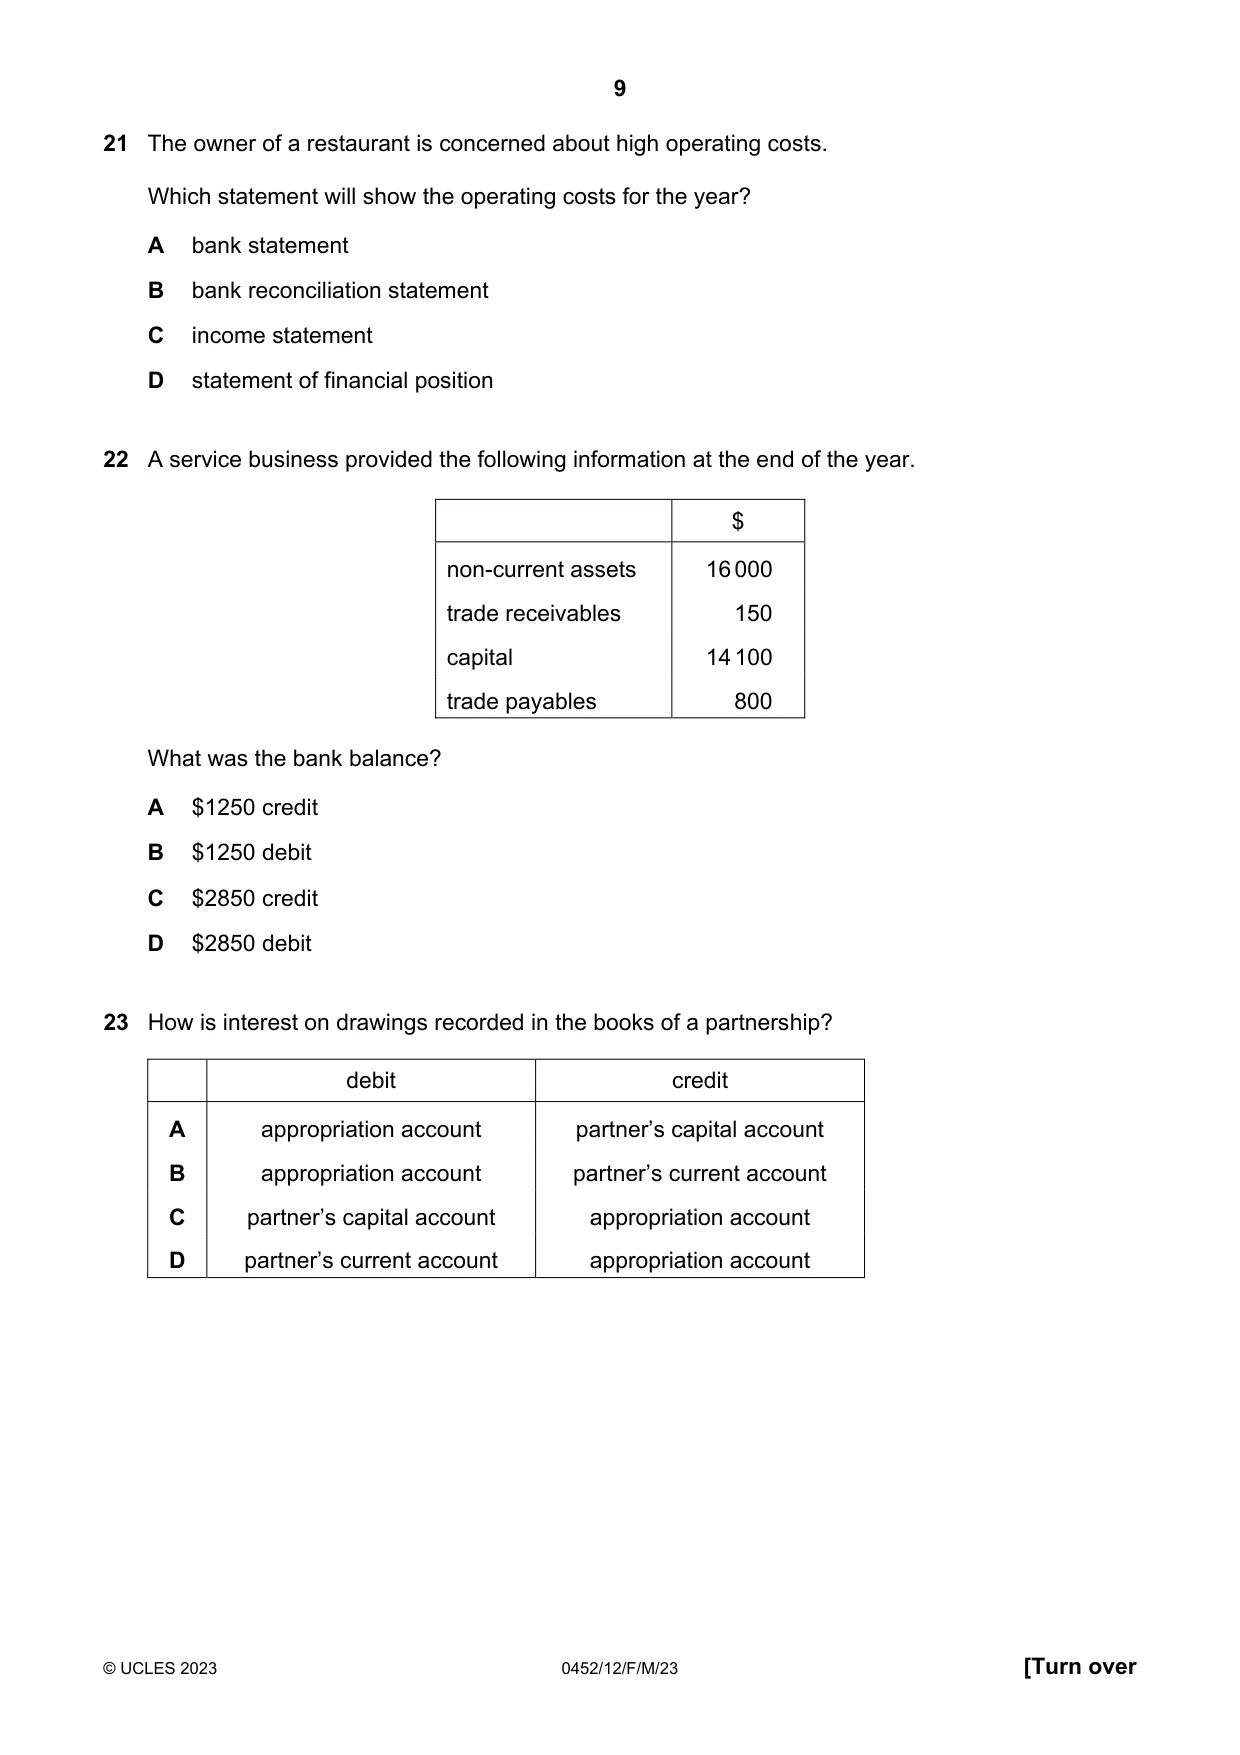
21 The owner of a restaurant is concerned about high operating costs. Which statement will show the operating costs for the year? A bank statement B bank reconciliation statement C income statement D statement of financial position
Mark scheme: C
Q22 · A service business provided the following information at the end of the year
22 A service business provided the following information at the end of the year. $ non-current assets 16 000 trade receivables 150 capital 14 100 trade payables 800 What was the bank balance? A $1250 credit B $1250 debit C $2850 credit D $2850 debit
Mark scheme: A
Q23 · How is interest on drawings recorded in the books of a partnership?
23 How is interest on drawings recorded in the books of a partnership? debit credit A appropriation account partner’s capital account B appropriation account partner’s current account C partner’s capital account appropriation account D partner’s current account appropriation account
Mark scheme: D
Q24 · Javed and Yani were in a partnership, sharing profits and losses equally
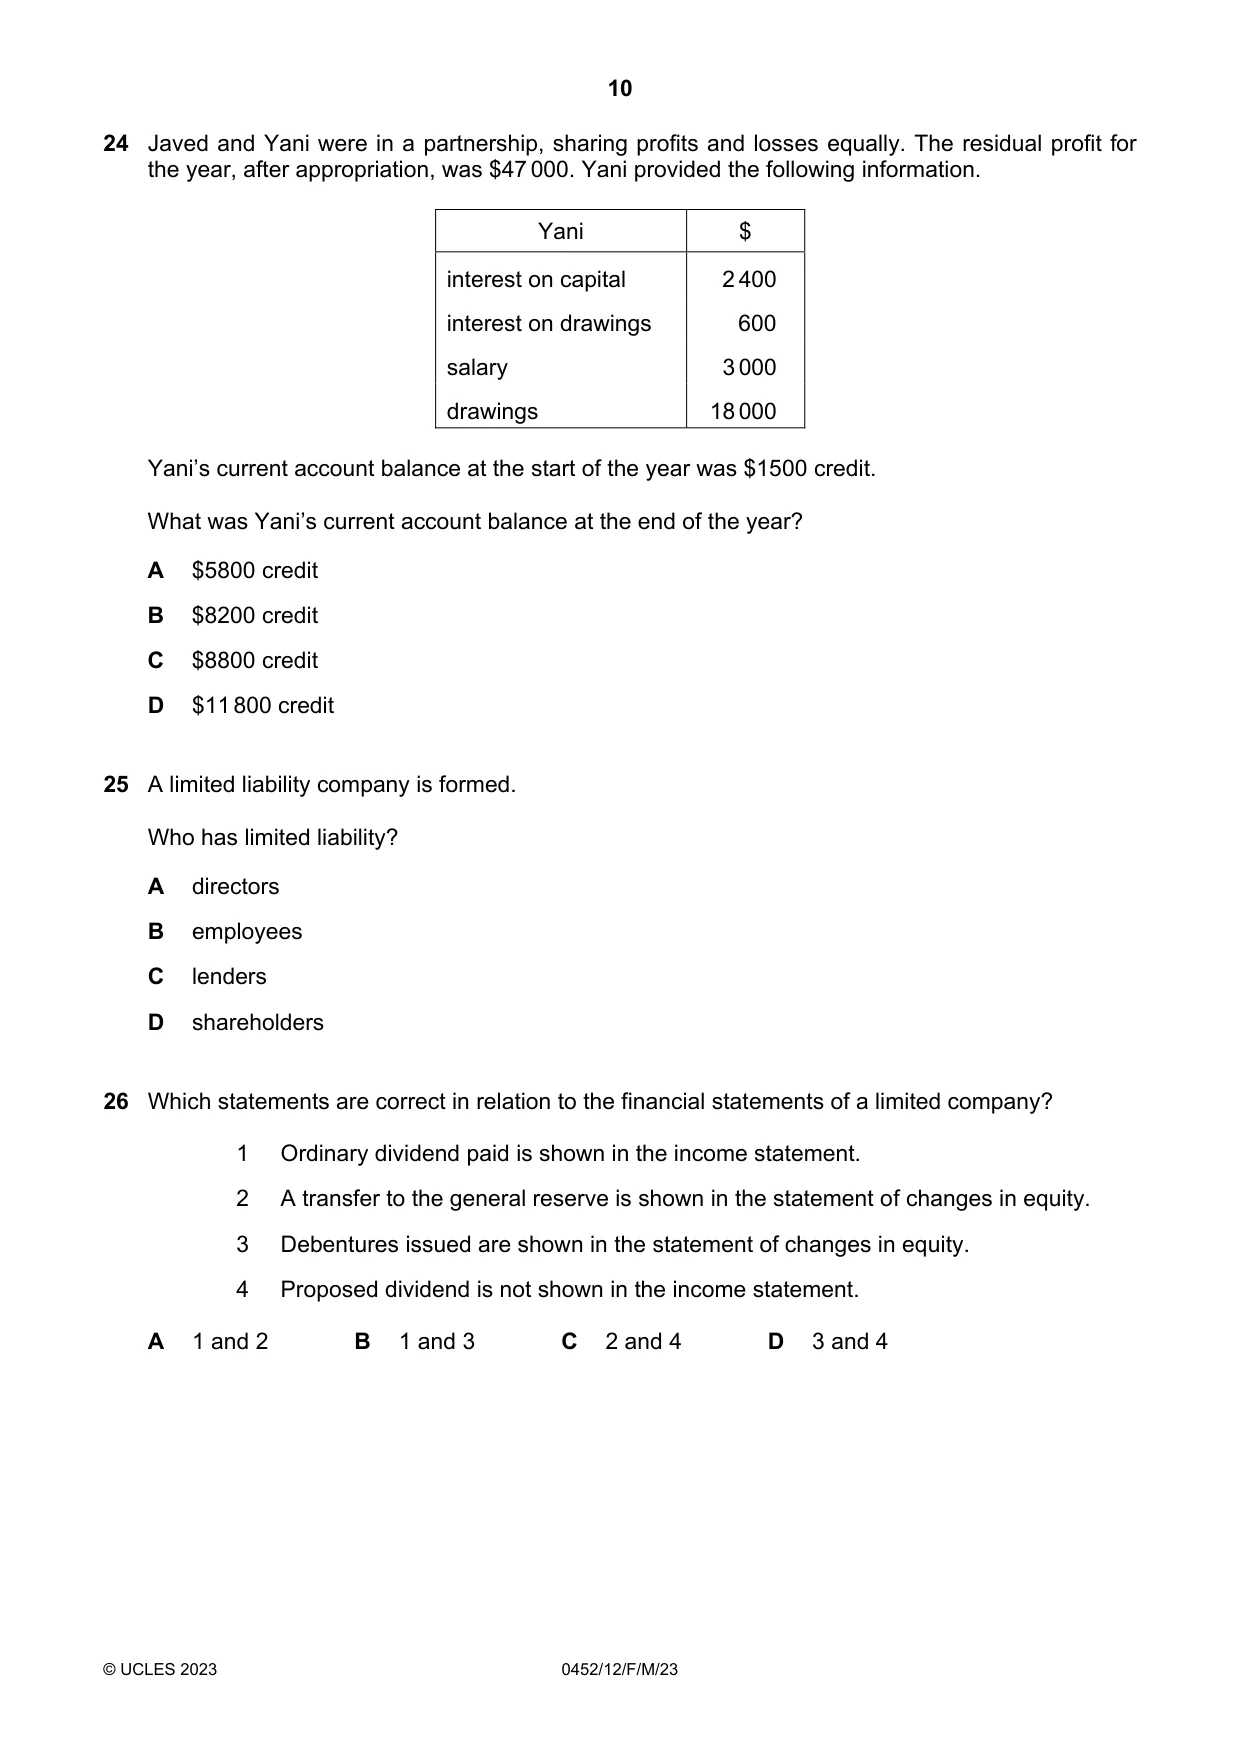
24 Javed and Yani were in a partnership, sharing profits and losses equally. The residual profit for the year, after appropriation, was $47 000. Yani provided the following information. Yani $ interest on capital 2 400 interest on drawings 600 salary 3 000 drawings 18 000 Yani’s current account balance at the start of the year was $1500 credit. What was Yani’s current account balance at the end of the year? A $5800 credit B $8200 credit C $8800 credit D $11 800 credit
Mark scheme: D
Q25 · A limited liability company is formed
25 A limited liability company is formed. Who has limited liability? A directors B employees C lenders D shareholders
Mark scheme: D
Q26 · Which statements are correct in relation to the financial statements of a limited company?
26 Which statements are correct in relation to the financial statements of a limited company? 1 Ordinary dividend paid is shown in the income statement. 2 A transfer to the general reserve is shown in the statement of changes in equity. 3 Debentures issued are shown in the statement of changes in equity. 4 Proposed dividend is not shown in the income statement. A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
Mark scheme: C
Q27 · A golf club sells refreshments to its members
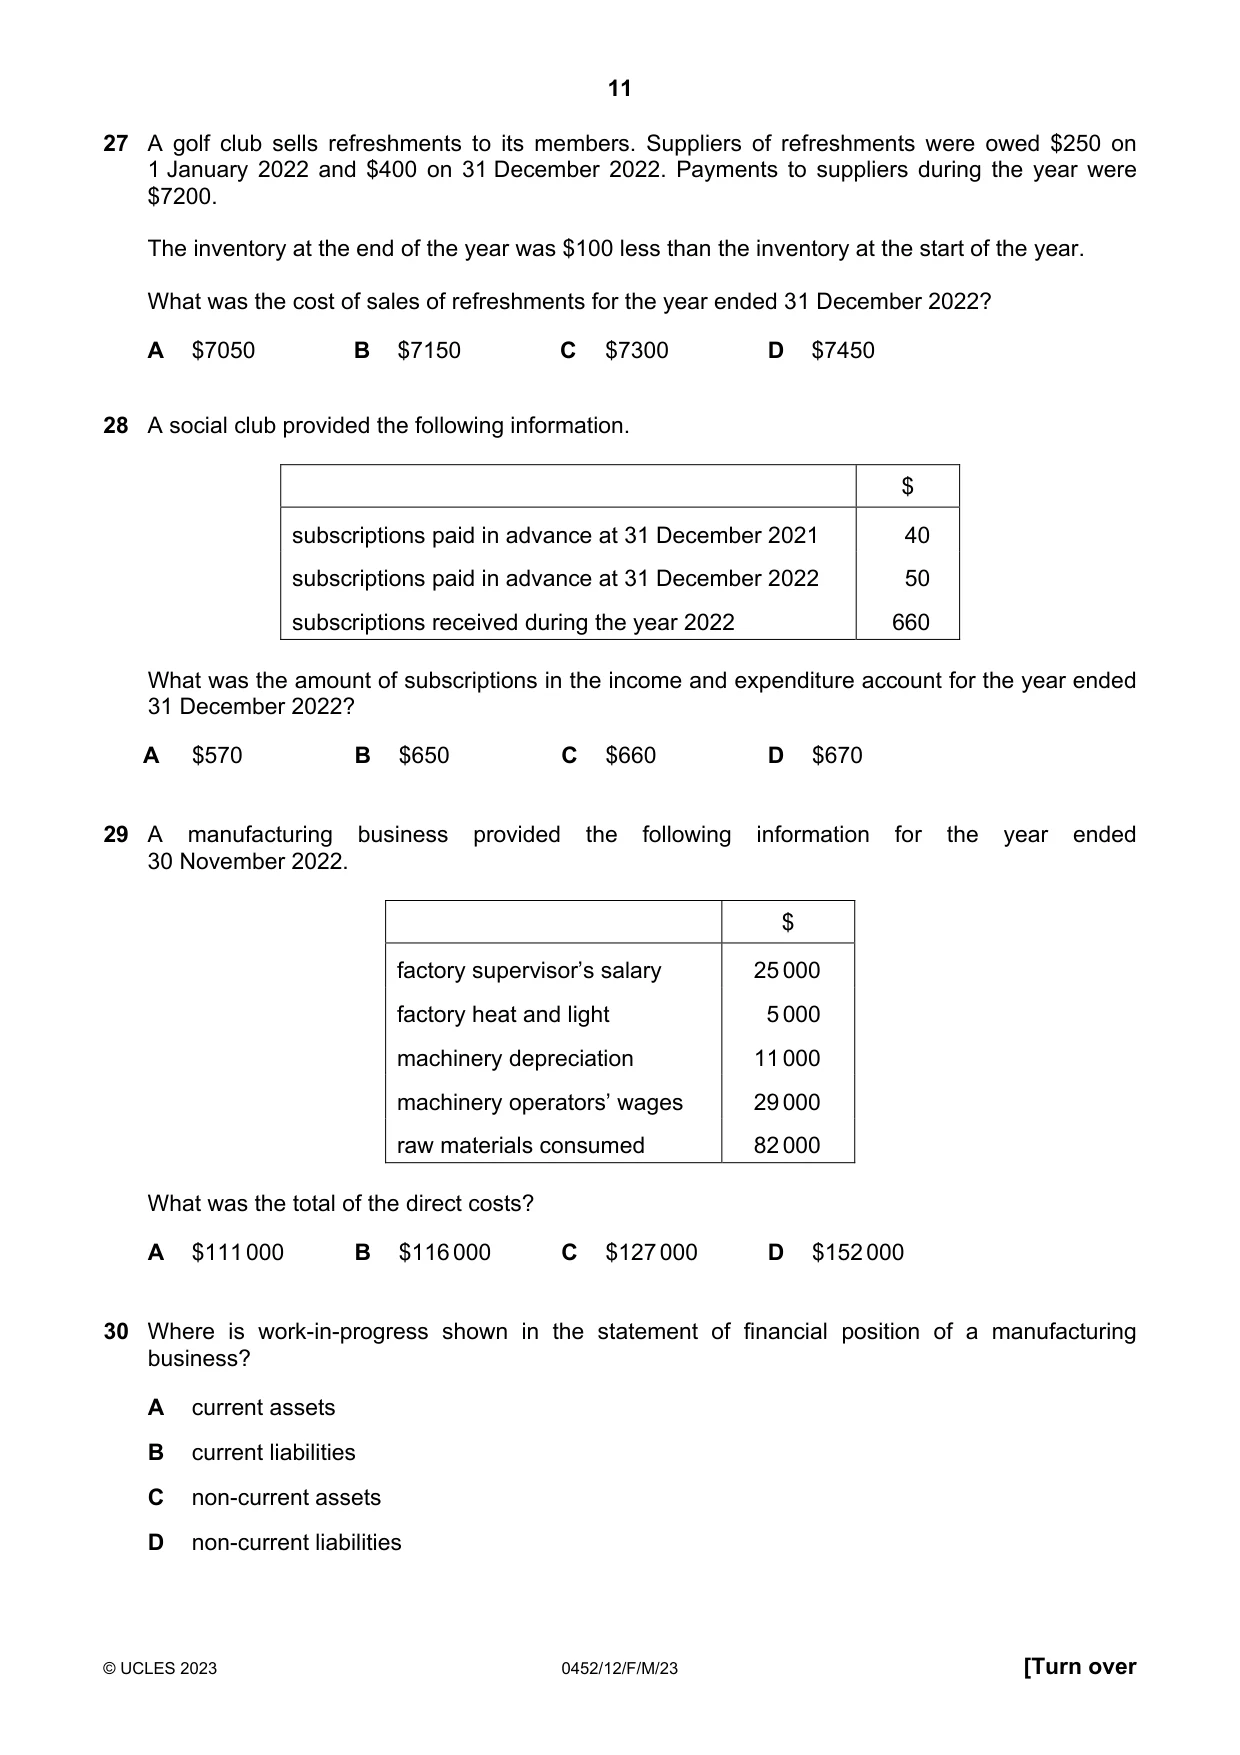
27 A golf club sells refreshments to its members. Suppliers of refreshments were owed $250 on 1 January 2022 and $400 on 31 December 2022. Payments to suppliers during the year were $7200. The inventory at the end of the year was $100 less than the inventory at the start of the year. What was the cost of sales of refreshments for the year ended 31 December 2022? A $7050 B $7150 C $7300 D $7450
Mark scheme: D
Q28 · A social club provided the following information
28 A social club provided the following information. $ subscriptions paid in advance at 31 December 2021 40 subscriptions paid in advance at 31 December 2022 50 subscriptions received during the year 2022 660 What was the amount of subscriptions in the income and expenditure account for the year ended 31 December 2022? A $570 B $650 C $660 D $670
Mark scheme: B
Q29 · A manufacturing business provided the following information for the year ended 30…
29 A manufacturing business provided the following information for the year ended 30 November 2022. $ factory supervisor’s salary 25 000 factory heat and light 5 000 machinery depreciation 11 000 machinery operators’ wages 29 000 raw materials consumed 82 000 What was the total of the direct costs? A $111 000 B $116 000 C $127 000 D $152 000
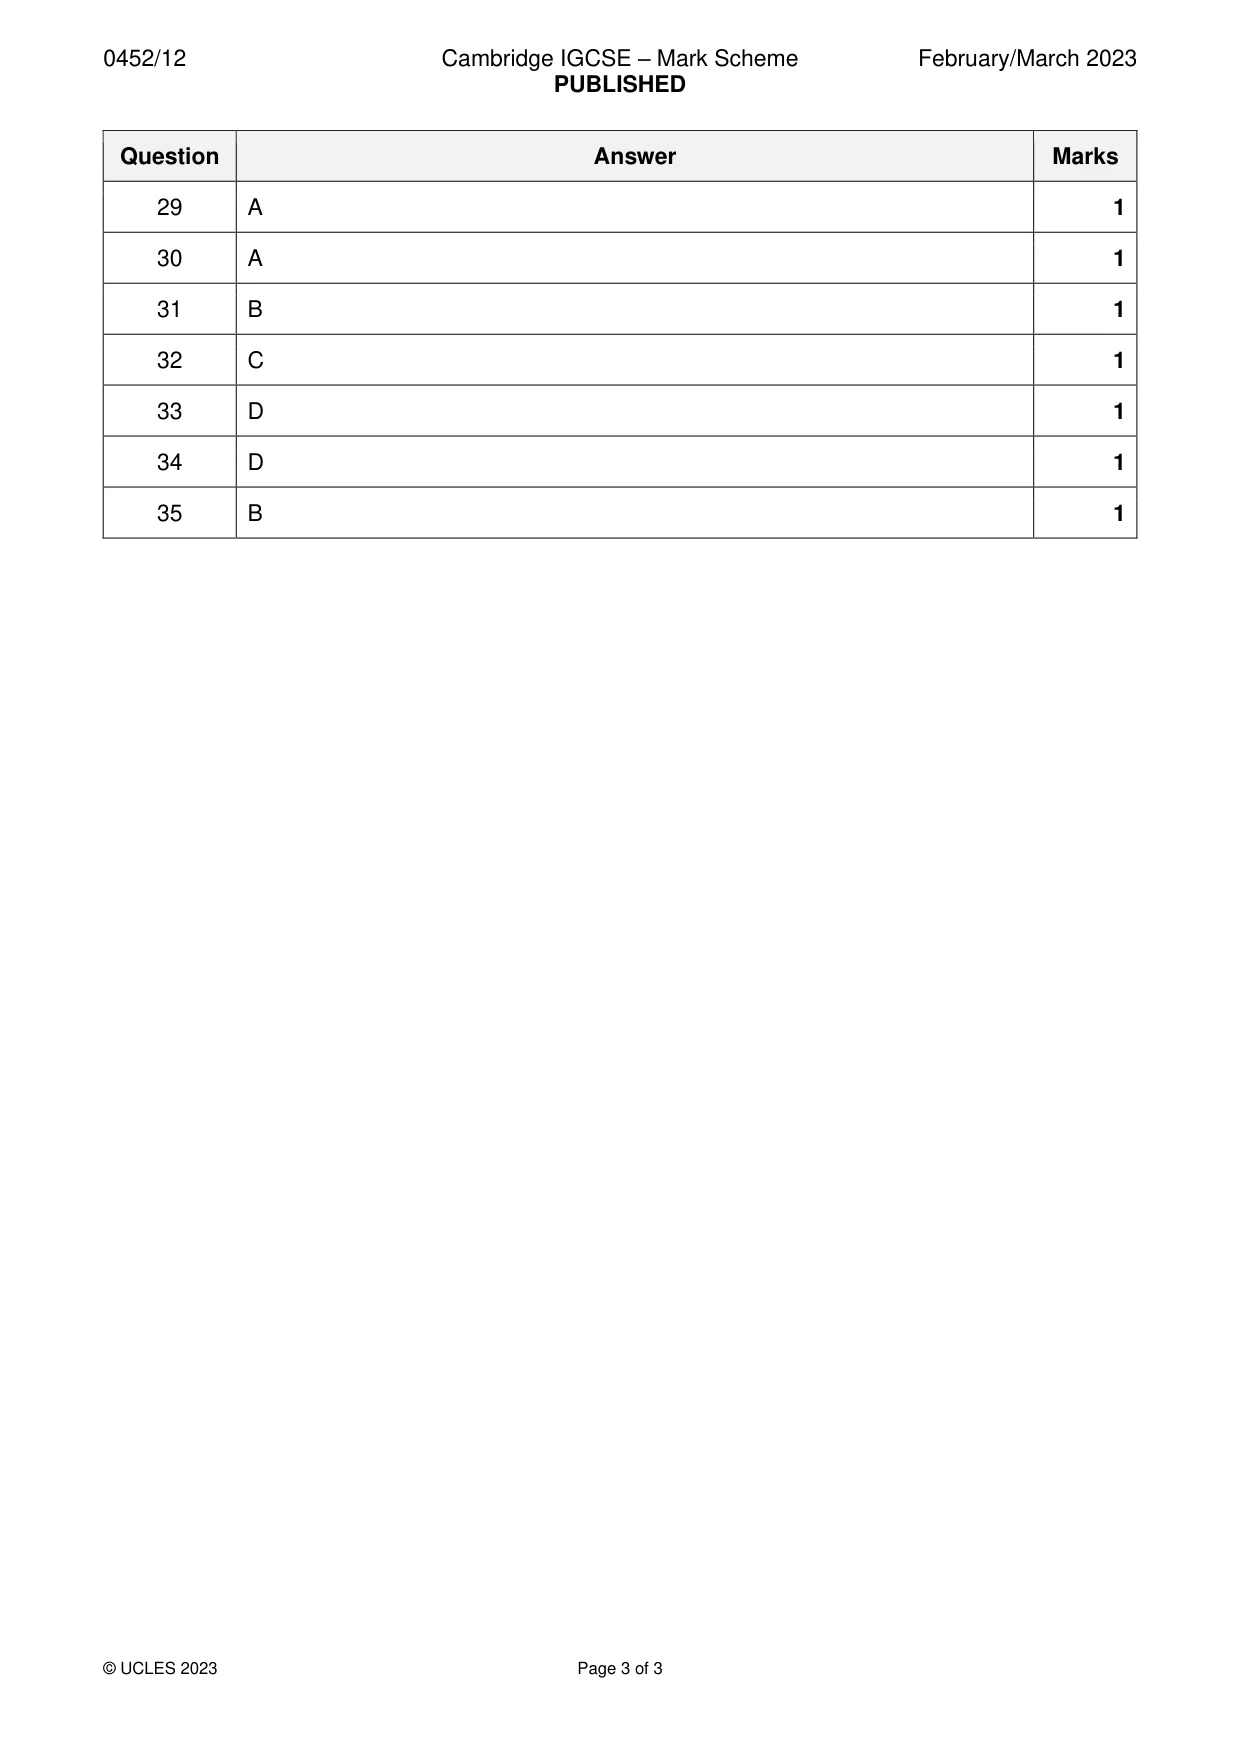
Mark scheme: A
Q30 · Where is work-in-progress shown in the statement of financial position of a manufacturing…
30 Where is work-in-progress shown in the statement of financial position of a manufacturing business? A current assets B current liabilities C non-current assets D non-current liabilities
Mark scheme: A
Q31 · How is profit calculated from incomplete records?
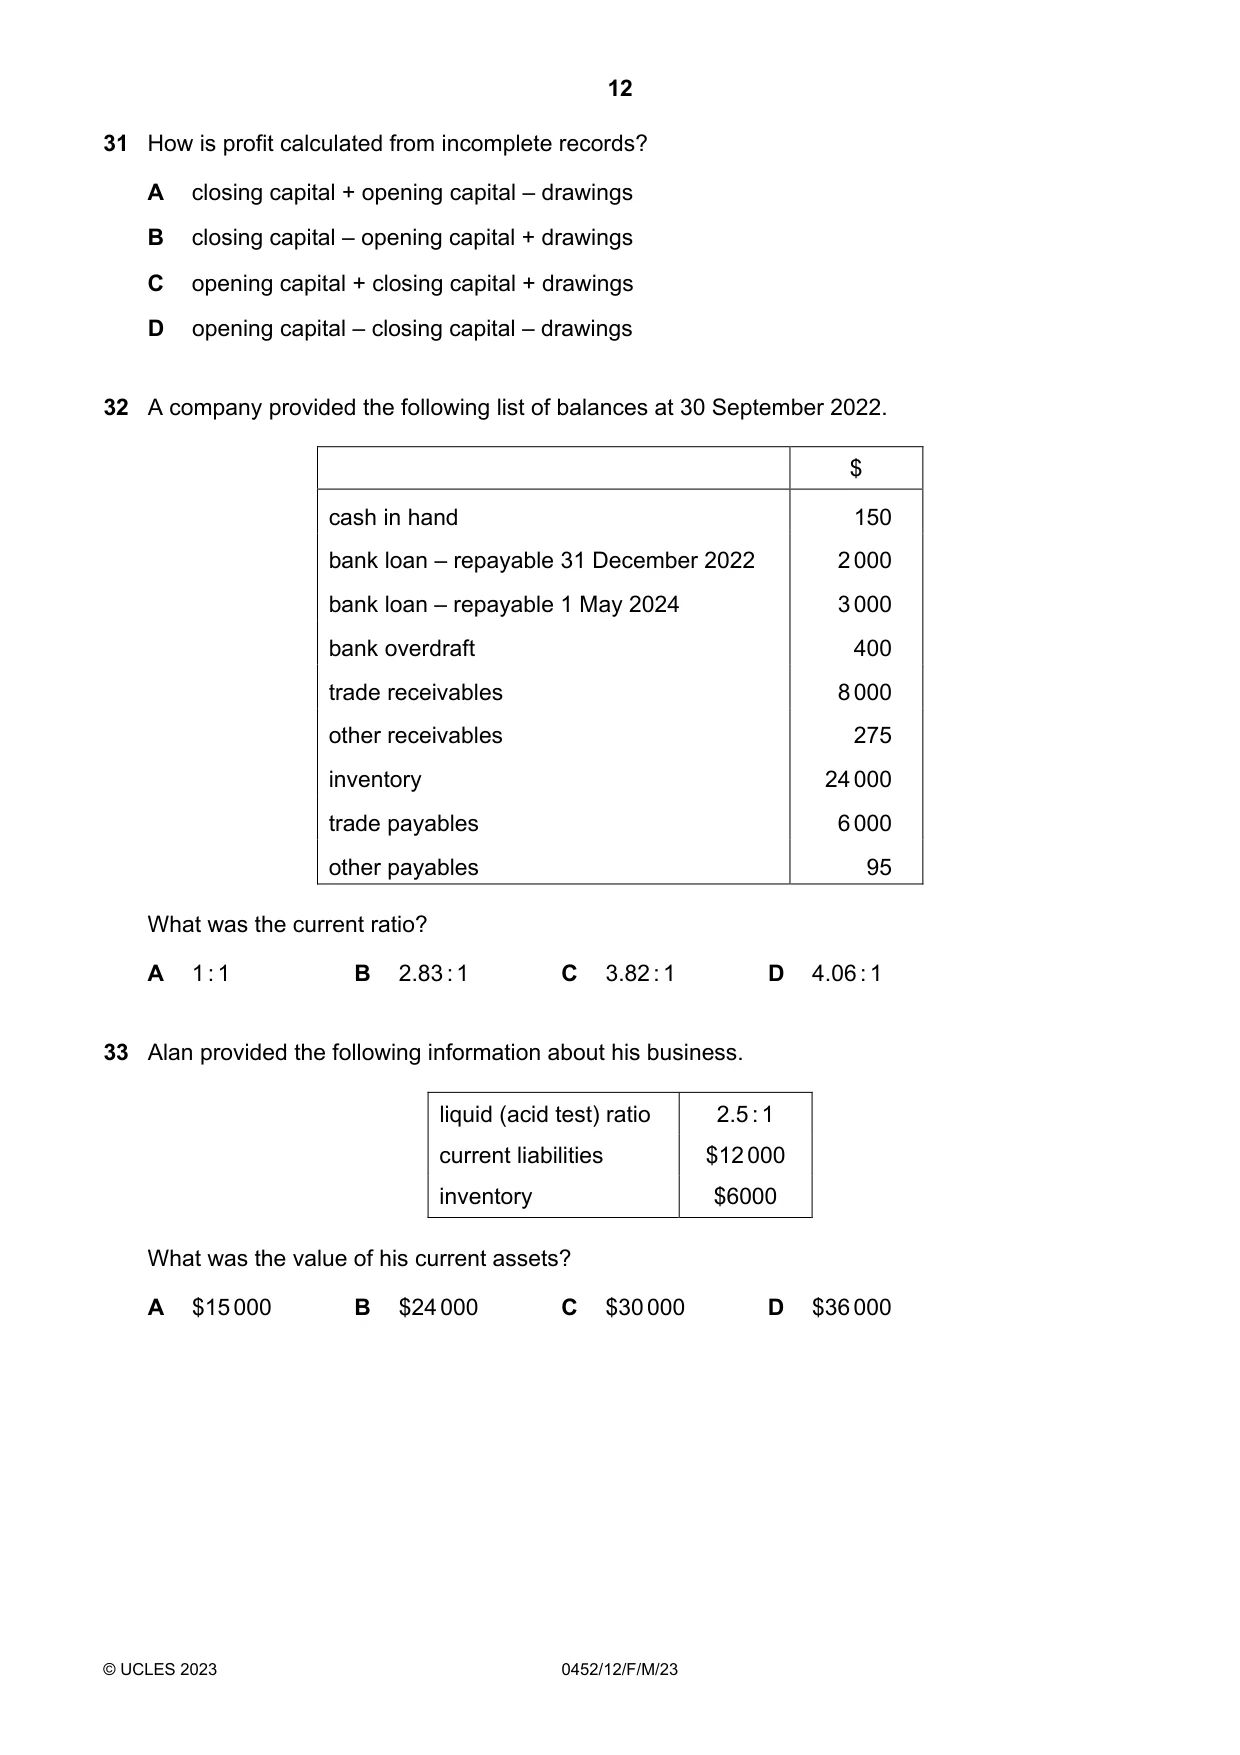
31 How is profit calculated from incomplete records? A closing capital + opening capital – drawings B closing capital – opening capital + drawings C opening capital + closing capital + drawings D opening capital – closing capital – drawings
Mark scheme: B
Q32 · A company provided the following list of balances at 30 September 2022
32 A company provided the following list of balances at 30 September 2022. $ cash in hand 150 bank loan – repayable 31 December 2022 2 000 bank loan – repayable 1 May 2024 3 000 bank overdraft 400 trade receivables 8 000 other receivables 275 inventory 24 000 trade payables 6 000 other payables 95 What was the current ratio? A 1 : 1 B 2.83 : 1 C 3.82 : 1 D 4.06 : 1
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
Q33 · Alan provided the following information about his business
33 Alan provided the following information about his business. liquid (acid test) ratio 2.5 : 1 current liabilities $12 000 inventory $6000 What was the value of his current assets? A $15 000 B $24 000 C $30 000 D $36 000
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
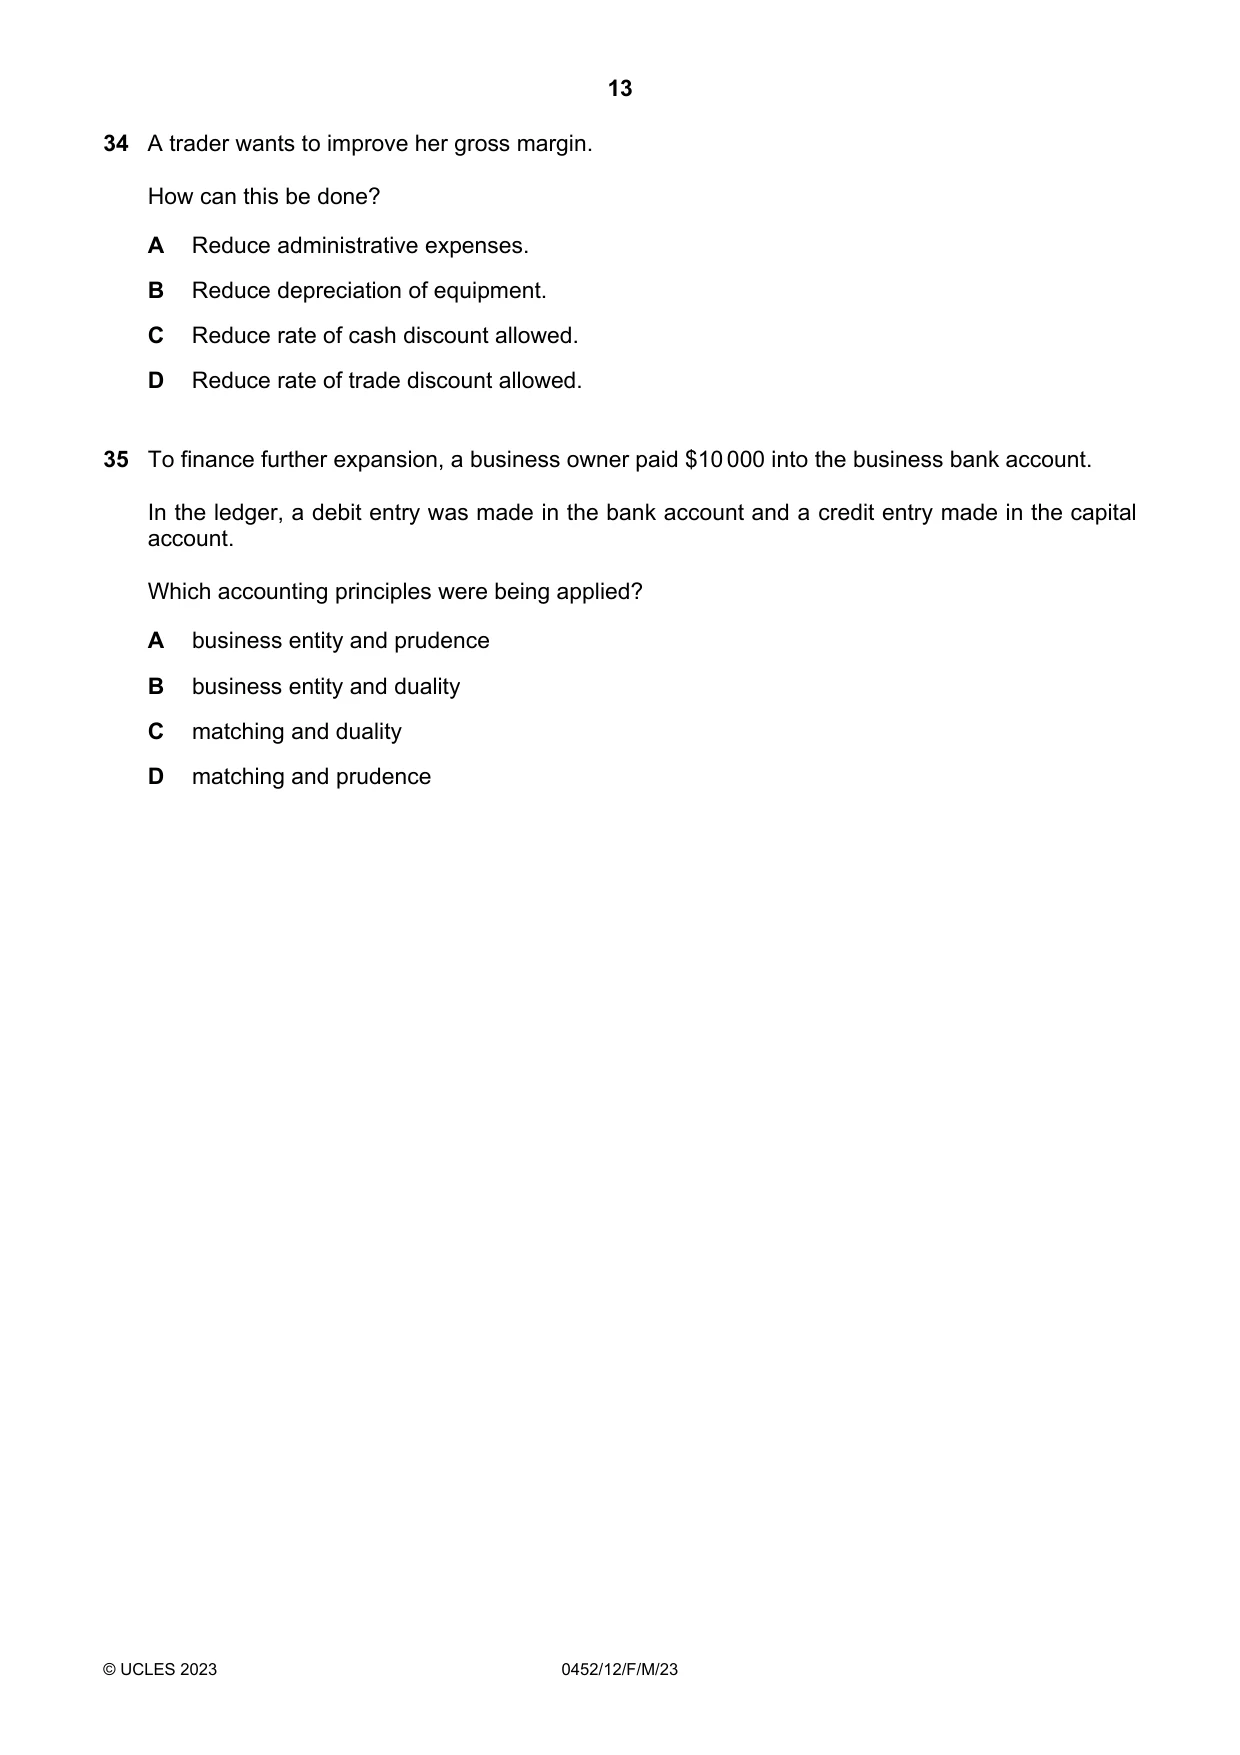
Q34 · A trader wants to improve her gross margin
34 A trader wants to improve her gross margin. How can this be done? A Reduce administrative expenses. B Reduce depreciation of equipment. C Reduce rate of cash discount allowed. D Reduce rate of trade discount allowed.
Mark scheme: D
Q35 · To finance further expansion, a business owner paid $10 000 into the business bank account
35 To finance further expansion, a business owner paid $10 000 into the business bank account. In the ledger, a debit entry was made in the bank account and a credit entry made in the capital account. Which accounting principles were being applied? A business entity and prudence B business entity and duality C matching and duality D matching and prudence
Mark scheme: B
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
4Control accounts3Corrections of errors3Accounting for depreciation and disposal of non-current assets2Calculation and understanding of accounting ratios2Clubs and societies2Irrecoverable debts and allowance for irrecoverable debts2Limited companies2Manufacturing accounts2Partnerships2The purpose of accounting2Accounting concepts1Bank reconciliation1Capital and revenue expenditure and receipts1Incomplete records1Interpretation of accounting ratios1Sole traders1The accounting equation1The trial balance1Valuation of inventory1What you needed in this session
Cambridge’s own grade thresholds for 2023 Feb/March, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.