Cambridge IGCSE Accounting 0452 — 2022 Oct/Nov Paper 1 · Variant 2
0452/12/O/N/22 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Which transaction will increase both assets and capital by the same amount?
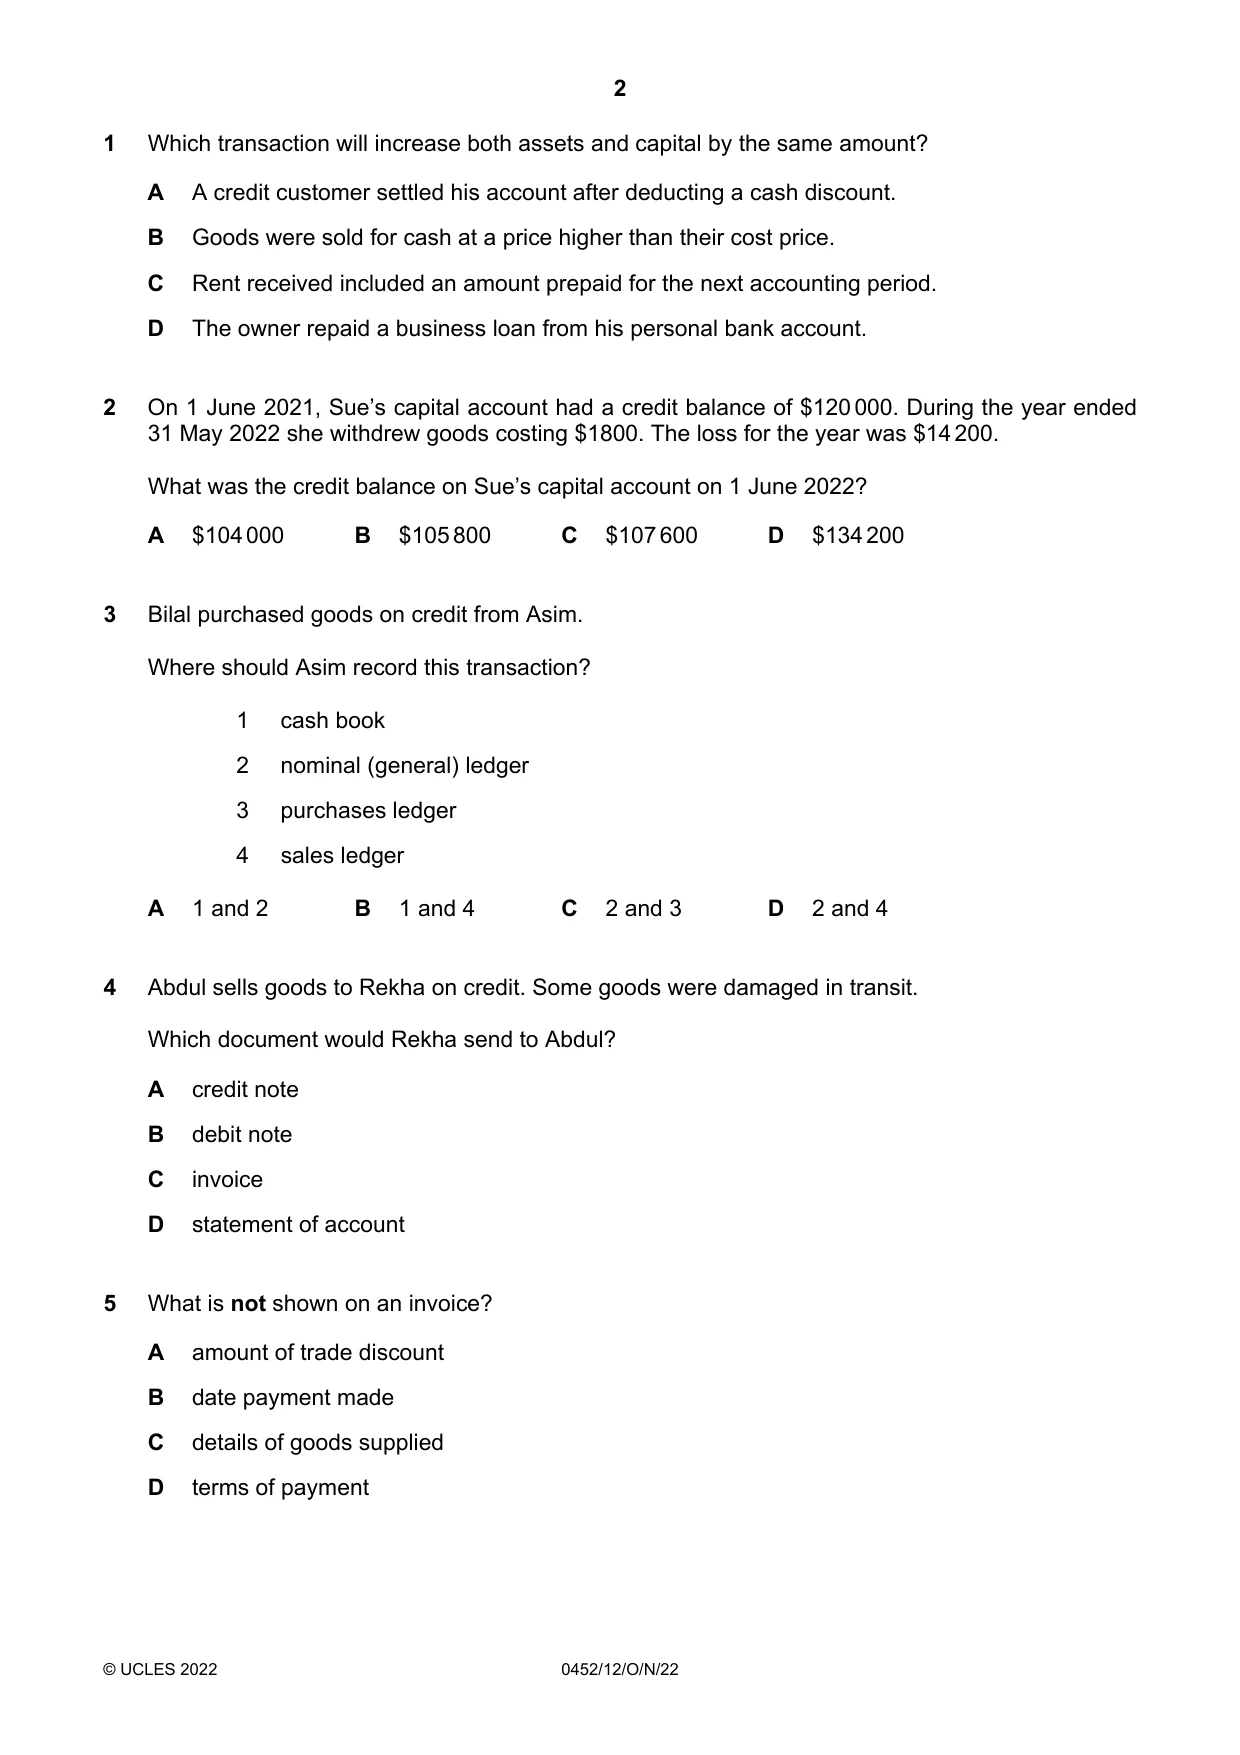
1 Which transaction will increase both assets and capital by the same amount? A A credit customer settled his account after deducting a cash discount. B Goods were sold for cash at a price higher than their cost price. C Rent received included an amount prepaid for the next accounting period. D The owner repaid a business loan from his personal bank account.
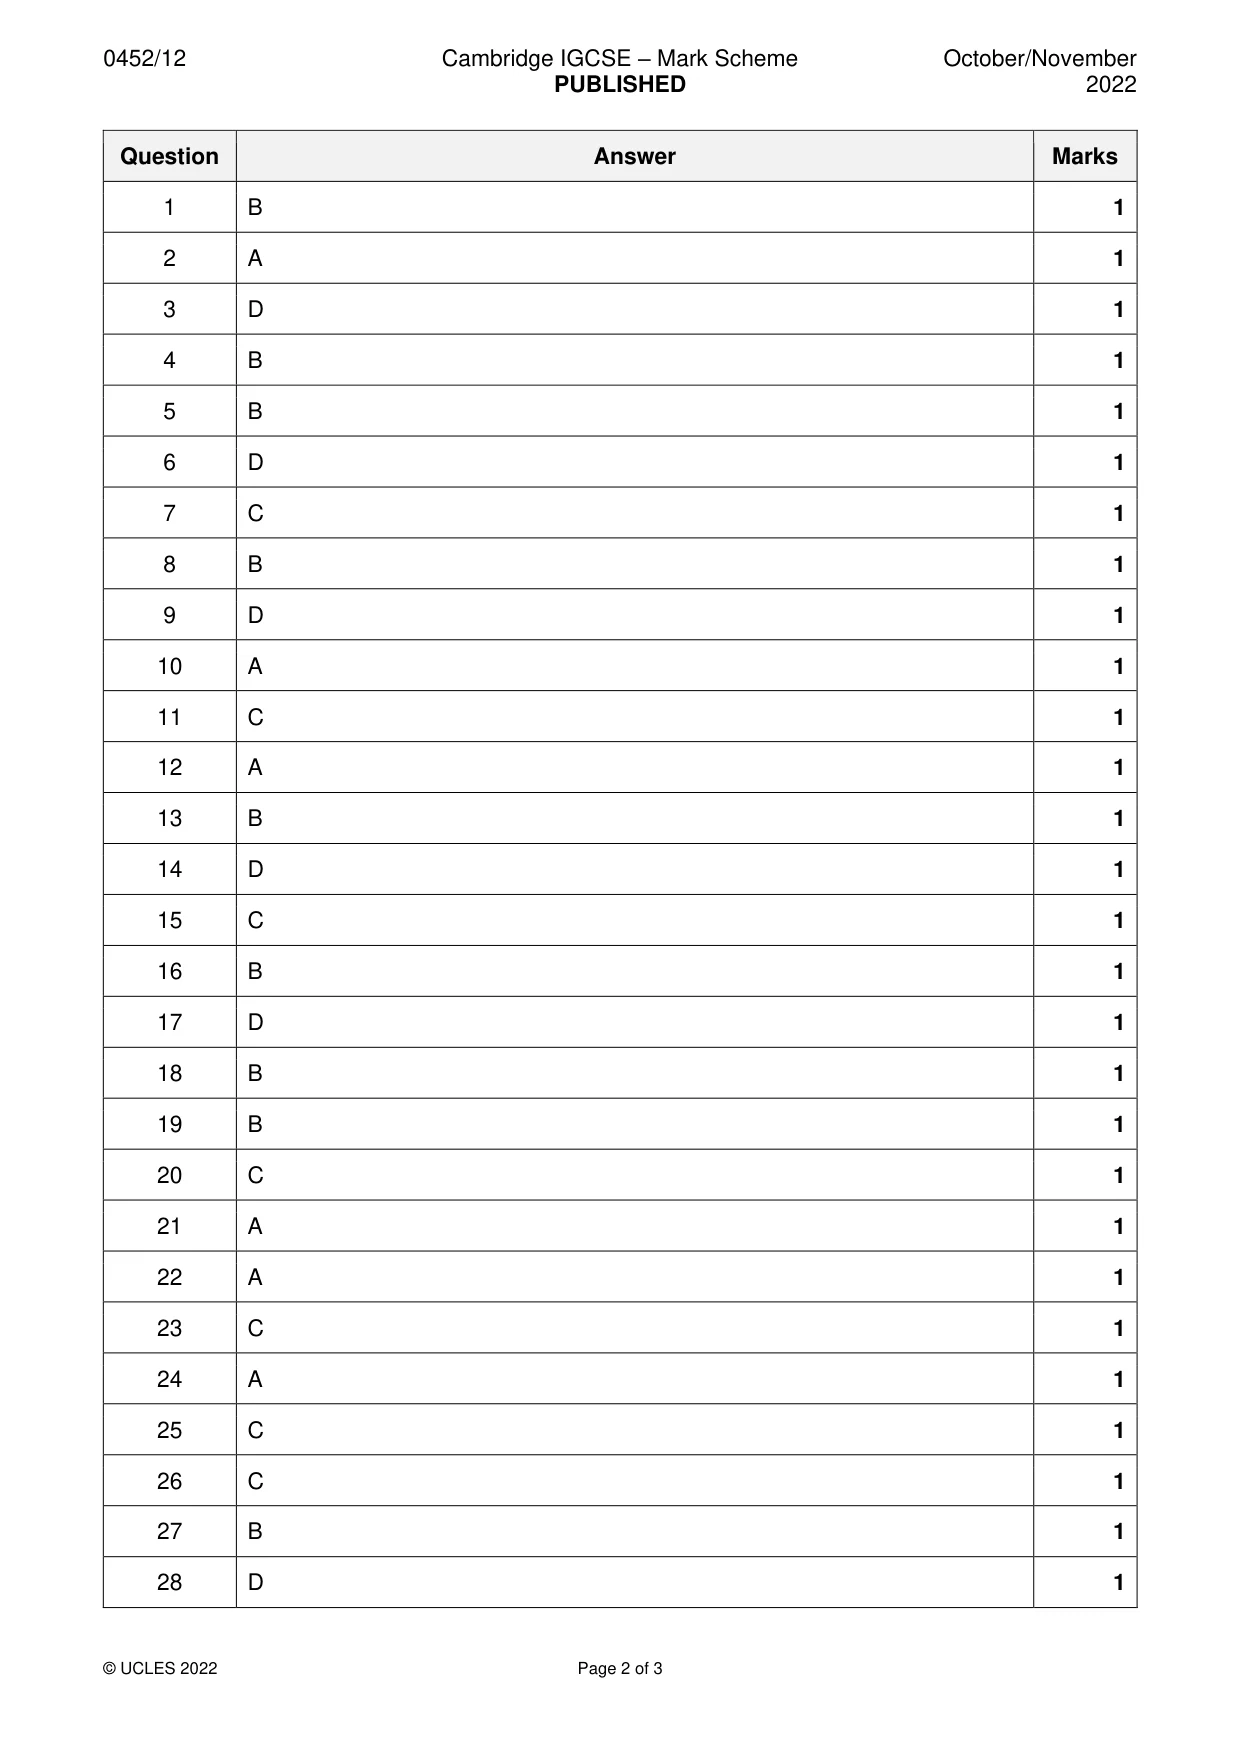
Mark scheme: B
Q2 · On 1 June 2021, Sue’s capital account had a credit balance of $120 000
2 On 1 June 2021, Sue’s capital account had a credit balance of $120 000. During the year ended 31 May 2022 she withdrew goods costing $1800. The loss for the year was $14 200. What was the credit balance on Sue’s capital account on 1 June 2022? A $104 000 B $105 800 C $107 600 D $134 200
Mark scheme: A
Q3 · Bilal purchased goods on credit from Asim
3 Bilal purchased goods on credit from Asim. Where should Asim record this transaction? 1 cash book 2 nominal (general) ledger 3 purchases ledger 4 sales ledger A 1 and 2 B 1 and 4 C 2 and 3 D 2 and 4
Mark scheme: D
Q4 · Abdul sells goods to Rekha on credit
4 Abdul sells goods to Rekha on credit. Some goods were damaged in transit. Which document would Rekha send to Abdul? A credit note B debit note C invoice D statement of account
Mark scheme: B
Q5 · What is not shown on an invoice?
5 What is not shown on an invoice? A amount of trade discount B date payment made C details of goods supplied D terms of payment
Mark scheme: B
Q6 · On 1 September, Peter sent a cheque to his credit supplier, John
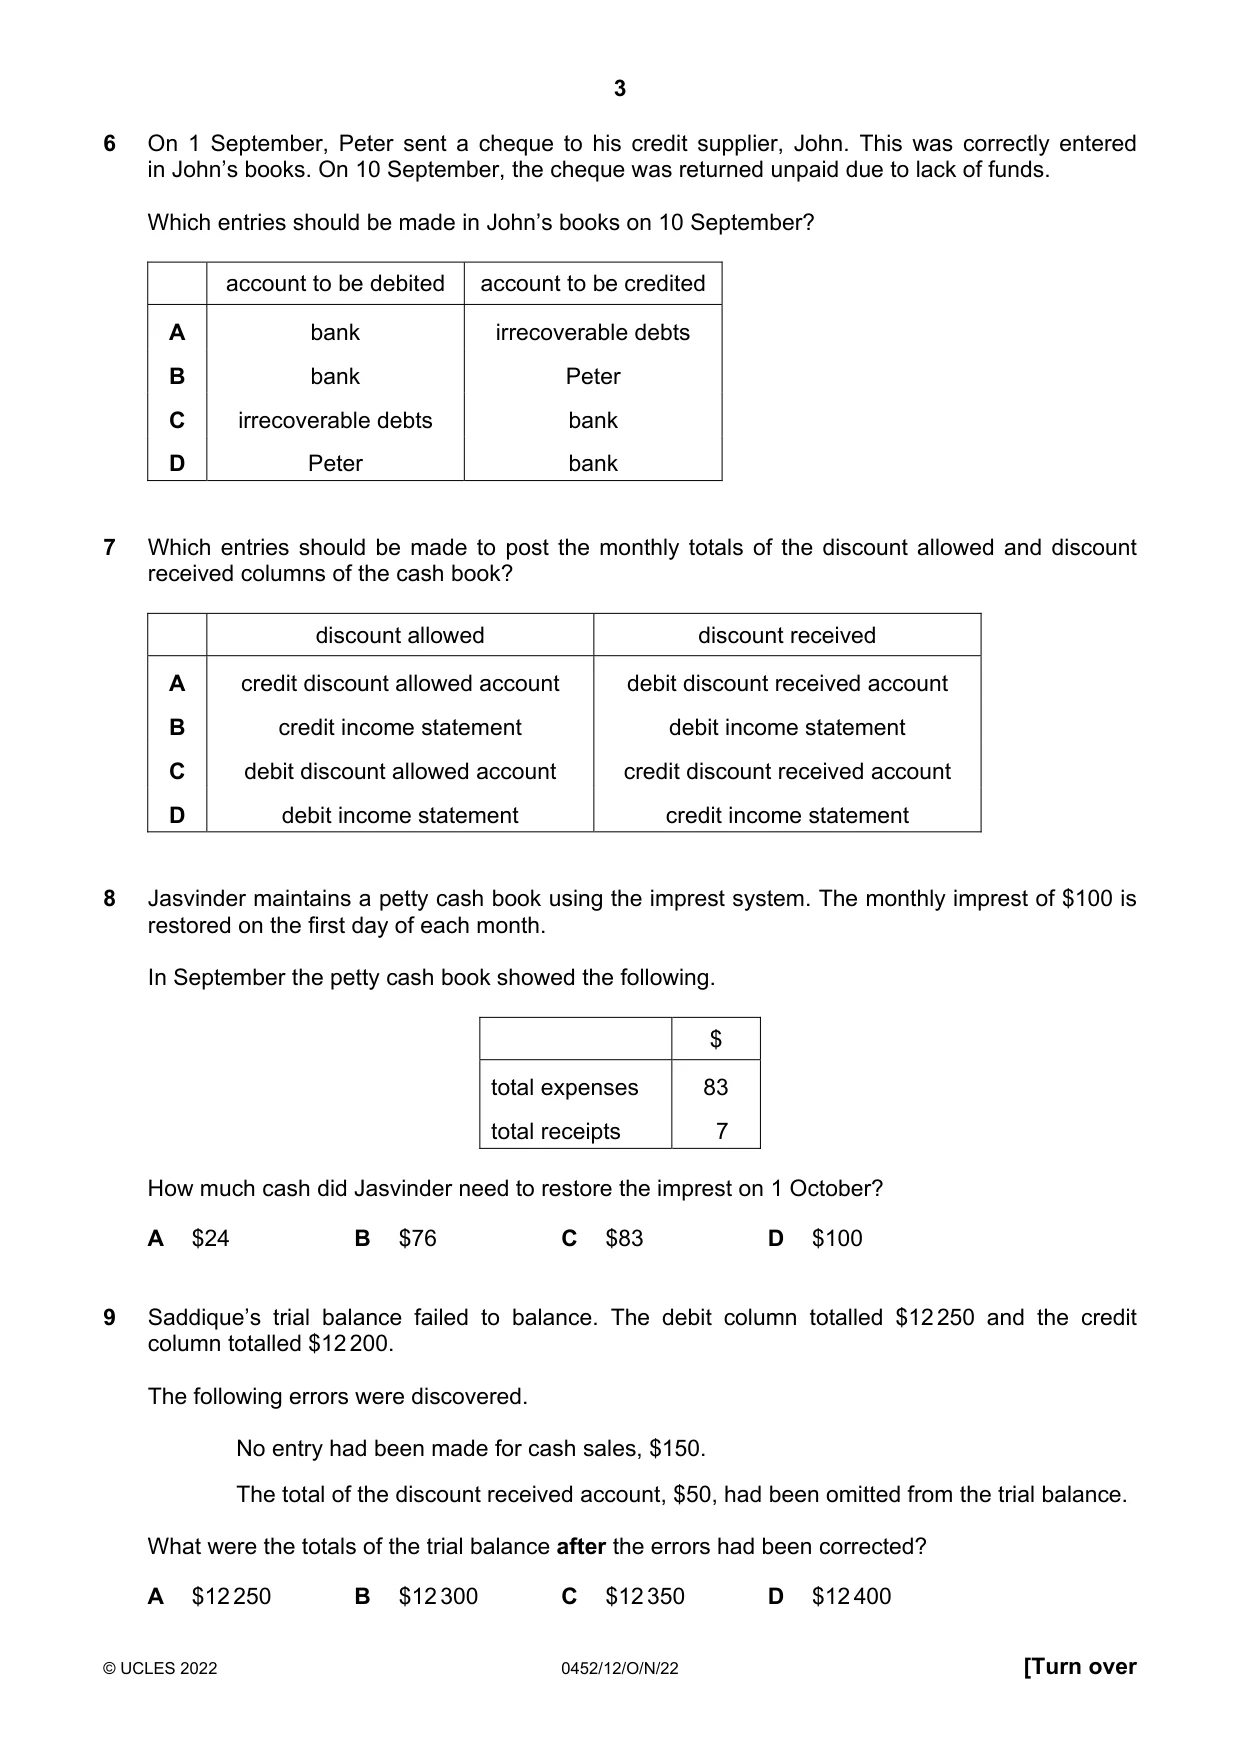
6 On 1 September, Peter sent a cheque to his credit supplier, John. This was correctly entered in John’s books. On 10 September, the cheque was returned unpaid due to lack of funds. Which entries should be made in John’s books on 10 September? account to be debited account to be credited A bank irrecoverable debts B bank Peter C irrecoverable debts bank D Peter bank
Mark scheme: D
Q7 · Which entries should be made to post the monthly totals of the discount allowed and…
7 Which entries should be made to post the monthly totals of the discount allowed and discount received columns of the cash book? discount allowed discount received A credit discount allowed account debit discount received account B credit income statement debit income statement C debit discount allowed account credit discount received account D debit income statement credit income statement
Mark scheme: C
Q8 · Jasvinder maintains a petty cash book using the imprest system
8 Jasvinder maintains a petty cash book using the imprest system. The monthly imprest of $100 is restored on the first day of each month. In September the petty cash book showed the following. $ total expenses 83 total receipts 7 How much cash did Jasvinder need to restore the imprest on 1 October? A $24 B $76 C $83 D $100
Mark scheme: B
Q9 · Saddique’s trial balance failed to balance
9 Saddique’s trial balance failed to balance. The debit column totalled $12 250 and the credit column totalled $12 200. The following errors were discovered. No entry had been made for cash sales, $150. The total of the discount received account, $50, had been omitted from the trial balance. What were the totals of the trial balance after the errors had been corrected? A $12 250 B $12 300 C $12 350 D $12 400
Mark scheme: D
Q10 · $68 paid by credit transfer for insurance was entered in the accounting records as $86
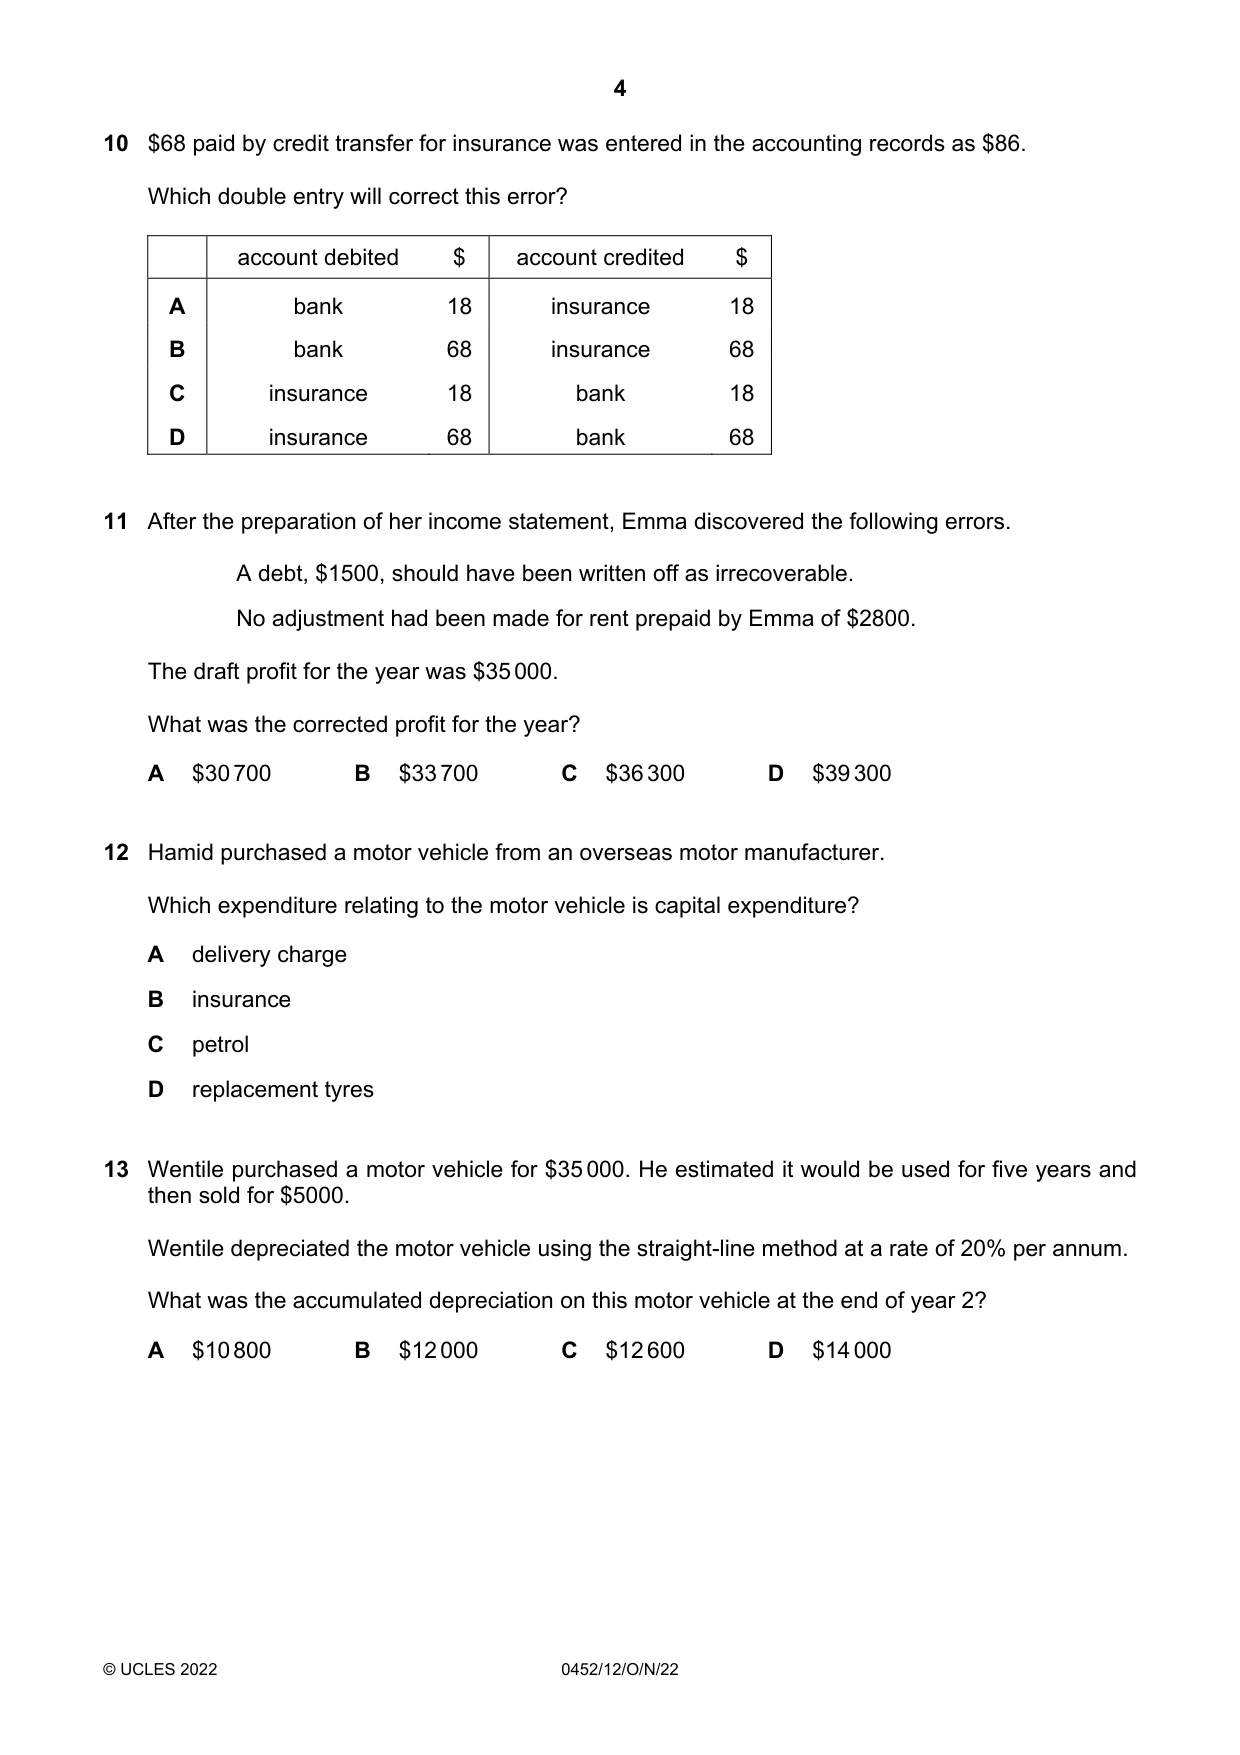
10 $68 paid by credit transfer for insurance was entered in the accounting records as $86. Which double entry will correct this error? account debited $ account credited $ A bank 18 insurance 18 B bank 68 insurance 68 C insurance 18 bank 18 D insurance 68 bank 68
Mark scheme: A
Q11 · After the preparation of her income statement, Emma discovered the following errors
11 After the preparation of her income statement, Emma discovered the following errors. A debt, $1500, should have been written off as irrecoverable. No adjustment had been made for rent prepaid by Emma of $2800. The draft profit for the year was $35 000. What was the corrected profit for the year? A $30 700 B $33 700 C $36 300 D $39 300
Mark scheme: C
Q12 · Hamid purchased a motor vehicle from an overseas motor manufacturer
12 Hamid purchased a motor vehicle from an overseas motor manufacturer. Which expenditure relating to the motor vehicle is capital expenditure? A delivery charge B insurance C petrol D replacement tyres
Mark scheme: A
More questions on Capital and revenue expenditure and receipts
Q13 · Wentile purchased a motor vehicle for $35 000
13 Wentile purchased a motor vehicle for $35 000. He estimated it would be used for five years and then sold for $5000. Wentile depreciated the motor vehicle using the straight-line method at a rate of 20% per annum. What was the accumulated depreciation on this motor vehicle at the end of year 2? A $10 800 B $12 000 C $12 600 D $14 000
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q14 · On the first day of his financial year, Jason purchased a new machine costing $20 000
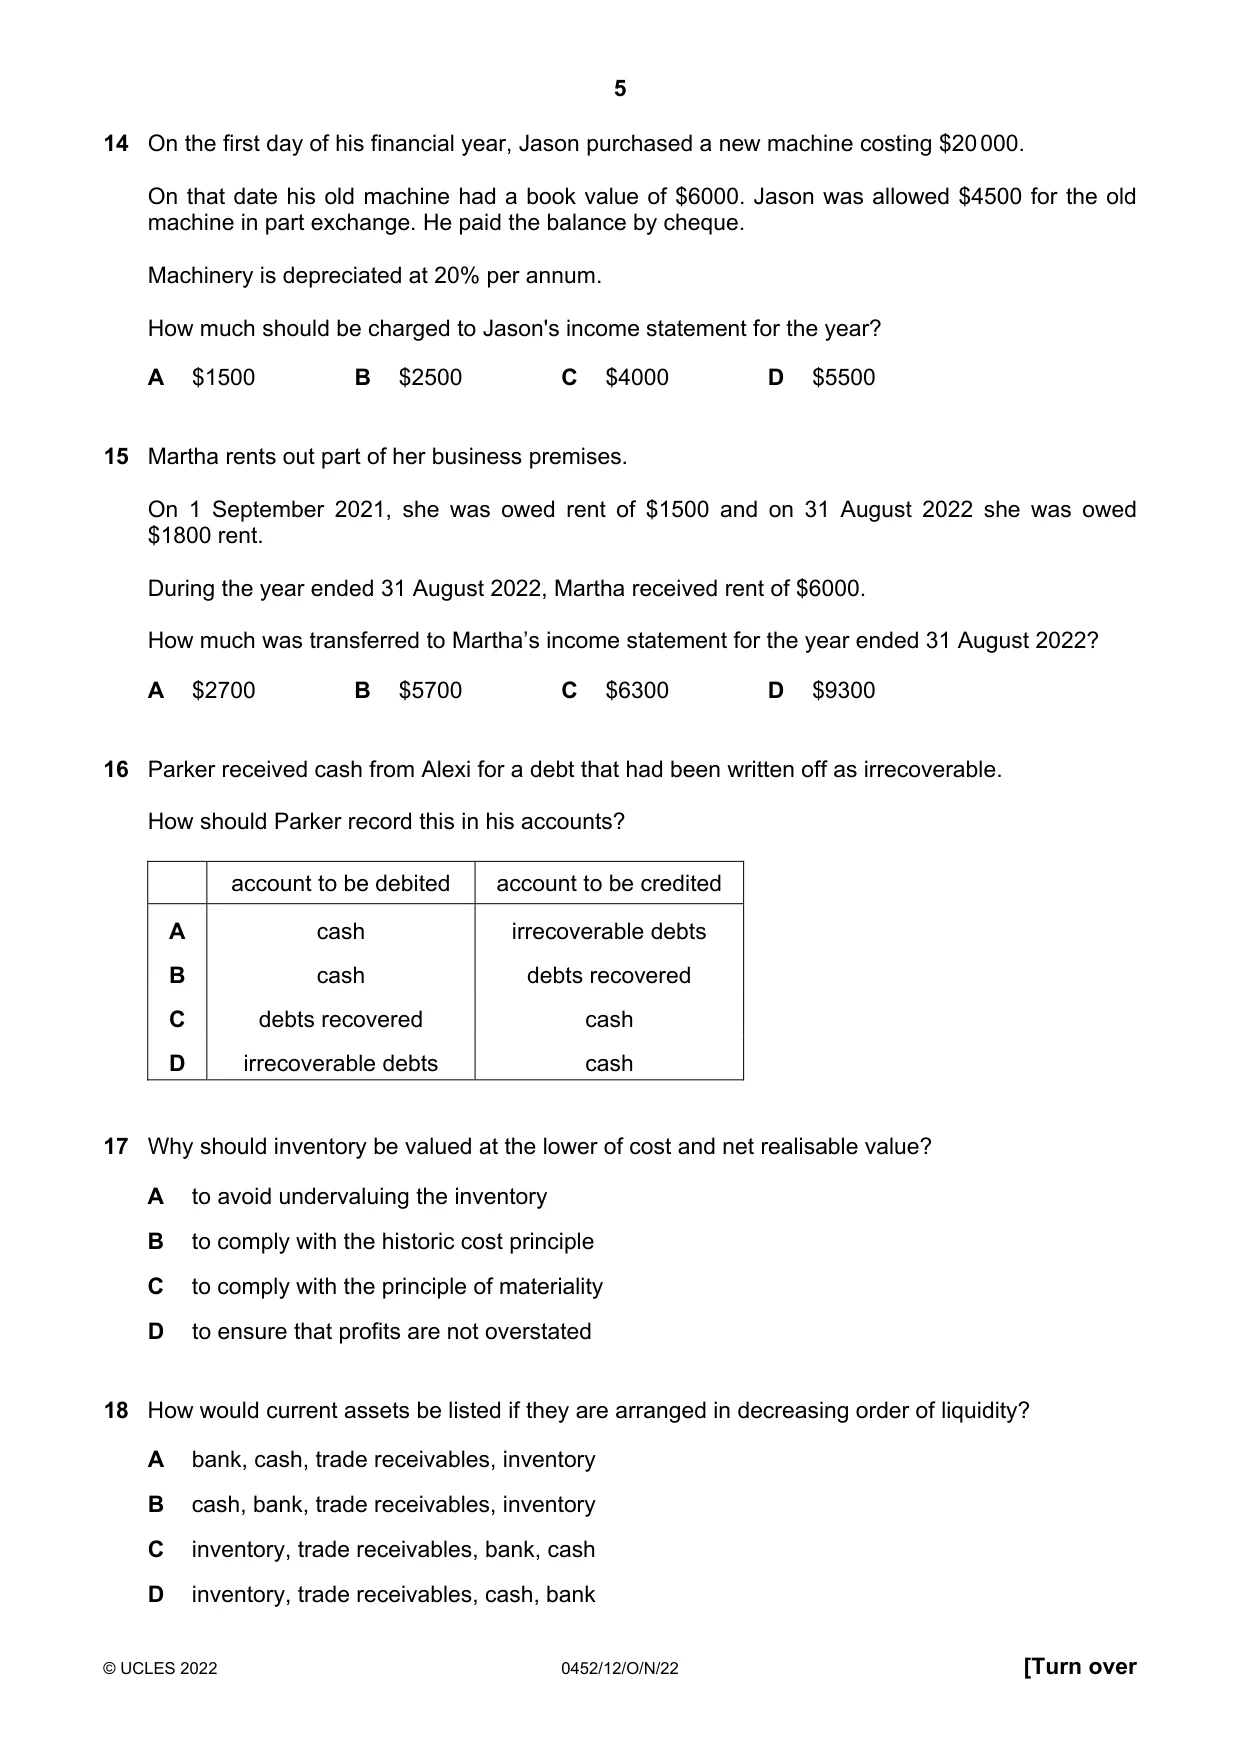
14 On the first day of his financial year, Jason purchased a new machine costing $20 000. On that date his old machine had a book value of $6000. Jason was allowed $4500 for the old machine in part exchange. He paid the balance by cheque. Machinery is depreciated at 20% per annum. How much should be charged to Jason's income statement for the year? A $1500 B $2500 C $4000 D $5500
Mark scheme: D
More questions on Accounting for depreciation and disposal of non-current assets
Q15 · Martha rents out part of her business premises
15 Martha rents out part of her business premises. On 1 September 2021, she was owed rent of $1500 and on 31 August 2022 she was owed $1800 rent. During the year ended 31 August 2022, Martha received rent of $6000. How much was transferred to Martha’s income statement for the year ended 31 August 2022? A $2700 B $5700 C $6300 D $9300
Mark scheme: C
Q16 · Parker received cash from Alexi for a debt that had been written off as irrecoverable
16 Parker received cash from Alexi for a debt that had been written off as irrecoverable. How should Parker record this in his accounts? account to be debited account to be credited A cash irrecoverable debts B cash debts recovered C debts recovered cash D irrecoverable debts cash
Mark scheme: B
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q17 · Why should inventory be valued at the lower of cost and net realisable value?
17 Why should inventory be valued at the lower of cost and net realisable value? A to avoid undervaluing the inventory B to comply with the historic cost principle C to comply with the principle of materiality D to ensure that profits are not overstated
Mark scheme: D
Q18 · How would current assets be listed if they are arranged in decreasing order of liquidity?
18 How would current assets be listed if they are arranged in decreasing order of liquidity? A bank, cash, trade receivables, inventory B cash, bank, trade receivables, inventory C inventory, trade receivables, bank, cash D inventory, trade receivables, cash, bank
Mark scheme: B
Q19 · During the year, Sam paid advertising expenses, some of which related to the following…
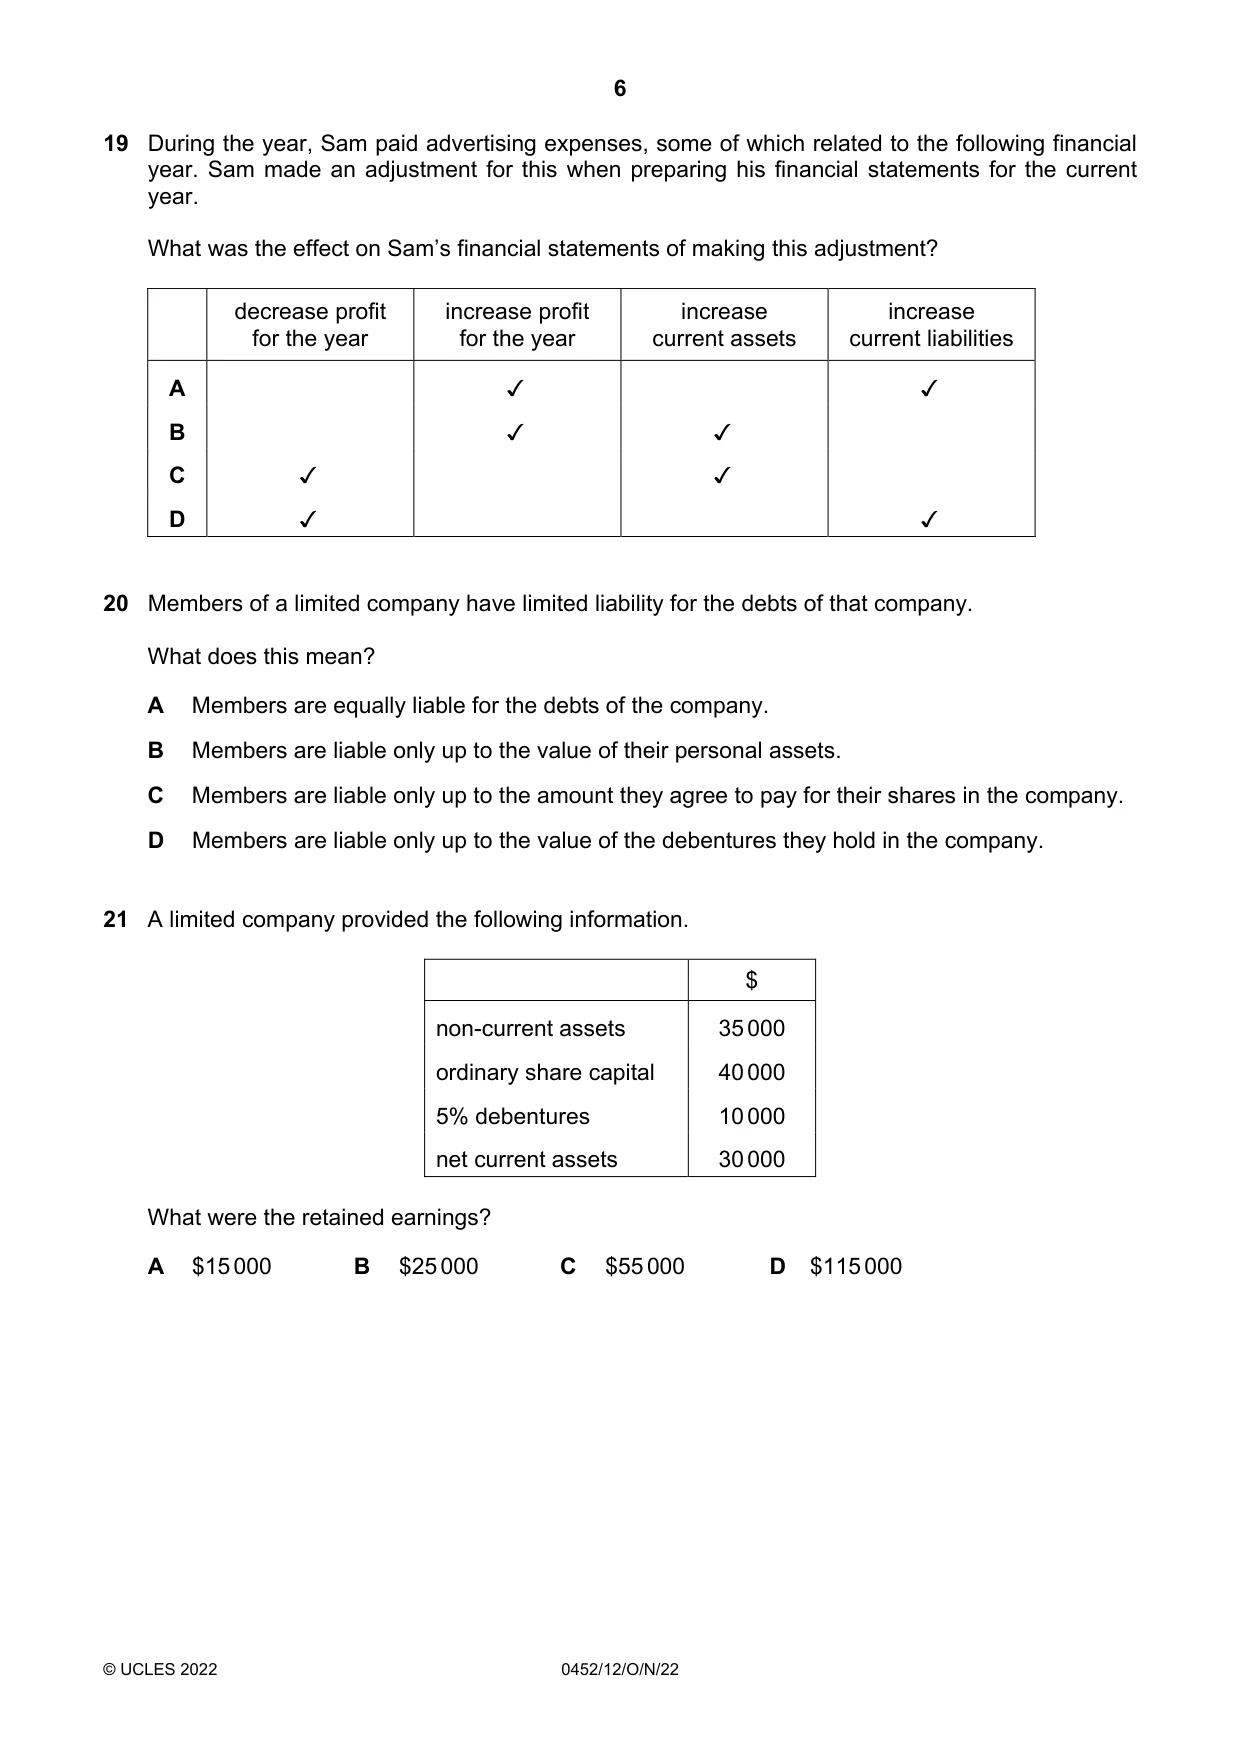
19 During the year, Sam paid advertising expenses, some of which related to the following financial year. Sam made an adjustment for this when preparing his financial statements for the current year. What was the effect on Sam’s financial statements of making this adjustment? decrease profit for the year increase profit for the year increase current assets increase current liabilities 0 0O WwW > v v v
Mark scheme: B
Q20 · Members of a limited company have limited liability for the debts of that company
20 Members of a limited company have limited liability for the debts of that company. What does this mean? A Members are equally liable for the debts of the company. B Members are liable only up to the value of their personal assets. C Members are liable only up to the amount they agree to pay for their shares in the company. D Members are liable only up to the value of the debentures they hold in the company.
Mark scheme: C
Q21 · A limited company provided the following information
21 A limited company provided the following information. $ non-current assets 35 000 ordinary share capital 40 000 5% debentures 10 000 net current assets 30 000 What were the retained earnings? A $15 000 B $25 000 C $55 000 D $115 000
Mark scheme: A
Q22 · What is included in the equity of a limited company?
22 What is included in the equity of a limited company? ordinary retained general : debentures share capital earnings reserve A v v v B v v Cc v v v D v v
Mark scheme: A
Q23 · The financial year of a club ends on 30 September
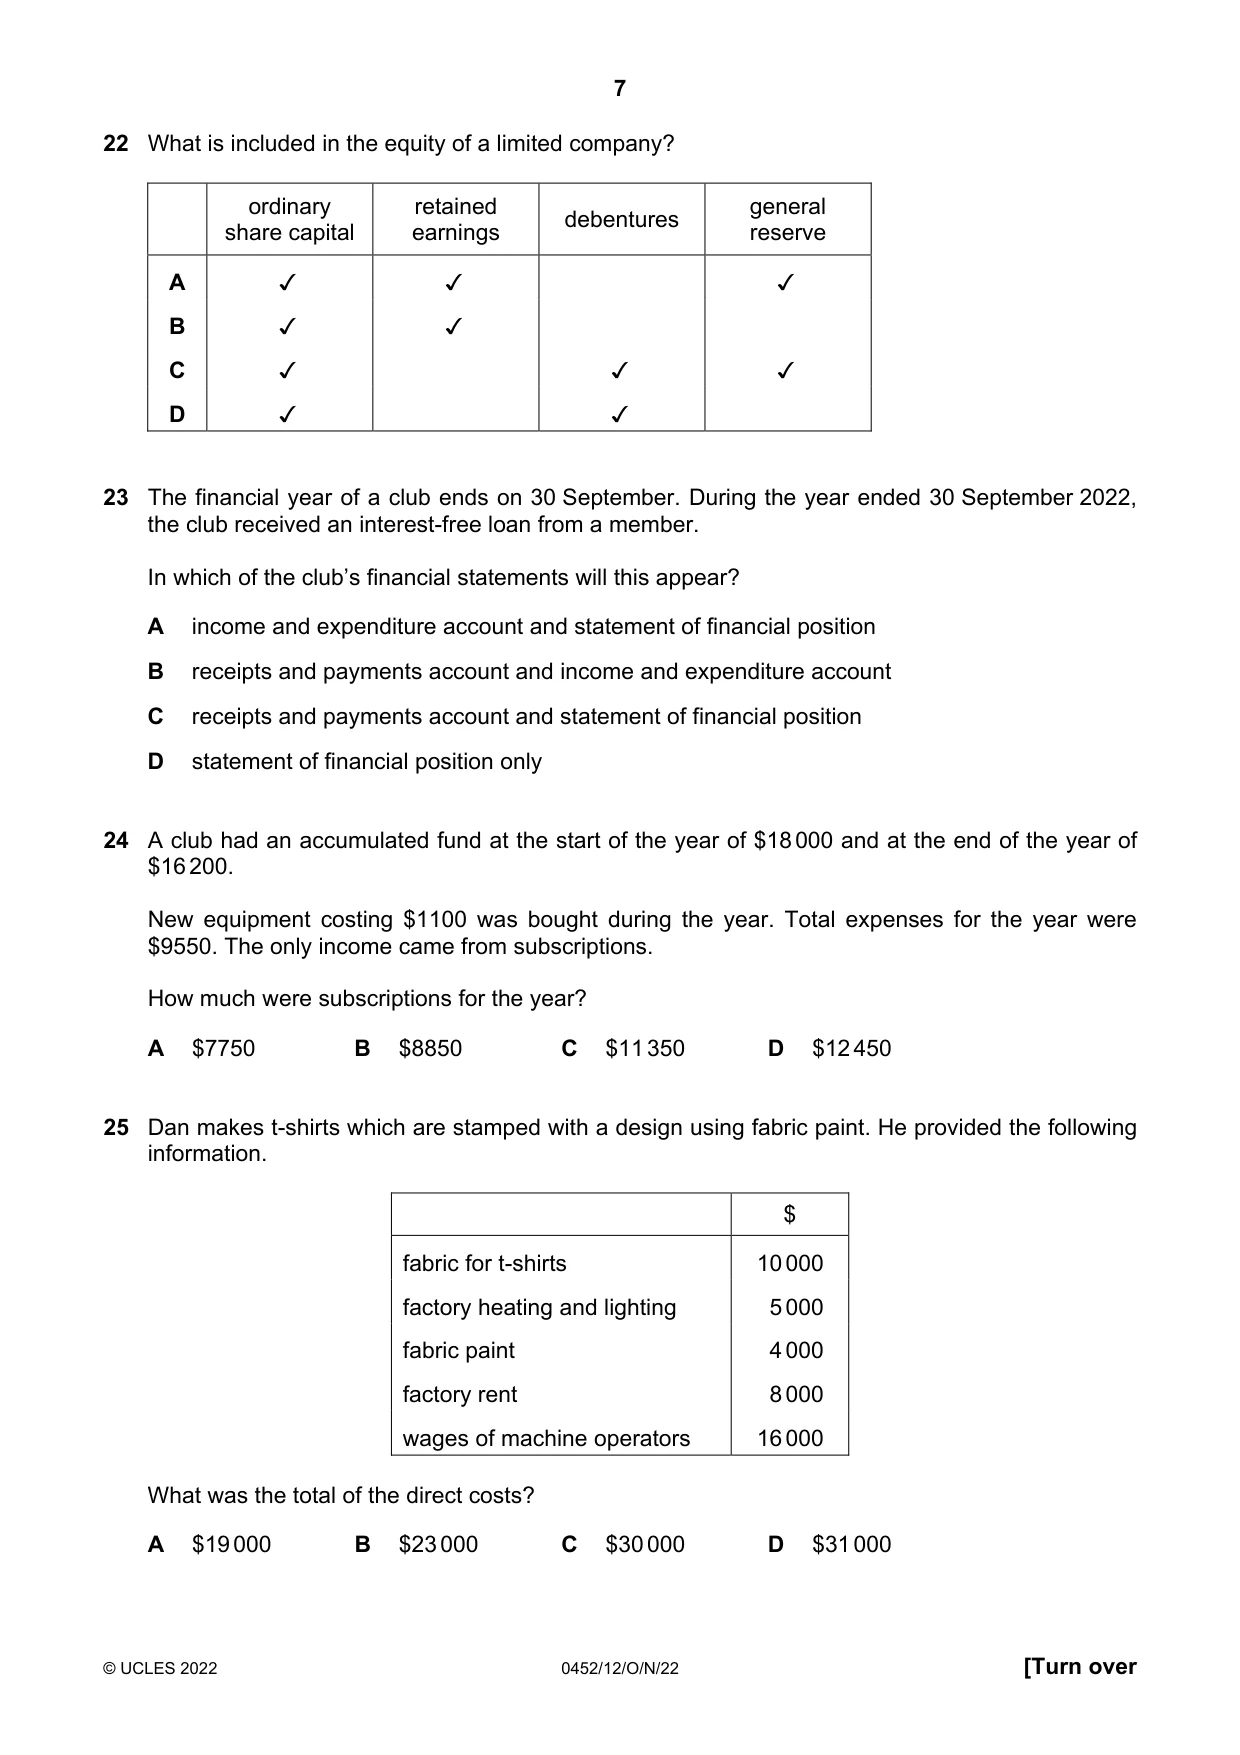
23 The financial year of a club ends on 30 September. During the year ended 30 September 2022, the club received an interest-free loan from a member. In which of the club’s financial statements will this appear? A income and expenditure account and statement of financial position B receipts and payments account and income and expenditure account C receipts and payments account and statement of financial position D statement of financial position only
Mark scheme: C
Q24 · A club had an accumulated fund at the start of the year of $18 000 and at the end of the…
24 A club had an accumulated fund at the start of the year of $18 000 and at the end of the year of $16 200. New equipment costing $1100 was bought during the year. Total expenses for the year were $9550. The only income came from subscriptions. How much were subscriptions for the year? A $7750 B $8850 C $11 350 D $12 450
Mark scheme: A
Q25 · Dan makes t-shirts which are stamped with a design using fabric paint
25 Dan makes t-shirts which are stamped with a design using fabric paint. He provided the following information. $ fabric for t-shirts 10 000 factory heating and lighting 5 000 fabric paint 4 000 factory rent 8 000 wages of machine operators 16 000 What was the total of the direct costs? A $19 000 B $23 000 C $30 000 D $31 000
Mark scheme: C
Q26 · In a manufacturing account, carriage on raw materials was incorrectly treated as a…
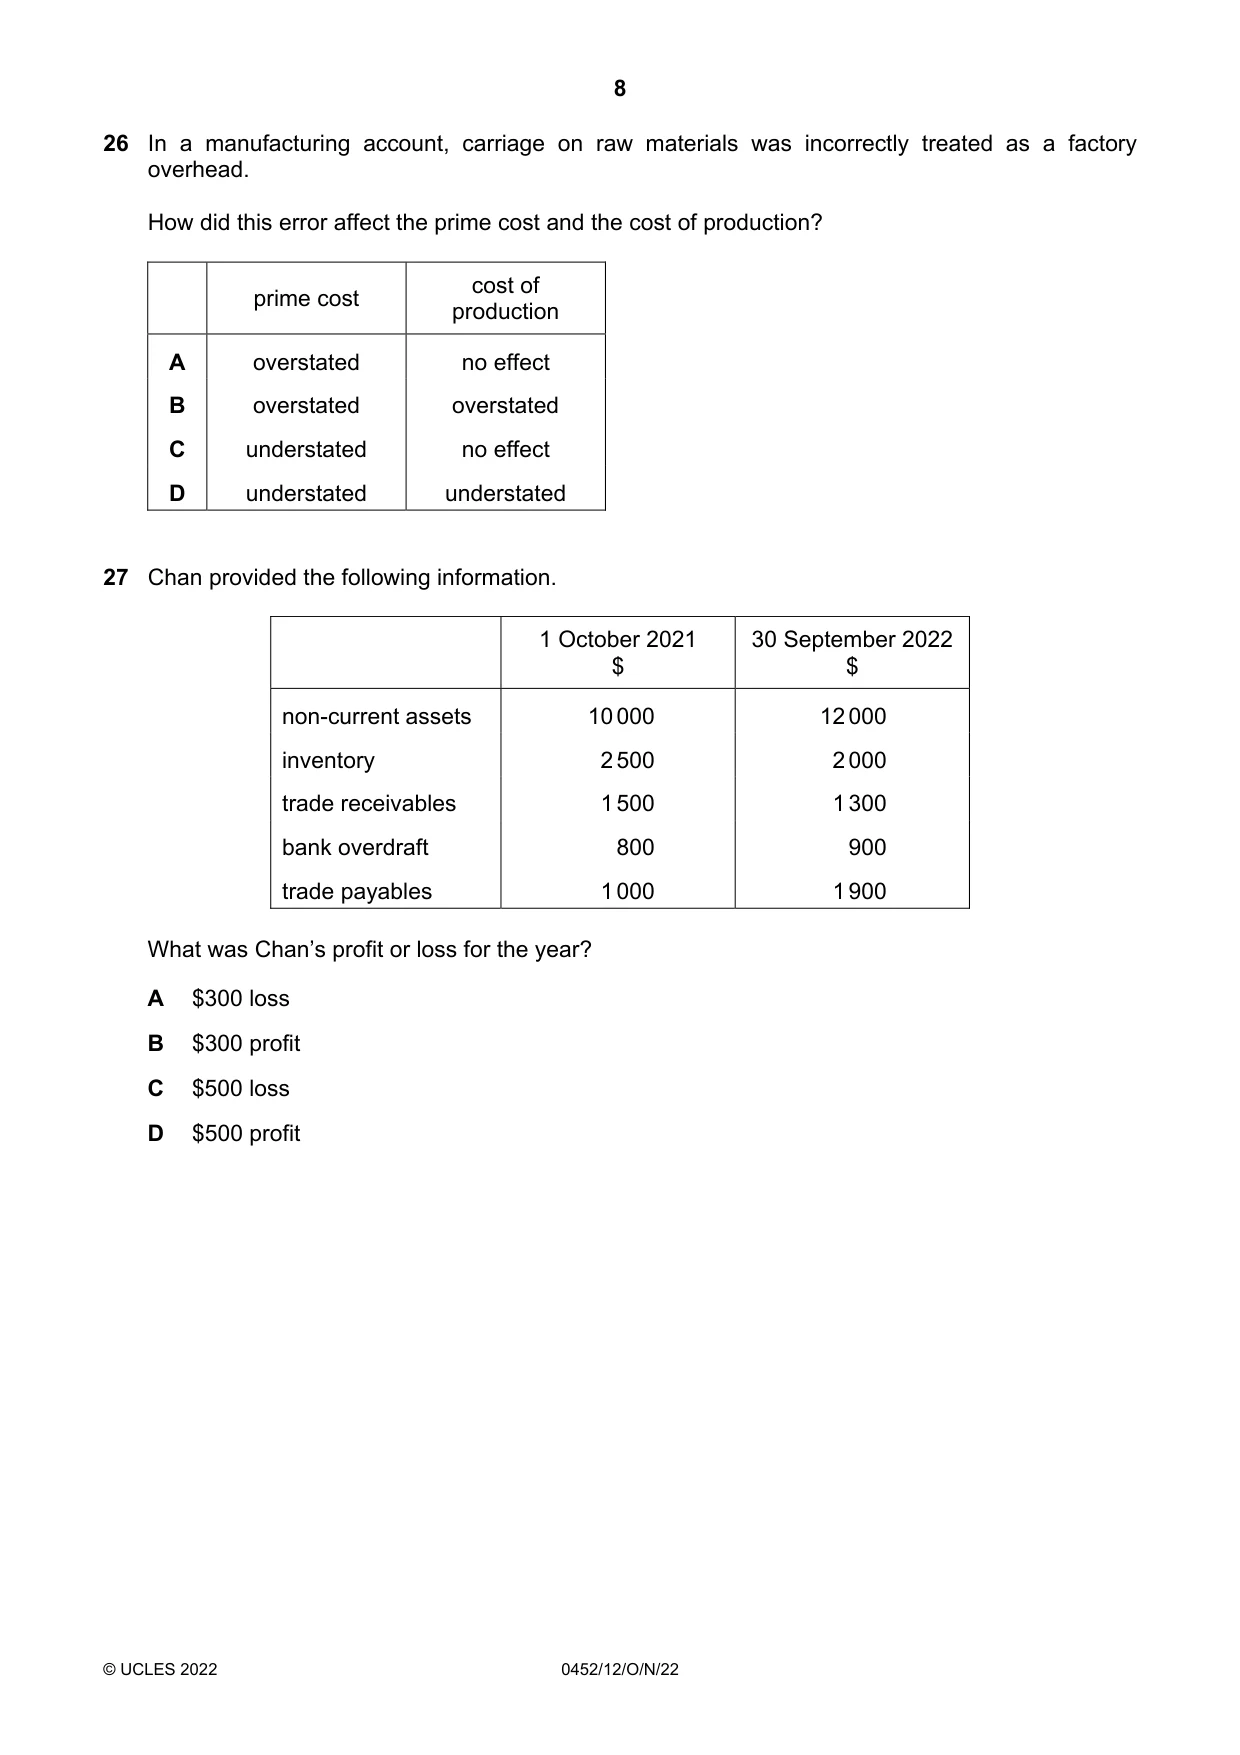
26 In a manufacturing account, carriage on raw materials was incorrectly treated as a factory overhead. How did this error affect the prime cost and the cost of production? cost of prime cost production A overstated no effect B overstated overstated C understated no effect D understated understated
Mark scheme: C
Q27 · Chan provided the following information
27 Chan provided the following information. 1 October 2021 30 September 2022 $ $ non-current assets 10 000 12 000 inventory 2 500 2 000 trade receivables 1 500 1 300 bank overdraft 800 900 trade payables 1 000 1 900 What was Chan’s profit or loss for the year? A $300 loss B $300 profit C $500 loss D $500 profit
Mark scheme: B
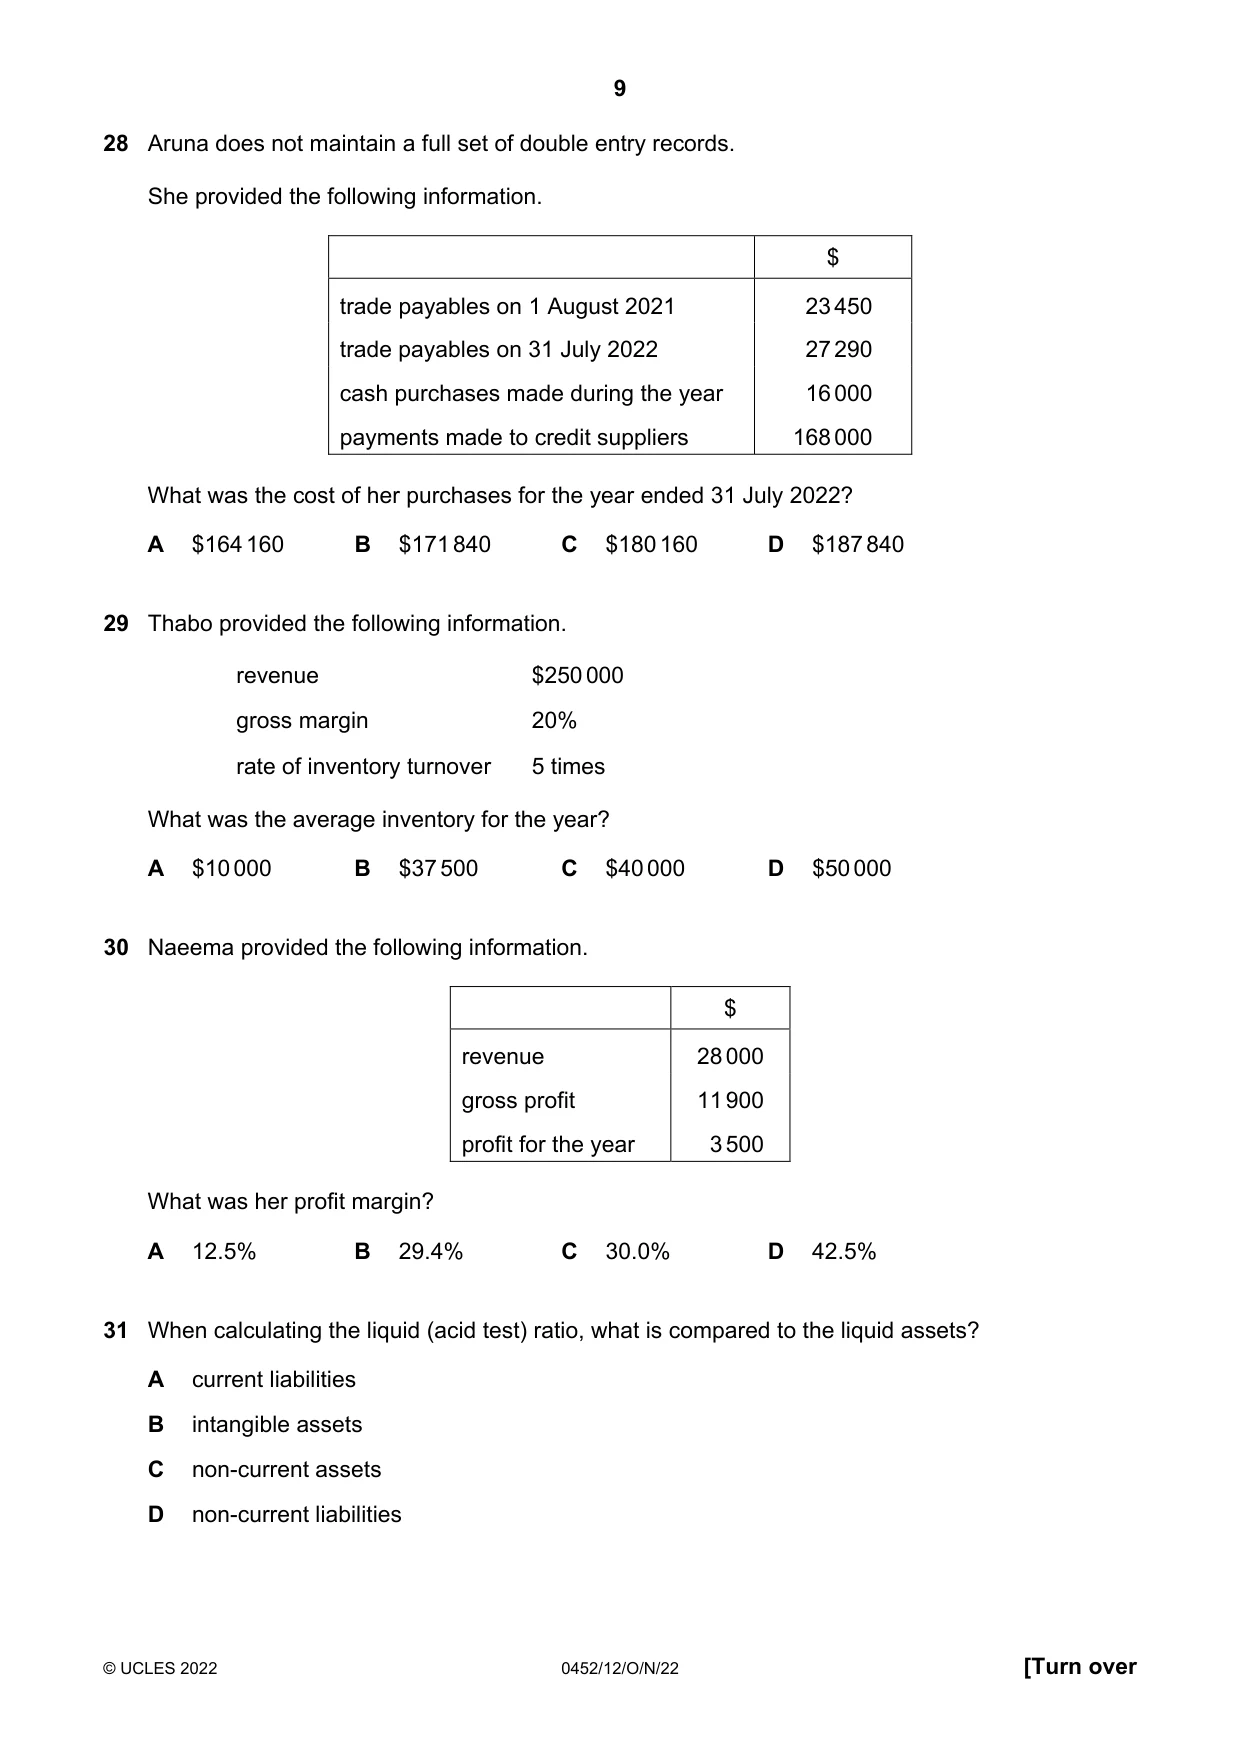
Q28 · Aruna does not maintain a full set of double entry records
28 Aruna does not maintain a full set of double entry records. She provided the following information. $ trade payables on 1 August 2021 23 450 trade payables on 31 July 2022 27 290 cash purchases made during the year 16 000 payments made to credit suppliers 168 000 What was the cost of her purchases for the year ended 31 July 2022? A $164 160 B $171 840 C $180 160 D $187 840
Mark scheme: D
Q29 · Thabo provided the following information
29 Thabo provided the following information. revenue $250 000 gross margin 20% rate of inventory turnover 5 times What was the average inventory for the year? A $10 000 B $37 500 C $40 000 D $50 000
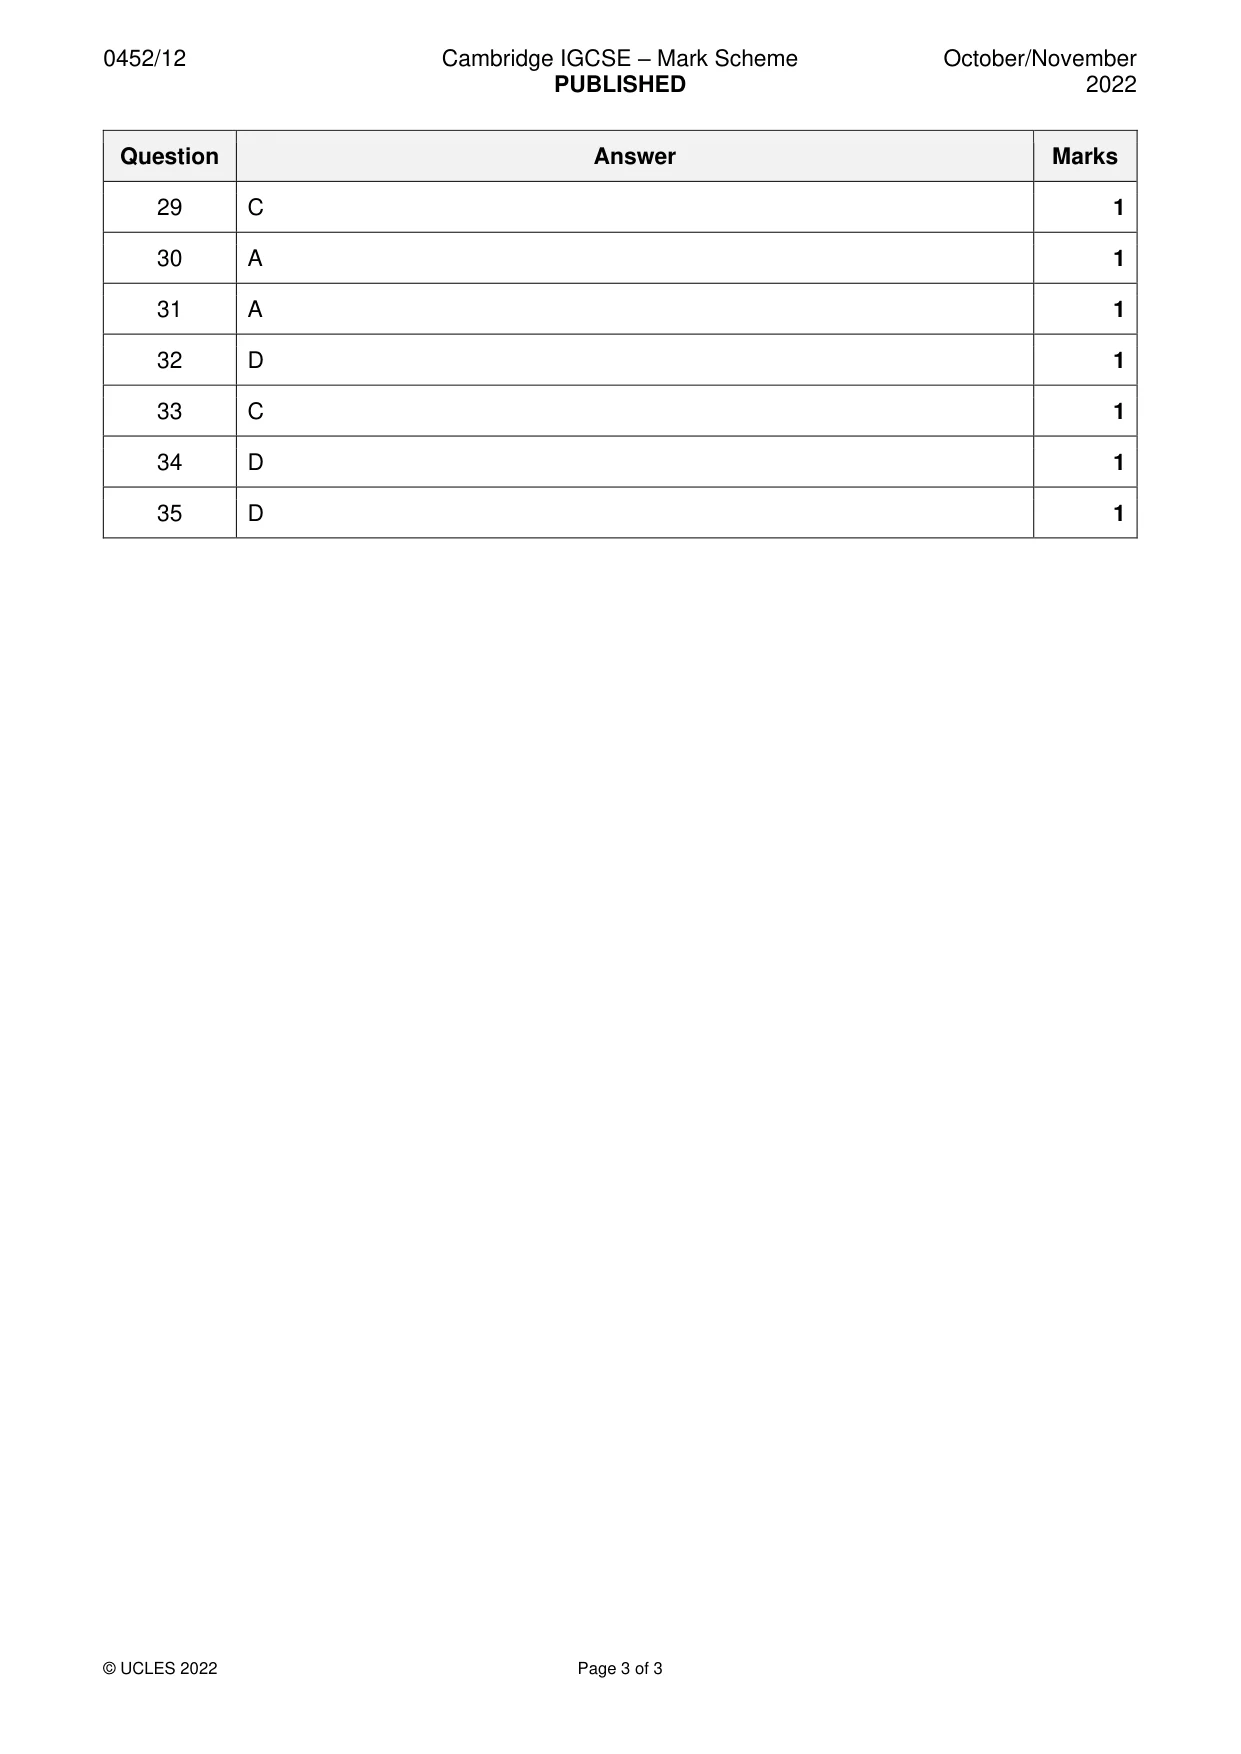
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
Q30 · Naeema provided the following information
30 Naeema provided the following information. $ revenue 28 000 gross profit 11 900 profit for the year 3 500 What was her profit margin? A 12.5% B 29.4% C 30.0% D 42.5%
Mark scheme: A
More questions on Calculation and understanding of accounting ratios
Q31 · When calculating the liquid (acid test) ratio, what is compared to the liquid assets?
31 When calculating the liquid (acid test) ratio, what is compared to the liquid assets? A current liabilities B intangible assets C non-current assets D non-current liabilities
Mark scheme: A
More questions on Calculation and understanding of accounting ratios
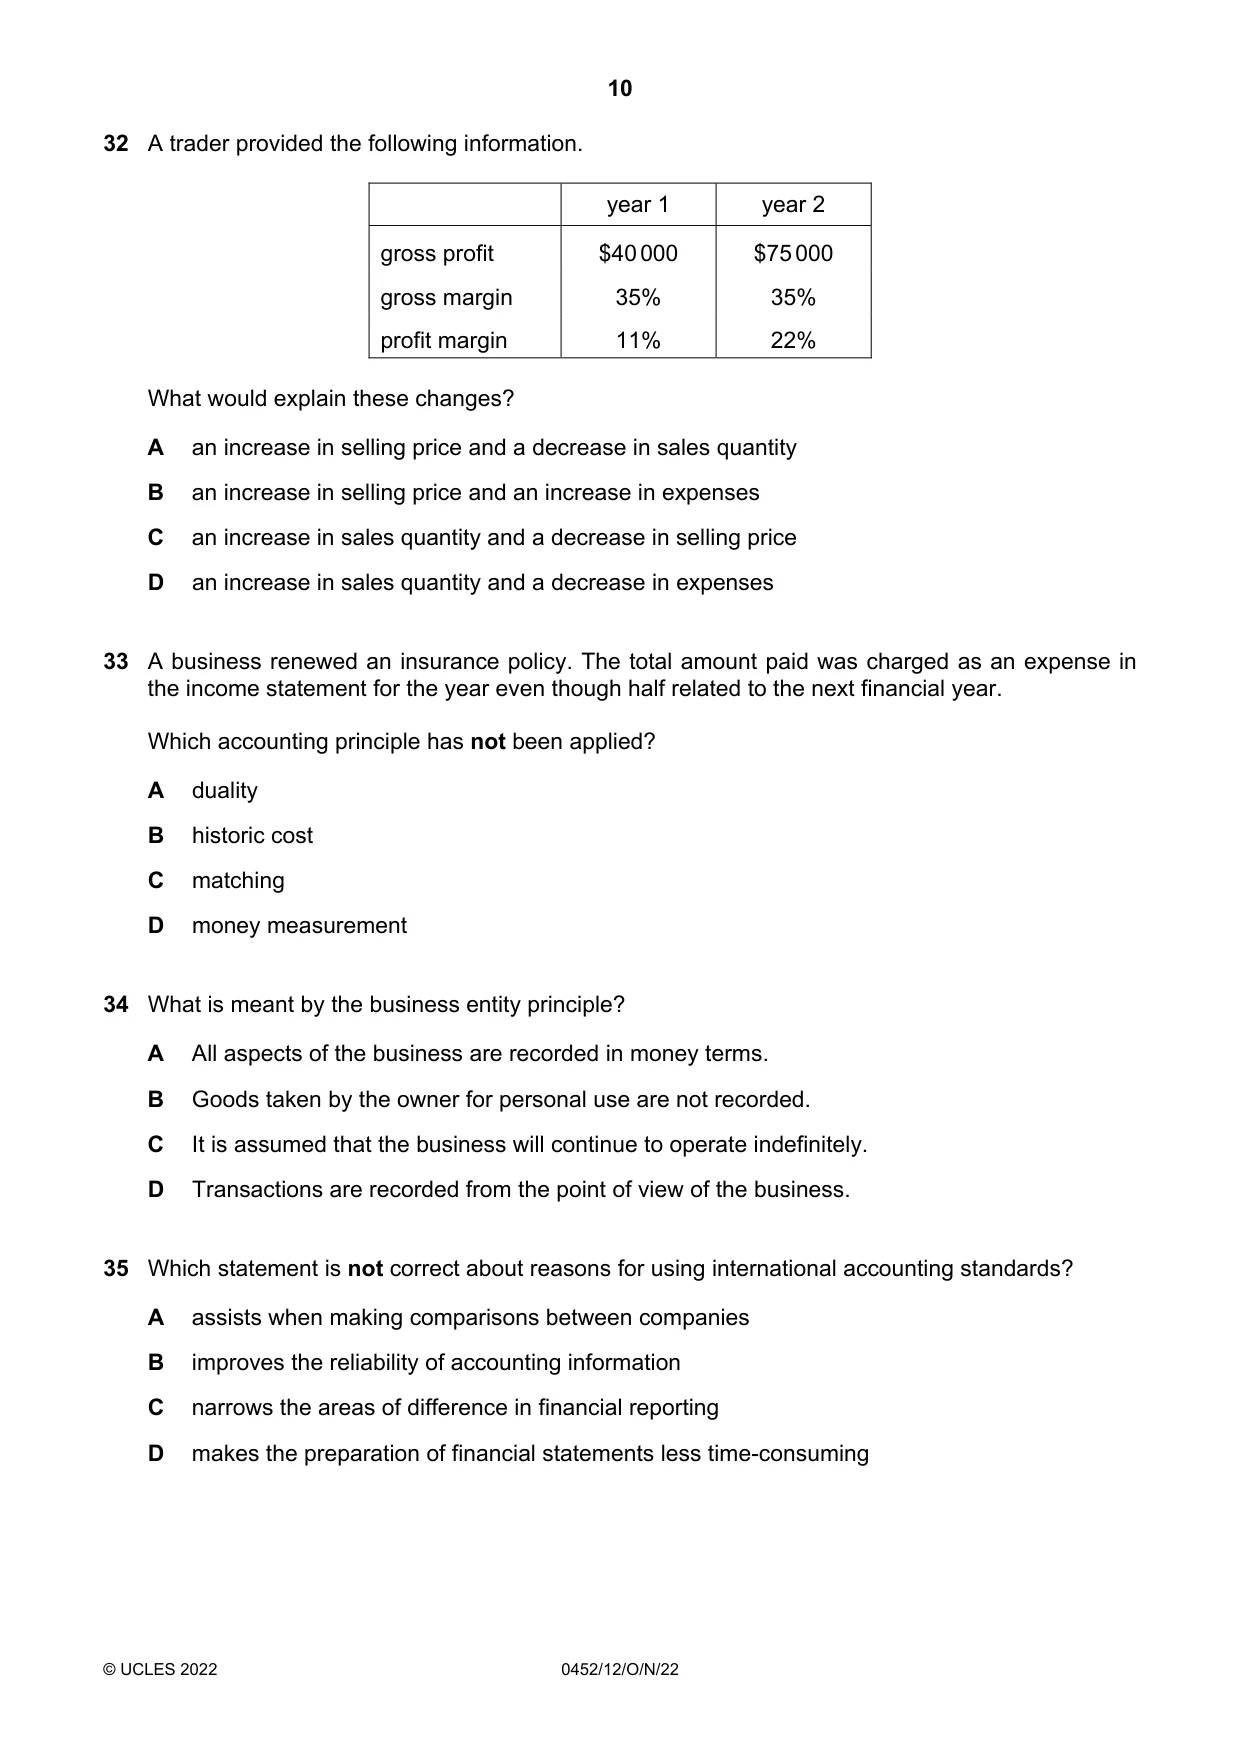
Q32 · A trader provided the following information
32 A trader provided the following information. year 1 year 2 gross profit $40 000 $75 000 gross margin 35% 35% profit margin 11% 22% What would explain these changes? A an increase in selling price and a decrease in sales quantity B an increase in selling price and an increase in expenses C an increase in sales quantity and a decrease in selling price D an increase in sales quantity and a decrease in expenses
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
Q33 · A business renewed an insurance policy
33 A business renewed an insurance policy. The total amount paid was charged as an expense in the income statement for the year even though half related to the next financial year. Which accounting principle has not been applied? A duality B historic cost C matching D money measurement
Mark scheme: C
Q34 · What is meant by the business entity principle?
34 What is meant by the business entity principle? A All aspects of the business are recorded in money terms. B Goods taken by the owner for personal use are not recorded. C It is assumed that the business will continue to operate indefinitely. D Transactions are recorded from the point of view of the business.
Mark scheme: D
Q35 · Which statement is not correct about reasons for using international accounting standards?
35 Which statement is not correct about reasons for using international accounting standards? A assists when making comparisons between companies B improves the reliability of accounting information C narrows the areas of difference in financial reporting D makes the preparation of financial statements less time-consuming
Mark scheme: D
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
4Calculation and understanding of accounting ratios4Limited companies3Accounting for depreciation and disposal of non-current assets2Books of prime entry2Business documents2Clubs and societies2Corrections of errors2Incomplete records2Manufacturing accounts2Other payables and other receivables2The accounting equation2The double entry system of book-keeping2Capital and revenue expenditure and receipts1Irrecoverable debts and allowance for irrecoverable debts1Sole traders1The trial balance1What you needed in this session
Cambridge’s own grade thresholds for 2022 Oct/Nov, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.