Cambridge IGCSE Accounting 0452 — 2025 May/June Paper 1 · Variant 2
0452/12/M/J/25 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
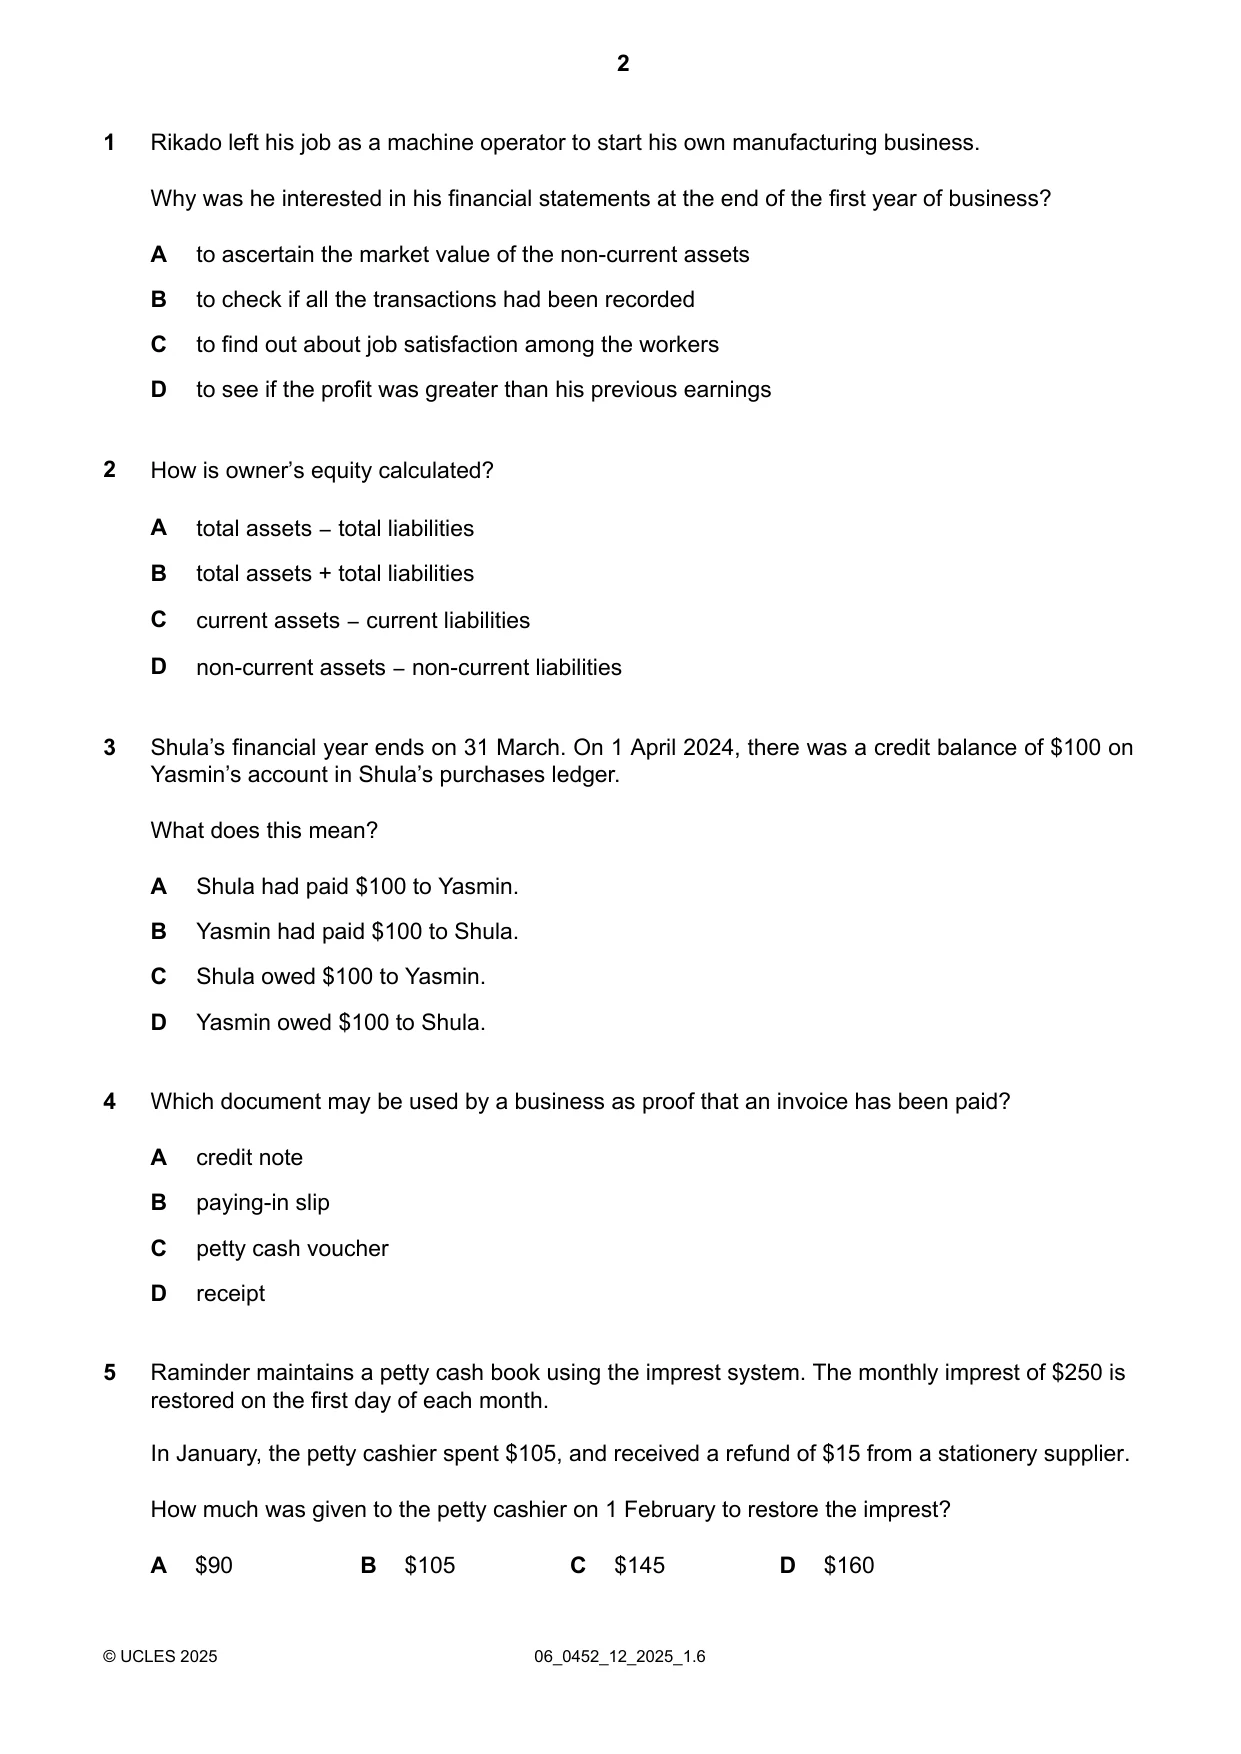
Q1 · Rikado left his job as a machine operator to start his own manufacturing business
1 Rikado left his job as a machine operator to start his own manufacturing business. Why was he interested in his financial statements at the end of the first year of business? A to ascertain the market value of the non-current assets B to check if all the transactions had been recorded C to find out about job satisfaction among the workers D to see if the profit was greater than his previous earnings
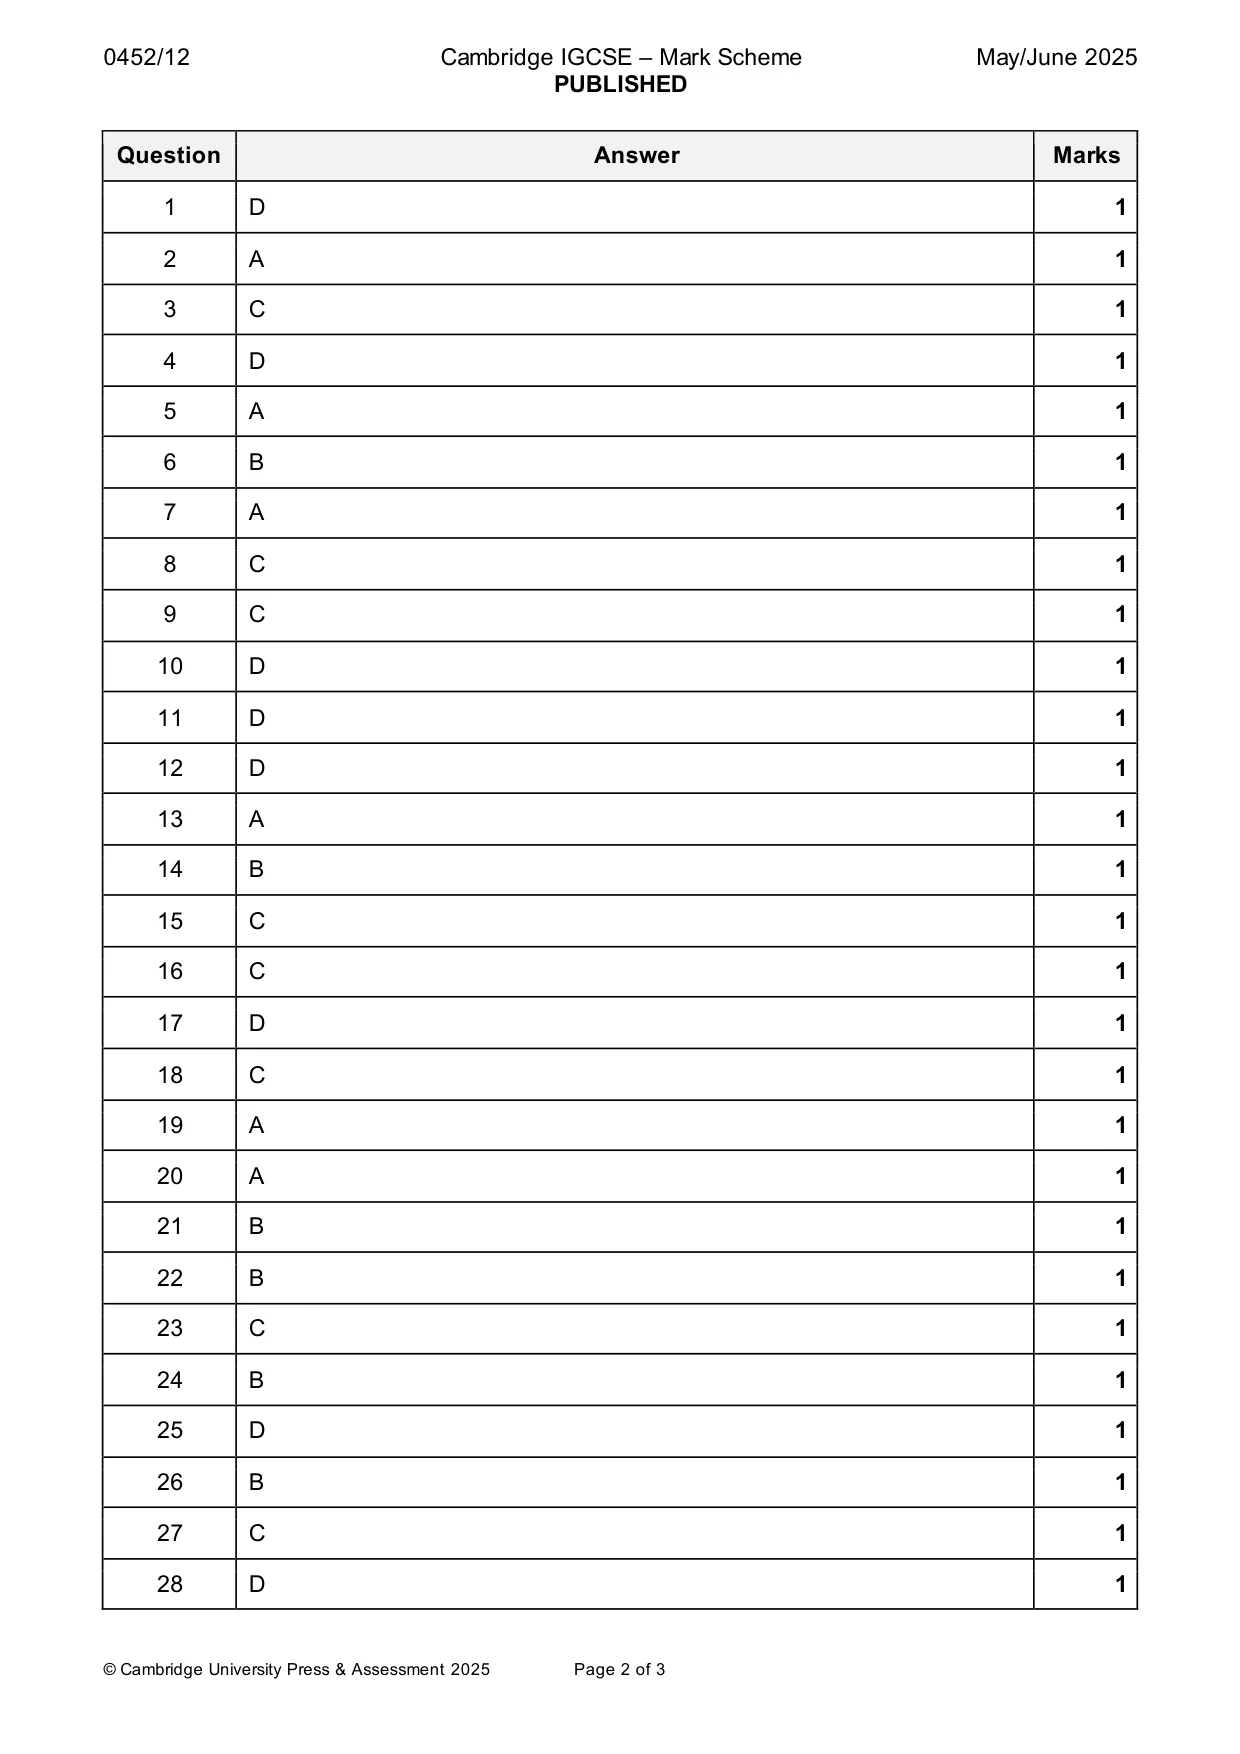
Mark scheme: D
Q2 · How is owner’s equity calculated?
2 How is owner’s equity calculated? A total assets −total liabilities B total assets + total liabilities C current assets −current liabilities D non-current assets −non-current liabilities
Mark scheme: A
Q3 · Shula’s financial year ends on 31 March
3 Shula’s financial year ends on 31 March. On 1 April 2024, there was a credit balance of $100 on Yasmin’s account in Shula’s purchases ledger. What does this mean? A Shula had paid $100 to Yasmin. B Yasmin had paid $100 to Shula. C Shula owed $100 to Yasmin. D Yasmin owed $100 to Shula.
Mark scheme: C
Q4 · Which document may be used by a business as proof that an invoice has been paid?
4 Which document may be used by a business as proof that an invoice has been paid? A credit note B paying-in slip C petty cash voucher D receipt
Mark scheme: D
Q5 · Raminder maintains a petty cash book using the imprest system
5 Raminder maintains a petty cash book using the imprest system. The monthly imprest of $250 is restored on the first day of each month. In January, the petty cashier spent $105, and received a refund of $15 from a stationery supplier. How much was given to the petty cashier on 1 February to restore the imprest? A $90 B $105 C $145 D $160
Mark scheme: A
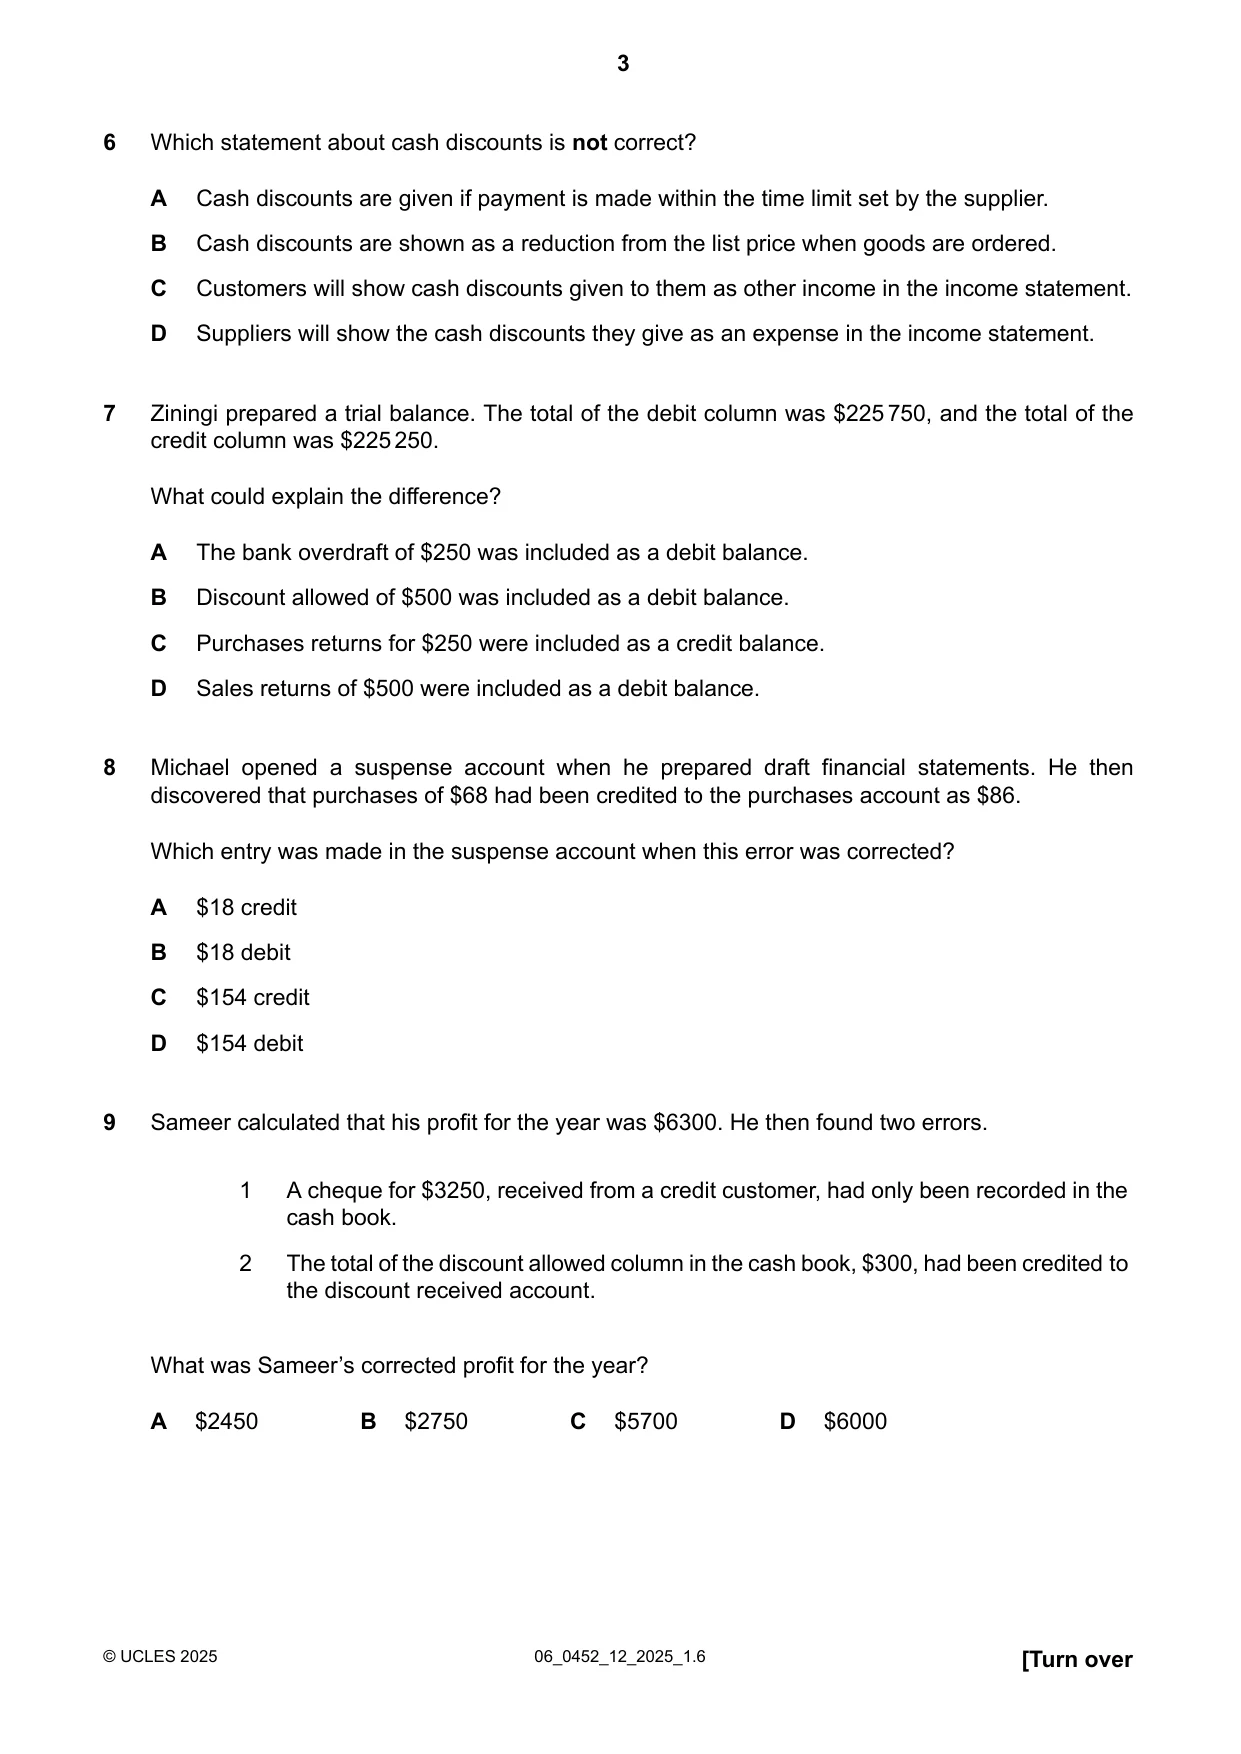
Q6 · Which statement about cash discounts is not correct?
6 Which statement about cash discounts is not correct? A Cash discounts are given if payment is made within the time limit set by the supplier. B Cash discounts are shown as a reduction from the list price when goods are ordered. C Customers will show cash discounts given to them as other income in the income statement. D Suppliers will show the cash discounts they give as an expense in the income statement.
Mark scheme: B
Q7 · Ziningi prepared a trial balance
7 Ziningi prepared a trial balance. The total of the debit column was $225750, and the total of the credit column was $225250. What could explain the difference? A The bank overdraft of $250 was included as a debit balance. B Discount allowed of $500 was included as a debit balance. C Purchases returns for $250 were included as a credit balance. D Sales returns of $500 were included as a debit balance.
Mark scheme: A
Q8 · Michael opened a suspense account when he prepared draft financial statements
8 Michael opened a suspense account when he prepared draft financial statements. He then discovered that purchases of $68 had been credited to the purchases account as $86. Which entry was made in the suspense account when this error was corrected? A $18 credit B $18 debit C $154 credit D $154 debit
Mark scheme: C
Q9 · Sameer calculated that his profit for the year was $6300
9 Sameer calculated that his profit for the year was $6300. He then found two errors. 1 A cheque for $3250, received from a credit customer, had only been recorded in the cash book. 2 The total of the discount allowed column in the cash book, $300, had been credited to the discount received account. What was Sameer’s corrected profit for the year? A $2450 B $2750 C $5700 D $6000
Mark scheme: C
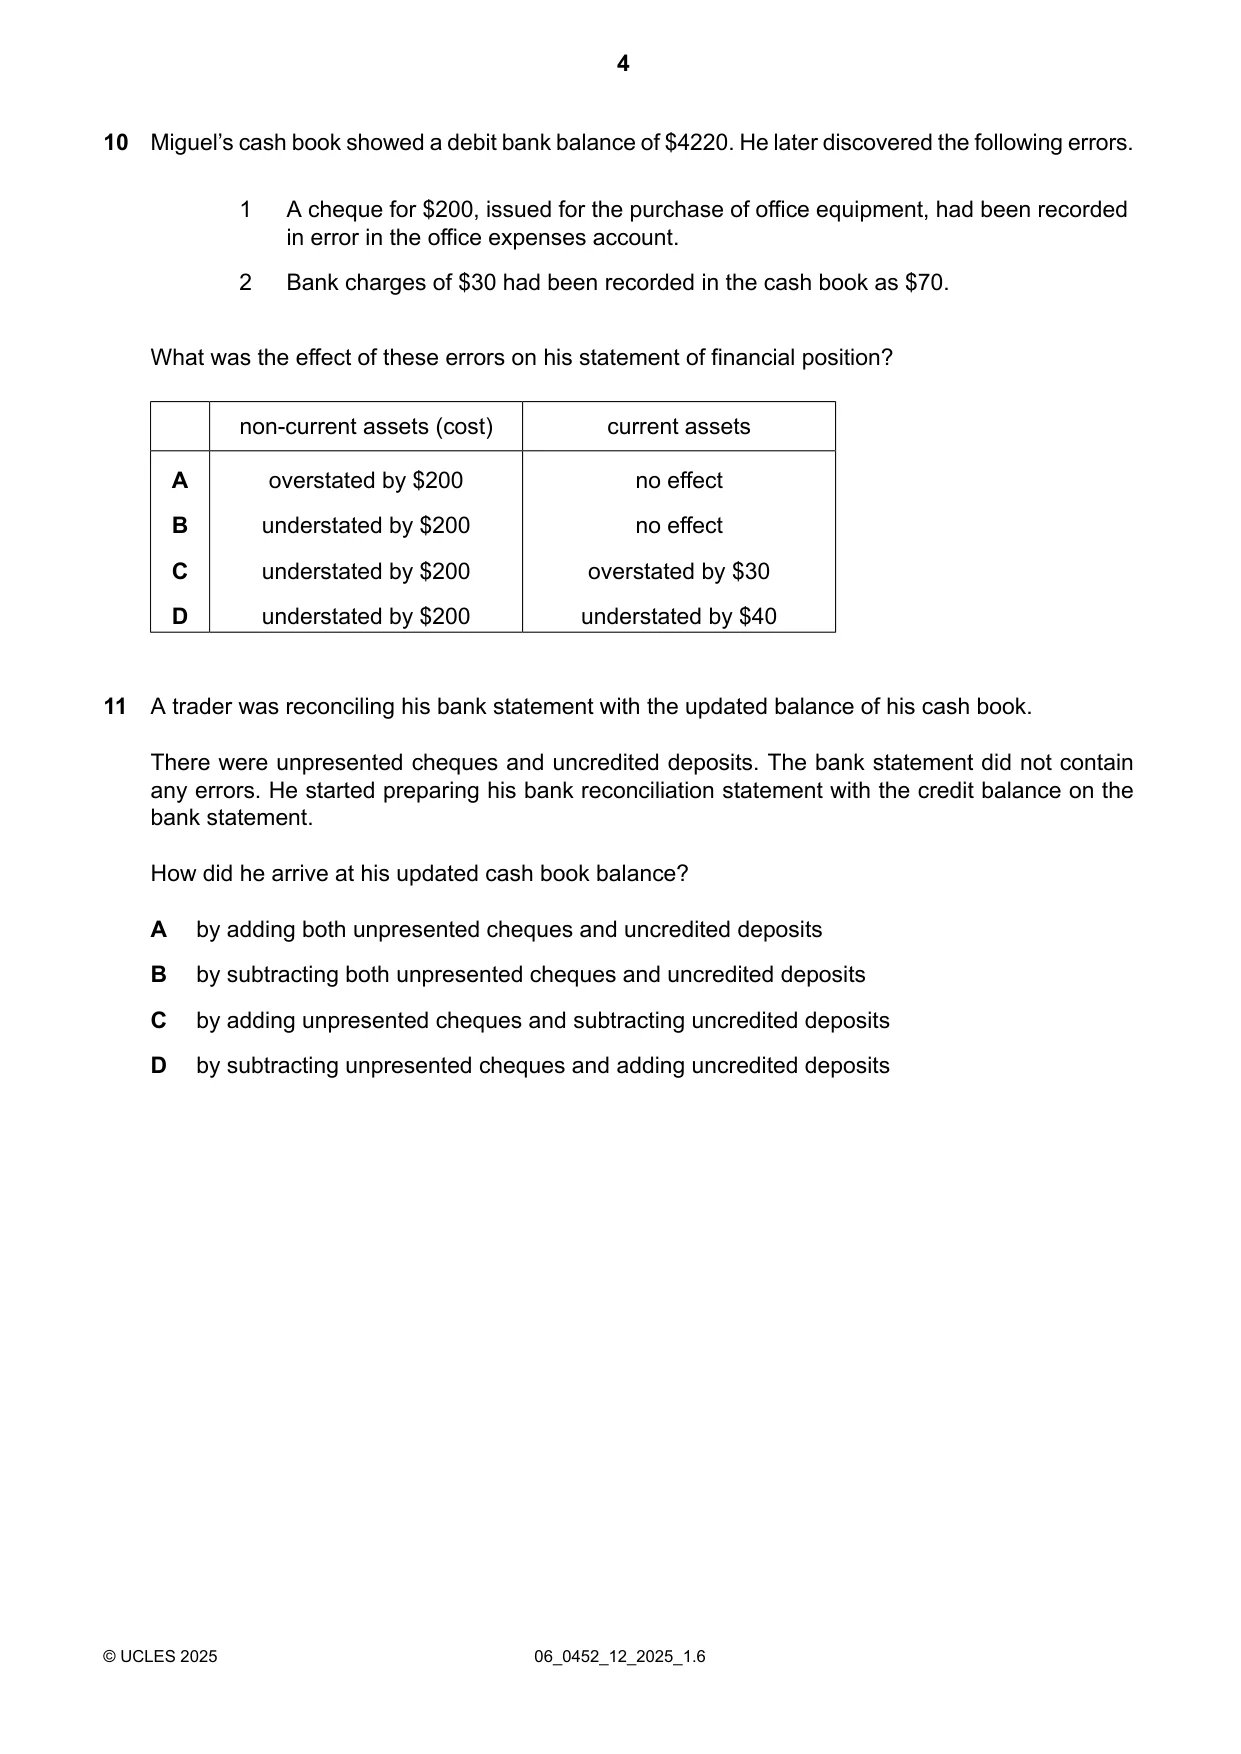
Q10 · Miguel’s cash book showed a debit bank balance of $4220
10 Miguel’s cash book showed a debit bank balance of $4220. He later discovered the following errors. 1 A cheque for $200, issued for the purchase of office equipment, had been recorded in error in the office expenses account. 2 Bank charges of $30 had been recorded in the cash book as $70. What was the effect of these errors on his statement of financial position? non-current assets (cost) current assets A overstated by $200 no effect B understated by $200 no effect C understated by $200 overstated by $30 D understated by $200 understated by $40
Mark scheme: D
Q11 · A trader was reconciling his bank statement with the updated balance of his cash book
11 A trader was reconciling his bank statement with the updated balance of his cash book. There were unpresented cheques and uncredited deposits. The bank statement did not contain any errors. He started preparing his bank reconciliation statement with the credit balance on the bank statement. How did he arrive at his updated cash book balance? A by adding both unpresented cheques and uncredited deposits B by subtracting both unpresented cheques and uncredited deposits C by adding unpresented cheques and subtracting uncredited deposits D by subtracting unpresented cheques and adding uncredited deposits
Mark scheme: D
Q12 · Mary is a trader
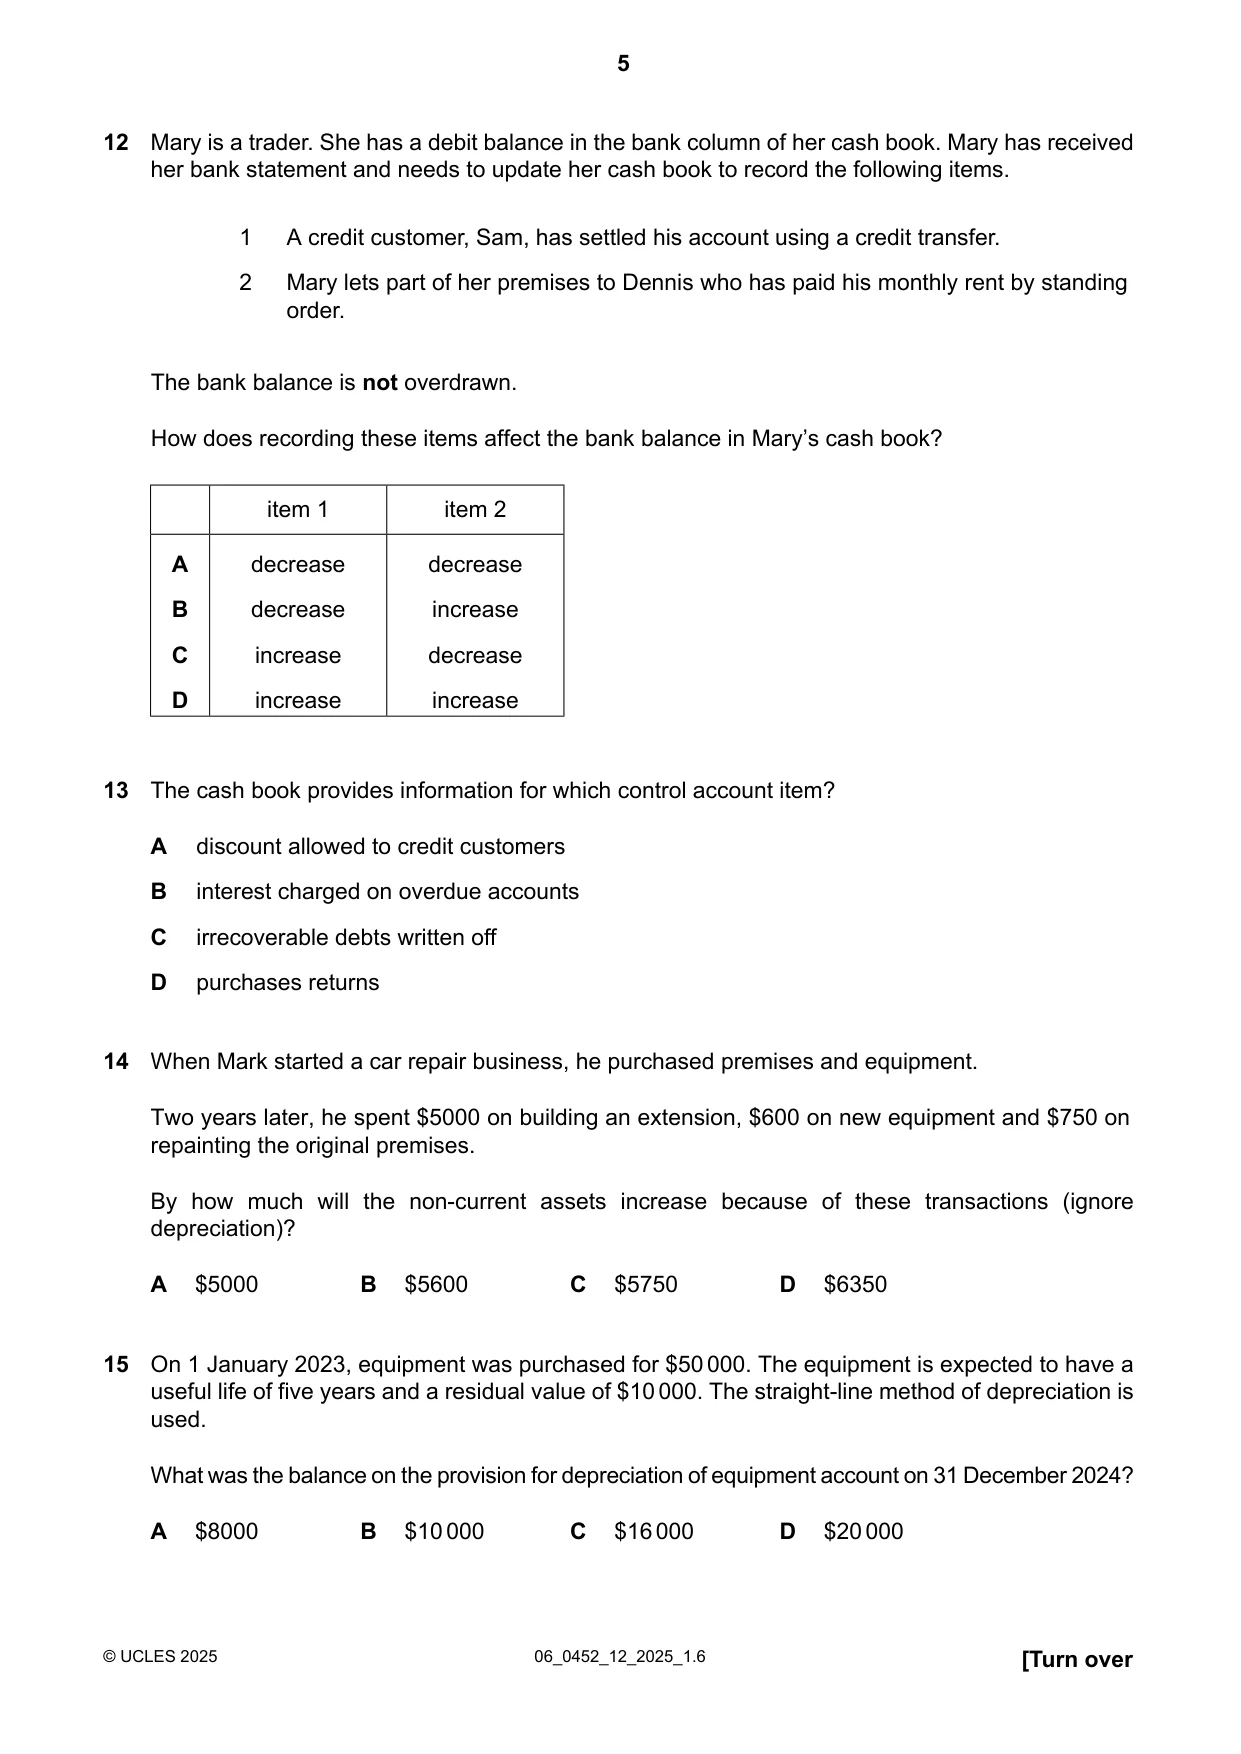
12 Mary is a trader. She has a debit balance in the bank column of her cash book. Mary has received her bank statement and needs to update her cash book to record the following items. 1 A credit customer, Sam, has settled his account using a credit transfer. 2 Mary lets part of her premises to Dennis who has paid his monthly rent by standing order. The bank balance is not overdrawn. How does recording these items affect the bank balance in Mary’s cash book? item 1 item 2 A decrease decrease B decrease increase C increase decrease D increase increase
Mark scheme: D
Q13 · The cash book provides information for which control account item?
13 The cash book provides information for which control account item? A discount allowed to credit customers B interest charged on overdue accounts C irrecoverable debts written off D purchases returns
Mark scheme: A
Q14 · When Mark started a car repair business, he purchased premises and equipment
14 When Mark started a car repair business, he purchased premises and equipment. Two years later, he spent $5000 on building an extension, $600 on new equipment and $750 on repainting the original premises. By how much will the non-current assets increase because of these transactions (ignore depreciation)? A $5000 B $5600 C $5750 D $6350
Mark scheme: B
More questions on Capital and revenue expenditure and receipts
Q15 · On 1 January 2023, equipment was purchased for $50000
15 On 1 January 2023, equipment was purchased for $50000. The equipment is expected to have a useful life of five years and a residual value of $10000. The straight-line method of depreciation is used. What was the balance on the provision for depreciation of equipment account on 31 December 2024? A $8000 B $10000 C $16000 D $20000
Mark scheme: C
More questions on Accounting for depreciation and disposal of non-current assets
Q16 · Anjum rents part of her premises to Ajay for $6120 per annum
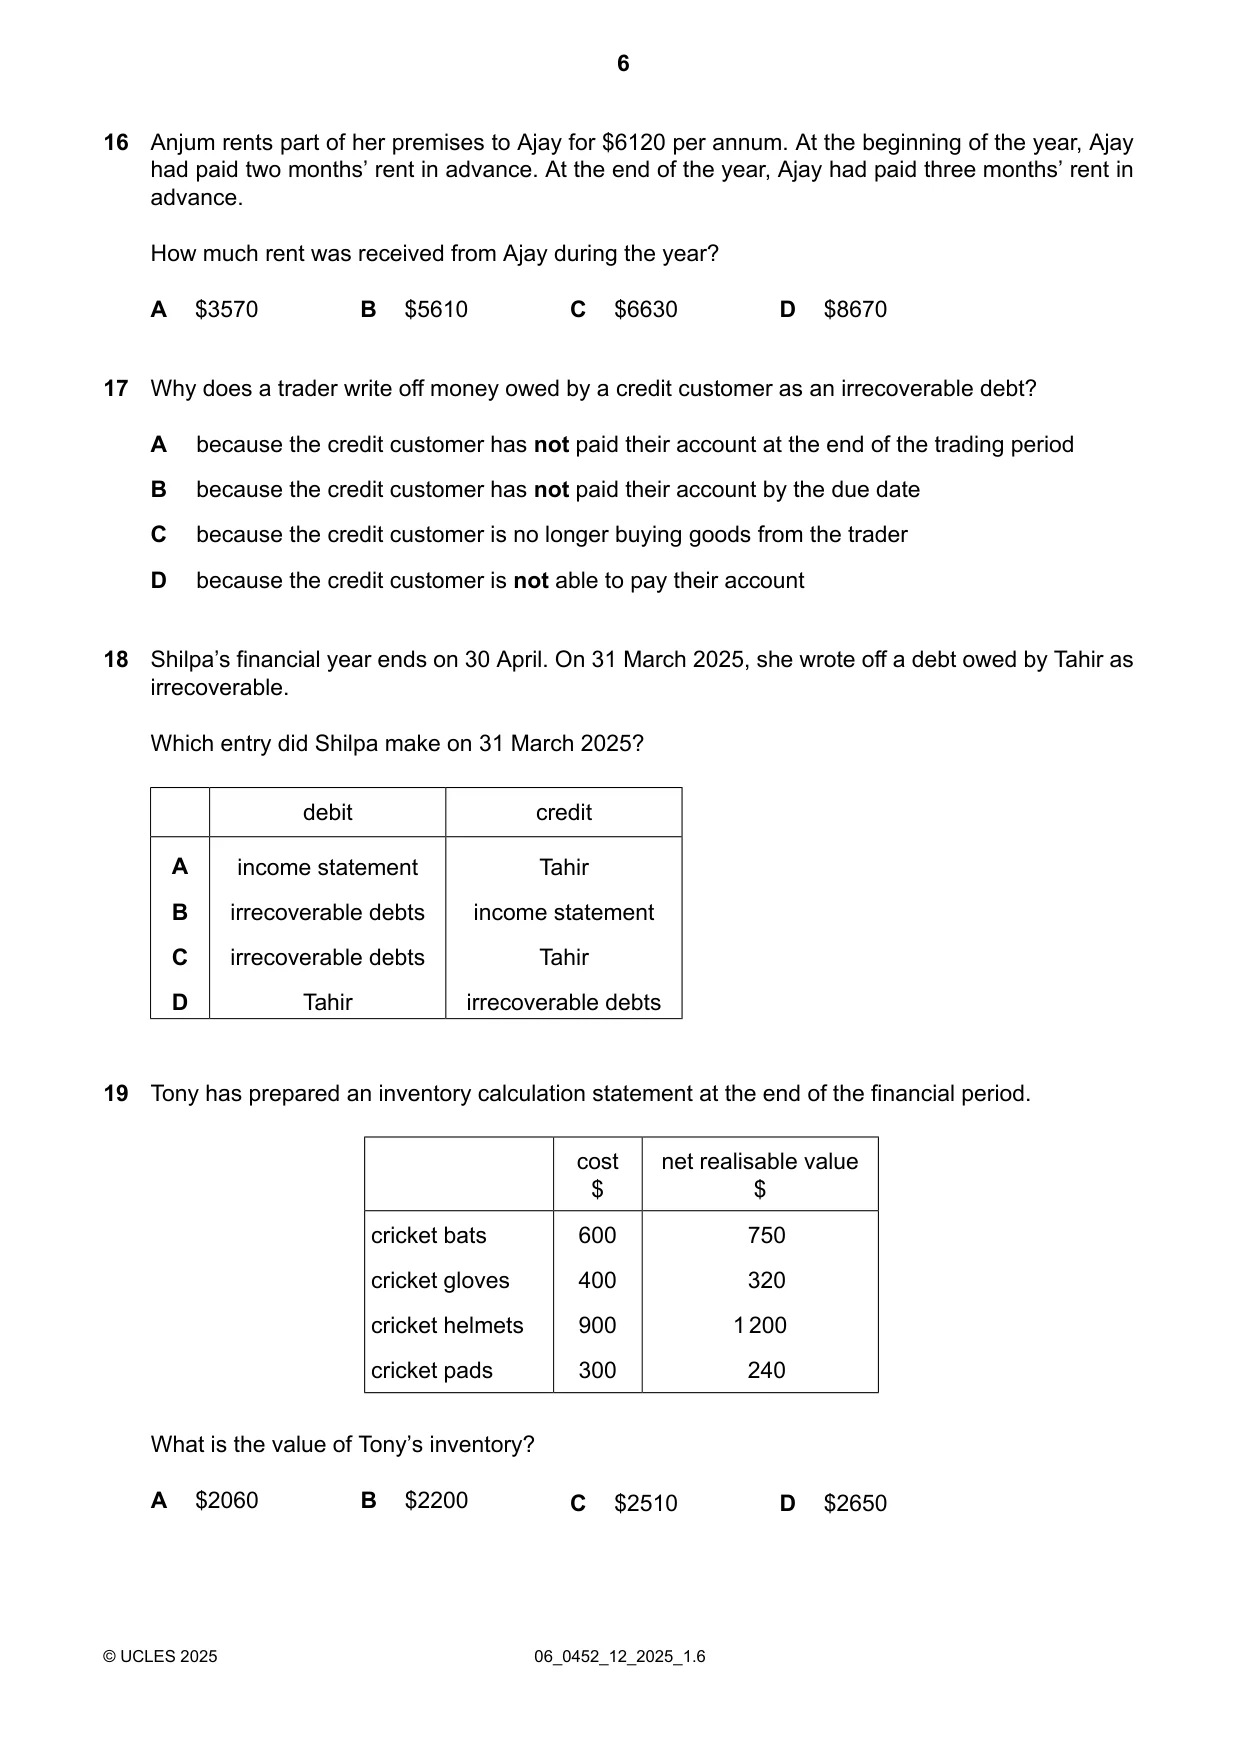
16 Anjum rents part of her premises to Ajay for $6120 per annum. At the beginning of the year, Ajay had paid two months’ rent in advance. At the end of the year, Ajay had paid three months’ rent in advance. How much rent was received from Ajay during the year? A $3570 B $5610 C $6630 D $8670
Mark scheme: C
Q17 · Why does a trader write off money owed by a credit customer as an irrecoverable debt?
17 Why does a trader write off money owed by a credit customer as an irrecoverable debt? A because the credit customer has not paid their account at the end of the trading period B because the credit customer has not paid their account by the due date C because the credit customer is no longer buying goods from the trader D because the credit customer is not able to pay their account
Mark scheme: D
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q18 · Shilpa’s financial year ends on 30 April
18 Shilpa’s financial year ends on 30 April. On 31 March 2025, she wrote off a debt owed by Tahir as irrecoverable. Which entry did Shilpa make on 31 March 2025? debit credit A income statement Tahir B irrecoverable debts income statement C irrecoverable debts Tahir D Tahir irrecoverable debts
Mark scheme: C
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q19 · Tony has prepared an inventory calculation statement at the end of the financial period
19 Tony has prepared an inventory calculation statement at the end of the financial period. cost net realisable value $ $ cricket bats 600 750 cricket gloves 400 320 cricket helmets 900 1200 cricket pads 300 240 What is the value of Tony’s inventory? A $2060 B $2200 C $2510 D $2650
Mark scheme: A
Q20 · Which statement is correct?
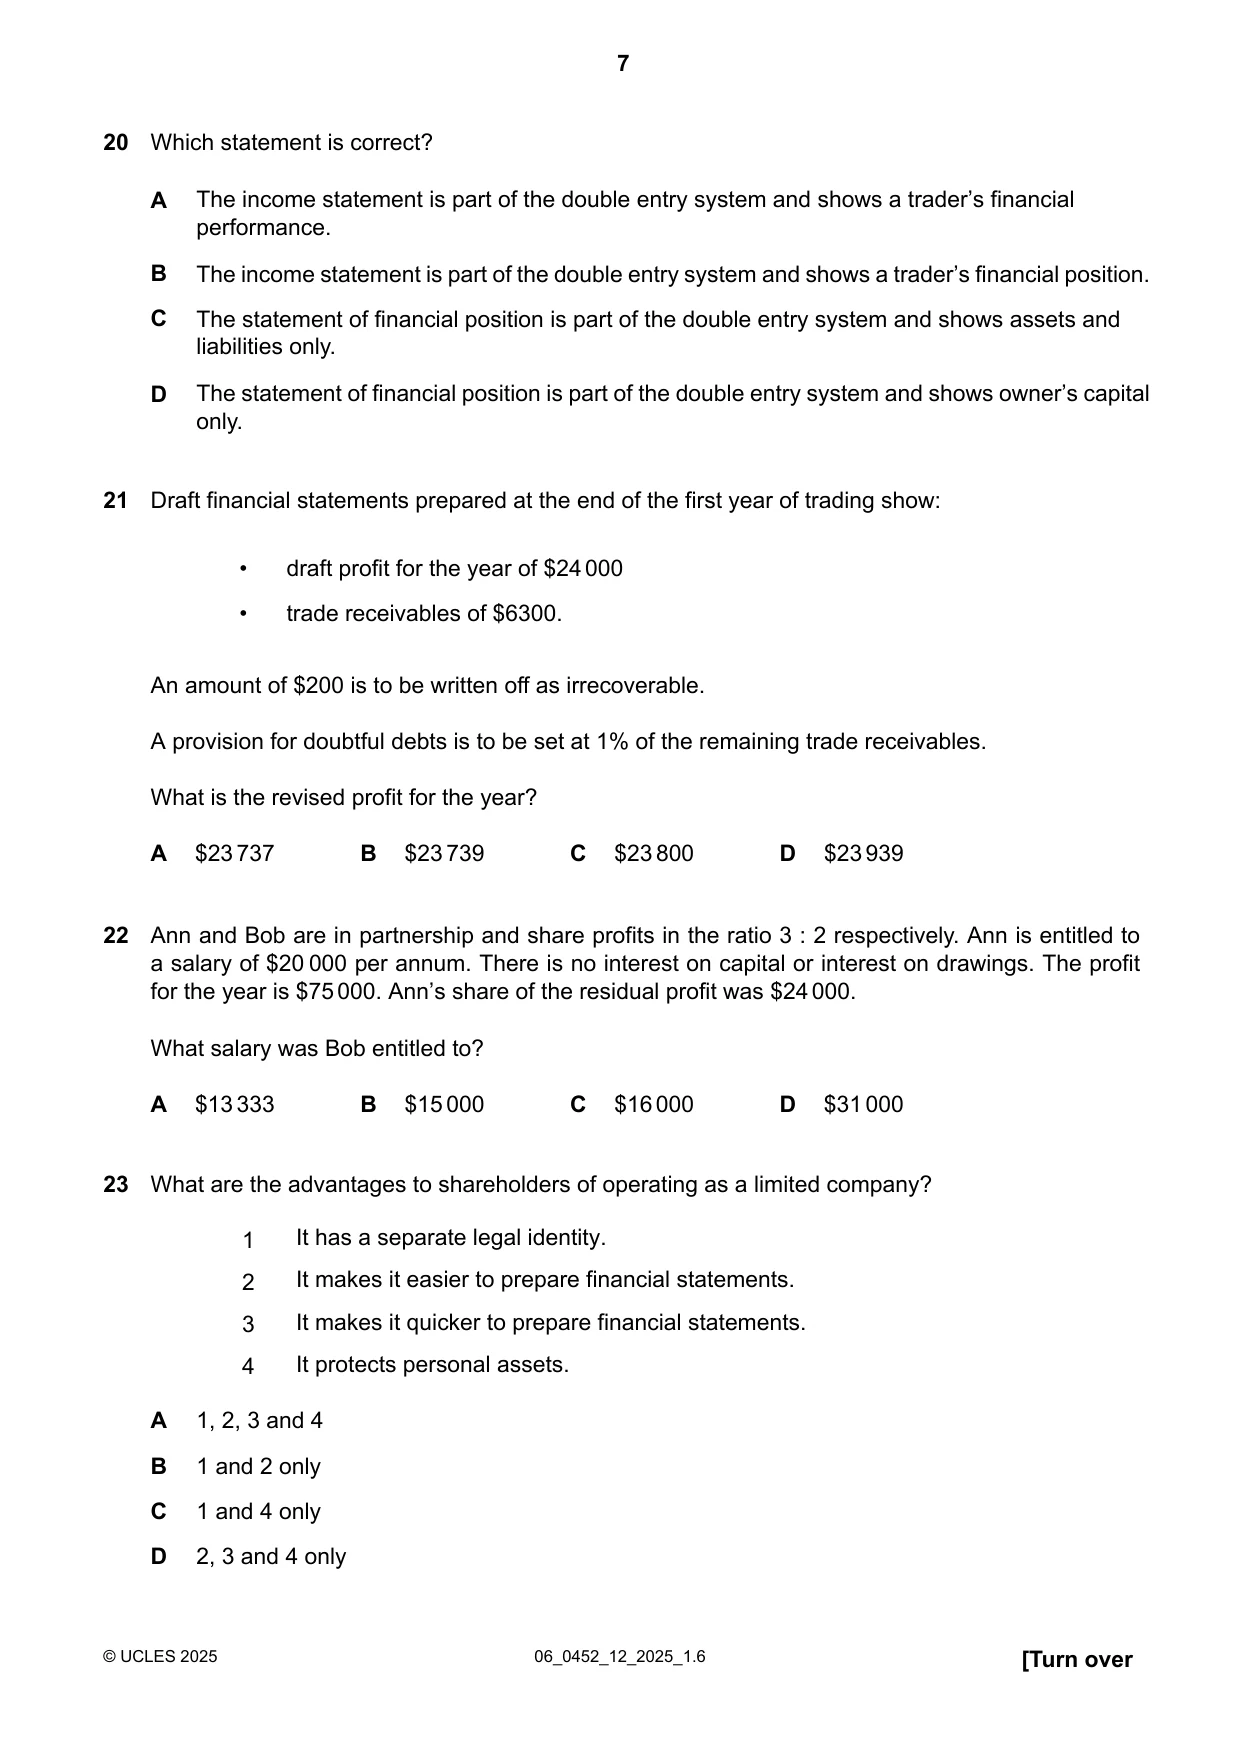
20 Which statement is correct? A The income statement is part of the double entry system and shows a trader’s financial performance. B The income statement is part of the double entry system and shows a trader’s financial position. C The statement of financial position is part of the double entry system and shows assets and liabilities only. D The statement of financial position is part of the double entry system and shows owner’s capital only.
Mark scheme: A
Q21 · Draft financial statements prepared at the end of the first year of trading show: • draft…
21 Draft financial statements prepared at the end of the first year of trading show: • draft profit for the year of $24000 • trade receivables of $6300. An amount of $200 is to be written off as irrecoverable. A provision for doubtful debts is to be set at 1% of the remaining trade receivables. What is the revised profit for the year? A $23 737 B $23 739 C $23 800 D $23 939
Mark scheme: B
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q22 · Ann and Bob are in partnership and share profits in the ratio 3 : 2 respectively
22 Ann and Bob are in partnership and share profits in the ratio 3 : 2 respectively. Ann is entitled to a salary of $20 000 per annum. There is no interest on capital or interest on drawings. The profit for the year is $75 000. Ann’s share of the residual profit was $24 000. What salary was Bob entitled to? A $13333 B $15000 C $16000 D $31000
Mark scheme: B
Q23 · What are the advantages to shareholders of operating as a limited company?
23 What are the advantages to shareholders of operating as a limited company? 1 It has a separate legal identity. 2 It makes it easier to prepare financial statements. 3 It makes it quicker to prepare financial statements. 4 It protects personal assets. A 1, 2, 3 and 4 B 1 and 2 only C 1 and 4 only D 2, 3 and 4 only
Mark scheme: C
Q24 · During the year ended 31 March 2025, subscriptions received by a club amounted to $2500…
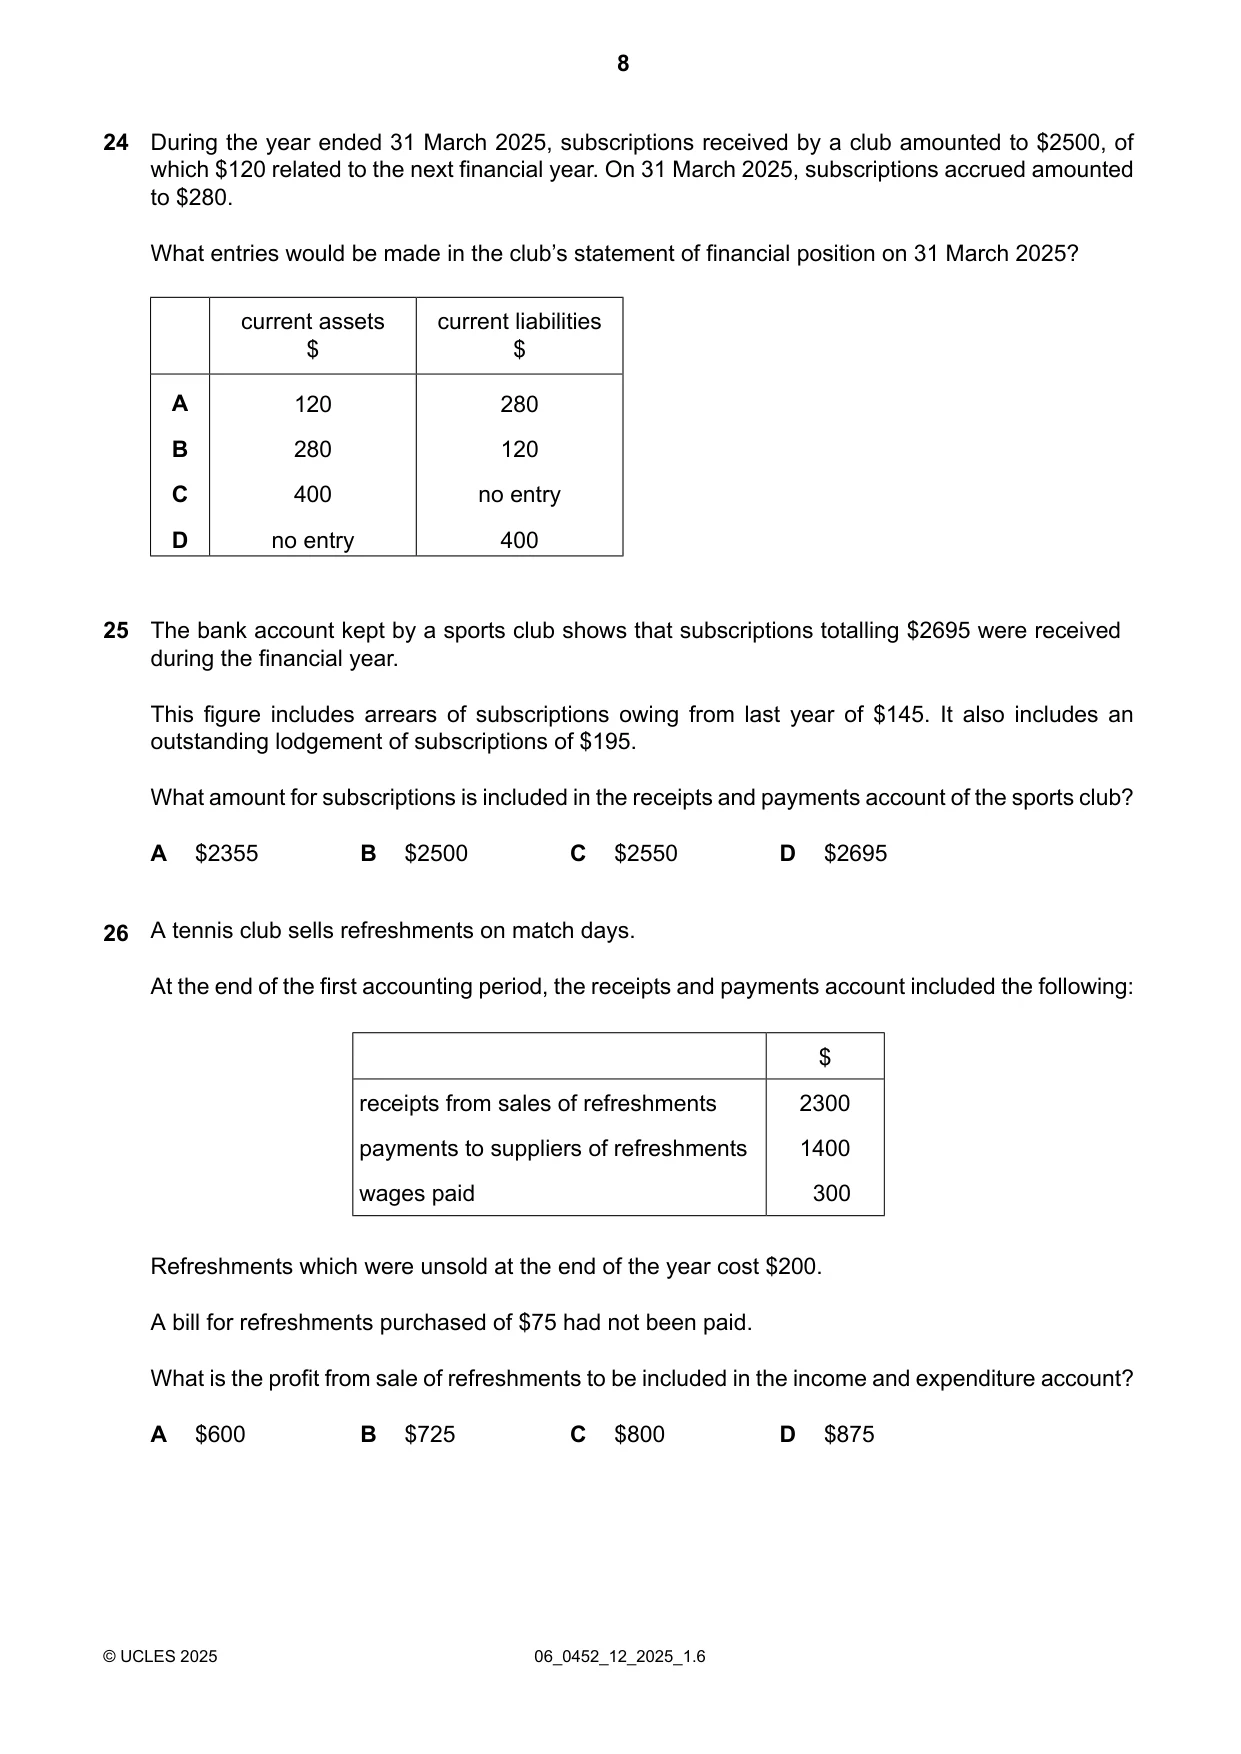
24 During the year ended 31 March 2025, subscriptions received by a club amounted to $2500, of which $120 related to the next financial year. On 31 March 2025, subscriptions accrued amounted to $280. What entries would be made in the club’s statement of financial position on 31 March 2025? current assets current liabilities $ $ A 120 280 B 280 120 C 400 no entry D no entry 400
Mark scheme: B
Q25 · The bank account kept by a sports club shows that subscriptions totalling $2695 were…
25 The bank account kept by a sports club shows that subscriptions totalling $2695 were received during the financial year. This figure includes arrears of subscriptions owing from last year of $145. It also includes an outstanding lodgement of subscriptions of $195. What amount for subscriptions is included in the receipts and payments account of the sports club? A $2355 B $2500 C $2550 D $2695 A tennis club sells refreshments on match days.
Mark scheme: D
Q26 · At the end of the first accounting period, the receipts and payments account included the…
26 At the end of the first accounting period, the receipts and payments account included the following: $ receipts from sales of refreshments 2300 payments to suppliers of refreshments 1400 wages paid 300 Refreshments which were unsold at the end of the year cost $200. A bill for refreshments purchased of $75 had not been paid. What is the profit from sale of refreshments to be included in the income and expenditure account? A $600 B $725 C $800 D $875
Mark scheme: B
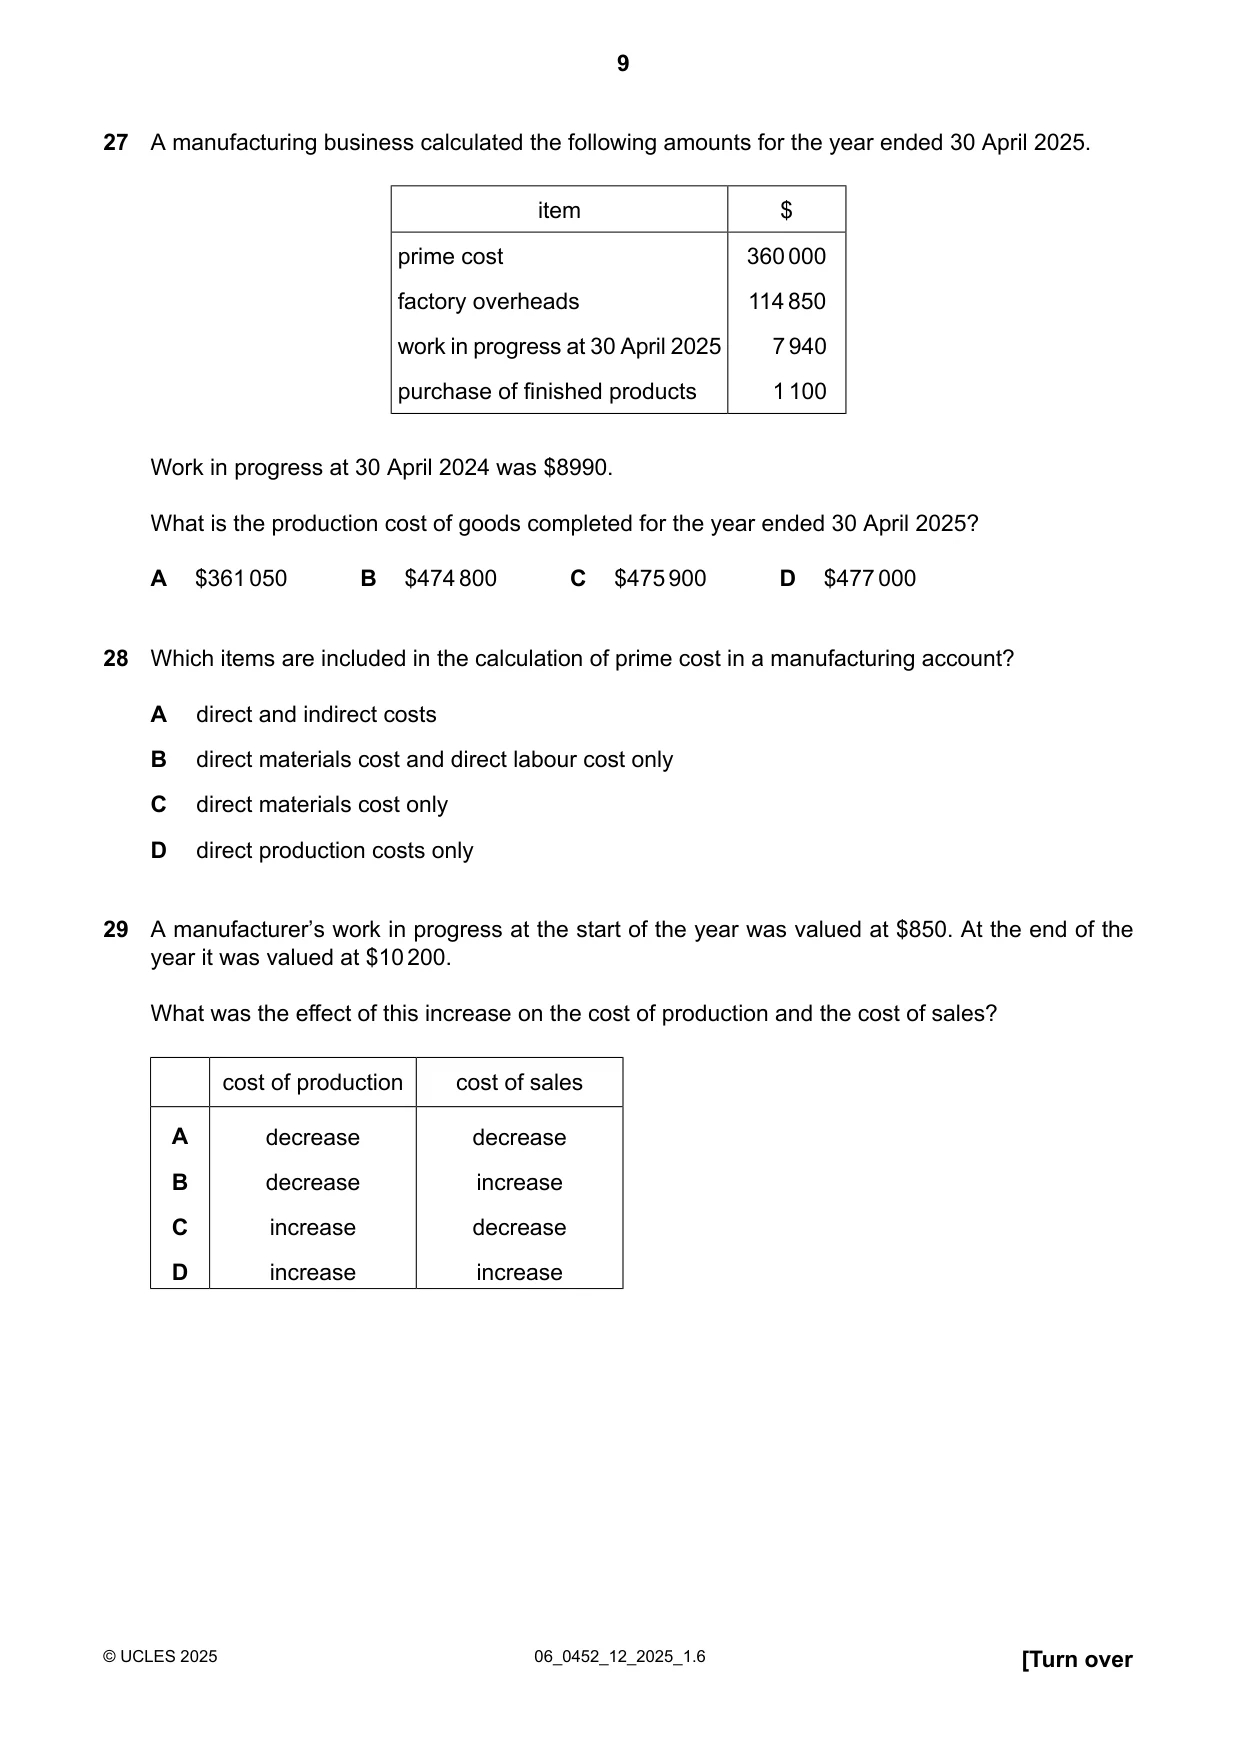
Q27 · A manufacturing business calculated the following amounts for the year ended 30 April 2025
27 A manufacturing business calculated the following amounts for the year ended 30 April 2025. item $ prime cost 360 000 factory overheads 114 850 work in progress at 30 April 2025 7940 purchase of finished products 1100 Work in progress at 30 April 2024 was $8990. What is the production cost of goods completed for the year ended 30 April 2025? A $361050 B $474800 C $475900 D $477000
Mark scheme: C
Q28 · Which items are included in the calculation of prime cost in a manufacturing account?
28 Which items are included in the calculation of prime cost in a manufacturing account? A direct and indirect costs B direct materials cost and direct labour cost only C direct materials cost only D direct production costs only
Mark scheme: D
Q29 · A manufacturer’s work in progress at the start of the year was valued at $850
29 A manufacturer’s work in progress at the start of the year was valued at $850. At the end of the year it was valued at $10 200. What was the effect of this increase on the cost of production and the cost of sales? cost of production cost of sales A decrease decrease B decrease increase C increase decrease D increase increase
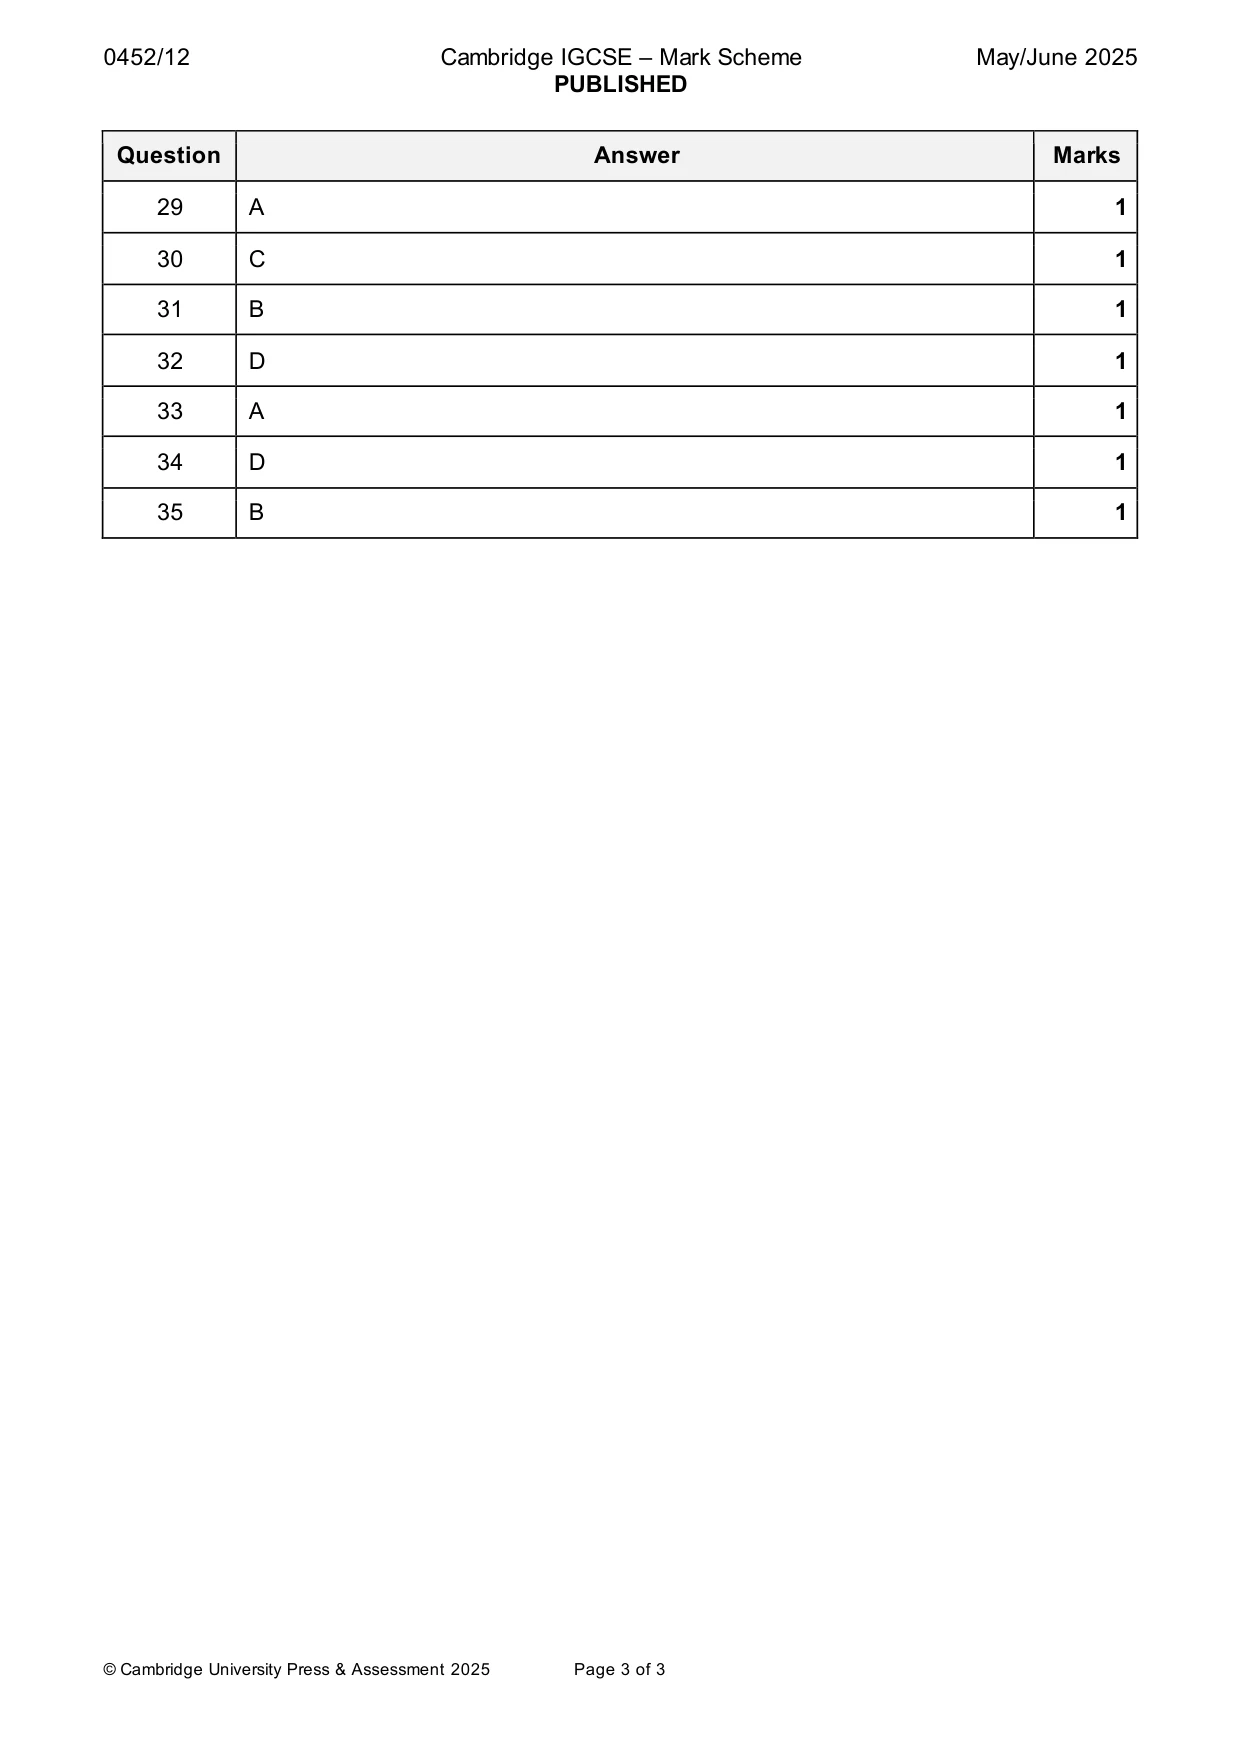
Mark scheme: A
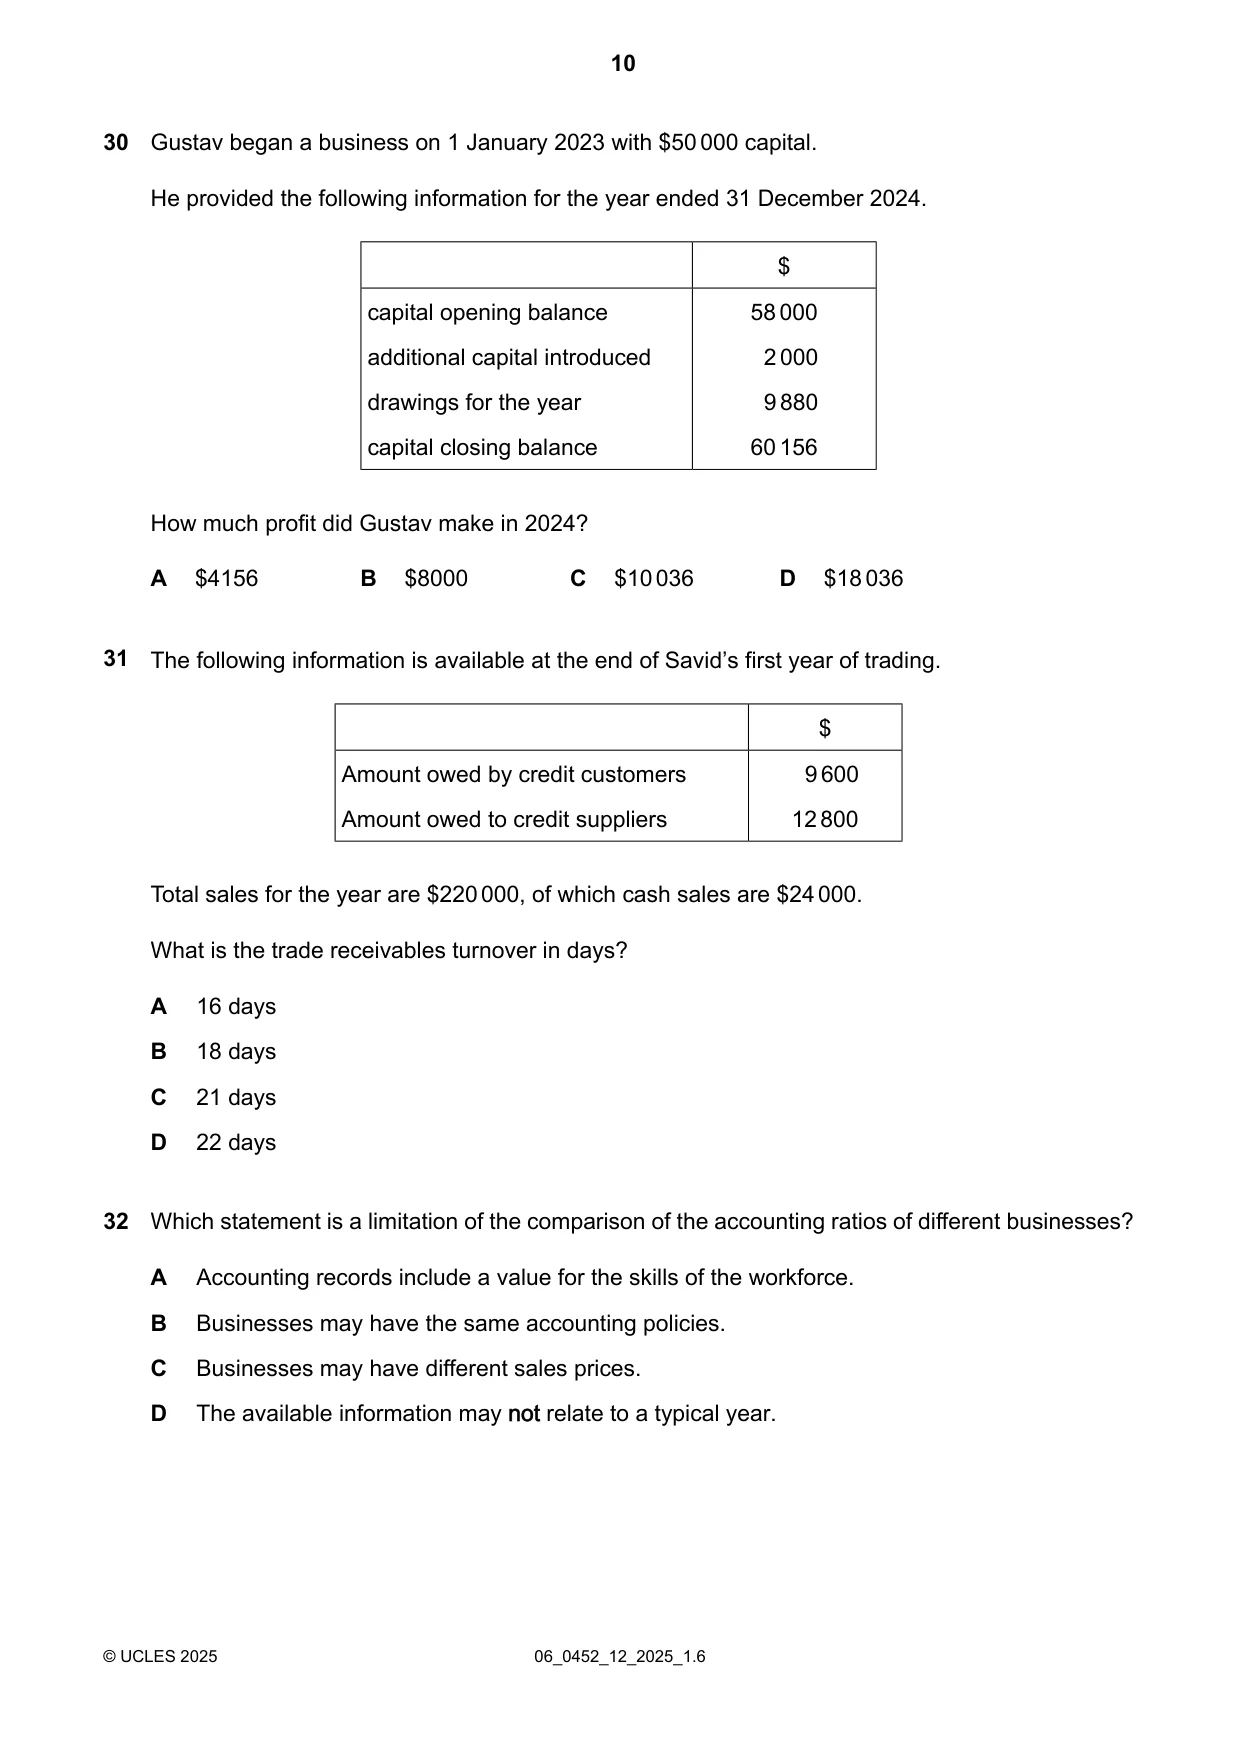
Q30 · Gustav began a business on 1 January 2023 with $50000 capital
30 Gustav began a business on 1 January 2023 with $50000 capital. He provided the following information for the year ended 31 December 2024. $ capital opening balance 58000 additional capital introduced 2000 drawings for the year 9880 capital closing balance 60156 How much profit did Gustav make in 2024? A $4156 B $8000 C $10036 D $18036
Mark scheme: C
Q31 · The following information is available at the end of Savid’s first year of trading
31 The following information is available at the end of Savid’s first year of trading. $ Amount owed by credit customers 9600 Amount owed to credit suppliers 12800 Total sales for the year are $220000, of which cash sales are $24000. What is the trade receivables turnover in days? A 16 days B 18 days C 21 days D 22 days
Mark scheme: B
More questions on Calculation and understanding of accounting ratios
Q32 · Which statement is a limitation of the comparison of the accounting ratios of different…
32 Which statement is a limitation of the comparison of the accounting ratios of different businesses? A Accounting records include a value for the skills of the workforce. B Businesses may have the same accounting policies. C Businesses may have different sales prices. D The available information may not relate to a typical year.
Mark scheme: D
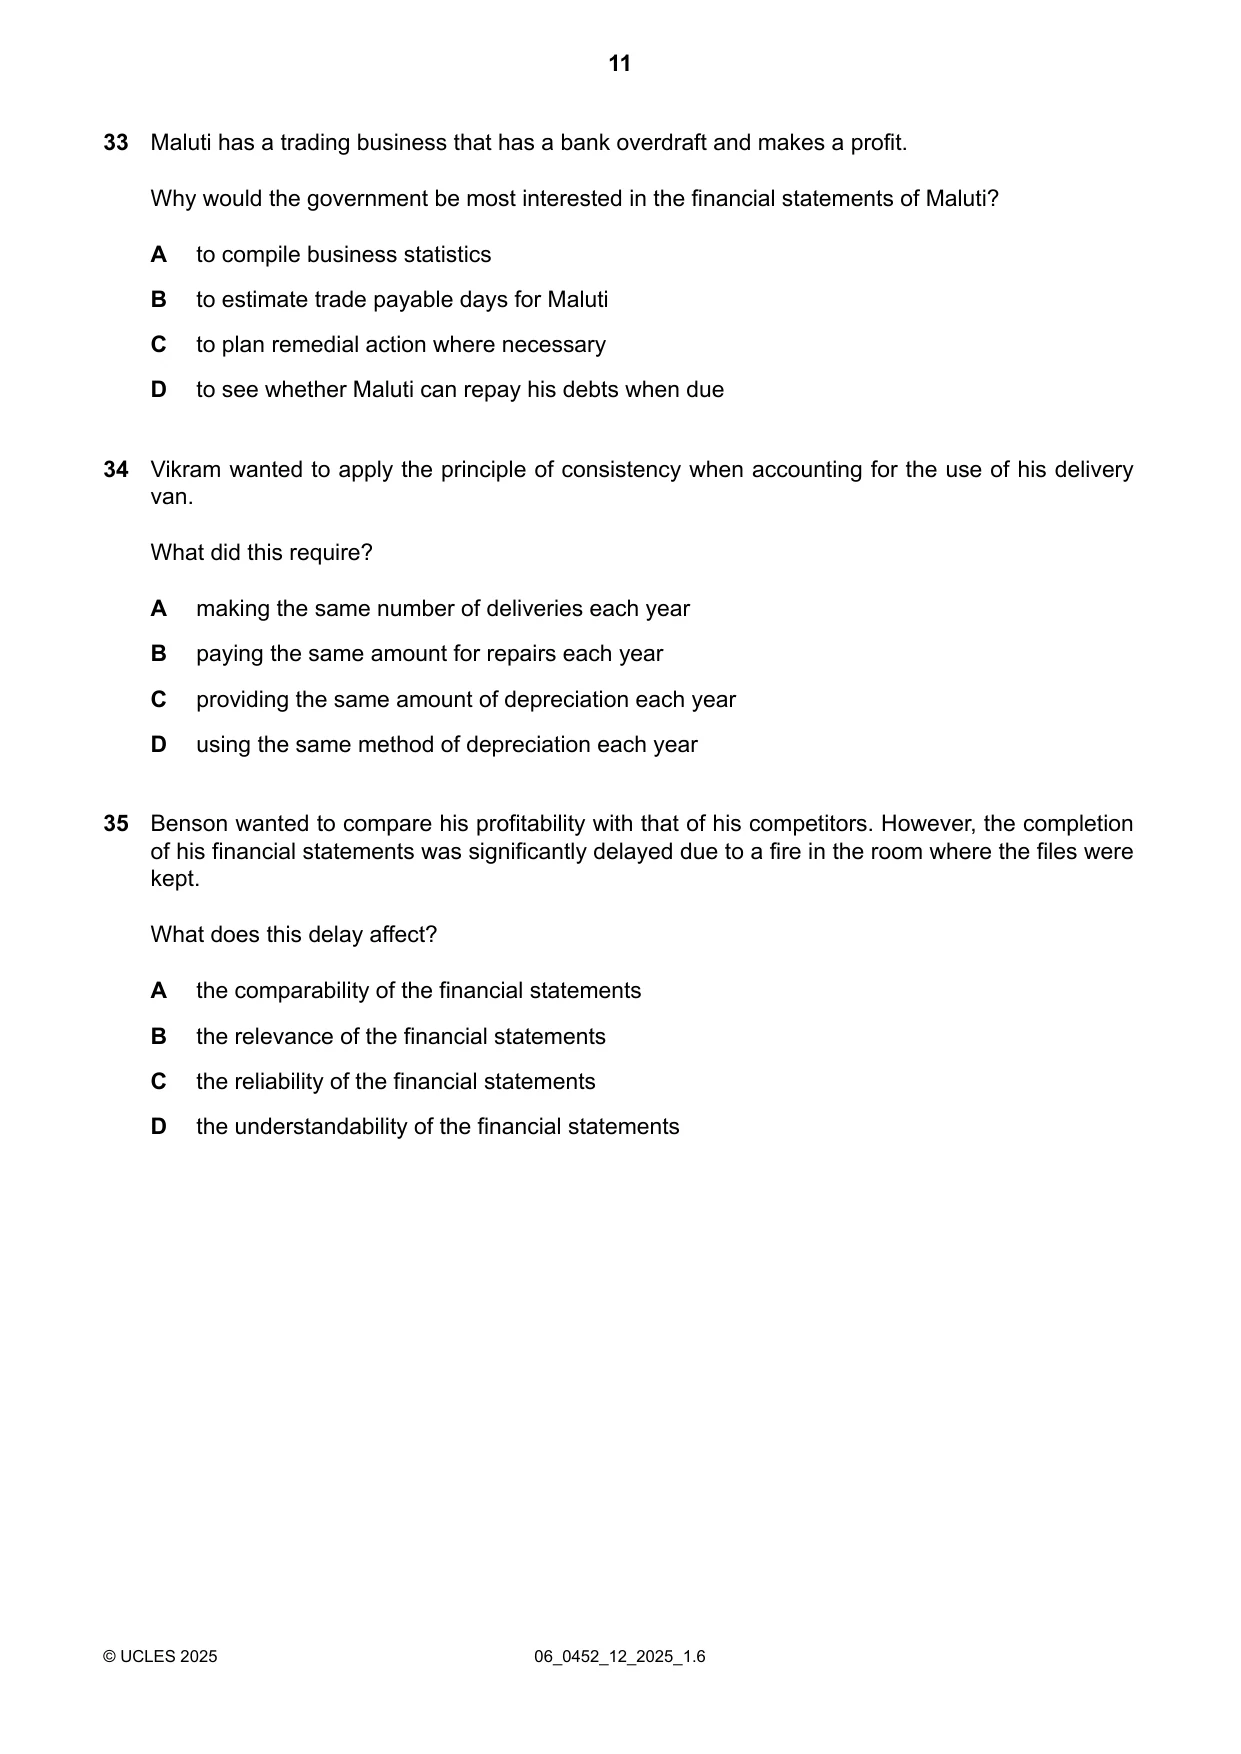
Q33 · Maluti has a trading business that has a bank overdraft and makes a profit
33 Maluti has a trading business that has a bank overdraft and makes a profit. Why would the government be most interested in the financial statements of Maluti? A to compile business statistics B to estimate trade payable days for Maluti C to plan remedial action where necessary D to see whether Maluti can repay his debts when due
Mark scheme: A
Q34 · Vikram wanted to apply the principle of consistency when accounting for the use of his…
34 Vikram wanted to apply the principle of consistency when accounting for the use of his delivery van. What did this require? A making the same number of deliveries each year B paying the same amount for repairs each year C providing the same amount of depreciation each year D using the same method of depreciation each year
Mark scheme: D
Q35 · Benson wanted to compare his profitability with that of his competitors
35 Benson wanted to compare his profitability with that of his competitors. However, the completion of his financial statements was significantly delayed due to a fire in the room where the files were kept. What does this delay affect? A the comparability of the financial statements B the relevance of the financial statements C the reliability of the financial statements D the understandability of the financial statements
Mark scheme: B
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
3Corrections of errors3Irrecoverable debts and allowance for irrecoverable debts3Manufacturing accounts3Accounting concepts2Bank reconciliation2Books of prime entry2Interested parties2The double entry system of book-keeping2Accounting for depreciation and disposal of non-current assets1Business documents1Calculation and understanding of accounting ratios1Capital and revenue expenditure and receipts1Control accounts1Incomplete records1Limitations of accounting statements1Limited companies1Other payables and other receivables1Partnerships1The accounting equation1The trial balance1Valuation of inventory1What you needed in this session
Cambridge’s own grade thresholds for 2025 May/June, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.