Cambridge IGCSE Accounting 0452 — 2025 Oct/Nov Paper 1 · Variant 3
0452/13/O/N/25 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
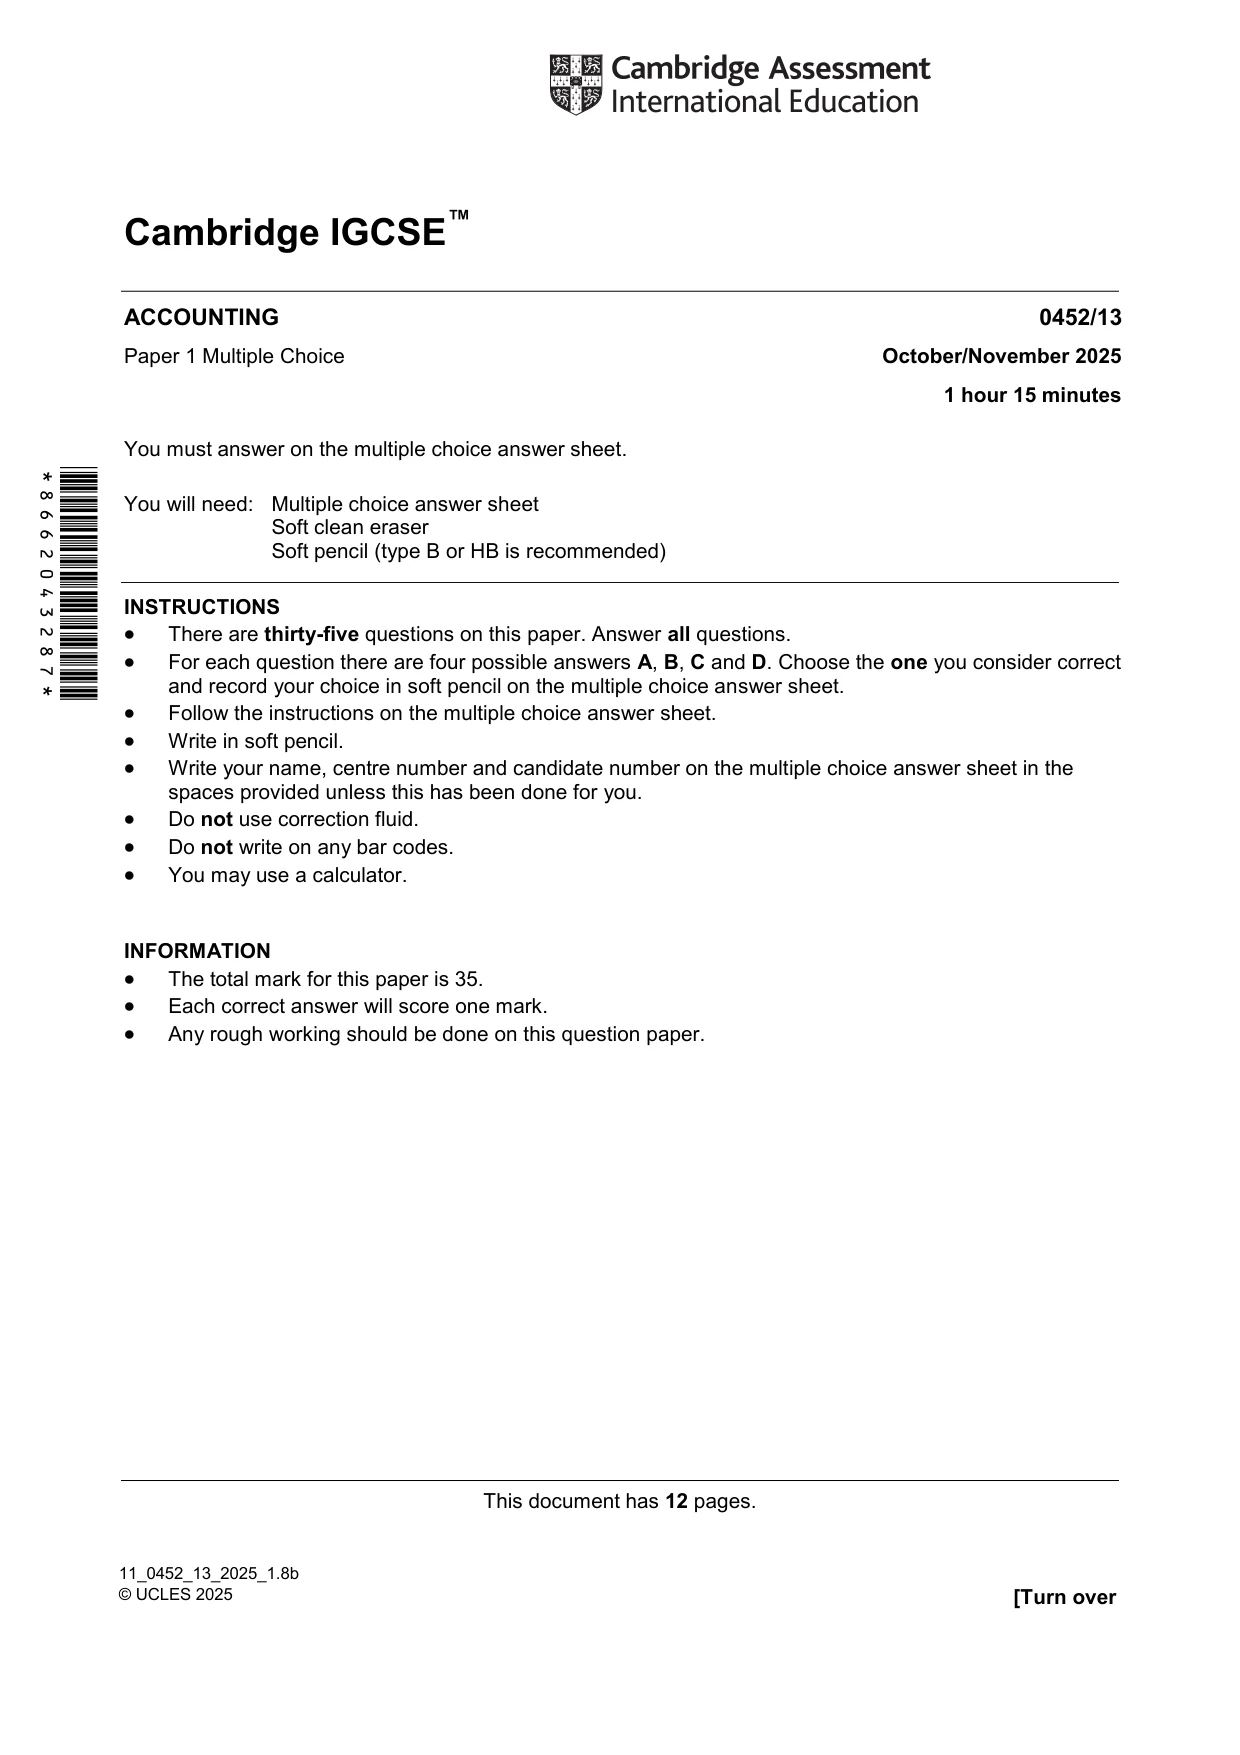
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · What is a purpose of calculating the profit of a sole trader?
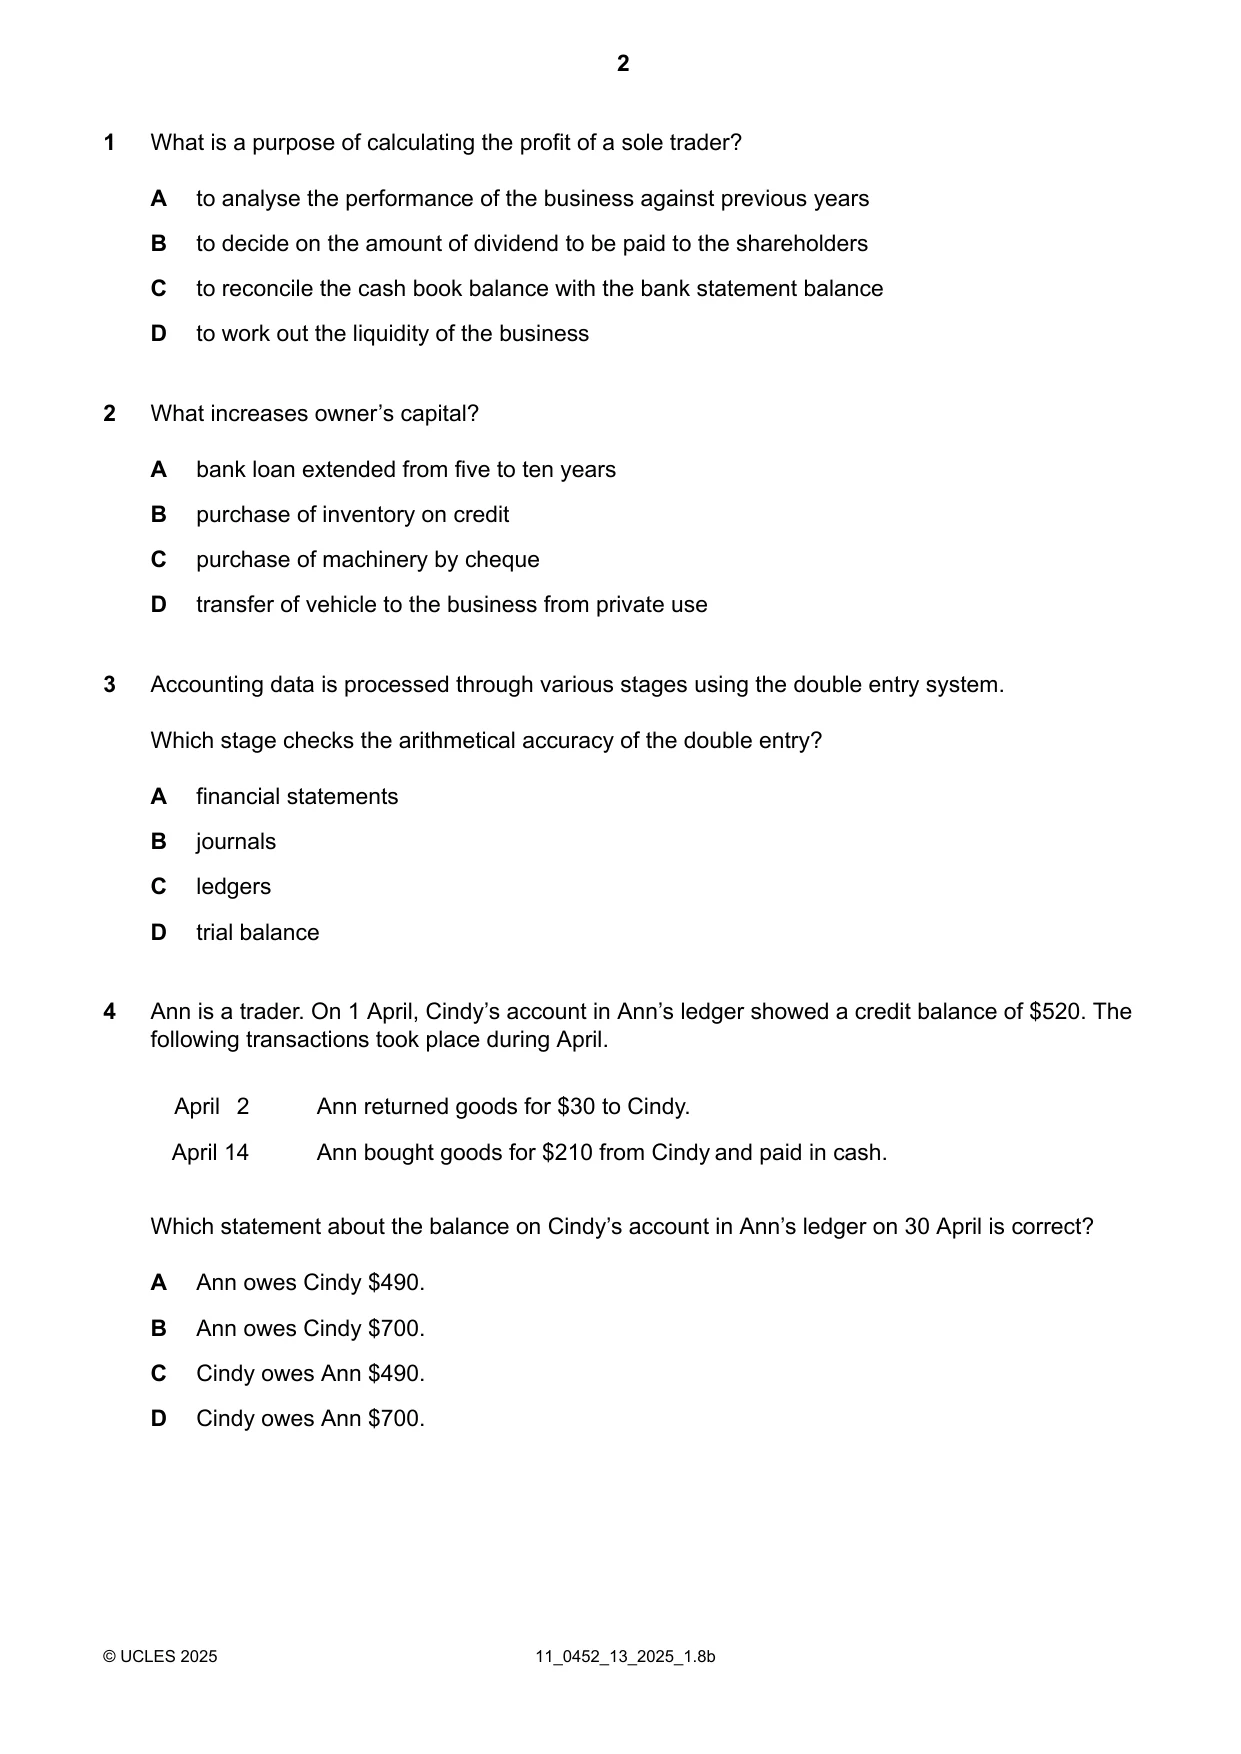
1 What is a purpose of calculating the profit of a sole trader? A to analyse the performance of the business against previous years B to decide on the amount of dividend to be paid to the shareholders C to reconcile the cash book balance with the bank statement balance D to work out the liquidity of the business
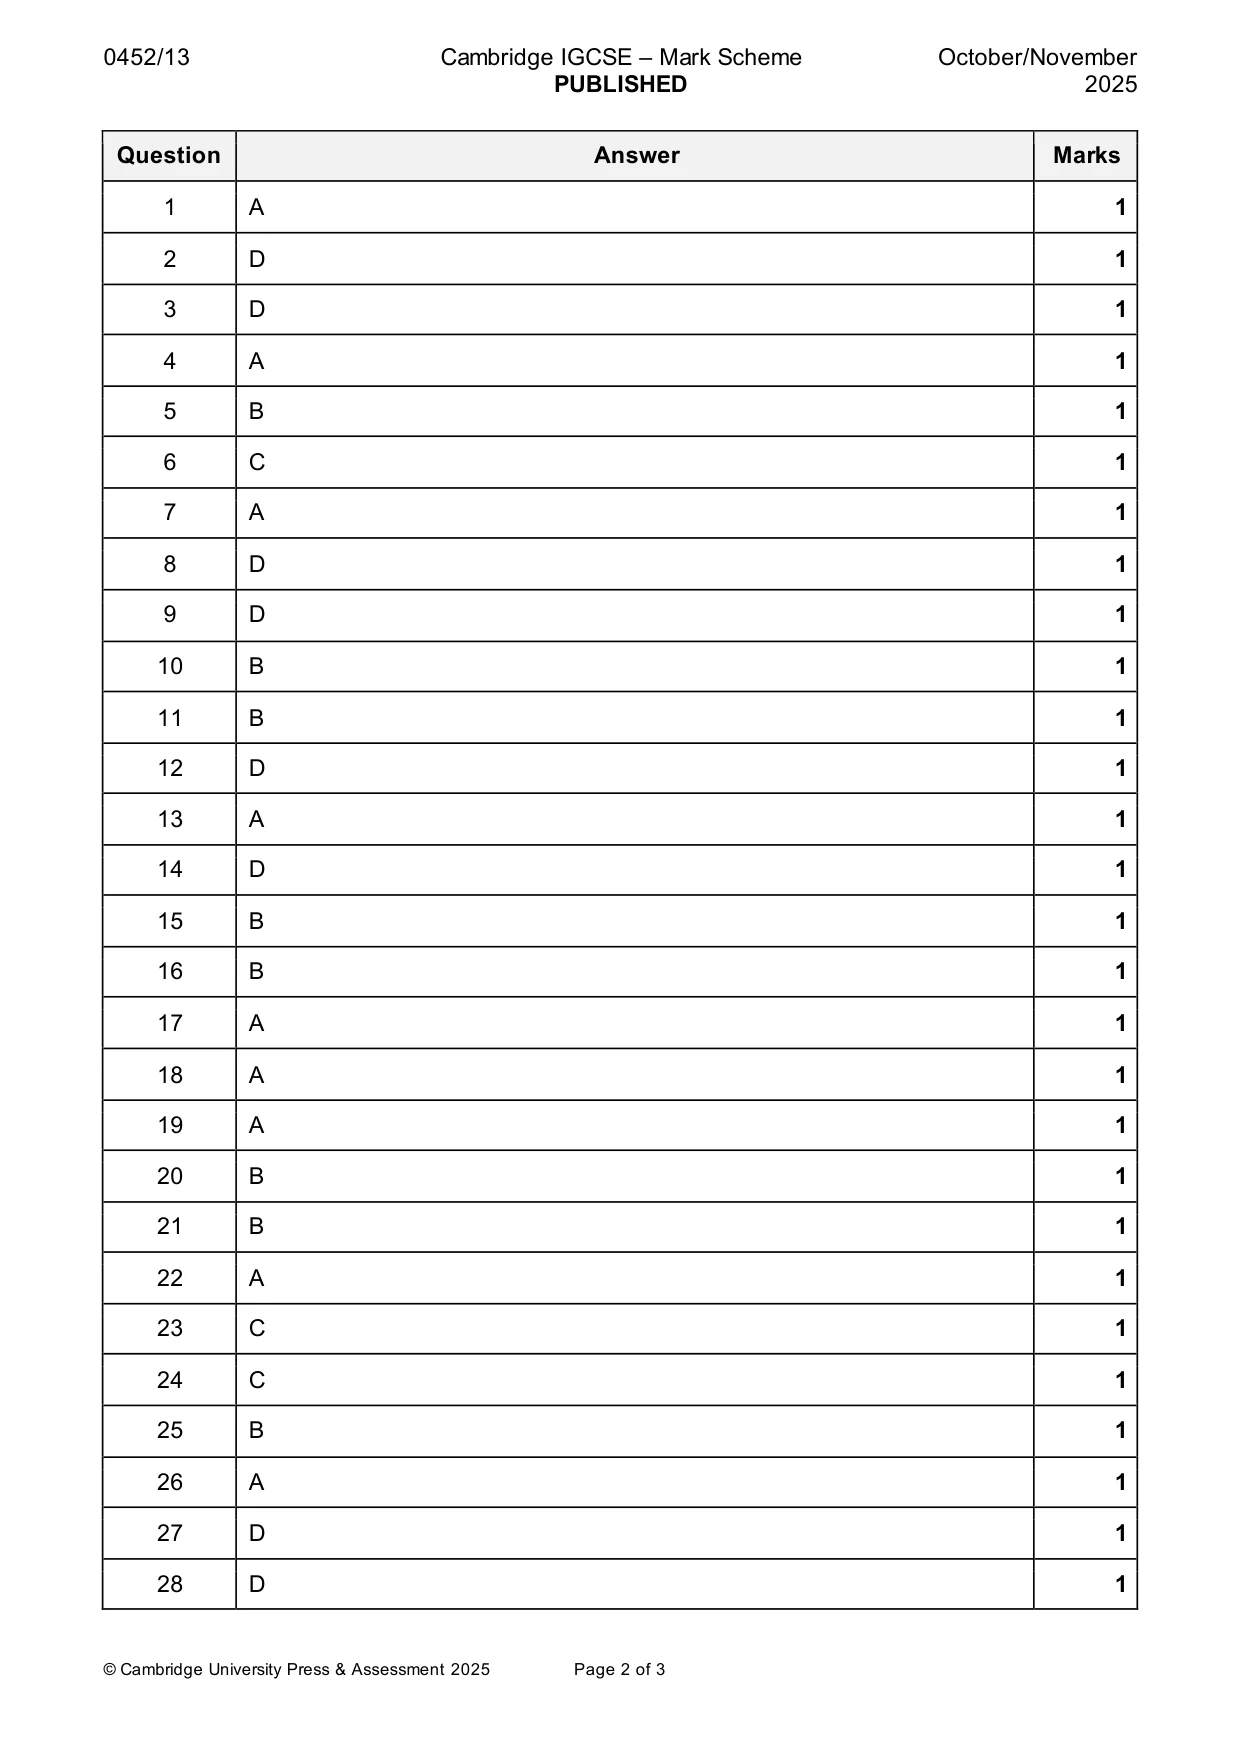
Mark scheme: A
Q2 · What increases owner’s capital?
2 What increases owner’s capital? A bank loan extended from five to ten years B purchase of inventory on credit C purchase of machinery by cheque D transfer of vehicle to the business from private use
Mark scheme: D
Q3 · Accounting data is processed through various stages using the double entry system
3 Accounting data is processed through various stages using the double entry system. Which stage checks the arithmetical accuracy of the double entry? A financial statements B journals C ledgers D trial balance
Mark scheme: D
Q4 · Ann is a trader
4 Ann is a trader. On 1 April, Cindy’s account in Ann’s ledger showed a credit balance of $520. The following transactions took place during April. April 2 Ann returned goods for $30 to Cindy. April 14 Ann bought goods for $210 from Cindy and paid in cash. Which statement about the balance on Cindy’s account in Ann’s ledger on 30 April is correct? A Ann owes Cindy $490. B Ann owes Cindy $700. C Cindy owes Ann $490. D Cindy owes Ann $700.
Mark scheme: A
Q5 · Hasina buys radios from Nazneen at a list price of $10 each
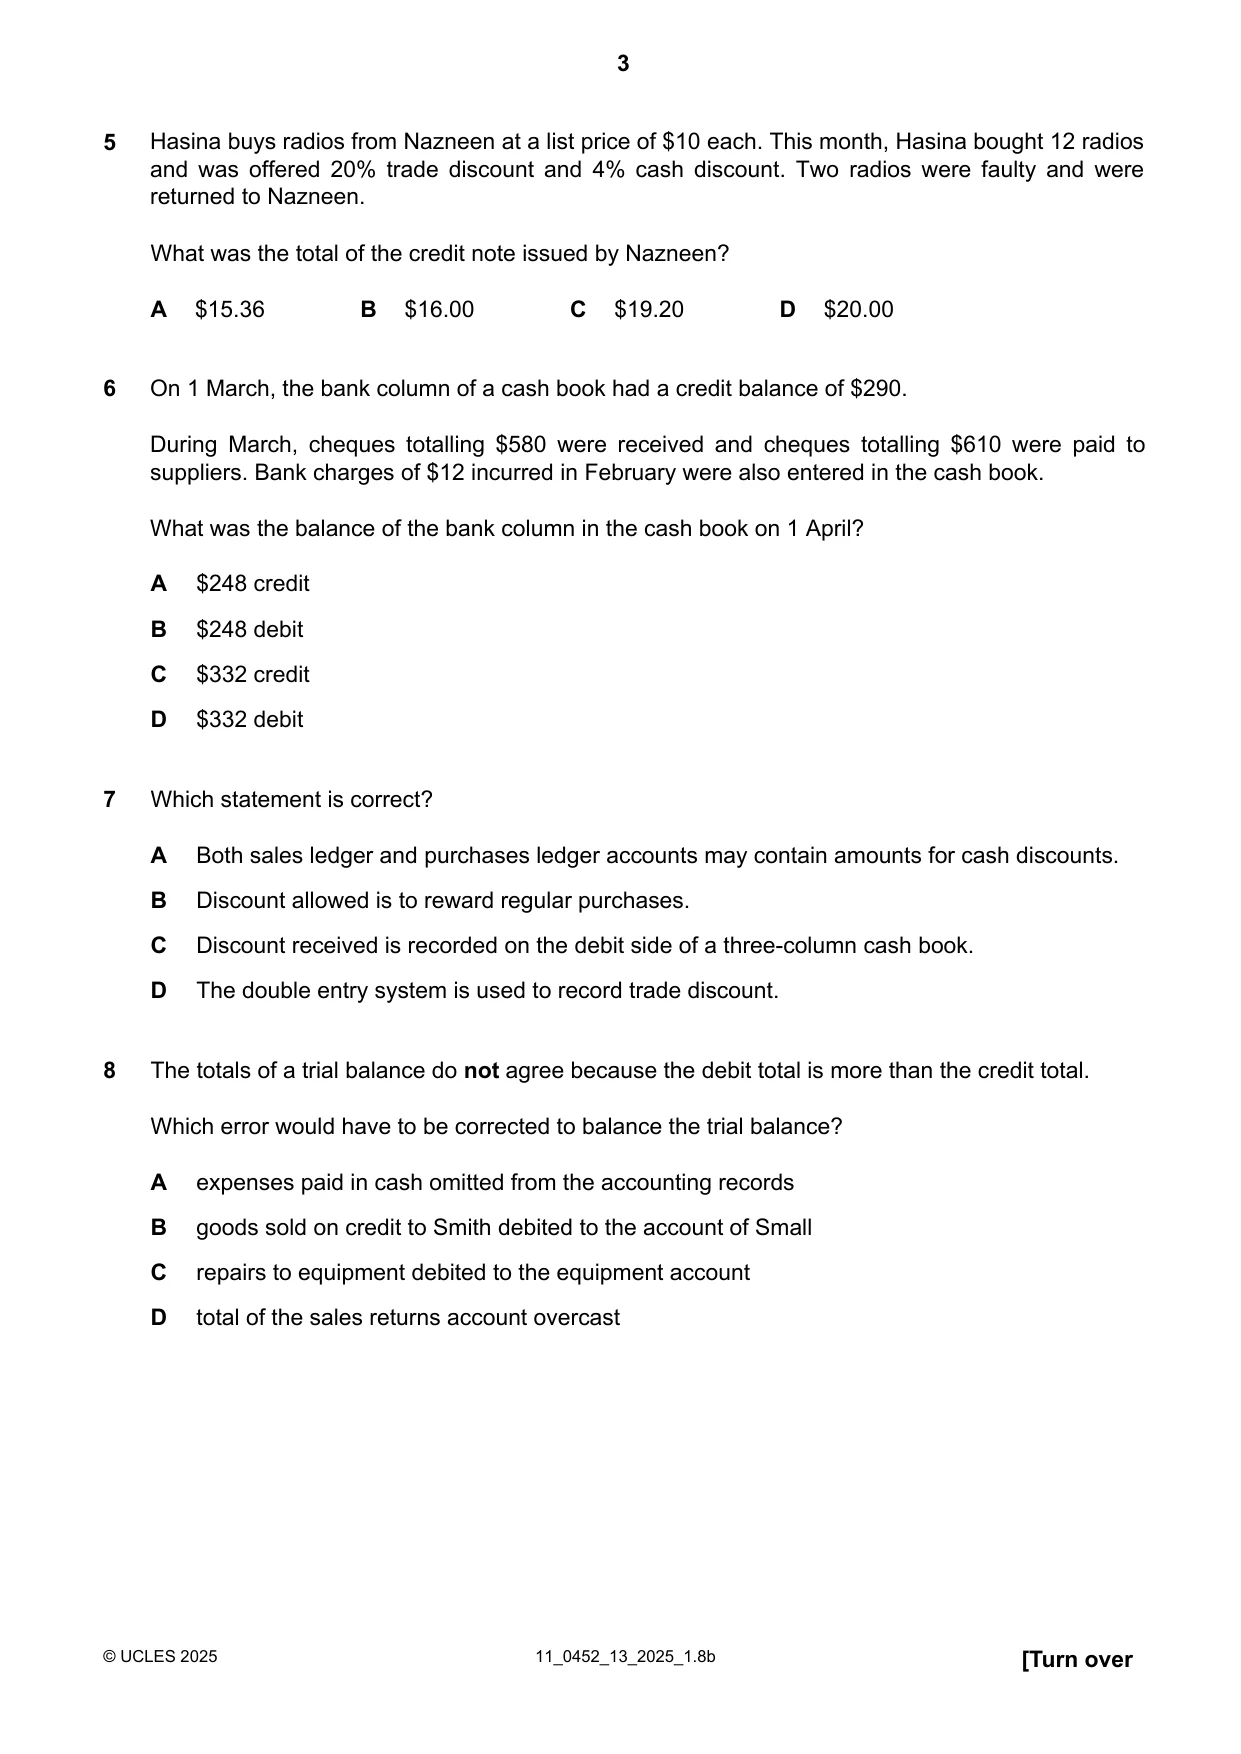
5 Hasina buys radios from Nazneen at a list price of $10 each. This month, Hasina bought 12 radios and was offered 20% trade discount and 4% cash discount. Two radios were faulty and were returned to Nazneen. What was the total of the credit note issued by Nazneen? A $15.36 B $16.00 C $19.20 D $20.00
Mark scheme: B
Q6 · On 1 March, the bank column of a cash book had a credit balance of $290
6 On 1 March, the bank column of a cash book had a credit balance of $290. During March, cheques totalling $580 were received and cheques totalling $610 were paid to suppliers. Bank charges of $12 incurred in February were also entered in the cash book. What was the balance of the bank column in the cash book on 1 April? A $248 credit B $248 debit C $332 credit D $332 debit
Mark scheme: C
Q7 · Which statement is correct?
7 Which statement is correct? A Both sales ledger and purchases ledger accounts may contain amounts for cash discounts. B Discount allowed is to reward regular purchases. C Discount received is recorded on the debit side of a three-column cash book. D The double entry system is used to record trade discount.
Mark scheme: A
Q8 · The totals of a trial balance do not agree because the debit total is more than the…
8 The totals of a trial balance do not agree because the debit total is more than the credit total. Which error would have to be corrected to balance the trial balance? A expenses paid in cash omitted from the accounting records B goods sold on credit to Smith debited to the account of Small C repairs to equipment debited to the equipment account D total of the sales returns account overcast
Mark scheme: D
Q9 · A trial balance did not agree, and a suspense account was opened
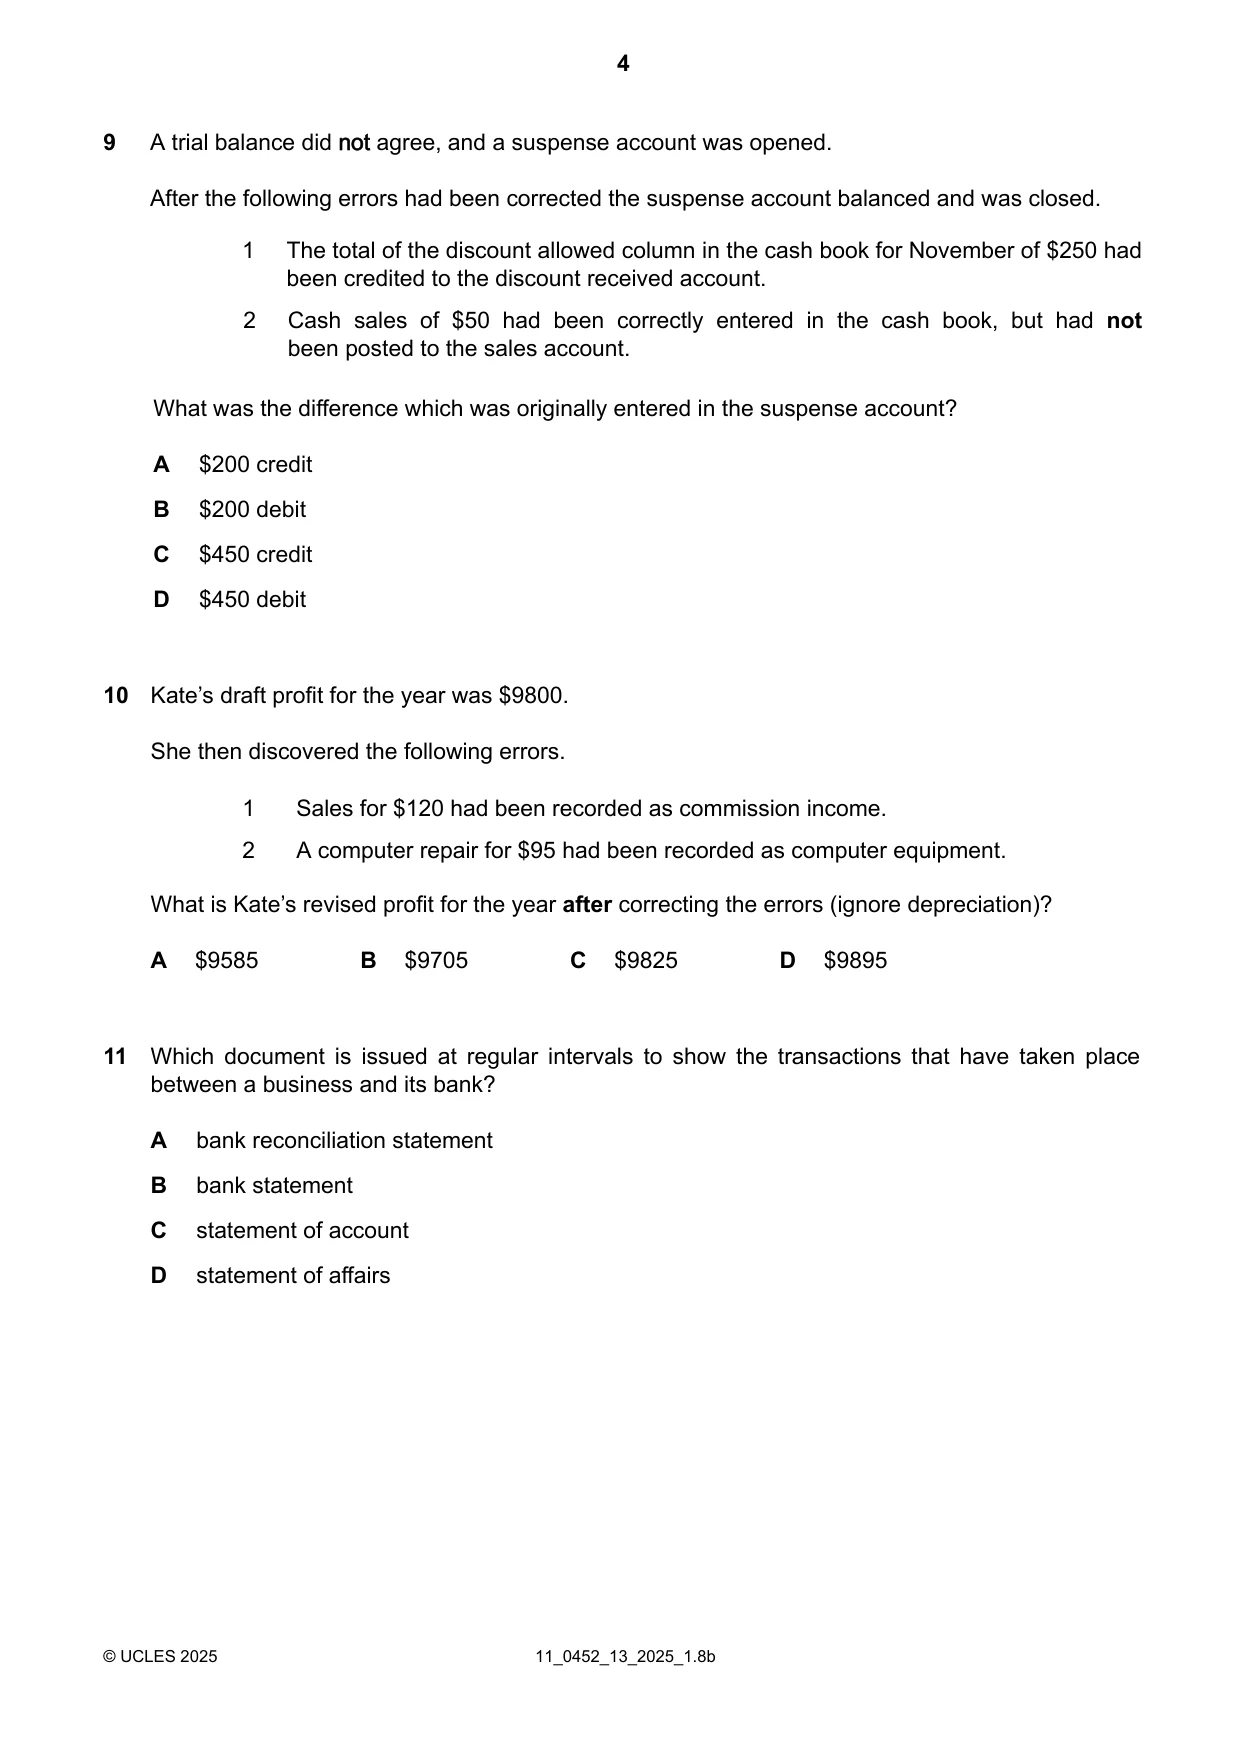
9 A trial balance did not agree, and a suspense account was opened. After the following errors had been corrected the suspense account balanced and was closed. 1 The total of the discount allowed column in the cash book for November of $250 had been credited to the discount received account. 2 Cash sales of $50 had been correctly entered in the cash book, but had not been posted to the sales account. What was the difference which was originally entered in the suspense account? A $200 credit B $200 debit C $450 credit D $450 debit
Mark scheme: D
Q10 · Kate’s draft profit for the year was $9800
10 Kate’s draft profit for the year was $9800. She then discovered the following errors. 1 Sales for $120 had been recorded as commission income. 2 A computer repair for $95 had been recorded as computer equipment. What is Kate’s revised profit for the year after correcting the errors (ignore depreciation)? A $9585 B $9705 C $9825 D $9895
Mark scheme: B
Q11 · Which document is issued at regular intervals to show the transactions that have taken…
11 Which document is issued at regular intervals to show the transactions that have taken place between a business and its bank? A bank reconciliation statement B bank statement C statement of account D statement of affairs
Mark scheme: B
Q12 · A standing order paid for rent has not been entered into the accounting records of a…
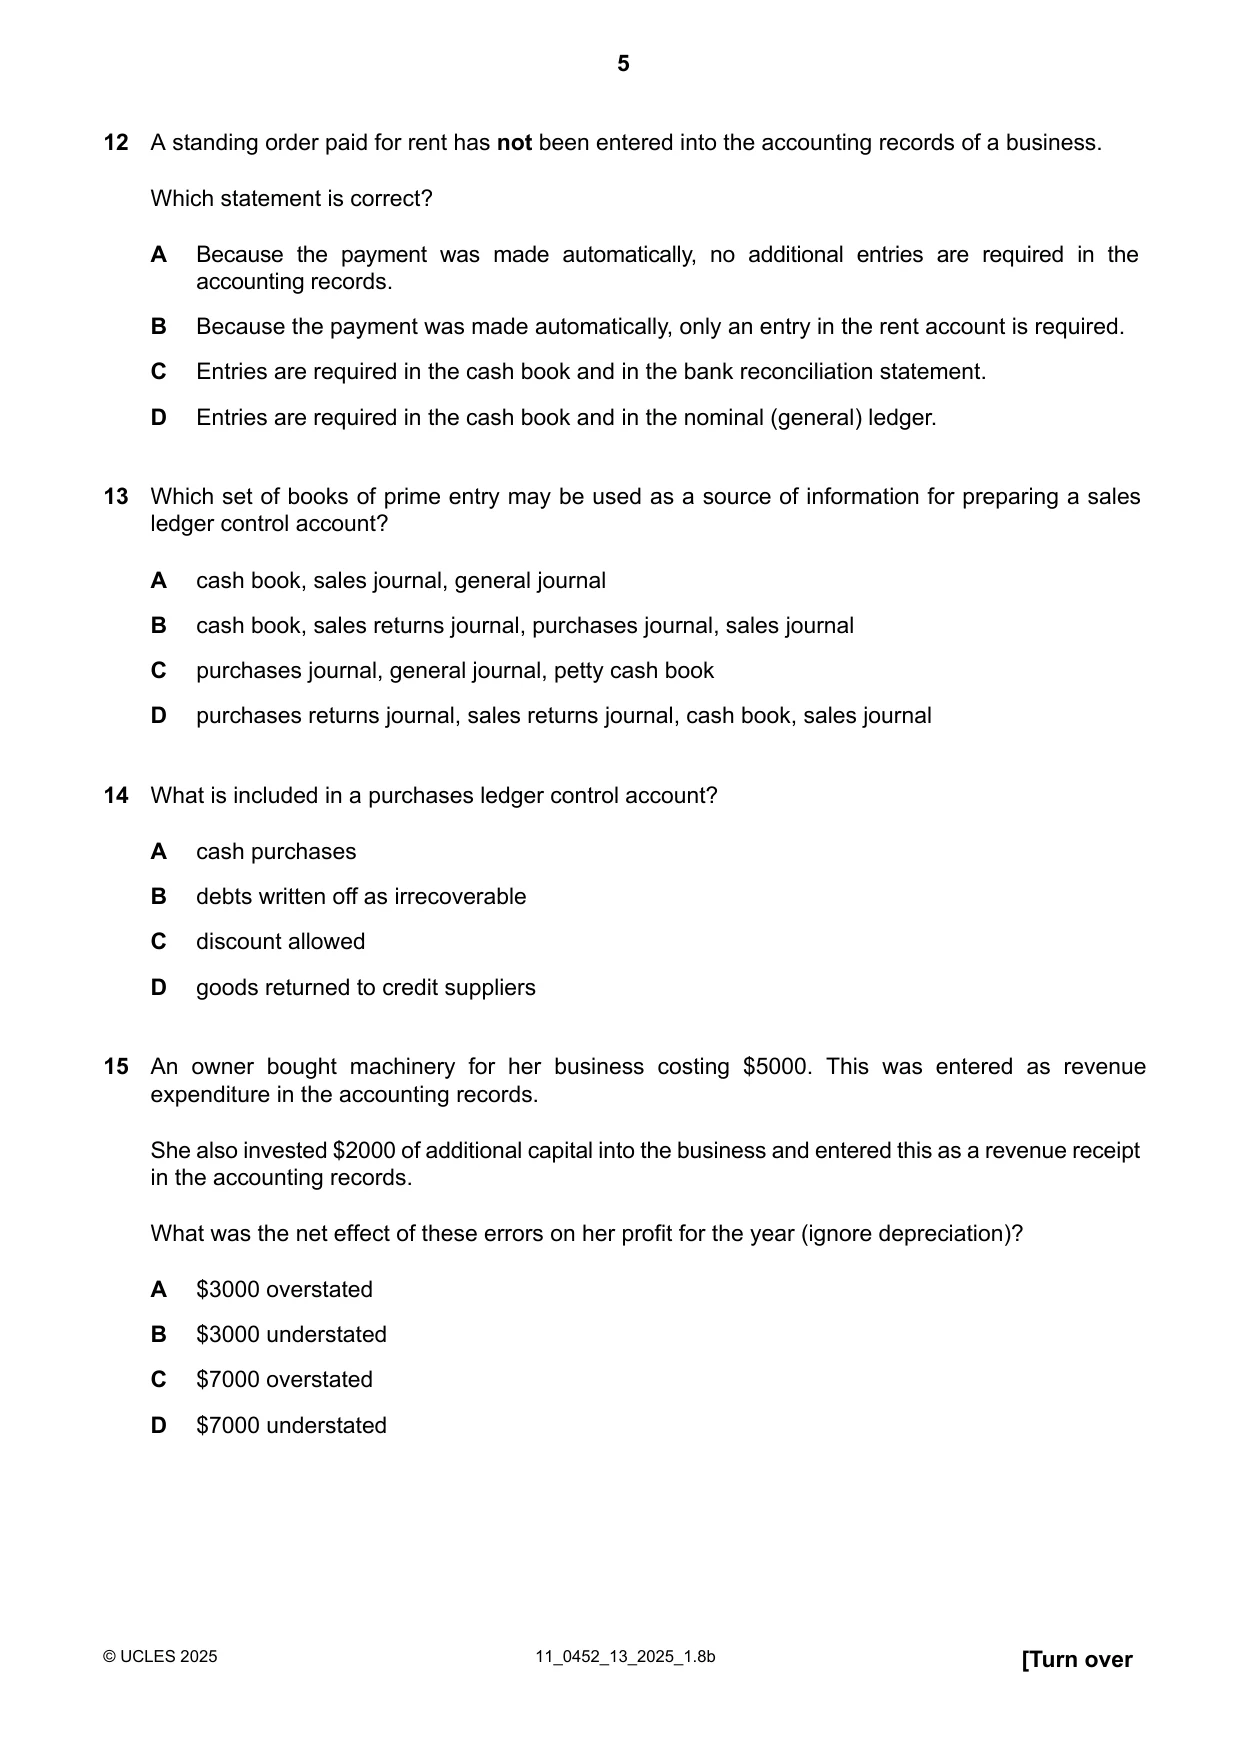
12 A standing order paid for rent has not been entered into the accounting records of a business. Which statement is correct? A Because the payment was made automatically, no additional entries are required in the accounting records. B Because the payment was made automatically, only an entry in the rent account is required. C Entries are required in the cash book and in the bank reconciliation statement. D Entries are required in the cash book and in the nominal (general) ledger.
Mark scheme: D
Q13 · Which set of books of prime entry may be used as a source of information for preparing a…
13 Which set of books of prime entry may be used as a source of information for preparing a sales ledger control account? A cash book, sales journal, general journal B cash book, sales returns journal, purchases journal, sales journal C purchases journal, general journal, petty cash book D purchases returns journal, sales returns journal, cash book, sales journal
Mark scheme: A
Q14 · What is included in a purchases ledger control account?
14 What is included in a purchases ledger control account? A cash purchases B debts written off as irrecoverable C discount allowed D goods returned to credit suppliers
Mark scheme: D
Q15 · An owner bought machinery for her business costing $5000
15 An owner bought machinery for her business costing $5000. This was entered as revenue expenditure in the accounting records. She also invested $2000 of additional capital into the business and entered this as a revenue receipt in the accounting records. What was the net effect of these errors on her profit for the year (ignore depreciation)? A $3000 overstated B $3000 understated C $7000 overstated D $7000 understated
Mark scheme: B
More questions on Capital and revenue expenditure and receipts
Q16 · A motor vehicle was bought by T Limited for $30000 on 1 January 2022
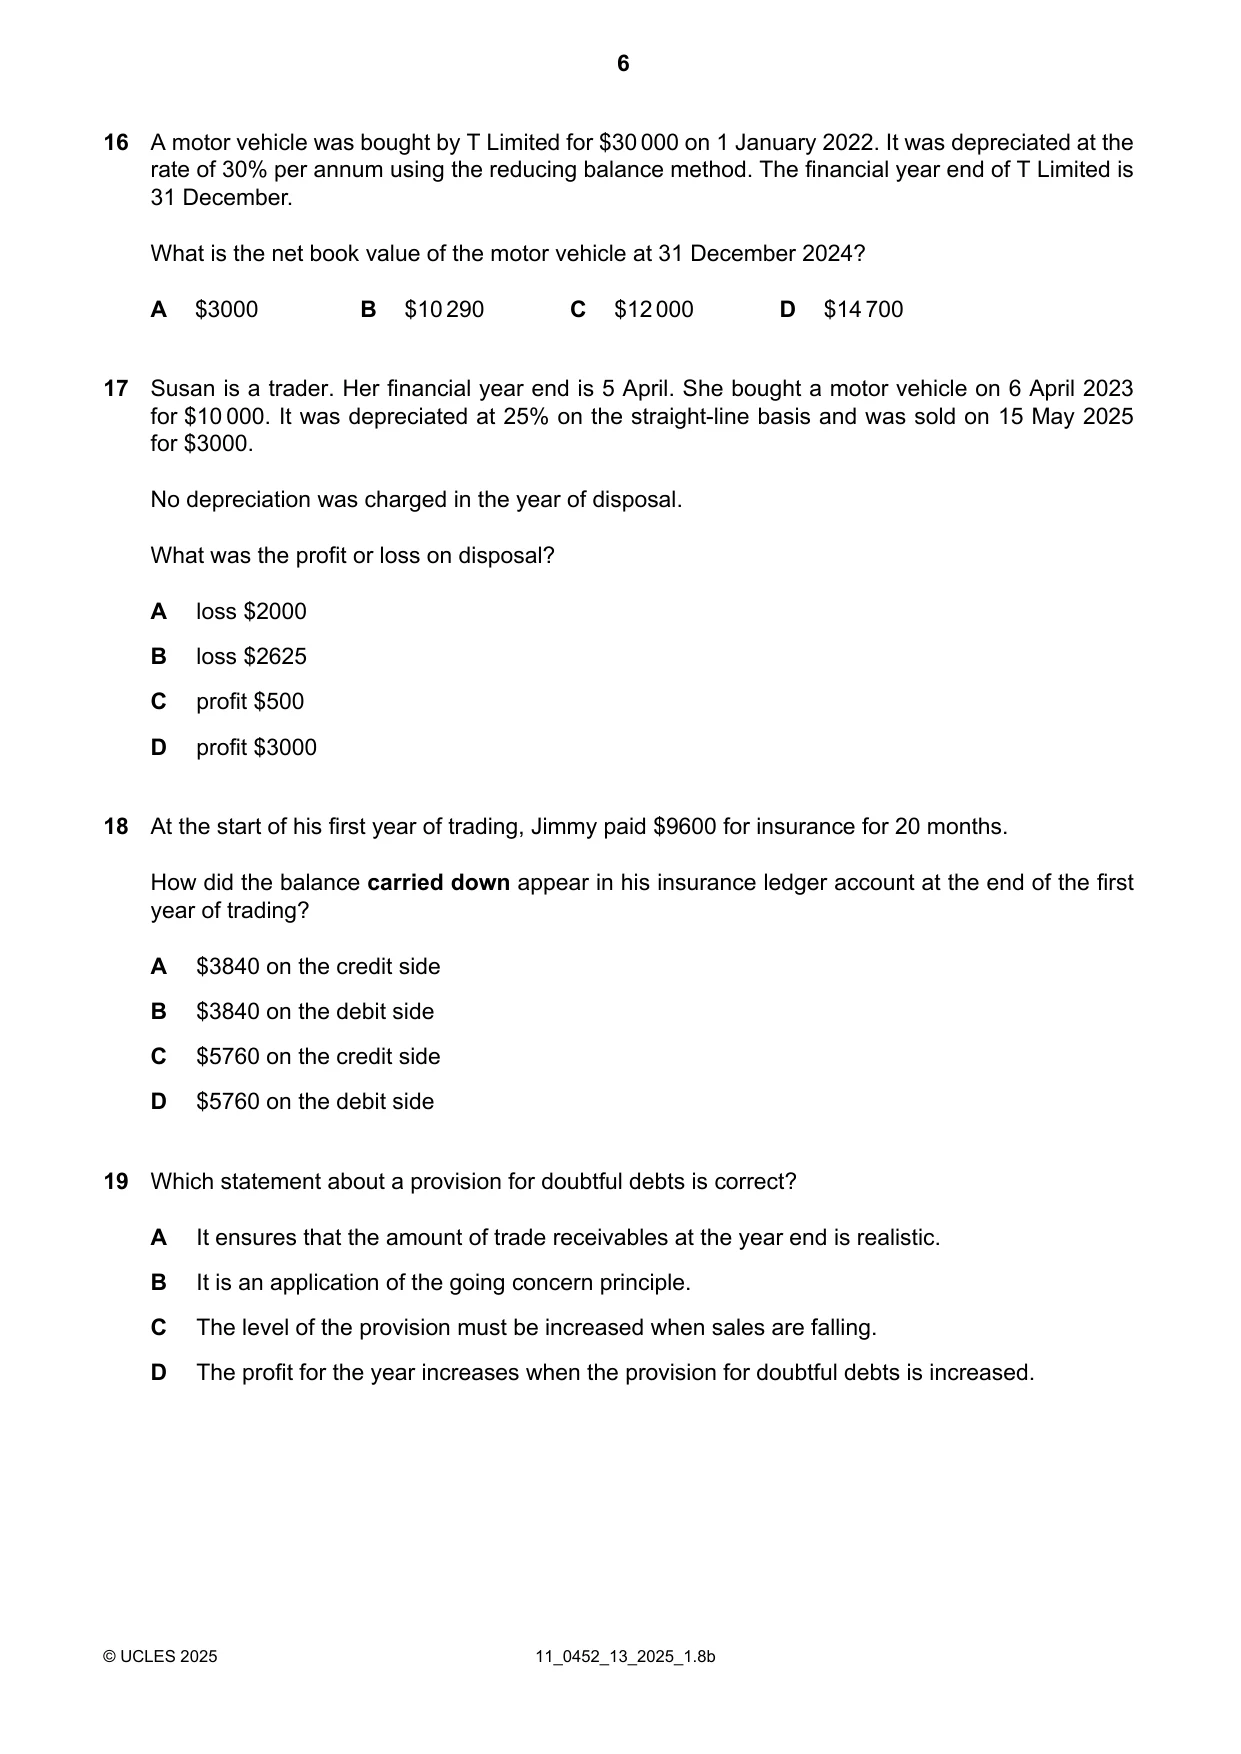
16 A motor vehicle was bought by T Limited for $30000 on 1 January 2022. It was depreciated at the rate of 30% per annum using the reducing balance method. The financial year end of T Limited is 31 December. What is the net book value of the motor vehicle at 31 December 2024? A $3000 B $10290 C $12000 D $14700
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q17 · Susan is a trader
17 Susan is a trader. Her financial year end is 5 April. She bought a motor vehicle on 6 April 2023 for $10 000. It was depreciated at 25% on the straight-line basis and was sold on 15 May 2025 for $3000. No depreciation was charged in the year of disposal. What was the profit or loss on disposal? A loss $2000 B loss $2625 C profit $500 D profit $3000
Mark scheme: A
More questions on Accounting for depreciation and disposal of non-current assets
Q18 · At the start of his first year of trading, Jimmy paid $9600 for insurance for 20 months
18 At the start of his first year of trading, Jimmy paid $9600 for insurance for 20 months. How did the balance carried down appear in his insurance ledger account at the end of the first year of trading? A $3840 on the credit side B $3840 on the debit side C $5760 on the credit side D $5760 on the debit side
Mark scheme: A
Q19 · Which statement about a provision for doubtful debts is correct?
19 Which statement about a provision for doubtful debts is correct? A It ensures that the amount of trade receivables at the year end is realistic. B It is an application of the going concern principle. C The level of the provision must be increased when sales are falling. D The profit for the year increases when the provision for doubtful debts is increased.
Mark scheme: A
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q20 · A company provided the following information about its closing inventory
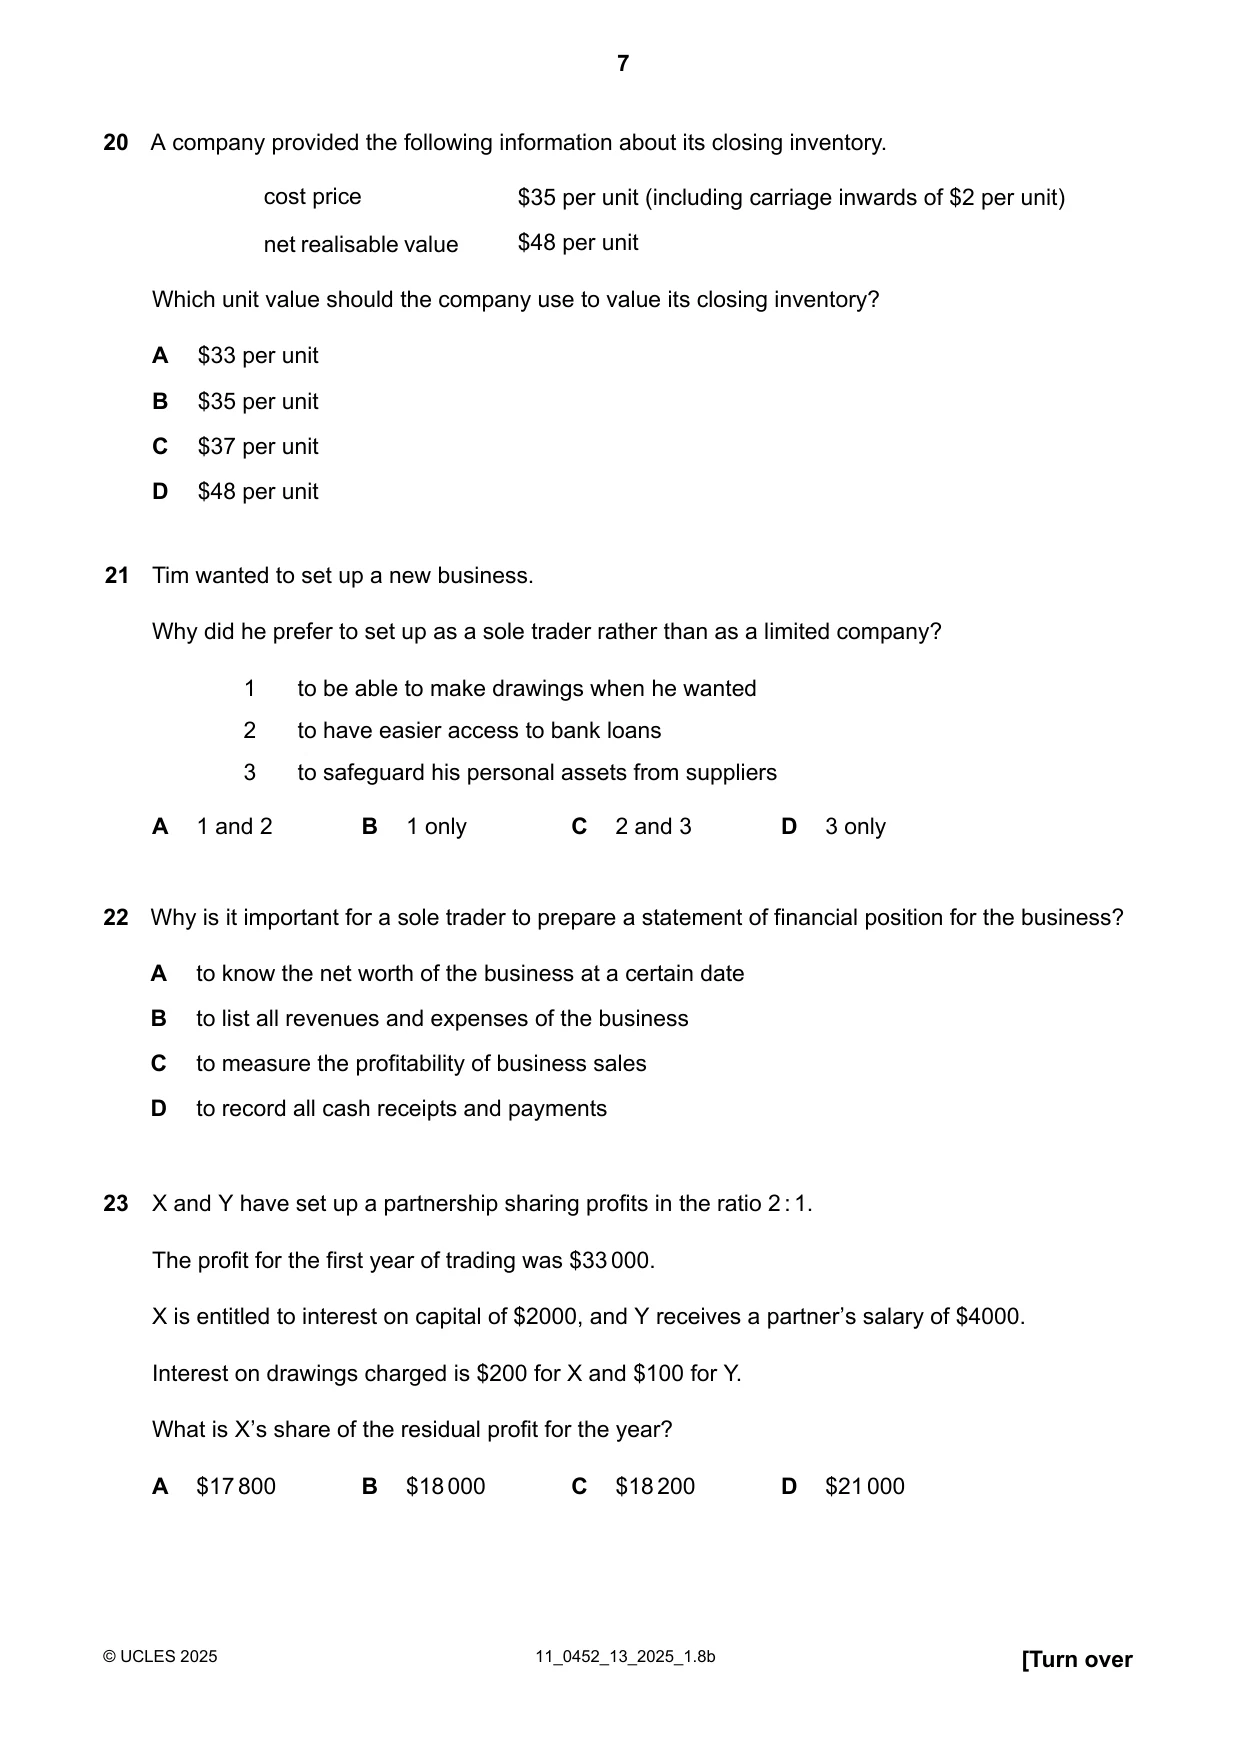
20 A company provided the following information about its closing inventory. cost price $35 per unit (including carriage inwards of $2 per unit) net realisable value $48 per unit Which unit value should the company use to value its closing inventory? A $33 per unit B $35 per unit C $37 per unit D $48 per unit
Mark scheme: B
Q21 · Tim wanted to set up a new business
21 Tim wanted to set up a new business. Why did he prefer to set up as a sole trader rather than as a limited company? 1 to be able to make drawings when he wanted 2 to have easier access to bank loans 3 to safeguard his personal assets from suppliers A 1 and 2 B 1 only C 2 and 3 D 3 only
Mark scheme: B
Q22 · Why is it important for a sole trader to prepare a statement of financial position for…
22 Why is it important for a sole trader to prepare a statement of financial position for the business? A to know the net worth of the business at a certain date B to list all revenues and expenses of the business C to measure the profitability of business sales D to record all cash receipts and payments
Mark scheme: A
Q23 · X and Y have set up a partnership sharing profits in the ratio 2 : 1
23 X and Y have set up a partnership sharing profits in the ratio 2 : 1. The profit for the first year of trading was $33 000. X is entitled to interest on capital of $2000, and Y receives a partner’s salary of $4000. Interest on drawings charged is $200 for X and $100 for Y. What is X’s share of the residual profit for the year? A $17 800 B $18 000 C $18 200 D $21 000
Mark scheme: C
Q24 · What is the correct order of preparing accounts for a partnership?
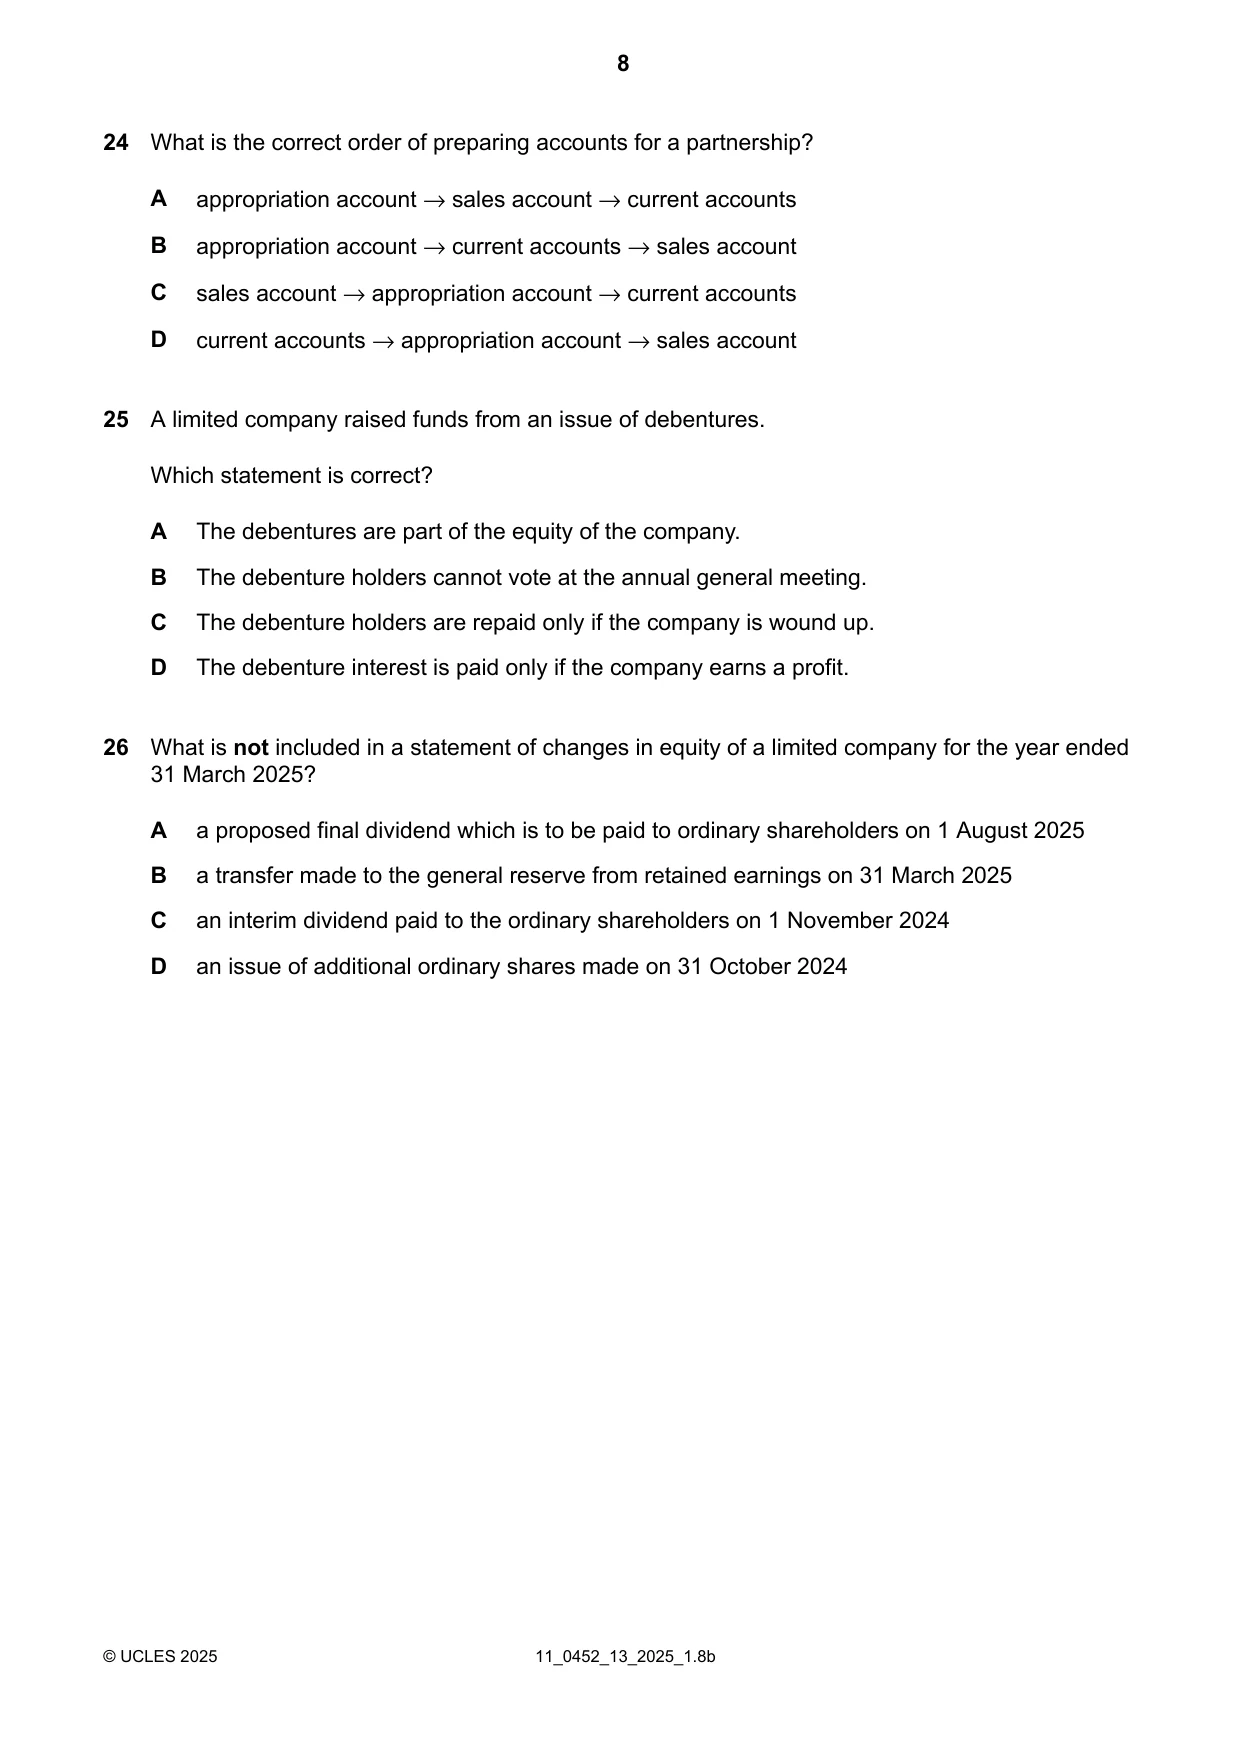
24 What is the correct order of preparing accounts for a partnership? A appropriation account →sales account →current accounts B appropriation account →current accounts →sales account C sales account →appropriation account →current accounts D current accounts →appropriation account →sales account
Mark scheme: C
Q25 · A limited company raised funds from an issue of debentures
25 A limited company raised funds from an issue of debentures. Which statement is correct? A The debentures are part of the equity of the company. B The debenture holders cannot vote at the annual general meeting. C The debenture holders are repaid only if the company is wound up. D The debenture interest is paid only if the company earns a profit.
Mark scheme: B
Q26 · What is not included in a statement of changes in equity of a limited company for the…
26 What is not included in a statement of changes in equity of a limited company for the year ended 31 March 2025? A a proposed final dividend which is to be paid to ordinary shareholders on 1 August 2025 B a transfer made to the general reserve from retained earnings on 31 March 2025 C an interim dividend paid to the ordinary shareholders on 1 November 2024 D an issue of additional ordinary shares made on 31 October 2024
Mark scheme: A
Q27 · A club’s income and expenditure for the year was as follows: $ $ income: subscriptions…
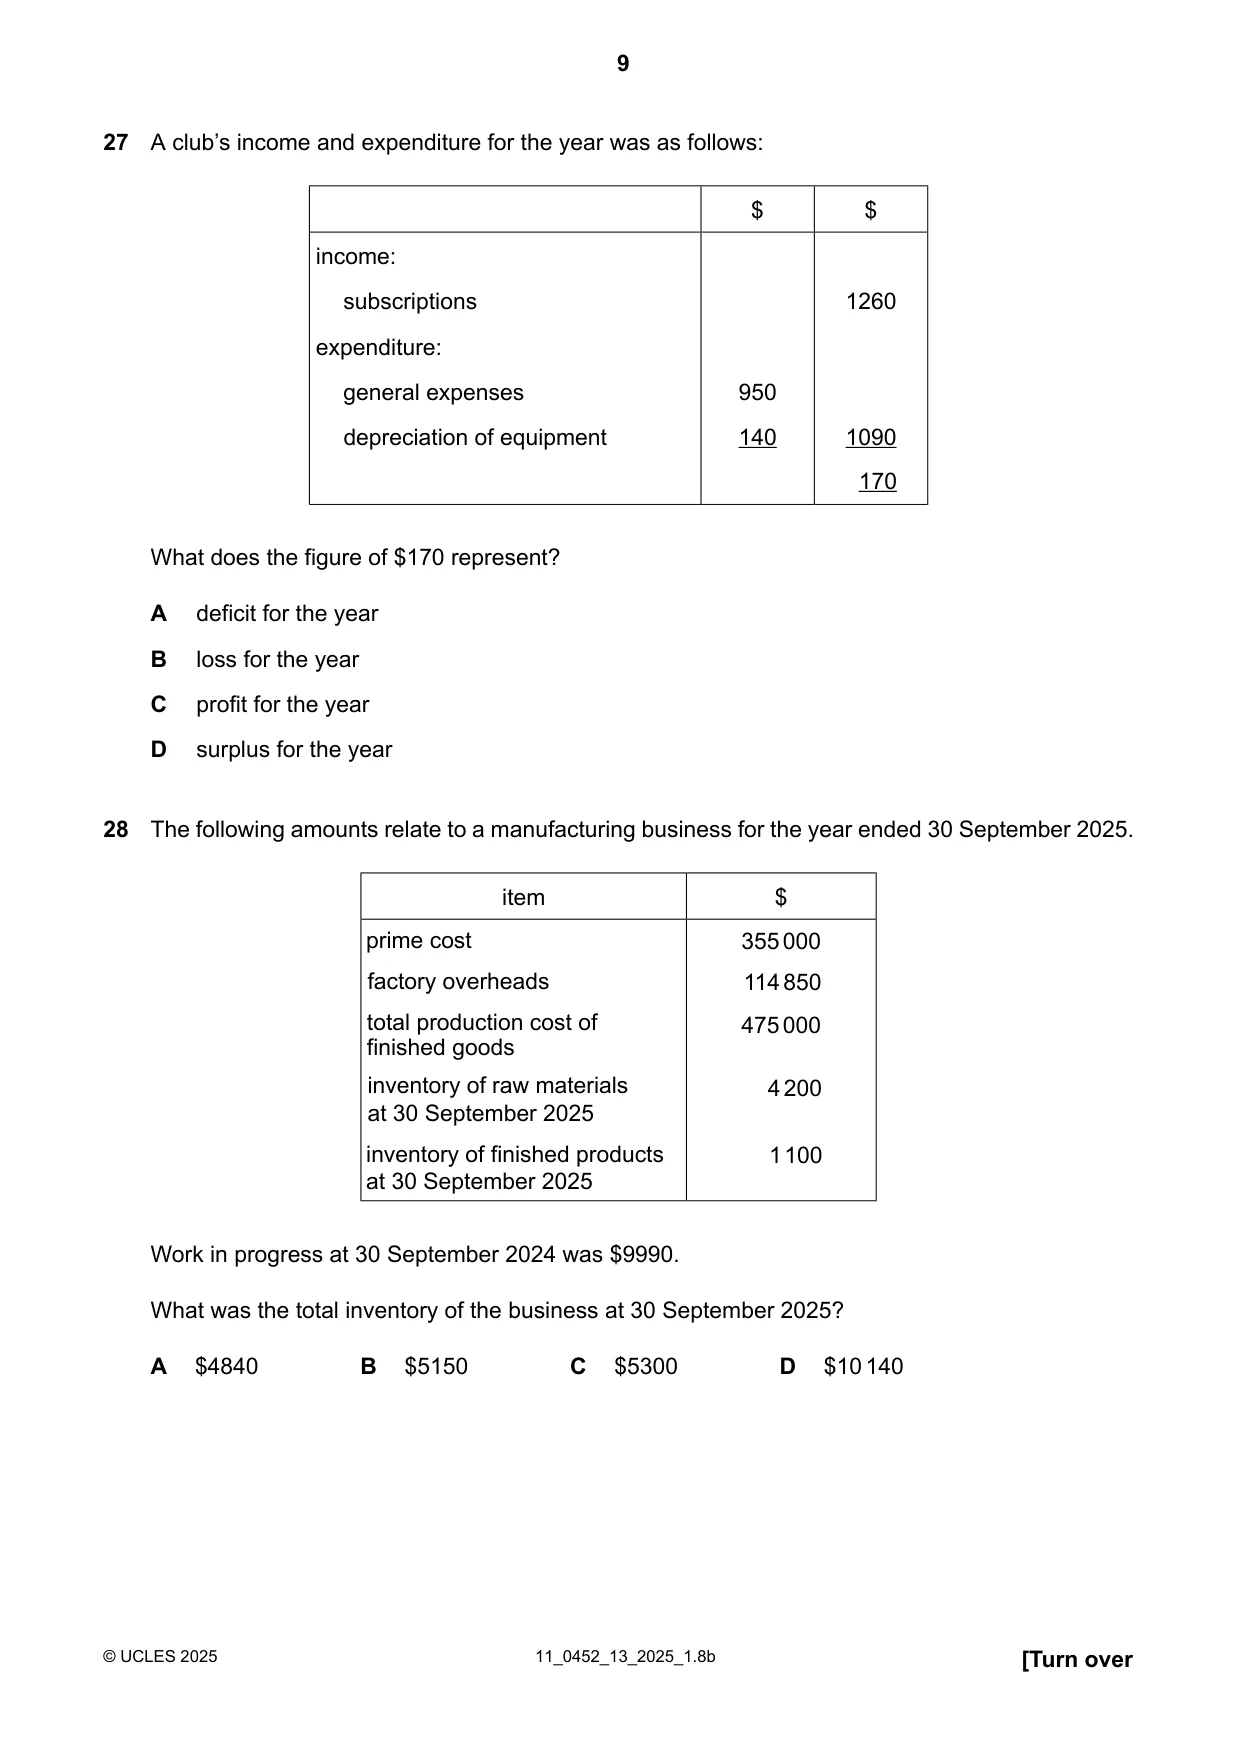
27 A club’s income and expenditure for the year was as follows: $ $ income: subscriptions 1260 expenditure: general expenses 950 depreciation of equipment 140 1090 170 What does the figure of $170 represent? A deficit for the year B loss for the year C profit for the year D surplus for the year
Mark scheme: D
Q28 · The following amounts relate to a manufacturing business for the year ended 30 September…
28 The following amounts relate to a manufacturing business for the year ended 30 September 2025. item $ prime cost 355000 factory overheads 114 850 total production cost of 475000 finished goods inventory of raw materials 4200 at 30 September 2025 inventory of finished products 1 100 at 30 September 2025 Work in progress at 30 September 2024 was $9990. What was the total inventory of the business at 30 September 2025? A $4840 B $5150 C $5300 D $10140
Mark scheme: D
Q29 · A manufacturing account and income statement are being prepared for a business that makes…
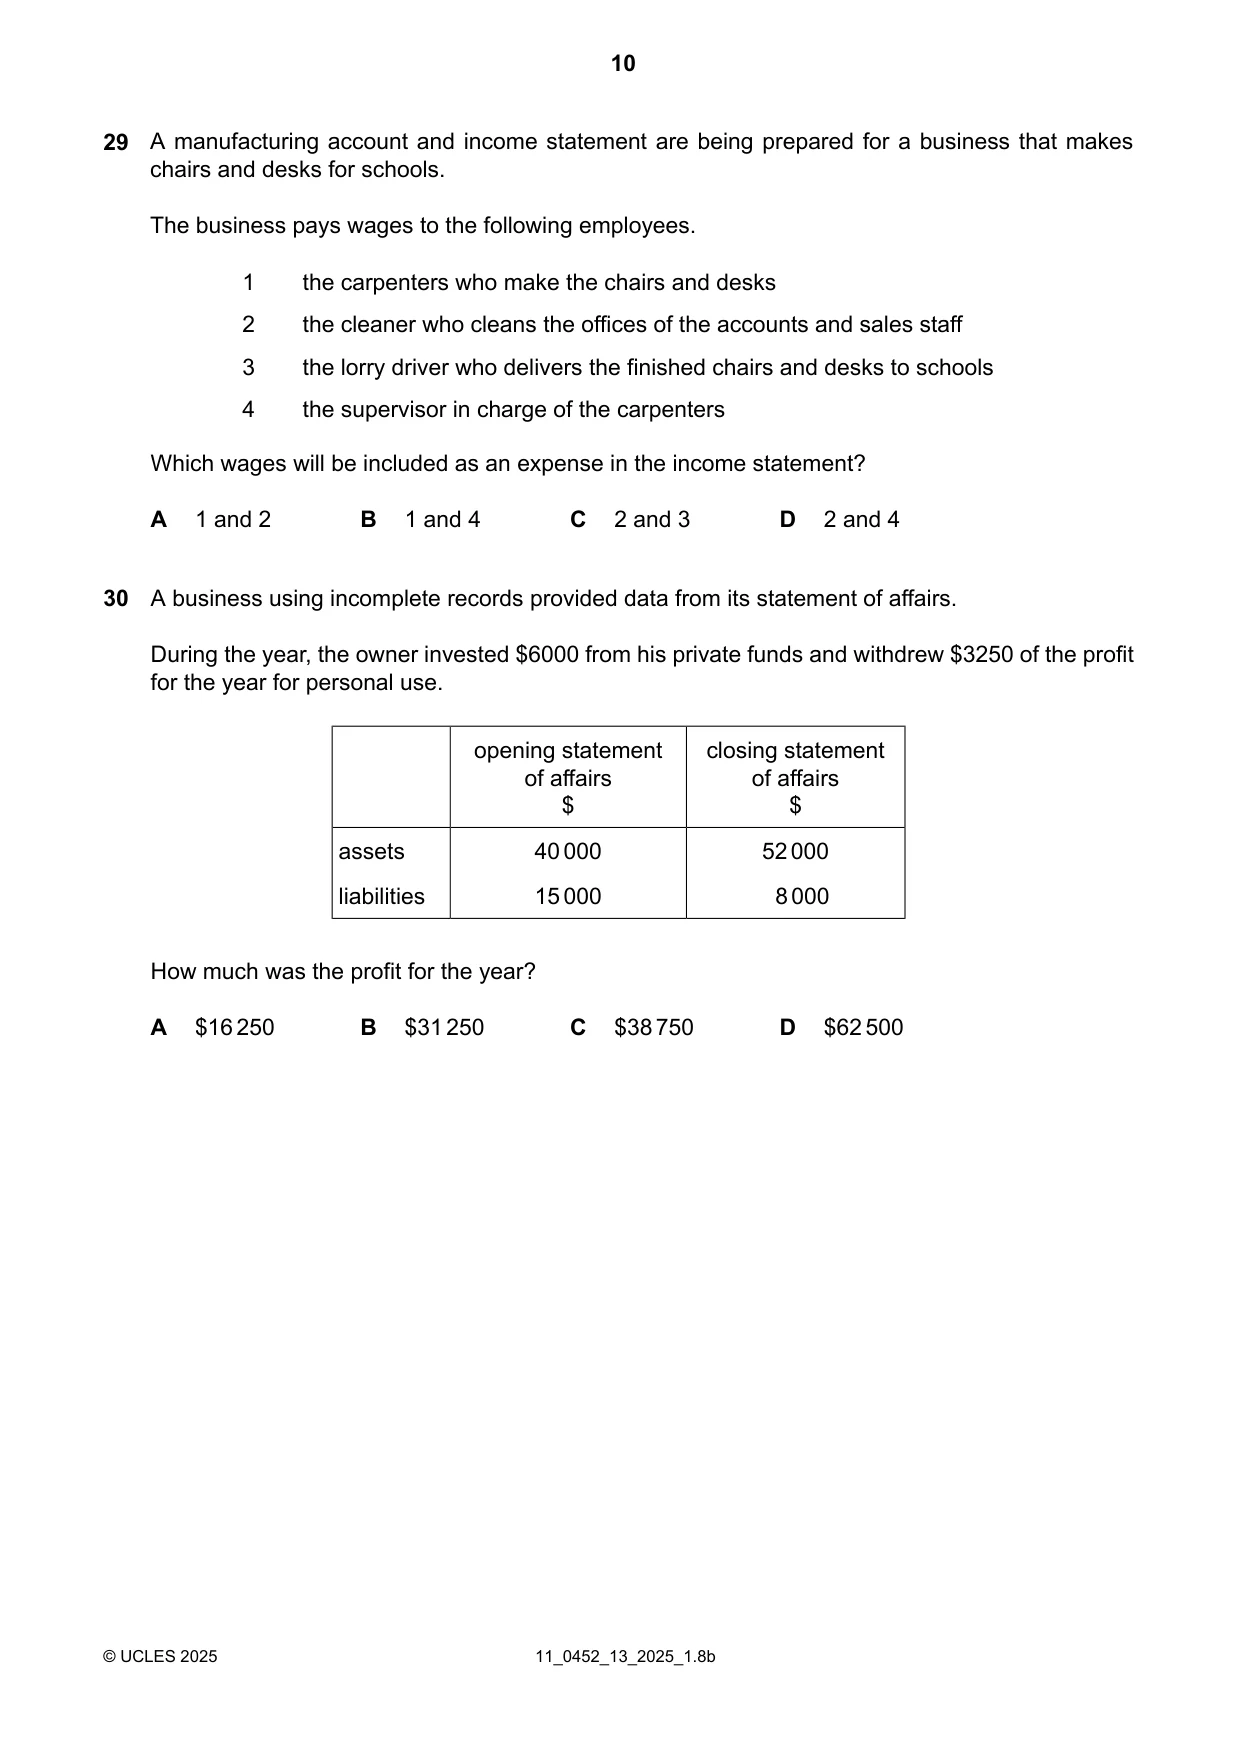
29 A manufacturing account and income statement are being prepared for a business that makes chairs and desks for schools. The business pays wages to the following employees. 1 the carpenters who make the chairs and desks 2 the cleaner who cleans the offices of the accounts and sales staff 3 the lorry driver who delivers the finished chairs and desks to schools 4 the supervisor in charge of the carpenters Which wages will be included as an expense in the income statement? A 1 and 2 B 1 and 4 C 2 and 3 D 2 and 4
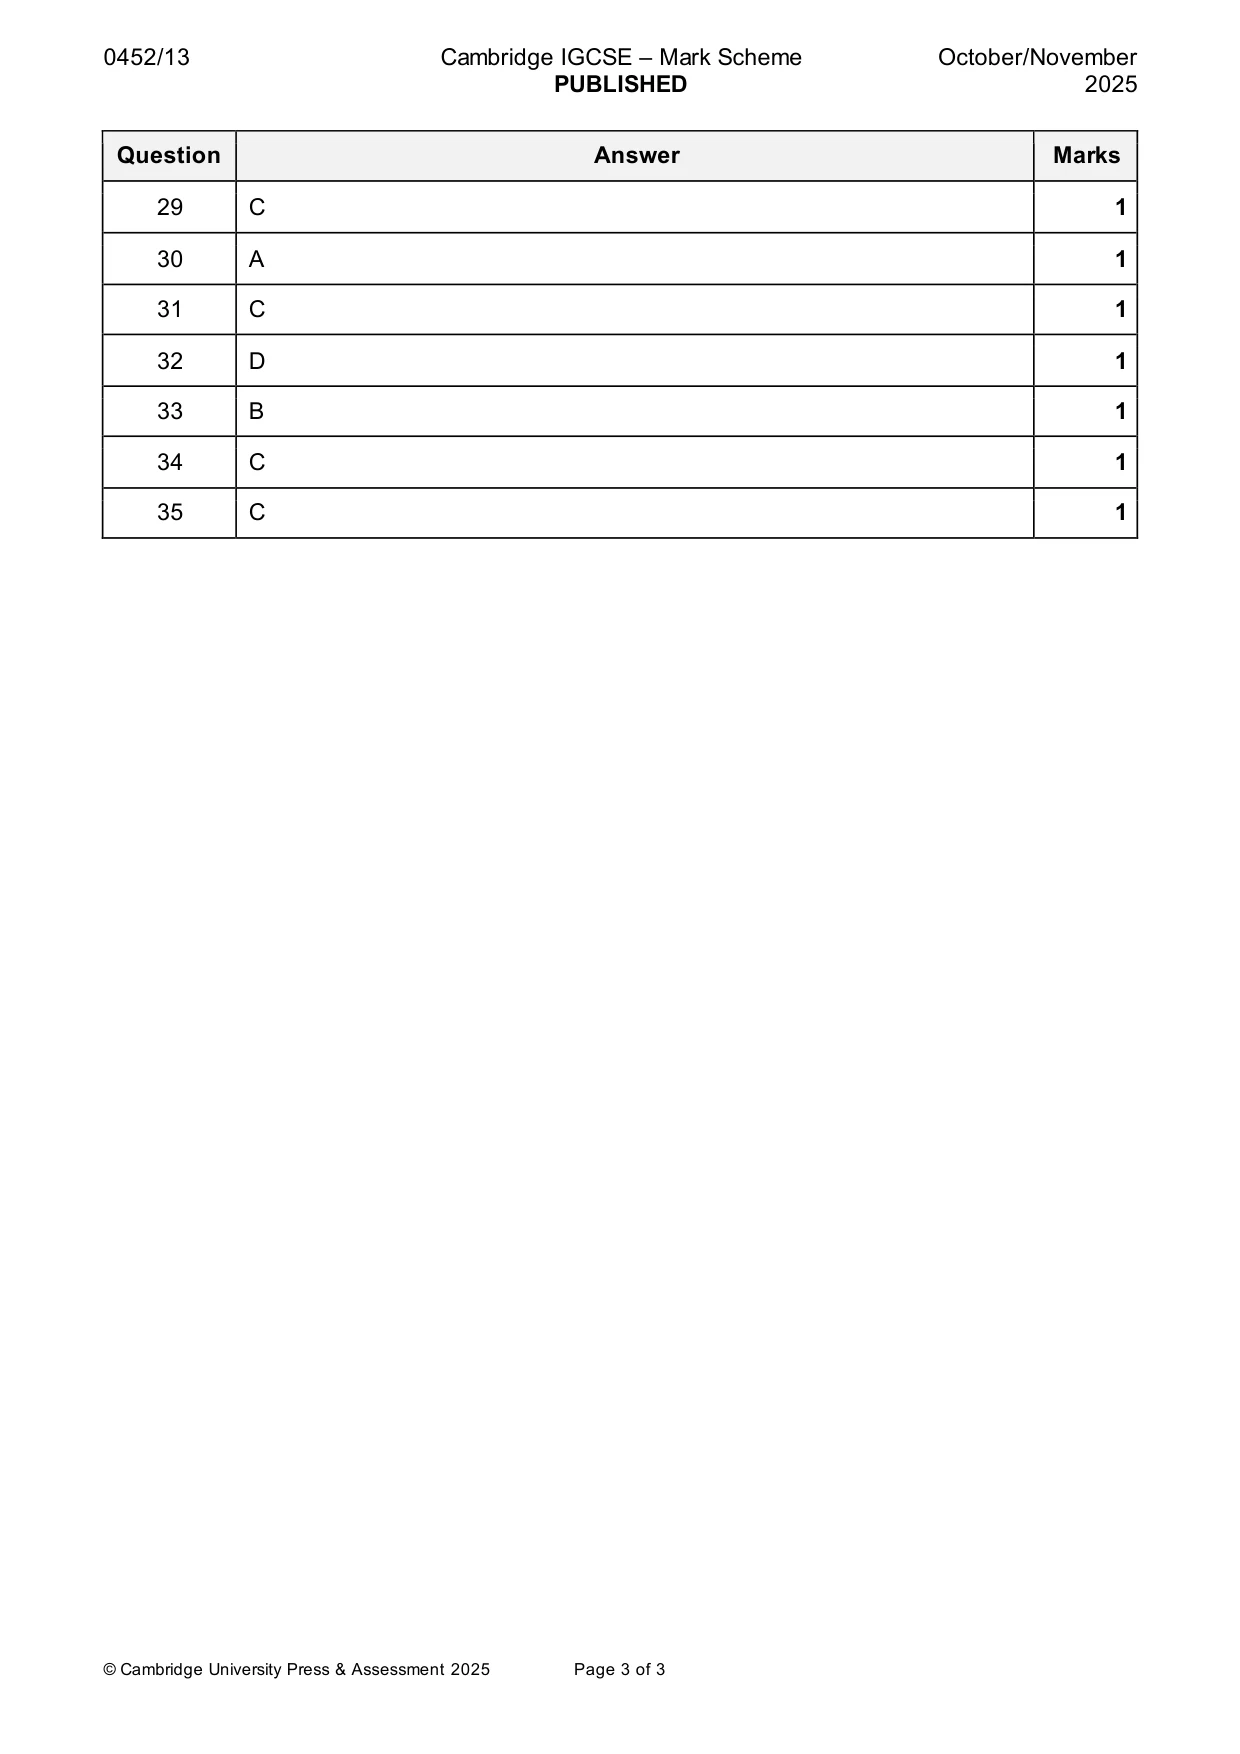
Mark scheme: C
Q30 · A business using incomplete records provided data from its statement of affairs
30 A business using incomplete records provided data from its statement of affairs. During the year, the owner invested $6000 from his private funds and withdrew $3250 of the profit for the year for personal use. opening statement closing statement of affairs of affairs $ $ assets 40000 52000 liabilities 15000 8000 How much was the profit for the year? A $16250 B $31250 C $38750 D $62500
Mark scheme: A
Q31 · Joseph does not maintain a full set of accounting records
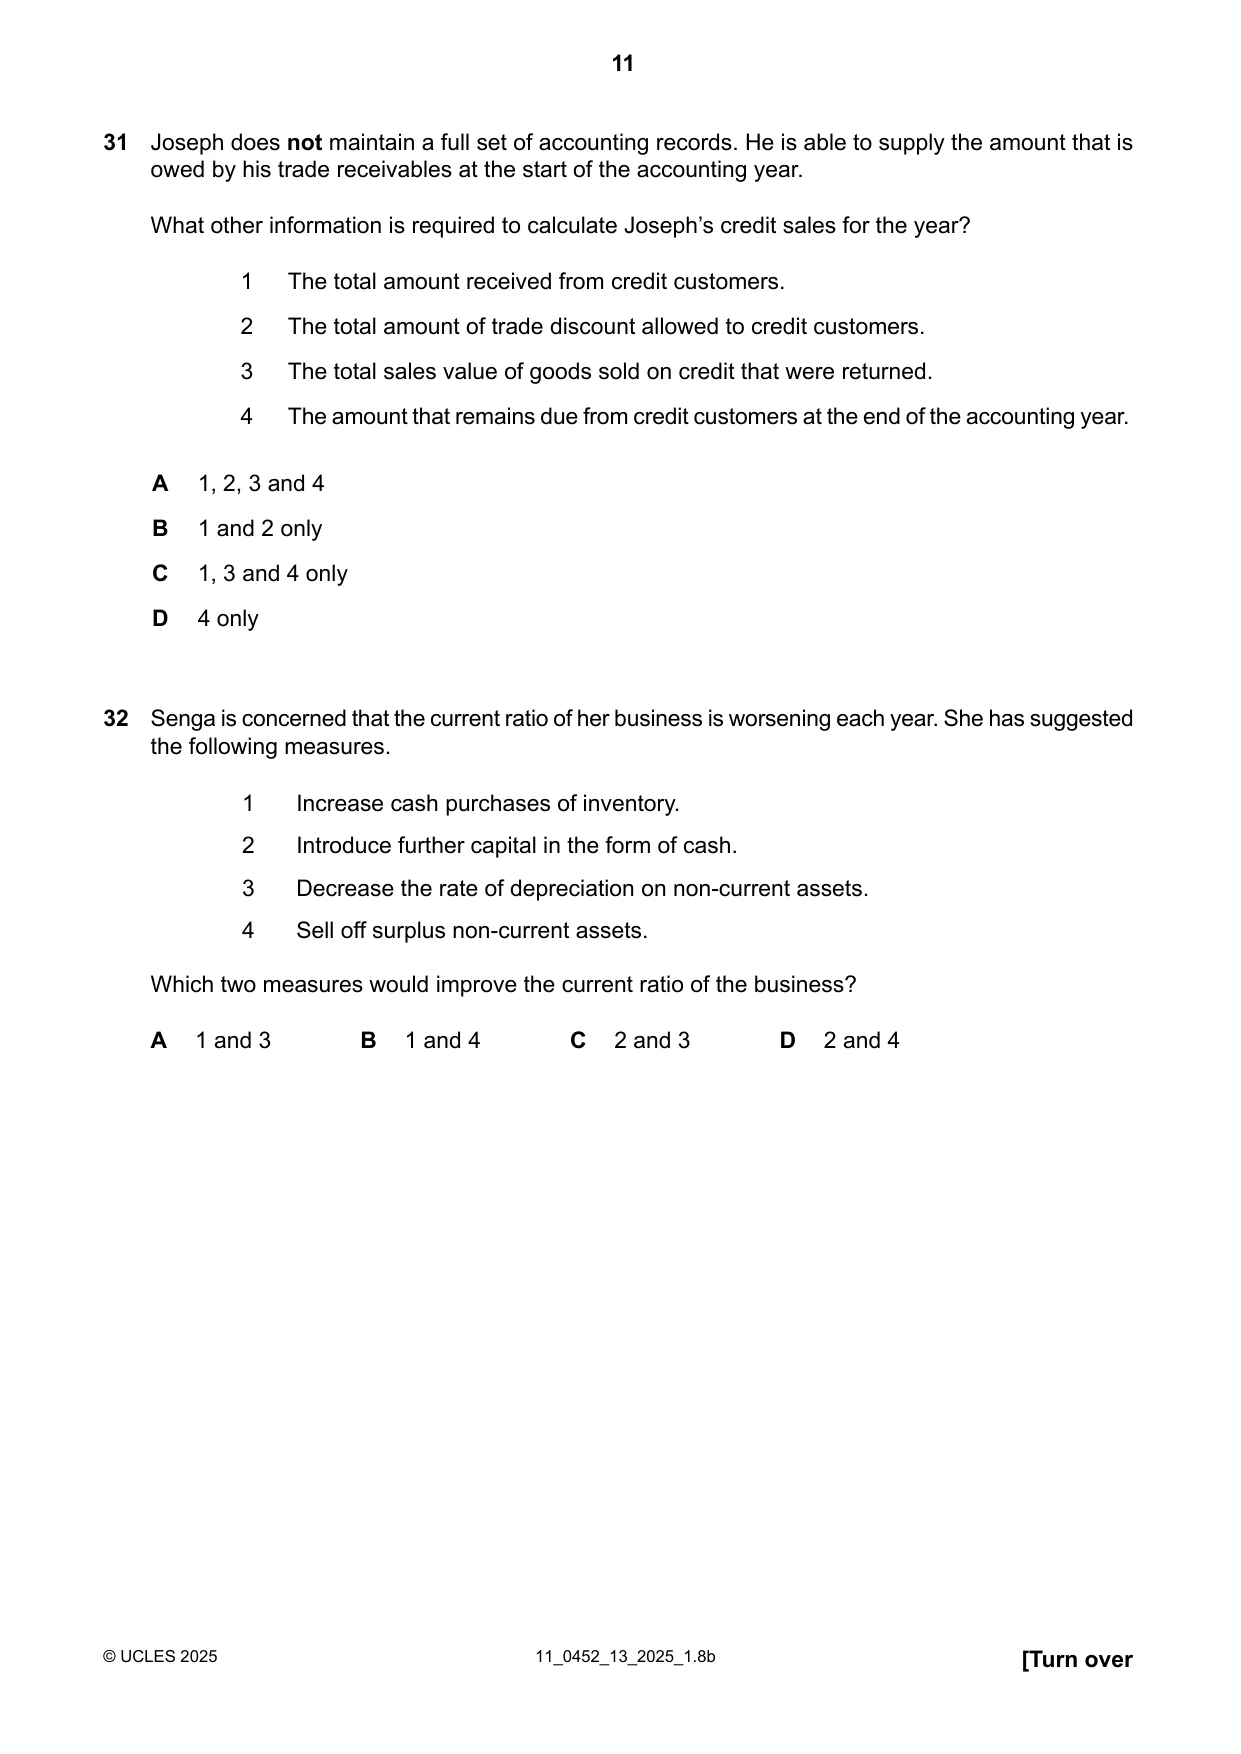
31 Joseph does not maintain a full set of accounting records. He is able to supply the amount that is owed by his trade receivables at the start of the accounting year. What other information is required to calculate Joseph’s credit sales for the year? 1 The total amount received from credit customers. 2 The total amount of trade discount allowed to credit customers. 3 The total sales value of goods sold on credit that were returned. 4 The amount that remains due from credit customers at the end of the accounting year. A 1, 2, 3 and 4 B 1 and 2 only C 1, 3 and 4 only D 4 only
Mark scheme: C
Q32 · Senga is concerned that the current ratio of her business is worsening each year
32 Senga is concerned that the current ratio of her business is worsening each year. She has suggested the following measures. 1 Increase cash purchases of inventory. 2 Introduce further capital in the form of cash. 3 Decrease the rate of depreciation on non-current assets. 4 Sell off surplus non-current assets. Which two measures would improve the current ratio of the business? A 1 and 3 B 1 and 4 C 2 and 3 D 2 and 4
Mark scheme: D
Q33 · Ali owns a clothing shop
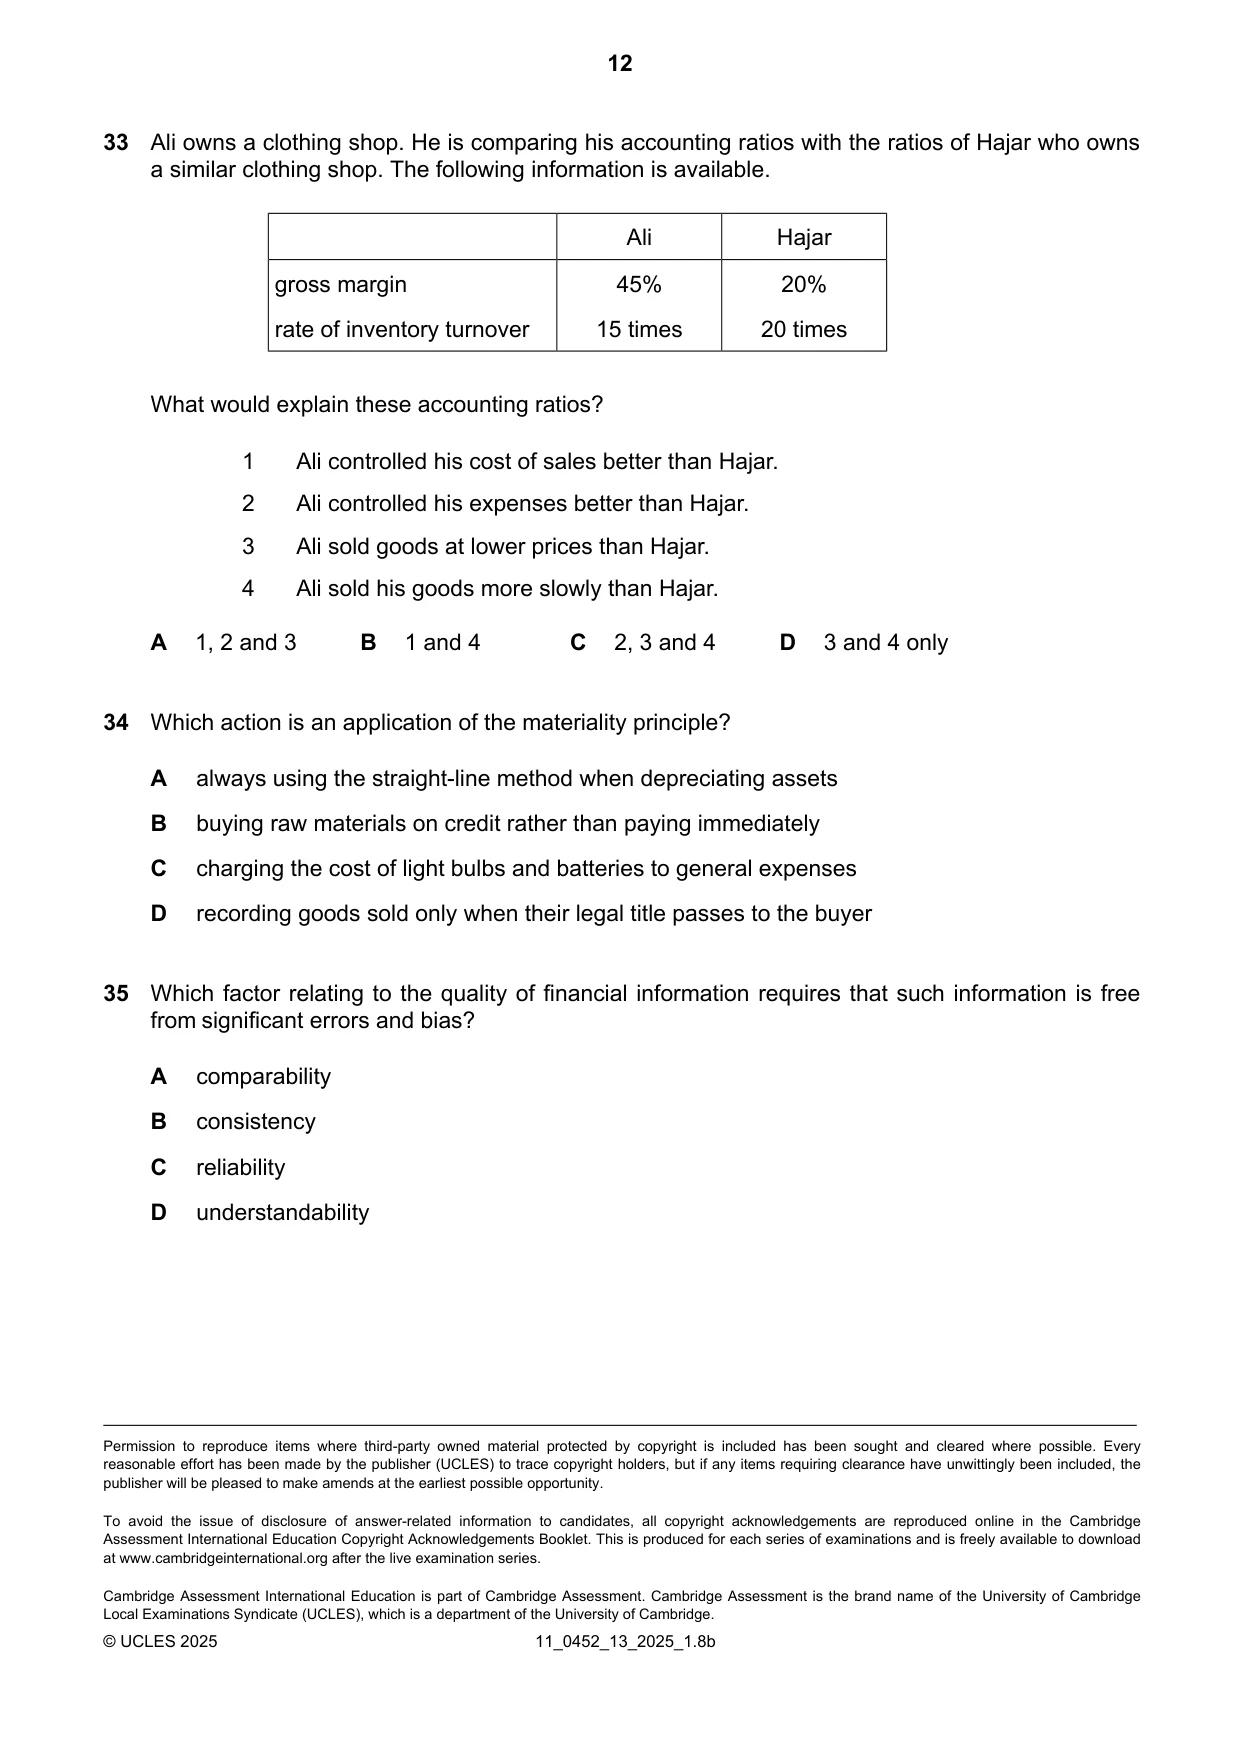
33 Ali owns a clothing shop. He is comparing his accounting ratios with the ratios of Hajar who owns a similar clothing shop. The following information is available. Ali Hajar gross margin 45% 20% rate of inventory turnover 15 times 20 times What would explain these accounting ratios? 1 Ali controlled his cost of sales better than Hajar. 2 Ali controlled his expenses better than Hajar. 3 Ali sold goods at lower prices than Hajar. 4 Ali sold his goods more slowly than Hajar. A 1, 2 and 3 B 1 and 4 C 2, 3 and 4 D 3 and 4 only
Mark scheme: B
Q34 · Which action is an application of the materiality principle?
34 Which action is an application of the materiality principle? A always using the straight-line method when depreciating assets B buying raw materials on credit rather than paying immediately C charging the cost of light bulbs and batteries to general expenses D recording goods sold only when their legal title passes to the buyer
Mark scheme: C
Q35 · Which factor relating to the quality of financial information requires that such…
35 Which factor relating to the quality of financial information requires that such information is free from significant errors and bias? A comparability B consistency C reliability D understandability
Mark scheme: C
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
3Accounting concepts2Accounting for depreciation and disposal of non-current assets2Books of prime entry2Control accounts2Incomplete records2Interpretation of accounting ratios2Limited companies2Manufacturing accounts2Partnerships2Sole traders2The double entry system of book-keeping2Bank reconciliation1Business documents1Capital and revenue expenditure and receipts1Clubs and societies1Irrecoverable debts and allowance for irrecoverable debts1Other payables and other receivables1The accounting equation1The purpose of accounting1The trial balance1Valuation of inventory1What you needed in this session
Cambridge’s own grade thresholds for 2025 Oct/Nov, Paper 1 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.