Questions as text
Q1 · Sumit does not maintain a full set of accounting records 0452/12 Feb/March 2020
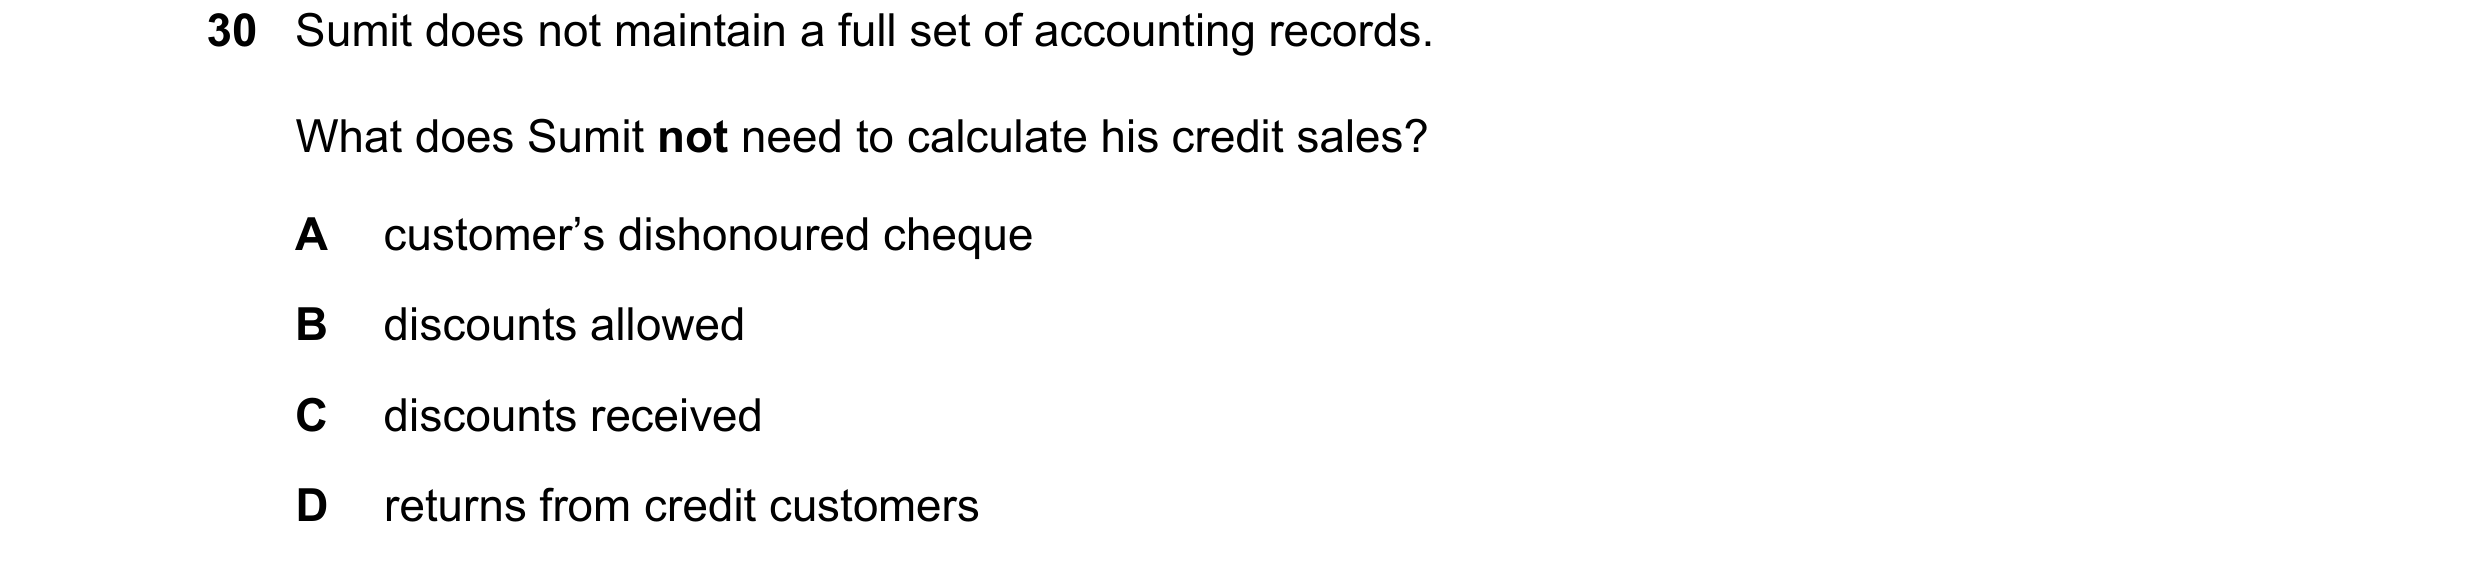
30 Sumit does not maintain a full set of accounting records. What does Sumit not need to calculate his credit sales? A customer’s dishonoured cheque B discounts allowed C discounts received D returns from credit customers
1 marks
Answer: C
This question in 0452/12 Feb/March 2020
Q2 · Hassan’s capital decreased by $200 over the year, even though he made a profit of $7000 0452/11 May/June 2020
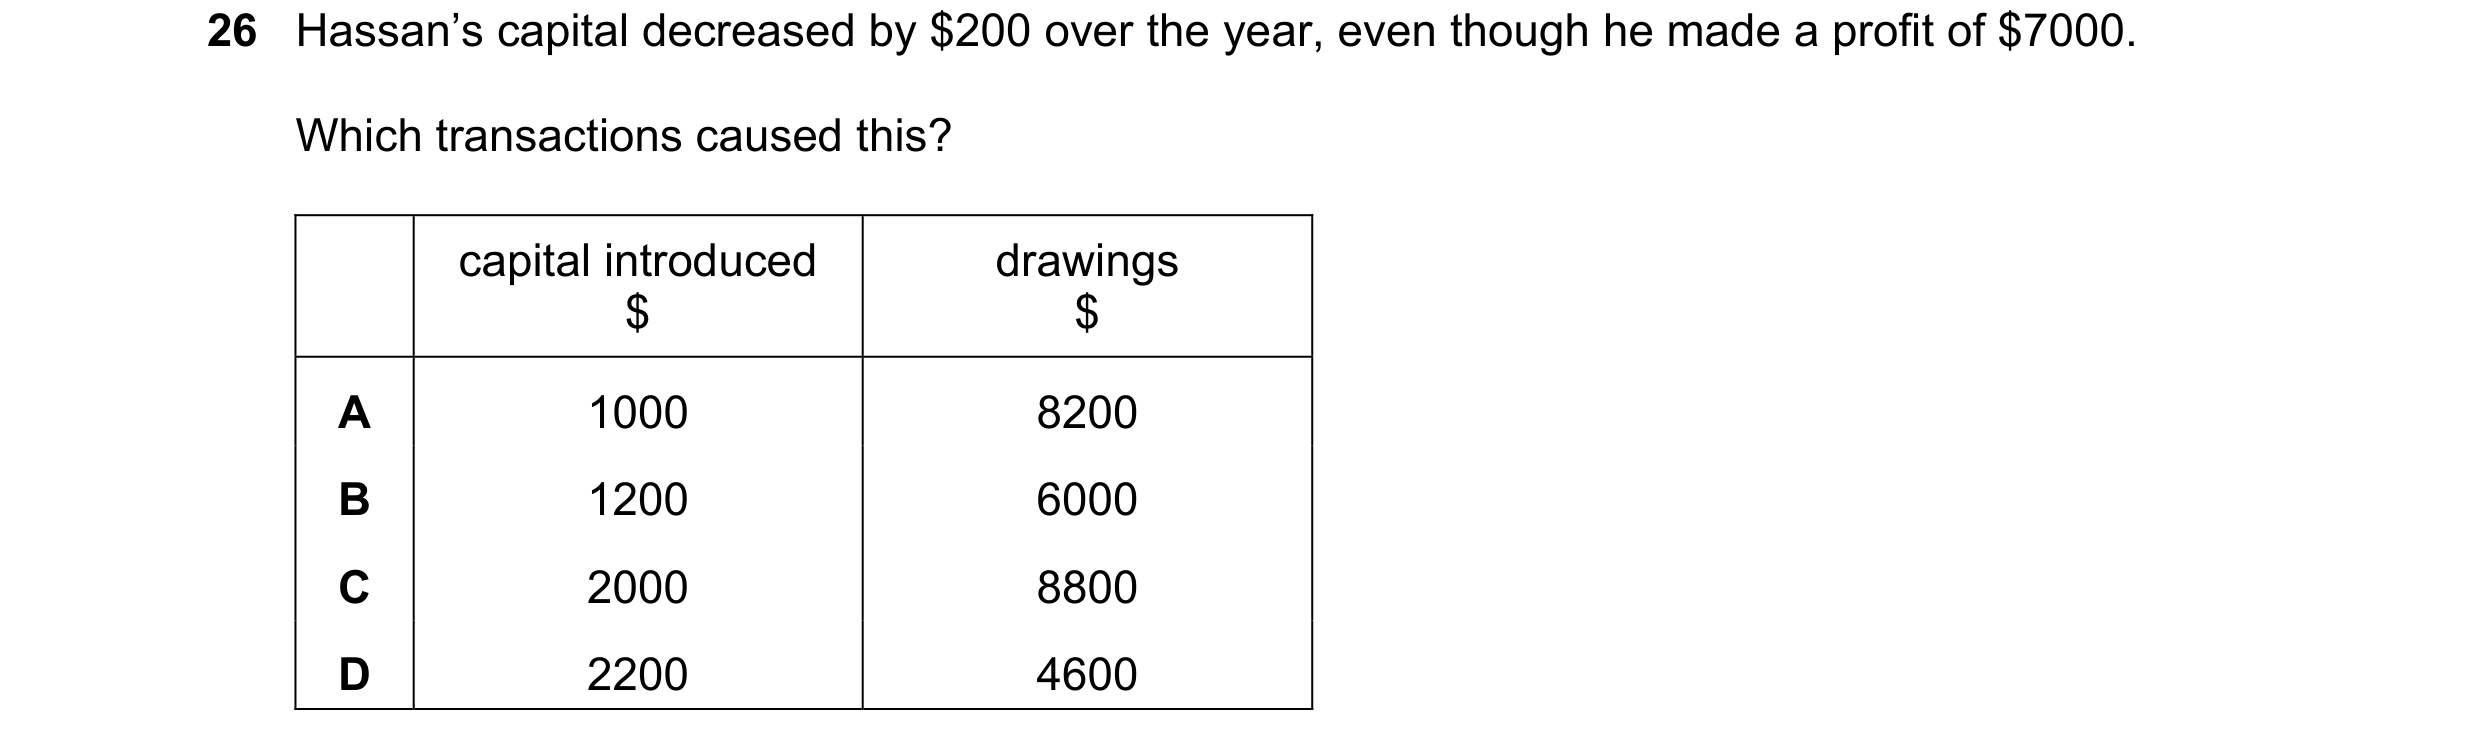
26 Hassan’s capital decreased by $200 over the year, even though he made a profit of $7000. Which transactions caused this? capital introduced drawings $ $ A 1000 8200 B 1200 6000 C 2000 8800 D 2200 4600
1 marks
Answer: A
This question in 0452/11 May/June 2020
Q3 · Anthony does not keep a full set of accounting records 0452/12 Oct/Nov 2020
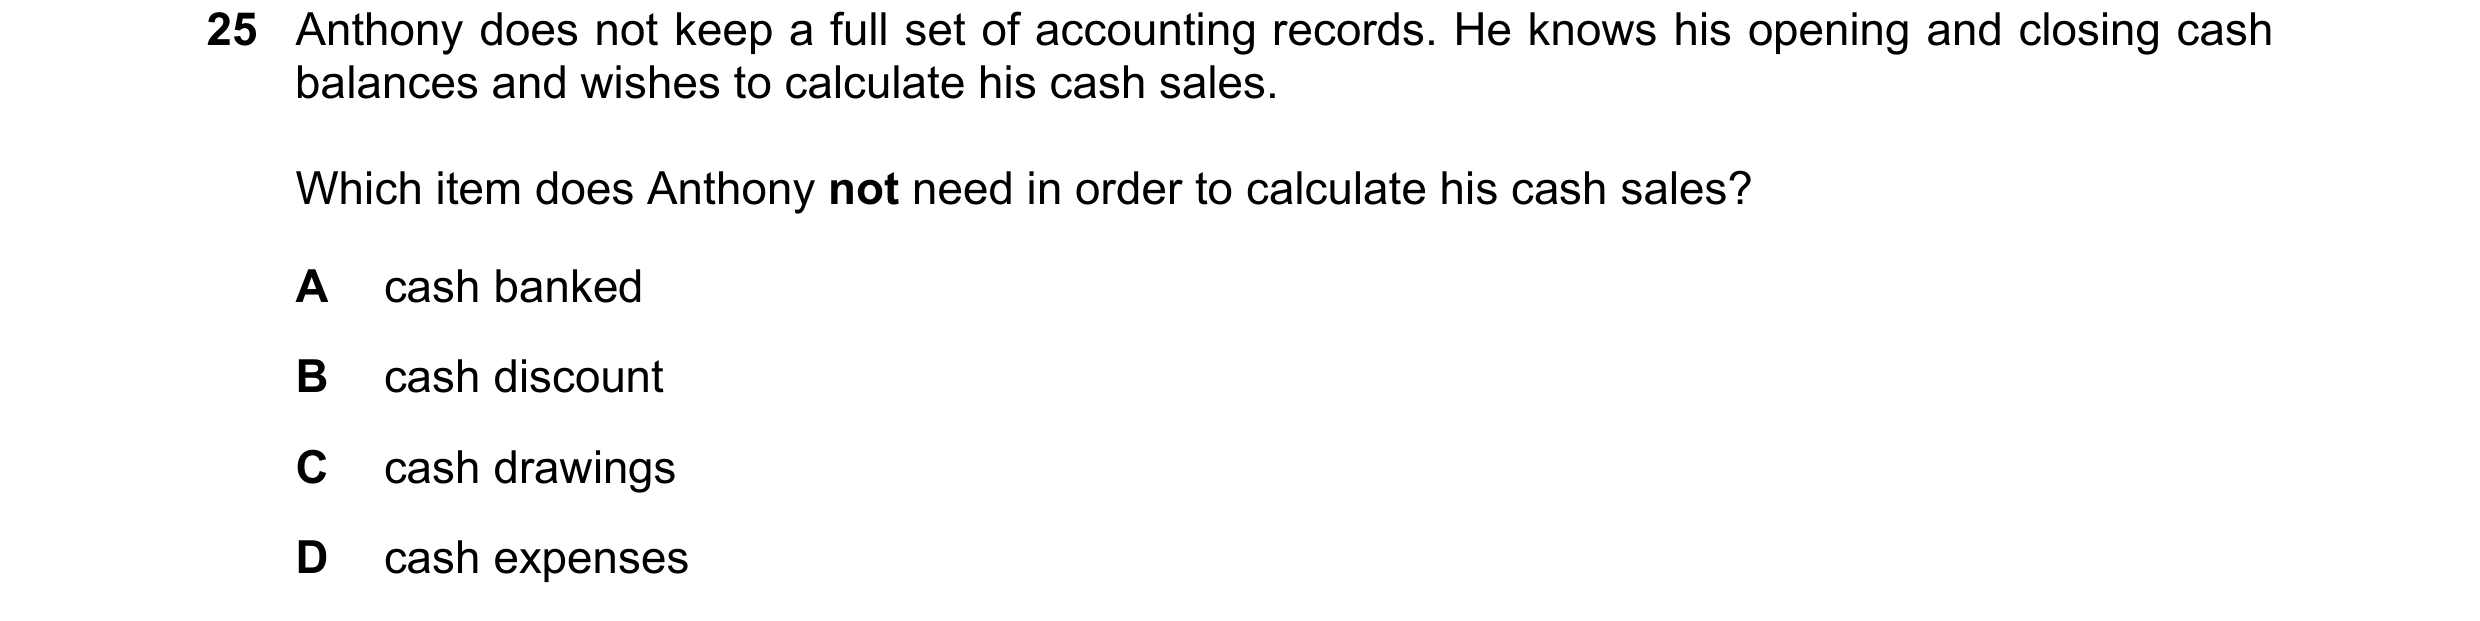
25 Anthony does not keep a full set of accounting records. He knows his opening and closing cash balances and wishes to calculate his cash sales. Which item does Anthony not need in order to calculate his cash sales? A cash banked B cash discount C cash drawings D cash expenses
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2020
Q4 · A trader has not maintained a full set of accounting records 0452/12 Oct/Nov 2020
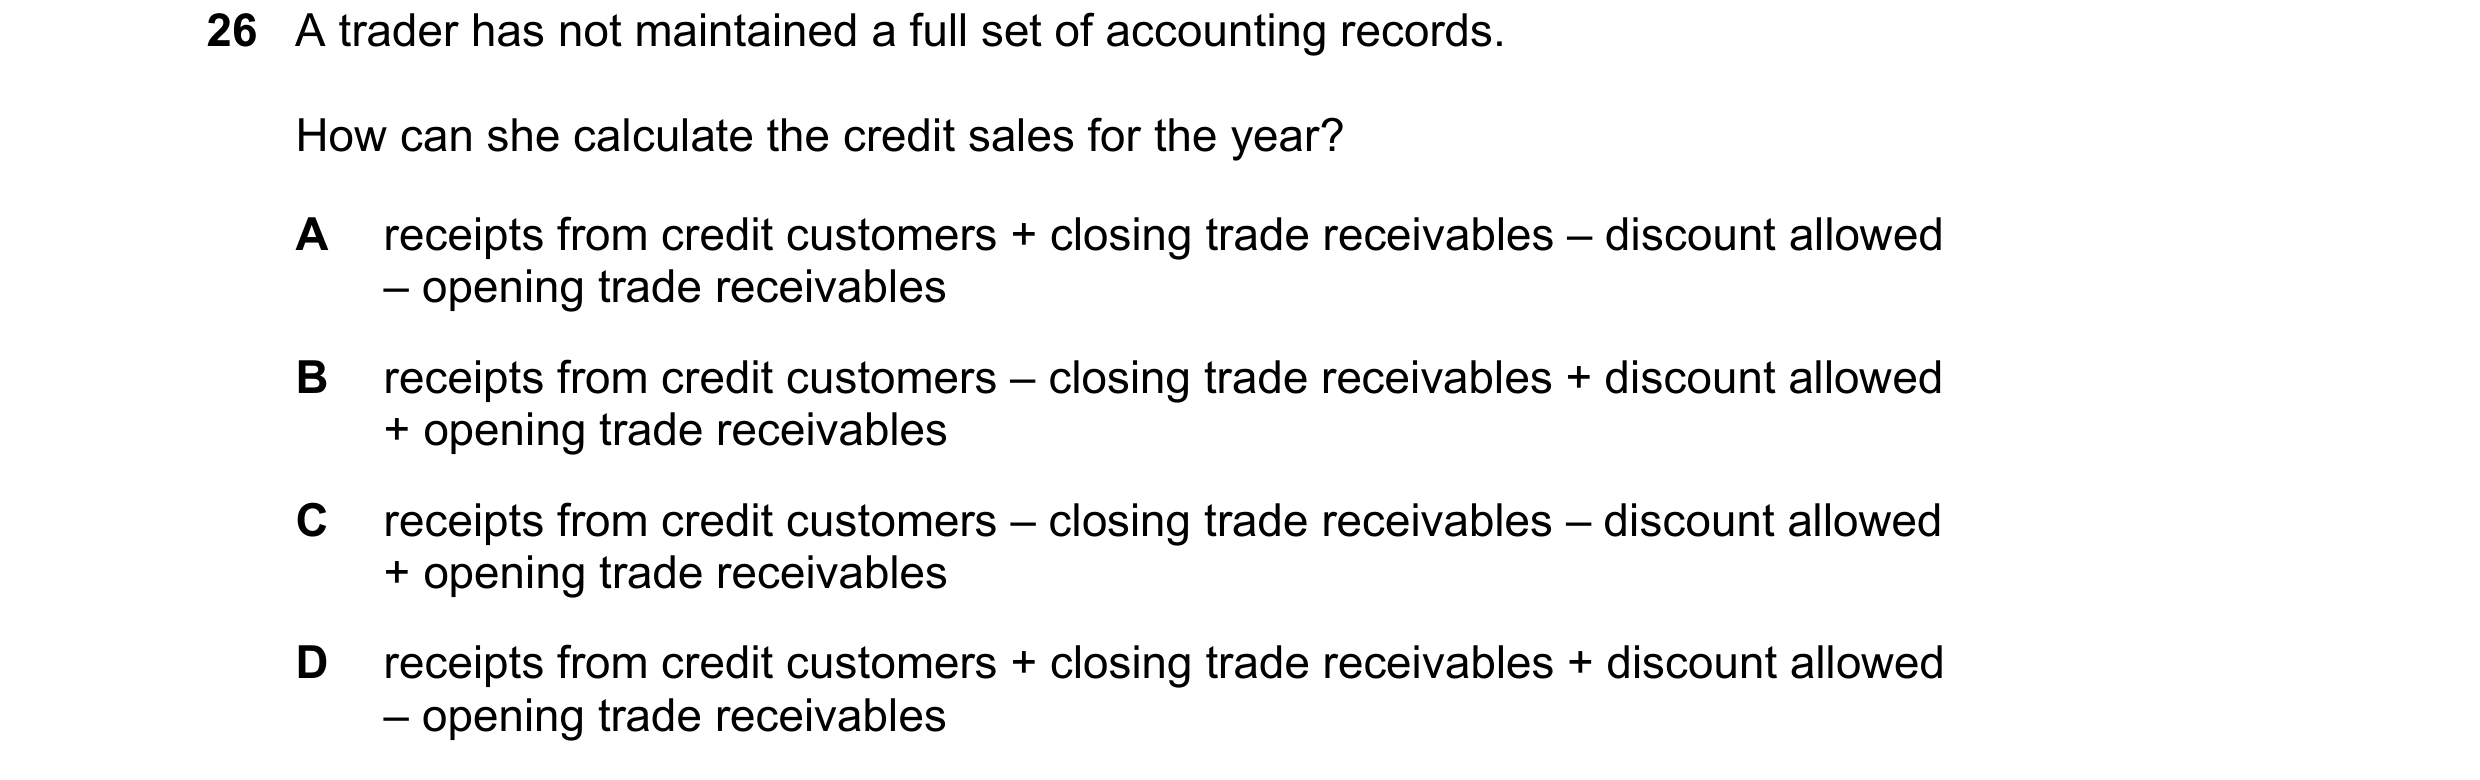
26 A trader has not maintained a full set of accounting records. How can she calculate the credit sales for the year? A receipts from credit customers + closing trade receivables – discount allowed – opening trade receivables B receipts from credit customers – closing trade receivables + discount allowed + opening trade receivables C receipts from credit customers – closing trade receivables – discount allowed + opening trade receivables D receipts from credit customers + closing trade receivables + discount allowed – opening trade receivables
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2020
Q5 · A trader provided the following information 0452/13 Oct/Nov 2020
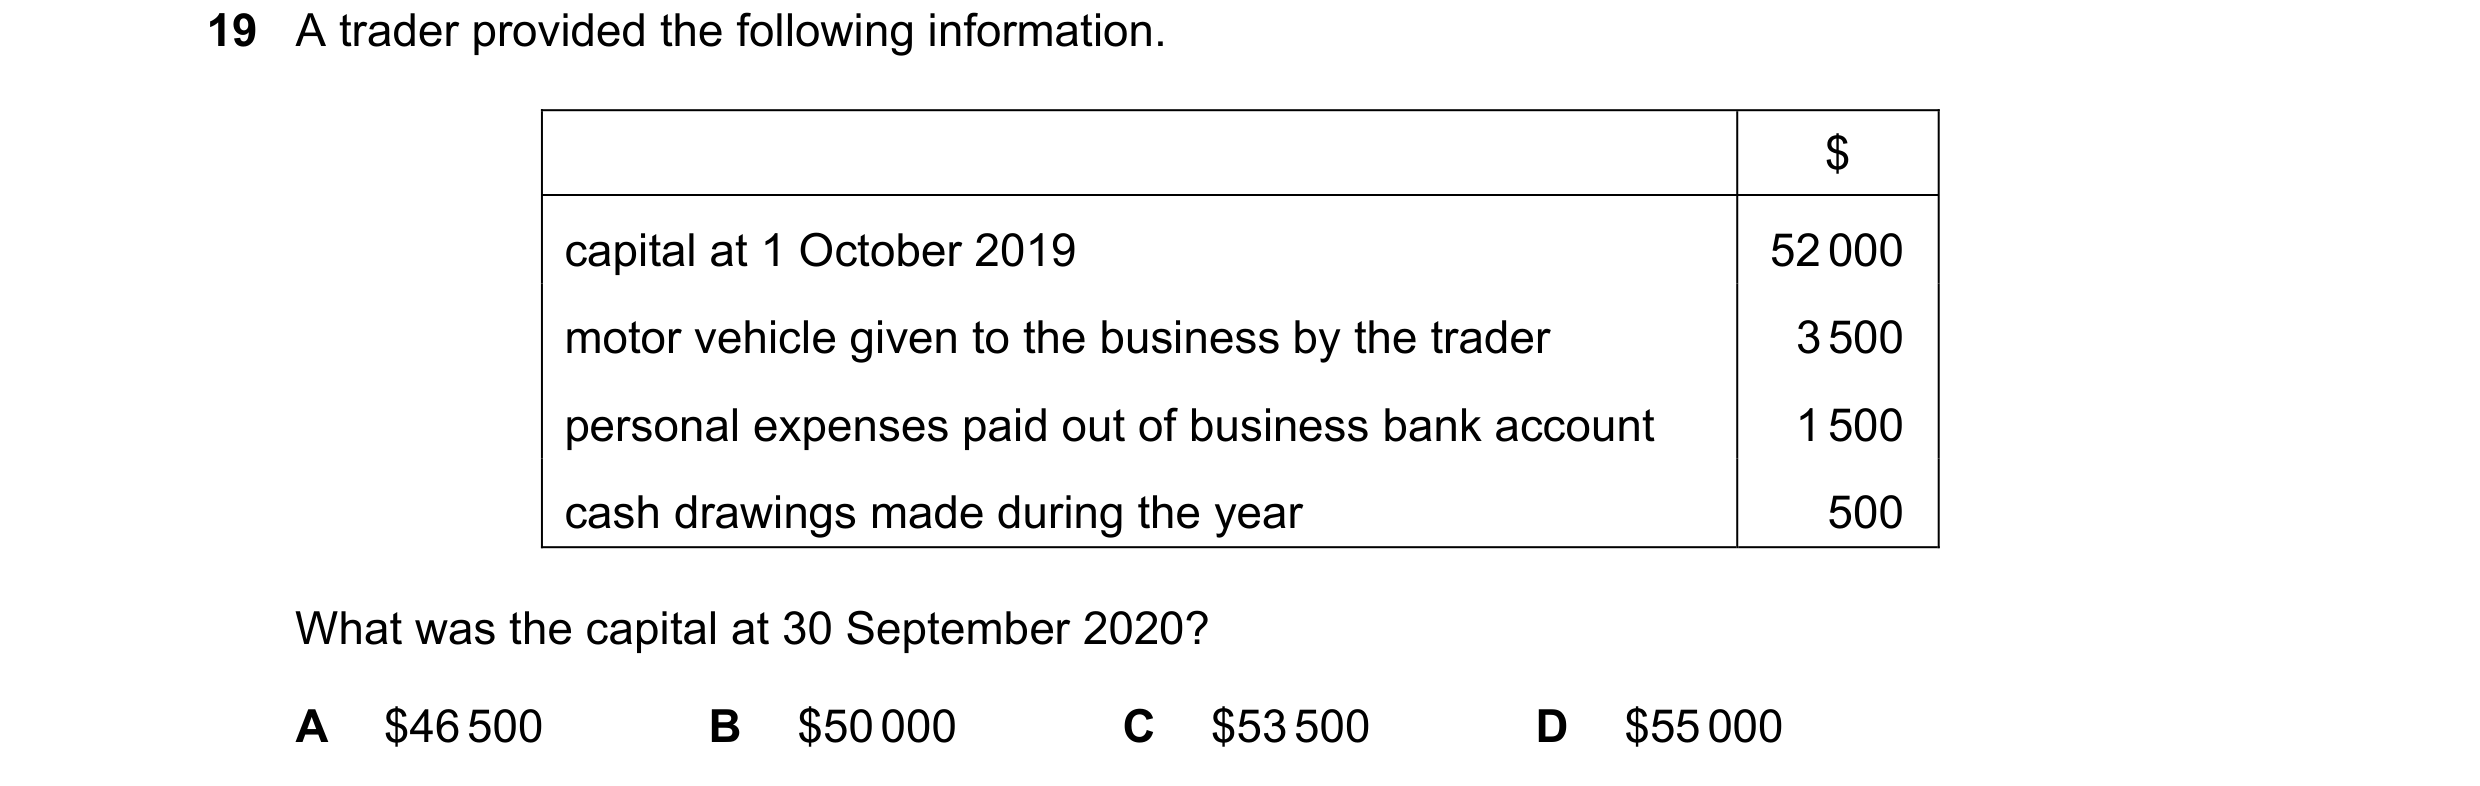
19 A trader provided the following information. $ capital at 1 October 2019 52 000 motor vehicle given to the business by the trader 3 500 personal expenses paid out of business bank account 1 500 cash drawings made during the year 500 What was the capital at 30 September 2020? A $46 500 B $50 000 C $53 500 D $55 000
1 marks
Answer: C
This question in 0452/13 Oct/Nov 2020
Q6 · Tariq provided the following information 0452/12 Feb/March 2021
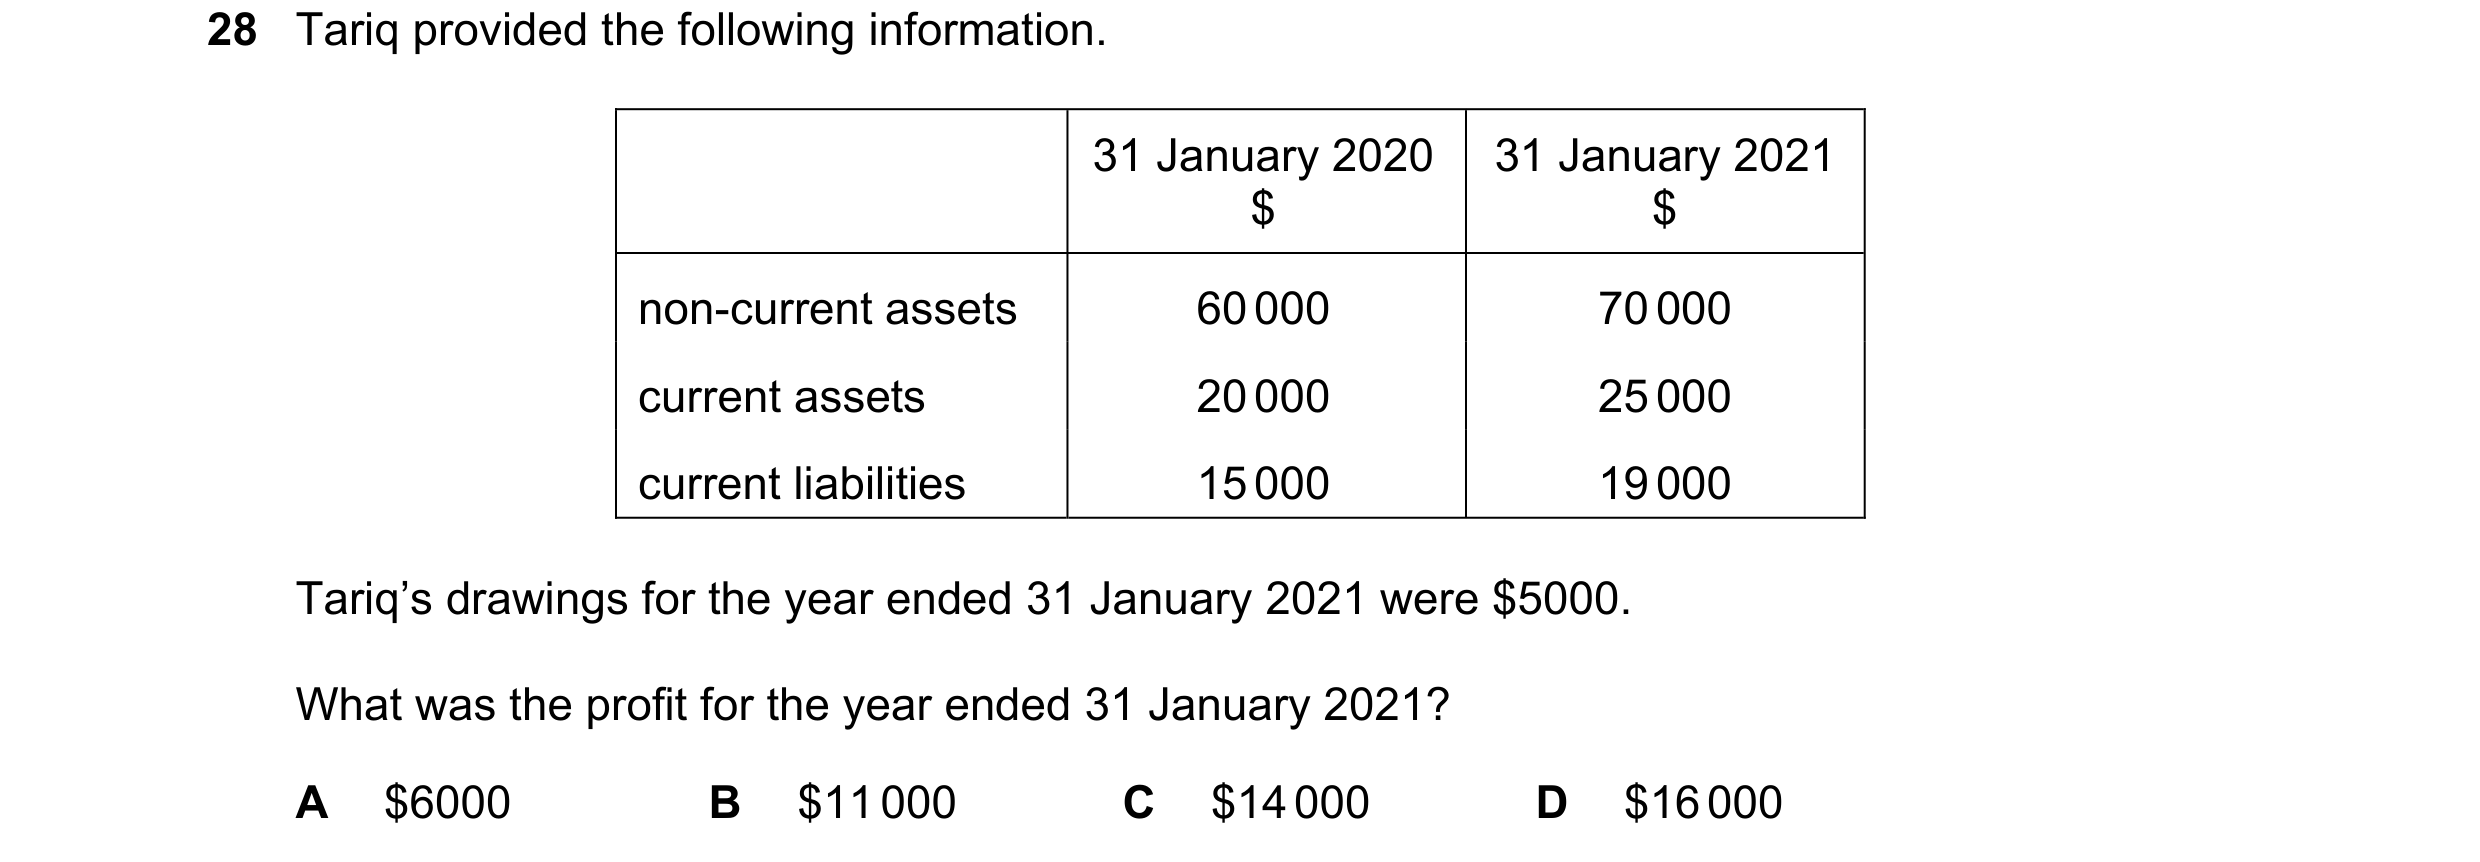
28 Tariq provided the following information. 31 January 2020 31 January 2021 $ $ non-current assets 60 000 70 000 current assets 20 000 25 000 current liabilities 15 000 19 000 Tariq’s drawings for the year ended 31 January 2021 were $5000. What was the profit for the year ended 31 January 2021? A $6000 B $11 000 C $14 000 D $16 000
1 marks
Answer: D
This question in 0452/12 Feb/March 2021
Q7 · Nour does not keep full accounting records 0452/12 Feb/March 2021
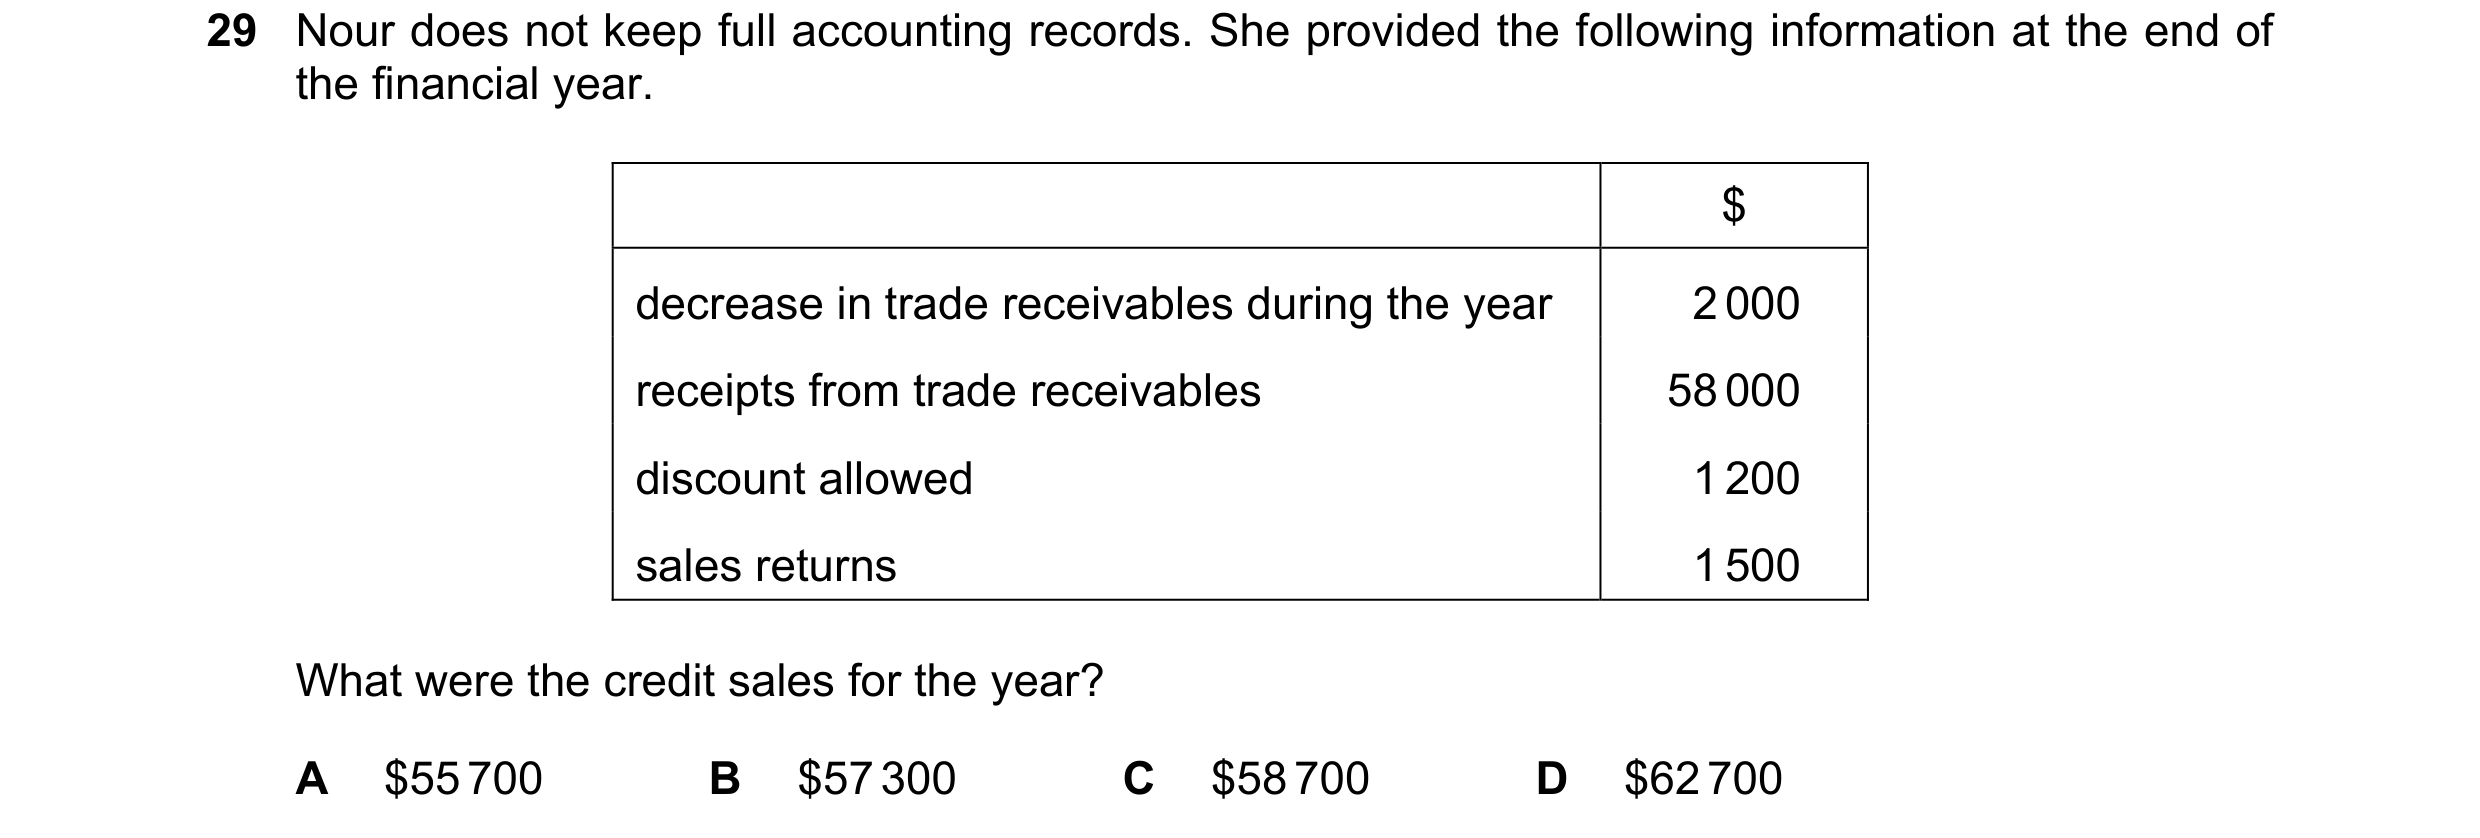
29 Nour does not keep full accounting records. She provided the following information at the end of the financial year. $ decrease in trade receivables during the year 2 000 receipts from trade receivables 58 000 discount allowed 1 200 sales returns 1 500 What were the credit sales for the year? A $55 700 B $57 300 C $58 700 D $62 700
1 marks
Answer: C
This question in 0452/12 Feb/March 2021
Q8 · Nula provided the following information for the year ended 31 March 2021 0452/11 May/June 2021
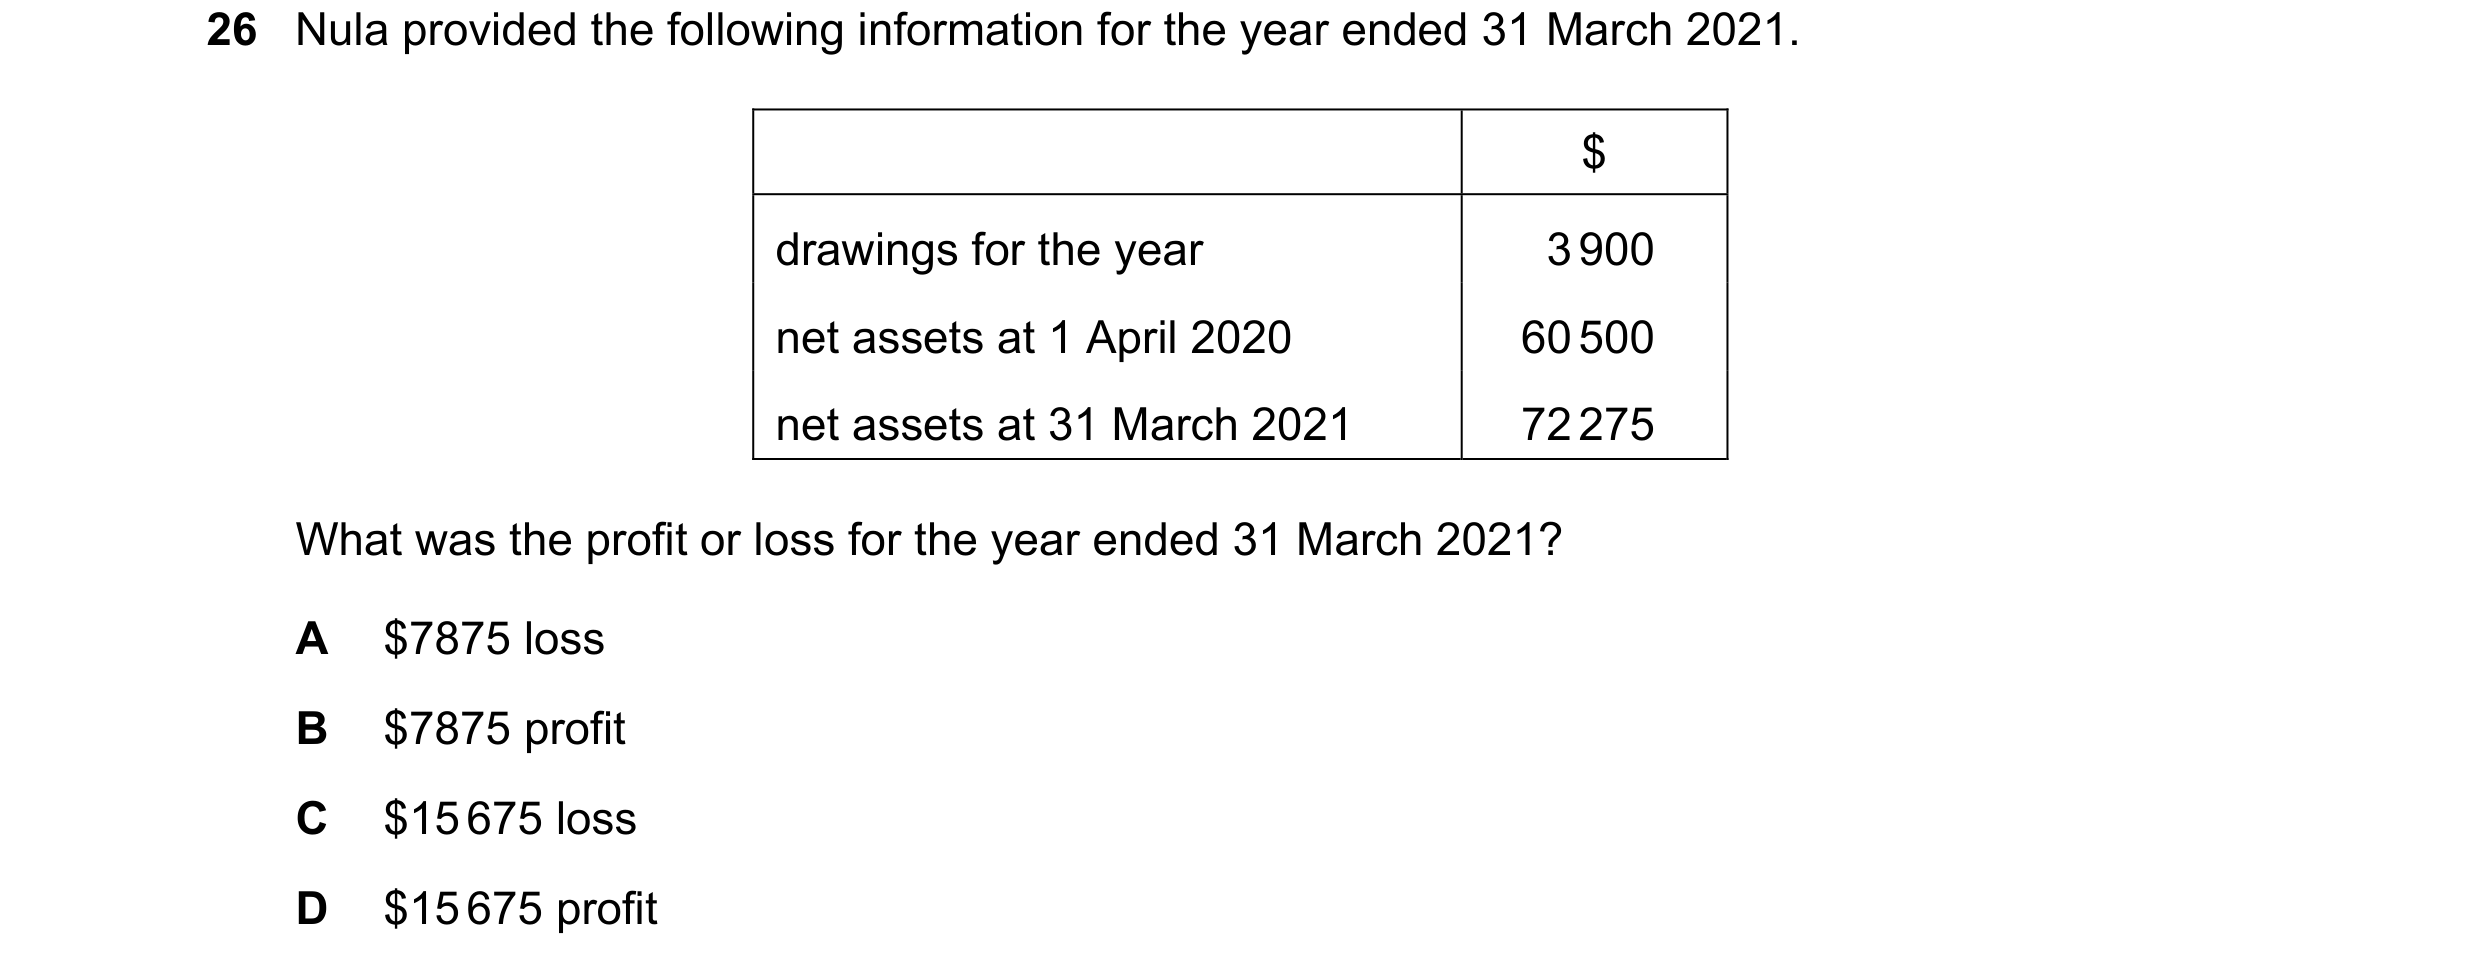
26 Nula provided the following information for the year ended 31 March 2021. $ drawings for the year 3 900 net assets at 1 April 2020 60 500 net assets at 31 March 2021 72 275 What was the profit or loss for the year ended 31 March 2021? A $7875 loss B $7875 profit C $15 675 loss D $15 675 profit
1 marks
Answer: D
This question in 0452/11 May/June 2021
Q9 · A trader who does not keep full accounting records was able to supply the following… 0452/11 May/June 2021
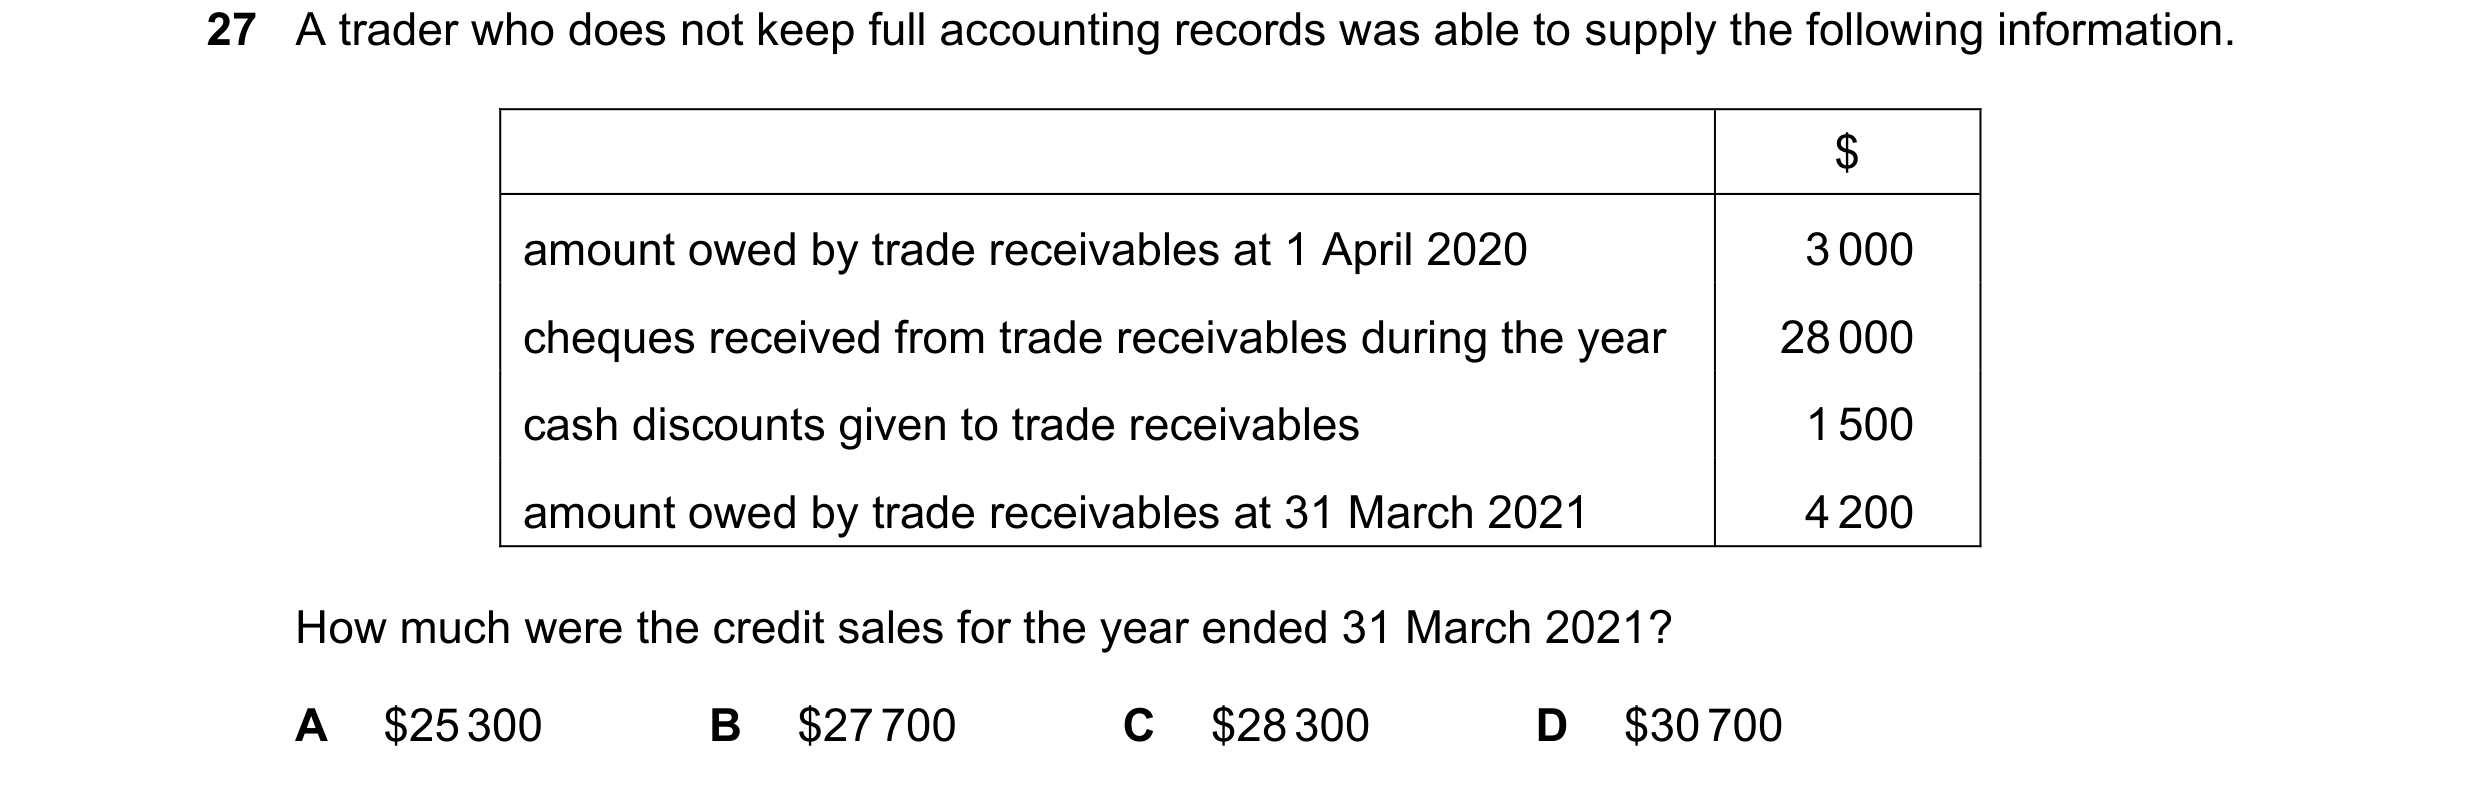
27 A trader who does not keep full accounting records was able to supply the following information. $ amount owed by trade receivables at 1 April 2020 3 000 cheques received from trade receivables during the year 28 000 cash discounts given to trade receivables 1 500 amount owed by trade receivables at 31 March 2021 4 200 How much were the credit sales for the year ended 31 March 2021? A $25 300 B $27 700 C $28 300 D $30 700
1 marks
Answer: D
This question in 0452/11 May/June 2021
Q10 · Nula provided the following information for the year ended 31 March 2021 0452/12 May/June 2021
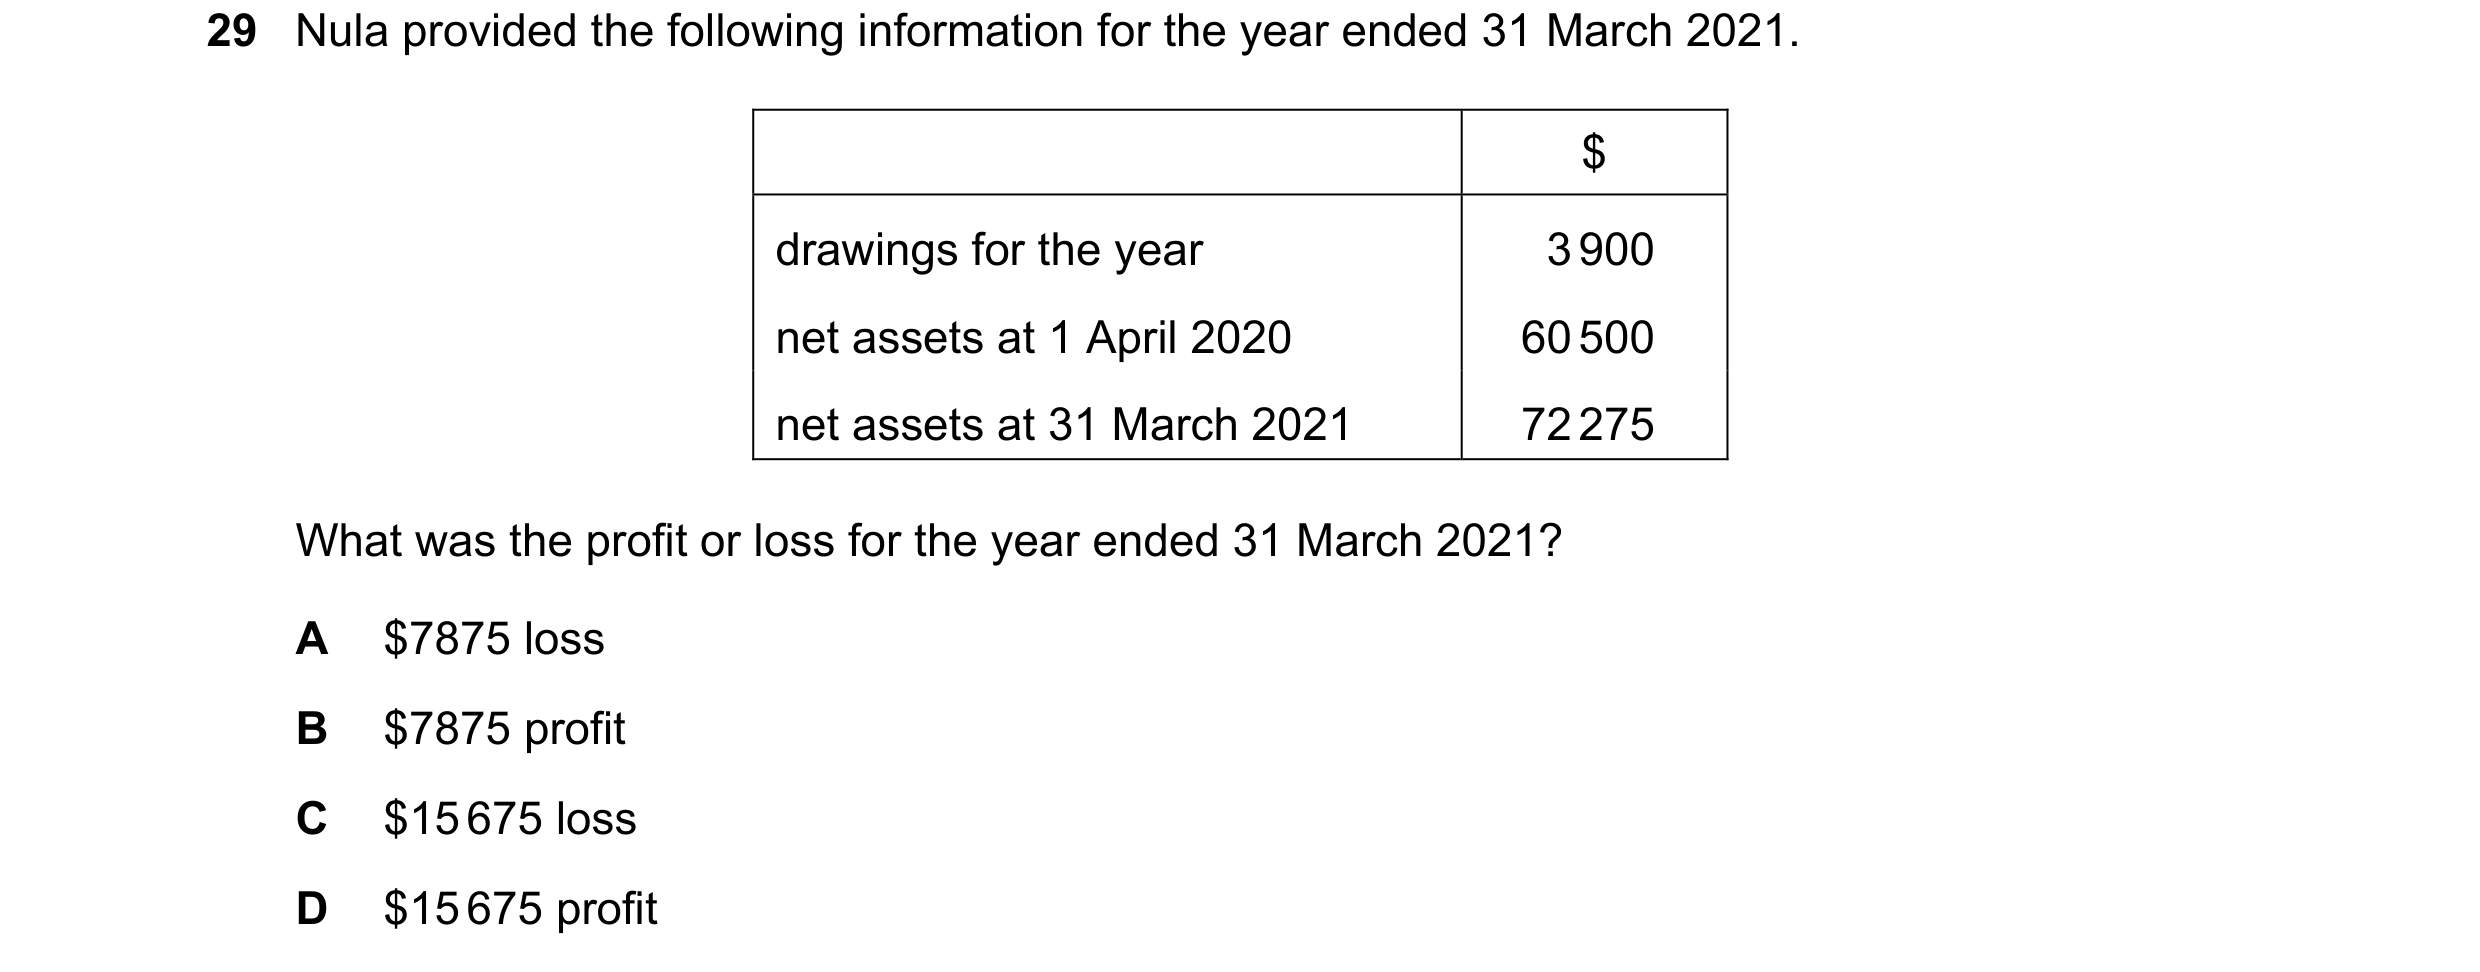
29 Nula provided the following information for the year ended 31 March 2021. $ drawings for the year 3 900 net assets at 1 April 2020 60 500 net assets at 31 March 2021 72 275 What was the profit or loss for the year ended 31 March 2021? A $7875 loss B $7875 profit C $15 675 loss D $15 675 profit
1 marks
Answer: D
This question in 0452/12 May/June 2021
Q11 · Nula provided the following information for the year ended 31 March 2021 0452/13 May/June 2021
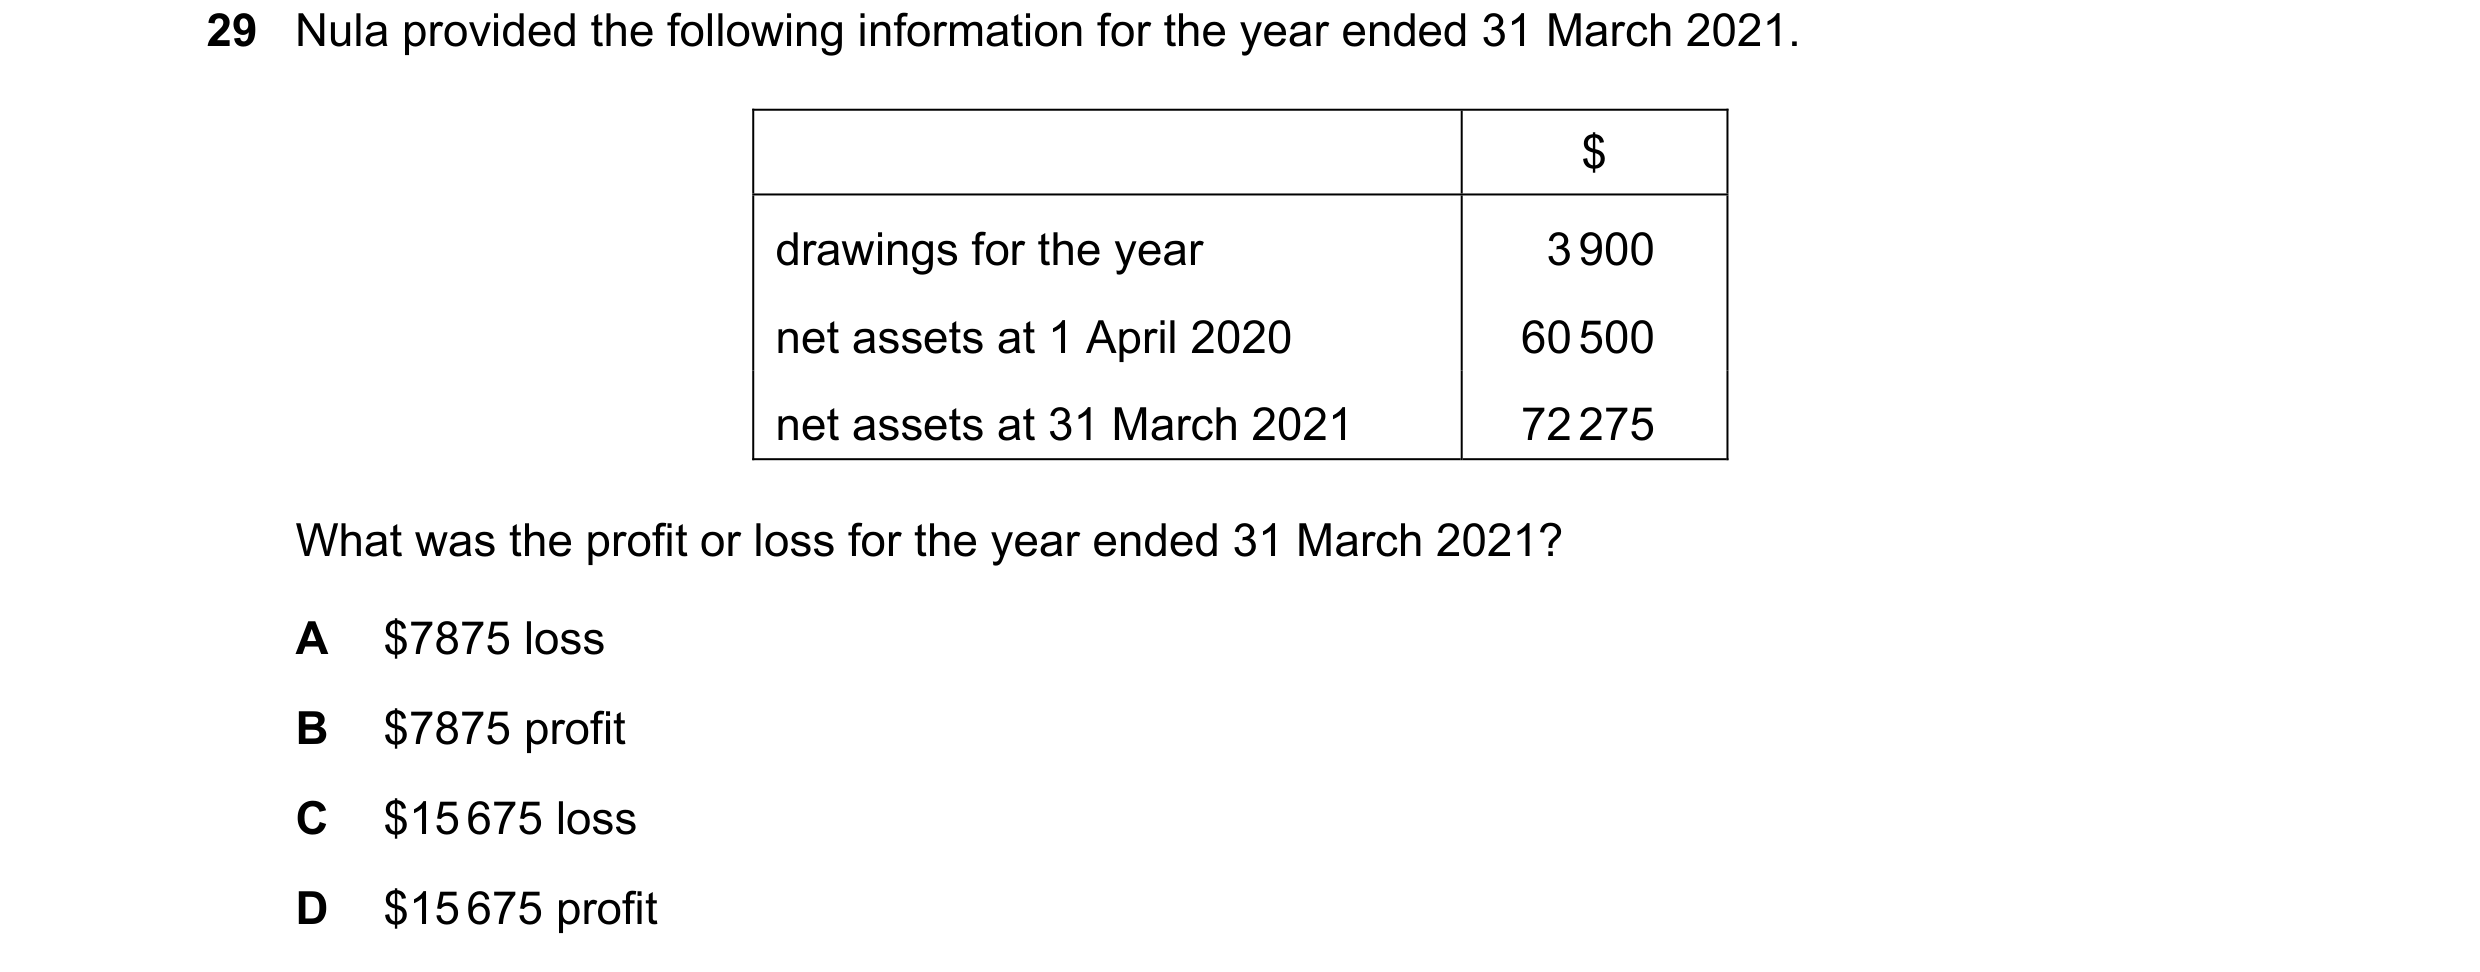
29 Nula provided the following information for the year ended 31 March 2021. $ drawings for the year 3 900 net assets at 1 April 2020 60 500 net assets at 31 March 2021 72 275 What was the profit or loss for the year ended 31 March 2021? A $7875 loss B $7875 profit C $15 675 loss D $15 675 profit
1 marks
Answer: D
This question in 0452/13 May/June 2021
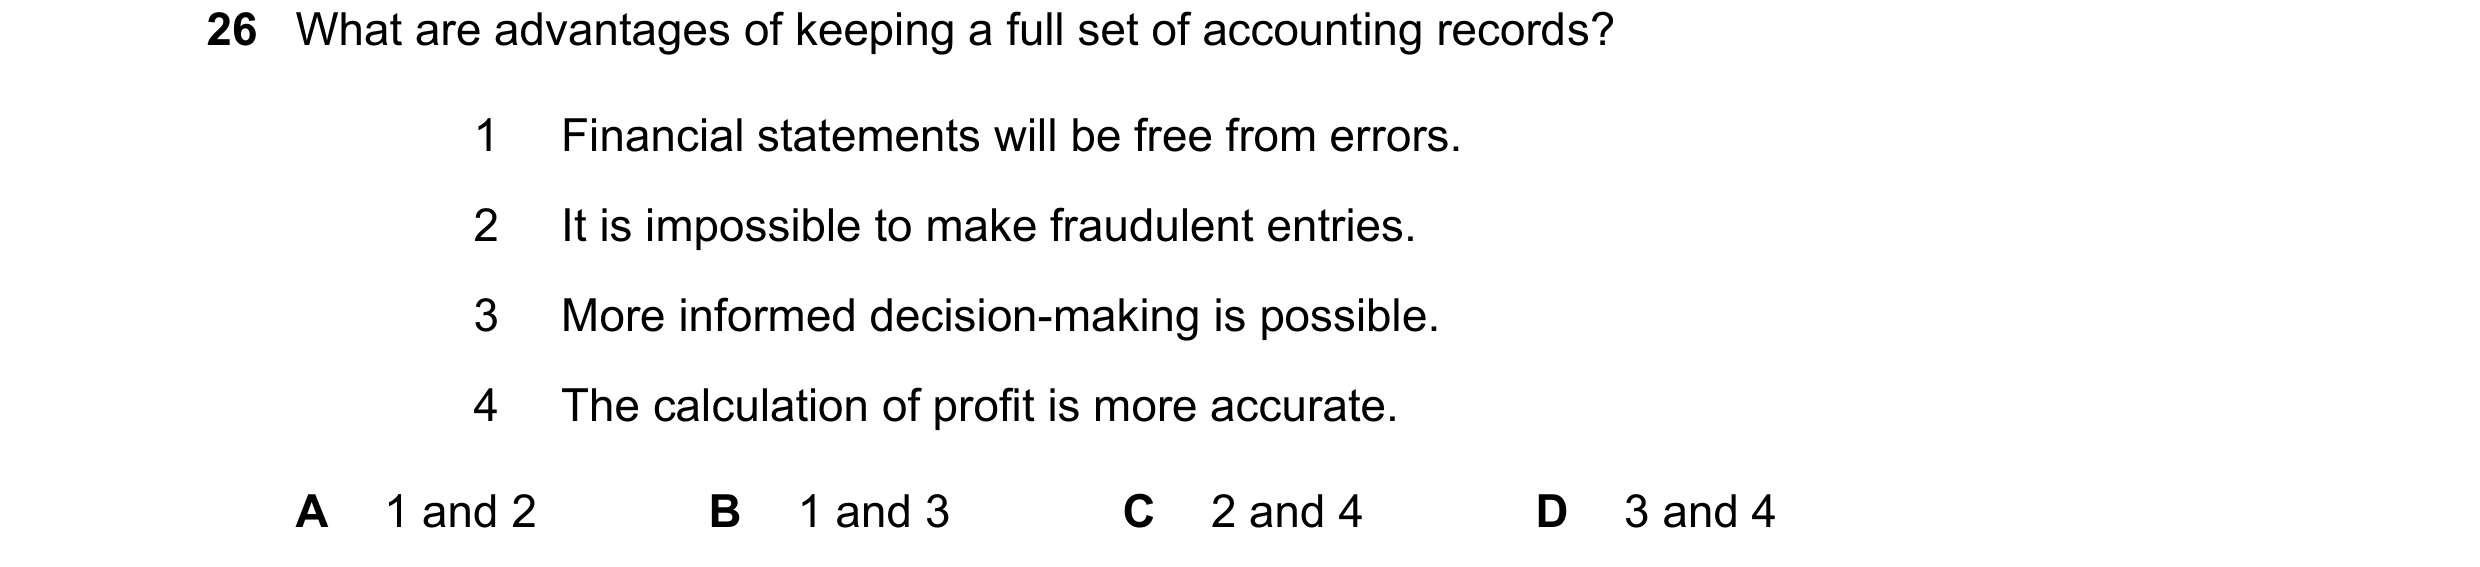
Q12 · What are advantages of keeping a full set of accounting records? 0452/11 Oct/Nov 2021
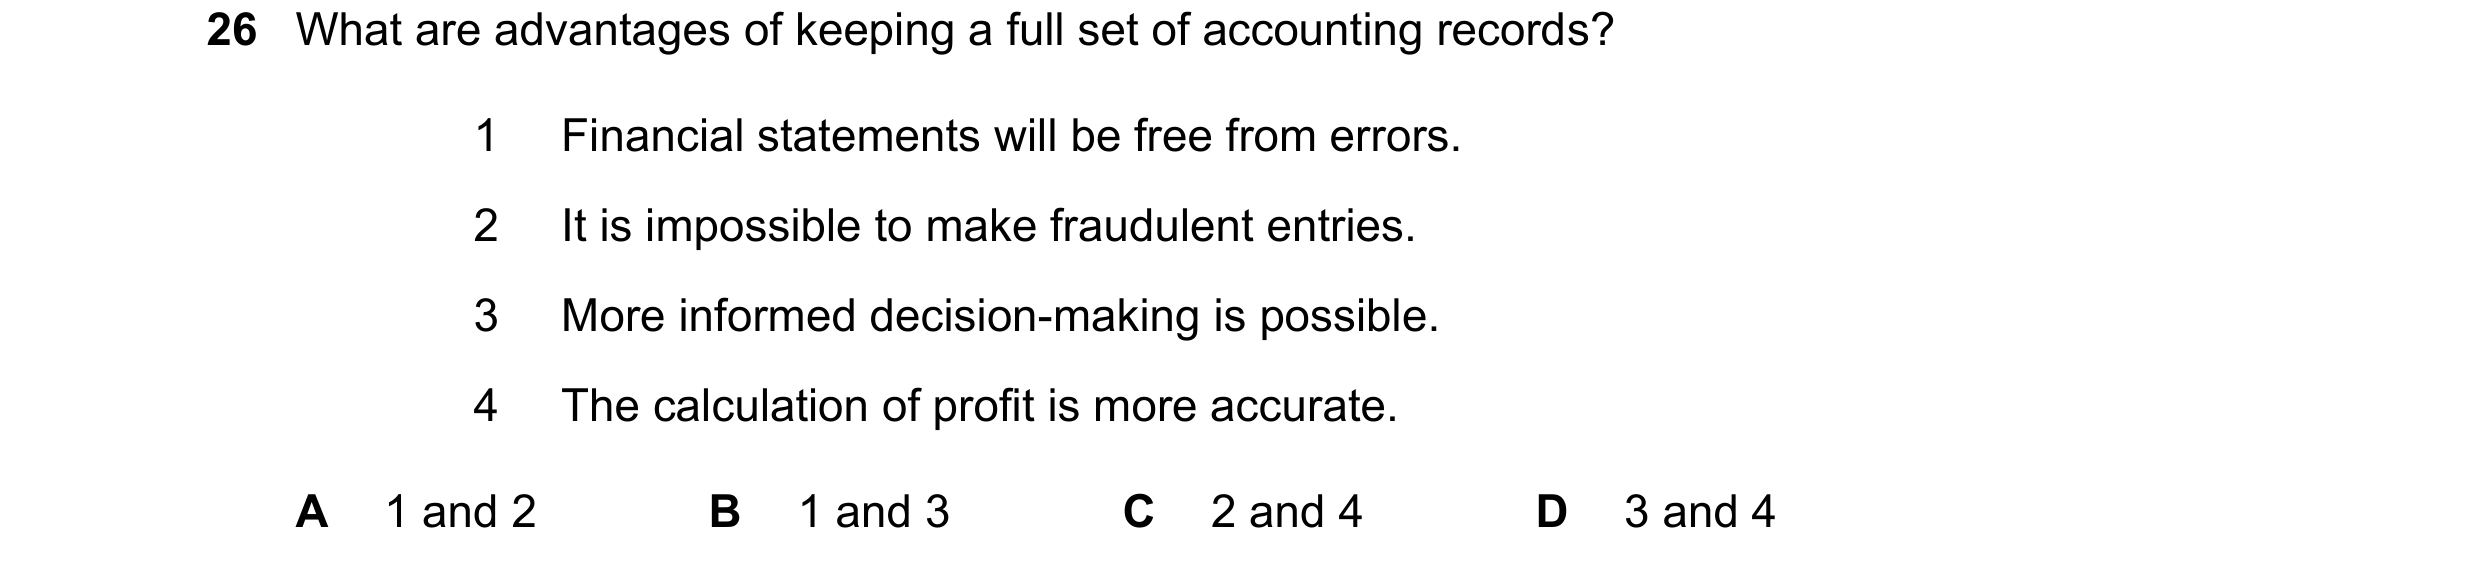
26 What are advantages of keeping a full set of accounting records? 1 Financial statements will be free from errors. 2 It is impossible to make fraudulent entries. 3 More informed decision-making is possible. 4 The calculation of profit is more accurate. A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2021
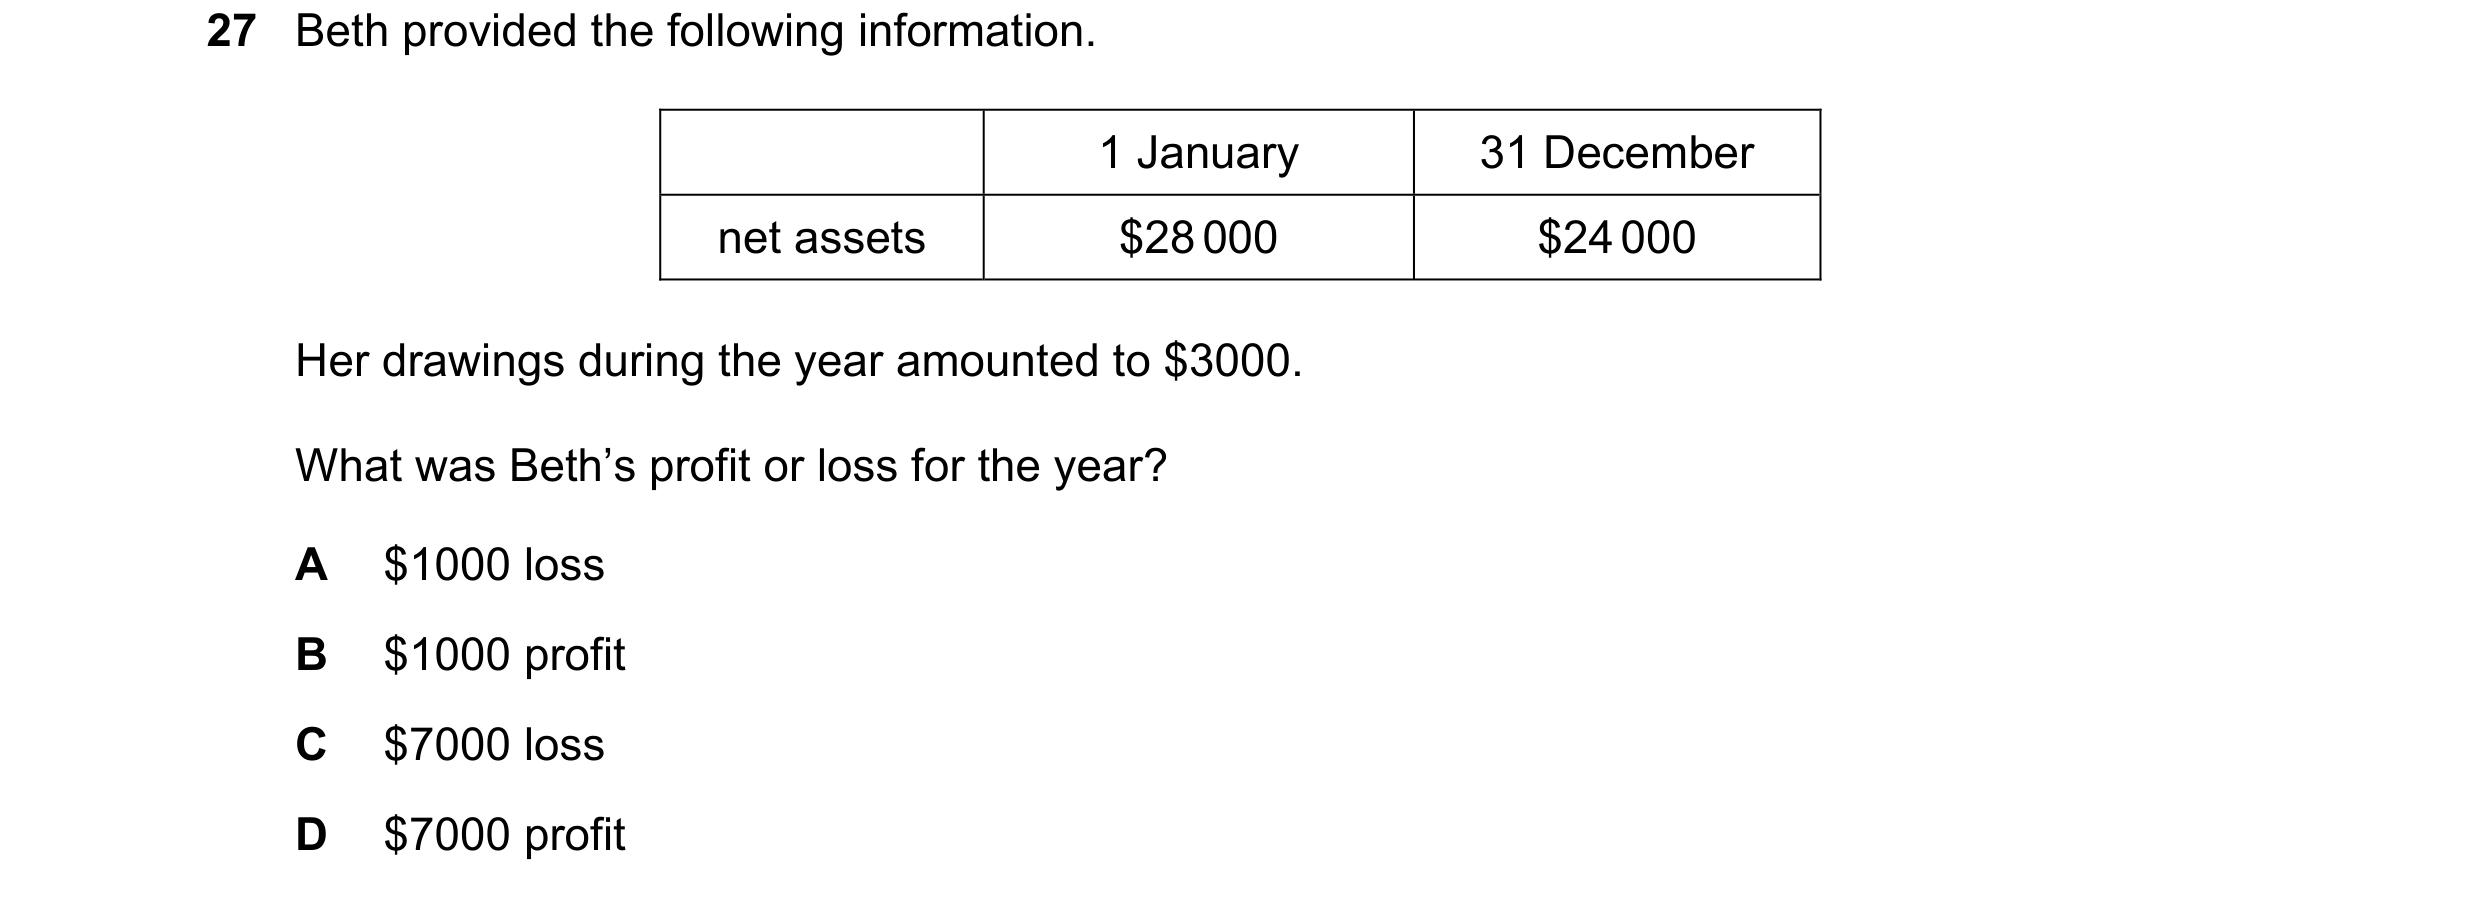
Q13 · Beth provided the following information 0452/11 Oct/Nov 2021
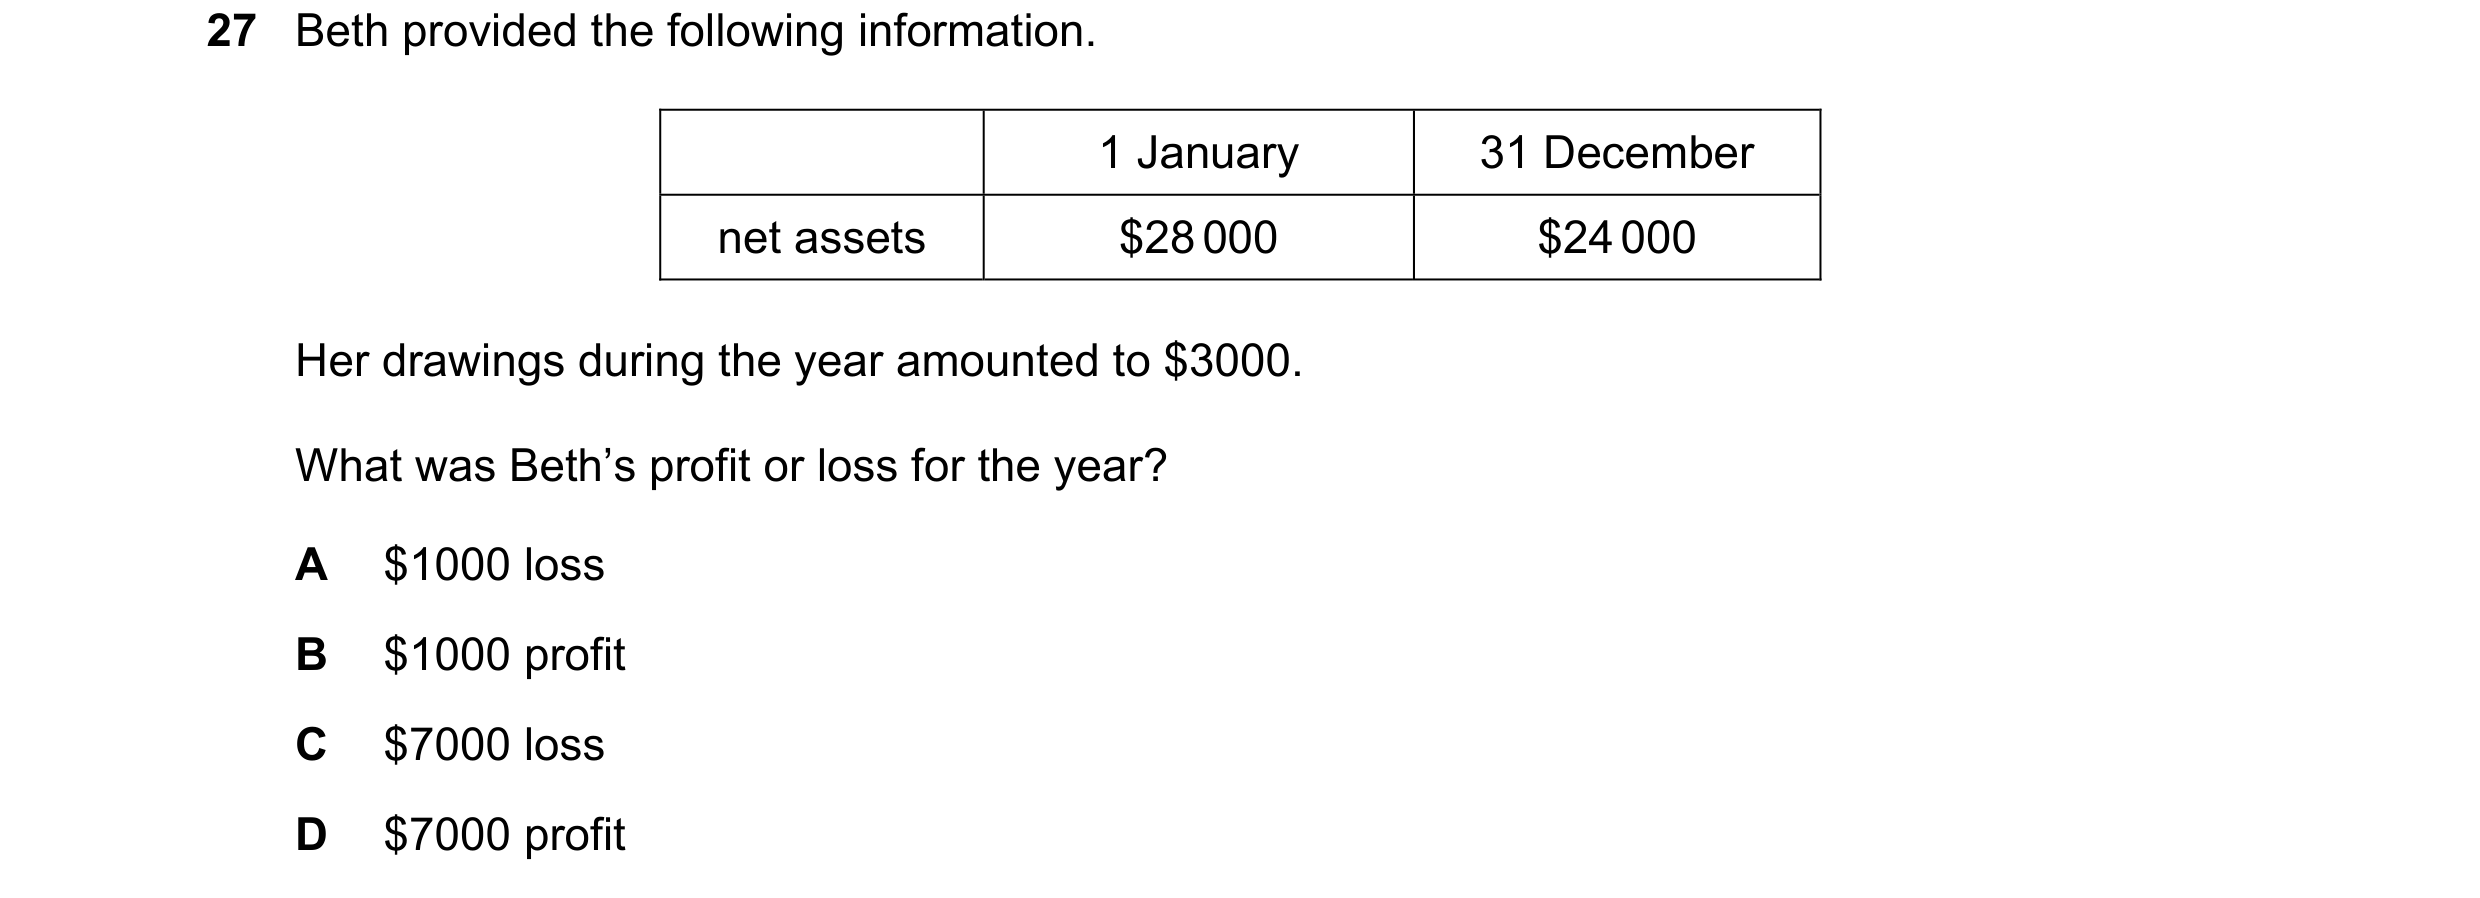
27 Beth provided the following information. 1 January 31 December net assets $28 000 $24 000 Her drawings during the year amounted to $3000. What was Beth’s profit or loss for the year? A $1000 loss B $1000 profit C $7000 loss D $7000 profit
1 marks
Answer: A
This question in 0452/11 Oct/Nov 2021
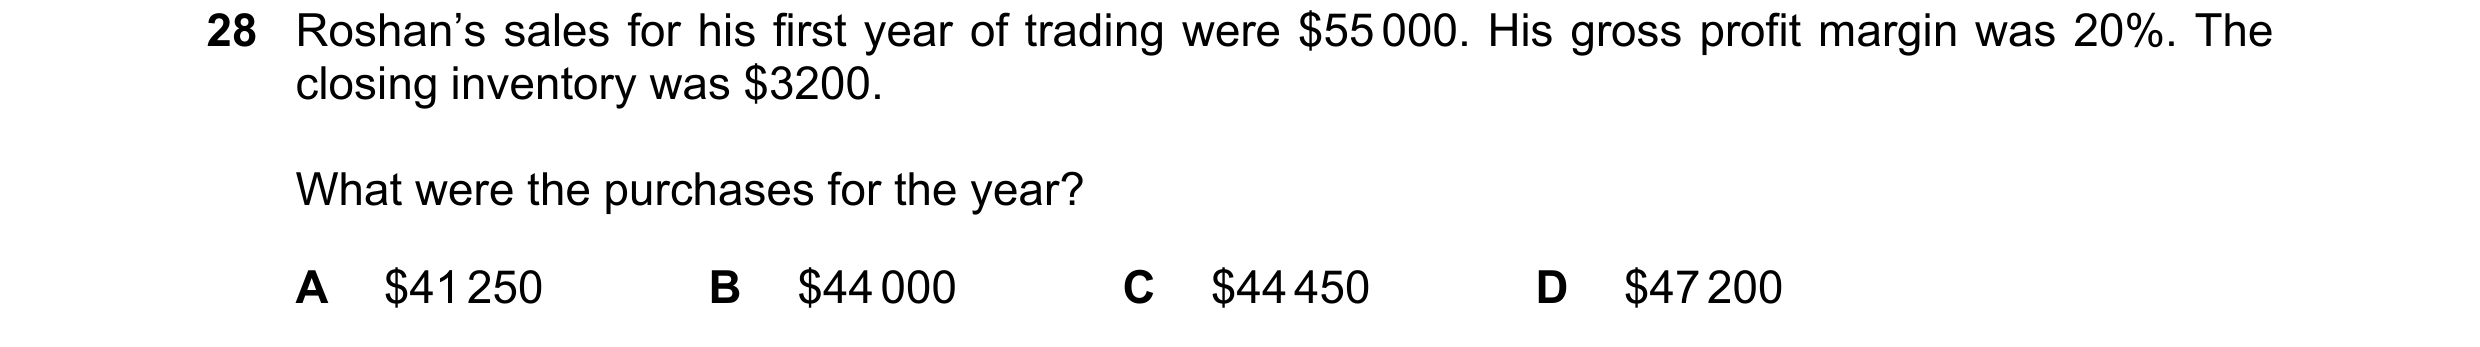
Q14 · Roshan’s sales for his first year of trading were $55 000 0452/11 Oct/Nov 2021
28 Roshan’s sales for his first year of trading were $55 000. His gross profit margin was 20%. The closing inventory was $3200. What were the purchases for the year? A $41 250 B $44 000 C $44 450 D $47 200
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2021
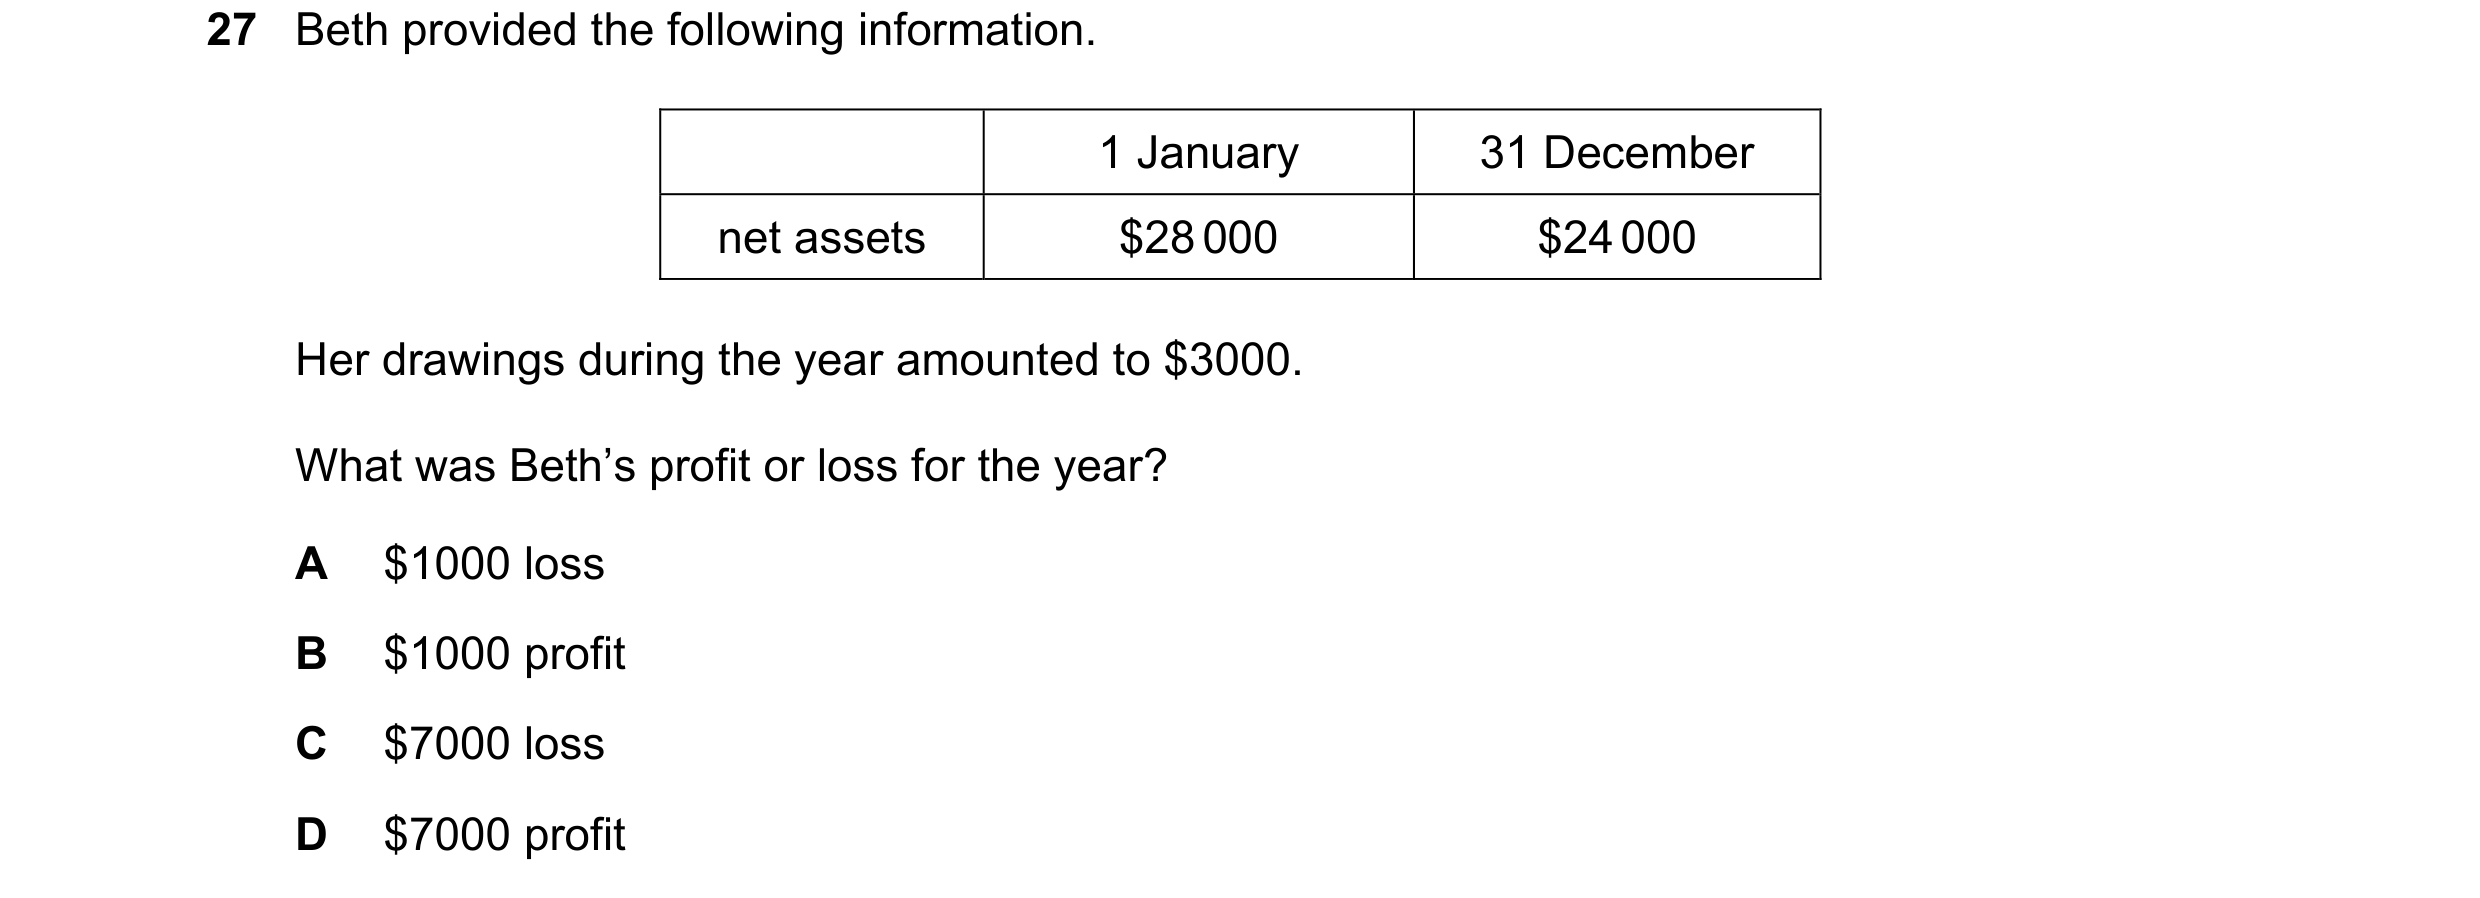
Q15 · Beth provided the following information 0452/12 Oct/Nov 2021
27 Beth provided the following information. 1 January 31 December net assets $28 000 $24 000 Her drawings during the year amounted to $3000. What was Beth’s profit or loss for the year? A $1000 loss B $1000 profit C $7000 loss D $7000 profit
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2021
Q16 · What are advantages of keeping a full set of accounting records? 0452/13 Oct/Nov 2021
26 What are advantages of keeping a full set of accounting records? 1 Financial statements will be free from errors. 2 It is impossible to make fraudulent entries. 3 More informed decision-making is possible. 4 The calculation of profit is more accurate. A 1 and 2 B 1 and 3 C 2 and 4 D 3 and 4
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2021
Q17 · Beth provided the following information 0452/13 Oct/Nov 2021
27 Beth provided the following information. 1 January 31 December net assets $28 000 $24 000 Her drawings during the year amounted to $3000. What was Beth’s profit or loss for the year? A $1000 loss B $1000 profit C $7000 loss D $7000 profit
1 marks
Answer: A
This question in 0452/13 Oct/Nov 2021
Q18 · Tarek produced a statement of affairs at 31 December year 1 and at 31 December year 2 0452/12 Feb/March 2022
30 Tarek produced a statement of affairs at 31 December year 1 and at 31 December year 2. During year 2, his long-term loan increased by $3000 and his net current assets decreased by $1000. Depreciation for the year was $500. By how much did the total of Tarek’s capital decrease? A $2500 B $3500 C $4000 D $4500
1 marks
Answer: D
This question in 0452/12 Feb/March 2022
Q19 · A trader does not keep full accounting records but was able to provide the following… 0452/11 May/June 2022
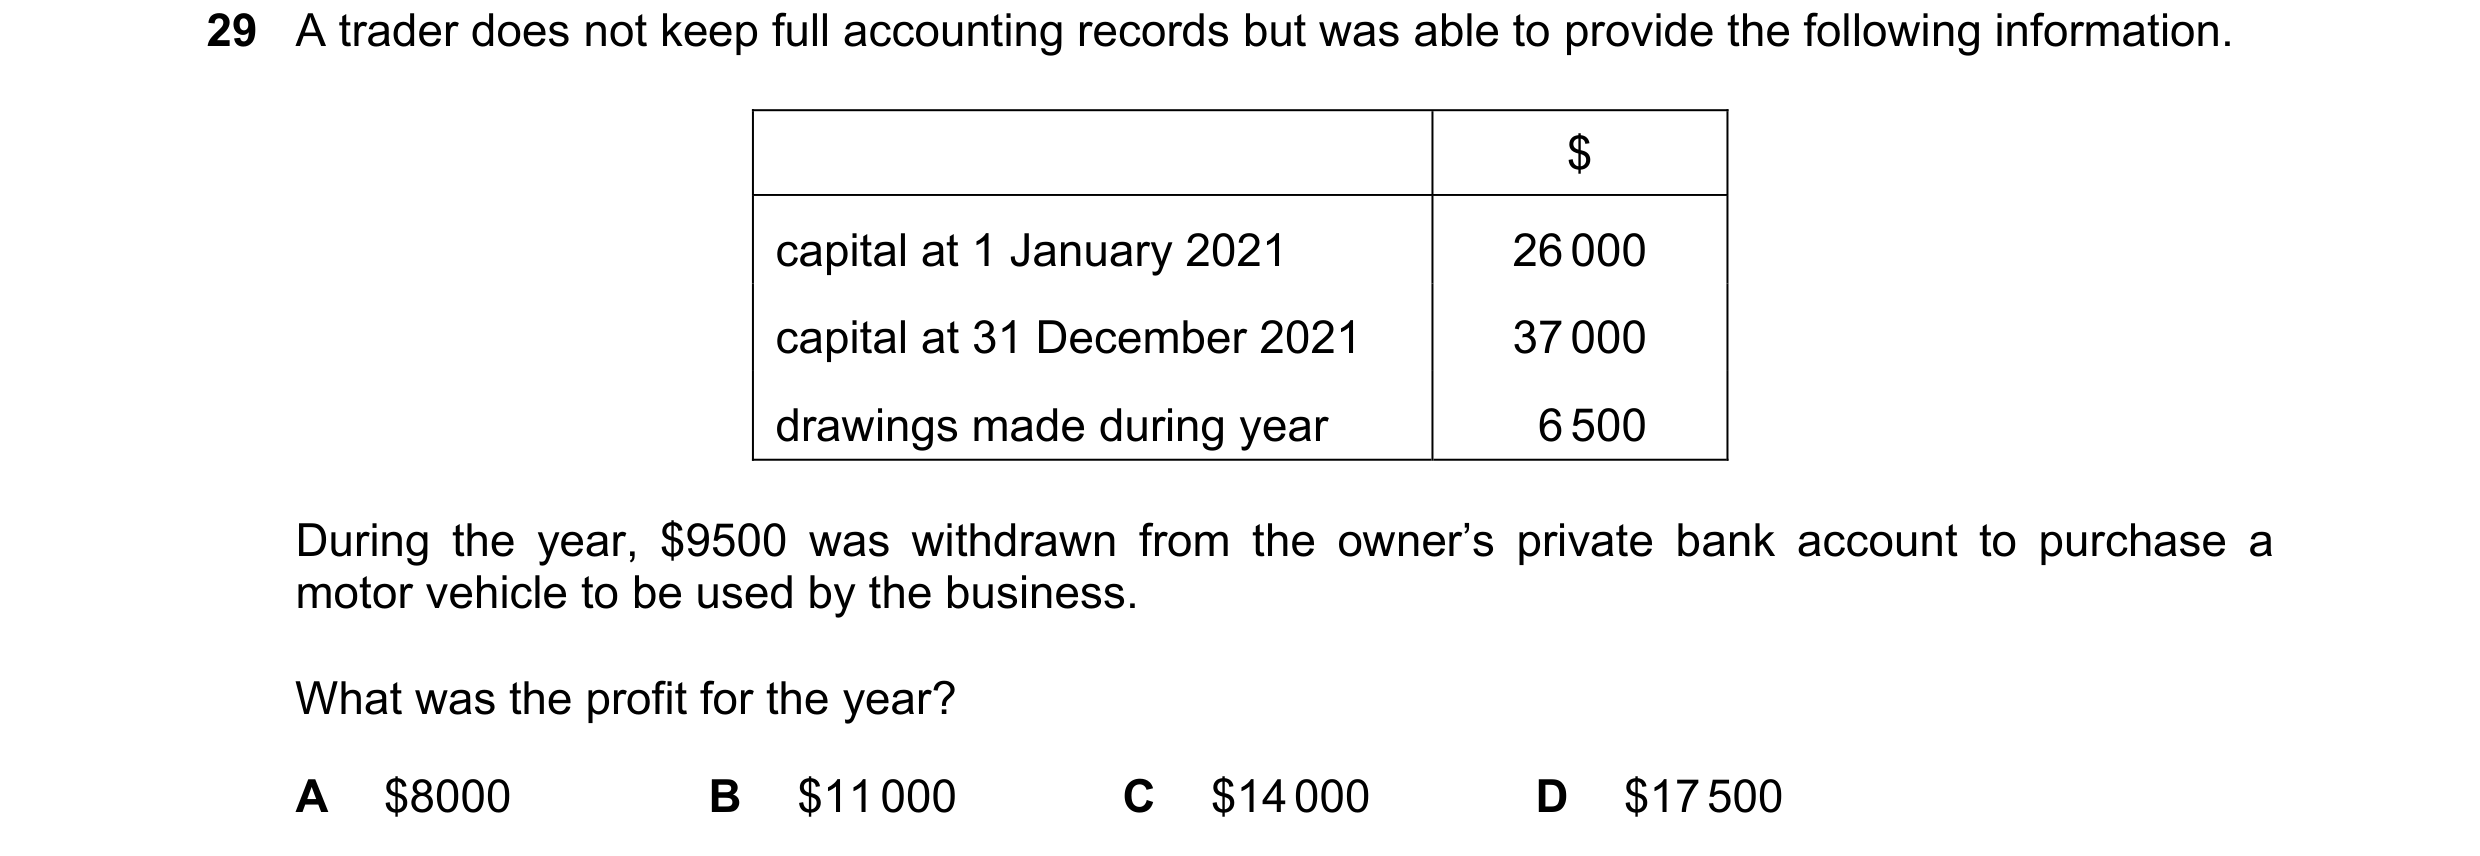
29 A trader does not keep full accounting records but was able to provide the following information. $ capital at 1 January 2021 26 000 capital at 31 December 2021 37 000 drawings made during year 6 500 During the year, $9500 was withdrawn from the owner’s private bank account to purchase a motor vehicle to be used by the business. What was the profit for the year? A $8000 B $11 000 C $14 000 D $17 500
1 marks
Answer: A
This question in 0452/11 May/June 2022
Q20 · Chan provided the following information 0452/11 Oct/Nov 2022
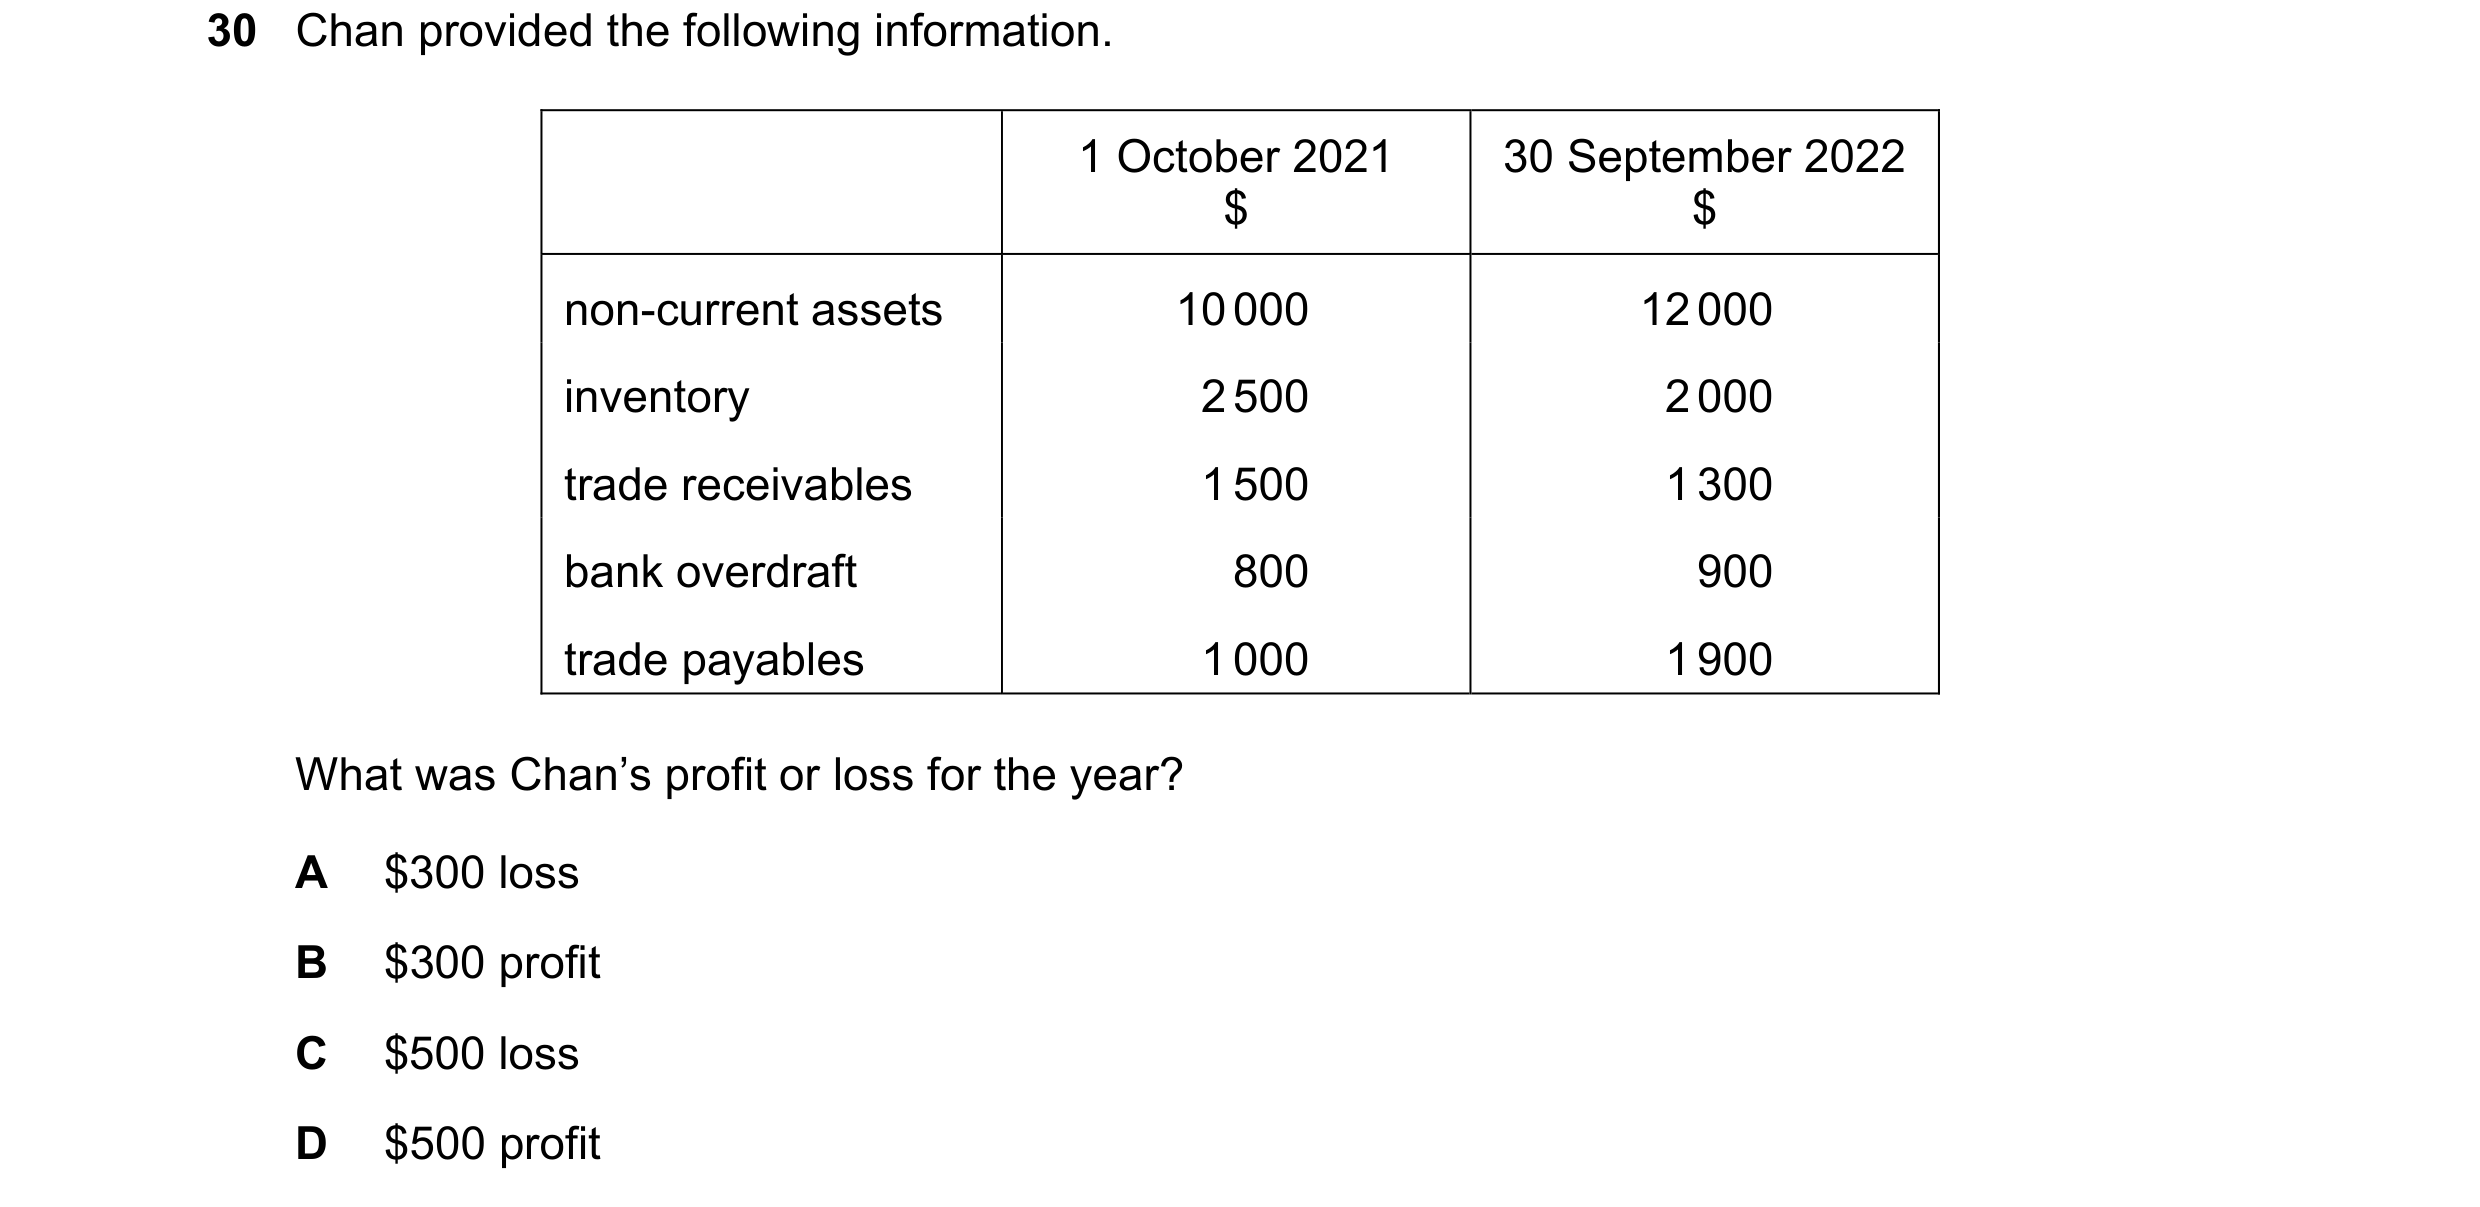
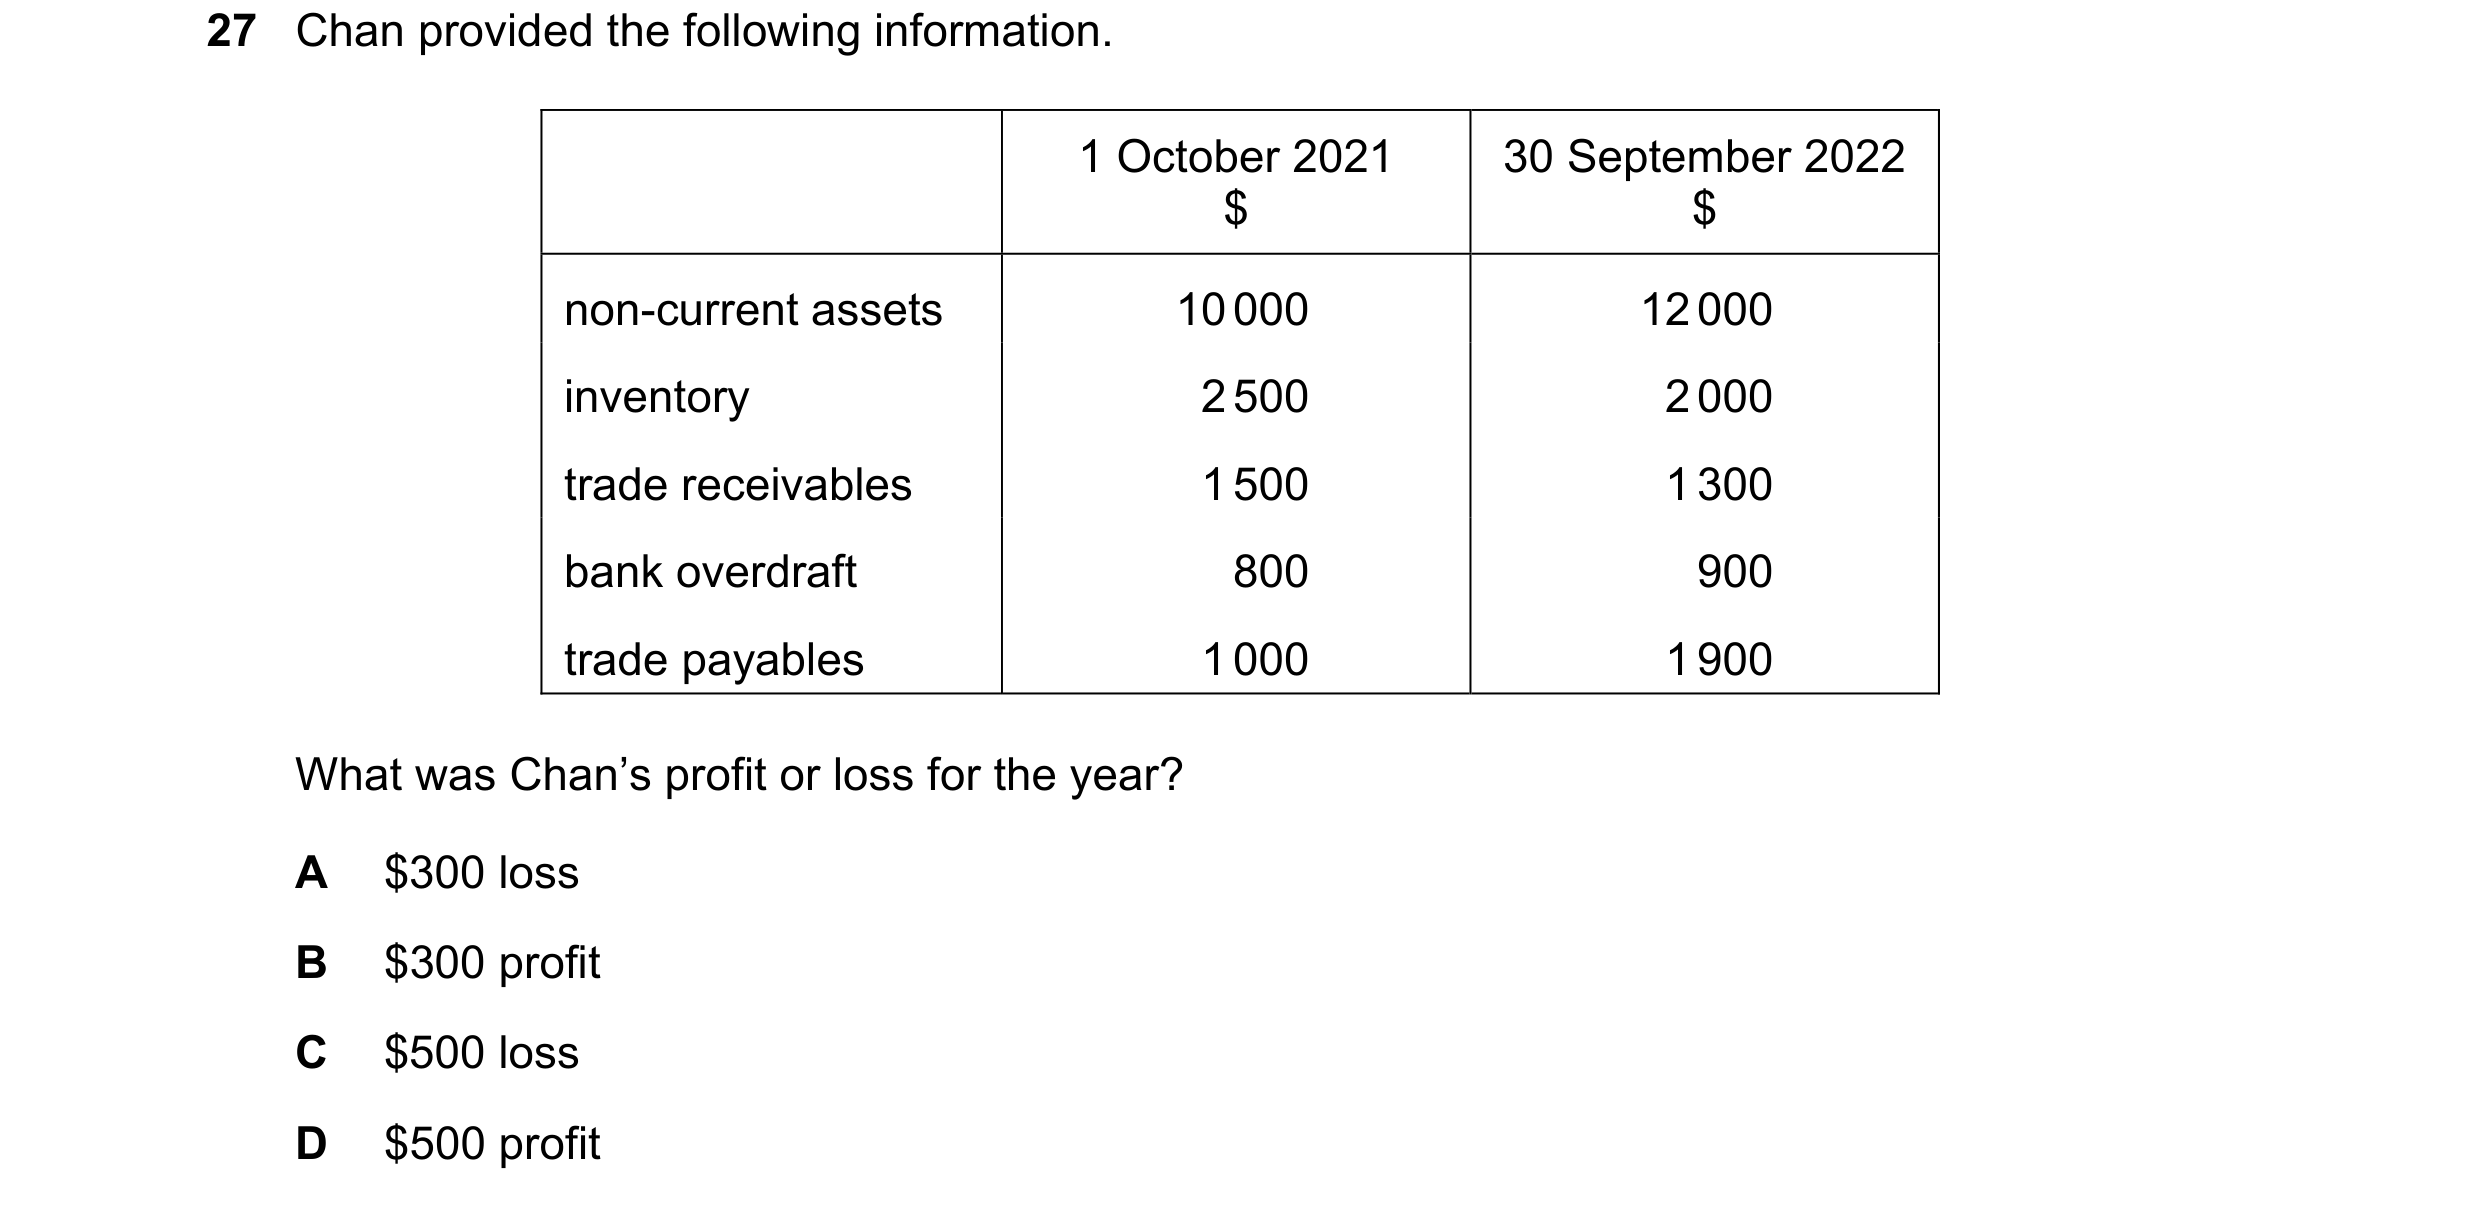
30 Chan provided the following information. 1 October 2021 30 September 2022 $ $ non-current assets 10 000 12 000 inventory 2 500 2 000 trade receivables 1 500 1 300 bank overdraft 800 900 trade payables 1 000 1 900 What was Chan’s profit or loss for the year? A $300 loss B $300 profit C $500 loss D $500 profit
1 marks
Answer: B
This question in 0452/11 Oct/Nov 2022
Q21 · Chan provided the following information 0452/12 Oct/Nov 2022
27 Chan provided the following information. 1 October 2021 30 September 2022 $ $ non-current assets 10 000 12 000 inventory 2 500 2 000 trade receivables 1 500 1 300 bank overdraft 800 900 trade payables 1 000 1 900 What was Chan’s profit or loss for the year? A $300 loss B $300 profit C $500 loss D $500 profit
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2022
Q22 · Aruna does not maintain a full set of double entry records 0452/12 Oct/Nov 2022
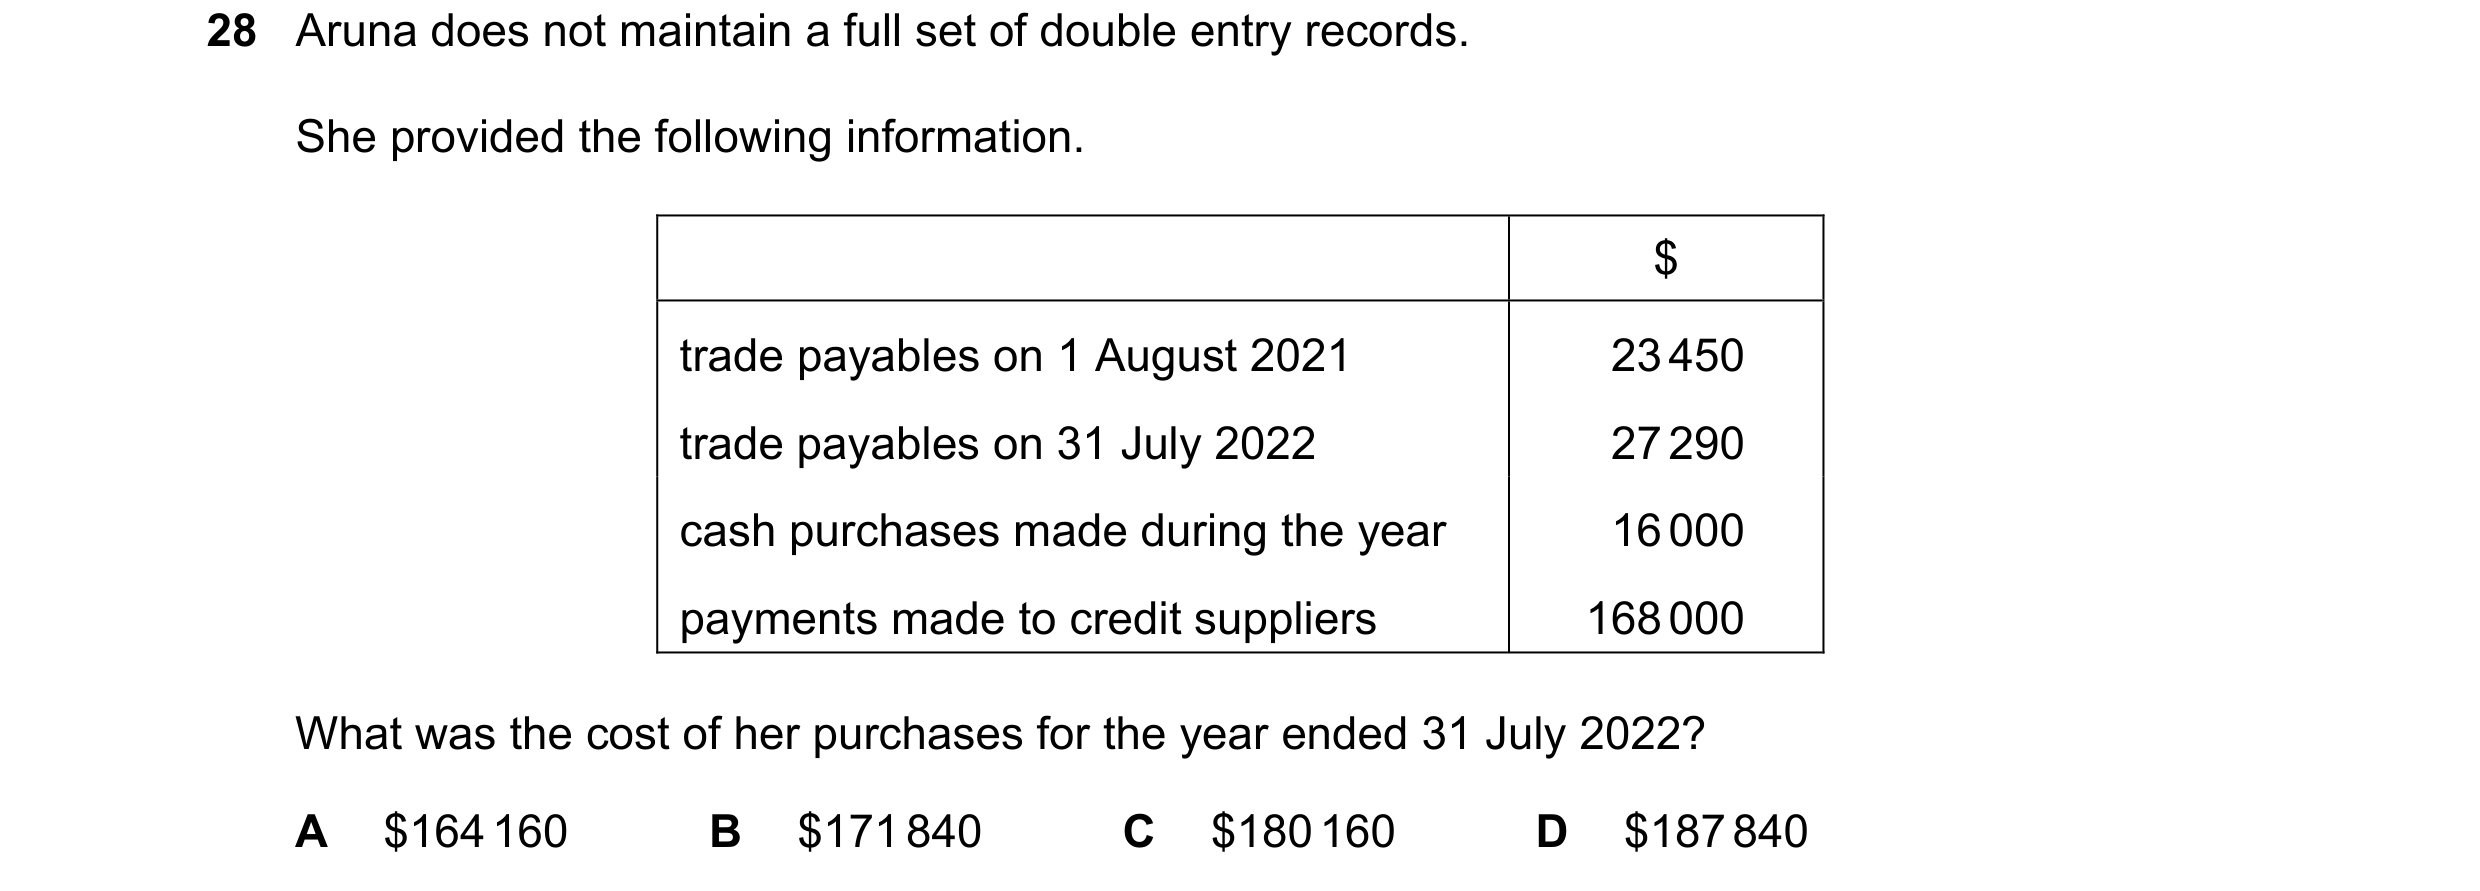
28 Aruna does not maintain a full set of double entry records. She provided the following information. $ trade payables on 1 August 2021 23 450 trade payables on 31 July 2022 27 290 cash purchases made during the year 16 000 payments made to credit suppliers 168 000 What was the cost of her purchases for the year ended 31 July 2022? A $164 160 B $171 840 C $180 160 D $187 840
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2022
Q23 · Chan provided the following information 0452/13 Oct/Nov 2022
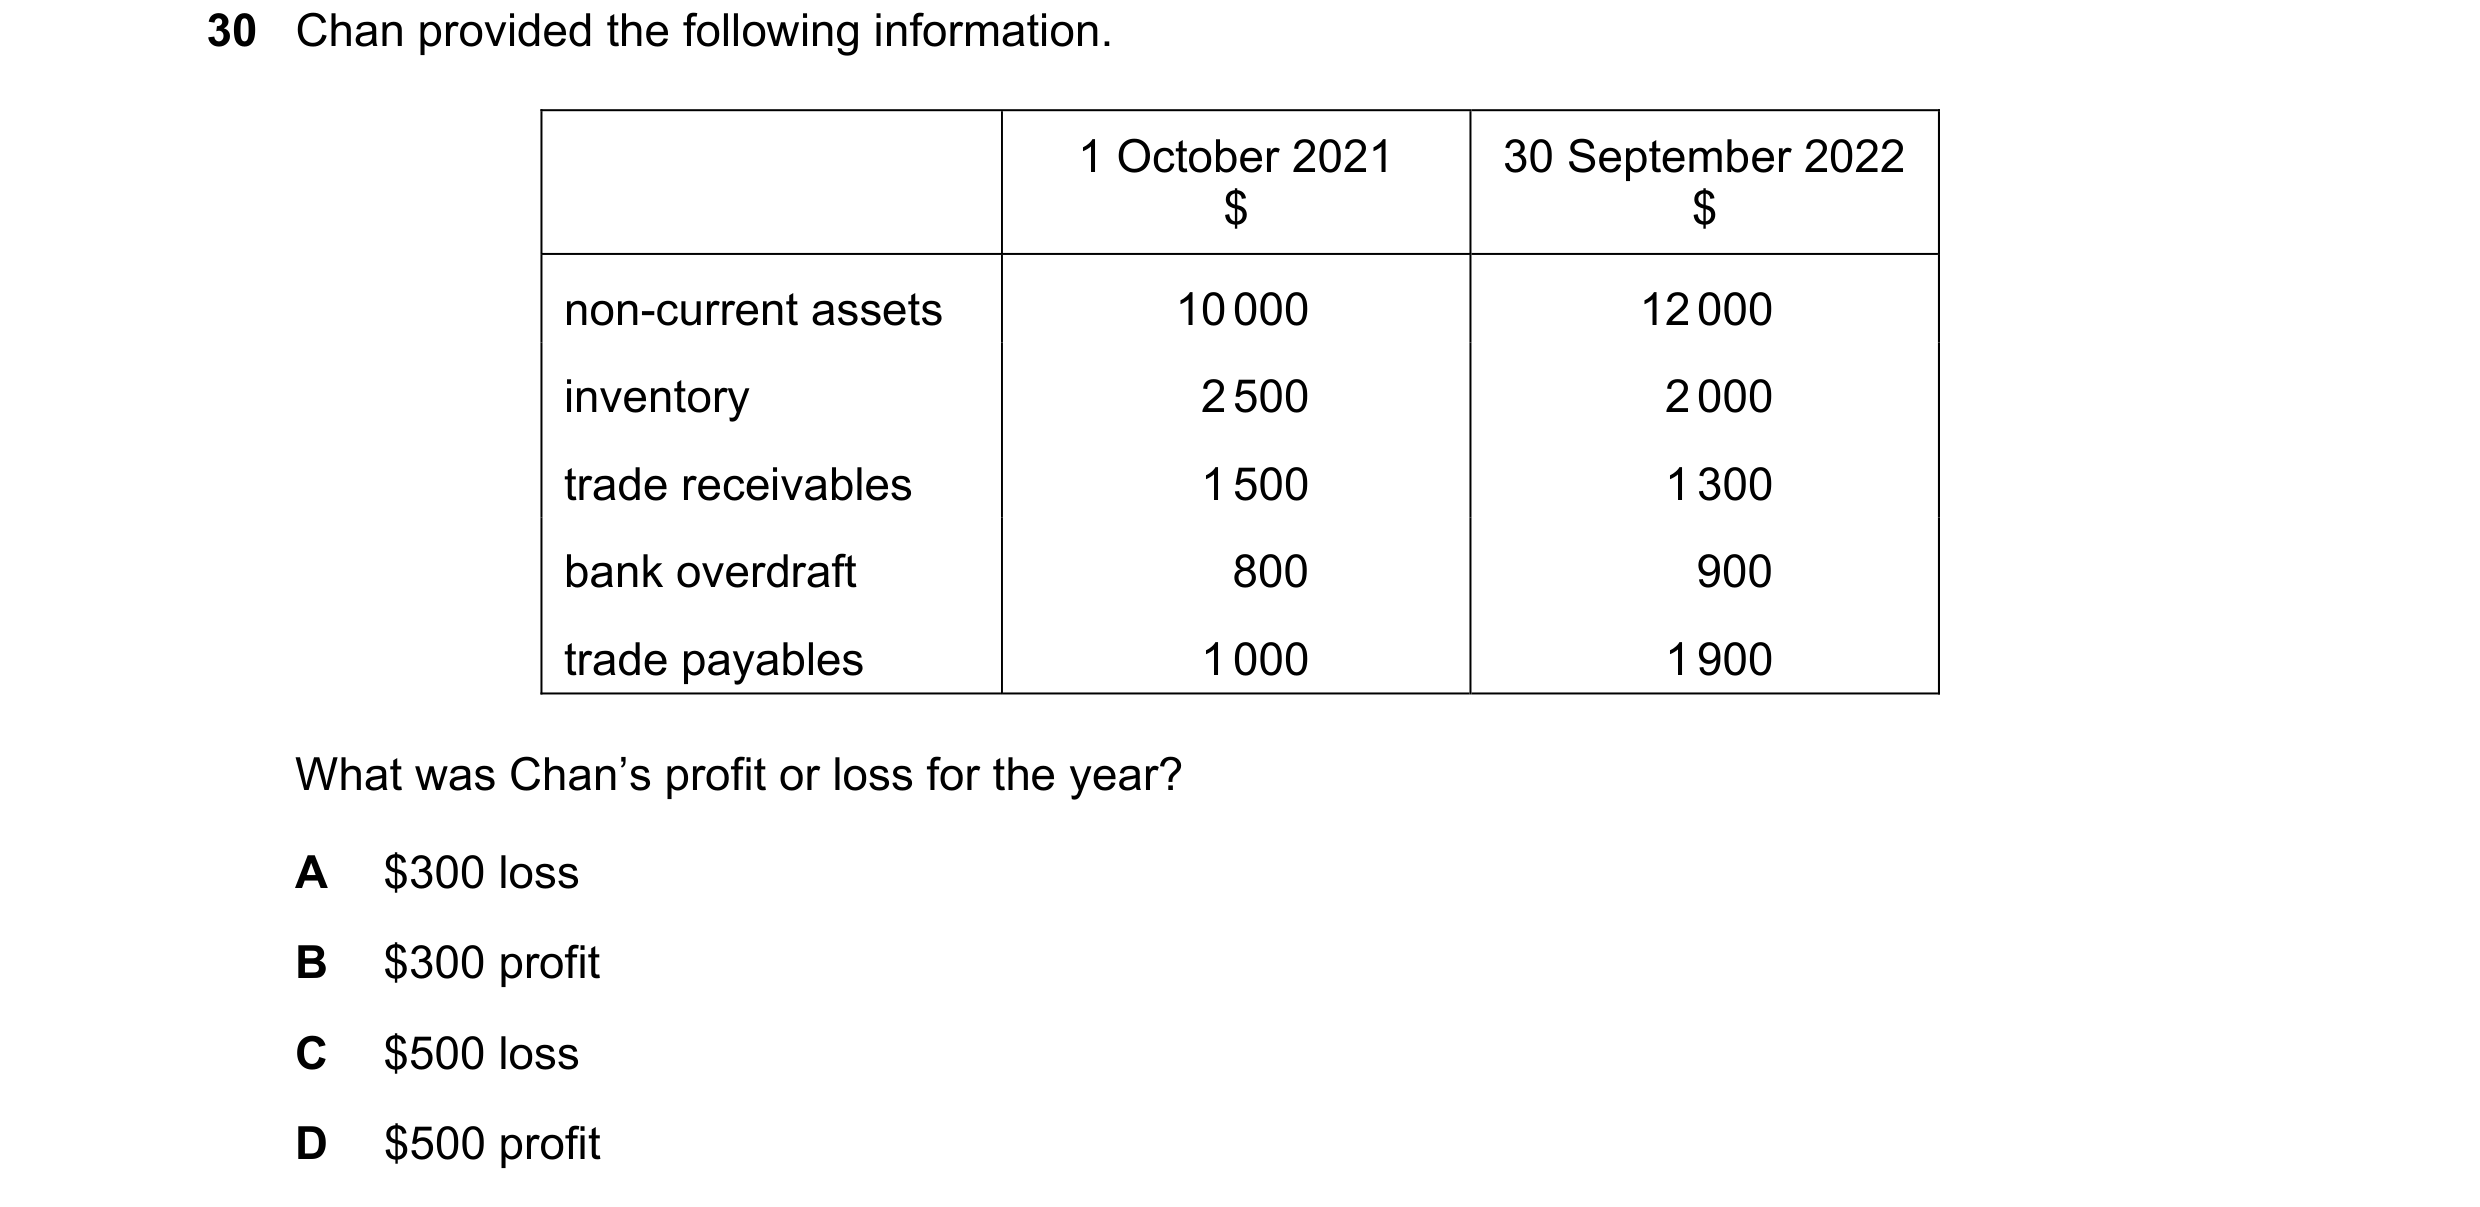
30 Chan provided the following information. 1 October 2021 30 September 2022 $ $ non-current assets 10 000 12 000 inventory 2 500 2 000 trade receivables 1 500 1 300 bank overdraft 800 900 trade payables 1 000 1 900 What was Chan’s profit or loss for the year? A $300 loss B $300 profit C $500 loss D $500 profit
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2022
Q24 · How is profit calculated from incomplete records? 0452/12 Feb/March 2023
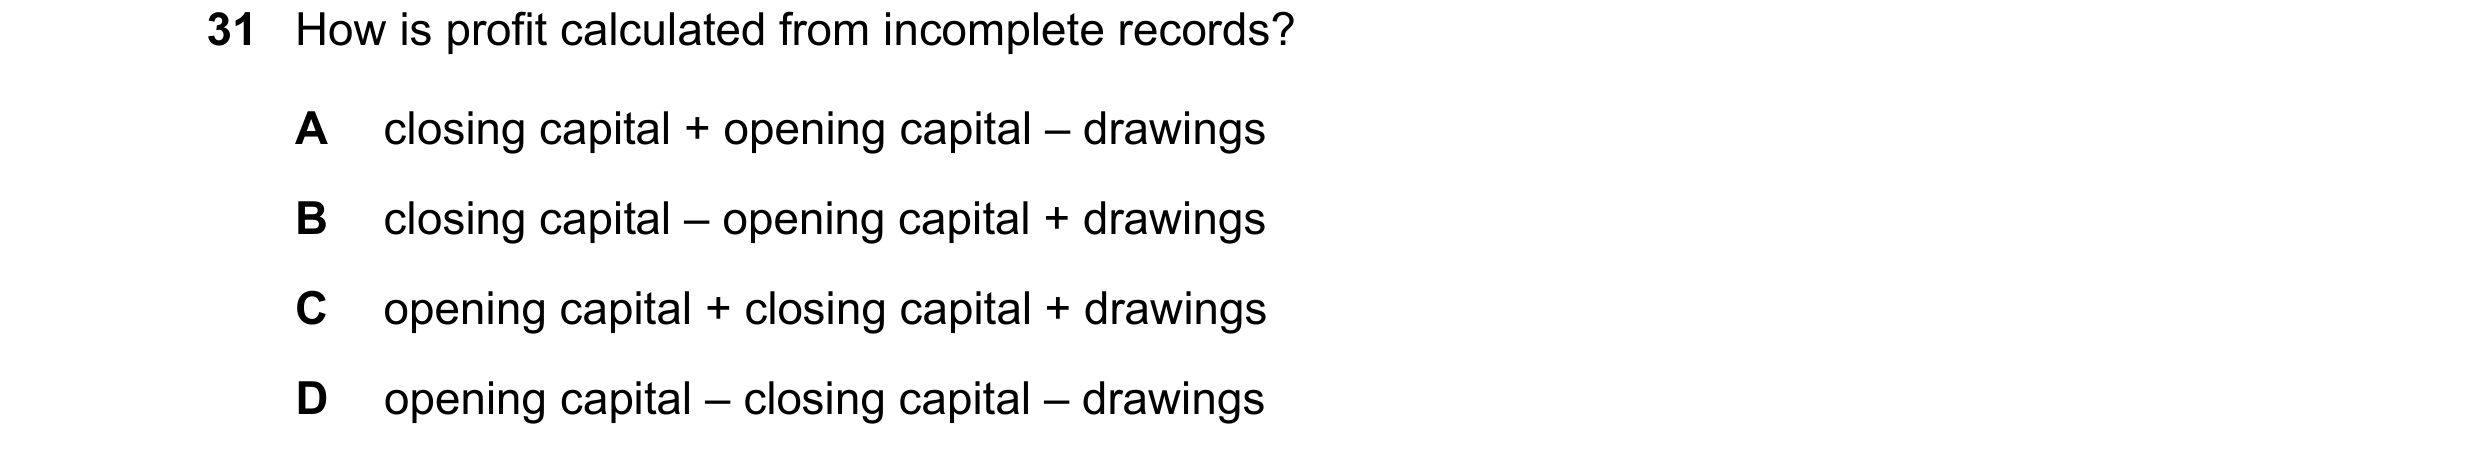
31 How is profit calculated from incomplete records? A closing capital + opening capital – drawings B closing capital – opening capital + drawings C opening capital + closing capital + drawings D opening capital – closing capital – drawings
1 marks
Answer: B
This question in 0452/12 Feb/March 2023
Q25 · Ashwin started a business as a taxi driver on 1 January 2022 0452/12 May/June 2023
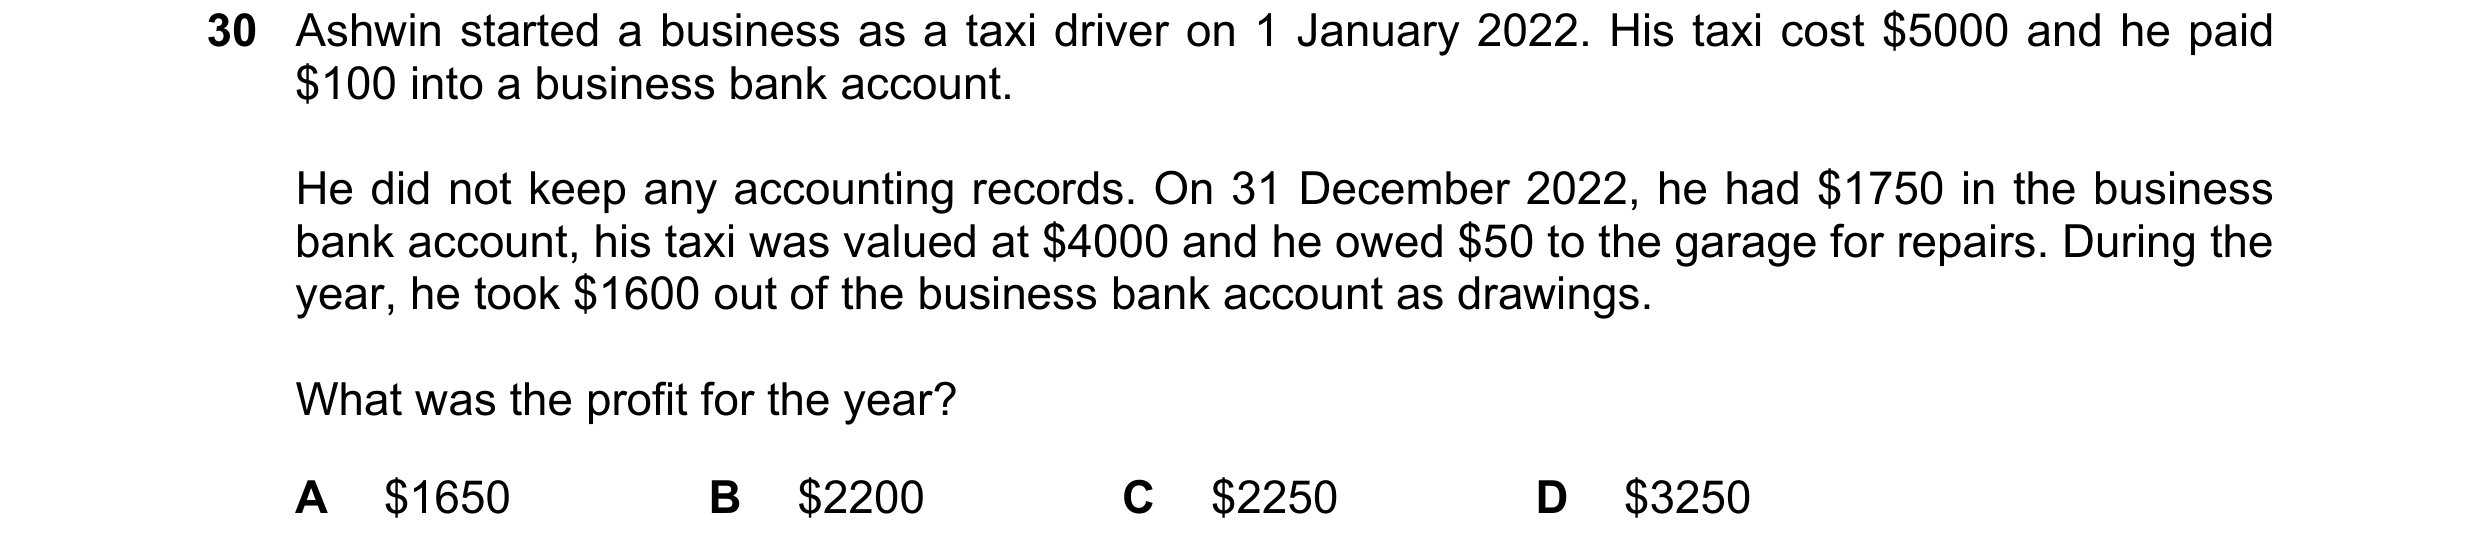
30 Ashwin started a business as a taxi driver on 1 January 2022. His taxi cost $5000 and he paid $100 into a business bank account. He did not keep any accounting records. On 31 December 2022, he had $1750 in the business bank account, his taxi was valued at $4000 and he owed $50 to the garage for repairs. During the year, he took $1600 out of the business bank account as drawings. What was the profit for the year? A $1650 B $2200 C $2250 D $3250
1 marks
Answer: B
This question in 0452/12 May/June 2023
Q26 · A trader did not keep a complete set of accounts 0452/12 May/June 2023
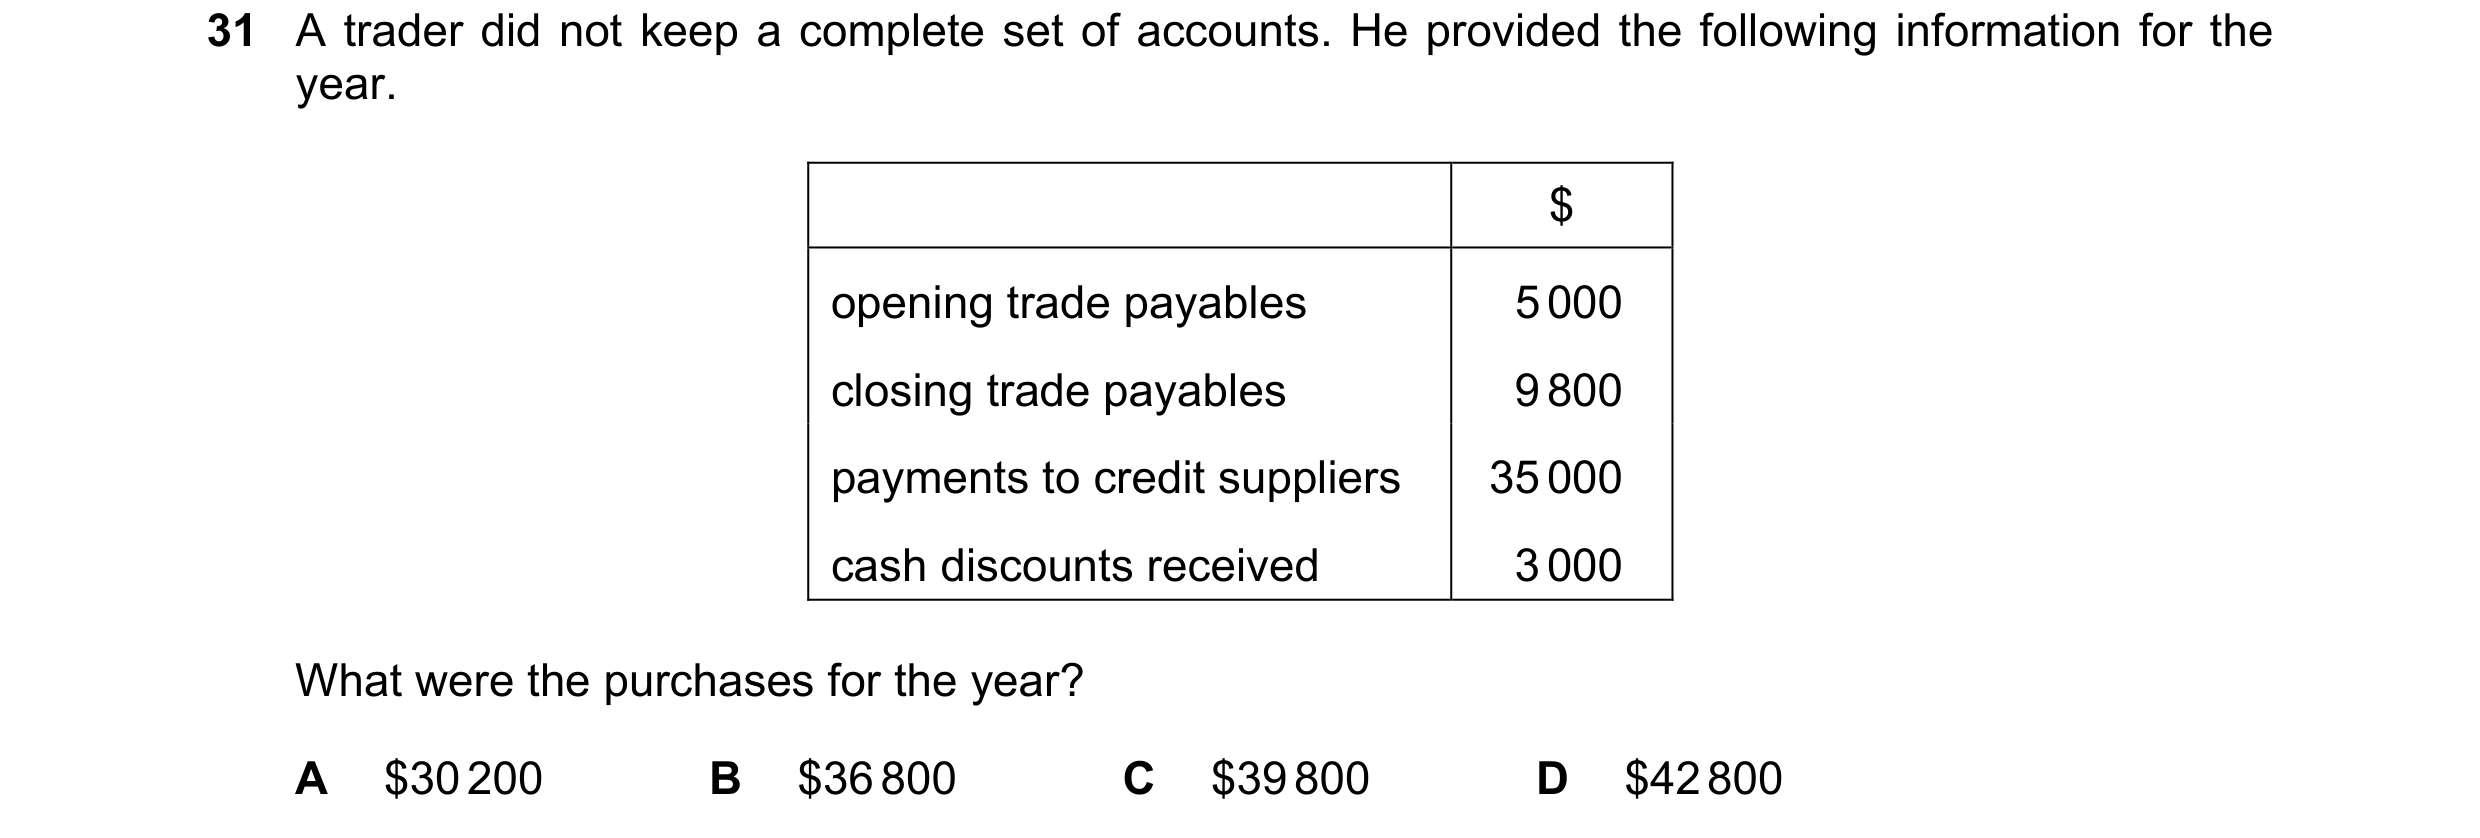
31 A trader did not keep a complete set of accounts. He provided the following information for the year. $ opening trade payables 5 000 closing trade payables 9 800 payments to credit suppliers 35 000 cash discounts received 3 000 What were the purchases for the year? A $30 200 B $36 800 C $39 800 D $42 800
1 marks
Answer: D
This question in 0452/12 May/June 2023
Q27 · Ashwin started a business as a taxi driver on 1 January 2022 0452/13 May/June 2023
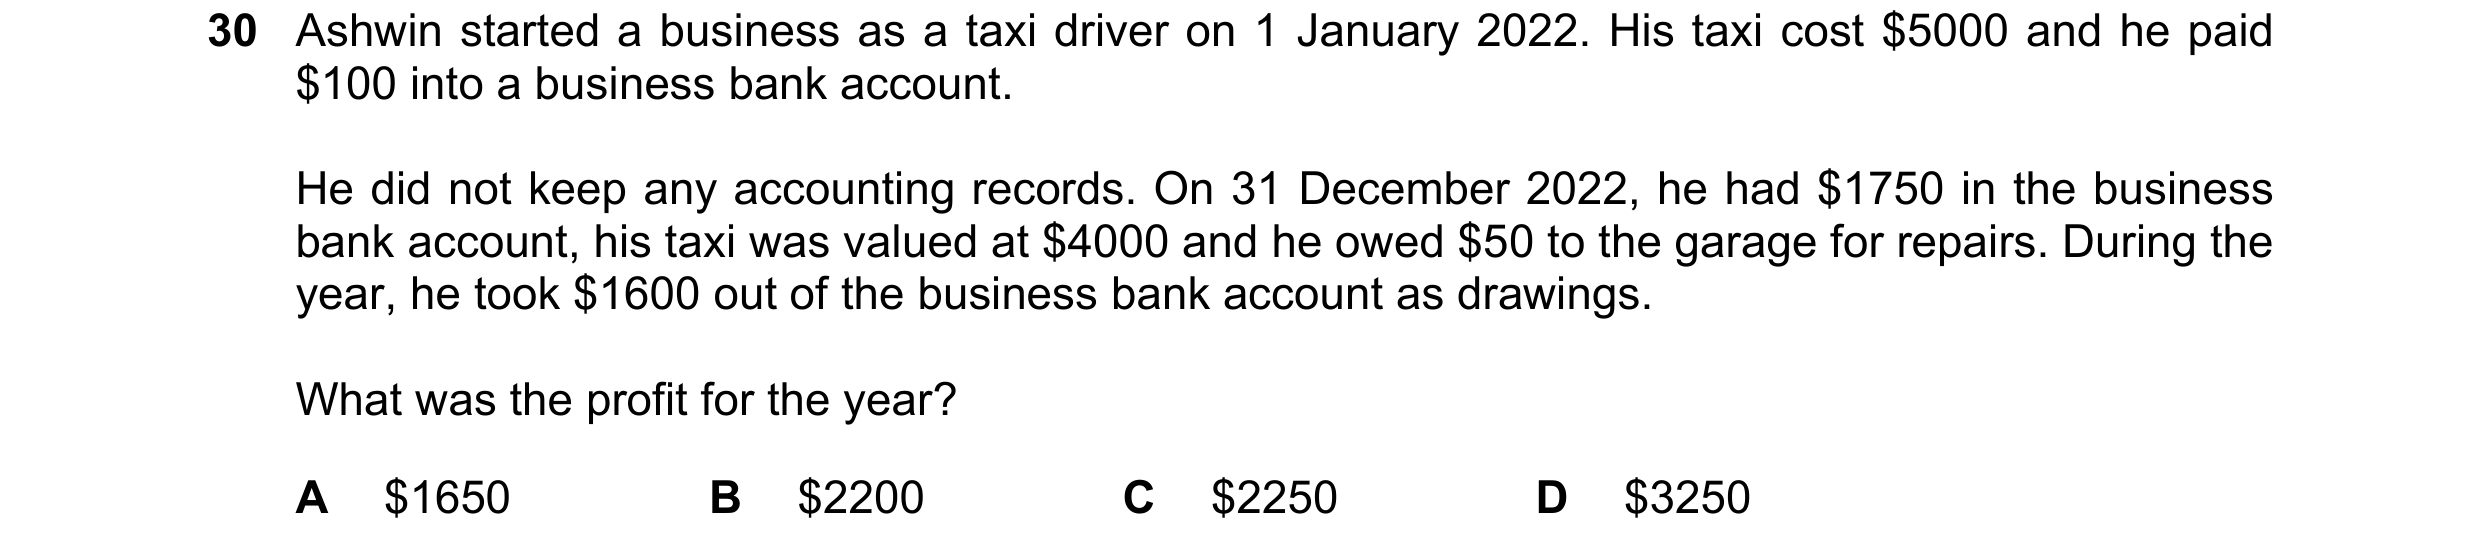
30 Ashwin started a business as a taxi driver on 1 January 2022. His taxi cost $5000 and he paid $100 into a business bank account. He did not keep any accounting records. On 31 December 2022, he had $1750 in the business bank account, his taxi was valued at $4000 and he owed $50 to the garage for repairs. During the year, he took $1600 out of the business bank account as drawings. What was the profit for the year? A $1650 B $2200 C $2250 D $3250
1 marks
Answer: B
This question in 0452/13 May/June 2023
Q28 · A trader did not keep a complete set of accounts 0452/13 May/June 2023
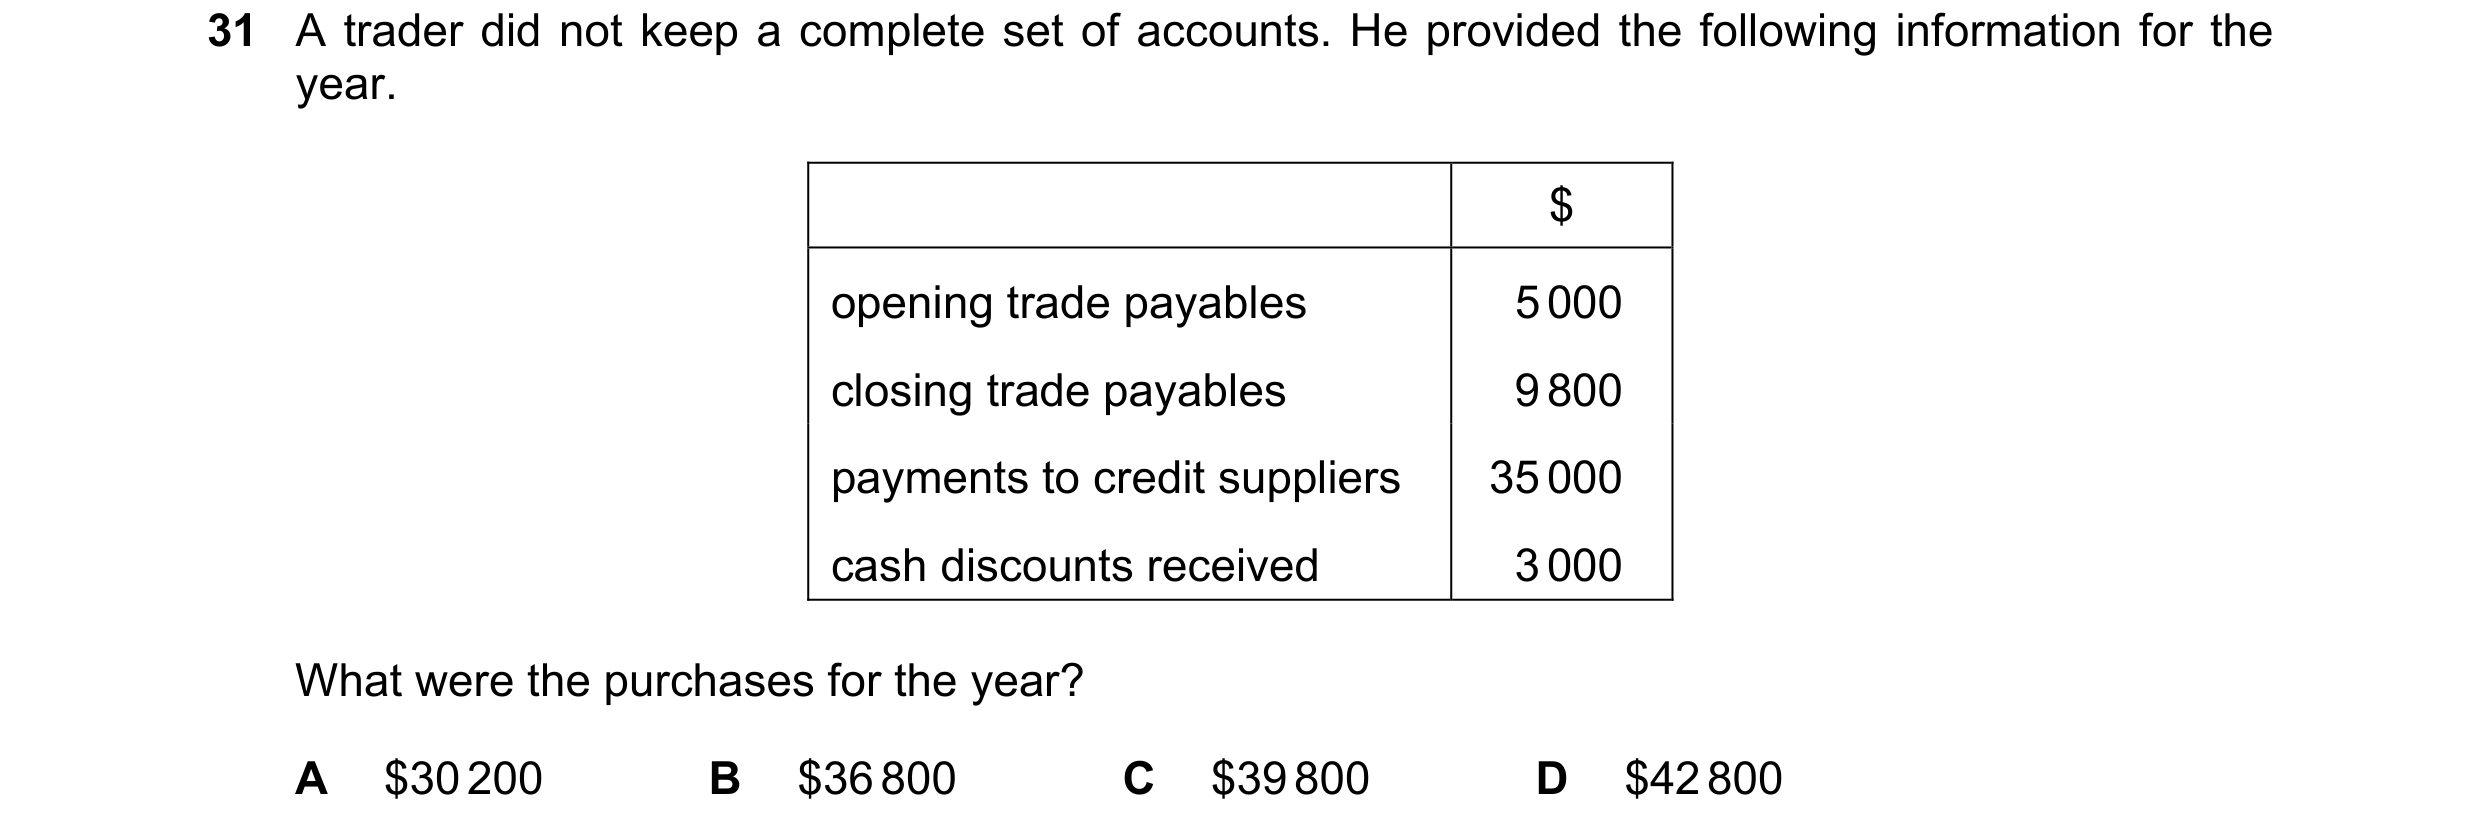
31 A trader did not keep a complete set of accounts. He provided the following information for the year. $ opening trade payables 5 000 closing trade payables 9 800 payments to credit suppliers 35 000 cash discounts received 3 000 What were the purchases for the year? A $30 200 B $36 800 C $39 800 D $42 800
1 marks
Answer: D
This question in 0452/13 May/June 2023
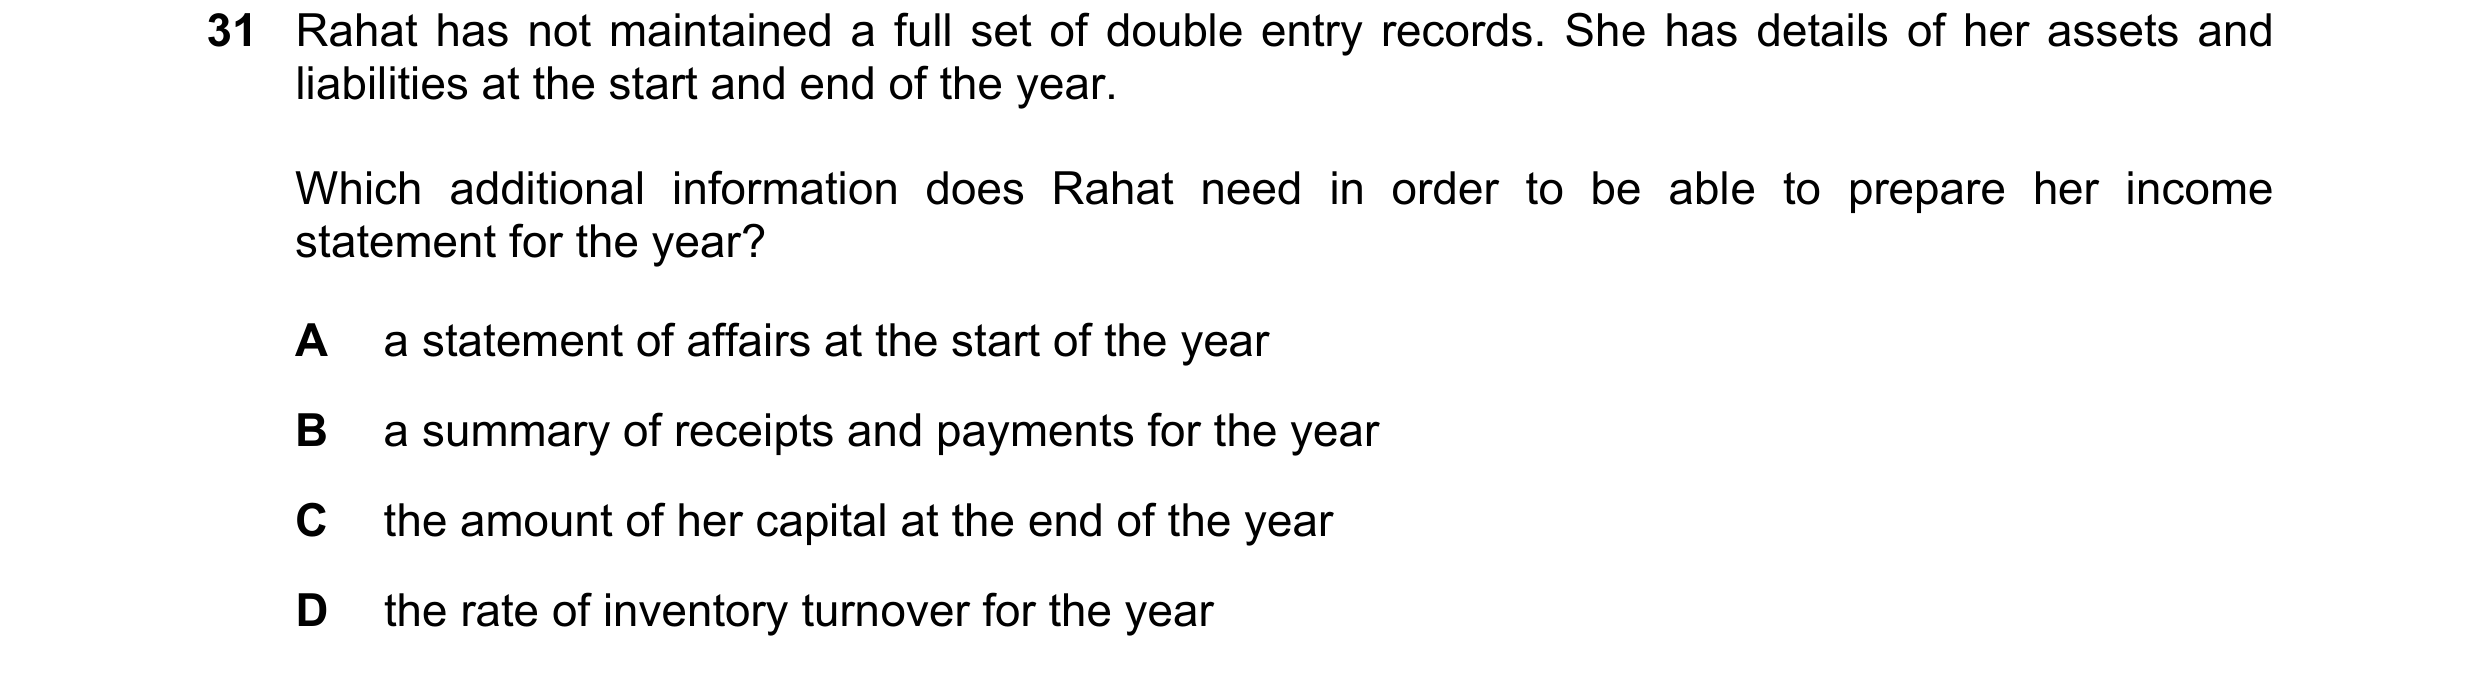
Q29 · Rahat has not maintained a full set of double entry records 0452/11 Oct/Nov 2023
31 Rahat has not maintained a full set of double entry records. She has details of her assets and liabilities at the start and end of the year. Which additional information does Rahat need in order to be able to prepare her income statement for the year? A a statement of affairs at the start of the year B a summary of receipts and payments for the year C the amount of her capital at the end of the year D the rate of inventory turnover for the year
1 marks
Answer: B
This question in 0452/11 Oct/Nov 2023
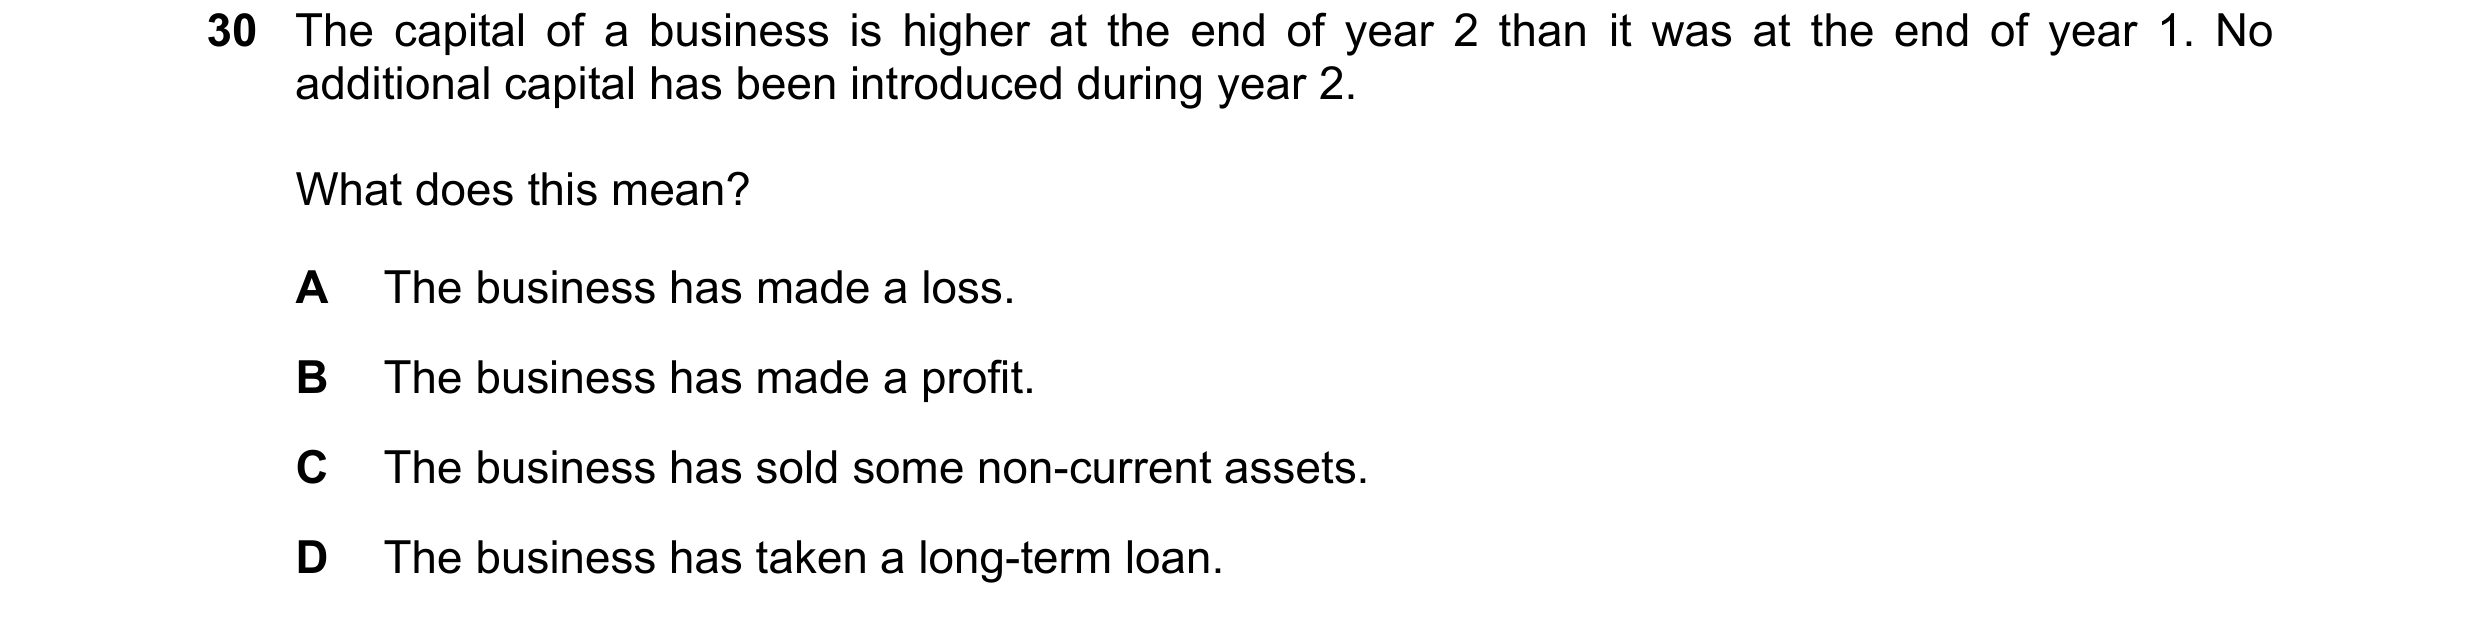
Q30 · The capital of a business is higher at the end of year 2 than it was at the end of year 1 0452/13 Oct/Nov 2023
30 The capital of a business is higher at the end of year 2 than it was at the end of year 1. No additional capital has been introduced during year 2. What does this mean? A The business has made a loss. B The business has made a profit. C The business has sold some non-current assets. D The business has taken a long-term loan.
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2023
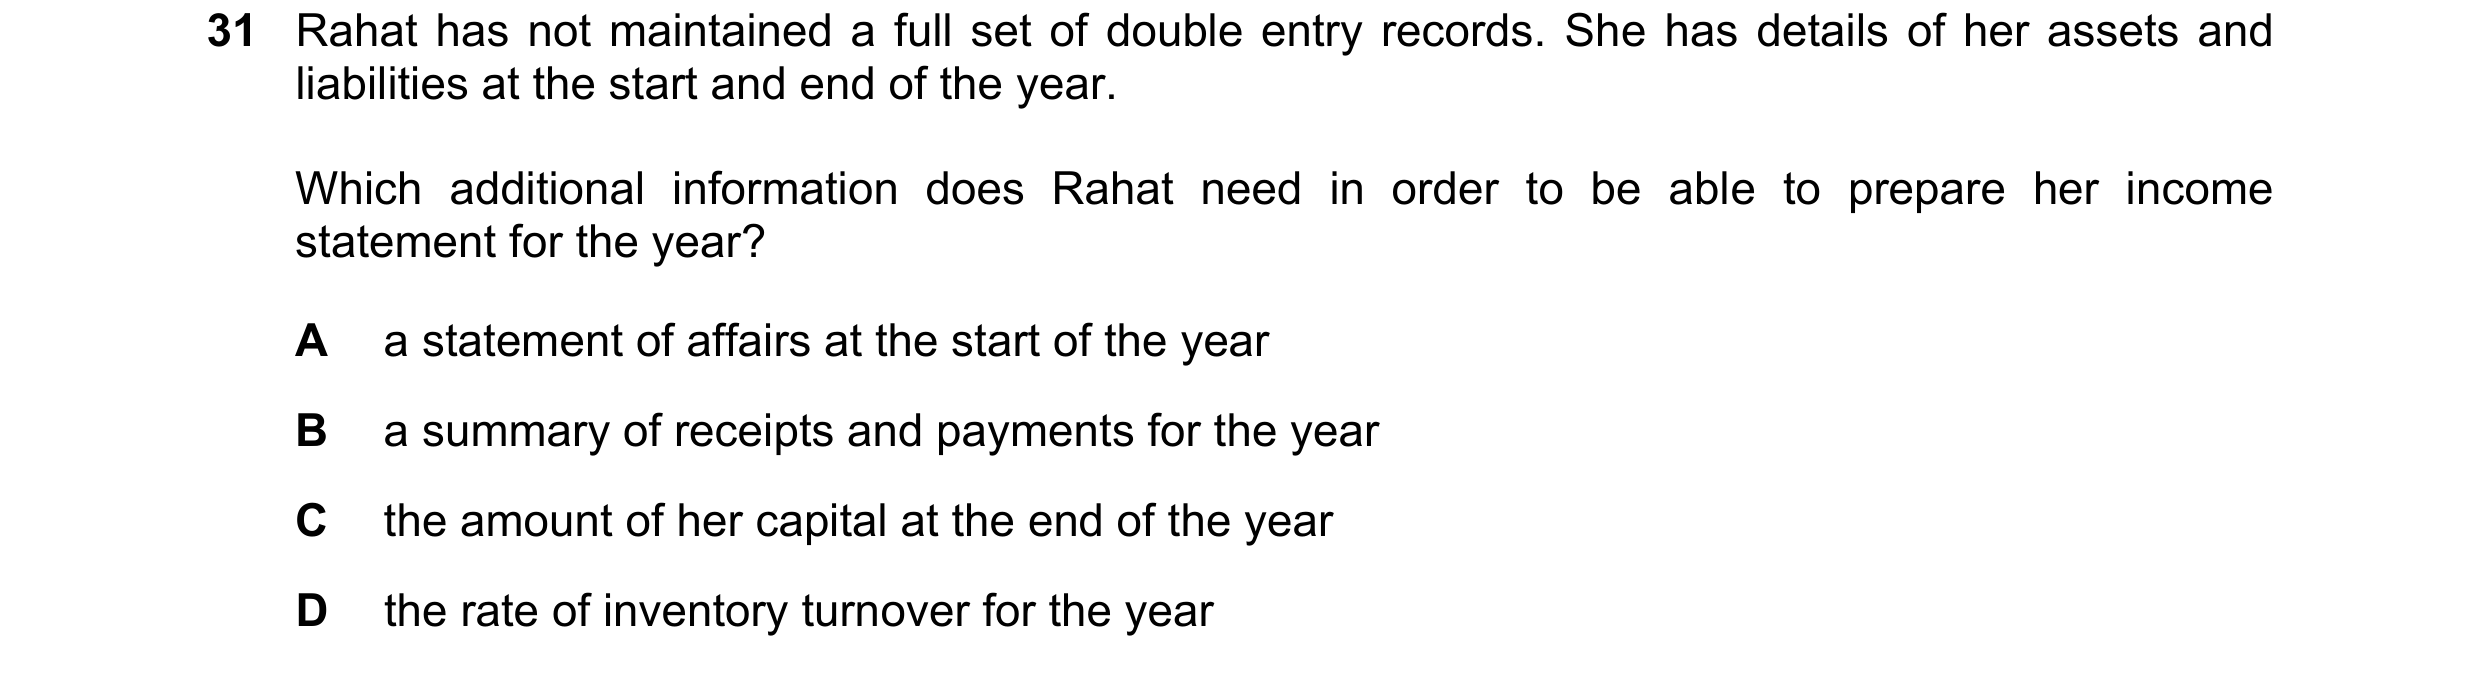
Q31 · Rahat has not maintained a full set of double entry records 0452/13 Oct/Nov 2023
31 Rahat has not maintained a full set of double entry records. She has details of her assets and liabilities at the start and end of the year. Which additional information does Rahat need in order to be able to prepare her income statement for the year? A a statement of affairs at the start of the year B a summary of receipts and payments for the year C the amount of her capital at the end of the year D the rate of inventory turnover for the year
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2023
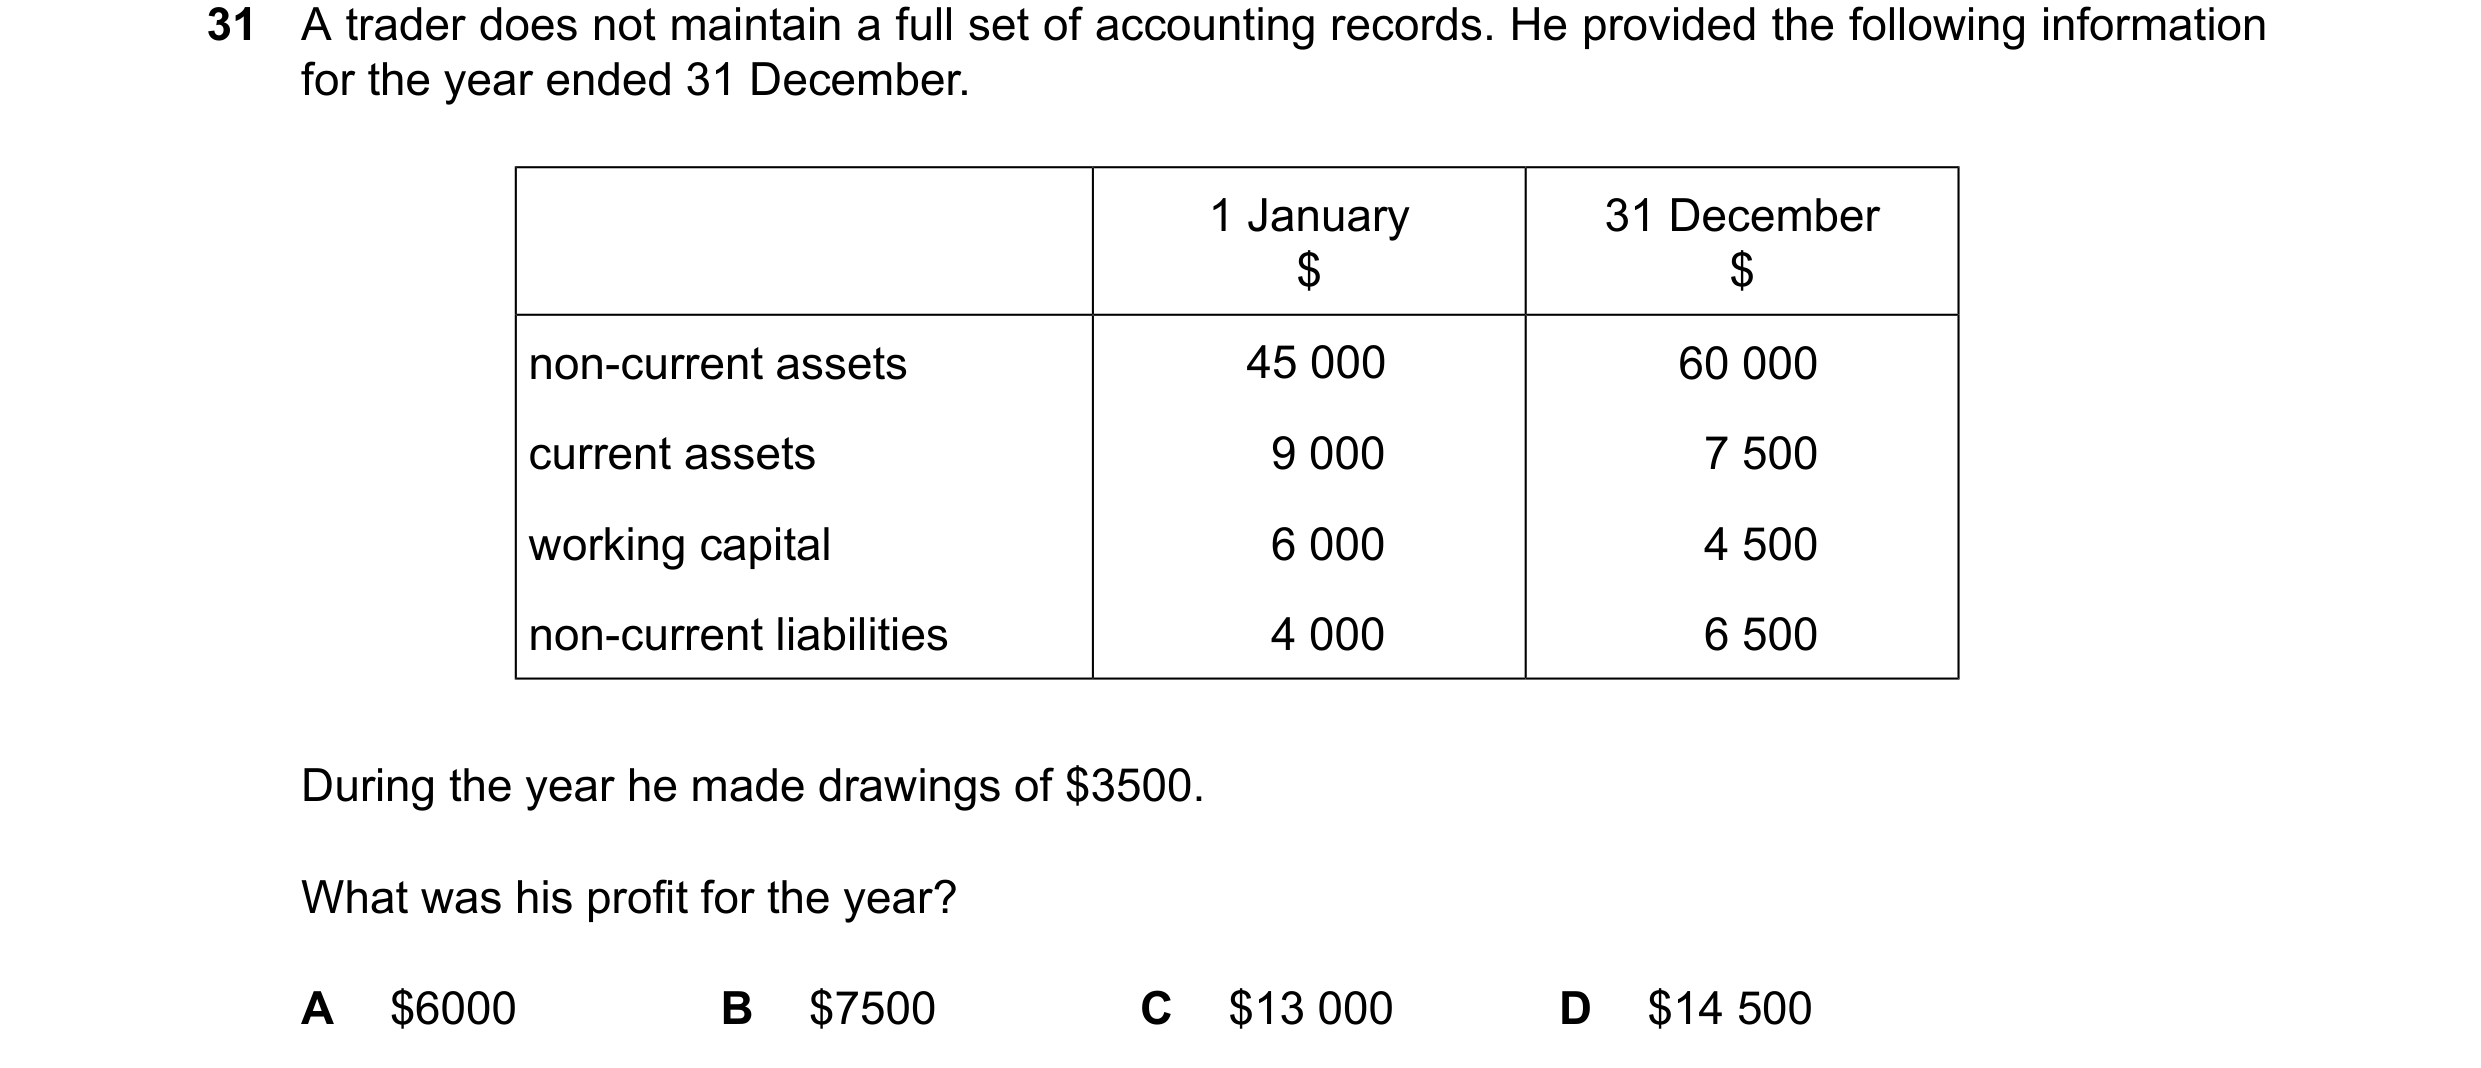
Q32 · A trader does not maintain a full set of accounting records 0452/12 Feb/March 2024
31 A trader does not maintain a full set of accounting records. He provided the following information for the year ended 31 December. 1 January 31 December $ $ non-current assets 45 000 60 000 current assets 9 000 7 500 working capital 6 000 4 500 non-current liabilities 4 000 6 500 During the year he made drawings of $3500. What was his profit for the year? A $6000 B $7500 C $13 000 D $14 500
1 marks
Answer: D
This question in 0452/12 Feb/March 2024
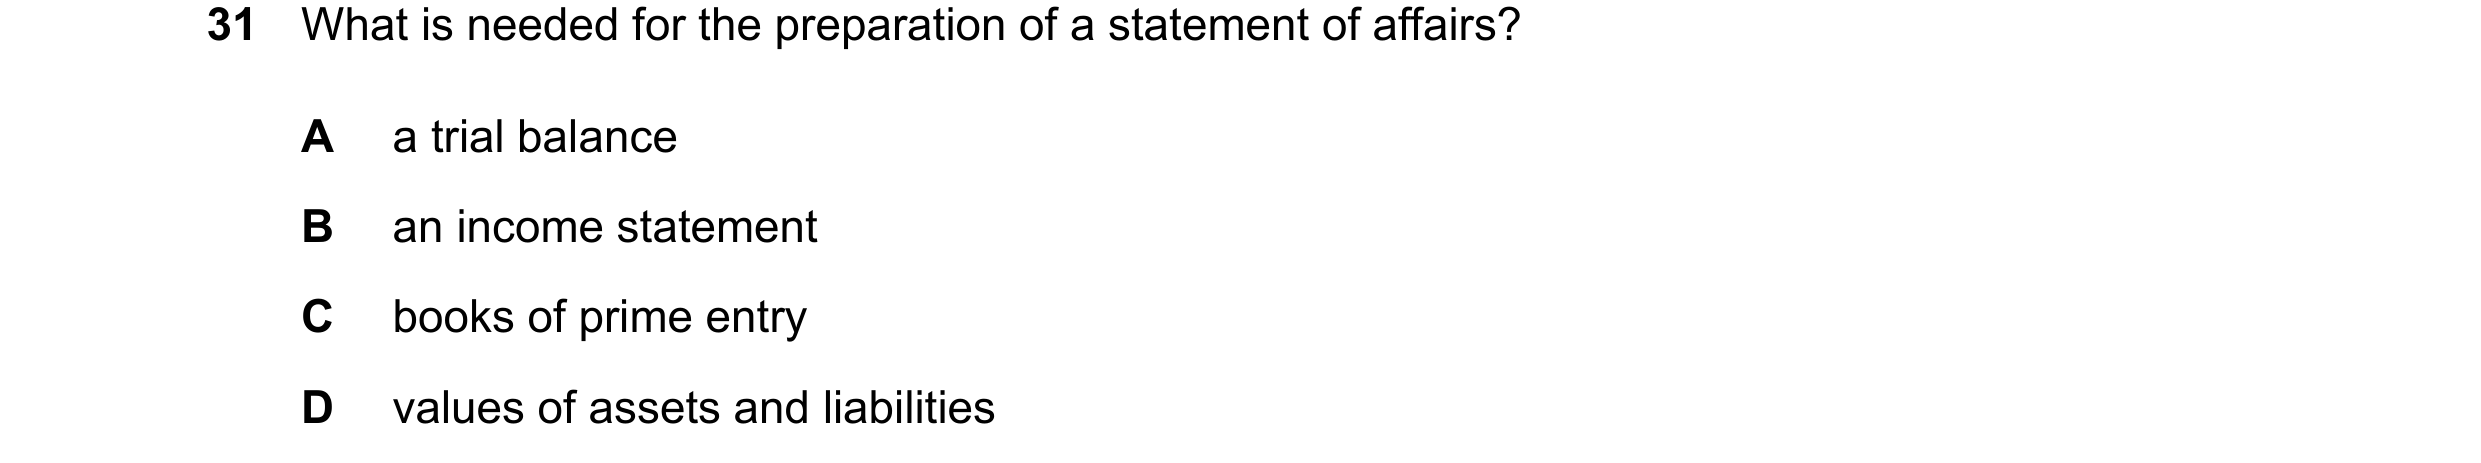
Q33 · What is needed for the preparation of a statement of affairs? 0452/11 May/June 2024
31 What is needed for the preparation of a statement of affairs? A a trial balance B an income statement C books of prime entry D values of assets and liabilities
1 marks
Answer: D
This question in 0452/11 May/June 2024
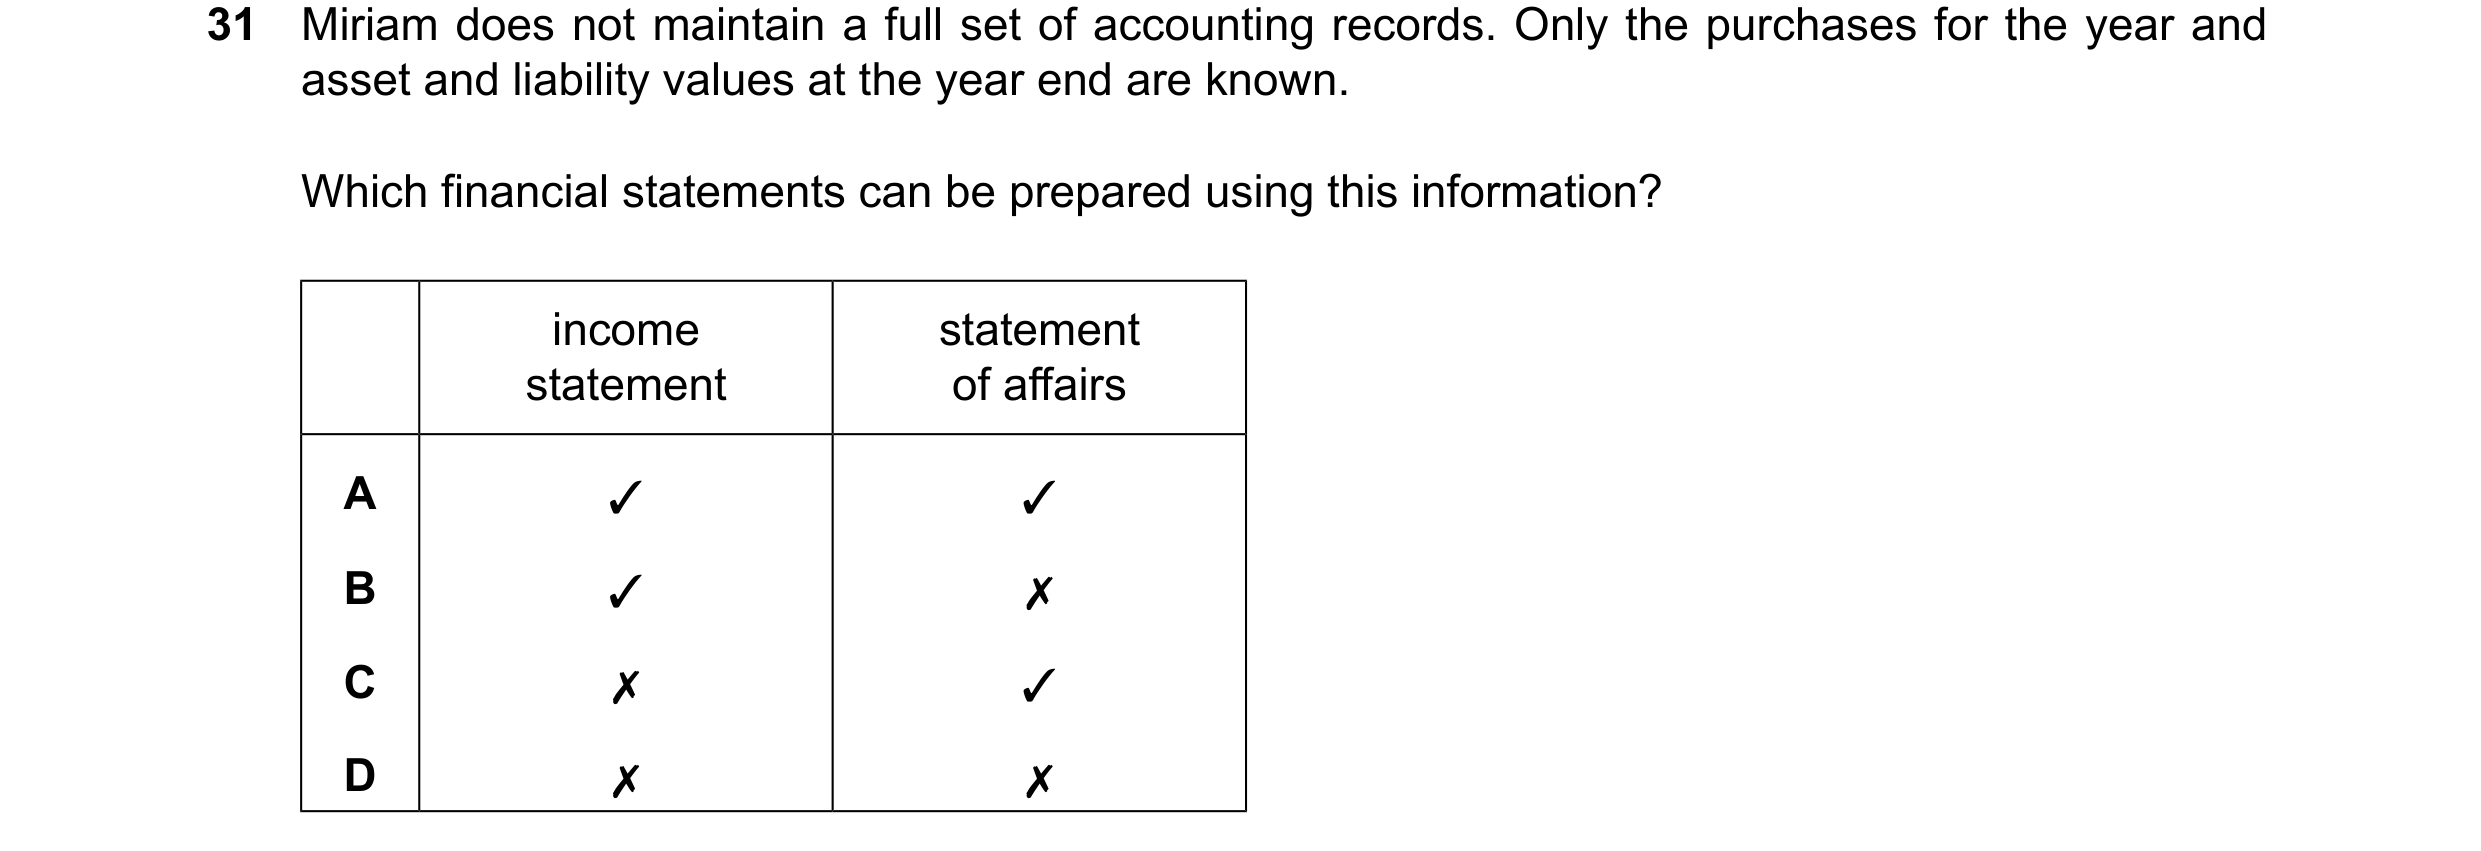
Q34 · Miriam does not maintain a full set of accounting records 0452/12 May/June 2024
31 Miriam does not maintain a full set of accounting records. Only the purchases for the year and asset and liability values at the year end are known. Which financial statements can be prepared using this information? income statement statement of affairs A ✓ ✓ B ✓ ✗ C ✗ ✓ D ✗ ✗
1 marks
Answer: C
This question in 0452/12 May/June 2024
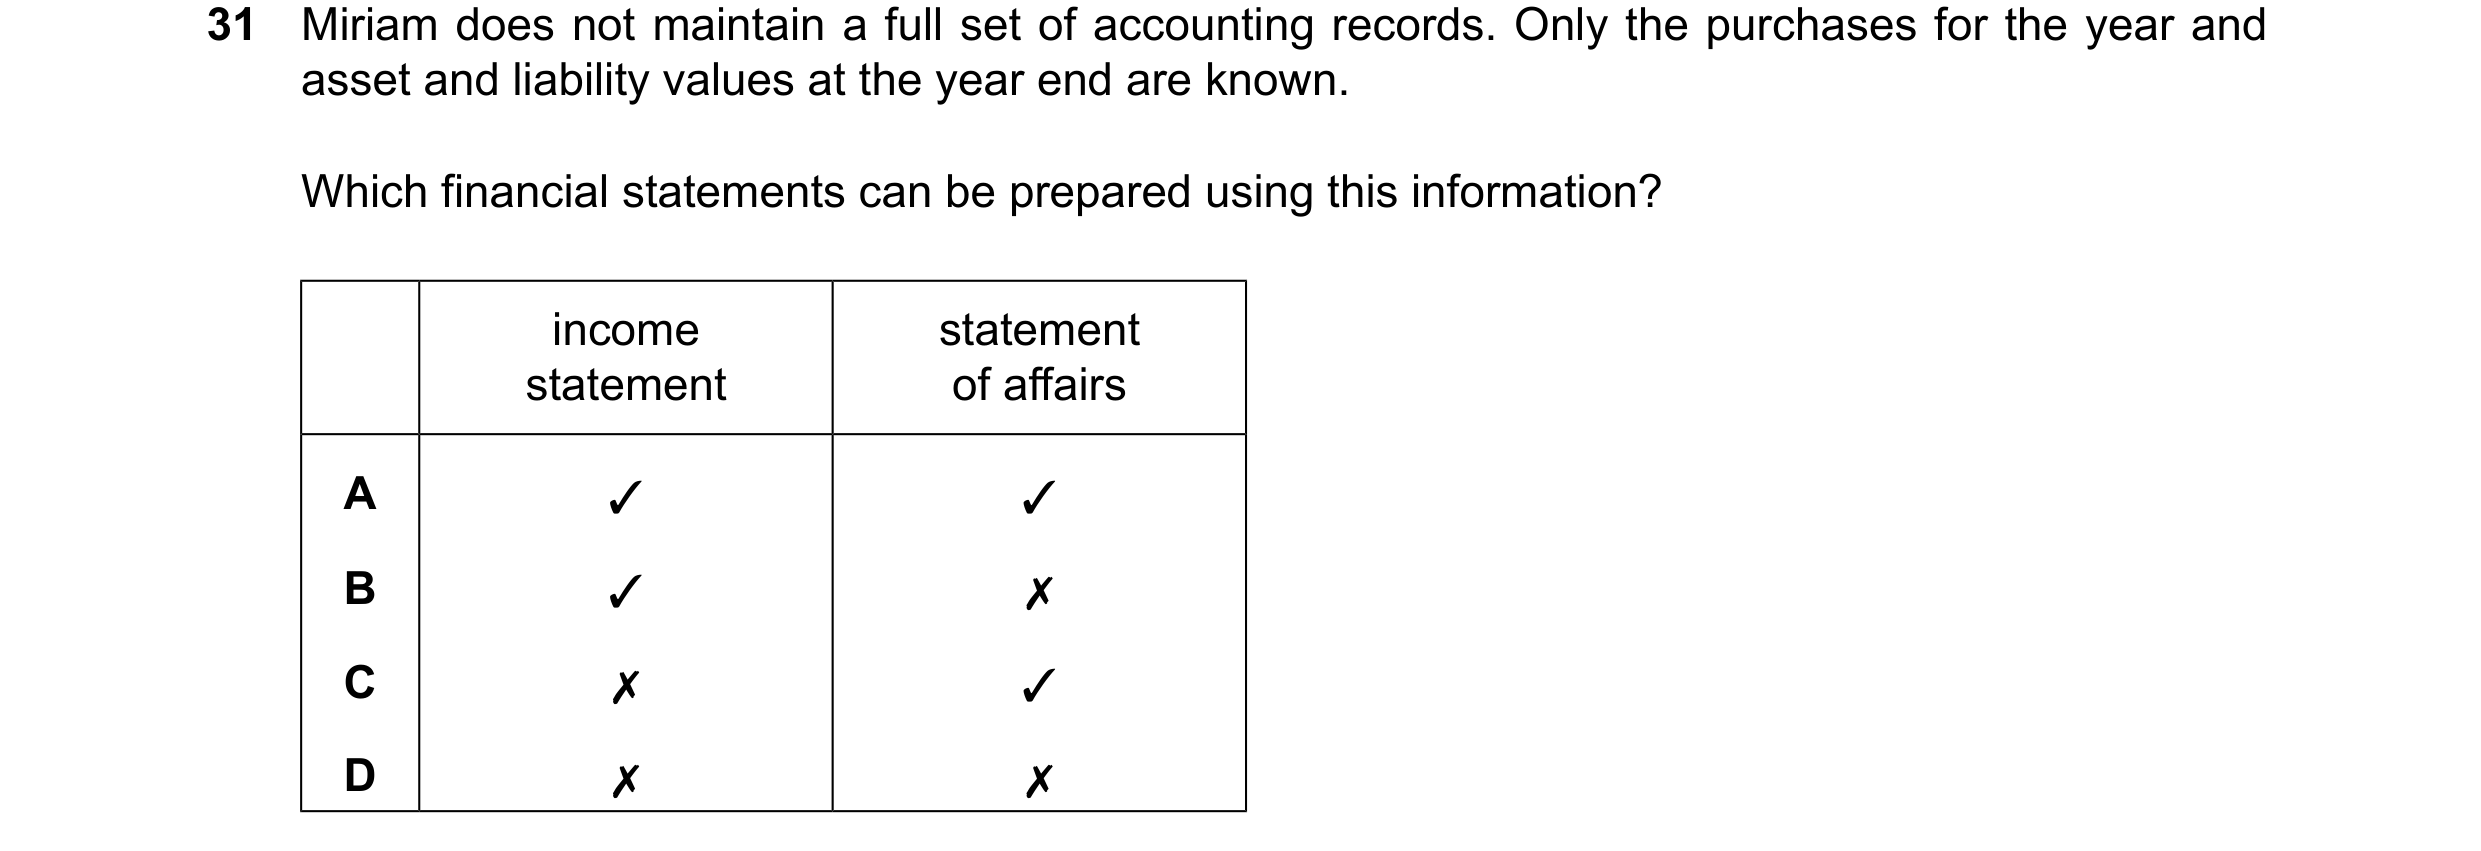
Q35 · Miriam does not maintain a full set of accounting records 0452/13 May/June 2024
31 Miriam does not maintain a full set of accounting records. Only the purchases for the year and asset and liability values at the year end are known. Which financial statements can be prepared using this information? income statement statement of affairs A ✓ ✓ B ✓ ✗ C ✗ ✓ D ✗ ✗
1 marks
Answer: C
This question in 0452/13 May/June 2024
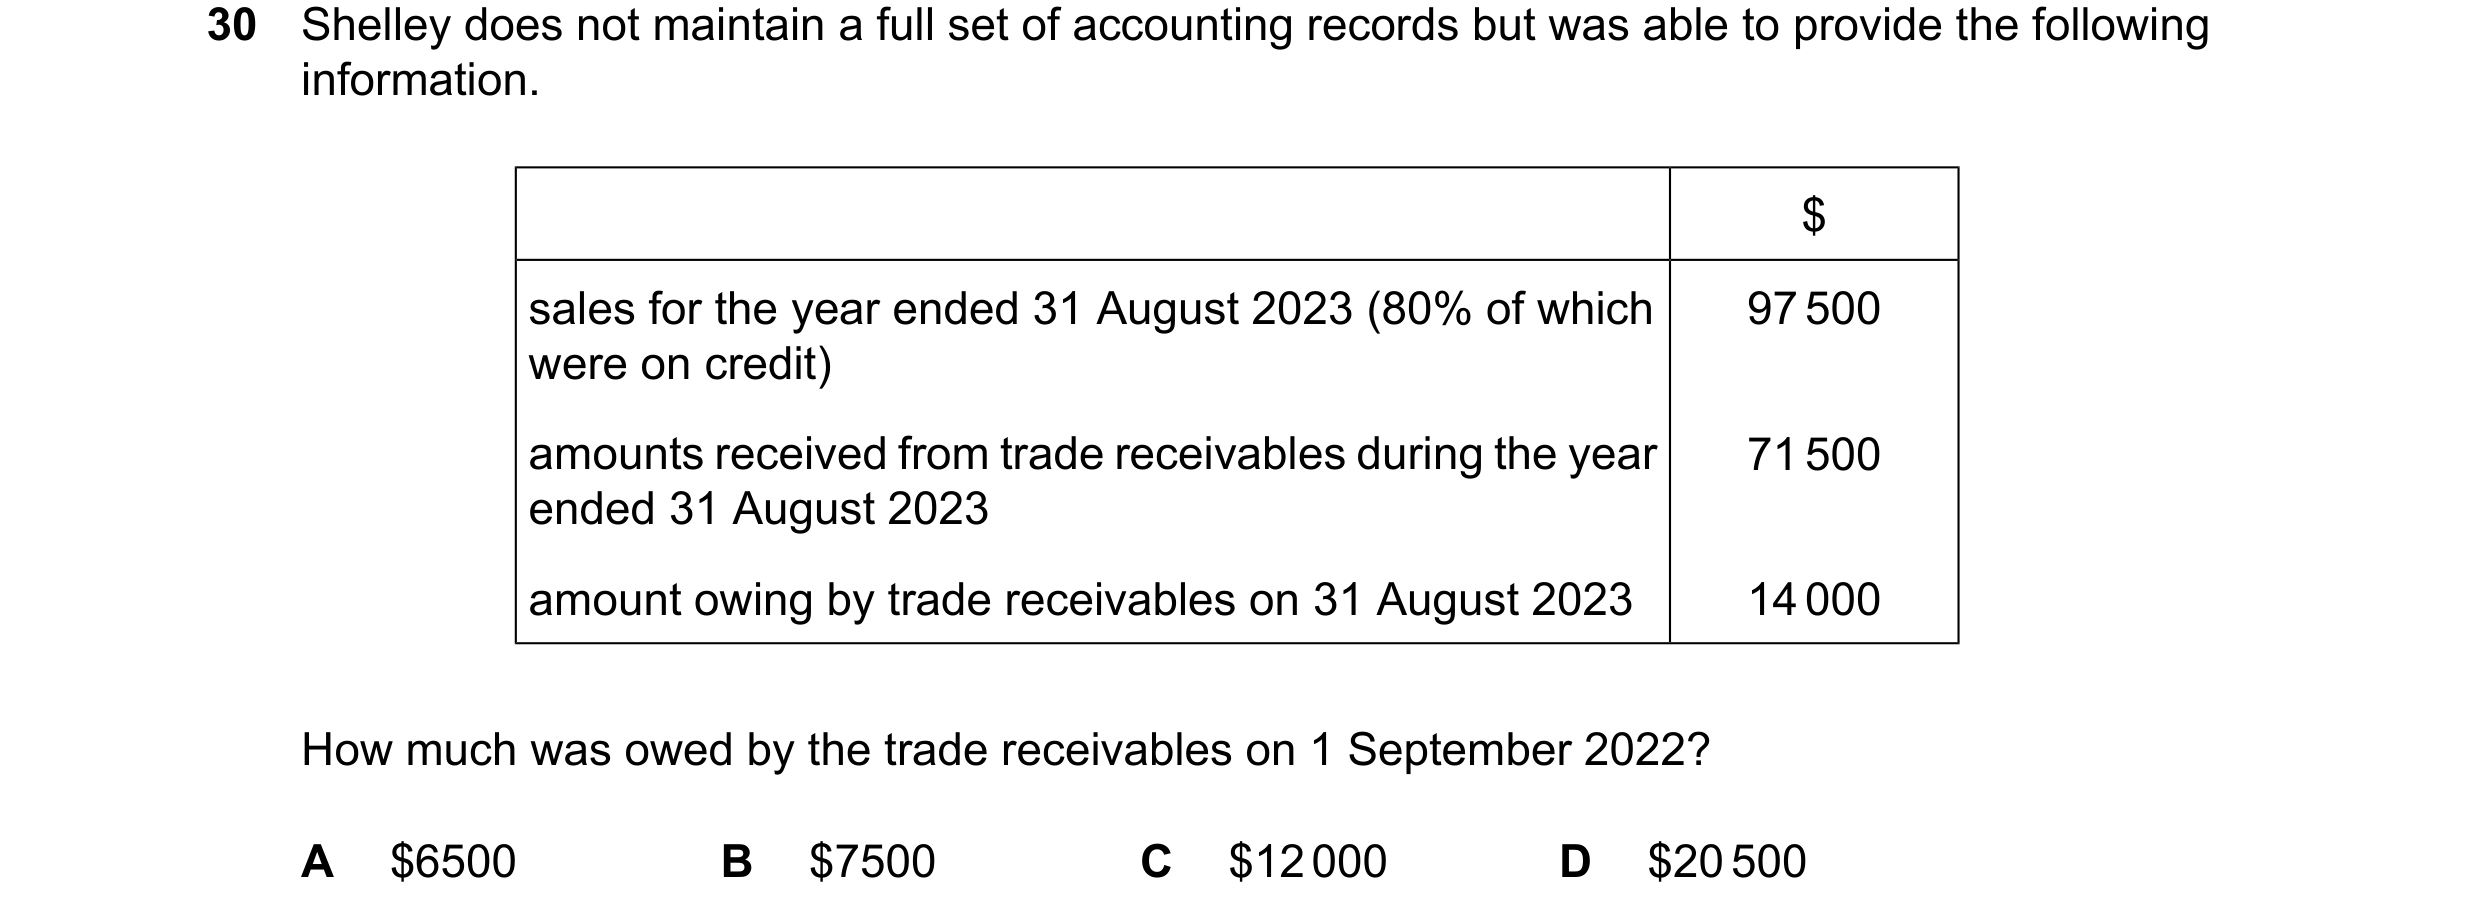
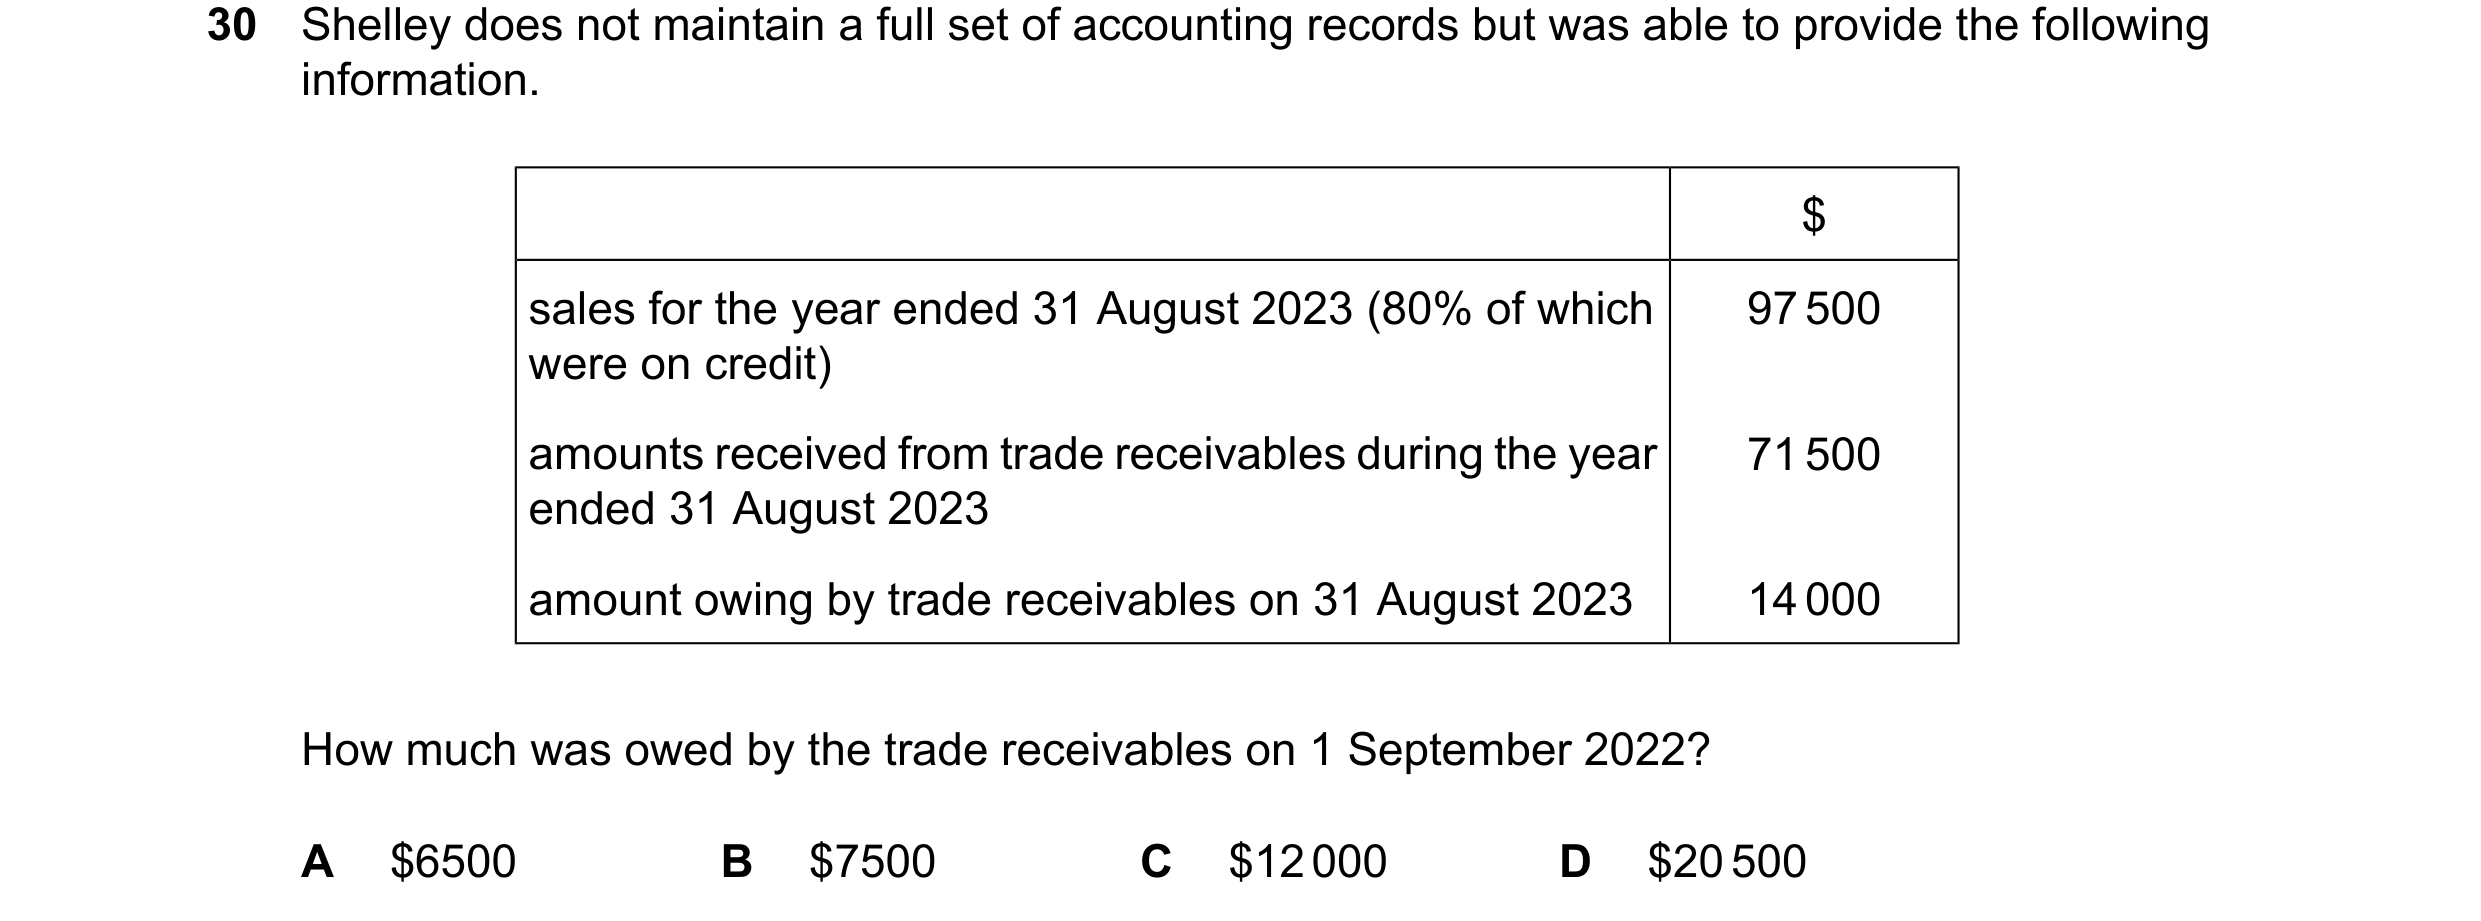
Q36 · Shelley does not maintain a full set of accounting records but was able to provide the… 0452/11 Oct/Nov 2024
30 Shelley does not maintain a full set of accounting records but was able to provide the following information. $ sales for the year ended 31 August 2023 (80% of which 97500 were on credit) amounts received from trade receivables during the year 71500 ended 31 August 2023 amount owing by trade receivables on 31 August 2023 14000 How much was owed by the trade receivables on 1 September 2022? A $6500 B $7500 C $12000 D $20500
1 marks
Answer: B
This question in 0452/11 Oct/Nov 2024
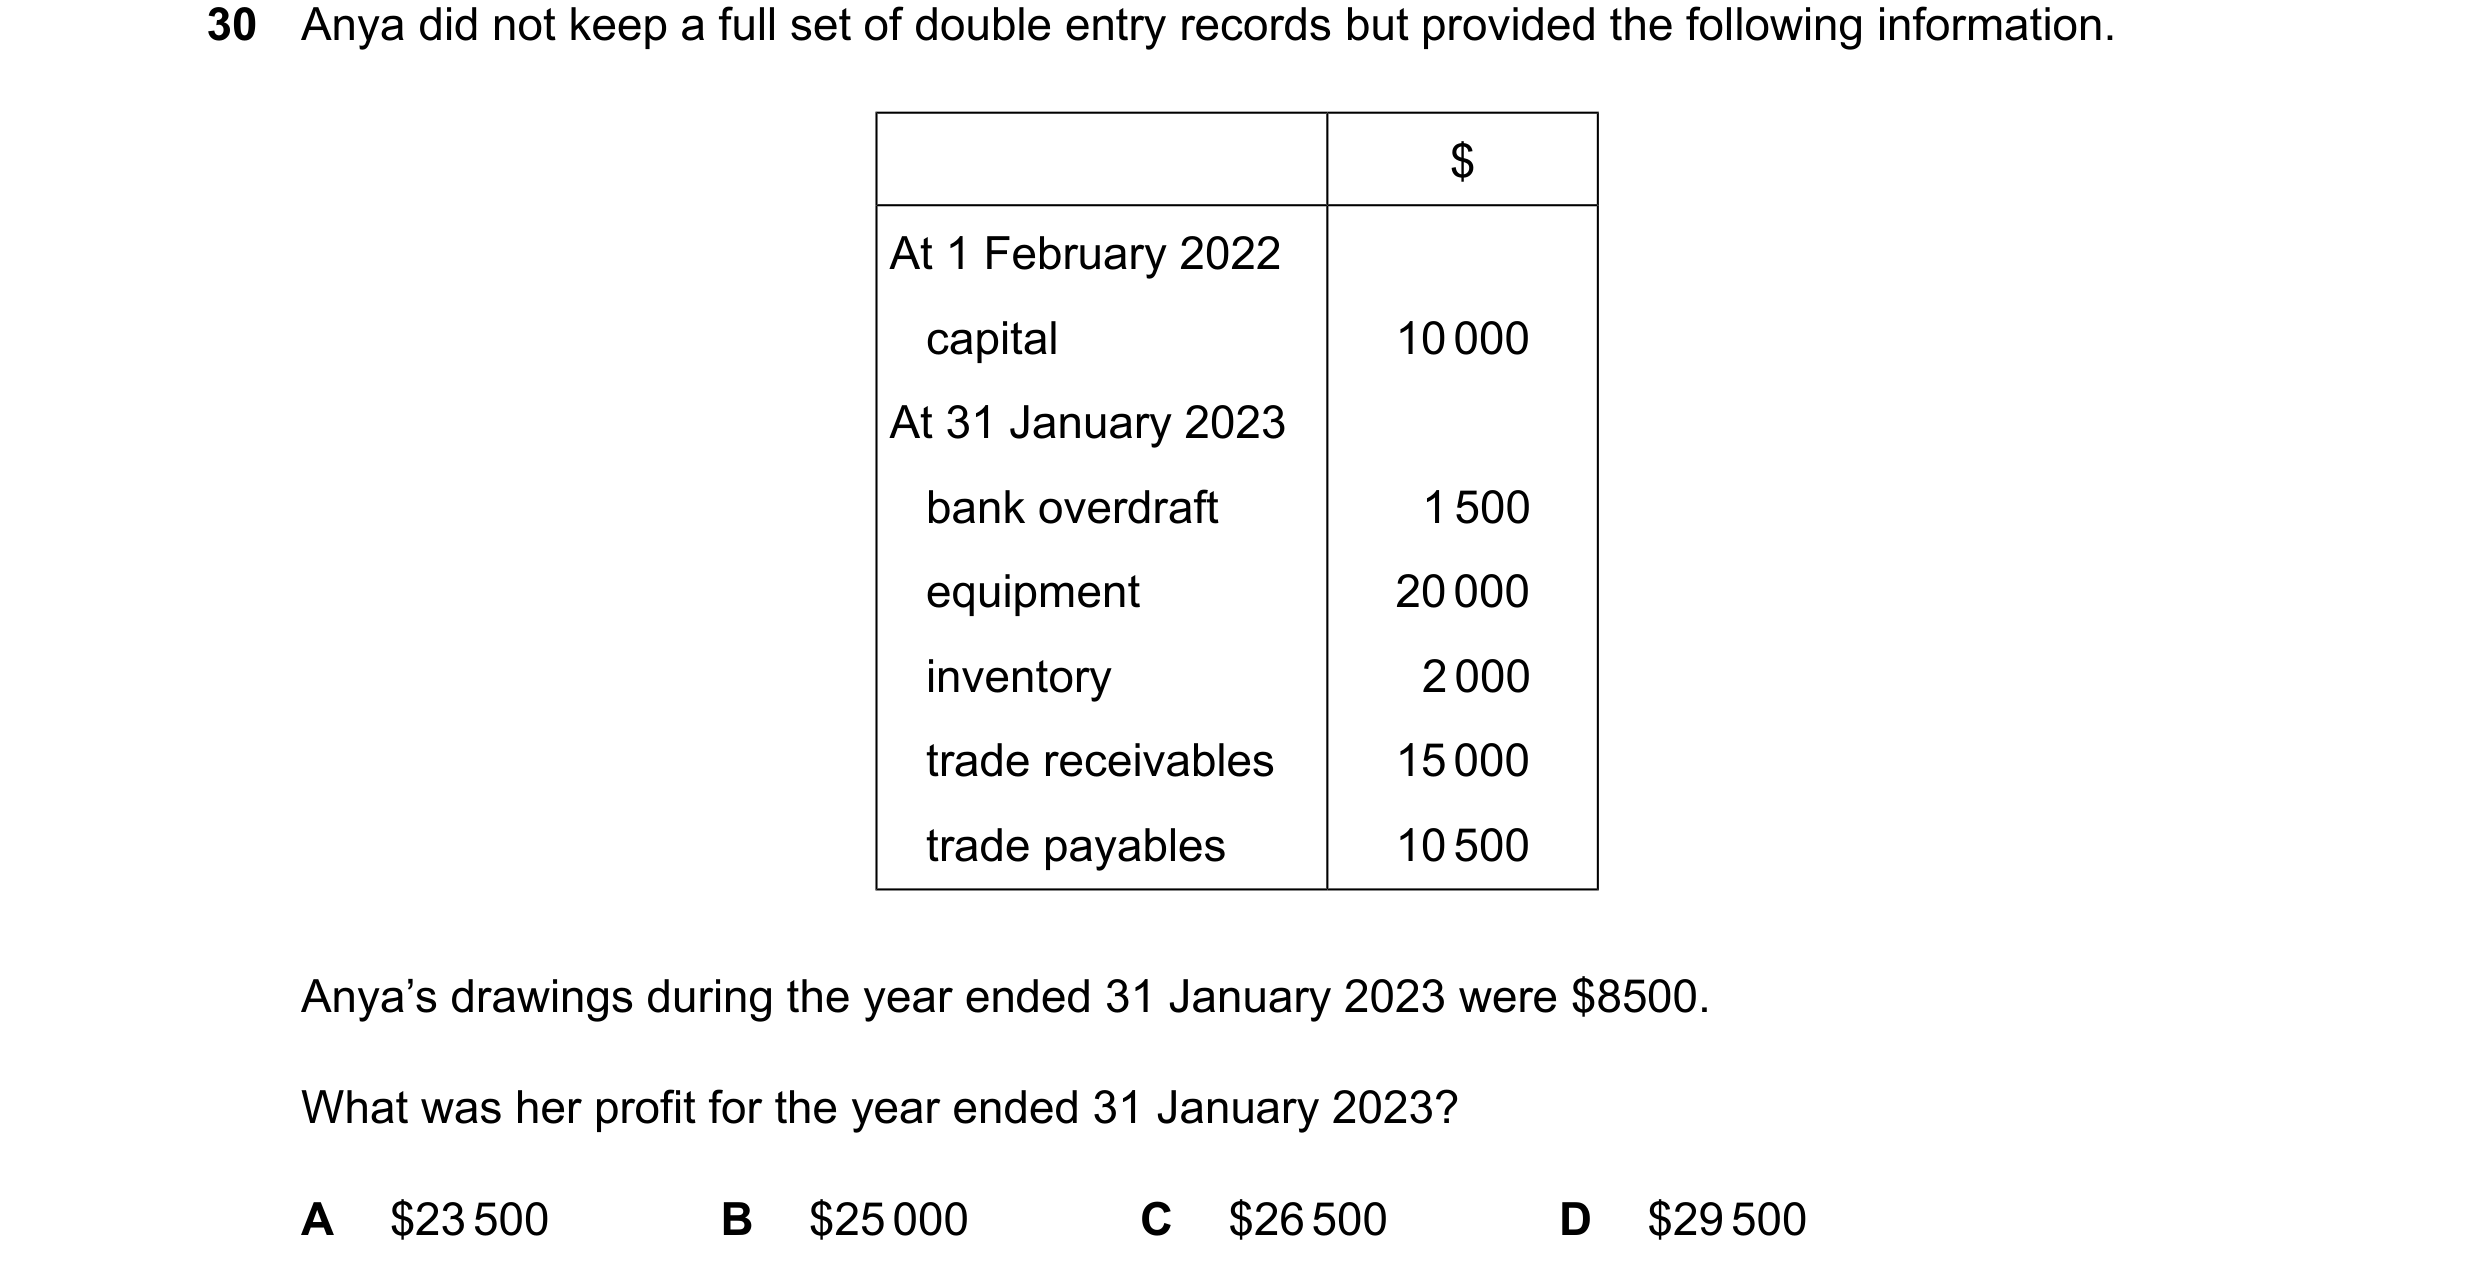
Q37 · Anya did not keep a full set of double entry records but provided the following… 0452/12 Oct/Nov 2024
30 Anya did not keep a full set of double entry records but provided the following information. $ At 1 February 2022 capital 10000 At 31 January 2023 bank overdraft 1500 equipment 20000 inventory 2000 trade receivables 15000 trade payables 10500 Anya’s drawings during the year ended 31 January 2023 were $8500. What was her profit for the year ended 31 January 2023? A $23500 B $25000 C $26500 D $29500
1 marks
Answer: A
This question in 0452/12 Oct/Nov 2024
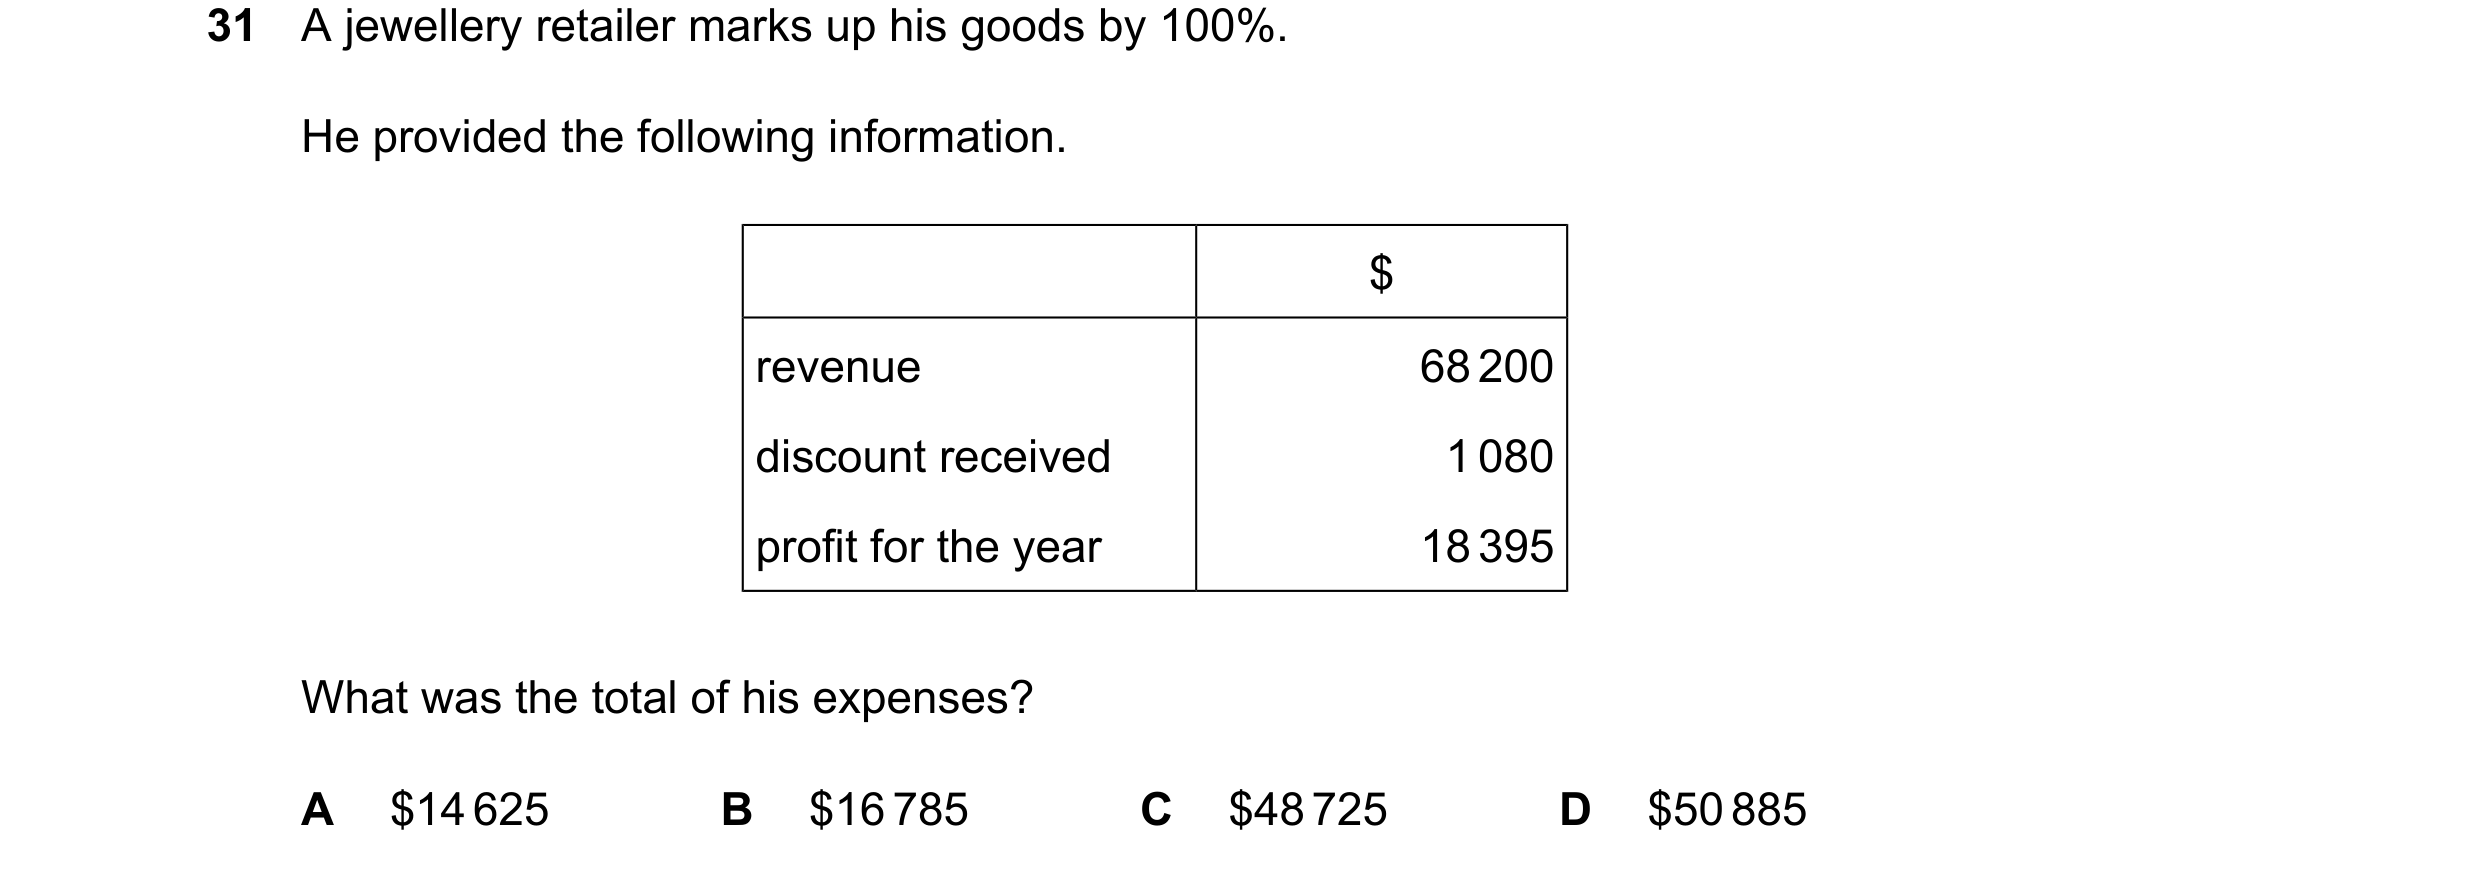
Q38 · A jewellery retailer marks up his goods by 100% 0452/12 Oct/Nov 2024
31 A jewellery retailer marks up his goods by 100%. He provided the following information. $ revenue 68200 discount received 1080 profit for the year 18395 What was the total of his expenses? A $14625 B $16785 C $48725 D $50885
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2024
Q39 · Shelley does not maintain a full set of accounting records but was able to provide the… 0452/13 Oct/Nov 2024
30 Shelley does not maintain a full set of accounting records but was able to provide the following information. $ sales for the year ended 31 August 2023 (80% of which 97500 were on credit) amounts received from trade receivables during the year 71500 ended 31 August 2023 amount owing by trade receivables on 31 August 2023 14000 How much was owed by the trade receivables on 1 September 2022? A $6500 B $7500 C $12000 D $20500
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2024
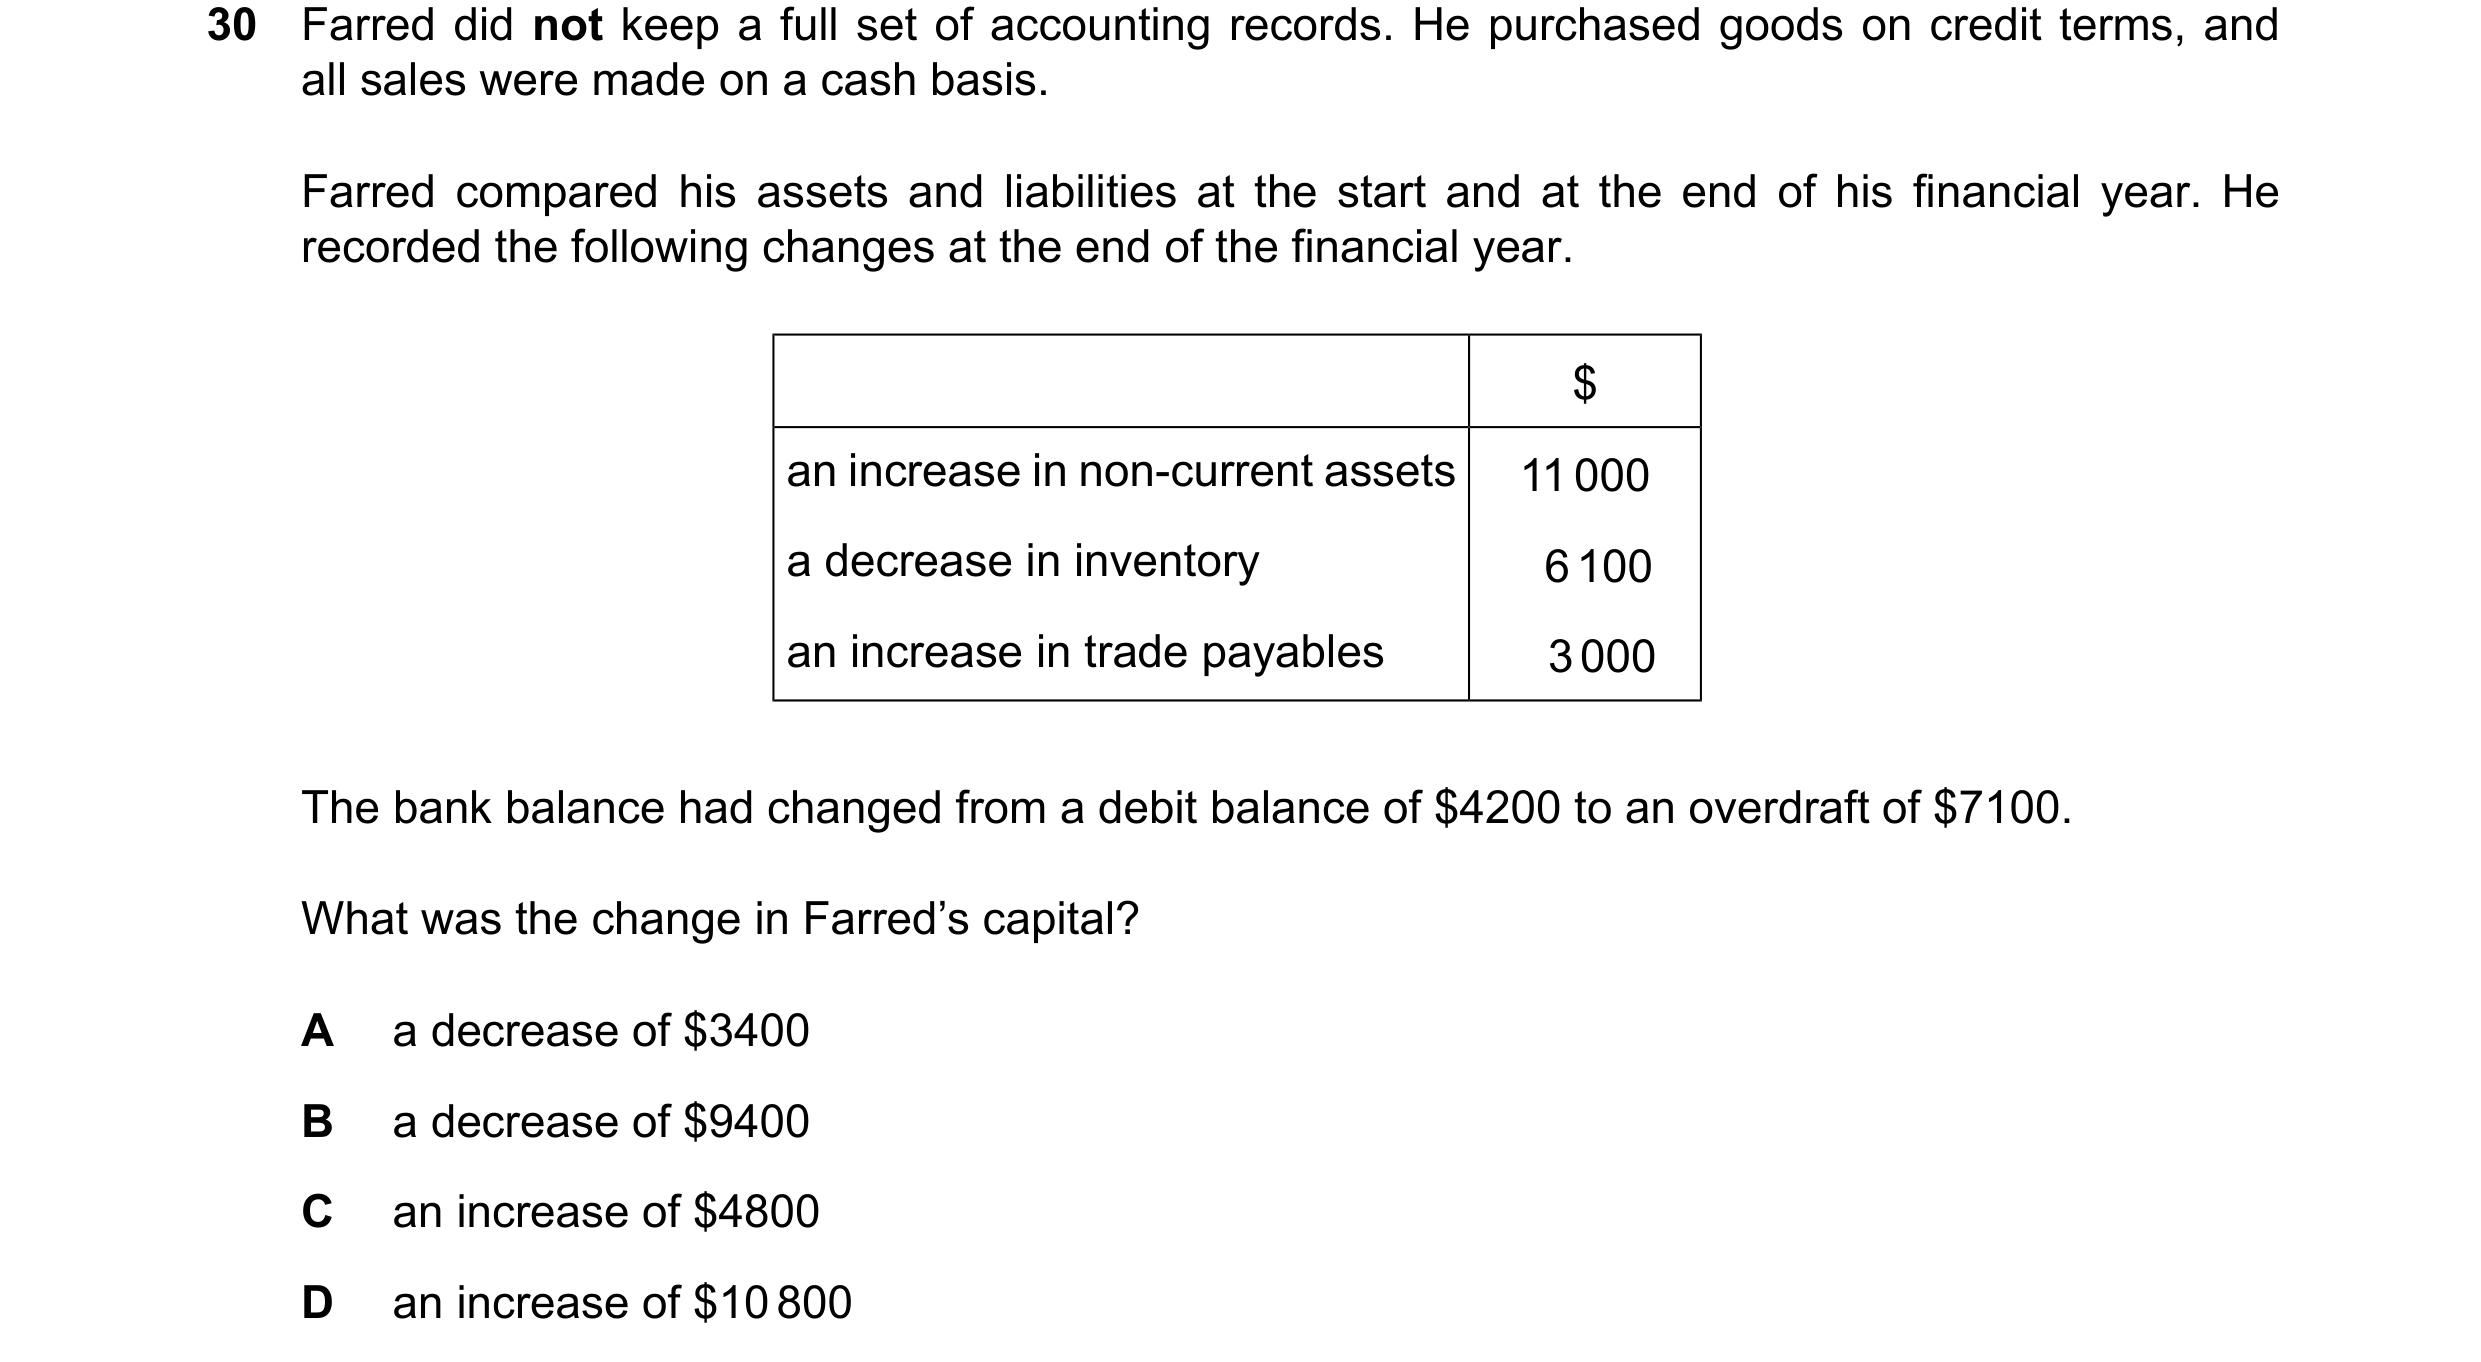
Q40 · Farred did not keep a full set of accounting records 0452/12 Feb/March 2025
30 Farred did not keep a full set of accounting records. He purchased goods on credit terms, and all sales were made on a cash basis. Farred compared his assets and liabilities at the start and at the end of his financial year. He recorded the following changes at the end of the financial year. $ an increase in non-current assets 11000 a decrease in inventory 6100 an increase in trade payables 3000 The bank balance had changed from a debit balance of $4200 to an overdraft of $7100. What was the change in Farred’s capital? A a decrease of $3400 B a decrease of $9400 C an increase of $4800 D an increase of $10800
1 marks
Answer: B
This question in 0452/12 Feb/March 2025
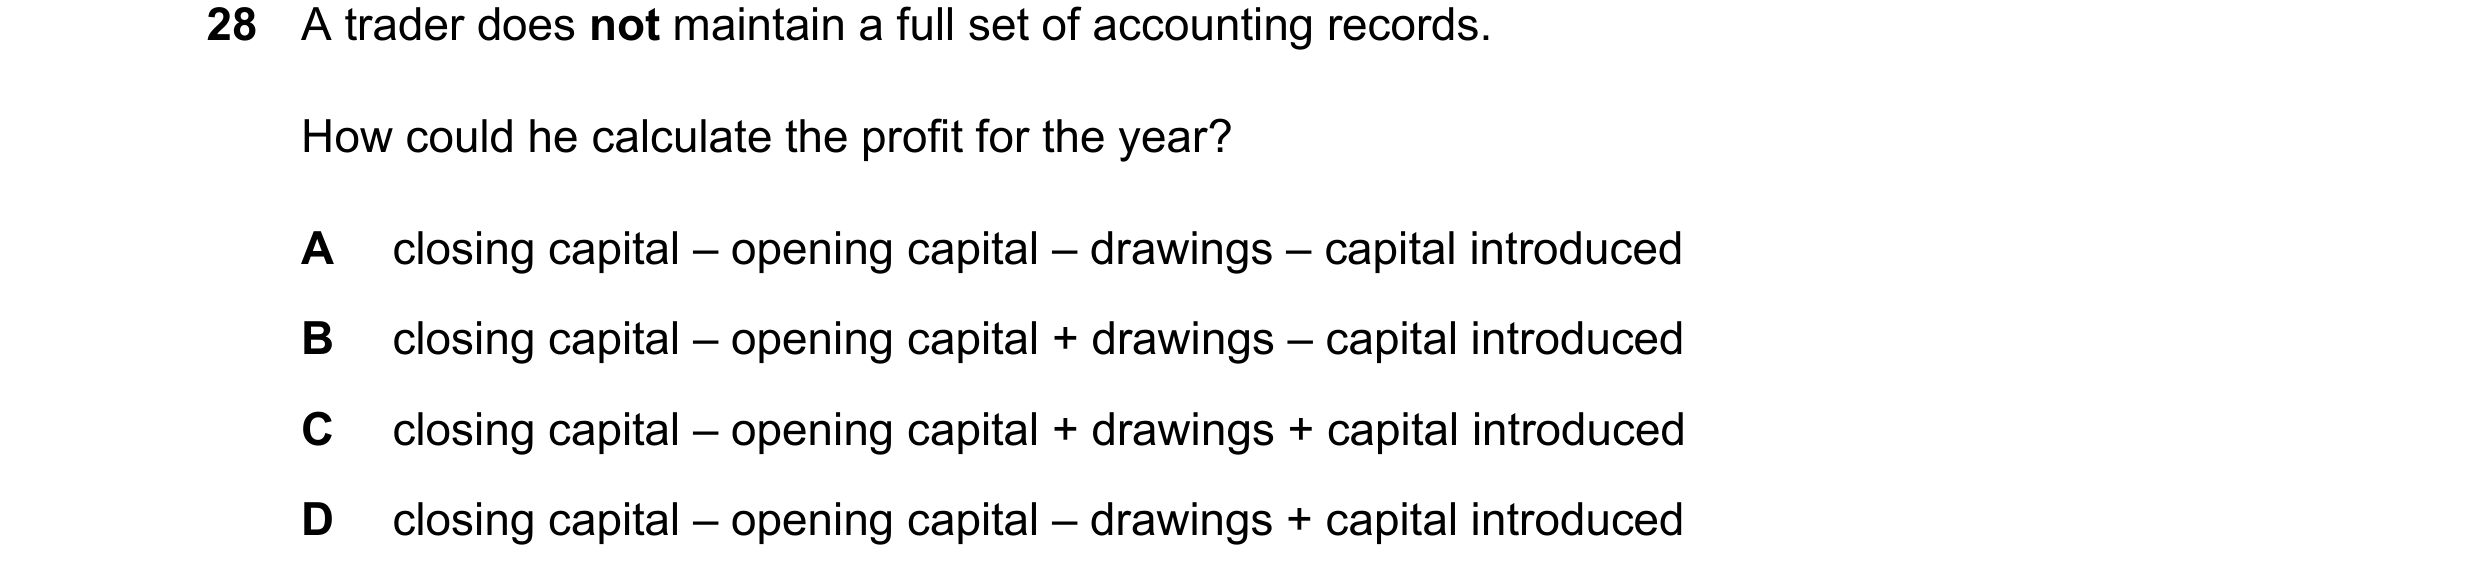
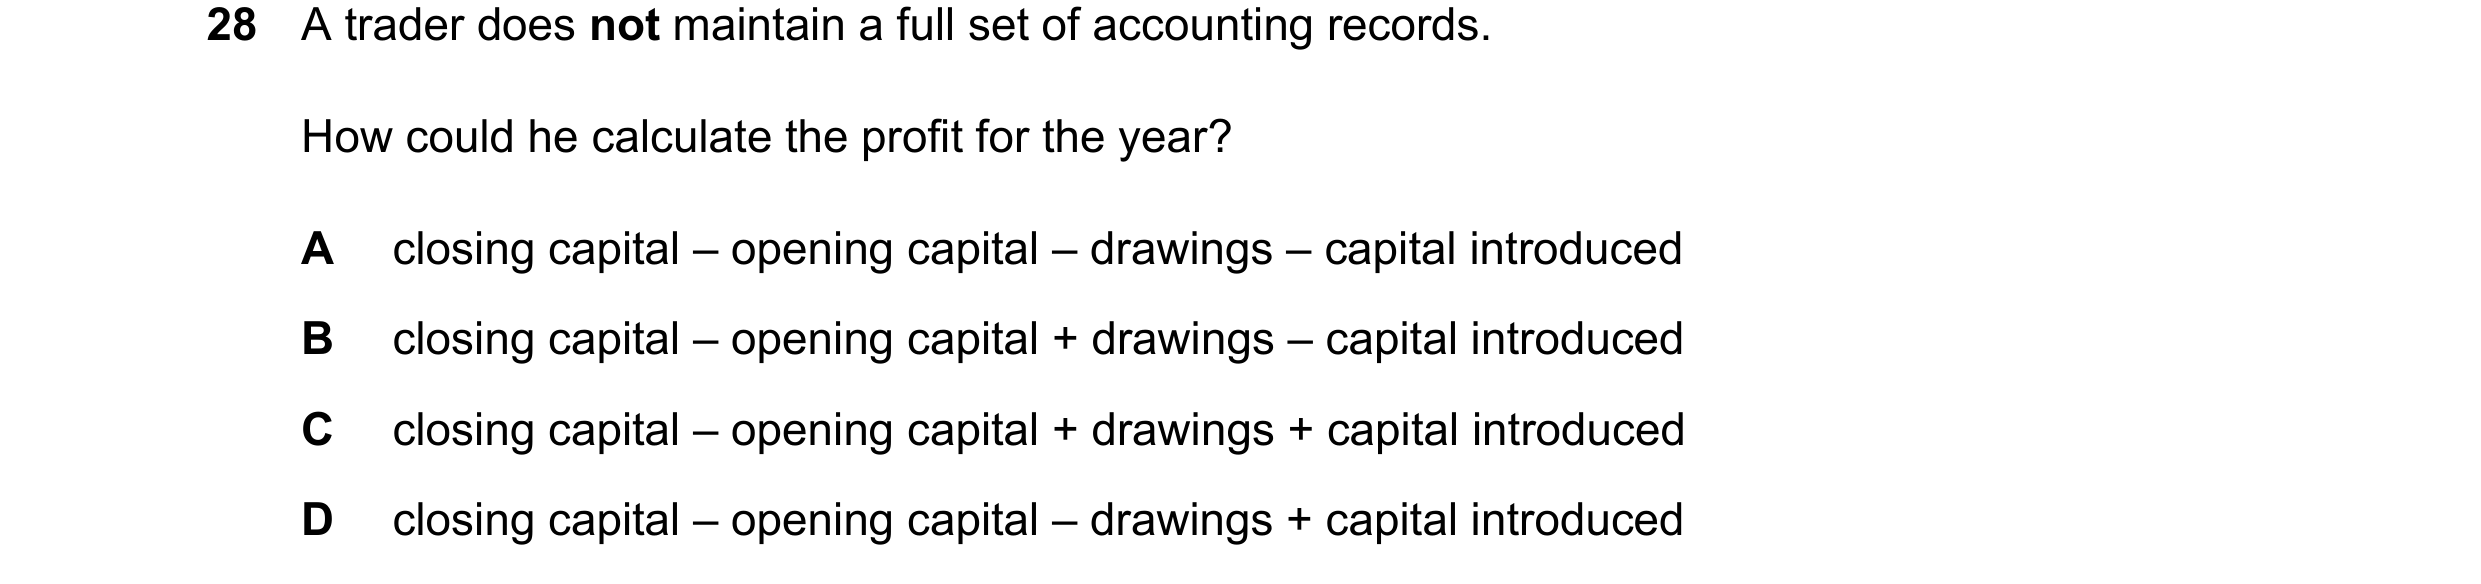
Q41 · A trader does not maintain a full set of accounting records 0452/11 May/June 2025
28 A trader does not maintain a full set of accounting records. How could he calculate the profit for the year? A closing capital – opening capital – drawings – capital introduced B closing capital – opening capital + drawings – capital introduced C closing capital – opening capital + drawings + capital introduced D closing capital – opening capital – drawings + capital introduced
1 marks
Answer: B
This question in 0452/11 May/June 2025
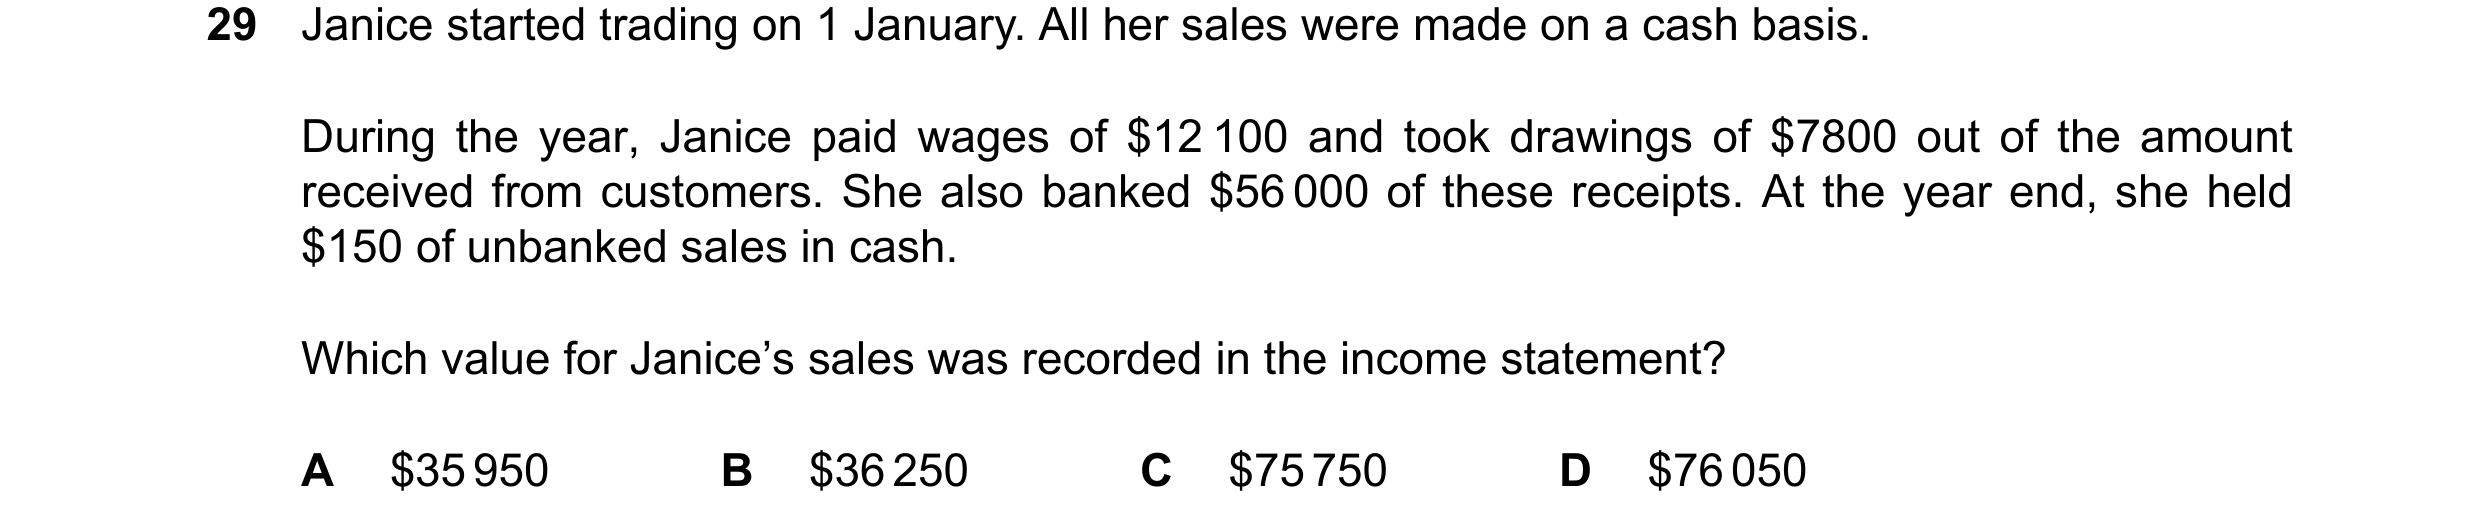
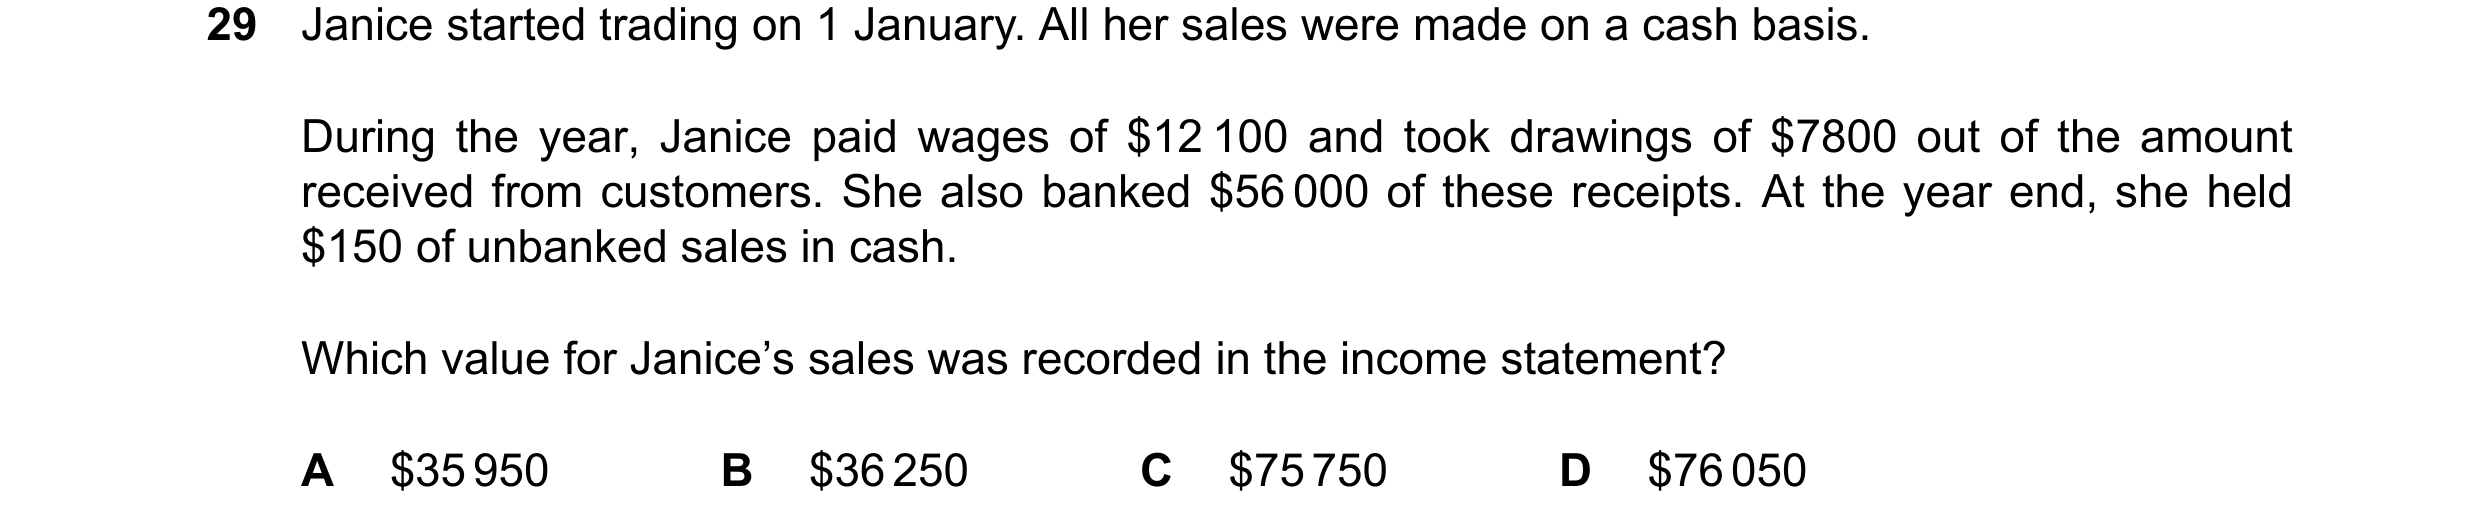
Q42 · Janice started trading on 1 January 0452/11 May/June 2025
29 Janice started trading on 1 January. All her sales were made on a cash basis. During the year, Janice paid wages of $12 100 and took drawings of $7800 out of the amount received from customers. She also banked $56 000 of these receipts. At the year end, she held $150 of unbanked sales in cash. Which value for Janice’s sales was recorded in the income statement? A $35950 B $36250 C $75750 D $76050
1 marks
Answer: D
This question in 0452/11 May/June 2025
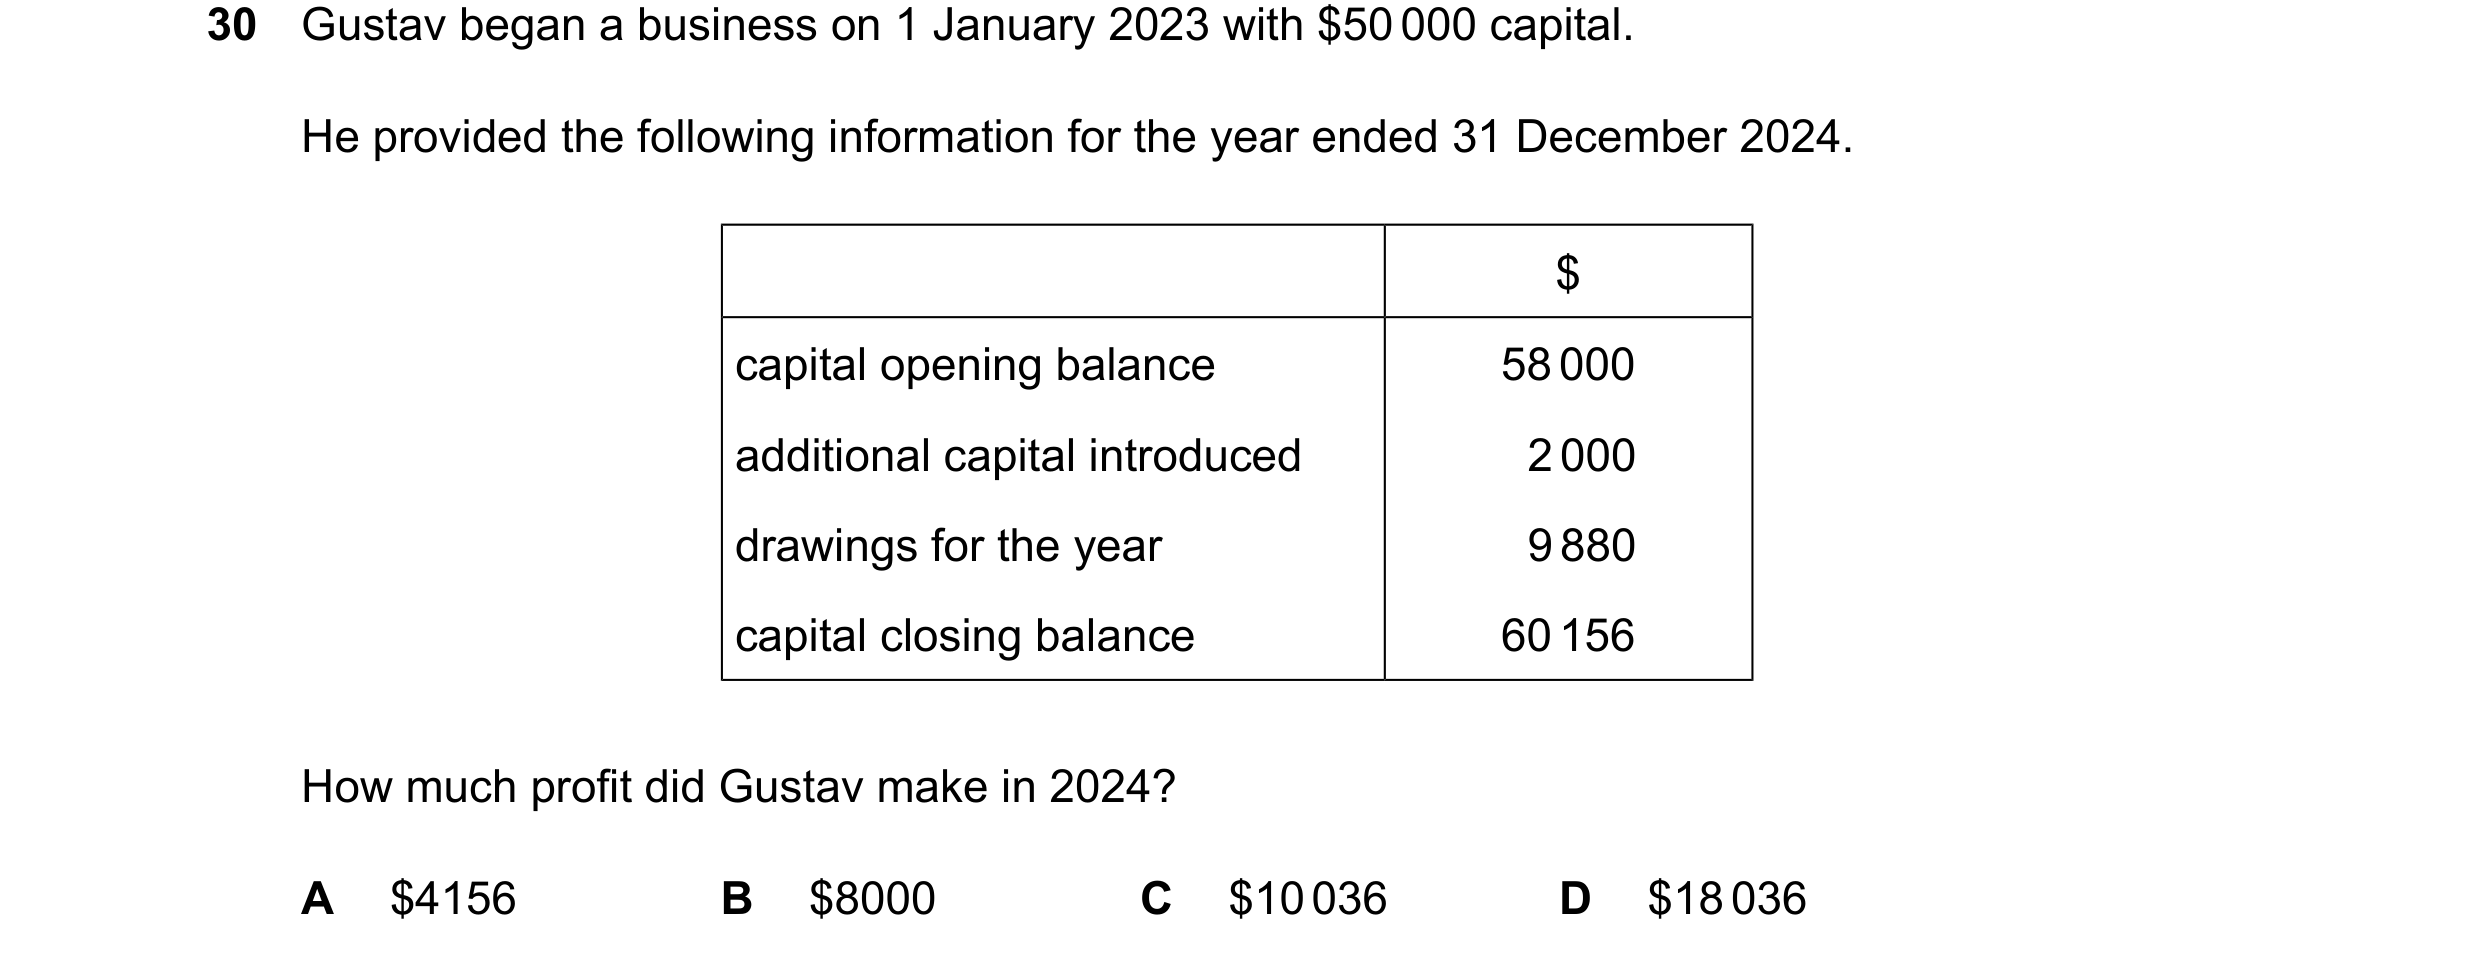
Q43 · Gustav began a business on 1 January 2023 with $50000 capital 0452/12 May/June 2025
30 Gustav began a business on 1 January 2023 with $50000 capital. He provided the following information for the year ended 31 December 2024. $ capital opening balance 58000 additional capital introduced 2000 drawings for the year 9880 capital closing balance 60156 How much profit did Gustav make in 2024? A $4156 B $8000 C $10036 D $18036
1 marks
Answer: C
This question in 0452/12 May/June 2025
Q44 · A trader’s assets increased by $25 000 and liabilities decreased by $5000 during the year 0452/13 May/June 2025
27 A trader’s assets increased by $25 000 and liabilities decreased by $5000 during the year. He took no drawings during the year. What was the profit or loss for the year? A $20000 loss B $20000 profit C $30000 loss D $30000 profit
1 marks
Answer: D
This question in 0452/13 May/June 2025
Q45 · A trader does not maintain a full set of accounting records 0452/13 May/June 2025
28 A trader does not maintain a full set of accounting records. How could he calculate the profit for the year? A closing capital – opening capital – drawings – capital introduced B closing capital – opening capital + drawings – capital introduced C closing capital – opening capital + drawings + capital introduced D closing capital – opening capital – drawings + capital introduced
1 marks
Answer: B
This question in 0452/13 May/June 2025
Q46 · Janice started trading on 1 January 0452/13 May/June 2025
29 Janice started trading on 1 January. All her sales were made on a cash basis. During the year, Janice paid wages of $12 100 and took drawings of $7800 out of the amount received from customers. She also banked $56 000 of these receipts. At the year end, she held $150 of unbanked sales in cash. Which value for Janice’s sales was recorded in the income statement? A $35950 B $36250 C $75750 D $76050
1 marks
Answer: D
This question in 0452/13 May/June 2025
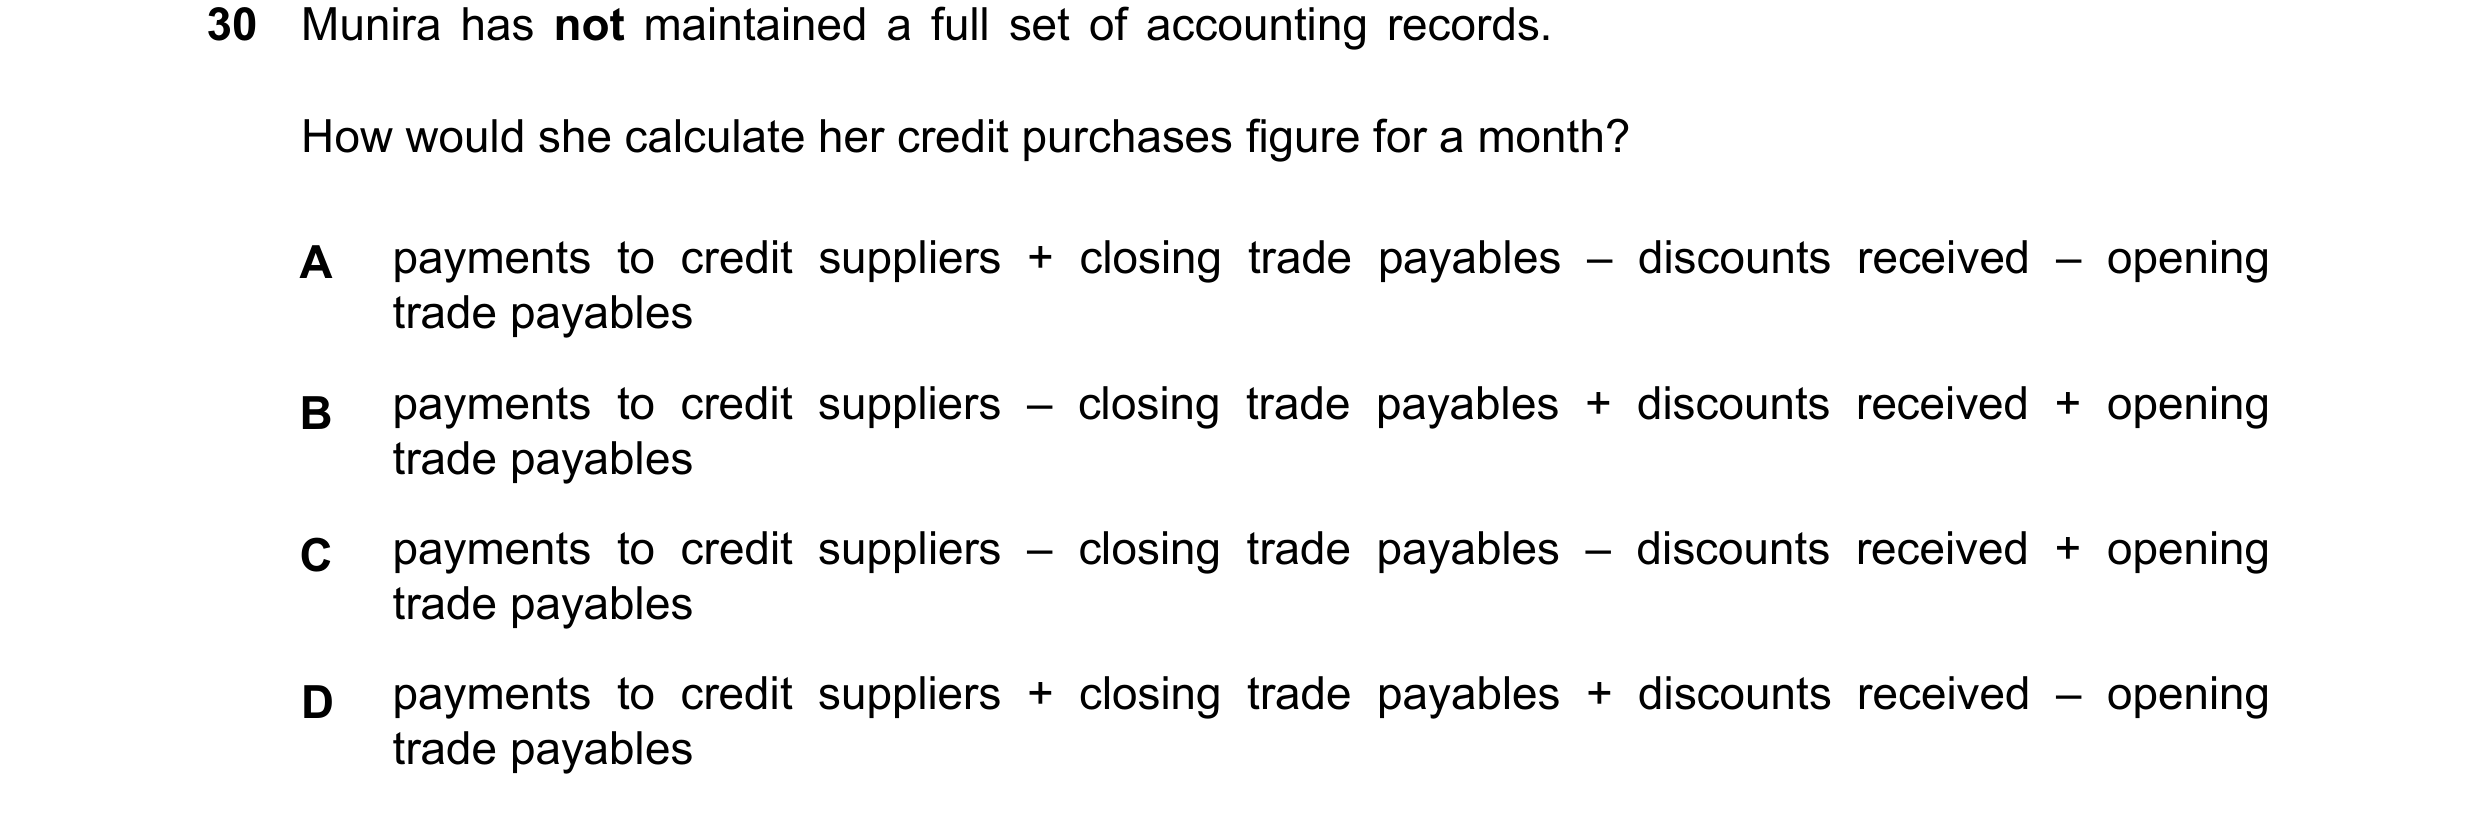
Q47 · Munira has not maintained a full set of accounting records 0452/12 Oct/Nov 2025
30 Munira has not maintained a full set of accounting records. How would she calculate her credit purchases figure for a month? A payments to credit suppliers + closing trade payables – discounts received – opening trade payables payments to credit suppliers – closing trade payables + discounts received + opening B trade payables C payments to credit suppliers – closing trade payables – discounts received + opening trade payables payments to credit suppliers + closing trade payables + discounts received – opening D trade payables
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2025
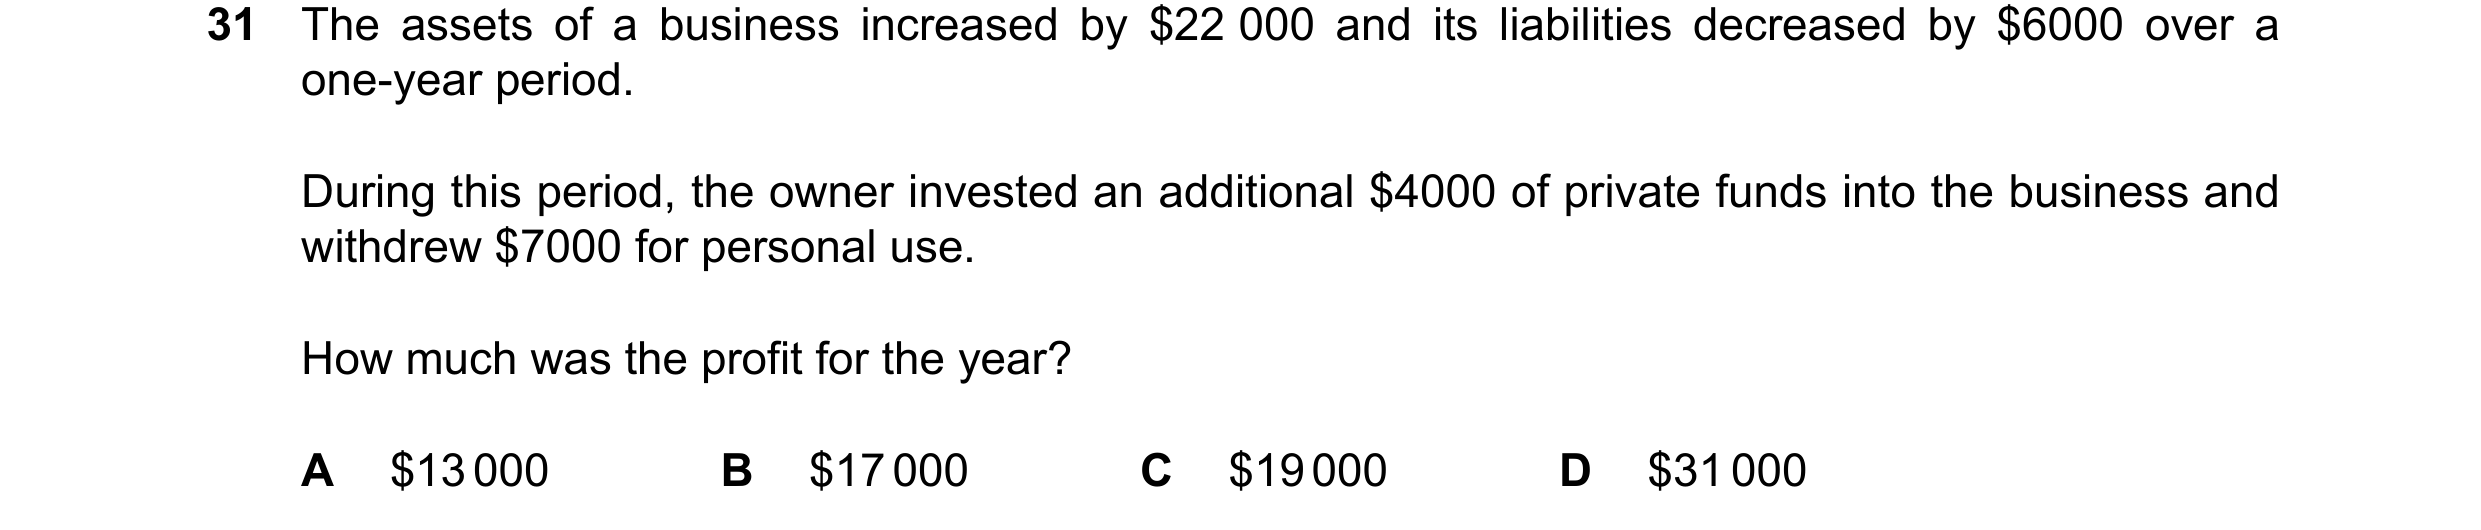
Q48 · The assets of a business increased by $22 000 and its liabilities decreased by $6000 over… 0452/12 Oct/Nov 2025
31 The assets of a business increased by $22 000 and its liabilities decreased by $6000 over a one-year period. During this period, the owner invested an additional $4000 of private funds into the business and withdrew $7000 for personal use. How much was the profit for the year? A $13000 B $17000 C $19000 D $31000
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2025
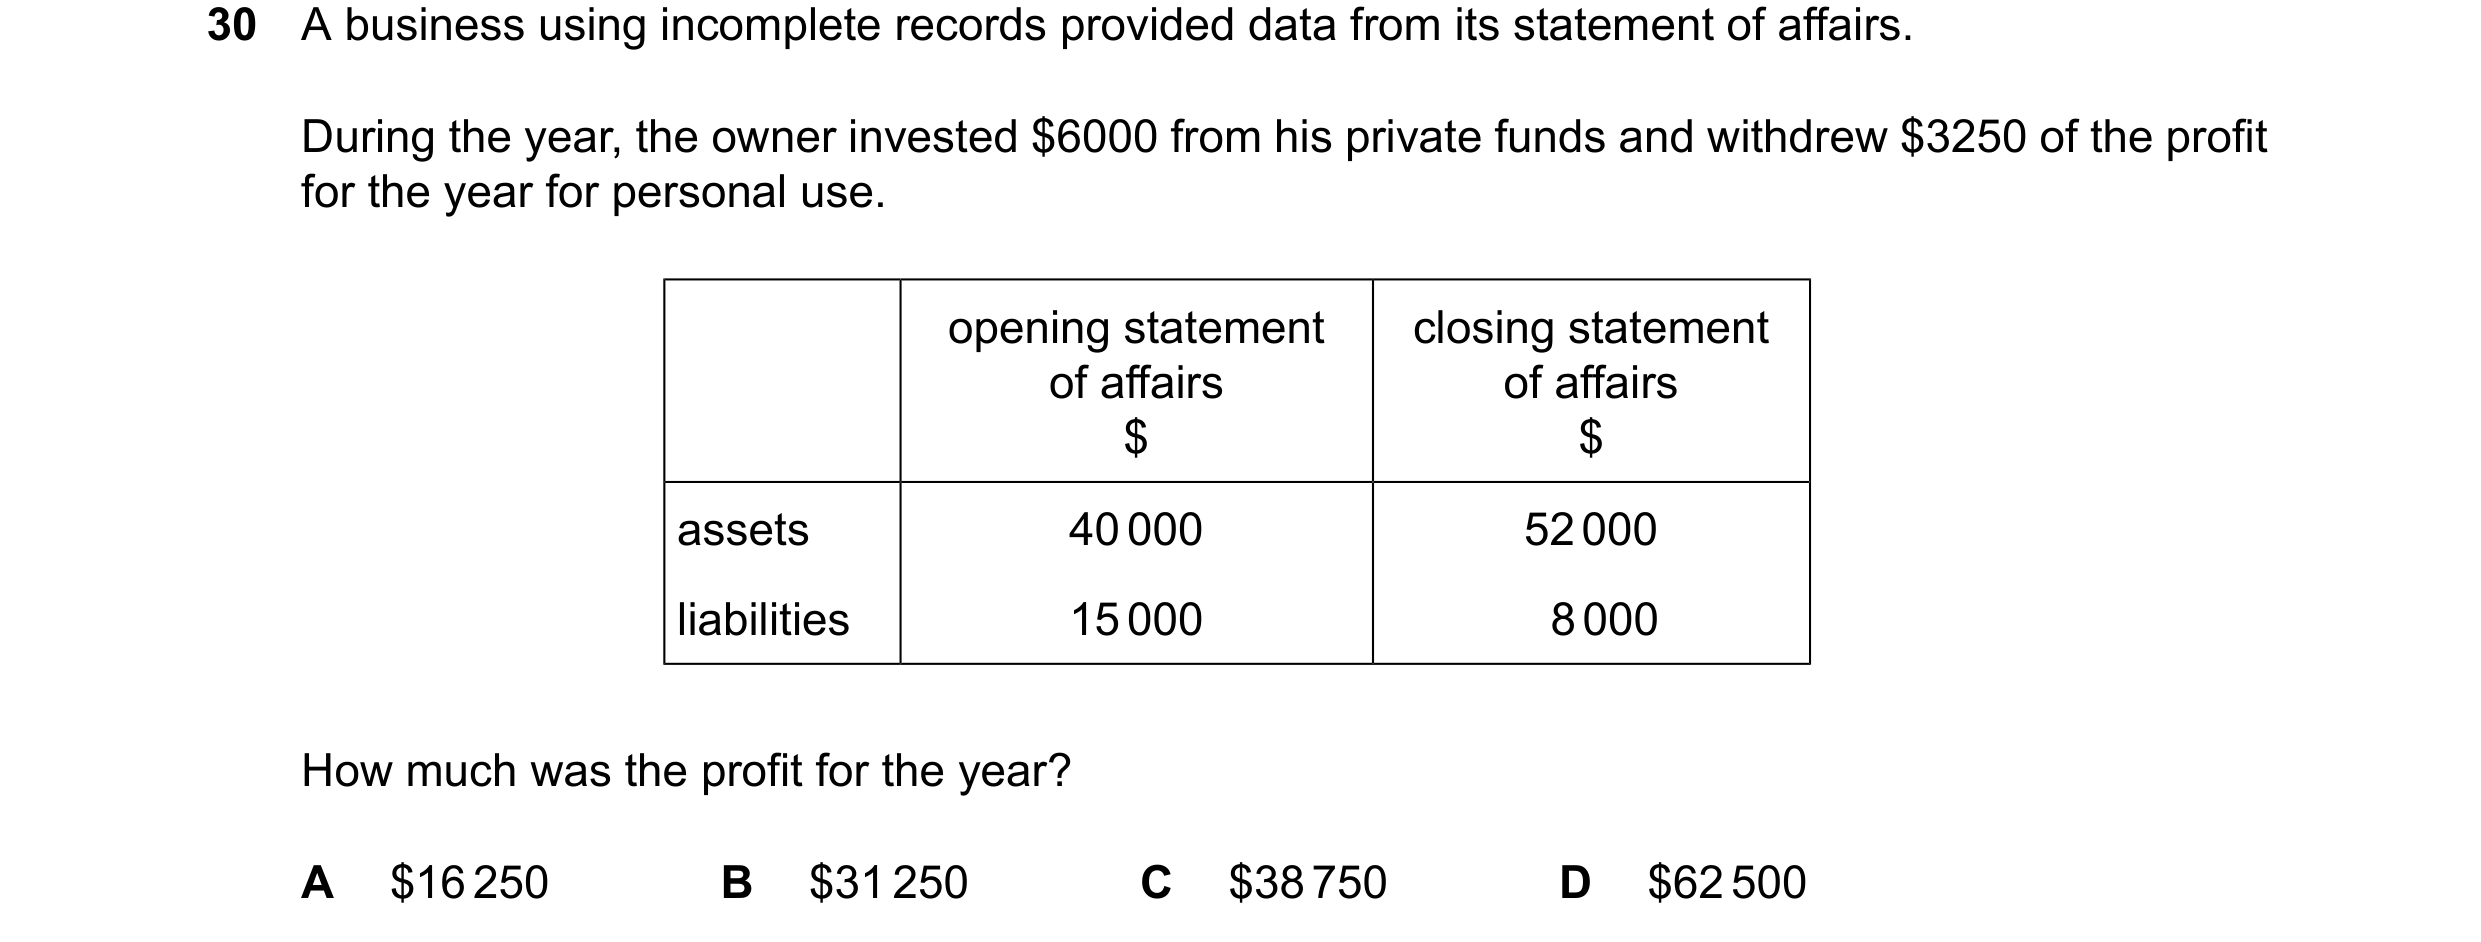
Q49 · A business using incomplete records provided data from its statement of affairs 0452/13 Oct/Nov 2025
30 A business using incomplete records provided data from its statement of affairs. During the year, the owner invested $6000 from his private funds and withdrew $3250 of the profit for the year for personal use. opening statement closing statement of affairs of affairs $ $ assets 40000 52000 liabilities 15000 8000 How much was the profit for the year? A $16250 B $31250 C $38750 D $62500
1 marks
Answer: A
This question in 0452/13 Oct/Nov 2025
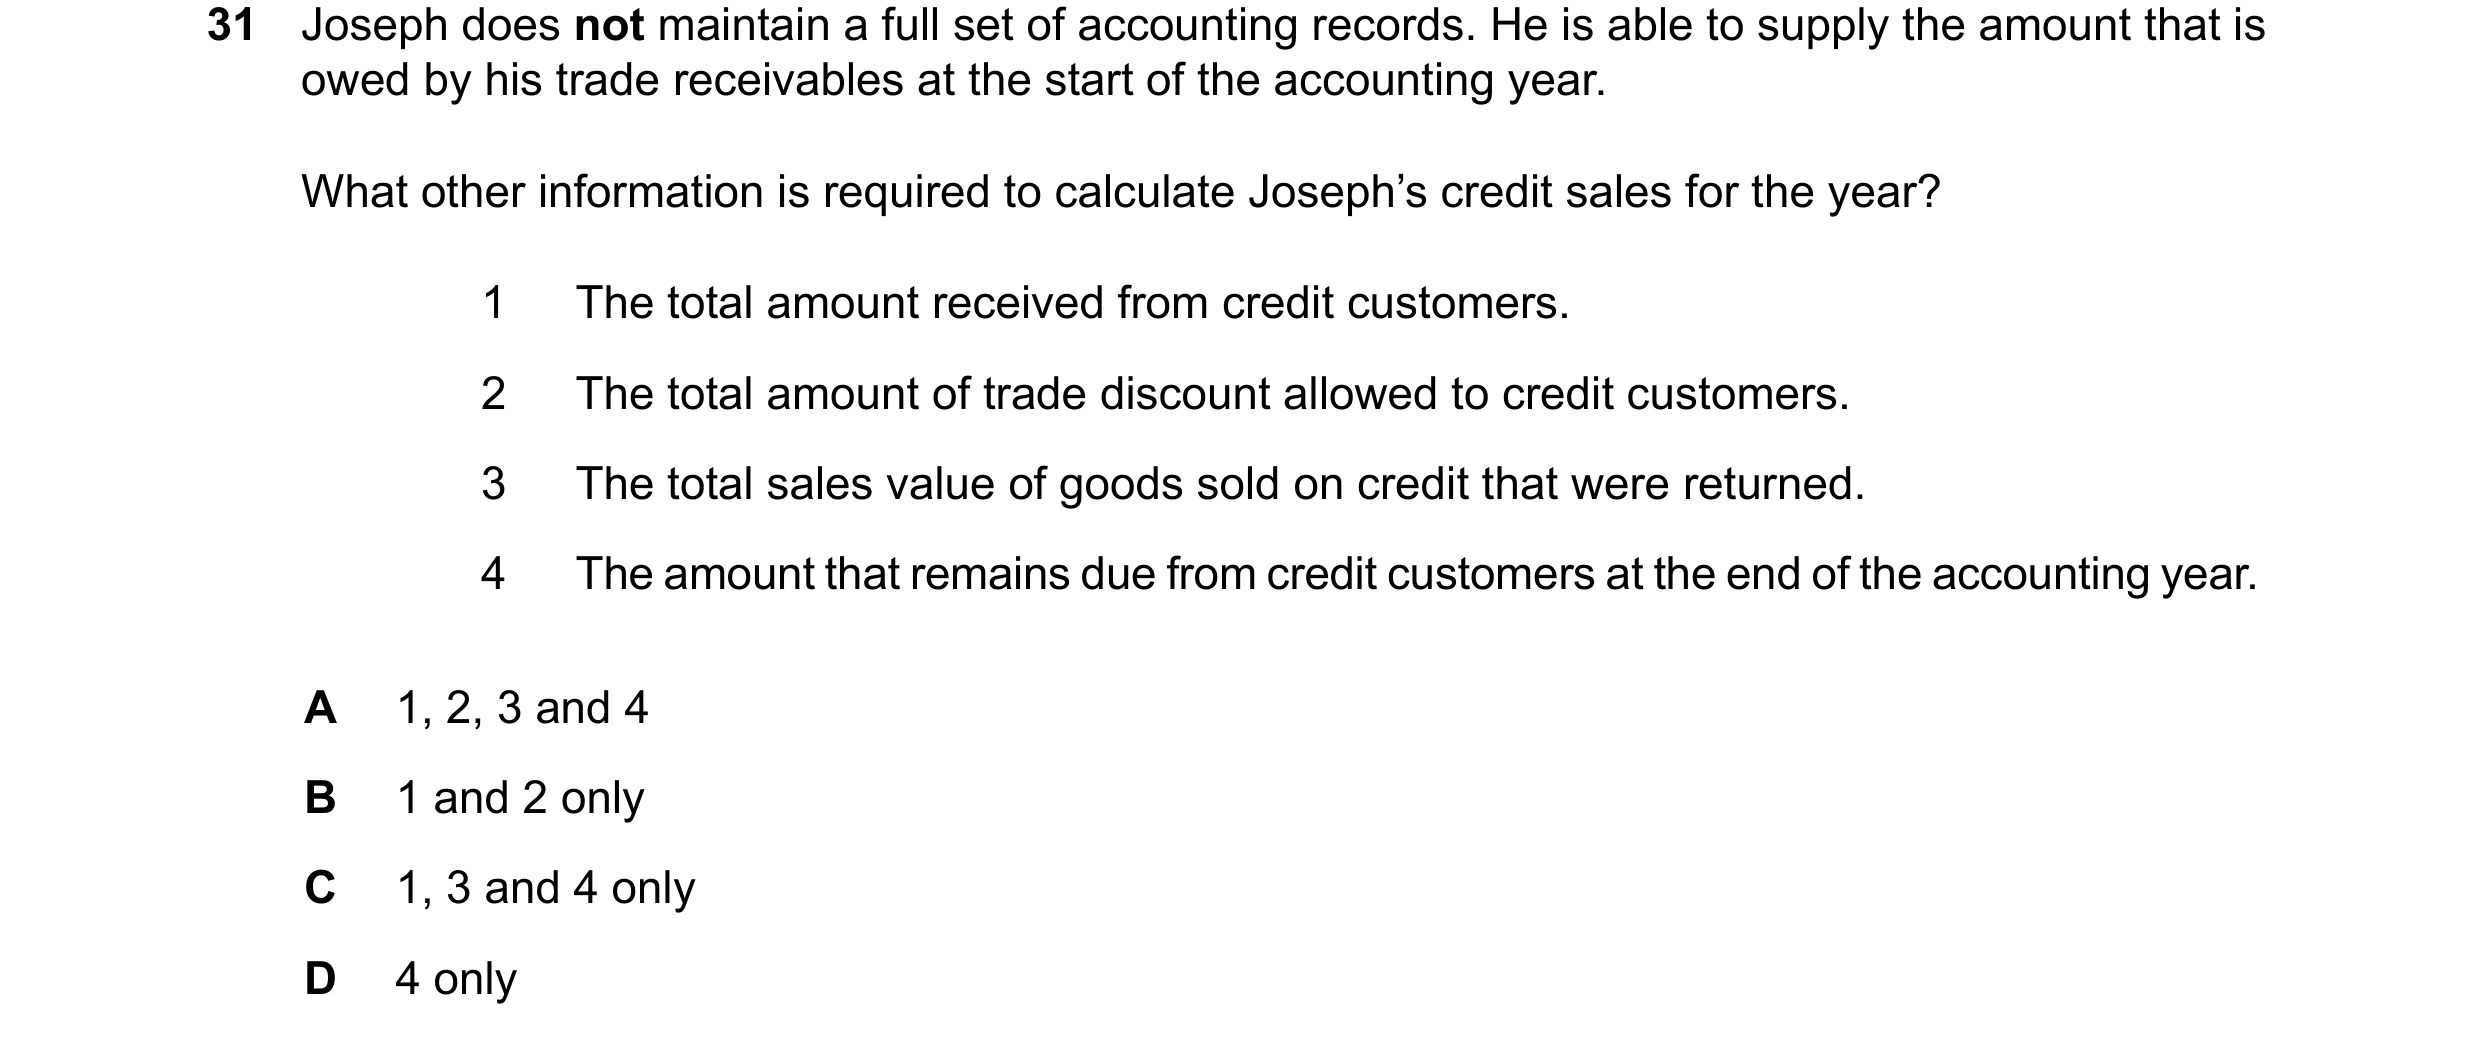
Q50 · Joseph does not maintain a full set of accounting records 0452/13 Oct/Nov 2025
31 Joseph does not maintain a full set of accounting records. He is able to supply the amount that is owed by his trade receivables at the start of the accounting year. What other information is required to calculate Joseph’s credit sales for the year? 1 The total amount received from credit customers. 2 The total amount of trade discount allowed to credit customers. 3 The total sales value of goods sold on credit that were returned. 4 The amount that remains due from credit customers at the end of the accounting year. A 1, 2, 3 and 4 B 1 and 2 only C 1, 3 and 4 only D 4 only
1 marks
Answer: C
This question in 0452/13 Oct/Nov 2025
 1 / 14
 2 / 14
 3 / 14
 4 / 14
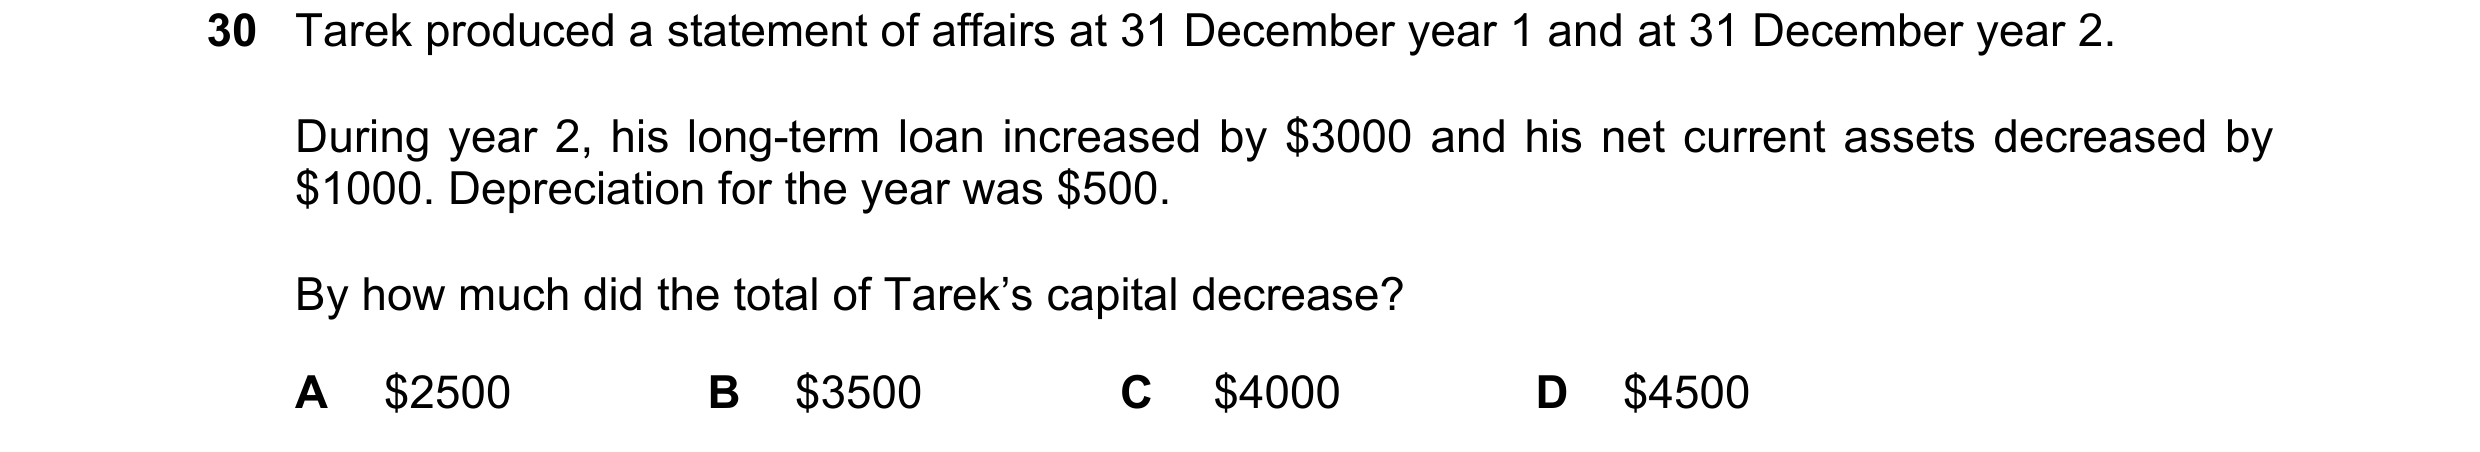 5 / 14
 6 / 14
 7 / 14
 8 / 14
 9 / 14
 10 / 14
 11 / 14
 12 / 14
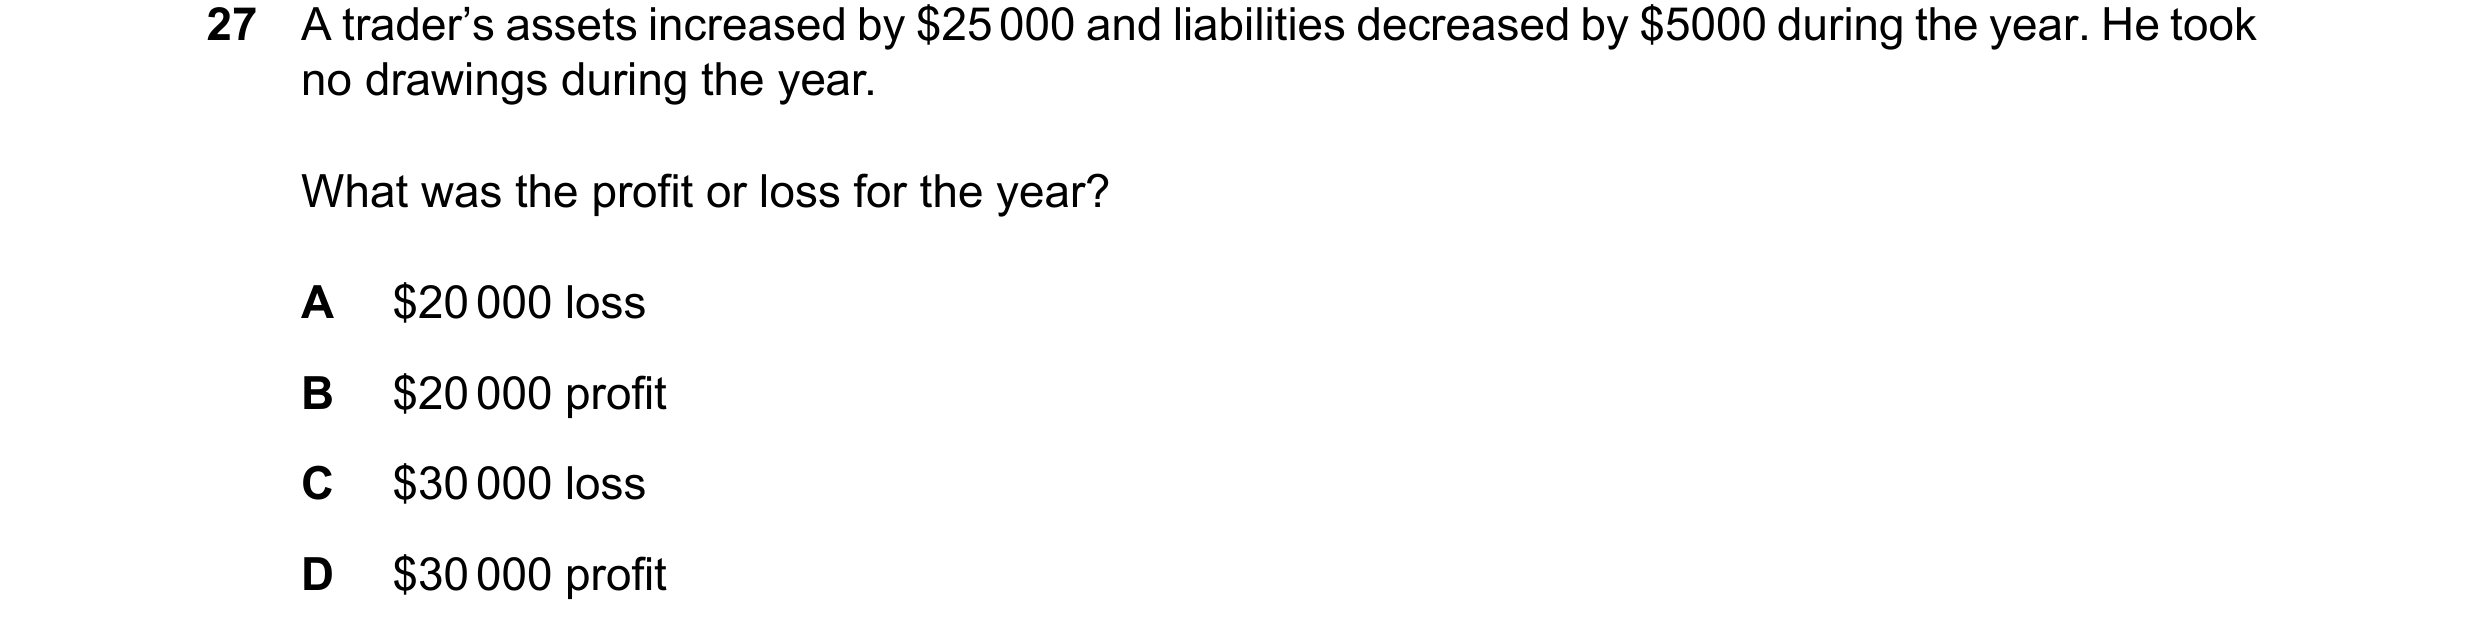
 13 / 14
 14 / 14