Questions as text
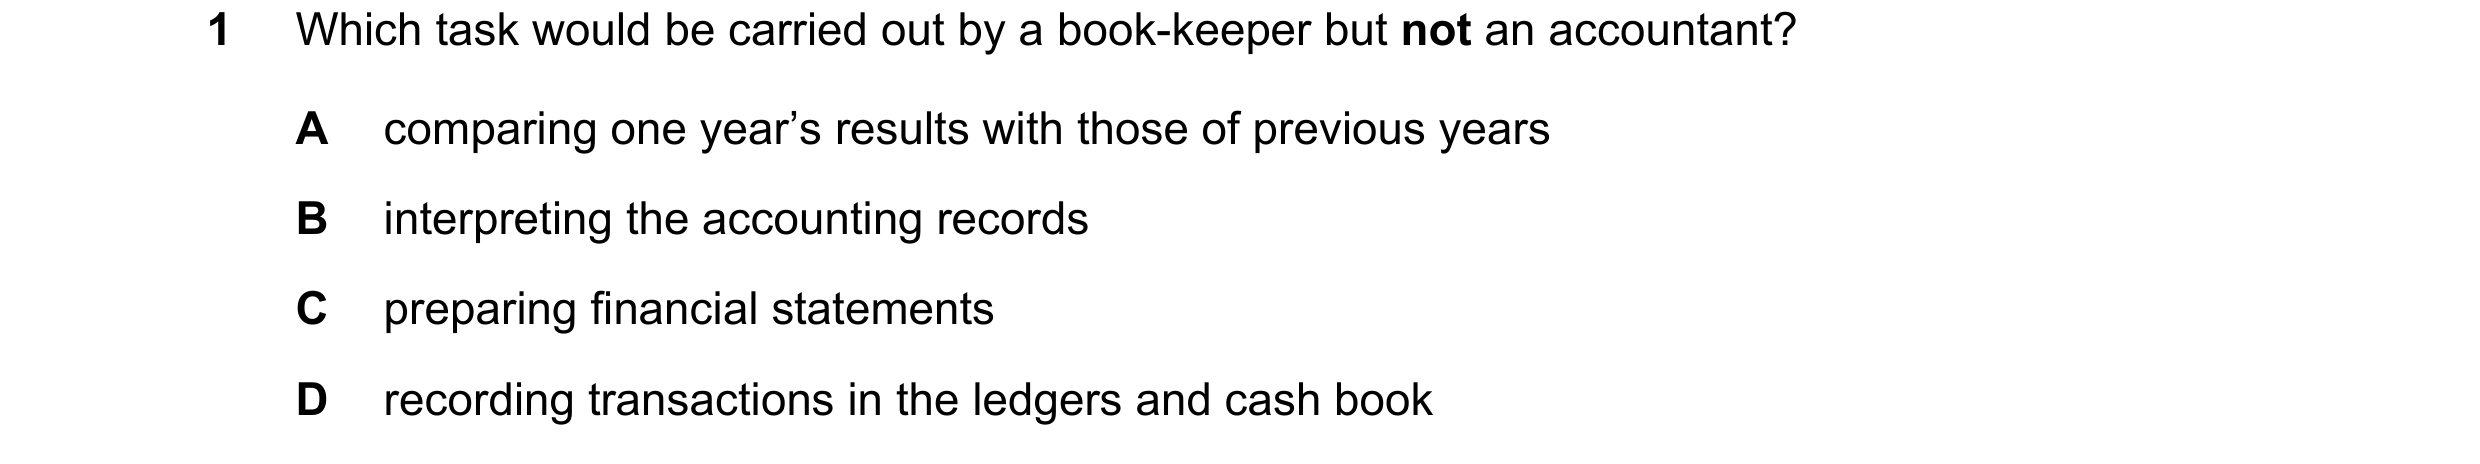
Q1 · Which task would be carried out by a book-keeper but not an accountant? 0452/12 Feb/March 2020
1 Which task would be carried out by a book-keeper but not an accountant? A comparing one year’s results with those of previous years B interpreting the accounting records C preparing financial statements D recording transactions in the ledgers and cash book
1 marks
Answer: D
This question in 0452/12 Feb/March 2020
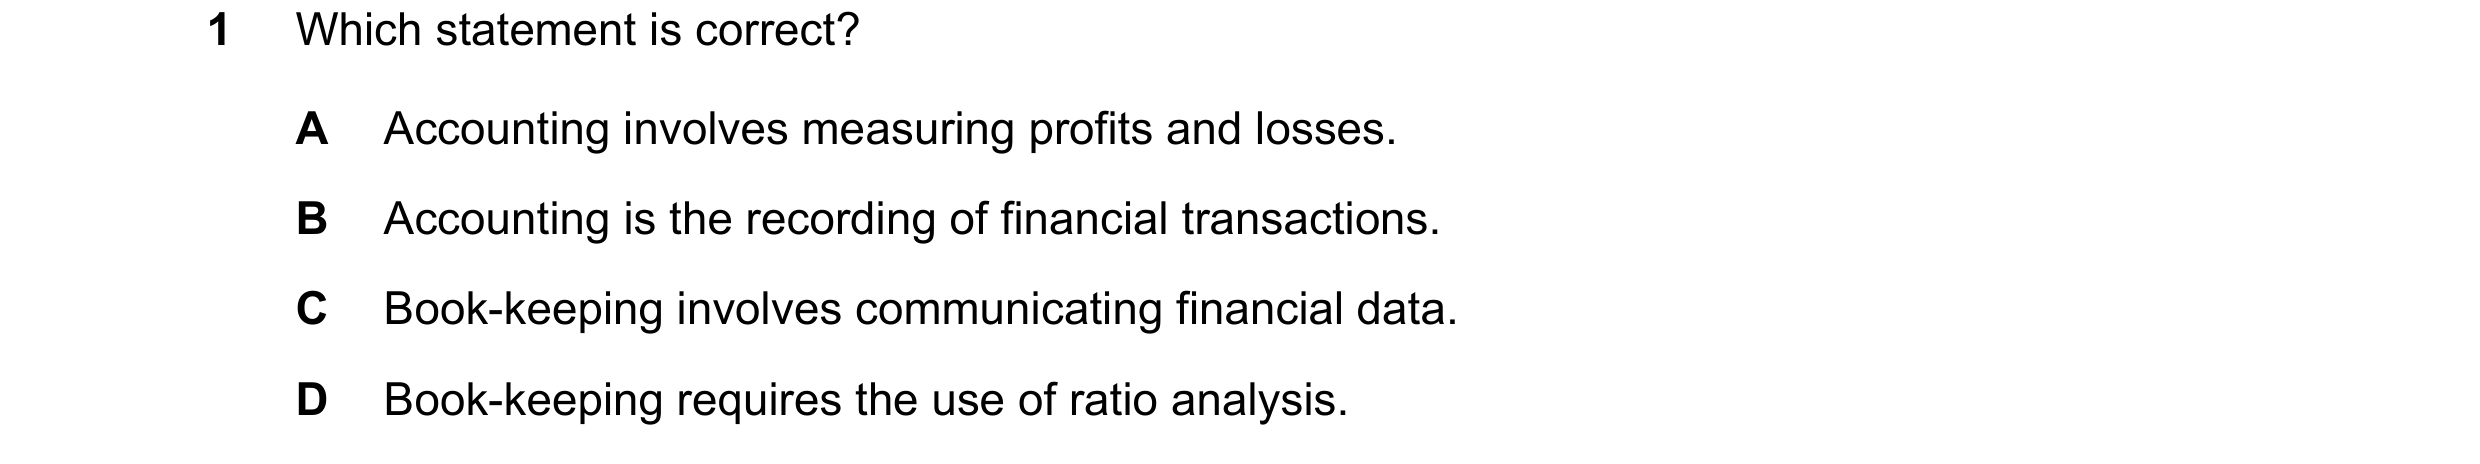
Q2 · Which statement is correct? 0452/11 May/June 2020
1 Which statement is correct? A Accounting involves measuring profits and losses. B Accounting is the recording of financial transactions. C Book-keeping involves communicating financial data. D Book-keeping requires the use of ratio analysis.
1 marks
Answer: A
This question in 0452/11 May/June 2020
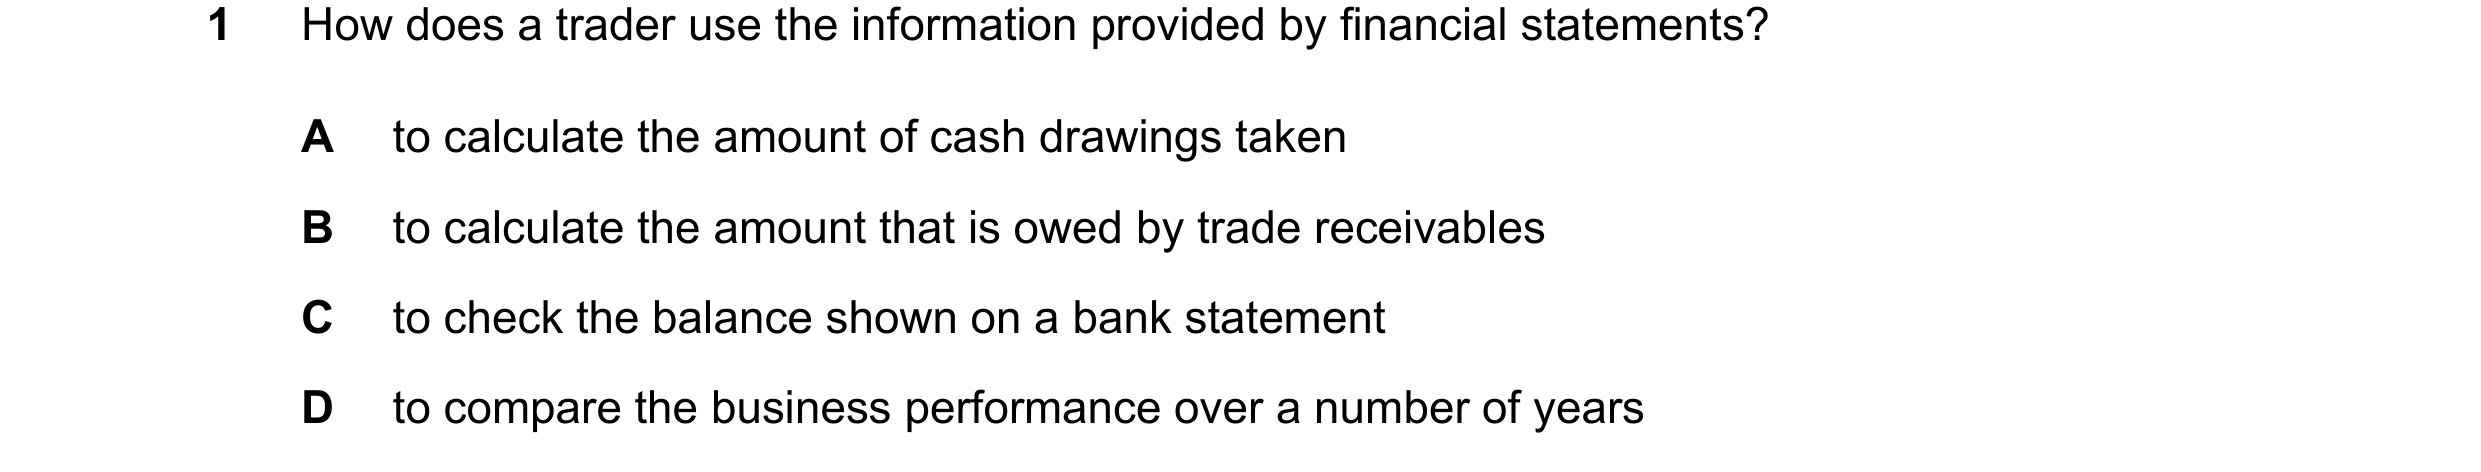
Q3 · How does a trader use the information provided by financial statements? 0452/12 May/June 2020
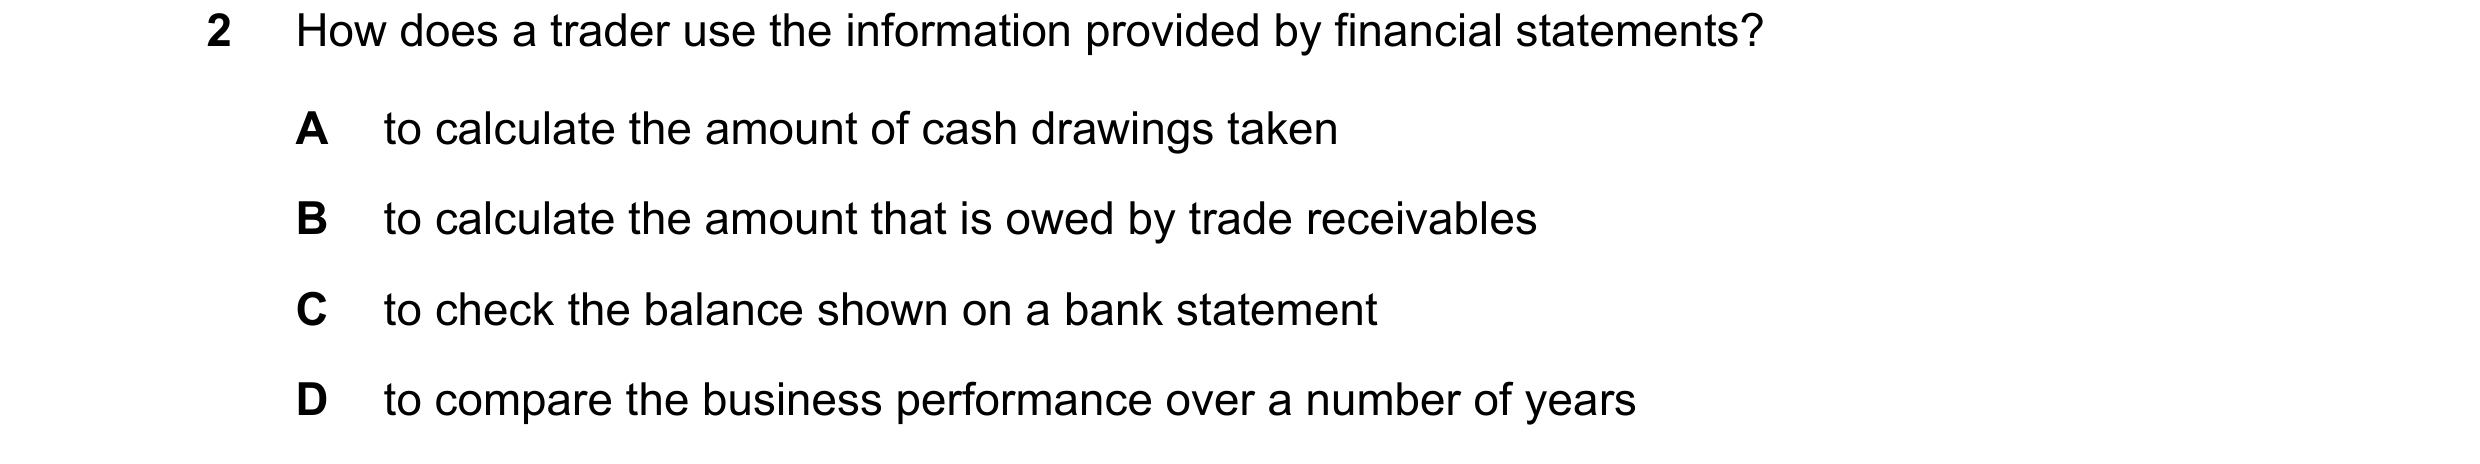
2 How does a trader use the information provided by financial statements? A to calculate the amount of cash drawings taken B to calculate the amount that is owed by trade receivables C to check the balance shown on a bank statement D to compare the business performance over a number of years
1 marks
Answer: D
This question in 0452/12 May/June 2020
Q4 · Which are examples of book-keeping? 0452/13 May/June 2020
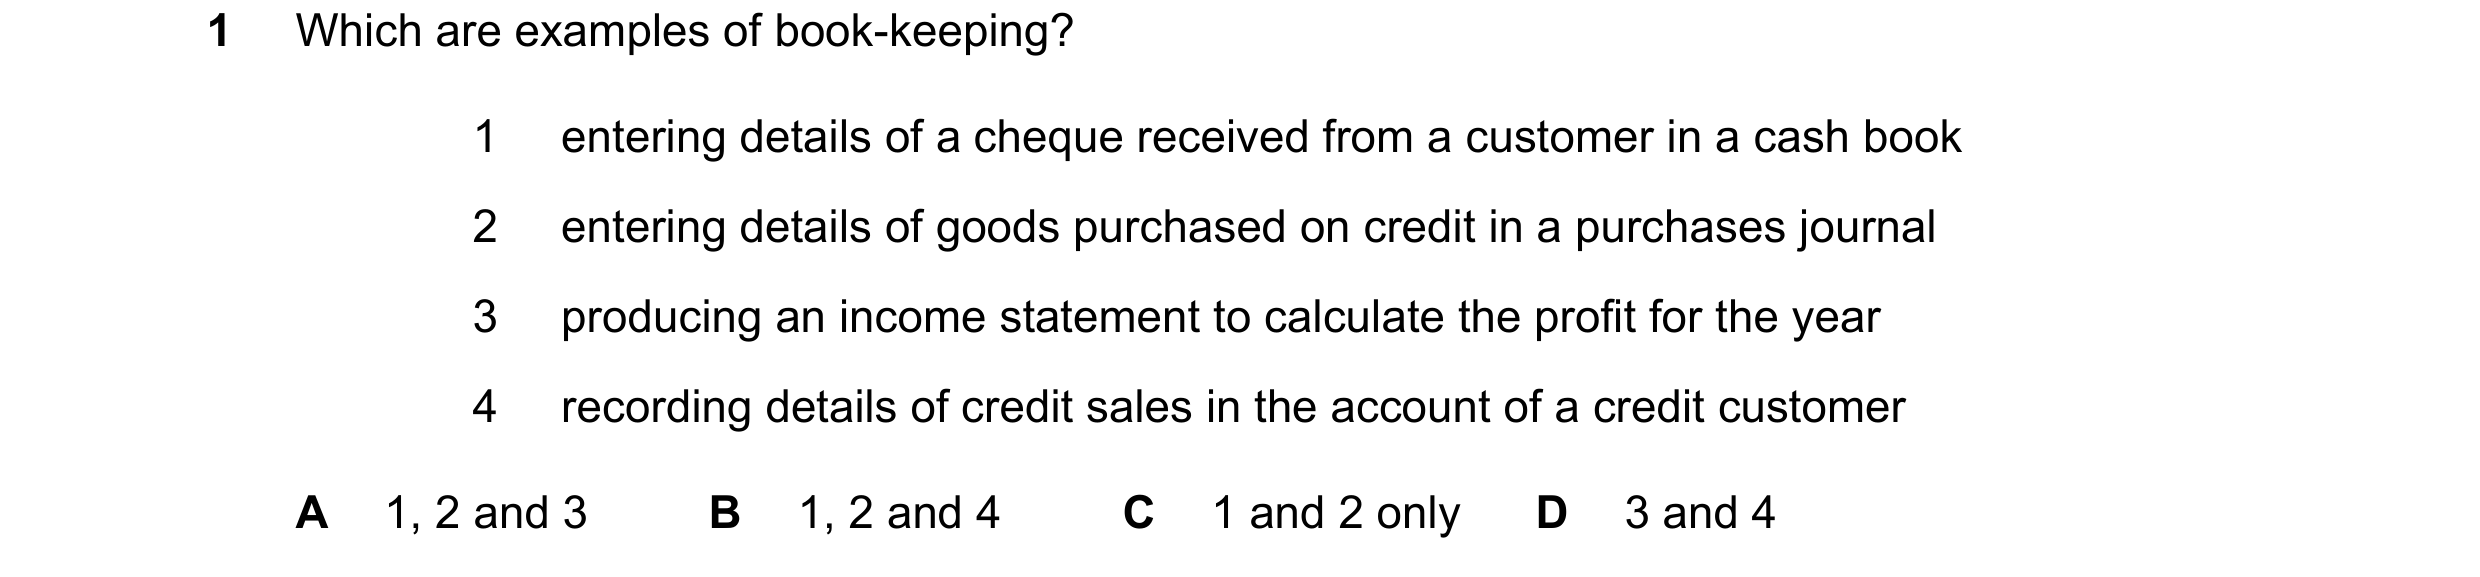
1 Which are examples of book-keeping? 1 entering details of a cheque received from a customer in a cash book 2 entering details of goods purchased on credit in a purchases journal 3 producing an income statement to calculate the profit for the year 4 recording details of credit sales in the account of a credit customer A 1, 2 and 3 B 1, 2 and 4 C 1 and 2 only D 3 and 4
1 marks
Answer: B
This question in 0452/13 May/June 2020
Q5 · How does a trader use the information provided by financial statements? 0452/13 May/June 2020
2 How does a trader use the information provided by financial statements? A to calculate the amount of cash drawings taken B to calculate the amount that is owed by trade receivables C to check the balance shown on a bank statement D to compare the business performance over a number of years
1 marks
Answer: D
This question in 0452/13 May/June 2020
Q6 · A trader prepares financial statements each year 0452/11 Oct/Nov 2020
1 A trader prepares financial statements each year. What do these assist the trader to do? A calculate the amount owing to credit suppliers B calculate the cash drawings C check the bank statement balance D make decisions about the future
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2020
Q7 · A trader prepares financial statements each year 0452/12 Oct/Nov 2020
1 A trader prepares financial statements each year. What do these assist the trader to do? A calculate the amount owing to credit suppliers B calculate the cash drawings C check the bank statement balance D make decisions about the future
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2020
Q8 · A trader prepares financial statements each year 0452/13 Oct/Nov 2020
1 A trader prepares financial statements each year. What do these assist the trader to do? A calculate the amount owing to credit suppliers B calculate the cash drawings C check the bank statement balance D make decisions about the future
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2020
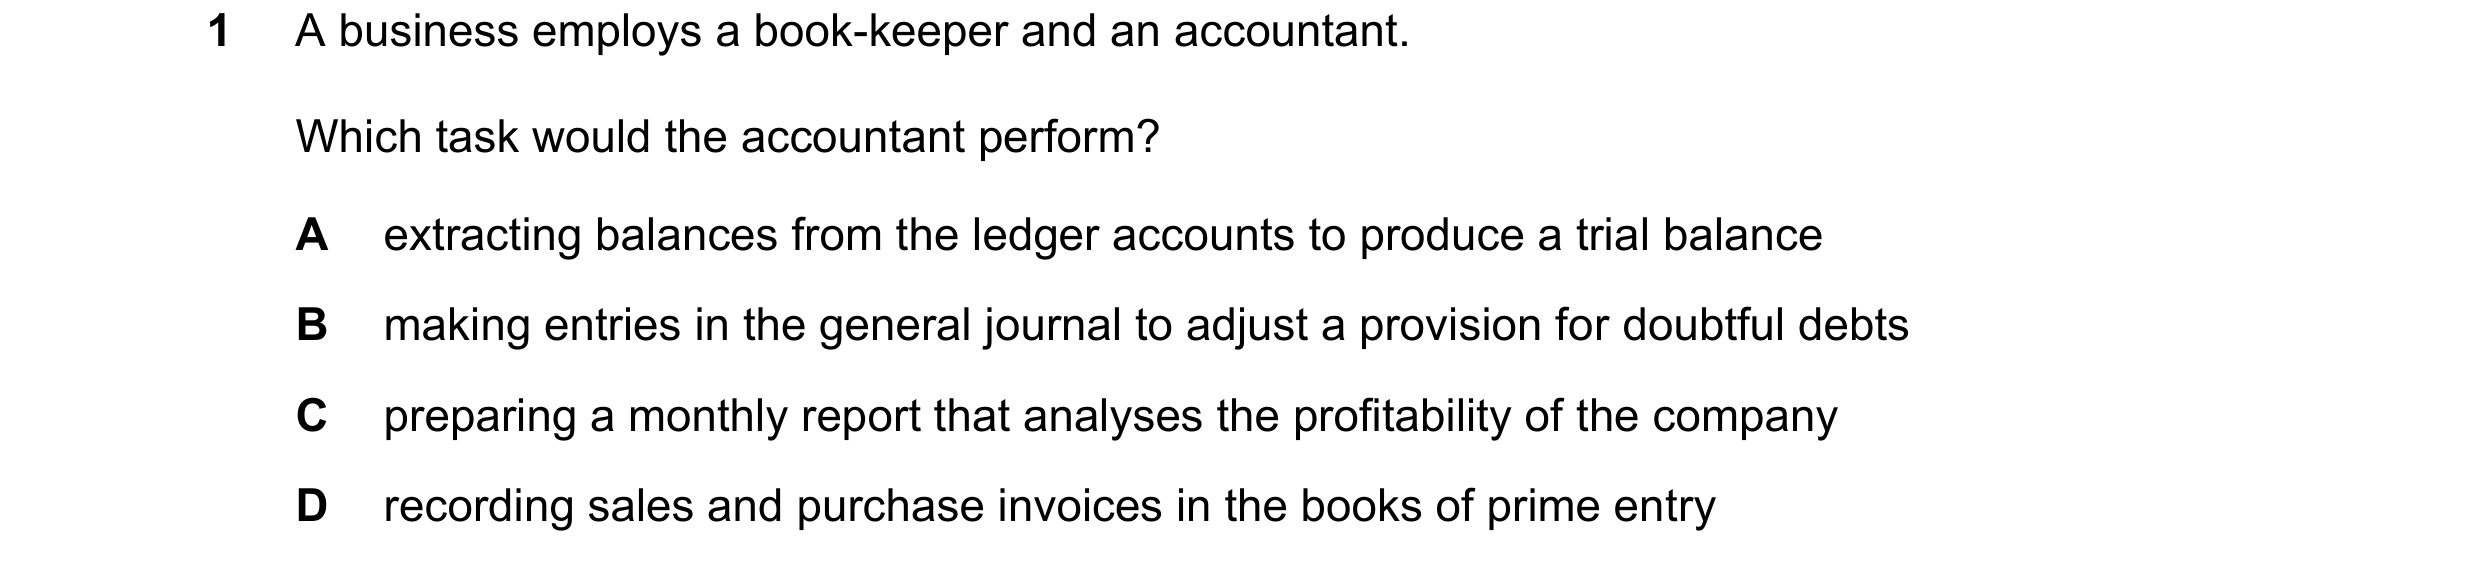
Q9 · A business employs a book-keeper and an accountant 0452/12 Feb/March 2021
1 A business employs a book-keeper and an accountant. Which task would the accountant perform? A extracting balances from the ledger accounts to produce a trial balance B making entries in the general journal to adjust a provision for doubtful debts C preparing a monthly report that analyses the profitability of the company D recording sales and purchase invoices in the books of prime entry
1 marks
Answer: C
This question in 0452/12 Feb/March 2021
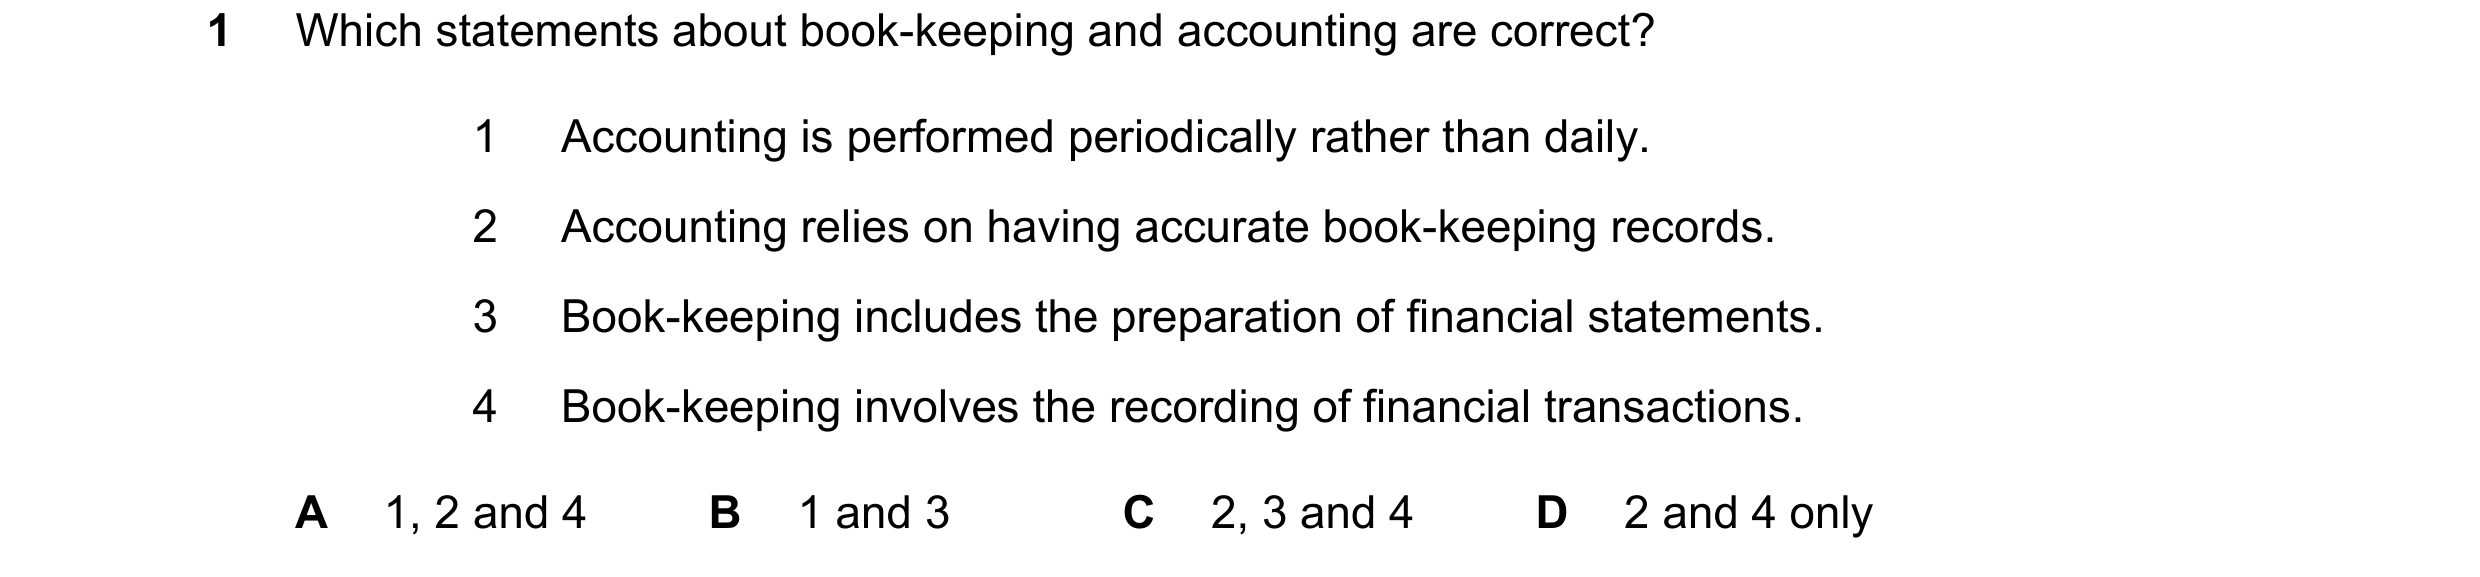
Q10 · Which statements about book-keeping and accounting are correct? 0452/11 May/June 2021
1 Which statements about book-keeping and accounting are correct? 1 Accounting is performed periodically rather than daily. 2 Accounting relies on having accurate book-keeping records. 3 Book-keeping includes the preparation of financial statements. 4 Book-keeping involves the recording of financial transactions. A 1, 2 and 4 B 1 and 3 C 2, 3 and 4 D 2 and 4 only
1 marks
Answer: A
This question in 0452/11 May/June 2021
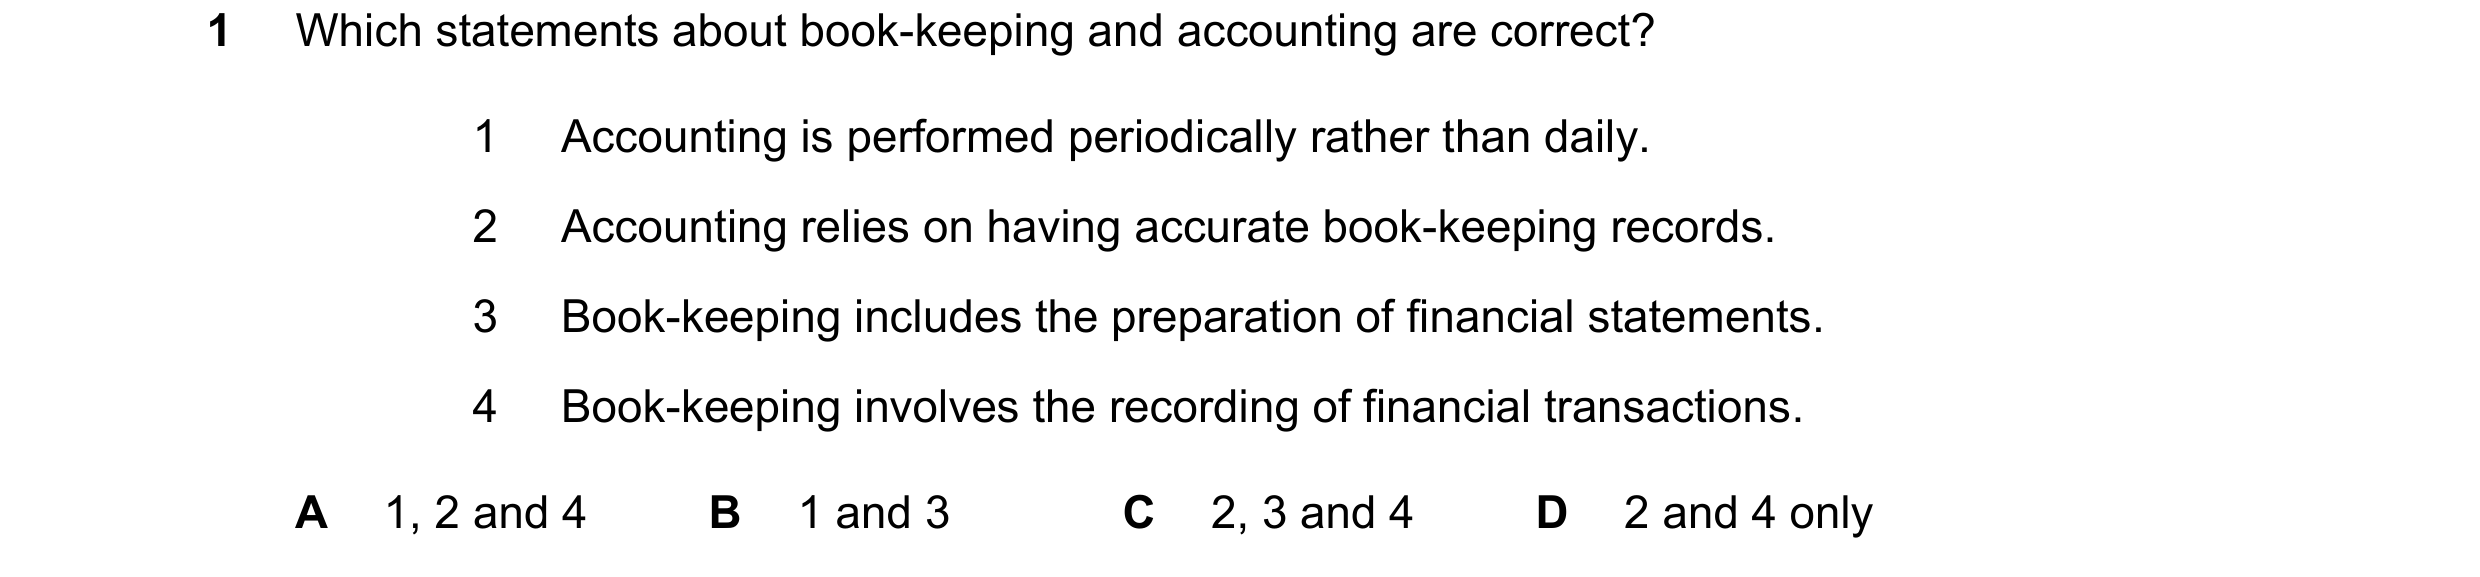
Q11 · Which statements about book-keeping and accounting are correct? 0452/12 May/June 2021
1 Which statements about book-keeping and accounting are correct? 1 Accounting is performed periodically rather than daily. 2 Accounting relies on having accurate book-keeping records. 3 Book-keeping includes the preparation of financial statements. 4 Book-keeping involves the recording of financial transactions. A 1, 2 and 4 B 1 and 3 C 2, 3 and 4 D 2 and 4 only
1 marks
Answer: A
This question in 0452/12 May/June 2021
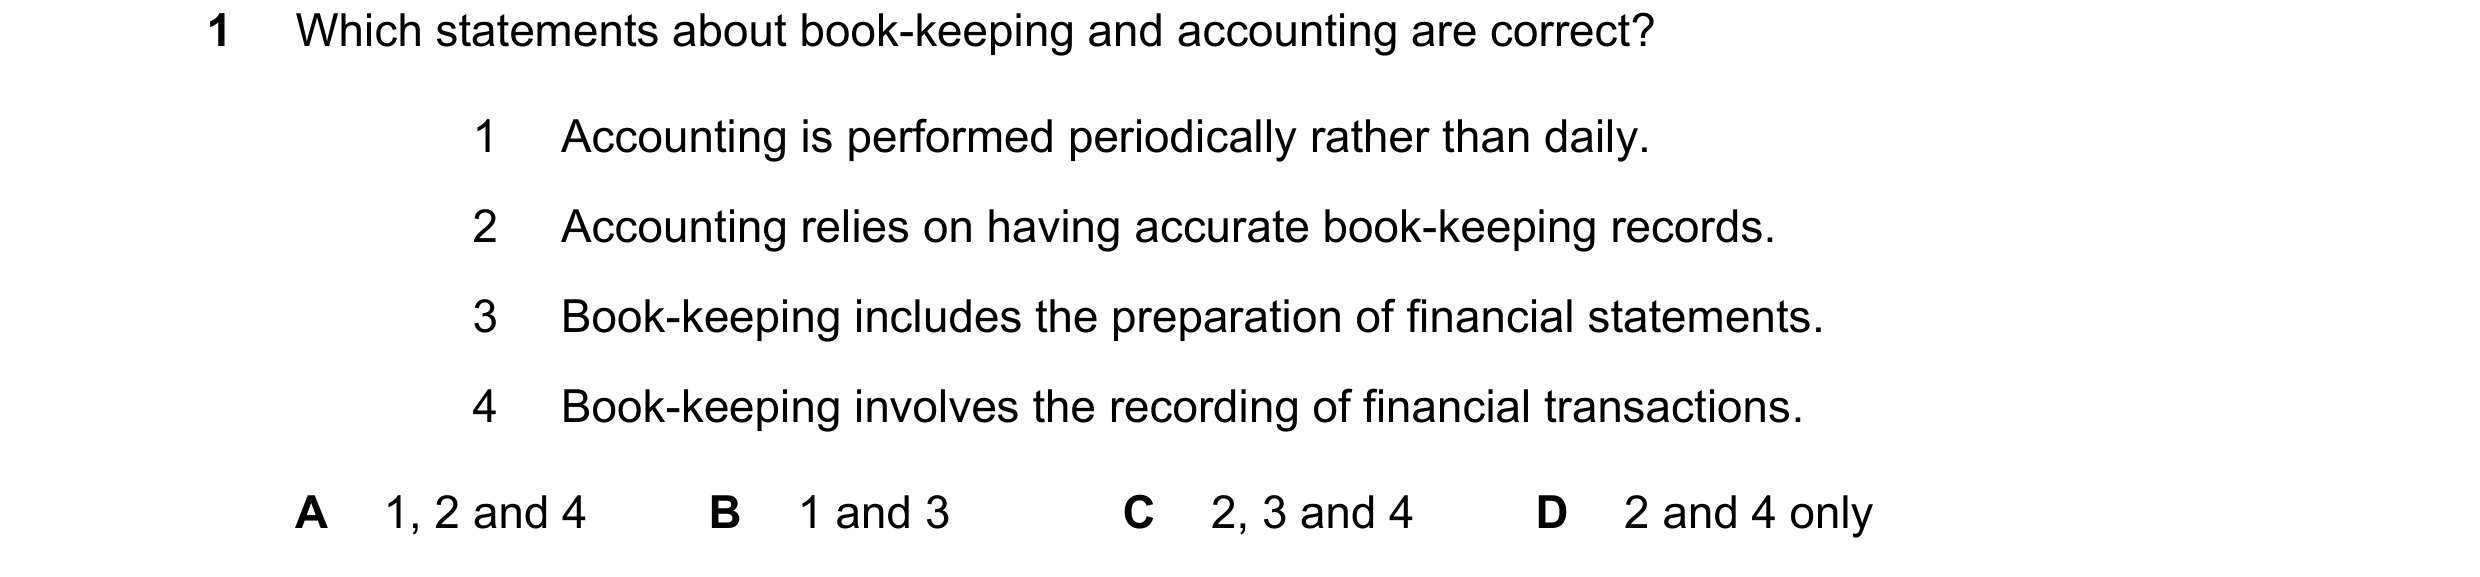
Q12 · Which statements about book-keeping and accounting are correct? 0452/13 May/June 2021
1 Which statements about book-keeping and accounting are correct? 1 Accounting is performed periodically rather than daily. 2 Accounting relies on having accurate book-keeping records. 3 Book-keeping includes the preparation of financial statements. 4 Book-keeping involves the recording of financial transactions. A 1, 2 and 4 B 1 and 3 C 2, 3 and 4 D 2 and 4 only
1 marks
Answer: A
This question in 0452/13 May/June 2021
Q13 · Why does a trader calculate the profit of his business? 0452/11 Oct/Nov 2021
1 Why does a trader calculate the profit of his business? A to calculate the interest payable on a loan B to calculate the provision for doubtful debts C to know the total expenses of the business D to know whether drawings are at a reasonable level
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2021
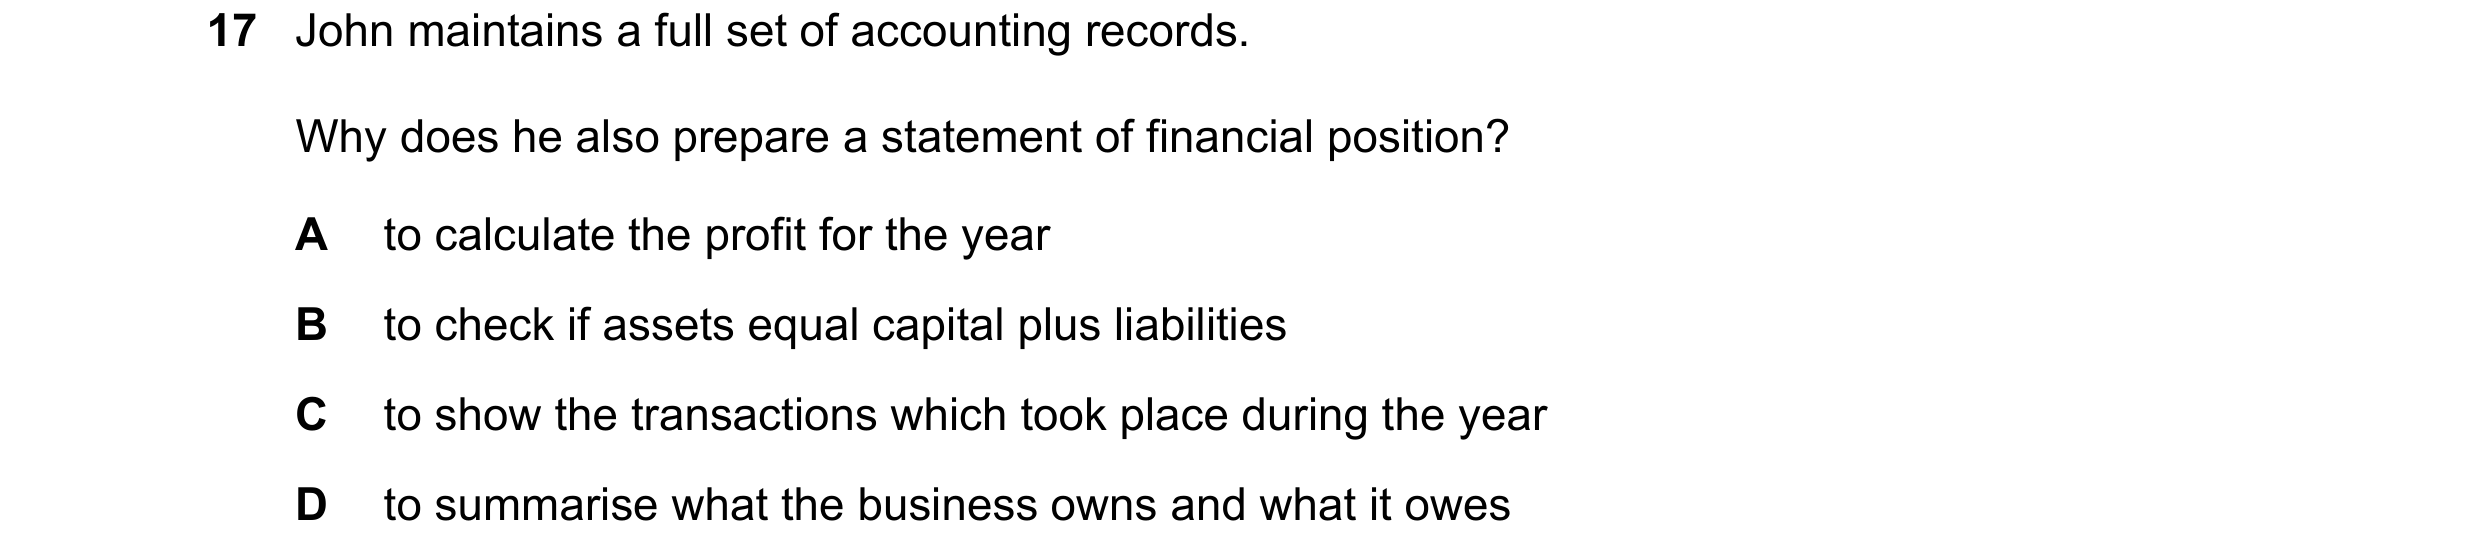
Q14 · John maintains a full set of accounting records 0452/11 Oct/Nov 2021
17 John maintains a full set of accounting records. Why does he also prepare a statement of financial position? A to calculate the profit for the year B to check if assets equal capital plus liabilities C to show the transactions which took place during the year D to summarise what the business owns and what it owes
1 marks
Answer: D
This question in 0452/11 Oct/Nov 2021
Q15 · Which statement is correct? 0452/12 Oct/Nov 2021
1 Which statement is correct? A The accountant prepares the trial balance and the book-keeper prepares the financial statements. B The accountant writes up the journals and the book-keeper writes up the ledger accounts. C The book-keeper writes up the journals and the accountant prepares the trial balance. D The book-keeper writes up the ledger accounts and the accountant prepares the financial statements.
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2021
Q16 · Why does a trader calculate the profit of his business? 0452/13 Oct/Nov 2021
1 Why does a trader calculate the profit of his business? A to calculate the interest payable on a loan B to calculate the provision for doubtful debts C to know the total expenses of the business D to know whether drawings are at a reasonable level
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2021
Q17 · John maintains a full set of accounting records 0452/13 Oct/Nov 2021
17 John maintains a full set of accounting records. Why does he also prepare a statement of financial position? A to calculate the profit for the year B to check if assets equal capital plus liabilities C to show the transactions which took place during the year D to summarise what the business owns and what it owes
1 marks
Answer: D
This question in 0452/13 Oct/Nov 2021
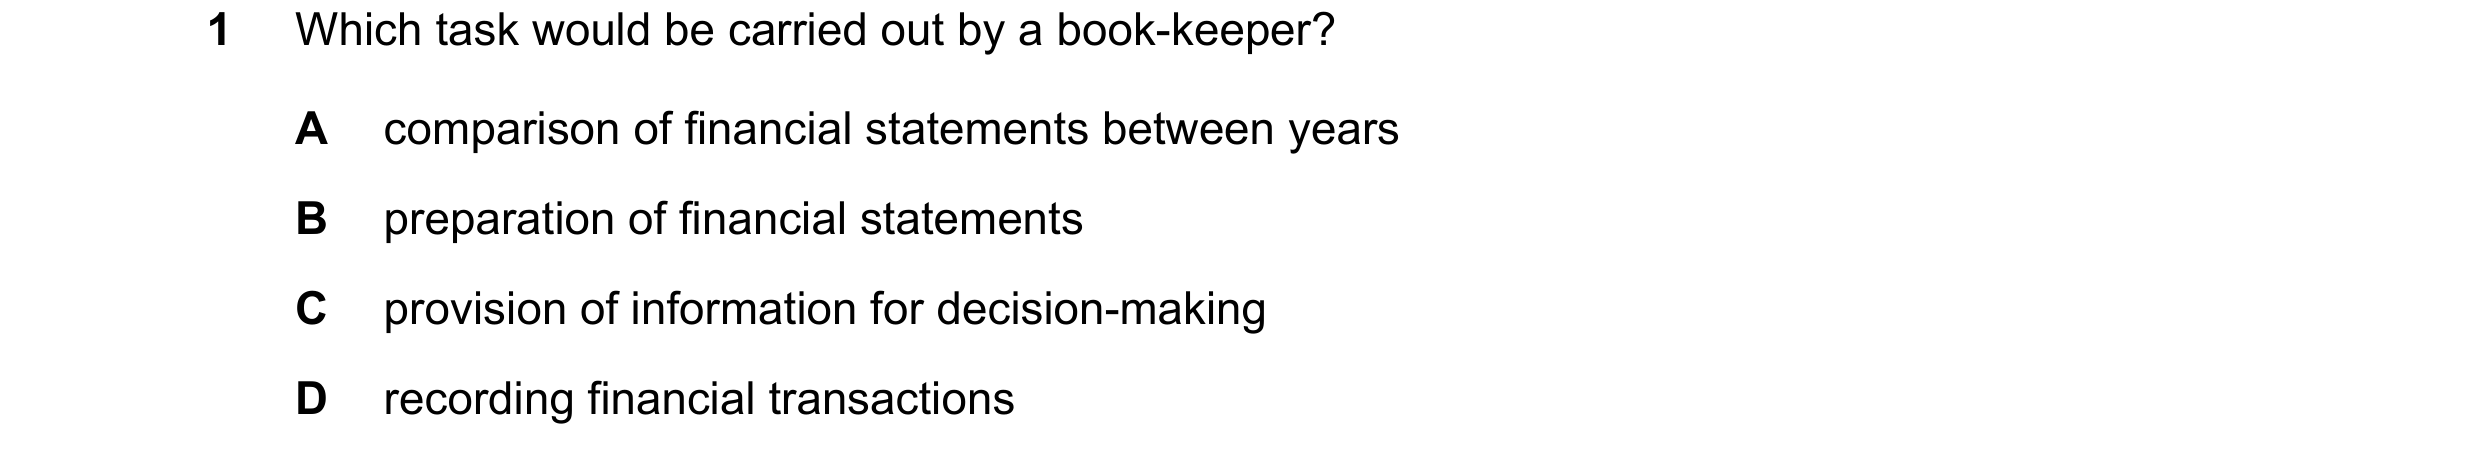
Q18 · Which task would be carried out by a book-keeper? 0452/11 May/June 2022
1 Which task would be carried out by a book-keeper? A comparison of financial statements between years B preparation of financial statements C provision of information for decision-making D recording financial transactions
1 marks
Answer: D
This question in 0452/11 May/June 2022
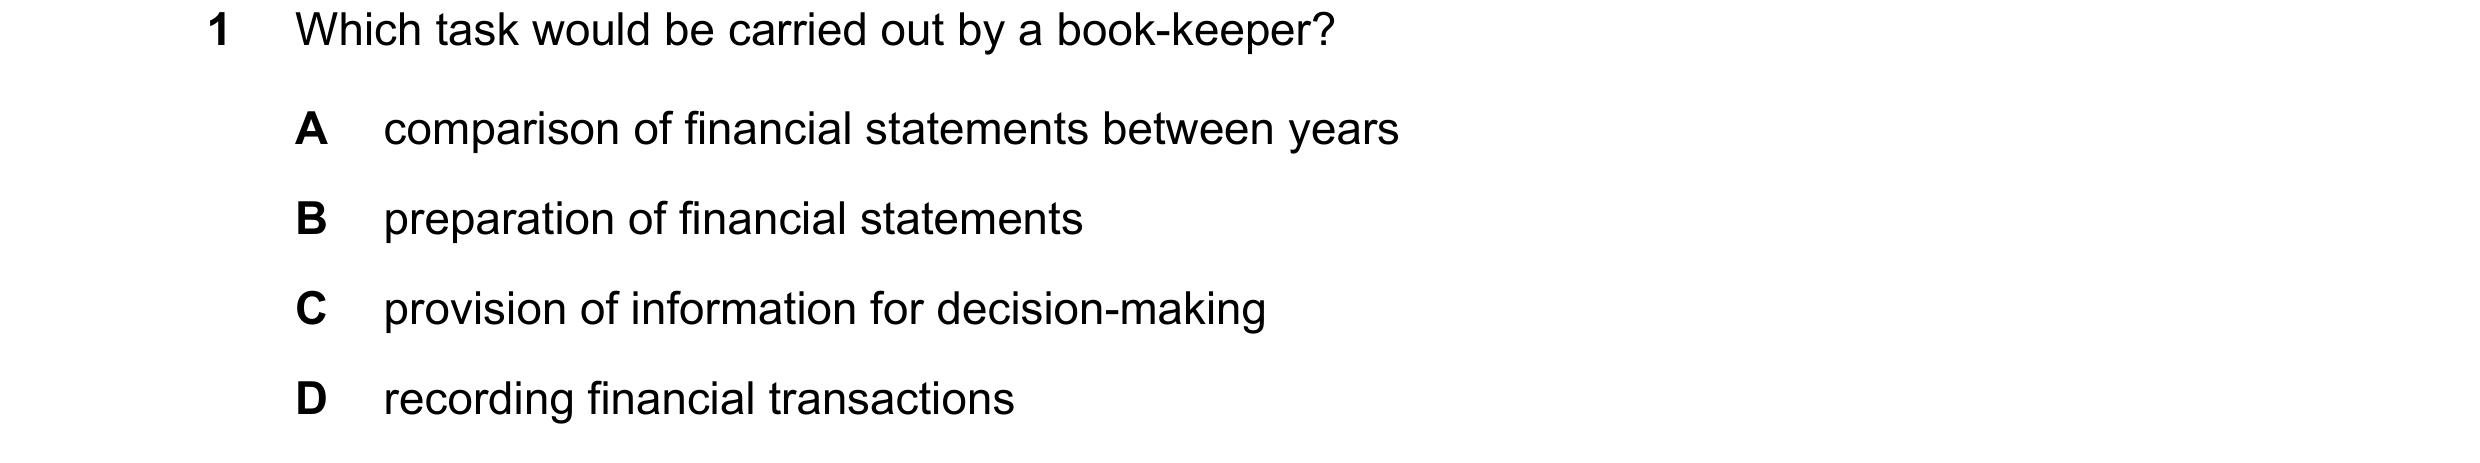
Q19 · Which task would be carried out by a book-keeper? 0452/12 May/June 2022
1 Which task would be carried out by a book-keeper? A comparison of financial statements between years B preparation of financial statements C provision of information for decision-making D recording financial transactions
1 marks
Answer: D
This question in 0452/12 May/June 2022
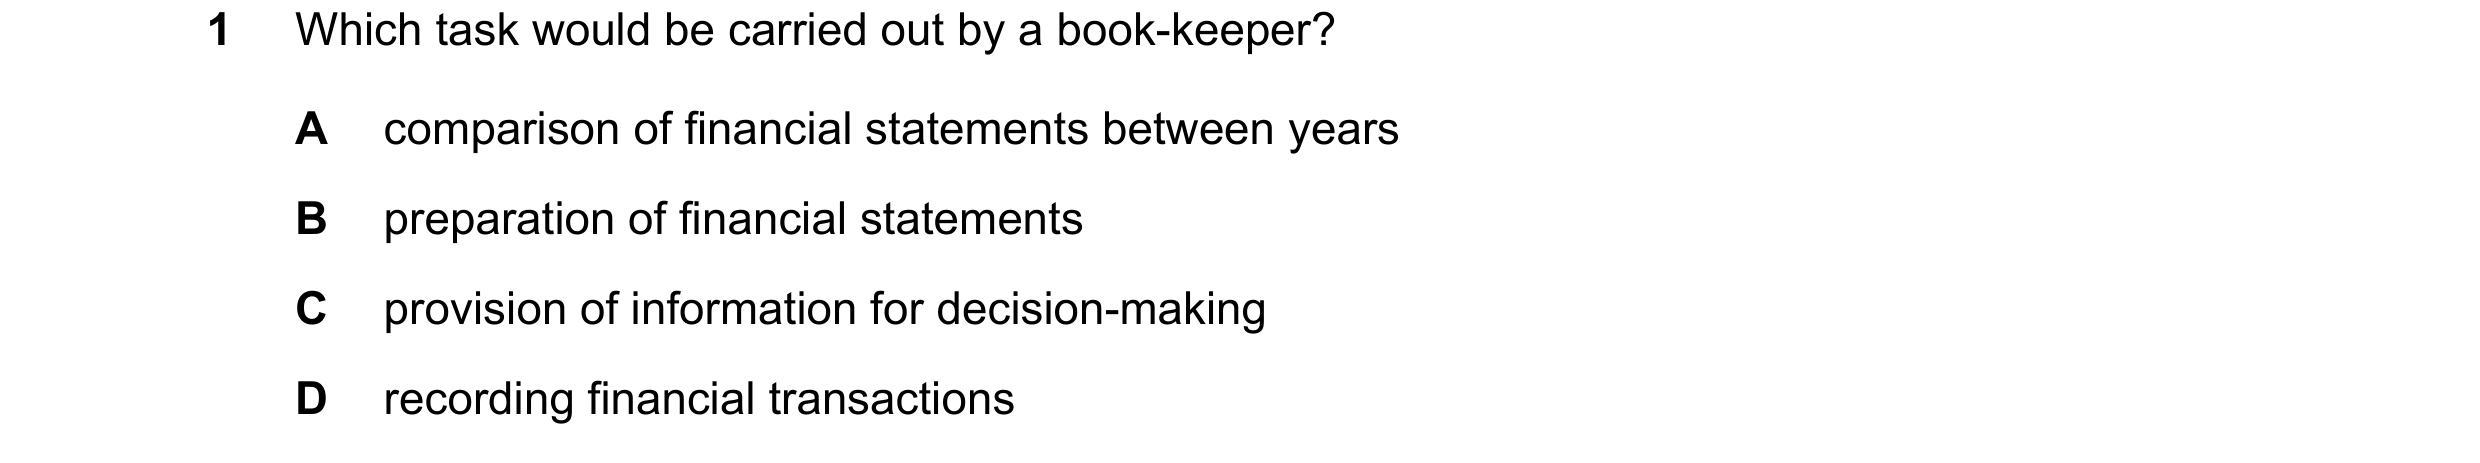
Q20 · Which task would be carried out by a book-keeper? 0452/13 May/June 2022
1 Which task would be carried out by a book-keeper? A comparison of financial statements between years B preparation of financial statements C provision of information for decision-making D recording financial transactions
1 marks
Answer: D
This question in 0452/13 May/June 2022
Q21 · Ahmed is a trader 0452/11 Oct/Nov 2022
1 Ahmed is a trader. Why should he prepare financial statements? A to apply the principle of business entity B to monitor his business’s performance C to prepare a bank reconciliation statement D to record changes to his personal wealth
1 marks
Answer: B
This question in 0452/11 Oct/Nov 2022
Q22 · For which purposes would a trader use his income statement and statement of financial… 0452/11 Oct/Nov 2022
19 For which purposes would a trader use his income statement and statement of financial position? 1 to enable decisions to be made about the performance of the business 2 to show the business bank account balance at a given date 3 to show the financial position of the business at a given date 4 to show whether the business made a profit or a loss in the financial year A 1 and 4 only B 1, 3 and 4 C 2 and 3 only D 2, 3 and 4
1 marks
Answer: B
This question in 0452/11 Oct/Nov 2022
Q23 · Ahmed is a trader 0452/13 Oct/Nov 2022
1 Ahmed is a trader. Why should he prepare financial statements? A to apply the principle of business entity B to monitor his business’s performance C to prepare a bank reconciliation statement D to record changes to his personal wealth
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2022
Q24 · For which purposes would a trader use his income statement and statement of financial… 0452/13 Oct/Nov 2022
19 For which purposes would a trader use his income statement and statement of financial position? 1 to enable decisions to be made about the performance of the business 2 to show the business bank account balance at a given date 3 to show the financial position of the business at a given date 4 to show whether the business made a profit or a loss in the financial year A 1 and 4 only B 1, 3 and 4 C 2 and 3 only D 2, 3 and 4
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2022
Q25 · What is the purpose of accounting? 0452/12 Feb/March 2023
1 What is the purpose of accounting? A to enter each business transaction twice in the books of account B to prepare financial statements and provide information for decision making C to prove that the total of the debit entries equals the total of the credit entries D to provide financial information for the business’s bank manager
1 marks
Answer: B
This question in 0452/12 Feb/March 2023
Q26 · How would a business owner know that he is receiving a return on his investment? 0452/12 Feb/March 2023
2 How would a business owner know that he is receiving a return on his investment? A His bank account is no longer overdrawn. B His drawings have increased. C His income statement shows a profit for the year. D His working capital has increased during the year.
1 marks
Answer: C
This question in 0452/12 Feb/March 2023
Q27 · Why does the accountant of a business analyse its financial statements? 0452/11 May/June 2023
1 Why does the accountant of a business analyse its financial statements? A to provide information for the customers B to provide information for the government C to provide information for the managers D to provide information for the suppliers
1 marks
Answer: C
This question in 0452/11 May/June 2023
Q28 · What is the main function of book-keeping? 0452/12 May/June 2023
1 What is the main function of book-keeping? A communicating information B interpreting information C recording information D summarising information
1 marks
Answer: C
This question in 0452/12 May/June 2023
Q29 · What does the statement of financial position of a business show? 0452/12 May/June 2023
21 What does the statement of financial position of a business show? A assets and liabilities at a certain date B calculation of the annual profit or loss C changes in equity during the financial year D income and expenditure for the financial year
1 marks
Answer: A
This question in 0452/12 May/June 2023
Q30 · What is the main function of book-keeping? 0452/13 May/June 2023
1 What is the main function of book-keeping? A communicating information B interpreting information C recording information D summarising information
1 marks
Answer: C
This question in 0452/13 May/June 2023
Q31 · Which group contains only service businesses? 0452/13 May/June 2023
20 Which group contains only service businesses? A book shop, language school, newsagent B jewellery repairer, taxi firm, food store C language school, taxi firm, jewellery repairer D taxi firm, newsagent, food store
1 marks
Answer: C
This question in 0452/13 May/June 2023
Q32 · What does the statement of financial position of a business show? 0452/13 May/June 2023
21 What does the statement of financial position of a business show? A assets and liabilities at a certain date B calculation of the annual profit or loss C changes in equity during the financial year D income and expenditure for the financial year
1 marks
Answer: A
This question in 0452/13 May/June 2023
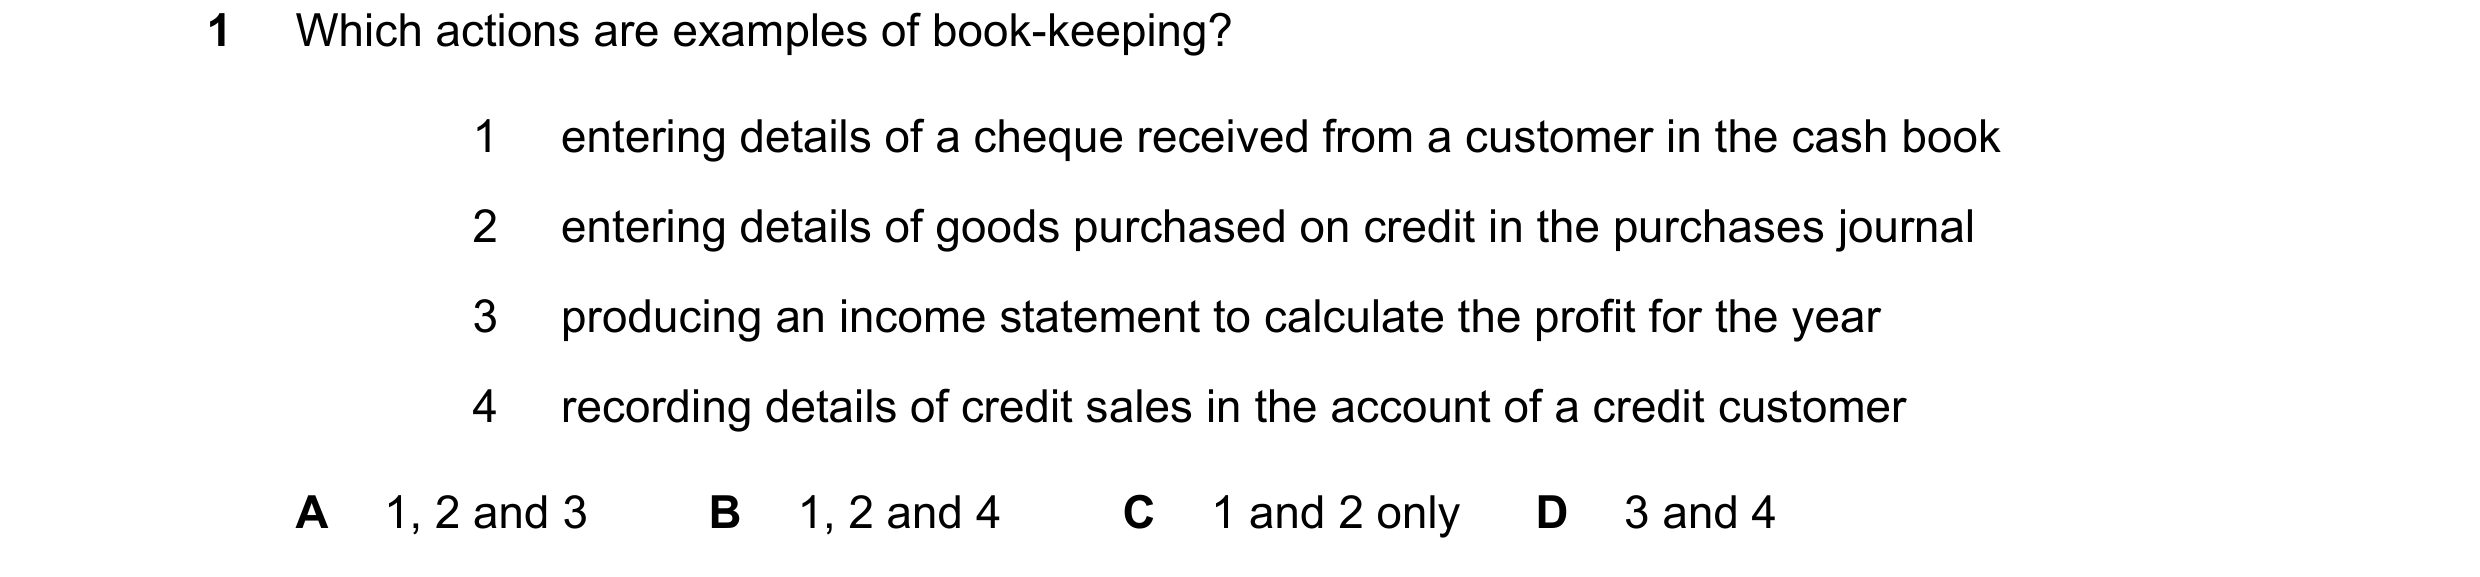
Q33 · Which actions are examples of book-keeping? 0452/12 Oct/Nov 2023
1 Which actions are examples of book-keeping? 1 entering details of a cheque received from a customer in the cash book 2 entering details of goods purchased on credit in the purchases journal 3 producing an income statement to calculate the profit for the year 4 recording details of credit sales in the account of a credit customer A 1, 2 and 3 B 1, 2 and 4 C 1 and 2 only D 3 and 4
1 marks
Answer: B
This question in 0452/12 Oct/Nov 2023
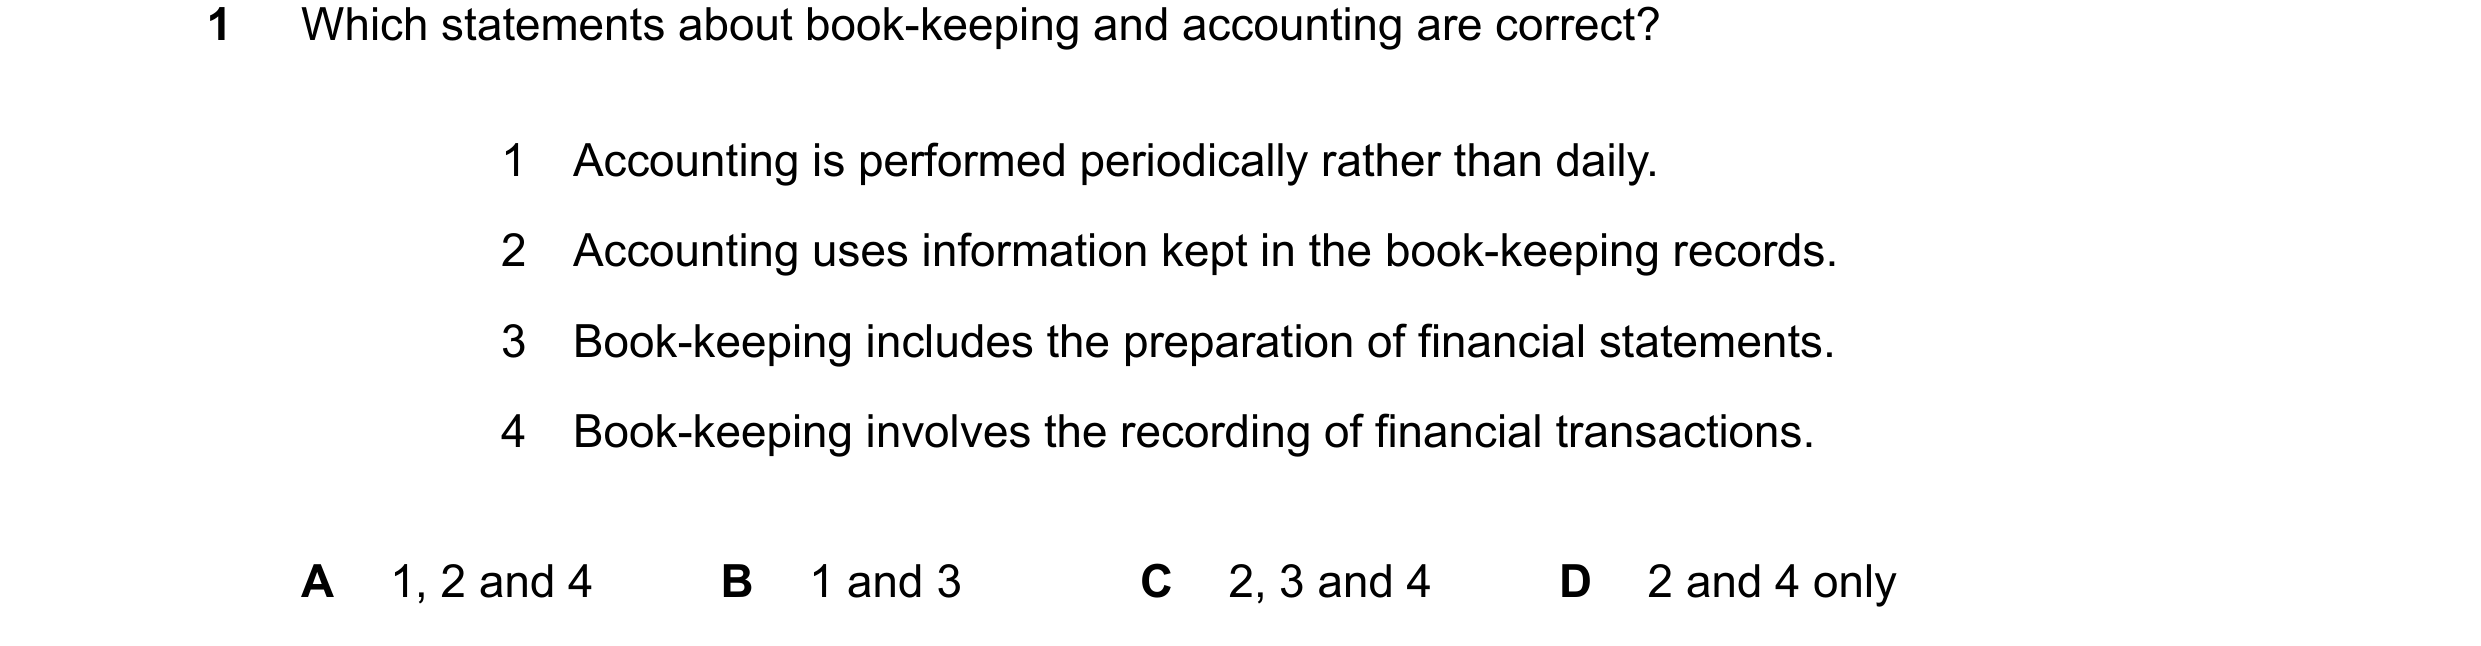
Q34 · Which statements about book-keeping and accounting are correct? 0452/12 Feb/March 2024
1 Which statements about book-keeping and accounting are correct? 1 Accounting is performed periodically rather than daily. 2 Accounting uses information kept in the book-keeping records. 3 Book-keeping includes the preparation of financial statements. 4 Book-keeping involves the recording of financial transactions. A 1, 2 and 4 B 1 and 3 C 2, 3 and 4 D 2 and 4 only
1 marks
Answer: A
This question in 0452/12 Feb/March 2024
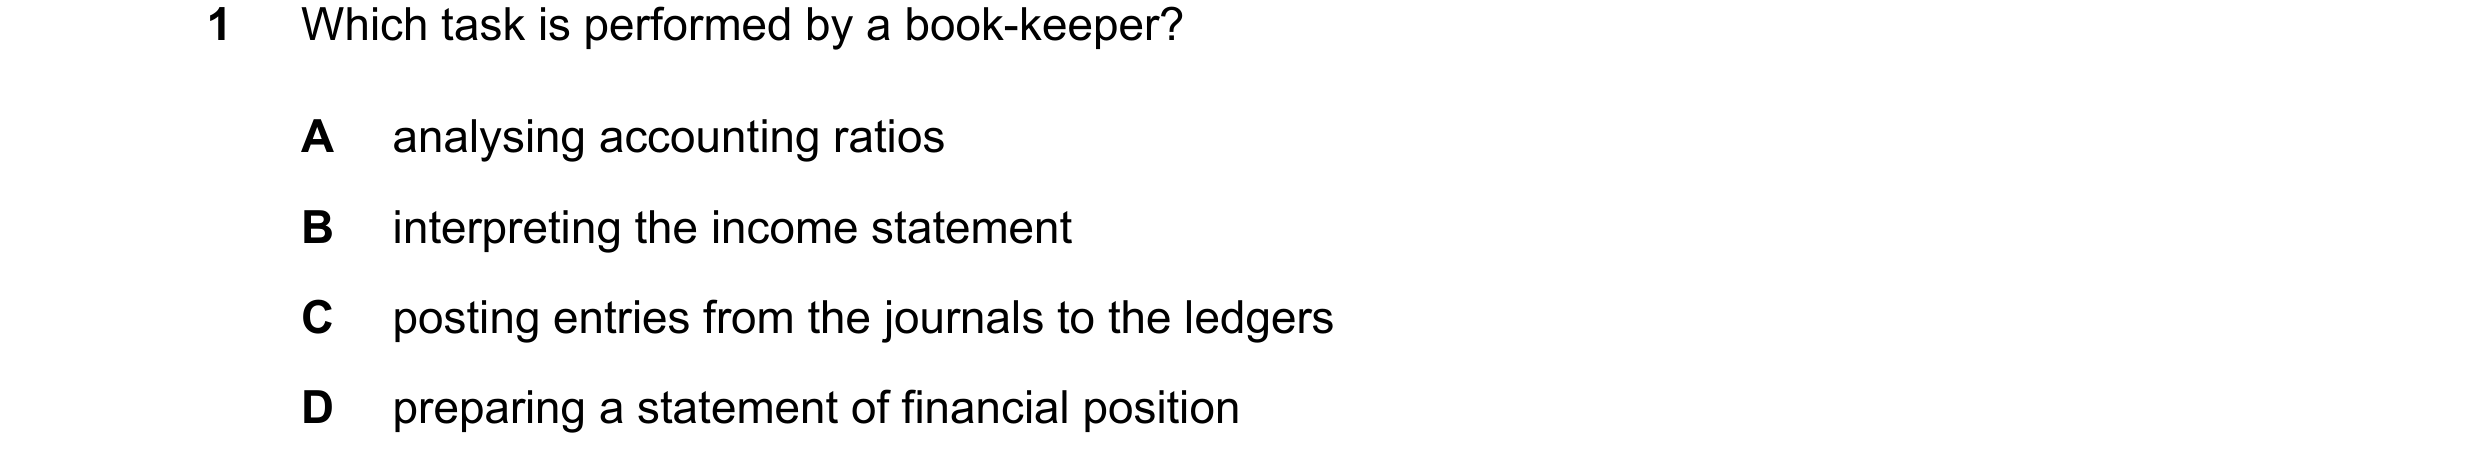
Q35 · Which task is performed by a book-keeper? 0452/11 May/June 2024
1 Which task is performed by a book-keeper? A analysing accounting ratios B interpreting the income statement C posting entries from the journals to the ledgers D preparing a statement of financial position
1 marks
Answer: C
This question in 0452/11 May/June 2024
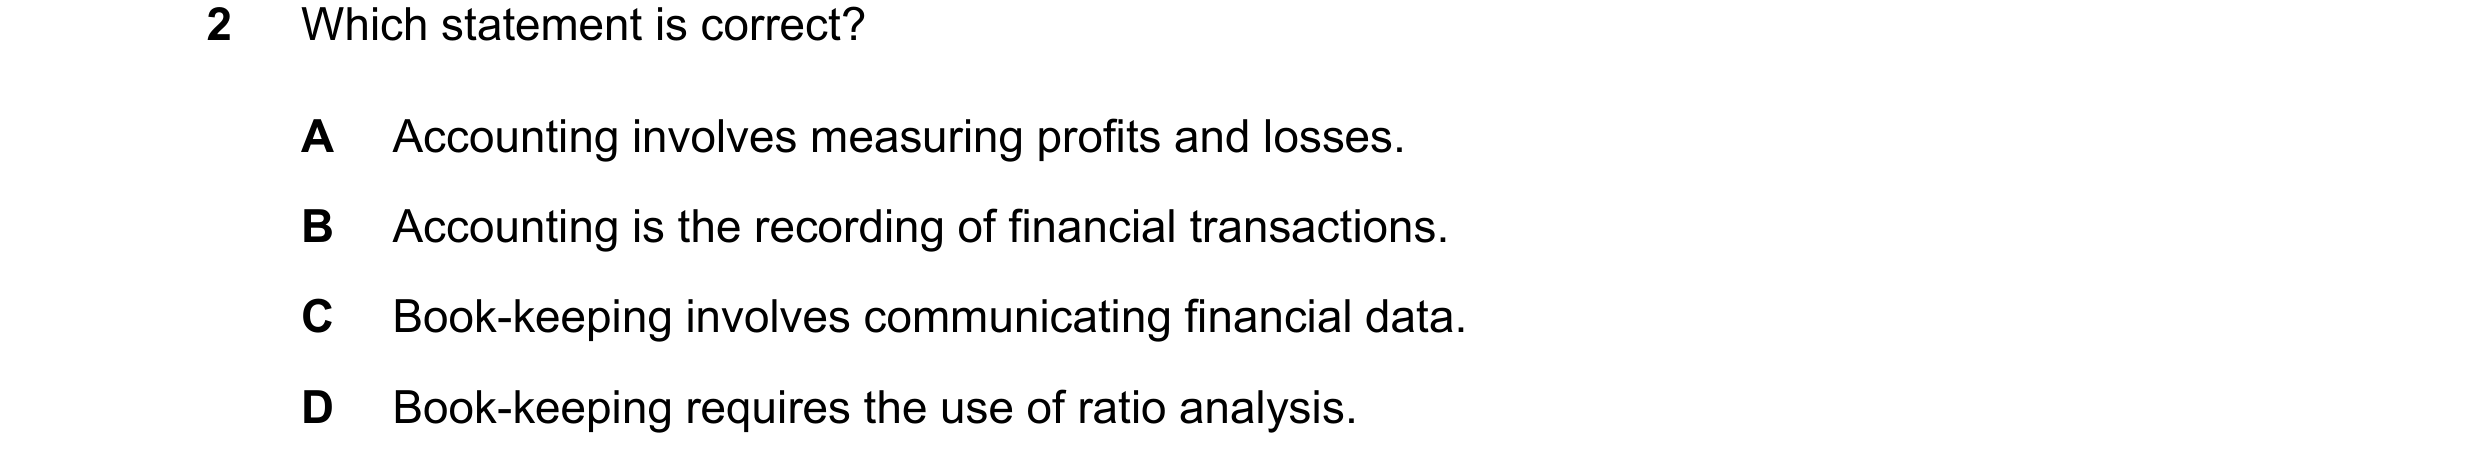
Q36 · Which statement is correct? 0452/11 May/June 2024
2 Which statement is correct? A Accounting involves measuring profits and losses. B Accounting is the recording of financial transactions. C Book-keeping involves communicating financial data. D Book-keeping requires the use of ratio analysis.
1 marks
Answer: A
This question in 0452/11 May/June 2024
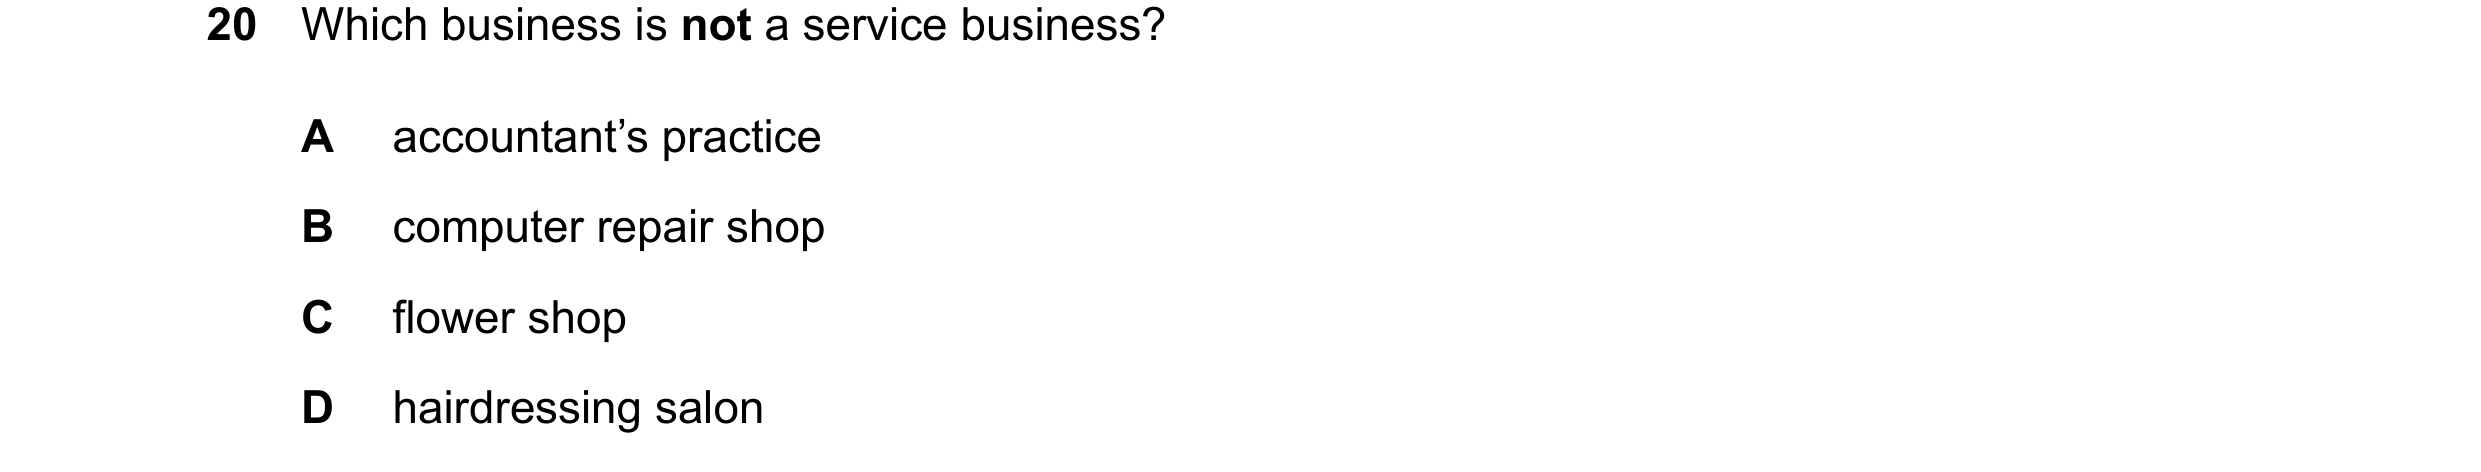
Q37 · Which business is not a service business? 0452/11 May/June 2024
20 Which business is not a service business? A accountant’s practice B computer repair shop C flower shop D hairdressing salon
1 marks
Answer: C
This question in 0452/11 May/June 2024
Q38 · How does a trader use the information provided by financial statements? 0452/12 May/June 2024
1 How does a trader use the information provided by financial statements? A to calculate the amount of cash drawings taken B to calculate the amount that is owed by trade receivables C to check the balance shown on a bank statement D to compare the business performance over a number of years
1 marks
Answer: D
This question in 0452/12 May/June 2024
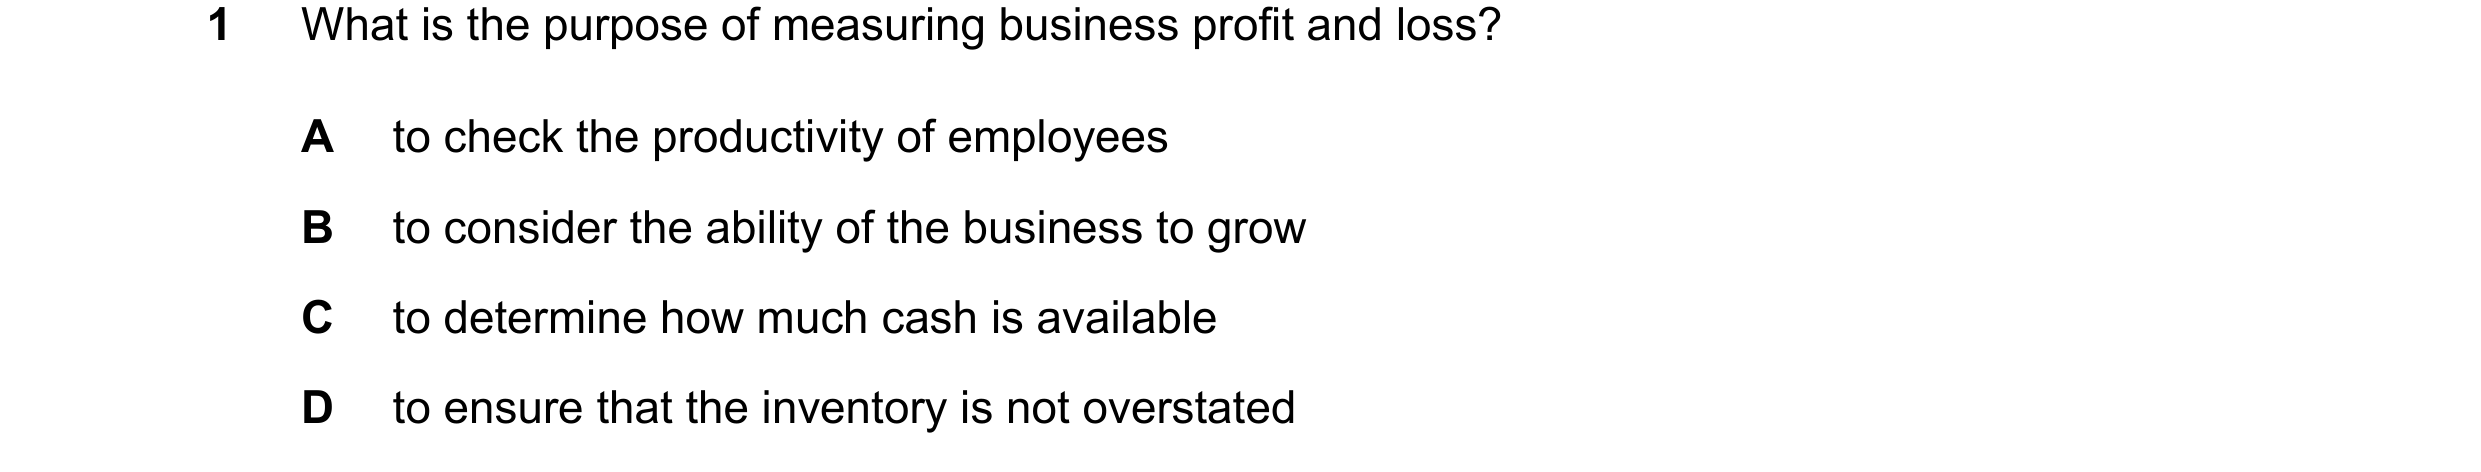
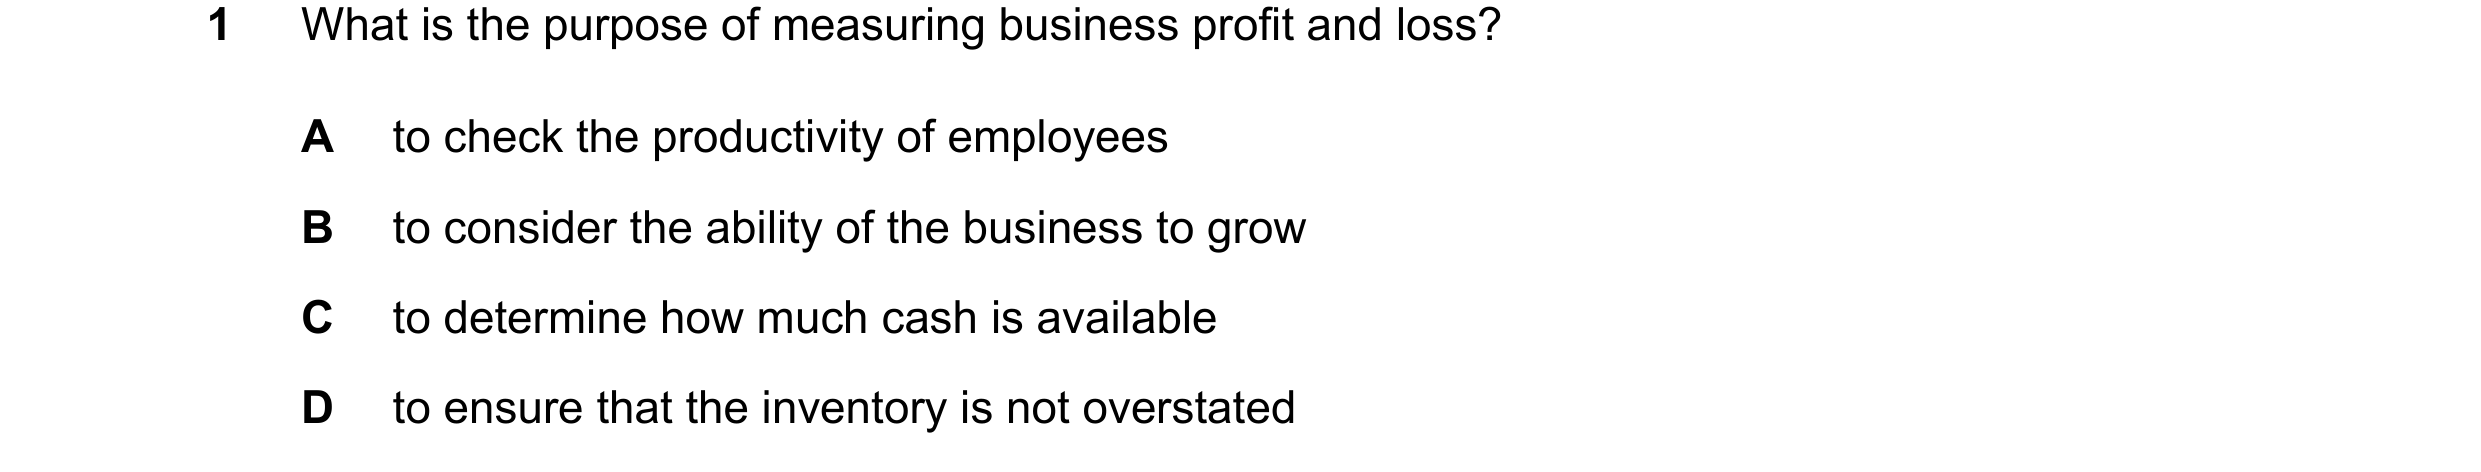
Q39 · What is the purpose of measuring business profit and loss? 0452/11 Oct/Nov 2024
1 What is the purpose of measuring business profit and loss? A to check the productivity of employees B to consider the ability of the business to grow C to determine how much cash is available D to ensure that the inventory is not overstated
1 marks
Answer: B
This question in 0452/11 Oct/Nov 2024
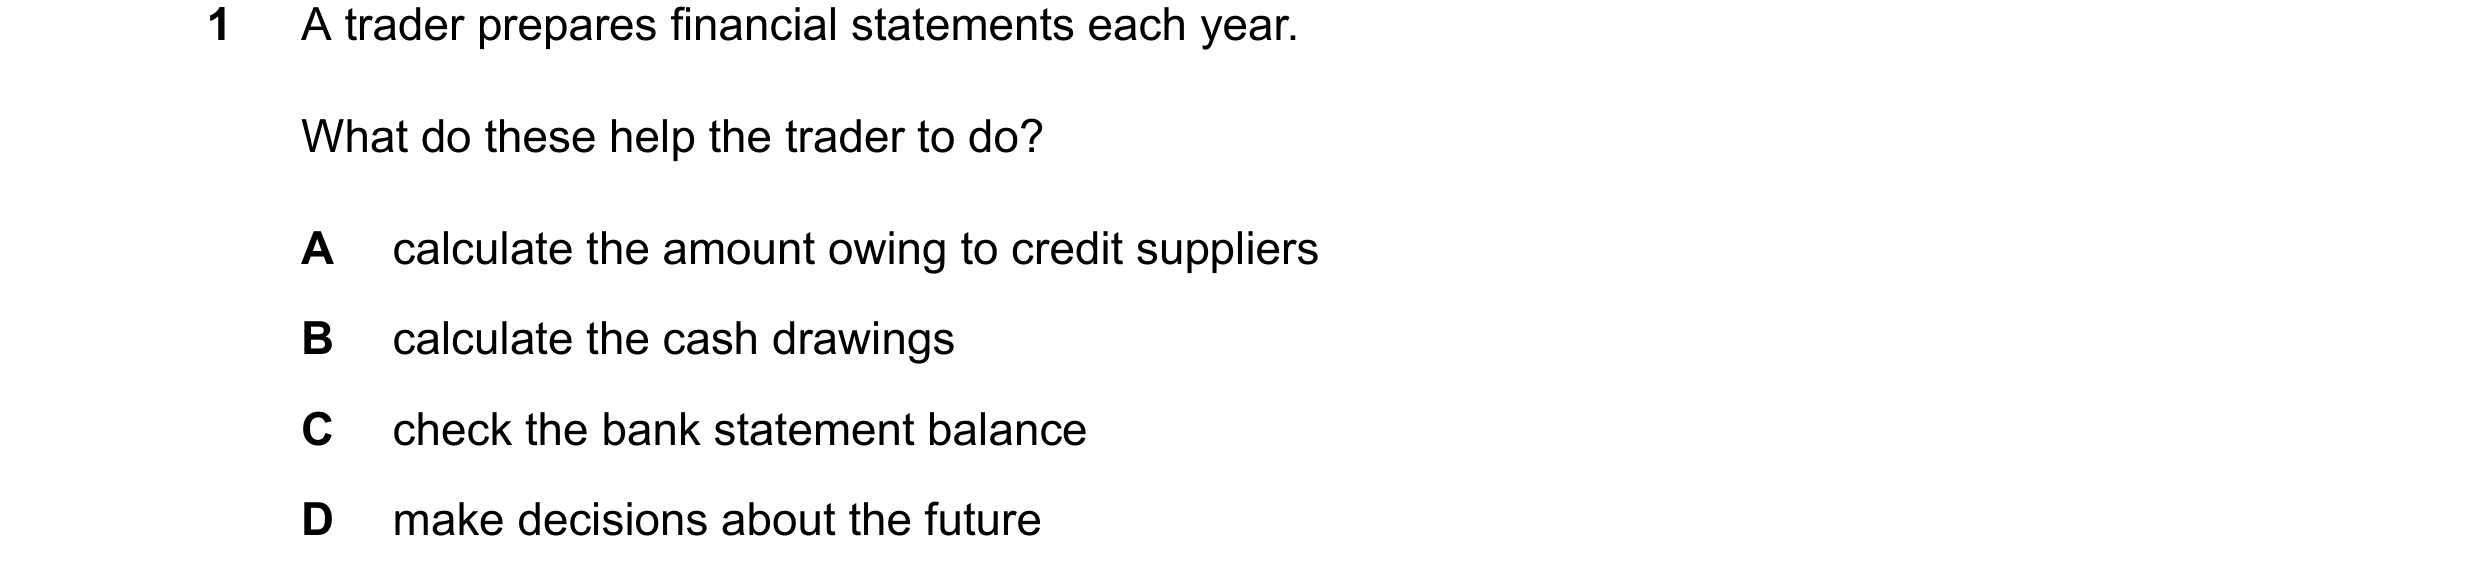
Q40 · A trader prepares financial statements each year 0452/12 Oct/Nov 2024
1 A trader prepares financial statements each year. What do these help the trader to do? A calculate the amount owing to credit suppliers B calculate the cash drawings C check the bank statement balance D make decisions about the future
1 marks
Answer: D
This question in 0452/12 Oct/Nov 2024
Q41 · What is the purpose of measuring business profit and loss? 0452/13 Oct/Nov 2024
1 What is the purpose of measuring business profit and loss? A to check the productivity of employees B to consider the ability of the business to grow C to determine how much cash is available D to ensure that the inventory is not overstated
1 marks
Answer: B
This question in 0452/13 Oct/Nov 2024
Q42 · A business employs a book-keeper and an accountant 0452/12 Feb/March 2025
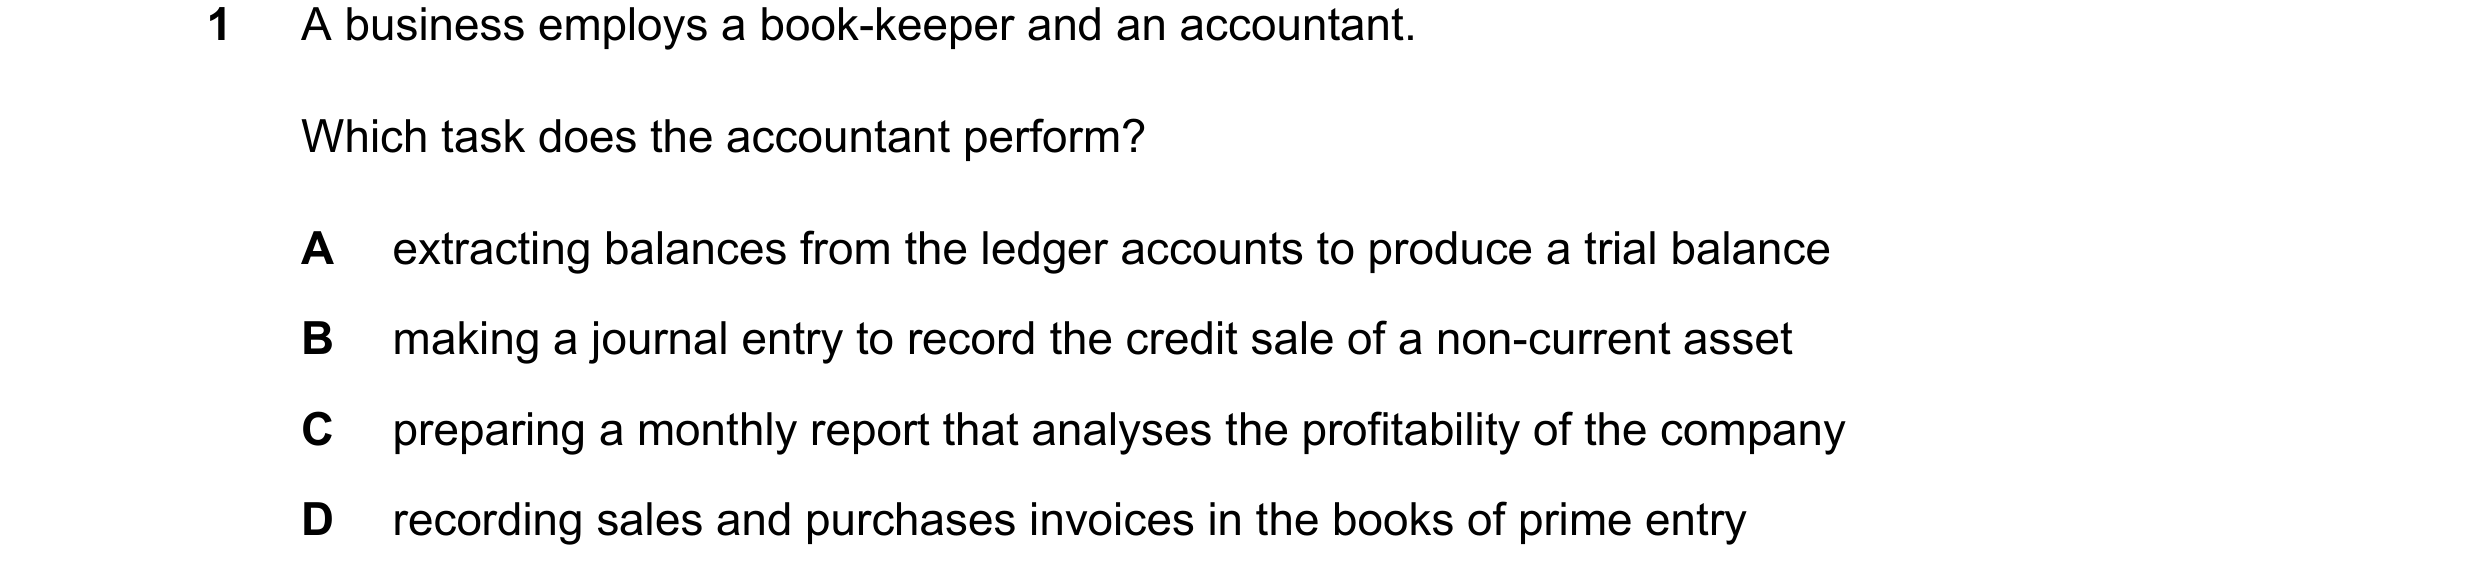
1 A business employs a book-keeper and an accountant. Which task does the accountant perform? A extracting balances from the ledger accounts to produce a trial balance B making a journal entry to record the credit sale of a non-current asset C preparing a monthly report that analyses the profitability of the company D recording sales and purchases invoices in the books of prime entry
1 marks
Answer: C
This question in 0452/12 Feb/March 2025
Q43 · Which task will not be performed by a book-keeper? 0452/11 May/June 2025
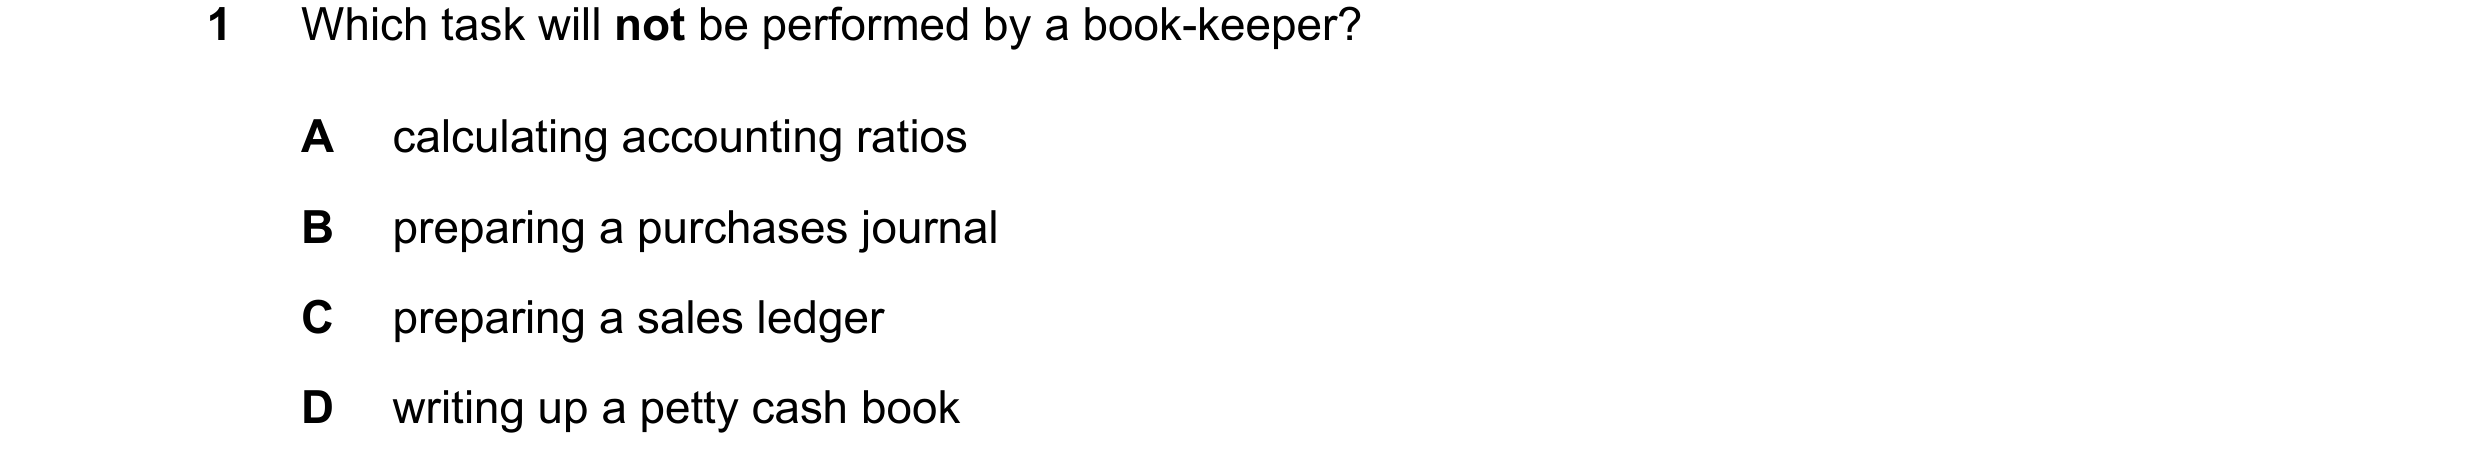
1 Which task will not be performed by a book-keeper? A calculating accounting ratios B preparing a purchases journal C preparing a sales ledger D writing up a petty cash book
1 marks
Answer: A
This question in 0452/11 May/June 2025
Q44 · Which task will not be performed by a book-keeper? 0452/13 May/June 2025
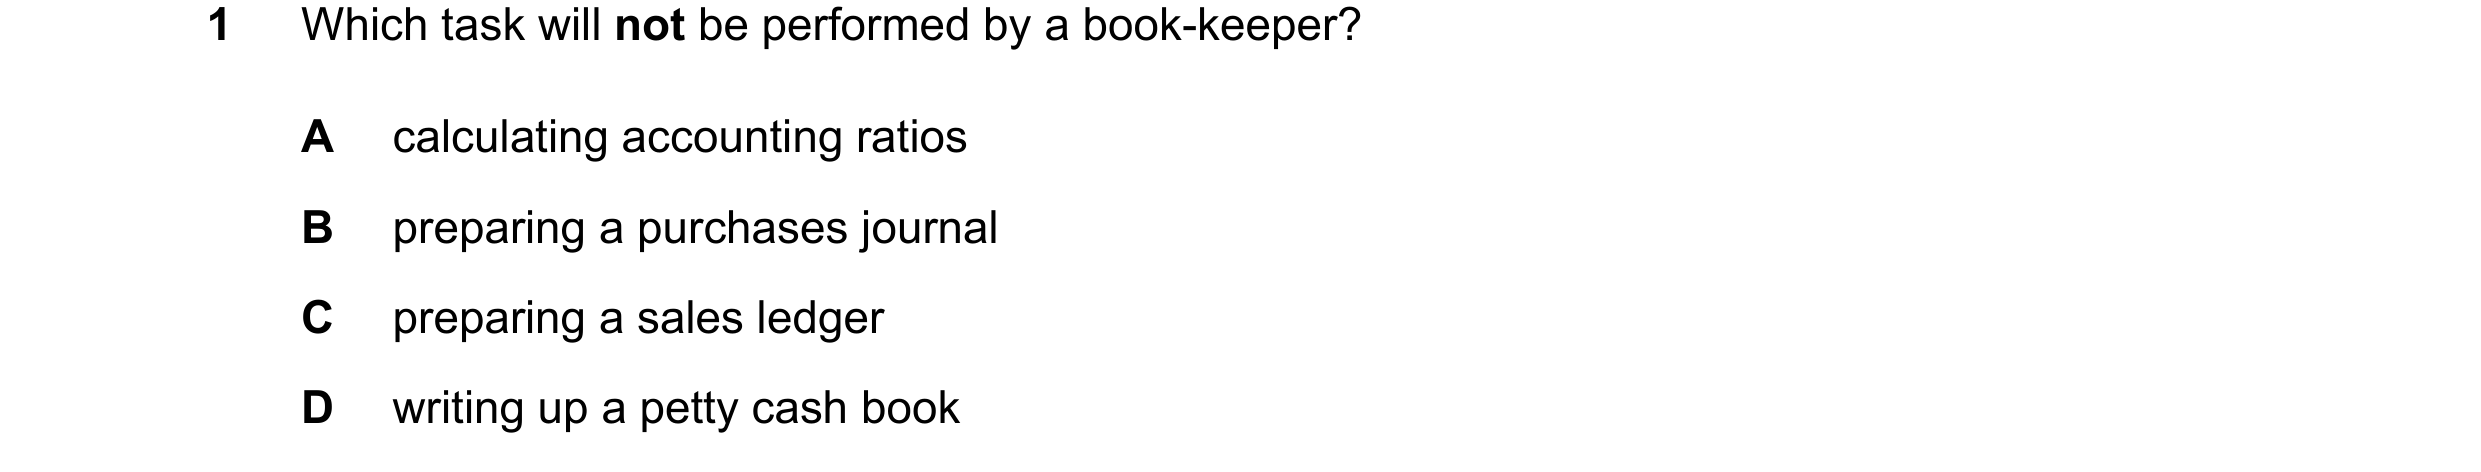
1 Which task will not be performed by a book-keeper? A calculating accounting ratios B preparing a purchases journal C preparing a sales ledger D writing up a petty cash book
1 marks
Answer: A
This question in 0452/13 May/June 2025
Q45 · What is a purpose of calculating the profit of a sole trader? 0452/13 Oct/Nov 2025
1 What is a purpose of calculating the profit of a sole trader? A to analyse the performance of the business against previous years B to decide on the amount of dividend to be paid to the shareholders C to reconcile the cash book balance with the bank statement balance D to work out the liquidity of the business
1 marks
Answer: A
This question in 0452/13 Oct/Nov 2025
 1 / 8
 2 / 8
 3 / 8
 4 / 8
 5 / 8
 6 / 8
 7 / 8
 8 / 8