Cambridge A Level Accounting 9706 — 2021 May/June Paper 2 · Variant 1
9706/21/M/J/21 · 7 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
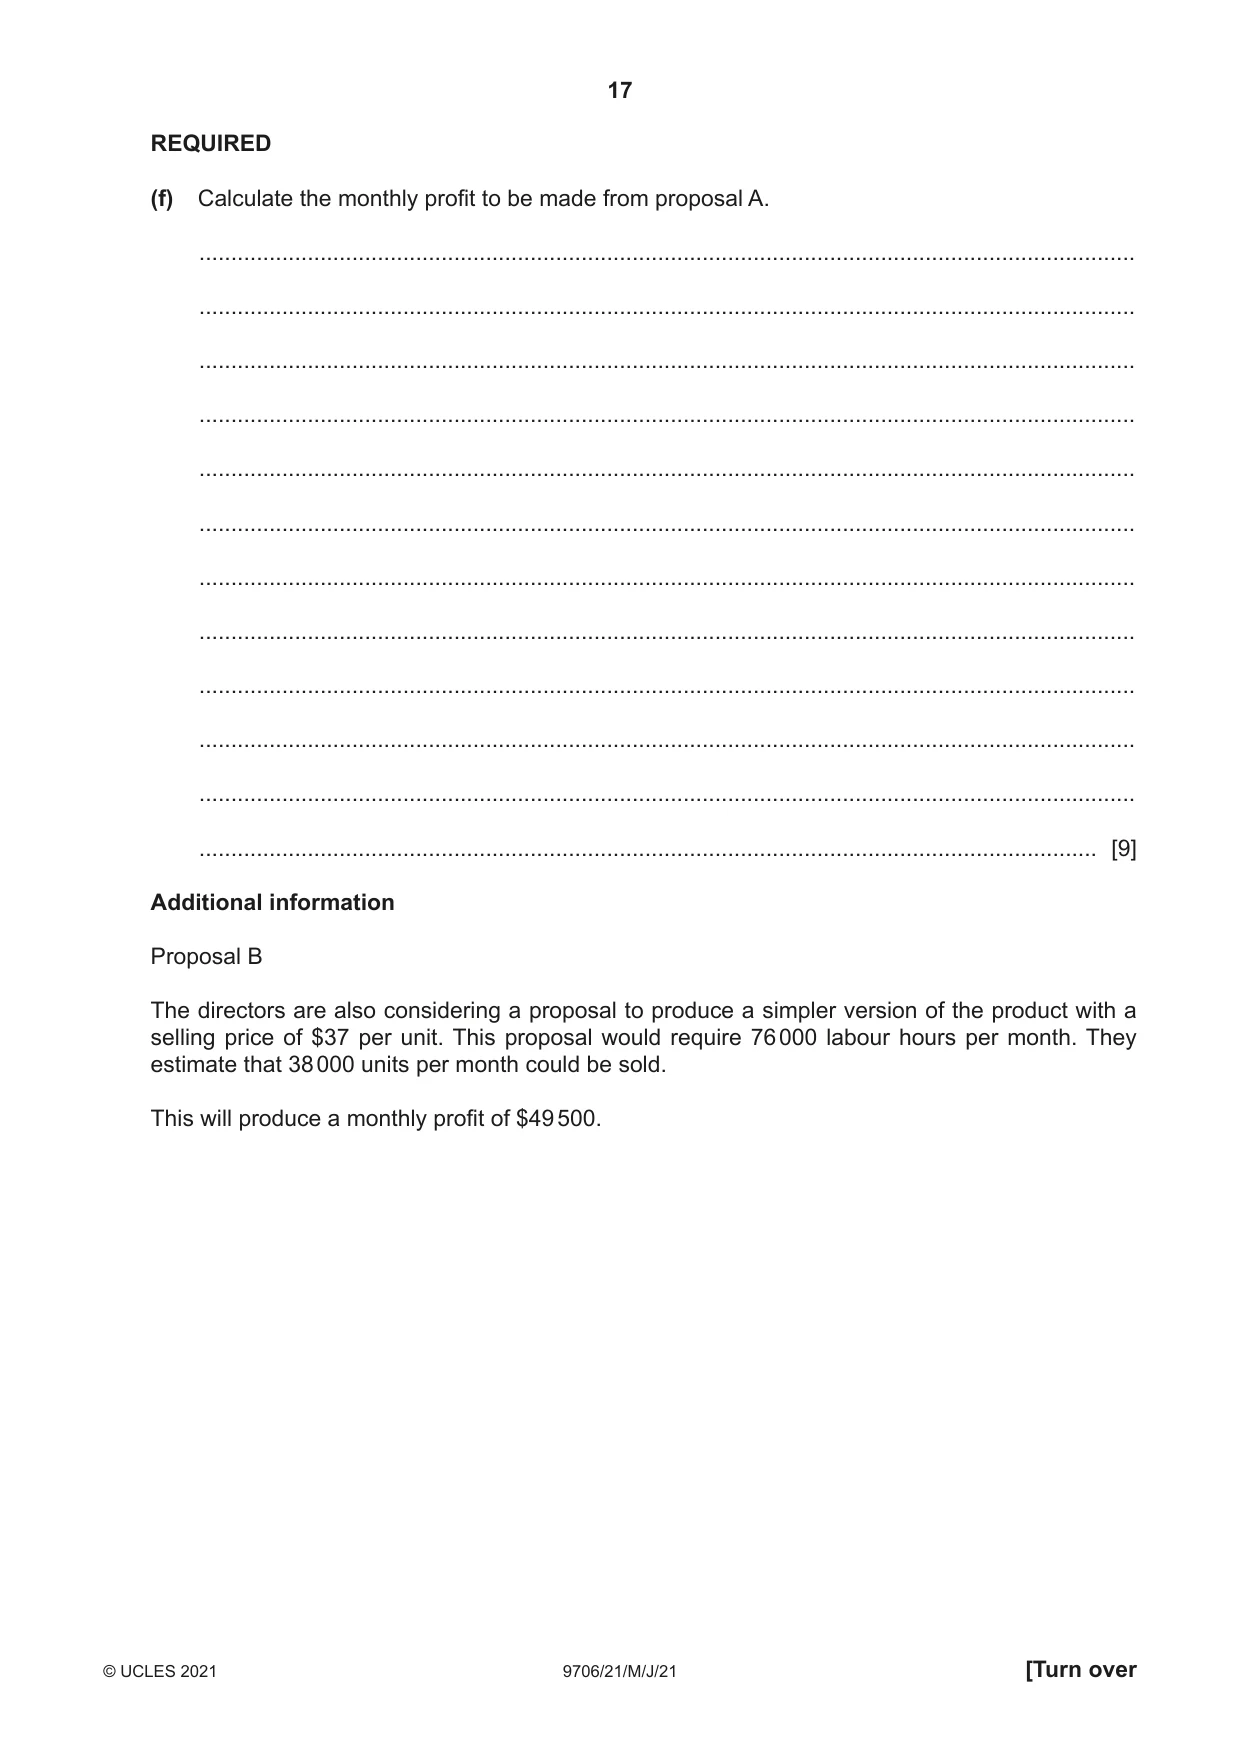
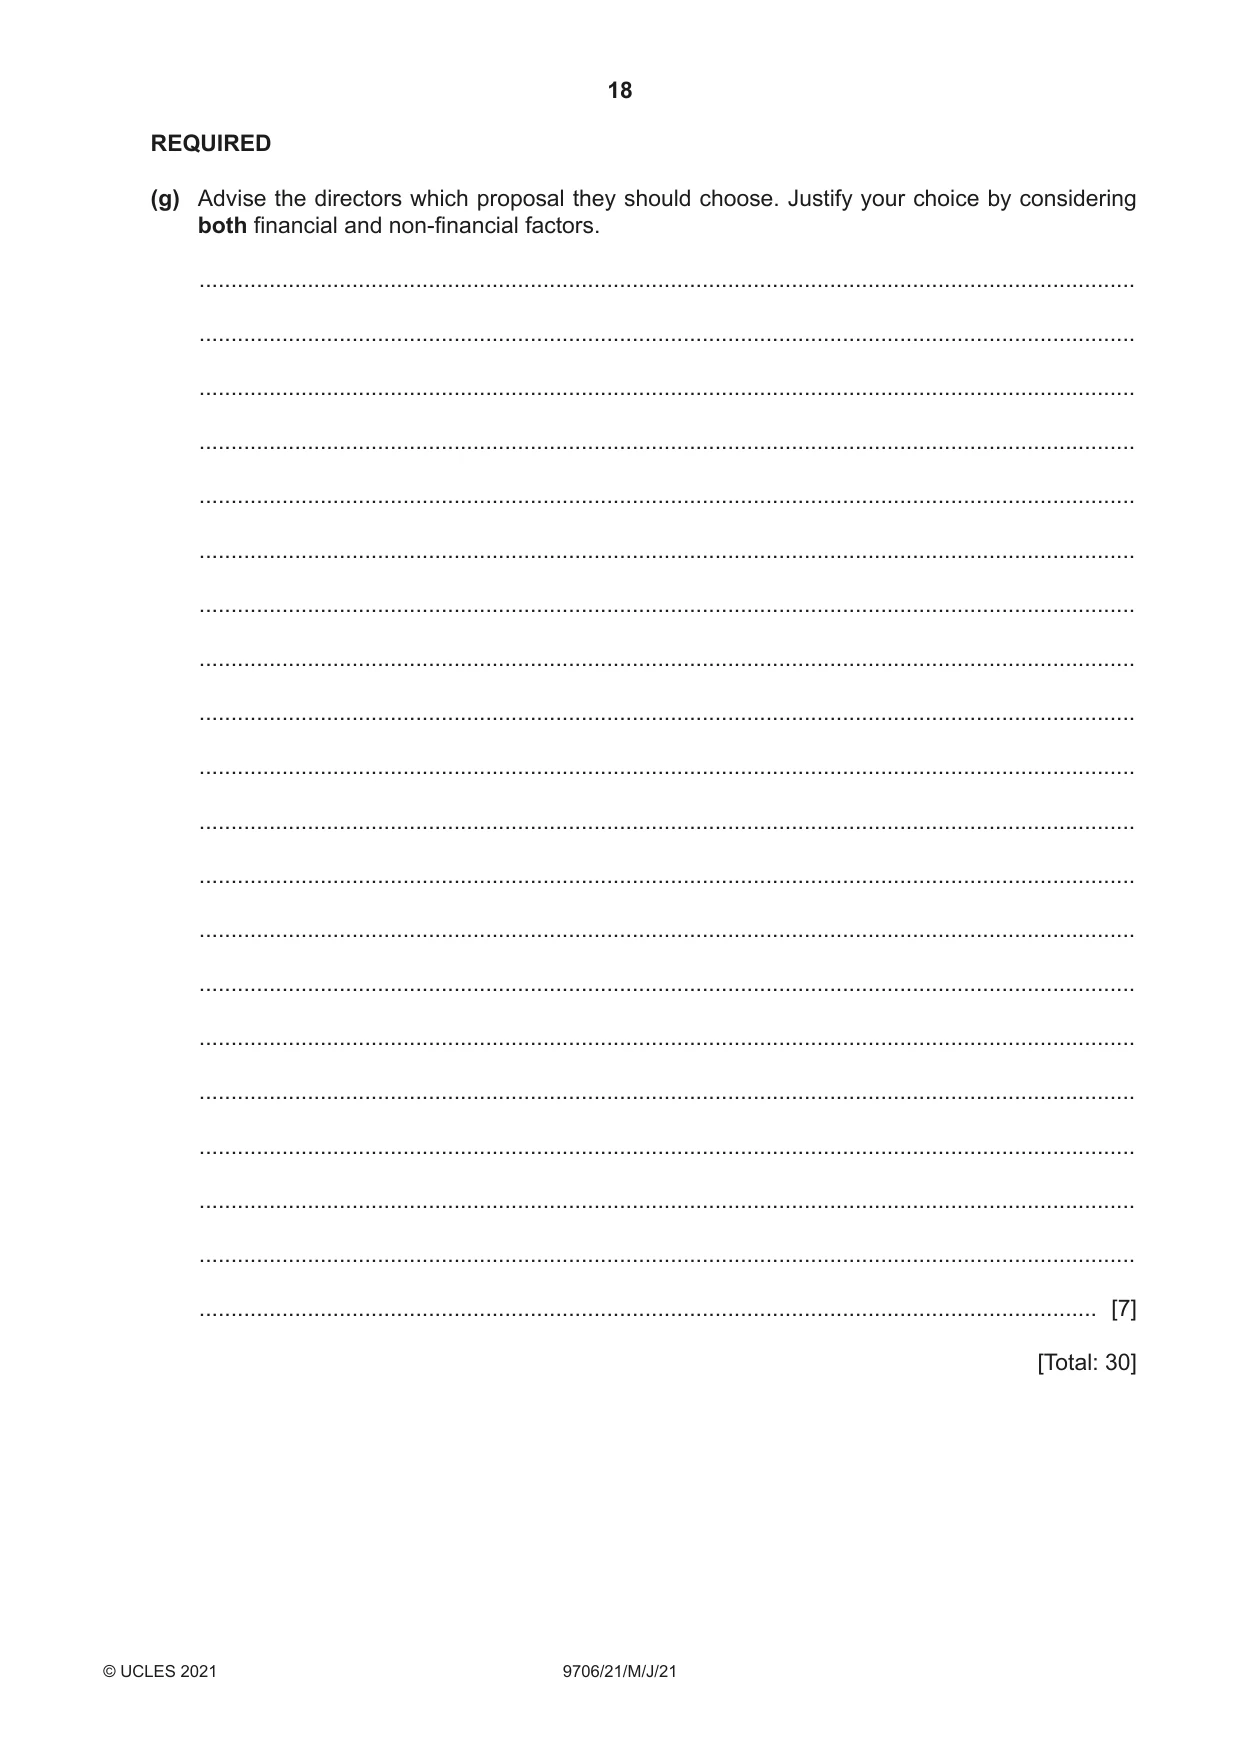
Mark scheme15 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Suyin owns a small retail business
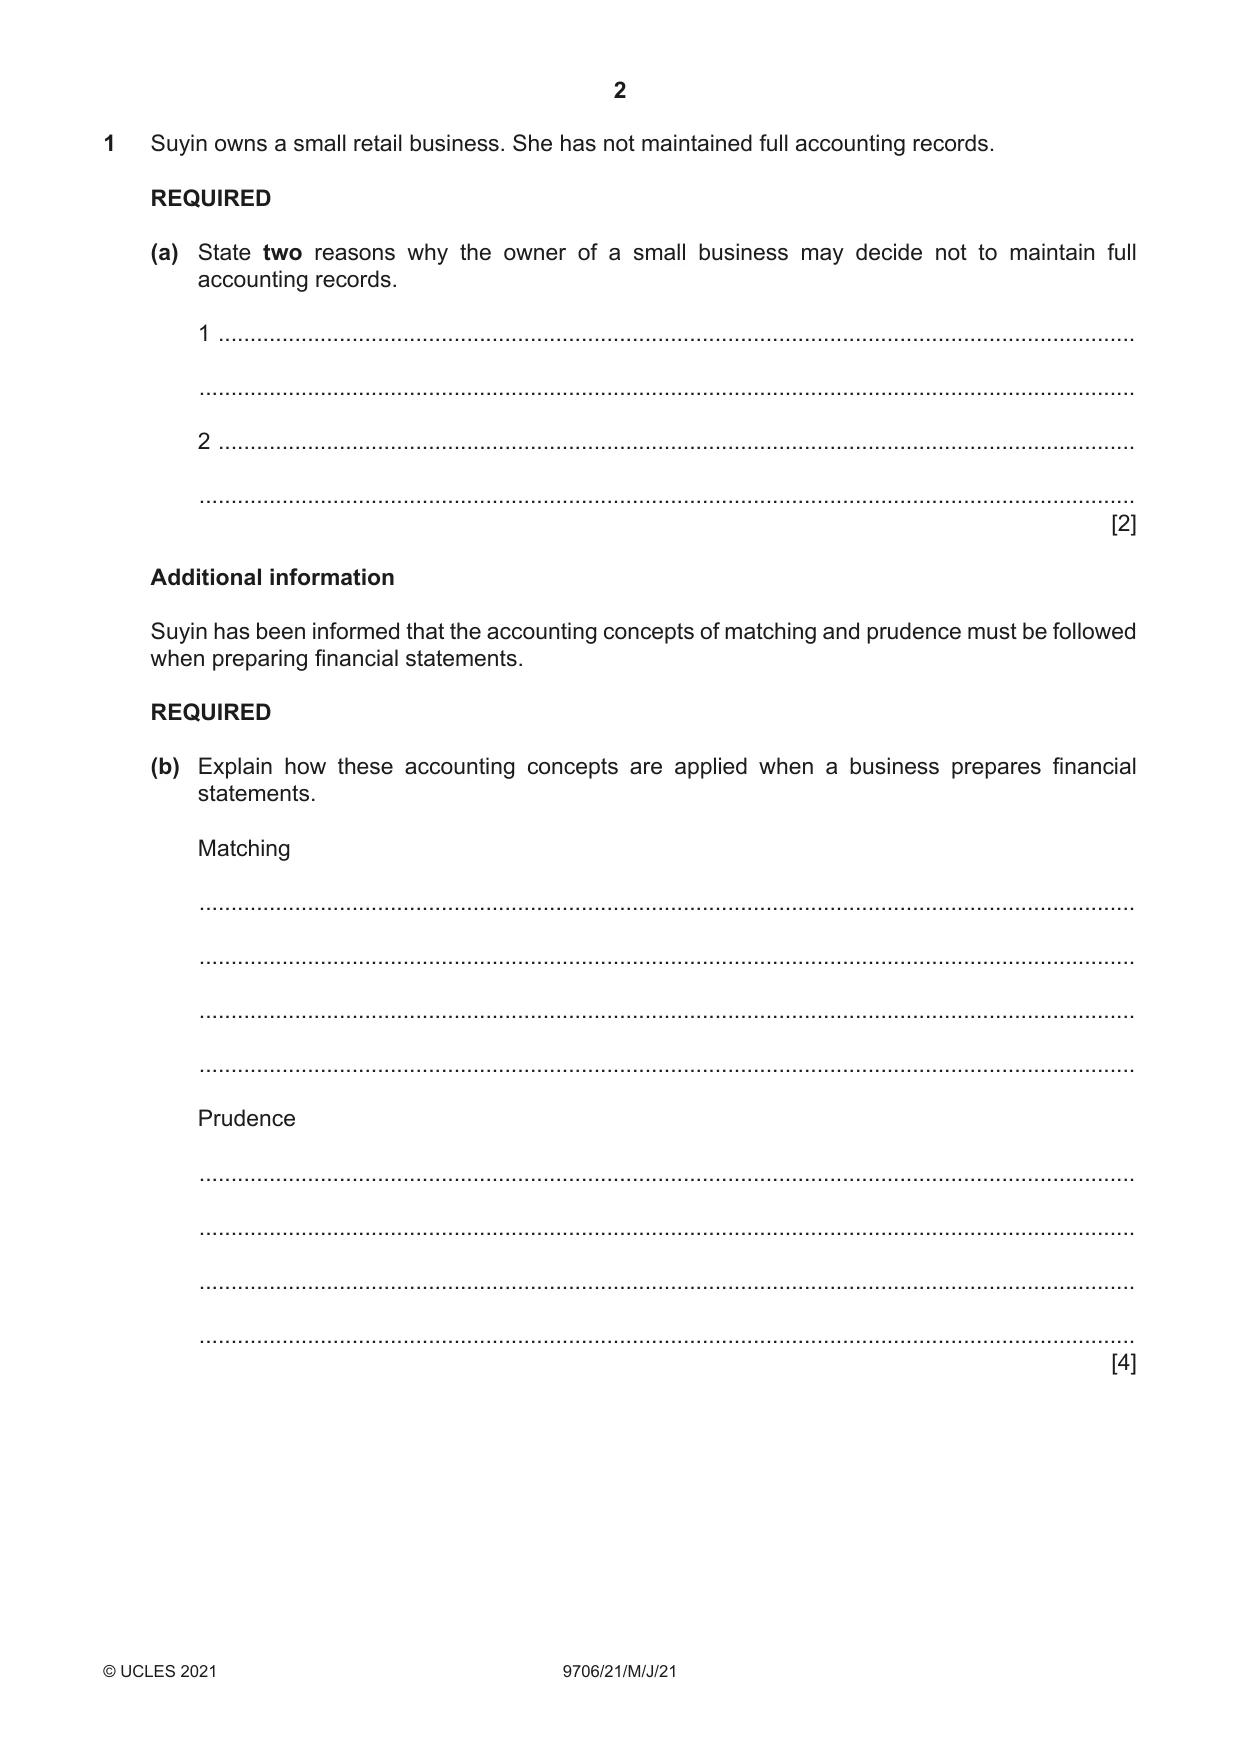
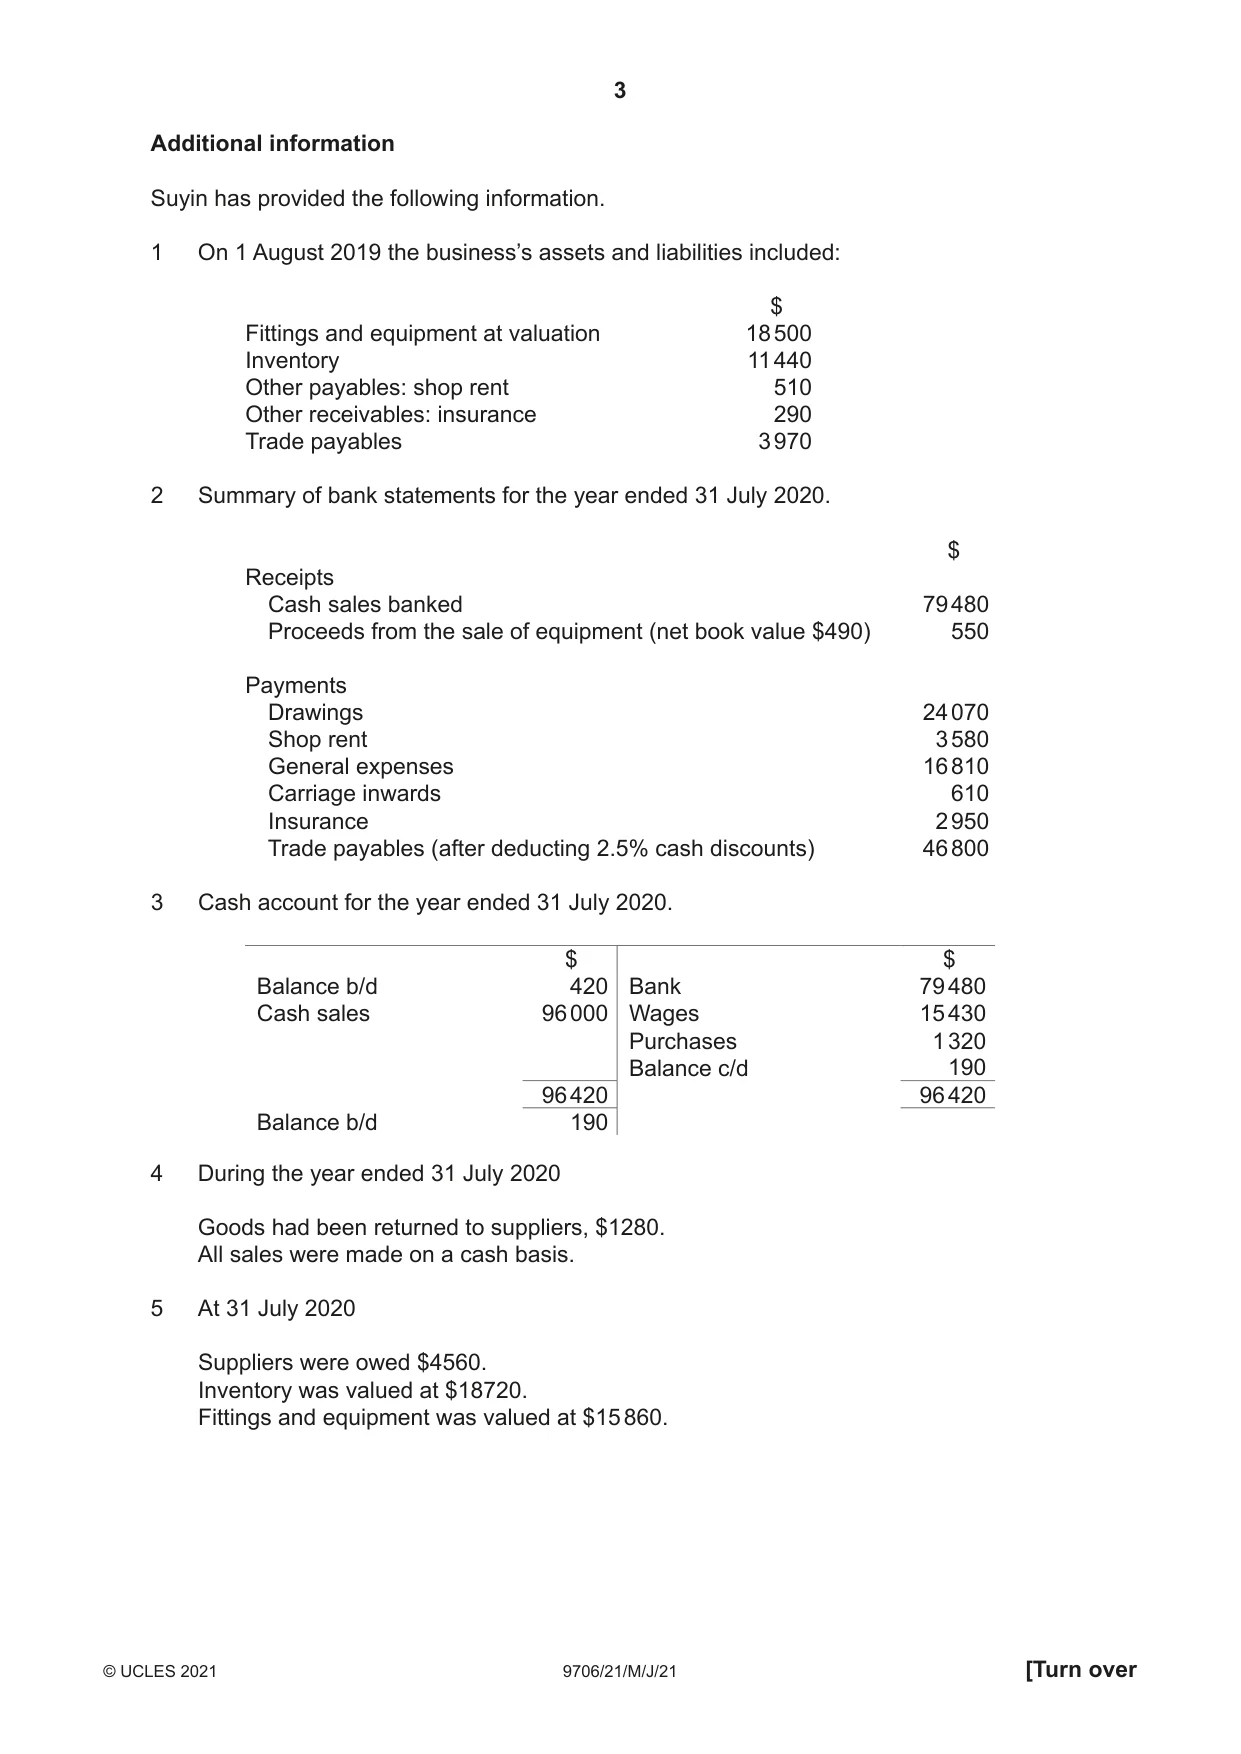
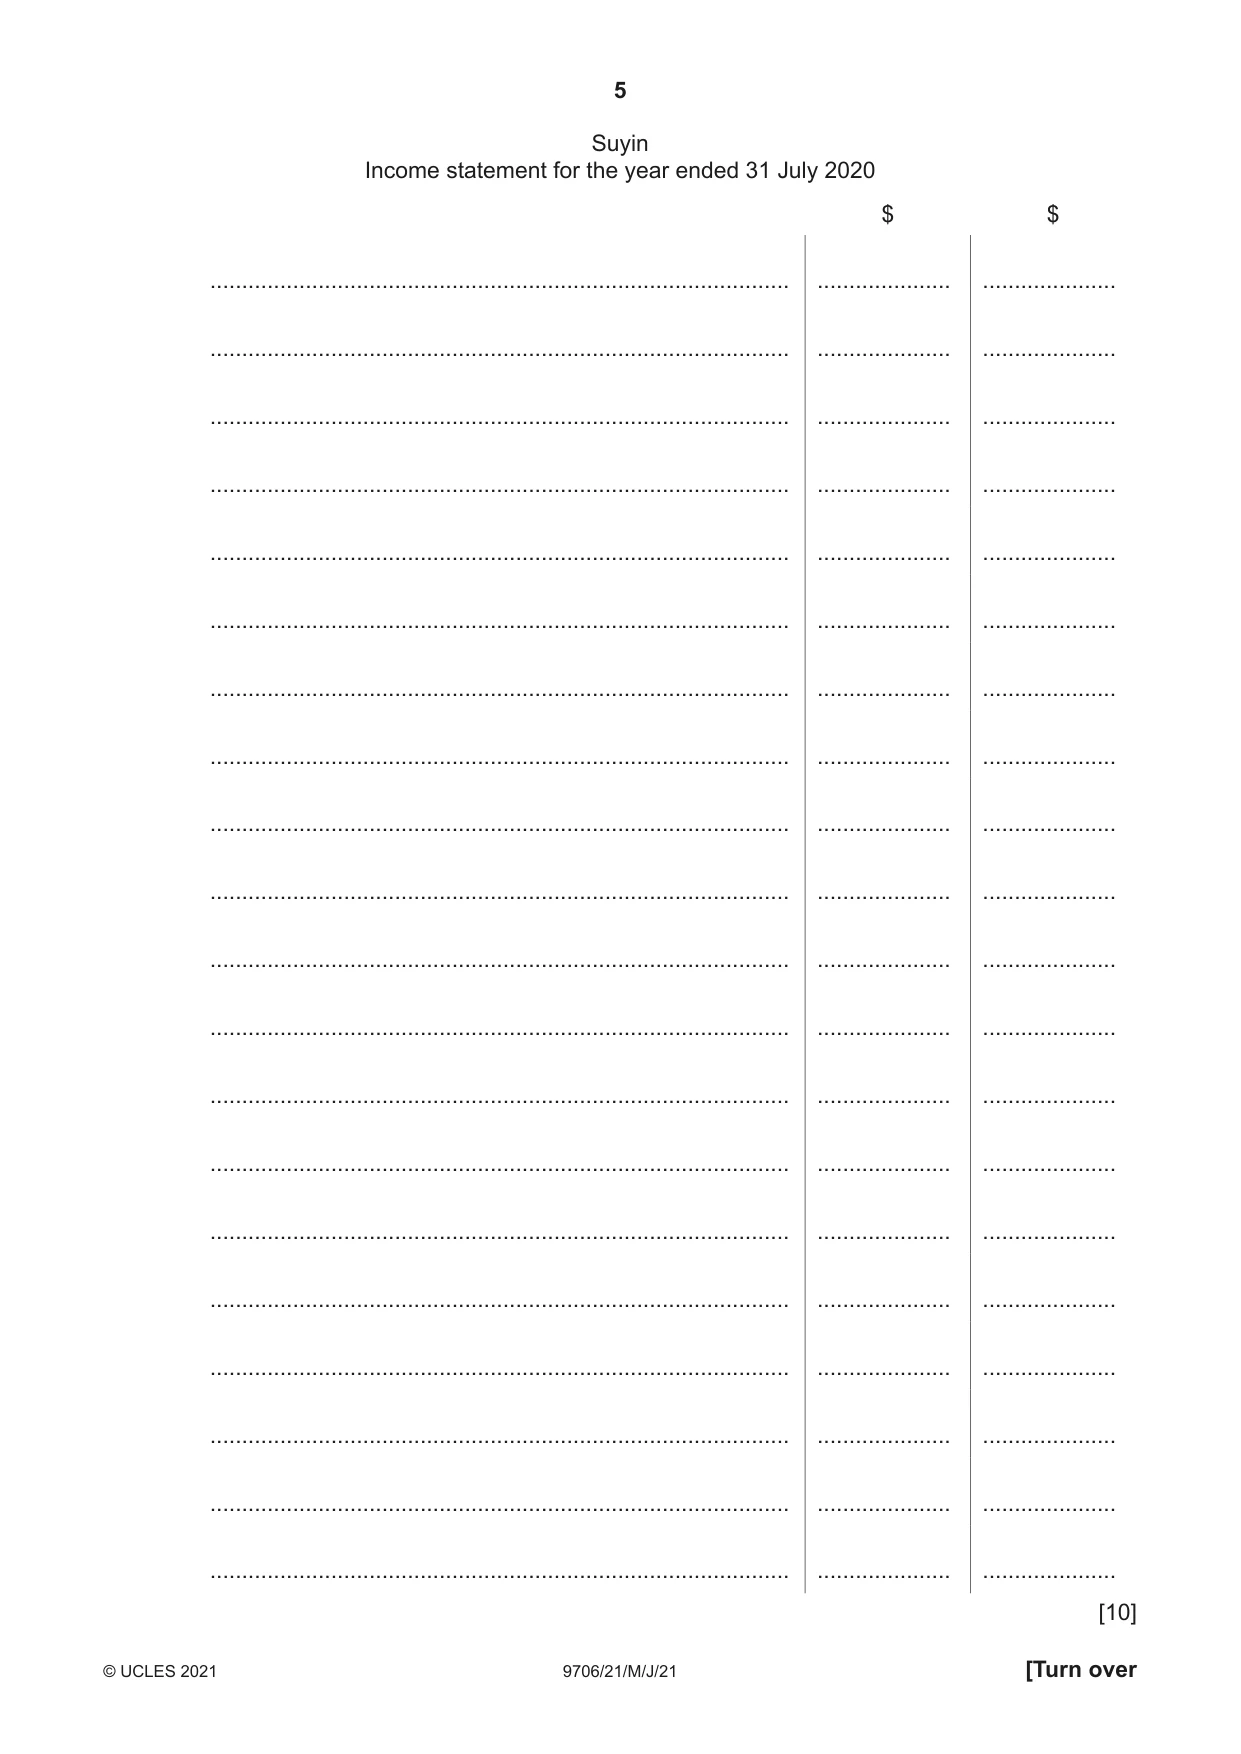
1 Suyin owns a small retail business. She has not maintained full accounting records. REQUIRED (a) State two reasons why the owner of a small business may decide not to maintain full accounting records. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information Suyin has been informed that the accounting concepts of matching and prudence must be followed when preparing financial statements. REQUIRED (b) Explain how these accounting concepts are applied when a business prepares financial statements. Matching ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Prudence ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] Additional information Suyin has provided the following information. 1 On 1 August 2019 the business’s assets and liabilities included: $ Fittings and equipment at valuation 18 500 Inventory 11 440 Other payables: shop rent 510 Other receivables: insurance 290 Trade payables 3 970
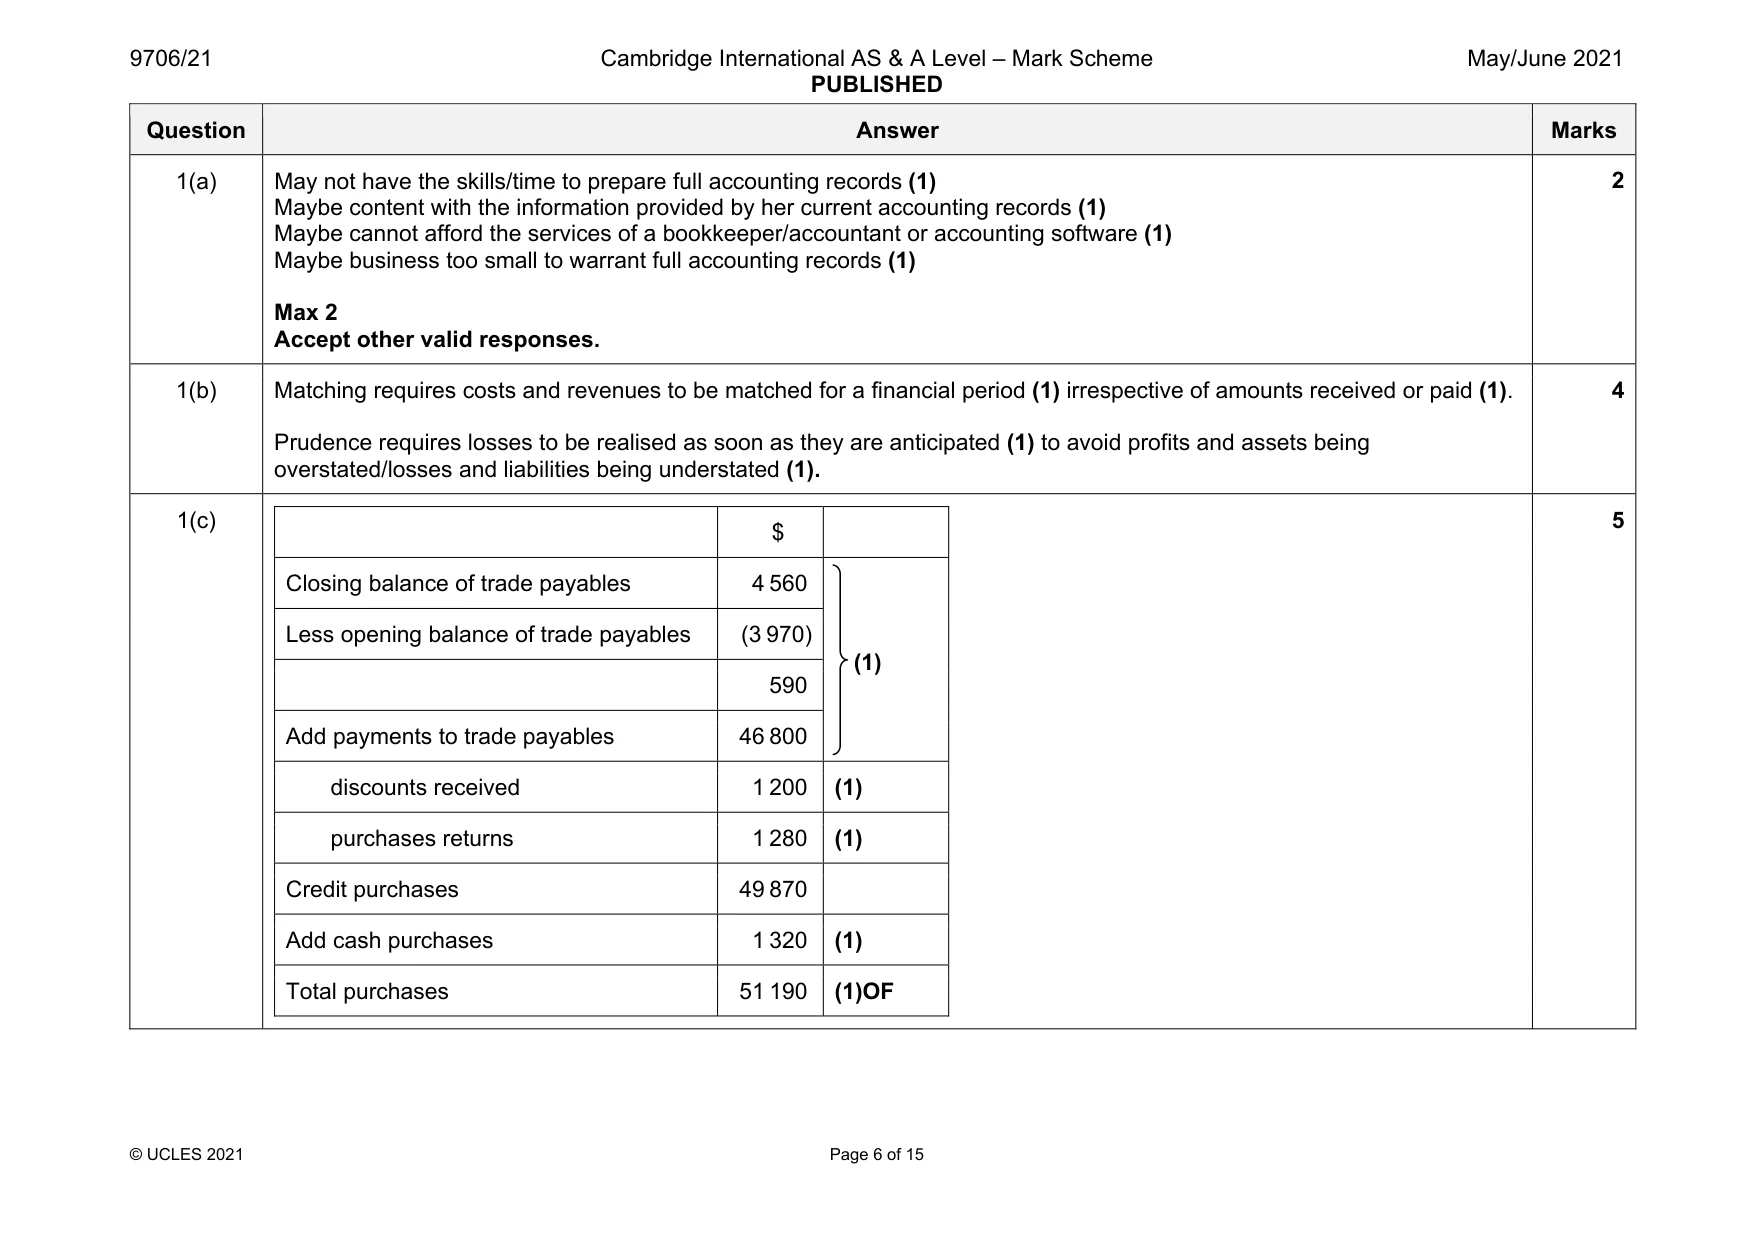
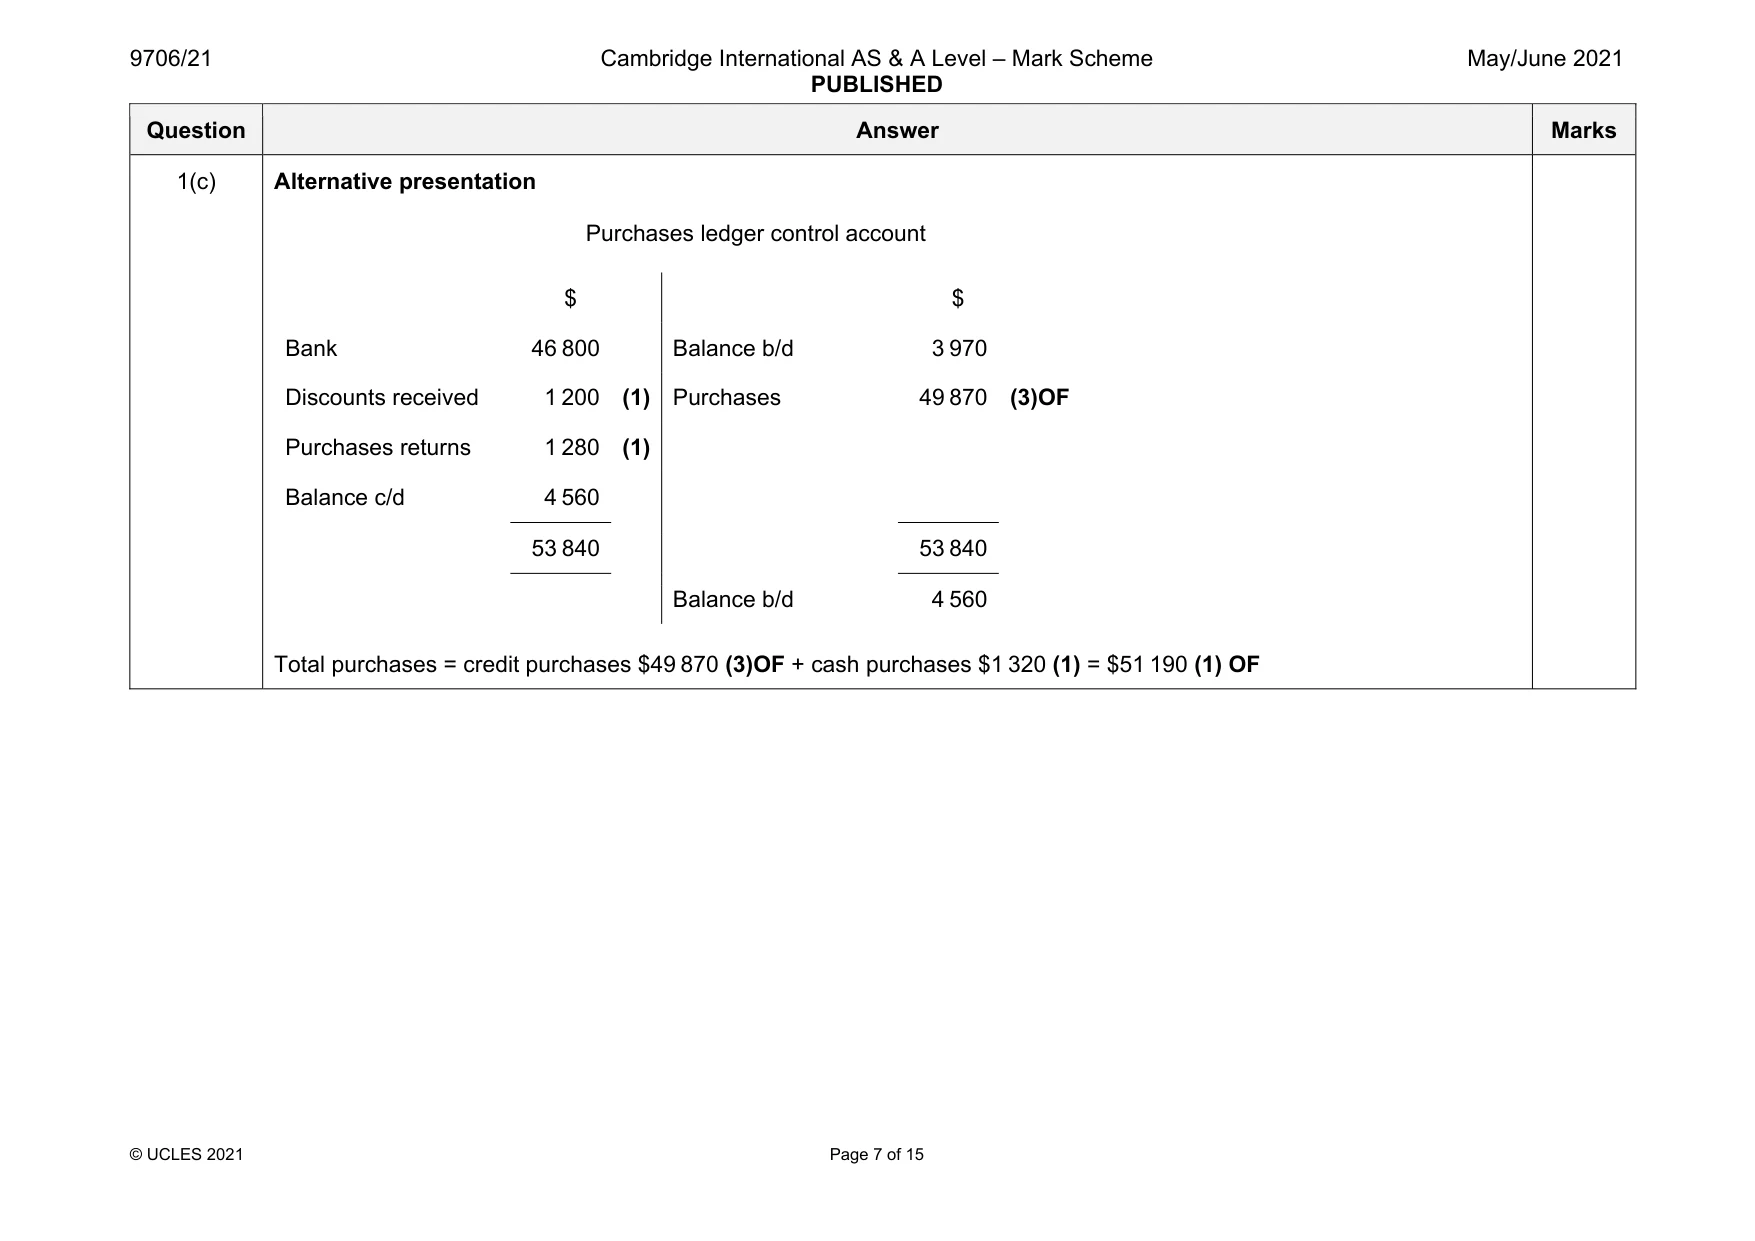
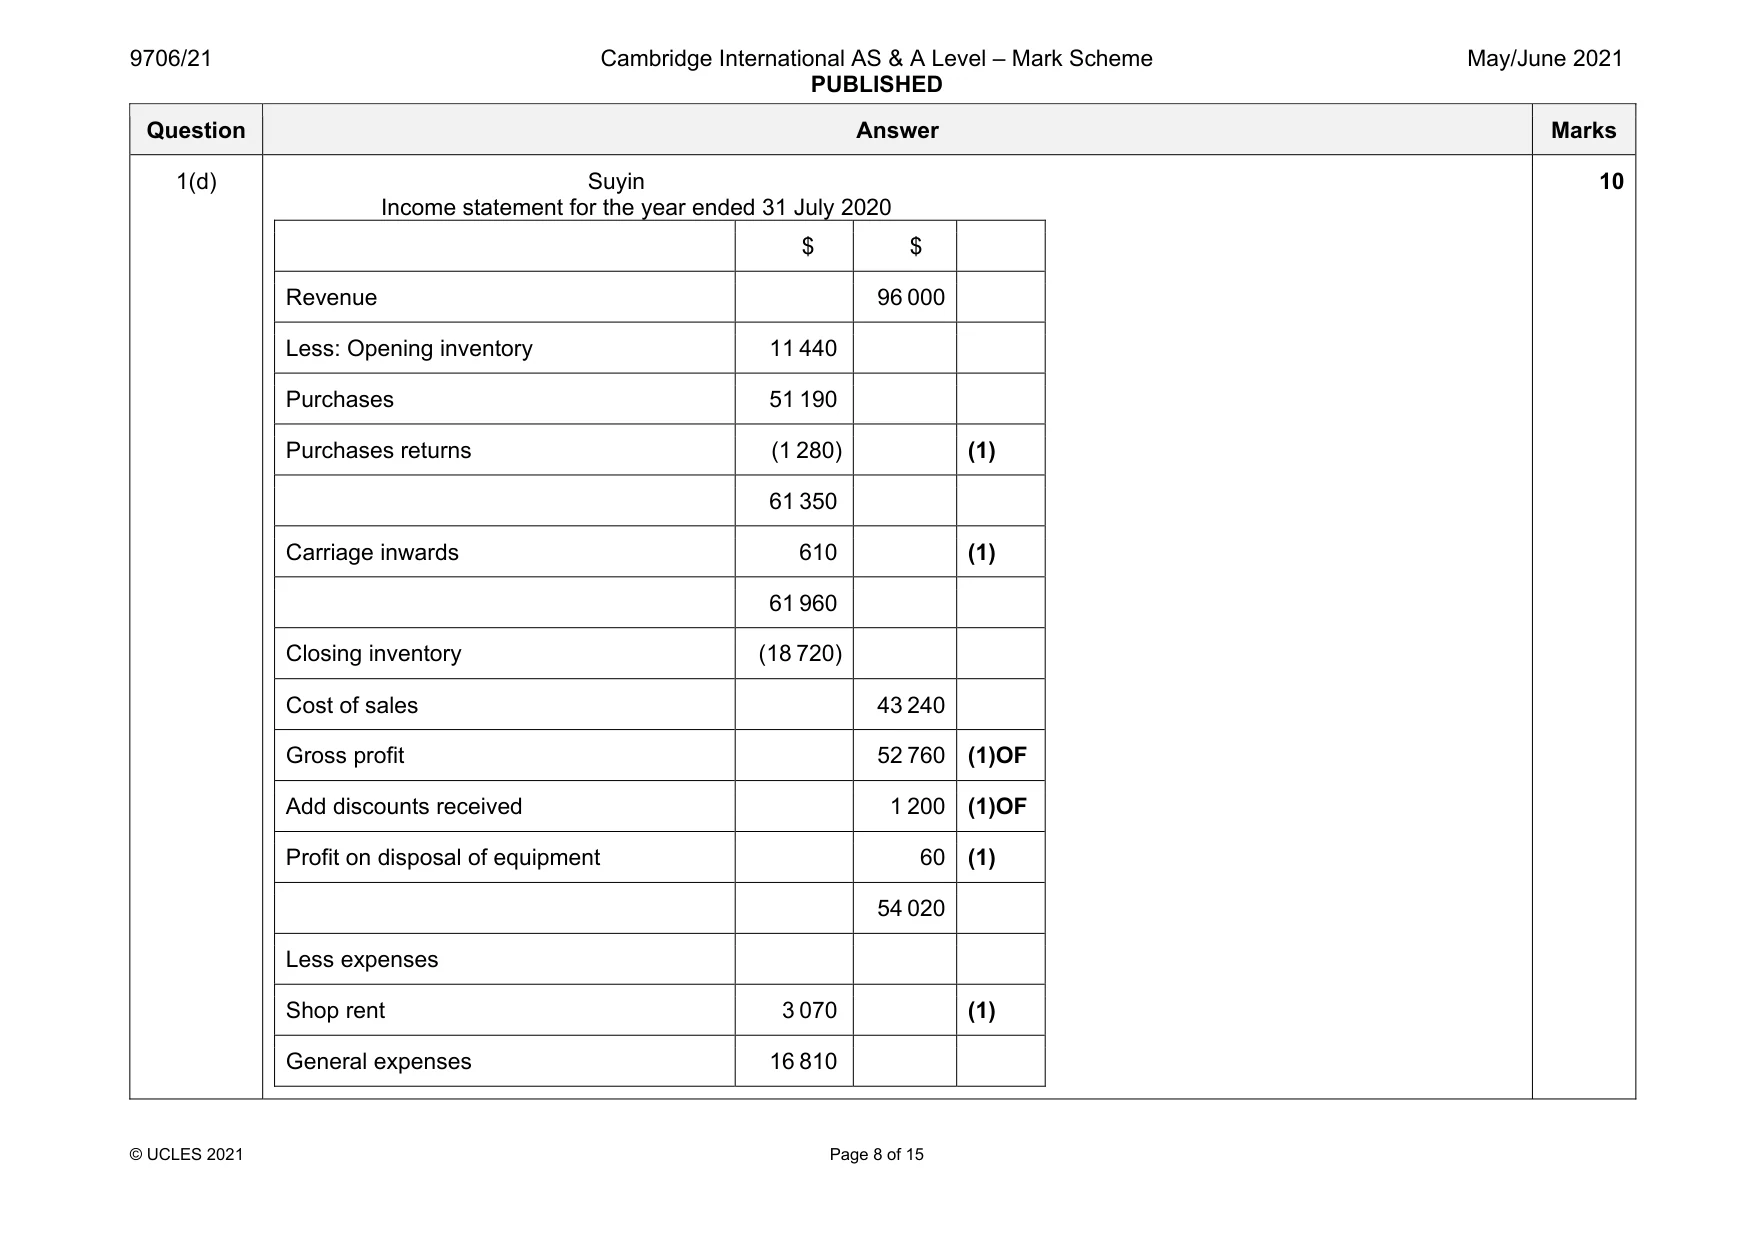
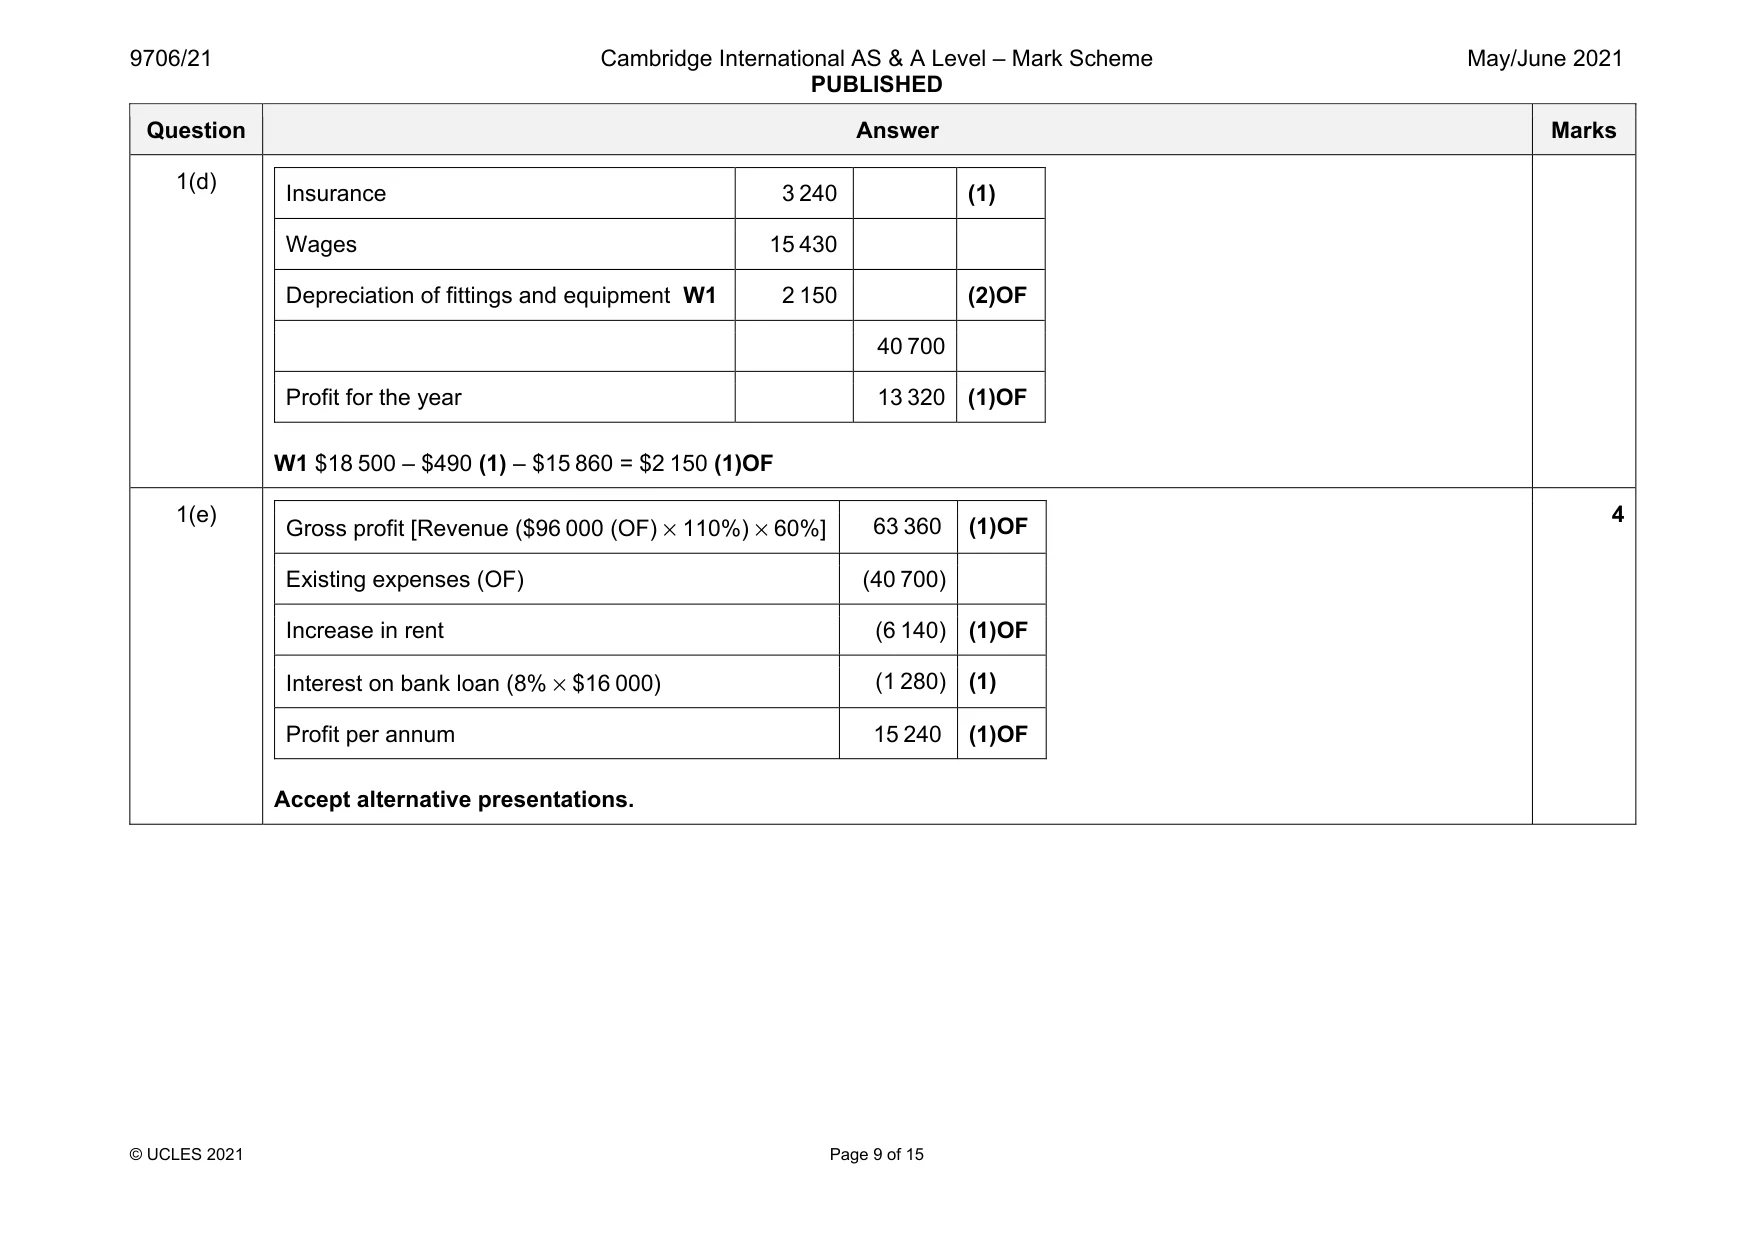
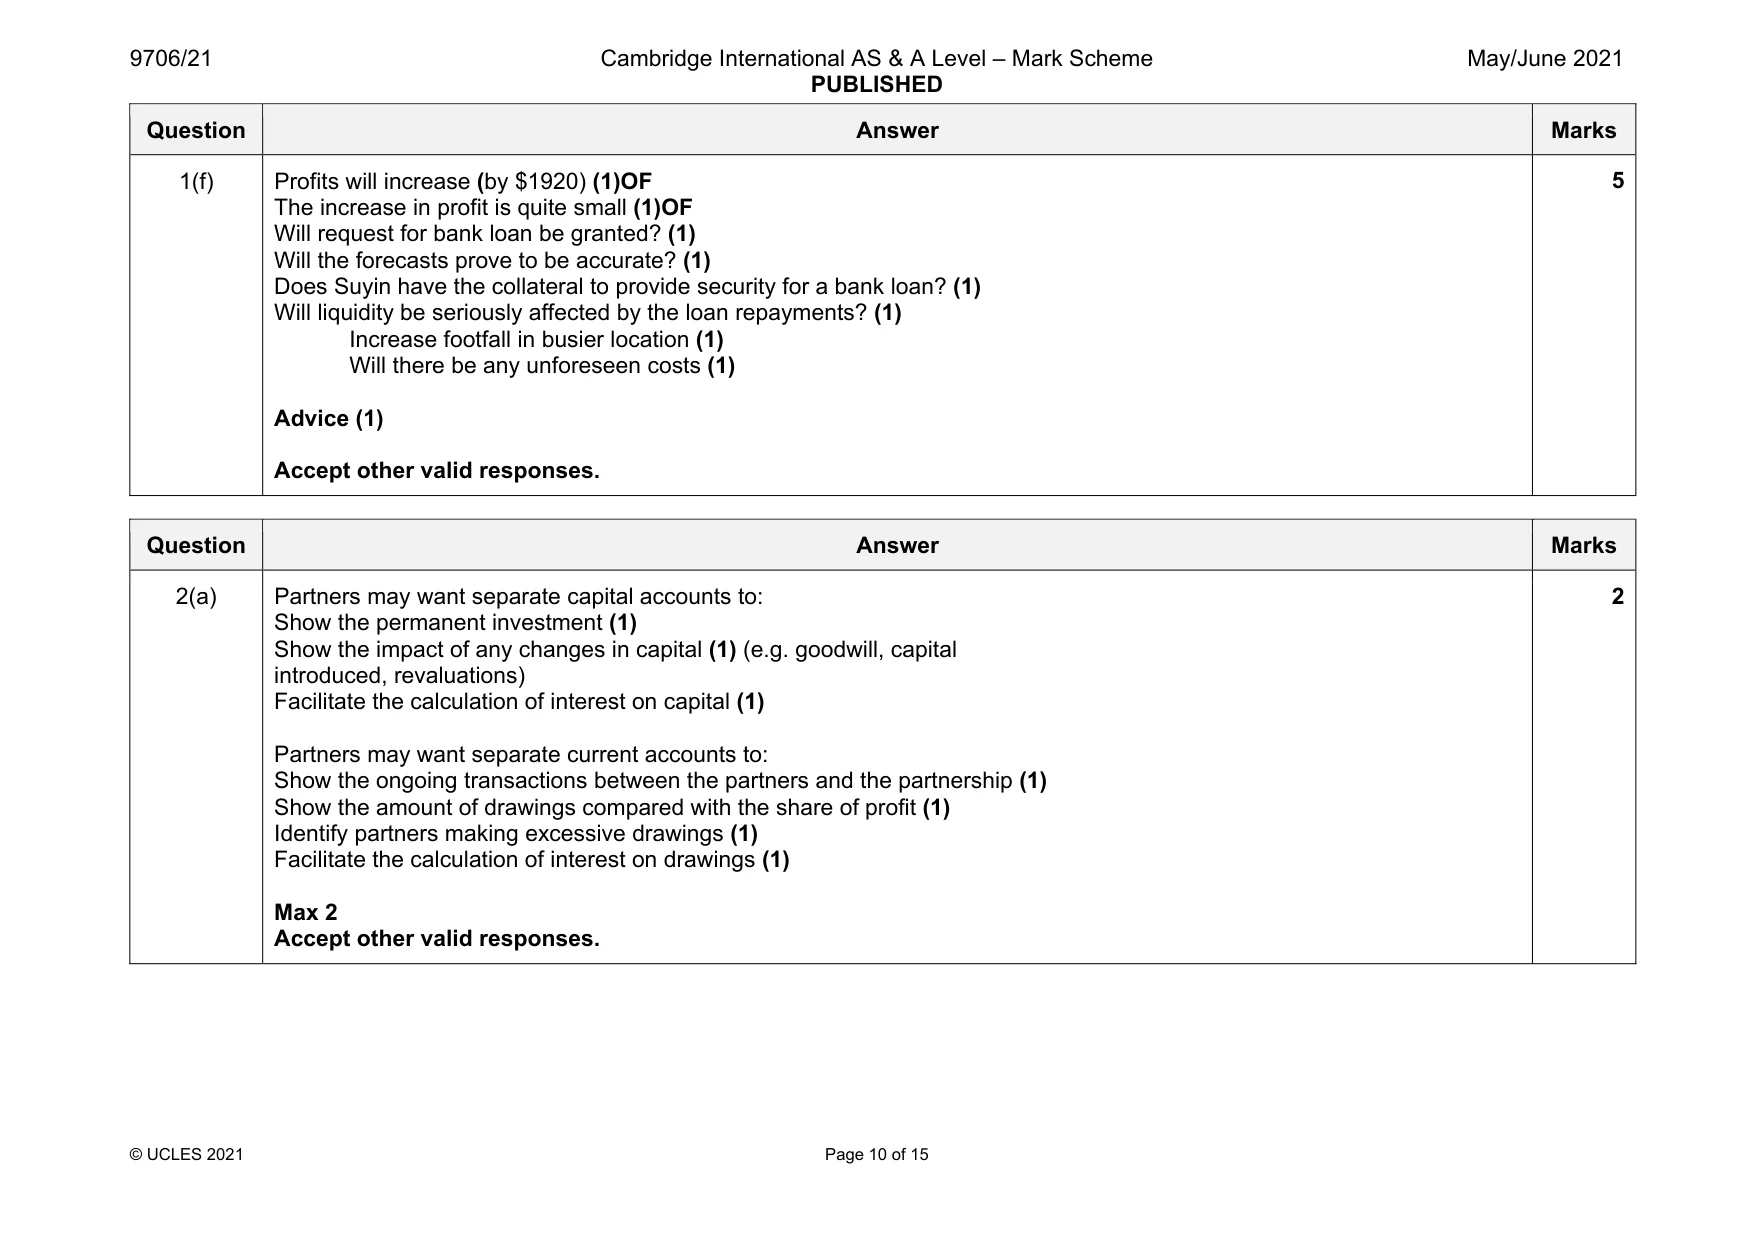
Mark scheme: 1(a) May not have the skills/time to prepare full accounting records (1) Maybe content with the information provided by her current accounting records (1) Maybe cannot afford the services of a bookkeeper/accountant or accounting software (1) Maybe business too small to warrant full accounting records (1) Max 2 Accept other valid responses. 1(b) Matching requires costs and revenues to be matched for a financial period (1) irrespective of amounts received or paid (1). Prudence requires losses to be realised as soon as they are anticipated (1) to avoid profits and assets being overstated/losses and liabilities being understated (1). 4 1(c) $ Closing balance of trade payables 4 560 (1) Less opening balance of trade payables (3 970) 590 Add payments to trade payables 46 800 discounts received 1 200 (1) purchases returns 1 280 (1) Credit purchases 49 870 Add cash purchases 1 320 (1) Total purchases 51 190 (1)OF 5 Question Answer Marks 1(c) Alternative presentation Purchases ledger control account $ $ Bank 46 800 Balance b/d 3 970 Discounts received 1 200 (1) Purchases 49 870 (3)OF Purchases returns 1 280 (1) Balance c/d 4 560 53 840 53 840 Balance b/d 4 560 Total purchases = credit purchases $49 870 (3)OF + cash purchases $1 320 (1) = $51 190 (1) OF Question Answer Marks 1(d) Suyin Income statement for the year ended 31 July 2020 $ $ Revenue 96 000 Less: Opening inventory 11 440 Purchases 51 190 Purchases returns (1 280) (1) 61 350 Carriage inwards 610 (1) 61 960 Closing inventory (18 720) Cost of sales 43 240 Gross profit 52 760 (1)OF Add discounts received 1 200 (1)OF Profit on disposal of equipment 60 (1) 54 020 Less expenses Shop rent 3 070 (1) General expenses 16 810 10 Question Answer Marks 1(d) Insurance 3 240 (1) Wages 15 430 Depreciation of fittings and equipment W1 2 150 (2)OF 40 700 Profit for the year 13 320 (1)OF W1 $18 500 – $490 (1) – $15 860 = $2 150 (1)OF 1(e) Gross profit [Revenue ($96 000 (OF) × 110%) × 60%] 63 360 (1)OF Existing expenses (OF) (40 700) Increase in rent (6 140) (1)OF Interest on bank loan (8% × $16 000) (1 280) (1) Profit per annum 15 240 (1)OF Accept alternative presentations. 4 Question Answer Marks 1(f) Profits will increase (by $1920) (1)OF The increase in profit is quite small (1)OF Will request for bank loan be granted? (1) Will the forecasts prove to be accurate? (1) Does Suyin have the collateral to provide security for a bank loan? (1) Will liquidity be seriously affected by the loan repayments? (1) Increase footfall in busier location (1) Will there be any unforeseen costs (1) Advice (1) Accept other valid responses. 5
Q2 · Summary of bank statements for the year ended 31 July 2020
2 Summary of bank statements for the year ended 31 July 2020. $ Receipts Cash sales banked 79 480 Proceeds from the sale of equipment (net book value $490) 550 Payments Drawings 24 070 Shop rent 3 580 General expenses 16 810 Carriage inwards 610 Insurance 2 950 Trade payables (after deducting 2.5% cash discounts) 46 800
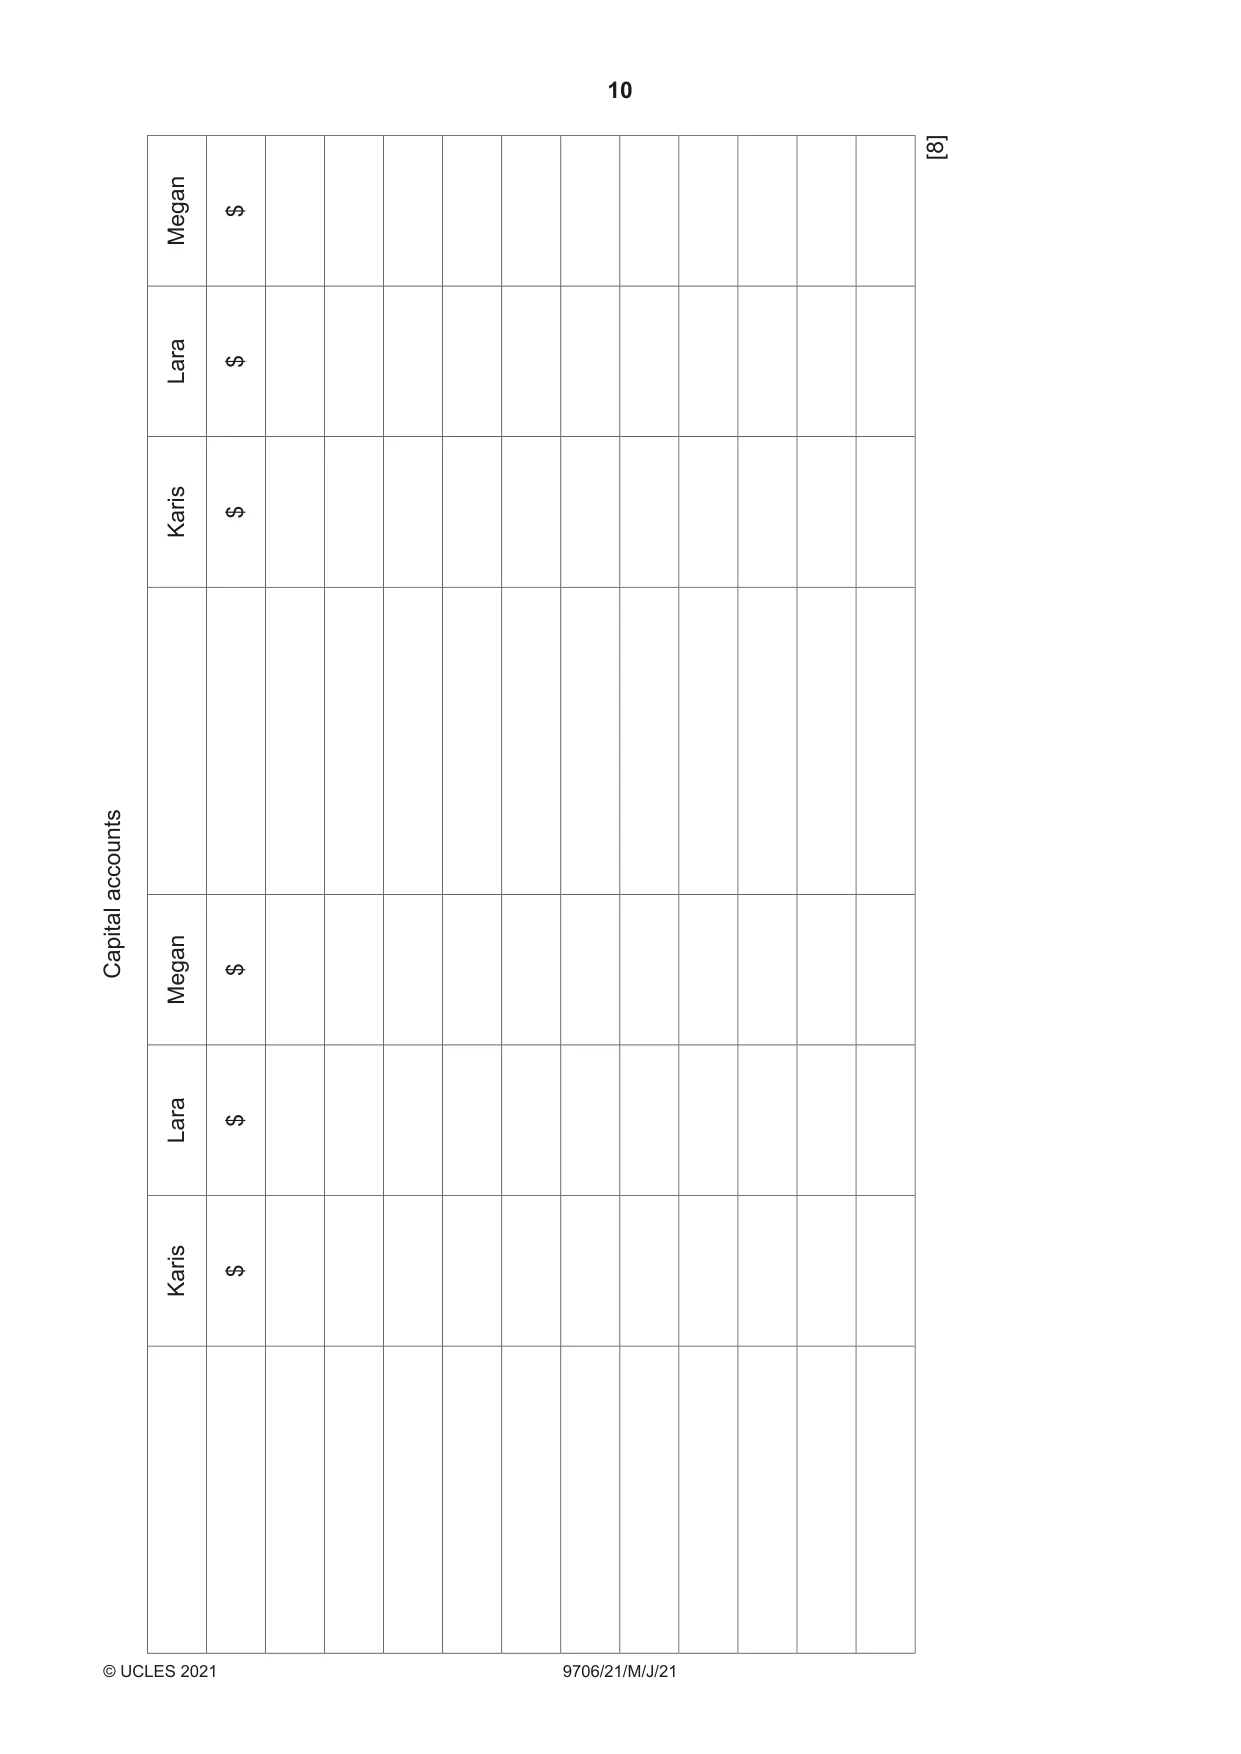
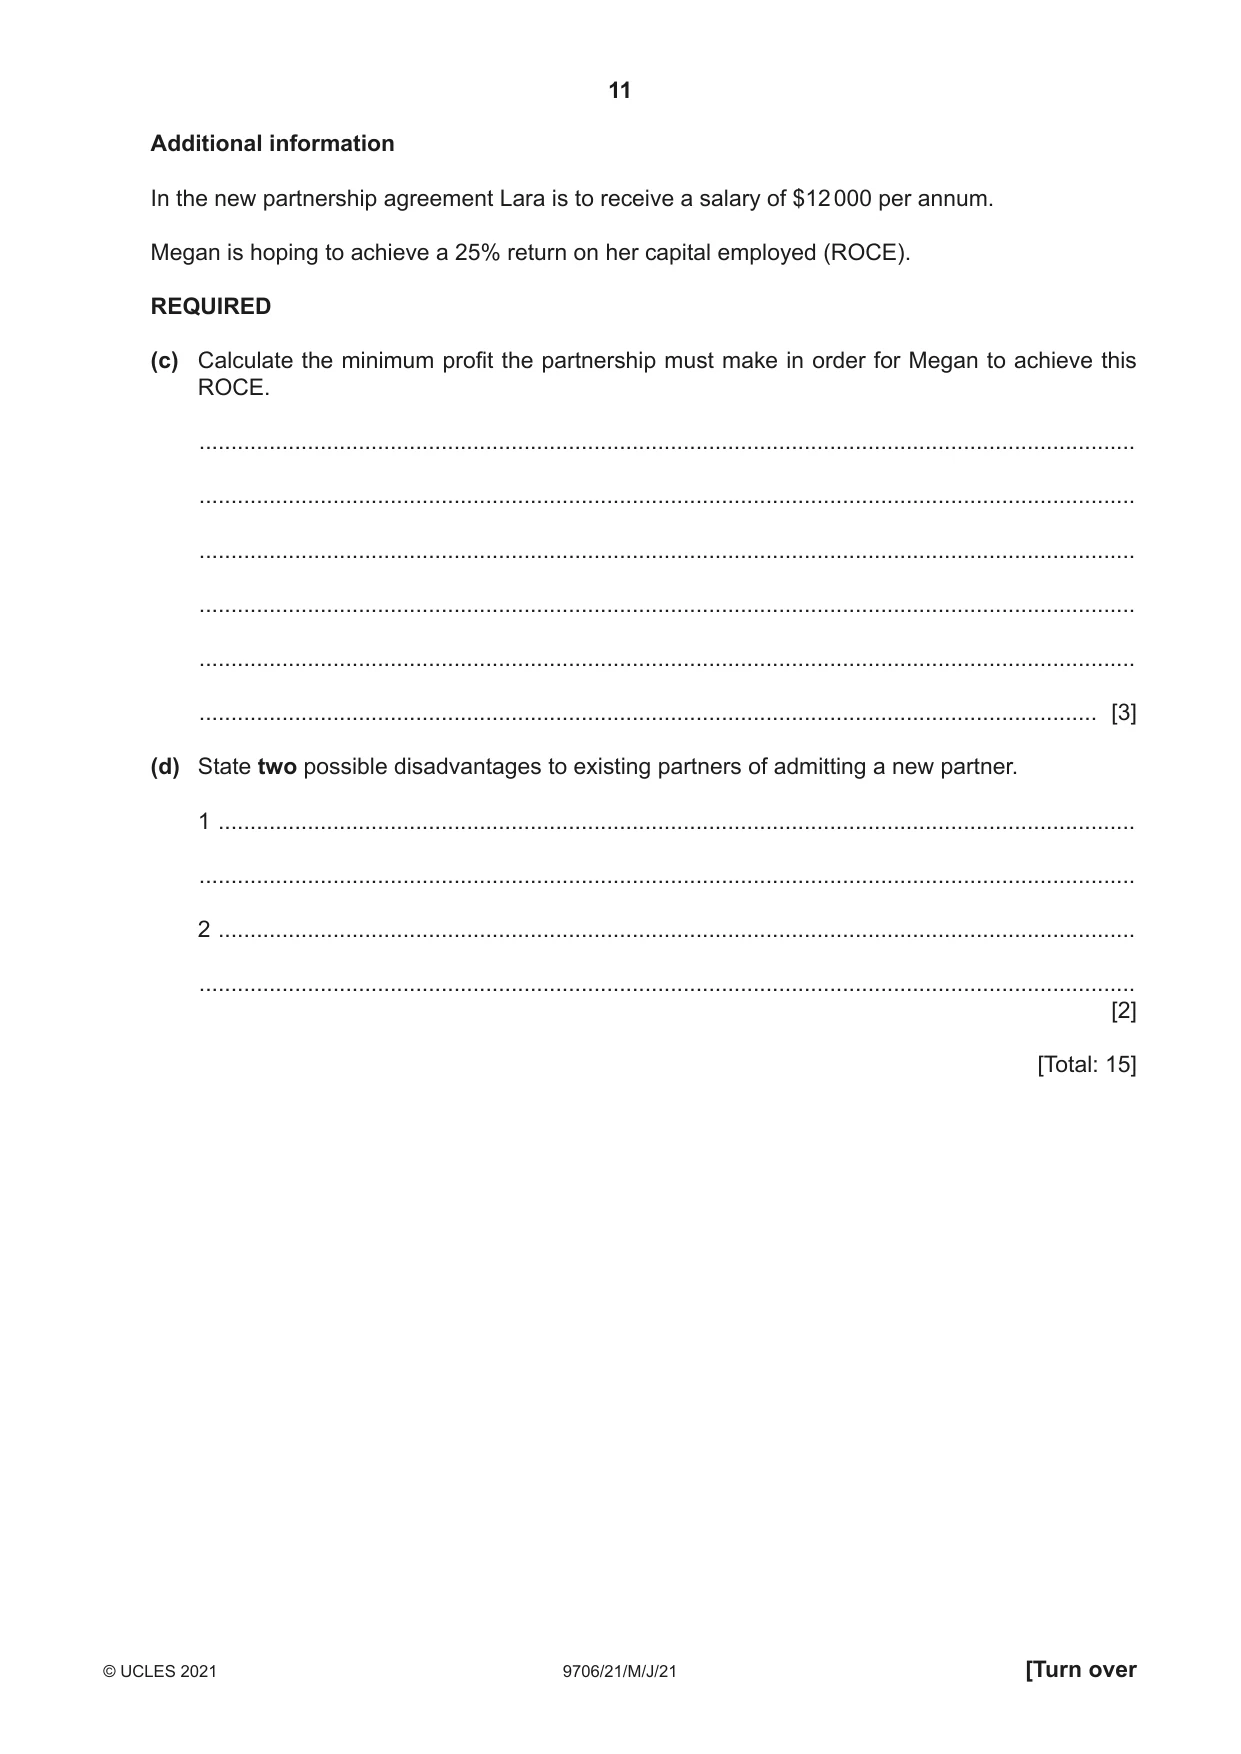
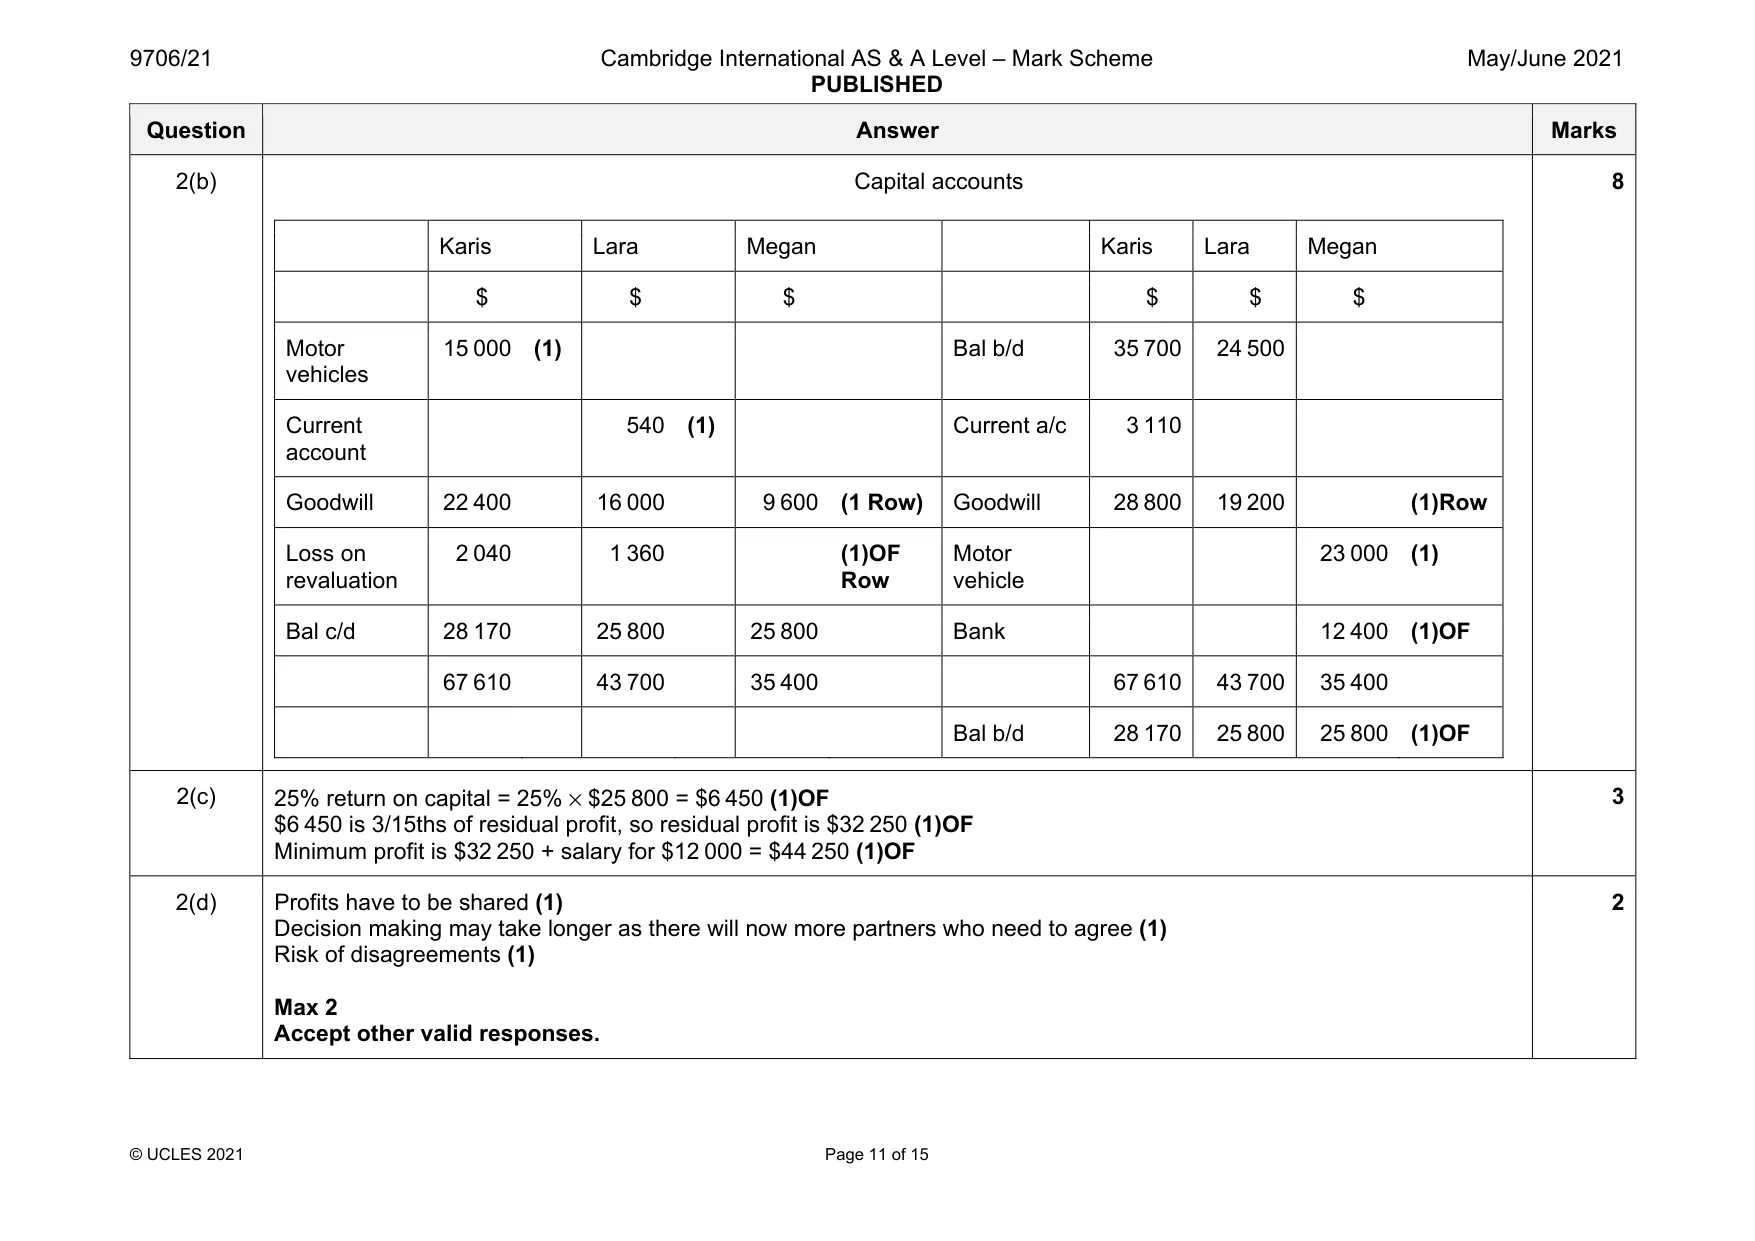
Mark scheme: 2(a) Partners may want separate capital accounts to: Show the permanent investment (1) Show the impact of any changes in capital (1) (e.g. goodwill, capital introduced, revaluations) Facilitate the calculation of interest on capital (1) Partners may want separate current accounts to: Show the ongoing transactions between the partners and the partnership (1) Show the amount of drawings compared with the share of profit (1) Identify partners making excessive drawings (1) Facilitate the calculation of interest on drawings (1) Max 2 Accept other valid responses. Question Answer Marks 2(b) Capital accounts Karis Lara Megan Karis Lara Megan $ $ $ $ $ $ Motor vehicles 15 000 (1) Bal b/d 35 700 24 500 Current account 540 (1) Current a/c 3 110 Goodwill 22 400 16 000 9 600 (1 Row) Goodwill 28 800 19 200 (1)Row Loss on revaluation 2 040 1 360 (1)OF Row Motor vehicle 23 000 (1) Bal c/d 28 170 25 800 25 800 Bank 12 400 (1)OF 67 610 43 700 35 400 67 610 43 700 35 400 Bal b/d 28 170 25 800 25 800 (1)OF 8 2(c) 25% return on capital = 25% × $25 800 = $6 450 (1)OF $6 450 is 3/15ths of residual profit, so residual profit is $32 250 (1)OF Minimum profit is $32 250 + salary for $12 000 = $44 250 (1)OF 3 2(d) Profits have to be shared (1) Decision making may take longer as there will now more partners who need to agree (1) Risk of disagreements (1) Max 2 Accept other valid responses. 2
Q3 · Cash account for the year ended 31 July 2020
3 Cash account for the year ended 31 July 2020. $ $ Balance b/d 420 Bank 79 480 Cash sales 96 000 Wages 15 430 Purchases 1 320 Balance c/d 190 96 420 96 420 Balance b/d 190
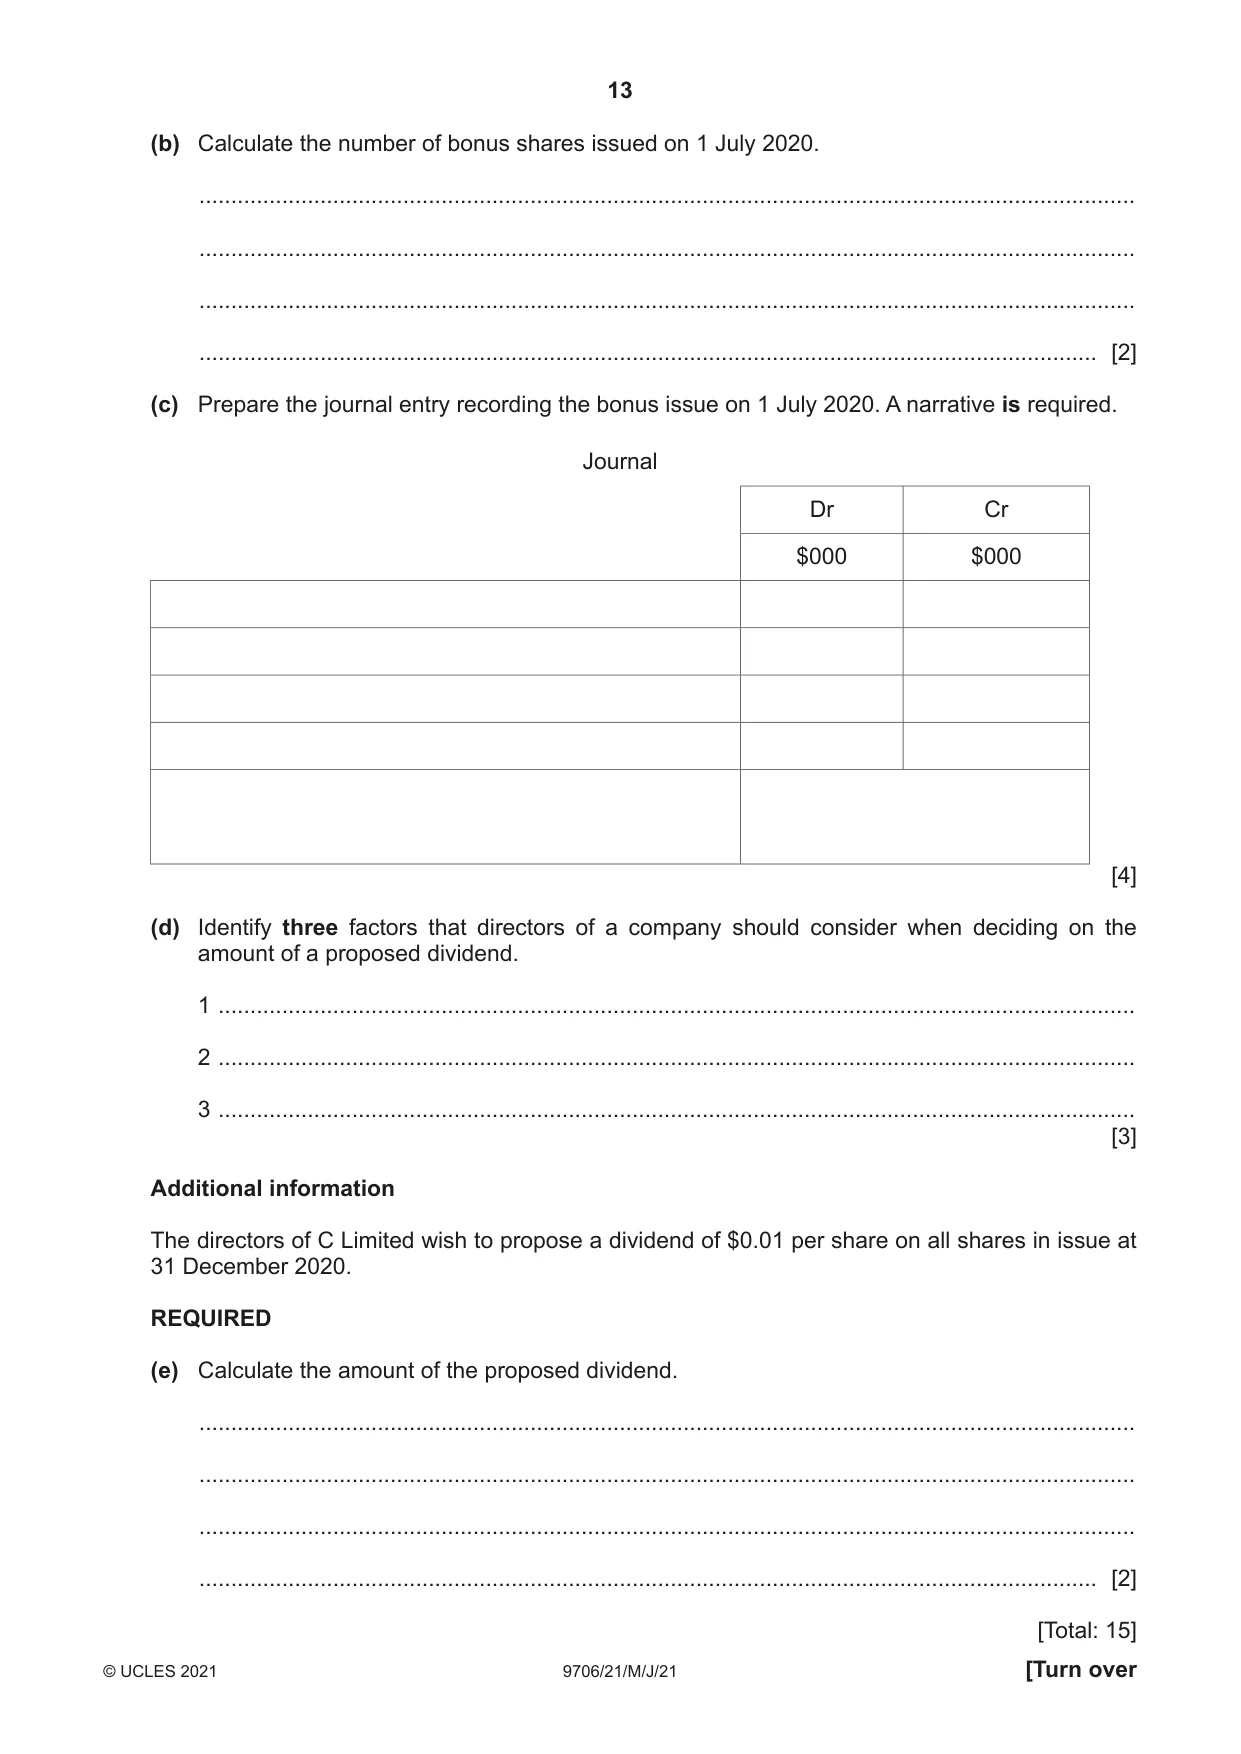
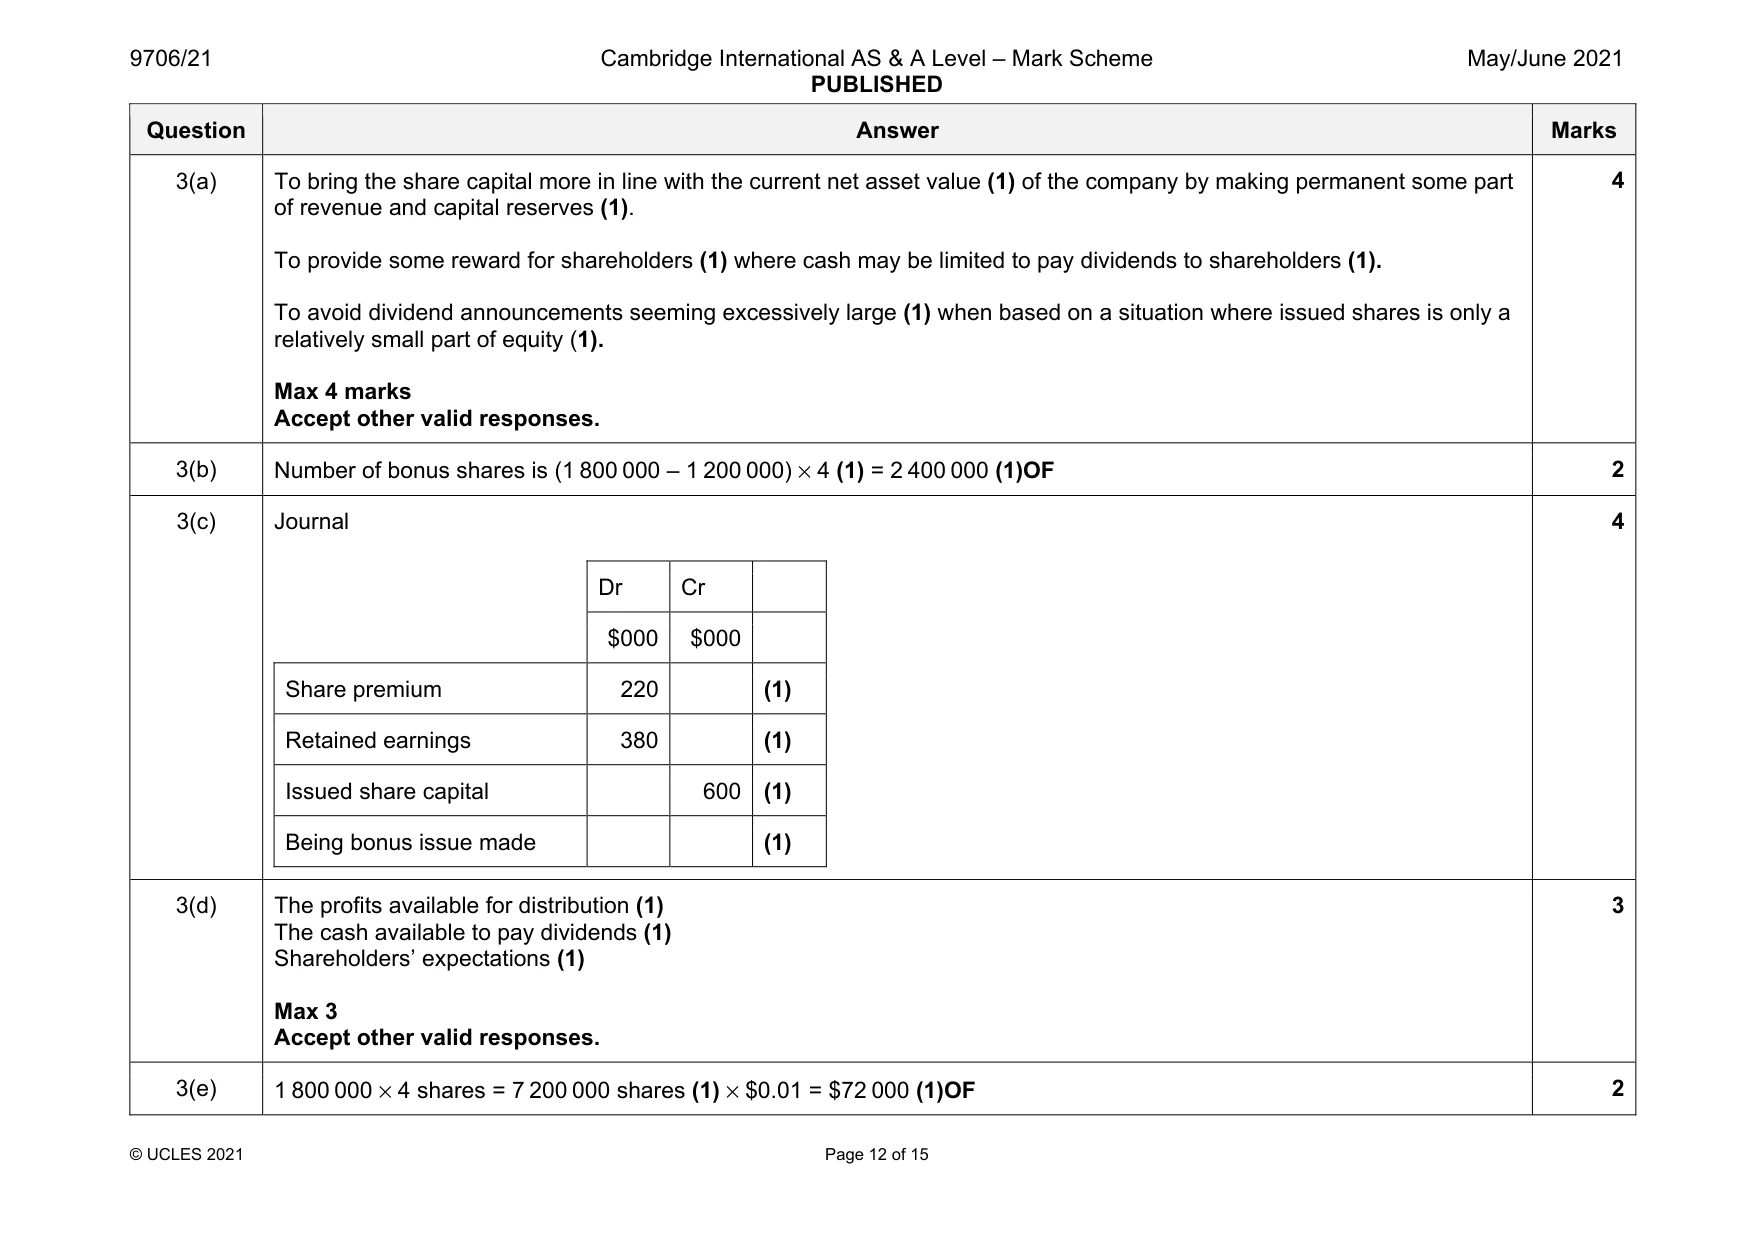
Mark scheme: 3(a) To bring the share capital more in line with the current net asset value (1) of the company by making permanent some part of revenue and capital reserves (1). To provide some reward for shareholders (1) where cash may be limited to pay dividends to shareholders (1). To avoid dividend announcements seeming excessively large (1) when based on a situation where issued shares is only a relatively small part of equity (1). Max 4 marks Accept other valid responses. 3(b) Number of bonus shares is (1 800 000 – 1 200 000) × 4 (1) = 2 400 000 (1)OF 2 3(c) Journal Dr Cr $000 $000 Share premium 220 (1) Retained earnings 380 (1) Issued share capital 600 (1) Being bonus issue made (1) 4 3(d) The profits available for distribution (1) The cash available to pay dividends (1) Shareholders’ expectations (1) Max 3 Accept other valid responses. 3 3(e) 1 800 000 × 4 shares = 7 200 000 shares (1) × $0.01 = $72 000 (1)OF 2
Q4 · During the year ended 31 July 2020 Goods had been returned to suppliers, $1280
4 During the year ended 31 July 2020 Goods had been returned to suppliers, $1280. All sales were made on a cash basis.
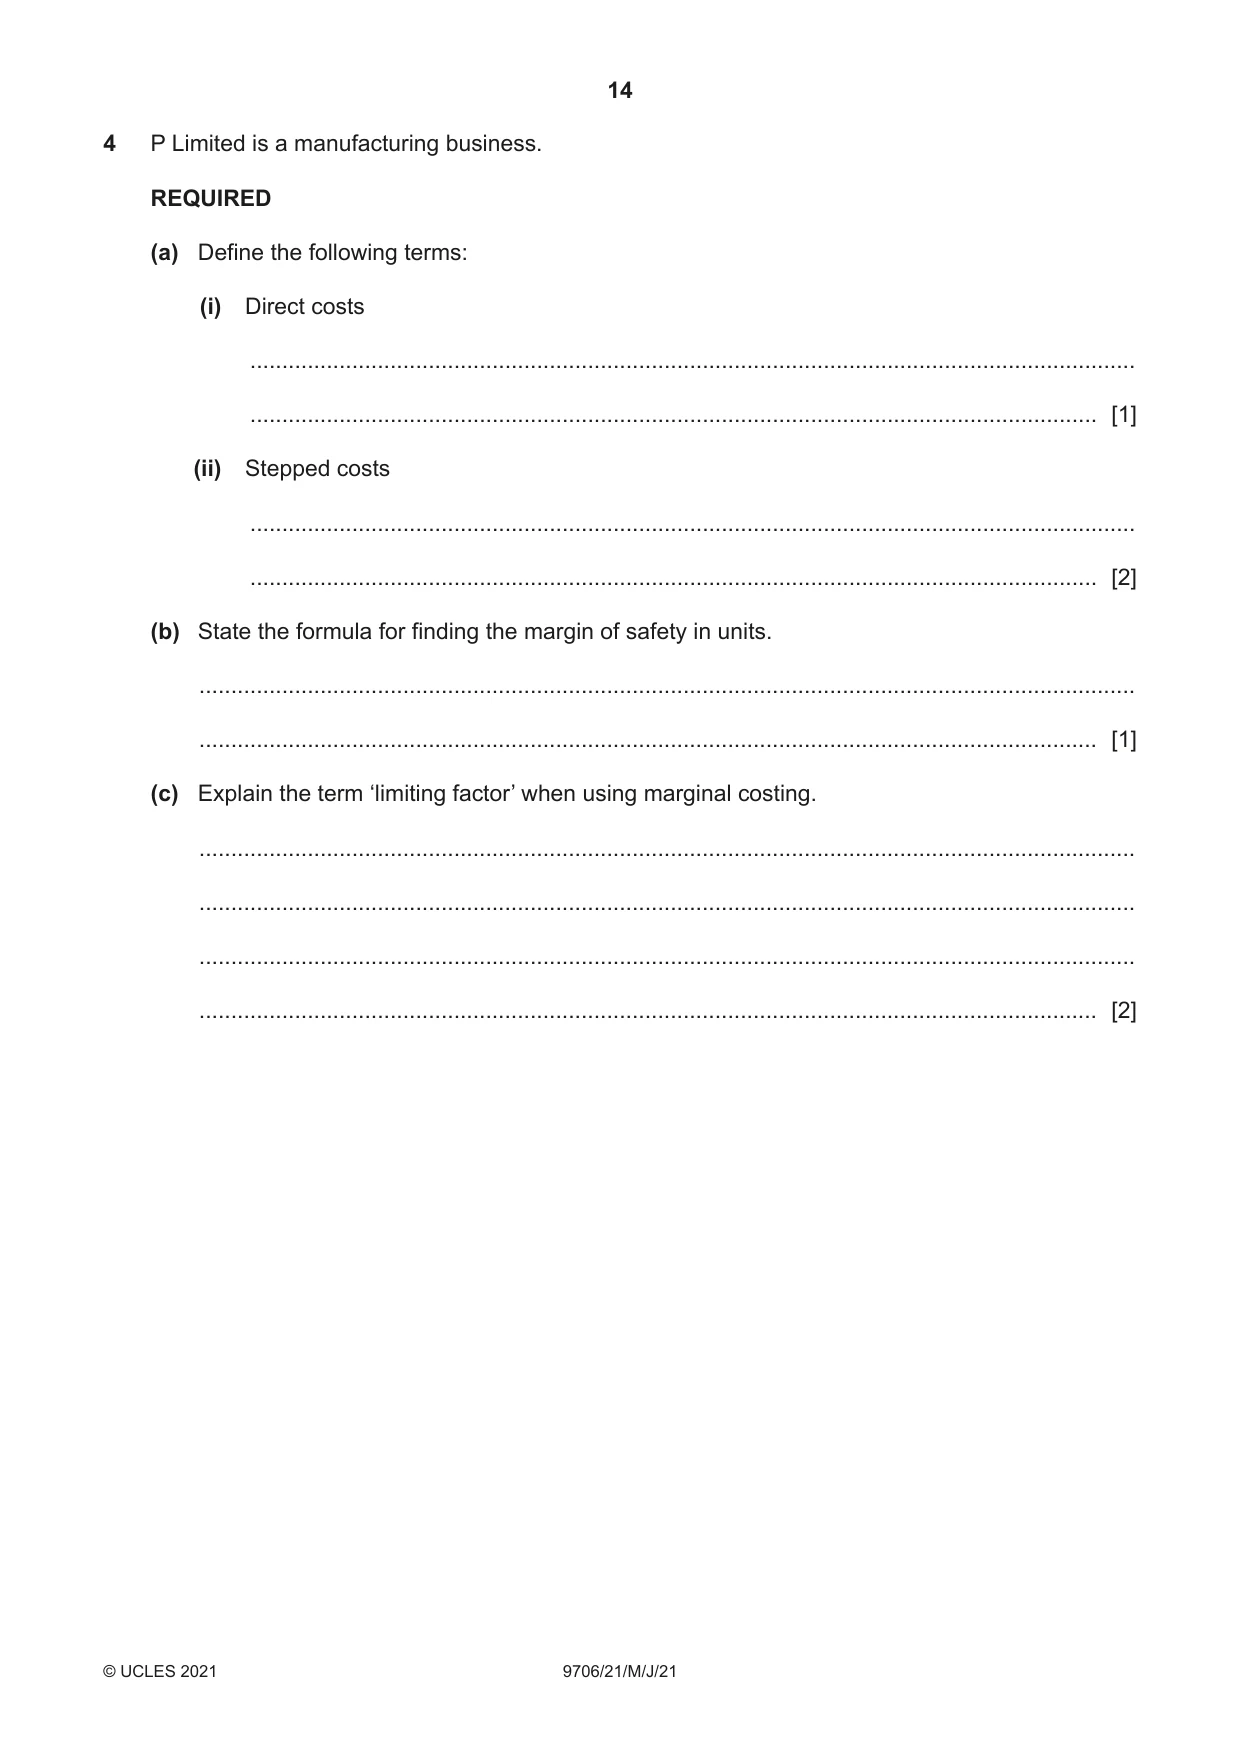
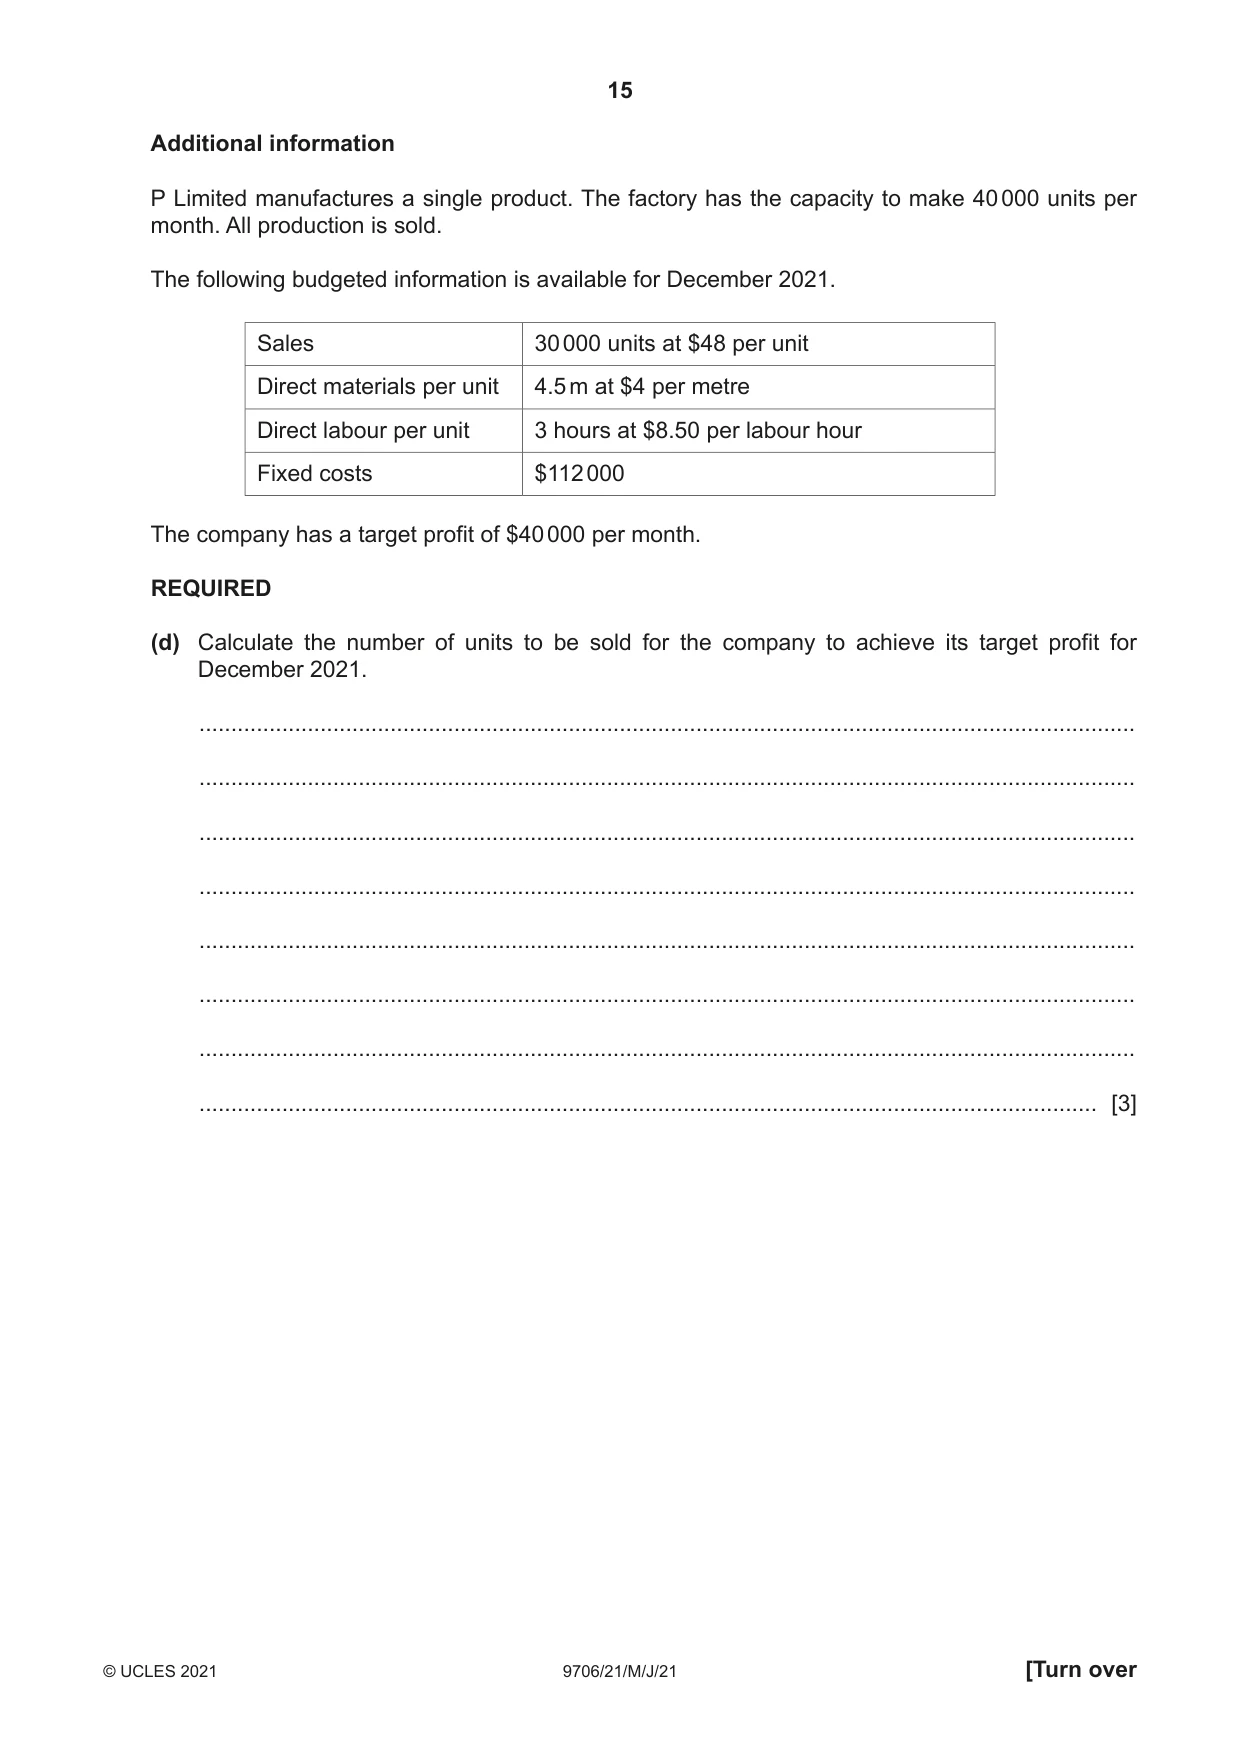
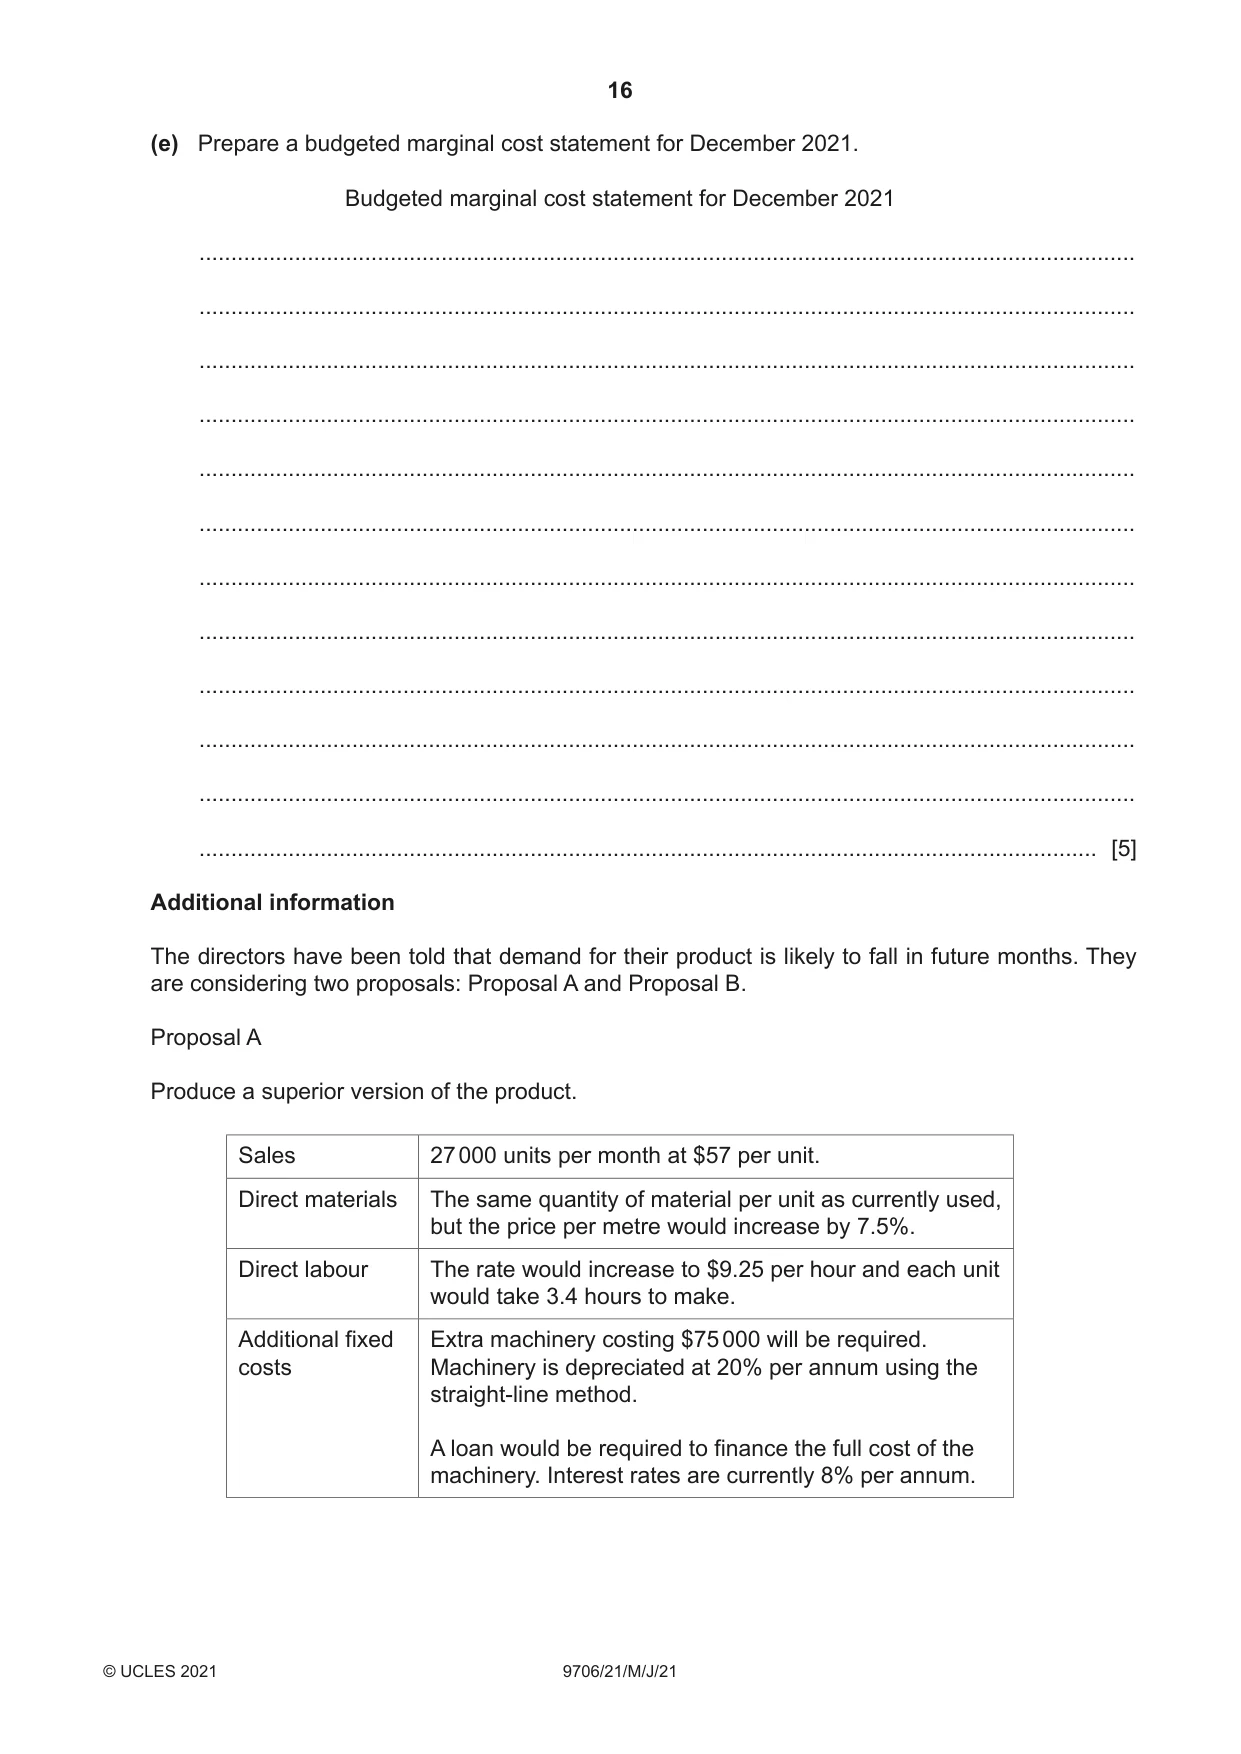
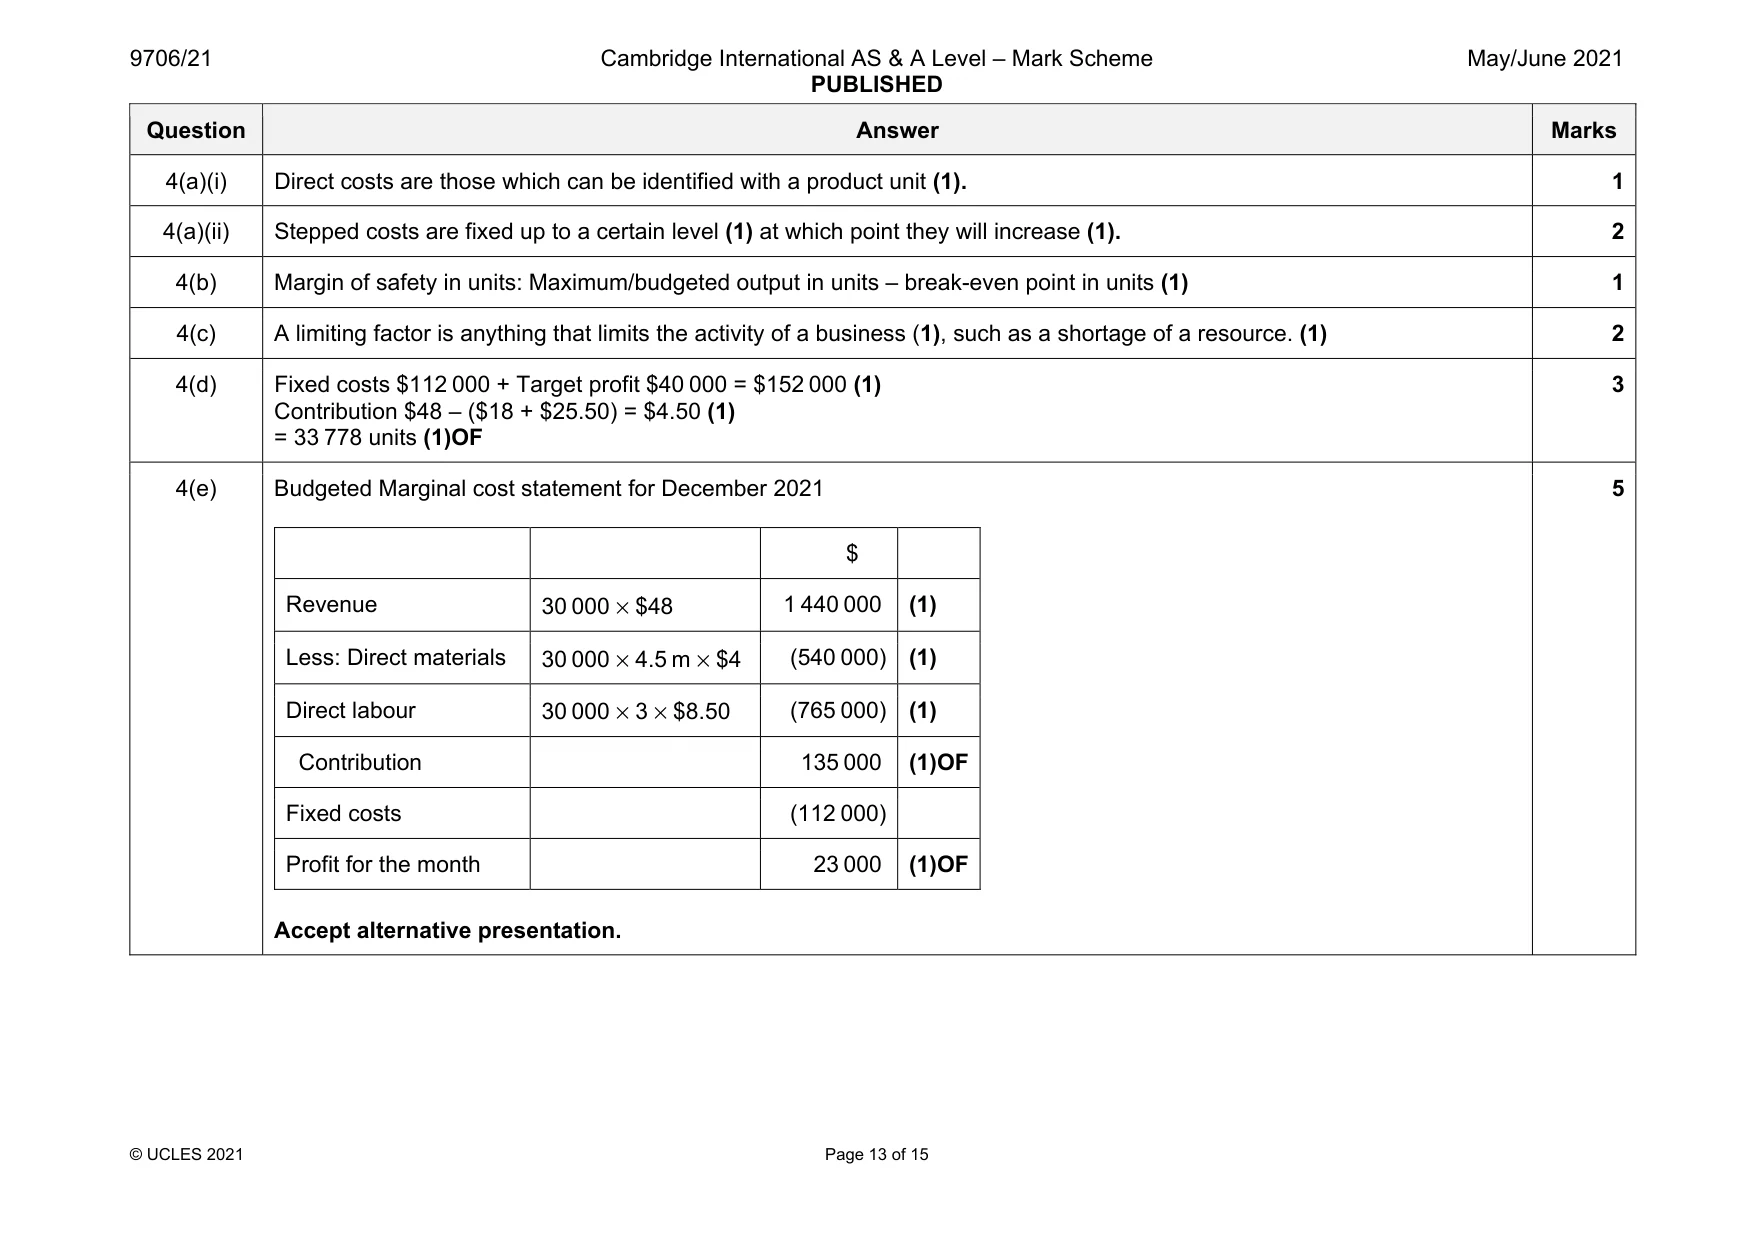
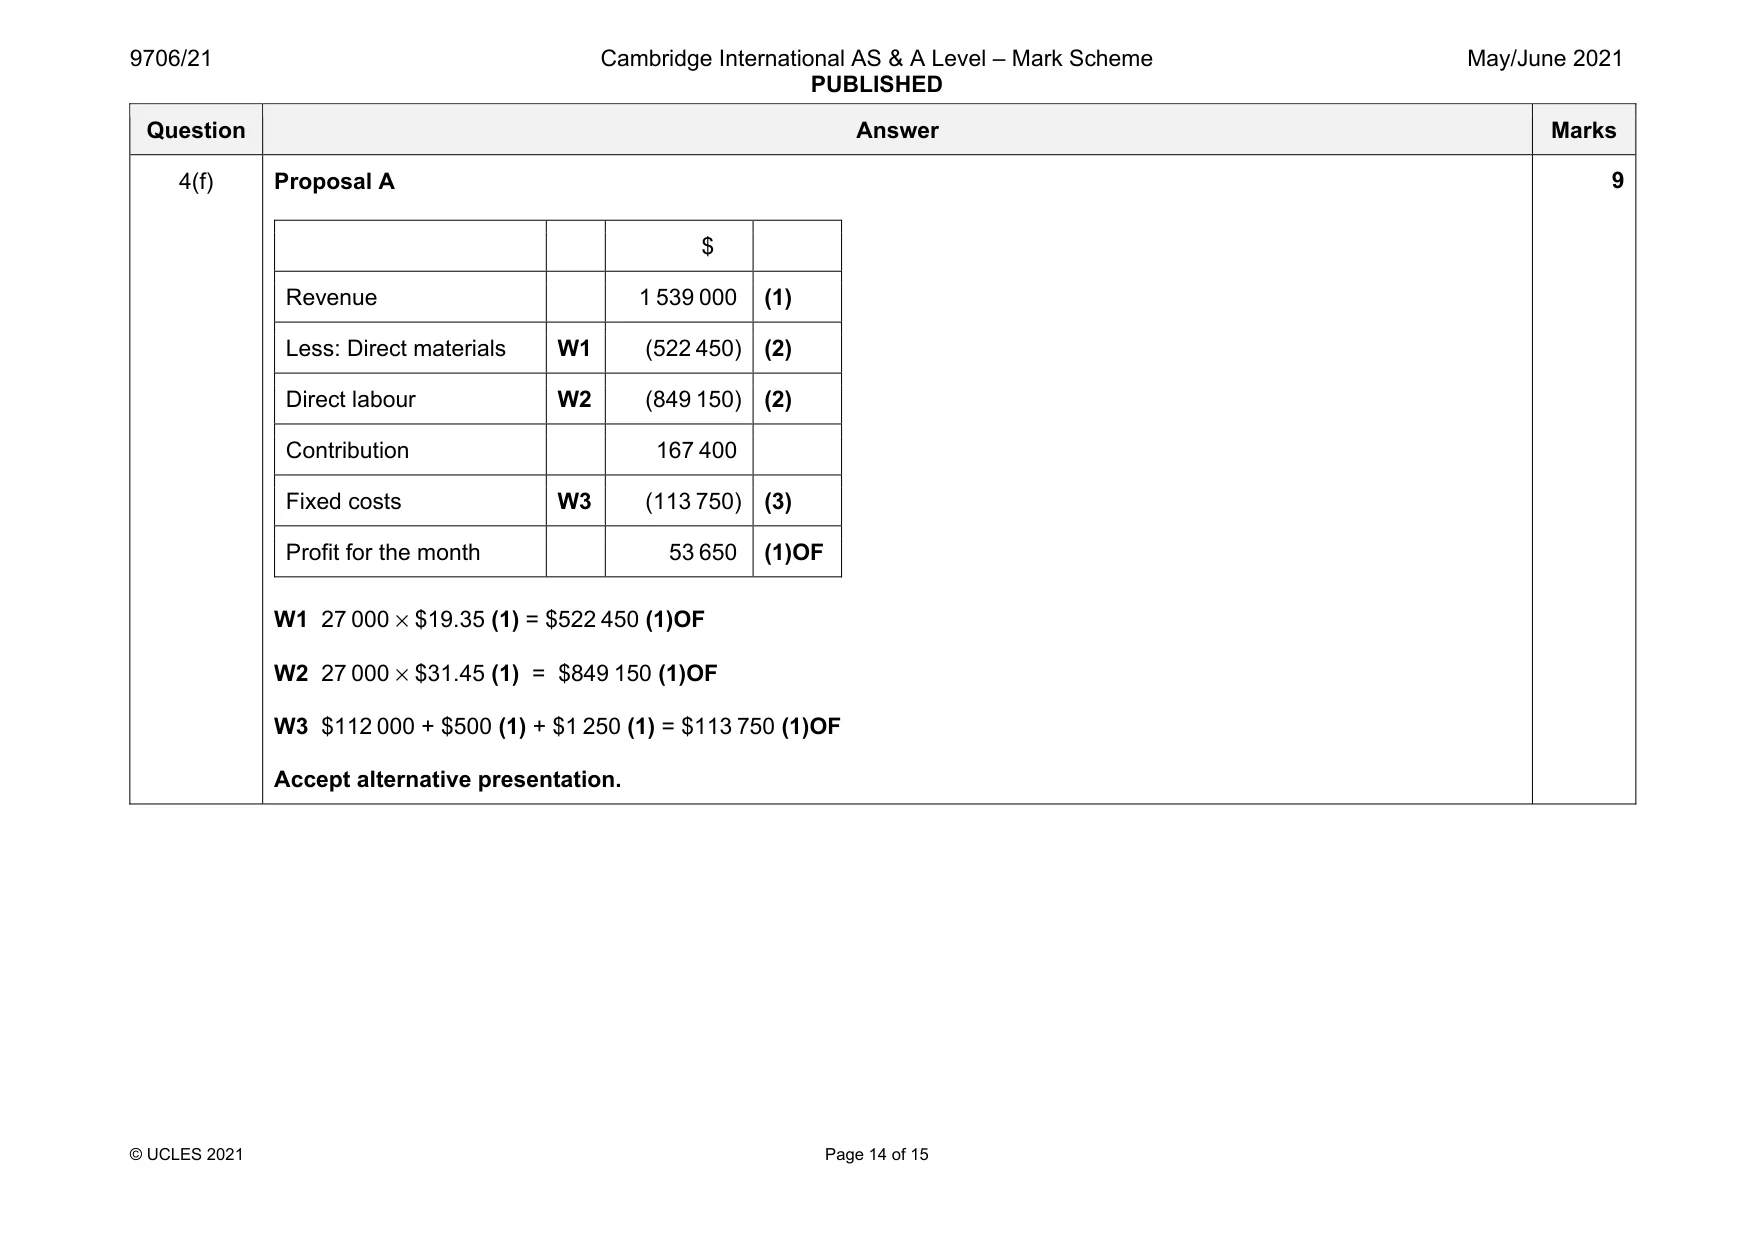
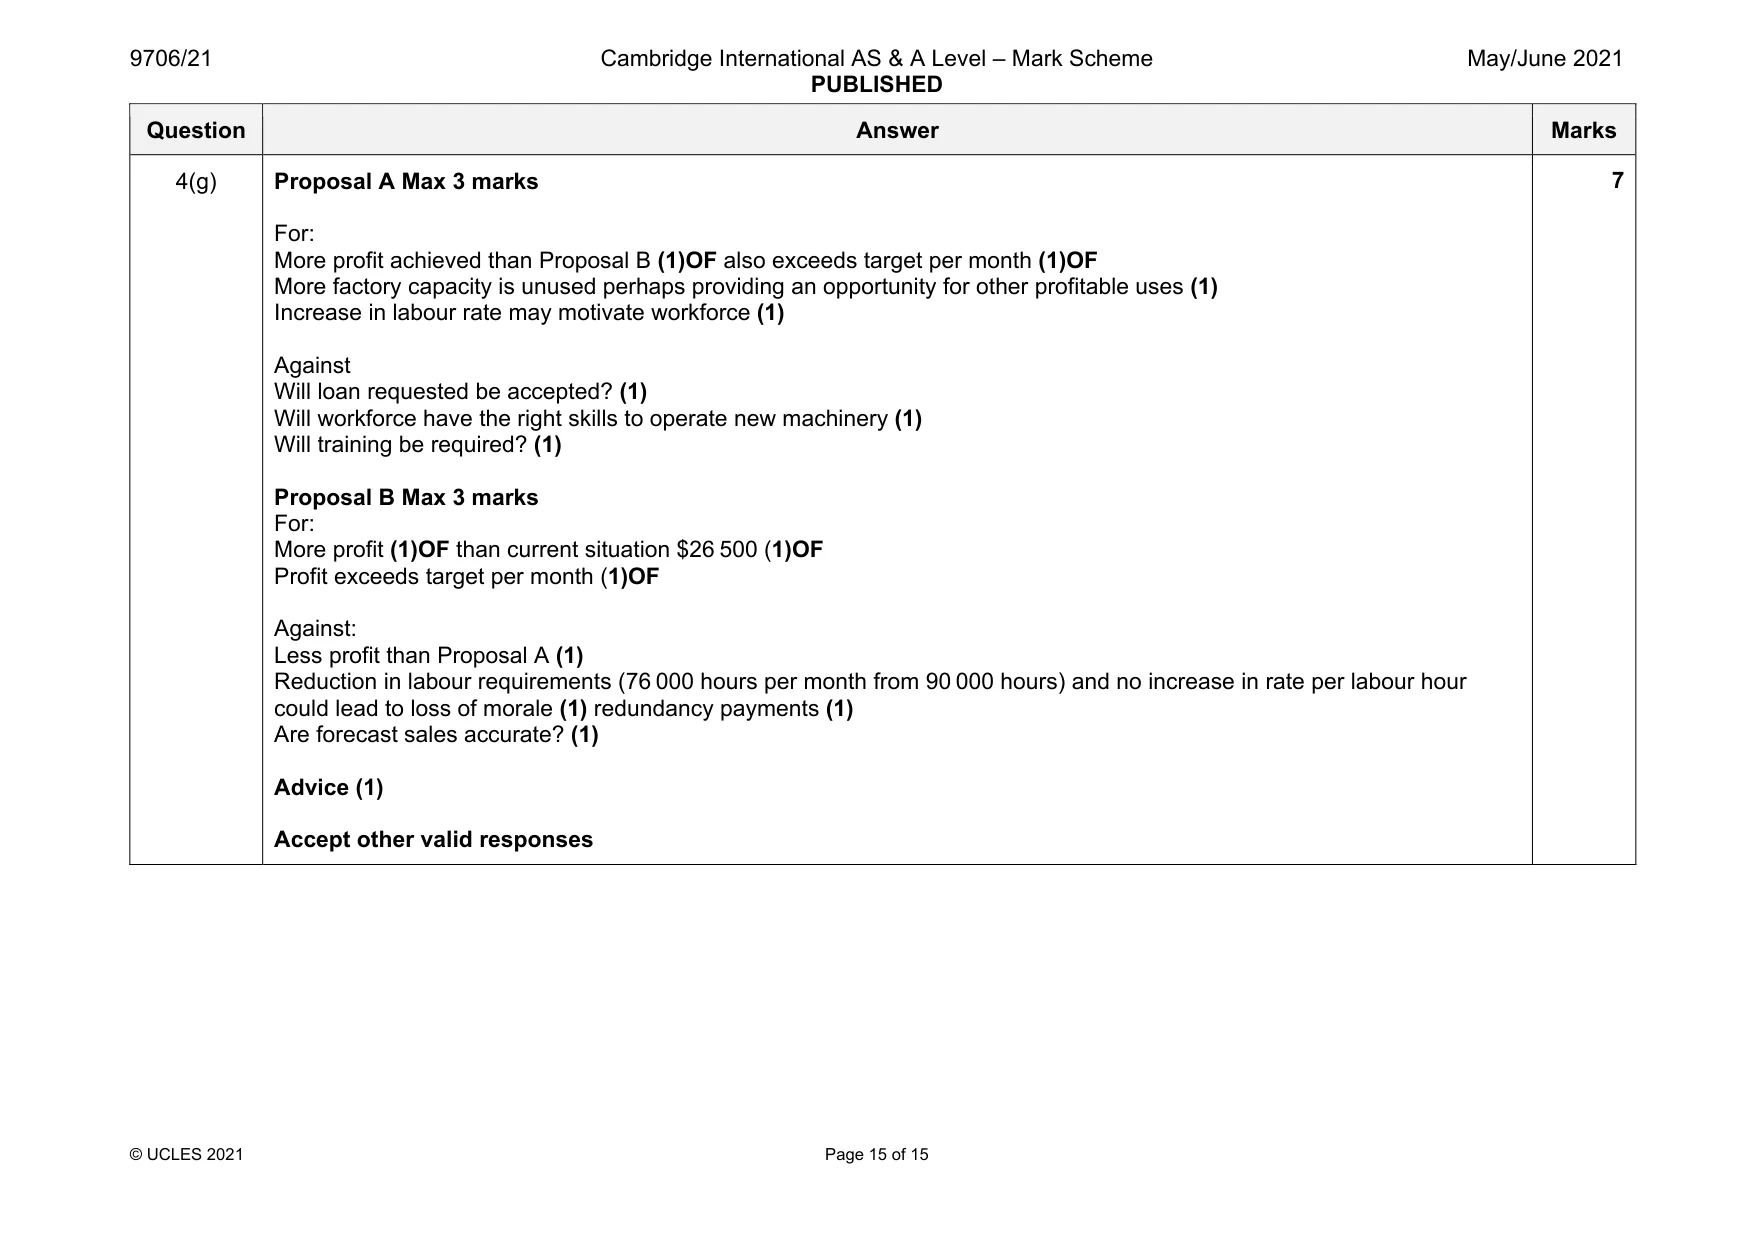
Mark scheme: 4(a)(i) Direct costs are those which can be identified with a product unit (1). 1 4(a)(ii) Stepped costs are fixed up to a certain level (1) at which point they will increase (1). 2 4(b) Margin of safety in units: Maximum/budgeted output in units – break-even point in units (1) 1 4(c) A limiting factor is anything that limits the activity of a business (1), such as a shortage of a resource. (1) 2 4(d) Fixed costs $112 000 + Target profit $40 000 = $152 000 (1) Contribution $48 – ($18 + $25.50) = $4.50 (1) = 33 778 units (1)OF 3 4(e) Budgeted Marginal cost statement for December 2021 $ Revenue 30 000 × $48 1 440 000 (1) Less: Direct materials 30 000 × 4.5 m × $4 (540 000) (1) Direct labour 30 000 × 3 × $8.50 (765 000) (1) Contribution 135 000 (1)OF Fixed costs (112 000) Profit for the month 23 000 (1)OF Accept alternative presentation. 5 Question Answer Marks 4(f) Proposal A $ Revenue 1 539 000 (1) Less: Direct materials W1 (522 450) (2) Direct labour W2 (849 150) (2) Contribution 167 400 Fixed costs W3 (113 750) (3) Profit for the month 53 650 (1)OF W1 27 000 × $19.35 (1) = $522 450 (1)OF W2 27 000 × $31.45 (1) = $849 150 (1)OF W3 $112 000 + $500 (1) + $1 250 (1) = $113 750 (1)OF Accept alternative presentation. 9 Question Answer Marks 4(g) Proposal A Max 3 marks For: More profit achieved than Proposal B (1)OF also exceeds target per month (1)OF More factory capacity is unused perhaps providing an opportunity for other profitable uses (1) Increase in labour rate may motivate workforce (1) Against Will loan requested be accepted? (1) Will workforce have the right skills to operate new machinery (1) Will training be required? (1) Proposal B Max 3 marks For: More profit (1)OF than current situation $26 500 (1)OF Profit exceeds target per month (1)OF Against: Less profit than Proposal A (1) Reduction in labour requirements (76 000 hours per month from 90 000 hours) and no increase in rate per labour hour could lead to loss of morale (1) redundancy payments (1) Are forecast sales accurate? (1) Advice (1) Accept other valid responses 7
Q5 · At 31 July 2020 Suppliers were owed $4560
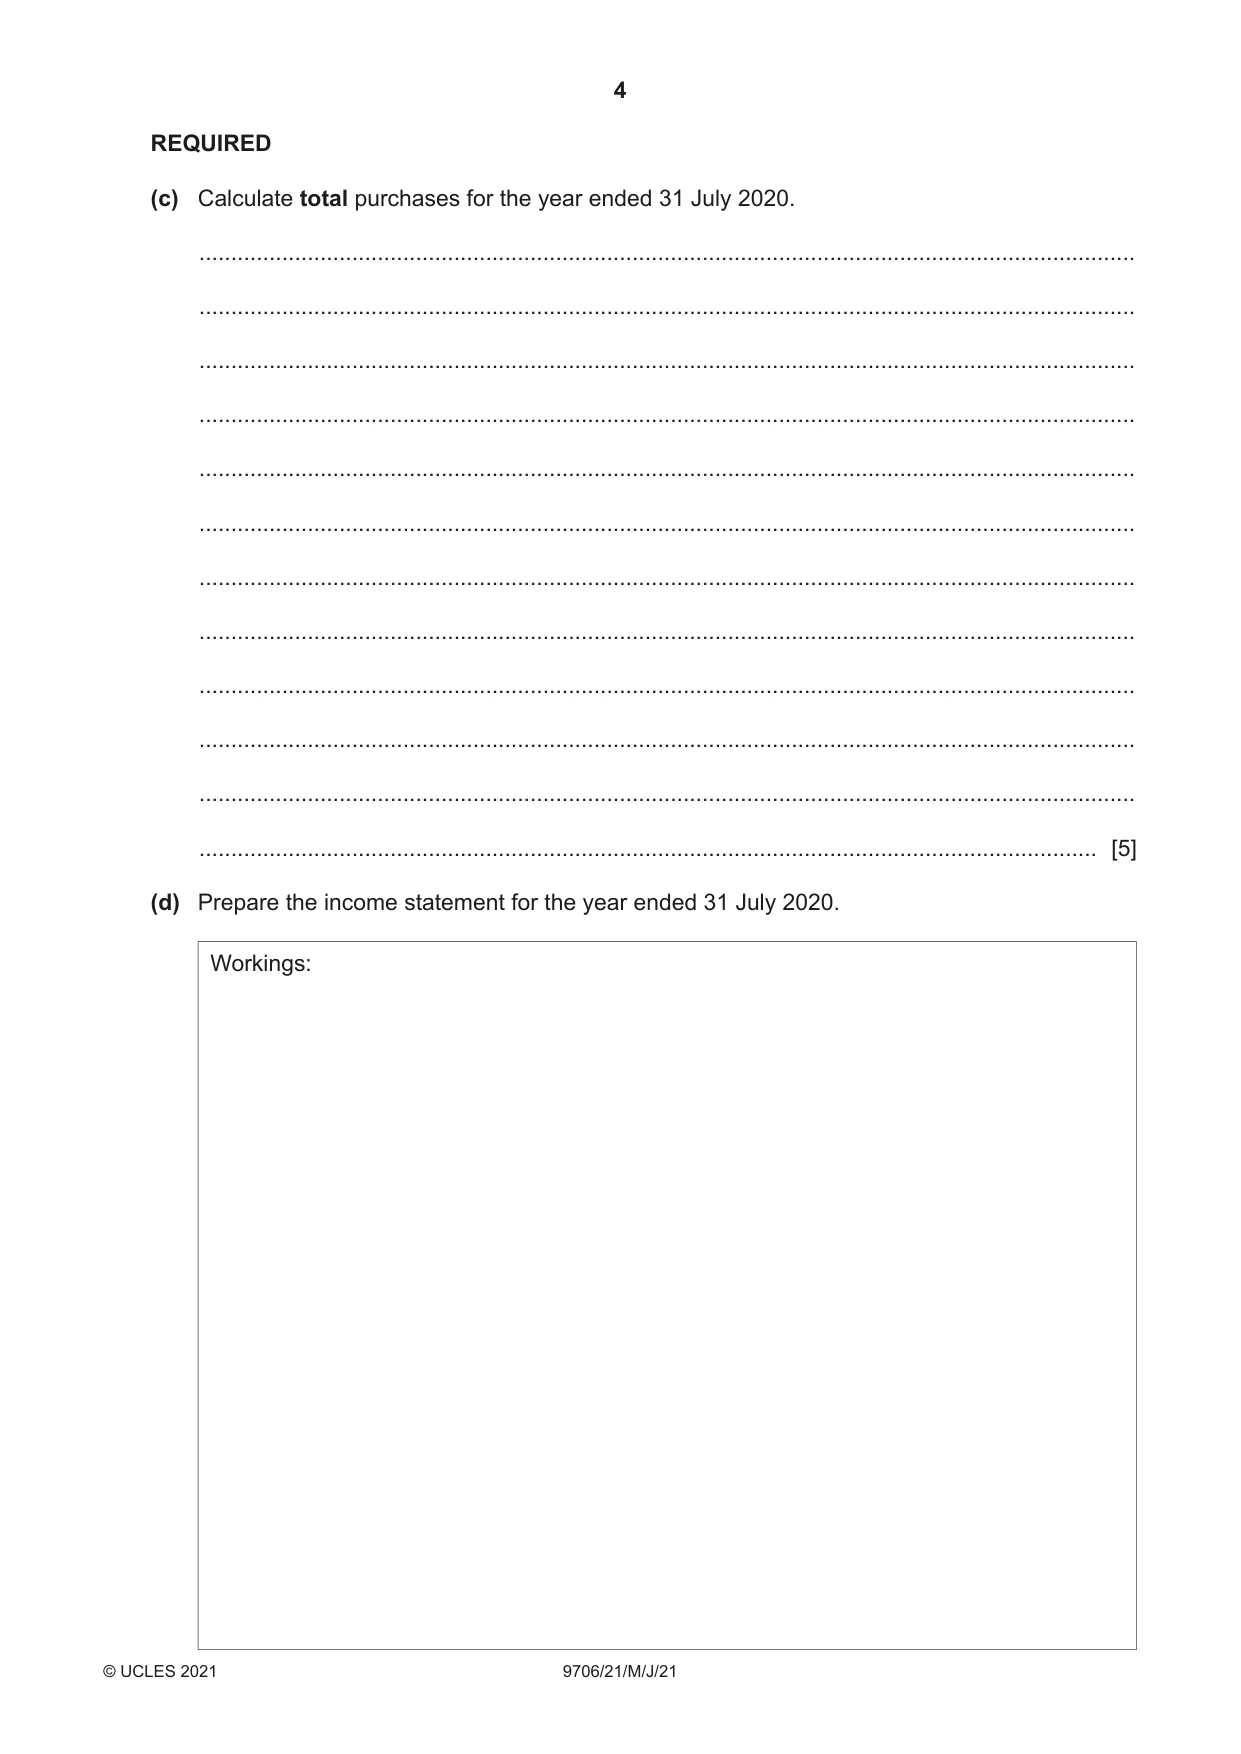
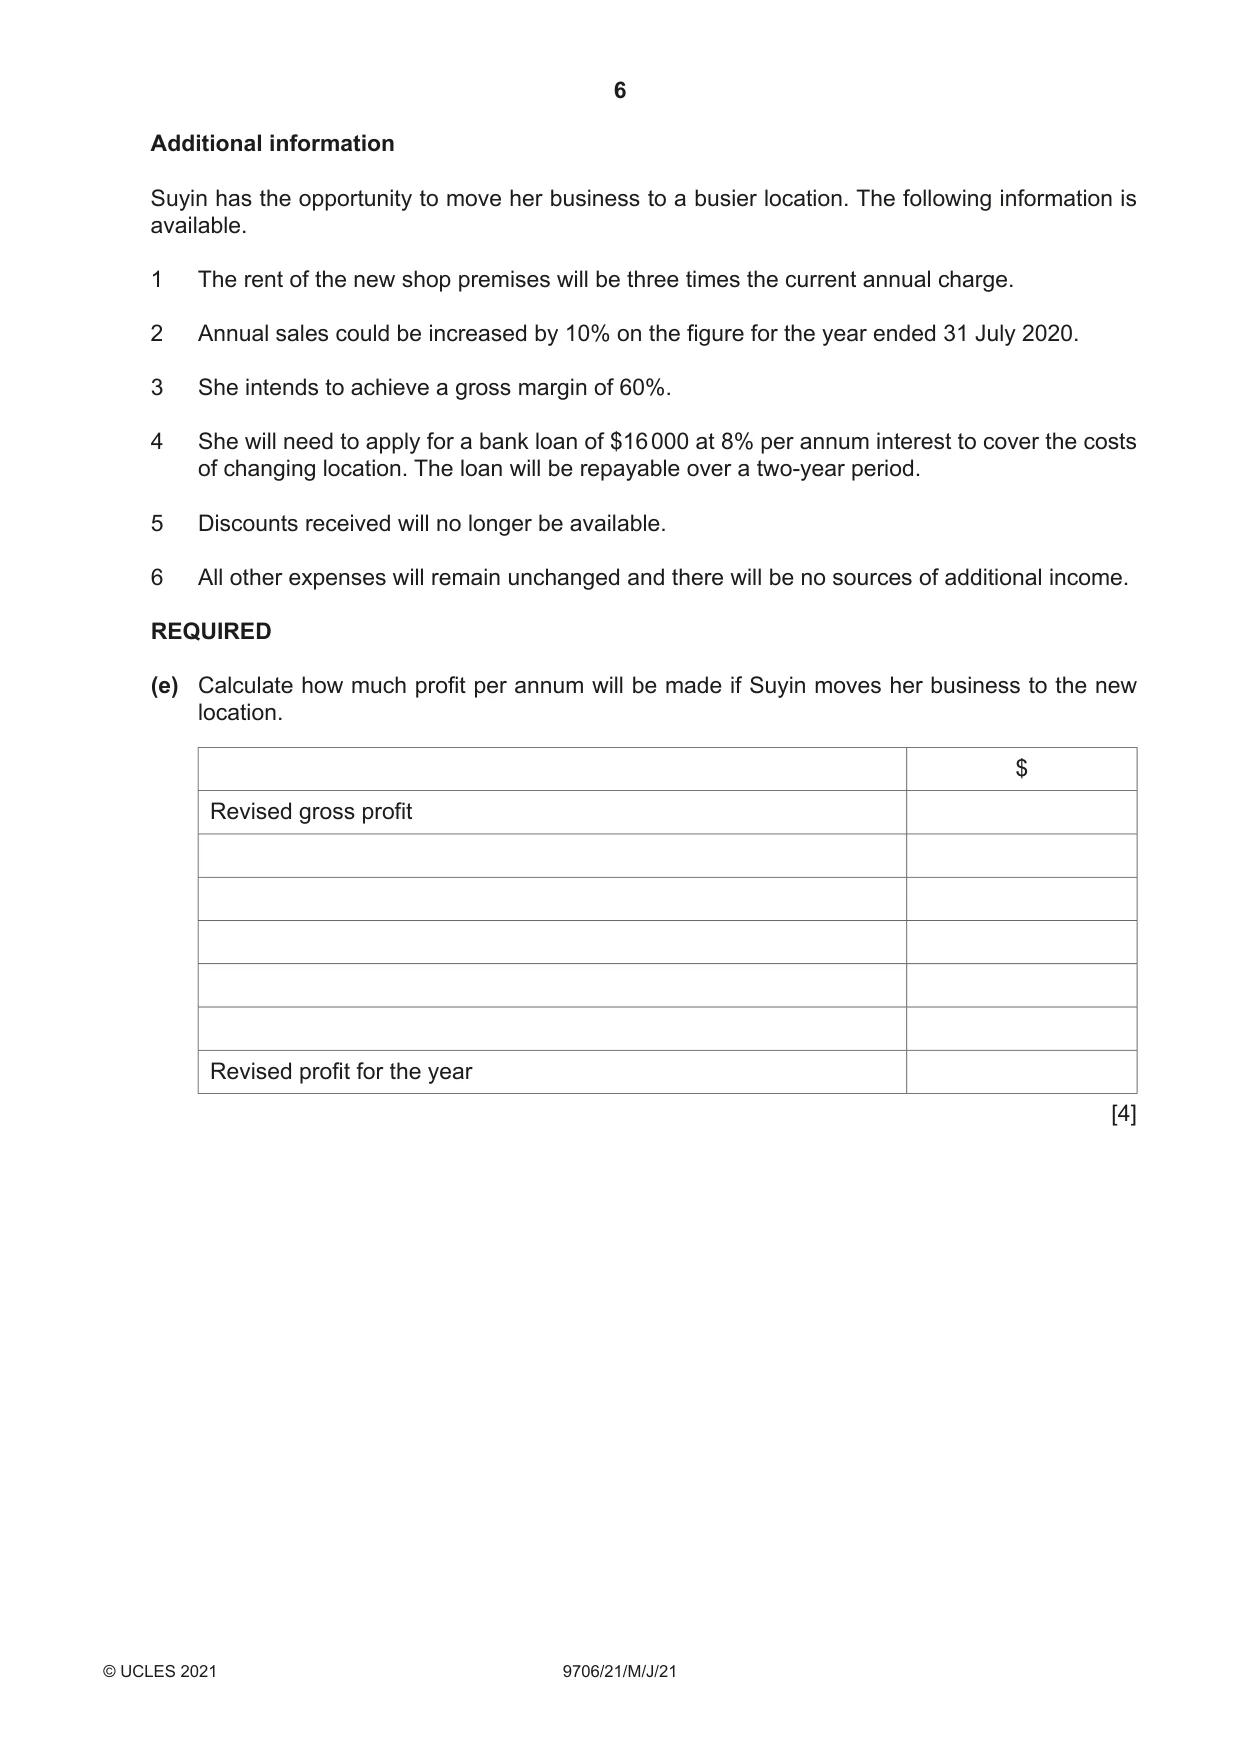
5 At 31 July 2020 Suppliers were owed $4560. Inventory was valued at $18720. Fittings and equipment was valued at $15 860. REQUIRED (c) Calculate total purchases for the year ended 31 July 2020. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) Prepare the income statement for the year ended 31 July 2020. Workings: Suyin Income statement for the year ended 31 July 2020 $ $ ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... ........................................................................................... ..................... ..................... [10] Additional information Suyin has the opportunity to move her business to a busier location. The following information is available. 1 The rent of the new shop premises will be three times the current annual charge. 2 Annual sales could be increased by 10% on the figure for the year ended 31 July 2020. 3 She intends to achieve a gross margin of 60%. 4 She will need to apply for a bank loan of $16 000 at 8% per annum interest to cover the costs of changing location. The loan will be repayable over a two-year period. 5 Discounts received will no longer be available.
Q6 · All other expenses will remain unchanged and there will be no sources of additional income
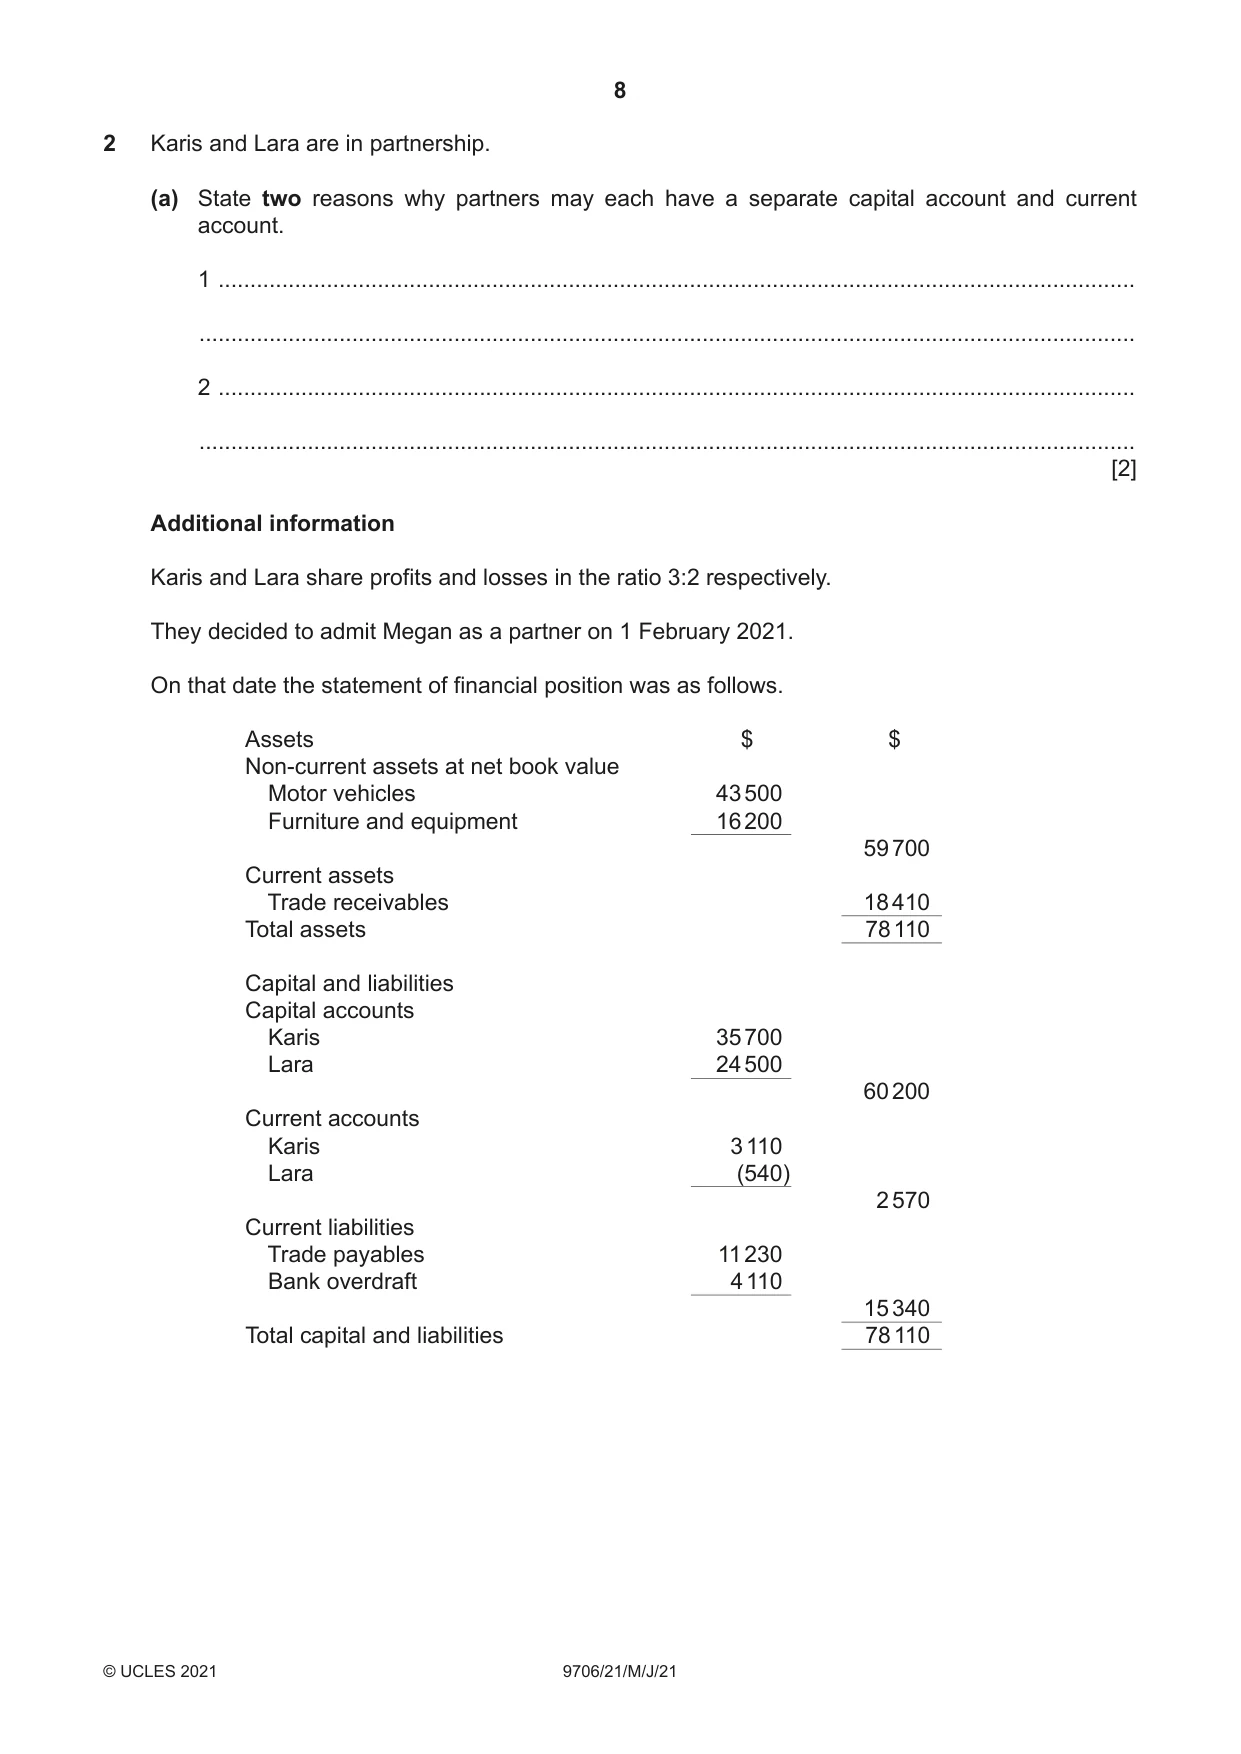
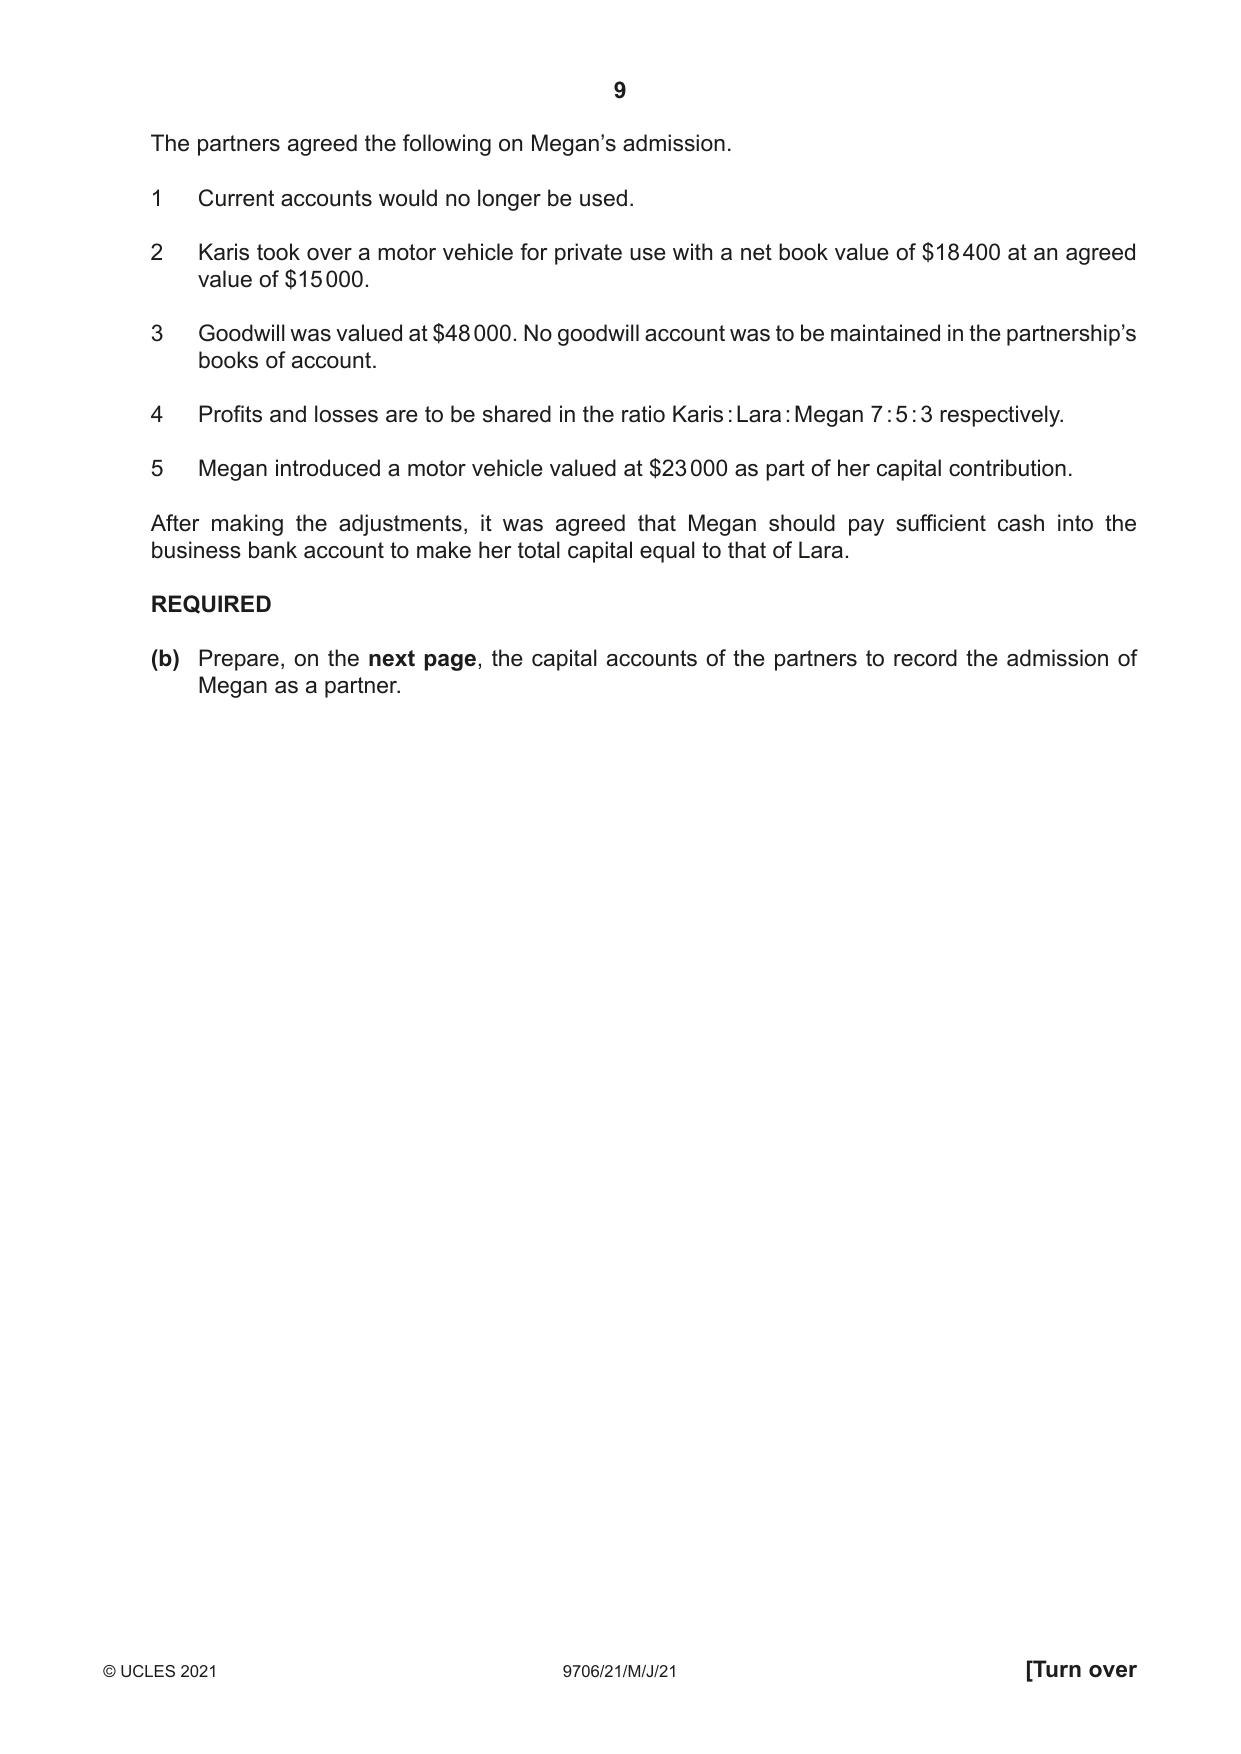
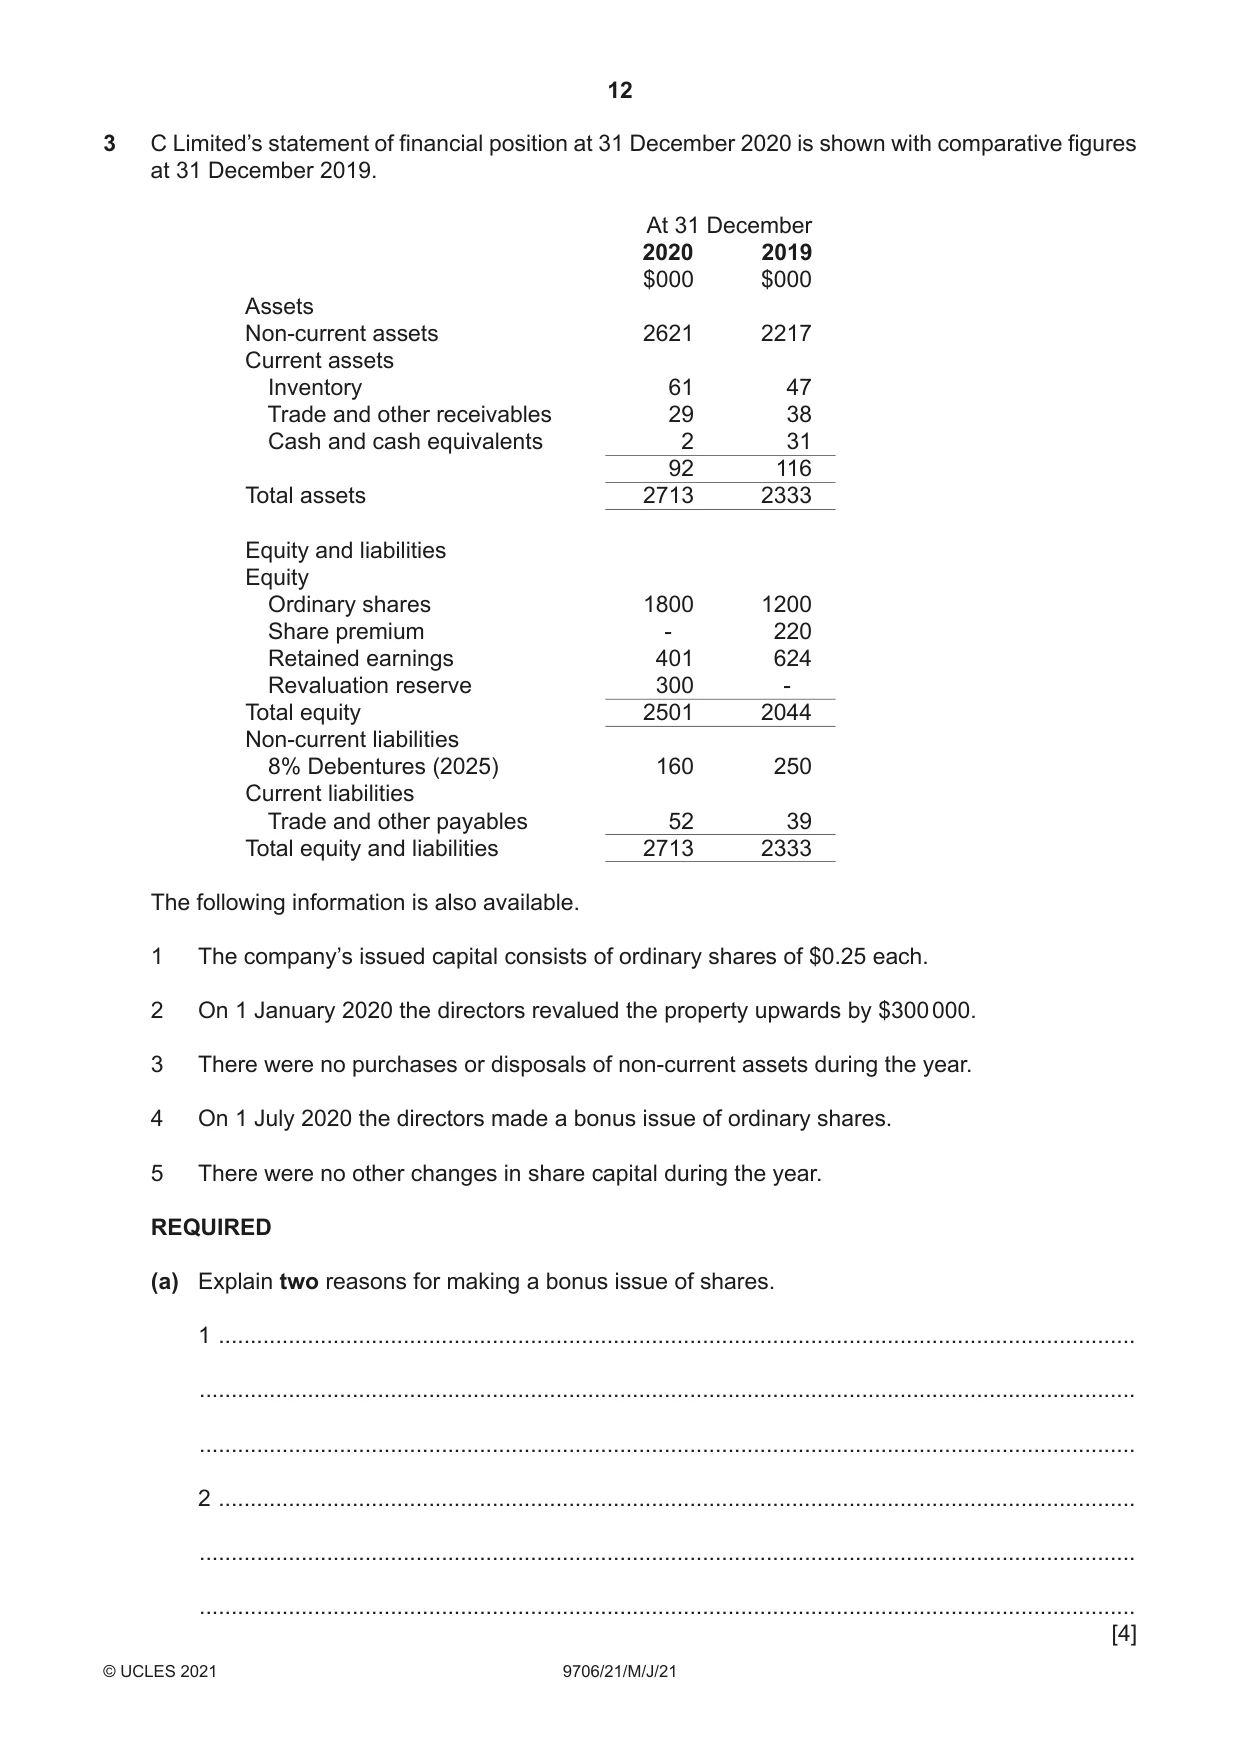
6 All other expenses will remain unchanged and there will be no sources of additional income. REQUIRED (e) Calculate how much profit per annum will be made if Suyin moves her business to the new location. $ Revised gross profit Revised profit for the year [4] (f) Advise Suyin whether or not she should change her business’s location. Justify your answer considering both financial and non-financial factors. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 30] 2 Karis and Lara are in partnership. (a) State two reasons why partners may each have a separate capital account and current account. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information Karis and Lara share profits and losses in the ratio 3:2 respectively. They decided to admit Megan as a partner on 1 February 2021. On that date the statement of financial position was as follows. Assets $ $ Non-current assets at net book value Motor vehicles 43 500 Furniture and equipment 16 200 59 700 Current assets Trade receivables 18 410 Total assets 78 110 Capital and liabilities Capital accounts Karis 35 700 Lara 24 500 60 200 Current accounts Karis 3 110 Lara (540) 2 570 Current liabilities Trade payables 11 230 Bank overdraft 4 110 15 340 Total capital and liabilities 78 110 The partners agreed the following on Megan’s admission. 1 Current accounts would no longer be used. 2 Karis took over a motor vehicle for private use with a net book value of $18 400 at an agreed value of $15 000. 3 Goodwill was valued at $48 000. No goodwill account was to be maintained in the partnership’s books of account. 4 Profits and losses are to be shared in the ratio Karis : Lara : Megan 7 : 5 : 3 respectively. 5 Megan introduced a motor vehicle valued at $23 000 as part of her capital contribution. After making the adjustments, it was agreed that Megan should pay sufficient cash into the business bank account to make her total capital equal to that of Lara. REQUIRED (b) Prepare, on the next page, the capital accounts of the partners to record the admission of Megan as a partner. [8] $ Megan $ Lara $ Karis accounts Capital $ Megan $ Lara $ Karis Additional information In the new partnership agreement Lara is to receive a salary of $12 000 per annum. Megan is hoping to achieve a 25% return on her capital employed (ROCE). REQUIRED (c) Calculate the minimum profit the partnership must make in order for Megan to achieve this ROCE. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (d) State two possible disadvantages to existing partners of admitting a new partner. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] [Total: 15] 3 C Limited’s statement of financial position at 31 December 2020 is shown with comparative figures at 31 December 2019. At 31 December 2020 2019 $000 $000 Assets Non-current assets 2621 2217 Current assets Inventory 61 47 Trade and other receivables 29 38 Cash and cash equivalents 2 31 92 116 Total assets 2713 2333 Equity and liabilities Equity Ordinary shares 1800 1200 Share premium - 220 Retained earnings 401 624 Revaluation reserve 300 - Total equity 2501 2044 Non-current liabilities 8% Debentures (2025) 160 250 Current liabilities Trade and other payables 52 39 Total equity and liabilities 2713 2333 The following information is also available. 1 The company’s issued capital consists of ordinary shares of $0.25 each. 2 On 1 January 2020 the directors revalued the property upwards by $300 000. 3 There were no purchases or disposals of non-current assets during the year. 4 On 1 July 2020 the directors made a bonus issue of ordinary shares. 5 There were no other changes in share capital during the year. REQUIRED (a) Explain two reasons for making a bonus issue of shares. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... [4] (b) Calculate the number of bonus shares issued on 1 July 2020. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (c) Prepare the journal entry recording the bonus issue on 1 July 2020. A narrative is required. Journal Dr Cr $000 $000 [4] (d) Identify three factors that directors of a company should consider when deciding on the amount of a proposed dividend. 1 ................................................................................................................................................ 2 ................................................................................................................................................ 3 ................................................................................................................................................ [3] Additional information The directors of C Limited wish to propose a dividend of $0.01 per share on all shares in issue at
More questions on Analysis and communication of accounting information
Question 31
31 December 2020. REQUIRED (e) Calculate the amount of the proposed dividend. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 15] 4 P Limited is a manufacturing business. REQUIRED (a) Define the following terms: (i) Direct costs ........................................................................................................................................... ..................................................................................................................................... [1] (ii) Stepped costs ........................................................................................................................................... ..................................................................................................................................... [2] (b) State the formula for finding the margin of safety in units. ................................................................................................................................................... ............................................................................................................................................. [1] (c) Explain the term ‘limiting factor’ when using marginal costing. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Additional information P Limited manufactures a single product. The factory has the capacity to make 40 000 units per month. All production is sold. The following budgeted information is available for December 2021. Sales 30 000 units at $48 per unit Direct materials per unit 4.5 m at $4 per metre Direct labour per unit 3 hours at $8.50 per labour hour Fixed costs $112 000 The company has a target profit of $40 000 per month. REQUIRED (d) Calculate the number of units to be sold for the company to achieve its target profit for December 2021. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3]
What was in this paper
The subtopics covered by these 7 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 May/June, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.