Cambridge A Level Accounting 9706 — 2021 Oct/Nov Paper 2 · Variant 2
9706/22/O/N/21 · 8 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme15 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · The following balances have been extracted from the books of P Limited at 31 August 2021
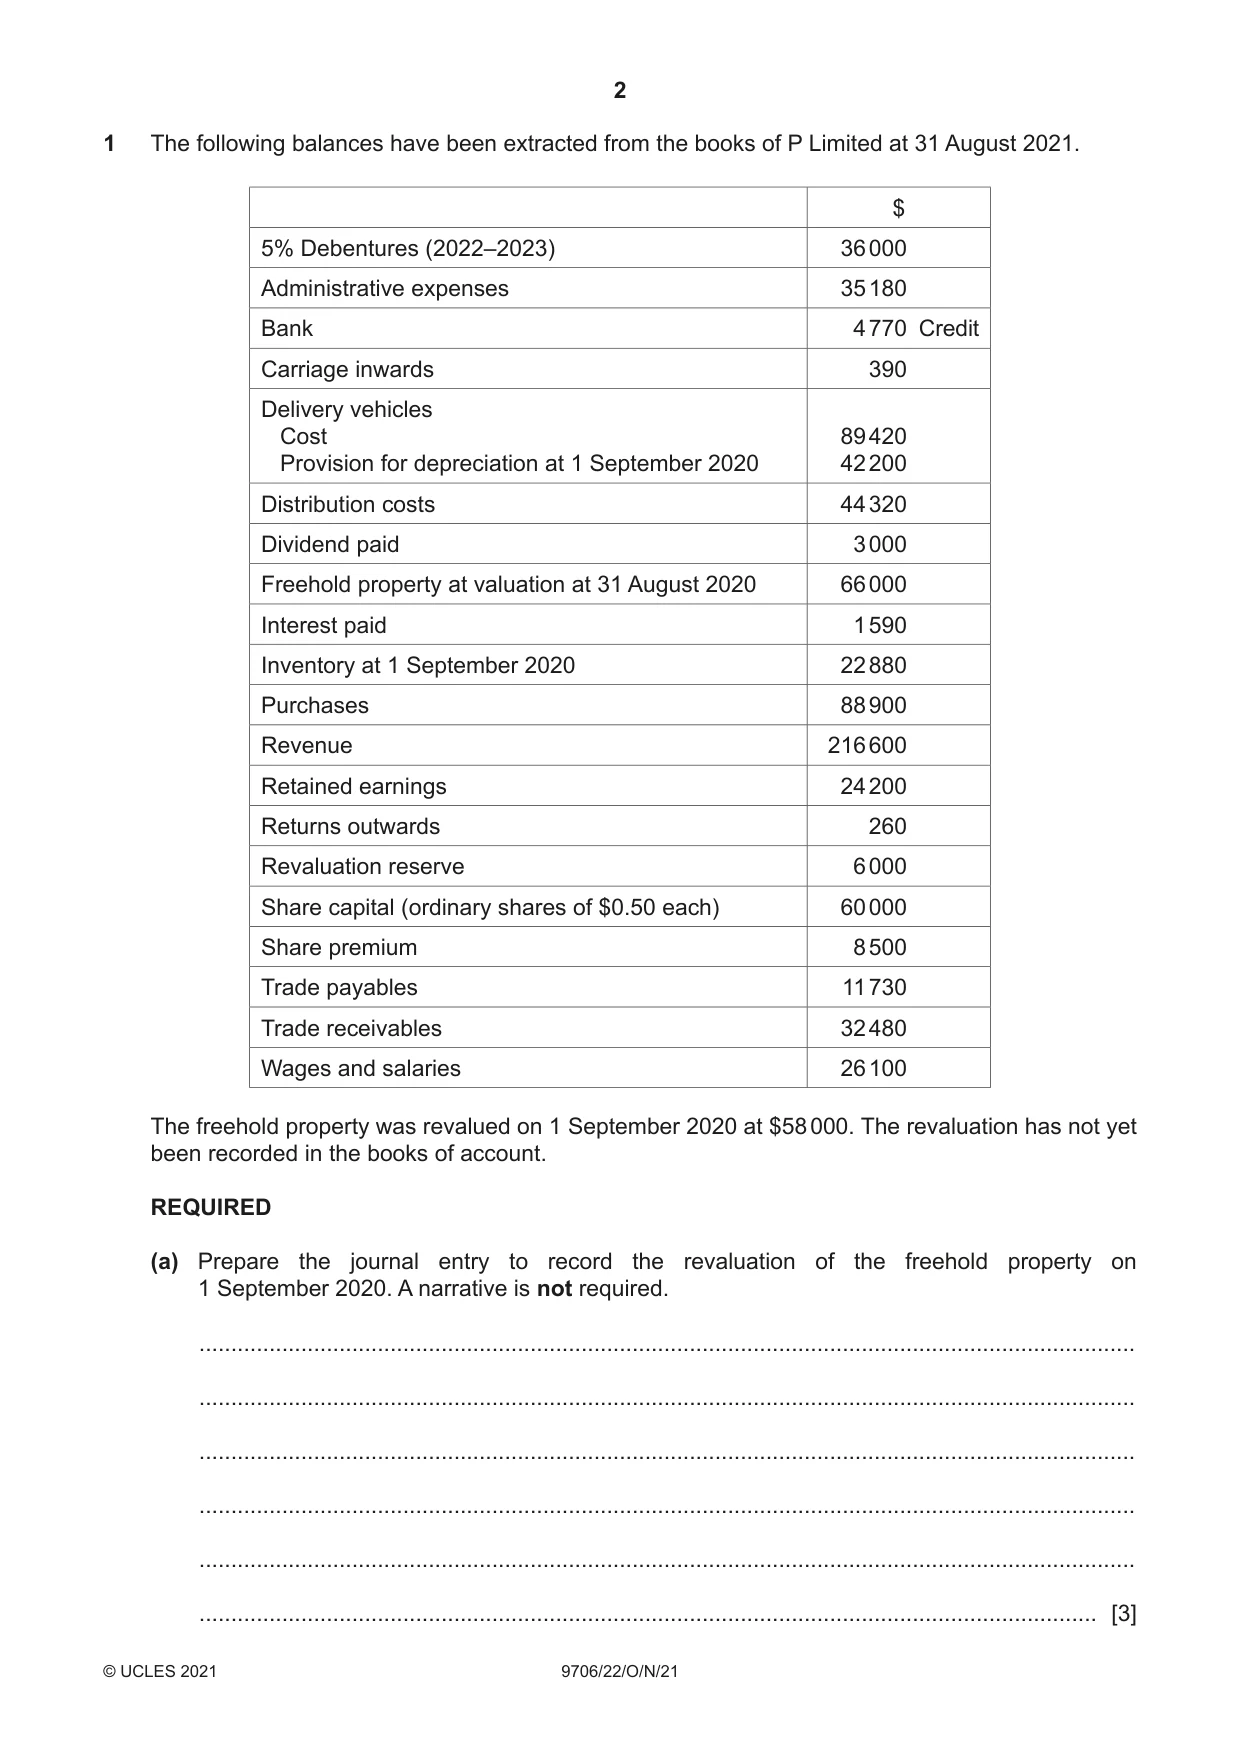
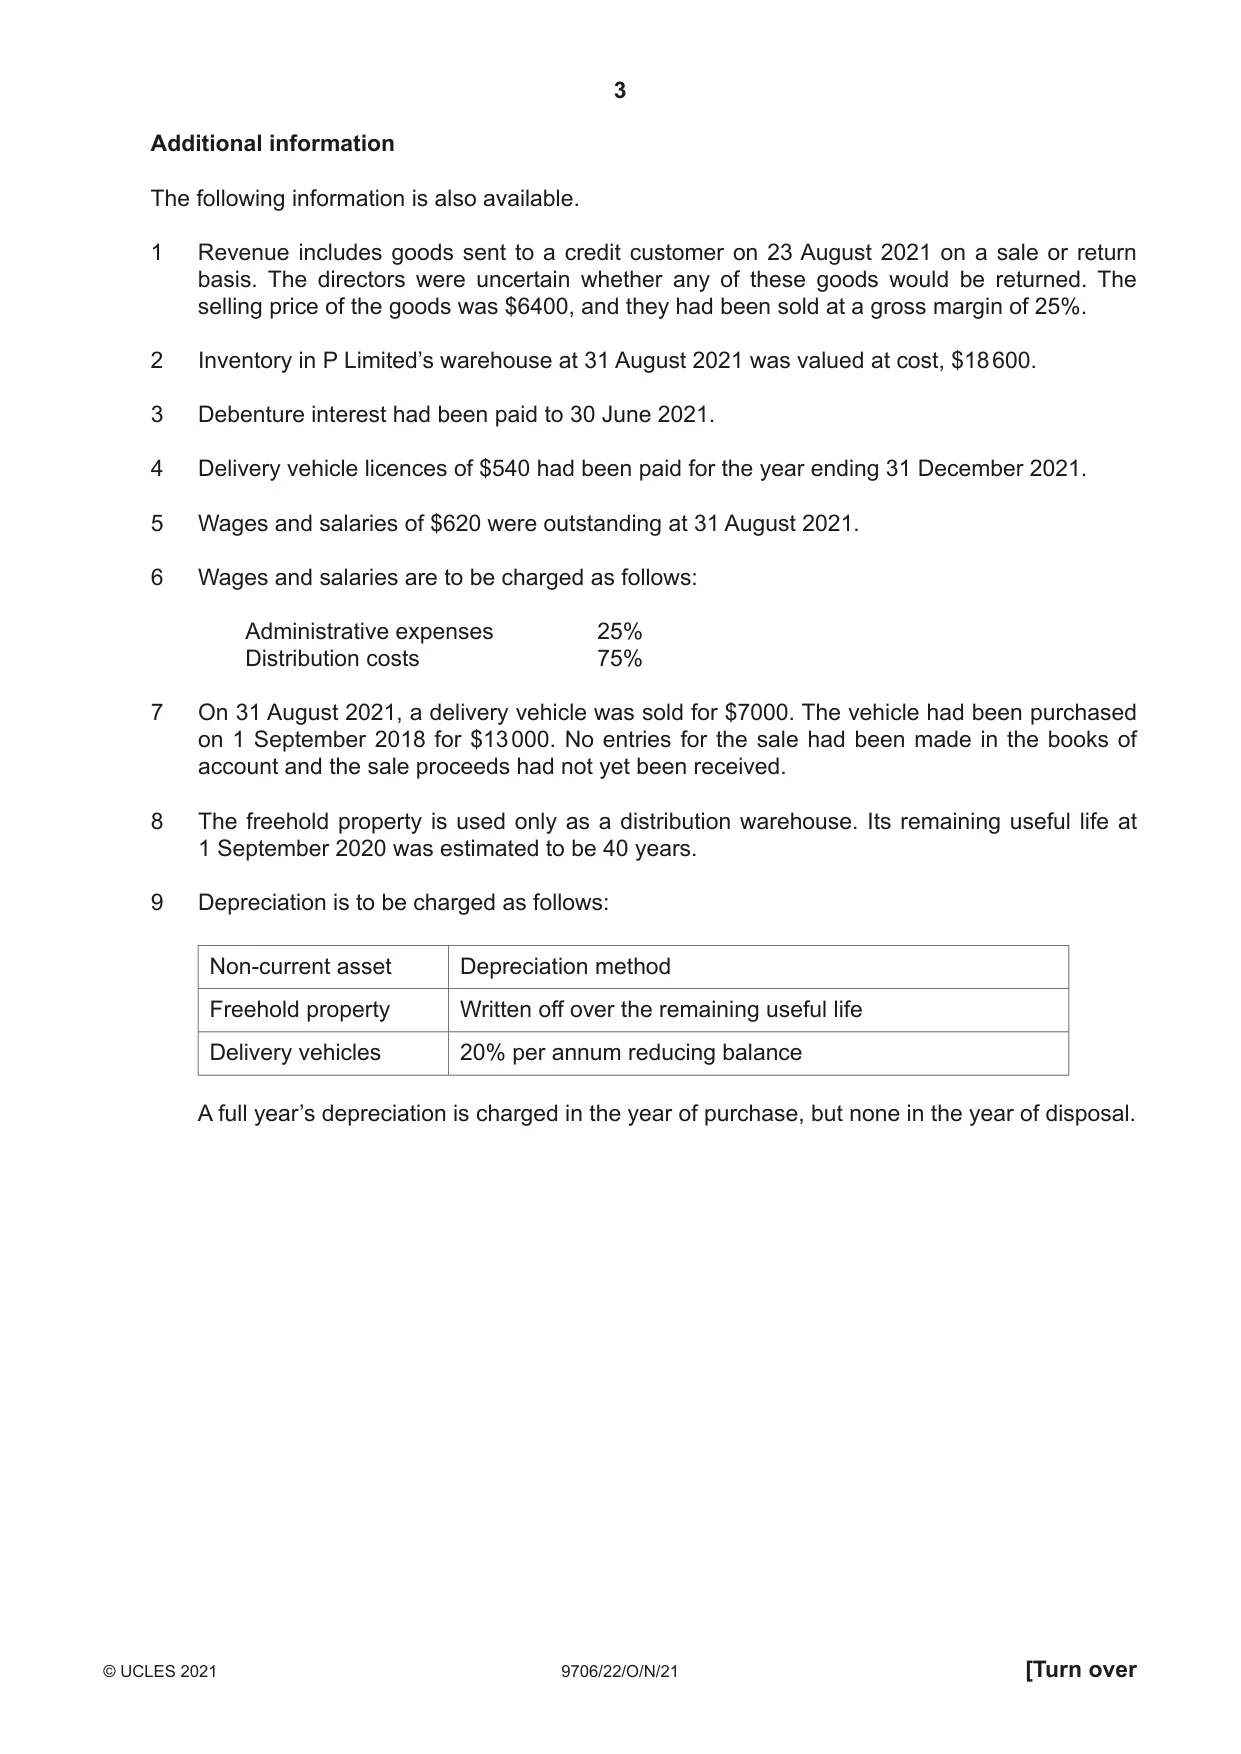
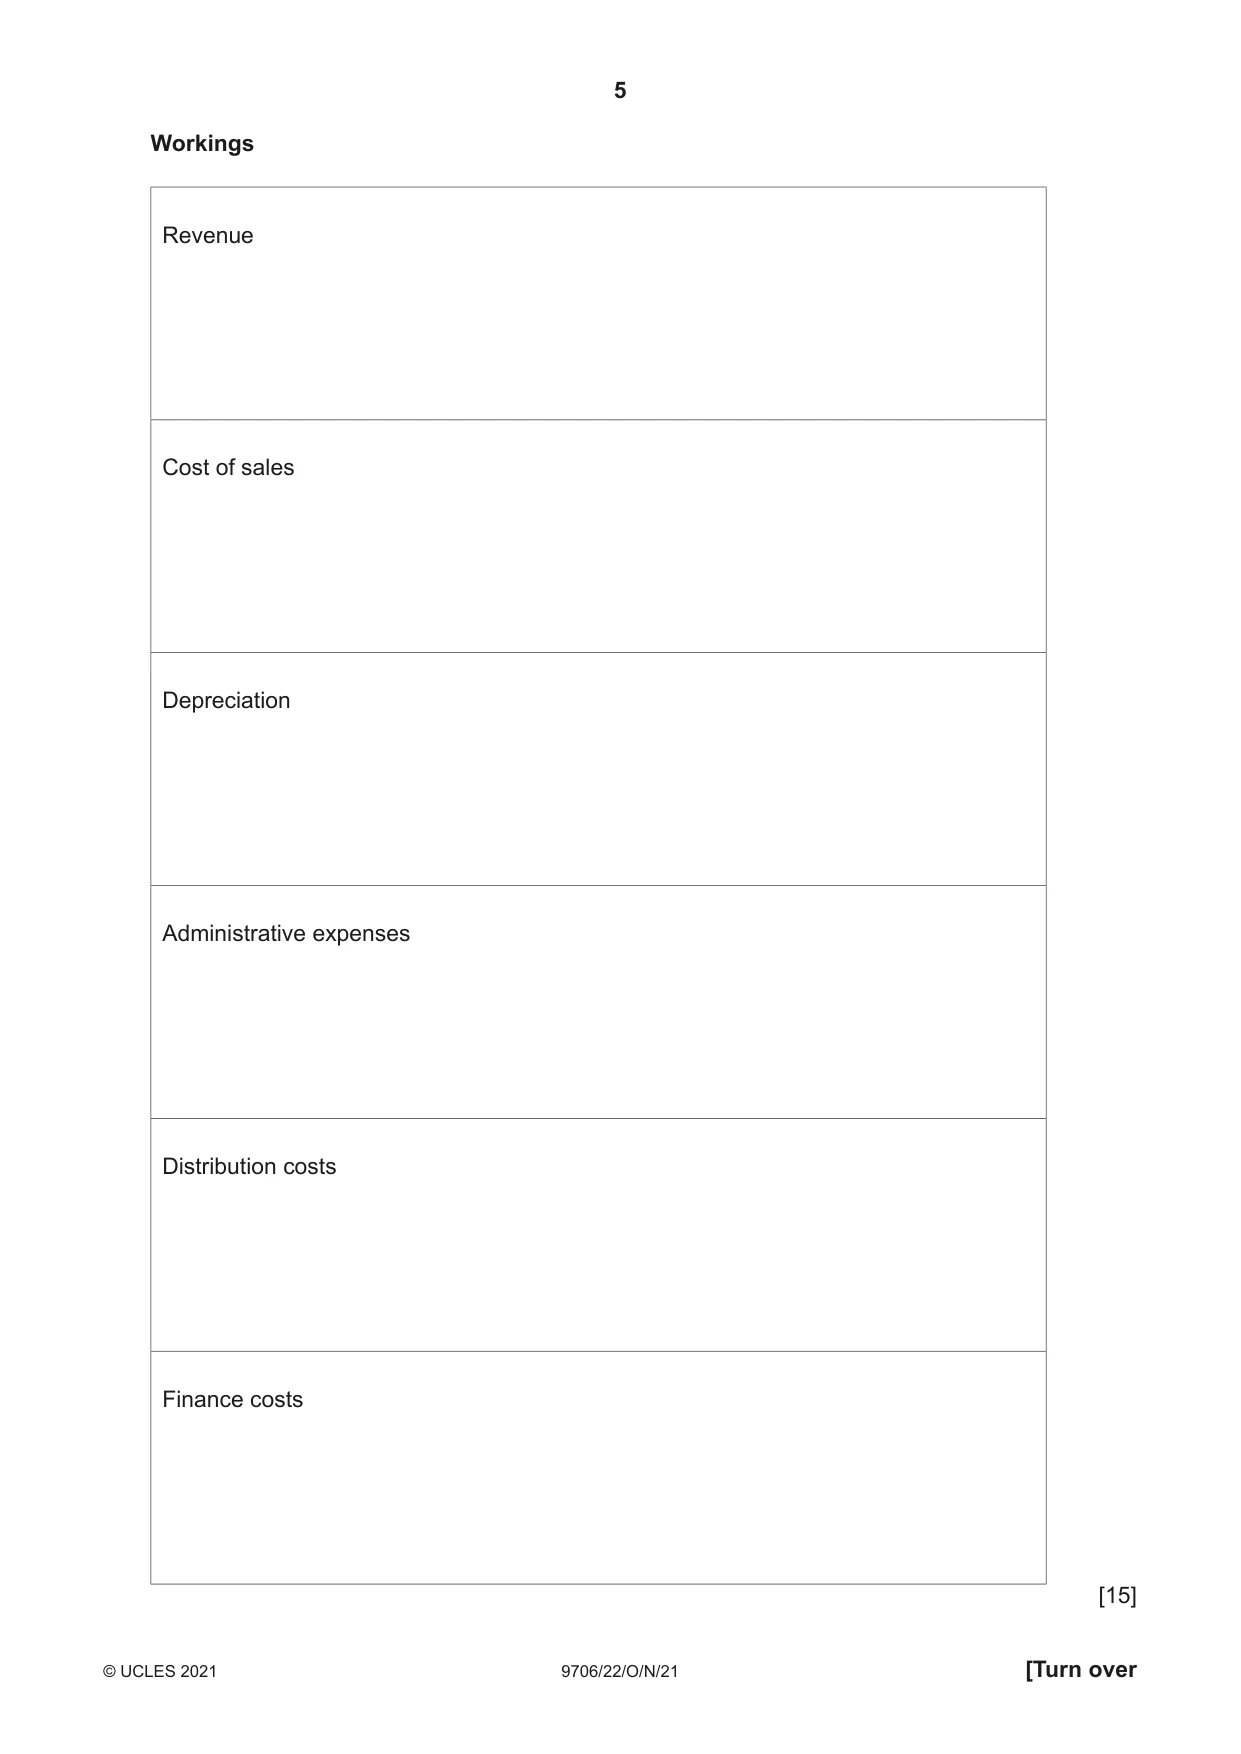
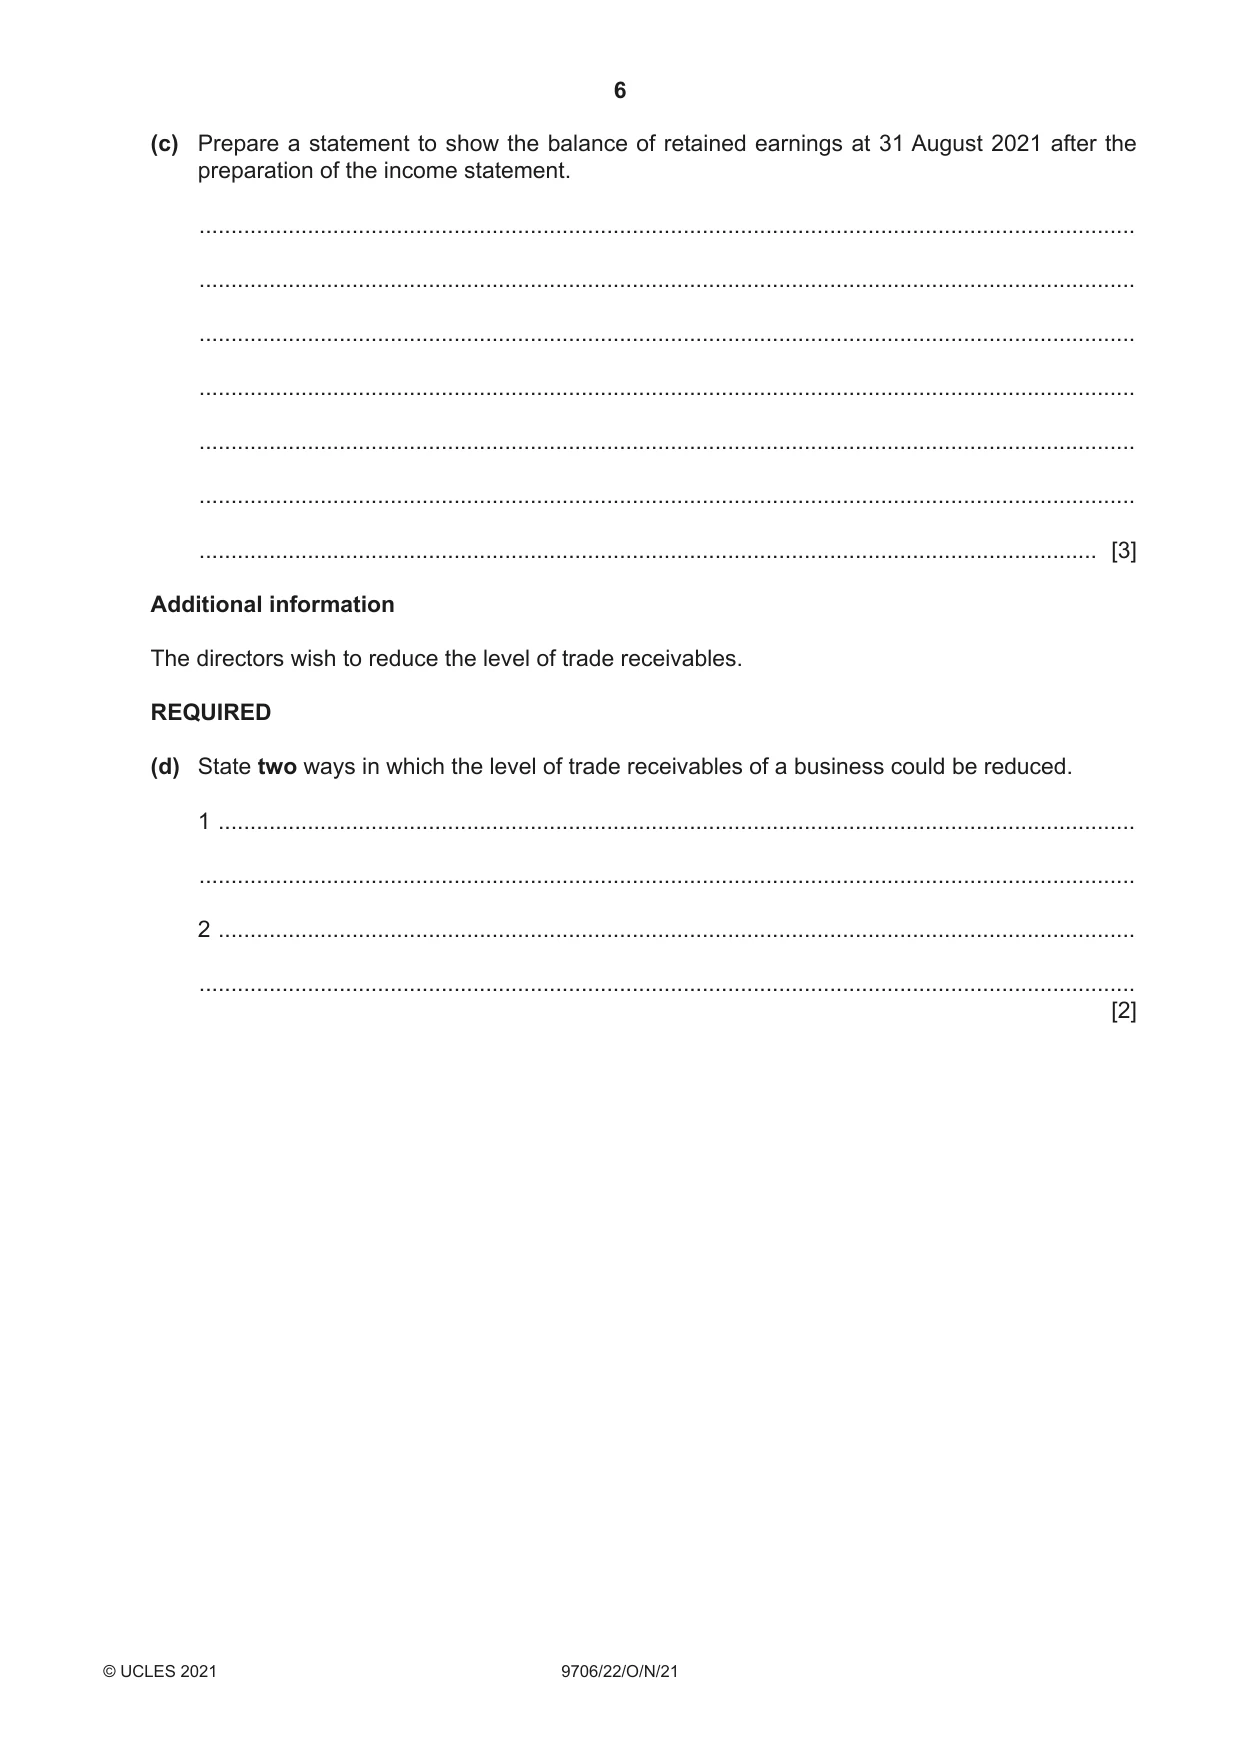
1 The following balances have been extracted from the books of P Limited at 31 August 2021. $ 5% Debentures (2022–2023) 36 000 Administrative expenses 35 180 Bank 4 770 Credit Carriage inwards 390 Delivery vehicles Cost 89 420 Provision for depreciation at 1 September 2020 42 200 Distribution costs 44 320 Dividend paid 3 000 Freehold property at valuation at 31 August 2020 66 000 Interest paid 1 590 Inventory at 1 September 2020 22 880 Purchases 88 900 Revenue 216 600 Retained earnings 24 200 Returns outwards 260 Revaluation reserve 6 000 Share capital (ordinary shares of $0.50 each) 60 000 Share premium 8 500 Trade payables 11 730 Trade receivables 32 480 Wages and salaries 26 100 The freehold property was revalued on 1 September 2020 at $58 000. The revaluation has not yet been recorded in the books of account. REQUIRED (a) Prepare the journal entry to record the revaluation of the freehold property on 1 September 2020. A narrative is not required. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Additional information The following information is also available. 1 Revenue includes goods sent to a credit customer on 23 August 2021 on a sale or return basis. The directors were uncertain whether any of these goods would be returned. The selling price of the goods was $6400, and they had been sold at a gross margin of 25%.
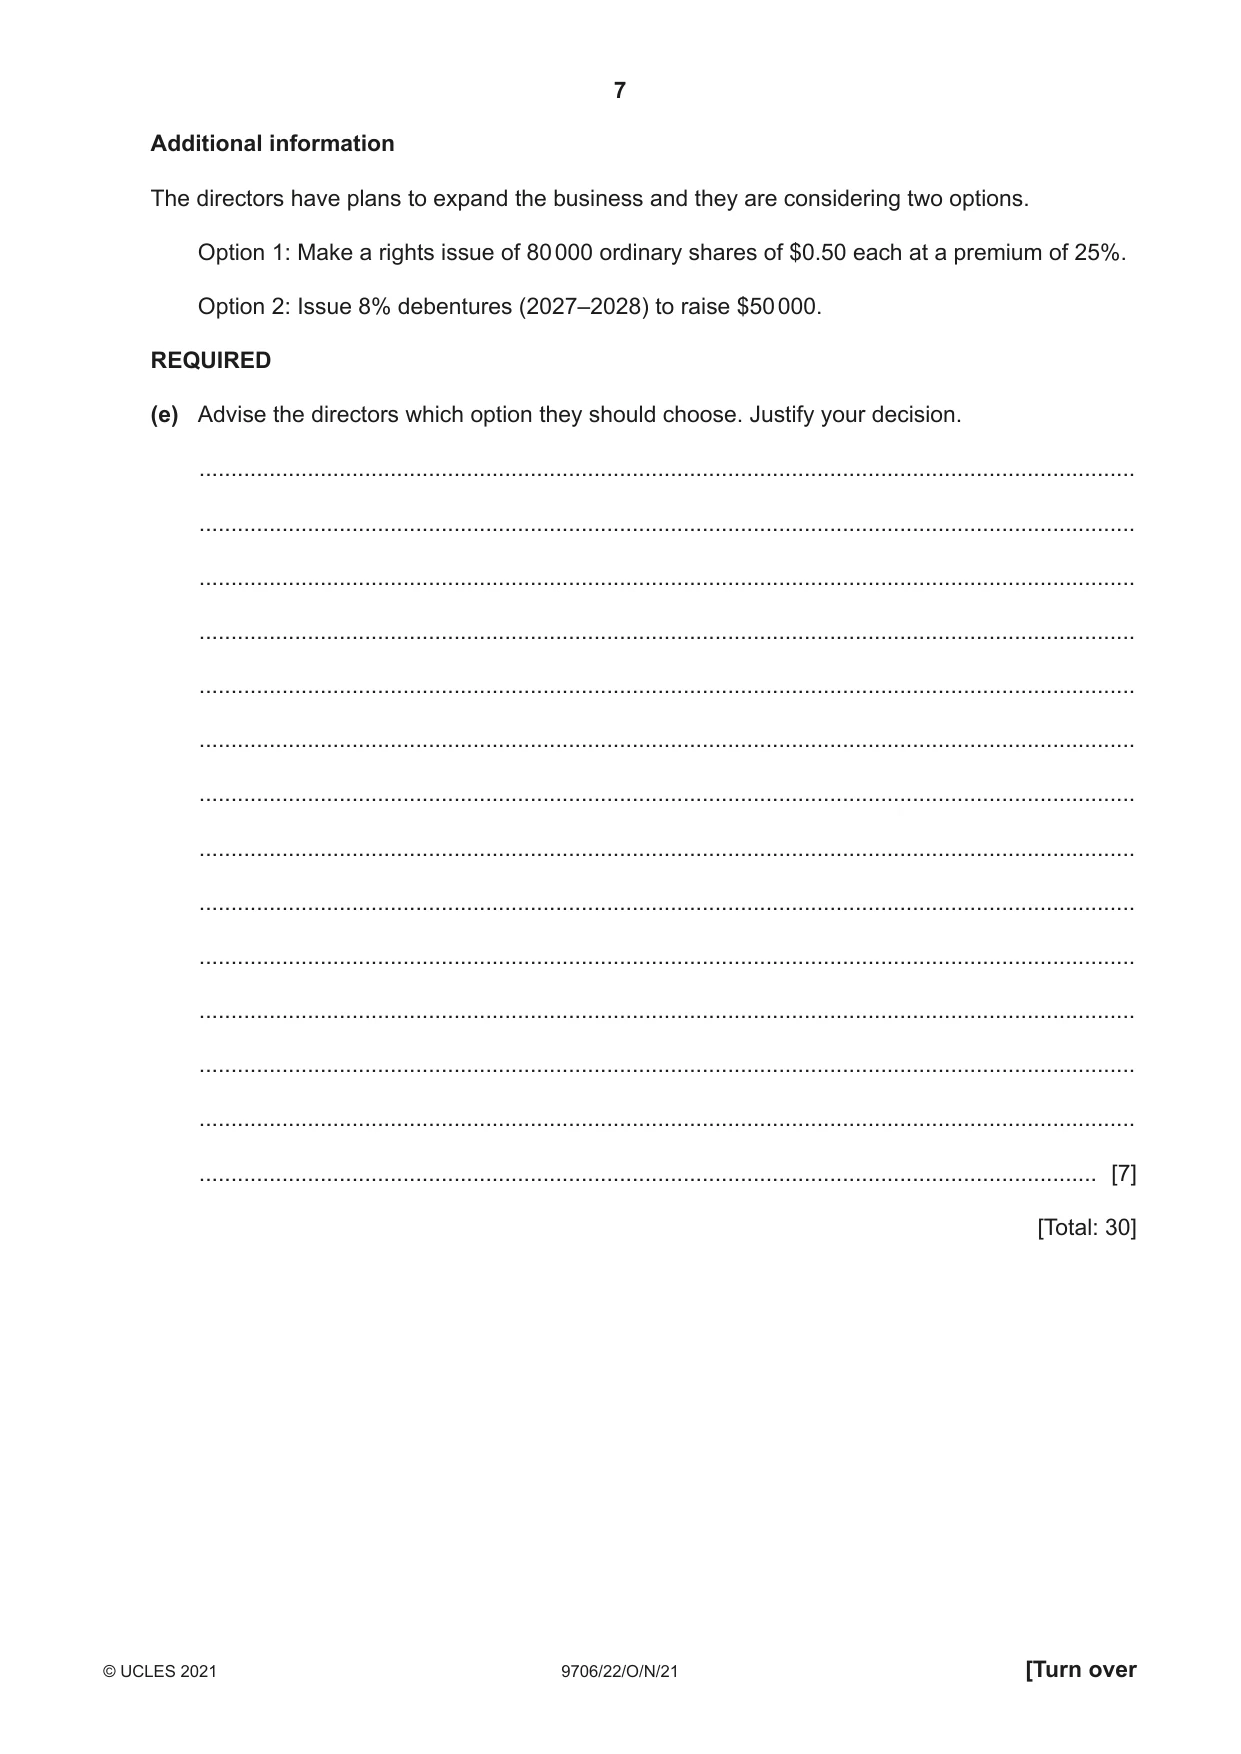
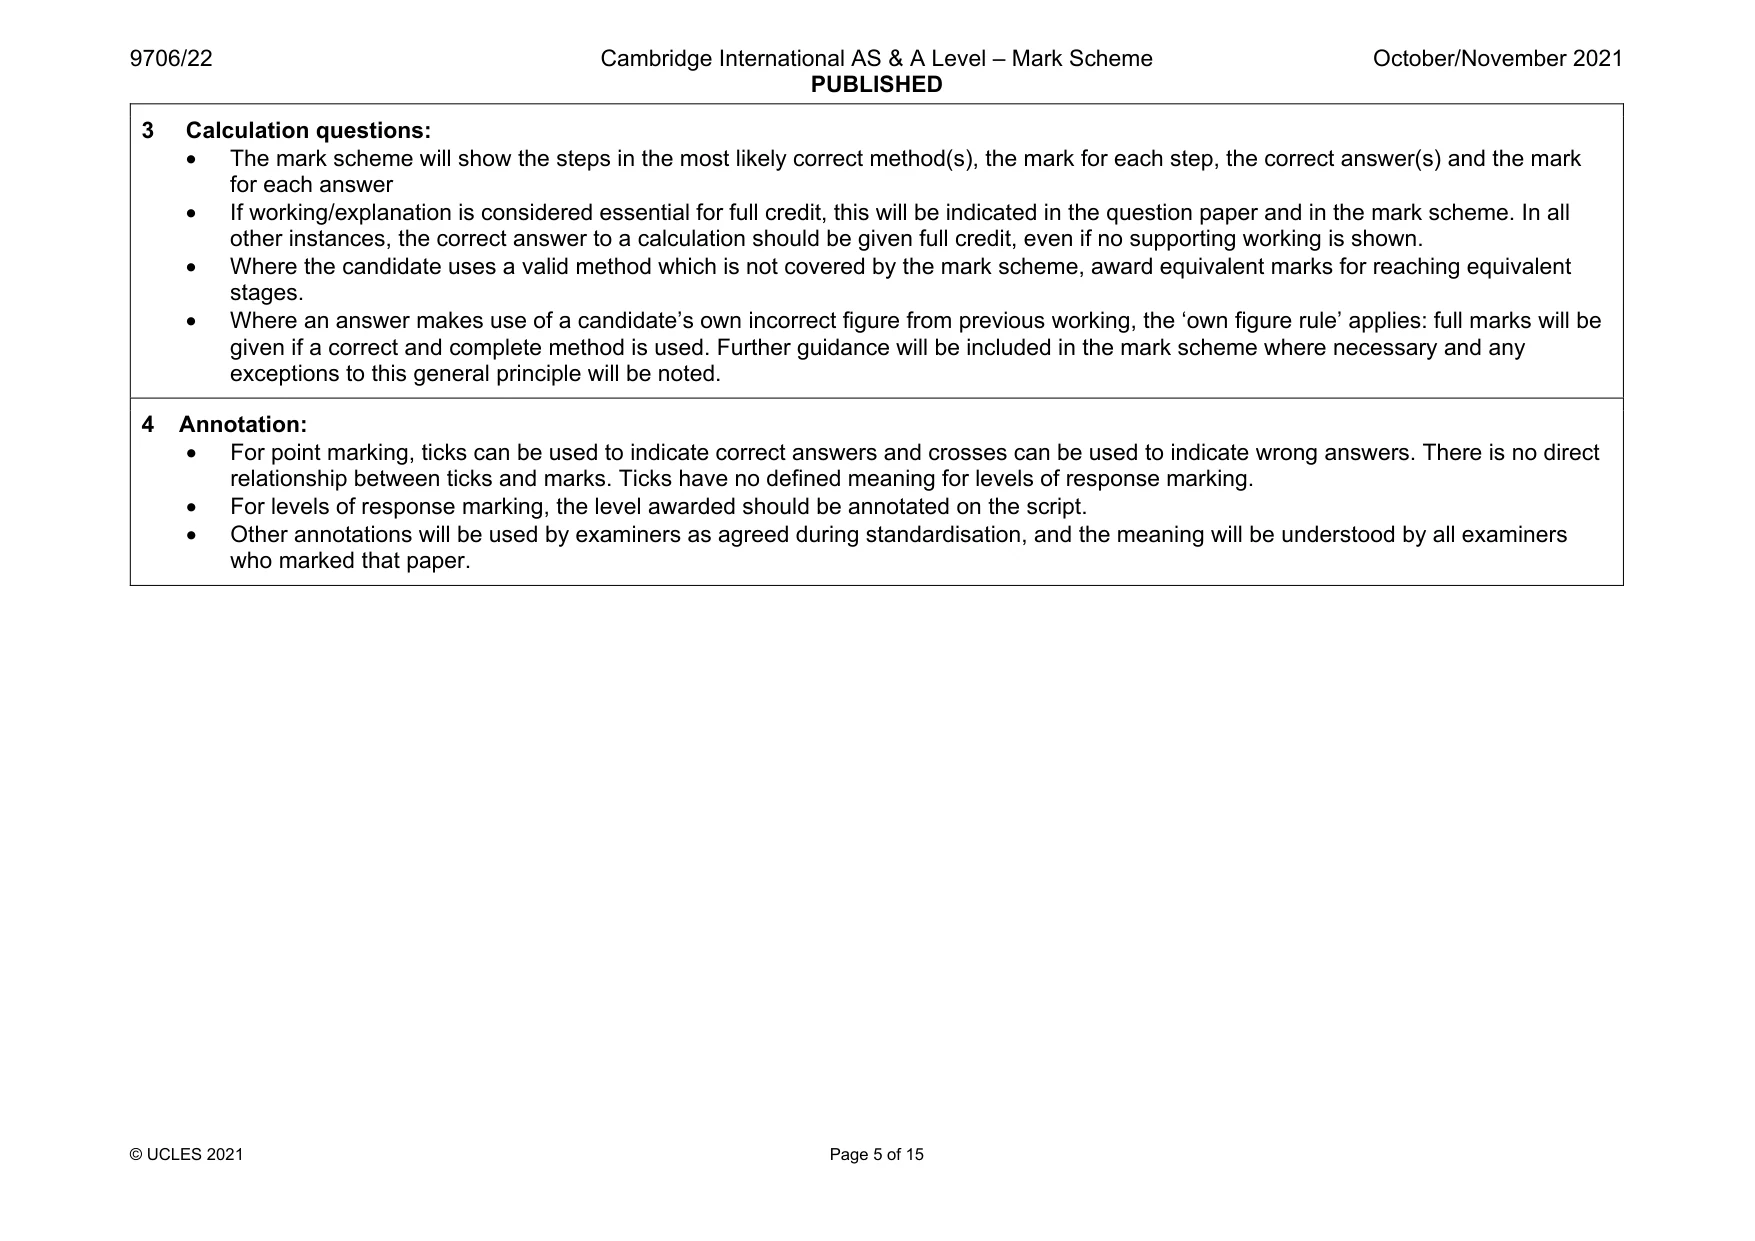
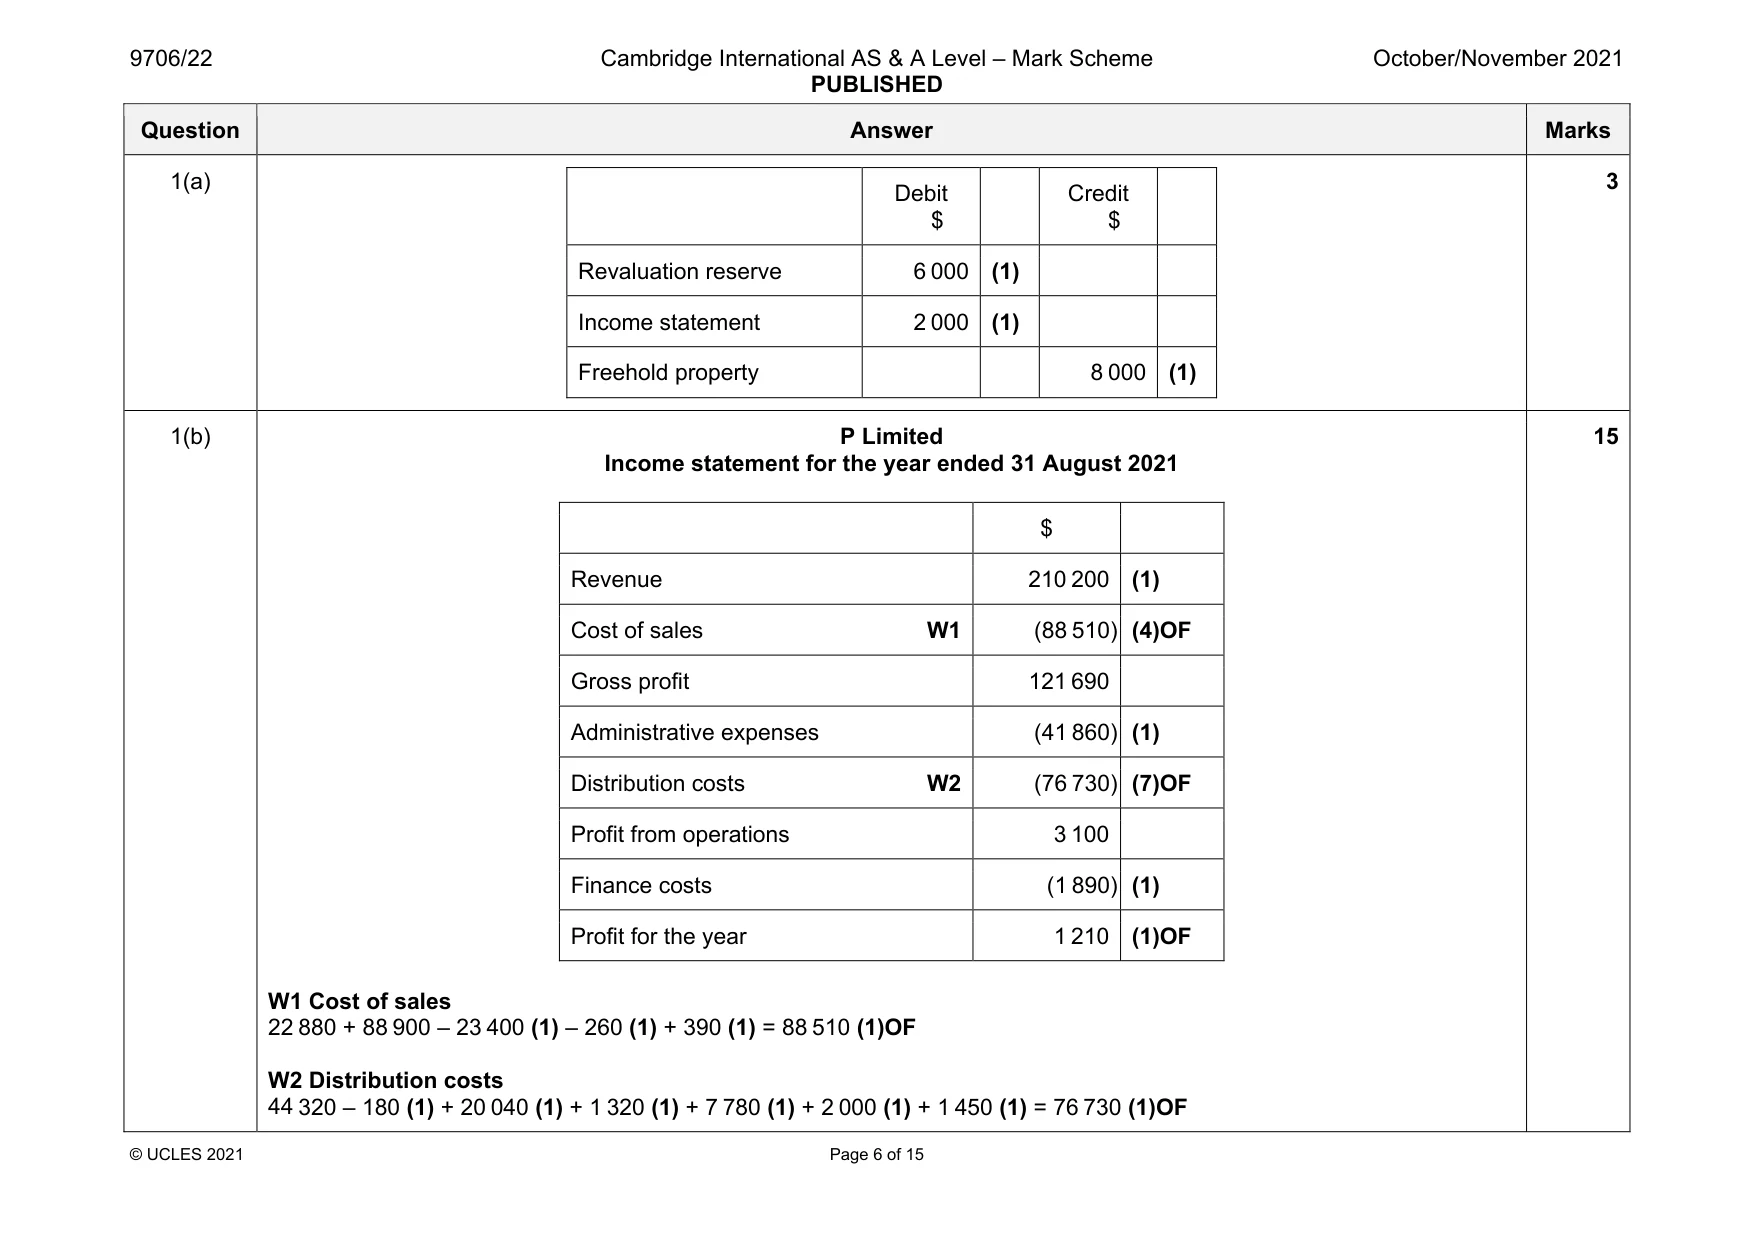
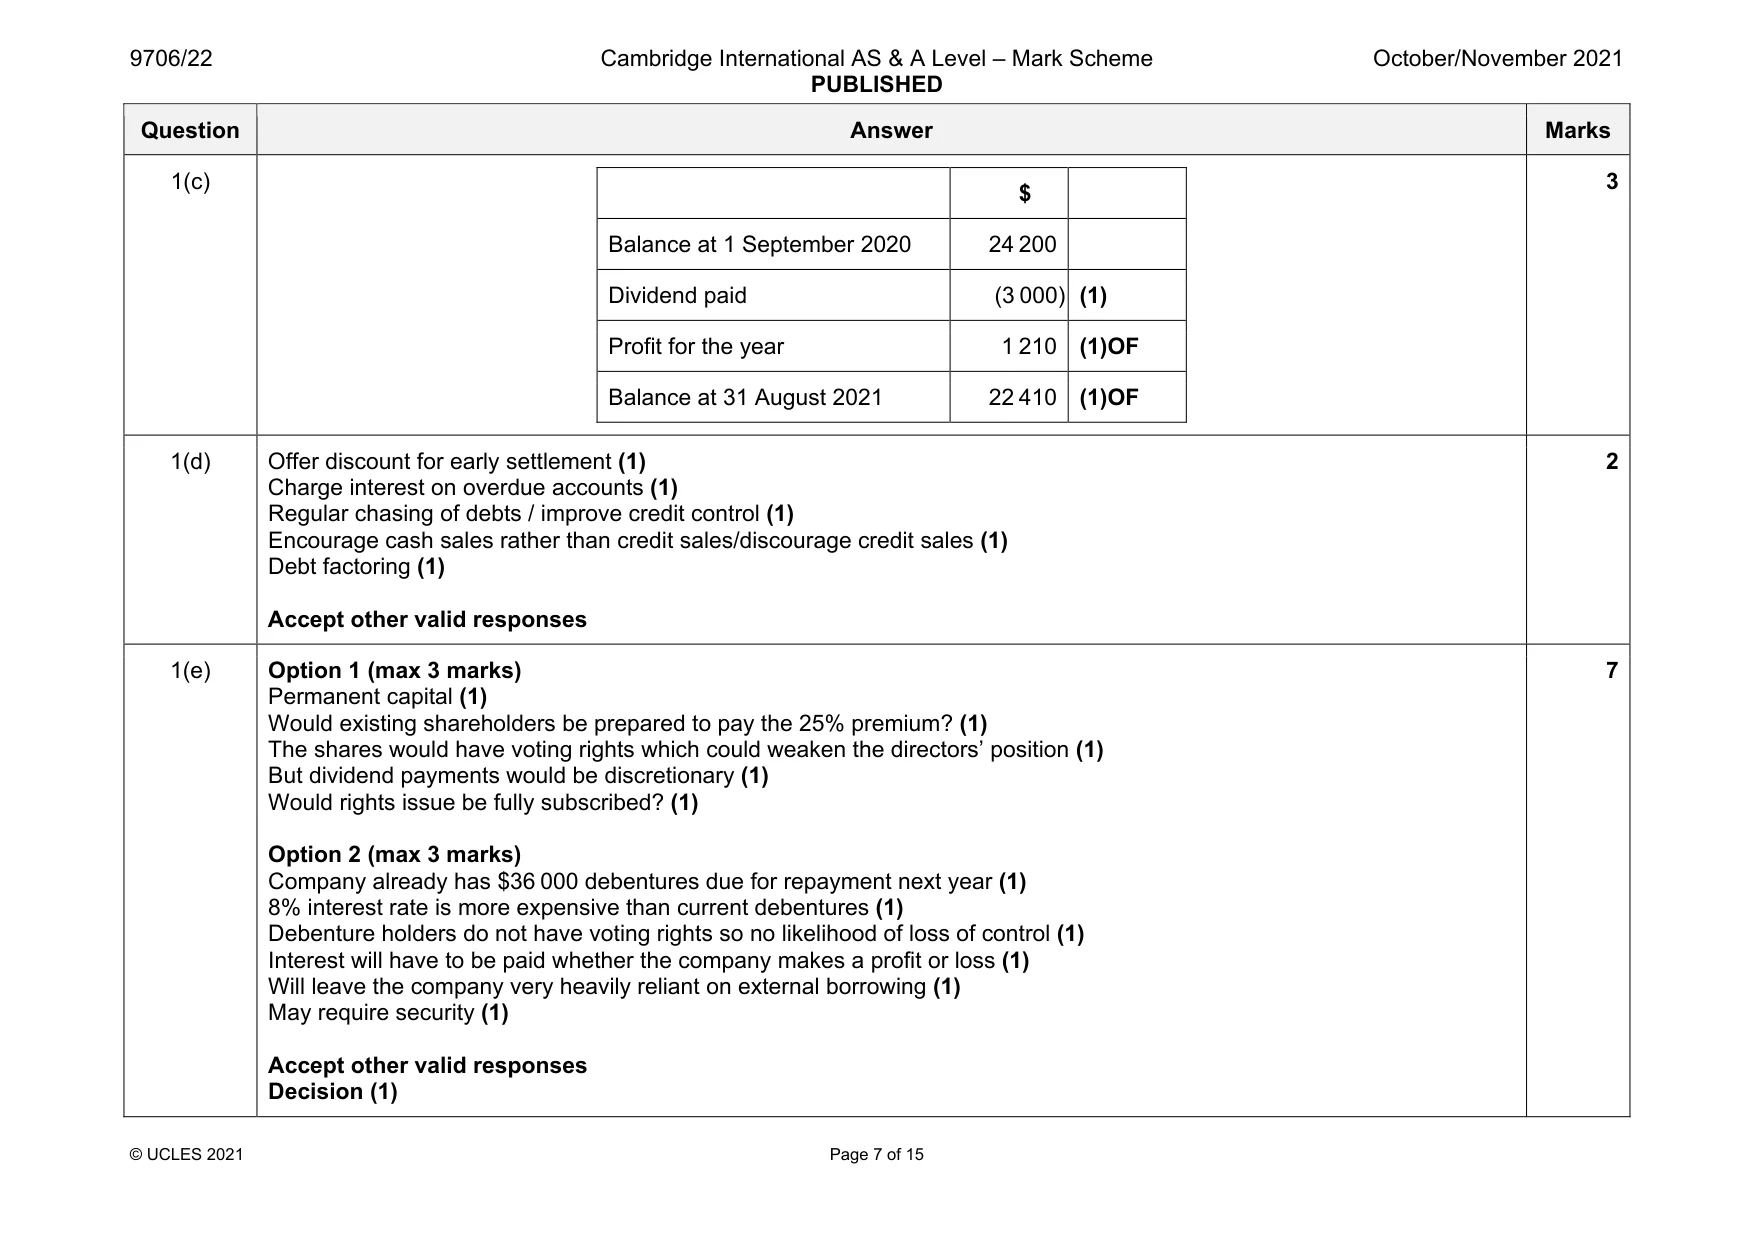
Mark scheme: 1(a) Debit $ Credit $ Revaluation reserve 6 000 (1) Income statement 2 000 (1) Freehold property 8 000 (1) 3 1(b) P Limited Income statement for the year ended 31 August 2021 $ Revenue 210 200 (1) Cost of sales W1 (88 510) (4)OF Gross profit 121 690 Administrative expenses (41 860) (1) Distribution costs W2 (76 730) (7)OF Profit from operations 3 100 Finance costs (1 890) (1) Profit for the year 1 210 (1)OF W1 Cost of sales 22 880 + 88 900 – 23 400 (1) – 260 (1) + 390 (1) = 88 510 (1)OF W2 Distribution costs 44 320 – 180 (1) + 20 040 (1) + 1 320 (1) + 7 780 (1) + 2 000 (1) + 1 450 (1) = 76 730 (1)OF 15 Question Answer Marks 1(c) $ Balance at 1 September 2020 24 200 Dividend paid (3 000) (1) Profit for the year 1 210 (1)OF Balance at 31 August 2021 22 410 (1)OF 3 1(d) Offer discount for early settlement (1) Charge interest on overdue accounts (1) Regular chasing of debts / improve credit control (1) Encourage cash sales rather than credit sales/discourage credit sales (1) Debt factoring (1) Accept other valid responses 2 1(e) Option 1 (max 3 marks) Permanent capital (1) Would existing shareholders be prepared to pay the 25% premium? (1) The shares would have voting rights which could weaken the directors’ position (1) But dividend payments would be discretionary (1) Would rights issue be fully subscribed? (1) Option 2 (max 3 marks) Company already has $36 000 debentures due for repayment next year (1) 8% interest rate is more expensive than current debentures (1) Debenture holders do not have voting rights so no likelihood of loss of control (1) Interest will have to be paid whether the company makes a profit or loss (1) Will leave the company very heavily reliant on external borrowing (1) May require security (1) Accept other valid responses Decision (1) 7
Q2 · Shamal maintains a full set of accounting records
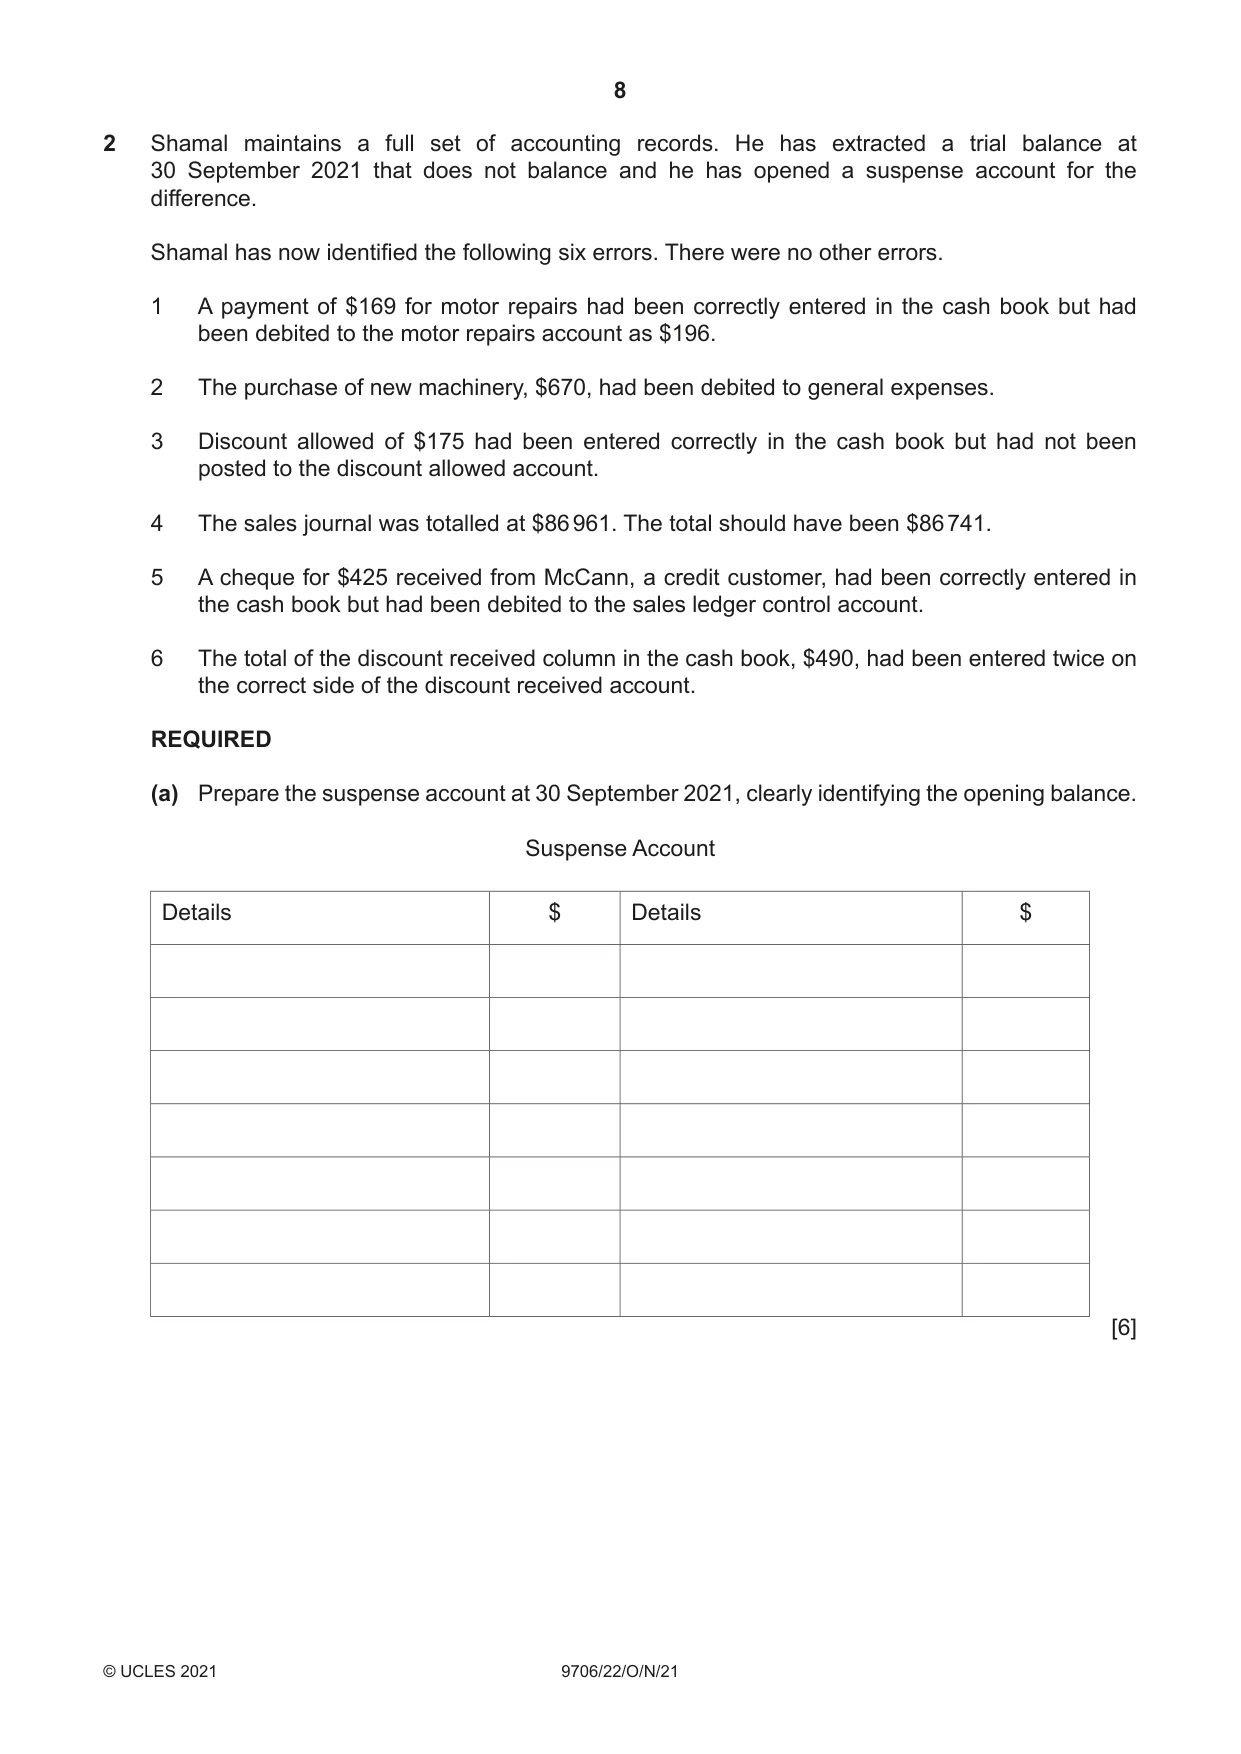
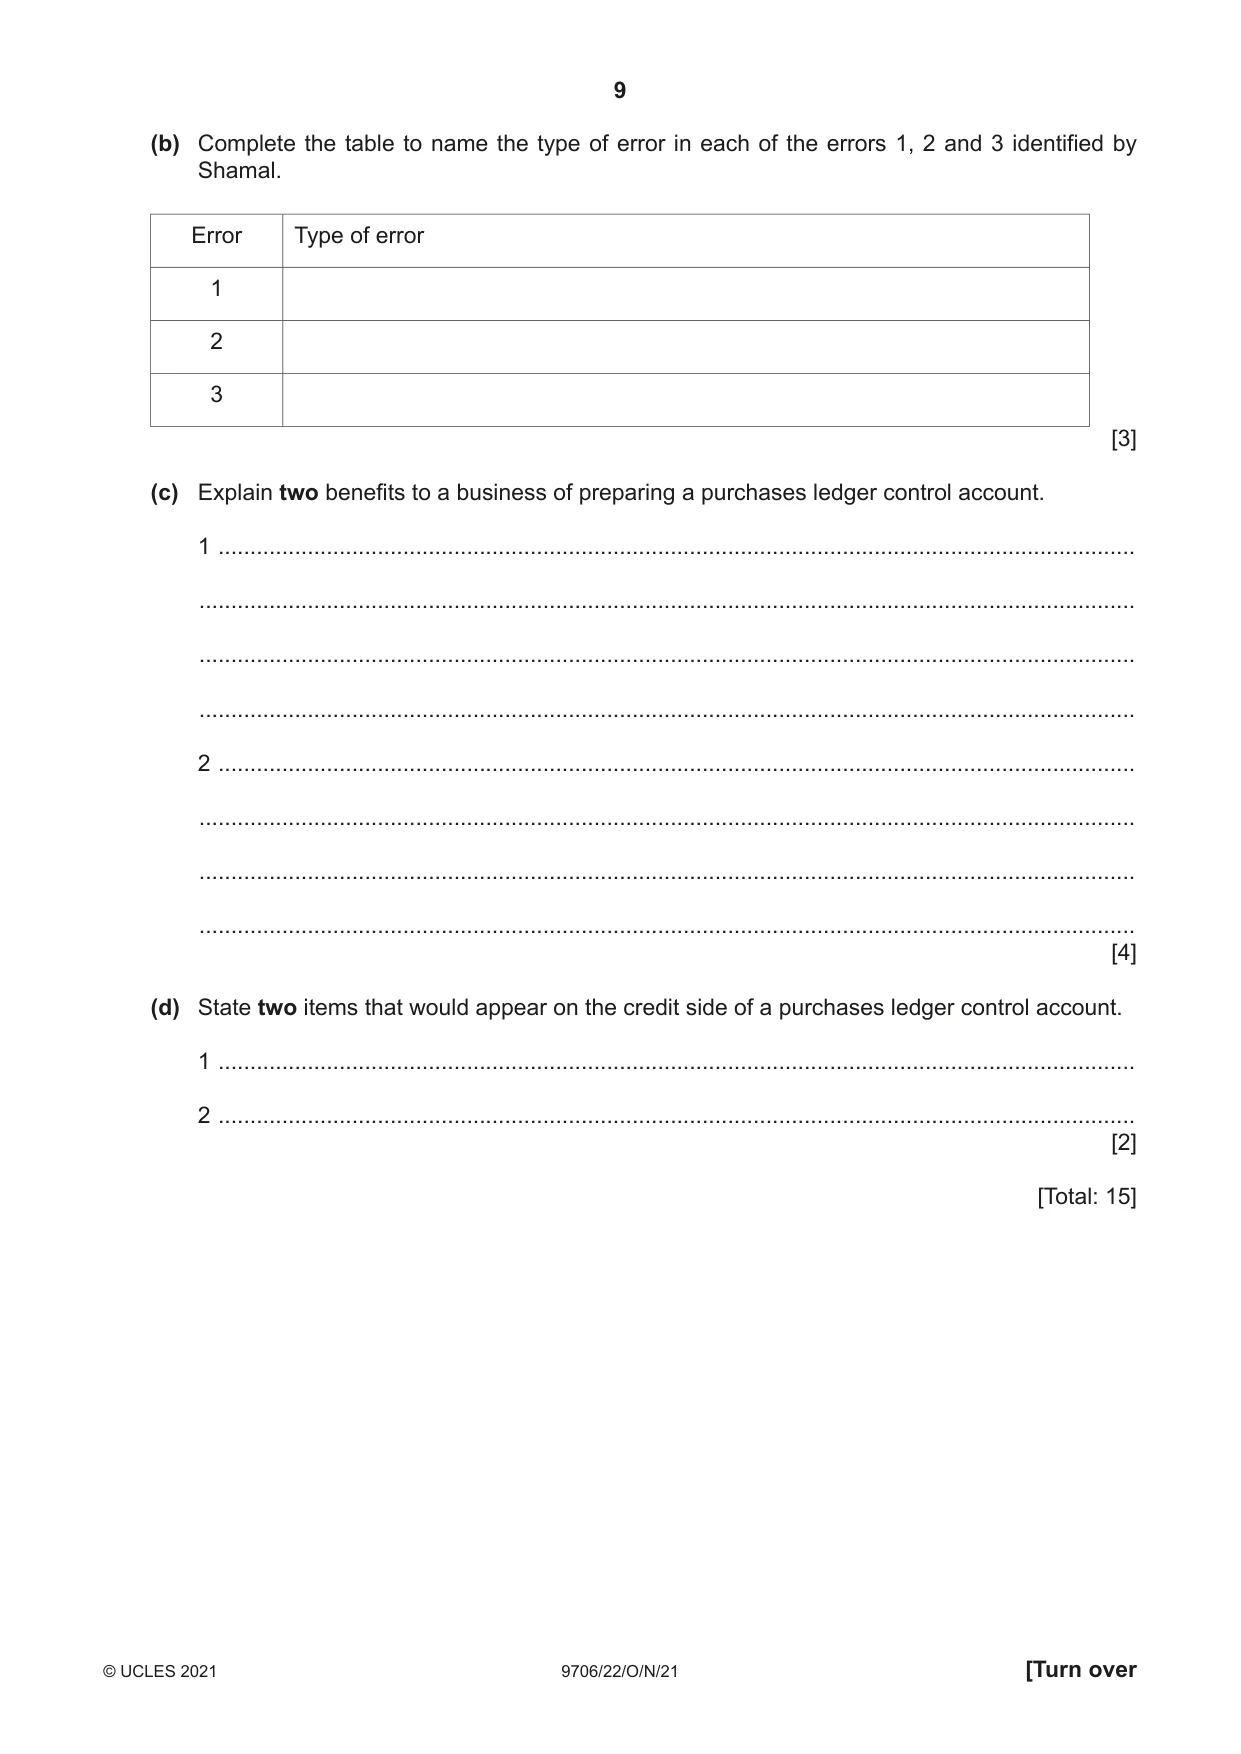
2 Shamal maintains a full set of accounting records. He has extracted a trial balance at 30 September 2021 that does not balance and he has opened a suspense account for the difference. Shamal has now identified the following six errors. There were no other errors. 1 A payment of $169 for motor repairs had been correctly entered in the cash book but had been debited to the motor repairs account as $196. 2 The purchase of new machinery, $670, had been debited to general expenses. 3 Discount allowed of $175 had been entered correctly in the cash book but had not been posted to the discount allowed account. 4 The sales journal was totalled at $86 961. The total should have been $86 741. 5 A cheque for $425 received from McCann, a credit customer, had been correctly entered in the cash book but had been debited to the sales ledger control account. 6 The total of the discount received column in the cash book, $490, had been entered twice on the correct side of the discount received account. REQUIRED (a) Prepare the suspense account at 30 September 2021, clearly identifying the opening balance. Suspense Account Details $ Details $ [6] (b) Complete the table to name the type of error in each of the errors 1, 2 and 3 identified by Shamal. Error Type of error 1 2 3 [3] (c) Explain two benefits to a business of preparing a purchases ledger control account. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] (d) State two items that would appear on the credit side of a purchases ledger control account. 1 ................................................................................................................................................ 2 ................................................................................................................................................ [2] [Total: 15]
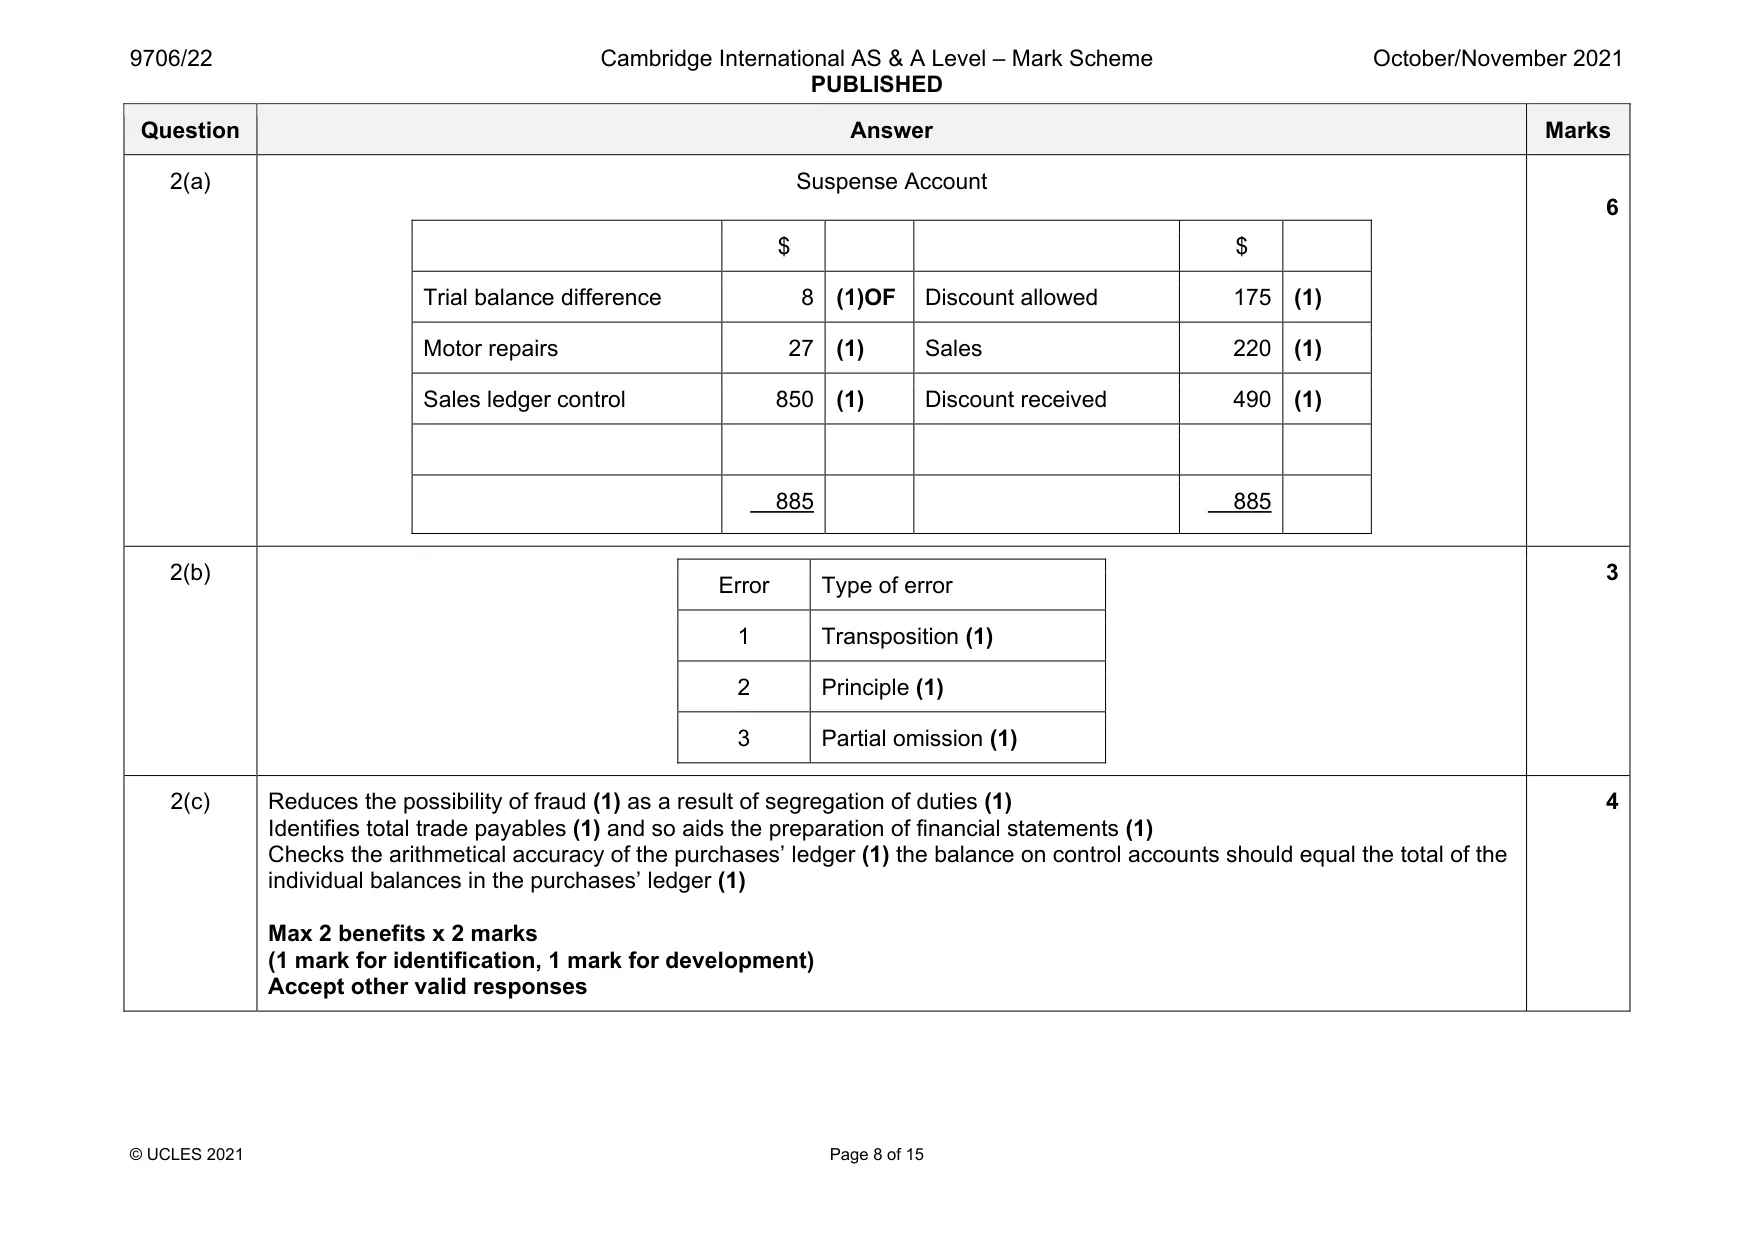
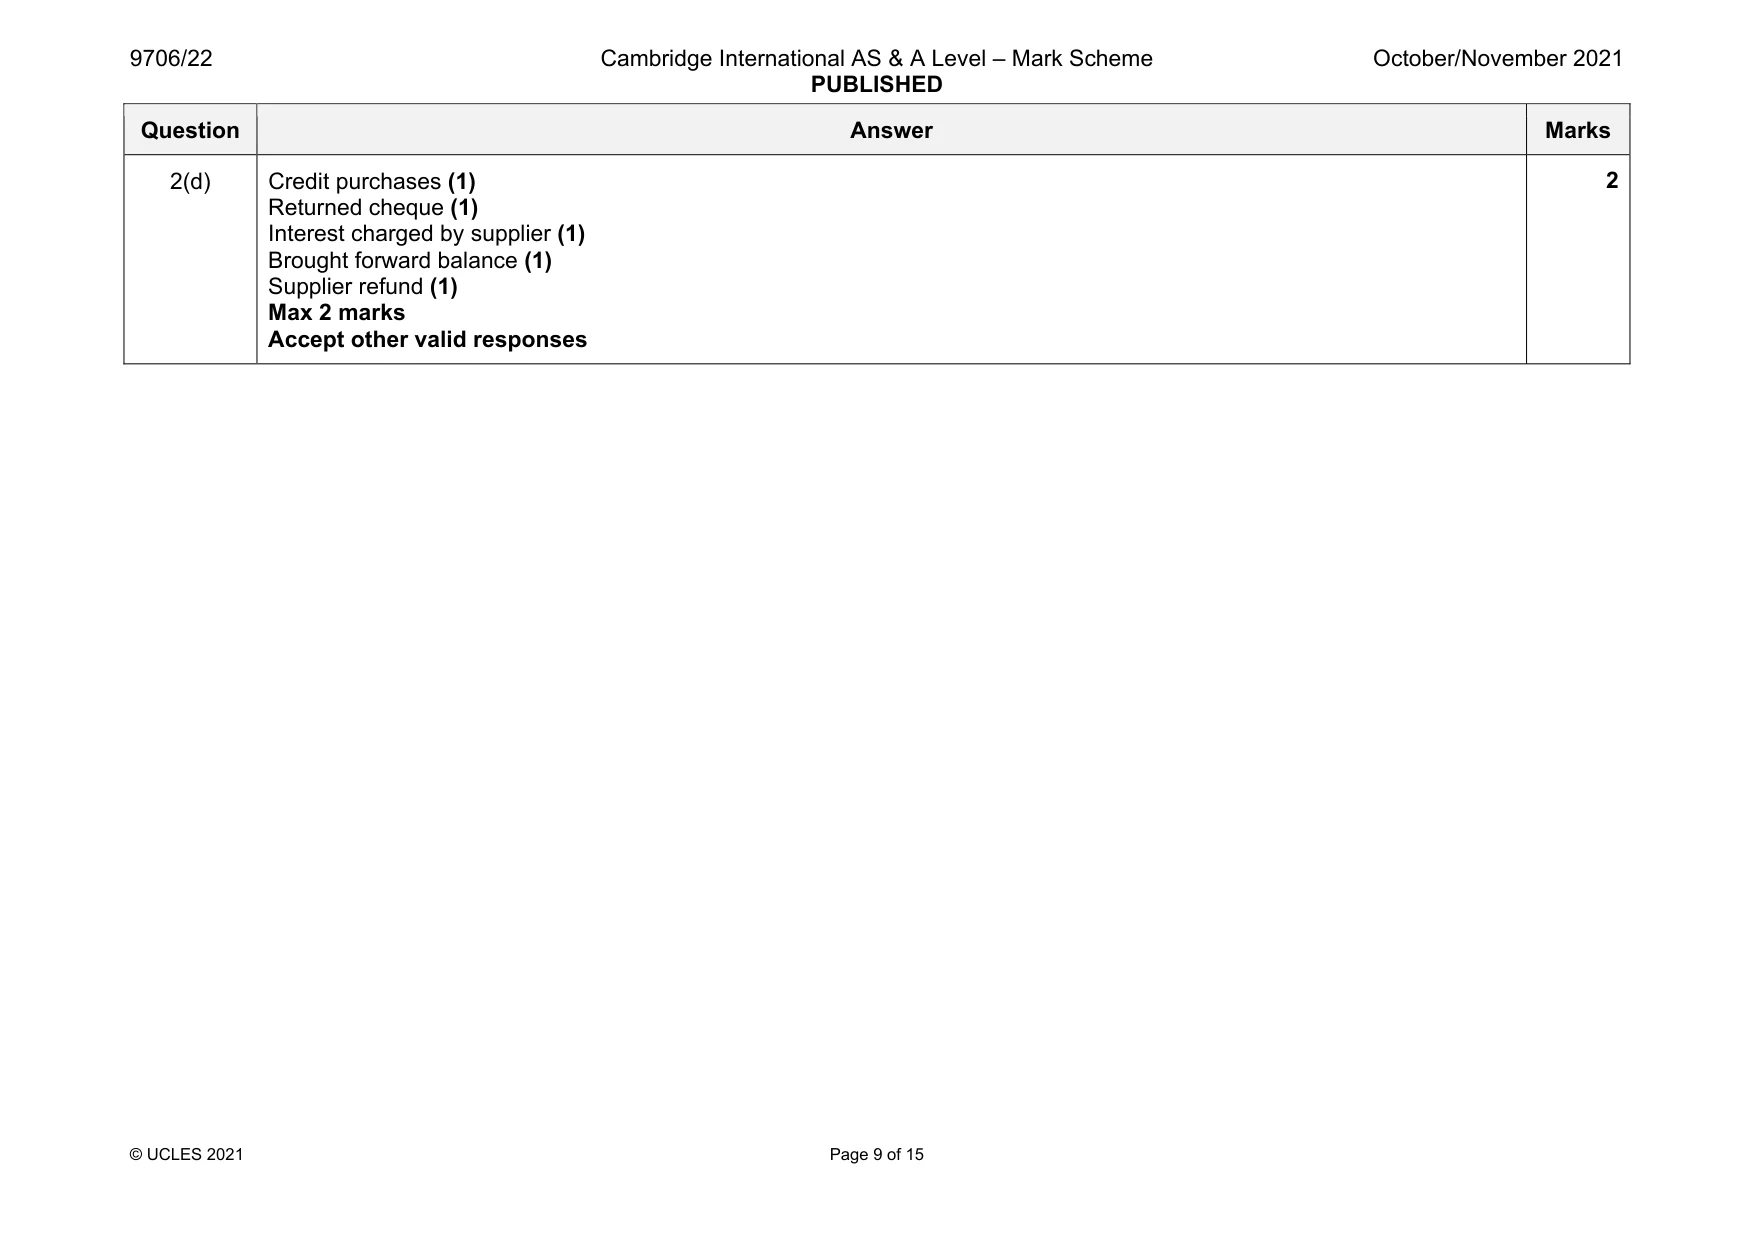
Mark scheme: 2(a) Suspense Account $ $ Trial balance difference 8 (1)OF Discount allowed 175 (1) Motor repairs 27 (1) Sales 220 (1) Sales ledger control 850 (1) Discount received 490 (1) 885 885 6 2(b) Error Type of error 1 Transposition (1) 2 Principle (1) 3 Partial omission (1) 3 2(c) Reduces the possibility of fraud (1) as a result of segregation of duties (1) Identifies total trade payables (1) and so aids the preparation of financial statements (1) Checks the arithmetical accuracy of the purchases’ ledger (1) the balance on control accounts should equal the total of the individual balances in the purchases’ ledger (1) Max 2 benefits x 2 marks (1 mark for identification, 1 mark for development) Accept other valid responses 4 Question Answer Marks 2(d) Credit purchases (1) Returned cheque (1) Interest charged by supplier (1) Brought forward balance (1) Supplier refund (1) Max 2 marks Accept other valid responses 2
Q3 · The following information has been extracted from the financial statements of D Limited…
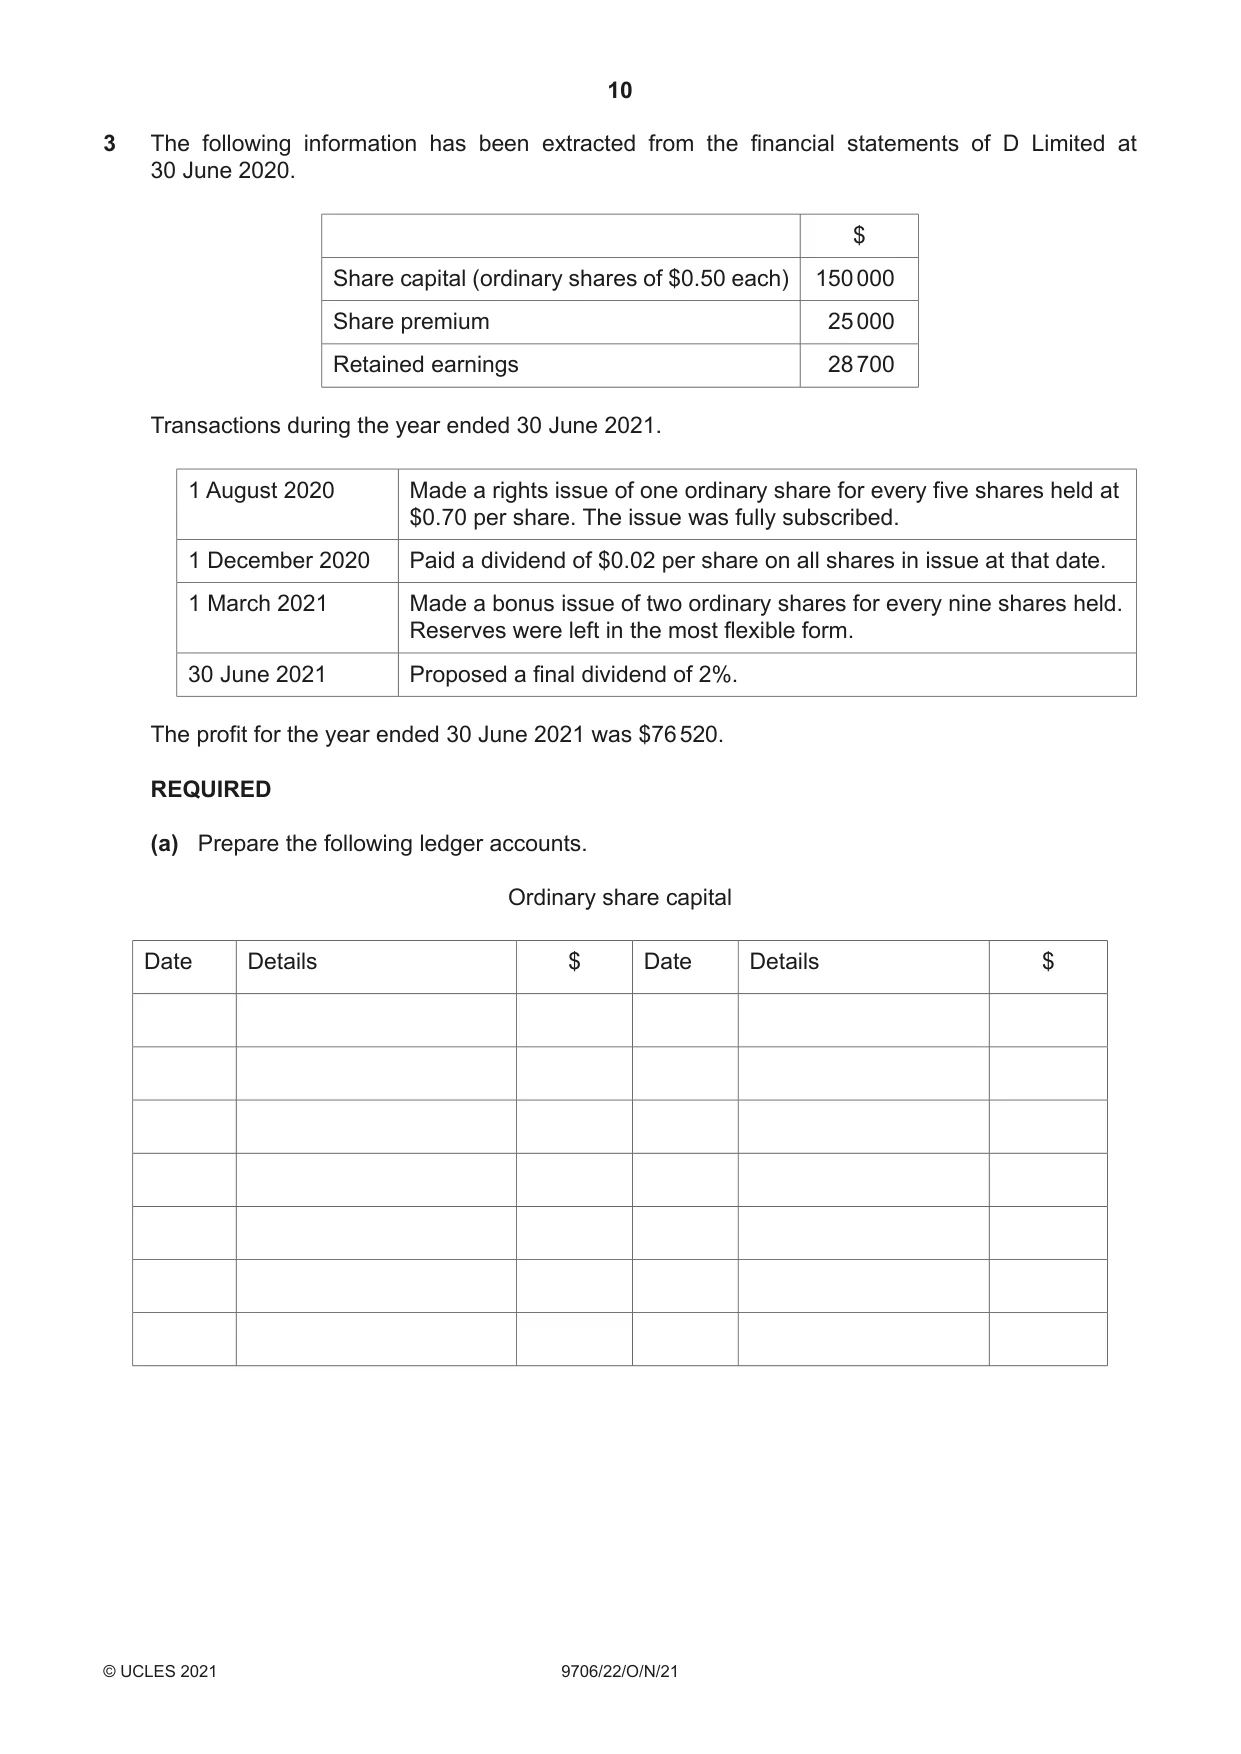
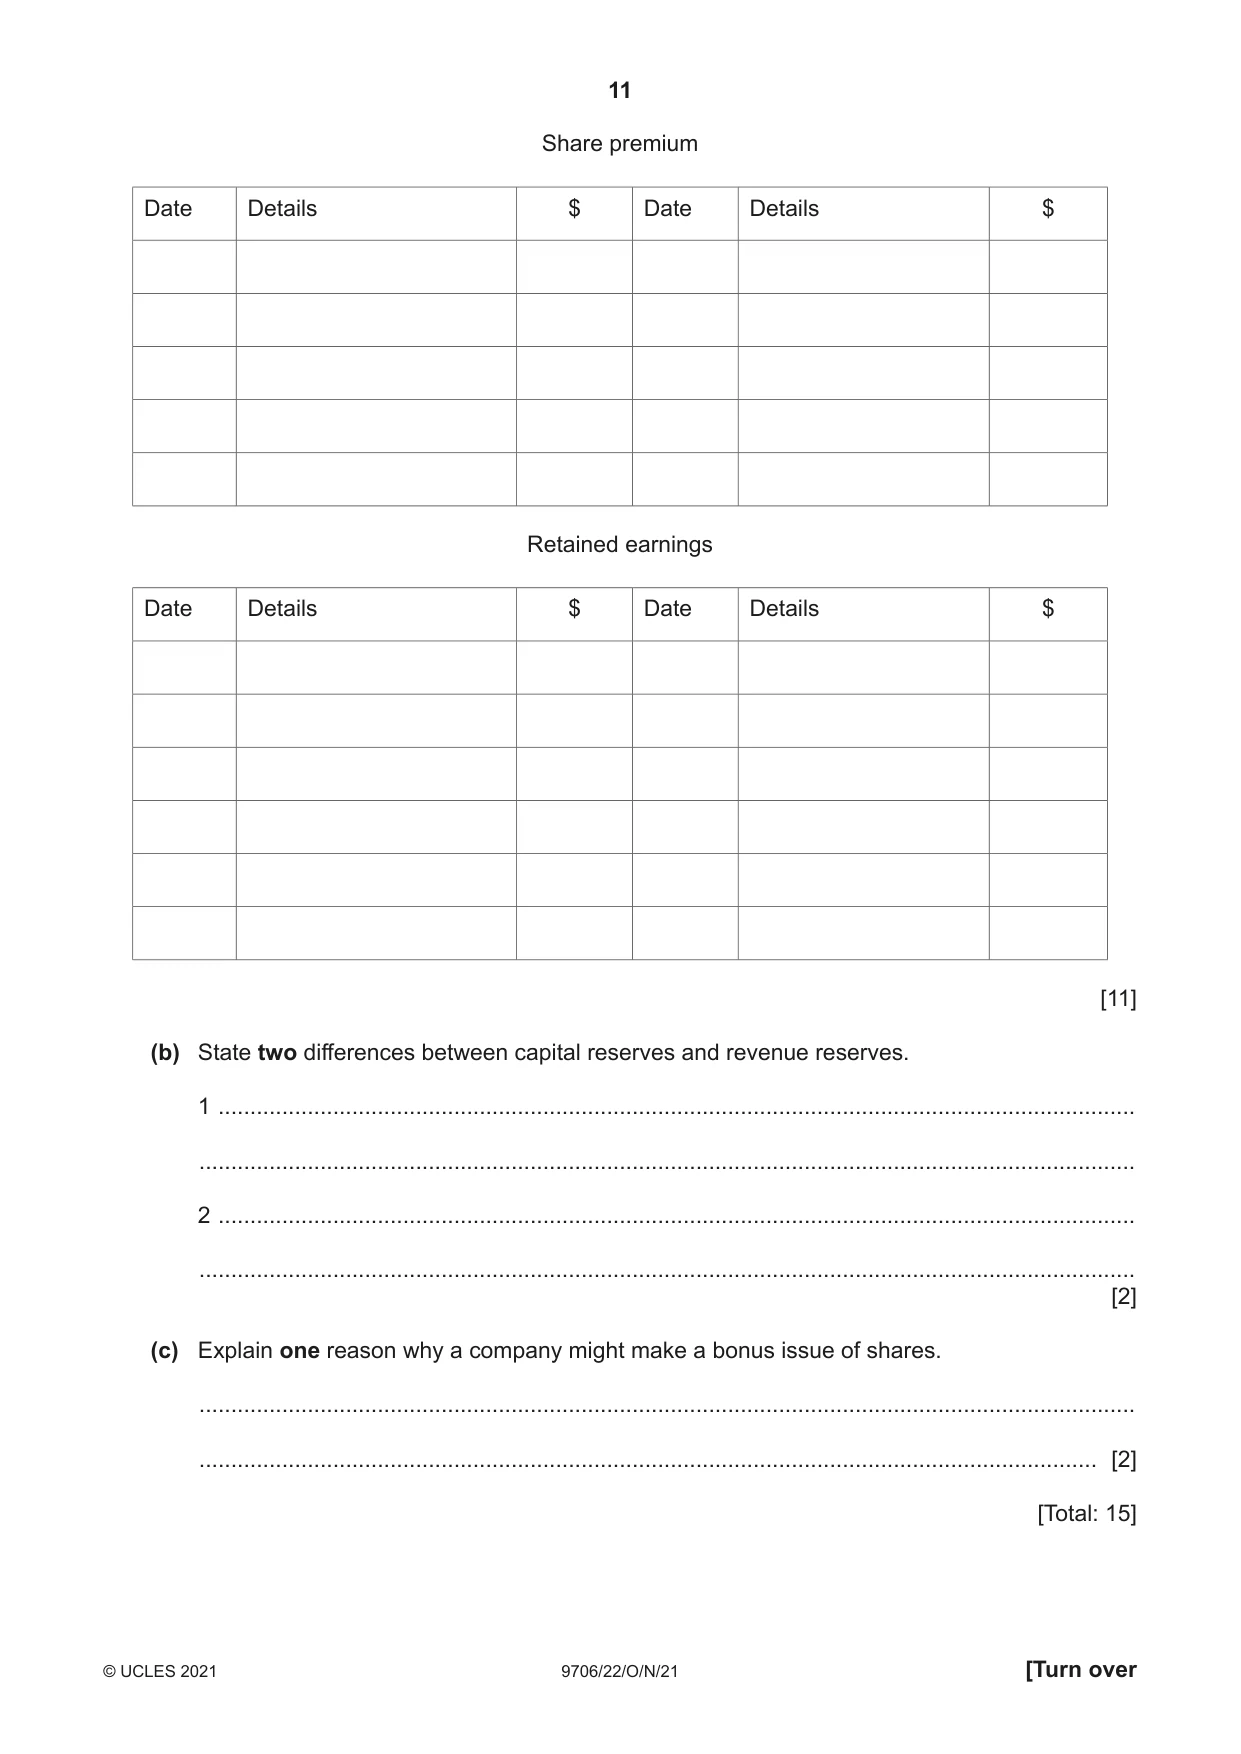
3 The following information has been extracted from the financial statements of D Limited at 30 June 2020. $ Share capital (ordinary shares of $0.50 each) 150 000 Share premium 25 000 Retained earnings 28 700 Transactions during the year ended 30 June 2021. 1 August 2020 Made a rights issue of one ordinary share for every five shares held at $0.70 per share. The issue was fully subscribed. 1 December 2020 Paid a dividend of $0.02 per share on all shares in issue at that date. 1 March 2021 Made a bonus issue of two ordinary shares for every nine shares held. Reserves were left in the most flexible form. 30 June 2021 Proposed a final dividend of 2%. The profit for the year ended 30 June 2021 was $76 520. REQUIRED (a) Prepare the following ledger accounts. Ordinary share capital Date Details $ Date Details $ Share premium Date Details $ Date Details $ Retained earnings Date Details $ Date Details $ [11] (b) State two differences between capital reserves and revenue reserves. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] (c) Explain one reason why a company might make a bonus issue of shares. ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 15]
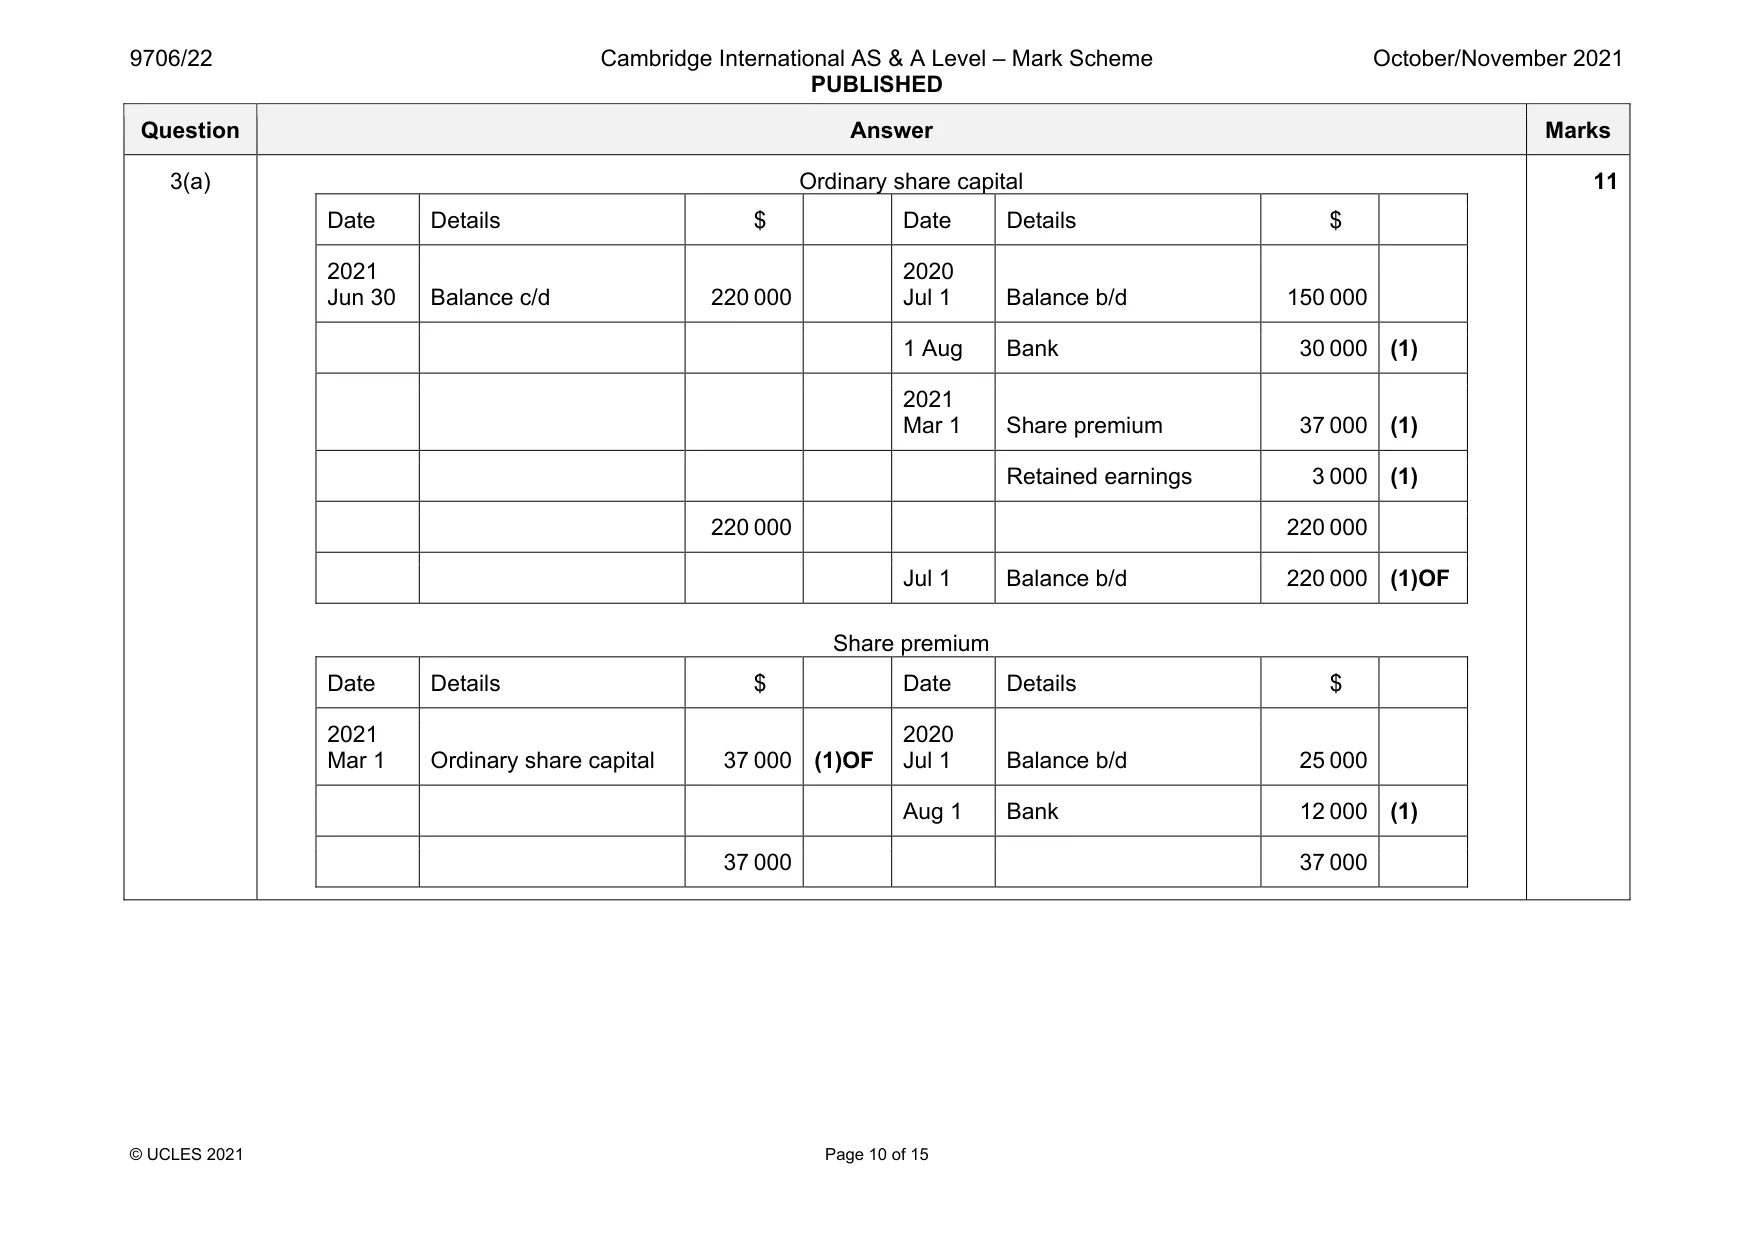
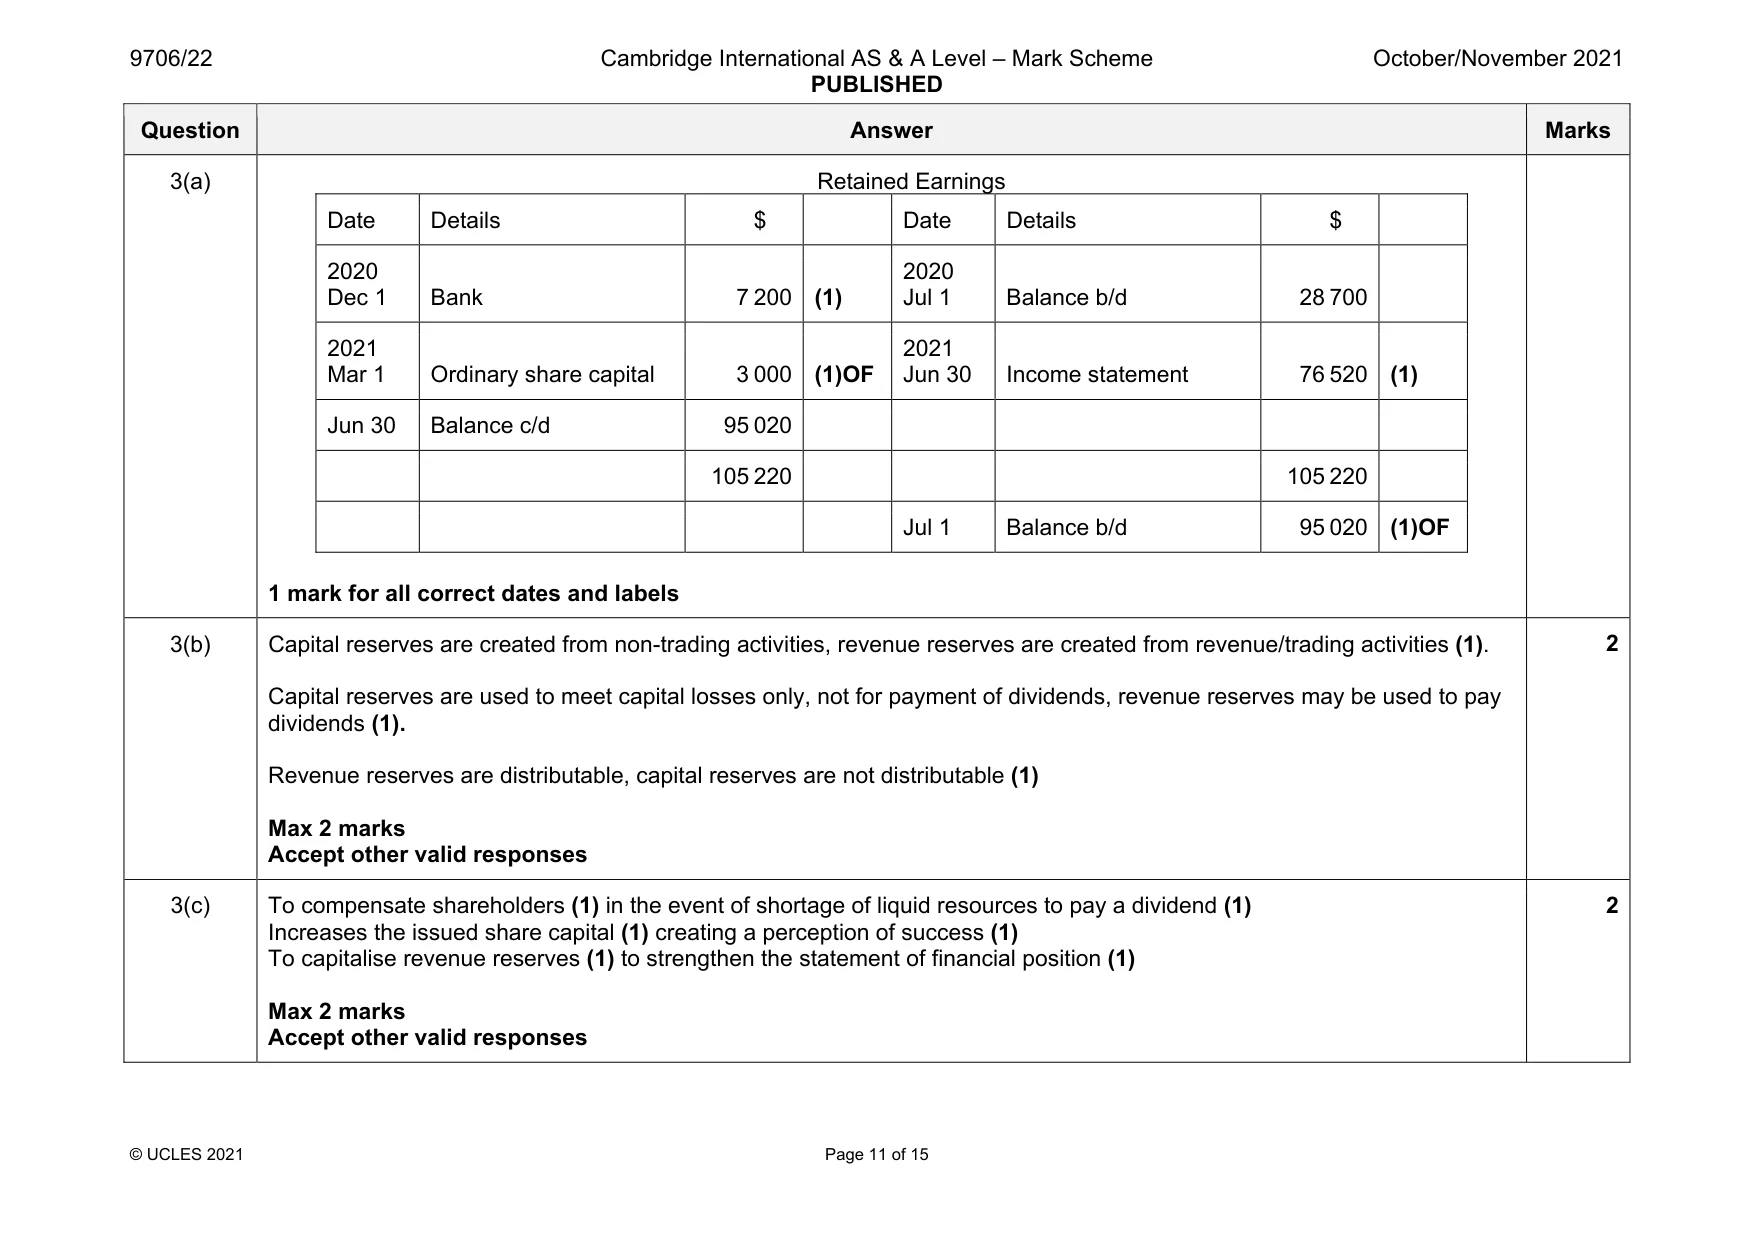
Mark scheme: 3(a) Ordinary share capital Date Details $ Date Details $ 2021 Jun 30 Balance c/d 220 000 2020 Jul 1 Balance b/d 150 000 1 Aug Bank 30 000 (1) 2021 Mar 1 Share premium 37 000 (1) Retained earnings 3 000 (1) 220 000 220 000 Jul 1 Balance b/d 220 000 (1)OF Share premium Date Details $ Date Details $ 2021 Mar 1 Ordinary share capital 37 000 (1)OF 2020 Jul 1 Balance b/d 25 000 Aug 1 Bank 12 000 (1) 37 000 37 000 11 Question Answer Marks 3(a) Retained Earnings Date Details $ Date Details $ 2020 Dec 1 Bank 7 200 (1) 2020 Jul 1 Balance b/d 28 700 2021 Mar 1 Ordinary share capital 3 000 (1)OF 2021 Jun 30 Income statement 76 520 (1) Jun 30 Balance c/d 95 020 105 220 105 220 Jul 1 Balance b/d 95 020 (1)OF 1 mark for all correct dates and labels 3(b) Capital reserves are created from non-trading activities, revenue reserves are created from revenue/trading activities (1). Capital reserves are used to meet capital losses only, not for payment of dividends, revenue reserves may be used to pay dividends (1). Revenue reserves are distributable, capital reserves are not distributable (1) Max 2 marks Accept other valid responses 2 3(c) To compensate shareholders (1) in the event of shortage of liquid resources to pay a dividend (1) Increases the issued share capital (1) creating a perception of success (1) To capitalise revenue reserves (1) to strengthen the statement of financial position (1) Max 2 marks Accept other valid responses 2
Q4 · Hayden manufactures two products, Aye and Bee
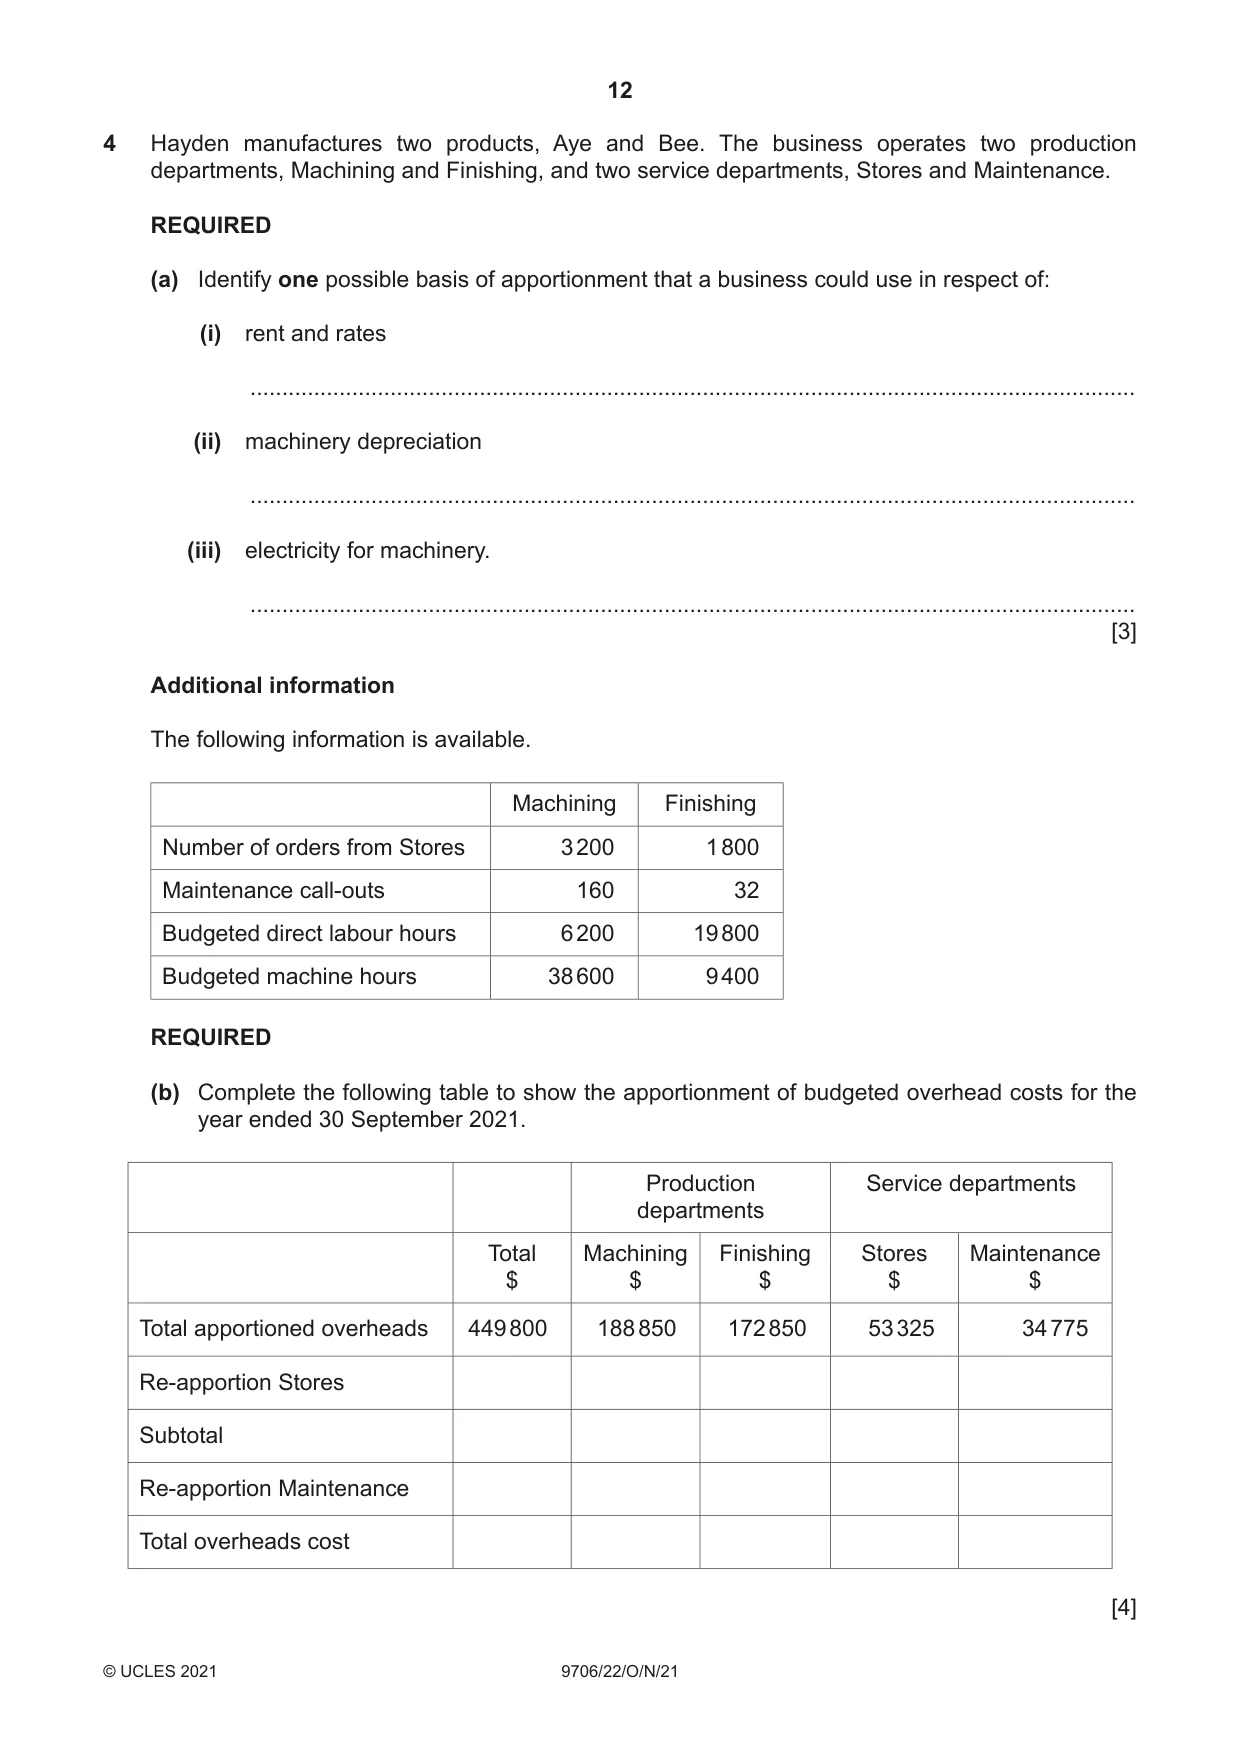
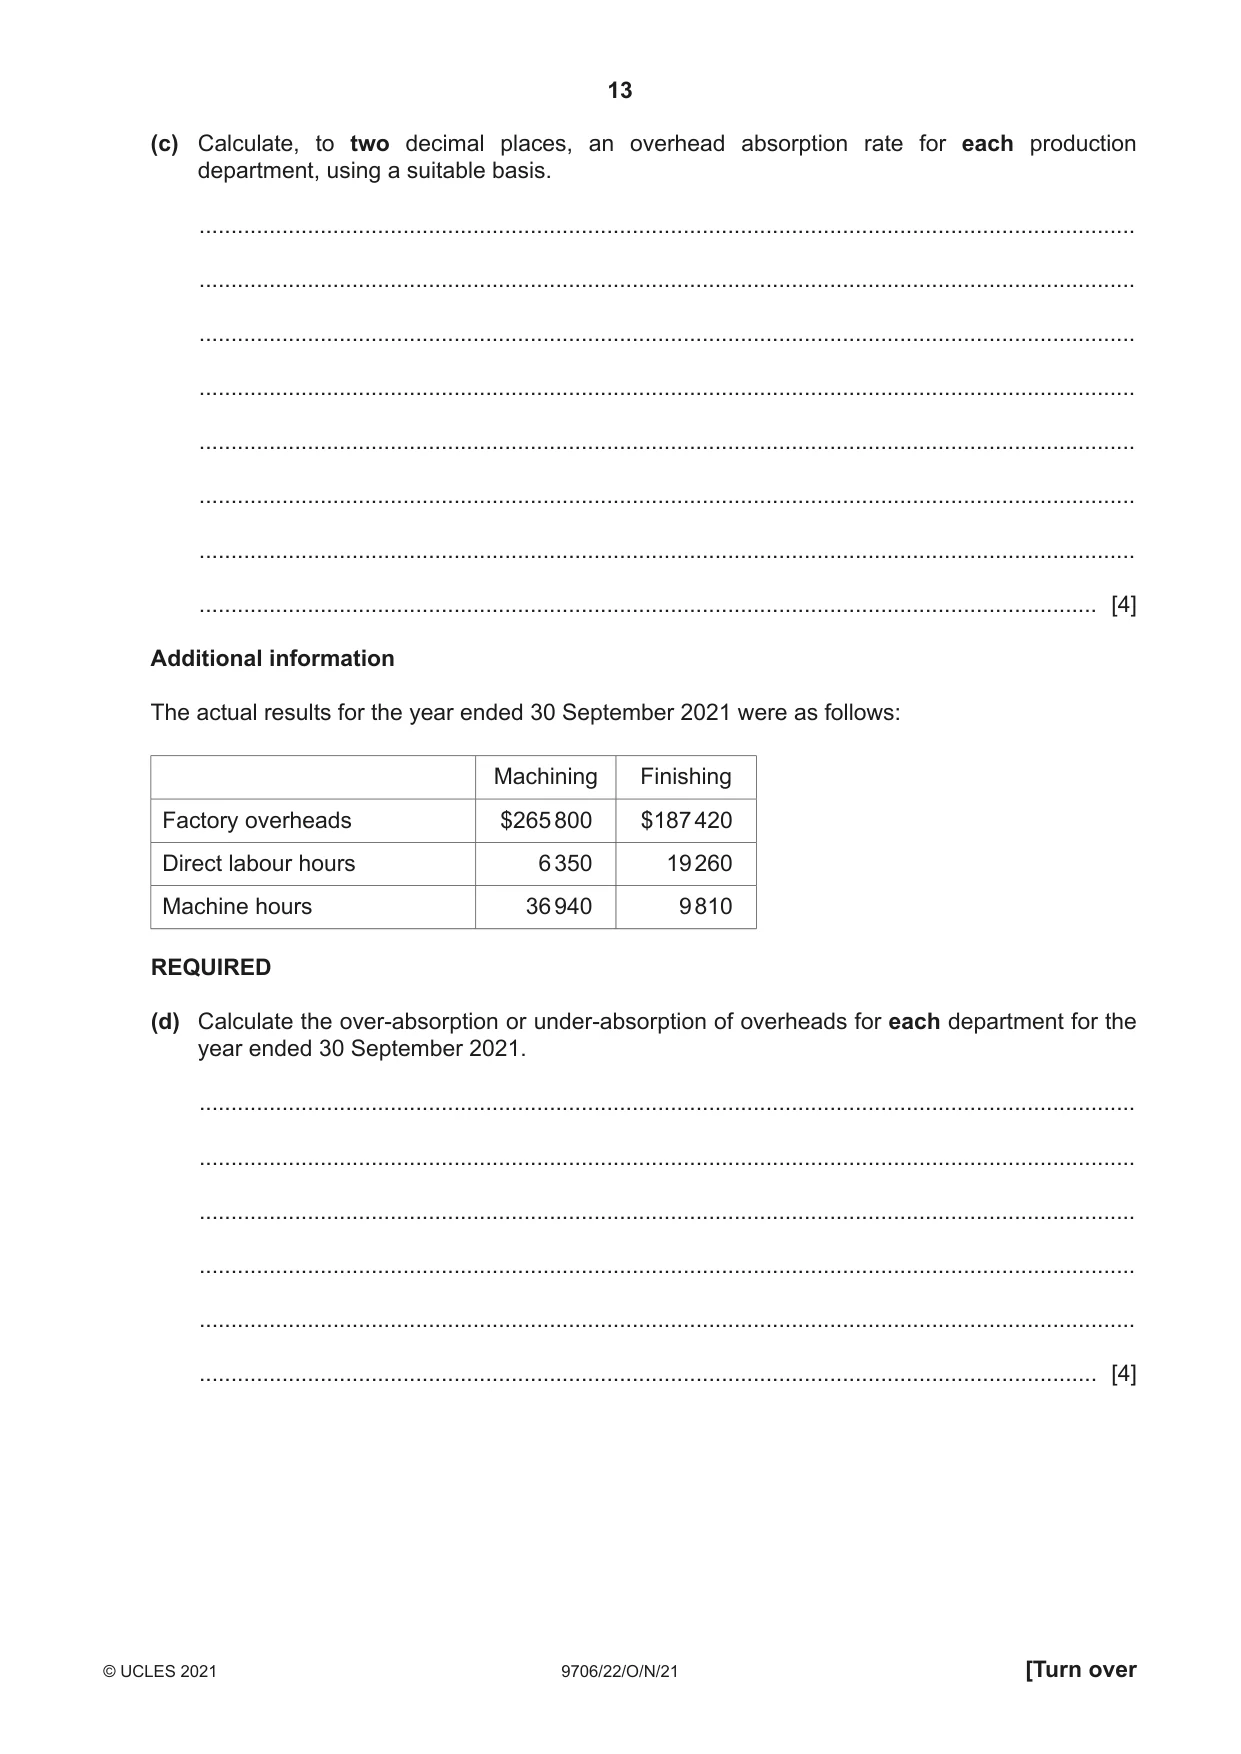
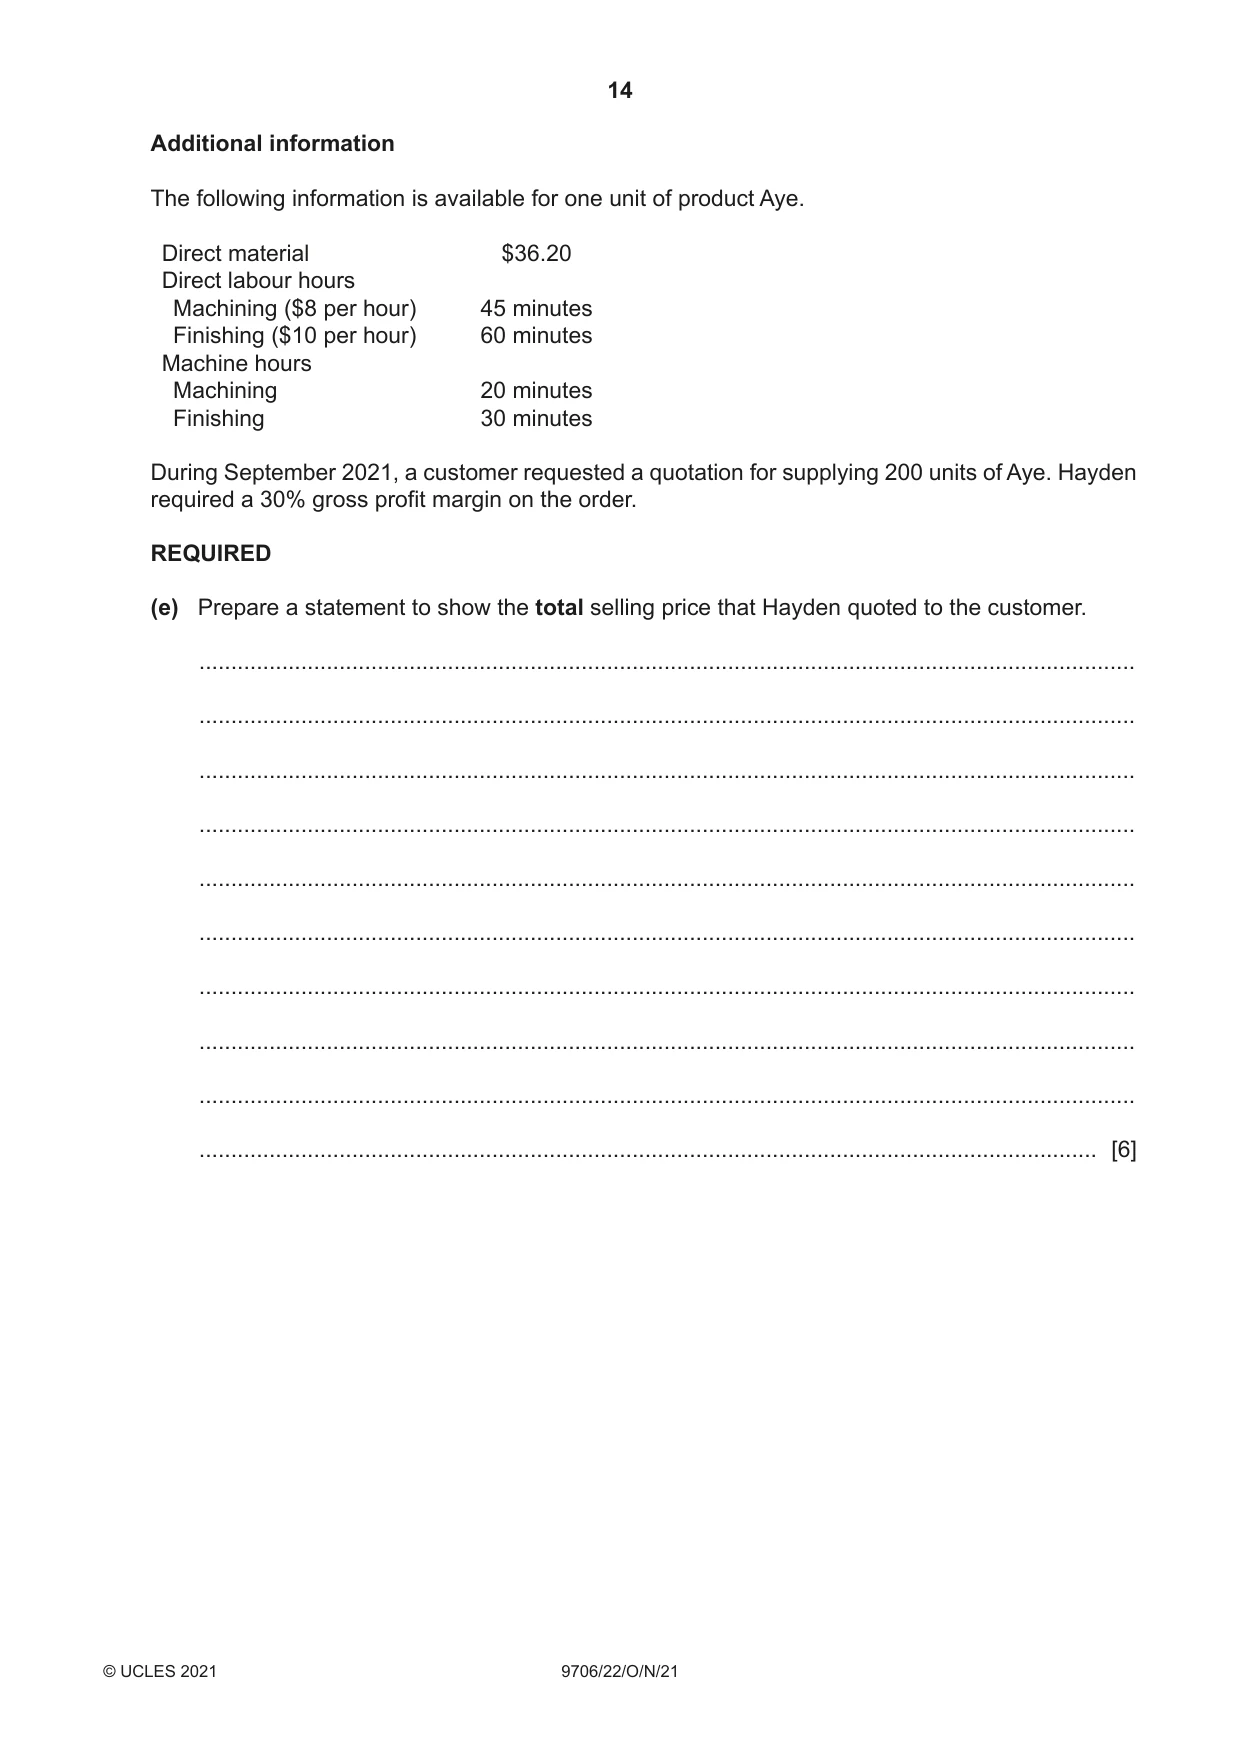
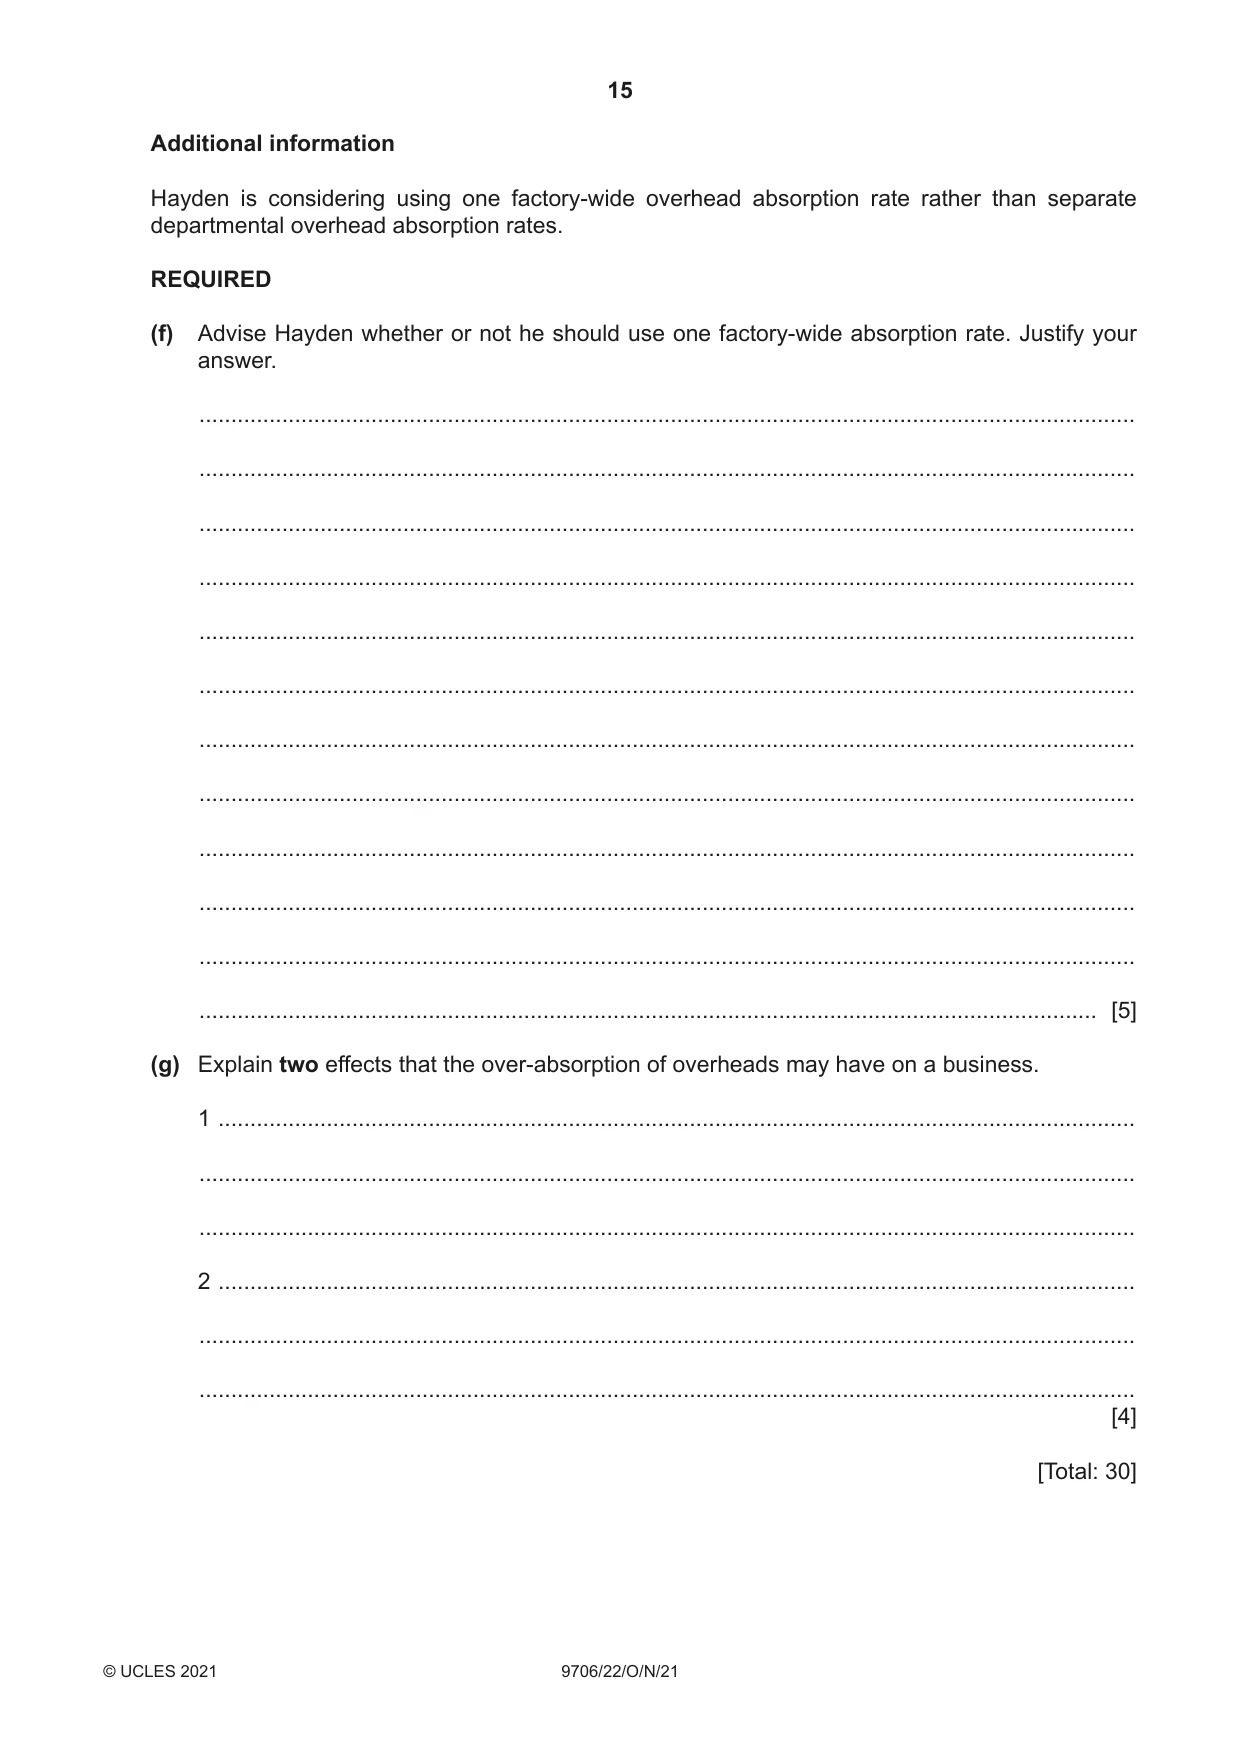
4 Hayden manufactures two products, Aye and Bee. The business operates two production departments, Machining and Finishing, and two service departments, Stores and Maintenance. REQUIRED (a) Identify one possible basis of apportionment that a business could use in respect of: (i) rent and rates ........................................................................................................................................... (ii) machinery depreciation ........................................................................................................................................... (iii) electricity for machinery. ........................................................................................................................................... [3] Additional information The following information is available. Machining Finishing Number of orders from Stores 3 200 1 800 Maintenance call-outs 160 32 Budgeted direct labour hours 6 200 19 800 Budgeted machine hours 38 600 9 400 REQUIRED (b) Complete the following table to show the apportionment of budgeted overhead costs for the year ended 30 September 2021. Production Service departments departments Total Machining Finishing Stores Maintenance $ $ $ $ $ Total apportioned overheads 449 800 188 850 172 850 53 325 34 775 Re-apportion Stores Subtotal Re-apportion Maintenance Total overheads cost [4] (c) Calculate, to two decimal places, an overhead absorption rate for each production department, using a suitable basis. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Additional information The actual results for the year ended 30 September 2021 were as follows: Machining Finishing Factory overheads $265 800 $187 420 Direct labour hours 6 350 19 260 Machine hours 36 940 9 810 REQUIRED (d) Calculate the over-absorption or under-absorption of overheads for each department for the year ended 30 September 2021. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Additional information The following information is available for one unit of product Aye. Direct material $36.20 Direct labour hours Machining ($8 per hour) 45 minutes Finishing ($10 per hour) 60 minutes Machine hours Machining 20 minutes Finishing 30 minutes During September 2021, a customer requested a quotation for supplying 200 units of Aye. Hayden required a 30% gross profit margin on the order. REQUIRED (e) Prepare a statement to show the total selling price that Hayden quoted to the customer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [6]
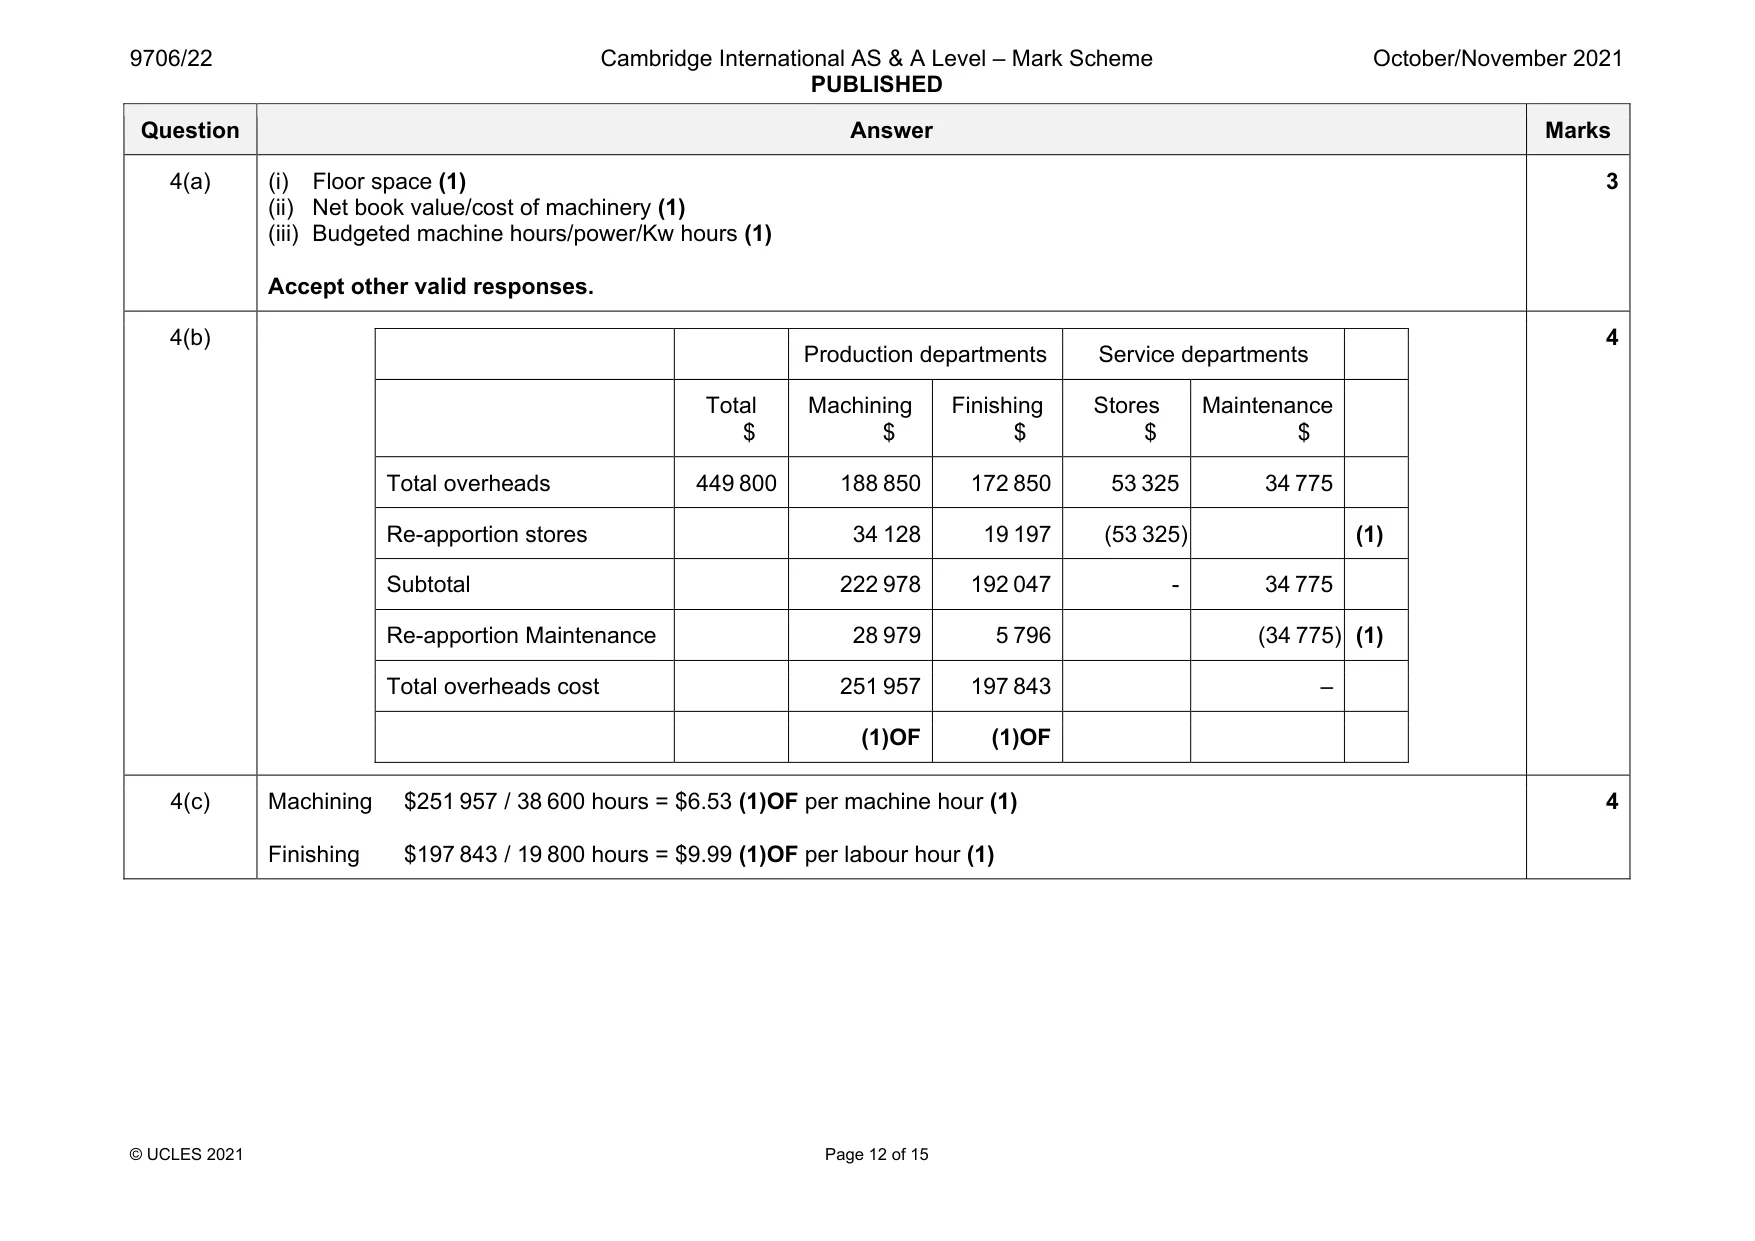
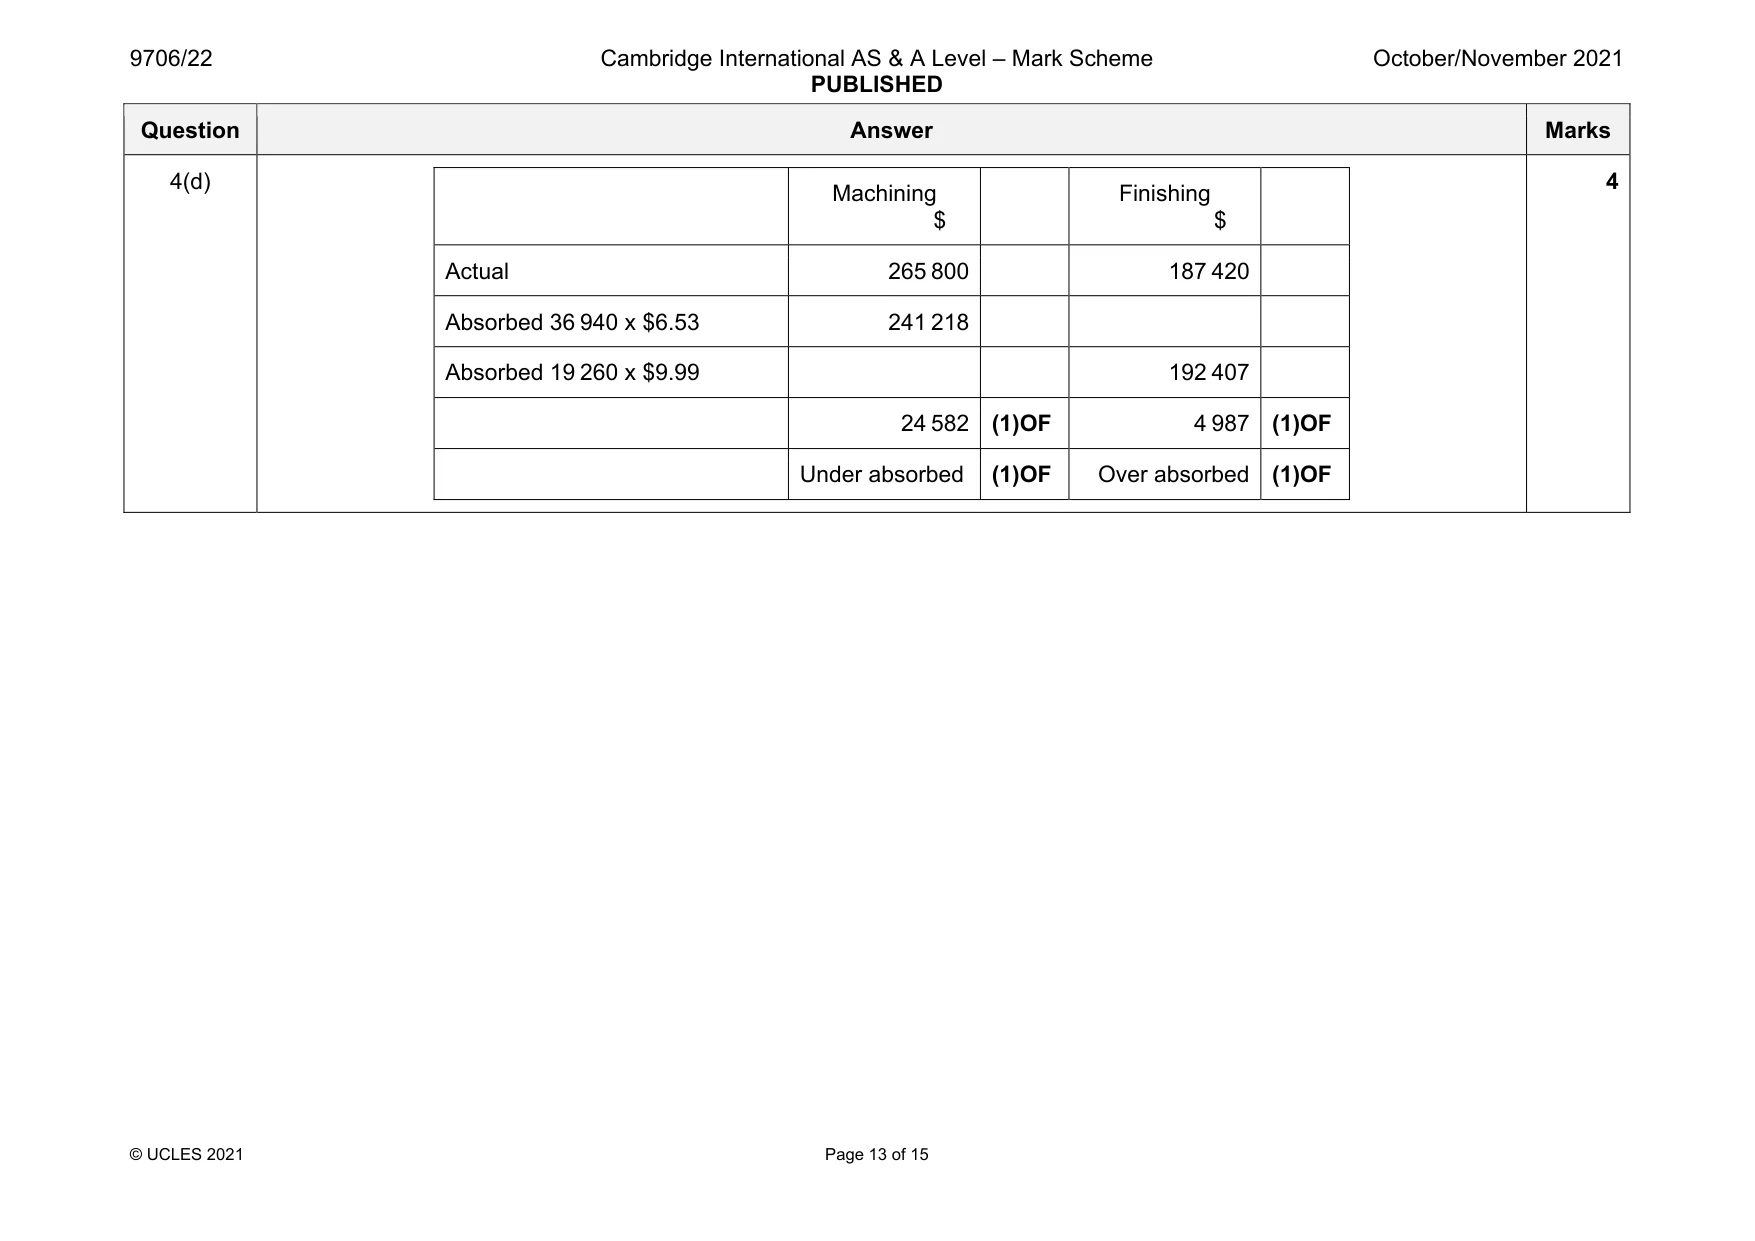
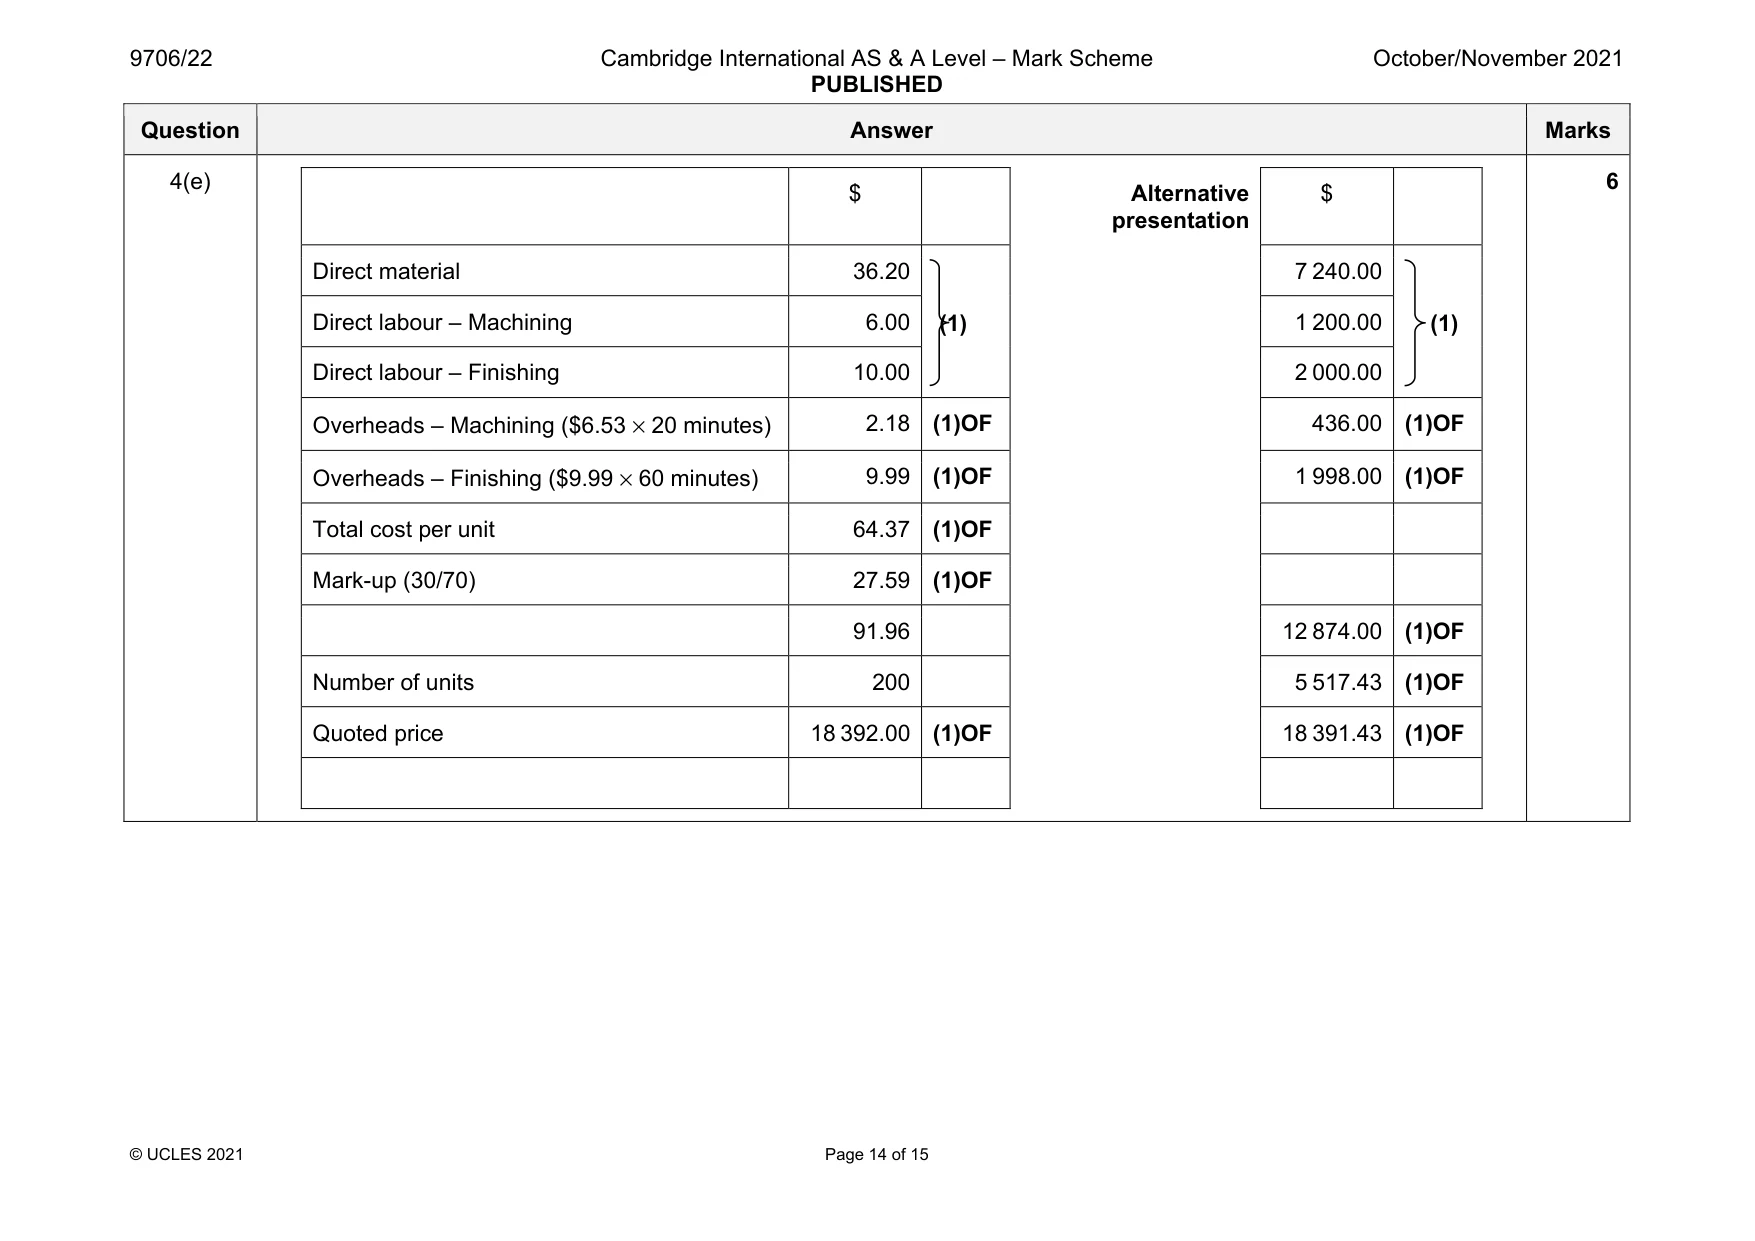
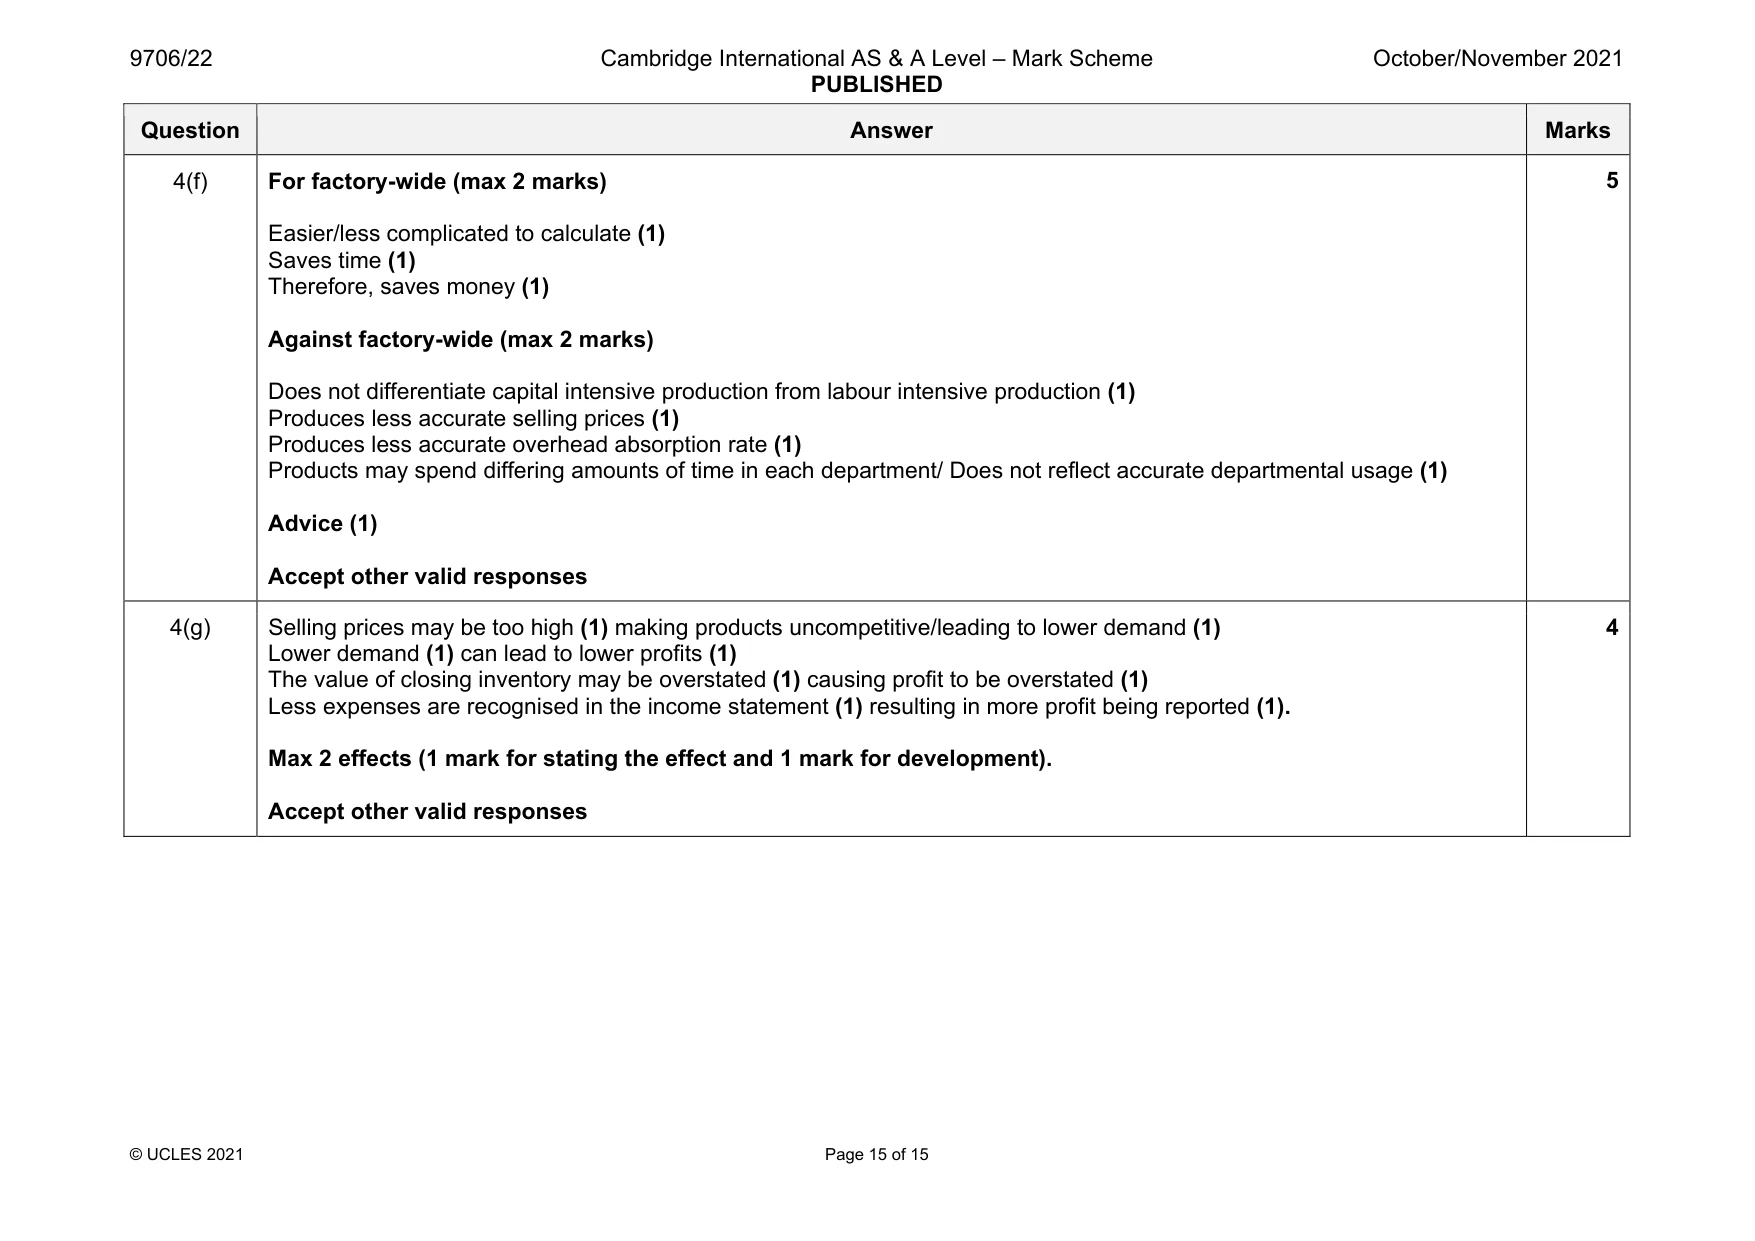
Mark scheme: 4(a) (i) Floor space (1) (ii) Net book value/cost of machinery (1) (iii) Budgeted machine hours/power/Kw hours (1) Accept other valid responses. 3 4(b) Production departments Service departments Total $ Machining $ Finishing $ Stores $ Maintenance $ Total overheads 449 800 188 850 172 850 53 325 34 775 Re-apportion stores 34 128 19 197 (53 325) (1) Subtotal 222 978 192 047 - 34 775 Re-apportion Maintenance 28 979 5 796 (34 775) (1) Total overheads cost 251 957 197 843 – (1)OF (1)OF 4 4(c) Machining $251 957 / 38 600 hours = $6.53 (1)OF per machine hour (1) Finishing $197 843 / 19 800 hours = $9.99 (1)OF per labour hour (1) 4 Question Answer Marks 4(d) Machining $ Finishing $ Actual 265 800 187 420 Absorbed 36 940 x $6.53 241 218 Absorbed 19 260 x $9.99 192 407 24 582 (1)OF 4 987 (1)OF Under absorbed (1)OF Over absorbed (1)OF 4 Question Answer Marks 4(e) $ Alternative presentation $ Direct material 36.20 (1) 7 240.00 (1) Direct labour – Machining 6.00 1 200.00 Direct labour – Finishing 10.00 2 000.00 Overheads – Machining ($6.53 × 20 minutes) 2.18 (1)OF 436.00 (1)OF Overheads – Finishing ($9.99 × 60 minutes) 9.99 (1)OF 1 998.00 (1)OF Total cost per unit 64.37 (1)OF Mark-up (30/70) 27.59 (1)OF 91.96 12 874.00 (1)OF Number of units 200 5 517.43 (1)OF Quoted price 18 392.00 (1)OF 18 391.43 (1)OF 6 Question Answer Marks 4(f) For factory-wide (max 2 marks) Easier/less complicated to calculate (1) Saves time (1) Therefore, saves money (1) Against factory-wide (max 2 marks) Does not differentiate capital intensive production from labour intensive production (1) Produces less accurate selling prices (1) Produces less accurate overhead absorption rate (1) Products may spend differing amounts of time in each department/ Does not reflect accurate departmental usage (1) Advice (1) Accept other valid responses 5 4(g) Selling prices may be too high (1) making products uncompetitive/leading to lower demand (1) Lower demand (1) can lead to lower profits (1) The value of closing inventory may be overstated (1) causing profit to be overstated (1) Less expenses are recognised in the income statement (1) resulting in more profit being reported (1). Max 2 effects (1 mark for stating the effect and 1 mark for development). Accept other valid responses 4
Q6 · Wages and salaries are to be charged as follows: Administrative expenses 25% Distribution…
6 Wages and salaries are to be charged as follows: Administrative expenses 25% Distribution costs 75%
Q7 · On 31 August 2021, a delivery vehicle was sold for $7000
7 On 31 August 2021, a delivery vehicle was sold for $7000. The vehicle had been purchased on 1 September 2018 for $13 000. No entries for the sale had been made in the books of account and the sale proceeds had not yet been received.
Q8 · The freehold property is used only as a distribution warehouse
8 The freehold property is used only as a distribution warehouse. Its remaining useful life at 1 September 2020 was estimated to be 40 years.
Q9 · Depreciation is to be charged as follows: Non-current asset Depreciation method Freehold…
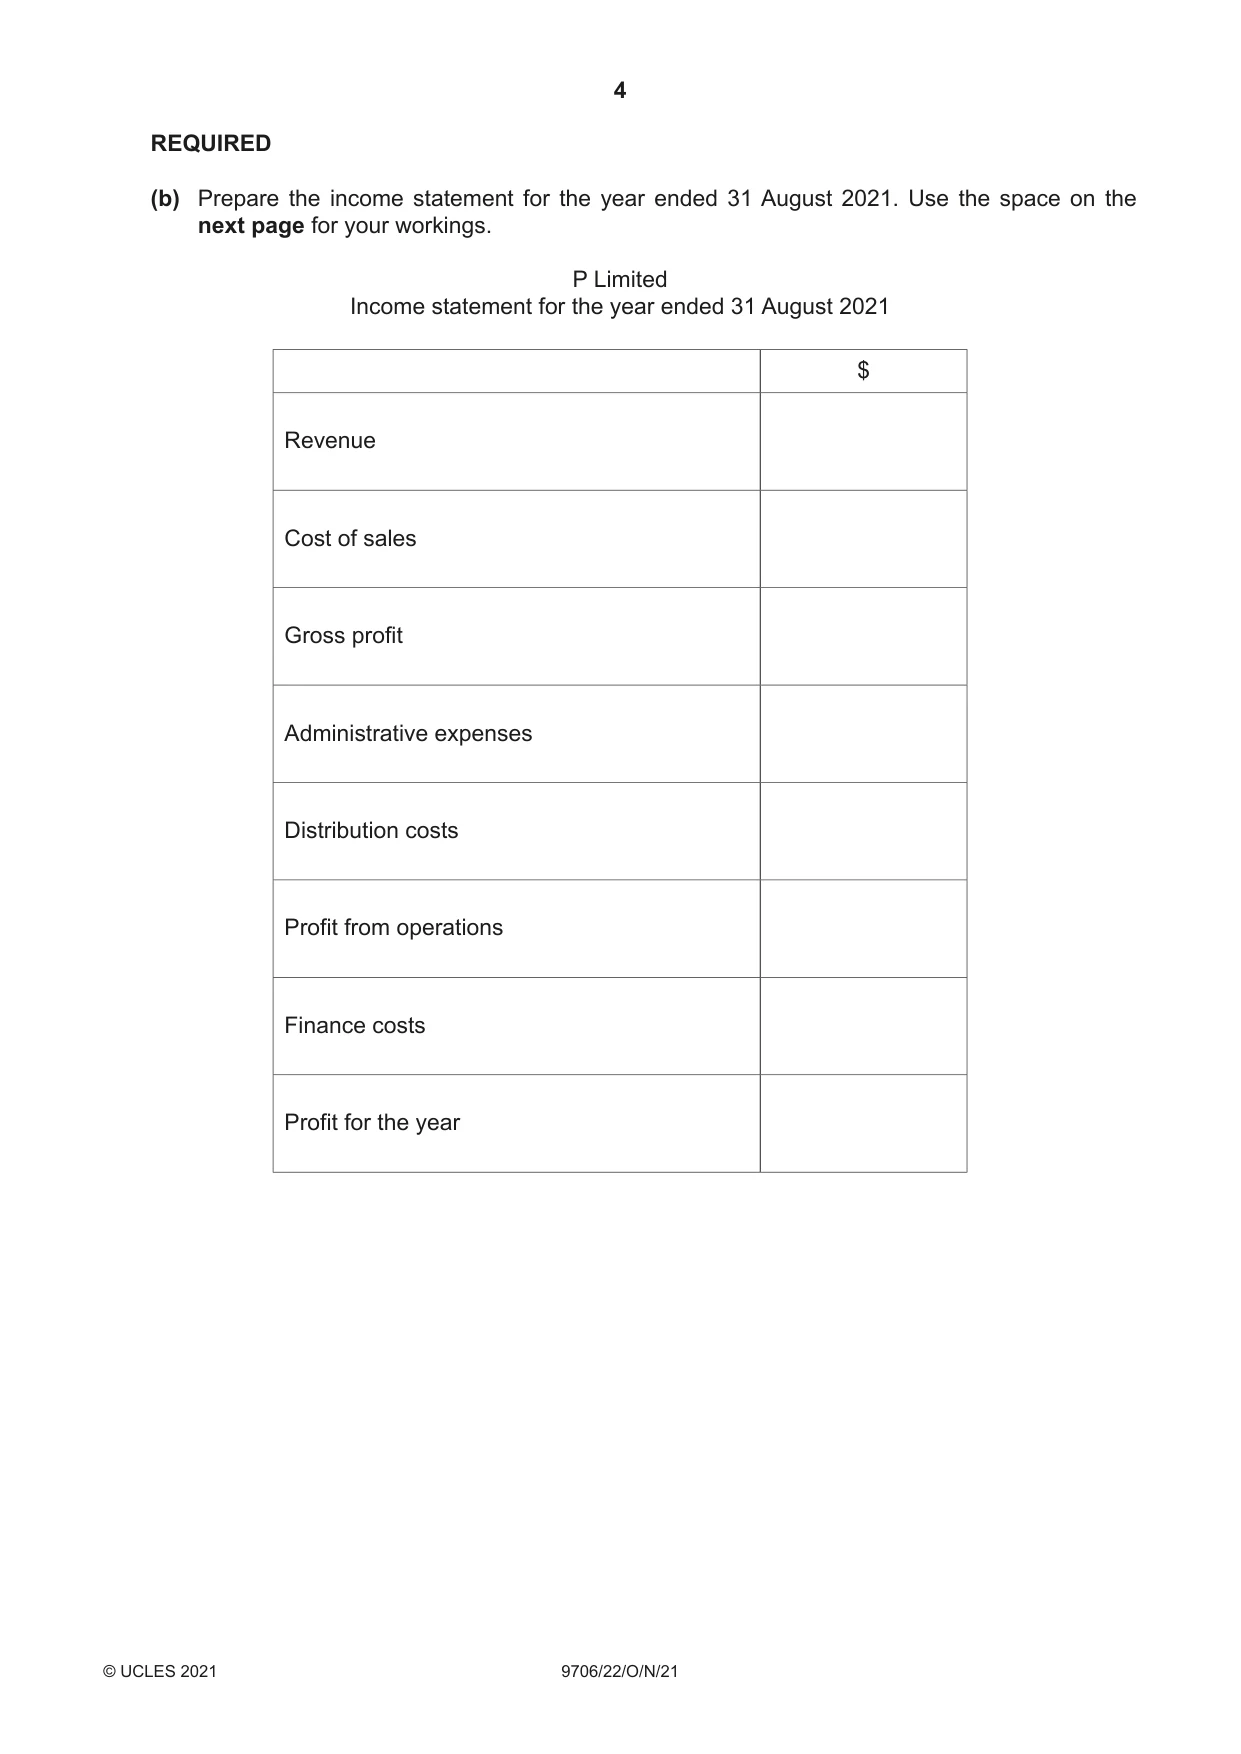
9 Depreciation is to be charged as follows: Non-current asset Depreciation method Freehold property Written off over the remaining useful life Delivery vehicles 20% per annum reducing balance A full year’s depreciation is charged in the year of purchase, but none in the year of disposal. REQUIRED (b) Prepare the income statement for the year ended 31 August 2021. Use the space on the next page for your workings. P Limited Income statement for the year ended 31 August 2021 $ Revenue Cost of sales Gross profit Administrative expenses Distribution costs Profit from operations Finance costs Profit for the year Workings Revenue Cost of sales Depreciation Administrative expenses Distribution costs Finance costs [15]
What was in this paper
The subtopics covered by these 8 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.