Cambridge A Level Accounting 9706 — 2022 Oct/Nov Paper 2 · Variant 3
9706/23/O/N/22 · 5 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme17 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Reece, a sole trader, does not maintain a full set of accounting records
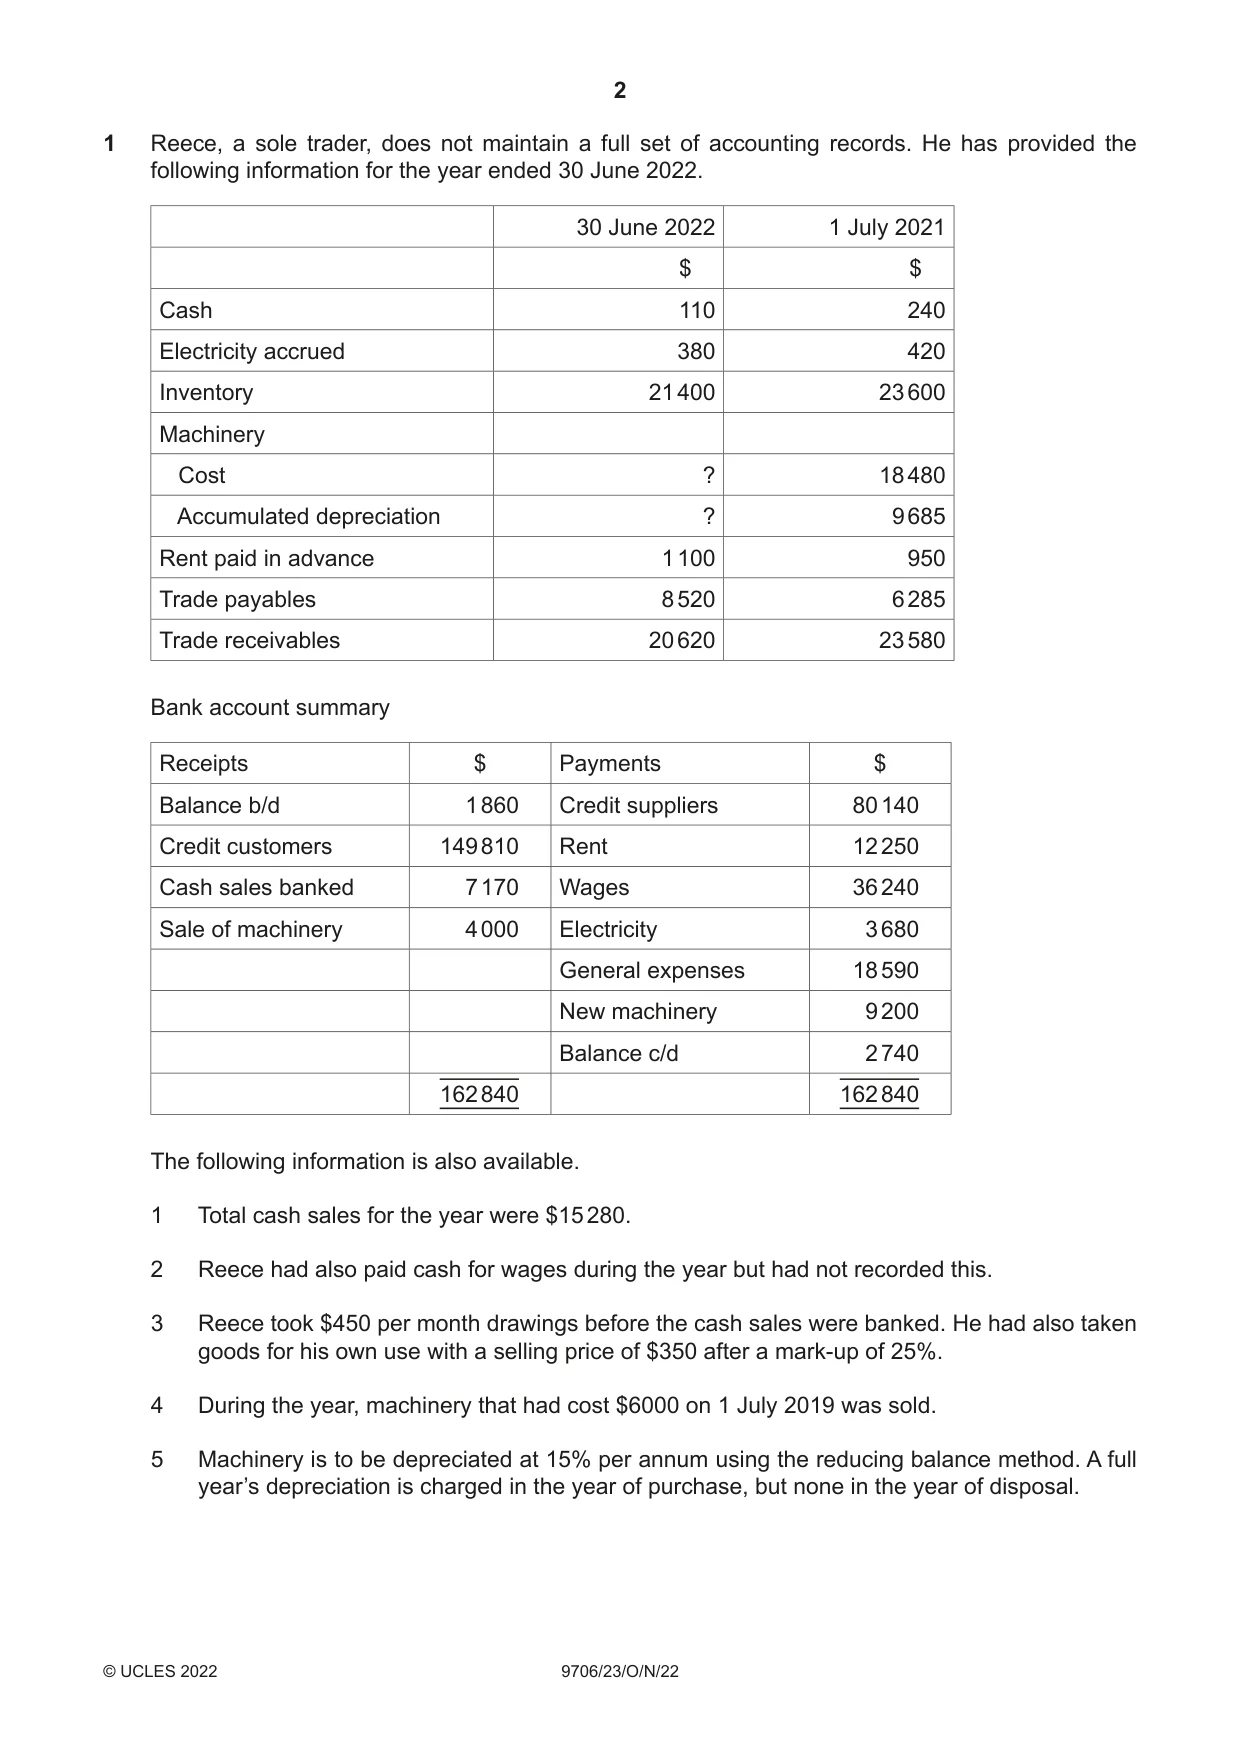
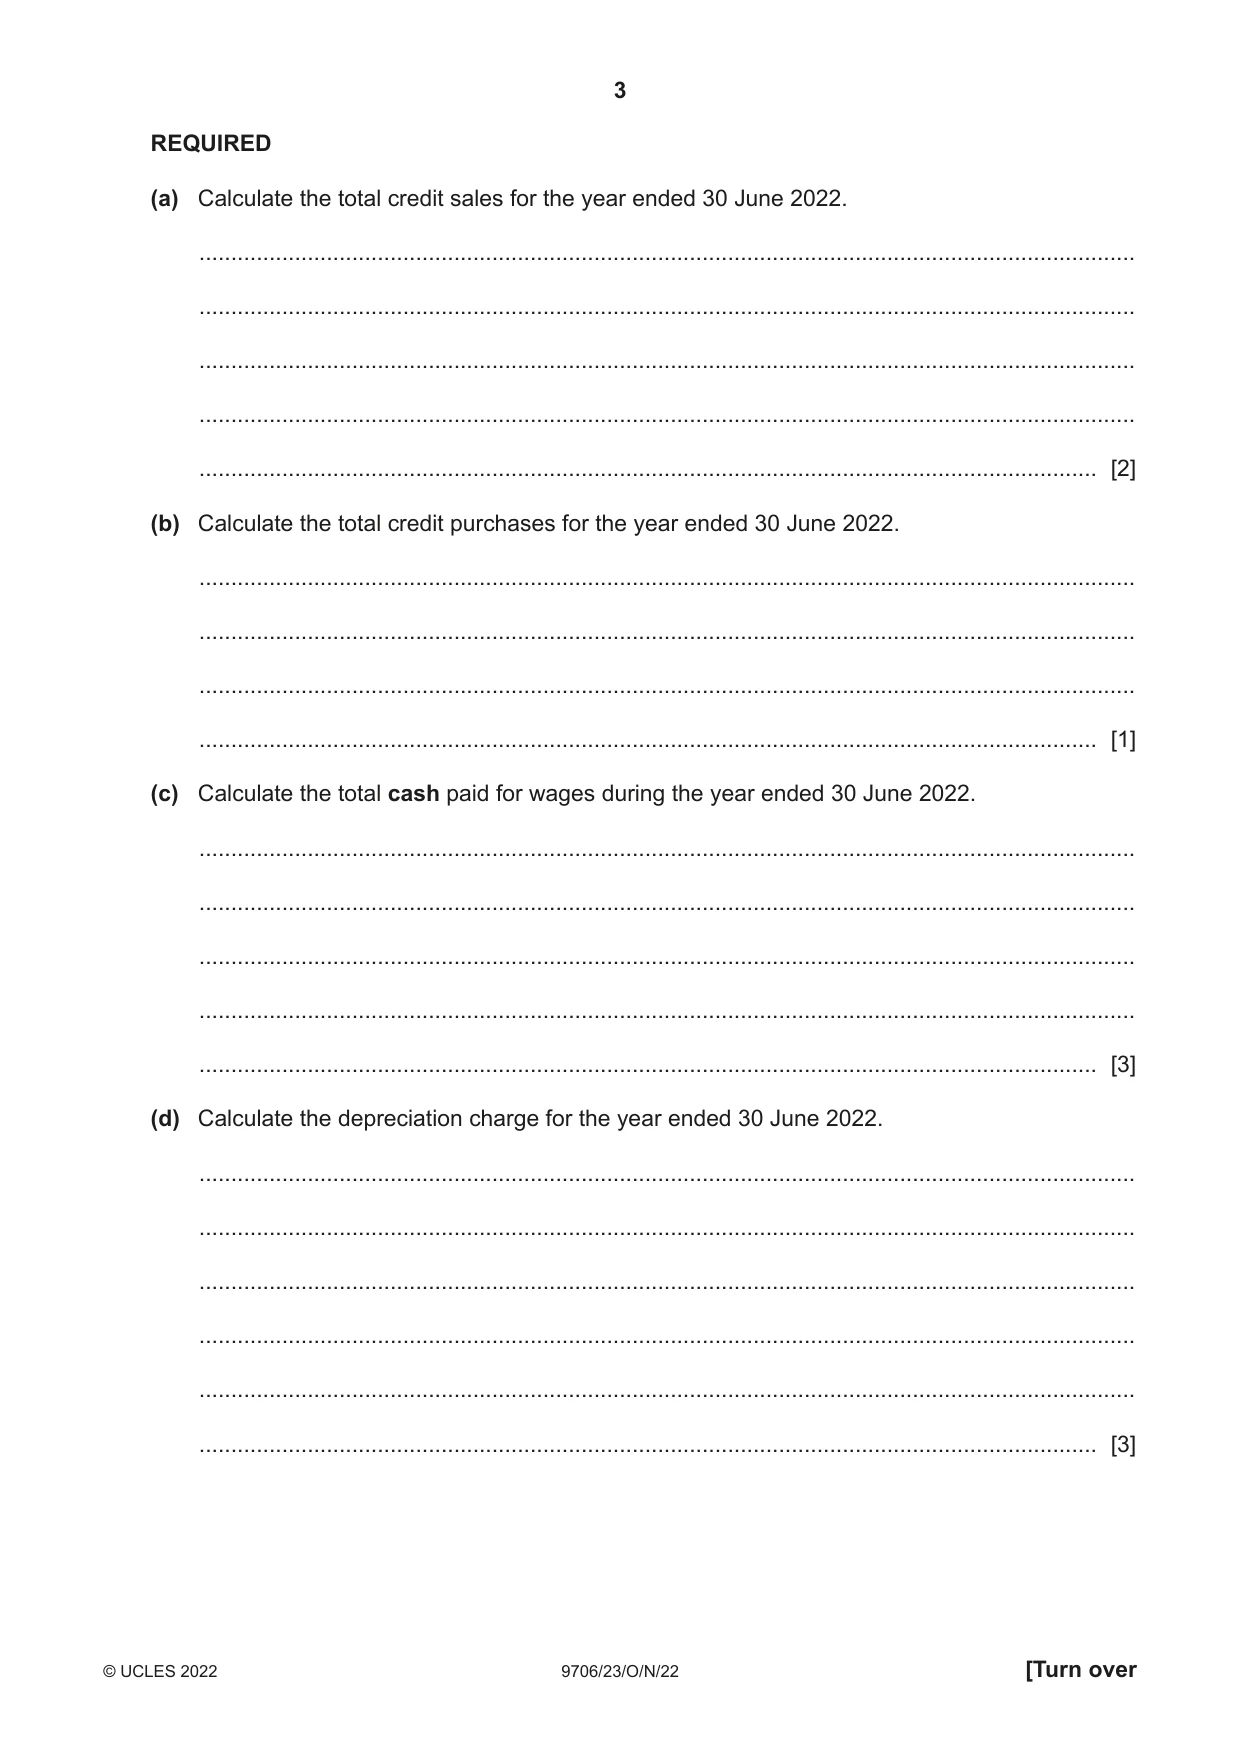
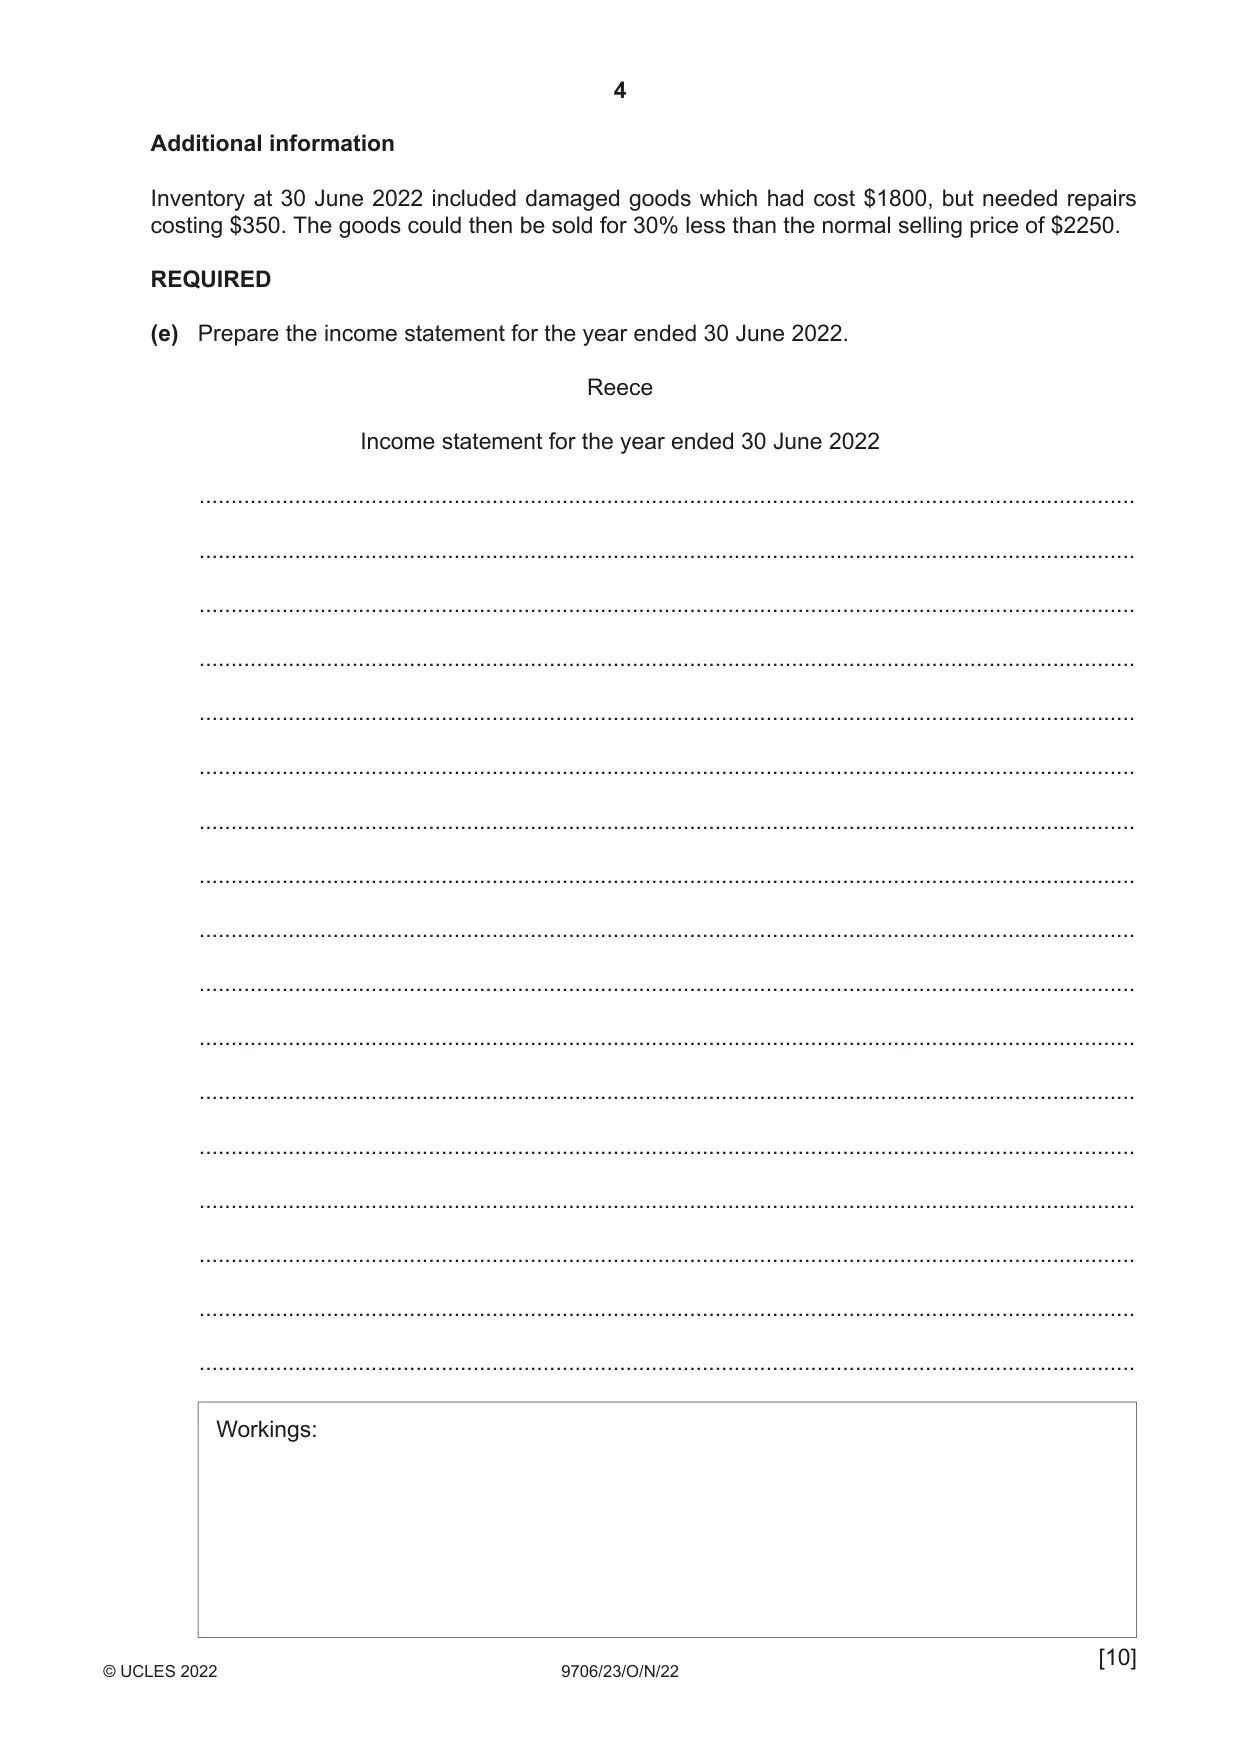
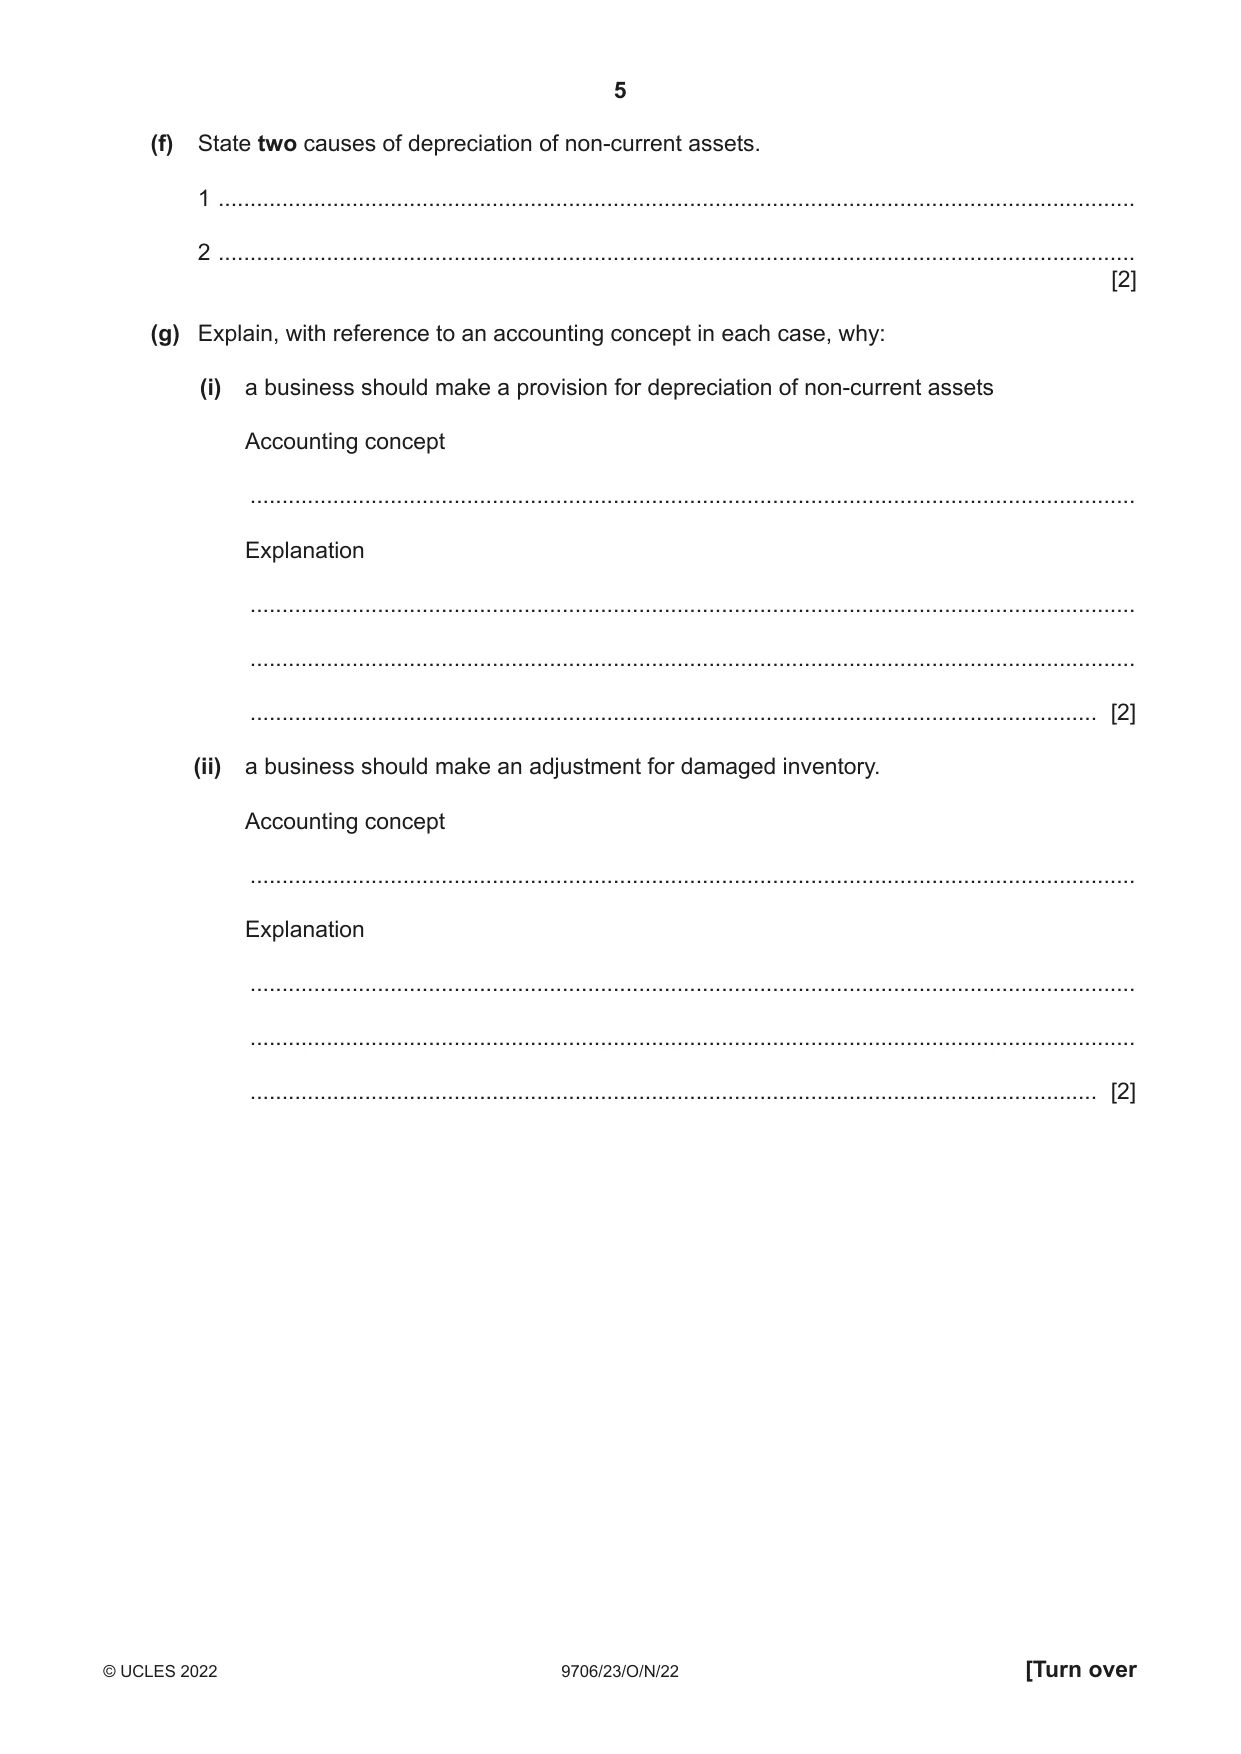
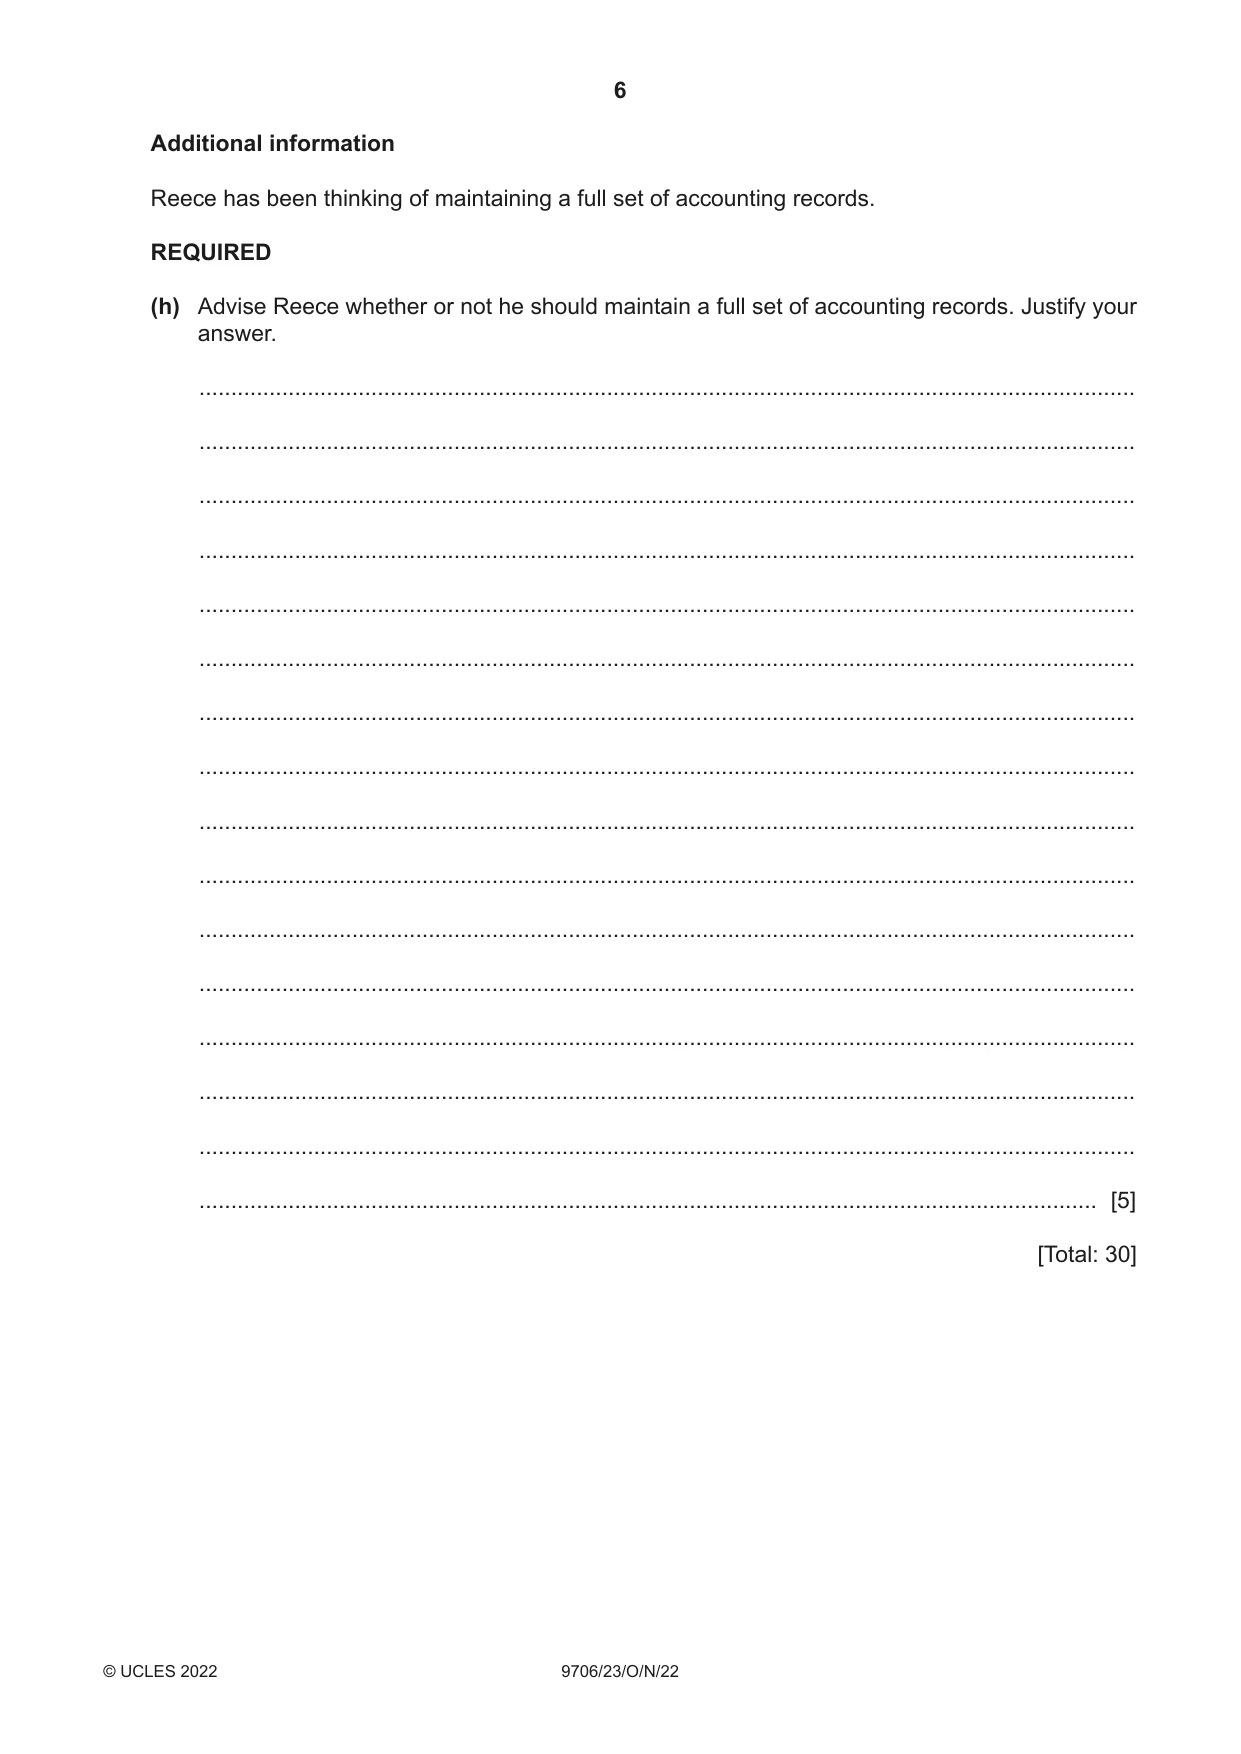
1 Reece, a sole trader, does not maintain a full set of accounting records. He has provided the following information for the year ended 30 June 2022. 30 June 2022 1 July 2021 $ $ Cash 110 240 Electricity accrued 380 420 Inventory 21 400 23 600 Machinery Cost ? 18 480 Accumulated depreciation ? 9 685 Rent paid in advance 1 100 950 Trade payables 8 520 6 285 Trade receivables 20 620 23 580 Bank account summary Receipts $ Payments $ Balance b/d 1 860 Credit suppliers 80 140 Credit customers 149 810 Rent 12 250 Cash sales banked 7 170 Wages 36 240 Sale of machinery 4 000 Electricity 3 680 General expenses 18 590 New machinery 9 200 Balance c/d 2 740 162 840 162 840 The following information is also available. 1 Total cash sales for the year were $15 280. 2 Reece had also paid cash for wages during the year but had not recorded this. 3 Reece took $450 per month drawings before the cash sales were banked. He had also taken goods for his own use with a selling price of $350 after a mark-up of 25%. 4 During the year, machinery that had cost $6000 on 1 July 2019 was sold. 5 Machinery is to be depreciated at 15% per annum using the reducing balance method. A full year’s depreciation is charged in the year of purchase, but none in the year of disposal. REQUIRED (a) Calculate the total credit sales for the year ended 30 June 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (b) Calculate the total credit purchases for the year ended 30 June 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [1] (c) Calculate the total cash paid for wages during the year ended 30 June 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (d) Calculate the depreciation charge for the year ended 30 June 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Additional information Inventory at 30 June 2022 included damaged goods which had cost $1800, but needed repairs costing $350. The goods could then be sold for 30% less than the normal selling price of $2250. REQUIRED (e) Prepare the income statement for the year ended 30 June 2022. Reece Income statement for the year ended 30 June 2022 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: (f) State two causes of depreciation of non-current assets. 1 ................................................................................................................................................ 2 ................................................................................................................................................ [2] (g) Explain, with reference to an accounting concept in each case, why: (i) a business should make a provision for depreciation of non-current assets Accounting concept ........................................................................................................................................... Explanation ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) a business should make an adjustment for damaged inventory. Accounting concept ........................................................................................................................................... Explanation ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] Additional information Reece has been thinking of maintaining a full set of accounting records. REQUIRED (h) Advise Reece whether or not he should maintain a full set of accounting records. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 30] PLEASE TURN OVER
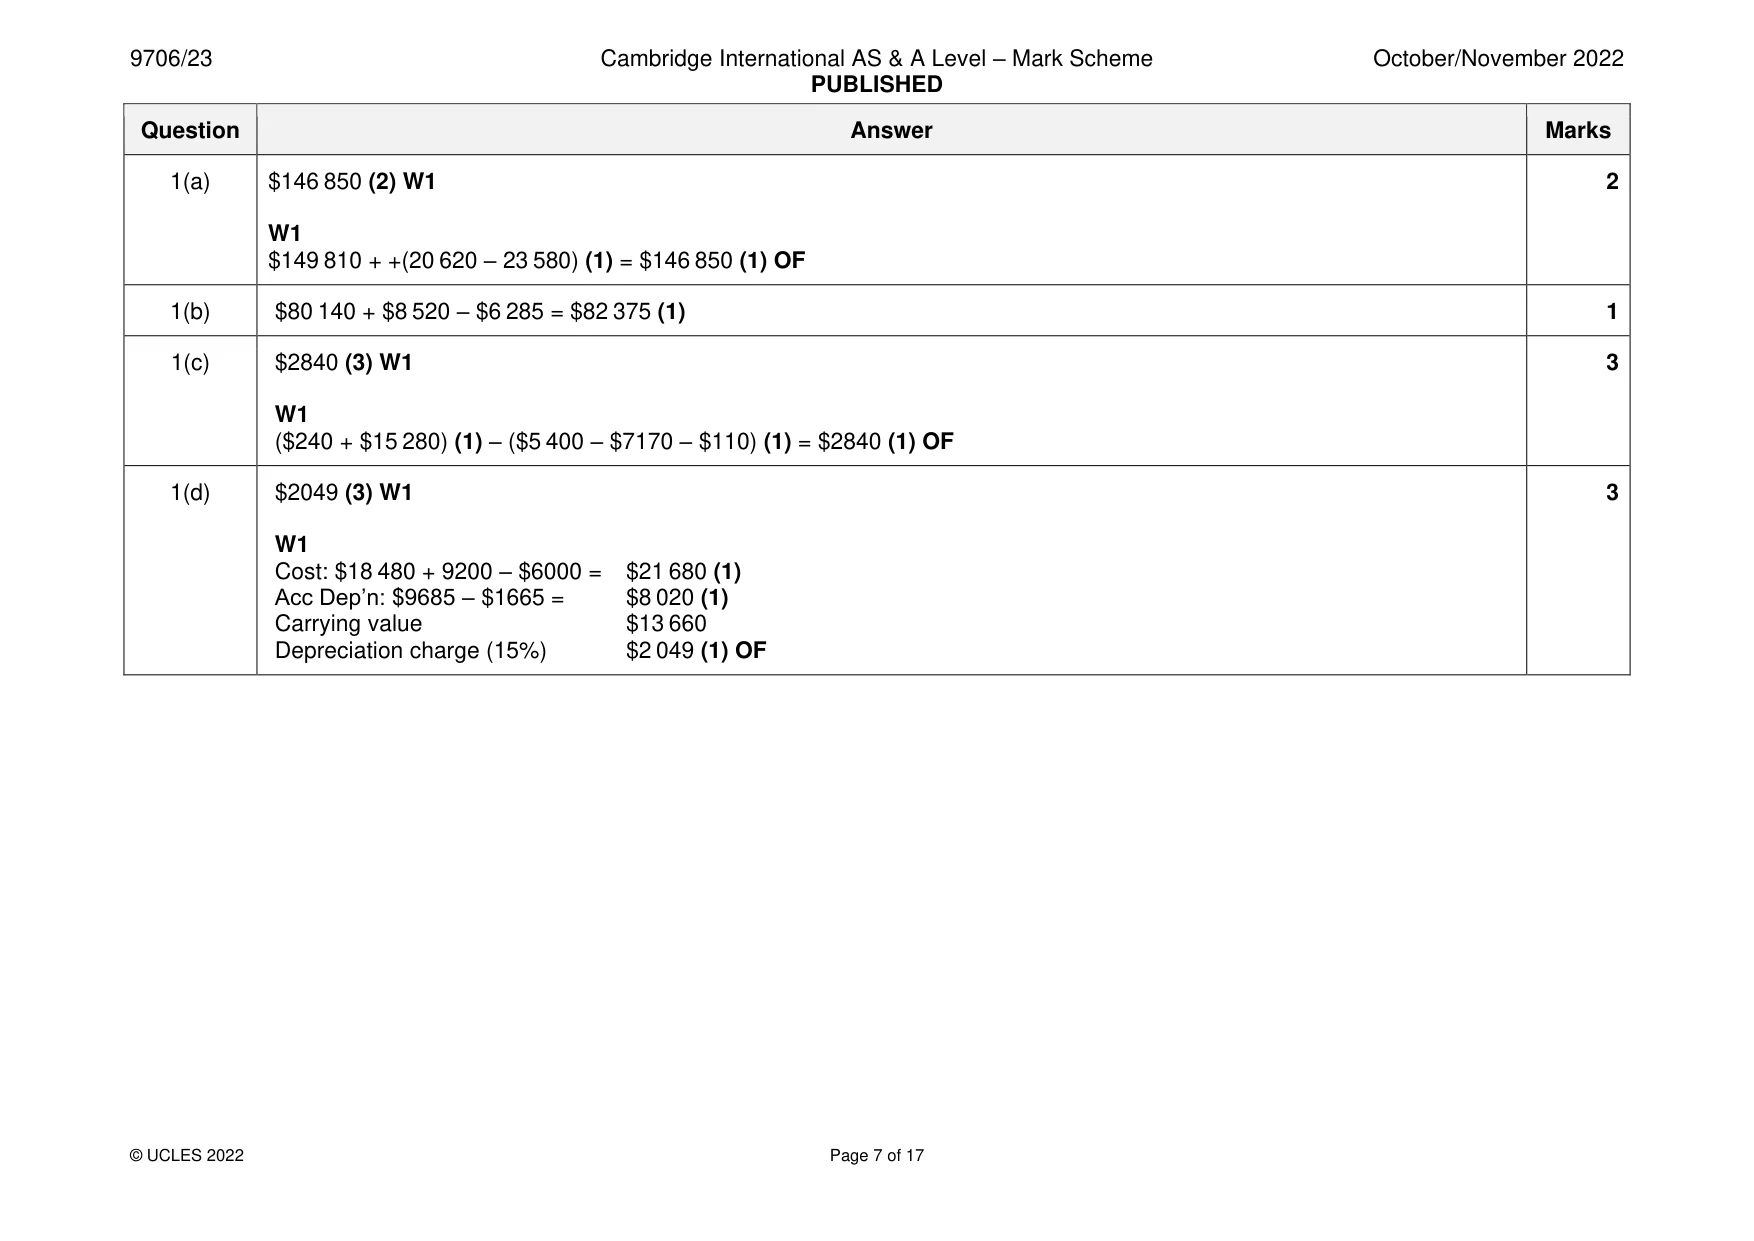
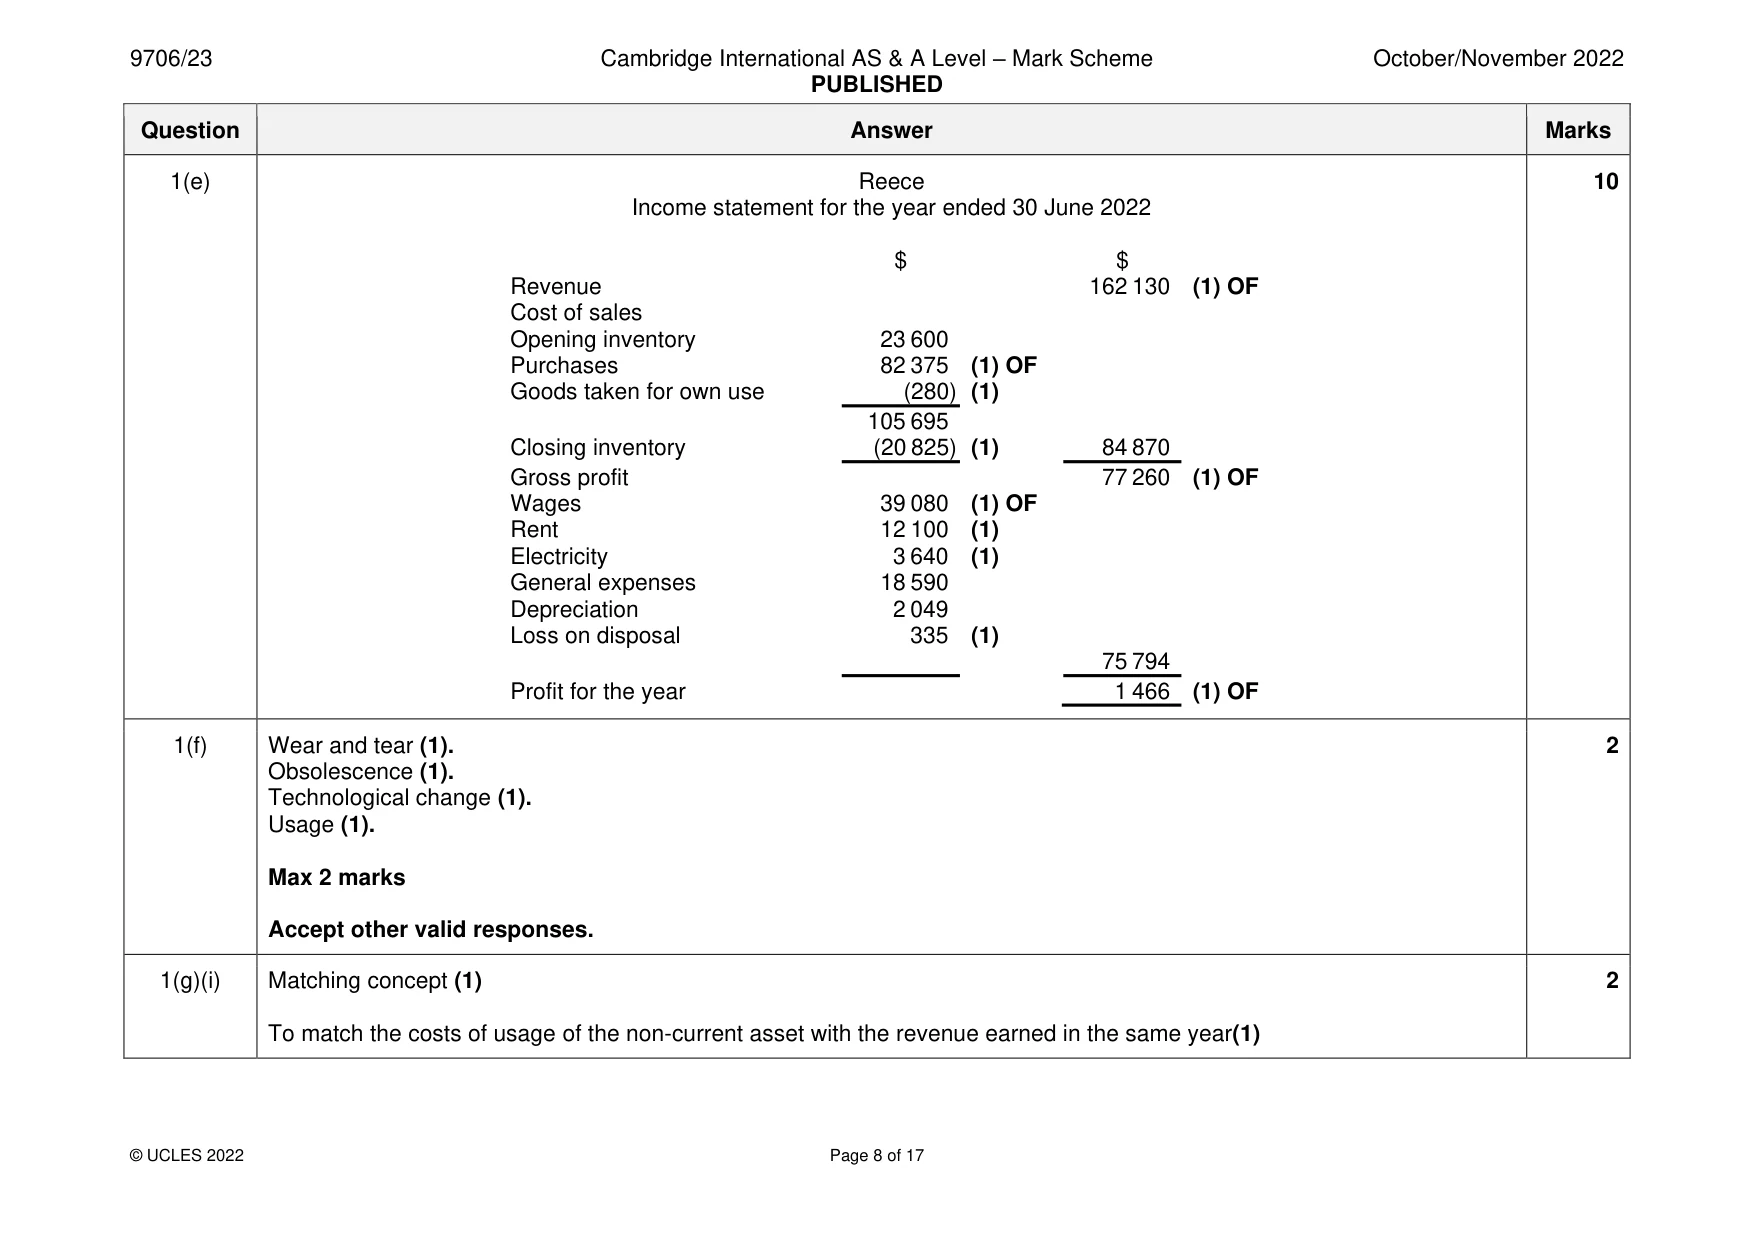
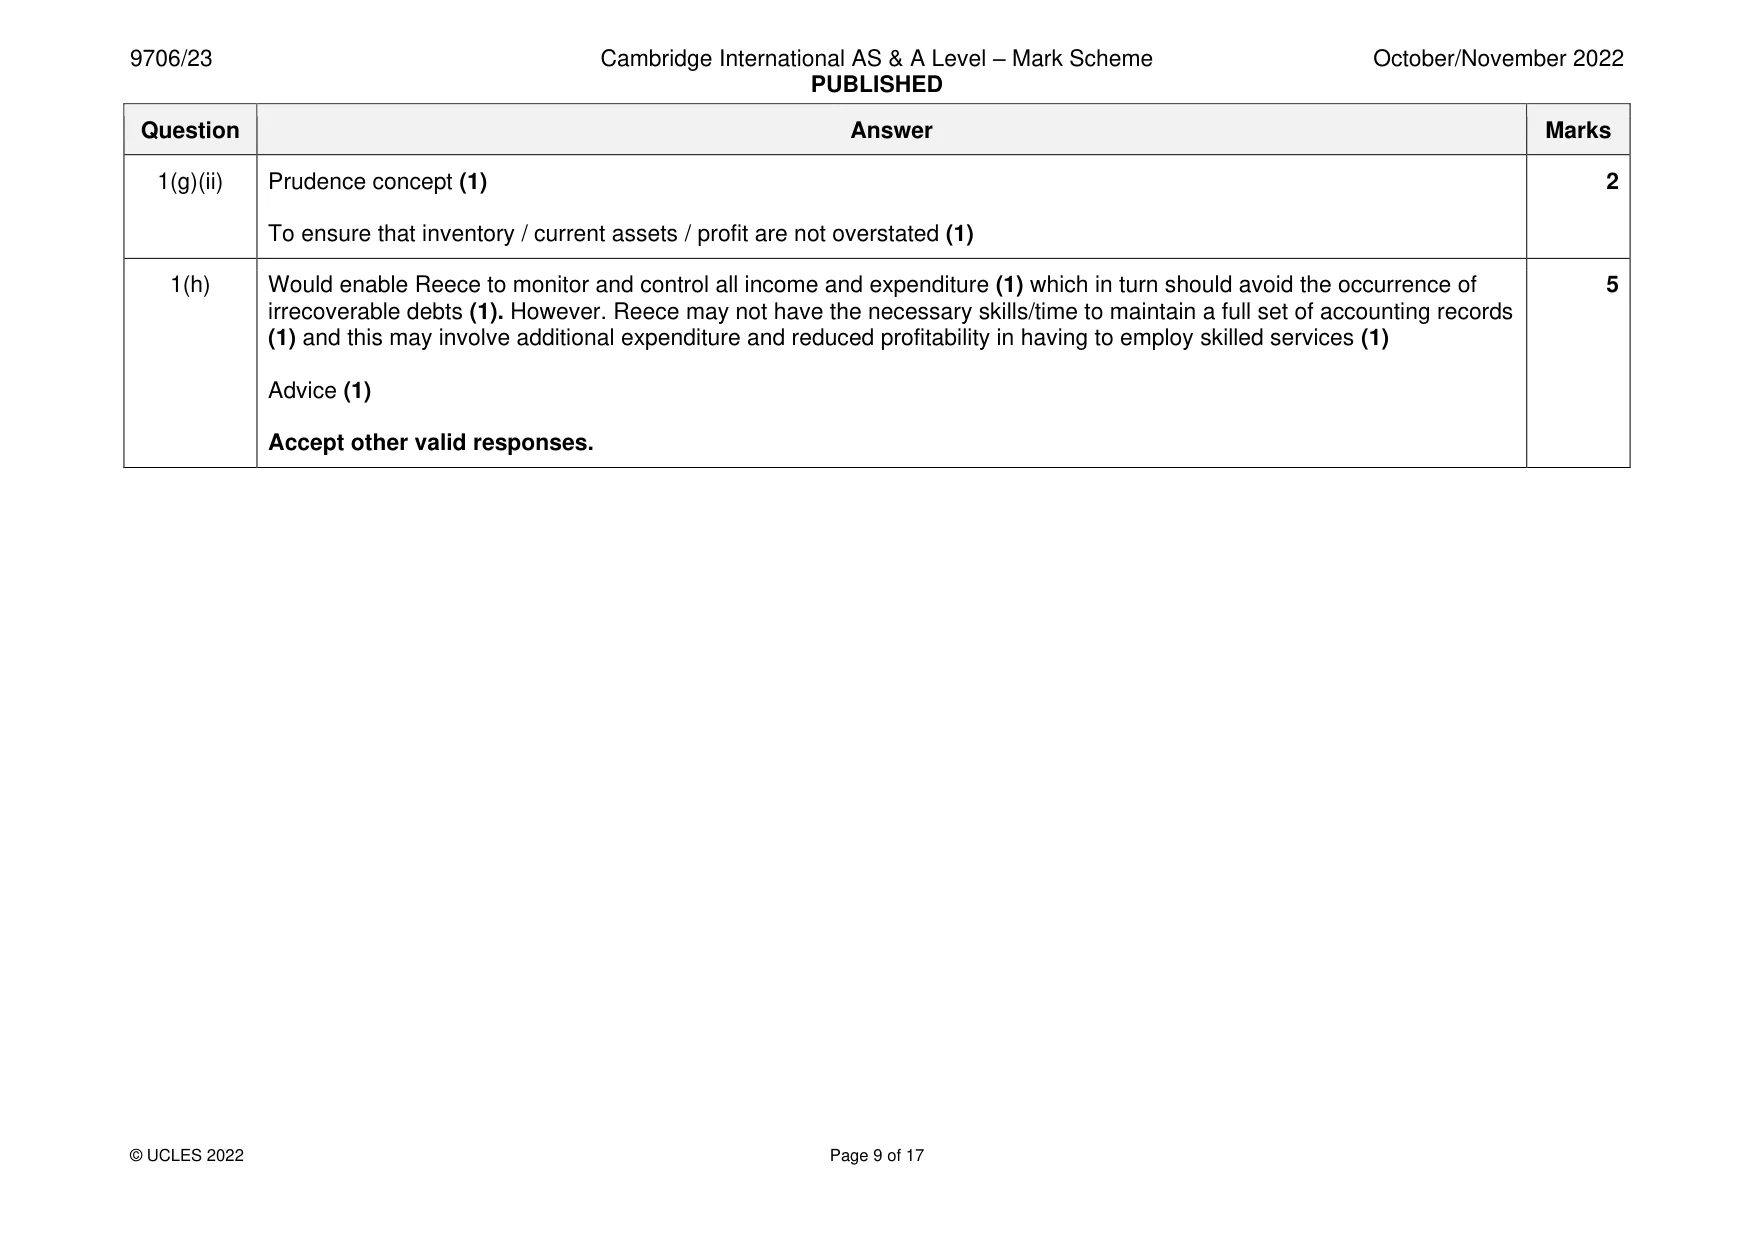
Mark scheme: Question Answer Marks 1(a) $146 850 (2) W1 2 W1 $149 810 + +(20 620 – 23 580) (1) = $146 850 (1) OF 1(b) $80 140 + $8 520 – $6 285 = $82 375 (1) 1 1(c) $2840 (3) W1 3 W1 ($240 + $15 280) (1) – ($5 400 – $7170 – $110) (1) = $2840 (1) OF 1(d) $2049 (3) W1 3 W1 Cost: $18 480 + 9200 – $6000 = $21 680 (1) Acc Dep’n: $9685 – $1665 = $8 020 (1) Carrying value $13 660 Depreciation charge (15%) $2 049 (1) OF 1(e) Reece 10 Income statement for the year ended 30 June 2022 $ $ Revenue 162 130 (1) OF Cost of sales Opening inventory 23 600 Purchases 82 375 (1) OF Goods taken for own use (280) (1) 105 695 Closing inventory (20 825) (1) 84 870 Gross profit 77 260 (1) OF Wages 39 080 (1) OF Rent 12 100 (1) Electricity 3 640 (1) General expenses 18 590 Depreciation 2 049 Loss on disposal 335 (1) 75 794 Profit for the year 1 466 (1) OF 1(f) Wear and tear (1). 2 Obsolescence (1). Technological change (1). Usage (1). Max 2 marks Accept other valid responses. 1(g)(i) Matching concept (1) 2 To match the costs of usage of the non-current asset with the revenue earned in the same year(1) 1(g)(ii) Prudence concept (1) 2 To ensure that inventory / current assets / profit are not overstated (1) 1(h) Would enable Reece to monitor and control all income and expenditure (1) which in turn should avoid the occurrence of 5 irrecoverable debts (1). However. Reece may not have the necessary skills/time to maintain a full set of accounting records (1) and this may involve additional expenditure and reduced profitability in having to employ skilled services (1) Advice (1) Accept other valid responses.
Q2 · Darius and Ewan are in partnership sharing profits and losses in the ratio 5 : 3
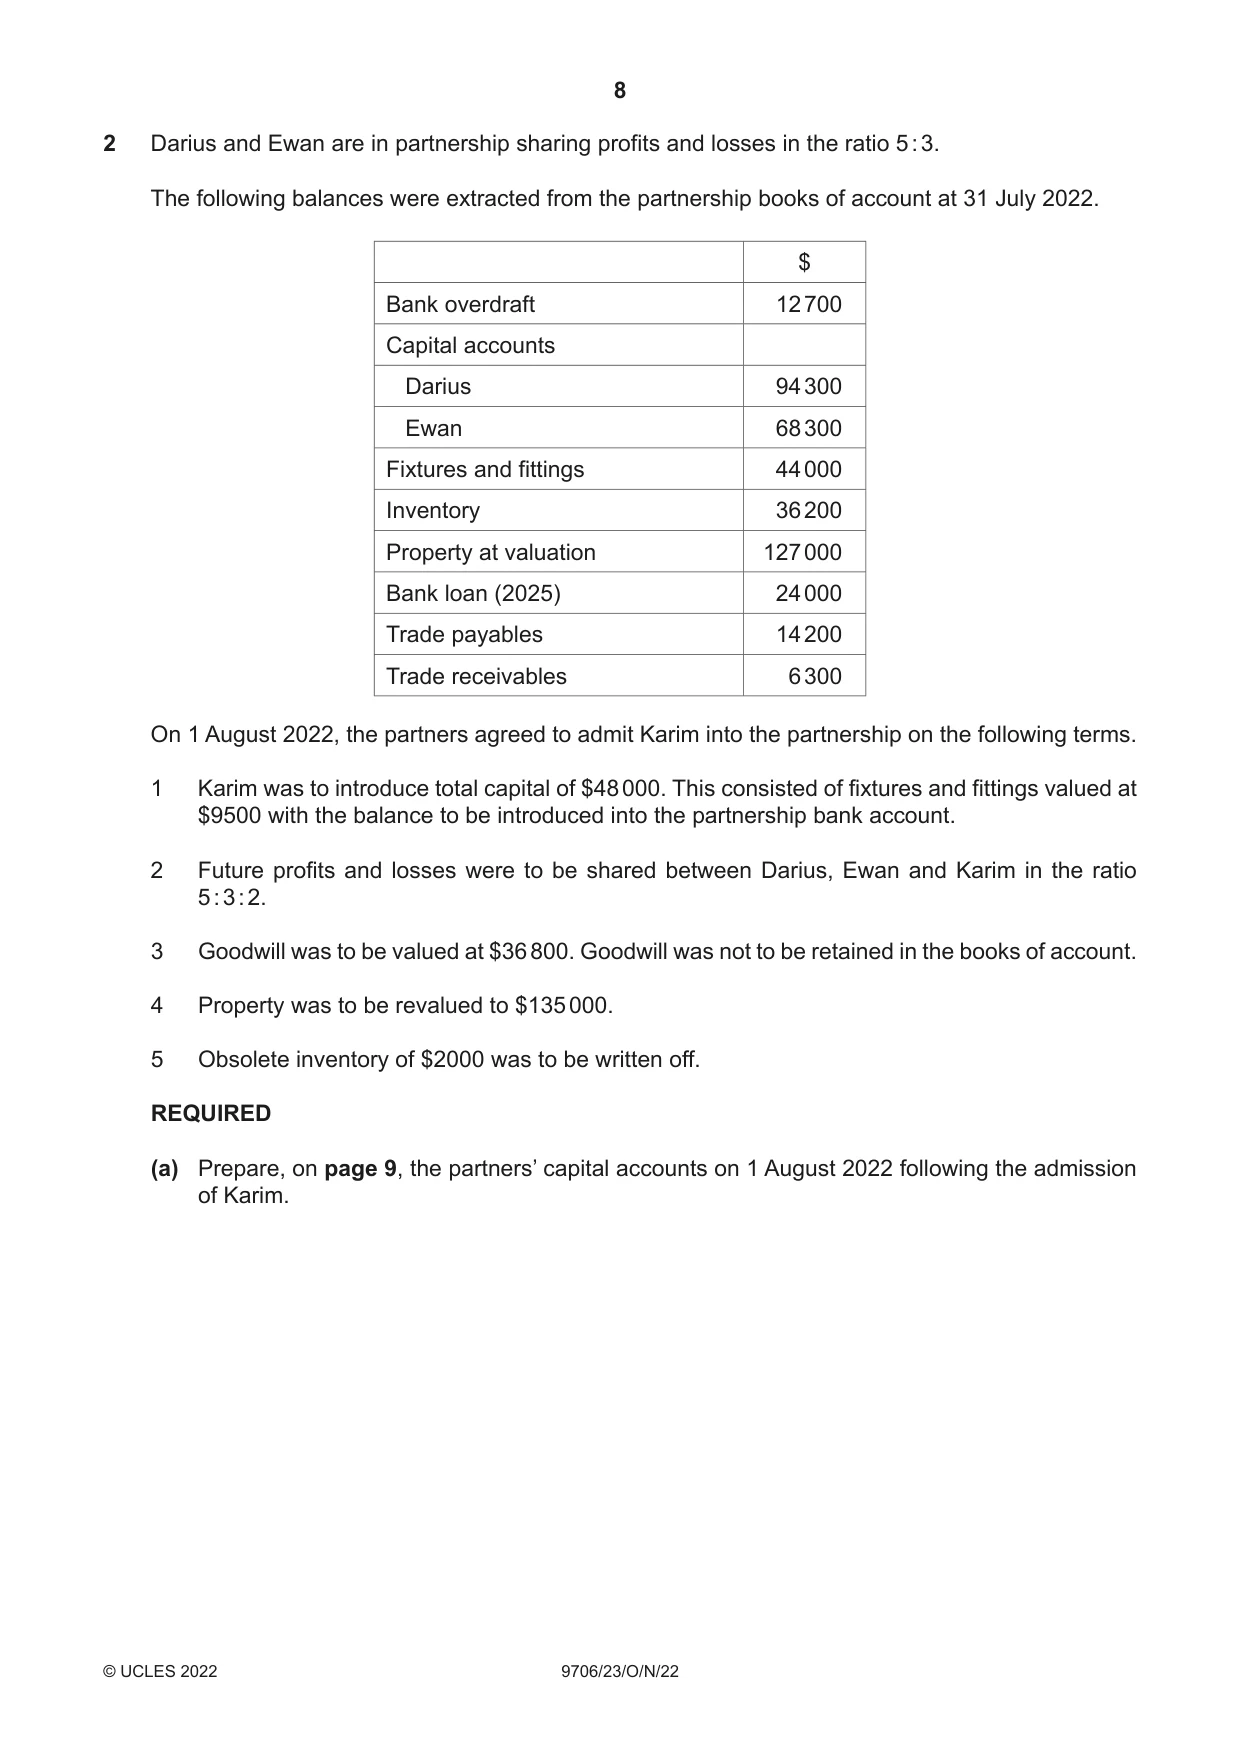
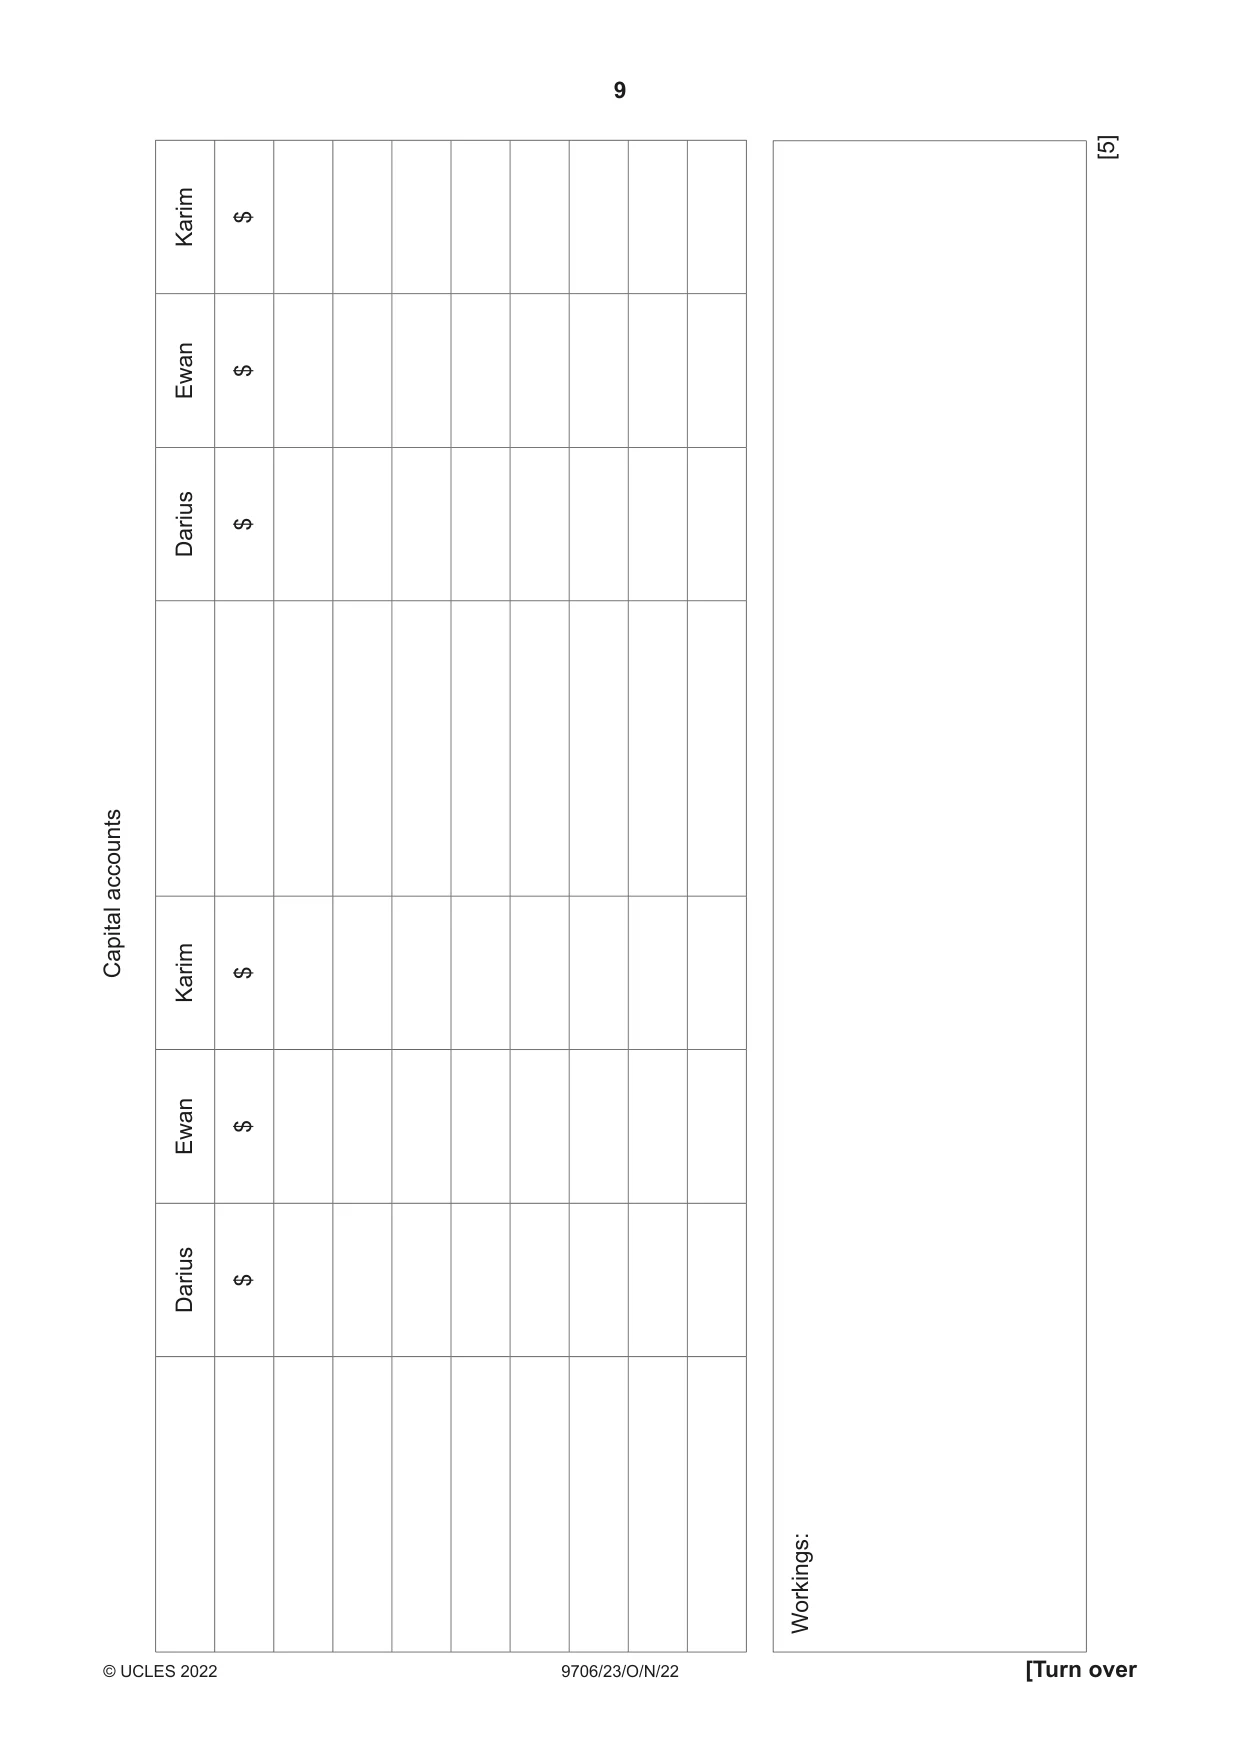
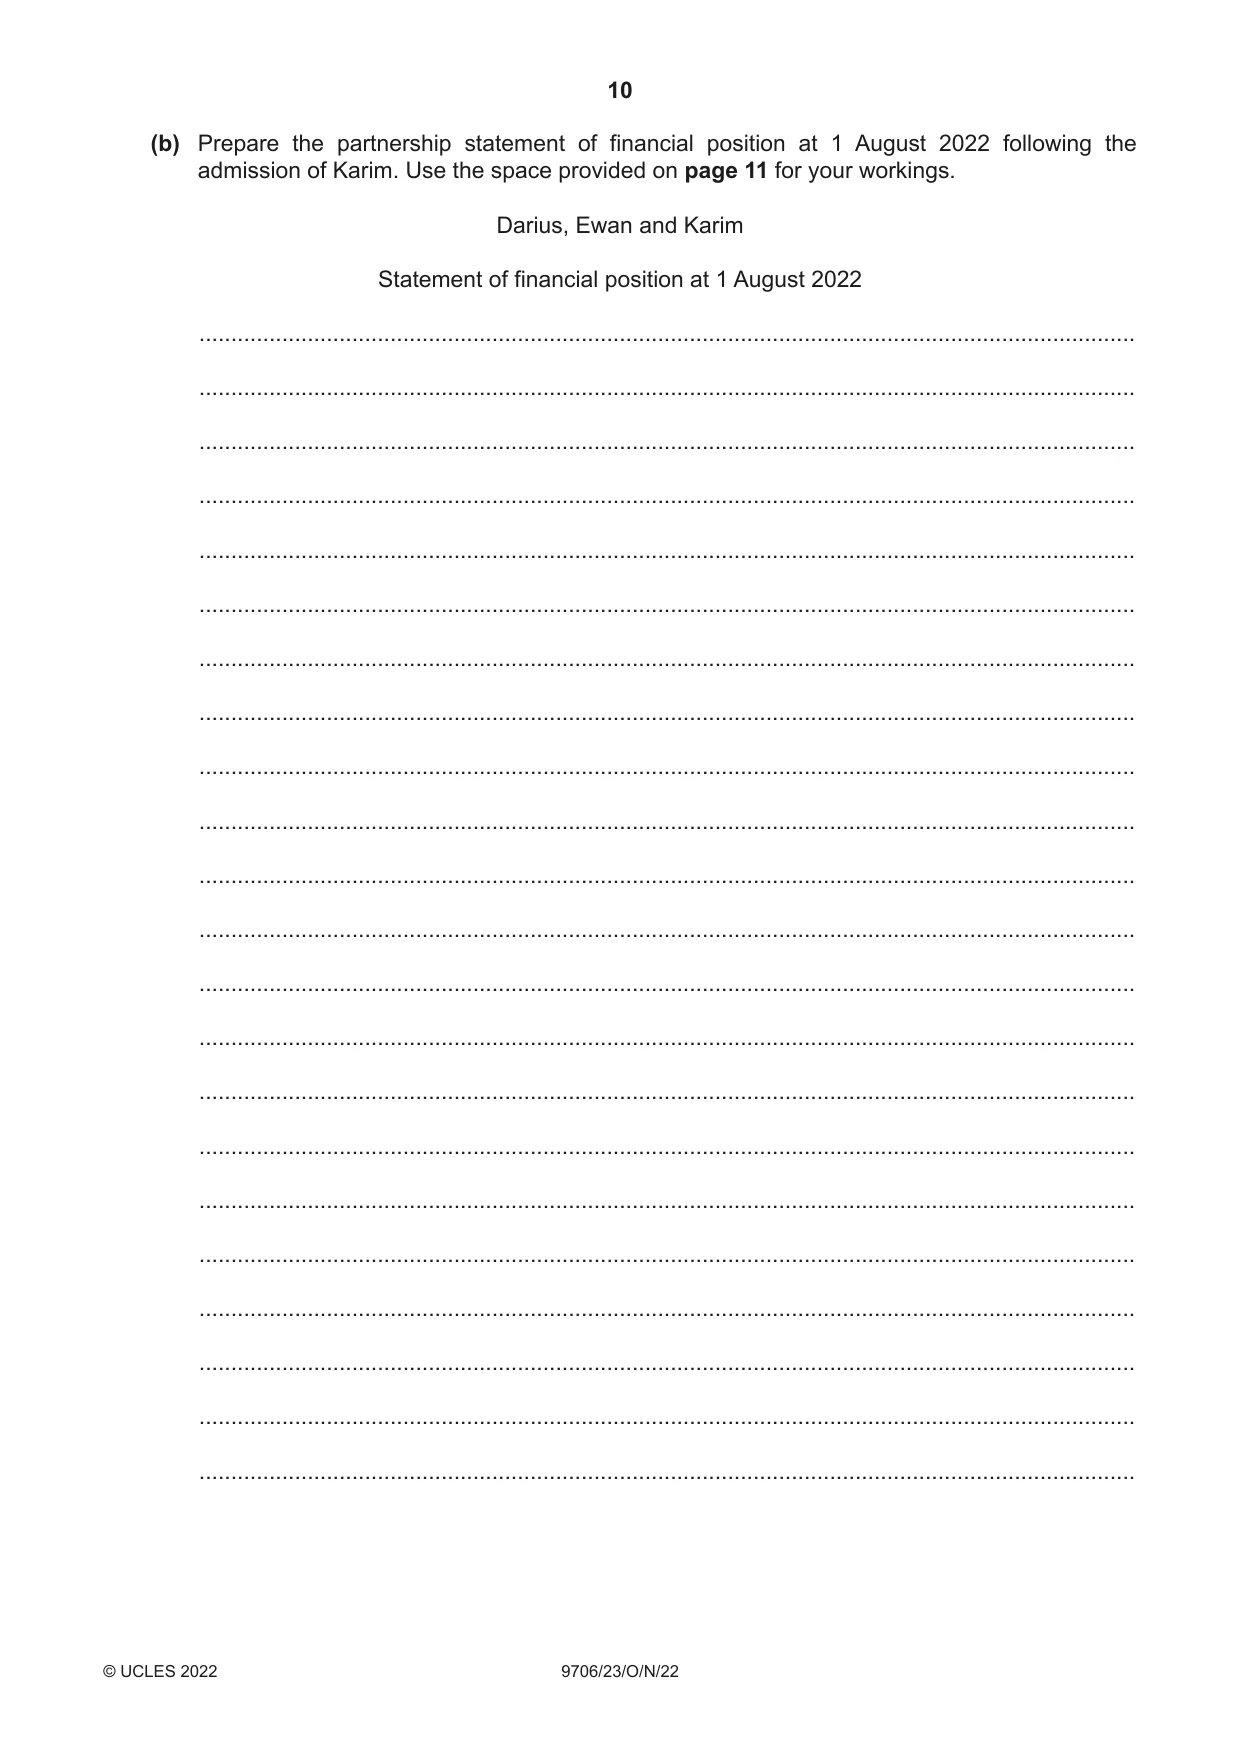
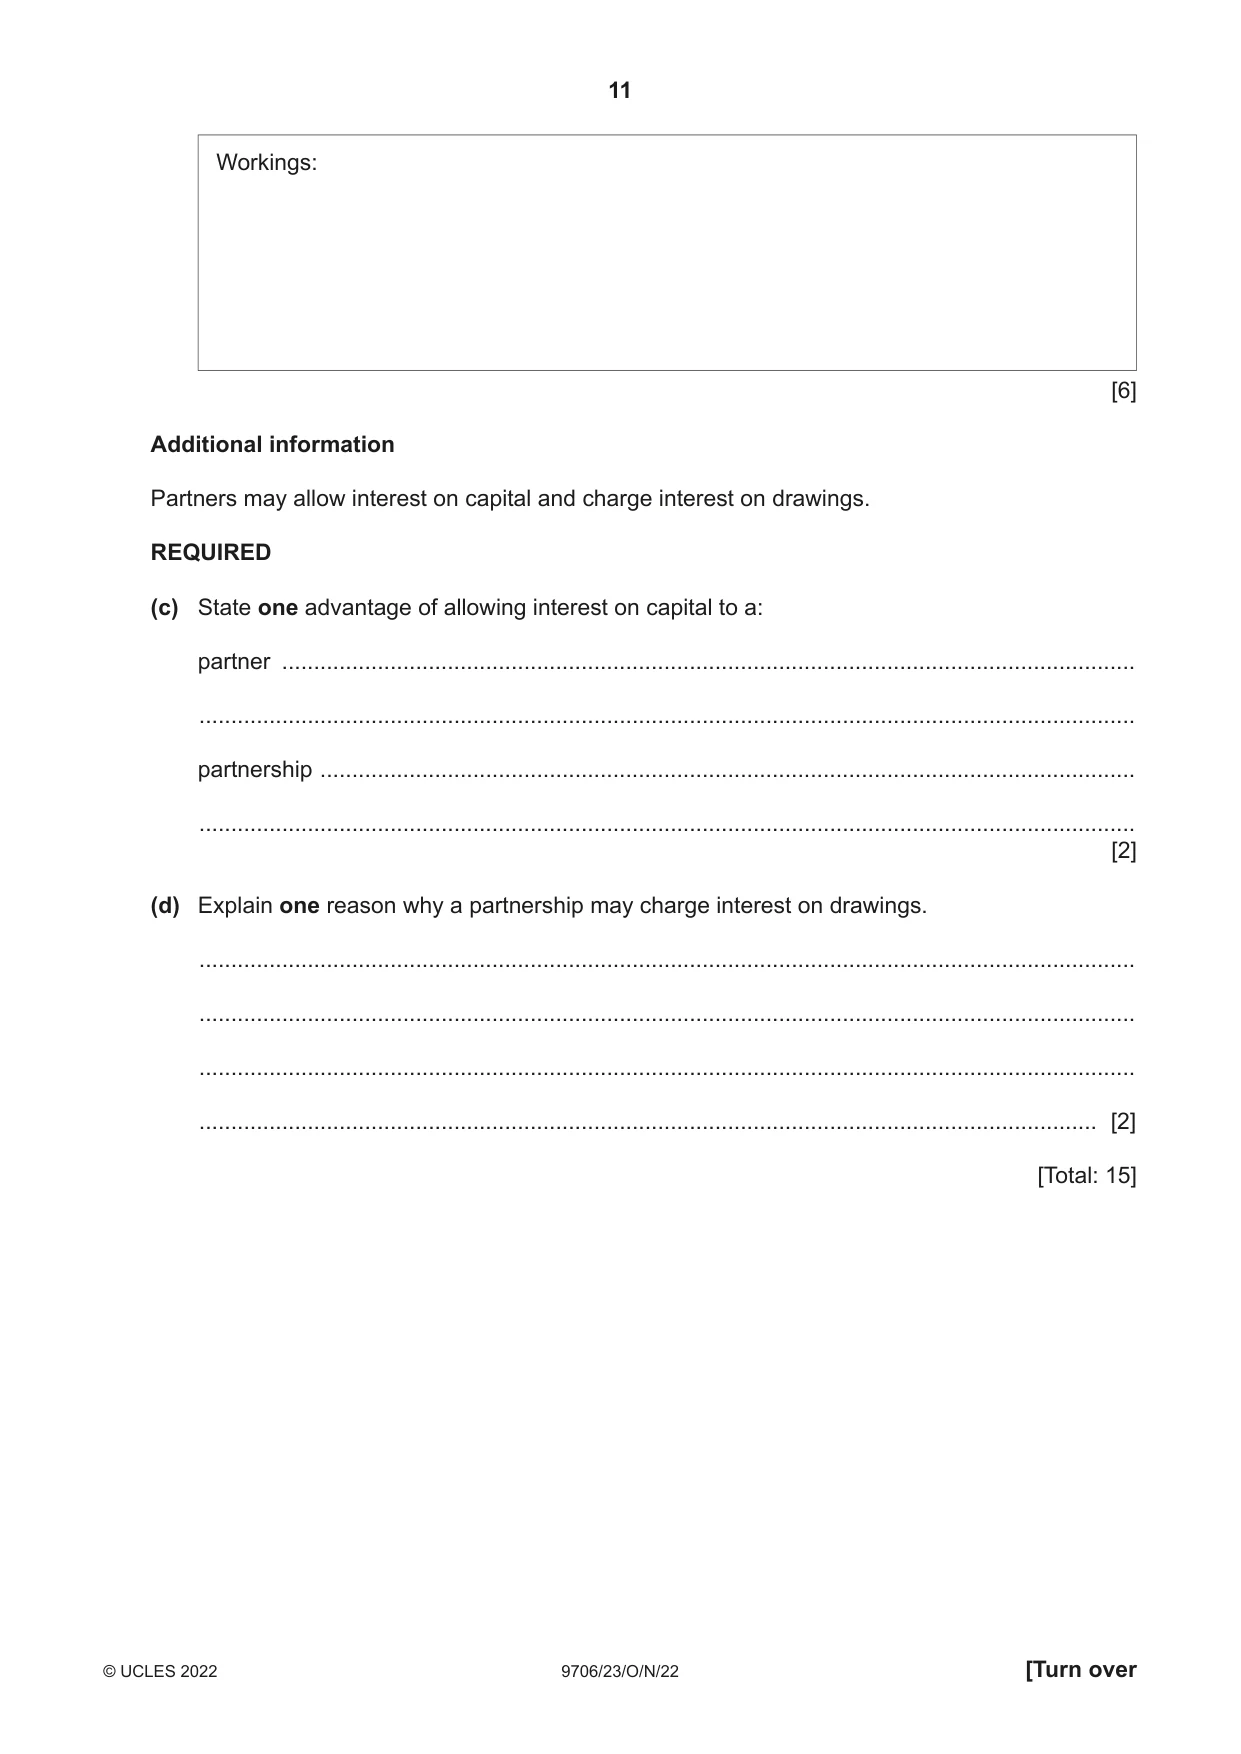
2 Darius and Ewan are in partnership sharing profits and losses in the ratio 5 : 3. The following balances were extracted from the partnership books of account at 31 July 2022. $ Bank overdraft 12 700 Capital accounts Darius 94 300 Ewan 68 300 Fixtures and fittings 44 000 Inventory 36 200 Property at valuation 127 000 Bank loan (2025) 24 000 Trade payables 14 200 Trade receivables 6 300 On 1 August 2022, the partners agreed to admit Karim into the partnership on the following terms. 1 Karim was to introduce total capital of $48 000. This consisted of fixtures and fittings valued at $9500 with the balance to be introduced into the partnership bank account. 2 Future profits and losses were to be shared between Darius, Ewan and Karim in the ratio 5 : 3 : 2. 3 Goodwill was to be valued at $36 800. Goodwill was not to be retained in the books of account. 4 Property was to be revalued to $135 000. 5 Obsolete inventory of $2000 was to be written off. REQUIRED (a) Prepare, on page 9, the partners’ capital accounts on 1 August 2022 following the admission of Karim. [5] (b) Prepare the partnership statement of financial position at 1 August 2022 following the admission of Karim. Use the space provided on page 11 for your workings. Darius, Ewan and Karim Statement of financial position at 1 August 2022 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: [6] Additional information Partners may allow interest on capital and charge interest on drawings. REQUIRED (c) State one advantage of allowing interest on capital to a: partner ...................................................................................................................................... ................................................................................................................................................... partnership ................................................................................................................................ ................................................................................................................................................... [2] (d) Explain one reason why a partnership may charge interest on drawings. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 15]
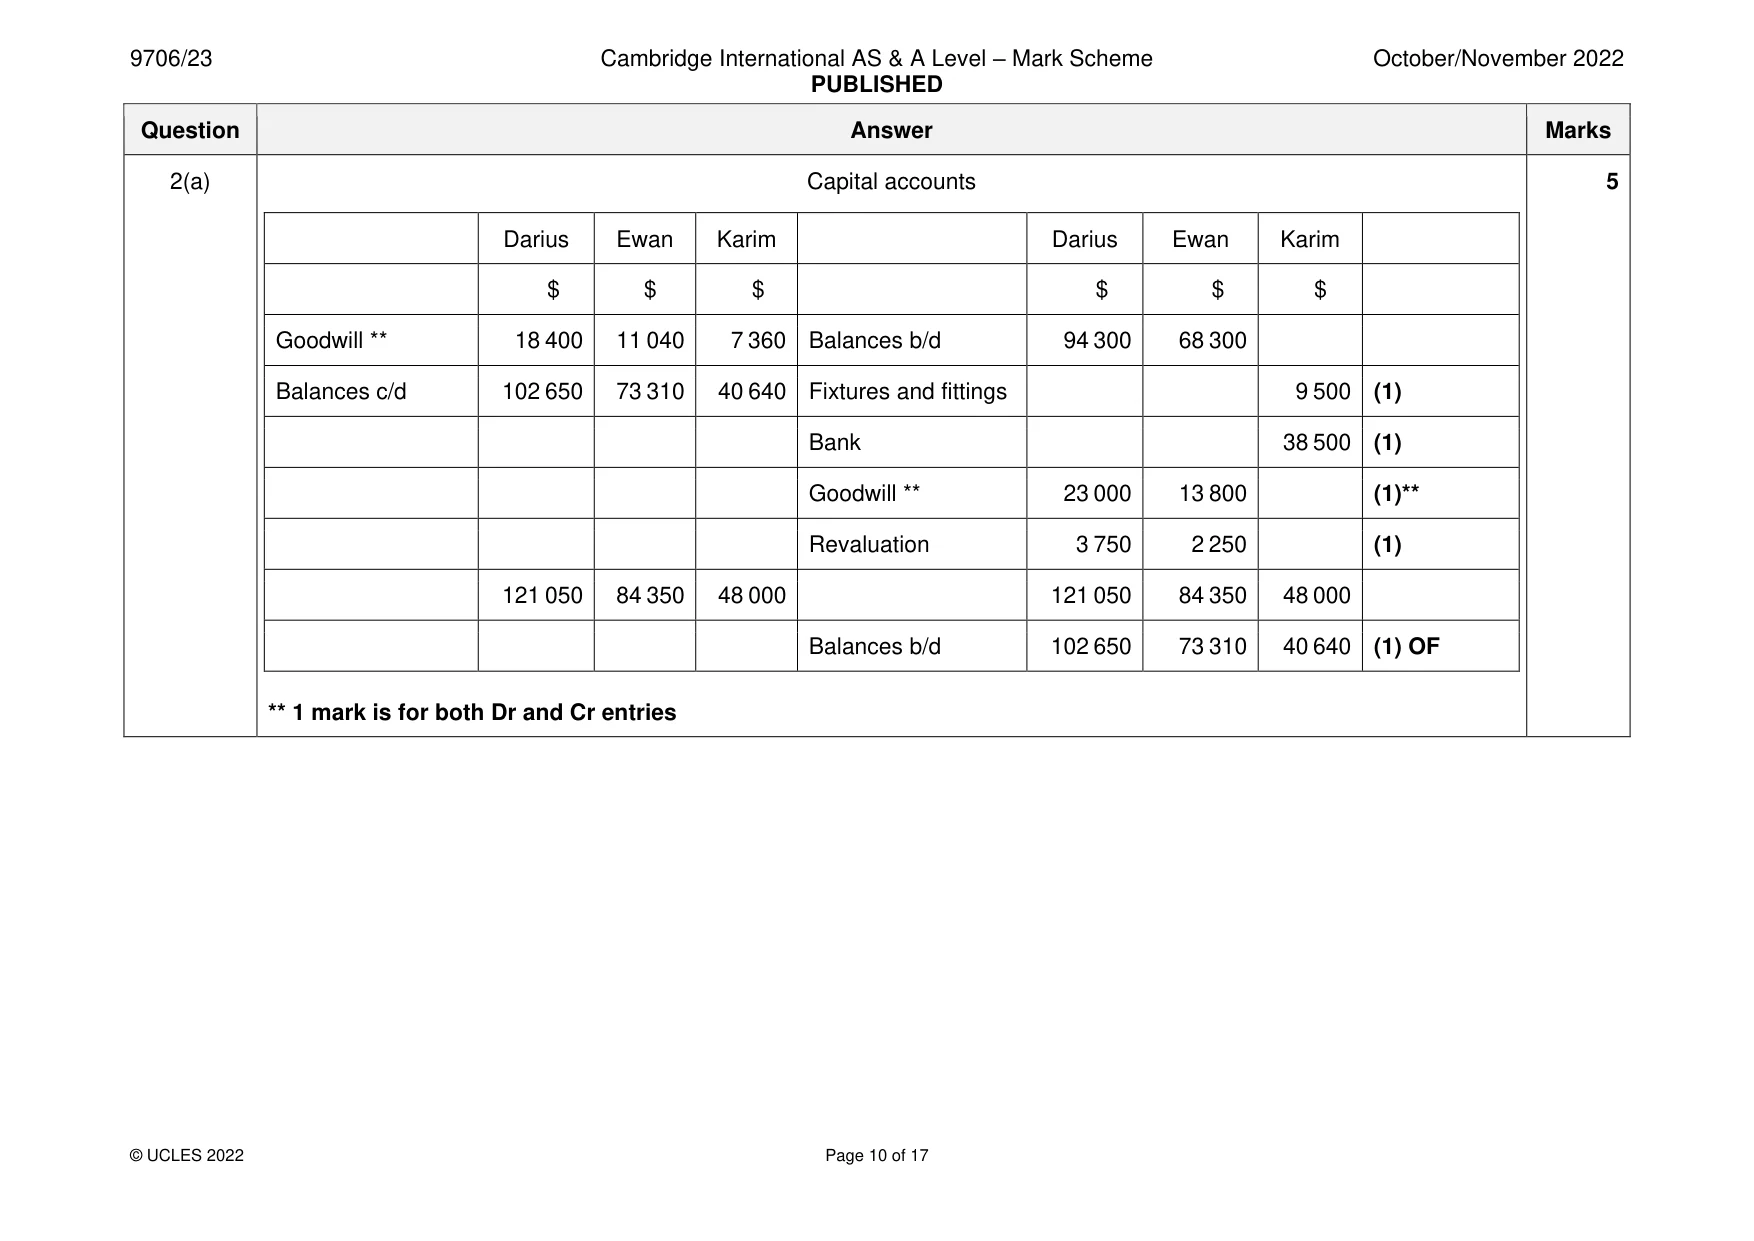
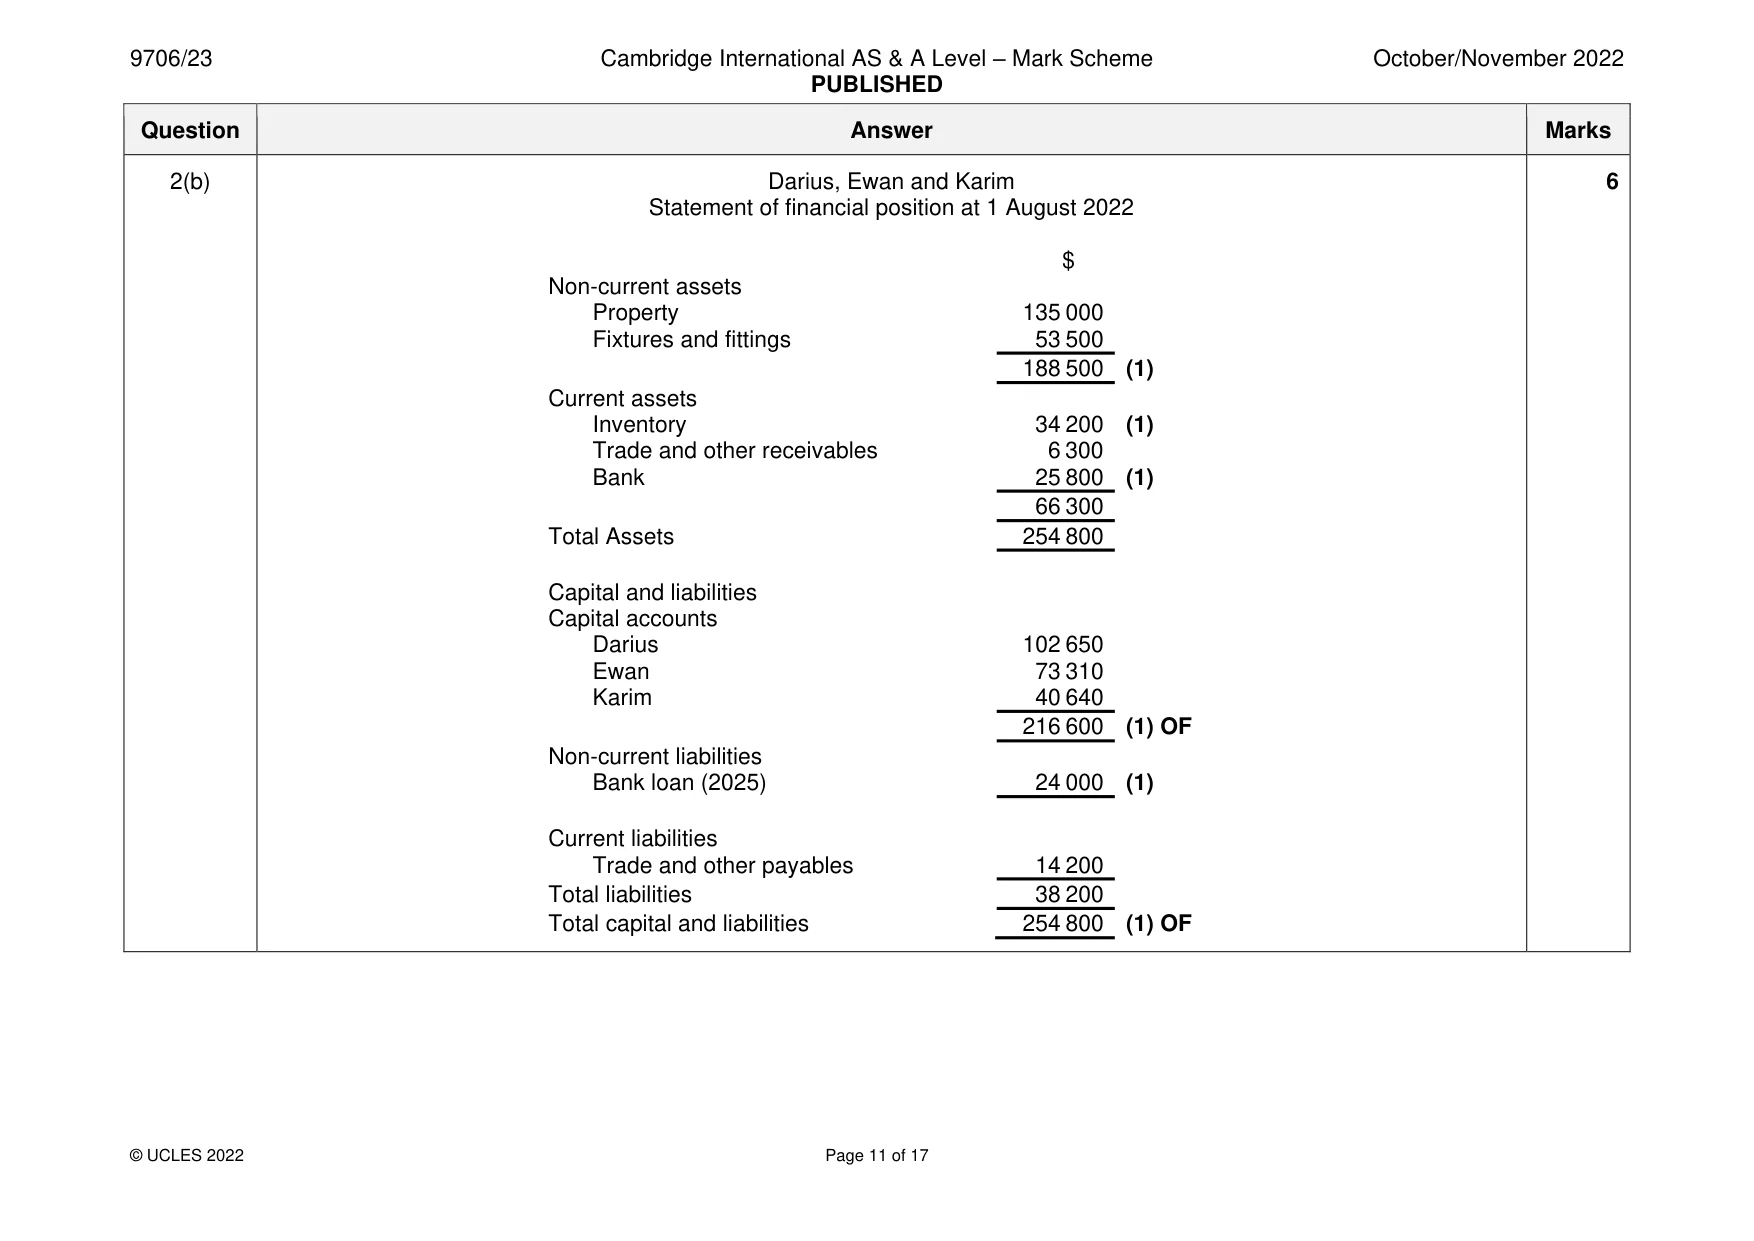
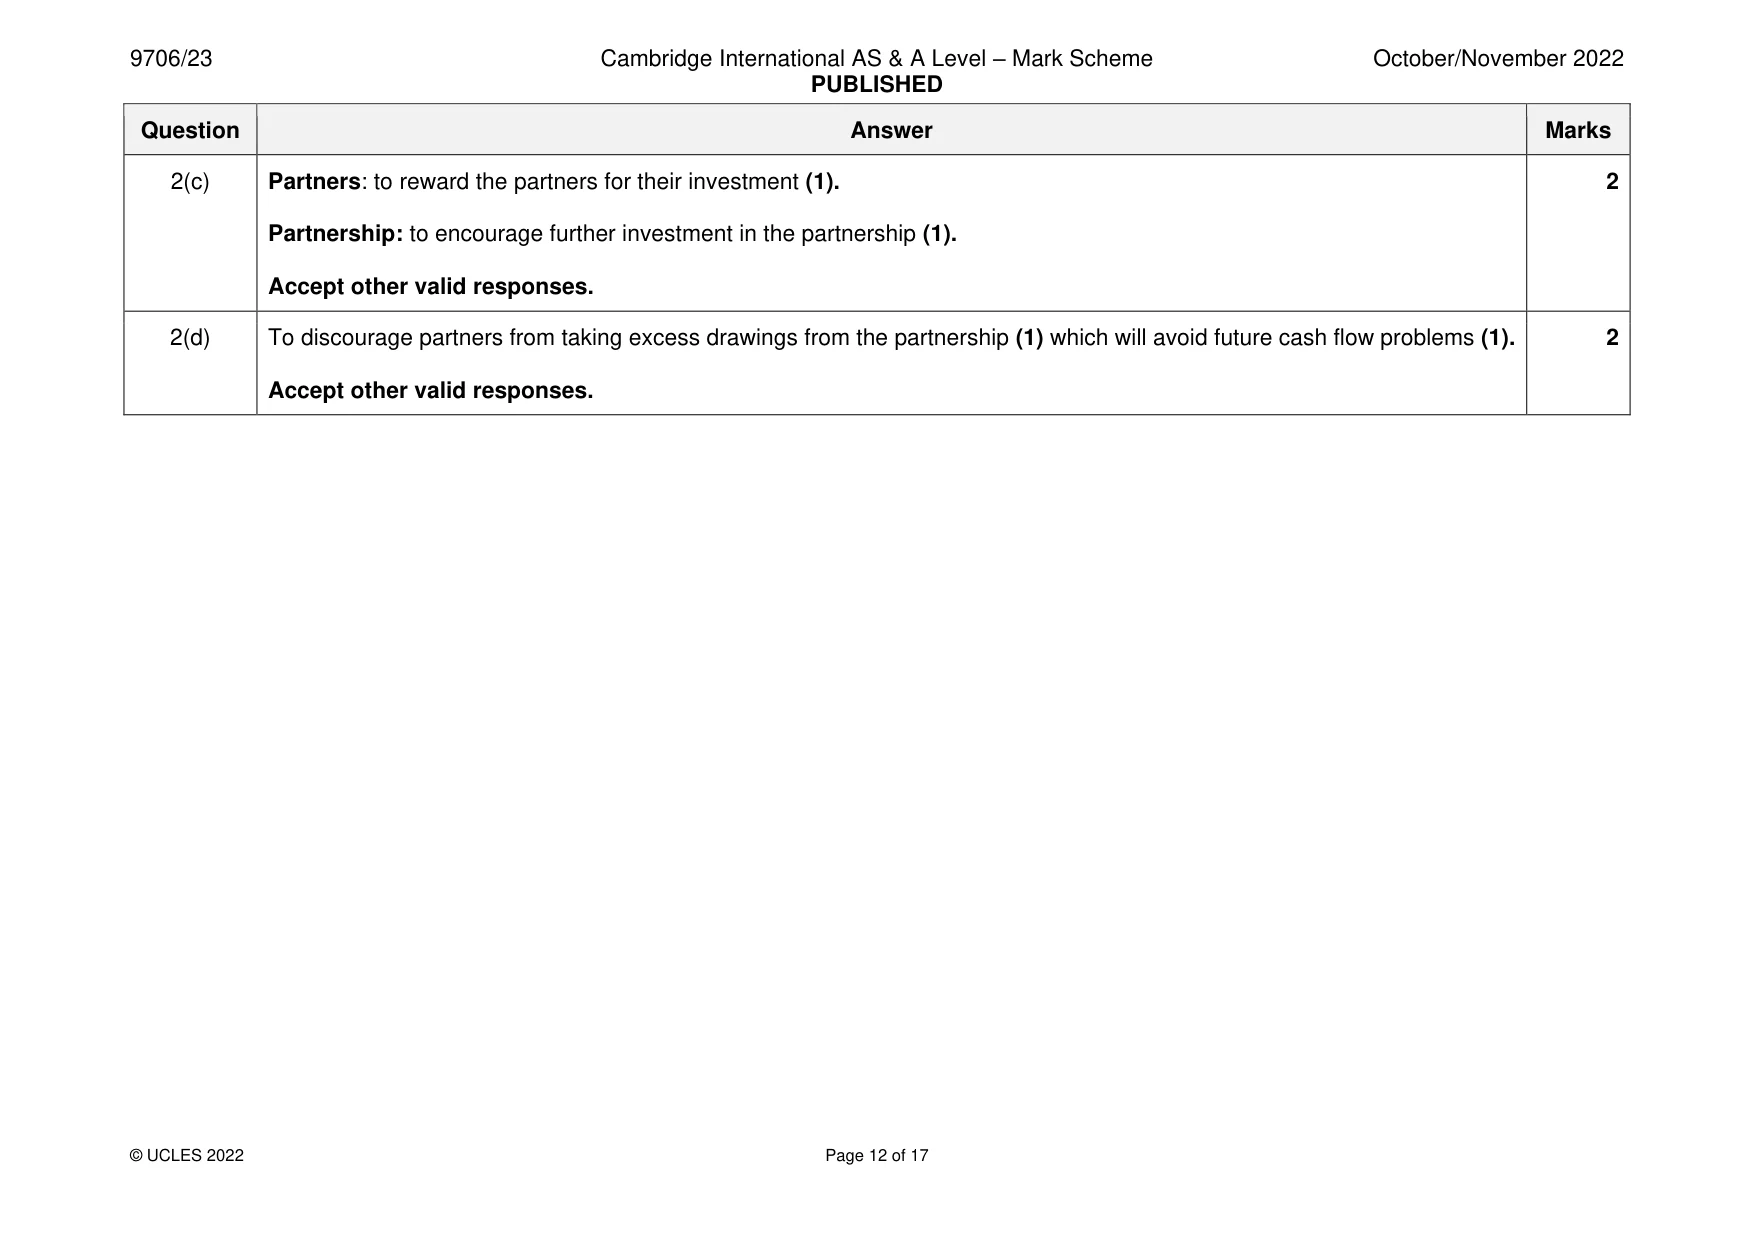
Mark scheme: 2(a) Capital accounts 5 Darius Ewan Karim Darius Ewan Karim $ $ $ $ $ $ Goodwill ** 18 400 11 040 7 360 Balances b/d 94 300 68 300 Balances c/d 102 650 73 310 40 640 Fixtures and fittings 9 500 (1) Bank 38 500 (1) Goodwill ** 23 000 13 800 (1)** Revaluation 3 750 2 250 (1) 121 050 84 350 48 000 121 050 84 350 48 000 Balances b/d 102 650 73 310 40 640 (1) OF ** 1 mark is for both Dr and Cr entries 2(b) Darius, Ewan and Karim 6 Statement of financial position at 1 August 2022 $ Non-current assets Property 135 000 Fixtures and fittings 53 500 188 500 (1) Current assets Inventory 34 200 (1) Trade and other receivables 6 300 Bank 25 800 (1) 66 300 Total Assets 254 800 Capital and liabilities Capital accounts Darius 102 650 Ewan 73 310 Karim 40 640 216 600 (1) OF Non-current liabilities Bank loan (2025) 24 000 (1) Current liabilities Trade and other payables 14 200 Total liabilities 38 200 Total capital and liabilities 254 800 (1) OF 2(c) Partners: to reward the partners for their investment (1). 2 Partnership: to encourage further investment in the partnership (1). Accept other valid responses. 2(d) To discourage partners from taking excess drawings from the partnership (1) which will avoid future cash flow problems (1). 2 Accept other valid responses.
Q3 · R Limited is a retail company
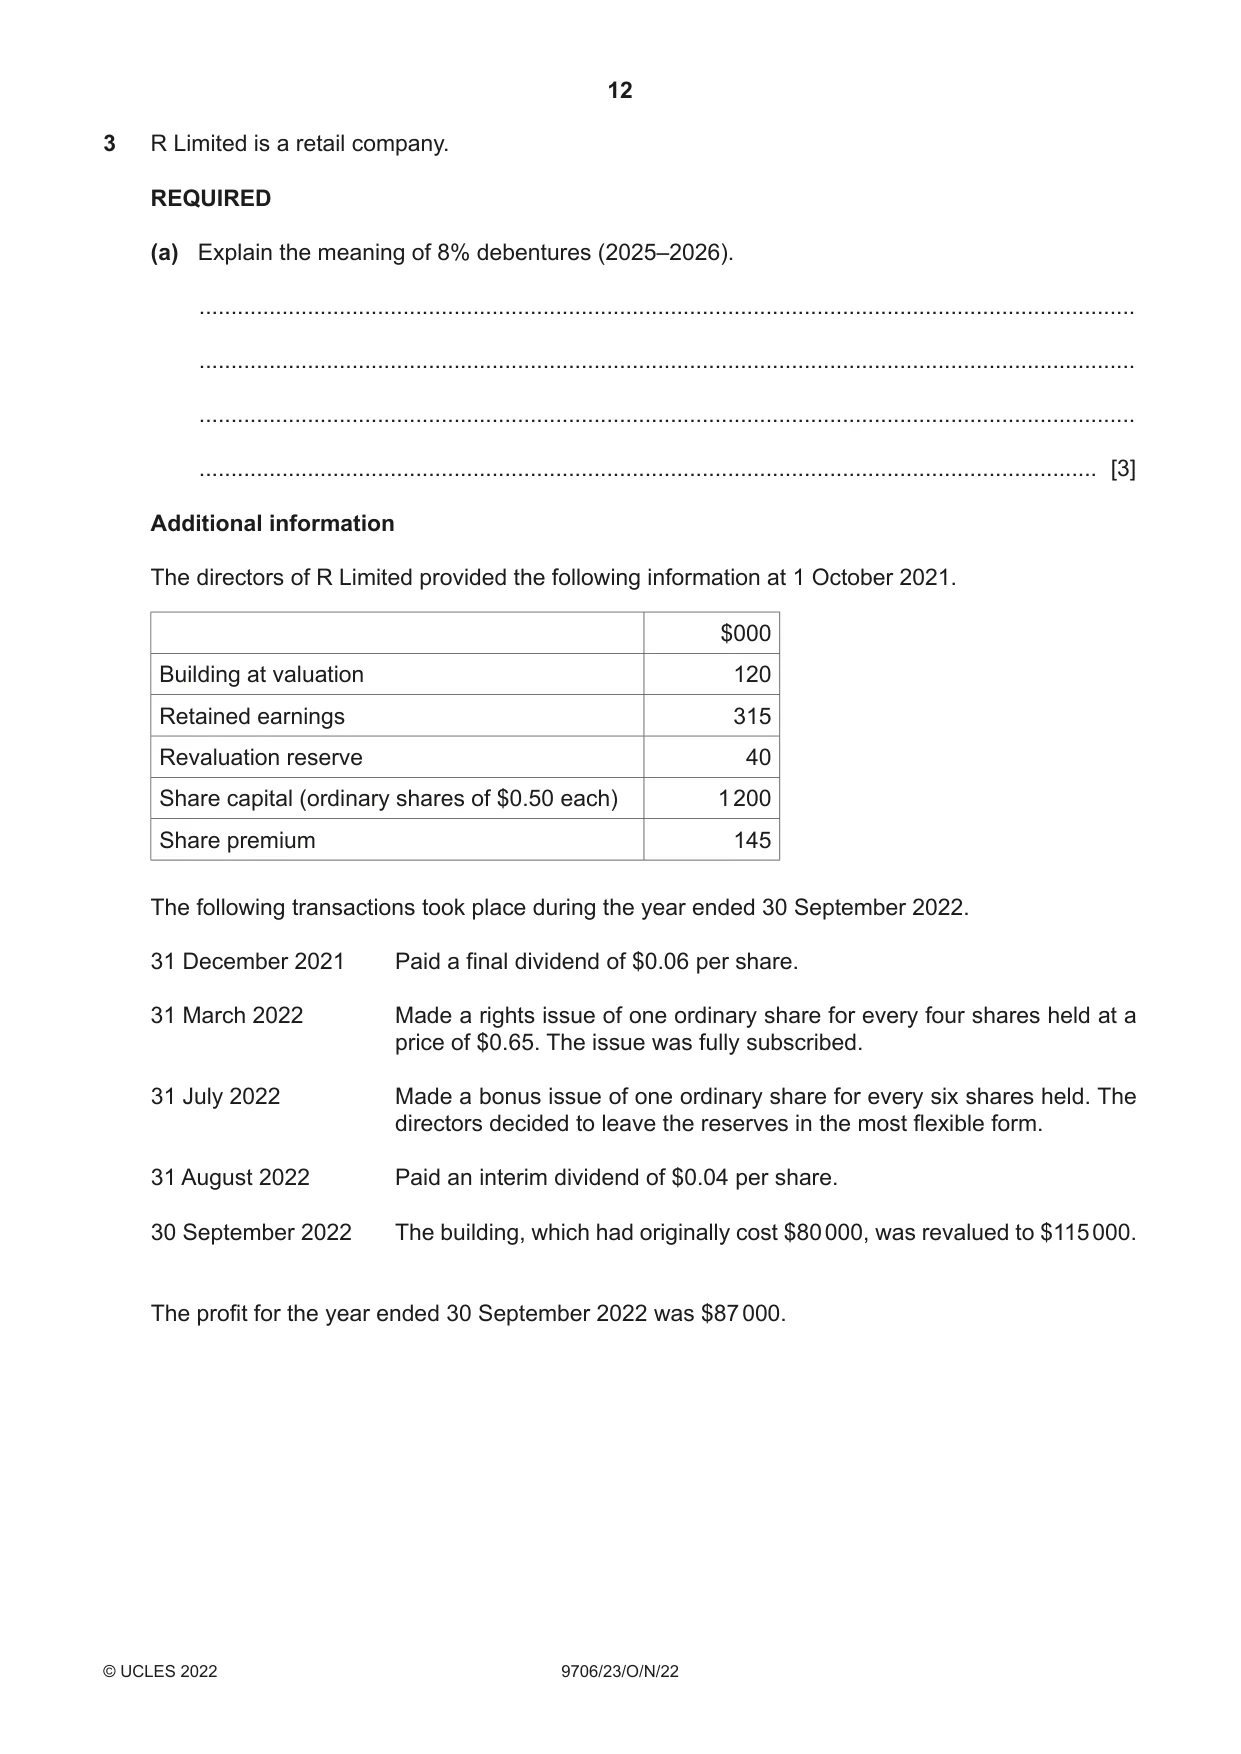
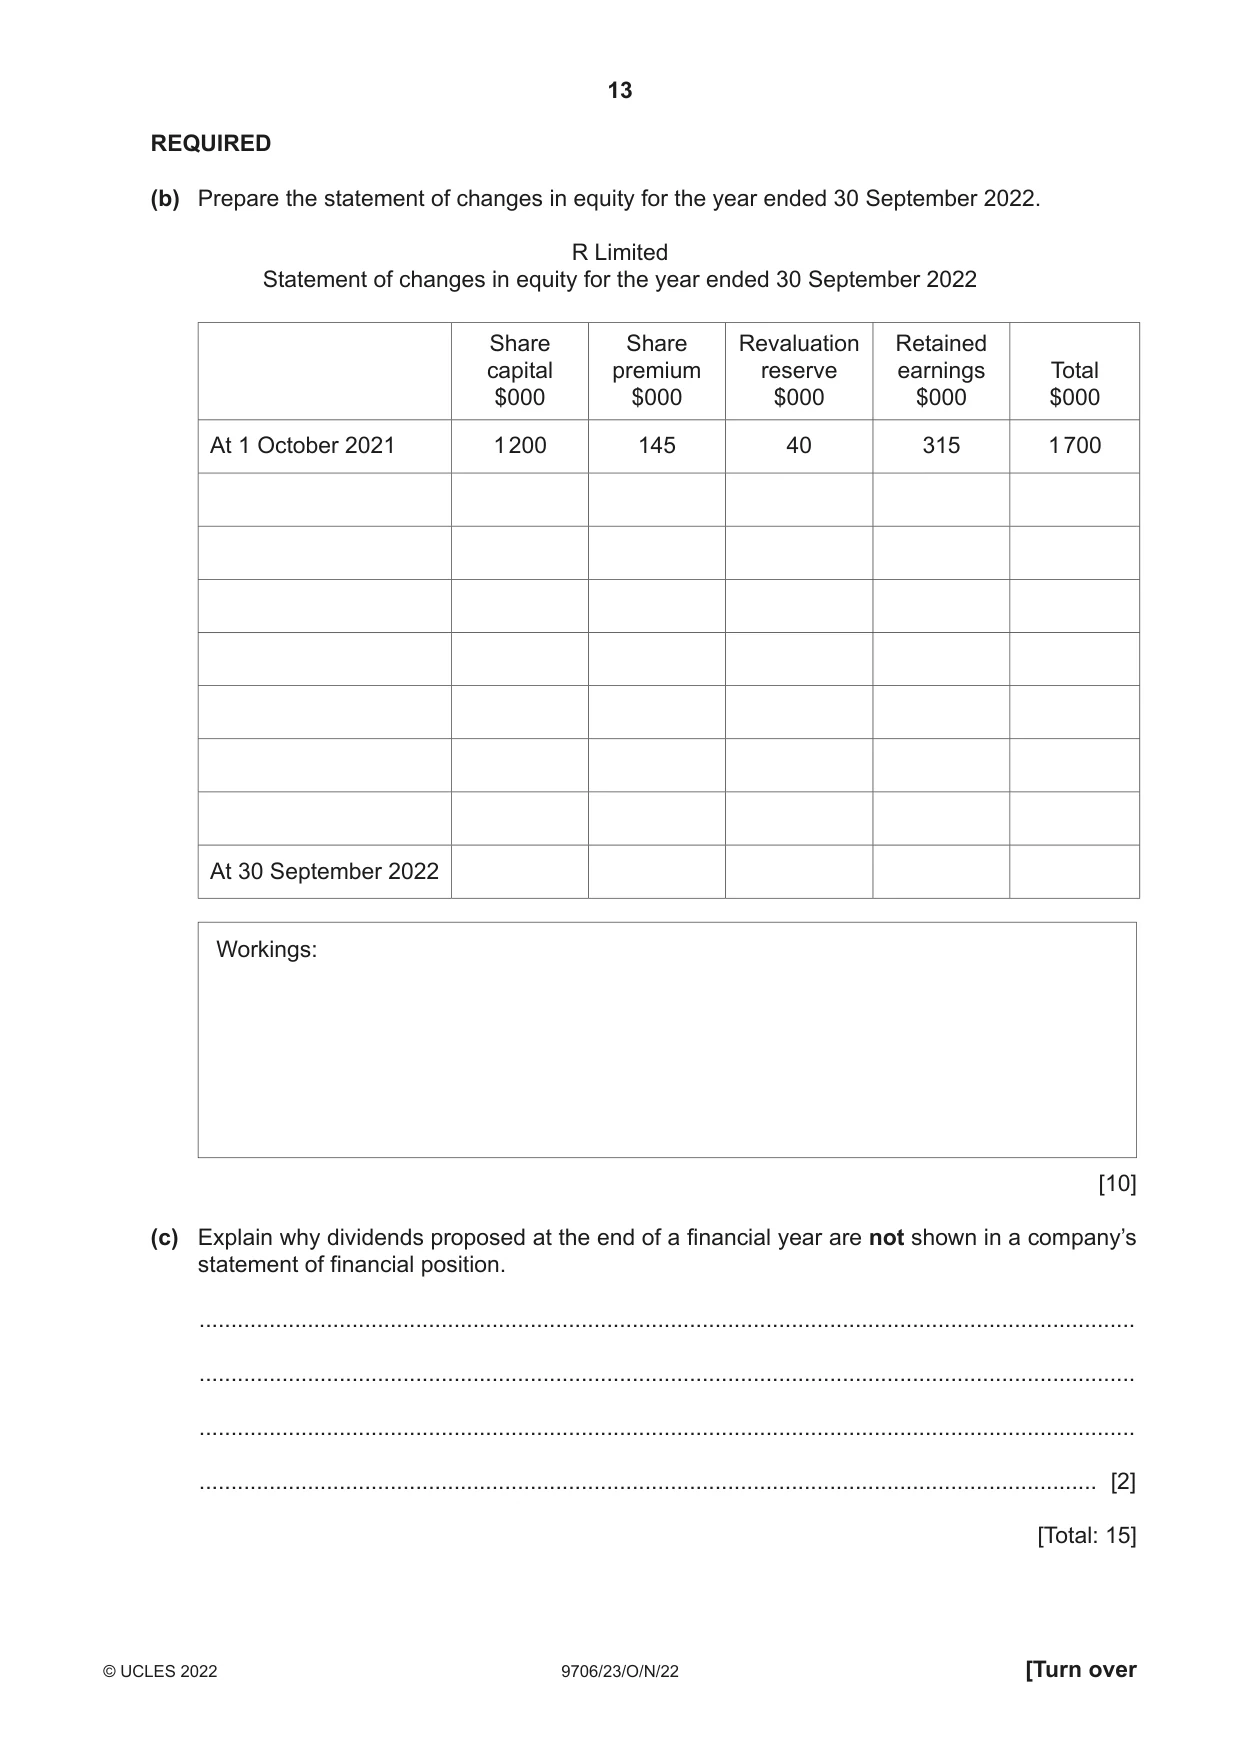
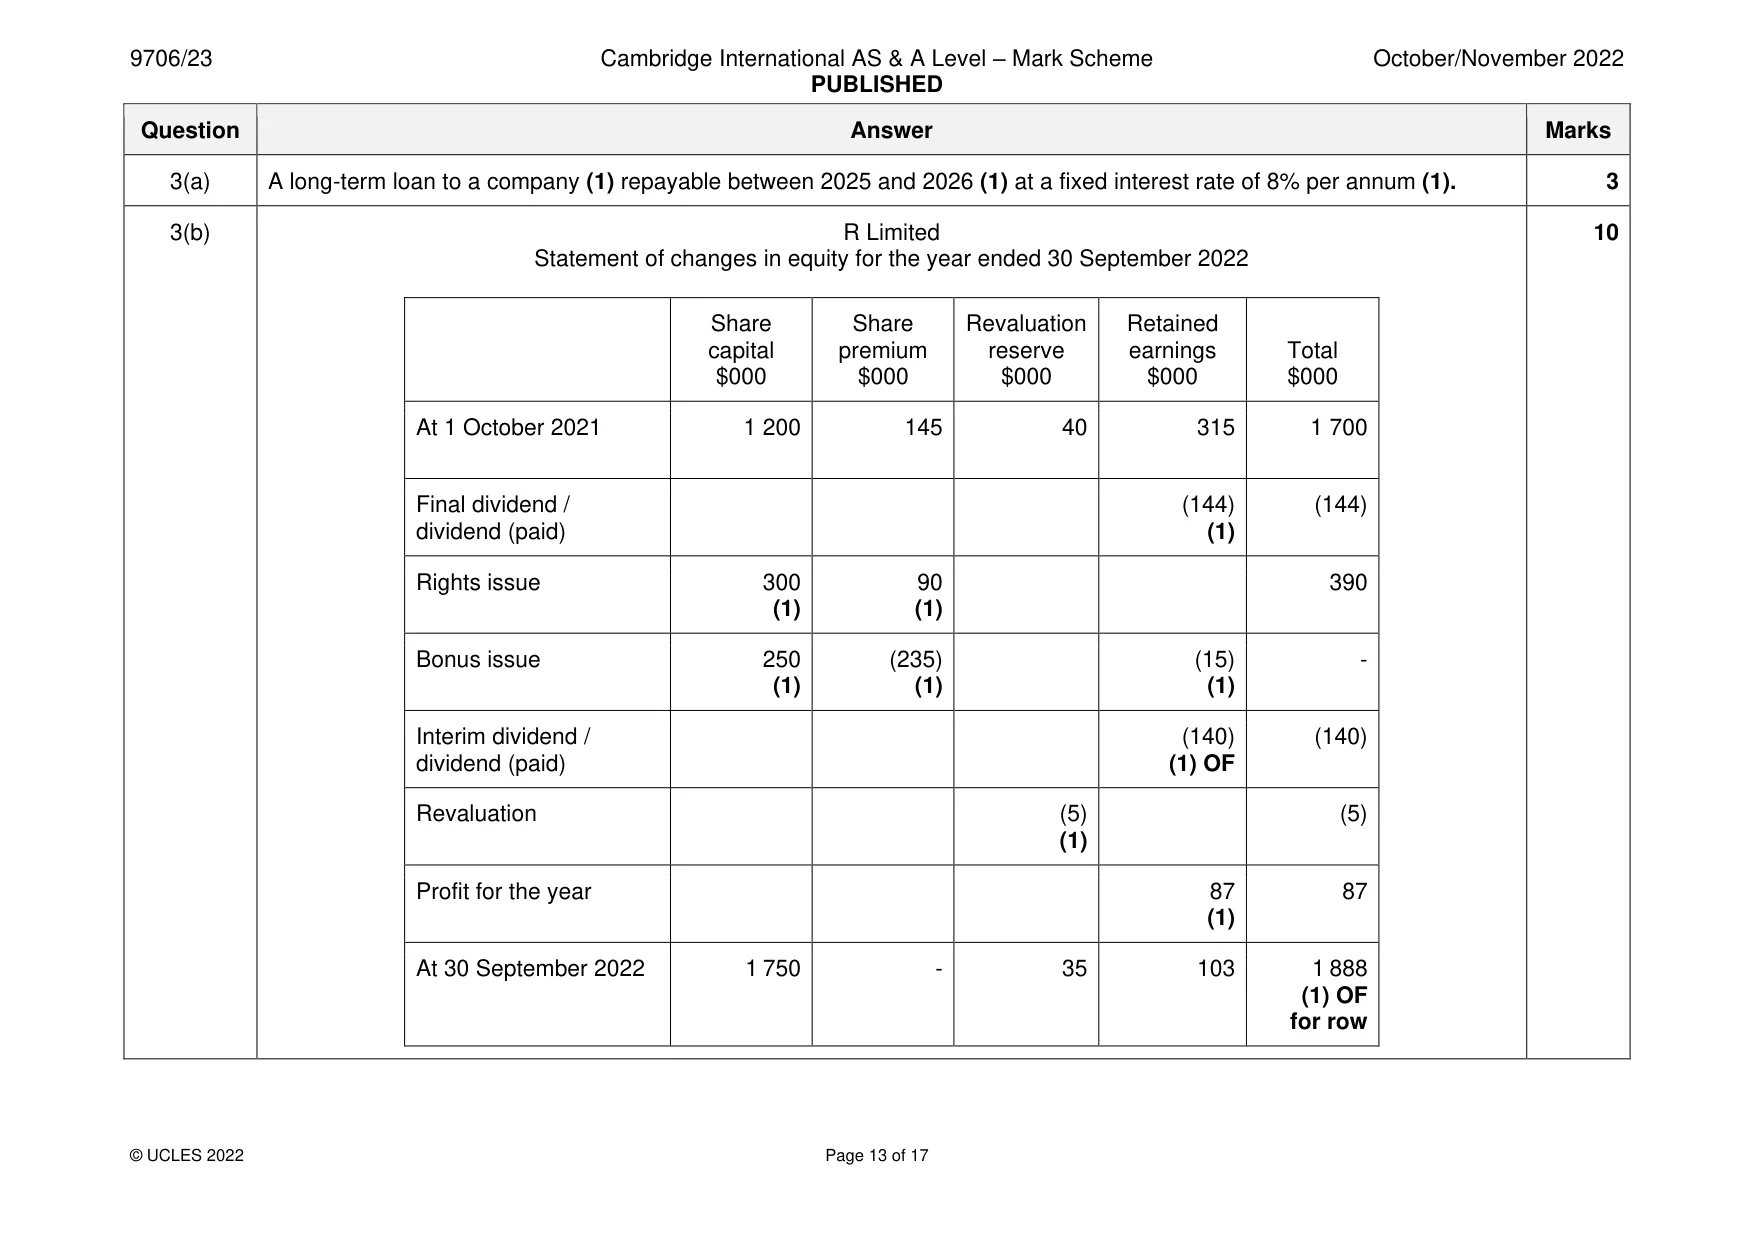
3 R Limited is a retail company. REQUIRED (a) Explain the meaning of 8% debentures (2025–2026). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Additional information The directors of R Limited provided the following information at 1 October 2021. $000 Building at valuation 120 Retained earnings 315 Revaluation reserve 40 Share capital (ordinary shares of $0.50 each) 1 200 Share premium 145 The following transactions took place during the year ended 30 September 2022. 31 December 2021 Paid a final dividend of $0.06 per share. 31 March 2022 Made a rights issue of one ordinary share for every four shares held at a price of $0.65. The issue was fully subscribed. 31 July 2022 Made a bonus issue of one ordinary share for every six shares held. The directors decided to leave the reserves in the most flexible form. 31 August 2022 Paid an interim dividend of $0.04 per share. 30 September 2022 The building, which had originally cost $80 000, was revalued to $115 000. The profit for the year ended 30 September 2022 was $87 000. REQUIRED (b) Prepare the statement of changes in equity for the year ended 30 September 2022. R Limited Statement of changes in equity for the year ended 30 September 2022 Share Share Revaluation Retained capital premium reserve earnings Total $000 $000 $000 $000 $000 At 1 October 2021 1 200 145 40 315 1 700 At 30 September 2022 Workings: [10] (c) Explain why dividends proposed at the end of a financial year are not shown in a company’s statement of financial position. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 15]
Mark scheme: 3(a) A long-term loan to a company (1) repayable between 2025 and 2026 (1) at a fixed interest rate of 8% per annum (1). 3 3(b) R Limited 10 Statement of changes in equity for the year ended 30 September 2022 Share Share Revaluation Retained capital premium reserve earnings Total $000 $000 $000 $000 $000 At 1 October 2021 1 200 145 40 315 1 700 Final dividend / (144) (144) dividend (paid) (1) Rights issue 300 90 390 (1) (1) Bonus issue 250 (235) (15) - (1) (1) (1) Interim dividend / (140) (140) dividend (paid) (1) OF Revaluation (5) (5) (1) Profit for the year 87 87 (1) At 30 September 2022 1 750 - 35 103 1 888 (1) OF for row 3(c) A proposed dividend should be shown as a note to the accounts but should not be shown as a liability (1) as at the reporting 2 date it has not been approved by the shareholders and as such there is no certainty that it will be paid (1) Accept other valid responses.
Q4 · X Limited is a manufacturing business operating two production departments, Machining and…
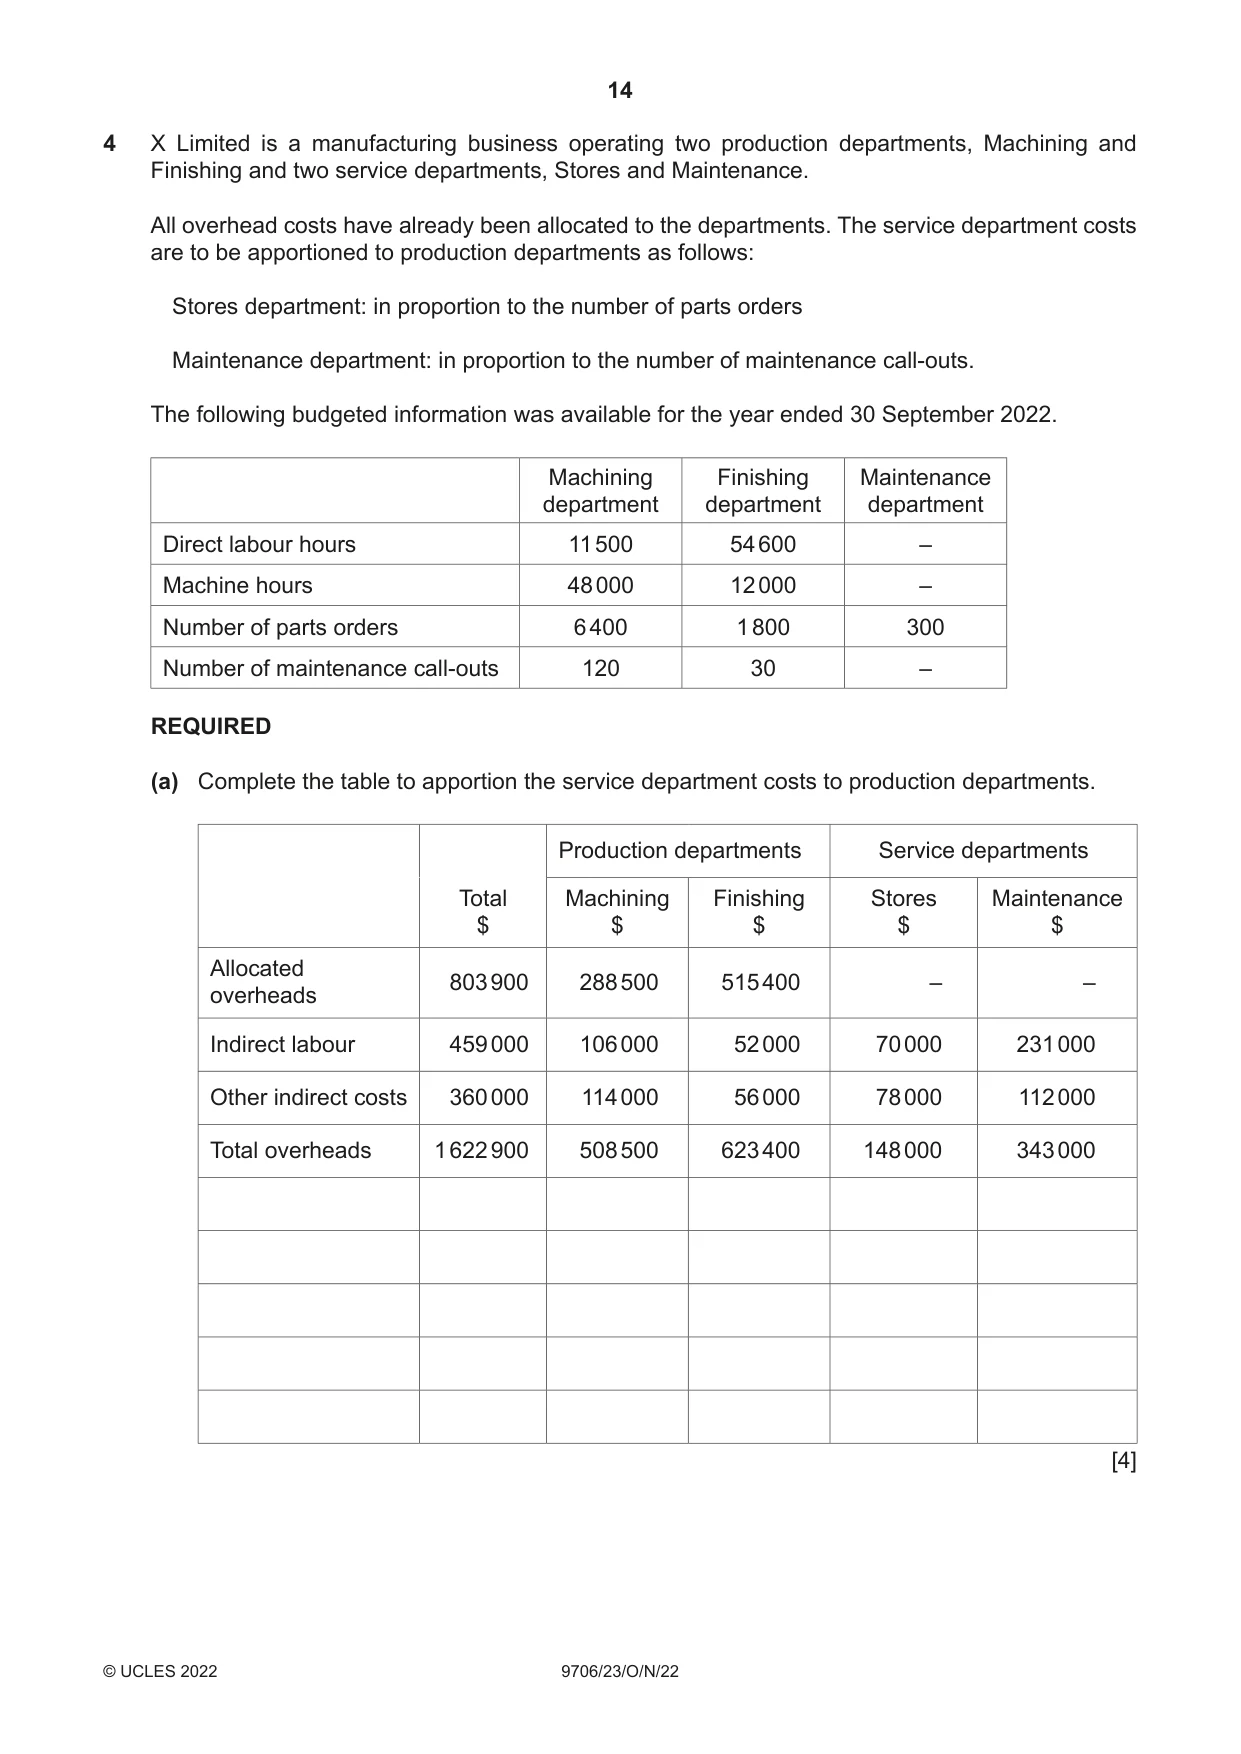
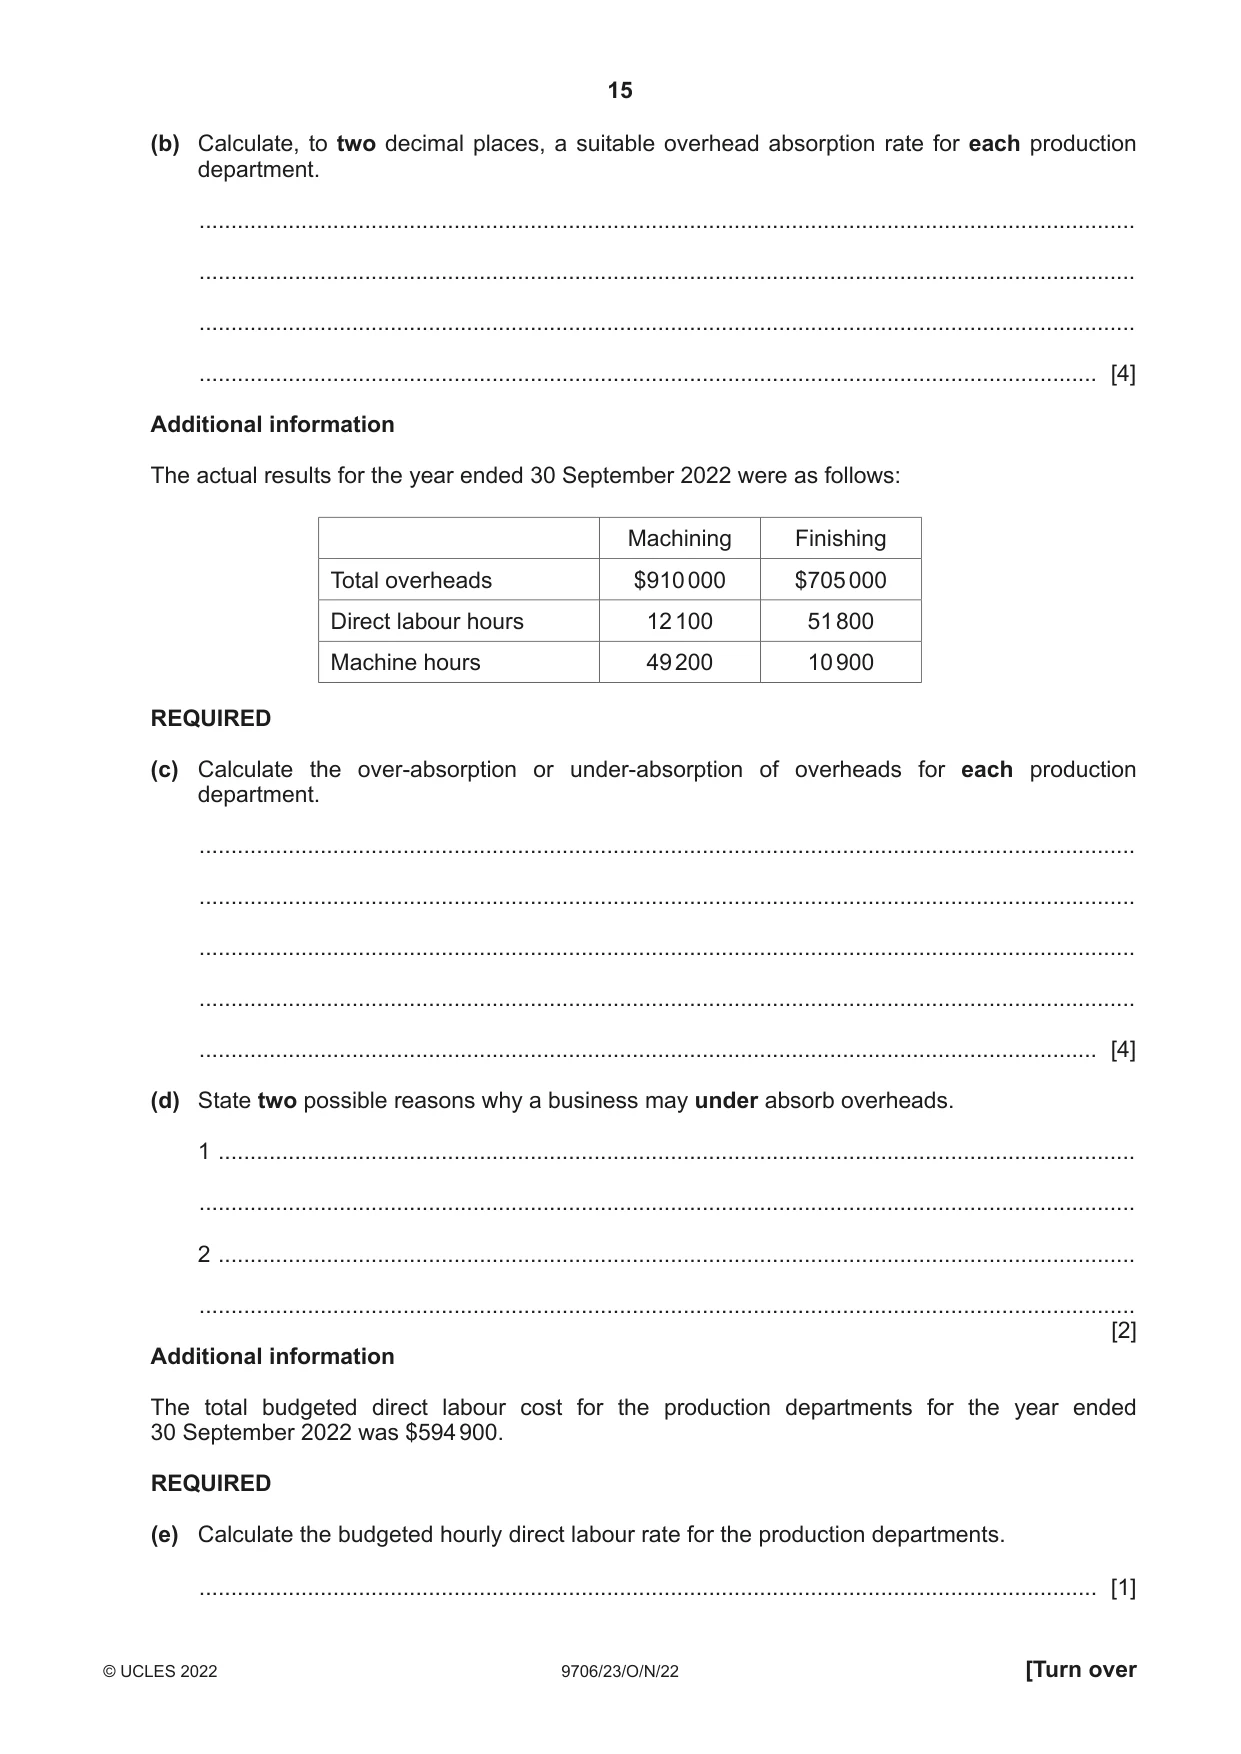
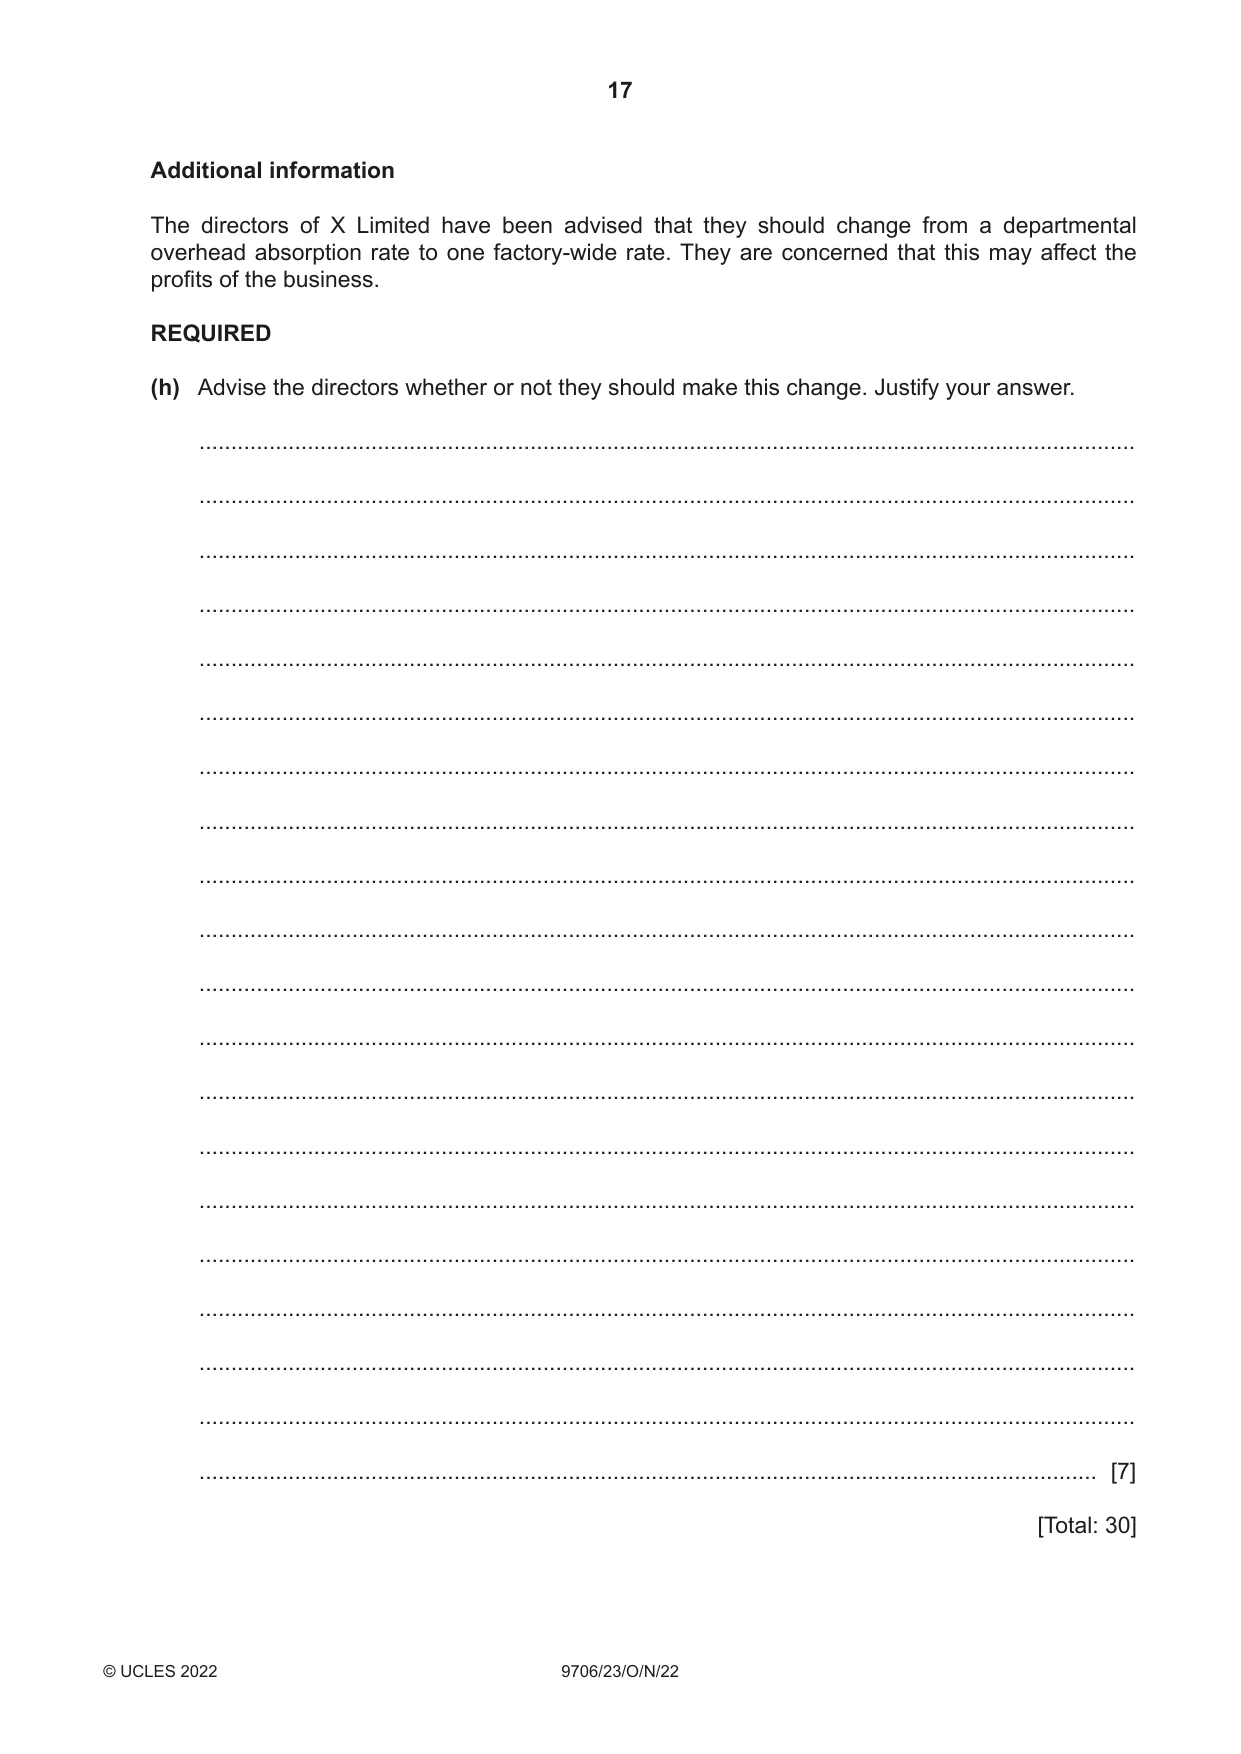
4 X Limited is a manufacturing business operating two production departments, Machining and Finishing and two service departments, Stores and Maintenance. All overhead costs have already been allocated to the departments. The service department costs are to be apportioned to production departments as follows: Stores department: in proportion to the number of parts orders Maintenance department: in proportion to the number of maintenance call-outs. The following budgeted information was available for the year ended 30 September 2022. Machining Finishing Maintenance department department department Direct labour hours 11 500 54 600 – Machine hours 48 000 12 000 – Number of parts orders 6 400 1 800 300 Number of maintenance call-outs 120 30 – REQUIRED (a) Complete the table to apportion the service department costs to production departments. Production departments Service departments Total Machining Finishing Stores Maintenance $ $ $ $ $ Allocated 803 900 288 500 515 400 – – overheads Indirect labour 459 000 106 000 52 000 70 000 231 000 Other indirect costs 360 000 114 000 56 000 78 000 112 000 Total overheads 1 622 900 508 500 623 400 148 000 343 000 [4] (b) Calculate, to two decimal places, a suitable overhead absorption rate for each production department. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Additional information The actual results for the year ended 30 September 2022 were as follows: Machining Finishing Total overheads $910 000 $705 000 Direct labour hours 12 100 51 800 Machine hours 49 200 10 900 REQUIRED (c) Calculate the over-absorption or under-absorption of overheads for each production department. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (d) State two possible reasons why a business may under absorb overheads. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information The total budgeted direct labour cost for the production departments for the year ended
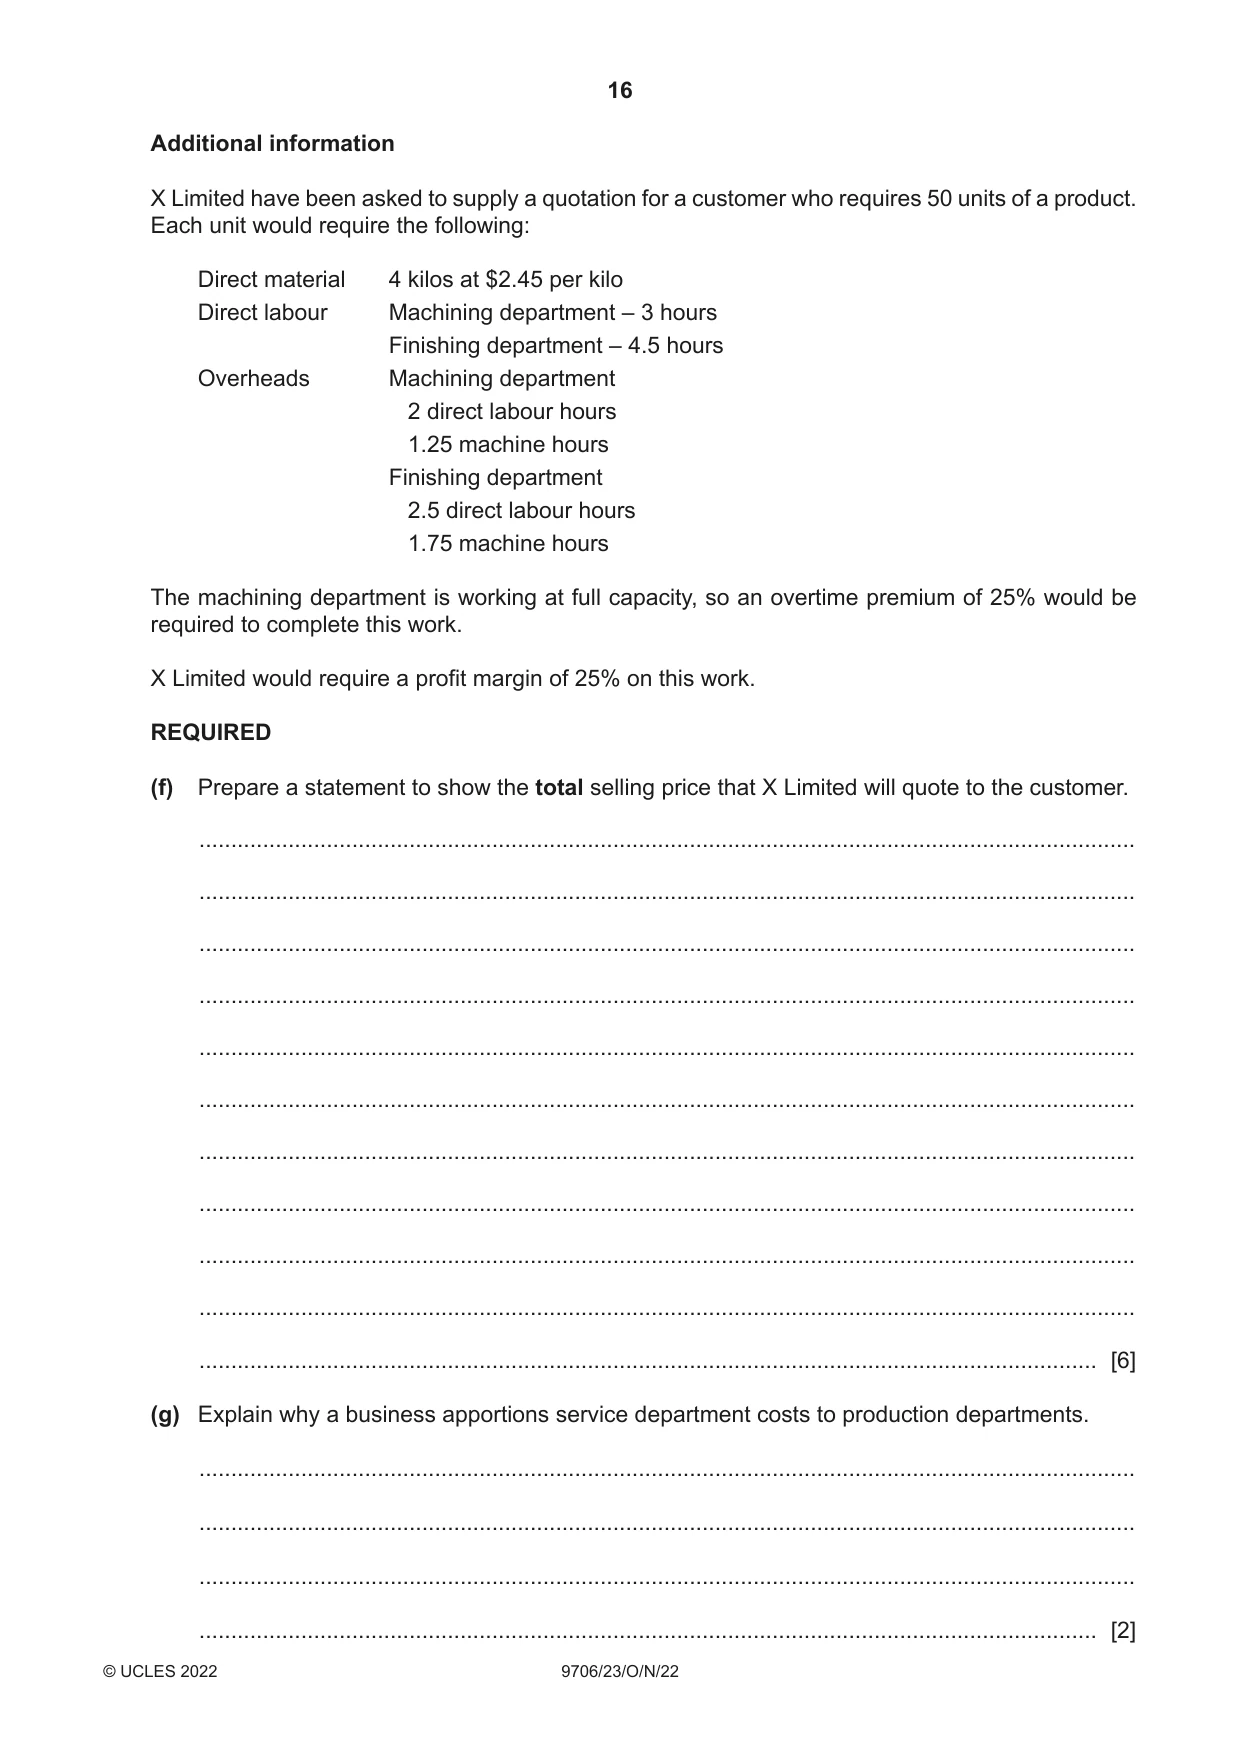
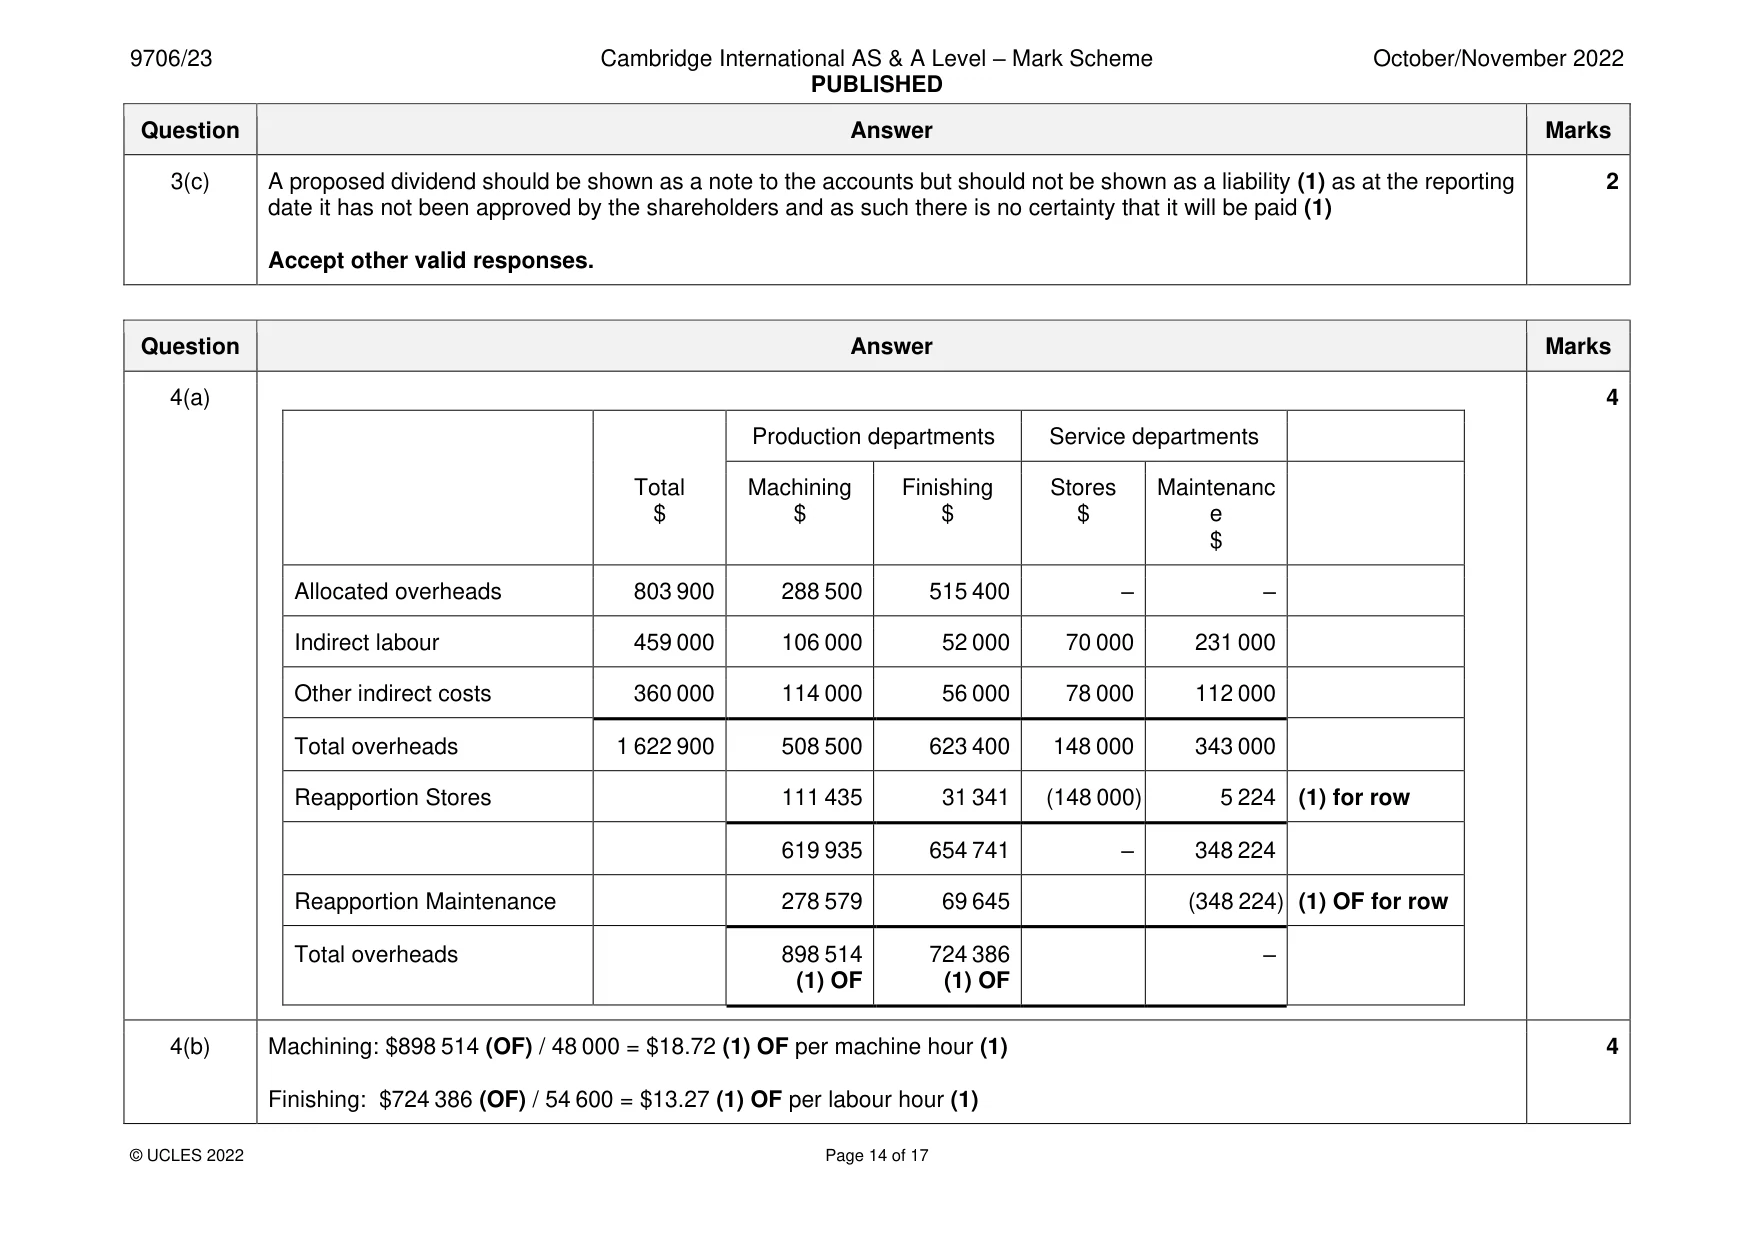
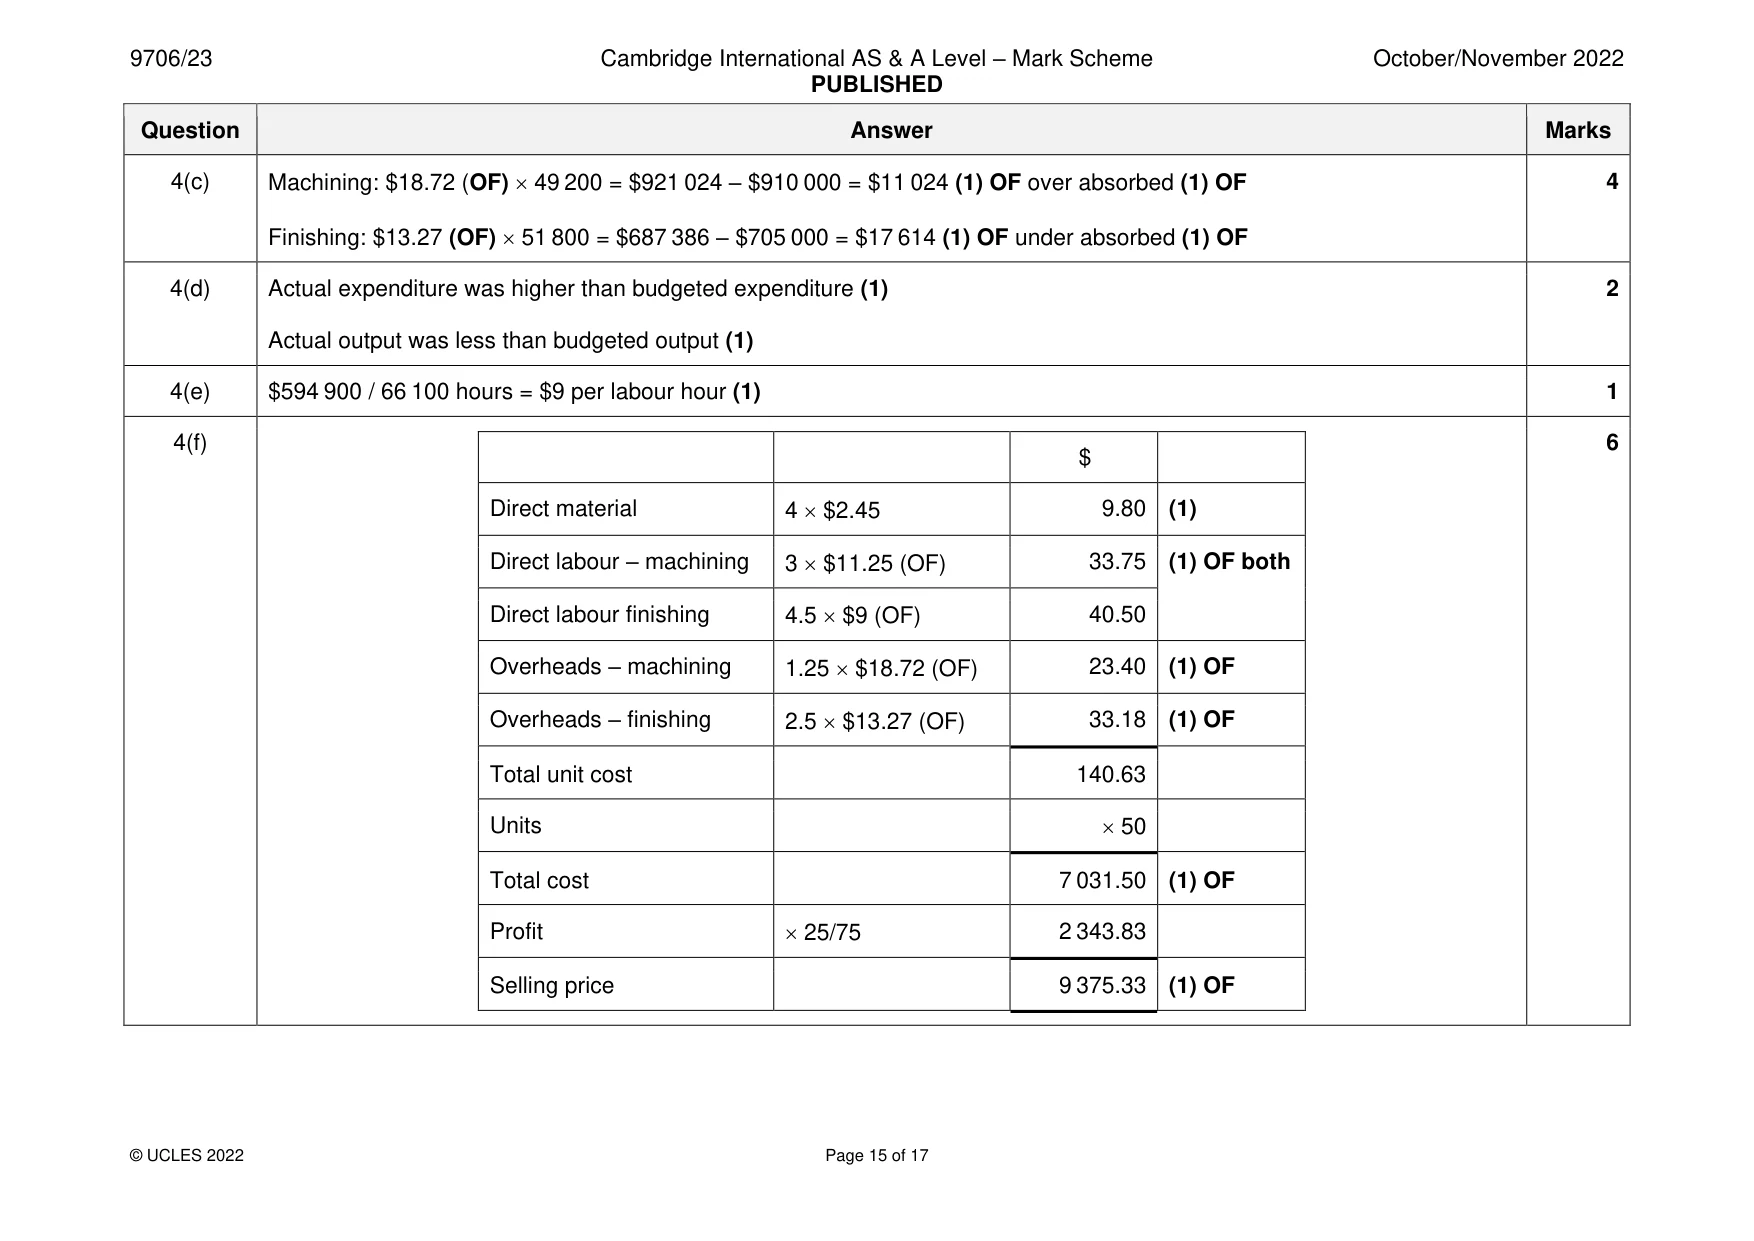
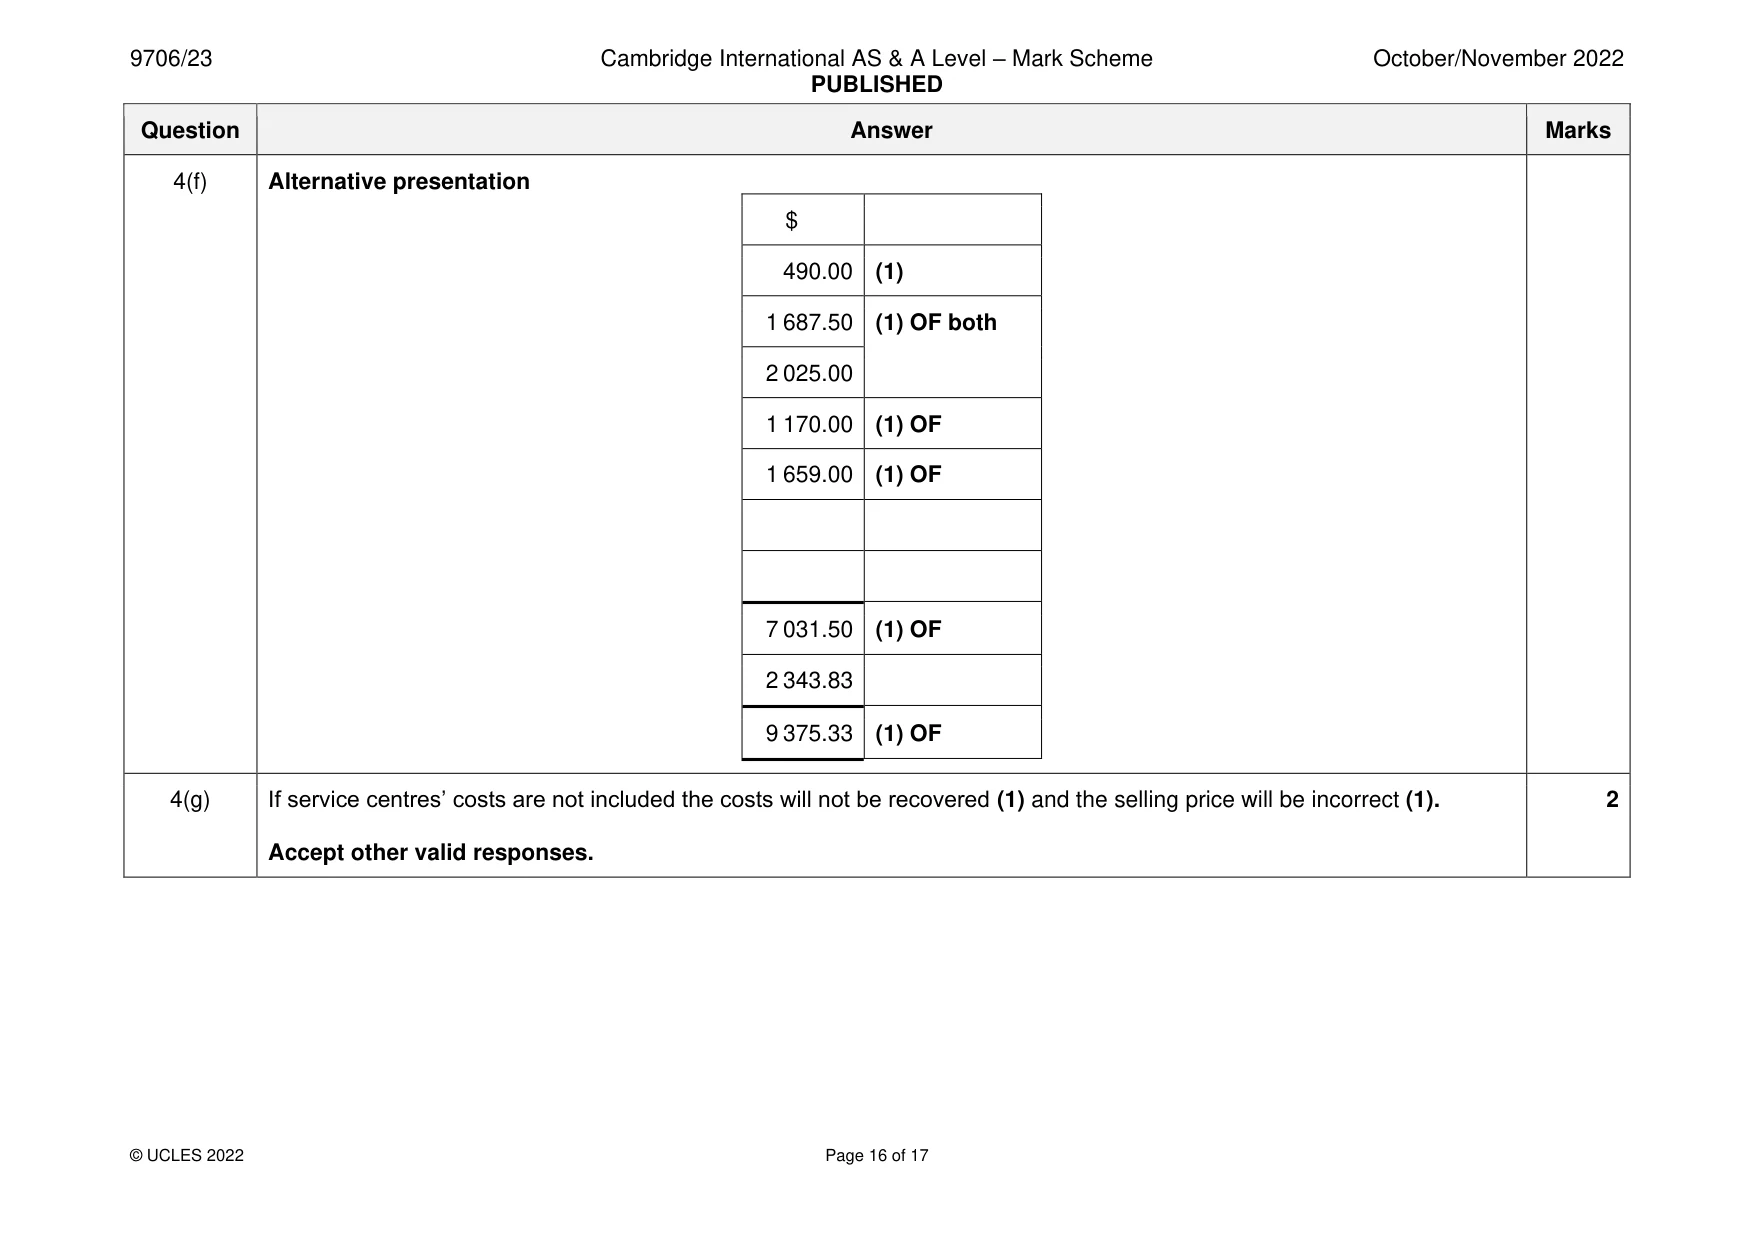
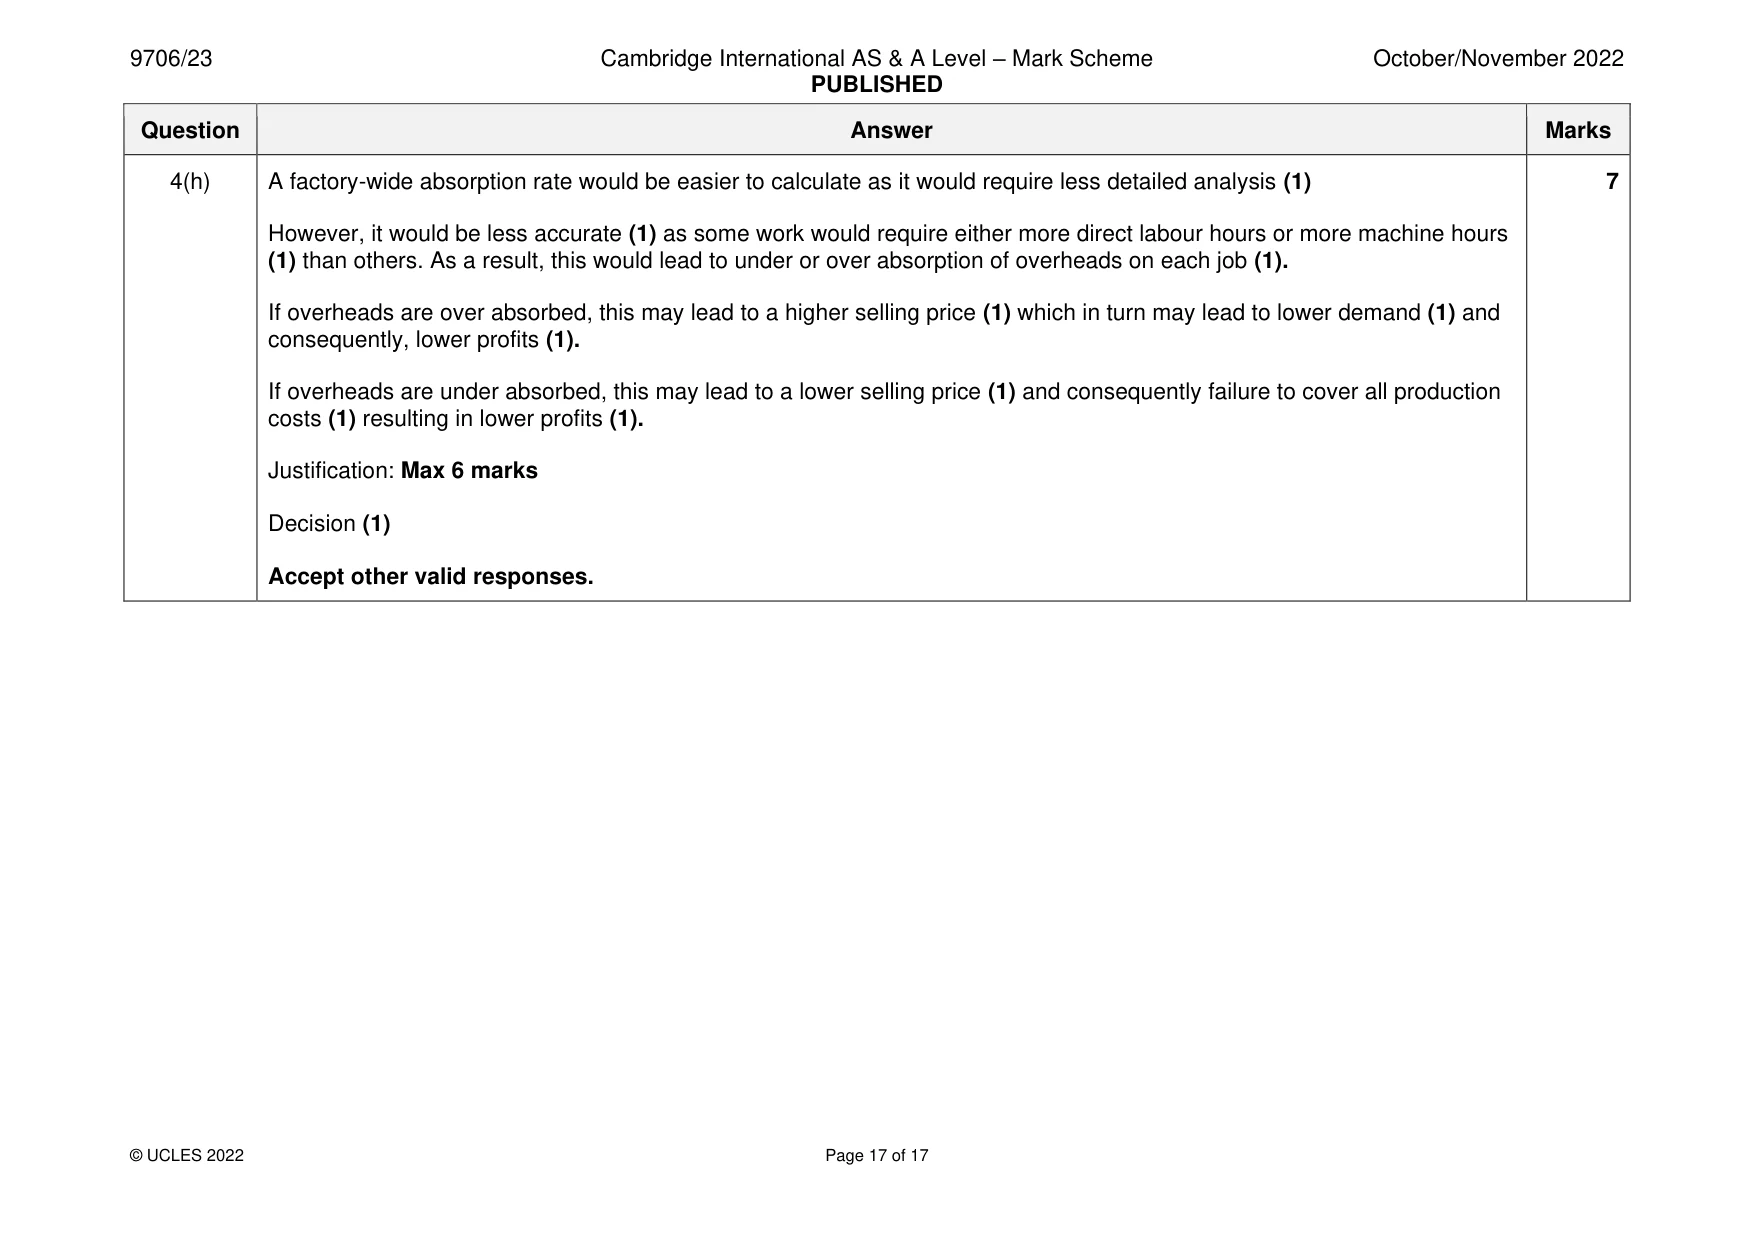
Mark scheme: 4(a) 4 Production departments Service departments Total Machining Finishing Stores Maintenanc $ $ $ $ e $ Allocated overheads 803 900 288 500 515 400 – – Indirect labour 459 000 106 000 52 000 70 000 231 000 Other indirect costs 360 000 114 000 56 000 78 000 112 000 Total overheads 1 622 900 508 500 623 400 148 000 343 000 Reapportion Stores 111 435 31 341 (148 000) 5 224 (1) for row 619 935 654 741 – 348 224 Reapportion Maintenance 278 579 69 645 (348 224) (1) OF for row Total overheads 898 514 724 386 – (1) OF (1) OF 4(b) Machining: $898 514 (OF) / 48 000 = $18.72 (1) OF per machine hour (1) 4 Finishing: $724 386 (OF) / 54 600 = $13.27 (1) OF per labour hour (1) 4(c) Machining: $18.72 (OF) 49 200 = $921 024 – $910 000 = $11 024 (1) OF over absorbed (1) OF 4 Finishing: $13.27 (OF) 51 800 = $687 386 – $705 000 = $17 614 (1) OF under absorbed (1) OF 4(d) Actual expenditure was higher than budgeted expenditure (1) 2 Actual output was less than budgeted output (1) 4(e) $594 900 / 66 100 hours = $9 per labour hour (1) 1 4(f) 6 $ Direct material 4 $2.45 9.80 (1) Direct labour – machining 3 $11.25 (OF) 33.75 (1) OF both Direct labour finishing 4.5 $9 (OF) 40.50 Overheads – machining 1.25 $18.72 (OF) 23.40 (1) OF Overheads – finishing 2.5 $13.27 (OF) 33.18 (1) OF Total unit cost 140.63 Units 50 Total cost 7 031.50 (1) OF Profit 25/75 2 343.83 Selling price 9 375.33 (1) OF 4(f) Alternative presentation $ 490.00 (1) 1 687.50 (1) OF both 2 025.00 1 170.00 (1) OF 1 659.00 (1) OF 7 031.50 (1) OF 2 343.83 9 375.33 (1) OF 4(g) If service centres’ costs are not included the costs will not be recovered (1) and the selling price will be incorrect (1). 2 Accept other valid responses. 4(h) A factory-wide absorption rate would be easier to calculate as it would require less detailed analysis (1) 7 However, it would be less accurate (1) as some work would require either more direct labour hours or more machine hours (1) than others. As a result, this would lead to under or over absorption of overheads on each job (1). If overheads are over absorbed, this may lead to a higher selling price (1) which in turn may lead to lower demand (1) and consequently, lower profits (1). If overheads are under absorbed, this may lead to a lower selling price (1) and consequently failure to cover all production costs (1) resulting in lower profits (1). Justification: Max 6 marks Decision (1) Accept other valid responses.
Q30 · September 2022 was $594 900
30 September 2022 was $594 900. REQUIRED (e) Calculate the budgeted hourly direct labour rate for the production departments. ............................................................................................................................................. [1] Additional information X Limited have been asked to supply a quotation for a customer who requires 50 units of a product. Each unit would require the following: Direct material 4 kilos at $2.45 per kilo Direct labour Machining department – 3 hours Finishing department – 4.5 hours Overheads Machining department 2 direct labour hours 1.25 machine hours Finishing department 2.5 direct labour hours 1.75 machine hours The machining department is working at full capacity, so an overtime premium of 25% would be required to complete this work. X Limited would require a profit margin of 25% on this work. REQUIRED (f) Prepare a statement to show the total selling price that X Limited will quote to the customer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [6] (g) Explain why a business apportions service department costs to production departments. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Additional information The directors of X Limited have been advised that they should change from a departmental overhead absorption rate to one factory-wide rate. They are concerned that this may affect the profits of the business. REQUIRED (h) Advise the directors whether or not they should make this change. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 30]
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2022 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.