Cambridge A Level Accounting 9706 — 2024 May/June Paper 2 · Variant 3
9706/23/M/J/24 · 7 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme21 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · K Limited provided the following extract from the company’s draft statement of profit or…
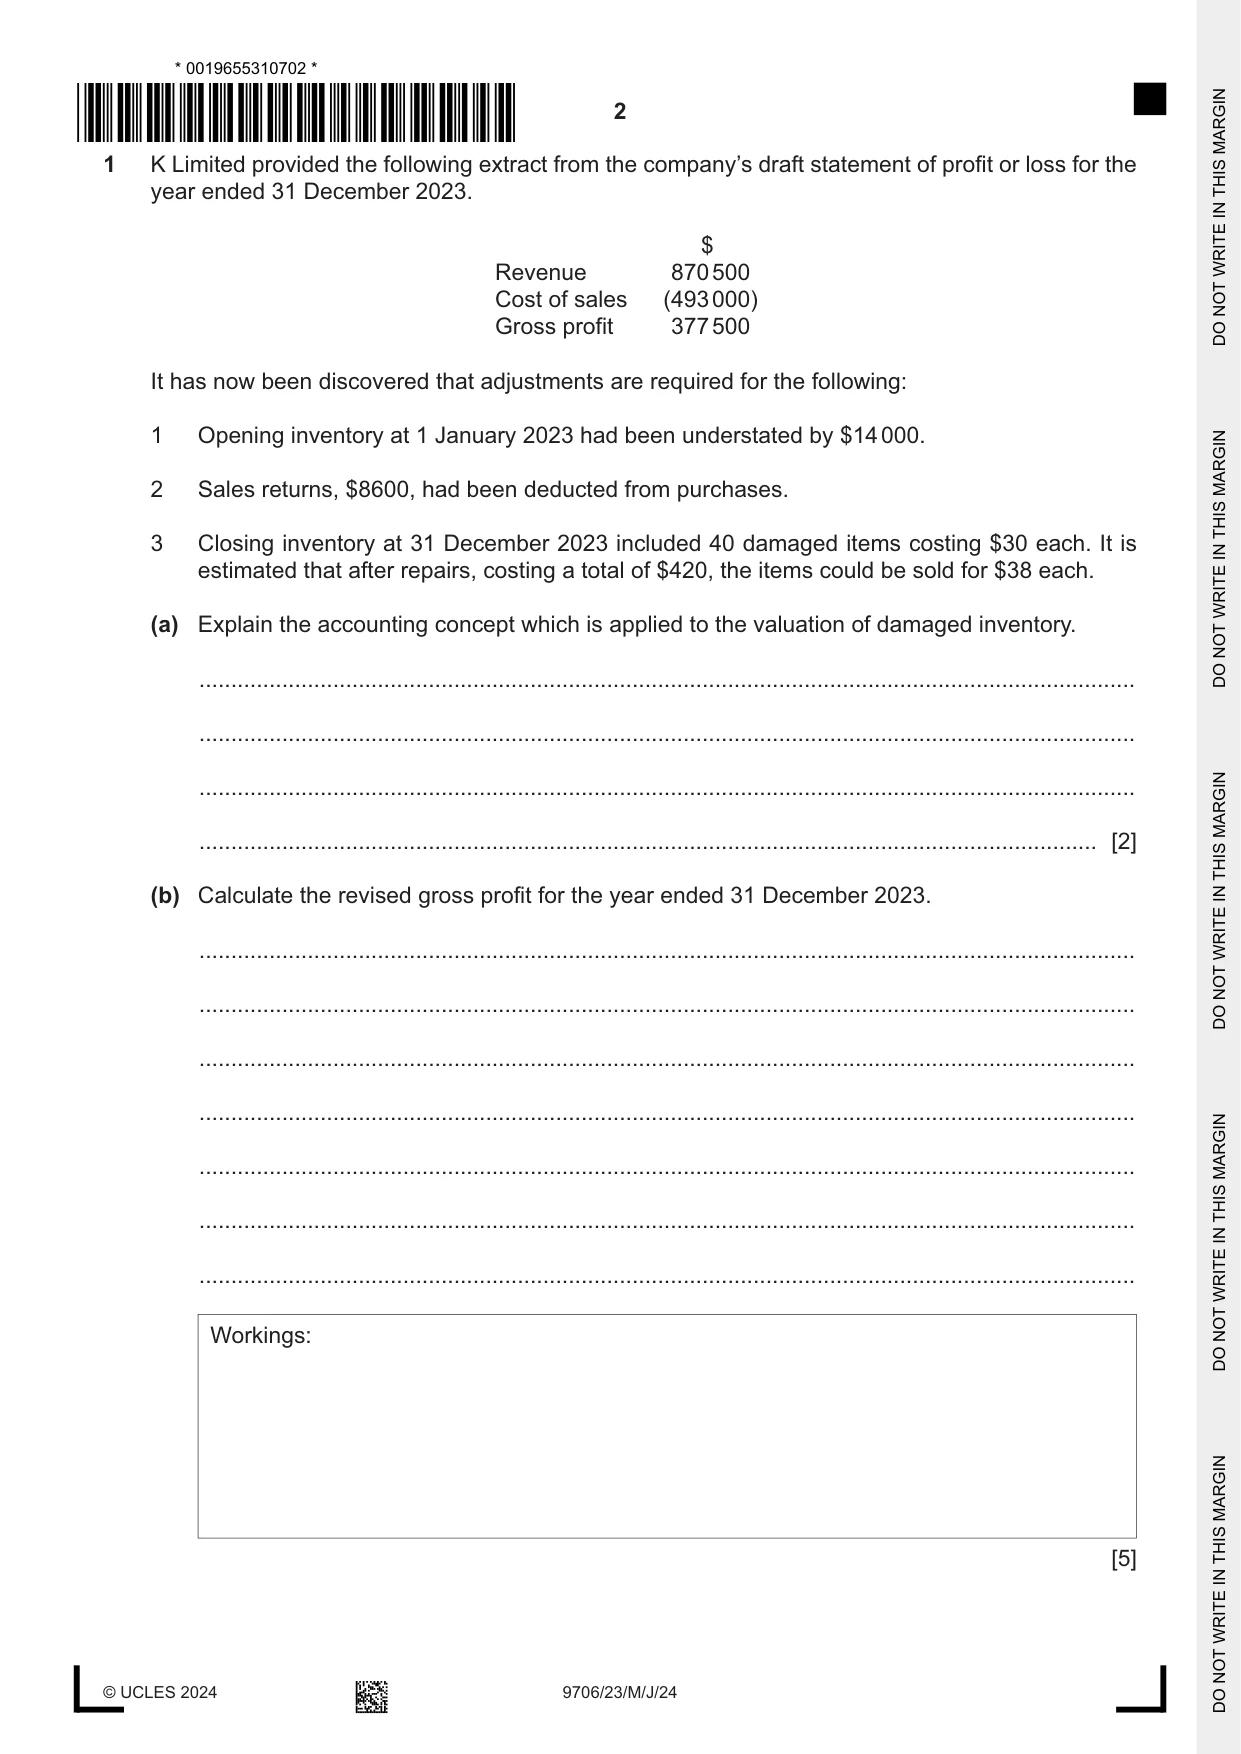
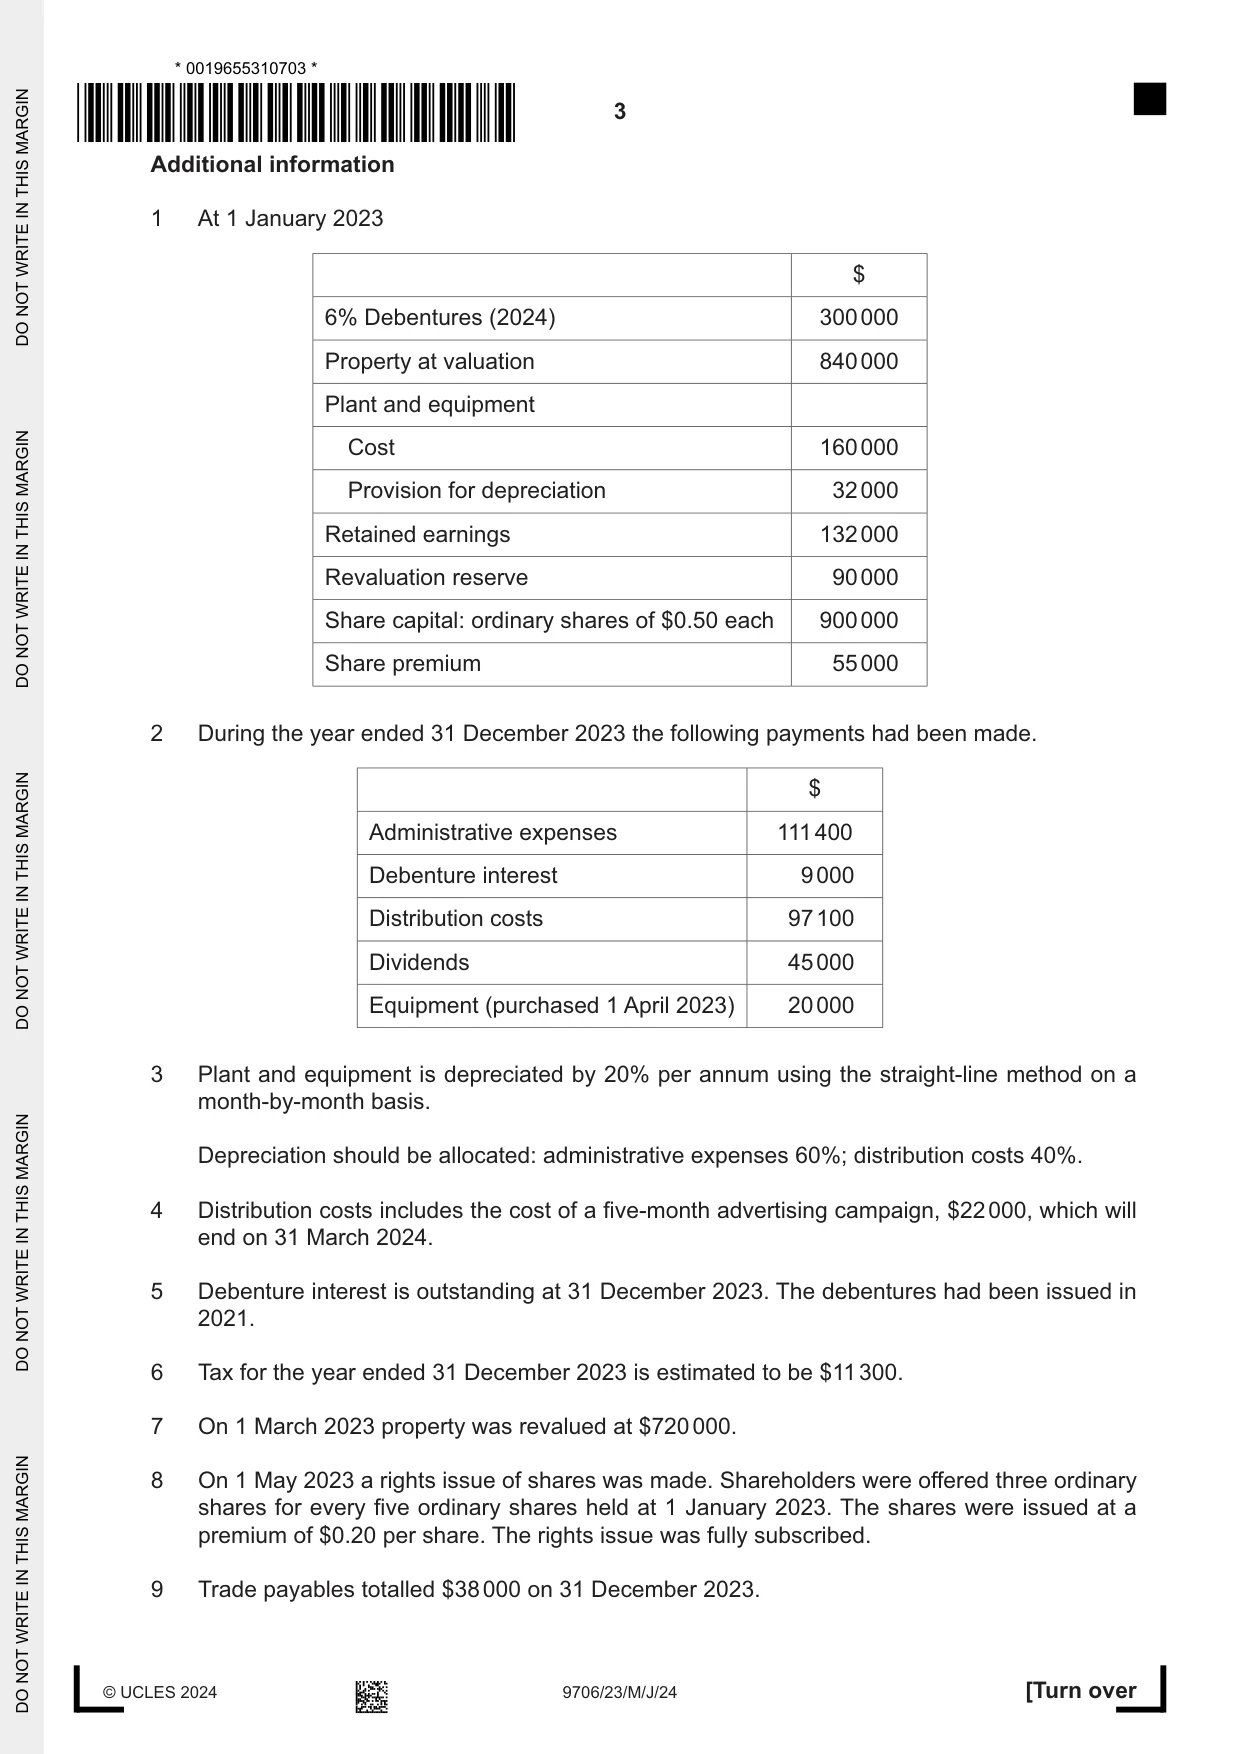
1 K Limited provided the following extract from the company’s draft statement of profit or loss for the year ended 31 December 2023. $ Revenue 870 500 Cost of sales (493 000) Gross profit 377 500 It has now been discovered that adjustments are required for the following: 1 Opening inventory at 1 January 2023 had been understated by $14 000. 2 Sales returns, $8600, had been deducted from purchases. 3 Closing inventory at 31 December 2023 included 40 damaged items costing $30 each. It is estimated that after repairs, costing a total of $420, the items could be sold for $38 each. (a) Explain the accounting concept which is applied to the valuation of damaged inventory. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (b) Calculate the revised gross profit for the year ended 31 December 2023. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: [5] Additional information 1 At 1 January 2023 $ 6% Debentures (2024) 300 000 Property at valuation 840 000 Plant and equipment Cost 160 000 Provision for depreciation 32 000 Retained earnings 132 000 Revaluation reserve 90 000 Share capital: ordinary shares of $0.50 each 900 000 Share premium 55 000
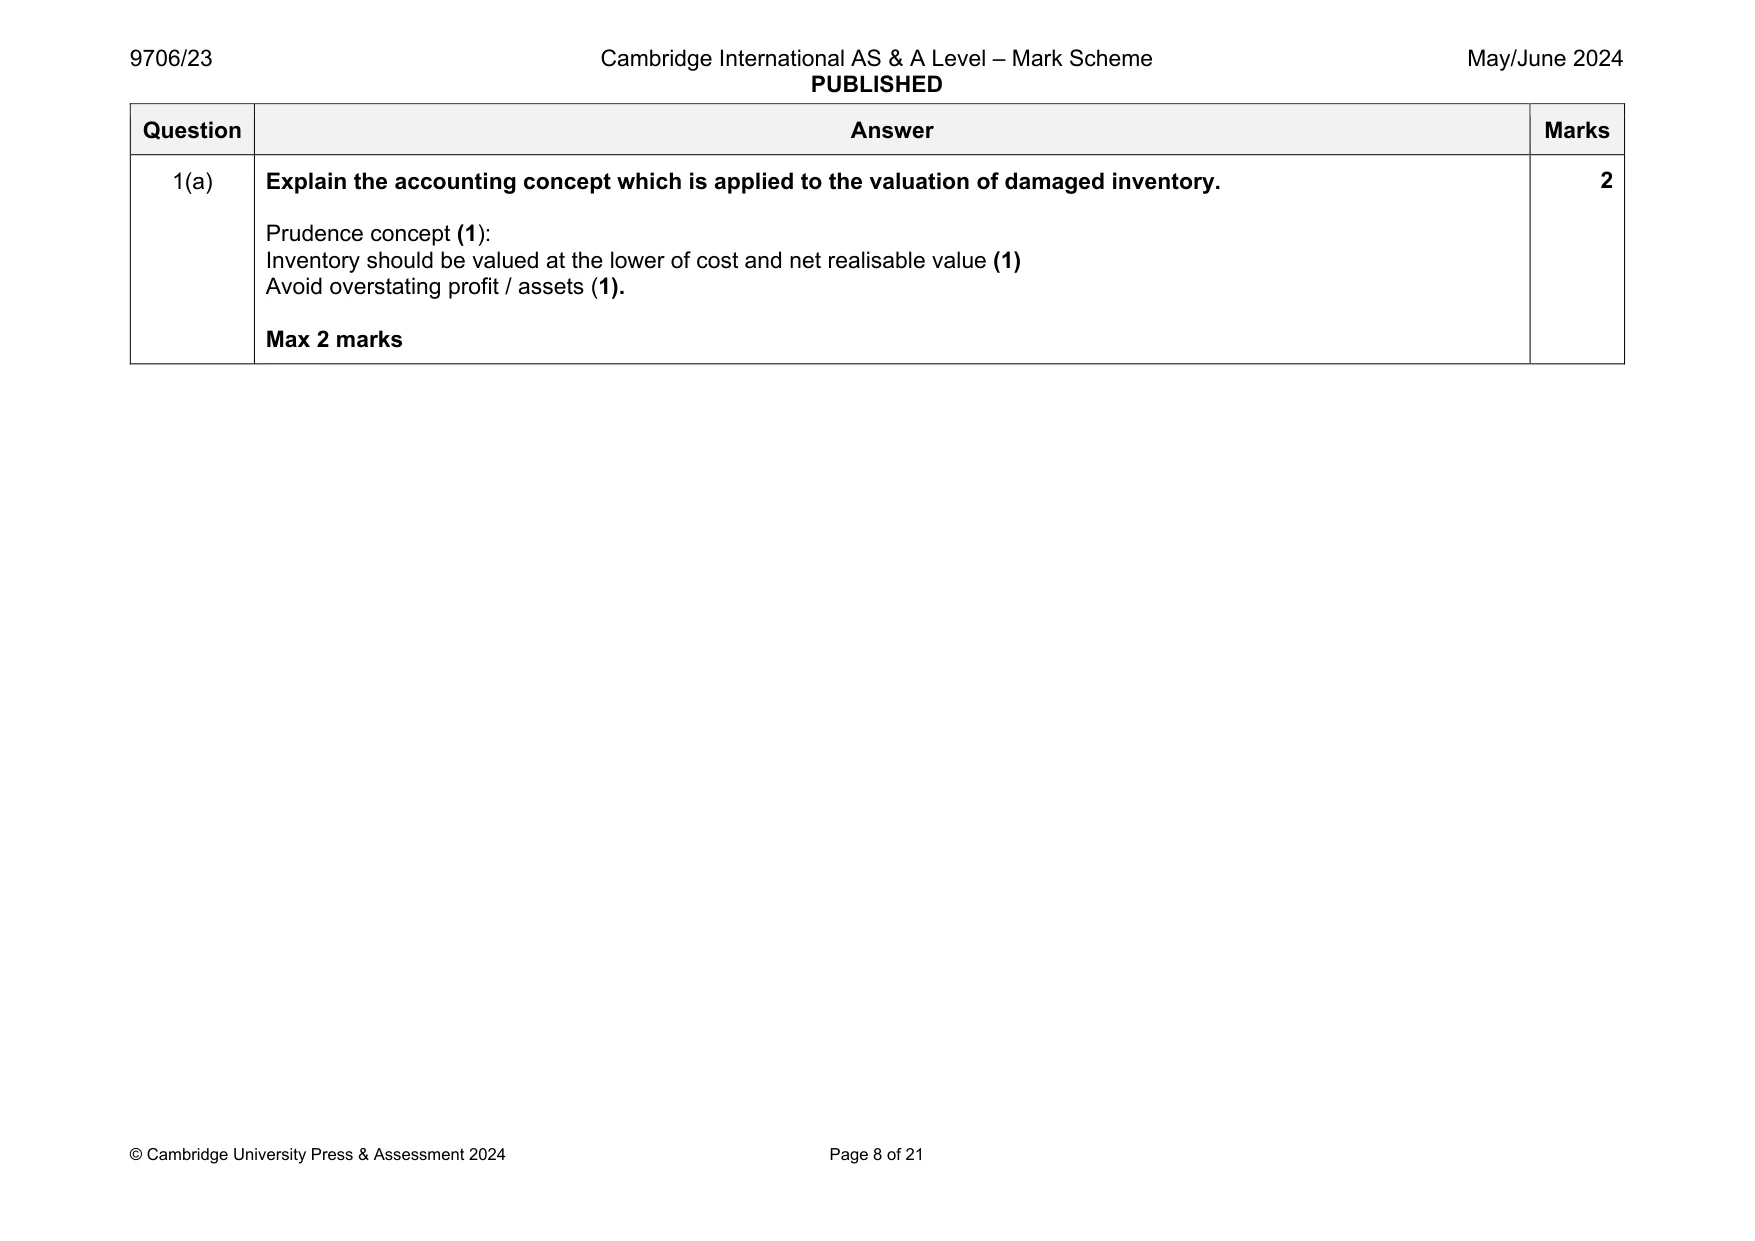
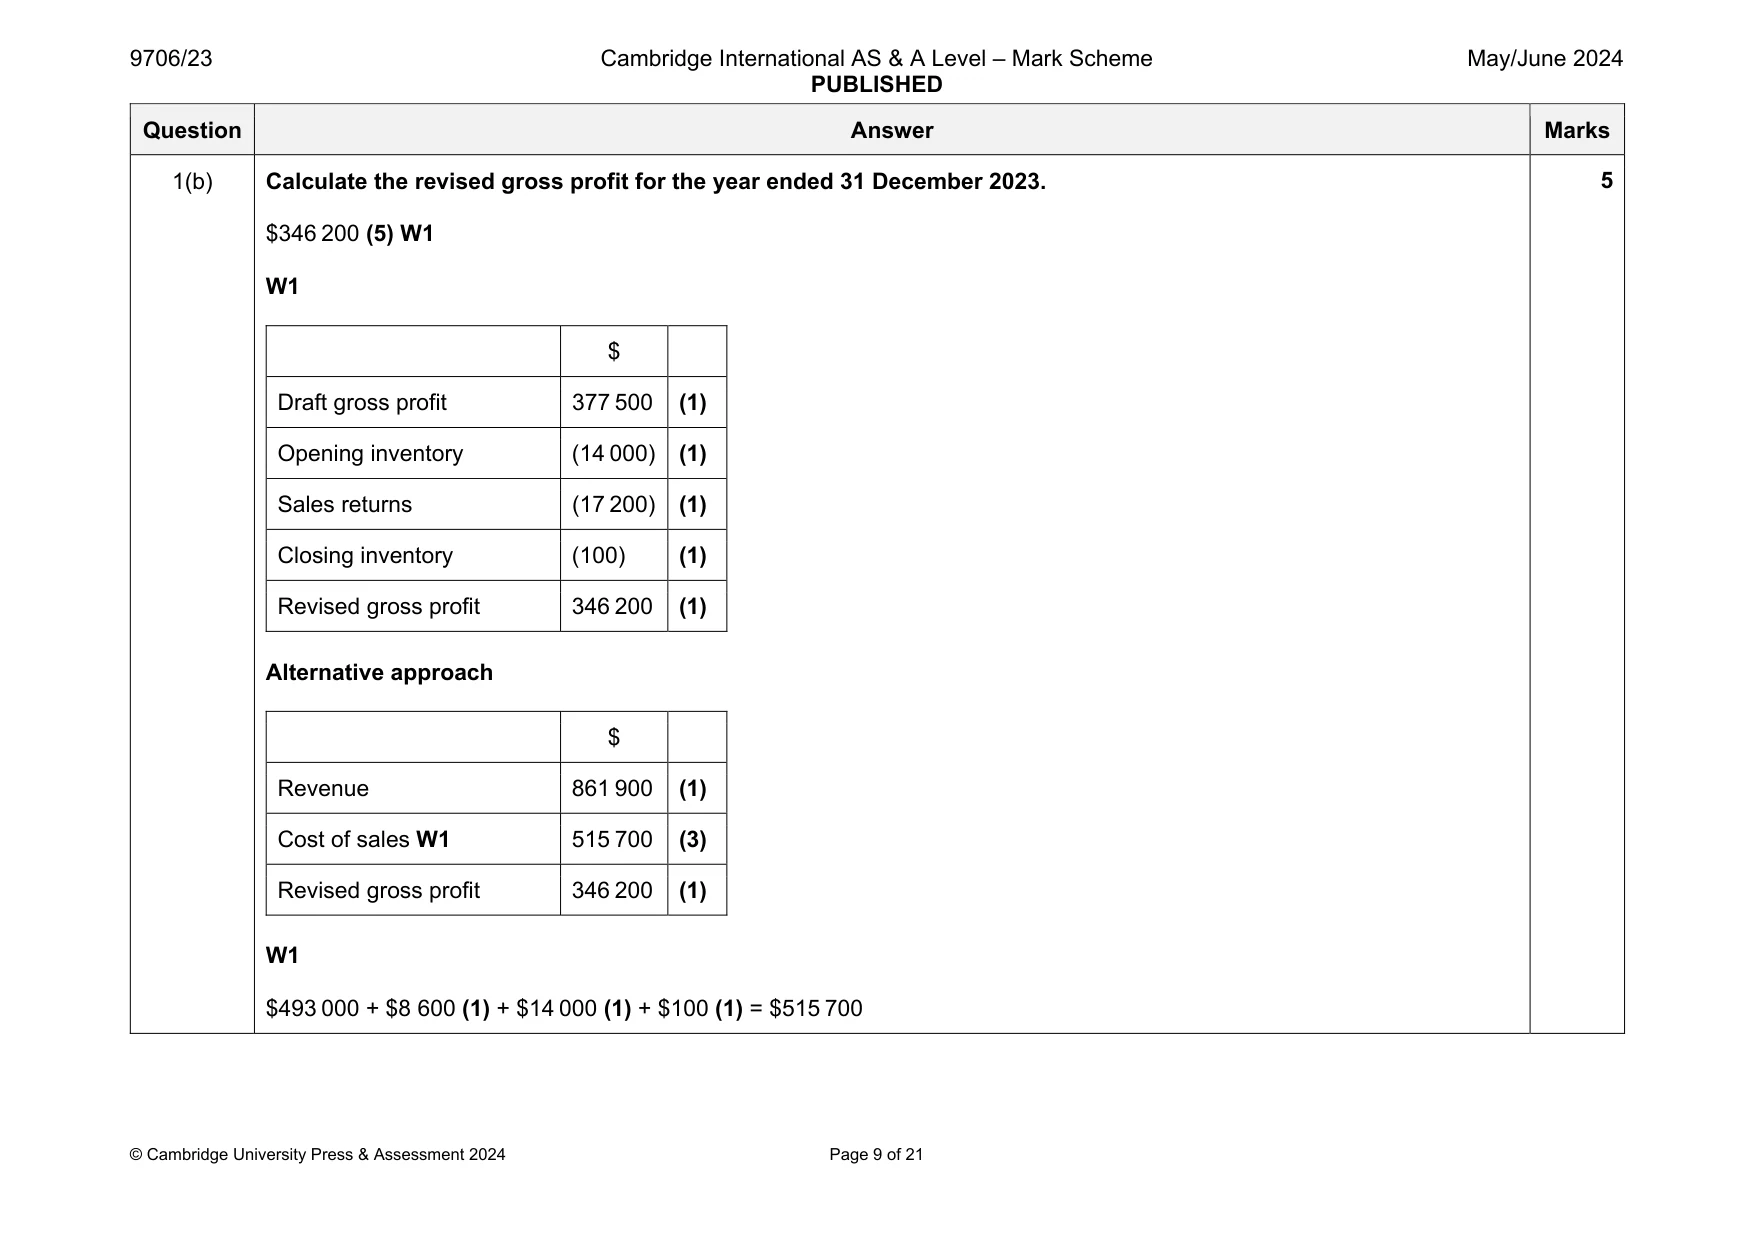
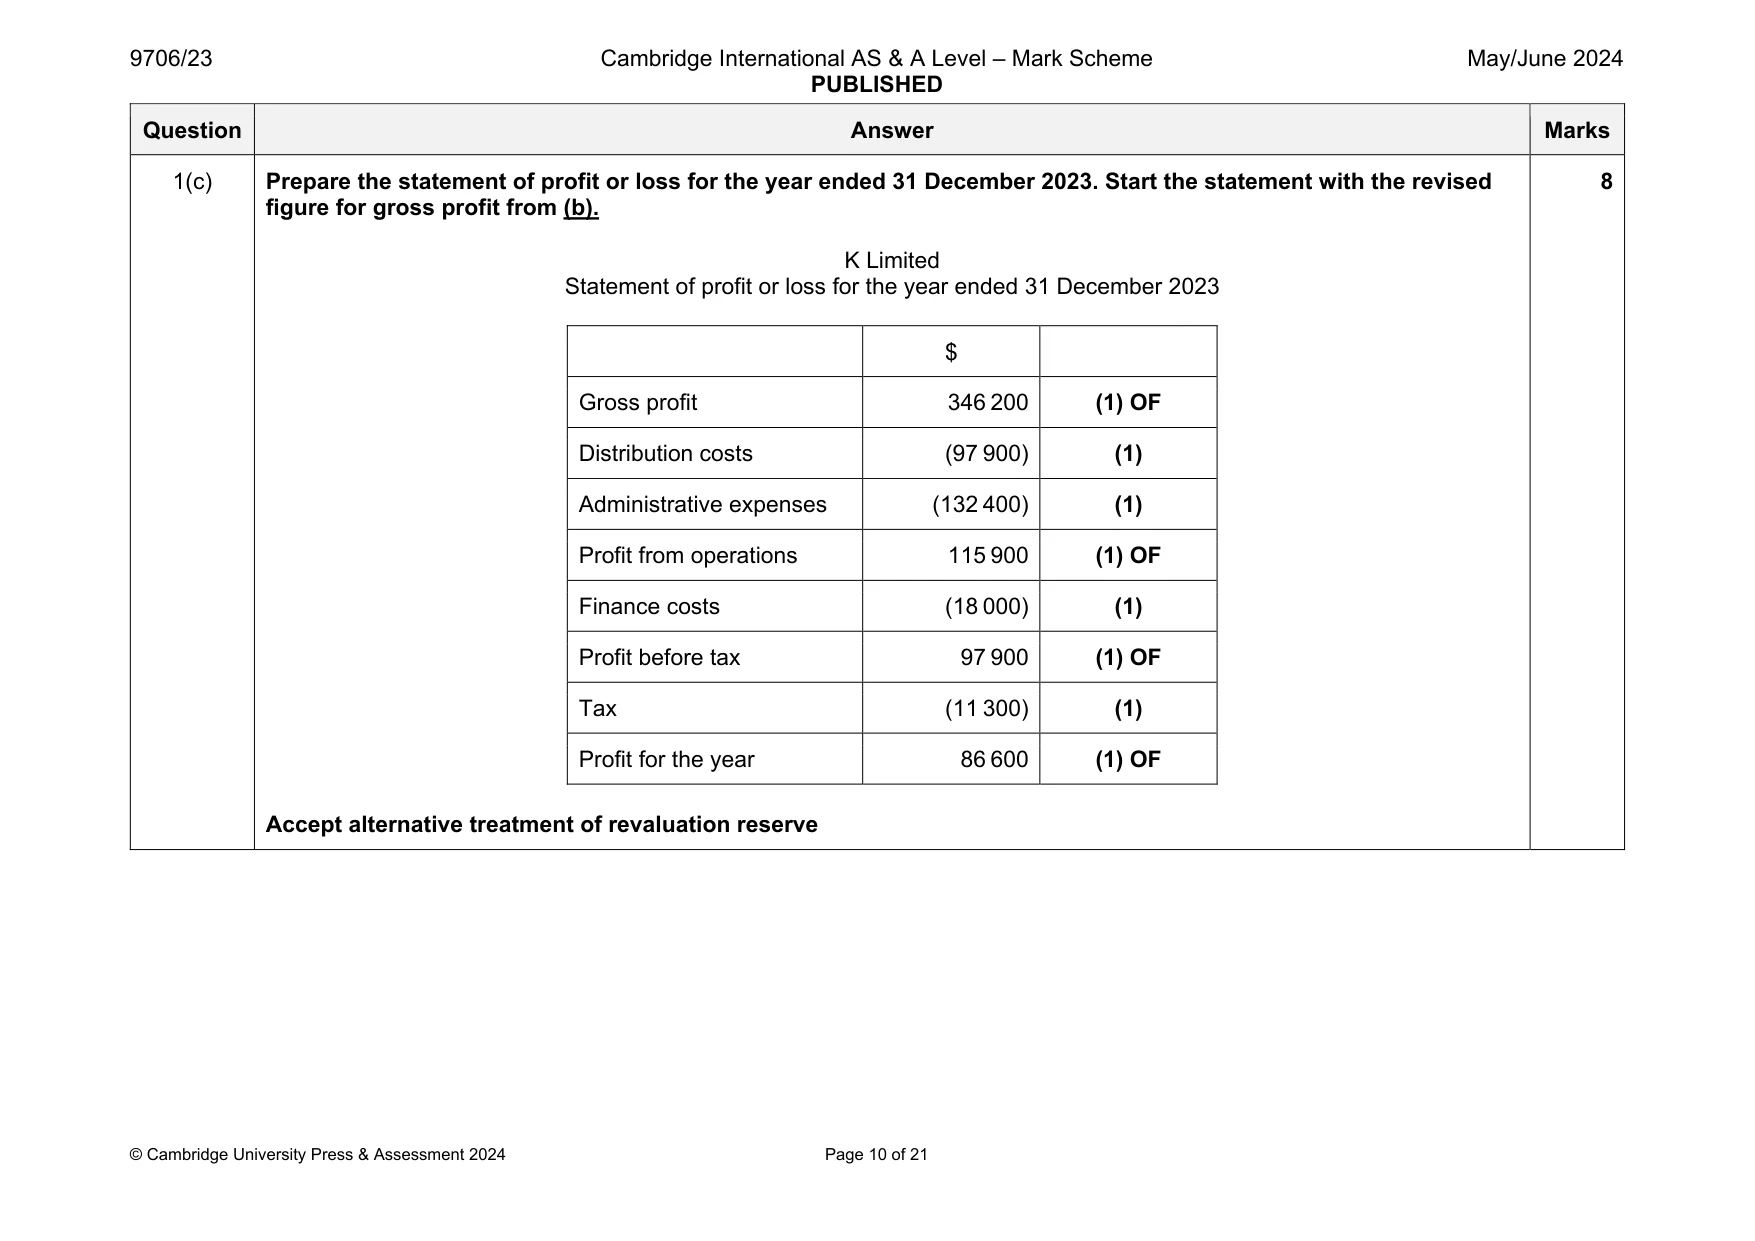
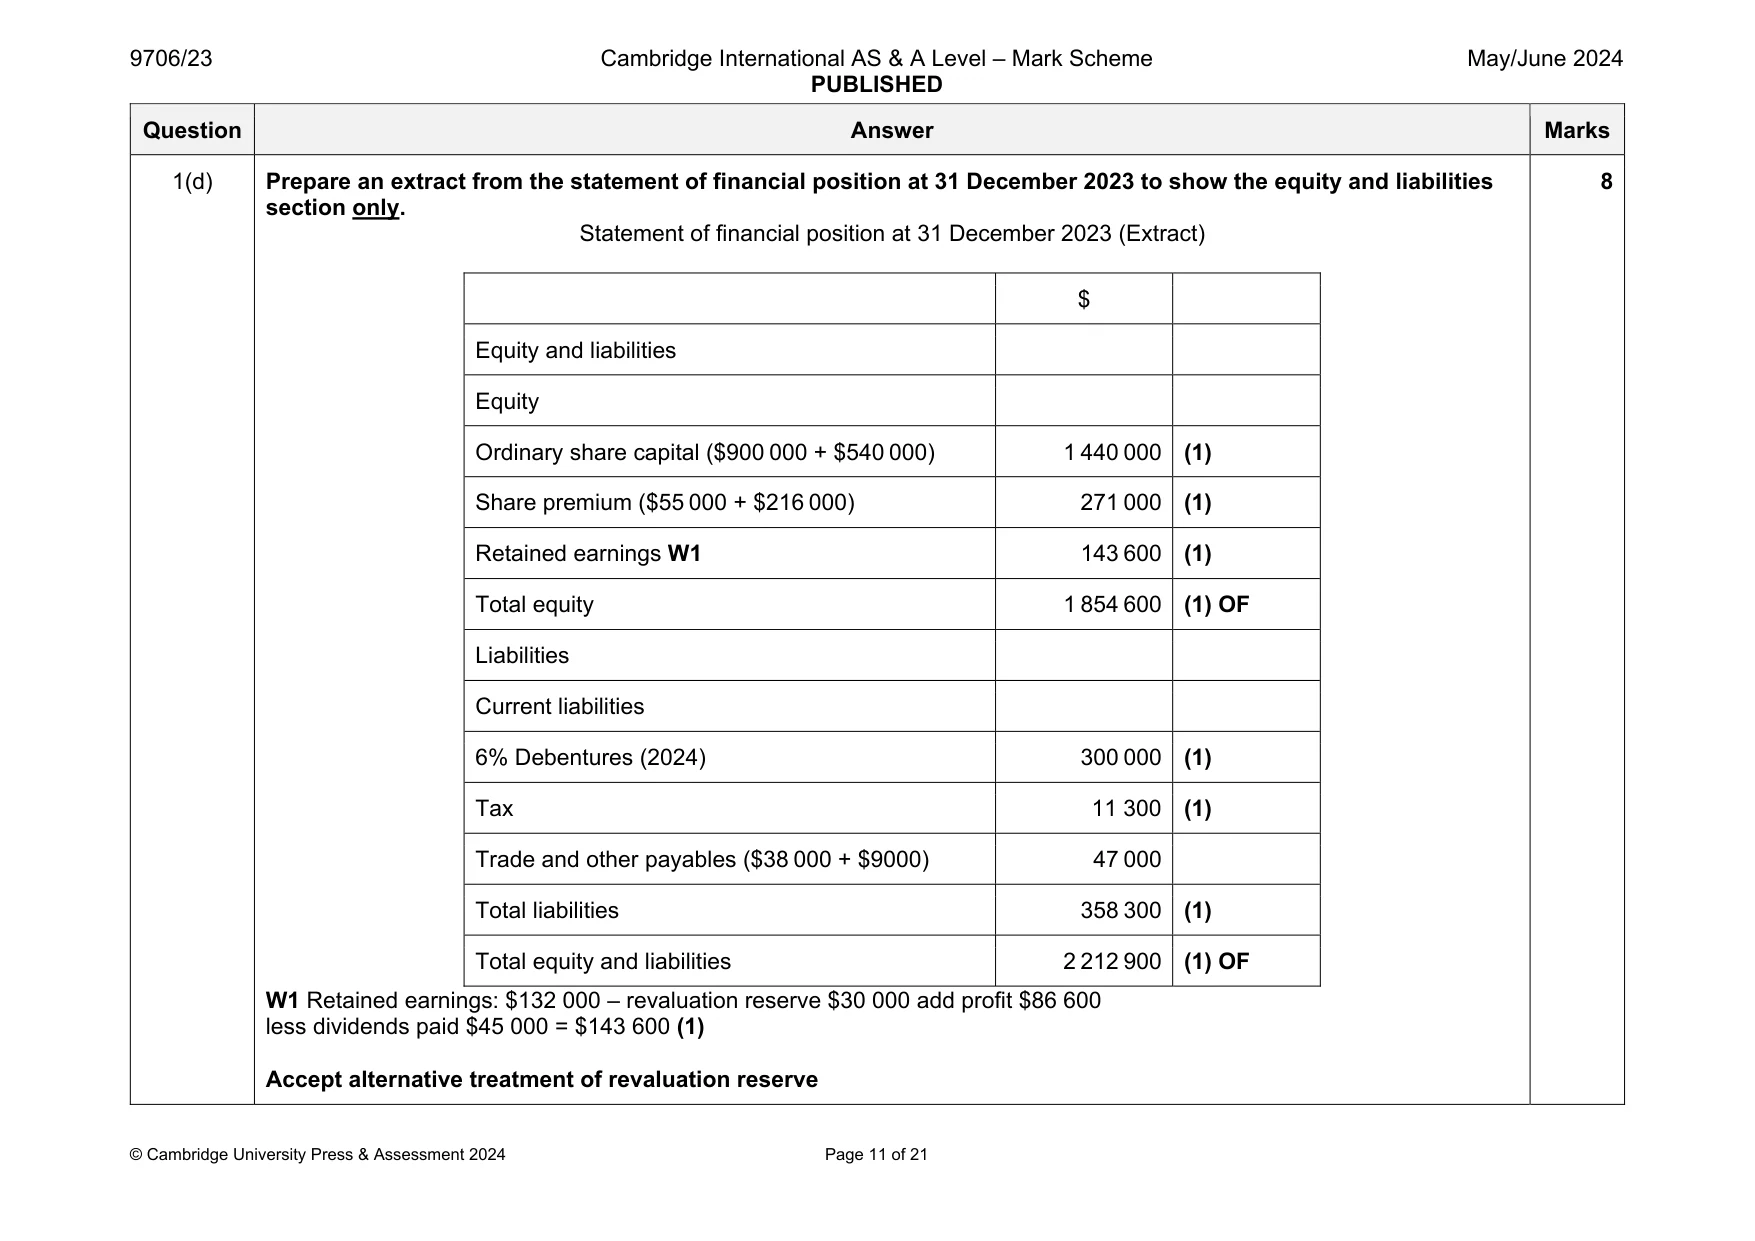
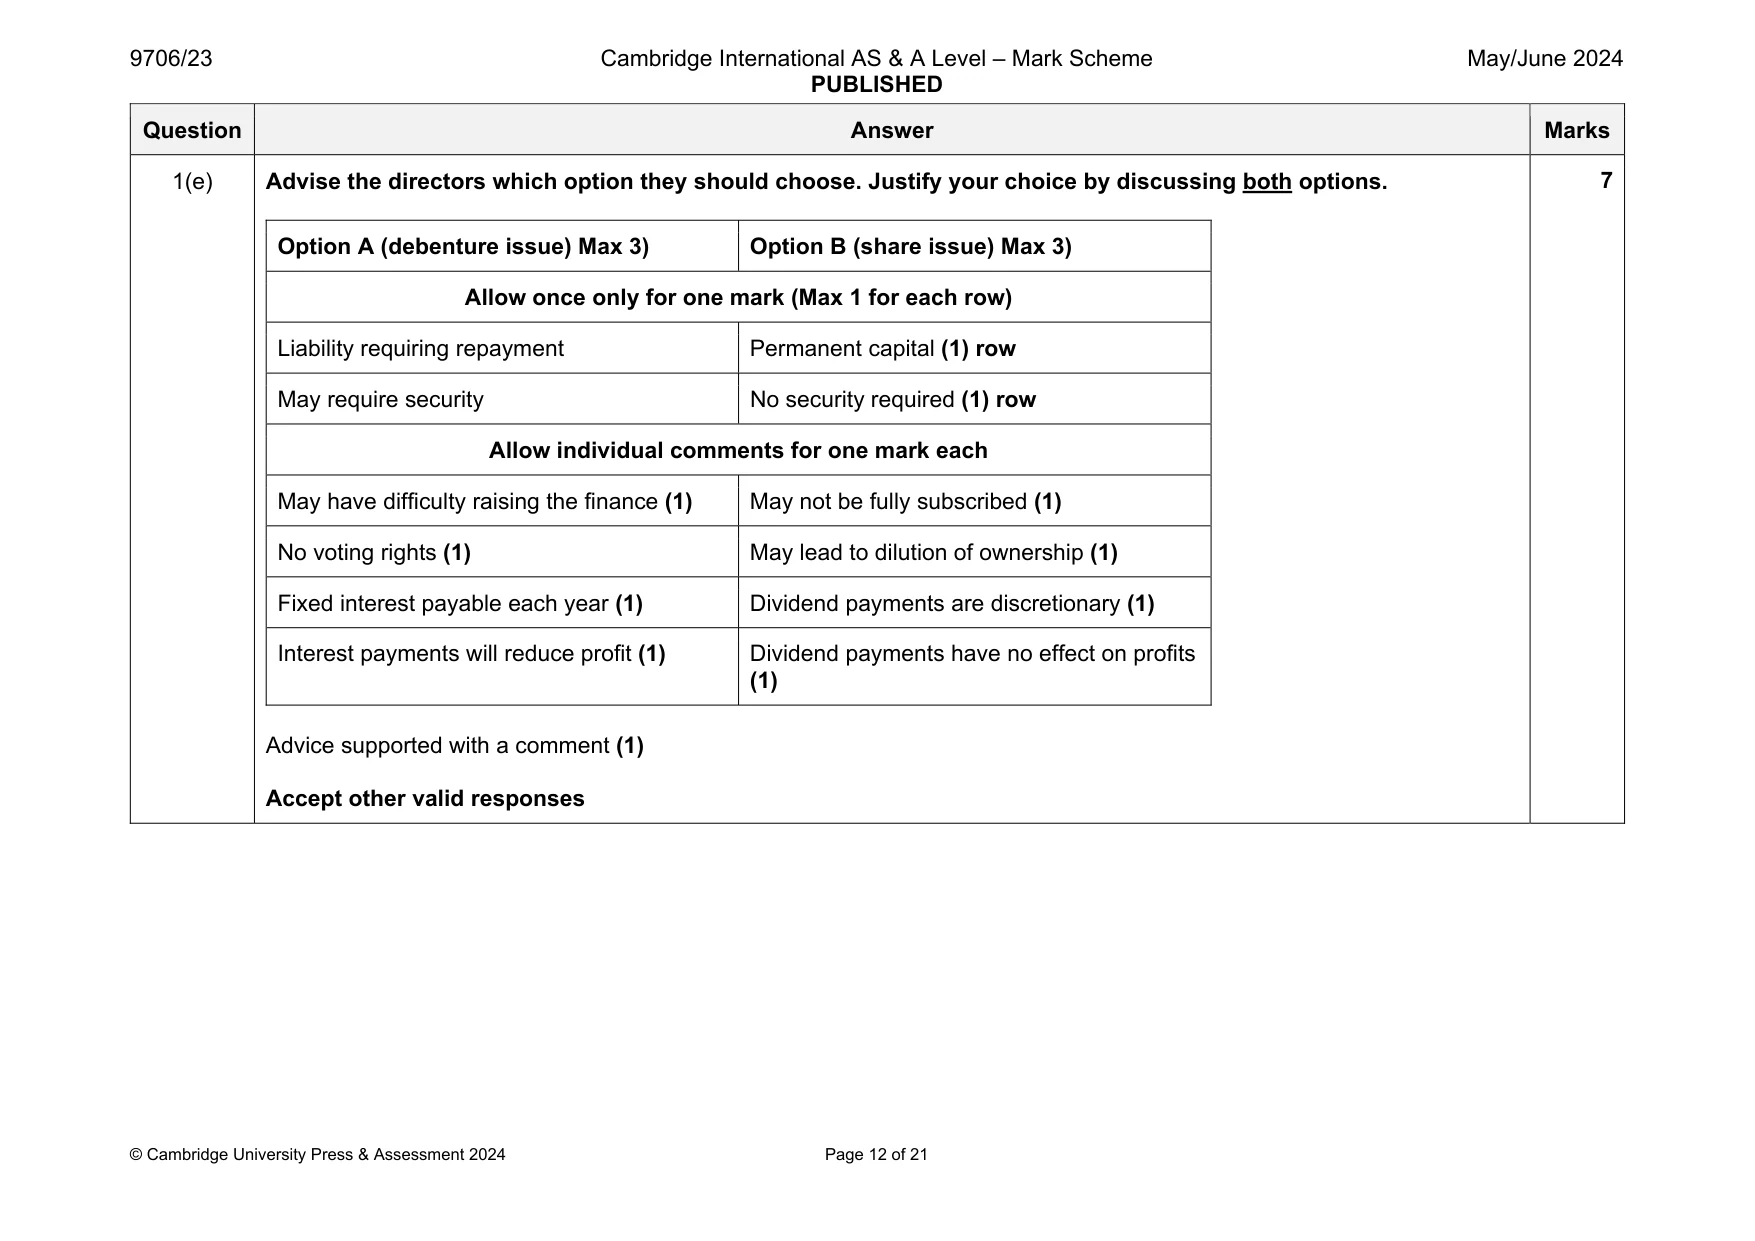
Mark scheme: 1(a) Explain the accounting concept which is applied to the valuation of damaged inventory. Prudence concept (1): Inventory should be valued at the lower of cost and net realisable value (1) Avoid overstating profit / assets (1). Max 2 marks Question Answer Marks 1(b) Calculate the revised gross profit for the year ended 31 December 2023. $346 200 (5) W1 W1 $ Draft gross profit 377 500 (1) Opening inventory (14 000) (1) Sales returns (17 200) (1) Closing inventory (100) (1) Revised gross profit 346 200 (1) Alternative approach $ Revenue 861 900 (1) Cost of sales W1 515 700 (3) Revised gross profit 346 200 (1) W1 $493 000 + $8 600 (1) + $14 000 (1) + $100 (1) = $515 700 5 Question Answer Marks 1(c) Prepare the statement of profit or loss for the year ended 31 December 2023. Start the statement with the revised figure for gross profit from (b). K Limited Statement of profit or loss for the year ended 31 December 2023 $ Gross profit 346 200 (1) OF Distribution costs (97 900) (1) Administrative expenses (132 400) (1) Profit from operations 115 900 (1) OF Finance costs (18 000) (1) Profit before tax 97 900 (1) OF Tax (11 300) (1) Profit for the year 86 600 (1) OF Accept alternative treatment of revaluation reserve 8 Question Answer Marks 1(d) Prepare an extract from the statement of financial position at 31 December 2023 to show the equity and liabilities section only. Statement of financial position at 31 December 2023 (Extract) $ Equity and liabilities Equity Ordinary share capital ($900 000 + $540 000) 1 440 000 (1) Share premium ($55 000 + $216 000) 271 000 (1) Retained earnings W1 143 600 (1) Total equity 1 854 600 (1) OF Liabilities Current liabilities 6% Debentures (2024) 300 000 (1) Tax 11 300 (1) Trade and other payables ($38 000 + $9000) 47 000 Total liabilities 358 300 (1) Total equity and liabilities 2 212 900 (1) OF W1 Retained earnings: $132 000 – revaluation reserve $30 000 add profit $86 600 less dividends paid $45 000 = $143 600 (1) Accept alternative treatment of revaluation reserve 8 Question Answer Marks 1(e) Advise the directors which option they should choose. Justify your choice by discussing both options. Option A (debenture issue) Max 3) Option B (share issue) Max 3) Allow once only for one mark (Max 1 for each row) Liability requiring repayment Permanent capital (1) row May require security No security required (1) row Allow individual comments for one mark each May have difficulty raising the finance (1) May not be fully subscribed (1) No voting rights (1) May lead to dilution of ownership (1) Fixed interest payable each year (1) Dividend payments are discretionary (1) Interest payments will reduce profit (1) Dividend payments have no effect on profits (1) Advice supported with a comment (1) Accept other valid responses 7
Q2 · During the year ended 31 December 2023 the following payments had been made
2 During the year ended 31 December 2023 the following payments had been made. $ Administrative expenses 111 400 Debenture interest 9 000 Distribution costs 97 100 Dividends 45 000 Equipment (purchased 1 April 2023) 20 000
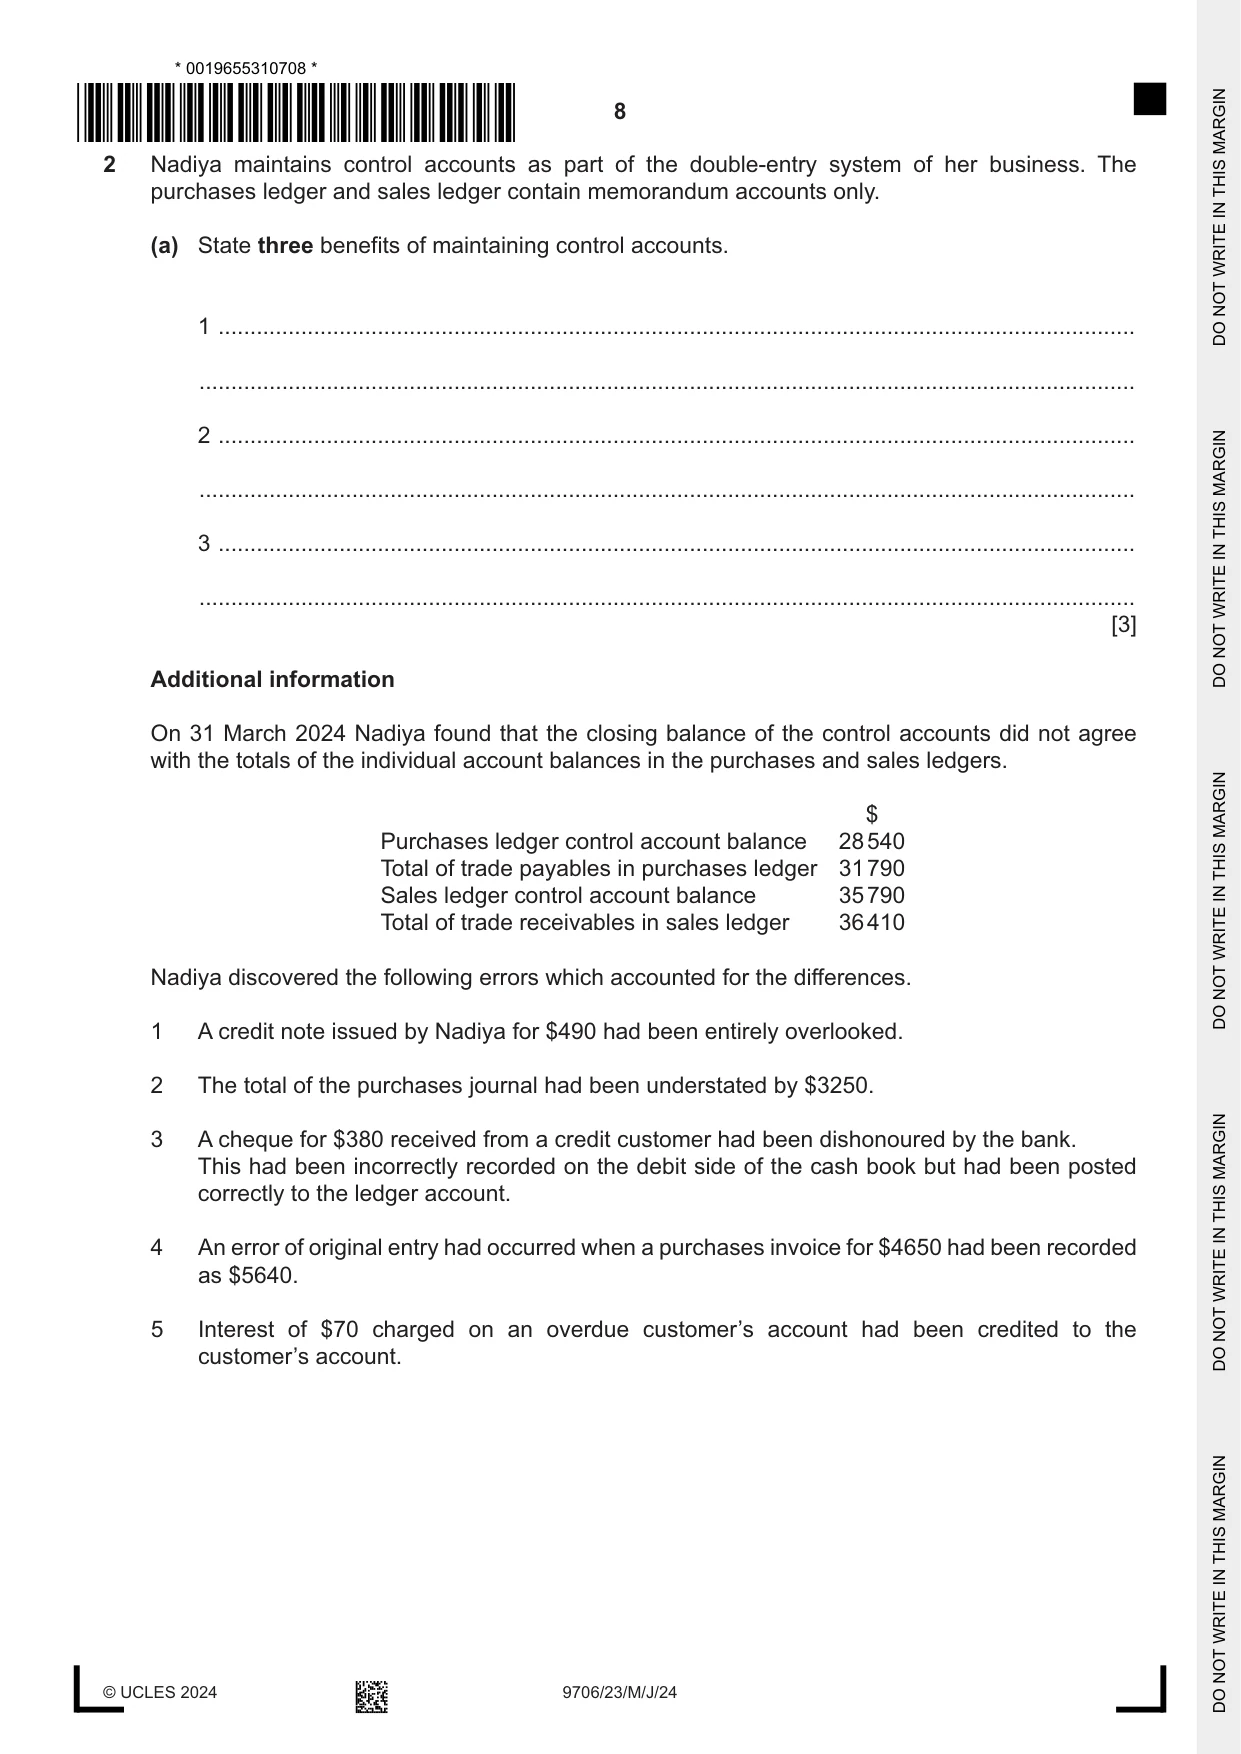
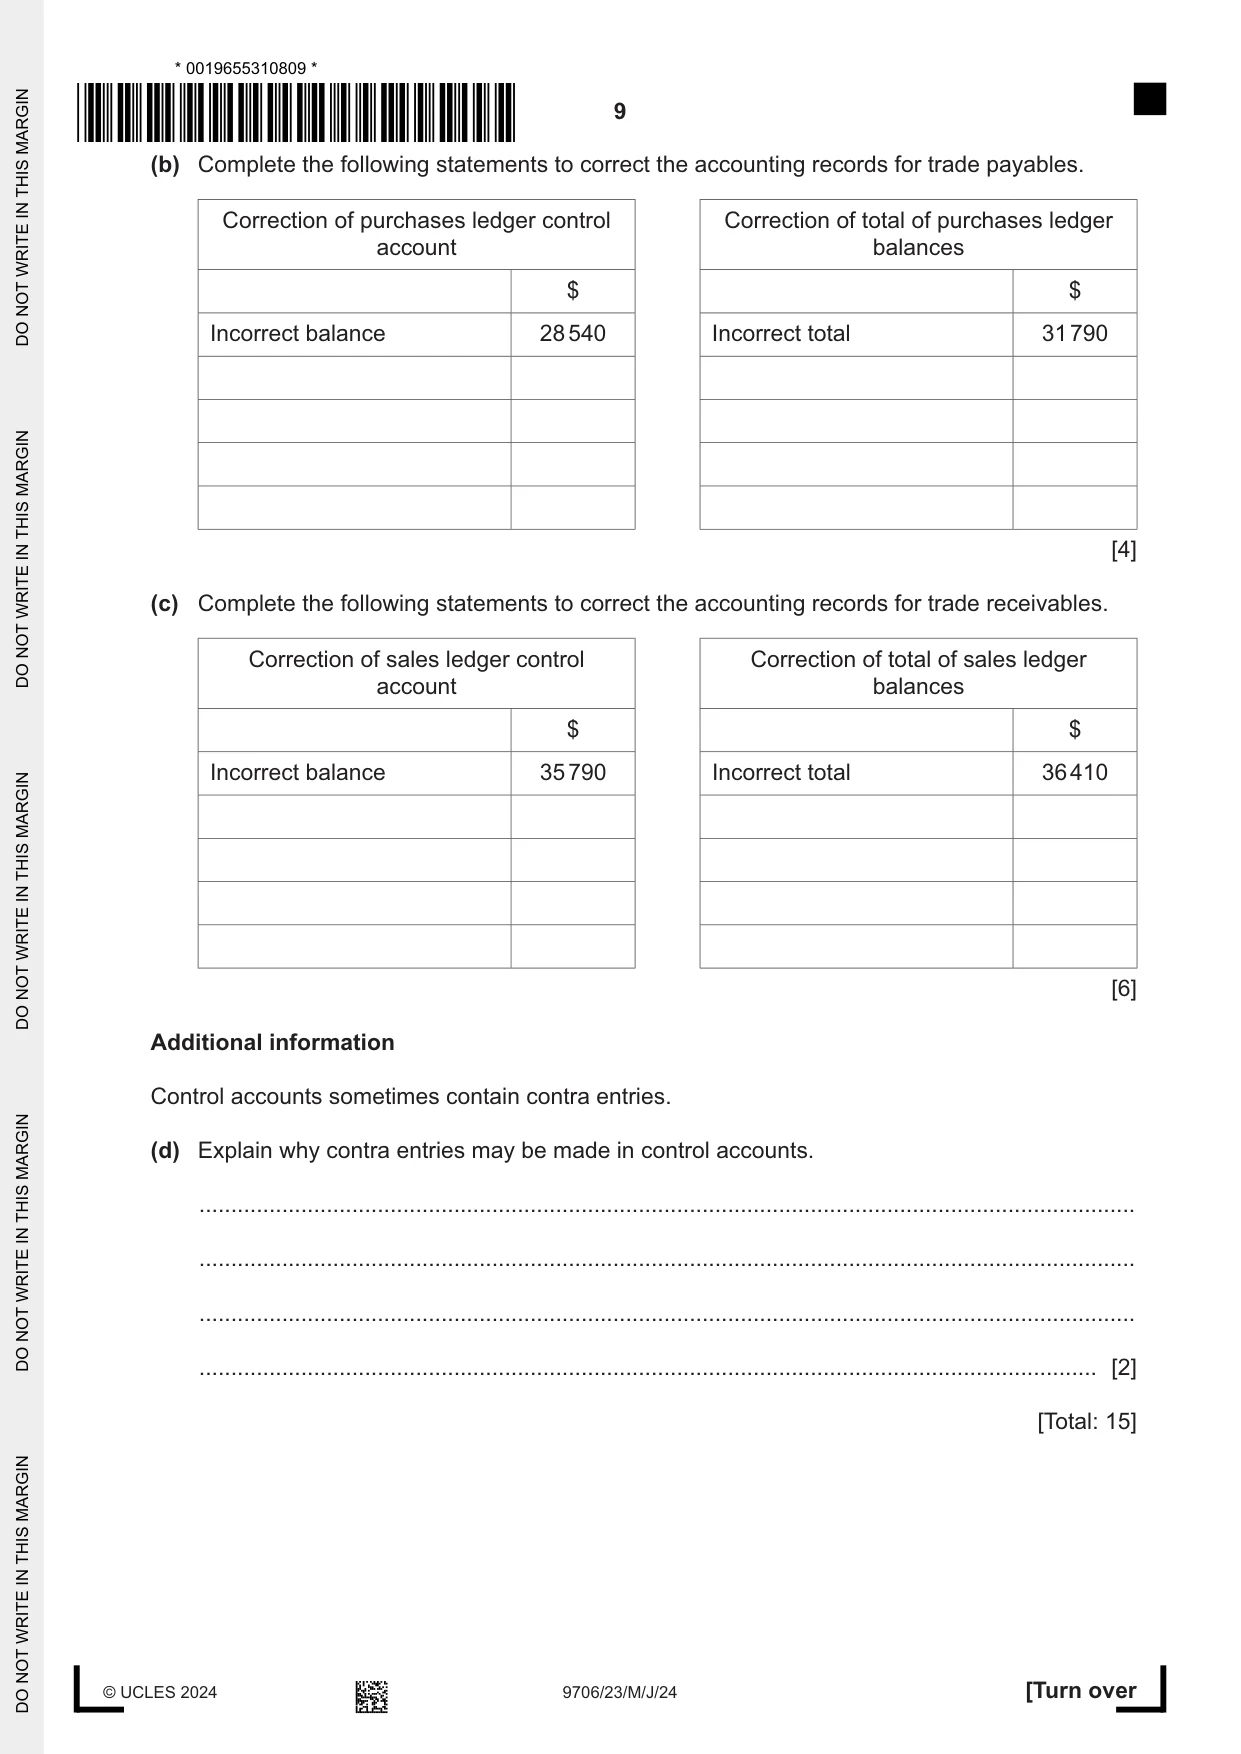
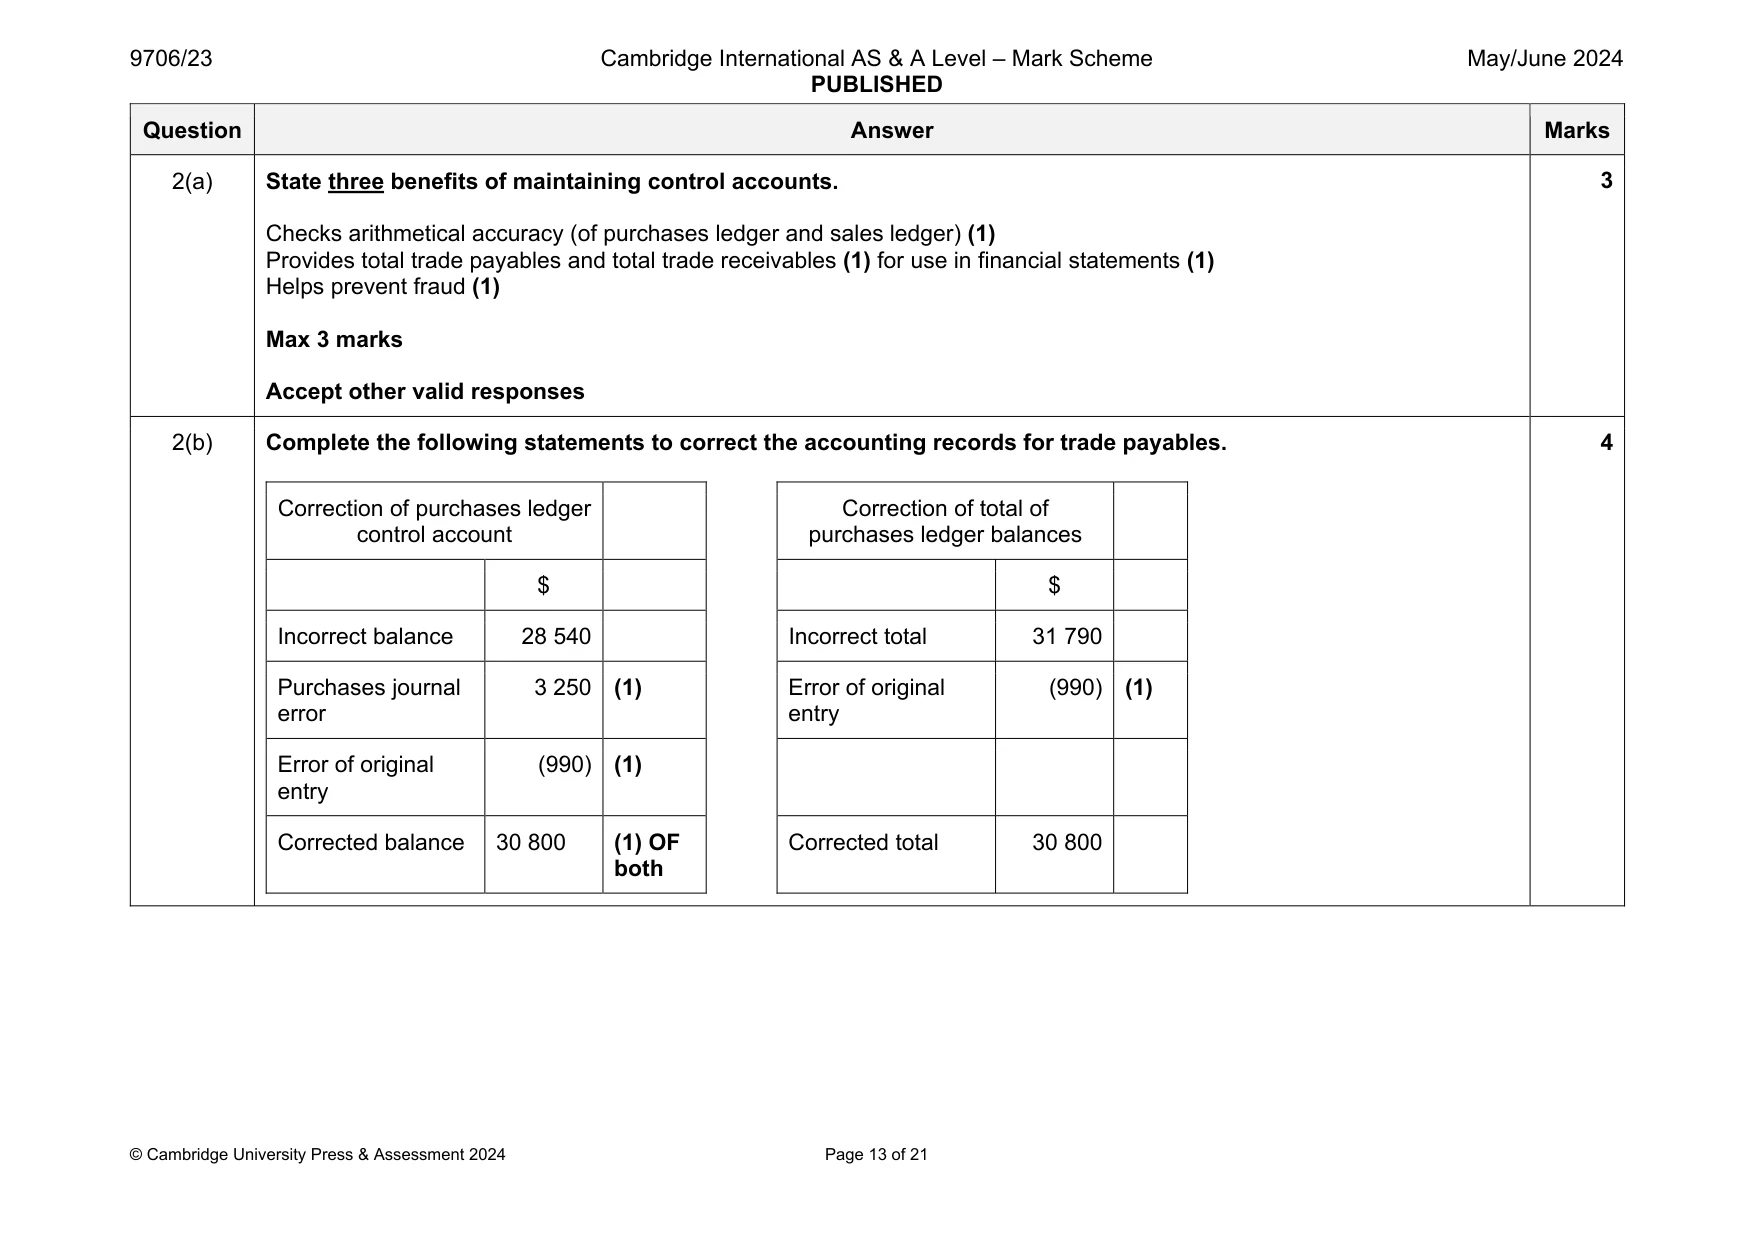
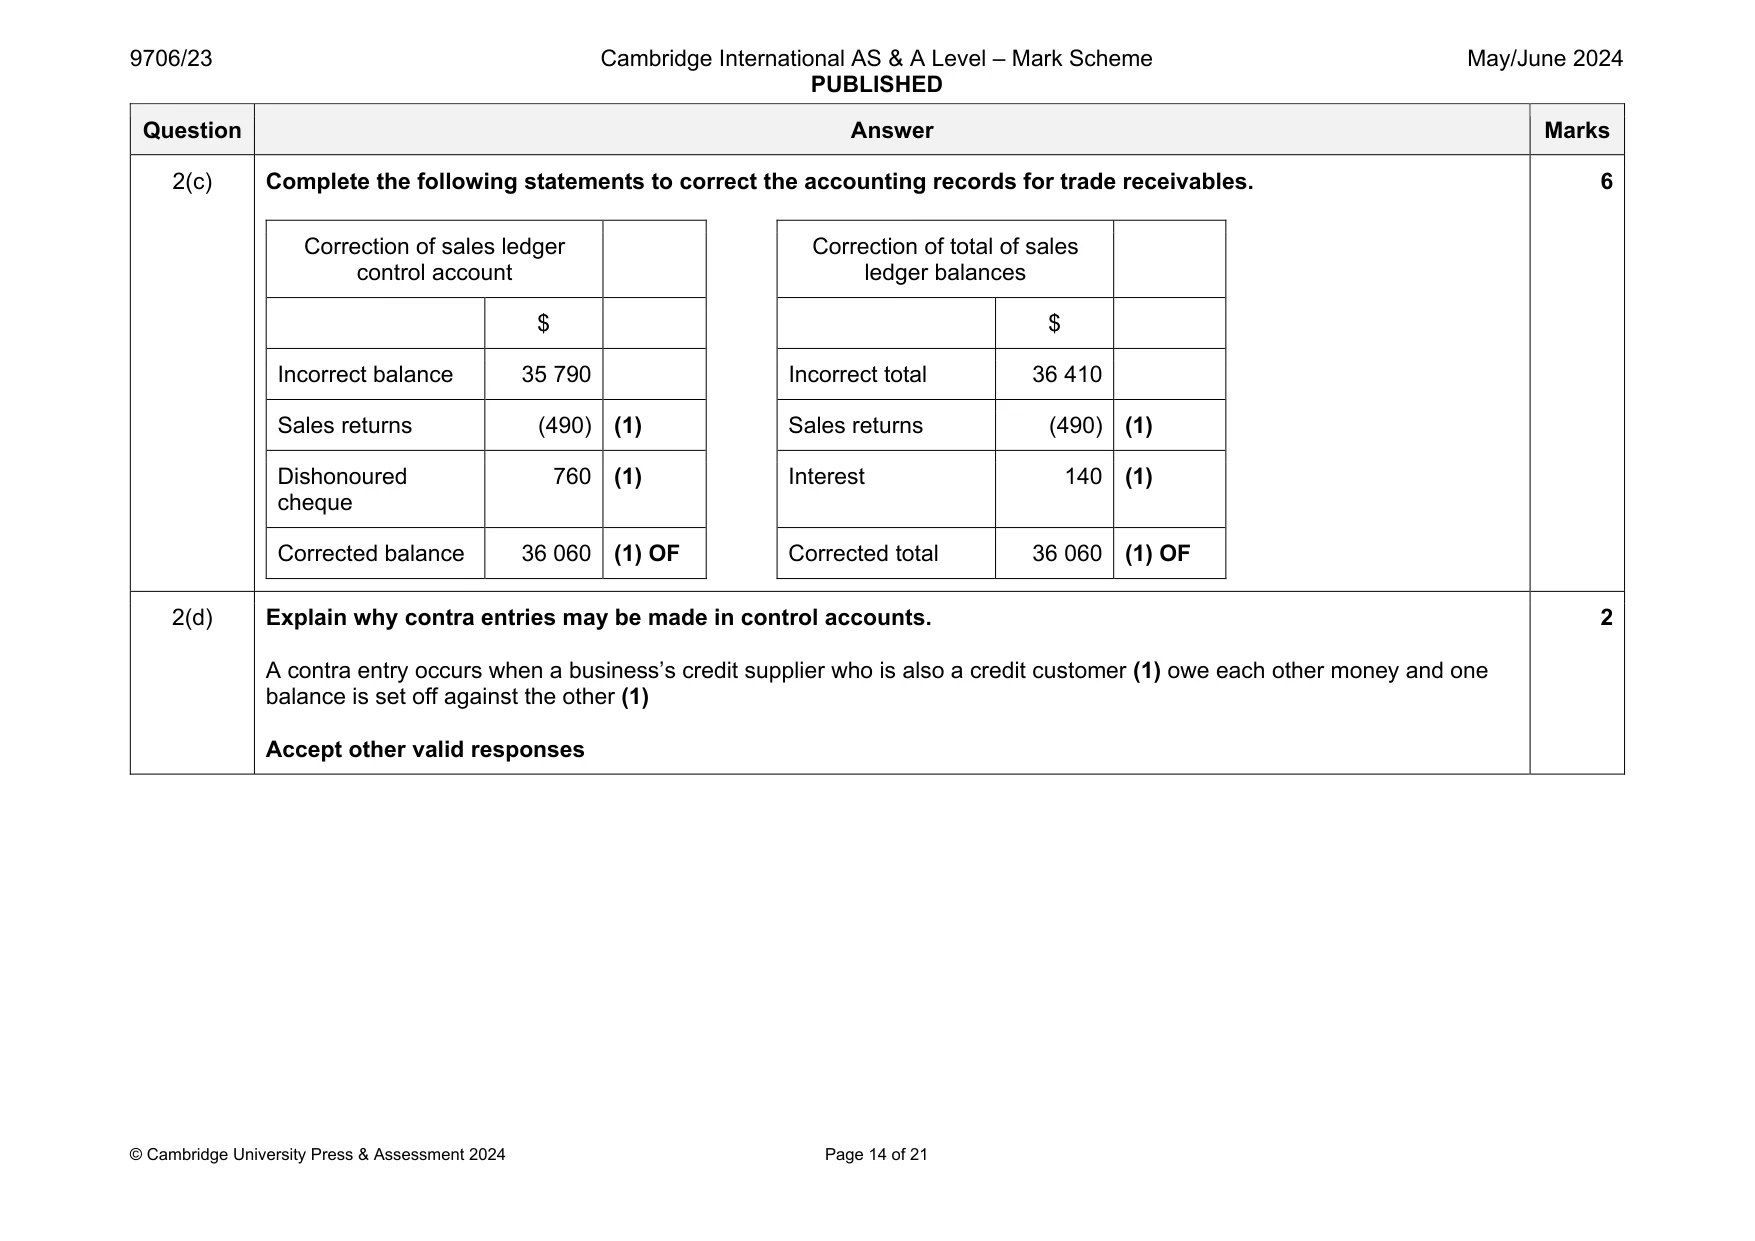
Mark scheme: 2(a) State three benefits of maintaining control accounts. Checks arithmetical accuracy (of purchases ledger and sales ledger) (1) Provides total trade payables and total trade receivables (1) for use in financial statements (1) Helps prevent fraud (1) Max 3 marks Accept other valid responses 2(b) Complete the following statements to correct the accounting records for trade payables. Correction of purchases ledger control account Correction of total of purchases ledger balances $ $ Incorrect balance 28 540 Incorrect total 31 790 Purchases journal error 3 250 (1) Error of original entry (990) (1) Error of original entry (990) (1) Corrected balance 30 800 (1) OF both Corrected total 30 800 4 Question Answer Marks 2(c) Complete the following statements to correct the accounting records for trade receivables. Correction of sales ledger control account Correction of total of sales ledger balances $ $ Incorrect balance 35 790 Incorrect total 36 410 Sales returns (490) (1) Sales returns (490) (1) Dishonoured cheque 760 (1) Interest 140 (1) Corrected balance 36 060 (1) OF Corrected total 36 060 (1) OF 6 2(d) Explain why contra entries may be made in control accounts. A contra entry occurs when a business’s credit supplier who is also a credit customer (1) owe each other money and one balance is set off against the other (1) Accept other valid responses 2
Q3 · Plant and equipment is depreciated by 20% per annum using the straight-line method on a…
3 Plant and equipment is depreciated by 20% per annum using the straight-line method on a month-by-month basis. Depreciation should be allocated: administrative expenses 60%; distribution costs 40%.
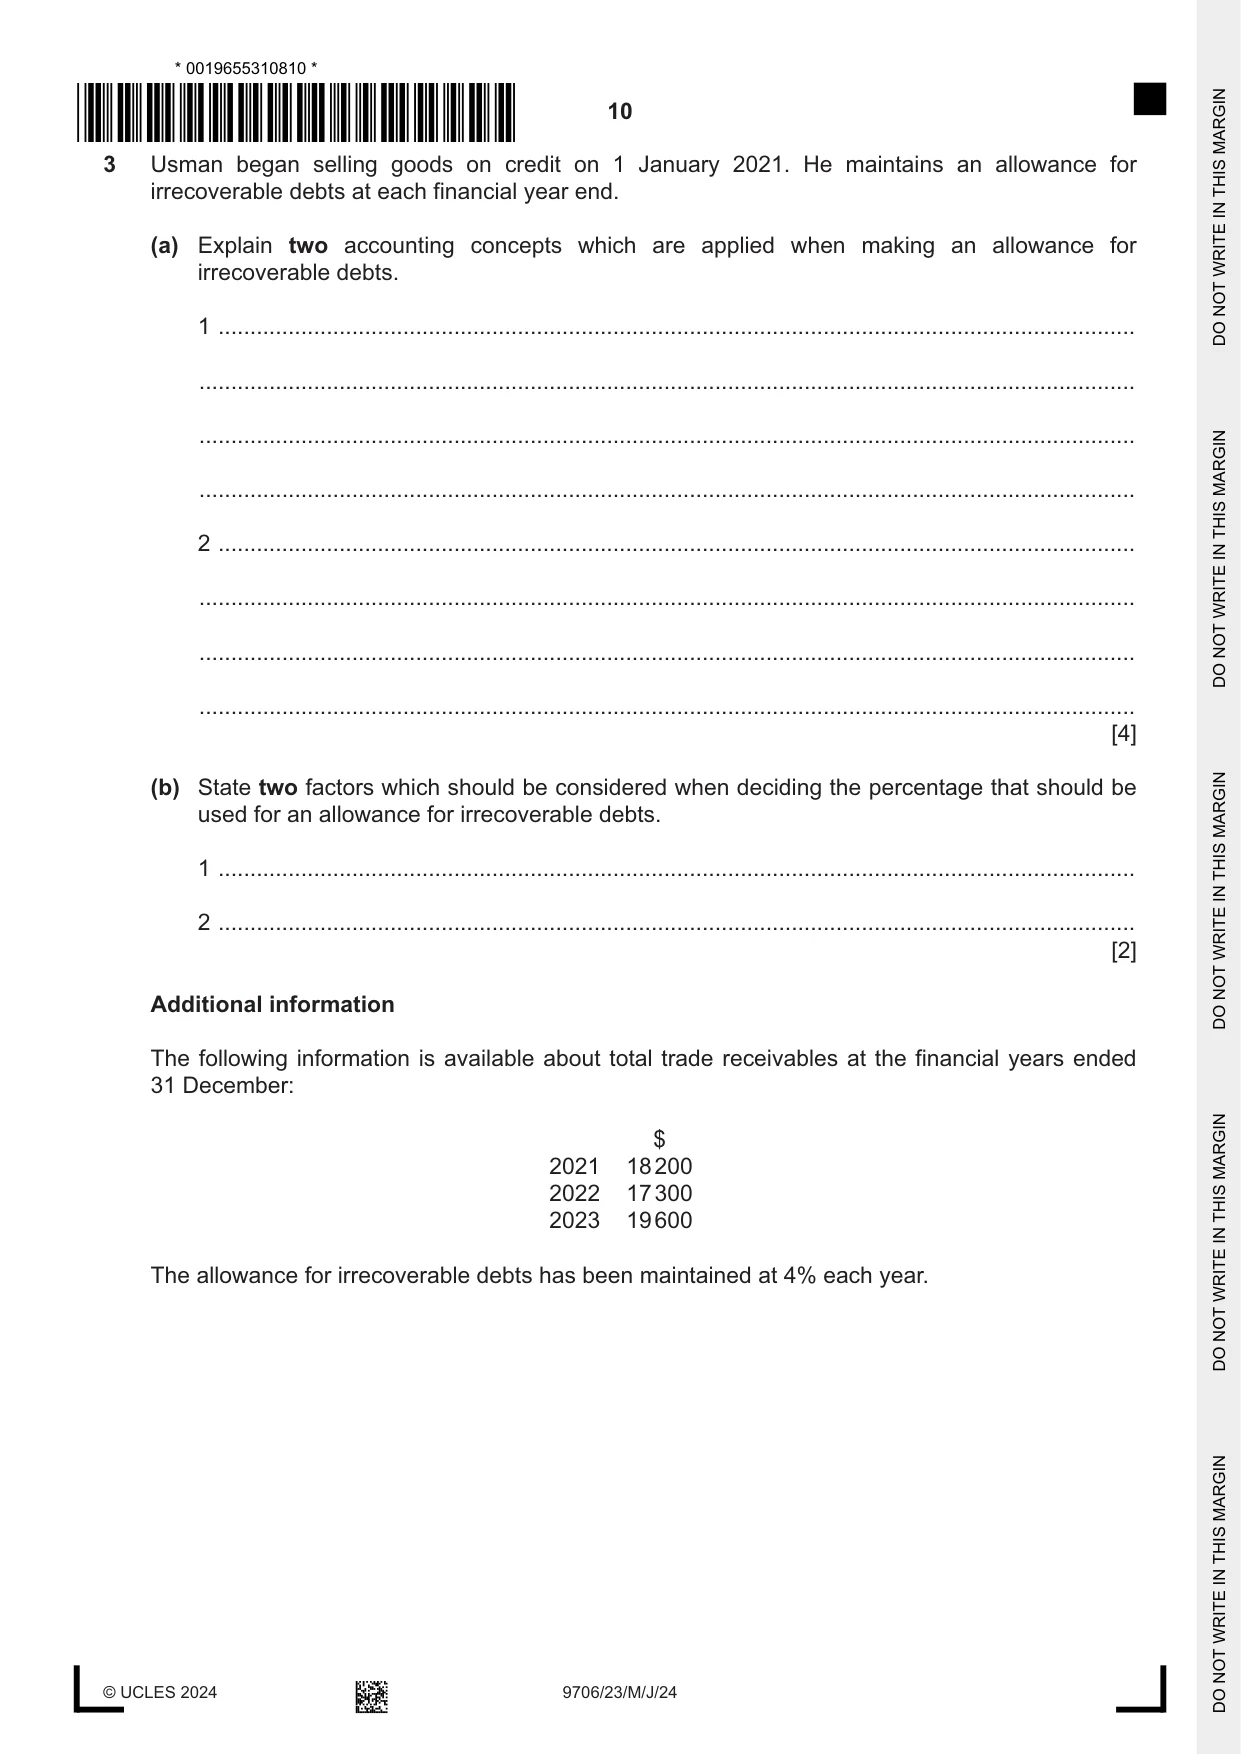
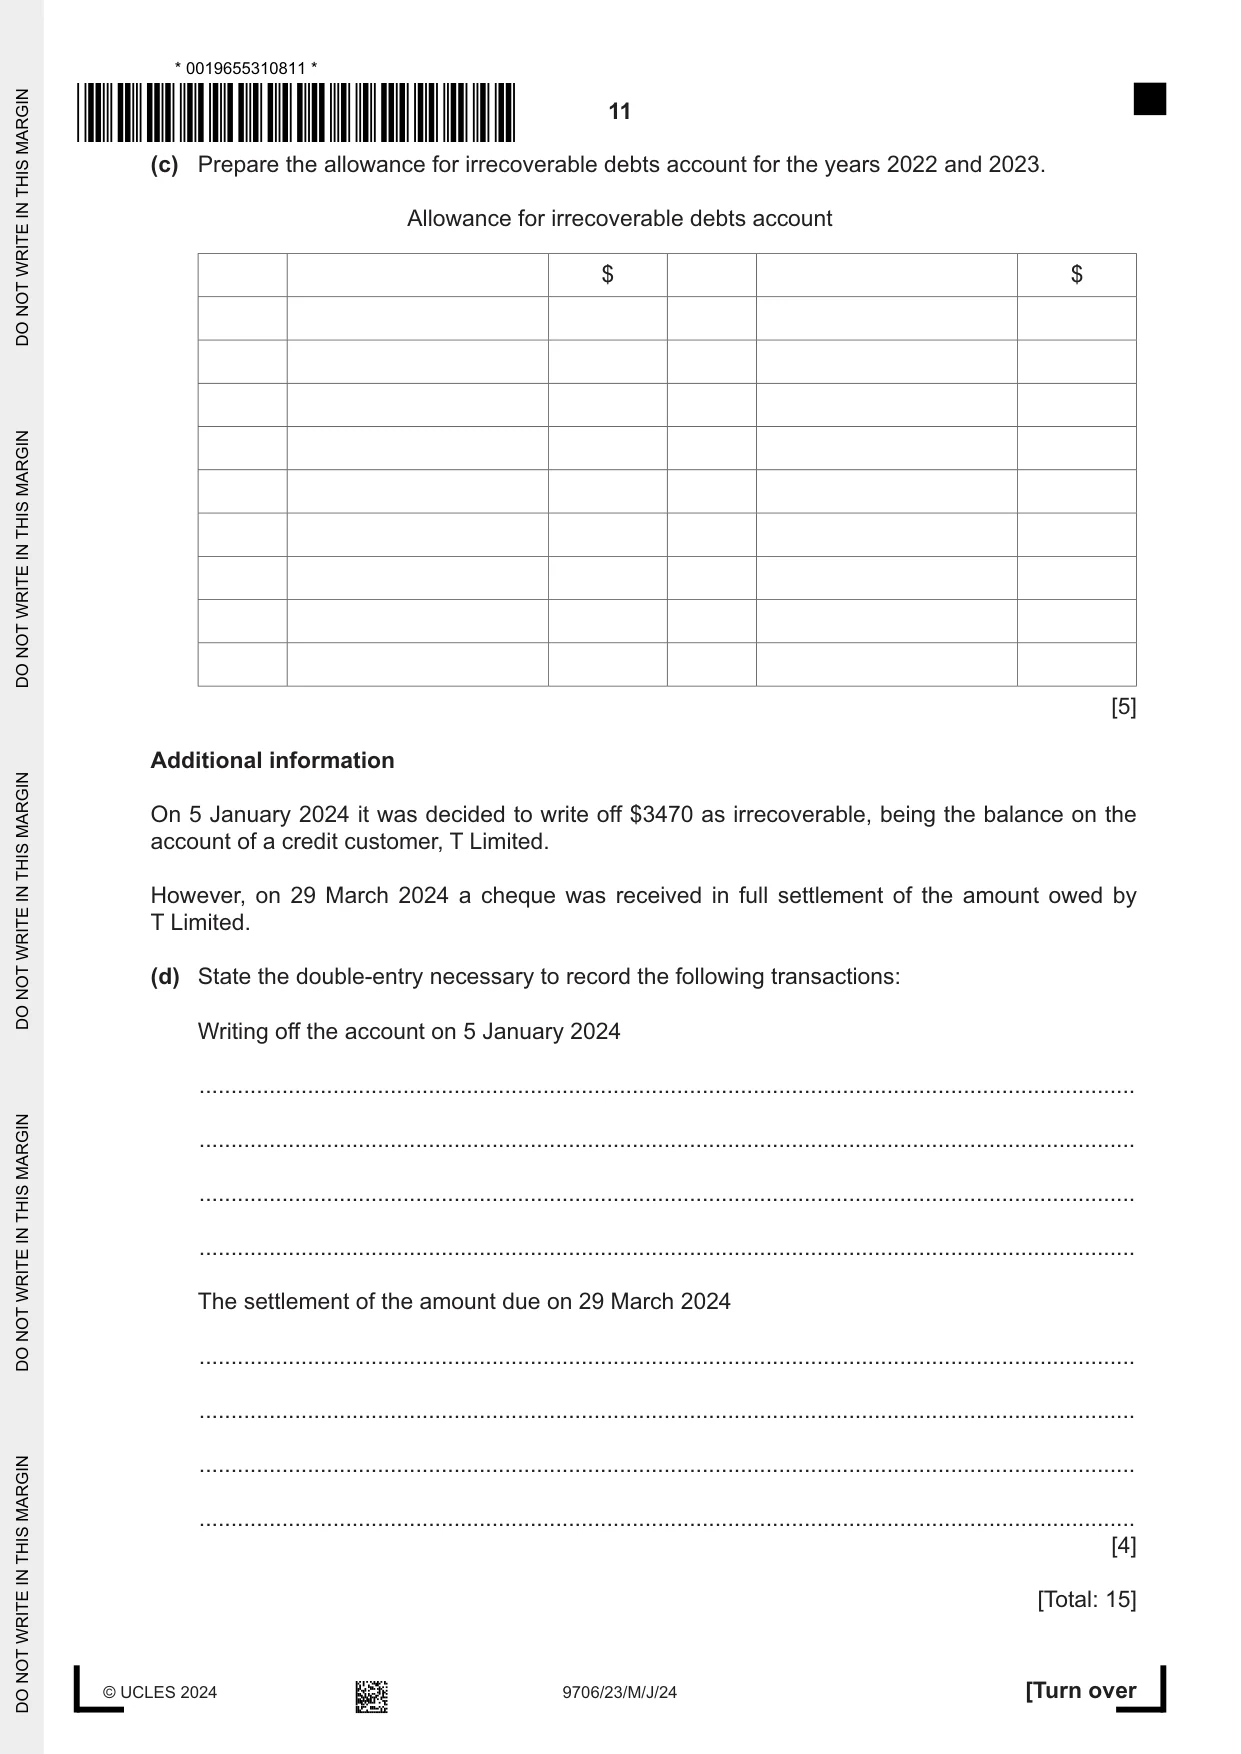
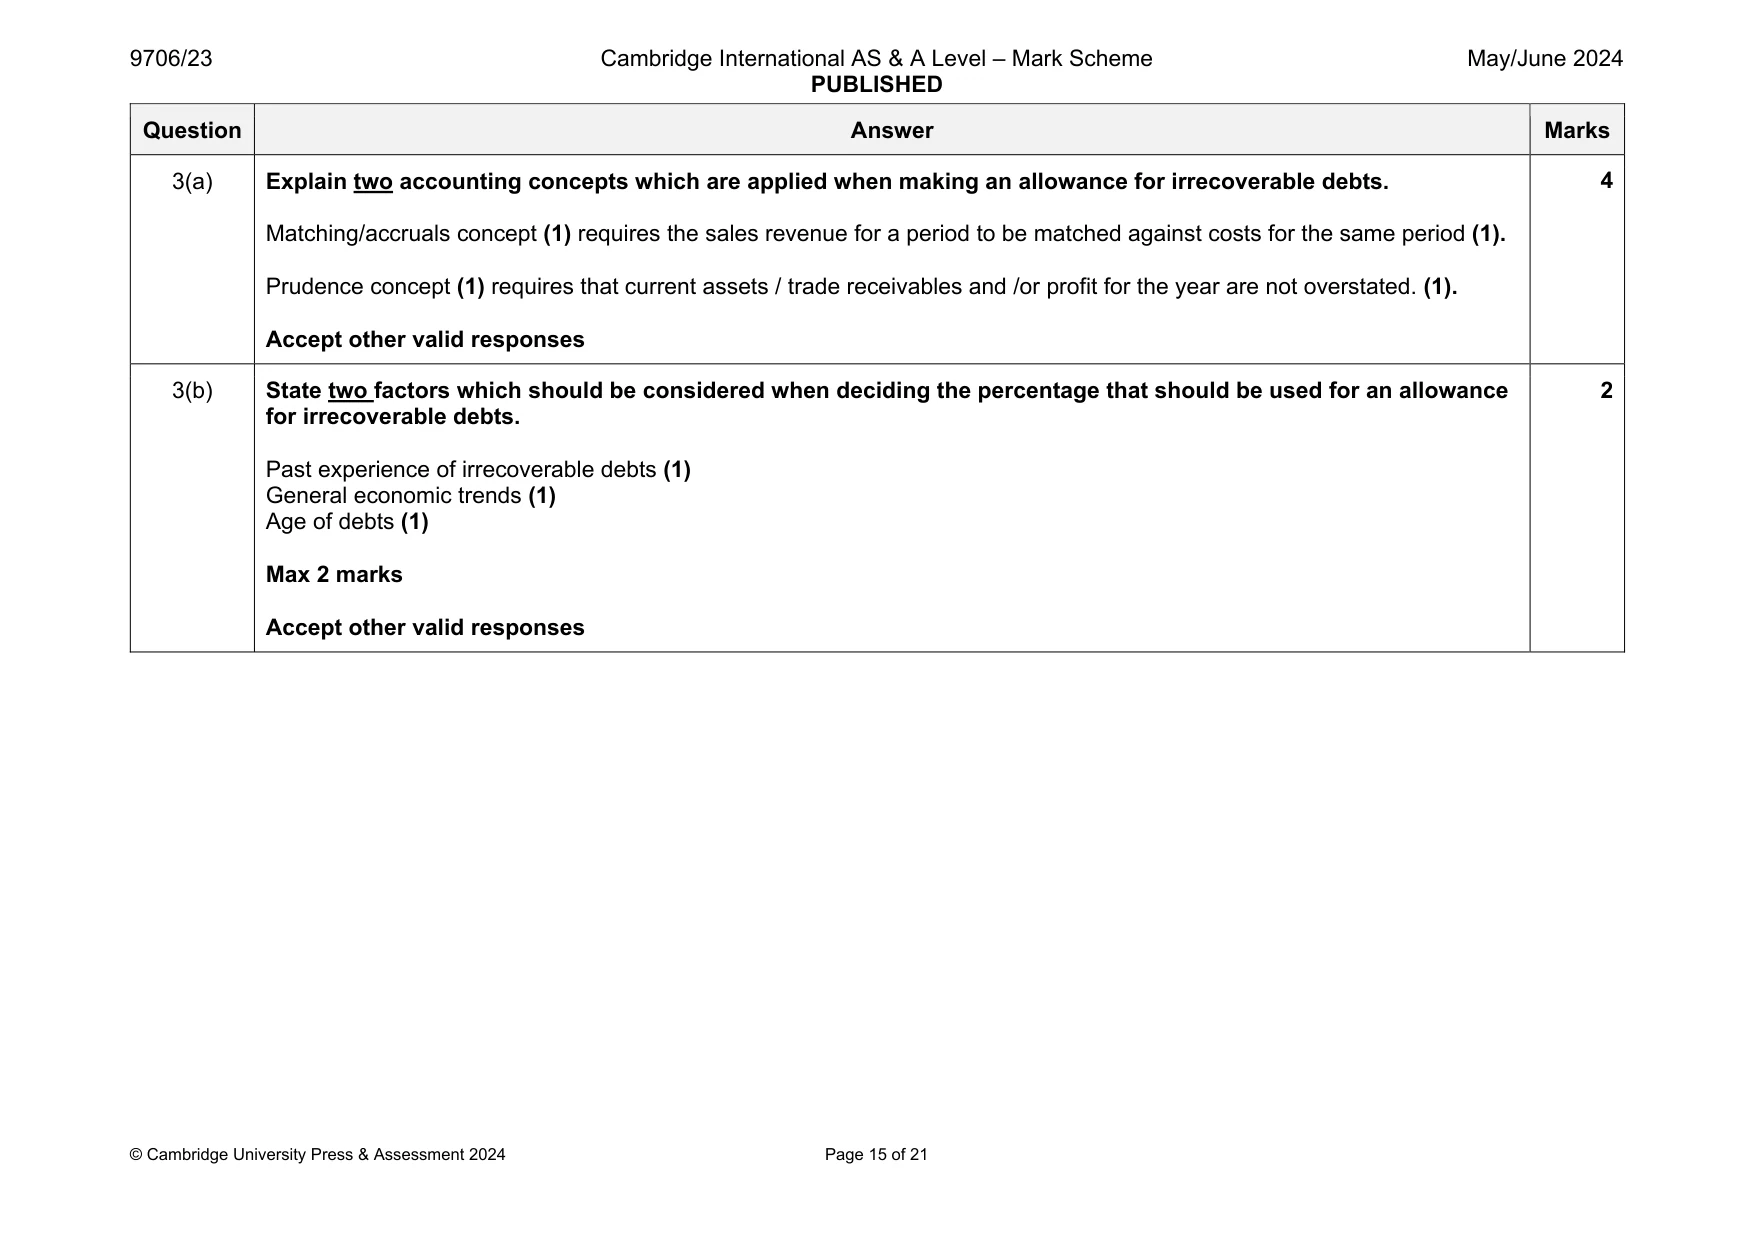
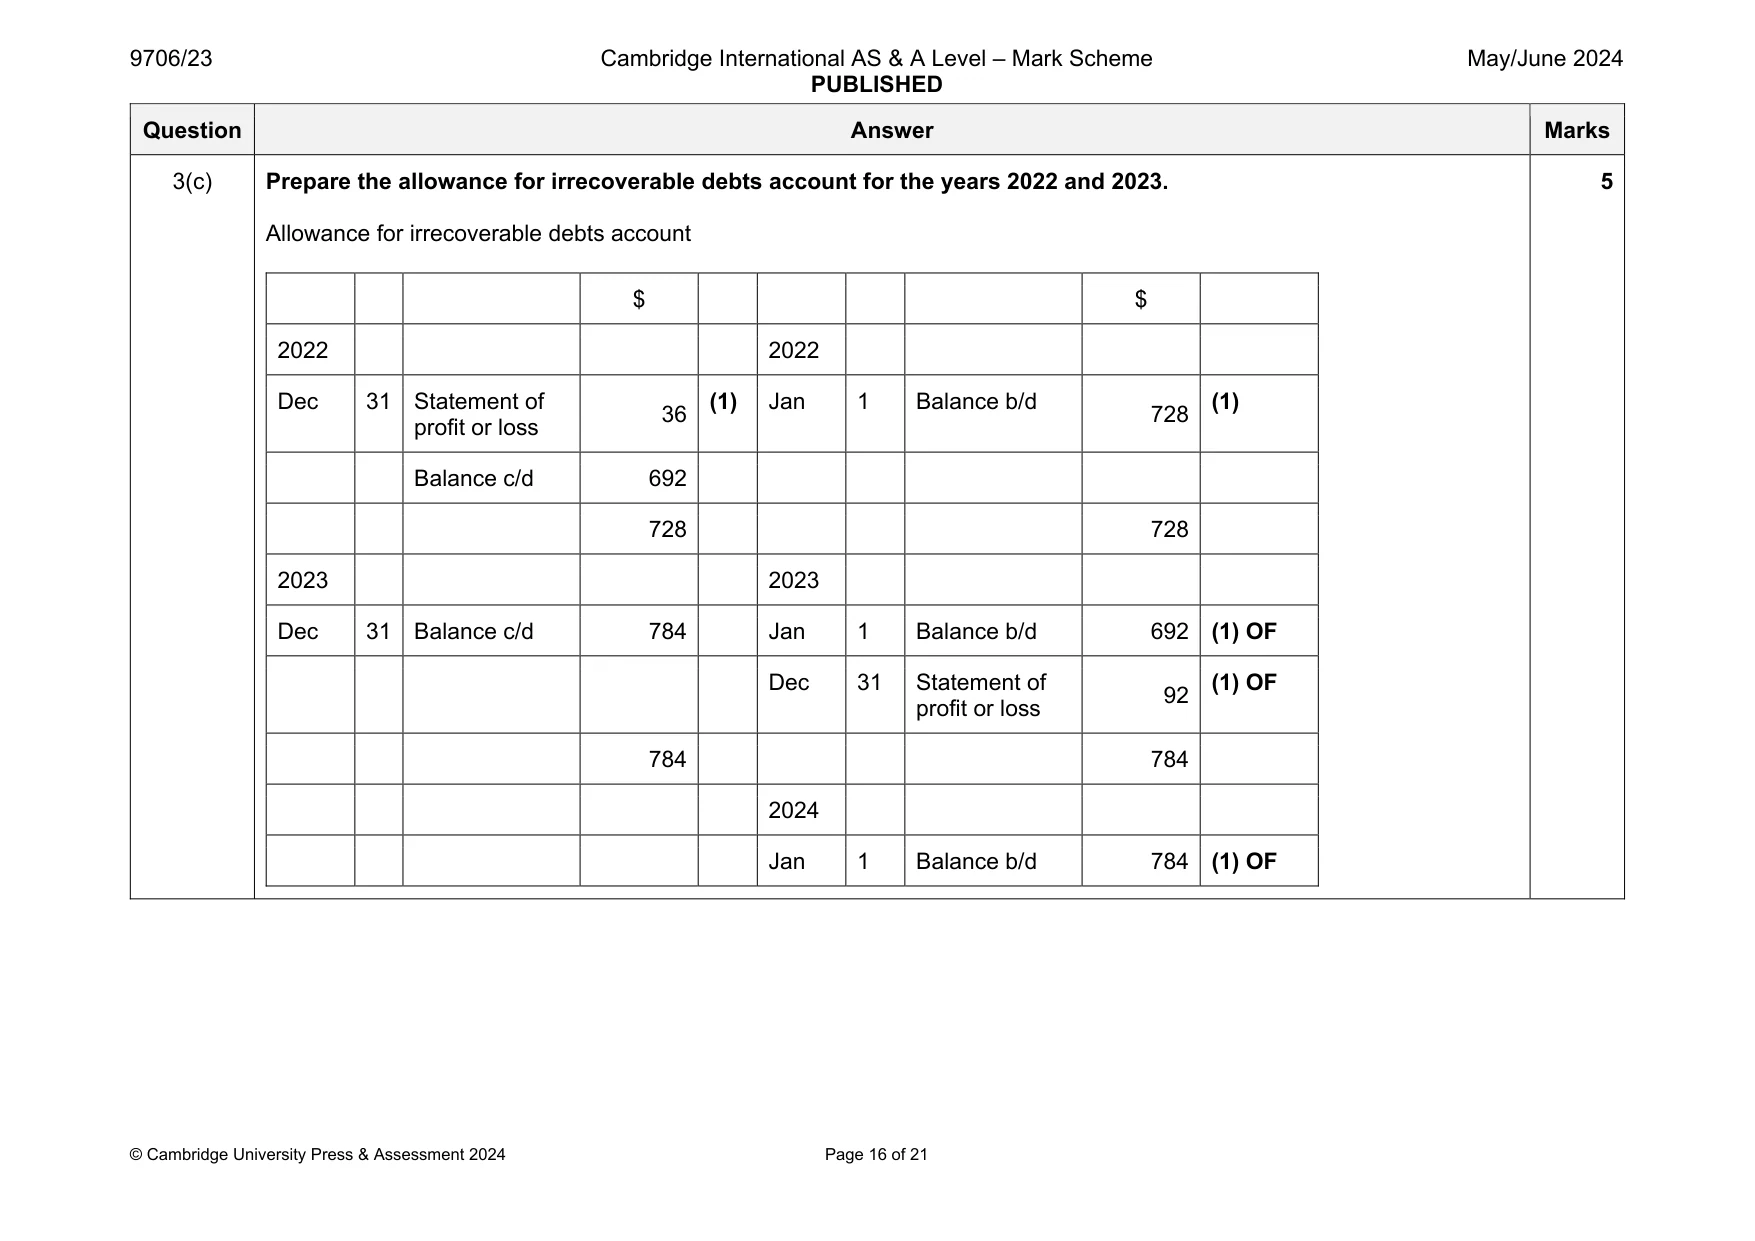
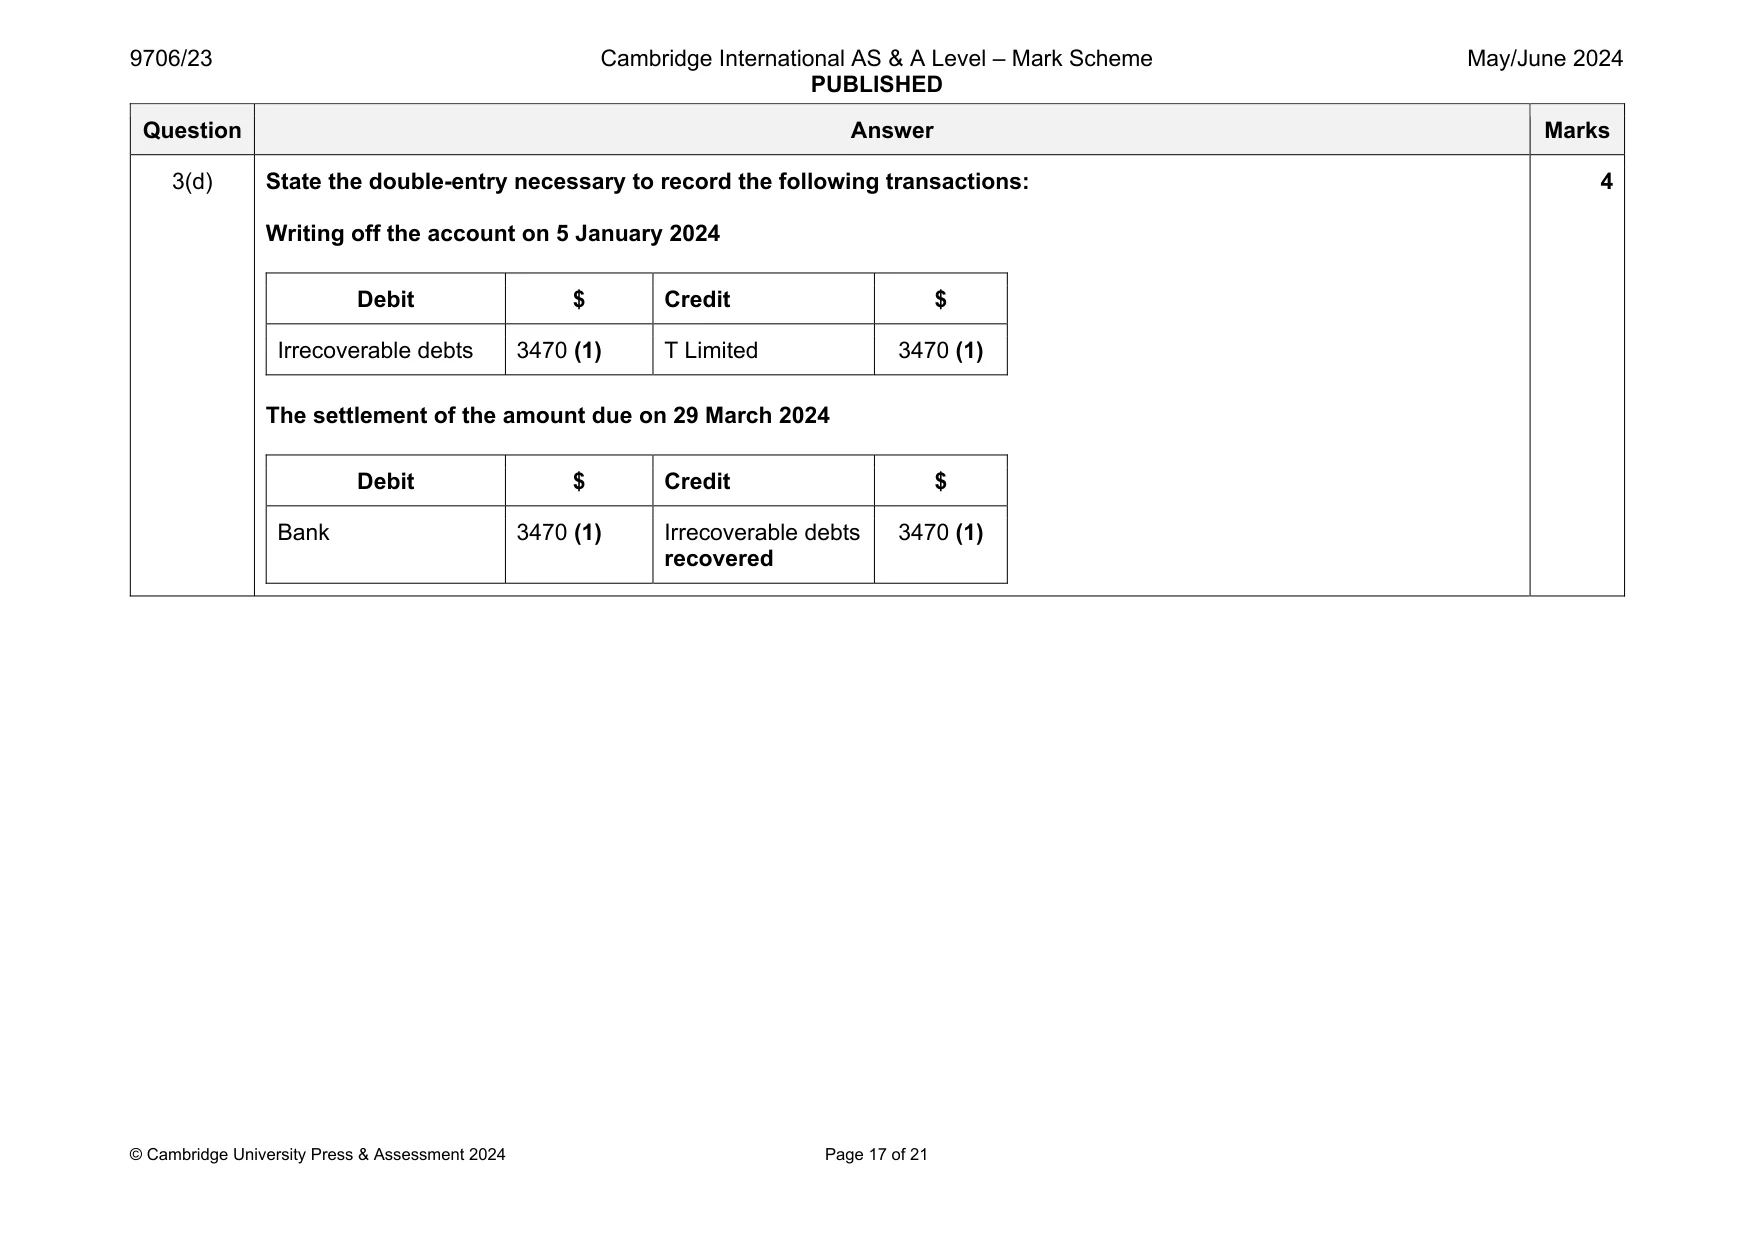
Mark scheme: 3(a) Explain two accounting concepts which are applied when making an allowance for irrecoverable debts. Matching/accruals concept (1) requires the sales revenue for a period to be matched against costs for the same period (1). Prudence concept (1) requires that current assets / trade receivables and /or profit for the year are not overstated. (1). Accept other valid responses 3(b) State two factors which should be considered when deciding the percentage that should be used for an allowance for irrecoverable debts. Past experience of irrecoverable debts (1) General economic trends (1) Age of debts (1) Max 2 marks Accept other valid responses 2 Question Answer Marks 3(c) Prepare the allowance for irrecoverable debts account for the years 2022 and 2023. Allowance for irrecoverable debts account $ $ 2022 2022 Dec 31 Statement of profit or loss 36 (1) Jan 1 Balance b/d 728 (1) Balance c/d 692 728 728 2023 2023 Dec 31 Balance c/d 784 Jan 1 Balance b/d 692 (1) OF Dec 31 Statement of profit or loss 92 (1) OF 784 784 2024 Jan 1 Balance b/d 784 (1) OF 5 Question Answer Marks 3(d) State the double-entry necessary to record the following transactions: Writing off the account on 5 January 2024 Debit $ Credit $ Irrecoverable debts 3470 (1) T Limited 3470 (1) The settlement of the amount due on 29 March 2024 Debit $ Credit $ Bank 3470 (1) Irrecoverable debts recovered 3470 (1) 4
Q4 · Distribution costs includes the cost of a five-month advertising campaign, $22 000, which…
4 Distribution costs includes the cost of a five-month advertising campaign, $22 000, which will end on 31 March 2024.
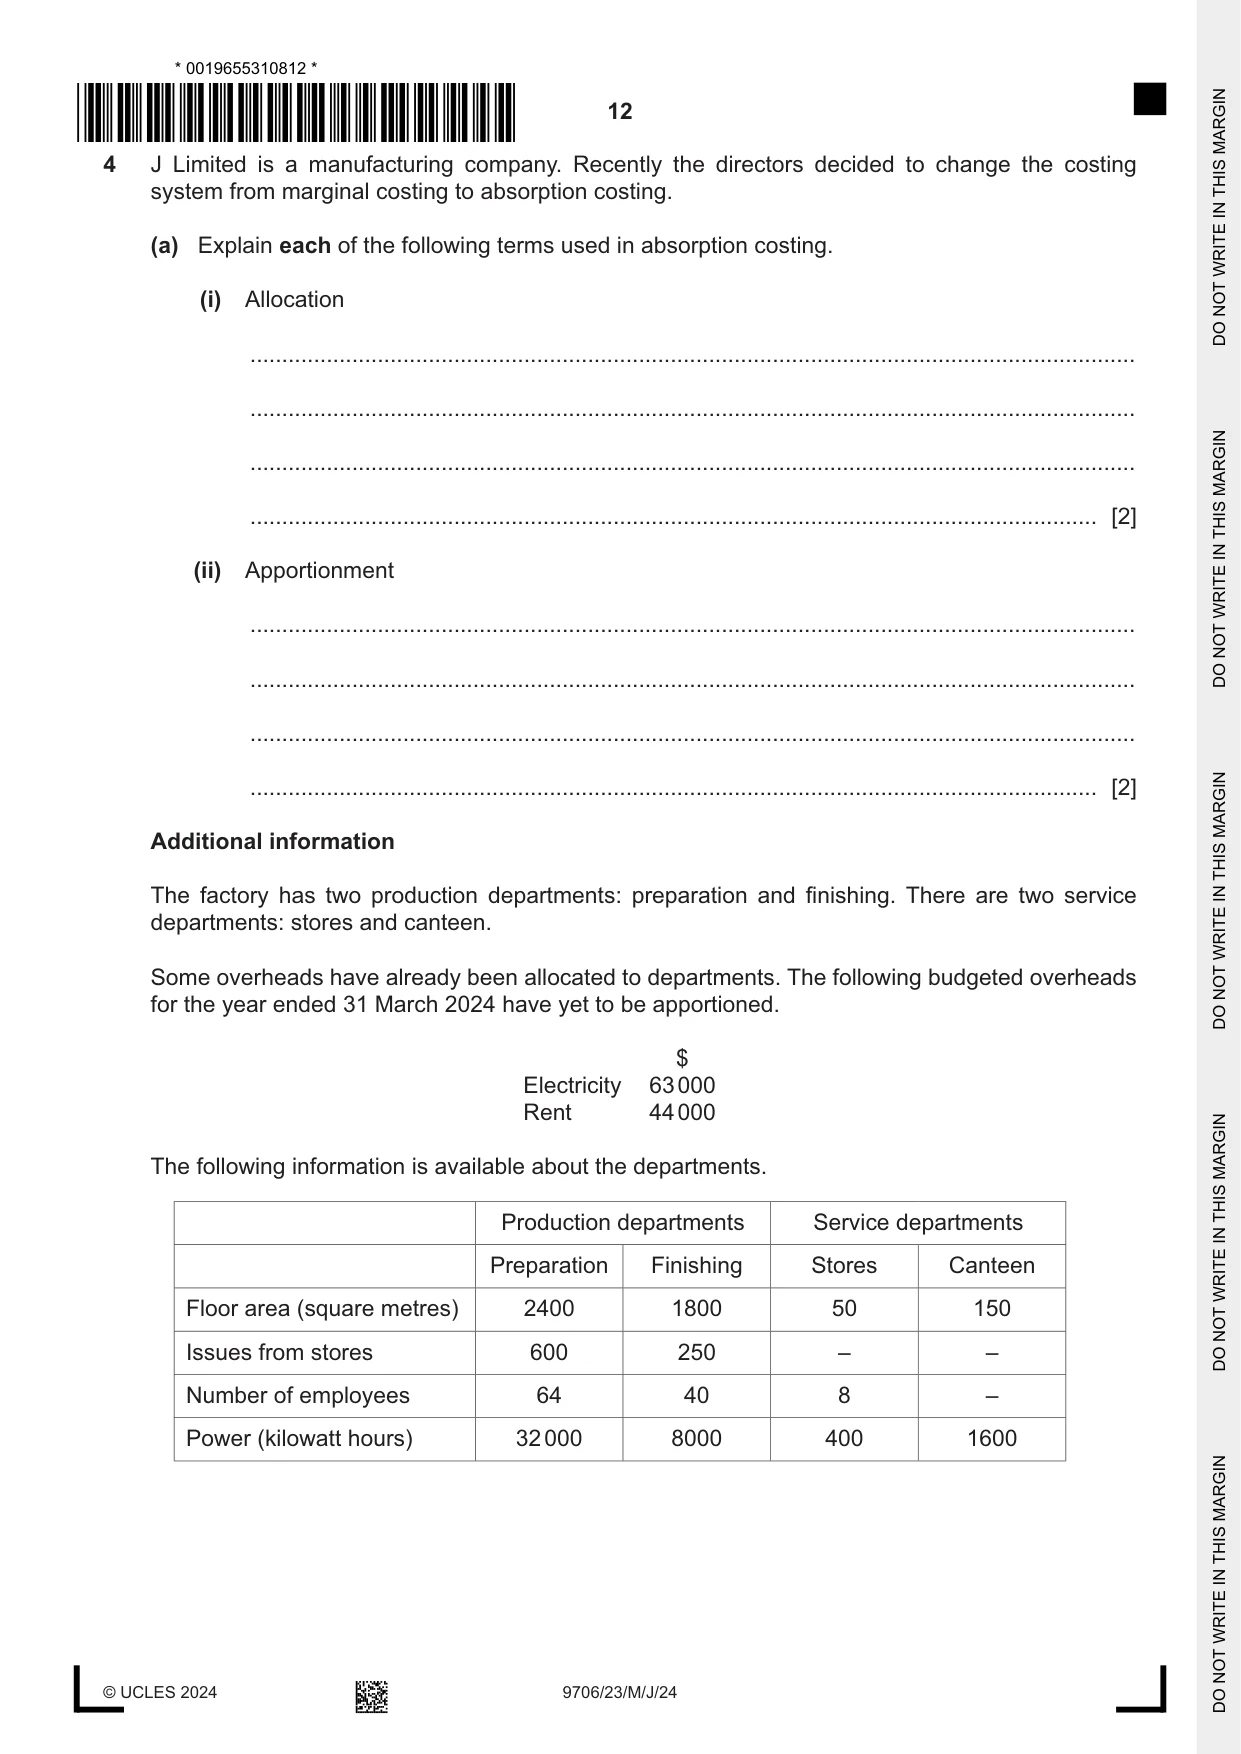
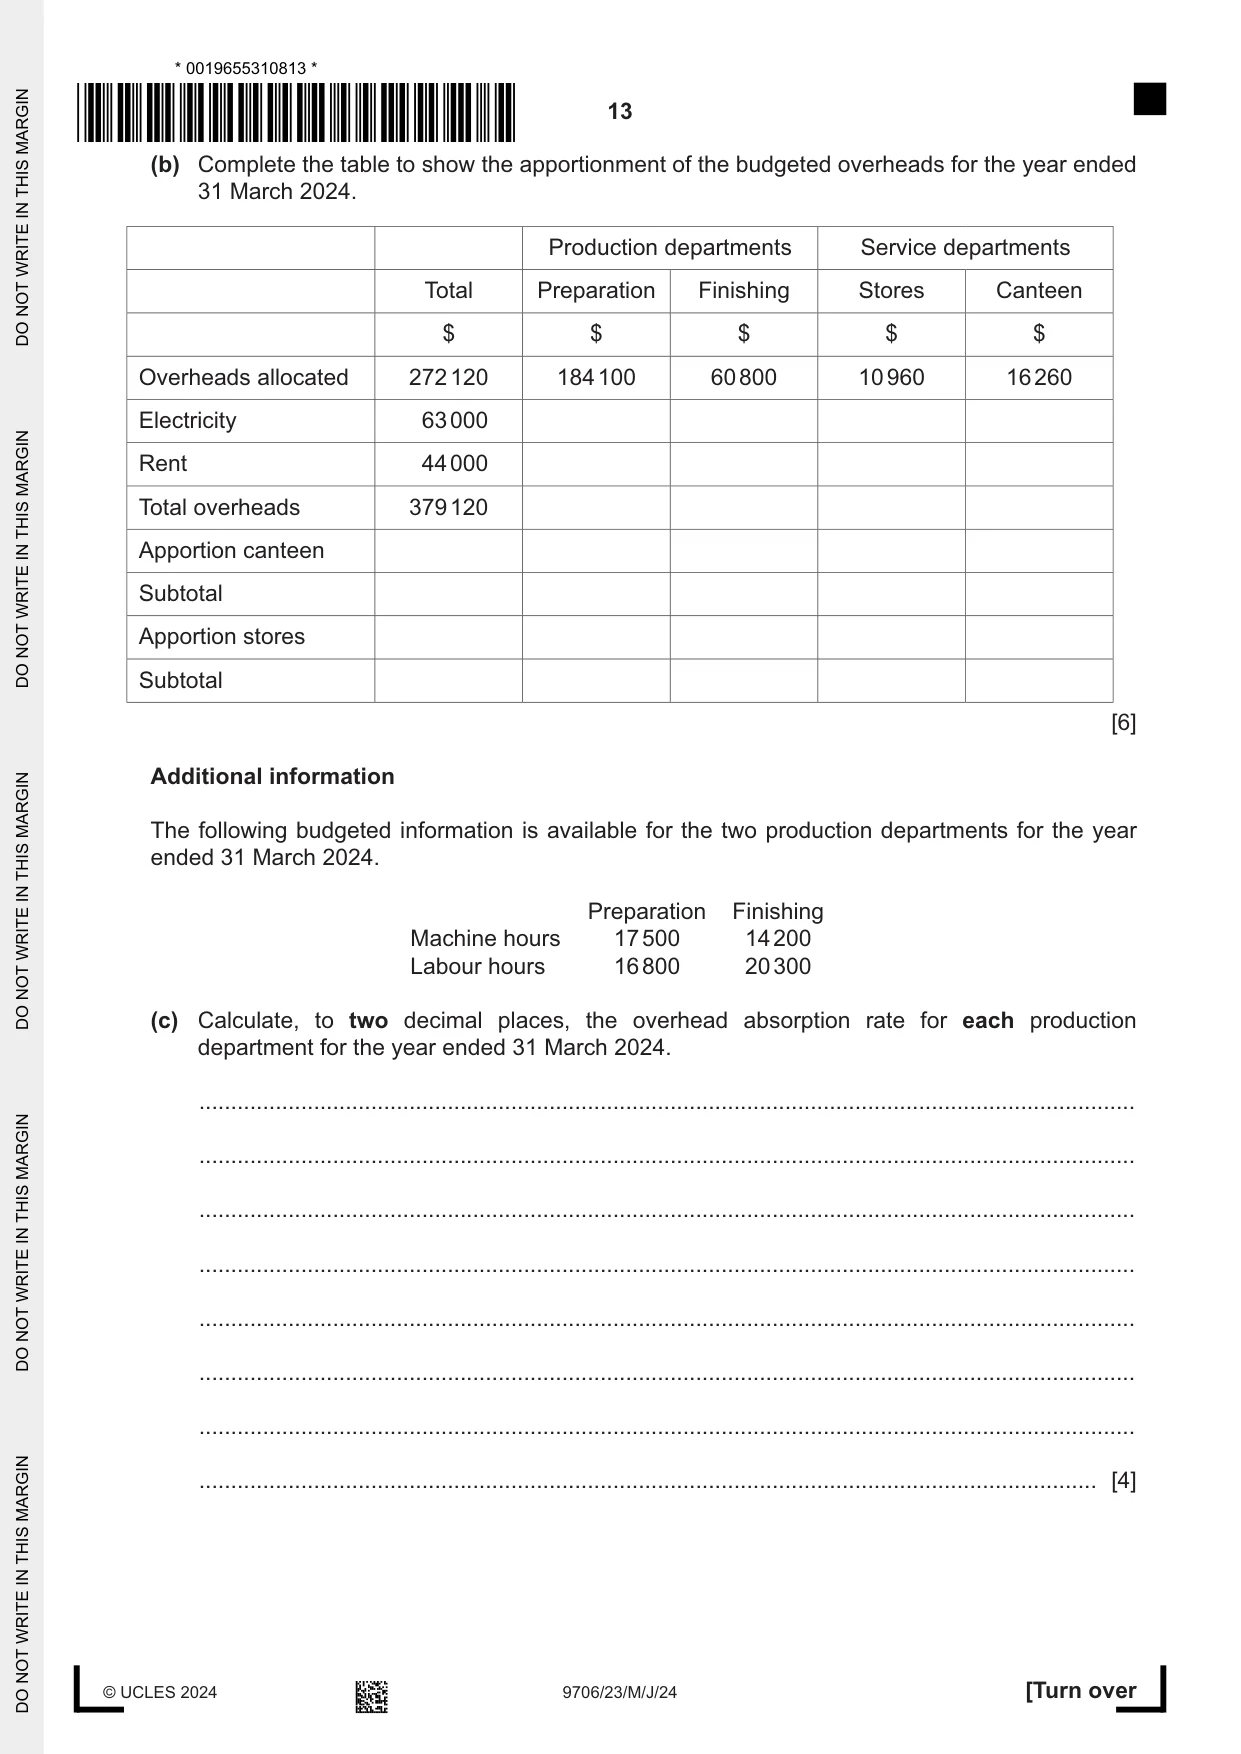
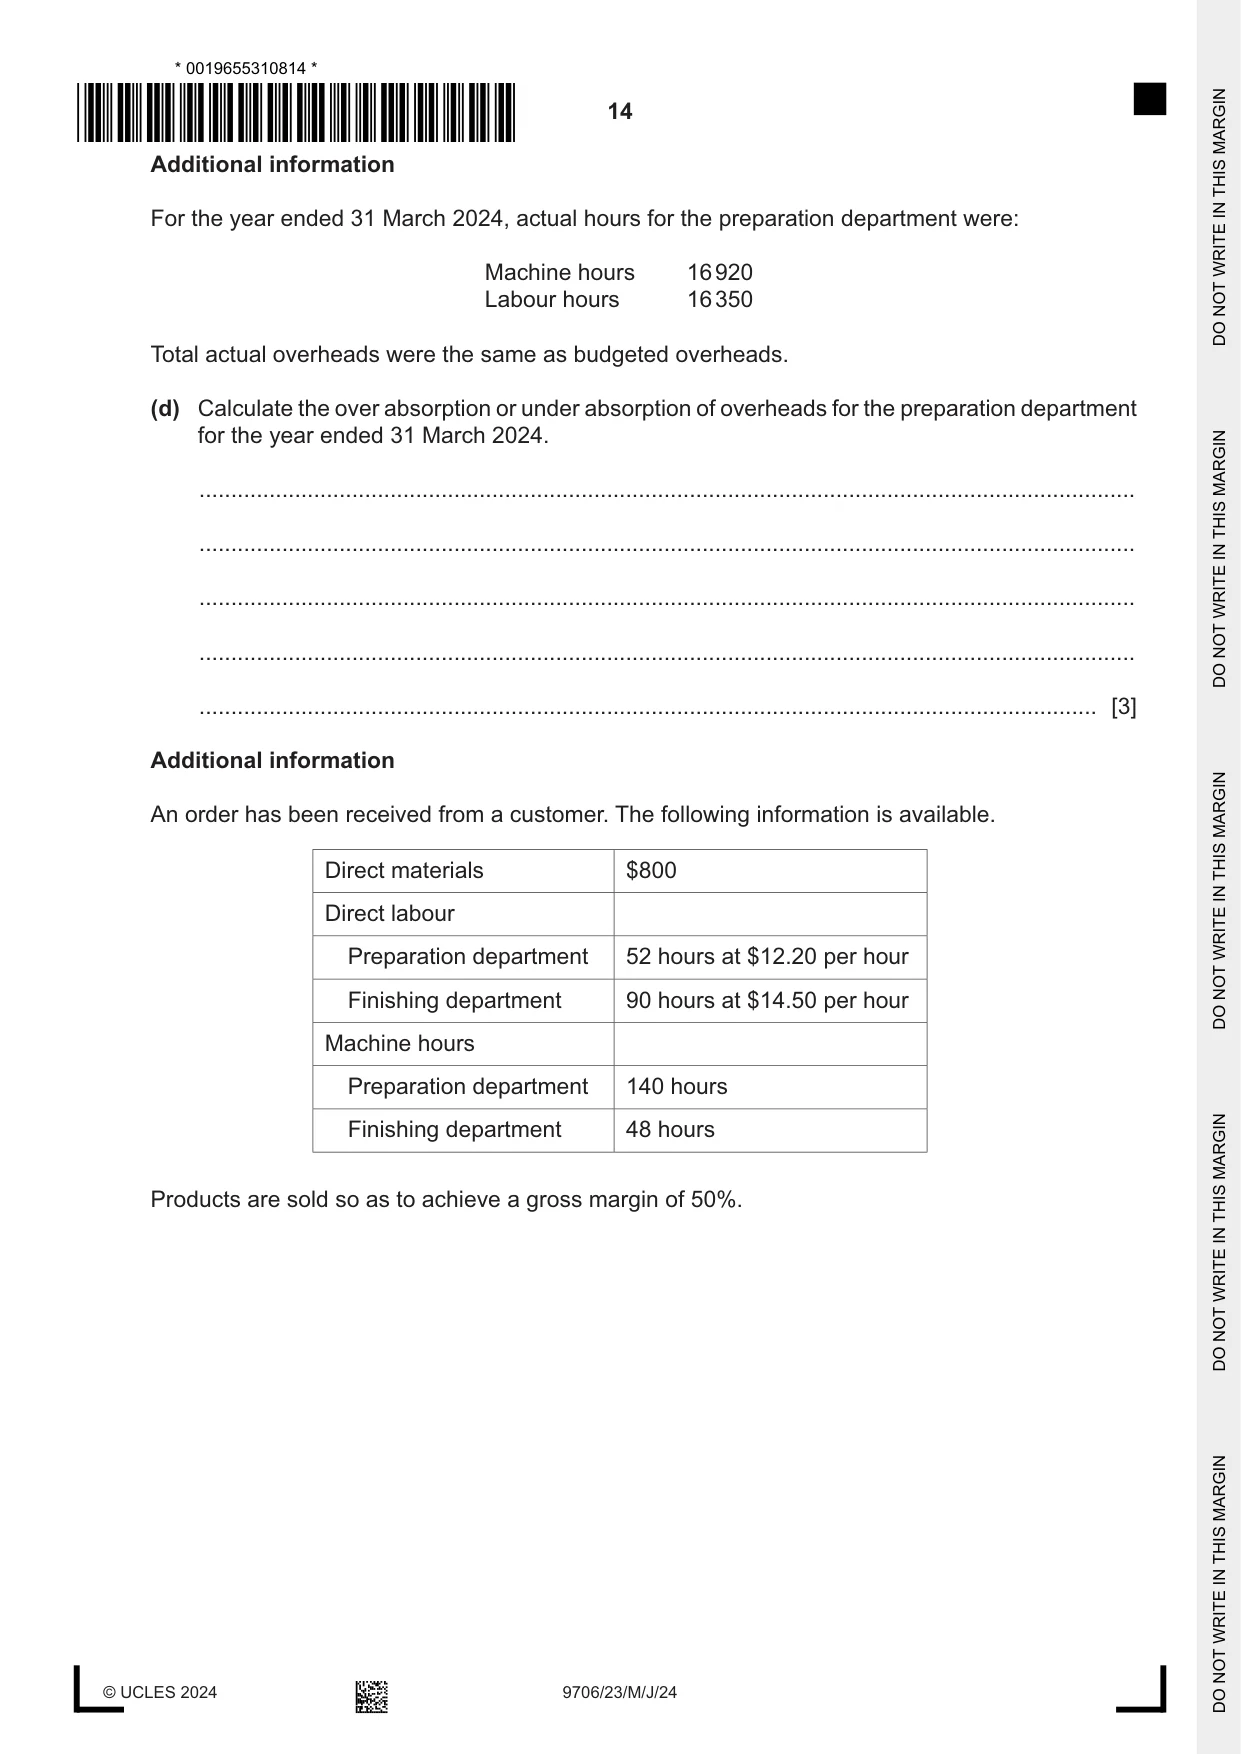
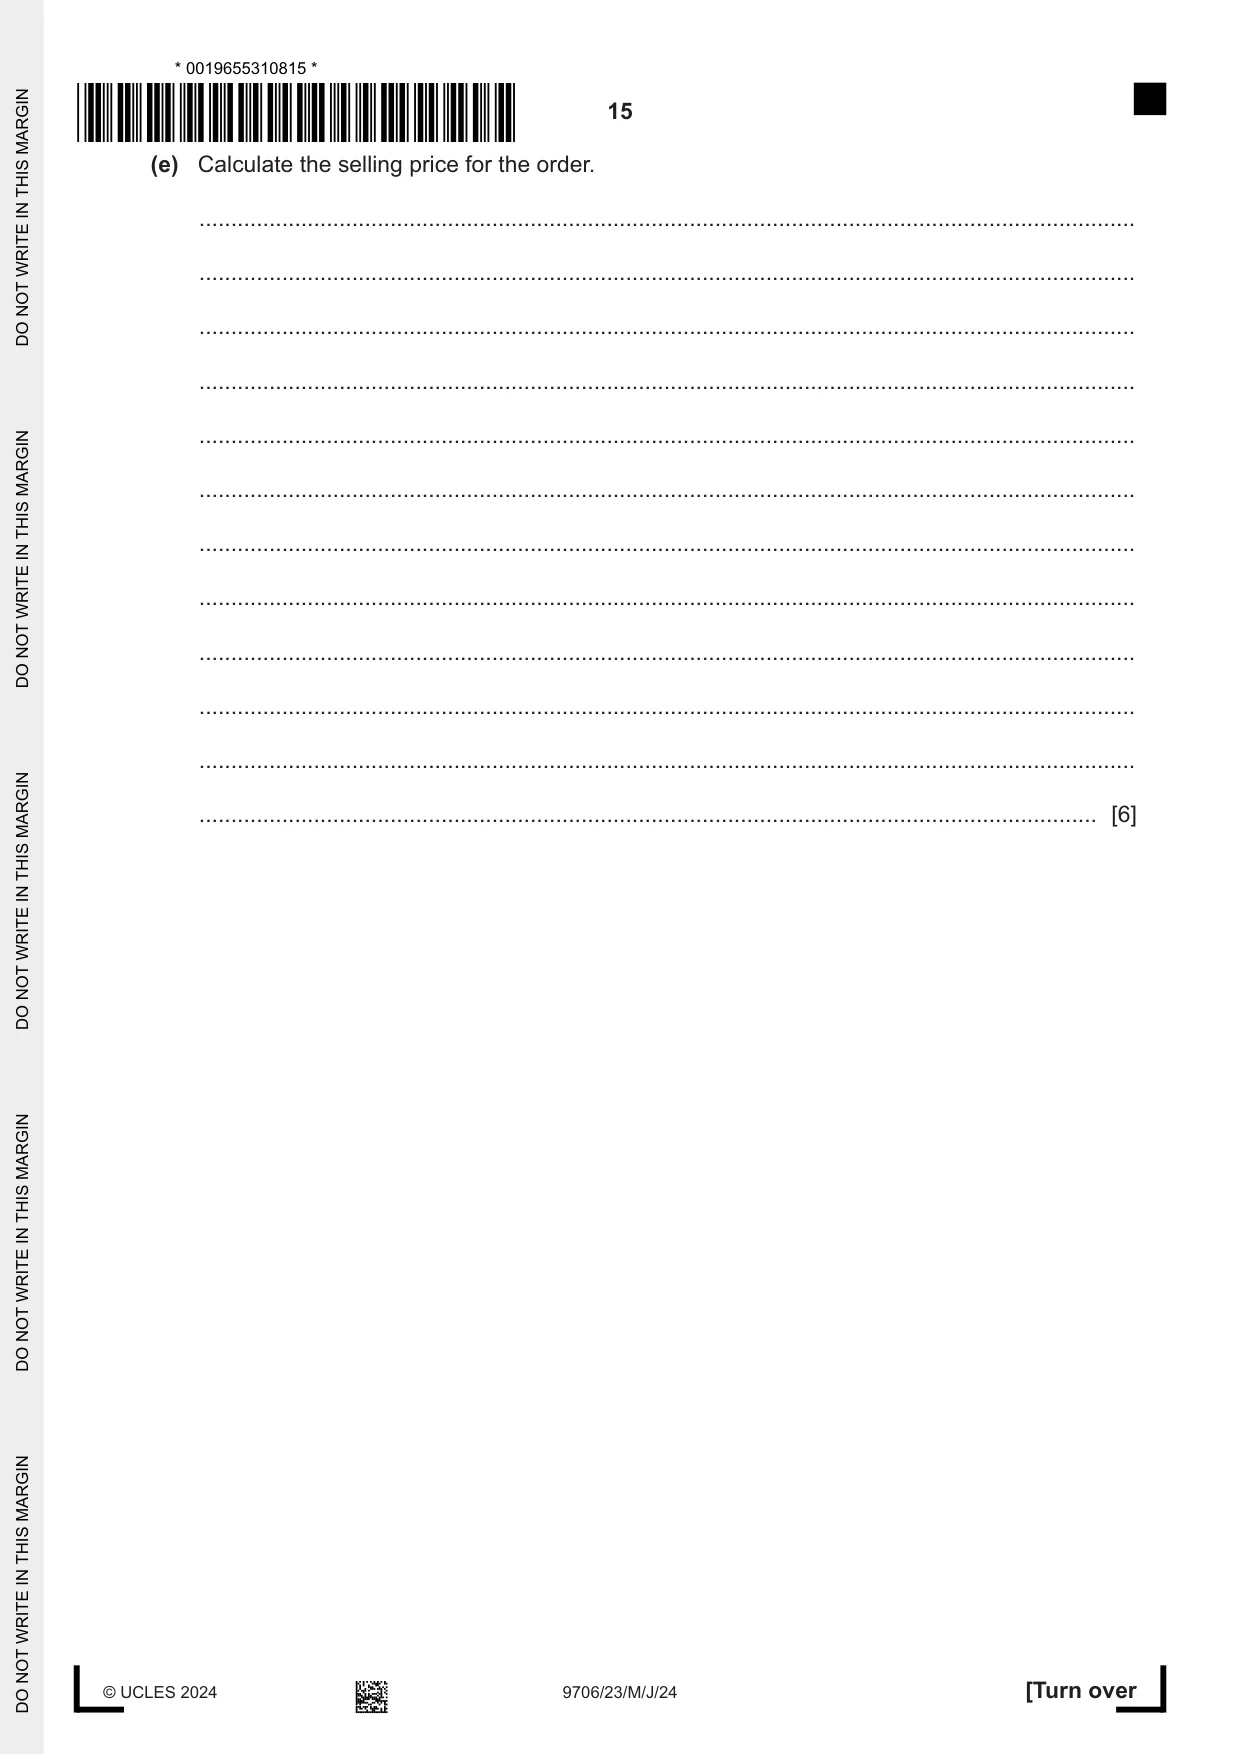
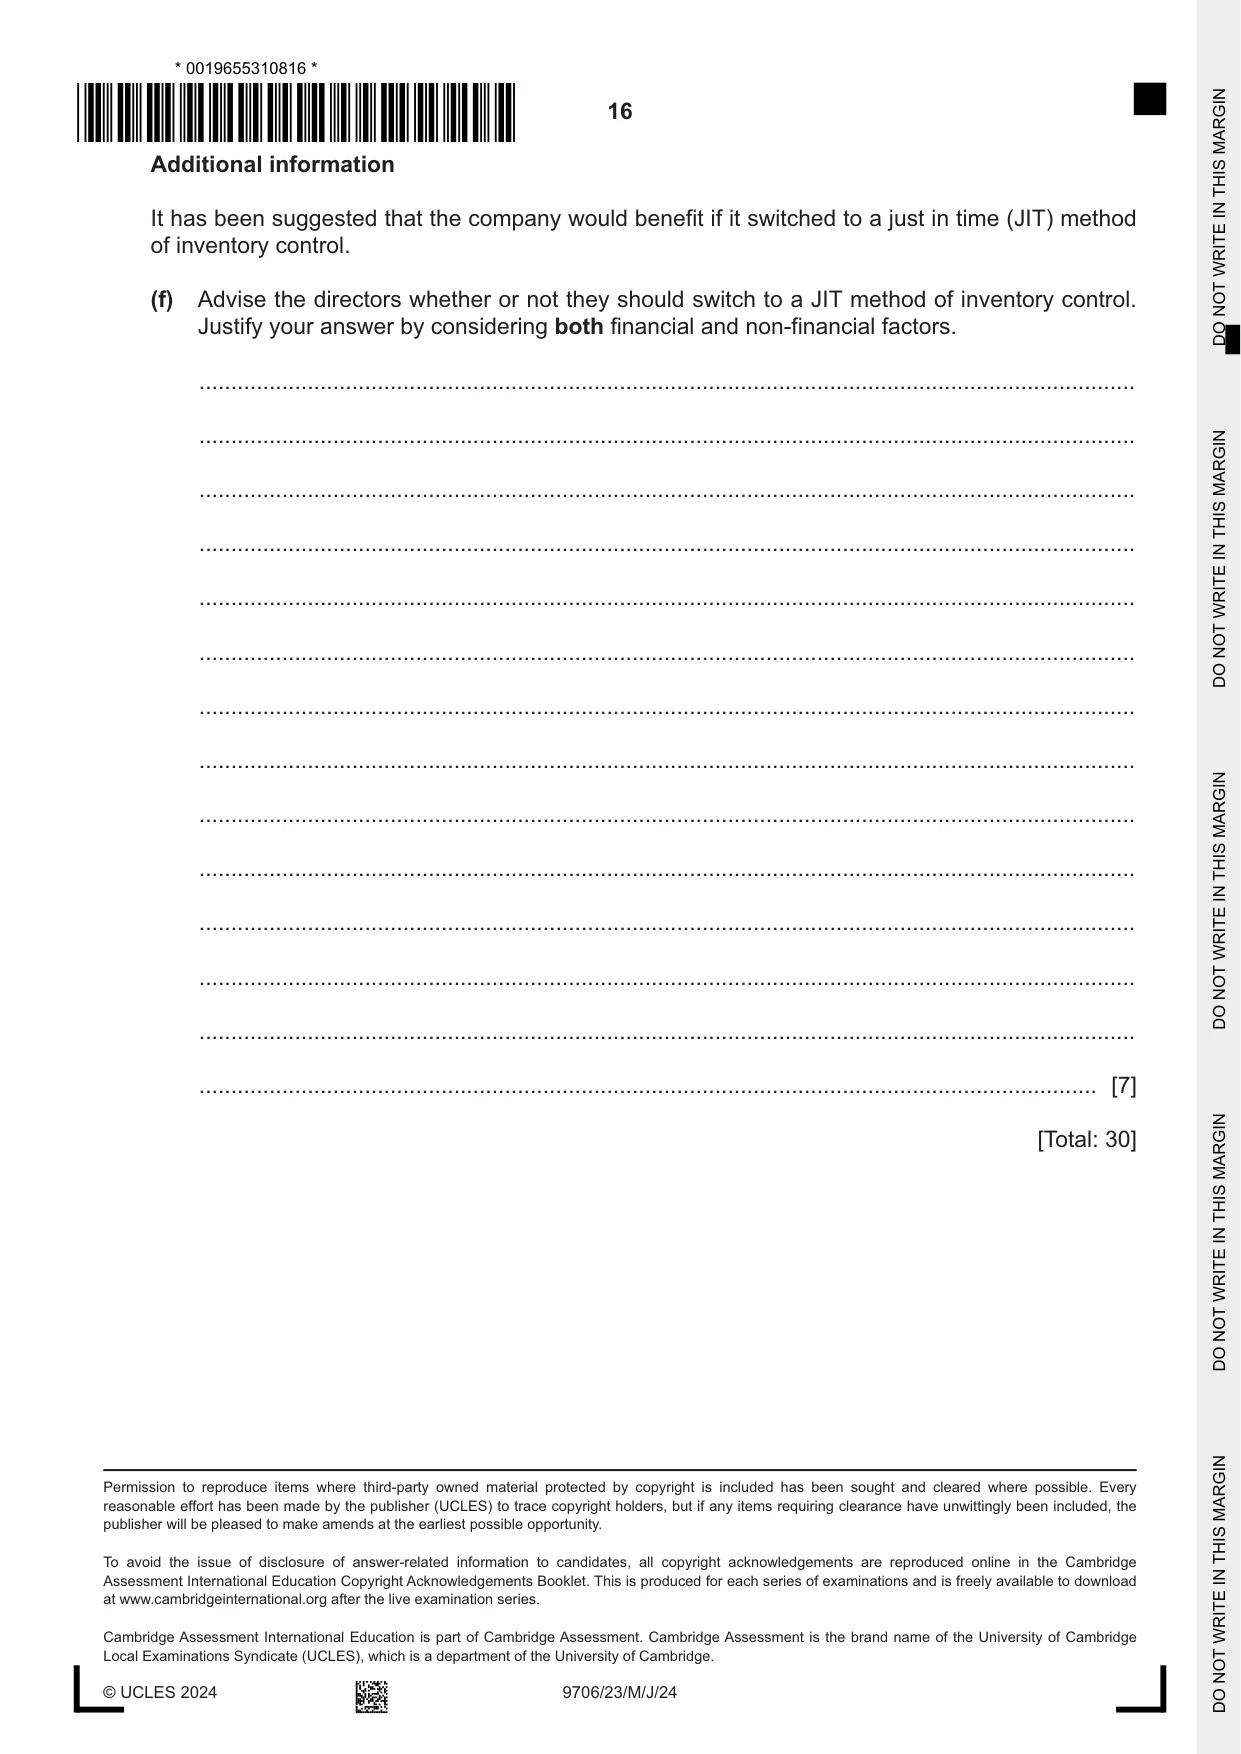
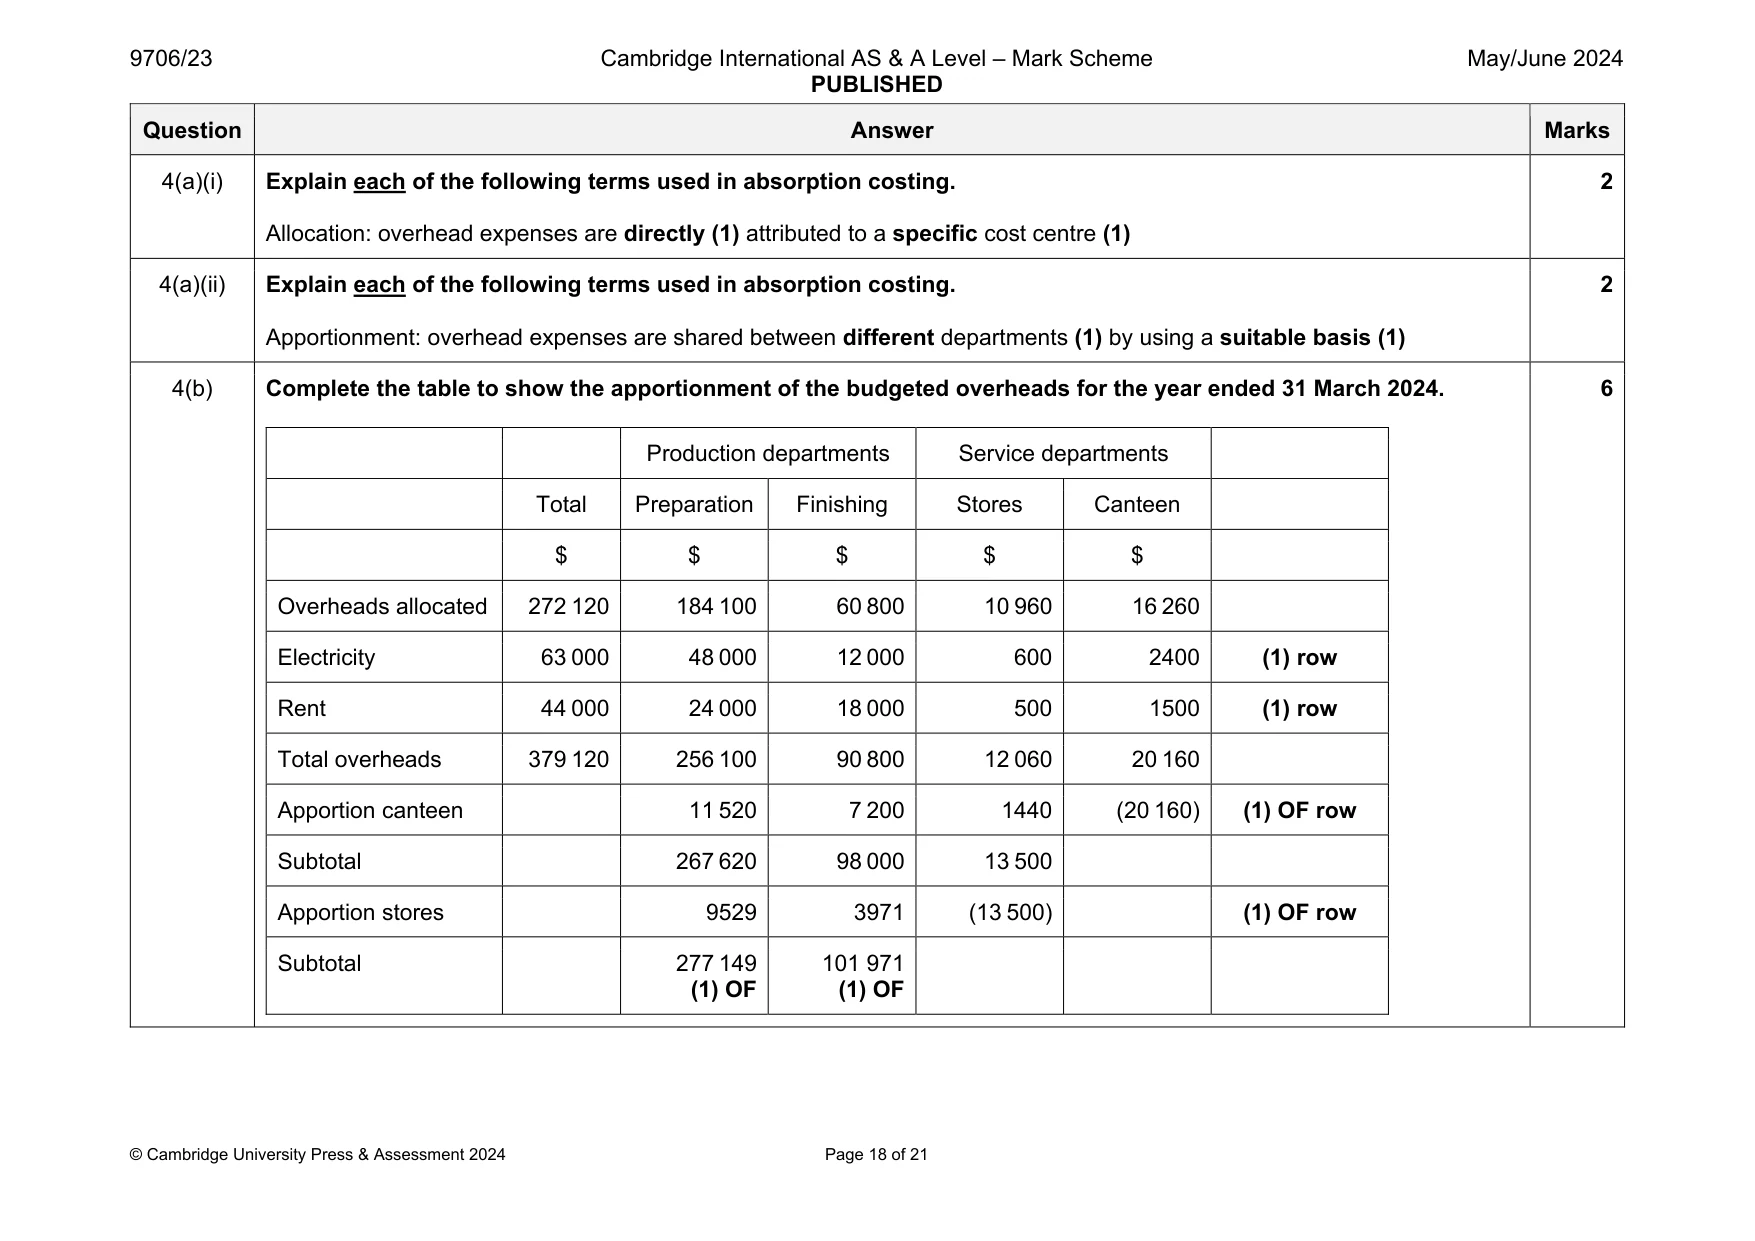
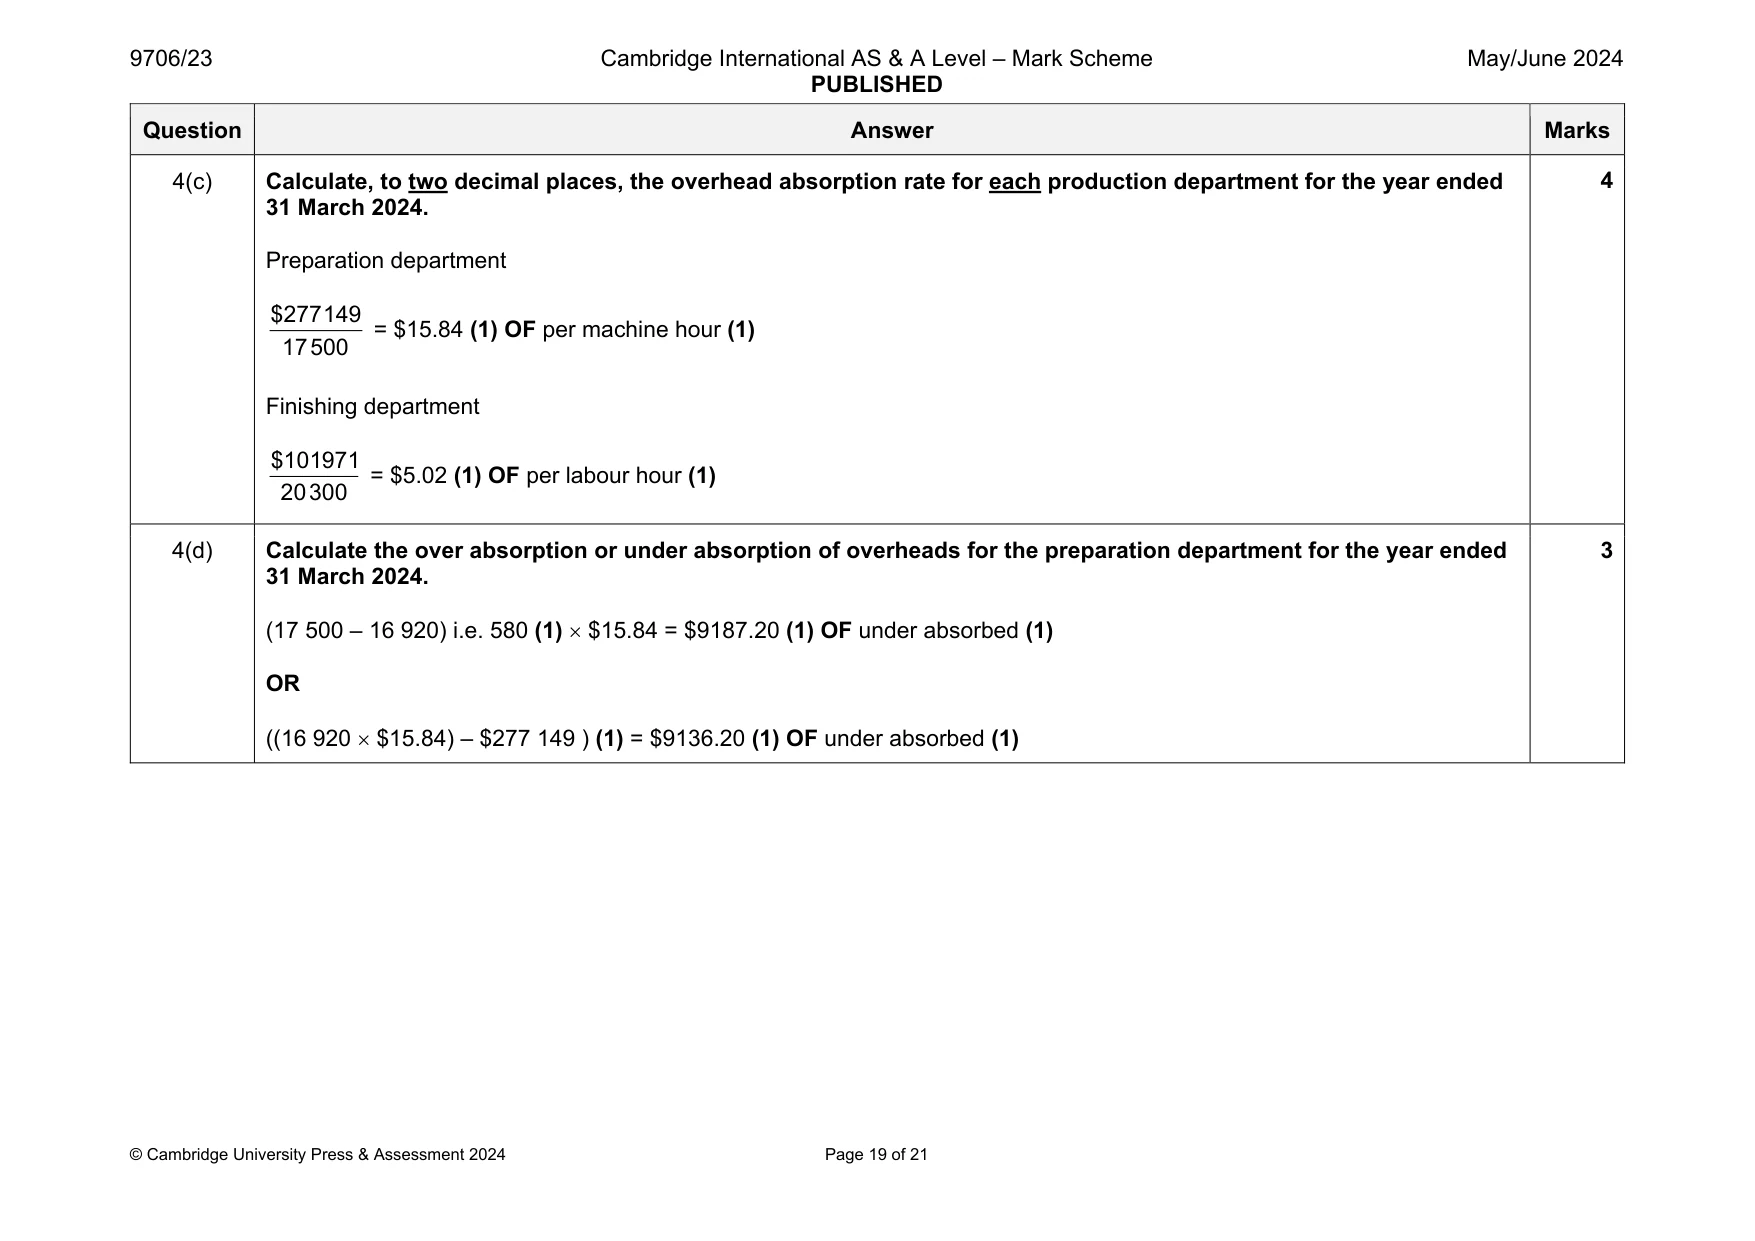
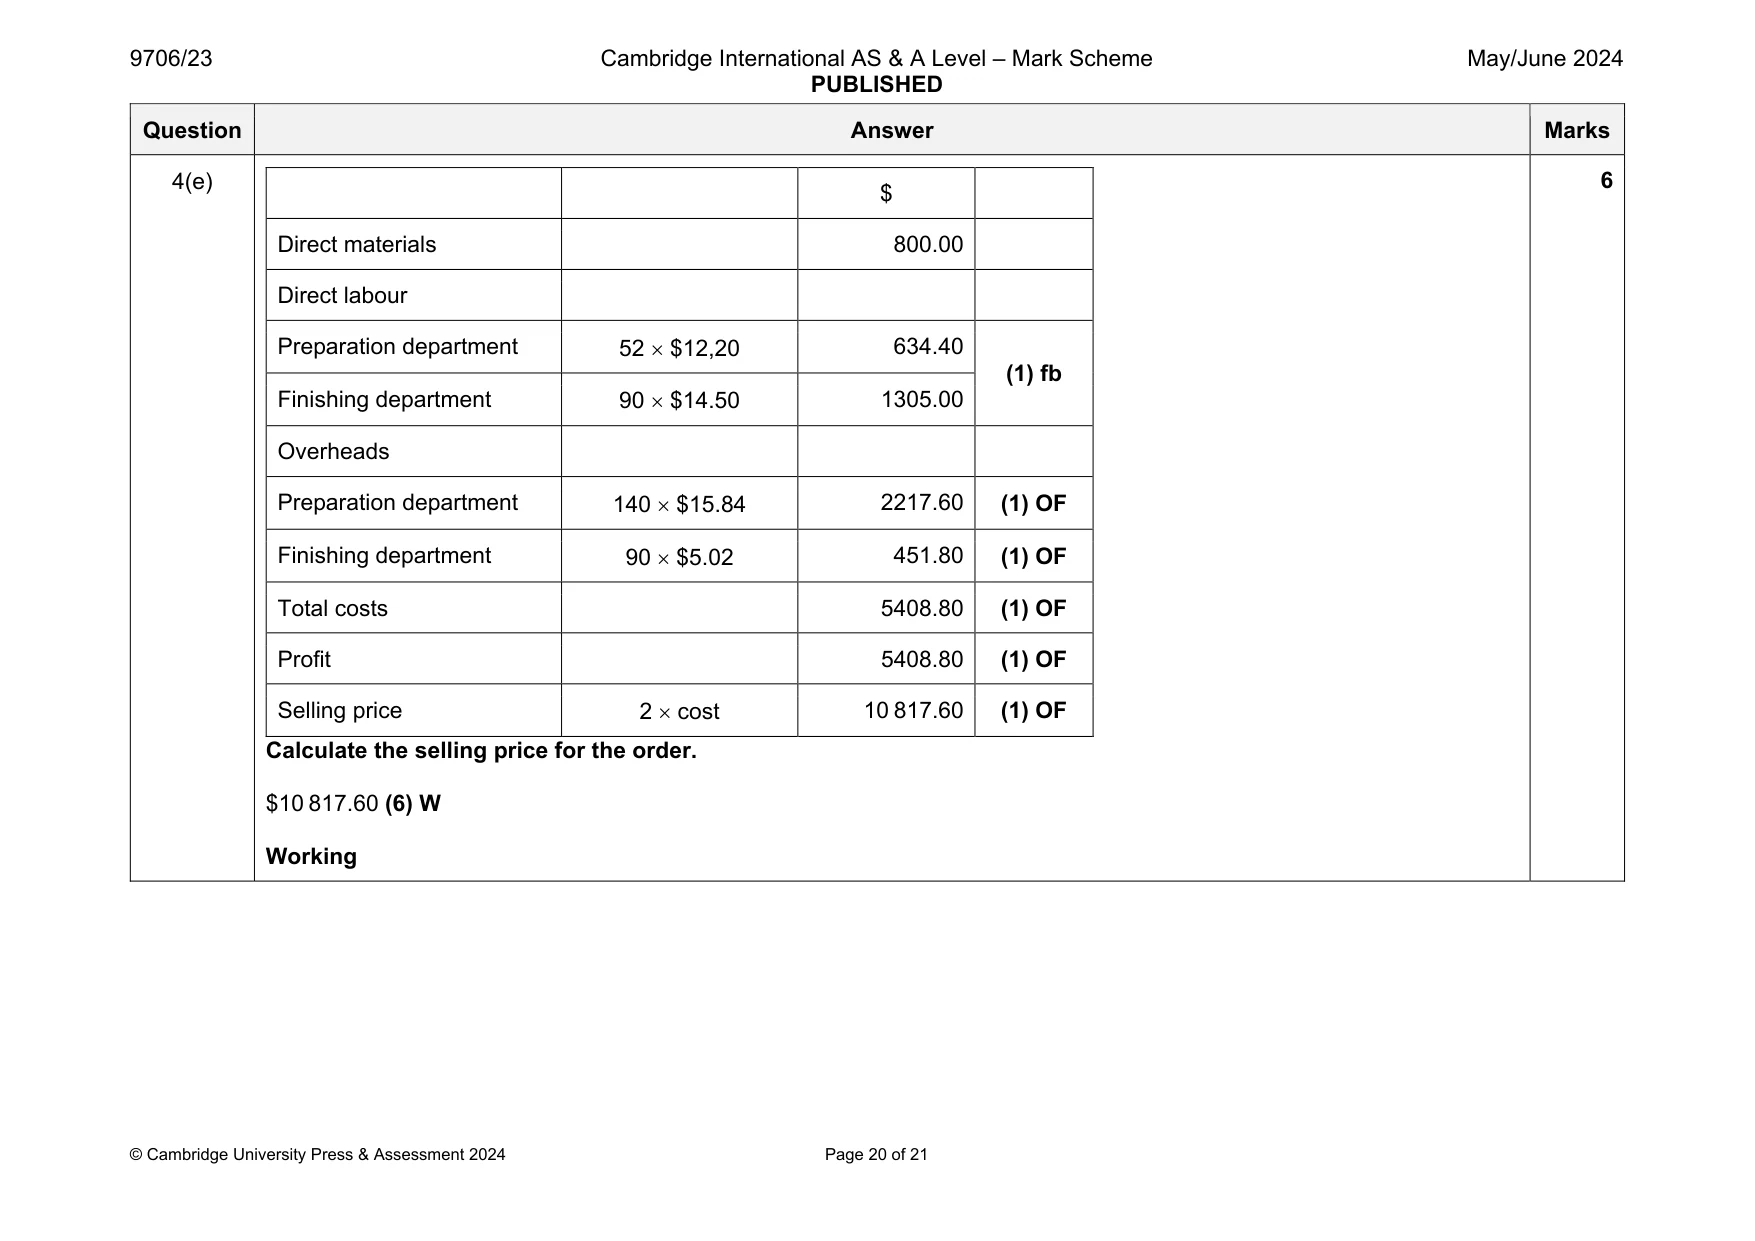
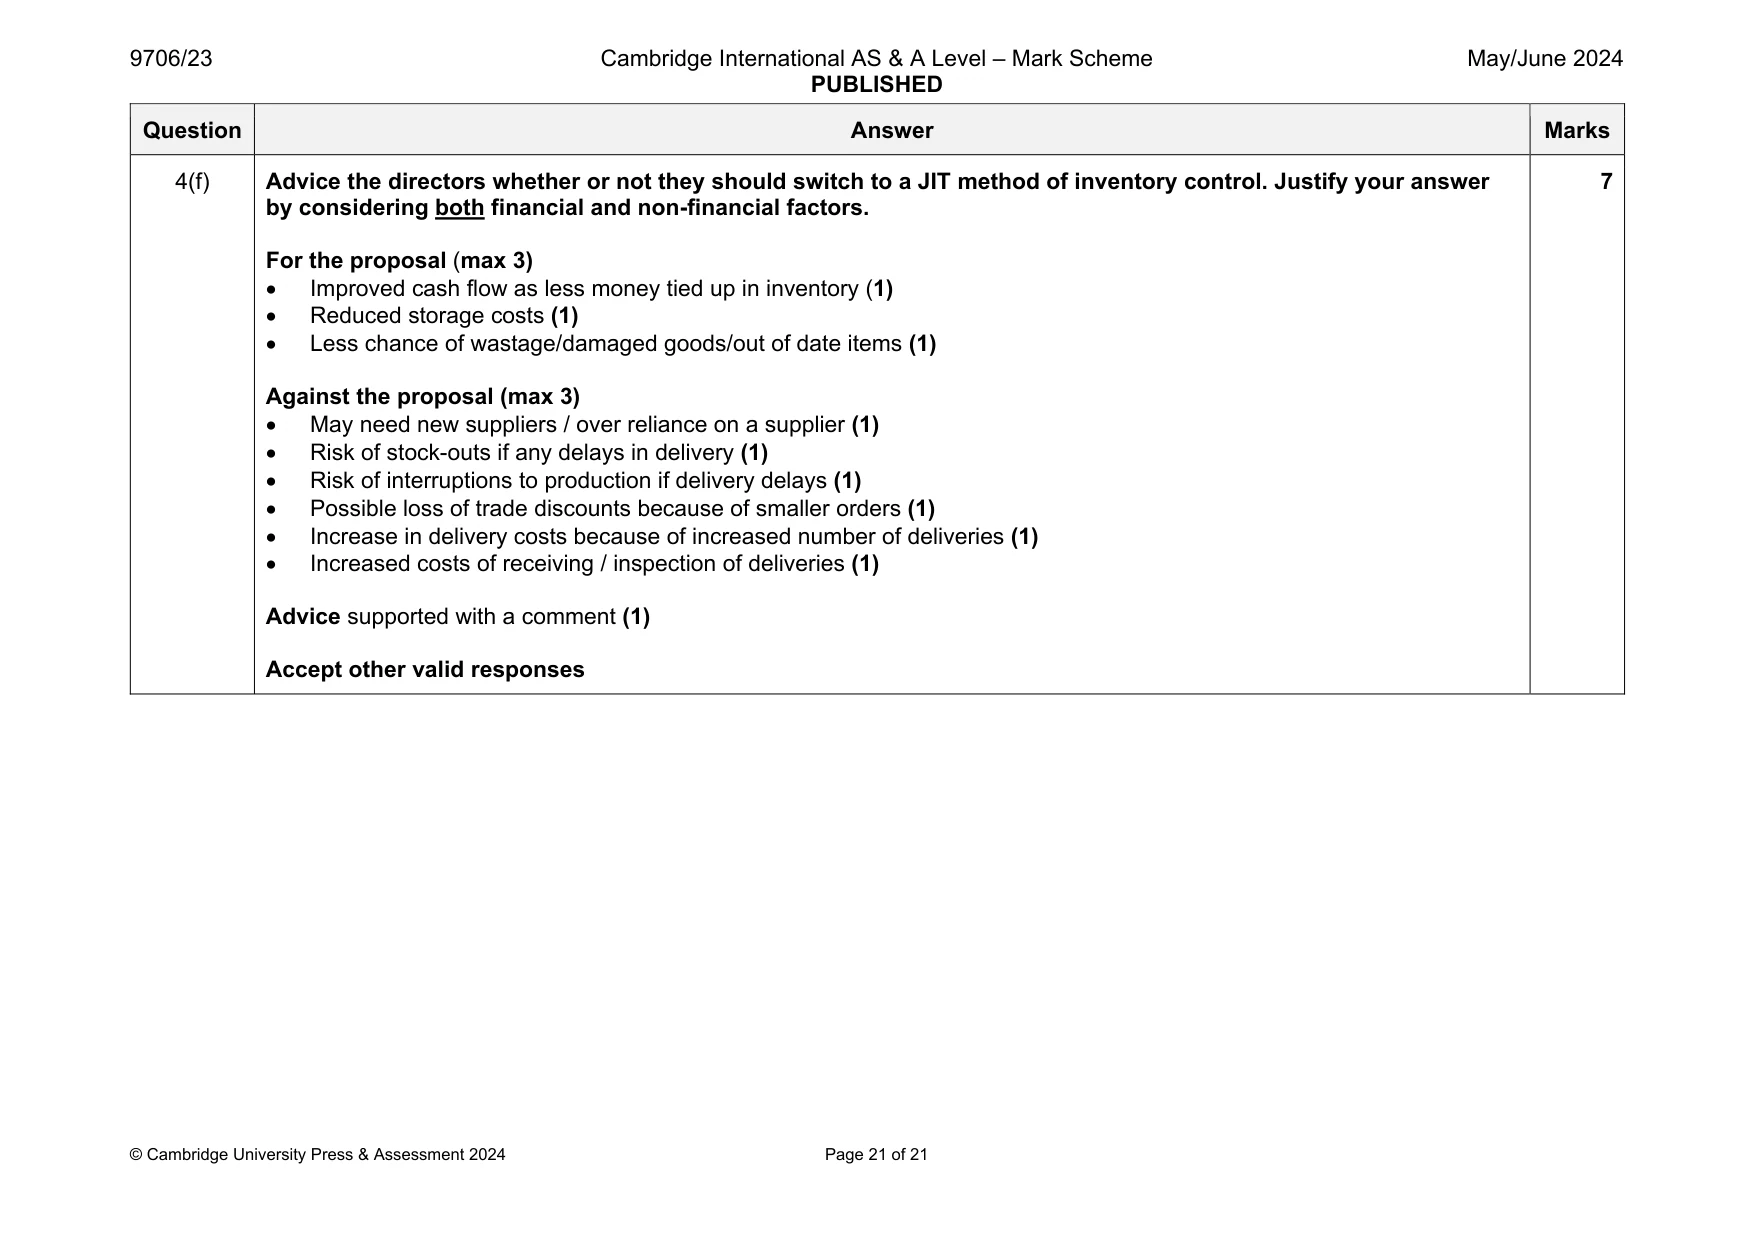
Mark scheme: 4(a)(i) Explain each of the following terms used in absorption costing. Allocation: overhead expenses are directly (1) attributed to a specific cost centre (1) 2 4(a)(ii) Explain each of the following terms used in absorption costing. Apportionment: overhead expenses are shared between different departments (1) by using a suitable basis (1) 2 4(b) Complete the table to show the apportionment of the budgeted overheads for the year ended 31 March 2024. Production departments Service departments Total Preparation Finishing Stores Canteen $ $ $ $ $ Overheads allocated 272 120 184 100 60 800 10 960 16 260 Electricity 63 000 48 000 12 000 600 2400 (1) row Rent 44 000 24 000 18 000 500 1500 (1) row Total overheads 379 120 256 100 90 800 12 060 20 160 Apportion canteen 11 520 7 200 1440 (20 160) (1) OF row Subtotal 267 620 98 000 13 500 Apportion stores 9529 3971 (13 500) (1) OF row Subtotal 277 149 (1) OF 101 971 (1) OF 6 Question Answer Marks 4(c) Calculate, to two decimal places, the overhead absorption rate for each production department for the year ended 31 March 2024. Preparation department $277149 17500 = $15.84 (1) OF per machine hour (1) Finishing department $101971 20300 = $5.02 (1) OF per labour hour (1) 4 4(d) Calculate the over absorption or under absorption of overheads for the preparation department for the year ended 31 March 2024. (17 500 – 16 920) i.e. 580 (1) $15.84 = $9187.20 (1) OF under absorbed (1) OR ((16 920 $15.84) – $277 149 ) (1) = $9136.20 (1) OF under absorbed (1) 3 Question Answer Marks 4(e) $ Direct materials 800.00 Direct labour Preparation department 52 $12,20 634.40 (1) fb Finishing department 90 $14.50 1305.00 Overheads Preparation department 140 $15.84 2217.60 (1) OF Finishing department 90 $5.02 451.80 (1) OF Total costs 5408.80 (1) OF Profit 5408.80 (1) OF Selling price 2 cost 10 817.60 (1) OF Calculate the selling price for the order. $10 817.60 (6) W Working 6 Question Answer Marks 4(f) Advice the directors whether or not they should switch to a JIT method of inventory control. Justify your answer by considering both financial and non-financial factors. For the proposal (max 3) Improved cash flow as less money tied up in inventory (1) Reduced storage costs (1) Less chance of wastage/damaged goods/out of date items (1) Against the proposal (max 3) May need new suppliers / over reliance on a supplier (1) Risk of stock-outs if any delays in delivery (1) Risk of interruptions to production if delivery delays (1) Possible loss of trade discounts because of smaller orders (1) Increase in delivery costs because of increased number of deliveries (1) Increased costs of receiving / inspection of deliveries (1) Advice supported with a comment (1) Accept other valid responses 7
Q5 · Debenture interest is outstanding at 31 December 2023
5 Debenture interest is outstanding at 31 December 2023. The debentures had been issued in 2021.
Q8 · On 1 May 2023 a rights issue of shares was made
8 On 1 May 2023 a rights issue of shares was made. Shareholders were offered three ordinary shares for every five ordinary shares held at 1 January 2023. The shares were issued at a premium of $0.20 per share. The rights issue was fully subscribed.
Q9 · Prepare the statement of profit or loss for the year ended 31 December 2023
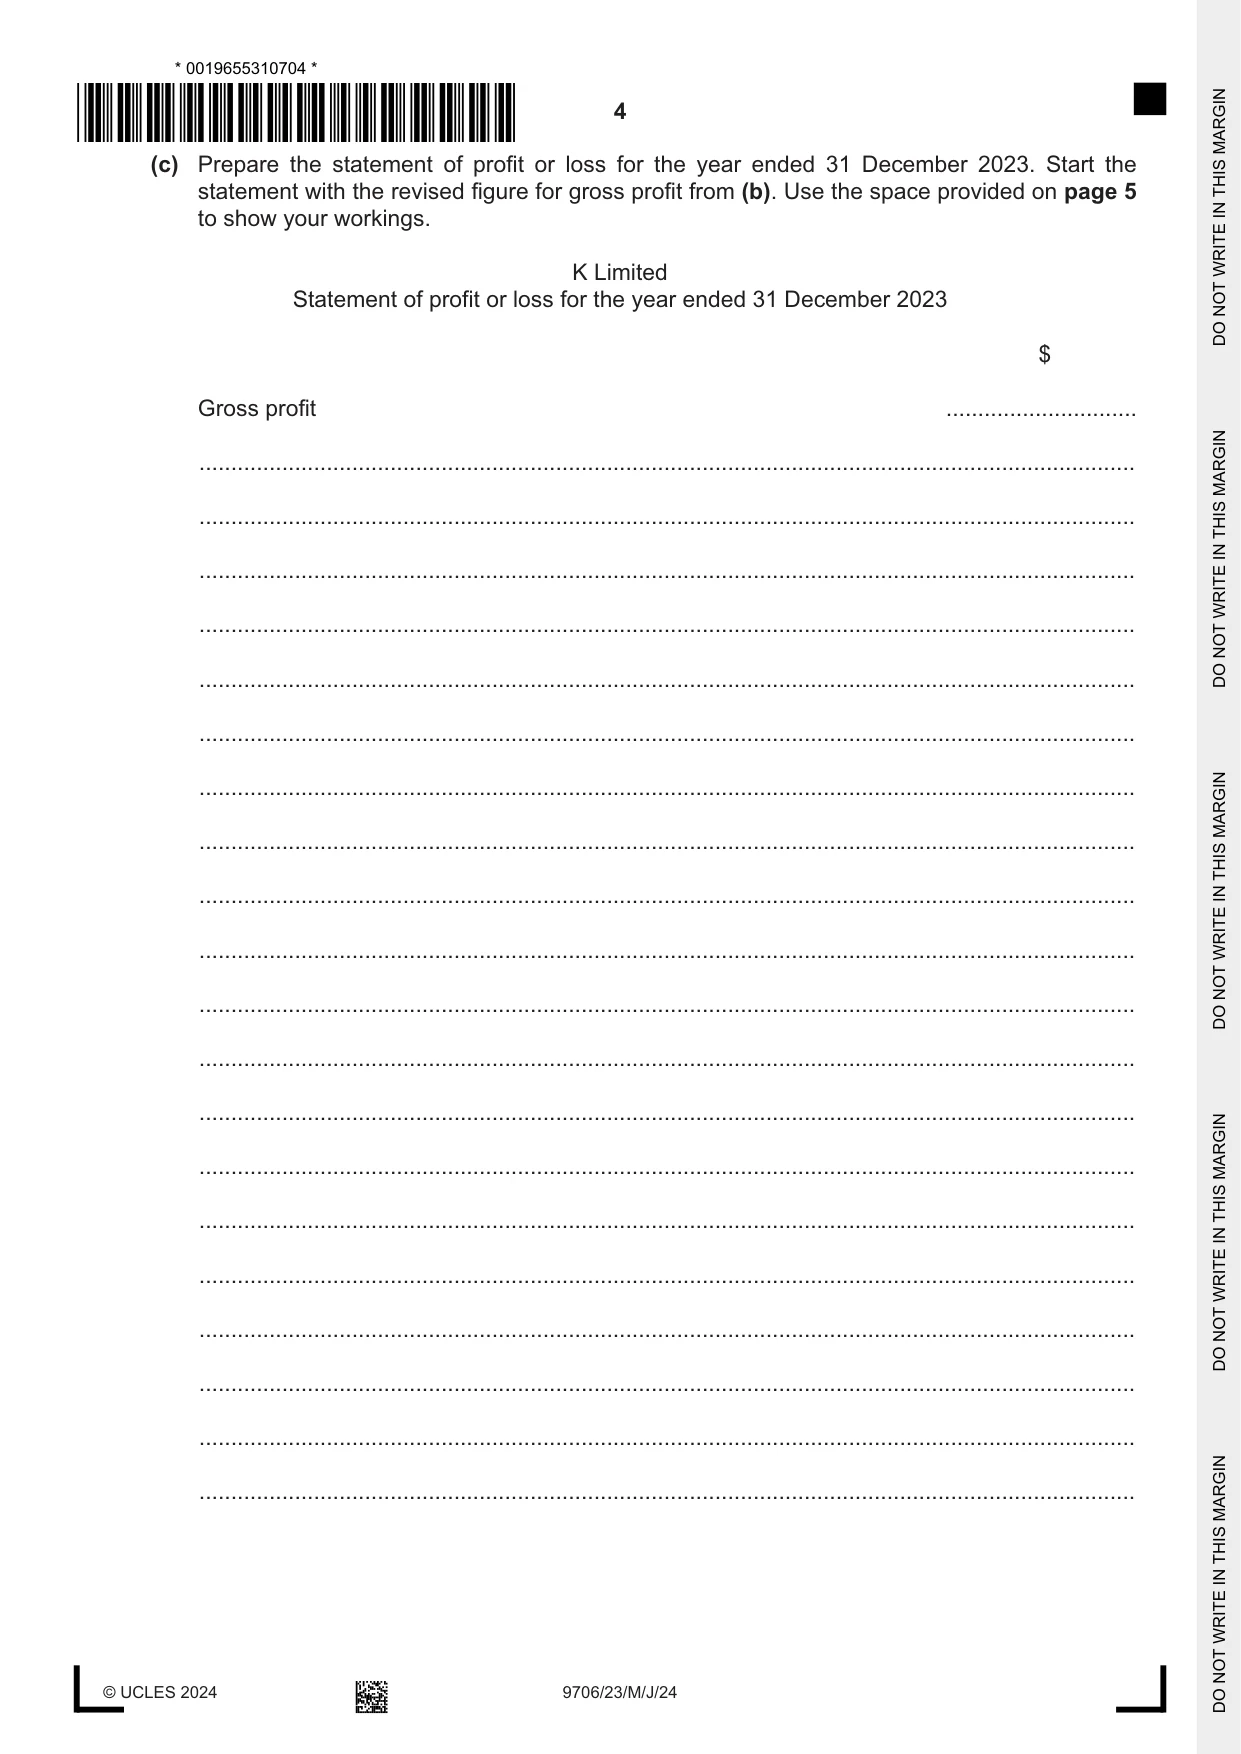
(c) Prepare the statement of profit or loss for the year ended 31 December 2023. Start the statement with the revised figure for gross profit from (b). Use the space provided on page 5 to show your workings. K Limited Statement of profit or loss for the year ended 31 December 2023 $ Gross profit .............................. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: Depreciation of plant and equipment Distribution costs Administrative expenses Finance charges [8]
What was in this paper
The subtopics covered by these 7 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2024 May/June, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.