Cambridge A Level Accounting 9706 — 2025 Oct/Nov Paper 2 · Variant 1
9706/21/O/N/25 · 4 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · The following balances were extracted from the books of T plc after the preparation of…
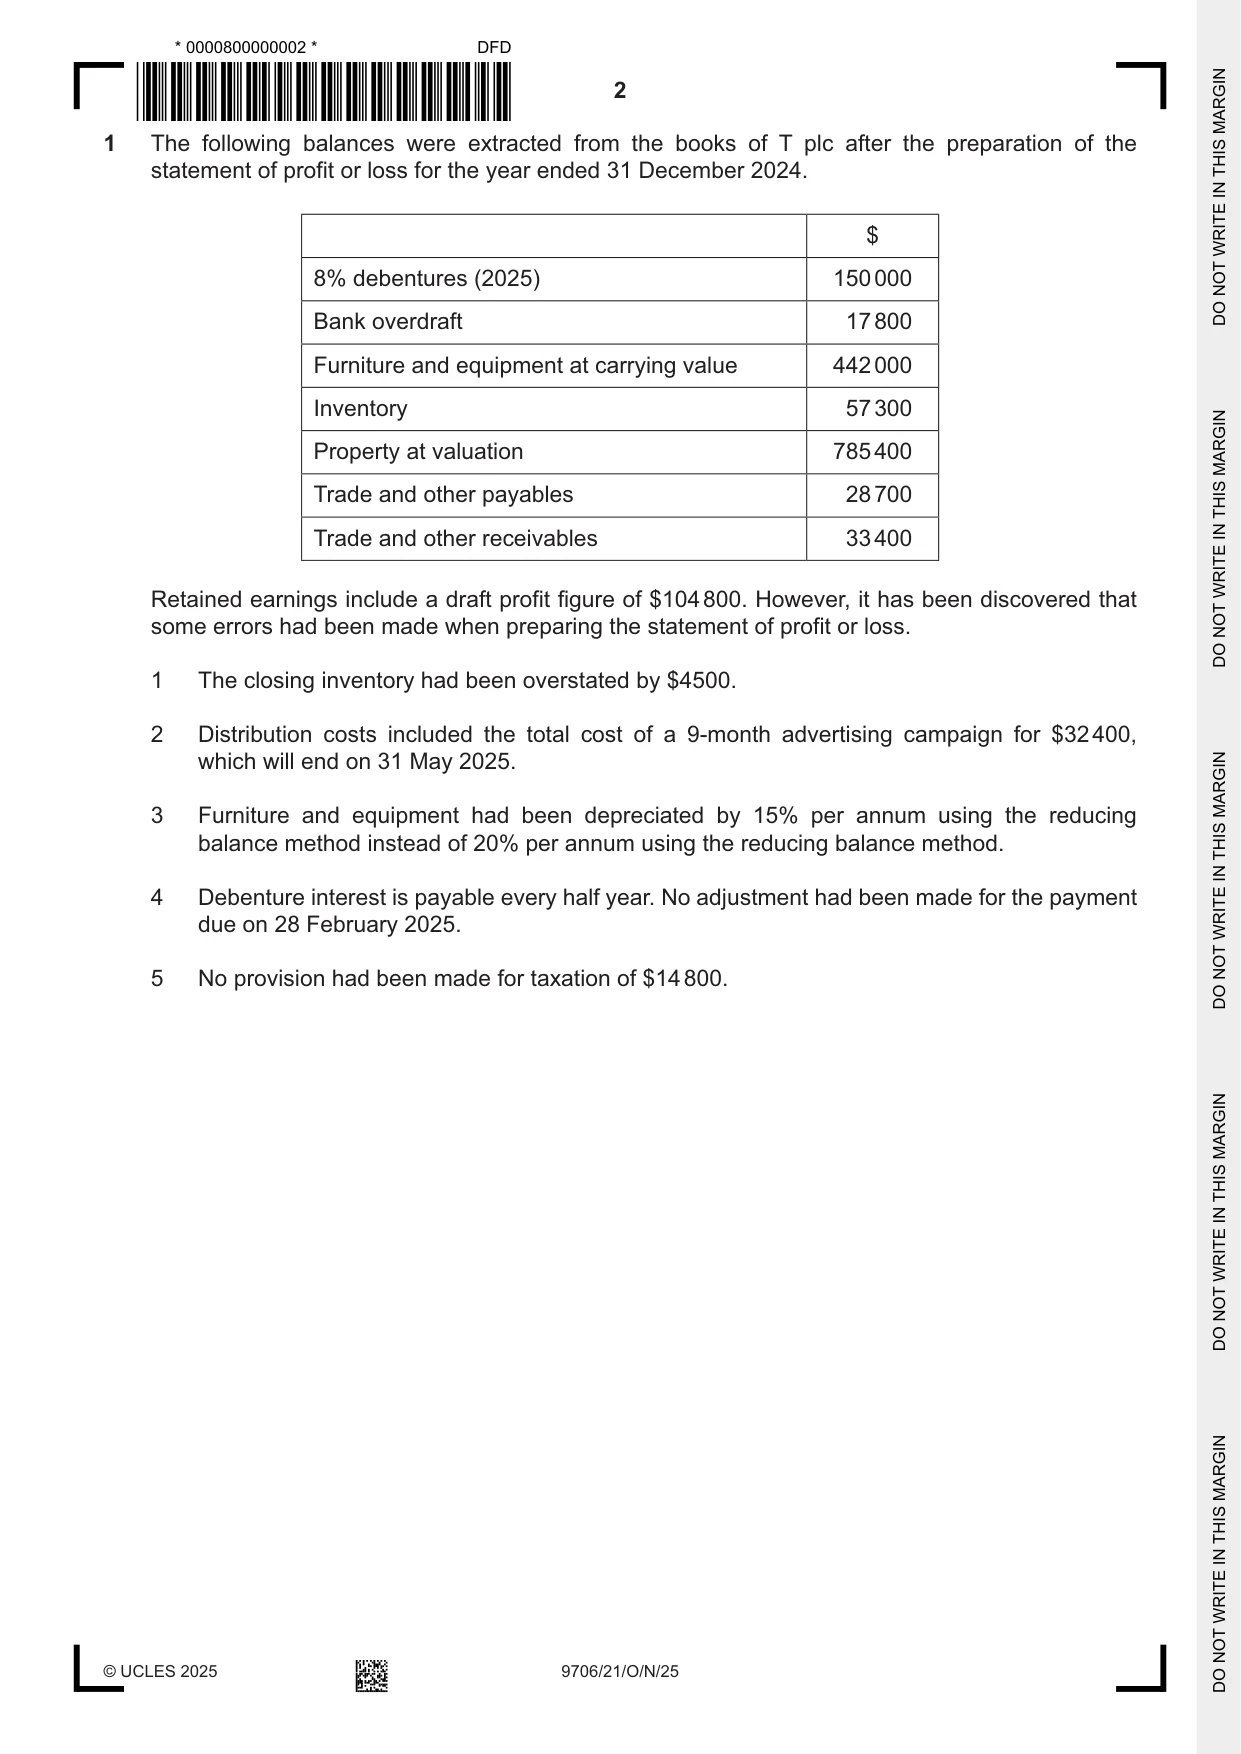
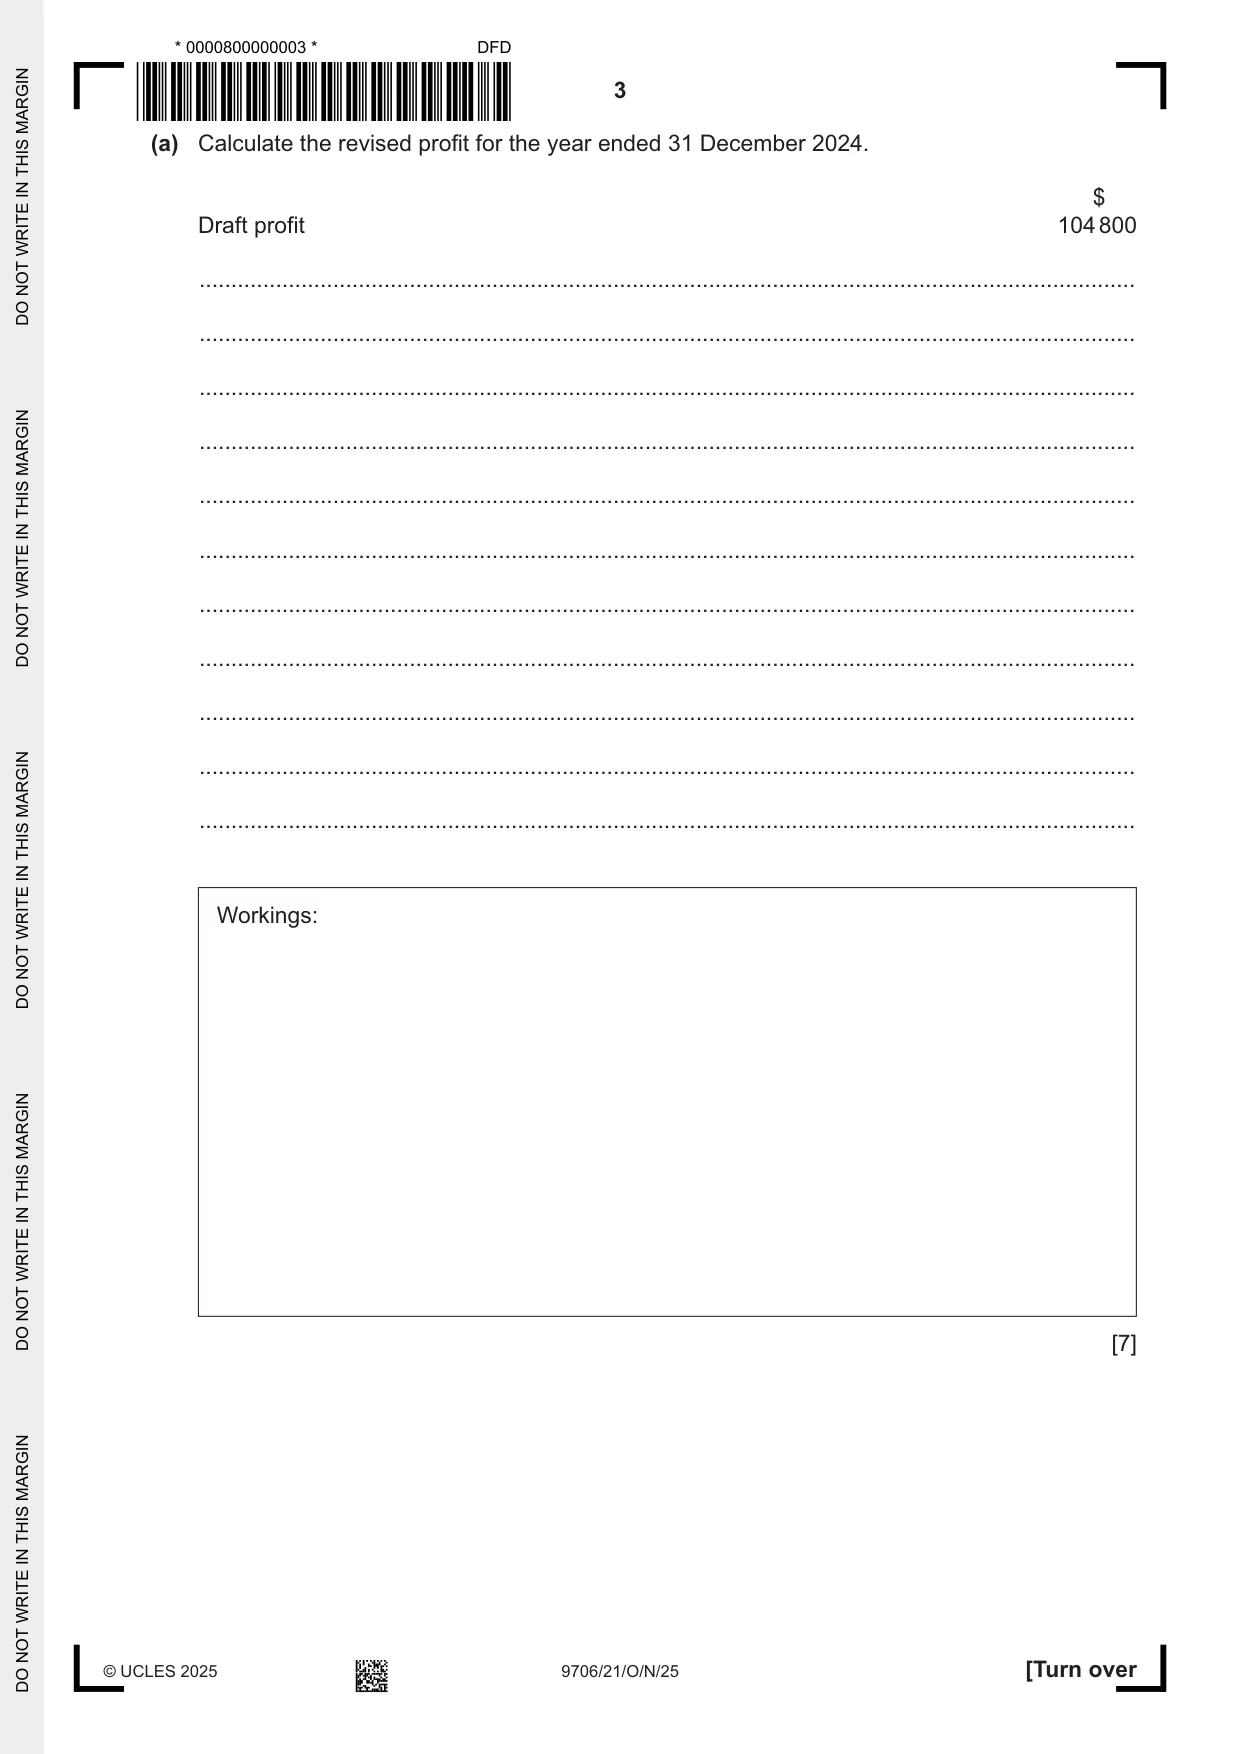
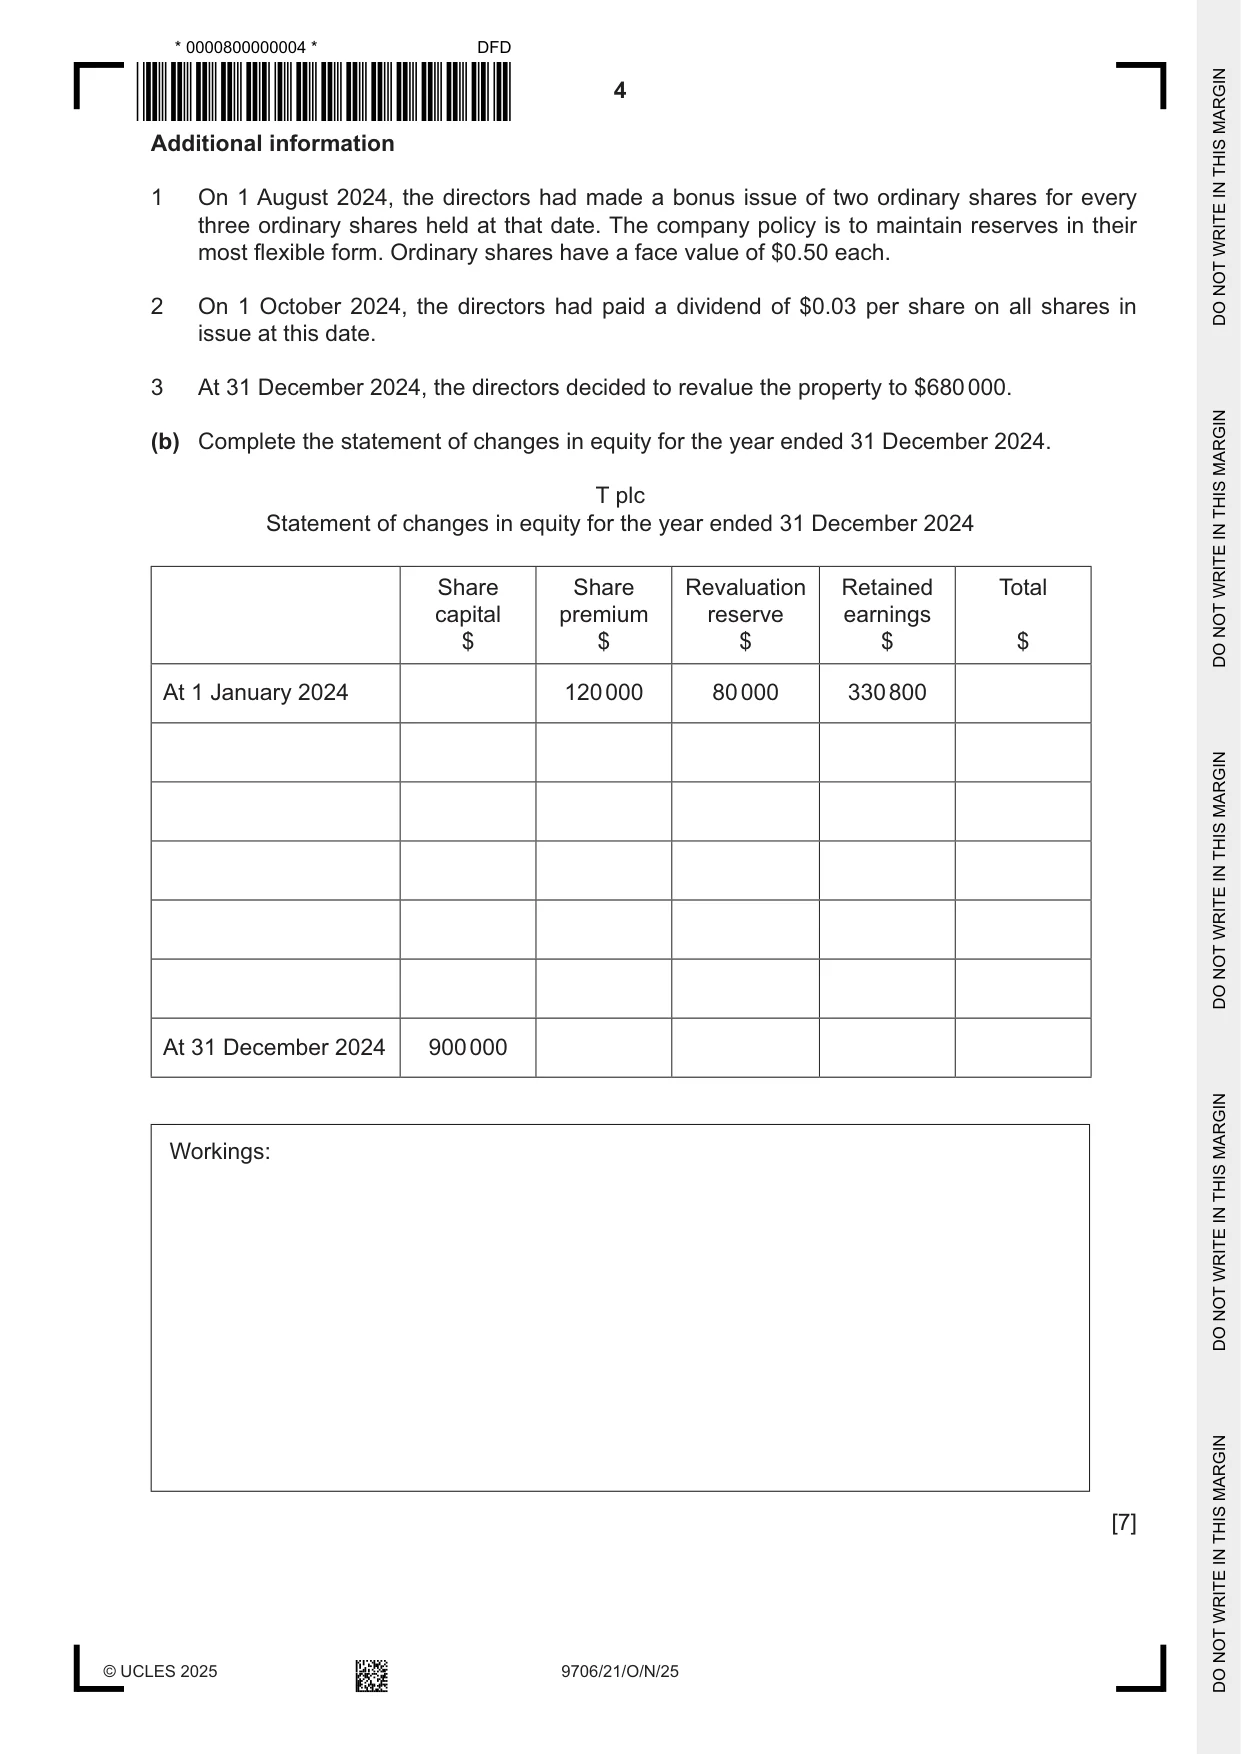
1 The following balances were extracted from the books of T plc after the preparation of the statement of profit or loss for the year ended 31 December 2024. $ 8% debentures (2025) 150 000 Bank overdraft 17 800 Furniture and equipment at carrying value 442 000 Inventory 57 300 Property at valuation 785 400 Trade and other payables 28 700 Trade and other receivables 33 400 Retained earnings include a draft profit figure of $104 800. However, it has been discovered that some errors had been made when preparing the statement of profit or loss. 1 The closing inventory had been overstated by $4500. 2 Distribution costs included the total cost of a 9-month advertising campaign for $32 400, which will end on 31 May 2025. 3 Furniture and equipment had been depreciated by 15% per annum using the reducing balance method instead of 20% per annum using the reducing balance method. 4 Debenture interest is payable every half year. No adjustment had been made for the payment due on 28 February 2025. 5 No provision had been made for taxation of $14 800. (a) Calculate the revised profit for the year ended 31 December 2024. $ Draft profit 104 800 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: [7] Additional information 1 On 1 August 2024, the directors had made a bonus issue of two ordinary shares for every three ordinary shares held at that date. The company policy is to maintain reserves in their most flexible form. Ordinary shares have a face value of $0.50 each.
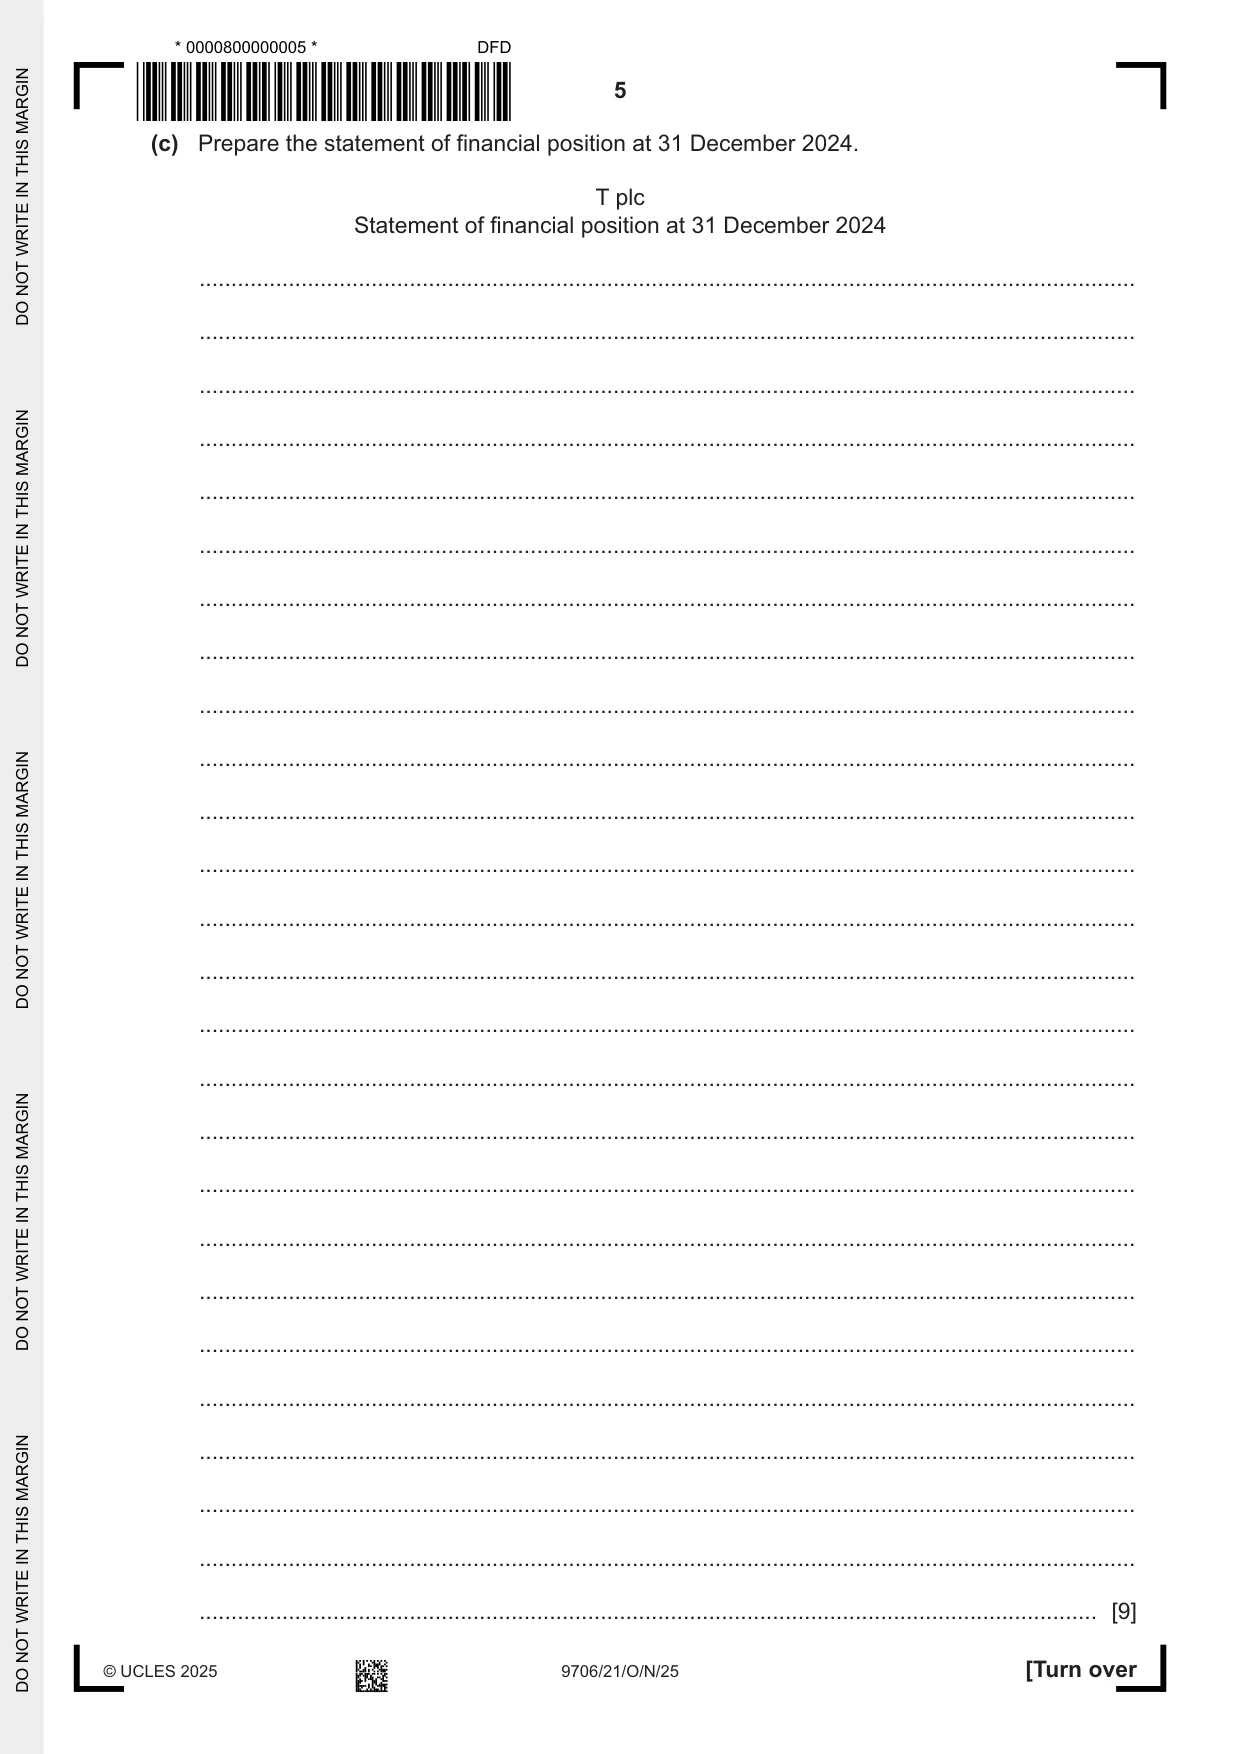
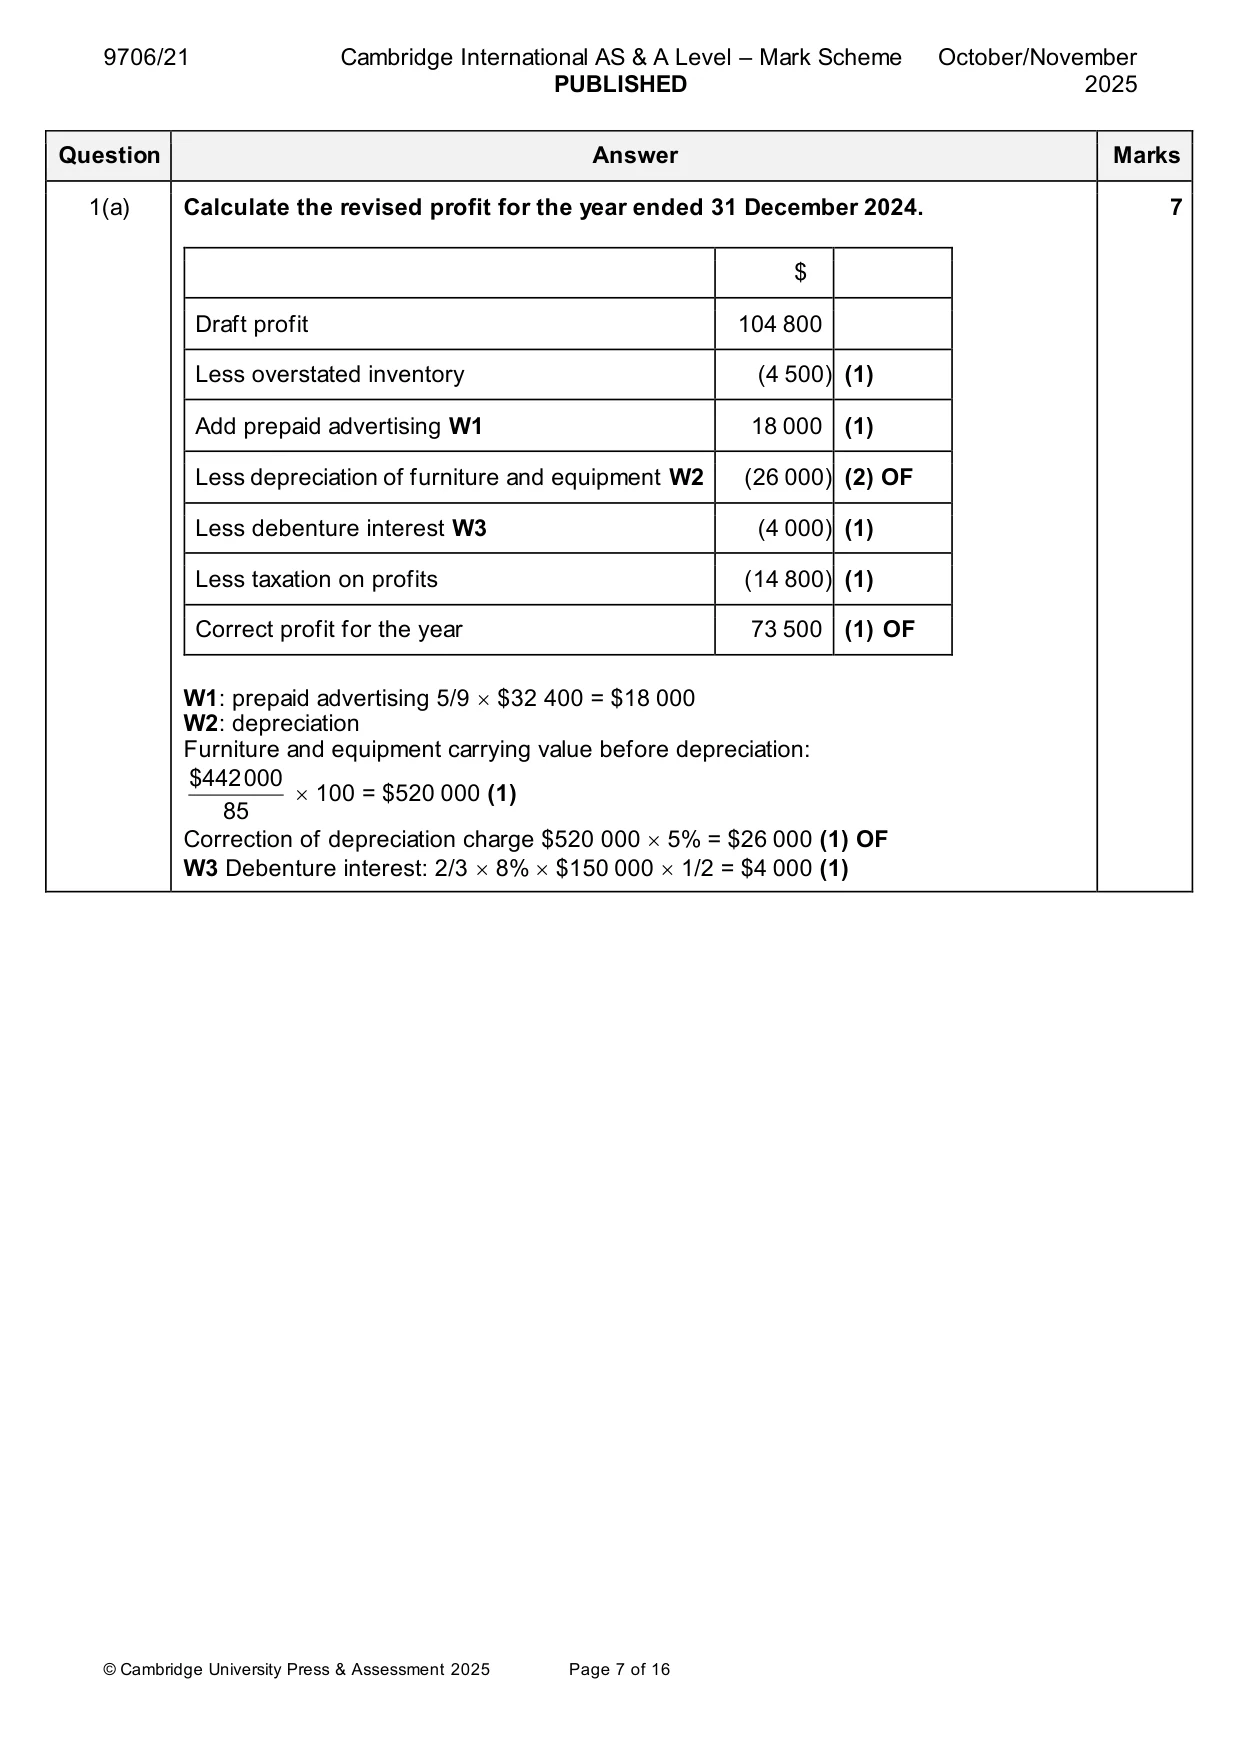
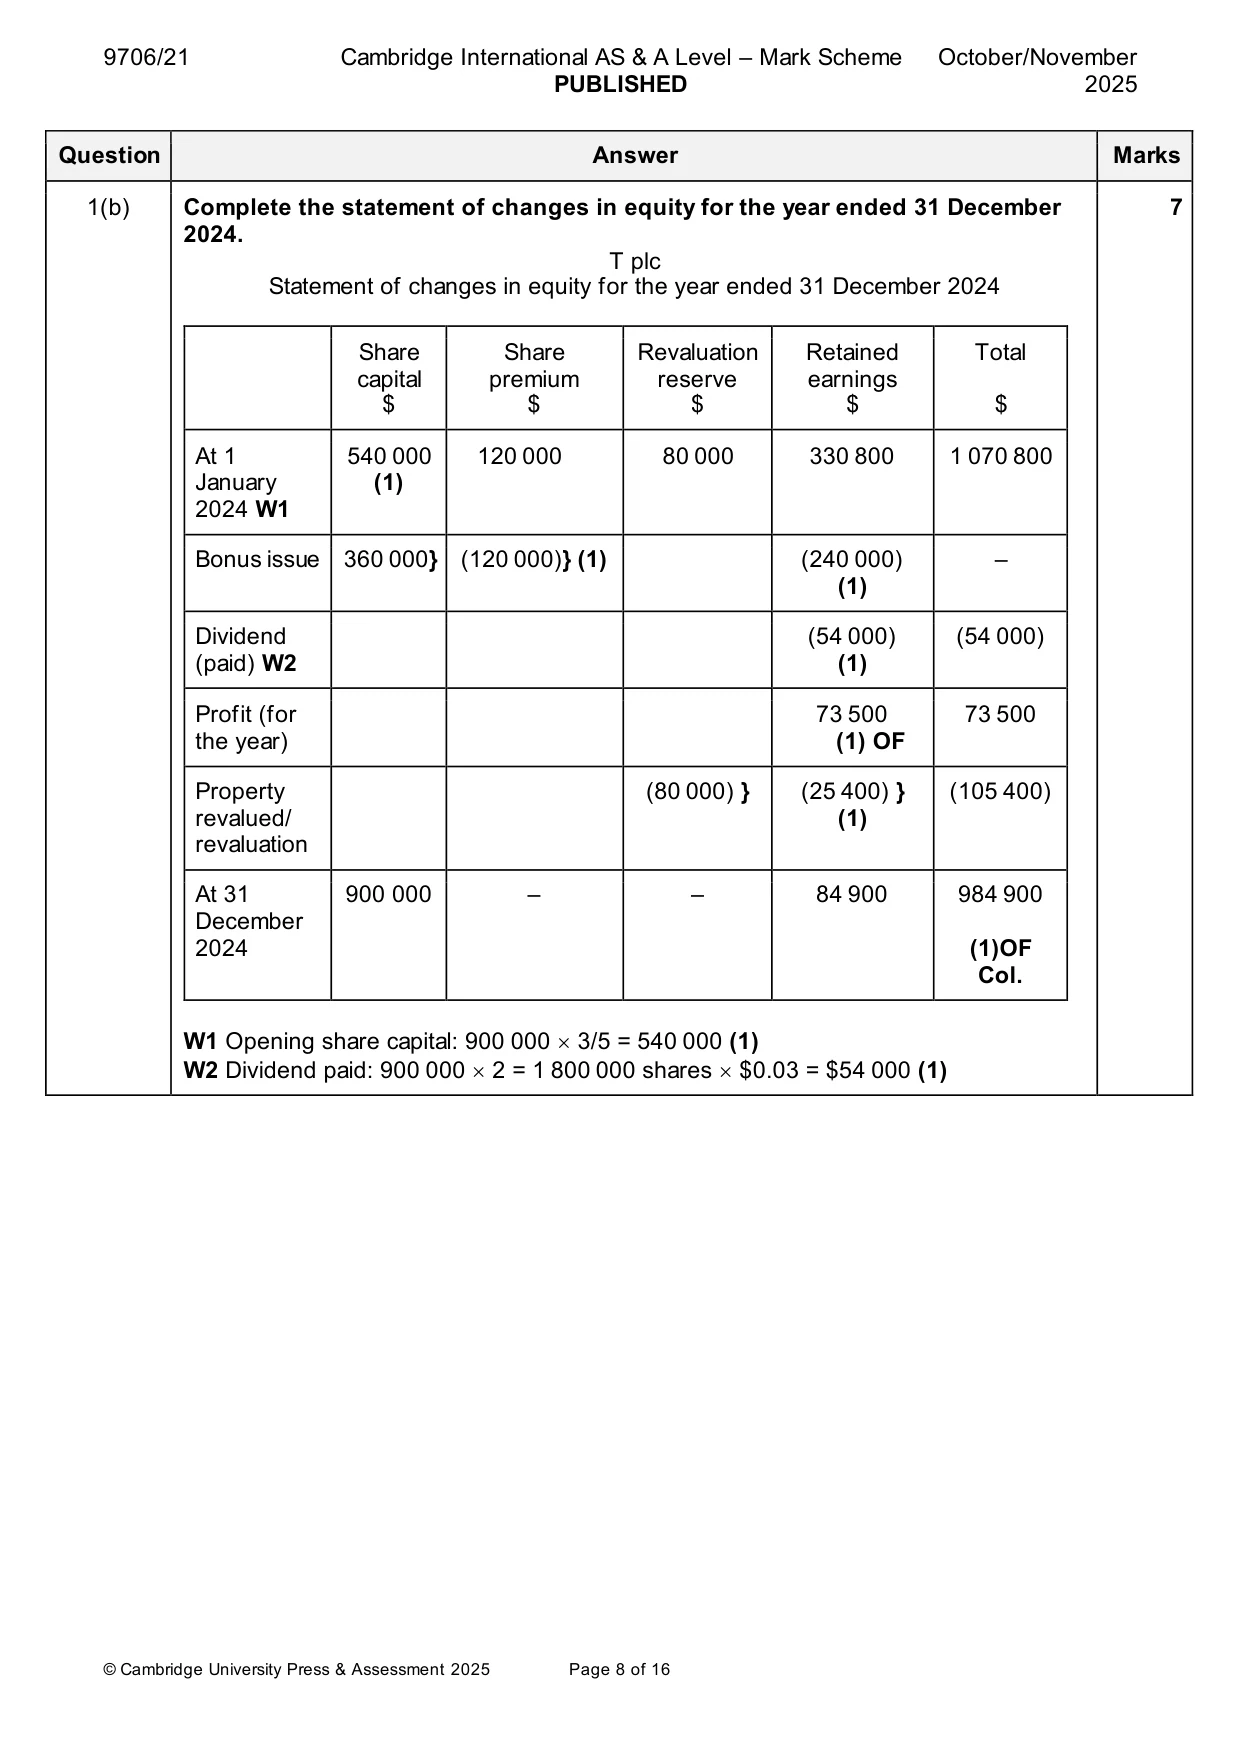
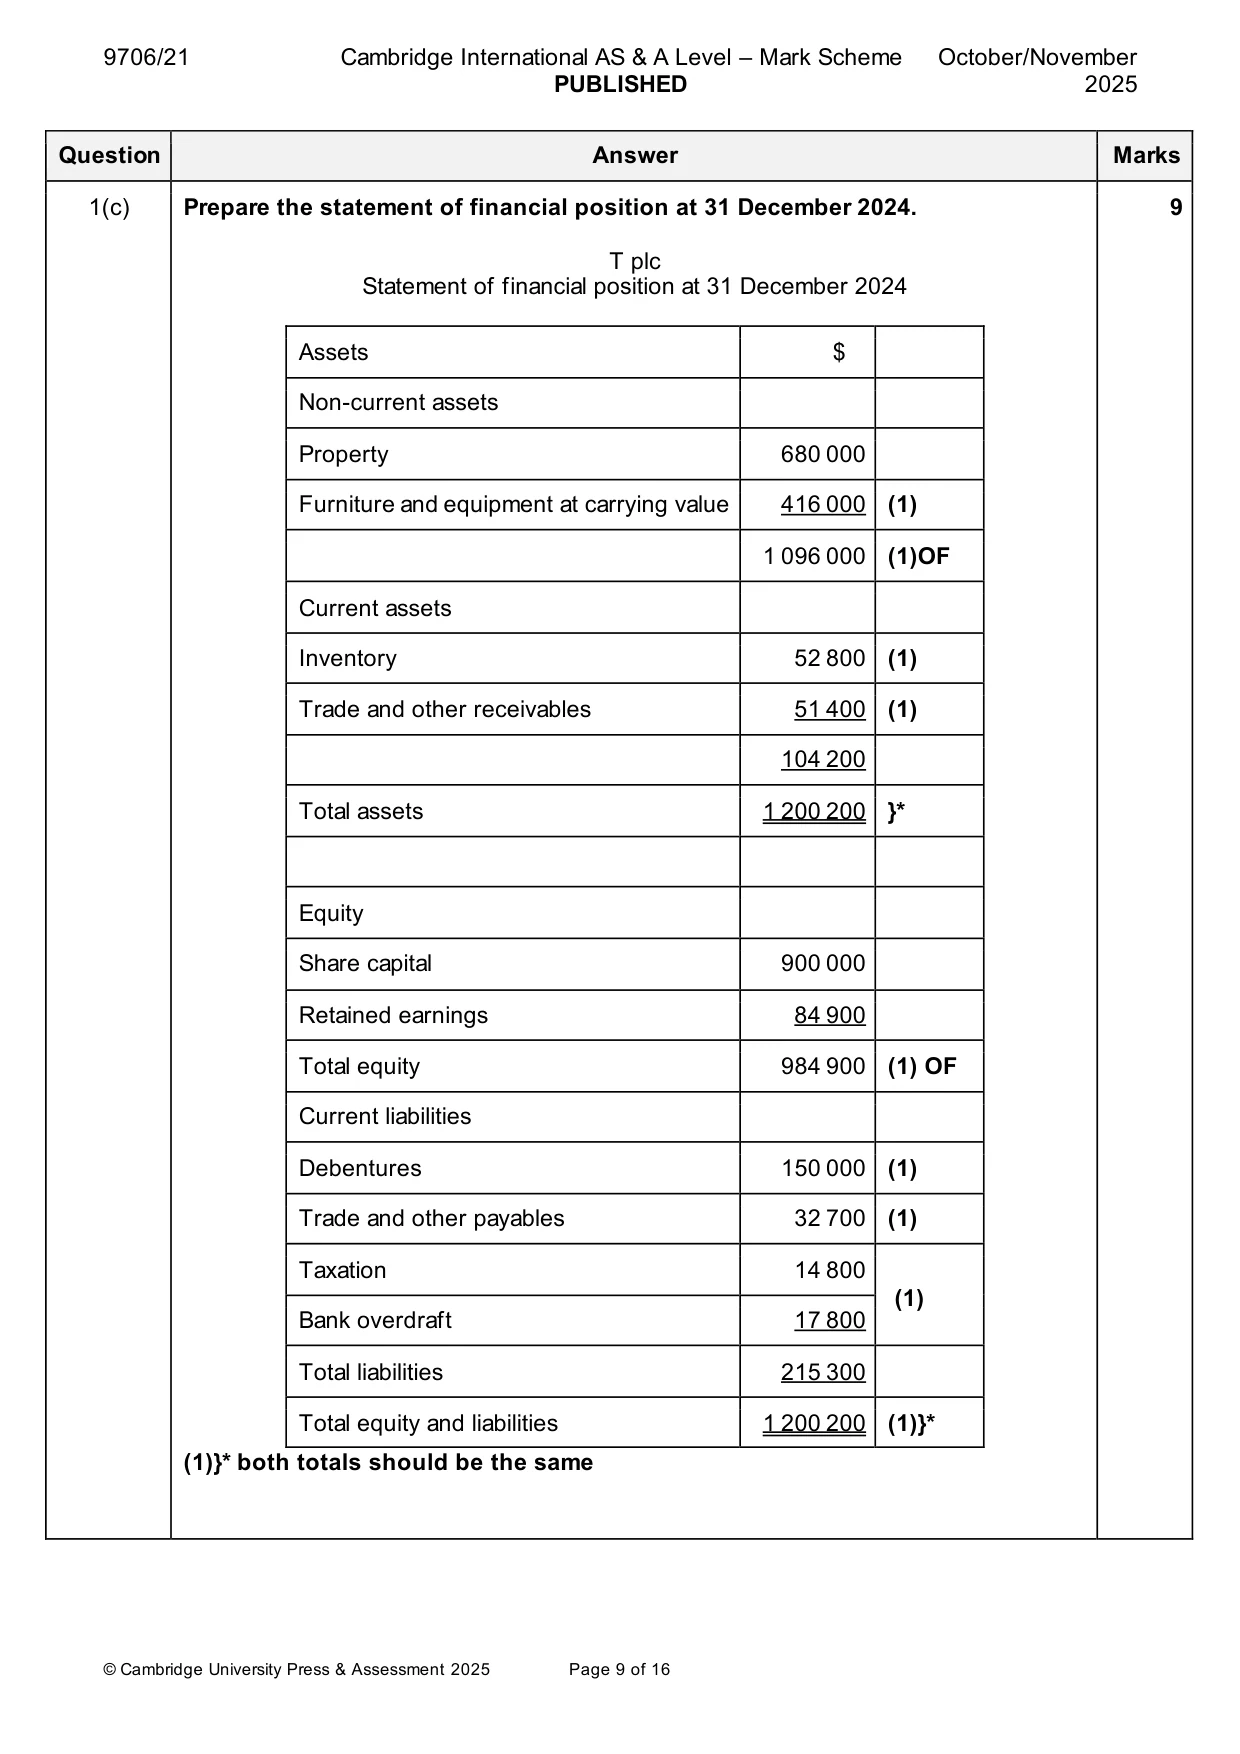
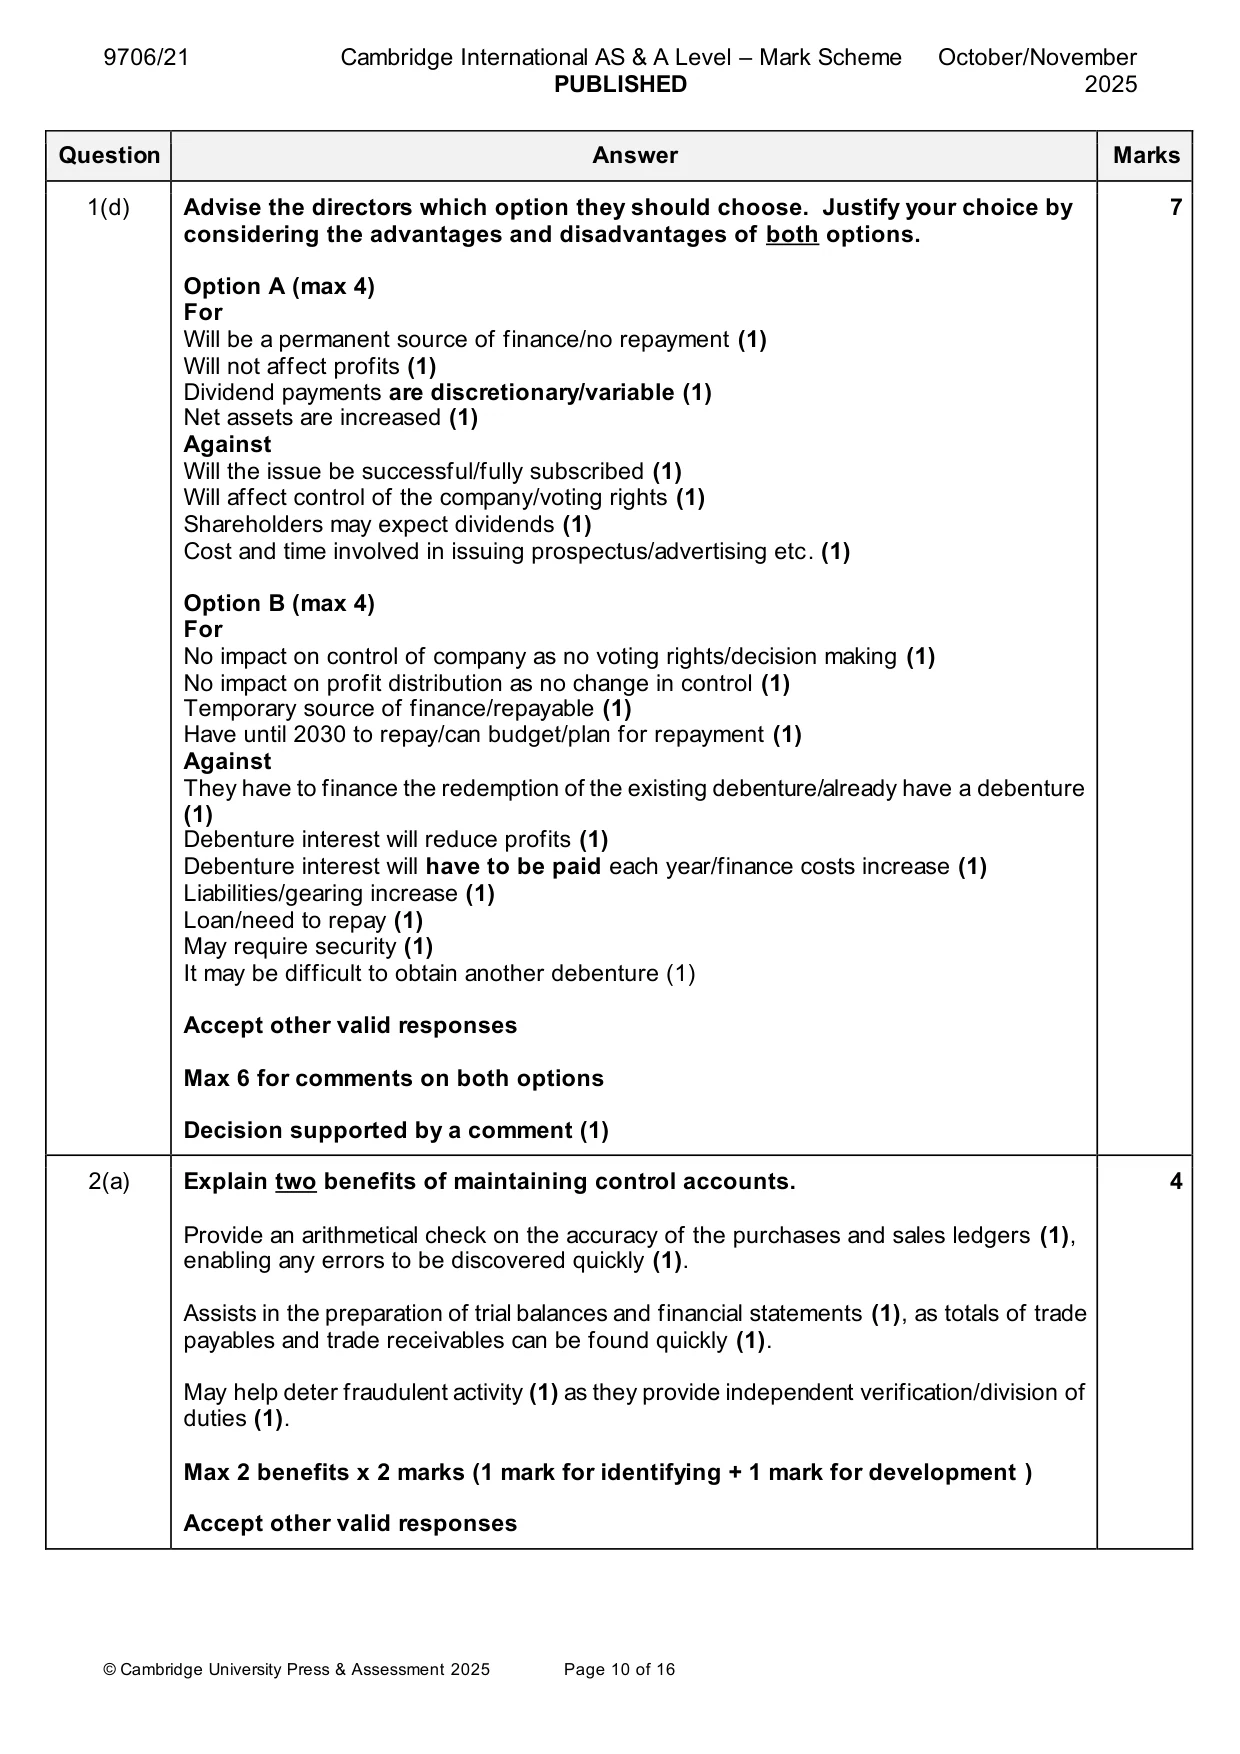
Mark scheme: Question Answer Marks 1(a) Calculate the revised profit for the year ended 31 December 2024. 7 $ Draft profit 104 800 Less overstated inventory (4 500) (1) Add prepaid advertising W1 18 000 (1) Less depreciation of furniture and equipment W2 (26 000) (2) OF Less debenture interest W3 (4 000) (1) Less taxation on profits (14 800) (1) Correct profit for the year 73 500 (1) OF W1: prepaid advertising 5/9 $32 400 = $18 000 W2: depreciation Furniture and equipment carrying value before depreciation: $442000 100 = $520 000 (1) 85 Correction of depreciation charge $520 000 5% = $26 000 (1) OF W3 Debenture interest: 2/3 8% $150 000 1/2 = $4 000 (1) 1(b) Complete the statement of changes in equity for the year ended 31 December 7 2024. T plc Statement of changes in equity for the year ended 31 December 2024 Share Share Revaluation Retained Total capital premium reserve earnings $ $ $ $ $ At 1 540 000 120 000 80 000 330 800 1 070 800 January (1) 2024 W1 Bonus issue 360 000} (120 000)} (1) (240 000) – (1) Dividend (54 000) (54 000) (paid) W2 (1) Profit (for 73 500 73 500 the year) (1) OF Property (80 000) } (25 400) } (105 400) revalued/ (1) revaluation At 31 900 000 – – 84 900 984 900 December 2024 (1)OF Col. W1 Opening share capital: 900 000 3/5 = 540 000 (1) W2 Dividend paid: 900 000 2 = 1 800 000 shares $0.03 = $54 000 (1) 1(c) Prepare the statement of financial position at 31 December 2024. 9 T plc Statement of financial position at 31 December 2024 Assets $ Non-current assets Property 680 000 Furniture and equipment at carrying value 416 000 (1) 1 096 000 (1)OF Current assets Inventory 52 800 (1) Trade and other receivables 51 400 (1) 104 200 Total assets 1 200 200 }* Equity Share capital 900 000 Retained earnings 84 900 Total equity 984 900 (1) OF Current liabilities Debentures 150 000 (1) Trade and other payables 32 700 (1) Taxation 14 800 (1) Bank overdraft 17 800 Total liabilities 215 300 Total equity and liabilities 1 200 200 (1)}* (1)}* both totals should be the same 1(d) Advise the directors which option they should choose. Justify your choice by 7 considering the advantages and disadvantages of both options. Option A (max 4) For Will be a permanent source of finance/no repayment (1) Will not affect profits (1) Dividend payments are discretionary/variable (1) Net assets are increased (1) Against Will the issue be successful/fully subscribed (1) Will affect control of the company/voting rights (1) Shareholders may expect dividends (1) Cost and time involved in issuing prospectus/advertising etc. (1) Option B (max 4) For No impact on control of company as no voting rights/decision making (1) No impact on profit distribution as no change in control (1) Temporary source of finance/repayable (1) Have until 2030 to repay/can budget/plan for repayment (1) Against They have to finance the redemption of the existing debenture/already have a debenture (1) Debenture interest will reduce profits (1) Debenture interest will have to be paid each year/finance costs increase (1) Liabilities/gearing increase (1) Loan/need to repay (1) May require security (1) It may be difficult to obtain another debenture (1) Accept other valid responses Max 6 for comments on both options Decision supported by a comment (1)
Q2 · On 1 October 2024, the directors had paid a dividend of $0.03 per share on all shares in…
2 On 1 October 2024, the directors had paid a dividend of $0.03 per share on all shares in issue at this date.
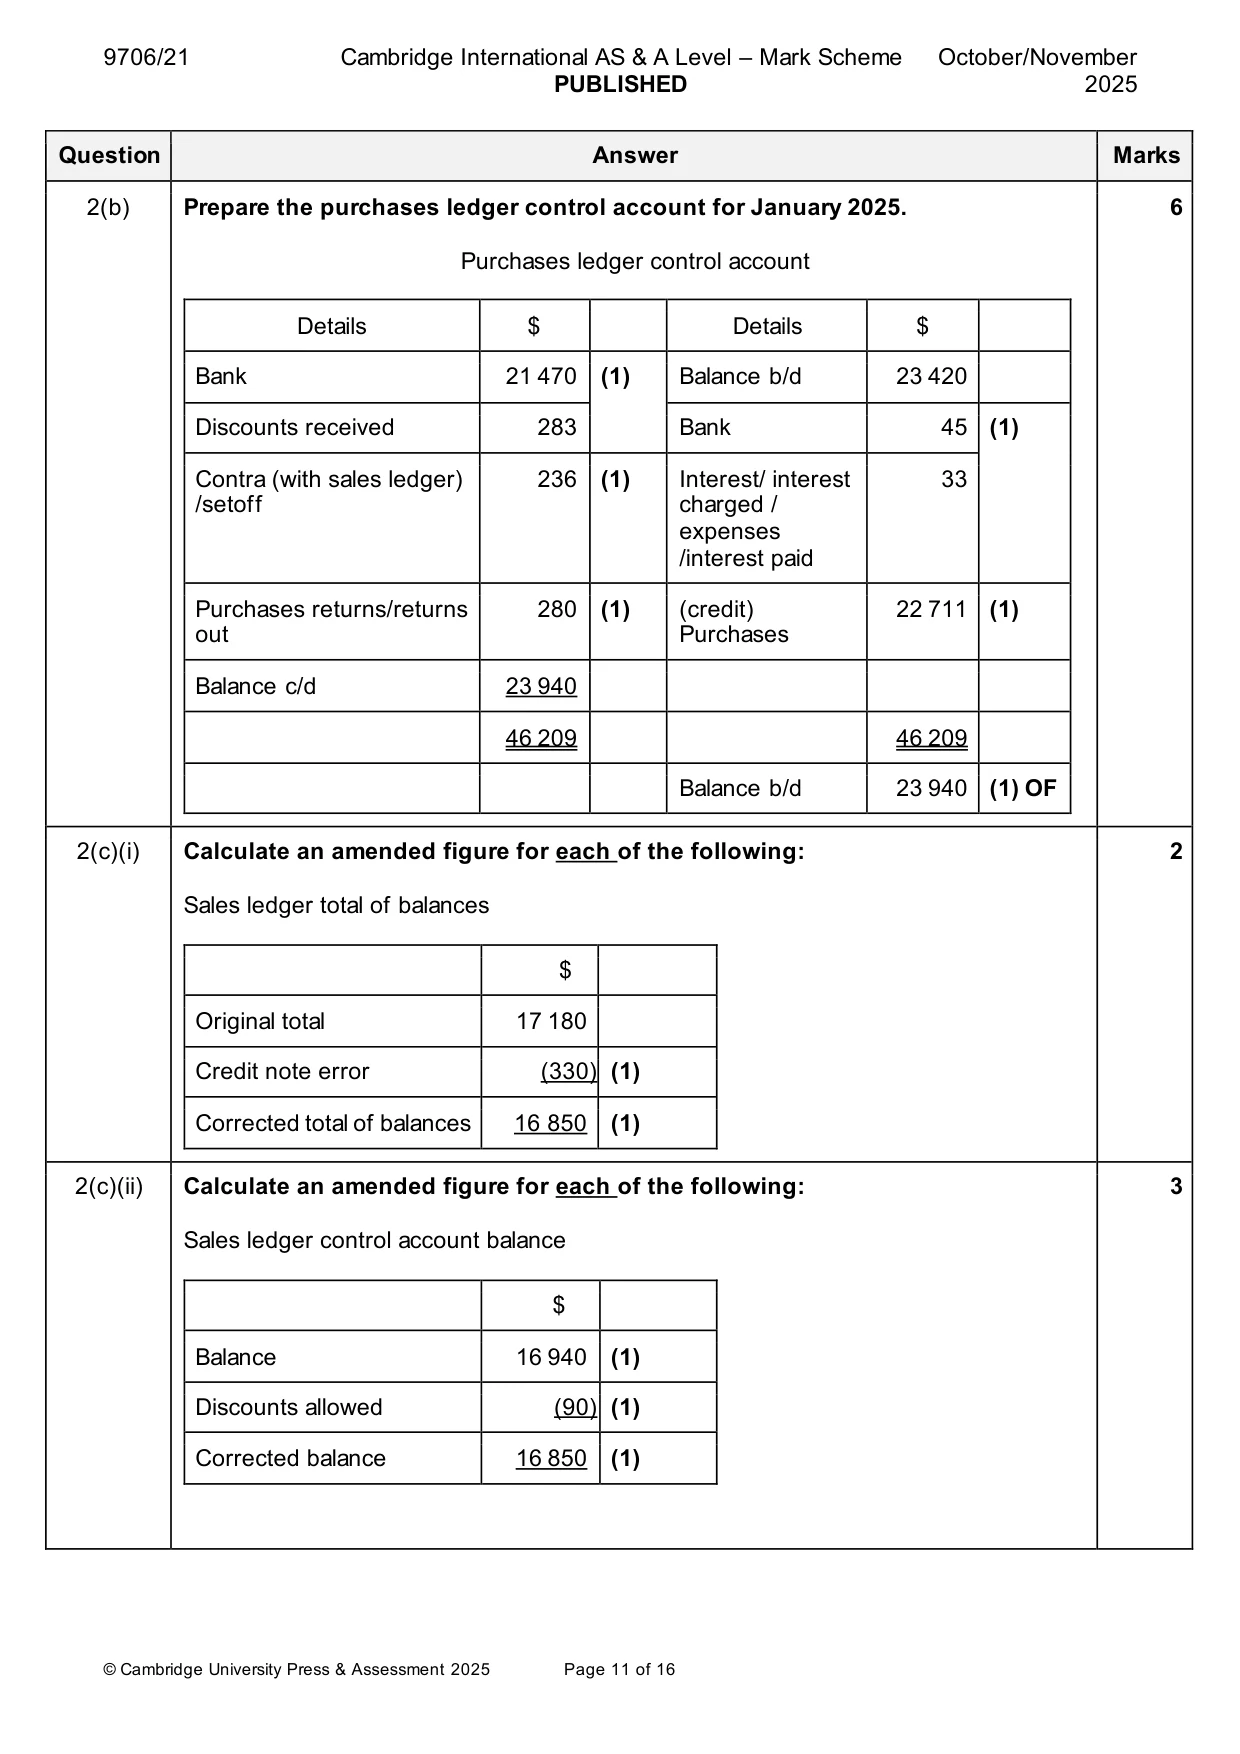
Mark scheme: 2(a) Explain two benefits of maintaining control accounts. 4 Provide an arithmetical check on the accuracy of the purchases and sales ledgers (1), enabling any errors to be discovered quickly (1). Assists in the preparation of trial balances and financial statements (1), as totals of trade payables and trade receivables can be found quickly (1). May help deter fraudulent activity (1) as they provide independent verification/division of duties (1). Max 2 benefits x 2 marks (1 mark for identifying + 1 mark for development ) Accept other valid responses 2(b) Prepare the purchases ledger control account for January 2025. 6 Purchases ledger control account Details $ Details $ Bank 21 470 (1) Balance b/d 23 420 Discounts received 283 Bank 45 (1) Contra (with sales ledger) 236 (1) Interest/ interest 33 /setoff charged / expenses /interest paid Purchases returns/returns 280 (1) (credit) 22 711 (1) out Purchases Balance c/d 23 940 46 209 46 209 Balance b/d 23 940 (1) OF 2(c)(i) Calculate an amended figure for each of the following: 2 Sales ledger total of balances $ Original total 17 180 Credit note error (330) (1) Corrected total of balances 16 850 (1) 2(c)(ii) Calculate an amended figure for each of the following: 3 Sales ledger control account balance $ Balance 16 940 (1) Discounts allowed (90) (1) Corrected balance 16 850 (1)
Q3 · At 31 December 2024, the directors decided to revalue the property to $680 000
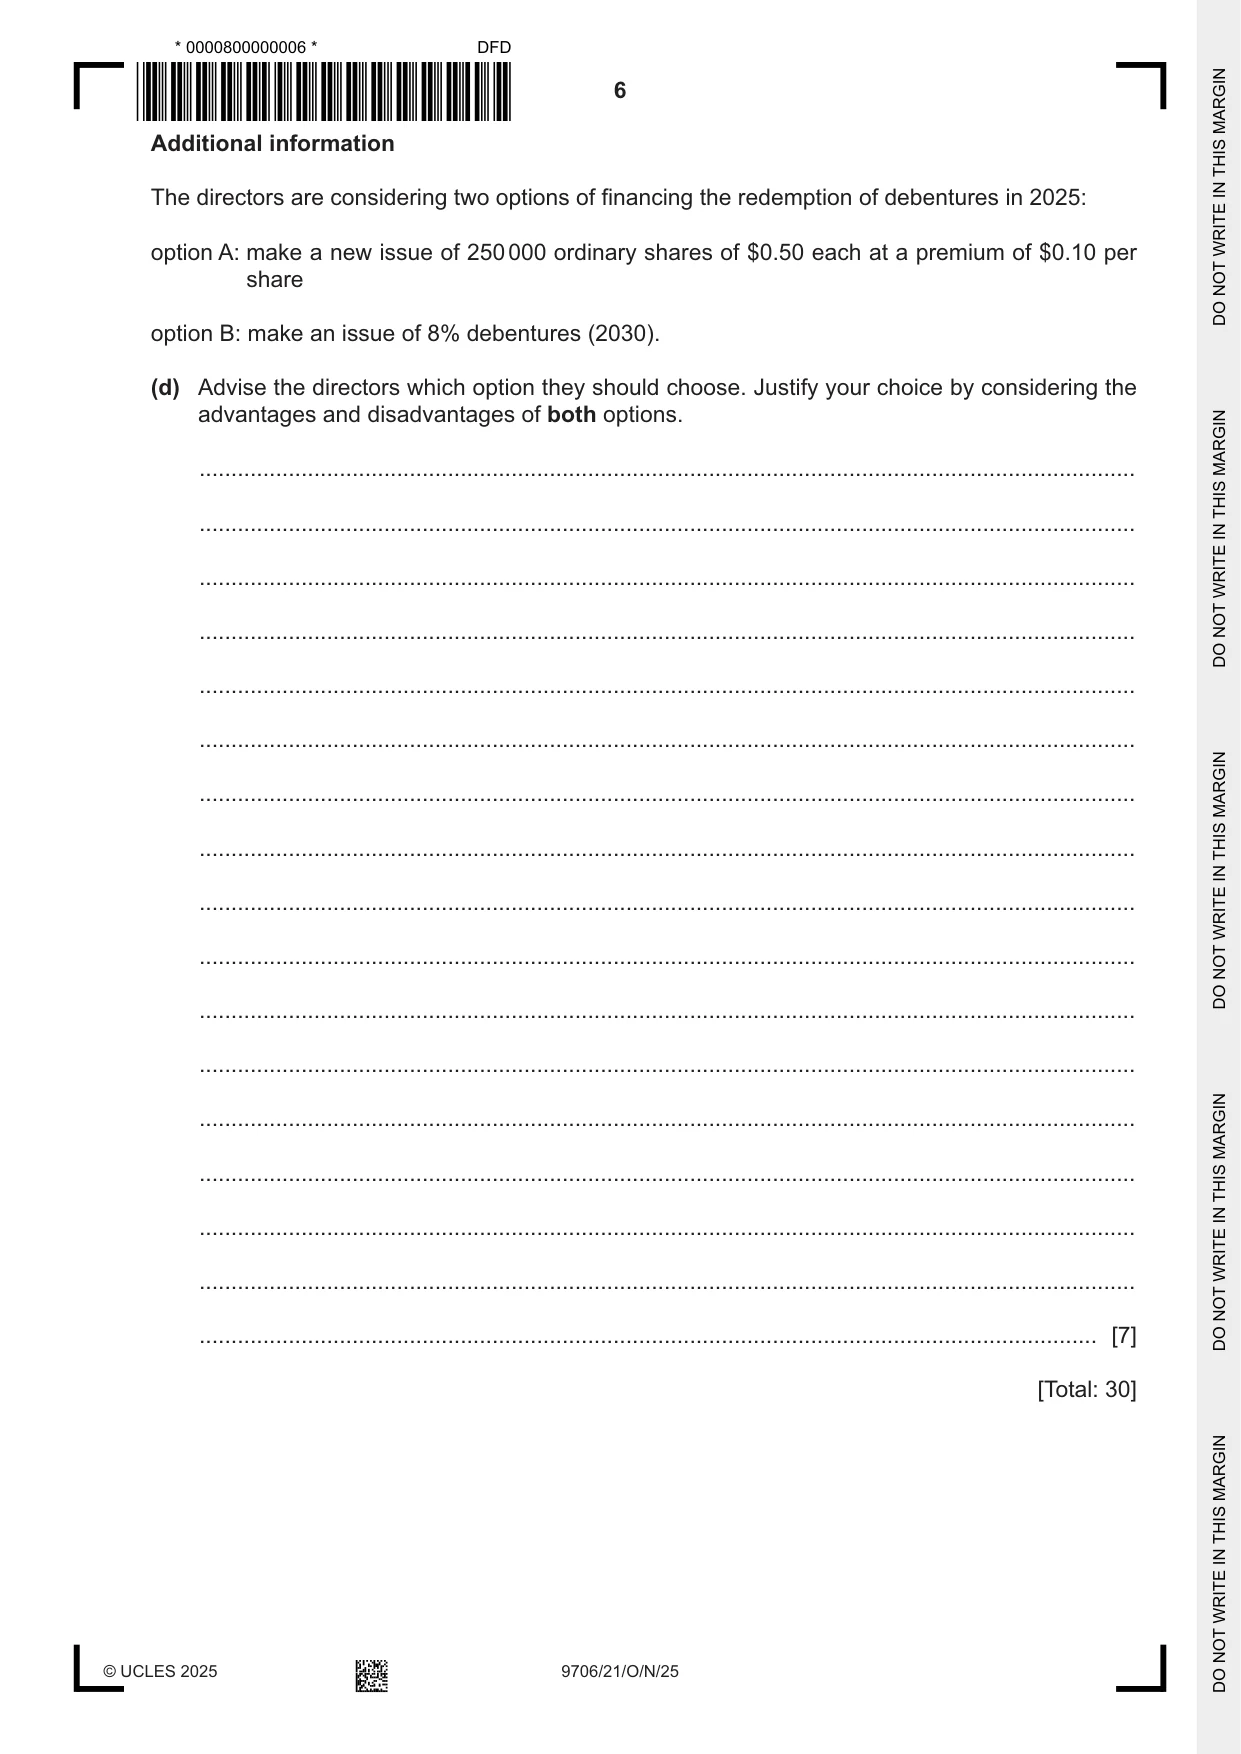
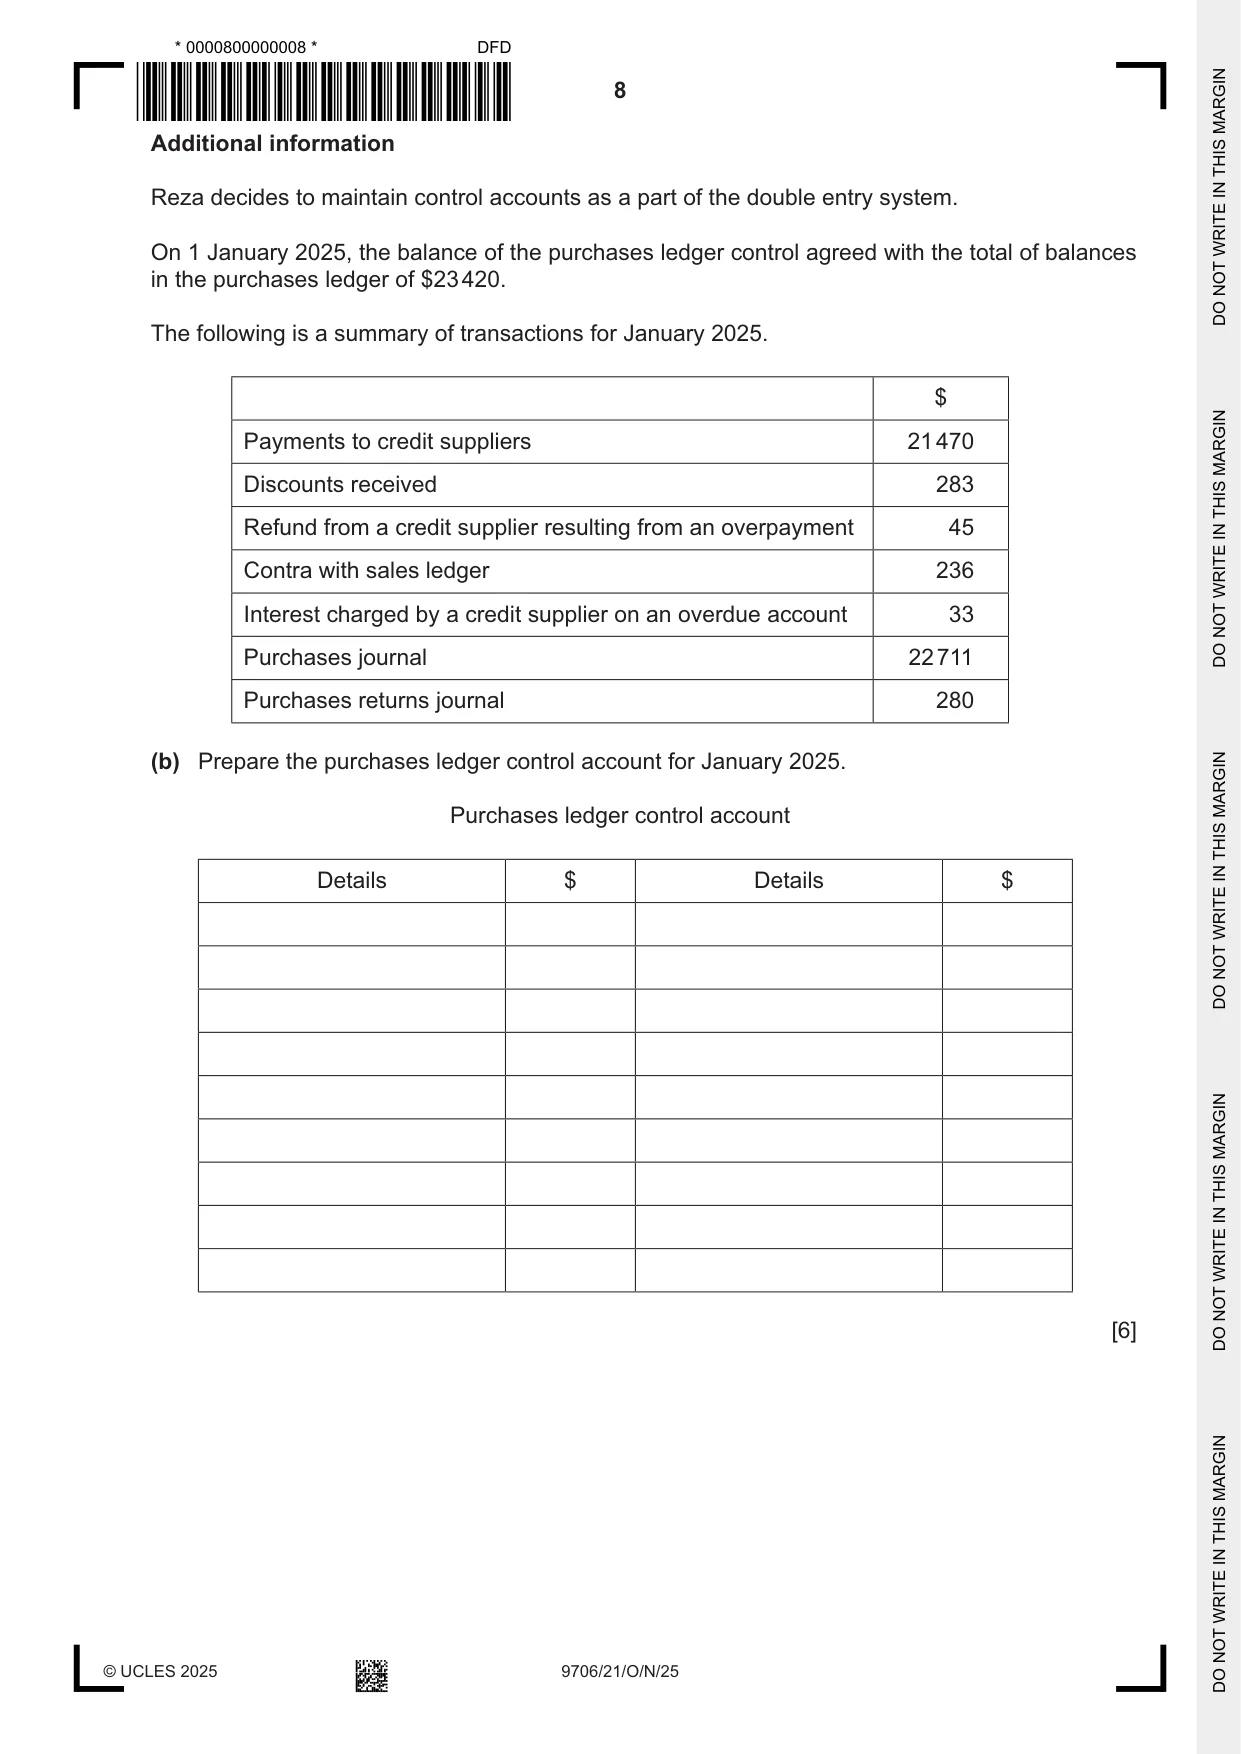
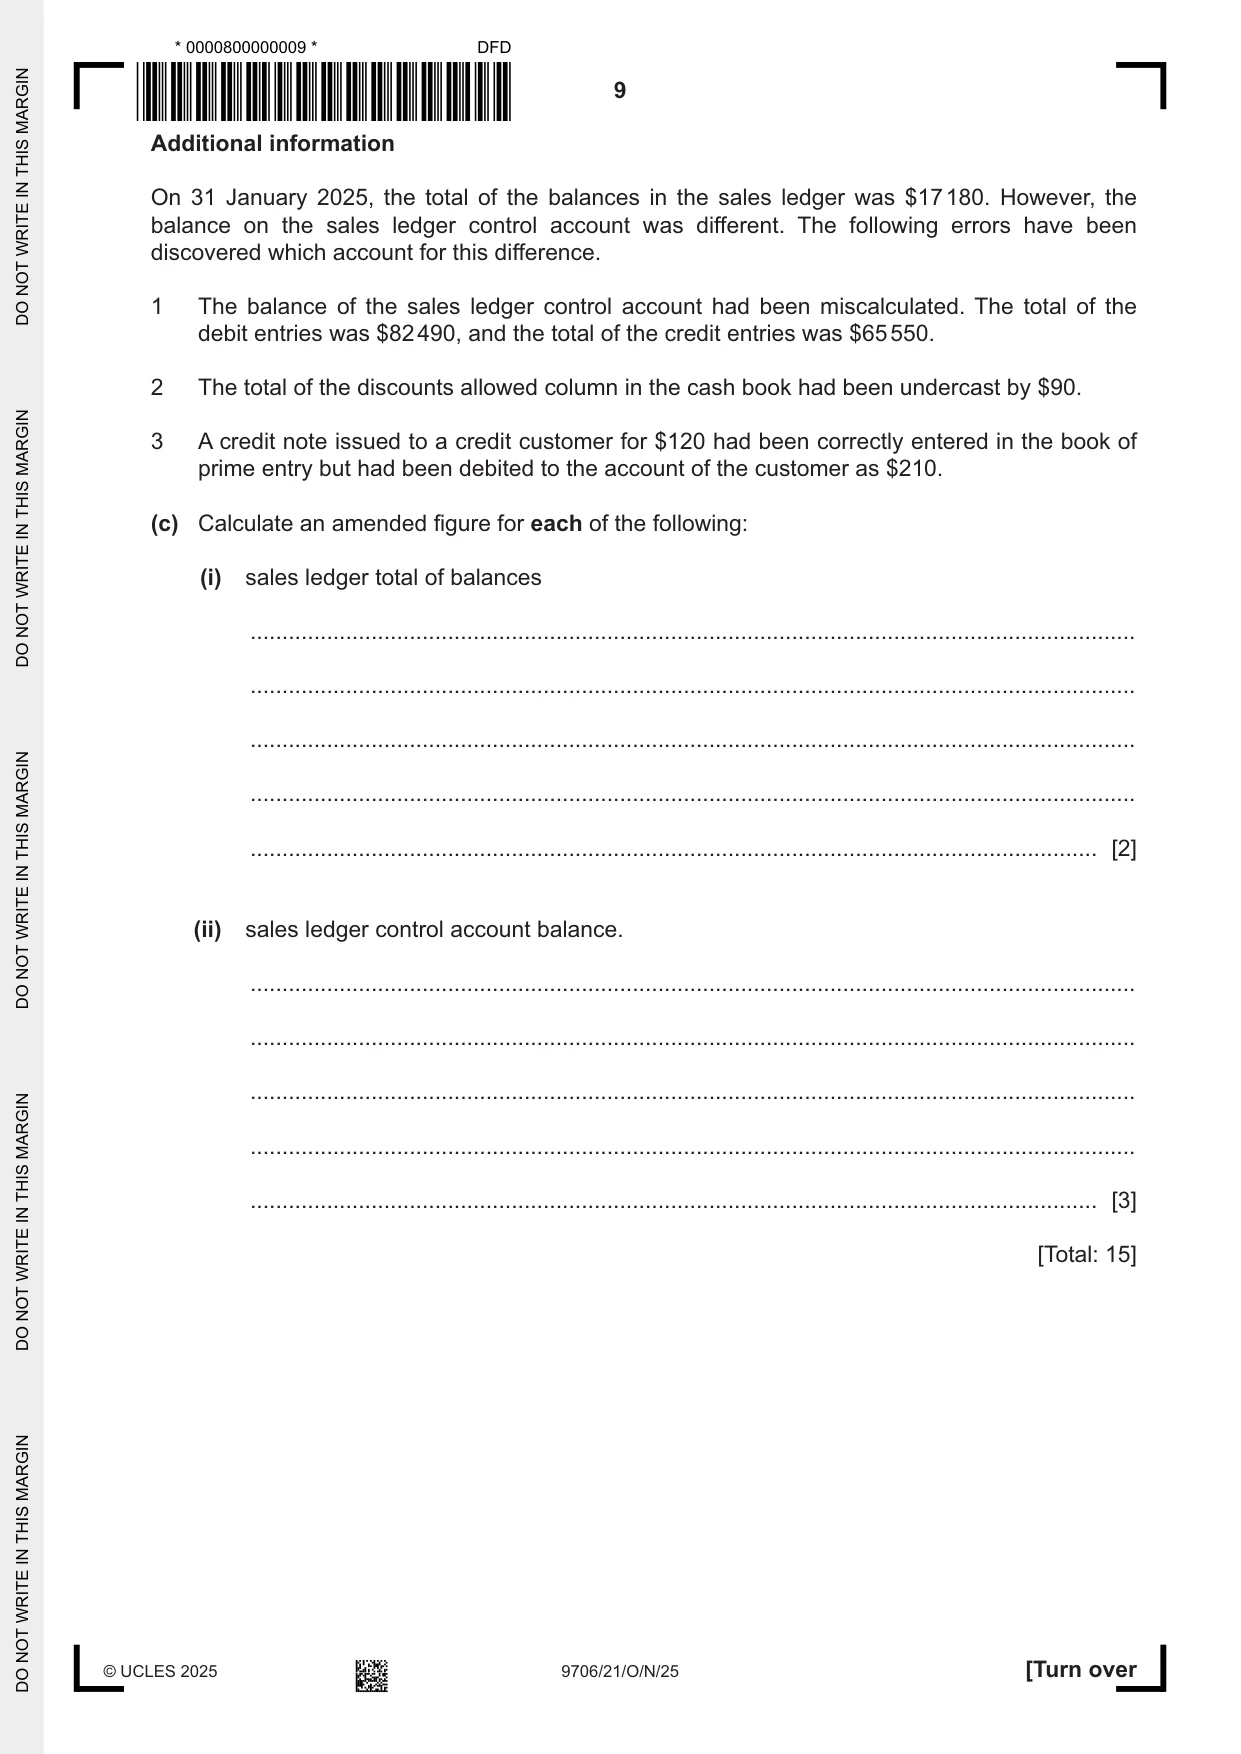
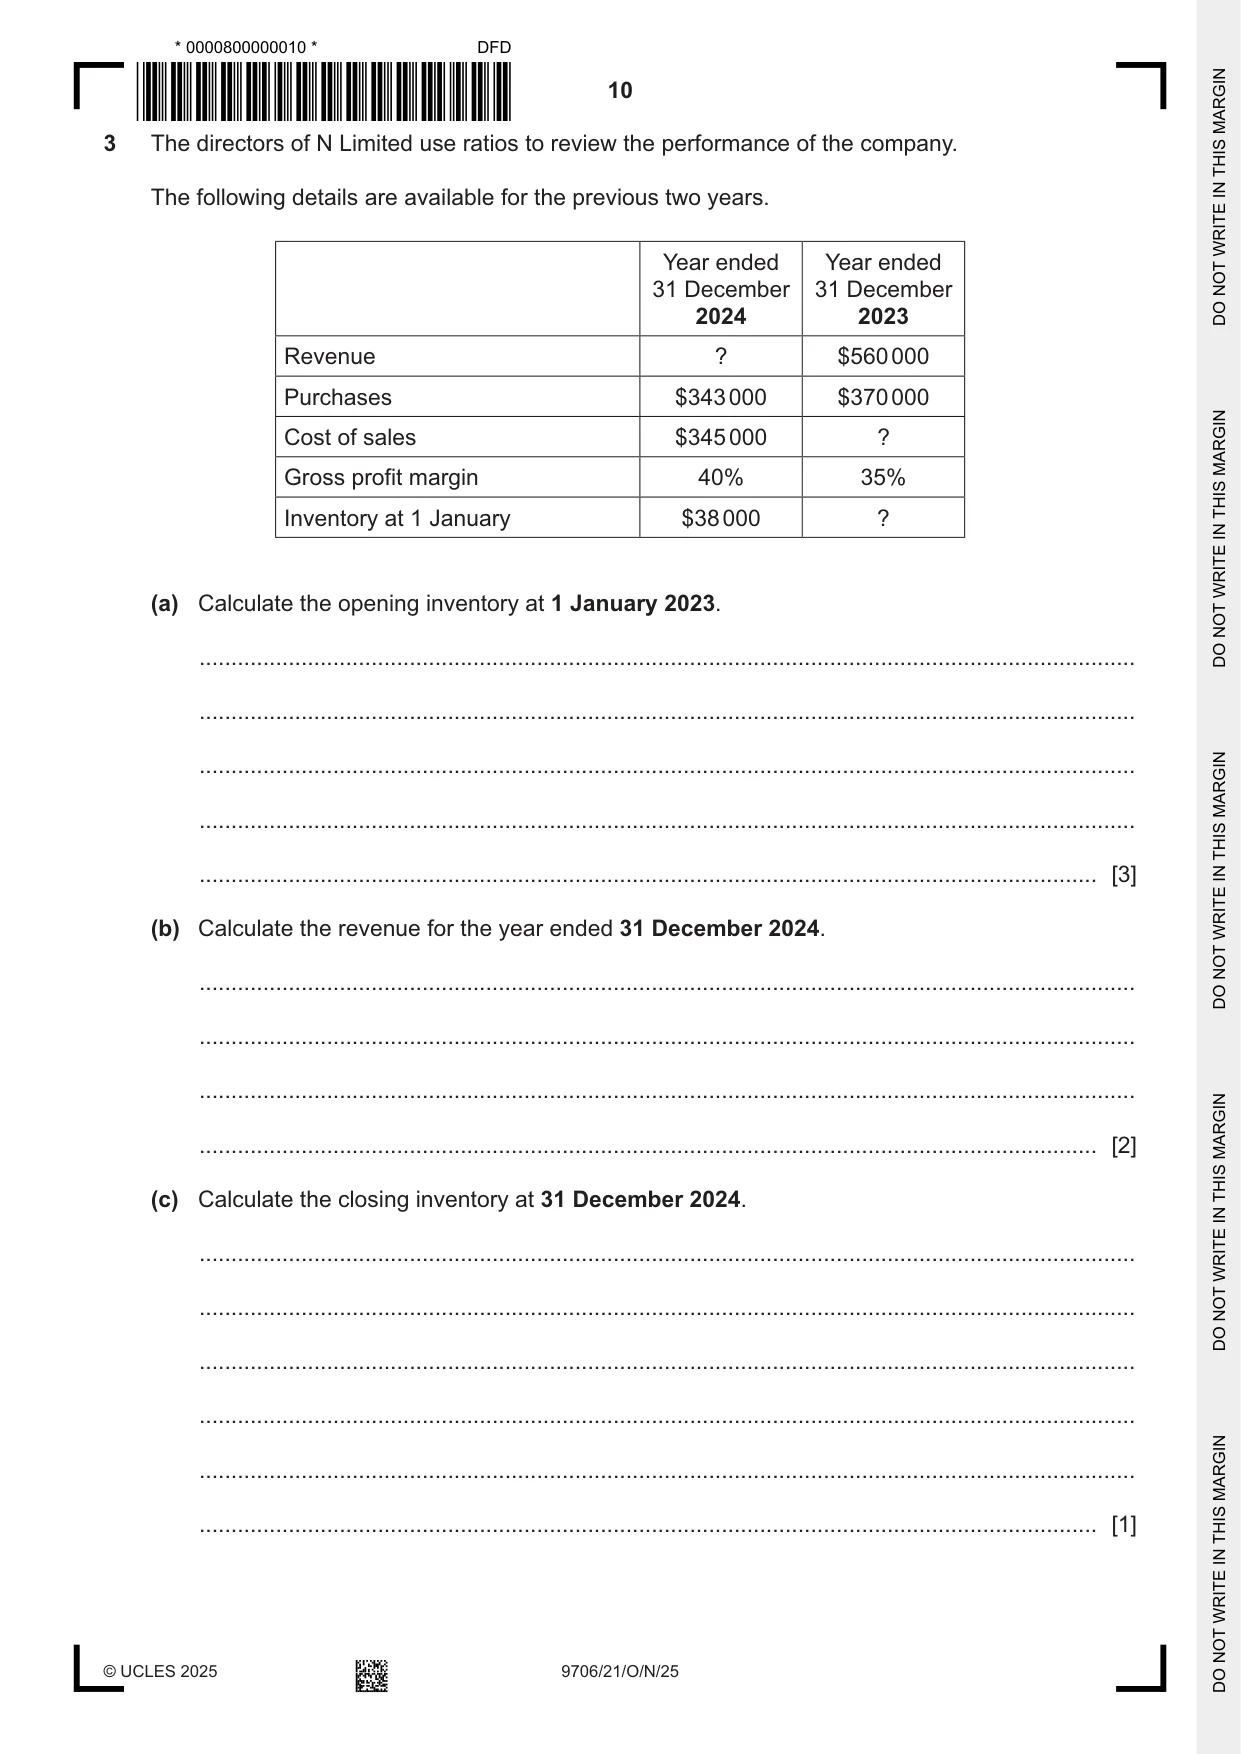
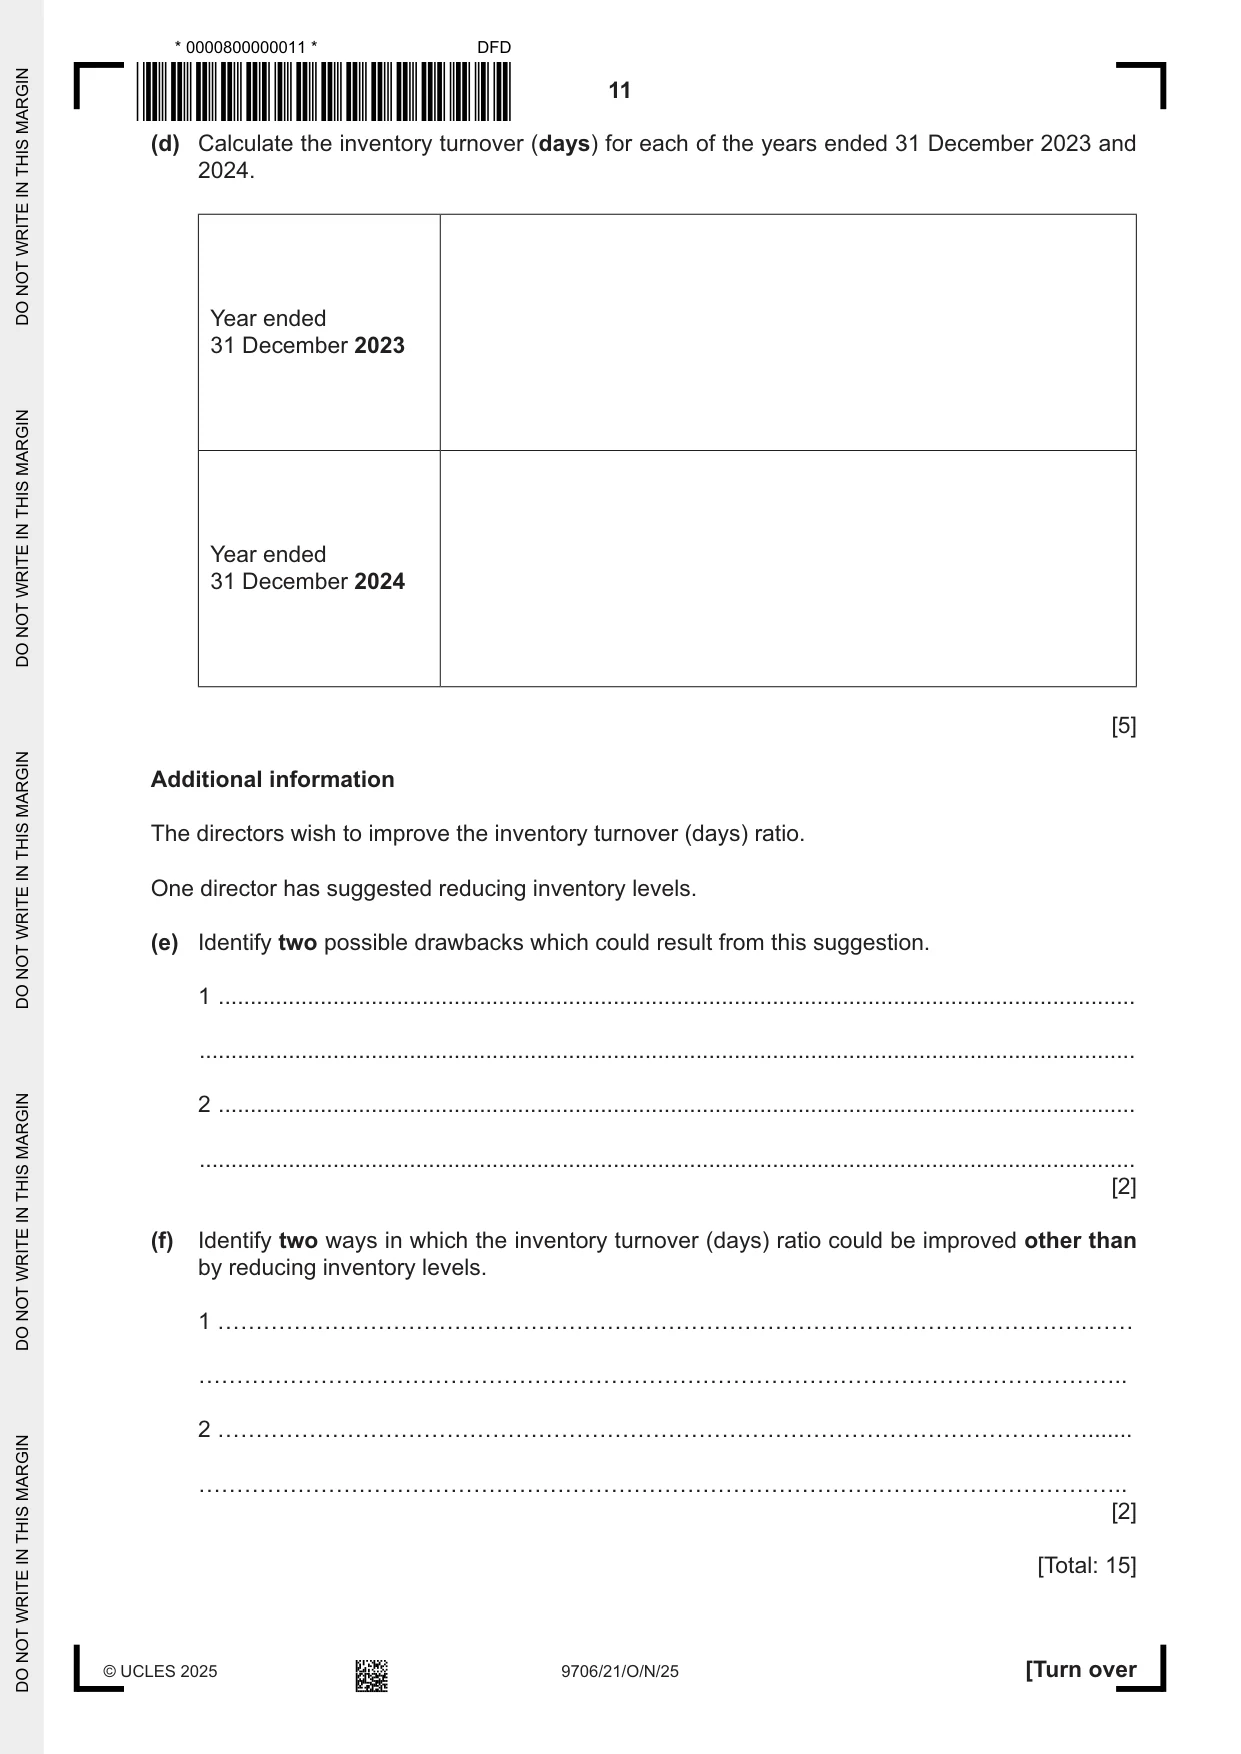
3 At 31 December 2024, the directors decided to revalue the property to $680 000. (b) Complete the statement of changes in equity for the year ended 31 December 2024. T plc Statement of changes in equity for the year ended 31 December 2024 Share Share Revaluation Retained Total capital premium reserve earnings $ $ $ $ $ At 1 January 2024 120 000 80 000 330 800 At 31 December 2024 900 000 Workings: [7] (c) Prepare the statement of financial position at 31 December 2024. T plc Statement of financial position at 31 December 2024 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [9] Additional information The directors are considering two options of financing the redemption of debentures in 2025: option A: make a new issue of 250 000 ordinary shares of $0.50 each at a premium of $0.10 per share option B: make an issue of 8% debentures (2030). (d) Advise the directors which option they should choose. Justify your choice by considering the advantages and disadvantages of both options. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 30] 2 Reza owns a large retail business. As the business has many credit customers and credit suppliers, she was advised to maintain purchases ledger and sales ledger control accounts. (a) Explain two benefits of maintaining control accounts. 1 ................................................................................................................................................. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] Additional information Reza decides to maintain control accounts as a part of the double entry system. On 1 January 2025, the balance of the purchases ledger control agreed with the total of balances in the purchases ledger of $23 420. The following is a summary of transactions for January 2025. $ Payments to credit suppliers 21 470 Discounts received 283 Refund from a credit supplier resulting from an overpayment 45 Contra with sales ledger 236 Interest charged by a credit supplier on an overdue account 33 Purchases journal 22 711 Purchases returns journal 280 (b) Prepare the purchases ledger control account for January 2025. Purchases ledger control account Details $ Details $ [6] Additional information On 31 January 2025, the total of the balances in the sales ledger was $17 180. However, the balance on the sales ledger control account was different. The following errors have been discovered which account for this difference. 1 The balance of the sales ledger control account had been miscalculated. The total of the debit entries was $82 490, and the total of the credit entries was $65 550. 2 The total of the discounts allowed column in the cash book had been undercast by $90. 3 A credit note issued to a credit customer for $120 had been correctly entered in the book of prime entry but had been debited to the account of the customer as $210. (c) Calculate an amended figure for each of the following: (i) sales ledger total of balances ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) sales ledger control account balance. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [3] [Total: 15] 3 The directors of N Limited use ratios to review the performance of the company. The following details are available for the previous two years. Year ended Year ended 31 December 31 December 2024 2023 Revenue ? $560 000 Purchases $343 000 $370 000 Cost of sales $345 000 ? Gross profit margin 40% 35% Inventory at 1 January $38 000 ? (a) Calculate the opening inventory at 1 January 2023. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (b) Calculate the revenue for the year ended 31 December 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (c) Calculate the closing inventory at 31 December 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [1] (d) Calculate the inventory turnover (days) for each of the years ended 31 December 2023 and 2024. Year ended 31 December 2023 Year ended 31 December 2024 [5] Additional information The directors wish to improve the inventory turnover (days) ratio. One director has suggested reducing inventory levels. (e) Identify two possible drawbacks which could result from this suggestion. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] (f) Identify two ways in which the inventory turnover (days) ratio could be improved other than by reducing inventory levels. [2] [Total: 15]
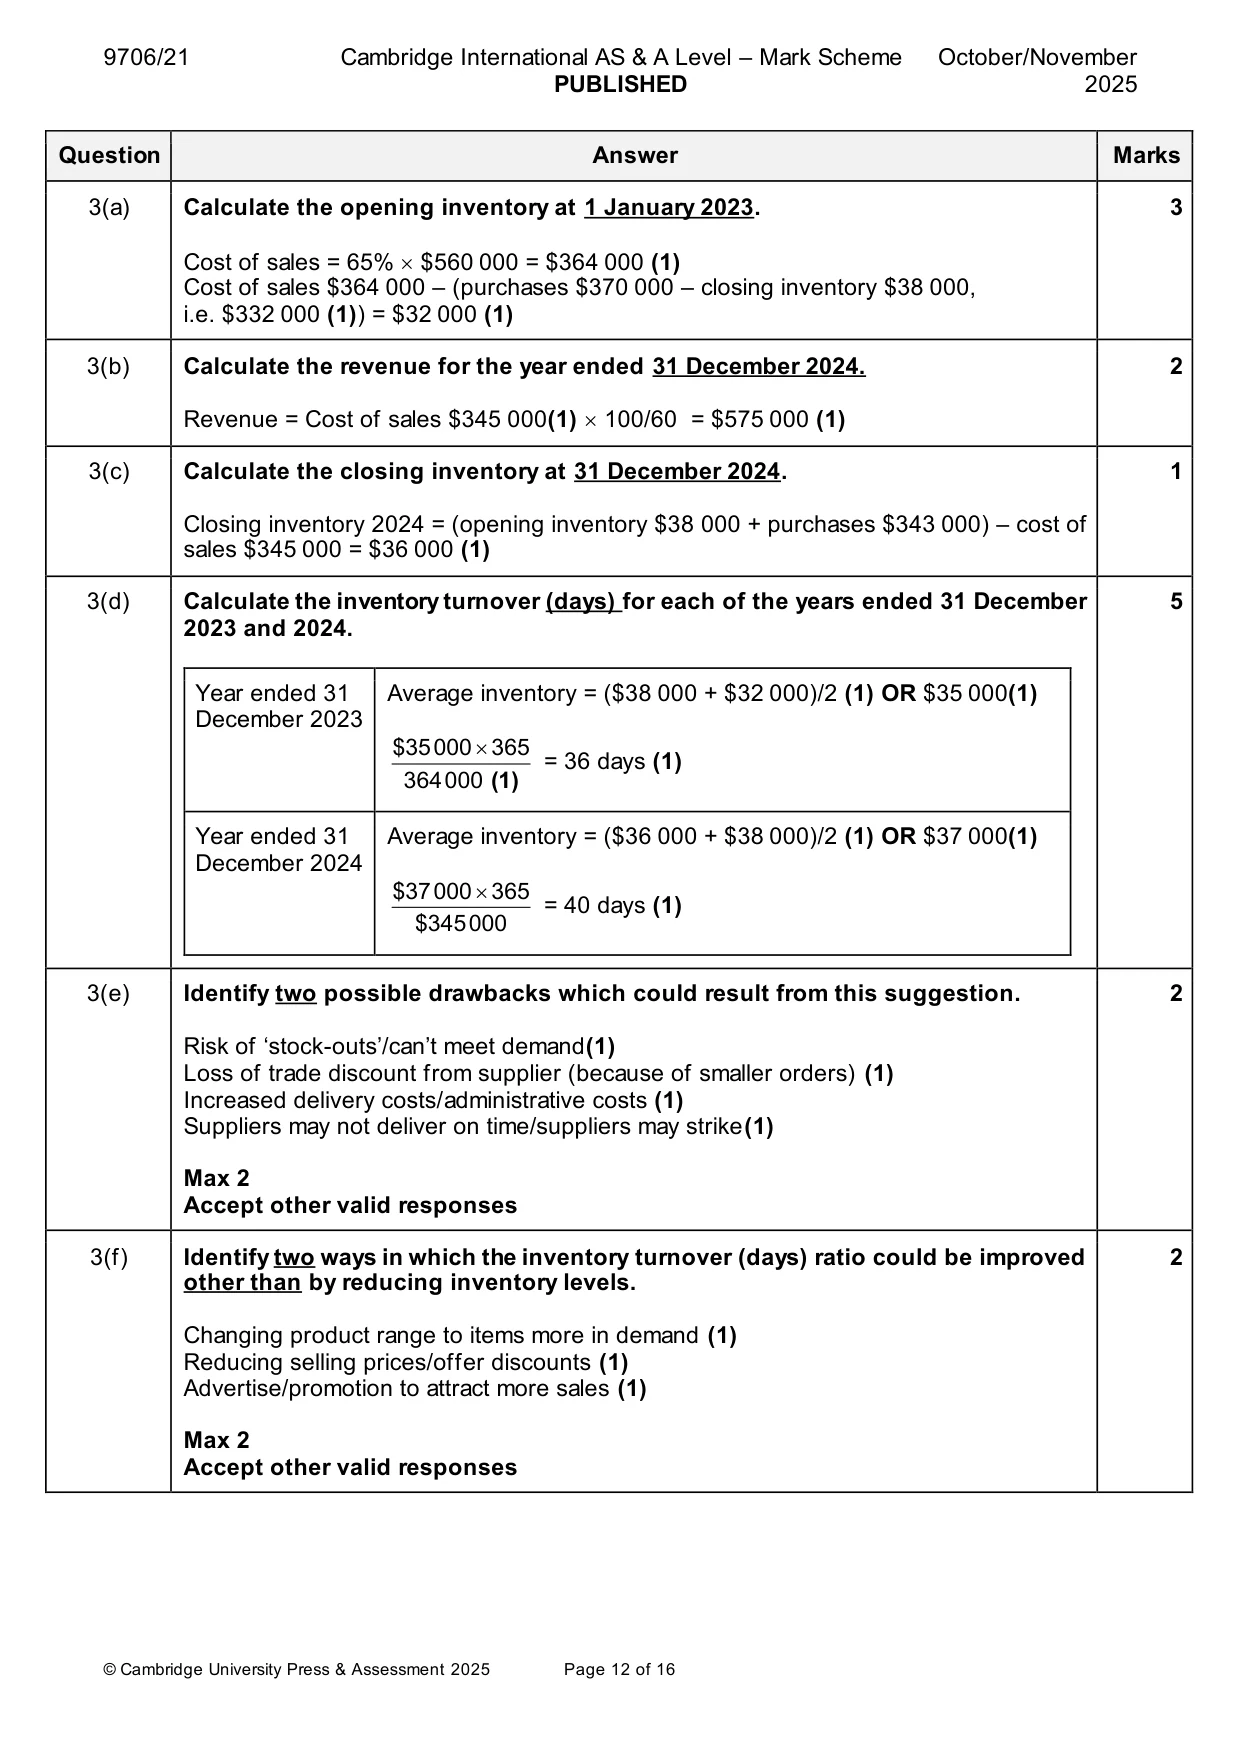
Mark scheme: 3(a) Calculate the opening inventory at 1 January 2023. 3 Cost of sales = 65% $560 000 = $364 000 (1) Cost of sales $364 000 – (purchases $370 000 – closing inventory $38 000, i.e. $332 000 (1)) = $32 000 (1) 3(b) Calculate the revenue for the year ended 31 December 2024. 2 Revenue = Cost of sales $345 000(1) 100/60 = $575 000 (1) 3(c) Calculate the closing inventory at 31 December 2024. 1 Closing inventory 2024 = (opening inventory $38 000 + purchases $343 000) – cost of sales $345 000 = $36 000 (1) 3(d) Calculate the inventory turnover (days) for each of the years ended 31 December 5 2023 and 2024. Year ended 31 Average inventory = ($38 000 + $32 000)/2 (1) OR $35 000(1) December 2023 $35000 365 = 36 days (1) 364000 (1) Year ended 31 Average inventory = ($36 000 + $38 000)/2 (1) OR $37 000(1) December 2024 $37000 365 = 40 days (1) $345000 3(e) Identify two possible drawbacks which could result from this suggestion. 2 Risk of ‘stock-outs’/can’t meet demand(1) Loss of trade discount from supplier (because of smaller orders) (1) Increased delivery costs/administrative costs (1) Suppliers may not deliver on time/suppliers may strike(1) Max 2 Accept other valid responses 3(f) Identify two ways in which the inventory turnover (days) ratio could be improved 2 other than by reducing inventory levels. Changing product range to items more in demand (1) Reducing selling prices/offer discounts (1) Advertise/promotion to attract more sales (1) Max 2 Accept other valid responses
Q4 · B Limited uses absorption costing at one of its factories where two products are made…
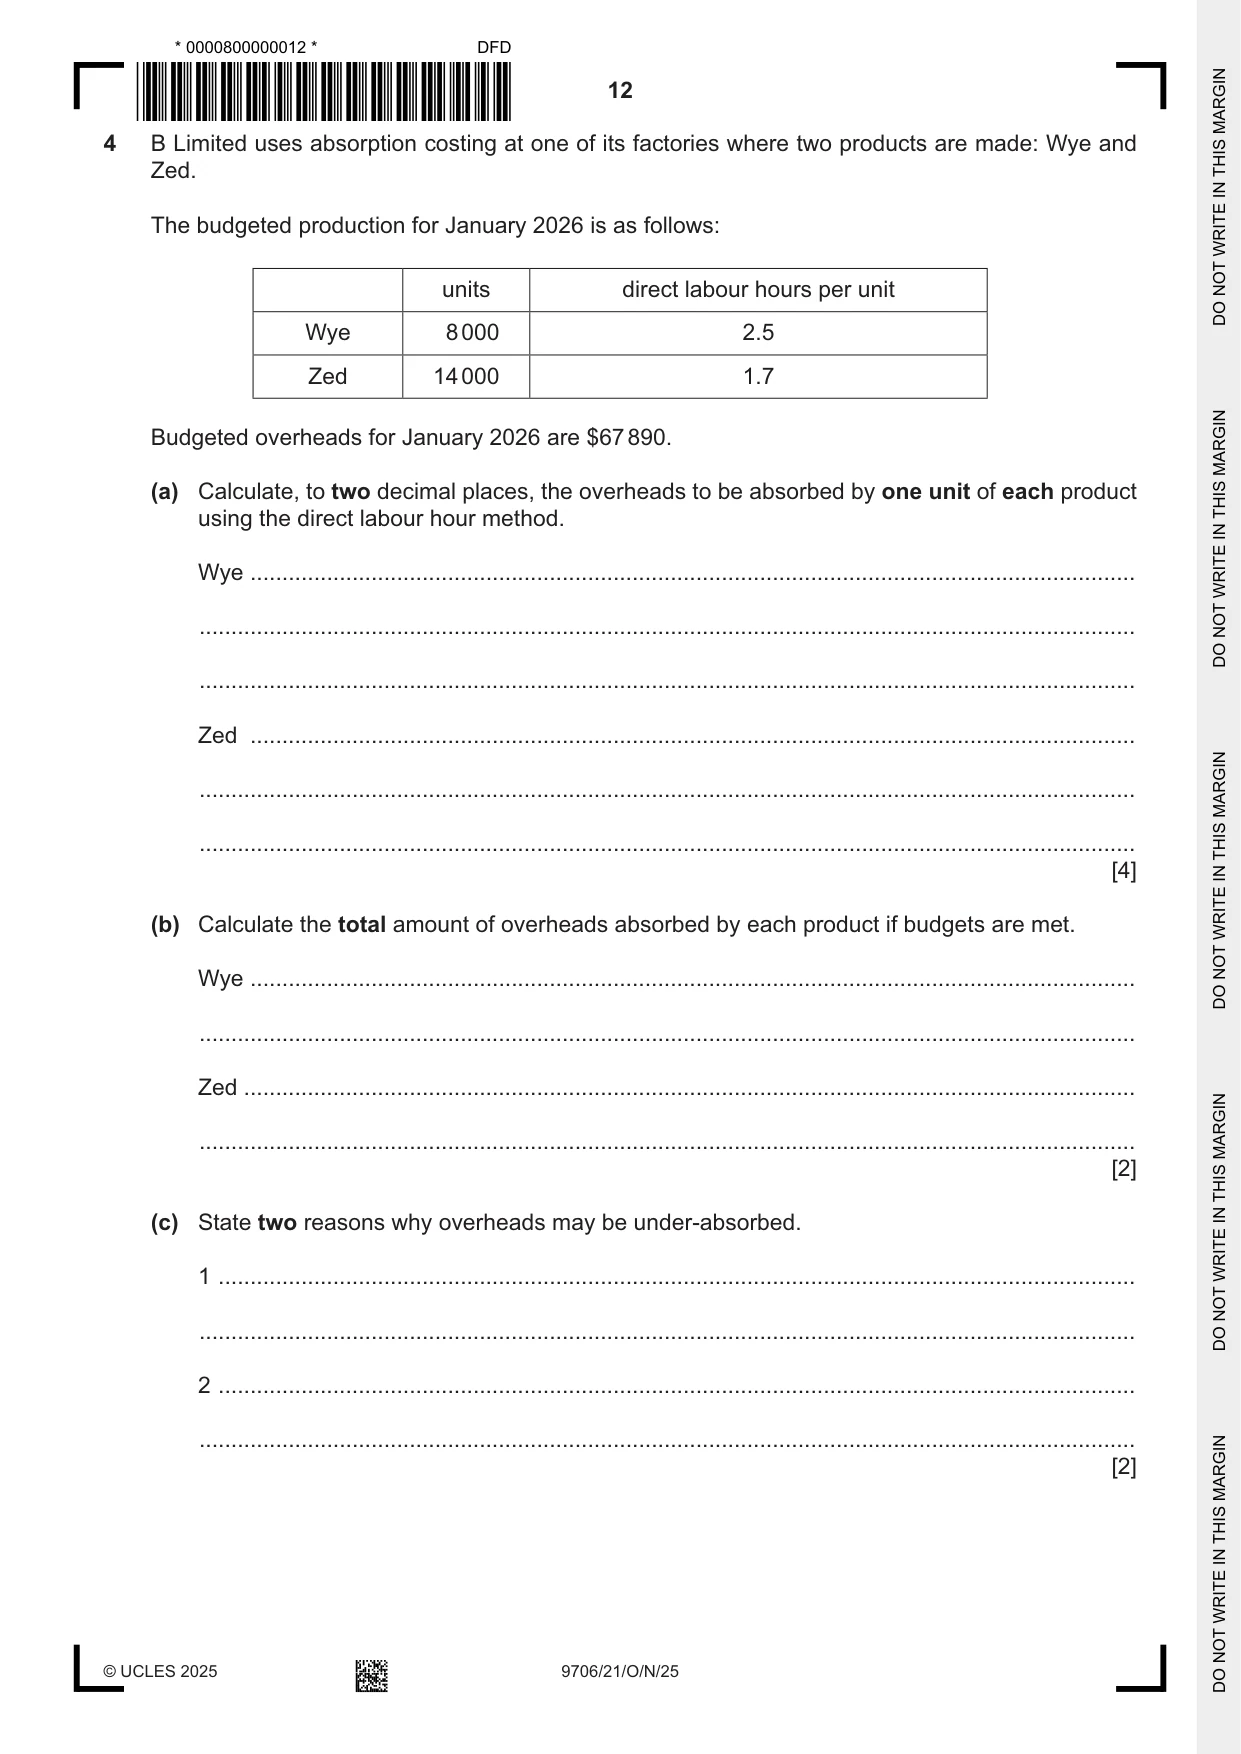
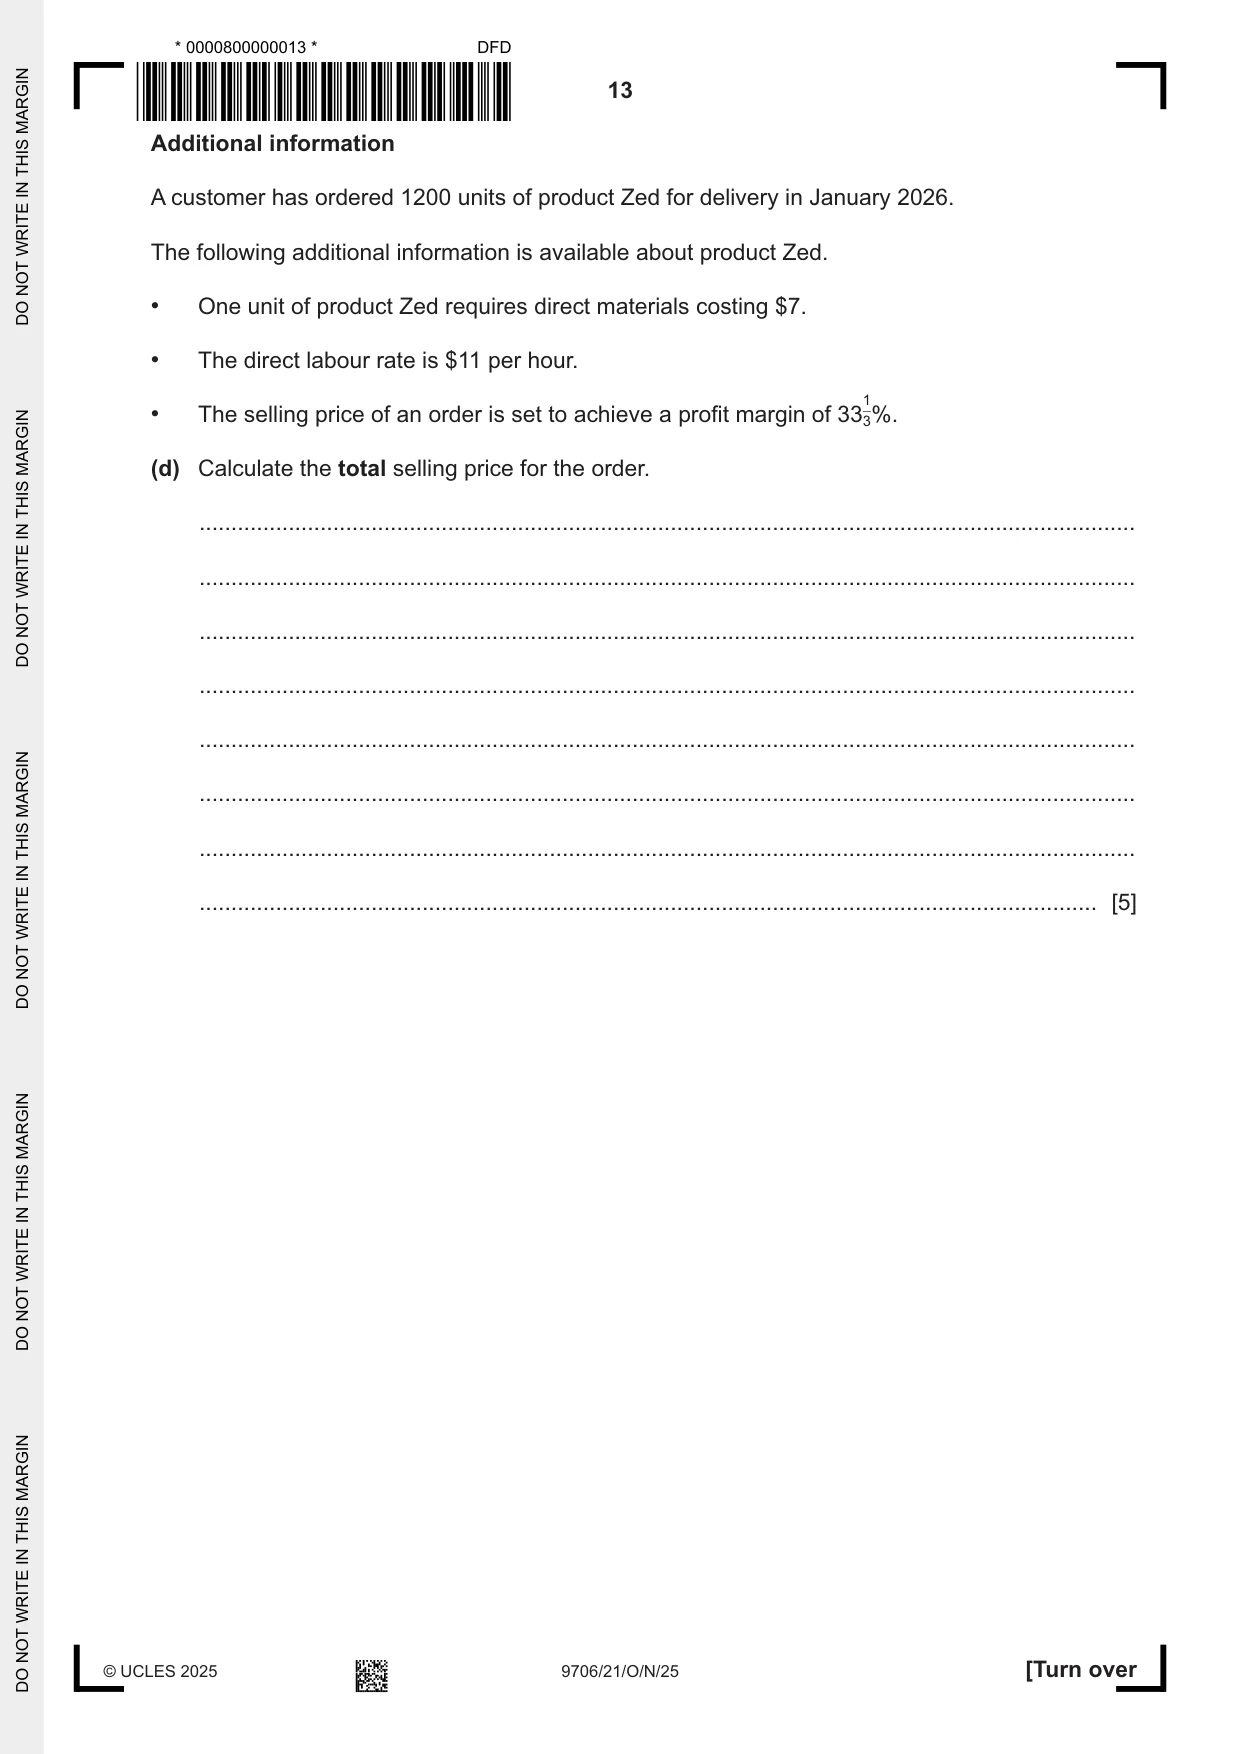
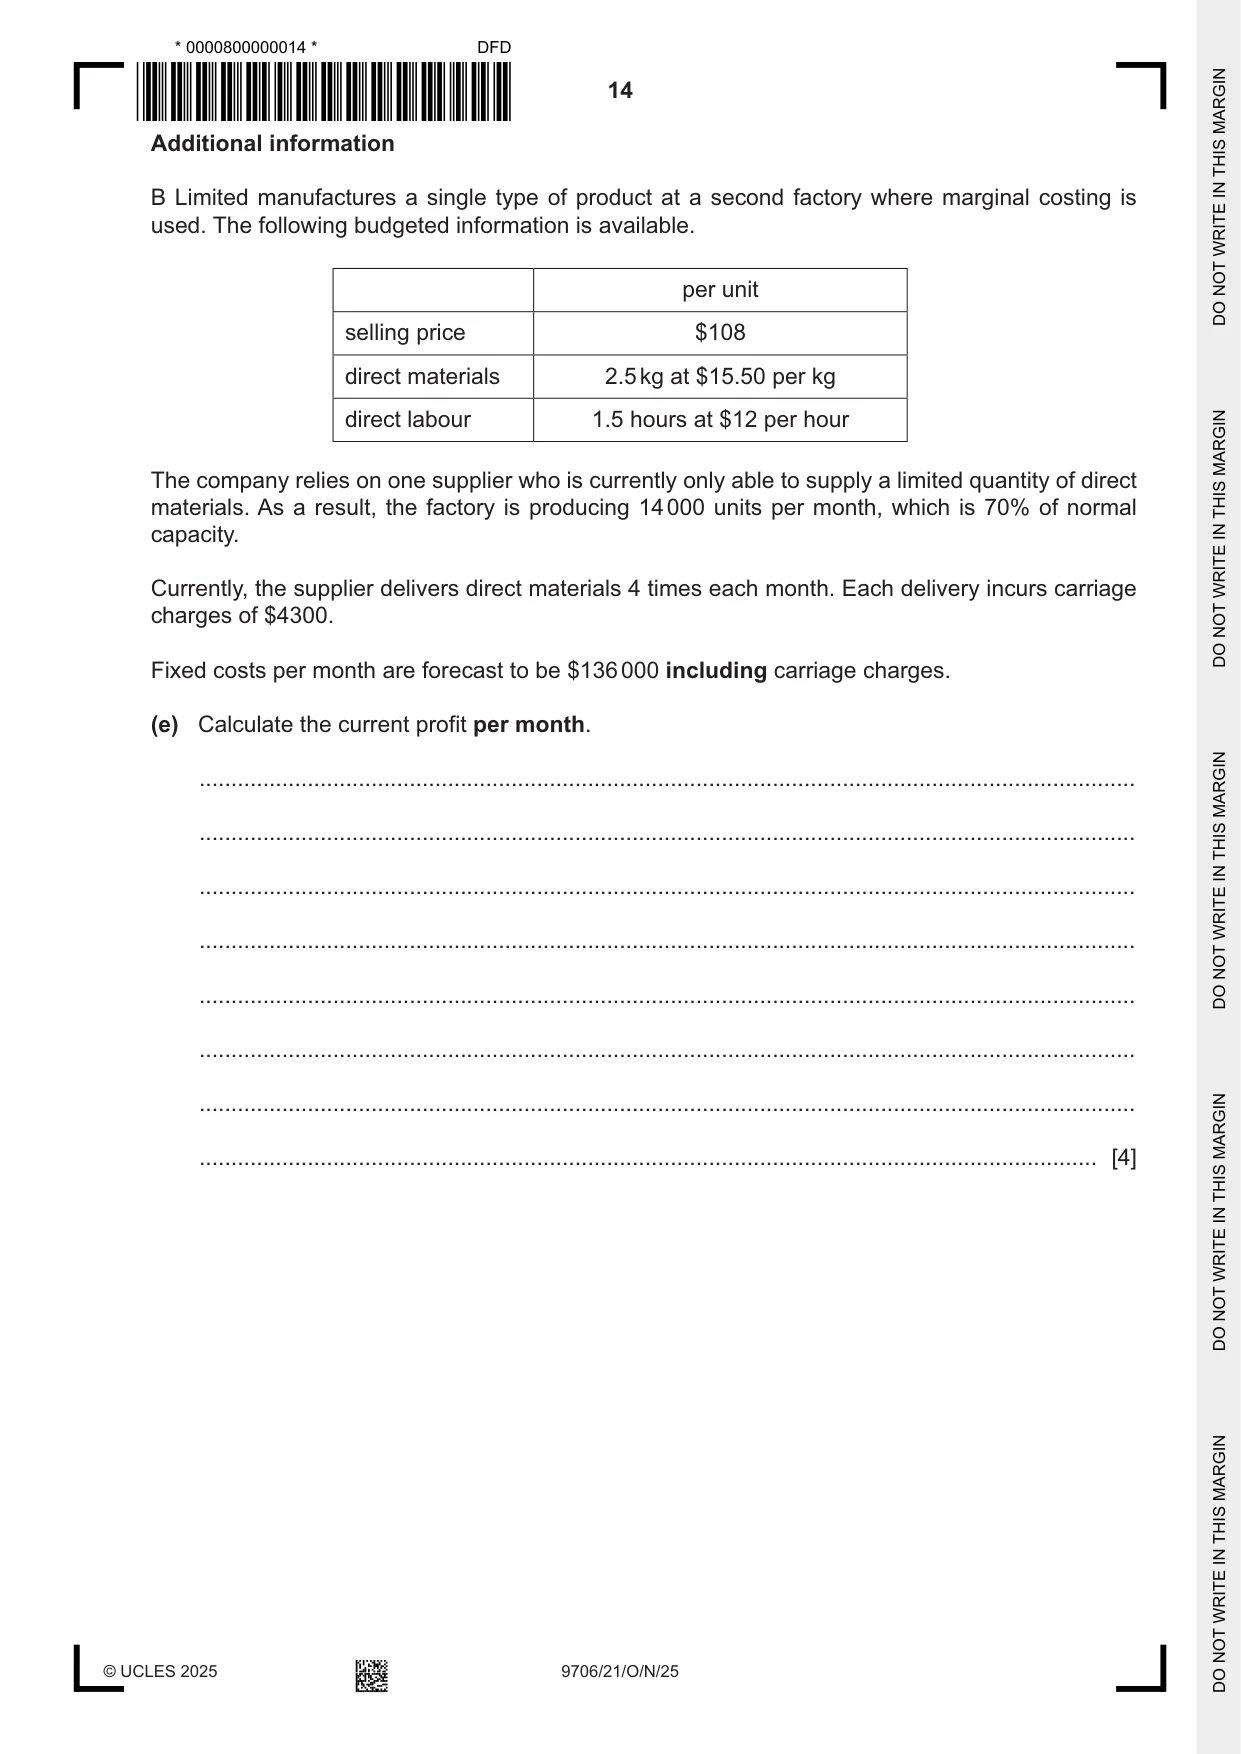
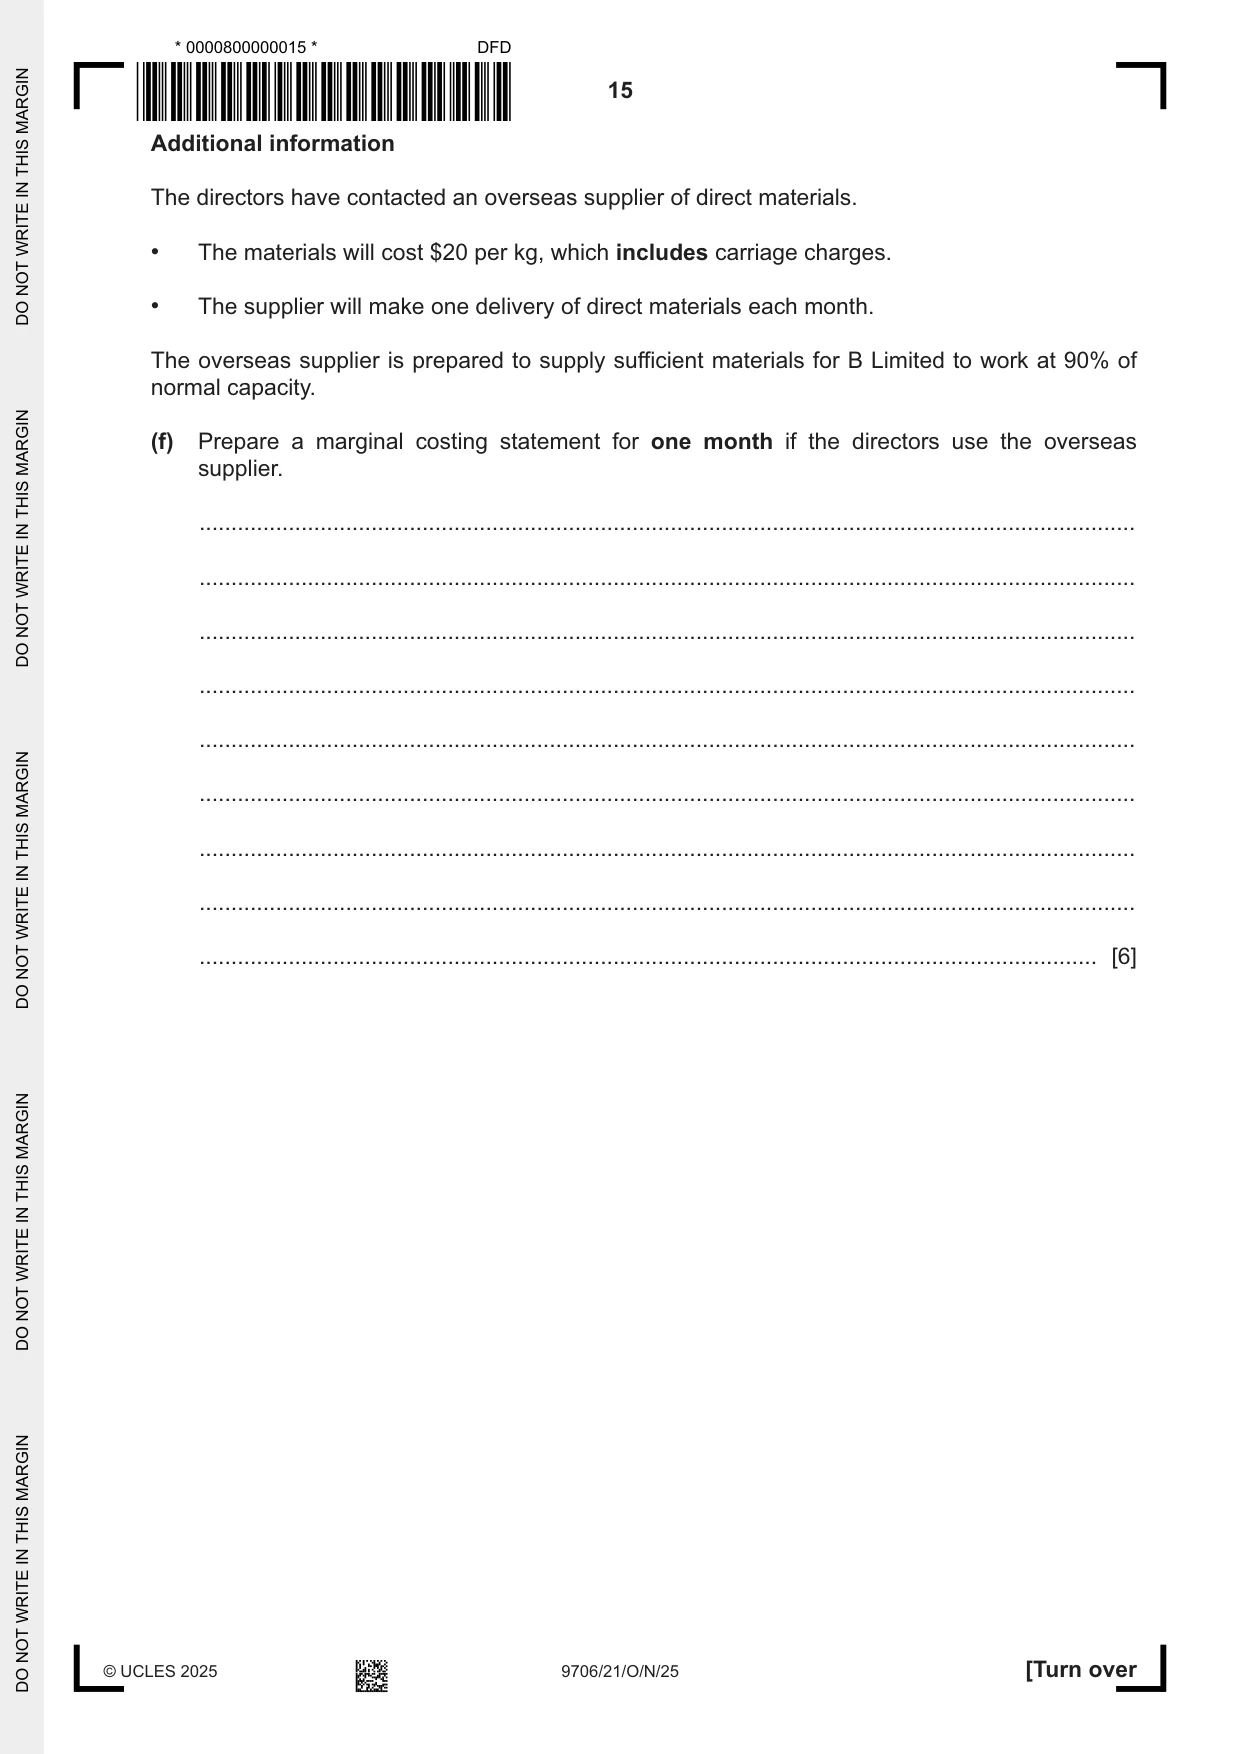
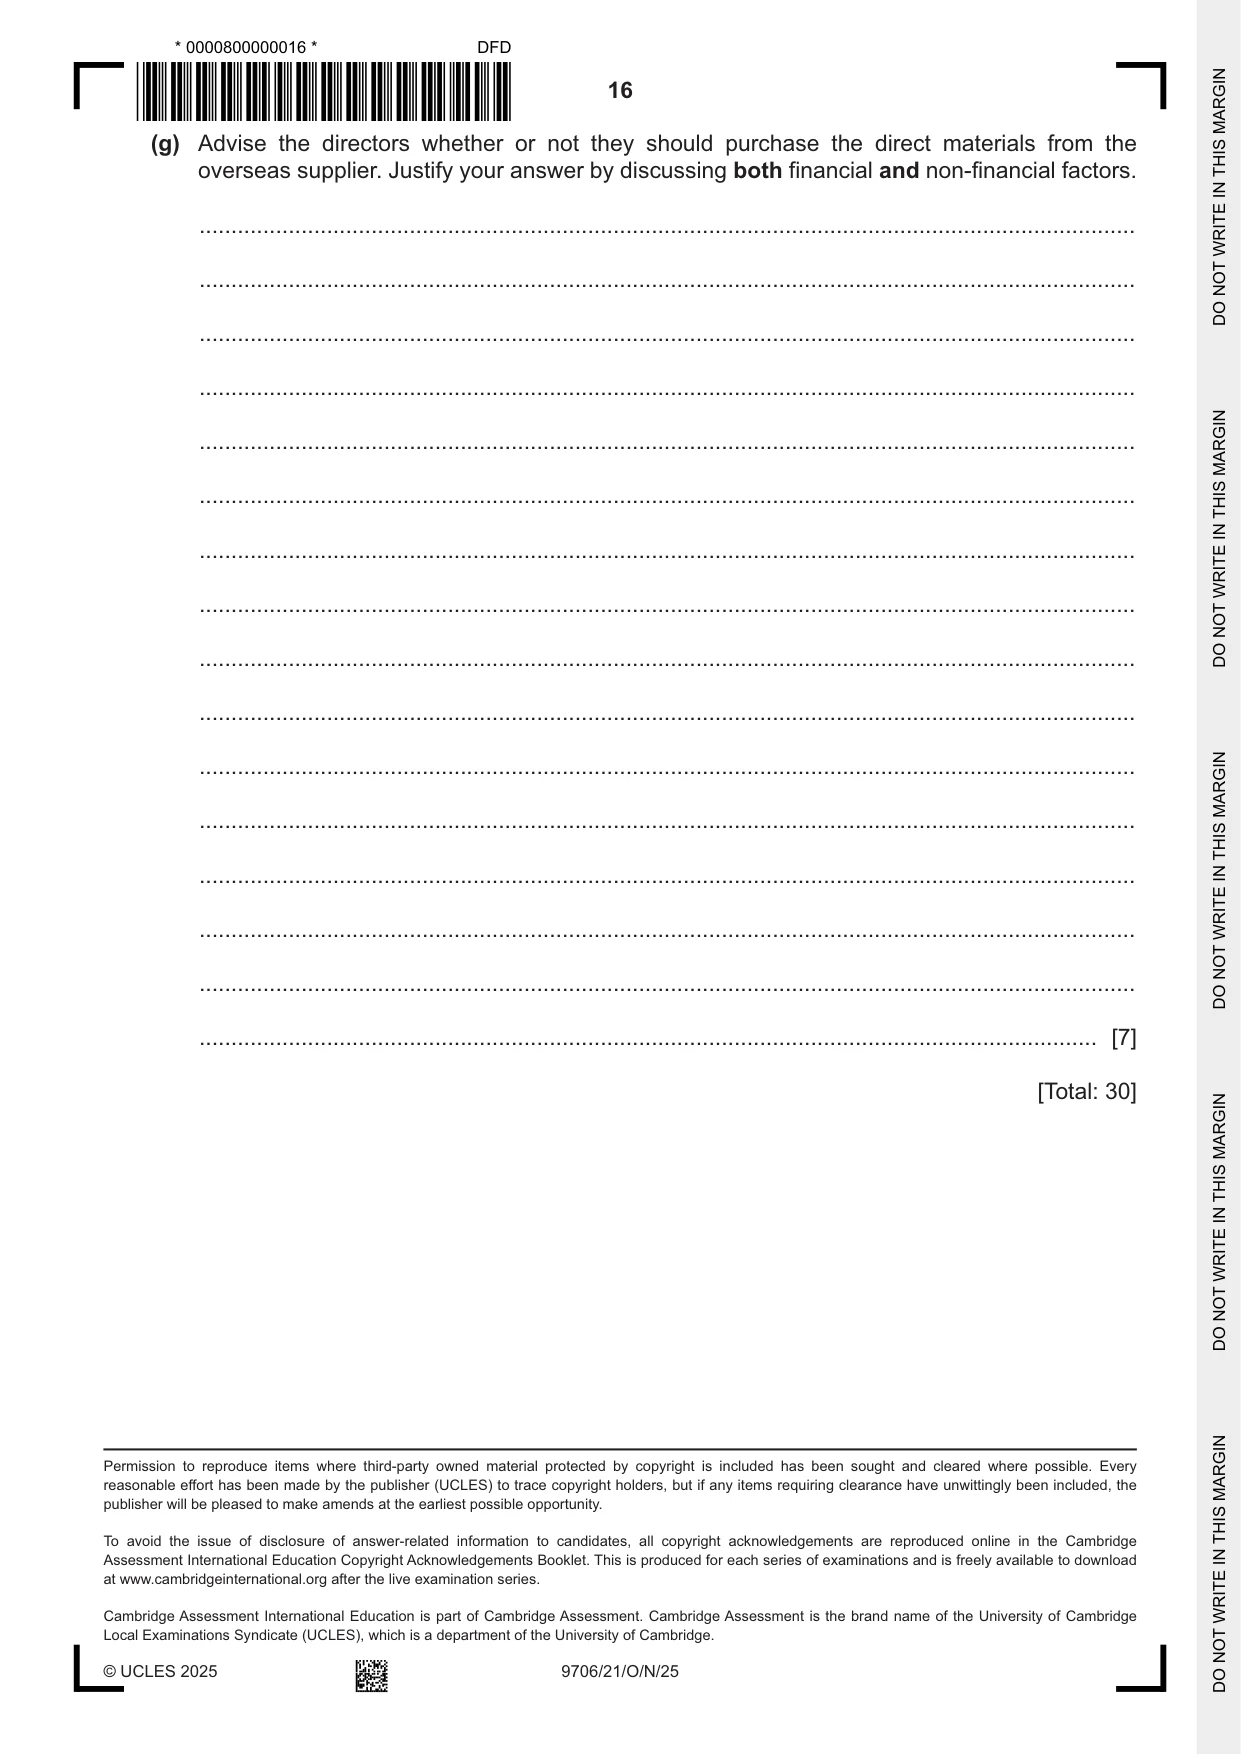
4 B Limited uses absorption costing at one of its factories where two products are made: Wye and Zed. The budgeted production for January 2026 is as follows: units direct labour hours per unit Wye 8 000 2.5 Zed 14 000 1.7 Budgeted overheads for January 2026 are $67 890. (a) Calculate, to two decimal places, the overheads to be absorbed by one unit of each product using the direct labour hour method. Wye ........................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Zed ........................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] (b) Calculate the total amount of overheads absorbed by each product if budgets are met. Wye ........................................................................................................................................... ................................................................................................................................................... Zed ............................................................................................................................................ ................................................................................................................................................... [2] (c) State two reasons why overheads may be under-absorbed. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information A customer has ordered 1200 units of product Zed for delivery in January 2026. The following additional information is available about product Zed. • One unit of product Zed requires direct materials costing $7. • The direct labour rate is $11 per hour. 1 • The selling price of an order is set to achieve a profit margin of 33 3%. (d) Calculate the total selling price for the order. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Additional information B Limited manufactures a single type of product at a second factory where marginal costing is used. The following budgeted information is available. per unit selling price $108 direct materials 2.5 kg at $15.50 per kg direct labour 1.5 hours at $12 per hour The company relies on one supplier who is currently only able to supply a limited quantity of direct materials. As a result, the factory is producing 14 000 units per month, which is 70% of normal capacity. Currently, the supplier delivers direct materials 4 times each month. Each delivery incurs carriage charges of $4300. Fixed costs per month are forecast to be $136 000 including carriage charges. (e) Calculate the current profit per month. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4]
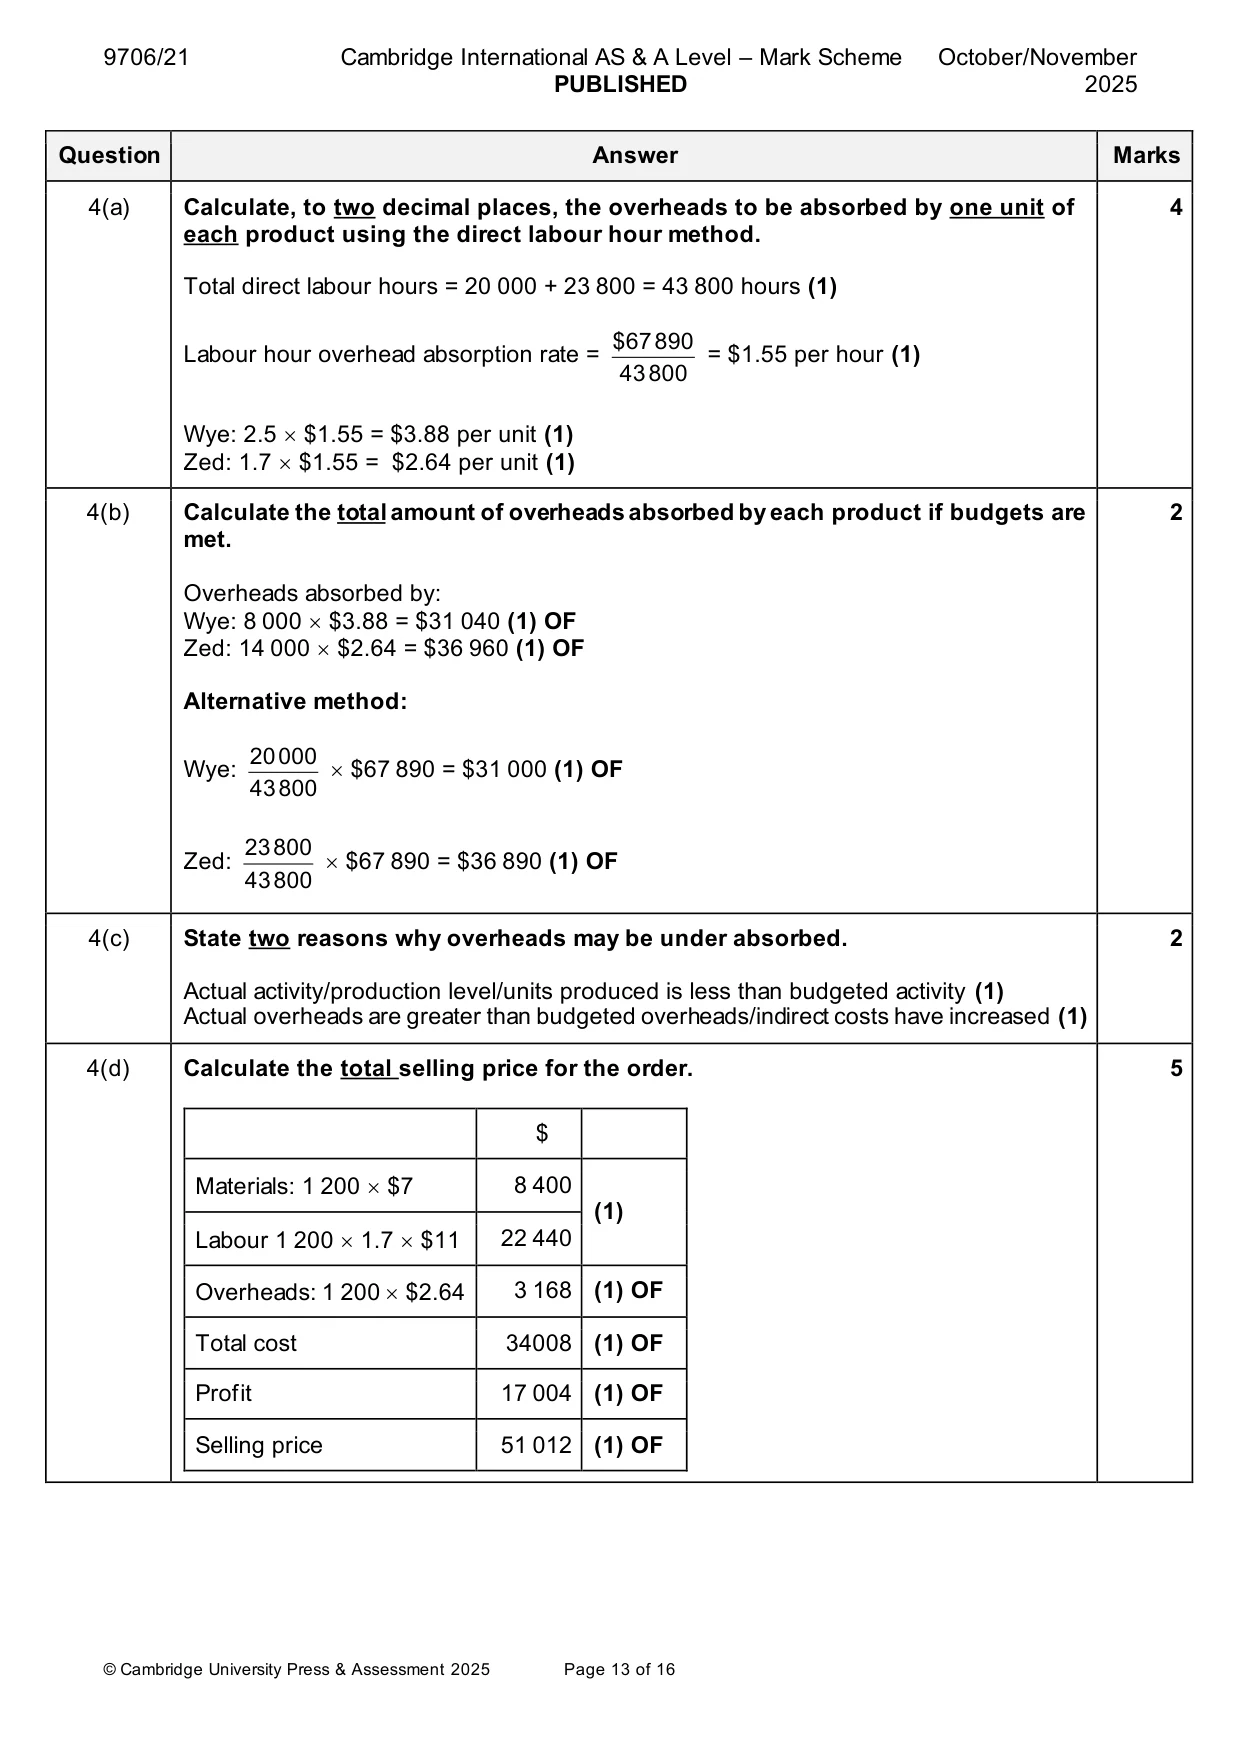
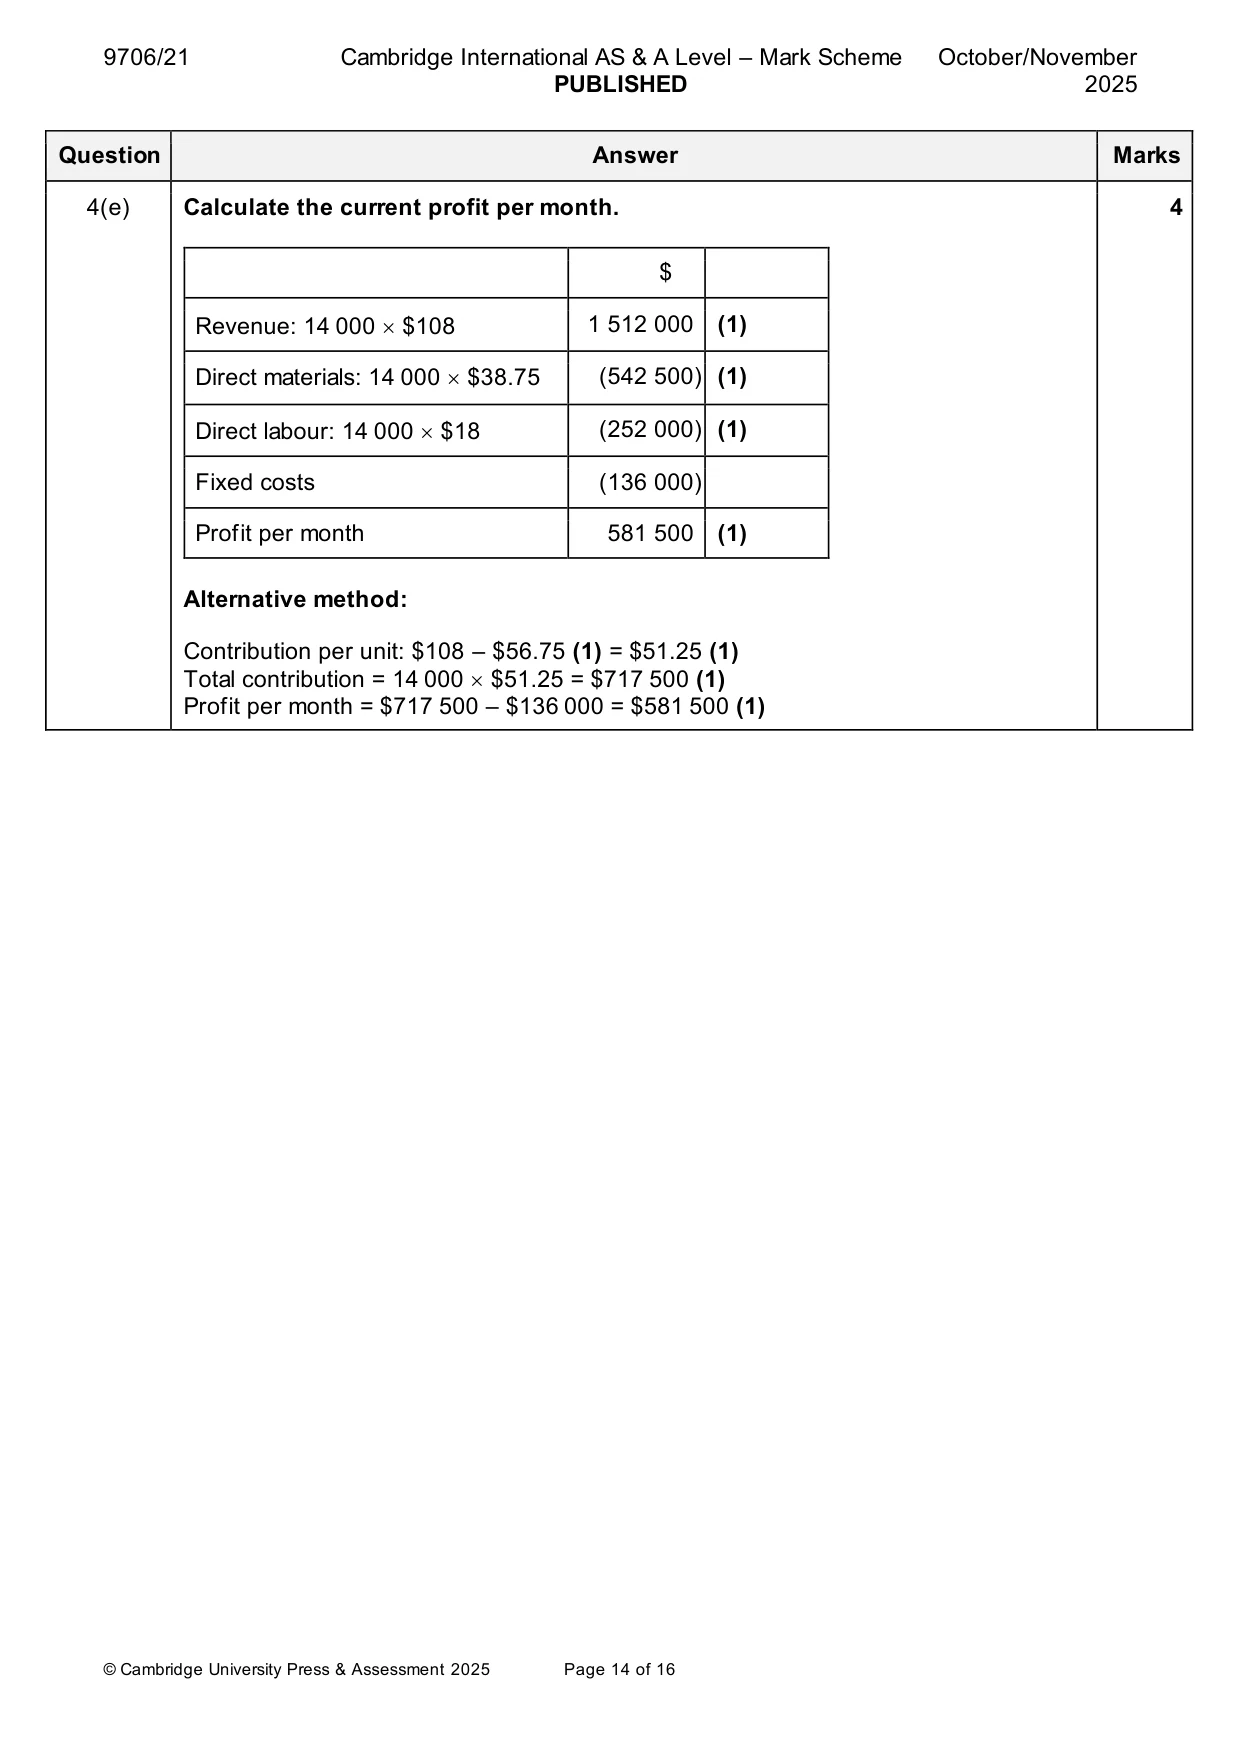
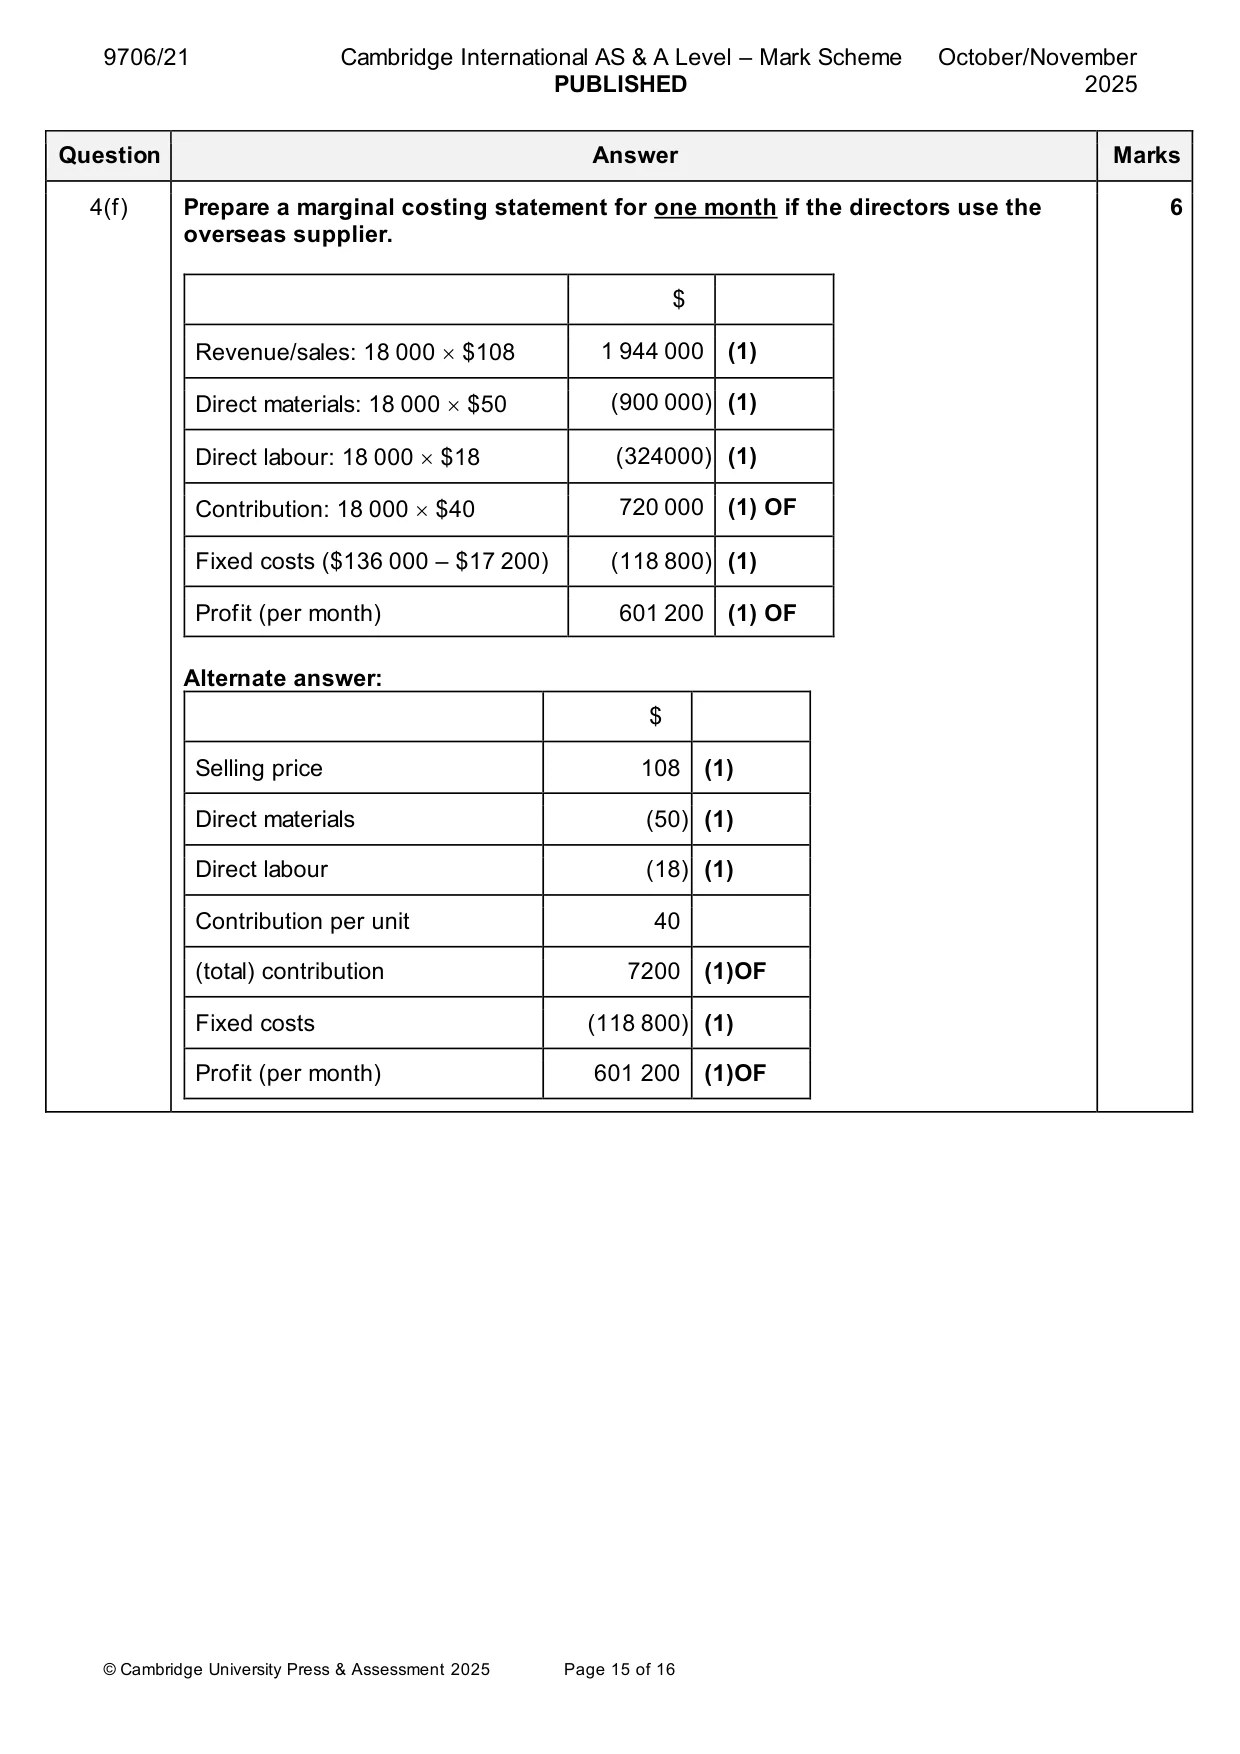
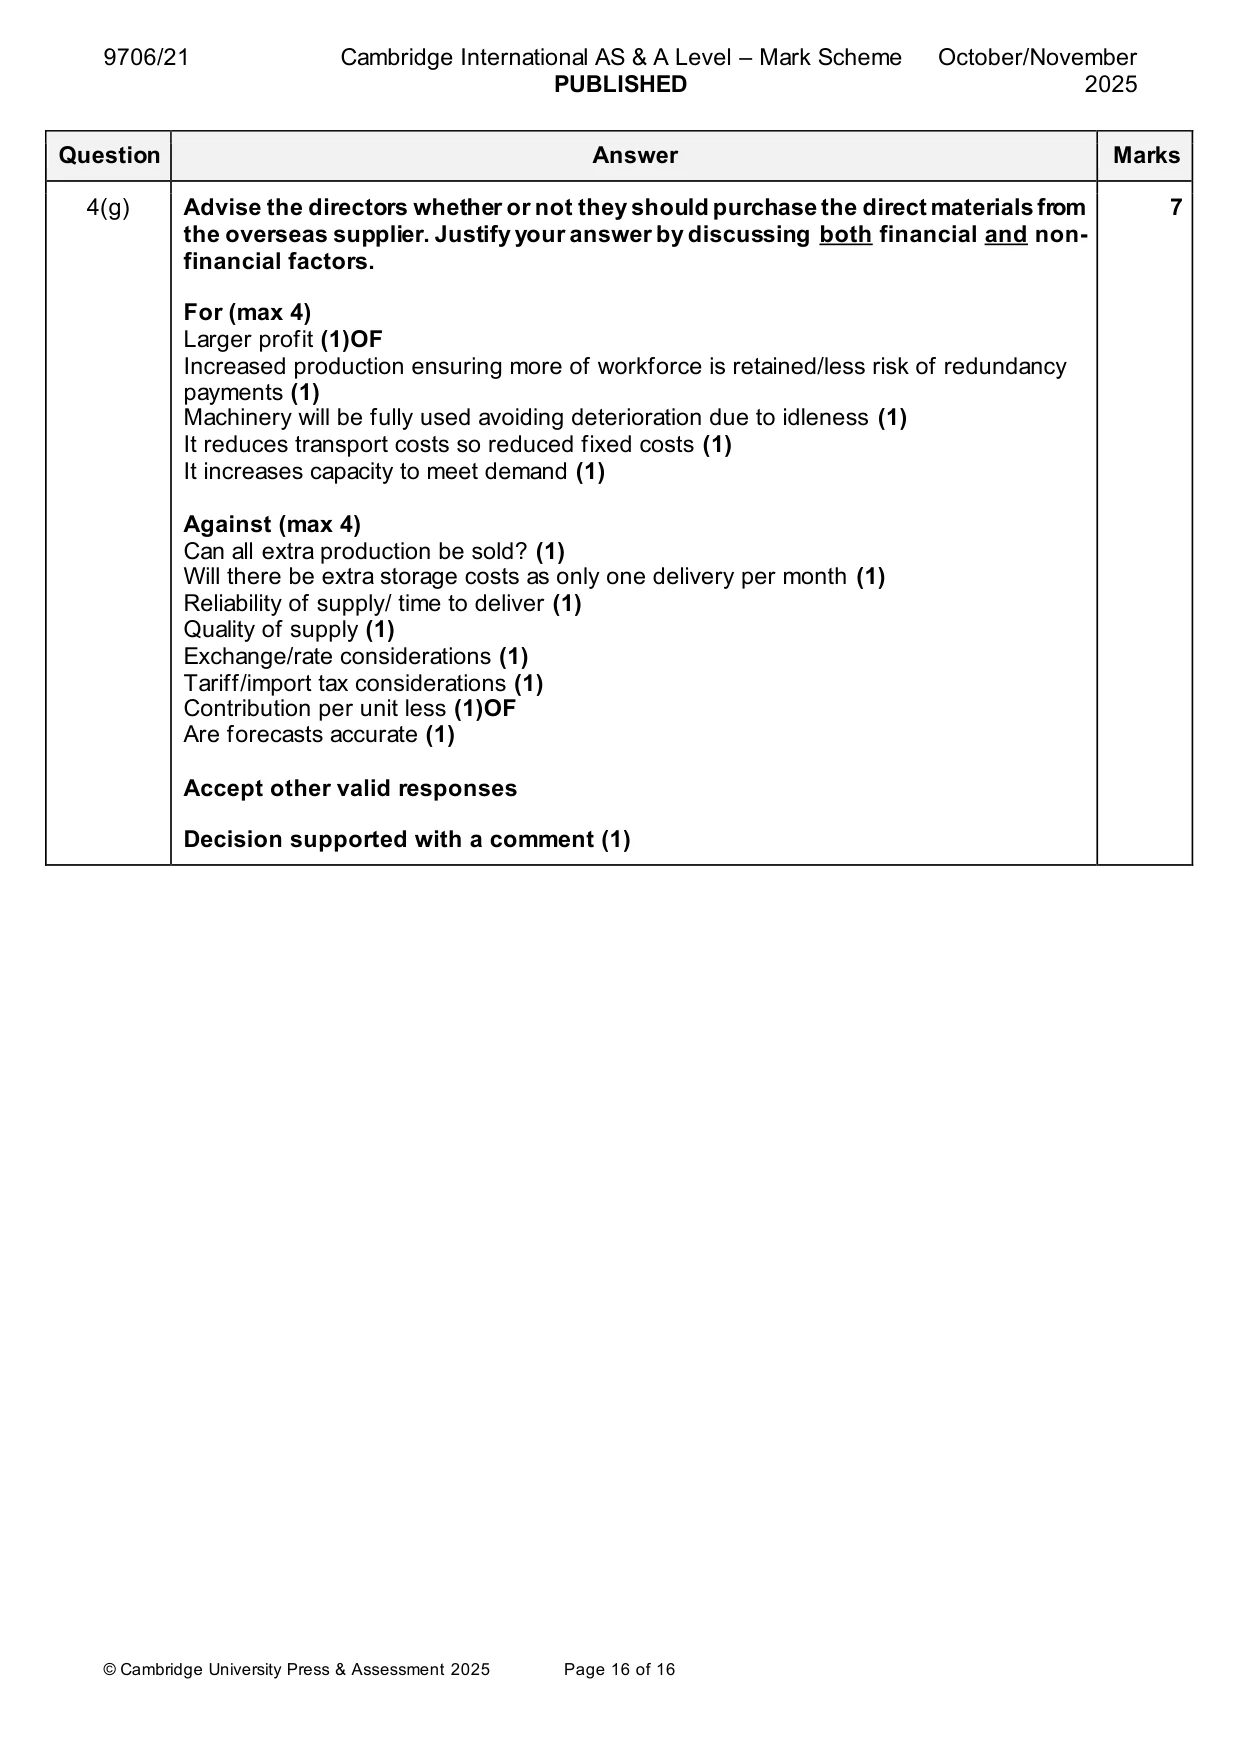
Mark scheme: 4(a) Calculate, to two decimal places, the overheads to be absorbed by one unit of 4 each product using the direct labour hour method. Total direct labour hours = 20 000 + 23 800 = 43 800 hours (1) $67890 Labour hour overhead absorption rate = = $1.55 per hour (1) 43800 Wye: 2.5 $1.55 = $3.88 per unit (1) Zed: 1.7 $1.55 = $2.64 per unit (1) 4(b) Calculate the total amount of overheads absorbed by each product if budgets are 2 met. Overheads absorbed by: Wye: 8 000 $3.88 = $31 040 (1) OF Zed: 14 000 $2.64 = $36 960 (1) OF Alternative method: 20000 Wye: $67 890 = $31 000 (1) OF 43800 23800 Zed: $67 890 = $36 890 (1) OF 43800 4(c) State two reasons why overheads may be under absorbed. 2 Actual activity/production level/units produced is less than budgeted activity (1) Actual overheads are greater than budgeted overheads/indirect costs have increased (1) 4(d) Calculate the total selling price for the order. 5 $ Materials: 1 200 $7 8 400 (1) Labour 1 200 1.7 $11 22 440 Overheads: 1 200 $2.64 3 168 (1) OF Total cost 34008 (1) OF Profit 17 004 (1) OF Selling price 51 012 (1) OF 4(e) Calculate the current profit per month. 4 $ Revenue: 14 000 $108 1 512 000 (1) Direct materials: 14 000 $38.75 (542 500) (1) Direct labour: 14 000 $18 (252 000) (1) Fixed costs (136 000) Profit per month 581 500 (1) Alternative method: Contribution per unit: $108 – $56.75 (1) = $51.25 (1) Total contribution = 14 000 $51.25 = $717 500 (1) Profit per month = $717 500 – $136 000 = $581 500 (1) 4(f) Prepare a marginal costing statement for one month if the directors use the 6 overseas supplier. $ Revenue/sales: 18 000 $108 1 944 000 (1) Direct materials: 18 000 $50 (900 000) (1) Direct labour: 18 000 $18 (324000) (1) Contribution: 18 000 $40 720 000 (1) OF Fixed costs ($136 000 – $17 200) (118 800) (1) Profit (per month) 601 200 (1) OF Alternate answer: $ Selling price 108 (1) Direct materials (50) (1) Direct labour (18) (1) Contribution per unit 40 (total) contribution 7200 (1)OF Fixed costs (118 800) (1) Profit (per month) 601 200 (1)OF 4(g) Advise the directors whether or not they should purchase the direct materials from 7 the overseas supplier. Justify your answer by discussing both financial and non- financial factors. For (max 4) Larger profit (1)OF Increased production ensuring more of workforce is retained/less risk of redundancy payments (1) Machinery will be fully used avoiding deterioration due to idleness (1) It reduces transport costs so reduced fixed costs (1) It increases capacity to meet demand (1) Against (max 4) Can all extra production be sold? (1) Will there be extra storage costs as only one delivery per month (1) Reliability of supply/ time to deliver (1) Quality of supply (1) Exchange/rate considerations (1) Tariff/import tax considerations (1) Contribution per unit less (1)OF Are forecasts accurate (1) Accept other valid responses Decision supported with a comment (1)
What was in this paper
The subtopics covered by these 4 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2025 Oct/Nov, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.