Cambridge A Level Accounting 9706 — 2023 Oct/Nov Paper 2 · Variant 2
9706/22/O/N/23 · 4 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme15 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · P Limited sells electronic goods online
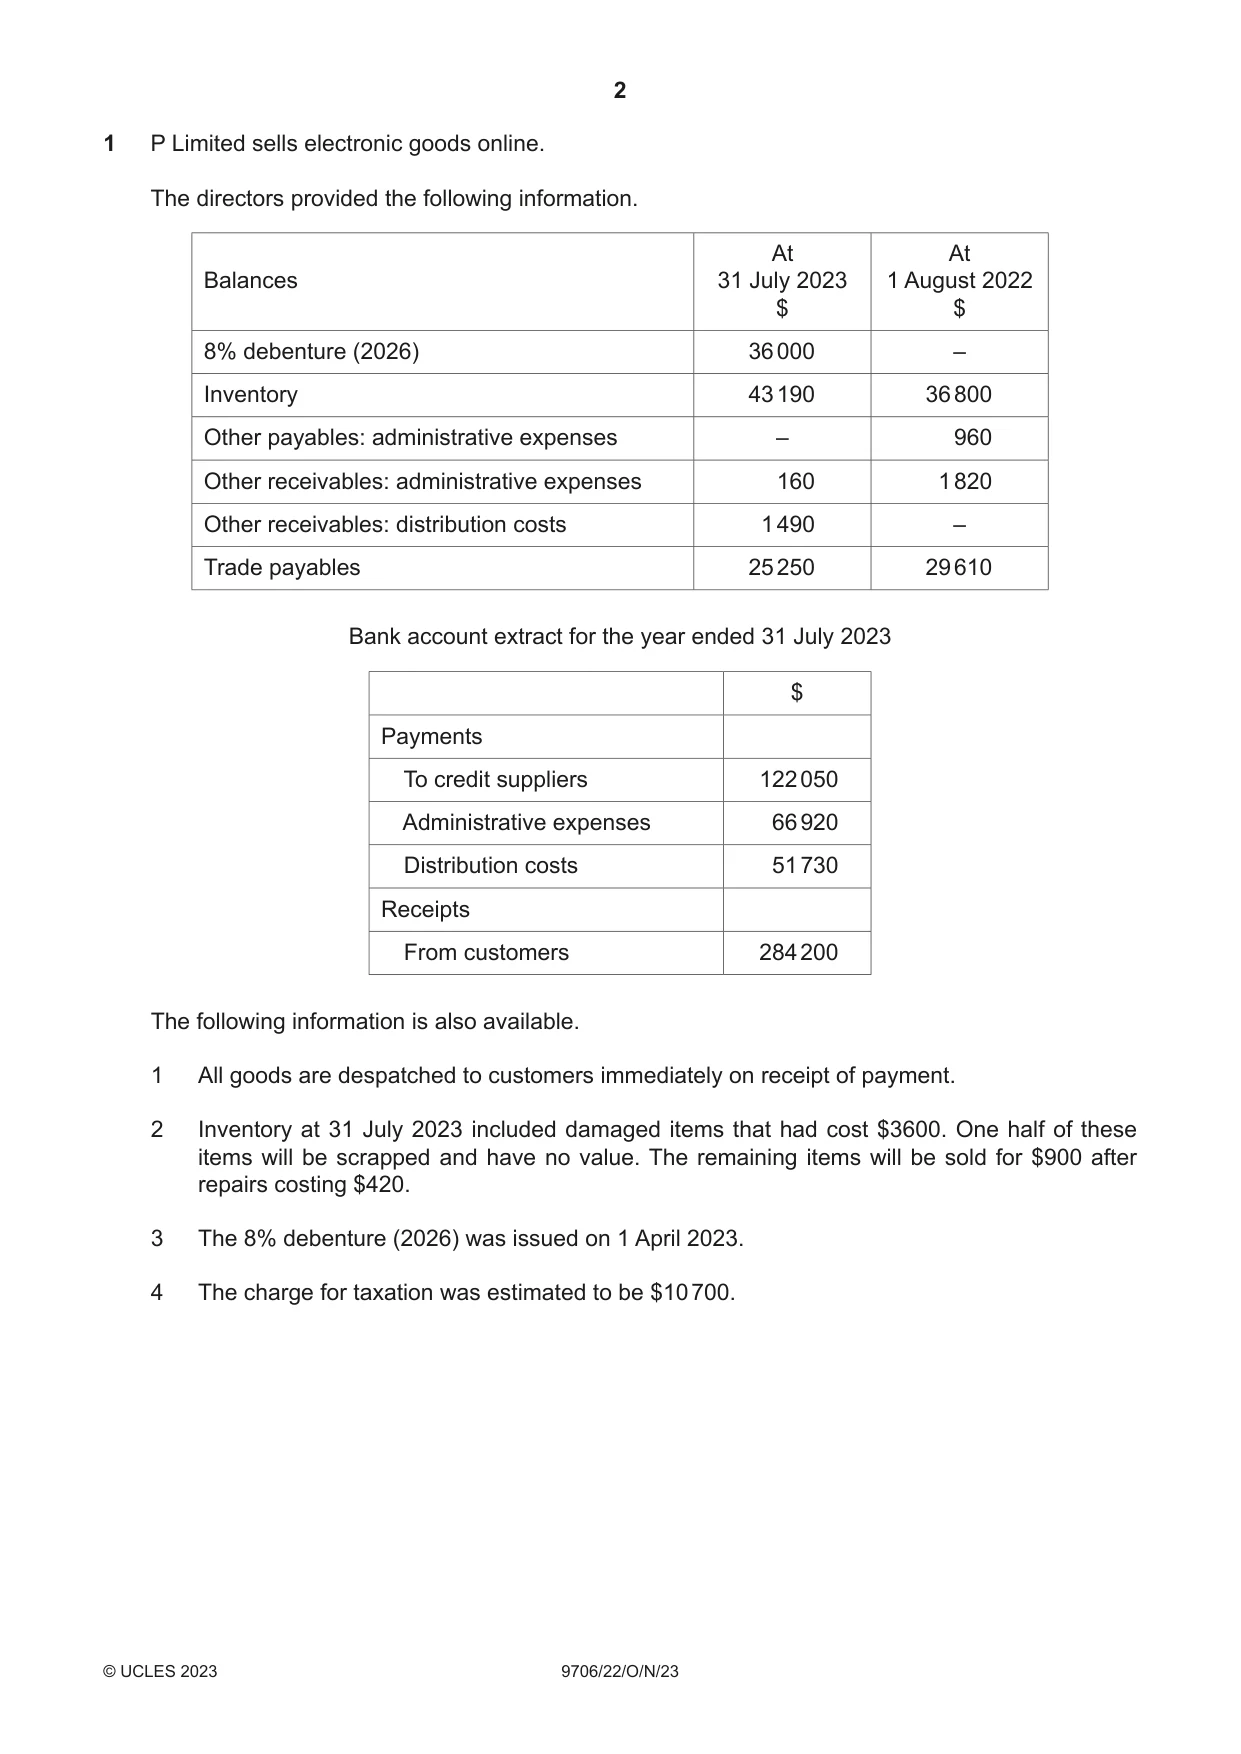
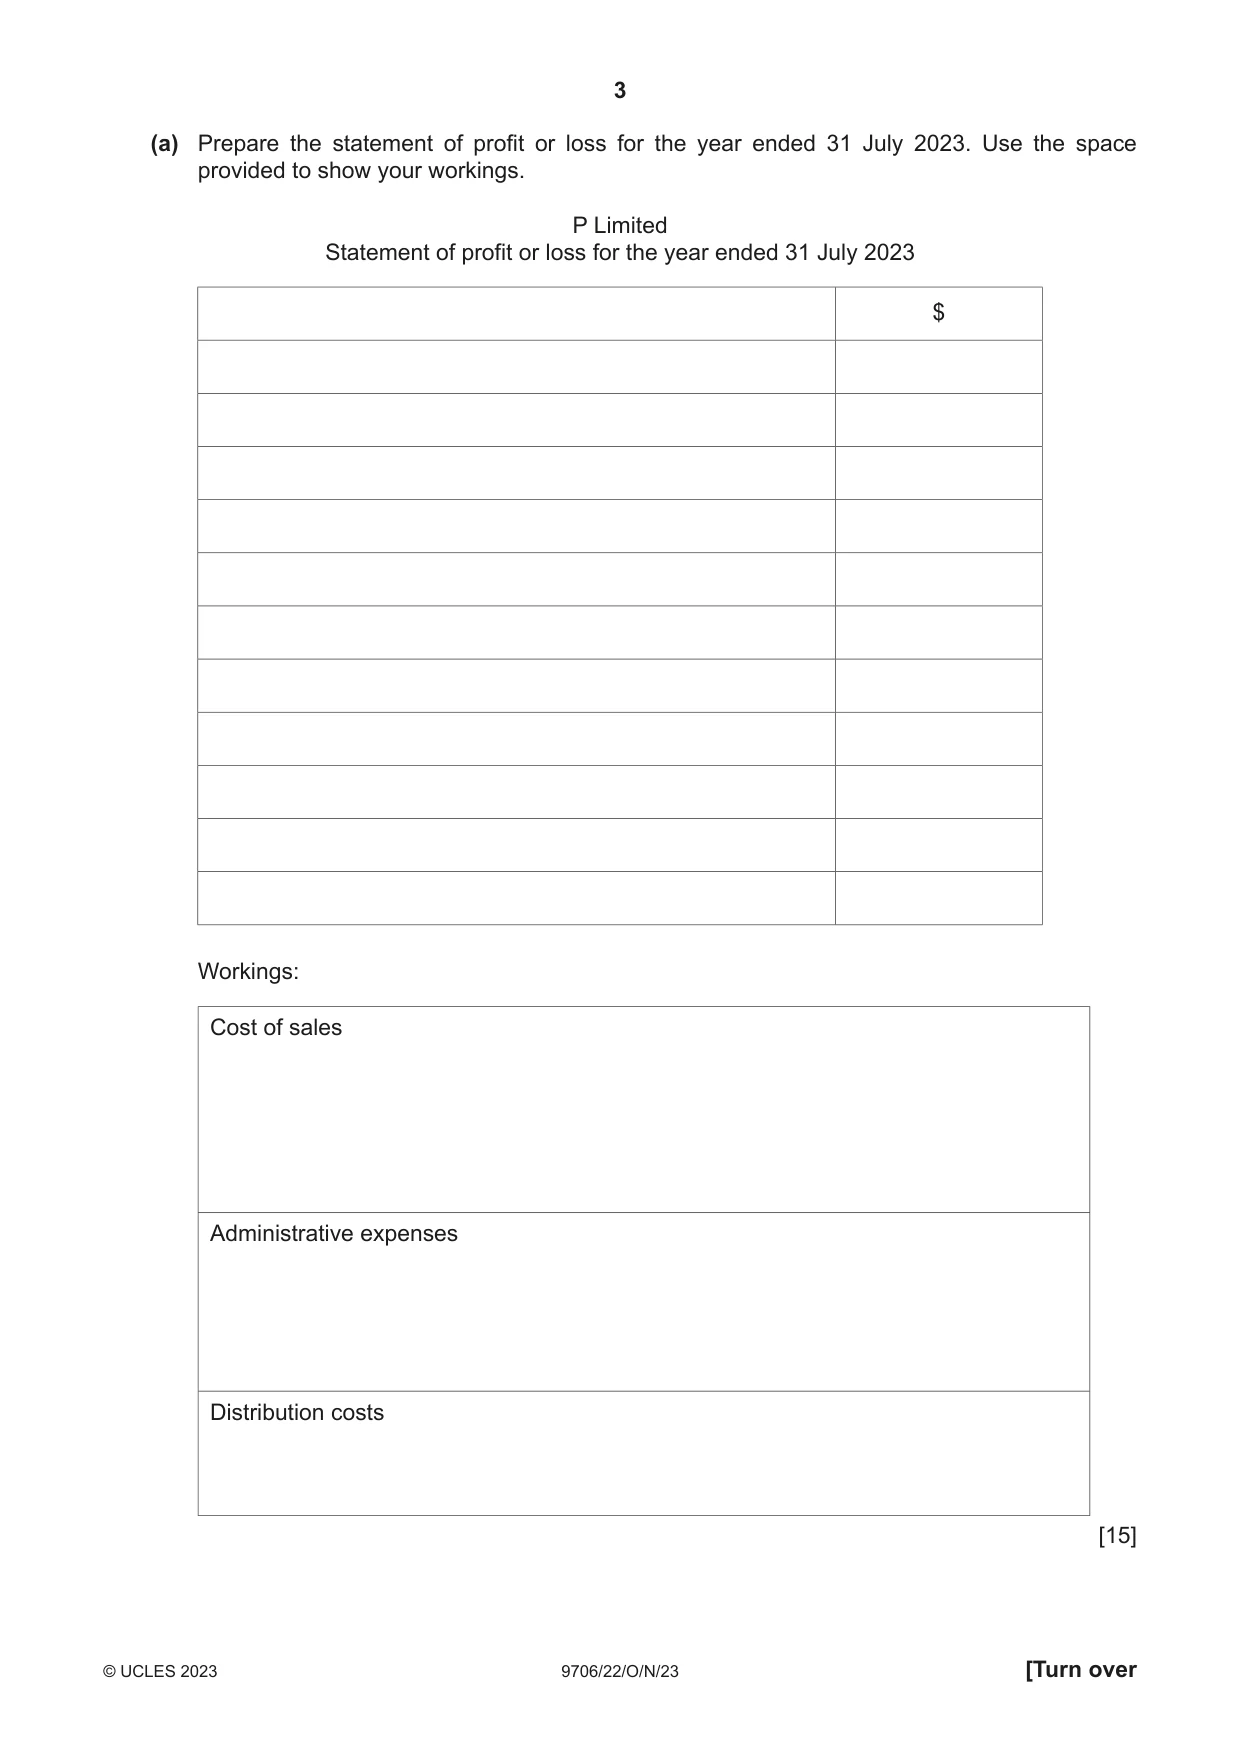
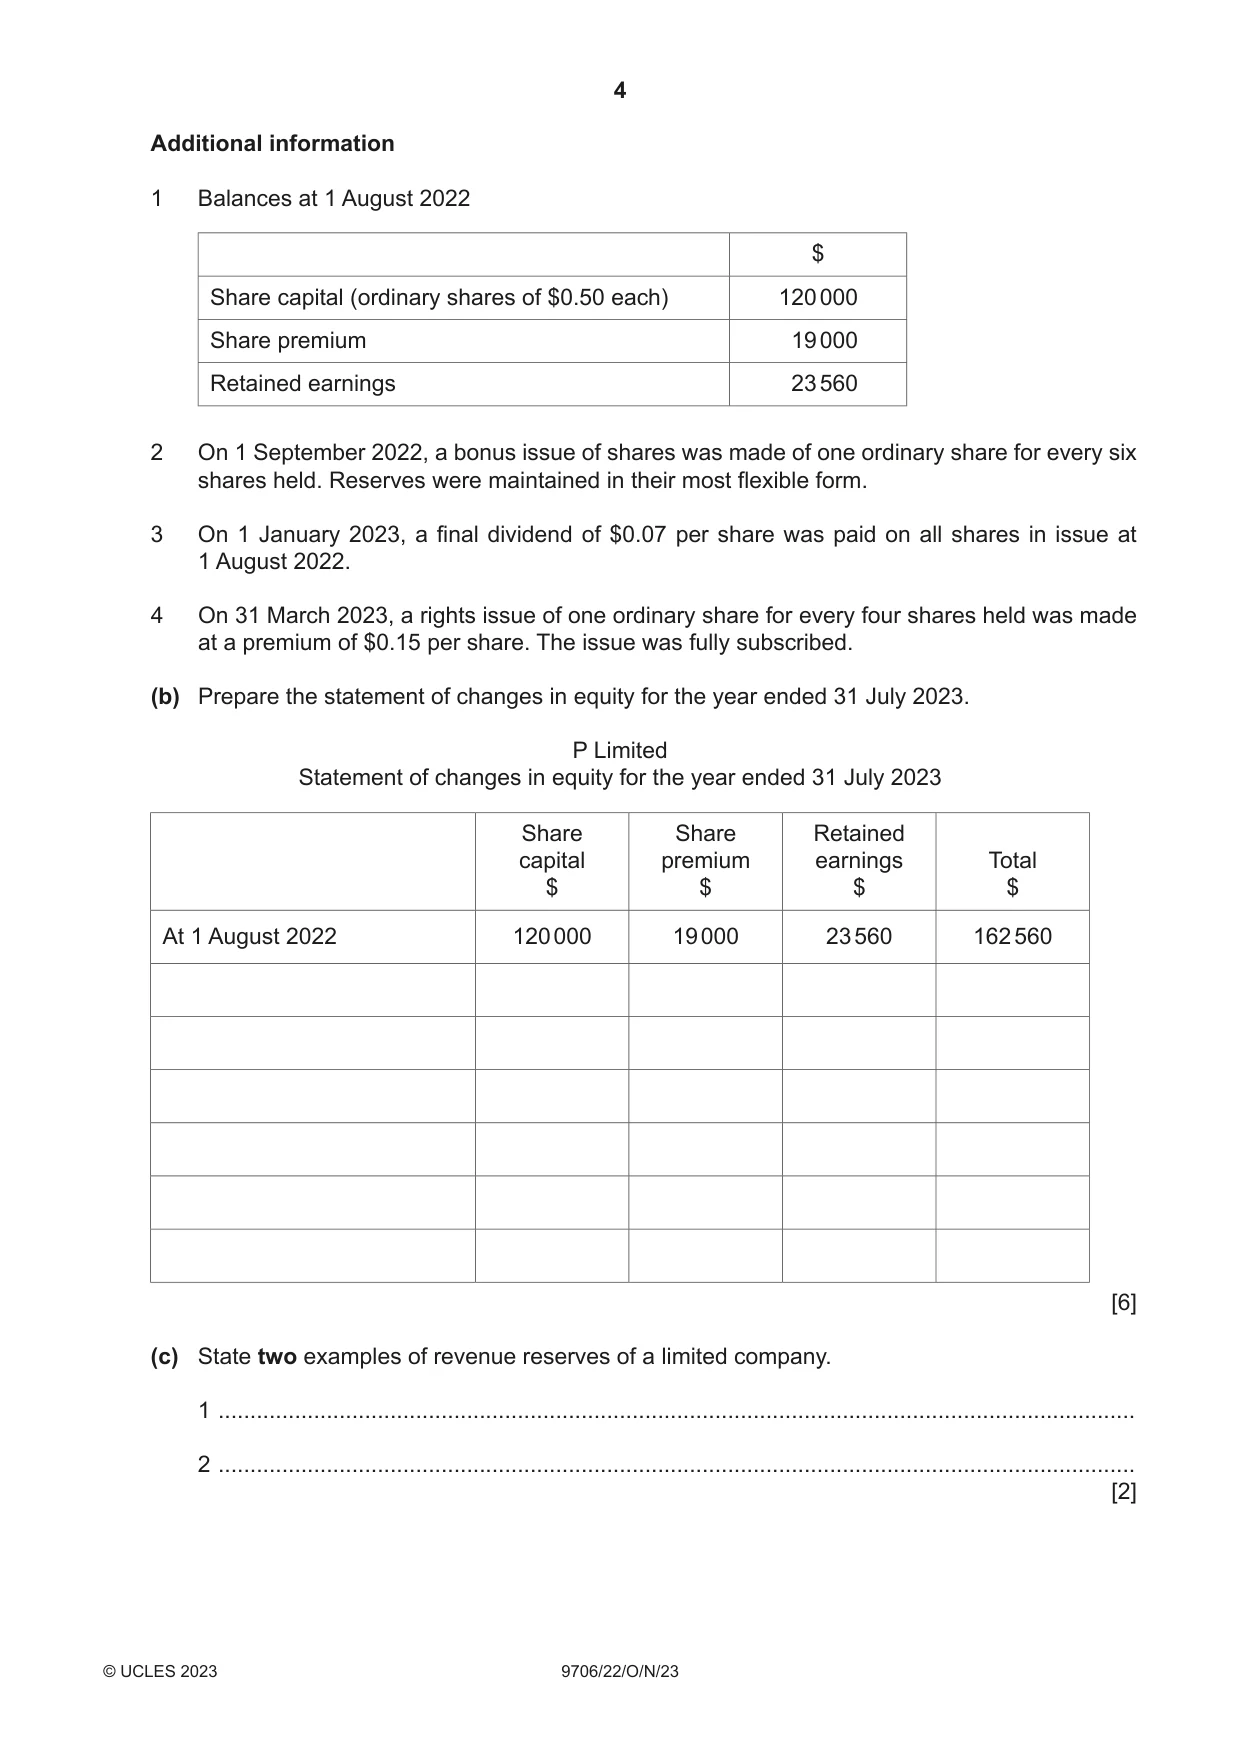
1 P Limited sells electronic goods online. The directors provided the following information. At At Balances 31 July 2023 1 August 2022 $ $ 8% debenture (2026) 36 000 – Inventory 43 190 36 800 Other payables: administrative expenses – 960 Other receivables: administrative expenses 160 1 820 Other receivables: distribution costs 1 490 – Trade payables 25 250 29 610 Bank account extract for the year ended 31 July 2023 $ Payments To credit suppliers 122 050 Administrative expenses 66 920 Distribution costs 51 730 Receipts From customers 284 200 The following information is also available. 1 All goods are despatched to customers immediately on receipt of payment. 2 Inventory at 31 July 2023 included damaged items that had cost $3600. One half of these items will be scrapped and have no value. The remaining items will be sold for $900 after repairs costing $420. 3 The 8% debenture (2026) was issued on 1 April 2023. 4 The charge for taxation was estimated to be $10 700. (a) Prepare the statement of profit or loss for the year ended 31 July 2023. Use the space provided to show your workings. P Limited Statement of profit or loss for the year ended 31 July 2023 $ Workings: Cost of sales Administrative expenses Distribution costs [15] Additional information 1 Balances at 1 August 2022 $ Share capital (ordinary shares of $0.50 each) 120 000 Share premium 19 000 Retained earnings 23 560
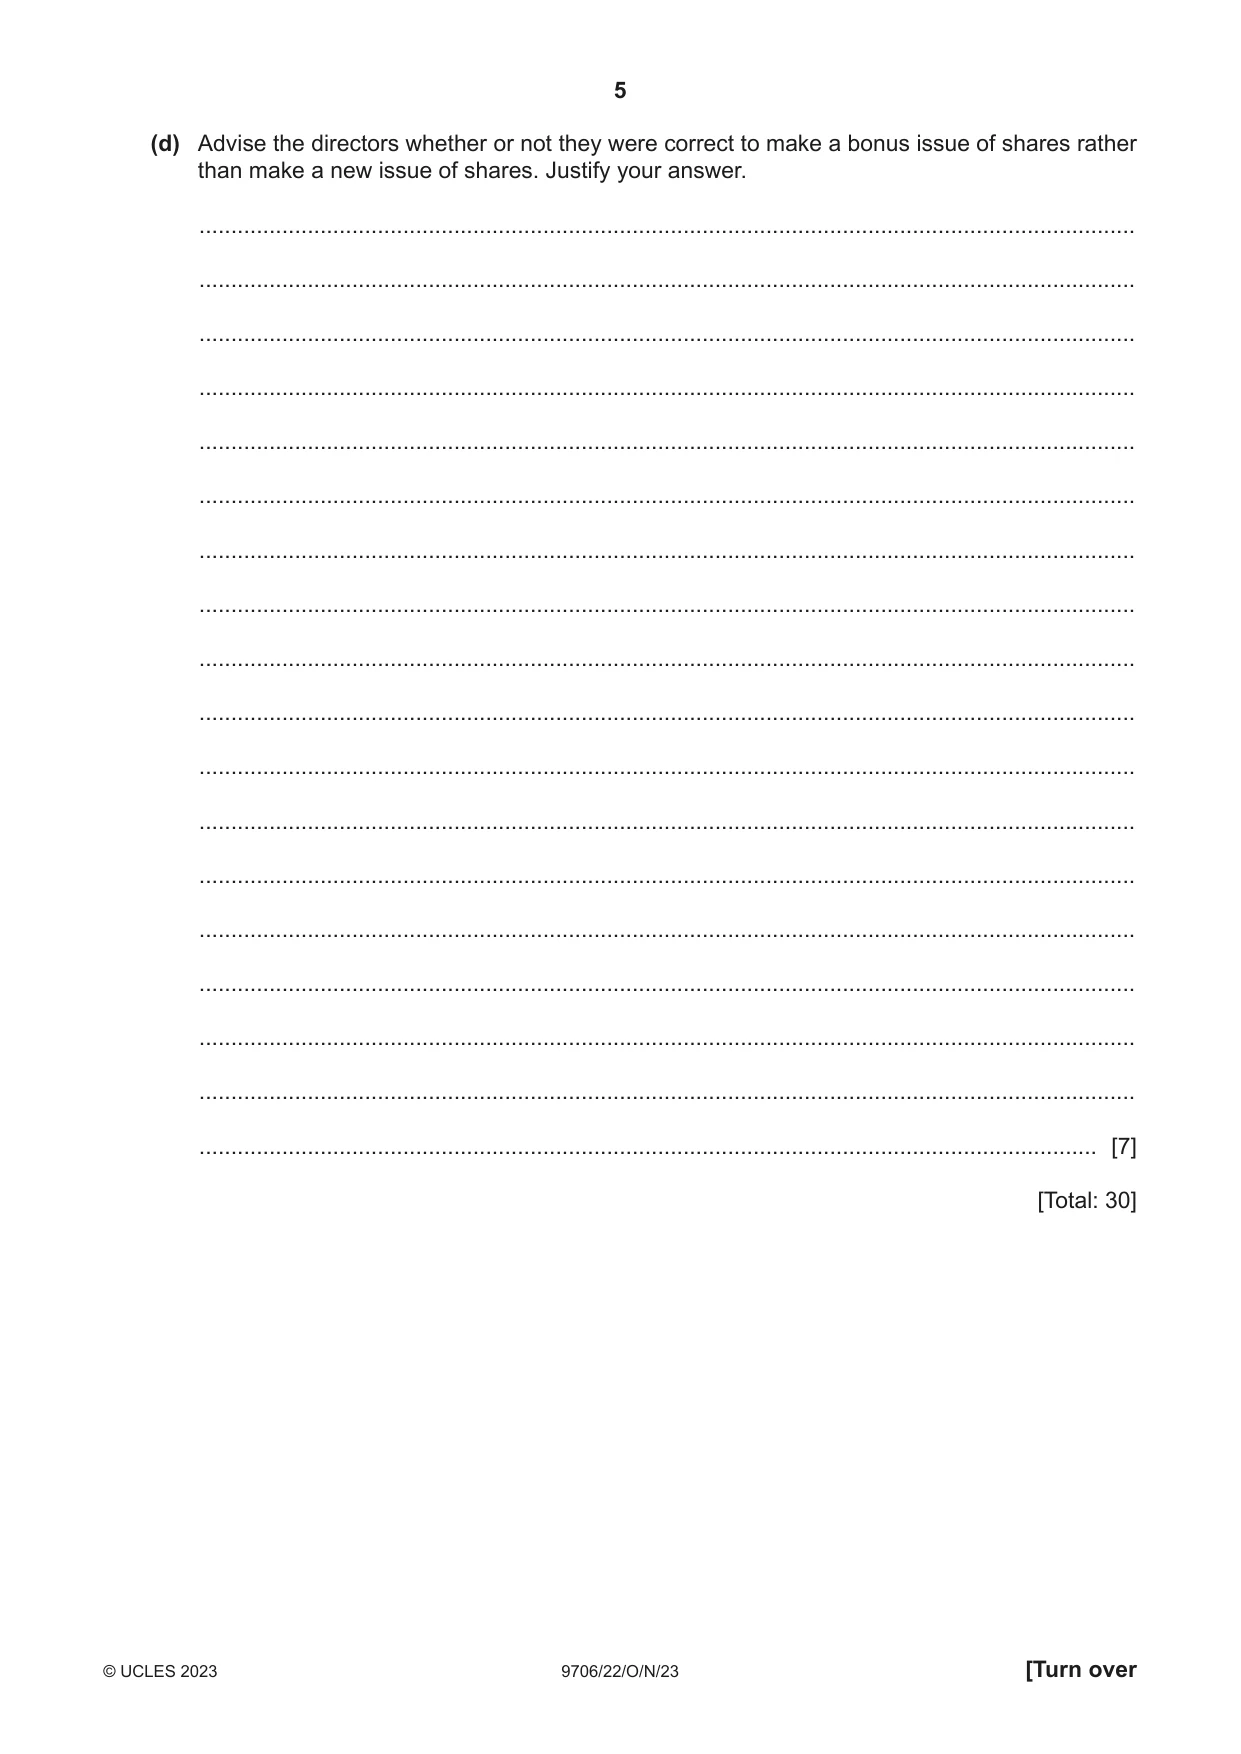
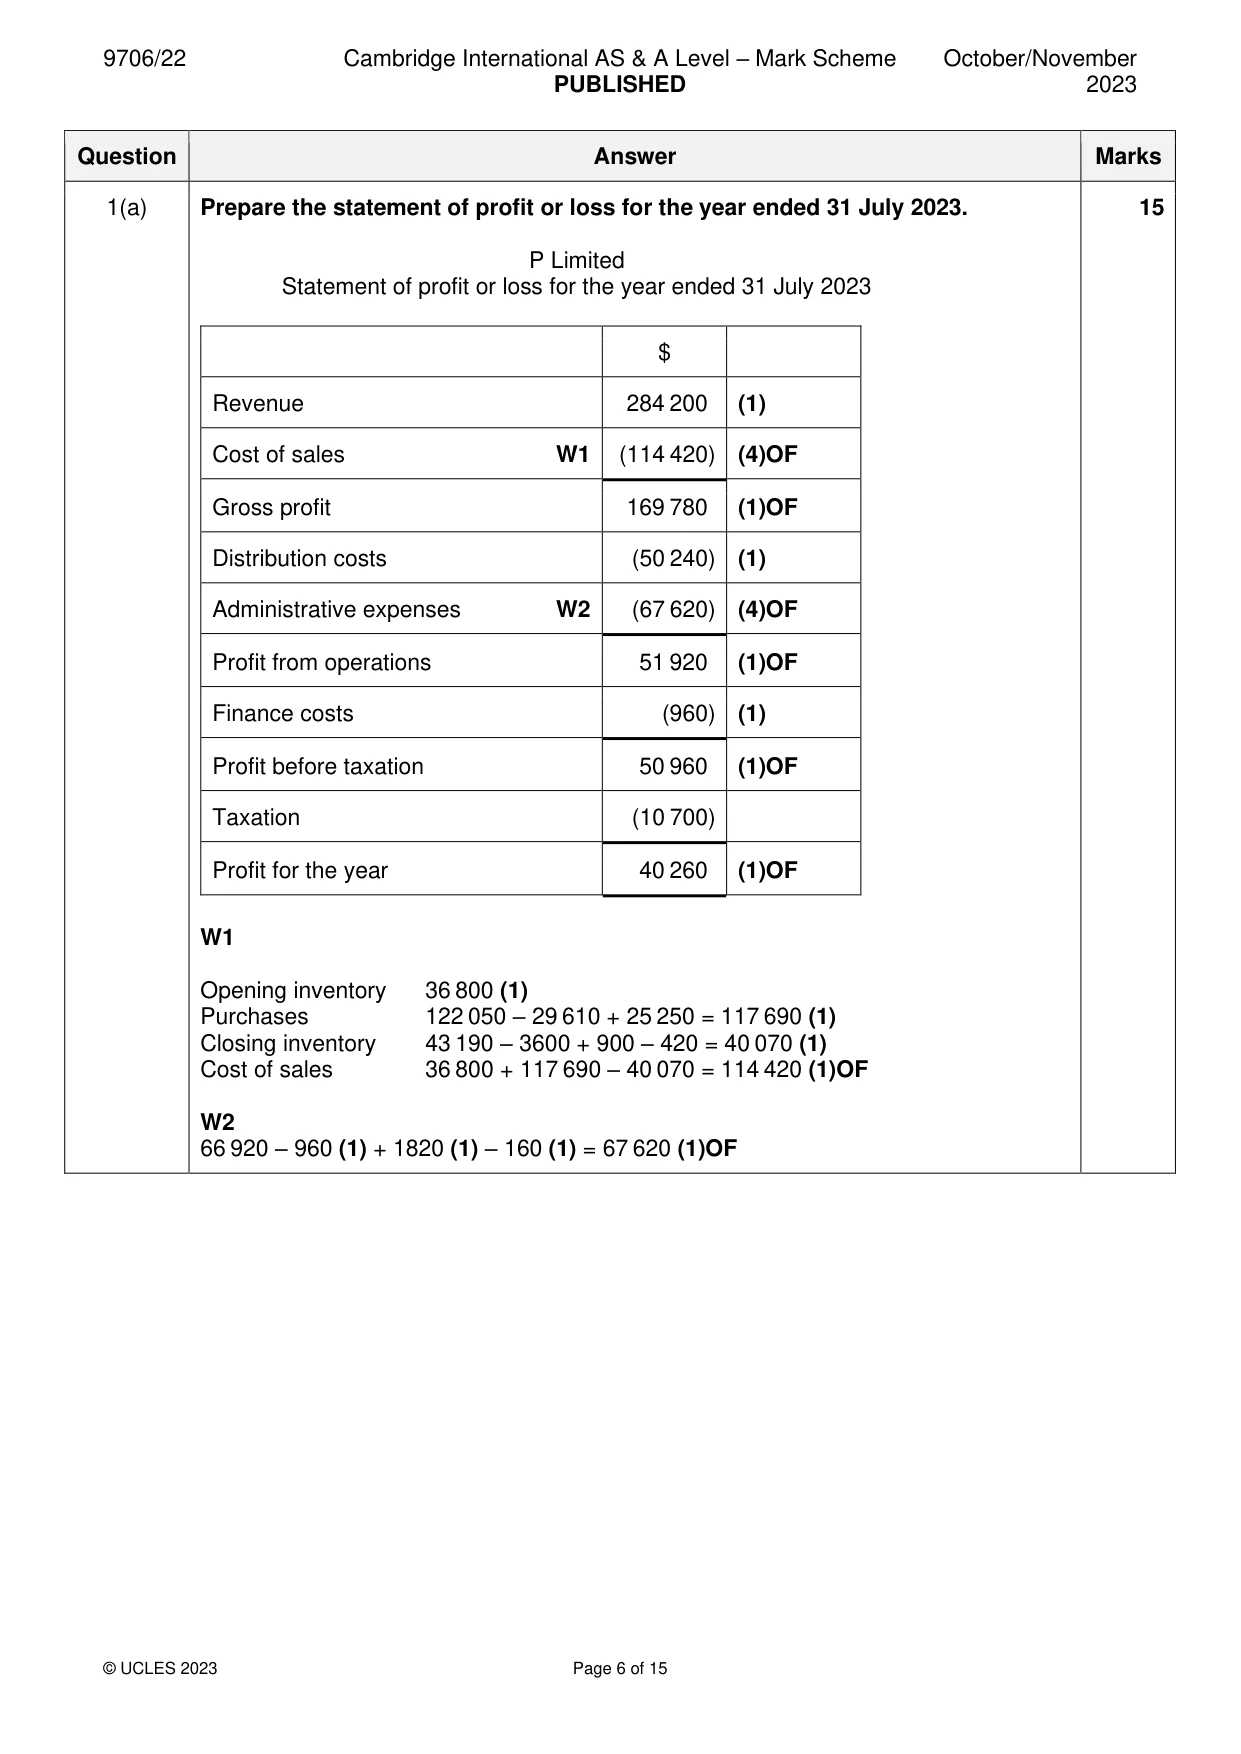
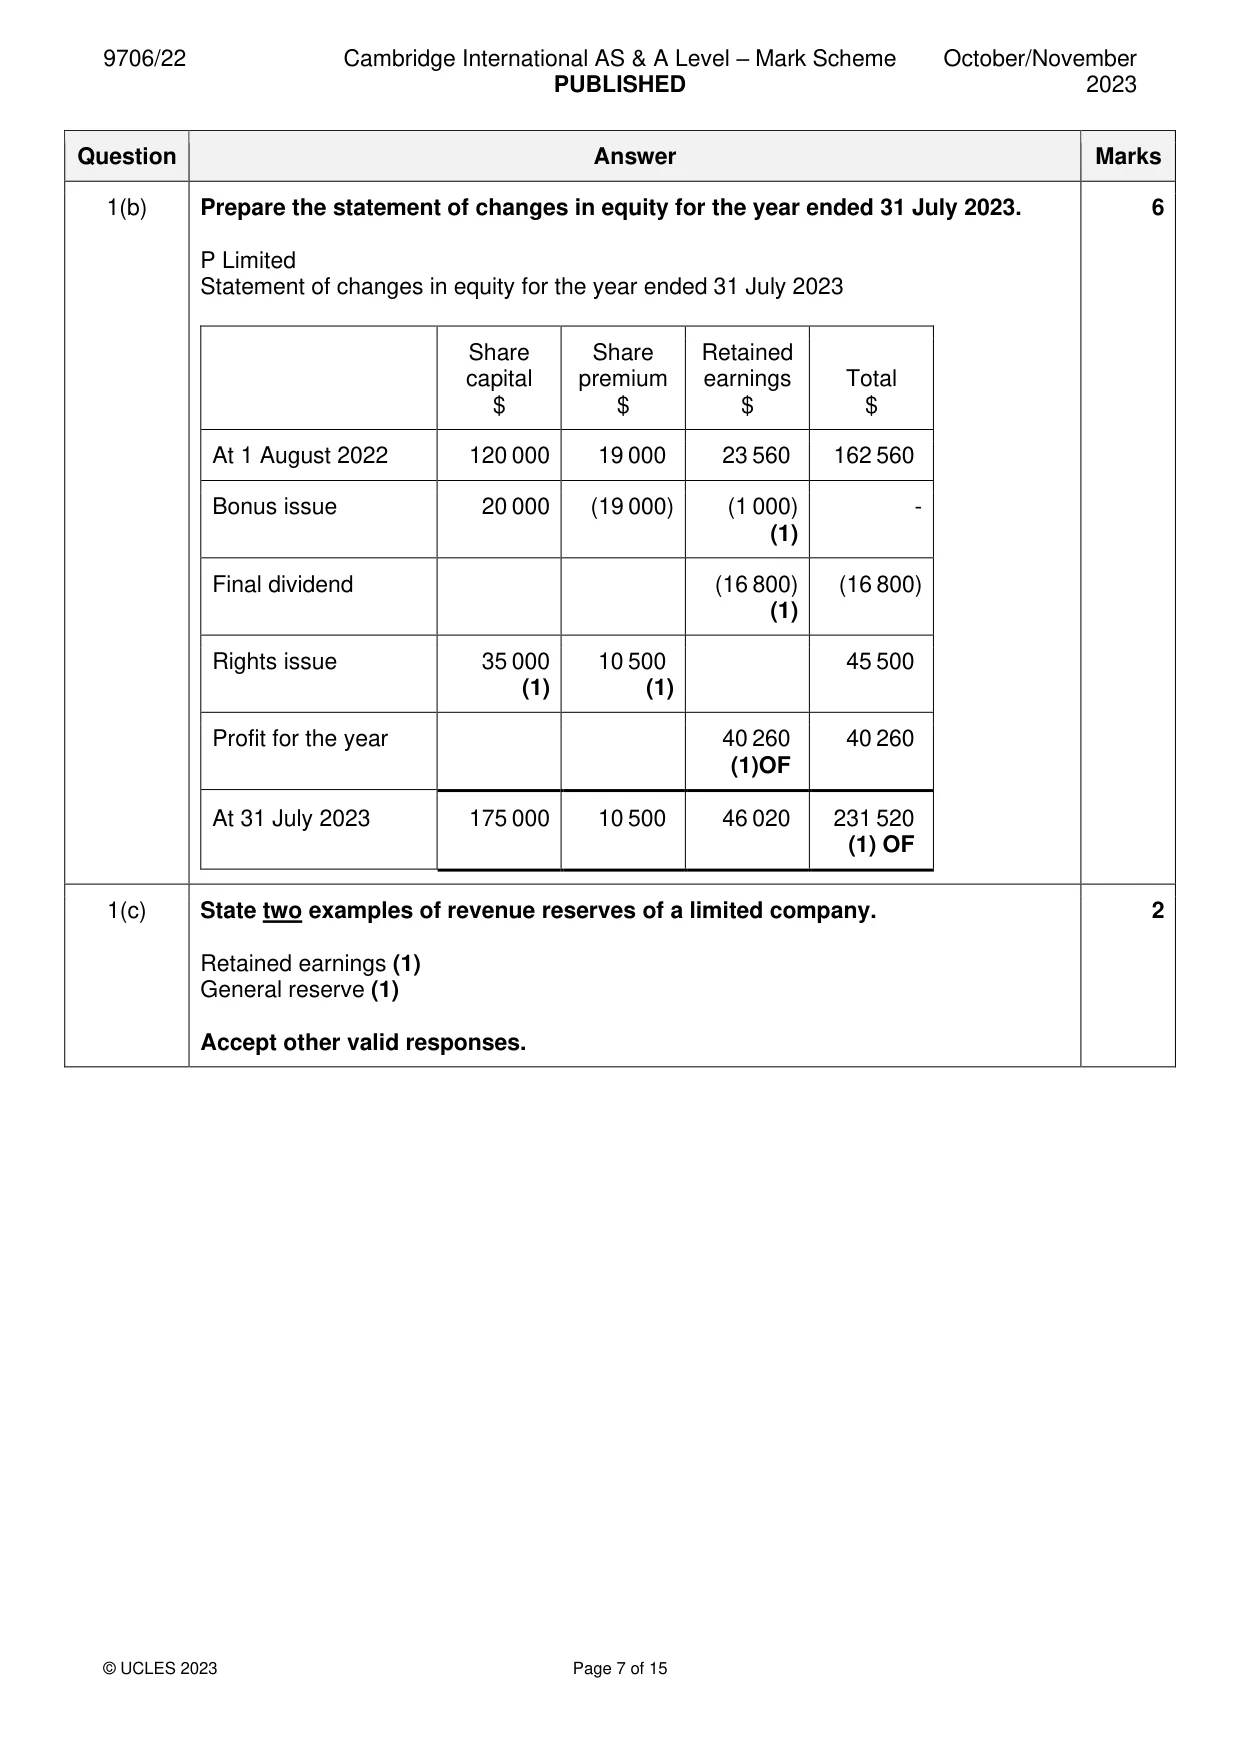
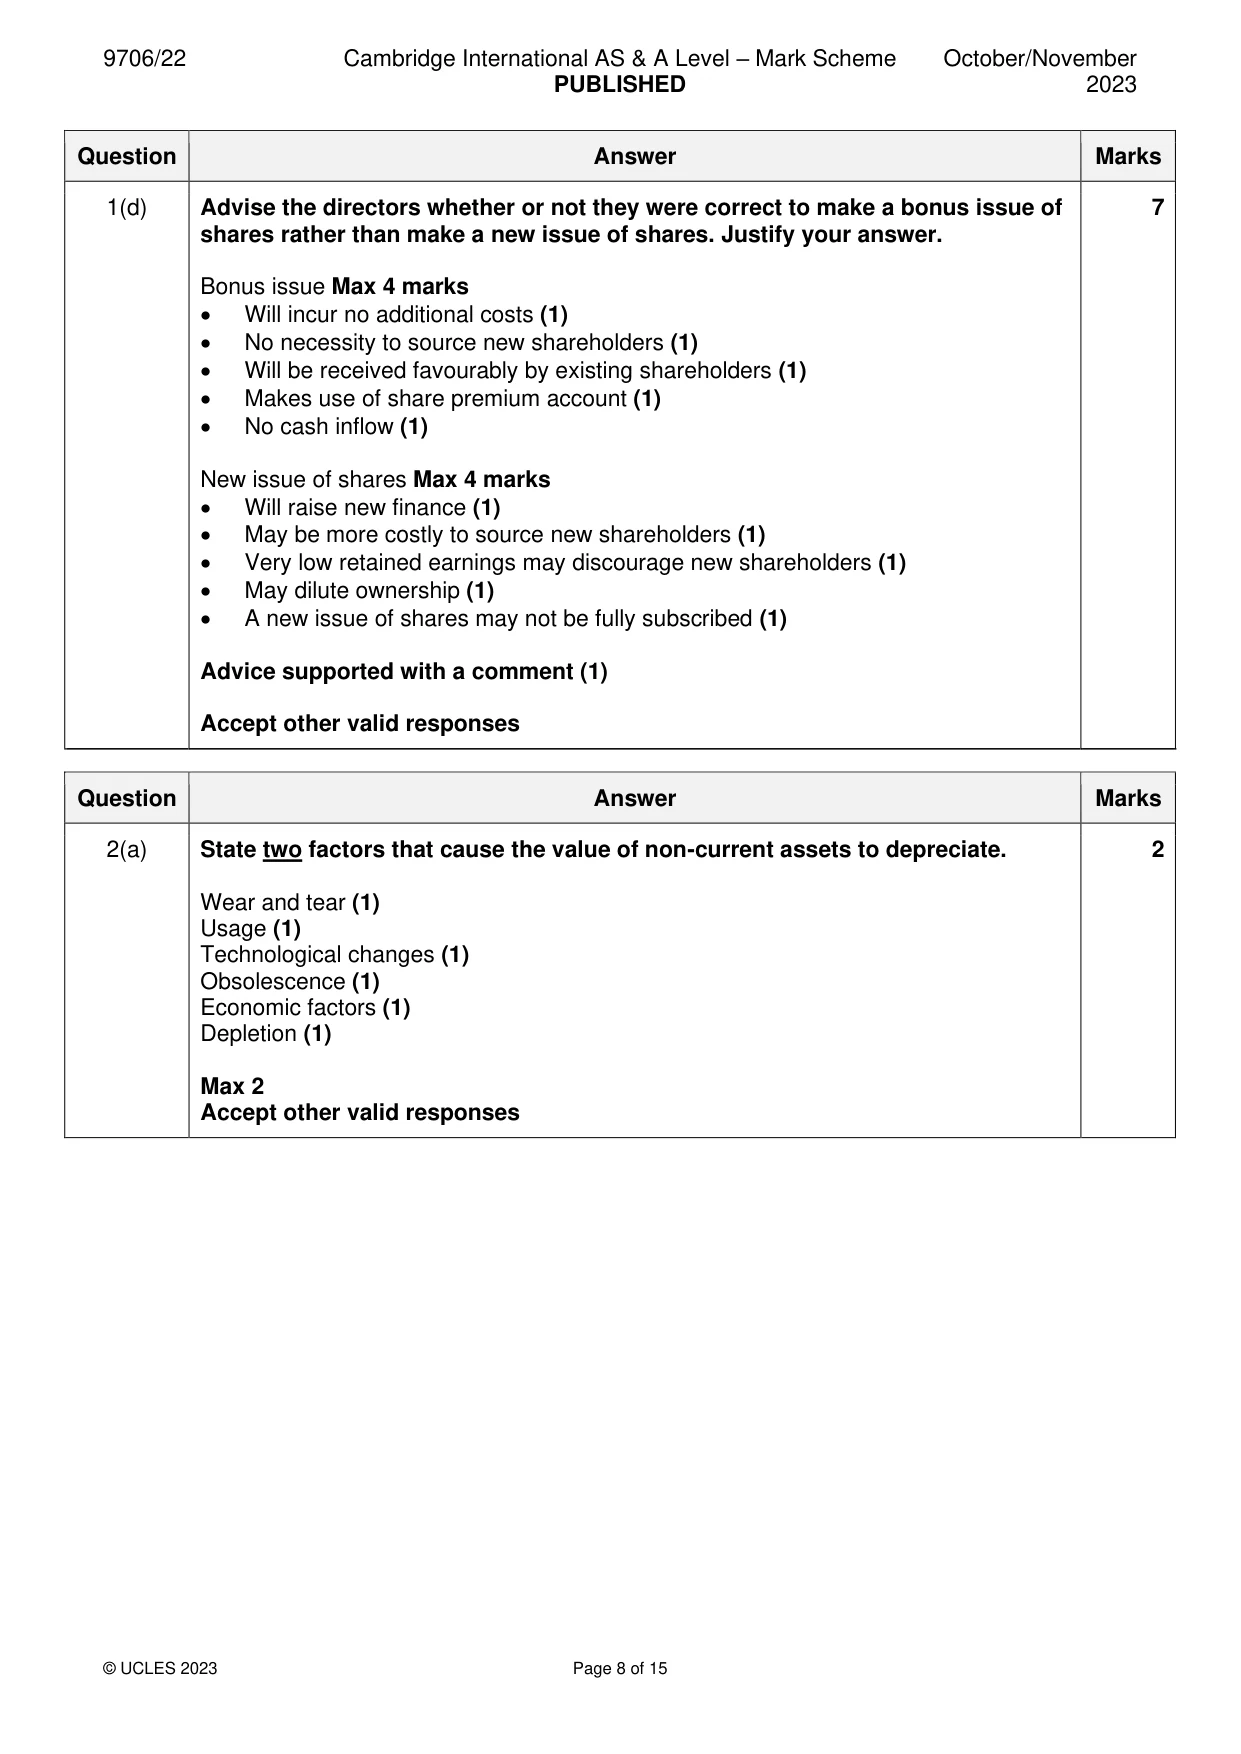
Mark scheme: Question Answer Marks 1(a) Prepare the statement of profit or loss for the year ended 31 July 2023. 15 P Limited Statement of profit or loss for the year ended 31 July 2023 $ Revenue 284 200 (1) Cost of sales W1 (114 420) (4)OF Gross profit 169 780 (1)OF Distribution costs (50 240) (1) Administrative expenses W2 (67 620) (4)OF Profit from operations 51 920 (1)OF Finance costs (960) (1) Profit before taxation 50 960 (1)OF Taxation (10 700) Profit for the year 40 260 (1)OF W1 Opening inventory 36 800 (1) Purchases 122 050 – 29 610 + 25 250 = 117 690 (1) Closing inventory 43 190 – 3600 + 900 – 420 = 40 070 (1) Cost of sales 36 800 + 117 690 – 40 070 = 114 420 (1)OF W2 66 920 – 960 (1) + 1820 (1) – 160 (1) = 67 620 (1)OF 1(b) Prepare the statement of changes in equity for the year ended 31 July 2023. 6 P Limited Statement of changes in equity for the year ended 31 July 2023 Share Share Retained capital premium earnings Total $ $ $ $ At 1 August 2022 120 000 19 000 23 560 162 560 Bonus issue 20 000 (19 000) (1 000) - (1) Final dividend (16 800) (16 800) (1) Rights issue 35 000 10 500 45 500 (1) (1) Profit for the year 40 260 40 260 (1)OF At 31 July 2023 175 000 10 500 46 020 231 520 (1) OF 1(c) State two examples of revenue reserves of a limited company. 2 Retained earnings (1) General reserve (1) Accept other valid responses. 1(d) Advise the directors whether or not they were correct to make a bonus issue of 7 shares rather than make a new issue of shares. Justify your answer. Bonus issue Max 4 marks • Will incur no additional costs (1) • No necessity to source new shareholders (1) • Will be received favourably by existing shareholders (1) • Makes use of share premium account (1) • No cash inflow (1) New issue of shares Max 4 marks • Will raise new finance (1) • May be more costly to source new shareholders (1) • Very low retained earnings may discourage new shareholders (1) • May dilute ownership (1) • A new issue of shares may not be fully subscribed (1) Advice supported with a comment (1) Accept other valid responses
Q2 · On 1 September 2022, a bonus issue of shares was made of one ordinary share for every six…
2 On 1 September 2022, a bonus issue of shares was made of one ordinary share for every six shares held. Reserves were maintained in their most flexible form.
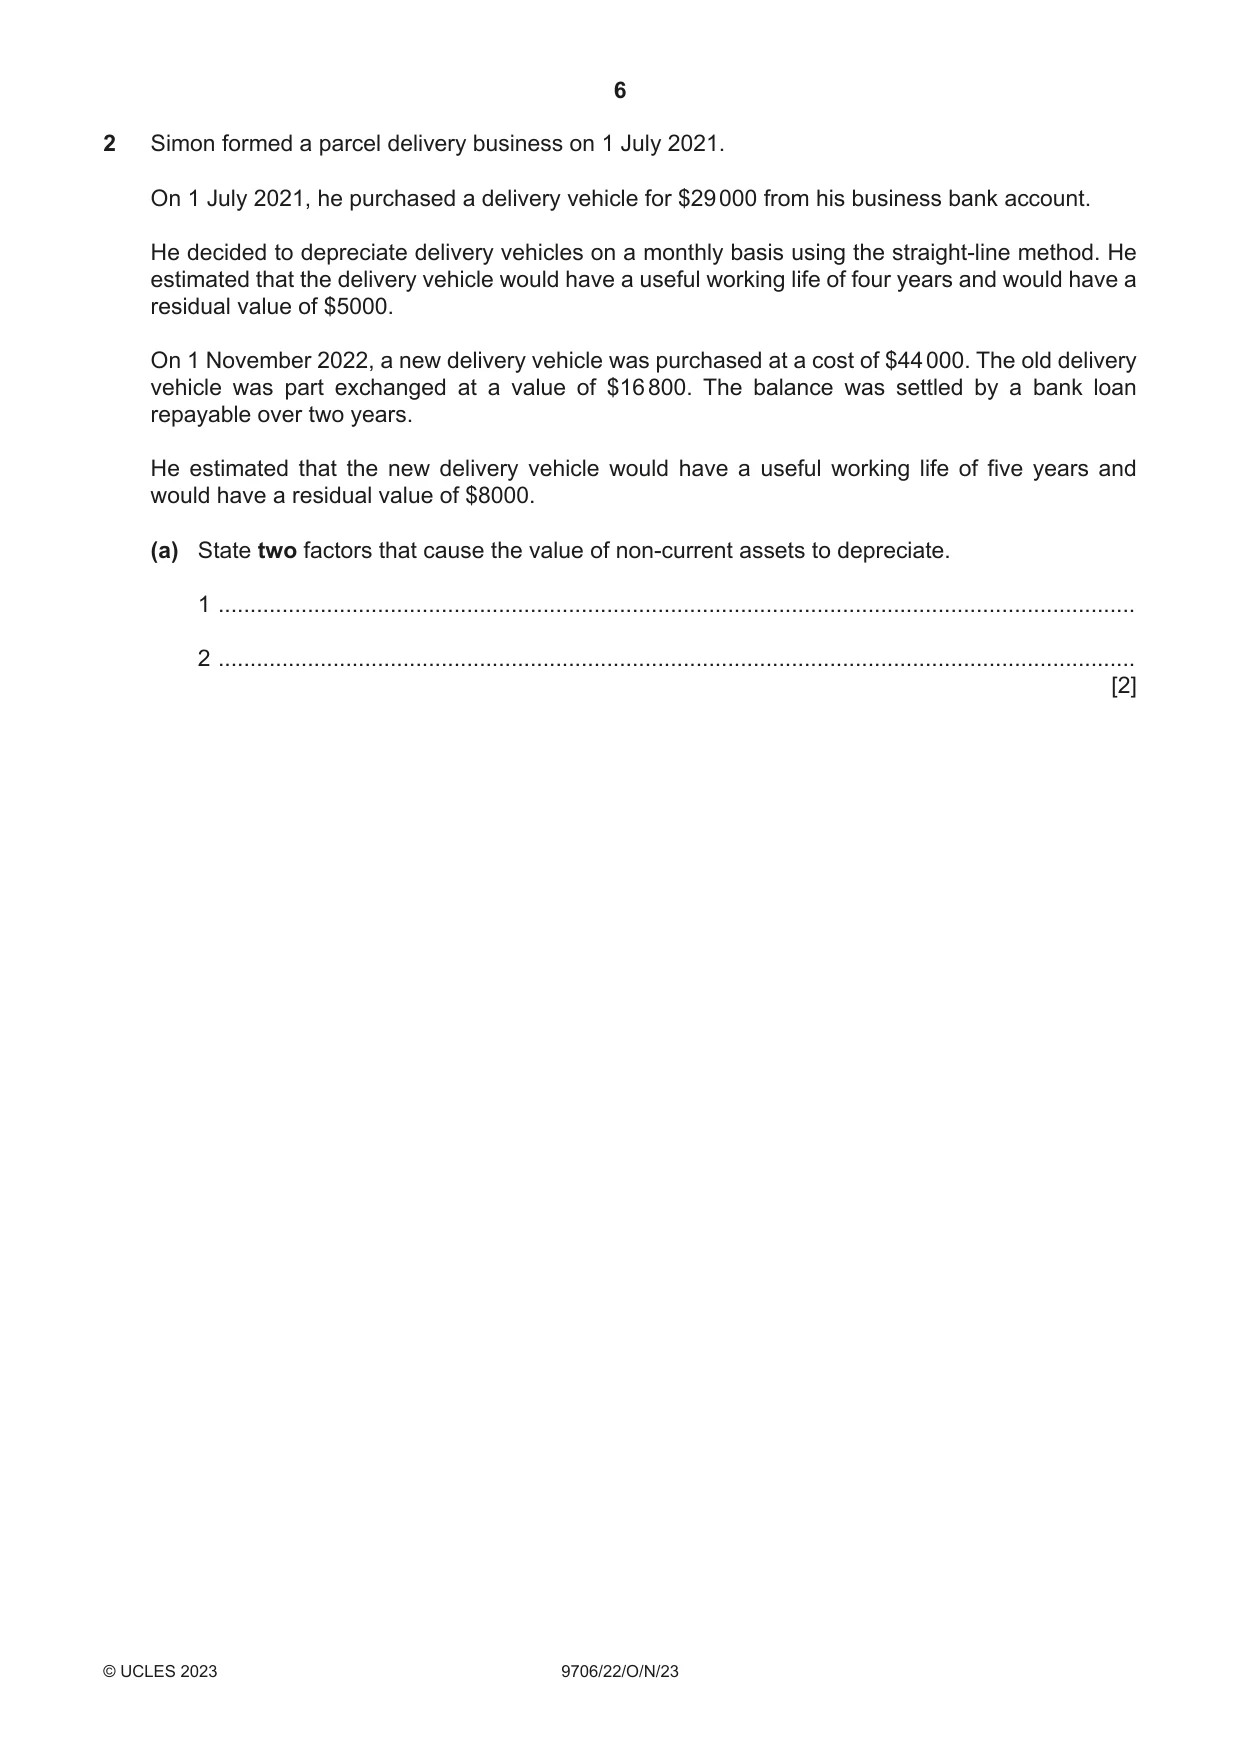
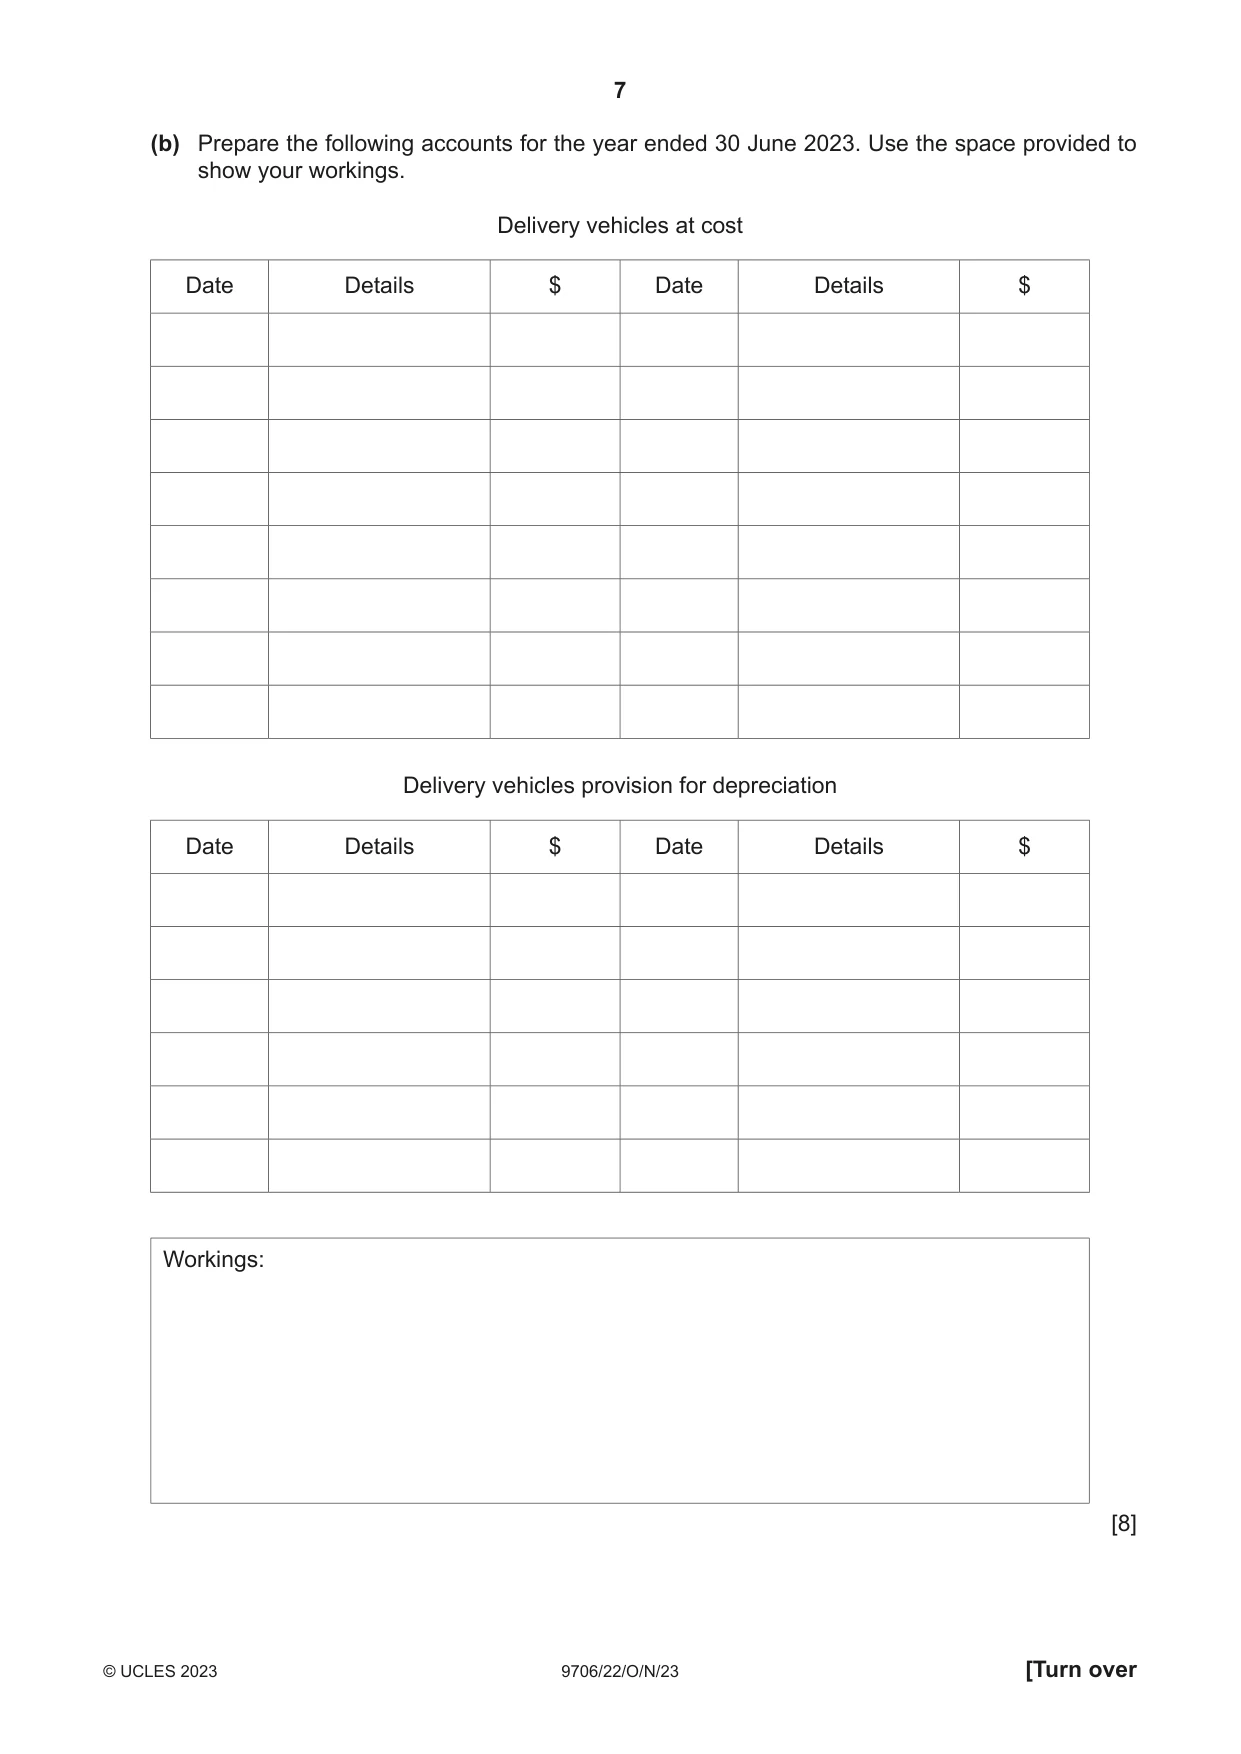
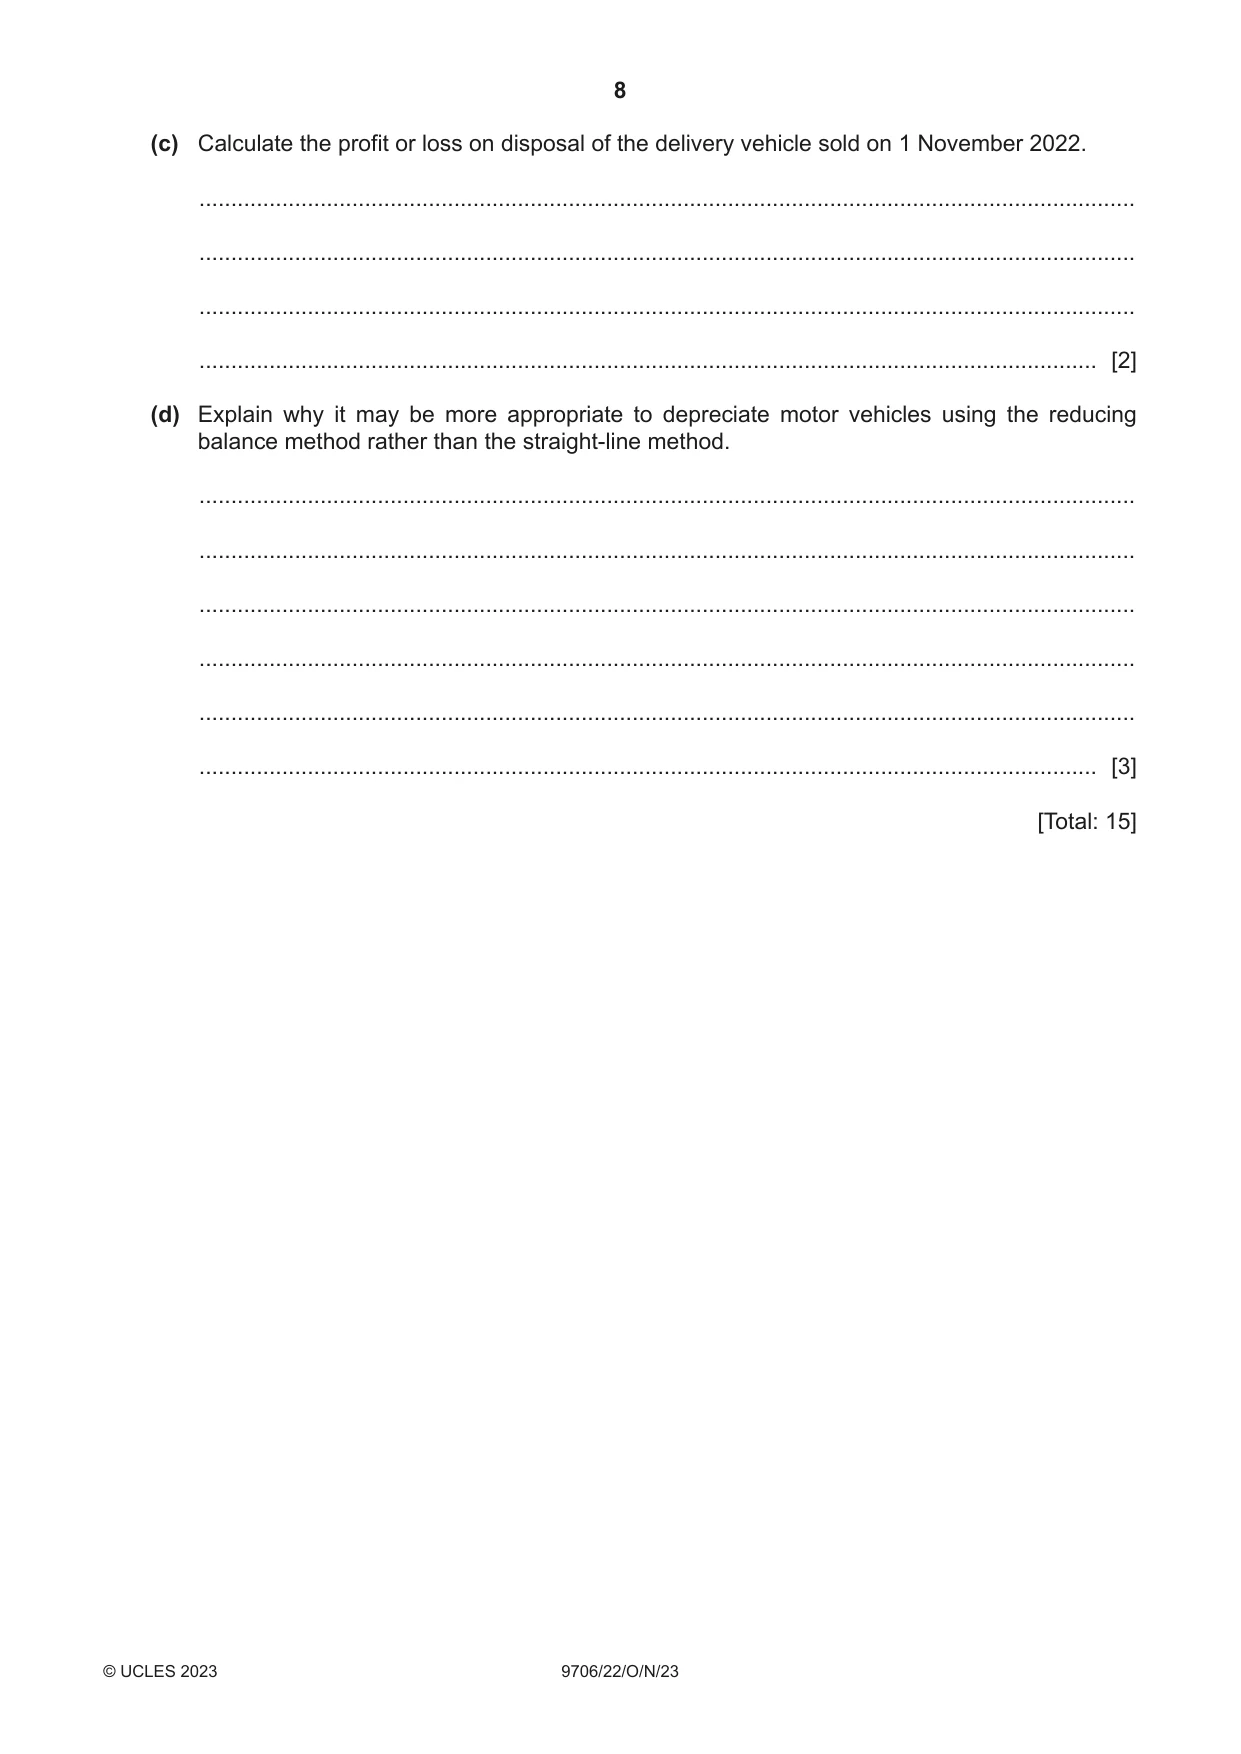
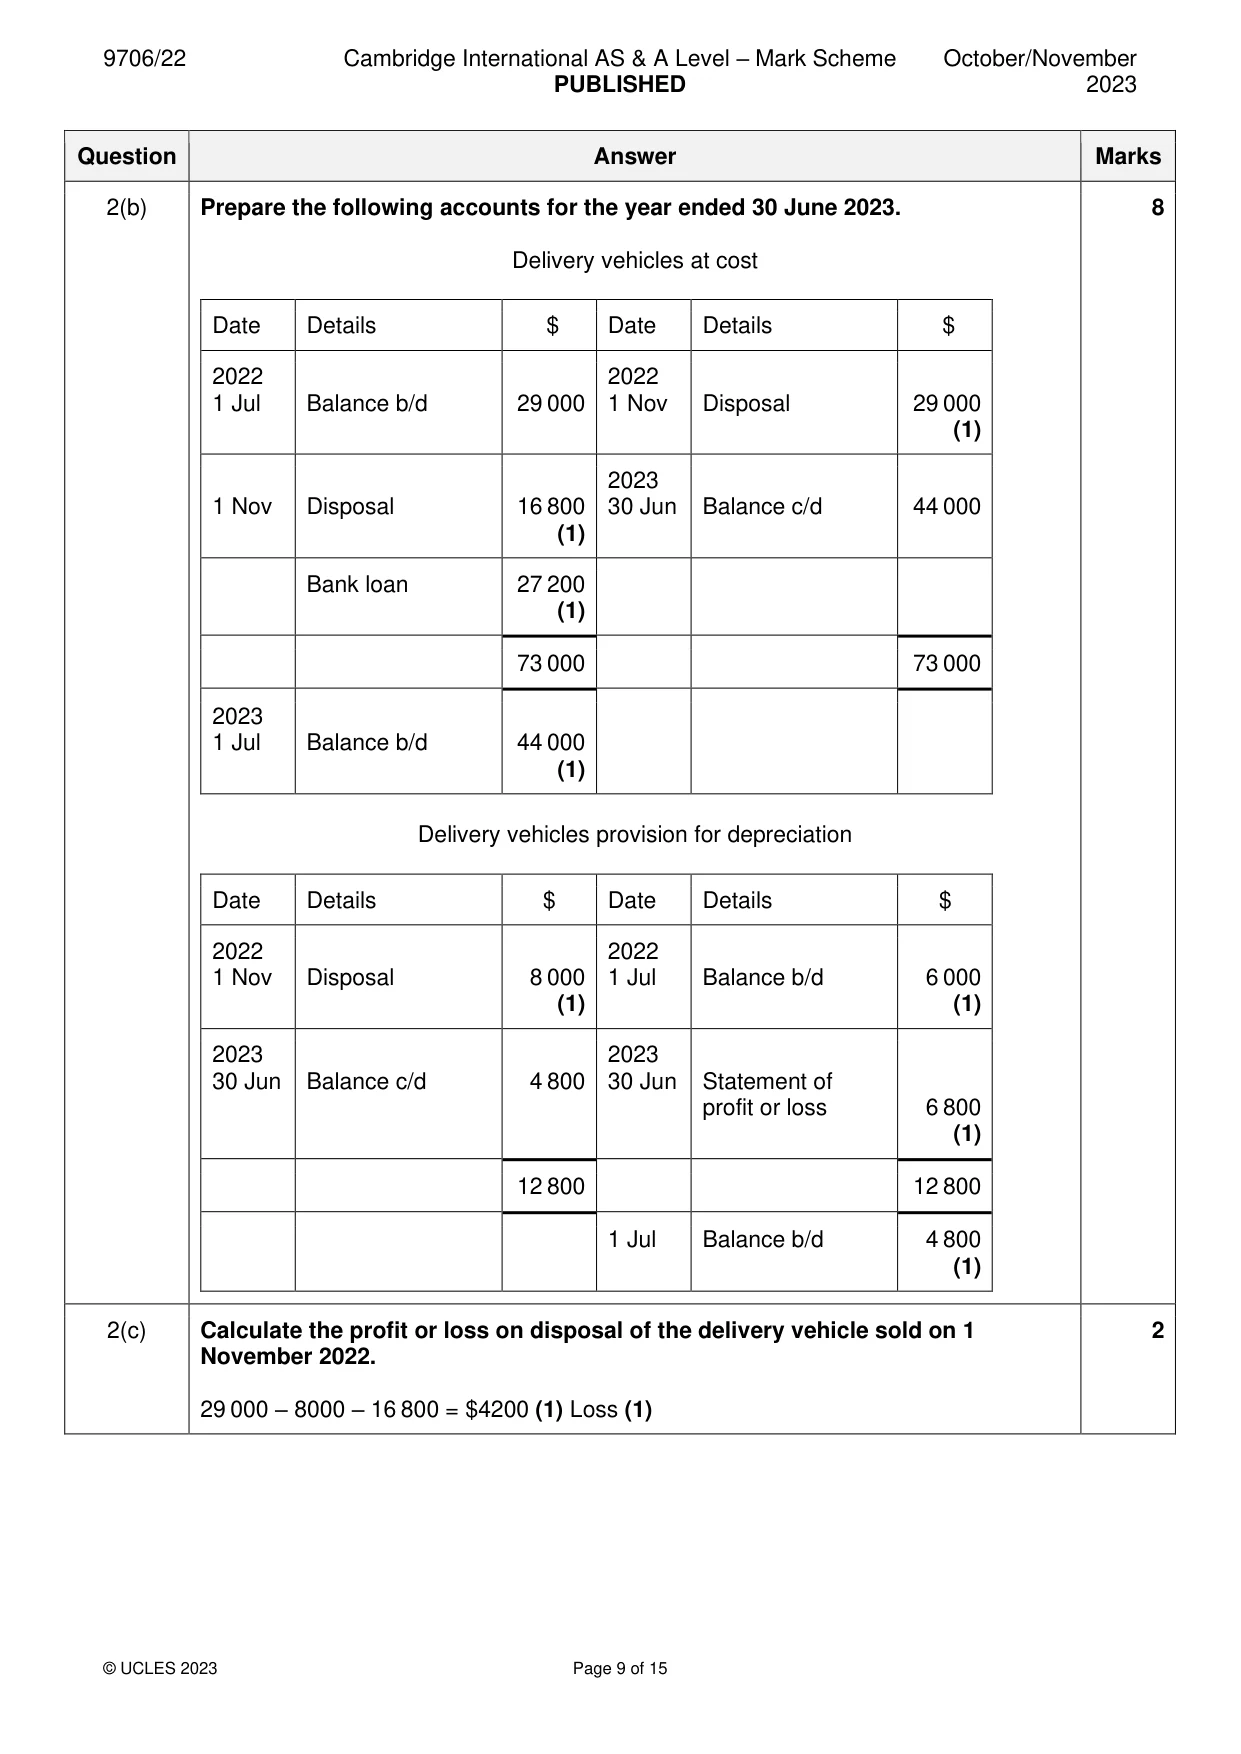
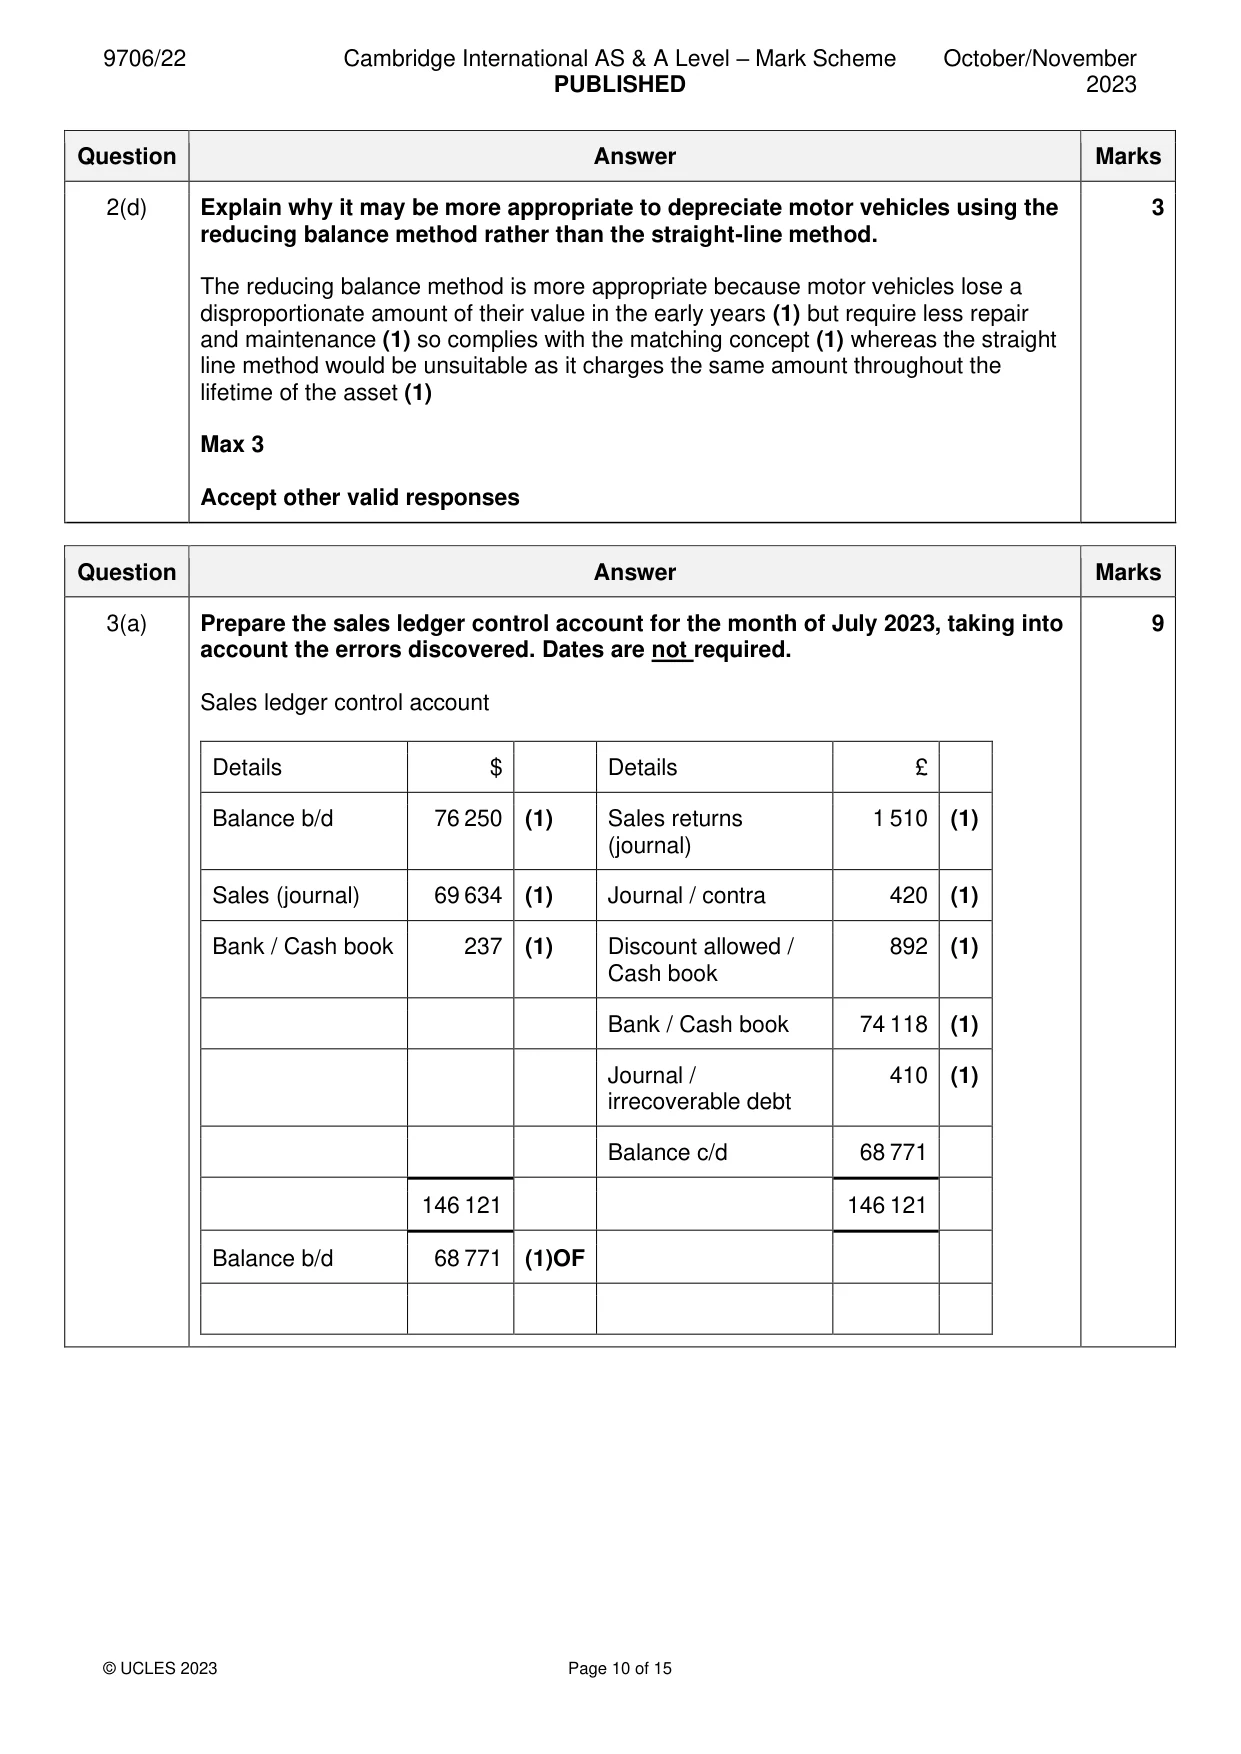
Mark scheme: 2(a) State two factors that cause the value of non-current assets to depreciate. 2 Wear and tear (1) Usage (1) Technological changes (1) Obsolescence (1) Economic factors (1) Depletion (1) Max 2 Accept other valid responses 2(b) Prepare the following accounts for the year ended 30 June 2023. 8 Delivery vehicles at cost Date Details $ Date Details $ 2022 2022 1 Jul Balance b/d 29 000 1 Nov Disposal 29 000 (1) 2023 1 Nov Disposal 16 800 30 Jun Balance c/d 44 000 (1) Bank loan 27 200 (1) 73 000 73 000 2023 1 Jul Balance b/d 44 000 (1) Delivery vehicles provision for depreciation Date Details $ Date Details $ 2022 2022 1 Nov Disposal 8 000 1 Jul Balance b/d 6 000 (1) (1) 2023 2023 30 Jun Balance c/d 4 800 30 Jun Statement of profit or loss 6 800 (1) 12 800 12 800 1 Jul Balance b/d 4 800 (1) 2(c) Calculate the profit or loss on disposal of the delivery vehicle sold on 1 2 November 2022. 29 000 – 8000 – 16 800 = $4200 (1) Loss (1) 2(d) Explain why it may be more appropriate to depreciate motor vehicles using the 3 reducing balance method rather than the straight-line method. The reducing balance method is more appropriate because motor vehicles lose a disproportionate amount of their value in the early years (1) but require less repair and maintenance (1) so complies with the matching concept (1) whereas the straight line method would be unsuitable as it charges the same amount throughout the lifetime of the asset (1) Max 3 Accept other valid responses
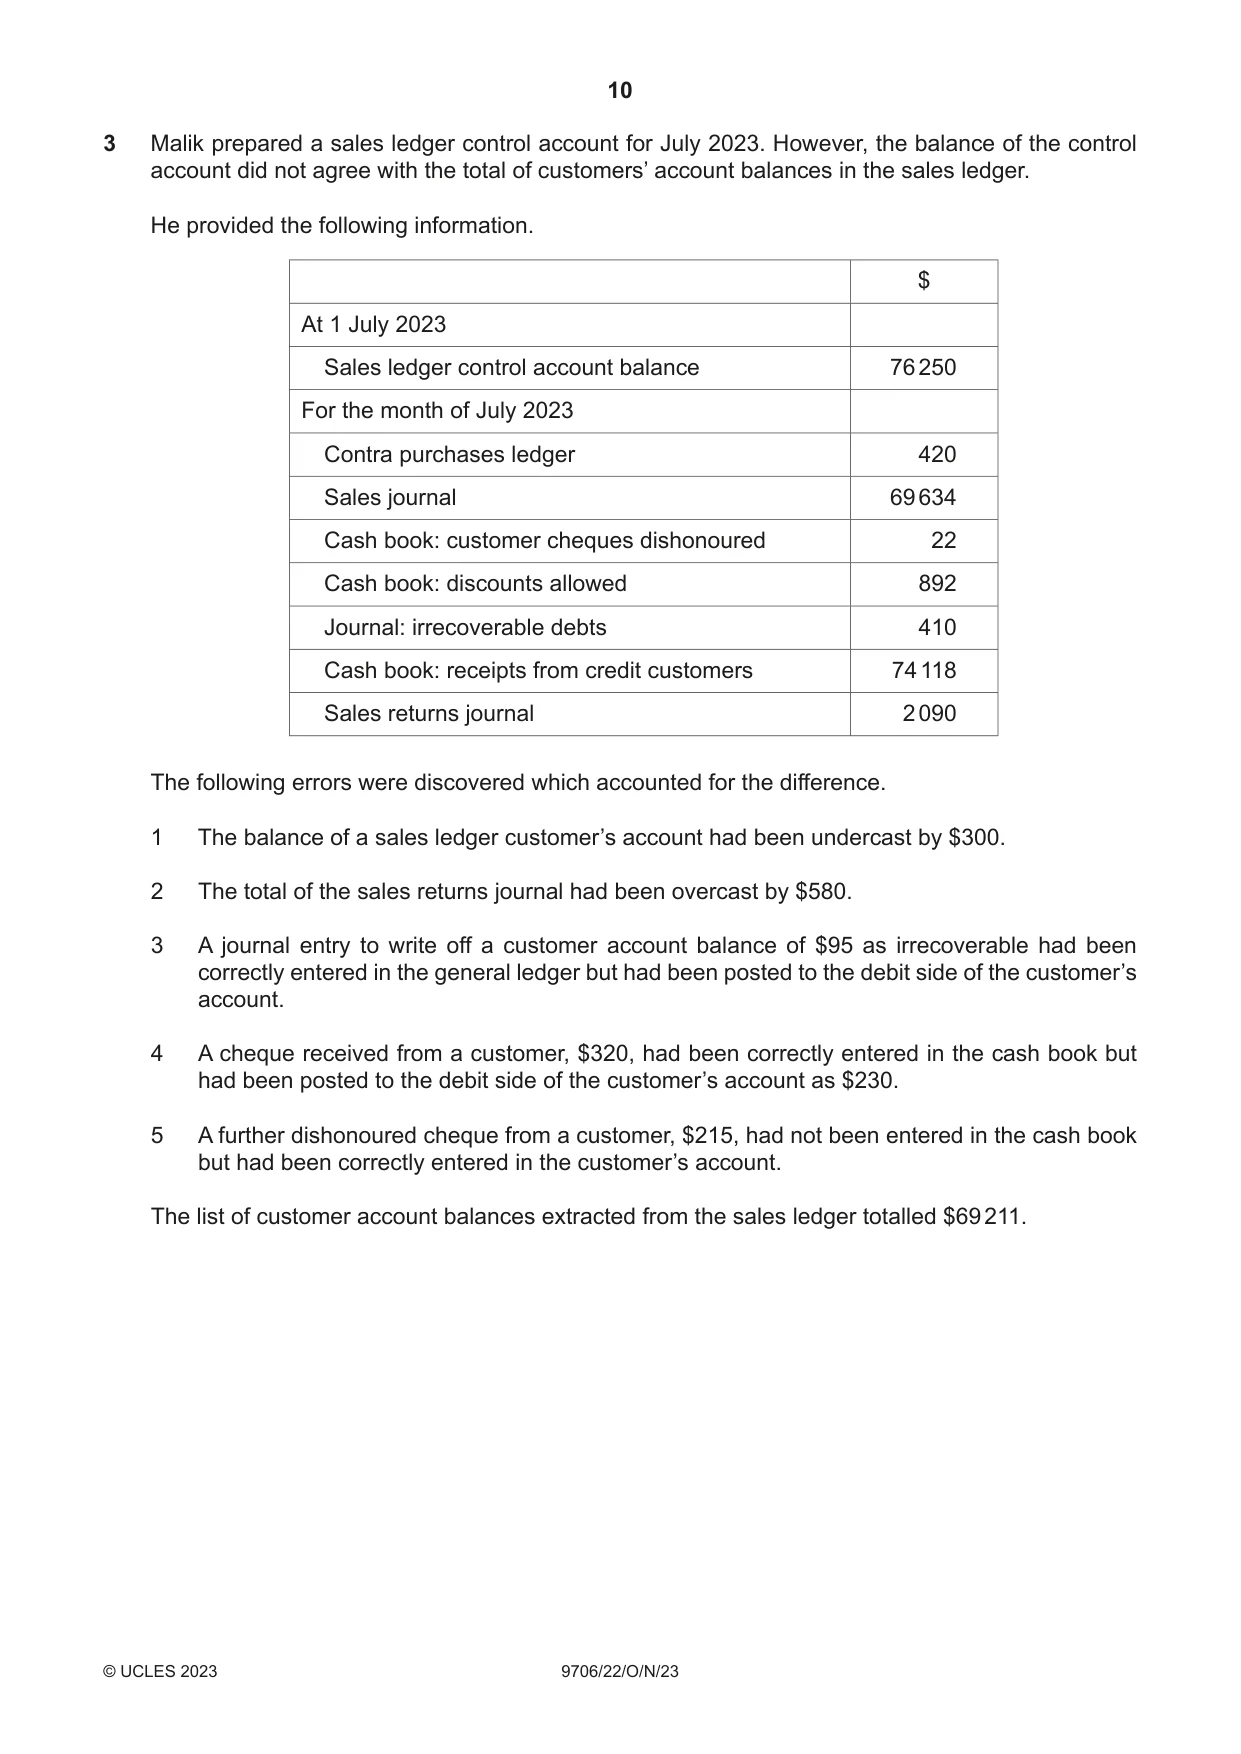
Q3 · On 1 January 2023, a final dividend of $0.07 per share was paid on all shares in issue at…
3 On 1 January 2023, a final dividend of $0.07 per share was paid on all shares in issue at 1 August 2022.
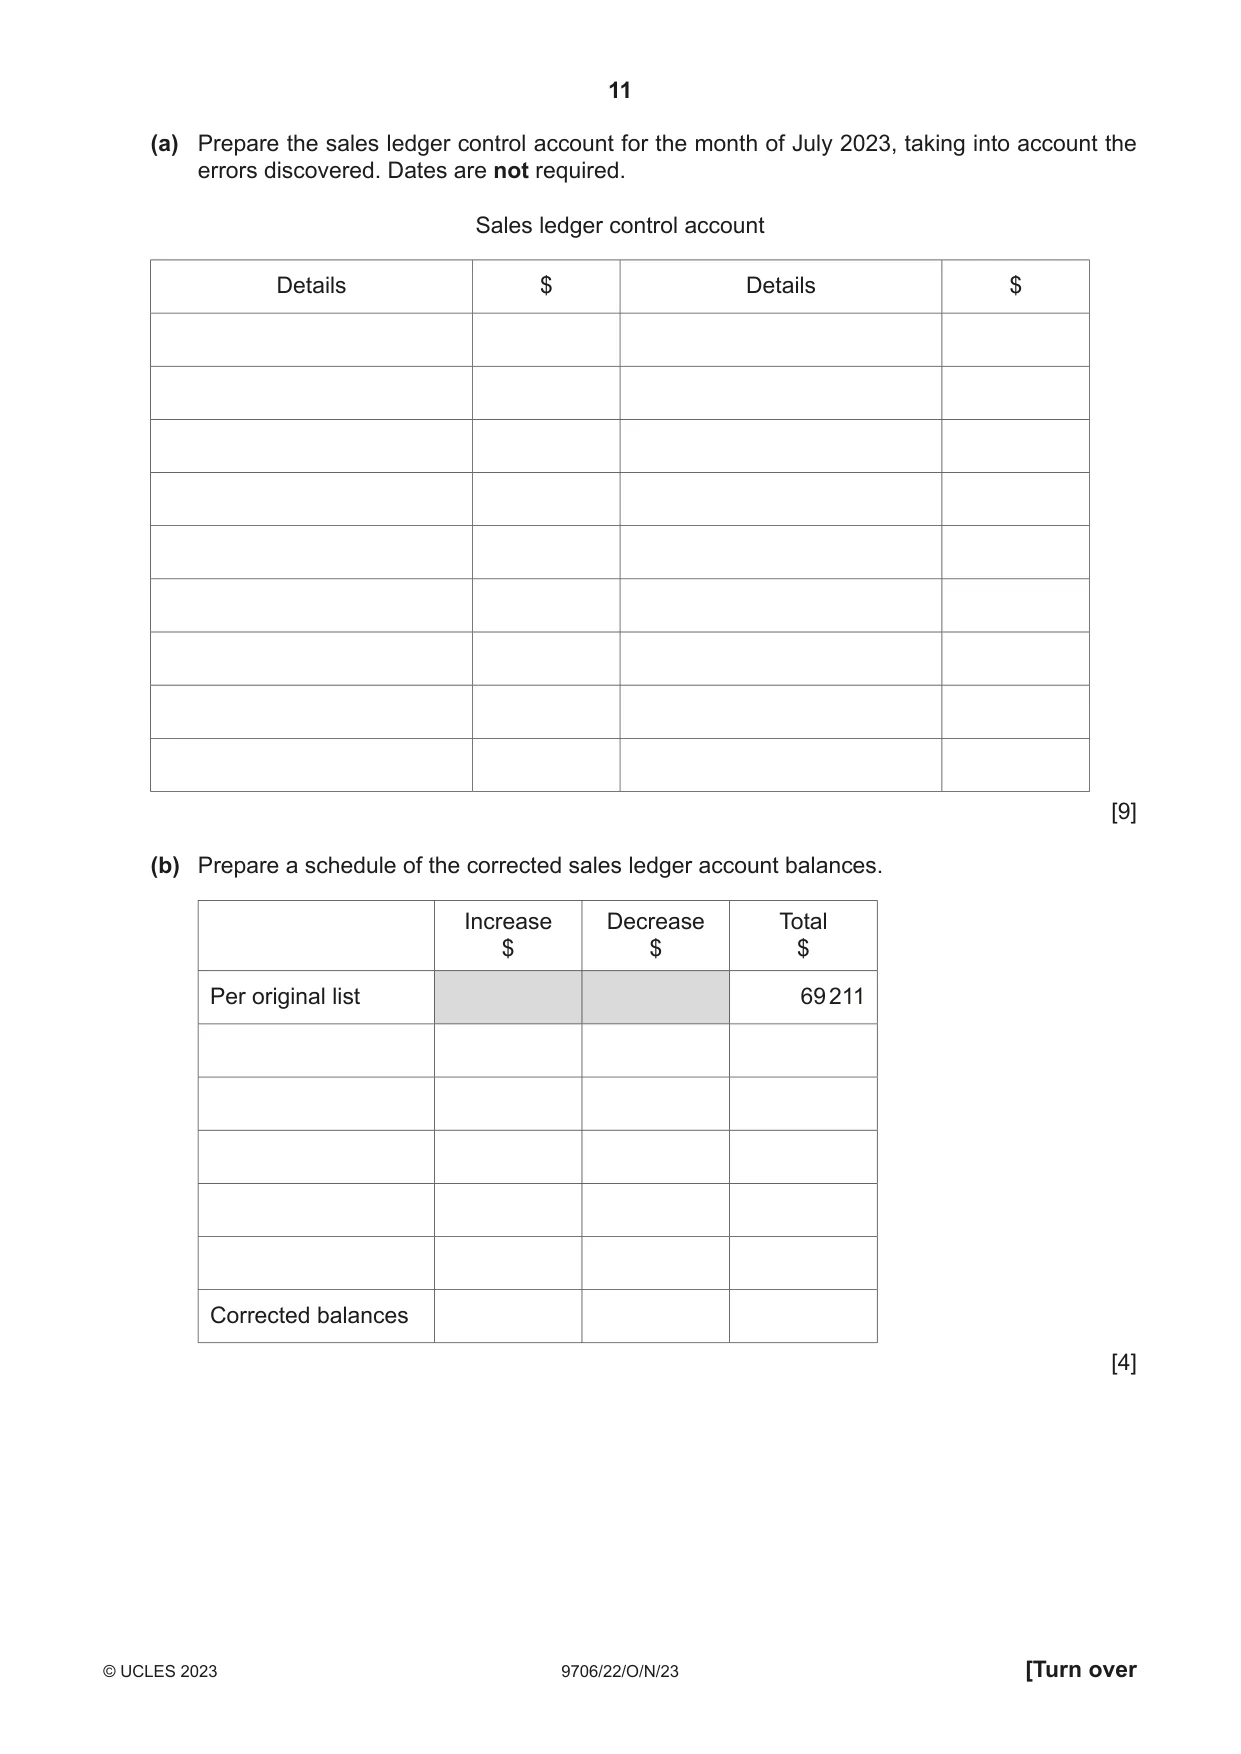
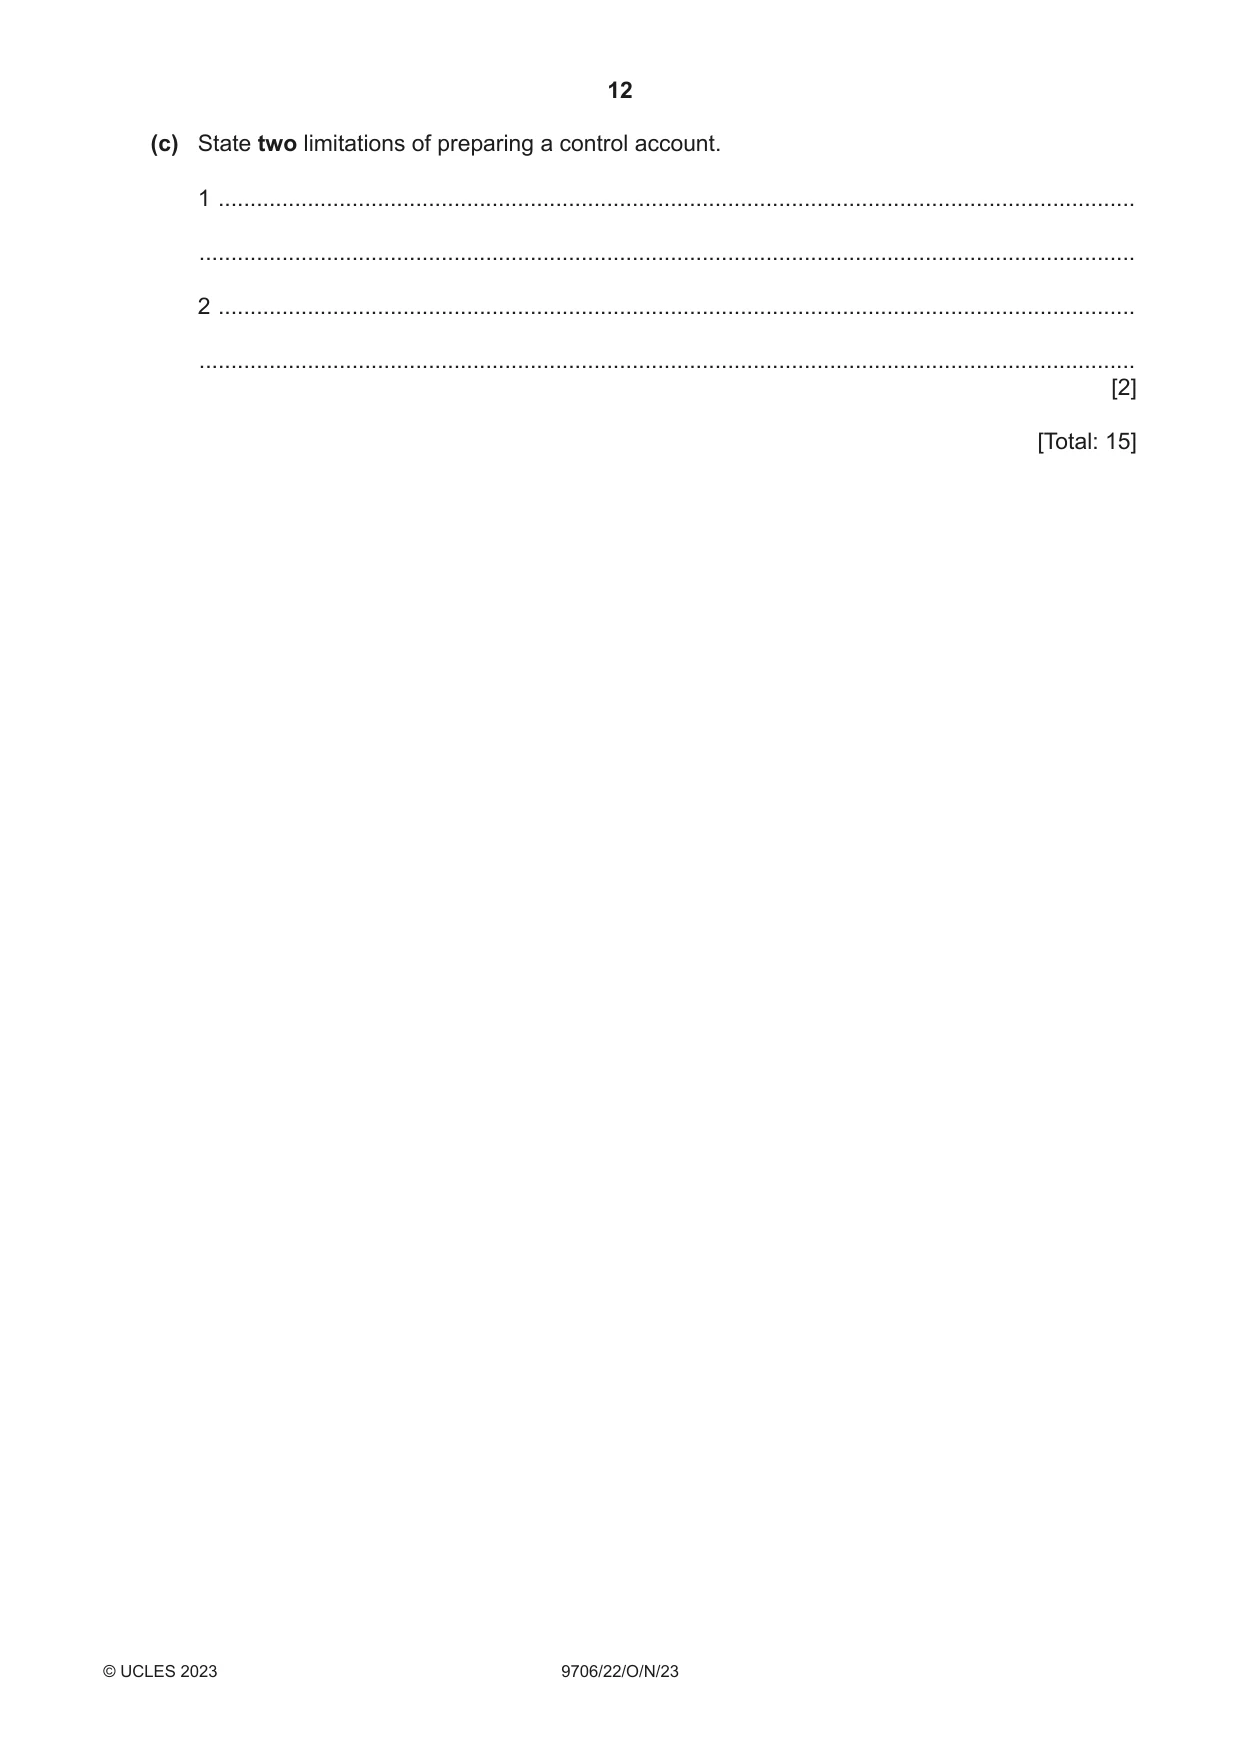
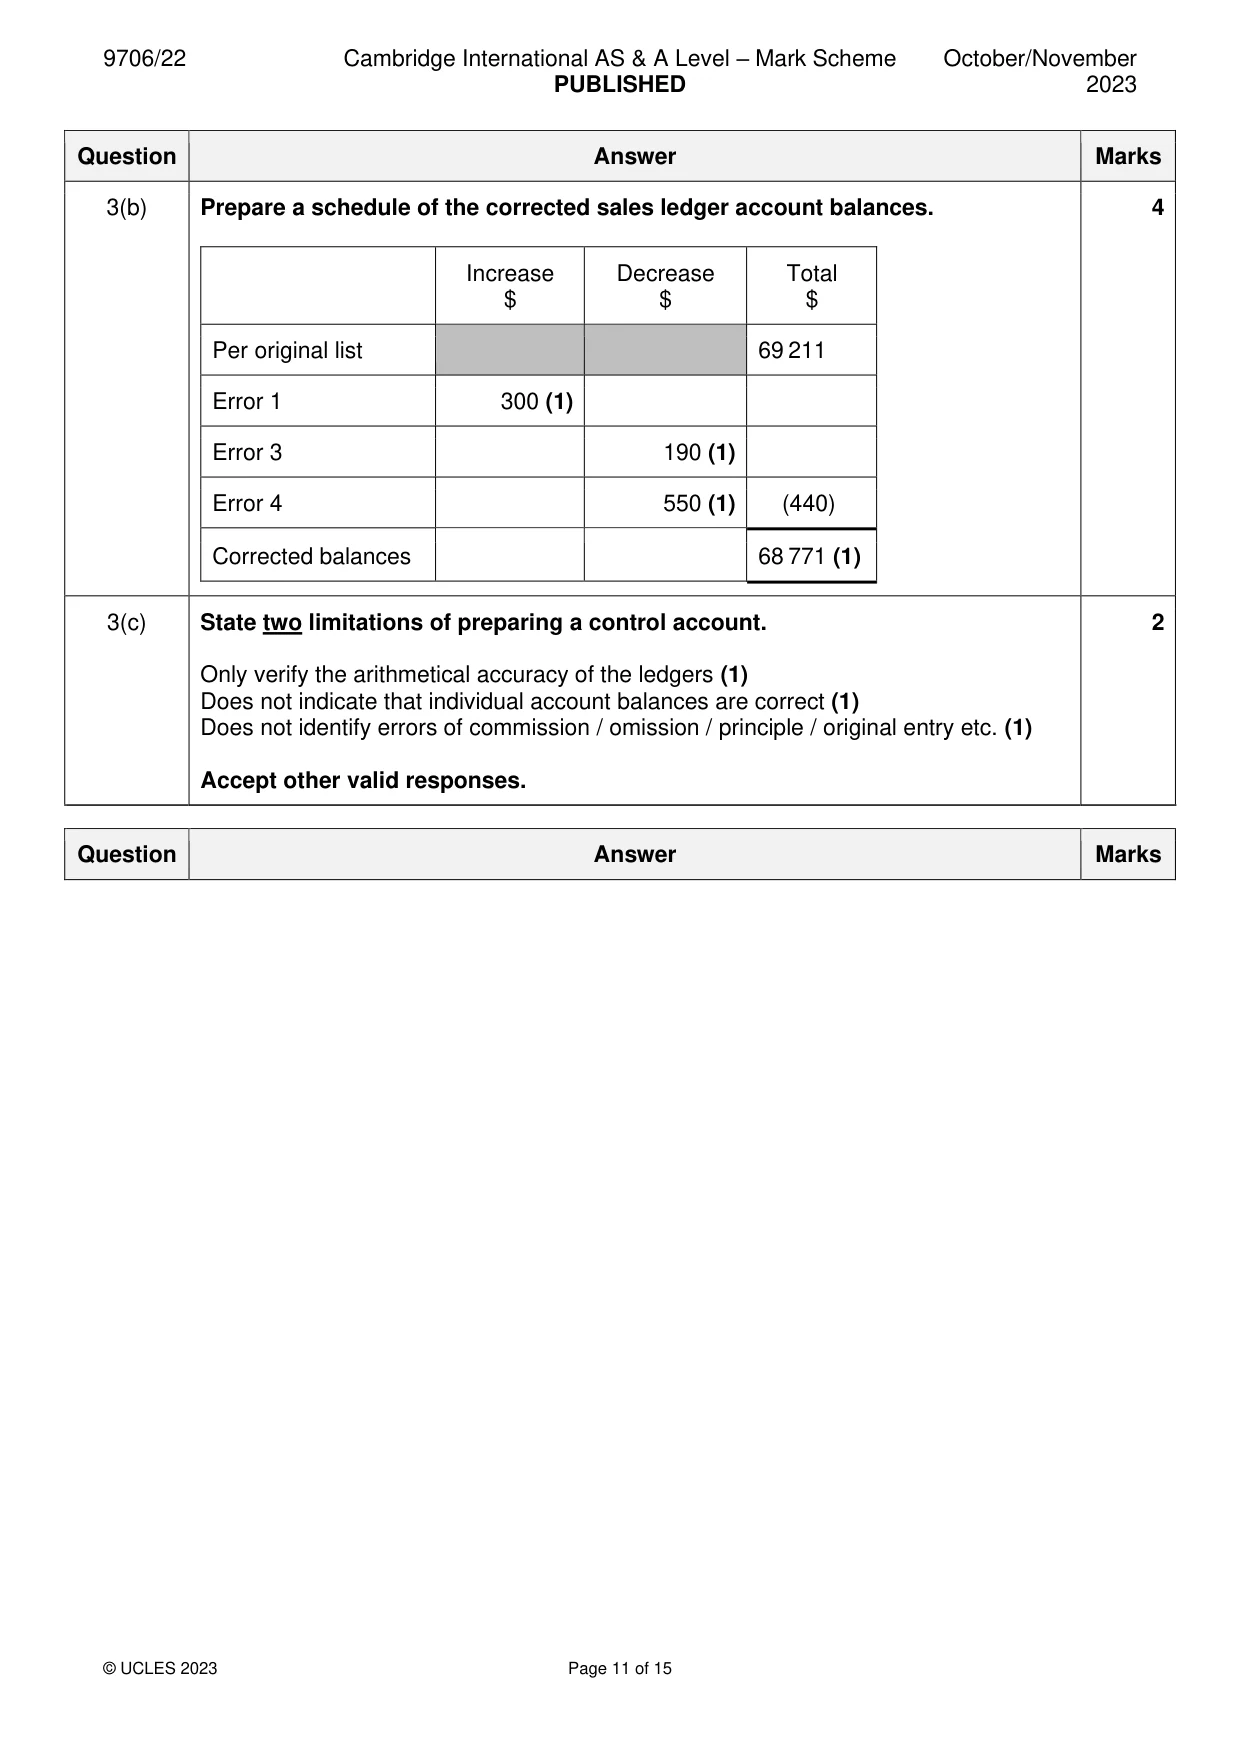
Mark scheme: 3(a) Prepare the sales ledger control account for the month of July 2023, taking into 9 account the errors discovered. Dates are not required. Sales ledger control account Details $ Details £ Balance b/d 76 250 (1) Sales returns 1 510 (1) (journal) Sales (journal) 69 634 (1) Journal / contra 420 (1) Bank / Cash book 237 (1) Discount allowed / 892 (1) Cash book Bank / Cash book 74 118 (1) Journal / 410 (1) irrecoverable debt Balance c/d 68 771 146 121 146 121 Balance b/d 68 771 (1)OF 3(b) Prepare a schedule of the corrected sales ledger account balances. 4 Increase Decrease Total $ $ $ Per original list 69 211 Error 1 300 (1) Error 3 190 (1) Error 4 550 (1) (440) Corrected balances 68 771 (1) 3(c) State two limitations of preparing a control account. 2 Only verify the arithmetical accuracy of the ledgers (1) Does not indicate that individual account balances are correct (1) Does not identify errors of commission / omission / principle / original entry etc. (1) Accept other valid responses. Question Answer Marks
Q4 · On 31 March 2023, a rights issue of one ordinary share for every four shares held was…
4 On 31 March 2023, a rights issue of one ordinary share for every four shares held was made at a premium of $0.15 per share. The issue was fully subscribed. (b) Prepare the statement of changes in equity for the year ended 31 July 2023. P Limited Statement of changes in equity for the year ended 31 July 2023 Share Share Retained capital premium earnings Total $ $ $ $ At 1 August 2022 120 000 19 000 23 560 162 560 [6] (c) State two examples of revenue reserves of a limited company. 1 ................................................................................................................................................ 2 ................................................................................................................................................ [2] (d) Advise the directors whether or not they were correct to make a bonus issue of shares rather than make a new issue of shares. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 30] 2 Simon formed a parcel delivery business on 1 July 2021. On 1 July 2021, he purchased a delivery vehicle for $29 000 from his business bank account. He decided to depreciate delivery vehicles on a monthly basis using the straight‑line method. He estimated that the delivery vehicle would have a useful working life of four years and would have a residual value of $5000. On 1 November 2022, a new delivery vehicle was purchased at a cost of $44 000. The old delivery vehicle was part exchanged at a value of $16 800. The balance was settled by a bank loan repayable over two years. He estimated that the new delivery vehicle would have a useful working life of five years and would have a residual value of $8000. (a) State two factors that cause the value of non‑current assets to depreciate. 1 ................................................................................................................................................ 2 ................................................................................................................................................ [2]
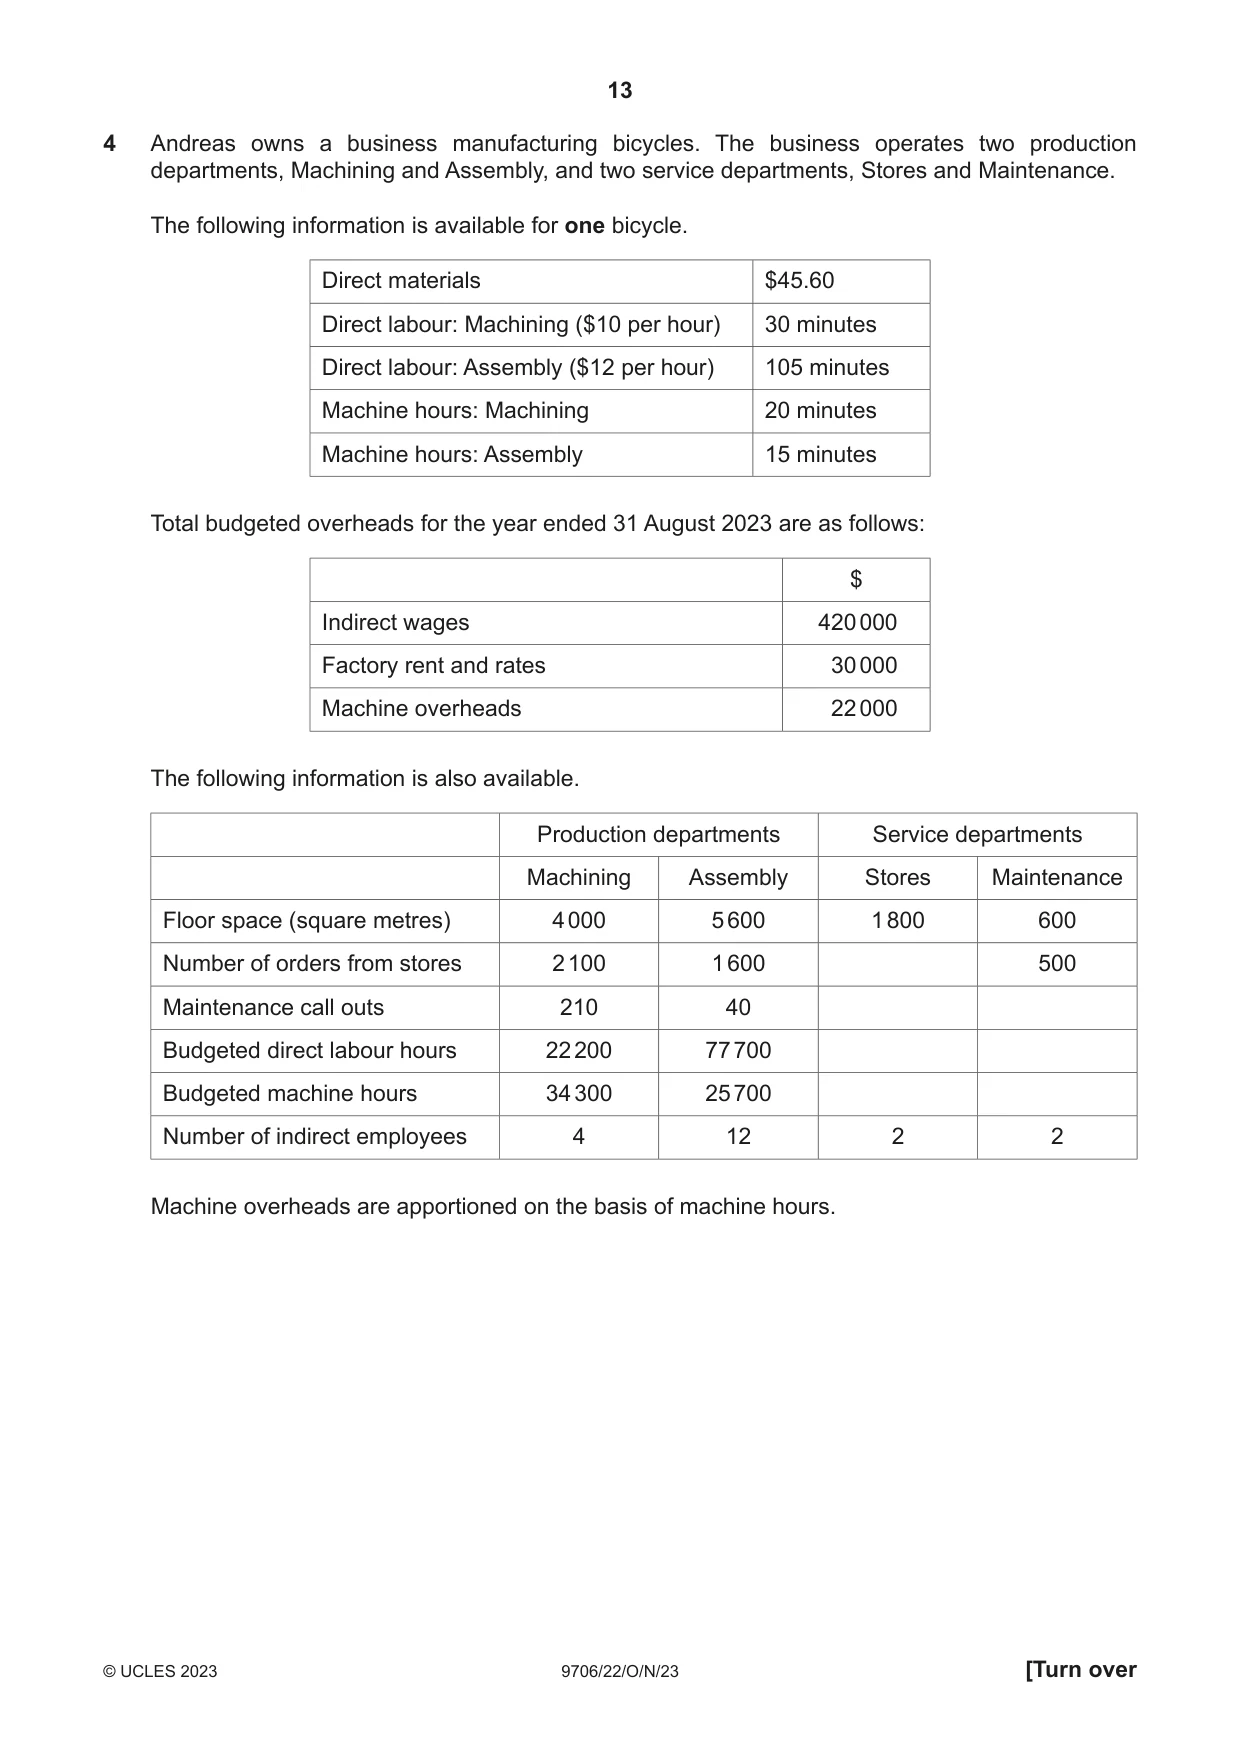
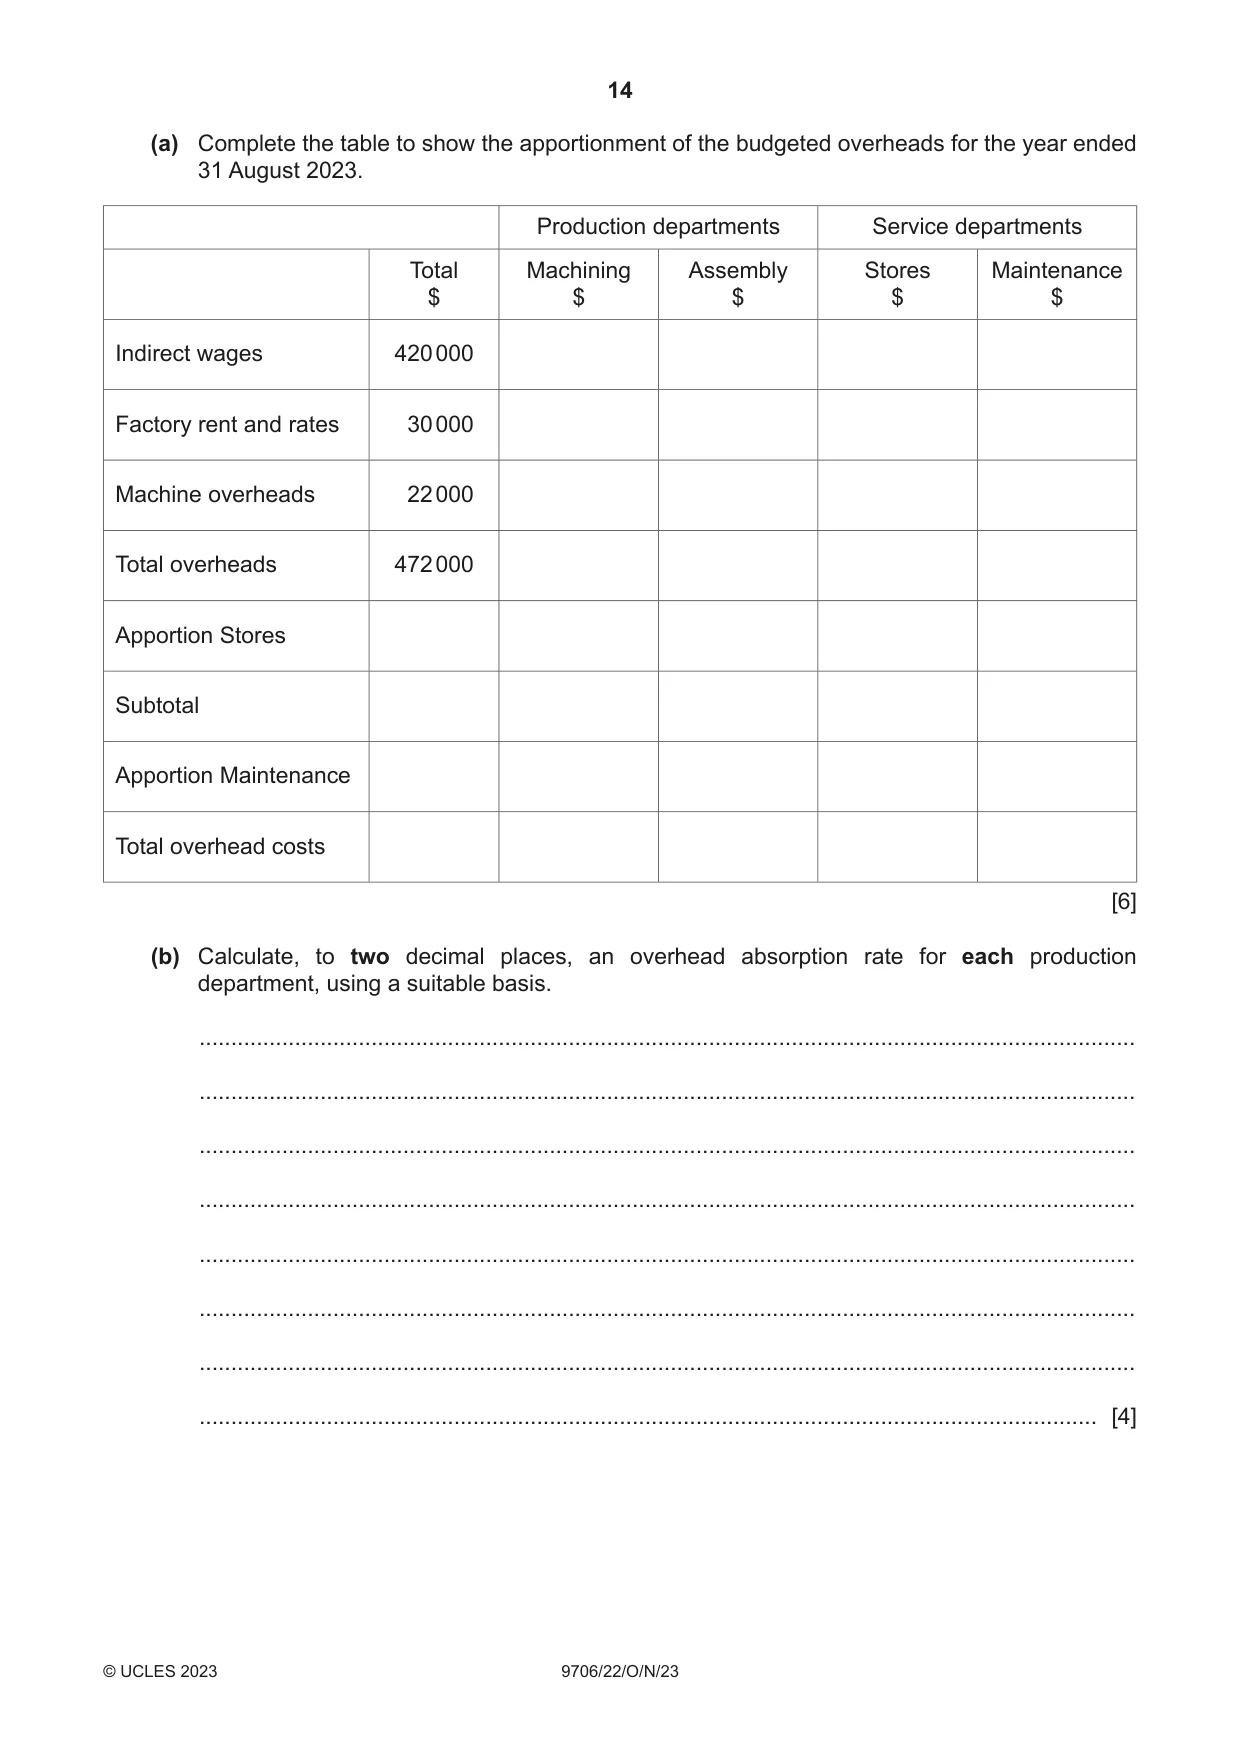
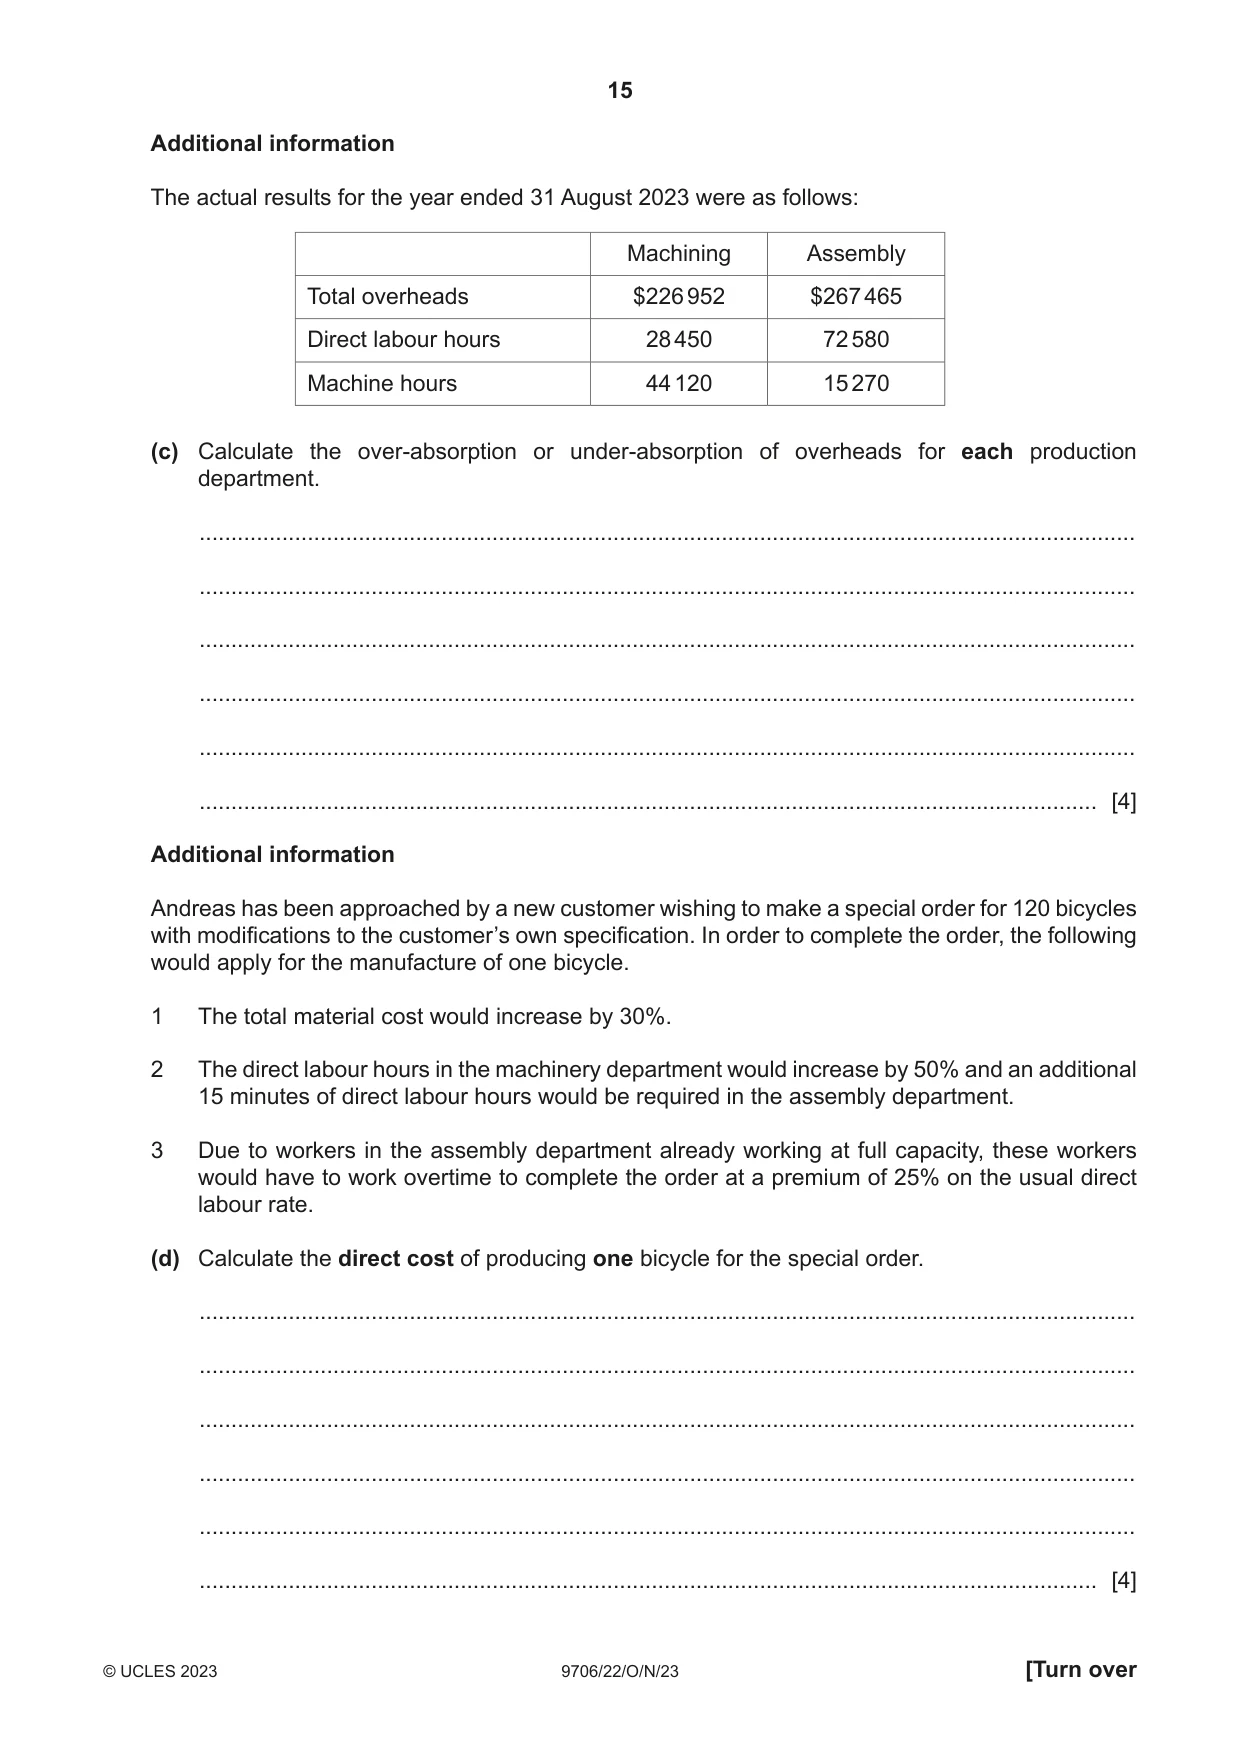
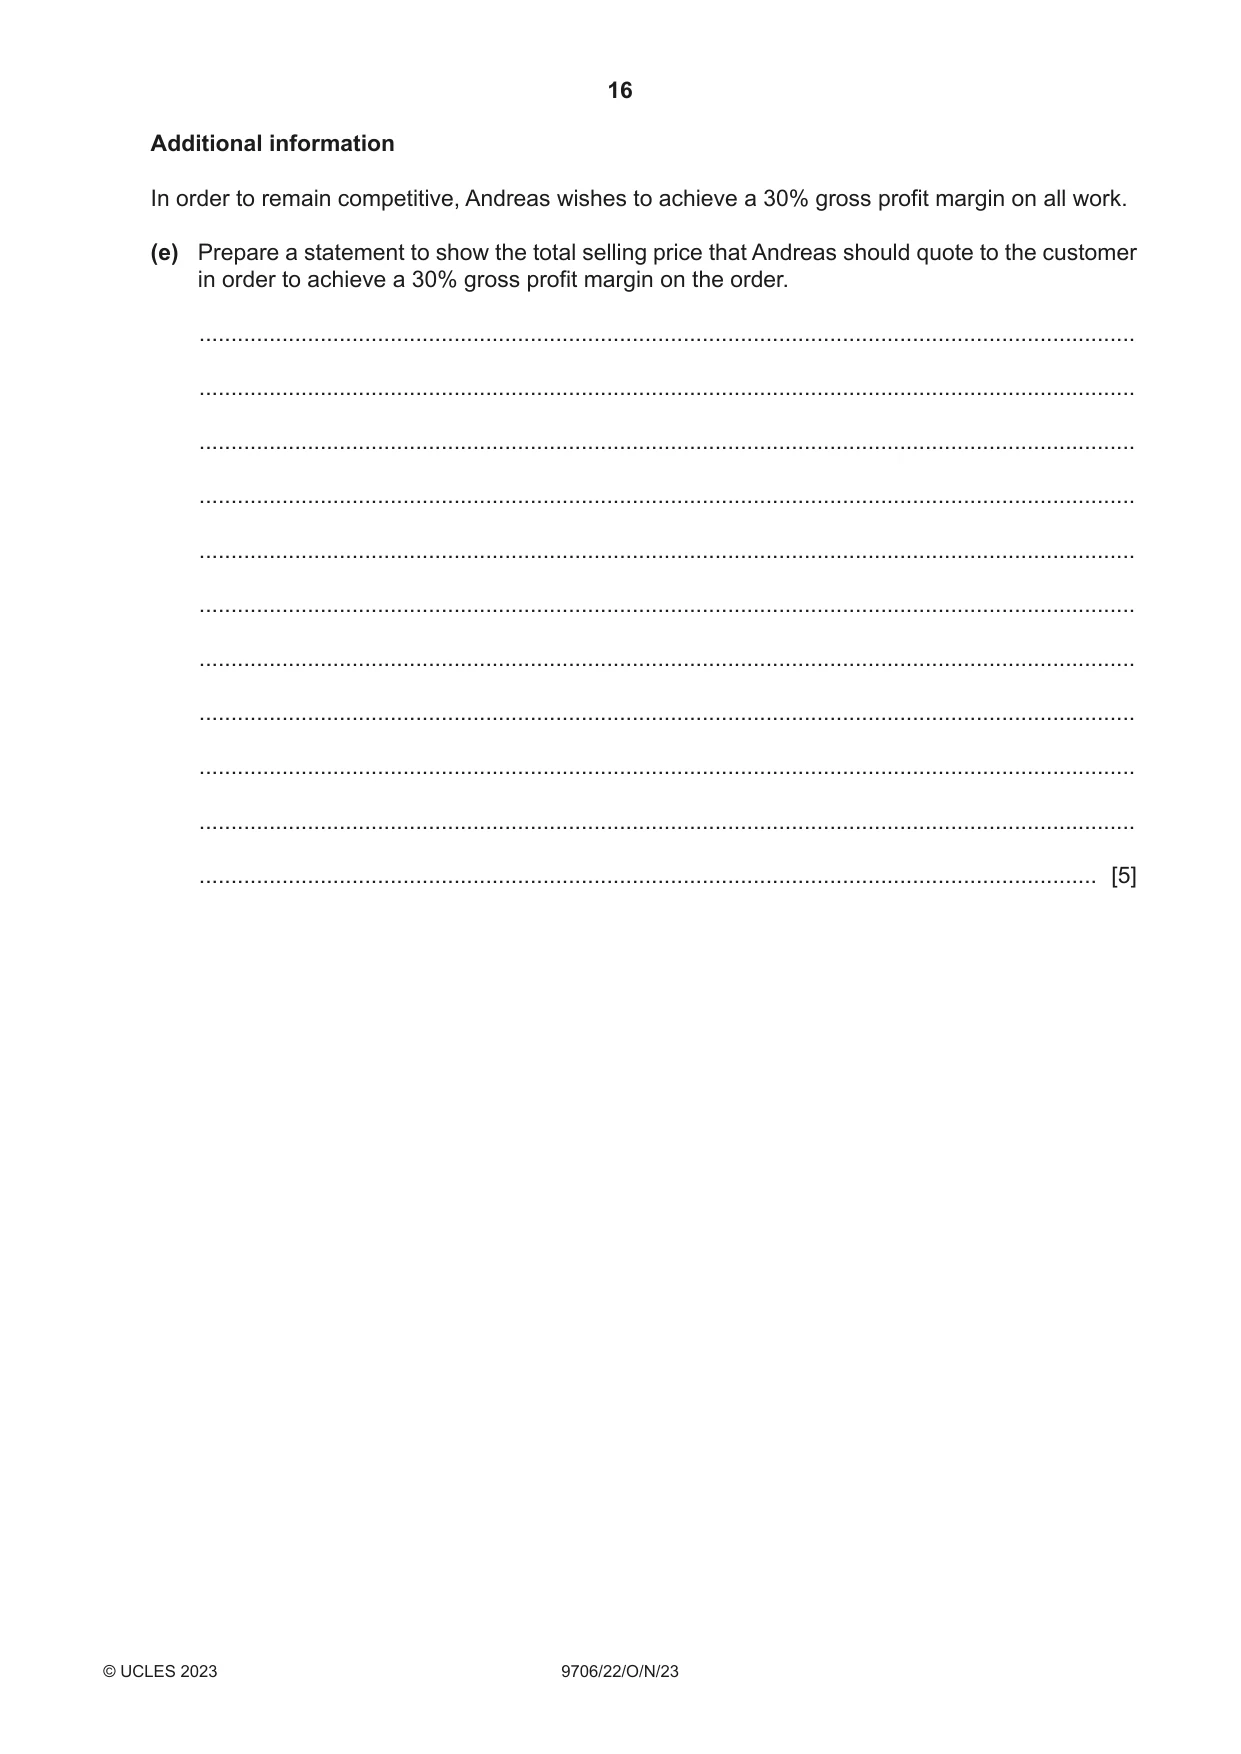
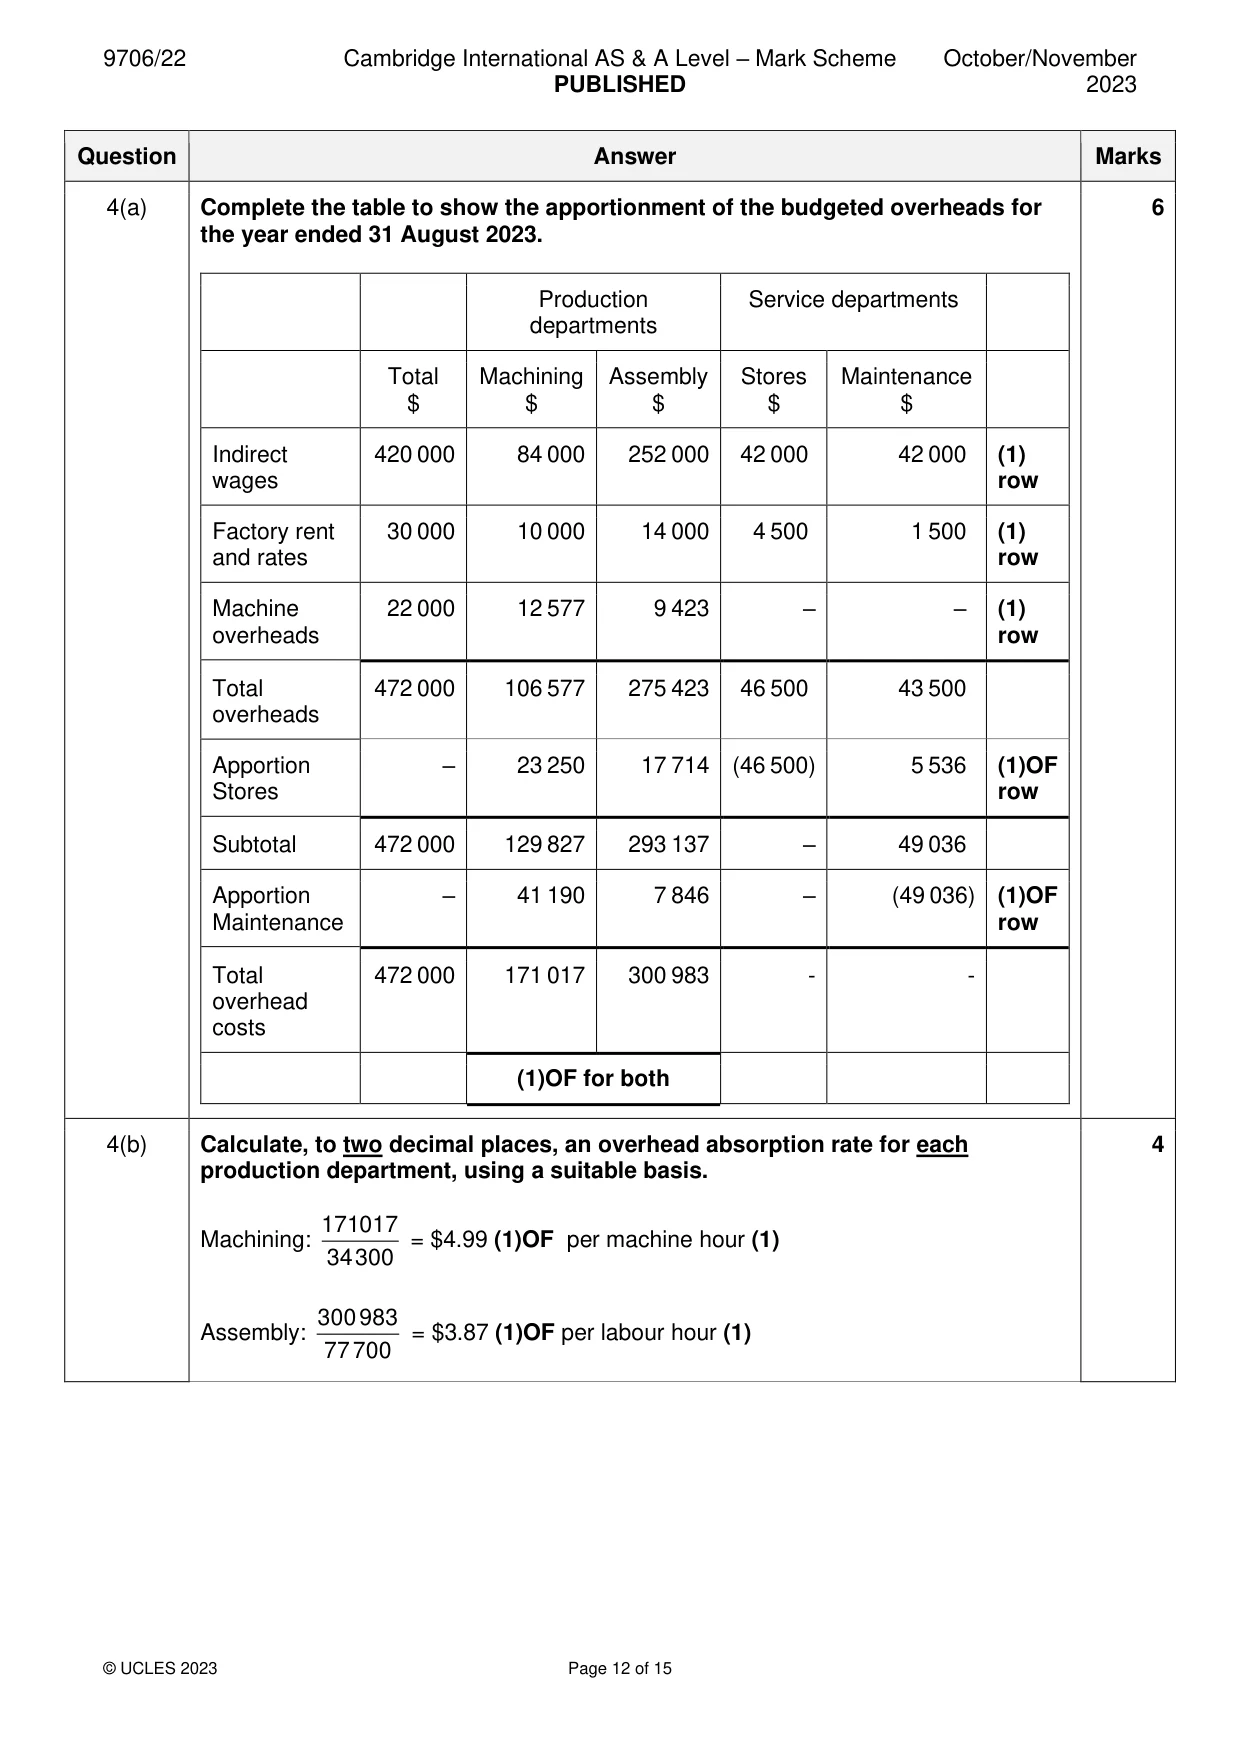
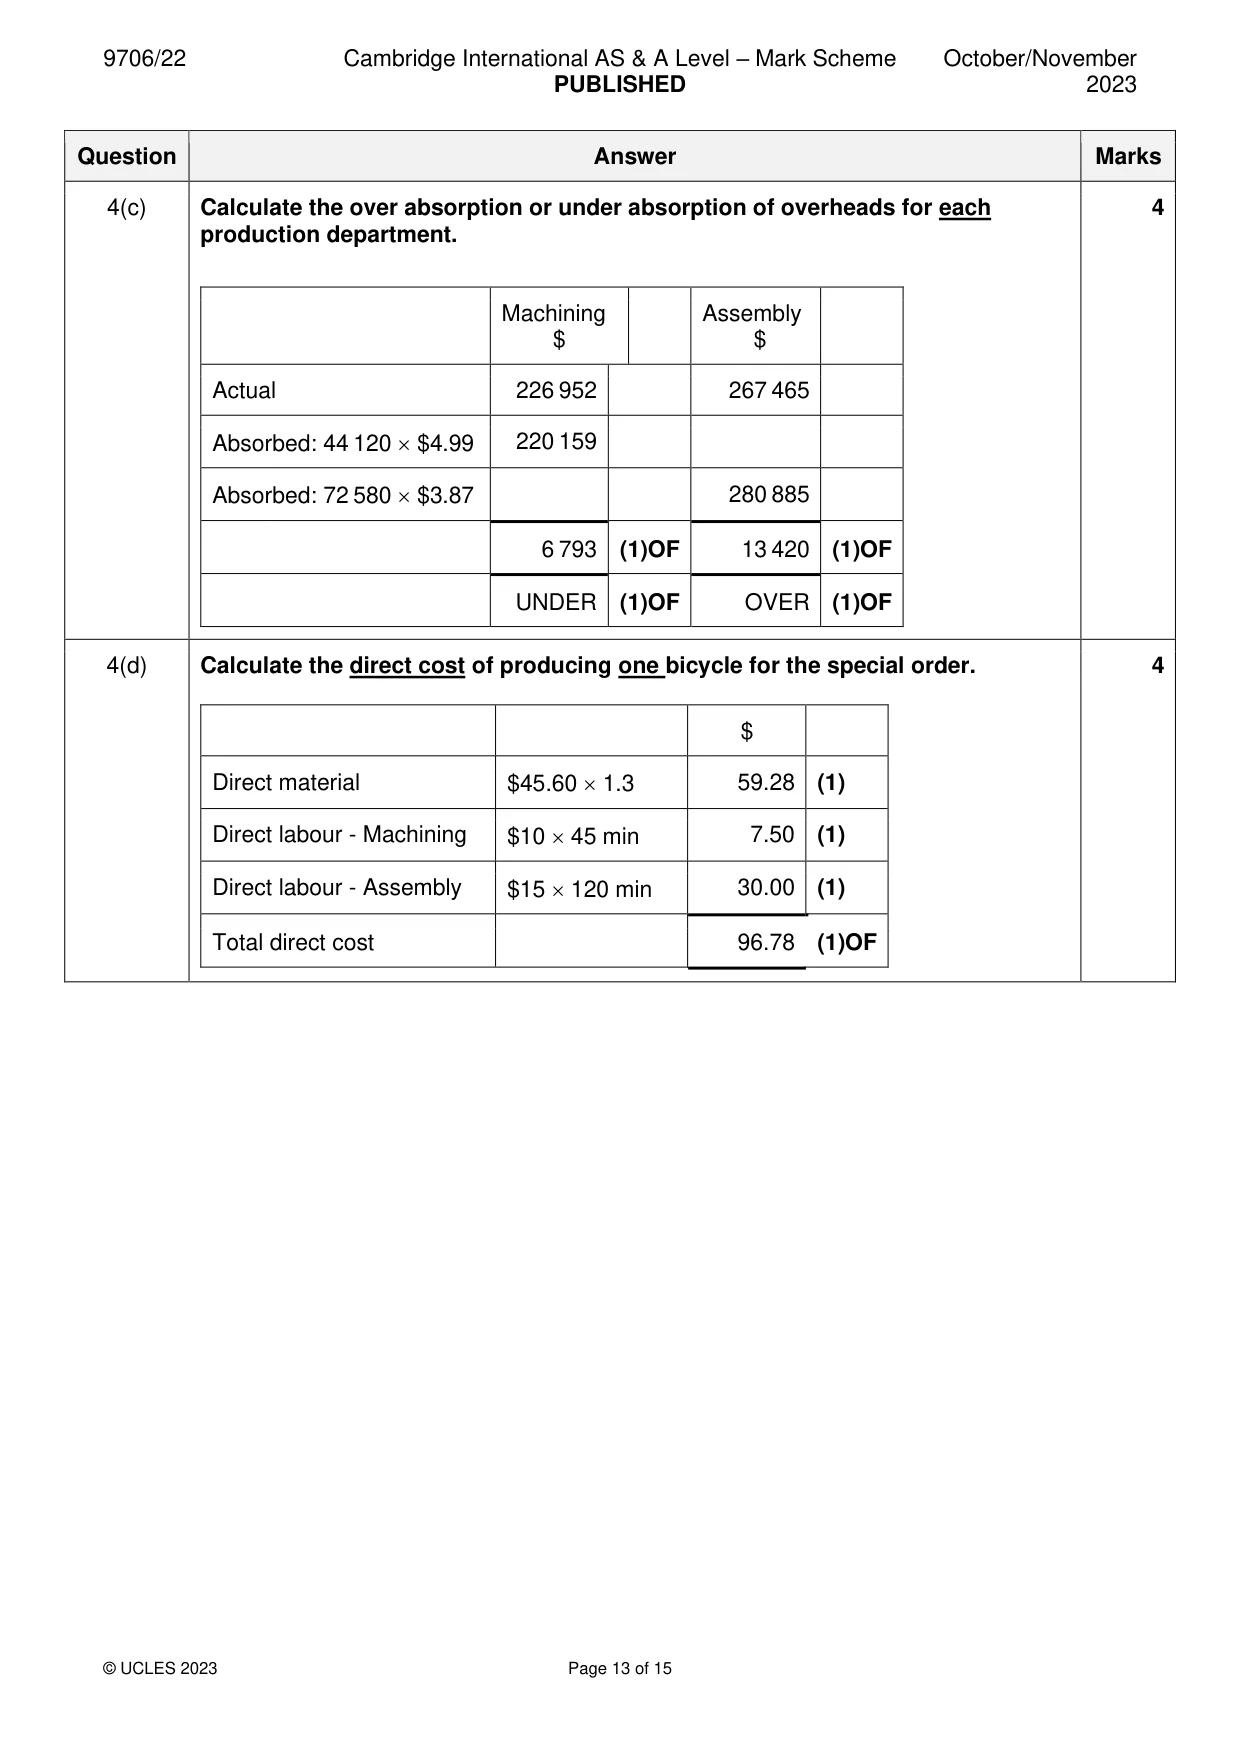
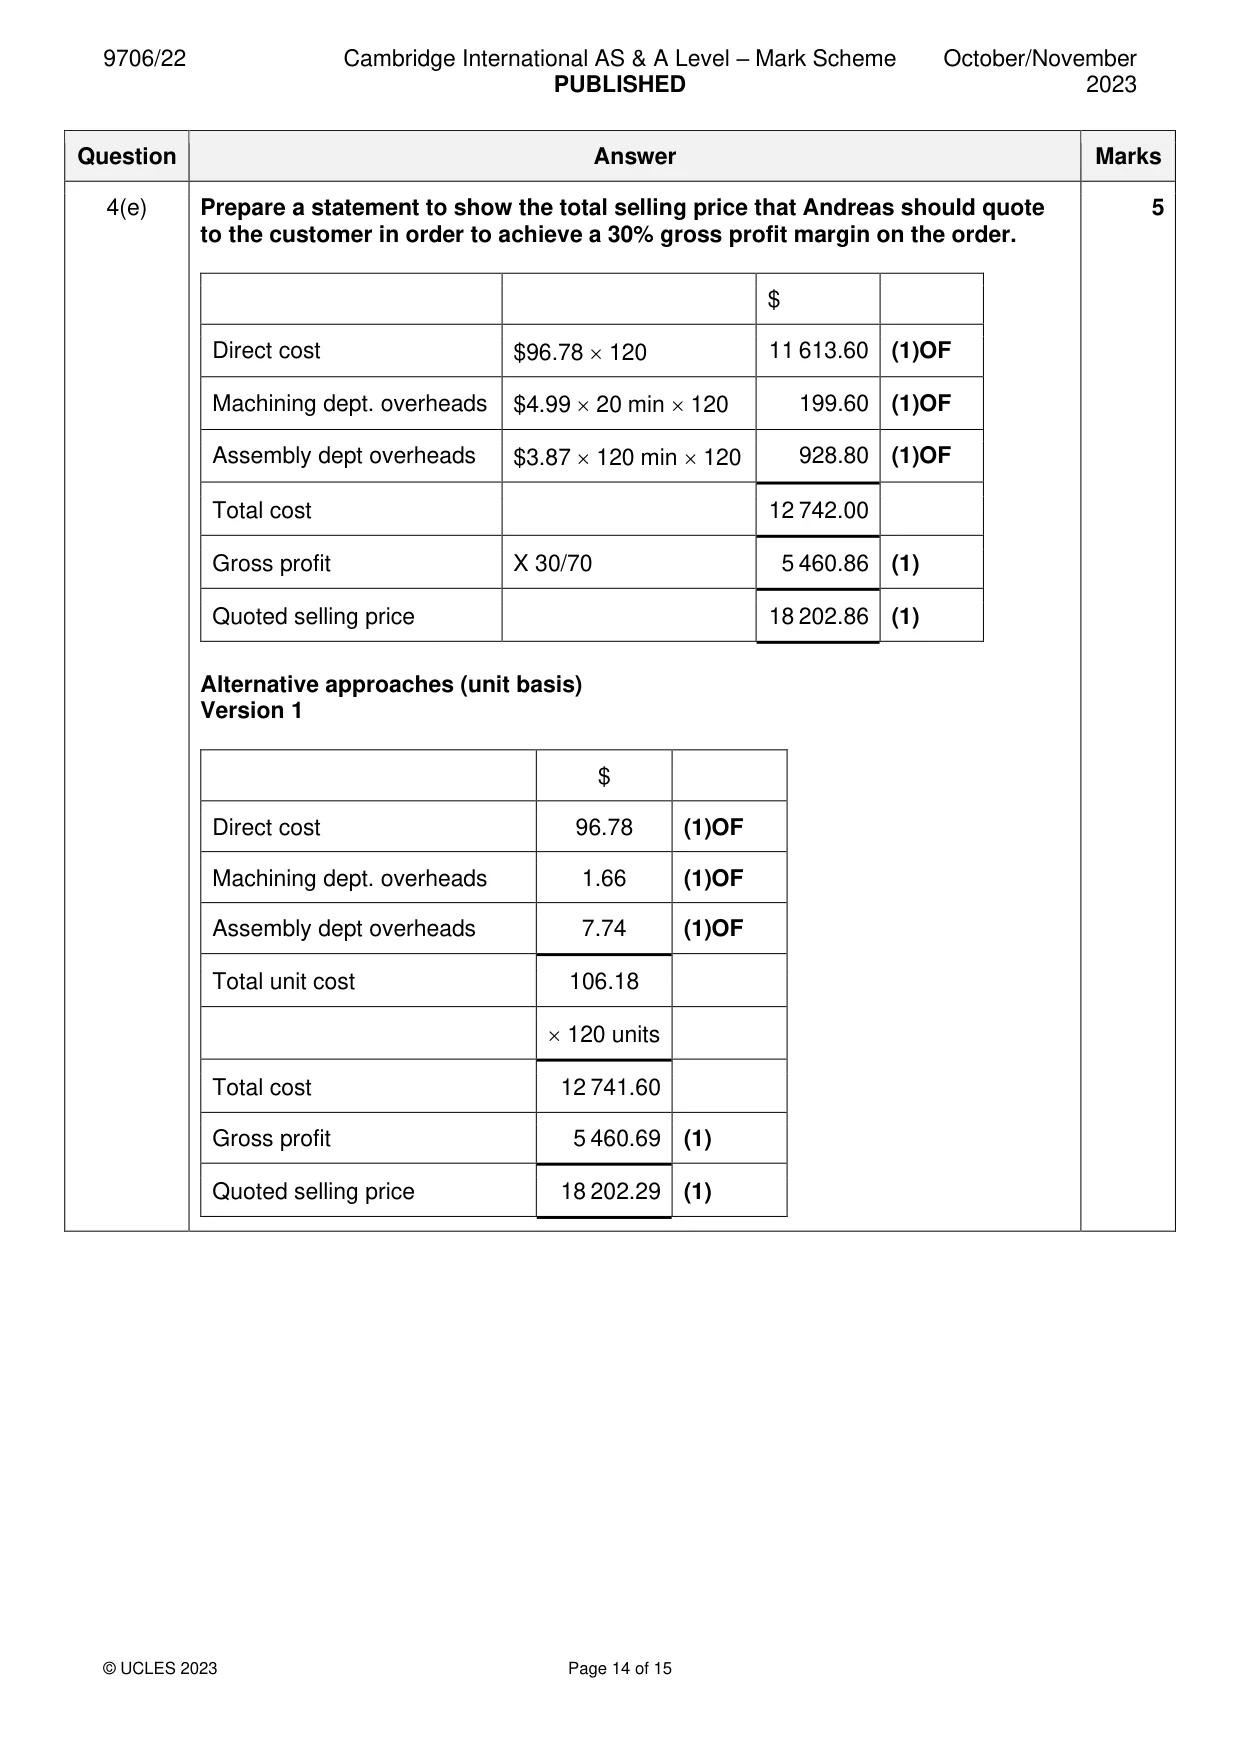
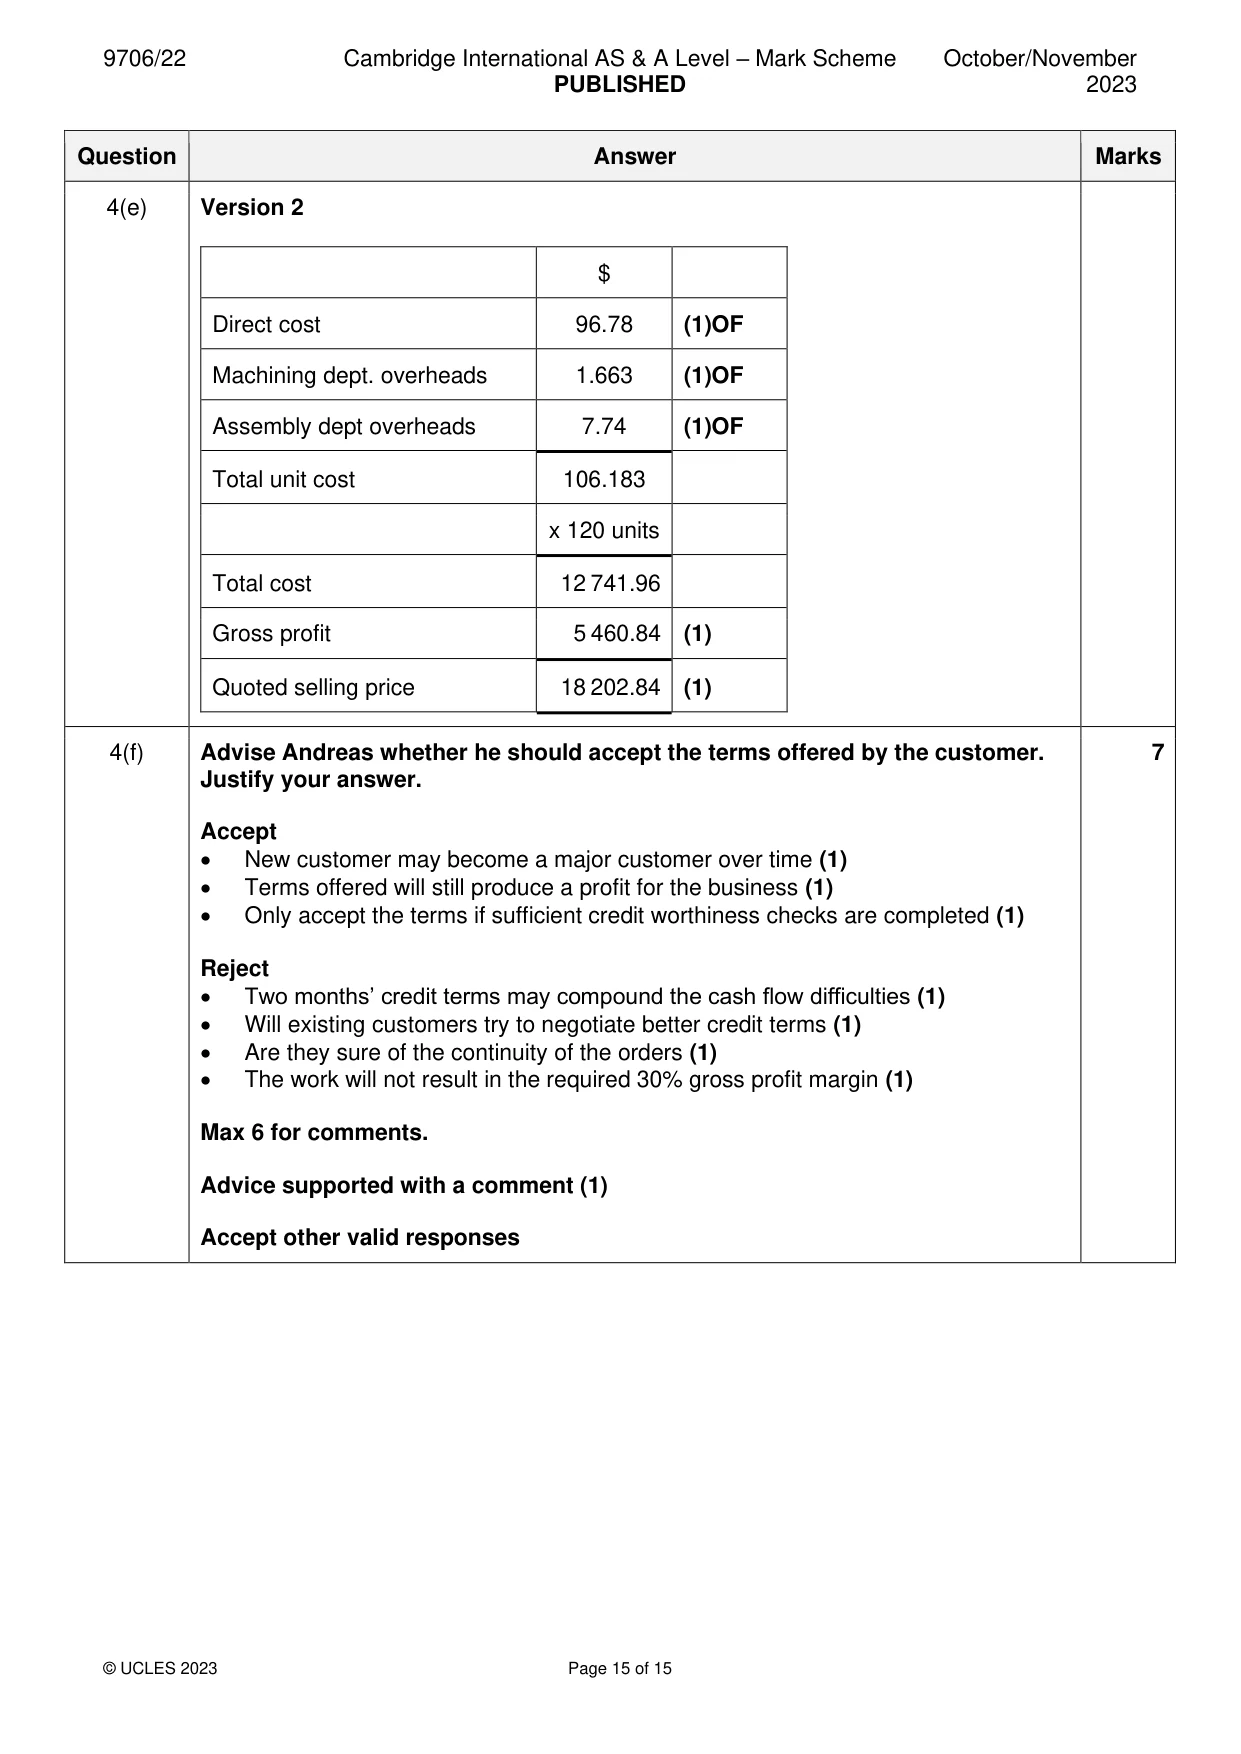
Mark scheme: 4(a) Complete the table to show the apportionment of the budgeted overheads for 6 the year ended 31 August 2023. Production Service departments departments Total Machining Assembly Stores Maintenance $ $ $ $ $ Indirect 420 000 84 000 252 000 42 000 42 000 (1) wages row Factory rent 30 000 10 000 14 000 4 500 1 500 (1) and rates row Machine 22 000 12 577 9 423 – – (1) overheads row Total 472 000 106 577 275 423 46 500 43 500 overheads Apportion – 23 250 17 714 (46 500) 5 536 (1)OF Stores row Subtotal 472 000 129 827 293 137 – 49 036 Apportion – 41 190 7 846 – (49 036) (1)OF Maintenance row Total 472 000 171 017 300 983 - - overhead costs (1)OF for both 4(b) Calculate, to two decimal places, an overhead absorption rate for each 4 production department, using a suitable basis. 171017 Machining: = $4.99 (1)OF per machine hour (1) 34300 300983 Assembly: = $3.87 (1)OF per labour hour (1) 77700 4(c) Calculate the over absorption or under absorption of overheads for each 4 production department. Machining Assembly $ $ Actual 226 952 267 465 Absorbed: 44 120 $4.99 220 159 Absorbed: 72 580 $3.87 280 885 6 793 (1)OF 13 420 (1)OF UNDER (1)OF OVER (1)OF 4(d) Calculate the direct cost of producing one bicycle for the special order. 4 $ Direct material $45.60 1.3 59.28 (1) Direct labour - Machining $10 45 min 7.50 (1) Direct labour - Assembly $15 120 min 30.00 (1) Total direct cost 96.78 (1)OF 4(e) Prepare a statement to show the total selling price that Andreas should quote 5 to the customer in order to achieve a 30% gross profit margin on the order. $ Direct cost $96.78 120 11 613.60 (1)OF Machining dept. overheads $4.99 20 min 120 199.60 (1)OF Assembly dept overheads $3.87 120 min 120 928.80 (1)OF Total cost 12 742.00 Gross profit X 30/70 5 460.86 (1) Quoted selling price 18 202.86 (1) Alternative approaches (unit basis) Version 1 $ Direct cost 96.78 (1)OF Machining dept. overheads 1.66 (1)OF Assembly dept overheads 7.74 (1)OF Total unit cost 106.18 120 units Total cost 12 741.60 Gross profit 5 460.69 (1) Quoted selling price 18 202.29 (1) 4(e) Version 2 $ Direct cost 96.78 (1)OF Machining dept. overheads 1.663 (1)OF Assembly dept overheads 7.74 (1)OF Total unit cost 106.183 x 120 units Total cost 12 741.96 Gross profit 5 460.84 (1) Quoted selling price 18 202.84 (1) 4(f) Advise Andreas whether he should accept the terms offered by the customer. 7 Justify your answer. Accept • New customer may become a major customer over time (1) • Terms offered will still produce a profit for the business (1) • Only accept the terms if sufficient credit worthiness checks are completed (1) Reject • Two months’ credit terms may compound the cash flow difficulties (1) • Will existing customers try to negotiate better credit terms (1) • Are they sure of the continuity of the orders (1) • The work will not result in the required 30% gross profit margin (1) Max 6 for comments. Advice supported with a comment (1) Accept other valid responses
More questions on Analysis and communication of accounting information
What was in this paper
The subtopics covered by these 4 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.