Questions as text
Q1 · The following list of expenditure relates to a newly purchased item of plant 9706/31 Oct/Nov 2009
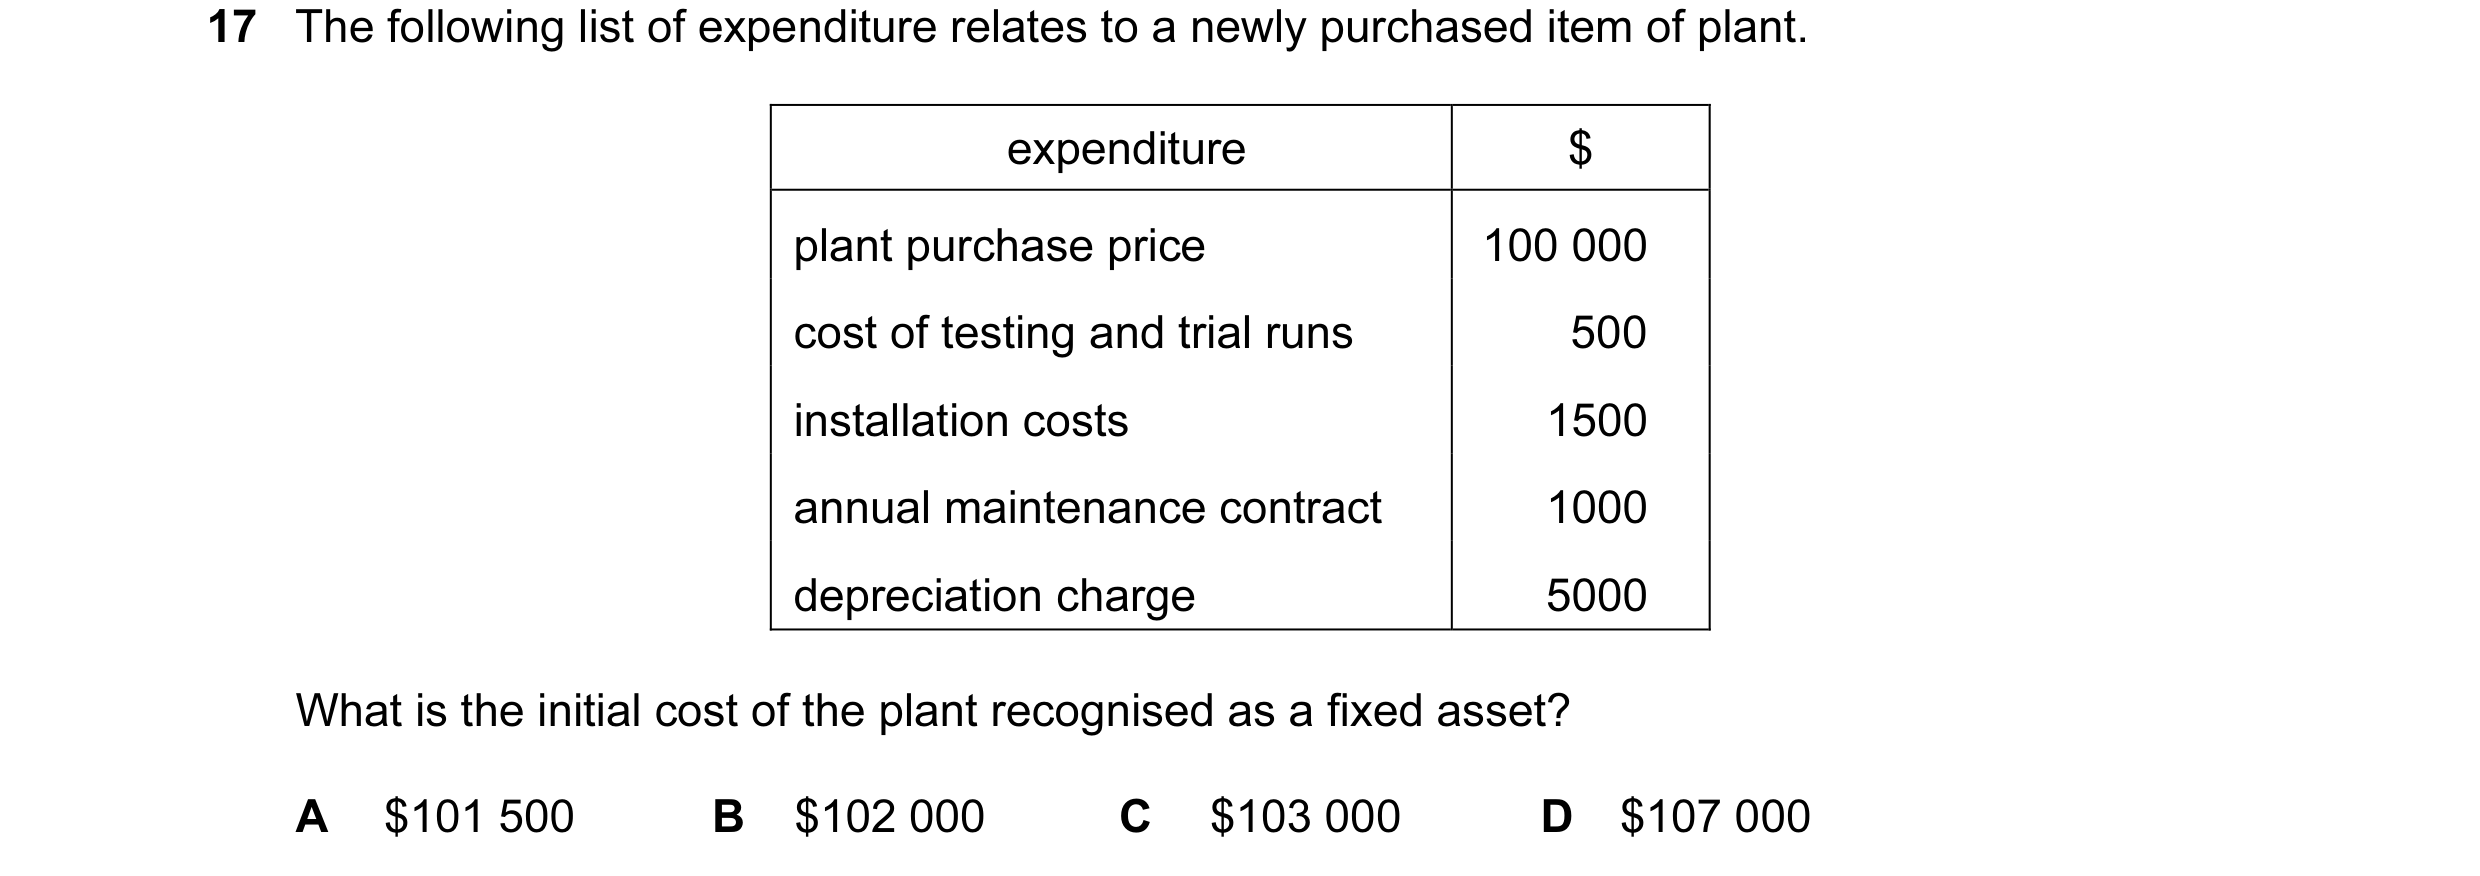
17 The following list of expenditure relates to a newly purchased item of plant. expenditure $ plant purchase price 100 000 cost of testing and trial runs 500 installation costs 1500 annual maintenance contract 1000 depreciation charge 5000 What is the initial cost of the plant recognised as a fixed asset? A $101 500 B $102 000 C $103 000 D $107 000
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2009
Q2 · The following list of expenditure relates to a newly purchased item of plant 9706/32 Oct/Nov 2009
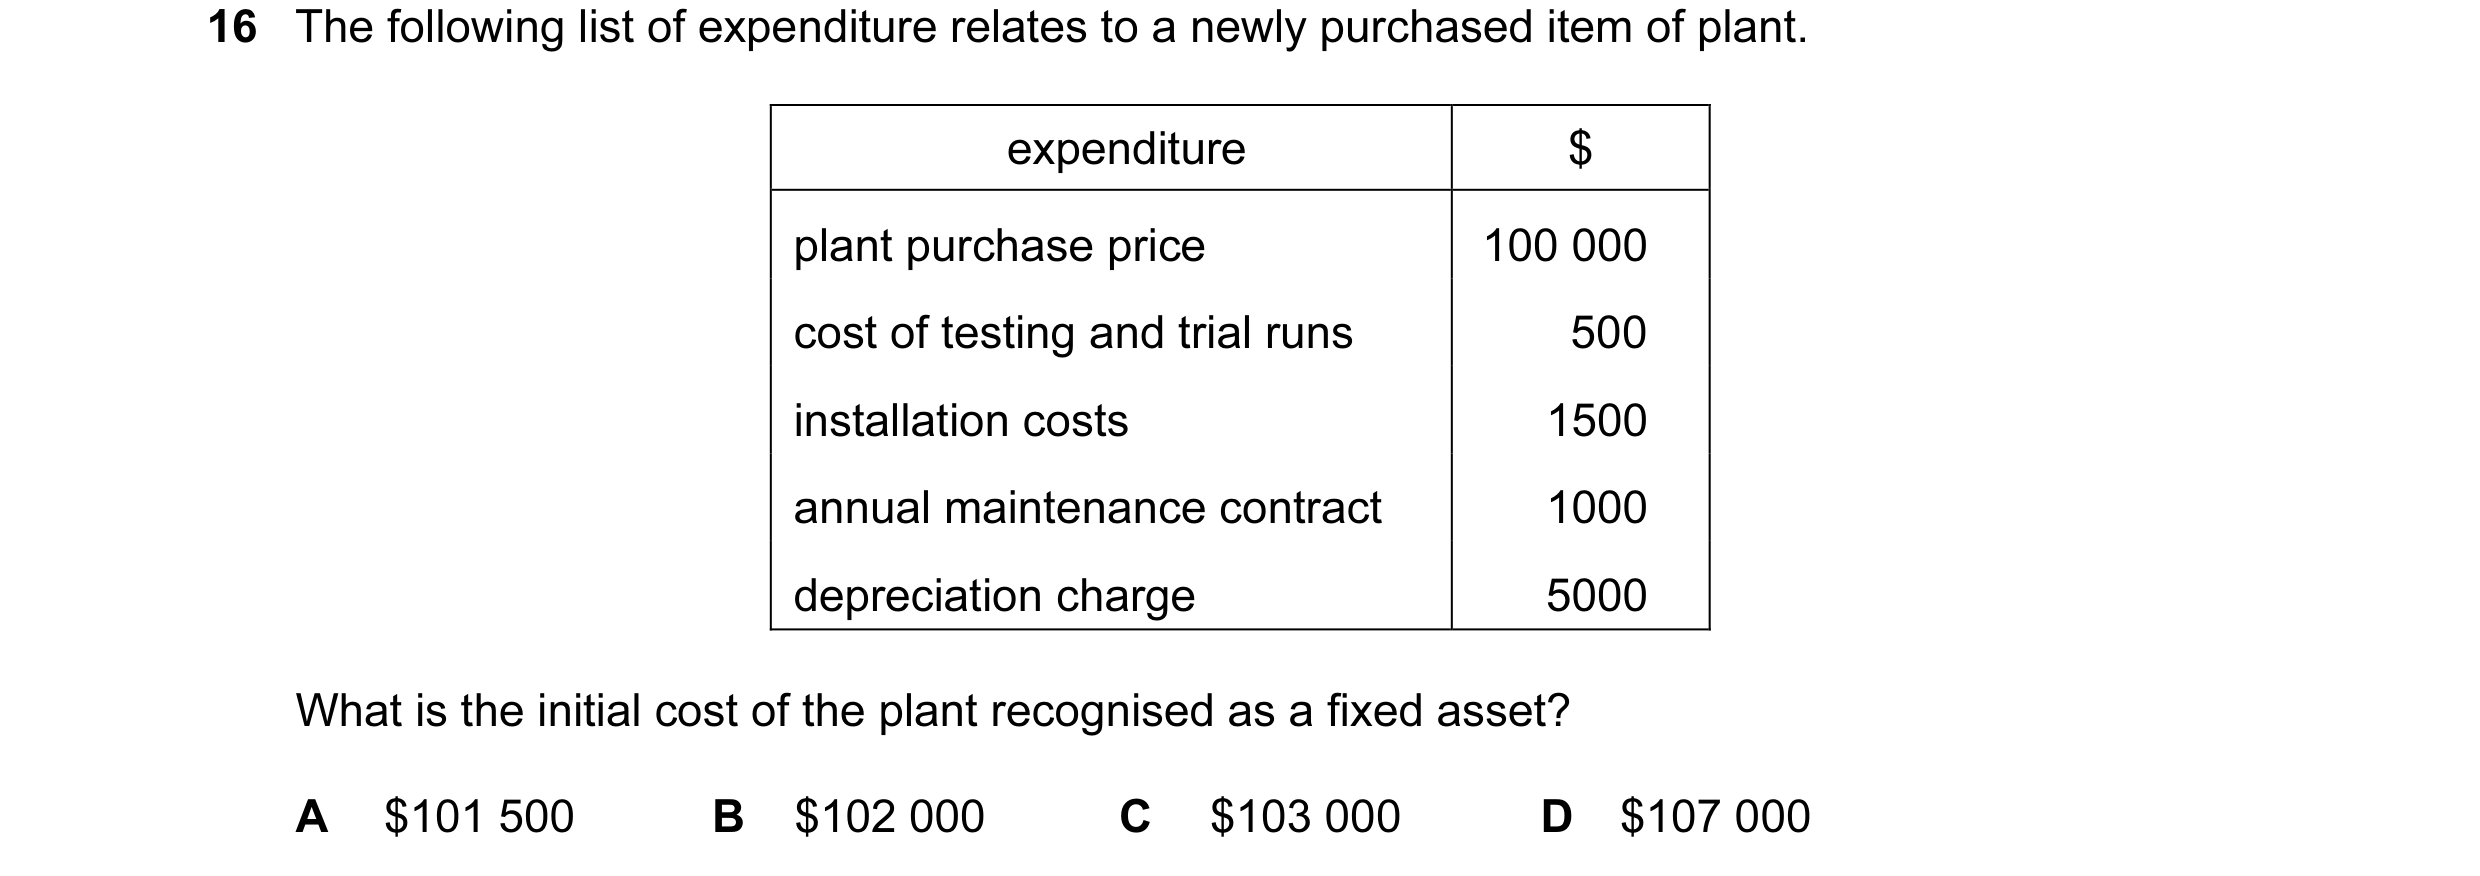
16 The following list of expenditure relates to a newly purchased item of plant. expenditure $ plant purchase price 100 000 cost of testing and trial runs 500 installation costs 1500 annual maintenance contract 1000 depreciation charge 5000 What is the initial cost of the plant recognised as a fixed asset? A $101 500 B $102 000 C $103 000 D $107 000
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2009
Q3 · X Plc incurred the following costs as a result of purchasing a new machine 9706/31 Oct/Nov 2010
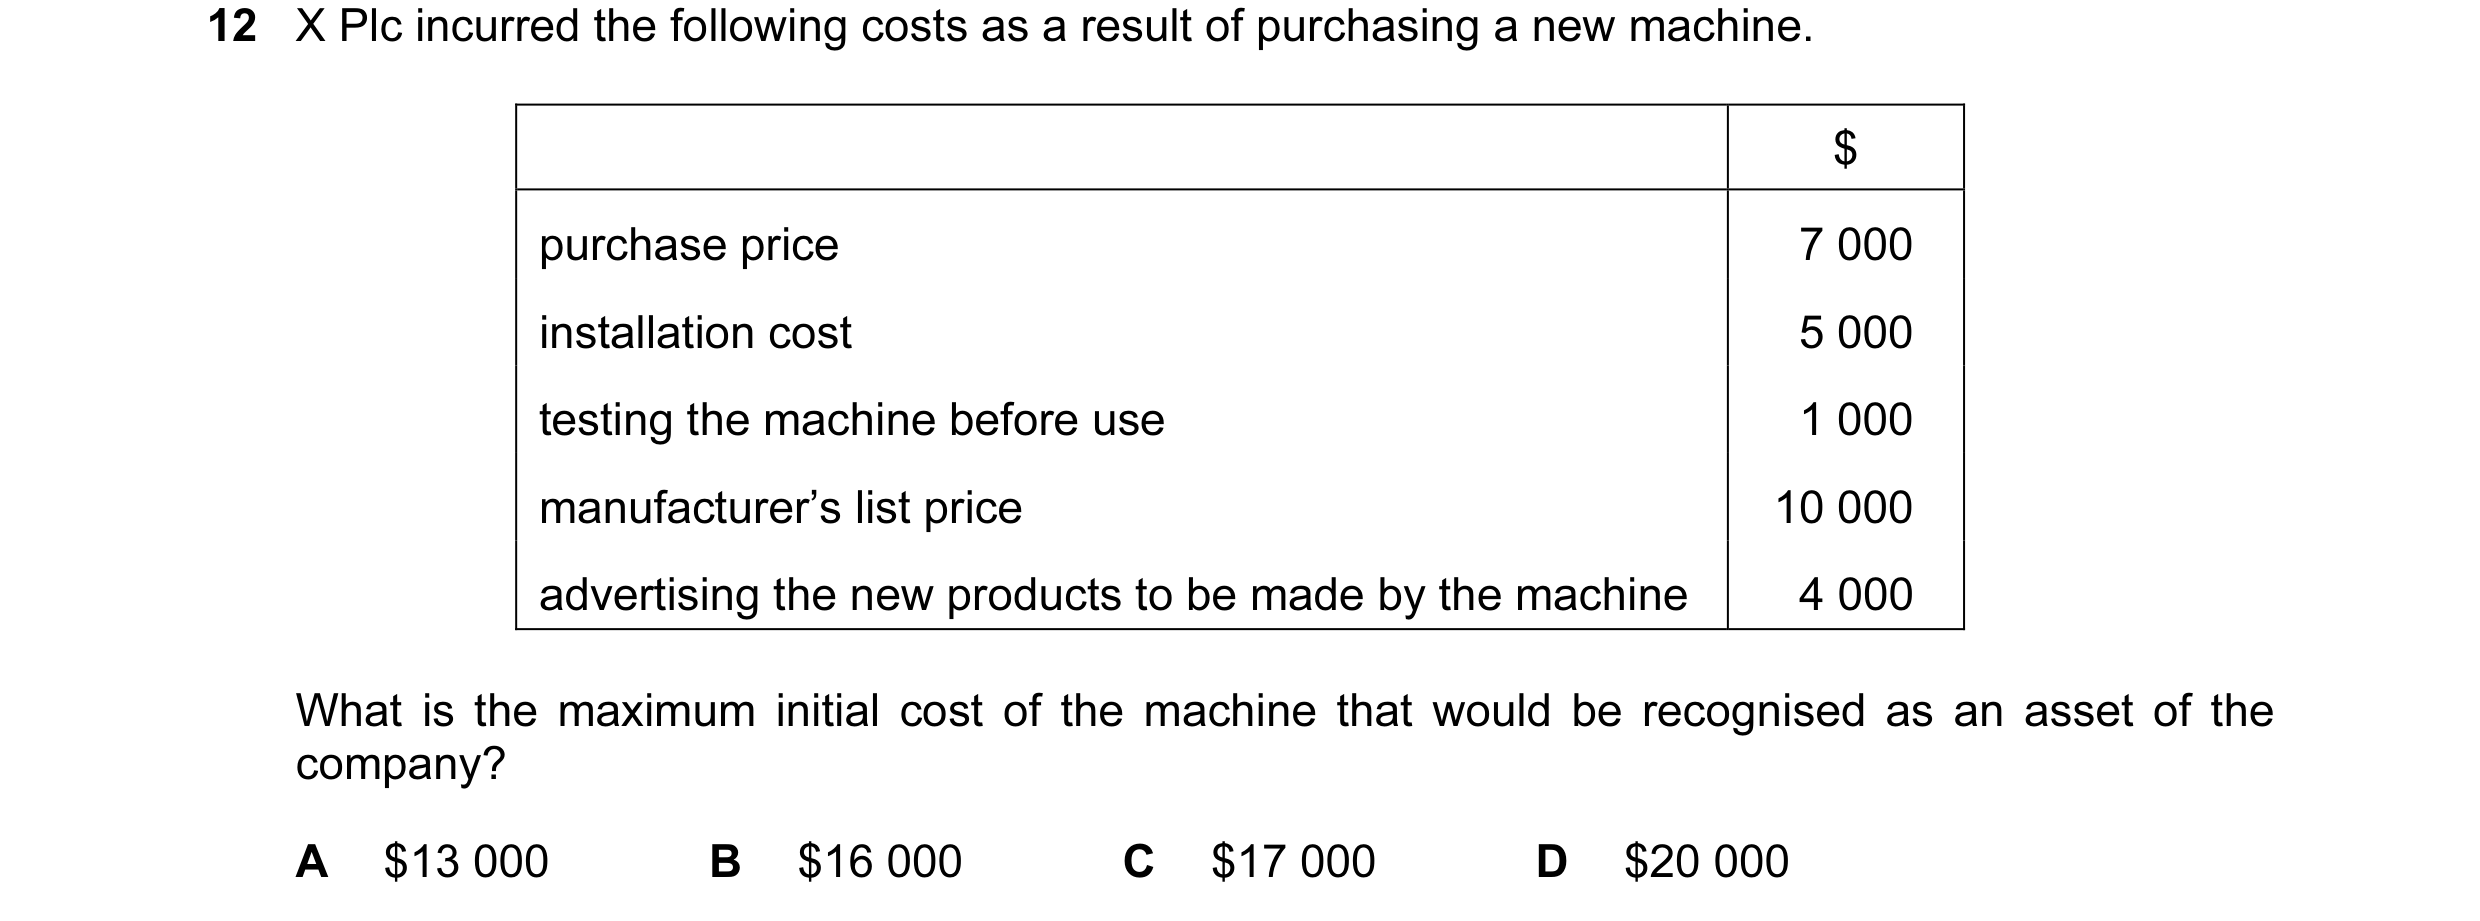
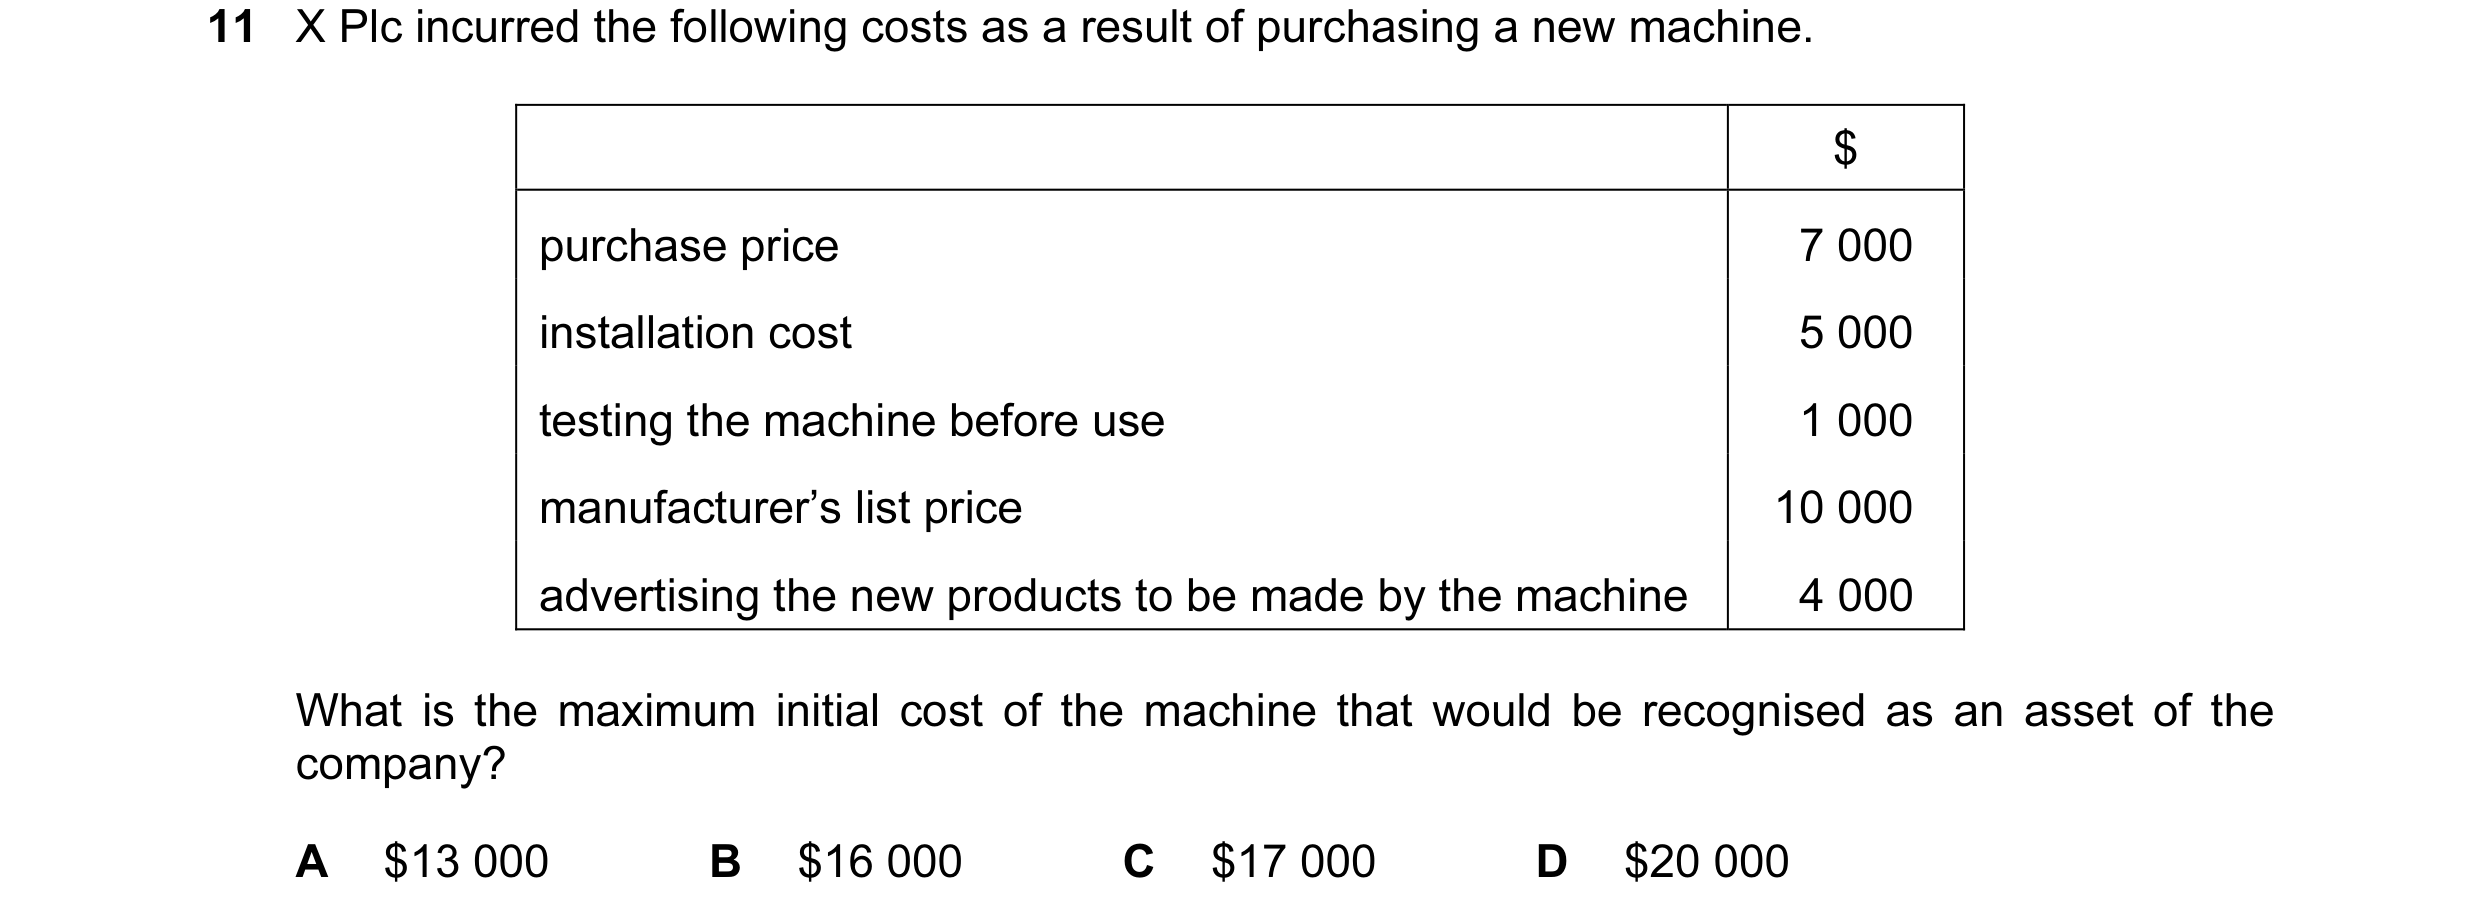
12 X Plc incurred the following costs as a result of purchasing a new machine. $ purchase price 7 000 installation cost 5 000 testing the machine before use 1 000 manufacturer’s list price 10 000 advertising the new products to be made by the machine 4 000 What is the maximum initial cost of the machine that would be recognised as an asset of the company? A $13 000 B $16 000 C $17 000 D $20 000
1 marks
Answer: A
This question in 9706/31 Oct/Nov 2010
Q4 · X Plc incurred the following costs as a result of purchasing a new machine 9706/32 Oct/Nov 2010
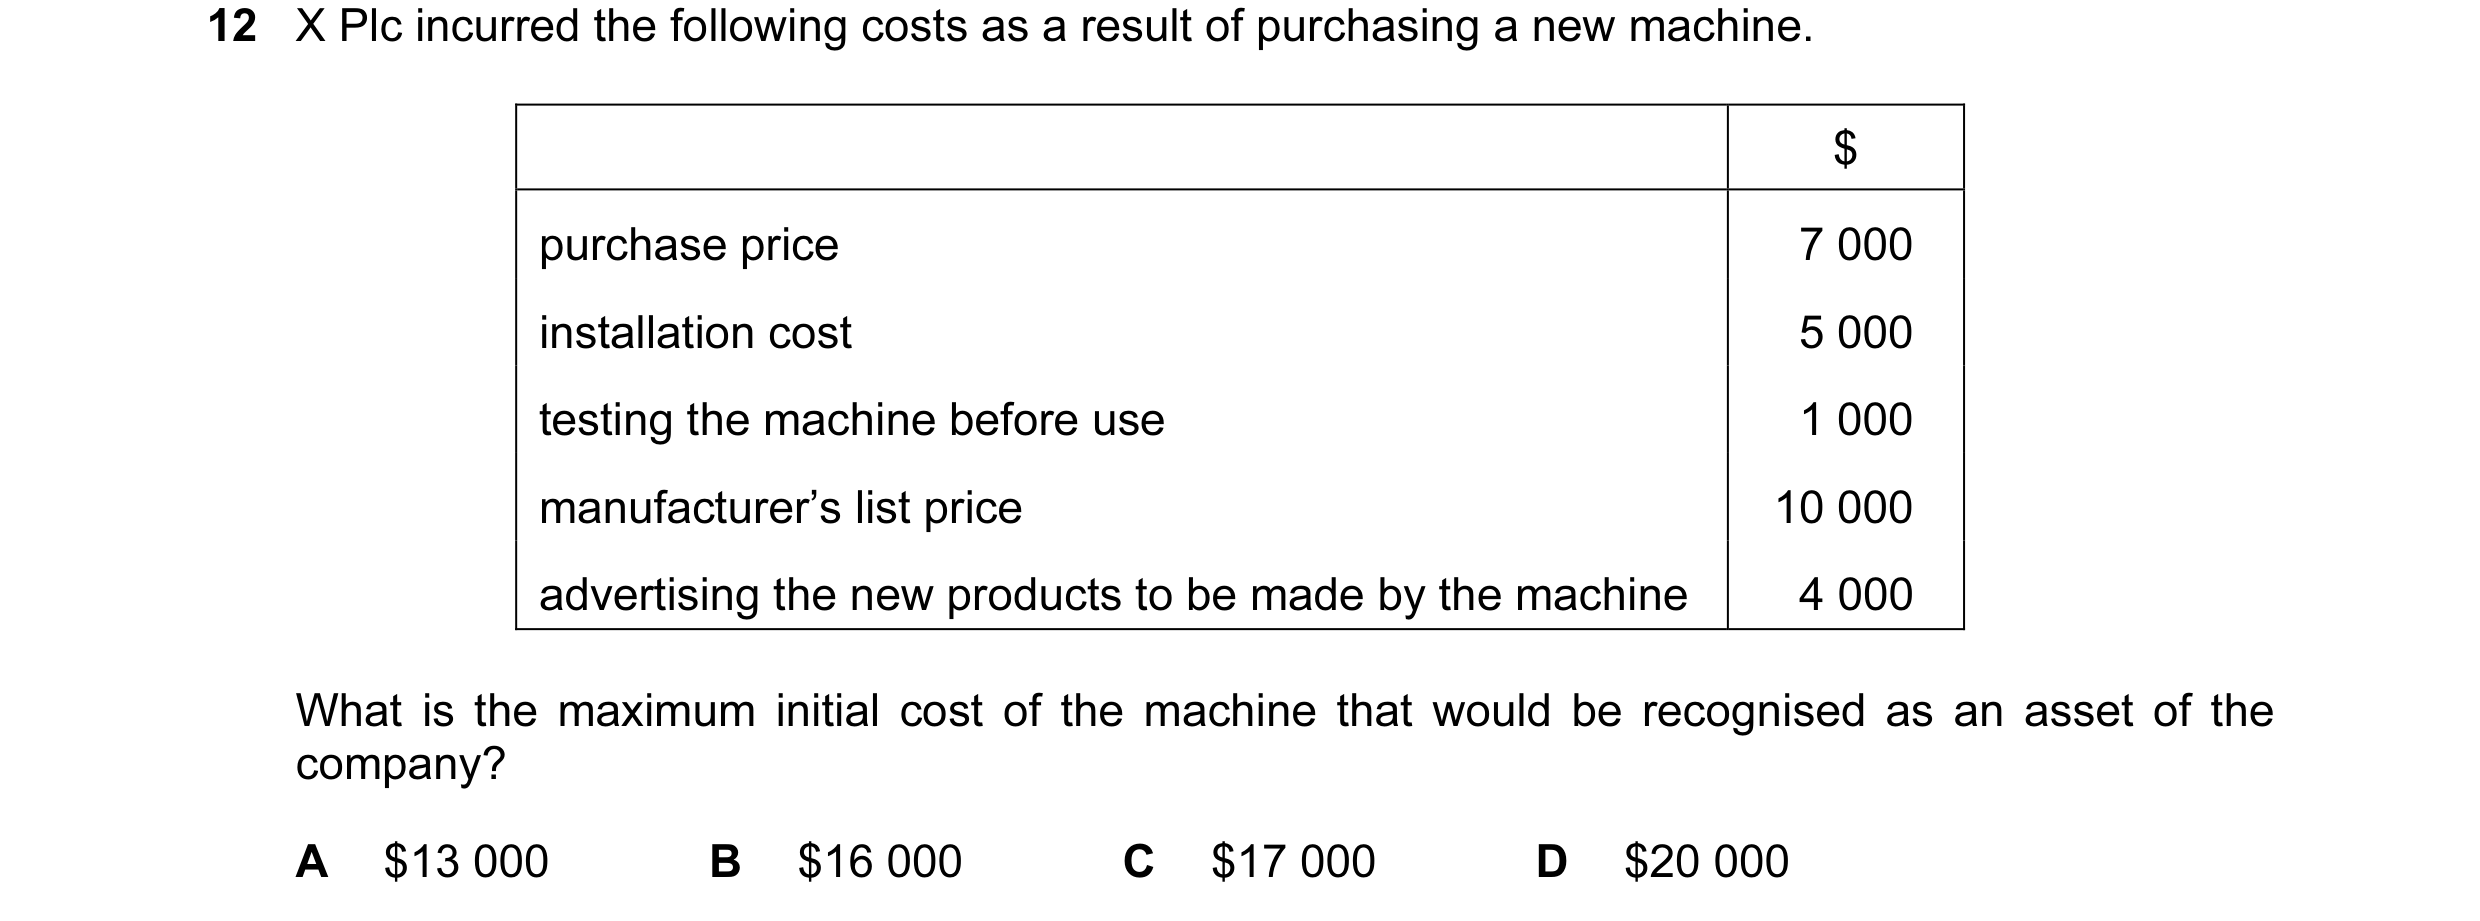
12 X Plc incurred the following costs as a result of purchasing a new machine. $ purchase price 7 000 installation cost 5 000 testing the machine before use 1 000 manufacturer’s list price 10 000 advertising the new products to be made by the machine 4 000 What is the maximum initial cost of the machine that would be recognised as an asset of the company? A $13 000 B $16 000 C $17 000 D $20 000
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2010
Q5 · X Plc incurred the following costs as a result of purchasing a new machine 9706/33 Oct/Nov 2010
11 X Plc incurred the following costs as a result of purchasing a new machine. $ purchase price 7 000 installation cost 5 000 testing the machine before use 1 000 manufacturer’s list price 10 000 advertising the new products to be made by the machine 4 000 What is the maximum initial cost of the machine that would be recognised as an asset of the company? A $13 000 B $16 000 C $17 000 D $20 000
1 marks
Answer: A
This question in 9706/33 Oct/Nov 2010
Q6 · At the start of the year a company has plant and machinery valued at $20 000 9706/32 Oct/Nov 2011
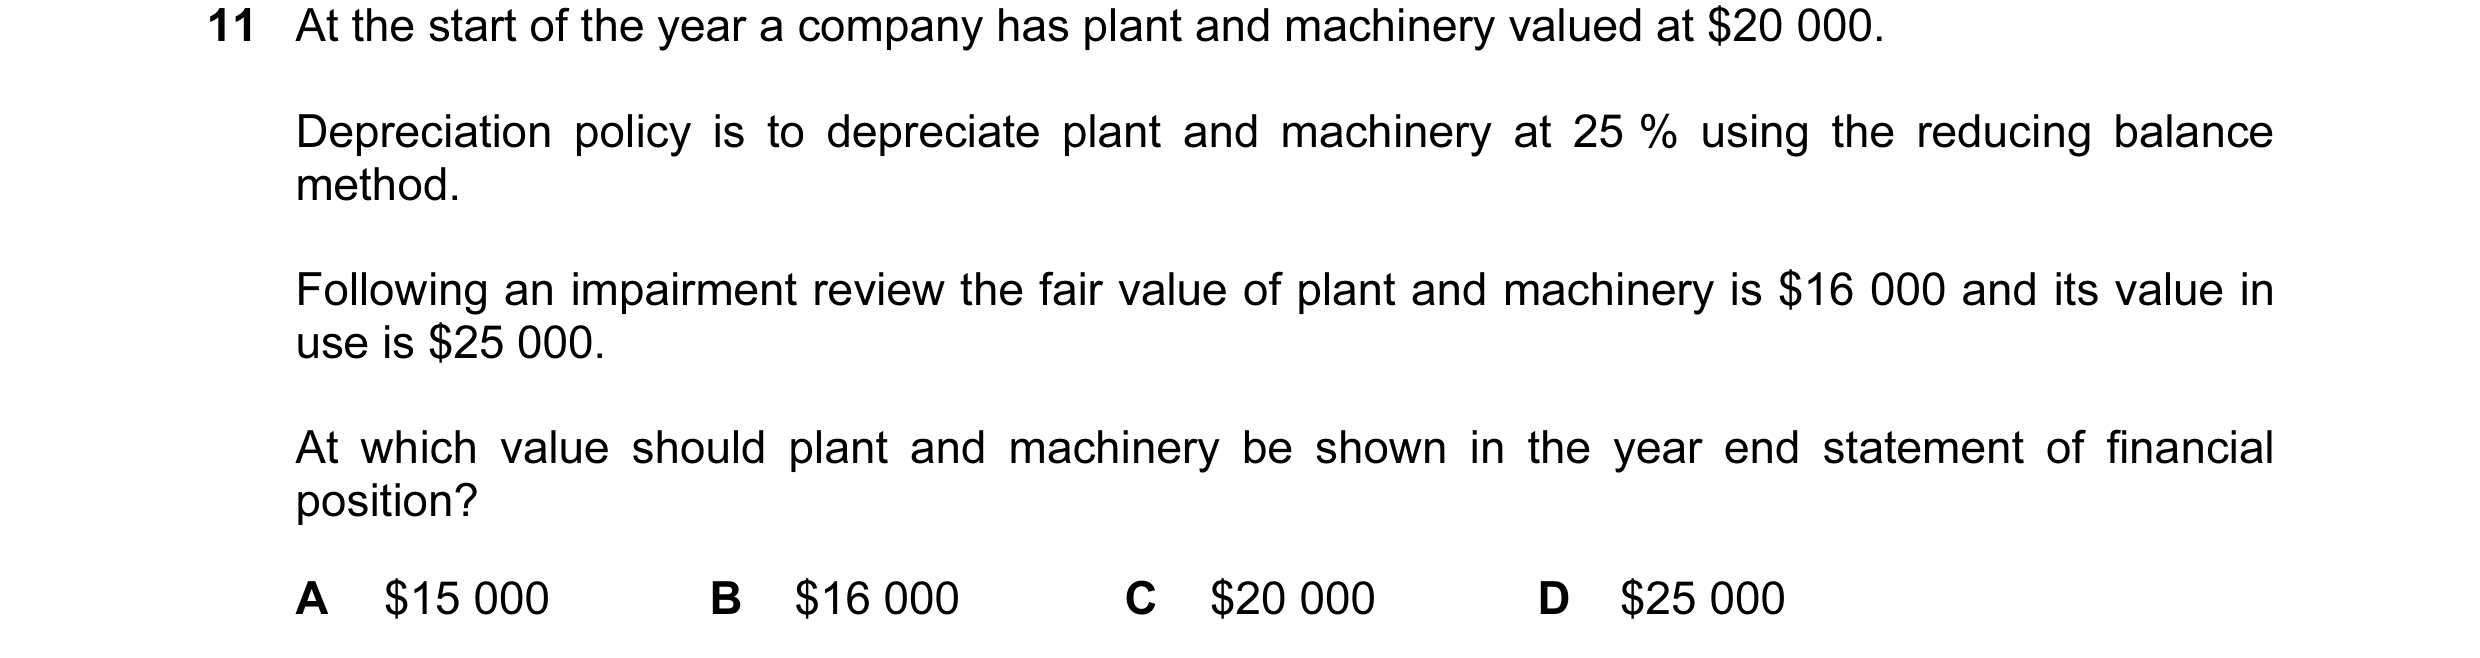
11 At the start of the year a company has plant and machinery valued at $20 000. Depreciation policy is to depreciate plant and machinery at 25 % using the reducing balance method. Following an impairment review the fair value of plant and machinery is $16 000 and its value in use is $25 000. At which value should plant and machinery be shown in the year end statement of financial position? A $15 000 B $16 000 C $20 000 D $25 000
1 marks
Answer: A
This question in 9706/32 Oct/Nov 2011
Q7 · A company’s year end is 30 April 9706/32 May/June 2012
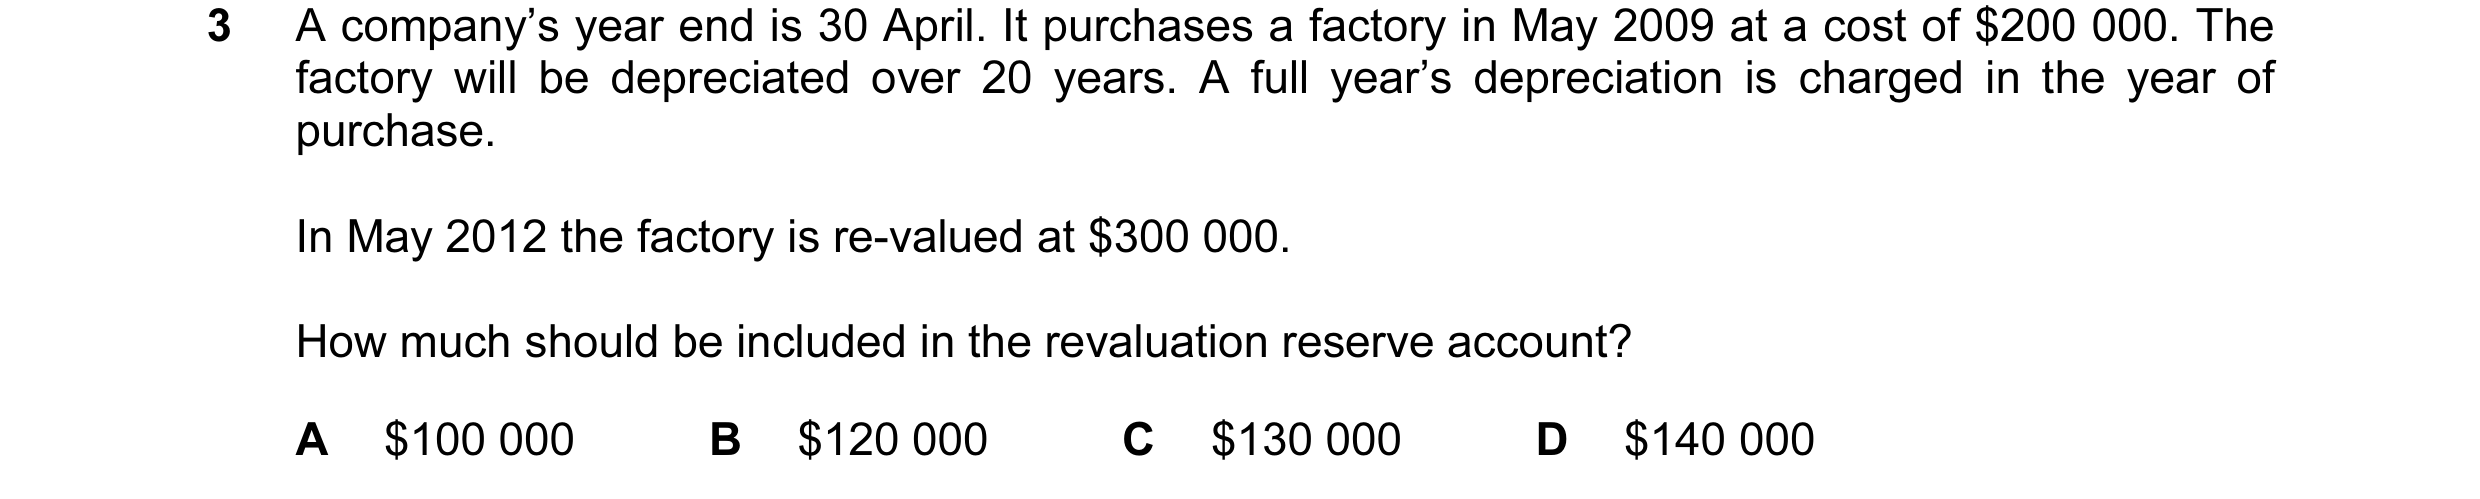
3 A company’s year end is 30 April. It purchases a factory in May 2009 at a cost of $200 000. The factory will be depreciated over 20 years. A full year’s depreciation is charged in the year of purchase. In May 2012 the factory is re-valued at $300 000. How much should be included in the revaluation reserve account? A $100 000 B $120 000 C $130 000 D $140 000
1 marks
Answer: C
This question in 9706/32 May/June 2012
Q8 · At 31 December 2010 an extract from a company’s non-current asset schedule showed the… 9706/31 Oct/Nov 2012
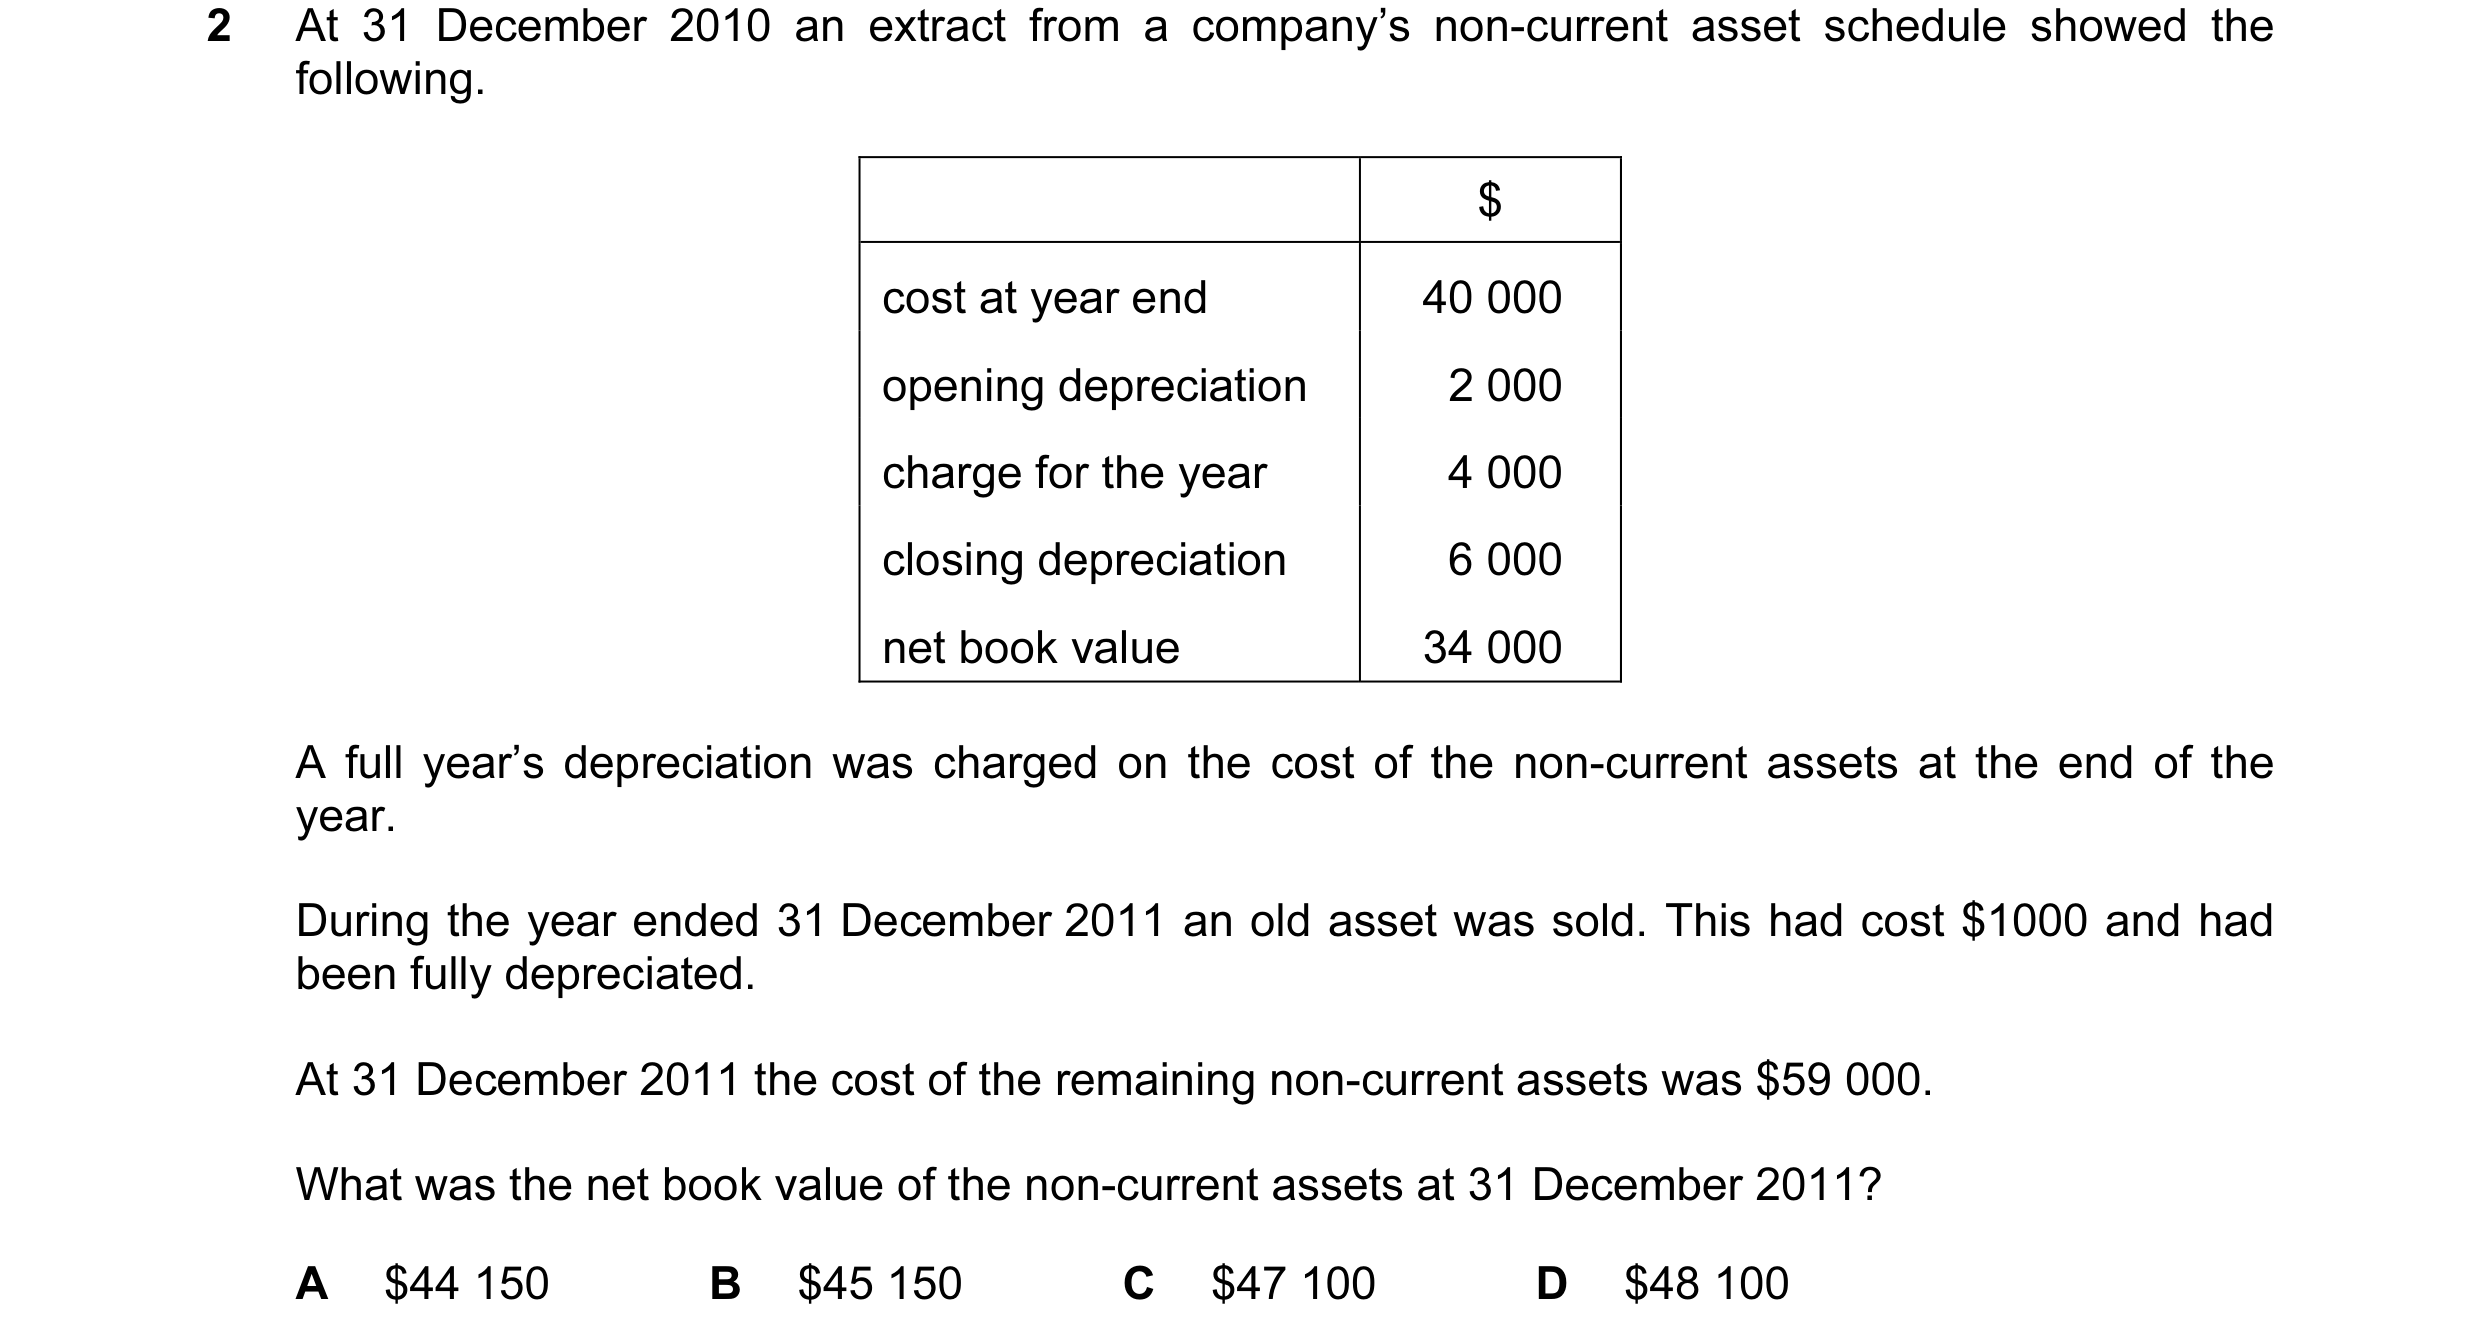
2 At 31 December 2010 an extract from a company’s non-current asset schedule showed the following. $ cost at year end 40 000 opening depreciation 2 000 charge for the year 4 000 closing depreciation 6 000 net book value 34 000 A full year’s depreciation was charged on the cost of the non-current assets at the end of the year. During the year ended 31 December 2011 an old asset was sold. This had cost $1000 and had been fully depreciated. At 31 December 2011 the cost of the remaining non-current assets was $59 000. What was the net book value of the non-current assets at 31 December 2011? A $44 150 B $45 150 C $47 100 D $48 100
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2012
Q9 · Which non-current asset need not be depreciated? 9706/31 Oct/Nov 2012
12 Which non-current asset need not be depreciated? A freehold buildings B freehold land C leasehold properties D plant and machinery
1 marks
Answer: B
This question in 9706/31 Oct/Nov 2012
Q10 · The following information relates to a company’s non-current assets 9706/33 Oct/Nov 2012
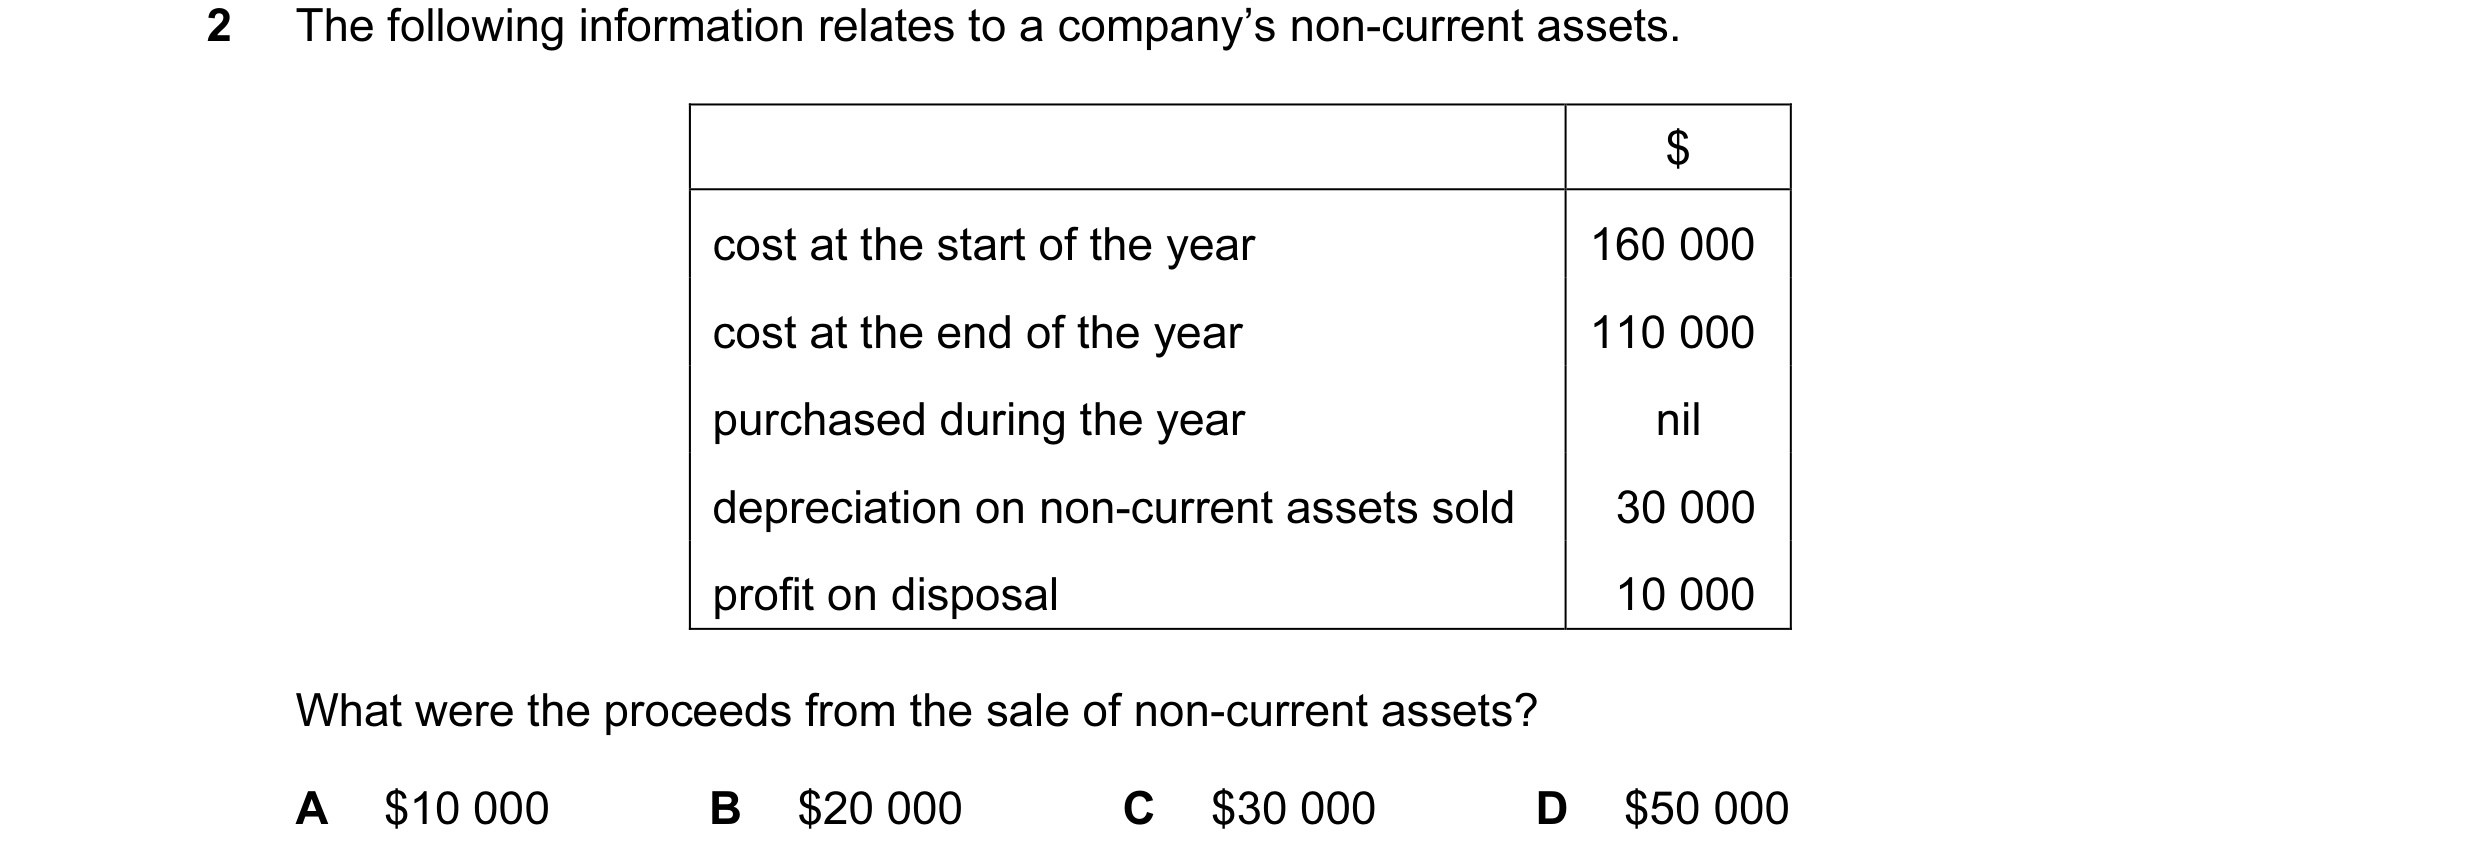
2 The following information relates to a company’s non-current assets. $ cost at the start of the year 160 000 cost at the end of the year 110 000 purchased during the year nil depreciation on non-current assets sold 30 000 profit on disposal 10 000 What were the proceeds from the sale of non-current assets? A $10 000 B $20 000 C $30 000 D $50 000
1 marks
Answer: C
This question in 9706/33 Oct/Nov 2012
Q11 · A company purchases a new machine 9706/31 May/June 2013
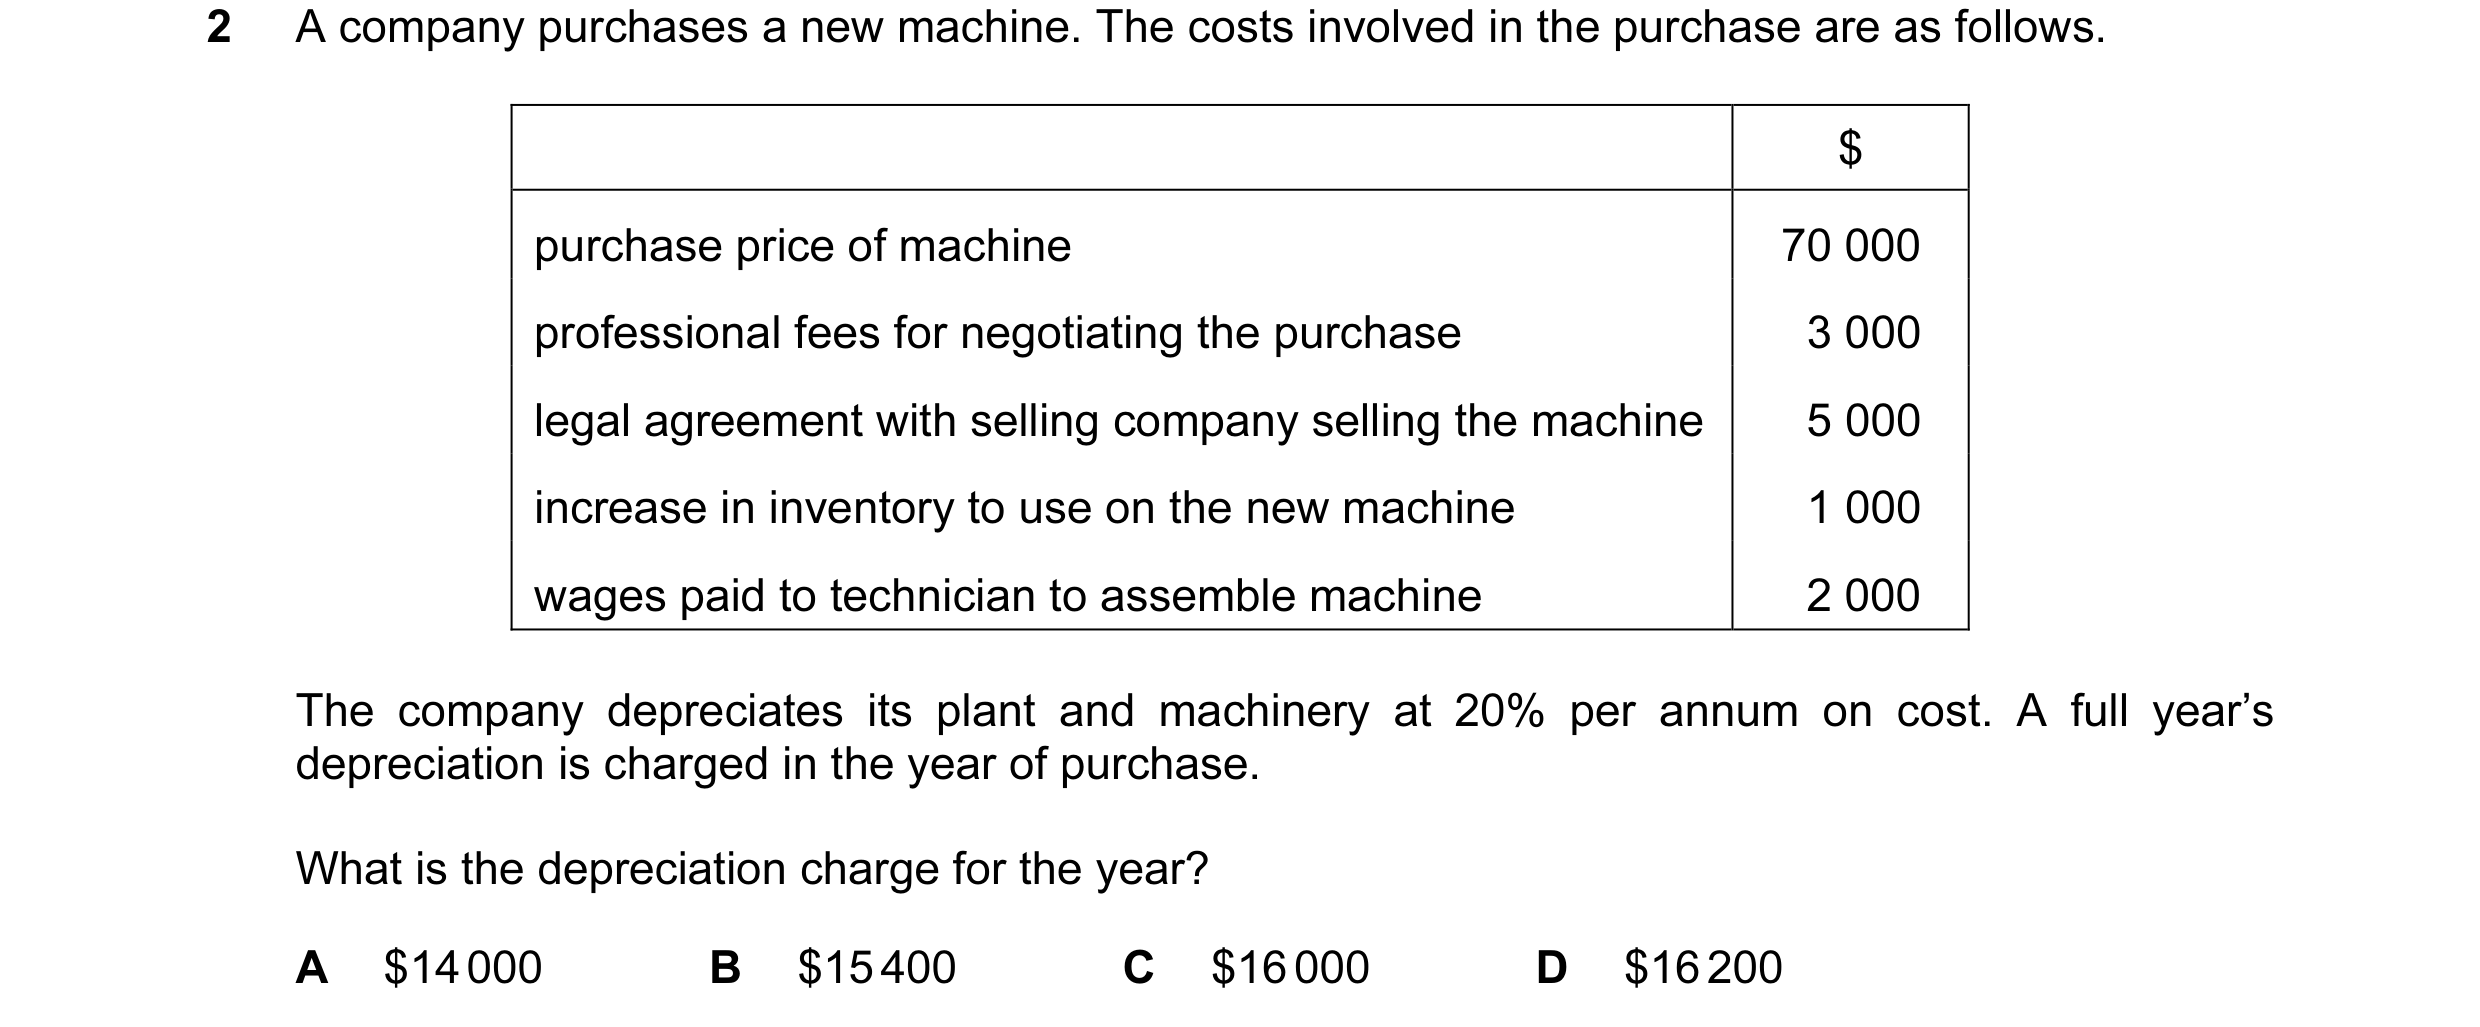
2 A company purchases a new machine. The costs involved in the purchase are as follows. $ purchase price of machine 70 000 professional fees for negotiating the purchase 3 000 legal agreement with selling company selling the machine 5 000 increase in inventory to use on the new machine 1 000 wages paid to technician to assemble machine 2 000 The company depreciates its plant and machinery at 20% per annum on cost. A full year’s depreciation is charged in the year of purchase. What is the depreciation charge for the year? A $14 000 B $15 400 C $16 000 D $16 200
1 marks
Answer: C
This question in 9706/31 May/June 2013
Q12 · A company purchased a machine with a cost price of $40 000 9706/32 May/June 2013
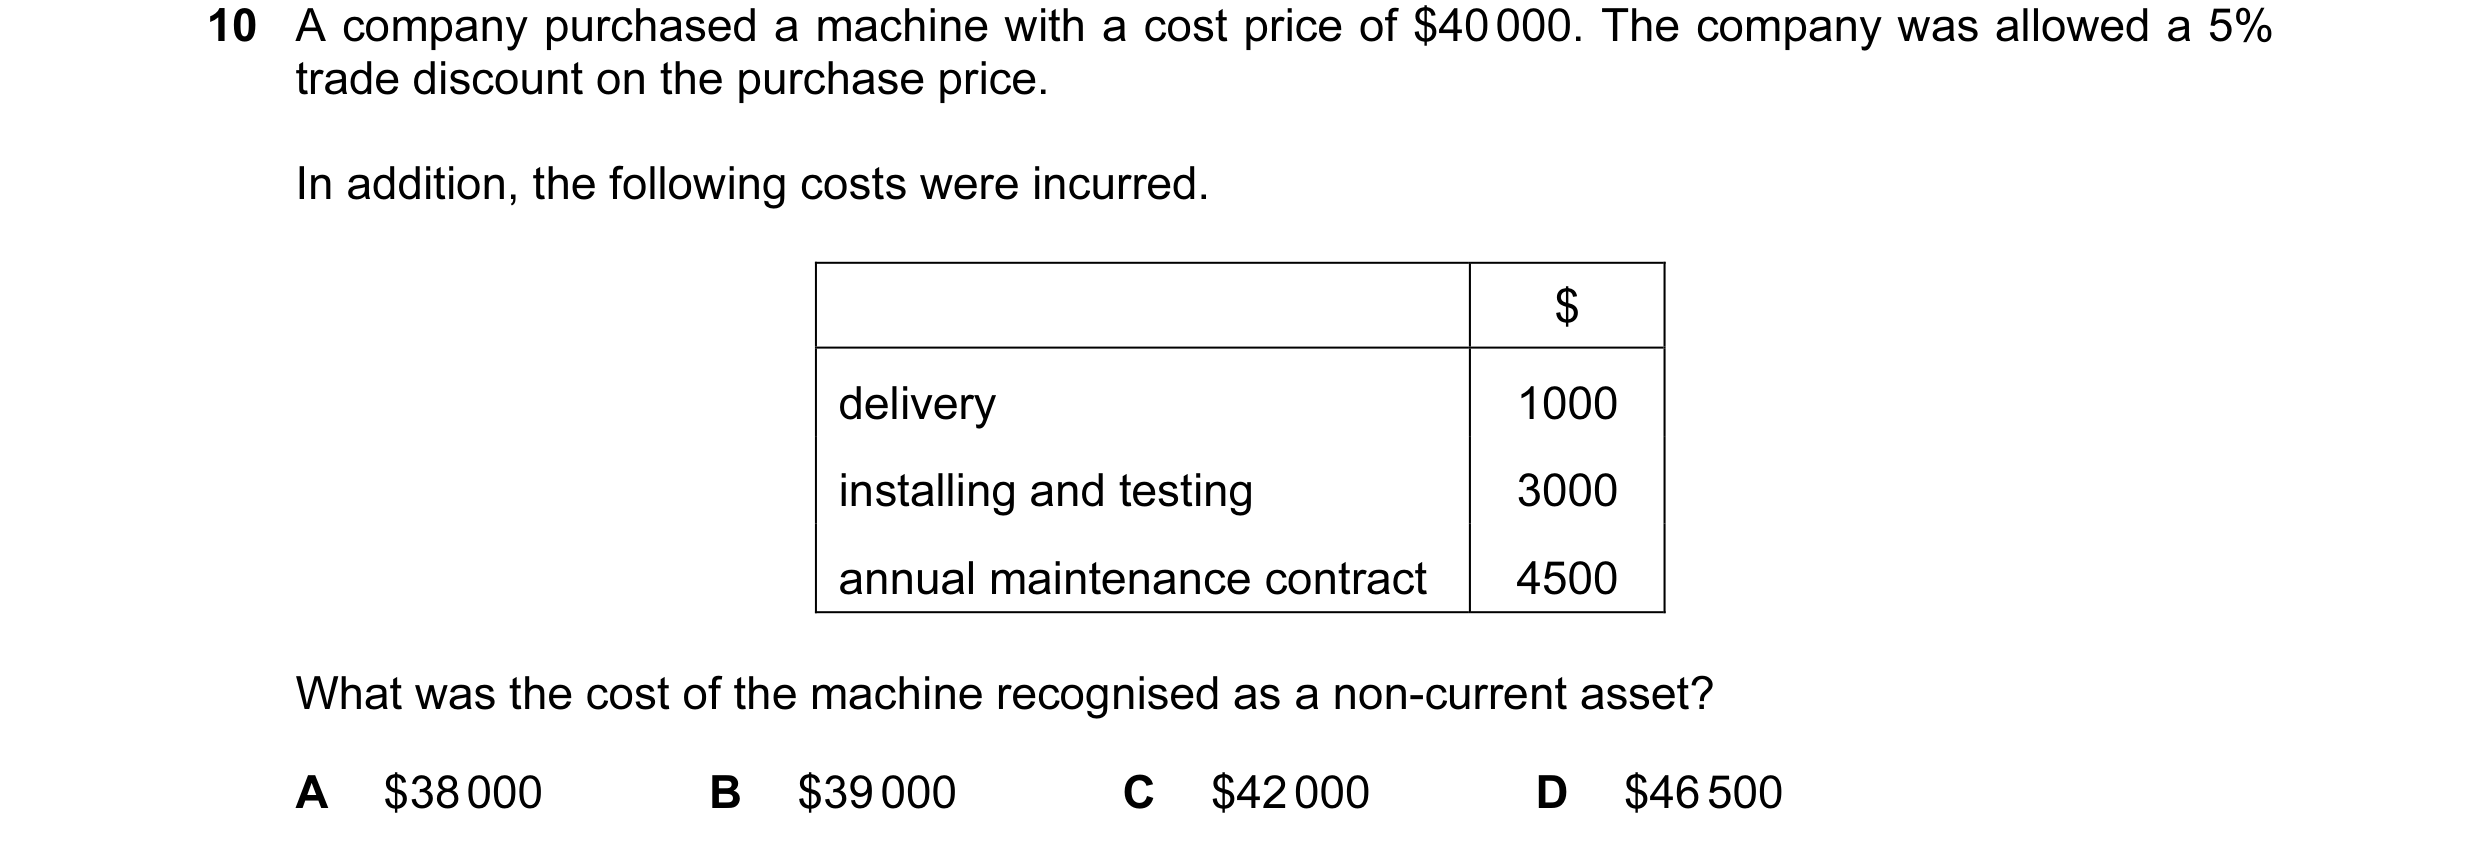
10 A company purchased a machine with a cost price of $40 000. The company was allowed a 5% trade discount on the purchase price. In addition, the following costs were incurred. $ delivery 1000 installing and testing 3000 annual maintenance contract 4500 What was the cost of the machine recognised as a non-current asset? A $38 000 B $39 000 C $42 000 D $46 500
1 marks
Answer: C
This question in 9706/32 May/June 2013
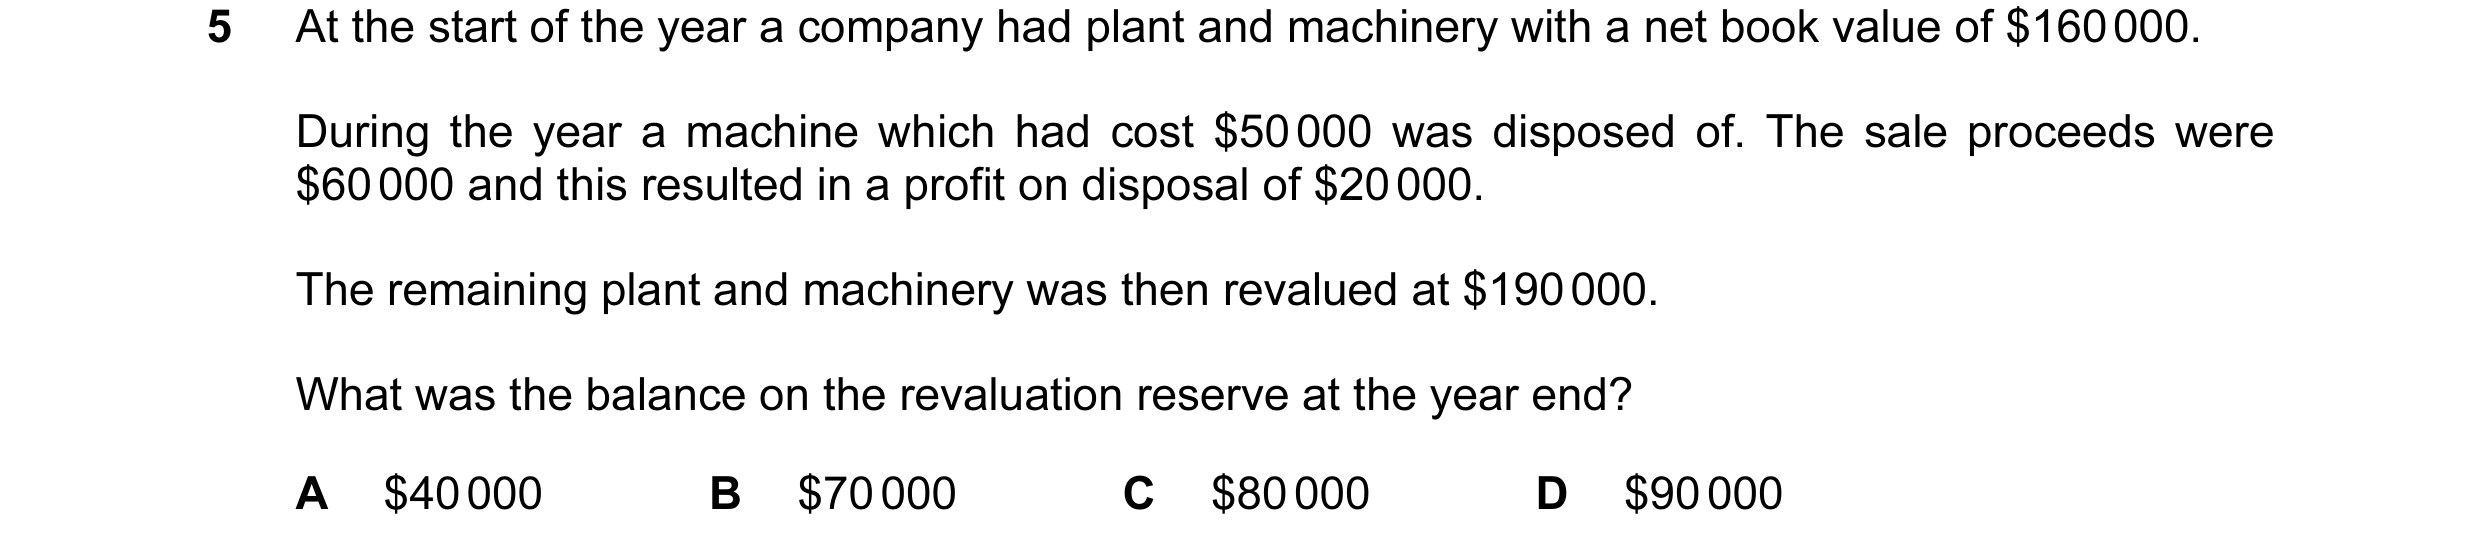
Q13 · At the start of the year a company had plant and machinery with a net book value of $160… 9706/33 May/June 2013
5 At the start of the year a company had plant and machinery with a net book value of $160 000. During the year a machine which had cost $50 000 was disposed of. The sale proceeds were $60 000 and this resulted in a profit on disposal of $20 000. The remaining plant and machinery was then revalued at $190 000. What was the balance on the revaluation reserve at the year end? A $40 000 B $70 000 C $80 000 D $90 000
1 marks
Answer: B
This question in 9706/33 May/June 2013
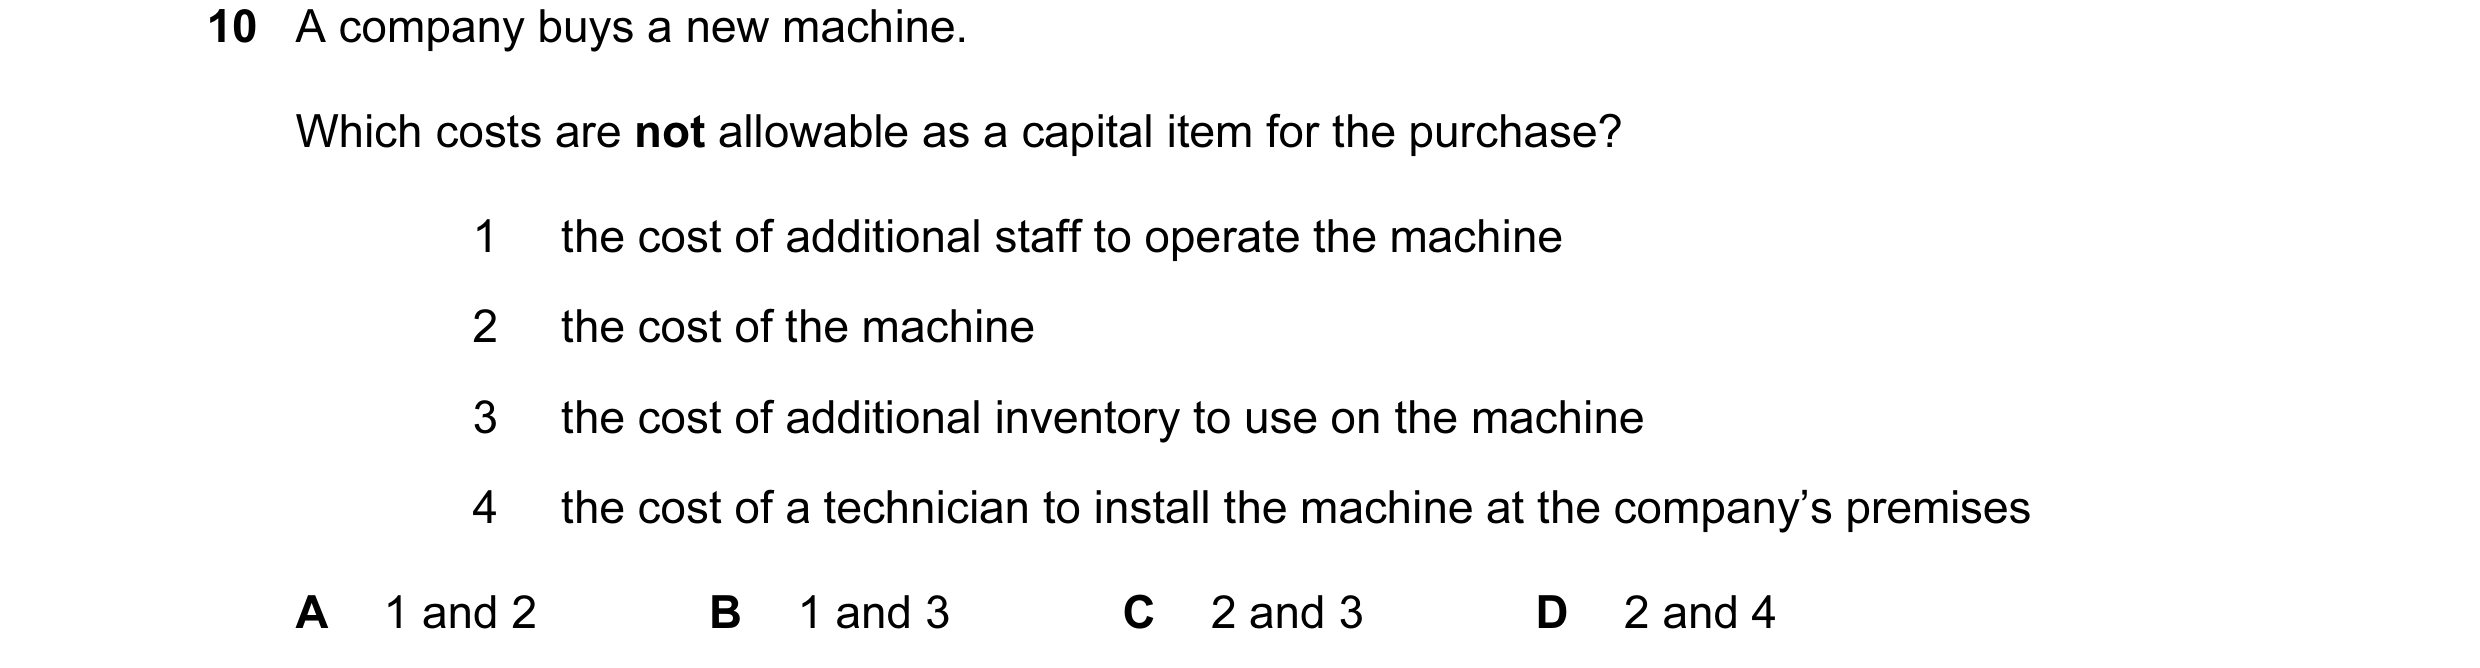
Q14 · A company buys a new machine 9706/33 May/June 2013
10 A company buys a new machine. Which costs are not allowable as a capital item for the purchase? 1 the cost of additional staff to operate the machine 2 the cost of the machine 3 the cost of additional inventory to use on the machine 4 the cost of a technician to install the machine at the company’s premises A 1 and 2 B 1 and 3 C 2 and 3 D 2 and 4
1 marks
Answer: B
This question in 9706/33 May/June 2013
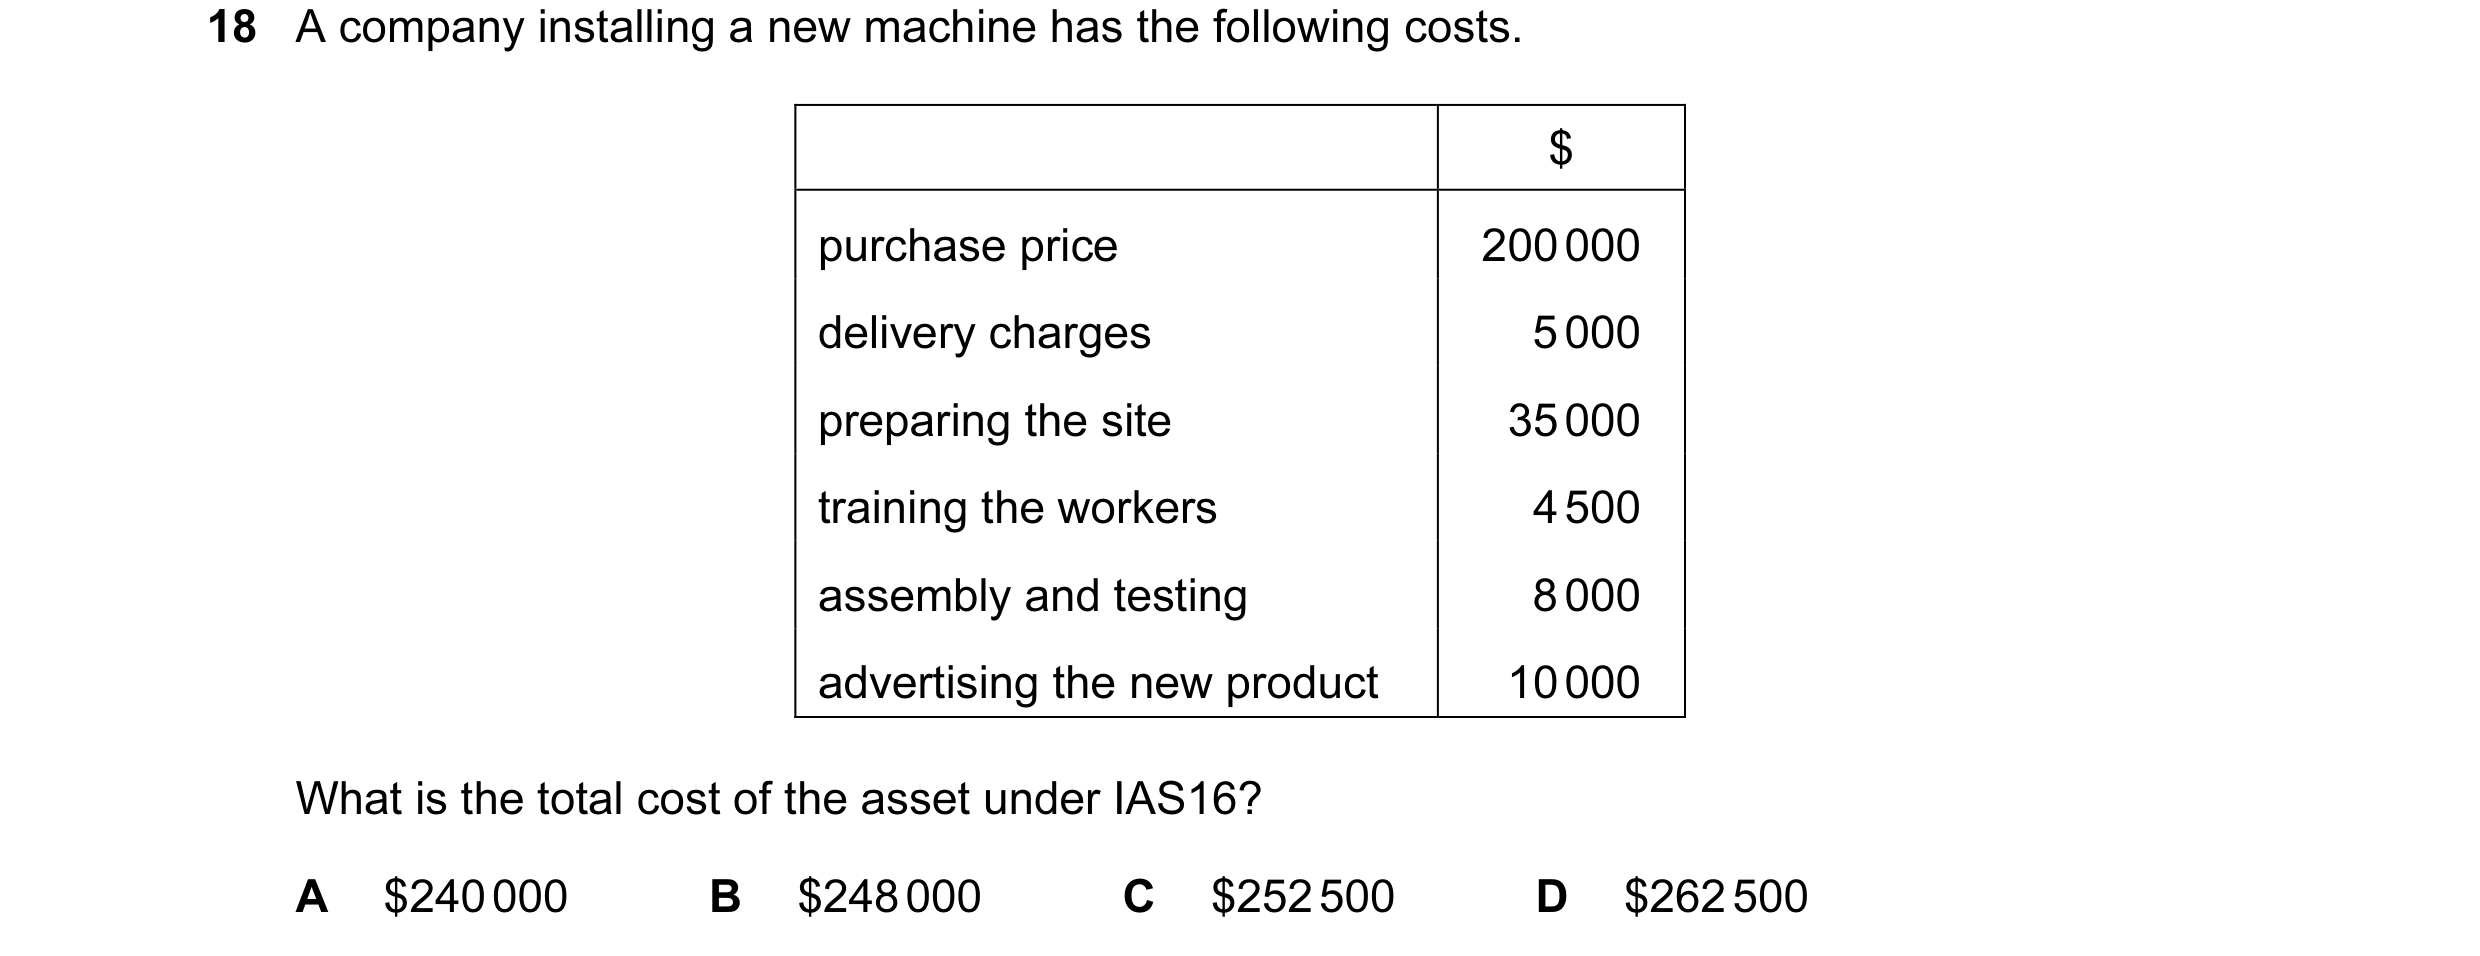
Q15 · A company installing a new machine has the following costs 9706/32 Oct/Nov 2013
18 A company installing a new machine has the following costs. $ purchase price 200 000 delivery charges 5 000 preparing the site 35 000 training the workers 4 500 assembly and testing 8 000 advertising the new product 10 000 What is the total cost of the asset under IAS16? A $240 000 B $248 000 C $252 500 D $262 500
1 marks
Answer: B
This question in 9706/32 Oct/Nov 2013
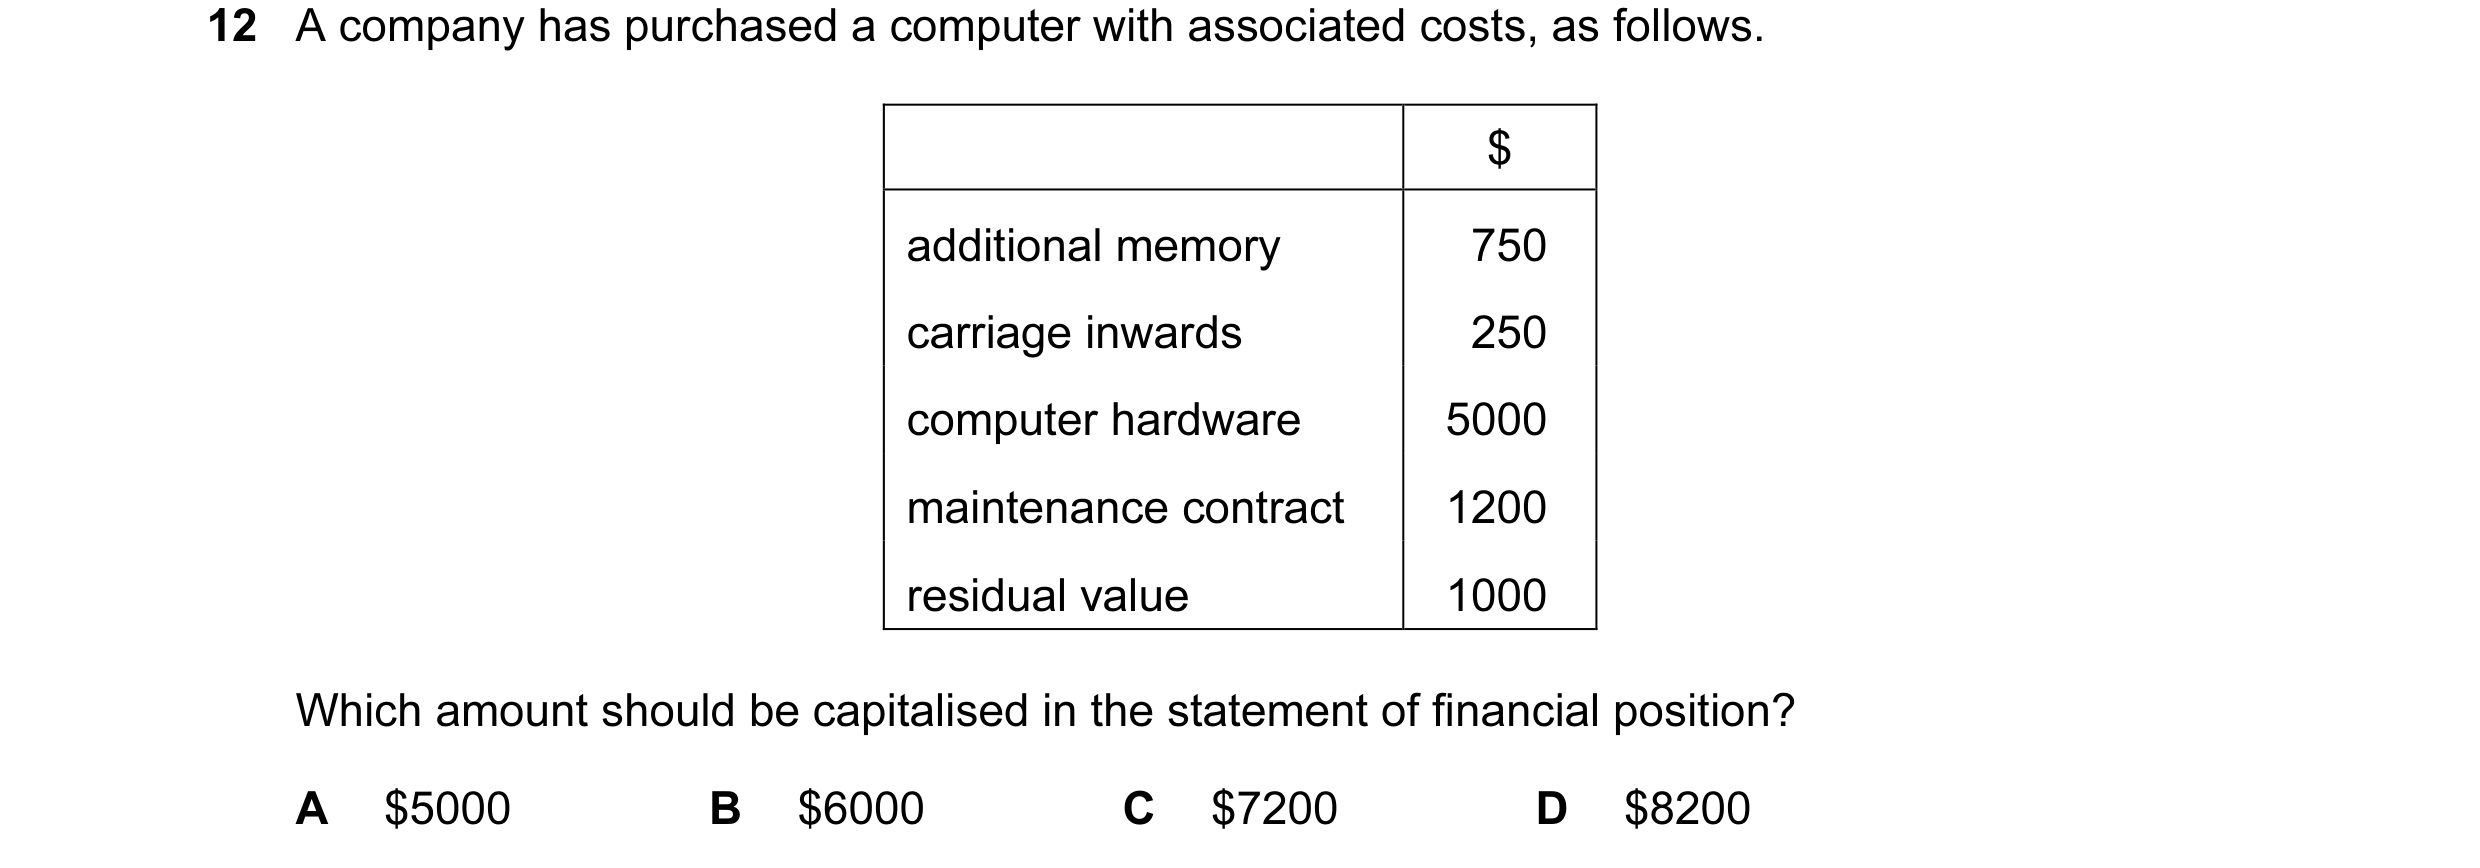
Q16 · A company has purchased a computer with associated costs, as follows 9706/33 Oct/Nov 2013
12 A company has purchased a computer with associated costs, as follows. $ additional memory 750 carriage inwards 250 computer hardware 5000 maintenance contract 1200 residual value 1000 Which amount should be capitalised in the statement of financial position? A $5000 B $6000 C $7200 D $8200
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2013
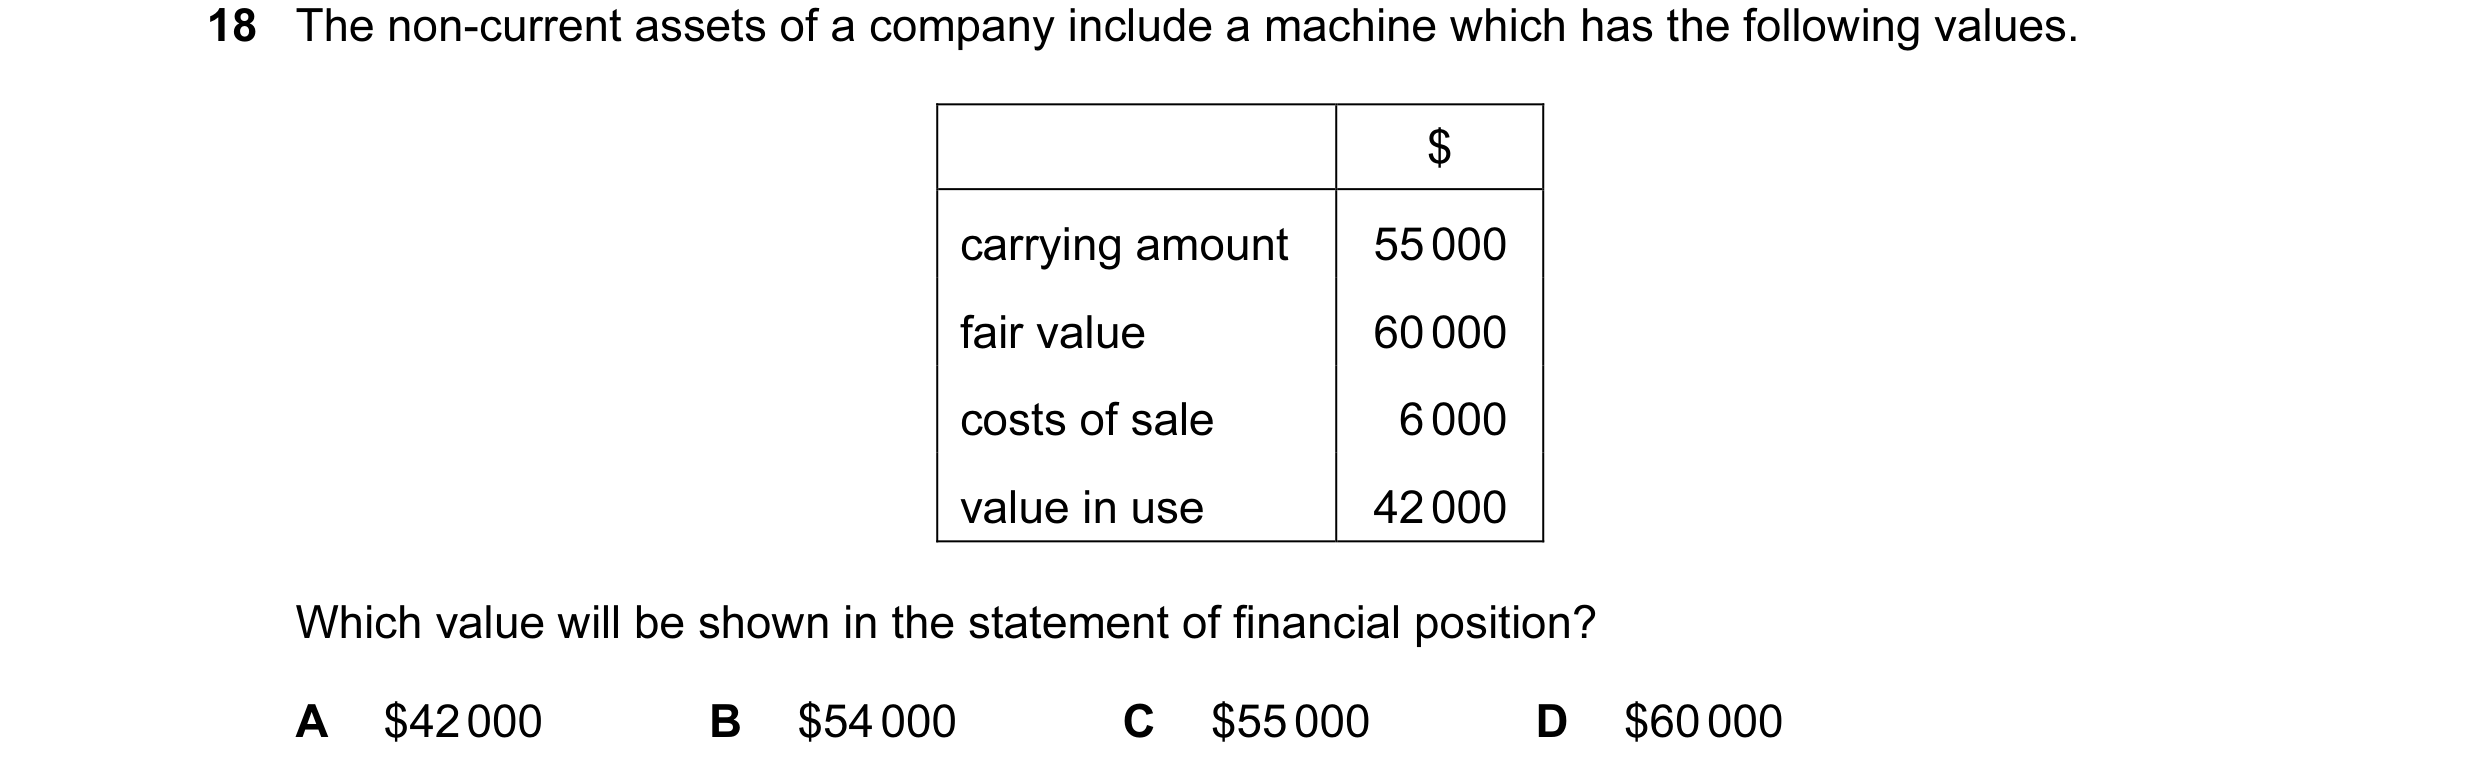
Q17 · The non-current assets of a company include a machine which has the following values 9706/33 Oct/Nov 2013
18 The non-current assets of a company include a machine which has the following values. $ carrying amount 55 000 fair value 60 000 costs of sale 6 000 value in use 42 000 Which value will be shown in the statement of financial position? A $42 000 B $54 000 C $55 000 D $60 000
1 marks
Answer: B
This question in 9706/33 Oct/Nov 2013
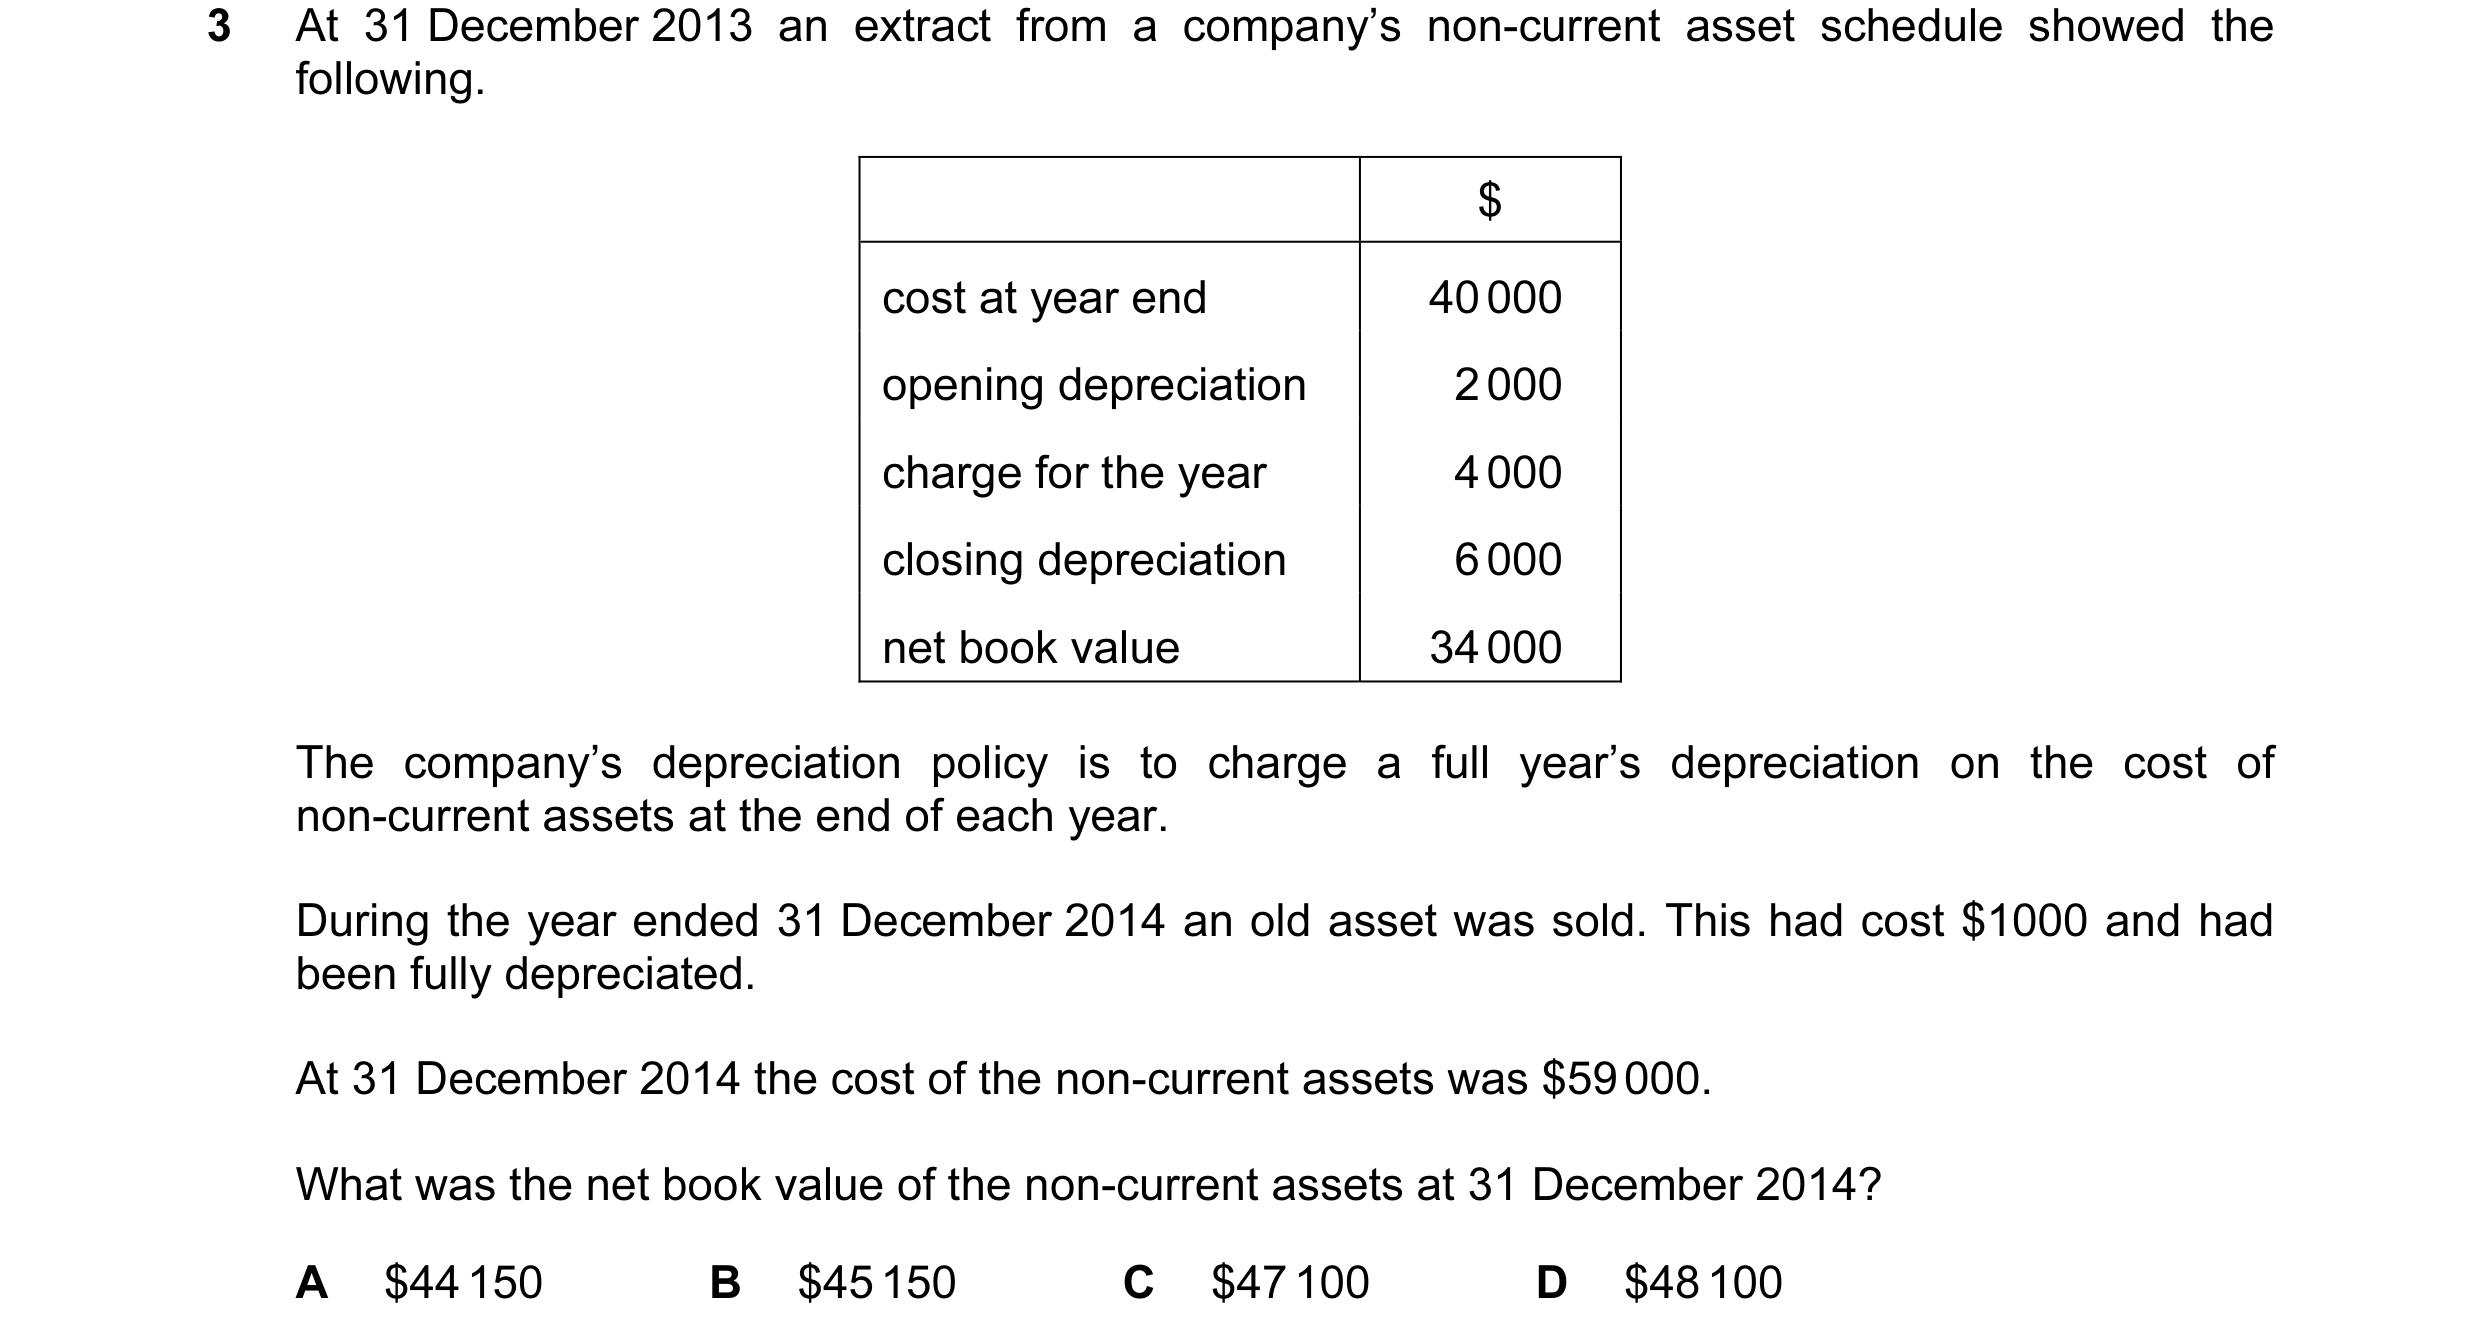
Q18 · At 31 December 2013 an extract from a company’s non-current asset schedule showed the… 9706/31 Oct/Nov 2015
3 At 31 December 2013 an extract from a company’s non-current asset schedule showed the following. $ cost at year end 40 000 opening depreciation 2 000 charge for the year 4 000 closing depreciation 6 000 net book value 34 000 The company’s depreciation policy is to charge a full year’s depreciation on the cost of non-current assets at the end of each year. During the year ended 31 December 2014 an old asset was sold. This had cost $1000 and had been fully depreciated. At 31 December 2014 the cost of the non-current assets was $59 000. What was the net book value of the non-current assets at 31 December 2014? A $44 150 B $45 150 C $47 100 D $48 100
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2015
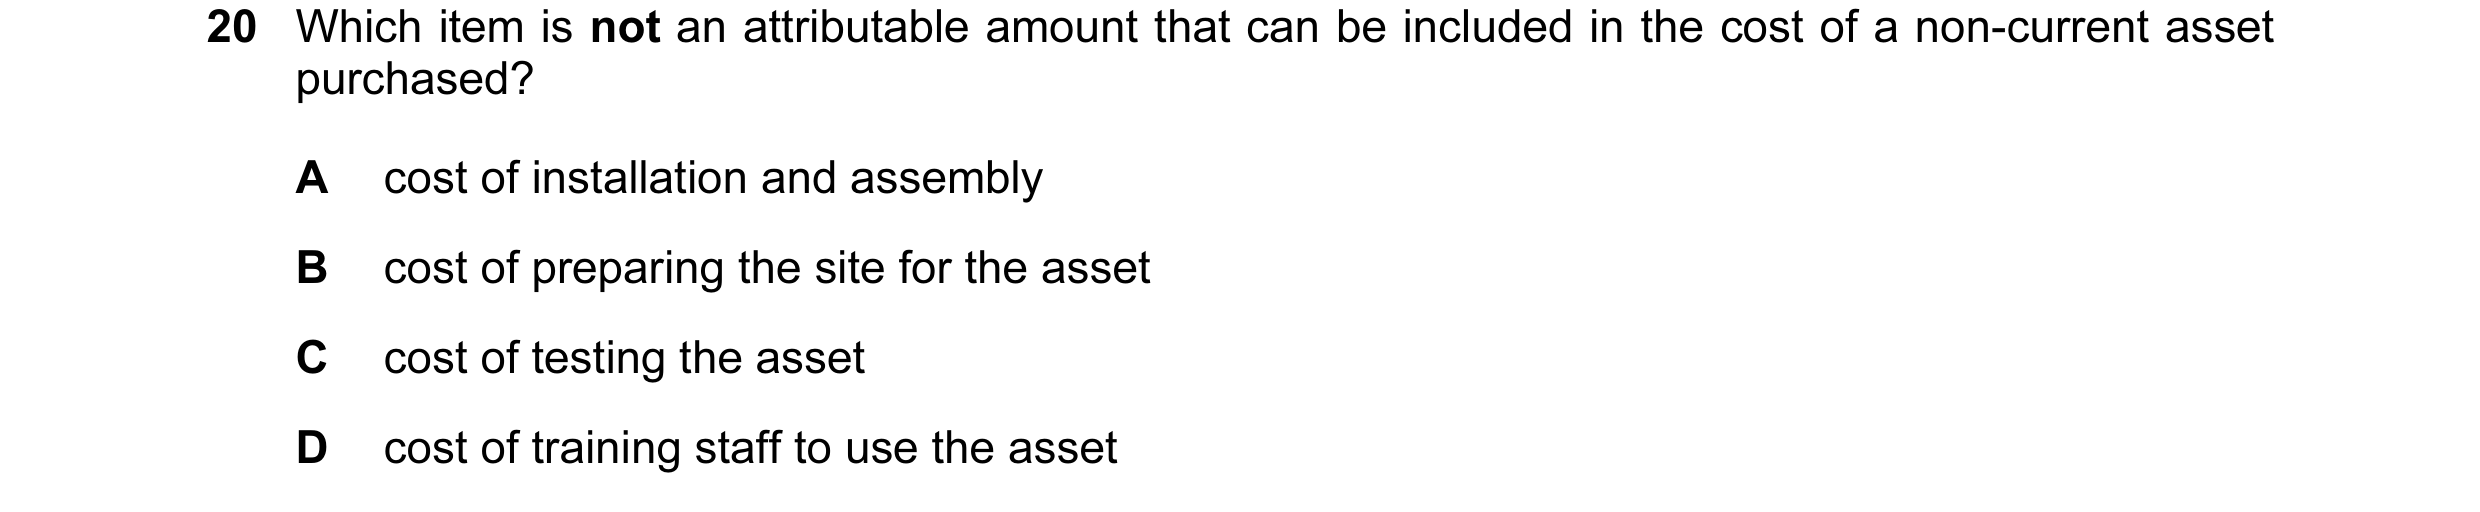
Q19 · Which item is not an attributable amount that can be included in the cost of a… 9706/31 Oct/Nov 2015
20 Which item is not an attributable amount that can be included in the cost of a non-current asset purchased? A cost of installation and assembly B cost of preparing the site for the asset C cost of testing the asset D cost of training staff to use the asset
1 marks
Answer: D
This question in 9706/31 Oct/Nov 2015
 1 / 6
 2 / 6
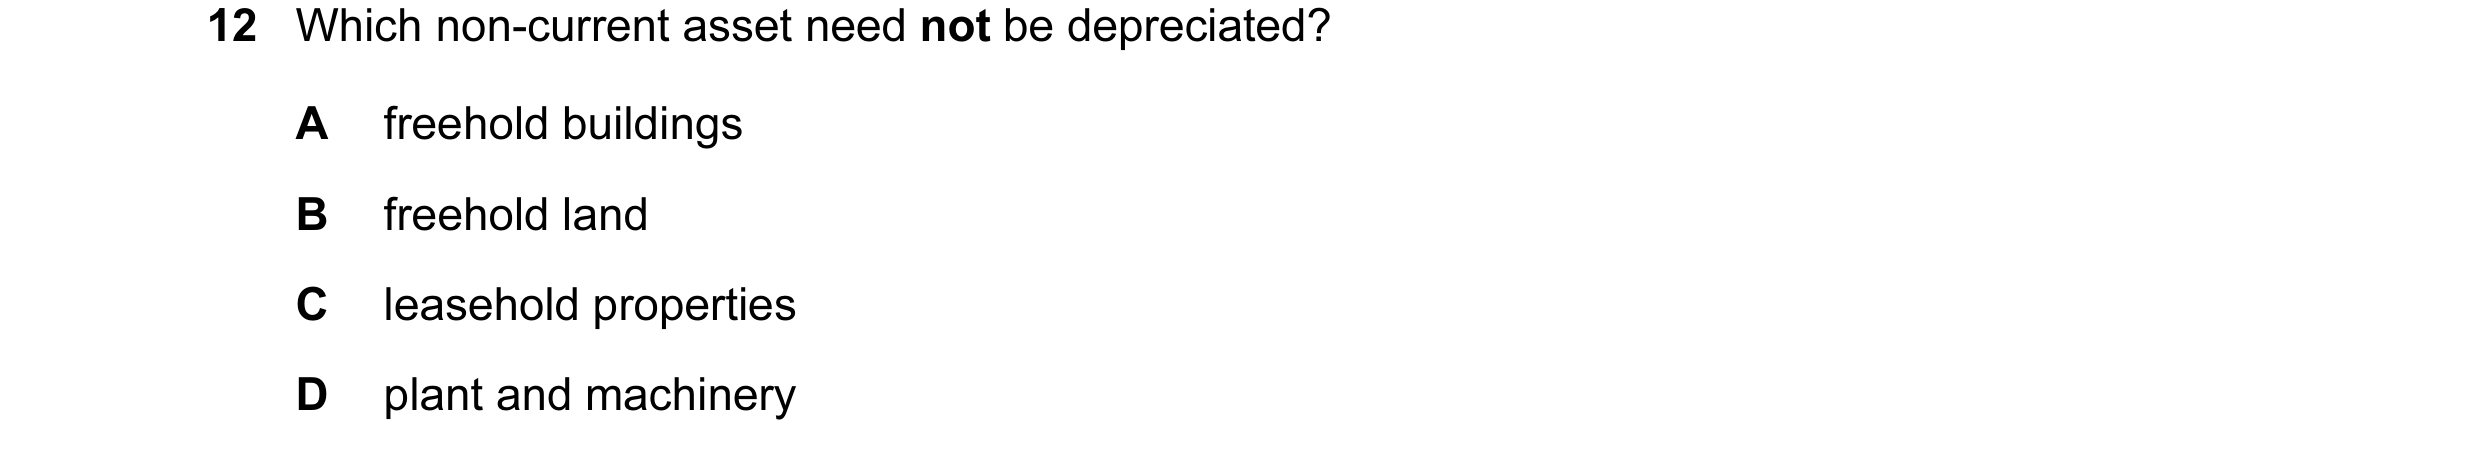
 3 / 6
 4 / 6
 5 / 6
 6 / 6