Questions as text
Q1 · Nadia is a trader 0985/22 May/June 2020
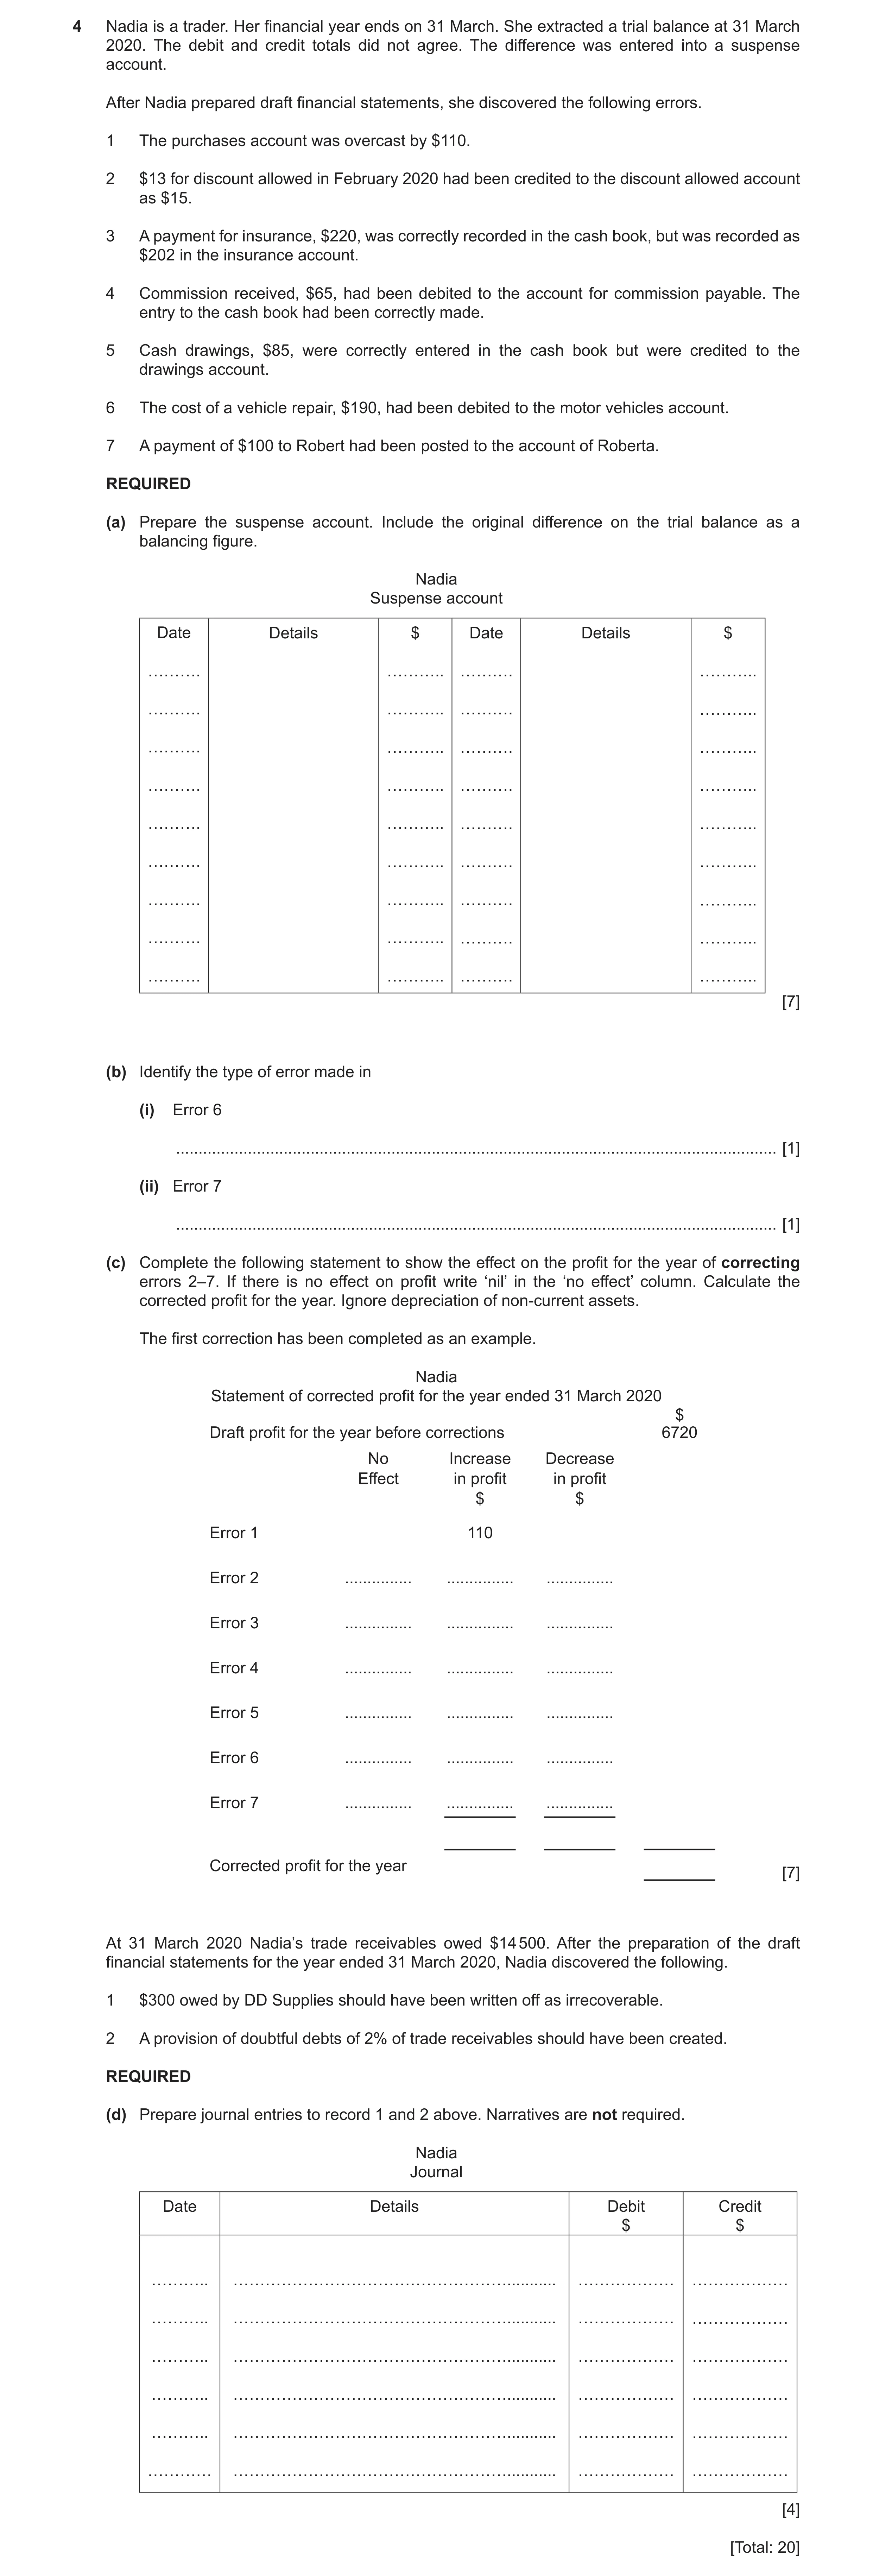
4 Nadia is a trader. Her financial year ends on 31 March. She extracted a trial balance at 31 March 2020. The debit and credit totals did not agree. The difference was entered into a suspense account. After Nadia prepared draft financial statements, she discovered the following errors. 1 The purchases account was overcast by $110. 2 $13 for discount allowed in February 2020 had been credited to the discount allowed account as $15. 3 A payment for insurance, $220, was correctly recorded in the cash book, but was recorded as $202 in the insurance account. 4 Commission received, $65, had been debited to the account for commission payable. The entry to the cash book had been correctly made. 5 Cash drawings, $85, were correctly entered in the cash book but were credited to the drawings account. 6 The cost of a vehicle repair, $190, had been debited to the motor vehicles account. 7 A payment of $100 to Robert had been posted to the account of Roberta. REQUIRED (a) Prepare the suspense account. Include the original difference on the trial balance as a balancing figure. Nadia Suspense account Date Details $ Date Details $ ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. [7] (b) Identify the type of error made in (i) Error 6 … [1] (ii) Error 7 … [1] (c) Complete the following statement to show the effect on the profit for the year of correcting errors 2–7. If there is no effect on profit write ‘nil’ in the ‘no effect’ column. Calculate the corrected profit for the year. Ignore depreciation of non-current assets. The first correction has been completed as an example. Nadia Statement of corrected profit for the year ended 31 March 2020 $ Draft profit for the year before corrections 6720 No Increase Decrease Effect in profit in profit $ $ Error 1 110 Error 2 … … … Error 3 … … … Error 4 … … … Error 5 … … … Error 6 … … … Error 7 … … … Corrected profit for the year [7] At 31 March 2020 Nadia’s trade receivables owed $14 500. After the preparation of the draft financial statements for the year ended 31 March 2020, Nadia discovered the following. 1 $300 owed by DD Supplies should have been written off as irrecoverable. 2 A provision of doubtful debts of 2% of trade receivables should have been created. REQUIRED (d) Prepare journal entries to record 1 and 2 above. Narratives are not required. Nadia Journal Date Details Debit Credit $ $ ……….. …………………………………………… … ……………… ……………… ……….. …………………………………………… … ……………… ……………… ……….. …………………………………………… … ……………… ……………… ……….. …………………………………………… … ……………… ……………… ……….. …………………………………………… … ……………… ……………… ………… …………………………………………… … ……………… ……………… [4] [Total: 20]
20 marks
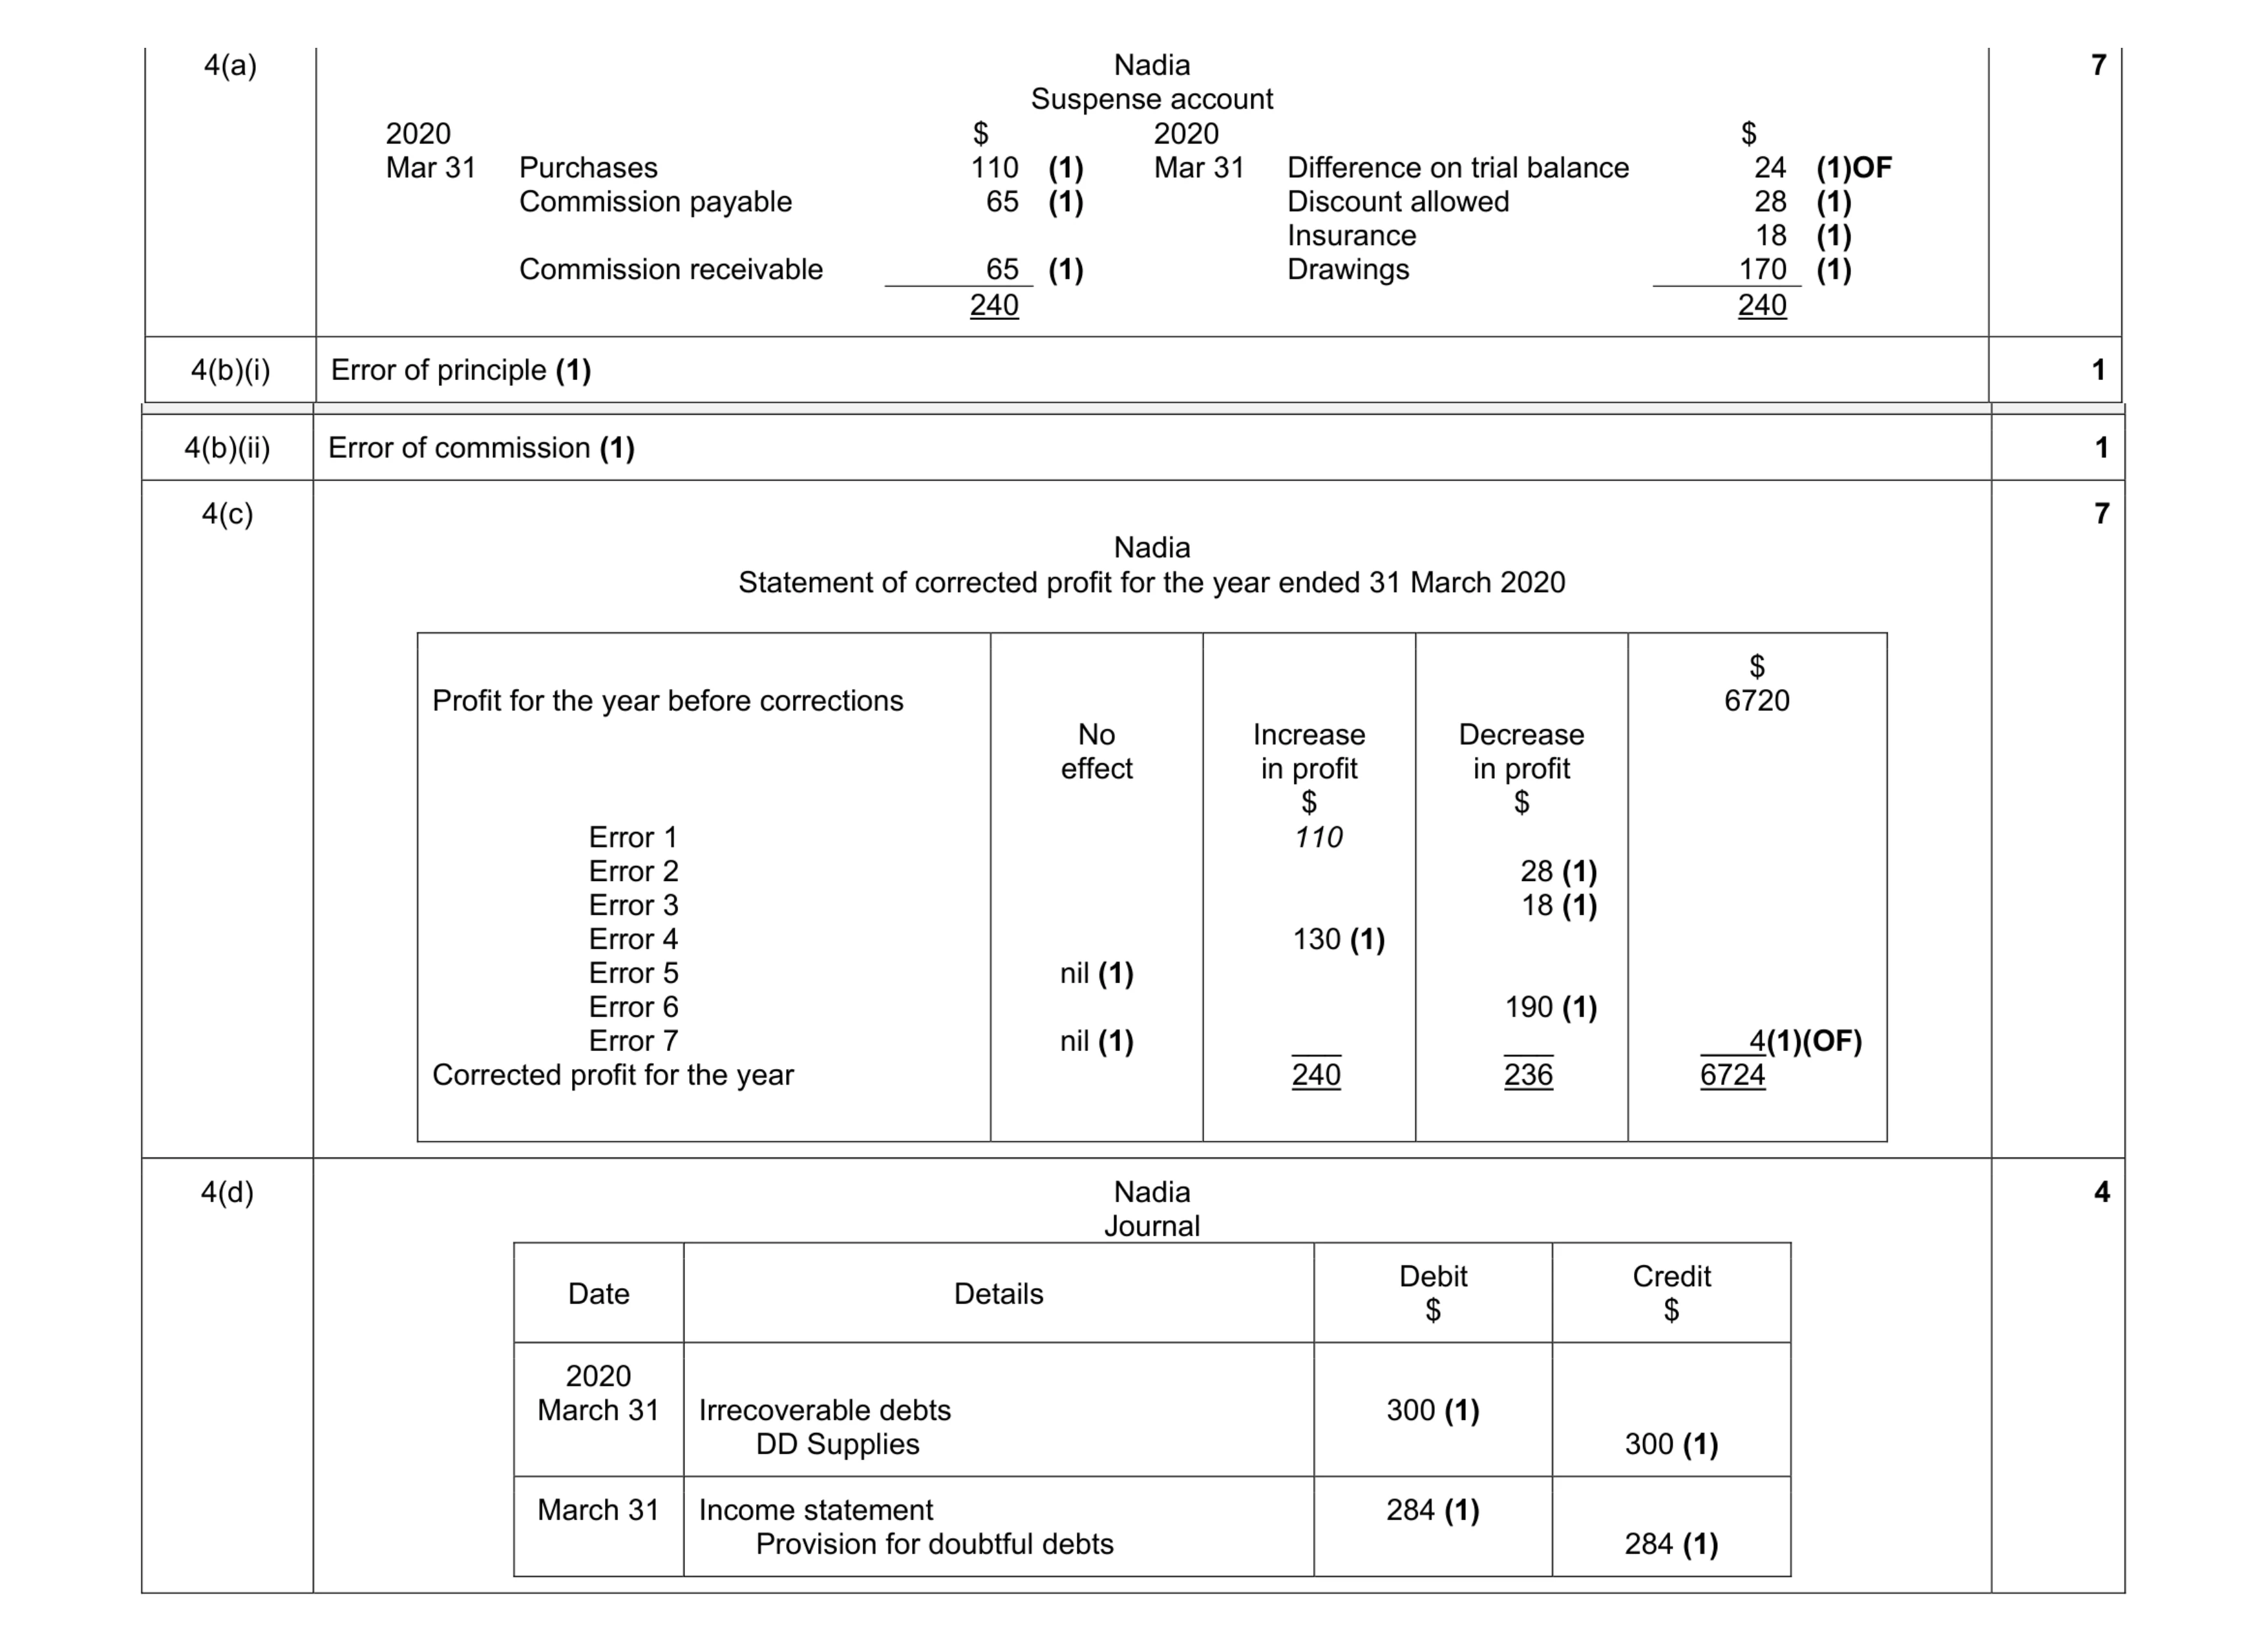
Mark scheme: 4(a) Nadia Suspense account 2020 $ 2020 $ Mar 31 Purchases 110 (1) Mar 31 Difference on trial balance 24 (1)OF Commission payable 65 (1) Discount allowed 28 (1) Insurance 18 (1) Commission receivable 65 (1) Drawings 170 (1) 240 240 7 4(b)(i) Error of principle (1) 1 Question Answer Marks 4(b)(ii) Error of commission (1) 1 4(c) Nadia Statement of corrected profit for the year ended 31 March 2020 Profit for the year before corrections Error 1 Error 2 Error 3 Error 4 Error 5 Error 6 Error 7 Corrected profit for the year No effect nil (1) nil (1) Increase in profit $ 110 130 (1) ___ 240 Decrease in profit $ 28 (1) 18 (1) 190 (1) ___ 236 $ 6720 4(1)(OF) 6724 7 4(d) Nadia Journal Date Details Debit $ Credit $ 2020 March 31 Irrecoverable debts DD Supplies 300 (1) 300 (1) March 31 Income statement Provision for doubtful debts 284 (1) 284 (1) 4
This question in 0985/22 May/June 2020
Q2 · Razia’s financial year ends on 30 September 0985/22 Oct/Nov 2020
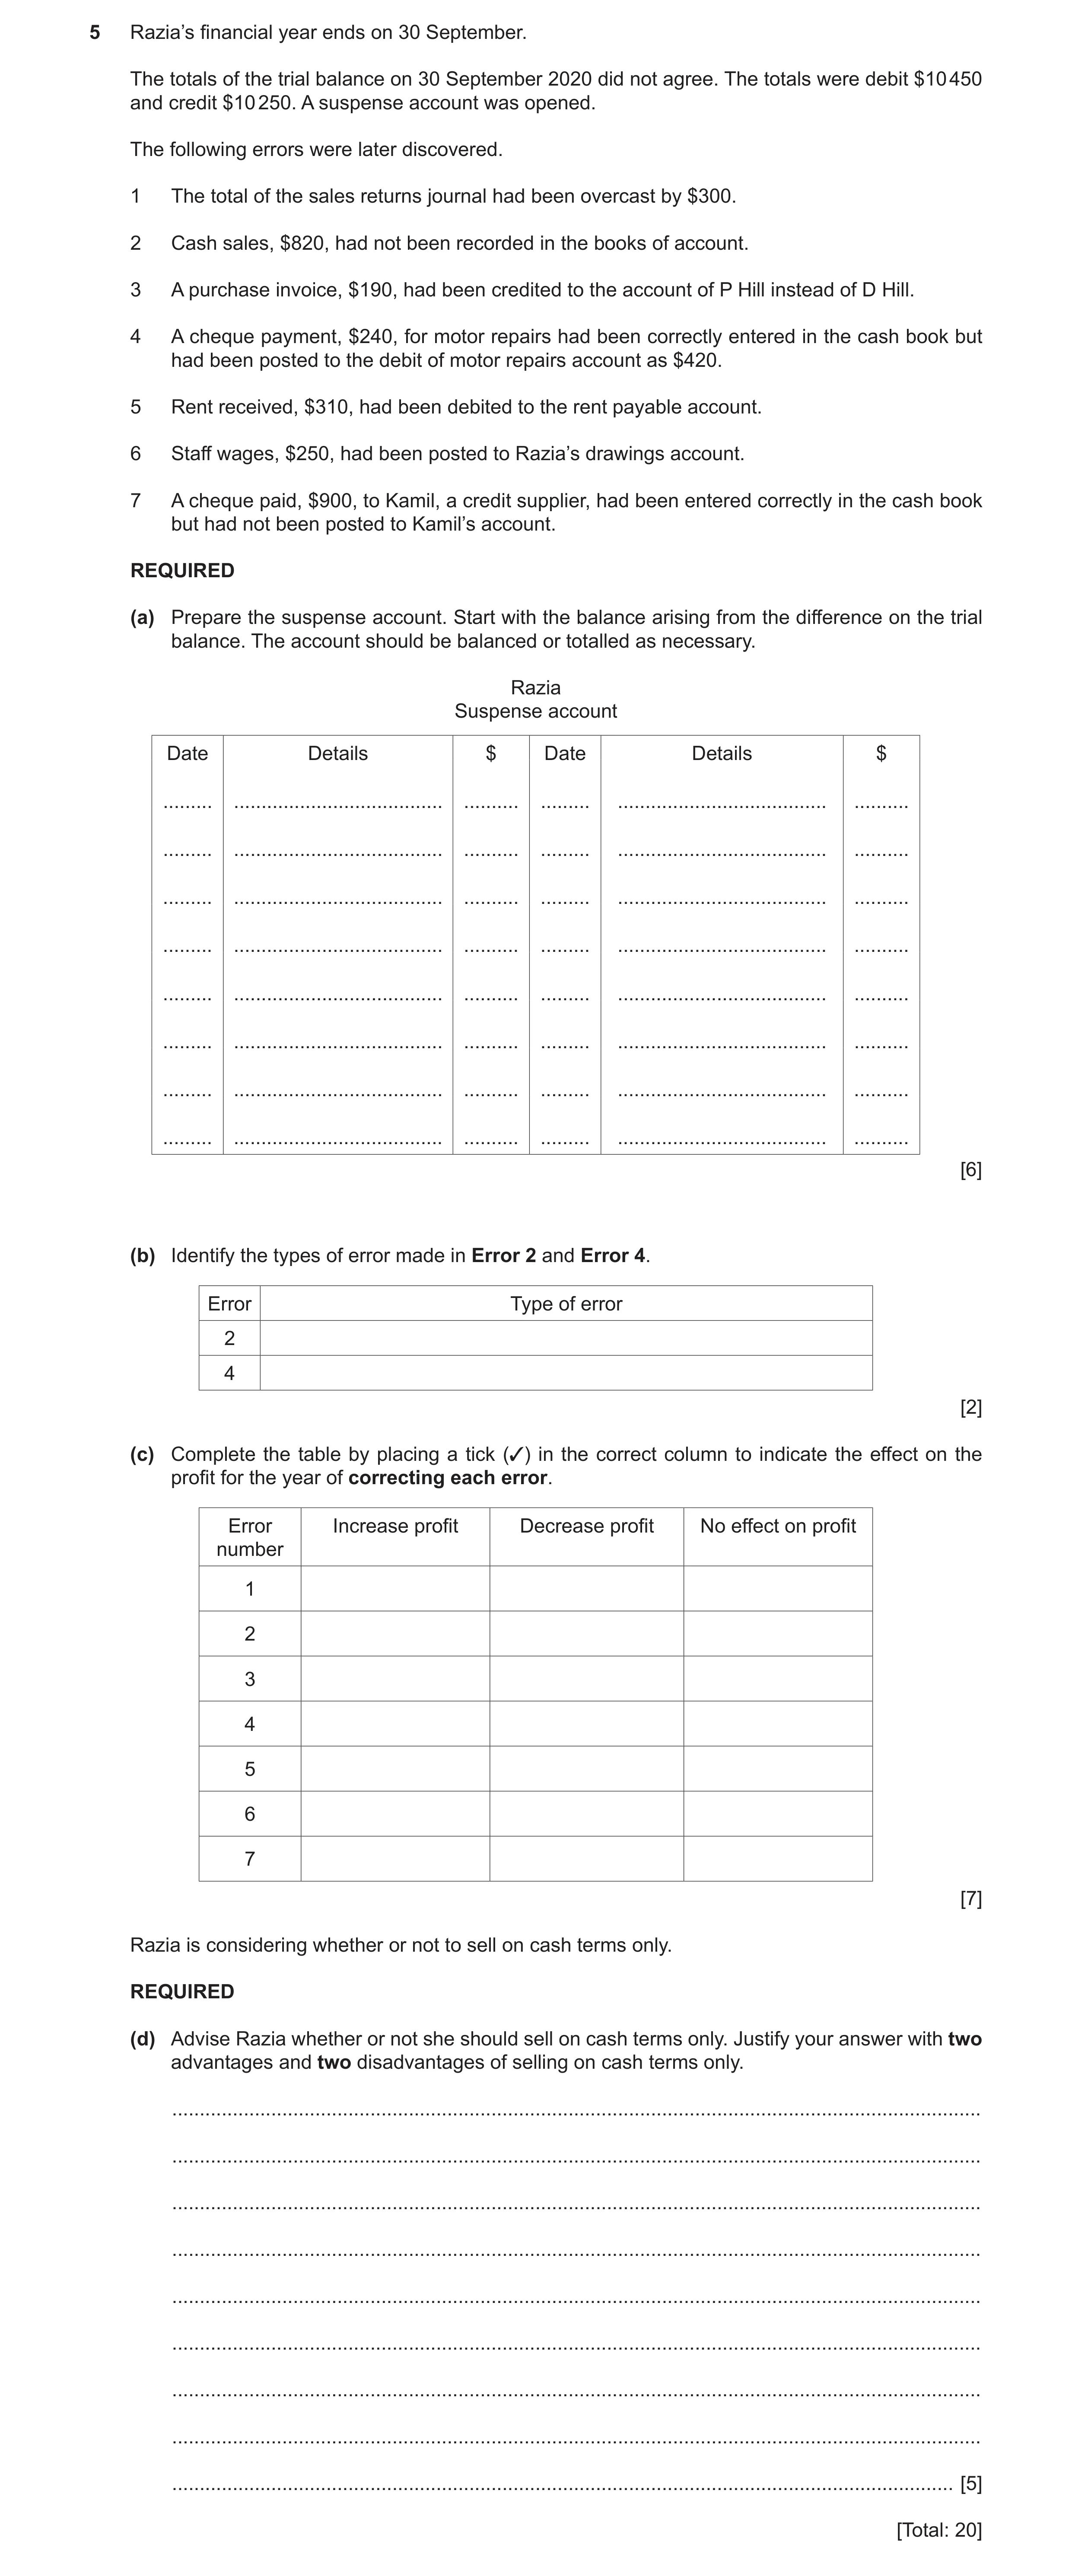
5 Razia’s financial year ends on 30 September. The totals of the trial balance on 30 September 2020 did not agree. The totals were debit $10 450 and credit $10 250. A suspense account was opened. The following errors were later discovered. 1 The total of the sales returns journal had been overcast by $300. 2 Cash sales, $820, had not been recorded in the books of account. 3 A purchase invoice, $190, had been credited to the account of P Hill instead of D Hill. 4 A cheque payment, $240, for motor repairs had been correctly entered in the cash book but had been posted to the debit of motor repairs account as $420. 5 Rent received, $310, had been debited to the rent payable account. 6 Staff wages, $250, had been posted to Razia’s drawings account. 7 A cheque paid, $900, to Kamil, a credit supplier, had been entered correctly in the cash book but had not been posted to Kamil’s account. REQUIRED (a) Prepare the suspense account. Start with the balance arising from the difference on the trial balance. The account should be balanced or totalled as necessary. Razia Suspense account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [6] (b) Identify the types of error made in Error 2 and Error 4. Error Type of error 2 4 [2] (c) Complete the table by placing a tick (✓) in the correct column to indicate the effect on the profit for the year of correcting each error. Error Increase profit Decrease profit No effect on profit number 1 2 3 4 5 6 7 [7] Razia is considering whether or not to sell on cash terms only. REQUIRED (d) Advise Razia whether or not she should sell on cash terms only. Justify your answer with two advantages and two disadvantages of selling on cash terms only. … … … … … … … … … [5] [Total: 20]
20 marks
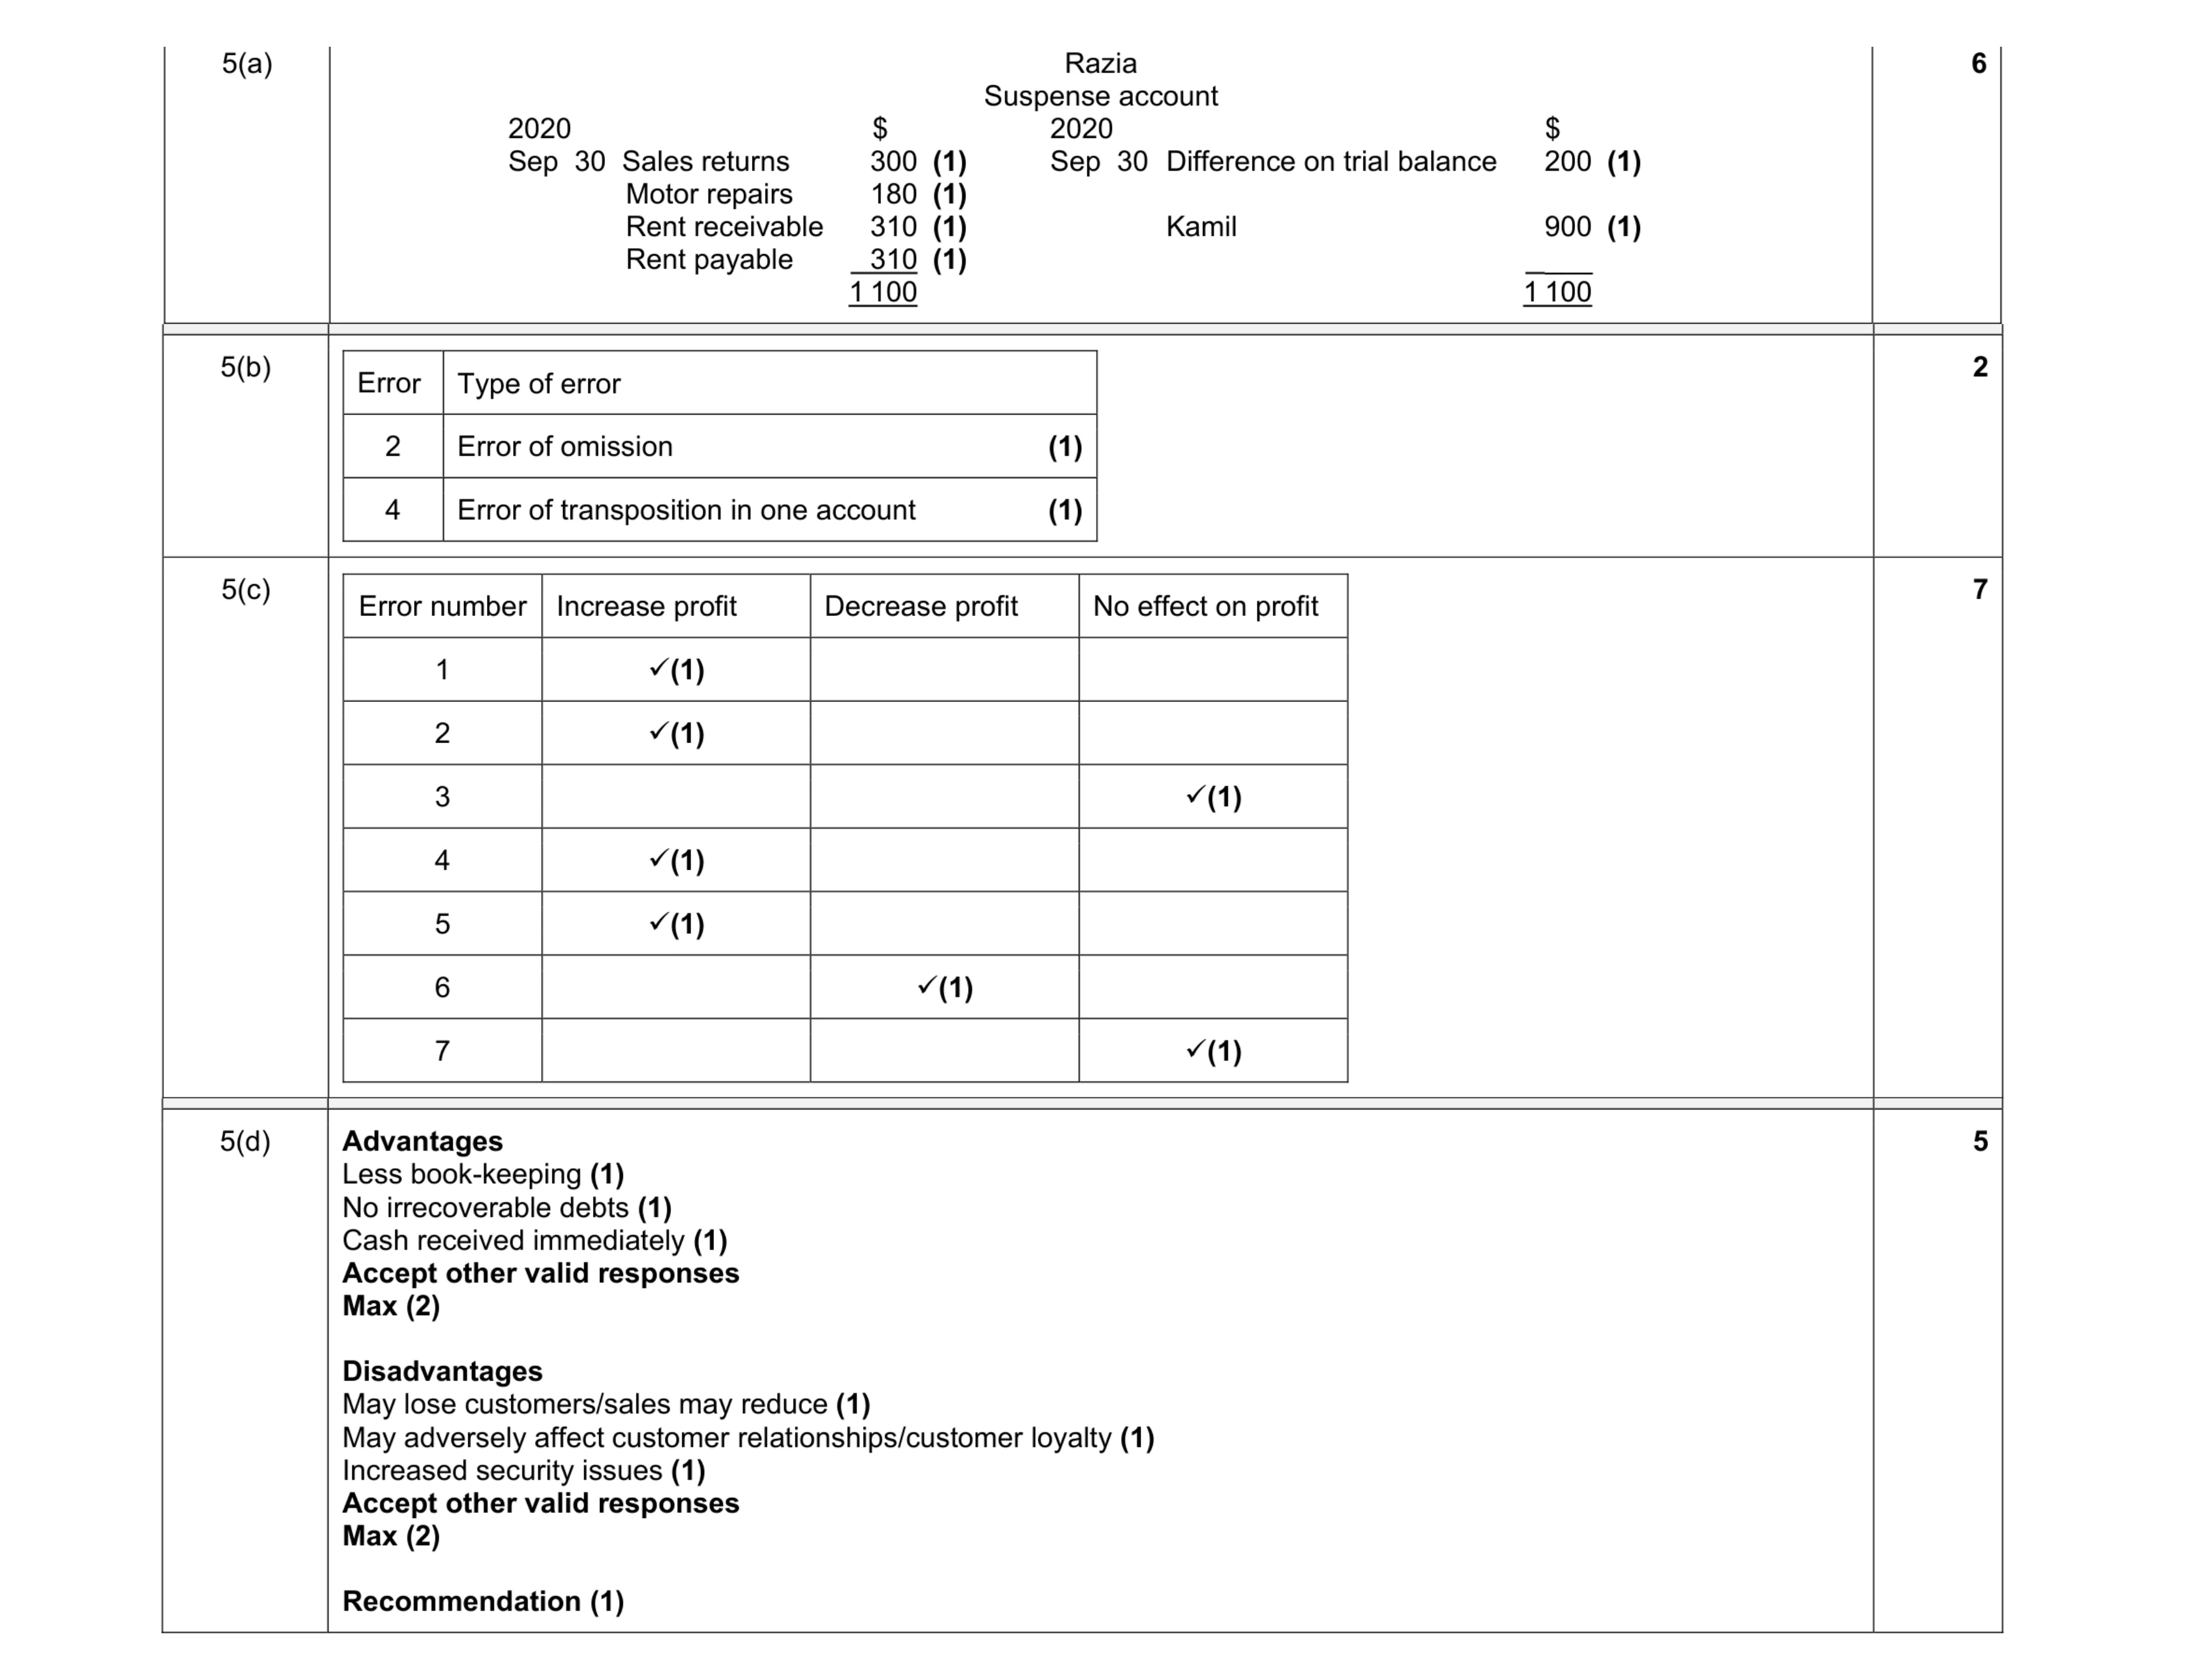
Mark scheme: 5(a) Razia Suspense account 2020 $ 2020 $ Sep 30 Sales returns 300 (1) Sep 30 Difference on trial balance 200 (1) Motor repairs 180 (1) Rent receivable 310 (1) Kamil 900 (1) Rent payable 310 (1) ___ 1 100 1 100 6 Question Answer Marks 5(b) Error Type of error 2 Error of omission (1) 4 Error of transposition in one account (1) 2 5(c) Error number Increase profit Decrease profit No effect on profit 1 (1) 2 (1) 3 (1) 4 (1) 5 (1) 6 (1) 7 (1) 7 Question Answer Marks 5(d) Advantages Less book-keeping (1) No irrecoverable debts (1) Cash received immediately (1) Accept other valid responses Max (2) Disadvantages May lose customers/sales may reduce (1) May adversely affect customer relationships/customer loyalty (1) Increased security issues (1) Accept other valid responses Max (2) Recommendation (1) 5
This question in 0985/22 Oct/Nov 2020
Q3 · Neith is a trader 0985/21 May/June 2021
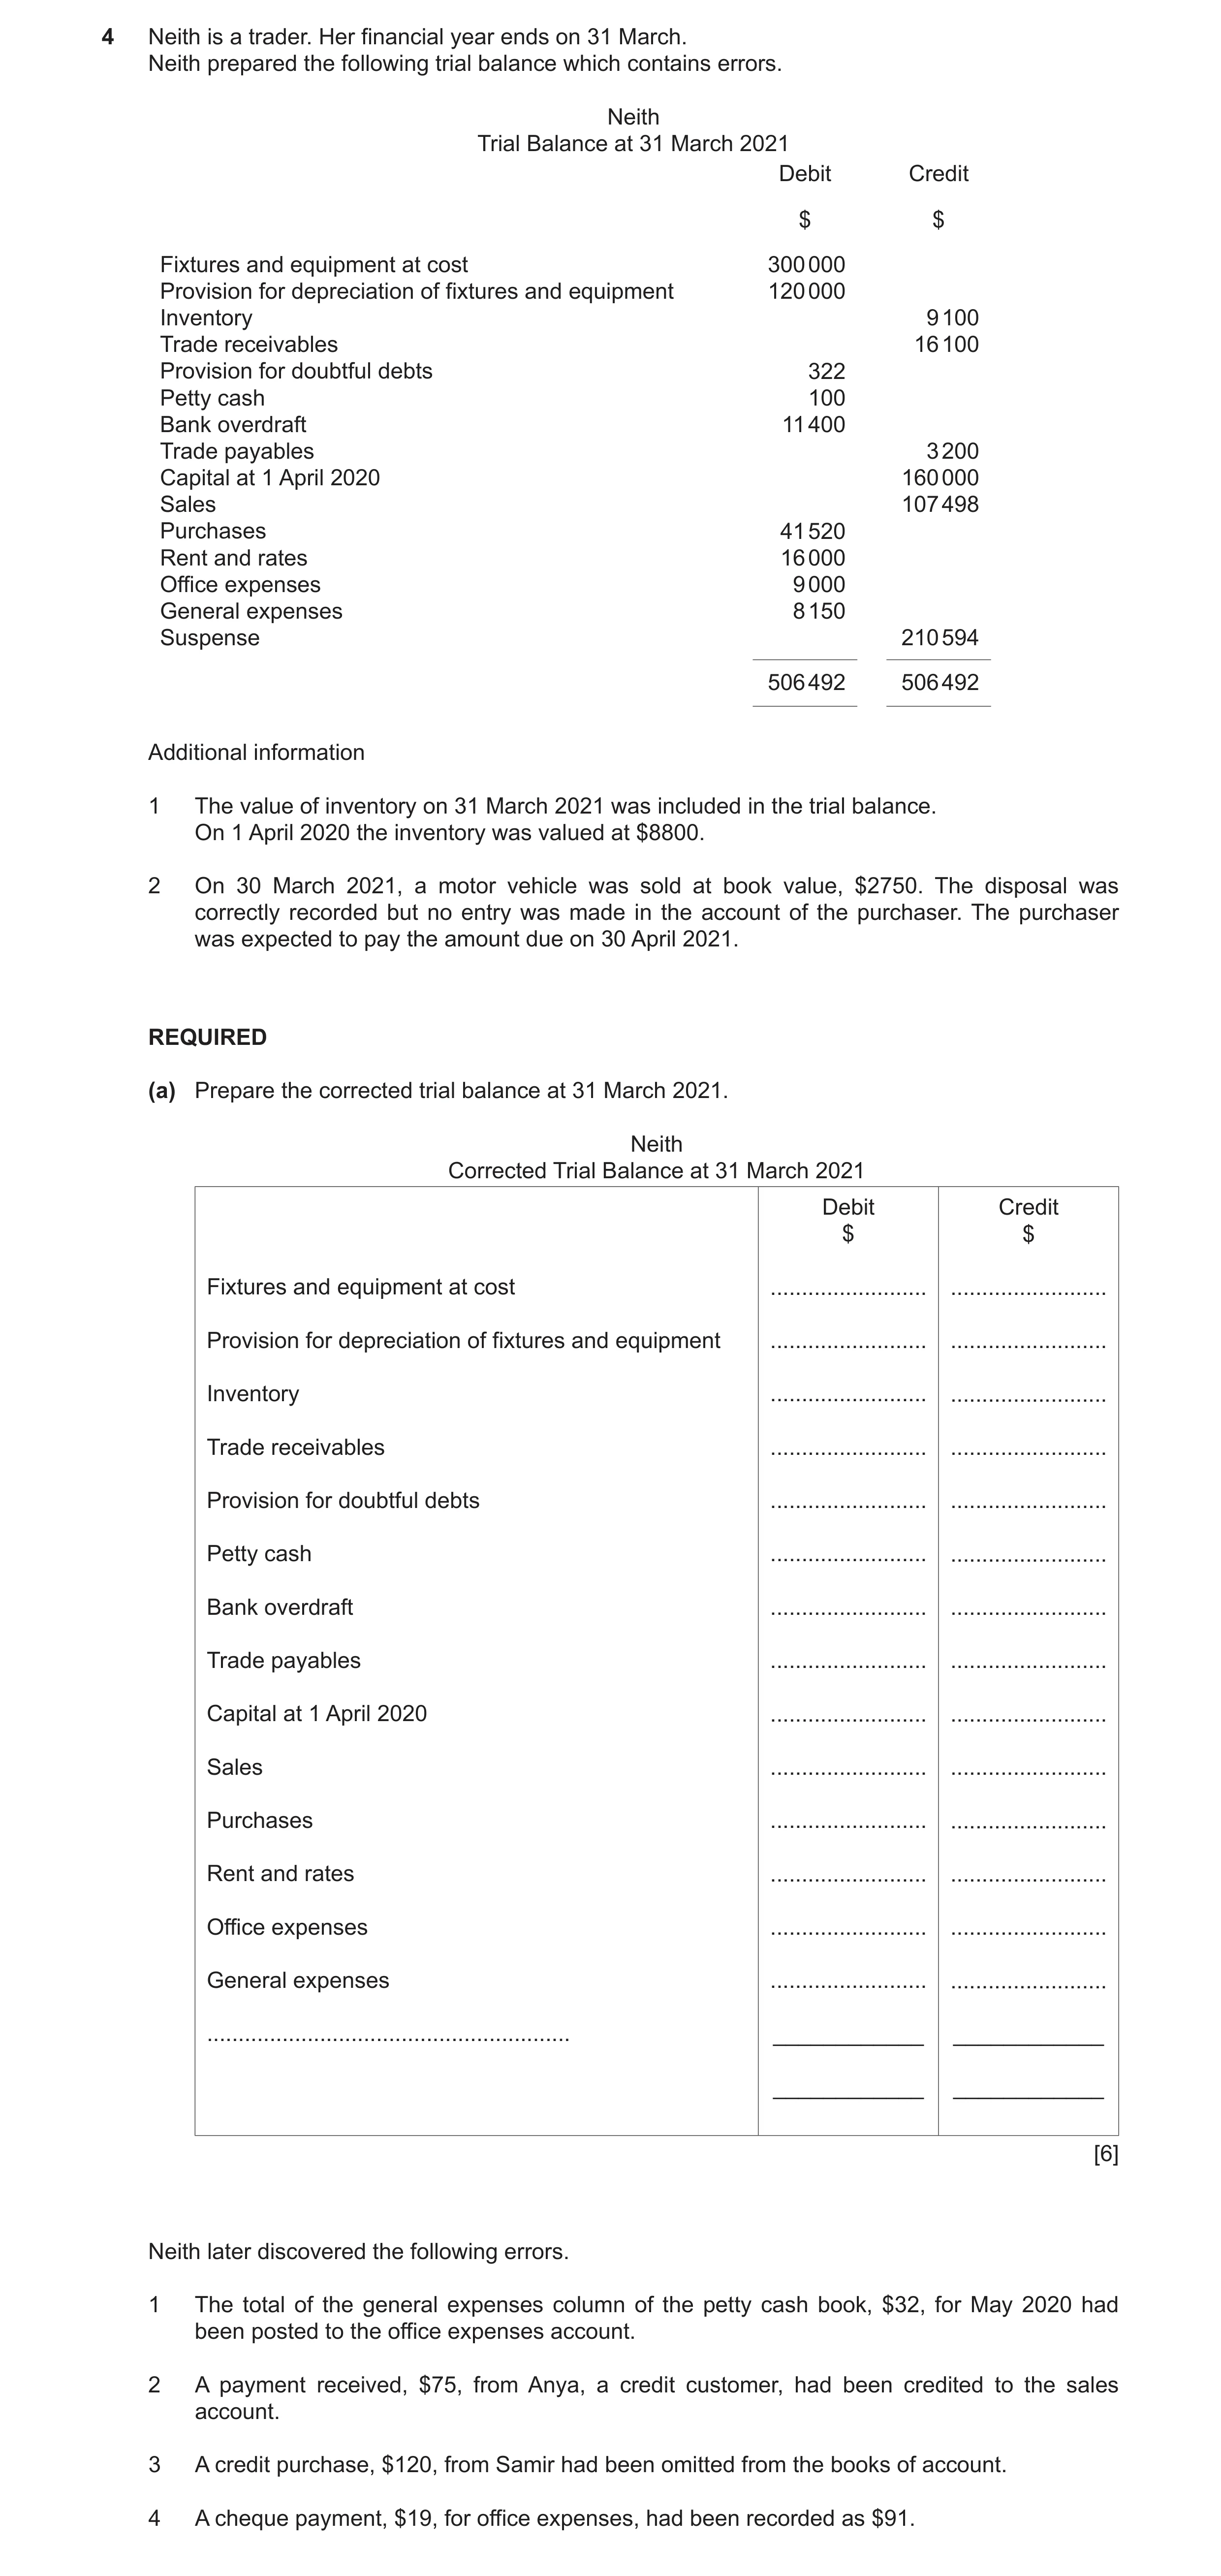
4 Neith is a trader. Her financial year ends on 31 March. Neith prepared the following trial balance which contains errors. Neith Trial Balance at 31 March 2021 Debit Credit $ $ Fixtures and equipment at cost 300 000 Provision for depreciation of fixtures and equipment 120 000 Inventory 9 100 Trade receivables 16 100 Provision for doubtful debts 322 Petty cash 100 Bank overdraft 11 400 Trade payables 3 200 Capital at 1 April 2020 160 000 Sales 107 498 Purchases 41 520 Rent and rates 16 000 Office expenses 9 000 General expenses 8 150 Suspense 210 594 506 492 506 492 Additional information 1 The value of inventory on 31 March 2021 was included in the trial balance. On 1 April 2020 the inventory was valued at $8800. 2 On 30 March 2021, a motor vehicle was sold at book value, $2750. The disposal was correctly recorded but no entry was made in the account of the purchaser. The purchaser was expected to pay the amount due on 30 April 2021. REQUIRED (a) Prepare the corrected trial balance at 31 March 2021. Neith Corrected Trial Balance at 31 March 2021 Debit Credit $ $ Fixtures and equipment at cost … … Provision for depreciation of fixtures and equipment … … Inventory … … Trade receivables … … Provision for doubtful debts … … Petty cash … … Bank overdraft … … Trade payables … … Capital at 1 April 2020 … … Sales … … Purchases … … Rent and rates … … Office expenses … … General expenses … … … ____________ ____________ ____________ ____________ [6] Neith later discovered the following errors. 1 The total of the general expenses column of the petty cash book, $32, for May 2020 had been posted to the office expenses account. 2 A payment received, $75, from Anya, a credit customer, had been credited to the sales account. 3 A credit purchase, $120, from Samir had been omitted from the books of account. 4 A cheque payment, $19, for office expenses, had been recorded as $91.
6 marks
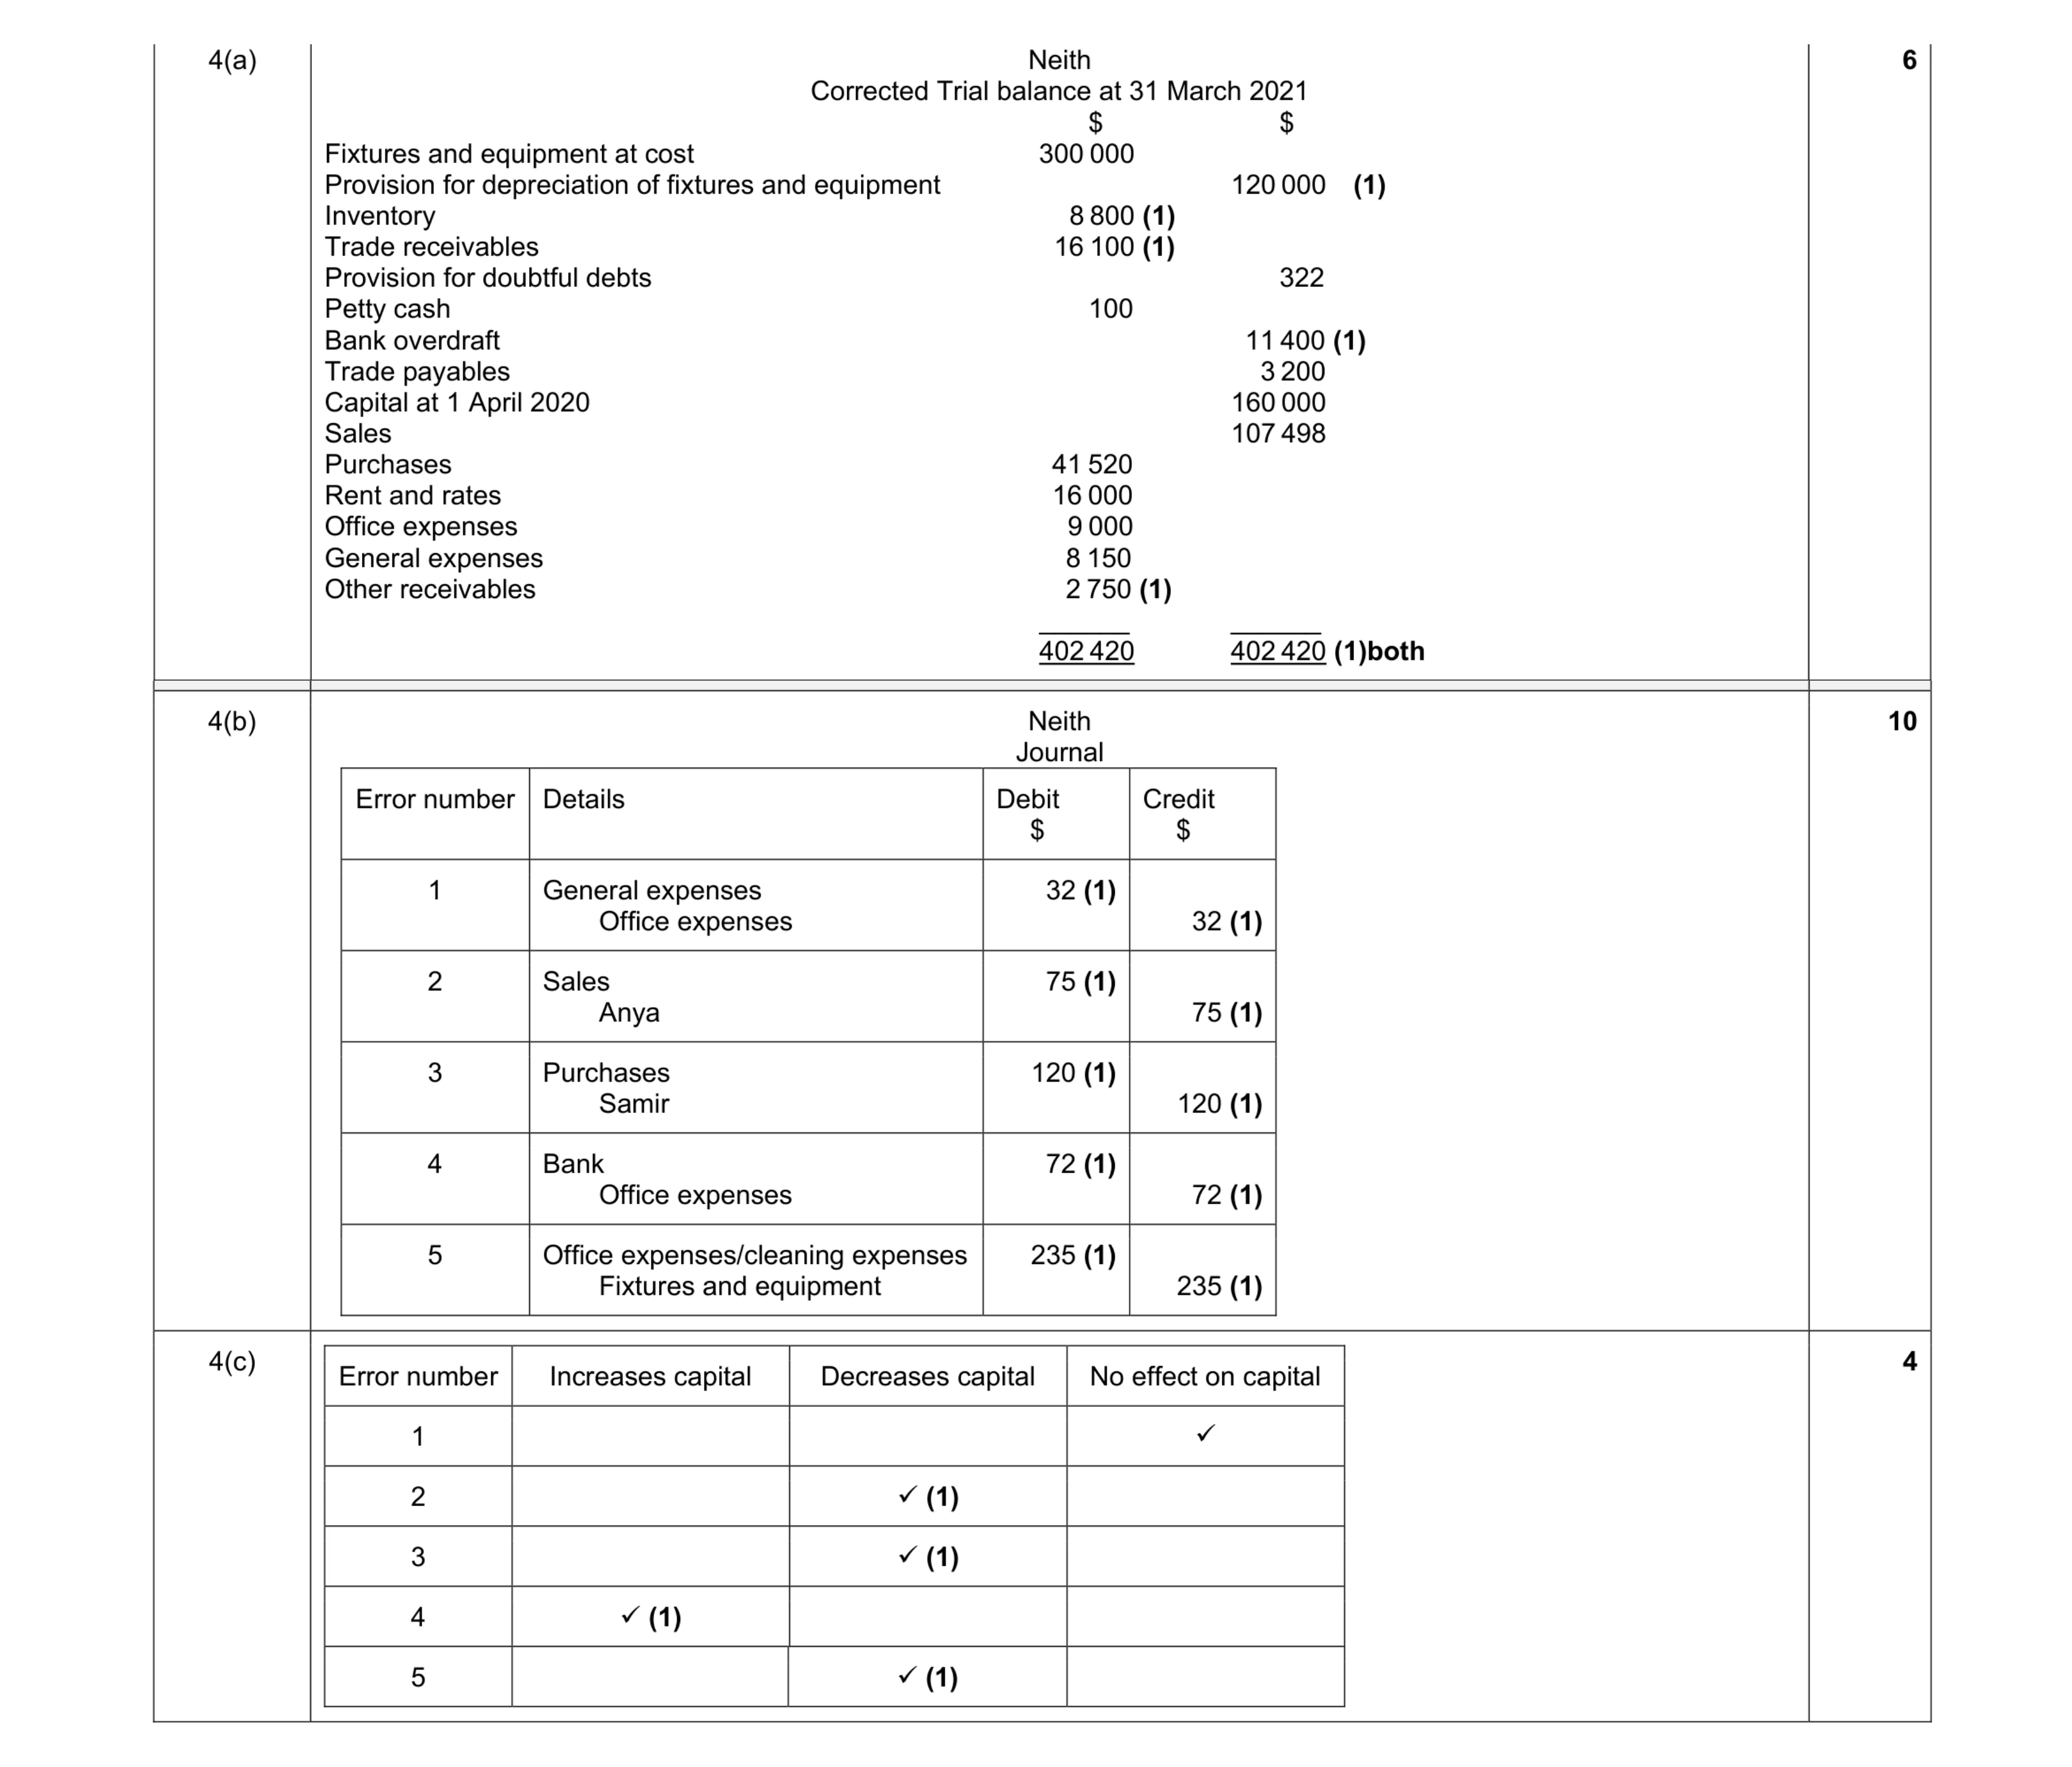
Mark scheme: 4(a) Neith Corrected Trial balance at 31 March 2021 $ $ Fixtures and equipment at cost 300 000 Provision for depreciation of fixtures and equipment 120 000 (1) Inventory 8 800 (1) Trade receivables 16 100 (1) Provision for doubtful debts 322 Petty cash 100 Bank overdraft 11 400 (1) Trade payables 3 200 Capital at 1 April 2020 160 000 Sales 107 498 Purchases 41 520 Rent and rates 16 000 Office expenses 9 000 General expenses 8 150 Other receivables 2 750 (1) ______ ______ 402 420 402 420 (1)both 6 Question Answer Marks 4(b) Neith Journal Error number Details Debit $ Credit $ 1 General expenses Office expenses 32 (1) 32 (1) 2 Sales Anya 75 (1) 75 (1) 3 Purchases Samir 120 (1) 120 (1) 4 Bank Office expenses 72 (1) 72 (1) 5 Office expenses/cleaning expenses Fixtures and equipment 235 (1) 235 (1) 10 4(c) Error number Increases capital Decreases capital No effect on capital 1 2 (1) 3 (1) 4 (1) 5 (1) 4
This question in 0985/21 May/June 2021
Q4 · An invoice for office cleaning, $235, had been debited to the fixtures and equipment… 0985/21 May/June 2021
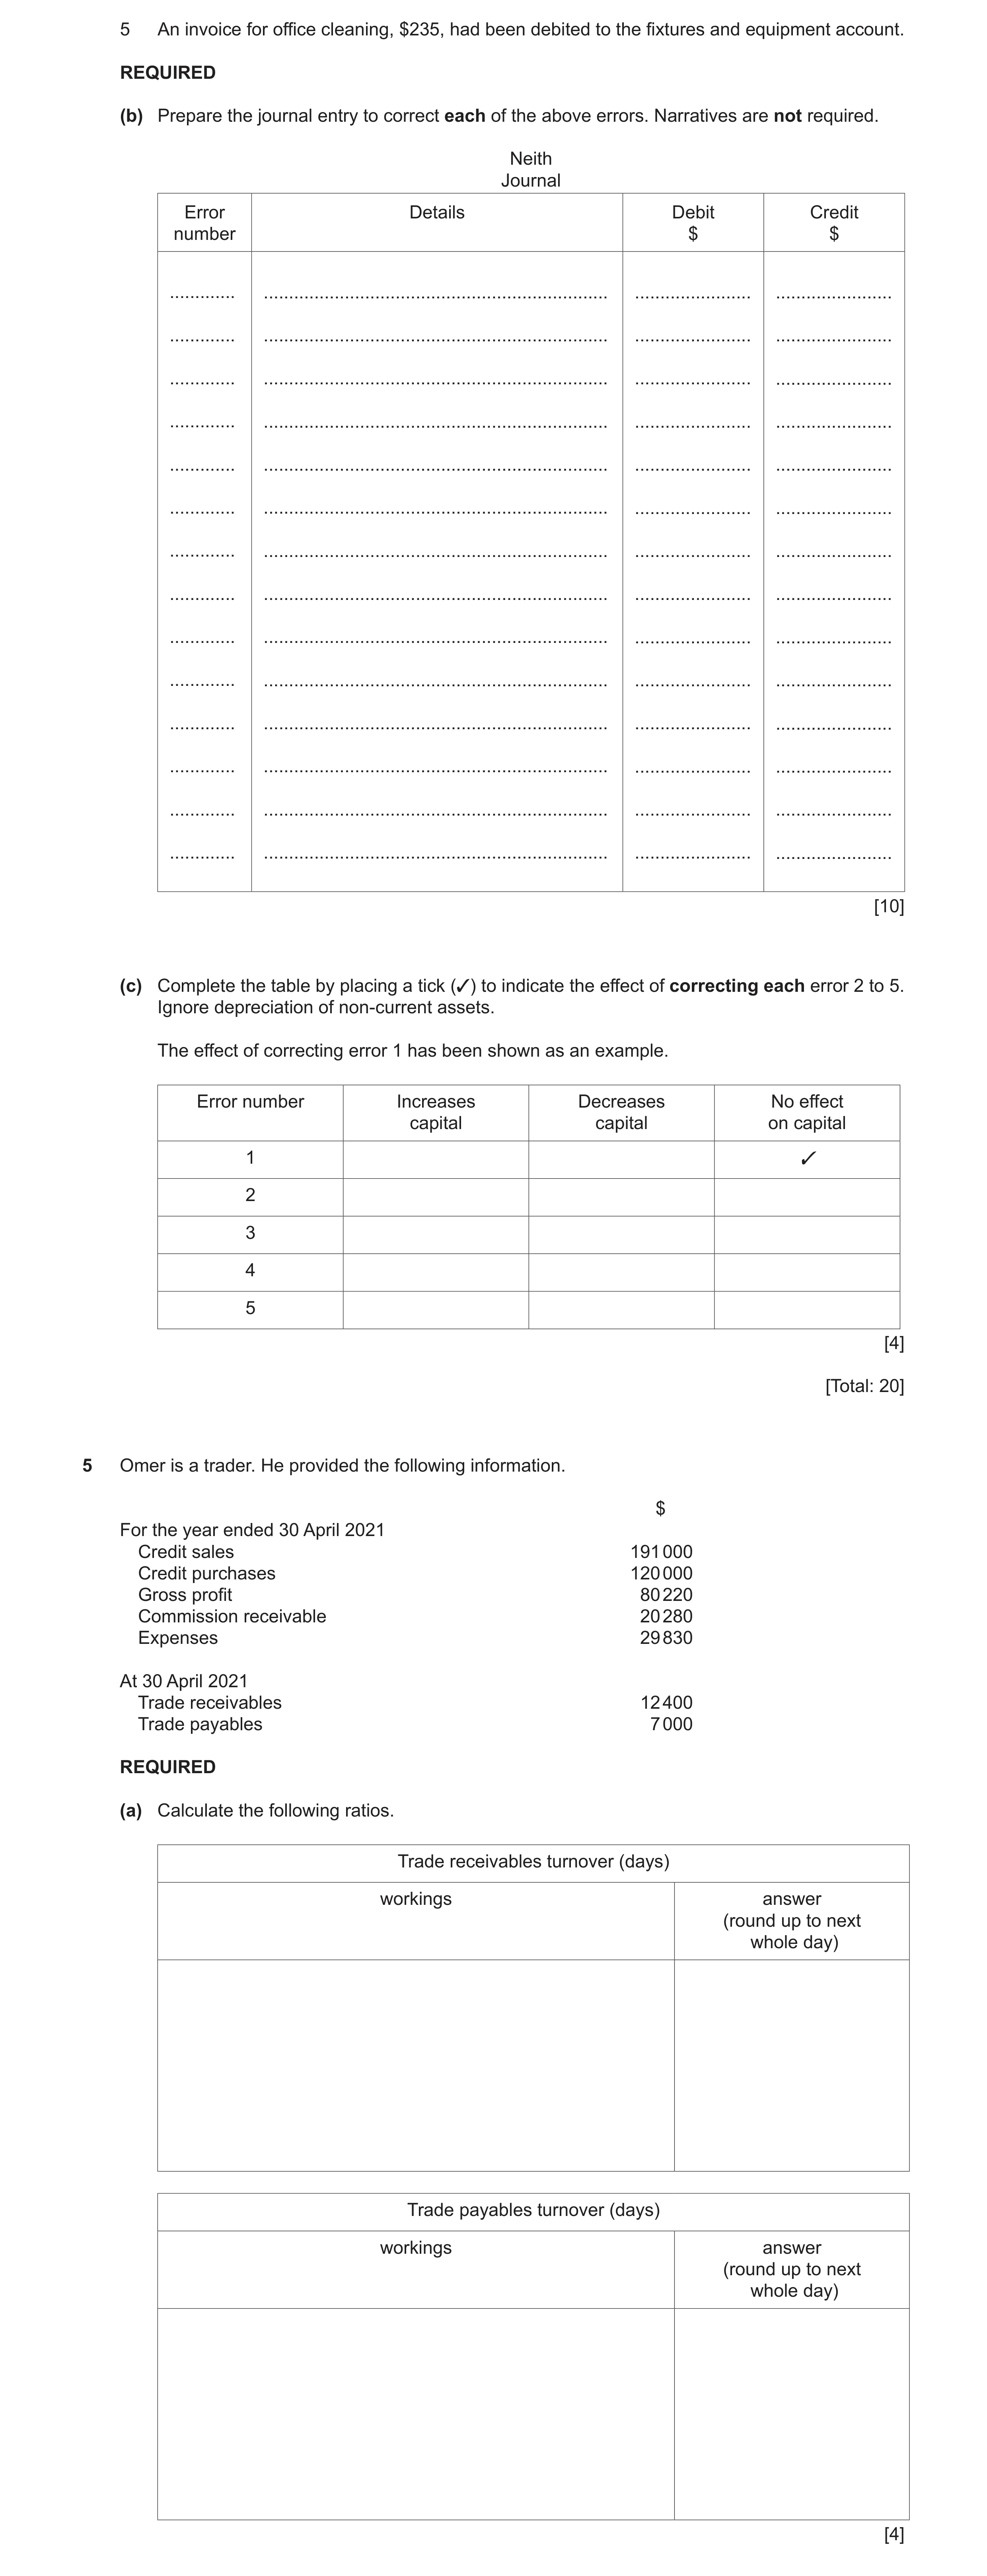
5 An invoice for office cleaning, $235, had been debited to the fixtures and equipment account. REQUIRED (b) Prepare the journal entry to correct each of the above errors. Narratives are not required. Neith Journal Error Details Debit Credit number $ $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [10] (c) Complete the table by placing a tick (3) to indicate the effect of correcting each error 2 to 5. Ignore depreciation of non-current assets. The effect of correcting error 1 has been shown as an example. Error number Increases Decreases No effect capital capital on capital 1 3 2 3 4 5 [4] [Total: 20] 5 Omer is a trader. He provided the following information. $ For the year ended 30 April 2021 Credit sales 191 000 Credit purchases 120 000 Gross profit 80 220 Commission receivable 20 280 Expenses 29 830 At 30 April 2021 Trade receivables 12 400 Trade payables 7 000 REQUIRED (a) Calculate the following ratios. Trade receivables turnover (days) workings answer (round up to next whole day) Trade payables turnover (days) workings answer (round up to next whole day) [4]
18 marks
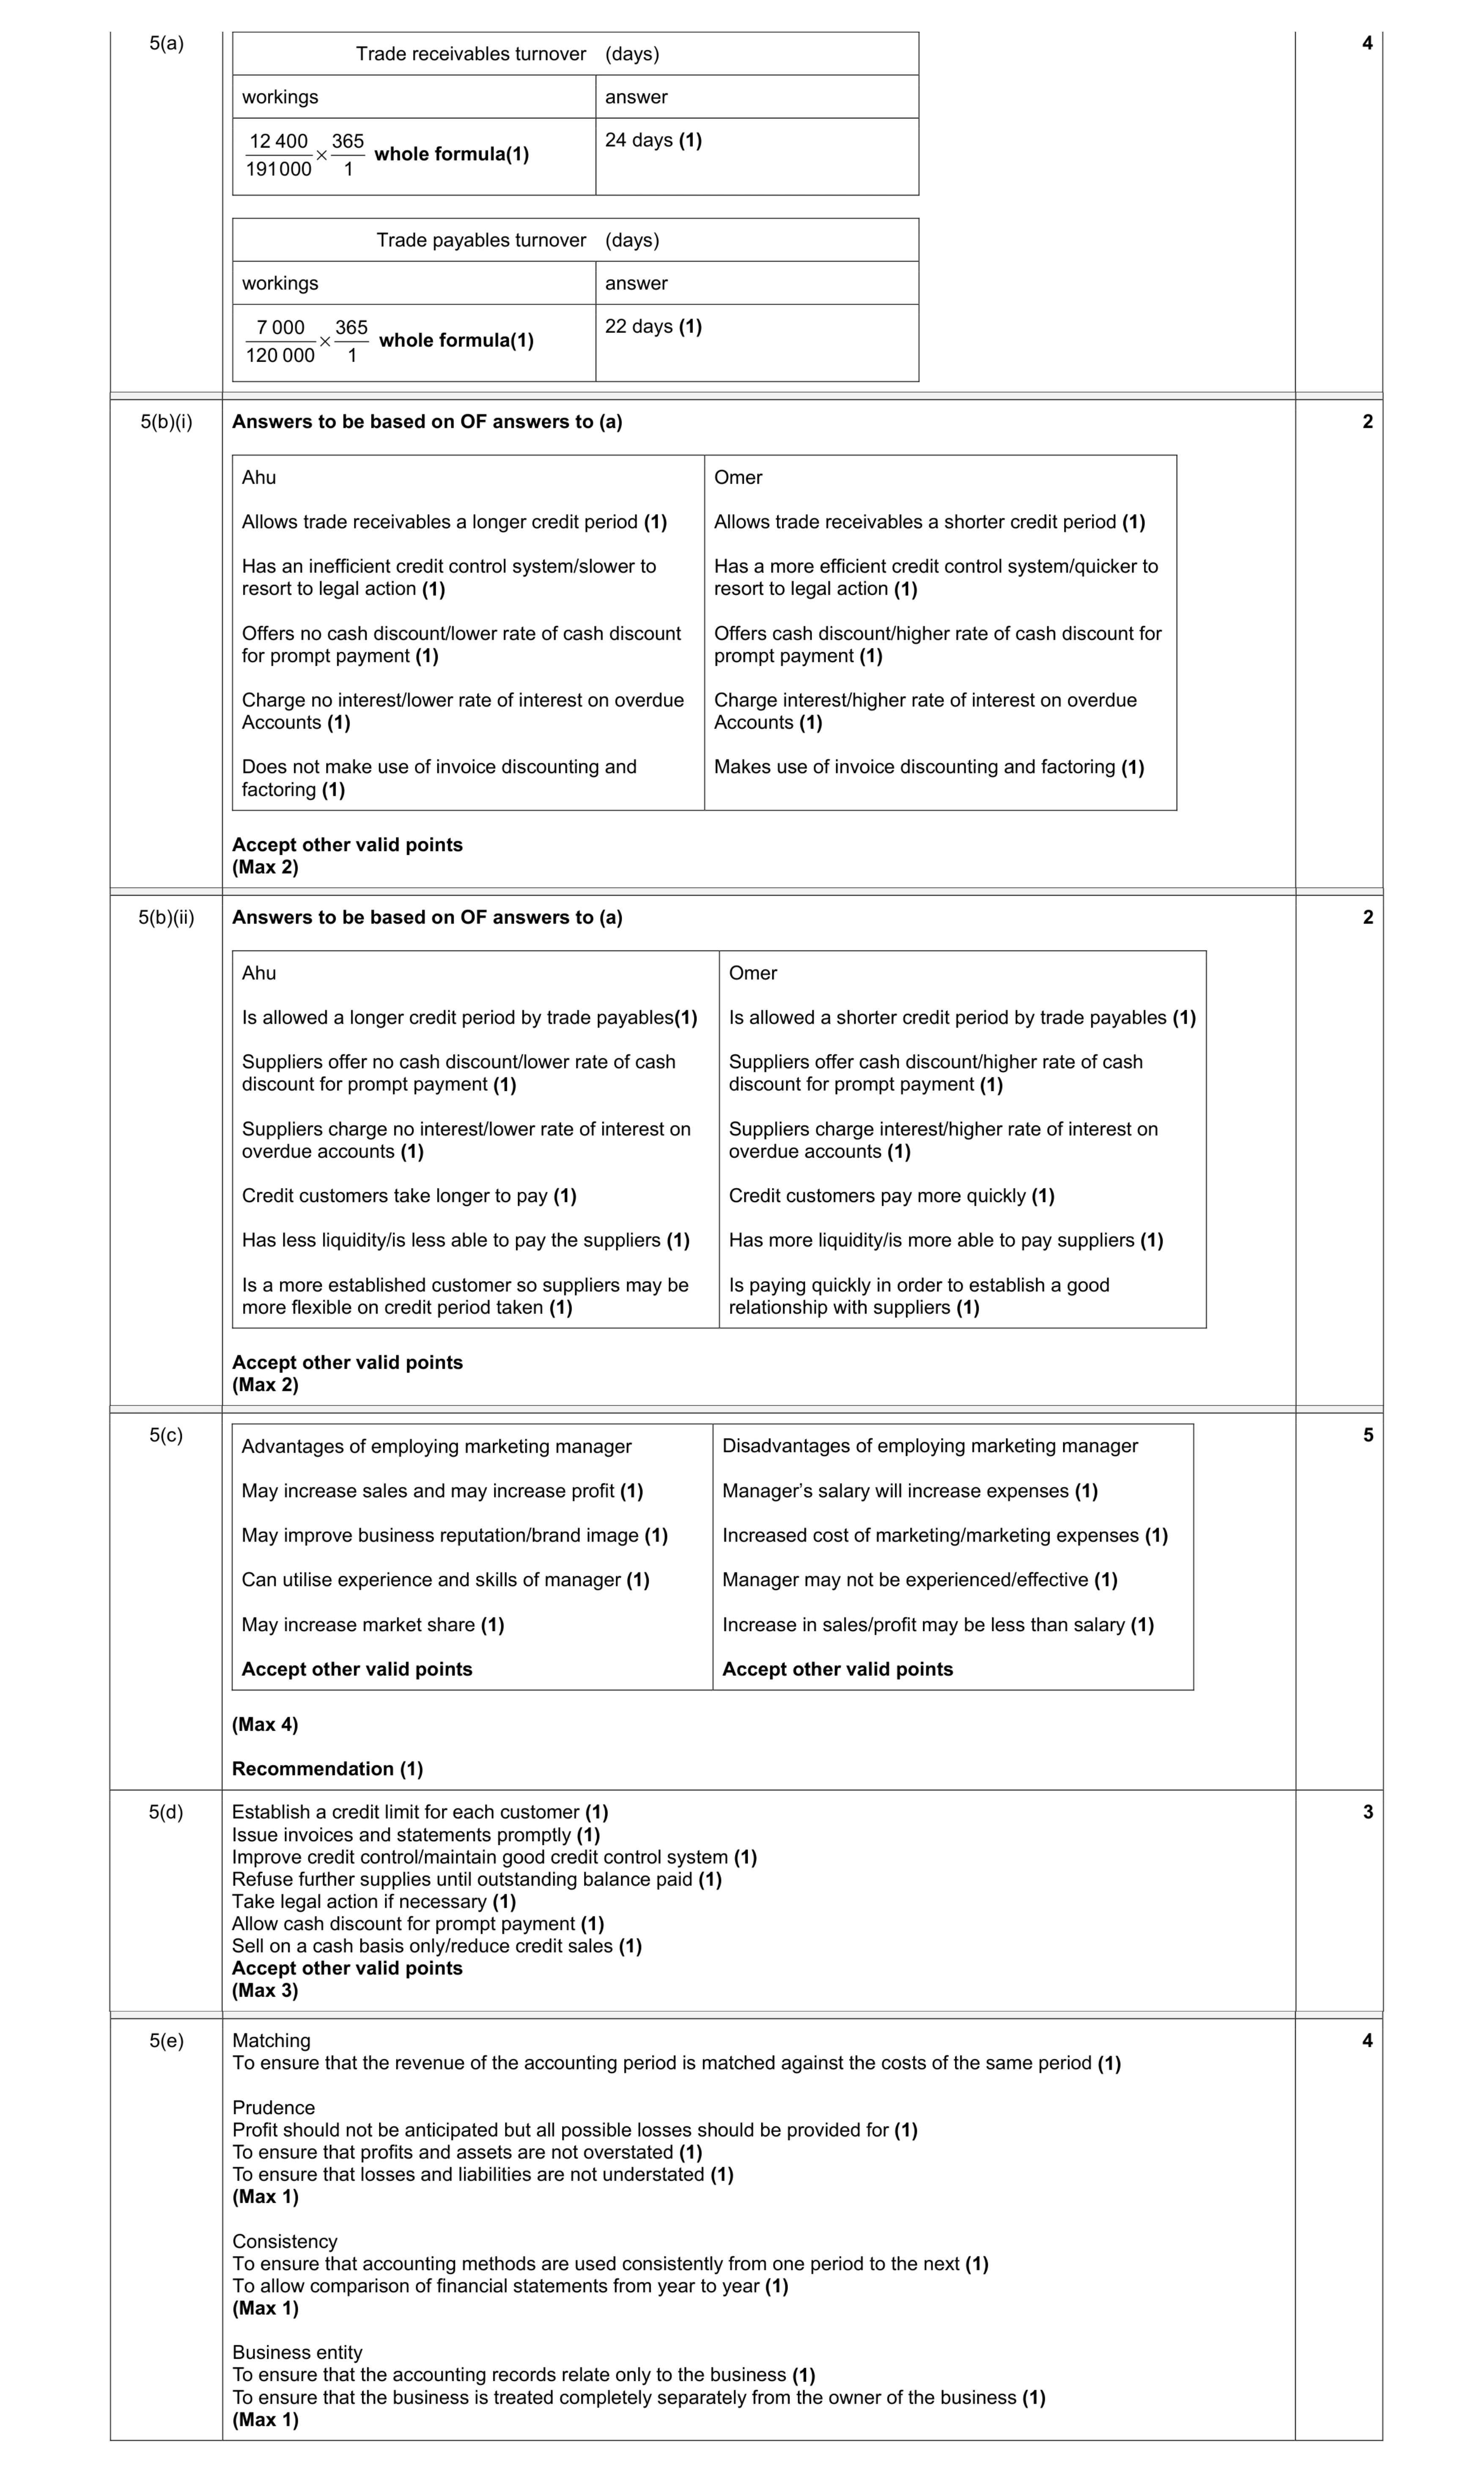
Mark scheme: 5(a) Trade receivables turnover (days) workings answer 12 400 365 191000 1 × whole formula(1) 24 days (1) Trade payables turnover (days) workings answer 7 000 365 120 000 1 × whole formula(1) 22 days (1) 4 Question Answer Marks 5(b)(i) Answers to be based on OF answers to (a) Ahu Allows trade receivables a longer credit period (1) Has an inefficient credit control system/slower to resort to legal action (1) Offers no cash discount/lower rate of cash discount for prompt payment (1) Charge no interest/lower rate of interest on overdue Accounts (1) Does not make use of invoice discounting and factoring (1) Omer Allows trade receivables a shorter credit period (1) Has a more efficient credit control system/quicker to resort to legal action (1) Offers cash discount/higher rate of cash discount for prompt payment (1) Charge interest/higher rate of interest on overdue Accounts (1) Makes use of invoice discounting and factoring (1) Accept other valid points (Max 2) 2 Question Answer Marks 5(b)(ii) Answers to be based on OF answers to (a) Ahu Is allowed a longer credit period by trade payables(1) Suppliers offer no cash discount/lower rate of cash discount for prompt payment (1) Suppliers charge no interest/lower rate of interest on overdue accounts (1) Credit customers take longer to pay (1) Has less liquidity/is less able to pay the suppliers (1) Is a more established customer so suppliers may be more flexible on credit period taken (1) Omer Is allowed a shorter credit period by trade payables (1) Suppliers offer cash discount/higher rate of cash discount for prompt payment (1) Suppliers charge interest/higher rate of interest on overdue accounts (1) Credit customers pay more quickly (1) Has more liquidity/is more able to pay suppliers (1) Is paying quickly in order to establish a good relationship with suppliers (1) Accept other valid points (Max 2) 2 Question Answer Marks 5(c) Advantages of employing marketing manager May increase sales and may increase profit (1) May improve business reputation/brand image (1) Can utilise experience and skills of manager (1) May increase market share (1) Accept other valid points Disadvantages of employing marketing manager Manager’s salary will increase expenses (1) Increased cost of marketing/marketing expenses (1) Manager may not be experienced/effective (1) Increase in sales/profit may be less than salary (1) Accept other valid points (Max 4) Recommendation (1) 5 5(d) Establish a credit limit for each customer (1) Issue invoices and statements promptly (1) Improve credit control/maintain good credit control system (1) Refuse further supplies until outstanding balance paid (1) Take legal action if necessary (1) Allow cash discount for prompt payment (1) Sell on a cash basis only/reduce credit sales (1) Accept other valid points (Max 3) 3 Question Answer Marks 5(e) Matching To ensure that the revenue of the accounting period is matched against the costs of the same period (1) Prudence Profit should not be anticipated but all possible losses should be provided for (1) To ensure that profits and assets are not overstated (1) To ensure that losses and liabilities are not understated (1) (Max 1) Consistency To ensure that accounting methods are used consistently from one period to the next (1) To allow comparison of financial statements from year to year (1) (Max 1) Business entity To ensure that the accounting records relate only to the business (1) To ensure that the business is treated completely separately from the owner of the business (1) (Max 1) 4
This question in 0985/21 May/June 2021
Q5 · Kia is a trader 0985/22 May/June 2021
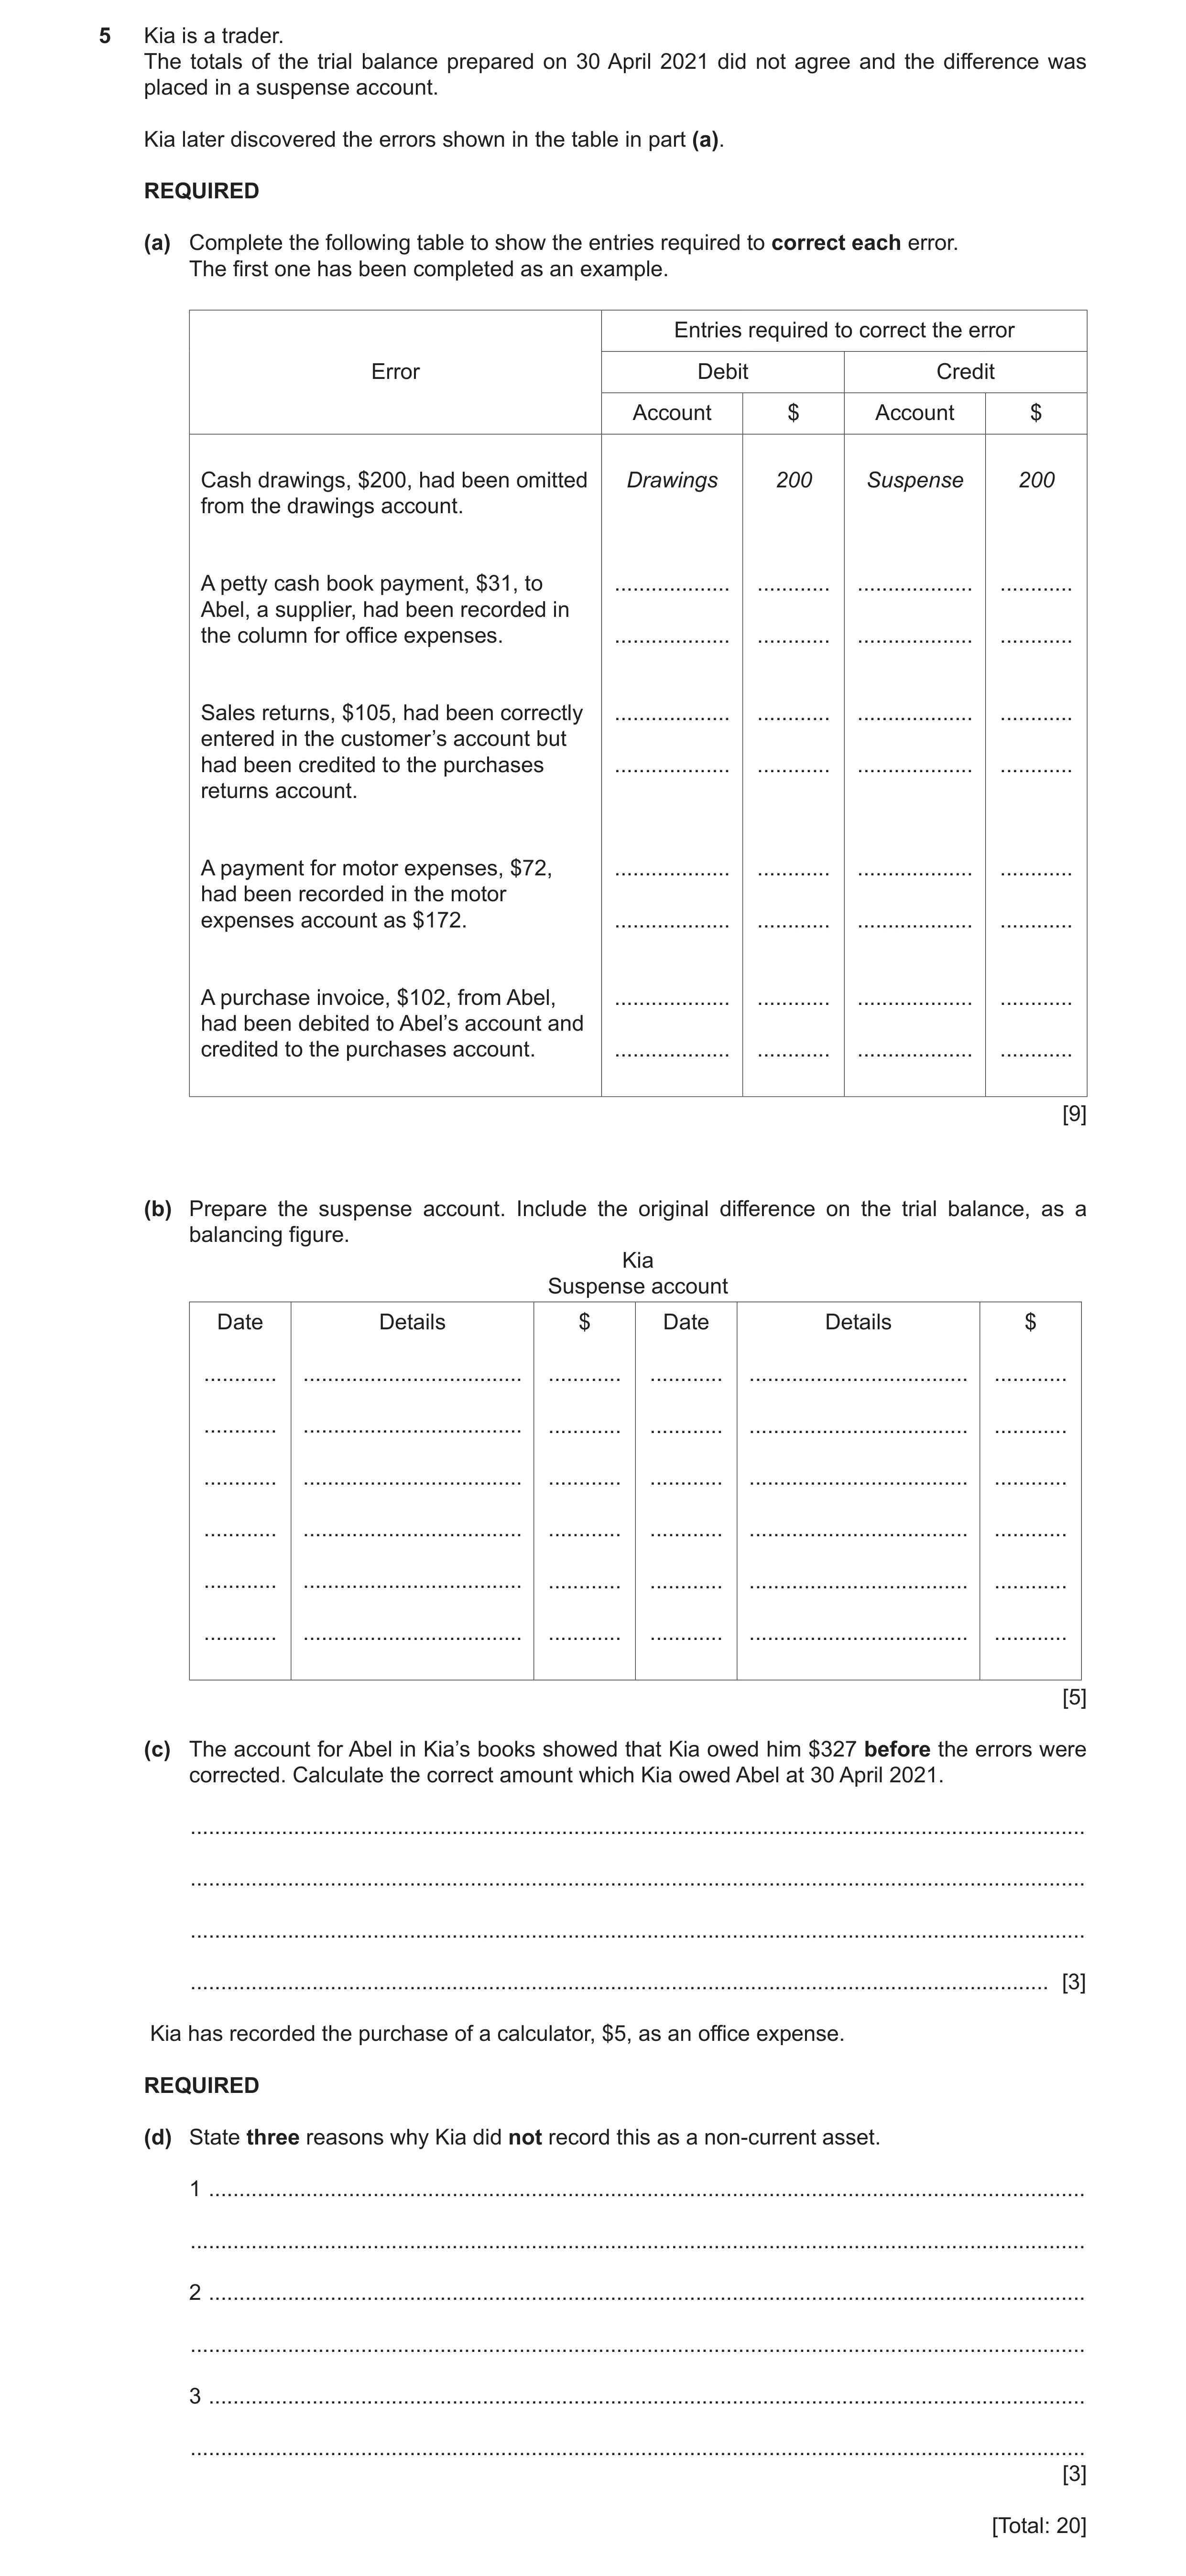
5 Kia is a trader. The totals of the trial balance prepared on 30 April 2021 did not agree and the difference was placed in a suspense account. Kia later discovered the errors shown in the table in part (a). REQUIRED (a) Complete the following table to show the entries required to correct each error. The first one has been completed as an example. Entries required to correct the error Error Debit Credit Account $ Account $ Cash drawings, $200, had been omitted Drawings 200 Suspense 200 from the drawings account. A petty cash book payment, $31, to … … … … Abel, a supplier, had been recorded in the column for office expenses. … … … … Sales returns, $105, had been correctly … … … … entered in the customer’s account but had been credited to the purchases … … … … returns account. A payment for motor expenses, $72, … … … … had been recorded in the motor expenses account as $172. … … … … A purchase invoice, $102, from Abel, … … … … had been debited to Abel’s account and credited to the purchases account. … … … … [9] (b) Prepare the suspense account. Include the original difference on the trial balance, as a balancing figure. Kia Suspense account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [5] (c) The account for Abel in Kia’s books showed that Kia owed him $327 before the errors were corrected. Calculate the correct amount which Kia owed Abel at 30 April 2021. … … … … [3] Kia has recorded the purchase of a calculator, $5, as an office expense. REQUIRED (d) State three reasons why Kia did not record this as a non-current asset. 1 … … 2 … … 3 … … [3] [Total: 20]
20 marks
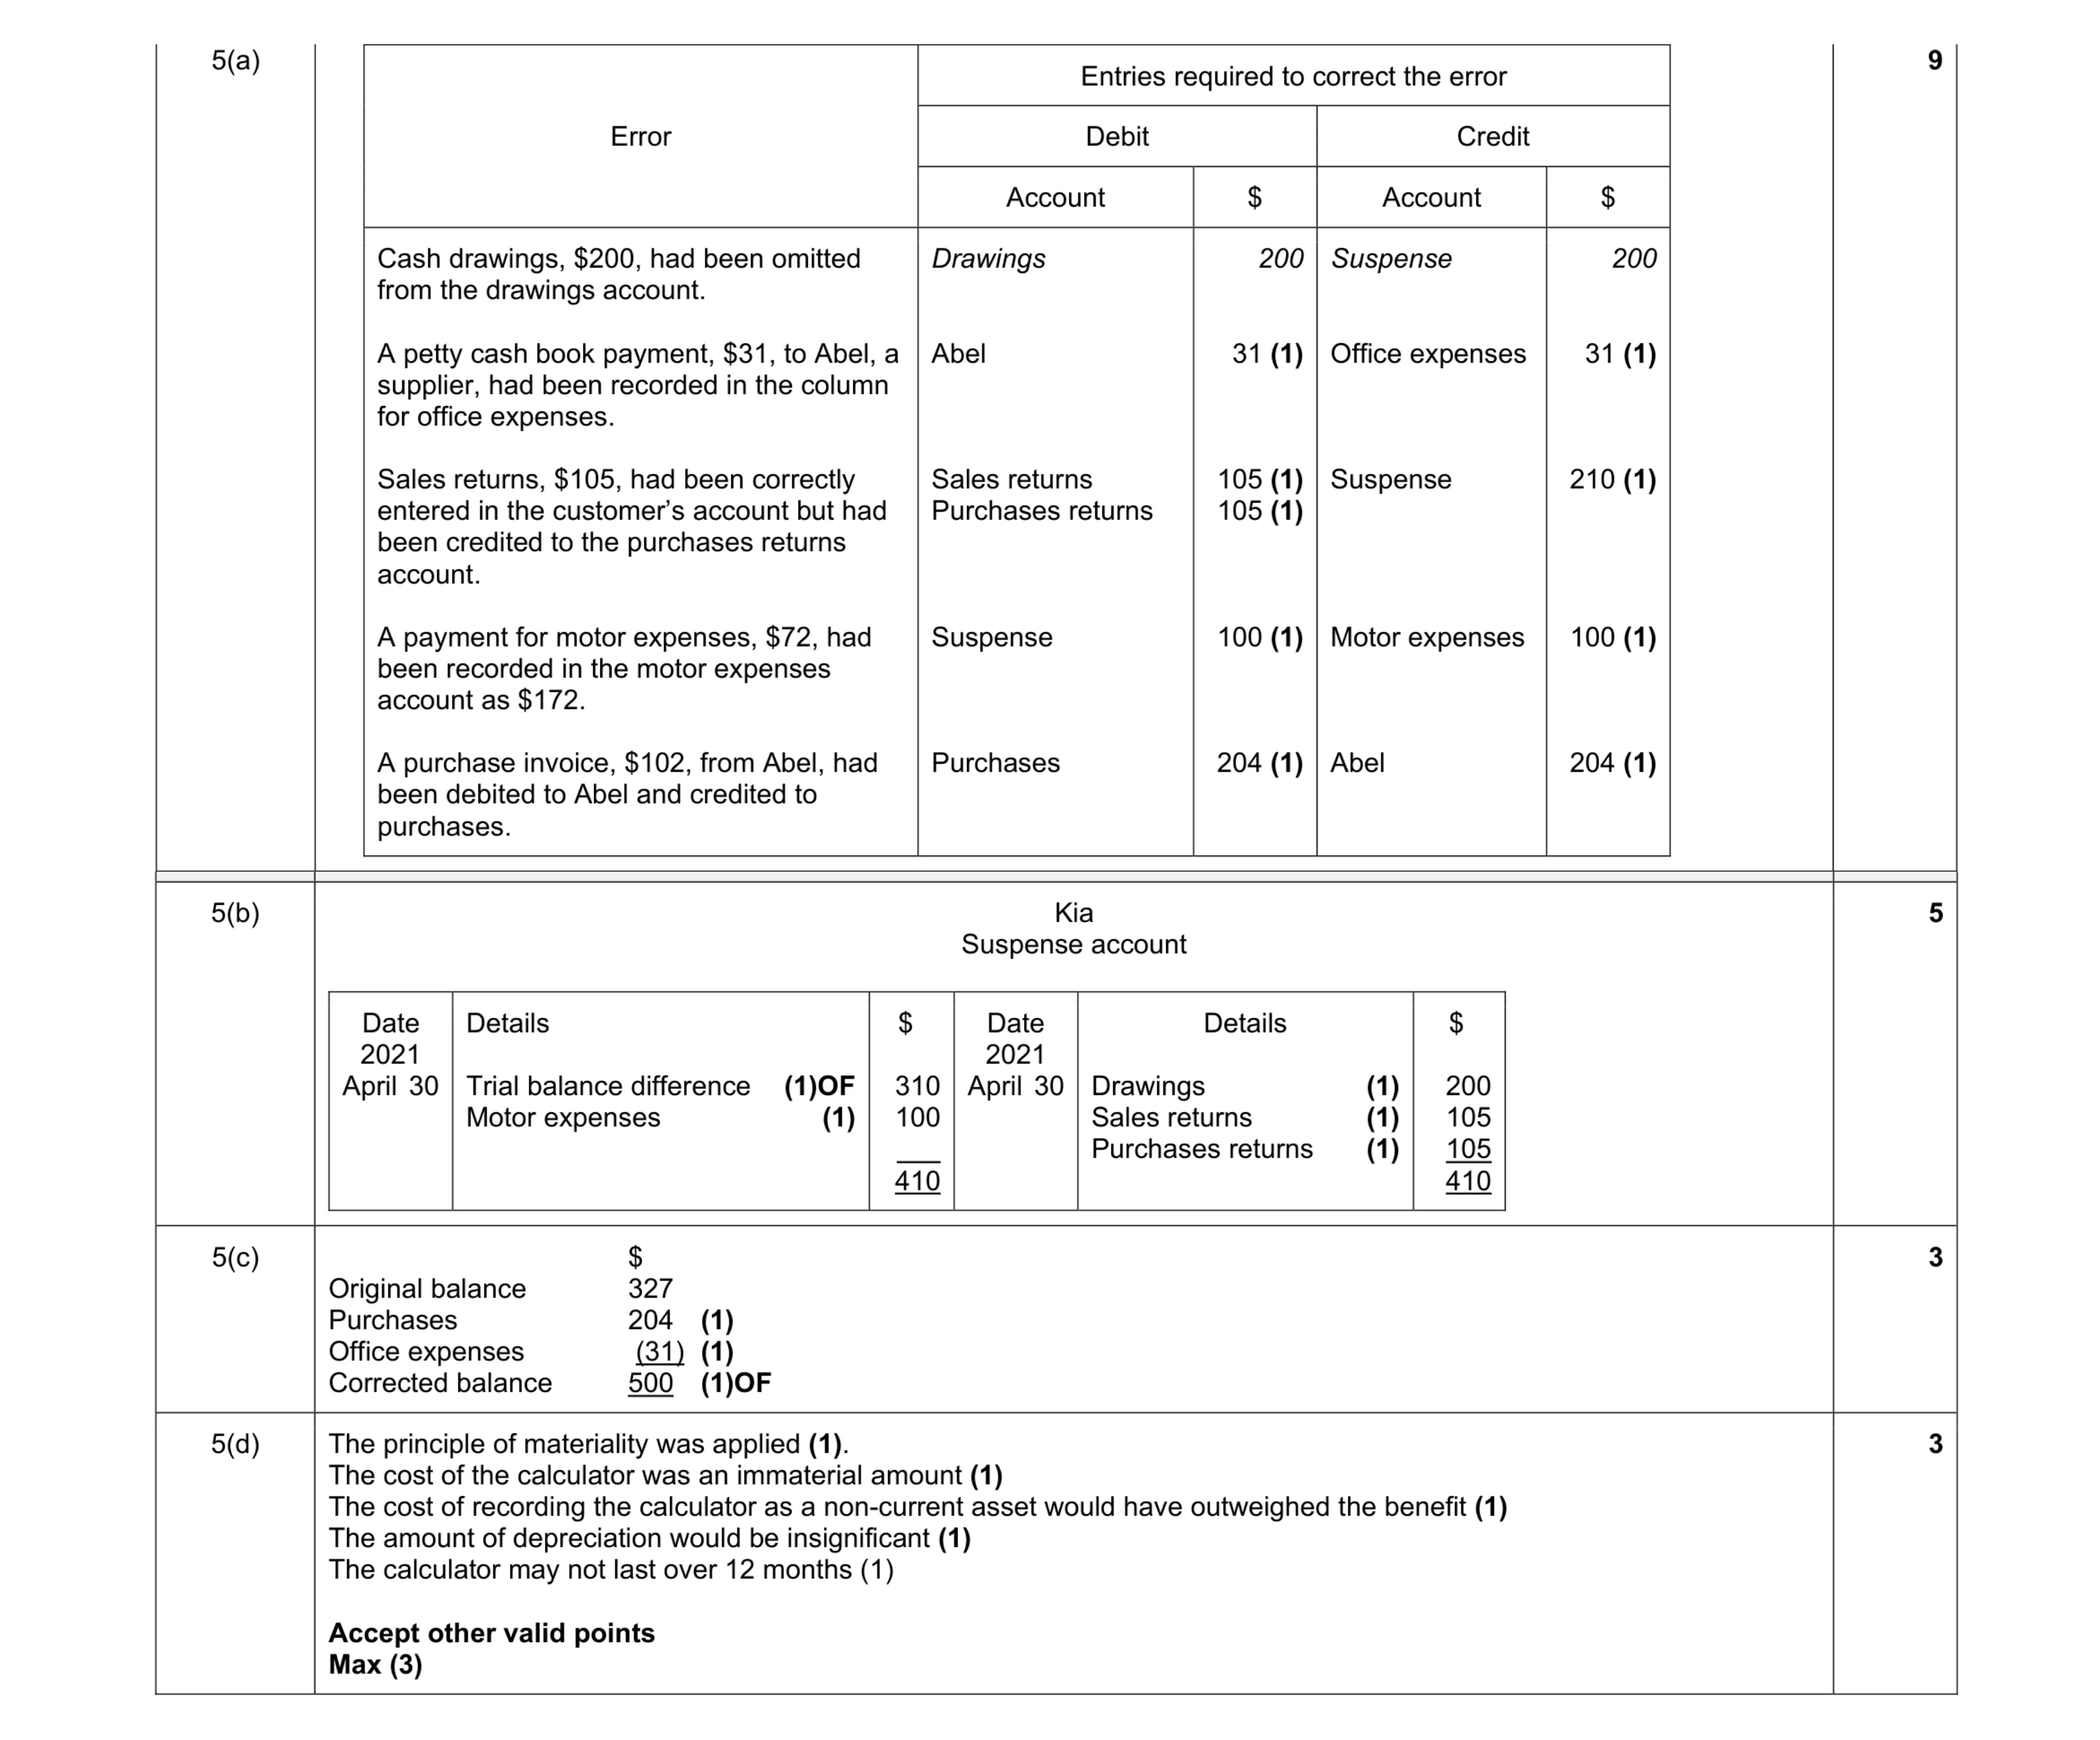
Mark scheme: 5(a) Error Entries required to correct the error Debit Credit Account $ Account $ Cash drawings, $200, had been omitted from the drawings account. A petty cash book payment, $31, to Abel, a supplier, had been recorded in the column for office expenses. Sales returns, $105, had been correctly entered in the customer’s account but had been credited to the purchases returns account. A payment for motor expenses, $72, had been recorded in the motor expenses account as $172. A purchase invoice, $102, from Abel, had been debited to Abel and credited to purchases. Drawings Abel Sales returns Purchases returns Suspense Purchases 200 31 (1) 105 (1) 105 (1) 100 (1) 204 (1) Suspense Office expenses Suspense Motor expenses Abel 200 31 (1) 210 (1) 100 (1) 204 (1) 9 Question Answer Marks 5(b) Kia Suspense account Date 2021 April 30 Details Trial balance difference (1)OF Motor expenses (1) $ 310 100 410 Date 2021 April 30 Details Drawings (1) Sales returns (1) Purchases returns (1) $ 200 105 105 410 5 5(c) $ Original balance 327 Purchases 204 (1) Office expenses (31) (1) Corrected balance 500 (1)OF 3 5(d) The principle of materiality was applied (1). The cost of the calculator was an immaterial amount (1) The cost of recording the calculator as a non-current asset would have outweighed the benefit (1) The amount of depreciation would be insignificant (1) The calculator may not last over 12 months (1) Accept other valid points Max (3) 3
This question in 0985/22 May/June 2021
Q6 · Nikita is a trader 0985/22 Oct/Nov 2021
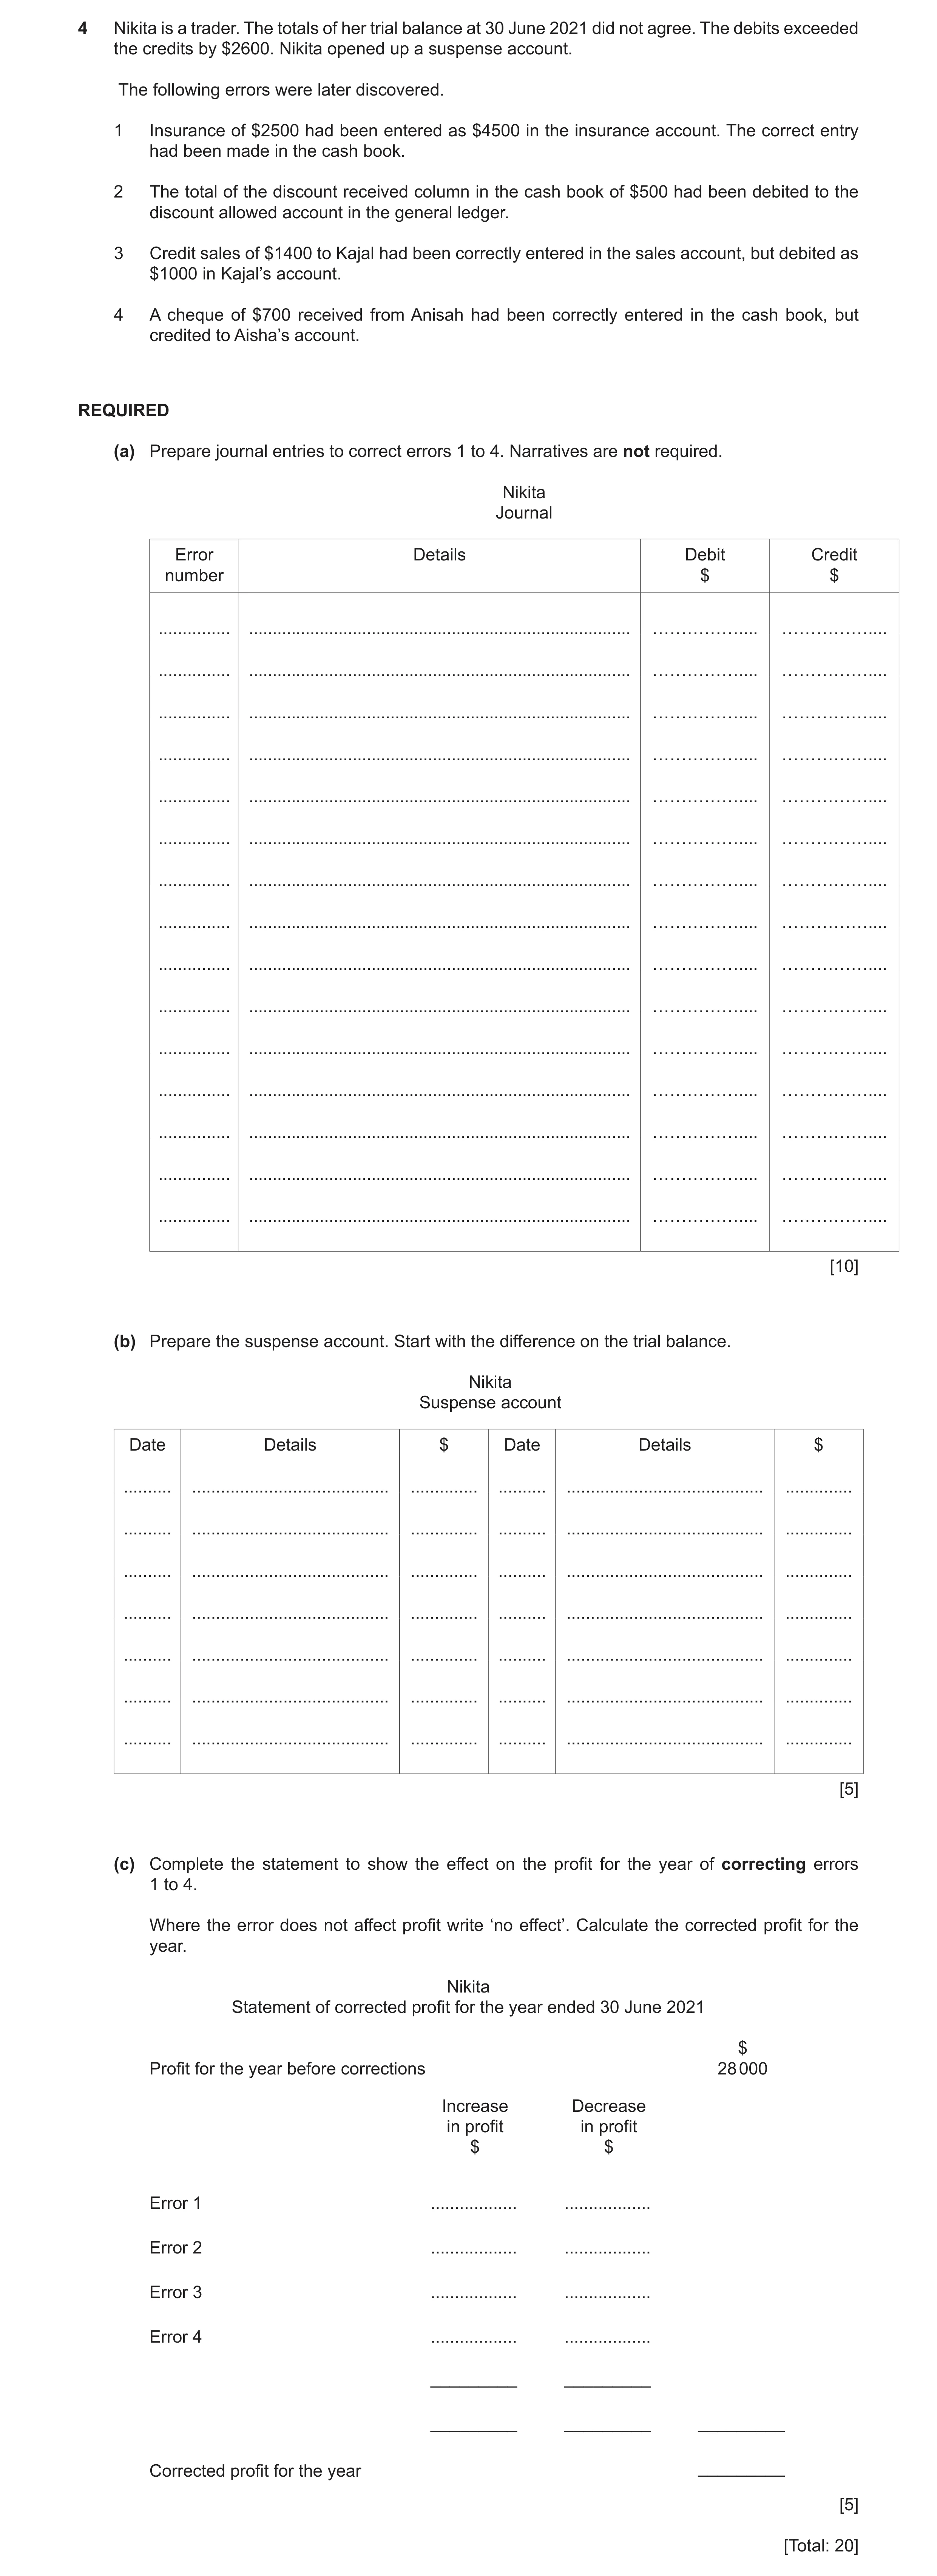
4 Nikita is a trader. The totals of her trial balance at 30 June 2021 did not agree. The debits exceeded the credits by $2600. Nikita opened up a suspense account. The following errors were later discovered. 1 Insurance of $2500 had been entered as $4500 in the insurance account. The correct entry had been made in the cash book. 2 The total of the discount received column in the cash book of $500 had been debited to the discount allowed account in the general ledger. 3 Credit sales of $1400 to Kajal had been correctly entered in the sales account, but debited as $1000 in Kajal’s account. 4 A cheque of $700 received from Anisah had been correctly entered in the cash book, but credited to Aisha’s account. REQUIRED (a) Prepare journal entries to correct errors 1 to 4. Narratives are not required. Nikita Journal Error Details Debit Credit number $ $ … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … … … …………… … …………… … [10] (b) Prepare the suspense account. Start with the difference on the trial balance. Nikita Suspense account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [5] (c) Complete the statement to show the effect on the profit for the year of correcting errors 1 to 4. Where the error does not affect profit write ‘no effect’. Calculate the corrected profit for the year. Nikita Statement of corrected profit for the year ended 30 June 2021 $ Profit for the year before corrections 28 000 Increase Decrease in profit in profit $ $ Error 1 … … Error 2 … … Error 3 … … Error 4 … … _________ _________ _________ _________ _________ Corrected profit for the year _________ [5] [Total: 20]
20 marks
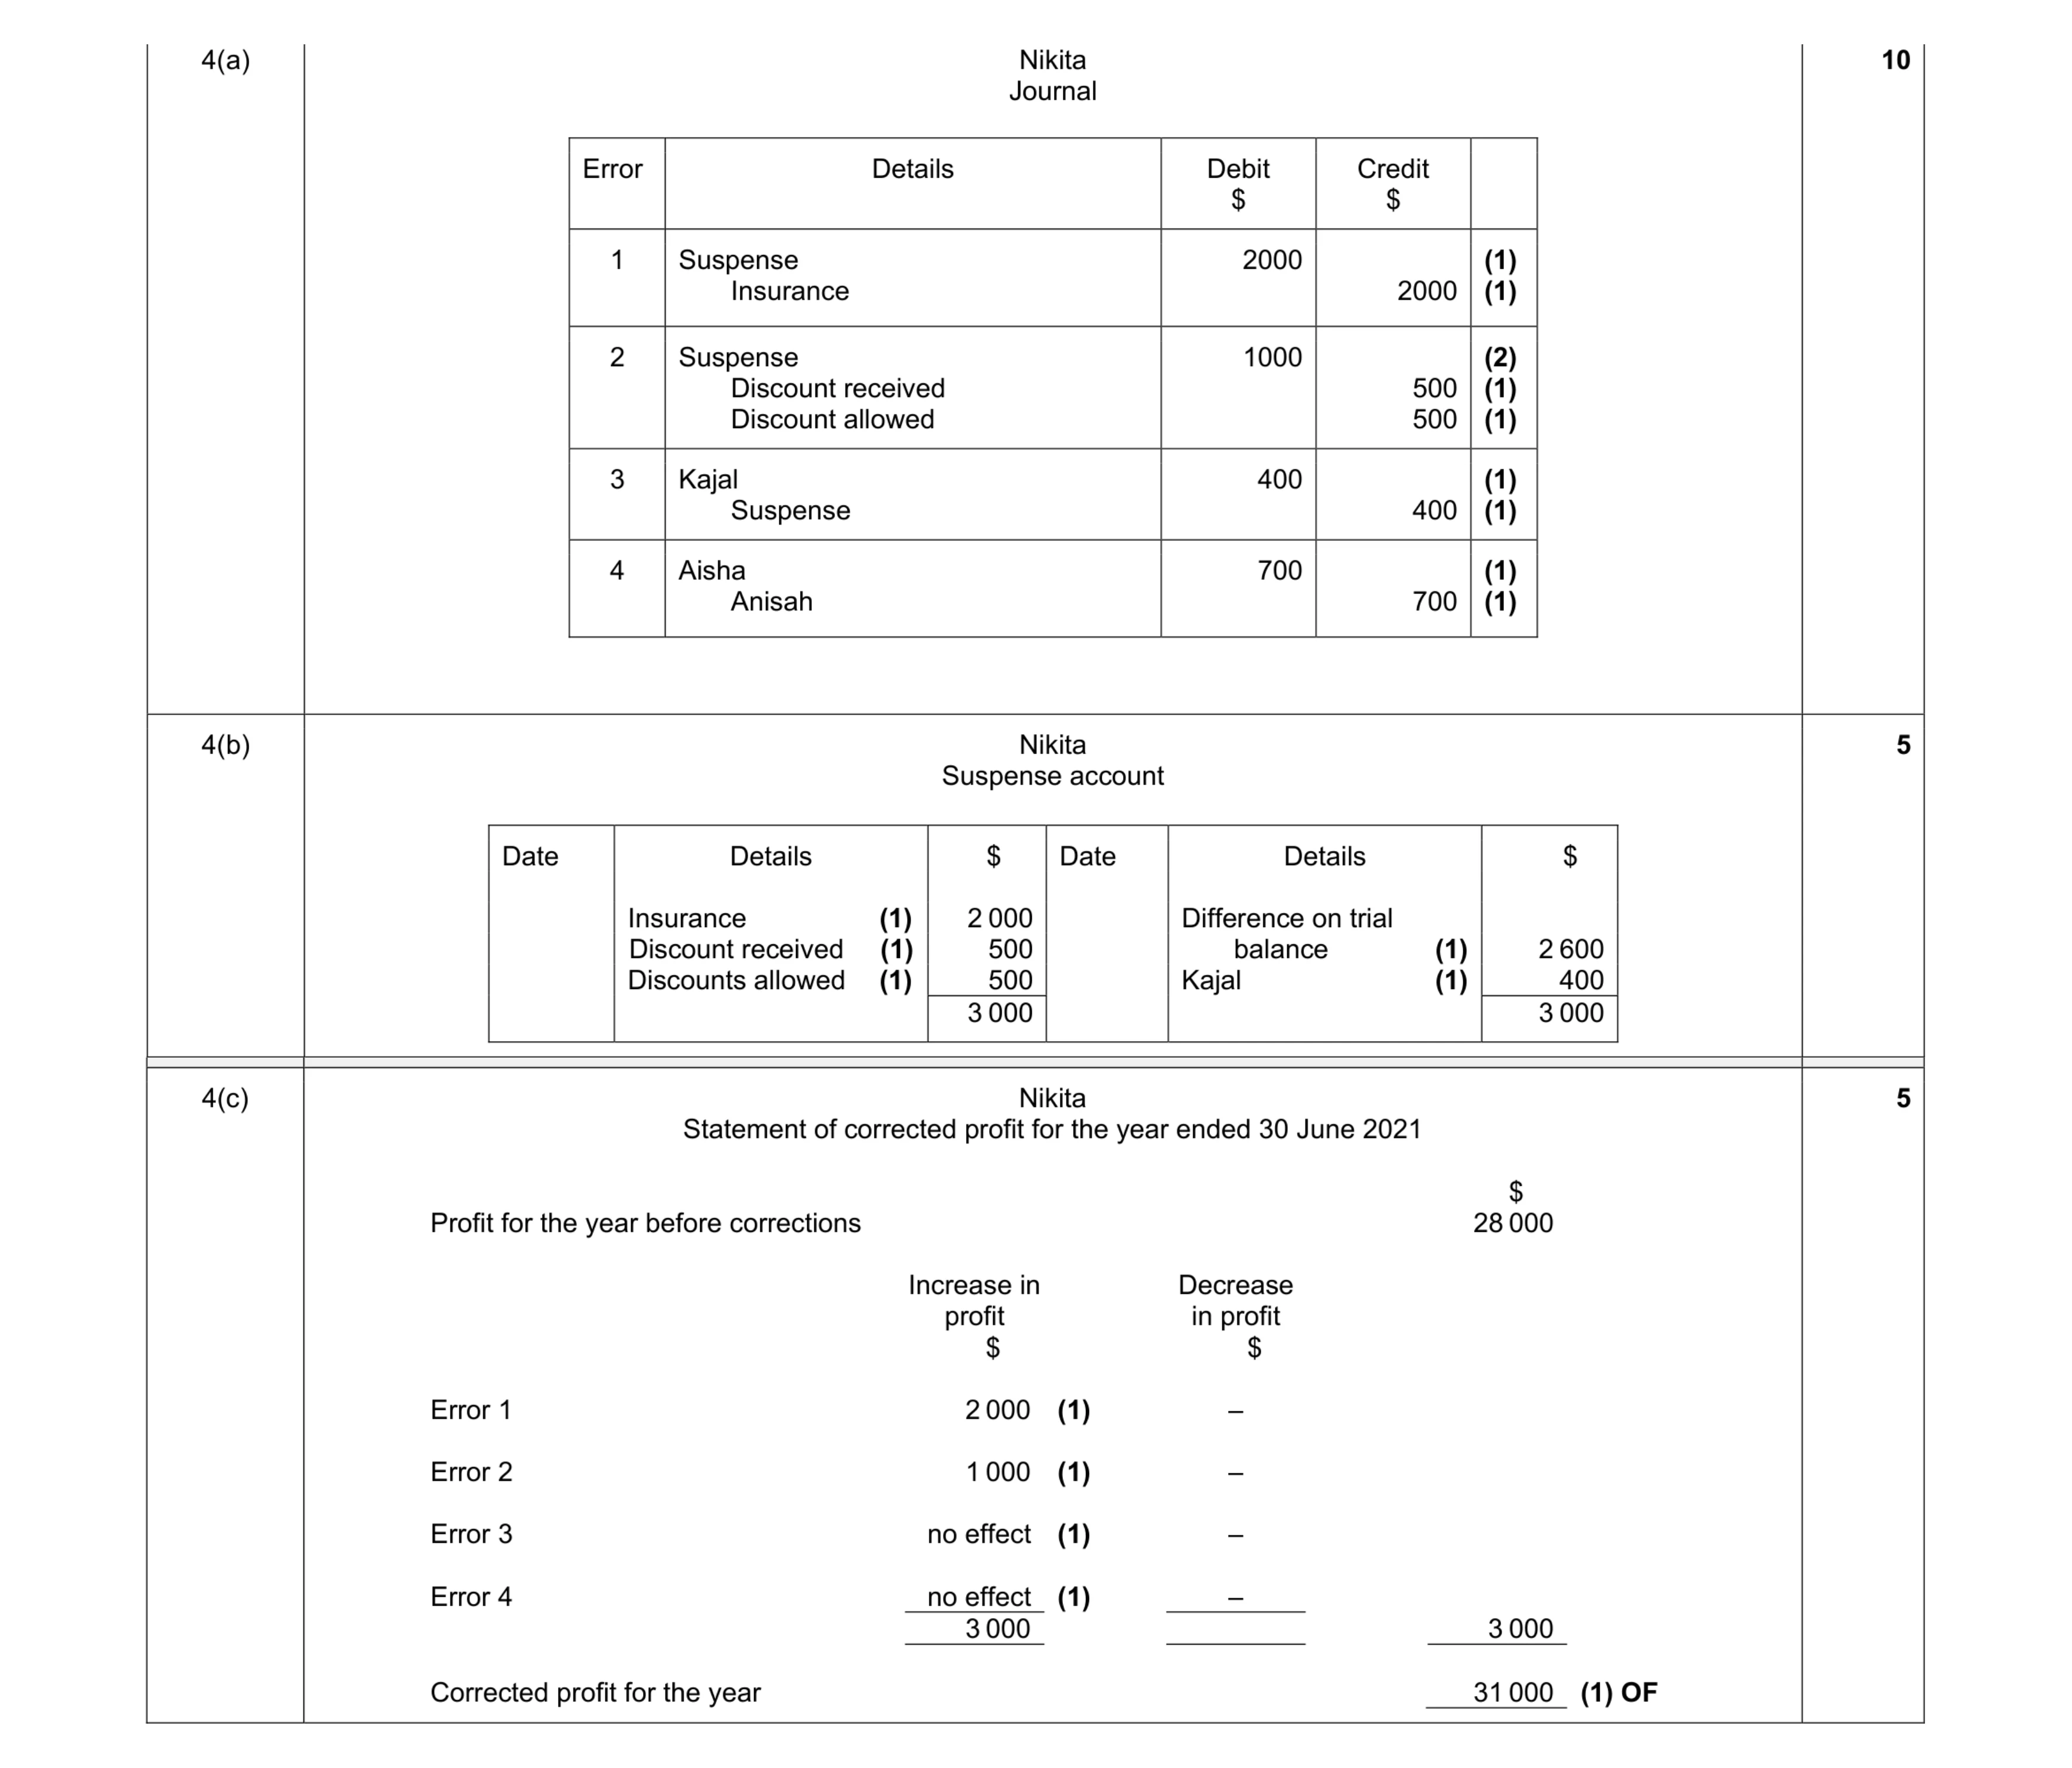
Mark scheme: 4(a) Nikita Journal Error Details Debit $ Credit $ 1 Suspense Insurance 2000 2000 (1) (1) 2 Suspense Discount received Discount allowed 1000 500 500 (2) (1) (1) 3 Kajal Suspense 400 400 (1) (1) 4 Aisha Anisah 700 700 (1) (1) 10 4(b) Nikita Suspense account Date Details $ Date Details $ Insurance (1) 2 000 Difference on trial Discount received (1) 500 balance (1) 2 600 Discounts allowed (1) 500 Kajal (1) 400 3 000 3 000 5 Question Answer Marks 4(c) Nikita Statement of corrected profit for the year ended 30 June 2021 $ Profit for the year before corrections 28 000 Increase in profit Decrease in profit $ $ Error 1 2 000 (1) – Error 2 1 000 (1) – Error 3 no effect (1) – Error 4 no effect (1) – 3 000 3 000 Corrected profit for the year 31 000 (1) OF 5
This question in 0985/22 Oct/Nov 2021
Q7 · The discount received total for January 2022, $38, had been debited to the discount… 0985/21 May/June 2022
4 The discount received total for January 2022, $38, had been debited to the discount received account.
0 marks
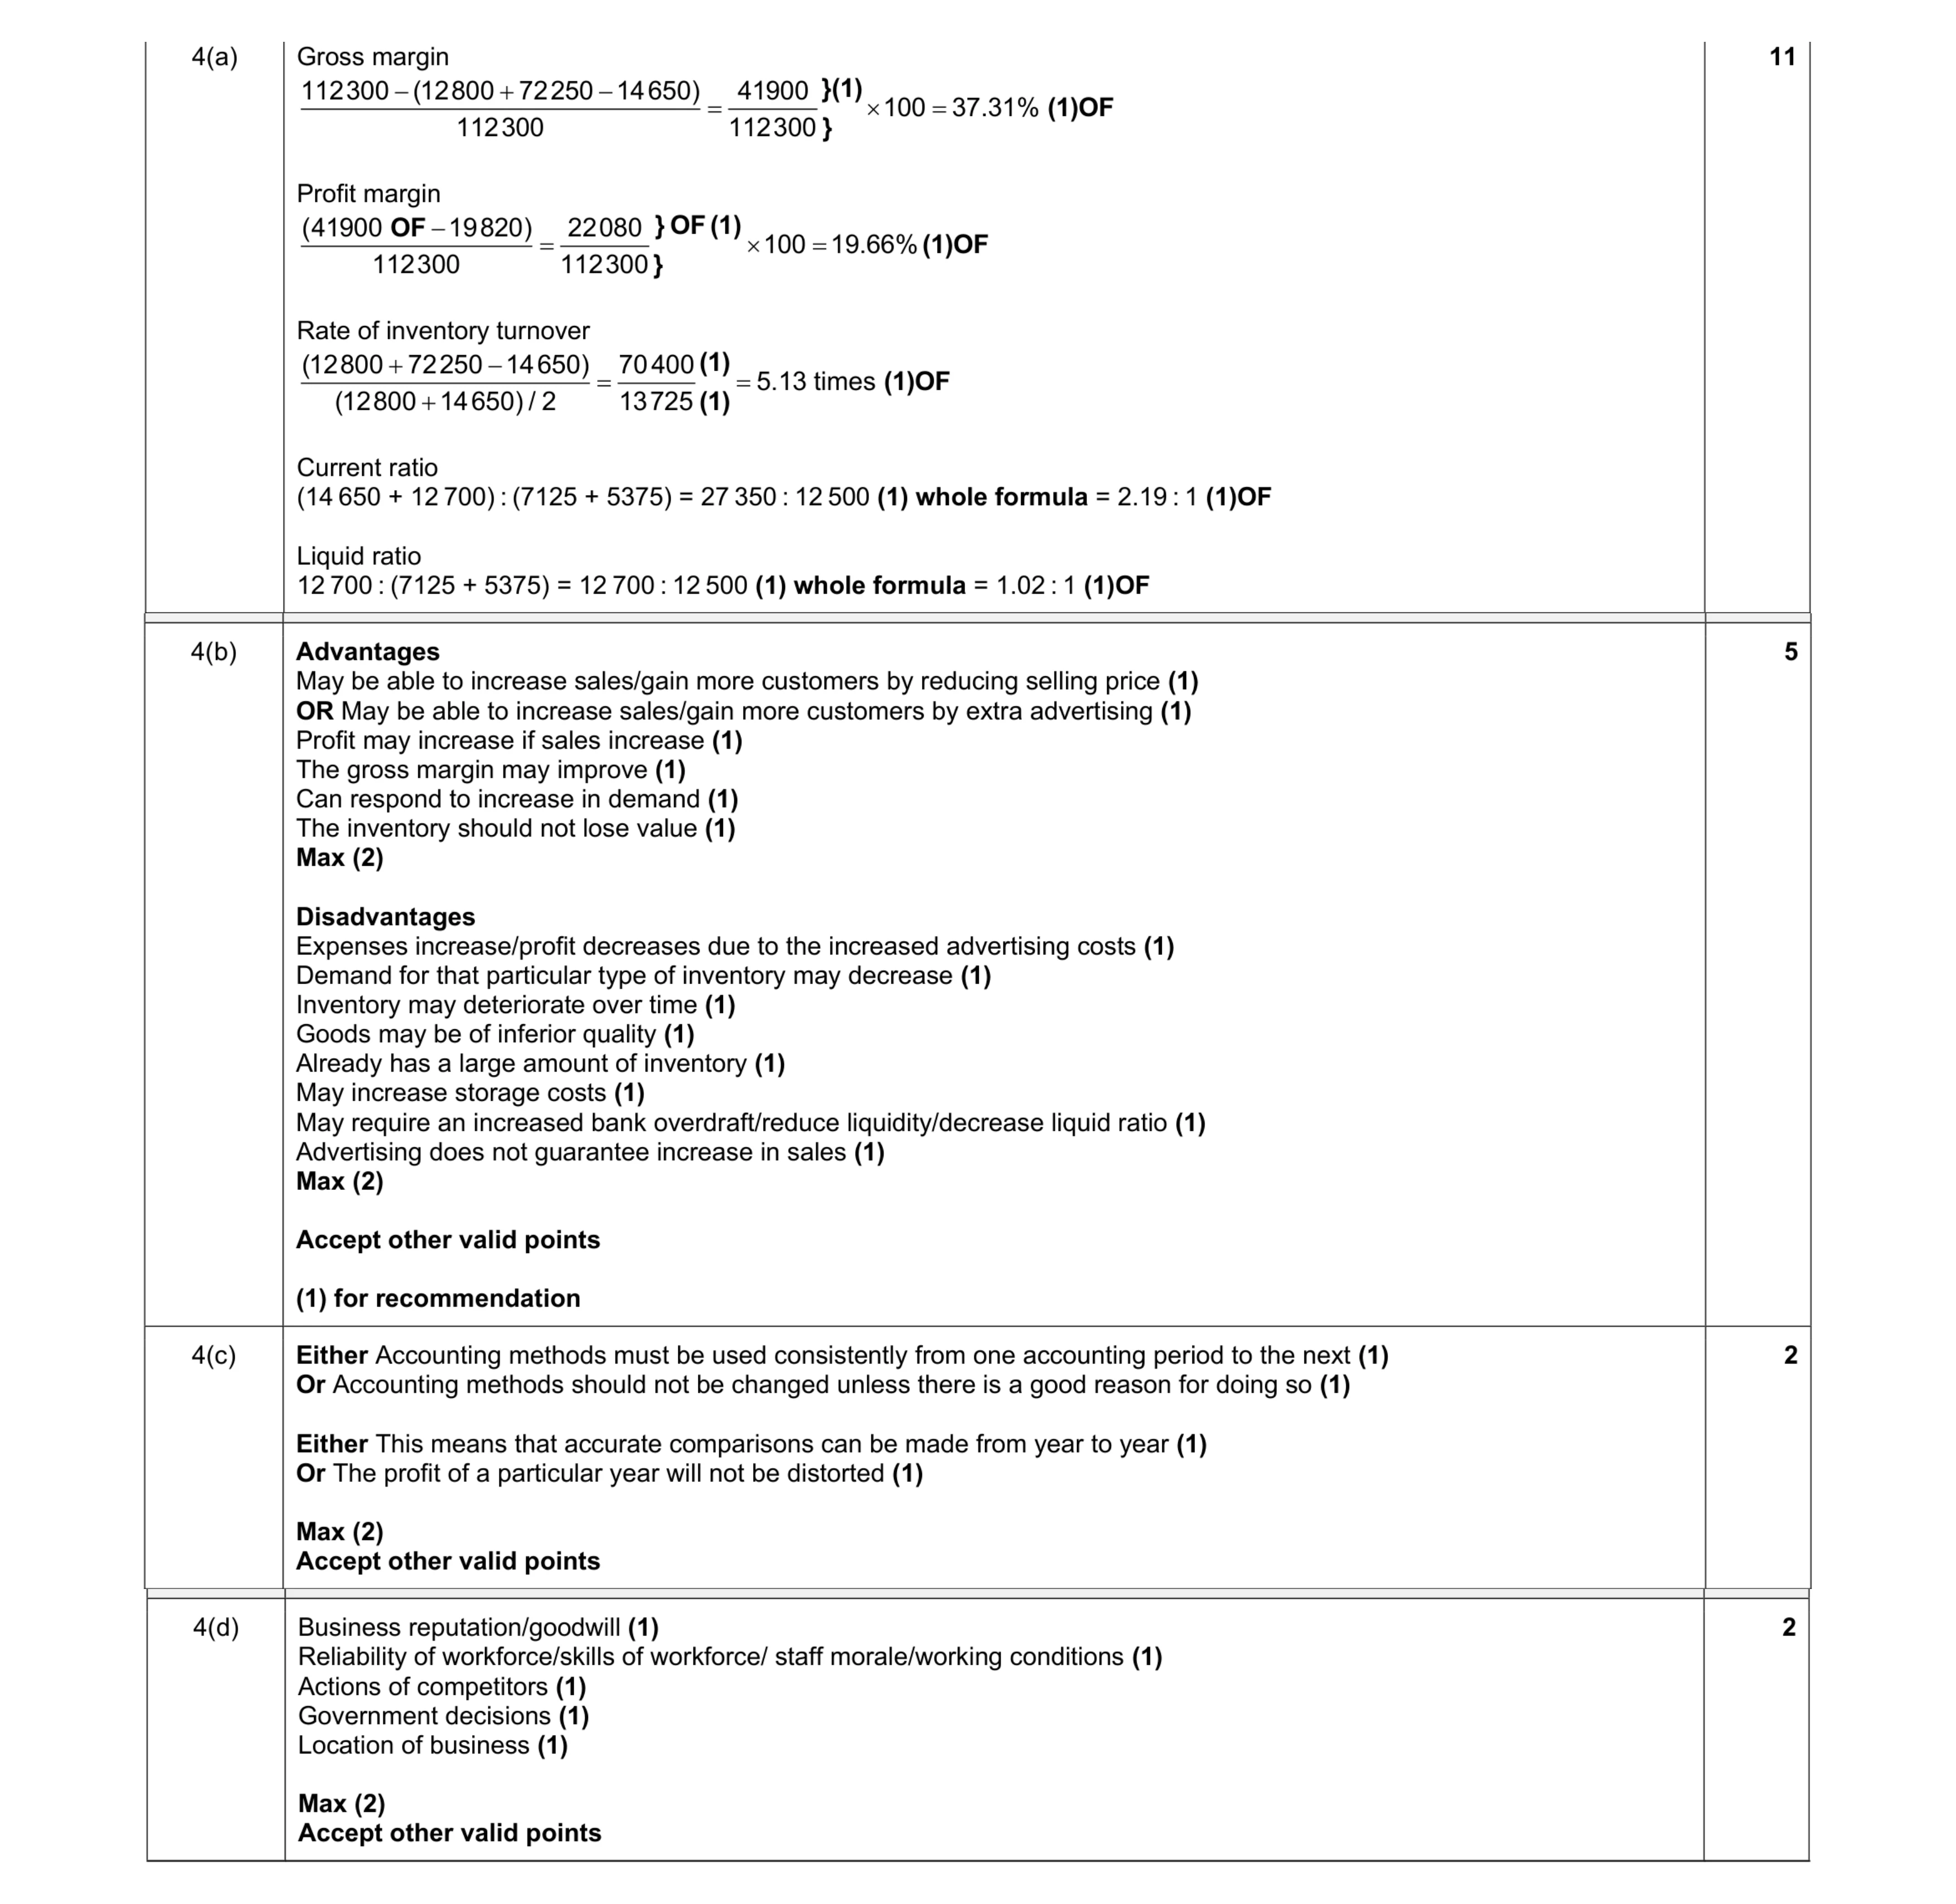
Mark scheme: 4(a) Gross margin 112300 (12800 72250 14650) 41900 100 37.31% 112300 112300 }(1) (1)OF } Profit margin (41900 19820) 22080 100 19.66% 112300 112300 } OF (1) OF (1)OF } Rate of inventory turnover (12800 72250 14650) 70400 5.13 times (12800 14650) / 2 13725 (1) (1)OF (1) Current ratio (14 650 + 12 700) : (7125 + 5375) = 27 350 : 12 500 (1) whole formula = 2.19 : 1 (1)OF Liquid ratio 12 700 : (7125 + 5375) = 12 700 : 12 500 (1) whole formula = 1.02 : 1 (1)OF Question Answer Marks 4(b) Advantages May be able to increase sales/gain more customers by reducing selling price (1) OR May be able to increase sales/gain more customers by extra advertising (1) Profit may increase if sales increase (1) The gross margin may improve (1) Can respond to increase in demand (1) The inventory should not lose value (1) Max (2) Disadvantages Expenses increase/profit decreases due to the increased advertising costs (1) Demand for that particular type of inventory may decrease (1) Inventory may deteriorate over time (1) Goods may be of inferior quality (1) Already has a large amount of inventory (1) May increase storage costs (1) May require an increased bank overdraft/reduce liquidity/decrease liquid ratio (1) Advertising does not guarantee increase in sales (1) Max (2) Accept other valid points (1) for recommendation 5 4(c) Either Accounting methods must be used consistently from one accounting period to the next (1) Or Accounting methods should not be changed unless there is a good reason for doing so (1) Either This means that accurate comparisons can be made from year to year (1) Or The profit of a particular year will not be distorted (1) Max (2) Accept other valid points 2 Question Answer Marks 4(d) Business reputation/goodwill (1) Reliability of workforce/skills of workforce/ staff morale/working conditions (1) Actions of competitors (1) Government decisions (1) Location of business (1) Max (2) Accept other valid points 2
This question in 0985/21 May/June 2022
Q8 · The account for rent and the account for commission receivable had both been overcast by… 0985/21 May/June 2022
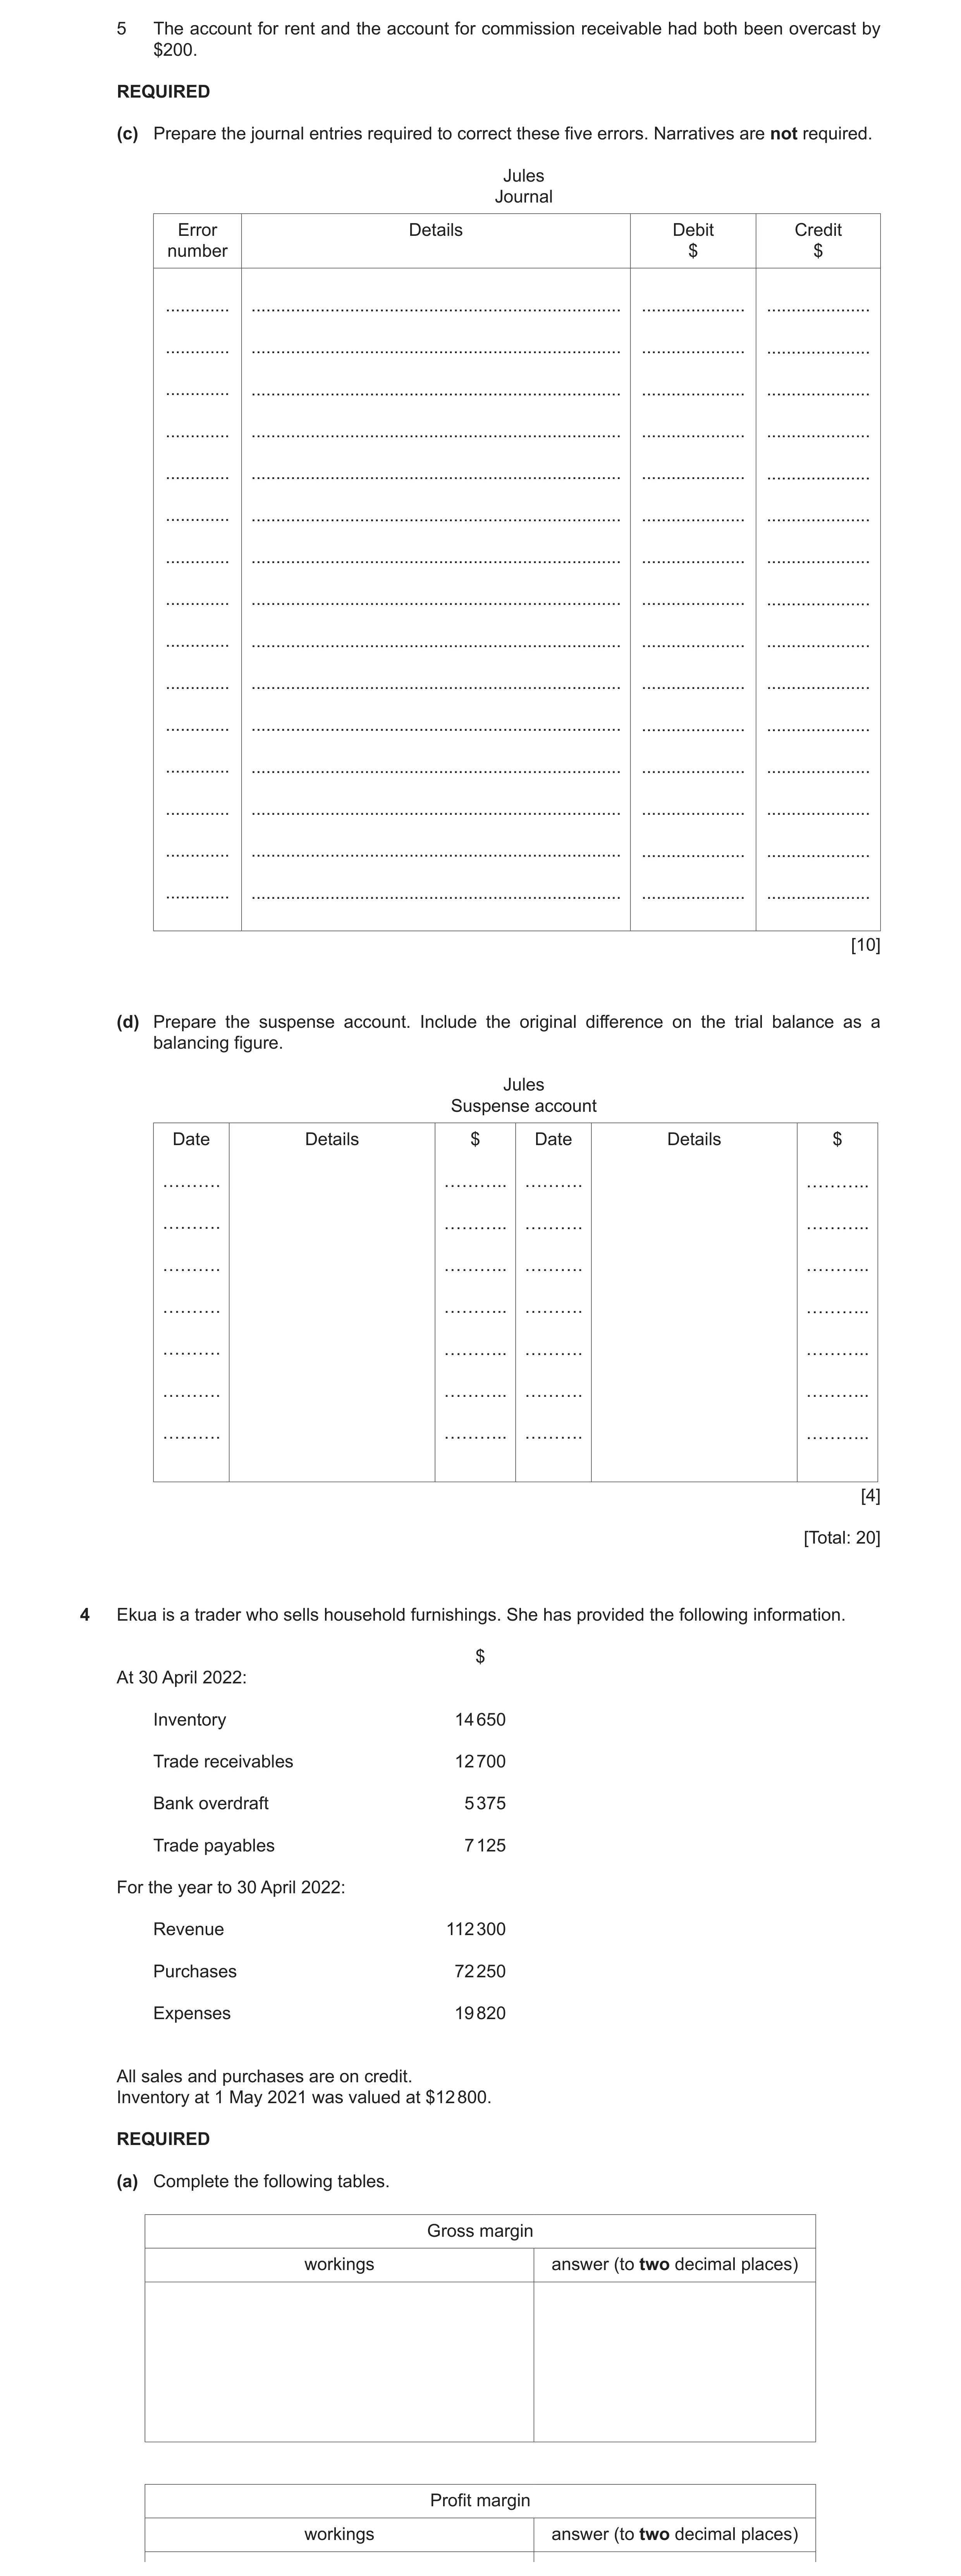
5 The account for rent and the account for commission receivable had both been overcast by $200. REQUIRED (c) Prepare the journal entries required to correct these five errors. Narratives are not required. Jules Journal Error Details Debit Credit number $ $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [10] (d) Prepare the suspense account. Include the original difference on the trial balance as a balancing figure. Jules Suspense account Date Details $ Date Details $ ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. [4] [Total: 20] 4 Ekua is a trader who sells household furnishings. She has provided the following information. $ At 30 April 2022: Inventory 14 650 Trade receivables 12 700 Bank overdraft 5 375 Trade payables 7 125 For the year to 30 April 2022: Revenue 112 300 Purchases 72 250 Expenses 19 820 All sales and purchases are on credit. Inventory at 1 May 2021 was valued at $12 800. REQUIRED (a) Complete the following tables. Gross margin workings answer (to two decimal places) Profit margin workings answer (to two decimal places)
14 marks
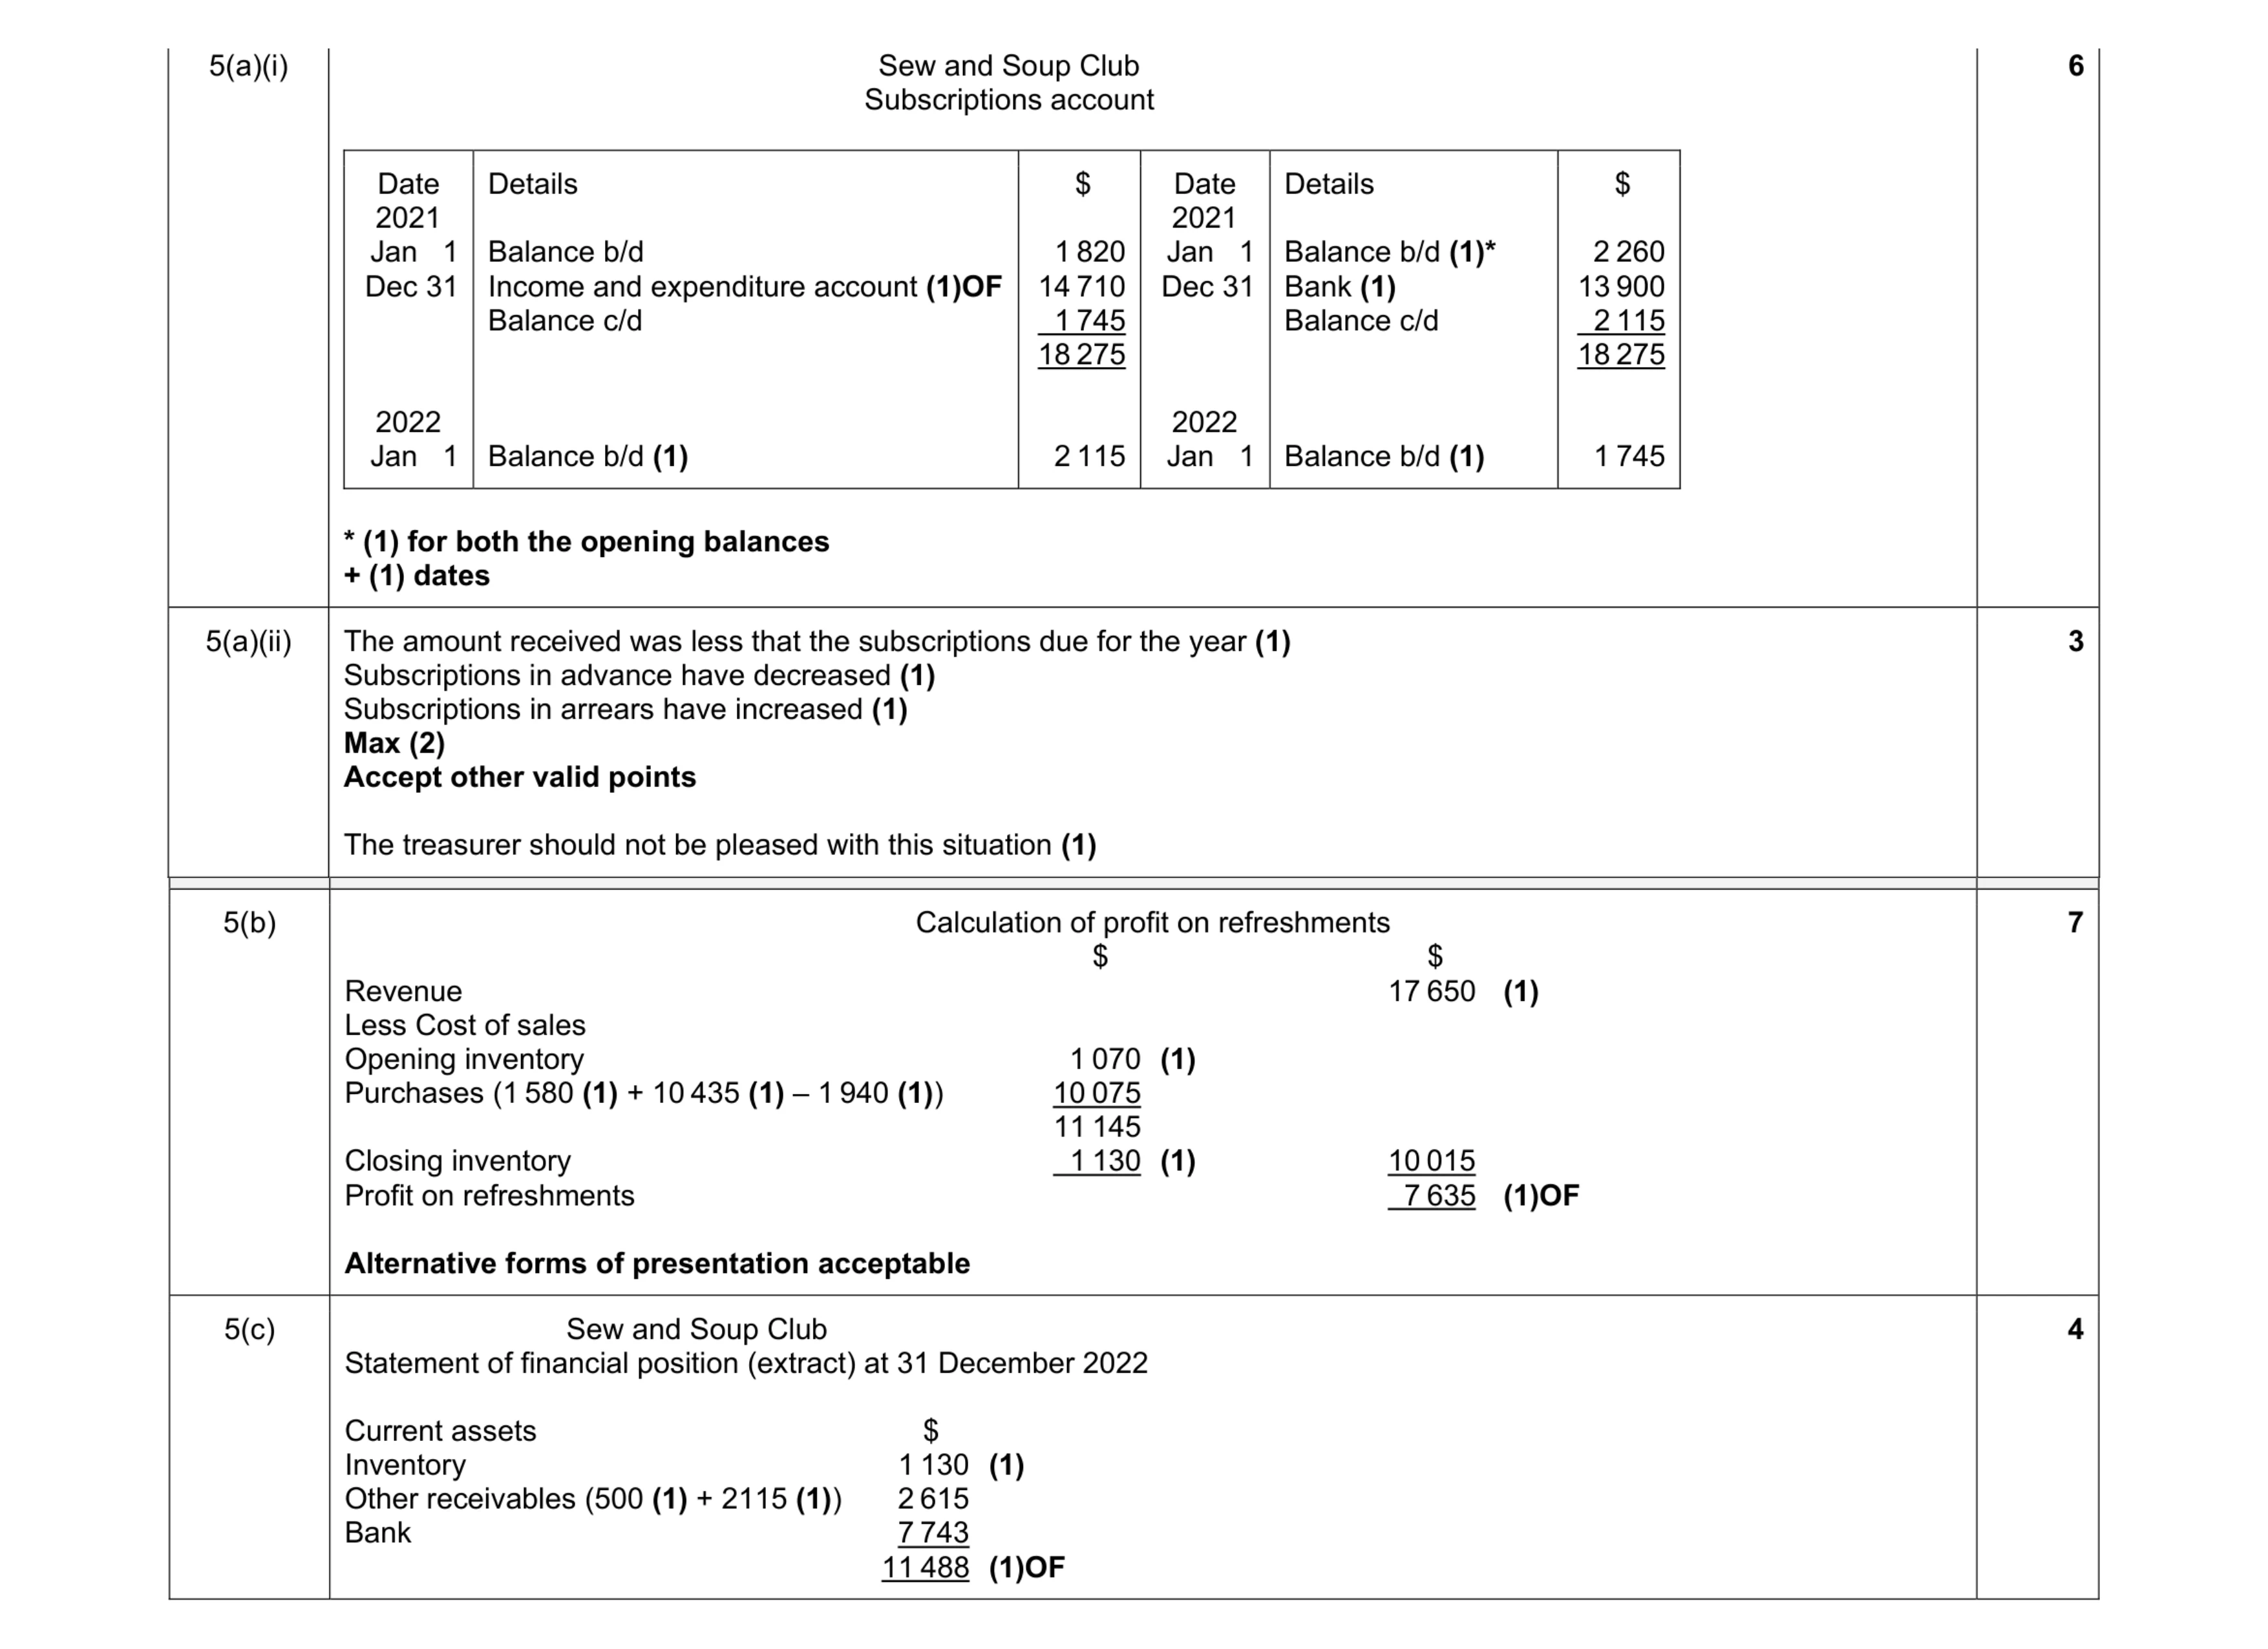
Mark scheme: 5(a)(i) Sew and Soup Club Subscriptions account Date 2021 Jan 1 Dec 31 2022 Jan 1 Details Balance b/d Income and expenditure account (1)OF Balance c/d Balance b/d (1) $ 1 820 14 710 1 745 18 275 2 115 Date 2021 Jan 1 Dec 31 2022 Jan 1 Details Balance b/d (1)* Bank (1) Balance c/d Balance b/d (1) $ 2 260 13 900 2 115 18 275 1 745 * (1) for both the opening balances + (1) dates 5(a)(ii) The amount received was less that the subscriptions due for the year (1) Subscriptions in advance have decreased (1) Subscriptions in arrears have increased (1) Max (2) Accept other valid points The treasurer should not be pleased with this situation (1) 3 Question Answer Marks 5(b) Calculation of profit on refreshments $ $ Revenue 17 650 (1) Less Cost of sales Opening inventory 1 070 (1) Purchases (1 580 (1) + 10 435 (1) – 1 940 (1)) 10 075 11 145 Closing inventory 1 130 (1) 10 015 Profit on refreshments 7 635 (1)OF Alternative forms of presentation acceptable 7 5(c) Sew and Soup Club Statement of financial position (extract) at 31 December 2022 Current assets $ Inventory 1 130 (1) Other receivables (500 (1) + 2115 (1)) 2 615 Bank 7 743 11 488 (1)OF 4
This question in 0985/21 May/June 2022
Q9 · Mosi is a trader 0985/22 May/June 2022
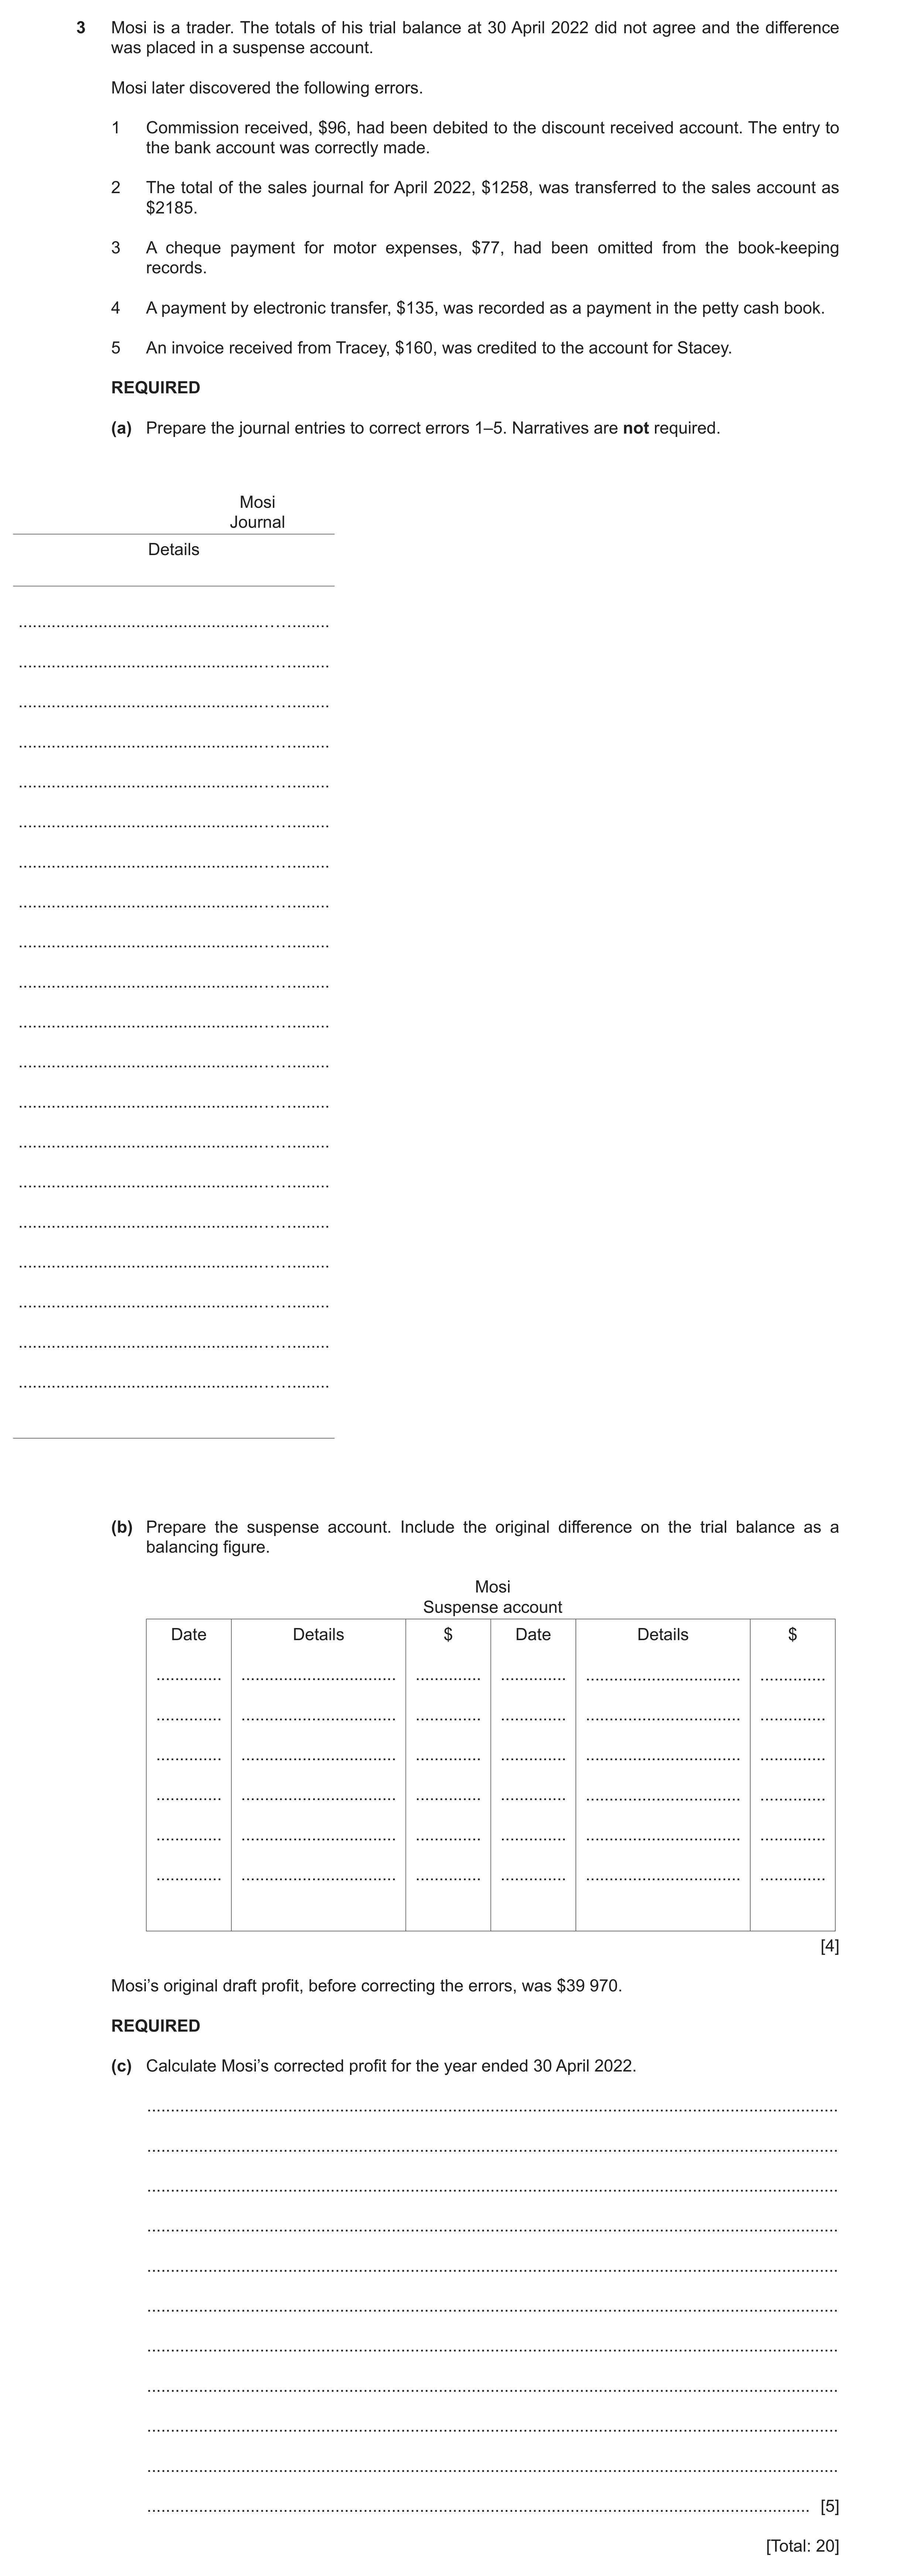
3 Mosi is a trader. The totals of his trial balance at 30 April 2022 did not agree and the difference was placed in a suspense account. Mosi later discovered the following errors. 1 Commission received, $96, had been debited to the discount received account. The entry to the bank account was correctly made. 2 The total of the sales journal for April 2022, $1258, was transferred to the sales account as $2185. 3 A cheque payment for motor expenses, $77, had been omitted from the book-keeping records. 4 A payment by electronic transfer, $135, was recorded as a payment in the petty cash book. 5 An invoice received from Tracey, $160, was credited to the account for Stacey. REQUIRED (a) Prepare the journal entries to correct errors 1–5. Narratives are not required. Mosi Journal Details … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … … …… … (b) Prepare the suspense account. Include the original difference on the trial balance as a balancing figure. Mosi Suspense account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [4] Mosi’s original draft profit, before correcting the errors, was $39 970. REQUIRED (c) Calculate Mosi’s corrected profit for the year ended 30 April 2022. … … … … … … … … … … … [5] [Total: 20]
20 marks
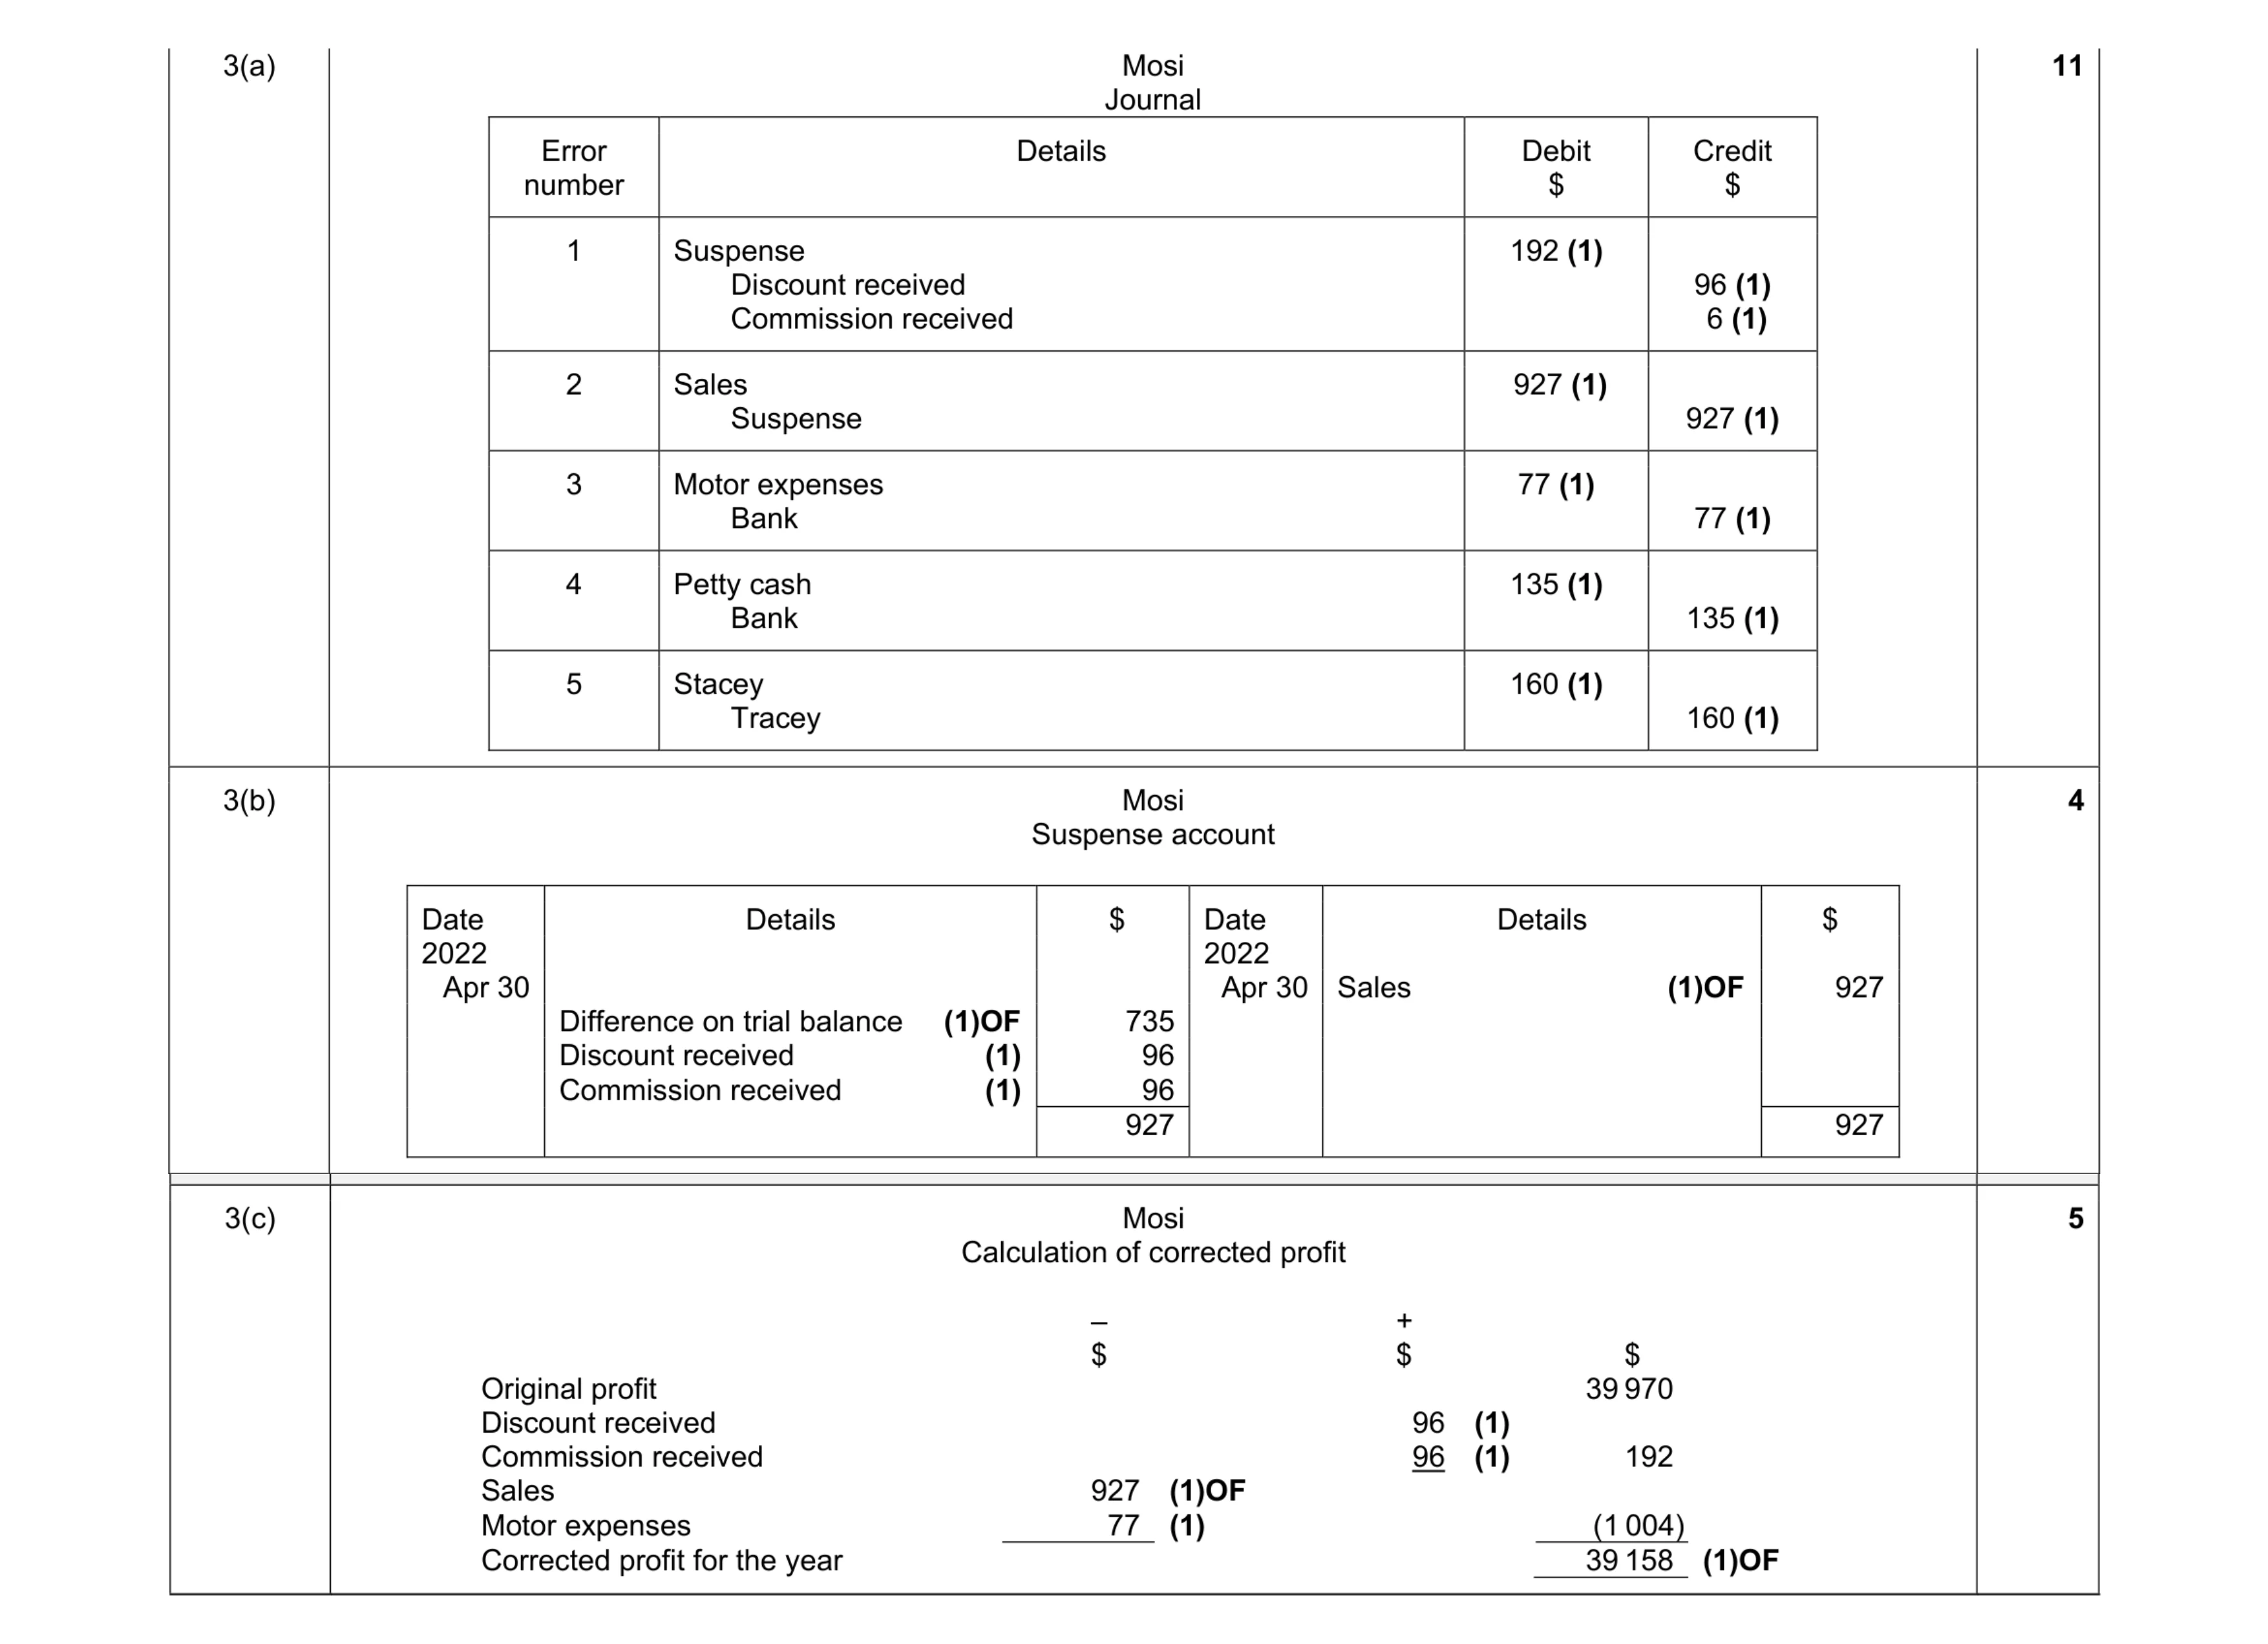
Mark scheme: 3(a) Mosi Journal Error number Details Debit $ Credit $ 1 Suspense Discount received Commission received 192 (1) 96 (1) 6 (1) 2 Sales Suspense 927 (1) 927 (1) 3 Motor expenses Bank 77 (1) 77 (1) 4 Petty cash Bank 135 (1) 135 (1) 5 Stacey Tracey 160 (1) 160 (1) 11 3(b) Mosi Suspense account Date Details $ Date Details $ 2022 2022 Apr 30 Apr 30 Sales (1)OF 927 Difference on trial balance (1)OF 735 Discount received (1) 96 Commission received (1) 96 927 927 4 Question Answer Marks 3(c) Mosi Calculation of corrected profit – $ + $ $ Original profit 39 970 Discount received 96 (1) Commission received 96 (1) 192 Sales 927 (1)OF Motor expenses 77 (1) (1 004) Corrected profit for the year 39 158 (1)OF 5
This question in 0985/22 May/June 2022
Q10 · Nala is a trader who buys and sells stationery 0985/22 May/June 2022
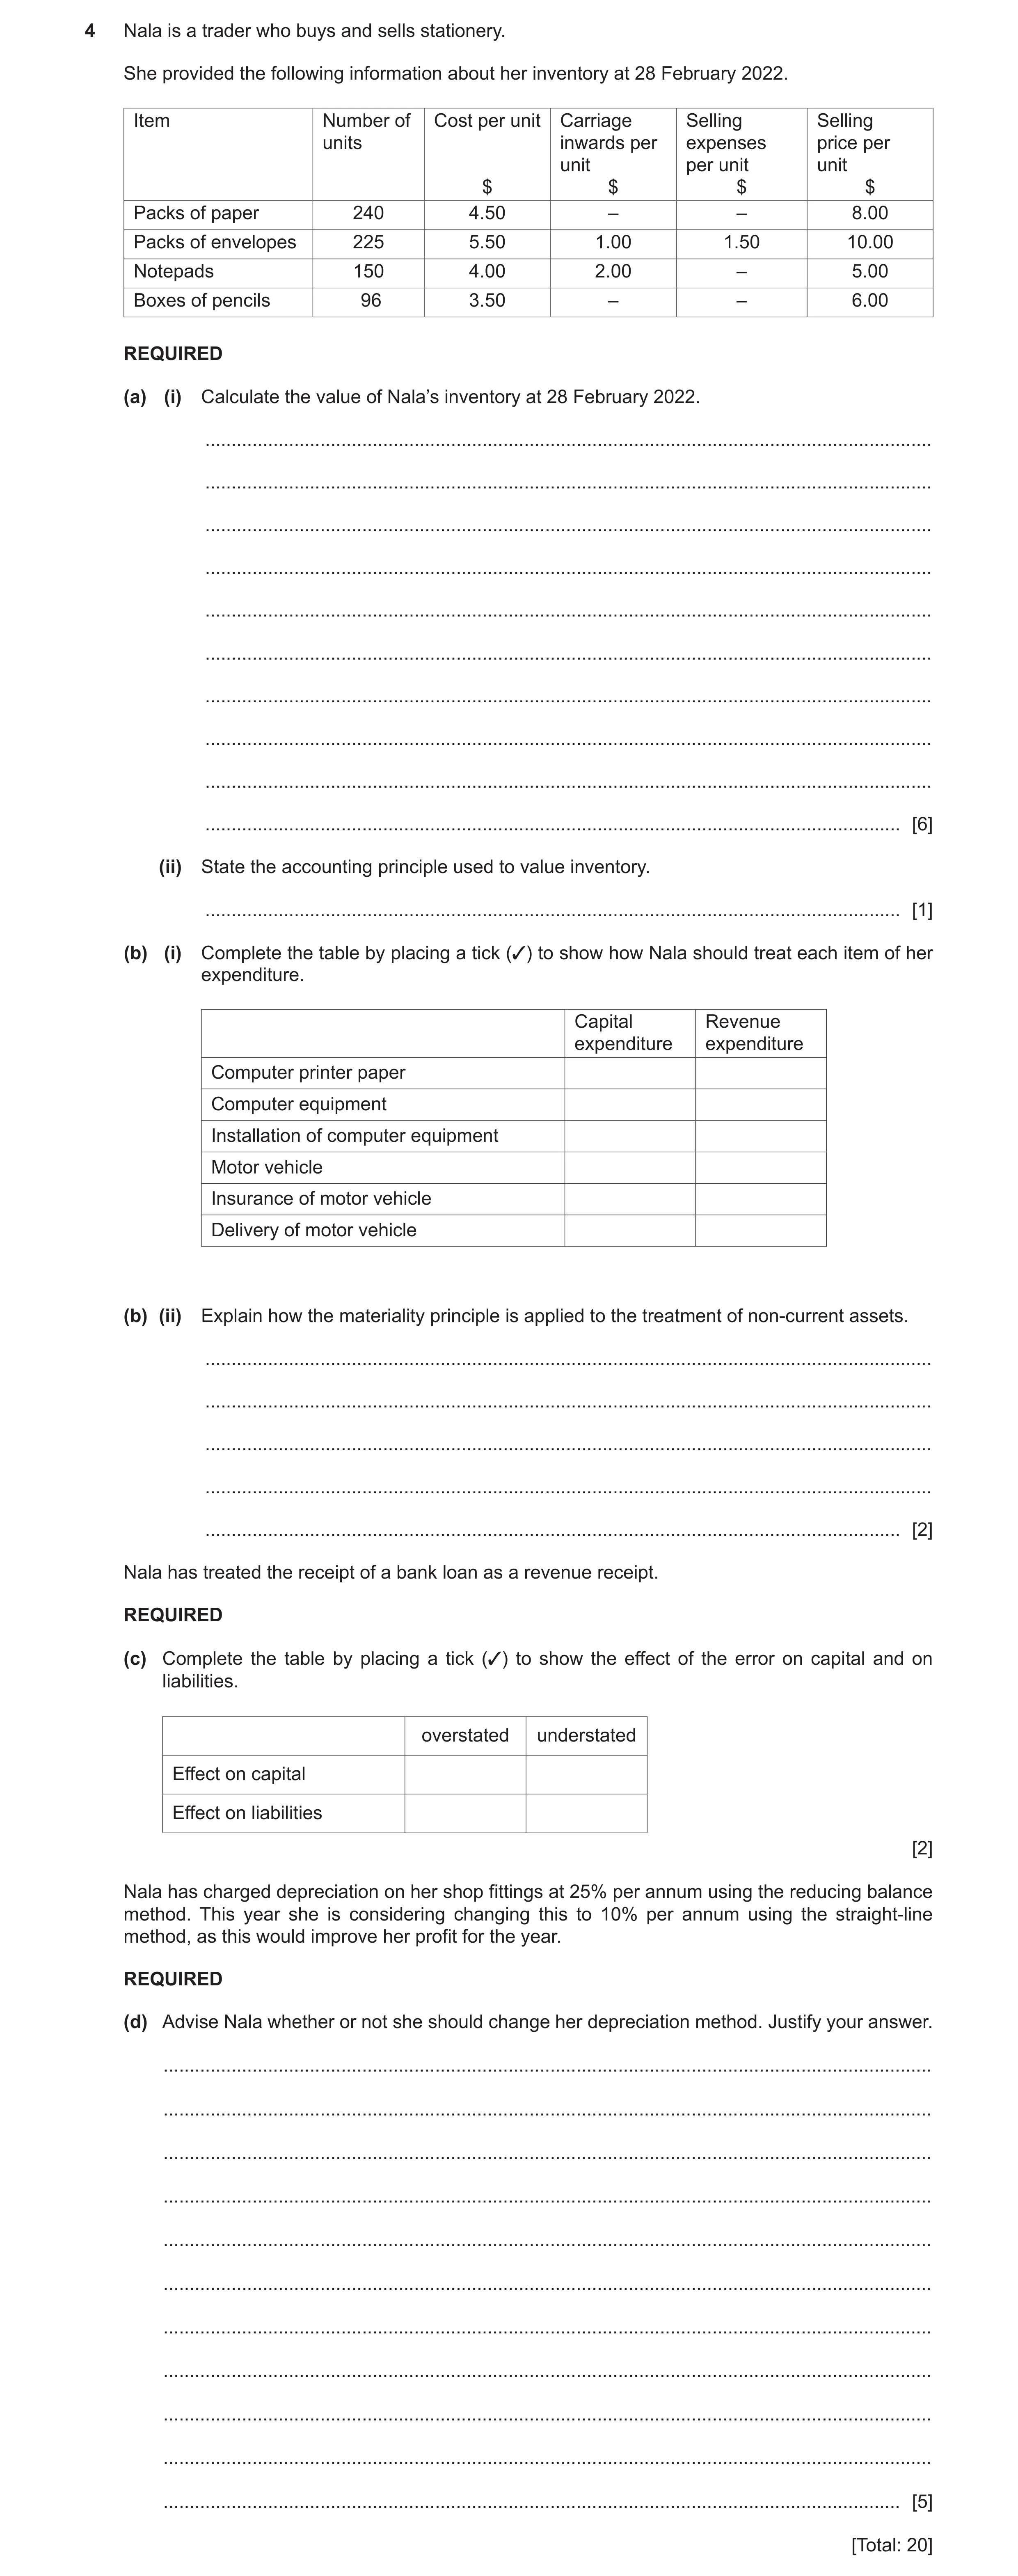
4 Nala is a trader who buys and sells stationery. She provided the following information about her inventory at 28 February 2022. Item Number of Cost per unit Carriage Selling Selling units inwards per expenses price per unit per unit unit $ $ $ $ Packs of paper 240 4.50 – – 8.00 Packs of envelopes 225 5.50 1.00 1.50 10.00 Notepads 150 4.00 2.00 – 5.00 Boxes of pencils 96 3.50 – – 6.00 REQUIRED (a) (i) Calculate the value of Nala’s inventory at 28 February 2022. … … … … … … … … … … [6] (ii) State the accounting principle used to value inventory. … [1] (b) (i) Complete the table by placing a tick (✓) to show how Nala should treat each item of her expenditure. Capital Revenue expenditure expenditure Computer printer paper Computer equipment Installation of computer equipment Motor vehicle Insurance of motor vehicle Delivery of motor vehicle (b) (ii) Explain how the materiality principle is applied to the treatment of non-current assets. … … … … … [2] Nala has treated the receipt of a bank loan as a revenue receipt. REQUIRED (c) Complete the table by placing a tick (✓) to show the effect of the error on capital and on liabilities. overstated understated Effect on capital Effect on liabilities [2] Nala has charged depreciation on her shop fittings at 25% per annum using the reducing balance method. This year she is considering changing this to 10% per annum using the straight-line method, as this would improve her profit for the year. REQUIRED (d) Advise Nala whether or not she should change her depreciation method. Justify your answer. … … … … … … … … … … … [5] [Total: 20]
20 marks
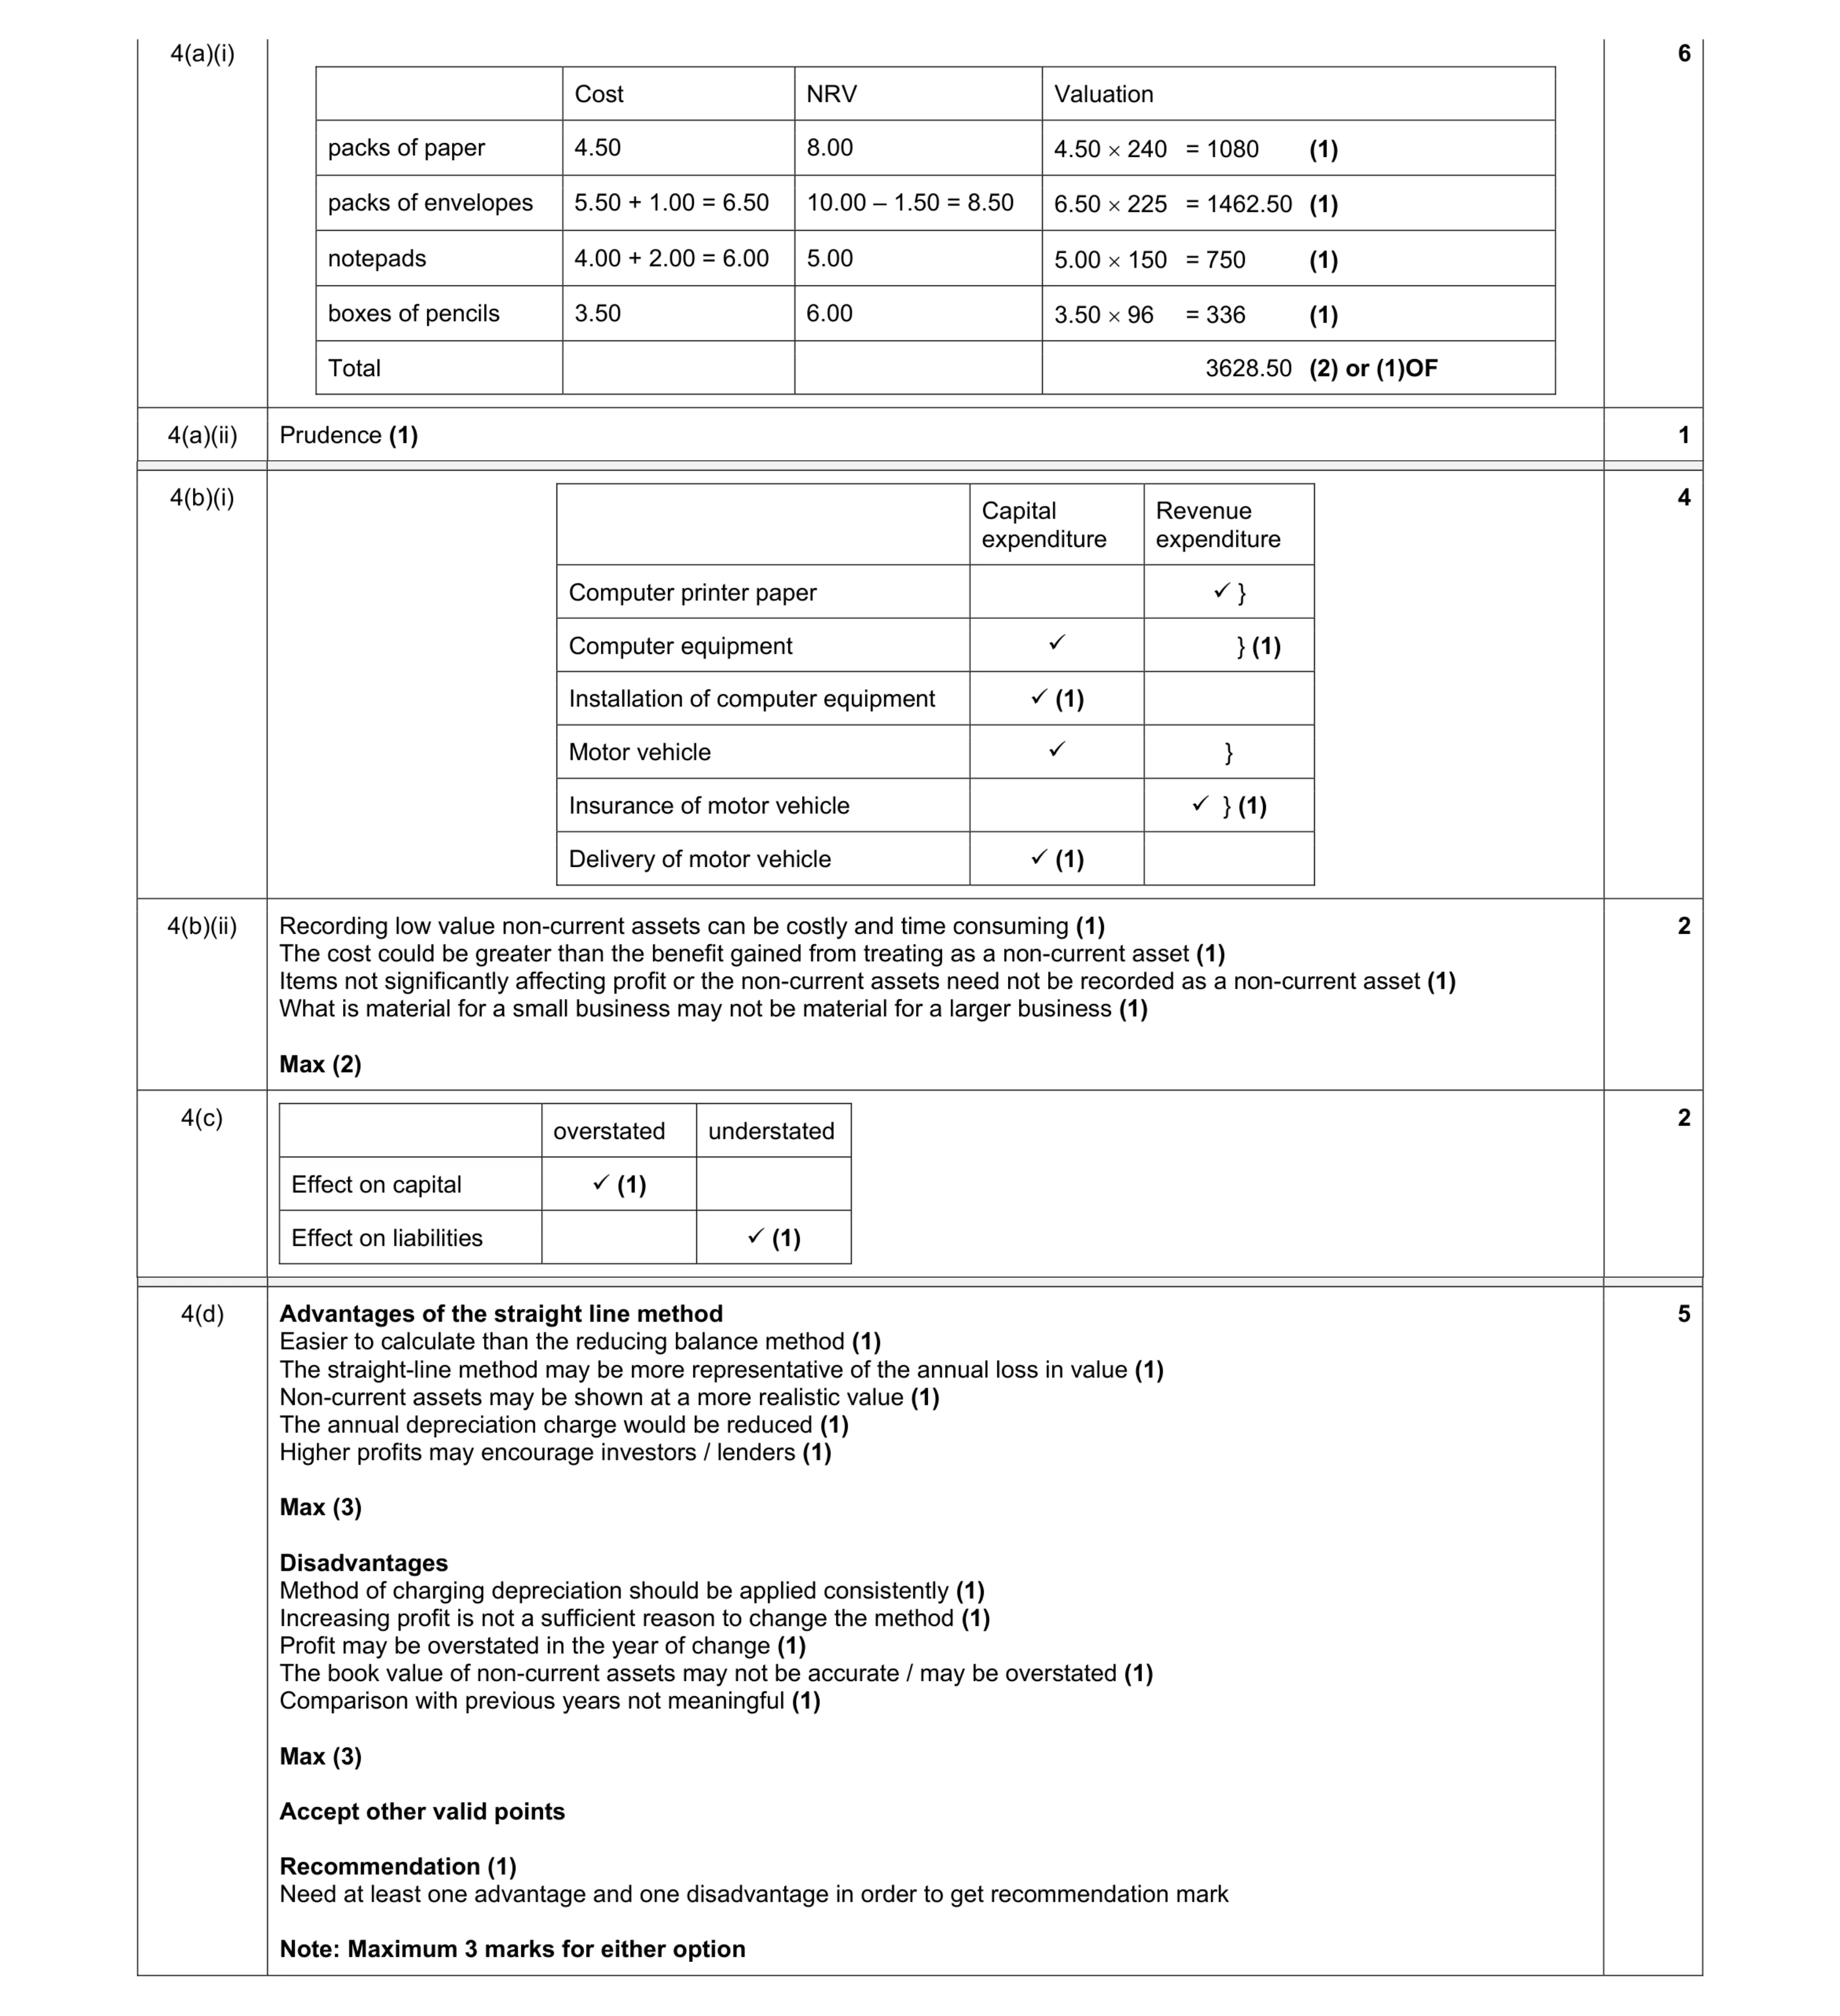
Mark scheme: 4(a)(i) Cost NRV Valuation packs of paper 4.50 8.00 4.50 240 = 1080 (1) packs of envelopes 5.50 + 1.00 = 6.50 10.00 – 1.50 = 8.50 6.50 225 = 1462.50 (1) notepads 4.00 + 2.00 = 6.00 5.00 5.00 150 = 750 (1) boxes of pencils 3.50 6.00 3.50 96 = 336 (1) Total 3628.50 (2) or (1)OF 6 4(a)(ii) Prudence (1) 1 Question Answer Marks 4(b)(i) Capital expenditure Revenue expenditure Computer printer paper } Computer equipment } (1) Installation of computer equipment (1) Motor vehicle } Insurance of motor vehicle } (1) Delivery of motor vehicle (1) 4 4(b)(ii) Recording low value non-current assets can be costly and time consuming (1) The cost could be greater than the benefit gained from treating as a non-current asset (1) Items not significantly affecting profit or the non-current assets need not be recorded as a non-current asset (1) What is material for a small business may not be material for a larger business (1) Max (2) 2 4(c) overstated understated Effect on capital (1) Effect on liabilities (1) 2 Question Answer Marks 4(d) Advantages of the straight line method Easier to calculate than the reducing balance method (1) The straight-line method may be more representative of the annual loss in value (1) Non-current assets may be shown at a more realistic value (1) The annual depreciation charge would be reduced (1) Higher profits may encourage investors / lenders (1) Max (3) Disadvantages Method of charging depreciation should be applied consistently (1) Increasing profit is not a sufficient reason to change the method (1) Profit may be overstated in the year of change (1) The book value of non-current assets may not be accurate / may be overstated (1) Comparison with previous years not meaningful (1) Max (3) Accept other valid points Recommendation (1) Need at least one advantage and one disadvantage in order to get recommendation mark Note: Maximum 3 marks for either option 5
This question in 0985/22 May/June 2022
Q11 · Eshe is a trader 0985/21 May/June 2023
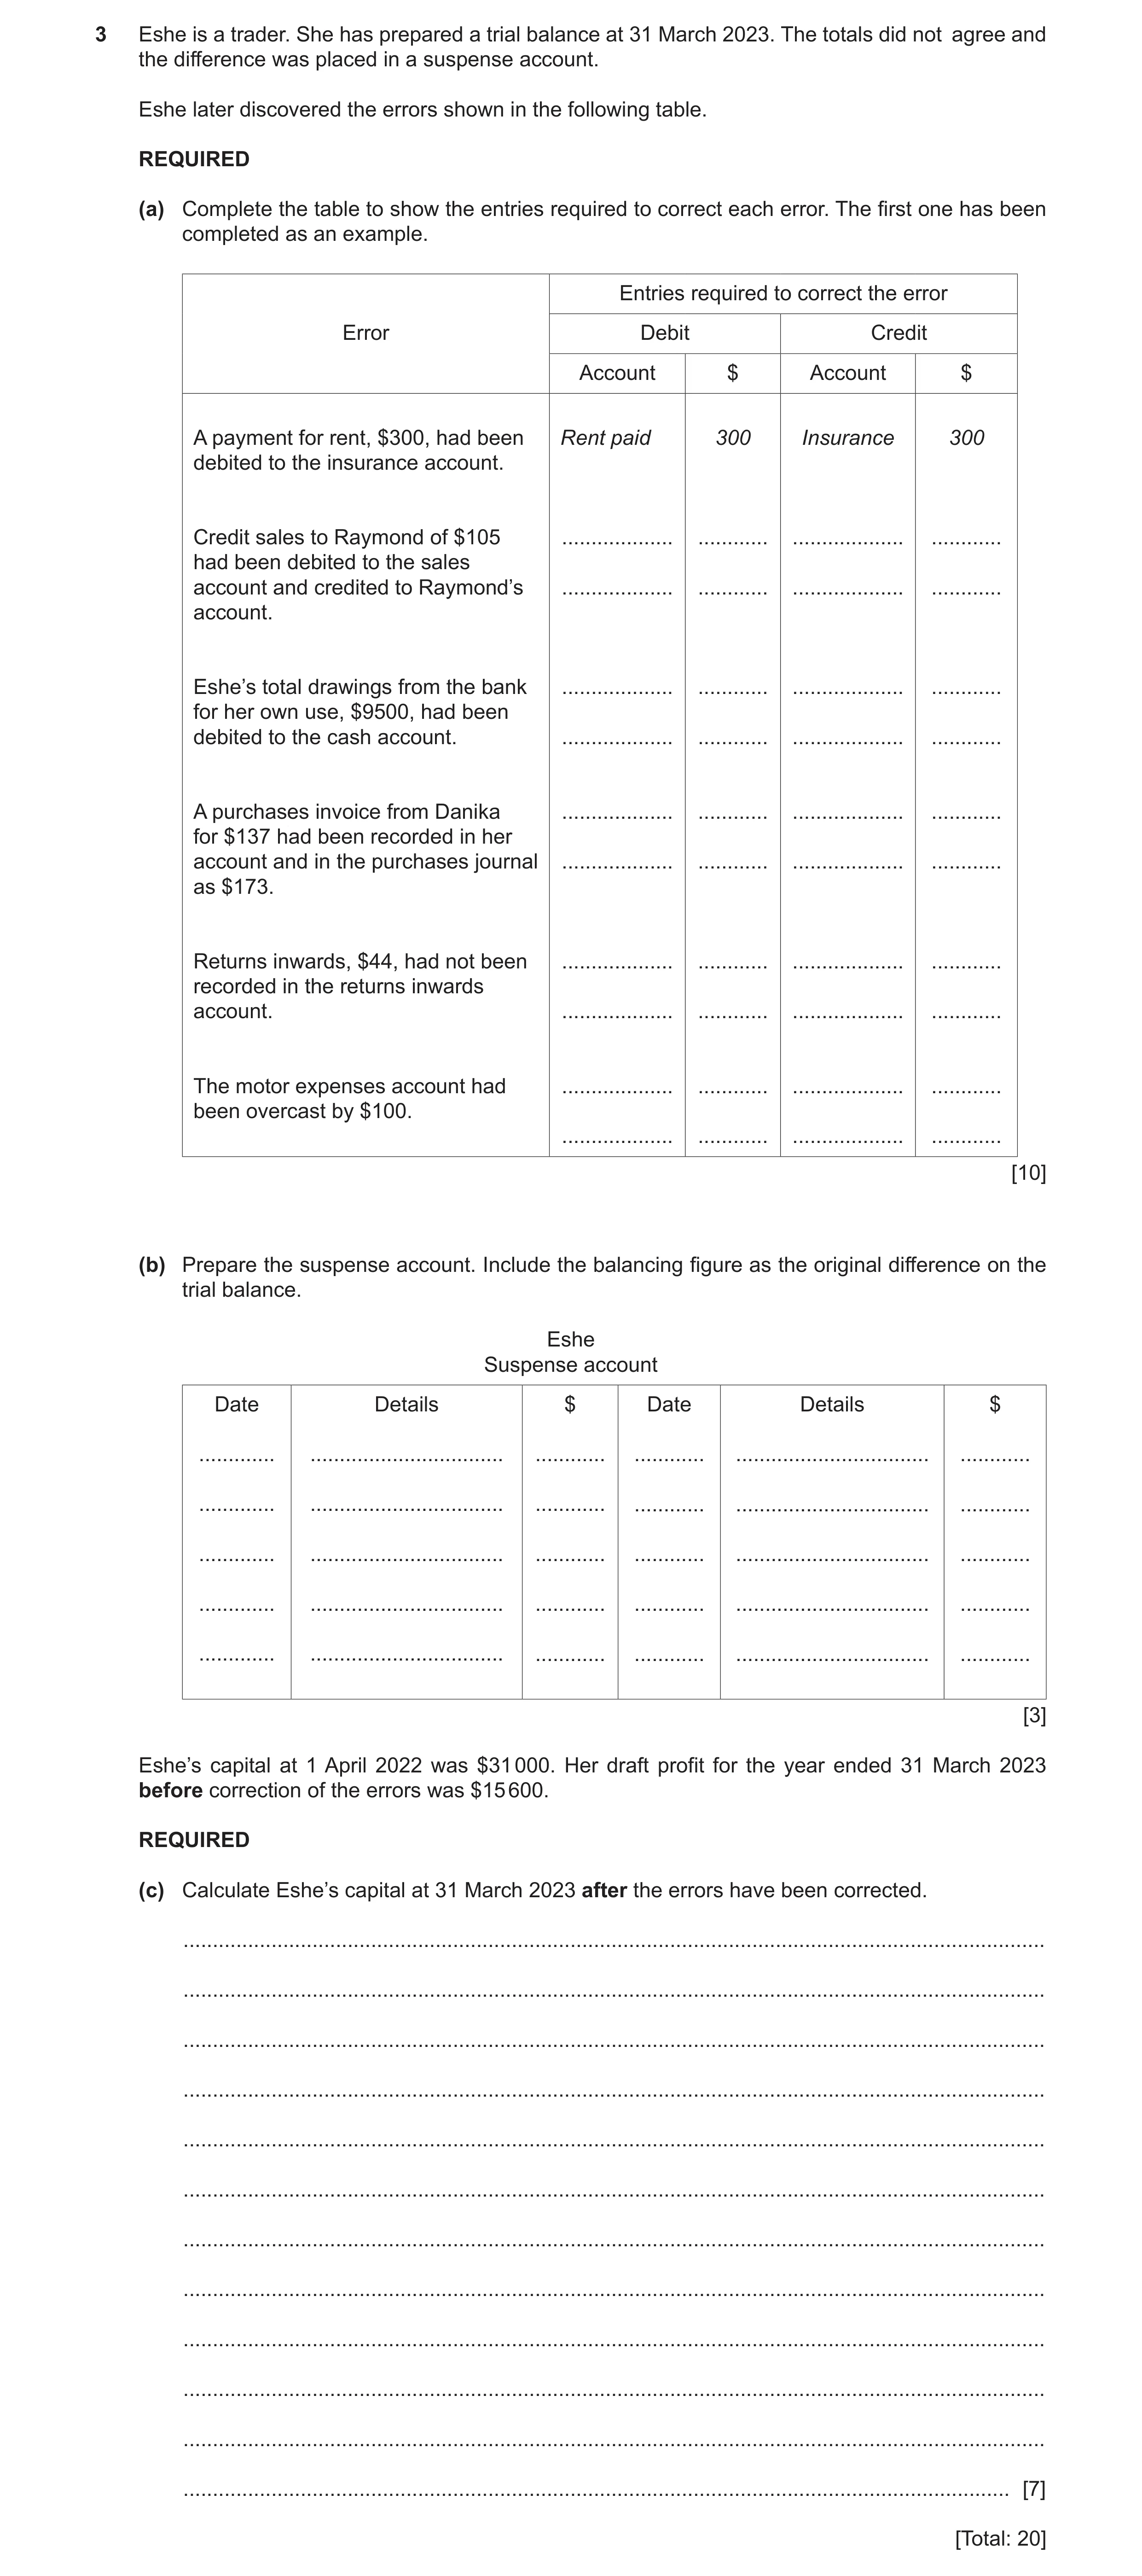
3 Eshe is a trader. She has prepared a trial balance at 31 March 2023. The totals did not agree and the difference was placed in a suspense account. Eshe later discovered the errors shown in the following table. REQUIRED (a) Complete the table to show the entries required to correct each error. The first one has been completed as an example. Entries required to correct the error Error Debit Credit Account $ Account $ A payment for rent, $300, had been Rent paid 300 Insurance 300 debited to the insurance account. Credit sales to Raymond of $105 … … … … had been debited to the sales account and credited to Raymond’s … … … … account. Eshe’s total drawings from the bank … … … … for her own use, $9500, had been debited to the cash account. … … … … A purchases invoice from Danika … … … … for $137 had been recorded in her account and in the purchases journal … … … … as $173. Returns inwards, $44, had not been … … … … recorded in the returns inwards account. … … … … The motor expenses account had … … … … been overcast by $100. … … … … [10] (b) Prepare the suspense account. Include the balancing figure as the original difference on the trial balance. Eshe Suspense account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [3] Eshe’s capital at 1 April 2022 was $31 000. Her draft profit for the year ended 31 March 2023 before correction of the errors was $15 600. REQUIRED (c) Calculate Eshe’s capital at 31 March 2023 after the errors have been corrected. … … … … … … … … … … … … [7] [Total: 20]
20 marks
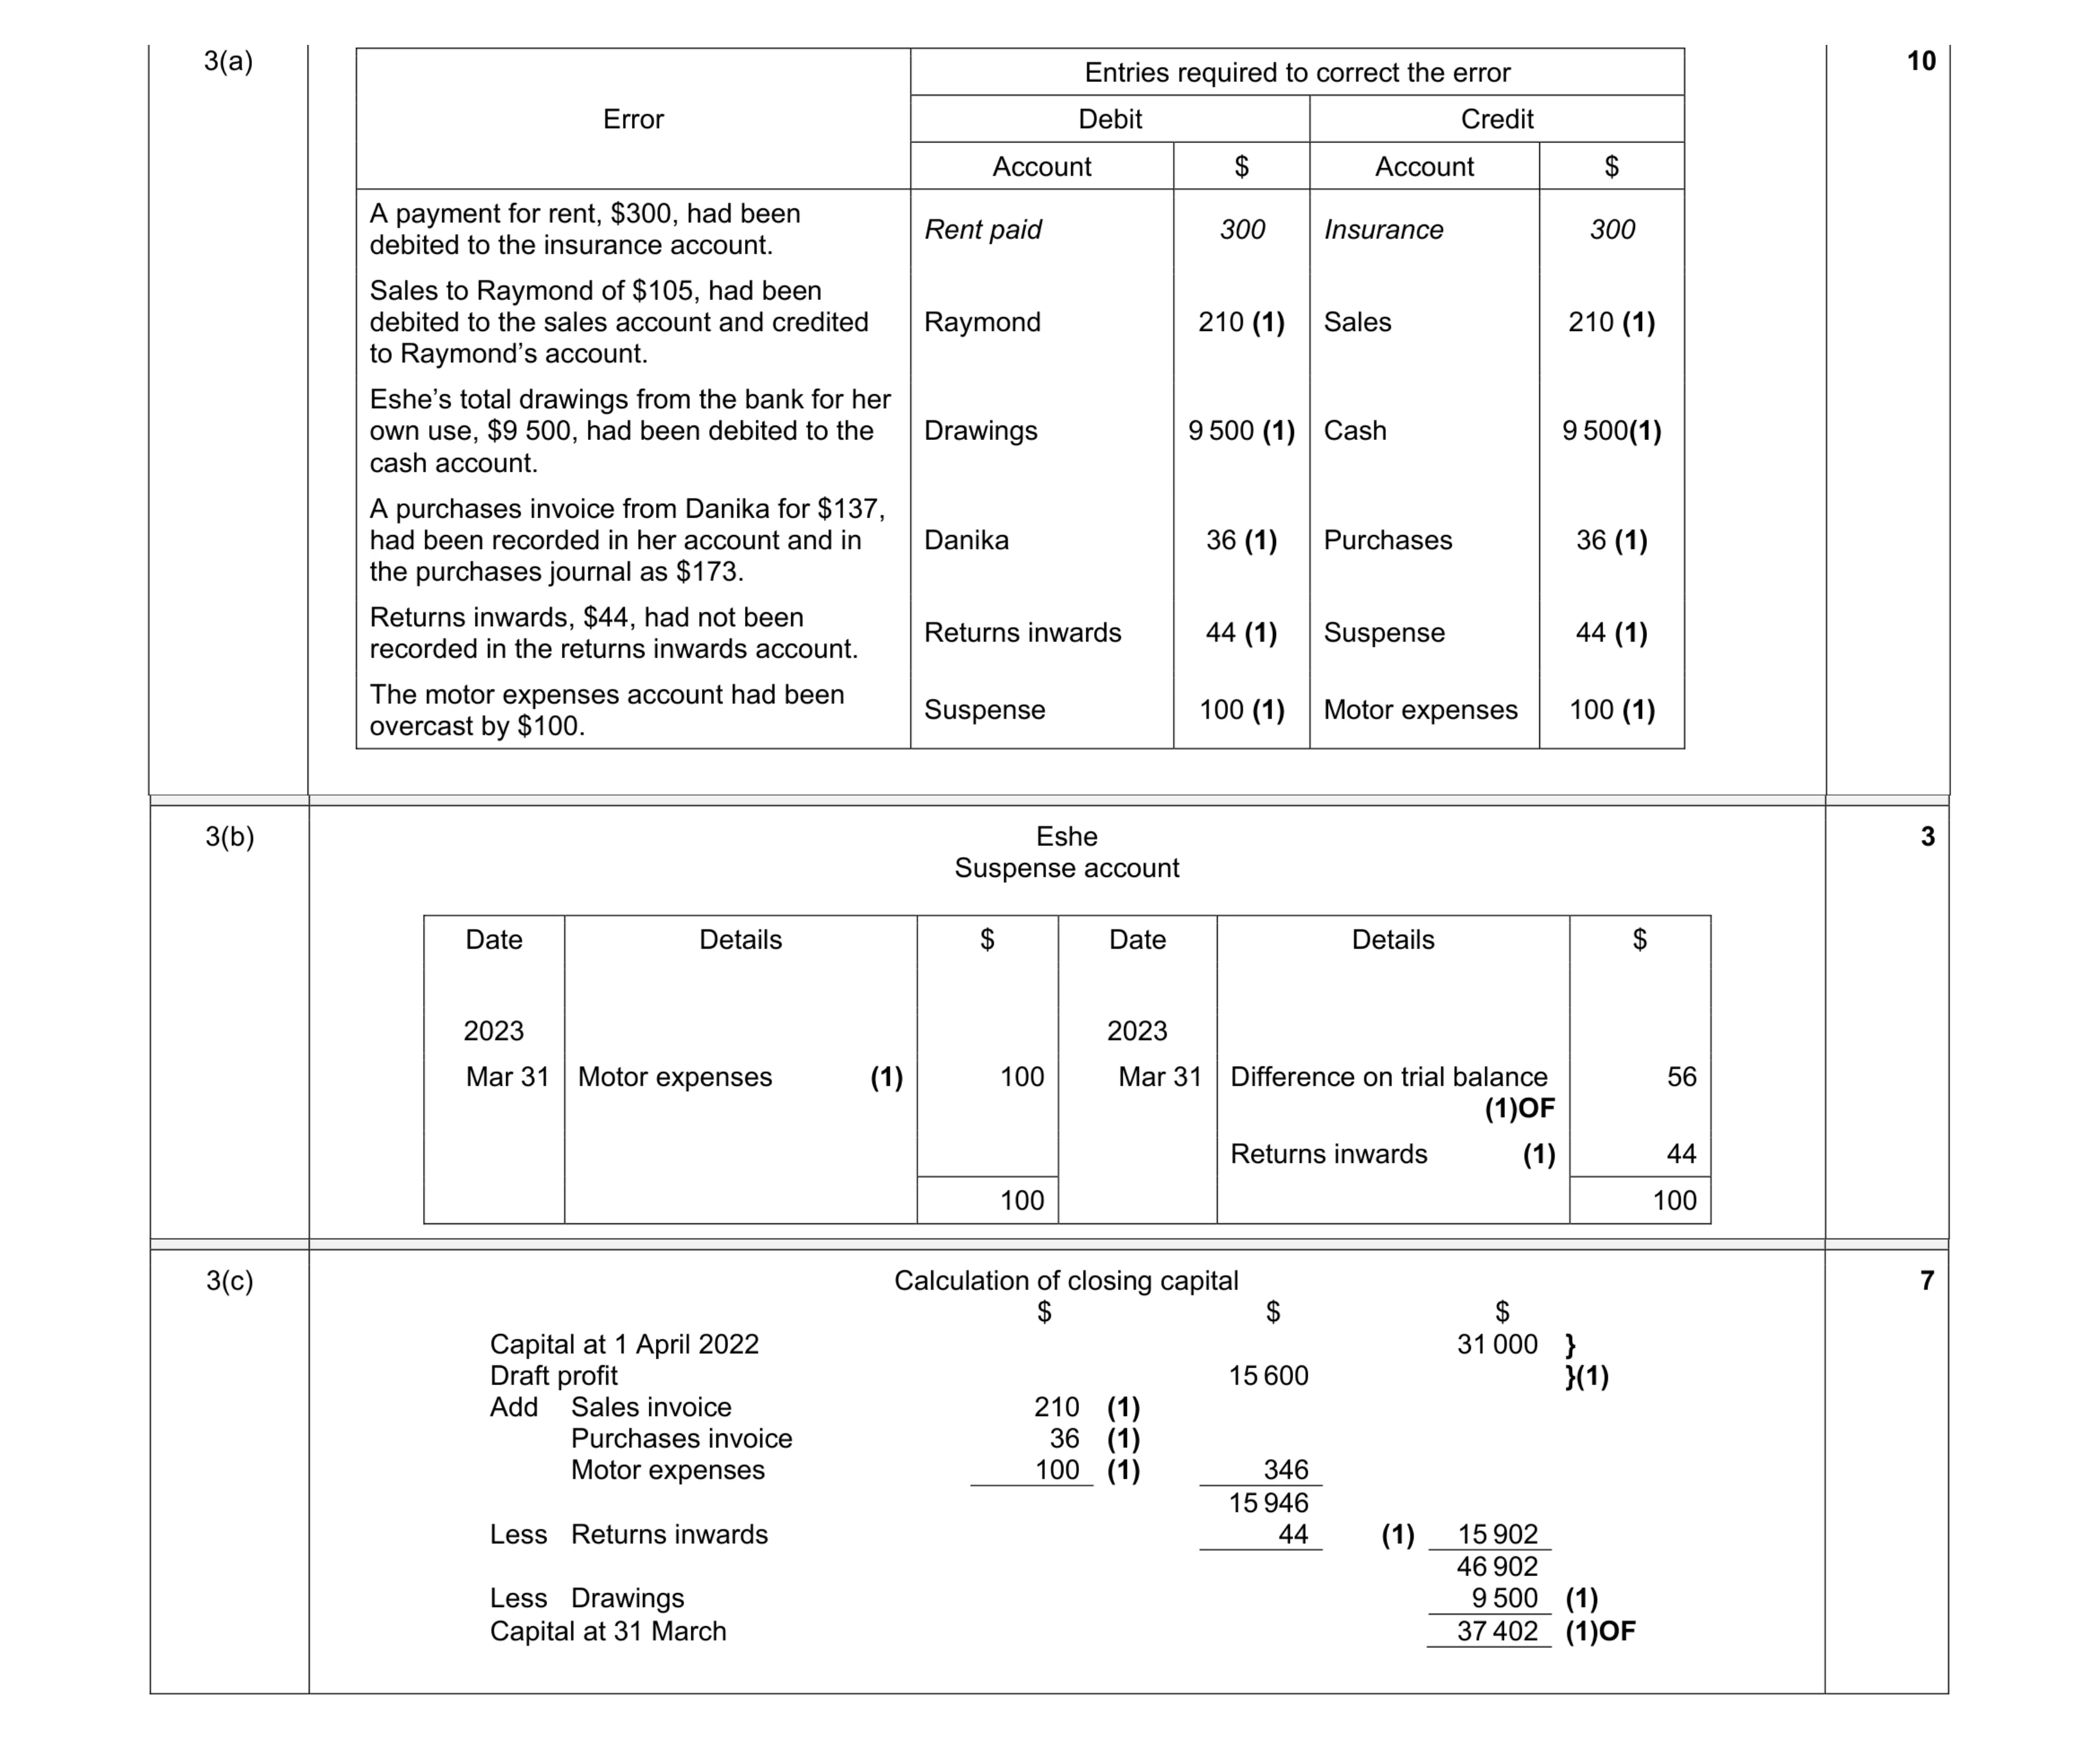
Mark scheme: 3(a) Error Entries required to correct the error Debit Credit Account $ Account $ A payment for rent, $300, had been debited to the insurance account. Rent paid 300 Insurance 300 Sales to Raymond of $105, had been debited to the sales account and credited to Raymond’s account. Raymond 210 (1) Sales 210 (1) Eshe’s total drawings from the bank for her own use, $9 500, had been debited to the cash account. Drawings 9 500 (1) Cash 9 500(1) A purchases invoice from Danika for $137, had been recorded in her account and in the purchases journal as $173. Danika 36 (1) Purchases 36 (1) Returns inwards, $44, had not been recorded in the returns inwards account. Returns inwards 44 (1) Suspense 44 (1) The motor expenses account had been overcast by $100. Suspense 100 (1) Motor expenses 100 (1) Question Answer Marks 3(b) Eshe Suspense account Date Details $ Date Details $ 2023 2023 Mar 31 Motor expenses (1) 100 Mar 31 Difference on trial balance (1)OF 56 Returns inwards (1) 44 100 100 3 Question Answer Marks 3(c) Calculation of closing capital $ $ $ Capital at 1 April 2022 31 000 } Draft profit 15 600 }(1) Add Sales invoice 210 (1) Purchases invoice 36 (1) Motor expenses 100 (1) 346 15 946 Less Returns inwards 44 (1) 15 902 46 902 Less Drawings 9 500 (1) Capital at 31 March 37 402 (1)OF 7
This question in 0985/21 May/June 2023
Q12 · Ramla has calculated her draft profit figure for the year ended 28 February 2023 0985/22 May/June 2023
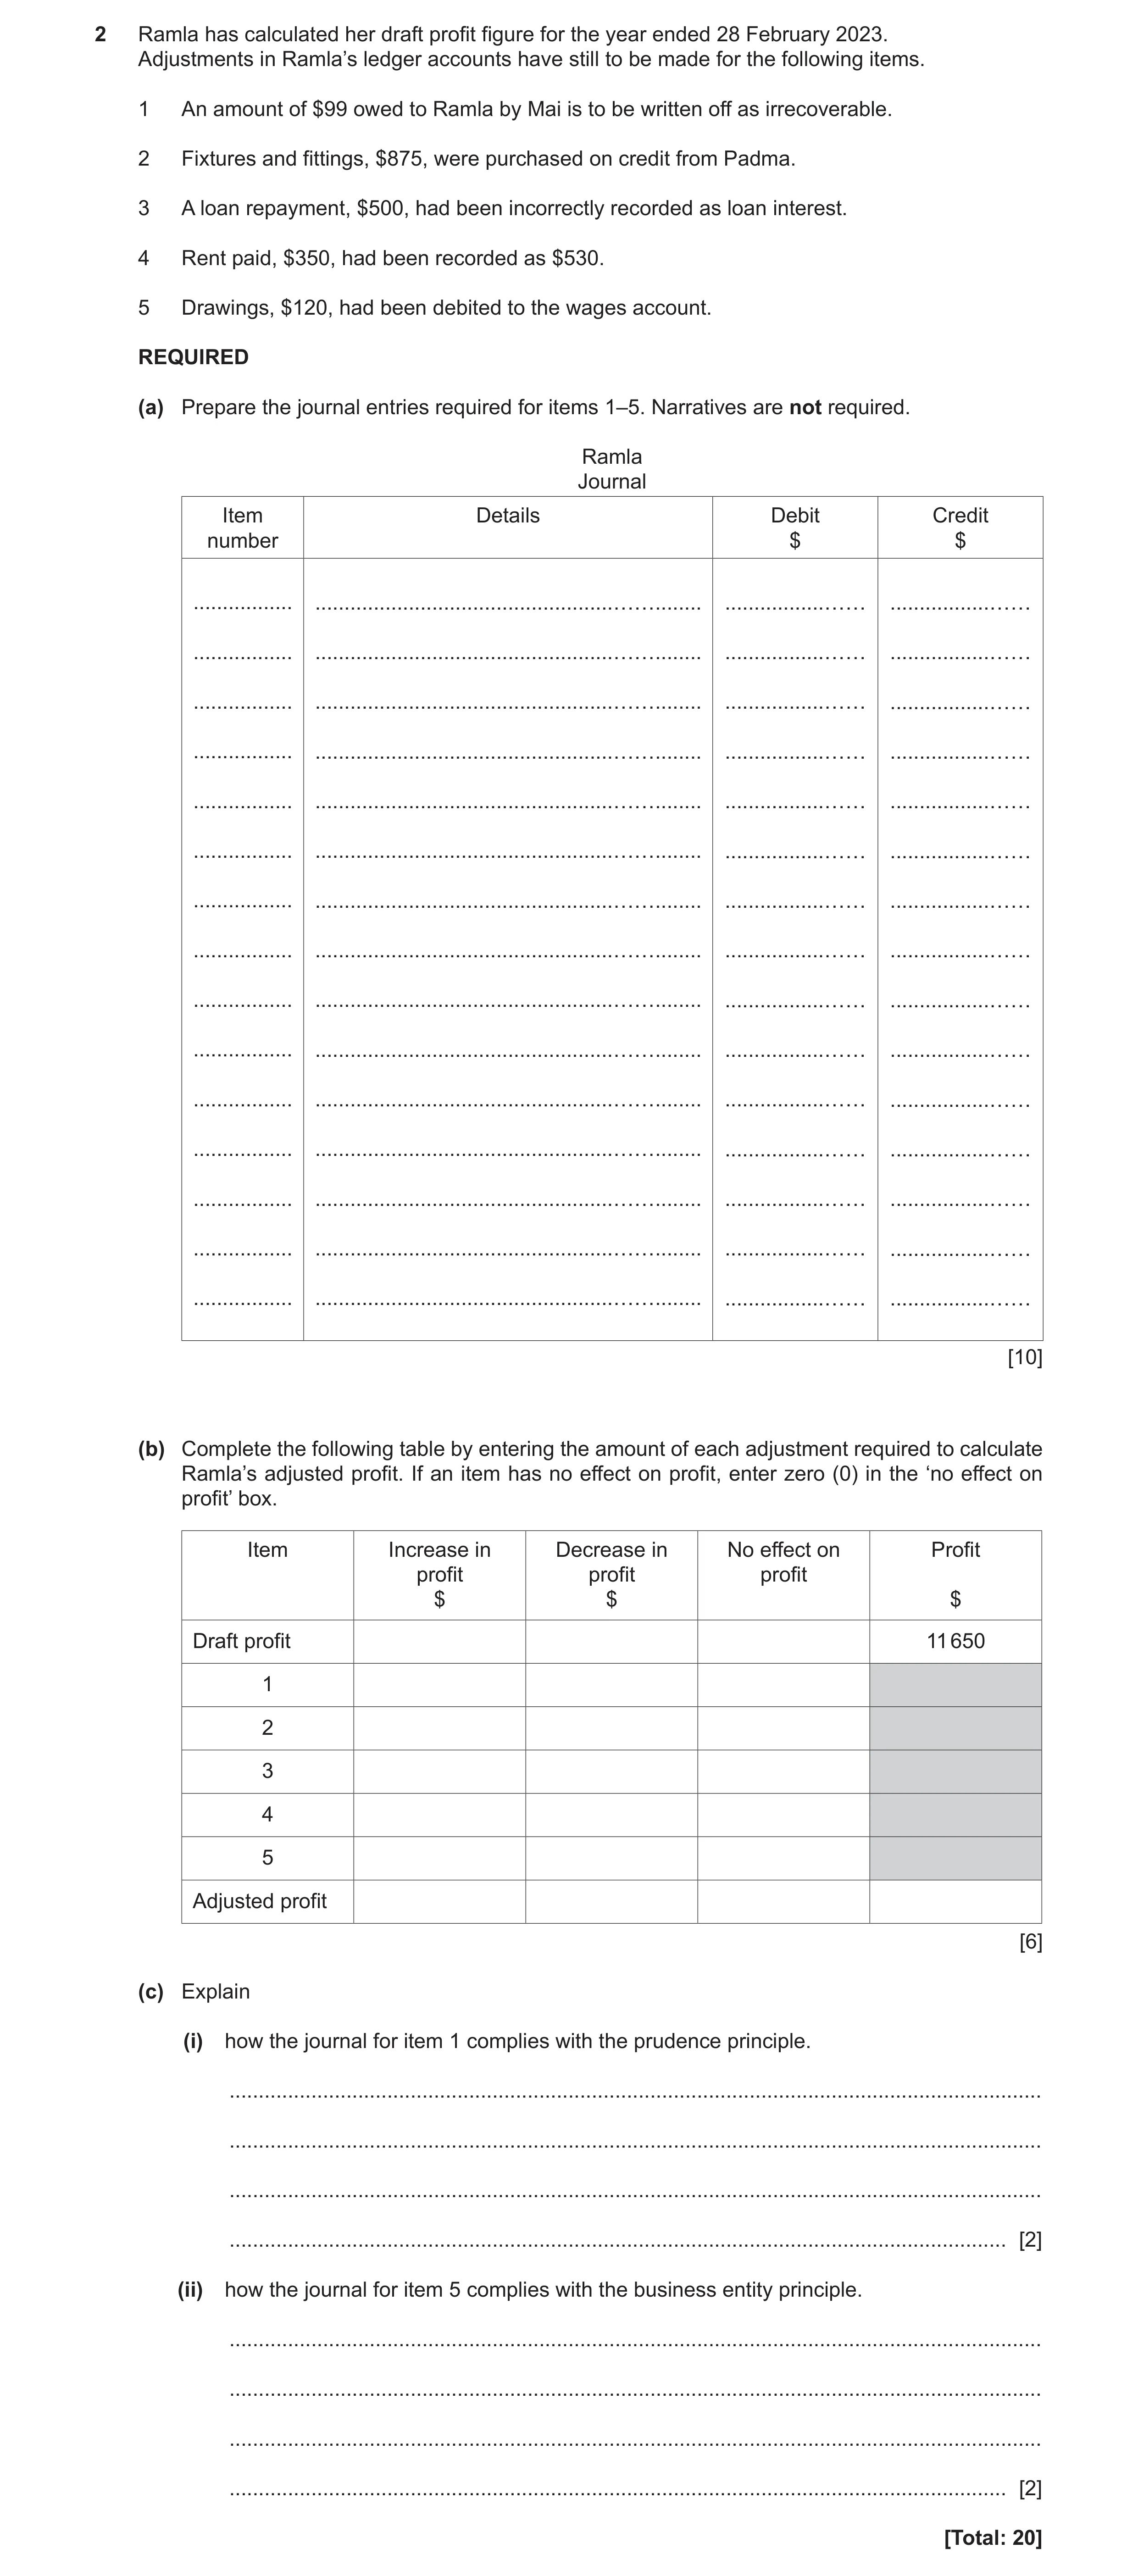
2 Ramla has calculated her draft profit figure for the year ended 28 February 2023. Adjustments in Ramla’s ledger accounts have still to be made for the following items. 1 An amount of $99 owed to Ramla by Mai is to be written off as irrecoverable. 2 Fixtures and fittings, $875, were purchased on credit from Padma. 3 A loan repayment, $500, had been incorrectly recorded as loan interest. 4 Rent paid, $350, had been recorded as $530. 5 Drawings, $120, had been debited to the wages account. REQUIRED (a) Prepare the journal entries required for items 1–5. Narratives are not required. Ramla Journal Item Details Debit Credit number $ $ … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… … … …… … … …… … …… [10] (b) Complete the following table by entering the amount of each adjustment required to calculate Ramla’s adjusted profit. If an item has no effect on profit, enter zero (0) in the ‘no effect on profit’ box. Item Increase in Decrease in No effect on Profit profit profit profit $ $ $ Draft profit 11 650 1 2 3 4 5 Adjusted profit [6] (c) Explain (i) how the journal for item 1 complies with the prudence principle. … … … … [2] (ii) how the journal for item 5 complies with the business entity principle. … … … … [2] [Total: 20]
20 marks
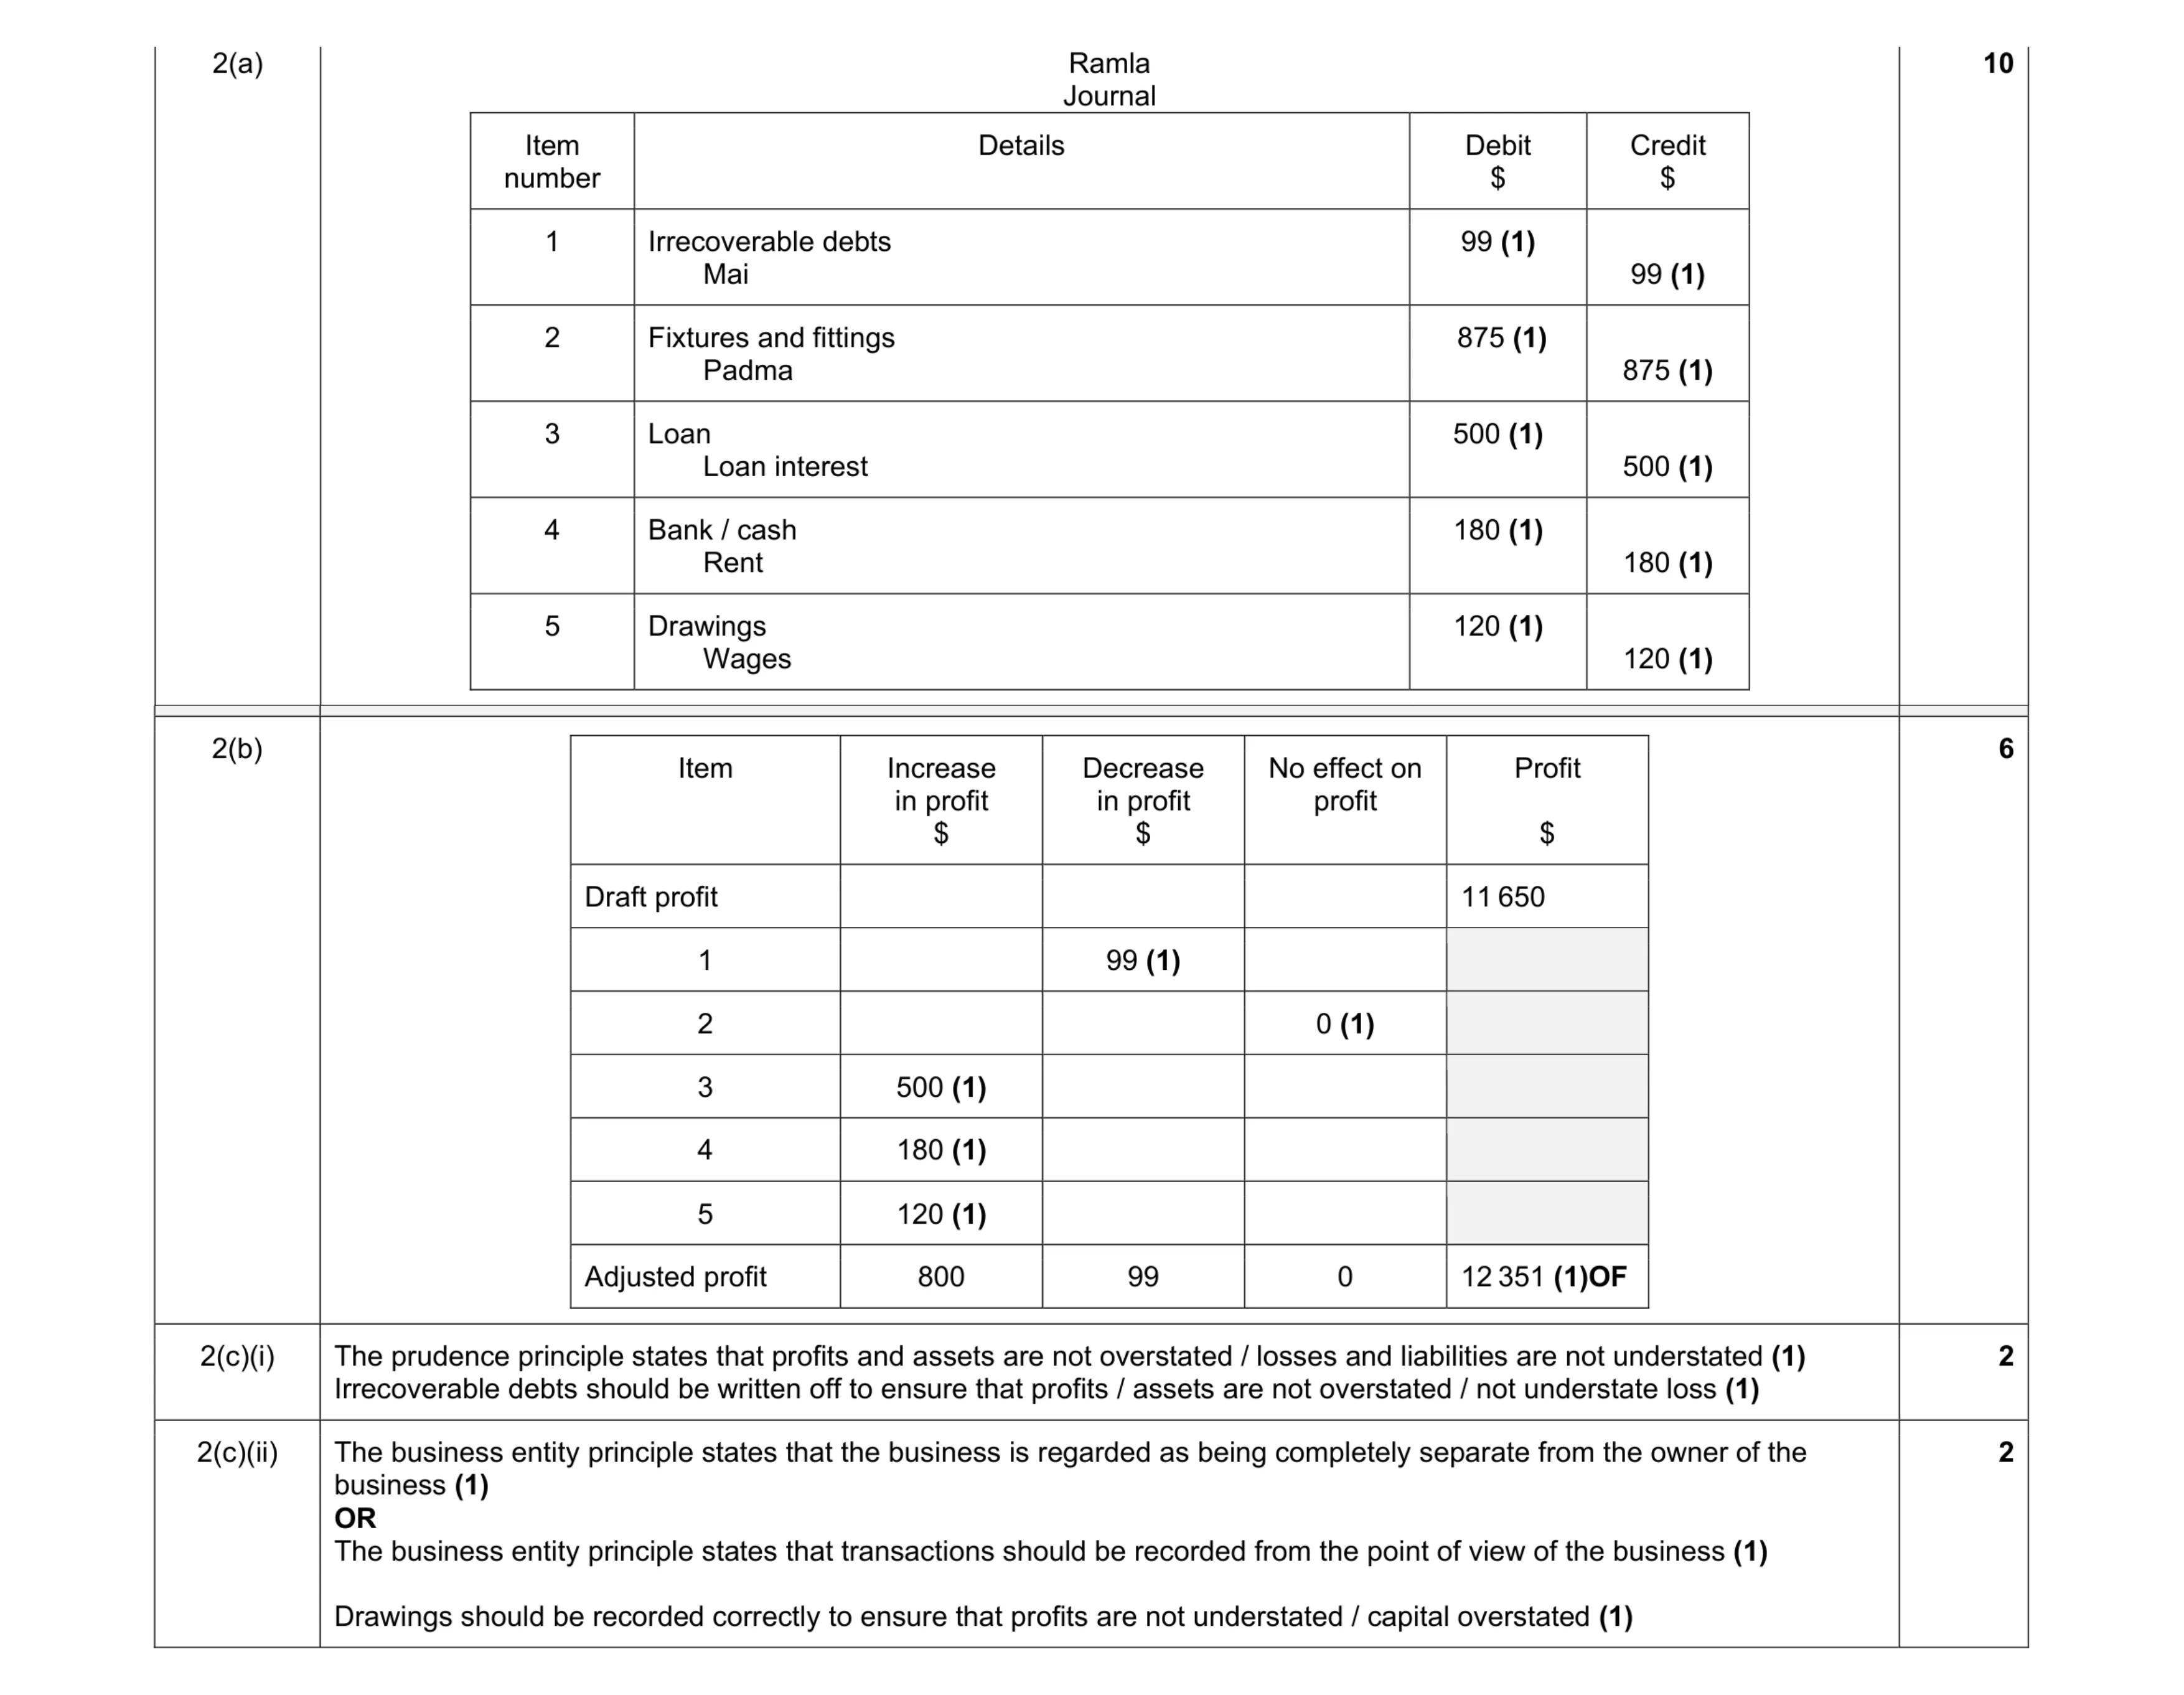
Mark scheme: 2(a) Ramla Journal Item number Details Debit $ Credit $ 1 Irrecoverable debts Mai 99 (1) 99 (1) 2 Fixtures and fittings Padma 875 (1) 875 (1) 3 Loan Loan interest 500 (1) 500 (1) 4 Bank / cash Rent 180 (1) 180 (1) 5 Drawings Wages 120 (1) 120 (1) 10 Question Answer Marks 2(b) Item Increase in profit $ Decrease in profit $ No effect on profit Profit $ Draft profit 11 650 1 99 (1) 2 0 (1) 3 500 (1) 4 180 (1) 5 120 (1) Adjusted profit 800 99 0 12 351 (1)OF 6 2(c)(i) The prudence principle states that profits and assets are not overstated / losses and liabilities are not understated (1) Irrecoverable debts should be written off to ensure that profits / assets are not overstated / not understate loss (1) 2 2(c)(ii) The business entity principle states that the business is regarded as being completely separate from the owner of the business (1) OR The business entity principle states that transactions should be recorded from the point of view of the business (1) Drawings should be recorded correctly to ensure that profits are not understated / capital overstated (1) 2
This question in 0985/22 May/June 2023
Q13 · Amadi prepared the following trial balance which is not yet totalled and contains errors 0985/22 May/June 2023
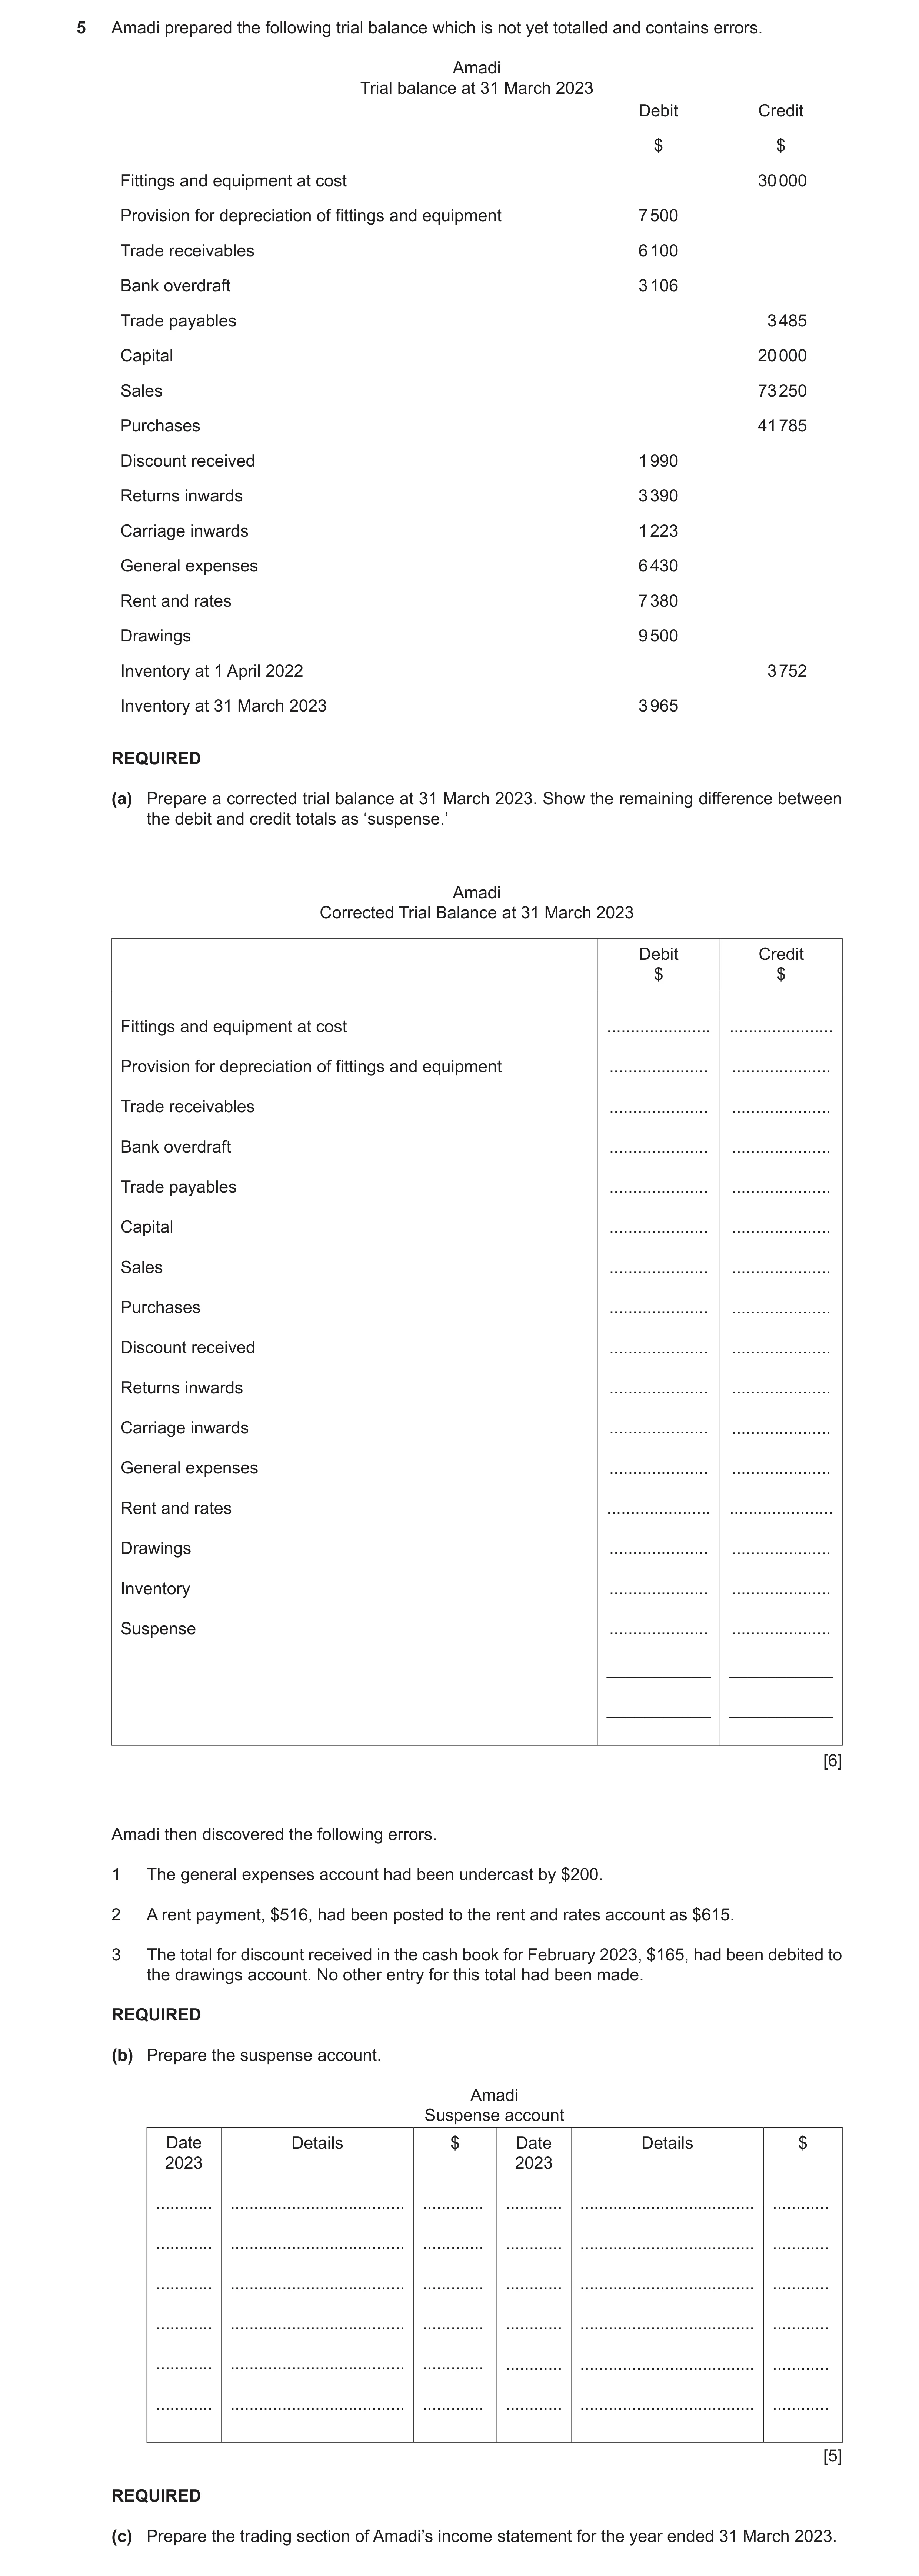
5 Amadi prepared the following trial balance which is not yet totalled and contains errors. Amadi Trial balance at 31 March 2023 Debit Credit $ $ Fittings and equipment at cost 30 000 Provision for depreciation of fittings and equipment 7 500 Trade receivables 6 100 Bank overdraft 3 106 Trade payables 3 485 Capital 20 000 Sales 73 250 Purchases 41 785 Discount received 1 990 Returns inwards 3 390 Carriage inwards 1 223 General expenses 6 430 Rent and rates 7 380 Drawings 9 500 Inventory at 1 April 2022 3 752 Inventory at 31 March 2023 3 965 REQUIRED (a) Prepare a corrected trial balance at 31 March 2023. Show the remaining difference between the debit and credit totals as ‘suspense.’ Amadi Corrected Trial Balance at 31 March 2023 Debit Credit $ $ Fittings and equipment at cost … … Provision for depreciation of fittings and equipment … … Trade receivables … … Bank overdraft … … Trade payables … … Capital … … Sales … … Purchases … … Discount received … … Returns inwards … … Carriage inwards … … General expenses … … Rent and rates … … Drawings … … Inventory … … Suspense … … ___________ ___________ ___________ ___________ [6] Amadi then discovered the following errors. 1 The general expenses account had been undercast by $200. 2 A rent payment, $516, had been posted to the rent and rates account as $615. 3 The total for discount received in the cash book for February 2023, $165, had been debited to the drawings account. No other entry for this total had been made. REQUIRED (b) Prepare the suspense account. Amadi Suspense account Date Details $ Date Details $ 2023 2023 … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [5] REQUIRED (c) Prepare the trading section of Amadi’s income statement for the year ended 31 March 2023.
11 marks
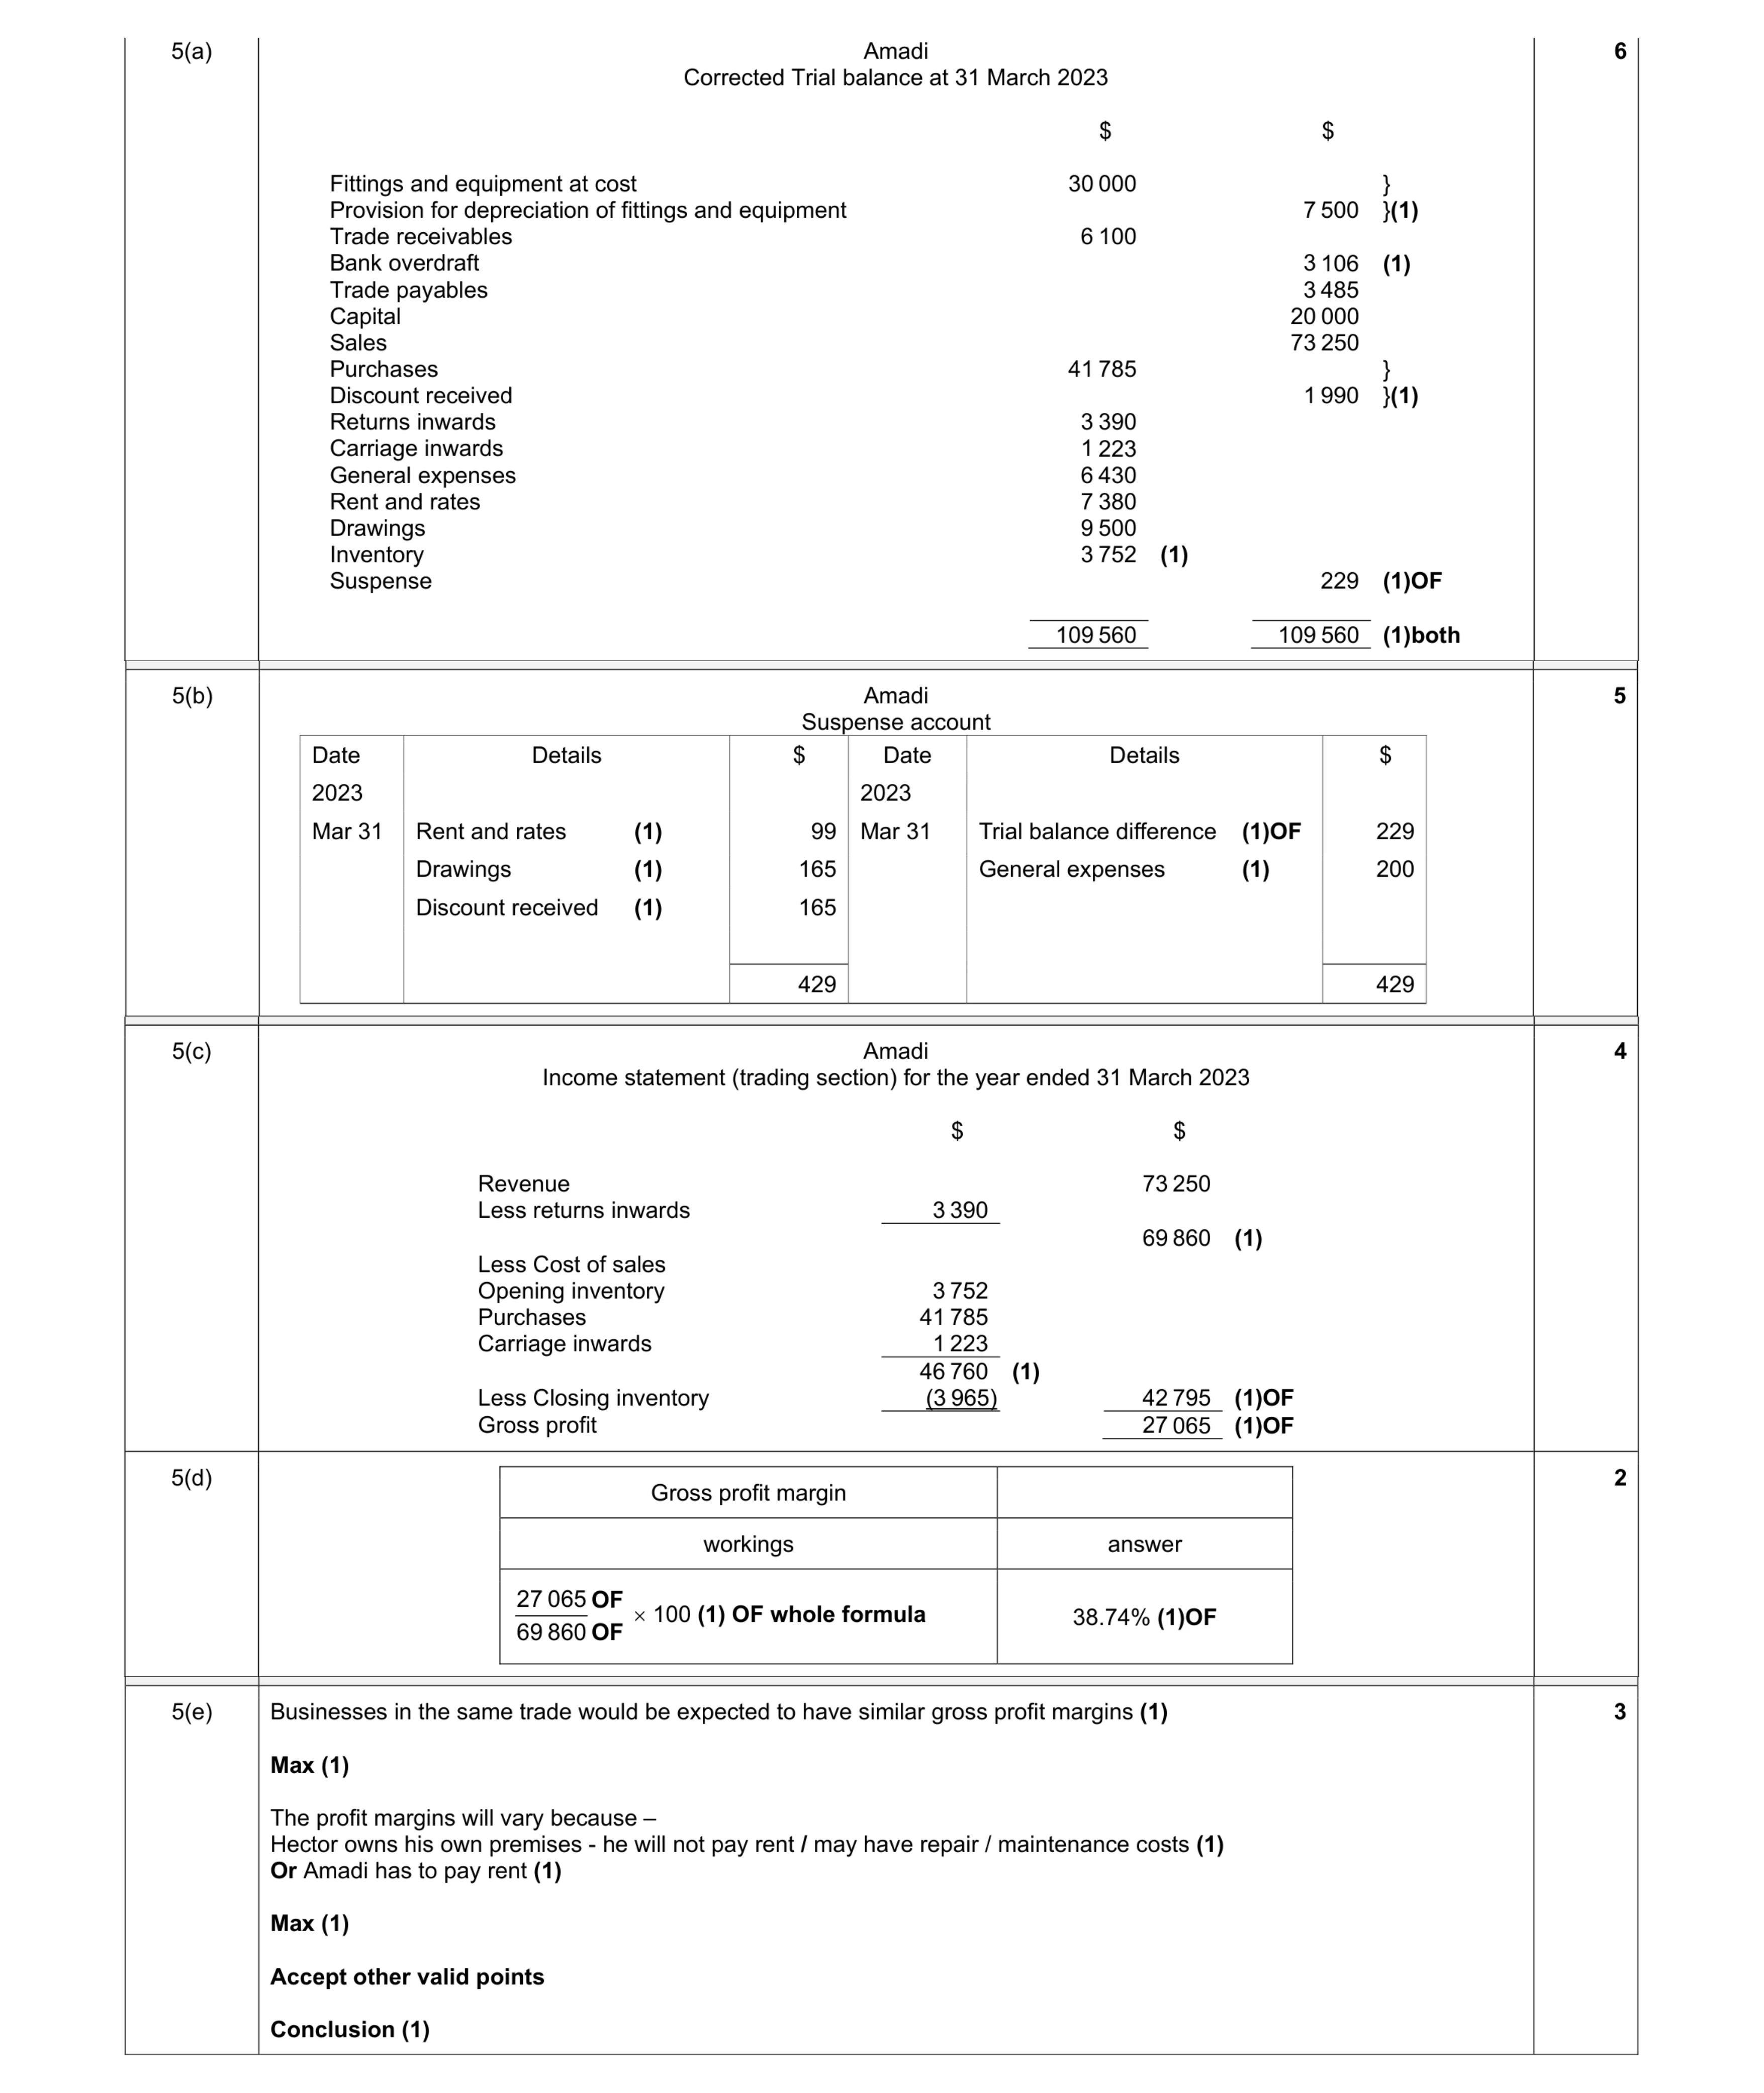
Mark scheme: 5(a) Amadi Corrected Trial balance at 31 March 2023 $ $ Fittings and equipment at cost 30 000 } Provision for depreciation of fittings and equipment 7 500 }(1) Trade receivables 6 100 Bank overdraft 3 106 (1) Trade payables 3 485 Capital 20 000 Sales 73 250 Purchases 41 785 } Discount received 1 990 }(1) Returns inwards 3 390 Carriage inwards 1 223 General expenses 6 430 Rent and rates 7 380 Drawings 9 500 Inventory 3 752 (1) Suspense 229 (1)OF 109 560 109 560 (1)both 6 Question Answer Marks 5(b) Amadi Suspense account Date Details $ Date Details $ 2023 2023 Mar 31 Rent and rates (1) 99 Mar 31 Trial balance difference (1)OF 229 Drawings (1) 165 General expenses (1) 200 Discount received (1) 165 429 429 5 Question Answer Marks 5(c) Amadi Income statement (trading section) for the year ended 31 March 2023 $ $ Revenue 73 250 Less returns inwards 3 390 69 860 (1) Less Cost of sales Opening inventory 3 752 Purchases 41 785 Carriage inwards 1 223 46 760 (1) Less Closing inventory (3 965) 42 795 (1)OF Gross profit 27 065 (1)OF 4 5(d) Gross profit margin workings answer 27 065 69 860 OF OF 100 (1) OF whole formula 38.74% (1)OF 2 Question Answer Marks 5(e) Businesses in the same trade would be expected to have similar gross profit margins (1) Max (1) The profit margins will vary because – Hector owns his own premises - he will not pay rent / may have repair / maintenance costs (1) Or Amadi has to pay rent (1) Max (1) Accept other valid points Conclusion (1) 3
This question in 0985/22 May/June 2023
Q14 · Rachel is a trader 0985/22 Oct/Nov 2023
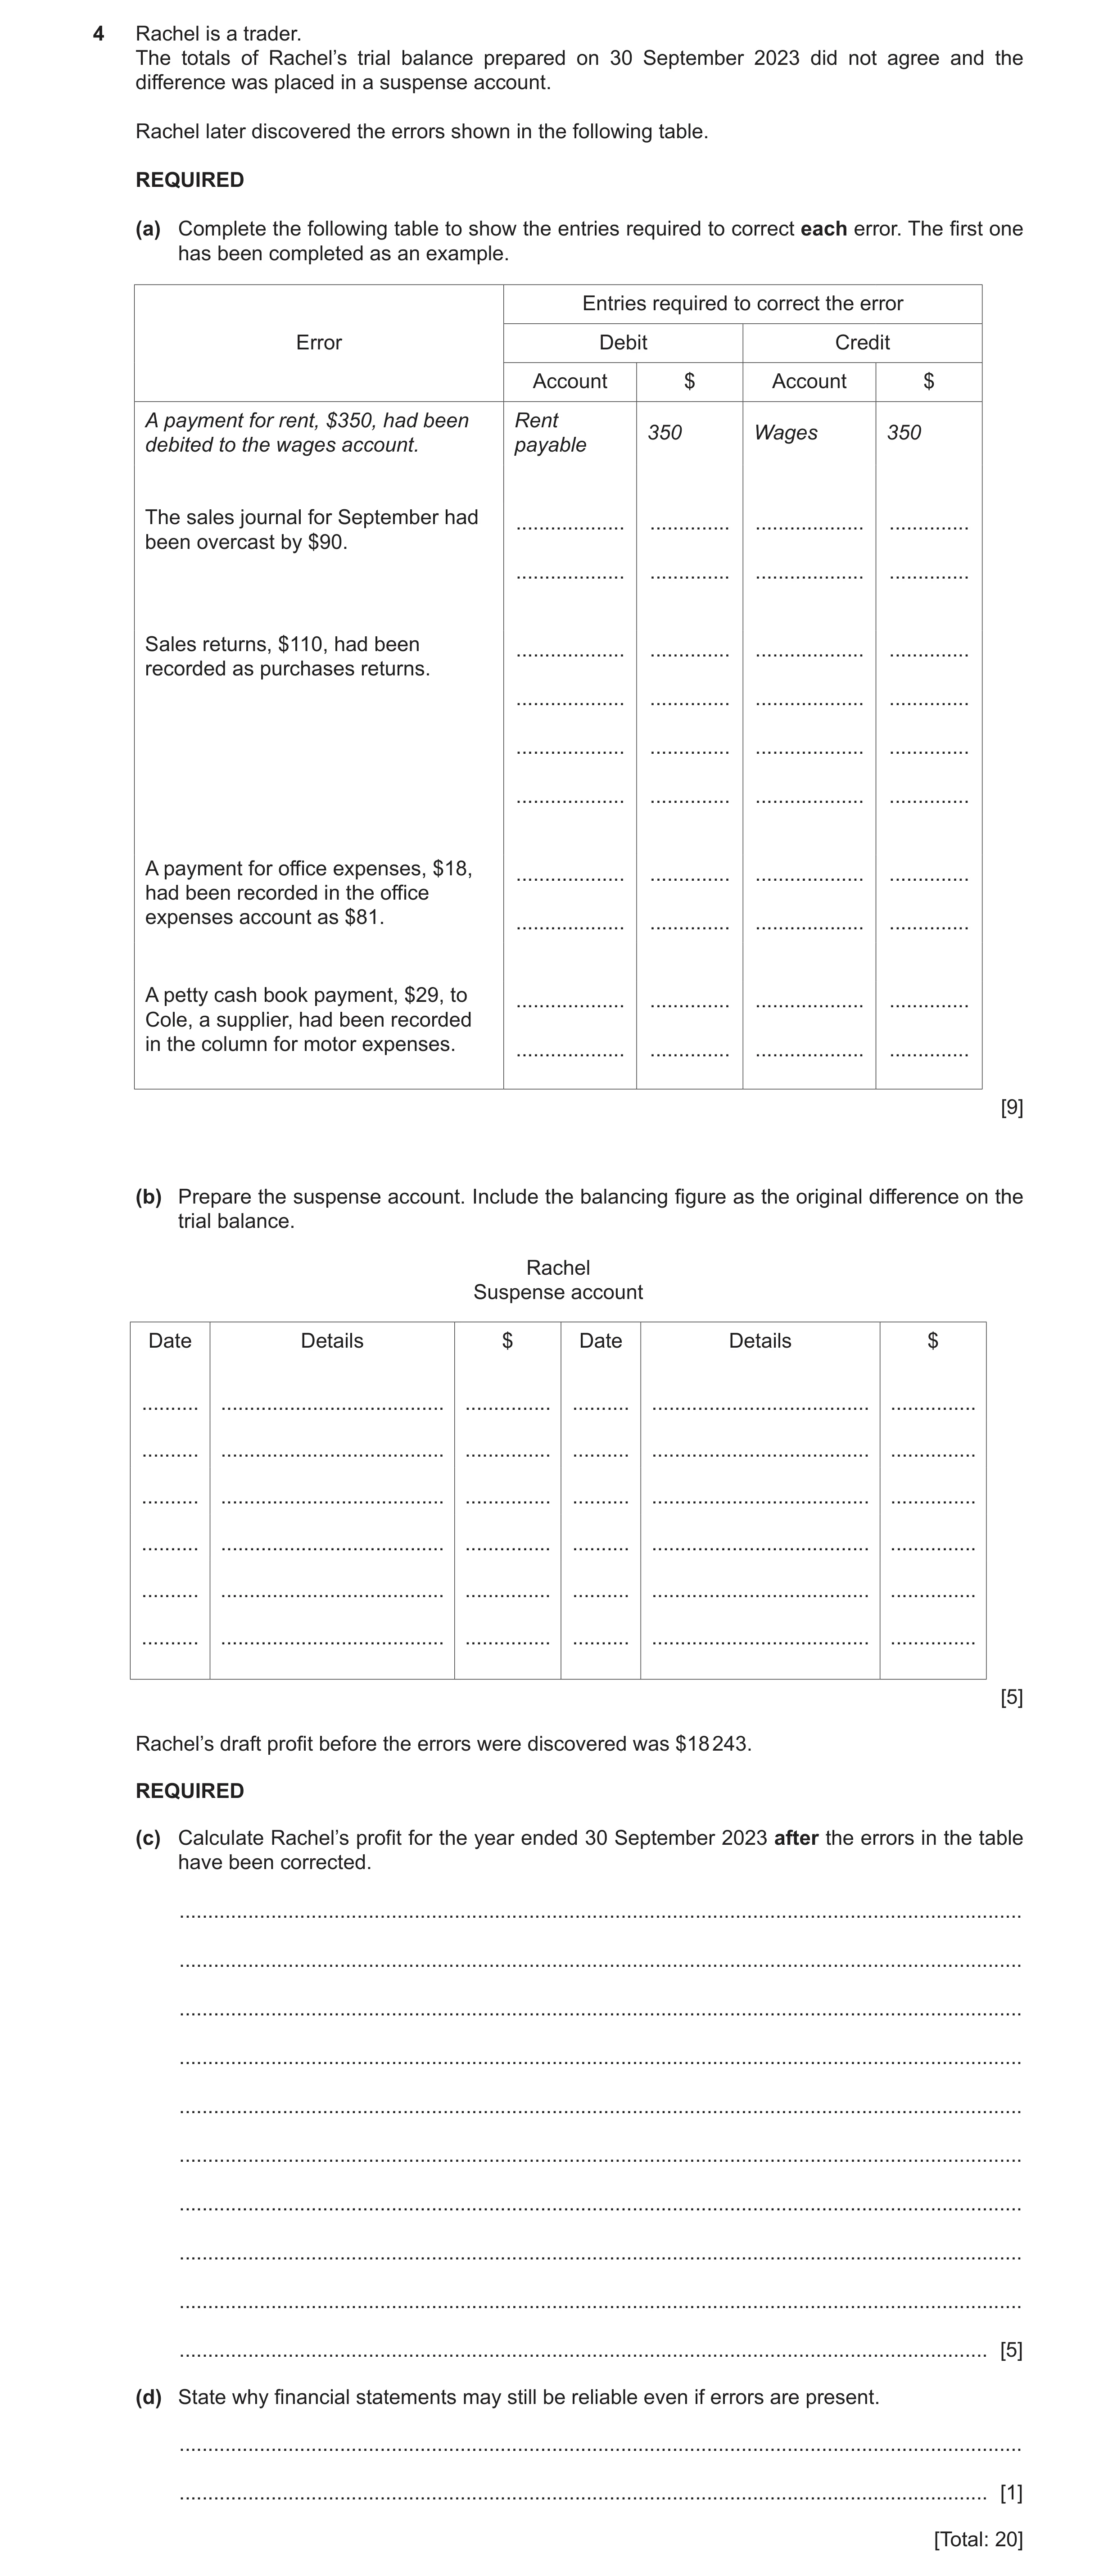
4 Rachel is a trader. The totals of Rachel’s trial balance prepared on 30 September 2023 did not agree and the difference was placed in a suspense account. Rachel later discovered the errors shown in the following table. REQUIRED (a) Complete the following table to show the entries required to correct each error. The first one has been completed as an example. Entries required to correct the error Error Debit Credit Account $ Account $ A payment for rent, $350, had been Rent 350 Wages 350 debited to the wages account. payable The sales journal for September had … … … … been overcast by $90. … … … … Sales returns, $110, had been … … … … recorded as purchases returns. … … … … … … … … … … … … A payment for office expenses, $18, … … … … had been recorded in the office expenses account as $81. … … … … A petty cash book payment, $29, to … … … … Cole, a supplier, had been recorded in the column for motor expenses. … … … … [9] (b) Prepare the suspense account. Include the balancing figure as the original difference on the trial balance. Rachel Suspense account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [5] Rachel’s draft profit before the errors were discovered was $18 243. REQUIRED (c) Calculate Rachel’s profit for the year ended 30 September 2023 after the errors in the table have been corrected. … … … … … … … … … … [5] (d) State why financial statements may still be reliable even if errors are present. … … [1] [Total: 20]
20 marks
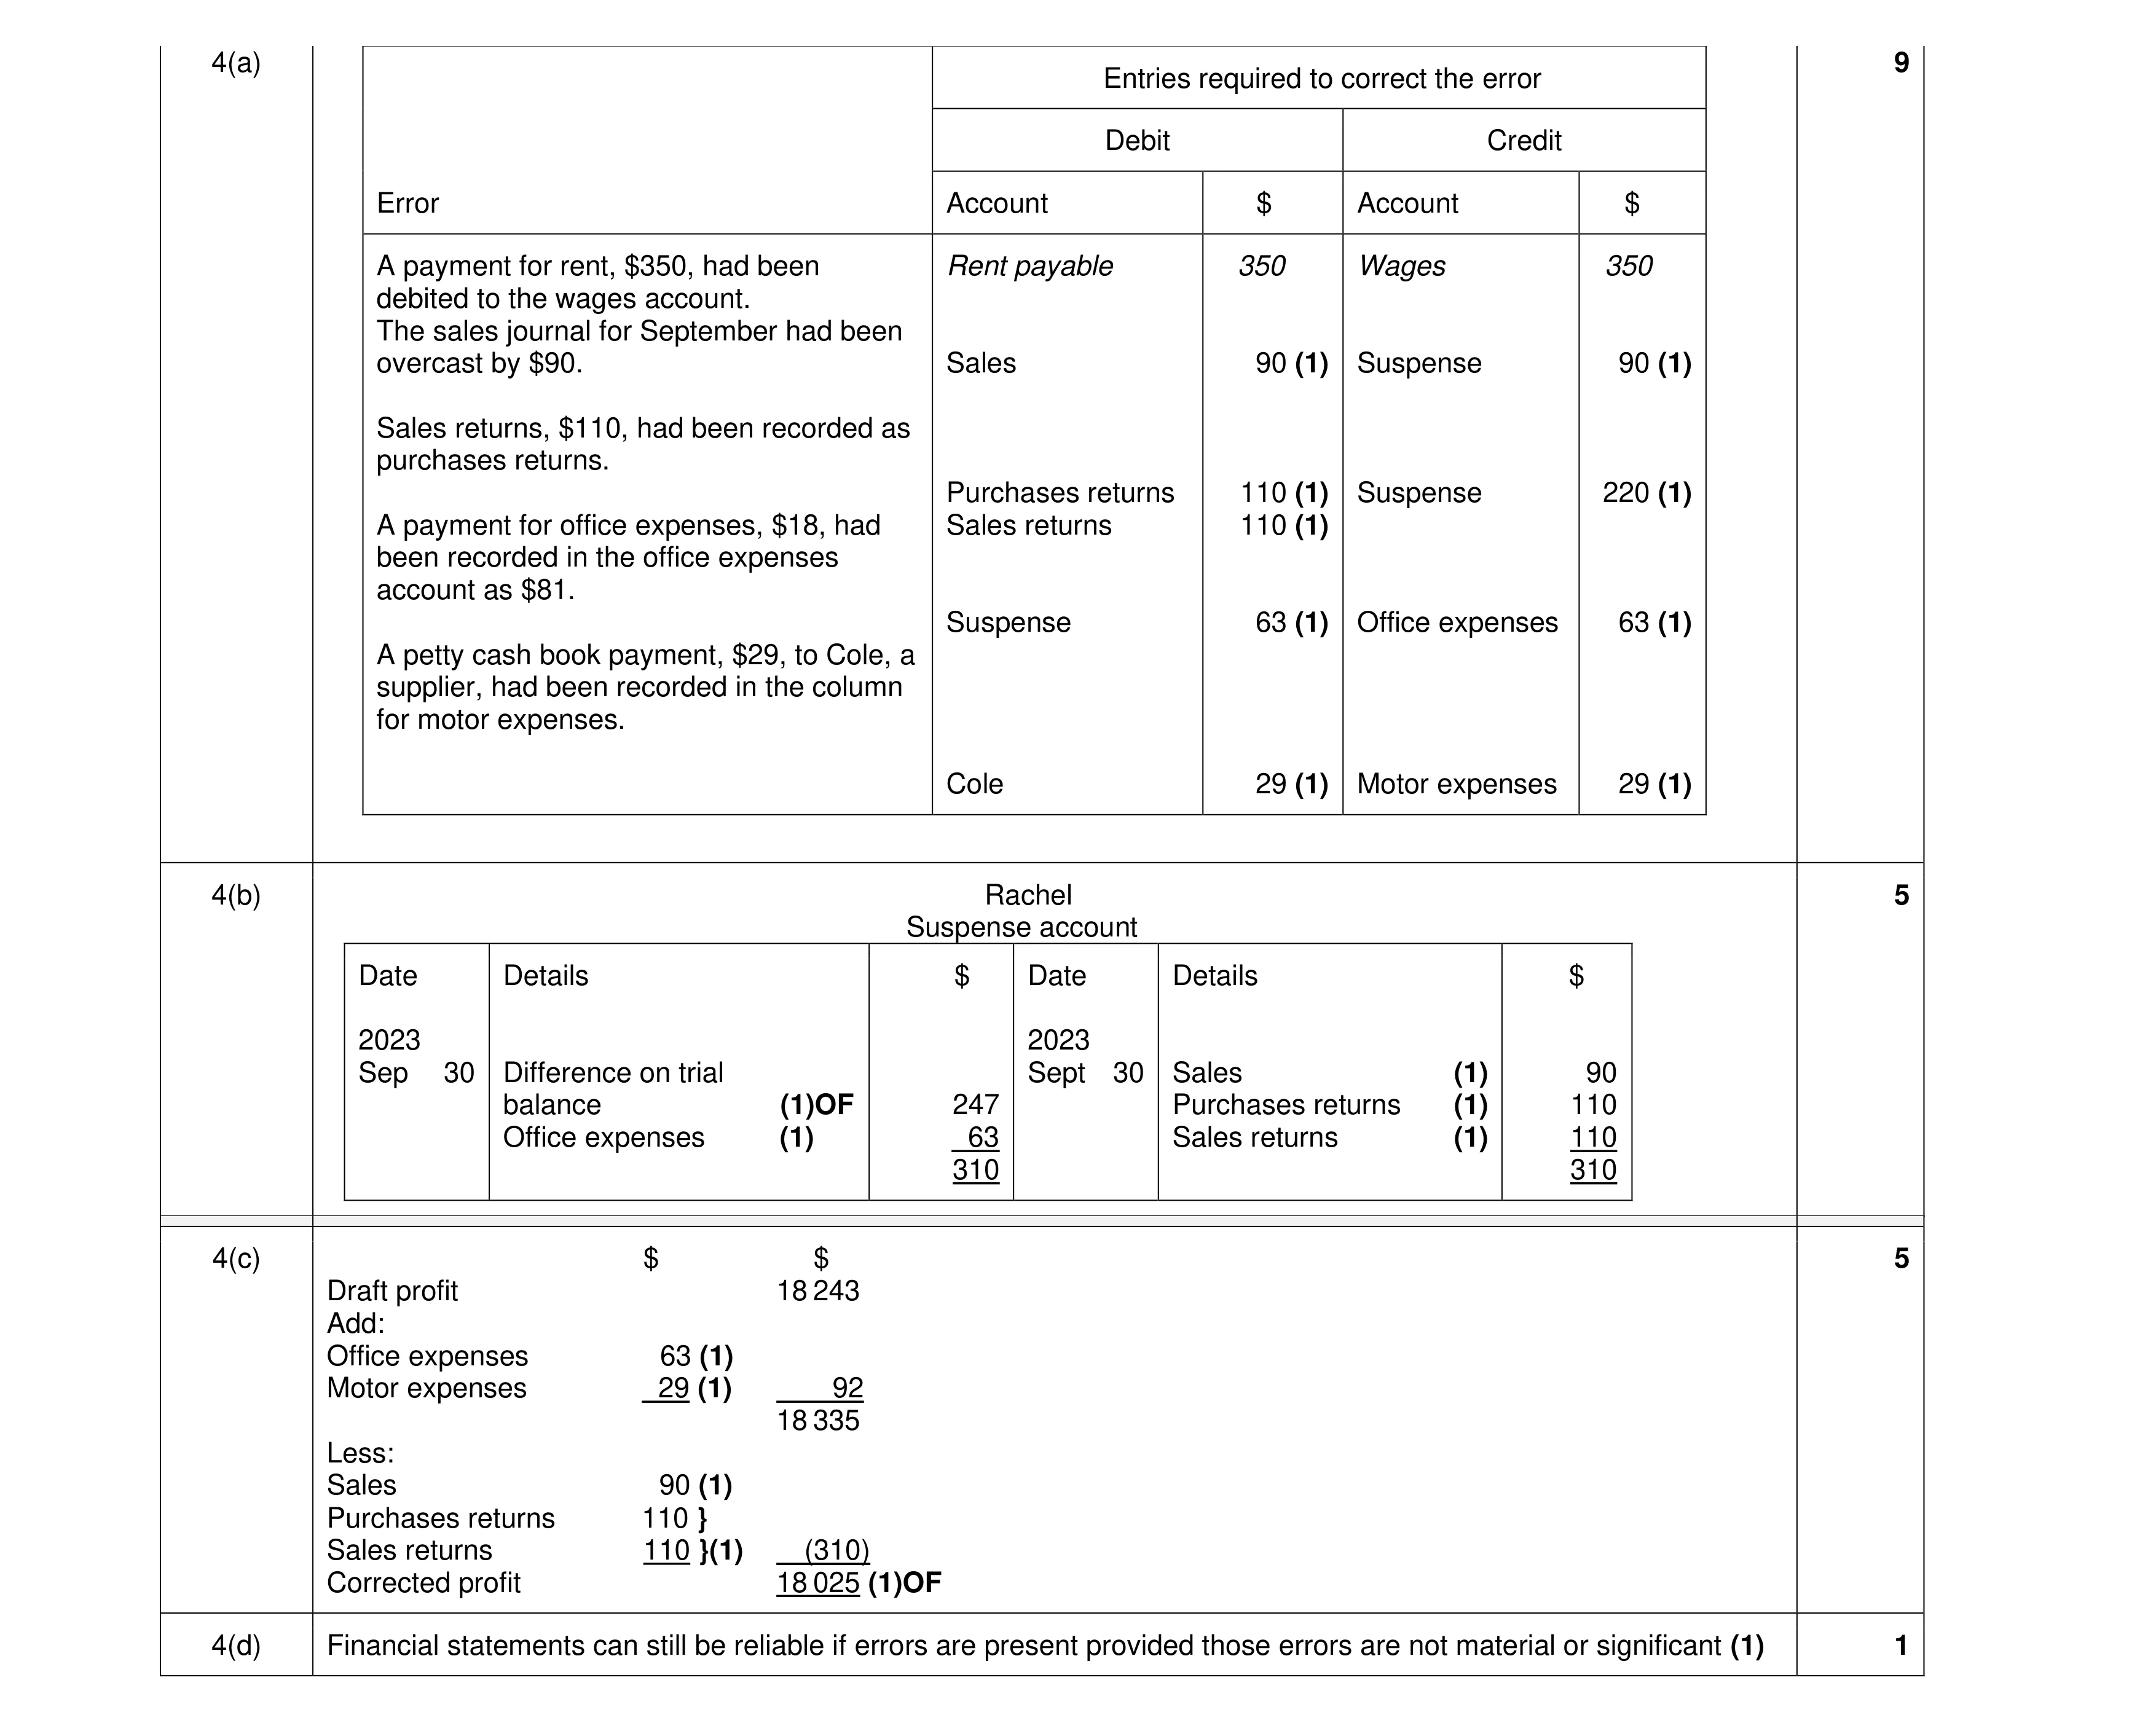
Mark scheme: 4(a) 9 Entries required to correct the error Debit Credit Error Account $ Account $ A payment for rent, $350, had been Rent payable 350 Wages 350 debited to the wages account. The sales journal for September had been overcast by $90. Sales 90 (1) Suspense 90 (1) Sales returns, $110, had been recorded as purchases returns. Purchases returns 110 (1) Suspense 220 (1) A payment for office expenses, $18, had Sales returns 110 (1) been recorded in the office expenses account as $81. Suspense 63 (1) Office expenses 63 (1) A petty cash book payment, $29, to Cole, a supplier, had been recorded in the column for motor expenses. Cole 29 (1) Motor expenses 29 (1) 4(b) Rachel 5 Suspense account Date Details $ Date Details $ 2023 2023 Sep 30 Difference on trial Sept 30 Sales (1) 90 balance (1)OF 247 Purchases returns (1) 110 Office expenses (1) 63 Sales returns (1) 110 310 310 4(c) $ $ 5 Draft profit 18 243 Add: Office expenses 63 (1) Motor expenses 29 (1) 92 18 335 Less: Sales 90 (1) Purchases returns 110 } Sales returns 110 }(1) (310) Corrected profit 18 025 (1)OF 4(d) Financial statements can still be reliable if errors are present provided those errors are not material or significant (1) 1
This question in 0985/22 Oct/Nov 2023
Q15 · Paul is a trader 0985/21 May/June 2024
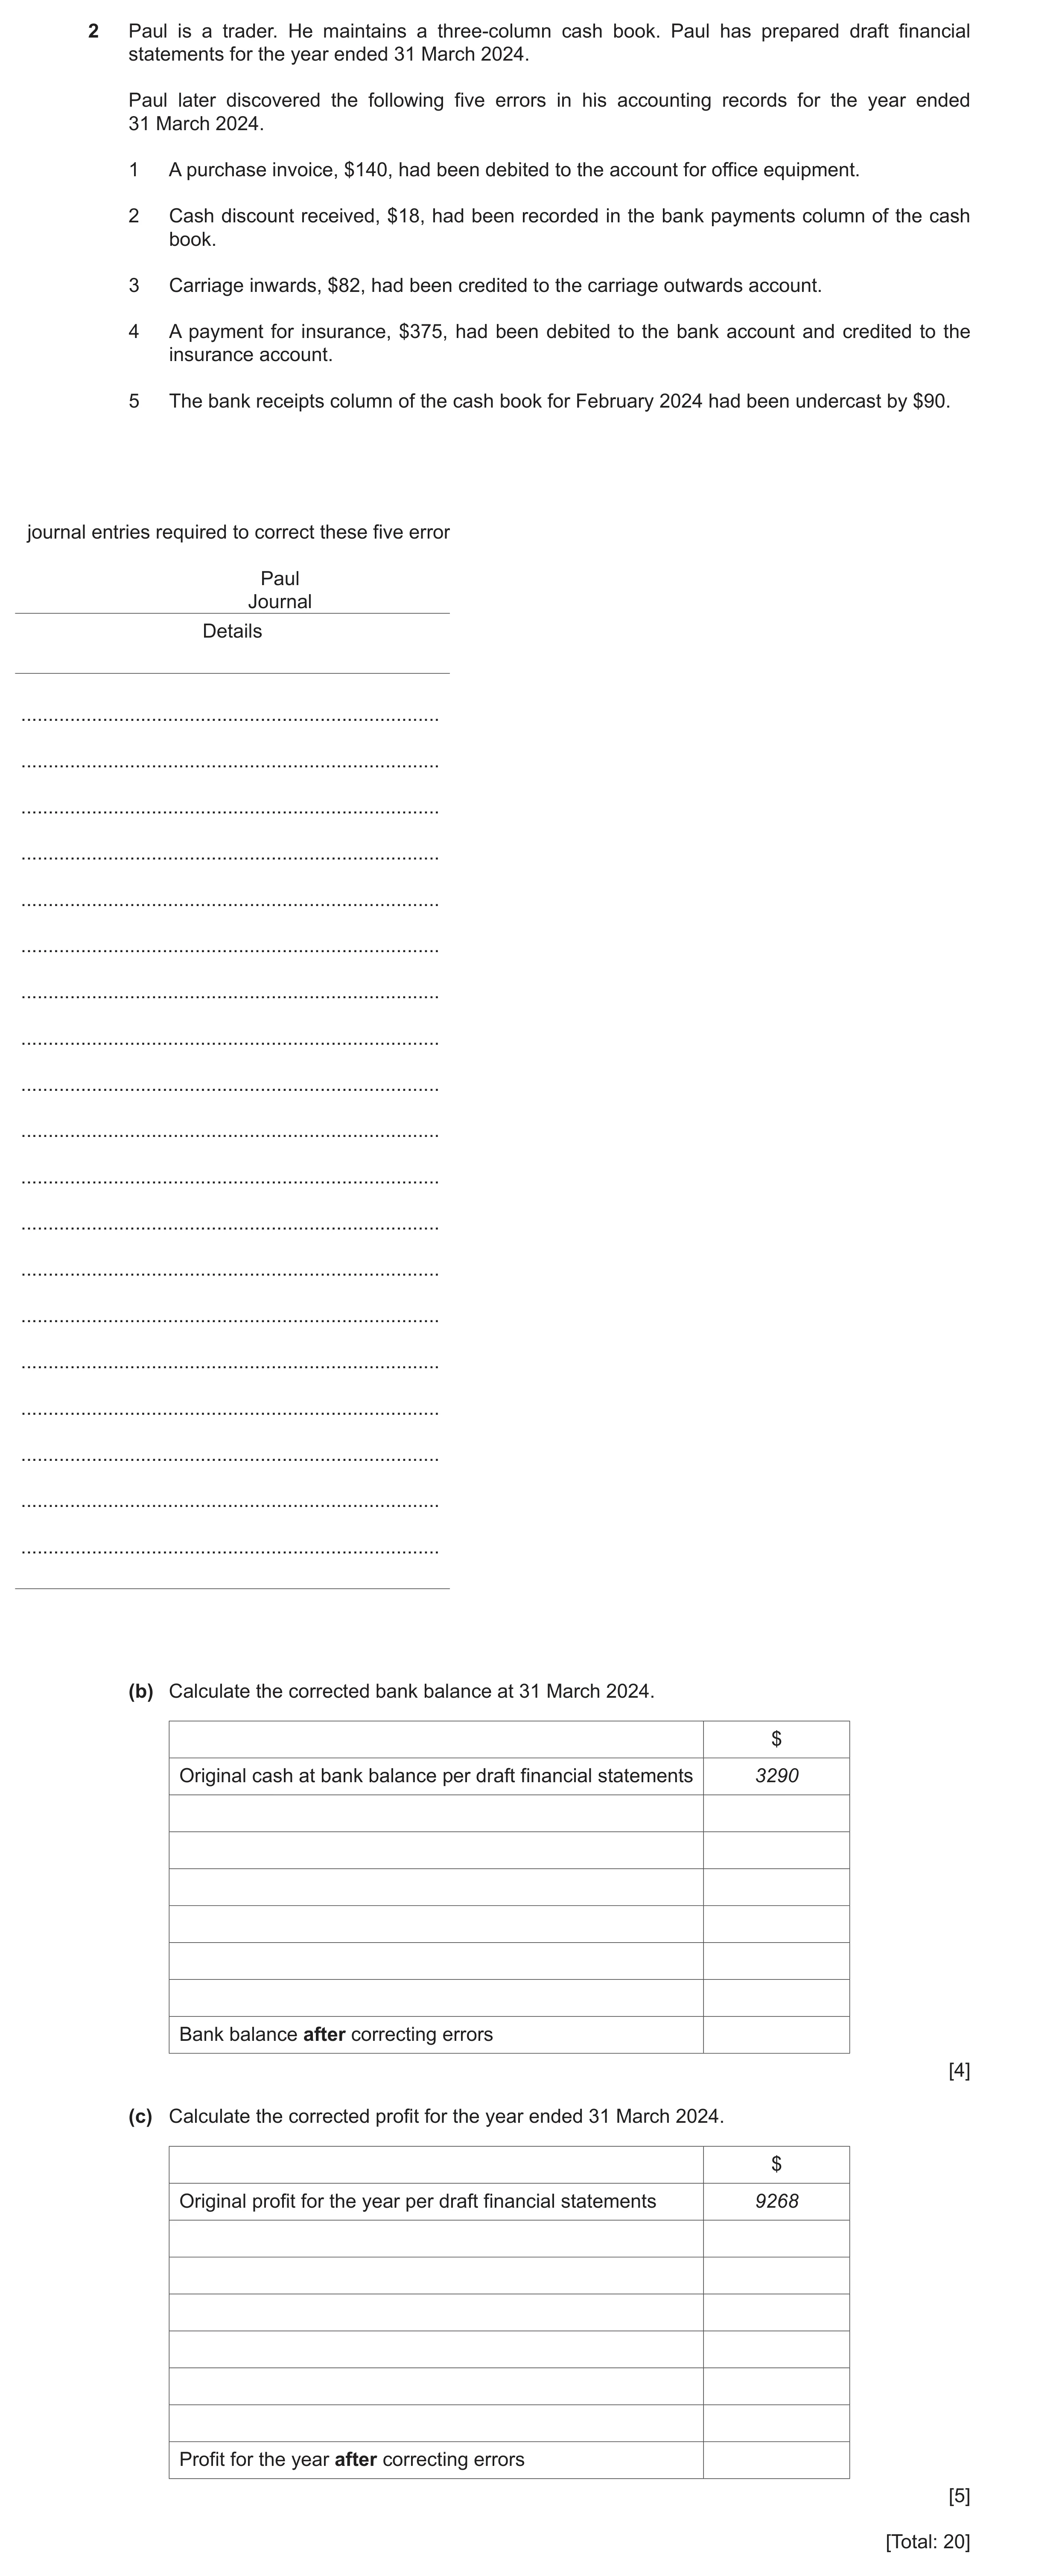
2 Paul is a trader. He maintains a three-column cash book. Paul has prepared draft financial statements for the year ended 31 March 2024. Paul later discovered the following five errors in his accounting records for the year ended 31 March 2024. 1 A purchase invoice, $140, had been debited to the account for office equipment. 2 Cash discount received, $18, had been recorded in the bank payments column of the cash book. 3 Carriage inwards, $82, had been credited to the carriage outwards account. 4 A payment for insurance, $375, had been debited to the bank account and credited to the insurance account. 5 The bank receipts column of the cash book for February 2024 had been undercast by $90. journal entries required to correct these five error Paul Journal Details … … … … … … … … … … … … … … … … … … … (b) Calculate the corrected bank balance at 31 March 2024. $ Original cash at bank balance per draft financial statements 3290 Bank balance after correcting errors [4] (c) Calculate the corrected profit for the year ended 31 March 2024. $ Original profit for the year per draft financial statements 9268 Profit for the year after correcting errors [5] [Total: 20]
20 marks
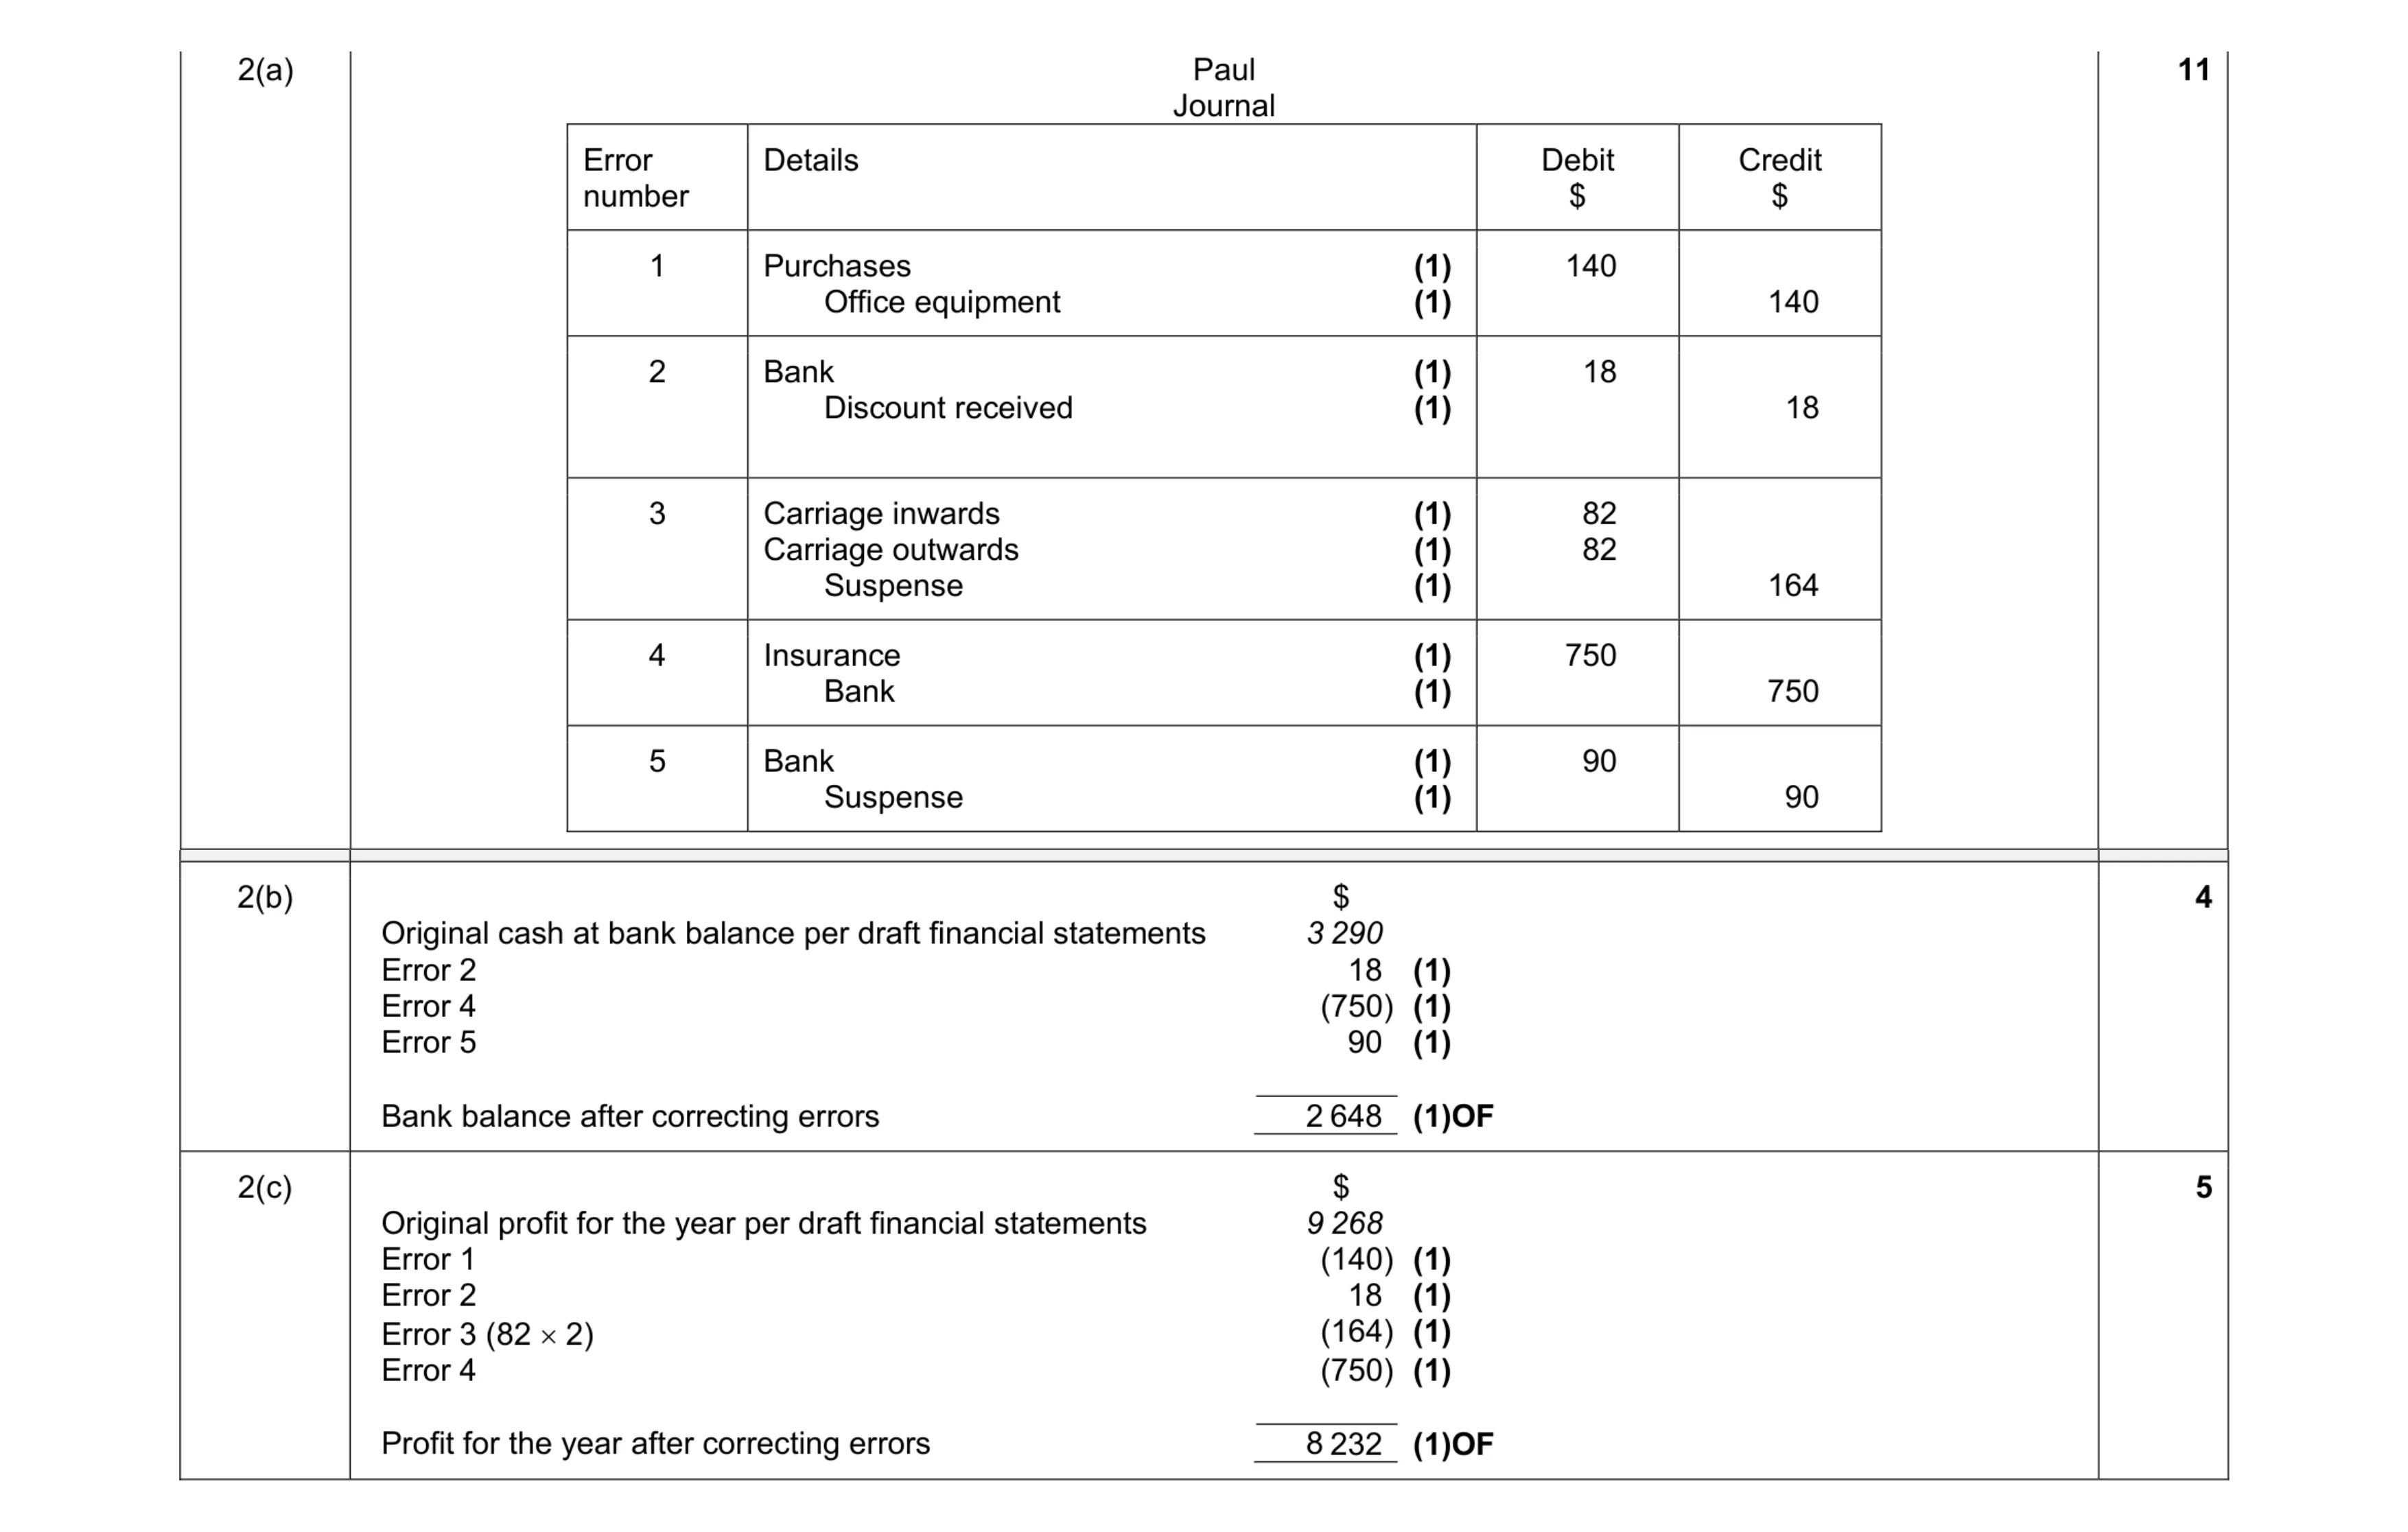
Mark scheme: 2(a) Paul Journal Error number Details Debit $ Credit $ 1 Purchases (1) Office equipment (1) 140 140 2 Bank (1) Discount received (1) 18 18 3 Carriage inwards (1) Carriage outwards (1) Suspense (1) 82 82 164 4 Insurance (1) Bank (1) 750 750 5 Bank (1) Suspense (1) 90 90 11 Question Answer Marks 2(b) $ Original cash at bank balance per draft financial statements 3 290 Error 2 18 (1) Error 4 (750) (1) Error 5 90 (1) Bank balance after correcting errors 2 648 (1)OF 4 2(c) $ Original profit for the year per draft financial statements 9 268 Error 1 (140) (1) Error 2 18 (1) Error 3 (82 2) (164) (1) Error 4 (750) (1) Profit for the year after correcting errors 8 232 (1)OF 5
This question in 0985/21 May/June 2024
Q16 · Akil prepared his trial balance at 29 February 2024 0985/22 May/June 2024
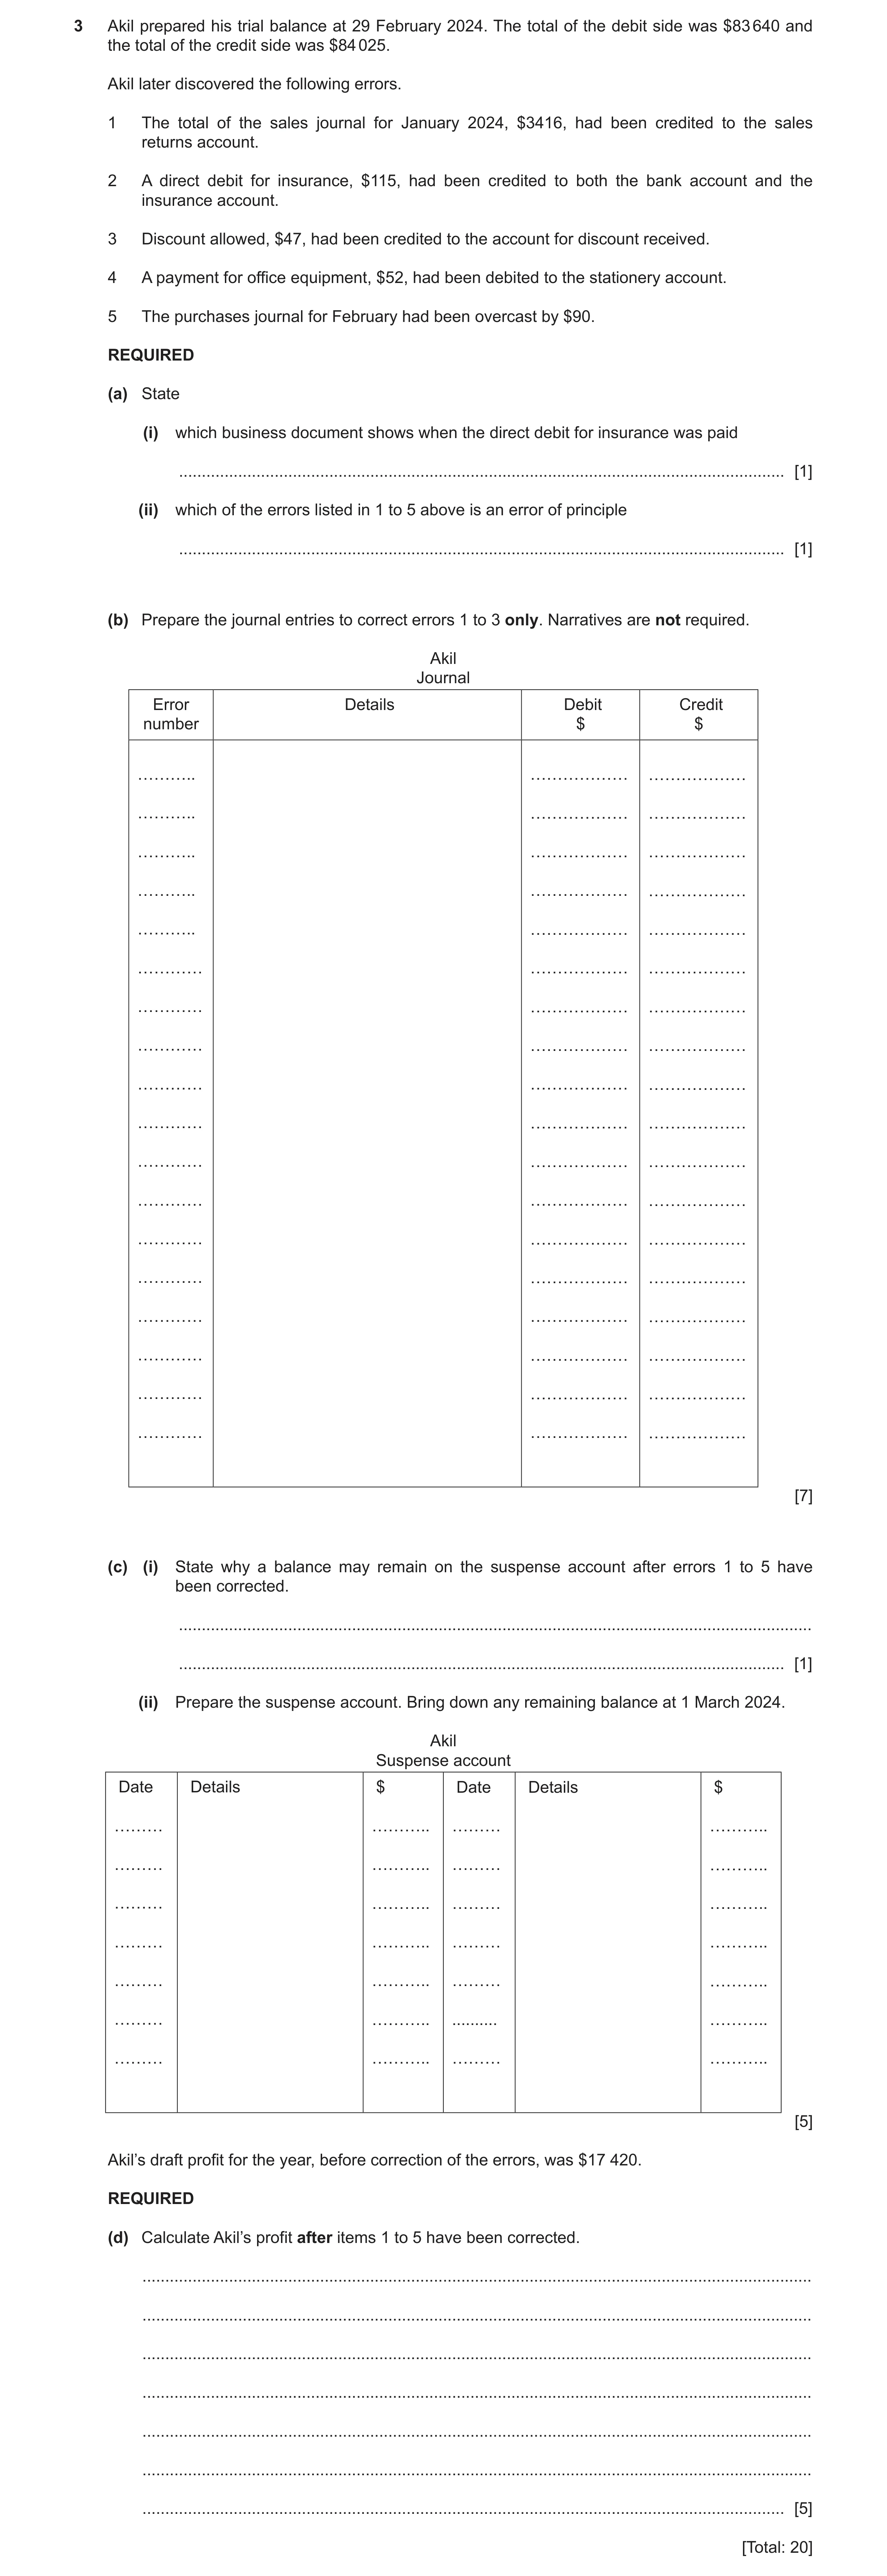
3 Akil prepared his trial balance at 29 February 2024. The total of the debit side was $83 640 and the total of the credit side was $84 025. Akil later discovered the following errors. 1 The total of the sales journal for January 2024, $3416, had been credited to the sales returns account. 2 A direct debit for insurance, $115, had been credited to both the bank account and the insurance account. 3 Discount allowed, $47, had been credited to the account for discount received. 4 A payment for office equipment, $52, had been debited to the stationery account. 5 The purchases journal for February had been overcast by $90. REQUIRED (a) State (i) which business document shows when the direct debit for insurance was paid … [1] (ii) which of the errors listed in 1 to 5 above is an error of principle … [1] (b) Prepare the journal entries to correct errors 1 to 3 only. Narratives are not required. Akil Journal Error Details Debit Credit number $ $ ……….. ……………… ……………… ……….. ……………… ……………… ……….. ……………… ……………… ……….. ……………… ……………… ……….. ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… [7] (c) (i) State why a balance may remain on the suspense account after errors 1 to 5 have been corrected. … … [1] (ii) Prepare the suspense account. Bring down any remaining balance at 1 March 2024. Akil Suspense account Date Details $ Date Details $ ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. … ……….. ……… ……….. ……… ……….. [5] Akil’s draft profit for the year, before correction of the errors, was $17 420. REQUIRED (d) Calculate Akil’s profit after items 1 to 5 have been corrected. … … … … … … … [5] [Total: 20]
20 marks
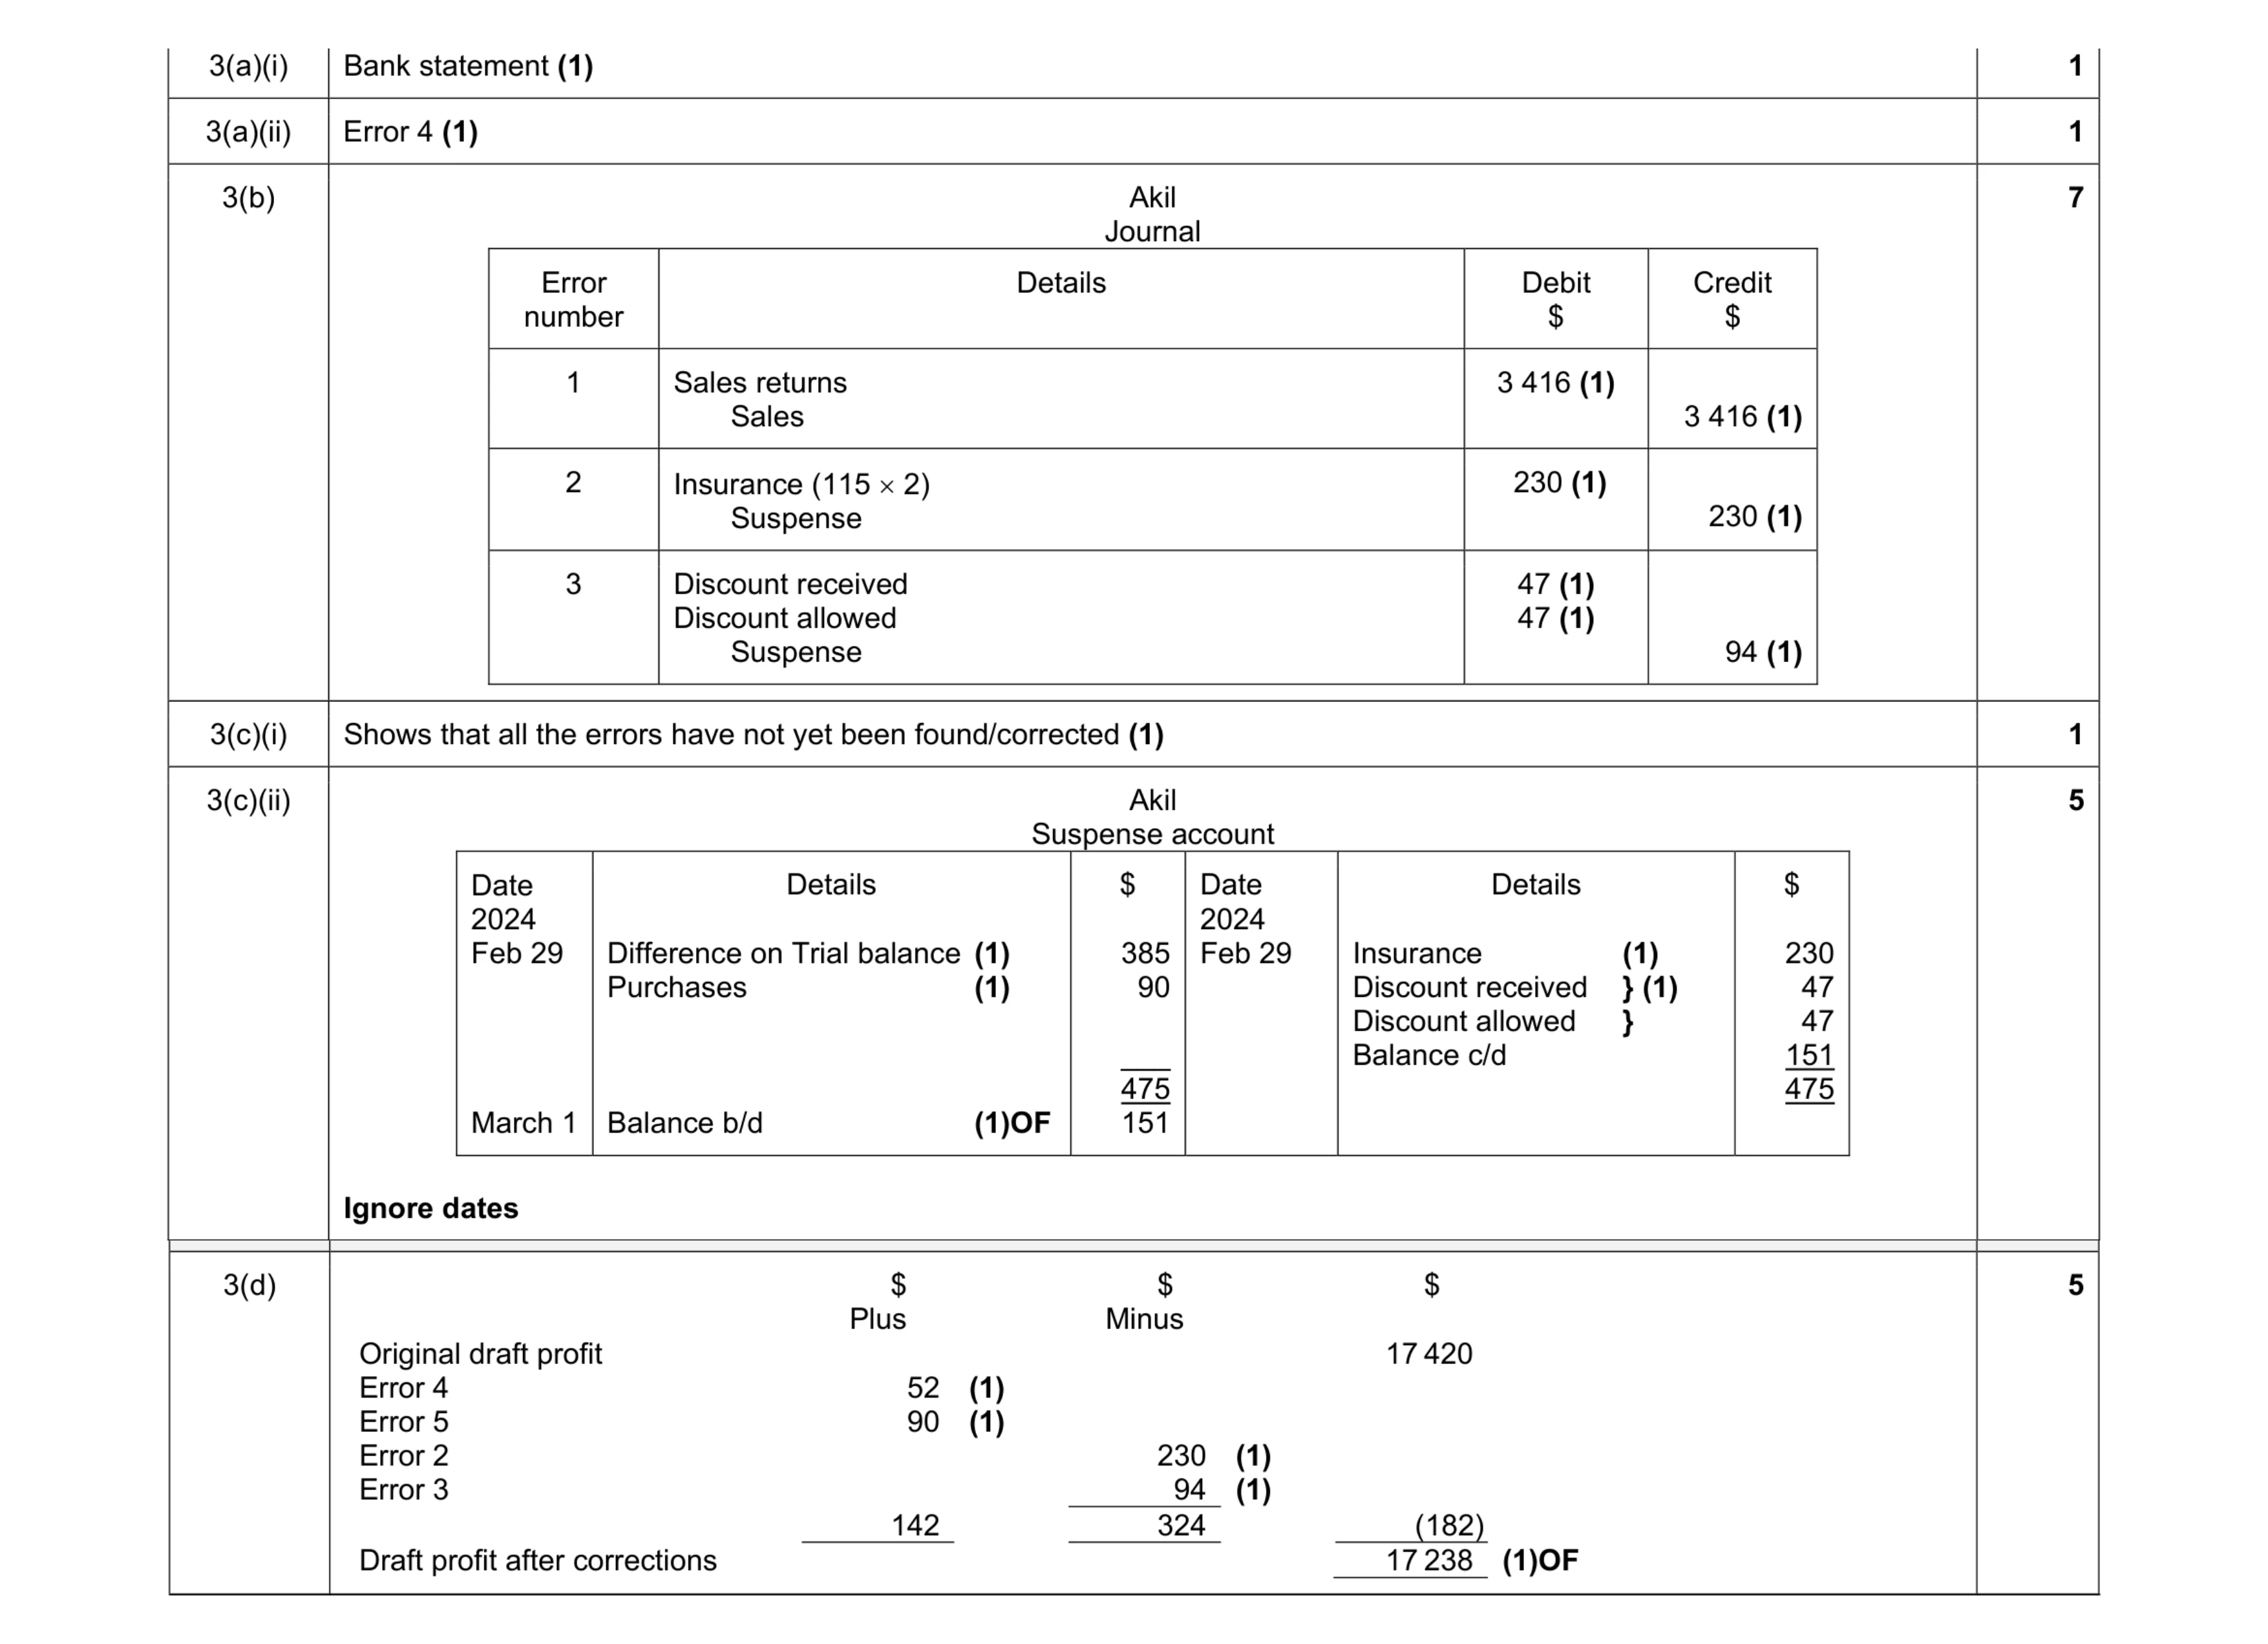
Mark scheme: 3(a)(i) Bank statement (1) 1 3(a)(ii) Error 4 (1) 1 3(b) Akil Journal Error number Details Debit $ Credit $ 1 Sales returns Sales 3 416 (1) 3 416 (1) 2 Insurance (115 2) Suspense 230 (1) 230 (1) 3 Discount received Discount allowed Suspense 47 (1) 47 (1) 94 (1) 7 3(c)(i) Shows that all the errors have not yet been found/corrected (1) 1 3(c)(ii) Akil Suspense account Date 2024 Feb 29 March 1 Details Difference on Trial balance (1) Purchases (1) Balance b/d (1)OF $ 385 90 ___ 475 151 Date 2024 Feb 29 Details Insurance (1) Discount received } (1) Discount allowed } Balance c/d $ 230 47 47 151 475 Ignore dates 5 Question Answer Marks 3(d) $ $ $ Plus Minus Original draft profit 17 420 Error 4 52 (1) Error 5 90 (1) Error 2 230 (1) Error 3 94 (1) 142 324 (182) Draft profit after corrections 17 238 (1)OF 5
This question in 0985/22 May/June 2024
Q17 · Azim is a wholesaler 0985/22 Oct/Nov 2024
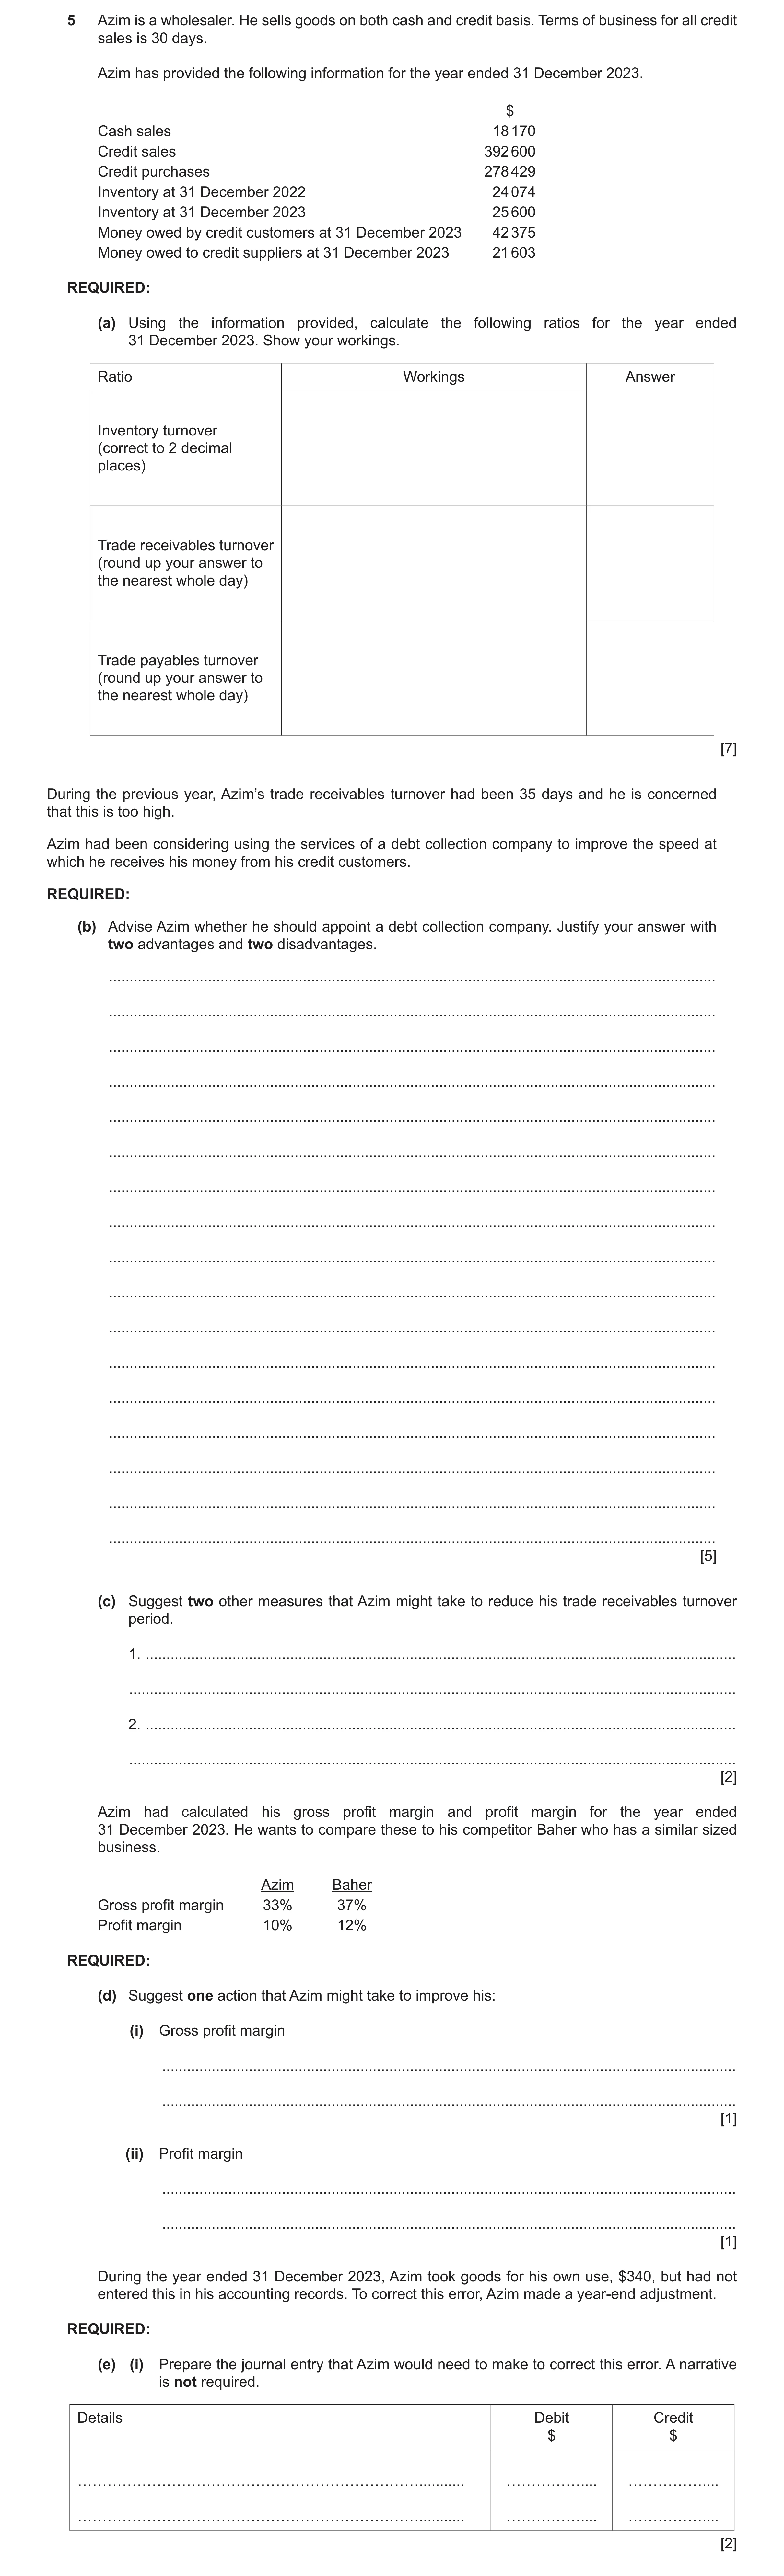
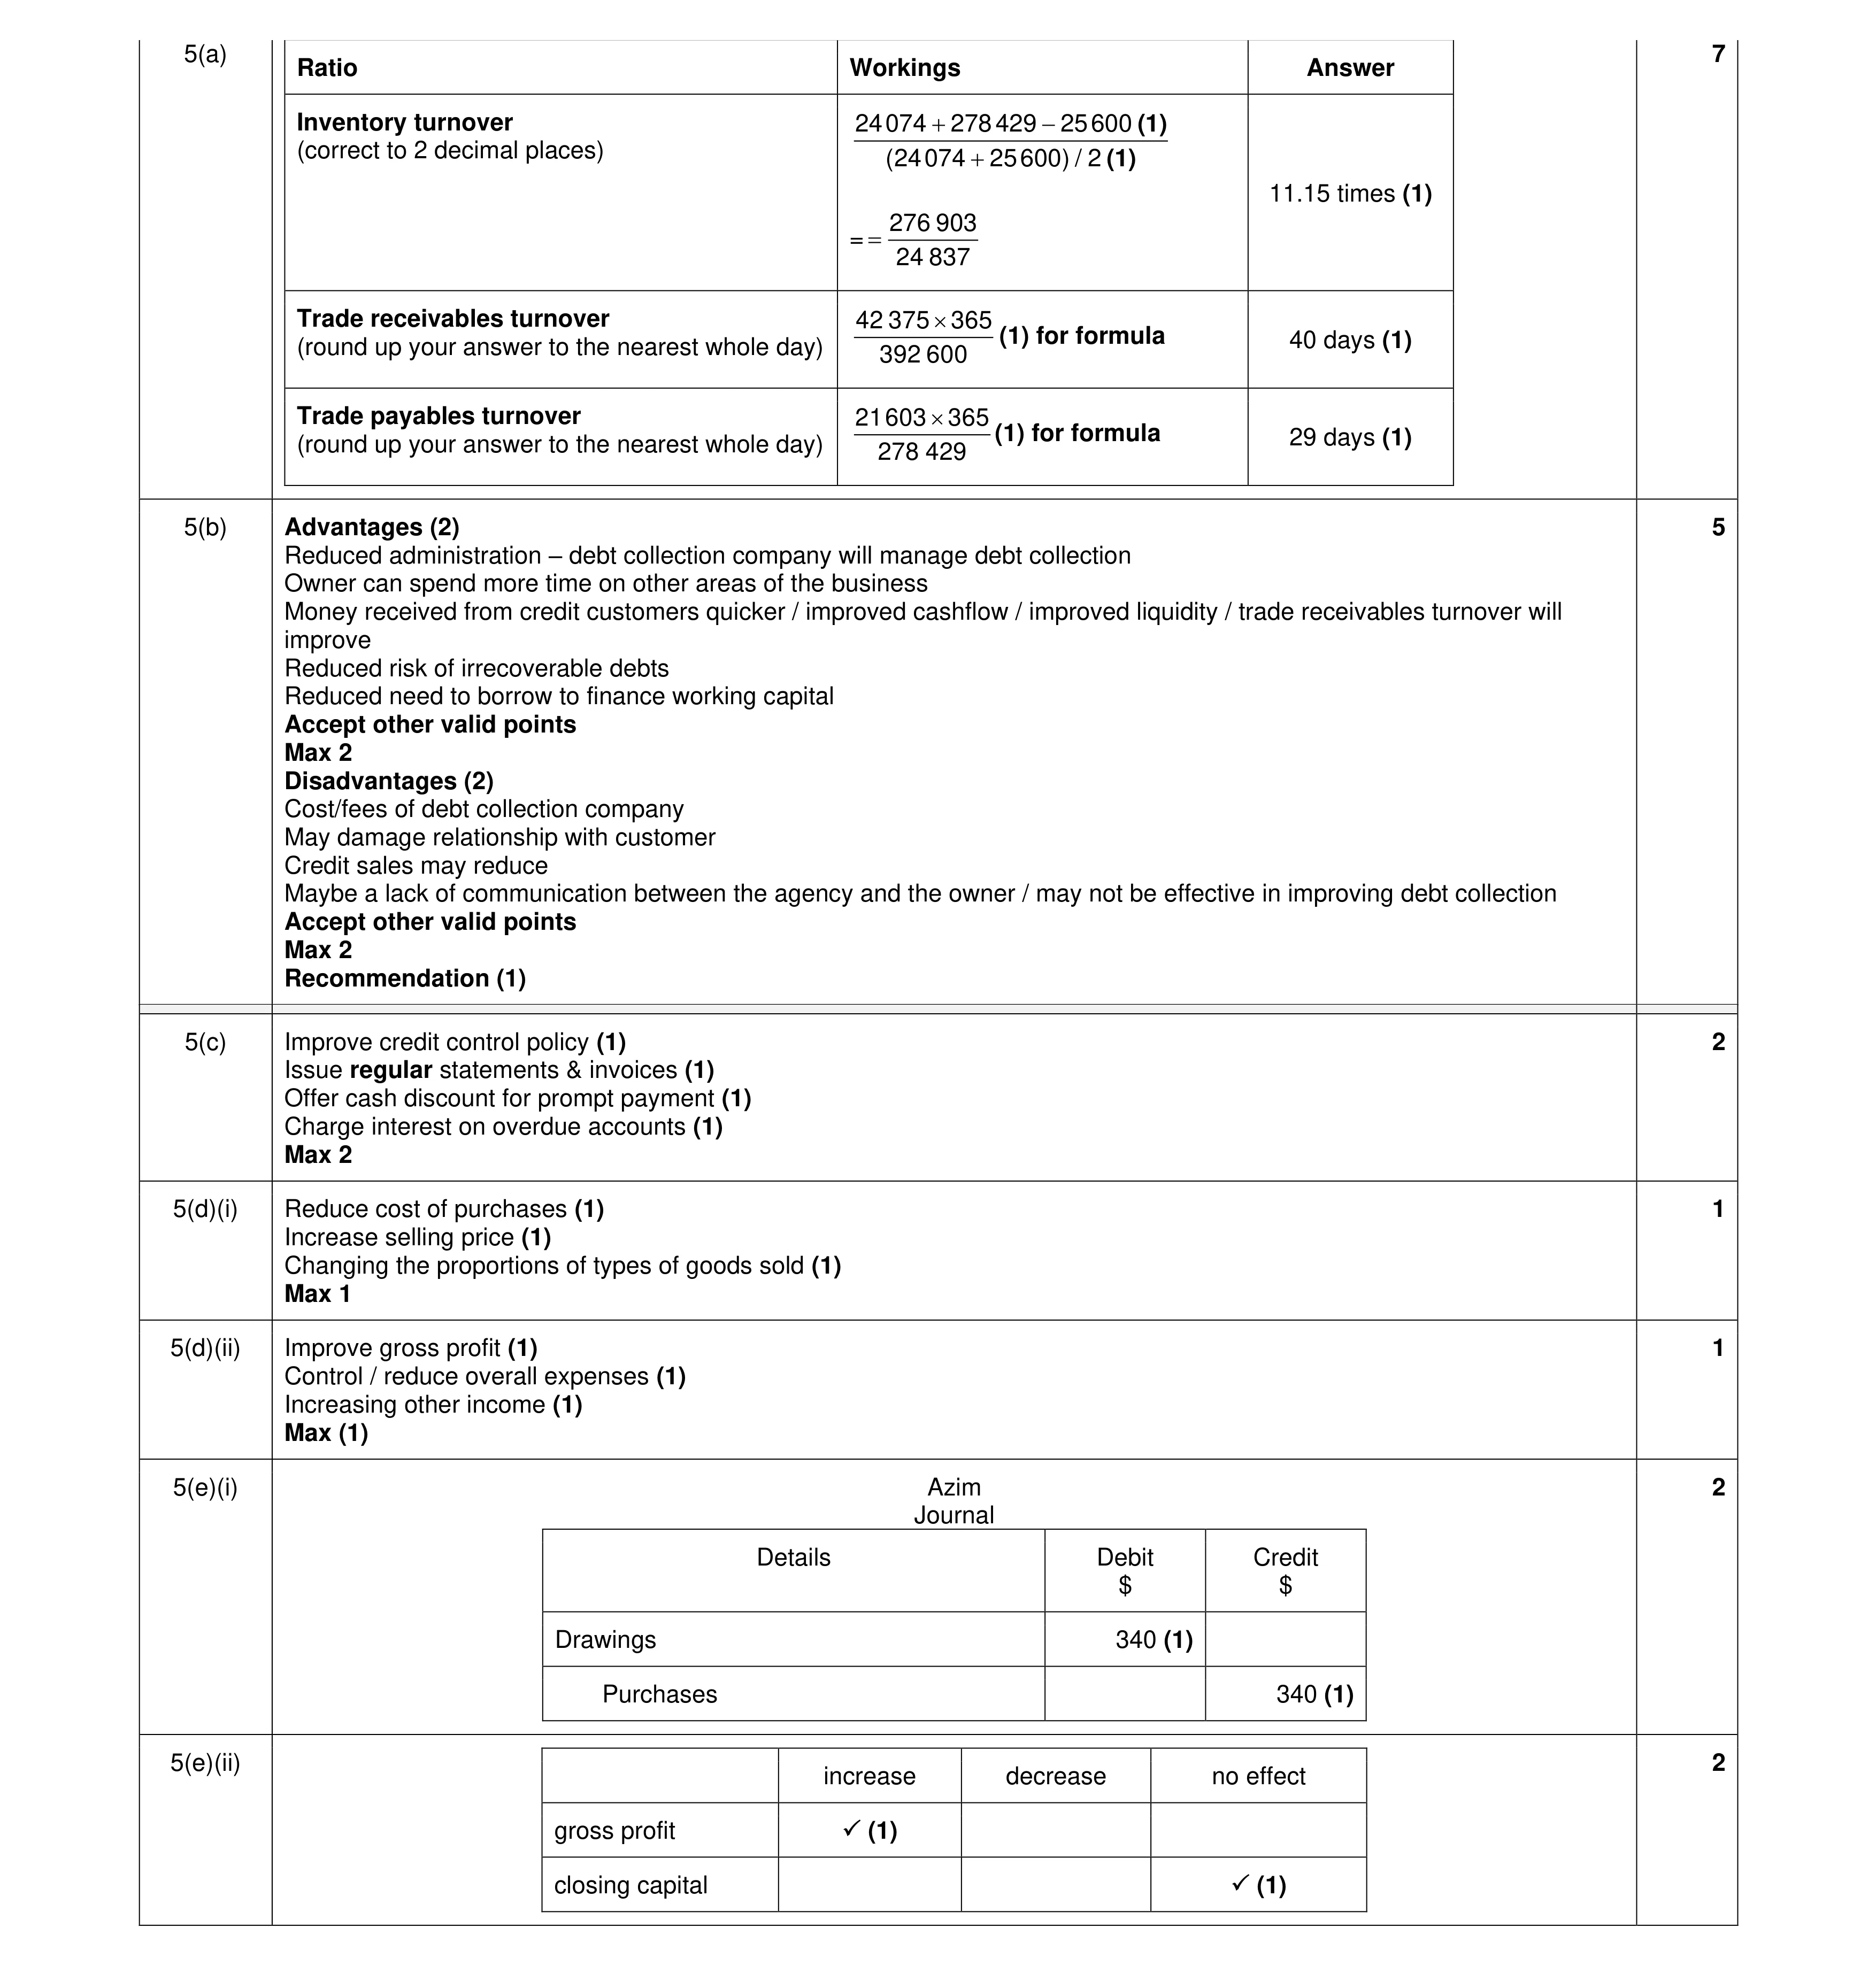
5 Azim is a wholesaler. He sells goods on both cash and credit basis. Terms of business for all credit sales is 30 days. Azim has provided the following information for the year ended 31 December 2023. $ Cash sales 18 170 Credit sales 392 600 Credit purchases 278 429 Inventory at 31 December 2022 24 074 Inventory at 31 December 2023 25 600 Money owed by credit customers at 31 December 2023 42 375 Money owed to credit suppliers at 31 December 2023 21 603 REQUIRED: (a) Using the information provided, calculate the following ratios for the year ended 31 December 2023. Show your workings. Ratio Workings Answer Inventory turnover (correct to 2 decimal places) Trade receivables turnover (round up your answer to the nearest whole day) Trade payables turnover (round up your answer to the nearest whole day) [7] During the previous year, Azim’s trade receivables turnover had been 35 days and he is concerned that this is too high. Azim had been considering using the services of a debt collection company to improve the speed at which he receives his money from his credit customers. REQUIRED: (b) Advise Azim whether he should appoint a debt collection company. Justify your answer with two advantages and two disadvantages. … … … … … … … … … … … … … … … … … [5] (c) Suggest two other measures that Azim might take to reduce his trade receivables turnover period. 1. … … 2. … … [2] Azim had calculated his gross profit margin and profit margin for the year ended 31 December 2023. He wants to compare these to his competitor Baher who has a similar sized business. Azim Baher Gross profit margin 33% 37% Profit margin 10% 12% REQUIRED: (d) Suggest one action that Azim might take to improve his: (i) Gross profit margin … … [1] (ii) Profit margin … … [1] During the year ended 31 December 2023, Azim took goods for his own use, $340, but had not entered this in his accounting records. To correct this error, Azim made a year-end adjustment. REQUIRED: (e) (i) Prepare the journal entry that Azim would need to make to correct this error. A narrative is not required. Details Debit Credit $ $ …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … [2]
18 marks
Mark scheme: 5(a) 7 Ratio Workings Answer Inventory turnover 24074 + 278429 − 25600 (1) (correct to 2 decimal places) (24074 + 25600) / 2 (1) 11.15 times (1) 276 903 = = 24 837 Trade receivables turnover 42 375 365 (1) for formula 40 days (1) (round up your answer to the nearest whole day) 392 600 Trade payables turnover 21603 365 (1) for formula 29 days (1) (round up your answer to the nearest whole day) 278 429 5(b) Advantages (2) 5 Reduced administration – debt collection company will manage debt collection Owner can spend more time on other areas of the business Money received from credit customers quicker / improved cashflow / improved liquidity / trade receivables turnover will improve Reduced risk of irrecoverable debts Reduced need to borrow to finance working capital Accept other valid points Max 2 Disadvantages (2) Cost/fees of debt collection company May damage relationship with customer Credit sales may reduce Maybe a lack of communication between the agency and the owner / may not be effective in improving debt collection Accept other valid points Max 2 Recommendation (1) 5(c) Improve credit control policy (1) 2 Issue regular statements & invoices (1) Offer cash discount for prompt payment (1) Charge interest on overdue accounts (1) Max 2 5(d)(i) Reduce cost of purchases (1) 1 Increase selling price (1) Changing the proportions of types of goods sold (1) Max 1 5(d)(ii) Improve gross profit (1) 1 Control / reduce overall expenses (1) Increasing other income (1) Max (1) 5(e)(i) Azim 2 Journal Details Debit Credit $ $ Drawings 340 (1) Purchases 340 (1) 5(e)(ii) 2 increase decrease no effect gross profit (1) closing capital (1)
This question in 0985/22 Oct/Nov 2024
Q18 · Nabil prepared a trial balance at 30 April 2025 0985/21 May/June 2025
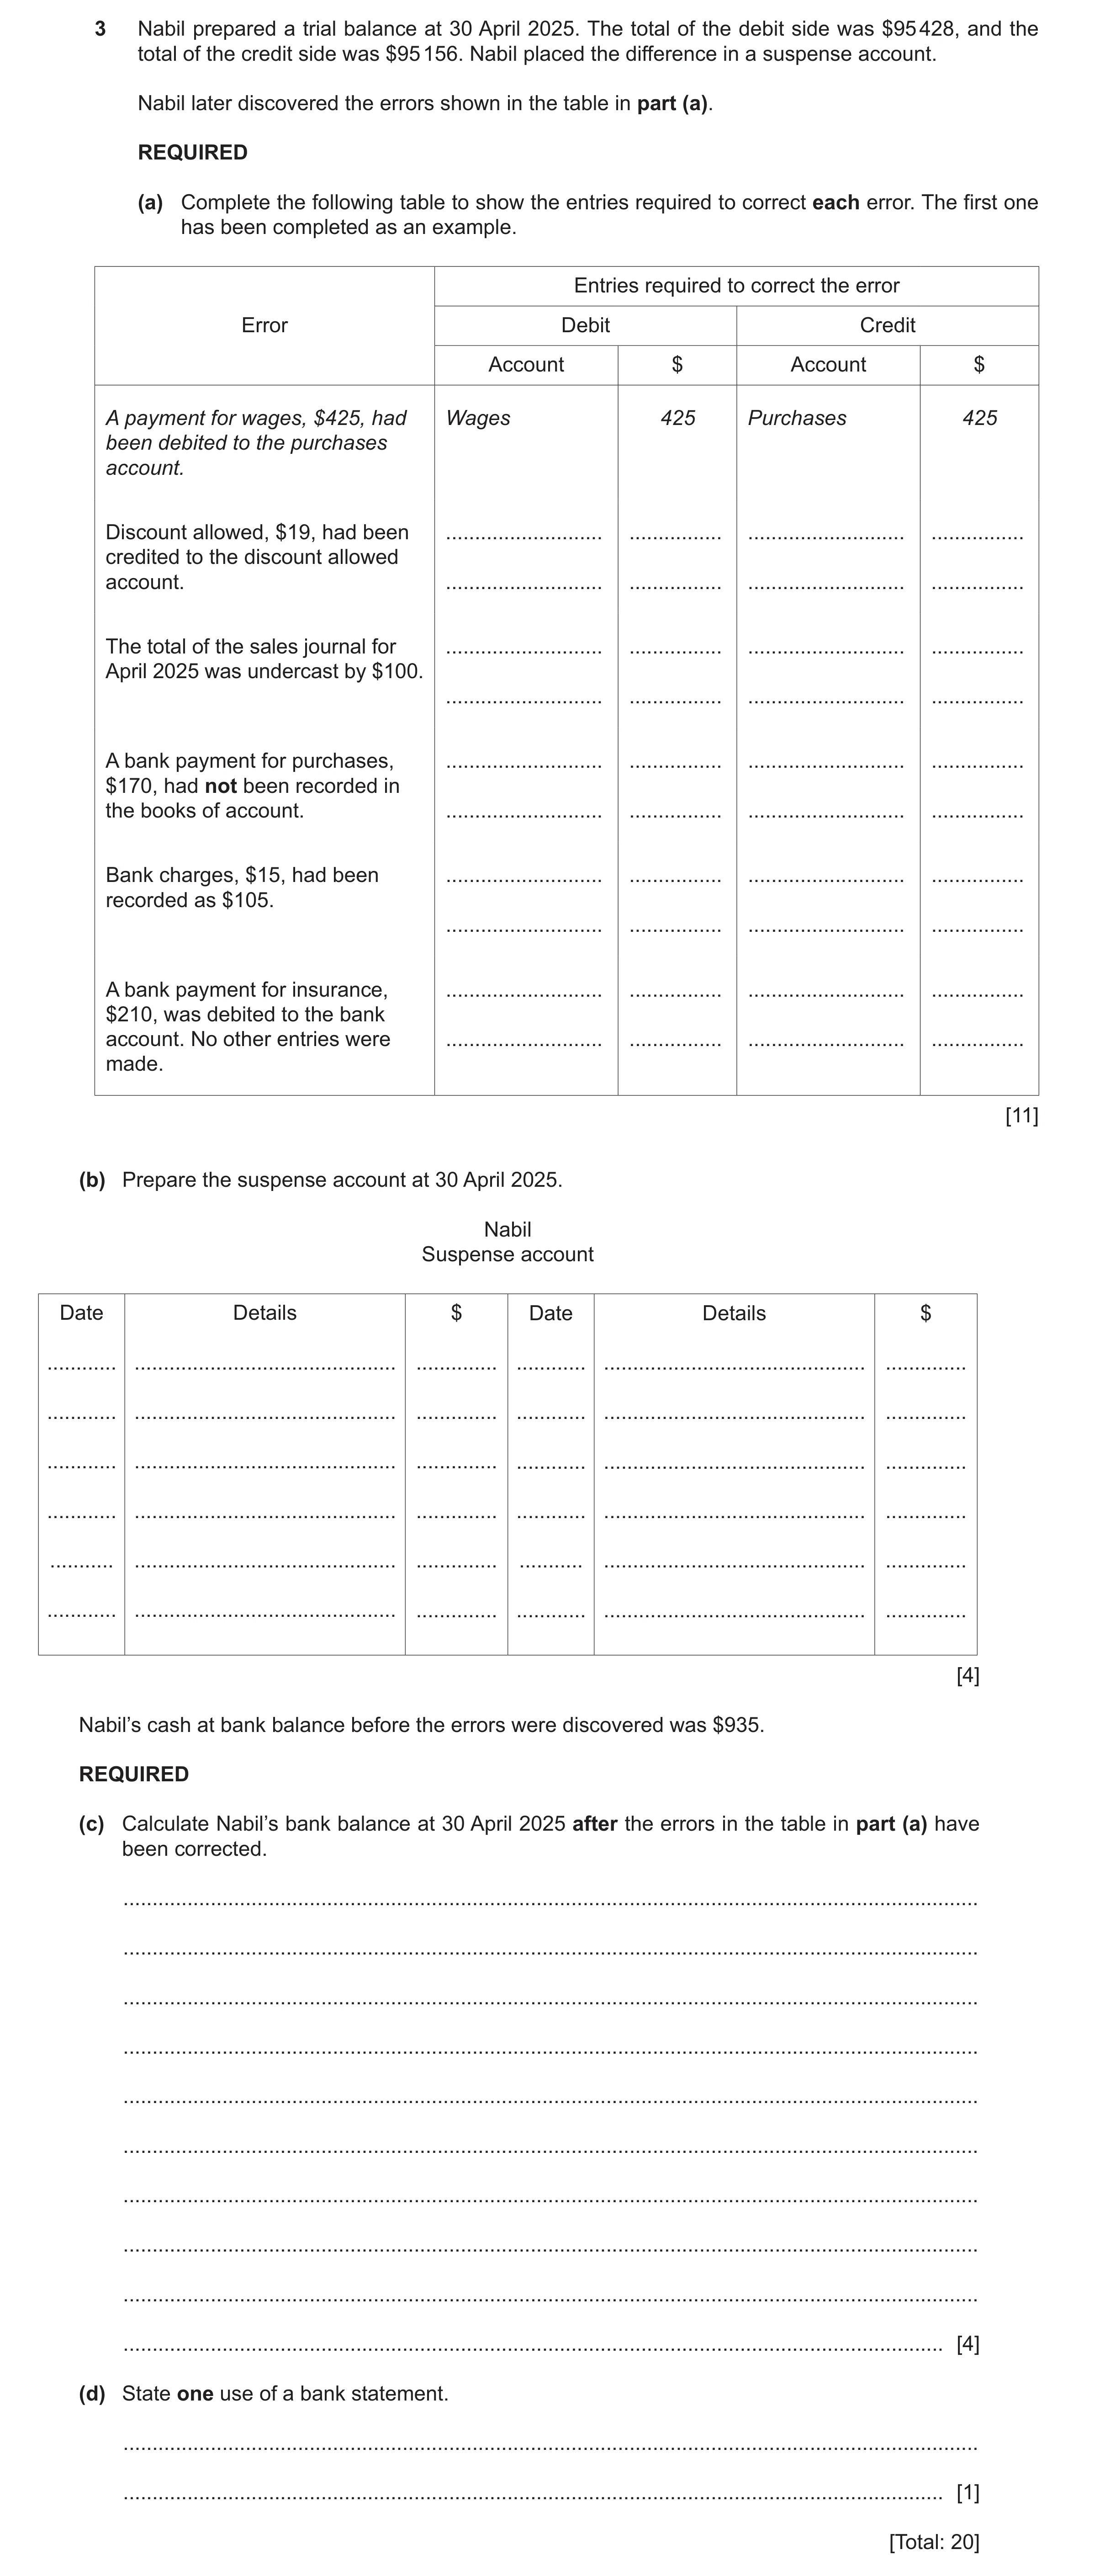
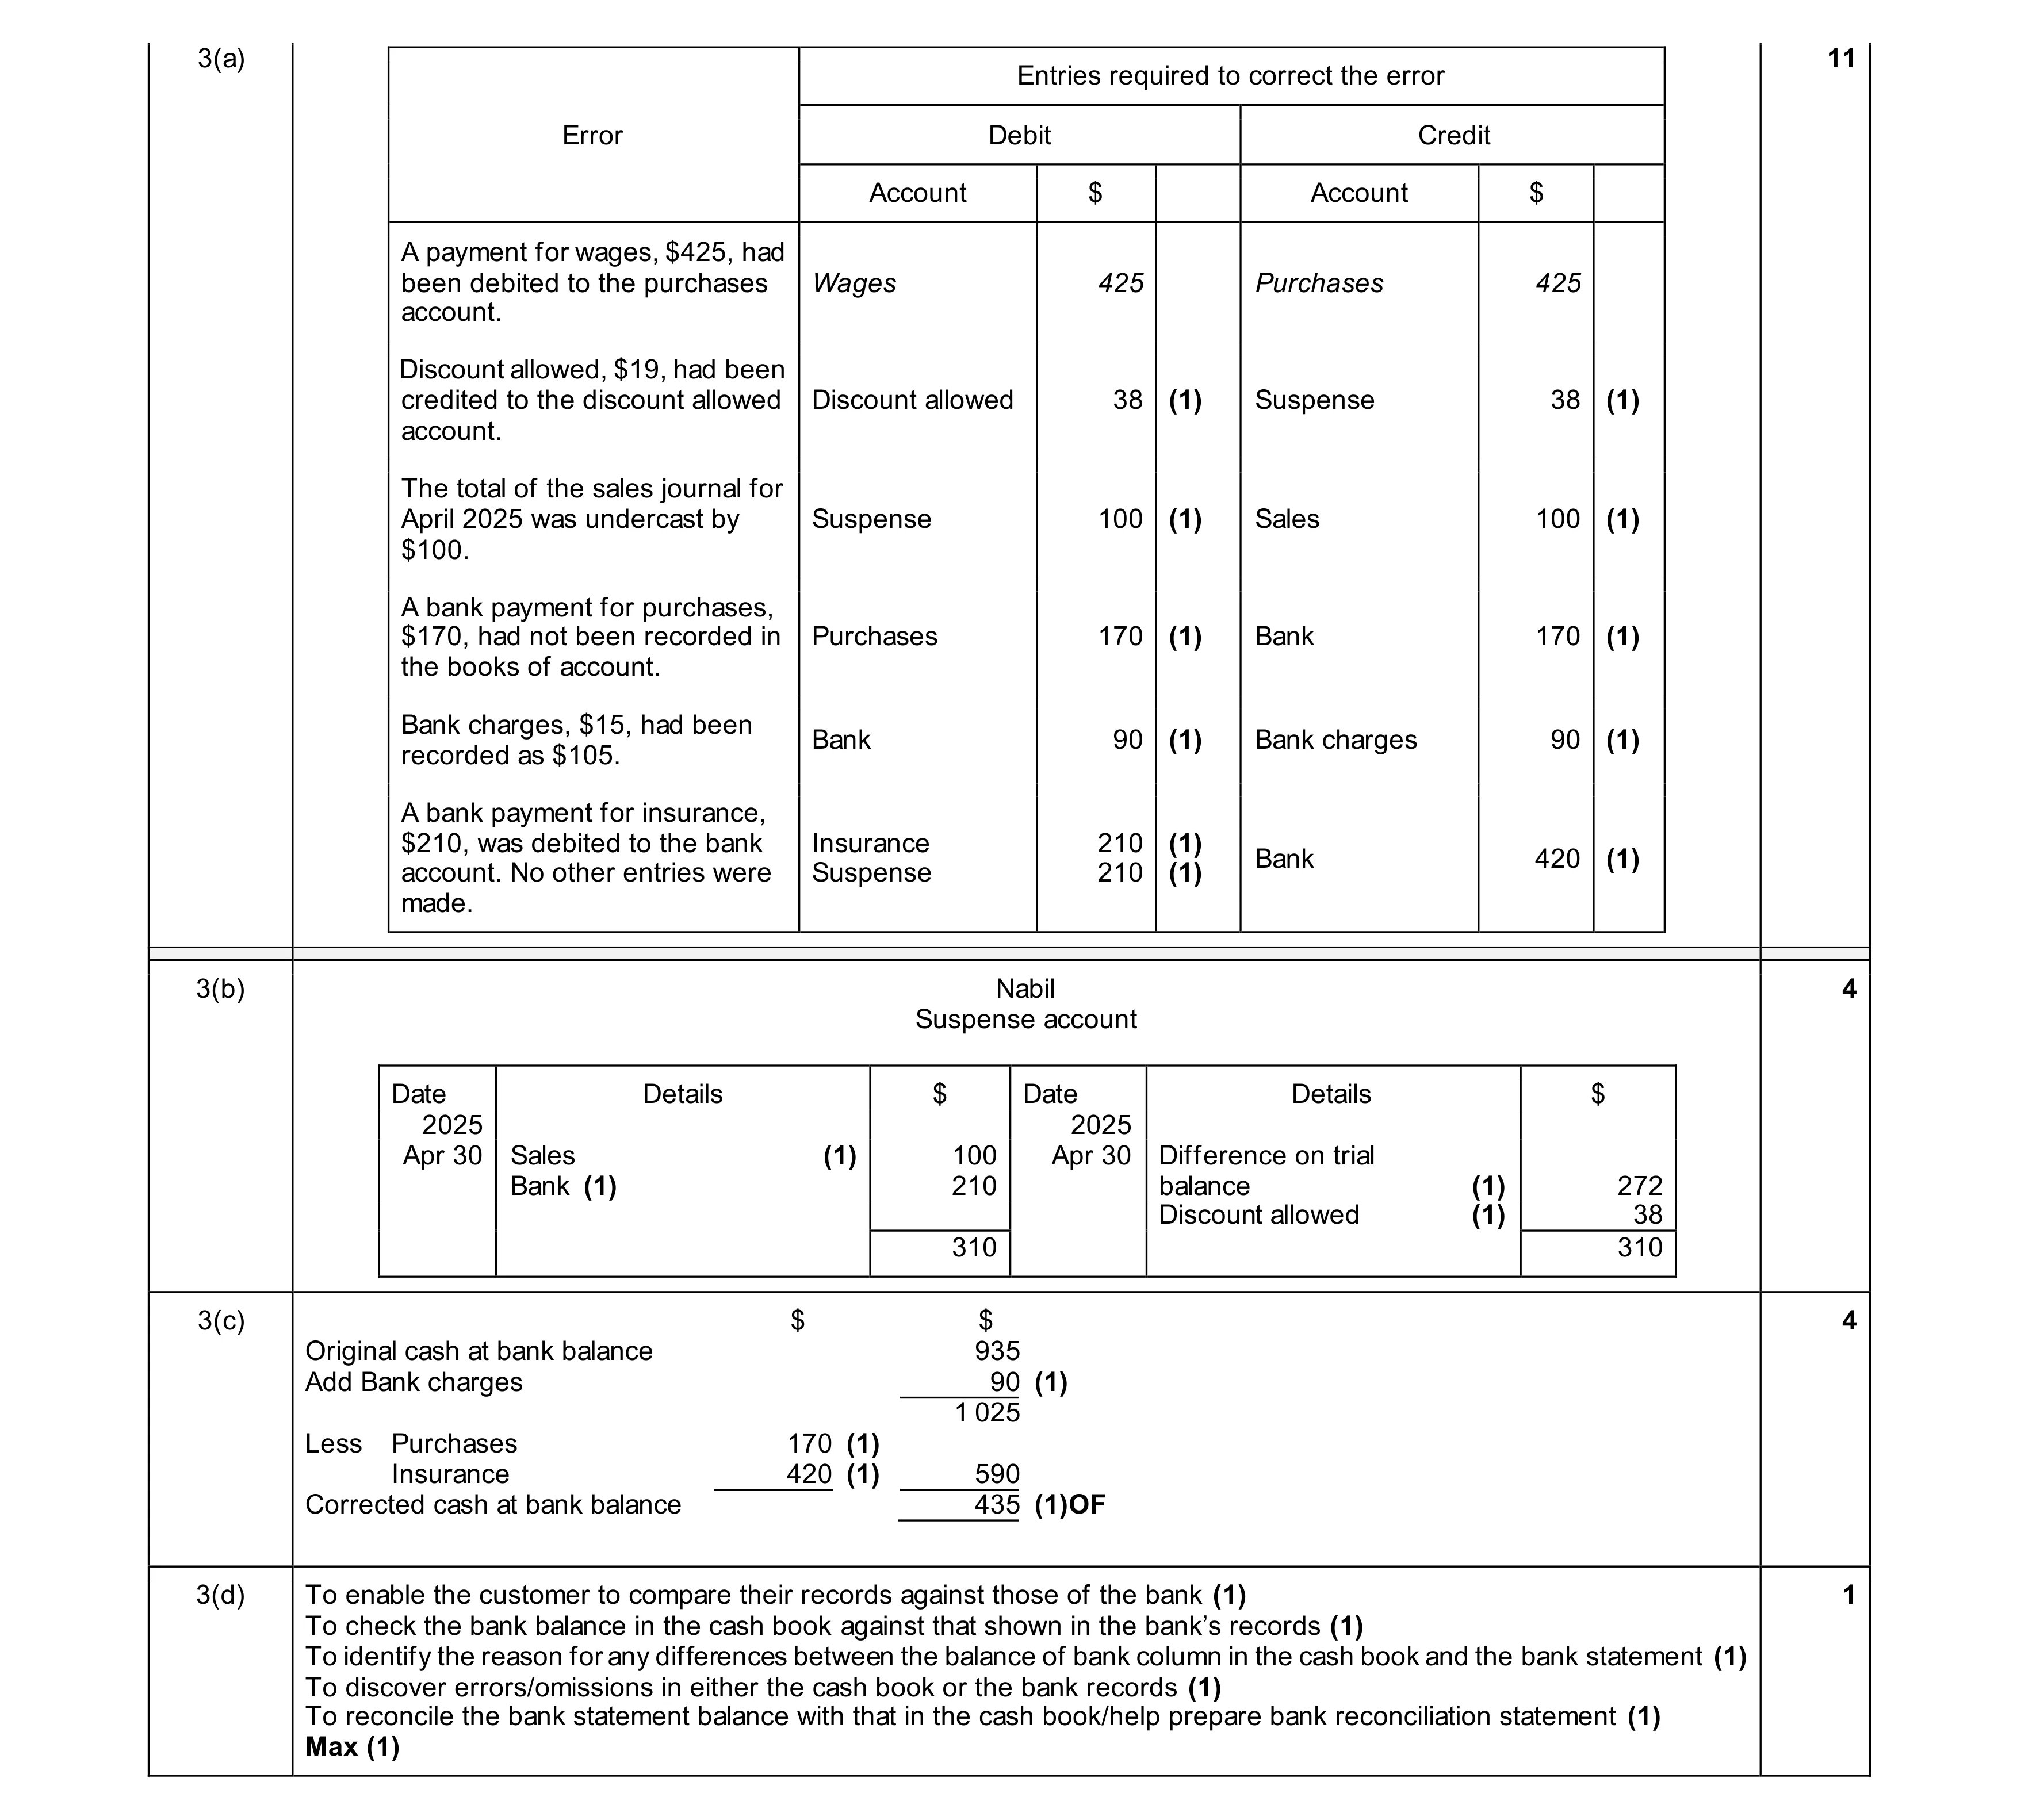
3 Nabil prepared a trial balance at 30 April 2025. The total of the debit side was $95 428, and the total of the credit side was $95 156. Nabil placed the difference in a suspense account. Nabil later discovered the errors shown in the table in part (a). REQUIRED (a) Complete the following table to show the entries required to correct each error. The first one has been completed as an example. Entries required to correct the error Error Debit Credit Account $ Account $ A payment for wages, $425, had Wages 425 Purchases 425 been debited to the purchases account. Discount allowed, $19, had been … … … … credited to the discount allowed account. … … … … The total of the sales journal for … … … … April 2025 was undercast by $100. … … … … A bank payment for purchases, … … … … $170, had not been recorded in the books of account. … … … … Bank charges, $15, had been … … … … recorded as $105. … … … … A bank payment for insurance, … … … … $210, was debited to the bank account. No other entries were … … … … made. [11] (b) Prepare the suspense account at 30 April 2025. Nabil Suspense account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [4] Nabil’s cash at bank balance before the errors were discovered was $935. REQUIRED (c) Calculate Nabil’s bank balance at 30 April 2025 after the errors in the table in part (a) have been corrected. … … … … … … … … … … [4] (d) State one use of a bank statement. … … [1] [Total: 20]
20 marks
Mark scheme: 3(a) 11 Entries required to correct the error Error Debit Credit Account $ Account $ A payment for wages, $425, had been debited to the purchases Wages 425 Purchases 425 account. Discount allowed, $19, had been credited to the discount allowed Discount allowed 38 (1) Suspense 38 (1) account. The total of the sales journal for April 2025 was undercast by Suspense 100 (1) Sales 100 (1) $100. A bank payment for purchases, $170, had not been recorded in Purchases 170 (1) Bank 170 (1) the books of account. Bank charges, $15, had been Bank 90 (1) Bank charges 90 (1) recorded as $105. A bank payment for insurance, $210, was debited to the bank Insurance 210 (1) Bank 420 (1) account. No other entries were Suspense 210 (1) made. 3(b) Nabil 4 Suspense account Date Details $ Date Details $ 2025 2025 Apr 30 Sales (1) 100 Apr 30 Difference on trial Bank (1) 210 balance (1) 272 Discount allowed (1) 38 310 310 3(c) $ $ 4 Original cash at bank balance 935 Add Bank charges 90 (1) 1 025 Less Purchases 170 (1) Insurance 420 (1) 590 Corrected cash at bank balance 435 (1)OF 3(d) To enable the customer to compare their records against those of the bank (1) 1 To check the bank balance in the cash book against that shown in the bank’s records (1) To identify the reason for any differences between the balance of bank column in the cash book and the bank statement (1) To discover errors/omissions in either the cash book or the bank records (1) To reconcile the bank statement balance with that in the cash book/help prepare bank reconciliation statement (1) Max (1)
This question in 0985/21 May/June 2025
Q19 · Bilal prepared a trial balance at 31 December 2024 0985/22 May/June 2025
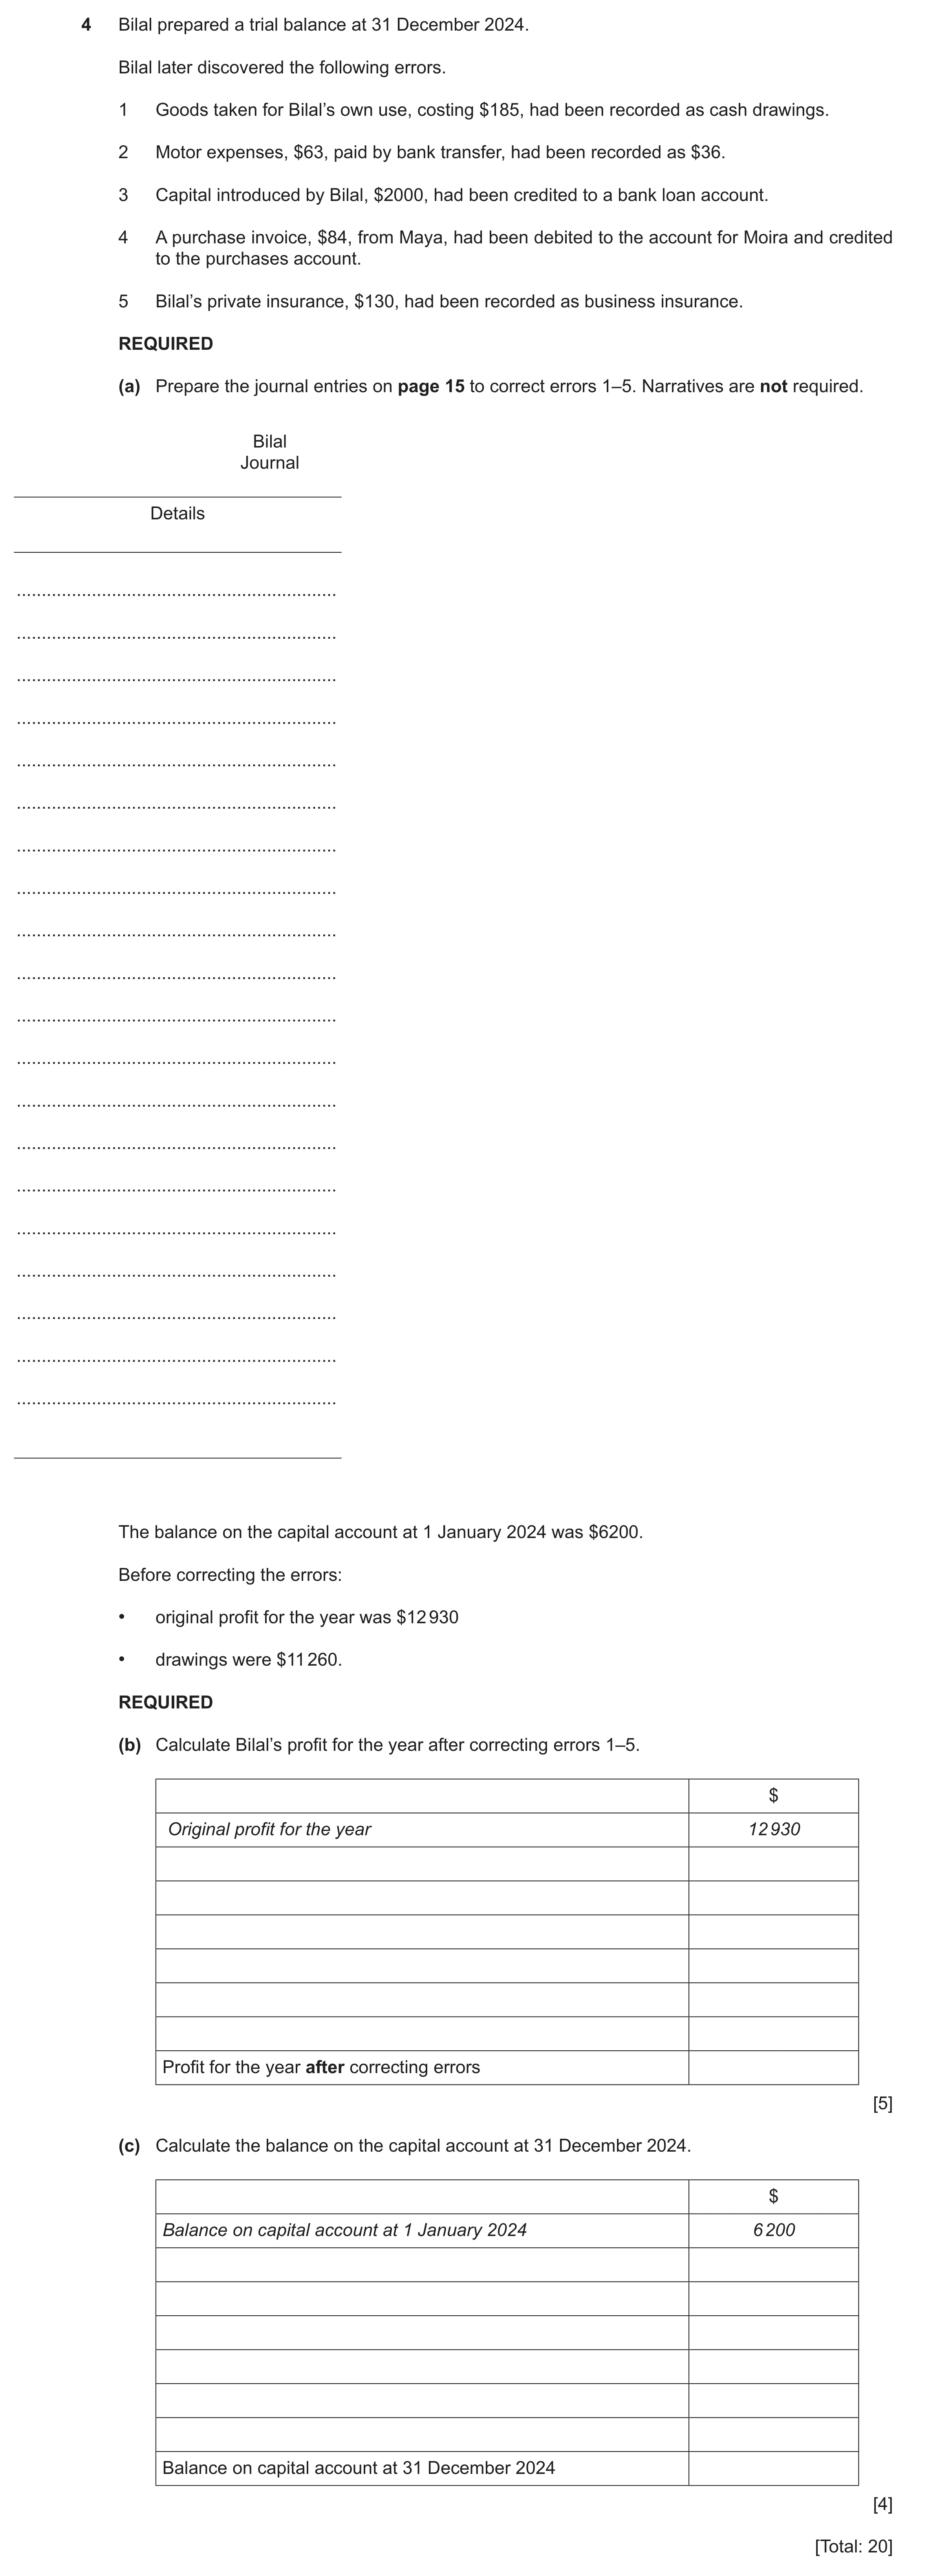
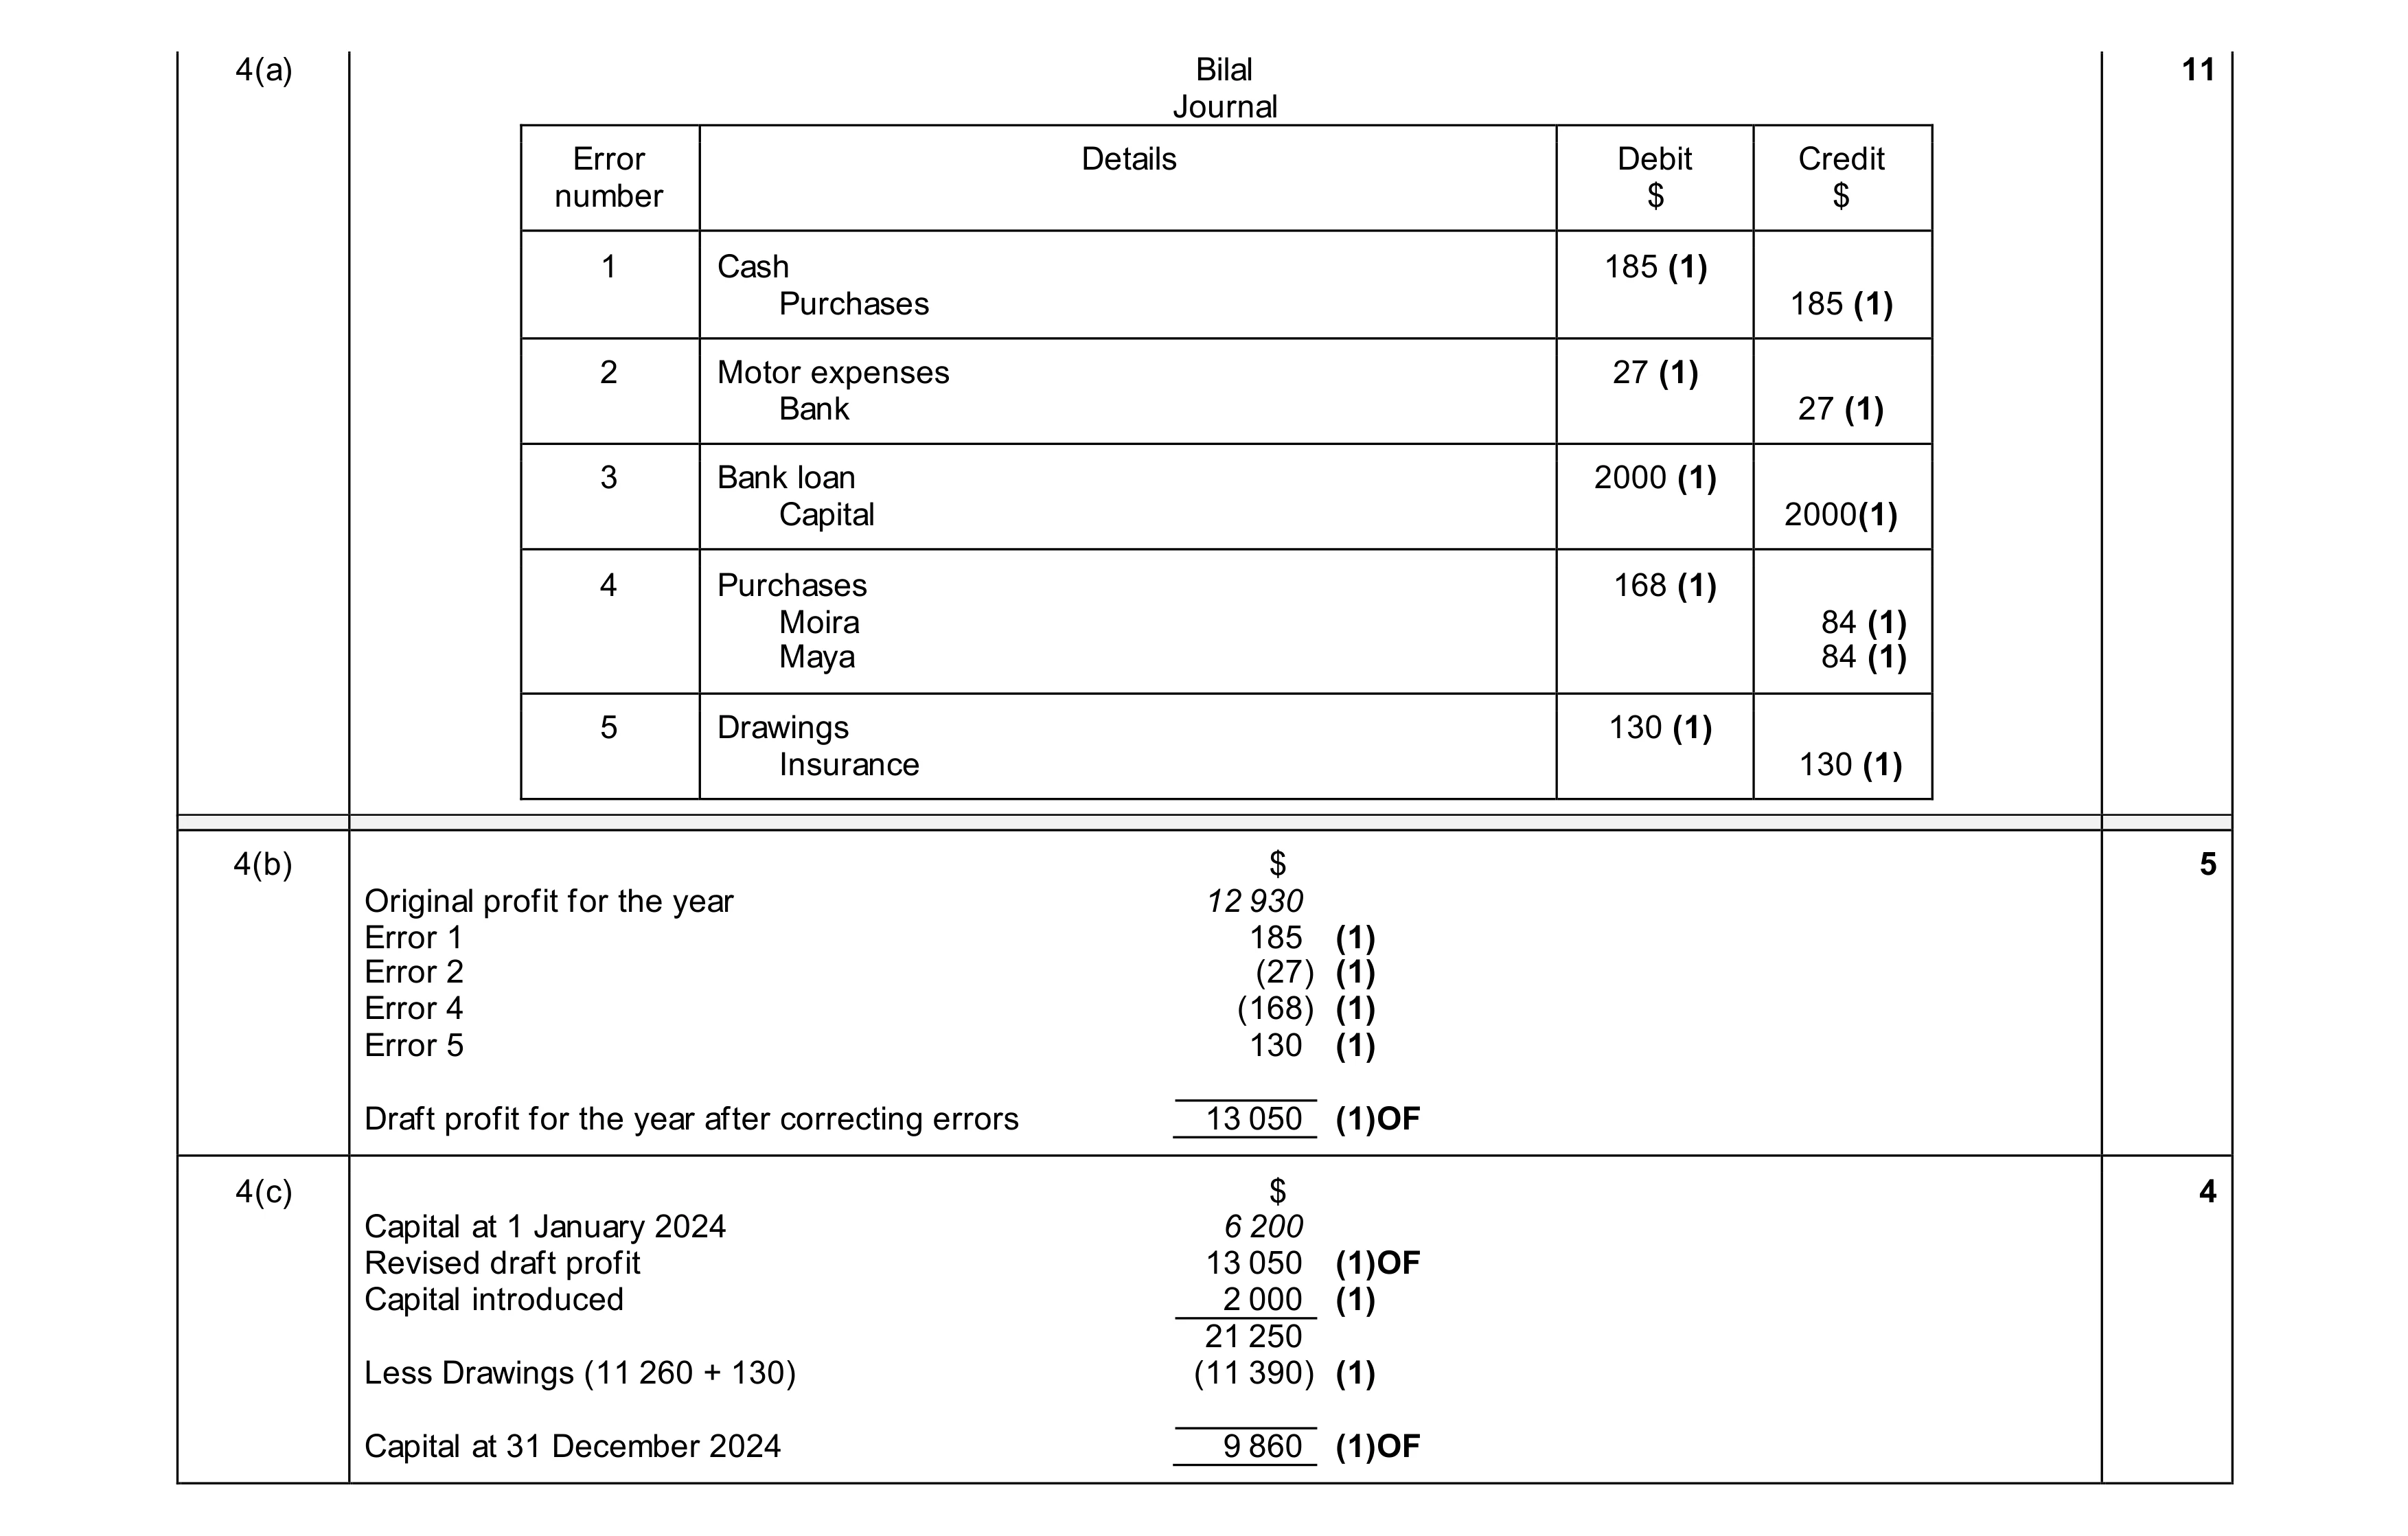
4 Bilal prepared a trial balance at 31 December 2024. Bilal later discovered the following errors. 1 Goods taken for Bilal’s own use, costing $185, had been recorded as cash drawings. 2 Motor expenses, $63, paid by bank transfer, had been recorded as $36. 3 Capital introduced by Bilal, $2000, had been credited to a bank loan account. 4 A purchase invoice, $84, from Maya, had been debited to the account for Moira and credited to the purchases account. 5 Bilal’s private insurance, $130, had been recorded as business insurance. REQUIRED (a) Prepare the journal entries on page 15 to correct errors 1–5. Narratives are not required. Bilal Journal Details … … … … … … … … … … … … … … … … … … … … The balance on the capital account at 1 January 2024 was $6200. Before correcting the errors: • original profit for the year was $12 930 • drawings were $11 260. REQUIRED (b) Calculate Bilal’s profit for the year after correcting errors 1–5. $ Original profit for the year 12 930 Profit for the year after correcting errors [5] (c) Calculate the balance on the capital account at 31 December 2024. $ Balance on capital account at 1 January 2024 6 200 Balance on capital account at 31 December 2024 [4] [Total: 20]
20 marks
Mark scheme: 4(a) Bilal 11 Journal Error Details Debit Credit number $ $ 1 Cash 185 (1) Purchases 185 (1) 2 Motor expenses 27 (1) Bank 27 (1) 3 Bank loan 2000 (1) Capital 2000(1) 4 Purchases 168 (1) Moira 84 (1) Maya 84 (1) 5 Drawings 130 (1) Insurance 130 (1) 4(b) $ 5 Original profit for the year 12 930 Error 1 185 (1) Error 2 (27) (1) Error 4 (168) (1) Error 5 130 (1) Draft profit for the year after correcting errors 13 050 (1)OF 4(c) $ 4 Capital at 1 January 2024 6 200 Revised draft profit 13 050 (1)OF Capital introduced 2 000 (1) 21 250 Less Drawings (11 260 + 130) (11 390) (1) Capital at 31 December 2024 9 860 (1)OF
This question in 0985/22 May/June 2025
Q20 · Jaya is a trader 0985/22 Oct/Nov 2025
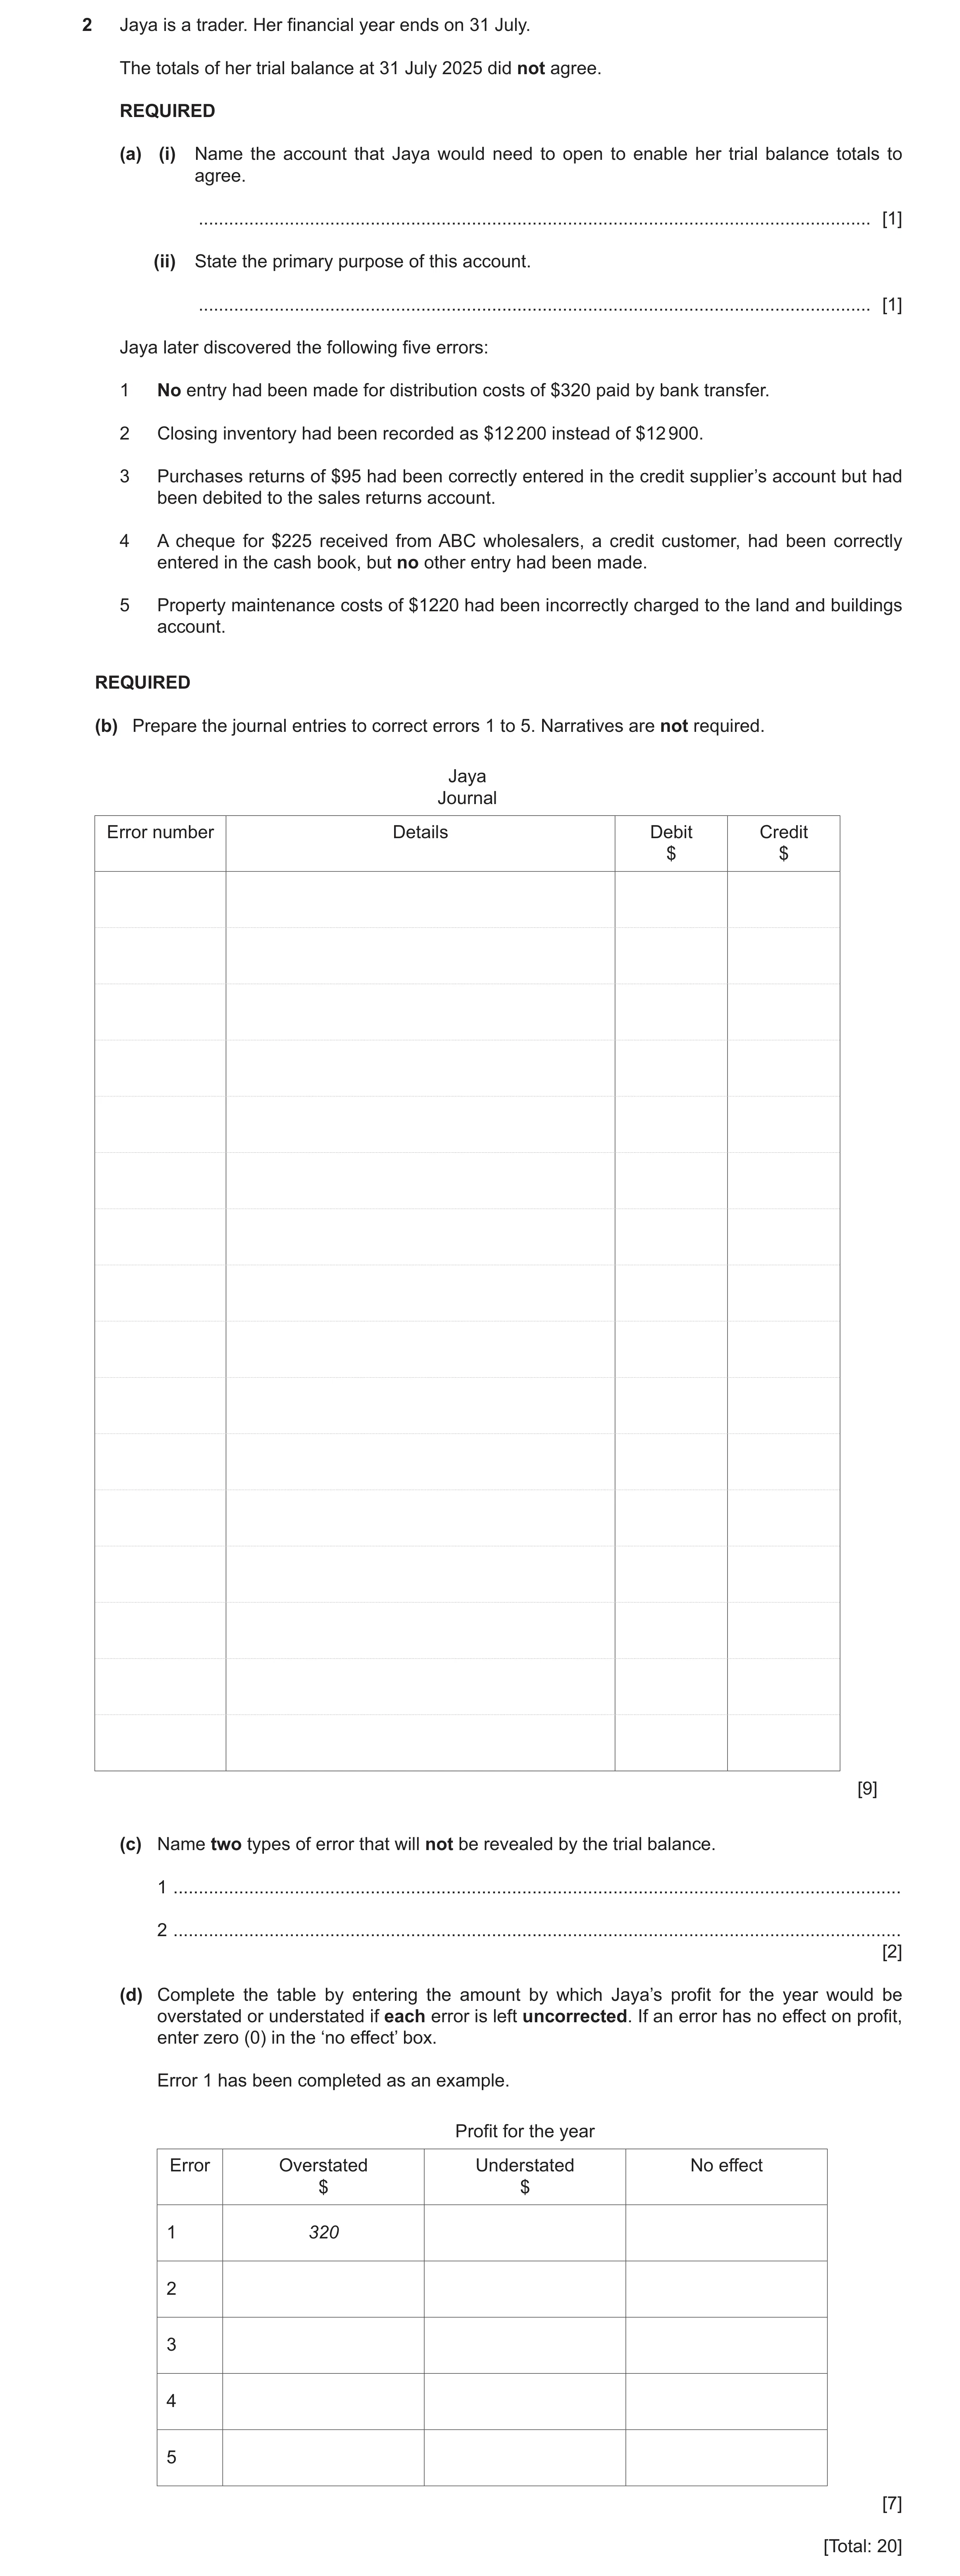
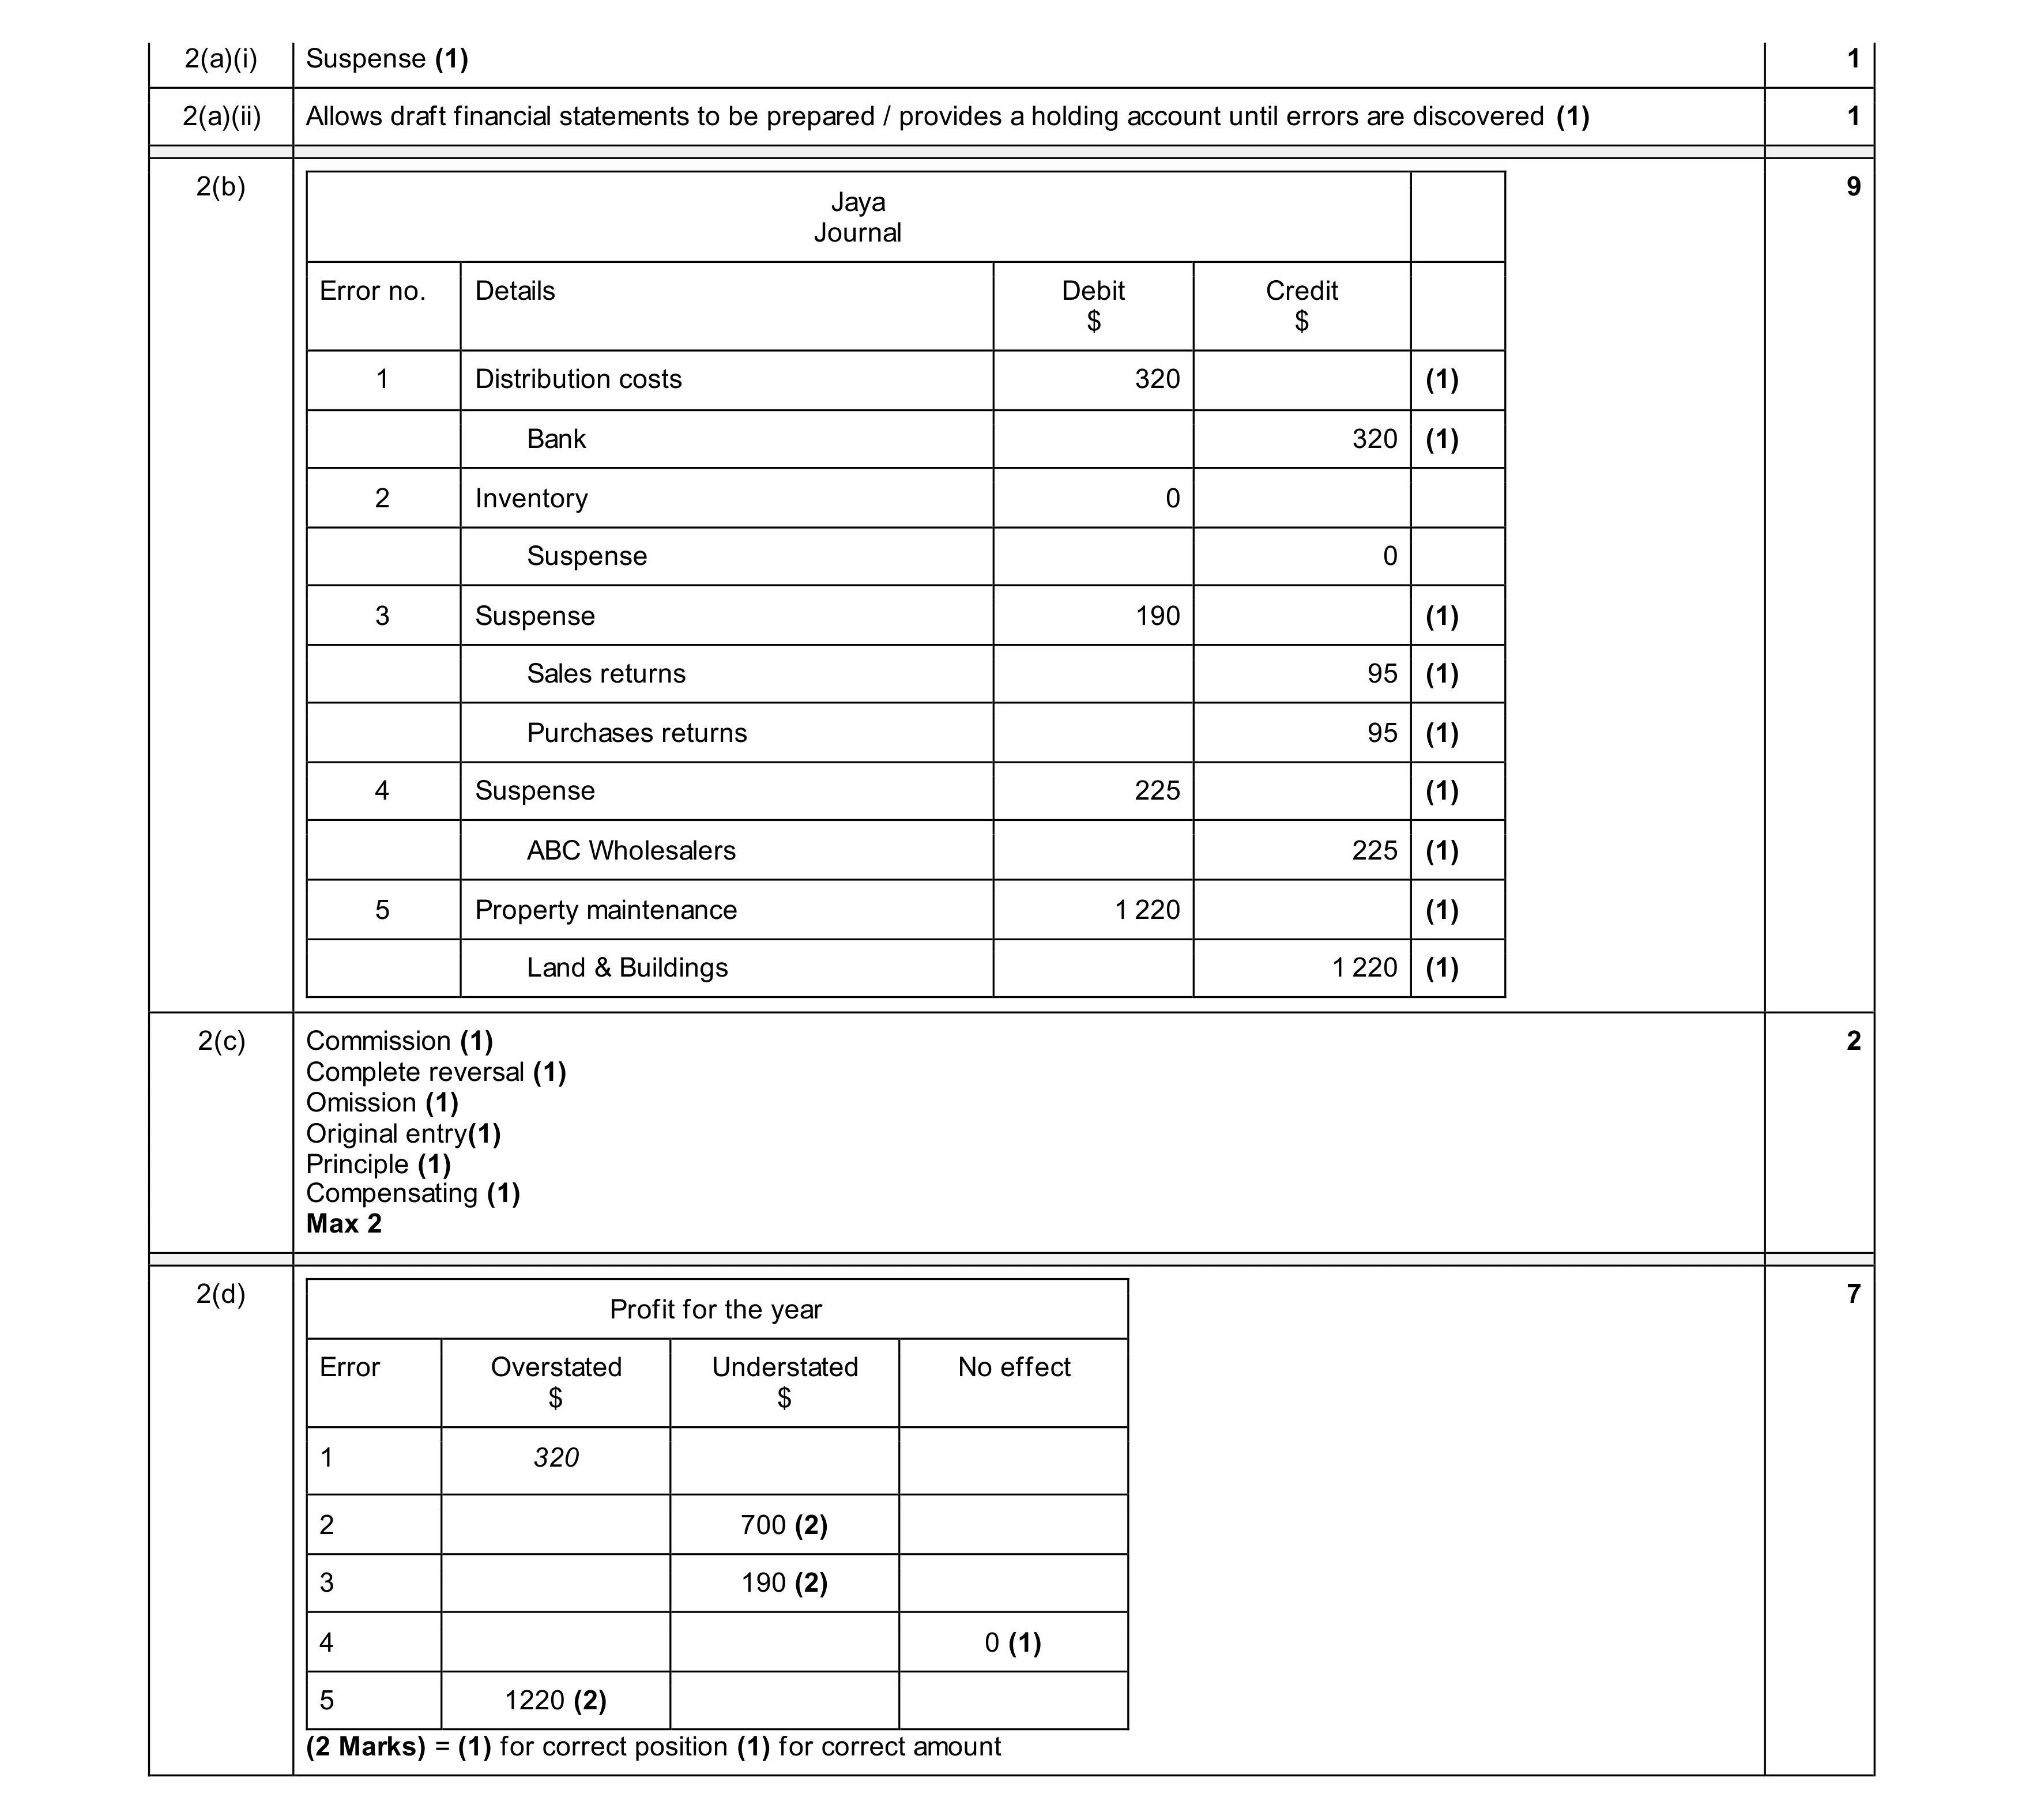
2 Jaya is a trader. Her financial year ends on 31 July. The totals of her trial balance at 31 July 2025 did not agree. REQUIRED (a) (i) Name the account that Jaya would need to open to enable her trial balance totals to agree. … [1] (ii) State the primary purpose of this account. … [1] Jaya later discovered the following five errors: 1 No entry had been made for distribution costs of $320 paid by bank transfer. 2 Closing inventory had been recorded as $12 200 instead of $12 900. 3 Purchases returns of $95 had been correctly entered in the credit supplier’s account but had been debited to the sales returns account. 4 A cheque for $225 received from ABC wholesalers, a credit customer, had been correctly entered in the cash book, but no other entry had been made. 5 Property maintenance costs of $1220 had been incorrectly charged to the land and buildings account. REQUIRED (b) Prepare the journal entries to correct errors 1 to 5. Narratives are not required. Jaya Journal Error number Details Debit Credit $ $ [9] (c) Name two types of error that will not be revealed by the trial balance. 1 … 2 … [2] (d) Complete the table by entering the amount by which Jaya’s profit for the year would be overstated or understated if each error is left uncorrected. If an error has no effect on profit, enter zero (0) in the ‘no effect’ box. Error 1 has been completed as an example. Profit for the year Error Overstated Understated No effect $ $ 1 320 2 3 4 5 [7] [Total: 20]
20 marks
Mark scheme: 2(a)(i) Suspense (1) 1 2(a)(ii) Allows draft financial statements to be prepared / provides a holding account until errors are discovered (1) 1 2(b) 9 Jaya Journal Error no. Details Debit Credit $ $ 1 Distribution costs 320 (1) Bank 320 (1) 2 Inventory 0 Suspense 0 3 Suspense 190 (1) Sales returns 95 (1) Purchases returns 95 (1) 4 Suspense 225 (1) ABC Wholesalers 225 (1) 5 Property maintenance 1 220 (1) Land & Buildings 1 220 (1) 2(c) Commission (1) 2 Complete reversal (1) Omission (1) Original entry(1) Principle (1) Compensating (1) Max 2 2(d) 7 Profit for the year Error Overstated Understated No effect $ $ 1 320 2 700 (2) 3 190 (2) 4 0 (1) 5 1220 (2) (2 Marks) = (1) for correct position (1) for correct amount
This question in 0985/22 Oct/Nov 2025
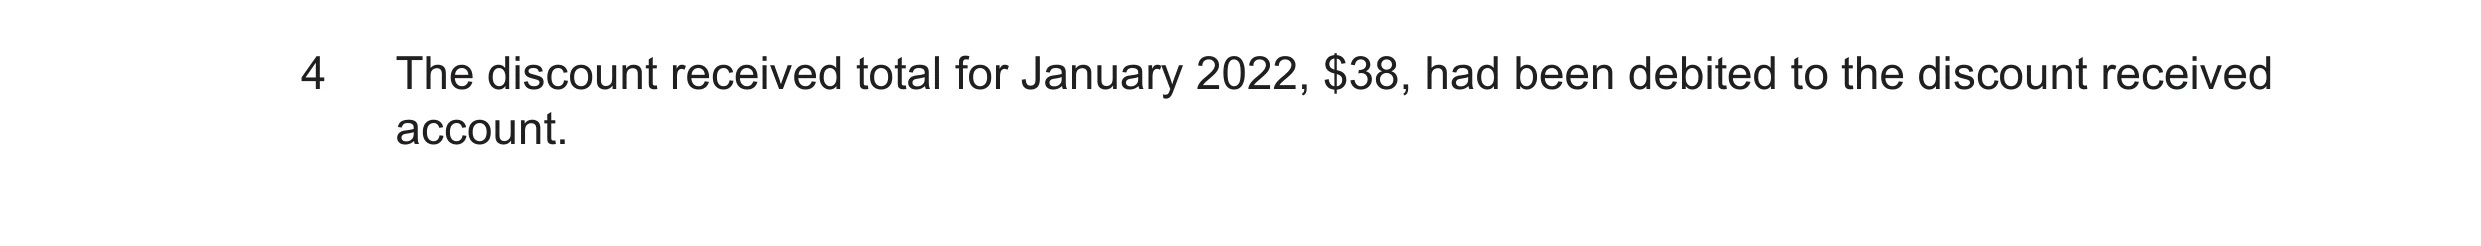 13 / 42
 20
 20
 6
 18
 20
 20
 0
 14
 20
 20
 20
 20
 11
 20
 20
 20
 18
 20
 20
 20