Cambridge IGCSE Accounting (9-1) 0985 — 2020 May/June Paper 2 · Variant 2
0985/22/M/J/20 · 6 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme12 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Bilal is a trader
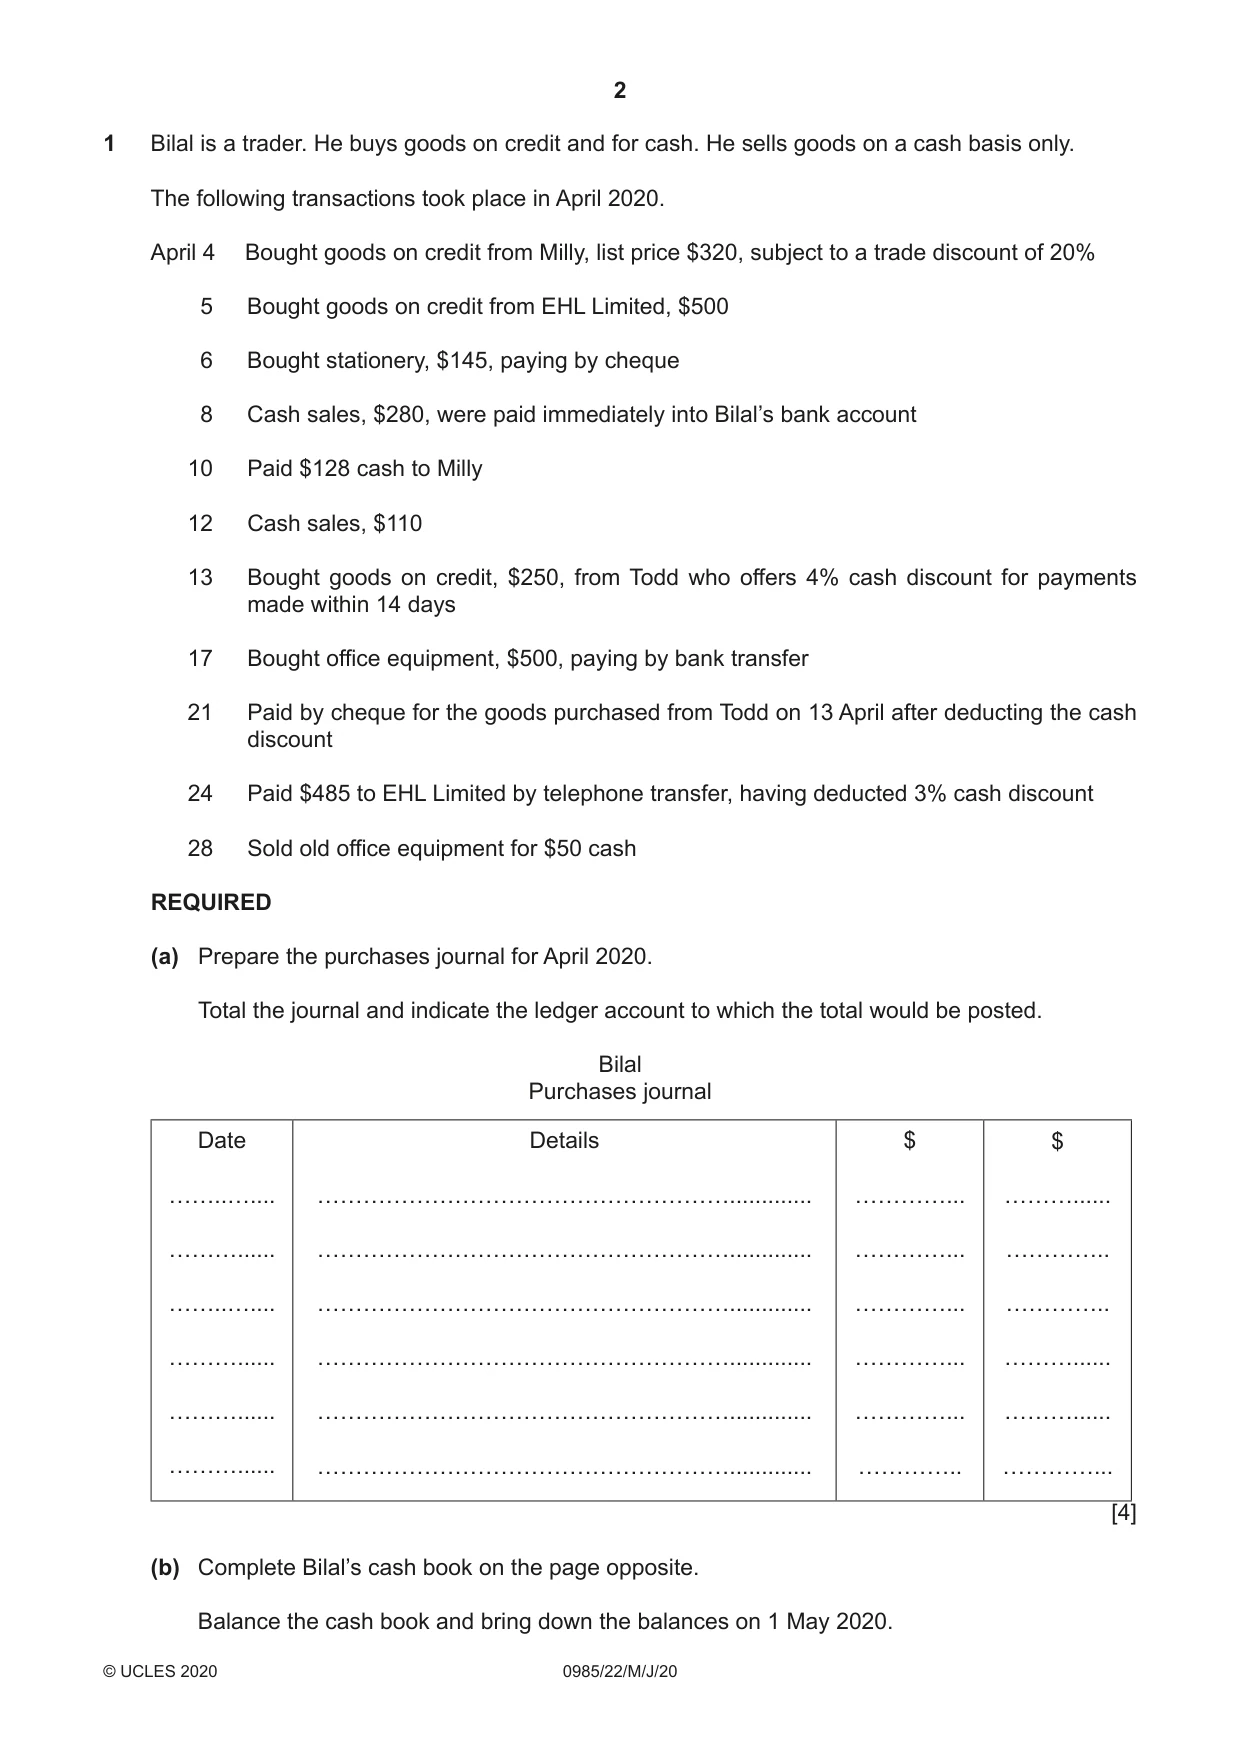
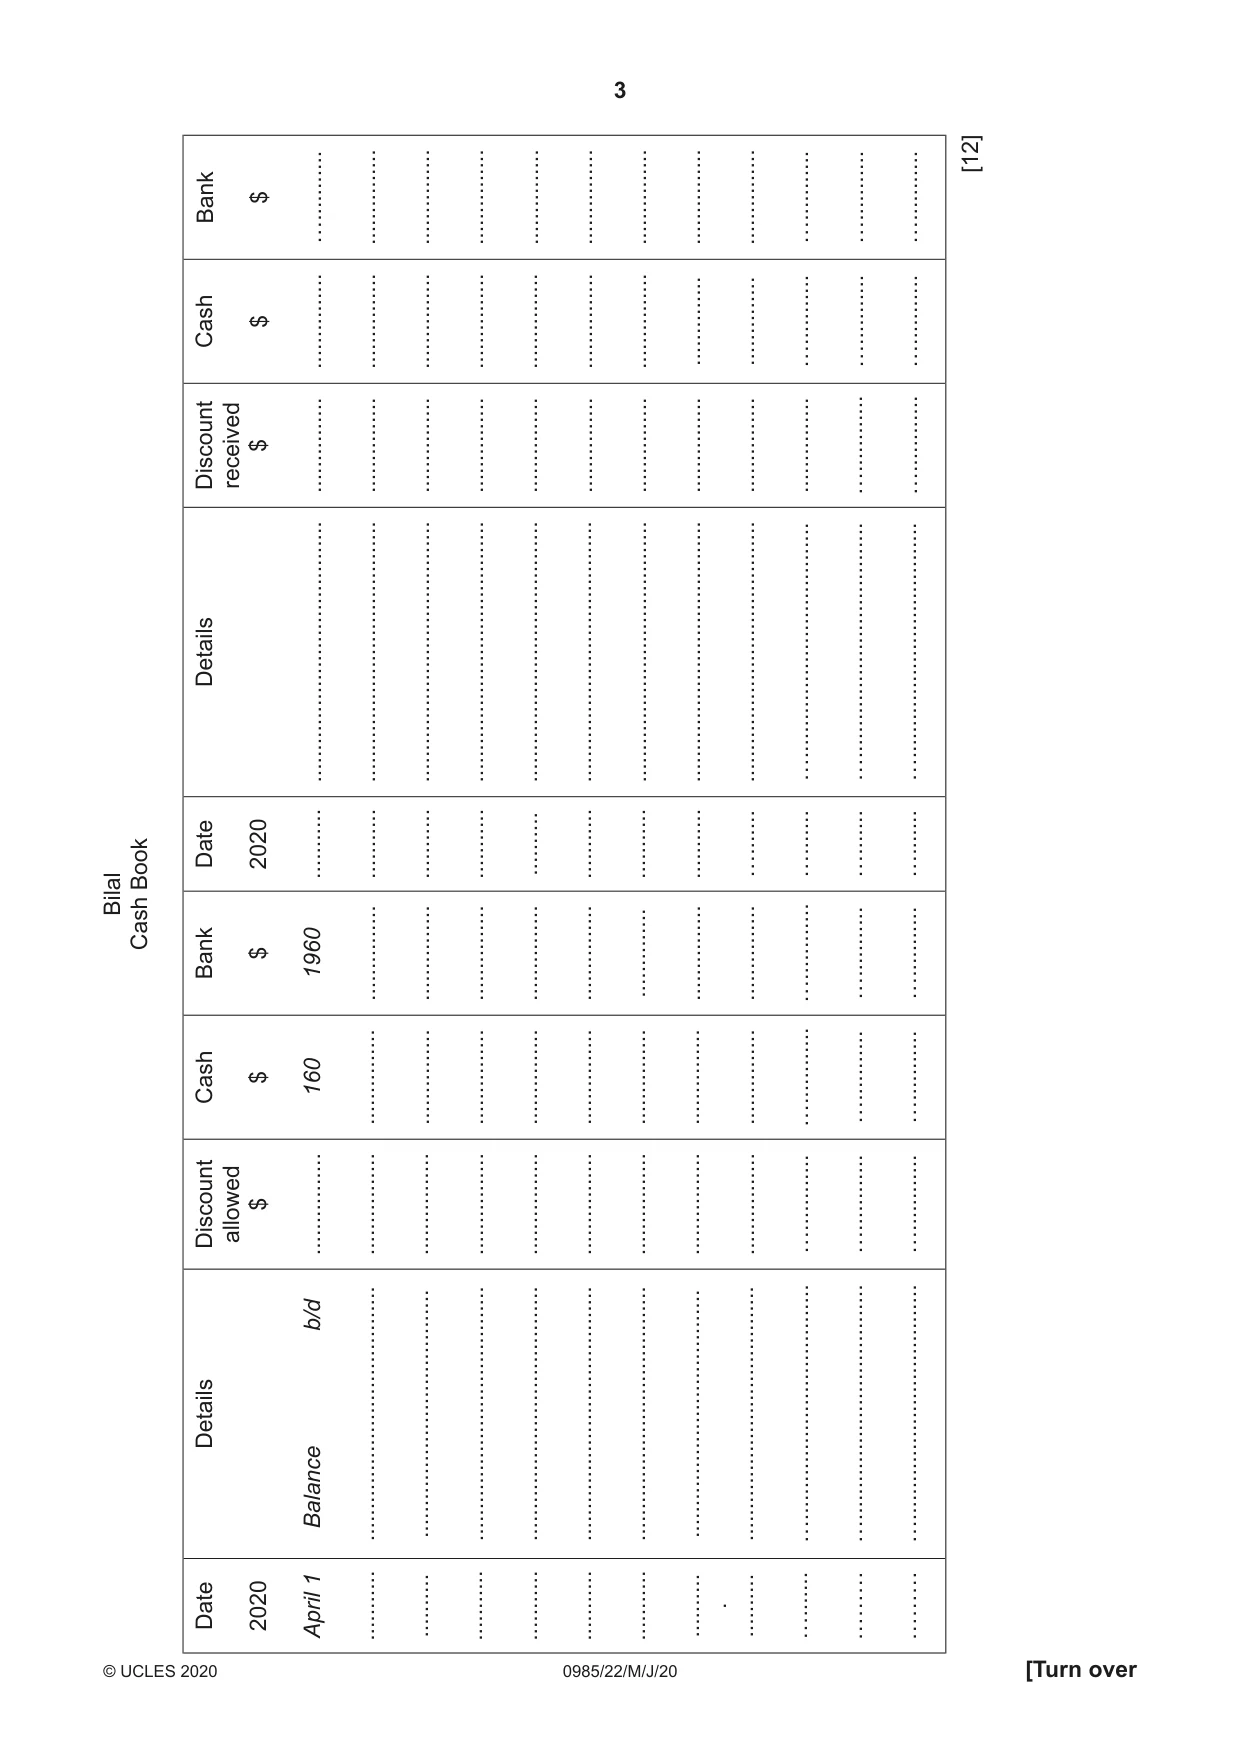
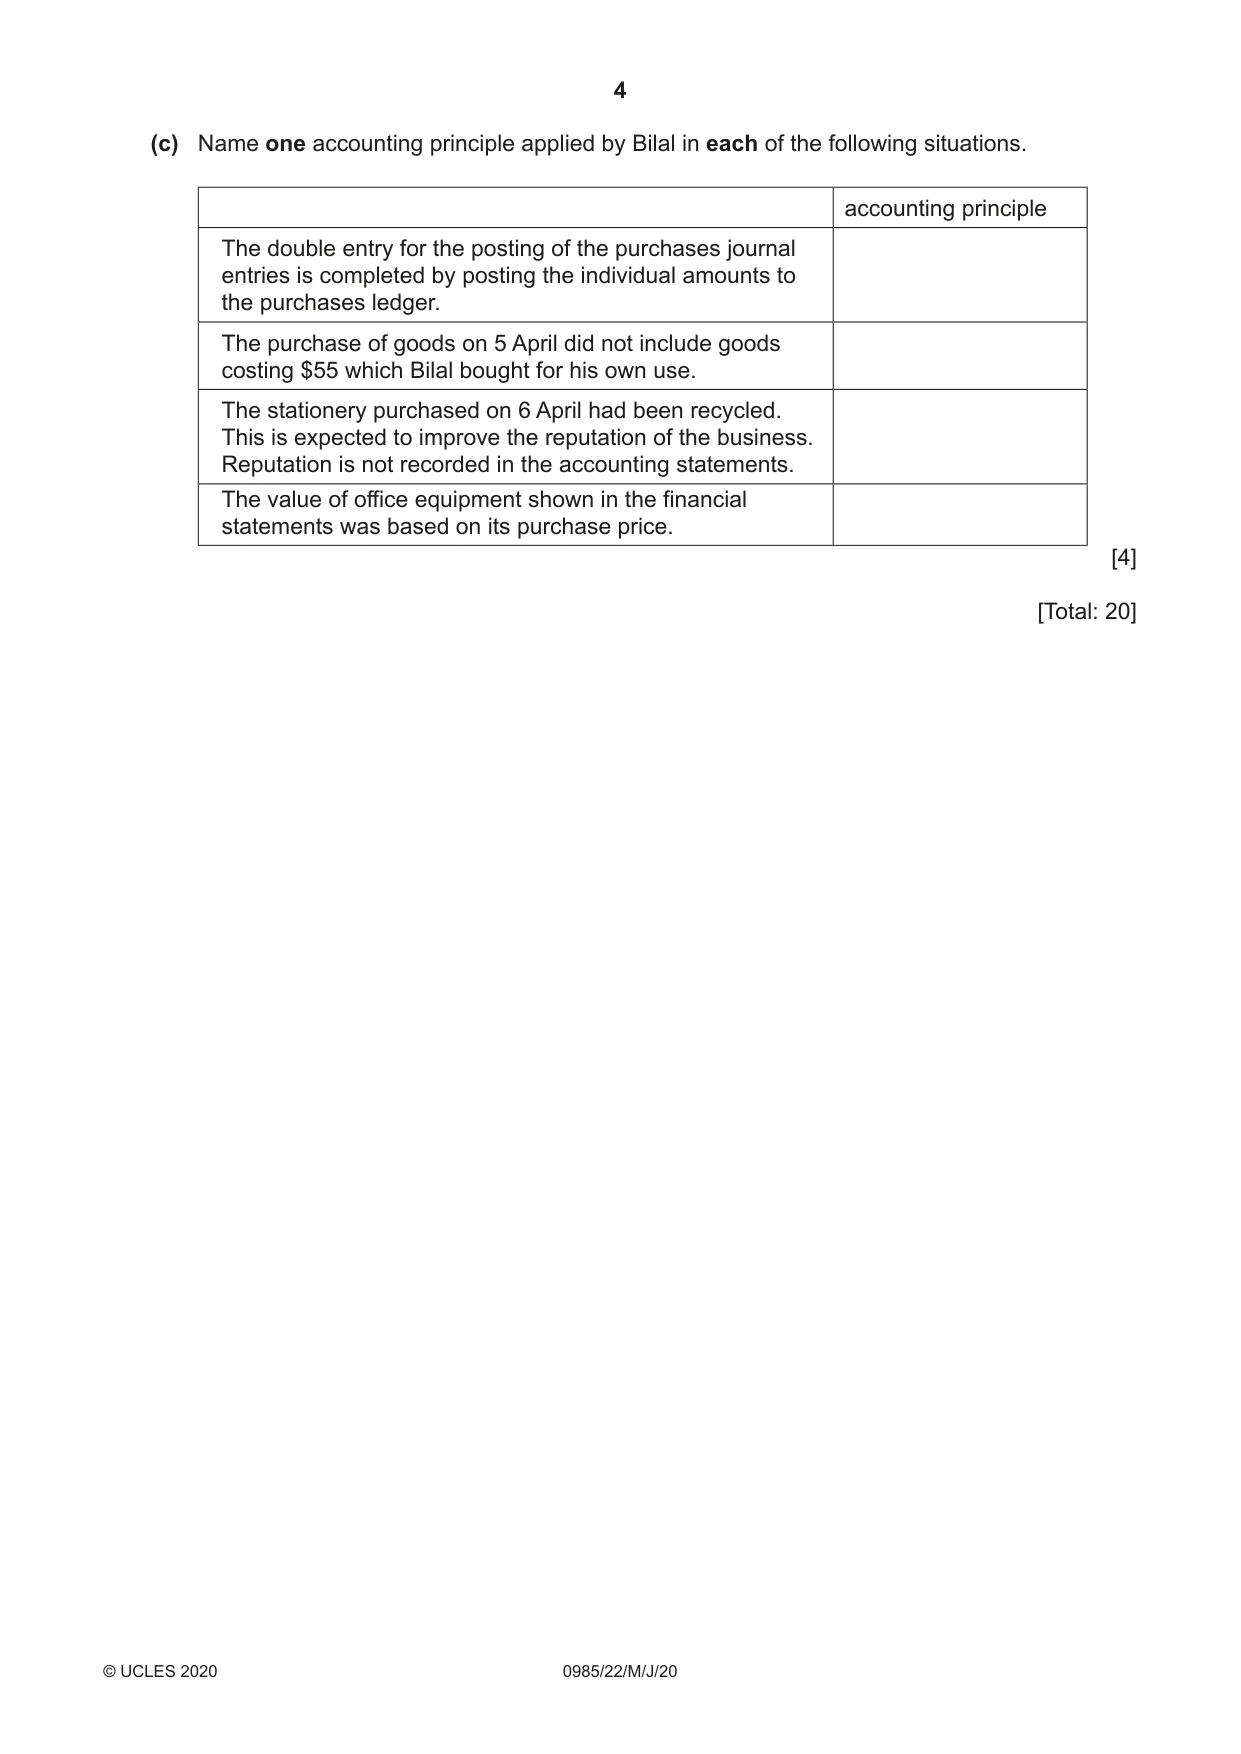
1 Bilal is a trader. He buys goods on credit and for cash. He sells goods on a cash basis only. The following transactions took place in April 2020. April 4 Bought goods on credit from Milly, list price $320, subject to a trade discount of 20% 5 Bought goods on credit from EHL Limited, $500 6 Bought stationery, $145, paying by cheque 8 Cash sales, $280, were paid immediately into Bilal’s bank account 10 Paid $128 cash to Milly 12 Cash sales, $110 13 Bought goods on credit, $250, from Todd who offers 4% cash discount for payments made within 14 days 17 Bought office equipment, $500, paying by bank transfer 21 Paid by cheque for the goods purchased from Todd on 13 April after deducting the cash discount 24 Paid $485 to EHL Limited by telephone transfer, having deducted 3% cash discount 28 Sold old office equipment for $50 cash REQUIRED (a) Prepare the purchases journal for April 2020. Total the journal and indicate the ledger account to which the total would be posted. Bilal Purchases journal Date Details $ $ ……..….... ………………………………………………............. …………... ………...... ………...... ………………………………………………............. …………... ………….. ……..….... ………………………………………………............. …………... ………….. ………...... ………………………………………………............. …………... ………...... ………...... ………………………………………………............. …………... ………...... ………...... ………………………………………………............. ………….. …………... [4] (b) Complete Bilal’s cash book on the page opposite. Balance the cash book and bring down the balances on 1 May 2020. [12] $ Bank …........... ............... ............... ............... ............... ............... ............... ............... ............... …........... …........... …........... $ Cash ............... ............... ............... ............... ............... ............... ............... .............. .............. …........... …........... …........... $ Discountreceived ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... …............ …............ Details ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... …..................................... …..................................... …..................................... Date 2020 ........... ........... ........... ........... .......... ........... ........... ........... …....... …....... …....... …....... Book Bilal Cash $ Bank 1960 ............... ............... ............... ............... ............... .............. ............... ............... …............ …........... …........... $ 160 Cash ............... ............... ............... ............... ............... ............... ............... ............... …............ …........... …........... $ Discountallowed ................ ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ b/d Details Balance ........................................ ....................................... ........................................ ........................................ ........................................ ........................................ ....................................... ........................................ …..................................... …..................................... …..................................... (c) Name one accounting principle applied by Bilal in each of the following situations. accounting principle The double entry for the posting of the purchases journal entries is completed by posting the individual amounts to the purchases ledger. The purchase of goods on 5 April did not include goods costing $55 which Bilal bought for his own use. The stationery purchased on 6 April had been recycled. This is expected to improve the reputation of the business. Reputation is not recorded in the accounting statements. The value of office equipment shown in the financial statements was based on its purchase price. [4] [Total: 20] PLEASE TURN OVER
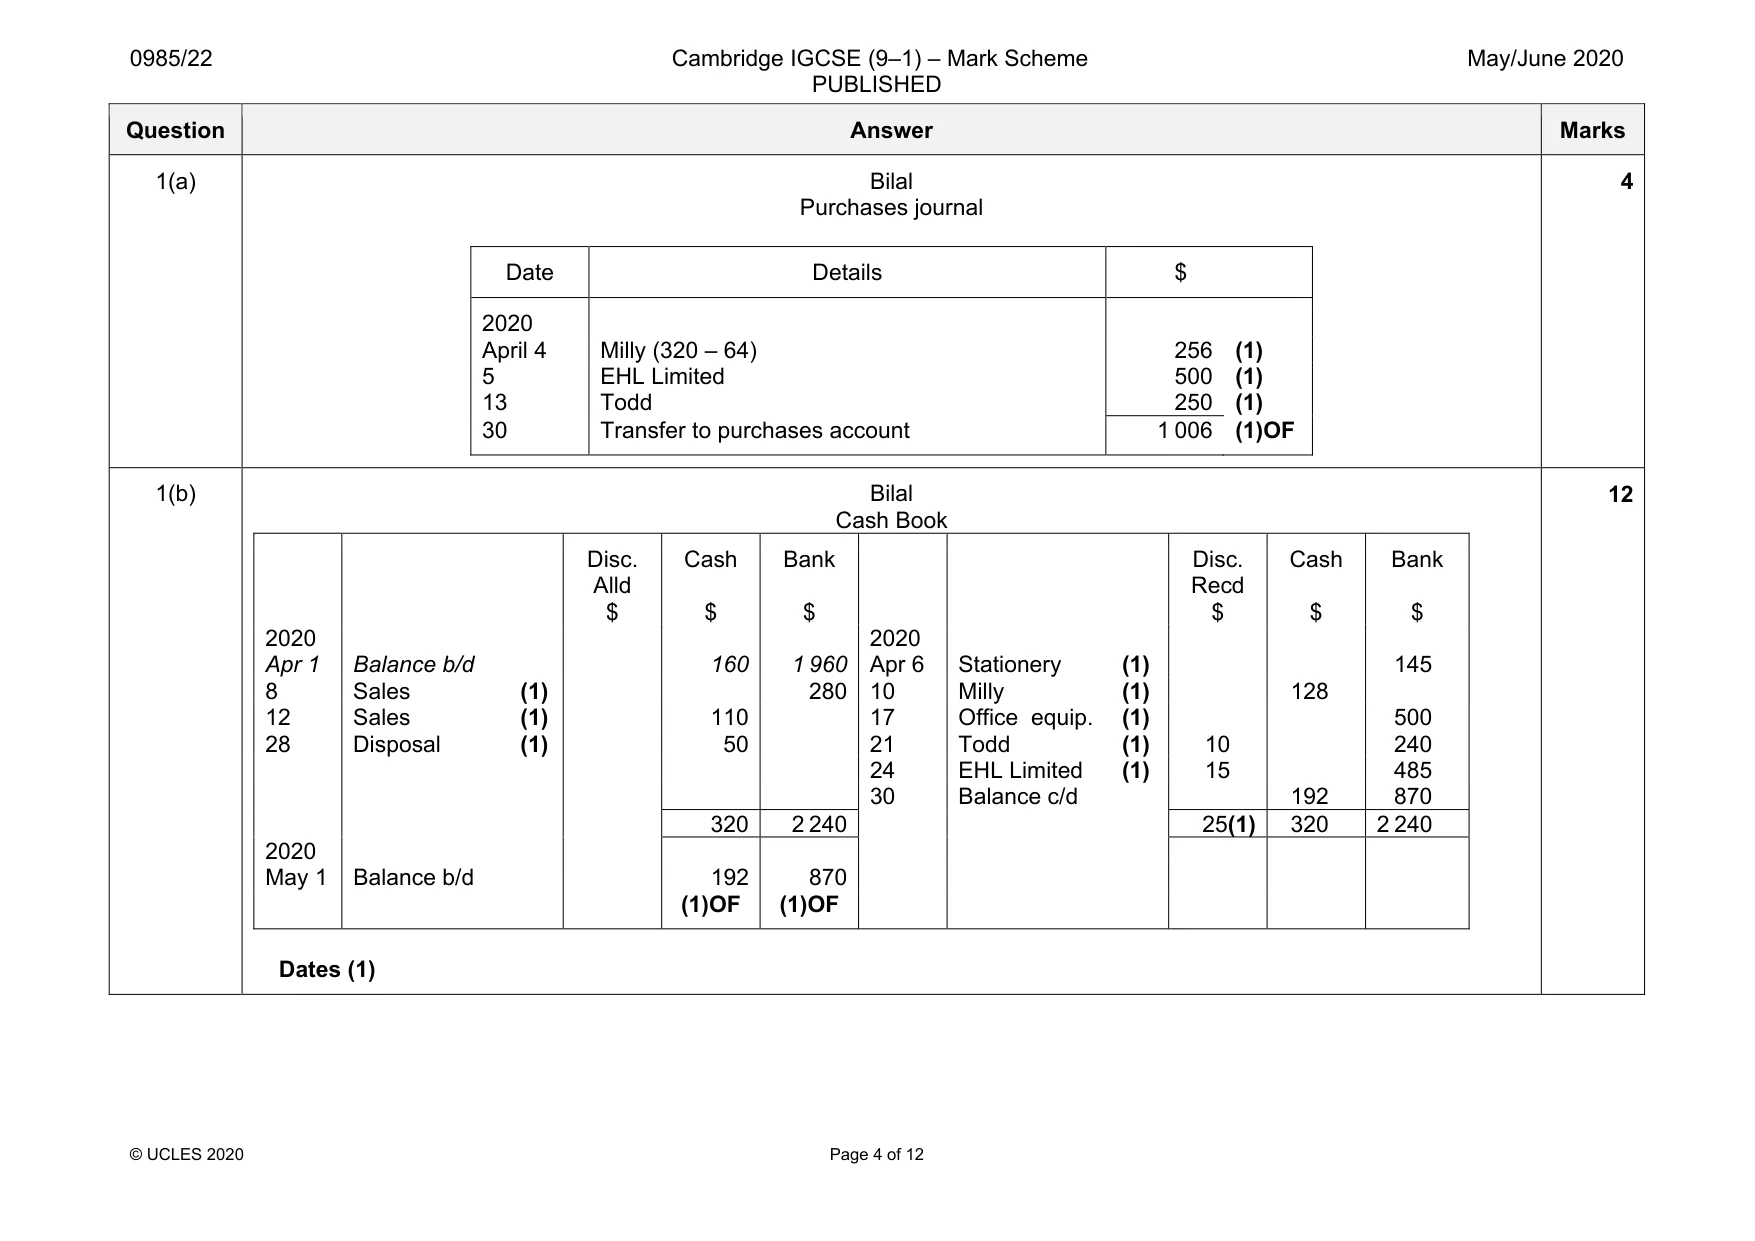
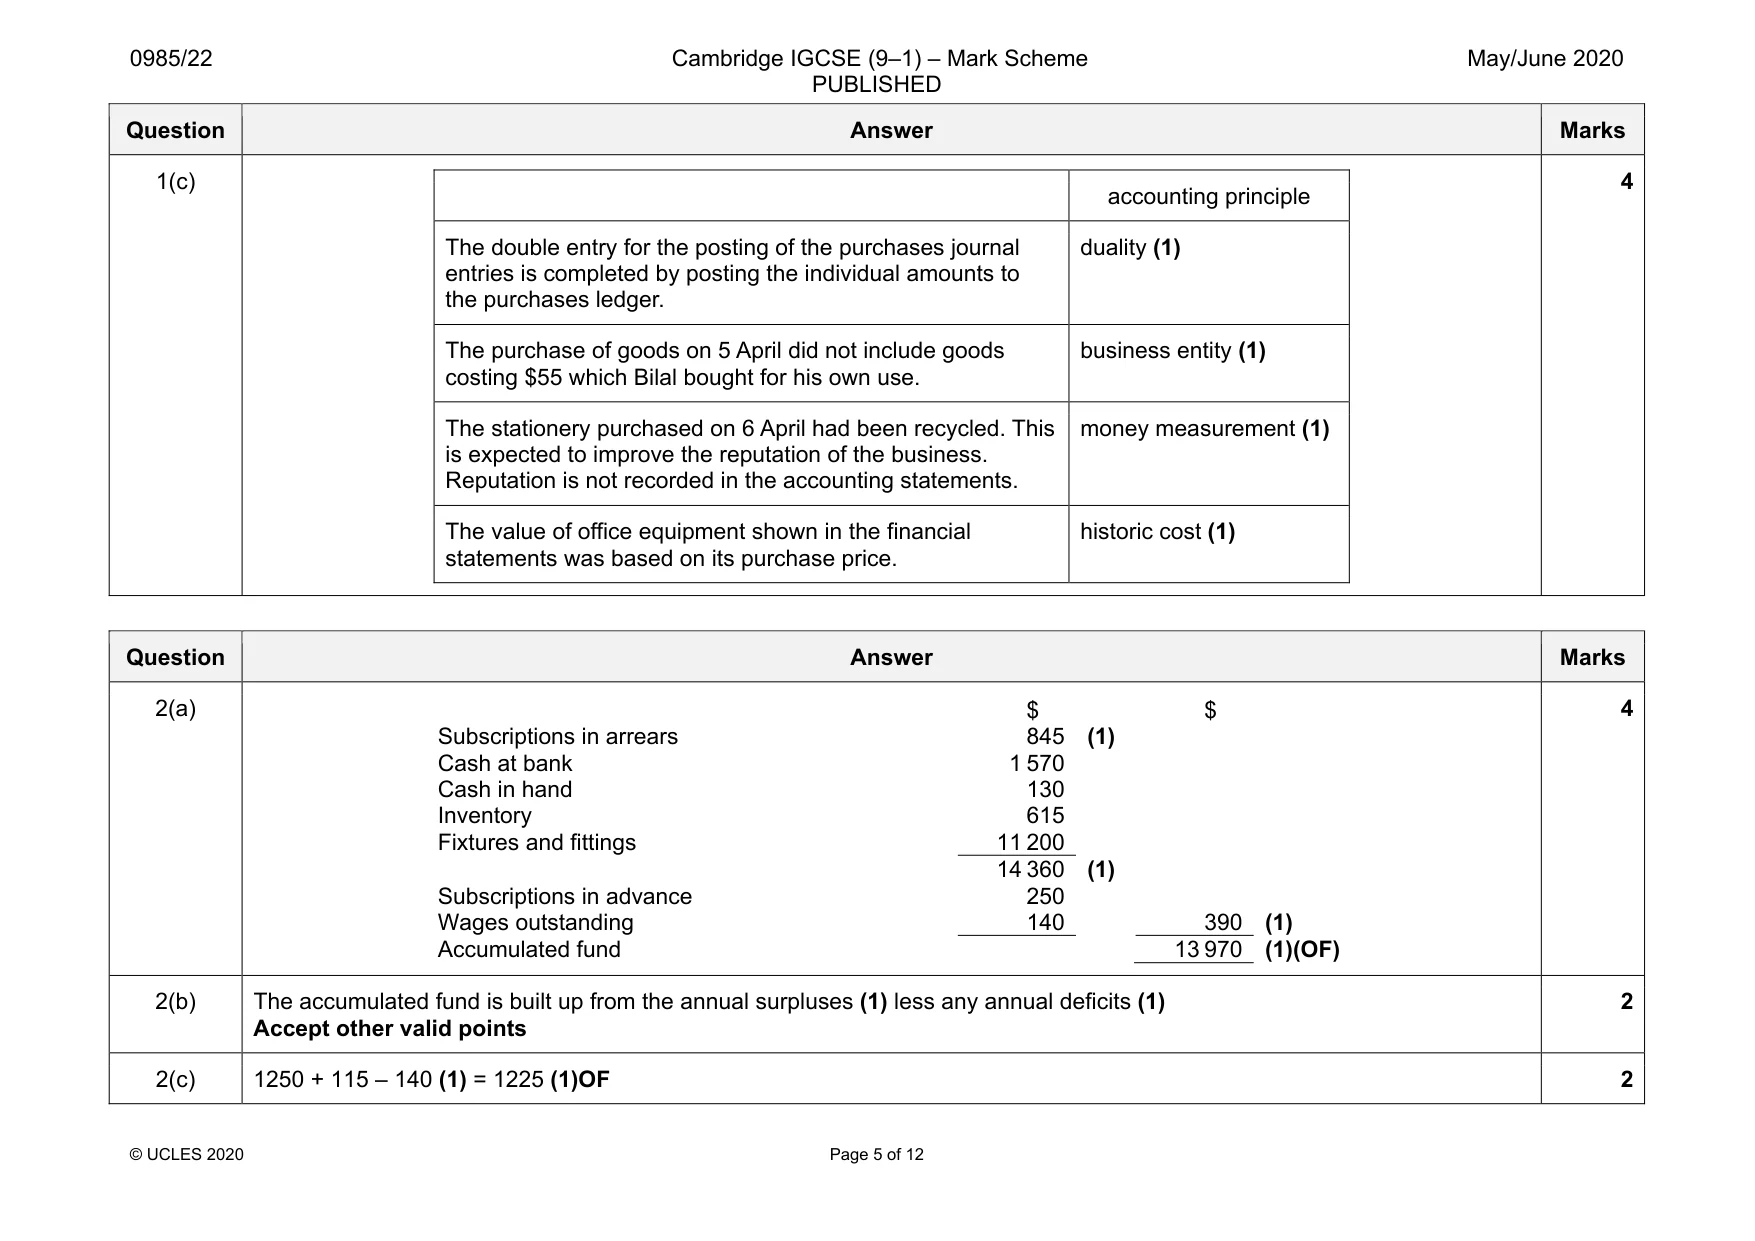
Mark scheme: 1(a) Bilal Purchases journal Date Details $ 2020 April 4 Milly (320 – 64) 256 (1) 5 EHL Limited 500 (1) 13 Todd 250 (1) 30 Transfer to purchases account 1 006 (1)OF 4 1(b) Bilal Cash Book Disc. Alld $ Cash $ Bank $ Disc. Recd $ Cash $ Bank $ 2020 2020 Apr 1 Balance b/d 160 1 960 Apr 6 Stationery (1) 145 8 Sales (1) 280 10 Milly (1) 128 12 Sales (1) 110 17 Office equip. (1) 500 28 Disposal (1) 50 21 Todd (1) 10 240 24 EHL Limited (1) 15 485 30 Balance c/d 192 870 320 2 240 25(1) 320 2 240 2020 May 1 Balance b/d 192 870 (1)OF (1)OF Dates (1) 12 Question Answer Marks 1(c) accounting principle The double entry for the posting of the purchases journal entries is completed by posting the individual amounts to the purchases ledger. duality (1) The purchase of goods on 5 April did not include goods costing $55 which Bilal bought for his own use. business entity (1) The stationery purchased on 6 April had been recycled. This is expected to improve the reputation of the business. Reputation is not recorded in the accounting statements. money measurement (1) The value of office equipment shown in the financial statements was based on its purchase price. historic cost (1) 4
Q2 · The K Music Club provides facilities for listening to music and also provides a…
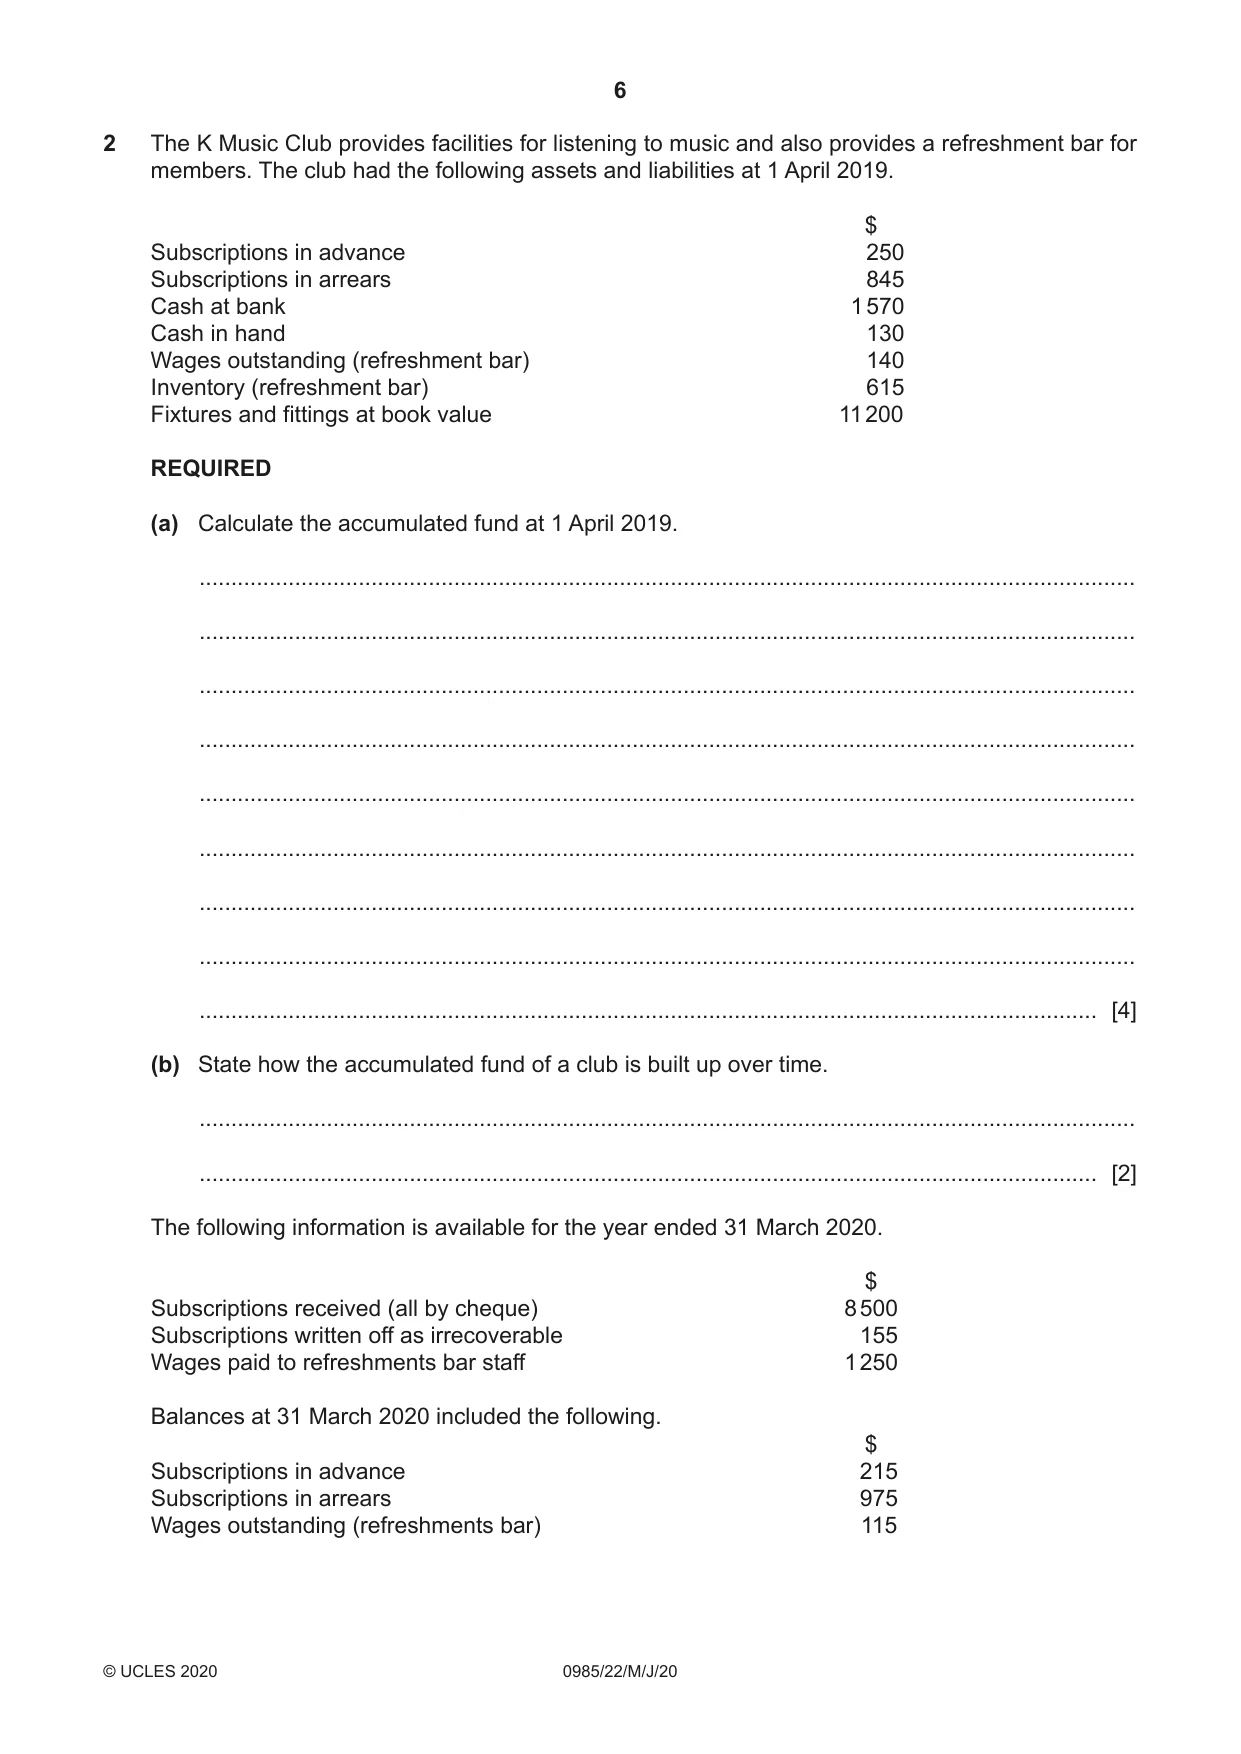
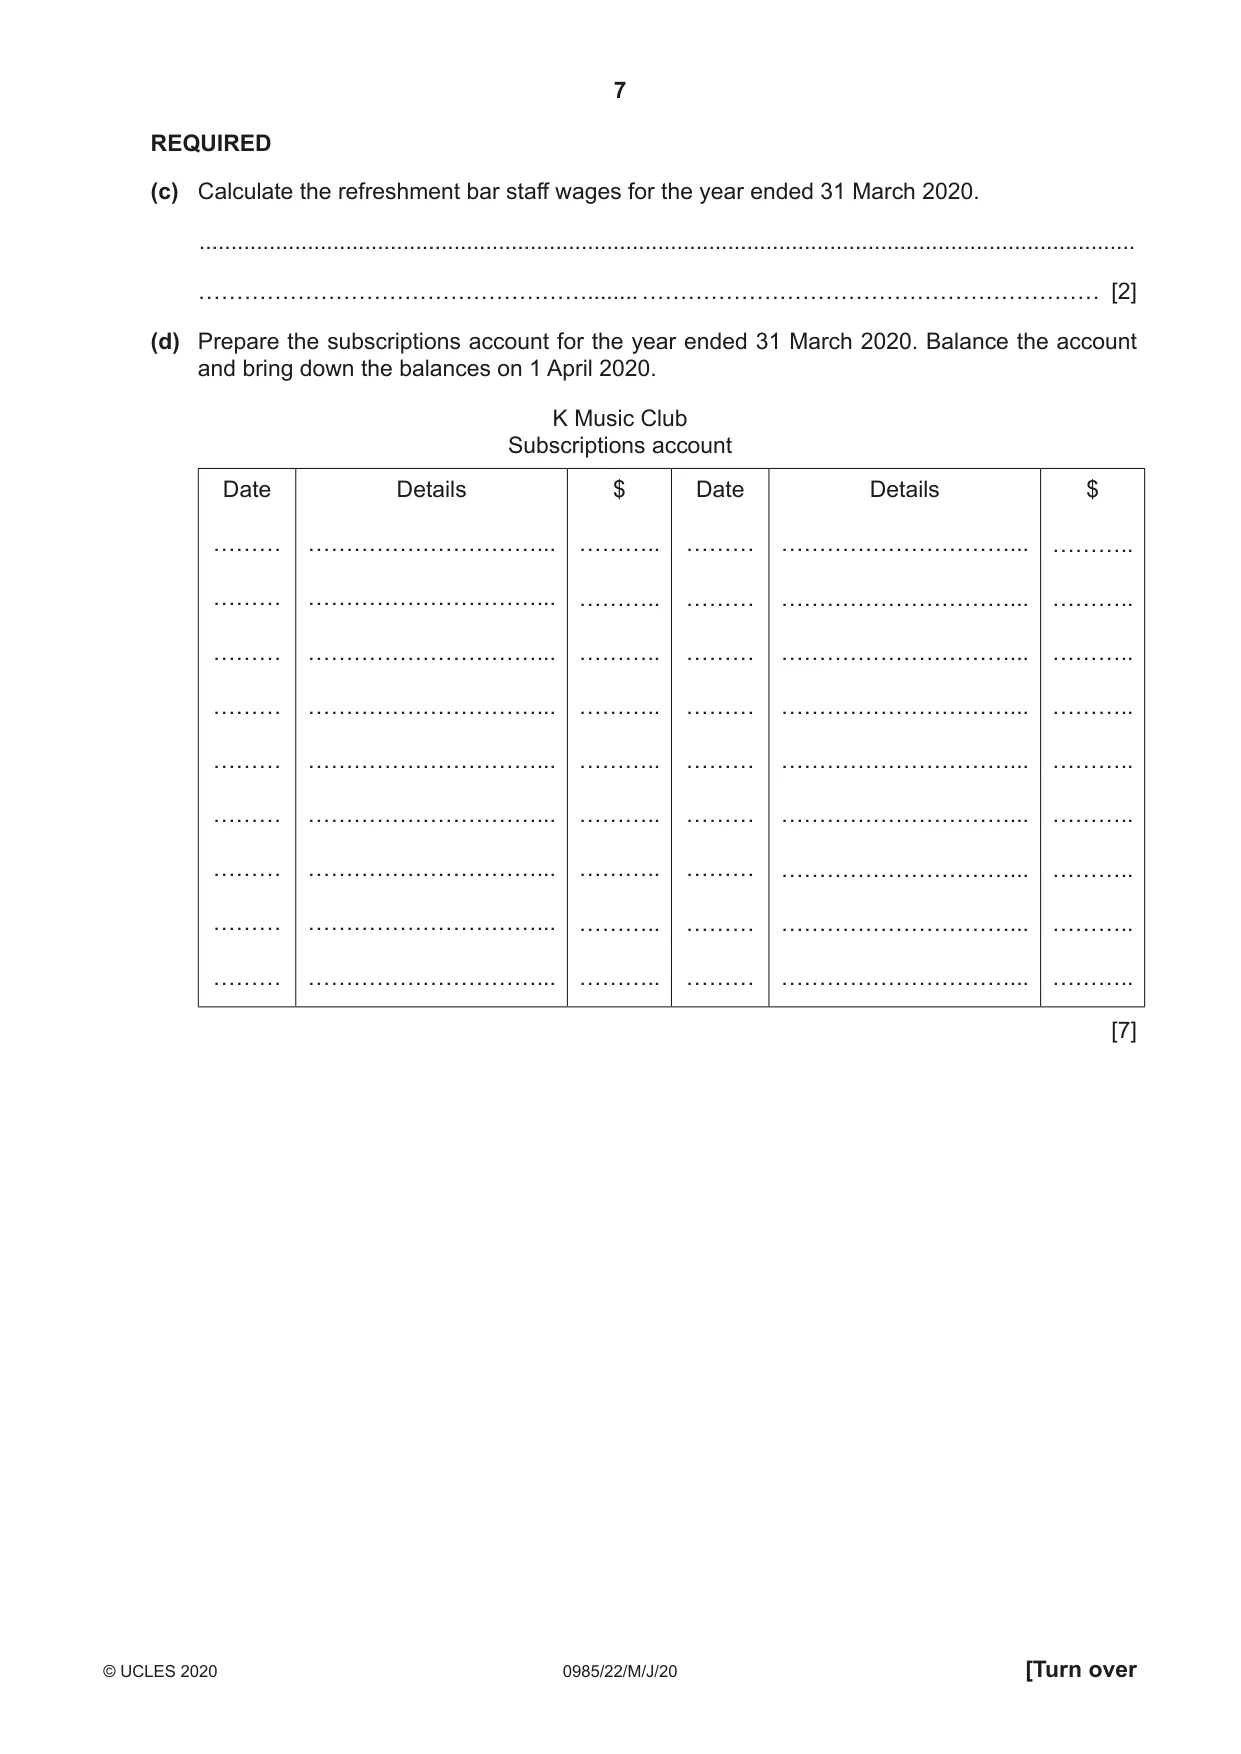
2 The K Music Club provides facilities for listening to music and also provides a refreshment bar for members. The club had the following assets and liabilities at 1 April 2019. $ Subscriptions in advance 250 Subscriptions in arrears 845 Cash at bank 1 570 Cash in hand 130 Wages outstanding (refreshment bar) 140 Inventory (refreshment bar) 615 Fixtures and fittings at book value 11 200 REQUIRED (a) Calculate the accumulated fund at 1 April 2019. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (b) State how the accumulated fund of a club is built up over time. ................................................................................................................................................... ............................................................................................................................................. [2] The following information is available for the year ended 31 March 2020. $ Subscriptions received (all by cheque) 8 500 Subscriptions written off as irrecoverable 155 Wages paid to refreshments bar staff 1 250 Balances at 31 March 2020 included the following. $ Subscriptions in advance 215 Subscriptions in arrears 975 Wages outstanding (refreshments bar) 115 REQUIRED (c) Calculate the refreshment bar staff wages for the year ended 31 March 2020. ................................................................................................................................................... (d) Prepare the subscriptions account for the year ended 31 March 2020. Balance the account and bring down the balances on 1 April 2020. K Music Club Subscriptions account Date Details $ Date Details $ ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. [7] (e) Advise the club treasurer whether or not club members should be required to pay their subscriptions by direct debit. Justify your answer by providing two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20] PLEASE TURN OVER
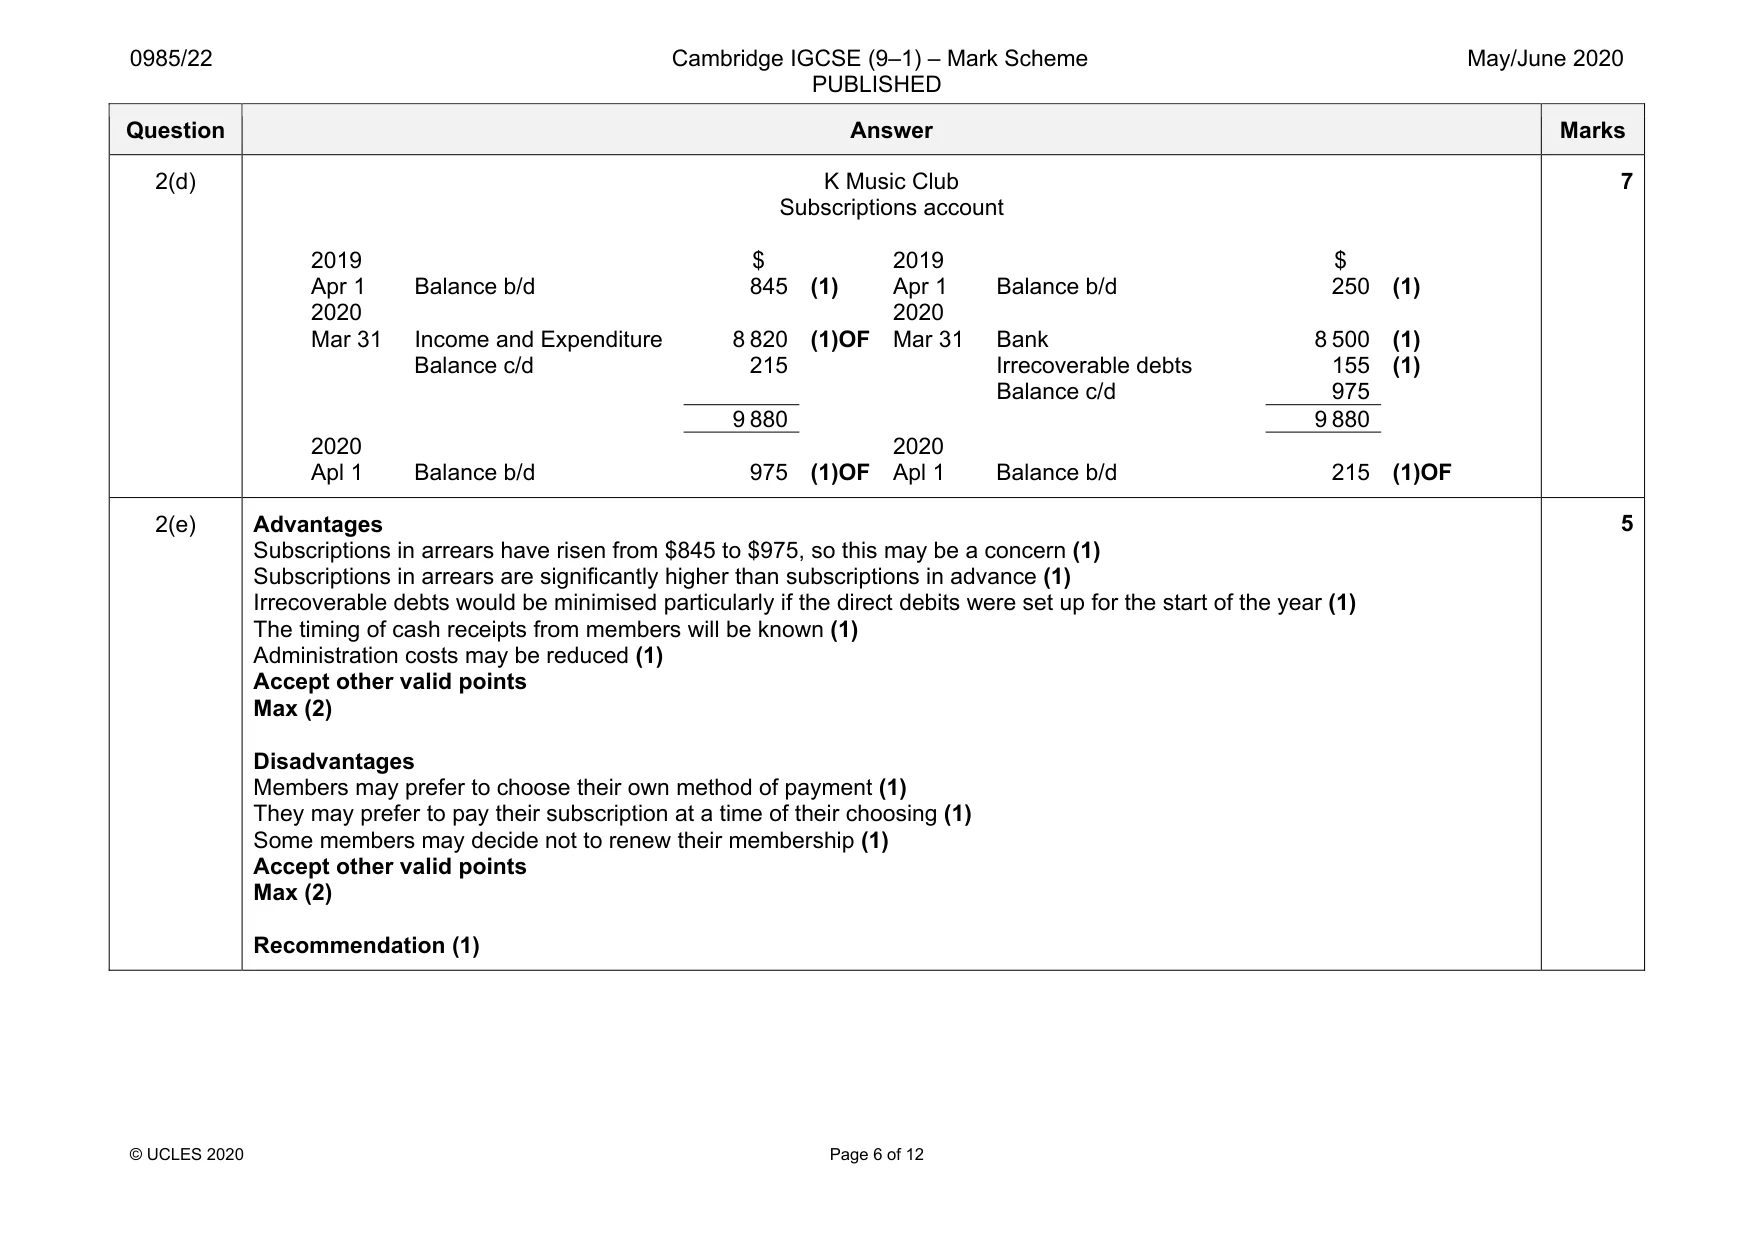
Mark scheme: 2(a) $ $ Subscriptions in arrears 845 (1) Cash at bank 1 570 Cash in hand 130 Inventory 615 Fixtures and fittings 11 200 14 360 (1) Subscriptions in advance 250 Wages outstanding 140 390 (1) Accumulated fund 13 970 (1)(OF) 4 2(b) The accumulated fund is built up from the annual surpluses (1) less any annual deficits (1) Accept other valid points 2 2(c) 1250 + 115 – 140 (1) = 1225 (1)OF 2 Question Answer Marks 2(d) K Music Club Subscriptions account 2019 $ 2019 $ Apr 1 Balance b/d 845 (1) Apr 1 Balance b/d 250 (1) 2020 2020 Mar 31 Income and Expenditure 8 820 (1)OF Mar 31 Bank 8 500 (1) Balance c/d 215 Irrecoverable debts 155 (1) Balance c/d 975 9 880 9 880 2020 2020 Apl 1 Balance b/d 975 (1)OF Apl 1 Balance b/d 215 (1)OF 7 2(e) Advantages Subscriptions in arrears have risen from $845 to $975, so this may be a concern (1) Subscriptions in arrears are significantly higher than subscriptions in advance (1) Irrecoverable debts would be minimised particularly if the direct debits were set up for the start of the year (1) The timing of cash receipts from members will be known (1) Administration costs may be reduced (1) Accept other valid points Max (2) Disadvantages Members may prefer to choose their own method of payment (1) They may prefer to pay their subscription at a time of their choosing (1) Some members may decide not to renew their membership (1) Accept other valid points Max (2) Recommendation (1) 5
Q3 · Gok is a wholesaler
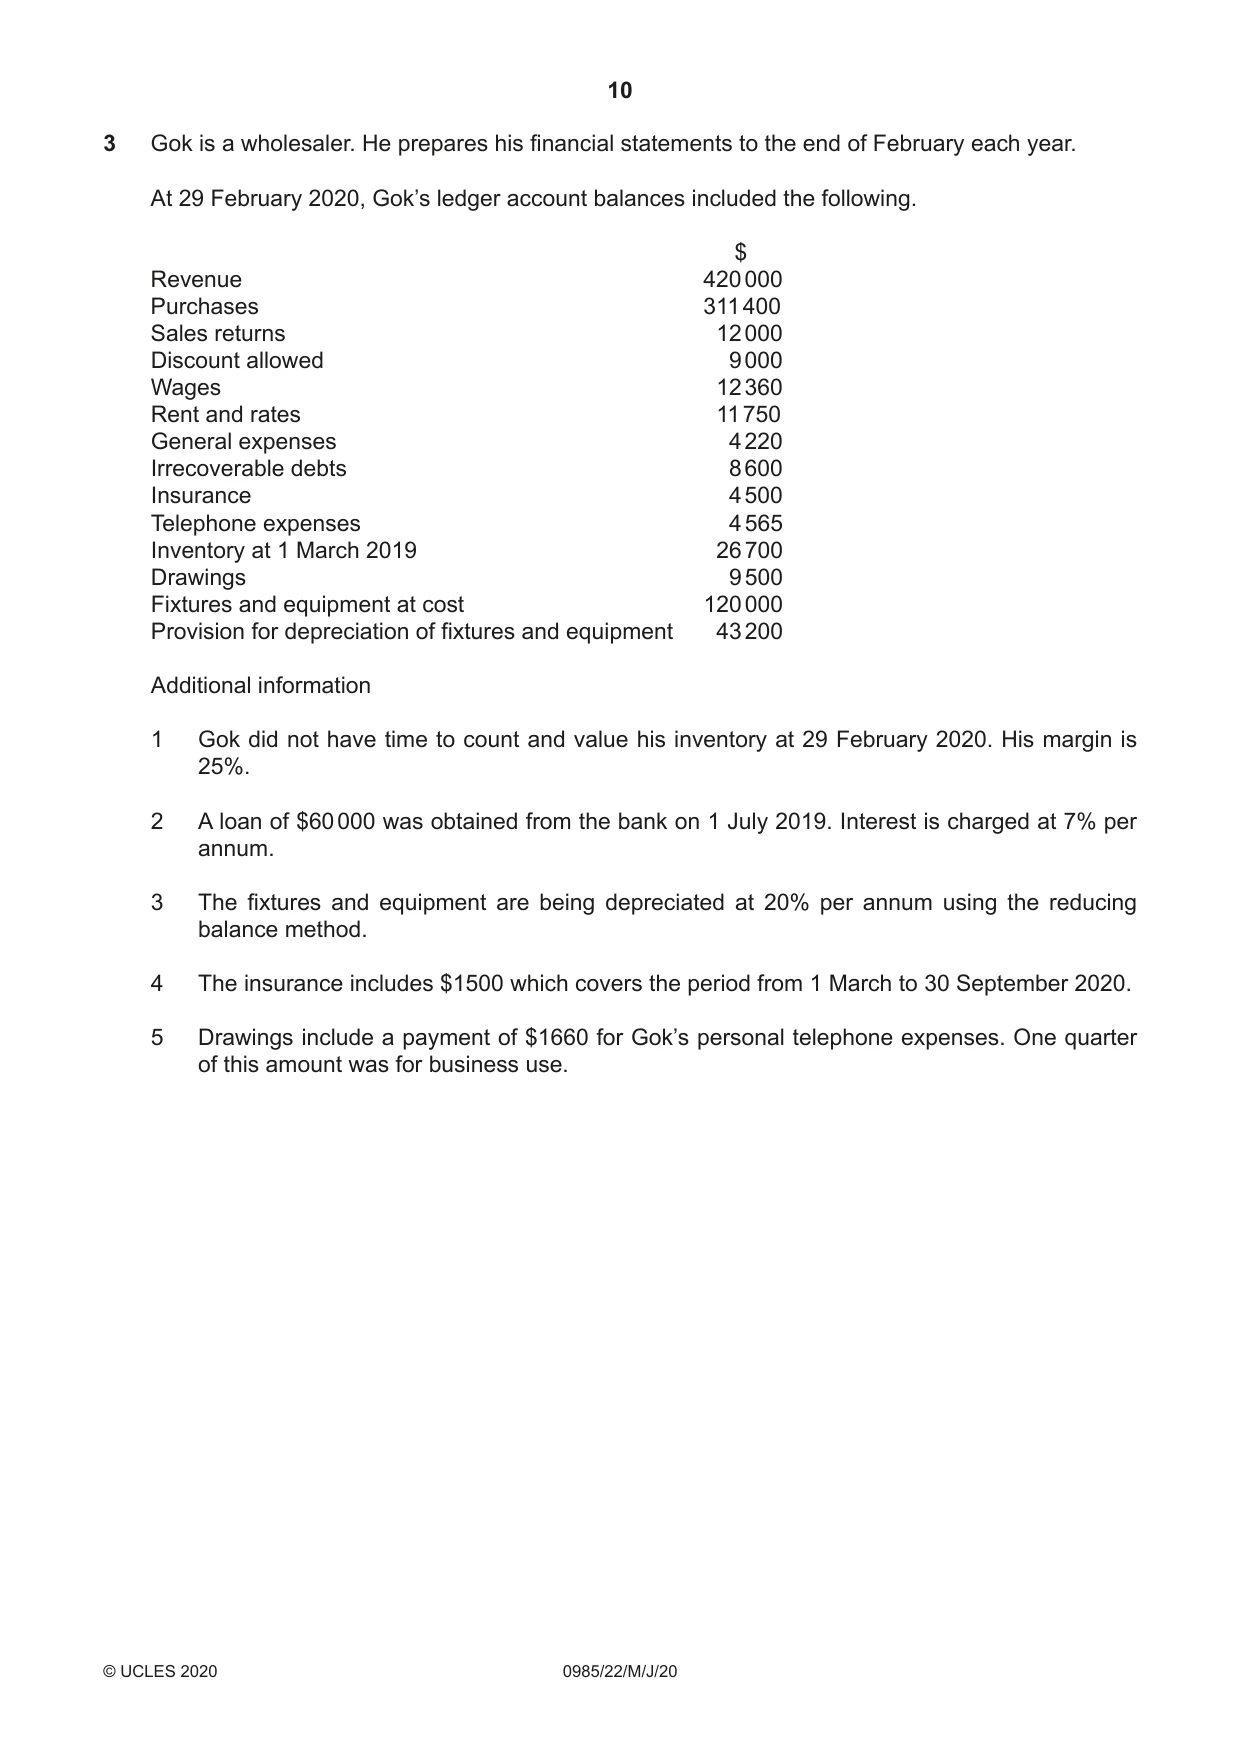
3 Gok is a wholesaler. He prepares his financial statements to the end of February each year. At 29 February 2020, Gok’s ledger account balances included the following. $ Revenue 420 000 Purchases 311 400 Sales returns 12 000 Discount allowed 9 000 Wages 12 360 Rent and rates 11 750 General expenses 4 220 Irrecoverable debts 8 600 Insurance 4 500 Telephone expenses 4 565 Inventory at 1 March 2019 26 700 Drawings 9 500 Fixtures and equipment at cost 120 000 Provision for depreciation of fixtures and equipment 43 200 Additional information 1 Gok did not have time to count and value his inventory at 29 February 2020. His margin is 25%. 2 A loan of $60 000 was obtained from the bank on 1 July 2019. Interest is charged at 7% per annum. 3 The fixtures and equipment are being depreciated at 20% per annum using the reducing balance method. 4 The insurance includes $1500 which covers the period from 1 March to 30 September 2020. 5 Drawings include a payment of $1660 for Gok’s personal telephone expenses. One quarter of this amount was for business use. REQUIRED (a) Prepare Gok’s income statement for the year ended 29 Fe Gok Income Statement for the year ended 29 Fe ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ ……………………………………………………………............ The wages paid by Gok are to his part-time warehouse assistant, Aiman. REQUIRED (b) Advise Gok whether or not he should offer Aiman a partnership in the business. Justify your answer with two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [5] [Total: 20] PLEASE TURN OVER
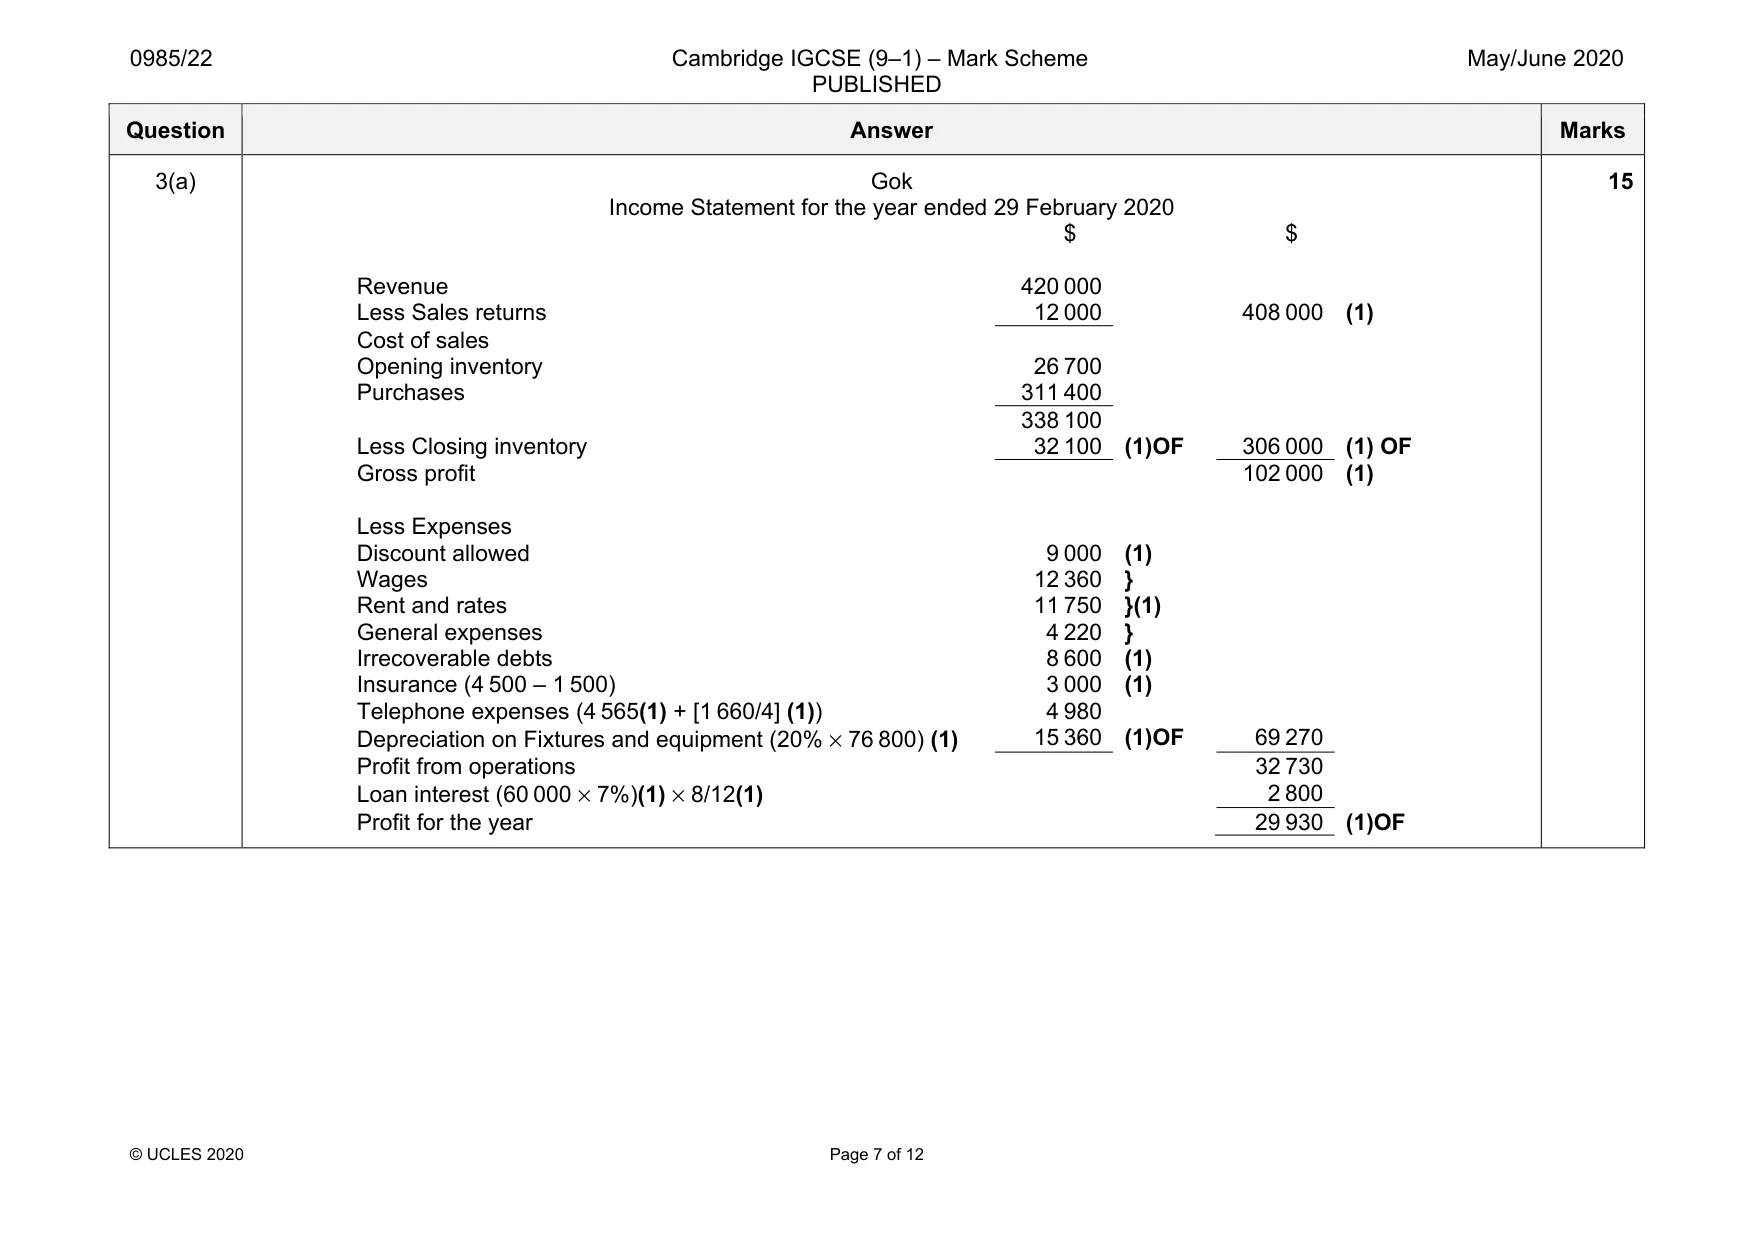
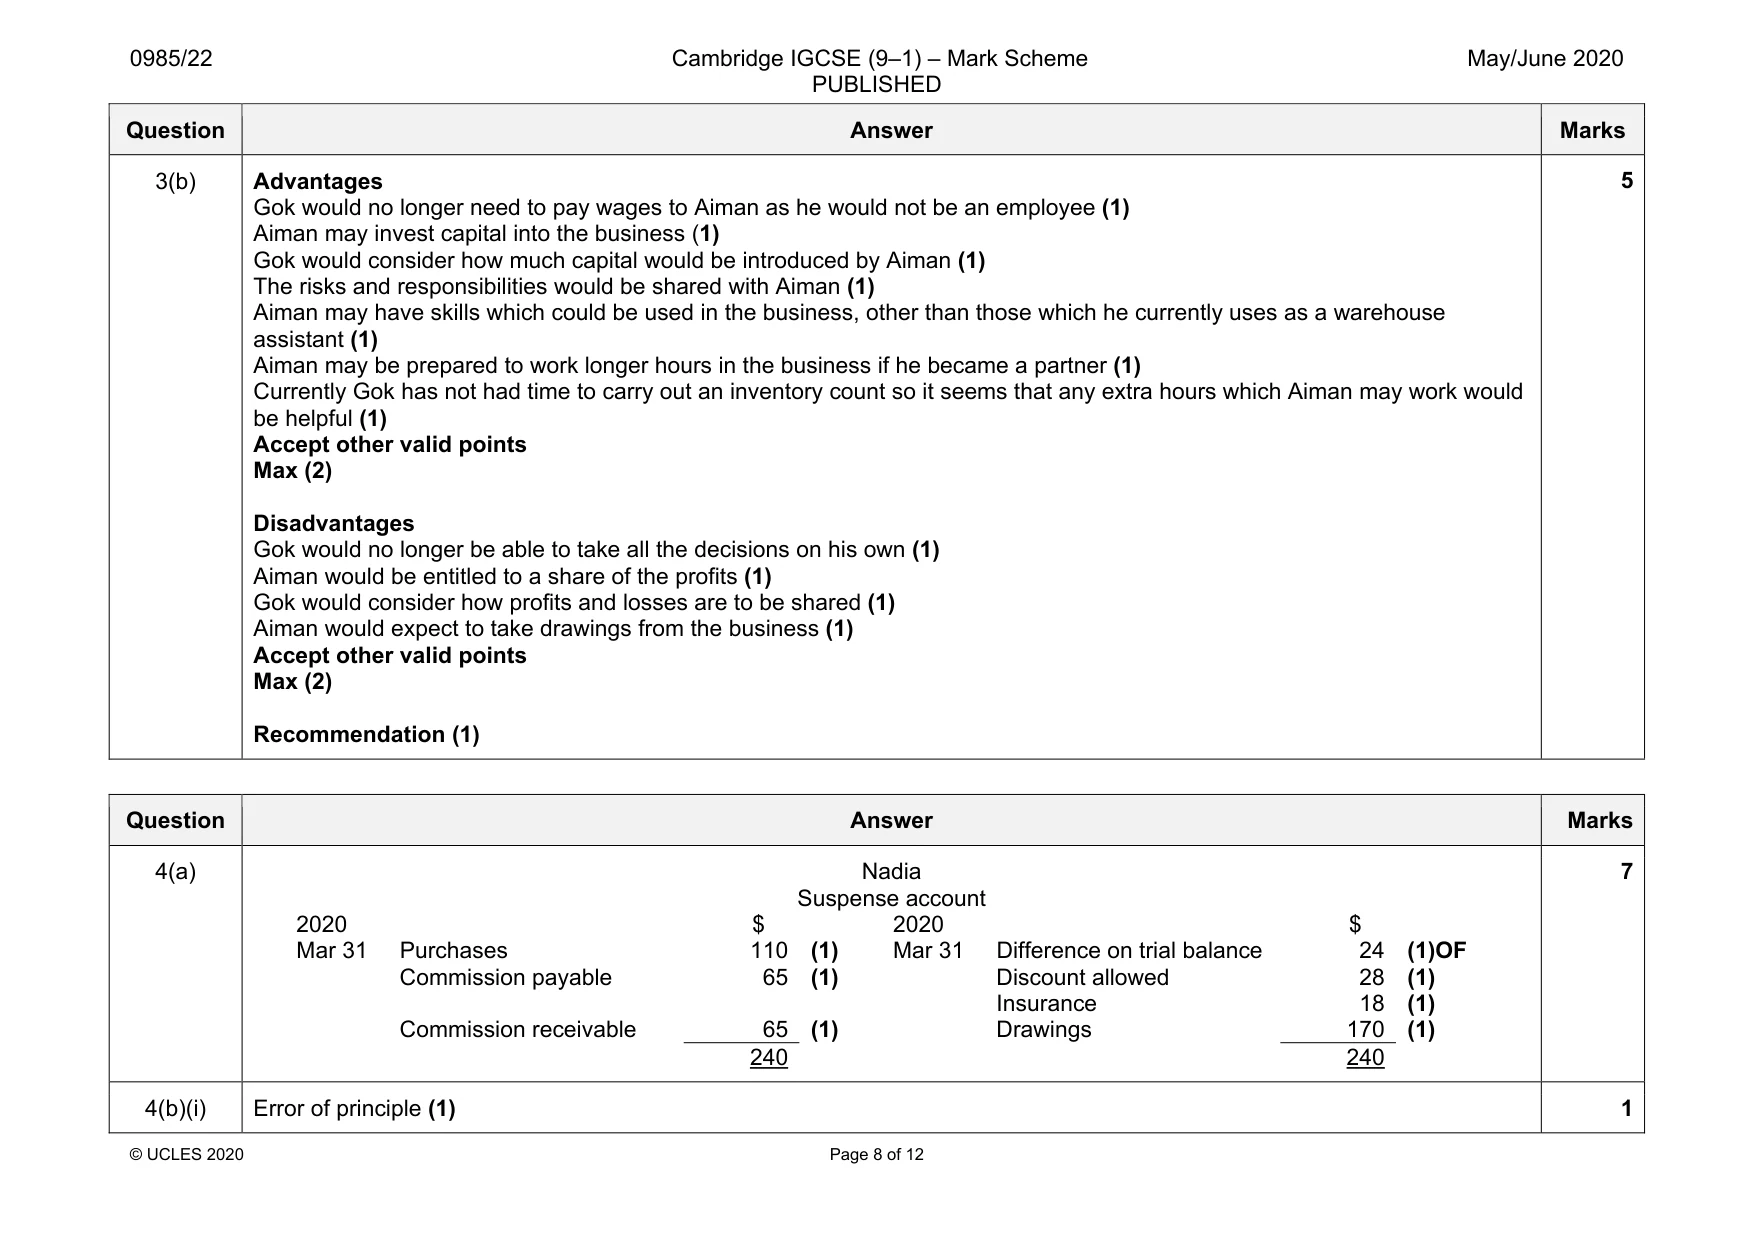
Mark scheme: 3(a) Gok Income Statement for the year ended 29 February 2020 $ $ Revenue 420 000 Less Sales returns 12 000 408 000 (1) Cost of sales Opening inventory 26 700 Purchases 311 400 338 100 Less Closing inventory 32 100 (1)OF 306 000 (1) OF Gross profit 102 000 (1) Less Expenses Discount allowed 9 000 (1) Wages 12 360 } Rent and rates 11 750 }(1) General expenses 4 220 } Irrecoverable debts 8 600 (1) Insurance (4 500 – 1 500) 3 000 (1) Telephone expenses (4 565(1) + [1 660/4] (1)) 4 980 Depreciation on Fixtures and equipment (20% × 76 800) (1) 15 360 (1)OF 69 270 Profit from operations 32 730 Loan interest (60 000 × 7%)(1) × 8/12(1) 2 800 Profit for the year 29 930 (1)OF 15 Question Answer Marks 3(b) Advantages Gok would no longer need to pay wages to Aiman as he would not be an employee (1) Aiman may invest capital into the business (1) Gok would consider how much capital would be introduced by Aiman (1) The risks and responsibilities would be shared with Aiman (1) Aiman may have skills which could be used in the business, other than those which he currently uses as a warehouse assistant (1) Aiman may be prepared to work longer hours in the business if he became a partner (1) Currently Gok has not had time to carry out an inventory count so it seems that any extra hours which Aiman may work would be helpful (1) Accept other valid points Max (2) Disadvantages Gok would no longer be able to take all the decisions on his own (1) Aiman would be entitled to a share of the profits (1) Gok would consider how profits and losses are to be shared (1) Aiman would expect to take drawings from the business (1) Accept other valid points Max (2) Recommendation (1) 5
Q4 · Nadia is a trader
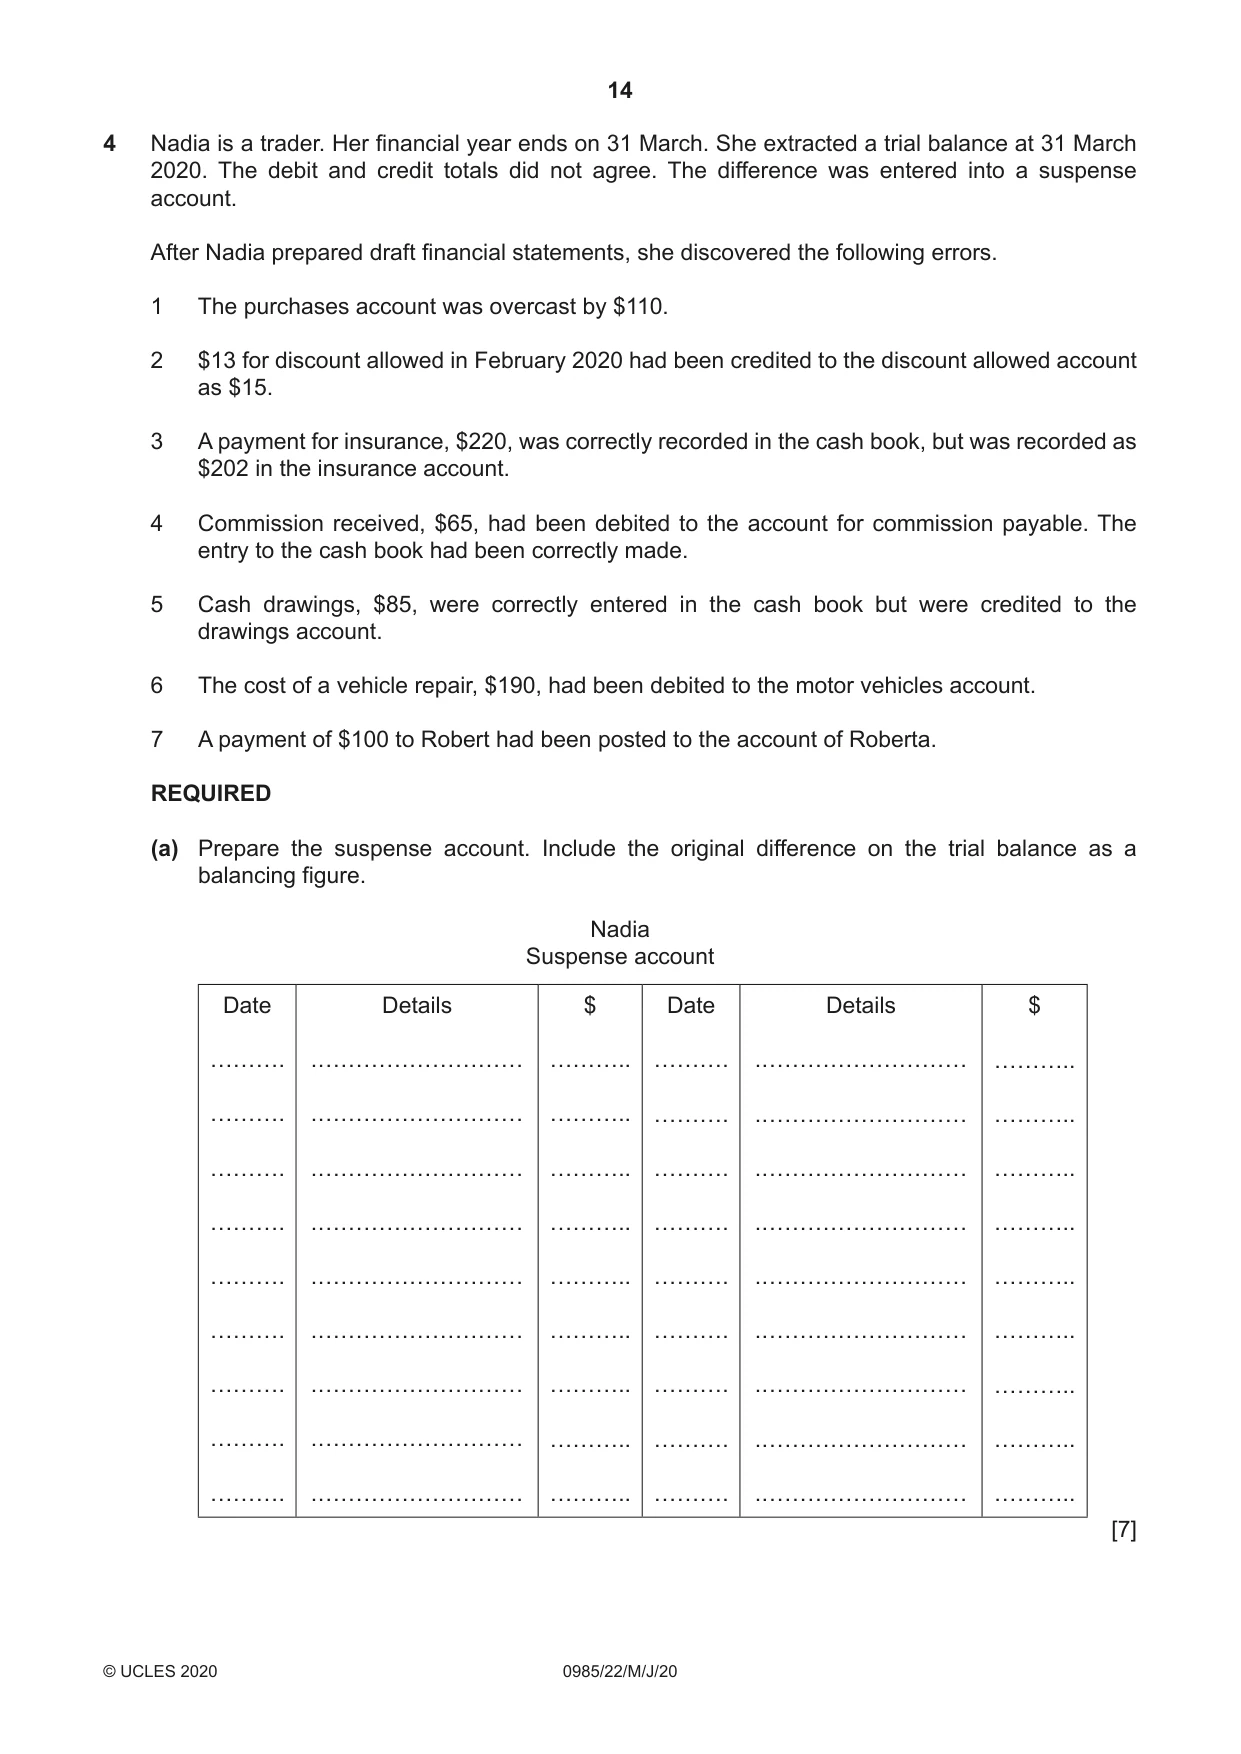
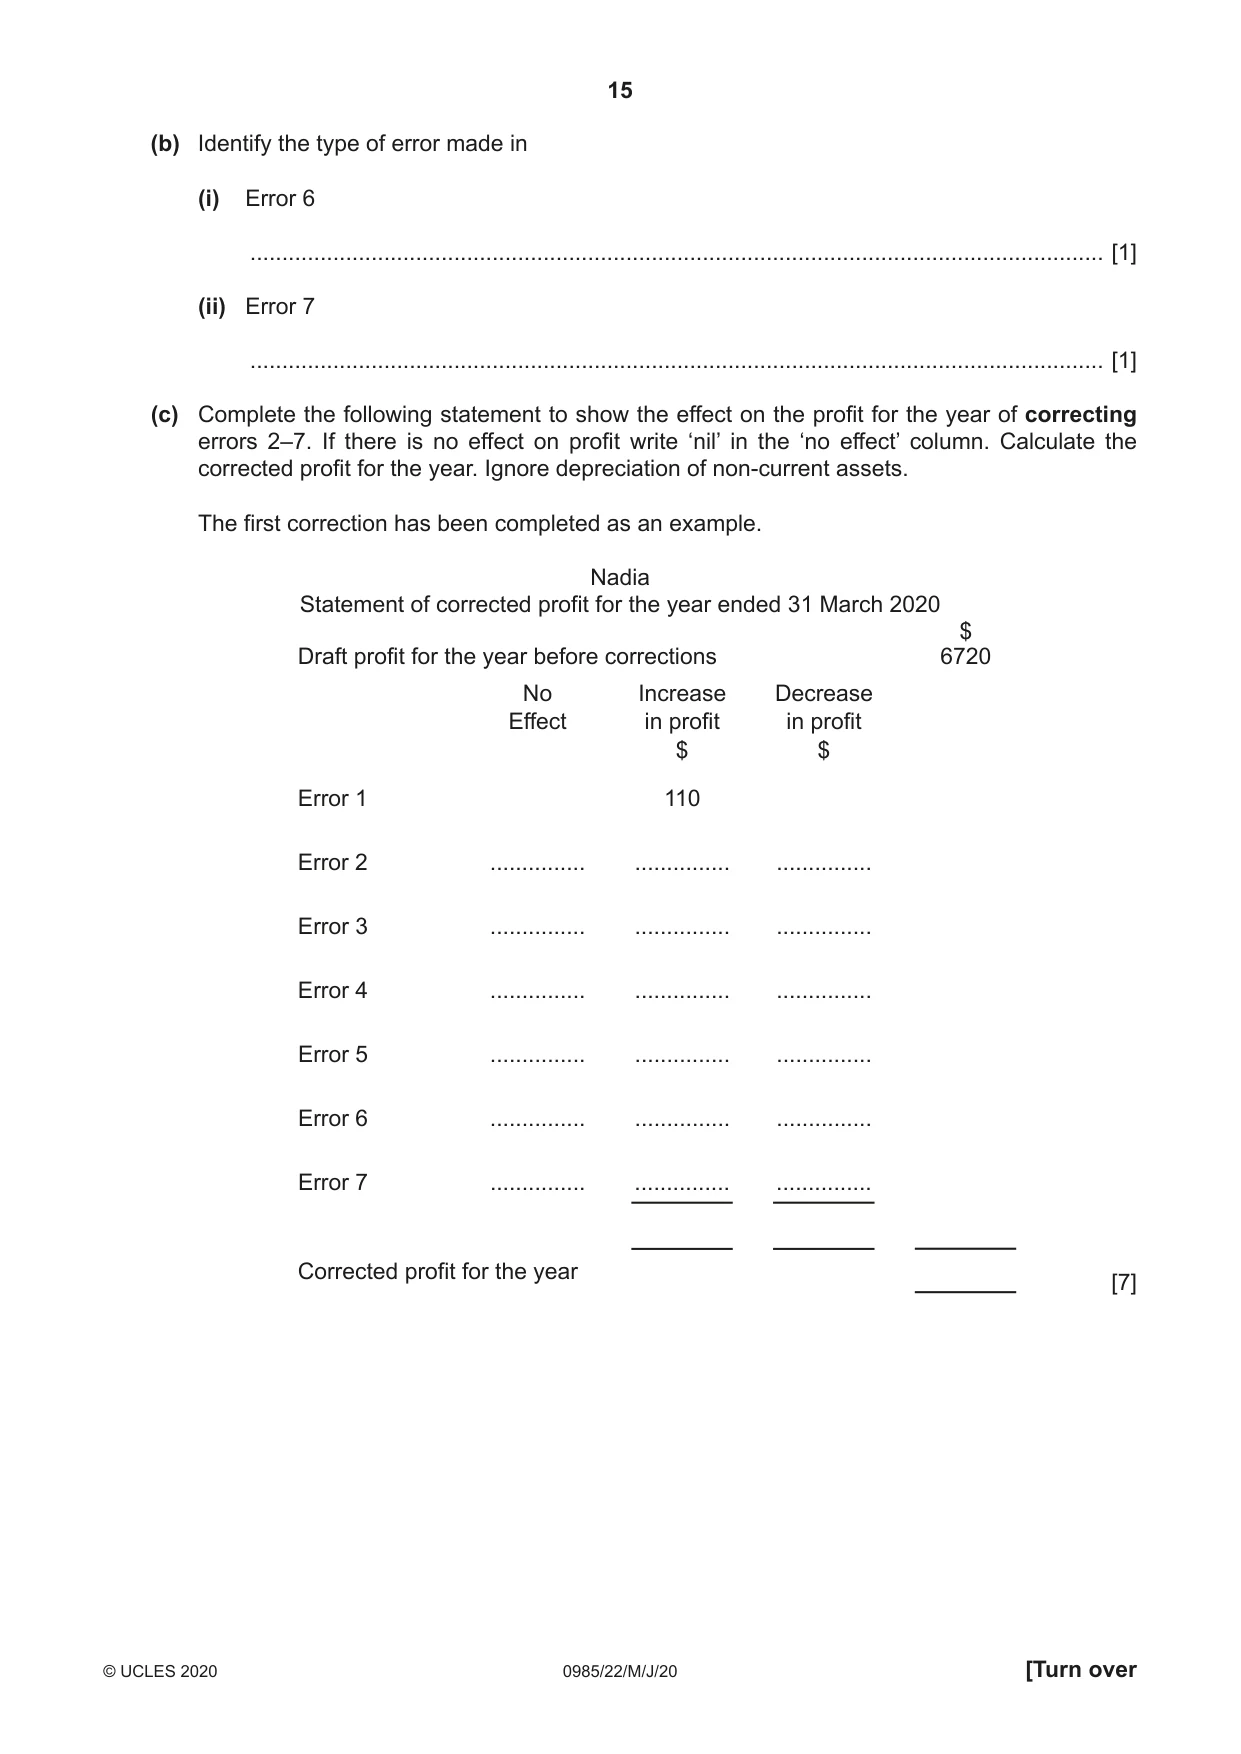
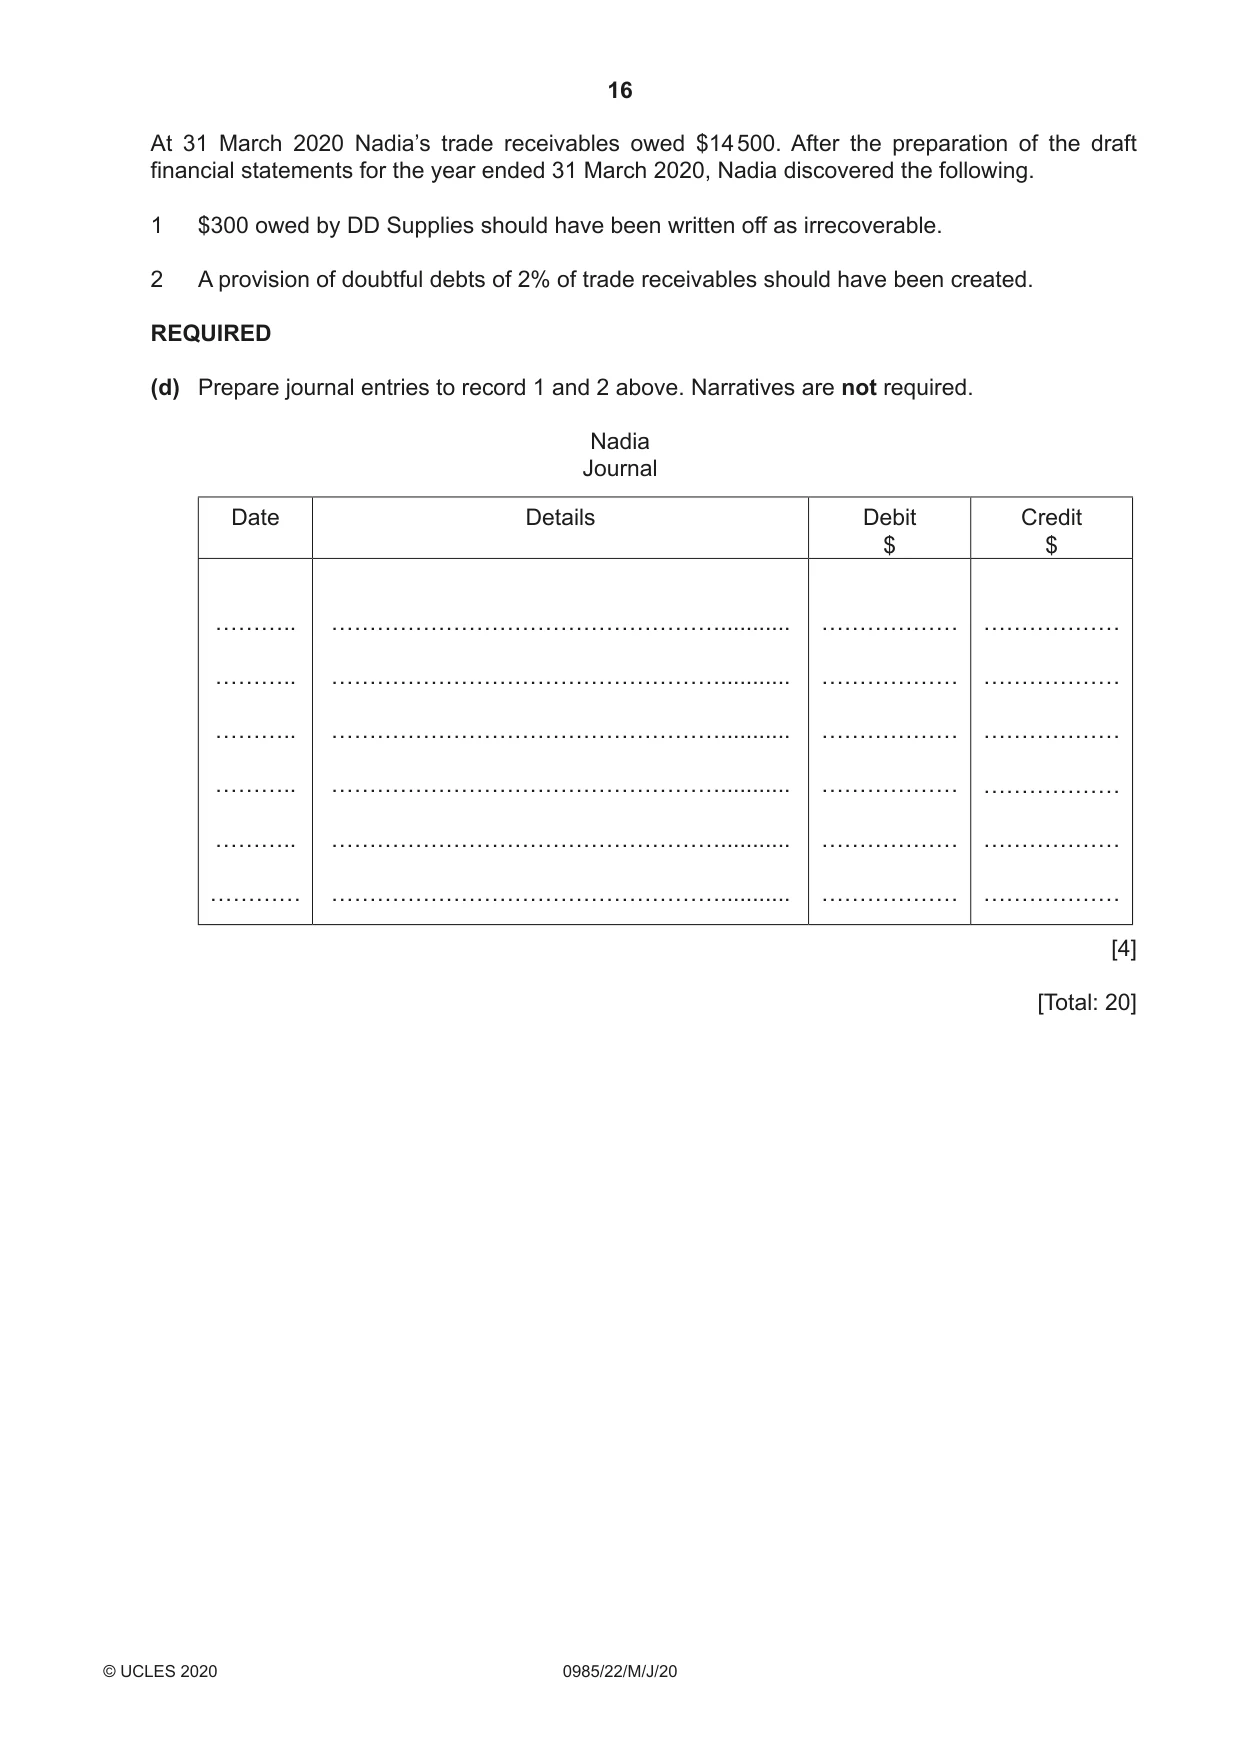
4 Nadia is a trader. Her financial year ends on 31 March. She extracted a trial balance at 31 March 2020. The debit and credit totals did not agree. The difference was entered into a suspense account. After Nadia prepared draft financial statements, she discovered the following errors. 1 The purchases account was overcast by $110. 2 $13 for discount allowed in February 2020 had been credited to the discount allowed account as $15. 3 A payment for insurance, $220, was correctly recorded in the cash book, but was recorded as $202 in the insurance account. 4 Commission received, $65, had been debited to the account for commission payable. The entry to the cash book had been correctly made. 5 Cash drawings, $85, were correctly entered in the cash book but were credited to the drawings account. 6 The cost of a vehicle repair, $190, had been debited to the motor vehicles account. 7 A payment of $100 to Robert had been posted to the account of Roberta. REQUIRED (a) Prepare the suspense account. Include the original difference on the trial balance as a balancing figure. Nadia Suspense account Date Details $ Date Details $ ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. [7] (b) Identify the type of error made in (i) Error 6 ...................................................................................................................................... [1] (ii) Error 7 ...................................................................................................................................... [1] (c) Complete the following statement to show the effect on the profit for the year of correcting errors 2–7. If there is no effect on profit write ‘nil’ in the ‘no effect’ column. Calculate the corrected profit for the year. Ignore depreciation of non-current assets. The first correction has been completed as an example. Nadia Statement of corrected profit for the year ended 31 March 2020 $ Draft profit for the year before corrections 6720 No Increase Decrease Effect in profit in profit $ $ Error 1 110 Error 2 ............... ............... ............... Error 3 ............... ............... ............... Error 4 ............... ............... ............... Error 5 ............... ............... ............... Error 6 ............... ............... ............... Error 7 ............... ............... ............... Corrected profit for the year [7] At 31 March 2020 Nadia’s trade receivables owed $14 500. After the preparation of the draft financial statements for the year ended 31 March 2020, Nadia discovered the following. 1 $300 owed by DD Supplies should have been written off as irrecoverable. 2 A provision of doubtful debts of 2% of trade receivables should have been created. REQUIRED (d) Prepare journal entries to record 1 and 2 above. Narratives are not required. Nadia Journal Date Details Debit Credit $ $ ……….. ……………………………………………........... ……………… ……………… ……….. ……………………………………………........... ……………… ……………… ……….. ……………………………………………........... ……………… ……………… ……….. ……………………………………………........... ……………… ……………… ……….. ……………………………………………........... ……………… ……………… ………… ……………………………………………........... ……………… ……………… [4] [Total: 20]
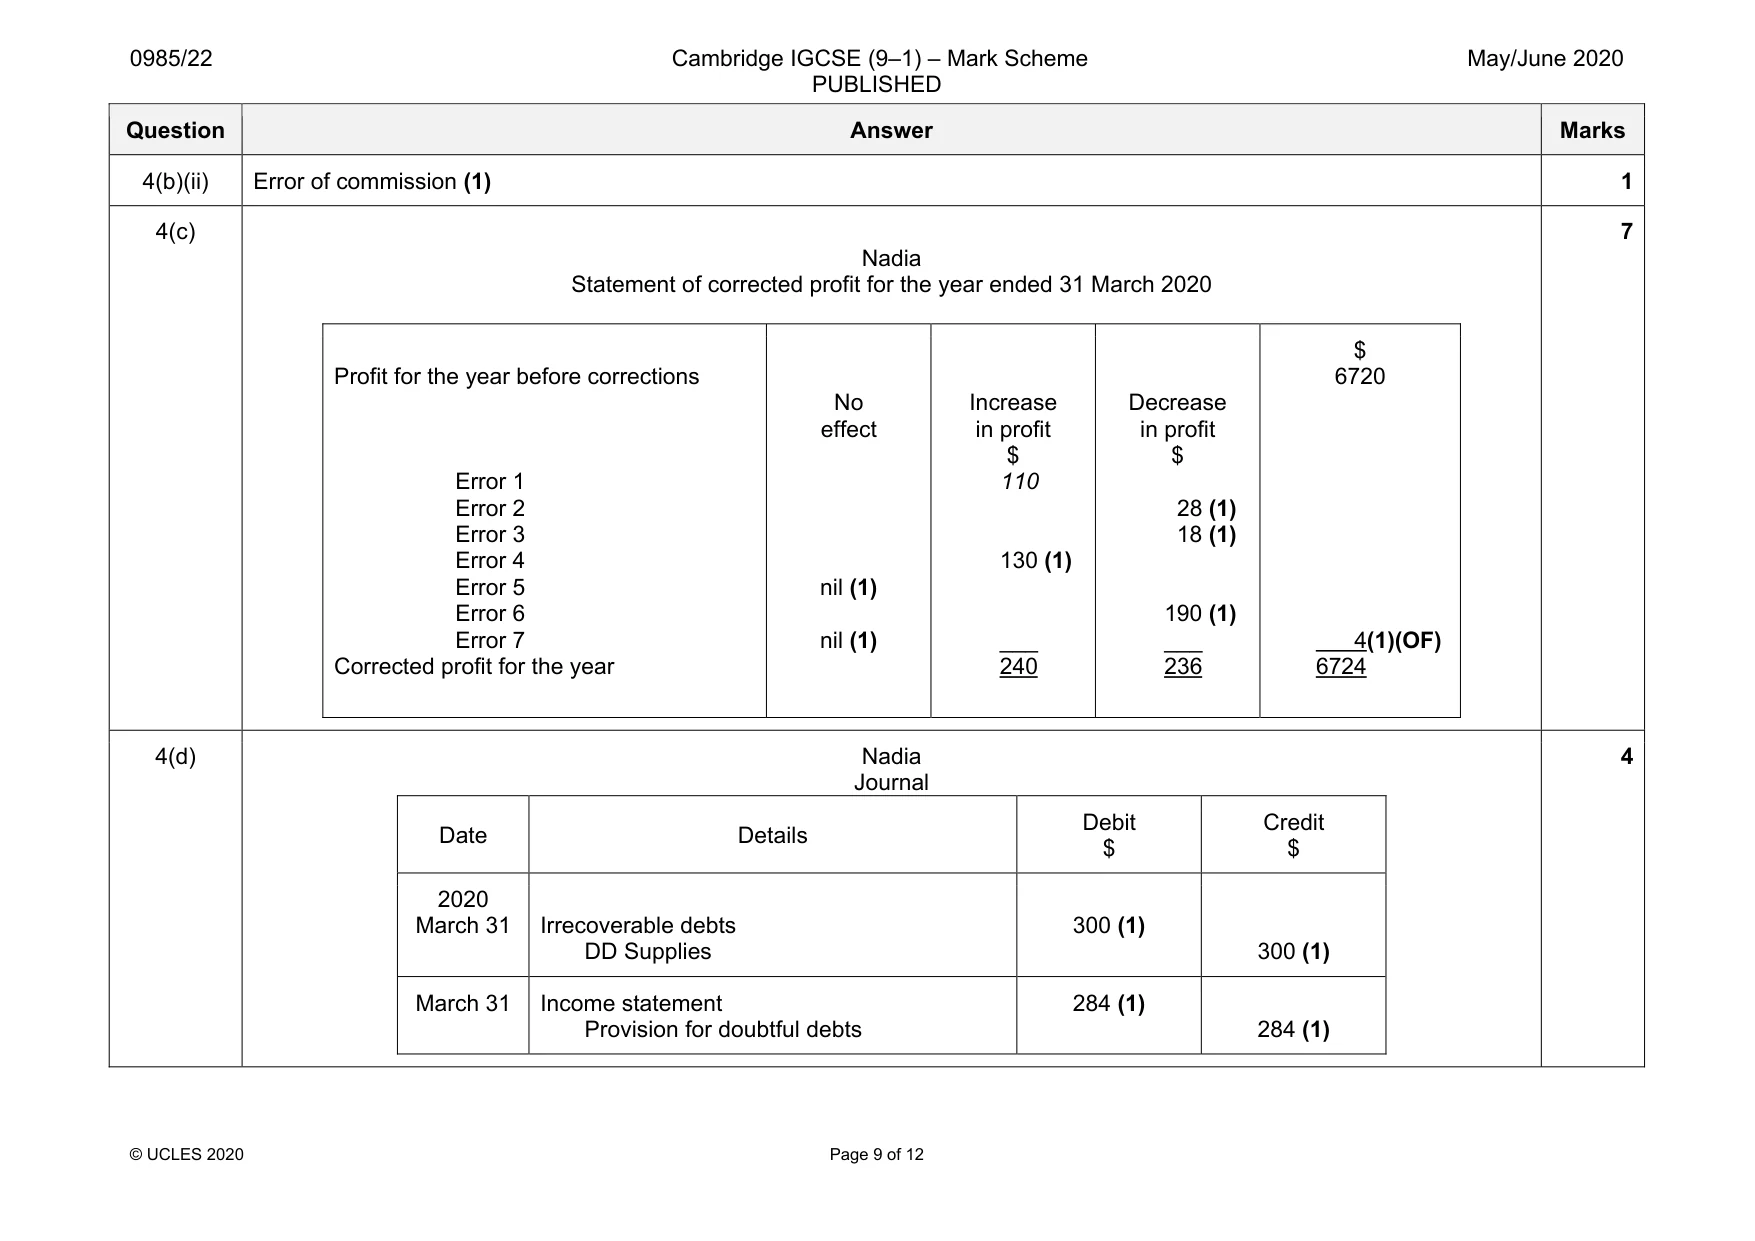
Mark scheme: 4(a) Nadia Suspense account 2020 $ 2020 $ Mar 31 Purchases 110 (1) Mar 31 Difference on trial balance 24 (1)OF Commission payable 65 (1) Discount allowed 28 (1) Insurance 18 (1) Commission receivable 65 (1) Drawings 170 (1) 240 240 7 4(b)(i) Error of principle (1) 1 Question Answer Marks 4(b)(ii) Error of commission (1) 1 4(c) Nadia Statement of corrected profit for the year ended 31 March 2020 Profit for the year before corrections Error 1 Error 2 Error 3 Error 4 Error 5 Error 6 Error 7 Corrected profit for the year No effect nil (1) nil (1) Increase in profit $ 110 130 (1) ___ 240 Decrease in profit $ 28 (1) 18 (1) 190 (1) ___ 236 $ 6720 4(1)(OF) 6724 7 4(d) Nadia Journal Date Details Debit $ Credit $ 2020 March 31 Irrecoverable debts DD Supplies 300 (1) 300 (1) March 31 Income statement Provision for doubtful debts 284 (1) 284 (1) 4
Q5 · The directors of JKY Limited provided the following information
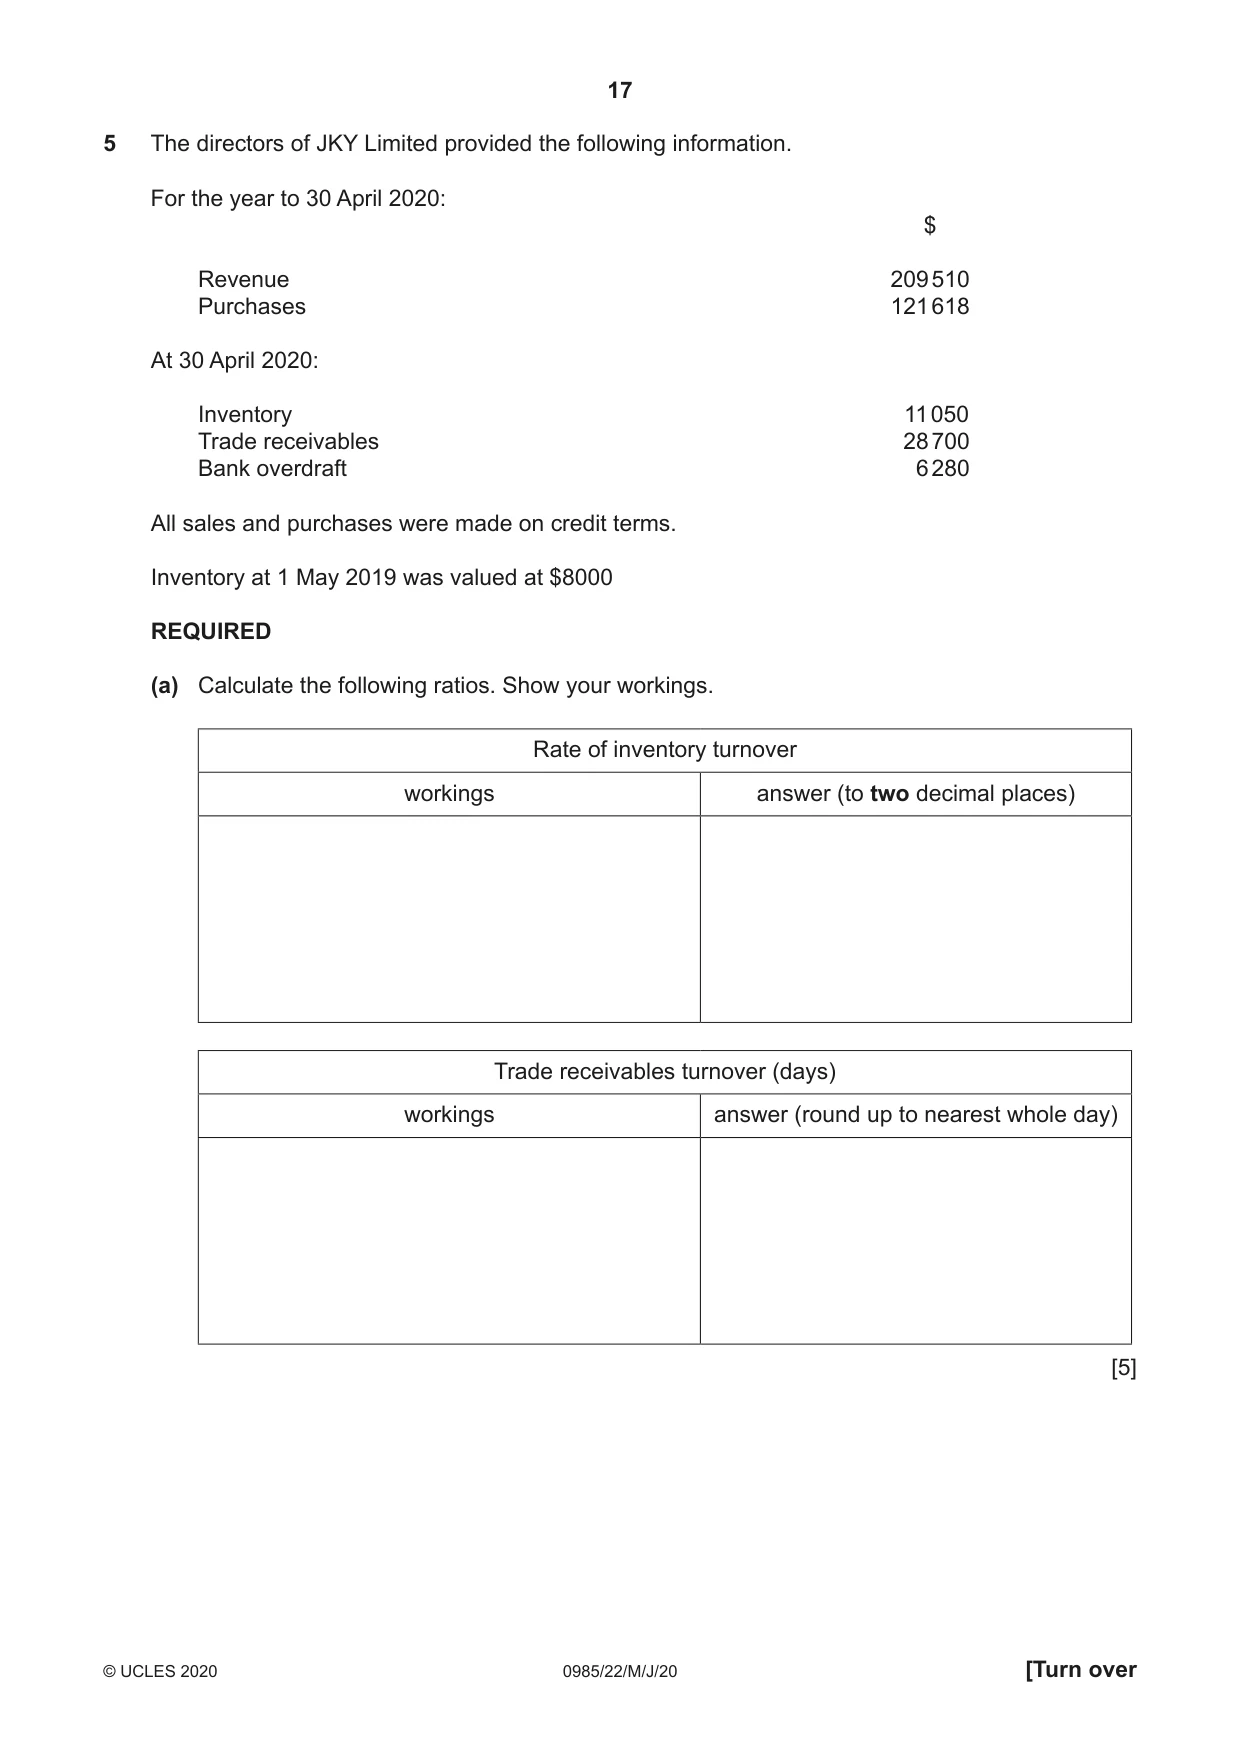
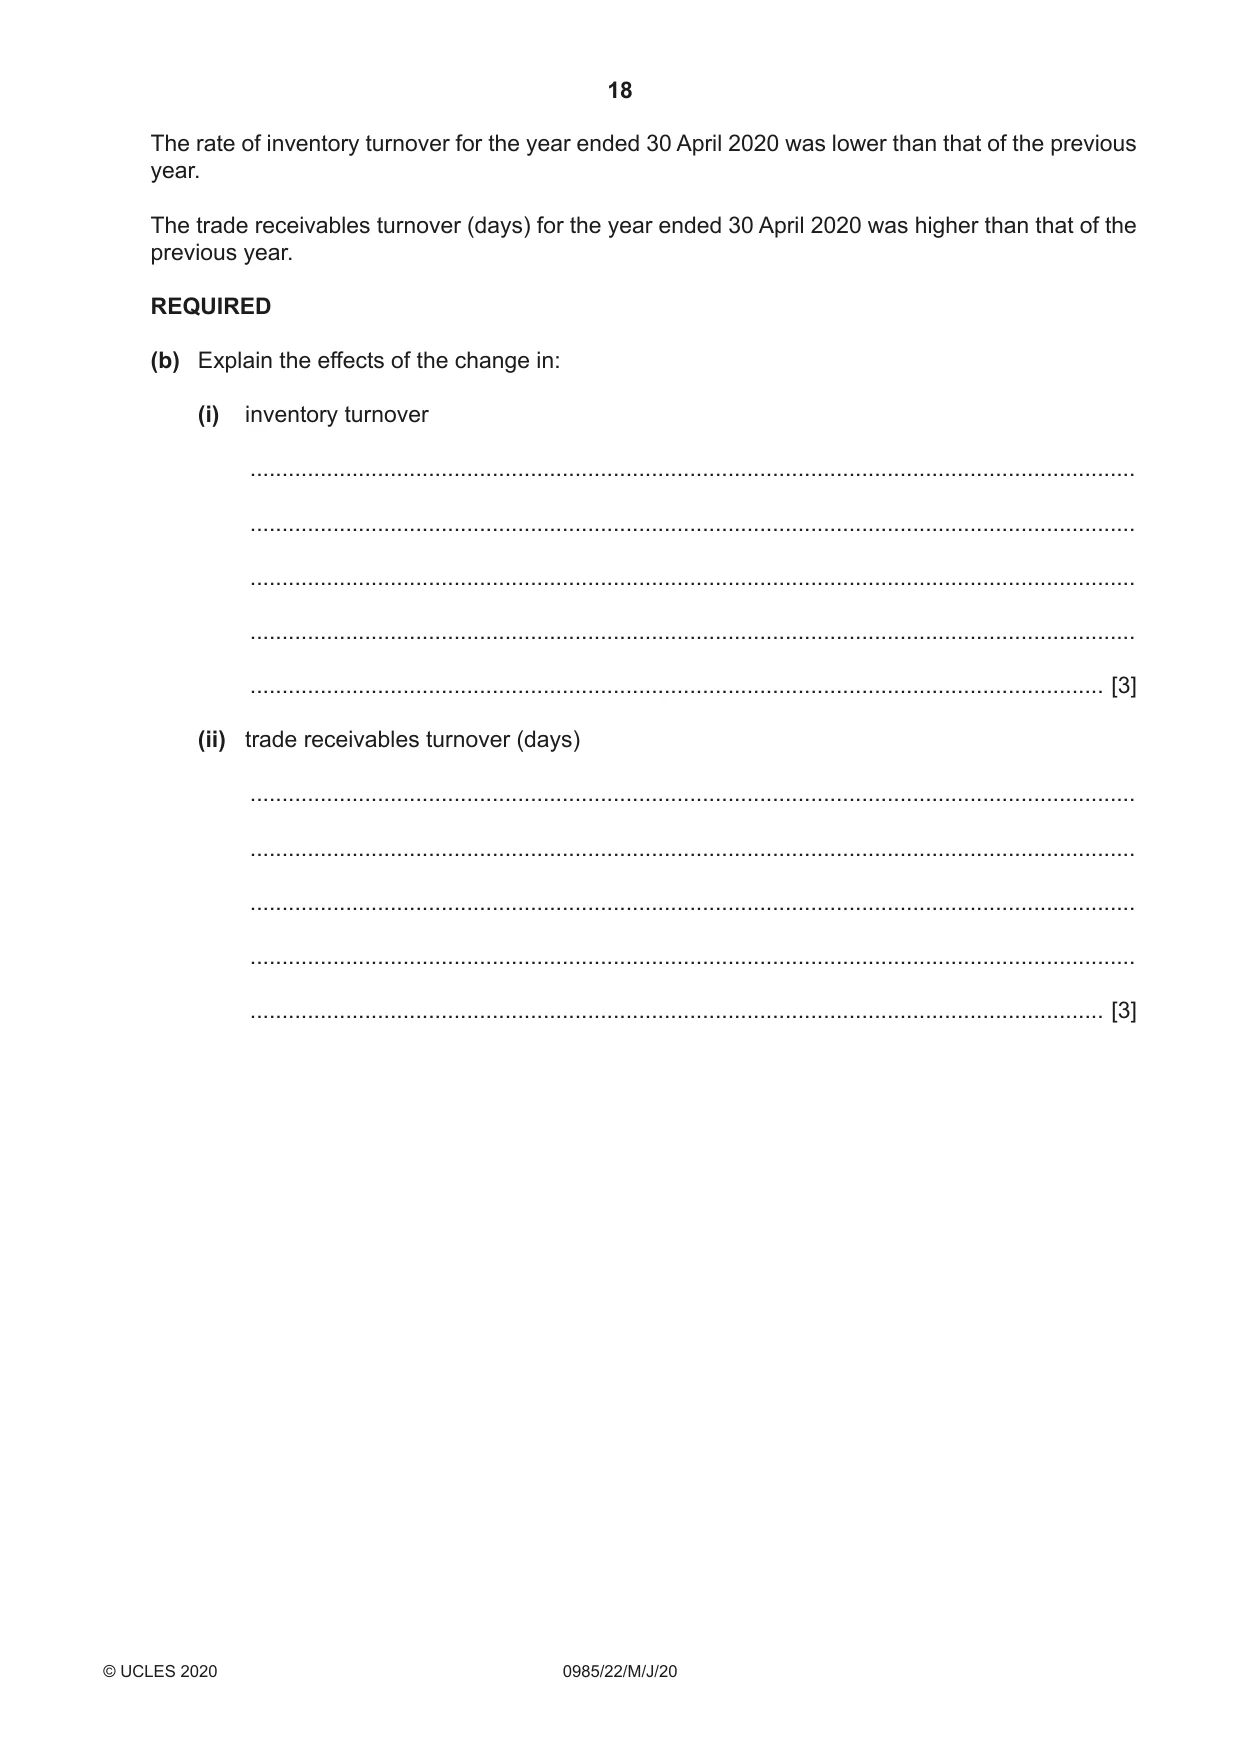
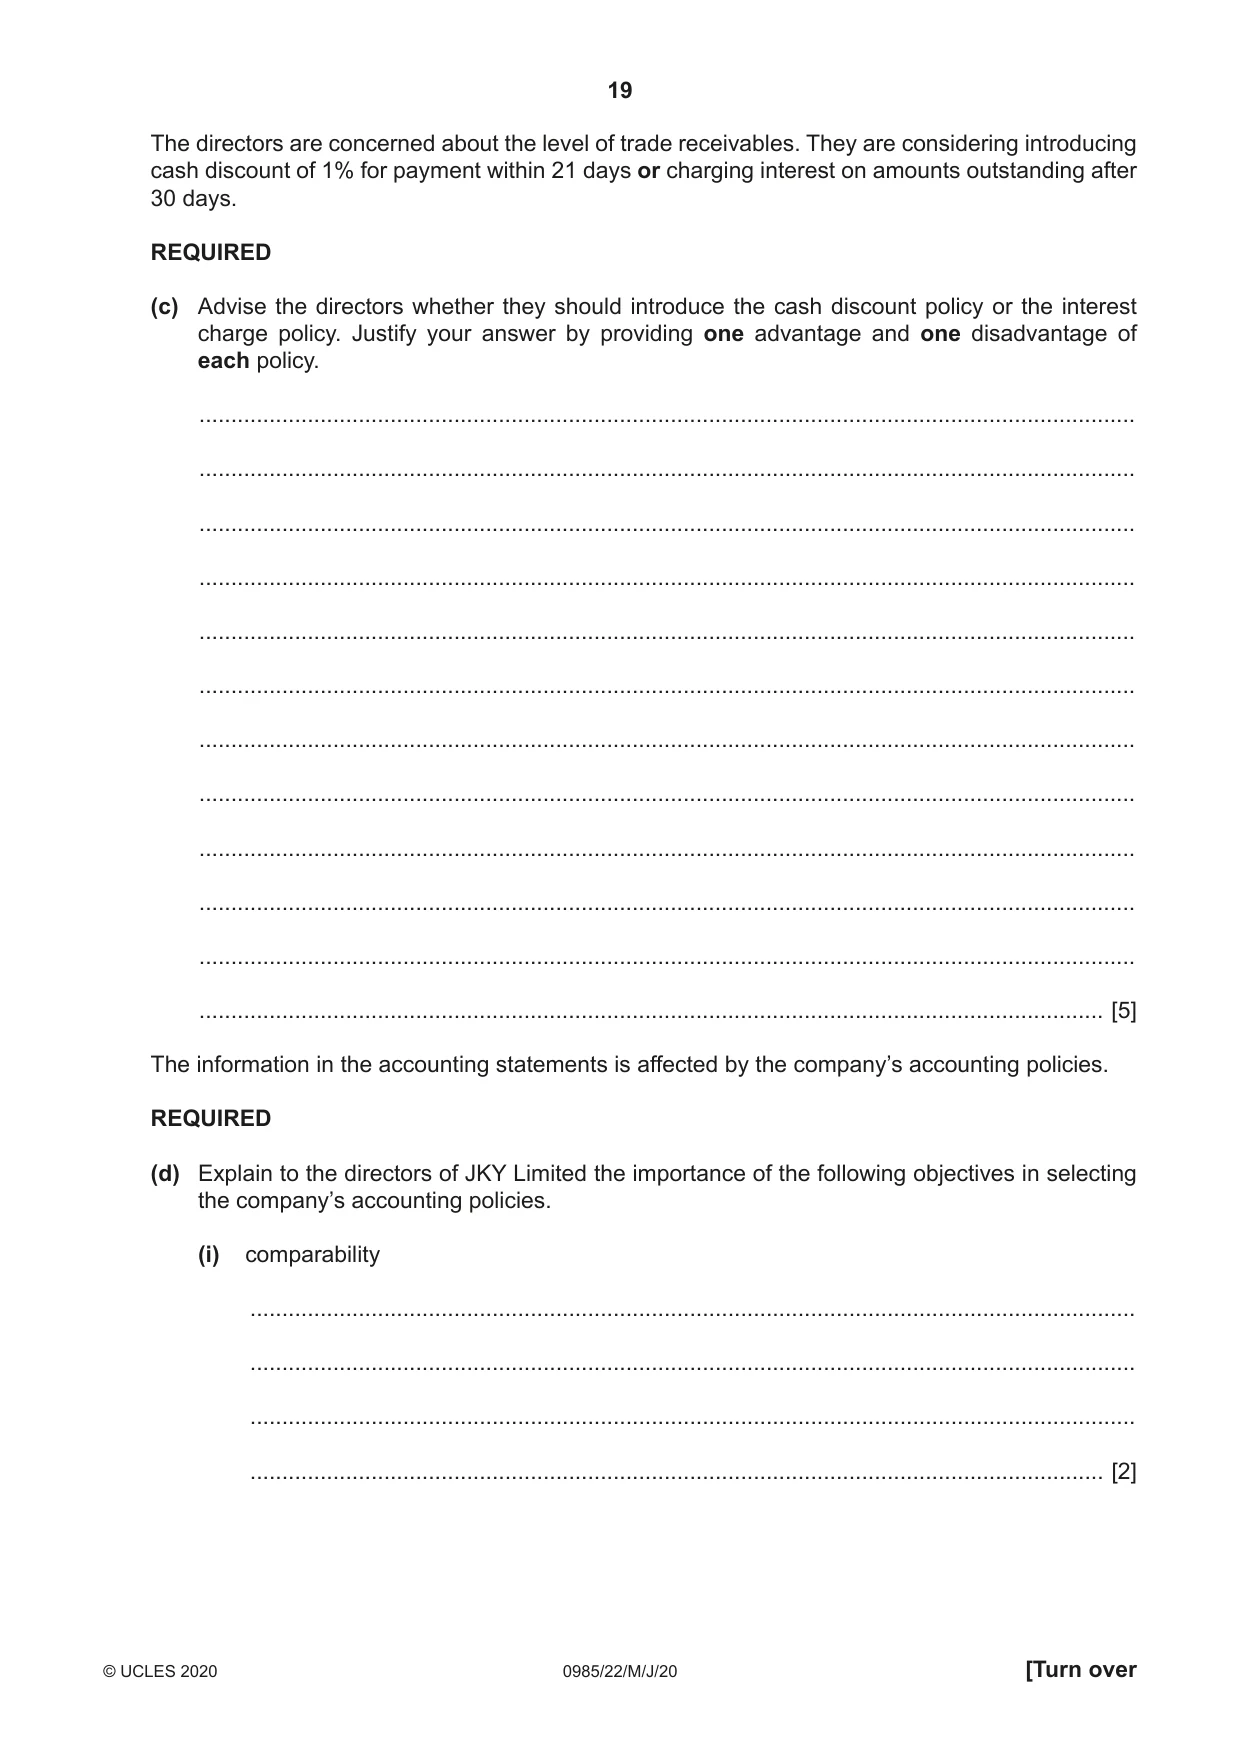
5 The directors of JKY Limited provided the following information. For the year to 30 April 2020: $ Revenue 209 510 Purchases 121 618 At 30 April 2020: Inventory 11 050 Trade receivables 28 700 Bank overdraft 6 280 All sales and purchases were made on credit terms. Inventory at 1 May 2019 was valued at $8000 REQUIRED (a) Calculate the following ratios. Show your workings. Rate of inventory turnover workings answer (to two decimal places) Trade receivables turnover (days) workings answer (round up to nearest whole day) [5] The rate of inventory turnover for the year ended 30 April 2020 was lower than that of the previous year. The trade receivables turnover (days) for the year ended 30 April 2020 was higher than that of the previous year. REQUIRED (b) Explain the effects of the change in: (i) inventory turnover ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [3] (ii) trade receivables turnover (days) ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [3] The directors are concerned about the level of trade receivables. They are considering introducing cash discount of 1% for payment within 21 days or charging interest on amounts outstanding after
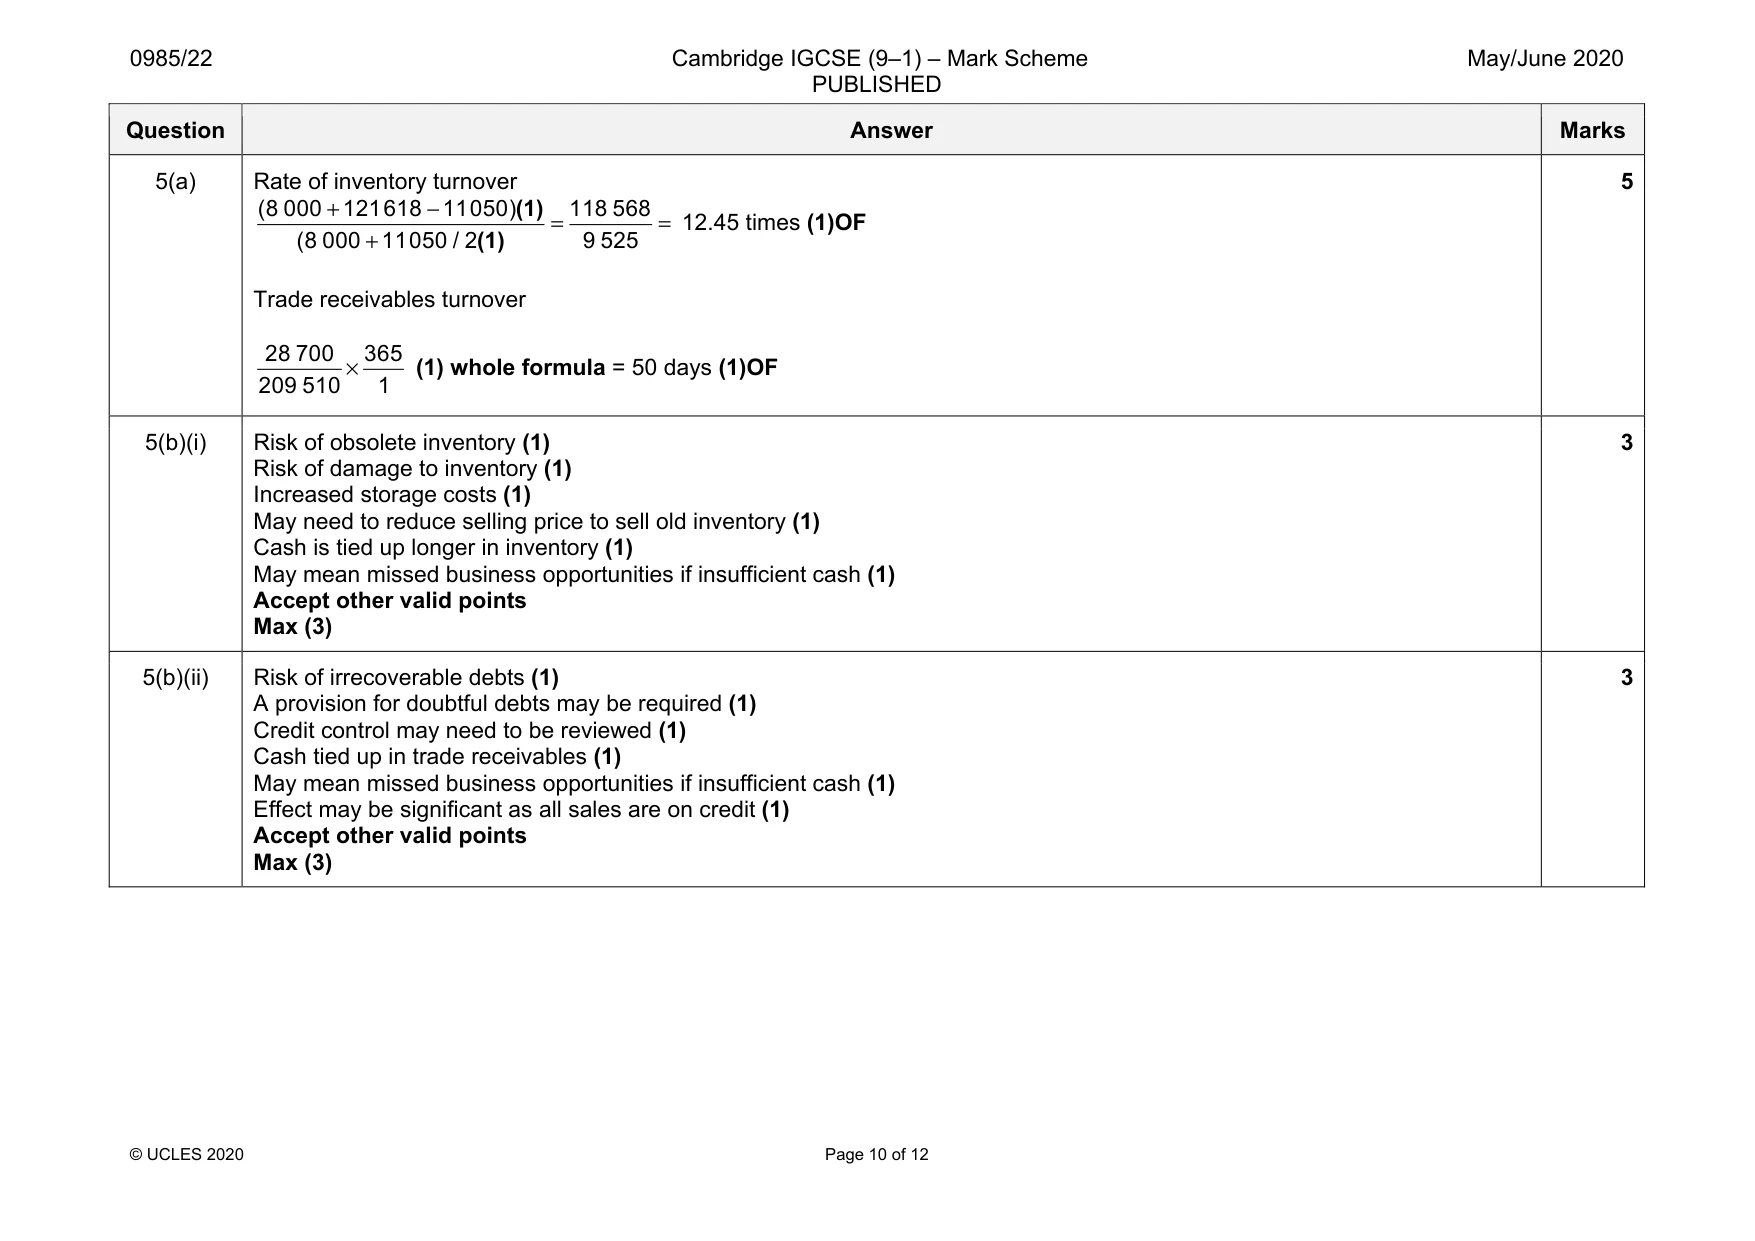
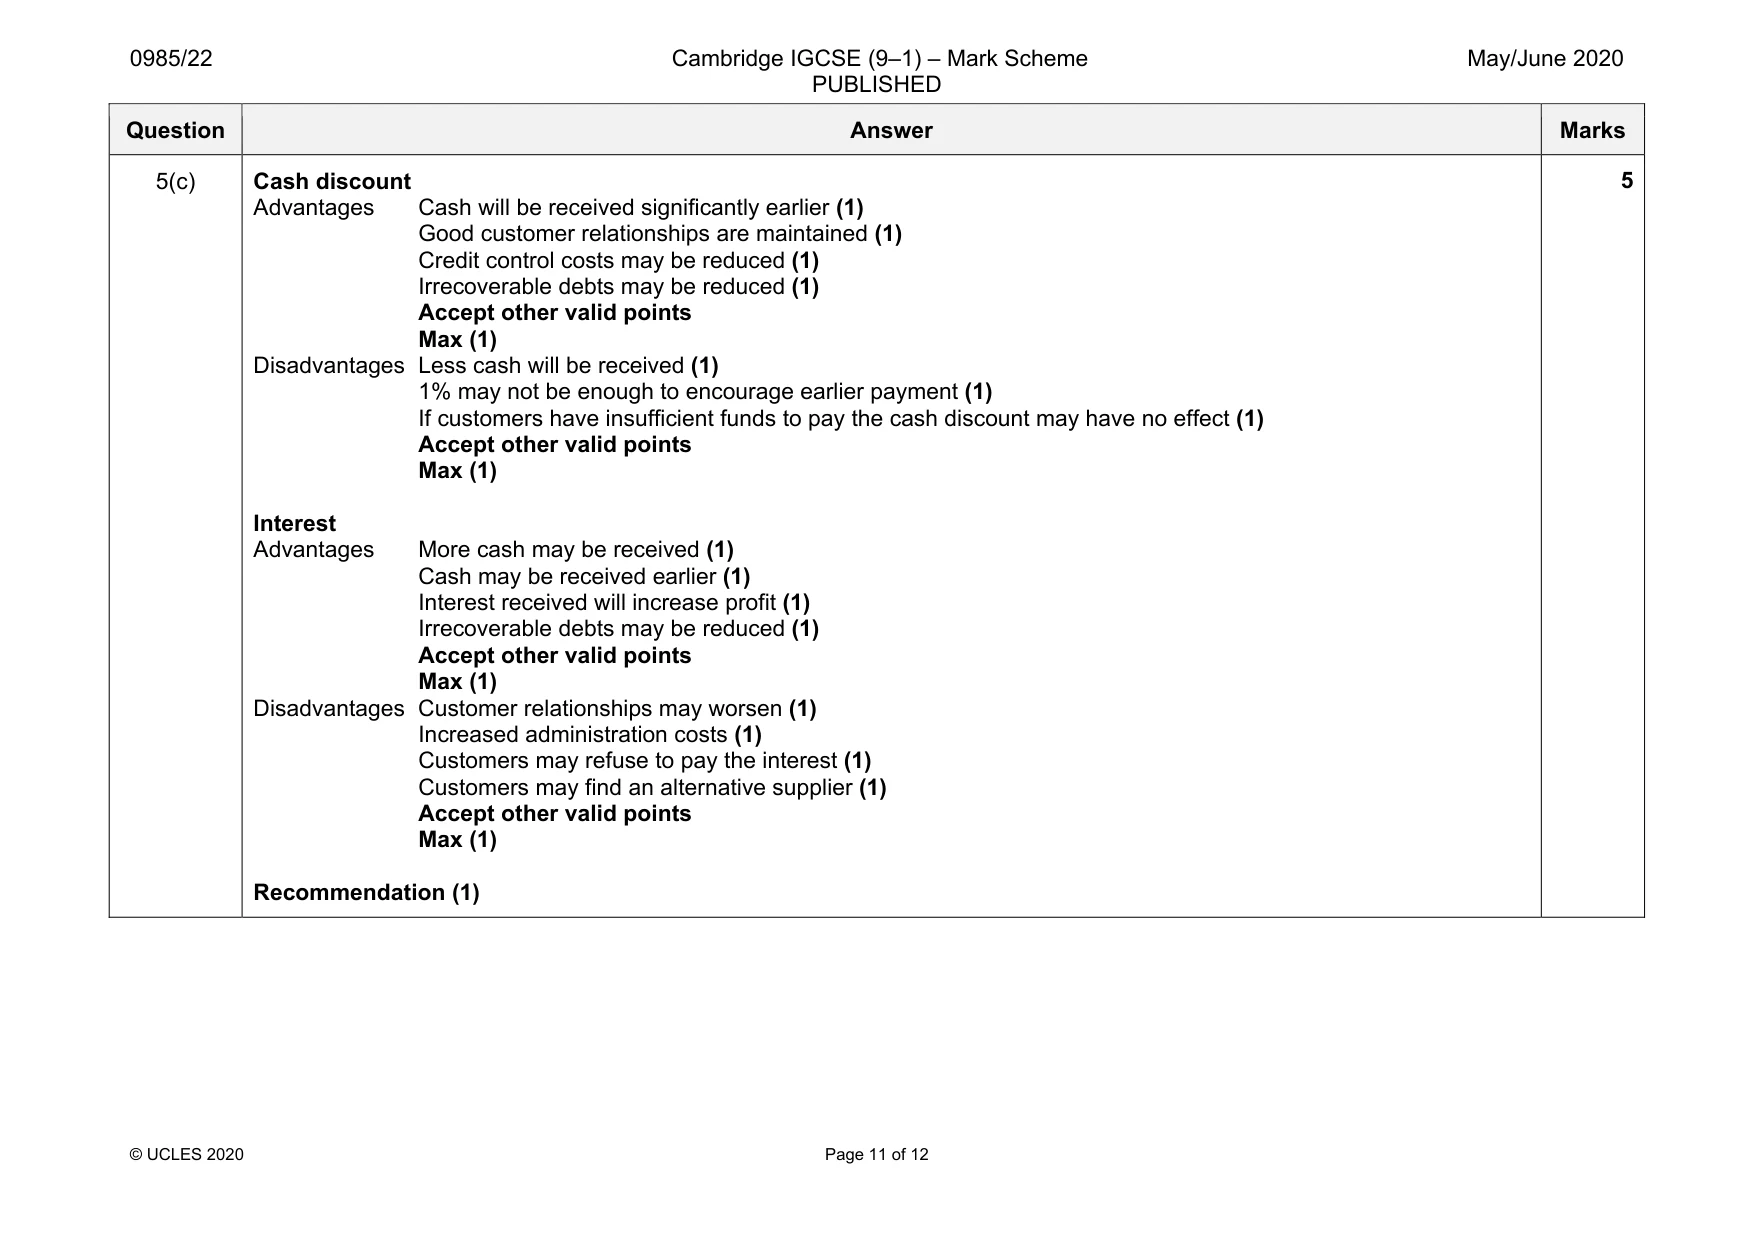
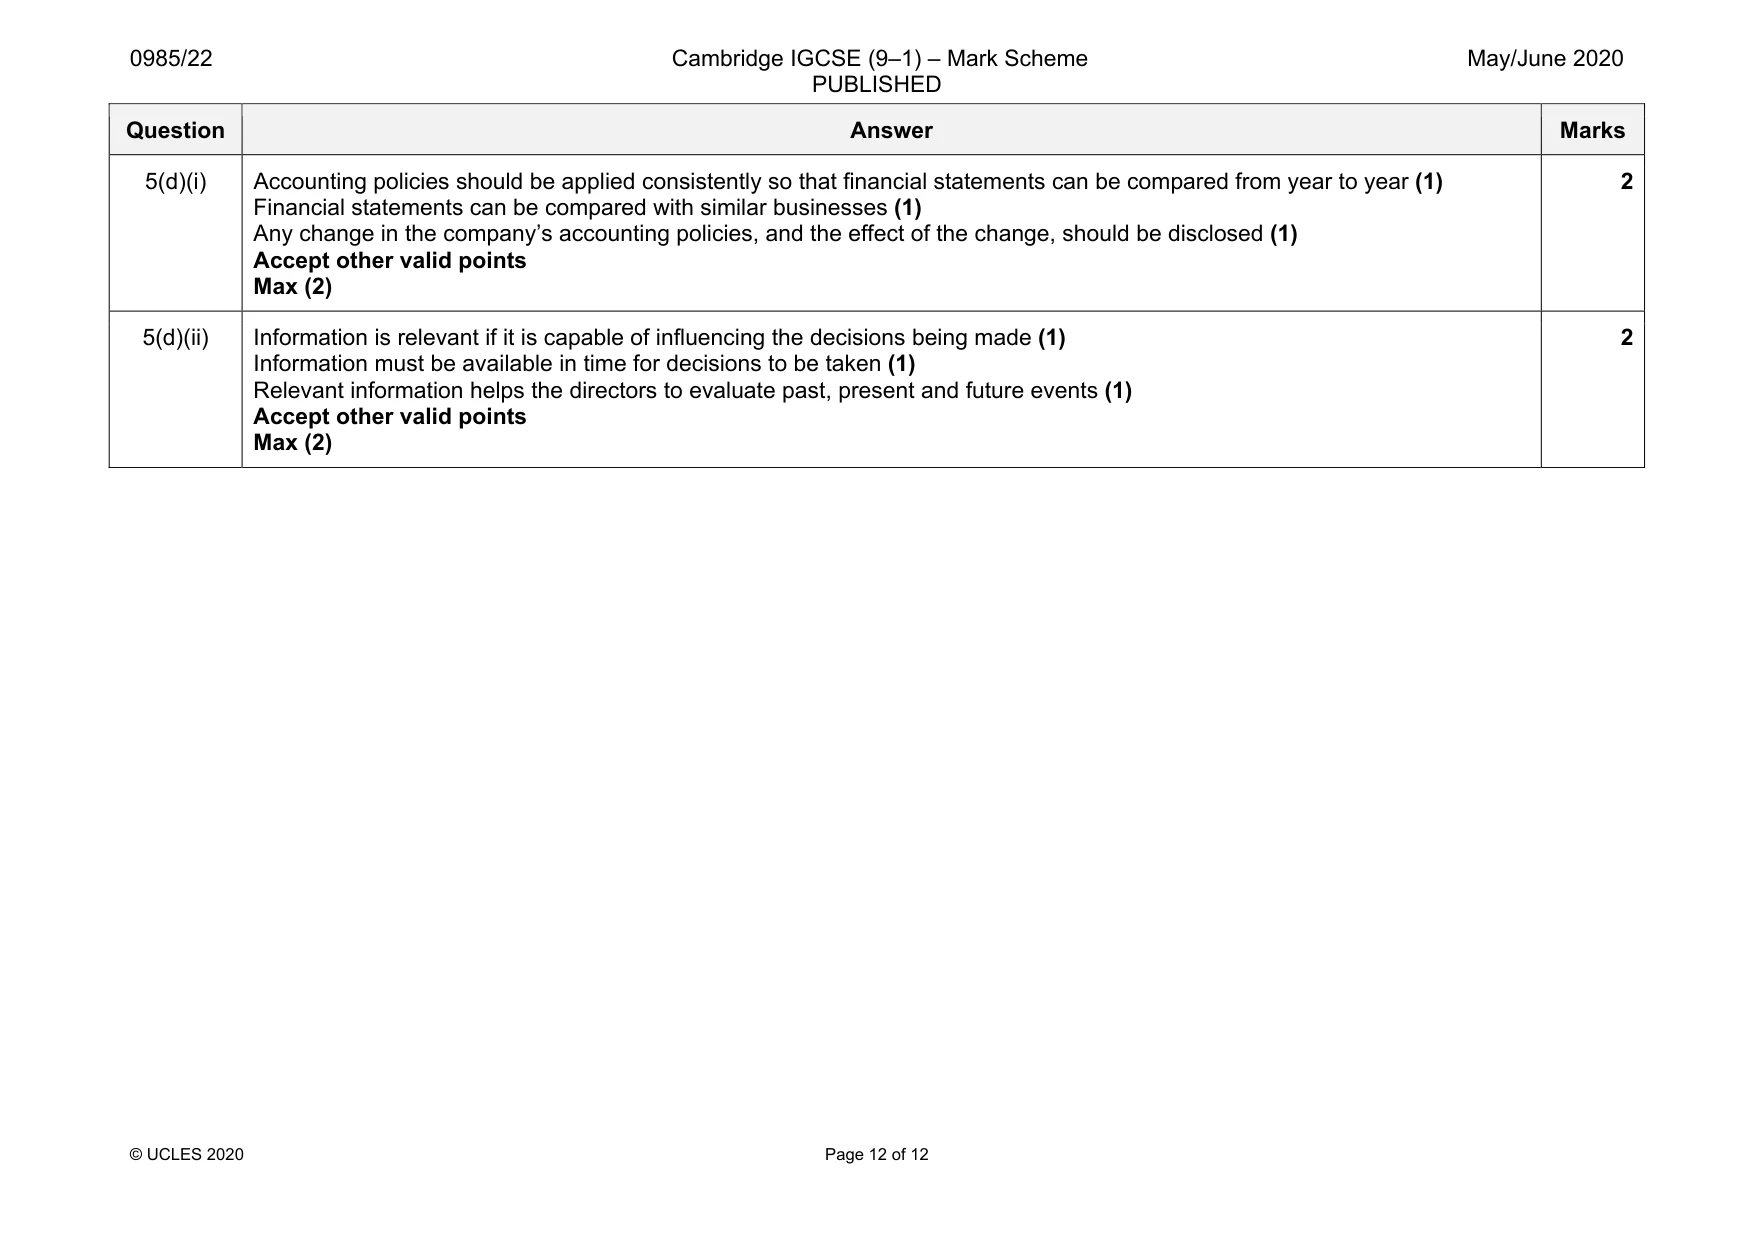
Mark scheme: 5(a) Rate of inventory turnover (8 000 121618 11050) 118 568 (8 000 11050 / 2 9 525 + − = = + (1) (1) 12.45 times (1)OF Trade receivables turnover 28 700 365 209 510 1 × (1) whole formula = 50 days (1)OF 5 5(b)(i) Risk of obsolete inventory (1) Risk of damage to inventory (1) Increased storage costs (1) May need to reduce selling price to sell old inventory (1) Cash is tied up longer in inventory (1) May mean missed business opportunities if insufficient cash (1) Accept other valid points Max (3) 3 5(b)(ii) Risk of irrecoverable debts (1) A provision for doubtful debts may be required (1) Credit control may need to be reviewed (1) Cash tied up in trade receivables (1) May mean missed business opportunities if insufficient cash (1) Effect may be significant as all sales are on credit (1) Accept other valid points Max (3) 3 Question Answer Marks 5(c) Cash discount Advantages Cash will be received significantly earlier (1) Good customer relationships are maintained (1) Credit control costs may be reduced (1) Irrecoverable debts may be reduced (1) Accept other valid points Max (1) Disadvantages Less cash will be received (1) 1% may not be enough to encourage earlier payment (1) If customers have insufficient funds to pay the cash discount may have no effect (1) Accept other valid points Max (1) Interest Advantages More cash may be received (1) Cash may be received earlier (1) Interest received will increase profit (1) Irrecoverable debts may be reduced (1) Accept other valid points Max (1) Disadvantages Customer relationships may worsen (1) Increased administration costs (1) Customers may refuse to pay the interest (1) Customers may find an alternative supplier (1) Accept other valid points Max (1) Recommendation (1) 5 Question Answer Marks 5(d)(i) Accounting policies should be applied consistently so that financial statements can be compared from year to year (1) Financial statements can be compared with similar businesses (1) Any change in the company’s accounting policies, and the effect of the change, should be disclosed (1) Accept other valid points Max (2) 2 5(d)(ii) Information is relevant if it is capable of influencing the decisions being made (1) Information must be available in time for decisions to be taken (1) Relevant information helps the directors to evaluate past, present and future events (1) Accept other valid points Max (2) 2
Question 30
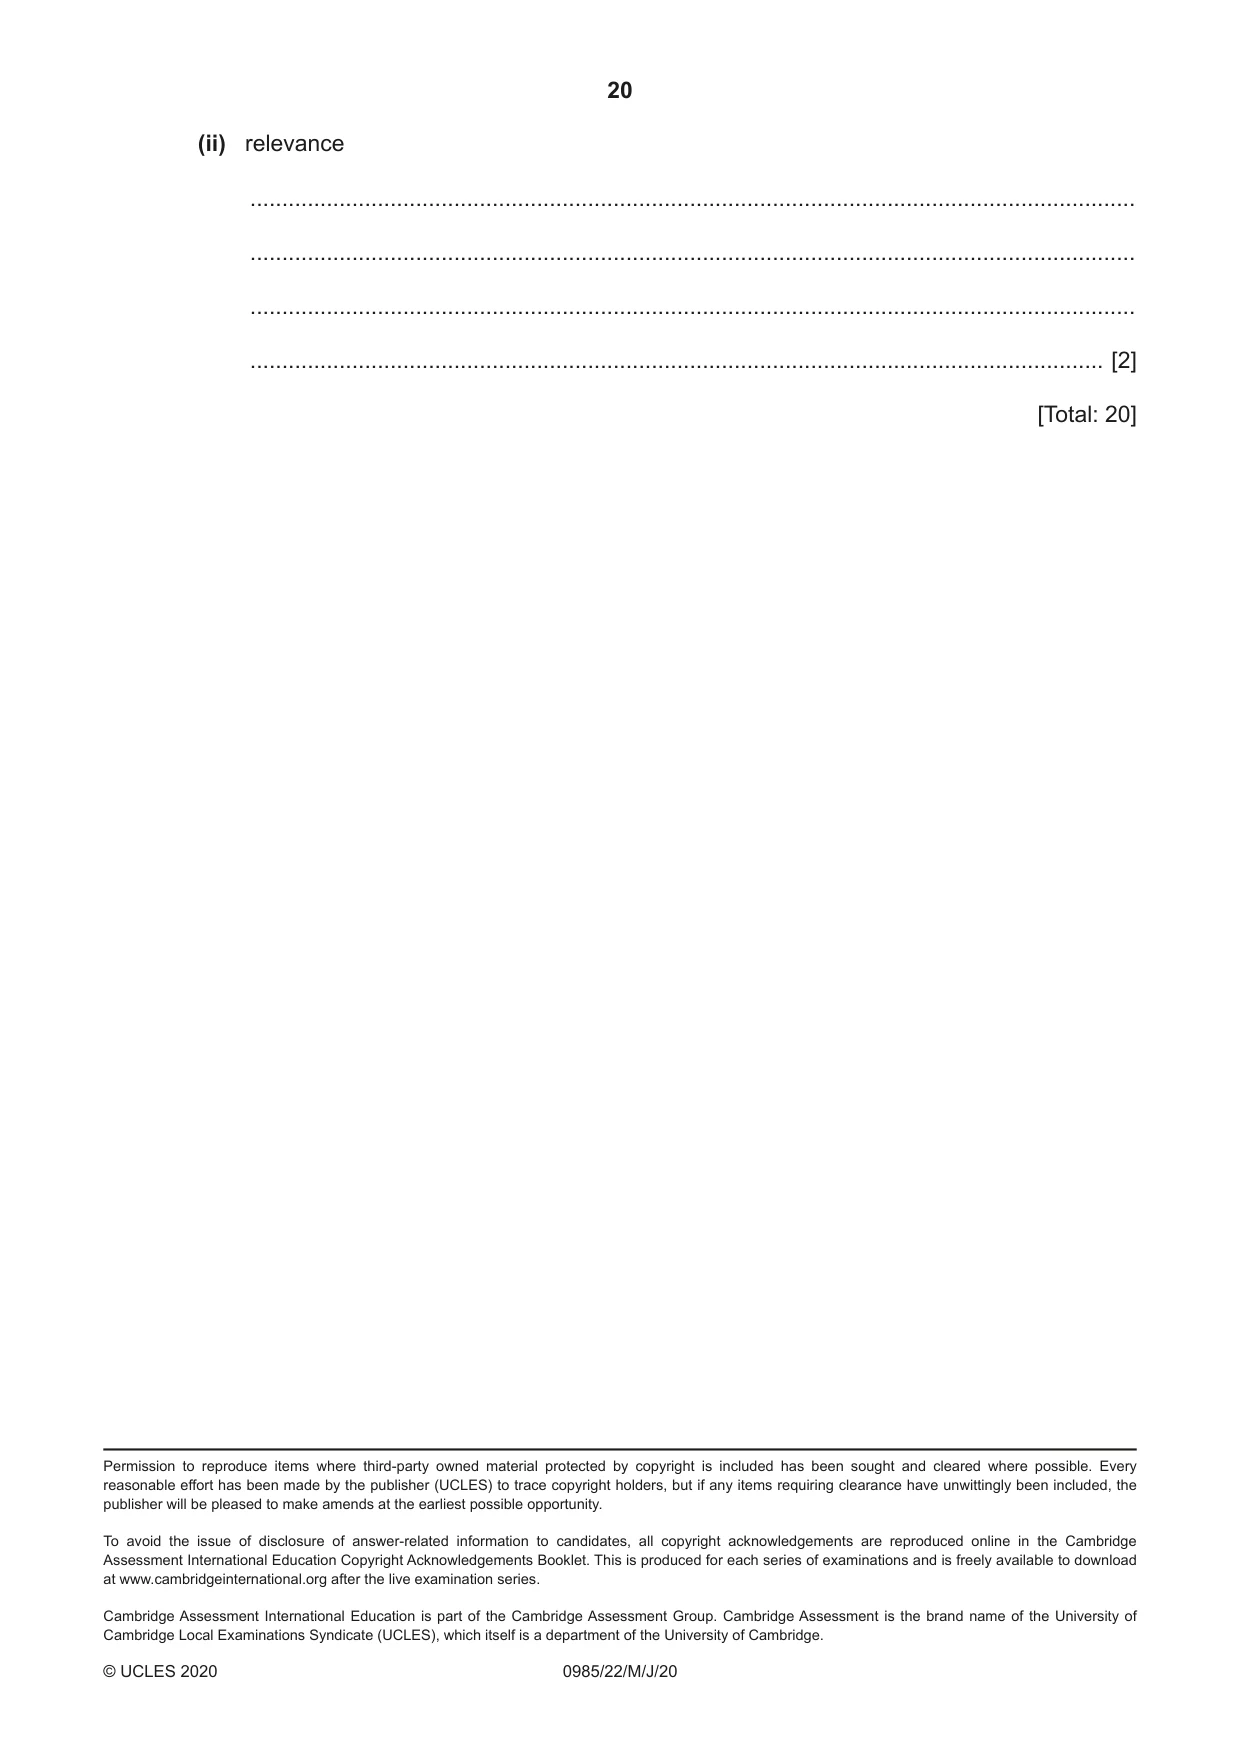
30 days. REQUIRED (c) Advise the directors whether they should introduce the cash discount policy or the interest charge policy. Justify your answer by providing one advantage and one disadvantage of each policy. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [5] The information in the accounting statements is affected by the company’s accounting policies. REQUIRED (d) Explain to the directors of JKY Limited the importance of the following objectives in selecting the company’s accounting policies. (i) comparability ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [2] (ii) relevance ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [2] [Total: 20]
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.